Exhibit 99.2
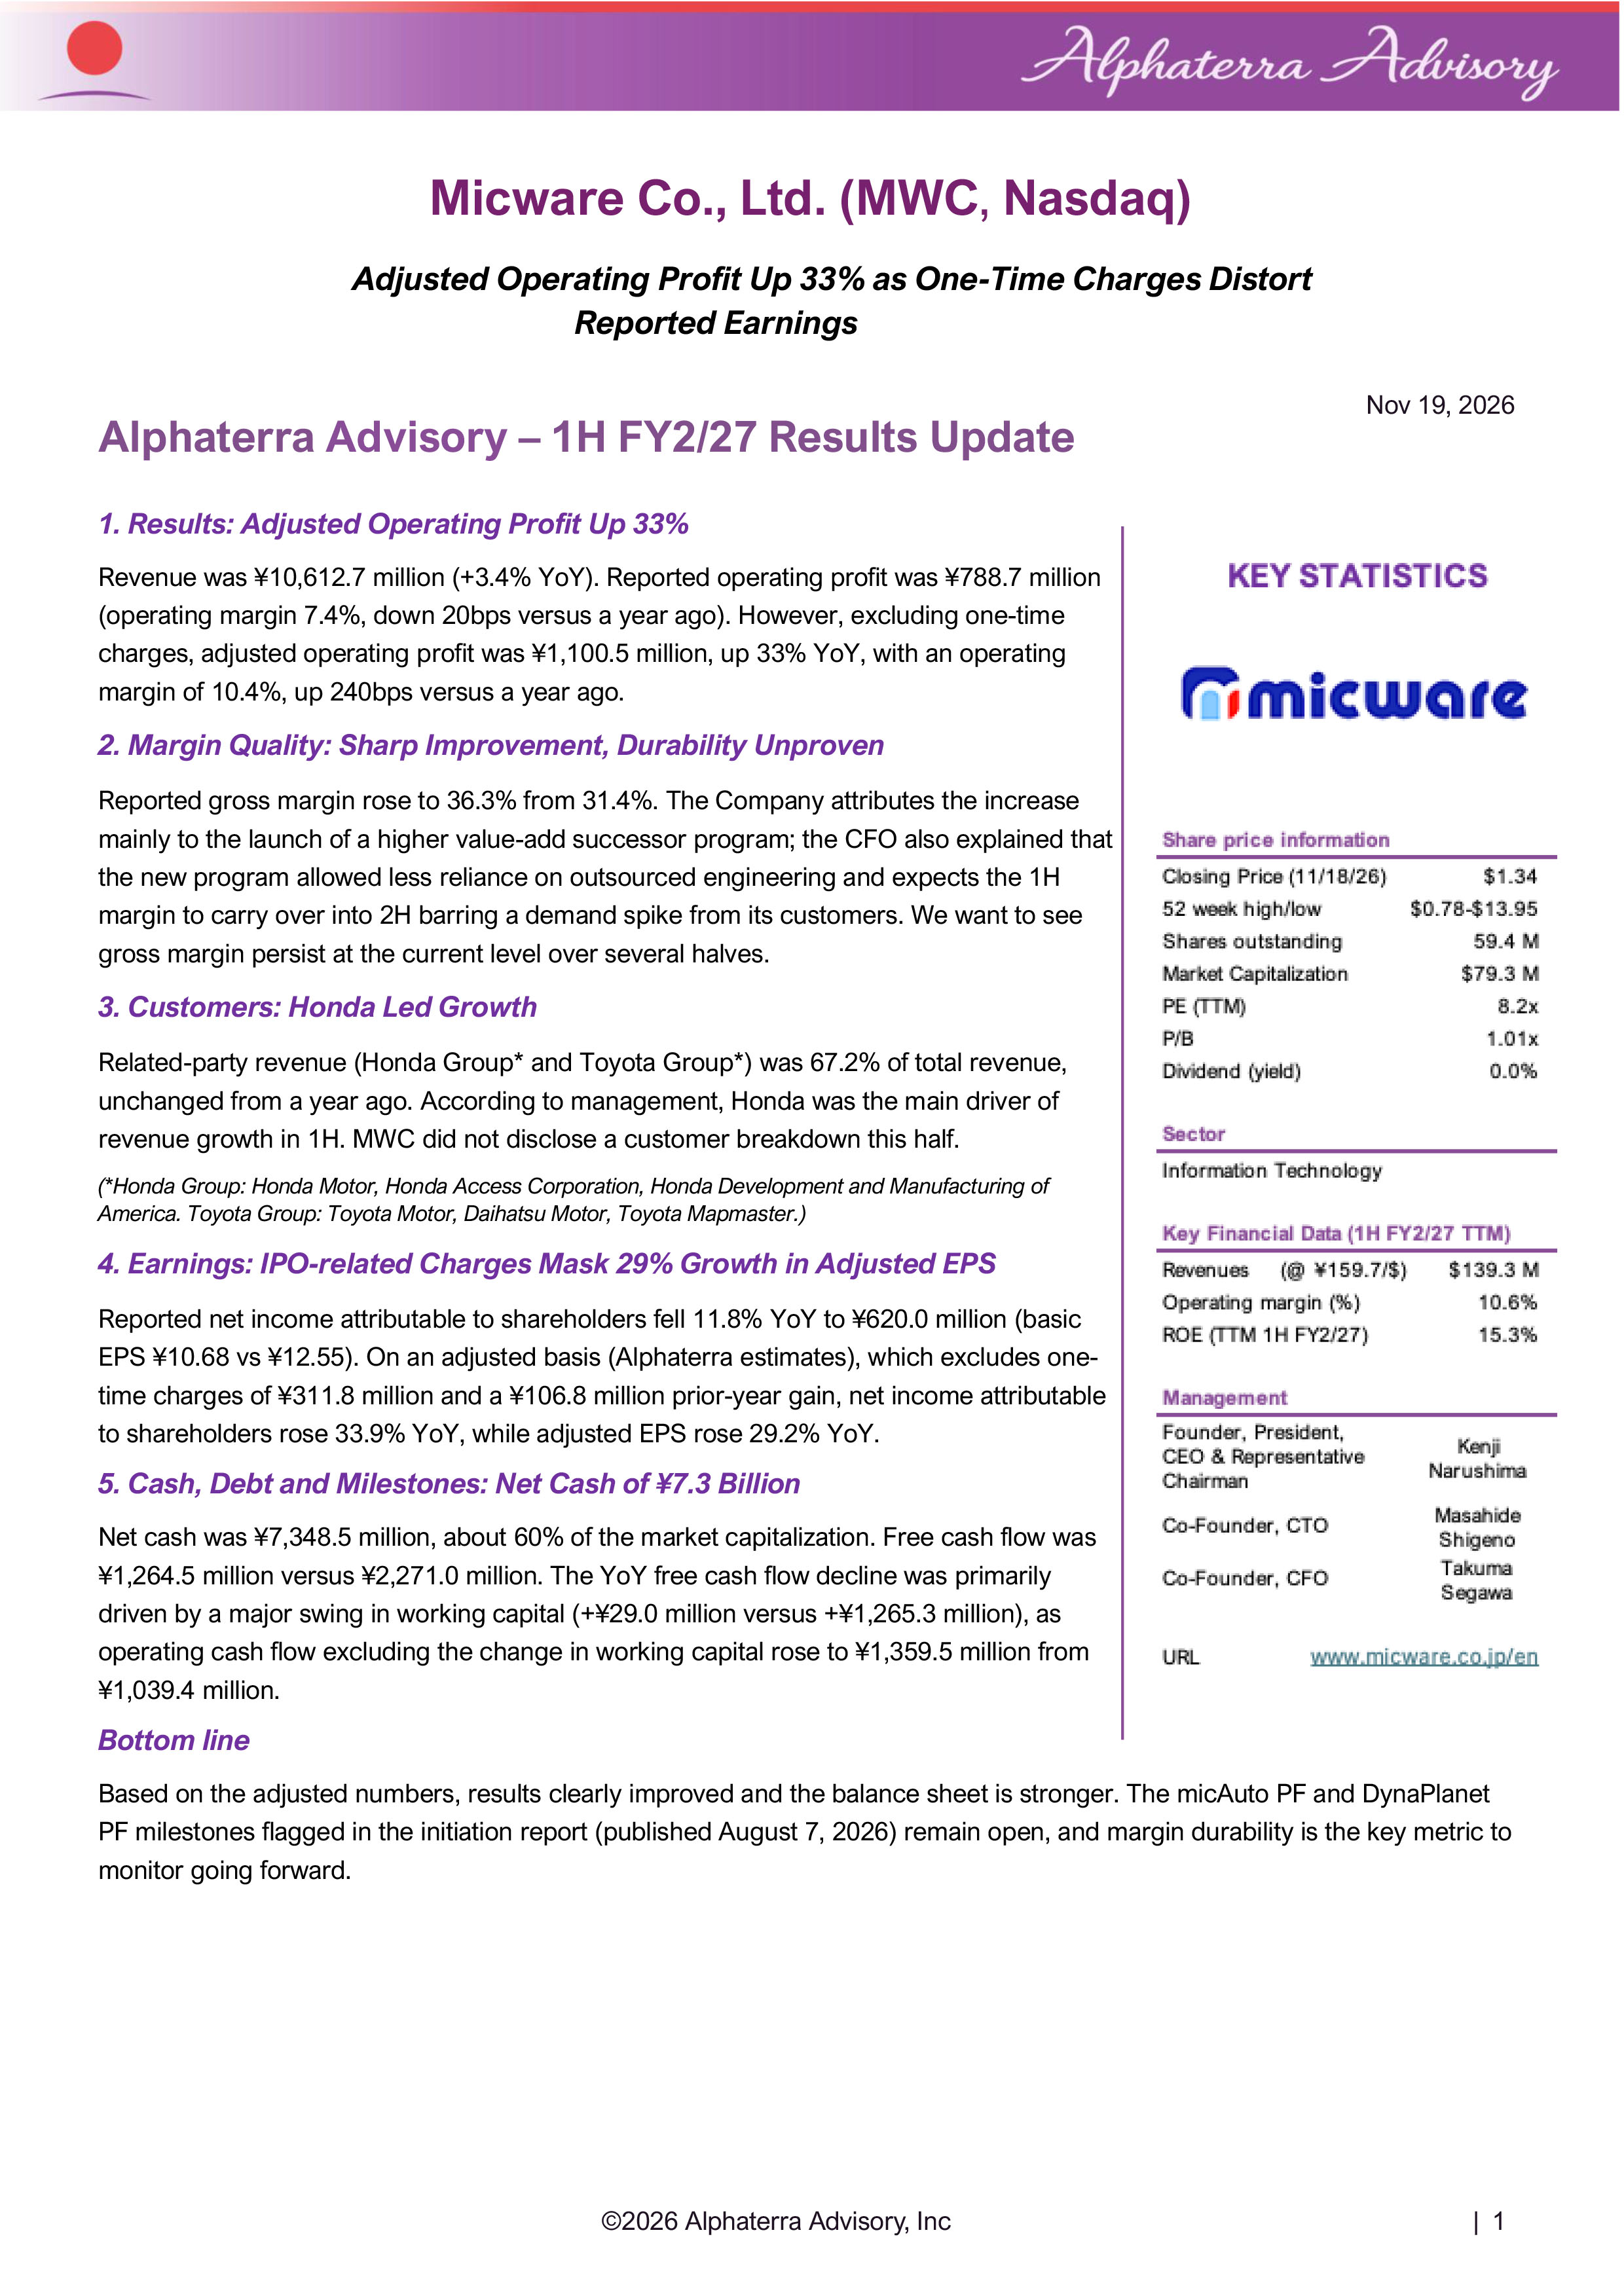
Micware Co., Ltd. (MWC , Nasdaq) Adjusted Operating Profit Up 33% as One - Time Charges Distort Reported Earnings Alphaterra Advisory 1H FY2/27 Results Update 1. Results: Adjusted Operating Profit Up 33% Revenue was ¥10,612.7 million (+3.4% YoY). Reported operating profit was ¥788.7 million (operating margin 7.4%, down 20bps versus a year ago). However, excluding one - time charges, adjusted operating profit was ¥1,100.5 million, up 33% YoY, with an operating margin of 10.4%, up 240bps versus a year ago. 2. Margin Quality: Sharp Improvement, Durability Unproven Reported gross margin rose to 36.3% from 31.4%. The Company attributes the increase mainly to the launch of a higher value - add successor program; the CFO also explained that the new program allowed less reliance on outsourced engineering and expects the 1H margin to carry over into 2H barring a demand spike from its customers. We want to see gross margin persist at the current level over several halves. 3. Customers: Honda Led Growth Related - party revenue (Honda Group* and Toyota Group*) was 67.2% of total revenue, unchanged from a year ago. According to management, Honda was the main driver of revenue growth in 1H. MWC did not disclose a customer breakdown this half. (*Honda Group: Honda Motor, Honda Access Corporation, Honda Development and Manufacturing of America. Toyota Group: Toyota Motor, Daihatsu Motor, Toyota Mapmaster.) 4. Earnings: IPO - related Charges Mask 29% Growth in Adjusted EPS Reported net income attributable to shareholders fell 11.8% YoY to ¥620.0 million (basic EPS ¥10.68 vs ¥12.55). On an adjusted basis (Alphaterra estimates), which excludes one - time charges of ¥311.8 million and a ¥106.8 million prior - year gain, net income attributable to shareholders rose 33.9% YoY, while adjusted EPS rose 29.2% YoY. 5. Cash, Debt and Milestones: Net Cash of ¥7.3 Billion Net cash was ¥7,348.5 million, about 60% of the market capitalization. Free cash flow was ¥1,264.5 million versus ¥2,271.0 million. The YoY free cash flow decline was primarily driven by a major swing in working capital (+¥29.0 million versus +¥1,265.3 million), as operating cash flow excluding the change in working capital rose to ¥1,359.5 million from ¥1,039.4 million. Bottom line Based on the adjusted numbers, results clearly improved and the balance sheet is stronger. The micAuto PF and DynaPlanet PF milestones flagged in the initiation report (published August 7, 2026) remain open, and margin durability is the key metric to monitor going forward. Nov 19, 2026 ‹ $OSKDWHUUD $GYLVRU\ ,QF | 1
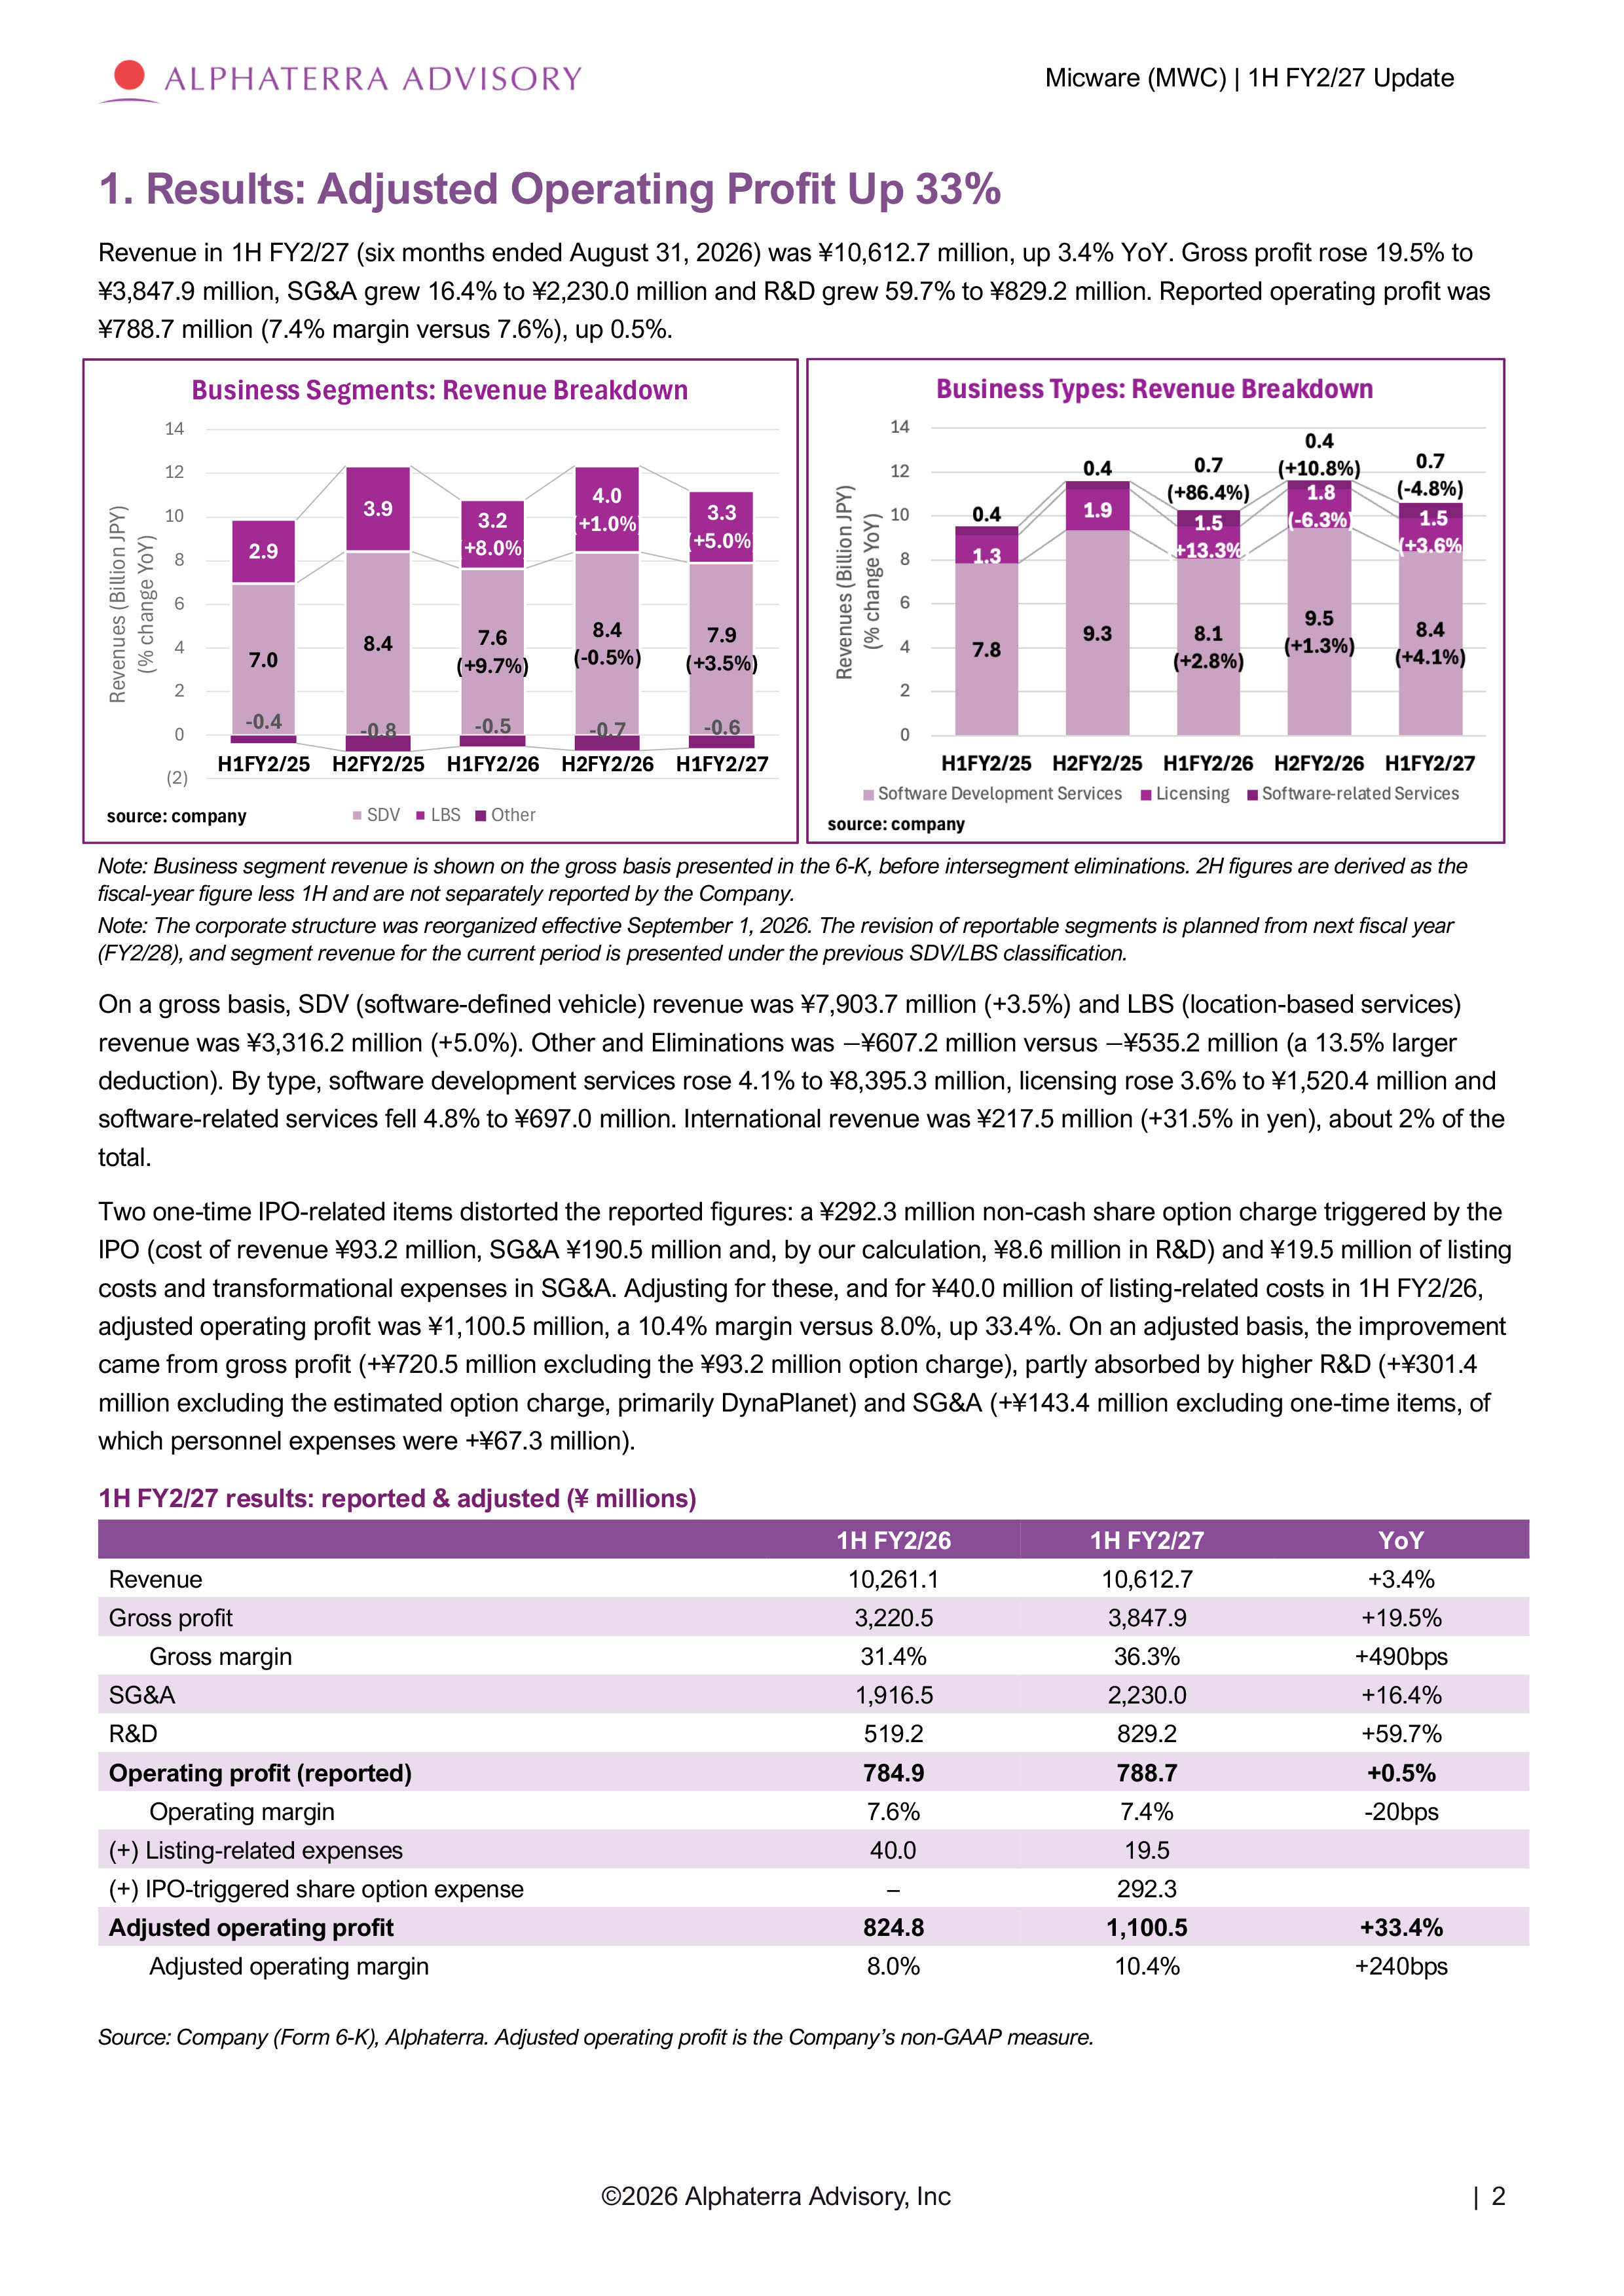
YoY 1H FY2/27 1H FY2/26 +3.4 % 10,612.7 10,261.1 Revenue +19.5 % 3,847.9 3,220.5 Gross profit +490 bp s 36.3% 31.4% Gross margin +16.4 % 2,230.0 1,916.5 SG&A +59.7 % 829.2 519.2 R&D +0.5 % 788.7 784.9 Operating profit (reported) - 20 bp s 7.4% 7.6% Operating margin 19.5 40.0 (+) Listing - related expenses 292.3 (+) IPO - triggered share option expense +33.4 % 1,100.5 824.8 Adjusted operating profit +240 bp s 10.4% 8.0% Adjusted operating margin Source: Company (Form 6 - K), Alphaterra. Adjusted operating profit is the Company’s non - GAAP measure. Micware (MWC) | 1H FY2/27 Update 1. Results: Adjusted Operating Profit Up 33% Revenue in 1H FY2/27 (six months ended August 31, 2026) was ¥10,612.7 million, up 3.4% YoY. Gross profit rose 19.5% to ¥3,847.9 million, SG&A grew 16.4% to ¥2,230.0 million and R&D grew 59.7% to ¥829.2 million. Reported operating profit was ¥788.7 million (7.4% margin versus 7.6%), up 0.5%. Note: Business segment revenue is shown on the gross basis presented in the 6 - K, before intersegment eliminations. 2H figures are derived as the fiscal - year figure less 1H and are not separately reported by the Company. Note: The corporate structure was reorganized effective September 1, 2026. The revision of reportable segments is planned from next fiscal year (FY2/28), and segment revenue for the current period is presented under the previous SDV/LBS classification. On a gross basis, SDV (software - defined vehicle) revenue was ¥7,903.7 million (+3.5%) and LBS (location - based services) revenue was ¥3,316.2 million (+5.0%). Other and Eliminations was − ¥607.2 million versus − ¥535.2 million (a 13.5% larger deduction). By type, software development services rose 4.1% to ¥8,395.3 million, licensing rose 3.6% to ¥1,520.4 million and software - related services fell 4.8% to ¥697.0 million. International revenue was ¥217.5 million (+31.5% in yen), about 2% of the total. Two one - time IPO - related items distorted the reported figures: a ¥292.3 million non - cash share option charge triggered by the IPO (cost of revenue ¥93.2 million, SG&A ¥190.5 million and, by our calculation, ¥8.6 million in R&D) and ¥19.5 million of listing costs and transformational expenses in SG&A. Adjusting for these, and for ¥40.0 million of listing - related costs in 1H FY2/26, adjusted operating profit was ¥1,100.5 million, a 10.4% margin versus 8.0%, up 33.4%. On an adjusted basis, the improvement came from gross profit (+¥720.5 million excluding the ¥93.2 million option charge), partly absorbed by higher R&D (+¥301.4 million excluding the estimated option charge, primarily DynaPlanet) and SG&A (+¥143.4 million excluding one - time items, of which personnel expenses were +¥67.3 million). 1H FY2/27 results: reported & adjusted (¥ millions) ‹ $OSKDWHUUD $GYLVRU\ ,QF | 2
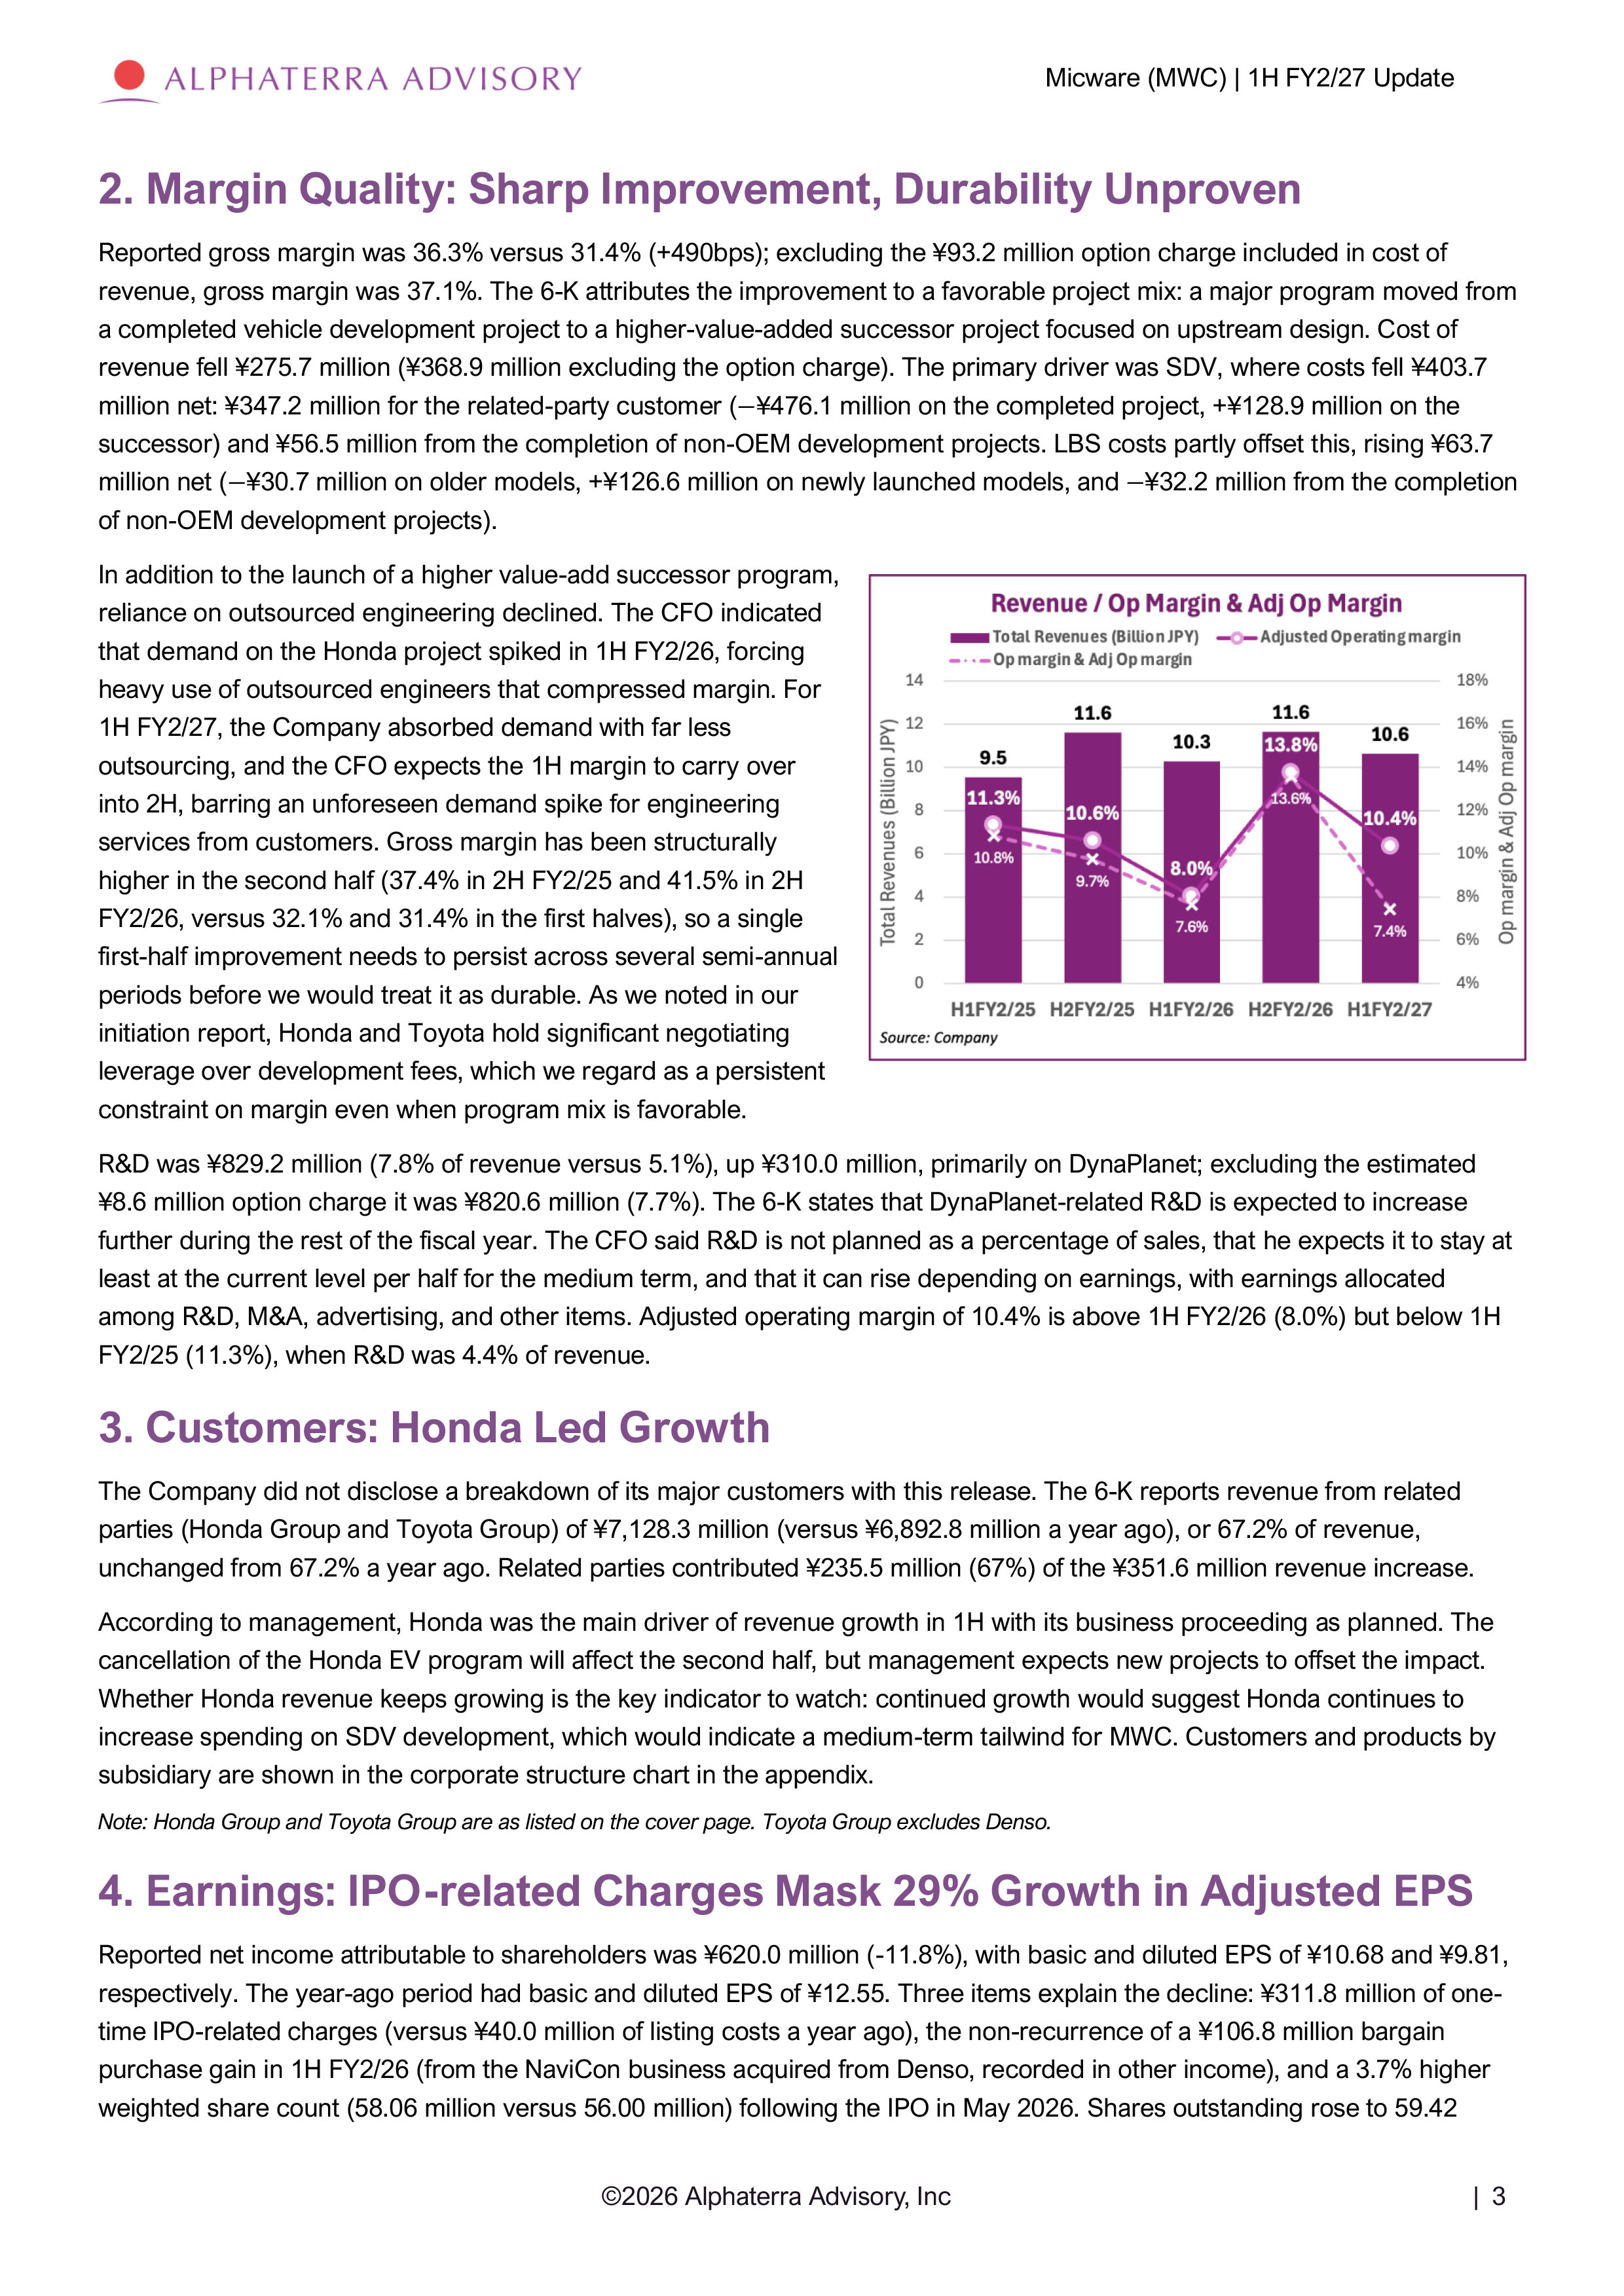
Micware (MWC) | 1H FY2/27 Update 2. Margin Quality: Sharp Improvement, Durability Unproven Reported gross margin was 36.3% versus 31.4% (+490bps); excluding the ¥93.2 million option charge included in cost of revenue, gross margin was 37.1%. The 6 - K attributes the improvement to a favorable project mix: a major program moved from a completed vehicle development project to a higher - value - added successor project focused on upstream design. Cost of revenue fell ¥275.7 million (¥368.9 million excluding the option charge). The primary driver was SDV, where costs fell ¥403.7 million net: ¥347.2 million for the related - party customer ( − ¥476.1 million on the completed project, +¥128.9 million on the successor) and ¥56.5 million from the completion of non - OEM development projects. LBS costs partly offset this, rising ¥63.7 million net ( − ¥30.7 million on older models, +¥126.6 million on newly launched models, and − ¥32.2 million from the completion of non - OEM development projects). In addition to the launch of a higher value - add successor program, reliance on outsourced engineering declined. The CFO indicated that demand on the Honda project spiked in 1H FY2/26, forcing heavy use of outsourced engineers that compressed margin. For 1H FY2/27, the Company absorbed demand with far less outsourcing, and the CFO expects the 1H margin to carry over into 2H, barring an unforeseen demand spike for engineering services from customers. Gross margin has been structurally higher in the second half (37.4% in 2H FY2/25 and 41.5% in 2H FY2/26, versus 32.1% and 31.4% in the first halves), so a single first - half improvement needs to persist across several semi - annual periods before we would treat it as durable. As we noted in our initiation report, Honda and Toyota hold significant negotiating leverage over development fees, which we regard as a persistent constraint on margin even when program mix is favorable. R&D was ¥829.2 million (7.8% of revenue versus 5.1%), up ¥310.0 million, primarily on DynaPlanet; excluding the estimated ¥8.6 million option charge it was ¥820.6 million (7.7%). The 6 - K states that DynaPlanet - related R&D is expected to increase further during the rest of the fiscal year. The CFO said R&D is not planned as a percentage of sales, that he expects it to stay at least at the current level per half for the medium term, and that it can rise depending on earnings, with earnings allocated among R&D, M&A, advertising, and other items. Adjusted operating margin of 10.4% is above 1H FY2/26 (8.0%) but below 1H FY2/25 (11.3%), when R&D was 4.4% of revenue. 3. Customers: Honda Led Growth The Company did not disclose a breakdown of its major customers with this release. The 6 - K reports revenue from related parties (Honda Group and Toyota Group) of ¥7,128.3 million (versus ¥6,892.8 million a year ago), or 67.2% of revenue, unchanged from 67.2% a year ago. Related parties contributed ¥235.5 million (67%) of the ¥351.6 million revenue increase. According to management, Honda was the main driver of revenue growth in 1H with its business proceeding as planned. The cancellation of the Honda EV program will affect the second half, but management expects new projects to offset the impact. Whether Honda revenue keeps growing is the key indicator to watch: continued growth would suggest Honda continues to increase spending on SDV development, which would indicate a medium - term tailwind for MWC. Customers and products by subsidiary are shown in the corporate structure chart in the appendix. Note: Honda Group and Toyota Group are as listed on the cover page. Toyota Group excludes Denso. 4. Earnings: IPO - related Charges Mask 29% Growth in Adjusted EPS Reported net income attributable to shareholders was ¥620.0 million ( - 11.8%), with basic and diluted EPS of ¥10.68 and ¥9.81, respectively. The year - ago period had basic and diluted EPS of ¥12.55. Three items explain the decline: ¥311.8 million of one - time IPO - related charges (versus ¥40.0 million of listing costs a year ago), the non - recurrence of a ¥106.8 million bargain purchase gain in 1H FY2/26 (from the NaviCon business acquired from Denso, recorded in other income), and a 3.7% higher weighted share count (58.06 million versus 56.00 million) following the IPO in May 2026. Shares outstanding rose to 59.42 ‹ $OSKDWHUUD $GYLVRU\ ,QF | 3
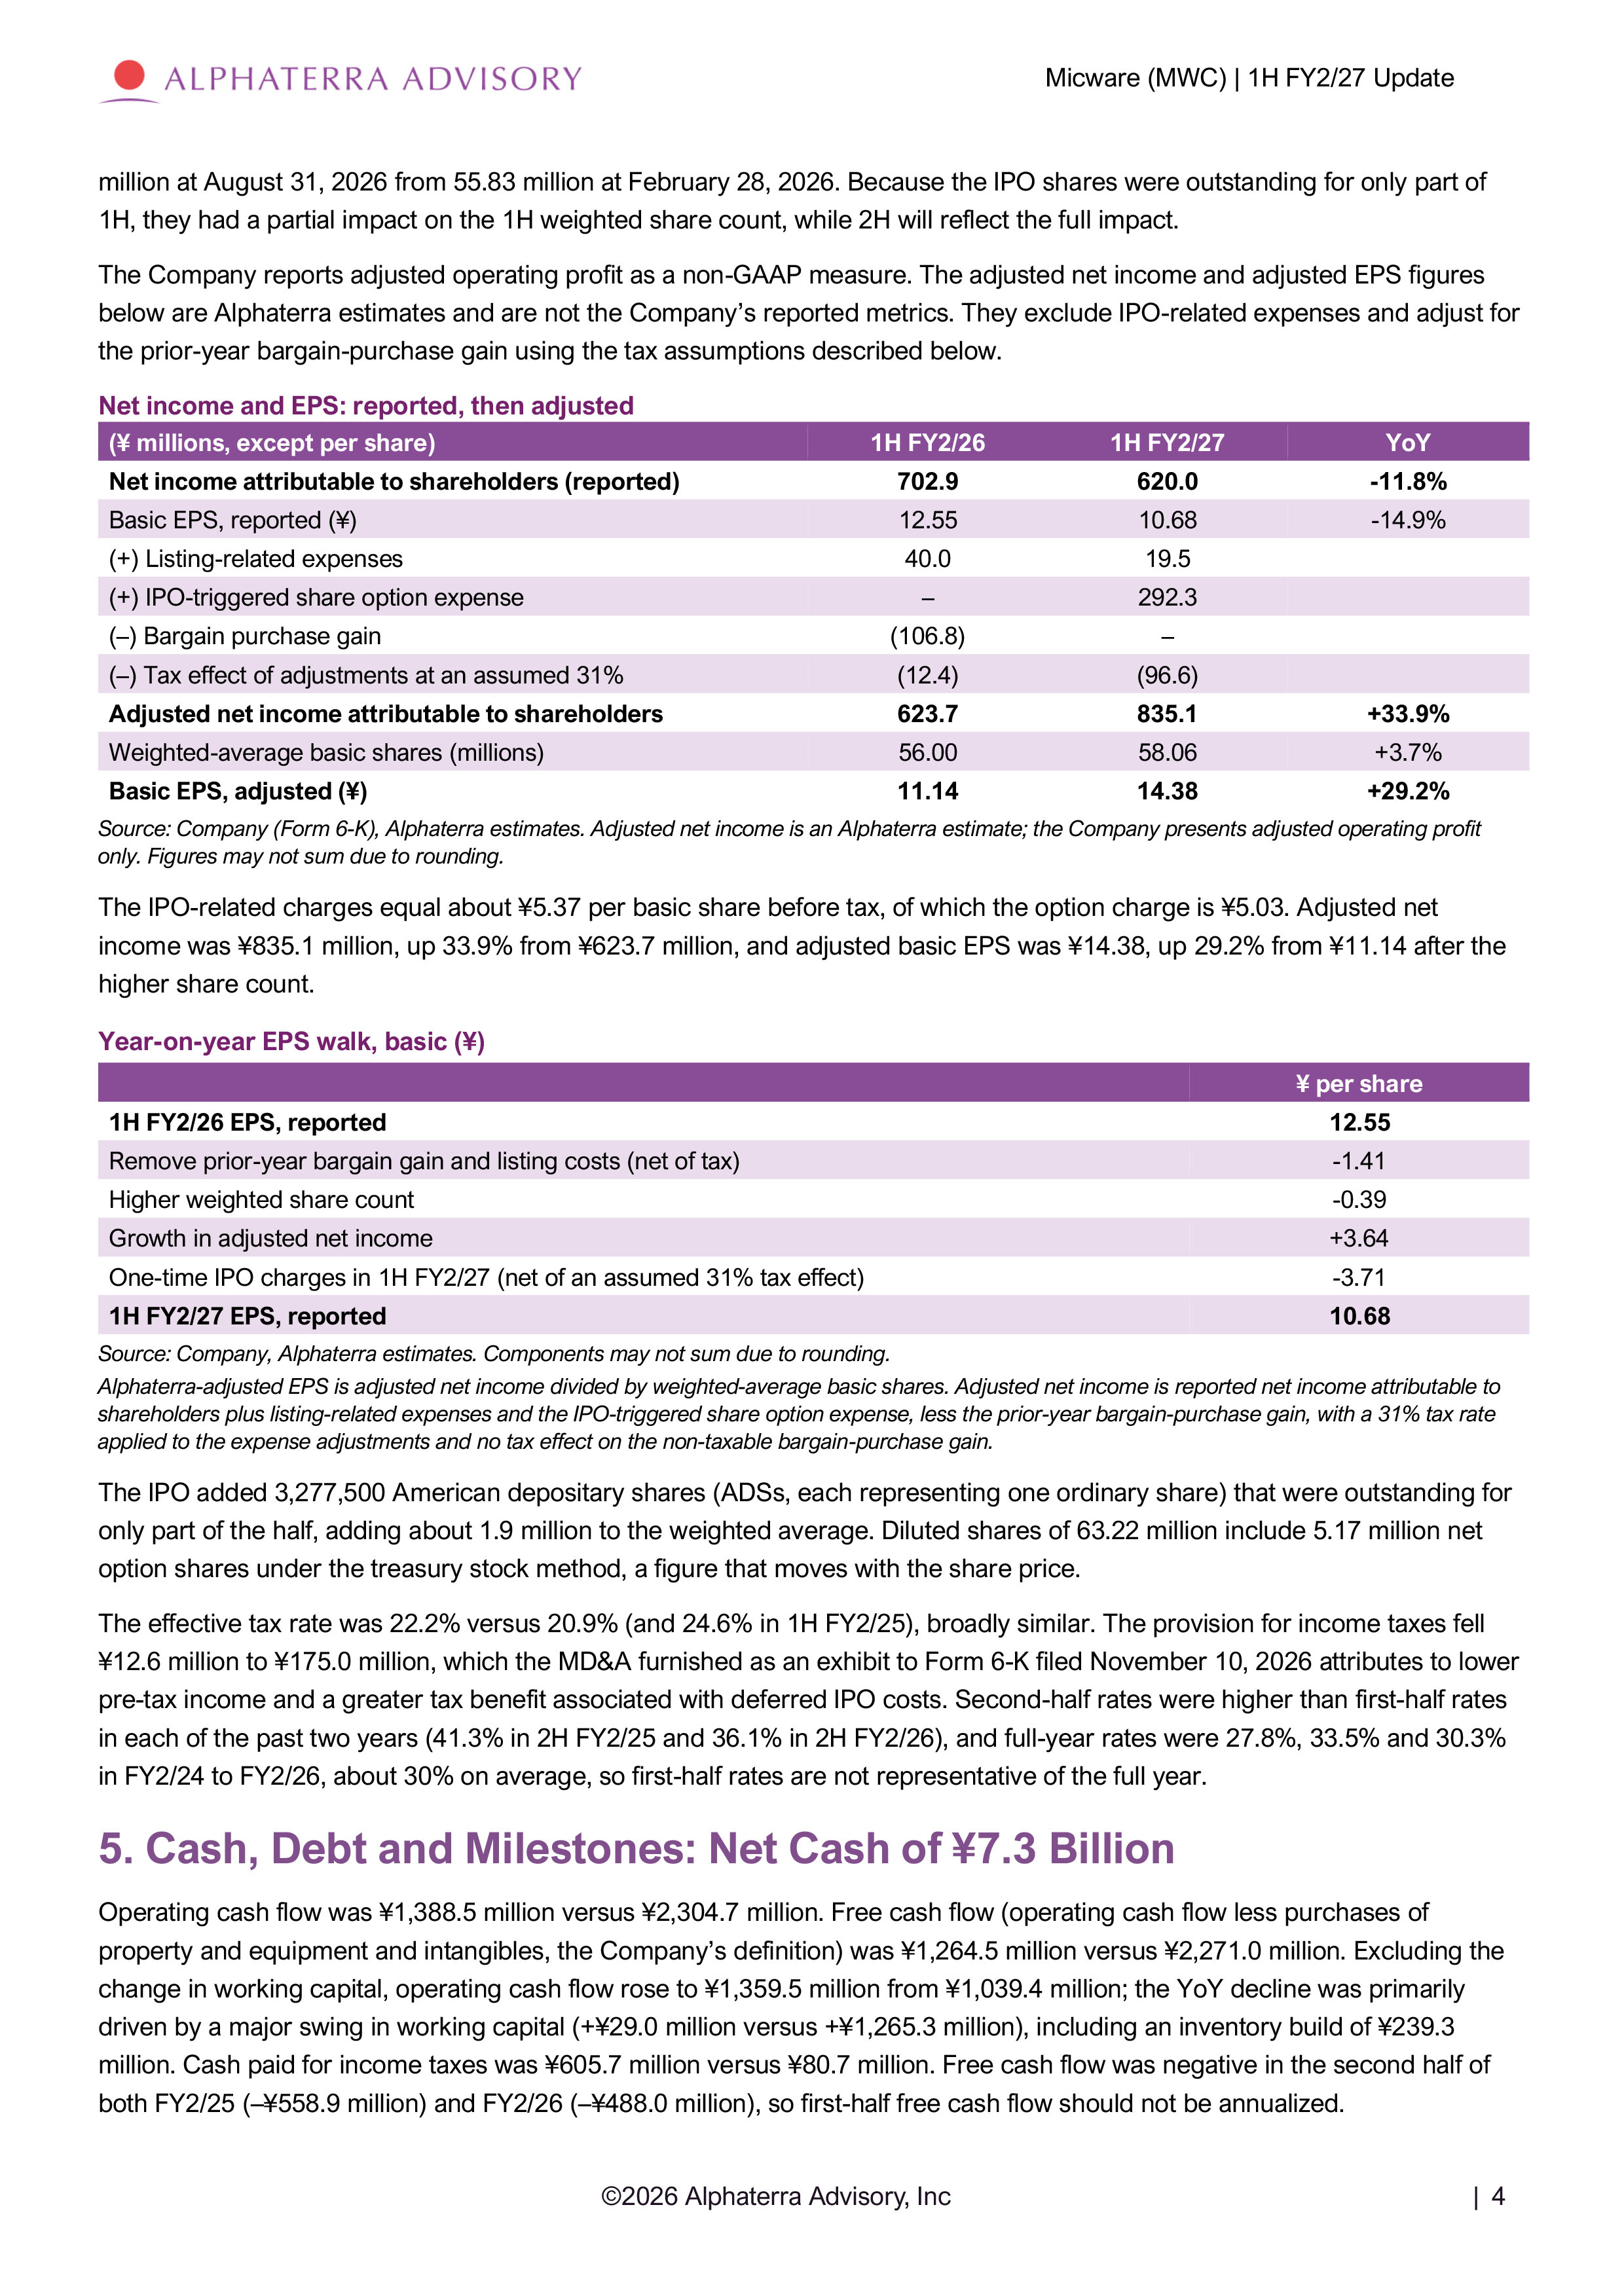
Micware (MWC) | 1H FY2/27 Update million at August 31, 2026 from 55.83 million at February 28, 2026. Because the IPO shares were outstanding for only part of 1H, they had a partial impact on the 1H weighted share count, while 2H will reflect the full impact. The Company reports adjusted operating profit as a non - GAAP measure. The adjusted net income and adjusted EPS figures below are Alphaterra estimates and are not the Company’s reported metrics. They exclude IPO - related expenses and adjust for the prior - year bargain - purchase gain using the tax assumptions described below. Net income and EPS: reported, then adjusted ‹ $OSKDWHUUD $GYLVRU\ ,QF | 4 YoY 1H FY2/27 1H FY2/26 (¥ millions, except per share) - 11.8% 620.0 702.9 Net income attributable to shareholders (reported) - 14.9% 10.68 12.55 Basic EPS, reported (¥) 19.5 40.0 (+) Listing - related expenses 292.3 (+) IPO - triggered share option expense (106.8) ( ) Bargain purchase gain (96.6) (12.4) 7D[ HIIHFW RI DGMXVWPHQWV DW DQ DVVXPHG +33.9% 835.1 623.7 Adjusted net income attributable to shareholders +3.7% 58.06 56.00 Weighted - average basic shares (millions) +29.2% 14.38 11.14 Basic EPS, adjusted (¥) Source: Company (Form 6 - K), Alphaterra estimates. Adjusted net income is an Alphaterra estimate; the Company presents adjusted operating profit only. Figures may not sum due to rounding. The IPO - related charges equal about ¥5.37 per basic share before tax, of which the option charge is ¥5.03. Adjusted net income was ¥835.1 million, up 33.9% from ¥623.7 million, and adjusted basic EPS was ¥14.38, up 29.2% from ¥11.14 after the higher share count. Year - on - year EPS walk, basic (¥) ¥ per share 12.55 1H FY2/26 EPS, reported - 1.41 Remove prior - year bargain gain and listing costs (net of tax) - 0.39 Higher weighted share count +3.64 Growth in adjusted net income - 3.71 One - time IPO charges in 1H FY2/27 (net of an assumed 31% tax effect) 10.68 1H FY2/27 EPS, reported 6RXUFH &RPSDQ\ $OSKDWHUUD HVWLPDWHV &RPSRQHQWV PD\ QRW VXP GXH WR URXQGLQJ $OSKDWHUUD DGMXVWHG (36 LV DGMXVWHG QHW LQFRPH GLYLGHG E\ ZHLJKWHG DYHUDJH EDVLF VKDUHV $GMXVWHG QHW LQFRPH LV UHSRUWHG QHW LQFRPH DWWULEXWDEOH WR VKDUHKROGHUV SOXV OLVWLQJ UHODWHG H[SHQVHV DQG WKH ,32 WULJJHUHG VKDUH RSWLRQ H[SHQVH OHVV WKH SULRU \HDU EDUJDLQ SXUFKDVH JDLQ ZLWK D WD[ UDWH DSSOLHG WR WKH H[SHQVH DGMXVWPHQWV DQG QR WD[ HIIHFW RQ WKH QRQ WD[DEOH EDUJDLQ SXUFKDVH JDLQ 7KH ,32 DGGHG $PHULFDQ GHSRVLWDU\ VKDUHV $'6V HDFK UHSUHVHQWLQJ RQH RUGLQDU\ VKDUH WKDW ZHUH RXWVWDQGLQJ IRU RQO\ SDUW RI WKH KDOI DGGLQJ DERXW PLOOLRQ WR WKH ZHLJKWHG DYHUDJH 'LOXWHG VKDUHV RI PLOOLRQ LQFOXGH PLOOLRQ QHW RSWLRQ VKDUHV XQGHU WKH WUHDVXU\ VWRFN PHWKRG D ILJXUH WKDW PRYHV ZLWK WKH VKDUH SULFH 7KH HIIHFWLYH WD[ UDWH ZDV YHUVXV DQG LQ + )< EURDGO\ VLPLODU 7KH SURYLVLRQ IRU LQFRPH WD[HV IHOO – PLOOLRQ WR – PLOOLRQ ZKLFK WKH 0' $ IXUQLVKHG DV DQ H[KLELW WR )RUP . ILOHG 1RYHPEHU DWWULEXWHV WR ORZHU SUH WD[ LQFRPH DQG D JUHDWHU WD[ EHQHILW DVVRFLDWHG ZLWK GHIHUUHG ,32 FRVWV 6HFRQG KDOI UDWHV ZHUH KLJKHU WKDQ ILUVW KDOI UDWHV LQ HDFK RI WKH SDVW WZR \HDUV LQ + )< DQG LQ + )< DQG IXOO \HDU UDWHV ZHUH DQG LQ )< WR )< DERXW RQ DYHUDJH VR ILUVW KDOI UDWHV DUH QRW UHSUHVHQWDWLYH RI WKH IXOO \HDU &DVK 'HEW DQG 0LOHVWRQHV 1HW &DVK RI – %LOOLRQ 2SHUDWLQJ FDVK IORZ ZDV – PLOOLRQ YHUVXV – PLOOLRQ )UHH FDVK IORZ RSHUDWLQJ FDVK IORZ OHVV SXUFKDVHV RI SURSHUW\ DQG HTXLSPHQW DQG LQWDQJLEOHV WKH &RPSDQ\ ¶ V GHILQLWLRQ ZDV – PLOOLRQ YHUVXV – PLOOLRQ ([FOXGLQJ WKH FKDQJH LQ ZRUNLQJ FDSLWDO RSHUDWLQJ FDVK IORZ URVH WR – PLOOLRQ IURP PLOOLRQ WKH <R< GHFOLQH ZDV SULPDULO\ GULYHQ E\ D PDMRU VZLQJ LQ ZRUNLQJ FDSLWDO PLOOLRQ YHUVXV PLOOLRQ LQFOXGLQJ DQ LQYHQWRU\ EXLOG RI – PLOOLRQ &DVK SDLG IRU LQFRPH WD[HV ZDV – PLOOLRQ YHUVXV – PLOOLRQ )UHH FDVK IORZ ZDV QHJDWLYH LQ WKH VHFRQG KDOI RI ERWK )< – PLOOLRQ DQG )< – PLOOLRQ VR ILUVW KDOI IUHH FDVK IORZ VKRXOG QRW EH DQQXDOL]HG
Micware (MWC) | 1H FY2/27 Update Financing cash flow included IPO net proceeds of ¥3,781.0 million, which likely supported the cash position. They likely also enabled the ¥353.5 million acquisition of the remaining non - controlling interests in Micware North America and Micware Asia Pacific on July 31, 2026, which made both wholly owned subsidiaries. Total debt fell to ¥3,237.8 million from ¥5,387.1 million at February 28, 2026. The Company repaid ¥2,449.3 million of borrowings against ¥300.0 million of new borrowing. No short - term loans remain; the current portion of long - term borrowings is ¥1,428.1 million (44% of the total) and the non - current portion ¥1,809.7 million. Cash was ¥10,586.3 million, leaving net cash of ¥7,348.5 million, about 60% of the market capitalization shown on the cover. In its growth strategy (Form 6 - K filed September 4, 2026), which post - dates our initiation report, the Company introduced management revenue targets for the two categories adopted in its September 1 reorganization. For micAuto - PF, which covers Micware Automotive (MAC), Micware Mobility (MMC), and Micware North America (MNA), the targets are ¥19.0 billion for FY2/27, ¥31.5 billion for FY2/30 and ¥55.0 billion for FY2/33. For DynaPlanet - PF, which covers Micware Spacia (MSC), they are ¥3.5 billion, ¥10.5 billion and ¥33.0 billion. The Company states that these are not earnings forecasts, are derived by working back from an internal goal rather than built up from individual projects, and are on a different basis from consolidated revenue (¥21.9 billion in FY2/26), so they cannot be summed or compared with reported results. The Company also states that the FY2/27 micAuto - PF target is generated entirely through existing OEM consulting contracts, with SDV Service planned at ¥2.0 billion by FY2/30, and, in its investor presentation of September 9, 2026, that no OEM has yet signed a contract for the micAuto - PF platform product itself, which it describes as the key validation milestone. The FY2/27 DynaPlanet - PF target includes existing businesses such as cloud - related services, MvCube and NaviCon. We report these for completeness. The scorecard below tracks the issues we flagged in the initiation report (published August 7, 2026). Only the balance sheet has clearly improved; the remaining items are either unresolved or not yet visible in the numbers. ‹ $OSKDWHUUD $GYLVRU\ ,QF | 5 Next marker Status 1H FY2/27 evidence Initiation item Honda revenue trend in 2H as the program rolls off Open Honda business proceeded as planned in 1H; EV cancellation affects 2H; management expects new projects to offset Honda EV program uncertainty Toyota Group trend in 2H Open No customer breakdown disclosed this half Toyota cost review Whether customer disclosure resumes Limited visibility Breakdown not disclosed; related parties 67.2% of revenue, unchanged Customer concentration Persistence across several semi - annual periods Open 36.3% versus 31.4%; successor program mix and less outsourcing Gross margin and mix A first contract would be a positive, but to close this item we want a contract that pays royalties Open No new bookings in 1H; first contracts expected to be development projects rather than royalties micAuto PF first external contract DynaPlanet Studio launch (January 2027 ) would be a positive, but revenue from this business line needs to become material before this item closes Open Minor commercial project (Prespot, limited revenue in 1H); total company R&D spend was ¥829.2 million in 1H FY2/27, with the YoY increase driven primarily by DynaPlanet. DynaPlanet Repayment of the ¥1,428.1 million current portion of long - term borrowings Strengthened Debt ¥3,237.8 million versus ¥5,387.1 million; net cash ¥7,348.5 million Balance sheet and debt Renewal disclosure Open Not addressed in the 1H materials Honda development agreement (ends 12/31/26) Announcement Open No update provided CEO succession Source: Company, Alphaterra.
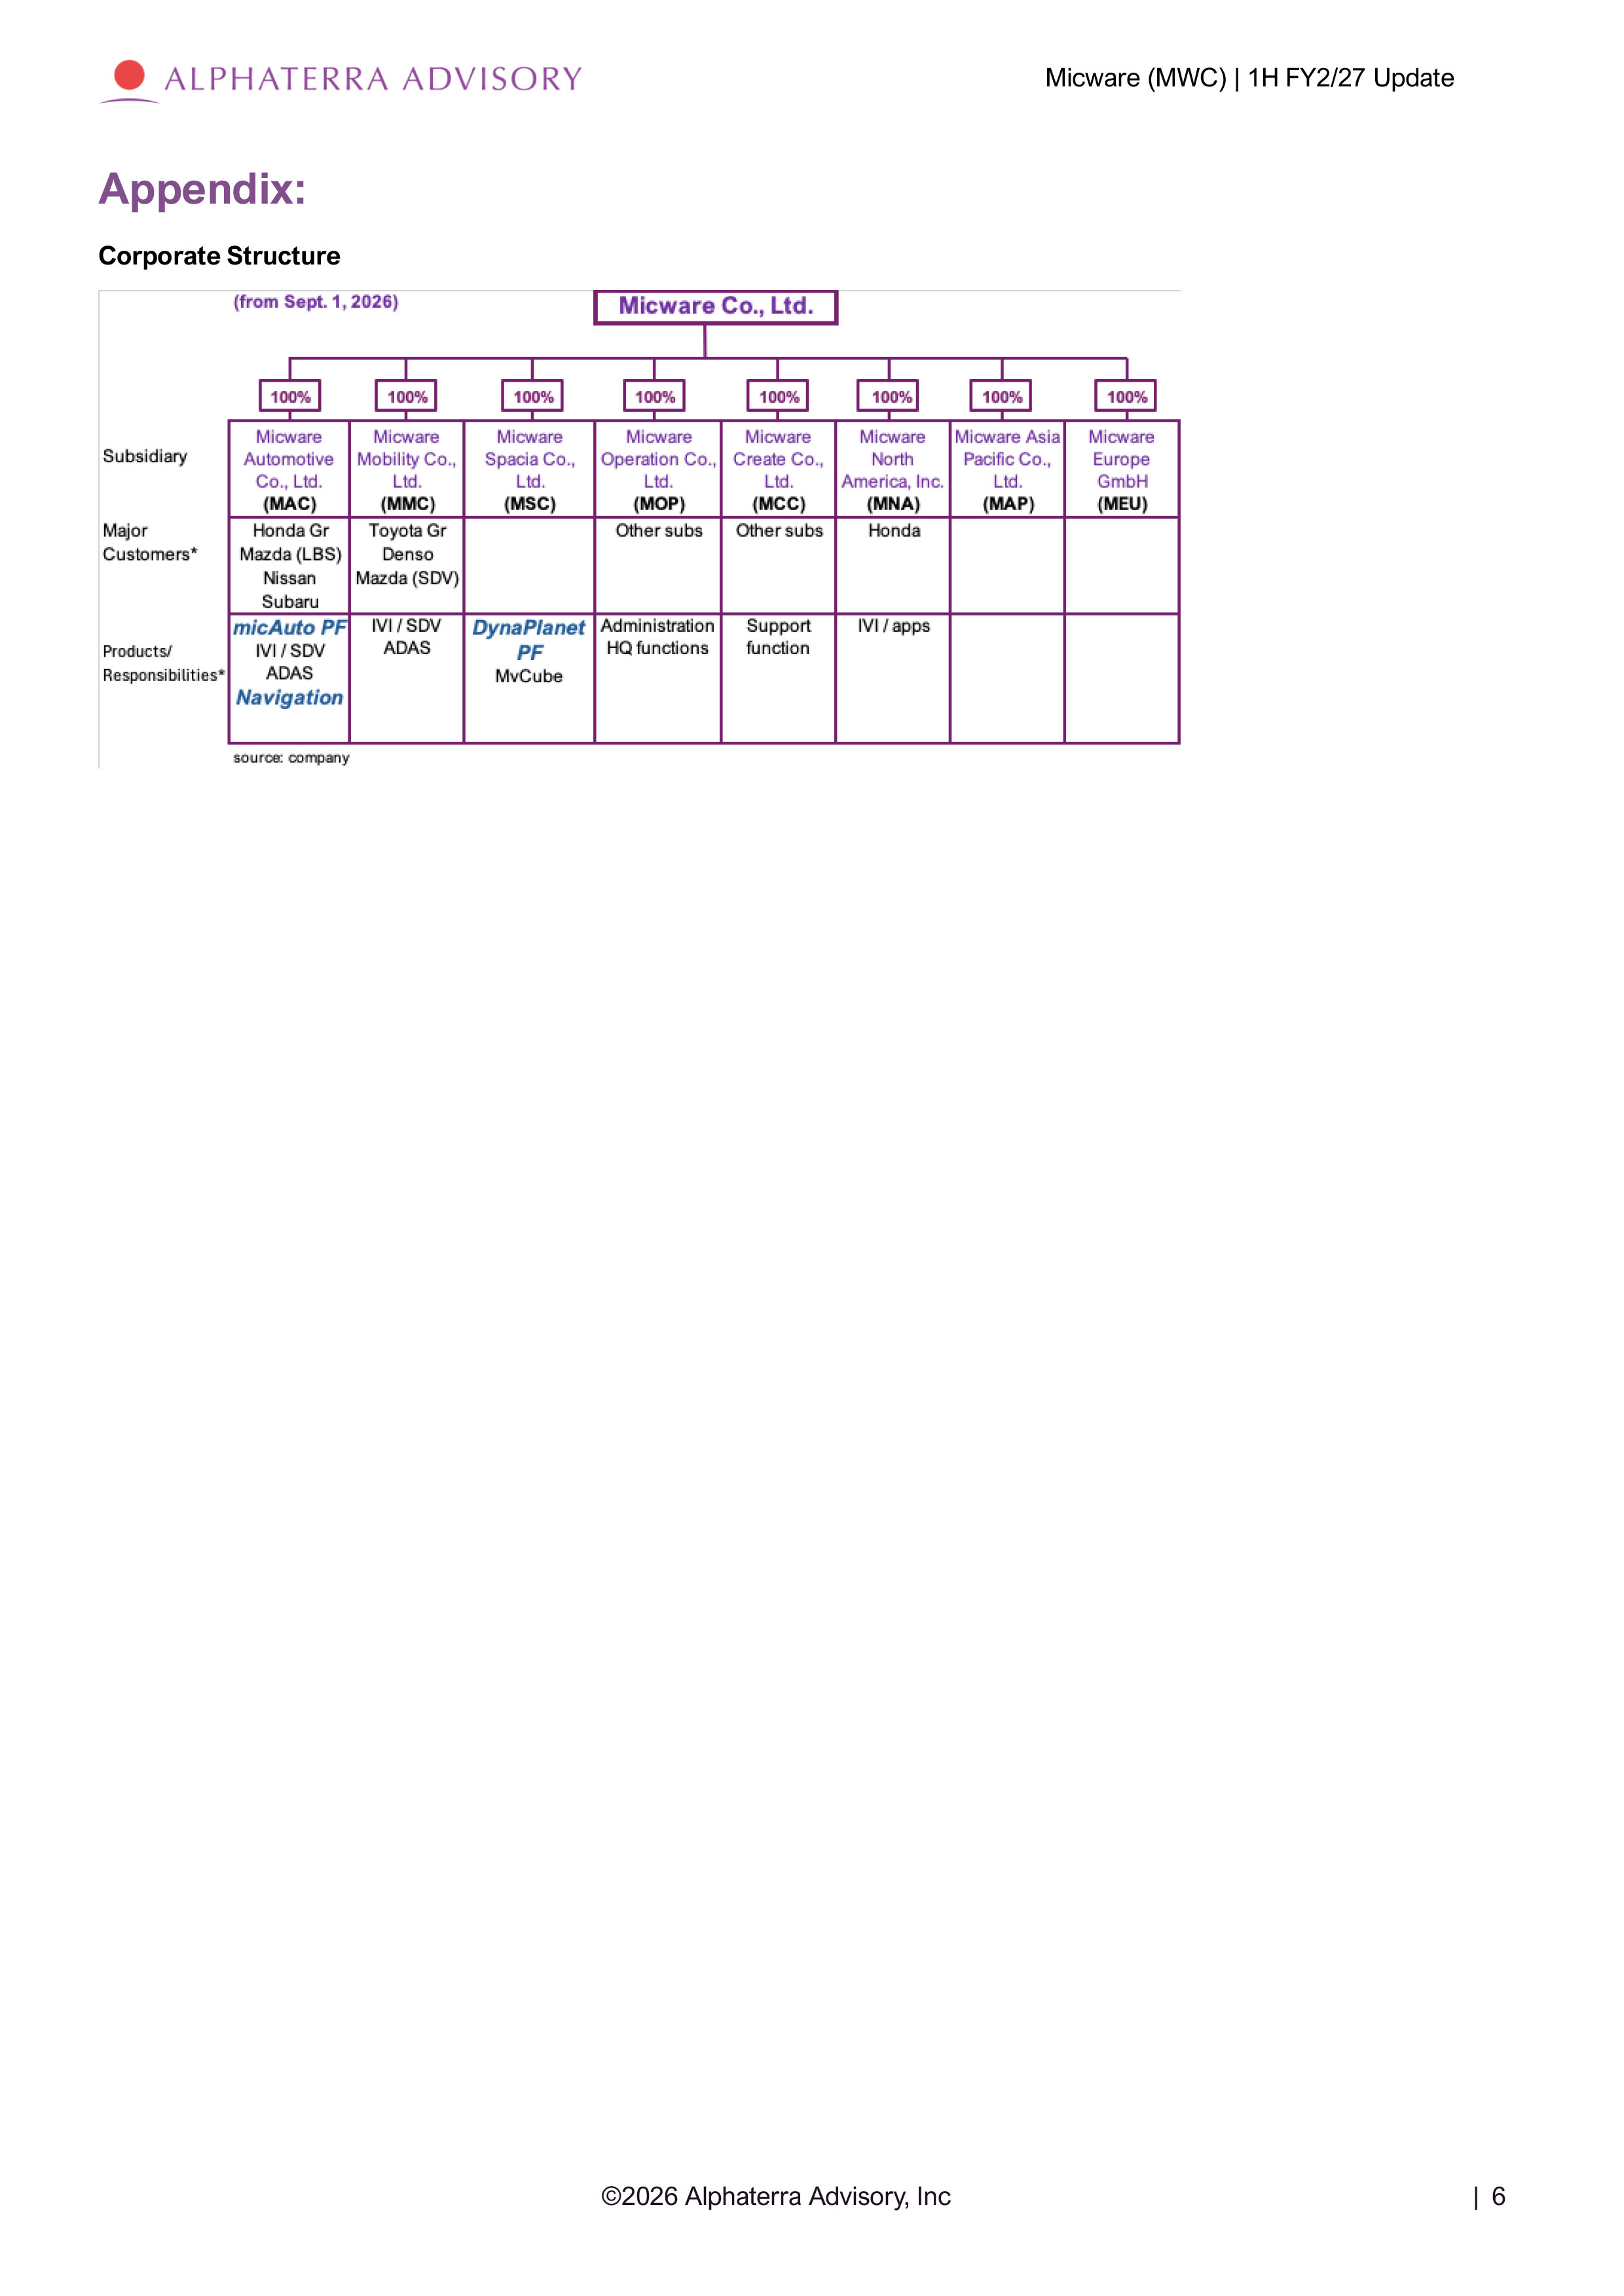
Micware (MWC) | 1H FY2/27 Update Appendix: Corporate Structure ‹ $OSKDWHUUD $GYLVRU\ ,QF _
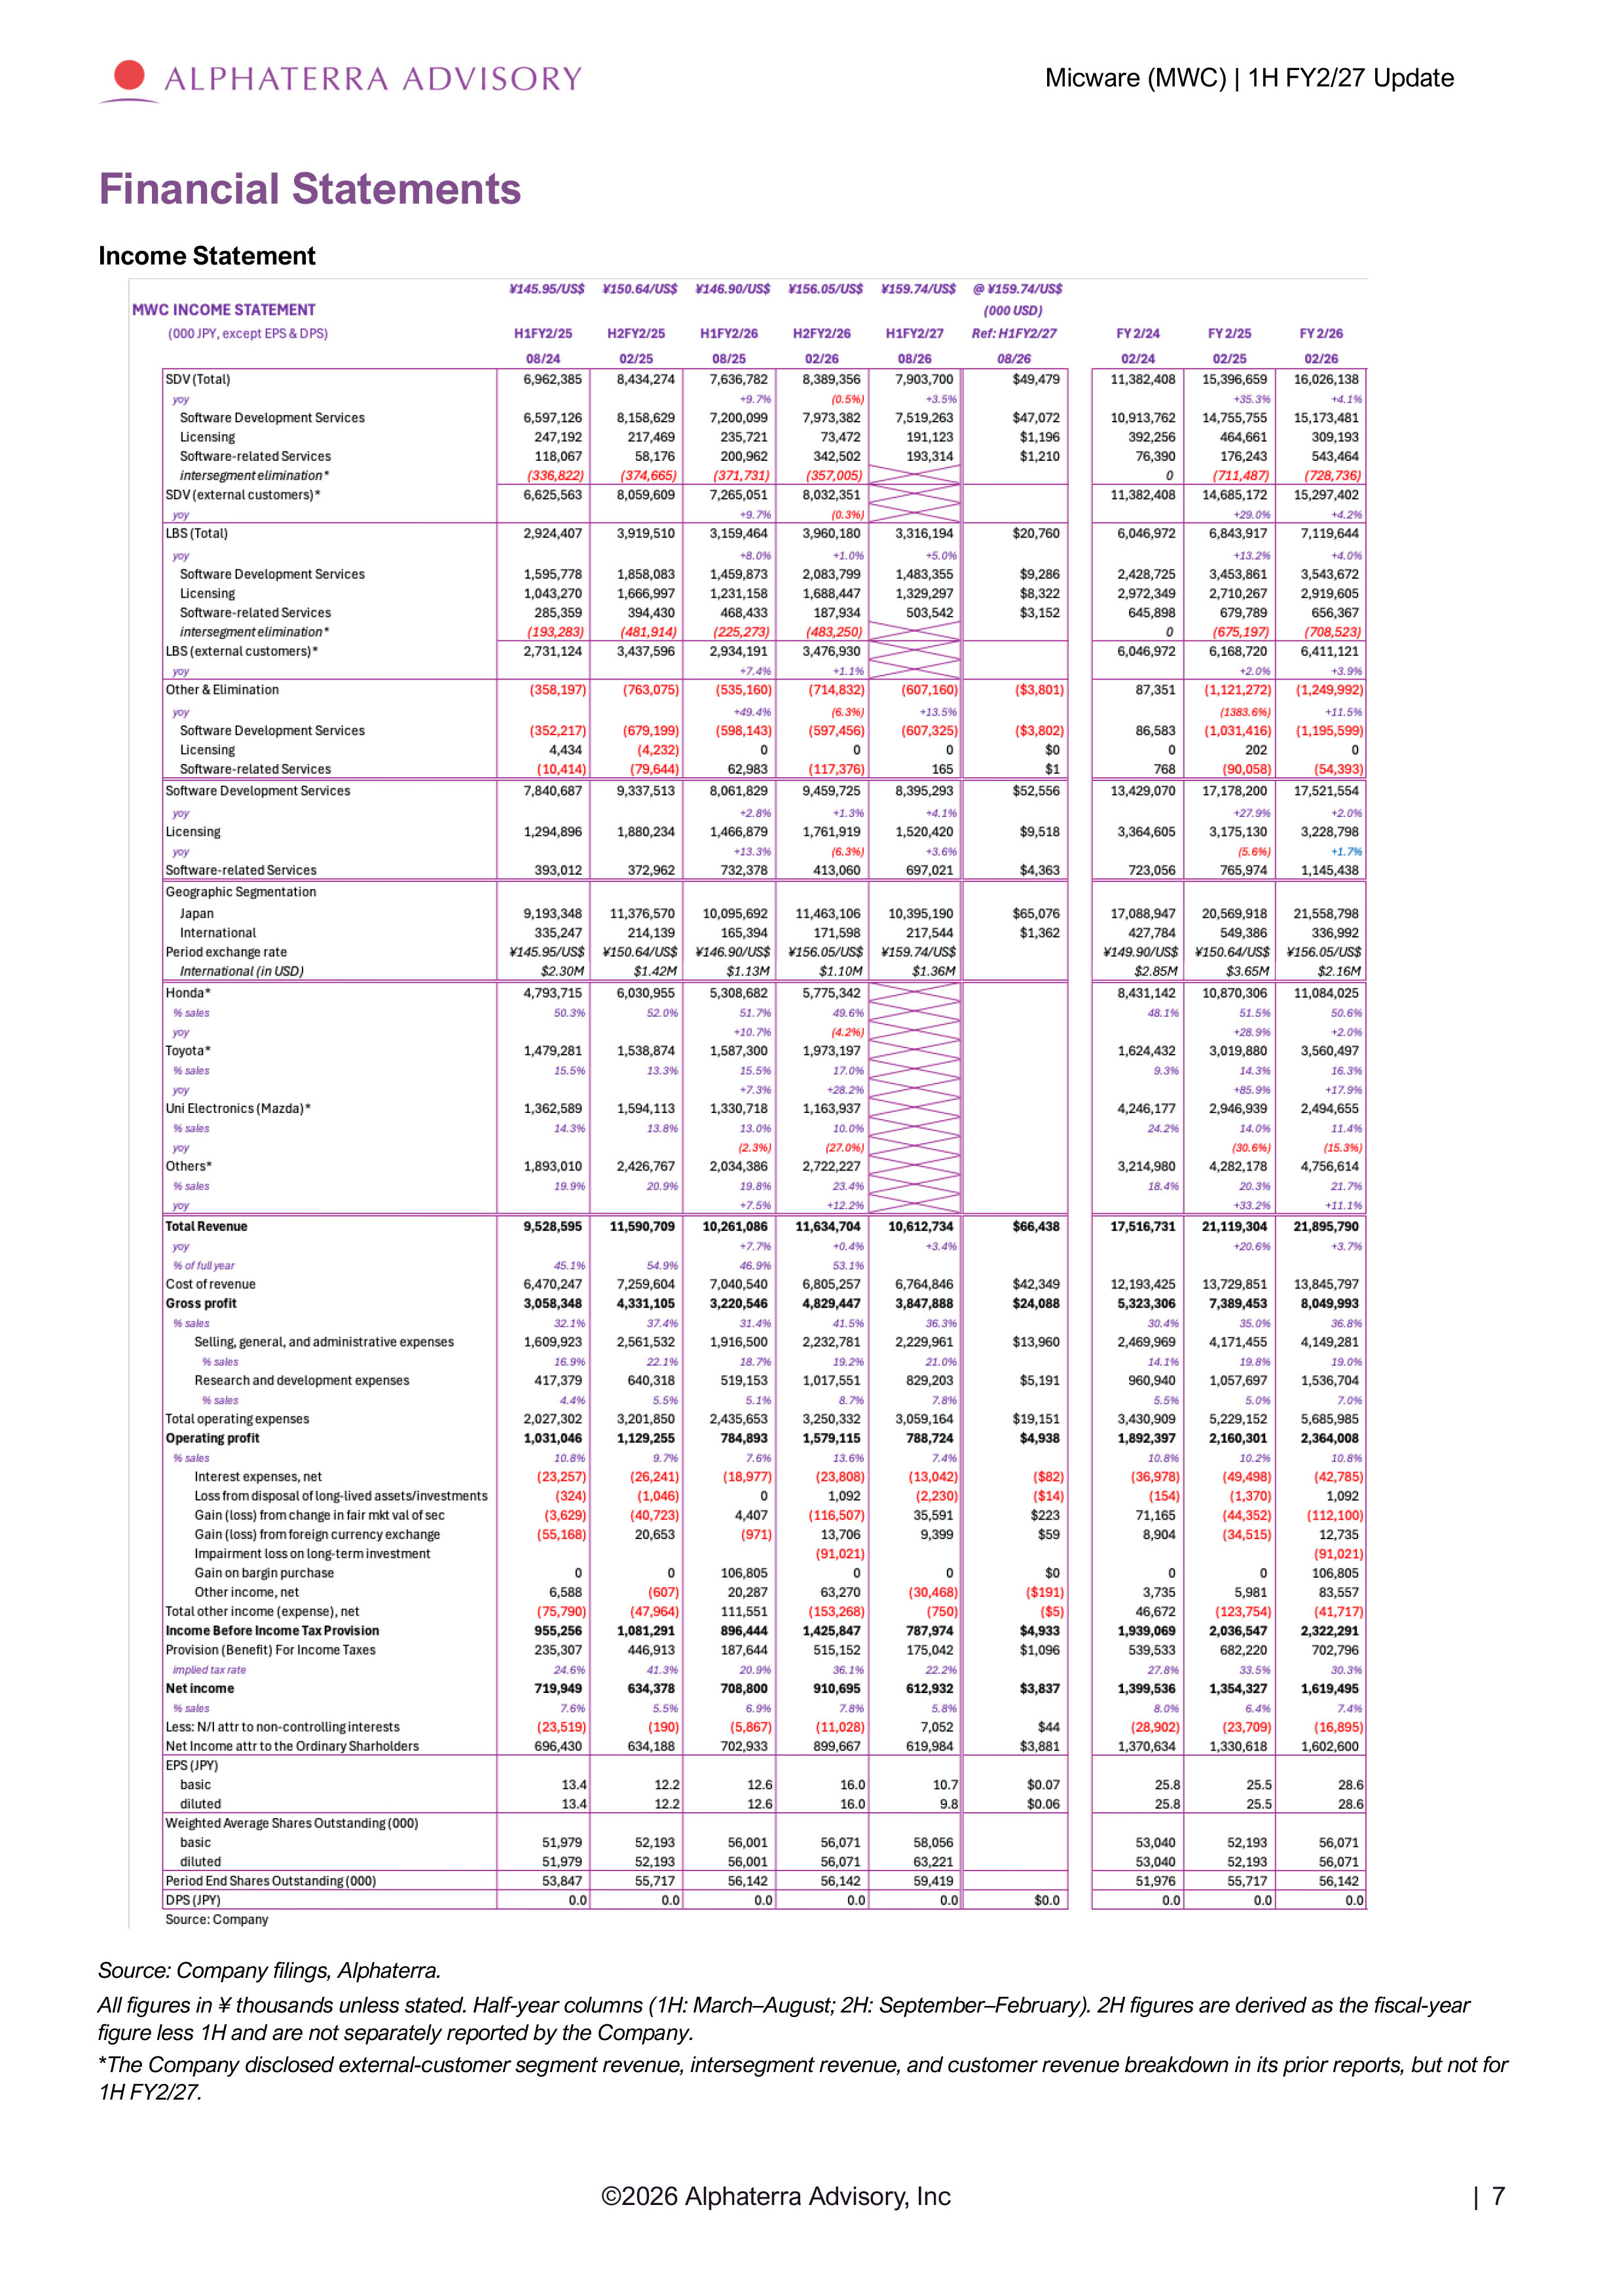
Micware (MWC) | 1H FY2/27 Update )LQDQFLDO 6WDWHPHQWV ,QFRPH 6WDWHPHQW Source: Company filings, Alphaterra. All figures in ¥ thousands unless stated. Half - year columns (1H: March August; 2H: September February). 2H figures are derived as the fiscal - year figure less 1H and are not separately reported by the Company. *The Company disclosed external - customer segment revenue, intersegment revenue, and customer revenue breakdown in its prior reports, but not for 1H FY2/27. ‹ $OSKDWHUUD $GYLVRU\ ,QF | 7
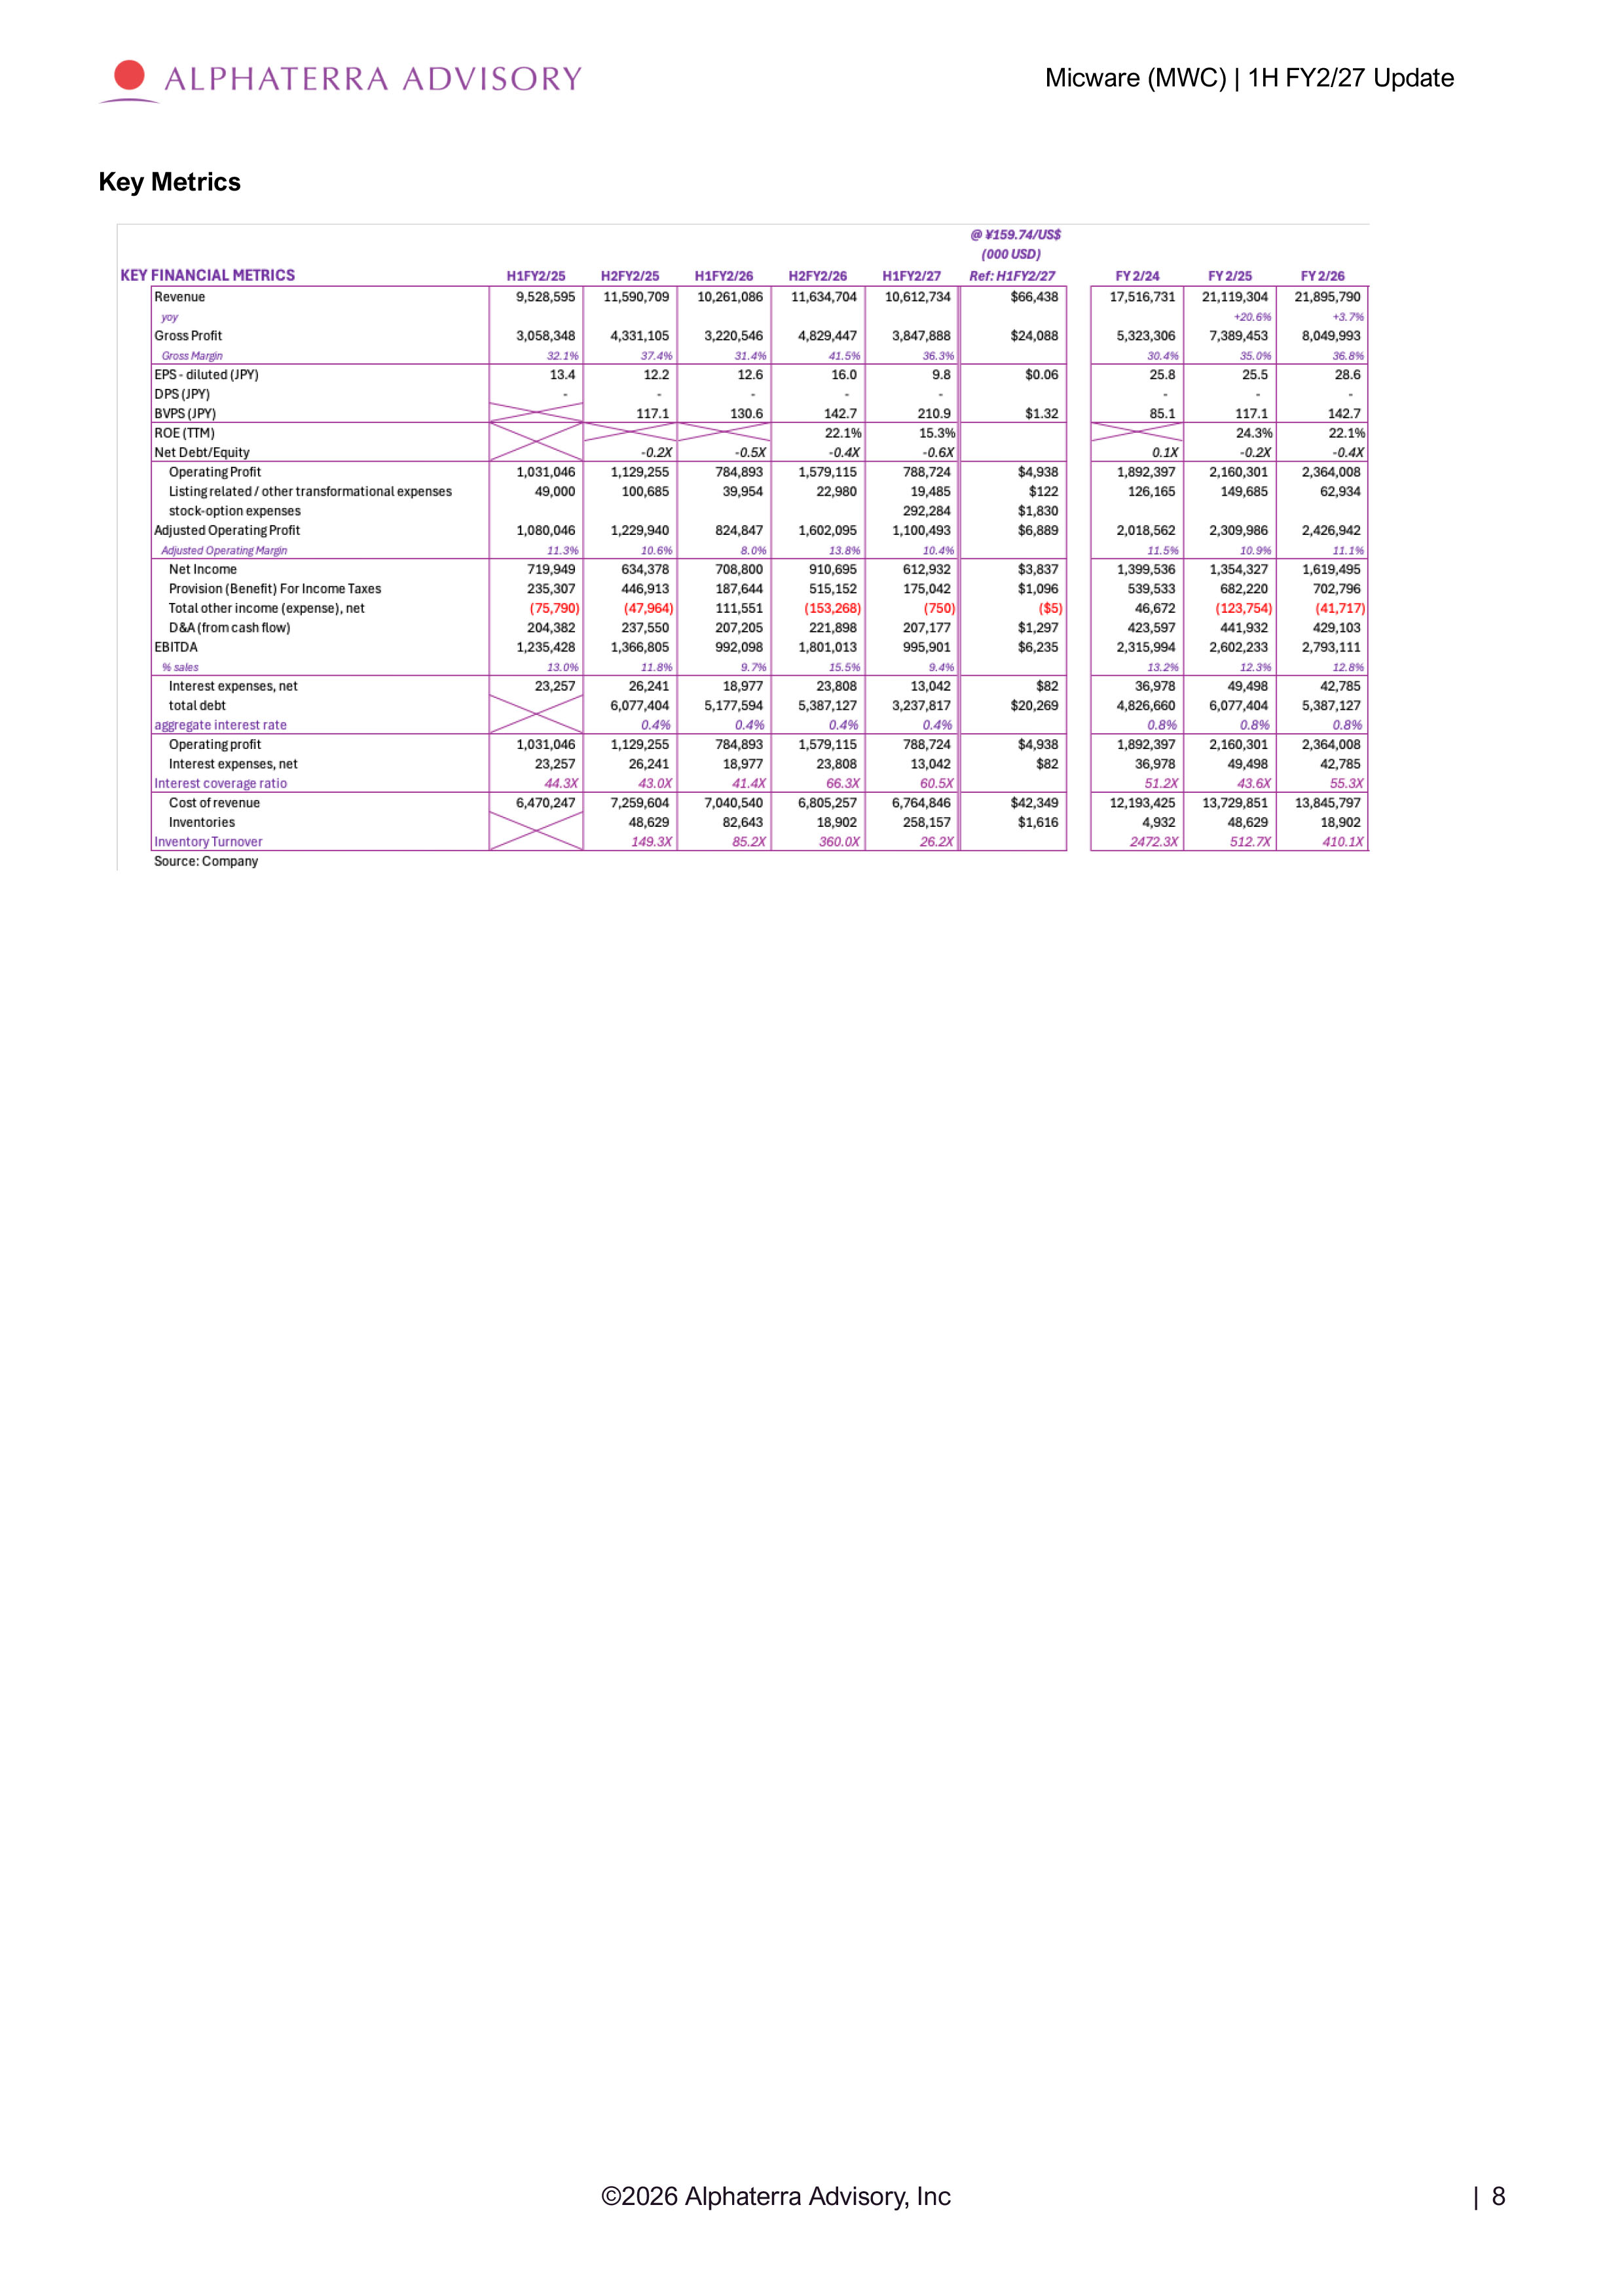
Micware (MWC) | 1H FY2/27 Update .H\ 0HWULFV ‹ $OSKDWHUUD $GYLVRU\ ,QF | 8
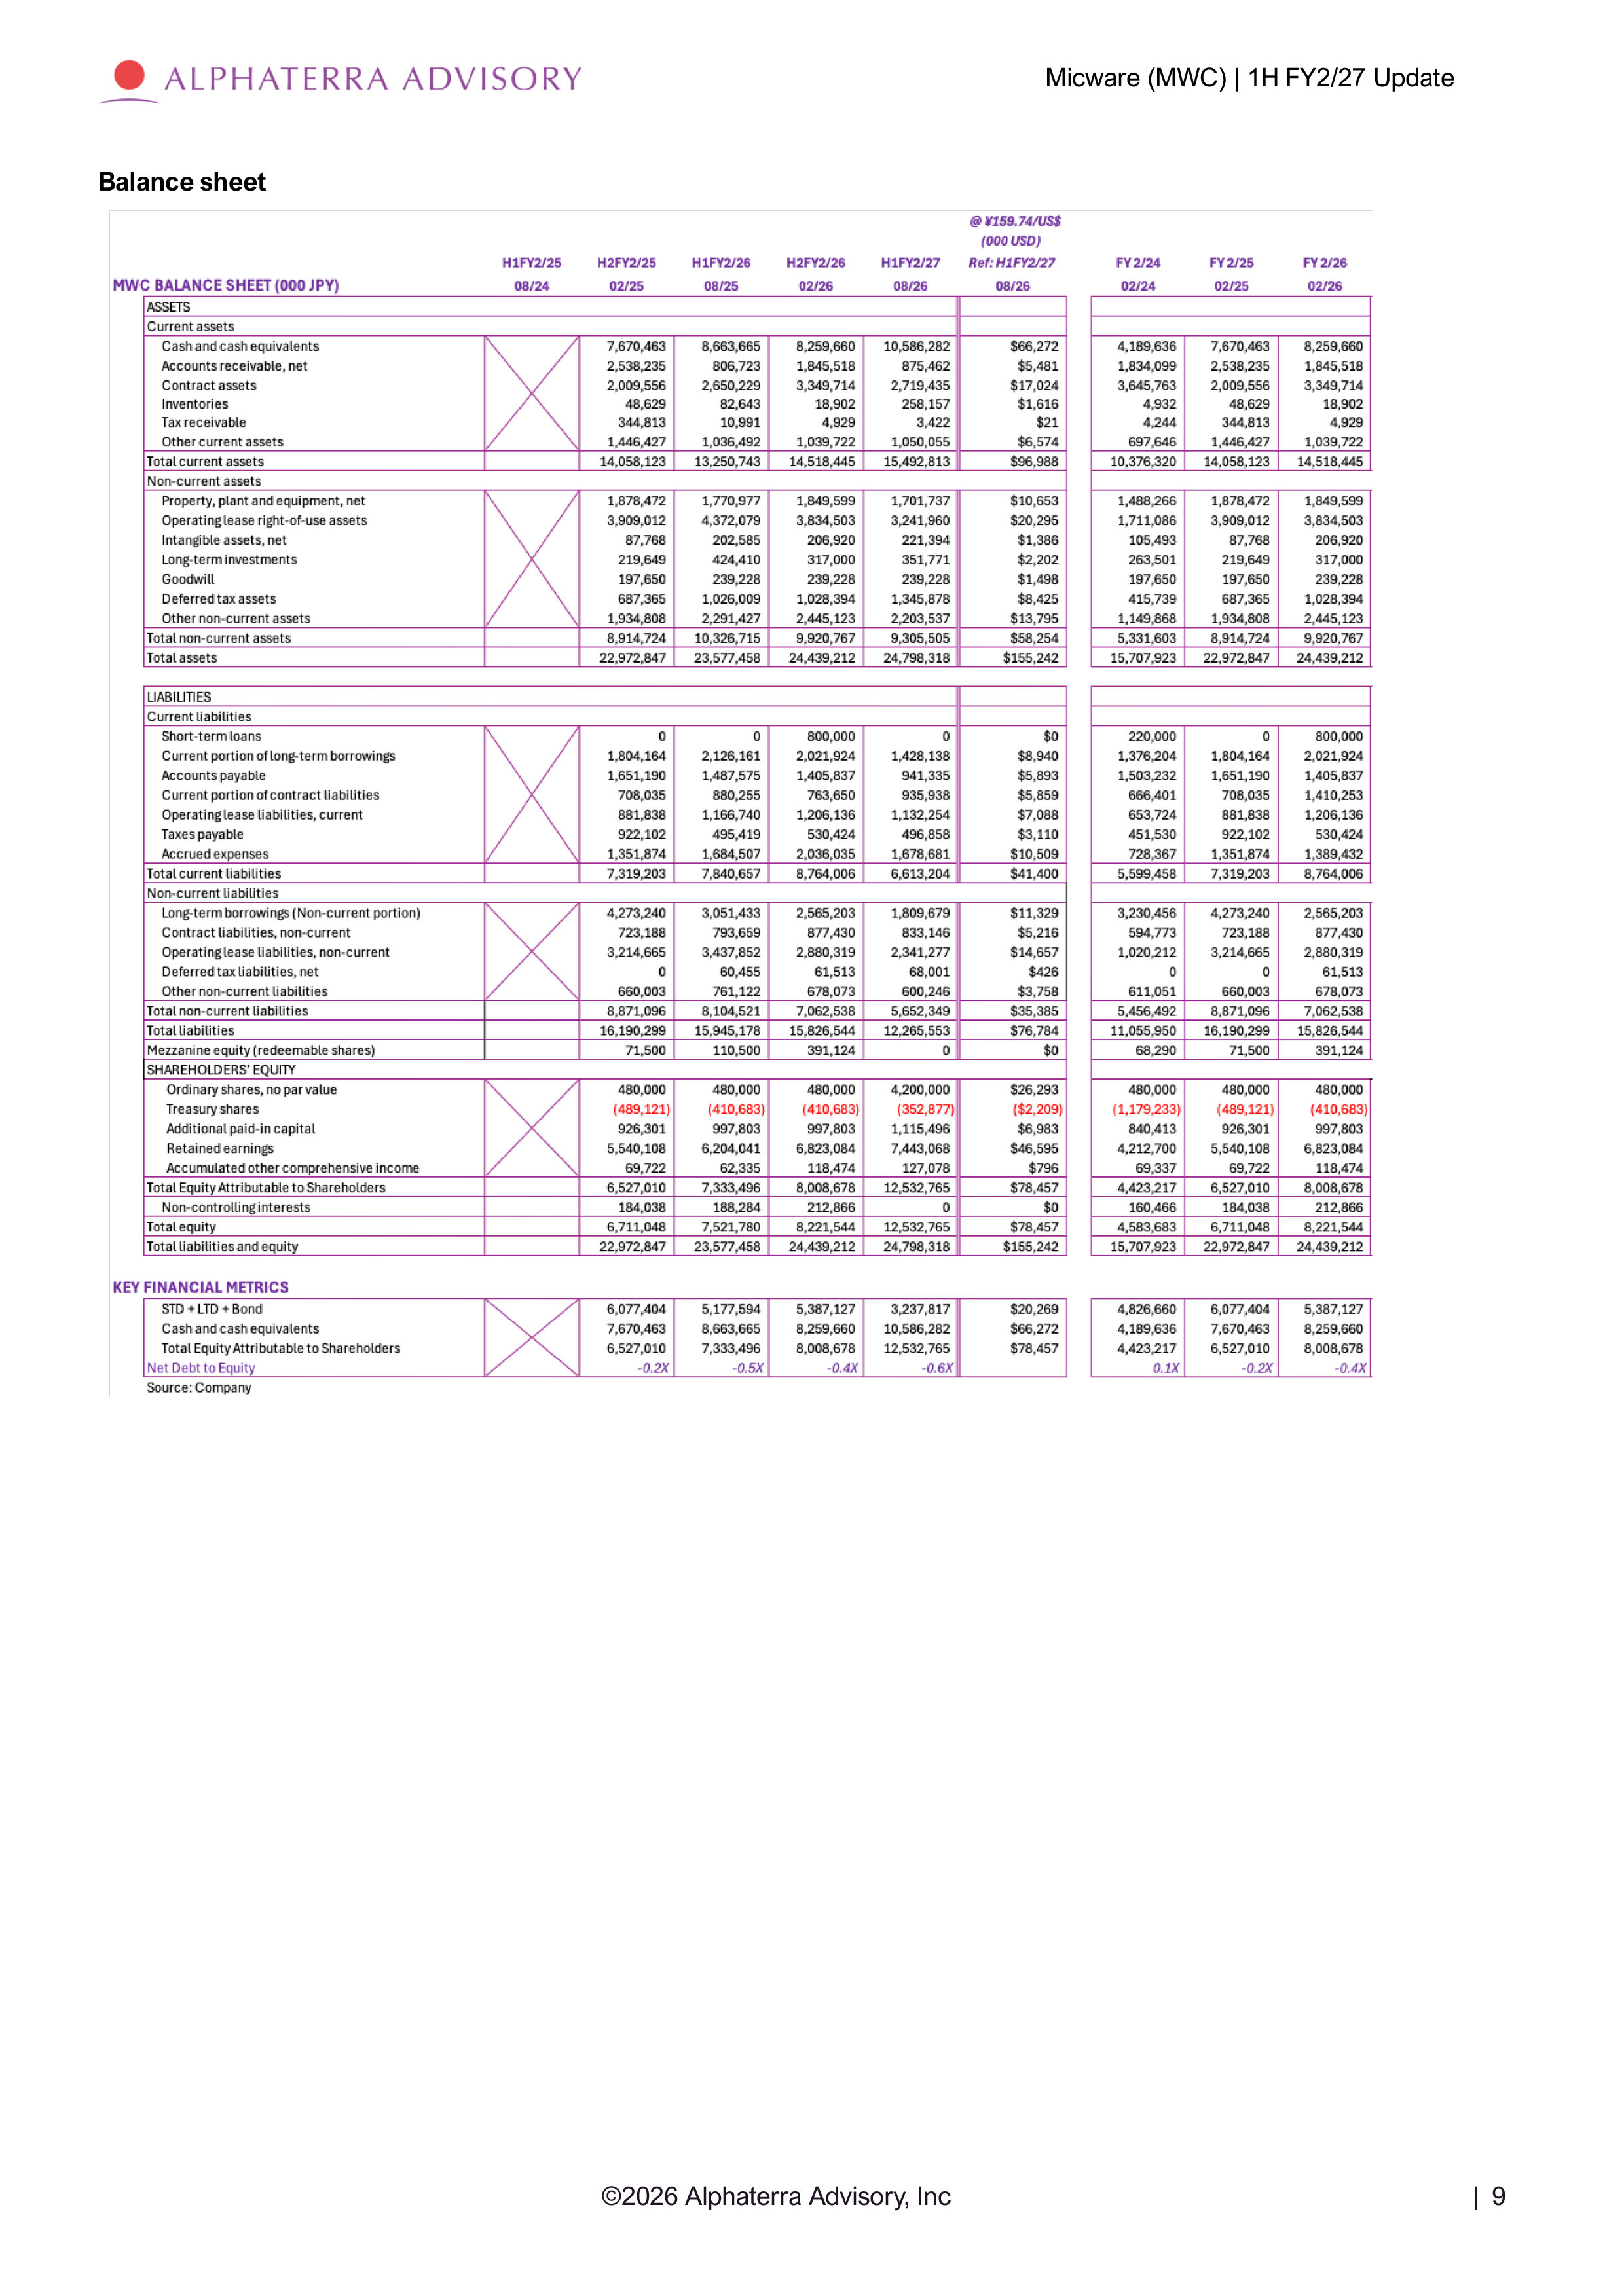
0LFZDUH 0:& _ + )< 8SGDWH Balance sheet ‹ $OSKDWHUUD $GYLVRU\ ,QF | 9
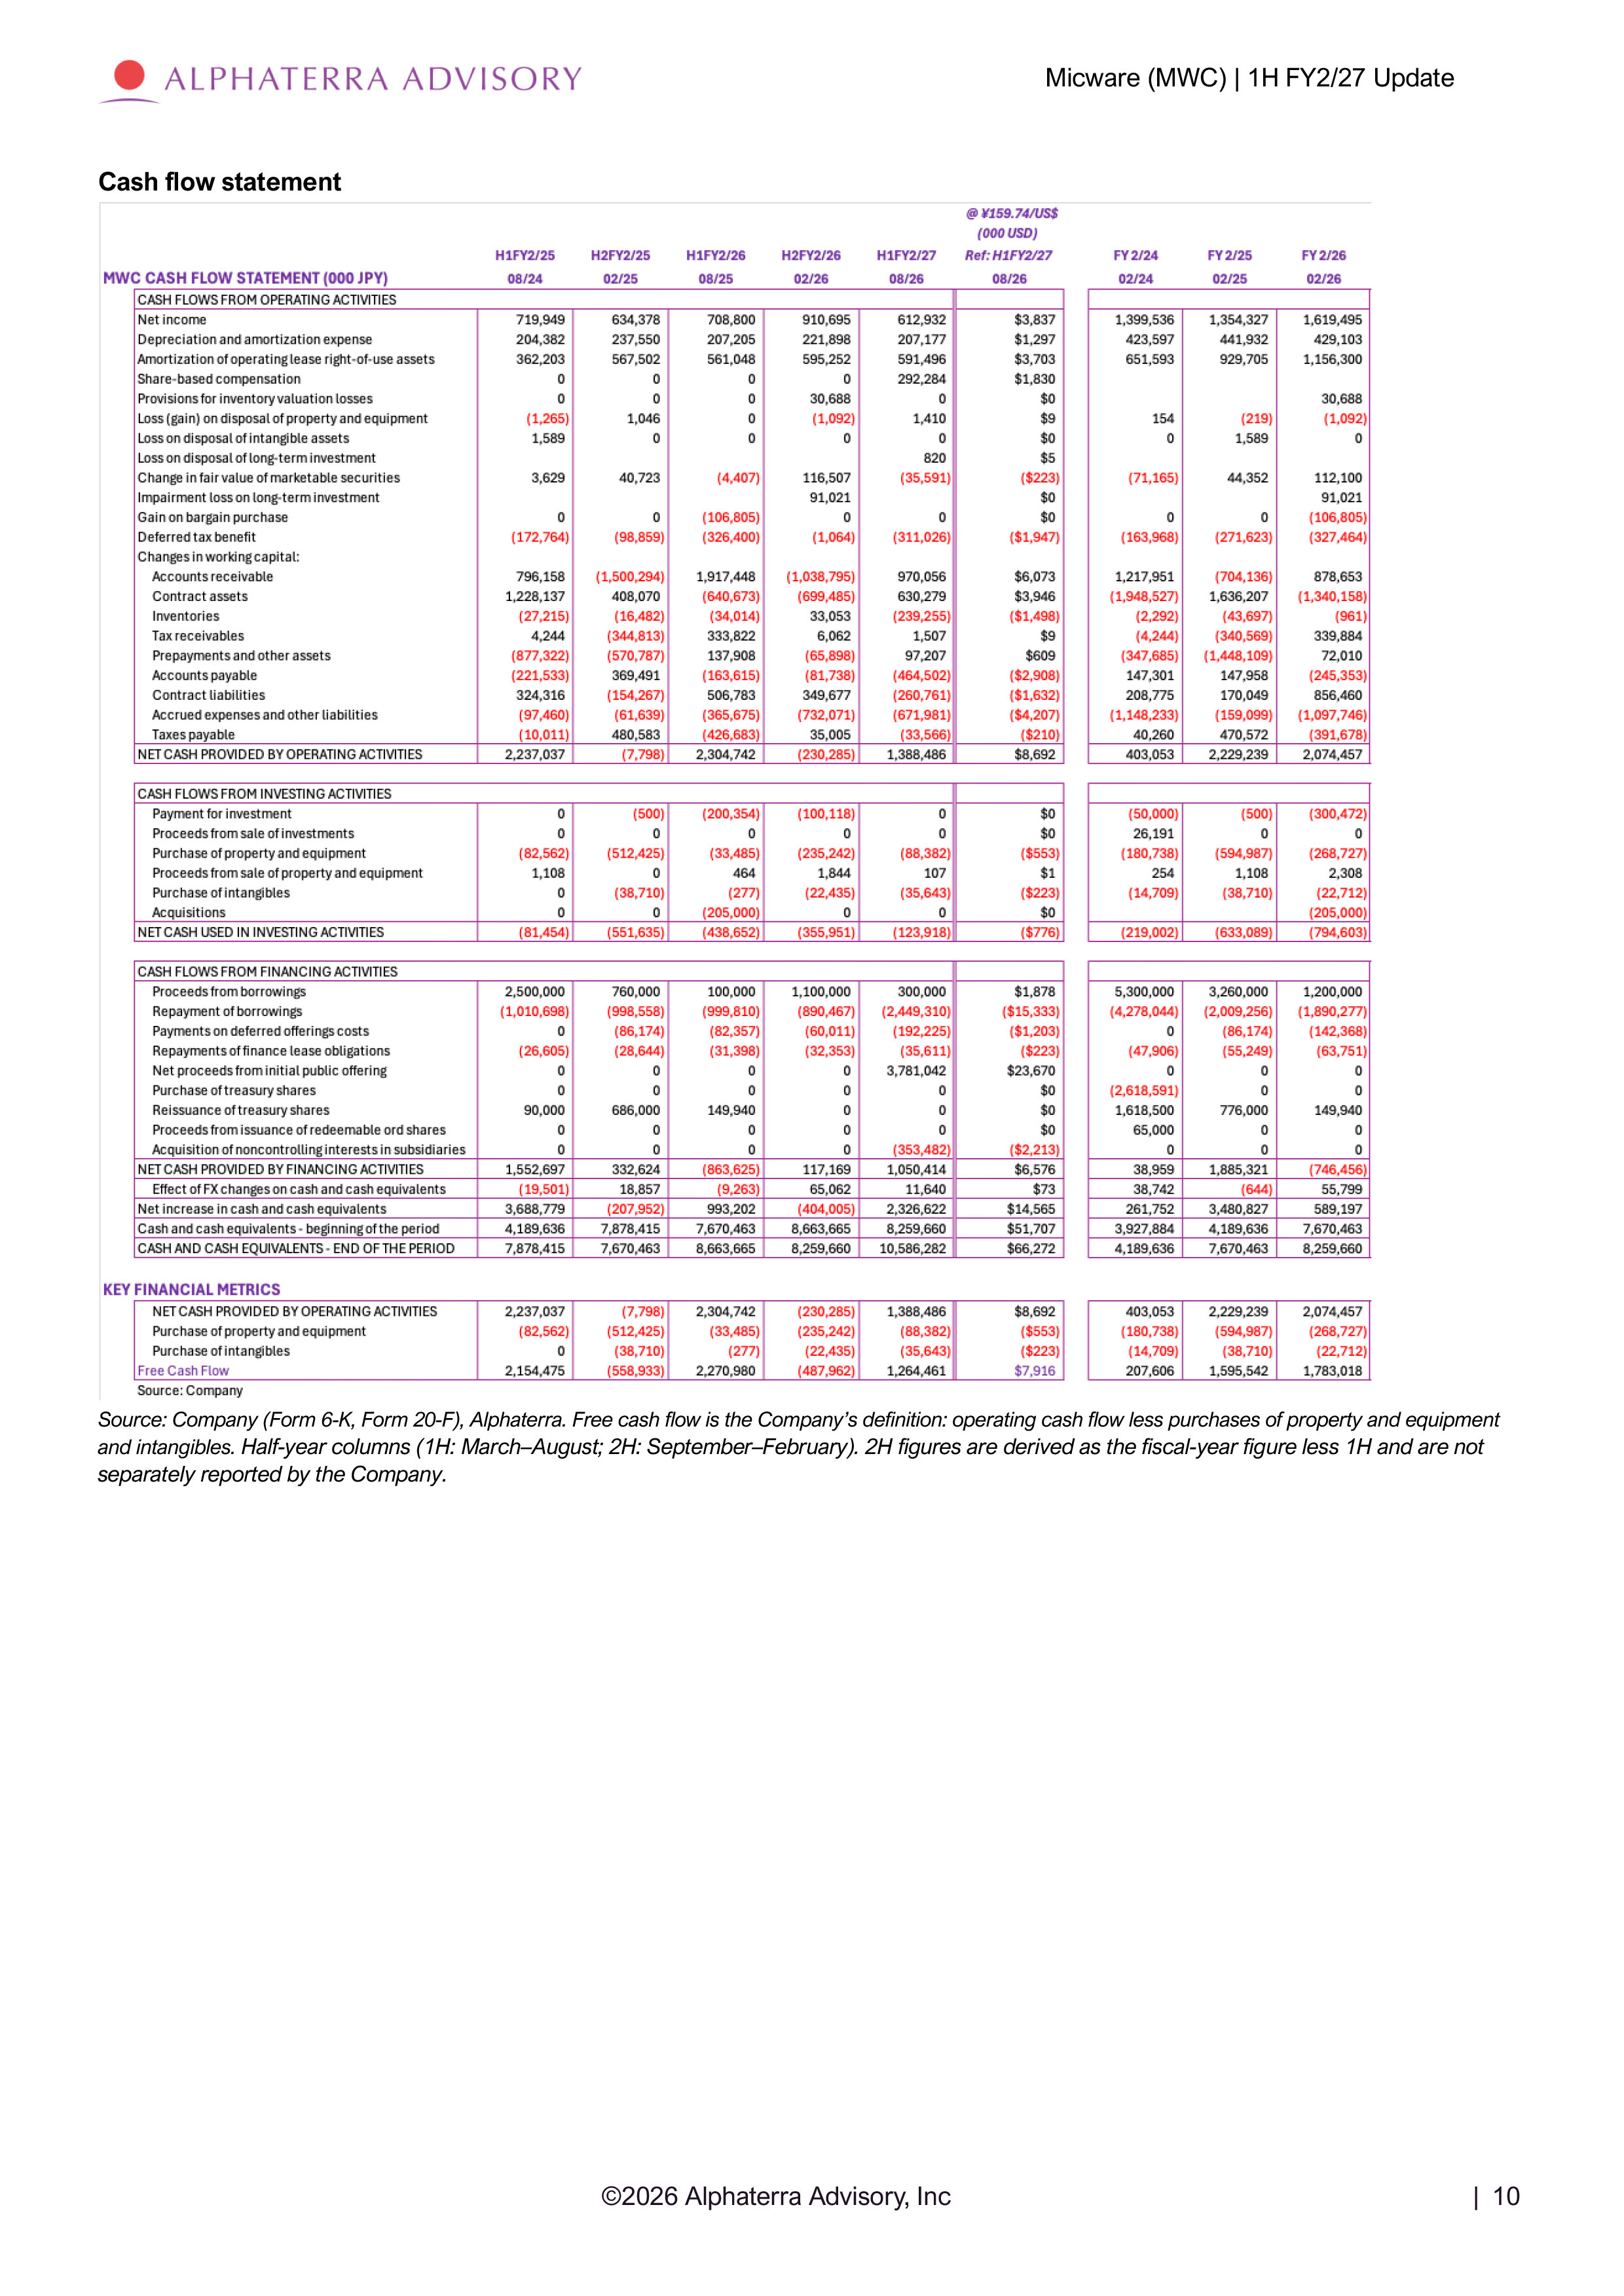
Micware (MWC) | 1H FY2/27 Update &DVK IORZ VWDWHPHQW 6RXUFH &RPSDQ\ )RUP . )RUP ) $OSKDWHUUD )UHH FDVK IORZ LV WKH &RPSDQ\ ¶ V GHILQLWLRQ RSHUDWLQJ FDVK IORZ OHVV SXUFKDVHV RI SURSHUW\ DQG HTXLSPHQW DQG LQWDQJLEOHV +DOI \HDU FROXPQV + 0DUFK $XJXVW + 6HSWHPEHU )HEUXDU\ + ILJXUHV DUH GHULYHG DV WKH ILVFDO \HDU ILJXUH OHVV + DQG DUH QRW VHSDUDWHO\ UHSRUWHG E\ WKH &RPSDQ\ ‹ $OSKDWHUUD $GYLVRU\ ,QF _
Micware (MWC) | 1H FY2/27 Update 'LVFODLPHU This update report has been prepared by Alphaterra Advisory Inc. (“Alphaterra,” “we,” “our” or “us”) at the request of, and for a fee paid by, Micware Co., Ltd. (the “Company”), following the initiation report published on August 7, 2026. Alphaterra received $50,000 in cash from the Company for the preparation and publication of the initiation report, and the fee also covers this update report. This update report is provided for general information purposes only and does not constitute a solicitation, recommendation, personal investment advice, or brokerage/dealer advice or service with respect to any securities. Alphaterra is not a registered broker - dealer or investment adviser and is not a financial instruments business operator in the United States and is not registered as a Financial Instruments Business Operator under Japan’s Financial Instruments and Exchange Act. This update report does not assign a rating, price target or investment recommendation of any kind. Information and opinions are based on sources believed to be reliable and/or publicly available; however, no representation or warranty is made as to accuracy, completeness, or timeliness. Forward - looking statements are as of the date hereof and are subject to change without notice. As of the publication date, Alphaterra and its author/analyst do not hold any securities of the Company. Alphaterra accepts no liability for any loss arising from the use of this update report. Any investment decision is made solely at the reader’s own risk. Copyright and all related rights in this update report are owned by the Company, and no part of this update report may be copied, reproduced, or redistributed without the Company’s prior consent. Distribution may be restricted in certain jurisdictions; recipients are responsible for compliance with applicable laws. ‹ $OSKDWHUUD $GYLVRU\ ,QF _ 3UHSDUHG E\ $OSKDWHUUD $GYLVRU\ ,QF $OSKDWHUUD :HEVLWH KWWSV DOSKDWHUUDDGYLVRU\ FRP (PDLO LQIR#DOSKDWHUUDDGYLVRU\ FRP