Exhibit 99.C
Bradley & Daytona Railway and Land Co.
5753 Highway 85 N #5974
Crestview, FL 32536
Via UPS and via Email
November 17, 2026
Power REIT
301 Winding Road
Old Bethpage, NY 11804
Attn: Messrs. D’Aguilar, Haynes, Morrison and Susman, Independent Trustees of Power REIT
Re: Power REIT – A Path Forward
Dear Independent Trustees of Power REIT:
On Friday, November 13, 2026, the SEC approved a NYSE American rule change establishing a $5.0 million minimum average market capitalization requirement over a consecutive 30-trading-day period, below which a listed security may face immediate suspension and delisting proceedings (Release No. 34-106893; File No. SR-NYSEAMER-2026-17). Power REIT (the “Trust”), with its current market cap of approximately $2.5 million, has a limited window in which to take decisive action, restore investor confidence, and put itself on a viable path forward while preserving its public market listing.
Unfortunately, Power REIT has spent the better part of 2026 pursuing a proposed 0.5-for-1 conversion of its Series A Preferred Stock into common shares. From the outset, this proposal had no realistic prospect of securing the necessary two-thirds preferred stockholder approval. Rather than addressing the Trust's underlying problems and developing a solution which would create value for all stakeholders, the Trust has devoted valuable time and resources to a proposal that appears principally designed to preserve David Lesser's position and control. The result has been lost time, continued uncertainty, further erosion of investor confidence in Power REIT’s leadership, and deterioration in the Trust's financial condition.
As the independent trustees, you have fiduciary responsibilities to Power REIT and its stakeholders—not to its CEO. Your obligation is to exercise independent judgment and act in the best interests of the Trust and its shareholders. That obligation is especially important now, when the Trust’s future, its listing, and the value of its enterprise are at stake. The interests of the Trust cannot be subordinated to the personal interests, preferences, or continued tenure of any one executive.
We believe there is an alternative that can be implemented immediately, that has meaningful support among both preferred and common shareholders, and that offers a realistic opportunity to preserve Power REIT's listing while creating immediate value and positioning the Trust for long-term growth.
Exhibit 99.C
Bradley & Daytona Railway and Land Co.
5753 Highway 85 N #5974
Crestview, FL 32536
Our Proposed Plan – A Path Forward for Power REIT
We are prepared to work with the independent trustees to implement the following four-part plan:
1. Convert the Series A Preferred Stock at a 4-for-1 ratio.
We propose a conversion of each Series A Preferred share into four common shares. The preferred shareholders currently have an economic value of $32.75 per share, representing the $25 liquidation preference plus accrued dividends of $7.75 as of September 30, 2026, as disclosed by the Trust in its Quarterly Report on Form 10-Q for the quarter ended September 30, 2026. Based on Power REIT’s closing stock price as of November 11, 2026, of $6.68, a 4-to-1 conversion represents an implied conversion value of $26.72 per share, which is a discount to what the Series A shares are contractually due and provides a path to resolve the Trust's outstanding preferred stock overhang. As amongst the largest owners of both the common and preferred shares, with collective ownership of 16,631 common shares and 40,853 preferred shares as of the date of this letter, we would receive the same economics we are proposing and are 100% aligned with Power REIT shareholders. We further believe the proposal would be supported by preferred shareholders and would receive the requisite two-thirds approval.
2. Sell the Pittsburgh & West Virginia Railroad.
The Pittsburgh & West Virginian Railroad (the “PWVRR”) is attractive asset, but one which has been fully levered by current management and is no longer a core asset to the Trust. A sale of the PWVRR would (i) remove over $14 million in liabilities from the Trust’s balance sheet, (ii) create millions in book equity value, and (iii) provide an immediate injection of capital to the Trust. We believe there are interested counterparties in the marketplace for the PWVRR that can close quickly on a purchase of PWVRR, subject to finalization of customary due diligence and standard deal closing requirements.
3. Remove David Lesser and reconstitute the Board.
A meaningful turnaround cannot occur under the continued leadership of the current CEO whose tenure has overseen the Trust's prolonged decline and stewarded Power REIT to its current precarious position. We propose removing Lesser from his executive and management positions and reconstituting the Board with independent leadership capable of acting in the interests of all stakeholders. Board members will have substantive expertise in the various asset classes of the Trust.
4. Transition management to our group at no cost to Power REIT.
Following Mr. Lesser's removal, our group is prepared to assume responsibility for managing Power REIT without charging the Trust management fees or other compensation for our services for a minimum term of two years. We would also immediately address unnecessary corporate overhead, including eliminating approximately $216,000 of cash expense pertaining to annual salaries paid to the current executive team. This would materially reduce the Trust's cash burn and allow a greater proportion of its resources to be directed toward turning around the business for the benefit of its stakeholders.
Exhibit 99.C
Bradley & Daytona Railway and Land Co.
5753 Highway 85 N #5974
Crestview, FL 32536
Taken together, these measures offer a practical path to resolve the preferred stock overhang, monetize a significant asset, reduce corporate expenses, restore governance credibility, and create a more viable platform for future value creation. They are not simply proposals for further discussion; they are actionable steps that can be implemented imminently to retain the Trust’s NYSE American listing and create a platform for long-term shareholder value creation.
Why a change in leadership is essential
The removal of David Lesser is paramount to any credible strategy to save Power REIT. The Trust's current predicament did not arise overnight. It is the culmination of years of deteriorating shareholder value, questionable related-party relationships, governance failures, and inadequate financial controls under Mr. Lesser's leadership. It was in fact these extensive related-party relationships and ongoing governance failures that were amongst the reasons cited by Institutional Shareholder Services (ISS), the leading independent proxy advisory firm, in recommending that shareholders WITHHOLD their votes for Mr. Lesser and other trustees at the 2026 annual common shareholder meeting.
Consider the following:
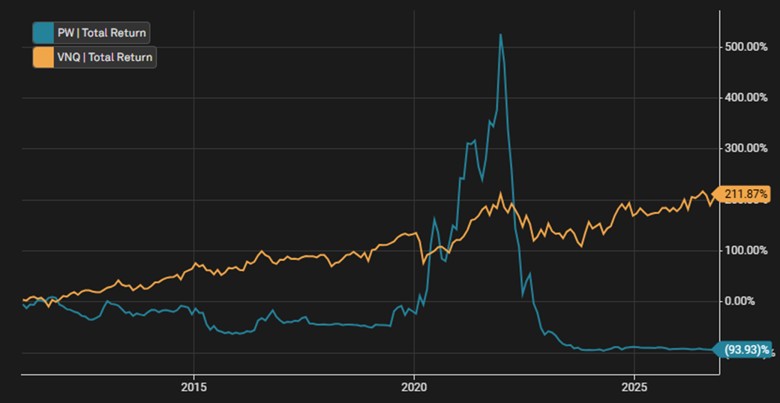
Extraordinary destruction of shareholder value. During Mr. Lesser's tenure, Power REIT has suffered a profound erosion in shareholder value. Since Mr. Lesser assumed the CEO role on February 14, 2011, through close of market on November 16, 2026, Power REIT’s total shareholder return has been staggering negative return of -94%, compared to a gain of 212% for the Vanguard REIT Index (VNQ).
Exhibit 99.C
Bradley & Daytona Railway and Land Co.
5753 Highway 85 N #5974
Crestview, FL 32536
Moreover, Power REIT went from being a dependable dividend payer to common shareholders for over four decades prior to Mr. Lesser assuming control, to no longer paying any dividend to either common shareholders or preferred stockholders. Shareholders simply cannot afford more of these results.
Related-party relationships and conflicts of interest. Mr. Lesser’s tenure has further been marked by repeated related-party transactions that have directly contributed to the erosion of shareholder value. Shortly after assuming control of the Trust, Power REIT became involved in litigation with its then sole tenant, Norfolk Southern, that lasted through 2017. During that time period, the Trust paid in excess of $3 million in legal fees on the litigation to Morrison Cohen, where Mr. Lesser’s wife is a partner. In return for this greater than $3 million on legal fees to Morrison Cohen, Power REIT lost the litigation on all counts. The ROI on this spend for the Trust’s shareholders was zilch.
Moreover, Mr. Lesser has simultaneously held leadership positions at Power REIT and Millennium Sustainable Ventures Corp. (formerly Millennium Investment and Acquisition Company, Inc., or MILC). During this period, Power REIT invested more than $20 million in cannabis-related properties leased to entities affiliated with MILC. Those properties subsequently became associated with significant impairments, tenant defaults, and terminated leases. The Trust's disclosures also identify financing relationships involving MILC and its affiliates, as well as $162,700 in payroll reimbursements to MILC during 2023 for employees maintaining a Nebraska property. The disclosed leases were reported as being in default and terminated as of June 30, 2025, with no rental income recognized from the affiliated tenants for the periods identified in that disclosure. Given Mr. Lesser's overlapping leadership positions, these circumstances raise serious questions about conflicts of interest, transaction oversight, the economic outcomes for Power REIT, and the adequacy of independent Board review.
The 2017 Norfolk Southern fraud ruling. In the aforementioned Norfolk Southern Railway Co. v. Pittsburgh & West Virginia Railroad, on August 29, 2017, the United States Court of Appeals for the Third Circuit affirmed the District Court’s finding that PWVRR committed fraud in obtaining Norfolk Southern’s consent to the 2011 rights offering. The court described the fraud as arising from “Lesser’s fraudulent misrepresentations and omissions in seeking Norfolk Southern’s consent” (870 F.3d 244). This was not a minor contractual disagreement: the appellate court expressly affirmed the finding of fraud. The fact that such a finding arose from conduct involving the Trust's CEO should have been a significant governance concern for the Board then, and it remains relevant when evaluating the Trust's leadership today.
Unremediated material weakness in financial controls. Power REIT's November 6, 2026 Form 10-Q, consistent with prior financial reports, is troubling. Management conceded that the Trust’s disclosure controls and procedures were not effective as of September 30, 2026, due to a material weakness in controls relating to accounting for complex transactions. That weakness was originally identified in the quarterly period ended June 30, 2024, and has remained unremediated more than two years later. Specifically, the Trust historically classified its Series A Preferred Stock as mezzanine equity rather than equity. Management's stated remediation plan is to engage outside consultants to assist with complex transaction accounting. The persistence of this weakness raises serious questions about the Board's oversight of financial reporting and the Trust's ability to produce reliable financial information.
Exhibit 99.C
Bradley & Daytona Railway and Land Co.
5753 Highway 85 N #5974
Crestview, FL 32536
These are not isolated matters. Taken together, they demonstrate why simply continuing with the existing management structure and hoping for a different outcome is not a credible turnaround strategy. The independent trustees must ask whether the current leadership has demonstrated the judgment, independence, and ability necessary to preserve the Trust and protect its stakeholders.
The responsibility now rests with the independent trustees
The SEC's approval of the NYSE American rule change has made the consequences of continued inaction even more serious. Power REIT cannot afford to spend additional months pursuing a conversion proposal that preferred shareholders have no reason to accept and only entrenches the current leadership that has led Power REIT to its present precarious position, while the Trust's financial state and listing remain at risk.
You have an opportunity and obligation to change that trajectory. Our proposal offers a concrete alternative, a willing group prepared to execute it without charging the Trust management fees, and a path toward reducing expenses and creating value for shareholders.
We ask that the independent trustees evaluate this proposal immediately and independently of Mr. Lesser. We further request an opportunity to meet with the independent trustees, without Mr. Lesser or other members of current management present, to discuss the proposal, its implementation, and the steps necessary to put Power REIT on a sustainable path forward.
The Trust does not need another round of delay, another proposal designed around the preferences of its CEO, or another exercise in shareholder value destruction. It needs independent leadership, decisive action, and a credible plan.
The opportunity to save Power REIT is still available, but the window is narrowing. We are prepared to execute this plan. The question is whether the independent trustees are prepared to act in the best interests of the Trust and its stakeholders rather than in the best interest of the CEO.
Sincerely,
/s/ Alexander Kachmar
Alexander Kachmar
Bradley & Daytona Railway and Land Co. LLC
/s/ David Cacciapaglia
David Cacciapaglia