Capital Markets Day 2026 Opening Keynote Telecom & Infrastructure Financial Services Digital Life NeoV Financial Model Closing Ahmet Kayhan, Chief Payments & Digital Assets Officer VEON Digital Finance Group (DFG)
I M P O R T A N T N O T I C E Disclaimer BASIS OF PRESENTATION VEON's results and other financial information presented in this presentation are, unless otherwise stated, prepared in accordance with International Financial Reporting Standards (“IFRS”) and have not been externally reviewed and audited. The financial information included in this presentation is preliminary and is based on a number of assumptions that are subject to inherent uncertainties and subject to change. The financial information presented herein is based on internal management accounts, is the responsibility of management and has not been audited, reviewed or verified. Certain amounts and percentages that appear in this presentation have been subject to rounding adjustments. As a result, certain numerical figures shown as totals, including those in the tables, may not be an exact arithmetic aggregation of the figures that precede or follow them. Although we believe the information to be reasonable, actual results may vary from the information contained above and such variations could be material. As such, you should not place undue reliance on this information. This information may not be indicative of the actual results for the current period or any future period. FORWARD-LOOKING STATEMENTS This presentation contains “forward-looking statements”, within the meaning of Section 27A of the U.S. Securities Act of 1933, as amended, and Section 21E of the U.S. Securities Exchange Act of 1934, as amended. Such forward-looking statements may be identified by words such as “may,” “will,” “expect,” “plan,” “anticipate,” “potential,” “continue,” “aim,” “goal,” “target,” and other similar words. Forward-looking statements include statements relating to, among other things, VEON’s plans to implement its strategic priorities, operating model and development plans; VEON's ability to achieve anticipated performance results, including VEON’s aspirations for the performance of VEON Digital Finance Group by 2030; VEON’s intended expansion of its digital experience, including the expansion of JazzCash, Mobilink Microfinance Bank (“MMBL”) and JazzSure, a possible offering in Ukraine (an option only) and diaspora remittance corridors through VEON’s UAE hub; VEON’s assessment of the impact of the war in Ukraine, including recent escalations, on its current and future operations and financial condition; VEON’s assessment of the impact of political instability in Bangladesh; future market developments and trends in digital financial services and remittances; the receipt, timing and scope of licences and approvals, including a Digital Retail Bank licence and launch approval in Pakistan and the launch of a digital bank in Bangladesh; deposit and loan growth and credit quality; the benefits of AI in financial services; VEON’s ability to execute its strategic transactions in the timeframes anticipated, or at all; and VEON’s ability to realize its targets and commercial initiatives in its various countries of operation. While the forward-looking statements included in this presentation are based on management’s best assessment, there are numerous risks and uncertainties that could cause VEON’s actual results, plans and objectives to differ materially from those expressed, such as those risks discussed in the section entitled “Risk Factors” in VEON’s 2025 Form 20-F filed with the SEC on March 16, 2026 and other public filings made by VEON with the SEC. The forward- looking statements speak only as of the date hereof and we disclaim any obligation to update them, except to the extent required by law. NON-IFRS MEASURES AND OPERATING METRICS This presentation includes financial measures not presented in accordance with IFRS, including EBITDA, EBITDA margin and pre-provision operating profit for VEON Pakistan Financial Services (presented on a management basis, which may differ from VEON’s IFRS financial statements and from the stand-alone accounts of Mobilink Microfinance Bank (“MMBL”) prepared under SBP requirements). Operating, banking and regulatory metrics, including gross transaction value, customers (users active in 3Q26), deposits, loan portfolio, credit revenue, NPL ratio, recovery rate and capital adequacy, are unaudited and may be defined differently by other companies. These measures are supplemental, should not be considered in isolation or as a substitute for, or superior to, IFRS measures, and may not be comparable to similarly titled measures of other companies. Reconciliations to the most directly comparable IFRS measures are included in VEON’s Earnings Release and Operating Highlights for the Third Quarter and Nine Months ended September 30, 2026, available on the VEON and SEC websites. MARKET DATA AND THIRD-PARTY INFORMATION Market, industry and population data are derived from third-party sources, including GSMA Intelligence, the UN, the IMF, the World Bank (including Global Findex), the State Bank of Pakistan, national regulators and public company disclosures, as well as VEON estimates. VEON has not independently verified third-party data, and estimates and projections to 2030 are inherently uncertain. Peer company information is included for illustrative purposes only and is not an indication of the value of VEON or any of its businesses. Information on Slide 6 is taken from publicly available materials Customer journeys, including “Ayesha’s story,” are illustrative and do not represent any actual customer or typical results. INSIDE INFORMATION Furthermore, elements of this presentation contain or may contain, “inside information” as defined under the Market Abuse Regulation (EU) No. 596/2014.
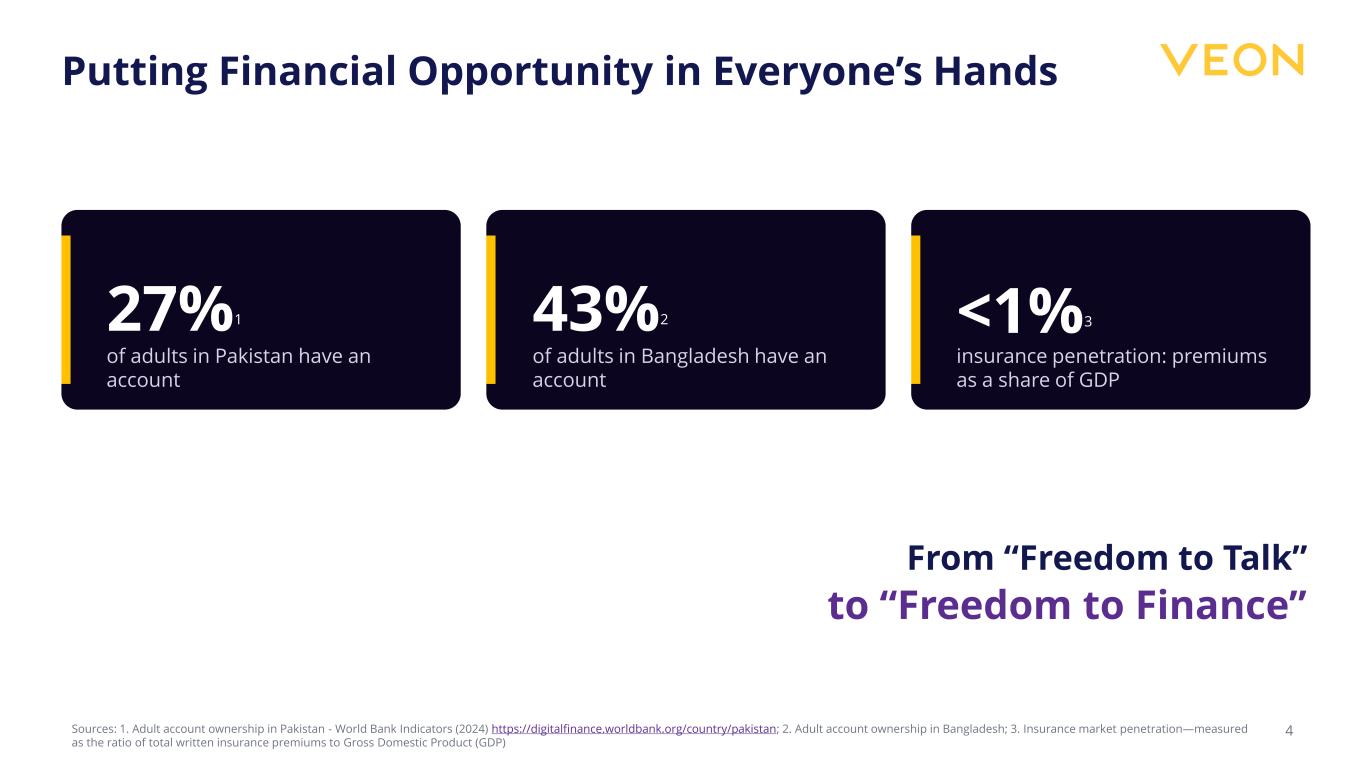
Putting Financial Opportunity in Everyone’s Hands 4Sources: 1. Adult account ownership in Pakistan - World Bank Indicators (2024) https://digitalfinance.worldbank.org/country/pakistan; 2. Adult account ownership in Bangladesh; 3. Insurance market penetration—measured as the ratio of total written insurance premiums to Gross Domestic Product (GDP) 27%1 43%2 <1%3 From “Freedom to Talk” to “Freedom to Finance” of adults in Pakistan have an account of adults in Bangladesh have an account insurance penetration: premiums as a share of GDP
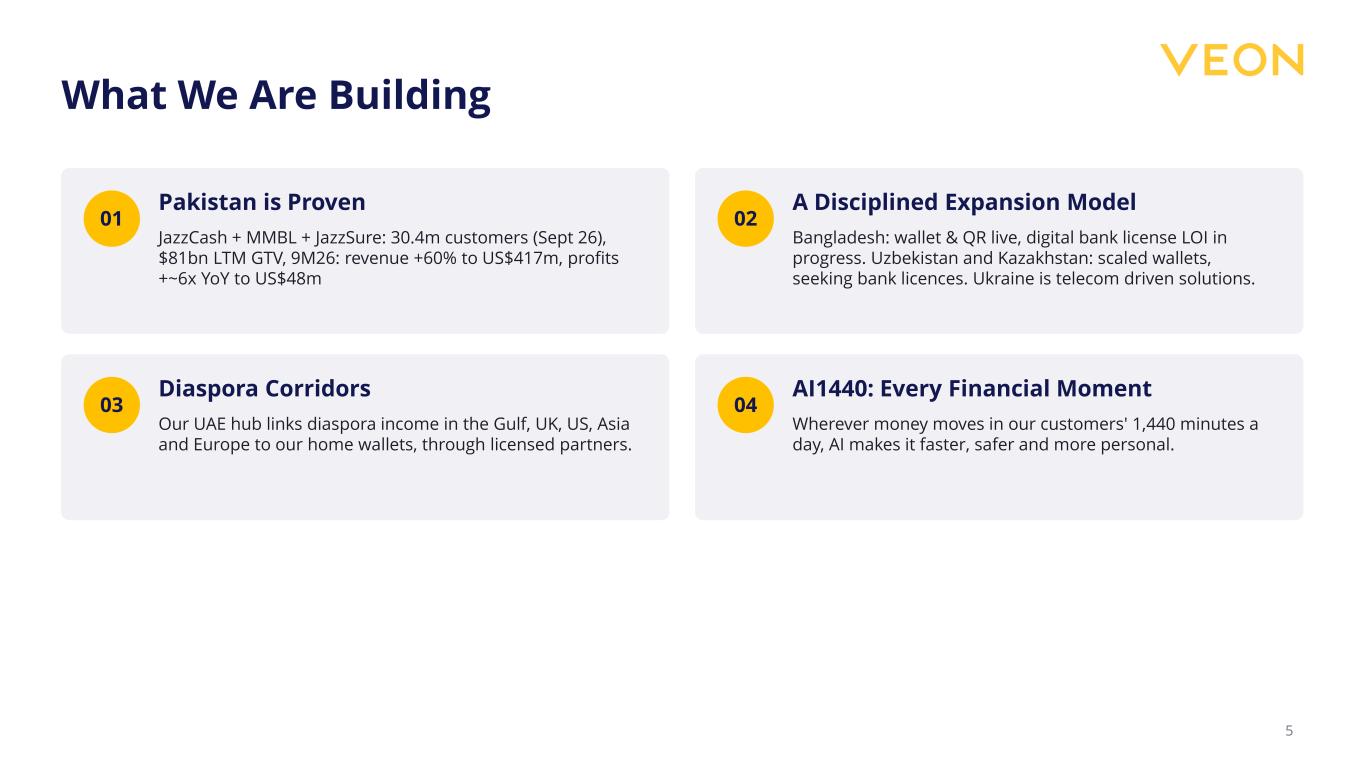
What We Are Building 01 Pakistan is Proven JazzCash + MMBL + JazzSure: 30.4m customers (Sept 26), $81bn LTM GTV, 9M26: revenue +60% to US$417m, profits +~6x YoY to US$48m 02 A Disciplined Expansion Model Bangladesh: wallet & QR live, digital bank license LOI in progress. Uzbekistan and Kazakhstan: scaled wallets, seeking bank licences. Ukraine is telecom driven solutions. 03 Diaspora Corridors Our UAE hub links diaspora income in the Gulf, UK, US, Asia and Europe to our home wallets, through licensed partners. 04 AI1440: Every Financial Moment Wherever money moves in our customers' 1,440 minutes a day, AI makes it faster, safer and more personal. 5
01 One Group. Five Markets. Many Corridors. How the VEON flywheel turns telecom reach into financial relationships. 6
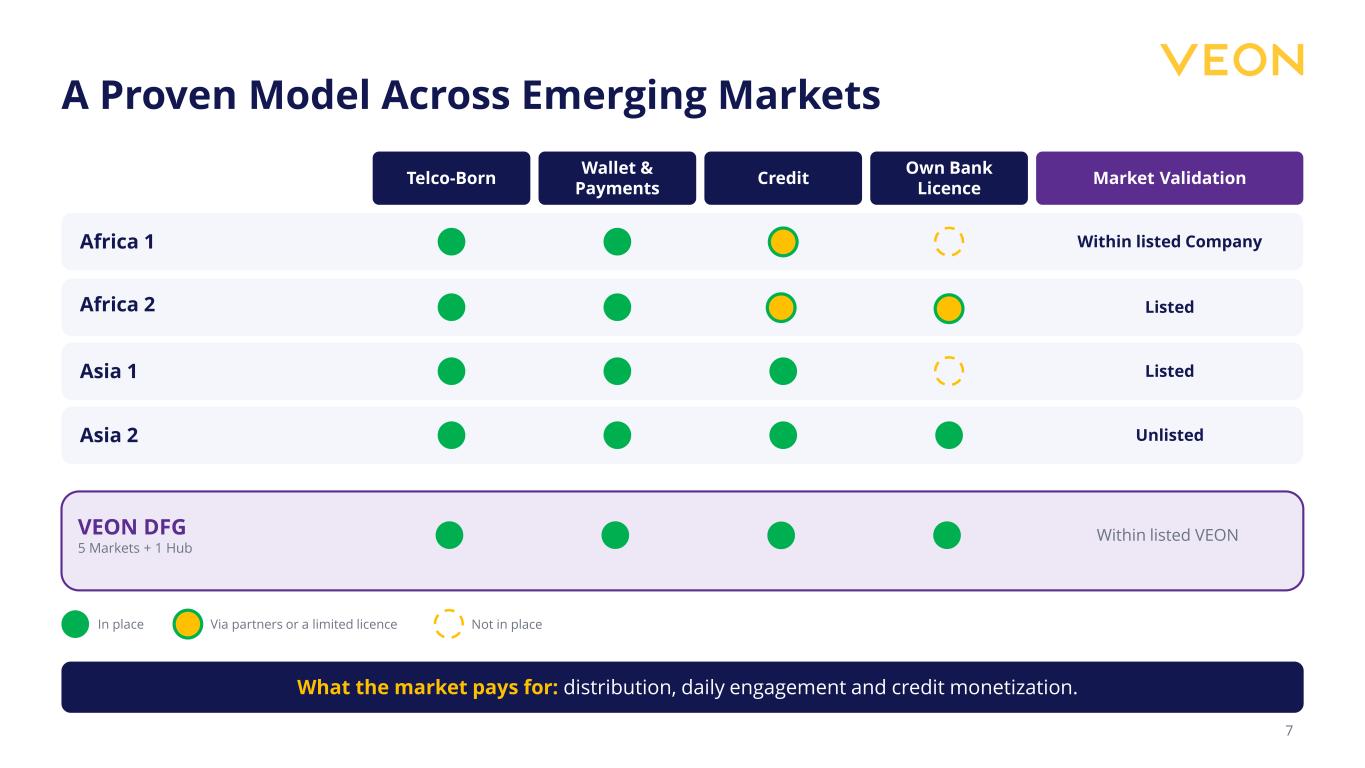
A Proven Model Across Emerging Markets 7 What the market pays for: distribution, daily engagement and credit monetization. Telco-Born Wallet & Payments Credit Own Bank Licence Market Validation Africa 1 Within listed Company Listed Asia 1 Listed Asia 2 Unlisted VEON DFG 5 Markets + 1 Hub Within listed VEON In place Via partners or a limited licence Not in place Africa 2
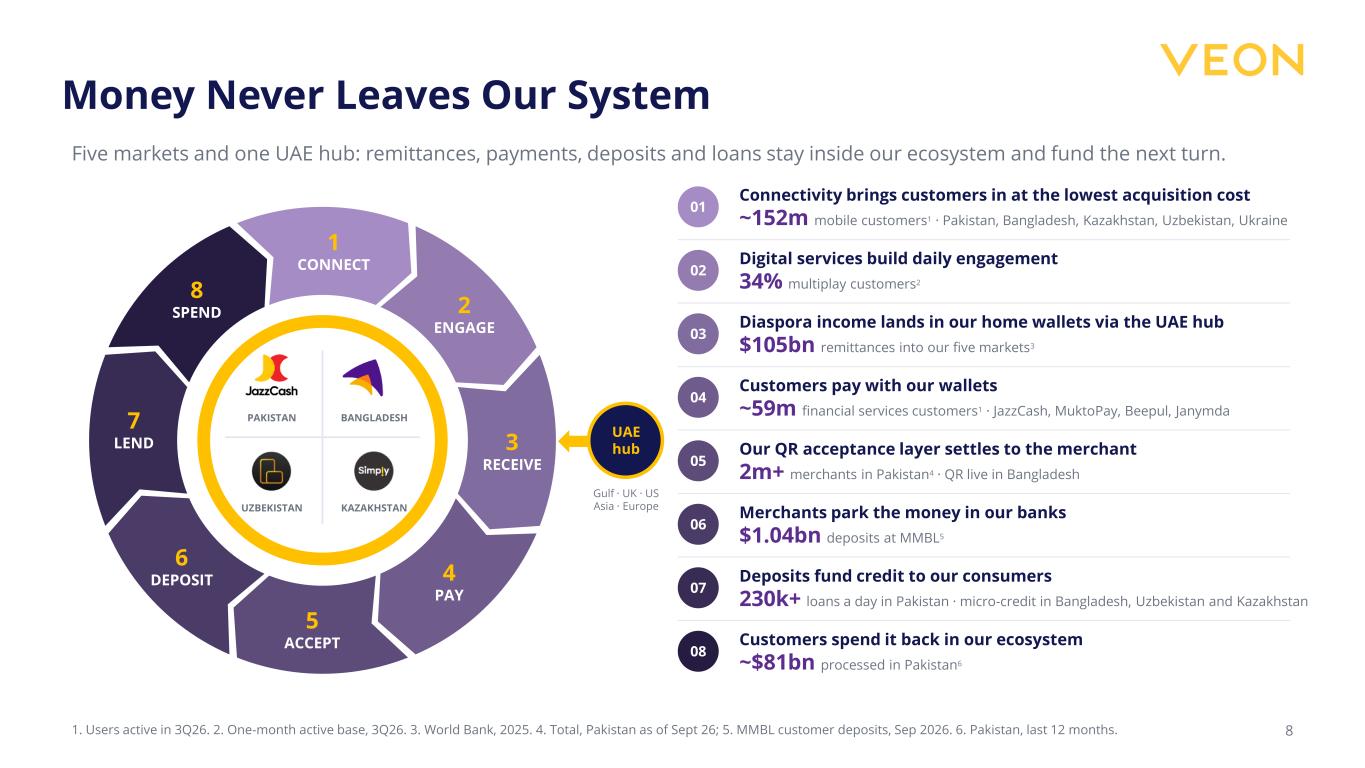
Money Never Leaves Our System 1. Users active in 3Q26. 2. One-month active base, 3Q26. 3. World Bank, 2025. 4. Total, Pakistan as of Sept 26; 5. MMBL customer deposits, Sep 2026. 6. Pakistan, last 12 months. 8 Five markets and one UAE hub: remittances, payments, deposits and loans stay inside our ecosystem and fund the next turn. 1 CONNECT 2 ENGAGE 3 RECEIVE 4 PAY 5 ACCEPT 6 DEPOSIT 7 LEND 8 SPEND PAKISTAN BANGLADESH UZBEKISTAN KAZAKHSTAN UAE hub Gulf · UK · US Asia · Europe 01 Connectivity brings customers in at the lowest acquisition cost ~152m mobile customers1 · Pakistan, Bangladesh, Kazakhstan, Uzbekistan, Ukraine 02 Digital services build daily engagement 34% multiplay customers2 03 Diaspora income lands in our home wallets via the UAE hub $105bn remittances into our five markets3 04 Customers pay with our wallets ~59m financial services customers1 · JazzCash, MuktoPay, Beepul, Janymda 05 Our QR acceptance layer settles to the merchant 2m+ merchants in Pakistan4 · QR live in Bangladesh 06 Merchants park the money in our banks $1.04bn deposits at MMBL5 07 Deposits fund credit to our consumers 230k+ loans a day in Pakistan · micro-credit in Bangladesh, Uzbekistan and Kazakhstan 08 Customers spend it back in our ecosystem ~$81bn processed in Pakistan6
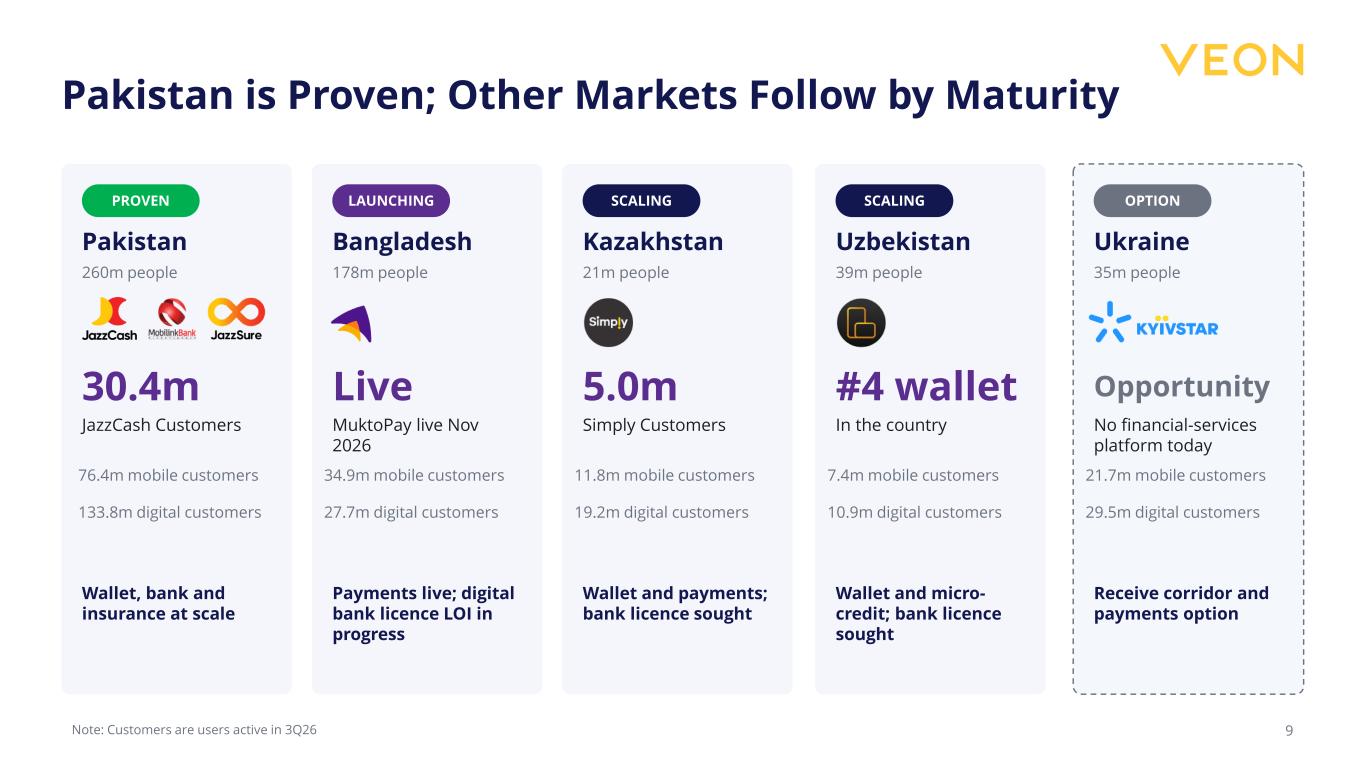
Pakistan is Proven; Other Markets Follow by Maturity PROVEN Pakistan 260m people 30.4m JazzCash Customers 76.4m mobile customers Wallet, bank and insurance at scale OPTION Ukraine 35m people Opportunity No financial-services platform today 21.7m mobile customers Receive corridor and payments option 9Note: Customers are users active in 3Q26 133.8m digital customers SCALING Kazakhstan 21m people 5.0m Simply Customers 11.8m mobile customers Wallet and payments; bank licence sought SCALING Uzbekistan 39m people #4 wallet In the country 7.4m mobile customers Wallet and micro- credit; bank licence sought 19.2m digital customers 10.9m digital customers 29.5m digital customers LAUNCHING Bangladesh 178m people Live MuktoPay live Nov 2026 34.9m mobile customers Payments live; digital bank licence LOI in progress 27.7m digital customers
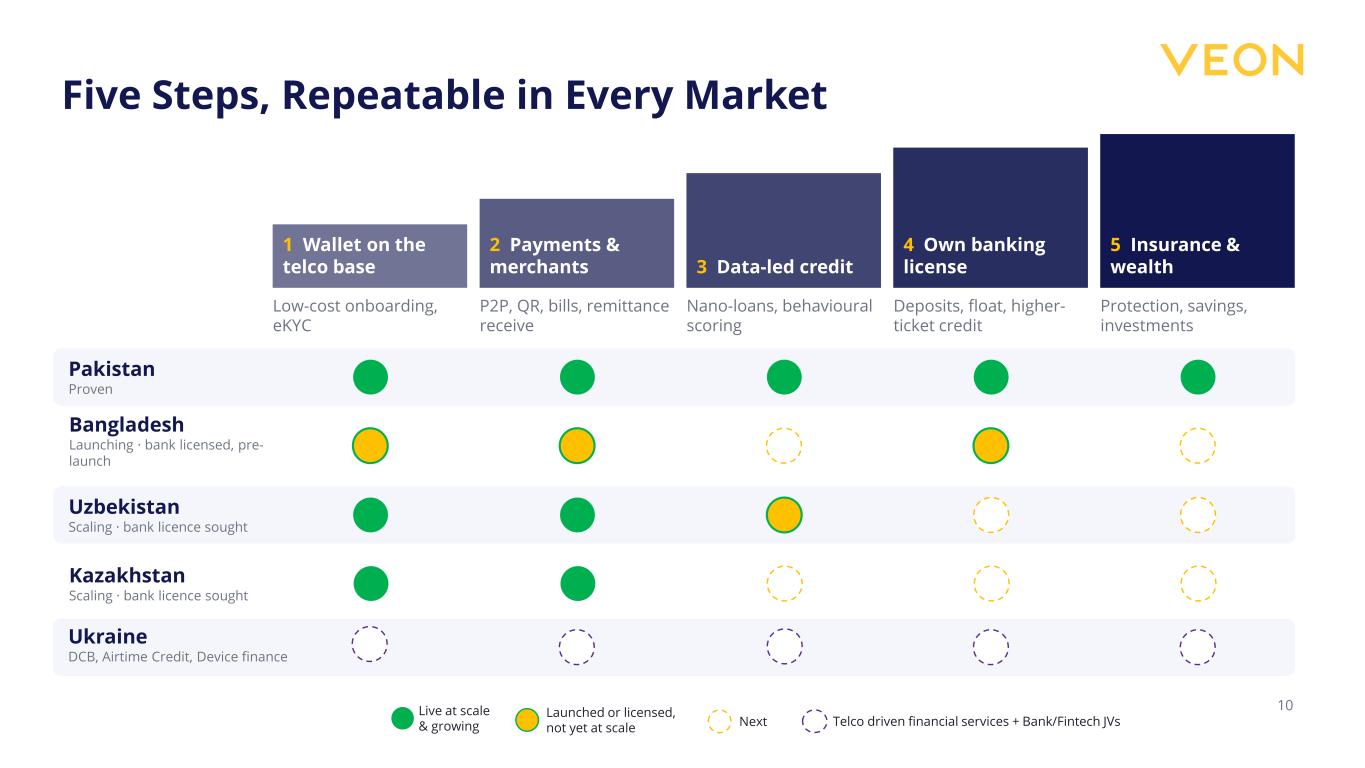
Five Steps, Repeatable in Every Market 1 Wallet on the telco base Low-cost onboarding, eKYC 2 Payments & merchants P2P, QR, bills, remittance receive 3 Data-led credit Nano-loans, behavioural scoring 4 Own banking license Deposits, float, higher- ticket credit 5 Insurance & wealth Protection, savings, investments Pakistan Proven Bangladesh Launching · bank licensed, pre- launch Live at scale & growing Launched or licensed, not yet at scale Next 10 Uzbekistan Scaling · bank licence sought Kazakhstan Scaling · bank licence sought Ukraine DCB, Airtime Credit, Device finance Telco driven financial services + Bank/Fintech JVs
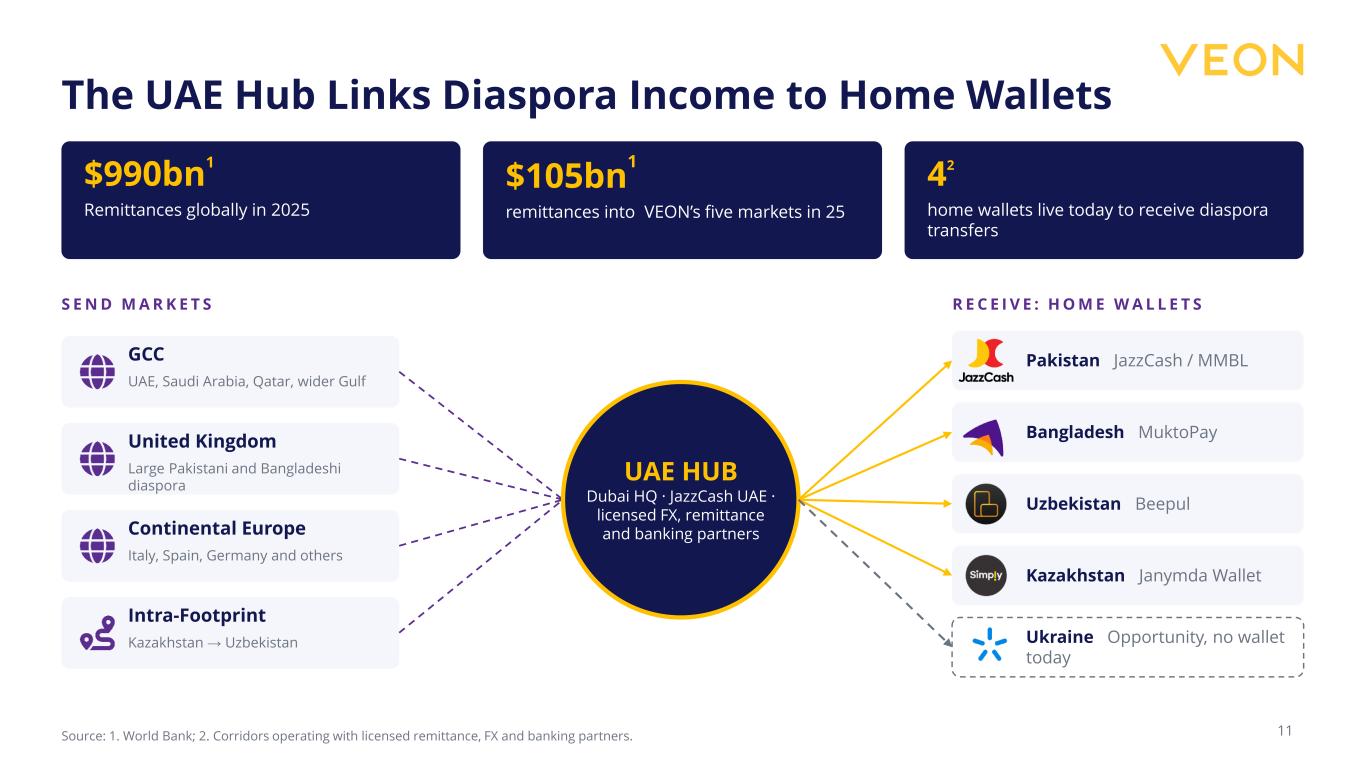
The UAE Hub Links Diaspora Income to Home Wallets 42 home wallets live today to receive diaspora transfers Source: 1. World Bank; 2. Corridors operating with licensed remittance, FX and banking partners. 11 $105bn 1 remittances into VEON’s five markets in 25 $990bn 1 Remittances globally in 2025 S E N D M A R K E T S R E C E I V E : H O M E W A L L E T S GCC UAE, Saudi Arabia, Qatar, wider Gulf United Kingdom Large Pakistani and Bangladeshi diaspora Continental Europe Italy, Spain, Germany and others Intra-Footprint Kazakhstan → Uzbekistan UAE HUB Dubai HQ · JazzCash UAE · licensed FX, remittance and banking partners Pakistan JazzCash / MMBL Bangladesh MuktoPay Uzbekistan Beepul Kazakhstan Janymda Wallet Ukraine Opportunity, no wallet today
02 Pakistan: The Proven Business JazzCash, MMBL and JazzSure. Built on Jazz. 12
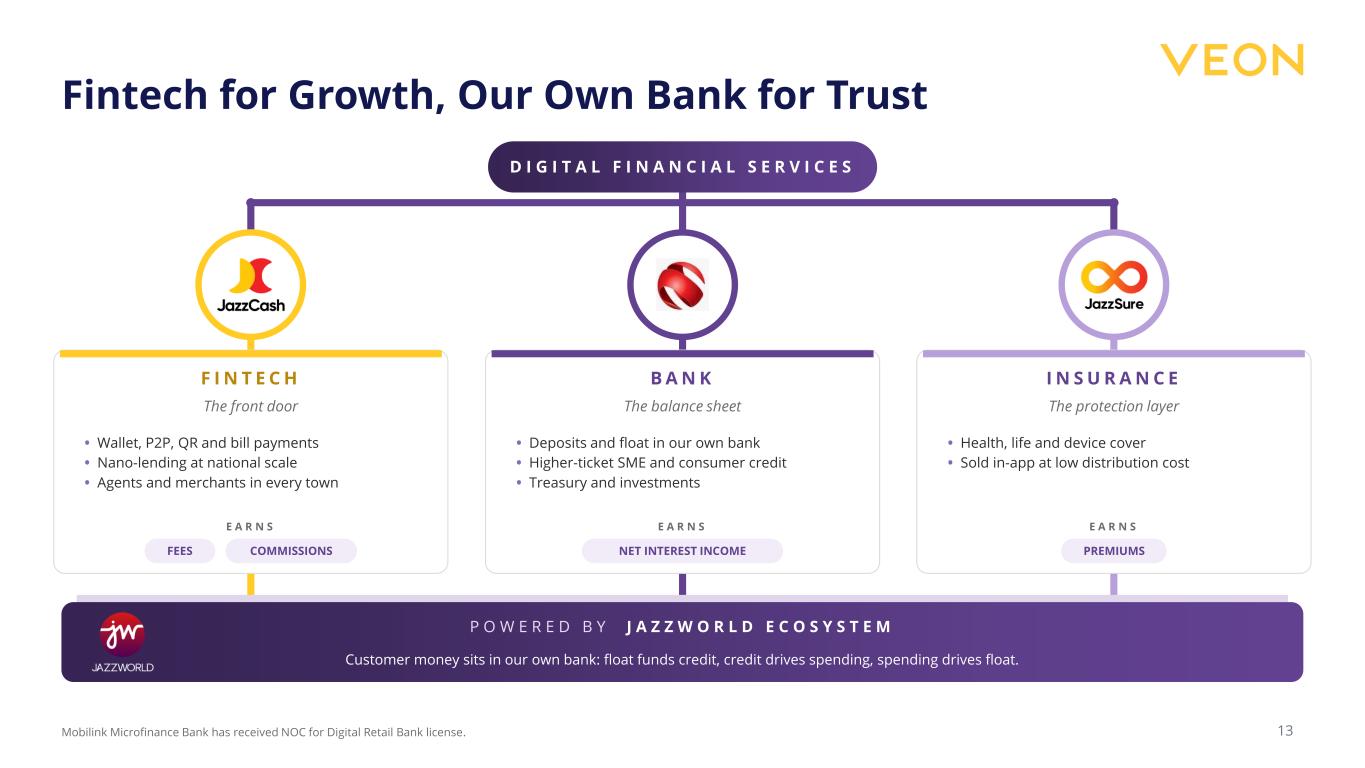
Fintech for Growth, Our Own Bank for Trust Mobilink Microfinance Bank has received NOC for Digital Retail Bank license. 13 D I G I T A L F I N A N C I A L S E R V I C E S F I N T E C H The front door • Wallet, P2P, QR and bill payments • Nano-lending at national scale • Agents and merchants in every town E A R N S FEES COMMISSIONS B A N K The balance sheet • Deposits and float in our own bank • Higher-ticket SME and consumer credit • Treasury and investments E A R N S NET INTEREST INCOME I N S U R A N C E The protection layer • Health, life and device cover • Sold in-app at low distribution cost E A R N S PREMIUMS P O W E R E D B Y J A Z Z W O R L D E C O S Y S T E M Customer money sits in our own bank: float funds credit, credit drives spending, spending drives float.
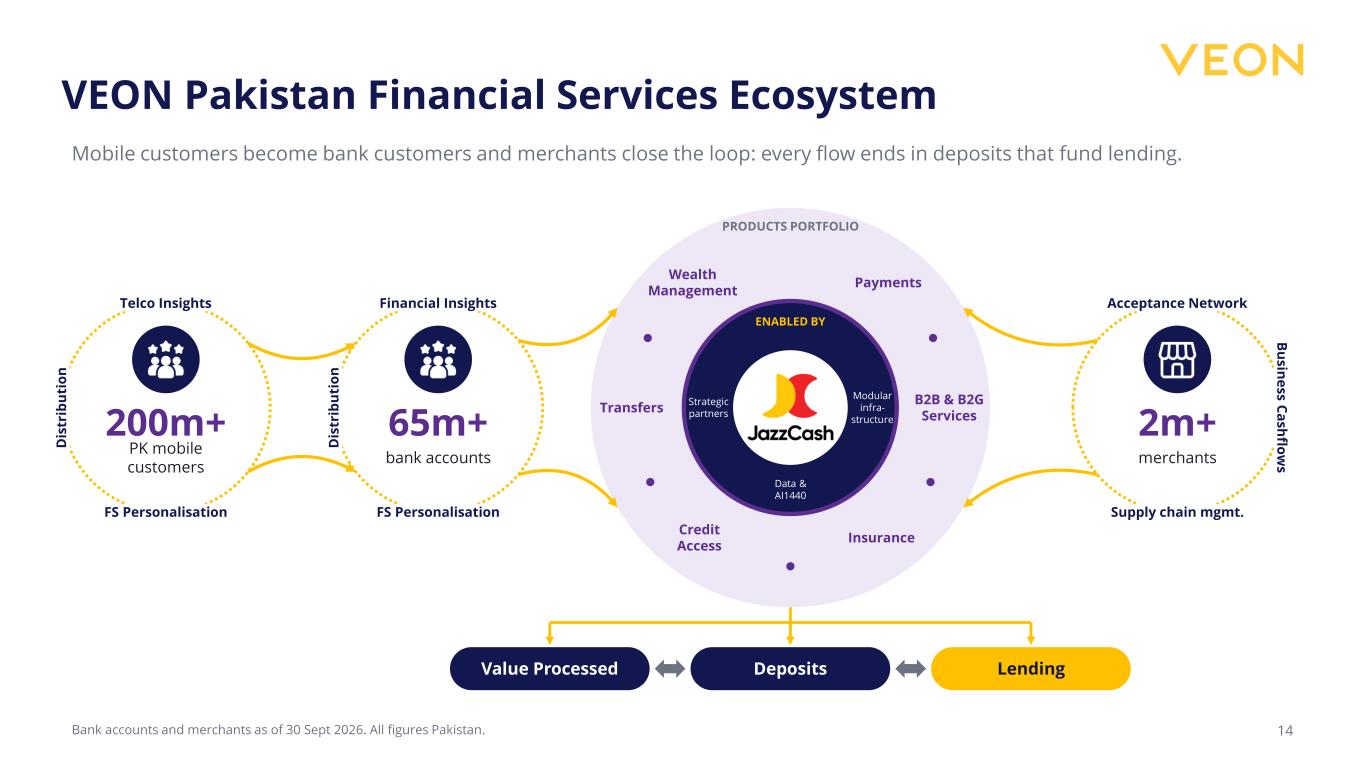
VEON Pakistan Financial Services Ecosystem Bank accounts and merchants as of 30 Sept 2026. All figures Pakistan. 14 Mobile customers become bank customers and merchants close the loop: every flow ends in deposits that fund lending. 200m+ PK mobile customers Telco Insights FS Personalisation D is tr ib u ti o n 65m+ bank accounts Financial Insights FS Personalisation D is tr ib u ti o n 2m+ merchants Acceptance Network Supply chain mgmt. B u sin e ss C a sh flo w s PRODUCTS PORTFOLIO Payments B2B & B2G Services Insurance Credit Access Transfers Wealth Management ENABLED BY Strategic partners Modular infra- structure Data & AI1440 Value Processed Deposits Lending
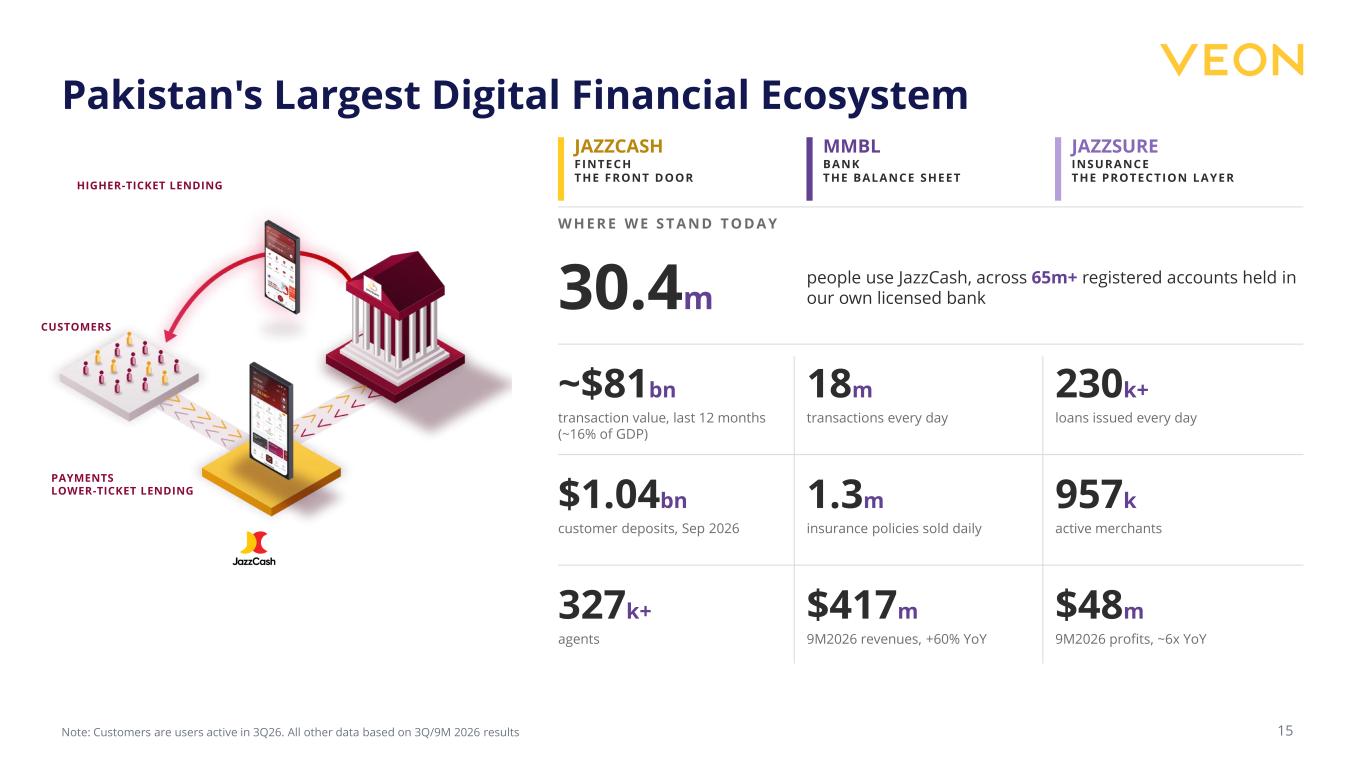
Pakistan's Largest Digital Financial Ecosystem Note: Customers are users active in 3Q26. All other data based on 3Q/9M 2026 results 15 HIGHER-TICKET LENDING CUSTOMERS PAYMENTS LOWER-TICKET LENDING JAZZCASH FINTECH THE FRONT DOOR MMBL BANK THE BALANCE SHEET JAZZSURE INSURANCE THE PROTECTION LAYER W H E R E W E S T A N D T O D A Y 30.4m people use JazzCash, across 65m+ registered accounts held in our own licensed bank ~$81bn transaction value, last 12 months (~16% of GDP) 18m transactions every day 230k+ loans issued every day $1.04bn customer deposits, Sep 2026 1.3m insurance policies sold daily 957k active merchants 327k+ agents $417m 9M2026 revenues, +60% YoY $48m 9M2026 profits, ~6x YoY
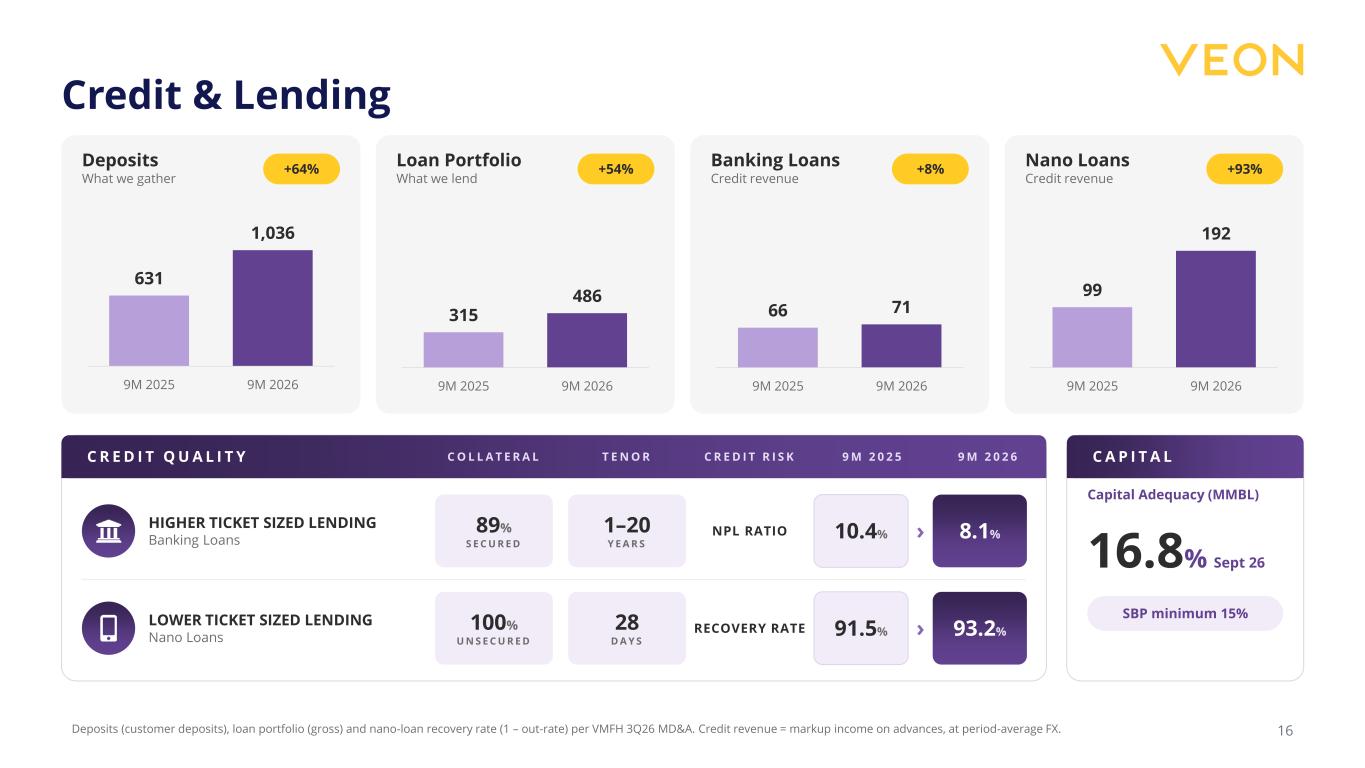
Credit & Lending Deposits (customer deposits), loan portfolio (gross) and nano-loan recovery rate (1 – out-rate) per VMFH 3Q26 MD&A. Credit revenue = markup income on advances, at period-average FX. 16 Deposits What we gather +64% 631 1,036 9M 2025 9M 2026 Loan Portfolio What we lend +54% 315 486 9M 2025 9M 2026 Banking Loans Credit revenue +8% 66 71 9M 2025 9M 2026 Nano Loans Credit revenue +93% 99 192 9M 2025 9M 2026 C R E D I T Q U A L I T Y C O L L A T E R A L T E N O R C R E D I T R I S K 9 M 2 0 2 5 9 M 2 0 2 6 HIGHER TICKET SIZED LENDING Banking Loans 89% S E C U R E D 1–20 Y E A R S NPL RATIO 10.4% › 8.1% LOWER TICKET SIZED LENDING Nano Loans 100% U N S E C U R E D 28 D A Y S RECOVERY RATE 91.5% › 93.2% C A P I T A L Capital Adequacy (MMBL) 16.8% Sept 26 SBP minimum 15%
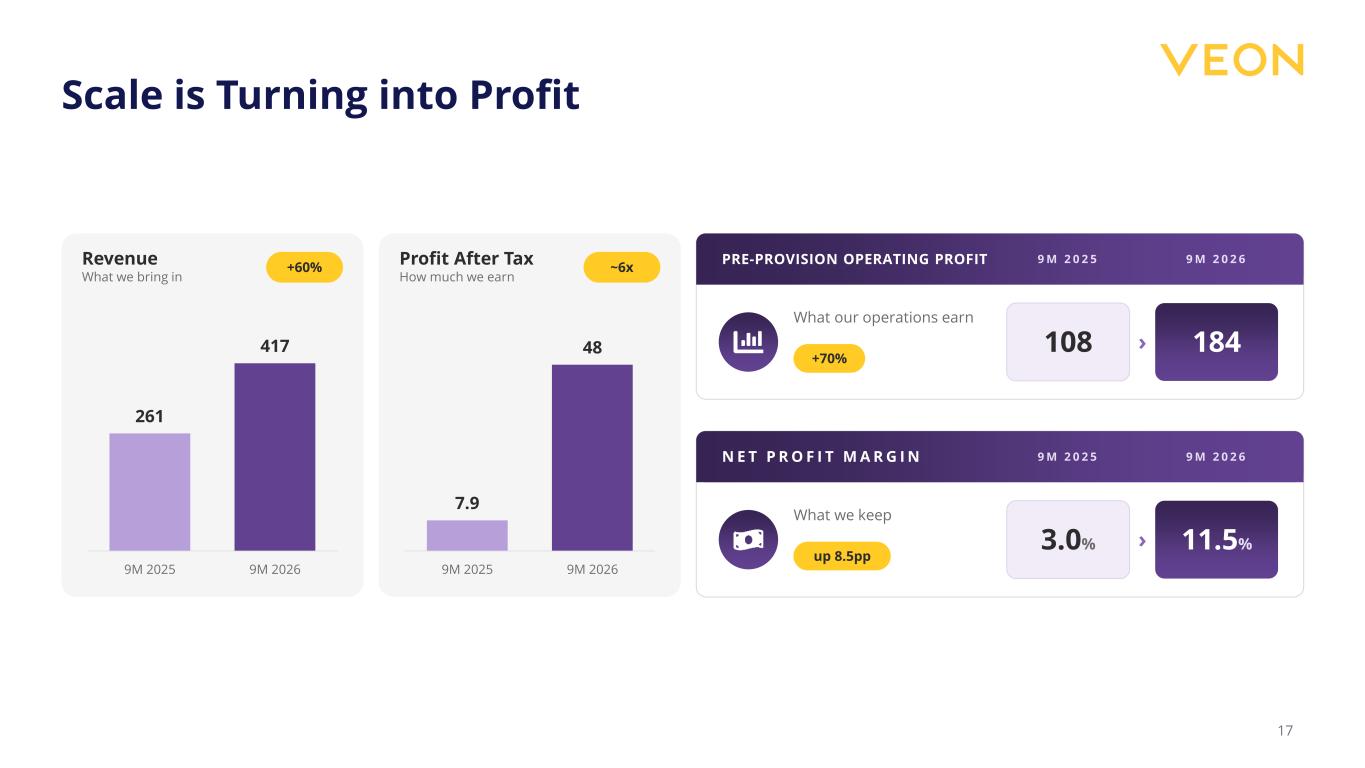
Scale is Turning into Profit 17 Revenue What we bring in +60% 261 417 9M 2025 9M 2026 Profit After Tax How much we earn ~6x 7.9 48 9M 2025 9M 2026 PRE-PROVISION OPERATING PROFIT 9 M 2 0 2 5 9 M 2 0 2 6 What our operations earn +70% 108 › 184 N E T P R O F I T M A R G I N 9 M 2 0 2 5 9 M 2 0 2 6 What we keep up 8.5pp 3.0% › 11.5%
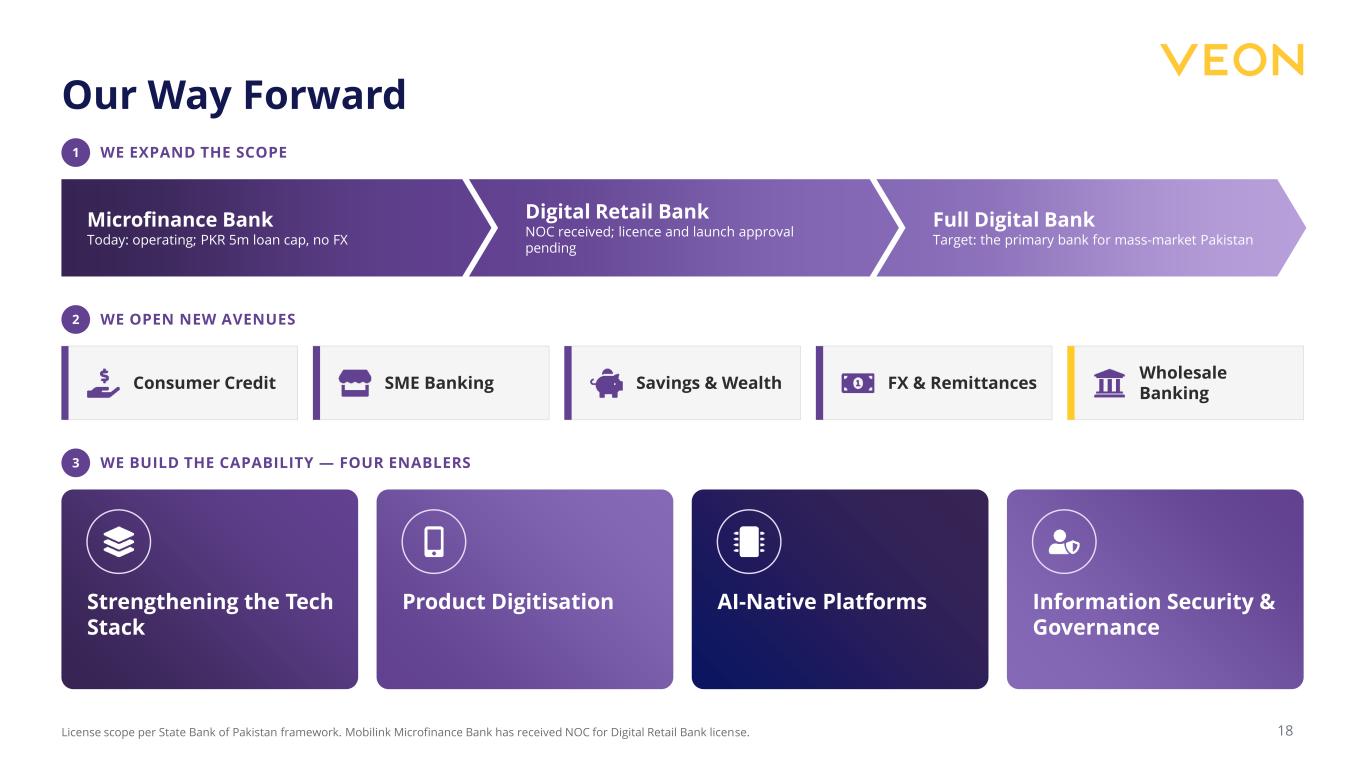
Our Way Forward License scope per State Bank of Pakistan framework. Mobilink Microfinance Bank has received NOC for Digital Retail Bank license. 18 1 WE EXPAND THE SCOPE Microfinance Bank Today: operating; PKR 5m loan cap, no FX Digital Retail Bank NOC received; licence and launch approval pending Full Digital Bank Target: the primary bank for mass-market Pakistan 2 WE OPEN NEW AVENUES Consumer Credit SME Banking Savings & Wealth FX & Remittances Wholesale Banking 3 WE BUILD THE CAPABILITY — FOUR ENABLERS Strengthening the Tech Stack Product Digitisation AI-Native Platforms Information Security & Governance
03 Ayesha's Story 1440 minutes in a day. Wherever money moves in our customer's day, we are there. 19
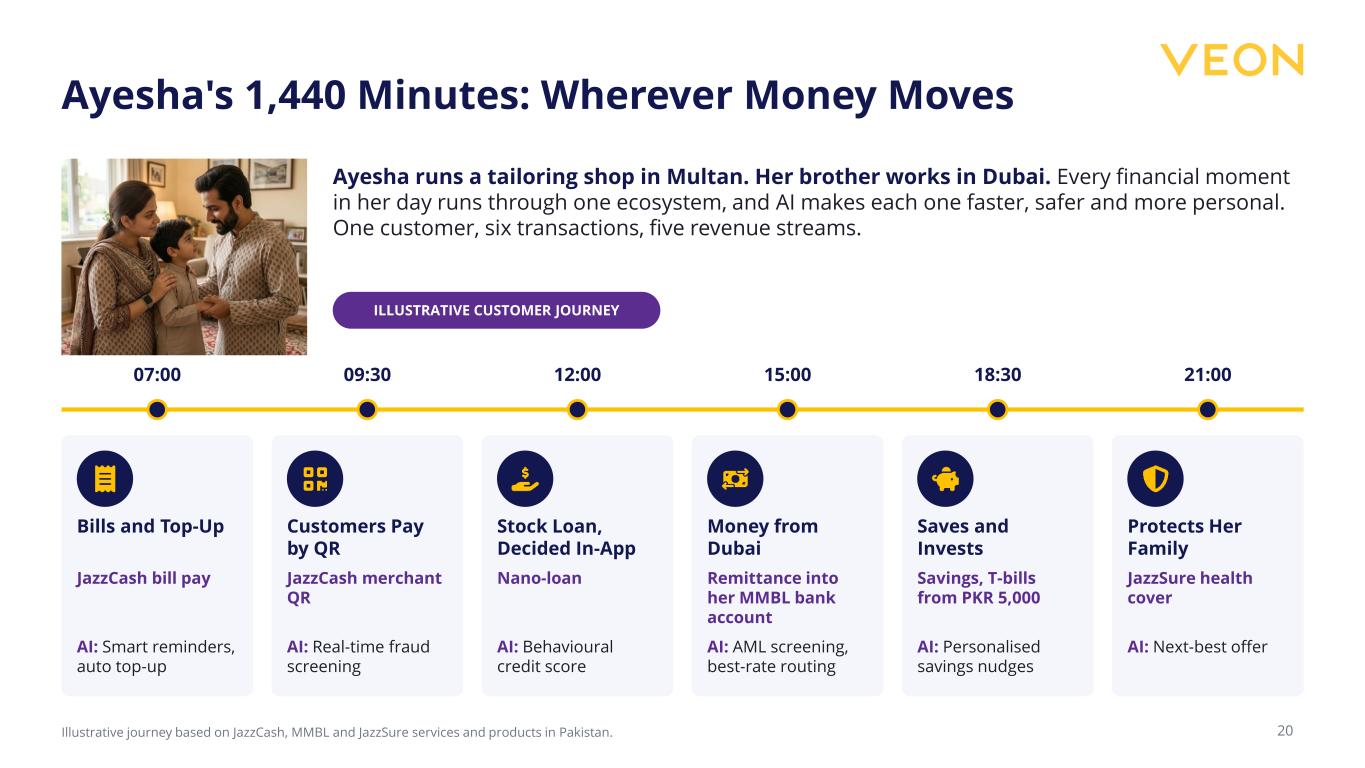
Ayesha's 1,440 Minutes: Wherever Money Moves Ayesha runs a tailoring shop in Multan. Her brother works in Dubai. Every financial moment in her day runs through one ecosystem, and AI makes each one faster, safer and more personal. One customer, six transactions, five revenue streams. ILLUSTRATIVE CUSTOMER JOURNEY 07:00 Bills and Top-Up JazzCash bill pay AI: Smart reminders, auto top-up 09:30 Customers Pay by QR JazzCash merchant QR AI: Real-time fraud screening 12:00 Stock Loan, Decided In-App Nano-loan AI: Behavioural credit score 15:00 Money from Dubai Remittance into her MMBL bank account AI: AML screening, best-rate routing 18:30 Saves and Invests Savings, T-bills from PKR 5,000 AI: Personalised savings nudges 21:00 Protects Her Family JazzSure health cover AI: Next-best offer Illustrative journey based on JazzCash, MMBL and JazzSure services and products in Pakistan. 20
Every Customer. Every Day. Our 2030 Plan $2bn+ Plan for VEON Digital Finance Group revenues by 2030 5 operating markets on one playbook 1 UAE hub connecting diaspora income remittance to every live home wallet