Hawaiian Electric Industries (NYSE:HE) November 2026 Investor Meetings
Non-GAAP Financial Information This presentation refers to certain financial measures that were not prepared in accordance with U.S. generally accepted accounting principles, including Core Earnings Per Share (EPS), Core Net Income, Core Return on Equity and other Core measures. Reconciliations of those non-GAAP financial measures to the most directly comparable GAAP financial measures can be found in the Appendix herein. See Appendix for definition of Core Earnings, Core EPS and Core Return on Equity. This report and other presentations made by Hawaiian Electric Industries, Inc. (HEI) and Hawaiian Electric Company, Inc. (Hawaiian Electric) and their subsidiaries (collectively, the Company) contain “forward-looking statements.” These forward-looking statements are not guarantees of future performance and actual results and financial condition may differ materially from those indicated in the forward-looking statements. Factors that could cause actual results to differ materially from expectations can be found in the appendix herein, in the Company’s SEC filings and in the Investor Relations section of the Company’s website. 2
Table of Contents 3 Hawaii’s Essential Utility A Strong, Durable Franchise Lower Operating Risk 4 15 9 Restoring Financial Strength21 A Path Back to Sustainable Returns27 Revealing the Value38
Hawaii’s Essential Utility 4 A durable franchise at the heart of the islands’ economy, serving Hawaii since 1891
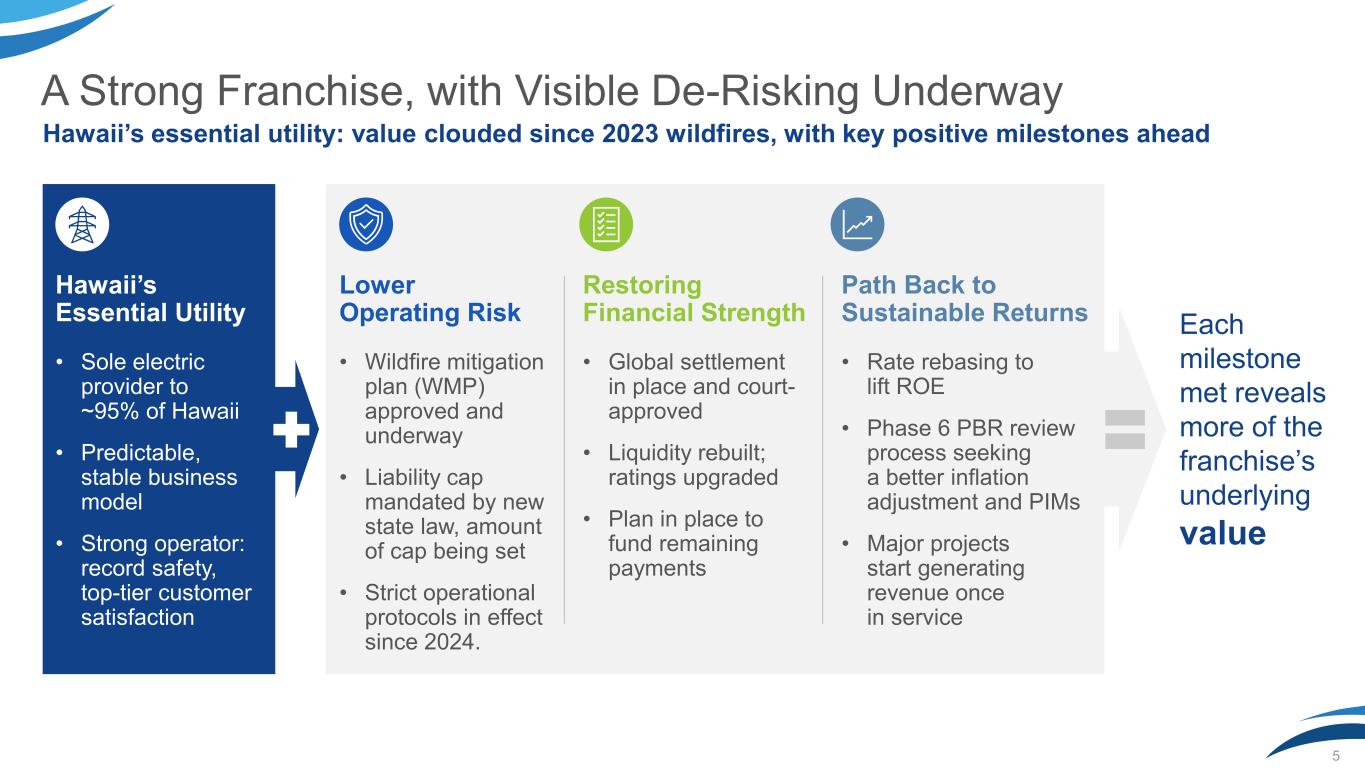
Lower Operating Risk • Wildfire mitigation plan (WMP) approved and underway • Liability cap mandated by new state law, amount of cap being set • Strict operational protocols in effect since 2024. Restoring Financial Strength • Global settlement in place and court- approved • Liquidity rebuilt; ratings upgraded • Plan in place to fund remaining payments 5 Hawaii’s essential utility: value clouded since 2023 wildfires, with key positive milestones ahead A Strong Franchise, with Visible De-Risking Underway Path Back to Sustainable Returns • Rate rebasing to lift ROE • Phase 6 PBR review process seeking a better inflation adjustment and PIMs • Major projects start generating revenue once in service Each milestone met reveals more of the franchise’s underlying value Hawaii’s Essential Utility • Sole electric provider to ~95% of Hawaii • Predictable, stable business model • Strong operator: record safety, top-tier customer satisfaction
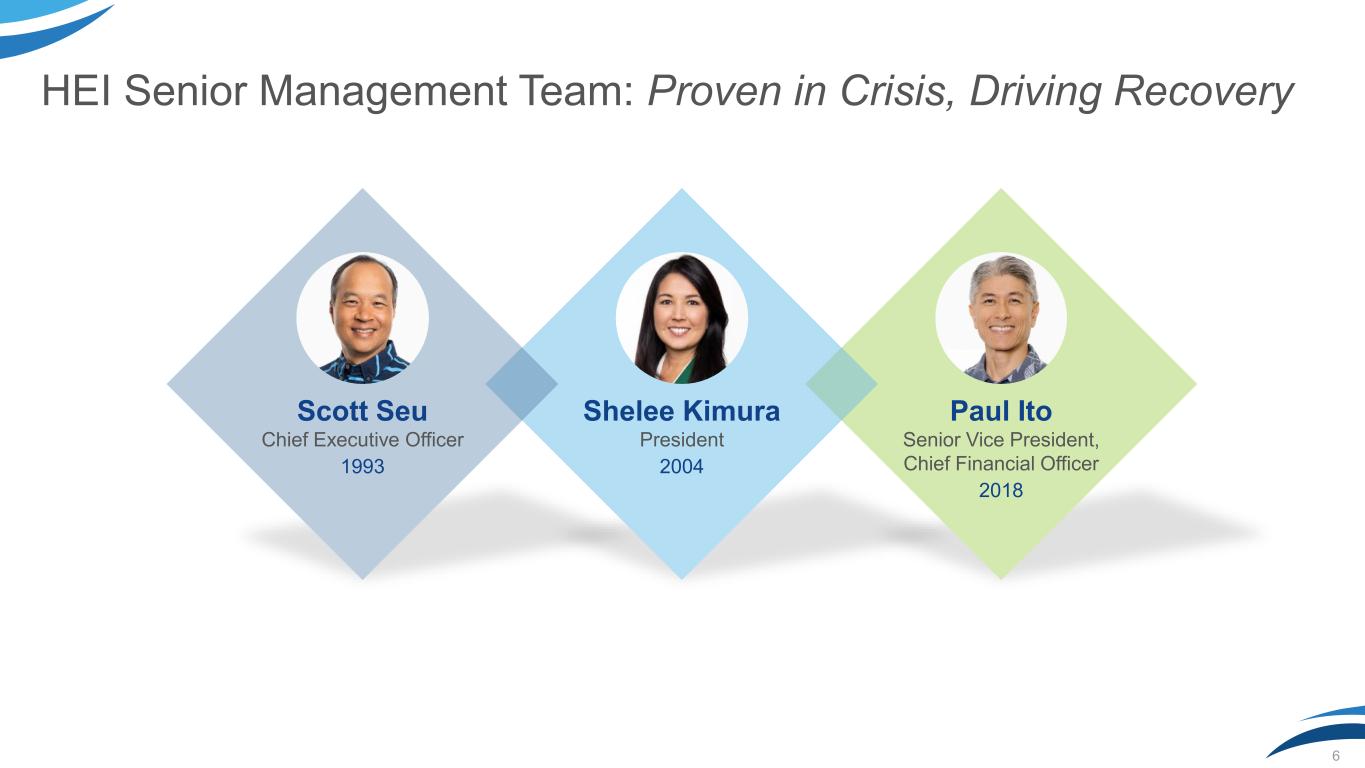
HEI Senior Management Team: Proven in Crisis, Driving Recovery 6 Scott Seu Chief Executive Officer 1993 Paul Ito Senior Vice President, Chief Financial Officer 2018 Shelee Kimura President 2004
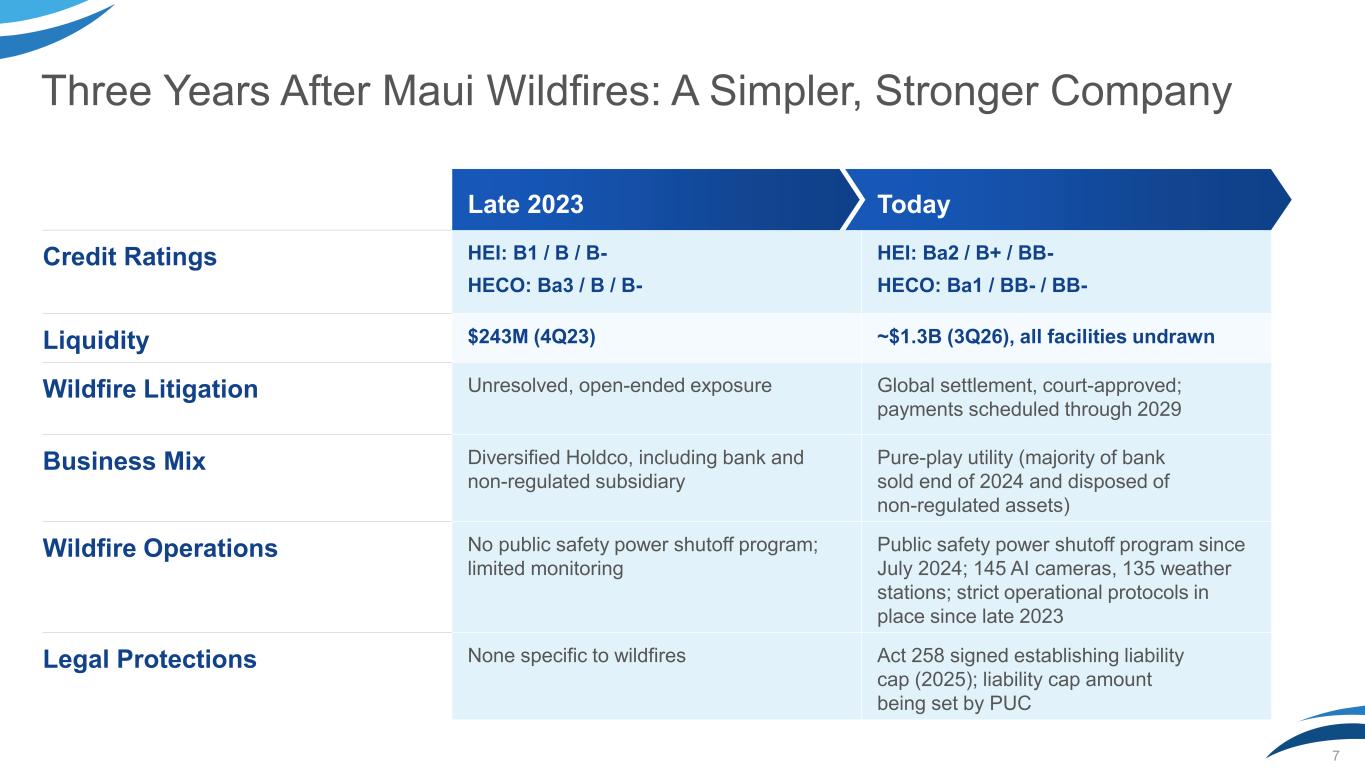
Three Years After Maui Wildfires: A Simpler, Stronger Company Late 2023 Today Credit Ratings HEI: B1 / B / B- HECO: Ba3 / B / B- HEI: Ba2 / B+ / BB- HECO: Ba1 / BB- / BB- Liquidity $243M (4Q23) ~$1.3B (3Q26), all facilities undrawn Wildfire Litigation Unresolved, open-ended exposure Global settlement, court-approved; payments scheduled through 2029 Business Mix Diversified Holdco, including bank and non-regulated subsidiary Pure-play utility (majority of bank sold end of 2024 and disposed of non-regulated assets) Wildfire Operations No public safety power shutoff program; limited monitoring Public safety power shutoff program since July 2024; 145 AI cameras, 135 weather stations; strict operational protocols in place since late 2023 Legal Protections None specific to wildfires Act 258 signed establishing liability cap (2025); liability cap amount being set by PUC 7
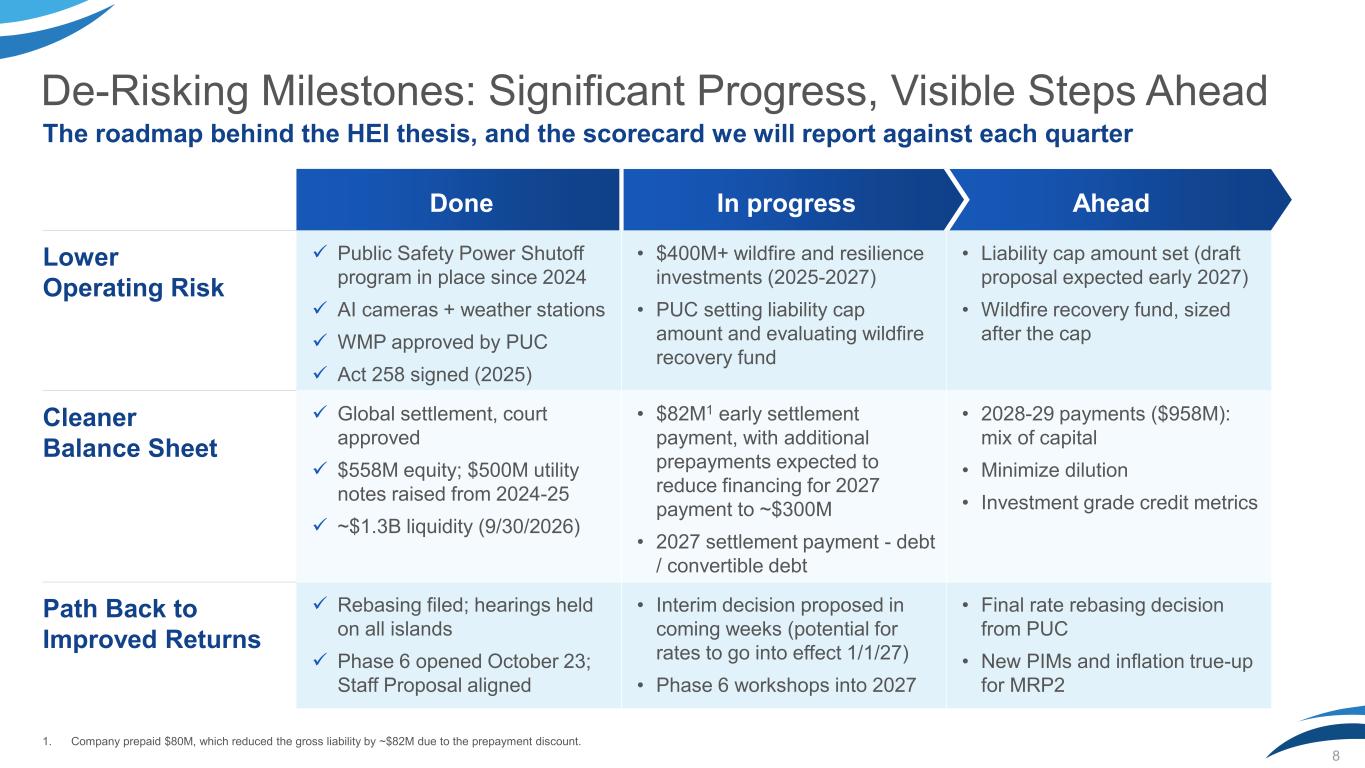
De-Risking Milestones: Significant Progress, Visible Steps Ahead Done In progress Ahead Lower Operating Risk ✓ Public Safety Power Shutoff program in place since 2024 ✓ AI cameras + weather stations ✓ WMP approved by PUC ✓ Act 258 signed (2025) • $400M+ wildfire and resilience investments (2025-2027) • PUC setting liability cap amount and evaluating wildfire recovery fund • Liability cap amount set (draft proposal expected early 2027) • Wildfire recovery fund, sized after the cap Cleaner Balance Sheet ✓ Global settlement, court approved ✓ $558M equity; $500M utility notes raised from 2024-25 ✓ ~$1.3B liquidity (9/30/2026) • $82M1 early settlement payment, with additional prepayments expected to reduce financing for 2027 payment to ~$300M • 2027 settlement payment - debt / convertible debt • 2028-29 payments ($958M): mix of capital • Minimize dilution • Investment grade credit metrics Path Back to Improved Returns ✓ Rebasing filed; hearings held on all islands ✓ Phase 6 opened October 23; Staff Proposal aligned • Interim decision proposed in coming weeks (potential for rates to go into effect 1/1/27) • Phase 6 workshops into 2027 • Final rate rebasing decision from PUC • New PIMs and inflation true-up for MRP2 8 The roadmap behind the HEI thesis, and the scorecard we will report against each quarter 1. Company prepaid $80M, which reduced the gross liability by ~$82M due to the prepayment discount.
A Strong, Durable Franchise Sole electric provider to ~95% of Hawaii across five islands, with decoupled revenues and long record of disciplined operations 9
At Our Core: A High-Quality Regulated Utility Franchise 10 The foundation of the HEI investment case An island fortress Sole electric provider to ~95% of Hawaii An essential service Powering homes, businesses, military bases and the tourist economy A predictable business model Revenues set for multi-year rate periods and not tied to sales A pure-play utility Fully focused on the regulated utility, with more than a century serving Hawaii
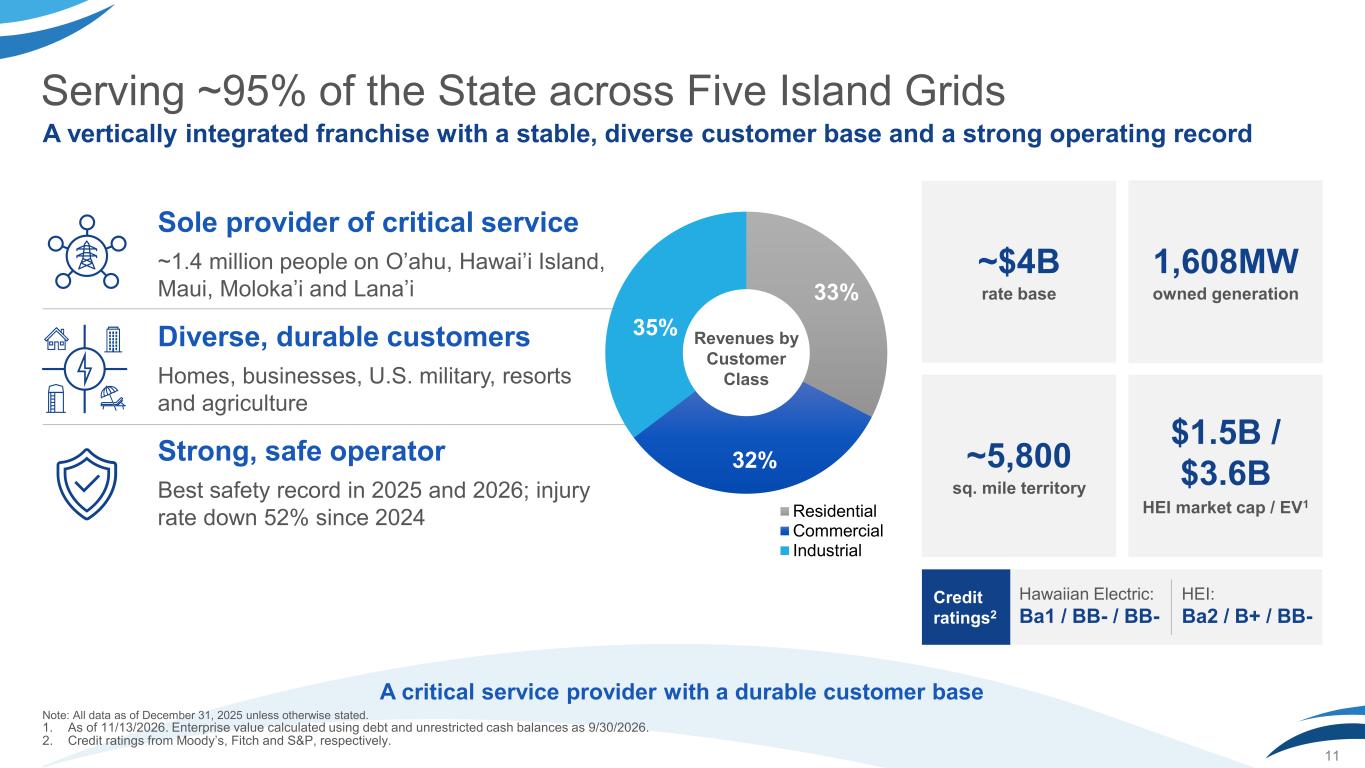
11 Sole provider of critical service ~1.4 million people on O’ahu, Hawai’i Island, Maui, Moloka’i and Lana’i Diverse, durable customers Homes, businesses, U.S. military, resorts and agriculture Strong, safe operator Best safety record in 2025 and 2026; injury rate down 52% since 2024 33% 32% 35% Residential Commercial Industrial Revenues by Customer Class Serving ~95% of the State across Five Island Grids ~$4B rate base $1.5B / $3.6B HEI market cap / EV1 1,608MW owned generation ~5,800 sq. mile territory A critical service provider with a durable customer base Note: All data as of December 31, 2025 unless otherwise stated. 1. As of 11/13/2026. Enterprise value calculated using debt and unrestricted cash balances as 9/30/2026. 2. Credit ratings from Moody’s, Fitch and S&P, respectively. A vertically integrated franchise with a stable, diverse customer base and a strong operating record Credit ratings2 Hawaiian Electric: Ba1 / BB- / BB- HEI: Ba2 / B+ / BB-
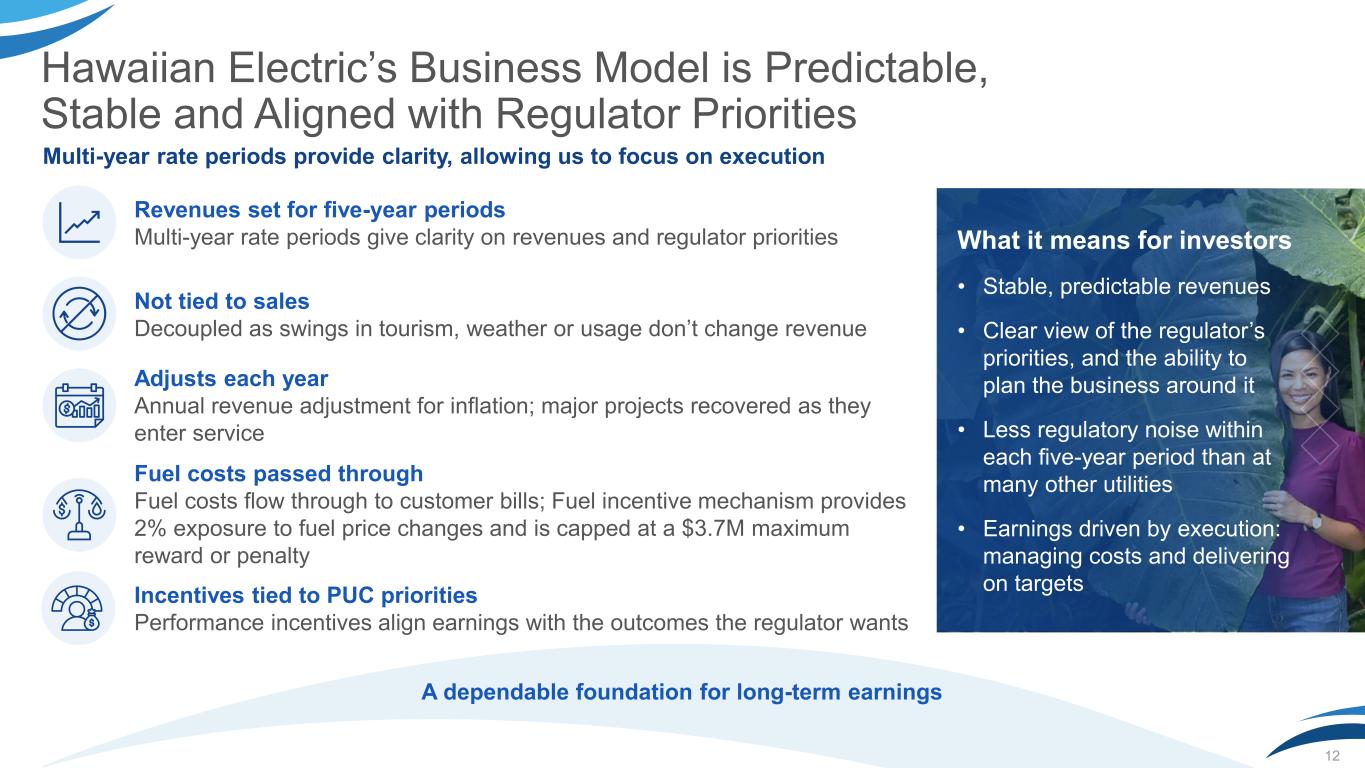
Hawaiian Electric’s Business Model is Predictable, Stable and Aligned with Regulator Priorities 12 Multi-year rate periods provide clarity, allowing us to focus on execution What it means for investors • Stable, predictable revenues • Clear view of the regulator’s priorities, and the ability to plan the business around it • Less regulatory noise within each five-year period than at many other utilities • Earnings driven by execution: managing costs and delivering on targets A dependable foundation for long-term earnings Revenues set for five-year periods Multi-year rate periods give clarity on revenues and regulator priorities Not tied to sales Decoupled as swings in tourism, weather or usage don’t change revenue Adjusts each year Annual revenue adjustment for inflation; major projects recovered as they enter service Fuel costs passed through Fuel costs flow through to customer bills; Fuel incentive mechanism provides 2% exposure to fuel price changes and is capped at a $3.7M maximum reward or penalty Incentives tied to PUC priorities Performance incentives align earnings with the outcomes the regulator wants
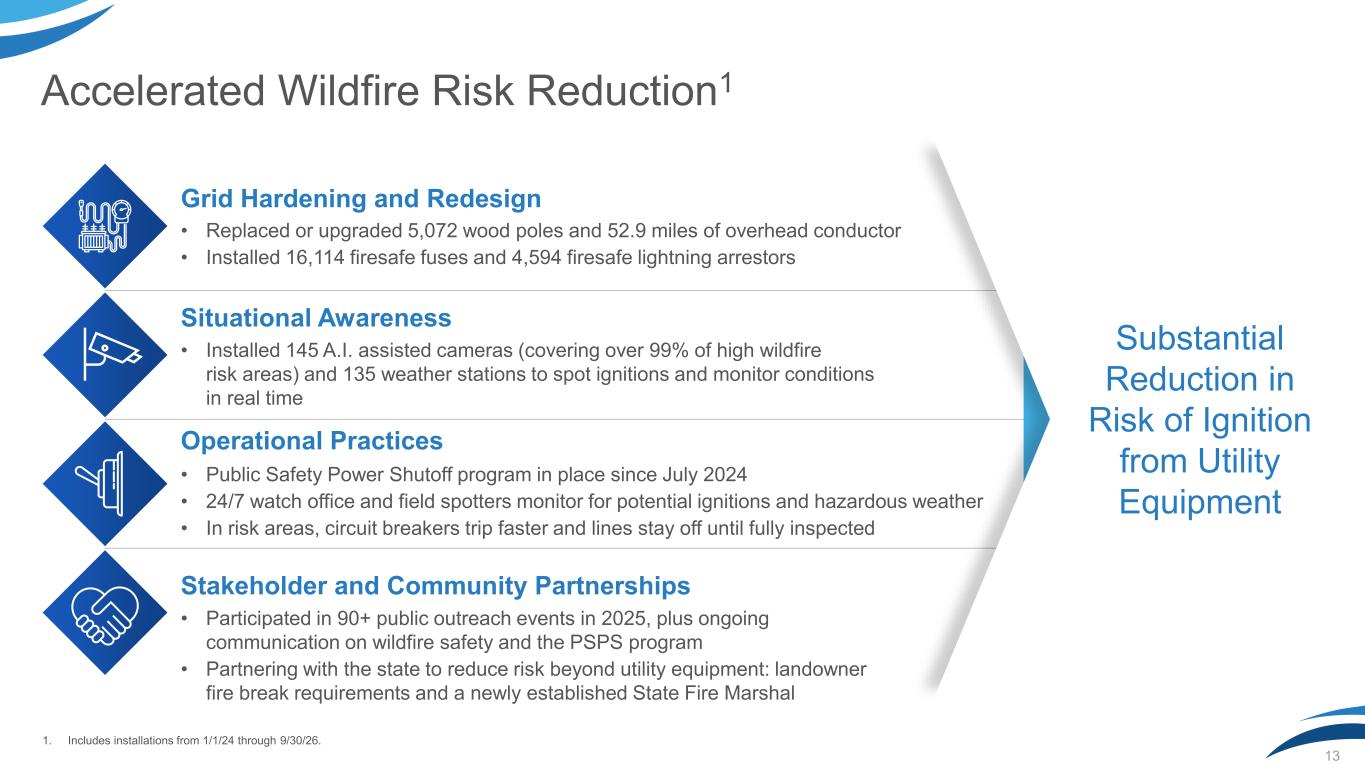
Accelerated Wildfire Risk Reduction1 1. Includes installations from 1/1/24 through 9/30/26. 13 • Installed 145 A.I. assisted cameras (covering over 99% of high wildfire risk areas) and 135 weather stations to spot ignitions and monitor conditions in real time Situational Awareness • Replaced or upgraded 5,072 wood poles and 52.9 miles of overhead conductor • Installed 16,114 firesafe fuses and 4,594 firesafe lightning arrestors Grid Hardening and Redesign • Public Safety Power Shutoff program in place since July 2024 • 24/7 watch office and field spotters monitor for potential ignitions and hazardous weather • In risk areas, circuit breakers trip faster and lines stay off until fully inspected Operational Practices • Participated in 90+ public outreach events in 2025, plus ongoing communication on wildfire safety and the PSPS program • Partnering with the state to reduce risk beyond utility equipment: landowner fire break requirements and a newly established State Fire Marshal Stakeholder and Community Partnerships Substantial Reduction in Risk of Ignition from Utility Equipment
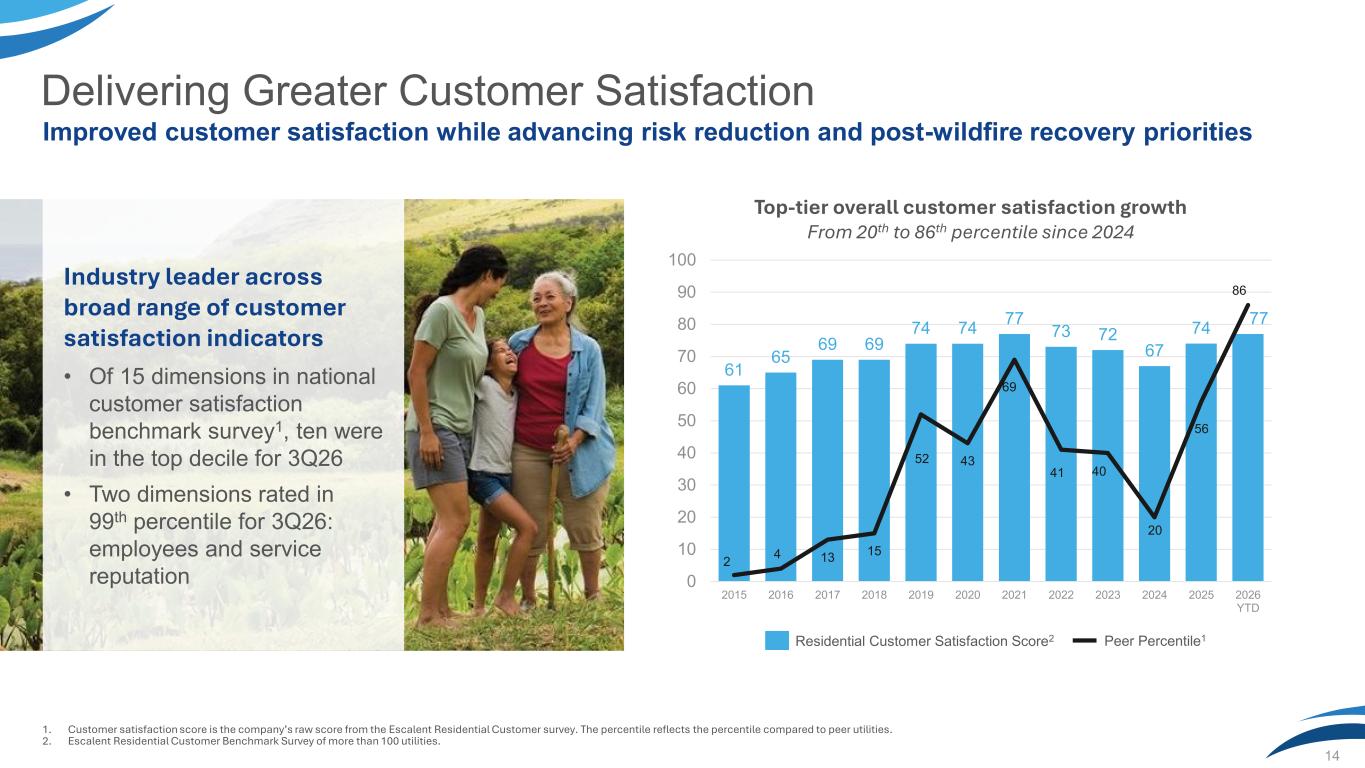
1. Customer satisfaction score is the company’s raw score from the Escalent Residential Customer survey. The percentile reflects the percentile compared to peer utilities. 2. Escalent Residential Customer Benchmark Survey of more than 100 utilities. 14 61 65 69 69 74 74 77 73 72 67 74 77 2 4 13 15 52 43 69 41 40 20 56 86 0 10 20 30 40 50 60 70 80 90 100 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026 YTD Residential Customer Satisfaction Score2 Peer Percentile1 Top-tier overall customer satisfaction growth From 20th to 86th percentile since 2024 Industry leader across broad range of customer satisfaction indicators • Of 15 dimensions in national customer satisfaction benchmark survey1, ten were in the top decile for 3Q26 • Two dimensions rated in 99th percentile for 3Q26: employees and service reputation Improved customer satisfaction while advancing risk reduction and post-wildfire recovery priorities Delivering Greater Customer Satisfaction
Lower Operating Risk Wildfire risk is structurally lower than wildfire-affected utilities on the mainland, actively managed, and backed by new legal protections 15
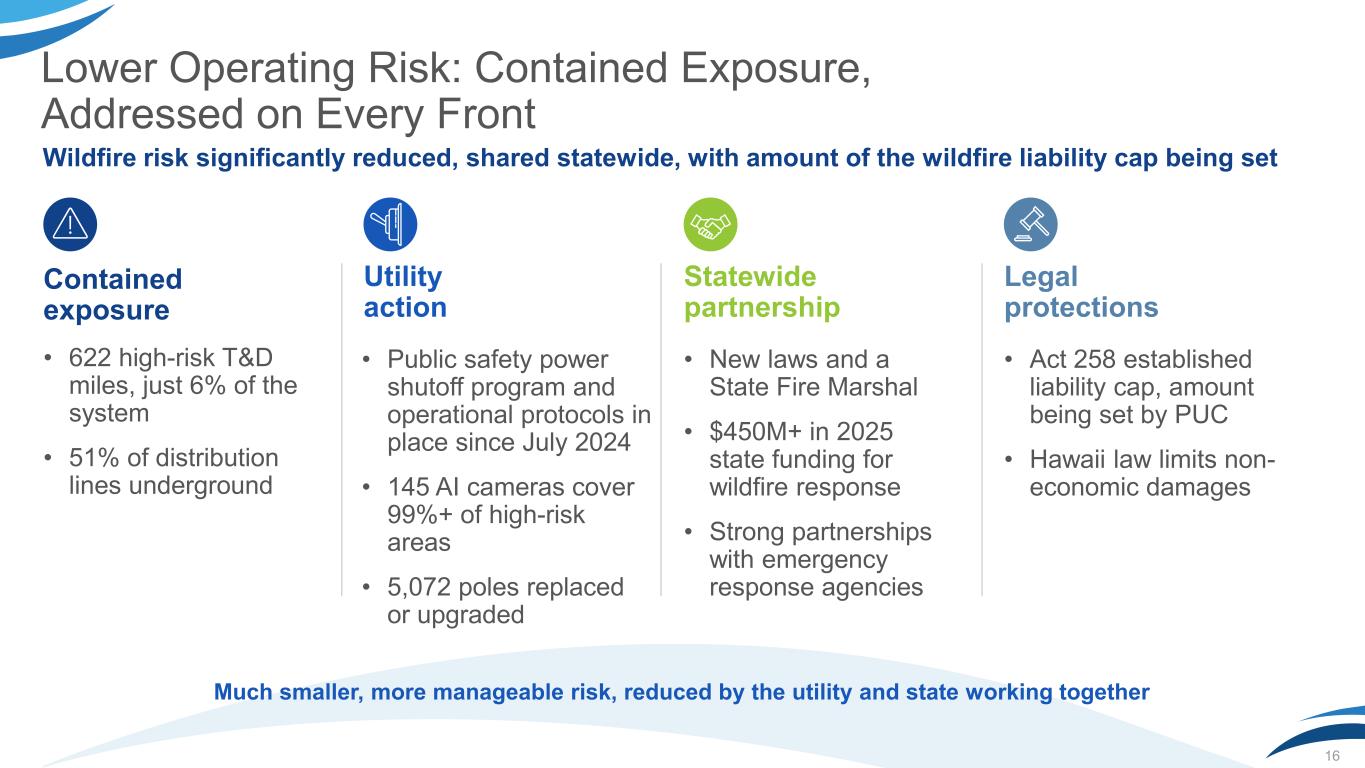
Utility action • Public safety power shutoff program and operational protocols in place since July 2024 • 145 AI cameras cover 99%+ of high-risk areas • 5,072 poles replaced or upgraded Statewide partnership • New laws and a State Fire Marshal • $450M+ in 2025 state funding for wildfire response • Strong partnerships with emergency response agencies 16 Wildfire risk significantly reduced, shared statewide, with amount of the wildfire liability cap being set Lower Operating Risk: Contained Exposure, Addressed on Every Front Legal protections • Act 258 established liability cap, amount being set by PUC • Hawaii law limits non- economic damages Much smaller, more manageable risk, reduced by the utility and state working together Contained exposure • 622 high-risk T&D miles, just 6% of the system • 51% of distribution lines underground
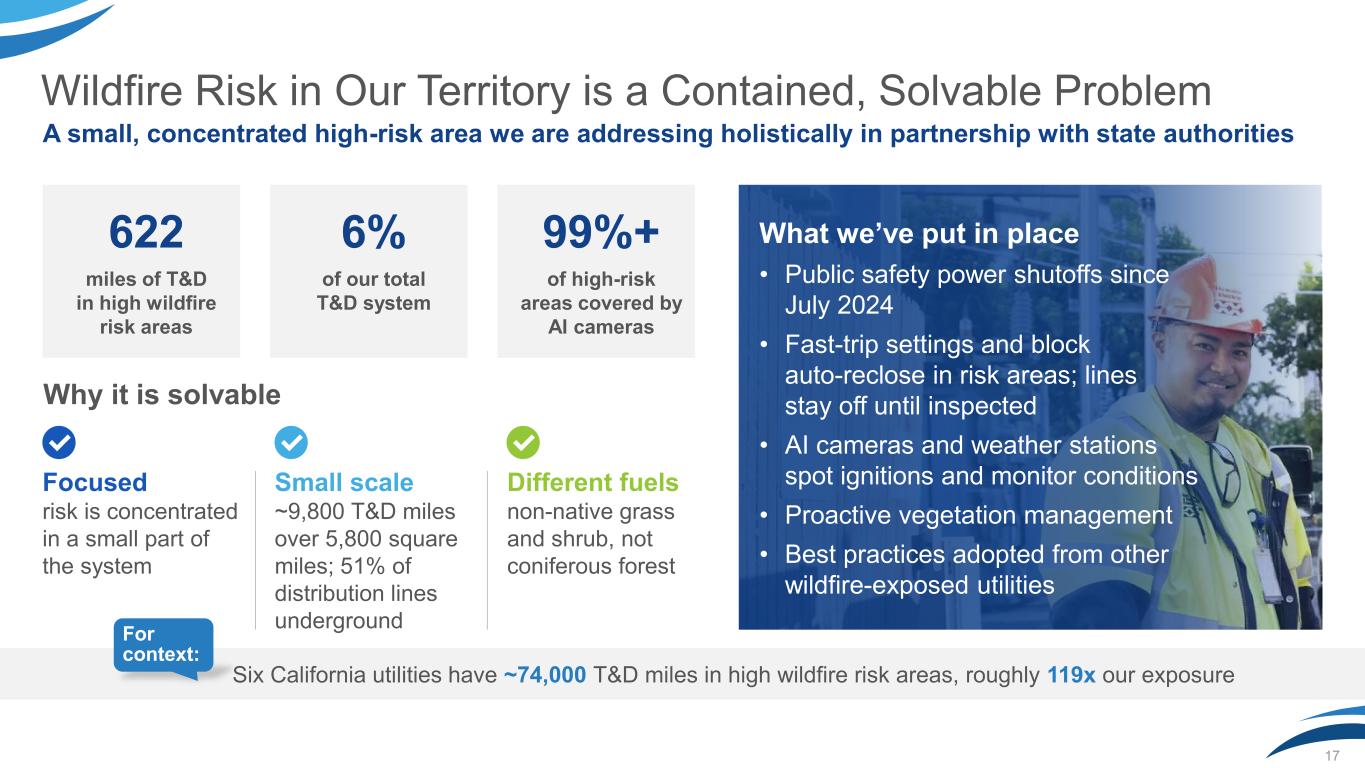
Wildfire Risk in Our Territory is a Contained, Solvable Problem 17 622 miles of T&D in high wildfire risk areas 6% of our total T&D system 99%+ of high-risk areas covered by AI cameras A small, concentrated high-risk area we are addressing holistically in partnership with state authorities Focused risk is concentrated in a small part of the system Small scale ~9,800 T&D miles over 5,800 square miles; 51% of distribution lines underground Different fuels non-native grass and shrub, not coniferous forest Why it is solvable What we’ve put in place • Public safety power shutoffs since July 2024 • Fast-trip settings and block auto-reclose in risk areas; lines stay off until inspected • AI cameras and weather stations spot ignitions and monitor conditions • Proactive vegetation management • Best practices adopted from other wildfire-exposed utilities Six California utilities have ~74,000 T&D miles in high wildfire risk areas, roughly 119x our exposure For context:
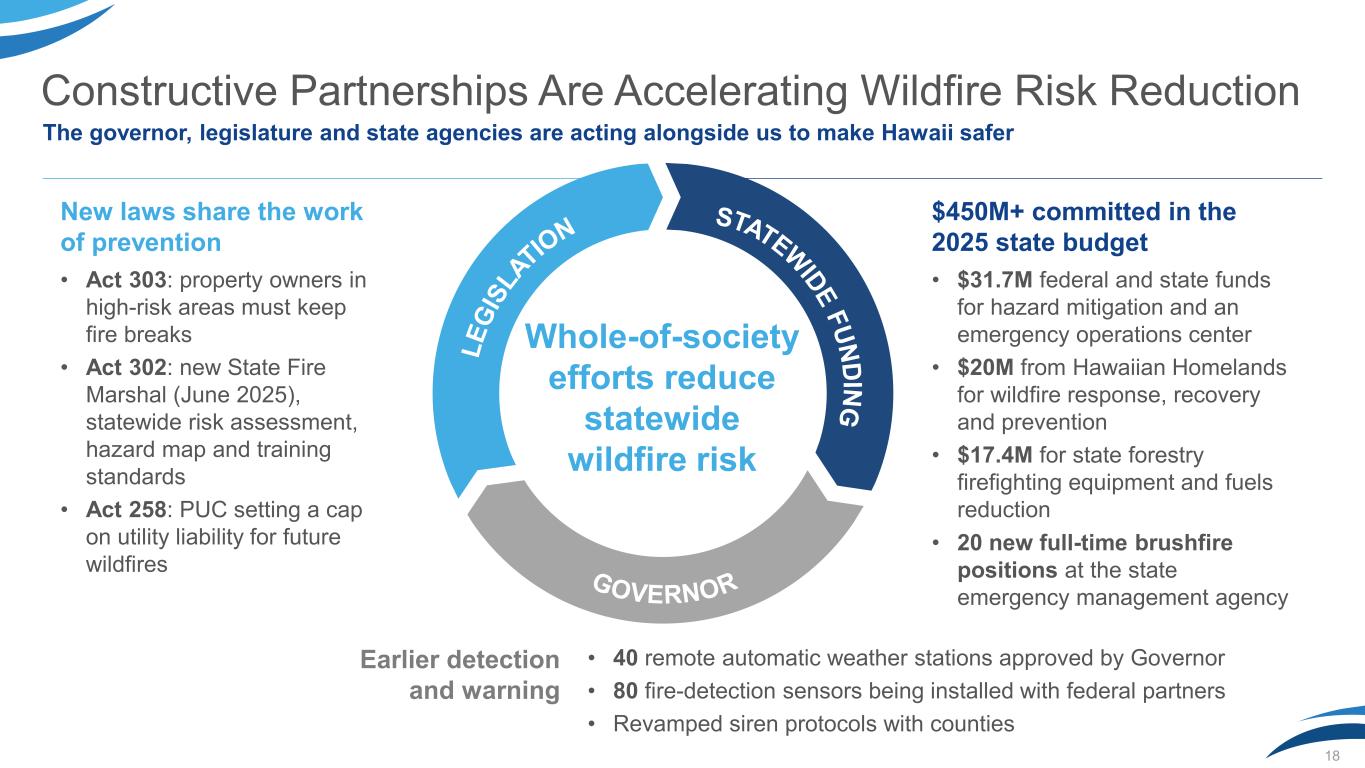
18 New laws share the work of prevention • Act 303: property owners in high-risk areas must keep fire breaks • Act 302: new State Fire Marshal (June 2025), statewide risk assessment, hazard map and training standards • Act 258: PUC setting a cap on utility liability for future wildfires $450M+ committed in the 2025 state budget • $31.7M federal and state funds for hazard mitigation and an emergency operations center • $20M from Hawaiian Homelands for wildfire response, recovery and prevention • $17.4M for state forestry firefighting equipment and fuels reduction • 20 new full-time brushfire positions at the state emergency management agency L E G IS L AT IO N GOVERNOR STATEW ID E F U N D IN G Whole-of-society efforts reduce statewide wildfire risk Constructive Partnerships Are Accelerating Wildfire Risk Reduction The governor, legislature and state agencies are acting alongside us to make Hawaii safer Earlier detection and warning • 40 remote automatic weather stations approved by Governor • 80 fire-detection sensors being installed with federal partners • Revamped siren protocols with counties
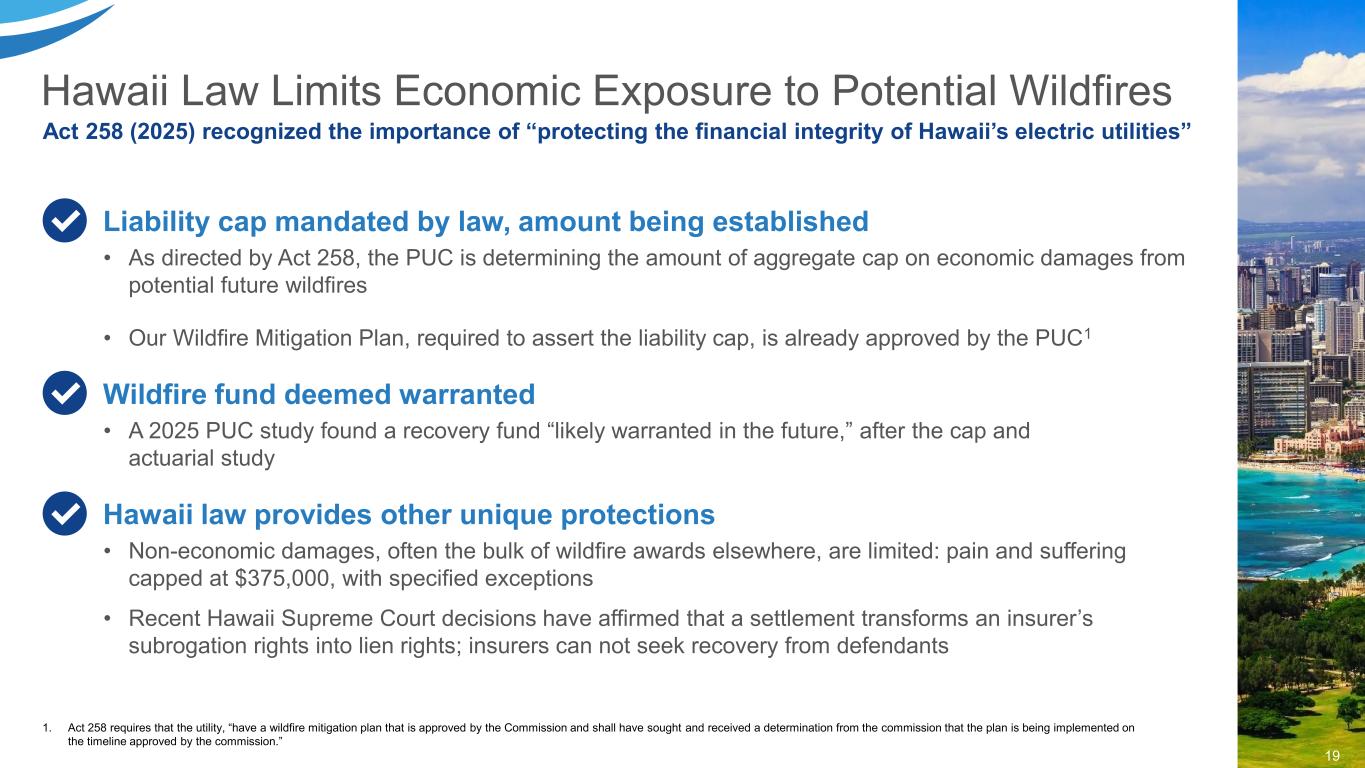
Hawaii Law Limits Economic Exposure to Potential Wildfires 1. Act 258 requires that the utility, “have a wildfire mitigation plan that is approved by the Commission and shall have sought and received a determination from the commission that the plan is being implemented on the timeline approved by the commission.” 19 Liability cap mandated by law, amount being established • As directed by Act 258, the PUC is determining the amount of aggregate cap on economic damages from potential future wildfires • Our Wildfire Mitigation Plan, required to assert the liability cap, is already approved by the PUC1 Wildfire fund deemed warranted • A 2025 PUC study found a recovery fund “likely warranted in the future,” after the cap and actuarial study Hawaii law provides other unique protections • Non-economic damages, often the bulk of wildfire awards elsewhere, are limited: pain and suffering capped at $375,000, with specified exceptions • Recent Hawaii Supreme Court decisions have affirmed that a settlement transforms an insurer’s subrogation rights into lien rights; insurers can not seek recovery from defendants Act 258 (2025) recognized the importance of “protecting the financial integrity of Hawaii’s electric utilities”
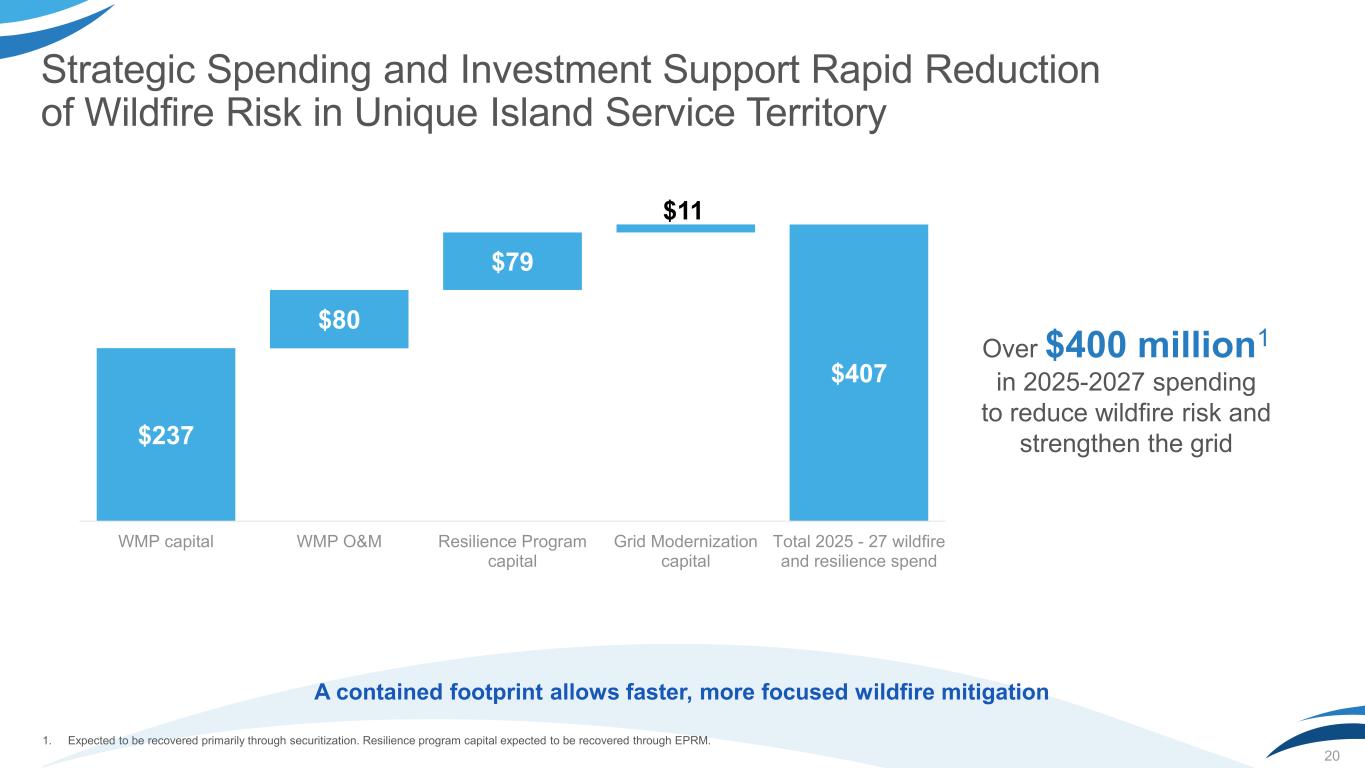
Strategic Spending and Investment Support Rapid Reduction of Wildfire Risk in Unique Island Service Territory 1. Expected to be recovered primarily through securitization. Resilience program capital expected to be recovered through EPRM. 20 Over $400 million1 in 2025-2027 spending to reduce wildfire risk and strengthen the grid$237 $407 $80 $79 $11 WMP capital WMP O&M Resilience Program capital Grid Modernization capital Total 2025 - 27 wildfire and resilience spend A contained footprint allows faster, more focused wildfire mitigation
Restoring Financial Strength The settlement obligation is fixed with an established schedule, liquidity is the strongest it has ever been, and credit is recovering 21
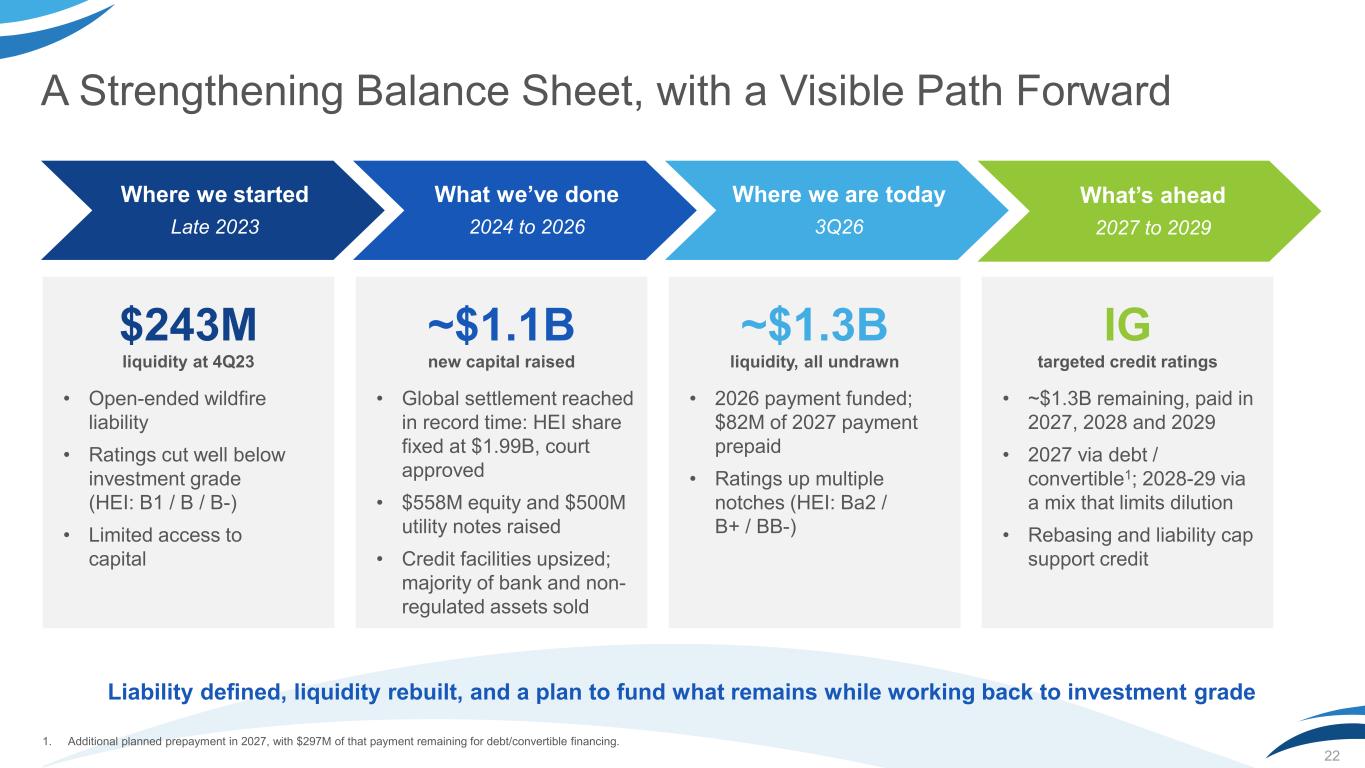
A Strengthening Balance Sheet, with a Visible Path Forward Where we started Late 2023 What we’ve done 2024 to 2026 Where we are today 3Q26 What’s ahead 2027 to 2029 22 $243M liquidity at 4Q23 • Open-ended wildfire liability • Ratings cut well below investment grade (HEI: B1 / B / B-) • Limited access to capital ~$1.1B new capital raised • Global settlement reached in record time: HEI share fixed at $1.99B, court approved • $558M equity and $500M utility notes raised • Credit facilities upsized; majority of bank and non- regulated assets sold ~$1.3B liquidity, all undrawn • 2026 payment funded; $82M of 2027 payment prepaid • Ratings up multiple notches (HEI: Ba2 / B+ / BB-) IG targeted credit ratings • ~$1.3B remaining, paid in 2027, 2028 and 2029 • 2027 via debt / convertible1; 2028-29 via a mix that limits dilution • Rebasing and liability cap support credit Liability defined, liquidity rebuilt, and a plan to fund what remains while working back to investment grade 1. Additional planned prepayment in 2027, with $297M of that payment remaining for debt/convertible financing.
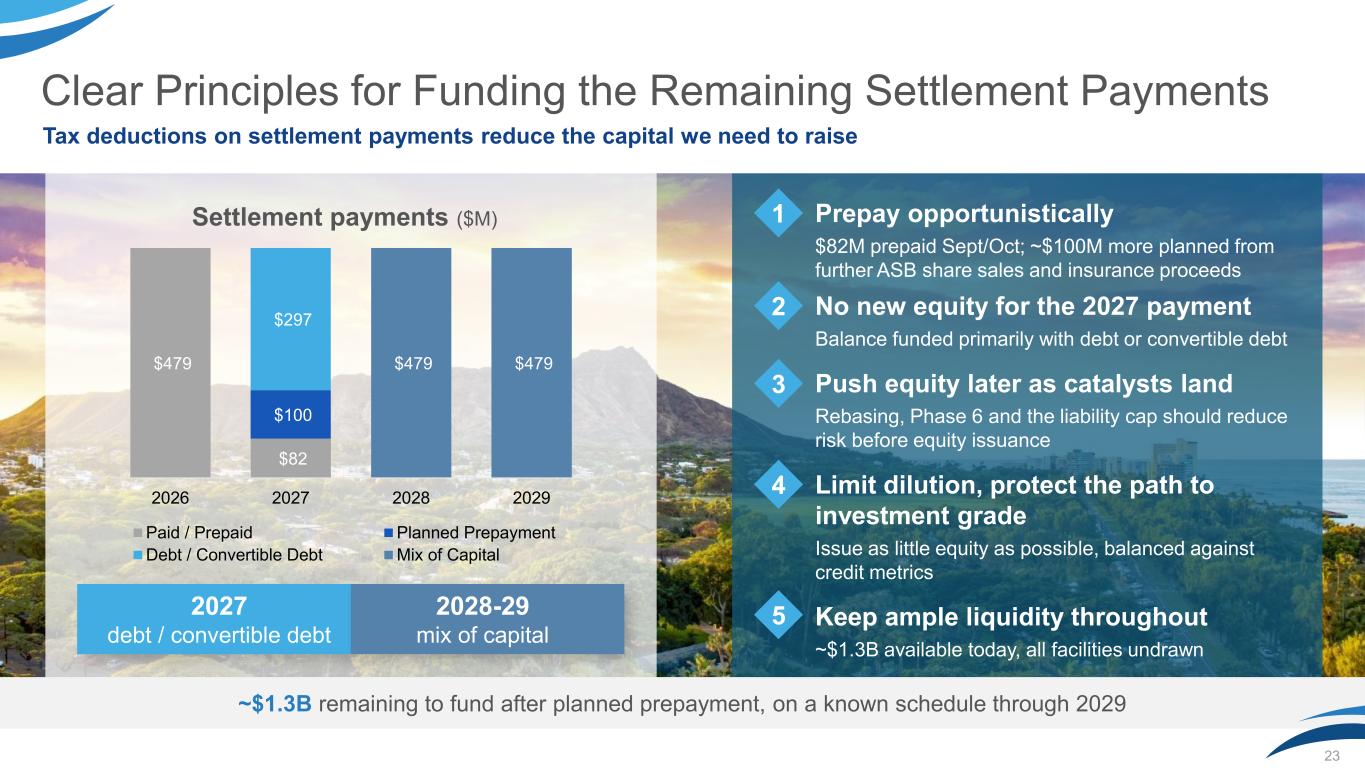
Clear Principles for Funding the Remaining Settlement Payments 23 Settlement payments ($M) Prepay opportunistically $82M prepaid Sept/Oct; ~$100M more planned from further ASB share sales and insurance proceeds No new equity for the 2027 payment Balance funded primarily with debt or convertible debt Push equity later as catalysts land Rebasing, Phase 6 and the liability cap should reduce risk before equity issuance Limit dilution, protect the path to investment grade Issue as little equity as possible, balanced against credit metrics Keep ample liquidity throughout ~$1.3B available today, all facilities undrawn 2 3 4 52027 debt / convertible debt 2028-29 mix of capital Tax deductions on settlement payments reduce the capital we need to raise 1 $479 $82 $100 $297 $479 $479 2026 2027 2028 2029 Paid / Prepaid Planned Prepayment Debt / Convertible Debt Mix of Capital ~$1.3B remaining to fund after planned prepayment, on a known schedule through 2029
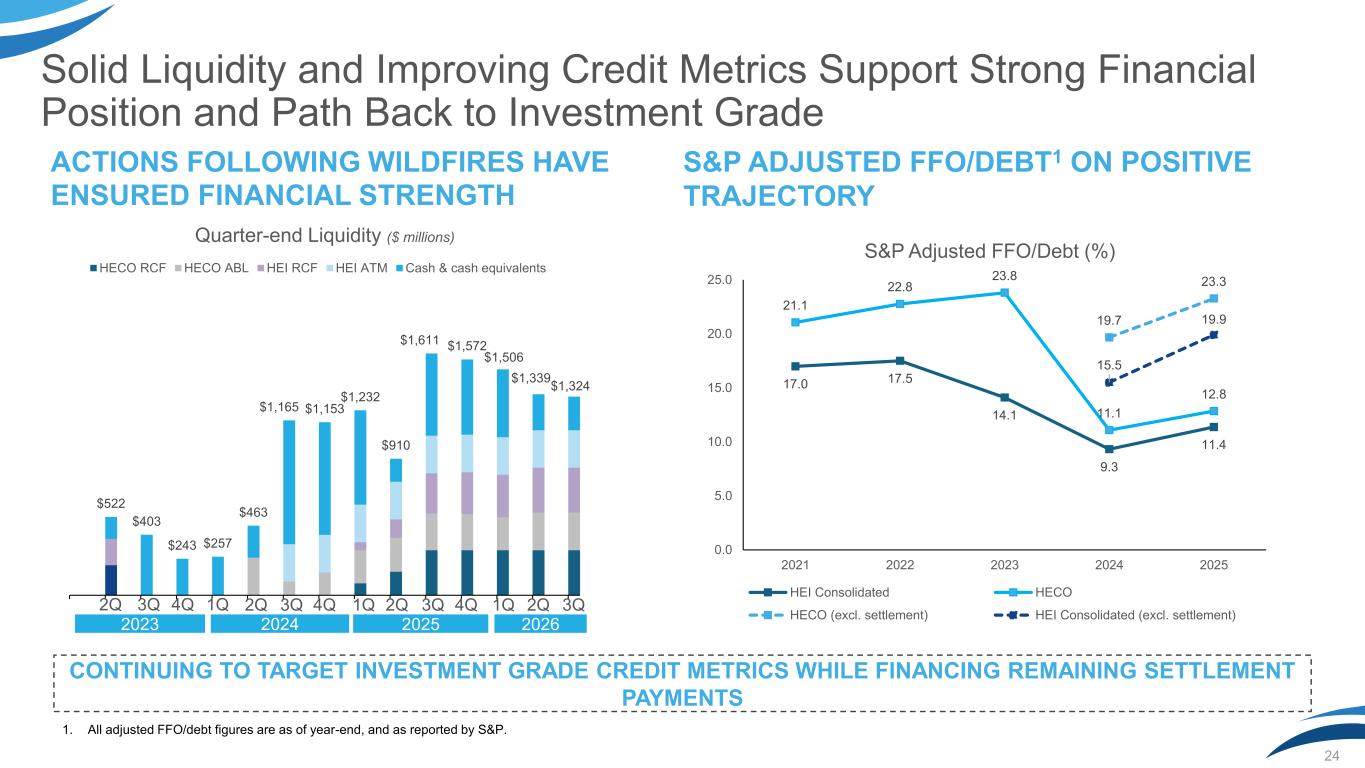
Solid Liquidity and Improving Credit Metrics Support Strong Financial Position and Path Back to Investment Grade 24 ACTIONS FOLLOWING WILDFIRES HAVE ENSURED FINANCIAL STRENGTH S&P ADJUSTED FFO/DEBT1 ON POSITIVE TRAJECTORY 1. All adjusted FFO/debt figures are as of year-end, and as reported by S&P. CONTINUING TO TARGET INVESTMENT GRADE CREDIT METRICS WHILE FINANCING REMAINING SETTLEMENT PAYMENTS $522 $403 $243 $257 $463 $1,165 $1,153 $1,232 $910 $1,611 $1,572 $1,506 $1,339 $1,324 Quarter-end Liquidity ($ millions) HECO RCF HECO ABL HEI RCF HEI ATM Cash & cash equivalents 2Q 3Q 4Q 1Q 2Q 3Q 4Q 1Q 2Q 3Q 4Q 1Q 2Q 2023 2024 2025 2026 17.0 17.5 14.1 9.3 11.4 21.1 22.8 23.8 11.1 12.8 19.7 23.3 15.5 19.9 0.0 5.0 10.0 15.0 20.0 25.0 2021 2022 2023 2024 2025 S&P Adjusted FFO/Debt (%) HEI Consolidated HECO HECO (excl. settlement) HEI Consolidated (excl. settlement) 3Q
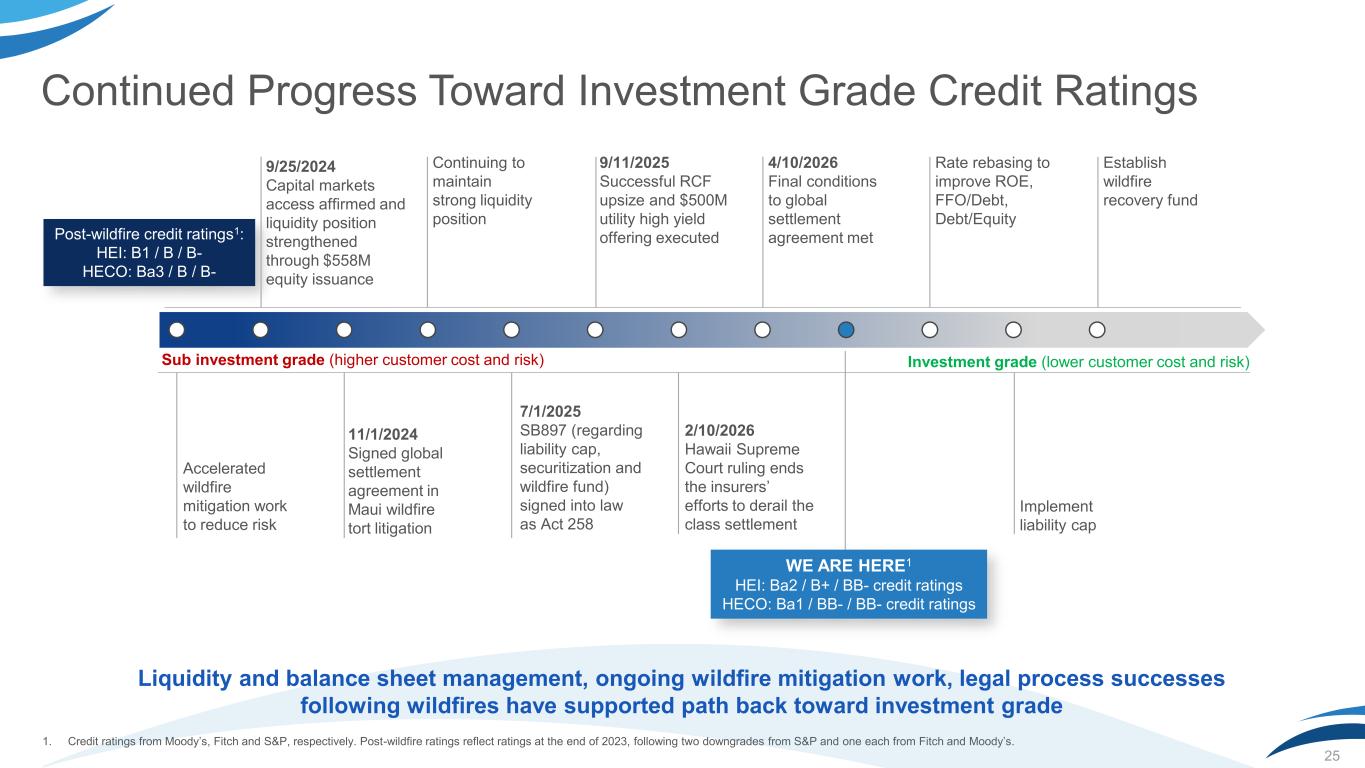
Rate rebasing to improve ROE, FFO/Debt, Debt/Equity Continued Progress Toward Investment Grade Credit Ratings 1. Credit ratings from Moody’s, Fitch and S&P, respectively. Post-wildfire ratings reflect ratings at the end of 2023, following two downgrades from S&P and one each from Fitch and Moody’s. 25 Sub investment grade (higher customer cost and risk) Investment grade (lower customer cost and risk) Accelerated wildfire mitigation work to reduce risk 11/1/2024 Signed global settlement agreement in Maui wildfire tort litigation Post-wildfire credit ratings1: HEI: B1 / B / B- HECO: Ba3 / B / B- 9/25/2024 Capital markets access affirmed and liquidity position strengthened through $558M equity issuance Continuing to maintain strong liquidity position 2/10/2026 Hawaii Supreme Court ruling ends the insurers’ efforts to derail the class settlement 7/1/2025 SB897 (regarding liability cap, securitization and wildfire fund) signed into law as Act 258 9/11/2025 Successful RCF upsize and $500M utility high yield offering executed 4/10/2026 Final conditions to global settlement agreement met WE ARE HERE1 HEI: Ba2 / B+ / BB- credit ratings HECO: Ba1 / BB- / BB- credit ratings Implement liability cap Establish wildfire recovery fund Liquidity and balance sheet management, ongoing wildfire mitigation work, legal process successes following wildfires have supported path back toward investment grade
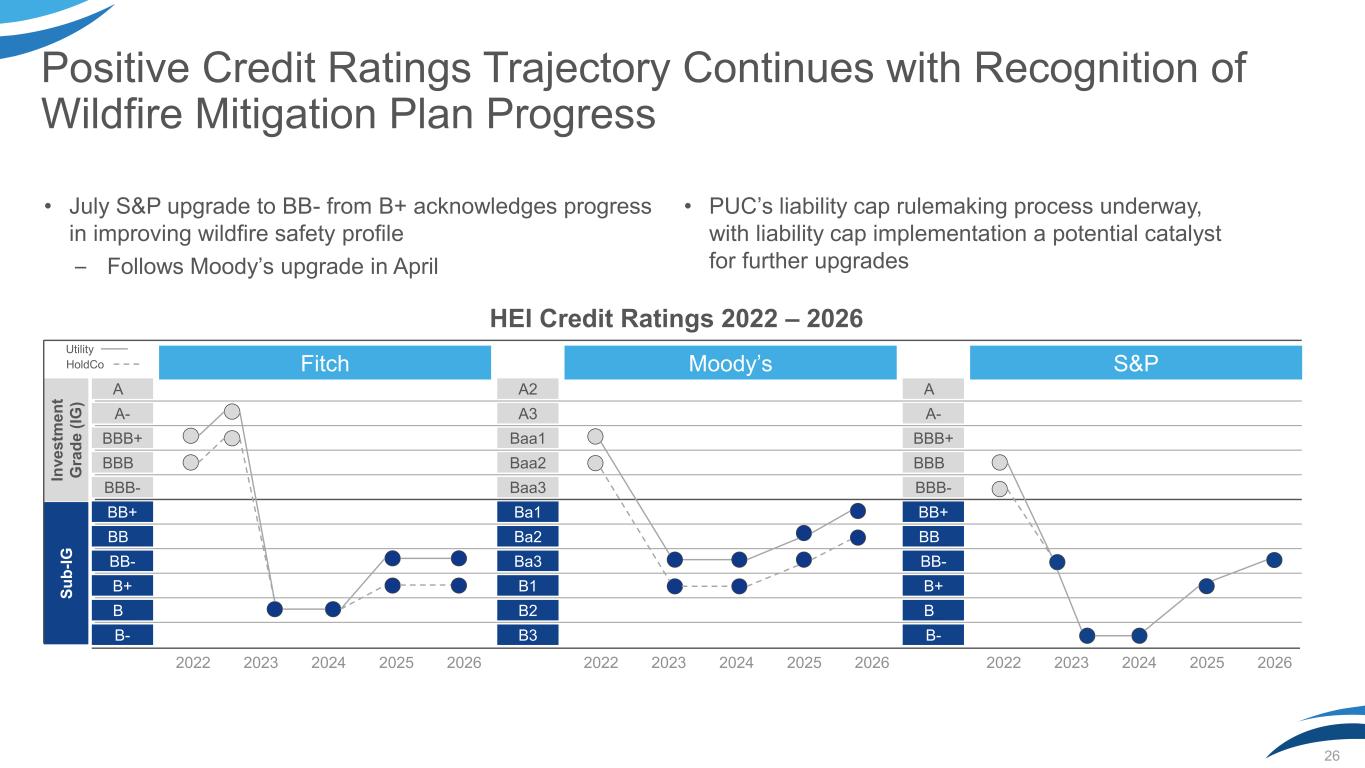
Positive Credit Ratings Trajectory Continues with Recognition of Wildfire Mitigation Plan Progress 26 HEI Credit Ratings 2022 – 2026 • July S&P upgrade to BB- from B+ acknowledges progress in improving wildfire safety profile – Follows Moody’s upgrade in April • PUC’s liability cap rulemaking process underway, with liability cap implementation a potential catalyst for further upgrades Fitch Moody’s S&P B- A_ A- BBB+ BBB_ BBB- BB+ BB_ BB- B+ B_ B- A2 A3 Baa1 Baa2 Baa3 Ba1 Ba2 Ba3 B1 B2 B3 A_ A- BBB+ BBB_ BBB- BB+ BB_ BB- B+ B_ B- In v e s tm e n t G ra d e ( IG ) S u b -I G 2022 2023 2024 2025 2026 2022 2023 2024 2025 2026 2022 2023 2024 2025 2026 HoldCo Utility
A Path Back to Sustainable Returns Rate rebasing and PBR potential reforms close the gap to normalized ROE, and new investment earns a return as it’s placed in service 27
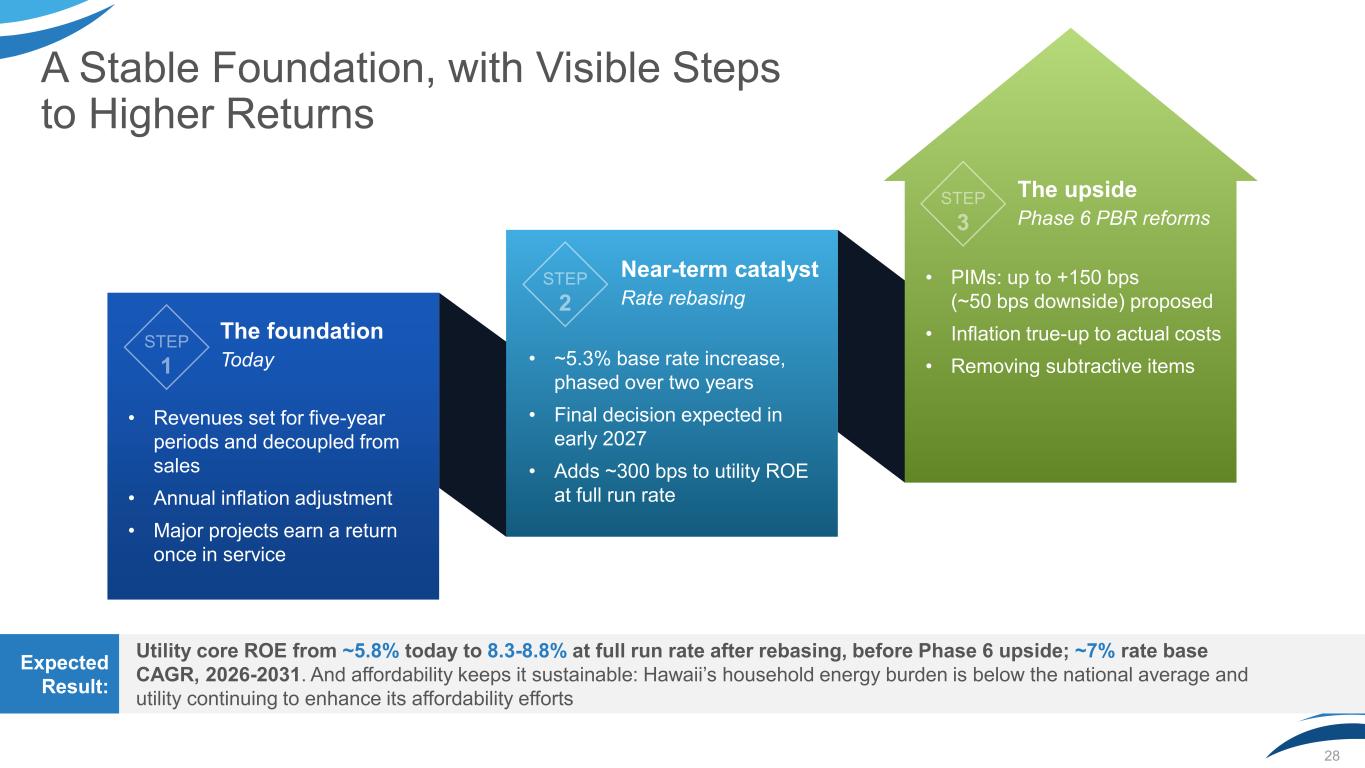
A Stable Foundation, with Visible Steps to Higher Returns 28 The foundation Today • Revenues set for five-year periods and decoupled from sales • Annual inflation adjustment • Major projects earn a return once in service Near-term catalyst Rate rebasing • ~5.3% base rate increase, phased over two years • Final decision expected in early 2027 • Adds ~300 bps to utility ROE at full run rate The upside Phase 6 PBR reforms • PIMs: up to +150 bps (~50 bps downside) proposed • Inflation true-up to actual costs • Removing subtractive items Expected Result: Utility core ROE from ~5.8% today to 8.3-8.8% at full run rate after rebasing, before Phase 6 upside; ~7% rate base CAGR, 2026-2031. And affordability keeps it sustainable: Hawaii’s household energy burden is below the national average and utility continuing to enhance its affordability efforts
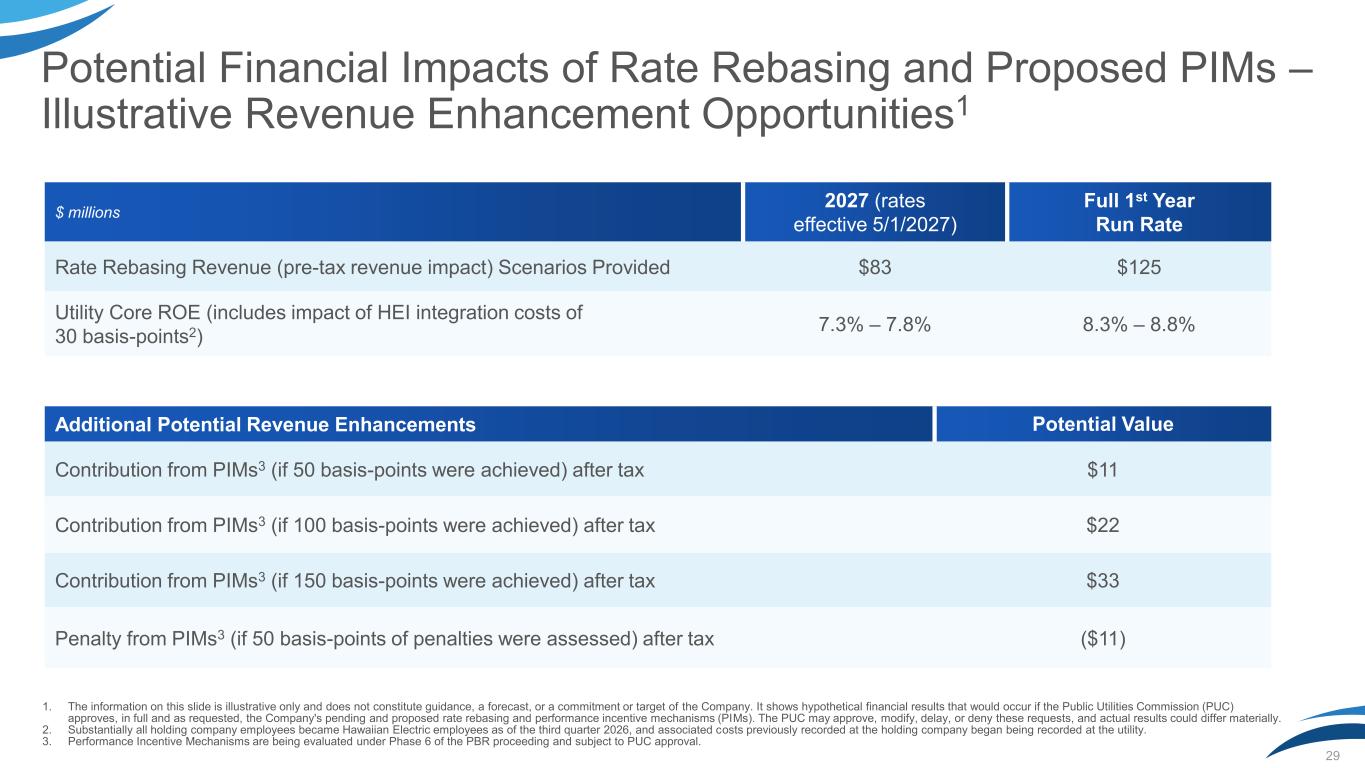
Potential Financial Impacts of Rate Rebasing and Proposed PIMs – Illustrative Revenue Enhancement Opportunities1 1. The information on this slide is illustrative only and does not constitute guidance, a forecast, or a commitment or target of the Company. It shows hypothetical financial results that would occur if the Public Utilities Commission (PUC) approves, in full and as requested, the Company's pending and proposed rate rebasing and performance incentive mechanisms (PIMs). The PUC may approve, modify, delay, or deny these requests, and actual results could differ materially. 2. Substantially all holding company employees became Hawaiian Electric employees as of the third quarter 2026, and associated costs previously recorded at the holding company began being recorded at the utility. 3. Performance Incentive Mechanisms are being evaluated under Phase 6 of the PBR proceeding and subject to PUC approval. 29 $ millions 2027 (rates effective 5/1/2027) Full 1st Year Run Rate Rate Rebasing Revenue (pre-tax revenue impact) Scenarios Provided $83 $125 Utility Core ROE (includes impact of HEI integration costs of 30 basis-points2) 7.3% – 7.8% 8.3% – 8.8% Additional Potential Revenue Enhancements Potential Value Contribution from PIMs3 (if 50 basis-points were achieved) after tax $11 Contribution from PIMs3 (if 100 basis-points were achieved) after tax $22 Contribution from PIMs3 (if 150 basis-points were achieved) after tax $33 Penalty from PIMs3 (if 50 basis-points of penalties were assessed) after tax ($11)
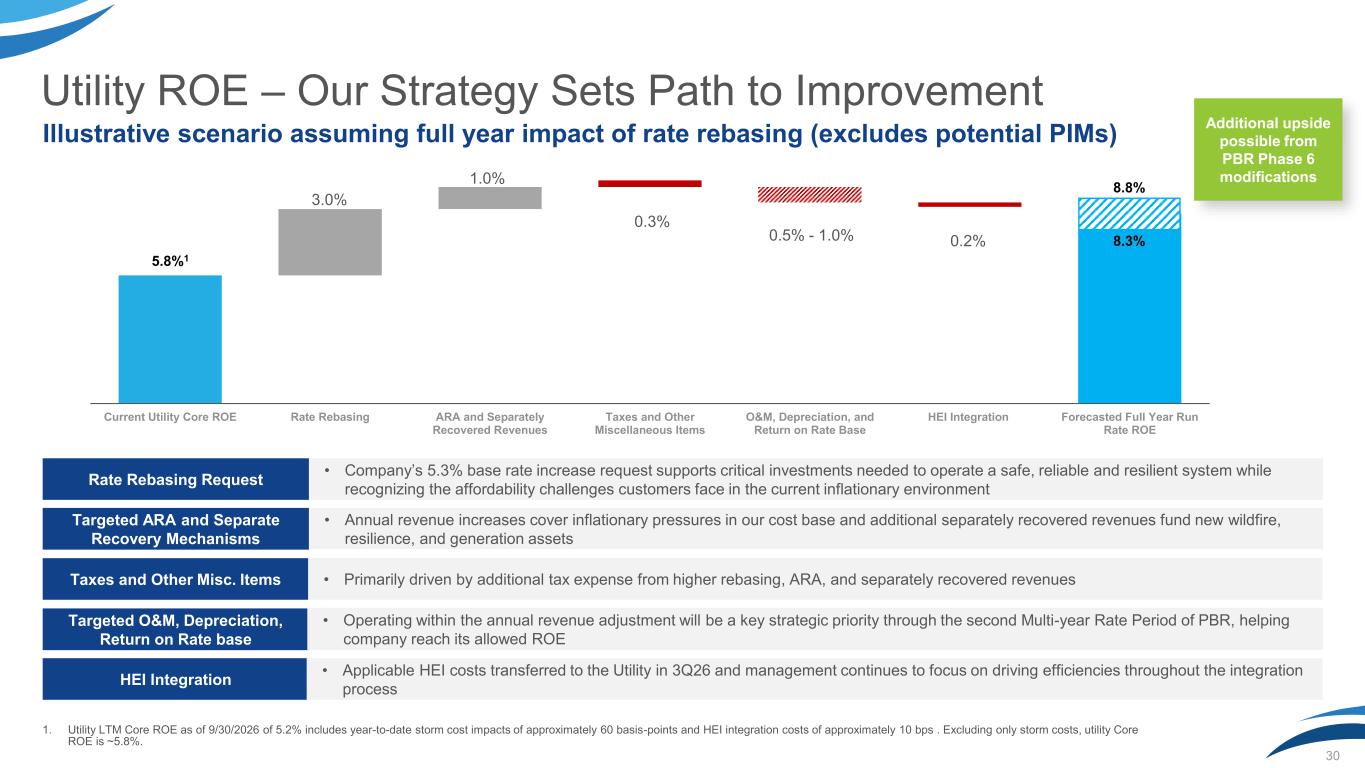
Utility ROE – Our Strategy Sets Path to Improvement 1. Utility LTM Core ROE as of 9/30/2026 of 5.2% includes year-to-date storm cost impacts of approximately 60 basis-points and HEI integration costs of approximately 10 bps . Excluding only storm costs, utility Core ROE is ~5.8%. Current Utility Core ROE Rate Rebasing ARA and Separately Recovered Revenues Taxes and Other Miscellaneous Items O&M, Depreciation, and Return on Rate Base HEI Integration Forecasted Full Year Run Rate ROE Rate Rebasing Request • Company’s 5.3% base rate increase request supports critical investments needed to operate a safe, reliable and resilient system while recognizing the affordability challenges customers face in the current inflationary environment Targeted ARA and Separate Recovery Mechanisms • Annual revenue increases cover inflationary pressures in our cost base and additional separately recovered revenues fund new wildfire, resilience, and generation assets 3.0% 8.8% 5.8%1 1.0% 0.3% 0.5% - 1.0% 0.2% Taxes and Other Misc. Items • Primarily driven by additional tax expense from higher rebasing, ARA, and separately recovered revenues Targeted O&M, Depreciation, Return on Rate base • Operating within the annual revenue adjustment will be a key strategic priority through the second Multi-year Rate Period of PBR, helping company reach its allowed ROE HEI Integration • Applicable HEI costs transferred to the Utility in 3Q26 and management continues to focus on driving efficiencies throughout the integration process 8.3% Illustrative scenario assuming full year impact of rate rebasing (excludes potential PIMs) 30 Additional upside possible from PBR Phase 6 modifications
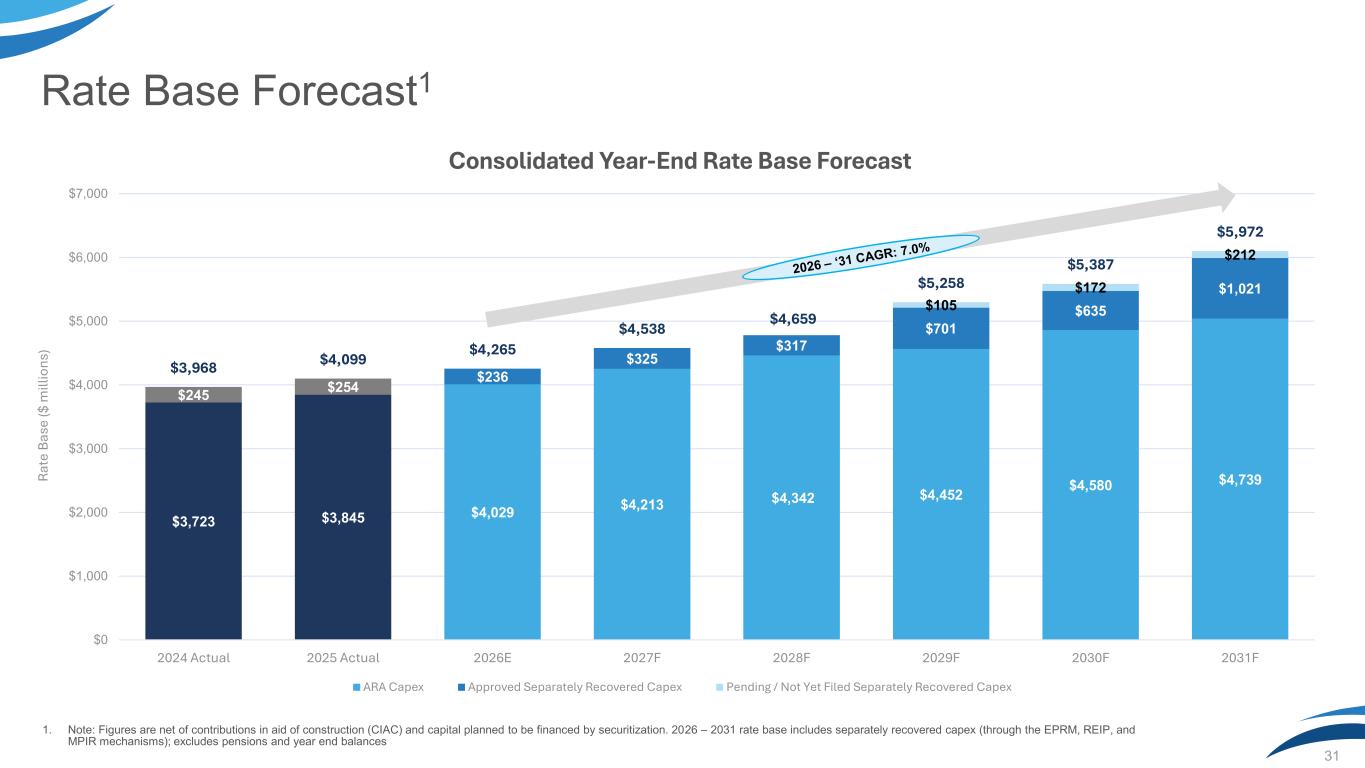
$3,723 $3,845 $4,029 $4,213 $4,342 $4,452 $4,580 $4,739 $245 $254 $236 $325 $317 $701 $635 $1,021 $105 $172 $212 $3,968 $4,099 $4,265 $4,538 $4,659 $5,258 $5,387 $5,972 $0 $1,000 $2,000 $3,000 $4,000 $5,000 $6,000 $7,000 2024 Actual 2025 Actual 2026E 2027F 2028F 2029F 2030F 2031F Ra te B as e ($ m ill io ns ) Consolidated Year-End Rate Base Forecast ARA Capex Approved Separately Recovered Capex Pending / Not Yet Filed Separately Recovered Capex Rate Base Forecast1 31 1. Note: Figures are net of contributions in aid of construction (CIAC) and capital planned to be financed by securitization. 2026 – 2031 rate base includes separately recovered capex (through the EPRM, REIP, and MPIR mechanisms); excludes pensions and year end balances
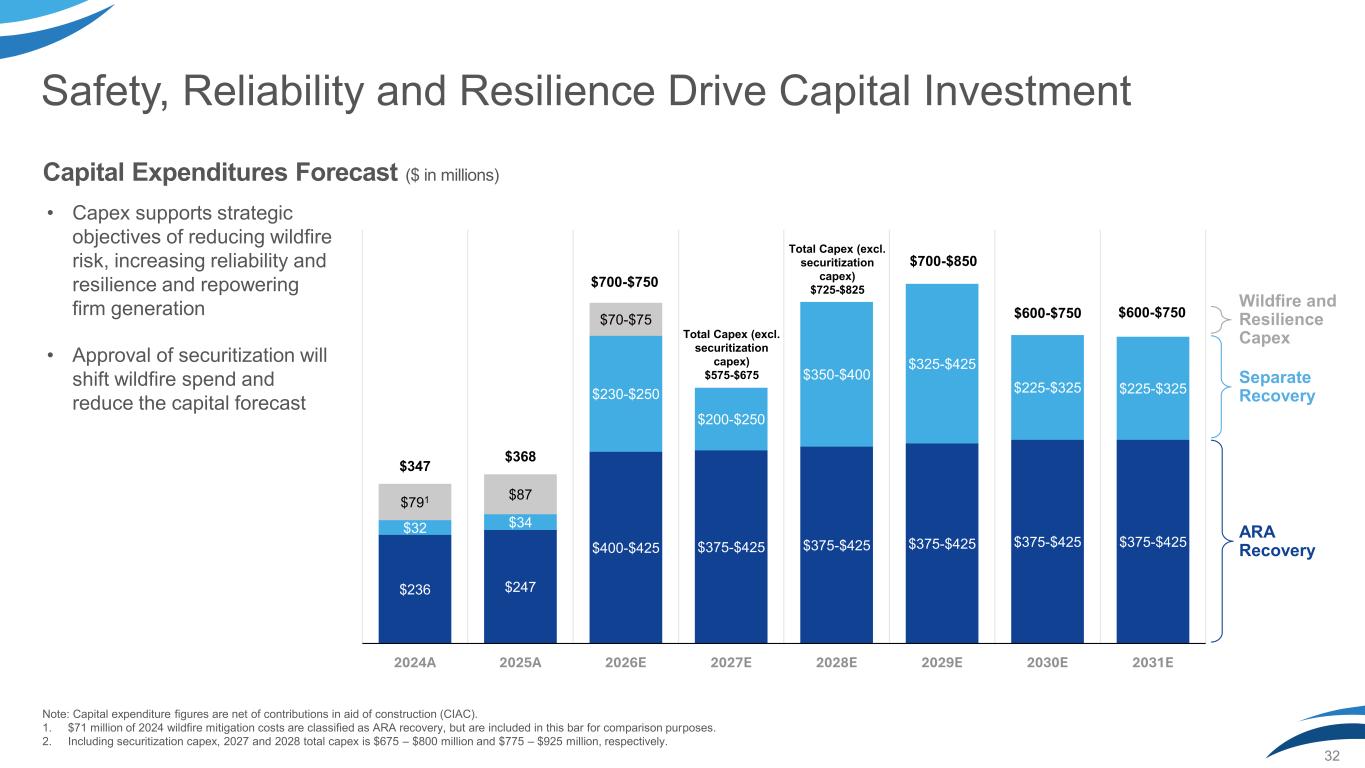
$236 $247 $400-$425 $375-$425 $375-$425 $375-$425 $375-$425 $375-$425 $32 $34 $230-$250 $200-$250 $350-$400 $325-$425 $225-$325 $225-$325 $791 $87 $70-$75 $347 $368 $700-$750 2024A 2025A 2026E 2027E 2028E 2029E 2030E 2031E ARA Recovery 32 • Capex supports strategic objectives of reducing wildfire risk, increasing reliability and resilience and repowering firm generation • Approval of securitization will shift wildfire spend and reduce the capital forecast Capital Expenditures Forecast ($ in millions) Separate Recovery Wildfire and Resilience CapexTotal Capex (excl. securitization capex) $575-$675 Total Capex (excl. securitization capex) $725-$825 $700-$850 $600-$750 $600-$750 Note: Capital expenditure figures are net of contributions in aid of construction (CIAC). 1. $71 million of 2024 wildfire mitigation costs are classified as ARA recovery, but are included in this bar for comparison purposes. 2. Including securitization capex, 2027 and 2028 total capex is $675 – $800 million and $775 – $925 million, respectively. Safety, Reliability and Resilience Drive Capital Investment
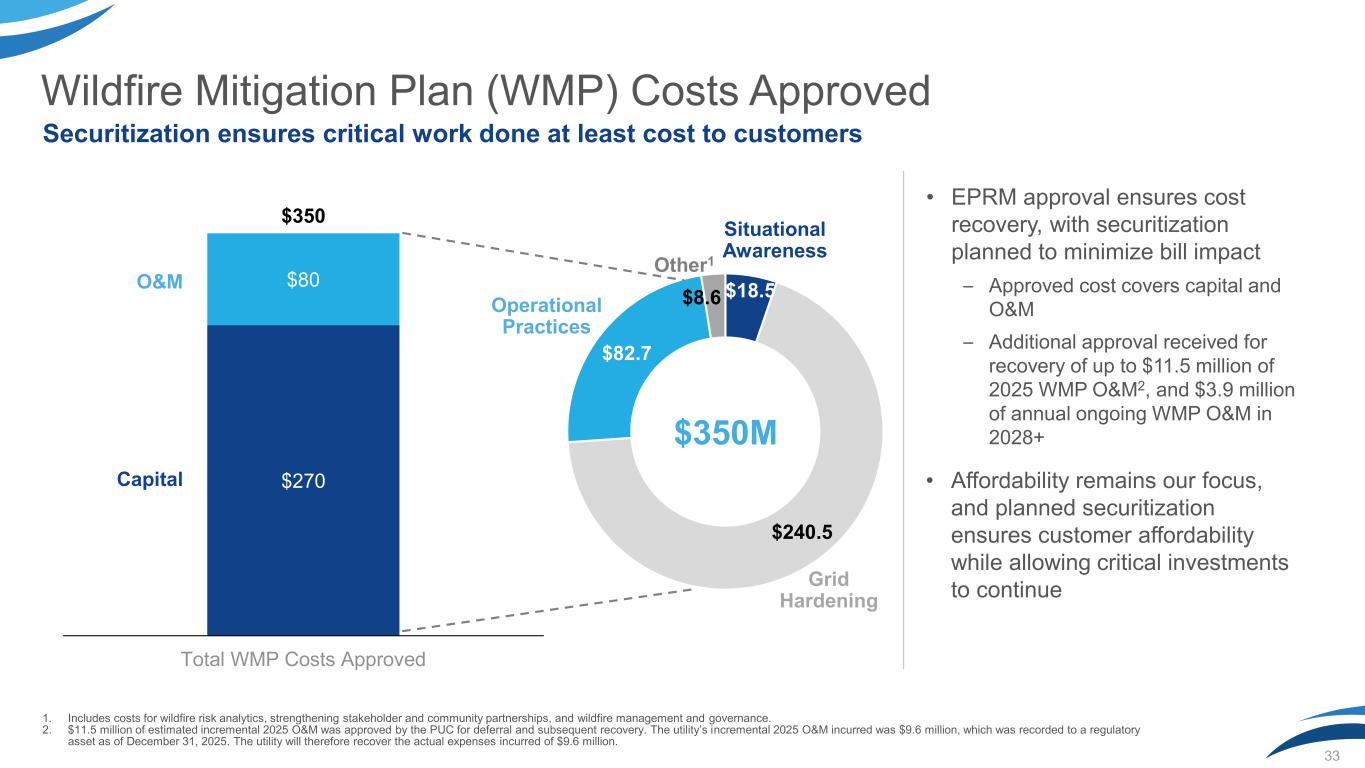
1. Includes costs for wildfire risk analytics, strengthening stakeholder and community partnerships, and wildfire management and governance. 2. $11.5 million of estimated incremental 2025 O&M was approved by the PUC for deferral and subsequent recovery. The utility’s incremental 2025 O&M incurred was $9.6 million, which was recorded to a regulatory asset as of December 31, 2025. The utility will therefore recover the actual expenses incurred of $9.6 million. 33 $270 $80 $350 Total WMP Costs Approved O&M Capital $18.5 $240.5 $82.7 $8.6 • EPRM approval ensures cost recovery, with securitization planned to minimize bill impact – Approved cost covers capital and O&M – Additional approval received for recovery of up to $11.5 million of 2025 WMP O&M2, and $3.9 million of annual ongoing WMP O&M in 2028+ • Affordability remains our focus, and planned securitization ensures customer affordability while allowing critical investments to continue Grid Hardening Operational Practices Situational Awareness Other1 $350M Wildfire Mitigation Plan (WMP) Costs Approved Securitization ensures critical work done at least cost to customers
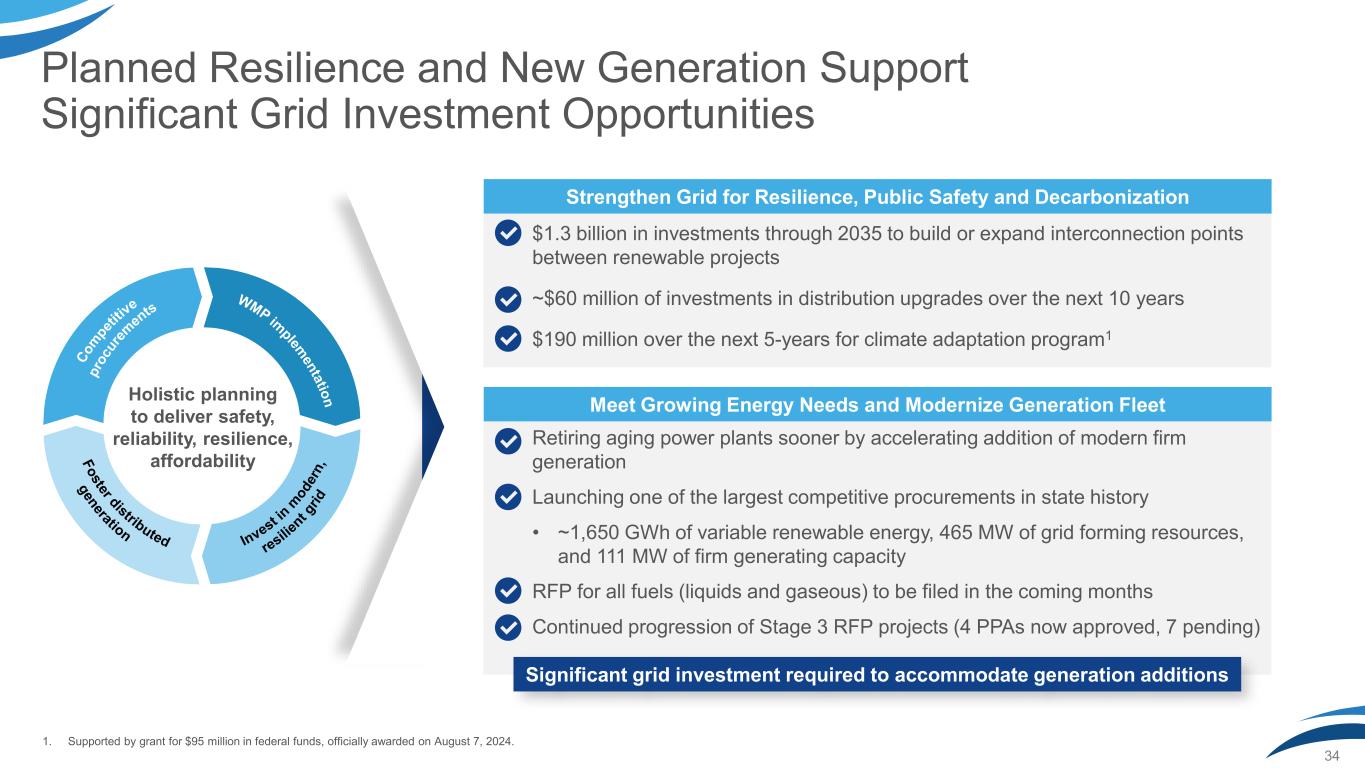
Planned Resilience and New Generation Support Significant Grid Investment Opportunities 1. Supported by grant for $95 million in federal funds, officially awarded on August 7, 2024. 34 WMP im plem en ta tio n C o m pe tit iv e p ro cu re m en ts F o ster distributed g en eration Invest in m o d e rn , re sili en t g ri d Holistic planning to deliver safety, reliability, resilience, affordability Retiring aging power plants sooner by accelerating addition of modern firm generation Launching one of the largest competitive procurements in state history • ~1,650 GWh of variable renewable energy, 465 MW of grid forming resources, and 111 MW of firm generating capacity RFP for all fuels (liquids and gaseous) to be filed in the coming months Continued progression of Stage 3 RFP projects (4 PPAs now approved, 7 pending) Meet Growing Energy Needs and Modernize Generation Fleet $1.3 billion in investments through 2035 to build or expand interconnection points between renewable projects ~$60 million of investments in distribution upgrades over the next 10 years $190 million over the next 5-years for climate adaptation program1 Strengthen Grid for Resilience, Public Safety and Decarbonization Significant grid investment required to accommodate generation additions
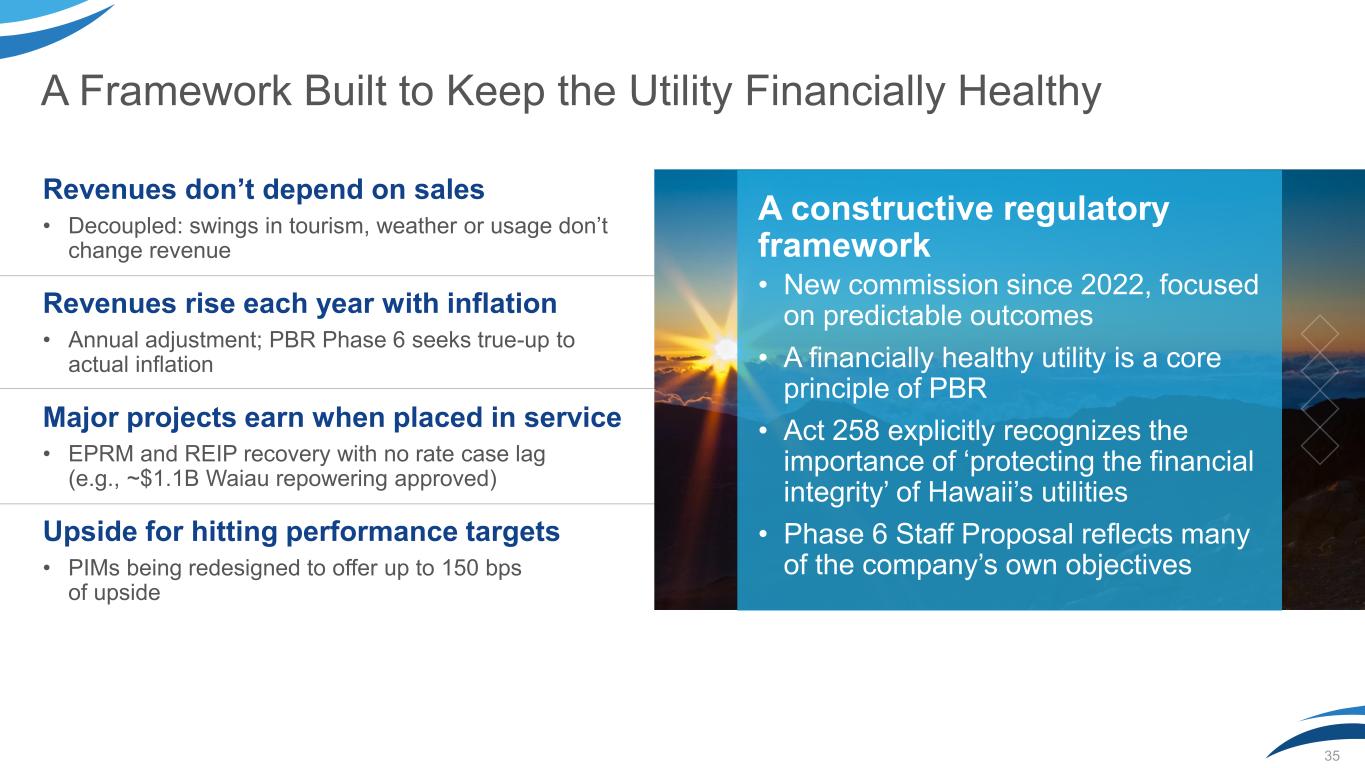
A Framework Built to Keep the Utility Financially Healthy Revenues don’t depend on sales • Decoupled: swings in tourism, weather or usage don’t change revenue Revenues rise each year with inflation • Annual adjustment; PBR Phase 6 seeks true-up to actual inflation Major projects earn when placed in service • EPRM and REIP recovery with no rate case lag (e.g., ~$1.1B Waiau repowering approved) Upside for hitting performance targets • PIMs being redesigned to offer up to 150 bps of upside A constructive regulatory framework • New commission since 2022, focused on predictable outcomes • A financially healthy utility is a core principle of PBR • Act 258 explicitly recognizes the importance of ‘protecting the financial integrity’ of Hawaii’s utilities • Phase 6 Staff Proposal reflects many of the company’s own objectives 35
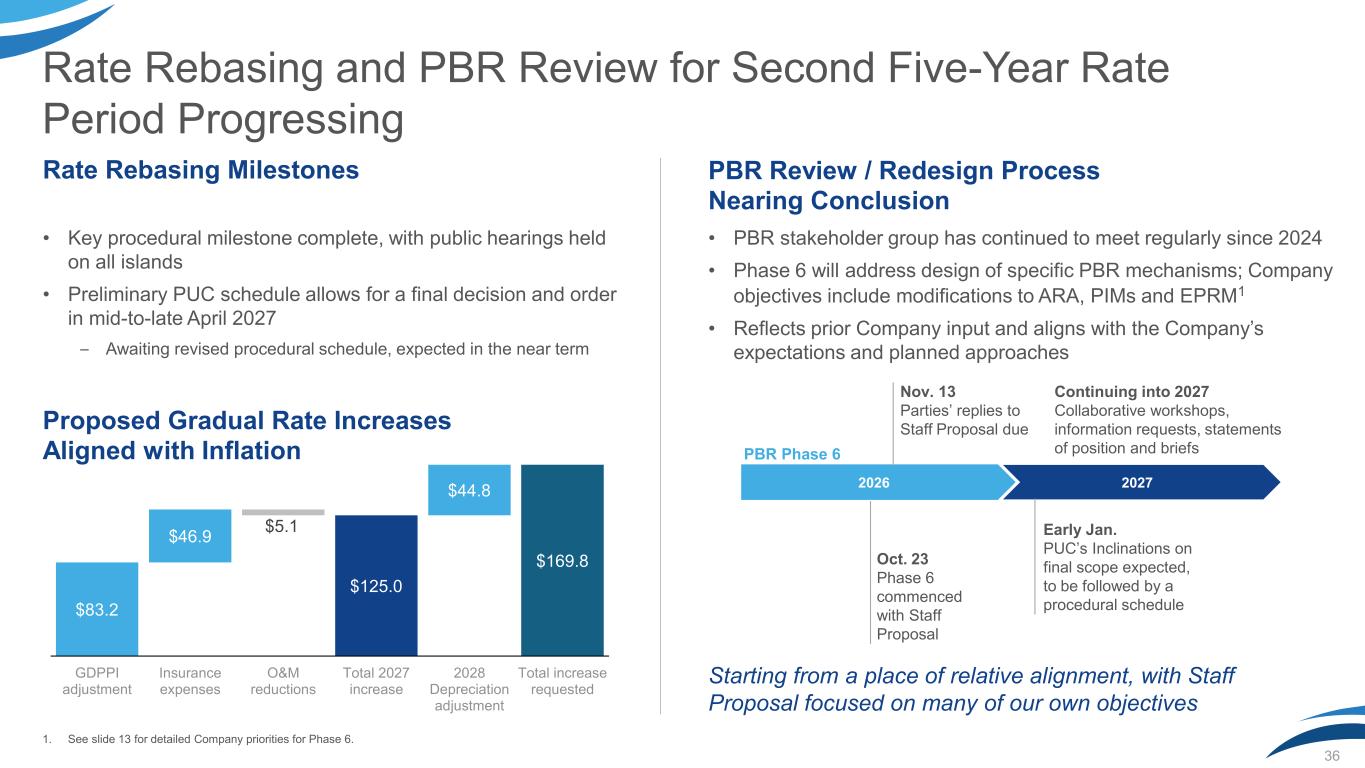
1. See slide 13 for detailed Company priorities for Phase 6. 36 PBR Review / Redesign Process Nearing Conclusion 20272026 Oct. 23 Phase 6 commenced with Staff Proposal Early Jan. PUC’s Inclinations on final scope expected, to be followed by a procedural schedule Nov. 13 Parties’ replies to Staff Proposal due Continuing into 2027 Collaborative workshops, information requests, statements of position and briefs • Key procedural milestone complete, with public hearings held on all islands • Preliminary PUC schedule allows for a final decision and order in mid-to-late April 2027 – Awaiting revised procedural schedule, expected in the near term Starting from a place of relative alignment, with Staff Proposal focused on many of our own objectives Rate Rebasing Milestones $83.2 $125.0 $169.8 $46.9 $5.1 $44.8 GDPPI adjustment Insurance expenses O&M reductions Total 2027 increase 2028 Depreciation adjustment Total increase requested Proposed Gradual Rate Increases Aligned with Inflation • PBR stakeholder group has continued to meet regularly since 2024 • Phase 6 will address design of specific PBR mechanisms; Company objectives include modifications to ARA, PIMs and EPRM1 • Reflects prior Company input and aligns with the Company’s expectations and planned approaches PBR Phase 6 Rate Rebasing and PBR Review for Second Five-Year Rate Period Progressing
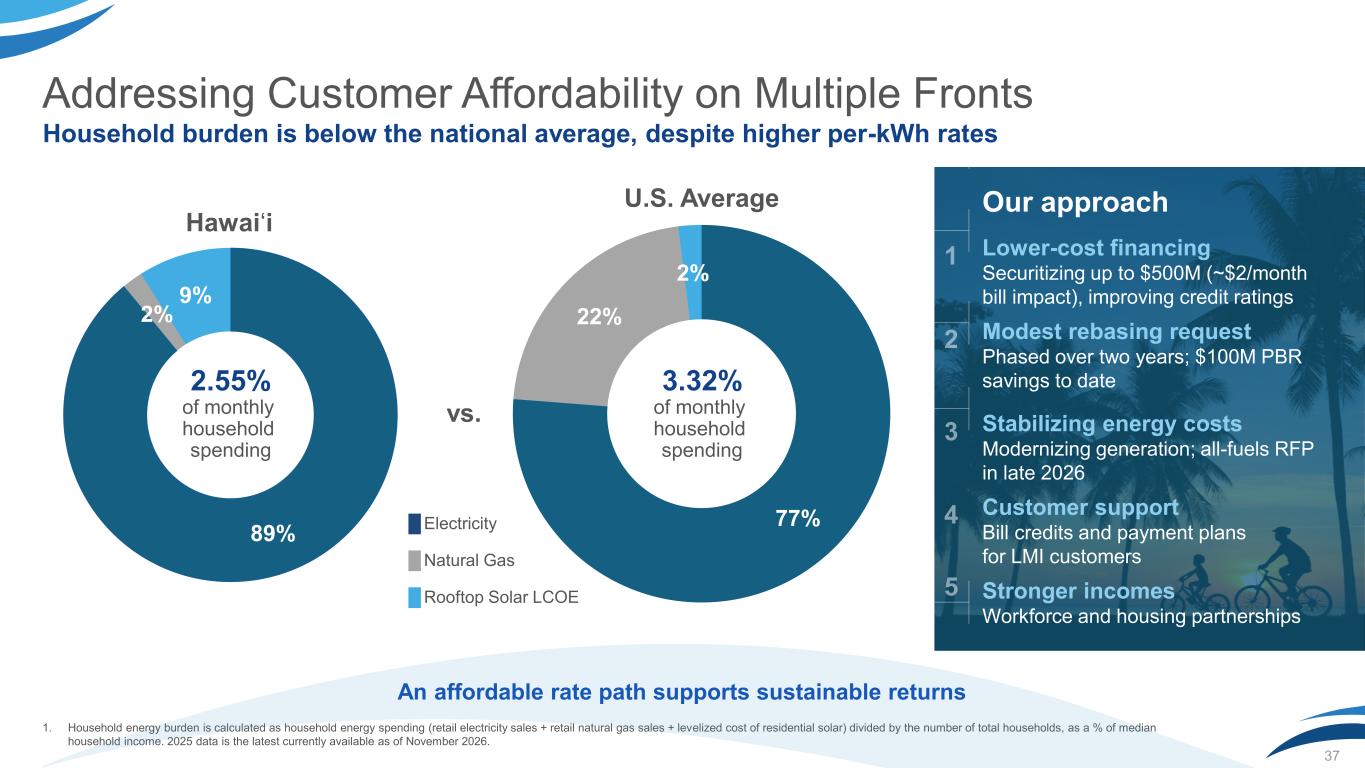
Addressing Customer Affordability on Multiple Fronts 1. Household energy burden is calculated as household energy spending (retail electricity sales + retail natural gas sales + levelized cost of residential solar) divided by the number of total households, as a % of median household income. 2025 data is the latest currently available as of November 2026. 37 89% 2% 9% 77% 22% 2% 3.32% of monthly household spending 2.55% of monthly household spending vs. █ Electricity █ Natural Gas █ Rooftop Solar LCOE Hawaiʻi U.S. Average Household burden is below the national average, despite higher per-kWh rates Lower-cost financing Securitizing up to $500M (~$2/month bill impact), improving credit ratings Modest rebasing request Phased over two years; $100M PBR savings to date Stabilizing energy costs Modernizing generation; all-fuels RFP in late 2026 Customer support Bill credits and payment plans for LMI customers Stronger incomes Workforce and housing partnerships Our approach An affordable rate path supports sustainable returns
Revealing the Value Strong execution to date, with key milestones still ahead 38
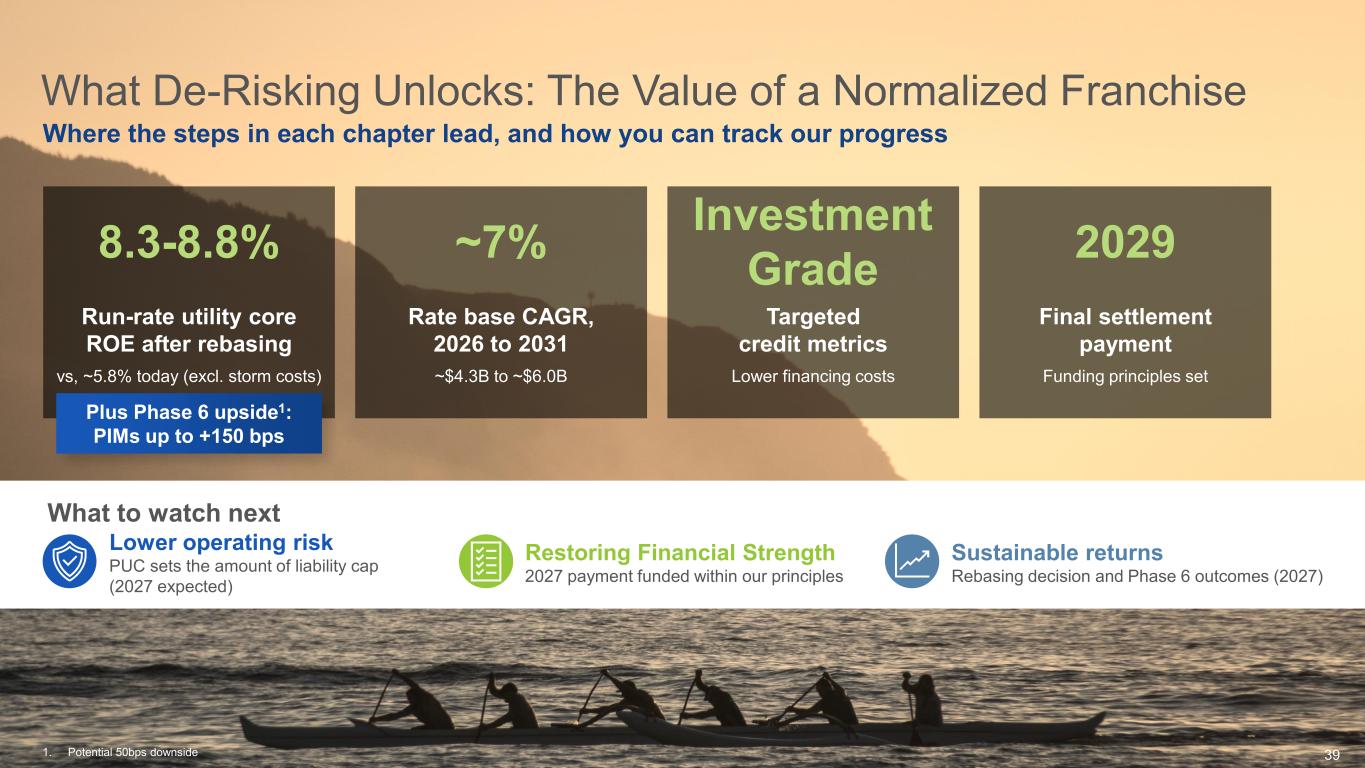
What De-Risking Unlocks: The Value of a Normalized Franchise 39 ~7% Rate base CAGR, 2026 to 2031 ~$4.3B to ~$6.0B Investment Grade Targeted credit metrics Lower financing costs 2029 Final settlement payment Funding principles set 8.3-8.8% Run-rate utility core ROE after rebasing vs, ~5.8% today (excl. storm costs) Lower operating risk PUC sets the amount of liability cap (2027 expected) Restoring Financial Strength 2027 payment funded within our principles Sustainable returns Rebasing decision and Phase 6 outcomes (2027) Plus Phase 6 upside1: PIMs up to +150 bps What to watch next Where the steps in each chapter lead, and how you can track our progress 1. Potential 50bps downside
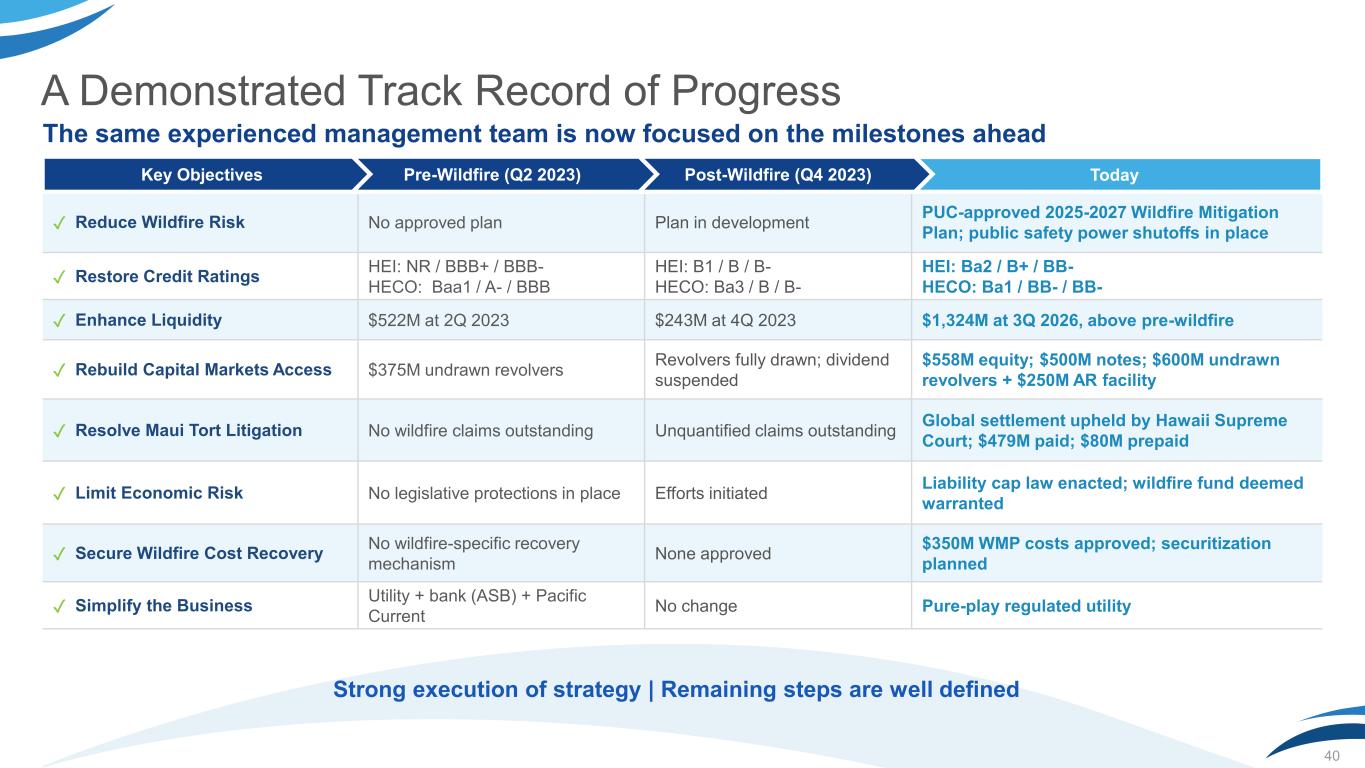
40 ✓ Reduce Wildfire Risk No approved plan Plan in development PUC-approved 2025-2027 Wildfire Mitigation Plan; public safety power shutoffs in place ✓ Restore Credit Ratings HEI: NR / BBB+ / BBB- HECO: Baa1 / A- / BBB HEI: B1 / B / B- HECO: Ba3 / B / B- HEI: Ba2 / B+ / BB- HECO: Ba1 / BB- / BB- ✓ Enhance Liquidity $522M at 2Q 2023 $243M at 4Q 2023 $1,324M at 3Q 2026, above pre-wildfire ✓ Rebuild Capital Markets Access $375M undrawn revolvers Revolvers fully drawn; dividend suspended $558M equity; $500M notes; $600M undrawn revolvers + $250M AR facility ✓ Resolve Maui Tort Litigation No wildfire claims outstanding Unquantified claims outstanding Global settlement upheld by Hawaii Supreme Court; $479M paid; $80M prepaid ✓ Limit Economic Risk No legislative protections in place Efforts initiated Liability cap law enacted; wildfire fund deemed warranted ✓ Secure Wildfire Cost Recovery No wildfire-specific recovery mechanism None approved $350M WMP costs approved; securitization planned ✓ Simplify the Business Utility + bank (ASB) + Pacific Current No change Pure-play regulated utility TodayPost-Wildfire (Q4 2023)Pre-Wildfire (Q2 2023)Key Objectives A Demonstrated Track Record of Progress Strong execution of strategy | Remaining steps are well defined The same experienced management team is now focused on the milestones ahead
Key Takeaways 41 • Well-positioned for long-term value creation, with a greatly improved risk profile, near-term catalysts to improved earnings, a favorable regulatory construct, and an elevated capex cycle ahead • Consistently executed on the objectives communicated since 2023, with each key objective of financial and operational strength moving in the right direction • Defined roadmap to achieve a stronger financial foundation through continued execution. Rate rebasing and other regulatory processes, and achieving efficiencies while executing through elevated capex cycle, are expected to lead to stronger credit metrics and returns on equity Positive Trajectory Track Record of Execution Clear Path and Visibility
Appendix
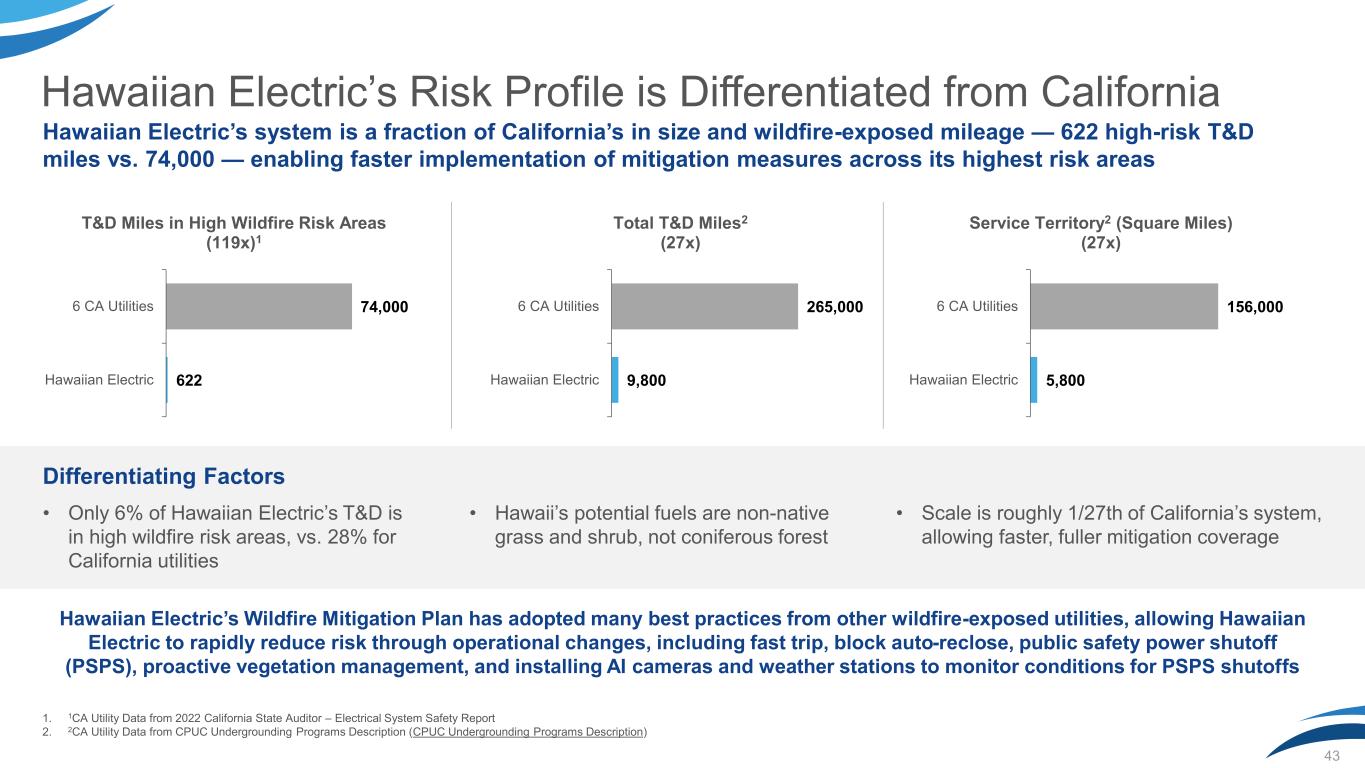
Hawaiian Electric’s Risk Profile is Differentiated from California 43 622 74,000 Hawaiian Electric 6 CA Utilities T&D Miles in High Wildfire Risk Areas (119x)1 9,800 265,000 Hawaiian Electric 6 CA Utilities Total T&D Miles2 (27x) 5,800 156,000 Hawaiian Electric 6 CA Utilities Service Territory2 (Square Miles) (27x) Differentiating Factors Hawaiian Electric’s Wildfire Mitigation Plan has adopted many best practices from other wildfire-exposed utilities, allowing Hawaiian Electric to rapidly reduce risk through operational changes, including fast trip, block auto-reclose, public safety power shutoff (PSPS), proactive vegetation management, and installing AI cameras and weather stations to monitor conditions for PSPS shutoffs Hawaiian Electric’s system is a fraction of California’s in size and wildfire-exposed mileage — 622 high-risk T&D miles vs. 74,000 — enabling faster implementation of mitigation measures across its highest risk areas • Only 6% of Hawaiian Electric’s T&D is in high wildfire risk areas, vs. 28% for California utilities • Hawaii’s potential fuels are non-native grass and shrub, not coniferous forest • Scale is roughly 1/27th of California’s system, allowing faster, fuller mitigation coverage 1. 1CA Utility Data from 2022 California State Auditor – Electrical System Safety Report 2. 2CA Utility Data from CPUC Undergrounding Programs Description (CPUC Undergrounding Programs Description)
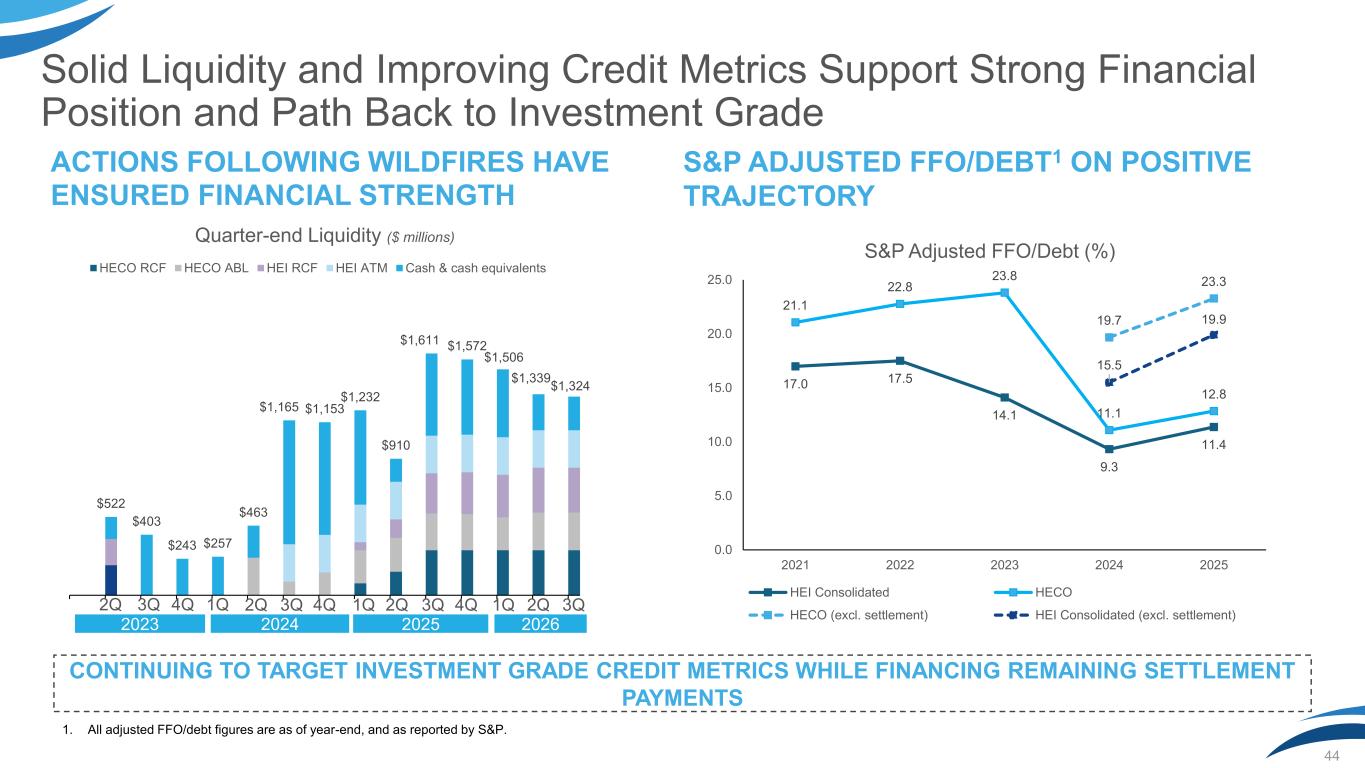
Solid Liquidity and Improving Credit Metrics Support Strong Financial Position and Path Back to Investment Grade 44 ACTIONS FOLLOWING WILDFIRES HAVE ENSURED FINANCIAL STRENGTH S&P ADJUSTED FFO/DEBT1 ON POSITIVE TRAJECTORY 1. All adjusted FFO/debt figures are as of year-end, and as reported by S&P. CONTINUING TO TARGET INVESTMENT GRADE CREDIT METRICS WHILE FINANCING REMAINING SETTLEMENT PAYMENTS $522 $403 $243 $257 $463 $1,165 $1,153 $1,232 $910 $1,611 $1,572 $1,506 $1,339 $1,324 Quarter-end Liquidity ($ millions) HECO RCF HECO ABL HEI RCF HEI ATM Cash & cash equivalents 2Q 3Q 4Q 1Q 2Q 3Q 4Q 1Q 2Q 3Q 4Q 1Q 2Q 2023 2024 2025 2026 17.0 17.5 14.1 9.3 11.4 21.1 22.8 23.8 11.1 12.8 19.7 23.3 15.5 19.9 0.0 5.0 10.0 15.0 20.0 25.0 2021 2022 2023 2024 2025 S&P Adjusted FFO/Debt (%) HEI Consolidated HECO HECO (excl. settlement) HEI Consolidated (excl. settlement) 3Q
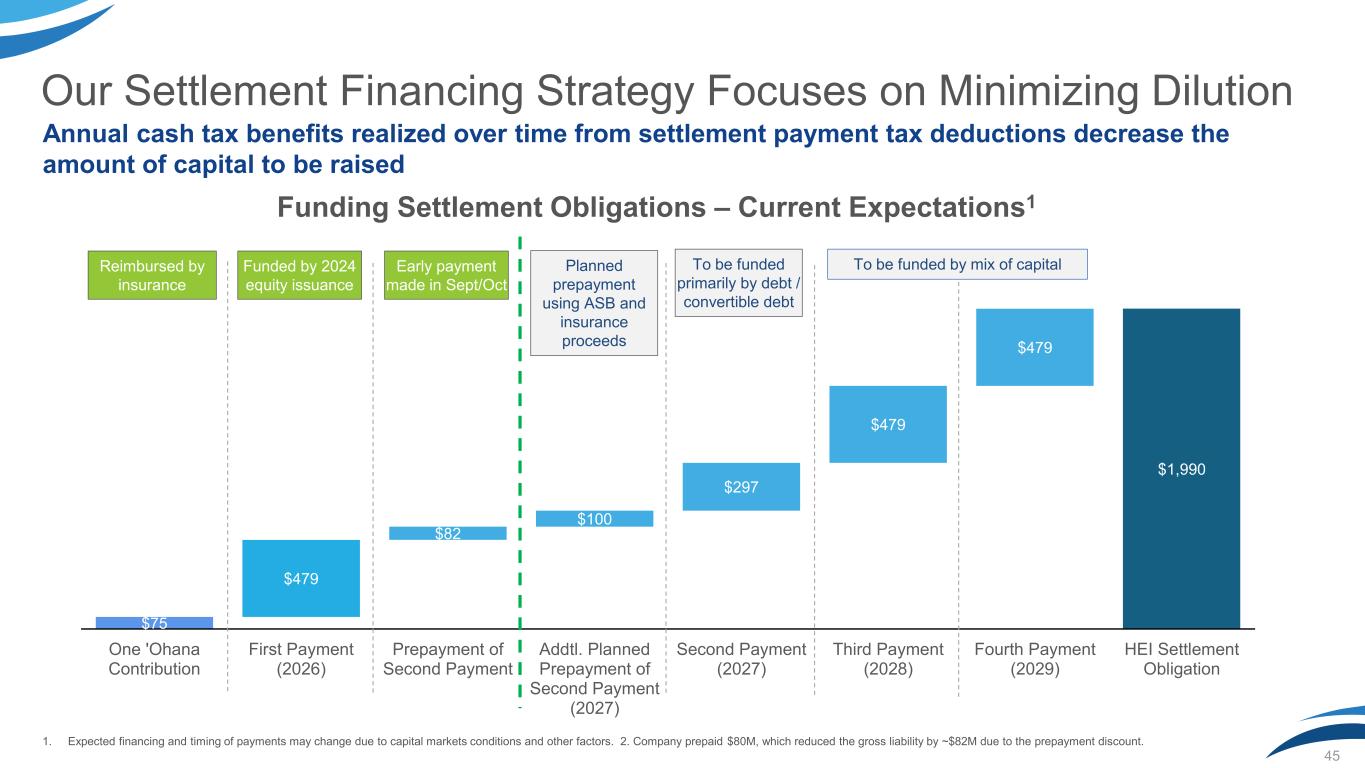
1. Expected financing and timing of payments may change due to capital markets conditions and other factors. 2. Company prepaid $80M, which reduced the gross liability by ~$82M due to the prepayment discount. 45 Funding Settlement Obligations – Current Expectations1 $75 $1,990 $479 $82 $100 $297 $479 $479 One 'Ohana Contribution First Payment (2026) Prepayment of Second Payment Addtl. Planned Prepayment of Second Payment (2027) Second Payment (2027) Third Payment (2028) Fourth Payment (2029) HEI Settlement Obligation Reimbursed by insurance Funded by 2024 equity issuance To be funded primarily by debt / convertible debt Early payment made in Sept/Oct Planned prepayment using ASB and insurance proceeds To be funded by mix of capital Our Settlement Financing Strategy Focuses on Minimizing Dilution Annual cash tax benefits realized over time from settlement payment tax deductions decrease the amount of capital to be raised
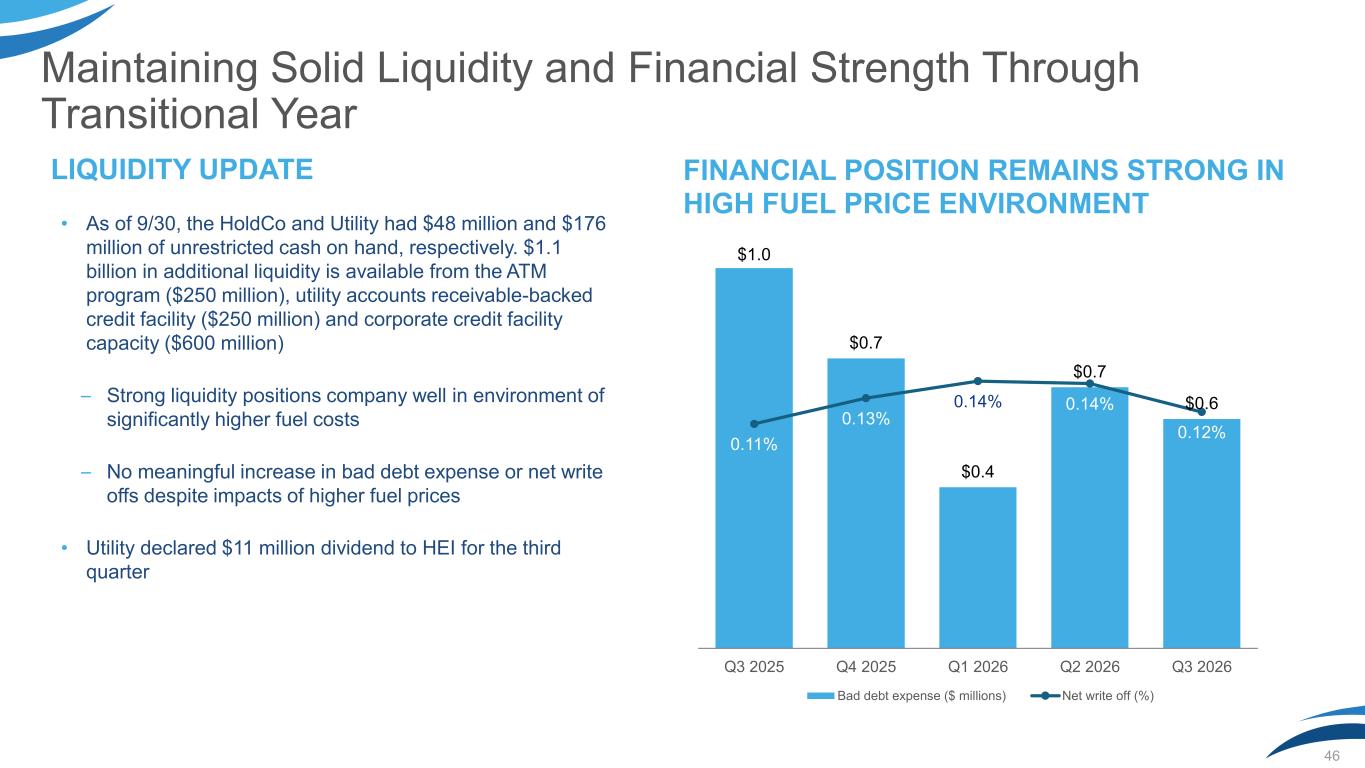
Maintaining Solid Liquidity and Financial Strength Through Transitional Year 46 • As of 9/30, the HoldCo and Utility had $48 million and $176 million of unrestricted cash on hand, respectively. $1.1 billion in additional liquidity is available from the ATM program ($250 million), utility accounts receivable-backed credit facility ($250 million) and corporate credit facility capacity ($600 million) – Strong liquidity positions company well in environment of significantly higher fuel costs – No meaningful increase in bad debt expense or net write offs despite impacts of higher fuel prices • Utility declared $11 million dividend to HEI for the third quarter LIQUIDITY UPDATE FINANCIAL POSITION REMAINS STRONG IN HIGH FUEL PRICE ENVIRONMENT $1.0 $0.7 $0.4 $0.7 $0.6 0.11% 0.13% 0.14% 0.14% 0.12% Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Bad debt expense ($ millions) Net write off (%)
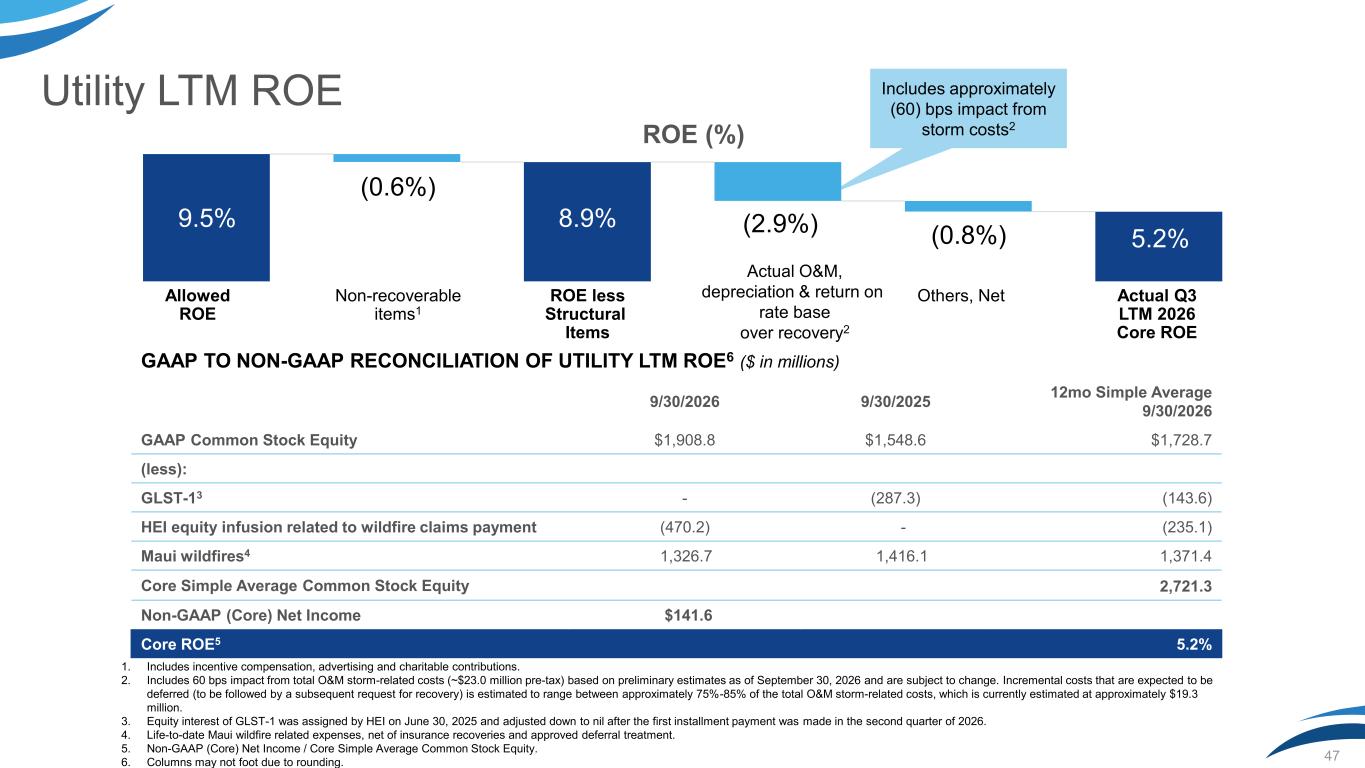
Utility LTM ROE 9.5% ROE (%) Non-recoverable items1 Allowed ROE 8.9% ROE less Structural Items Actual O&M, depreciation & return on rate base over recovery2 Actual Q3 LTM 2026 Core ROE Others, Net 5.2% GAAP TO NON-GAAP RECONCILIATION OF UTILITY LTM ROE6 ($ in millions) 9/30/2026 9/30/2025 12mo Simple Average 9/30/2026 GAAP Common Stock Equity $1,908.8 $1,548.6 $1,728.7 (less): GLST-13 - (287.3) (143.6) HEI equity infusion related to wildfire claims payment (470.2) - (235.1) Maui wildfires4 1,326.7 1,416.1 1,371.4 Core Simple Average Common Stock Equity 2,721.3 Non-GAAP (Core) Net Income $141.6 Core ROE5 5.2% 1. Includes incentive compensation, advertising and charitable contributions. 2. Includes 60 bps impact from total O&M storm-related costs (~$23.0 million pre-tax) based on preliminary estimates as of September 30, 2026 and are subject to change. Incremental costs that are expected to be deferred (to be followed by a subsequent request for recovery) is estimated to range between approximately 75%-85% of the total O&M storm-related costs, which is currently estimated at approximately $19.3 million. 3. Equity interest of GLST-1 was assigned by HEI on June 30, 2025 and adjusted down to nil after the first installment payment was made in the second quarter of 2026. 4. Life-to-date Maui wildfire related expenses, net of insurance recoveries and approved deferral treatment. 5. Non-GAAP (Core) Net Income / Core Simple Average Common Stock Equity. 6. Columns may not foot due to rounding. 47 9.5% (0.6%) 8.9% (2.9%) (0.8%) 5.2% Includes approximately (60) bps impact from storm costs2
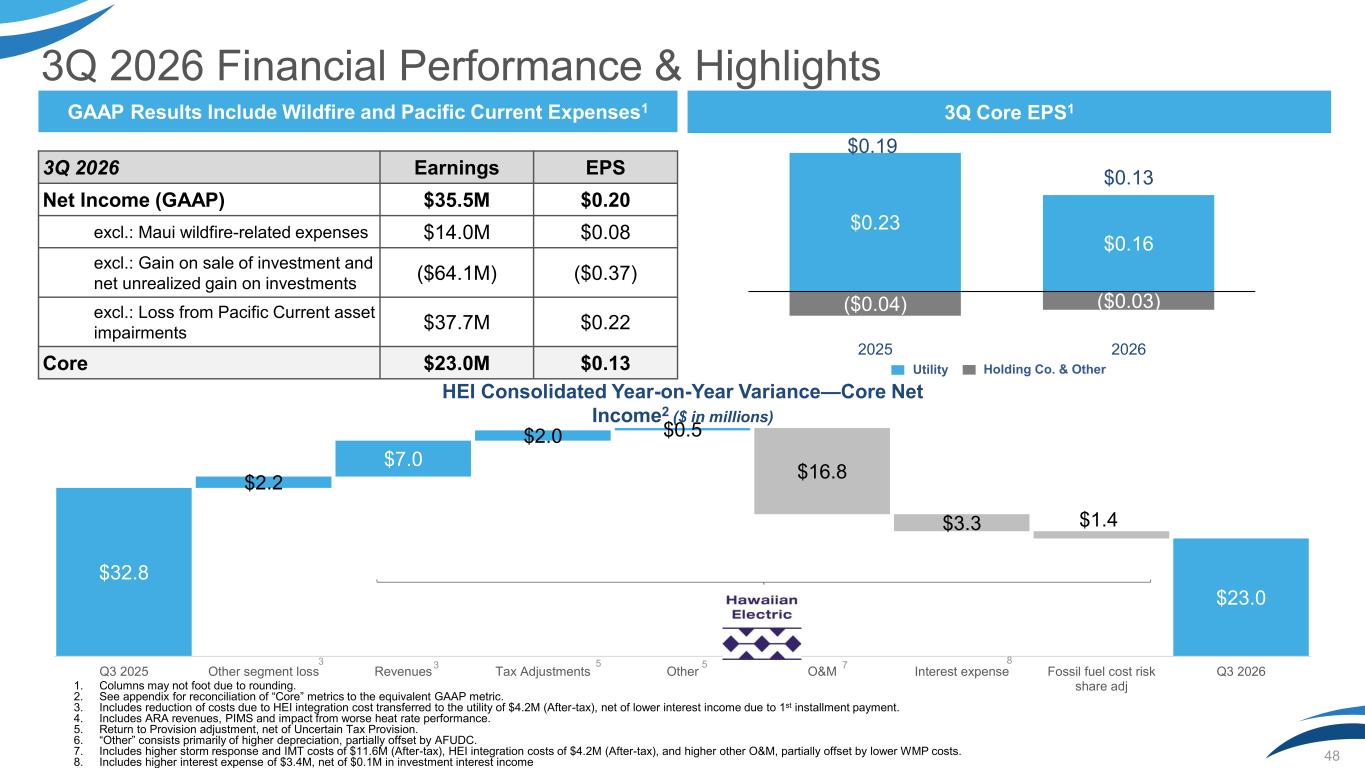
3Q 2026 Financial Performance & Highlights 48 GAAP Results Include Wildfire and Pacific Current Expenses1 Utility Holding Co. & Other 3Q 2026 Earnings EPS Net Income (GAAP) $35.5M $0.20 excl.: Maui wildfire-related expenses $14.0M $0.08 excl.: Gain on sale of investment and net unrealized gain on investments ($64.1M) ($0.37) excl.: Loss from Pacific Current asset impairments $37.7M $0.22 Core $23.0M $0.13 HEI Consolidated Year-on-Year Variance—Core Net Income2 ($ in millions) $0.23 $0.16 ($0.04) ($0.03) $0.19 $0.13 2025 2026 1. Columns may not foot due to rounding. 2. See appendix for reconciliation of “Core” metrics to the equivalent GAAP metric. 3. Includes reduction of costs due to HEI integration cost transferred to the utility of $4.2M (After-tax), net of lower interest income due to 1st installment payment. 4. Includes ARA revenues, PIMS and impact from worse heat rate performance. 5. Return to Provision adjustment, net of Uncertain Tax Provision. 6. “Other” consists primarily of higher depreciation, partially offset by AFUDC. 7. Includes higher storm response and IMT costs of $11.6M (After-tax), HEI integration costs of $4.2M (After-tax), and higher other O&M, partially offset by lower WMP costs. 8. Includes higher interest expense of $3.4M, net of $0.1M in investment interest income $32.8 $23.0 $2.2 $7.0 $2.0 $0.5 $16.8 $3.3 $1.4 Q3 2025 Other segment loss Revenues Tax Adjustments Other O&M Interest expense Fossil fuel cost risk share adj Q3 2026 3 5 3Q Core EPS1 85 73
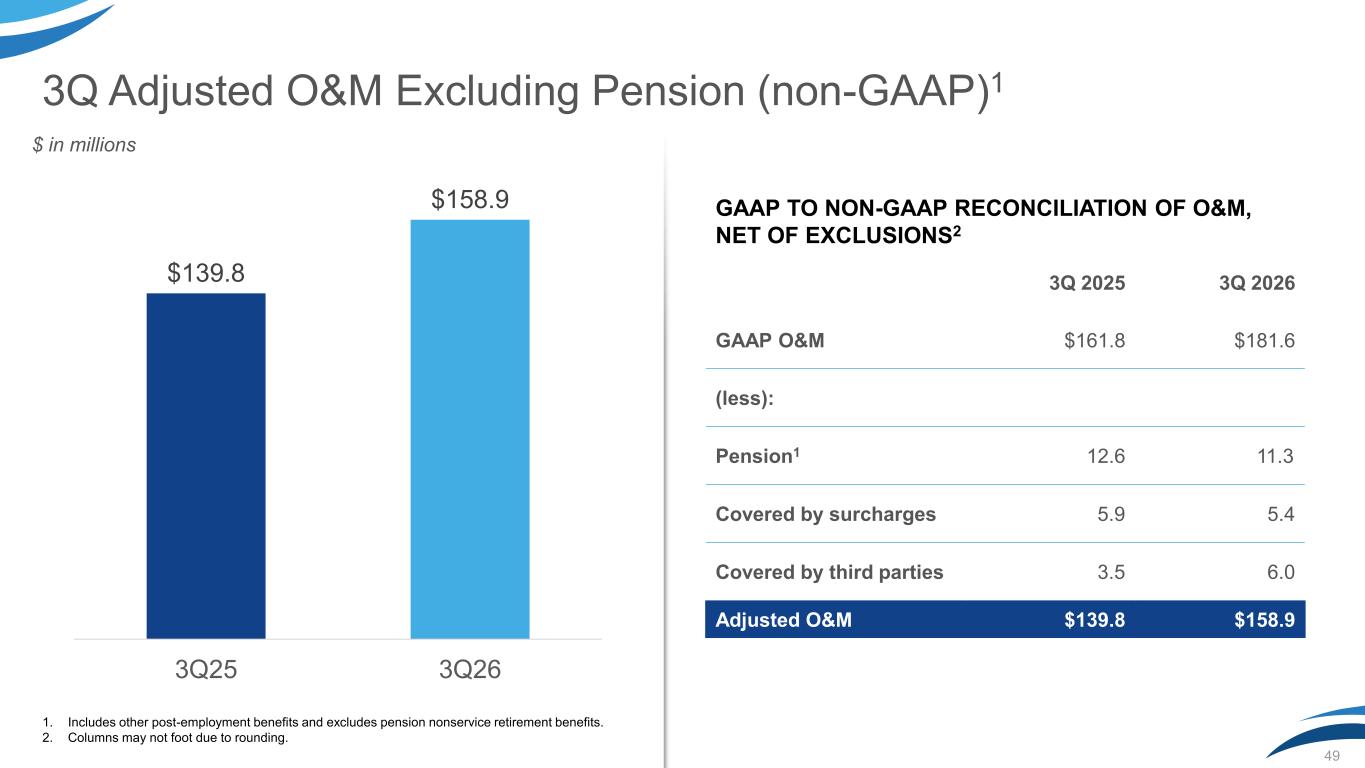
3Q Adjusted O&M Excluding Pension (non-GAAP)1 1. Includes other post-employment benefits and excludes pension nonservice retirement benefits. 2. Columns may not foot due to rounding. 49 $139.8 $158.9 3Q25 3Q26 GAAP TO NON-GAAP RECONCILIATION OF O&M, NET OF EXCLUSIONS2 3Q 2025 3Q 2026 GAAP O&M $161.8 $181.6 (less): Pension1 12.6 11.3 Covered by surcharges 5.9 5.4 Covered by third parties 3.5 6.0 Adjusted O&M $139.8 $158.9 $ in millions
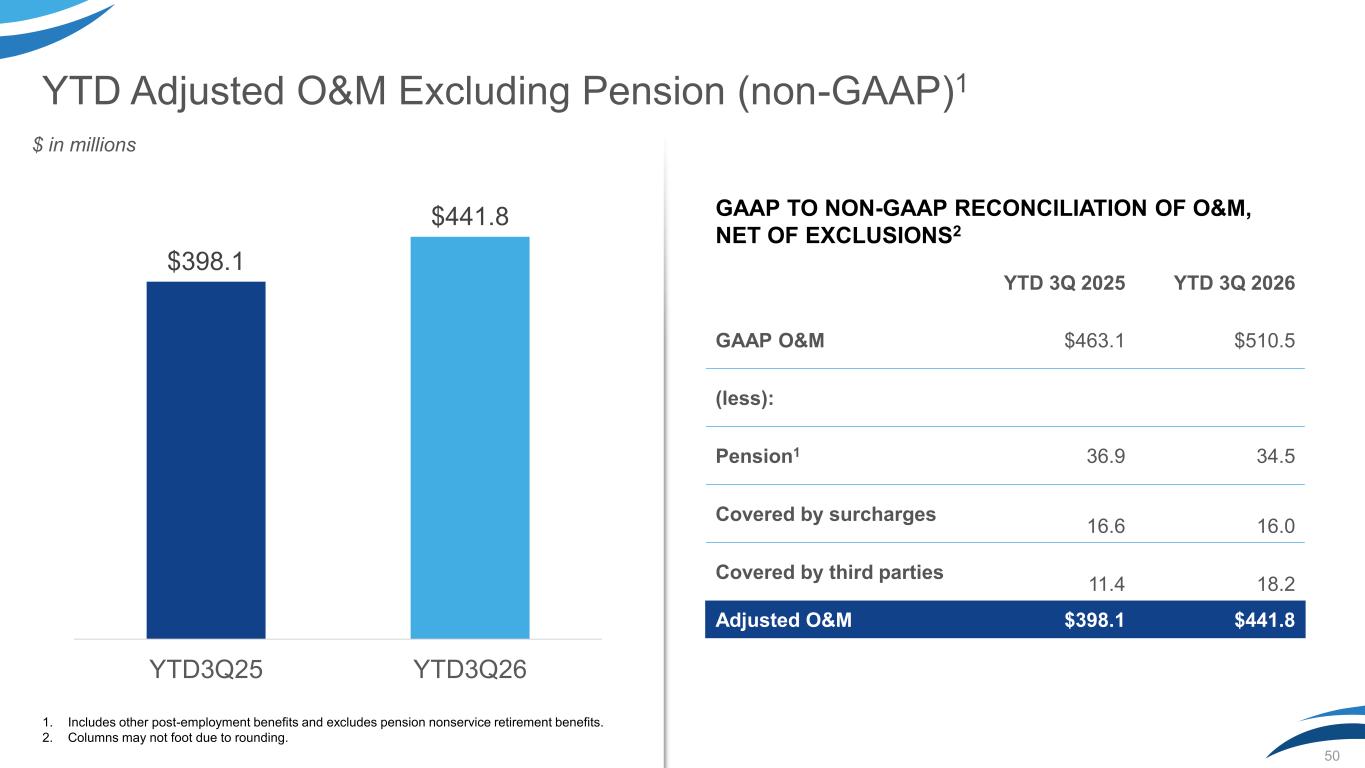
YTD Adjusted O&M Excluding Pension (non-GAAP)1 1. Includes other post-employment benefits and excludes pension nonservice retirement benefits. 2. Columns may not foot due to rounding. 50 $398.1 $441.8 YTD3Q25 YTD3Q26 GAAP TO NON-GAAP RECONCILIATION OF O&M, NET OF EXCLUSIONS2 YTD 3Q 2025 YTD 3Q 2026 GAAP O&M $463.1 $510.5 (less): Pension1 36.9 34.5 Covered by surcharges 16.6 16.0 Covered by third parties 11.4 18.2 Adjusted O&M $398.1 $441.8 $ in millions
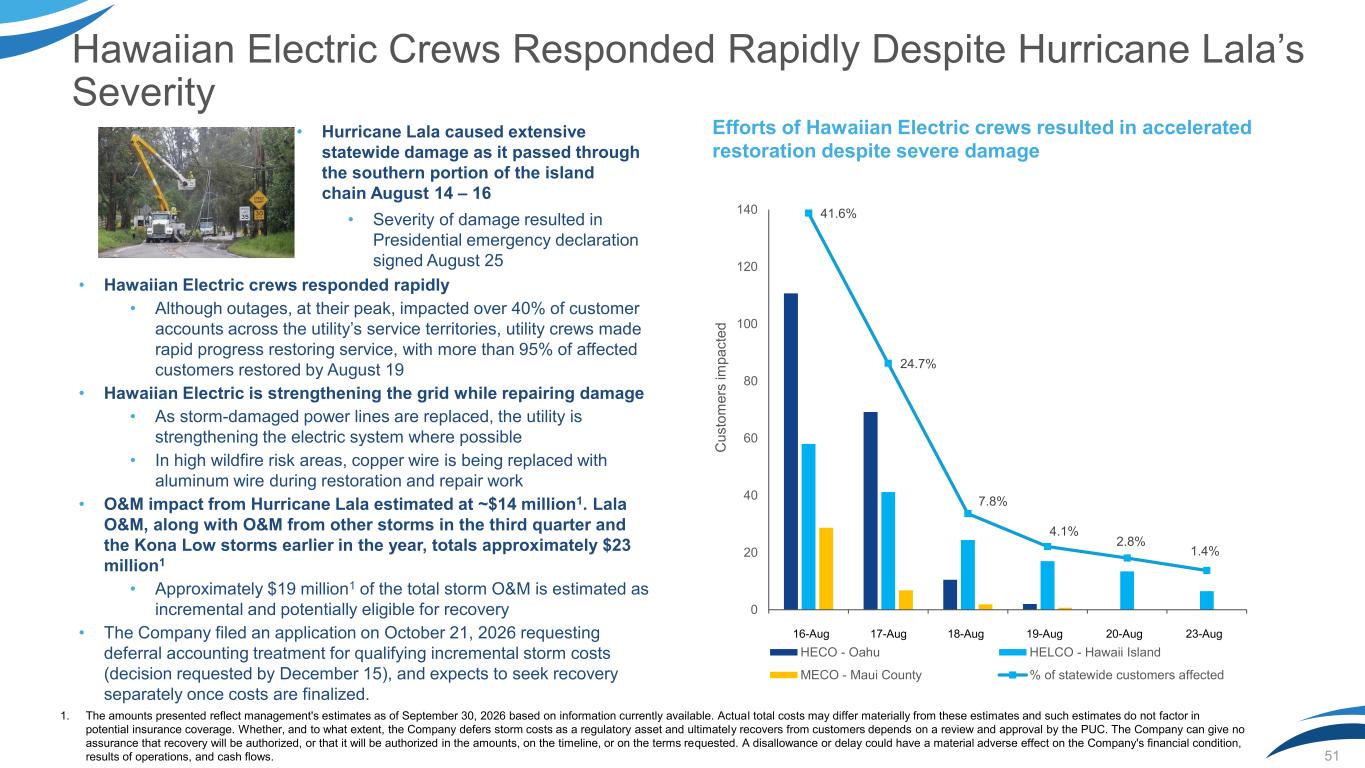
Hawaiian Electric Crews Responded Rapidly Despite Hurricane Lala’s Severity 51 • Hawaiian Electric crews responded rapidly • Although outages, at their peak, impacted over 40% of customer accounts across the utility’s service territories, utility crews made rapid progress restoring service, with more than 95% of affected customers restored by August 19 • Hawaiian Electric is strengthening the grid while repairing damage • As storm-damaged power lines are replaced, the utility is strengthening the electric system where possible • In high wildfire risk areas, copper wire is being replaced with aluminum wire during restoration and repair work • O&M impact from Hurricane Lala estimated at ~$14 million1. Lala O&M, along with O&M from other storms in the third quarter and the Kona Low storms earlier in the year, totals approximately $23 million1 • Approximately $19 million1 of the total storm O&M is estimated as incremental and potentially eligible for recovery • The Company filed an application on October 21, 2026 requesting deferral accounting treatment for qualifying incremental storm costs (decision requested by December 15), and expects to seek recovery separately once costs are finalized. 41.6% 24.7% 7.8% 4.1% 2.8% 1.4% 0 20 40 60 80 100 120 140 1.0 2.0 3.0 4.0 5.0 6.0 HECO - Oahu HELCO - Hawaii Island MECO - Maui County % of statewide customers affected 16-Aug 17-Aug 18-Aug 19-Aug 20-Aug 23-Aug Efforts of Hawaiian Electric crews resulted in accelerated restoration despite severe damage C u s to m e rs i m p a c te d • Hurricane Lala caused extensive statewide damage as it passed through the southern portion of the island chain August 14 – 16 • Severity of damage resulted in Presidential emergency declaration signed August 25 1. The amounts presented reflect management's estimates as of September 30, 2026 based on information currently available. Actual total costs may differ materially from these estimates and such estimates do not factor in potential insurance coverage. Whether, and to what extent, the Company defers storm costs as a regulatory asset and ultimately recovers from customers depends on a review and approval by the PUC. The Company can give no assurance that recovery will be authorized, or that it will be authorized in the amounts, on the timeline, or on the terms requested. A disallowance or delay could have a material adverse effect on the Company's financial condition, results of operations, and cash flows.
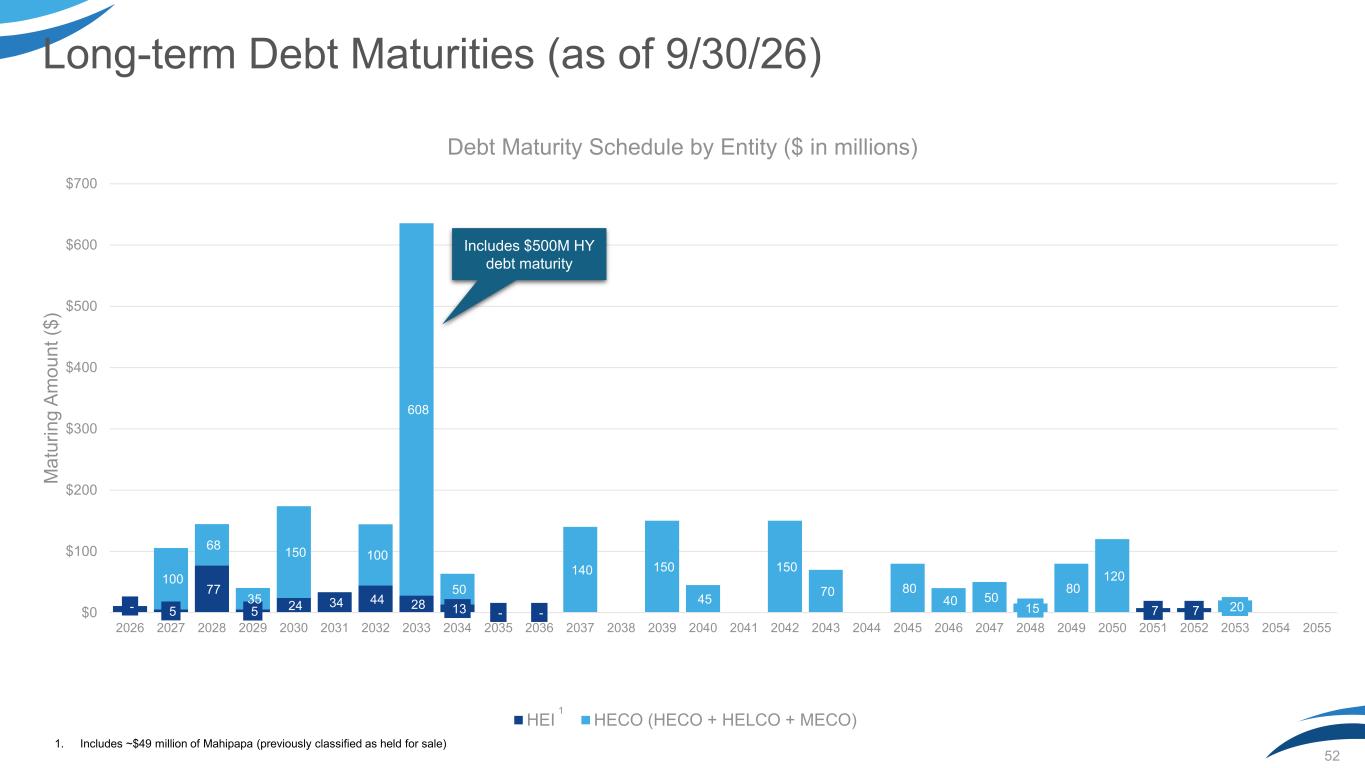
Long-term Debt Maturities (as of 9/30/26) 52 11 5 77 5 24 34 44 28 13 0 0 - - - - - - - - - - - - - - 7 7 - - - - 100 68 35 150 - 100 608 50 - - 140 150 45 150 70 80 40 50 15 80 120 - - 20 $0 $100 $200 $300 $400 $500 $600 $700 2026 2027 2028 2029 2030 2031 2032 2033 2034 2035 2036 2037 2038 2039 2040 2041 2042 2043 2044 2045 2046 2047 2048 2049 2050 2051 2052 2053 2054 2055 M a tu ri n g A m o u n t ($ ) Debt Maturity Schedule by Entity ($ in millions) HEI HECO (HECO + HELCO + MECO) Includes $500M HY debt maturity 1 1. Includes ~$49 million of Mahipapa (previously classified as held for sale)
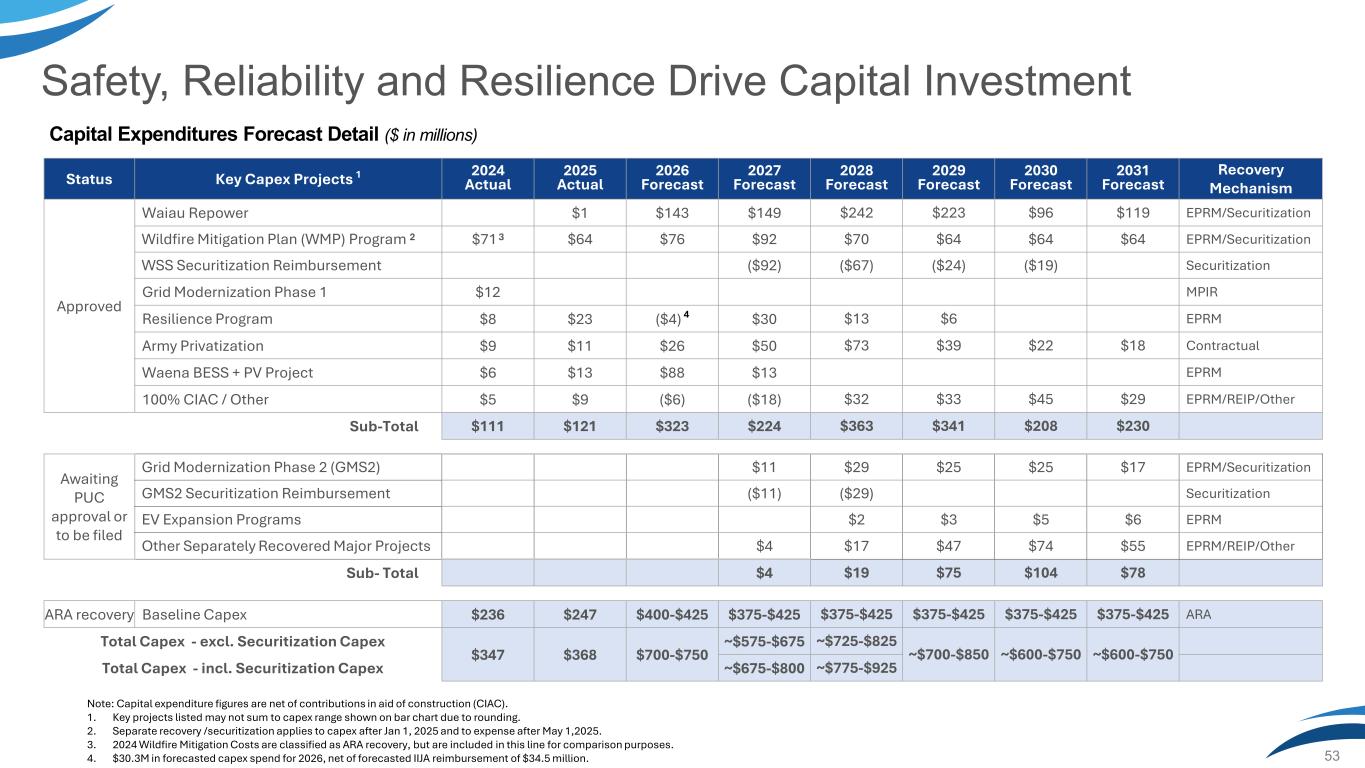
Note: Capital expenditure figures are net of contributions in aid of construction (CIAC). 1. Key projects listed may not sum to capex range shown on bar chart due to rounding. 2. Separate recovery /securitization applies to capex after Jan 1, 2025 and to expense after May 1,2025. 3. 2024 Wildfire Mitigation Costs are classified as ARA recovery, but are included in this line for comparison purposes. 4. $30.3M in forecasted capex spend for 2026, net of forecasted IIJA reimbursement of $34.5 million. Safety, Reliability and Resilience Drive Capital Investment 53 Capital Expenditures Forecast Detail ($ in millions) Status Key Capex Projects 1 2024 Actual 2025 Actual 2026 Forecast 2027 Forecast 2028 Forecast 2029 Forecast 2030 Forecast 2031 Forecast Recovery Mechanism Approved Waiau Repower $1 $143 $149 $242 $223 $96 $119 EPRM/Securitization Wildfire Mitigation Plan (WMP) Program 2 $71 3 $64 $76 $92 $70 $64 $64 $64 EPRM/Securitization WSS Securitization Reimbursement ($92) ($67) ($24) ($19) Securitization Grid Modernization Phase 1 $12 MPIR Resilience Program $8 $23 ($4) 4 $30 $13 $6 EPRM Army Privatization $9 $11 $26 $50 $73 $39 $22 $18 Contractual Waena BESS + PV Project $6 $13 $88 $13 EPRM 100% CIAC / Other $5 $9 ($6) ($18) $32 $33 $45 $29 EPRM/REIP/Other Sub-Total $111 $121 $323 $224 $363 $341 $208 $230 Awaiting PUC approval or to be filed Grid Modernization Phase 2 (GMS2) $11 $29 $25 $25 $17 EPRM/Securitization GMS2 Securitization Reimbursement ($11) ($29) Securitization EV Expansion Programs $2 $3 $5 $6 EPRM Other Separately Recovered Major Projects $4 $17 $47 $74 $55 EPRM/REIP/Other Sub- Total $4 $19 $75 $104 $78 ARA recovery Baseline Capex $236 $247 $400-$425 $375-$425 $375-$425 $375-$425 $375-$425 $375-$425 ARA Total Capex - excl. Securitization Capex $347 $368 $700-$750 ~$575-$675 ~$725-$825 ~$700-$850 ~$600-$750 ~$600-$750 Total Capex - incl. Securitization Capex ~$675-$800 ~$775-$925
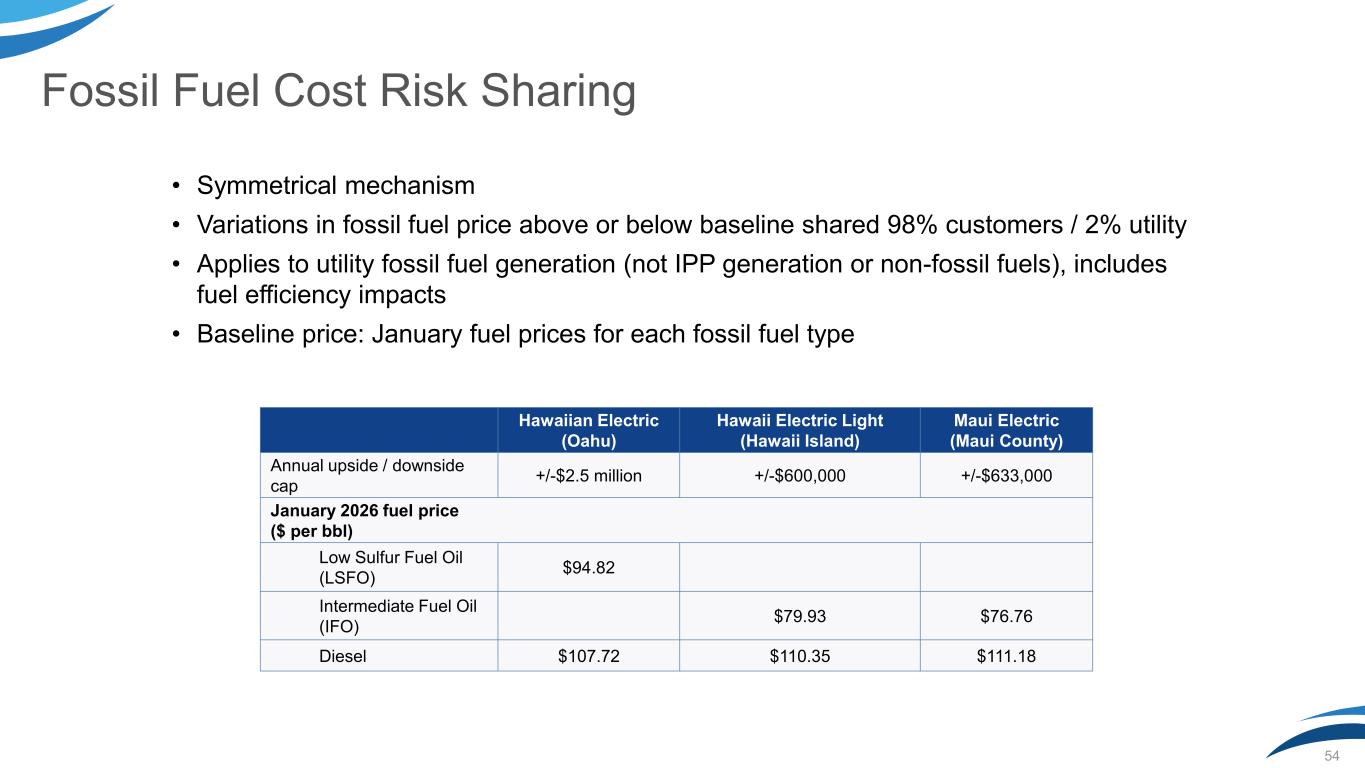
Fossil Fuel Cost Risk Sharing • Symmetrical mechanism • Variations in fossil fuel price above or below baseline shared 98% customers / 2% utility • Applies to utility fossil fuel generation (not IPP generation or non-fossil fuels), includes fuel efficiency impacts • Baseline price: January fuel prices for each fossil fuel type 54 Hawaiian Electric (Oahu) Hawaii Electric Light (Hawaii Island) Maui Electric (Maui County) Annual upside / downside cap +/-$2.5 million +/-$600,000 +/-$633,000 January 2026 fuel price ($ per bbl) Low Sulfur Fuel Oil (LSFO) $94.82 Intermediate Fuel Oil (IFO) $79.93 $76.76 Diesel $107.72 $110.35 $111.18
How Do Separate Recovery Mechanisms Work? • EPRM: Provide specific revenue requirements for each project. Revenues are accrued with minimal lag, starting the first day of the month following project completion ‒ Total revenue requirement (RR) for each project consists of a capital revenue requirement and an expense revenue requirement ‒ RR = O+T+D+r(RB); Operating expenses + taxes + depreciation + return on rate base • Pilot Projects: Intended to foster innovation by establishing an expedited implementation process for pilots that test new technologies, programs and business models. The utility can submit specific proposals and the PUC will target issuing a decision within 45 days, otherwise the proposal is considered approved as submitted ‒ Allows utility to defer and recover total annual expenditures, subject to an annual cap of $10M, over twelve months 55
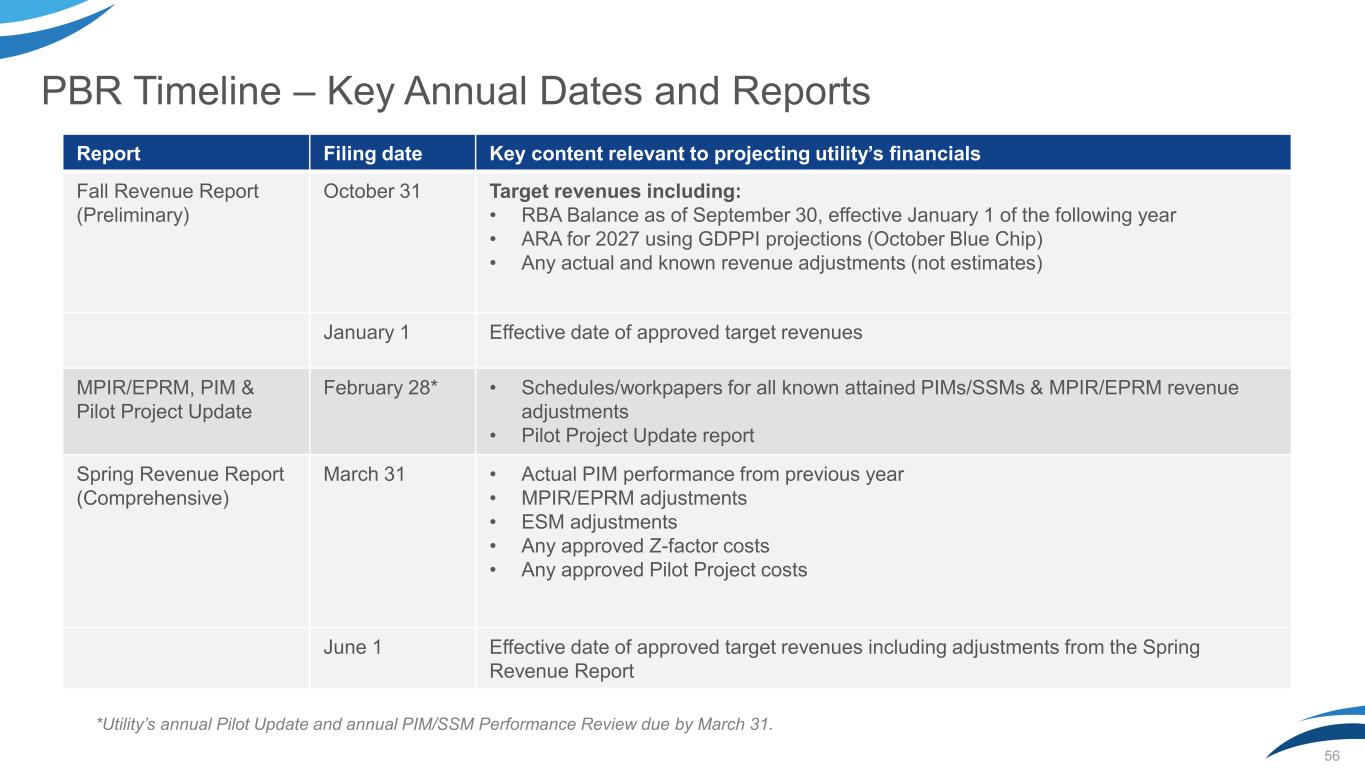
PBR Timeline – Key Annual Dates and Reports 56 *Utility’s annual Pilot Update and annual PIM/SSM Performance Review due by March 31. Report Filing date Key content relevant to projecting utility’s financials Fall Revenue Report (Preliminary) October 31 Target revenues including: • RBA Balance as of September 30, effective January 1 of the following year • ARA for 2027 using GDPPI projections (October Blue Chip) • Any actual and known revenue adjustments (not estimates) January 1 Effective date of approved target revenues MPIR/EPRM, PIM & Pilot Project Update February 28* • Schedules/workpapers for all known attained PIMs/SSMs & MPIR/EPRM revenue adjustments • Pilot Project Update report Spring Revenue Report (Comprehensive) March 31 • Actual PIM performance from previous year • MPIR/EPRM adjustments • ESM adjustments • Any approved Z-factor costs • Any approved Pilot Project costs June 1 Effective date of approved target revenues including adjustments from the Spring Revenue Report
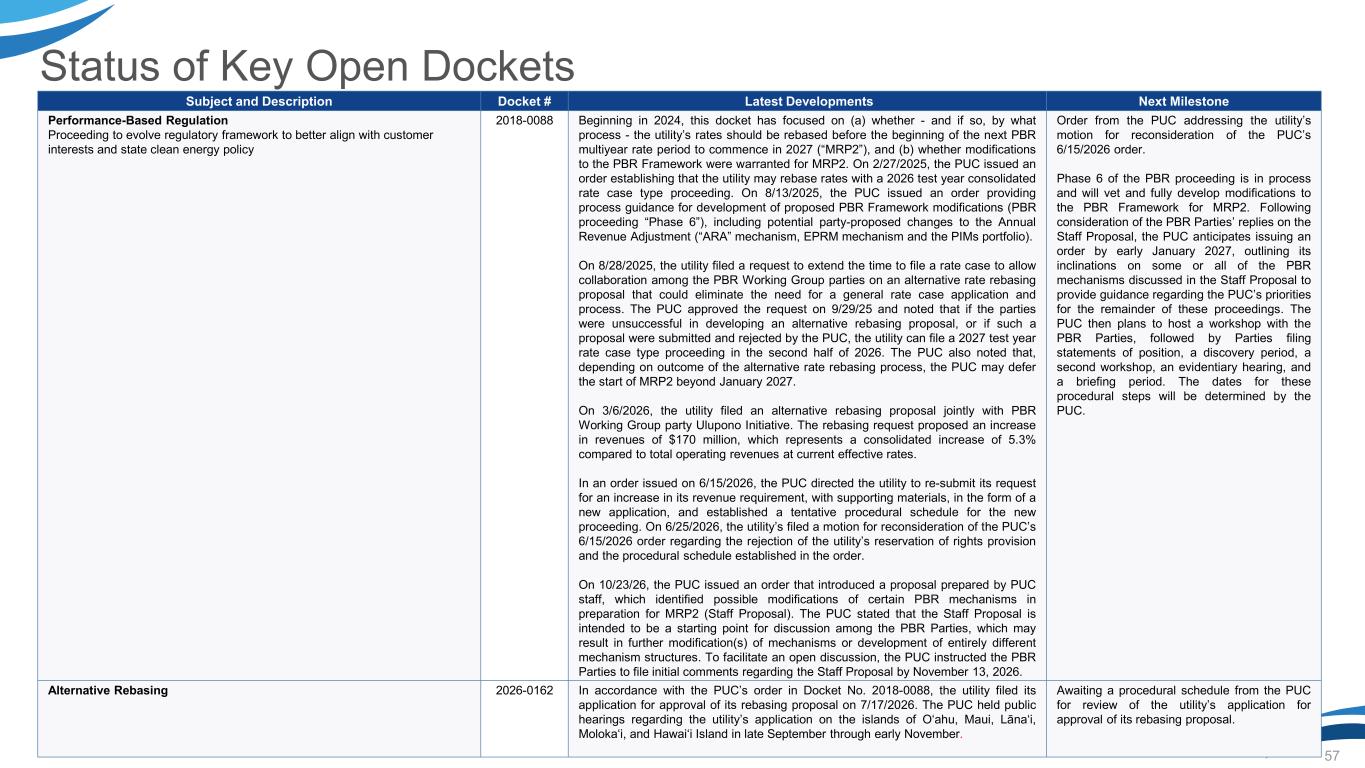
Status of Key Open Dockets 57 Subject and Description Docket # Latest Developments Next Milestone Performance-Based Regulation Proceeding to evolve regulatory framework to better align with customer interests and state clean energy policy 2018-0088 Beginning in 2024, this docket has focused on (a) whether - and if so, by what process - the utility’s rates should be rebased before the beginning of the next PBR multiyear rate period to commence in 2027 (“MRP2”), and (b) whether modifications to the PBR Framework were warranted for MRP2. On 2/27/2025, the PUC issued an order establishing that the utility may rebase rates with a 2026 test year consolidated rate case type proceeding. On 8/13/2025, the PUC issued an order providing process guidance for development of proposed PBR Framework modifications (PBR proceeding “Phase 6”), including potential party-proposed changes to the Annual Revenue Adjustment (“ARA” mechanism, EPRM mechanism and the PIMs portfolio). On 8/28/2025, the utility filed a request to extend the time to file a rate case to allow collaboration among the PBR Working Group parties on an alternative rate rebasing proposal that could eliminate the need for a general rate case application and process. The PUC approved the request on 9/29/25 and noted that if the parties were unsuccessful in developing an alternative rebasing proposal, or if such a proposal were submitted and rejected by the PUC, the utility can file a 2027 test year rate case type proceeding in the second half of 2026. The PUC also noted that, depending on outcome of the alternative rate rebasing process, the PUC may defer the start of MRP2 beyond January 2027. On 3/6/2026, the utility filed an alternative rebasing proposal jointly with PBR Working Group party Ulupono Initiative. The rebasing request proposed an increase in revenues of $170 million, which represents a consolidated increase of 5.3% compared to total operating revenues at current effective rates. In an order issued on 6/15/2026, the PUC directed the utility to re-submit its request for an increase in its revenue requirement, with supporting materials, in the form of a new application, and established a tentative procedural schedule for the new proceeding. On 6/25/2026, the utility’s filed a motion for reconsideration of the PUC’s 6/15/2026 order regarding the rejection of the utility’s reservation of rights provision and the procedural schedule established in the order. On 10/23/26, the PUC issued an order that introduced a proposal prepared by PUC staff, which identified possible modifications of certain PBR mechanisms in preparation for MRP2 (Staff Proposal). The PUC stated that the Staff Proposal is intended to be a starting point for discussion among the PBR Parties, which may result in further modification(s) of mechanisms or development of entirely different mechanism structures. To facilitate an open discussion, the PUC instructed the PBR Parties to file initial comments regarding the Staff Proposal by November 13, 2026. Order from the PUC addressing the utility’s motion for reconsideration of the PUC’s 6/15/2026 order. Phase 6 of the PBR proceeding is in process and will vet and fully develop modifications to the PBR Framework for MRP2. Following consideration of the PBR Parties’ replies on the Staff Proposal, the PUC anticipates issuing an order by early January 2027, outlining its inclinations on some or all of the PBR mechanisms discussed in the Staff Proposal to provide guidance regarding the PUC’s priorities for the remainder of these proceedings. The PUC then plans to host a workshop with the PBR Parties, followed by Parties filing statements of position, a discovery period, a second workshop, an evidentiary hearing, and a briefing period. The dates for these procedural steps will be determined by the PUC. Alternative Rebasing 2026-0162 In accordance with the PUC’s order in Docket No. 2018-0088, the utility filed its application for approval of its rebasing proposal on 7/17/2026. The PUC held public hearings regarding the utility’s application on the islands of O‘ahu, Maui, Lānaʻi, Molokaʻi, and Hawai‘i Island in late September through early November. Awaiting a procedural schedule from the PUC for review of the utility’s application for approval of its rebasing proposal.
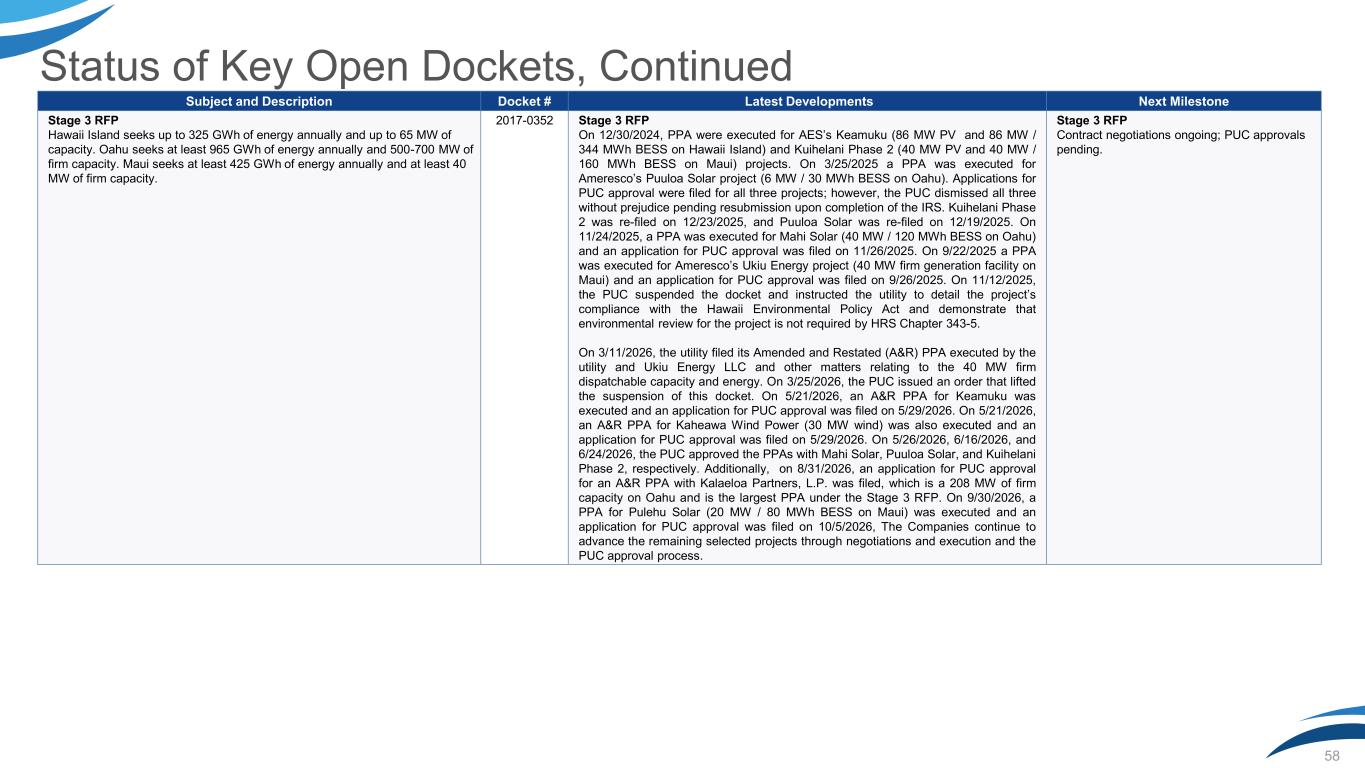
Status of Key Open Dockets, Continued 58 Subject and Description Docket # Latest Developments Next Milestone Stage 3 RFP Hawaii Island seeks up to 325 GWh of energy annually and up to 65 MW of capacity. Oahu seeks at least 965 GWh of energy annually and 500-700 MW of firm capacity. Maui seeks at least 425 GWh of energy annually and at least 40 MW of firm capacity. 2017-0352 Stage 3 RFP On 12/30/2024, PPA were executed for AES’s Keamuku (86 MW PV and 86 MW / 344 MWh BESS on Hawaii Island) and Kuihelani Phase 2 (40 MW PV and 40 MW / 160 MWh BESS on Maui) projects. On 3/25/2025 a PPA was executed for Ameresco’s Puuloa Solar project (6 MW / 30 MWh BESS on Oahu). Applications for PUC approval were filed for all three projects; however, the PUC dismissed all three without prejudice pending resubmission upon completion of the IRS. Kuihelani Phase 2 was re-filed on 12/23/2025, and Puuloa Solar was re-filed on 12/19/2025. On 11/24/2025, a PPA was executed for Mahi Solar (40 MW / 120 MWh BESS on Oahu) and an application for PUC approval was filed on 11/26/2025. On 9/22/2025 a PPA was executed for Ameresco’s Ukiu Energy project (40 MW firm generation facility on Maui) and an application for PUC approval was filed on 9/26/2025. On 11/12/2025, the PUC suspended the docket and instructed the utility to detail the project’s compliance with the Hawaii Environmental Policy Act and demonstrate that environmental review for the project is not required by HRS Chapter 343-5. On 3/11/2026, the utility filed its Amended and Restated (A&R) PPA executed by the utility and Ukiu Energy LLC and other matters relating to the 40 MW firm dispatchable capacity and energy. On 3/25/2026, the PUC issued an order that lifted the suspension of this docket. On 5/21/2026, an A&R PPA for Keamuku was executed and an application for PUC approval was filed on 5/29/2026. On 5/21/2026, an A&R PPA for Kaheawa Wind Power (30 MW wind) was also executed and an application for PUC approval was filed on 5/29/2026. On 5/26/2026, 6/16/2026, and 6/24/2026, the PUC approved the PPAs with Mahi Solar, Puuloa Solar, and Kuihelani Phase 2, respectively. Additionally, on 8/31/2026, an application for PUC approval for an A&R PPA with Kalaeloa Partners, L.P. was filed, which is a 208 MW of firm capacity on Oahu and is the largest PPA under the Stage 3 RFP. On 9/30/2026, a PPA for Pulehu Solar (20 MW / 80 MWh BESS on Maui) was executed and an application for PUC approval was filed on 10/5/2026, The Companies continue to advance the remaining selected projects through negotiations and execution and the PUC approval process. Stage 3 RFP Contract negotiations ongoing; PUC approvals pending.
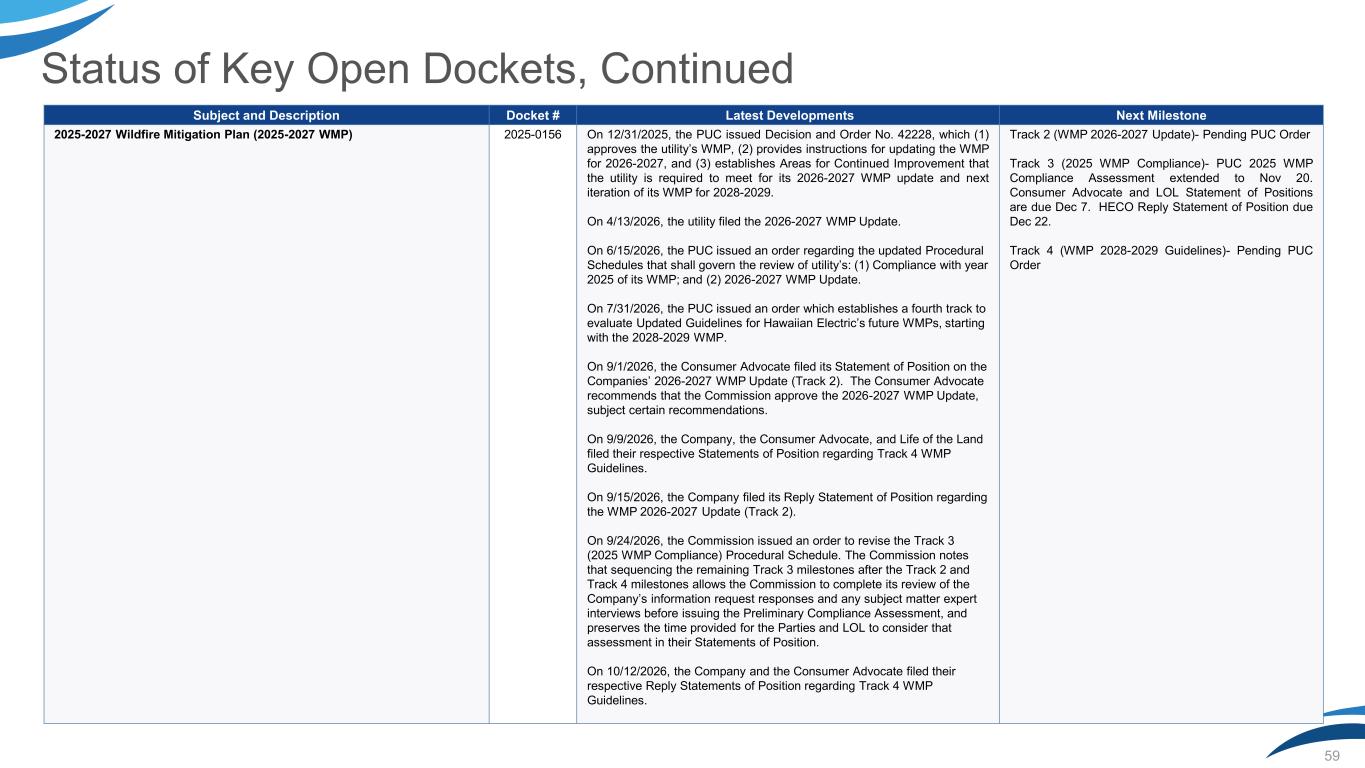
59 Subject and Description Docket # Latest Developments Next Milestone 2025-2027 Wildfire Mitigation Plan (2025-2027 WMP) 2025-0156 On 12/31/2025, the PUC issued Decision and Order No. 42228, which (1) approves the utility’s WMP, (2) provides instructions for updating the WMP for 2026-2027, and (3) establishes Areas for Continued Improvement that the utility is required to meet for its 2026-2027 WMP update and next iteration of its WMP for 2028-2029. On 4/13/2026, the utility filed the 2026-2027 WMP Update. On 6/15/2026, the PUC issued an order regarding the updated Procedural Schedules that shall govern the review of utility’s: (1) Compliance with year 2025 of its WMP; and (2) 2026-2027 WMP Update. On 7/31/2026, the PUC issued an order which establishes a fourth track to evaluate Updated Guidelines for Hawaiian Electric’s future WMPs, starting with the 2028-2029 WMP. On 9/1/2026, the Consumer Advocate filed its Statement of Position on the Companies’ 2026-2027 WMP Update (Track 2). The Consumer Advocate recommends that the Commission approve the 2026-2027 WMP Update, subject certain recommendations. On 9/9/2026, the Company, the Consumer Advocate, and Life of the Land filed their respective Statements of Position regarding Track 4 WMP Guidelines. On 9/15/2026, the Company filed its Reply Statement of Position regarding the WMP 2026-2027 Update (Track 2). On 9/24/2026, the Commission issued an order to revise the Track 3 (2025 WMP Compliance) Procedural Schedule. The Commission notes that sequencing the remaining Track 3 milestones after the Track 2 and Track 4 milestones allows the Commission to complete its review of the Company’s information request responses and any subject matter expert interviews before issuing the Preliminary Compliance Assessment, and preserves the time provided for the Parties and LOL to consider that assessment in their Statements of Position. On 10/12/2026, the Company and the Consumer Advocate filed their respective Reply Statements of Position regarding Track 4 WMP Guidelines. Track 2 (WMP 2026-2027 Update)- Pending PUC Order Track 3 (2025 WMP Compliance)- PUC 2025 WMP Compliance Assessment extended to Nov 20. Consumer Advocate and LOL Statement of Positions are due Dec 7. HECO Reply Statement of Position due Dec 22. Track 4 (WMP 2028-2029 Guidelines)- Pending PUC Order Status of Key Open Dockets, Continued
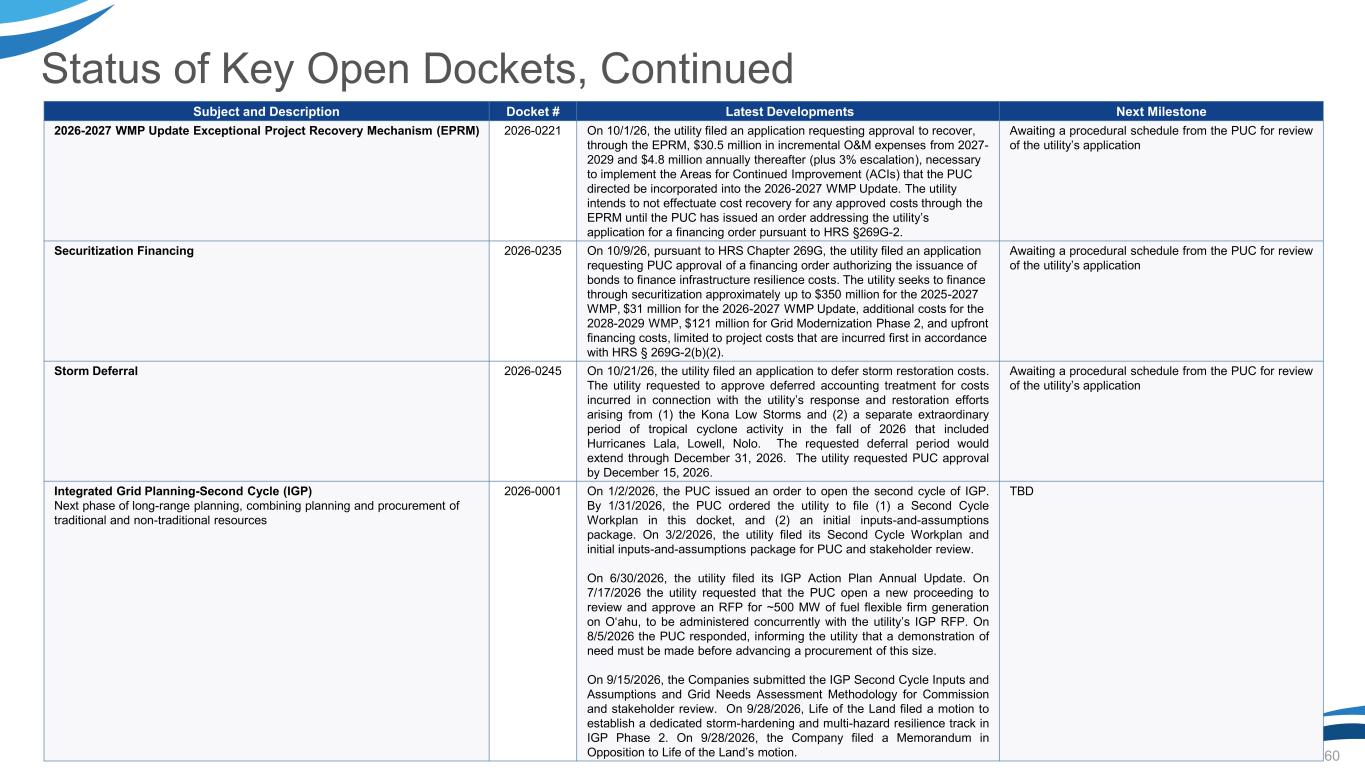
60 Subject and Description Docket # Latest Developments Next Milestone 2026-2027 WMP Update Exceptional Project Recovery Mechanism (EPRM) 2026-0221 On 10/1/26, the utility filed an application requesting approval to recover, through the EPRM, $30.5 million in incremental O&M expenses from 2027- 2029 and $4.8 million annually thereafter (plus 3% escalation), necessary to implement the Areas for Continued Improvement (ACIs) that the PUC directed be incorporated into the 2026-2027 WMP Update. The utility intends to not effectuate cost recovery for any approved costs through the EPRM until the PUC has issued an order addressing the utility’s application for a financing order pursuant to HRS §269G-2. Awaiting a procedural schedule from the PUC for review of the utility’s application Securitization Financing 2026-0235 On 10/9/26, pursuant to HRS Chapter 269G, the utility filed an application requesting PUC approval of a financing order authorizing the issuance of bonds to finance infrastructure resilience costs. The utility seeks to finance through securitization approximately up to $350 million for the 2025-2027 WMP, $31 million for the 2026-2027 WMP Update, additional costs for the 2028-2029 WMP, $121 million for Grid Modernization Phase 2, and upfront financing costs, limited to project costs that are incurred first in accordance with HRS § 269G-2(b)(2). Awaiting a procedural schedule from the PUC for review of the utility’s application Storm Deferral 2026-0245 On 10/21/26, the utility filed an application to defer storm restoration costs. The utility requested to approve deferred accounting treatment for costs incurred in connection with the utility’s response and restoration efforts arising from (1) the Kona Low Storms and (2) a separate extraordinary period of tropical cyclone activity in the fall of 2026 that included Hurricanes Lala, Lowell, Nolo. The requested deferral period would extend through December 31, 2026. The utility requested PUC approval by December 15, 2026. Awaiting a procedural schedule from the PUC for review of the utility’s application Integrated Grid Planning-Second Cycle (IGP) Next phase of long-range planning, combining planning and procurement of traditional and non-traditional resources 2026-0001 On 1/2/2026, the PUC issued an order to open the second cycle of IGP. By 1/31/2026, the PUC ordered the utility to file (1) a Second Cycle Workplan in this docket, and (2) an initial inputs-and-assumptions package. On 3/2/2026, the utility filed its Second Cycle Workplan and initial inputs-and-assumptions package for PUC and stakeholder review. On 6/30/2026, the utility filed its IGP Action Plan Annual Update. On 7/17/2026 the utility requested that the PUC open a new proceeding to review and approve an RFP for ~500 MW of fuel flexible firm generation on Oʻahu, to be administered concurrently with the utility’s IGP RFP. On 8/5/2026 the PUC responded, informing the utility that a demonstration of need must be made before advancing a procurement of this size. On 9/15/2026, the Companies submitted the IGP Second Cycle Inputs and Assumptions and Grid Needs Assessment Methodology for Commission and stakeholder review. On 9/28/2026, Life of the Land filed a motion to establish a dedicated storm-hardening and multi-hazard resilience track in IGP Phase 2. On 9/28/2026, the Company filed a Memorandum in Opposition to Life of the Land’s motion. TBD Status of Key Open Dockets, Continued
Cautionary Note Regarding Forward Looking Statements This report and other presentations made by Hawaiian Electric Industries, Inc. (HEI) and Hawaiian Electric Company, Inc. (Hawaiian Electric) and their subsidiaries contain “forward-looking statements,” which include statements that are predictive in nature, depend upon or refer to future events or conditions and usually include words such as “will,” “expects,” “anticipates,” “intends,” “plans,” “believes,” “predicts,” “estimates” or similar expressions. In addition, any statements concerning future financial performance, ongoing business strategies or prospects or possible future actions are also forward-looking statements. Forward-looking statements are based on current expectations and projections about future events and are subject to risks, uncertainties and the accuracy of assumptions concerning HEI and its subsidiaries (collectively, the Company), the performance of the industries in which they do business and economic, political and market factors, among other things. These forward-looking statements are not guarantees of future performance and actual results and financial condition may differ materially from those indicated in the forward-looking statements. • Risks, uncertainties and other important factors that could cause actual results to differ materially from those described in forward-looking statements and from historical results include, but are not limited to, the following: • the potential for further trade policy changes under the current administration could disrupt our supply chains and increase costs, e.g., the Utilities’ capital goods and equipment purchases and those of its independent power producers (IPPs) that contain components, sub-components, or raw materials sources from outside the U.S. could experience increases in costs, which could threaten the viability of projects and impact our ability to meet customer demand and the Utilities’ ability to achieve renewable portfolio standards (RPS) goals; • the impact of the Maui windstorm and wildfires, including potential liabilities in excess of settlement amounts and potential regulatory penalties, which may result in significant costs that may be unrecoverable (or not reimbursed on a timely basis) through insurance and/or rates; • an increase in insurance premiums and the inability to fully recover premiums through rates or the potential inability to obtain wildfire and general liability insurance coverage at reasonable rates, if available at all; • the ability to raise the amount of capital necessary on reasonable terms, if at all, for the Company’s and the Utilities’ contribution to the Maui wildfire tort litigation settlement in order to alleviate future conditions that may cause substantial doubt about HEI’s and the Utilities’ ability to continue as a going concern; • potential further dilution to existing shareholders if the Company raises funds by issuing additional equity or equity-linked securities; • the inability to execute financing plans to alleviate future conditions that may cause substantial doubt about HEI’s and the Utilities’ ability to continue as a going concern prior to the issuance of their respective annual financial statements, which could result in an event of default and an acceleration of the Company’s and the Utilities’ debt and lead to filing for bankruptcy protection if waivers from lenders are not received; • extreme weather events, including windstorms and other natural disasters, particularly those driven or exacerbated by evolving climate dynamics, which could increase the risk of the Utilities’ equipment being damaged, becoming inoperable or contributing to a wildfire; • future suspension, material reduction or extended delay in dividends or other distributions from operating subsidiaries to HEI; • further downgrades by credit rating agencies in their ratings of the securities of HEI and Hawaiian Electric and their impact on results of financing efforts; • the risks of suffering losses and incurring liabilities that are uninsured (e.g., damages to the Utilities’ transmission and distribution system and losses from business interruption) or underinsured (e.g., losses not covered as a result of insurance deductibles or other exclusions or exceeding policy limits), and the risks associated with the operation of transmission and distribution assets and power generation facilities, including public and employee safety issues, and assets causing or contributing to wildfires; • international, national and local economic and political conditions—including the state of the Hawaii tourism, defense and construction industries; the strength or weakness of the Hawaii and continental U.S. real estate markets; decisions concerning the extent of the presence of the federal government and military in Hawaii; the implications and potential impacts of federal government shutdowns, including the impact to the Utilities’ customers’ ability to pay their electric bills and the impact on the State of Hawaii economy; the implications and potential impacts of U.S. and foreign capital and credit market conditions and federal, state and international responses to those conditions; the potential impacts of global and local developments (including global economic conditions and uncertainties, unrest, terrorist acts, wars, conflicts, political protests, deadly virus epidemic or other crisis); the effects of changes that have or may occur in U.S. policy, such as with respect to immigration and trade; and pandemics; • the ability to adequately address risks and capitalize on opportunities related to the Company’s and the Utilities’ sustainab ility priority areas, which include safety, reliability and resilience, including relating to wildfires and other extreme weather events, decarbonization, economic health and affordability, secure digitalization, human capital management, employee engagement, and climate-related risks and opportunities; • citizen activism, including civil unrest, especially in times of severe economic depression and heightened social and political divisions, which could negatively impact customers and employees, impair the ability of the Company and the Utilities to operate and maintain their facilities in an effective and safe manner, and citizen or stakeholder activism that could delay the construction, increase project costs or preclude the completion of third-party or Utility projects that are required to meet electricity demand, resilience and reliability objectives and RPS and other climate-related goals; • the effects of actions or inaction of the U.S. government or related agencies, including those related to the U.S. debt ceiling or budget funding, monetary policy, trade policy, energy and environmental policy, and other policy and regulatory changes advanced or proposed by the current administration; 61
Cautionary Note Regarding Forward Looking Statements continued • weather, natural disasters (e.g., hurricanes, earthquakes, tsunamis, lightning strikes, lava flows and the effects of evolving climate dynamics, such as more severe storms, flooding, droughts, heat waves, and rising sea levels) and wildfires, including their impact on the resilience and reliability and cost of the Company’s and Util ities’ operations, and the economy; • the timing, speed and extent of changes in interest rates and the shape of the yield curve, which could result in higher borrowing costs and changes in market liquidity; • the continued ability of the Company and the Utilities to access the credit and capital markets to fund necessary investments and expenditures (e.g., to obtain short-term and long-term debt financing, including lines of credit, and, in the case of HEI, to issue common stock) under volatile and challenging market conditions, and the potential higher cost of such financings, if available, and due to the uncertainties associated with the costs related to the Maui windstorm and wildfires; • the risks inherent in changes in the value of the Company’s pension and other retirement plan assets, and the risks inherent in changes in the value of the Company’s pension liabilities, including changes driven by stock market values, interest rates and mortality improvements; • changes in laws, regulations (including tax regulations), market conditions, interest rates and other factors that result in changes in assumptions used to calculate retirement benefits costs and funding requirements; • the potential delay by the Public Utilities Commission of the State of Hawaii (PUC) in considering (and potential disapproval of actual or proposed) proposals related to rate rebasing, performance-based regulation (PBR), wildfire safety, renewable energy or grid resiliency, among others, and related costs; reliance by the Util ities on outside parties such as the State, IPPs and developers; supply-chain challenges; and uncertainties surrounding technologies, solar power, wind power, biofuels, liquefied natural gas, environmental assessments required to meet RPS and other climate-related goals; the impacts of implementation of the wildfire mitigation, renewable energy and resilience proposals on future costs of electricity and potential penalties imposed by the PUC for delays in the commercial operations of renewable energy projects; • the ability of the Utilities to develop, execute and recover the implementation costs of the Utilities’ action plans included in their Integrated Grid Plan, which was accepted by the PUC in 2024, due to the recent issuance of the PUC’s 2024 Inclinations on the Future of Energy in Hawaii, Governor Josh Green’s Executive Order No. 25-01, Accelerating Hawaii’s Transition Toward 100 Percent Renewable Energy, and the Hawaii State Energy Office’s Alternative Fuel, Repowering and Energy Transition Study on the aforementioned plans of the Util ities; • the ability of the Utilities to recover undepreciated cost of fossil fuel generating units, if they are required to be retired before the end of their expected useful life; • capacity and supply constraints or difficulties, especially if generating units (utility-owned or IPP-owned) fail or measures such as demand-side management, distributed generation, combined heat and power or other firm capacity supply-side resources fall short of achieving their forecasted benefits or are otherwise insufficient to reduce or meet peak demand; • high and/or volatile fuel prices, which increases working capital requirements and customer bills, or delivery of adequate fuel by suppliers (including as a result of the Iran war, Russia-Ukraine war and conflicts in the Middle East), which could affect the reliability of utility operations, and the continued availability to the Utilities of their Energy Cost Recovery Clauses (ECRCs); • the continued availability to the Utilities or modifications of other cost recovery mechanisms, including the Purchased Power Adjustment Clauses (PPACs), annual revenue adjustment (ARA) and pension and postretirement benefits other than pensions (OPEB) tracking mechanisms, and the continued decoupling of revenues from sales to mitigate the effects of declining kilowatt-hour sales; • the ability of the Utilities to recover increasing or additional costs (e.g., due to trade policies imposed by the current administration, tariffs, inflation, or other factors impacting prices) and earn a reasonable return on capital investments not covered by the ARA, while providing the customer dividend required by PBR; • the impact from the PUC’s modification of the PBR for the Utilities pursuant to Act 005, Session Laws 2018, including the potential changes to existing and/or addition of new Performance Incentive Mechanisms (PIMs), third-party proposals adopted by the PUC, and the implications of not achieving performance incentive goals; • the impact of fuel price levels and volatility on customer satisfaction and political and regulatory support for the Utilities; • unfavorable changes in economic conditions, such as sustained inflation, higher interest rates or recession, that negatively impact the ability of the Company’s customers to pay their utility bills and increase operating costs of the Utilities that cannot be passed on to, or recovered, from customers; • the risks associated with increasing reliance on renewable energy, including the availability and cost of non-fossil fuel supplies for renewable energy generation and the operational impacts and related cost impacts of adding intermittent sources of renewable energy to the electric grid; • the growing risk that energy production from renewable generating resources may be curtailed and the interconnection of additional resources will be constrained as more generating resources are added to the Utilities’ electric systems and as customers reduce their energy usage; • the ability of IPPs to deliver the firm capacity anticipated in their power purchase agreements (PPAs); • the potential that, as IPP contracts near the end of their terms, there may be less economic incentive for the IPPs to make investments in their units to ensure the availability of their units; • the ability of the Utilities to negotiate, periodically, favorable agreements for significant resources such as fuel supply contracts and collective bargaining agreements and avoid or mitigate labor disputes and work stoppages; 62
Cautionary Note Regarding Forward Looking Statements continued • new technological developments that could affect the operations and prospects of the Utilities or their competitors such as the commercial development of energy storage and microgrids; • the potential that cyber or physical security incidents, including potential incidents at HEI, its subsidiaries (including at electric utility plants), third-party service providers, contractors and customers with whom they have shared data (IPPs, distributed energy resources aggregators and customers enrolled under distributed energy resources programs) and incidents at data processing centers used, to the extent not prevented by physical and cybersecurity protections, could result in operational disruption; the misappropriation or loss of confidential or proprietary assets, information or data, including customer, employee, financial, or operating system information, or intellectual property; corruption of data; or potential costs, lost revenues, litigation, or reputational harm; • failure to achieve remaining cost savings commitment related to the management audit recommendations of $6.6 million per year during the multi-year rate period (MRP) from June 2021 to May 2026, and continuing until the second MRP begins; • federal, state, county and international governmental and regulatory actions, such as existing, new and changes in laws, rules and regulations applicable to HEI and the Utilities (including changes in taxation and tax rates, increases in capital requirements, regulatory policy changes, environmental laws and regulations (including result ing compliance costs and risks of fines and penalties and/or liabilities), the regulation of greenhouse gas emissions, governmental fees and assessments, and potential carbon pricing or “cap and trade” legislation that may fundamentally alter costs to produce electricity and accelerate the move to renewable generation); • the impact from the PUC’s implementation of wheeling for the Utilities, including cost shifting and customer equity considerations, the potential increased competition, and other legal and technical implications, pursuant to Act 266, which authorizes wheeling of renewable energy and requires the PUC to establish associated policies and procedures; • the impact of competitive pressures from third-party alternative generation resources and regulatory changes affecting the Company’s utility franchise may negatively impact its growth prospects, market position, and stock price; • developments in laws, regulations and policies governing protections for historic, archaeological and cultural sites, and plant and animal species and habitats, as well as developments in the implementation and enforcement of such laws, regulations and policies; • discovery of conditions that may be attributable to historical chemical releases, including any necessary investigation and remediation, and any associated enforcement, litigation or regulatory oversight; • decisions by the PUC in rate cases and other proceedings (including the risks of delays in the timing of decisions, adverse changes in final decisions from interim decisions and the disallowance of project costs as a result of adverse regulatory audit reports or otherwise); • decisions by the PUC and by other agencies and courts on land use, environmental and other permitting issues (such as required corrective actions, restrictions and penalties that may arise, such as with respect to environmental conditions or RPS); • the risks associated with the geographic concentration of HEI’s businesses; • changes in accounting principles applicable to HEI and its subsidiaries, including the adoption of new U.S. accounting standards, the potential discontinuance of regulatory accounting related to PBR or other regulatory changes, the effects of potentially required consolidation of variable interest entities (VIEs), or required finance lease or on-balance-sheet operating lease accounting for PPAs with IPPs; • the final outcome of tax positions taken by HEI and its subsidiaries; • the ability to effectively utilize federal and state net operating loss carryforwards; • the Company’s reliance on third parties and the risk of their non-performance; and • other risks or uncertainties described elsewhere in this report (e.g., Item 1A. Risk Factors) and in other reports previously and subsequently filed by HEI and/or Hawaiian Electric with the Securities and Exchange Commission (SEC). Forward-looking statements speak only as of the date of the report, presentation or filing in which they are made. Except to the extent required by the federal securities laws, HEI, Hawaiian Electric, Pacific Current and their subsidiaries undertake no obligation to publicly update or revise any forward-looking statements, whether written or oral and whether as a result of new information, future events or otherwise. 63
64 Explanation of HEI’s Use of Certain Unaudited Non-GAAP Measures HEI management uses certain non-GAAP measures to evaluate the performance of HEI. Management believes these non-GAAP measures provide useful information and are a better indicator of the companies’ core operating activities. Core earnings and other financial measures as presented here may not be comparable to similarly titled measures used by other companies, and they should be considered in addition to, and not as a substitute for, results prepared in accordance with GAAP. The accompanying tables provide a reconciliation of reported GAAP earnings to non-GAAP Core earnings. The reconciling adjustments from GAAP earnings to Core earnings are limited to the items related to the Maui wildfires, including the settlement remeasurement and accretion, impacts from HEI’s ownership stake in American Savings Bank, including realized and unrealized gains, and costs related to HEI’s exit from Pacific Current operating businesses. Management does not consider these items to be representative of the company’s fundamental Core earnings.
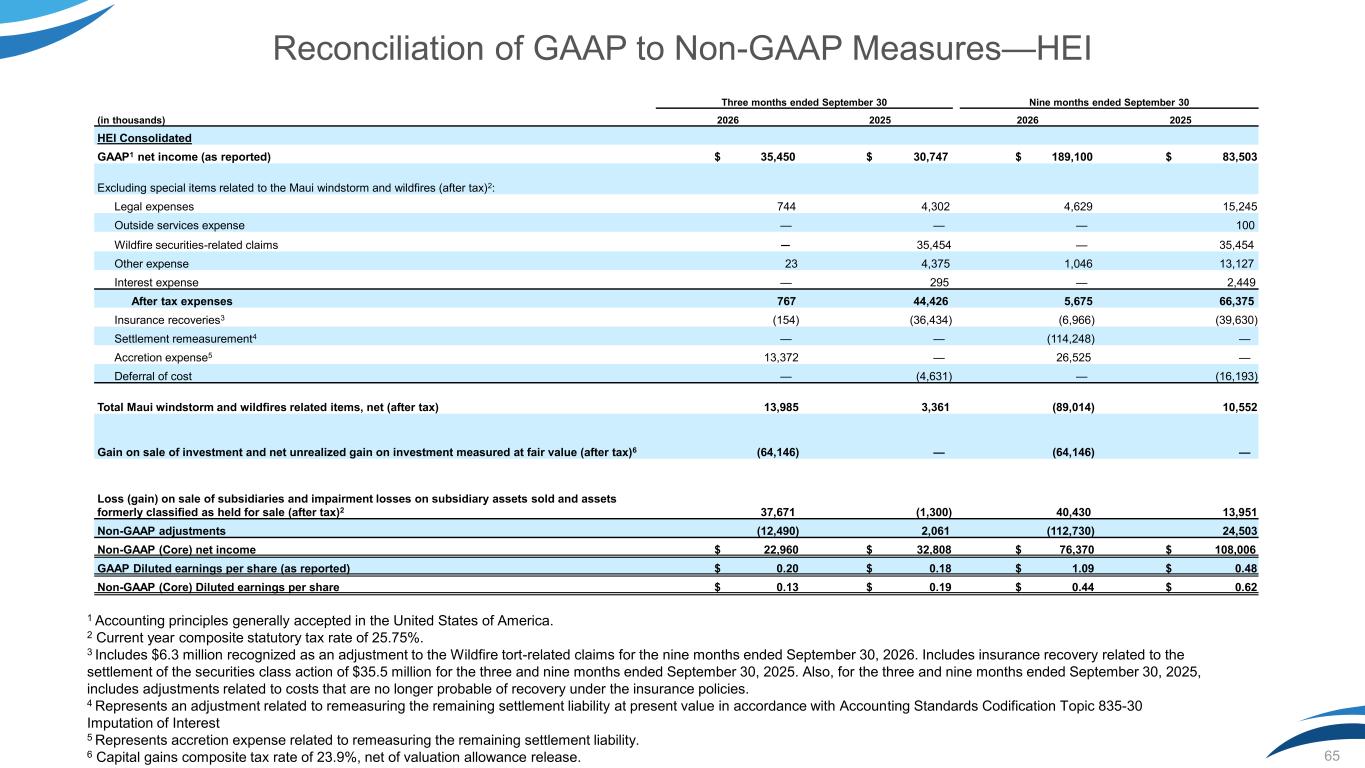
65 Reconciliation of GAAP to Non-GAAP Measures—HEI 1 Accounting principles generally accepted in the United States of America. 2 Current year composite statutory tax rate of 25.75%. 3 Includes $6.3 million recognized as an adjustment to the Wildfire tort-related claims for the nine months ended September 30, 2026. Includes insurance recovery related to the settlement of the securities class action of $35.5 million for the three and nine months ended September 30, 2025. Also, for the three and nine months ended September 30, 2025, includes adjustments related to costs that are no longer probable of recovery under the insurance policies. 4 Represents an adjustment related to remeasuring the remaining settlement liability at present value in accordance with Accounting Standards Codification Topic 835-30 Imputation of Interest 5 Represents accretion expense related to remeasuring the remaining settlement liability. 6 Capital gains composite tax rate of 23.9%, net of valuation allowance release. Three months ended September 30 Nine months ended September 30 (in thousands) 2026 2025 2026 2025 HEI Consolidated GAAP1 net income (as reported) $ 35,450 $ 30,747 $ 189,100 $ 83,503 Excluding special items related to the Maui windstorm and wildfires (after tax)2: Legal expenses 744 4,302 4,629 15,245 Outside services expense — — — 100 Wildfire securities-related claims — 35,454 — 35,454 Other expense 23 4,375 1,046 13,127 Interest expense — 295 — 2,449 After tax expenses 767 44,426 5,675 66,375 Insurance recoveries3 (154) (36,434) (6,966) (39,630) Settlement remeasurement4 — — (114,248) — Accretion expense5 13,372 — 26,525 — Deferral of cost — (4,631) — (16,193) Total Maui windstorm and wildfires related items, net (after tax) 13,985 3,361 (89,014) 10,552 Gain on sale of investment and net unrealized gain on investment measured at fair value (after tax)6 (64,146) — (64,146) — Loss (gain) on sale of subsidiaries and impairment losses on subsidiary assets sold and assets formerly classified as held for sale (after tax)2 37,671 (1,300) 40,430 13,951 Non-GAAP adjustments (12,490) 2,061 (112,730) 24,503 Non-GAAP (Core) net income $ 22,960 $ 32,808 $ 76,370 $ 108,006 GAAP Diluted earnings per share (as reported) $ 0.20 $ 0.18 $ 1.09 $ 0.48 Non-GAAP (Core) Diluted earnings per share $ 0.13 $ 0.19 $ 0.44 $ 0.62
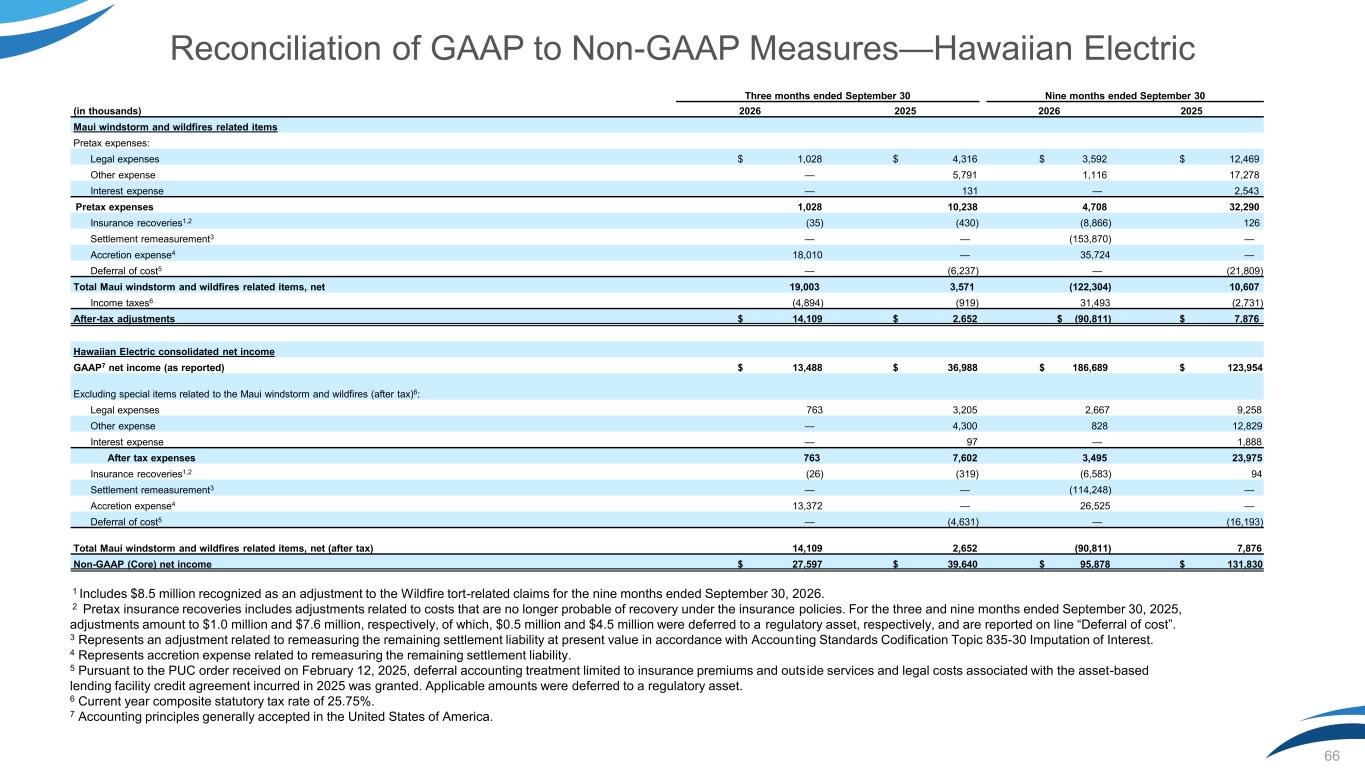
66 Reconciliation of GAAP to Non-GAAP Measures—Hawaiian Electric 1 Includes $8.5 million recognized as an adjustment to the Wildfire tort-related claims for the nine months ended September 30, 2026. 2 Pretax insurance recoveries includes adjustments related to costs that are no longer probable of recovery under the insurance policies. For the three and nine months ended September 30, 2025, adjustments amount to $1.0 million and $7.6 million, respectively, of which, $0.5 million and $4.5 million were deferred to a regulatory asset, respectively, and are reported on line “Deferral of cost”. 3 Represents an adjustment related to remeasuring the remaining settlement liability at present value in accordance with Accounting Standards Codification Topic 835-30 Imputation of Interest. 4 Represents accretion expense related to remeasuring the remaining settlement liability. 5 Pursuant to the PUC order received on February 12, 2025, deferral accounting treatment limited to insurance premiums and outside services and legal costs associated with the asset-based lending facility credit agreement incurred in 2025 was granted. Applicable amounts were deferred to a regulatory asset. 6 Current year composite statutory tax rate of 25.75%. 7 Accounting principles generally accepted in the United States of America. Three months ended September 30 Nine months ended September 30 (in thousands) 2026 2025 2026 2025 Maui windstorm and wildfires related items Pretax expenses: Legal expenses $ 1,028 $ 4,316 $ 3,592 $ 12,469 Other expense — 5,791 1,116 17,278 Interest expense — 131 — 2,543 Pretax expenses 1,028 10,238 4,708 32,290 Insurance recoveries1,2 (35) (430) (8,866) 126 Settlement remeasurement3 — — (153,870) — Accretion expense4 18,010 — 35,724 — Deferral of cost5 — (6,237) — (21,809) Total Maui windstorm and wildfires related items, net 19,003 3,571 (122,304) 10,607 Income taxes6 (4,894) (919) 31,493 (2,731) After-tax adjustments $ 14,109 $ 2,652 $ (90,811) $ 7,876 Hawaiian Electric consolidated net income GAAP7 net income (as reported) $ 13,488 $ 36,988 $ 186,689 $ 123,954 Excluding special items related to the Maui windstorm and wildfires (after tax)6: Legal expenses 763 3,205 2,667 9,258 Other expense — 4,300 828 12,829 Interest expense — 97 — 1,888 After tax expenses 763 7,602 3,495 23,975 Insurance recoveries1,2 (26) (319) (6,583) 94 Settlement remeasurement3 — — (114,248) — Accretion expense4 13,372 — 26,525 — Deferral of cost5 — (4,631) — (16,193) Total Maui windstorm and wildfires related items, net (after tax) 14,109 2,652 (90,811) 7,876 Non-GAAP (Core) net income $ 27,597 $ 39,640 $ 95,878 $ 131,830
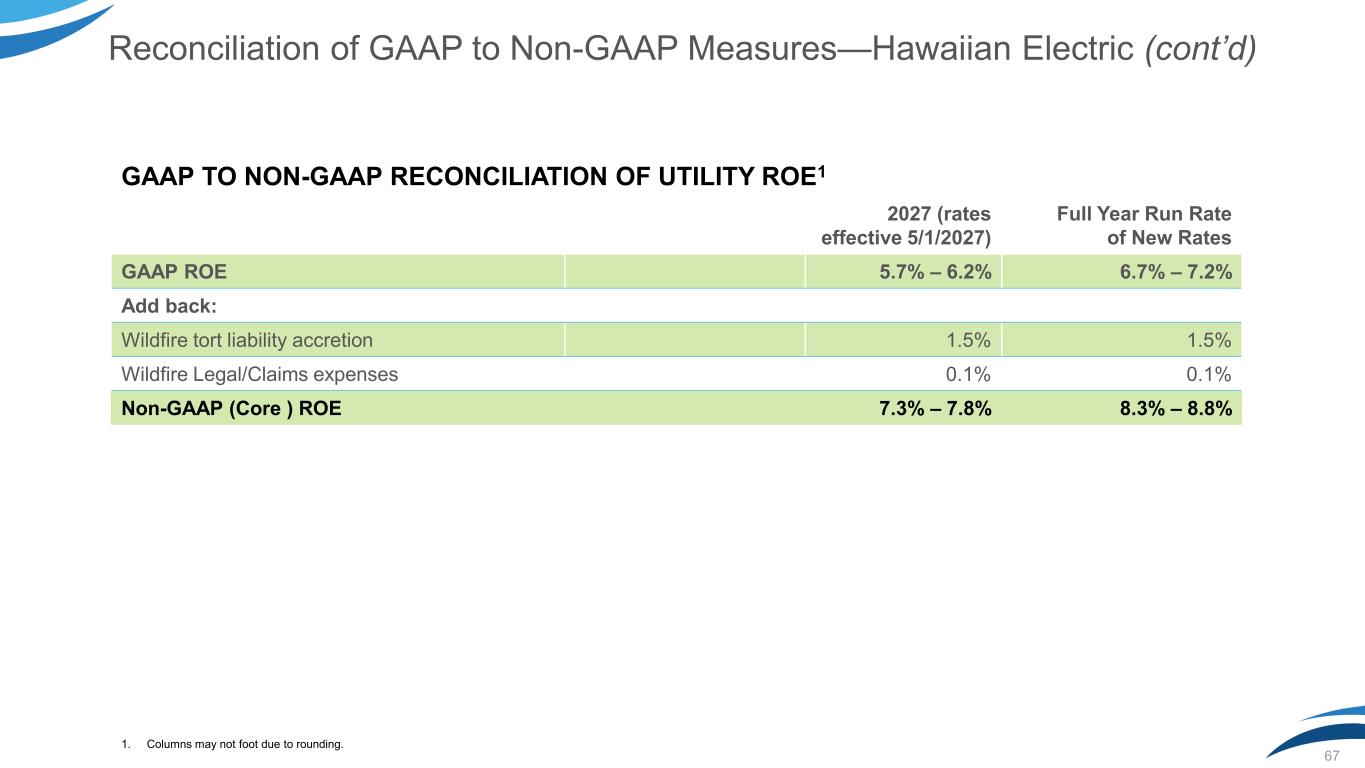
GAAP TO NON-GAAP RECONCILIATION OF UTILITY ROE1 2027 (rates effective 5/1/2027) Full Year Run Rate of New Rates GAAP ROE 5.7% – 6.2% 6.7% – 7.2% Add back: Wildfire tort liability accretion 1.5% 1.5% Wildfire Legal/Claims expenses 0.1% 0.1% Non-GAAP (Core ) ROE 7.3% – 7.8% 8.3% – 8.8% 1. Columns may not foot due to rounding. 67 Reconciliation of GAAP to Non-GAAP Measures—Hawaiian Electric (cont’d)
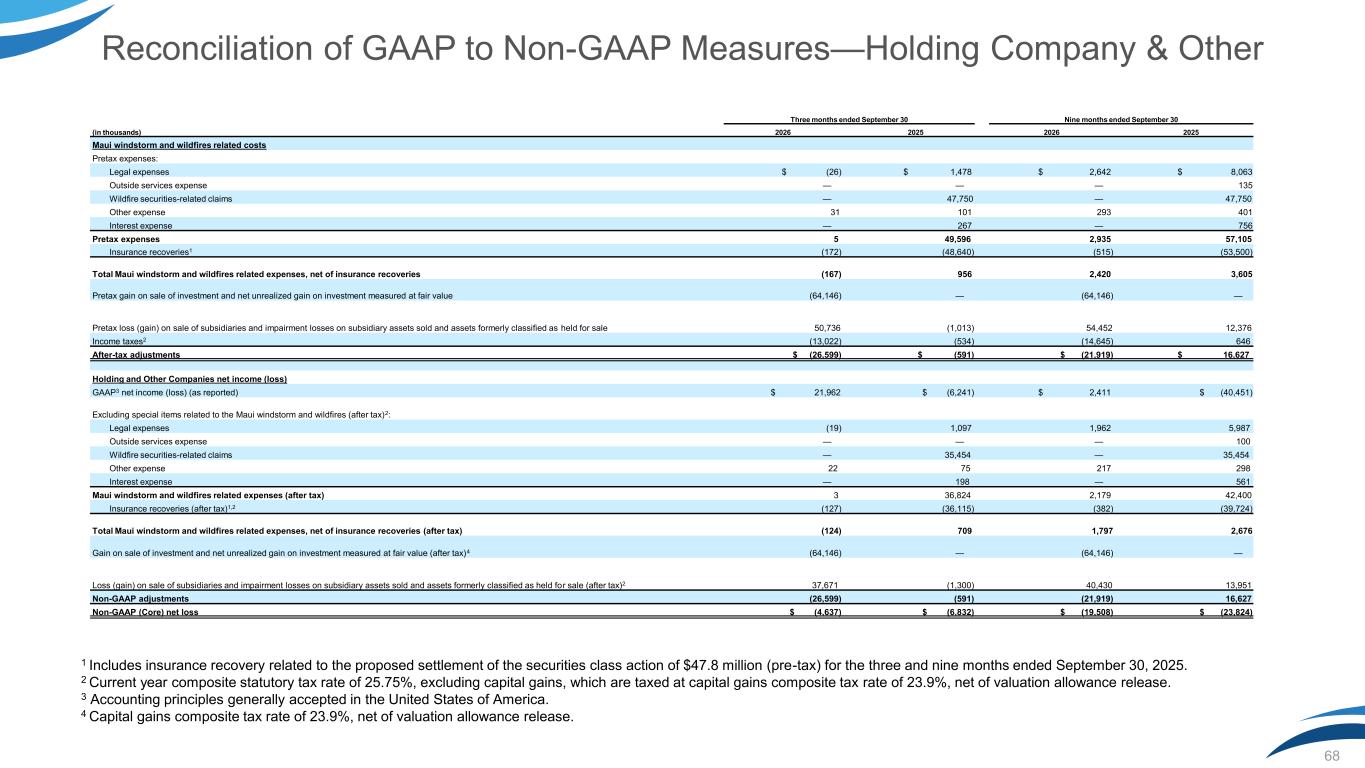
68 Reconciliation of GAAP to Non-GAAP Measures—Holding Company & Other 1 Includes insurance recovery related to the proposed settlement of the securities class action of $47.8 million (pre-tax) for the three and nine months ended September 30, 2025. 2 Current year composite statutory tax rate of 25.75%, excluding capital gains, which are taxed at capital gains composite tax rate of 23.9%, net of valuation allowance release. 3 Accounting principles generally accepted in the United States of America. 4 Capital gains composite tax rate of 23.9%, net of valuation allowance release. Three months ended September 30 Nine months ended September 30 (in thousands) 2026 2025 2026 2025 Maui windstorm and wildfires related costs Pretax expenses: Legal expenses $ (26) $ 1,478 $ 2,642 $ 8,063 Outside services expense — — — 135 Wildfire securities-related claims — 47,750 — 47,750 Other expense 31 101 293 401 Interest expense — 267 — 756 Pretax expenses 5 49,596 2,935 57,105 Insurance recoveries1 (172) (48,640) (515) (53,500) Total Maui windstorm and wildfires related expenses, net of insurance recoveries (167) 956 2,420 3,605 Pretax gain on sale of investment and net unrealized gain on investment measured at fair value (64,146) — (64,146) — Pretax loss (gain) on sale of subsidiaries and impairment losses on subsidiary assets sold and assets formerly classified as held for sale 50,736 (1,013) 54,452 12,376 Income taxes2 (13,022) (534) (14,645) 646 After-tax adjustments $ (26,599) $ (591) $ (21,919) $ 16,627 Holding and Other Companies net income (loss) GAAP3 net income (loss) (as reported) $ 21,962 $ (6,241) $ 2,411 $ (40,451) Excluding special items related to the Maui windstorm and wildfires (after tax)2: Legal expenses (19) 1,097 1,962 5,987 Outside services expense — — — 100 Wildfire securities-related claims — 35,454 — 35,454 Other expense 22 75 217 298 Interest expense — 198 — 561 Maui windstorm and wildfires related expenses (after tax) 3 36,824 2,179 42,400 Insurance recoveries (after tax)1,2 (127) (36,115) (382) (39,724) Total Maui windstorm and wildfires related expenses, net of insurance recoveries (after tax) (124) 709 1,797 2,676 Gain on sale of investment and net unrealized gain on investment measured at fair value (after tax)4 (64,146) — (64,146) — Loss (gain) on sale of subsidiaries and impairment losses on subsidiary assets sold and assets formerly classified as held for sale (after tax)2 37,671 (1,300) 40,430 13,951 Non-GAAP adjustments (26,599) (591) (21,919) 16,627 Non-GAAP (Core) net loss $ (4,637) $ (6,832) $ (19,508) $ (23,824)