IN QUÉBEC
OUTSIDE QUÉBEC

Exhibit 99.4
Hydro-Québec
Financial Results
Key Figures
Third Quarter 2026
| NET INCOME | INVESTMENTS | |
| $580M | $2,047M |
| ELECTRICITY SALES IN QUÉBEC |
ELECTRICITY SALES OUTSIDE QUÉBEC |
|
| 36.7 TWh | 5.1 TWh | |
| |
|
|
| $3,143M | $906M |
First Three Quarters of 2026
| NET INCOME | INVESTMENTS | |
| $2,600M | $5,486M |
| ELECTRICITY SALES IN QUÉBEC |
ELECTRICITY SALES OUTSIDE QUÉBEC |
|
| 135.5 TWh | 12.6 TWh | |
| |
|
|
| $11,614M | $1,853M |
| Management's Discussion and Analysis | |
| Context of first three quarters | The results for the first three quarters of 2026 continue to be set against the backdrop record low runoff conditions observed since 2023. Natural water inflows during this period have been lower than normal overall, due in particular to decreased precipitation and spring runoff. The company's financial performance was also marked by periods of intense cold, particularly at the end of January, when peak demand in Québec exceeded 38,000 MW for 7 consecutive days, a historic high. Temperatures were an average of 9°C colder than climate normals during this period. As a result, the company continued to rebuild its reserves through prudent and dynamic management, as well as its operational flexibility, in order to ensure Québec's energy security. This approach resulted in a decrease in short-term sales revenue outside Québec and an increase in electricity purchases. |
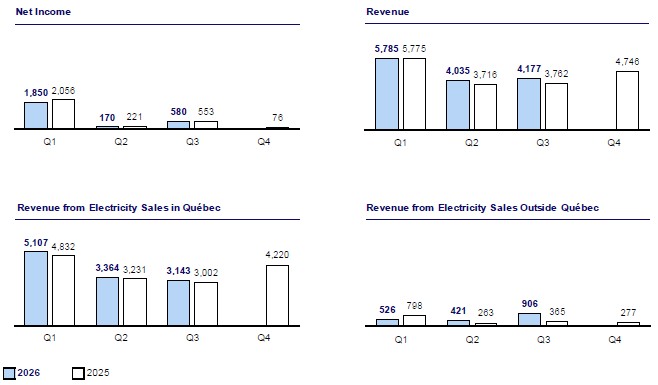
| Quarterly results | For the third quarter of 2026, Hydro-Québec's net income totalled $580 million, a $27-million increase compared to the $553 million recorded for the same period last year. |
| On markets outside Québec, electricity sales increased by $541 million, primarily due to the commercial commissioning in 2026 of the Appalaches-Maine (“NECEC”) and Hertel-New York (“CHPE”) interconnections. On the Québec market, sales increased by $141 million compared to the same quarter of 2025, primarily on account of the indexation of rates on April 1, 2026. However, these positive results were mitigated by two main factors. First, electricity purchases rose by $312 million due in part to increased short-term purchases to replenish energy reserves. Next, it is worth noting that a one-time gain of $256 million was recognized in 2025 upon the disposal of Hydro-Québec’s investment in Innergex énergie renouvelable inc. | |
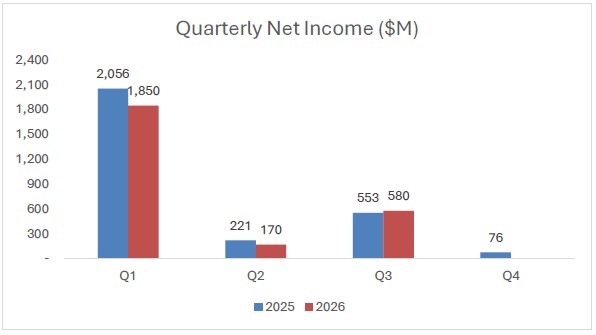 |
| Summary of results for the first three quarters | Hydro-Québec's net income totalled $2,600 million for the first nine months of 2026, a decrease of $230 million compared to the $2,830 million recorded for the same period the previous year. This decrease is attributable to an increase in electricity purchases, due to colder winter temperatures and low runoff, as well as to the one-time gain recognized in 2025 following the disposal of the investment in Innergex énergie renouvelable inc. However, these unfavourable factors were mitigated by sales growth in Québec as well as in markets outside Québec as a result of new export contracts. |
| Consolidated results for the first three quarters | Revenue totalled $13,997 million, a $744-million increase compared to the $13,253 million recorded in the first three quarters of 2025. |
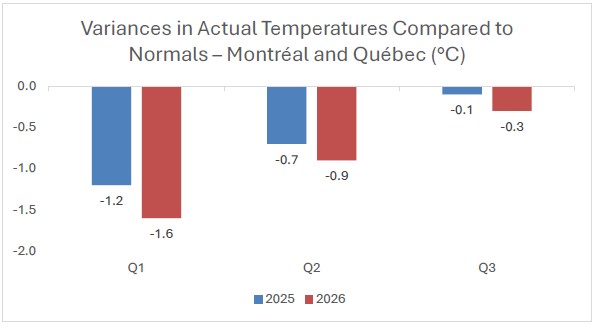
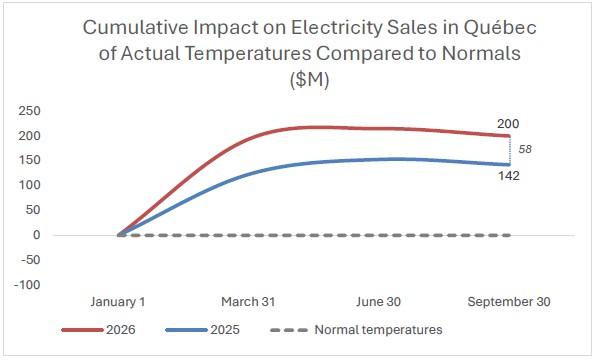
| In Québec, sales were $549 million higher than in the same period of the previous year, when they had reached $11,065 million. The effect of temperatures, particularly those of winter 2026, which were colder than the previous year, resulted in an increase in sales of 0.5 TWh, or $58 million. The increase is also due to the indexation of rates on April 1, 2025 and 2026, which resulted in a $332-million increase in revenue. Lastly, the favourable aluminum price fluctuation led to a $93-million increase in revenue associated with special contracts with certain large industrial customers. | |
 |
 |
|
| Electricity sales on external markets totalled $1,853 million, a $427-million increase from the $1,426 million recorded for the same period in 2025. This increase is primarily attributable to higher sales under long-term contracts, mainly due to the commercial commissioning of the NECEC and CHPE projects. It should be noted that these contracts will generate stable and significant income over the projected time frame. Regarding short-term sales, they decreased by 2.7 TWh. In fact, given the historically low natural water inflows and the high demand on the transmission system in Québec resulting from winter temperatures, short-term sales on the markets were considerably lower than those for the same period of the previous year. | |
| Revenue from other activities decreased by $198 million compared to a year ago. The decrease is partly due to the recognition of a one-time gain of $256 million in 2025 upon the disposal of Hydro-Québec's investment in Innergex énergie renouvelable inc. However, it was mitigated by the $87-million gain recognized in 2026 upon the disposal of Hydro-Québec's investment in Dana TM4. | |
| Total expenses amounted to $9,298 million, $837 million more than the $8,461 million recorded during the same period in 2025. This difference is due to two main factors. On one hand, electricity purchases increased by $987 million, mainly due to an increase in short-term supplies purchased on the markets, in particular to meet Québec's needs during periods of intense cold in the first quarter. A part of these purchases had to be made at higher prices, due in part to increased energy demand. In the second and third quarters, given the decline in prices as winter drew to a close, Hydro-Québec increased its purchases as a means of replenishing energy reserves. On the other hand, given that the actual cost of electricity supplies was higher than the costs forecast by the Régie de l'énergie's rate-setting purposes, the company was able to recognize a $263-million regulatory asset in regulatory deferrals, which led to a reduction in total expenses. It should be recalled that in March, further to a request made by Hydro-Québec as part of its 2026-2028 rate application, the Régie de l'énergie acknowledged that the use of all the variance accounts that were inoperative under An Act to simplify the process for establishing electricity distribution rates once again became applicable. |
| Financial expenses totalled $2,099 million, a $137-million increase from the $1,962 million recorded in the previous year. This increase is essentially due to the impact of new debt issues on interest expense, taking into account the increase in the borrowing program in connection with the planned investment activities under the Action Plan 2035. | |
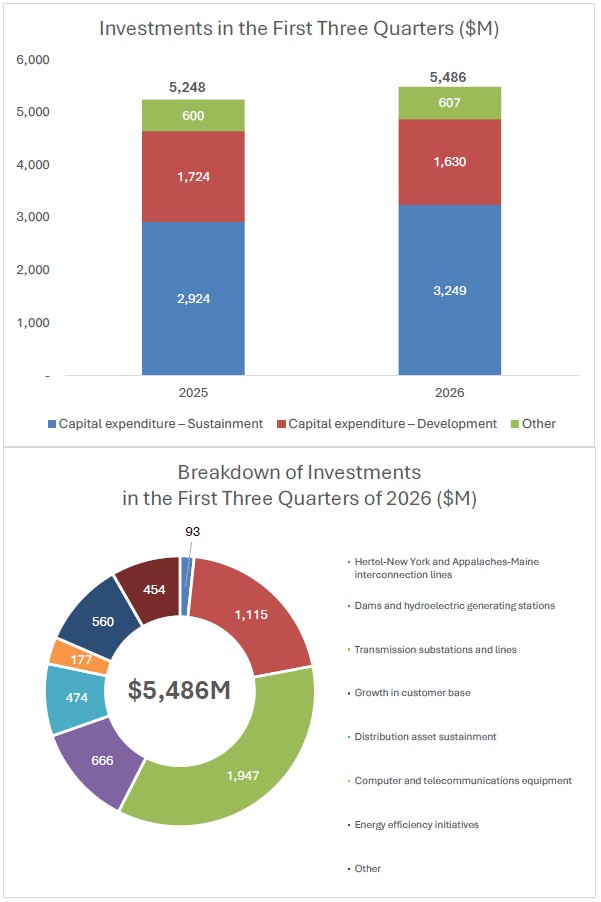
| Investments | Investments in property, plant and equipment and intangible assets for the first nine months of 2026 totalled $4,879 million, an increase of $231 million compared with the $4,648 million reported a year earlier. |
| Investments in asset sustainment totalled $3,249 million. In particular, Hydro-Québec continued to invest in its generating facilities to ensure their long-term operability and maximize their output. Work is underway at Rapide-Blanc and Carillon generating stations in the Mauricie and Laurentides regions, respectively, and at the Bersimis-2 development in the Côte-Nord region. Regarding power transmission, the company continued the installation of two new converter units at Châteauguay substation in the Montérégie region, as well as modernizing equipment and systems, including the replacement of grid control systems, special protection systems and substation protections and controls. It also continued the work on the architecture development plan for the 315-kV system on the island of Montréal. At the same time, it carried out work to optimize the operation of the distribution system and to maintain and improve the quality of its distribution assets. | |
| Investments in development projects totalled $1,630 million. In particular, Hydro-Québec allocated significant funds to various projects to meet the needs of a growing customer base in Québec and increase output capacity. As an example, investments are being made in Jean-Lesage, Outardes-2 and René-Lévesque generating stations, in the Côte-Nord region, to increase their capacity. It is also worth noting that two new interconnections have been commissioned. In fact, the Hertel-New York interconnection line, built to connect to the CHPE line to supply New York City, was commissioned last May, and the NECEC project, namely the 1,200-MW interconnection between Québec and New England, was commissioned in January. | |
| In addition to these investments in capital expenditure are, primarily, those allocated to the regulatory asset with respect to costs related to energy efficiency and demand response initiatives. As a result, total investments for the first nine months of 2026 amounted to $5,486 million, compared with $5,248 million for the same period in 2025. This increase of nearly 5% compared to last year and 63% since the launch of the Action Plan 2035 relates to several of the plan's priorities. The investments made reflect the company's commitment to reliable, high-quality service through sustained investment in its generating, transmission and distribution facilities, as well as to helping its customers consume energy more efficiently and achieve significant savings on their electricity bills. |
| These amounts are in addition to the direct investments made by Hydro-Québec's external partners. Collectively, such investments provide major support to the Québec economy. | |
 |
| Financing | During the third quarter of 2026, Hydro-Québec carried out two fixed-rate bond issues on the Canadian capital market at an average cost of 4.82%. These bonds will mature in 2065. |
| These financing activities raised $0.9 billion. That is in addition to the funds raised in the first half of the year, bringing the year-to-date total to $5.8 billion. | |
| The proceeds are being used, in particular, to finance part of the investment program and to repay maturing debt. |
CONSOLIDATED FINANCIAL STATEMENTS
(UNAUDITED)
Consolidated Statements of Operations
| In millions of Canadian dollars (unaudited) |
Three months ended September 30 |
Nine months ended September 30 |
|||||||||||
| Notes | 2026 | 2025 | 2026 | 2025 | |||||||||
| Revenue | 4 | 4,177 | 3,762 | 13,997 | 13,253 | ||||||||
| Expenses | |||||||||||||
| Operations | 1,125 | 1,009 | 3,484 | 3,289 | |||||||||
| Other components of employee future benefit cost | 9 | (244 | ) | (229 | ) | (732 | ) | (687 | ) | ||||
| Electricity purchases | 1,036 | 724 | 3,625 | 2,638 | |||||||||
| Depreciation and amortization | 789 | 780 | 2,401 | 2,305 | |||||||||
| Taxes | 282 | 273 | 945 | 916 | |||||||||
| Regulatory deferrals | (91 | ) | - | (425 | ) | - | |||||||
| 2,897 | 2,557 | 9,298 | 8,461 | ||||||||||
| Income before financial expenses | 1,280 | 1,205 | 4,699 | 4,792 | |||||||||
| Financial expenses | 5 | 700 | 652 | 2,099 | 1,962 | ||||||||
| Net income | 580 | 553 | 2,600 | 2,830 | |||||||||
Consolidated Statements of Comprehensive Income
| In millions of Canadian dollars (unaudited) |
Three months ended September 30 |
Nine months ended September 30 |
|||||||||||
| Notes | 2026 | 2025 | 2026 | 2025 | |||||||||
| Net income | 580 | 553 | 2,600 | 2,830 | |||||||||
| Other comprehensive income (loss) | 10 | ||||||||||||
| Net change in items designated as cash flow hedges | 7 | 74 | (5 | ) | (14 | ) | 207 | ||||||
| Net change in translation differences | (1 | ) | 55 | 50 | (52 | ) | |||||||
| Net change in items designated as net investment hedges | 7 | (9 | ) | (54 | ) | (89 | ) | 45 | |||||
| Other | 3 | (44 | ) | 3 | (23 | ) | |||||||
| 67 | (48 | ) | (50 | ) | 177 | ||||||||
| Comprehensive income | 647 | 505 | 2,550 | 3,007 | |||||||||
The accompanying notes are an integral part of the consolidated financial statements.
Consolidated Balance Sheets
| In millions of Canadian dollars (unaudited) |
Notes | As at September 30, 2026 |
As at December 31, 2025 |
||||
| ASSETS | |||||||
| Current assets | |||||||
| Cash and cash equivalents | 5,893 | 2,660 | |||||
| Short-term investments | 2,593 | 1,634 | |||||
| Accounts receivable and other assets | 4,009 | 4,947 | |||||
| 12,495 | 9,241 | ||||||
| Property, plant and equipment and intangible assets | 86,735 | 83,935 | |||||
| Regulatory assets | 2,858 | 2,038 | |||||
| Employee future benefit assets | 9,489 | 8,978 | |||||
| Other assets | 6 | 5,279 | 3,841 | ||||
| 116,856 | 108,033 | ||||||
| LIABILITIES | |||||||
| Current liabilities | |||||||
| Borrowings | 3,831 | 1 | |||||
| Accounts payable and other liabilities | 4,278 | 5,000 | |||||
| Dividend payable | - | 2,180 | |||||
| Current portion of long-term debt | 7 | 469 | 794 | ||||
| 8,578 | 7,975 | ||||||
| Long-term debt | 7 | 70,258 | 64,757 | ||||
| Employee future benefit liabilities | 1,200 | 1,188 | |||||
| Other liabilities | 4,151 | 3,953 | |||||
| 84,187 | 77,873 | ||||||
| EQUITY | |||||||
| Share capital | 4,374 | 4,374 | |||||
| Retained earnings | 26,861 | 24,302 | |||||
| Accumulated other comprehensive income | 10 | 1,434 | 1,484 | ||||
| 32,669 | 30,160 | ||||||
| 116,856 | 108,033 | ||||||
| Contingencies | 11 |
The accompanying notes are an integral part of the consolidated financial statements.
On behalf of the Board of Directors,
| /s/ Geneviève Brouillette | /s/ Manon Brouillette |
| Chair of the Audit Committee | Chair of the Board |
Consolidated Statements of Changes in Equity
| In millions of Canadian dollars (unaudited) |
Nine months ended September 30 |
||||||||||||
| Note | Share capital | Retained earnings |
Accumulated other comprehensive income |
Total equity | |||||||||
| Balance as at December 31, 2025 | 4,374 | 24,302 | 1,484 | 30,160 | |||||||||
| Net income | 2,600 | 2,600 | |||||||||||
| Other comprehensive income (loss) | 10 | (50 | ) | (50 | ) | ||||||||
| Other | (41 | ) | (41 | ) | |||||||||
| Balance as at September 30, 2026 | 4,374 | 26,861 | 1,434 | 32,669 | |||||||||
| Balance as at December 31, 2024 | 4,374 | 23,576 | 757 | 28,707 | |||||||||
| Net income | 2,830 | 2,830 | |||||||||||
| Other comprehensive income (loss) | 10 | 177 | 177 | ||||||||||
| Balance as at September 30, 2025 | 4,374 | 26,406 | 934 | 31,714 | |||||||||
The accompanying notes are an integral part of the consolidated financial statements.
Consolidated Statements of Cash Flows
| In millions of Canadian dollars (unaudited) |
Three months ended September 30 |
Nine months ended September 30 |
|||||||||||
| Notes | 2026 | 2025 | 2026 | 2025 | |||||||||
| Operating activities | |||||||||||||
| Net income | 580 | 553 | 2,600 | 2,830 | |||||||||
| Adjustments to determine net cash flows from operating activities | |||||||||||||
| Depreciation and amortization | 789 | 780 | 2,401 | 2,305 | |||||||||
| Deficit of net cost recognized with respect to amounts paid for employee future benefits | (166 | ) | (147 | ) | (498 | ) | (438 | ) | |||||
| Gain on disposal of an equity method investment | 6 | - | (260 | ) | (90 | ) | (260 | ) | |||||
| Other | (290 | ) | 93 | (224 | ) | 35 | |||||||
| Regulatory assets and liabilities | (248 | ) | (418 | ) | (856 | ) | (805 | ) | |||||
| Change in non-cash working capital items | 8 | (122 | ) | (41 | ) | (552 | ) | 12 | |||||
| 543 | 560 | 2,781 | 3,679 | ||||||||||
| Investing activities | |||||||||||||
| Additions to property, plant and equipment and intangible assets |
(1,797 | ) | (1,815 | ) | (4,879 | ) | (4,648 | ) | |||||
| Acquisition of short-term investments | (771 | ) | (1,834 | ) | (3,371 | ) | (5,069 | ) | |||||
| Acquisition of sinking fund securities | (382 | ) | - | (873 | ) | (313 | ) | ||||||
| Disposal of short-term investments | 1,041 | 1,550 | 2,421 | 2,243 | |||||||||
| Disposal of sinking fund securities |
724 | - | 724 | - | |||||||||
| Disposal of an equity method investment | 6 | - | 556 | 263 | 556 | ||||||||
| Increase in equity method investments | (129 | ) | (144 | ) | (267 | ) | (240 | ) | |||||
| Other | (37 | ) | - | (48 | ) | (20 | ) | ||||||
| (1,351 | ) | (1,687 | ) | (6,030 | ) | (7,491 | ) | ||||||
| Financing activities | |||||||||||||
| Issuance of long-term debt | 908 | 1,718 | 5,838 | 5,647 | |||||||||
| Repayment of long-term debt | (77 | ) | (39 | ) | (838 | ) | (187 | ) | |||||
| Cash receipts arising from credit risk management | 581 | 330 | 2,137 | 1,690 | |||||||||
| Cash payments arising from credit risk management | (532 | ) | (391 | ) | (2,272 | ) | (1,738 | ) | |||||
| Net change in debt securities with maturities of three months or less | 1,160 | 81 | 2,700 | 1,705 | |||||||||
| Issuance of short-term borrowings with maturities greater than three months | 650 | 312 | 1,969 | 1,275 | |||||||||
| Repayment of short-term borrowings with maturities greater than three months | (396 | ) | (574 | ) | (915 | ) | (959 | ) | |||||
| Dividend paid | - | - | (2,180 | ) | (1,997 | ) | |||||||
| Other | 7 | (4 | ) | 35 | 14 | ||||||||
| 2,301 | 1,433 | 6,474 | 5,450 | ||||||||||
| Foreign currency effect on cash and cash equivalents | 1 | 11 | 8 | (18 | ) | ||||||||
| Net change in cash and cash equivalents | 1,494 | 317 | 3,233 | 1,620 | |||||||||
| Cash and cash equivalents, beginning of period | 4,399 | 5,149 | 2,660 | 3,846 | |||||||||
| Cash and cash equivalents, end of period | 5,893 | 5,466 | 5,893 | 5,466 | |||||||||
| Supplementary cash flow information | 8 | ||||||||||||
The accompanying notes are an integral part of the consolidated financial statements.
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
(UNAUDITED)
For the three- and nine-month periods ended September 30, 2026 and 2025
Amounts in tables are in millions of Canadian dollars, unless otherwise indicated.
Note 1 - Basis of Presentation
| Hydro-Québec's consolidated financial statements have been prepared in accordance with United States generally accepted accounting principles. These quarterly consolidated financial statements, including these notes, do not contain all the required information regarding annual consolidated financial statements and should therefore be read in conjunction with the consolidated financial statements and accompanying notes in Hydro-Québec's Annual Report 2025. The accounting policies used to prepare the quarterly consolidated financial statements are consistent with those presented in Hydro-Québec's Annual Report 2025. |
Hydro-Québec's quarterly results are not necessarily indicative of results for the year on account of seasonal temperature fluctuations. Because of higher electricity demand during winter months, revenue from electricity sales in Québec is higher during the first and fourth quarters. Management has reviewed events occurring until November 13, 2026, the date of approval of these quarterly consolidated financial statements by the Board of Directors, to determine whether circumstances warranted consideration of events subsequent to the balance sheet date. |
Note 2 - Changes in Accounting Policies
|
Standard issued but not yet adopted Intangible assets In September 2025, the Financial Accounting Standards Board ("FASB") issued Accounting Standards Update ("ASU") 2025-06, Intangibles-Goodwill and Other-Internal-Use Software (Subtopic 350-40)-Targeted Improvements to the Accounting for Internal-Use Software. This ASU makes targeted improvements to accounting for internal-use software. Specifically, it removes all references to software development project stages and establishes a new cost capitalization criterion based on management's authorization and the probable-to-complete recognition threshold. It can be applied using one of three transition approaches: prospective, retrospective or modified prospective basis, to the financial statements for quarterly and annual periods beginning on or after January 1, 2028. Hydro-Québec is currently examining the impact of this ASU on its consolidated financial statements. Government grants In December 2025, the FASB issued ASU 2025-10, Government Grants (Topic 832)-Accounting for Government Grants Received by Business Entities. |
This ASU provides guidance on the initial measurement, recognition, presentation and disclosure of government grants. It can be applied using one of three approaches: a modified prospective approach, a modified retrospective approach or a retrospective approach to the quarterly and annual financial statements of years as of January 1, 2029. Hydro-Québec is currently examining the impact of this ASU on its consolidated financial statements. Environmental Credits and Environmental Credit Obligations In May 2026, the FASB issued ASU 2026-02, Environmental Credits and Environmental Credit Obligations (Topic 818). This ASU provides guidance for the recognition, measurement, presentation and disclosure of environmental credits and environmental credit obligations. It must be applied on a modified retrospective basis with a cumulative adjustment to the quarterly and annual financial statements beginning on or after January 1, 2028. Hydro-Québec is currently examining the impact of this ASU on its consolidated financial statements. |
Note 3 - Regulation
| Distribution activities As of April 1, 2026, in accordance with Decision D-2026-036 issued on March 26, 2026, rendered as part of the 2026-2028 regulatory cycle, rate increases of 3.0% for residential customers, and 3.8% for commercial, institutional and industrial customers were approved. The Régie de l'énergie du Québec (the "Régie") acknowledged in its March 13, 2026, Decision D-2026-033, the update of regulatory principles and accounting practices. In accordance with this decision, all variance accounts that were inoperative under An Act to simplify the process for establishing electricity distribution rates (S.Q. 2019, c. 27), became useful and available. These variances are recognized as regulatory assets or regulatory liabilities, as the case may be. |
As at September 30, 2026, the main variance accounts are as follows: Variances related to climate conditions Variances between actual revenue and forecast revenue in rate filings, established based on climate normals, have been recognized as regulatory liability in the amount of $94 million as at September 30, 2026. The offset has been recognized under Revenue from other activities. Variances related to electricity supplies Variances in price and volume between actual electricity supplies and those forecast in rate filings recognized by the Régie for electricity rate-setting purposes have been accounted for as a regulatory asset in the amount of $263 million as of September 30, 2026. The offset has been recognized under Regulatory deferrals. |
Note 4 - Revenue
| Three months ended September 30 |
Nine months ended September 30 |
|||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||
| Revenue from ordinary activitiesa | ||||||||||||
| Electricity sales | ||||||||||||
| In Québec | 3,143 | 3,002 | 11,614 | 11,065 | ||||||||
| Outside Québec | 906 | 365 | 1,853 | 1,426 | ||||||||
| 4,049 | 3,367 | 13,467 | 12,491 | |||||||||
| Other revenue from ordinary activities | 56 | 79 | 276 | 310 | ||||||||
| 4,105 | 3,446 | 13,743 | 12,801 | |||||||||
| Revenue from other activitiesb | 72 | 316 | c | 254 | c | 452 | c | |||||
| 4,177 | 3,762 | 13,997 | 13,253 | |||||||||
a) Including gains and losses on derivative instruments (see Note 7, Financial Instruments).
b) Including its share of income of equity method investments of $16 million and $75 million for the three- and nine-month periods, respectively, ended September 30, 2026 ($12 million and $57 million for the corresponding periods of 2025).
c) Including a gain of $87 million arising from the disposal of an equity method investment ($256 million in 2025) (see Note 6, Other Assets).
Note 5 - Financial Expenses
| Three months ended September 30 |
Nine months ended September 30 |
|||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||
| Net interest on long-term debta | 742 | 701 | 2,196 | 2,058 | ||||||||
| Capitalized financial expenses | (84 | ) | (72 | ) | (228 | ) | (196 | ) | ||||
| Net investment incomeb | (33 | ) | (46 | ) | (100 | ) | (121 | ) | ||||
| Otherc | 75 | 69 | 231 | 221 | ||||||||
| 700 | 652 | 2,099 | 1,962 | |||||||||
a) Including investment income of $22 million and $59 million for the three- and nine-month periods, respectively, ended September 30, 2026 ($12 million and $34 million for the corresponding periods of 2025) from securities held in the sinking funds allocated to repaying the long-term debt. The voluntary sinking fund strategy aims to issue additional bonds and to invest the funds raised in securities issued by certain provincial governments in Canada, so as to ensure the availability of funds when these debts mature in 2035.
b) Including interest of $17 million and $43 million for the three- and nine-month periods, respectively, ended September 30, 2026 ($19 million and $56 million for the corresponding periods of 2025) on short-term borrowings and cash received as collateral. As part of its liquidity risk management, Hydro-Québec has access to a commercial paper program whose limit is US$5 billion or equivalent in C$. The company aims to invest the funds raised in short-term investments and cash equivalents.
c) Including guarantee fees of $76 million and $227 million for the three- and nine-month periods, respectively, ended September 30, 2026 ($70 million and $210 million for the corresponding periods of 2025) that were paid to the Québec government related to debt securities, which are charged at a rate of 0.5%.
Note 6 - Other Assets
| On January 20, 2026, Hydro-Québec completed the sale of its 45% interest in Dana TM4 pursuant to the exercise of its put option, for a cash consideration of $263 million (US$190 million). This transaction resulted in a gain of $87 million, net of transaction costs, recognized in Revenue from other activities. The gain includes the reclassification of $16 million from Accumulated other comprehensive income, arising from translation differences from previous periods. For comparative purposes, on July 21, 2025, Hydro-Québec sold its investment in Innergex énergie renouvelable inc. ("Innergex") to the Caisse de dépôt et placement du Québec ("La Caisse"), a Québec state-owned enterprise, for a cash consideration of $556 million. |
This transaction followed the agreement concluded on February 24, 2025, between Innergex and La Caisse to acquire all issued and outstanding common shares of Innergex, including Hydro-Québec's 19.9% stake. This transaction resulted in a gain of $256 million, net of transaction costs, recognized in revenue from other activities. The gain includes the reclassification of $45 million from Accumulated other comprehensive income, arising from its share from previous periods. |
Note 7 - Financial Instruments
In the course of its operations, Hydro-Québec carries out transactions that expose it to certain financial risks, such as market and credit risk. Exposure to such risks and their impact on income are reduced through careful monitoring and implementation of strategies that include the use of derivative instruments.
Market risk
Market risk is the risk that the fair value or future cash flows of a financial instrument will fluctuate as a result of changes in market prices.
Currency risk
Hydro-Québec uses currency swaps and forward currency purchase contracts to manage the currency risk associated with U.S. dollar denominated short-term borrowings and long-term debt and forward currency sales contracts to manage exposure associated with probable sales in U.S. dollars. When designated as hedging items, these derivative instruments are recognized as cash flow hedges.
Hydro-Québec also uses forward currency sales contracts to cover its net investment in a foreign operation whose functional currency is the U.S. dollar. When designated as hedging items, these derivative instruments are recognized as net investment hedges.
Interest rate risk
Hydro-Québec uses interest rate swaps to convert certain fixed-rate debts into variable-rate debts and interest rate forward contracts to set the interest rate for certain future debt issues. When designated as hedging items, these derivative instruments are recognized based on the type of hedge: cash flow hedge or fair value hedge.
Price risk
Hydro-Québec uses mainly forward contracts and swaps to manage risk resulting from fluctuations in energy, aluminum and diesel prices. This aims to mitigate the impact of market price volatility on income from the sale and purchase of electricity and purchase of fuel indexed to these prices. When designated as hedging items, these derivative instruments are recognized as cash flow hedges.
The following table presents the notional amounts of forward contracts and swaps used to manage the main types of market risk:
| As at September 30, 2026 |
As at December 31, 2025 |
|||||
| Currency risk | ||||||
| Sale (US$ million) | 3,204 | 2,739 | ||||
| Purchase (US$ million) | 5,024 | 2,870 | ||||
| Interest rate risk | ||||||
| Variable-rate payer (C$ million) |
1,500 | 1,500 | ||||
| Fixed-rate payer (C$ million) |
2,000 | 2,000 | ||||
| Price risk | ||||||
| Electricity - Sale (TWh) | 14.7 | 4.9 | ||||
| Electricity - Purchase (TWh) | 0.2 | 2.8 | ||||
| Aluminum (tonnes) | 412,950 | 470,500 | ||||
| Diesel (millions of litres) | - | 5.0 |
Note 7 - Financial Instruments (continued)
| Credit risk Credit risk is the risk that one party to a financial asset will fail to meet its obligations. Hydro-Québec is exposed to credit risk related to accounts receivable and other financial assets such as cash and cash equivalents, short-term investments, sinking funds, deposits and derivative instruments. In terms of accounts receivable, this risk arises primarily from ongoing electricity sales inside and outside Québec. The risk exposure is limited due to Hydro-Québec's large and diverse customer base in addition to measures put in place such as security deposits, scheduled prepayments, payment arrangements and service interruptions. Management therefore believes that Hydro-Québec is not exposed to a high credit risk, particularly because sales in Québec are billed at rates that allow for recovery of costs based on the terms and conditions set by the Régie. |
As at September 30, 2026, Accounts receivable and other assets included an amount of $1,906 million ($2,422 million as at December 31, 2025) from contracts concluded with customers, including $1,014 million ($1,732 million as at December 31, 2025) in unbilled electricity deliveries. Amounts in Accounts receivable and other assets were presented net of the allowance for credit losses of $431 million ($404 million as at December 31, 2025). In order to reduce the exposure to credit risk related to other financial assets, Hydro-Québec deals with a number of issuers and financial institutions with high credit ratings. Furthermore, to offset exposure to risk related to derivative instruments, it has signed, with each counterparty, a collateral exchange agreement based on the International Swaps and Derivatives Association ("ISDA") guidelines, which limits the market value of the portfolio. A variation of this market value beyond the agreed-upon limit will therefore result in a cash receipt or payment. |
Fair value
Fair value of derivative instruments
The following tables present the fair value of derivative instruments, including the impact of offsets, by hedge type:
| As at September 30, 2026 | |||||||||||||||
| Fair value hedges |
Cash flow hedges |
Net investment hedges |
Derivatives not designated as hedges |
Total | |||||||||||
| Assets | |||||||||||||||
| Currency contracts | - | 483 | - | 102 | 585 | ||||||||||
| Interest rate contracts | 42 | 67 | - | - | 109 | ||||||||||
| Price contracts | - | 142 | - | 69 | 211 | ||||||||||
| Gross amounts recognized | 42 | 692 | - | 171 | 905 | ||||||||||
| Less | |||||||||||||||
| Impact of gross amounts offseta | 126 | ||||||||||||||
| Impact of cash received as collateralb | 512 | ||||||||||||||
| Net assets | 267 | c | |||||||||||||
| Liabilities | |||||||||||||||
| Currency contracts | - | 24 | 53 | 9 | 86 | ||||||||||
| Price contracts | - | 120 | - | 40 | 160 | ||||||||||
| Gross amounts recognized | - | 144 | 53 | 49 | 246 | ||||||||||
| Less | |||||||||||||||
| Impact of gross amounts offseta | 126 | ||||||||||||||
| Impact of cash paid as collateralb | 75 | ||||||||||||||
| Net liabilities | 45 | d | |||||||||||||
Note 7 - Financial Instruments (continued)
| As at December 31, 2025 | |||||||||||||||
| Fair value hedges |
Cash flow hedges |
Net investment hedges |
Derivatives not designated as hedges |
Total | |||||||||||
| Assets | |||||||||||||||
| Currency contracts | - | 527 | 1 | 16 | 544 | ||||||||||
| Interest rate contracts | 113 | 49 | - | - | 162 | ||||||||||
| Price contracts | - | - | - | 60 | 60 | ||||||||||
| Gross amounts recognized | 113 | 576 | 1 | 76 | 766 | ||||||||||
| Less | |||||||||||||||
| Impact of gross amounts offseta | 111 | ||||||||||||||
| Impact of cash received as collateralb | 581 | ||||||||||||||
| Net assets | 74 | c | |||||||||||||
| Liabilities | |||||||||||||||
| Currency contracts | - | 24 | 12 | 9 | 45 | ||||||||||
| Price contracts | - | 131 | - | 28 | 159 | ||||||||||
| Gross amounts recognized | - | 155 | 12 | 37 | 204 | ||||||||||
| Less | |||||||||||||||
| Impact of gross amounts offseta | 111 | ||||||||||||||
| Impact of cash paid as collateralb | 38 | ||||||||||||||
| Net liabilities | 55 | d | |||||||||||||
a) The impact of gross amounts offset is related to contracts traded according to ISDA guidelines and constituting enforceable master netting arrangements. Such master netting arrangements apply to all derivative instrument contracts traded over the counter.
b) Cash amounts offset are amounts received or paid under collateral exchange agreements signed in compliance with ISDA guidelines.
c) As at September 30, 2026, $96 million was recorded in Accounts receivable and other assets ($62 million as at December 31, 2025) and $171 million in Other assets
($12 million as at December 31, 2025).
d) As at September 30, 2026, $38 million was recorded in Accounts payable and other liabilities ($45 million as at December 31, 2025) and $7 million in Other liabilities ($10 million as at December 31, 2025).
| Moreover, although certain derivative instruments cannot be offset for lack of enforceable master netting arrangements, margin calls may result in amounts received from or paid to clearing agents, based on the fair value of the instruments concerned. Hydro-Québec may also transfer Treasury bills to a clearing agent as financial collateral. As at September 30, 2026, an amount of $4 million receivable in | consideration of net payments ($24 million as at December 31, 2025) and an amount of $23 million receivable in consideration of the transfer of Treasury bills ($46 million as at December 31, 2025) were included in Accounts receivable and other assets, whereas an amount of $32 million payable in consideration of net cash receipts was included in Accounts payable and other liabilities ($29 million as at December 31, 2025). When the Treasury bills mature, the clearing agent remits the proceeds, including interest, to Hydro-Québec. |
Fair value hierarchy
Fair value measurements of derivative instruments are classified according to a three-level hierarchy, based on the inputs used.
| As at September 30, 2026 | As at December 31, 2025 | |||||||||||||||||||||||
| Level 1 | a | Level 2 | b | Level 3 | c | Total | Level 1 | a | Level 2 | b | Level 3 | c | Total | |||||||||||
| Assets | 57 | 816 | 32 | 905 | 23 | 706 | 37 | 766 | ||||||||||||||||
| Liabilities | 30 | 216 | - | 246 | 38 | 165 | 1 | 204 | ||||||||||||||||
| 659 | 562 | |||||||||||||||||||||||
a) Fair values are derived from the closing price on the balance sheet date.
b) Fair values are obtained by discounting future cash flows, which are estimated on the basis of the spot rates, forward rates or forward prices (foreign exchange rates, interest rates, and energy, aluminum or diesel prices) in effect on the balance sheet date, and take into account the credit risk assessment. The valuation techniques make use of observable market inputs.
c) Fair values are not based on observable inputs. The valuation technique used to classify fixed price power purchase agreements of variable volumes is based on forward energy prices, taking the counterparty's historical consumption into consideration.
Note 7 - Financial Instruments (continued)
Impact of derivative instruments on income and other comprehensive income
The instruments traded, the impact of which is presented in the table below, reduce the volatility of income. Most of the derivative instruments are designated as hedges.
| Three months ended September 30 |
Nine months ended September 30 |
|||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||
| Gains (losses) on derivatives recognized in income | ||||||||||||
| Fair value hedges | ||||||||||||
| Interest rate contractsa | (59 | ) | 8 | (66 | ) | 4 | ||||||
| Derivatives not designated as hedges | ||||||||||||
| Currency contractsb | 57 | 50 | 86 | (81 | ) | |||||||
| Price contractsb | 195 | (5 | ) | 275 | 44 | |||||||
| 193 | c | 53 | c | 295 | c | (33) | c | |||||
| (Losses) gains on derivatives reclassified from other comprehensive income to income |
||||||||||||
| Cash flow hedges | ||||||||||||
| Currency contractsd | 3 | 77 | 108 | (134 | ) | |||||||
| Interest rate contractsa | 1 | 1 | 2 | 1 | ||||||||
| Price contractse | (51 | ) | 5 | (164 | ) | (16 | ) | |||||
| (47) | c | 83 | c | (54) | c | (149) | c | |||||
| Gains (losses) on derivatives recognized in other comprehensive income |
||||||||||||
| Cash flow hedges | ||||||||||||
| Currency contracts | (25 | ) | 80 | 23 | (41 | ) | ||||||
| Interest rate contracts | 166 | 17 | 126 | 148 | ||||||||
| Price contracts | (114 | ) | (19 | ) | (217 | ) | (49 | ) | ||||
| 27 | 78 | (68 | ) | 58 | ||||||||
| Net investment hedges | ||||||||||||
| Currency contracts | (9 | ) | (54 | ) | (89 | ) | 45 | |||||
| 18 | 24 | (157 | ) | 103 | ||||||||
a) These amounts were recognized in Financial expenses.
b) These derivative instruments are essentially traded as part of integrated risk management. Their impact on income is recognized in the line items affected by the managed risk. Therefore, for the three- and nine-month periods ended September 30, 2026, $208 million and $271 million, respectively, were recognized in Revenue [$(7) million and $50 million for the corresponding periods of 2025], $(12) million and $(14) million, respectively, in Electricity purchases [$(1) million and $(1) million for the corresponding periods of 2025], as well as $56 million and $104 million, respectively, in Financial expenses [$53 million and $(86) million for the corresponding periods of 2025].
c) The items Revenue, Electricity purchases, and Financial expenses totalled, respectively, $4,177 million, $1,036 million and $700 million, respectively, for the three-month period ended September 30, 2026, as well as $13,997 million, $3,625 million and $2,099 million, respectively, for the nine-month period ended on that date ($3,762 million, $724 million and $652 million for the three-month period ended September 30, 2025, as well as $13,253 million, $2,638 million and $1,962 million for the nine-month period ended on that date).
d) For the three- and nine-month periods ended September 30, 2026, $1 million and $4 million, respectively, were recognized in Revenue [$(5) million and $(18) million for the corresponding periods of 2025], as well as $2 million and $104 million, respectively, in Financial expenses [$82 million and $(116) million for the corresponding periods of 2025].
e) For the three- and nine-month periods ended September 30, 2026, $(54) million and $(167) million, respectively, were recognized in Revenue [$6 million and $(15) million for the corresponding periods of 2025], and $3 million and $3 million, in Electricity purchases [$(1) million and $(1) million for the corresponding periods of 2025].
| For the three- and nine-month periods ended September 30, 2026 and 2025, Hydro-Québec did not reclassify any amount from Accumulated other comprehensive income to income after having discontinued cash flow hedges. As at September 30, 2026, Hydro-Québec estimated that the total gains and losses on derivative instruments in Accumulated other comprehensive |
income that would be reclassified to income in the next 12 months amounted to a net loss of $108 million ($8 million as at September 30, 2025). As at September 30, 2026, the maximum period during which Hydro-Québec hedged its exposure to the variability of cash flows related to anticipated transactions was 13 years (5 years as at September 30, 2025). |
Note 7 - Financial Instruments (continued)
Fair value of other financial instruments
The carrying amount of cash equivalents, accounts receivable, deposits and other short-term financial assets and liabilities corresponds to their fair value due to their short maturity.
Fair value measurements for other financial instruments are Level 2 measurements. Fair value is obtained by discounting future cash flows, based on rates observed on the balance sheet date for similar instruments traded on financial markets. These items are presented in the following table:
| As at September 30, 2026 | As at December 31, 2025 | |||||||||||
| |
Carrying amount | Fair value | Carrying amount | Fair value | ||||||||
| Assets | ||||||||||||
| Sinking fundsa, b | 2,140 | 2,082 | 1,973 | 1,993 | ||||||||
| Liabilities | ||||||||||||
| Long-term debtb | 70,727 | c, d | 64,304 | 65,551 | c, d | 63,787 | ||||||
a) The voluntary sinking funds allocated to repaying the long-term debt consist of securities issued by certain provincial governments in Canada. As for the mandatory sinking fund, it matured on September 1, 2026.
b) Includes the current portion.
c) Includes an amount of $1,480 million as at September 30, 2026 ($1,483 million as at December 31, 2025), for debts subject to a fair value hedge, which resulted in an adjustment of $36 million as at September 30, 2026 ($101 million as at December 31, 2025), with respect to existing hedging relationships and of $(37) million as at September 30, 2026 [$(43) million as at December 31, 2025], for hedging relationships terminated by Hydro-Québec.
d) Excludes accrued interest in the amount of $459 million as at September 30, 2026 ($1,011 million as at December 31, 2025).
Note 8 - Supplementary Cash Flow Information
| Three months ended September 30 |
Nine months ended September 30 |
|||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||
| Change in non-cash working capital items | ||||||||||||
| Accounts receivable and other assets | 330 | 217 | 181 | 220 | ||||||||
| Accounts payable and other liabilities | (452 | ) | (258 | ) | (733 | ) | (208 | ) | ||||
| (122 | ) | (41 | ) | (552 | ) | 12 | ||||||
| Activities not affecting cash | ||||||||||||
| Increase in property, plant and equipment and intangible assets | 35 | 33 | 106 | 99 | ||||||||
| Increase in operating lease assets and liabilities | - | 10 | 131 | 23 | ||||||||
| 35 | 43 | 237 | 122 | |||||||||
| Interest paid | 1,239 | 1,151 | 2,467 | 2,304 | ||||||||
Note 9 - Employee Future Benefits
| Three months ended September 30 |
||||||||||||||||||
| Pension Plan | Other plans | Total | ||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||
| Current service cost | 89 | 93 | 12 | 13 | 101 | 106 | ||||||||||||
| Other components of employee future benefit cost | ||||||||||||||||||
| Interest on obligations | 283 | 279 | 16 | 14 | 299 | 293 | ||||||||||||
| Expected return on plan assets | (542 | ) | (522 | ) | (1 | ) | - | (543 | ) | (522 | ) | |||||||
| (259 | ) | (243 | ) | 15 | 14 | (244 | ) | (229 | ) | |||||||||
| Net (credit) cost recognized | (170 | ) | (150 | ) | 27 | 27 | (143 | ) | (123 | ) | ||||||||
| Nine months ended September 30 |
||||||||||||||||||
| Pension Plan | Other plans | Total | ||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||
| Current service cost | 266 | 279 | 38 | 38 | 304 | 317 | ||||||||||||
| Other components of employee future benefit cost | ||||||||||||||||||
| Interest on obligations | 848 | 834 | 47 | 46 | 895 | 880 | ||||||||||||
| Expected return on plan assets | (1,625 | ) | (1,565 | ) | (2 | ) | (2 | ) | (1,627 | ) | (1,567 | ) | ||||||
| (777 | ) | (731 | ) | 45 | 44 | (732 | ) | (687 | ) | |||||||||
| Net (credit) cost recognized | (511 | ) | (452 | ) | 83 | 82 | (428 | ) | (370 | ) | ||||||||
Note 10 - Accumulated Other Comprehensive Income
| Nine months ended September 30, 2026 |
||||||||||||||||||
| Cash flow hedges |
Translation differences |
Net investment hedges |
Employee future benefits |
Other | Accumulated other comprehensive income |
|||||||||||||
| Balance as at December 31, 2025 | 649 | 104 | (69 | ) | 799 | 1 | 1,484 | |||||||||||
| Other comprehensive income (loss) before reclassifications | (68 | ) | 66 | (89 | ) | - | 3 | (88 | ) | |||||||||
| Less | ||||||||||||||||||
| (Losses) gains reclassified outside of Accumulated other comprehensive income | (54 | ) | 16a | - | - | - | (38 | ) | ||||||||||
| Other comprehensive income (loss) | (14 | ) | 50 | (89 | ) | - | 3 | (50 | ) | |||||||||
| Balance as at September 30, 2026 | 635 | 154 | (158 | ) | 799 | 4 | 1,434 | |||||||||||
| Nine months ended September 30, 2025 |
||||||||||||||||||
| Cash flow hedges |
Translation differences |
Net investment hedges |
Employee future benefits |
Other | Accumulated other comprehensive income |
|||||||||||||
| Balance as at December 31, 2024 | 471 | 184 | (137 | ) | 210 | 29 | 757 | |||||||||||
| Other comprehensive income (loss) before reclassifications | 58 | (52 | ) | 45 | 1 | 21 | 73 | |||||||||||
| Less | ||||||||||||||||||
| (Losses) gains reclassified outside of Accumulated other comprehensive income |
(149 | ) | - | - | - | 45 | a | (104 | ) | |||||||||
| Other comprehensive income (loss) | 207 | (52 | ) | 45 | 1 | (24 | ) | 177 | ||||||||||
| Balance as at September 30, 2025 | 678 | 132 | (92 | ) | 211 | 5 | 934 | |||||||||||
a) Reclassification of a gain from Accumulated other comprehensive income to income, due to the disposal of an equity method investment (see Note 6, Other Assets).
Note 11 - Contingencies
|
Litigation In the normal course of its development and operations, Hydro-Québec is involved in claims and legal proceedings from time to time. Management believes that adequate provision has been made for such litigation. Consequently, it does not expect any material adverse effect of such contingent liabilities on the financial position or consolidated results of Hydro-Québec. Among other pending actions, certain First Nations and Inuit communities have instituted proceedings before the Québec courts against the governments of Canada and Québec and against Hydro-Québec based on claims of Aboriginal rights and titles. For example, the Innu of Uashat mak Mani-utenam are claiming $1.5 billion as compensation, namely, for various activities carried out on the territory they claim, including the generation and transmission of electricity. Hydro-Québec is contesting the merits of this claim. In addition, the Innu of Pessamit have brought an action seeking the recognition of their Aboriginal rights and title to lands in Québec where certain Hydro-Québec electricity generation and transmission facilities are located, including the Manic-Outardes and Bersimis hydroelectric complexes. They allege that these facilities infringe on their Aboriginal rights and title and are claiming $500 million in compensation. Although Hydro-Québec is contesting the merits of this claim, together with the government of Québec, it participated in negotiations with the Innu of Pessamit. In July 2026, the agreement submitted to the community for ratification was rejected. In addition, proceedings have been instituted against Hydro-Québec and Churchill Falls (Labrador) Corporation Limited ["CF(L)Co"] relative to the Churchill Falls hydroelectric complex in Labrador, which is owned and operated by CF(L)Co. In an action brought before the courts of Newfoundland and Labrador in October 2020, Innu Nation Inc. alleges that the construction and operation of this hydroelectric complex amount to a "common enterprise" of CF(L)Co and Hydro-Québec, and allegedly infringe on the Aboriginal rights and title of the Labrador Innu. Innu Nation Inc. seeks |
a disgorgement of the profits that CF(L)Co and Hydro-Québec have derived from the operation of this hydroelectric complex or, failing that, monetary compensation of $4 billion with regard to Hydro-Québec. However, on June 4, 2025, Hydro-Québec and Innu Nation Inc. agreed on a memorandum of understanding (MOU) in which the parties committed to settling their dispute and establishing the foundations and principles of a new relationship. In September 2025, an agreement to this effect was submitted to the two communities that make up Innu Nation Inc. with a view to ratification. As elements required to ratify the agreement are currently pending, Hydro-Québec and Innu Nation Inc. are pursuing their collaboration and will decide on future steps together. In another action brought in 2023 before the Québec Superior Court, the Innu of Uashat mak Mani-utenam and the Innu of Matimekush-Lac John allege that the Churchill Falls hydroelectric complex infringes on their Aboriginal rights and title, as well as their treaty rights. In addition to various judicial declarations and permanent injunction orders, these two communities are jointly claiming from Hydro-Québec $2 billion in compensatory damages, $200 million in punitive damages, and additional damages in the form of an annual payment equivalent to 12.5% of 15% of Hydro-Québec's annual profits from the date of the commencement of the proceedings. Hydro-Québec is contesting the merits of this claim. On October 27, 2025, the Kitigan Zibi Anishinabeg instituted proceedings before the Québec Superior Court based on the claims of Aboriginal rights and titles, targeting the Canadian and Québec governments as well as Hydro-Québec and the National Capital Commission, for damages totalling $5 billion. Regarding Hydro-Québec, they allege that economic benefits were gained from the Mercier hydroelectric dam, and are asking for compensation for loss of profits along with punitive damages. Hydro-Québec is contesting the merits of this claim. |
Note 12 - Information on the Operating Segment
Hydro-Québec has only one operating segment and manages its operations using a cross-functional approach. Its results and total assets are analyzed on a consolidated basis by the person acting as chief operating decision maker, i.e., the President and Chief Executive Officer. The latter uses net income to analyze actual and forecast results in order to assess Hydro-Québec's performance. Significant expenses that are submitted to the chief operating decision maker for this purpose on a regular basis over the course of the period are disclosed in the following table. Investments are also submitted to the chief operating decision maker.
| Three months ended September 30 |
Nine months ended September 30 |
||||||||||||
| Notes | 2026 | 2025 | 2026 | 2025 | |||||||||
| Revenue | 4 | 4,177 | 3,762 | 13,997 | 13,253 | ||||||||
| Expenses | |||||||||||||
| Current operationsa | 1,021 | 901 | 3,164 | 2,924 | |||||||||
| Electricity purchases | 1,036 | 724 | 3,625 | 2,638 | |||||||||
| Depreciation and amortization | 789 | 780 | 2,401 | 2,305 | |||||||||
| Regulatory deferrals | (91 | ) | - | (425 | ) | - | |||||||
| Otherb | 142 | 152 | 533 | 594 | |||||||||
| Financial expenses | 5 | 700 | 652 | 2,099 | 1,962 | ||||||||
| Net income | 580 | 553 | 2,600 | 2,830 | |||||||||
| Investmentsc | 2,047 | 1,956 | d | 5,486 | 5,248 | d | |||||||
| Equity method investments on September 30 | 1,828 | 1,602 | d | ||||||||||
a) Current operational expenses are mainly composed of payroll, the cost of external services, acquisition costs of tangible and intangible property, and operating lease expenses.
b) Other expenses are composed of taxes, subsidiary expenses, other components of employee future benefit cost, as well as, current service cost of the Pension Plan.
c) The investments, as presented in this case for management purposes, are mainly composed of investments in property, plant and equipment and intangible assets, and also include investments in the regulatory asset with respect to costs related to energy efficiency and demand response initiatives.
d) The comparative period data have been reclassified to conform to the presentation adopted in the current period.
CONSOLIDATED FINANCIAL HIGHLIGHTS
(UNAUDITED)
Amounts shown in tables are in millions of Canadian dollars.
| Three months ended September 30 |
Nine months ended September 30 |
|||||||||||||||||||||||
| Summary of Results | 2026 | 2025 | Change (%) | 2026 | 2025 | Change (%) | ||||||||||||||||||
| Revenue | 4,177 | 3,762 | 11.0 | ↑ | 13,997 | 13,253 | 5.6 | ↑ | ||||||||||||||||
| Expenses | 2,897 | 2,557 | 13.3 | ↑ | 9,298 | 8,461 | 9.9 | ↑ | ||||||||||||||||
| Financial expenses | 700 | 652 | 7.4 | ↑ | 2,099 | 1,962 | 7.0 | ↑ | ||||||||||||||||
| Net income | 580 | 553 | 4.9 | ↑ | 2,600 | 2,830 | 8.1 | ↓ | ||||||||||||||||
|
Hydro-Québec, 75, boul. René-Lévesque Ouest, Montréal (Québec) H2Z 1A4 Ce document est également publié en français.www.hydroquebec.com |