EARNINGS PRESENTATION Q3’26 Results November 12, 2026 Exhibit 99.2
Disclaimer This presentation (this "Presentation") has been prepared by AIR Global PLC ("AIR" or the "Company" and, together with its subsidiaries, the "Group") solely for informational purposes. This Presentation is not being made in connection with any offering of securities and does not constitute or form part of an offer to sell or issue, or a solicitation of an offer to buy or subscribe for, any securities of the Company in any jurisdiction, nor shall it or any part of it form the basis of, or be relied upon in connection with, any contract or investment decision. This Presentation does not constitute a "prospectus" within the meaning of the U.S. Securities Act of 1933, as amended, and there shall be no sale of securities in any jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of such jurisdiction. Nothing in this Presentation constitutes investment, legal, tax, accounting or other advice or a recommendation regarding any securities of the Company. The information in this Presentation is a summary only and does not purport to be complete. It should be read together with the Company's filings with the U.S. Securities and Exchange Commission (the "SEC") including its Annual Report on Form 20-F, its registration statement on Form F-1 and its Reports on Form 6-K, which are available at www.sec.gov. In the event of any inconsistency between this Presentation and those filings, the filings will prevail. The information in this Presentation is provided as of the date of this Presentation (unless otherwise indicated), and the Company undertakes no obligation to update it, except as required by law. Forward-Looking Statements. This Presentation contains forward-looking statements within the meaning of the U.S. Private Securities Litigation Reform Act of 1995 that relate to our current expectations and views of future events. We intend such forward-looking statements to be covered by the safe harbor provisions for forward-looking statements as contained in Section 27A of the U.S. Securities Act of 1933, as amended (the "Securities Act"), and Section 21E of the U.S. Securities Exchange Act of 1934, as amended (the "Exchange Act"). AIR Global PLC (NASDAQ: AIIR) is a public operating company that resulted from the business combination of AIR Limited with a special purpose acquisition company, which completed in May 2026, and is accordingly not a "blank check company" for purposes of these safe harbor provisions. Any express or implied statements contained in this Presentation that are not statements of historical fact may be deemed to be forward-looking statements, including, without limitation, statements regarding the Company's financial outlook and medium-term guidance, including expected shipment volumes, revenue, Adjusted EBITDA, effective tax rate and capital expenditure, expected growth, leverage and deleveraging, working capital, capital allocation, including intended dividends and share repurchases, the anticipated benefits of the Greentank investment and the potential exercise of the related warrant, supply chain recovery and the Group's factory reorganization, product development and commercialization, regulatory submissions and approvals, and market trends and opportunities. Words such as "expect," "anticipate," "intend," "plan," "believe," "estimate," "project," "forecast," "outlook," "guidance," "target," "aim," "potential," "continue," "may," "will," "should," "could" and similar expressions identify forward-looking statements. Forward-looking statements are neither promises nor guarantees, are based on management's current expectations and assumptions and are subject to known and unknown risks and uncertainties, many of which are beyond the Company's control, that could cause actual results to differ materially. These include, among others: disruptions to the Company's supply chain and shipments, including as a result of conflict in the Middle East or disruption of the Strait of Hormuz; increases in logistics and raw-material costs; dependence on distributors and suppliers; competition, including from next generation nicotine categories; the timing and outcome of regulatory submissions, including PMTA applications; the results of scientific studies and their acceptance by regulatory authorities; the preliminary nature of the McKinney pilot study data, which is subject to further testing and verification and may change materially as additional data becomes available; the Group's ability to realize the anticipated benefits of the Greentank investment; changes in tobacco and nicotine regulation, excise and taxation; illicit trade; consumer preferences; foreign exchange fluctuations; tariffs, trade policy and general economic conditions; the Group's indebtedness, including the senior notes; the Company's ability to generate sufficient equity free cash flow, and Board approval and legal, regulatory and contractual requirements, which may affect the amount and timing of any dividends or share repurchases; dilution from earnout shares and other equity arrangements; tax, legal and accounting developments; our history of previously identified material weaknesses in internal control over financial reporting; and the other factors described under "Risk Factors" in the Company's Annual Report on Form 20-F, as such factors may be updated from time to time in its other filings with the SEC, including its Reports on Form 6-K. Forward-looking statements made orally by management in connection with this Presentation, including on the related earnings call, are qualified in their entirety by this cautionary statement. You should not place undue reliance on forward-looking statements, which speak only as of the date of this Presentation. The Company disclaims any obligation to update or revise any forward-looking statement, whether as a result of new information, future events or otherwise, except as required by law. No Representations and Warranties. This Presentation is for informational purposes only. No representation or warranty, express or implied, is or will be given by AIR or any of its affiliates, directors, officers, employees or advisers or any other person as to the accuracy or completeness of the information in this Presentation, and no responsibility or liability whatsoever is accepted for the accuracy or sufficiency thereof or for any errors, omissions or misstatements, negligent or otherwise, relating thereto. The information contained in this Presentation is derived from various internal and external sources, is preliminary in nature and is subject to change, and any such changes may be material. Non-IFRS Financial Measures. This Presentation includes certain financial measures not presented in accordance with IFRS as issued by the IASB, including EBITDA, Adjusted EBITDA, Net Debt and Net Debt to Adjusted EBITDA. These measures are supplemental, are not substitutes for IFRS measures, may not be comparable to similarly titled measures used by other companies, and are unaudited. Definitions and reconciliations to the most directly comparable IFRS measures are included in the Glossary and Appendix. No reconciliation is provided for forward-looking non-IFRS measures because the Company cannot do so without unreasonable effort. Industry and Market Data. This Presentation includes market, industry and competitive data and estimates, including data derived from a market assessment report prepared by Arthur D. Little and commissioned by the Company, as well as the Company's internal estimates. These estimates involve assumptions and limitations, are intended as directional indications, and have not been independently verified by the Company. Market share and market size estimates may differ depending on the basis used, including whether they include duty-not-paid or counterfeit products. Such data are subject to change and should not be given undue weight. Third-Party and Market Information. Share prices, trading multiples and analyst estimates included in this Presentation are derived from third-party sources as of the date indicated, have not been verified, adopted or endorsed by the Company, and may not be calculated on a consistent basis. Comparisons with other companies are provided for informational purposes only; those companies differ from the Company in size, products, markets and regulatory profile. Nothing herein is an indication of the value of the Company's securities. Trademarks. This Presentation may contain trademarks, service marks, trade names and copyrights of the Group and of third parties, which are the property of their respective owners. The use of third-party marks does not imply any affiliation with, or endorsement by, those owners. Solely for convenience, some of the trademarks, service marks, trade names and copyrights referred to in this Presentation may be listed without the ™, SM, © or ® symbols, but the Company will assert, to the fullest extent under applicable law, the rights of the applicable owners, if any, to these trademarks, service marks, trade names and copyrights.
Gaurav Jain VP Investor Relations & Corporate Strategy Today’s Speakers Stuart Brazier Chief Executive Officer Bassem Lotfy Chief Financial Officer
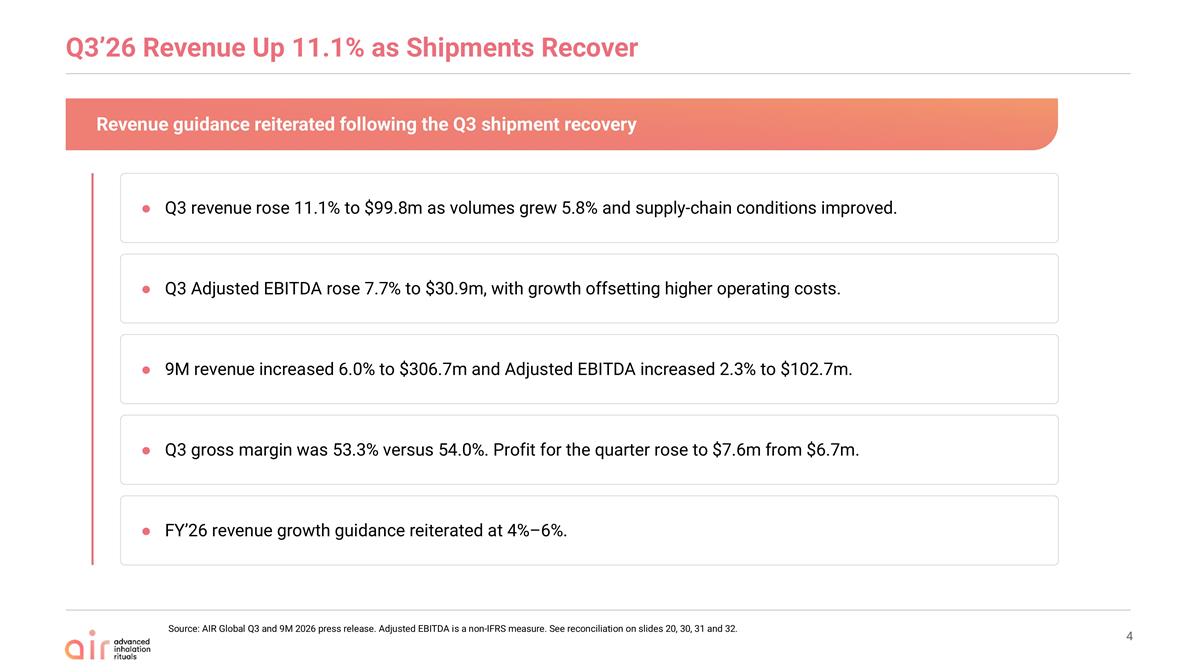
Q3’26 Revenue Up 11.1% as Shipments Recover Source: AIR Global Q3 and 9M 2026 press release. Adjusted EBITDA is a non-IFRS measure. See reconciliation on slides 20, 30, 31 and 32. Revenue guidance reiterated following the Q3 shipment recovery Q3 revenue rose 11.1% to $99.8m as volumes grew 5.8% and supply-chain conditions improved. Q3 Adjusted EBITDA rose 7.7% to $30.9m, with growth offsetting higher operating costs. 9M revenue increased 6.0% to $306.7m and Adjusted EBITDA increased 2.3% to $102.7m. Q3 gross margin was 53.3% versus 54.0%. Profit for the quarter rose to $7.6m from $6.7m. FY’26 revenue growth guidance reiterated at 4%–6%.
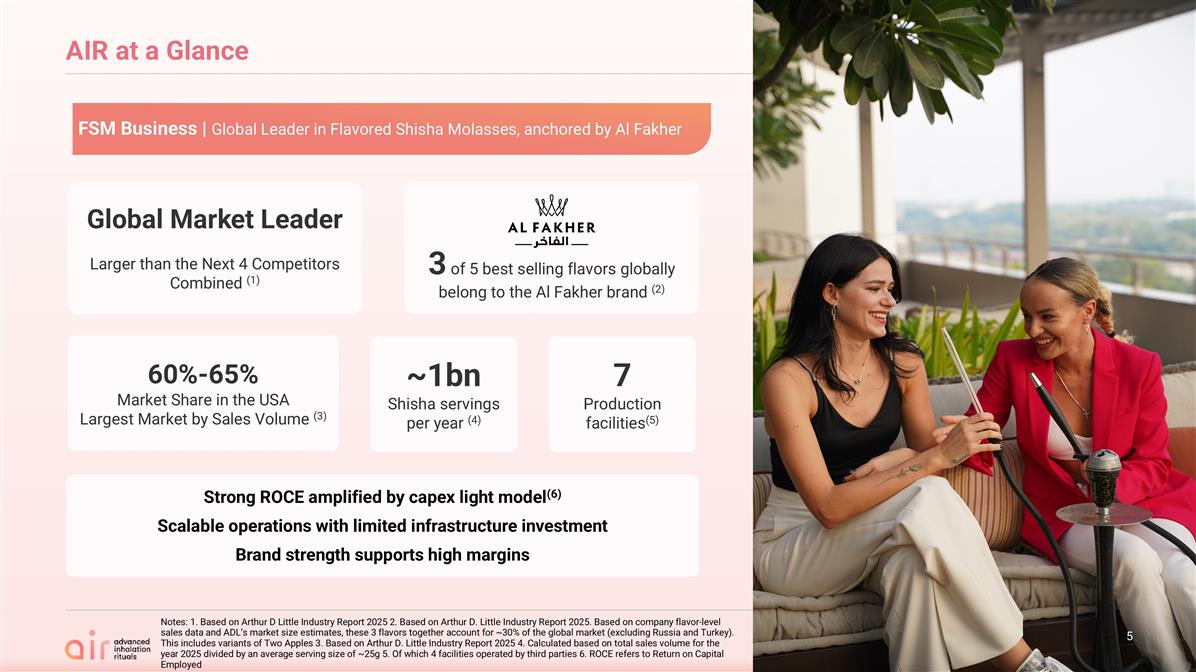
AIR at a Glance Strong ROCE amplified by capex light model(6) Scalable operations with limited infrastructure investment Brand strength supports high margins ~1bn Shisha servings per year (4) 7 Production facilities(5) 60%-65% Market Share in the USA Largest Market by Sales Volume (3) 3 of 5 best selling flavors globally belong to the Al Fakher brand (2) Global Market Leader Larger than the Next 4 Competitors Combined (1) Notes: 1. Based on Arthur D Little Industry Report 2025 2. Based on Arthur D. Little Industry Report 2025. Based on company flavor-level sales data and ADL’s market size estimates, these 3 flavors together account for ~30% of the global market (excluding Russia and Turkey). This includes variants of Two Apples 3. Based on Arthur D. Little Industry Report 2025 4. Calculated based on total sales volume for the year 2025 divided by an average serving size of ~25g 5. Of which 4 facilities operated by third parties 6. ROCE refers to Return on Capital Employed FSM Business | Global Leader in Flavored Shisha Molasses, anchored by Al Fakher
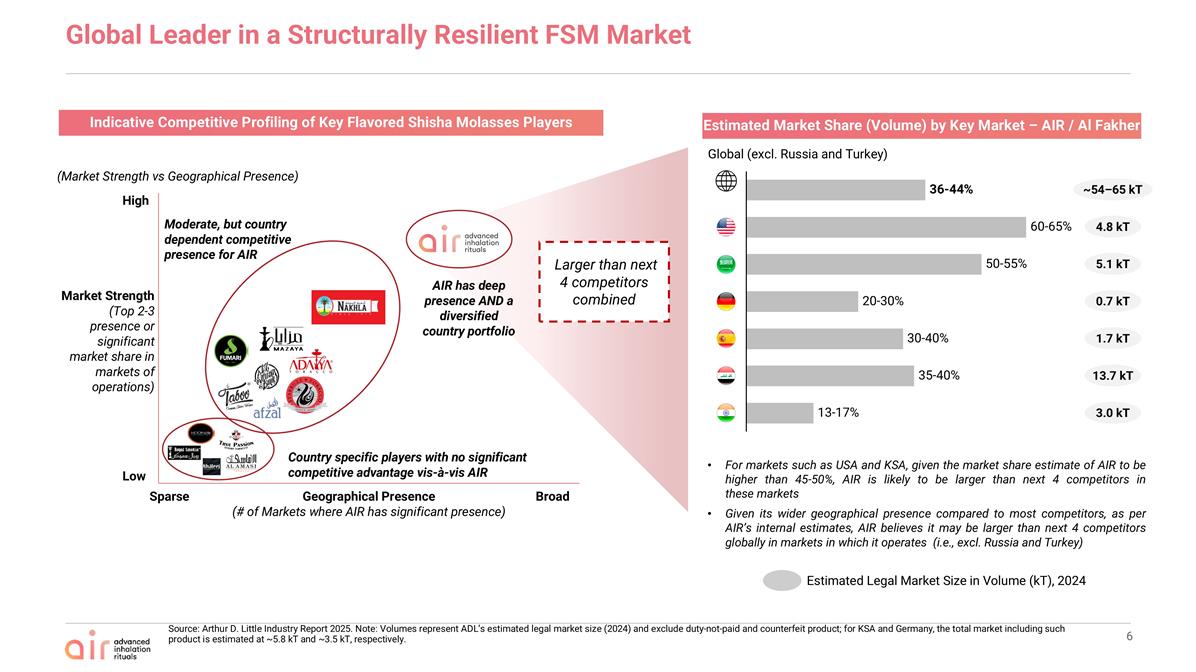
Indicative Competitive Profiling of Key Flavored Shisha Molasses Players Estimated Market Share (Volume) by Key Market – AIR / Al Fakher Source: Arthur D. Little Industry Report 2025. Note: Volumes represent ADL’s estimated legal market size (2024) and exclude duty-not-paid and counterfeit product; for KSA and Germany, the total market including such product is estimated at ~5.8 kT and ~3.5 kT, respectively. (Market Strength vs Geographical Presence) Moderate, but country dependent competitive presence for AIR AIR has deep presence AND a diversified country portfolio Country specific players with no significant competitive advantage vis-à-vis AIR Market Strength (Top 2-3 presence or significant market share in markets of operations) High Low Sparse Broad Geographical Presence (# of Markets where AIR has significant presence) For markets such as USA and KSA, given the market share estimate of AIR to be higher than 45-50%, AIR is likely to be larger than next 4 competitors in these markets Given its wider geographical presence compared to most competitors, as per AIR’s internal estimates, AIR believes it may be larger than next 4 competitors globally in markets in which it operates (i.e., excl. Russia and Turkey) Estimated Legal Market Size in Volume (kT), 2024 4.8 kT 5.1 kT 0.7 kT 1.7 kT 13.7 kT 3.0 kT Larger than next 4 competitors combined Global (excl. Russia and Turkey) 36-44% 60-65% 50-55% 20-30% 30-40% 35-40% 13-17% ~54–65 kT Global Leader in a Structurally Resilient FSM Market
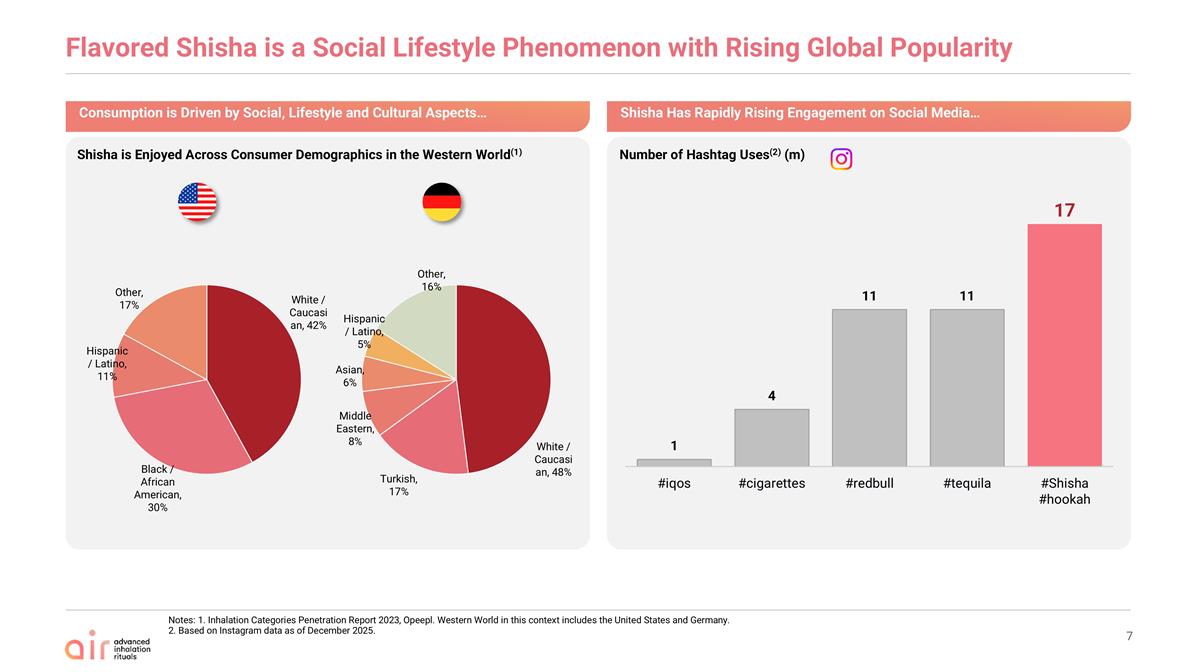
Flavored Shisha is a Social Lifestyle Phenomenon with Rising Global Popularity Consumption is Driven by Social, Lifestyle and Cultural Aspects… Shisha is Enjoyed Across Consumer Demographics in the Western World(1) Notes: 1. Inhalation Categories Penetration Report 2023, Opeepl. Western World in this context includes the United States and Germany. 2. Based on Instagram data as of December 2025. Number of Hashtag Uses(2) (m) Shisha Has Rapidly Rising Engagement on Social Media…
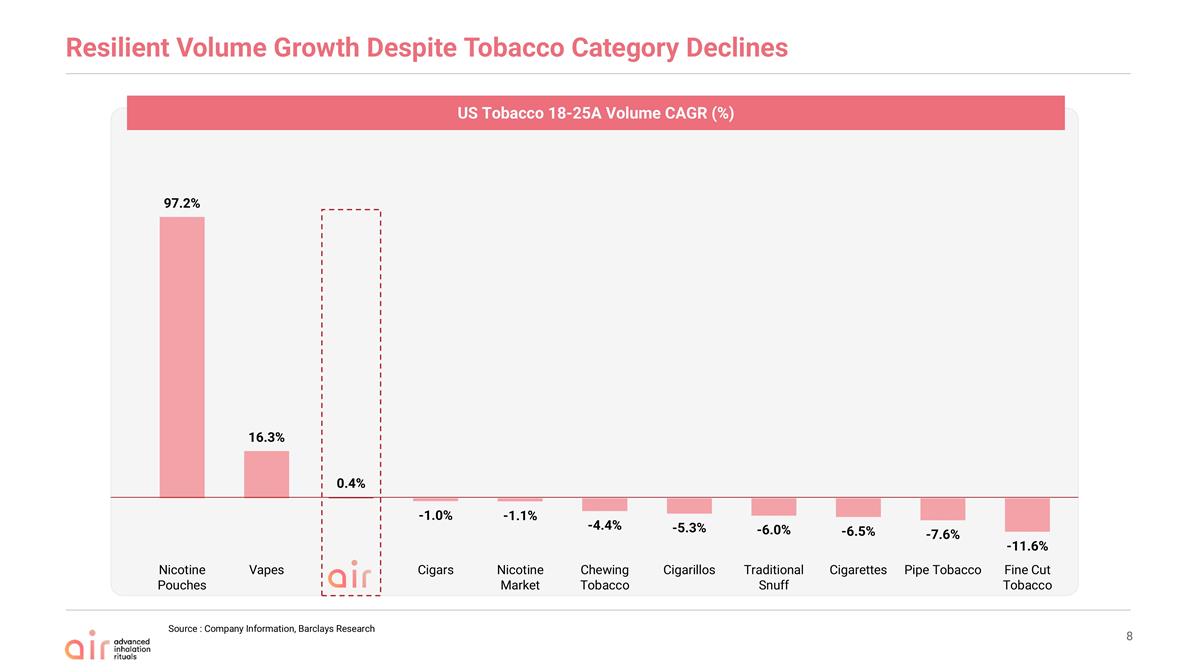
Resilient Volume Growth Despite Tobacco Category Declines Source : Company Information, Barclays Research Fine Cut Tobacco Traditional Snuff Cigarettes Pipe Tobacco Cigarillos Cigars Chewing Tobacco US Tobacco 18-25A Volume CAGR (%) Nicotine Pouches Vapes Nicotine Market
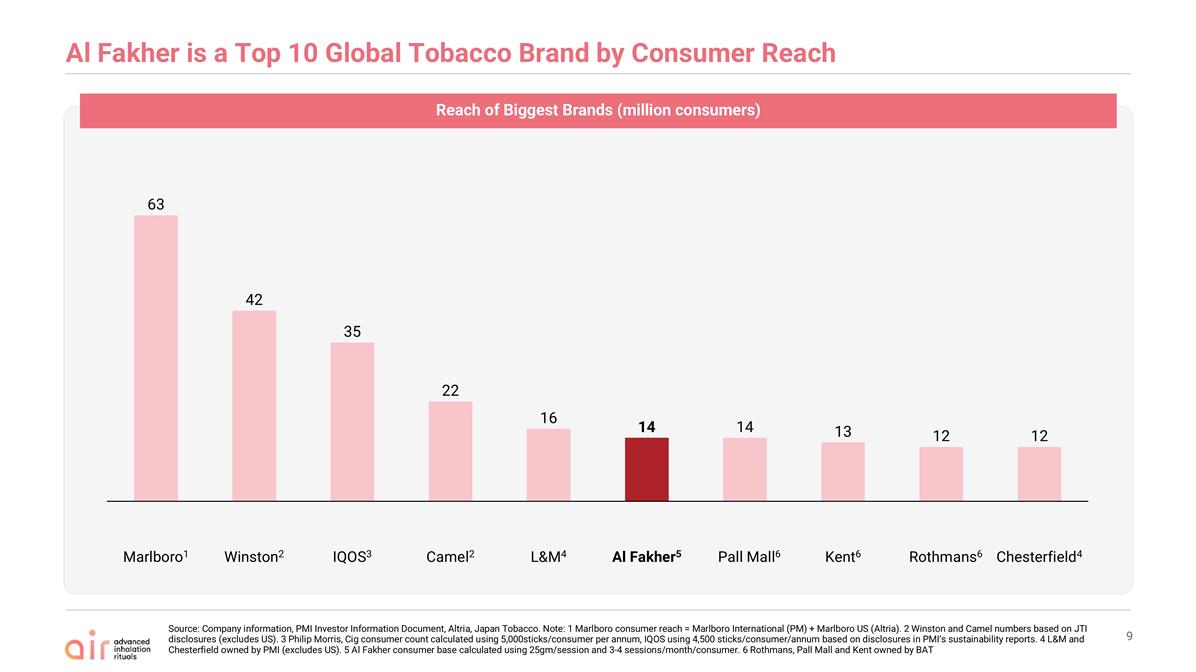
Al Fakher is a Top 10 Global Tobacco Brand by Consumer Reach Source: Company information, PMI Investor Information Document, Altria, Japan Tobacco. Note: 1 Marlboro consumer reach = Marlboro International (PM) + Marlboro US (Altria). 2 Winston and Camel numbers based on JTI disclosures (excludes US). 3 Philip Morris, Cig consumer count calculated using 5,000sticks/consumer per annum, IQOS using 4,500 sticks/consumer/annum based on disclosures in PMI’s sustainability reports. 4 L&M and Chesterfield owned by PMI (excludes US). 5 Al Fakher consumer base calculated using 25gm/session and 3-4 sessions/month/consumer. 6 Rothmans, Pall Mall and Kent owned by BAT Reach of Biggest Brands (million consumers) 1 2 3 2 4 5 6 6 Pall Mall6 4
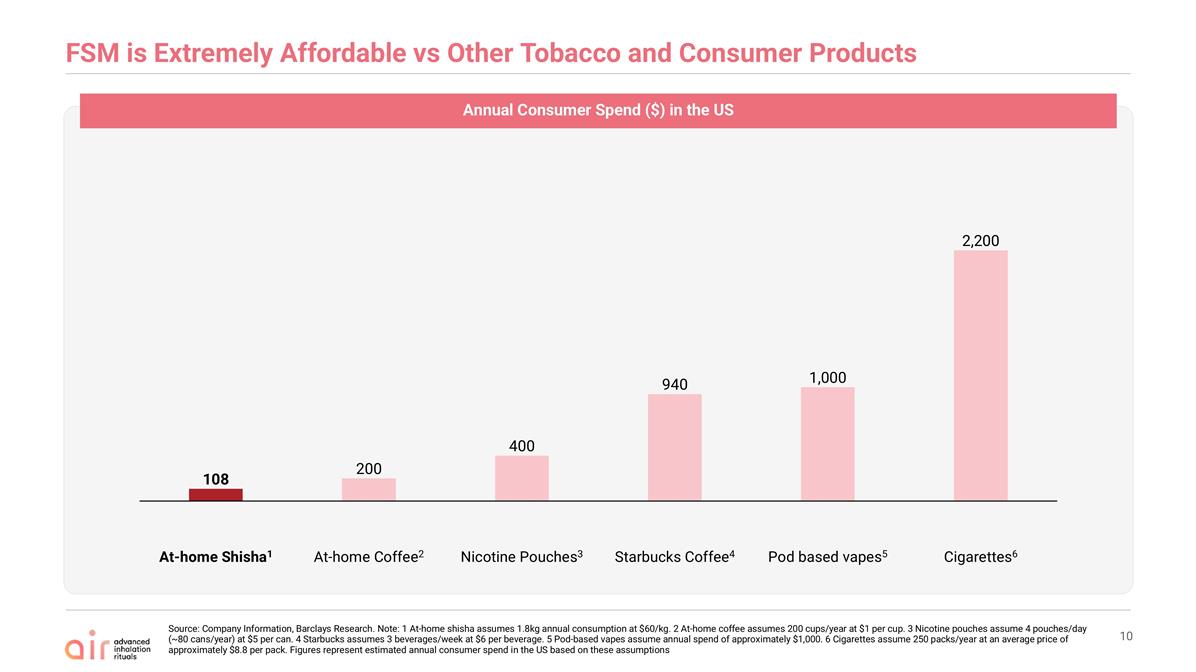
FSM is Extremely Affordable vs Other Tobacco and Consumer Products Source: Company Information, Barclays Research. Note: 1 At-home shisha assumes 1.8kg annual consumption at $60/kg. 2 At-home coffee assumes 200 cups/year at $1 per cup. 3 Nicotine pouches assume 4 pouches/day (~80 cans/year) at $5 per can. 4 Starbucks assumes 3 beverages/week at $6 per beverage. 5 Pod-based vapes assume annual spend of approximately $1,000. 6 Cigarettes assume 250 packs/year at an average price of approximately $8.8 per pack. Figures represent estimated annual consumer spend in the US based on these assumptions Annual Consumer Spend ($) in the US 1 2 3 4 5 6
GREAT TASTE, EVERY PUFF.
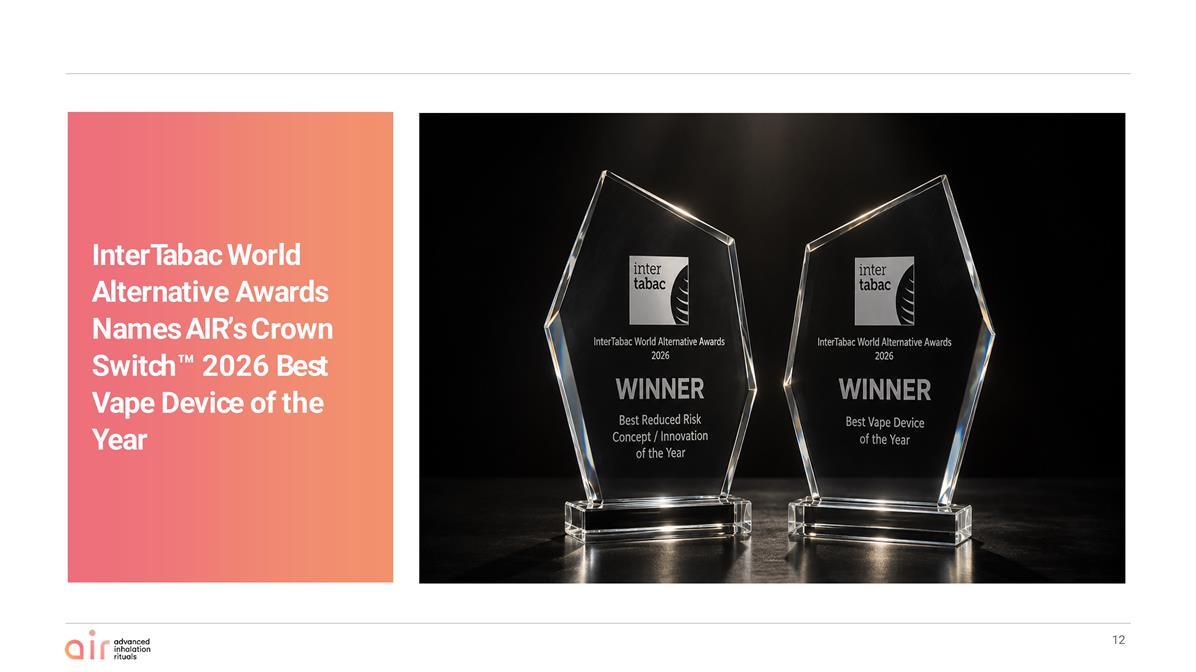
InterTabac World Alternative Awards Names AIR’s Crown Switch™ 2026 Best Vape Device of the Year
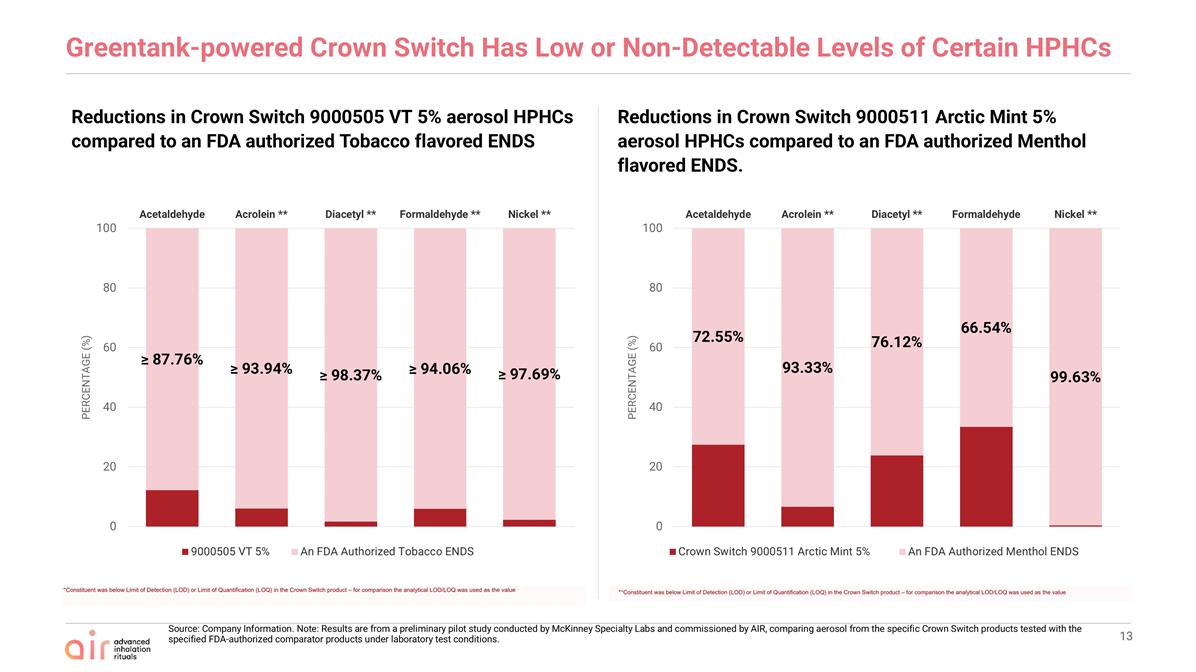
Greentank-powered Crown Switch Has Low or Non-Detectable Levels of Certain HPHCs Source: Company Information. Note: Results are from a preliminary pilot study conducted by McKinney Specialty Labs and commissioned by AIR, comparing aerosol from the specific Crown Switch products tested with the specified FDA-authorized comparator products under laboratory test conditions. Reductions in Crown Switch 9000505 VT 5% aerosol HPHCs compared to an FDA authorized Tobacco flavored ENDS Reductions in Crown Switch 9000511 Arctic Mint 5% aerosol HPHCs compared to an FDA authorized Menthol flavored ENDS.
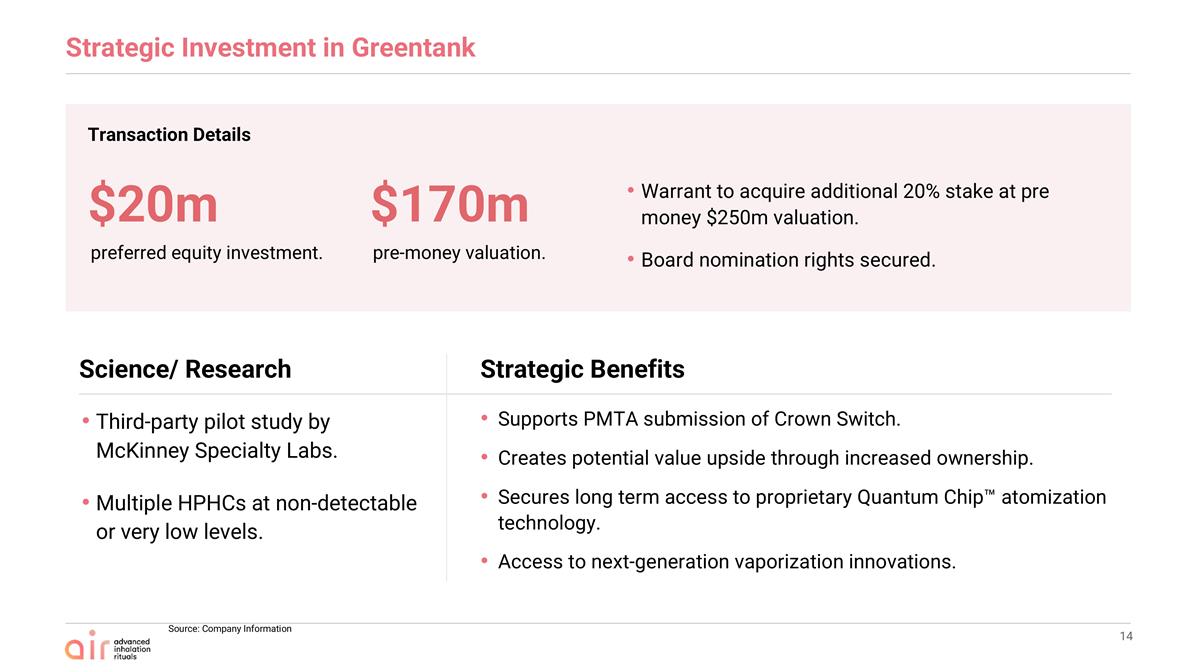
Strategic Investment in Greentank Warrant to acquire additional 20% stake at pre money $250m valuation. Board nomination rights secured. Source: Company Information Third-party pilot study by McKinney Specialty Labs. Multiple HPHCs at non-detectable or very low levels. Supports PMTA submission of Crown Switch. Creates potential value upside through increased ownership. Secures long term access to proprietary Quantum Chip™ atomization technology. Access to next-generation vaporization innovations. Transaction Details Science/ Research Strategic Benefits $20m preferred equity investment. $170m pre-money valuation.
Latest Results
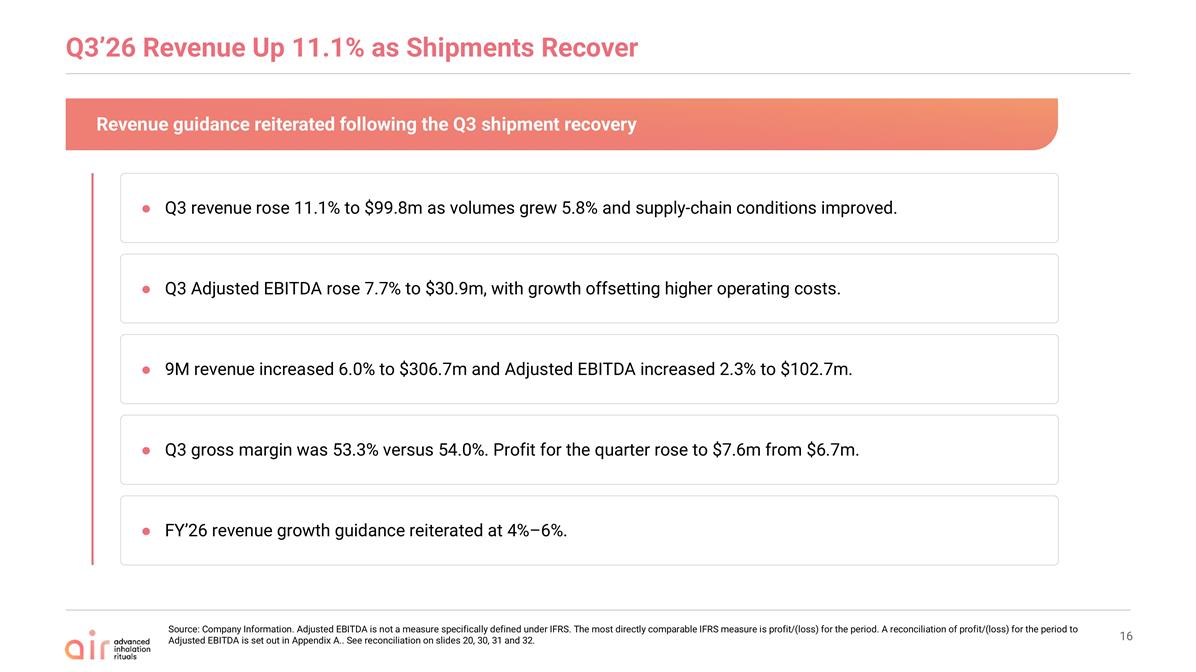
Q3’26 Revenue Up 11.1% as Shipments Recover Source: Company Information. Adjusted EBITDA is not a measure specifically defined under IFRS. The most directly comparable IFRS measure is profit/(loss) for the period. A reconciliation of profit/(loss) for the period to Adjusted EBITDA is set out in Appendix A.. See reconciliation on slides 20, 30, 31 and 32. Revenue guidance reiterated following the Q3 shipment recovery Q3 revenue rose 11.1% to $99.8m as volumes grew 5.8% and supply-chain conditions improved. Q3 Adjusted EBITDA rose 7.7% to $30.9m, with growth offsetting higher operating costs. 9M revenue increased 6.0% to $306.7m and Adjusted EBITDA increased 2.3% to $102.7m. Q3 gross margin was 53.3% versus 54.0%. Profit for the quarter rose to $7.6m from $6.7m. FY’26 revenue growth guidance reiterated at 4%–6%.
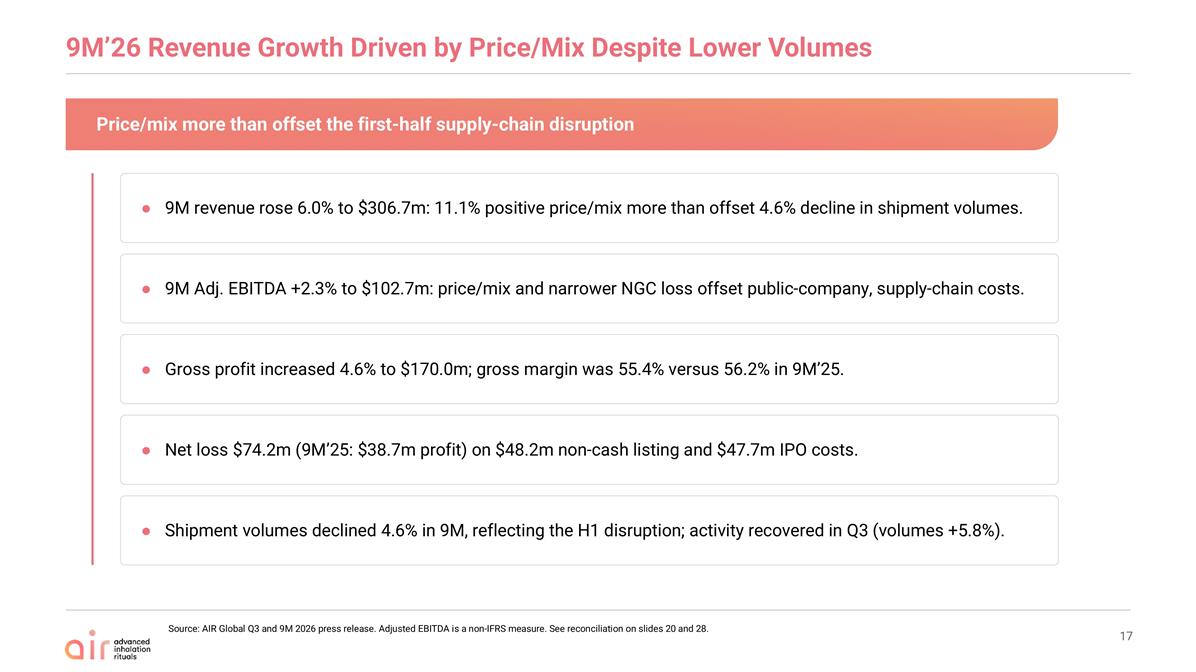
9M’26 Revenue Growth Driven by Price/Mix Despite Lower Volumes Source: AIR Global Q3 and 9M 2026 press release. Adjusted EBITDA is a non-IFRS measure. See reconciliation on slides 20 and 28. Price/mix more than offset the first-half supply-chain disruption 9M revenue rose 6.0% to $306.7m: 11.1% positive price/mix more than offset 4.6% decline in shipment volumes. 9M Adj. EBITDA +2.3% to $102.7m: price/mix and narrower NGC loss offset public-company, supply-chain costs. Gross profit increased 4.6% to $170.0m; gross margin was 55.4% versus 56.2% in 9M’25. Net loss $74.2m (9M’25: $38.7m profit) on $48.2m non-cash listing and $47.7m IPO costs. Shipment volumes declined 4.6% in 9M, reflecting the H1 disruption; activity recovered in Q3 (volumes +5.8%).
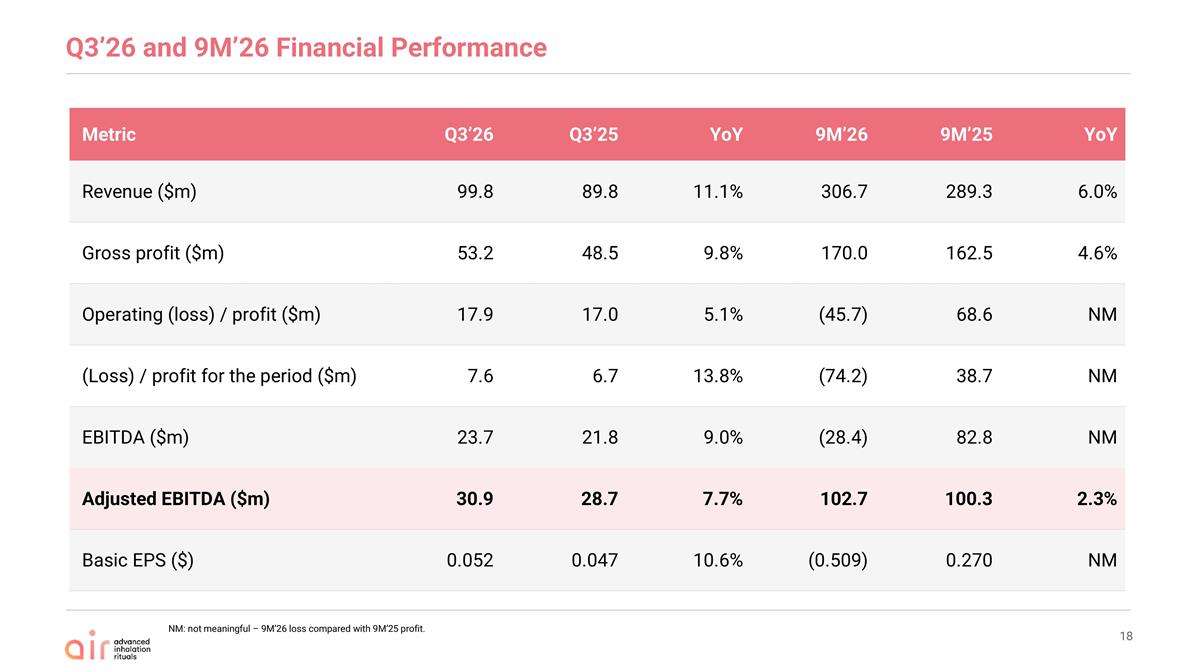
Q3’26 and 9M’26 Financial Performance NM: not meaningful – 9M’26 loss compared with 9M’25 profit. Metric Q3’26 Q3’25 YoY 9M’26 9M’25 YoY Revenue ($m) 99.8 89.8 11.1% 306.7 289.3 6.0% Gross profit ($m) 53.2 48.5 9.8% 170.0 162.5 4.6% Operating (loss) / profit ($m) 17.9 17.0 5.1% (45.7) 68.6 NM (Loss) / profit for the period ($m) 7.6 6.7 13.8% (74.2) 38.7 NM EBITDA ($m) 23.7 21.8 9.0% (28.4) 82.8 NM Adjusted EBITDA ($m) 30.9 28.7 7.7% 102.7 100.3 2.3% Basic EPS ($) 0.052 0.047 10.6% (0.509) 0.270 NM
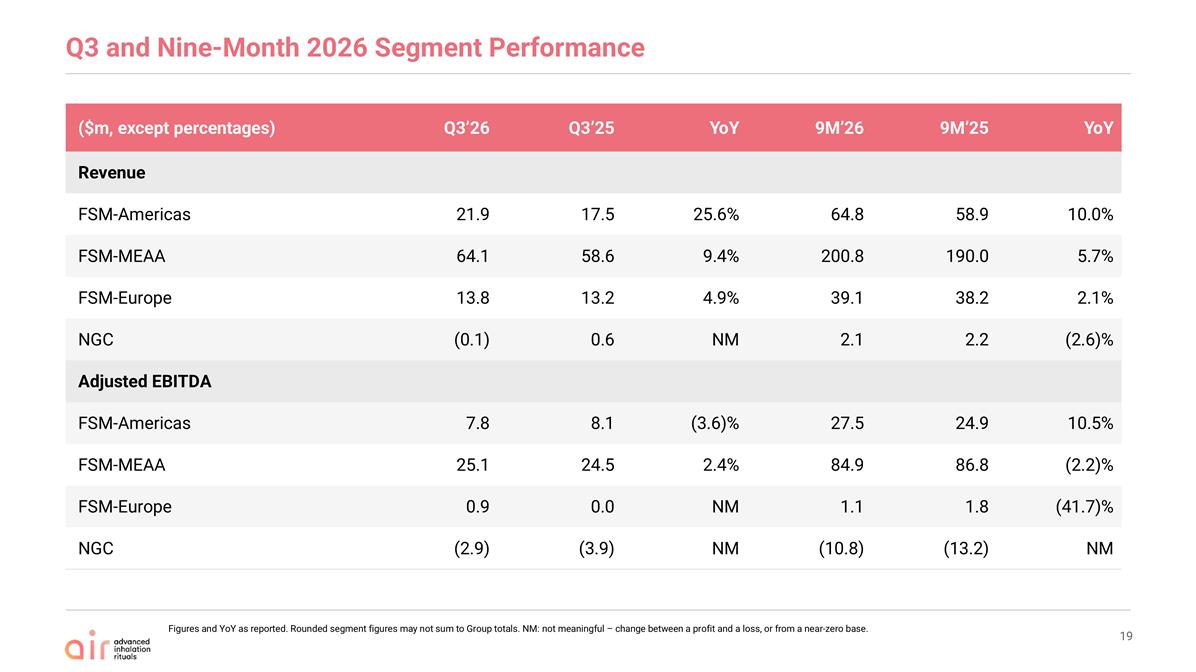
Q3 and Nine-Month 2026 Segment Performance ($m, except percentages) Q3’26 Q3’25 YoY 9M’26 9M’25 YoY Revenue FSM-Americas 21.9 17.5 25.6% 64.8 58.9 10.0% FSM-MEAA 64.1 58.6 9.4% 200.8 190.0 5.7% FSM-Europe 13.8 13.2 4.9% 39.1 38.2 2.1% NGC (0.1) 0.6 NM 2.1 2.2 (2.6)% Adjusted EBITDA FSM-Americas 7.8 8.1 (3.6)% 27.5 24.9 10.5% FSM-MEAA 25.1 24.5 2.4% 84.9 86.8 (2.2)% FSM-Europe 0.9 0.0 NM 1.1 1.8 (41.7)% NGC (2.9) (3.9) NM (10.8) (13.2) NM Figures and YoY as reported. Rounded segment figures may not sum to Group totals. NM: not meaningful – change between a profit and a loss, or from a near-zero base.
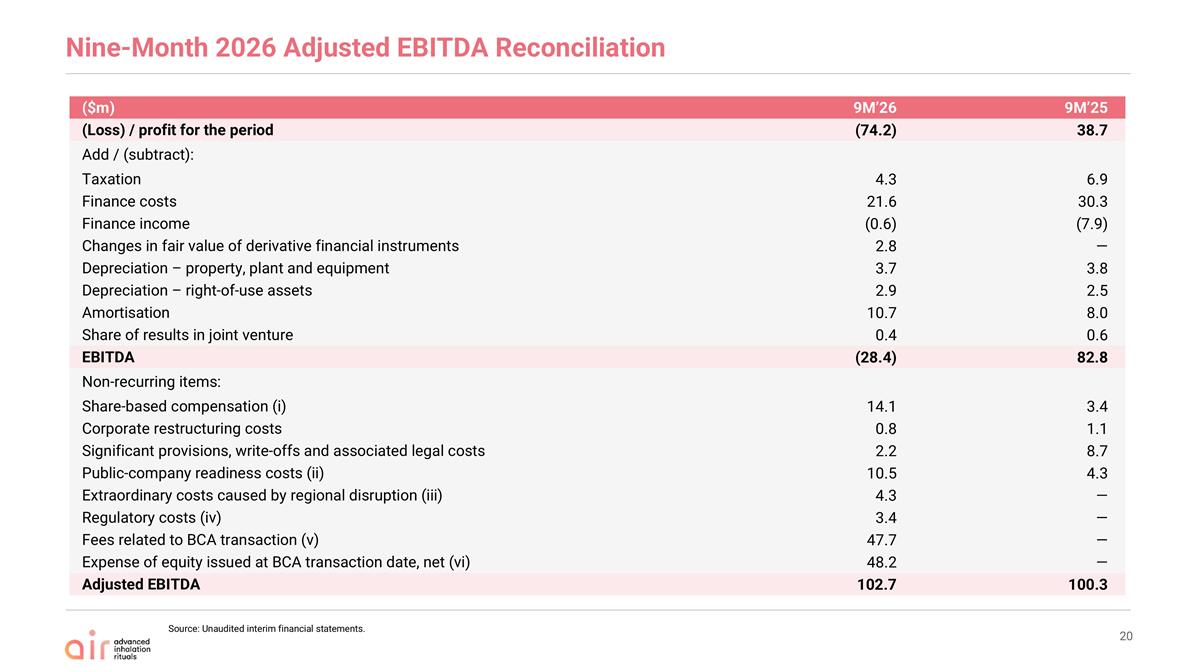
Nine-Month 2026 Adjusted EBITDA Reconciliation ($m) 9M’26 9M’25 (Loss) / profit for the period (74.2) 38.7 Add / (subtract): Taxation 4.3 6.9 Finance costs 21.6 30.3 Finance income (0.6) (7.9) Changes in fair value of derivative financial instruments 2.8 — Depreciation – property, plant and equipment 3.7 3.8 Depreciation – right-of-use assets 2.9 2.5 Amortisation 10.7 8.0 Share of results in joint venture 0.4 0.6 EBITDA (28.4) 82.8 Non-recurring items: Share-based compensation (i) 14.1 3.4 Corporate restructuring costs 0.8 1.1 Significant provisions, write-offs and associated legal costs 2.2 8.7 Public-company readiness costs (ii) 10.5 4.3 Extraordinary costs caused by regional disruption (iii) 4.3 — Regulatory costs (iv) 3.4 — Fees related to BCA transaction (v) 47.7 — Expense of equity issued at BCA transaction date, net (vi) 48.2 — Adjusted EBITDA 102.7 100.3 Source: Unaudited interim financial statements.
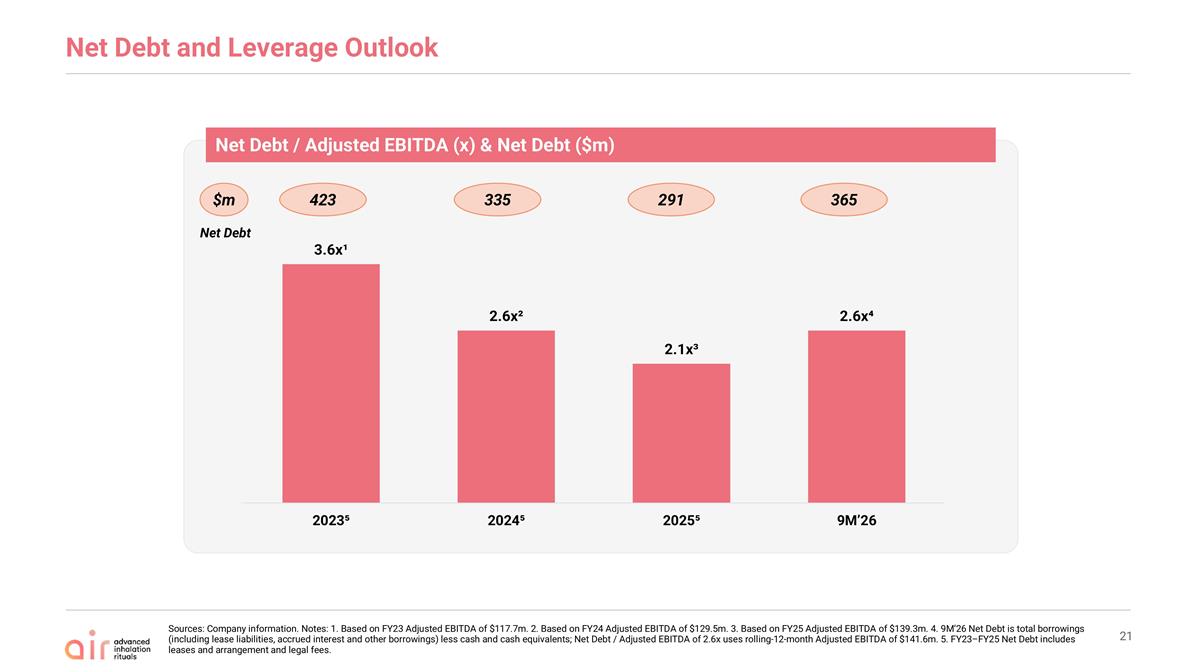
Net Debt and Leverage Outlook Net Debt / Adjusted EBITDA (x) & Net Debt ($m) Sources: Company information. Notes: 1. Based on FY23 Adjusted EBITDA of $117.7m. 2. Based on FY24 Adjusted EBITDA of $129.5m. 3. Based on FY25 Adjusted EBITDA of $139.3m. 4. 9M’26 Net Debt is total borrowings (including lease liabilities, accrued interest and other borrowings) less cash and cash equivalents; Net Debt / Adjusted EBITDA of 2.6x uses rolling-12-month Adjusted EBITDA of $141.6m. 5. FY23–FY25 Net Debt includes leases and arrangement and legal fees. $m 423 335 291 365 Net Debt
Outlook & Guidance
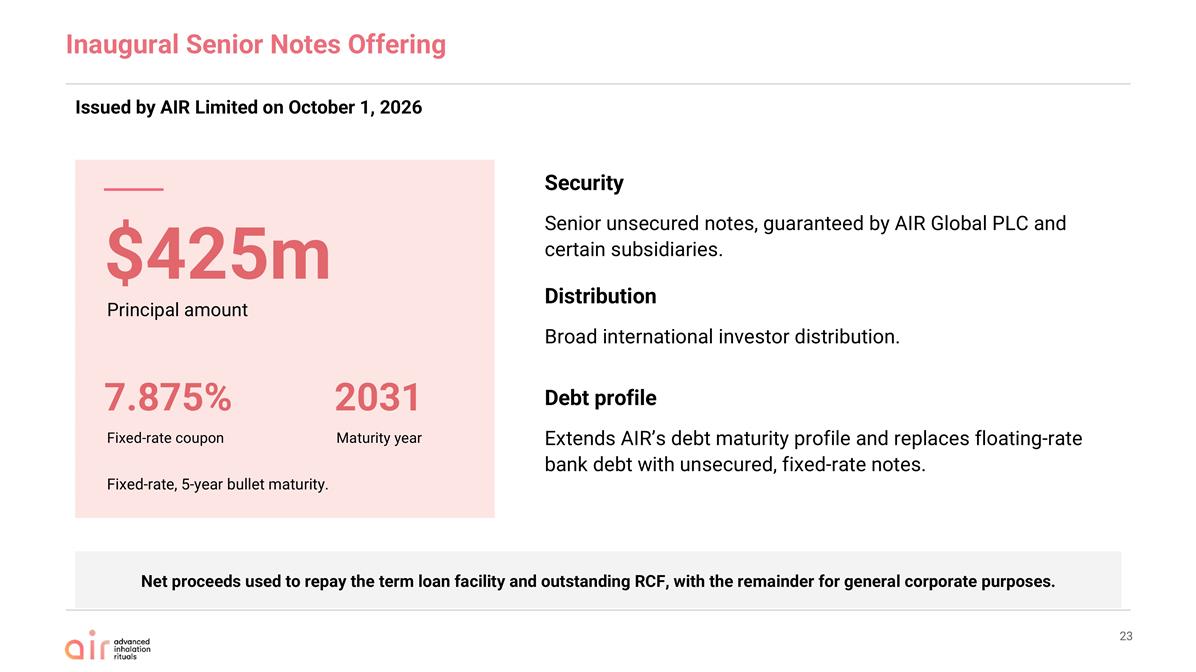
Issued by AIR Limited on October 1, 2026 Inaugural Senior Notes Offering Security Distribution Debt profile Maturity year 7.875% Net proceeds used to repay the term loan facility and outstanding RCF, with the remainder for general corporate purposes. Senior unsecured notes, guaranteed by AIR Global PLC and certain subsidiaries. Fixed-rate, 5-year bullet maturity. Broad international investor distribution. Extends AIR’s debt maturity profile and replaces floating-rate bank debt with unsecured, fixed-rate notes. $425m Principal amount Fixed-rate coupon 2031
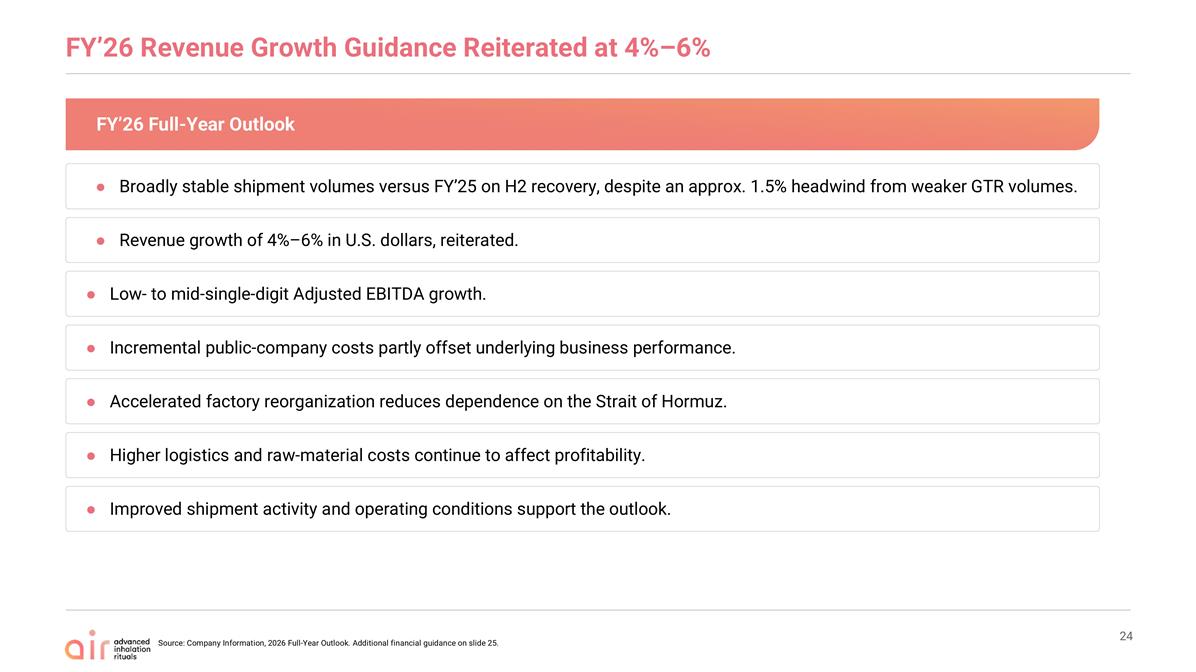
FY’26 Revenue Growth Guidance Reiterated at 4%–6% Broadly stable shipment volumes versus FY’25 on H2 recovery, despite an approx. 1.5% headwind from weaker GTR volumes. Revenue growth of 4%–6% in U.S. dollars, reiterated. Low- to mid-single-digit Adjusted EBITDA growth. Incremental public-company costs partly offset underlying business performance. Accelerated factory reorganization reduces dependence on the Strait of Hormuz. Higher logistics and raw-material costs continue to affect profitability. Improved shipment activity and operating conditions support the outlook. FY’26 Full-Year Outlook Source: Company Information, 2026 Full-Year Outlook. Additional financial guidance on slide 25.
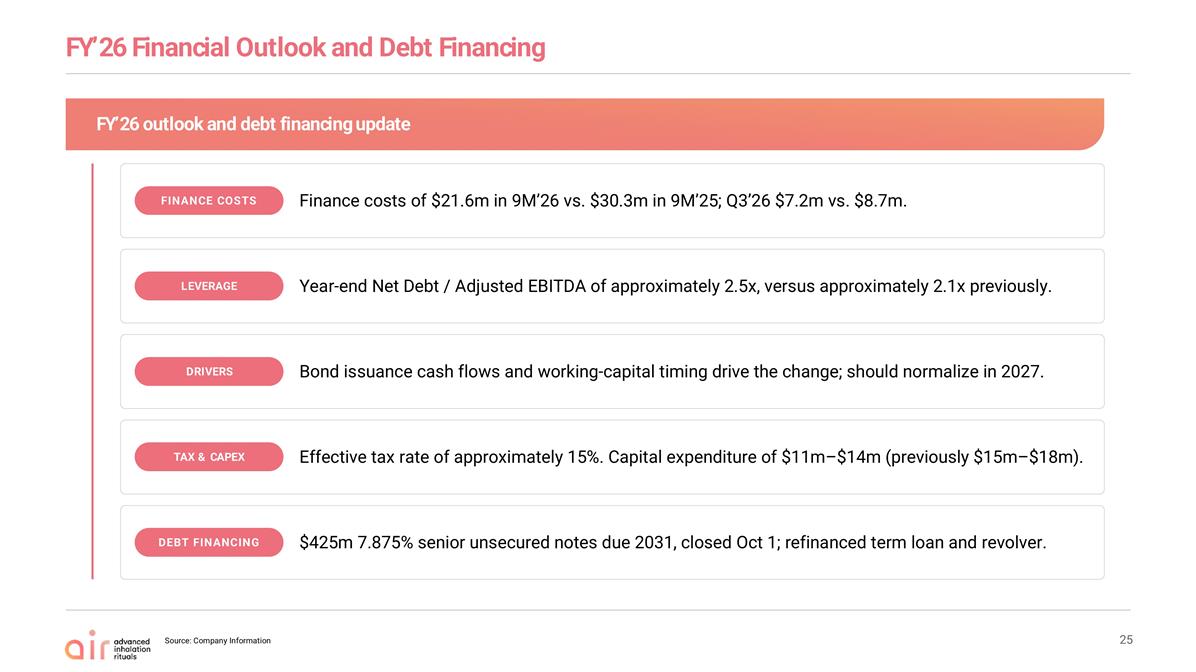
FY’26 Financial Outlook and Debt Financing Finance costs of $21.6m in 9M’26 vs. $30.3m in 9M’25; Q3’26 $7.2m vs. $8.7m. FY’26 outlook and debt financing update FINANCE COSTS Year-end Net Debt / Adjusted EBITDA of approximately 2.5x, versus approximately 2.1x previously. LEVERAGE Bond issuance cash flows and working-capital timing drive the change; should normalize in 2027. DRIVERS Effective tax rate of approximately 15%. Capital expenditure of $11m–$14m (previously $15m–$18m). TAX & CAPEX $425m 7.875% senior unsecured notes due 2031, closed Oct 1; refinanced term loan and revolver. DEBT FINANCING Source: Company Information
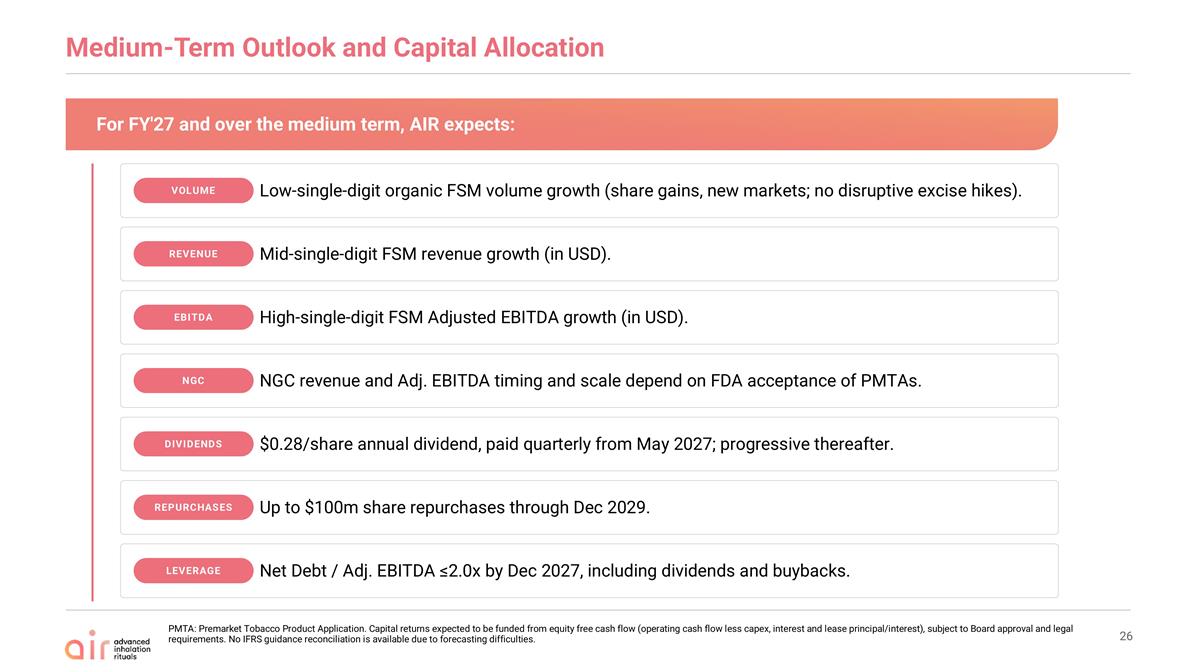
Medium-Term Outlook and Capital Allocation PMTA: Premarket Tobacco Product Application. Capital returns expected to be funded from equity free cash flow (operating cash flow less capex, interest and lease principal/interest), subject to Board approval and legal requirements. No IFRS guidance reconciliation is available due to forecasting difficulties. For FY'27 and over the medium term, AIR expects: Low-single-digit organic FSM volume growth (share gains, new markets; no disruptive excise hikes). VOLUME Mid-single-digit FSM revenue growth (in USD). REVENUE High-single-digit FSM Adjusted EBITDA growth (in USD). EBITDA NGC revenue and Adj. EBITDA timing and scale depend on FDA acceptance of PMTAs. NGC $0.28/share annual dividend, paid quarterly from May 2027; progressive thereafter. DIVIDENDS Net Debt / Adj. EBITDA ≤2.0x by Dec 2027, including dividends and buybacks. LEVERAGE Up to $100m share repurchases through Dec 2029. REPURCHASES
Glossary & Appendix
Glossary AIR defines EBITDA as earnings for the period before interest, taxation, depreciation and amortization. The most directly comparable IFRS measure is profit/ (loss) for the period. EBITDA is an intermediate step in AIR’s calculation of Adjusted EBITDA, as set out in the appendix. AIR defines Adjusted EBITDA as earnings before interest, taxes, depreciation, and amortization, further adjusted to exclude items such as non-recurring expenses, share-based compensation and other non-operating expenses. Adjusted EBITDA is not a measure specifically defined under IFRS. The most directly comparable IFRS measure is profit/(loss) for the period. A reconciliation of profit/(loss) for the period to Adjusted EBITDA is set out in appendix. AIR defines Net Debt as total borrowings (comprising current and non-current interest-bearing loans and borrowings and lease liabilities) less cash and cash equivalents, each as reported on AIR’s IFRS statement of financial position. AIR defines the ratio of Net Debt to Adjusted EBITDA (“leverage”) as Net Debt divided by Adjusted EBITDA. Neither Net Debt nor the Net Debt to Adjusted EBITDA ratio is presented in accordance with IFRS; the most directly comparable IFRS measures are total borrowings and cash and cash equivalents, each as reported on AIR’s statement of financial position. AIR believes this ratio is a useful measure of AIR’s capital structure and progress toward its target leverage. A reconciliation of profit/(loss) for the period to EBITDA and Adjusted EBITDA and total borrowings to Net Debt is set forth in the Appendix.
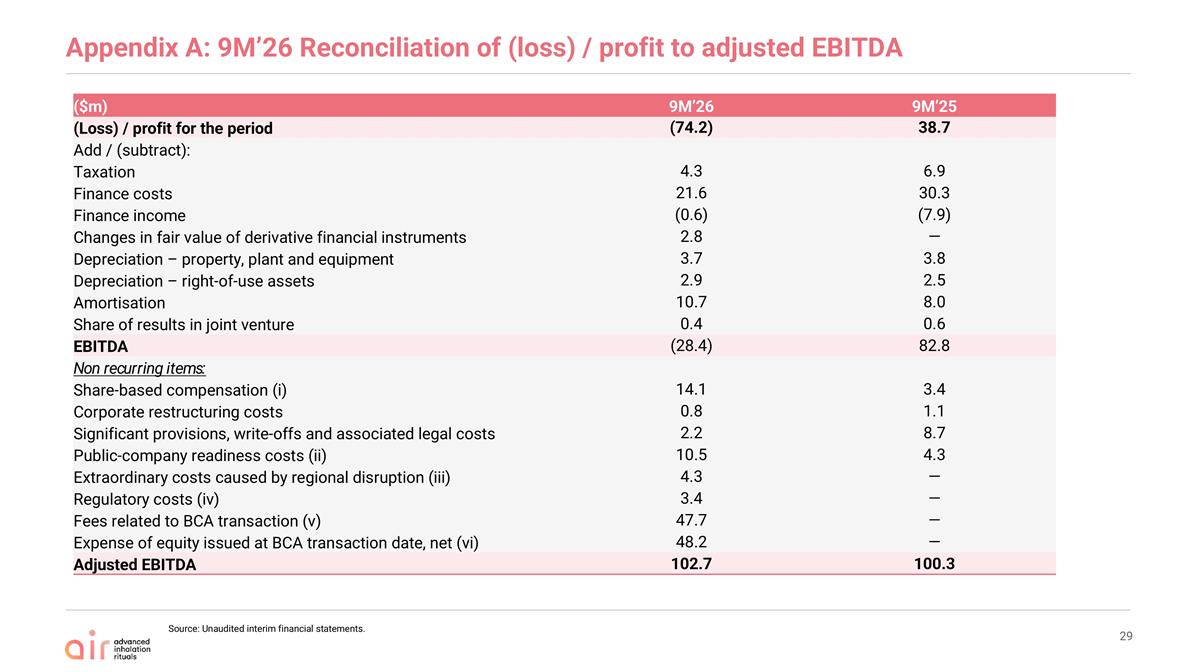
Appendix A: 9M’26 Reconciliation of (loss) / profit to adjusted EBITDA ($m) 9M’26 9M’25 (Loss) / profit for the period (74.2) 38.7 Add / (subtract): Taxation 4.3 6.9 Finance costs 21.6 30.3 Finance income (0.6) (7.9) Changes in fair value of derivative financial instruments 2.8 — Depreciation – property, plant and equipment 3.7 3.8 Depreciation – right-of-use assets 2.9 2.5 Amortisation 10.7 8.0 Share of results in joint venture 0.4 0.6 EBITDA (28.4) 82.8 Non recurring items: Share-based compensation (i) 14.1 3.4 Corporate restructuring costs 0.8 1.1 Significant provisions, write-offs and associated legal costs 2.2 8.7 Public-company readiness costs (ii) 10.5 4.3 Extraordinary costs caused by regional disruption (iii) 4.3 — Regulatory costs (iv) 3.4 — Fees related to BCA transaction (v) 47.7 — Expense of equity issued at BCA transaction date, net (vi) 48.2 — Adjusted EBITDA 102.7 100.3 Source: Unaudited interim financial statements.
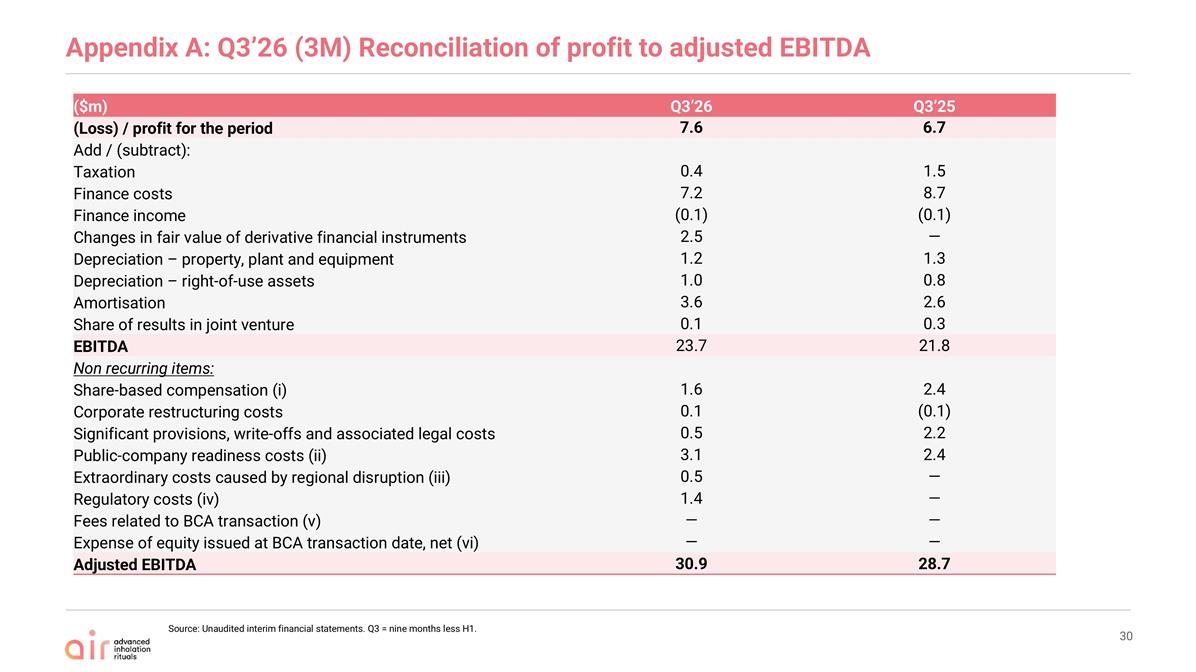
Appendix A: Q3’26 (3M) Reconciliation of profit to adjusted EBITDA ($m) Q3’26 Q3’25 (Loss) / profit for the period 7.6 6.7 Add / (subtract): Taxation 0.4 1.5 Finance costs 7.2 8.7 Finance income (0.1) (0.1) Changes in fair value of derivative financial instruments 2.5 — Depreciation – property, plant and equipment 1.2 1.3 Depreciation – right-of-use assets 1.0 0.8 Amortisation 3.6 2.6 Share of results in joint venture 0.1 0.3 EBITDA 23.7 21.8 Non recurring items: Share-based compensation (i) 1.6 2.4 Corporate restructuring costs 0.1 (0.1) Significant provisions, write-offs and associated legal costs 0.5 2.2 Public-company readiness costs (ii) 3.1 2.4 Extraordinary costs caused by regional disruption (iii) 0.5 — Regulatory costs (iv) 1.4 — Fees related to BCA transaction (v) — — Expense of equity issued at BCA transaction date, net (vi) — — Adjusted EBITDA 30.9 28.7 Source: Unaudited interim financial statements. Q3 = nine months less H1.
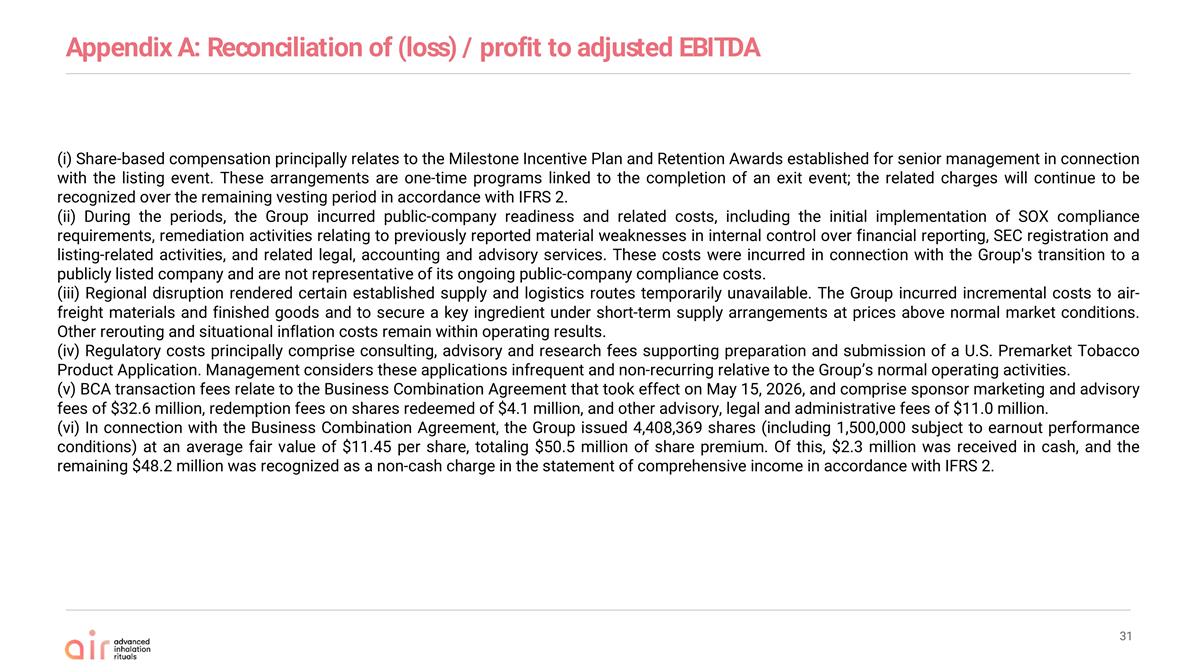
Appendix A: Reconciliation of (loss) / profit to adjusted EBITDA (i) Share-based compensation principally relates to the Milestone Incentive Plan and Retention Awards established for senior management in connection with the listing event. These arrangements are one-time programs linked to the completion of an exit event; the related charges will continue to be recognized over the remaining vesting period in accordance with IFRS 2. (ii) During the periods, the Group incurred public-company readiness and related costs, including the initial implementation of SOX compliance requirements, remediation activities relating to previously reported material weaknesses in internal control over financial reporting, SEC registration and listing-related activities, and related legal, accounting and advisory services. These costs were incurred in connection with the Group's transition to a publicly listed company and are not representative of its ongoing public-company compliance costs. (iii) Regional disruption rendered certain established supply and logistics routes temporarily unavailable. The Group incurred incremental costs to air-freight materials and finished goods and to secure a key ingredient under short-term supply arrangements at prices above normal market conditions. Other rerouting and situational inflation costs remain within operating results. (iv) Regulatory costs principally comprise consulting, advisory and research fees supporting preparation and submission of a U.S. Premarket Tobacco Product Application. Management considers these applications infrequent and non-recurring relative to the Group’s normal operating activities. (v) BCA transaction fees relate to the Business Combination Agreement that took effect on May 15, 2026, and comprise sponsor marketing and advisory fees of $32.6 million, redemption fees on shares redeemed of $4.1 million, and other advisory, legal and administrative fees of $11.0 million. (vi) In connection with the Business Combination Agreement, the Group issued 4,408,369 shares (including 1,500,000 subject to earnout performance conditions) at an average fair value of $11.45 per share, totaling $50.5 million of share premium. Of this, $2.3 million was received in cash, and the remaining $48.2 million was recognized as a non-cash charge in the statement of comprehensive income in accordance with IFRS 2.
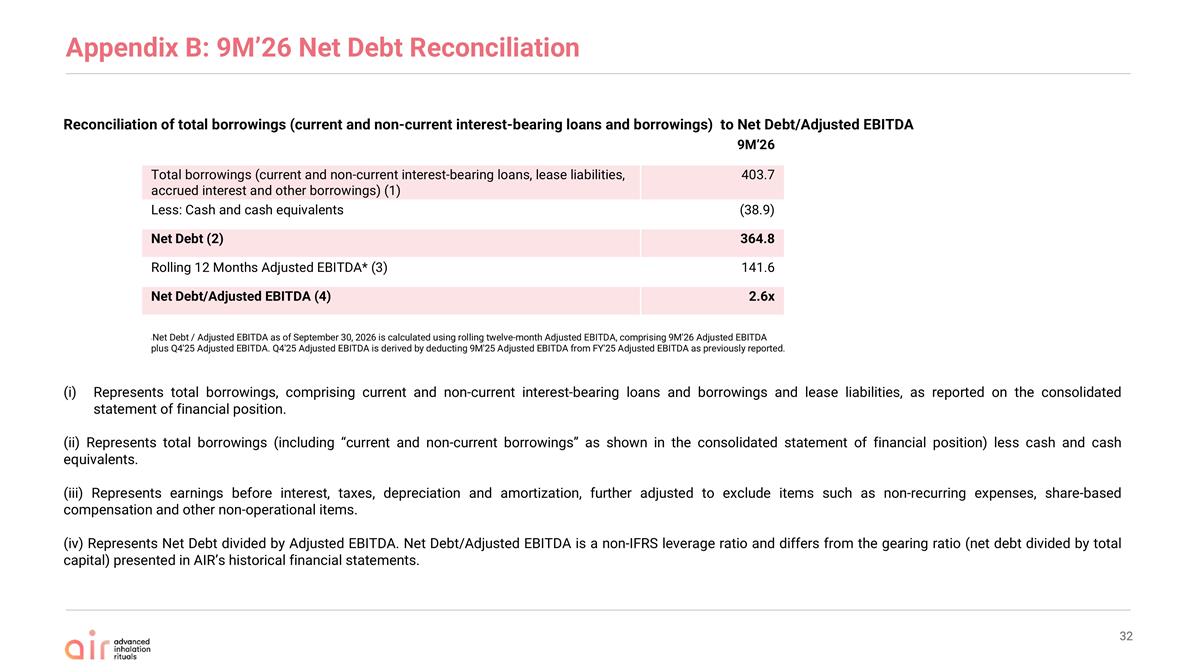
Appendix B: 9M’26 Net Debt Reconciliation Reconciliation of total borrowings (current and non-current interest-bearing loans and borrowings) to Net Debt/Adjusted EBITDA Represents total borrowings, comprising current and non-current interest-bearing loans and borrowings and lease liabilities, as reported on the consolidated statement of financial position. (ii) Represents total borrowings (including “current and non-current borrowings” as shown in the consolidated statement of financial position) less cash and cash equivalents. (iii) Represents earnings before interest, taxes, depreciation and amortization, further adjusted to exclude items such as non-recurring expenses, share-based compensation and other non-operational items. (iv) Represents Net Debt divided by Adjusted EBITDA. Net Debt/Adjusted EBITDA is a non-IFRS leverage ratio and differs from the gearing ratio (net debt divided by total capital) presented in AIR’s historical financial statements. 9M’26 Total borrowings (current and non-current interest-bearing loans, lease liabilities, accrued interest and other borrowings) (1) 403.7 Less: Cash and cash equivalents (38.9) Net Debt (2) 364.8 Rolling 12 Months Adjusted EBITDA* (3) 141.6 Net Debt/Adjusted EBITDA (4) 2.6x *Net Debt / Adjusted EBITDA as of September 30, 2026 is calculated using rolling twelve-month Adjusted EBITDA, comprising 9M'26 Adjusted EBITDA plus Q4'25 Adjusted EBITDA. Q4'25 Adjusted EBITDA is derived by deducting 9M'25 Adjusted EBITDA from FY'25 Adjusted EBITDA as previously reported.
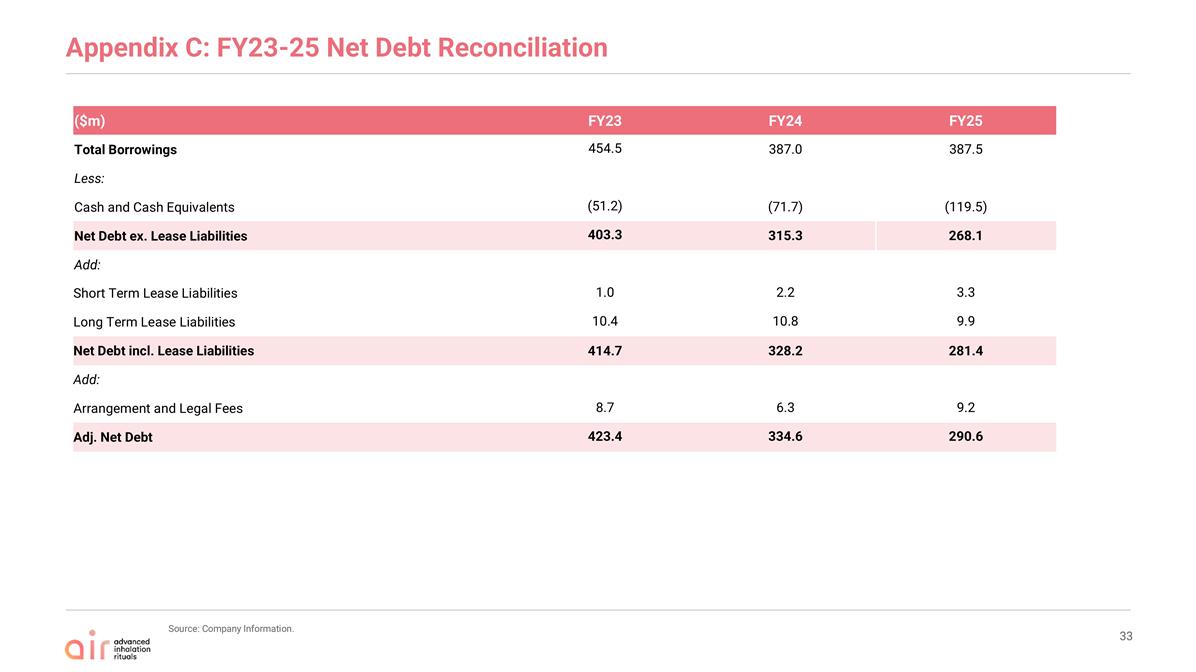
Appendix C: FY23-25 Net Debt Reconciliation ($m) FY23 FY24 FY25 Total Borrowings 454.5 387.0 387.5 Less: Cash and Cash Equivalents (51.2) (71.7) (119.5) Net Debt ex. Lease Liabilities 403.3 315.3 268.1 Add: Short Term Lease Liabilities 1.0 2.2 3.3 Long Term Lease Liabilities 10.4 10.8 9.9 Net Debt incl. Lease Liabilities 414.7 328.2 281.4 Add: Arrangement and Legal Fees 8.7 6.3 9.2 Adj. Net Debt 423.4 334.6 290.6 Source: Company Information.