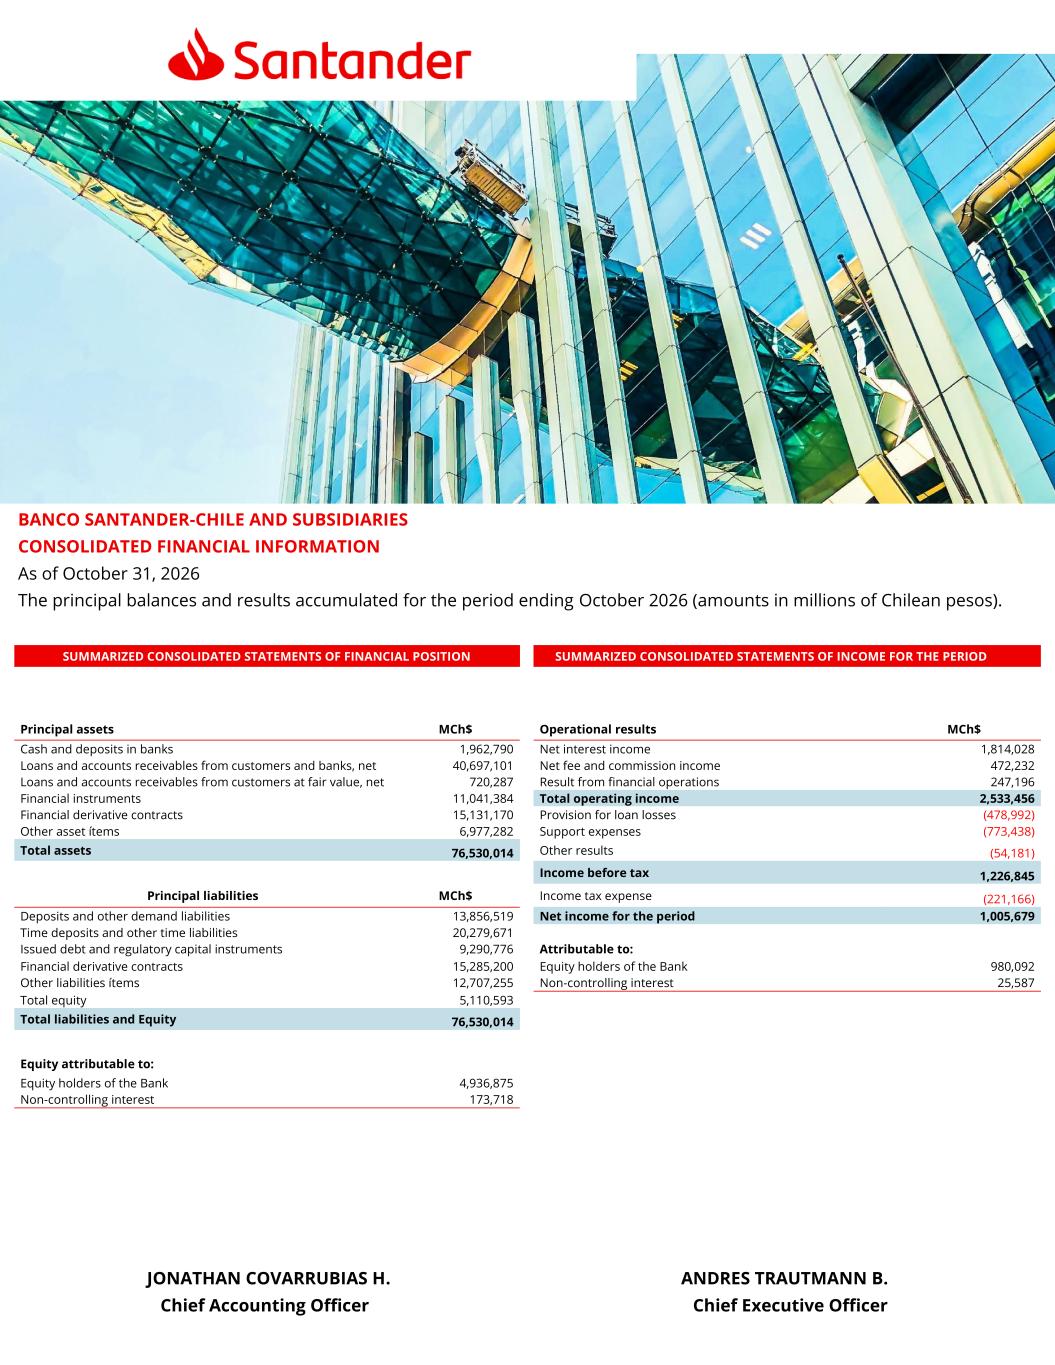
SUMMARIZED CONSOLIDATED STATEMENTS OF FINANCIAL POSITION SUMMARIZED CONSOLIDATED STATEMENTS OF INCOME FOR THE PERIOD Principal assets MCh$ Operational results MCh$ Cash and deposits in banks 1,962,790 Net interest income 1,814,028 Loans and accounts receivables from customers and banks, net 40,697,101 Net fee and commission income 472,232 Loans and accounts receivables from customers at fair value, net 720,287 Result from financial operations 247,196 Financial instruments 11,041,384 Total operating income 2,533,456 Financial derivative contracts 15,131,170 Provision for loan losses (478,992) Other asset ítems 6,977,282 Support expenses (773,438) Total assets 76,530,014 Other results (54,181) Income before tax 1,226,845 Principal liabilities MCh$ Income tax expense (221,166) Deposits and other demand liabilities 13,856,519 Net income for the period 1,005,679 Time deposits and other time liabilities 20,279,671 Issued debt and regulatory capital instruments 9,290,776 Attributable to: Financial derivative contracts 15,285,200 Equity holders of the Bank 980,092 Other liabilities ítems 12,707,255 Non-controlling interest 25,587 Total equity 5,110,593 Total liabilities and Equity 76,530,014 Equity attributable to: Equity holders of the Bank 4,936,875 Non-controlling interest 173,718 BANCO SANTANDER-CHILE AND SUBSIDIARIES CONSOLIDATED FINANCIAL INFORMATION As of October 31, 2026 The principal balances and results accumulated for the period ending October 2026 (amounts in millions of Chilean pesos). JONATHAN COVARRUBIAS H. ANDRES TRAUTMANN B. Chief Accounting Officer Chief Executive Officer
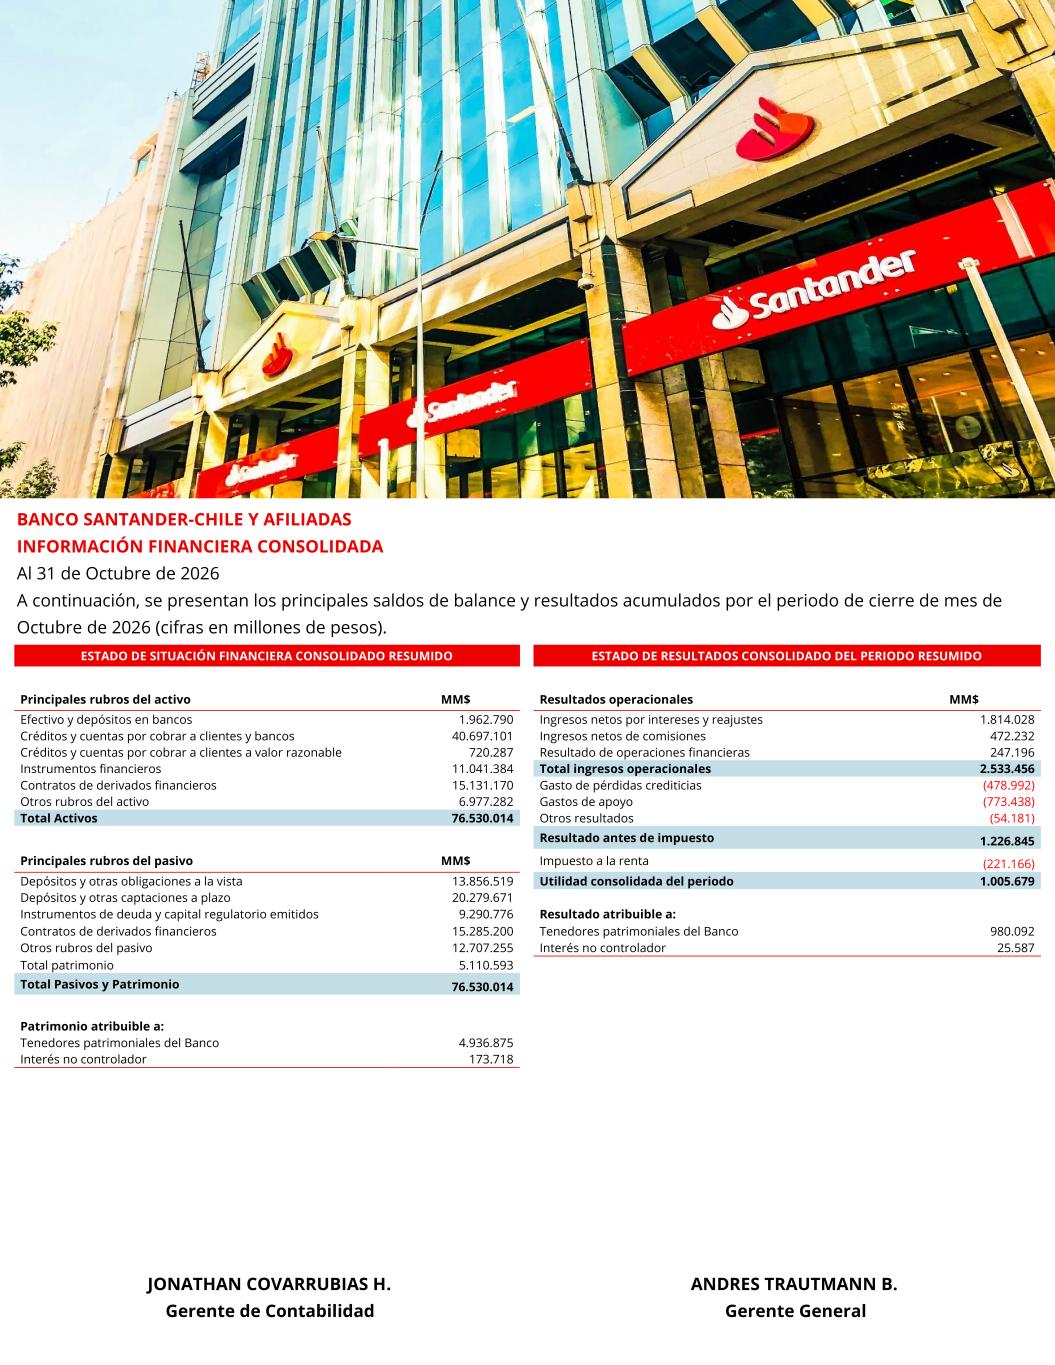
B ESTADO DE SITUACIÓN FINANCIERA CONSOLIDADO RESUMIDO ESTADO DE RESULTADOS CONSOLIDADO DEL PERIODO RESUMIDO Principales rubros del activo MM$ Resultados operacionales MM$ Efectivo y depósitos en bancos 1.962.790 Ingresos netos por intereses y reajustes 1.814.028 Créditos y cuentas por cobrar a clientes y bancos 40.697.101 Ingresos netos de comisiones 472.232 Créditos y cuentas por cobrar a clientes a valor razonable 720.287 Resultado de operaciones financieras 247.196 Instrumentos financieros 11.041.384 Total ingresos operacionales 2.533.456 Contratos de derivados financieros 15.131.170 Gasto de pérdidas crediticias (478.992) Otros rubros del activo 6.977.282 Gastos de apoyo (773.438) Total Activos 76.530.014 Otros resultados (54.181) Resultado antes de impuesto 1.226.845 Principales rubros del pasivo MM$ Impuesto a la renta (221.166) Depósitos y otras obligaciones a la vista 13.856.519 Utilidad consolidada del periodo 1.005.679 Depósitos y otras captaciones a plazo 20.279.671 Instrumentos de deuda y capital regulatorio emitidos 9.290.776 Resultado atribuible a: Contratos de derivados financieros 15.285.200 Tenedores patrimoniales del Banco 980.092 Otros rubros del pasivo 12.707.255 Interés no controlador 25.587 Total patrimonio 5.110.593 Total Pasivos y Patrimonio 76.530.014 Patrimonio atribuible a: Tenedores patrimoniales del Banco 4.936.875 Interés no controlador 173.718 BANCO SANTANDER-CHILE Y AFILIADAS INFORMACIÓN FINANCIERA CONSOLIDADA Al 31 de Octubre de 2026 A continuación, se presentan los principales saldos de balance y resultados acumulados por el periodo de cierre de mes de Octubre de 2026 (cifras en millones de pesos). JONATHAN COVARRUBIAS H. ANDRES TRAUTMANN B. Gerente de Contabilidad Gerente General
IMPORTANT NOTICE The unaudited financial information has been prepared in accordance with the Compendium of Accounting Standards for Banks effective from January 1, 2022 issued by the Financial Market Commission (FMC), The accounting principles issued by the FMC are substantially similar to IFRS but there are some exceptions, The FMC is the banking industry regulator according to article 2 of the General Banking Law, which by General Regulation establishes the accounting principles to be used by the banking industry, For those principles not covered by the Compendium of Accounting Standards for Banks, banks can use generally accepted accounting principles issued by the Chilean Accountant’s Association AG which coincide with International Financial Reporting Standards (IFRS) issued by the International Accounting Standards Board (IASB), If discrepancies exist between the accounting principles issued by the FMC (Compendium of Accounting Standards for Banks) and IFRS the Compendium of Accounting Standards for Banks will take precedence, ¿Qué podemos hacer por ti hoy?