Exhibit 99.2
Acquisition of Helen of Troy November 12, 2026
2 Disclaimer & Ledger THIS PRESENTATION IS FOR DISCUSSION AND INFORMATIONAL PURPOSES ONLY. THE VIEWS EXPRESSED HEREIN REPRESENT SOLELY THE OPINIONS OF EMPOWER BRANDS HOLDINGS GROUP, LLC (“EMPOWER BRANDS”) AS OF THE DATE HEREOF. EMPOWER BRANDS RESERVES THE RIGHT TO CHANGE OR MODIFY ANY OF ITS OPINIONS EXPRESSED HEREIN AT ANY TIME AN D F OR ANY REASON AND EXPRESSLY DISCLAIMS ANY OBLIGATION TO CORRECT, UPDATE OR REVISE THE INFORMATION CONTAINED HEREIN OR TO OTHERWISE PROVIDE ANY ADDITIONAL MATERIALS. ALL OF THE INFORMATION CONTAINED HEREIN IS BASED ON PUBLICLY AVAILABLE INFORMATION WITH RESPECT TO HELEN OF TROY LIMITED (THE “C OMPANY”, “HELE” OR “HELEN OF TROY”), INCLUDING FILINGS MADE BY THE COMPANY WITH THE SECURITIES AND EXCHANGE COMMISSION (THE “SEC”) AND OTHER SOURCES (INCLUDING THE COMPANY’S WEBSITE), AS WELL AS EMPOWER BRANDS’ ANALYSIS OF SUCH PUBLICLY AVAILABLE INFORMATION. EMPOWER BRANDS HAS RELIED UPON AND ASSUMED, WITHOUT INDEPENDENT VERIFICATION, THE ACCURACY AND COMPLETENESS OF A LL DATA AND INFORMATION AVAILABLE FROM PUBLIC SOURCES, AND NO REPRESENTATION OR WARRANTY IS MADE THAT ANY SUCH DATA OR INFORMATION IS ACCURATE. NO REPRESENTATION, WARRANTY OR UNDERTAKI NG, EXPRESS OR IMPLIED, IS GIVEN AS TO THE RELIABILITY, ACCURACY, FAIRNESS OR COMPLETENESS OF THE INFORMATION OR OPINIONS CONTAINED HEREIN, AND EMPOWER BRANDS AND EACH OF ITS MEMBERS AND AFFI LIA TES AND THEIR RESPECTIVE MEMBERS, PARTNERS, EMPLOYEES, REPRESENTATIVES AND AGENTS (COLLECTIVELY, “EMPOWER REPRESENTATIVES”) EXPRESSLY DISCLAIM ANY LIABILITY WHICH MAY ARISE FROM TH IS PRESENTATION AND ANY ERRORS CONTAINED HEREIN AND/OR OMISSIONS HERE FROM OR FROM ANY USE OF THE CONTENTS OF THIS PRESENTATION. EXCEPT FOR THE HISTORICAL INFORMATION CONTAINED HEREIN, THE INFORMATION AND OPINIONS INCLUDED IN THIS PRESENTATION CONSTITUTE FO RWARD - LOOKING STATEMENTS, INCLUDING ESTIMATES AND PROJECTIONS PREPARED WITH RESPECT TO, AMONG OTHER THINGS, THE COMPANY’S ANTICIPATED OPERATING PERFORMANCE, THE VALUE OF THE C OMP ANY’S SECURITIES, DEBT OR ANY RELATED FINANCIAL INSTRUMENTS THAT ARE BASED UPON OR RELATE TO THE VALUE OF SECURITIES OF THE COMPANY (COLLECTIVELY, “COMPANY SECURITIES”), GEN ERA L ECONOMIC AND MARKET CONDITIONS AND OTHER FUTURE EVENTS. YOU SHOULD BE AWARE THAT ALL FORWARD - LOOKING STATEMENTS, ESTIMATES AND PROJECTIONS ARE INHERENTLY UNCERTAIN AND SUBJECT TO SIGNI FICANT ECONOMIC, COMPETITIVE, AND OTHER UNCERTAINTIES AND CONTINGENCIES AND HAVE BEEN INCLUDED SOLELY FOR ILLUSTRATIVE PURPOSES. ACTUAL RESULTS MAY DIFFER MATERIALLY FROM THE INFORMAT ION CONTAINED HEREIN DUE TO REASONS THAT MAY OR MAY NOT BE FORESEEABLE. THERE CAN BE NO ASSURANCE THAT THE COMPANY SECURITIES WILL TRADE AT THE PRICES THAT MAY BE IMPLIED HEREIN, AND T HER E CAN BE NO ASSURANCE THAT ANY OPINION OR ASSUMPTION HEREIN IS, OR WILL BE PROVEN, CORRECT. THIS PRESENTATION AND ANY OPINIONS EXPRESSED HEREIN SHOULD IN NO WAY BE VIEWED AS ADVICE ON THE MERITS OF ANY INVESTMENT DECI SIO N WITH RESPECT TO THE COMPANY, COMPANY SECURITIES OR ANY TRANSACTION. THIS PRESENTATION IS NOT (AND MAY NOT BE CONSTRUED TO BE) LEGAL, TAX, INVESTMENT, FINANCIAL OR OTHER ADVICE. EAC H R ECIPIENT SHOULD CONSULT THEIR OWN LEGAL COUNSEL AND TAX AND FINANCIAL ADVISERS AS TO LEGAL AND OTHER MATTERS CONCERNING THE INFORMATION CONTAINED HEREIN. THIS PRESENTATION DOES NOT PURP ORT TO BE ALL - INCLUSIVE OR TO CONTAIN ALL OF THE INFORMATION THAT MAY BE RELEVANT TO AN EVALUATION OF THE COMPANY, COMPANY SECURITIES OR THE MATTERS DESCRIBED HEREIN. THIS PRESENTATION SHALL NOT CONSTITUTE AN OFFER TO SELL OR THE SOLICITATION OF AN OFFER TO BUY ANY SECURITIES, NOR SHALL THER E B E ANY SALE OF SECURITIES IN ANY JURISDICTION IN WHICH SUCH OFFER, SOLICITATION OR SALE WOULD BE UNLAWFUL PRIOR TO REGISTRATION OR QUALIFICATION UNDER THE SECURITIES LAWS OF ANY JURISDICTION. NO OFFERING OF SECURITIES SHALL BE MADE EXCEPT BY MEANS OF A PROSPECTUS MEETING THE REQUIREMENTS OF SECTION 10 OF THE SECURITIES ACT OF 1933, AS AMENDED. THIS PRESENTATION IS NEITHER A SOLICITATION OF A PROXY NOR A SUBSTITUTE FOR ANY PROXY STATEMENT OR OTHER FILING THAT MAY BE M ADE WITH THE SEC. NONETHELESS, SPECTRUM BRANDS HOLDINGS, INC. (“SPECTRUM BRANDS”), EMPOWER BRANDS AND THEIR RESPECTIVE DIRECTORS AND CERTAIN OF THEIR RESPECTIVE EXECUTIVE OFFICERS MAY BE CON SIDERED PARTICIPANTS IN THE SOLICITATION OF PROXIES IN CONNECTION WITH THE PROPOSED TRANSACTION. INFORMATION REGARDING SUCH PERSONS WHO MAY BE CONSIDERED PARTICIPANTS IN SUCH A SOL ICI TATION, INCLUDING A DESCRIPTION OF THEIR DIRECT OR INDIRECT INTERESTS IN SUCH MATTERS, BY SECURITY HOLDINGS OR OTHERWISE, ARE SET FORTH BELOW, AND WILL BE SET FORTH IN ANY PROXY STATEME NT( S) AND OTHER RELEVANT MATERIALS RELATED TO SUCH MATTERS IF AND WHEN THEY ARE FILED WITH THE SEC. ANY INFORMATION CONCERNING THE COMPANY CONTAINED IN THIS PRESENTATION HAS BEEN TAKEN FROM, OR BASED UPON, PUBLICLY AVAILABLE INF ORMATION. ALTHOUGH SPECTRUM BRANDS AND EMPOWER BRANDS DO NOT HAVE ANY INFORMATION THAT WOULD INDICATE THAT ANY INFORMATION CONTAINED IN THIS PRESENTATION THAT HAS BEEN TAKEN FROM SUC H D OCUMENTS IS INACCURATE OR INCOMPLETE, NEITHER SPECTRUM BRANDS NOR EMPOWER BRANDS TAKE ANY RESPONSIBILITY FOR THE ACCURACY OR COMPLETENESS OF SUCH INFORMATION. TO DATE, NEITHER SPEC TRU M BRANDS NOR EMPOWER BRANDS HAVE HAD ANY ACCESS TO THE BOOKS AND RECORDS OF THE COMPANY. AS OF THE DATE HEREOF, AN AFFILIATE OF EMPOWER BRANDS DIRECTLY BENEFICIALLY OWNS 1,049,356 COM MON SHARES, PAR VALUE $0.10 PER SHARE, OF THE COMPANY. EMPOWER BRANDS HAS NOT SOUGHT OR OBTAINED CONSENT FROM ANY THIRD PARTY TO USE ANY STATEMENTS OR INFORMATION CONTAINED HEREIN. AN Y SUCH STATEMENTS OR INFORMATION SHOULD NOT BE VIEWED AS INDICATING THE SUPPORT OF SUCH THIRD PARTY FOR THE VIEWS EXPRESSED HEREIN. ALL TRADEMARKS AND TRADE NAMES USED HEREIN ARE THE EXCLUSIVE PROPERTY OF THEIR RESPECTIVE OWNERS.
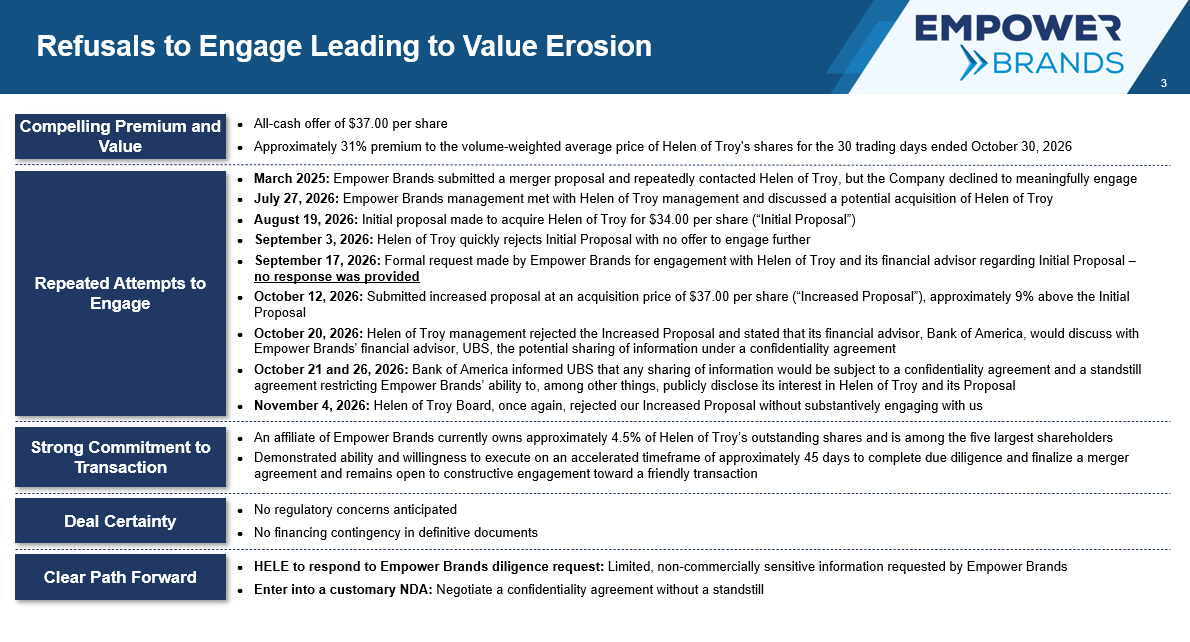
3 Refusals to Engage Leading to Value Erosion Compelling Premium and Value ● All - cash offer of $37.00 per share ● Approximately 31% premium to the volume - weighted average price of Helen of Troy's shares for the 30 trading days ended October 3 0, 2026 ● March 2025: Empower Brands submitted a merger proposal and repeatedly contacted Helen of Troy, but the Company declined to meaningfully e ng age ● July 27, 2026: Empower Brands management met with Helen of Troy management and discussed a potential acquisition of Helen of Troy ● August 19, 2026: Initial proposal made to acquire Helen of Troy for $34.00 per share (“Initial Proposal”) ● September 3, 2026: Helen of Troy quickly rejects Initial Proposal with no offer to engage further ● September 17, 2026: Formal request made by Empower Brands for engagement with Helen of Troy and its financial advisor regarding Initial Proposal – no response was provided ● October 12, 2026: Submitted increased proposal at an acquisition price of $37.00 per share (“Increased Proposal”), approximately 9% above the I ni tial Proposal ● October 20, 2026: Helen of Troy management rejected the Increased Proposal and stated that its financial advisor, Bank of America, would discus s with Empower Brands' financial advisor, UBS, the potential sharing of information under a confidentiality agreement ● October 21 and 26, 2026: Bank of America informed UBS that any sharing of information would be subject to a confidentiality agreement and a standstill agreement restricting Empower Brands’ ability to, among other things, publicly disclose its interest in Helen of Troy and its Pr oposal ● November 4, 2026: Helen of Troy Board, once again, rejected our Increased Proposal without substantively engaging with us ● An affiliate of Empower Brands currently owns approximately 4.5% of Helen of Troy’s outstanding shares and is among the five lar gest shareholders ● Demonstrated ability and willingness to execute on an accelerated timeframe of approximately 45 days to complete due diligenc e a nd finalize a merger agreement and remains open to constructive engagement toward a friendly transaction Repeated Attempts to Engage Strong Commitment to Transaction Deal Certainty ● No regulatory concerns anticipated ● No financing contingency in definitive documents Clear Path Forward ● HELE to respond to Empower Brands diligence request: Limited, non - commercially sensitive information requested by Empower Brands ● Enter into a customary NDA: Negotiate a confidentiality agreement without a standstill
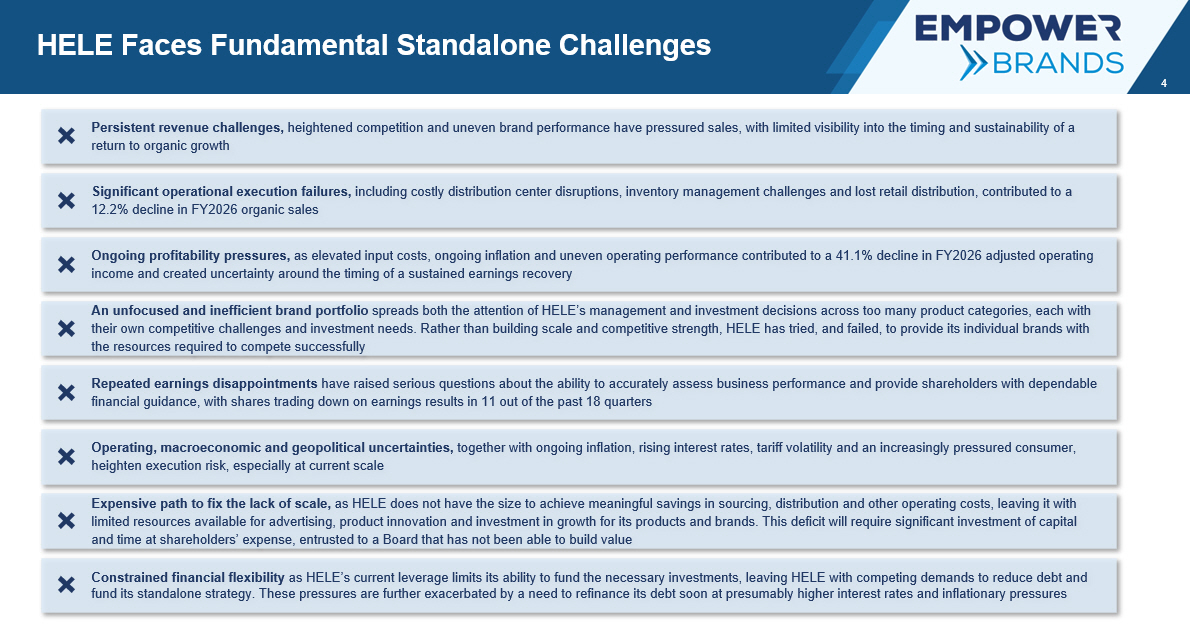
4 HELE Faces Fundamental Standalone Challenges Persistent revenue challenges, heightened competition and uneven brand performance have pressured sales, with limited visibility into the timing and sustain ab ility of a return to organic growth × An unfocused and inefficient brand portfolio spreads both the attention of HELE’s management and investment decisions across too many product categories, each with their own competitive challenges and investment needs. Rather than building scale and competitive strength, HELE has tried, a nd failed, to provide its individual brands with the resources required to compete successfully × Repeated earnings disappointments have raised serious questions about the ability to accurately assess business performance and provide shareholders with depen dab le financial guidance, with shares trading down on earnings results in 11 out of the past 18 quarters × Significant operational execution failures, including costly distribution center disruptions, inventory management challenges and lost retail distribution, contributed t o a 12.2% decline in FY2026 organic sales × Ongoing profitability pressures, as elevated input costs, ongoing inflation and uneven operating performance contributed to a 41.1% decline in FY2026 adjusted op erating income and created uncertainty around the timing of a sustained earnings recovery × Operating, macroeconomic and geopolitical uncertainties, together with ongoing inflation, rising interest rates, tariff volatility and an increasingly pressured consumer, heighten execution risk, especially at current scale × Expensive path to fix the lack of scale, as HELE does not have the size to achieve meaningful savings in sourcing, distribution and other operating costs, leaving it wit h limited resources available for advertising, product innovation and investment in growth for its products and brands. This de fic it will require significant investment of capital and time at shareholders’ expense, entrusted to a Board that has not been able to build value × Constrained financial flexibility as HELE’s current leverage limits its ability to fund the necessary investments, leaving HELE with competing demands to reduc e d ebt and fund its standalone strategy. These pressures are further exacerbated by a need to refinance its debt soon at presumably h igher interest rates and inflationary pressures ×
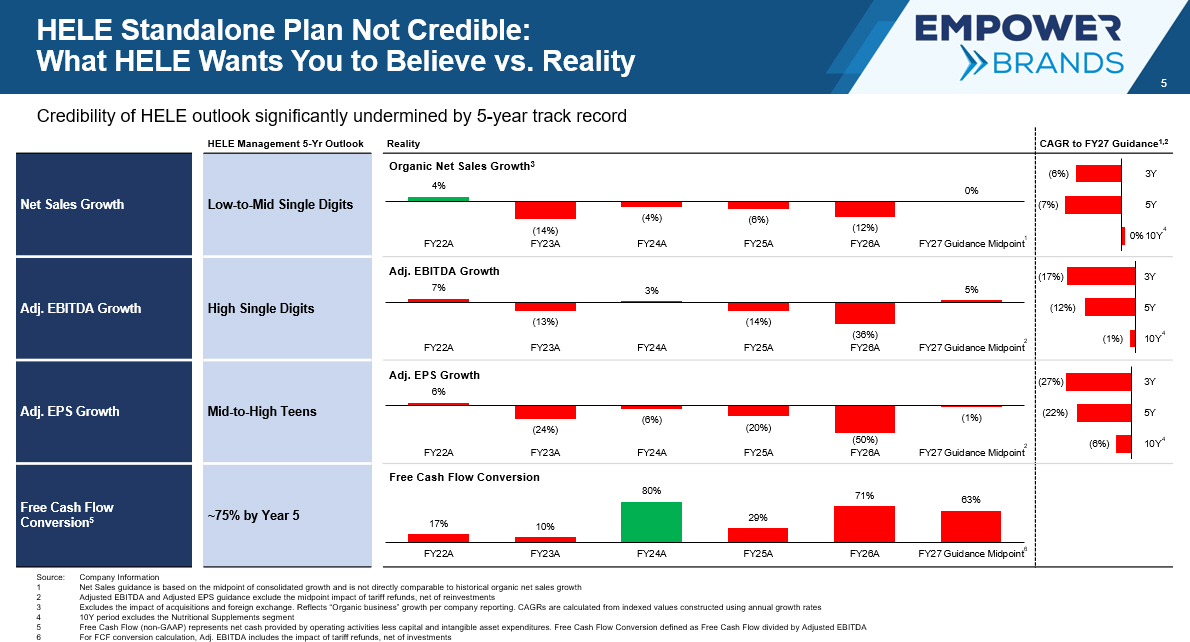
5 HELE Standalone Plan Not Credible: What HELE Wants You to Believe vs. Reality CAGR to FY27 Guidance 1,2 Reality HELE Management 5 - Yr Outlook Low - to - Mid Single Digits Net Sales Growth High Single Digits Adj. EBITDA Growth Mid - to - High Teens Adj. EPS Growth ~75% by Year 5 Free Cash Flow Conversion 5 4% (14%) (4%) (6%) (12%) 0% FY22A FY23A FY24A FY25A FY26A FY27 Guidance Midpoint Organic Net Sales Growth 3 7% (13%) 3% (14%) (36%) 5% FY22A FY23A FY24A FY25A FY26A FY27 Guidance Midpoint Adj. EBITDA Growth 6% (24%) (6%) (20%) (50%) (1%) FY22A FY23A FY24A FY25A FY26A FY27 Guidance Midpoint Adj. EPS Growth 17% 10% 80% 29% 71% 63% FY22A FY23A FY24A FY25A FY26A FY27 Guidance Midpoint Free Cash Flow Conversion Source: Company Information 1 Net Sales guidance is based on the midpoint of consolidated growth and is not directly comparable to historical organic net s a les growth 2 Adjusted EBITDA and Adjusted EPS guidance exclude the midpoint impact of tariff refunds, net of reinvestments 3 Excludes the impact of acquisitions and foreign exchange. Reflects “Organic business” growth per company reporting. CAGRs are calculated from indexed values constructed using annual growth rates 4 10Y period excludes the Nutritional Supplements segment 5 Free Cash Flow (non - GAAP) represents net cash provided by operating activities less capital and intangible asset expenditures. Free Cash Flow Conversion defined as Free Cash Flow divided by Adjusted EBITDA 6 For FCF conversion calculation, Adj. EBITDA includes the impact of tariff refunds, net of investments 0% (7%) (6%) 10Y 5Y 3Y (1%) (12%) (17%) 10Y 5Y 3Y (6%) (22%) (27%) 10Y 5Y 3Y 1 4 4 4 2 2 Credibility of HELE outlook significantly undermined by 5 - year track record 6
6 No Basis to Believe the HELE Standalone Plan: Significant Challenges HELE Shareholders Should Not Be Asked to Bear the Risk of Another Uncertain Turnaround Consistently Delivered Negative Results; Eroded Wall Street Confidence In 2023, Two - thirds of Current HELE Board Misguided Shareholders to a $200+ Share Price HELE 5 - Year Return is Among the Worst of its Peers
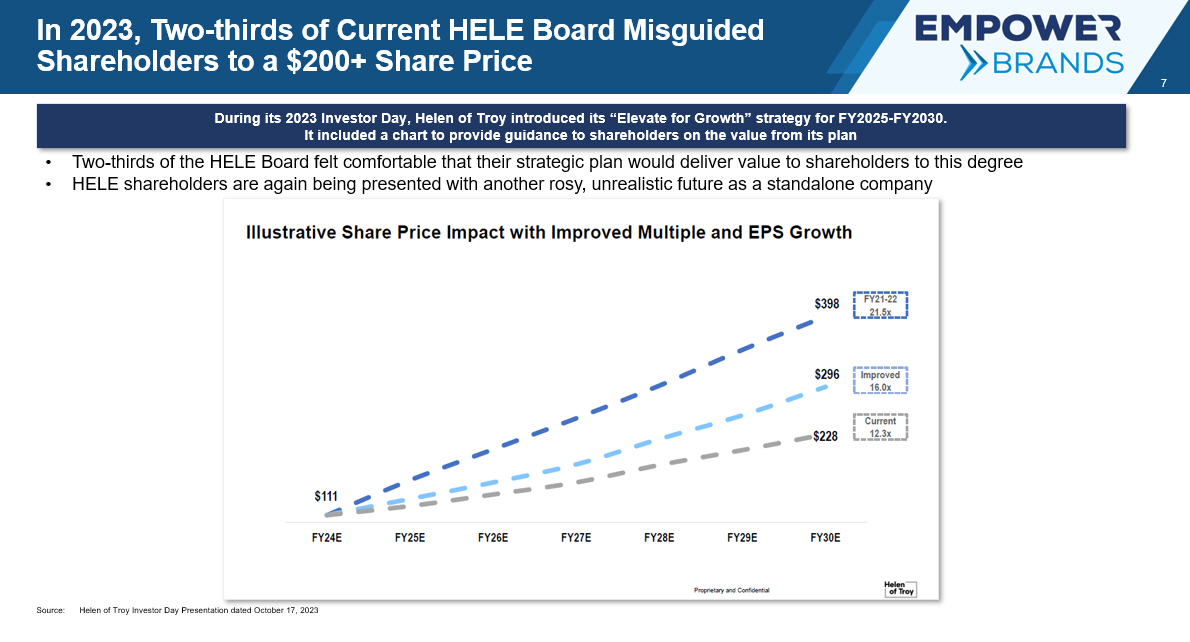
7 In 2023, Two - thirds of Current HELE Board Misguided Shareholders to a $200+ Share Price During its 2023 Investor Day, Helen of Troy introduced its “Elevate for Growth” strategy for FY2025 - FY2030. It included a chart to provide guidance to shareholders on the value from its plan Source: Helen of Troy Investor Day Presentation dated October 17, 2023 • Two - thirds of the HELE Board felt comfortable that their strategic plan would deliver value to shareholders to this degree • HELE shareholders are again being presented with another rosy, unrealistic future as a standalone company
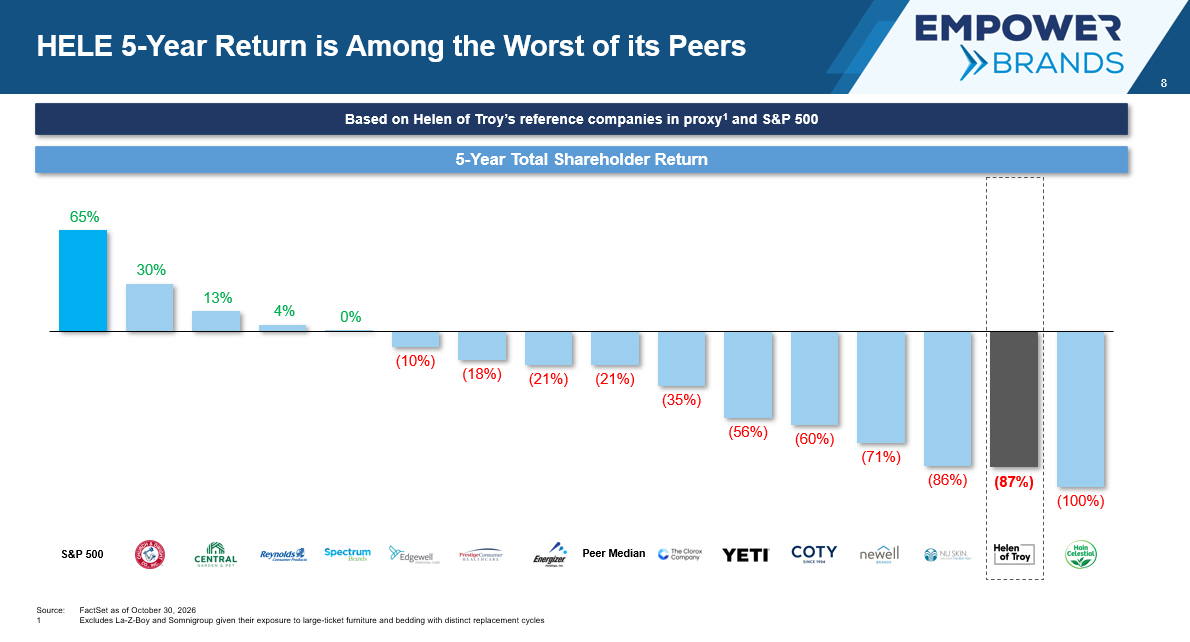
8 HELE 5 - Year Return is Among the Worst of its Peers Based on Helen of Troy’s reference companies in proxy 1 and S&P 500 65% 30% 13% 4% 0% (10%) (18%) (21%) (21%) (35%) (56%) (60%) (71%) (86%) (87%) (100%) 5 - Year Total Shareholder Return Peer Median S&P 500 Source: FactSet as of October 30, 2026 1 Excludes La - Z - Boy and Somnigroup given their exposure to large - ticket furniture and bedding with distinct replacement cycles
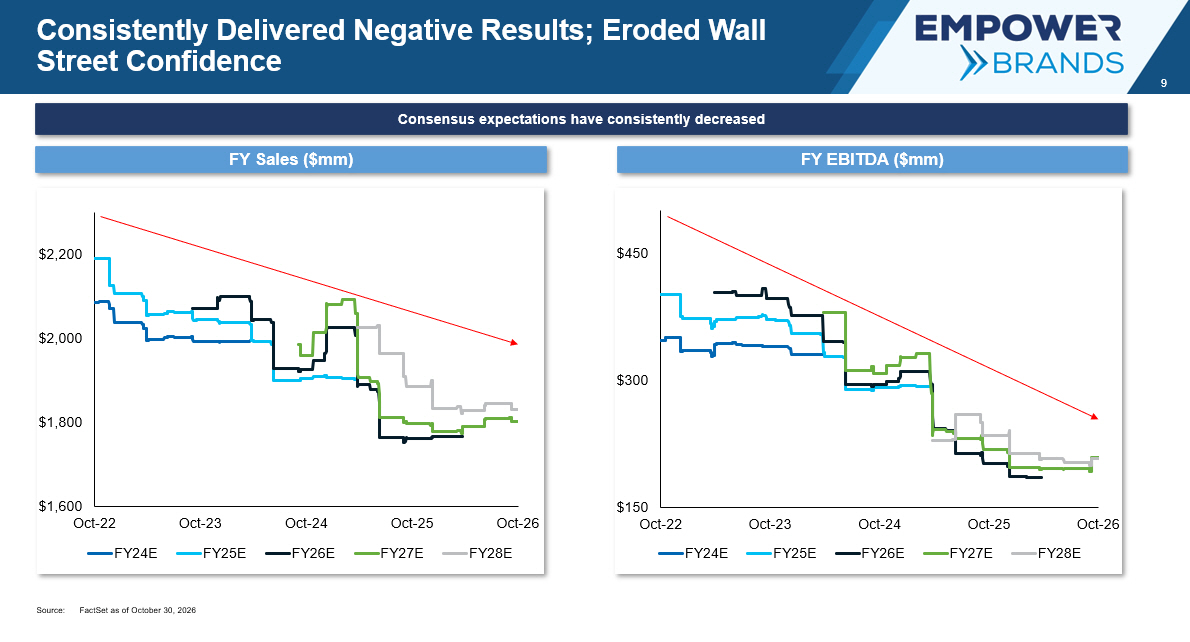
9 Consistently Delivered Negative Results; Eroded Wall Street Confidence $1,600 $1,800 $2,000 $2,200 Oct-22 Oct-23 Oct-24 Oct-25 Oct-26 FY24E FY25E FY26E FY27E FY28E $150 $300 $450 Oct-22 Oct-23 Oct-24 Oct-25 Oct-26 FY24E FY25E FY26E FY27E FY28E Source: FactSet as of October 30, 2026 Consensus expectations have consistently decreased FY Sales ($mm) FY EBITDA ($mm)
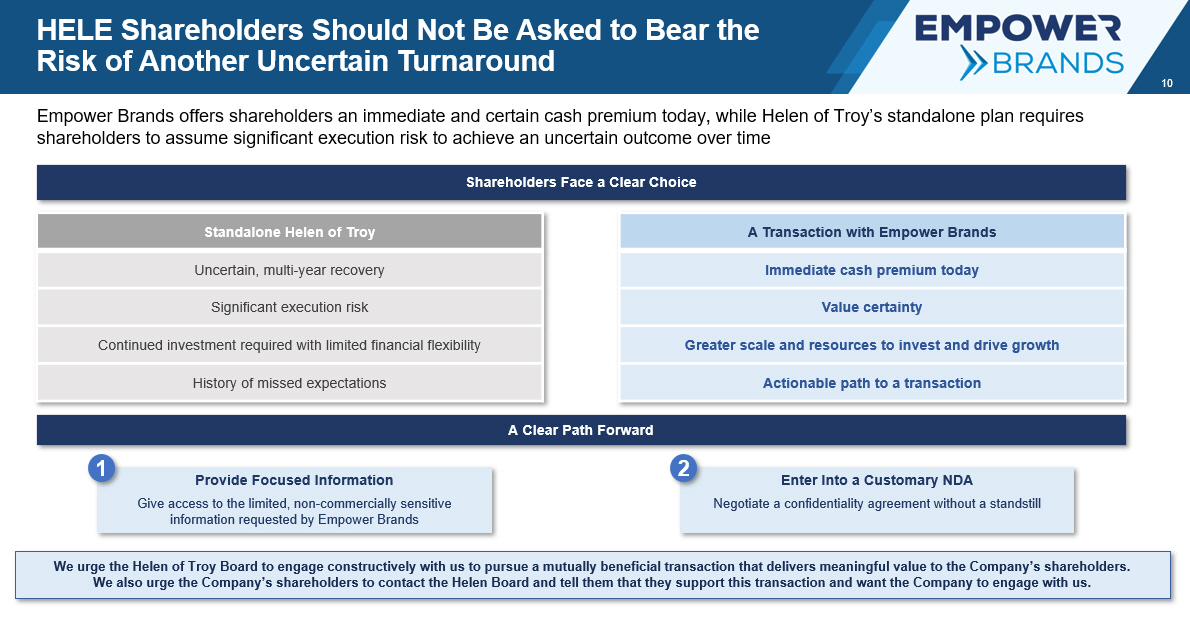
10 HELE Shareholders Should Not Be Asked to Bear the Risk of Another Uncertain Turnaround Shareholders Face a Clear Choice A Clear Path Forward Standalone Helen of Troy Uncertain, multi - year recovery Significant execution risk Continued investment required with limited financial flexibility History of missed expectations Provide Focused Information Give access to the limited, non - commercially sensitive information requested by Empower Brands 1 Enter Into a Customary NDA Negotiate a confidentiality agreement without a standstill 2 A Transaction with Empower Brands Immediate cash premium today Value certainty Greater scale and resources to invest and drive growth Actionable path to a transaction Empower Brands offers shareholders an immediate and certain cash premium today, while Helen of Troy’s standalone plan require s shareholders to assume significant execution risk to achieve an uncertain outcome over time We urge the Helen of Troy Board to engage constructively with us to pursue a mutually beneficial transaction that delivers me ani ngful value to the Company’s shareholders. We also urge the Company’s shareholders to contact the Helen Board and tell them that they support this transaction and want the Company to engage with us.
11 We Urge You to Contact the Company We urge you to contact the HELE Board and tell them that you support this transaction and want the Company to engage with us. You can contact the Company at: Chris Robertson Investor Relations croberts@helenoftroy.com Anne Rakunas Investor Relations investors@helenoftroy.com