ABS Investor Presentation November 10, 2026
Legal Disclosures The information contained in this electronic presentation (the “Information”) is being provided to you on a confidential basis solely for your review and may not be downloaded, copied, reproduced, or redistributed, in whole or in part, directly or indirectly, by you. The Information is provided to you solely for informational purposes, is intended for your use only, and does not constitute an offer or a commitment, a solicitation of an offer or commitment, or any advice or recommendation, to enter into or conclude any transaction (whether on the indicative terms shown or otherwise). The Information will not constitute an offer to sell or the solicitation of an offer to buy the Series 2026-1 Class A, Class B, Class C and Class D Notes (the "Offered Notes") contemplated to be issued by Regional Management Issuance Trust 2026-1 (the “Issuer”) discussed in the Information, nor will there be any offer to sell or solicitation of an offer to buy the Offered Notes in any jurisdiction or to any person in which or to whom such offer, solicitation, or sale would be unlawful. This electronic presentation is not an offering circular and the Information does not include all of the information required to be included in the offering circular relating to the Offered Notes. Any indicative terms described in the Information are subject to and qualified in their entirety by the offering circular relating to the Offered Notes, which will supersede the indicative terms described in the Information in their entirety, and other preliminary information made (or to be made) available to you. As such, the Information may not reflect the impact of all structural characteristics of the Offered Notes. The assumptions underlying the Information, including structure and collateral, are for preliminary discussion purposes only and may be modified to reflect changed circumstances. The Information does not purport to contain all of the information that an interested party may desire. In all cases, interested parties should conduct their own investigative analysis of the transaction described in the Information and the data set forth herein. Each person receiving these materials should make an independent assessment of the merits of pursuing a transaction described in these materials and should consult their own professional advisors. THIS ELECTRONIC PRESENTATION AND THE INFORMATION ARE NOT INTENDED TO FURNISH LEGAL, REGULATORY, TAX, ACCOUNTING, INVESTMENT, OR OTHER ADVICE TO ANY PROSPECTIVE INVESTOR IN THE OFFERED NOTES. This presentation contains summarized information concerning Regional Management Corp. (the “Company”) and the Company’s business, operations, financial performance, and trends. No representation is made that the Information in this document is complete. For additional financial, statistical, and business information concerning the Company, please see the Company’s most recent Annual Report on Form 10-K and Quarterly Reports on Form 10-Q filed with the U.S. Securities and Exchange Commission (the “SEC”), as well as the Company’s other reports filed with the SEC from time to time. Such reports are or will be available on the Company’s website (www.regionalmanagement.com) and on the SEC’s website (www.sec.gov). The information and opinions contained in this document are provided as of the date of this presentation and are subject to change without notice. This document has not been approved by any regulatory or supervisory authority. The Information and this presentation, the related remarks, and the responses to various questions may contain various “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Forward-looking statements are not statements of historical fact but instead represent the Company’s expectations or beliefs concerning future events. Forward-looking statements include, without limitation, statements concerning future plans, objectives, goals, projections, strategies, events, or performance, and underlying assumptions and other statements related thereto. Words such as “may,” “will,” “should,” “likely,” “anticipates,” “expects,” “intends,” “plans,” “projects,” “believes,” “estimates,” “outlook,” and similar expressions may be used to identify these forward-looking statements. Such forward-looking statements speak only as of the date on which they were made and are about matters that are inherently subject to risks and uncertainties, many of which are outside of the control of the Company. As a result, actual performance and results may differ materially from those contemplated by these forward-looking statements. Therefore, investors should not place undue reliance on such statements. 2
Legal Disclosures (continued) Factors that could cause actual results or performance to differ from the expectations expressed or implied in forward-looking statements include, but are not limited to, the following: managing growth effectively, implementing Regional Management's growth strategy, including launching its bank partnership program and opening new branches as planned; Regional Management's convenience check strategy; Regional Management's policies and procedures for underwriting, processing, and servicing loans; Regional Management's ability to collect on its loan portfolio; Regional Management's insurance operations; exposure to credit risk and repayment risk, which risks may increase in light of adverse or recessionary economic conditions; the implementation of evolving underwriting models and processes, including as to the effectiveness of Regional Management’s custom scorecards; changes in the competitive environment in which Regional Management operates or a decrease in the demand for its products; the geographic concentration of Regional Management's loan portfolio; the failure of third-party service providers, including those providing information technology products; changes in economic conditions in the markets Regional Management serves, including levels of unemployment and bankruptcies; the ability to achieve successful acquisitions and strategic alliances; the ability to make technological improvements as quickly as competitors; security breaches, cyber-attacks, failures in information systems, or fraudulent activity; the ability to originate loans; reliance on information technology resources and providers, including the risk of prolonged system outages; changes in current revenue and expense trends, including trends affecting delinquencies and credit losses; any future public health crises, including the impact of such crisis on our operations and financial condition; changes in operating and administrative expenses; the departure, transition, or replacement of key personnel; the ability to timely and effectively implement, transition to, and maintain the necessary information technology systems, infrastructure, processes, and controls to support Regional Management's operations and initiatives; changes in interest rates; existing sources of liquidity may become insufficient or access to these sources may become unexpectedly restricted; exposure to financial risk due to asset-backed securitization transactions; risks related to regulation and legal proceedings, including changes in laws or regulations or in the interpretation or enforcement of laws or regulations; changes in accounting standards, rules, and interpretations and the failure of related assumptions and estimates; the impact of changes in tax laws and guidance, including the timing and amount of revenues that may be recognized; risks related to the ownership of Regional Management's common stock, including volatility in the market price of shares of Regional Management's common stock; the timing and amount of future cash dividend payments; and anti-takeover provisions in Regional Management's charter documents and applicable state law. The foregoing factors and others are discussed in greater detail in the Company's filings with the SEC. The Company will not update or revise forward-looking statements to reflect events or circumstances after the date of this presentation or to reflect the occurrence of unanticipated events or the non-occurrence of anticipated events, whether as a result of new information, future developments, or otherwise, except as required by law. Except to the extent required by law, the Company, its respective agents, employees, and advisors, and BMO Capital Markets Corp., J.P. Morgan Securities LLC, Regions Securities, LLC, and Wells Fargo Securities, LLC (collectively, the “Initial Purchasers”) do not intend or have any duty or obligation to supplement, amend, update, or revise any forward-looking statement or other Information, whether as a result of new information, future developments, or otherwise. The Information and opinions contained in this document are provided as of the date of this presentation and are subject to change without notice. This document has not been approved by any regulatory or supervisory authority. The Initial Purchasers may, from time to time, participate or invest in other financing transactions with the Company and its affiliates, perform services for or solicit business from the Company and its affiliates, and/or have a position or effect transactions in the Notes or derivatives thereof. This presentation also contains certain financial terms and abbreviations. Please refer to the Appendix accompanying this presentation for a glossary of terms and abbreviations. 3
Transaction Overview
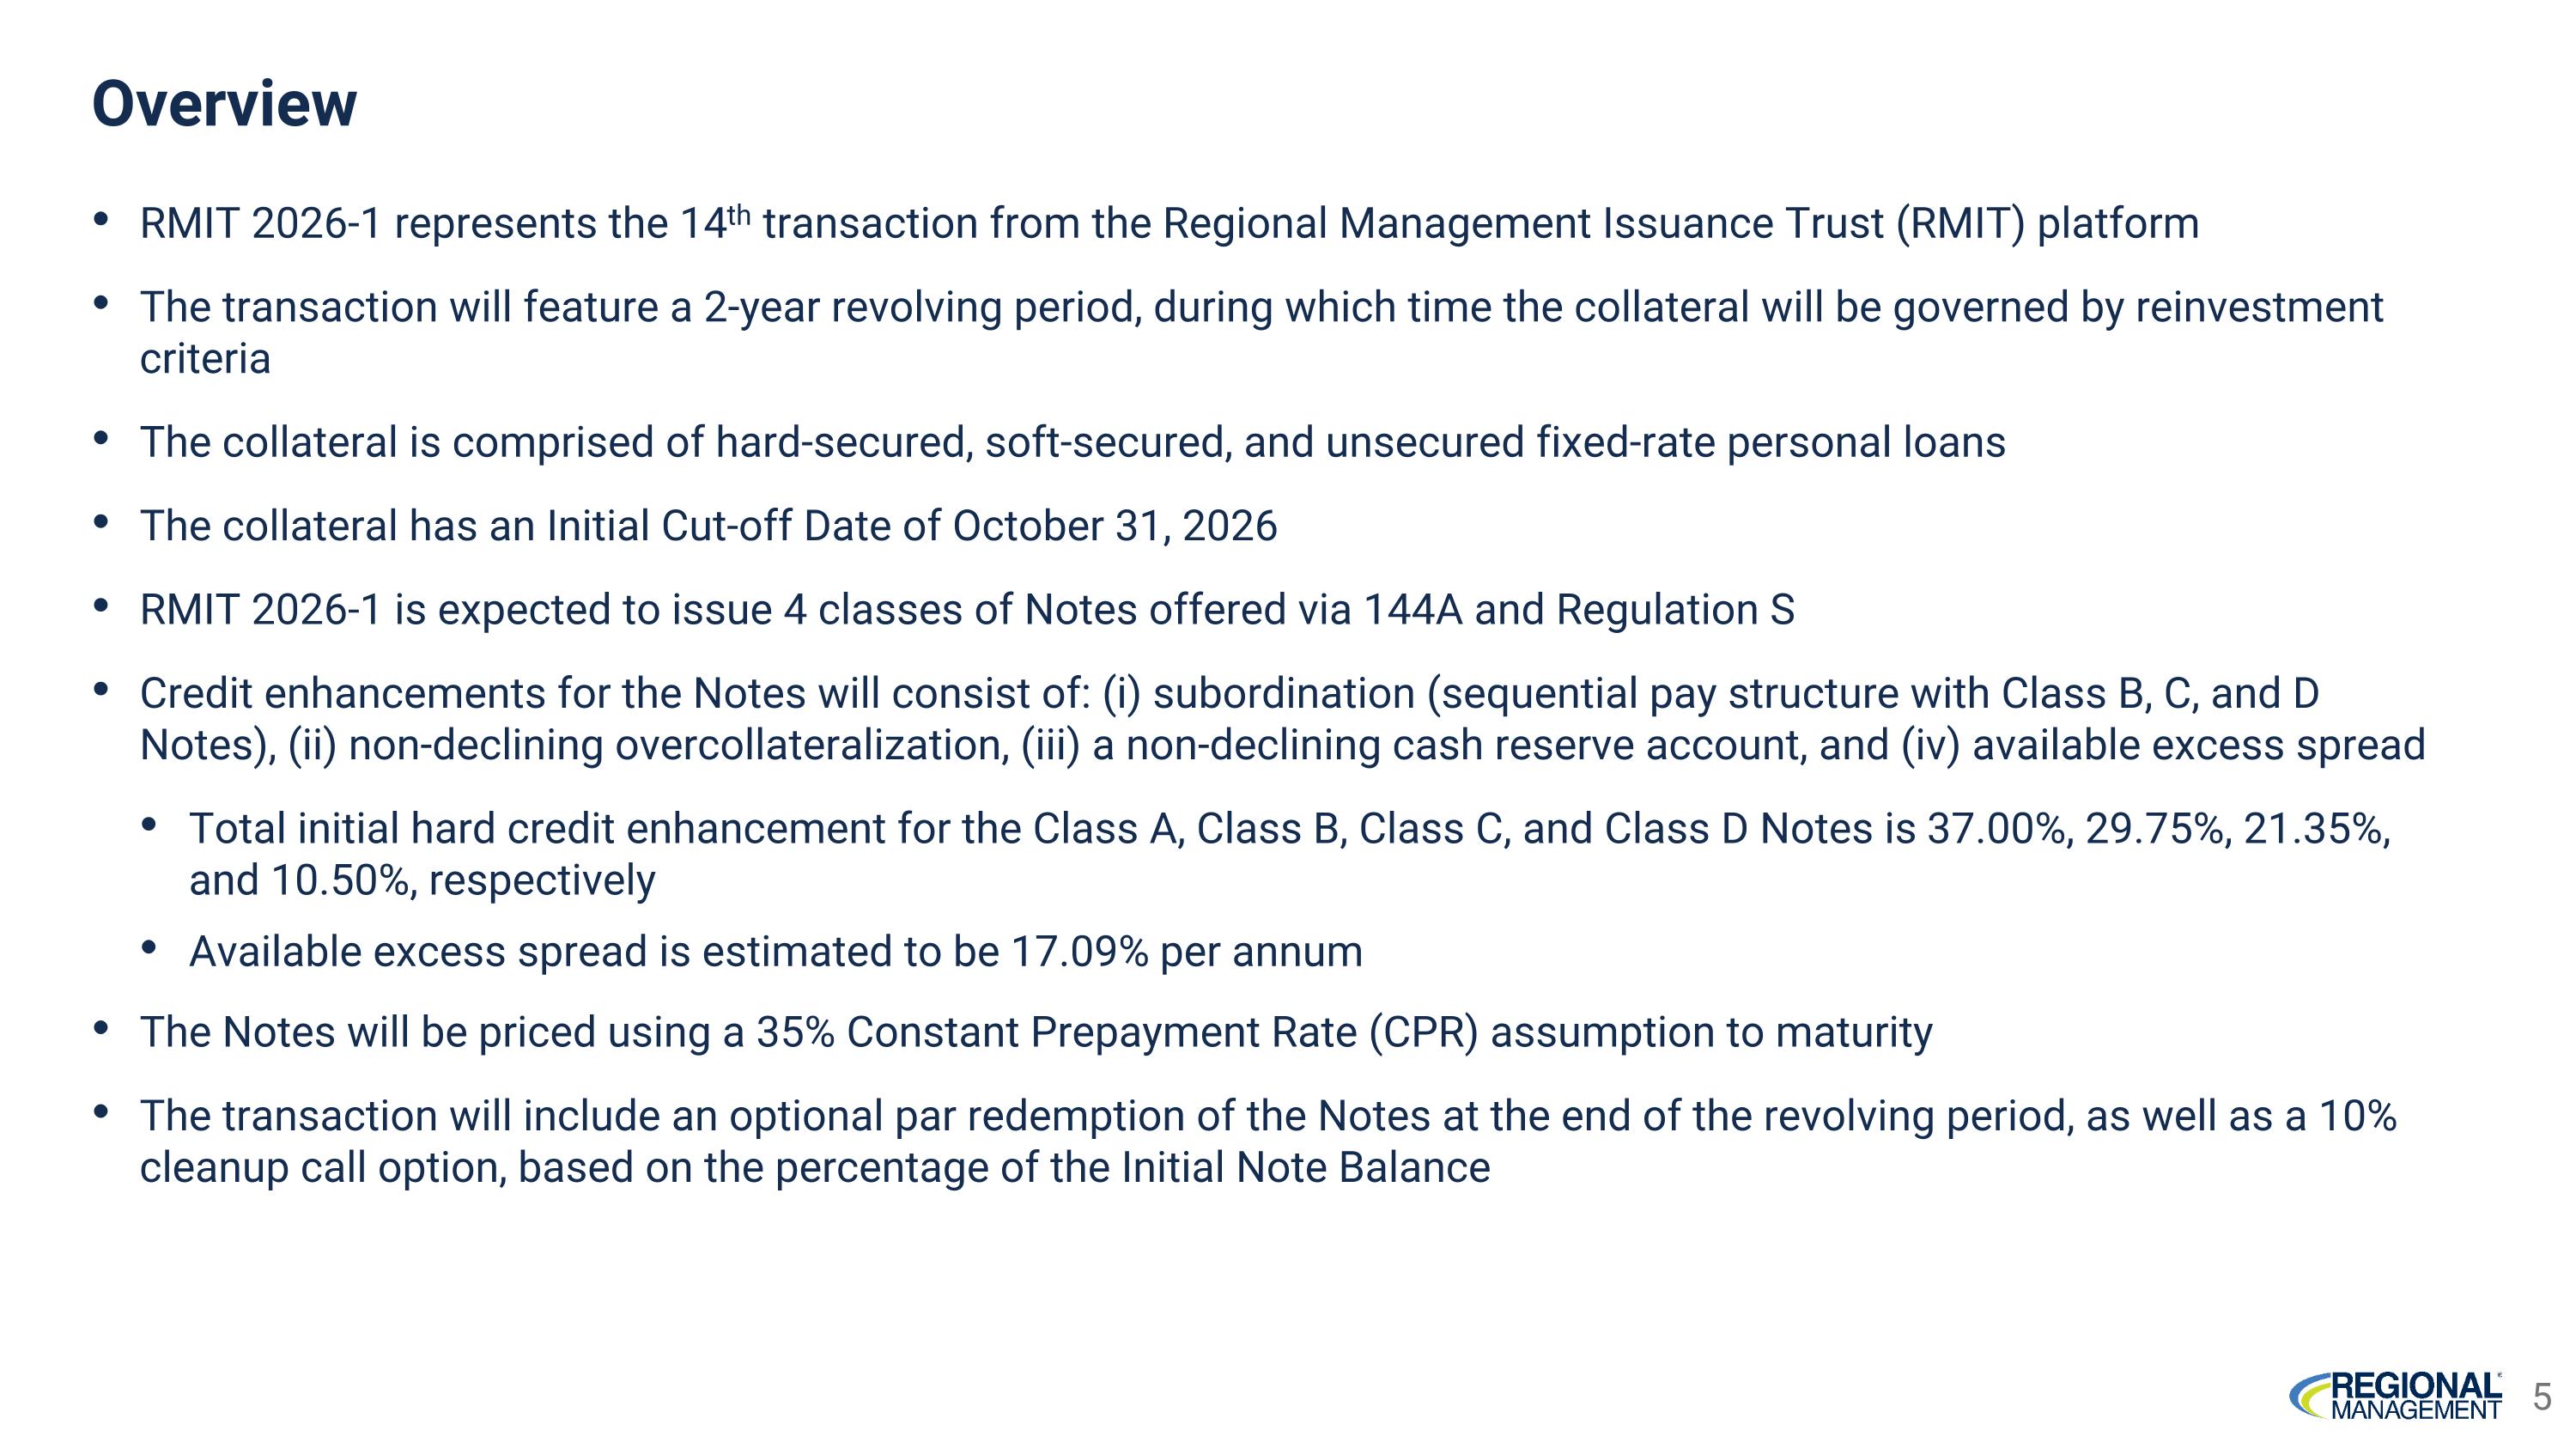
Overview RMIT 2026-1 represents the 14th transaction from the Regional Management Issuance Trust (RMIT) platform The transaction will feature a 2-year revolving period, during which time the collateral will be governed by reinvestment criteria The collateral is comprised of hard-secured, soft-secured, and unsecured fixed-rate personal loans The collateral has an Initial Cut-off Date of October 31, 2026 RMIT 2026-1 is expected to issue 4 classes of Notes offered via 144A and Regulation S Credit enhancements for the Notes will consist of: (i) subordination (sequential pay structure with Class B, C, and D Notes), (ii) non-declining overcollateralization, (iii) a non-declining cash reserve account, and (iv) available excess spread Total initial hard credit enhancement for the Class A, Class B, Class C, and Class D Notes is 37.00%, 29.75%, 21.35%, and 10.50%, respectively Available excess spread is estimated to be 17.09% per annum The Notes will be priced using a 35% Constant Prepayment Rate (CPR) assumption to maturity The transaction will include an optional par redemption of the Notes at the end of the revolving period, as well as a 10% cleanup call option, based on the percentage of the Initial Note Balance 5
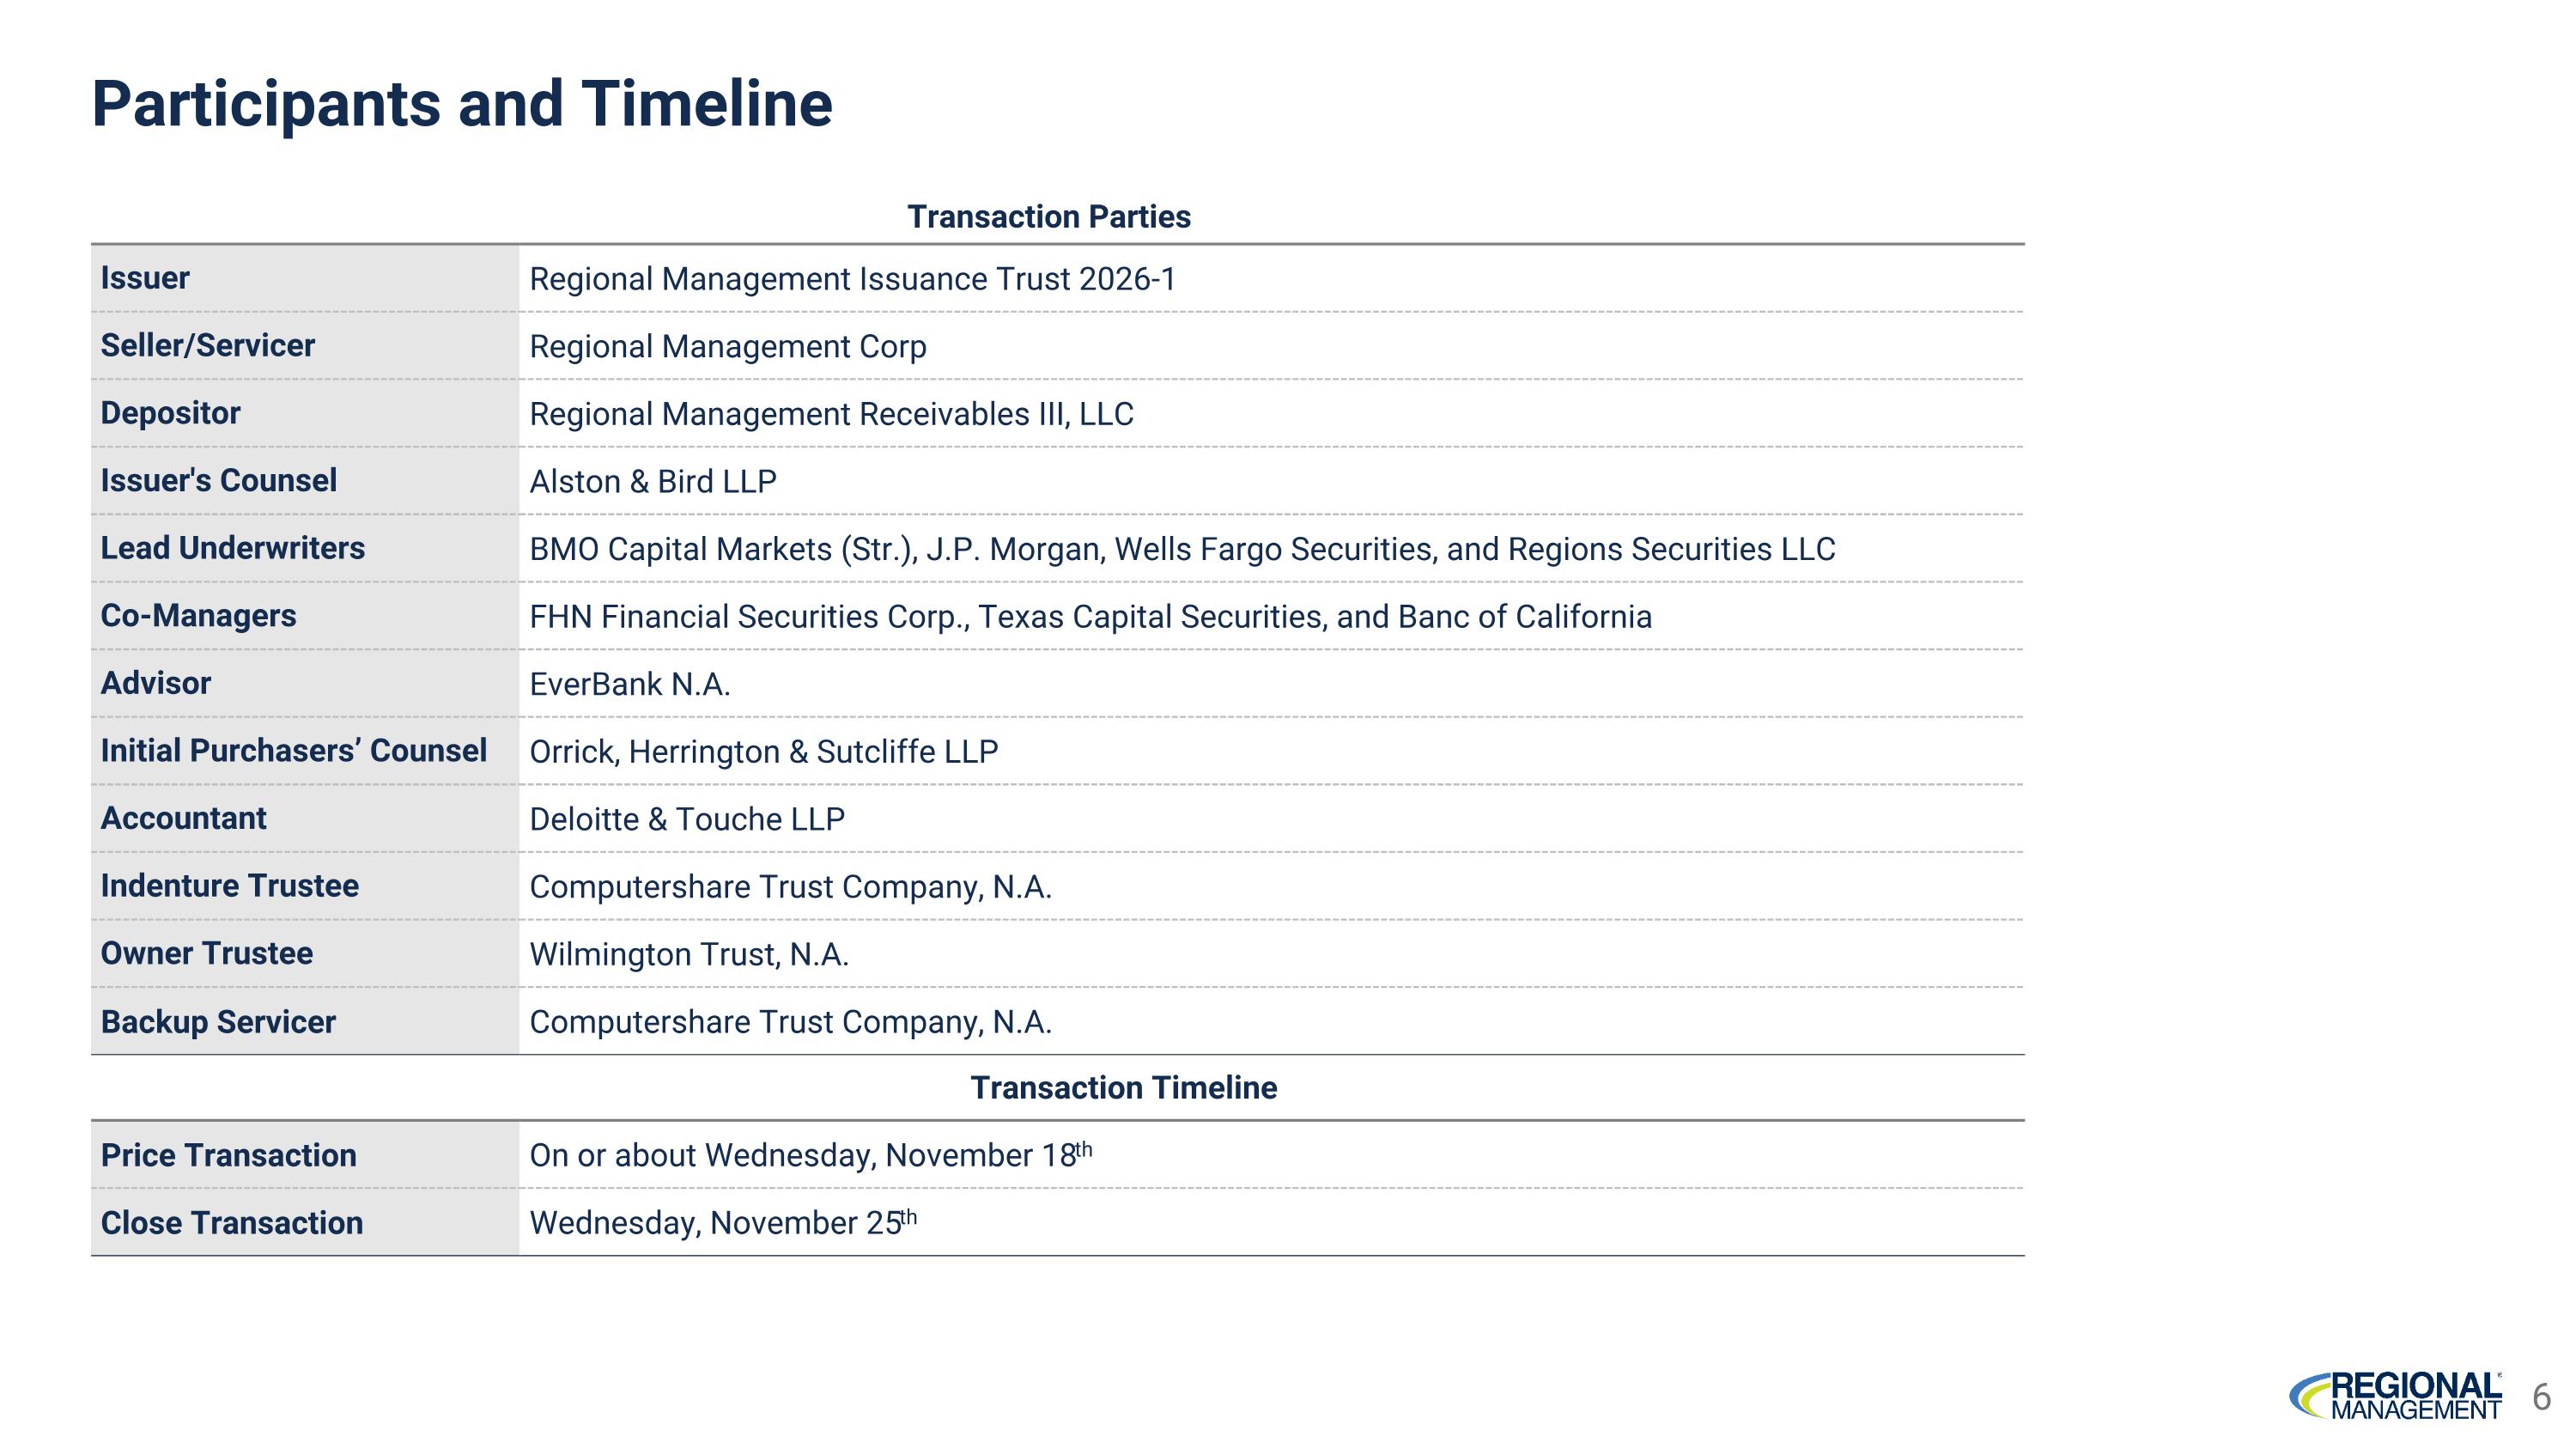
Participants and Timeline Transaction Timeline Price Transaction On or about Wednesday, November 18th Close Transaction Wednesday, November 25th Transaction Parties Transaction Parties Issuer Regional Management Issuance Trust 2026-1 Seller/Servicer Regional Management Corp Depositor Regional Management Receivables III, LLC Issuer's Counsel Alston & Bird LLP Lead Underwriters BMO Capital Markets (Str.), J.P. Morgan, Wells Fargo Securities, and Regions Securities LLC Co-Managers FHN Financial Securities Corp., Texas Capital Securities, and Banc of California Advisor EverBank N.A. Initial Purchasers’ Counsel Orrick, Herrington & Sutcliffe LLP Accountant Deloitte & Touche LLP Indenture Trustee Computershare Trust Company, N.A. Owner Trustee Wilmington Trust, N.A. Backup Servicer Computershare Trust Company, N.A. 6
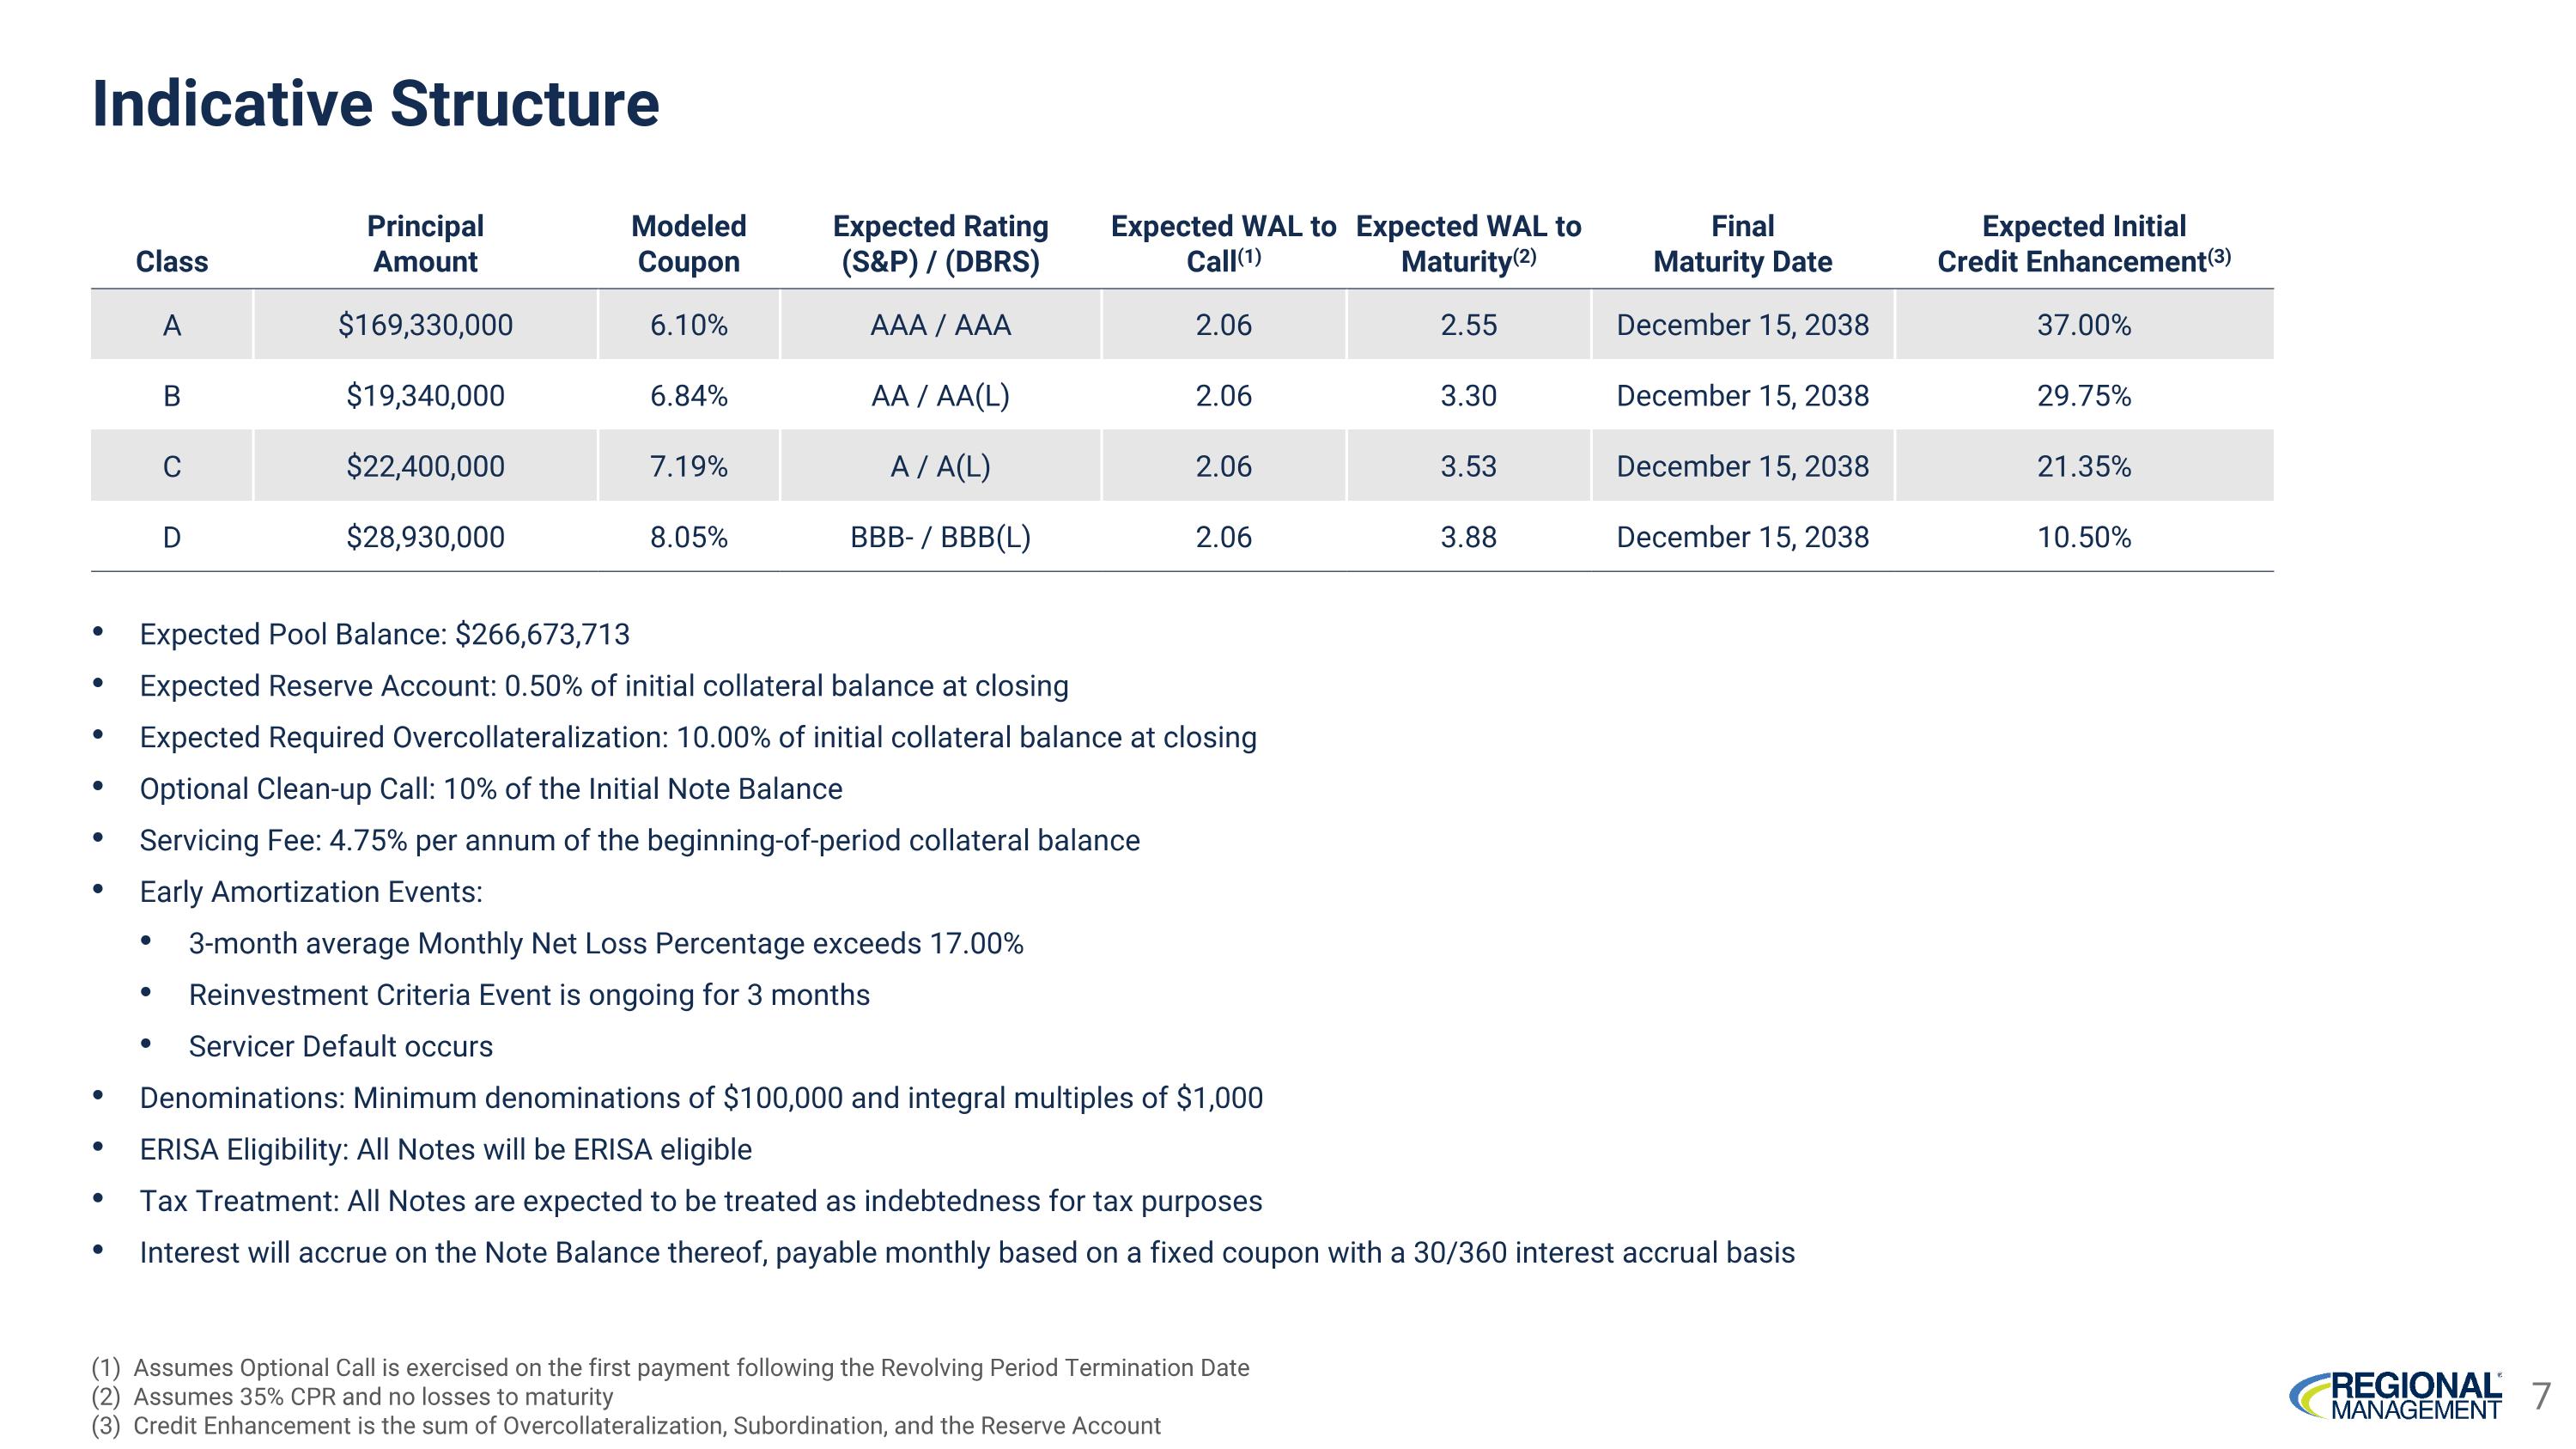
Indicative Structure Expected Pool Balance: $266,673,713 Expected Reserve Account: 0.50% of initial collateral balance at closing Expected Required Overcollateralization: 10.00% of initial collateral balance at closing Optional Clean-up Call: 10% of the Initial Note Balance Servicing Fee: 4.75% per annum of the beginning-of-period collateral balance Early Amortization Events: 3-month average Monthly Net Loss Percentage exceeds 17.00% Reinvestment Criteria Event is ongoing for 3 months Servicer Default occurs Denominations: Minimum denominations of $100,000 and integral multiples of $1,000 ERISA Eligibility: All Notes will be ERISA eligible Tax Treatment: All Notes are expected to be treated as indebtedness for tax purposes Interest will accrue on the Note Balance thereof, payable monthly based on a fixed coupon with a 30/360 interest accrual basis Class Principal Amount Modeled Coupon Expected Rating (S&P) / (DBRS) Expected WAL to Call(1) Expected WAL to Maturity(2) Final Maturity Date Expected Initial Credit Enhancement(3) A $169,330,000 6.10% AAA / AAA 2.06 2.55 December 15, 2038 37.00% B $19,340,000 6.84% AA / AA(L) 2.06 3.30 December 15, 2038 29.75% C $22,400,000 7.19% A / A(L) 2.06 3.53 December 15, 2038 21.35% D $28,930,000 8.05% BBB- / BBB(L) 2.06 3.88 December 15, 2038 10.50% (1) Assumes Optional Call is exercised on the first payment following the Revolving Period Termination Date (2) Assumes 35% CPR and no losses to maturity (3) Credit Enhancement is the sum of Overcollateralization, Subordination, and the Reserve Account 7
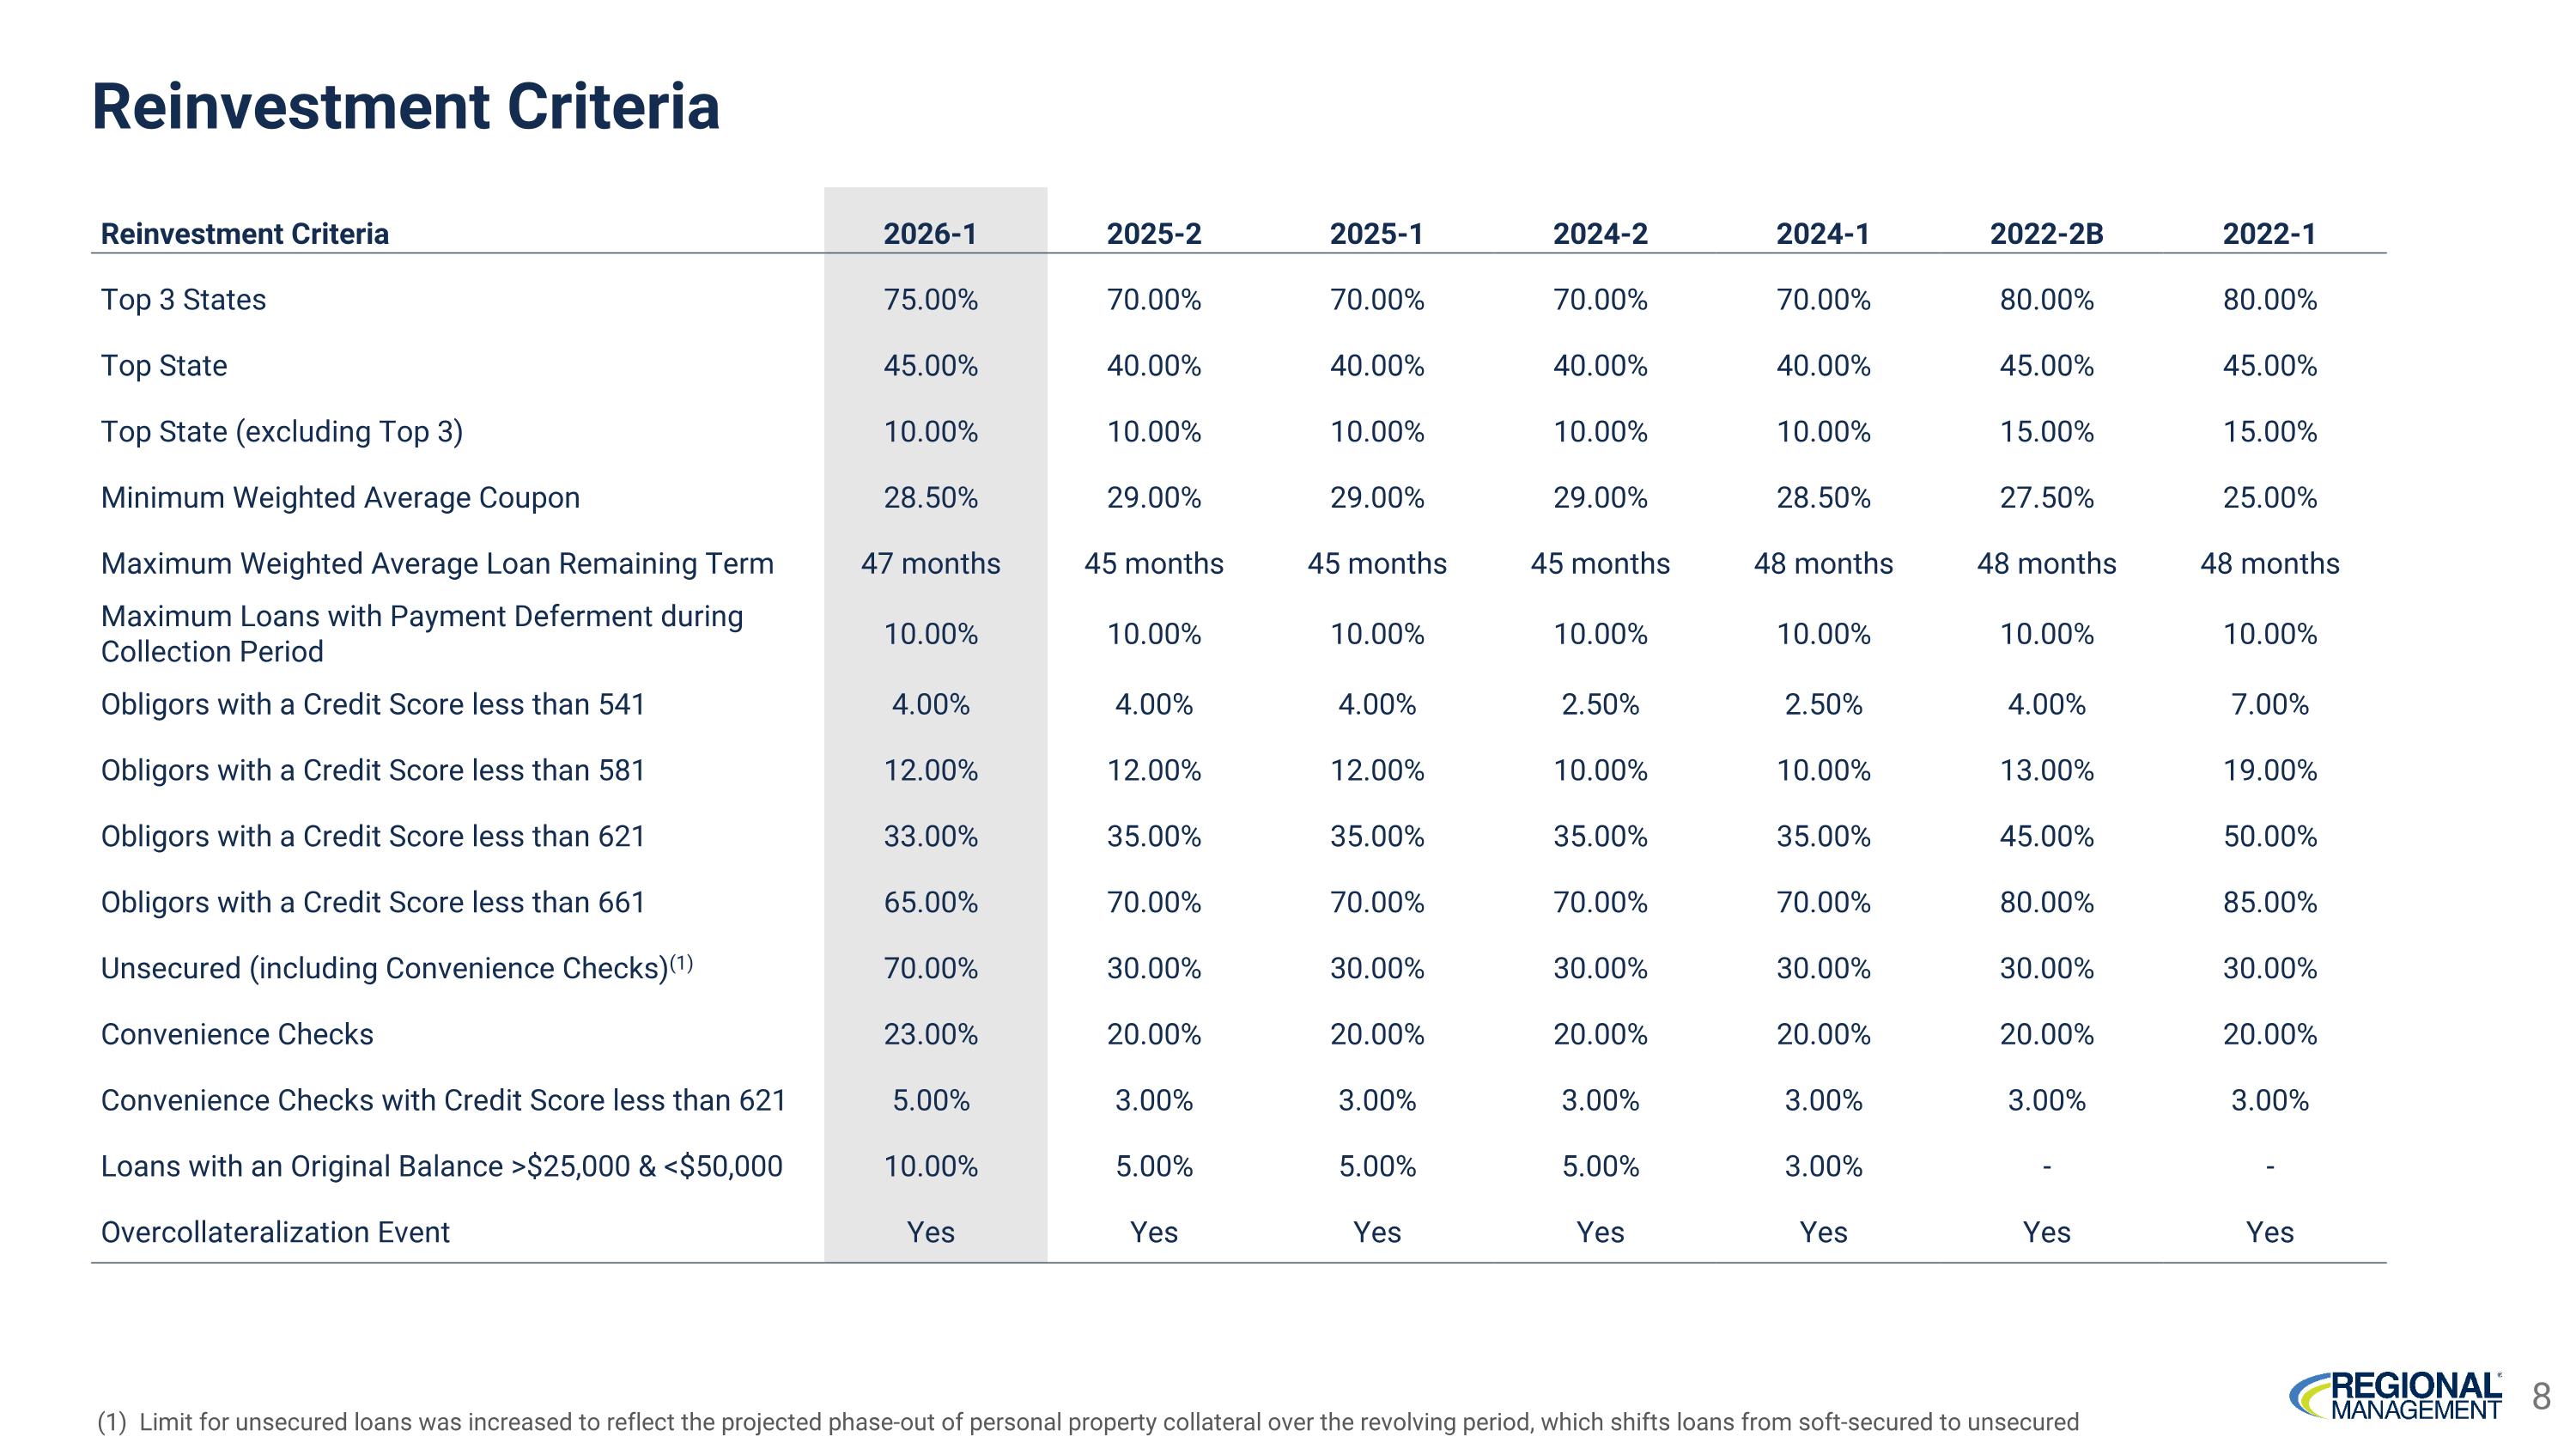
Reinvestment Criteria 2026-1 2025-2 2025-1 2024-2 2024-1 2022-2B 2022-1 Top 3 States 75.00% 70.00% 70.00% 70.00% 70.00% 80.00% 80.00% Top State 45.00% 40.00% 40.00% 40.00% 40.00% 45.00% 45.00% Top State (excluding Top 3) 10.00% 10.00% 10.00% 10.00% 10.00% 15.00% 15.00% Minimum Weighted Average Coupon 28.50% 29.00% 29.00% 29.00% 28.50% 27.50% 25.00% Maximum Weighted Average Loan Remaining Term 47 months 45 months 45 months 45 months 48 months 48 months 48 months Maximum Loans with Payment Deferment during Collection Period 10.00% 10.00% 10.00% 10.00% 10.00% 10.00% 10.00% Obligors with a Credit Score less than 541 4.00% 4.00% 4.00% 2.50% 2.50% 4.00% 7.00% Obligors with a Credit Score less than 581 12.00% 12.00% 12.00% 10.00% 10.00% 13.00% 19.00% Obligors with a Credit Score less than 621 33.00% 35.00% 35.00% 35.00% 35.00% 45.00% 50.00% Obligors with a Credit Score less than 661 65.00% 70.00% 70.00% 70.00% 70.00% 80.00% 85.00% Unsecured (including Convenience Checks)(1) 70.00% 30.00% 30.00% 30.00% 30.00% 30.00% 30.00% Convenience Checks 23.00% 20.00% 20.00% 20.00% 20.00% 20.00% 20.00% Convenience Checks with Credit Score less than 621 5.00% 3.00% 3.00% 3.00% 3.00% 3.00% 3.00% Loans with an Original Balance >$25,000 & <$50,000 10.00% 5.00% 5.00% 5.00% 3.00% - - Overcollateralization Event Yes Yes Yes Yes Yes Yes Yes Reinvestment Criteria (1) Limit for unsecured loans was increased to reflect the projected phase-out of personal property collateral over the revolving period, which shifts loans from soft-secured to unsecured 8
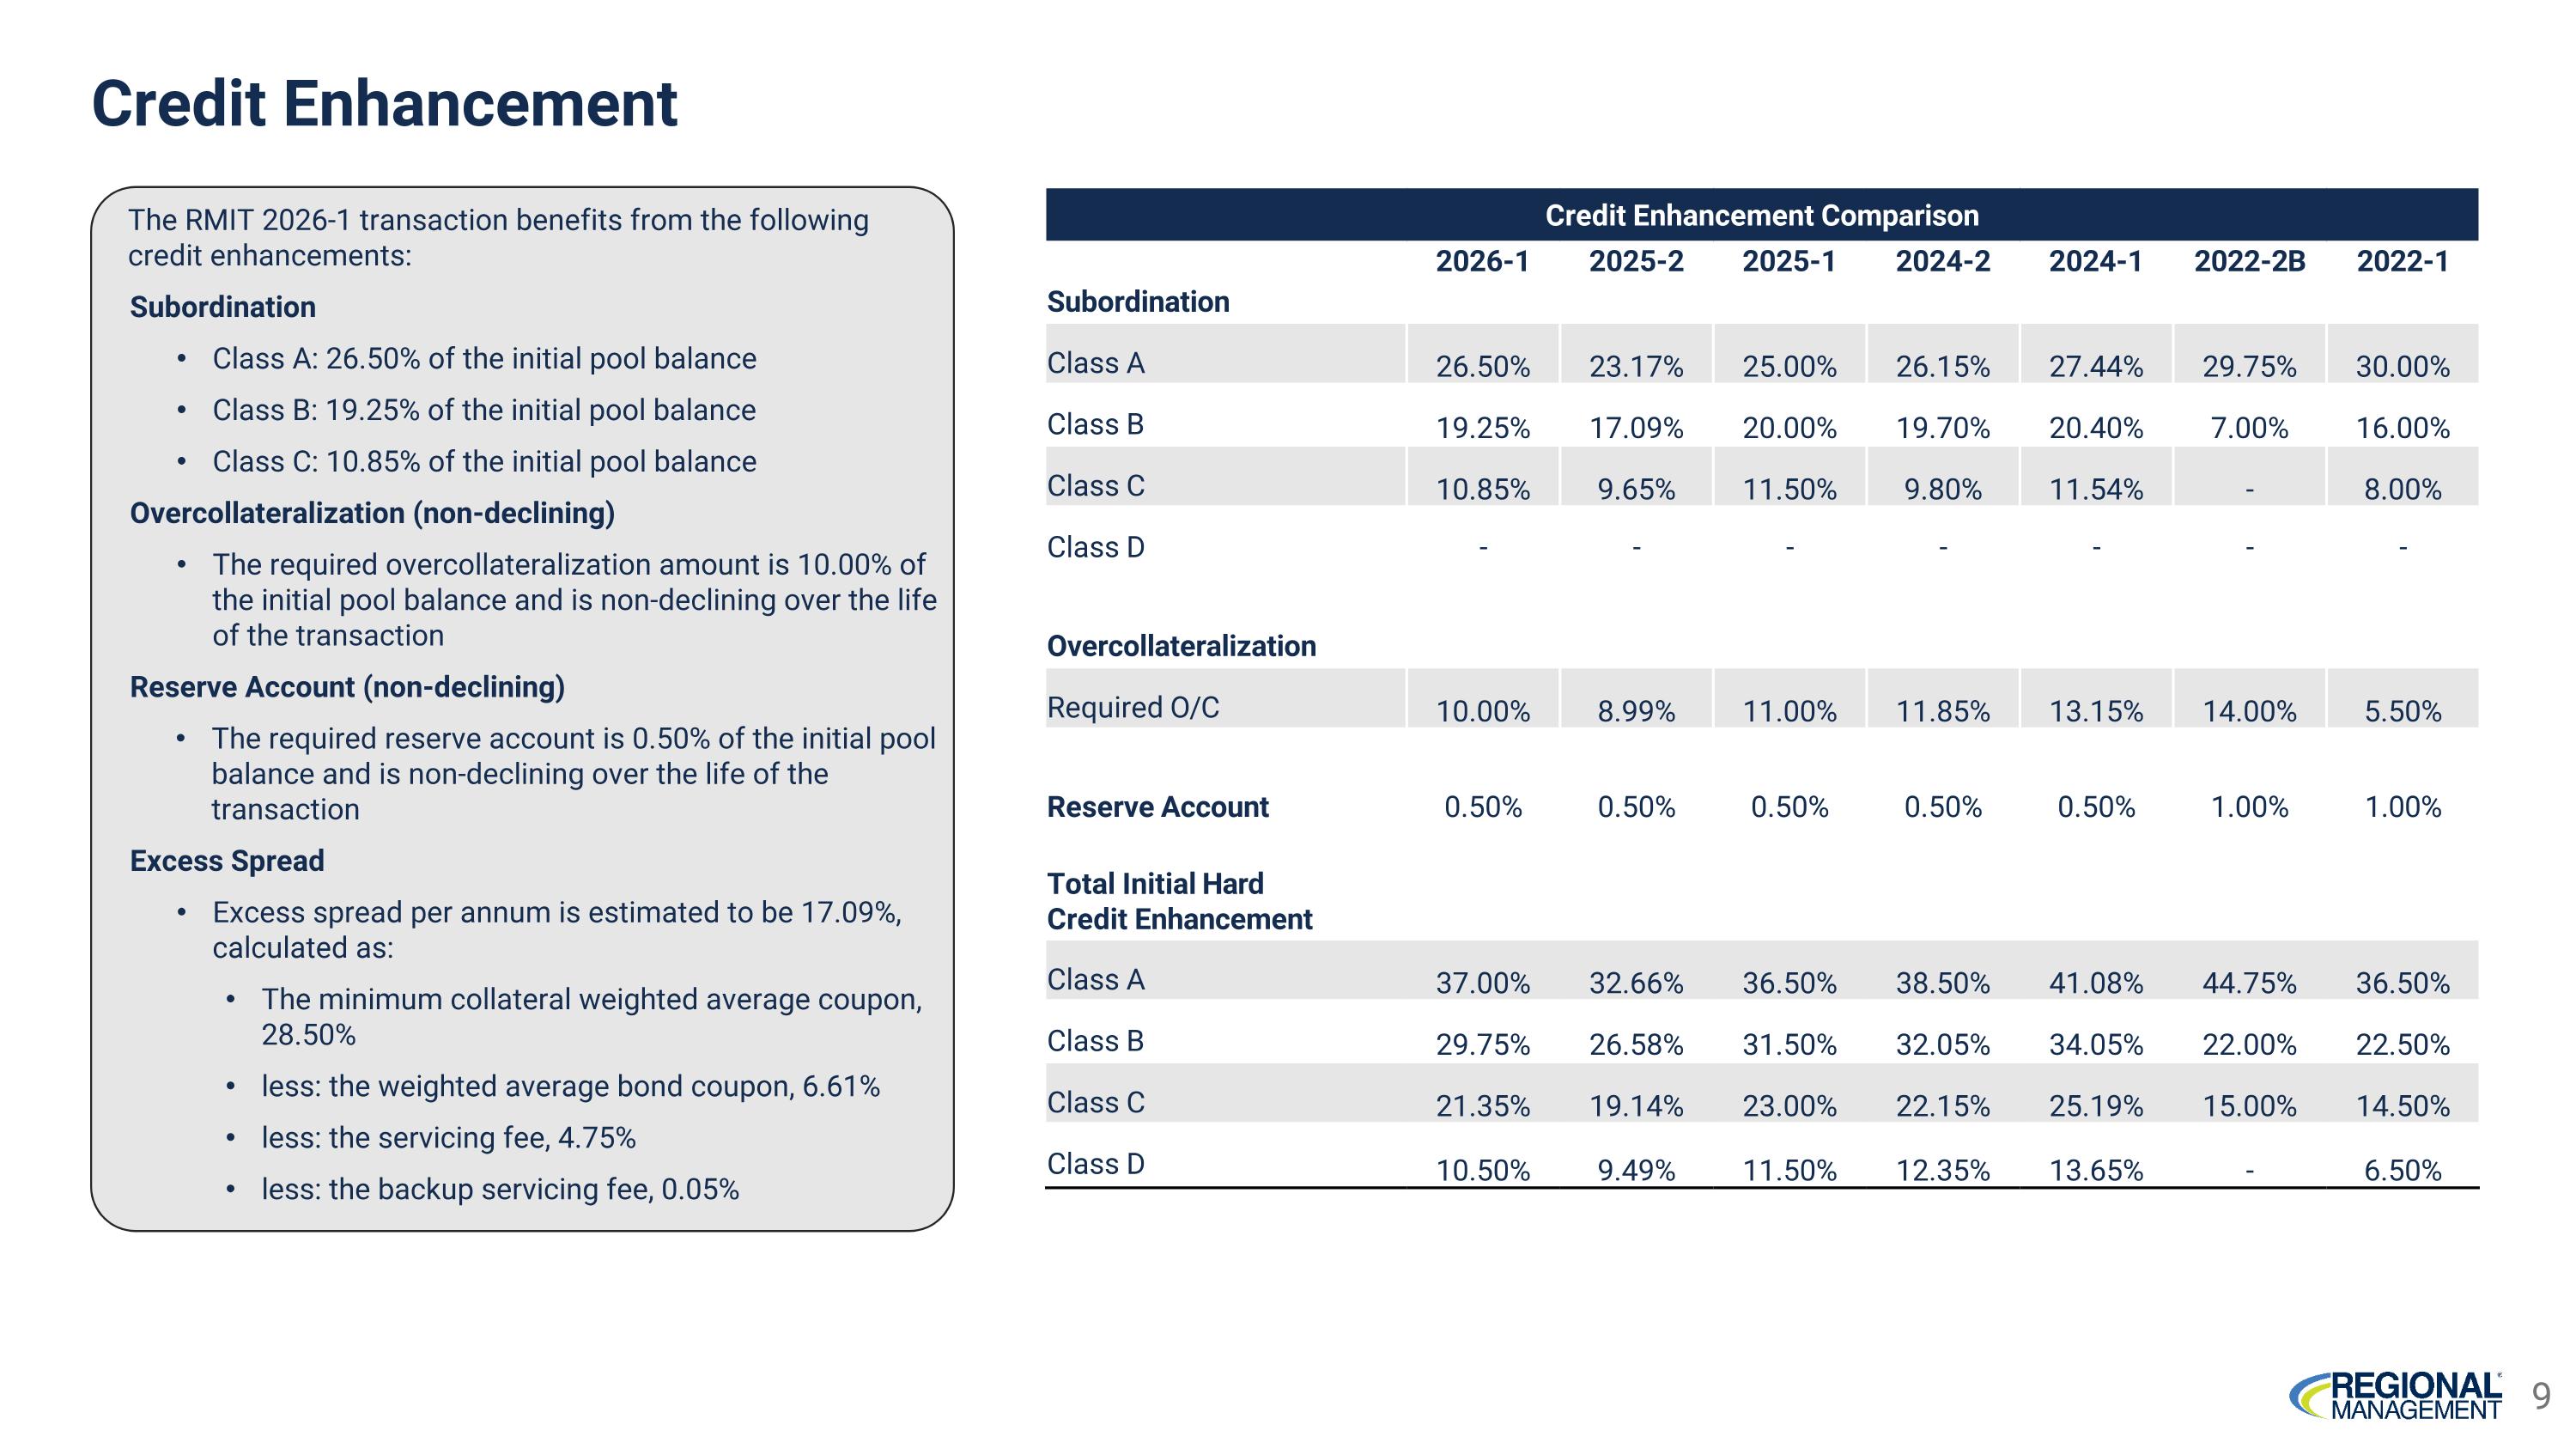
Credit Enhancement The RMIT 2026-1 transaction benefits from the following credit enhancements: Subordination Class A: 26.50% of the initial pool balance Class B: 19.25% of the initial pool balance Class C: 10.85% of the initial pool balance Overcollateralization (non-declining) The required overcollateralization amount is 10.00% of the initial pool balance and is non-declining over the life of the transaction Reserve Account (non-declining) The required reserve account is 0.50% of the initial pool balance and is non-declining over the life of the transaction Excess Spread Excess spread per annum is estimated to be 17.09%, calculated as: The minimum collateral weighted average coupon, 28.50% less: the weighted average bond coupon, 6.61% less: the servicing fee, 4.75% less: the backup servicing fee, 0.05% Credit Enhancement Comparison 2026-1 2025-2 2025-1 2024-2 2024-1 2022-2B 2022-1 Subordination Class A 26.50% 23.17% 25.00% 26.15% 27.44% 29.75% 30.00% Class B 19.25% 17.09% 20.00% 19.70% 20.40% 7.00% 16.00% Class C 10.85% 9.65% 11.50% 9.80% 11.54% - 8.00% Class D - - - - - - - Overcollateralization Required O/C 10.00% 8.99% 11.00% 11.85% 13.15% 14.00% 5.50% Reserve Account 0.50% 0.50% 0.50% 0.50% 0.50% 1.00% 1.00% Total Initial Hard Credit Enhancement Class A 37.00% 32.66% 36.50% 38.50% 41.08% 44.75% 36.50% Class B 29.75% 26.58% 31.50% 32.05% 34.05% 22.00% 22.50% Class C 21.35% 19.14% 23.00% 22.15% 25.19% 15.00% 14.50% Class D 10.50% 9.49% 11.50% 12.35% 13.65% - 6.50% 9
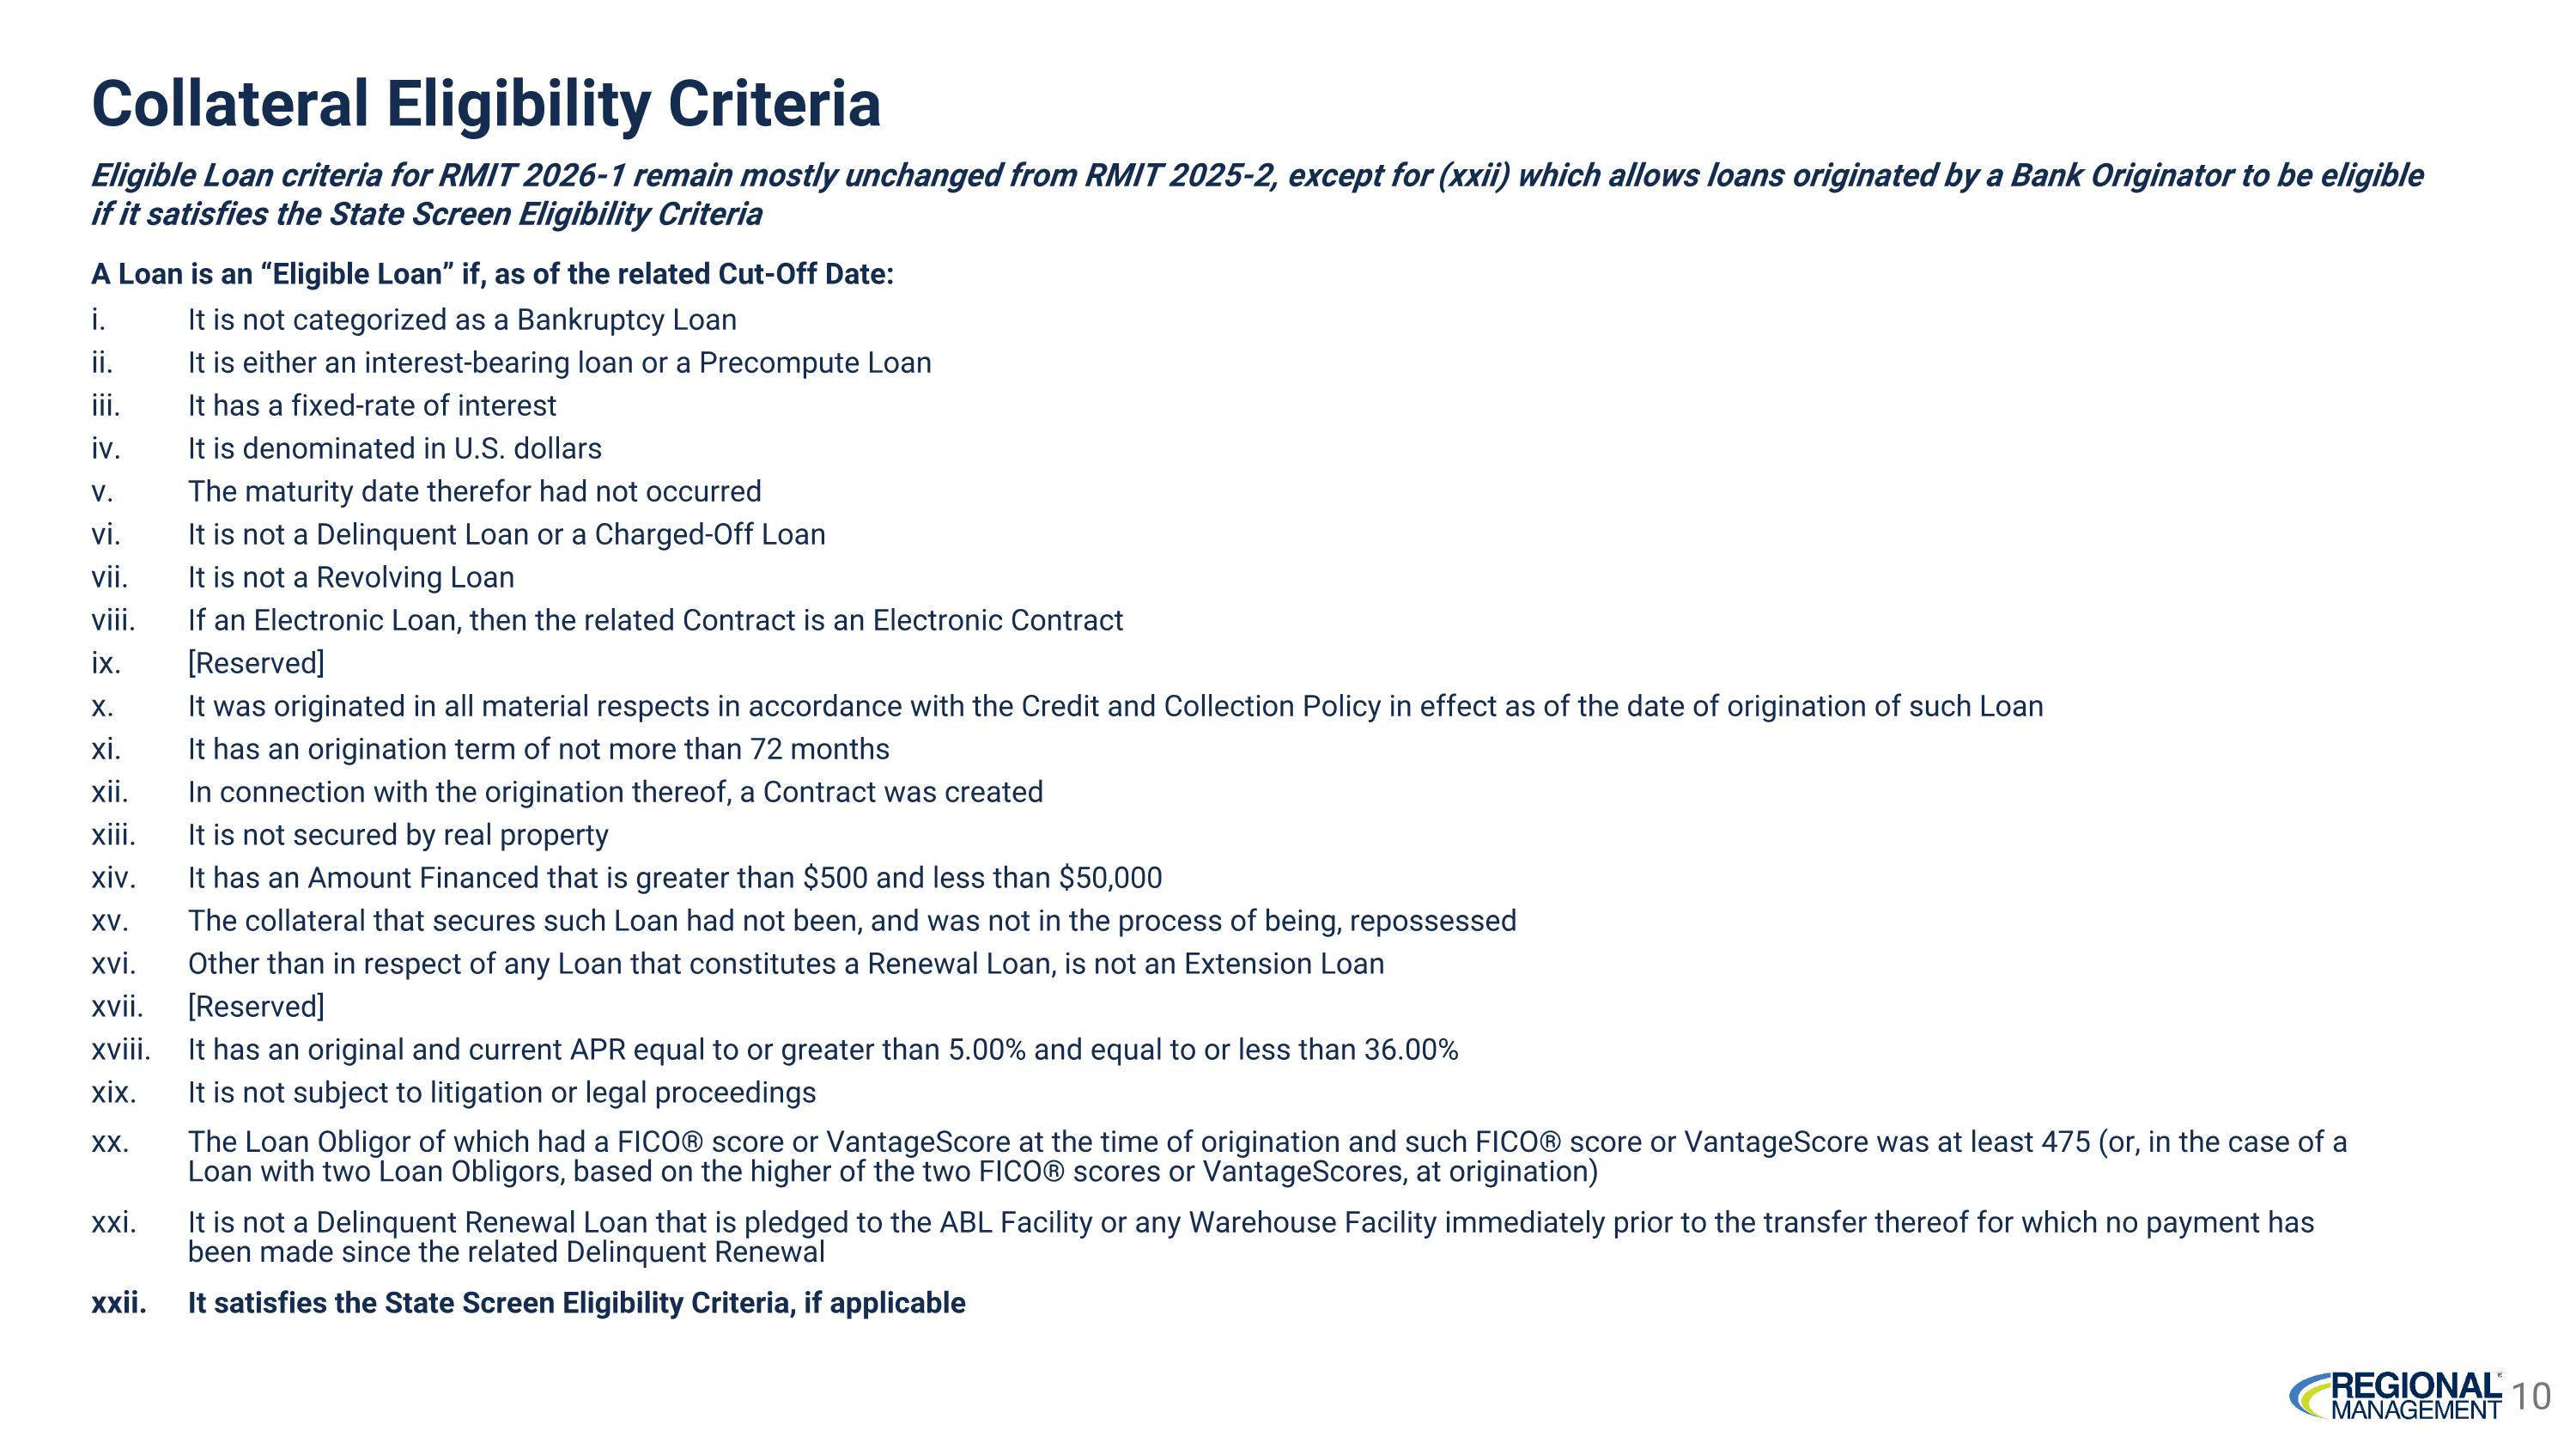
Collateral Eligibility Criteria A Loan is an “Eligible Loan” if, as of the related Cut-Off Date: It is not categorized as a Bankruptcy Loan It is either an interest-bearing loan or a Precompute Loan It has a fixed-rate of interest It is denominated in U.S. dollars The maturity date therefor had not occurred It is not a Delinquent Loan or a Charged-Off Loan It is not a Revolving Loan If an Electronic Loan, then the related Contract is an Electronic Contract [Reserved] It was originated in all material respects in accordance with the Credit and Collection Policy in effect as of the date of origination of such Loan It has an origination term of not more than 72 months In connection with the origination thereof, a Contract was created It is not secured by real property It has an Amount Financed that is greater than $500 and less than $50,000 The collateral that secures such Loan had not been, and was not in the process of being, repossessed Other than in respect of any Loan that constitutes a Renewal Loan, is not an Extension Loan [Reserved] It has an original and current APR equal to or greater than 5.00% and equal to or less than 36.00% It is not subject to litigation or legal proceedings The Loan Obligor of which had a FICO® score or VantageScore at the time of origination and such FICO® score or VantageScore was at least 475 (or, in the case of a Loan with two Loan Obligors, based on the higher of the two FICO® scores or VantageScores, at origination) It is not a Delinquent Renewal Loan that is pledged to the ABL Facility or any Warehouse Facility immediately prior to the transfer thereof for which no payment has been made since the related Delinquent Renewal It satisfies the State Screen Eligibility Criteria, if applicable Eligible Loan criteria for RMIT 2026-1 remain mostly unchanged from RMIT 2025-2, except for (xxii) which allows loans originated by a Bank Originator to be eligible if it satisfies the State Screen Eligibility Criteria 10
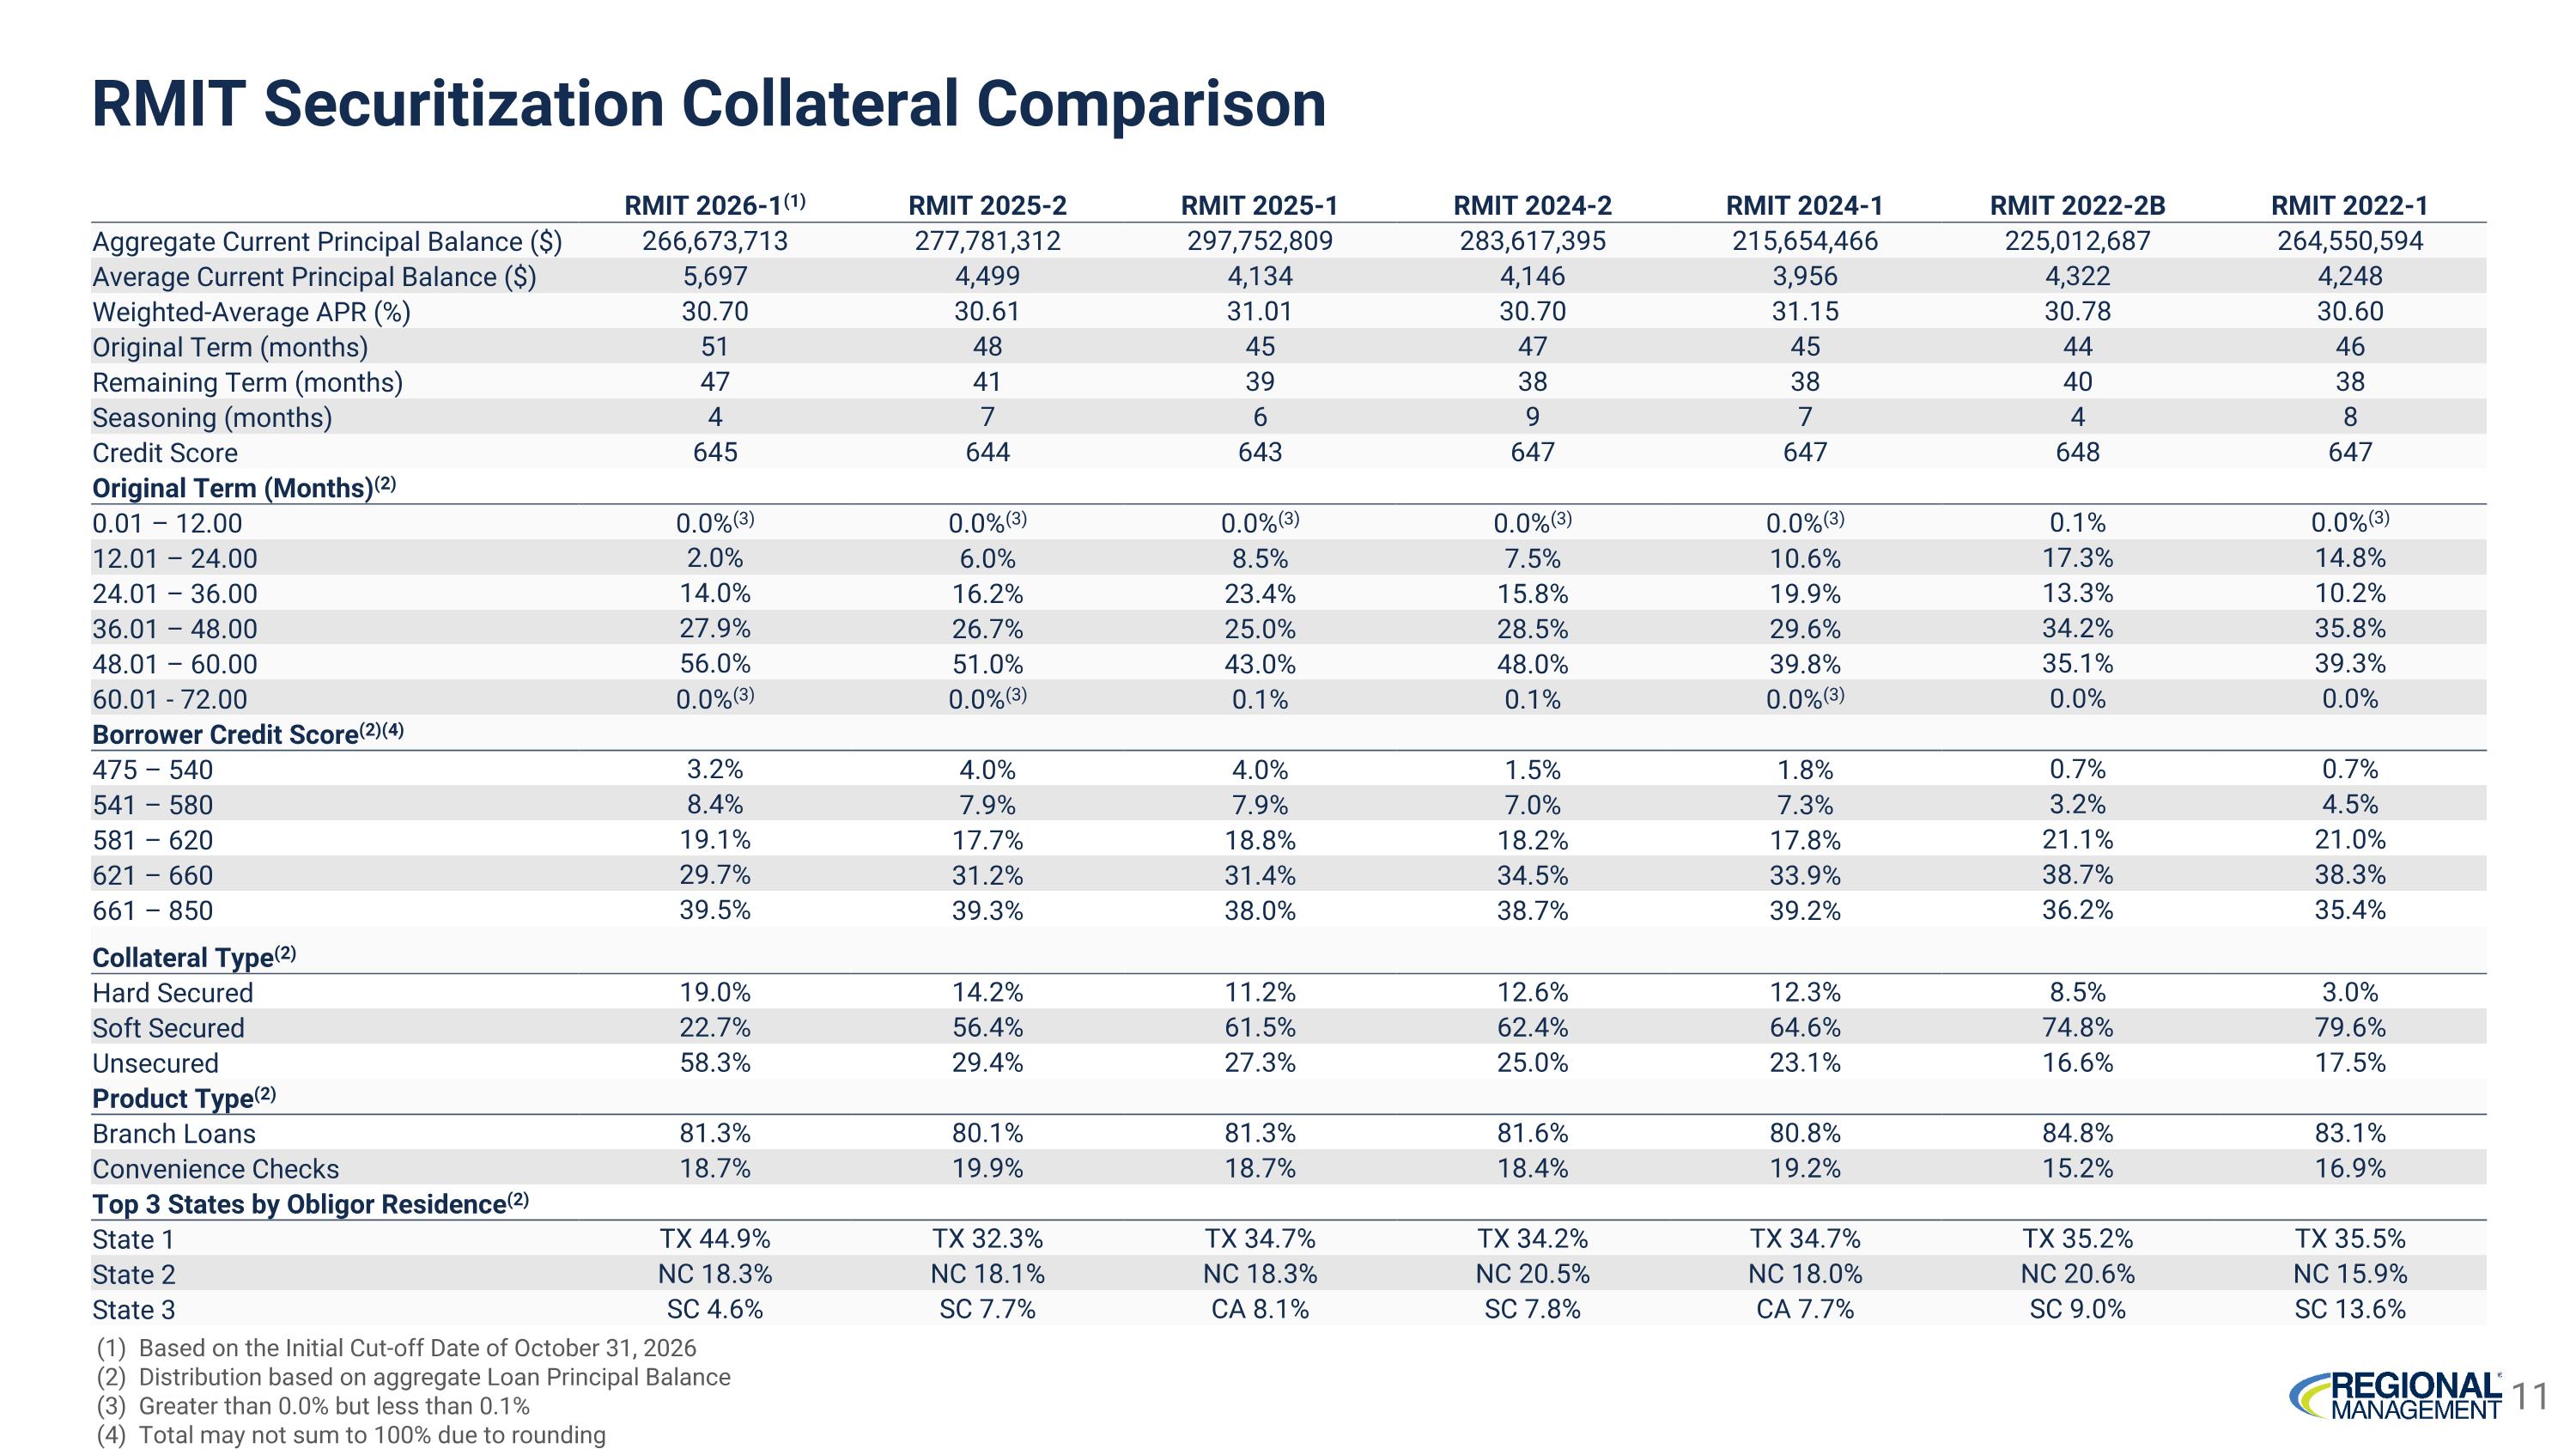
RMIT Securitization Collateral Comparison RMIT 2026-1(1) RMIT 2025-2 RMIT 2025-1 RMIT 2024-2 RMIT 2024-1 RMIT 2022-2B RMIT 2022-1 Aggregate Current Principal Balance ($) 266,673,713 277,781,312 297,752,809 283,617,395 215,654,466 225,012,687 264,550,594 Average Current Principal Balance ($) 5,697 4,499 4,134 4,146 3,956 4,322 4,248 Weighted-Average APR (%) 30.70 30.61 31.01 30.70 31.15 30.78 30.60 Original Term (months) 51 48 45 47 45 44 46 Remaining Term (months) 47 41 39 38 38 40 38 Seasoning (months) 4 7 6 9 7 4 8 Credit Score 645 644 643 647 647 648 647 Original Term (Months)(2) 0.01 – 12.00 0.0%(3) 0.0%(3) 0.0%(3) 0.0%(3) 0.0%(3) 0.1% 0.0%(3) 12.01 – 24.00 2.0% 6.0% 8.5% 7.5% 10.6% 17.3% 14.8% 24.01 – 36.00 14.0% 16.2% 23.4% 15.8% 19.9% 13.3% 10.2% 36.01 – 48.00 27.9% 26.7% 25.0% 28.5% 29.6% 34.2% 35.8% 48.01 – 60.00 56.0% 51.0% 43.0% 48.0% 39.8% 35.1% 39.3% 60.01 - 72.00 0.0%(3) 0.0%(3) 0.1% 0.1% 0.0%(3) 0.0% 0.0% Borrower Credit Score(2)(4) 475 – 540 3.2% 4.0% 4.0% 1.5% 1.8% 0.7% 0.7% 541 – 580 8.4% 7.9% 7.9% 7.0% 7.3% 3.2% 4.5% 581 – 620 19.1% 17.7% 18.8% 18.2% 17.8% 21.1% 21.0% 621 – 660 29.7% 31.2% 31.4% 34.5% 33.9% 38.7% 38.3% 661 – 850 39.5% 39.3% 38.0% 38.7% 39.2% 36.2% 35.4% Collateral Type(2) Hard Secured 19.0% 14.2% 11.2% 12.6% 12.3% 8.5% 3.0% Soft Secured 22.7% 56.4% 61.5% 62.4% 64.6% 74.8% 79.6% Unsecured 58.3% 29.4% 27.3% 25.0% 23.1% 16.6% 17.5% Product Type(2) Branch Loans 81.3% 80.1% 81.3% 81.6% 80.8% 84.8% 83.1% Convenience Checks 18.7% 19.9% 18.7% 18.4% 19.2% 15.2% 16.9% Top 3 States by Obligor Residence(2) State 1 TX 44.9% TX 32.3% TX 34.7% TX 34.2% TX 34.7% TX 35.2% TX 35.5% State 2 NC 18.3% NC 18.1% NC 18.3% NC 20.5% NC 18.0% NC 20.6% NC 15.9% State 3 SC 4.6% SC 7.7% CA 8.1% SC 7.8% CA 7.7% SC 9.0% SC 13.6% (1) Based on the Initial Cut-off Date of October 31, 2026 (2) Distribution based on aggregate Loan Principal Balance (3) Greater than 0.0% but less than 0.1% (4) Total may not sum to 100% due to rounding 11
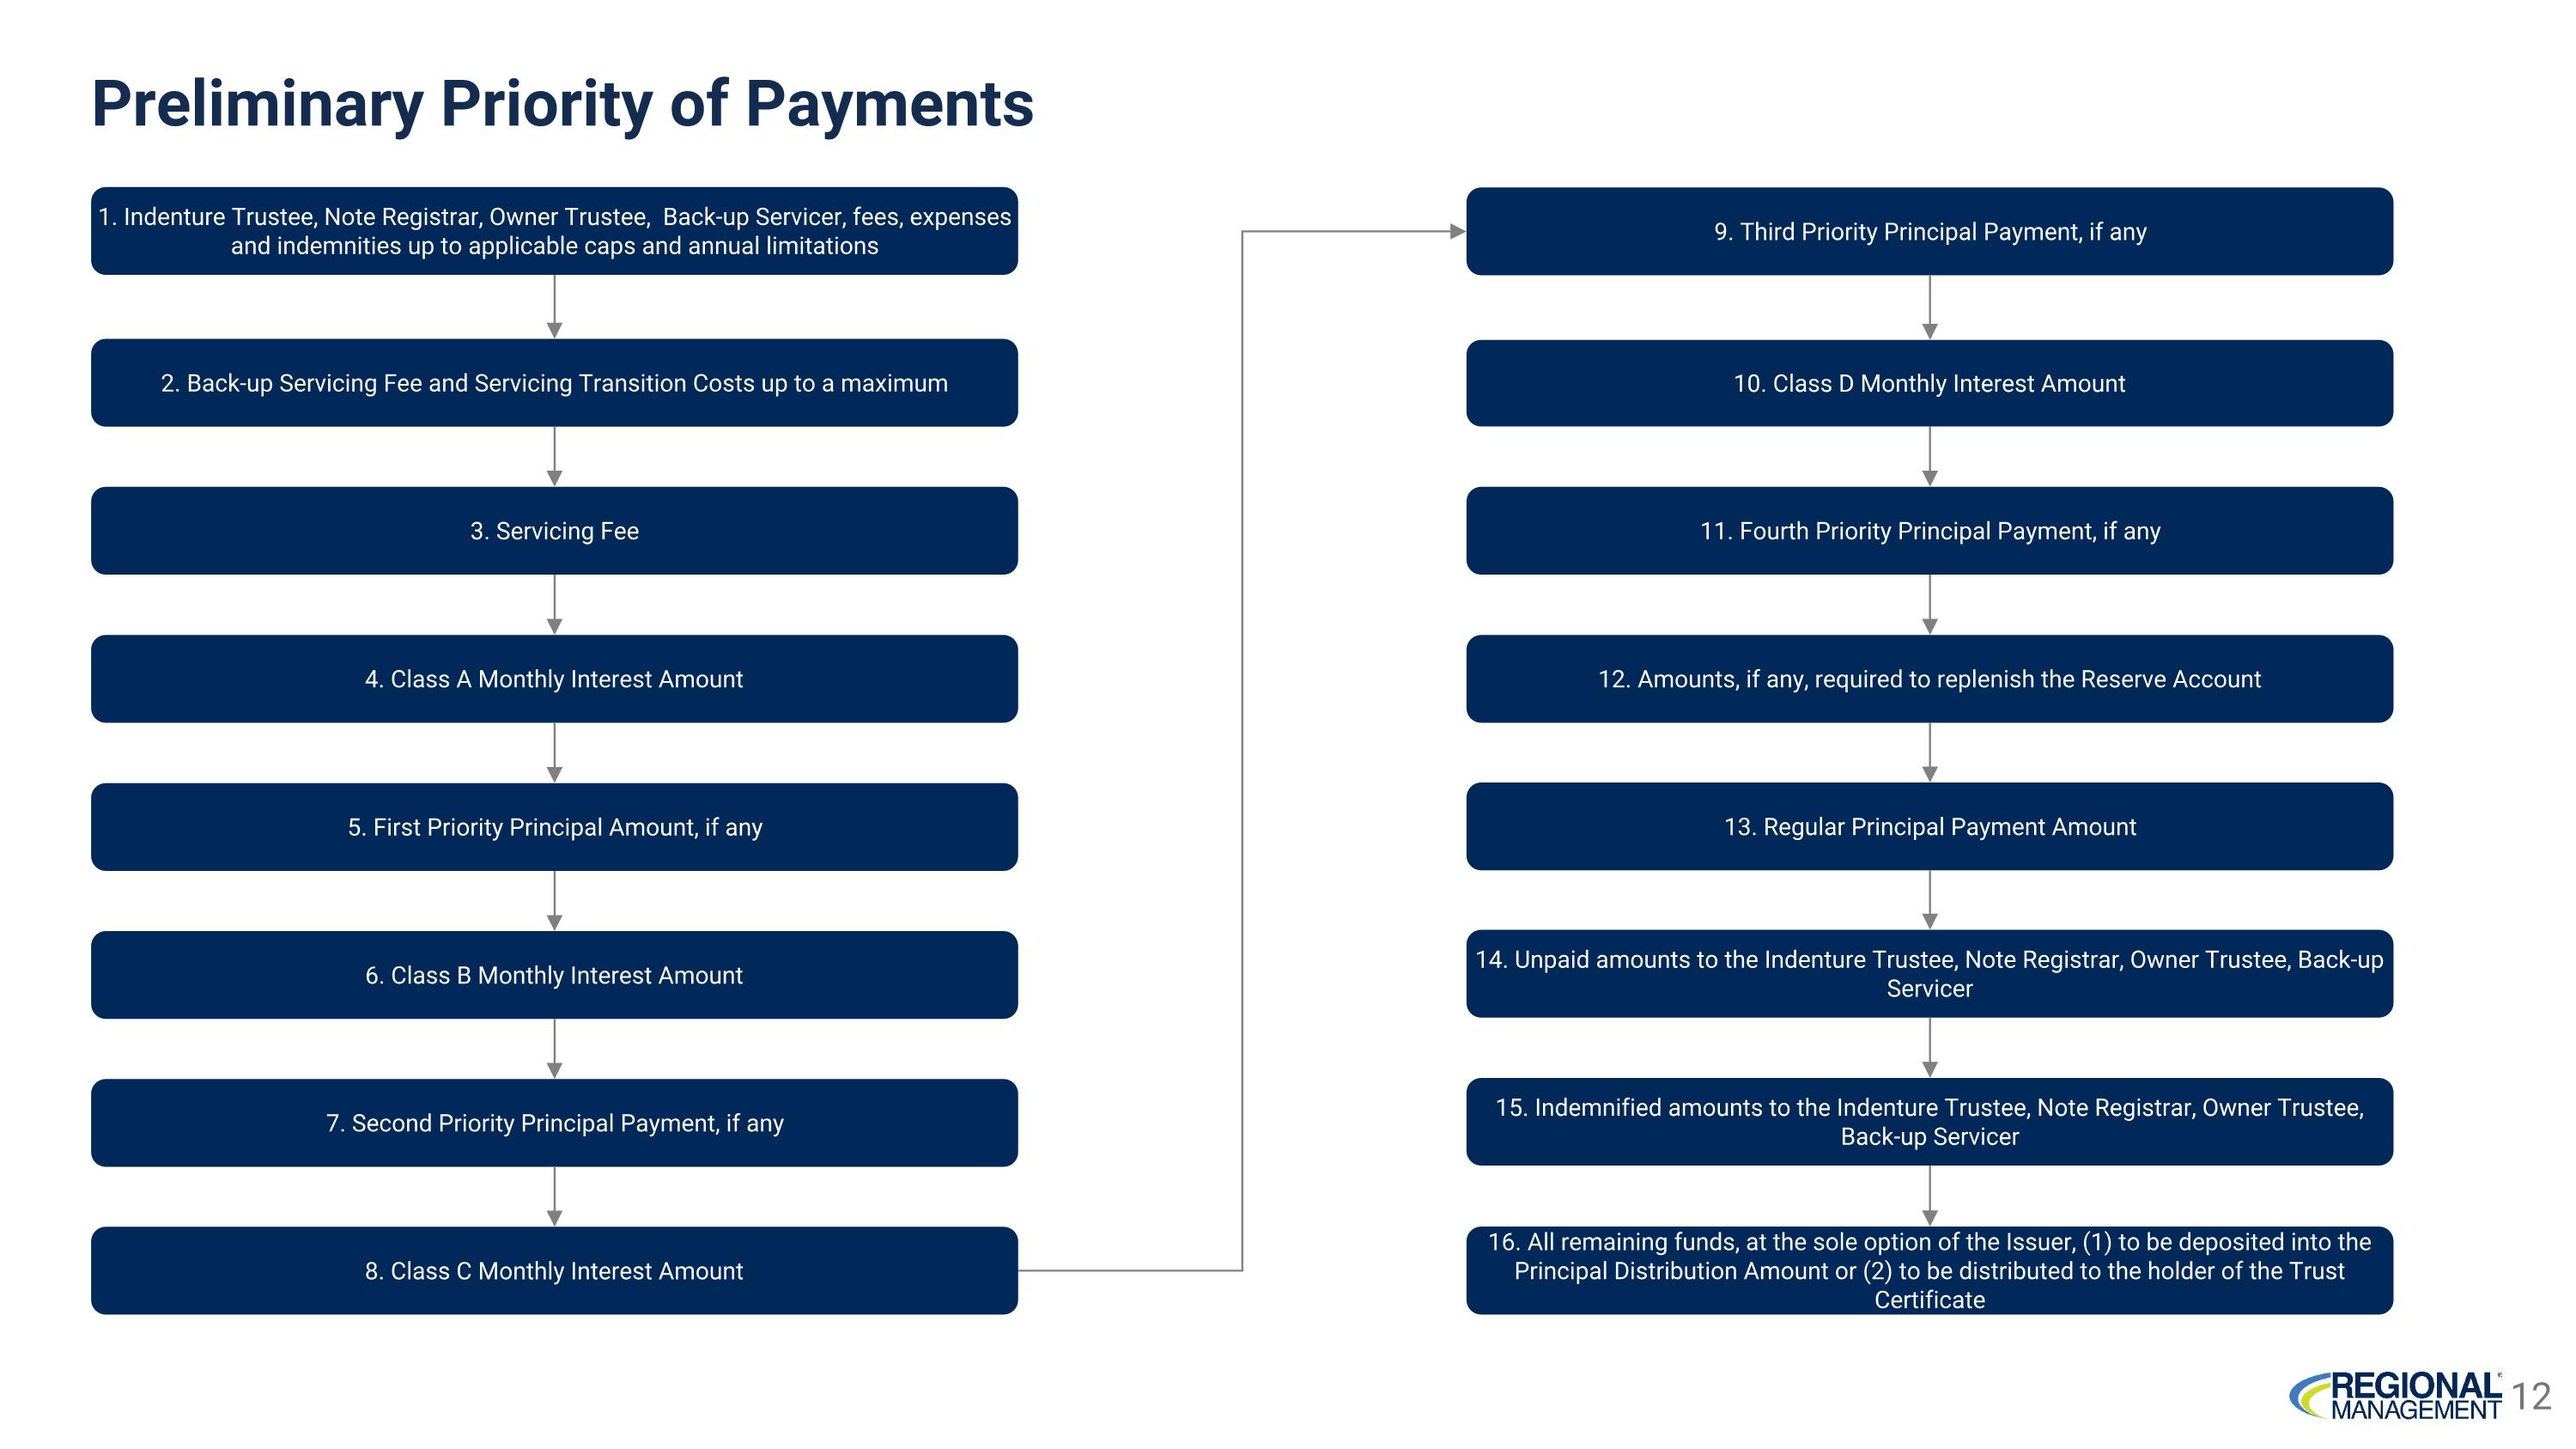
Preliminary Priority of Payments 12. Amounts, if any, required to replenish the Reserve Account 13. Regular Principal Payment Amount 14. Unpaid amounts to the Indenture Trustee, Note Registrar, Owner Trustee, Back-up Servicer 15. Indemnified amounts to the Indenture Trustee, Note Registrar, Owner Trustee, Back-up Servicer 9. Third Priority Principal Payment, if any 2. Back-up Servicing Fee and Servicing Transition Costs up to a maximum 3. Servicing Fee 4. Class A Monthly Interest Amount 5. First Priority Principal Amount, if any 6. Class B Monthly Interest Amount 7. Second Priority Principal Payment, if any 8. Class C Monthly Interest Amount 1. Indenture Trustee, Note Registrar, Owner Trustee, Back-up Servicer, fees, expenses and indemnities up to applicable caps and annual limitations 11. Fourth Priority Principal Payment, if any 10. Class D Monthly Interest Amount 16. All remaining funds, at the sole option of the Issuer, (1) to be deposited into the Principal Distribution Amount or (2) to be distributed to the holder of the Trust Certificate 12
Company Overview
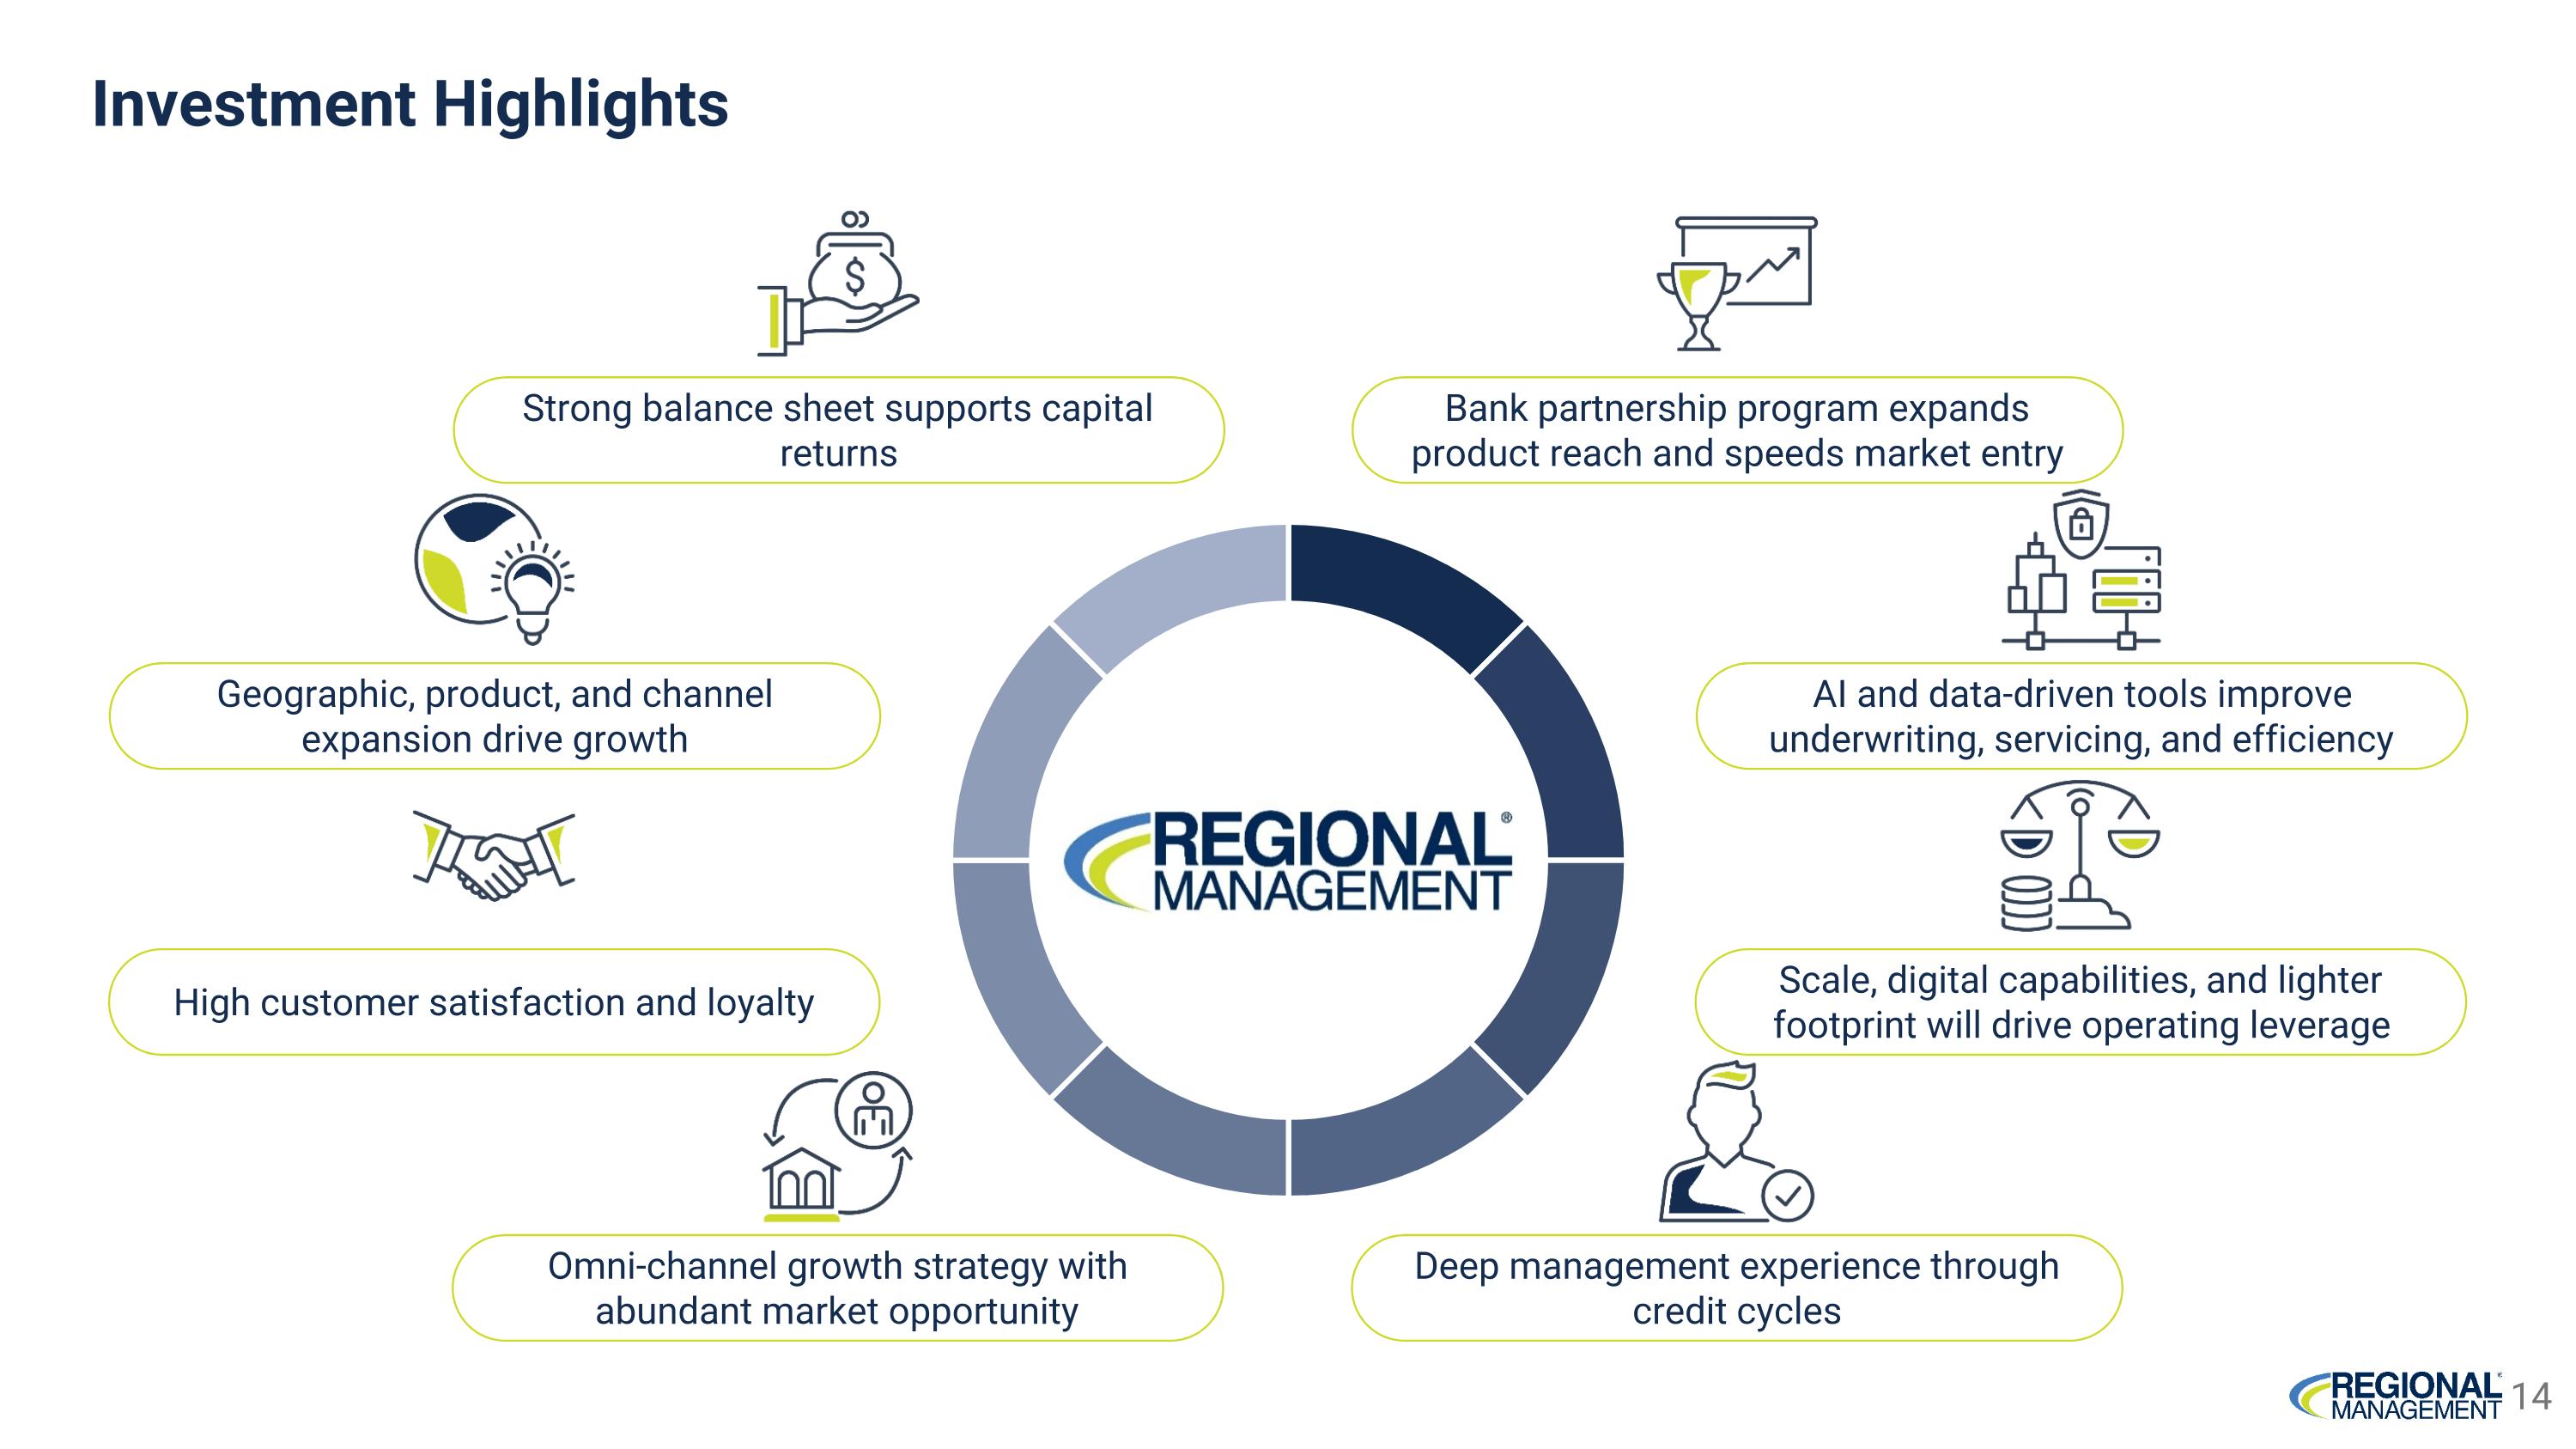
Investment Highlights Strong balance sheet supports capital returns Geographic, product, and channel expansion drive growth Omni-channel growth strategy with abundant market opportunity Bank partnership program expands product reach and speeds market entry AI and data-driven tools improve underwriting, servicing, and efficiency Deep management experience through credit cycles High customer satisfaction and loyalty Scale, digital capabilities, and lighter footprint will drive operating leverage 14
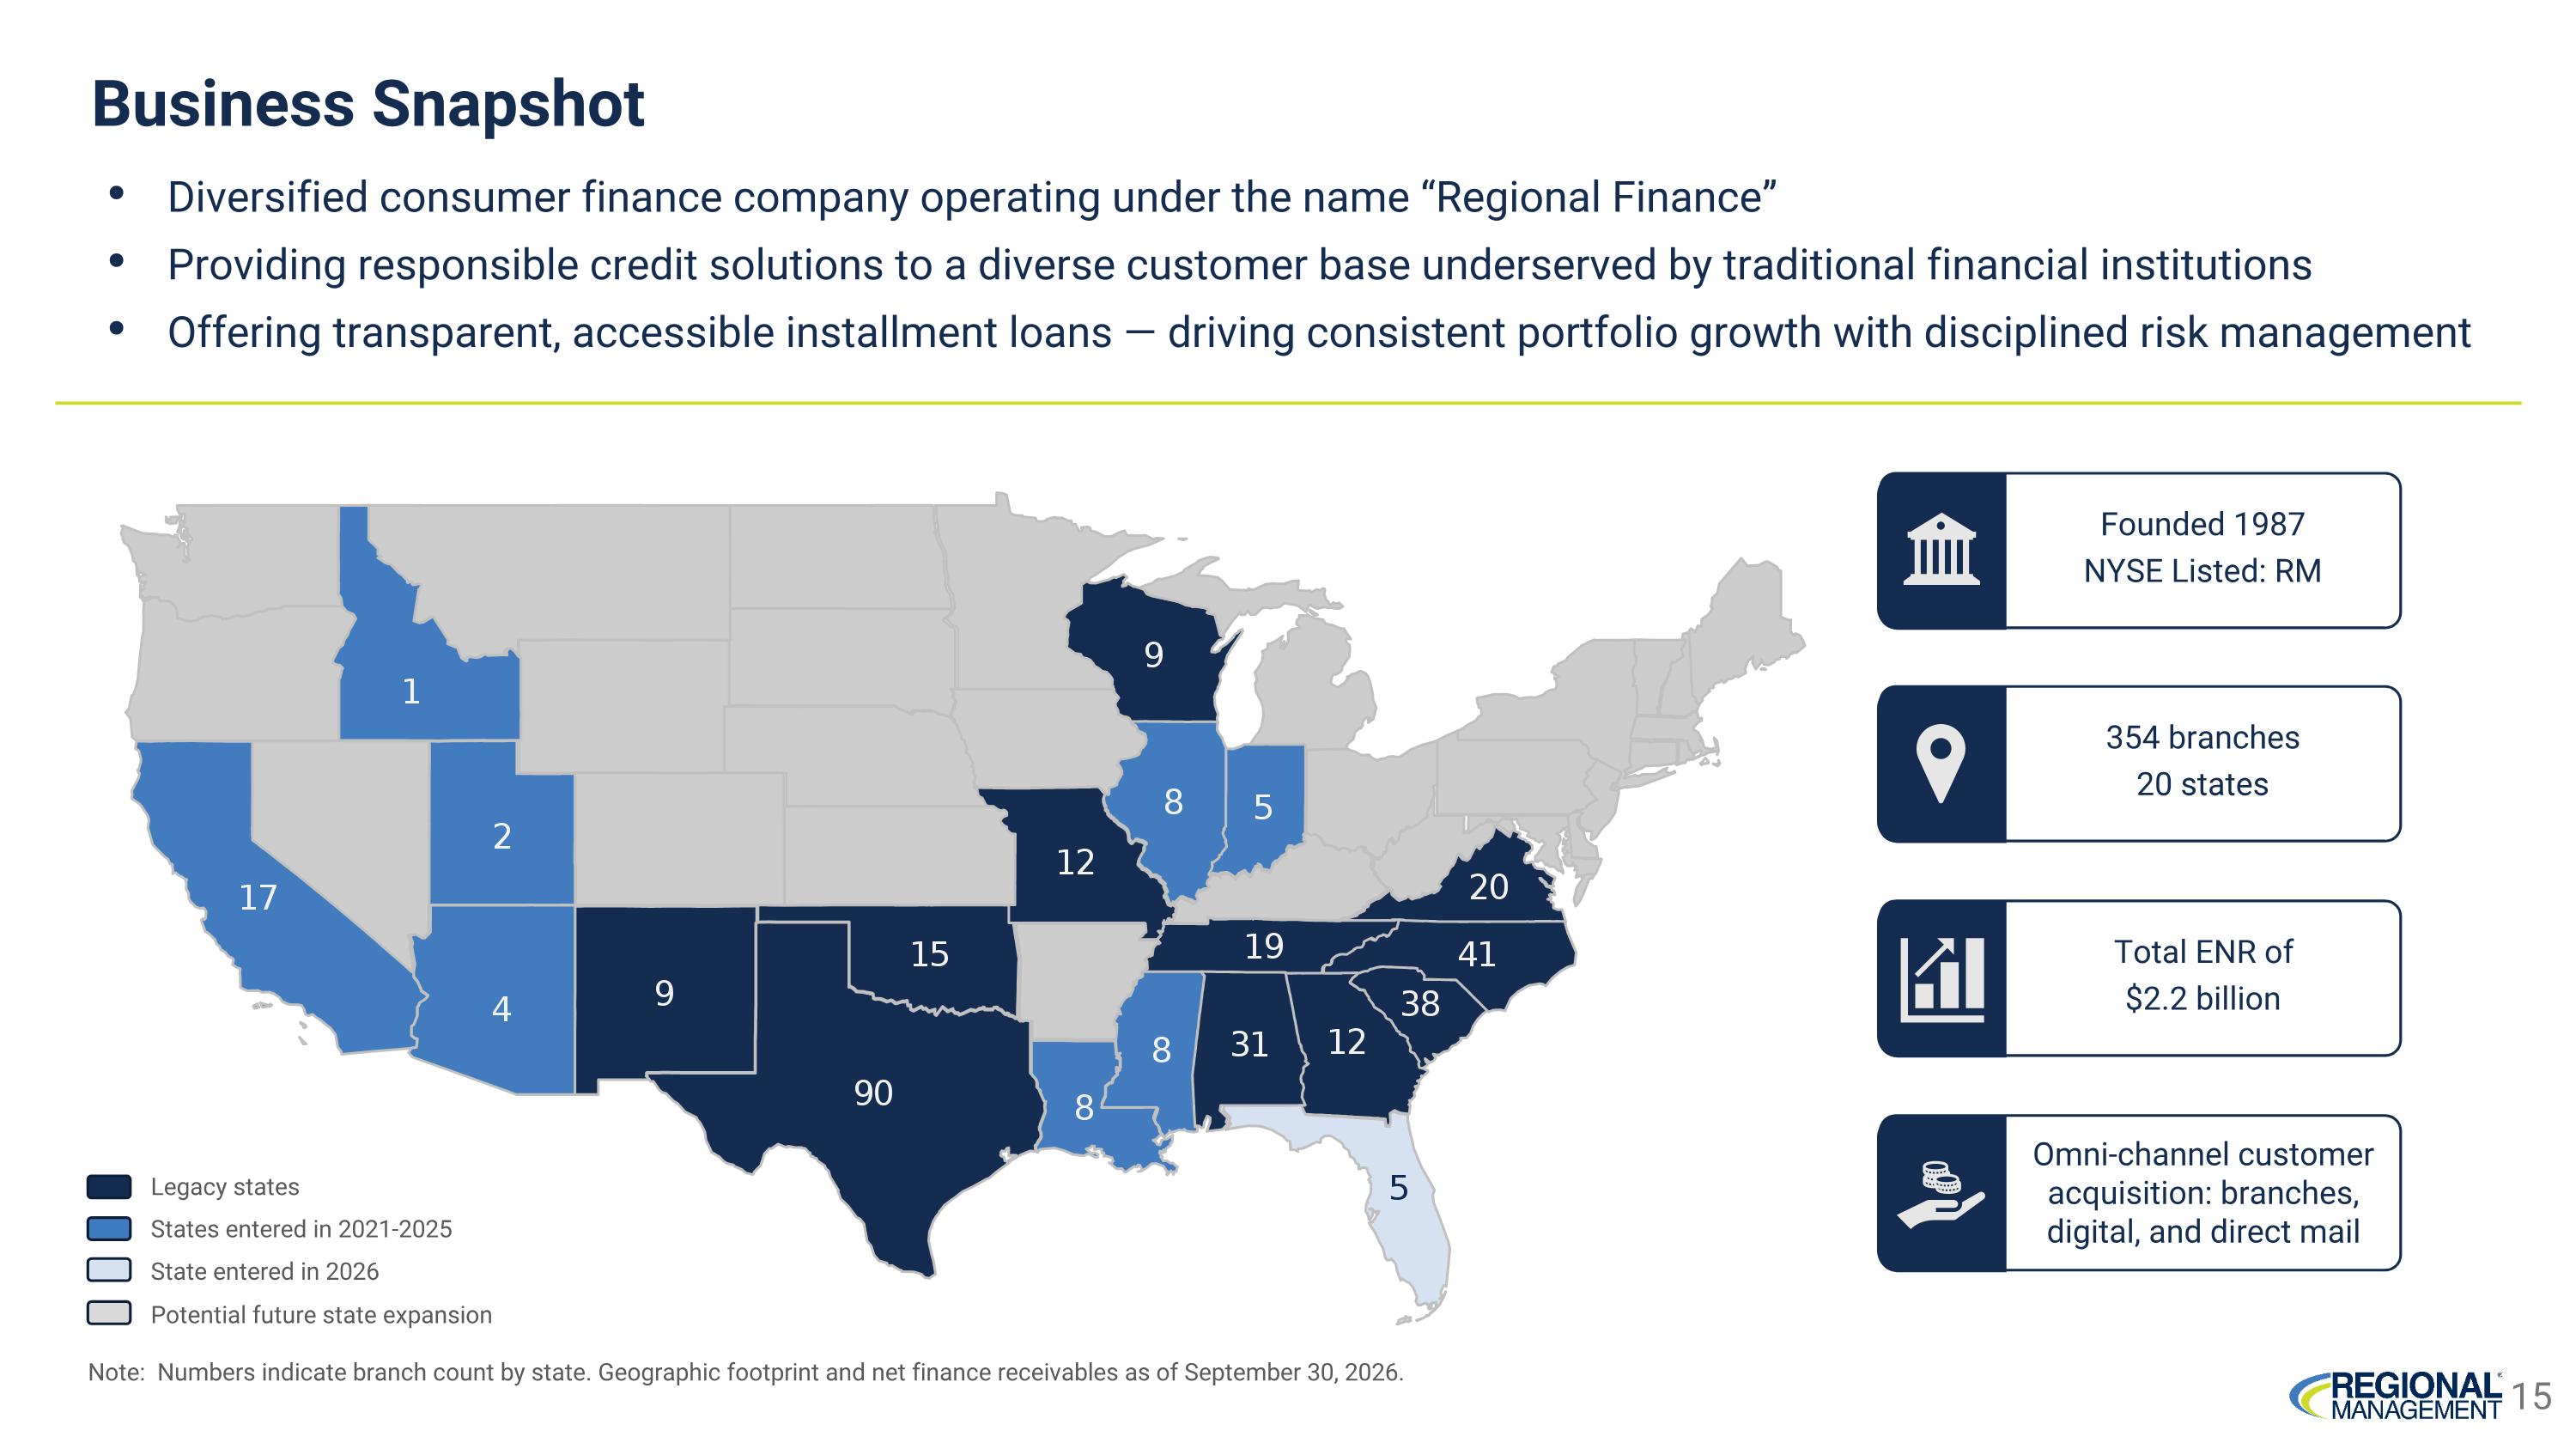
Business Snapshot Founded 1987 NYSE Listed: RM State entered in 2026 Potential future state expansion Note: Numbers indicate branch count by state. Geographic footprint and net finance receivables as of September 30, 2026. States entered in 2021-2025 Legacy states 354 branches 20 states Total ENR of $2.2 billion Omni-channel customer acquisition: branches, digital, and direct mail Diversified consumer finance company operating under the name “Regional Finance” Providing responsible credit solutions to a diverse customer base underserved by traditional financial institutions Offering transparent, accessible installment loans — driving consistent portfolio growth with disciplined risk management 15
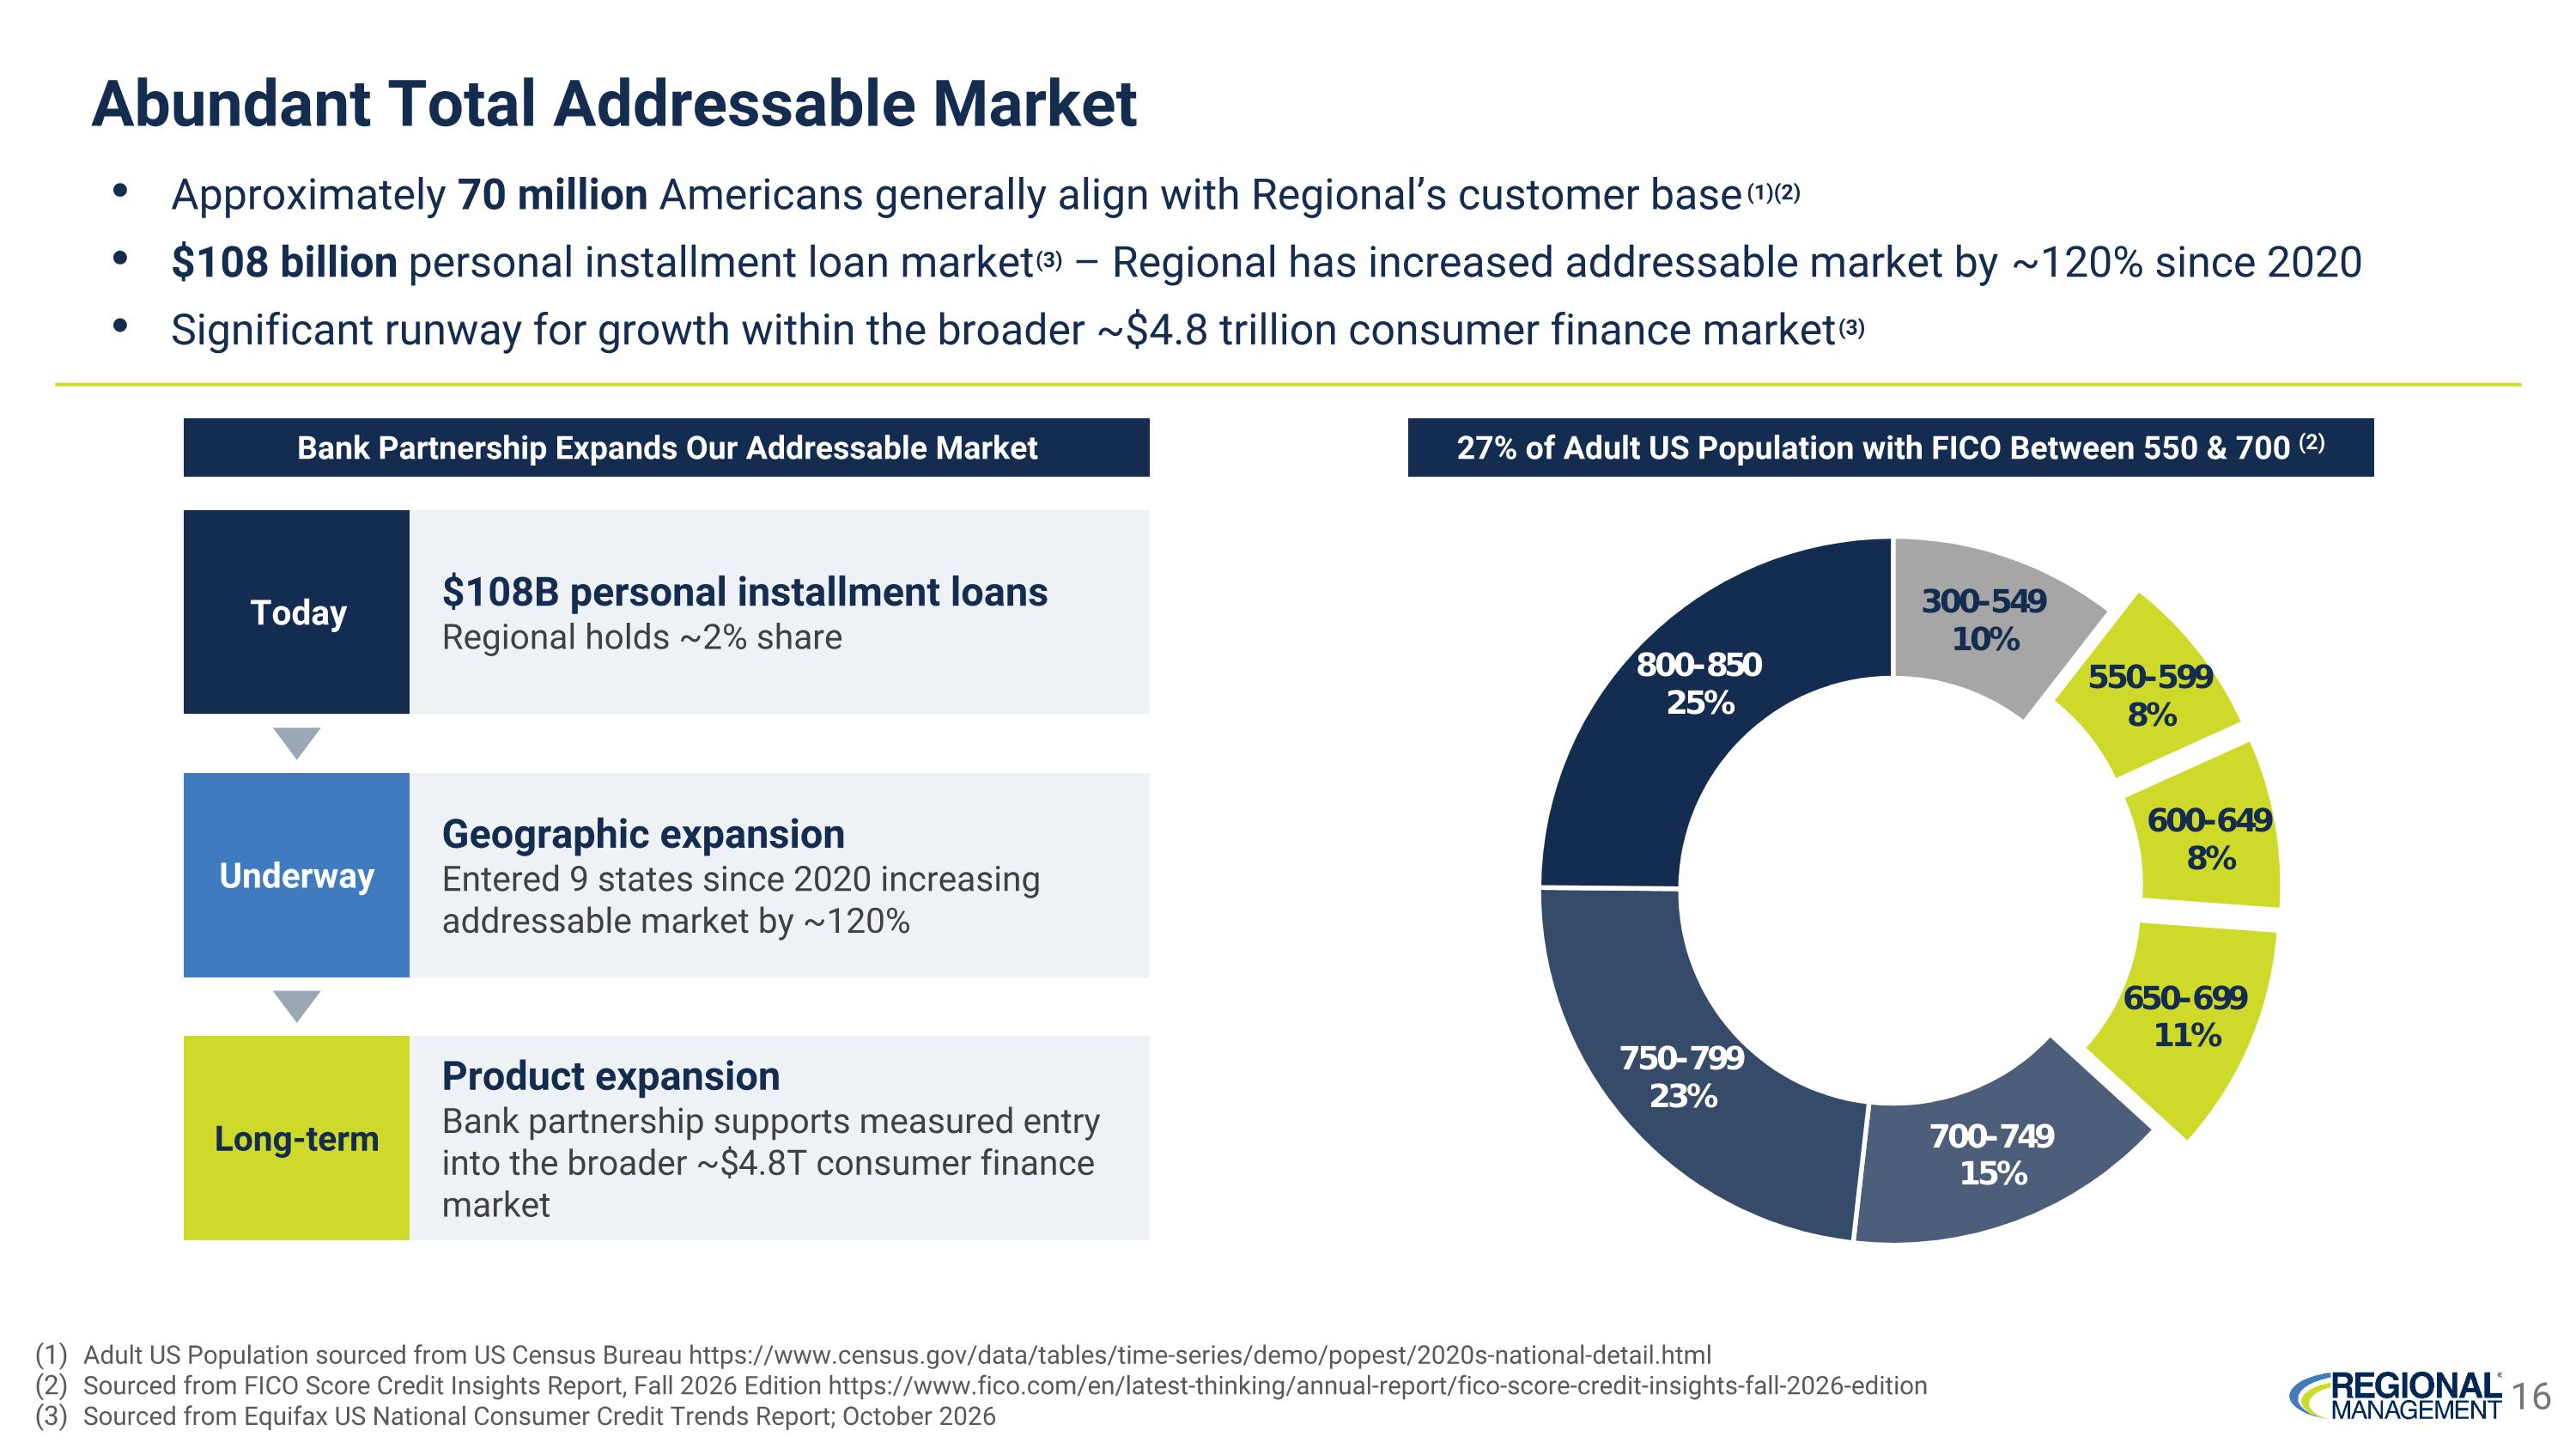
Abundant Total Addressable Market Approximately 70 million Americans generally align with Regional’s customer base (1)(2) $108 billion personal installment loan market(3) – Regional has increased addressable market by ~120% since 2020 Significant runway for growth within the broader ~$4.8 trillion consumer finance market(3) Bank Partnership Expands Our Addressable Market 27% of Adult US Population with FICO Between 550 & 700 (2) Today $108B personal installment loans Regional holds ~2% share Underway Geographic expansion Entered 9 states since 2020 increasing addressable market by ~120% Long-term Product expansion Bank partnership supports measured entry into the broader ~$4.8T consumer finance market Adult US Population sourced from US Census Bureau https://www.census.gov/data/tables/time-series/demo/popest/2020s-national-detail.html Sourced from FICO Score Credit Insights Report, Fall 2026 Edition https://www.fico.com/en/latest-thinking/annual-report/fico-score-credit-insights-fall-2026-edition Sourced from Equifax US National Consumer Credit Trends Report; October 2026 16
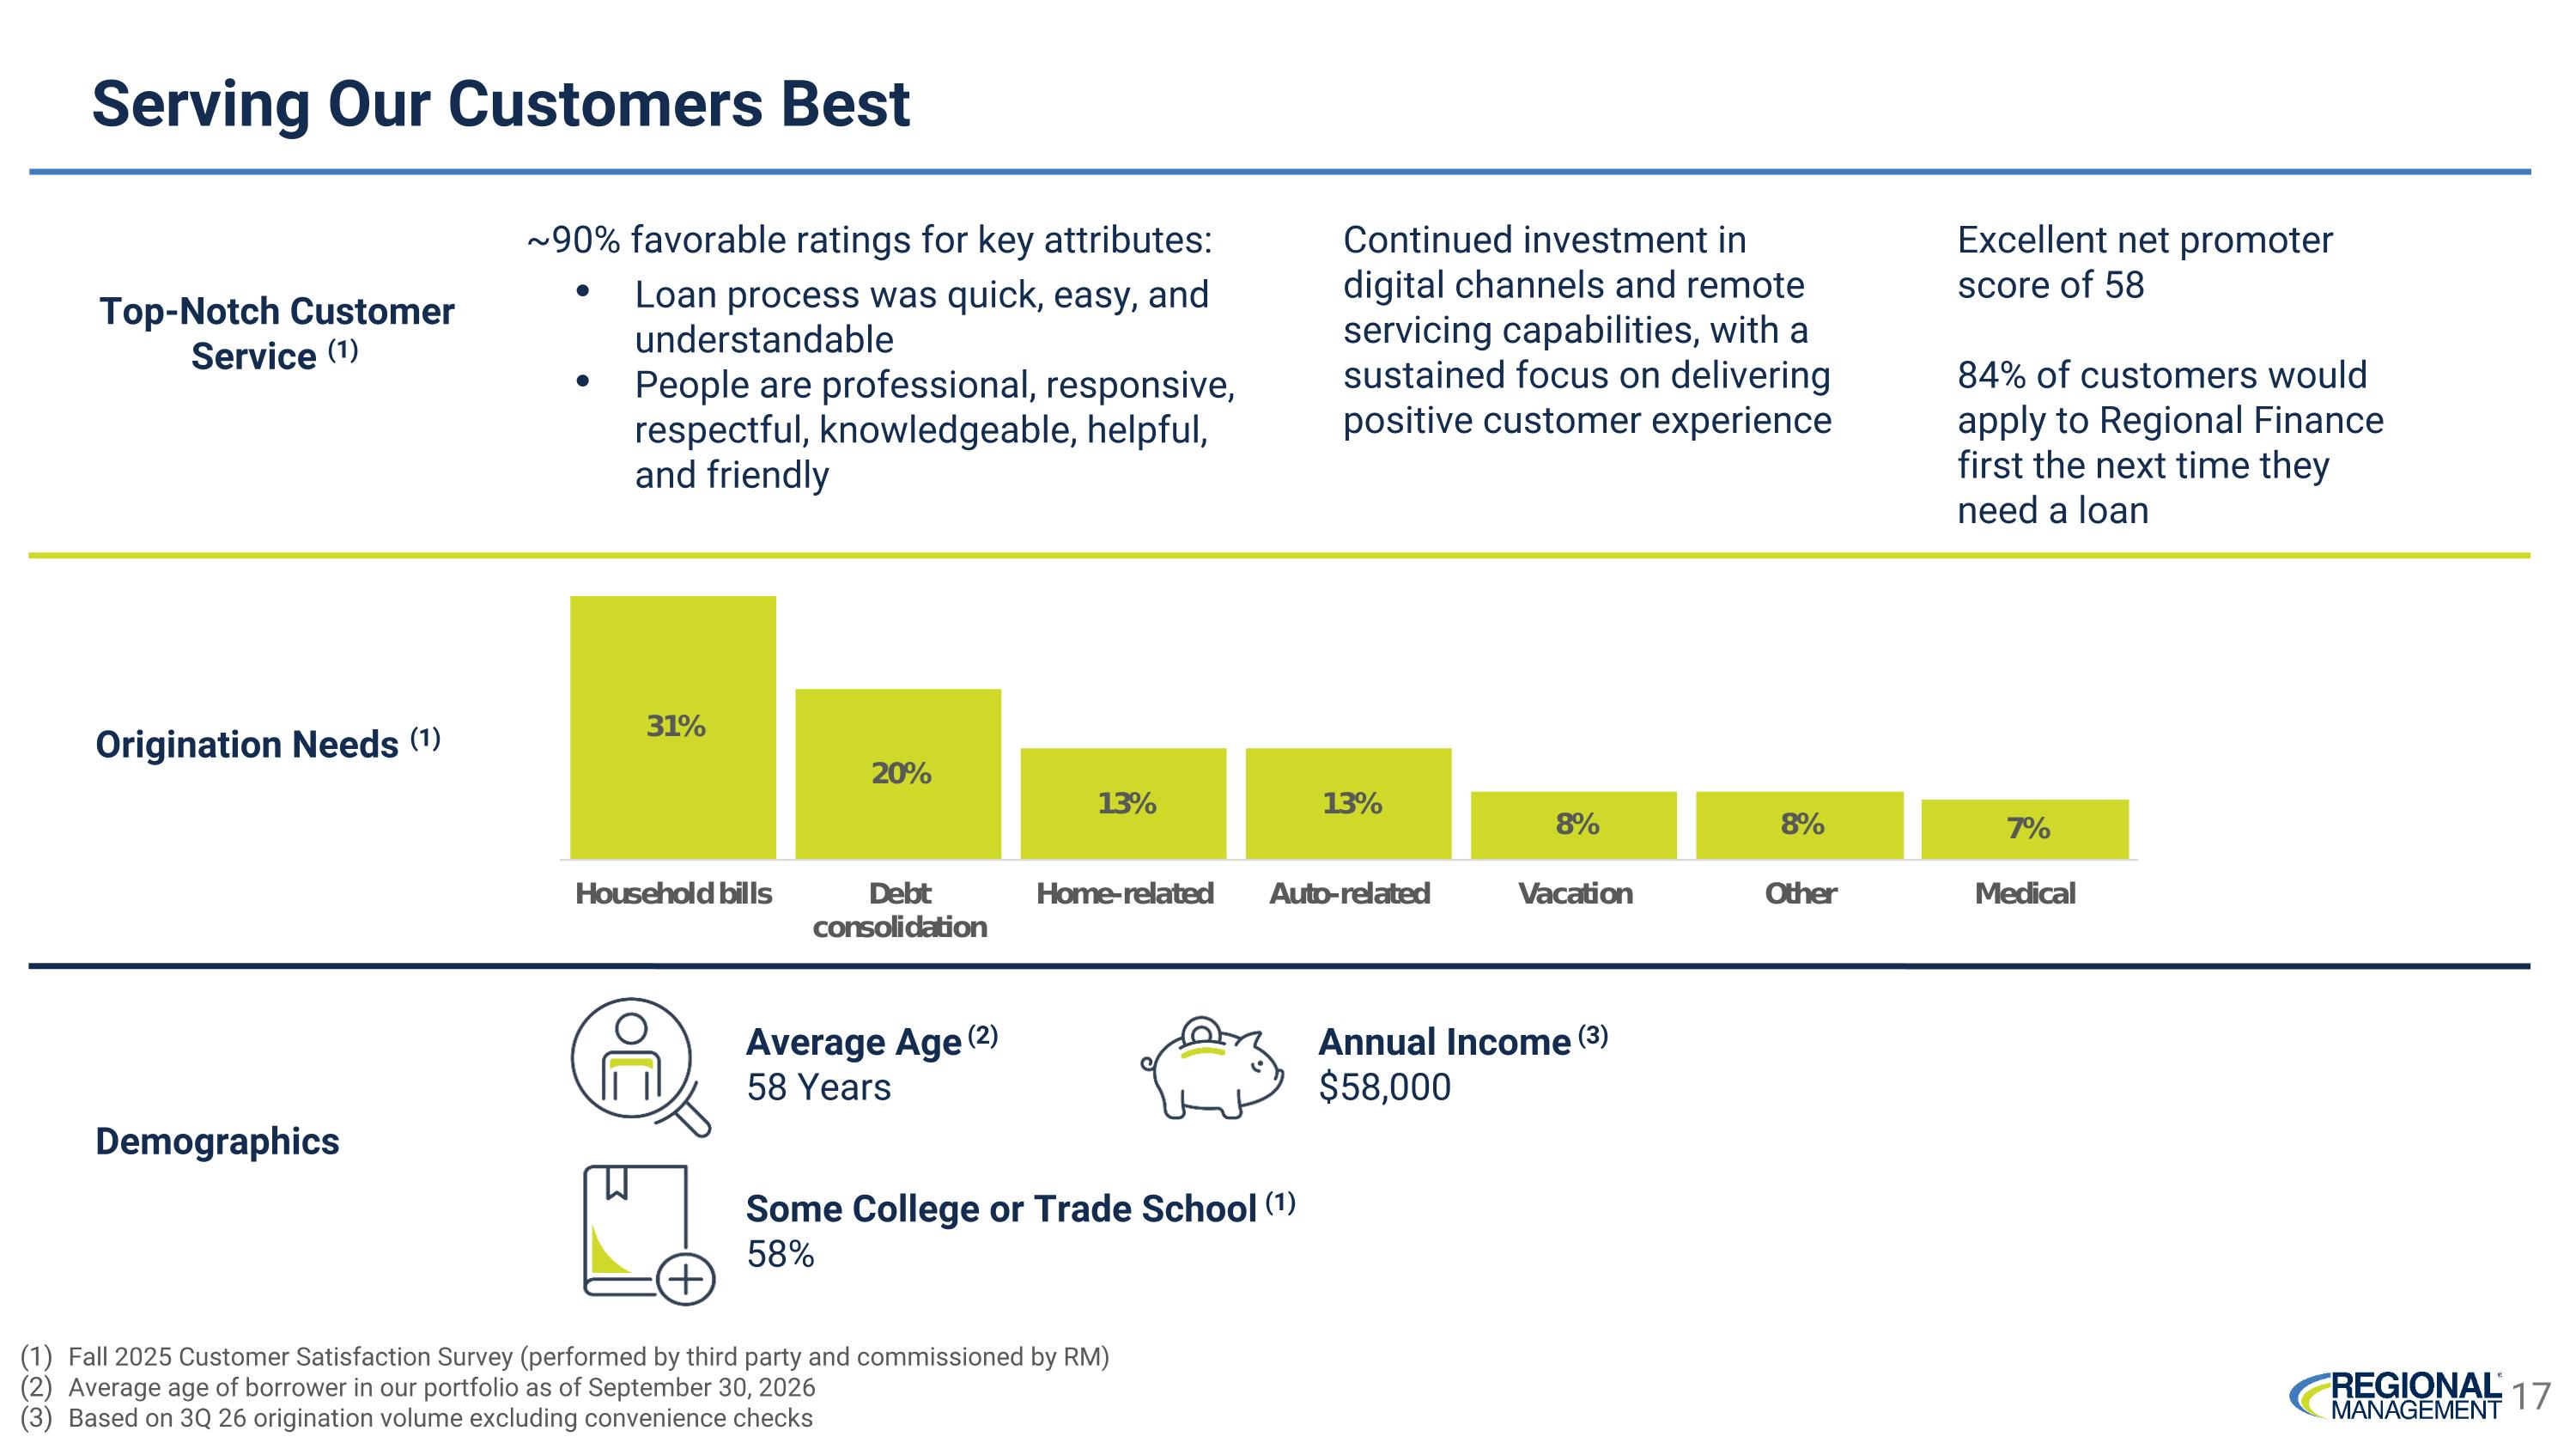
Serving Our Customers Best Excellent net promoter score of 58 84% of customers would apply to Regional Finance first the next time they need a loan ~90% favorable ratings for key attributes: Loan process was quick, easy, and understandable People are professional, responsive, respectful, knowledgeable, helpful, and friendly Continued investment in digital channels and remote servicing capabilities, with a sustained focus on delivering positive customer experience Origination Needs (1) Demographics Top-Notch Customer Service (1) Average Age (2) 58 Years Annual Income (3) $58,000 Some College or Trade School (1) 58% Fall 2025 Customer Satisfaction Survey (performed by third party and commissioned by RM) Average age of borrower in our portfolio as of September 30, 2026 Based on 3Q 26 origination volume excluding convenience checks 17
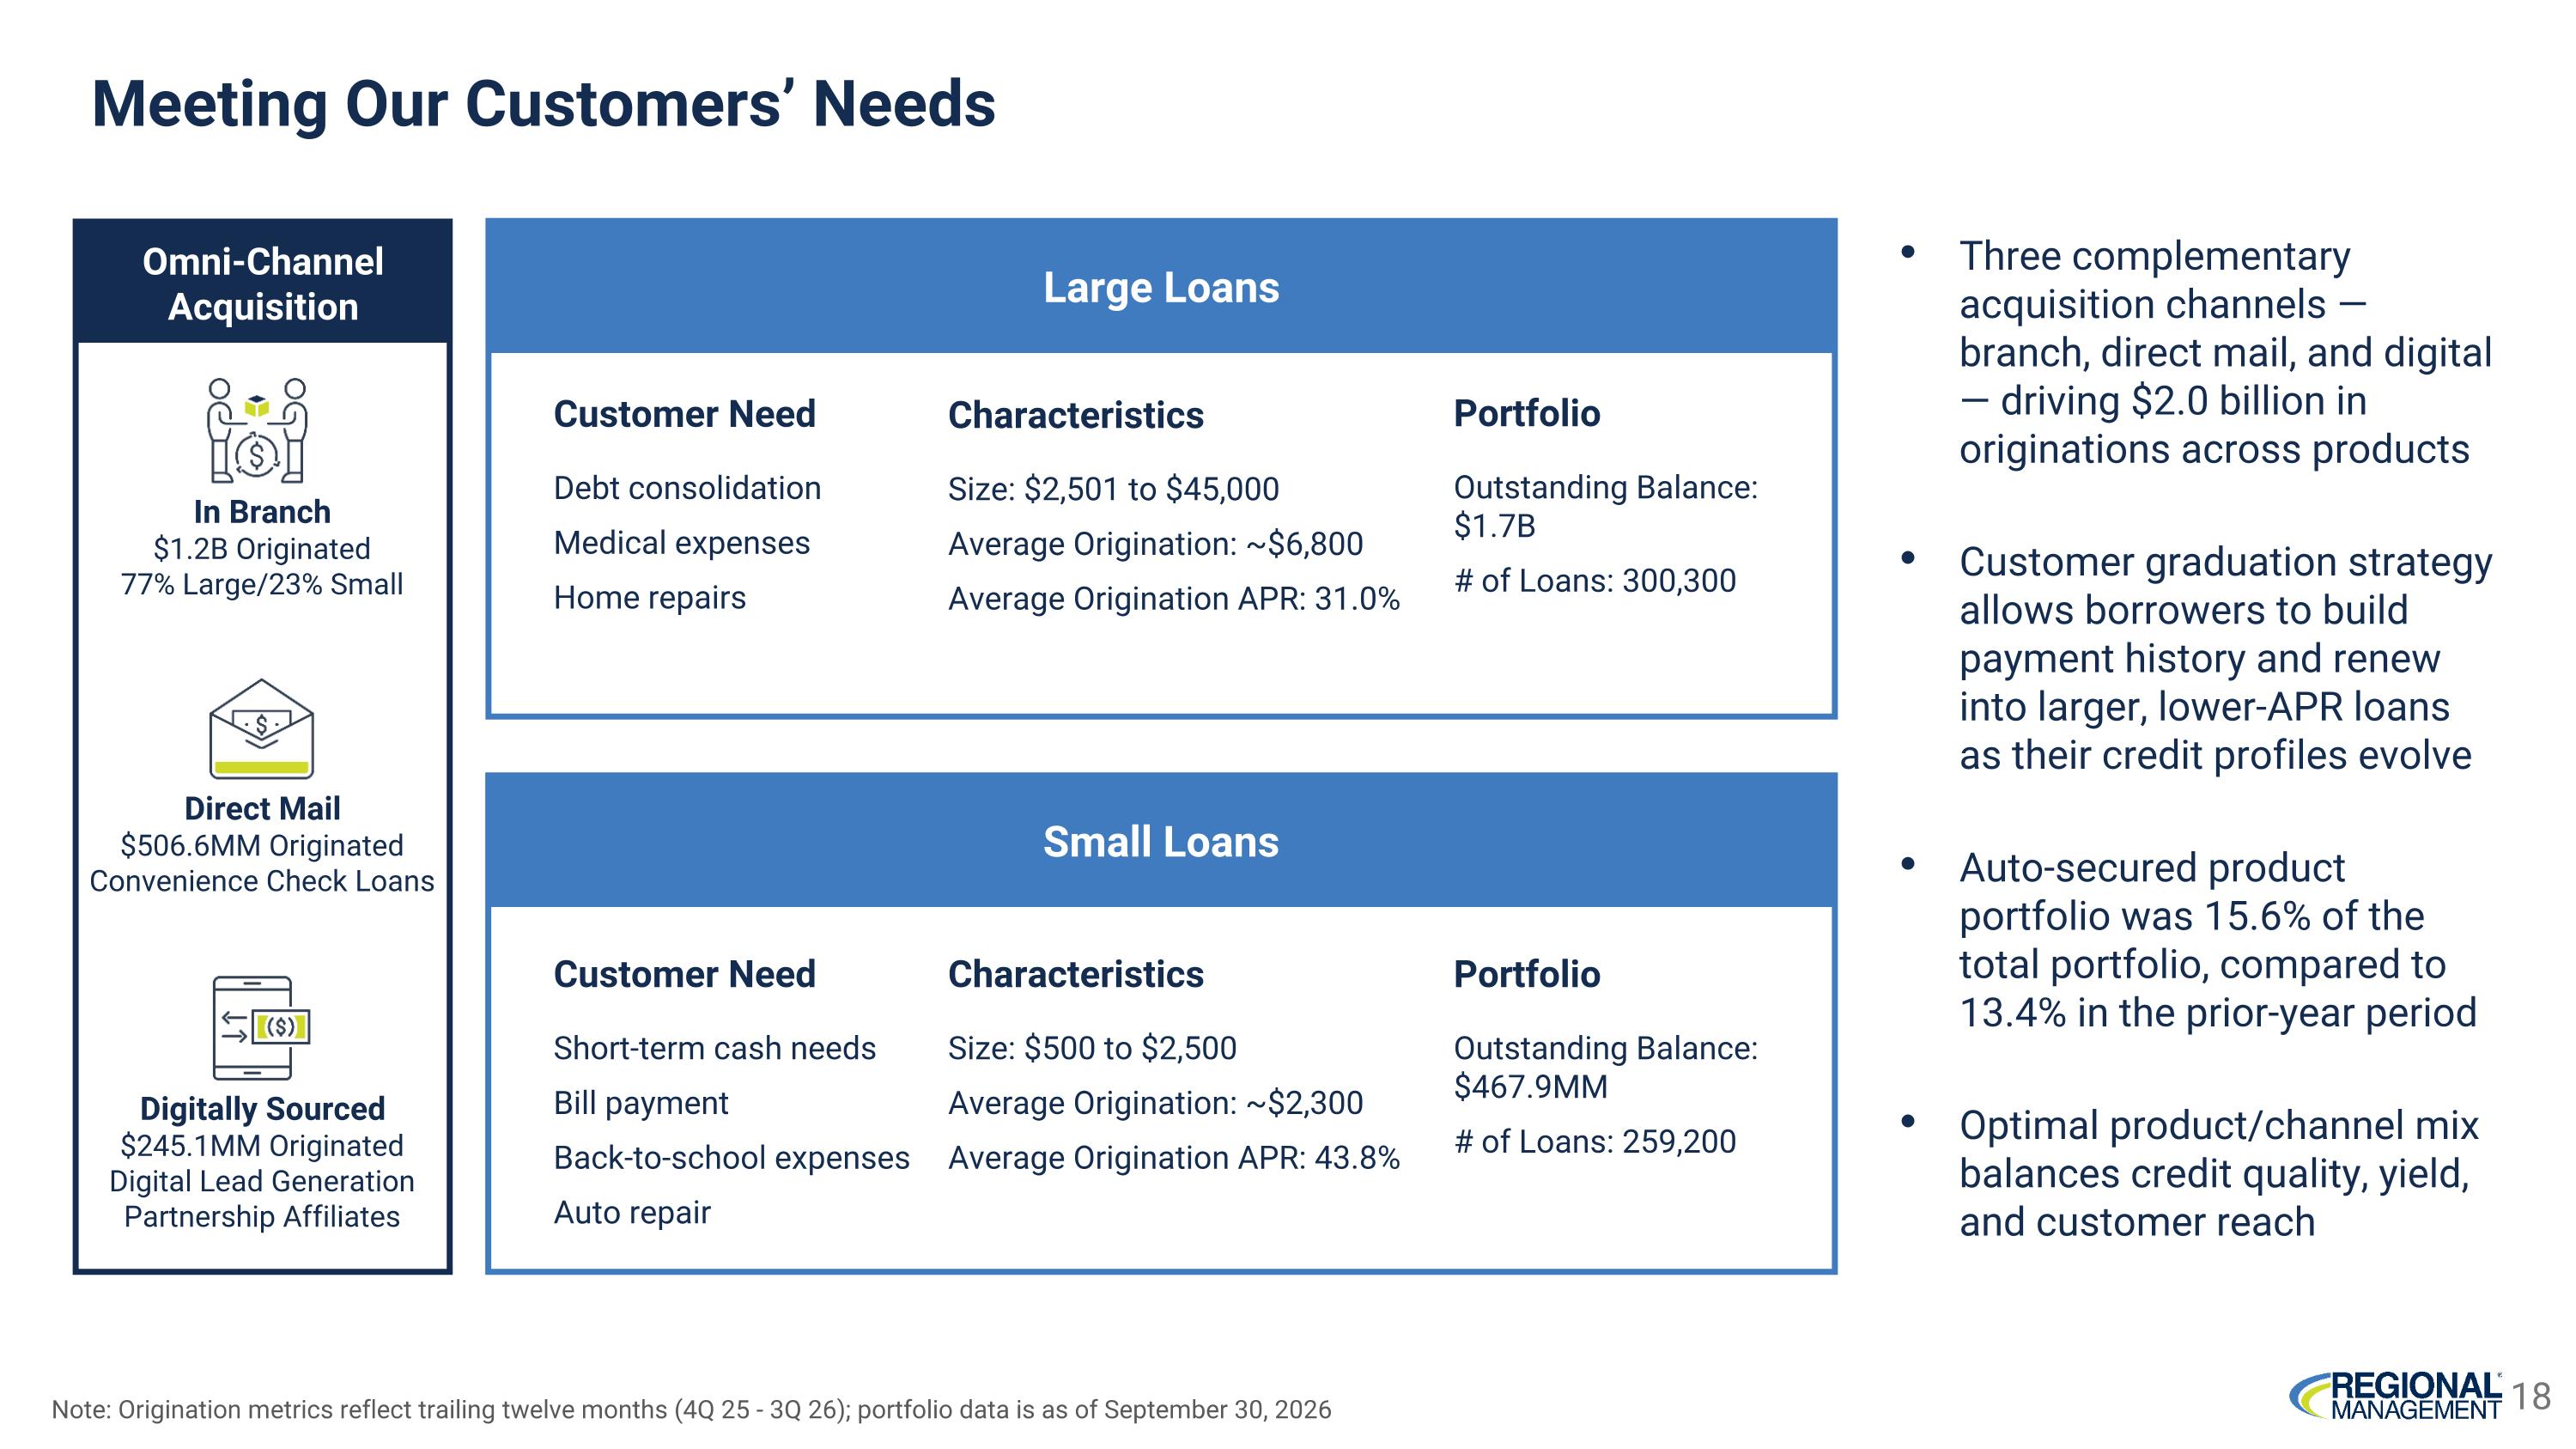
Meeting Our Customers’ Needs Omni-Channel Acquisition Small Loans In Branch $1.2B Originated 77% Large/23% Small Direct Mail $506.6MM Originated Convenience Check Loans Digitally Sourced $245.1MM Originated Digital Lead Generation Partnership Affiliates Customer Need Short-term cash needs Bill payment Back-to-school expenses Auto repair Characteristics Size: $500 to $2,500 Average Origination: ~$2,300 Average Origination APR: 43.8% Portfolio Outstanding Balance: $467.9MM # of Loans: 259,200 Note: Origination metrics reflect trailing twelve months (4Q 25 - 3Q 26); portfolio data is as of September 30, 2026 Three complementary acquisition channels — branch, direct mail, and digital — driving $2.0 billion in originations across products Customer graduation strategy allows borrowers to build payment history and renew into larger, lower-APR loans as their credit profiles evolve Auto-secured product portfolio was 15.6% of the total portfolio, compared to 13.4% in the prior-year period Optimal product/channel mix balances credit quality, yield, and customer reach Large Loans Customer Need Debt consolidation Medical expenses Home repairs Characteristics Size: $2,501 to $45,000 Average Origination: ~$6,800 Average Origination APR: 31.0% Portfolio Outstanding Balance: $1.7B # of Loans: 300,300 18
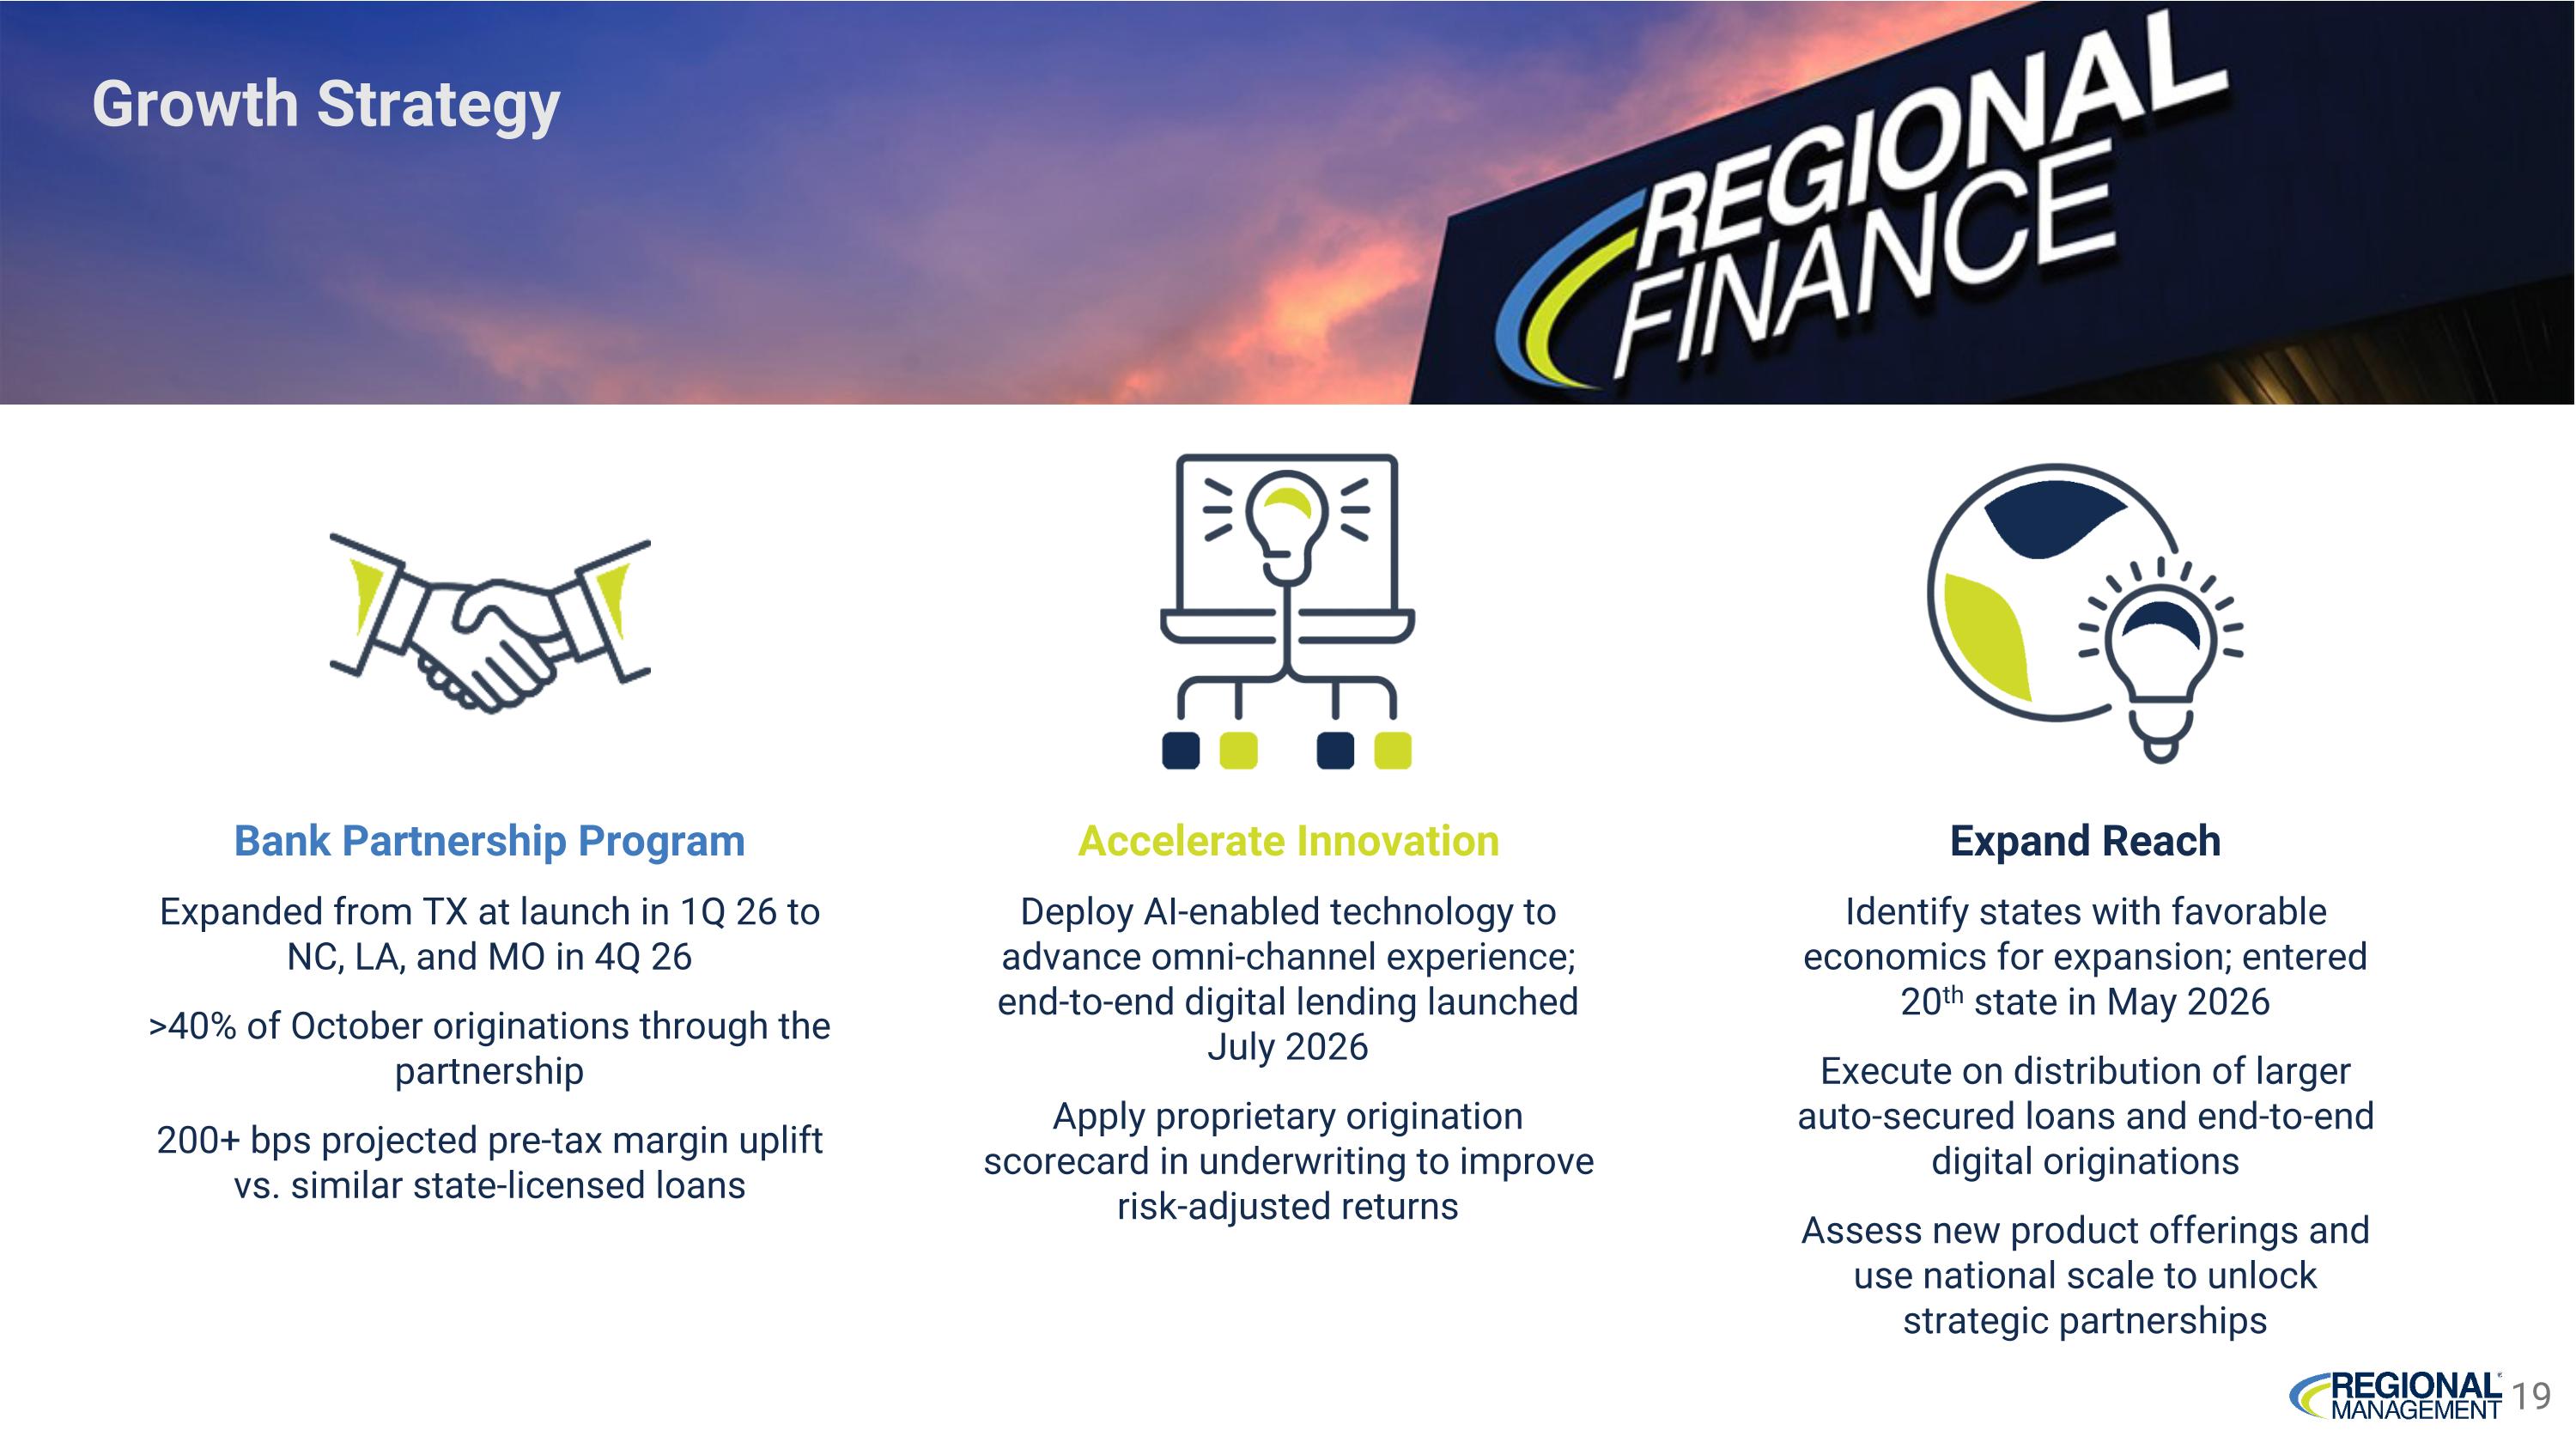
Accelerate Innovation Deploy AI-enabled technology to advance omni-channel experience; end-to-end digital lending launched July 2026 Apply proprietary origination scorecard in underwriting to improve risk-adjusted returns Growth Strategy Bank Partnership Program Expanded from TX at launch in 1Q 26 to NC, LA, and MO in 4Q 26 >40% of October originations through the partnership 200+ bps projected pre-tax margin uplift vs. similar state-licensed loans Expand Reach Identify states with favorable economics for expansion; entered 20th state in May 2026 Execute on distribution of larger auto-secured loans and end-to-end digital originations Assess new product offerings and use national scale to unlock strategic partnerships 19
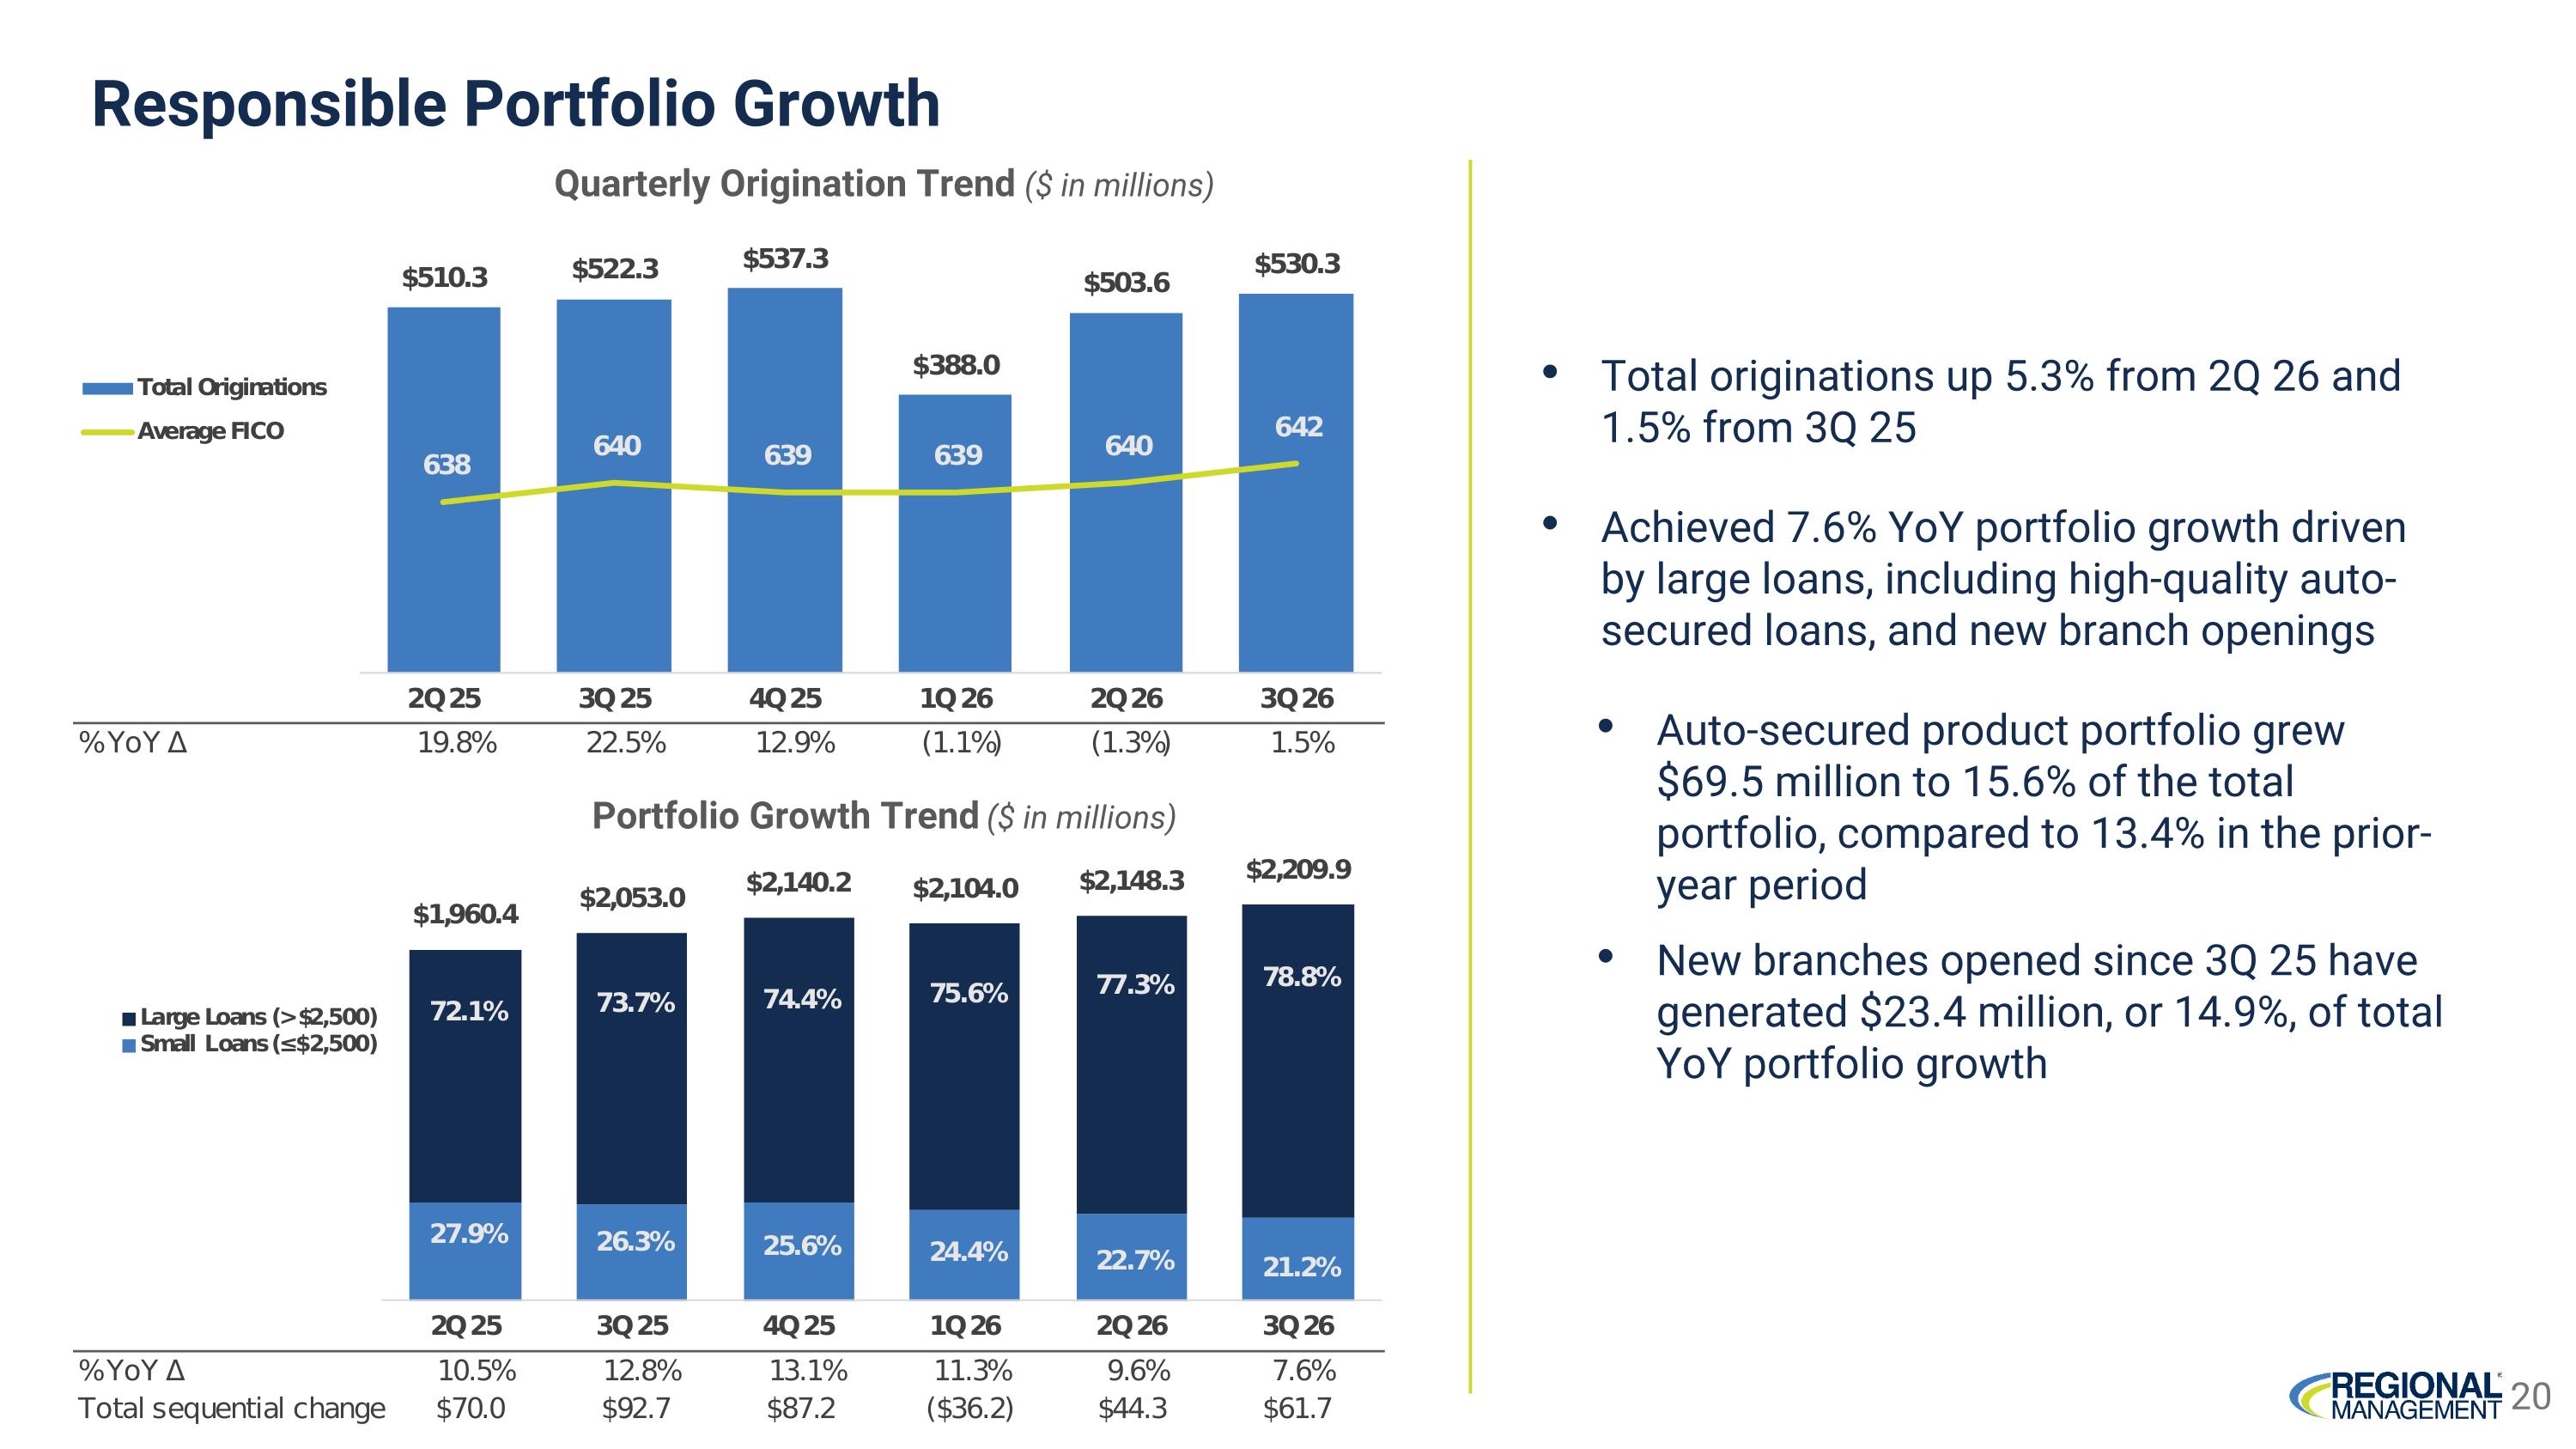
Responsible Portfolio Growth Portfolio Growth Trend ($ in millions) Total originations up 5.3% from 2Q 26 and 1.5% from 3Q 25 Achieved 7.6% YoY portfolio growth driven by large loans, including high-quality auto-secured loans, and new branch openings Auto-secured product portfolio grew $69.5 million to 15.6% of the total portfolio, compared to 13.4% in the prior-year period New branches opened since 3Q 25 have generated $23.4 million, or 14.9%, of total YoY portfolio growth Quarterly Origination Trend ($ in millions) 20
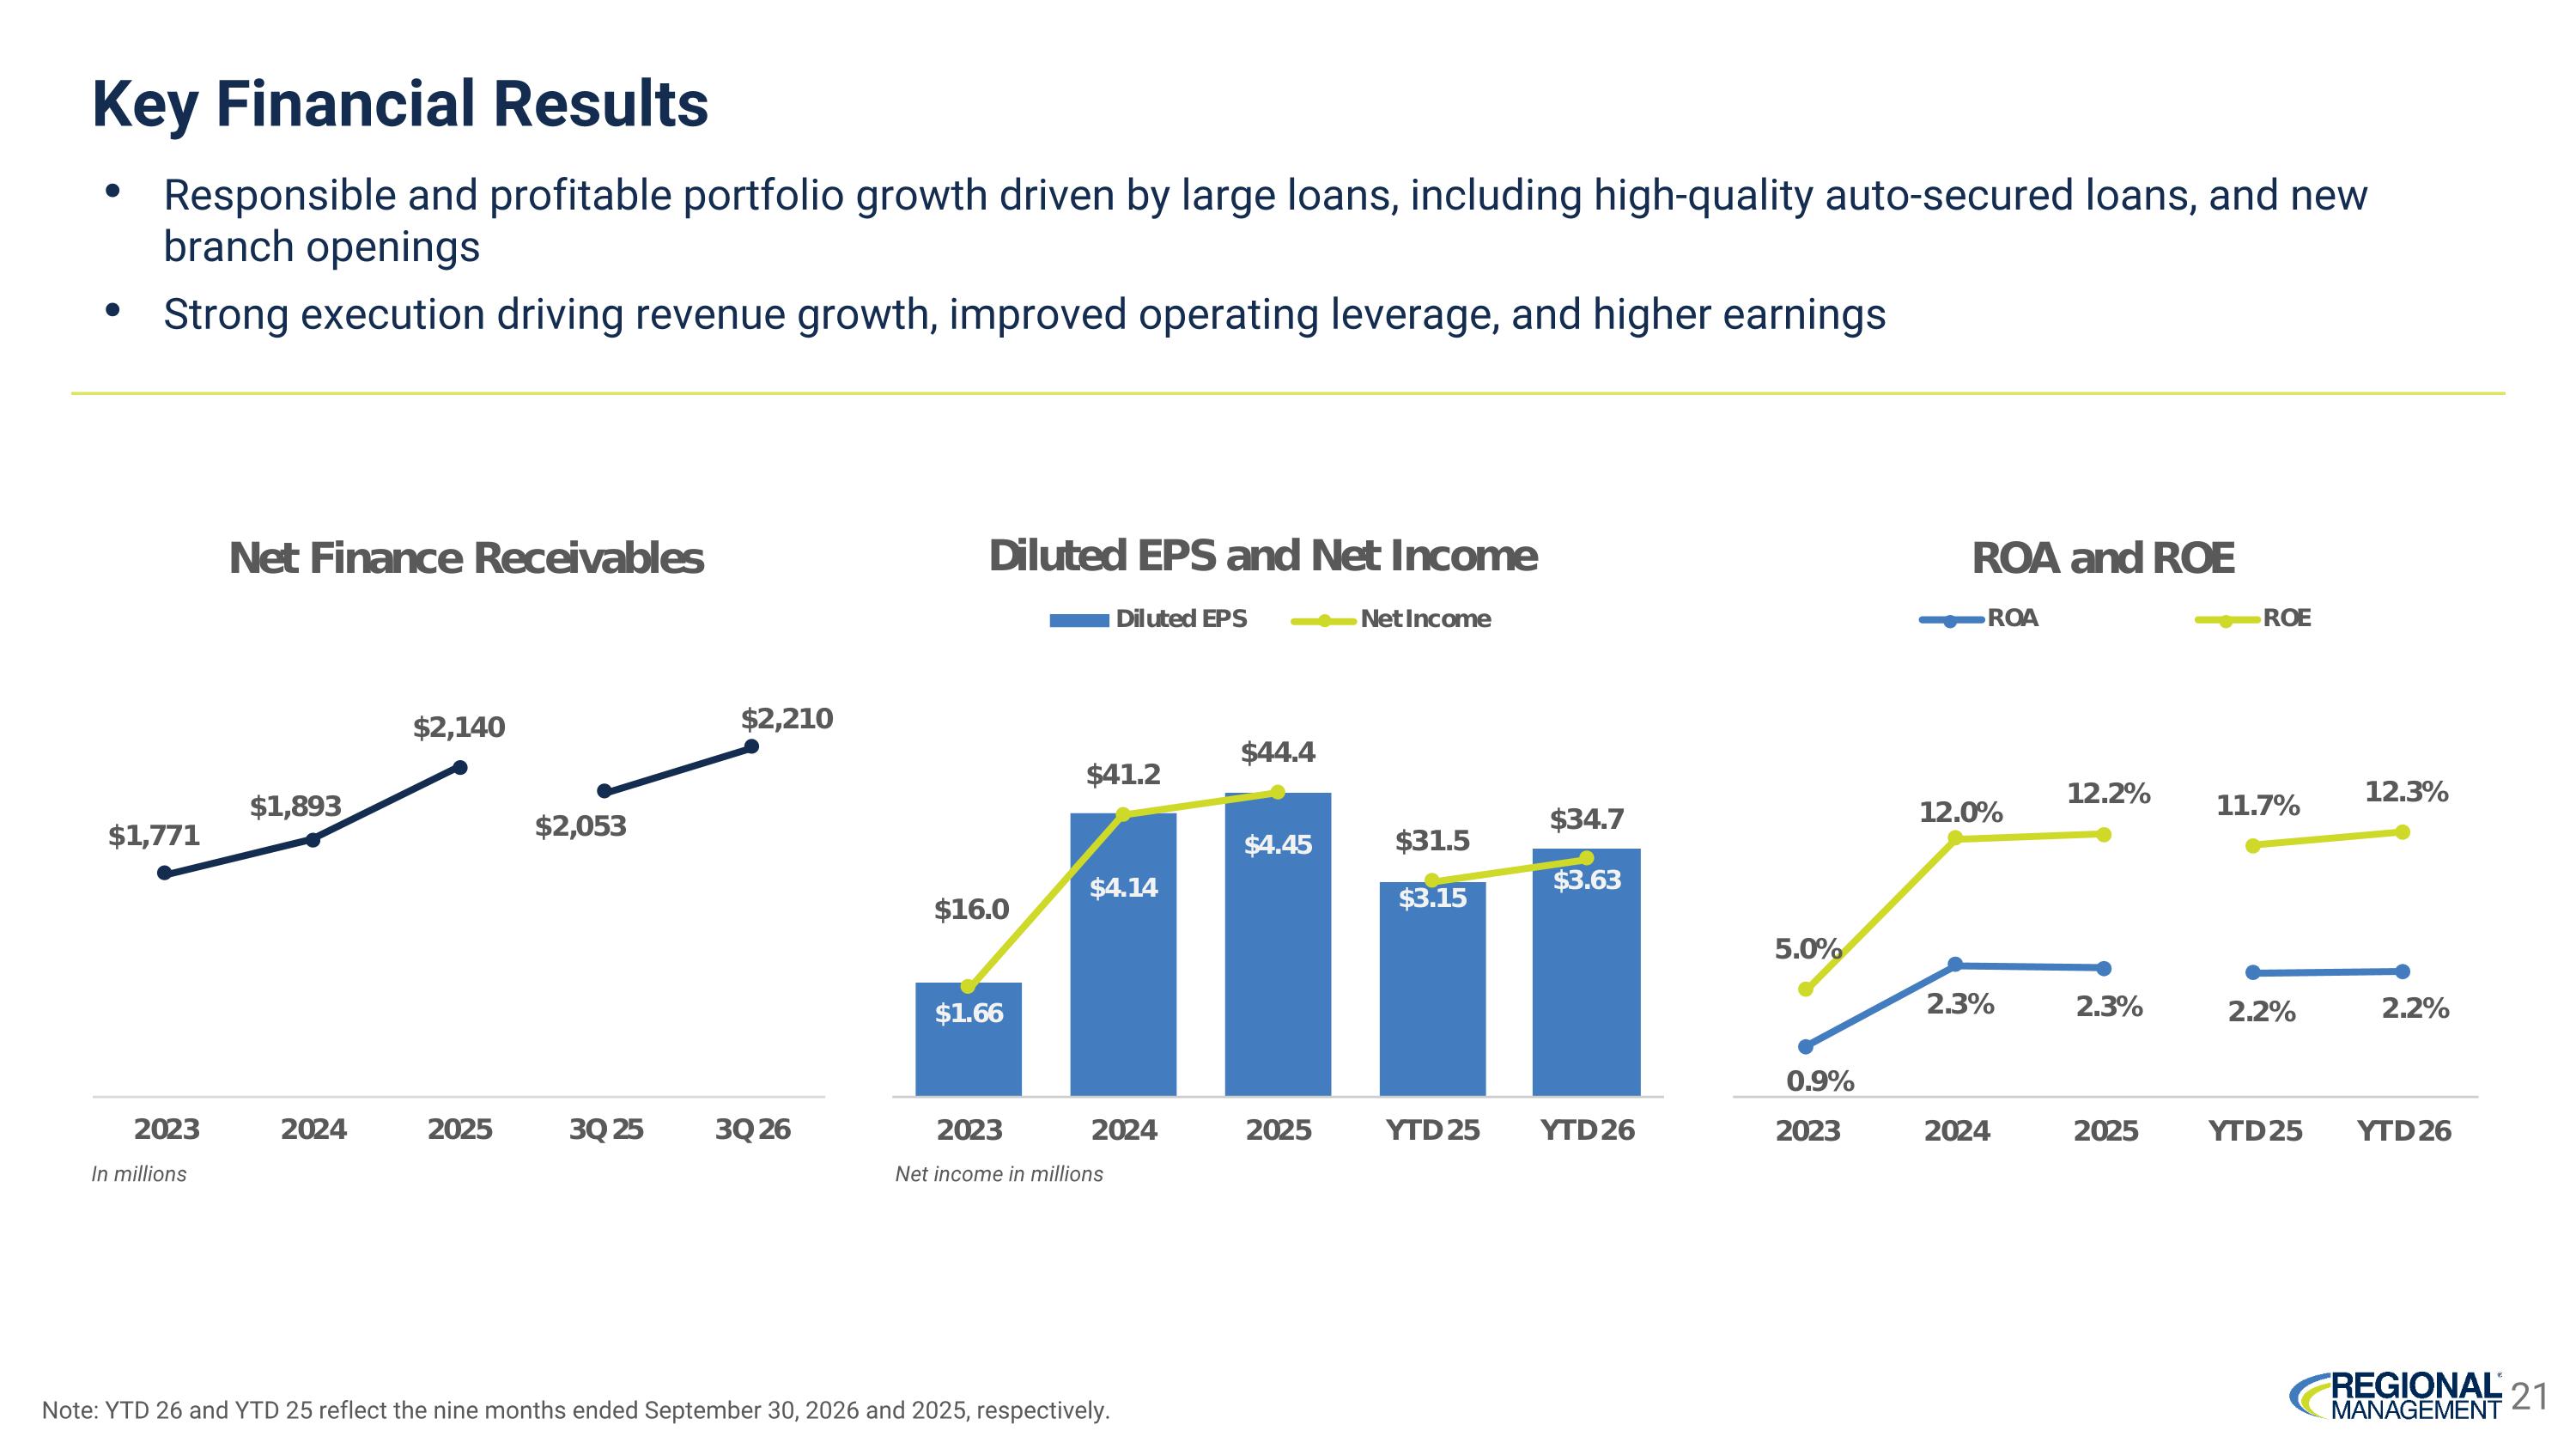
Key Financial Results Note: YTD 26 and YTD 25 reflect the nine months ended September 30, 2026 and 2025, respectively. Responsible and profitable portfolio growth driven by large loans, including high-quality auto-secured loans, and new branch openings Strong execution driving revenue growth, improved operating leverage, and higher earnings 21 Net income in millions In millions
Funding
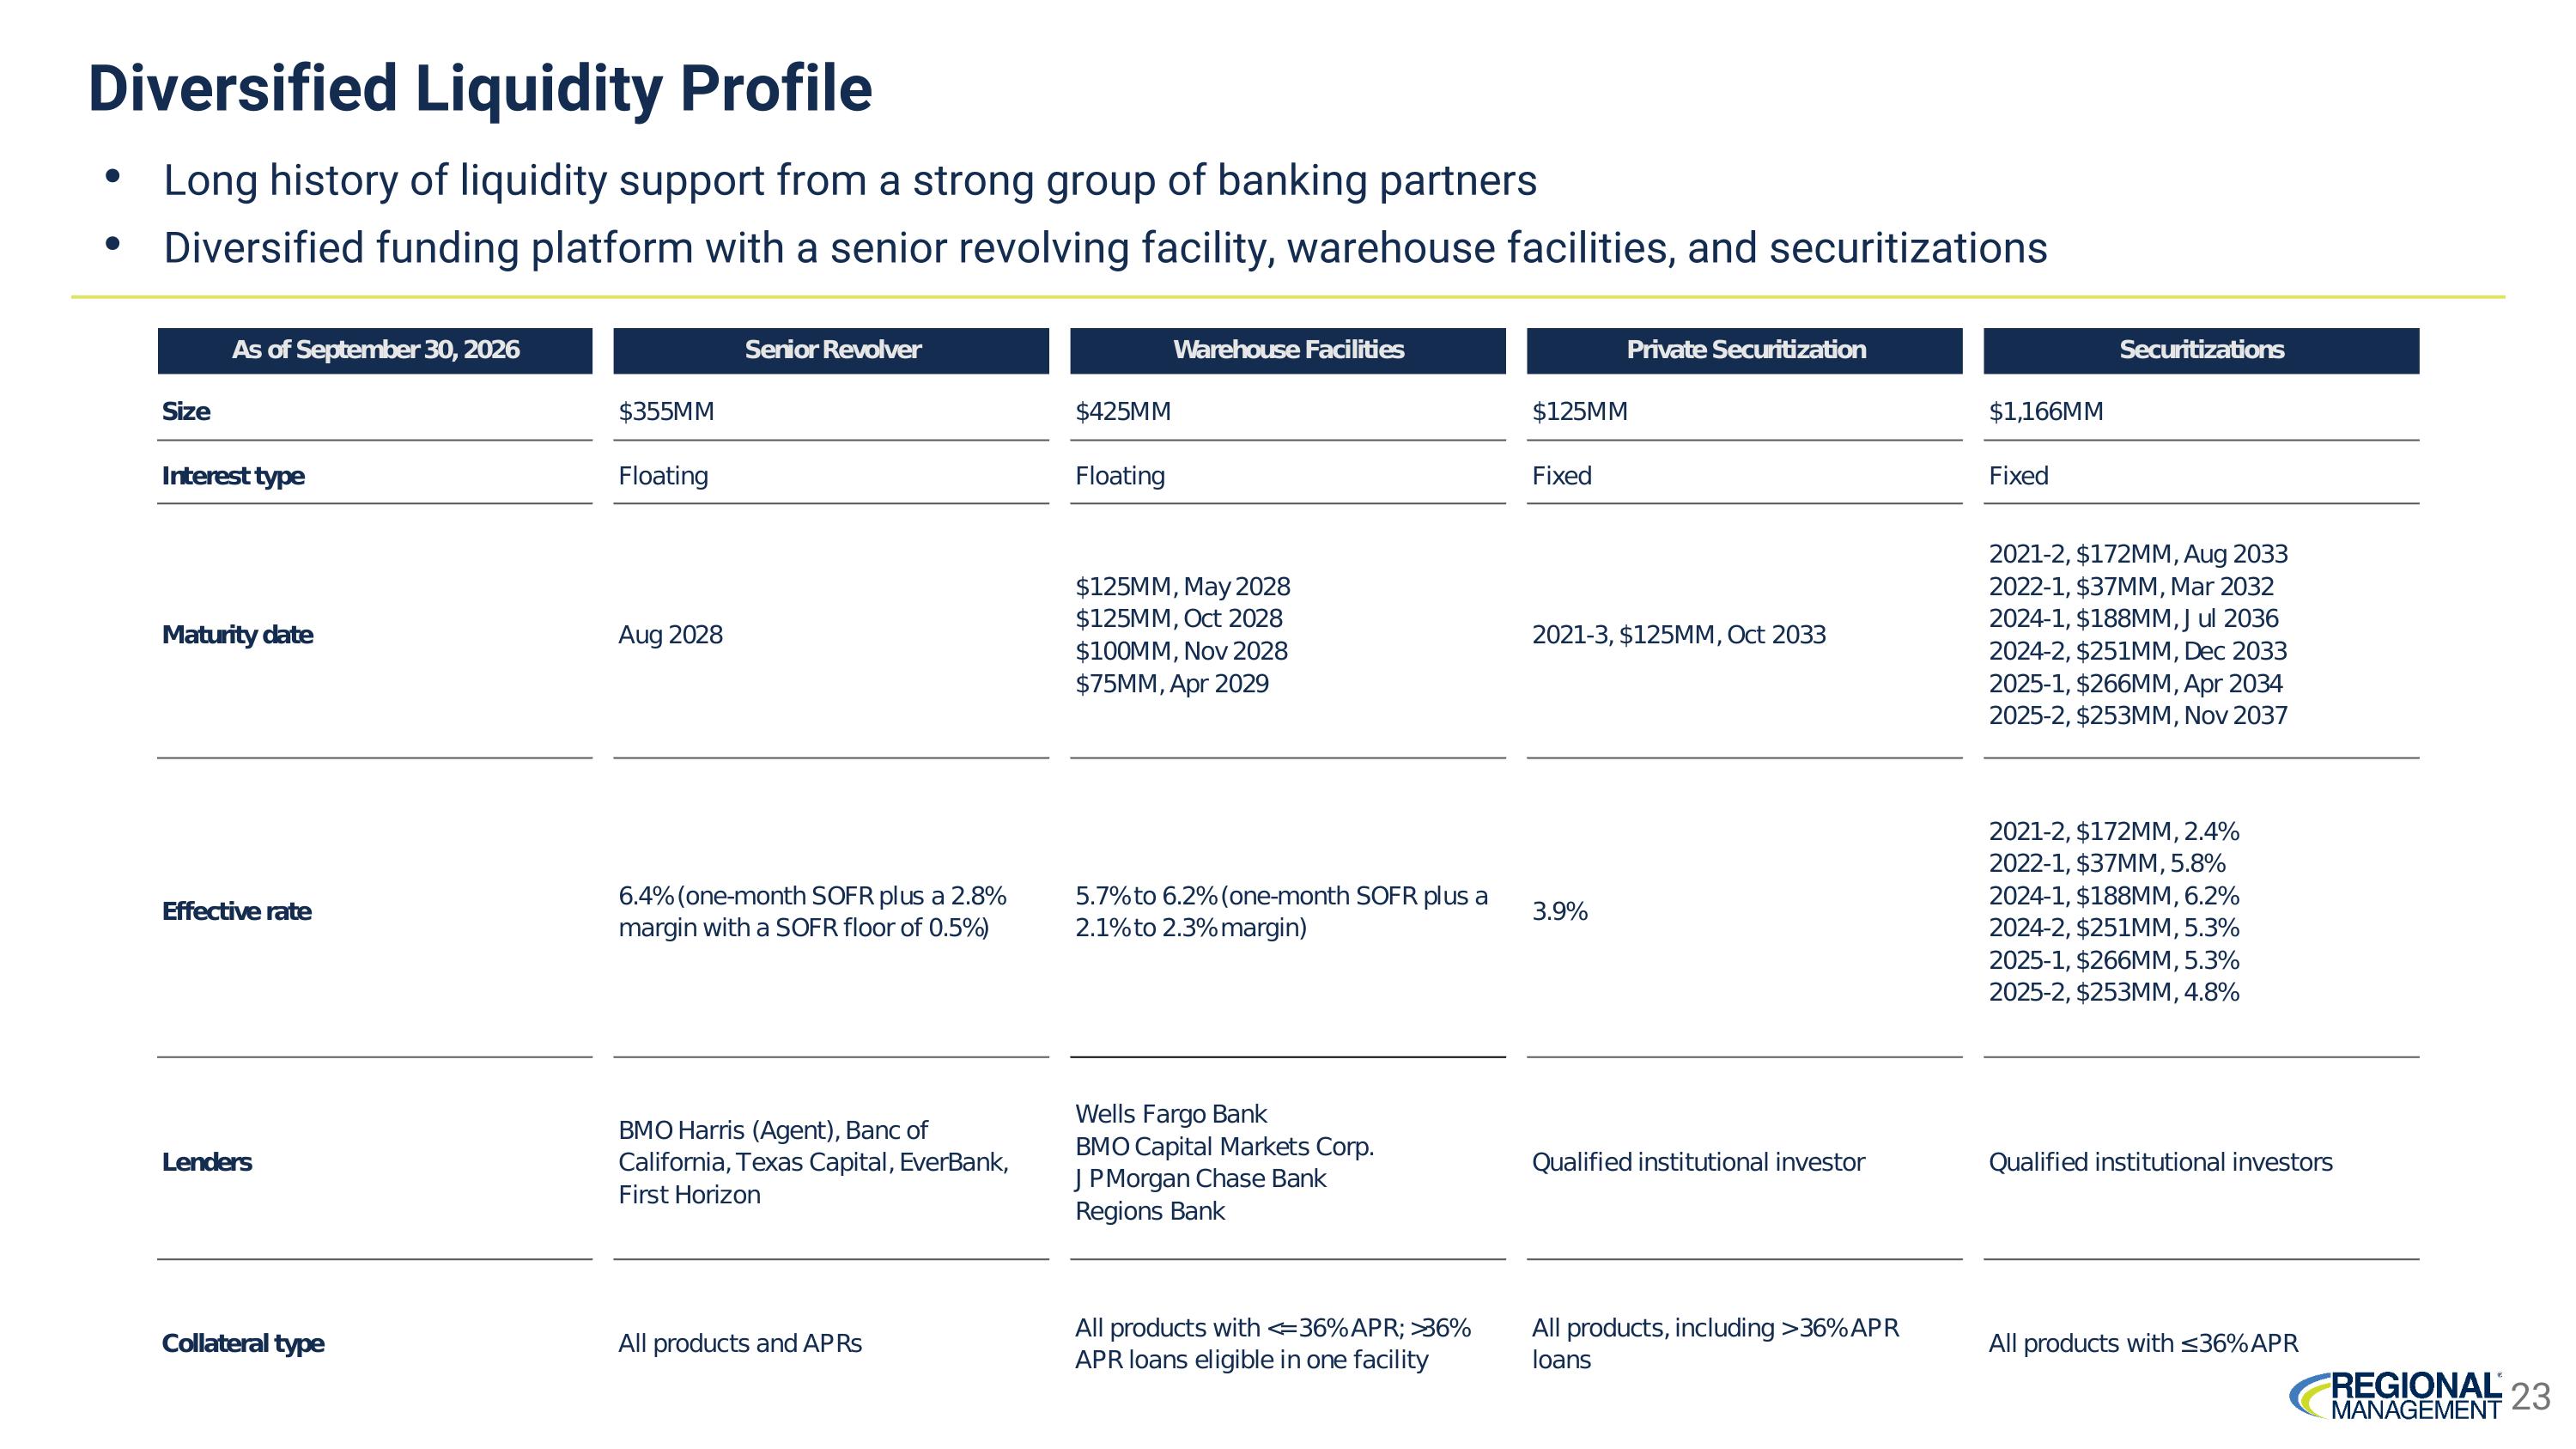
Diversified Liquidity Profile Long history of liquidity support from a strong group of banking partners Diversified funding platform with a senior revolving facility, warehouse facilities, and securitizations
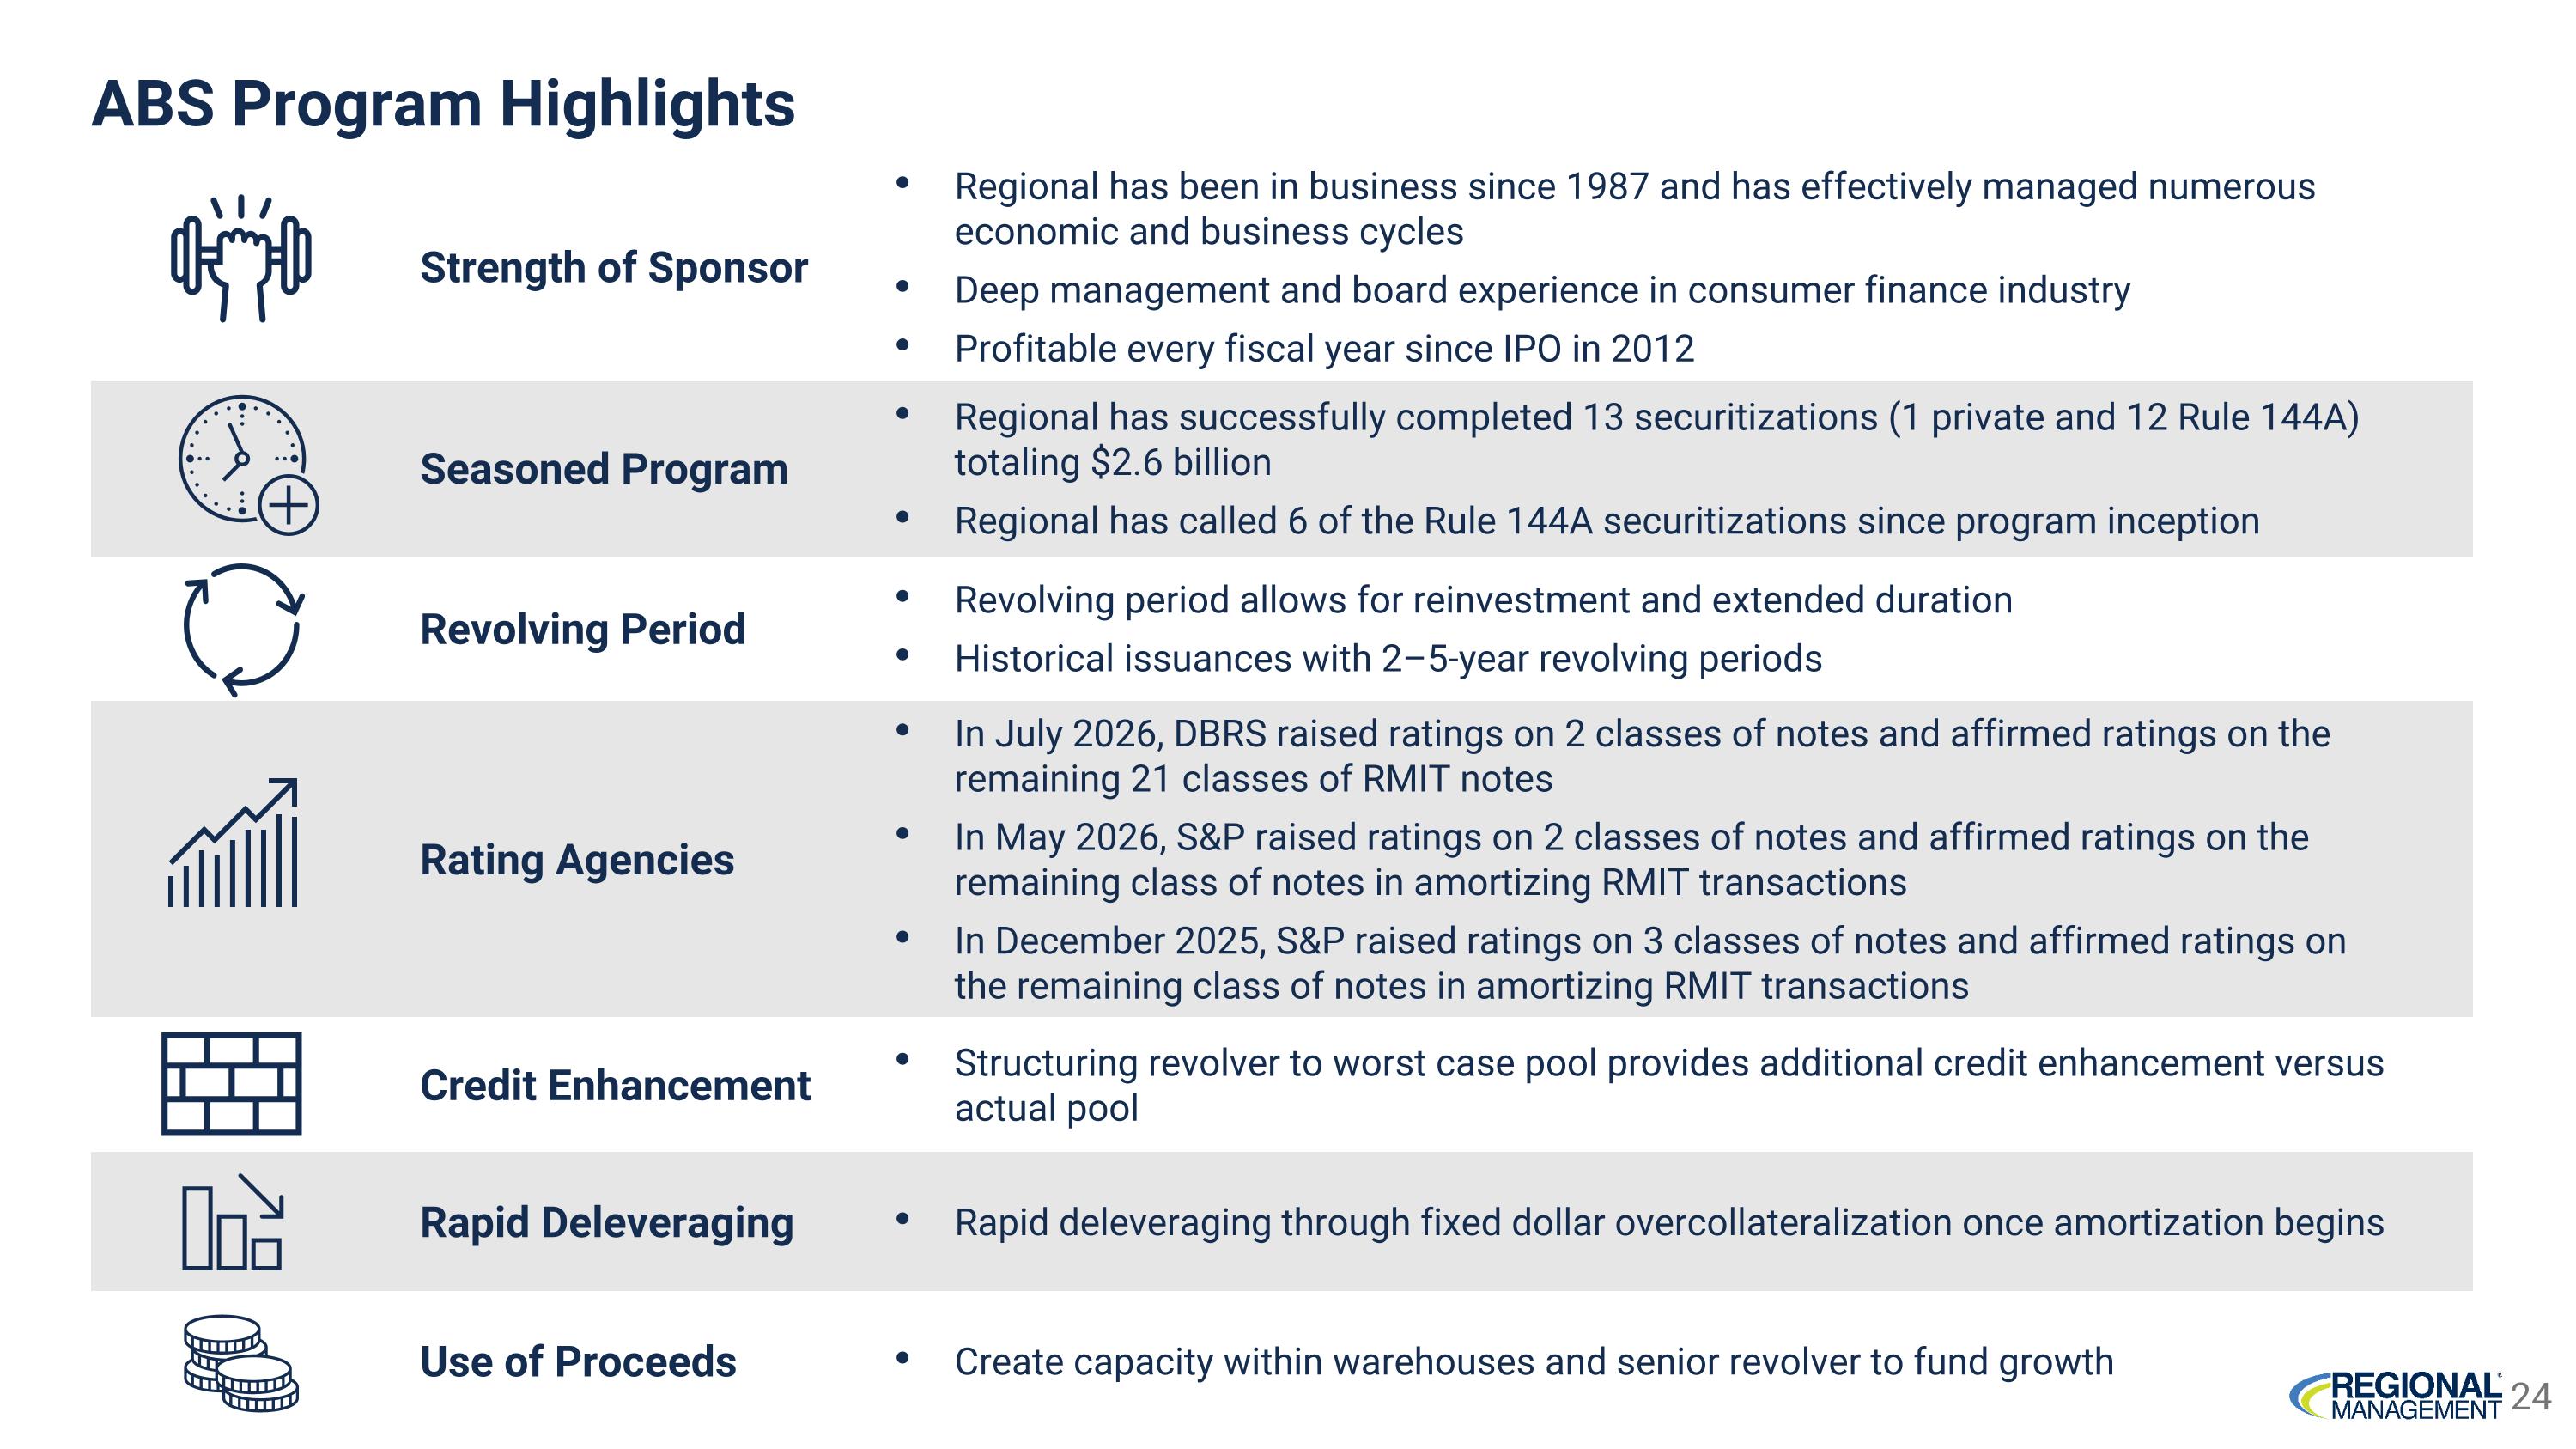
Strength of Sponsor Regional has been in business since 1987 and has effectively managed numerous economic and business cycles Deep management and board experience in consumer finance industry Profitable every fiscal year since IPO in 2012 Seasoned Program Regional has successfully completed 13 securitizations (1 private and 12 Rule 144A) totaling $2.6 billion Regional has called 6 of the Rule 144A securitizations since program inception Revolving Period Revolving period allows for reinvestment and extended duration Historical issuances with 2–5-year revolving periods Rating Agencies In July 2026, DBRS raised ratings on 2 classes of notes and affirmed ratings on the remaining 21 classes of RMIT notes In May 2026, S&P raised ratings on 2 classes of notes and affirmed ratings on the remaining class of notes in amortizing RMIT transactions In December 2025, S&P raised ratings on 3 classes of notes and affirmed ratings on the remaining class of notes in amortizing RMIT transactions Credit Enhancement Structuring revolver to worst case pool provides additional credit enhancement versus actual pool Rapid Deleveraging Rapid deleveraging through fixed dollar overcollateralization once amortization begins Use of Proceeds Create capacity within warehouses and senior revolver to fund growth ABS Program Highlights
Governance & Controls
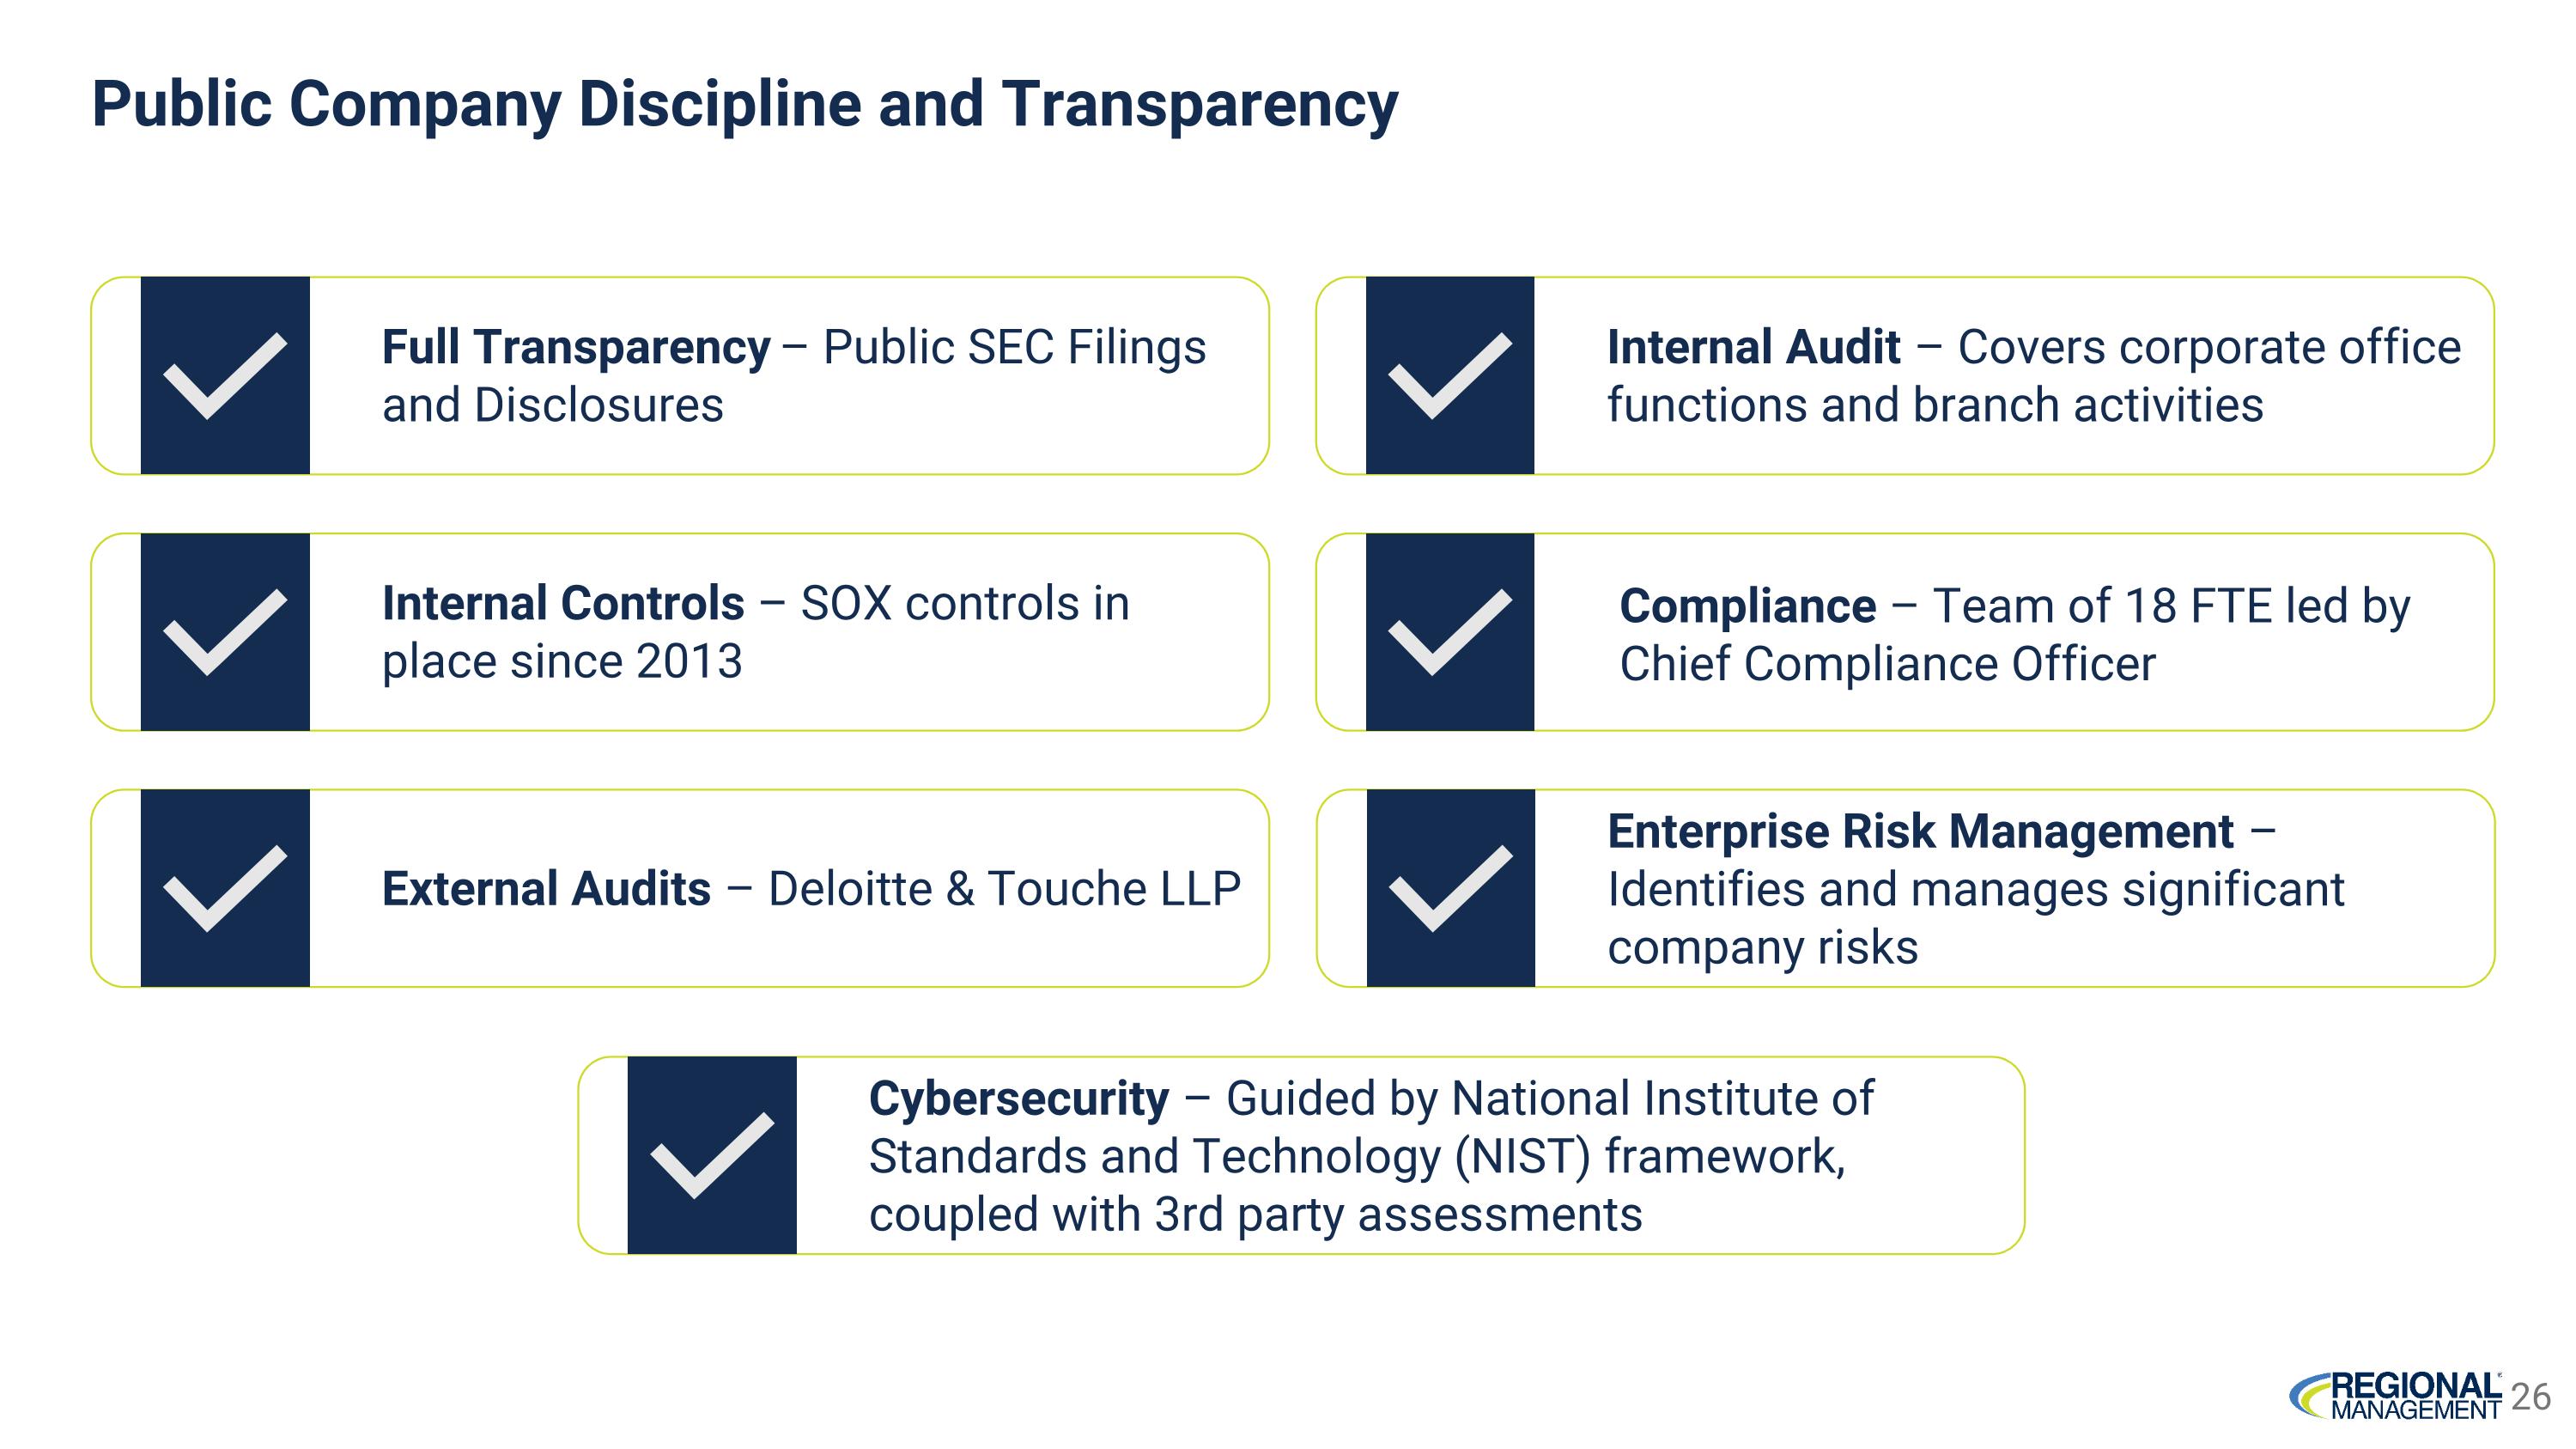
Public Company Discipline and Transparency Full Transparency – Public SEC Filings and Disclosures Internal Controls – SOX controls in place since 2013 External Audits – Deloitte & Touche LLP Compliance – Team of 18 FTE led by Chief Compliance Officer Enterprise Risk Management – Identifies and manages significant company risks Internal Audit – Covers corporate office functions and branch activities Cybersecurity – Guided by National Institute of Standards and Technology (NIST) framework, coupled with 3rd party assessments
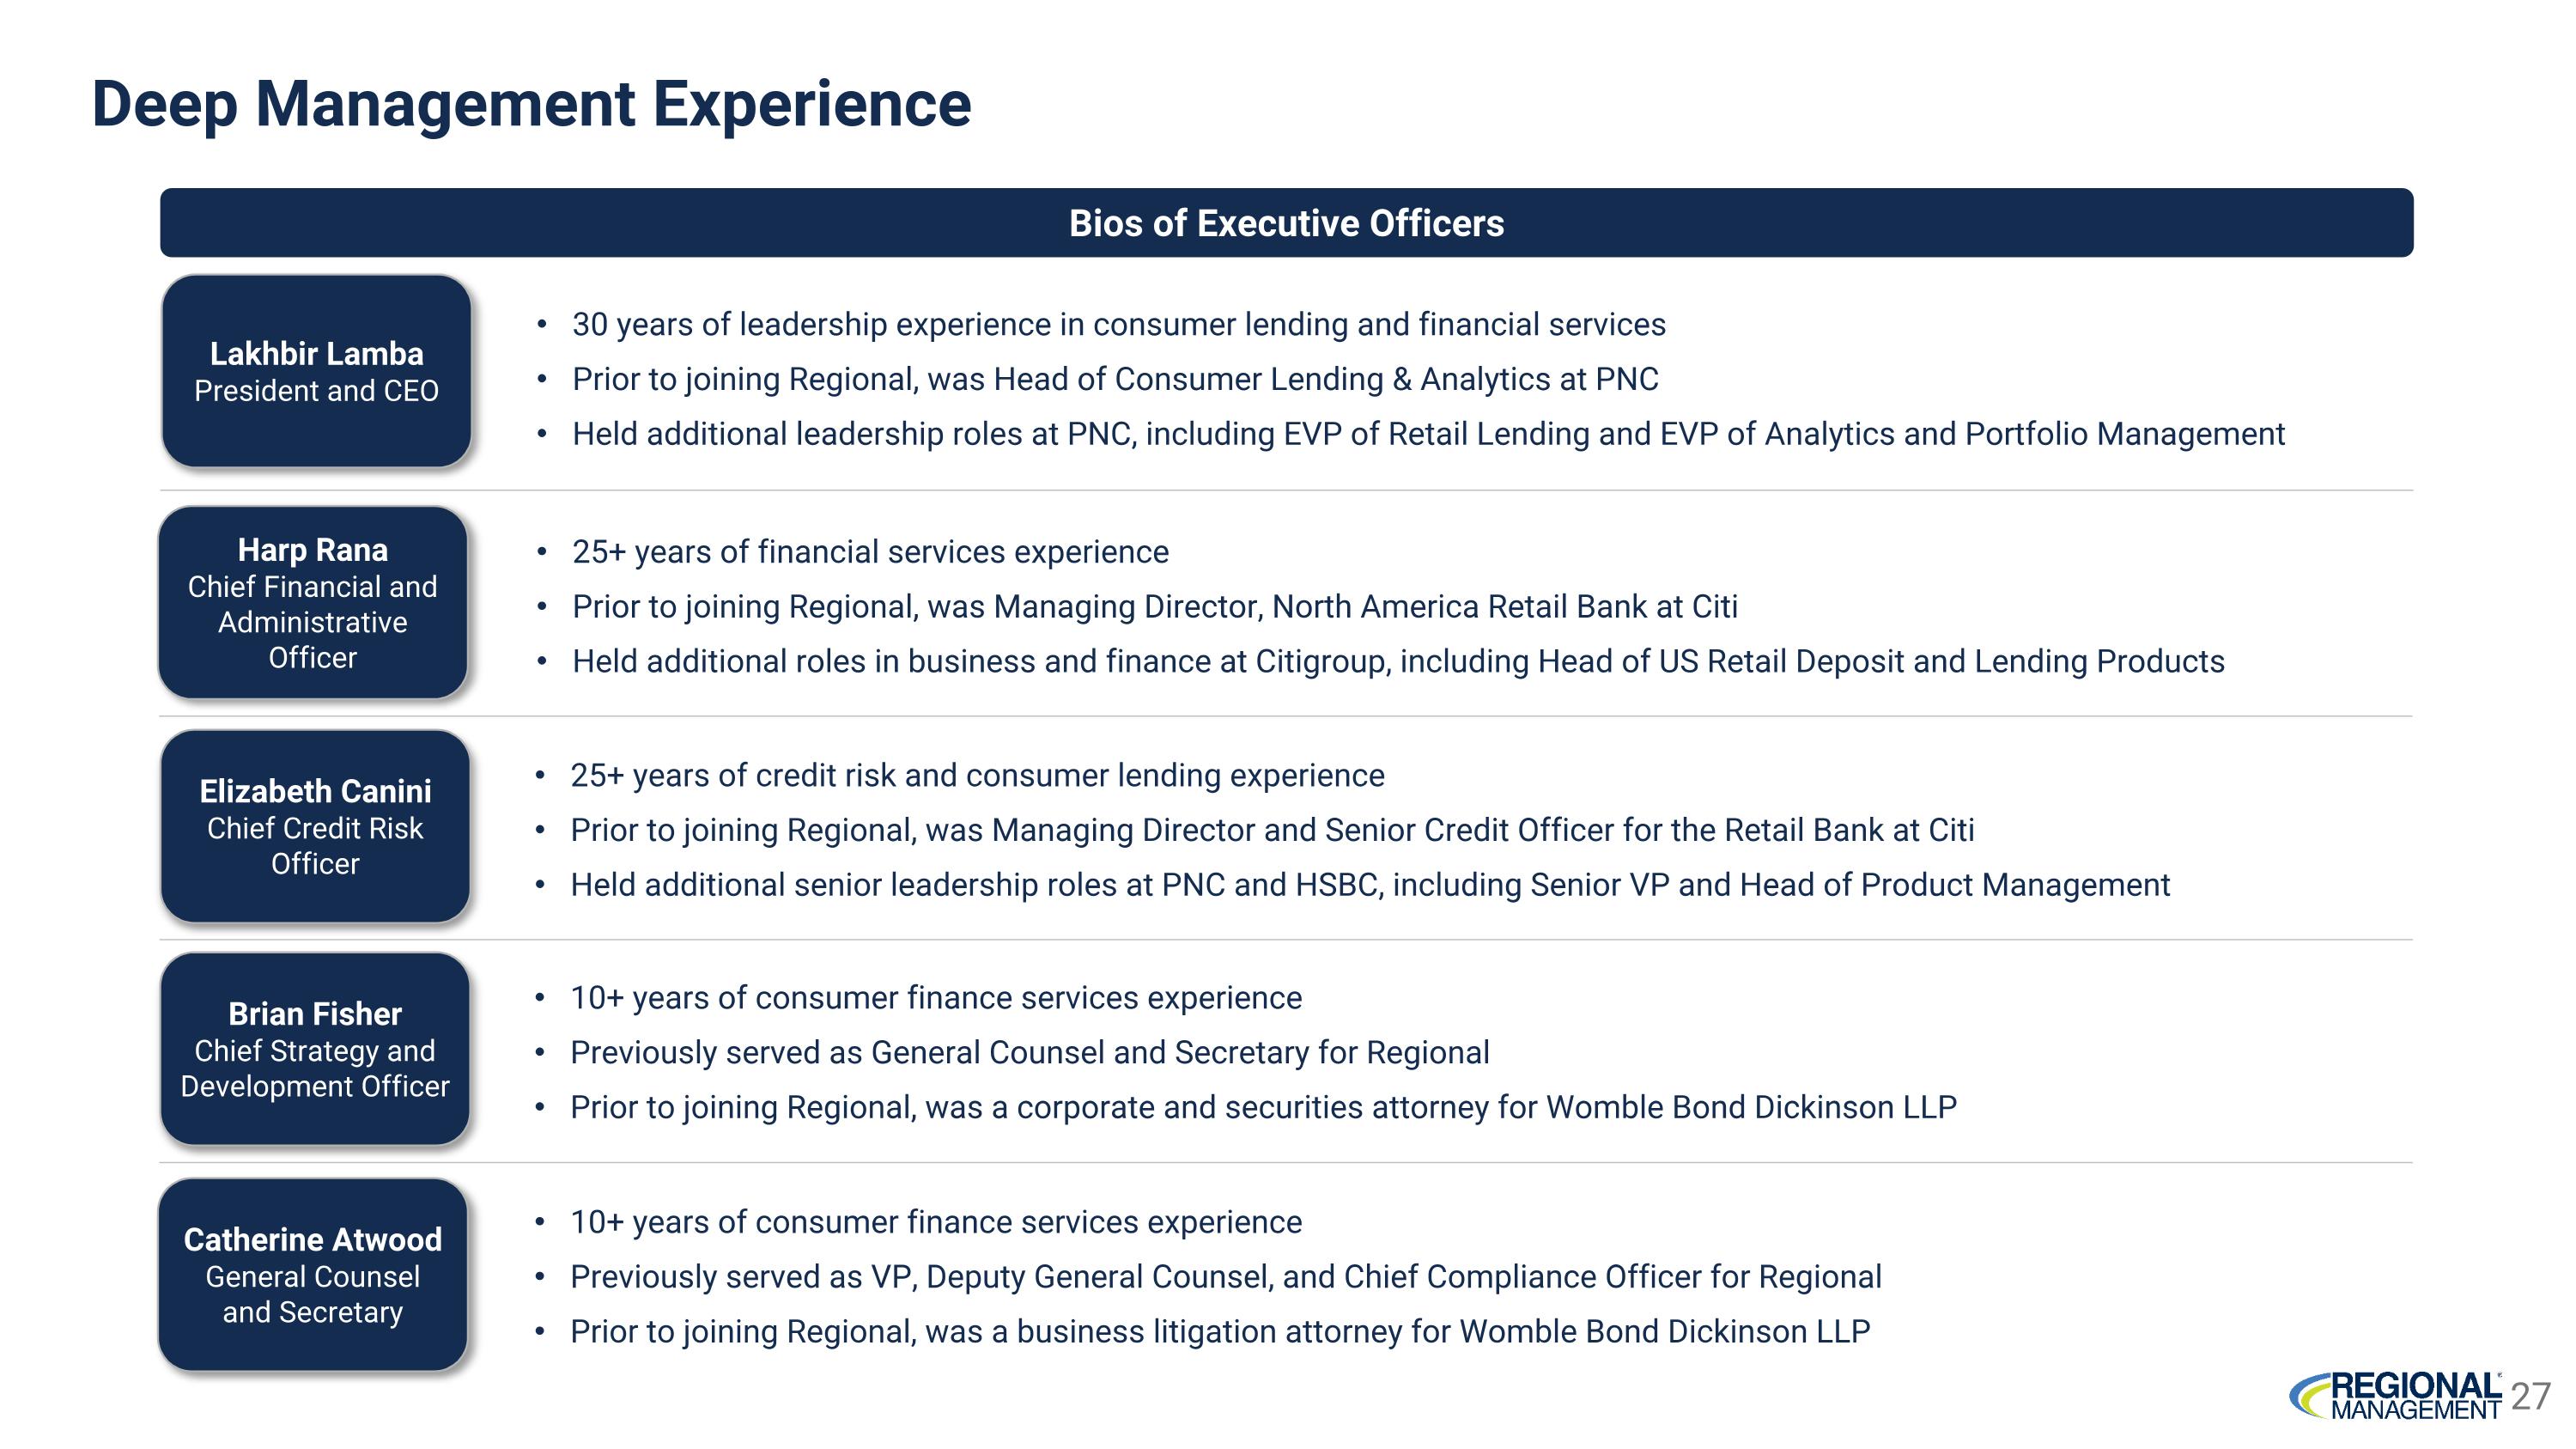
Deep Management Experience Catherine Atwood General Counsel and Secretary 10+ years of consumer finance services experience Previously served as VP, Deputy General Counsel, and Chief Compliance Officer for Regional Prior to joining Regional, was a business litigation attorney for Womble Bond Dickinson LLP Brian Fisher Chief Strategy and Development Officer 10+ years of consumer finance services experience Previously served as General Counsel and Secretary for Regional Prior to joining Regional, was a corporate and securities attorney for Womble Bond Dickinson LLP Lakhbir Lamba President and CEO Elizabeth Canini Chief Credit Risk Officer Harp Rana Chief Financial and Administrative Officer 25+ years of financial services experience Prior to joining Regional, was Managing Director, North America Retail Bank at Citi Held additional roles in business and finance at Citigroup, including Head of US Retail Deposit and Lending Products 25+ years of credit risk and consumer lending experience Prior to joining Regional, was Managing Director and Senior Credit Officer for the Retail Bank at Citi Held additional senior leadership roles at PNC and HSBC, including Senior VP and Head of Product Management 30 years of leadership experience in consumer lending and financial services Prior to joining Regional, was Head of Consumer Lending & Analytics at PNC Held additional leadership roles at PNC, including EVP of Retail Lending and EVP of Analytics and Portfolio Management Bios of Executive Officers 27
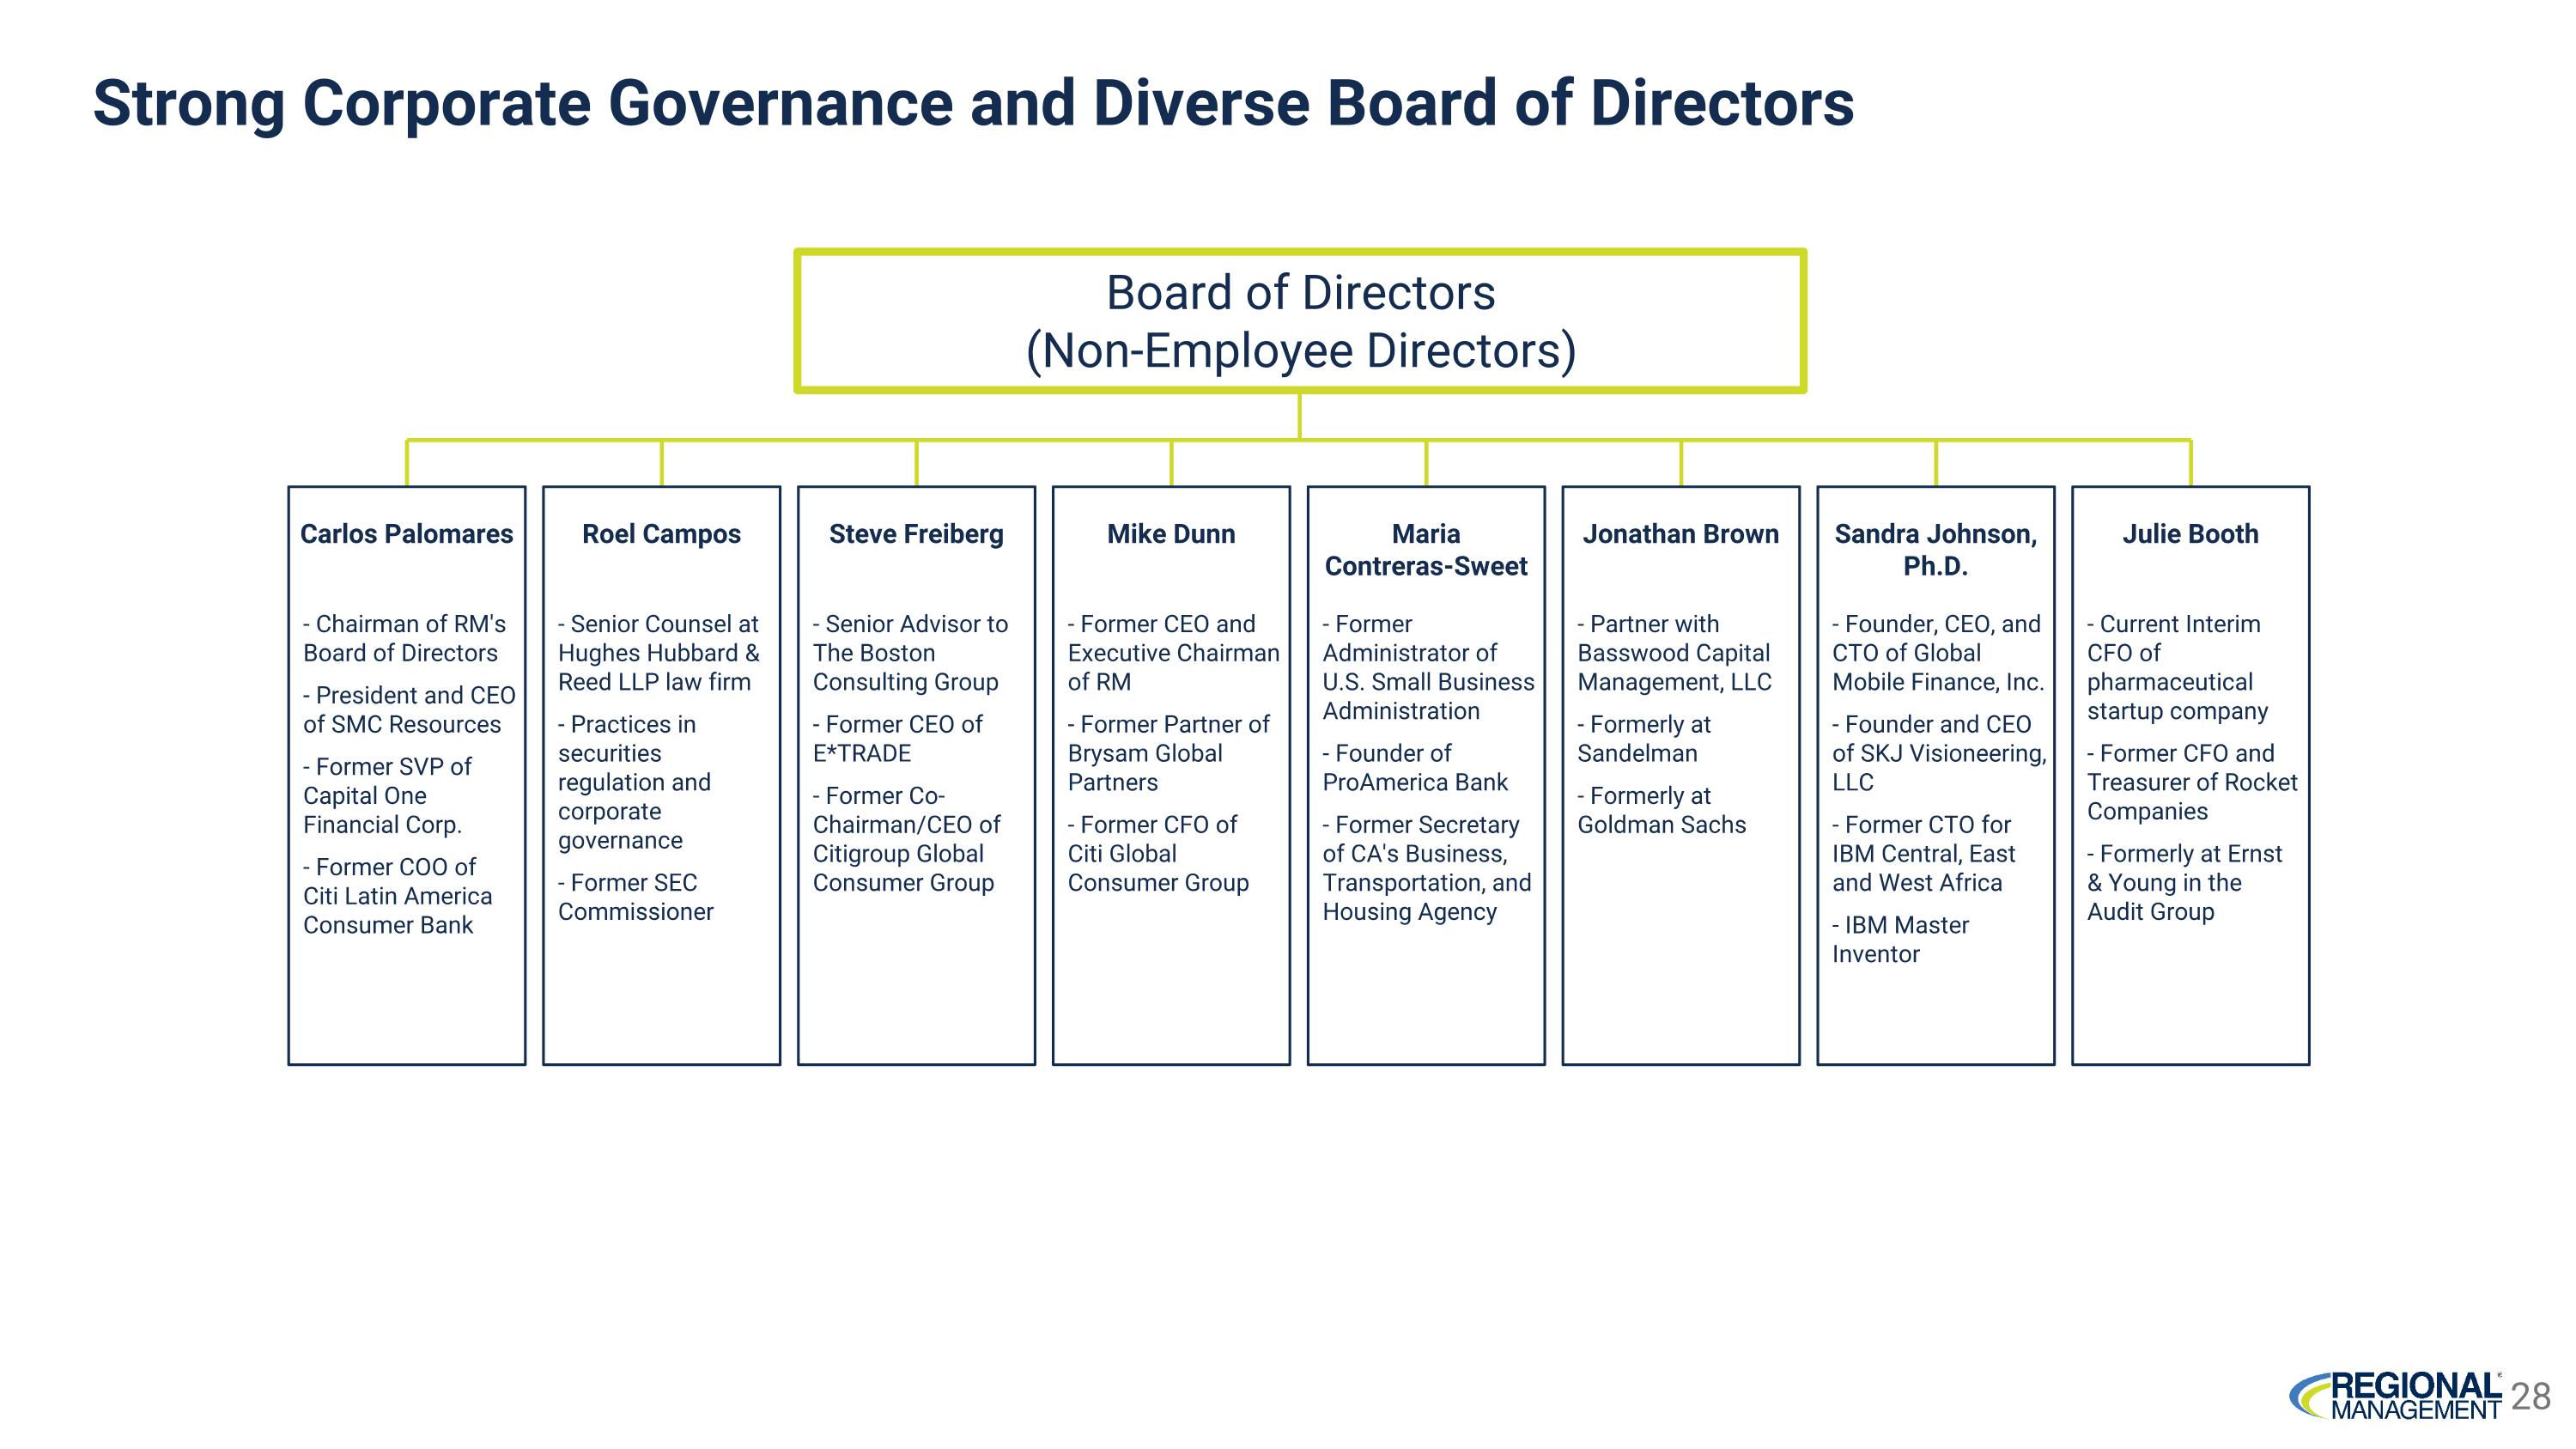
Strong Corporate Governance and Diverse Board of Directors Board of Directors (Non-Employee Directors) Carlos Palomares - Chairman of RM's Board of Directors - President and CEO of SMC Resources - Former SVP of Capital One Financial Corp. - Former COO of Citi Latin America Consumer Bank Roel Campos - Senior Counsel at Hughes Hubbard & Reed LLP law firm - Practices in securities regulation and corporate governance - Former SEC Commissioner Steve Freiberg - Senior Advisor to The Boston Consulting Group - Former CEO of E*TRADE - Former Co- Chairman/CEO of Citigroup Global Consumer Group Mike Dunn - Former CEO and Executive Chairman of RM - Former Partner of Brysam Global Partners - Former CFO of Citi Global Consumer Group Maria Contreras-Sweet - Former Administrator of U.S. Small Business Administration - Founder of ProAmerica Bank - Former Secretary of CA's Business, Transportation, and Housing Agency Jonathan Brown - Partner with Basswood Capital Management, LLC - Formerly at Sandelman - Formerly at Goldman Sachs Sandra Johnson, Ph.D. - Founder, CEO, and CTO of Global Mobile Finance, Inc. - Founder and CEO of SKJ Visioneering, LLC - Former CTO for IBM Central, East and West Africa - IBM Master Inventor Julie Booth - Current Interim CFO of pharmaceutical startup company - Former CFO and Treasurer of Rocket Companies - Formerly at Ernst & Young in the Audit Group 28
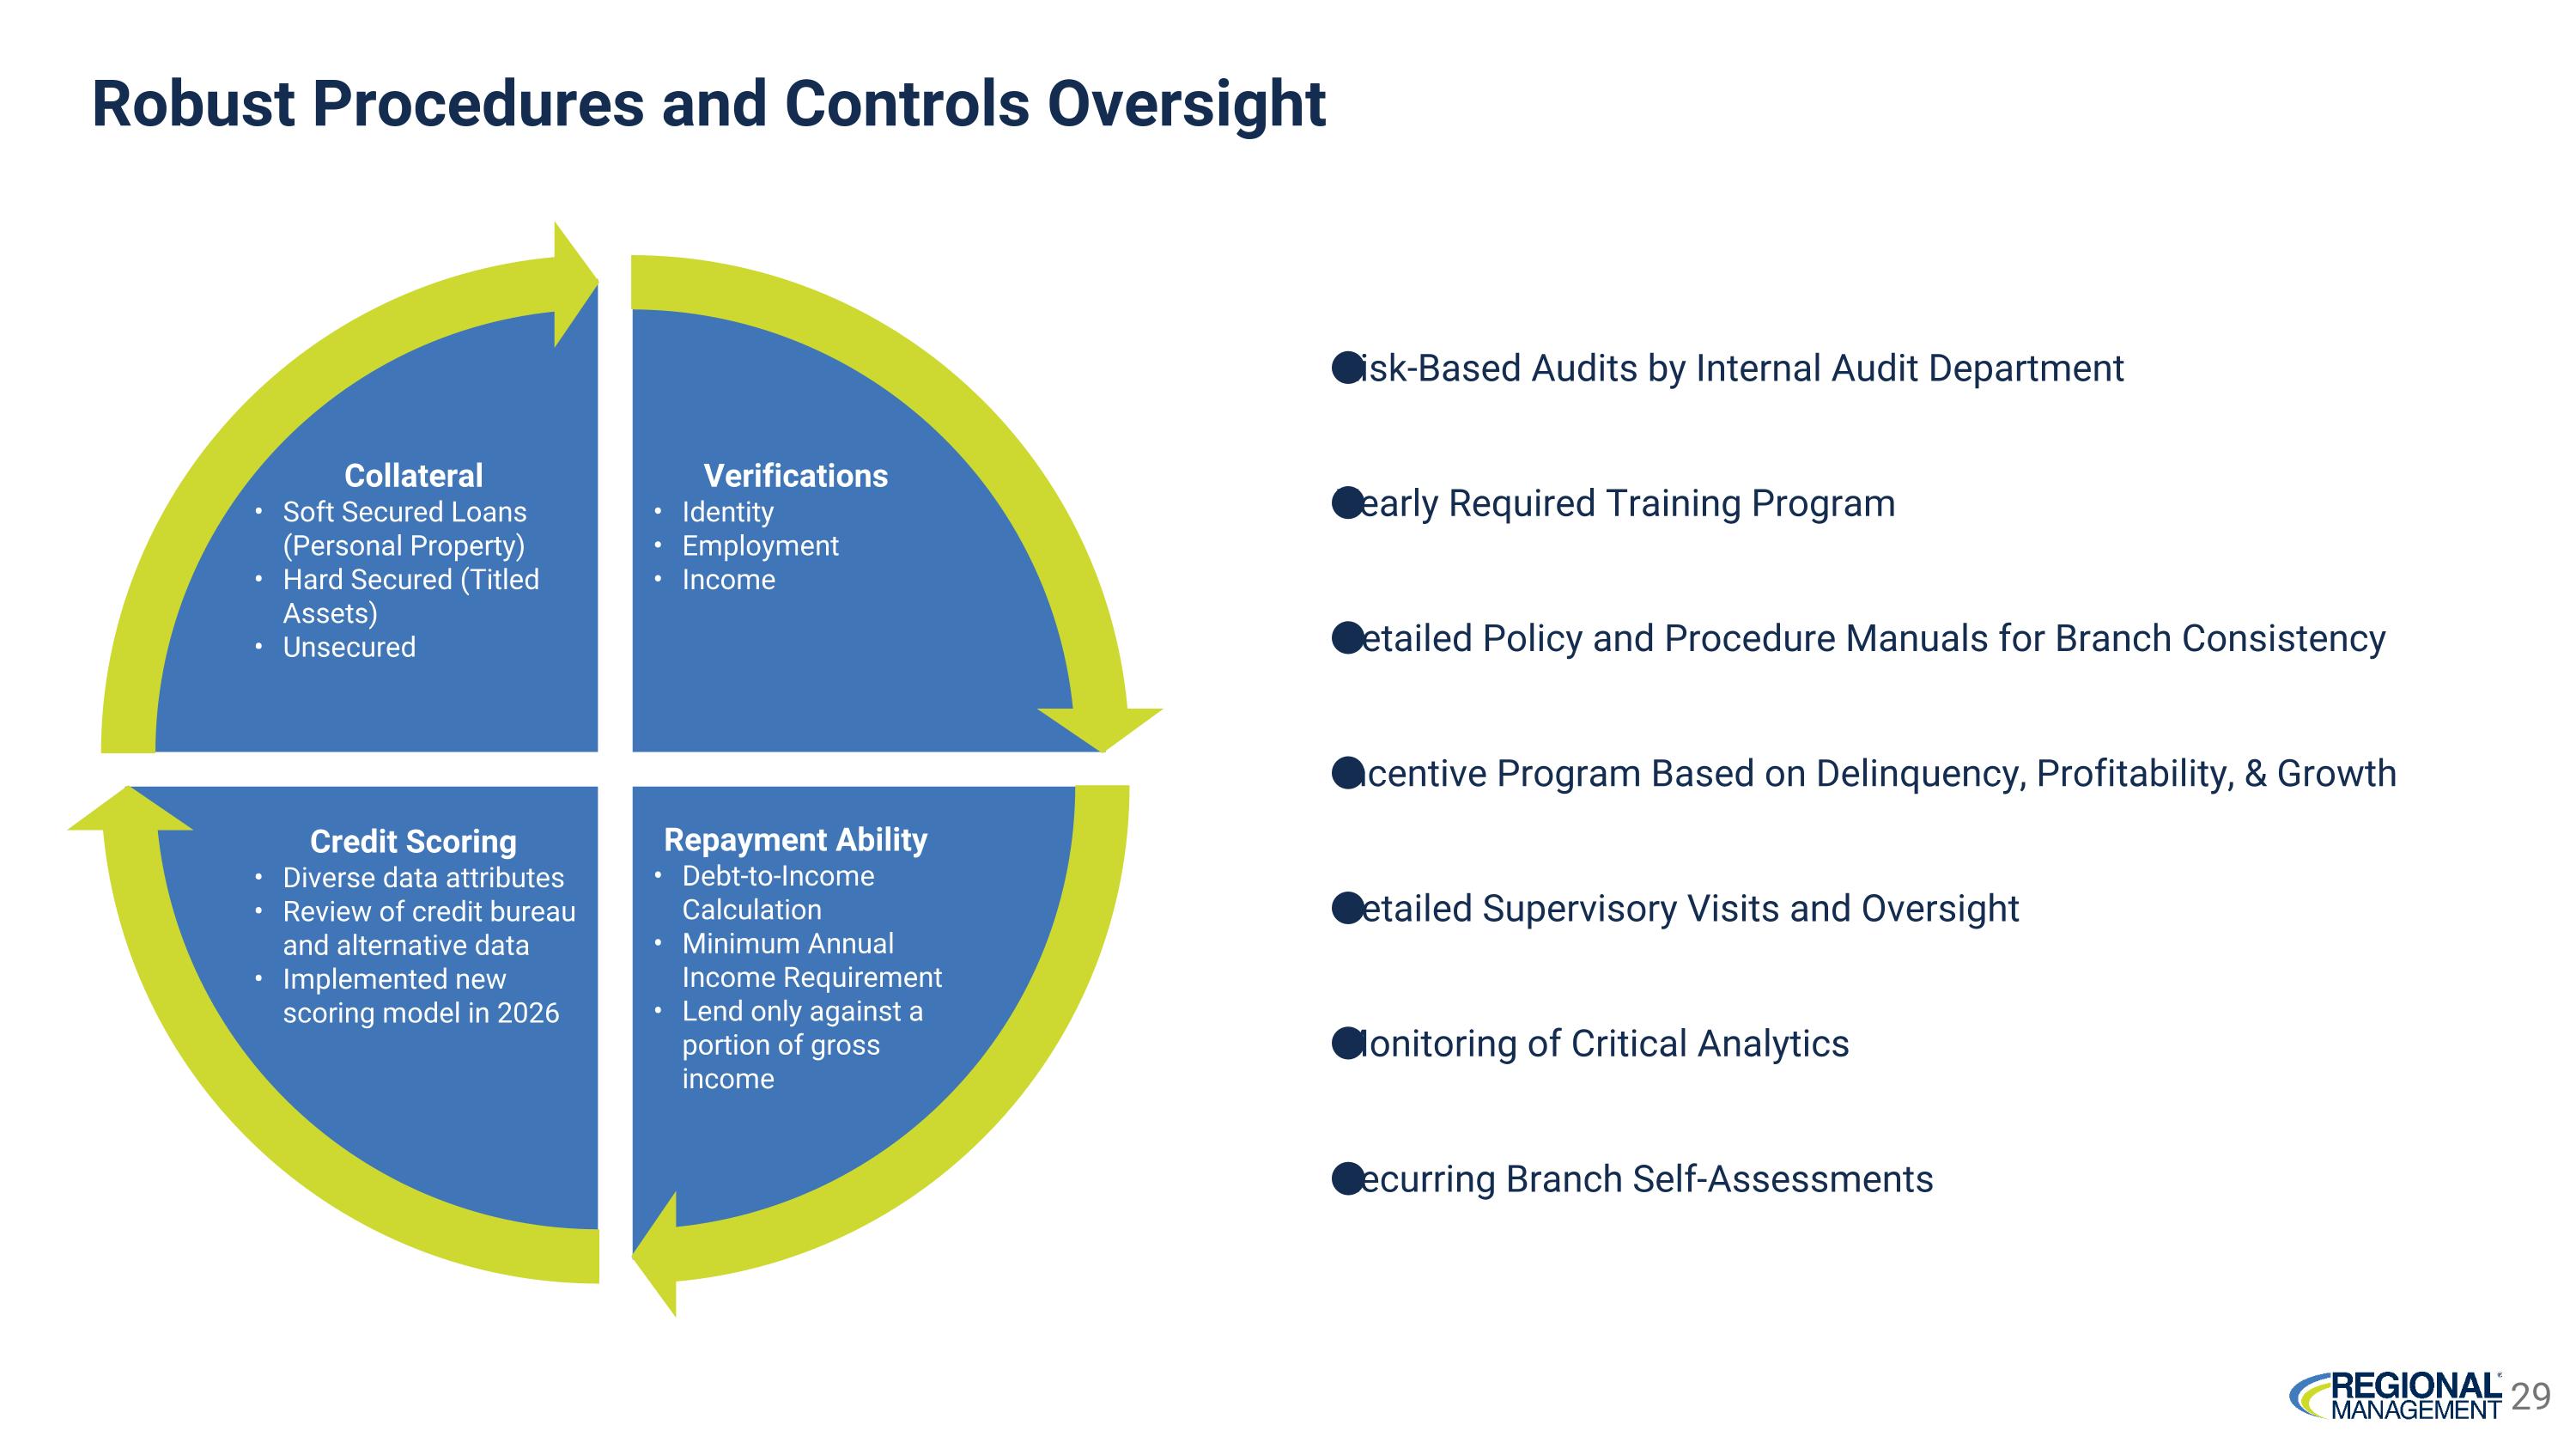
Robust Procedures and Controls Oversight Collateral All borrowers must provide collateral Secured by titled assets (hard secured) or personal property (soft secured) Verifications Identity Employment Income Credit Scoring Diverse data attributes Review of credit bureau information Implementation of custom scorecards in 2018 Repayment Ability Debt to Income Calculation Minimum Annual Income Requirement Lend only against a portion of gross income Collateral Soft Secured Loans (Personal Property) Hard Secured (Titled Assets) Unsecured Verifications Identity Employment Income Credit Scoring Diverse data attributes Review of credit bureau and alternative data Implemented new scoring model in 2026 Repayment Ability Debt-to-Income Calculation Minimum Annual Income Requirement Lend only against a portion of gross income Risk-Based Audits by Internal Audit Department Yearly Required Training Program Detailed Policy and Procedure Manuals for Branch Consistency Incentive Program Based on Delinquency, Profitability, & Growth Detailed Supervisory Visits and Oversight Monitoring of Critical Analytics Recurring Branch Self-Assessments
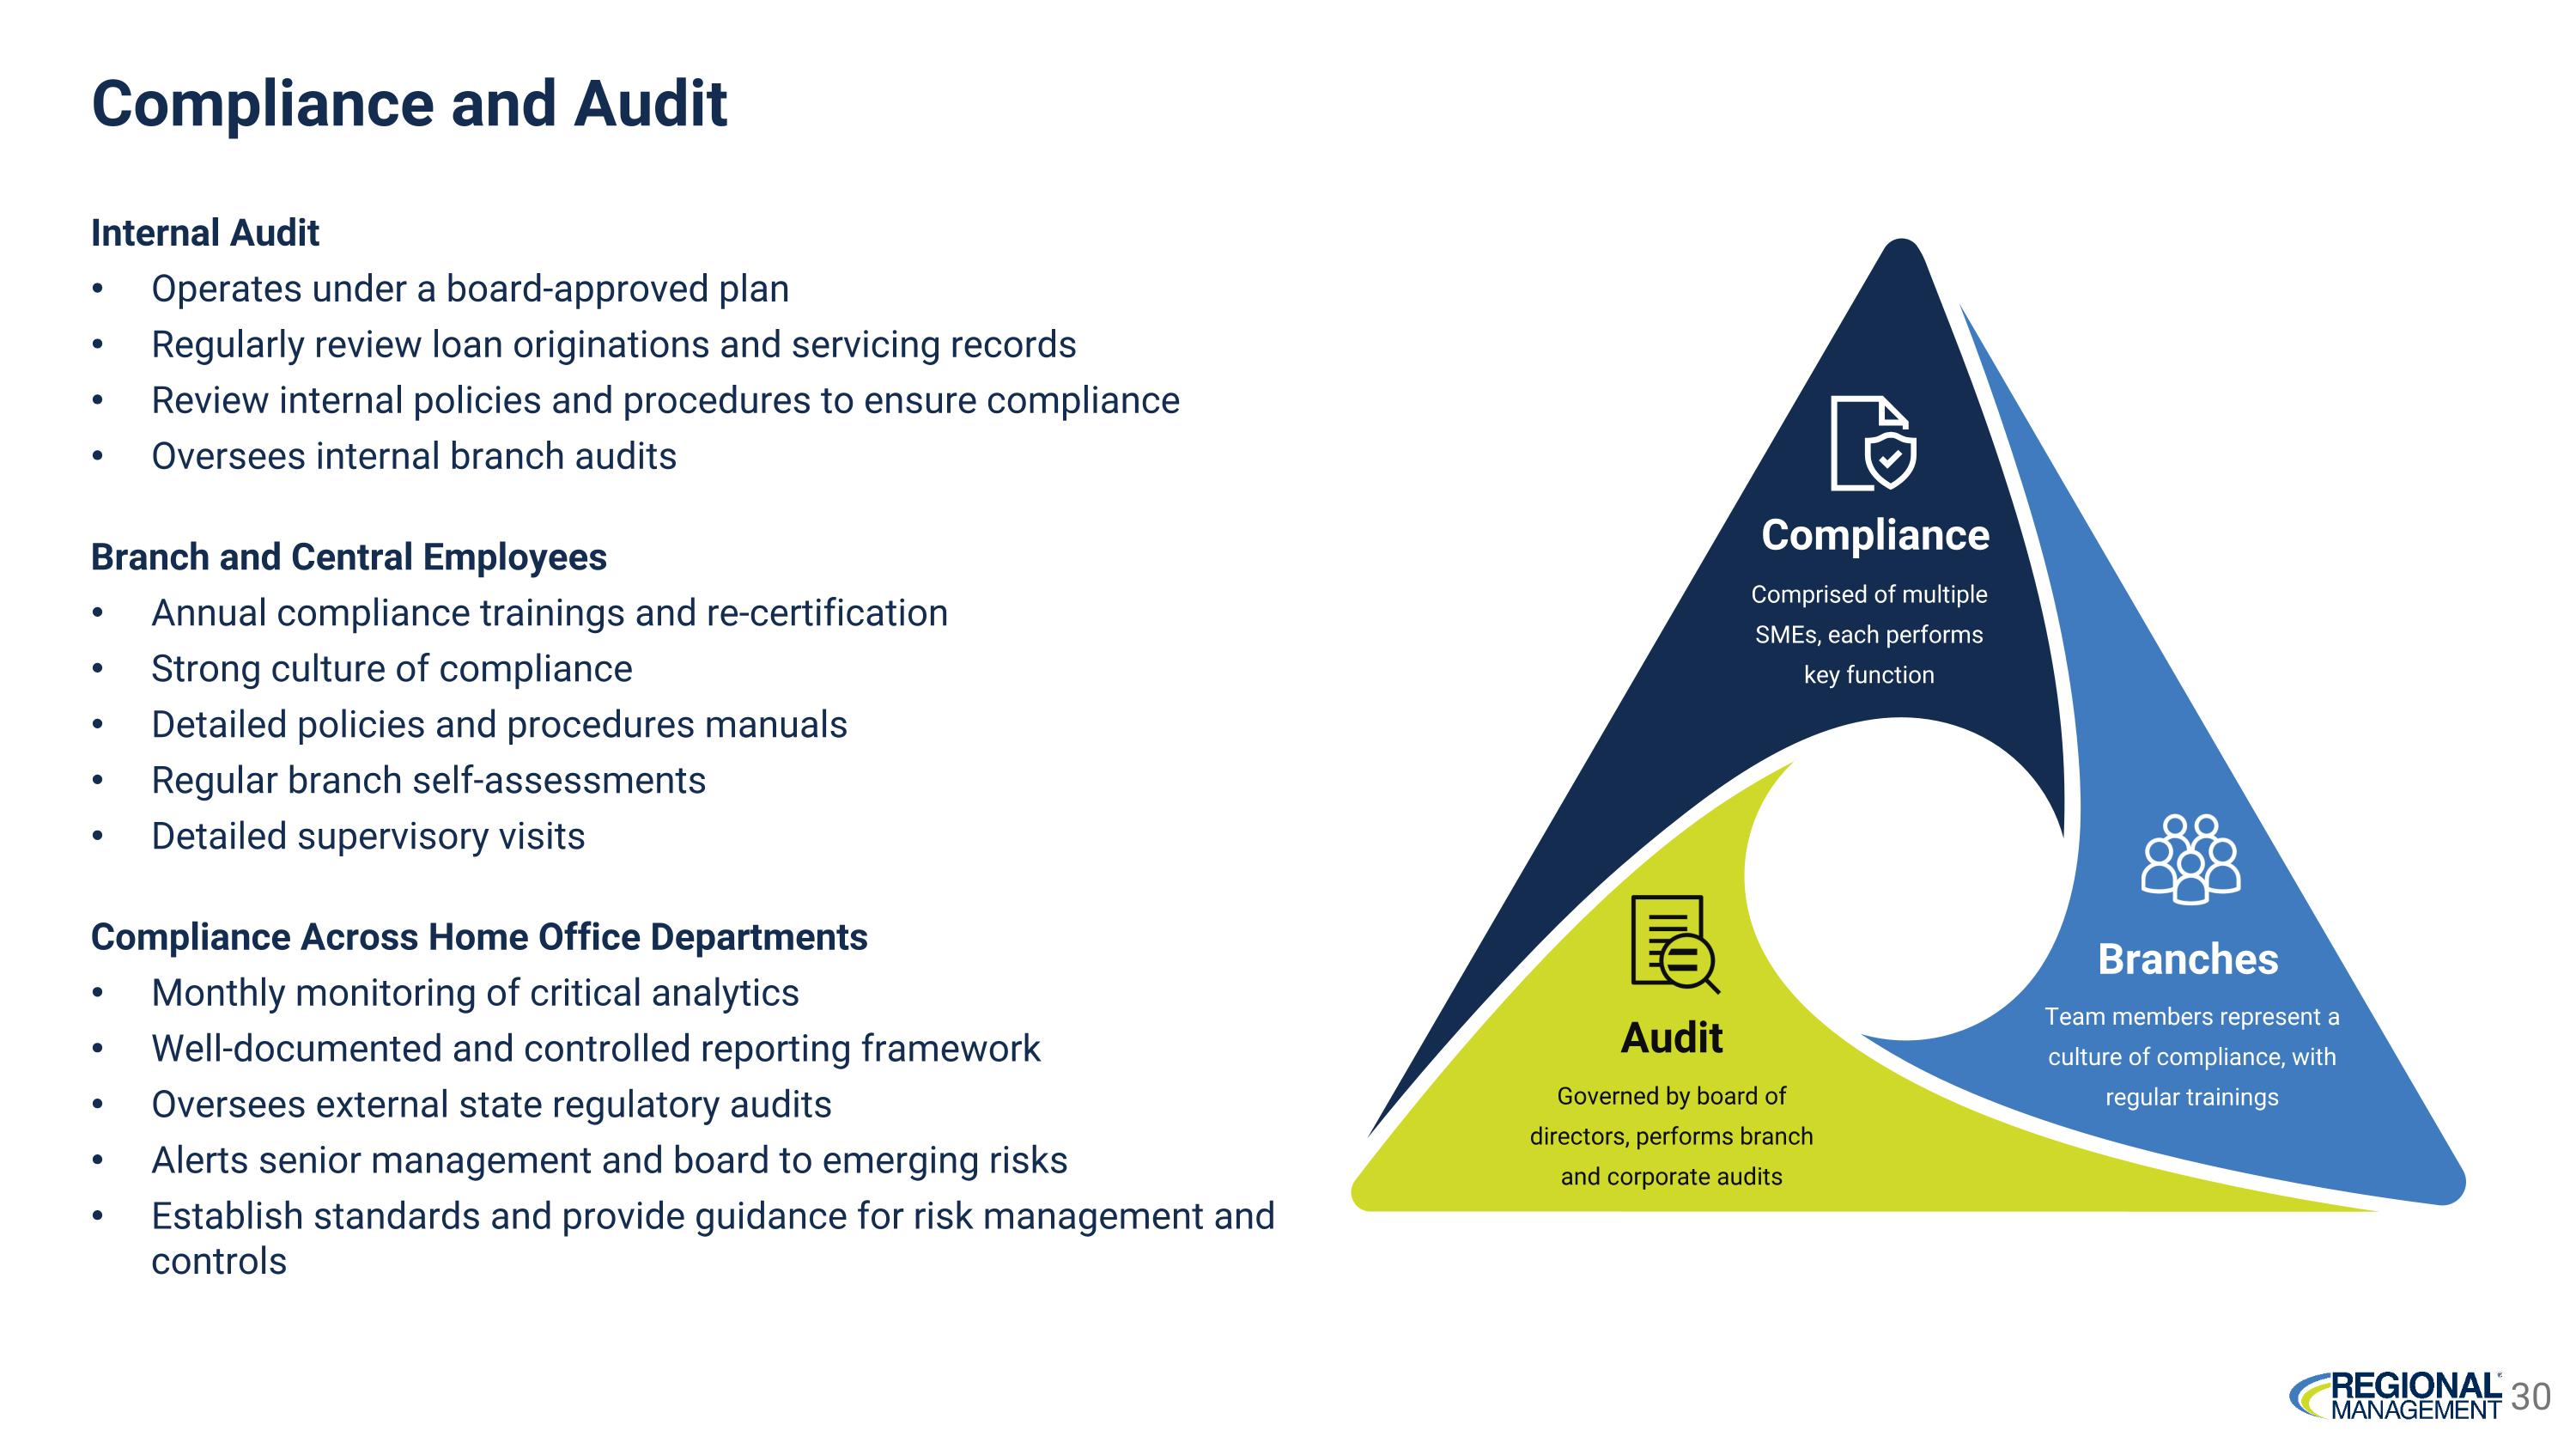
Compliance and Audit Internal Audit Operates under a board-approved plan Regularly review loan originations and servicing records Review internal policies and procedures to ensure compliance Oversees internal branch audits Branch and Central Employees Annual compliance trainings and re-certification Strong culture of compliance Detailed policies and procedures manuals Regular branch self-assessments Detailed supervisory visits Compliance Across Home Office Departments Monthly monitoring of critical analytics Well-documented and controlled reporting framework Oversees external state regulatory audits Alerts senior management and board to emerging risks Establish standards and provide guidance for risk management and controls Governed by board of directors, performs branch and corporate audits Audit Comprised of multiple SMEs, each performs key function Compliance Team members represent a culture of compliance, with regular trainings Branches
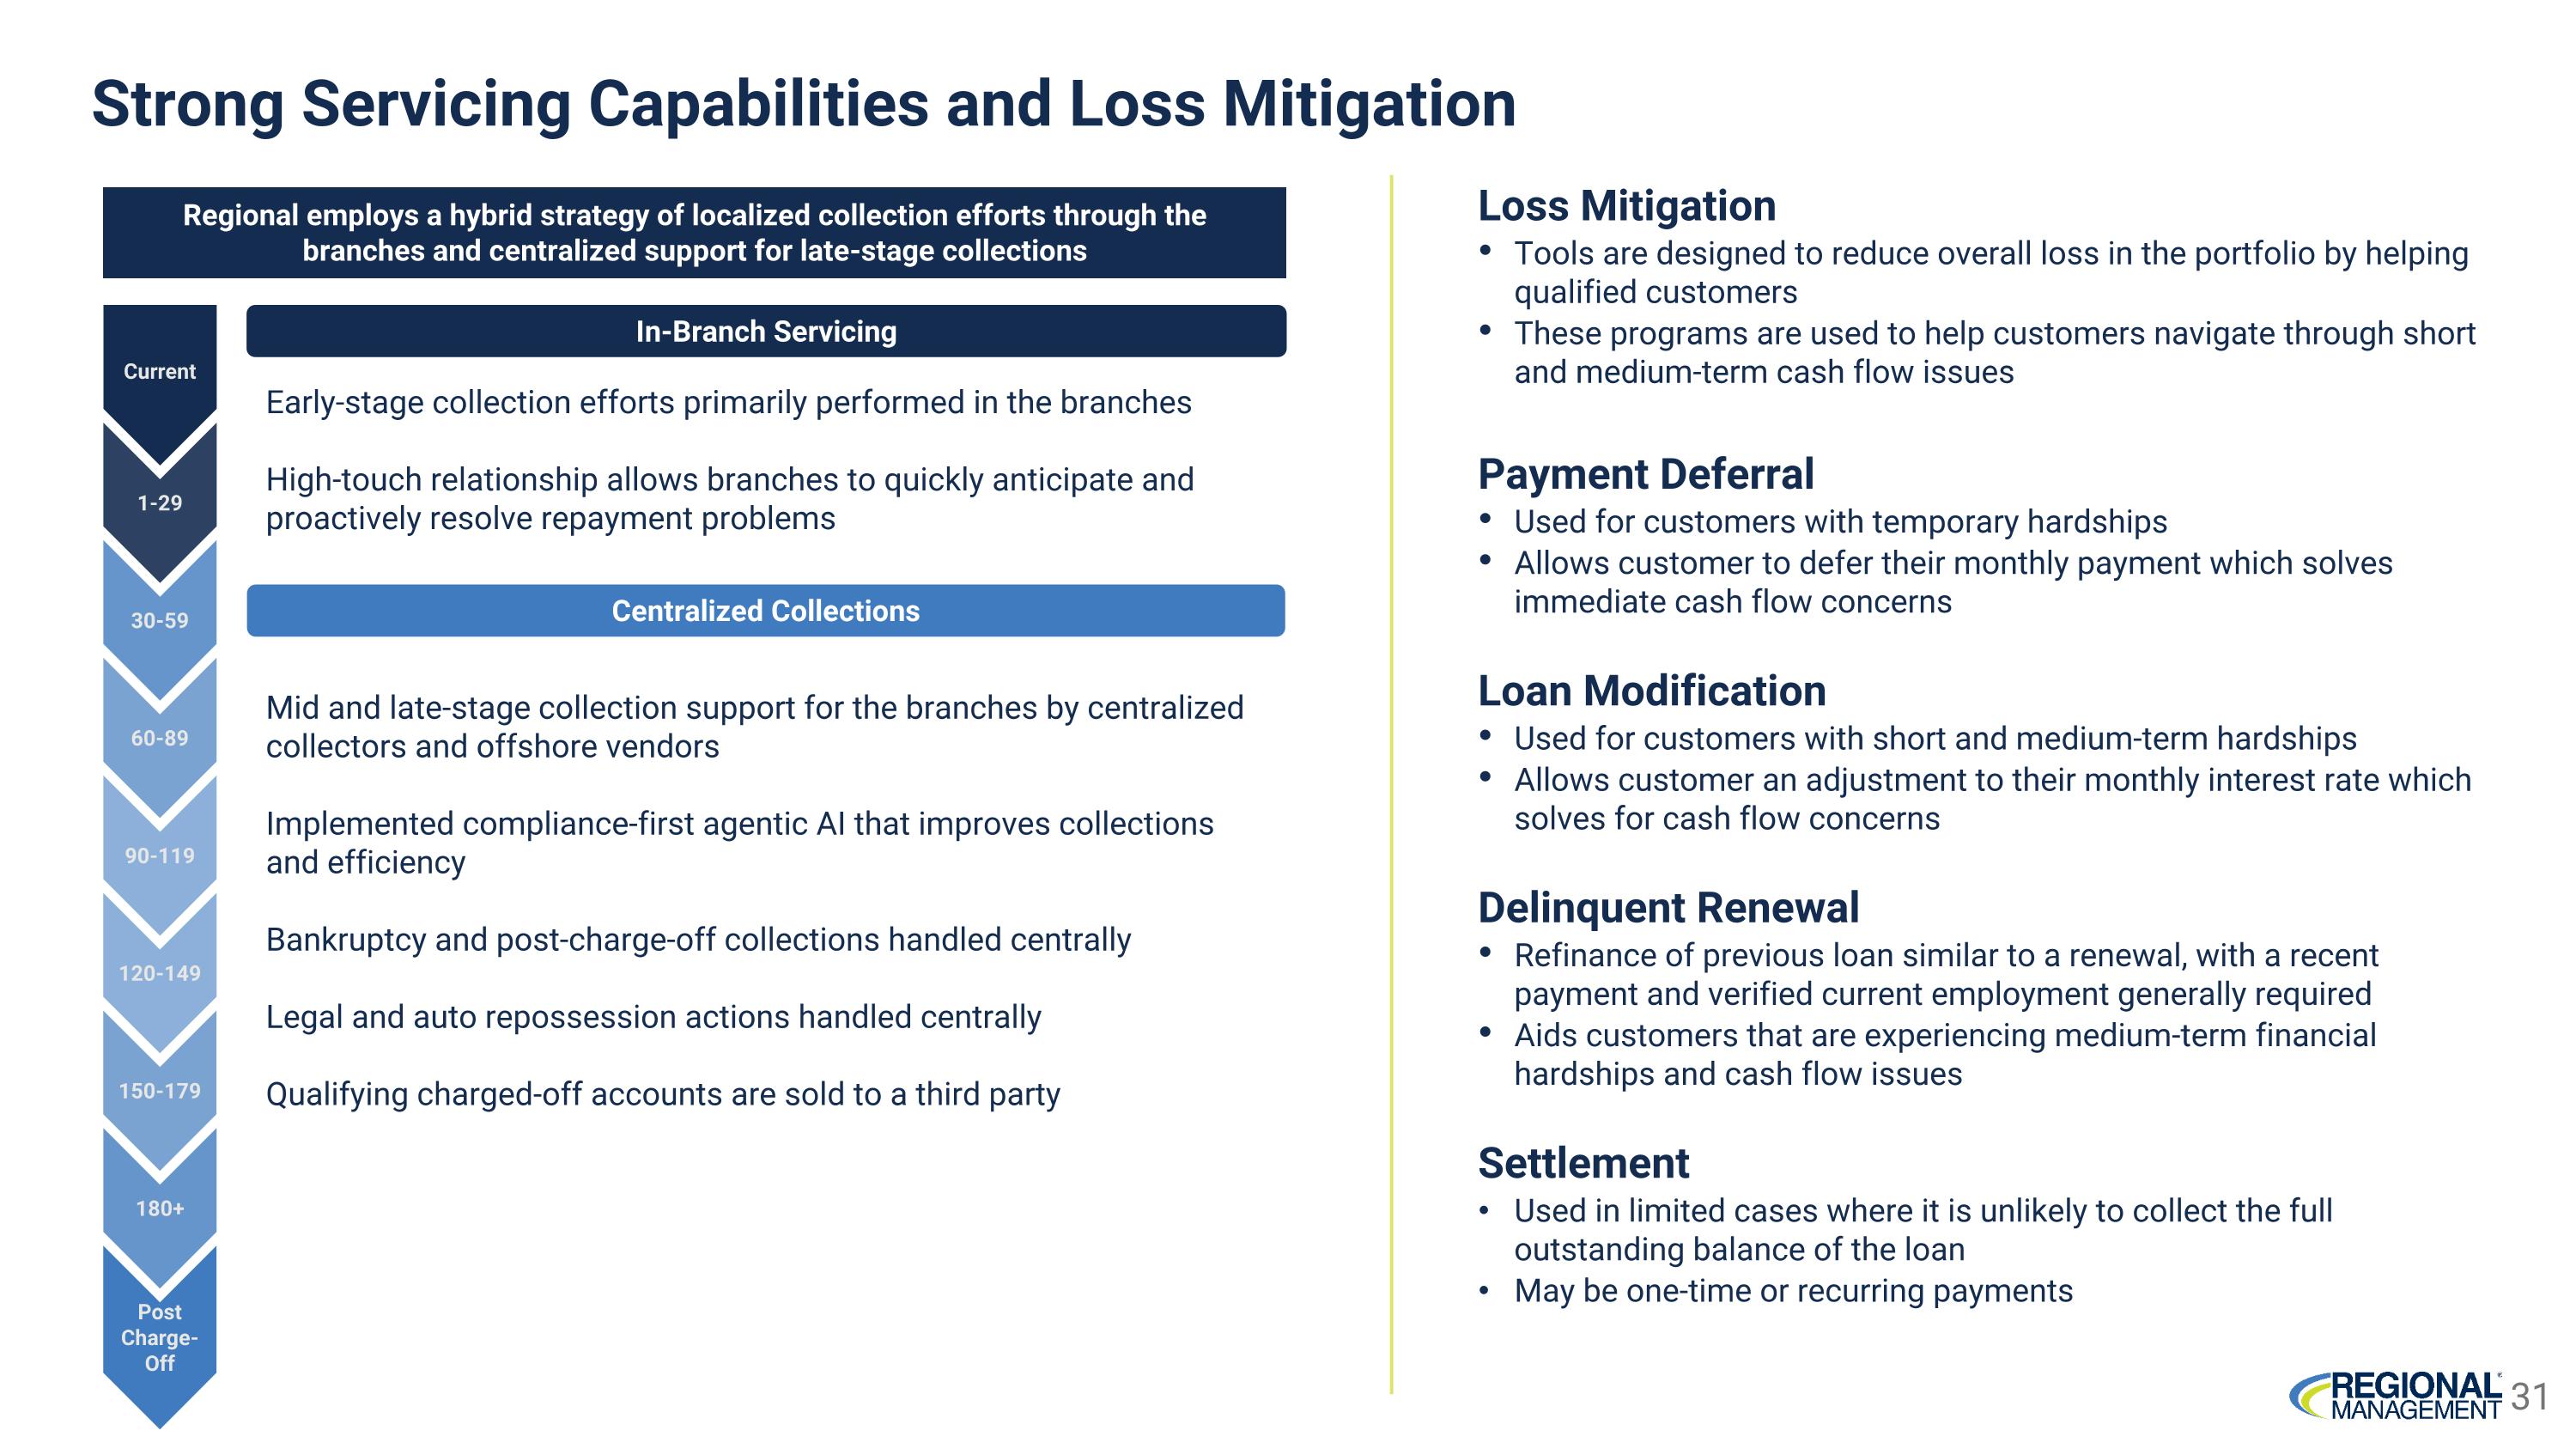
Loss Mitigation Tools are designed to reduce overall loss in the portfolio by helping qualified customers These programs are used to help customers navigate through short and medium-term cash flow issues Payment Deferral Used for customers with temporary hardships Allows customer to defer their monthly payment which solves immediate cash flow concerns Loan Modification Used for customers with short and medium-term hardships Allows customer an adjustment to their monthly interest rate which solves for cash flow concerns Delinquent Renewal Refinance of previous loan similar to a renewal, with a recent payment and verified current employment generally required Aids customers that are experiencing medium-term financial hardships and cash flow issues Settlement Used in limited cases where it is unlikely to collect the full outstanding balance of the loan May be one-time or recurring payments Strong Servicing Capabilities and Loss Mitigation Early-stage collection efforts primarily performed in the branches High-touch relationship allows branches to quickly anticipate and proactively resolve repayment problems Mid and late-stage collection support for the branches by centralized collectors and offshore vendors Implemented compliance-first agentic AI that improves collections and efficiency Bankruptcy and post-charge-off collections handled centrally Legal and auto repossession actions handled centrally Qualifying charged-off accounts are sold to a third party Regional employs a hybrid strategy of localized collection efforts through the branches and centralized support for late-stage collections In-Branch Servicing Centralized Collections Current 1-29 30-59 60-89 90-119 120-149 150-179 180+ Post Charge-Off
Credit Performance
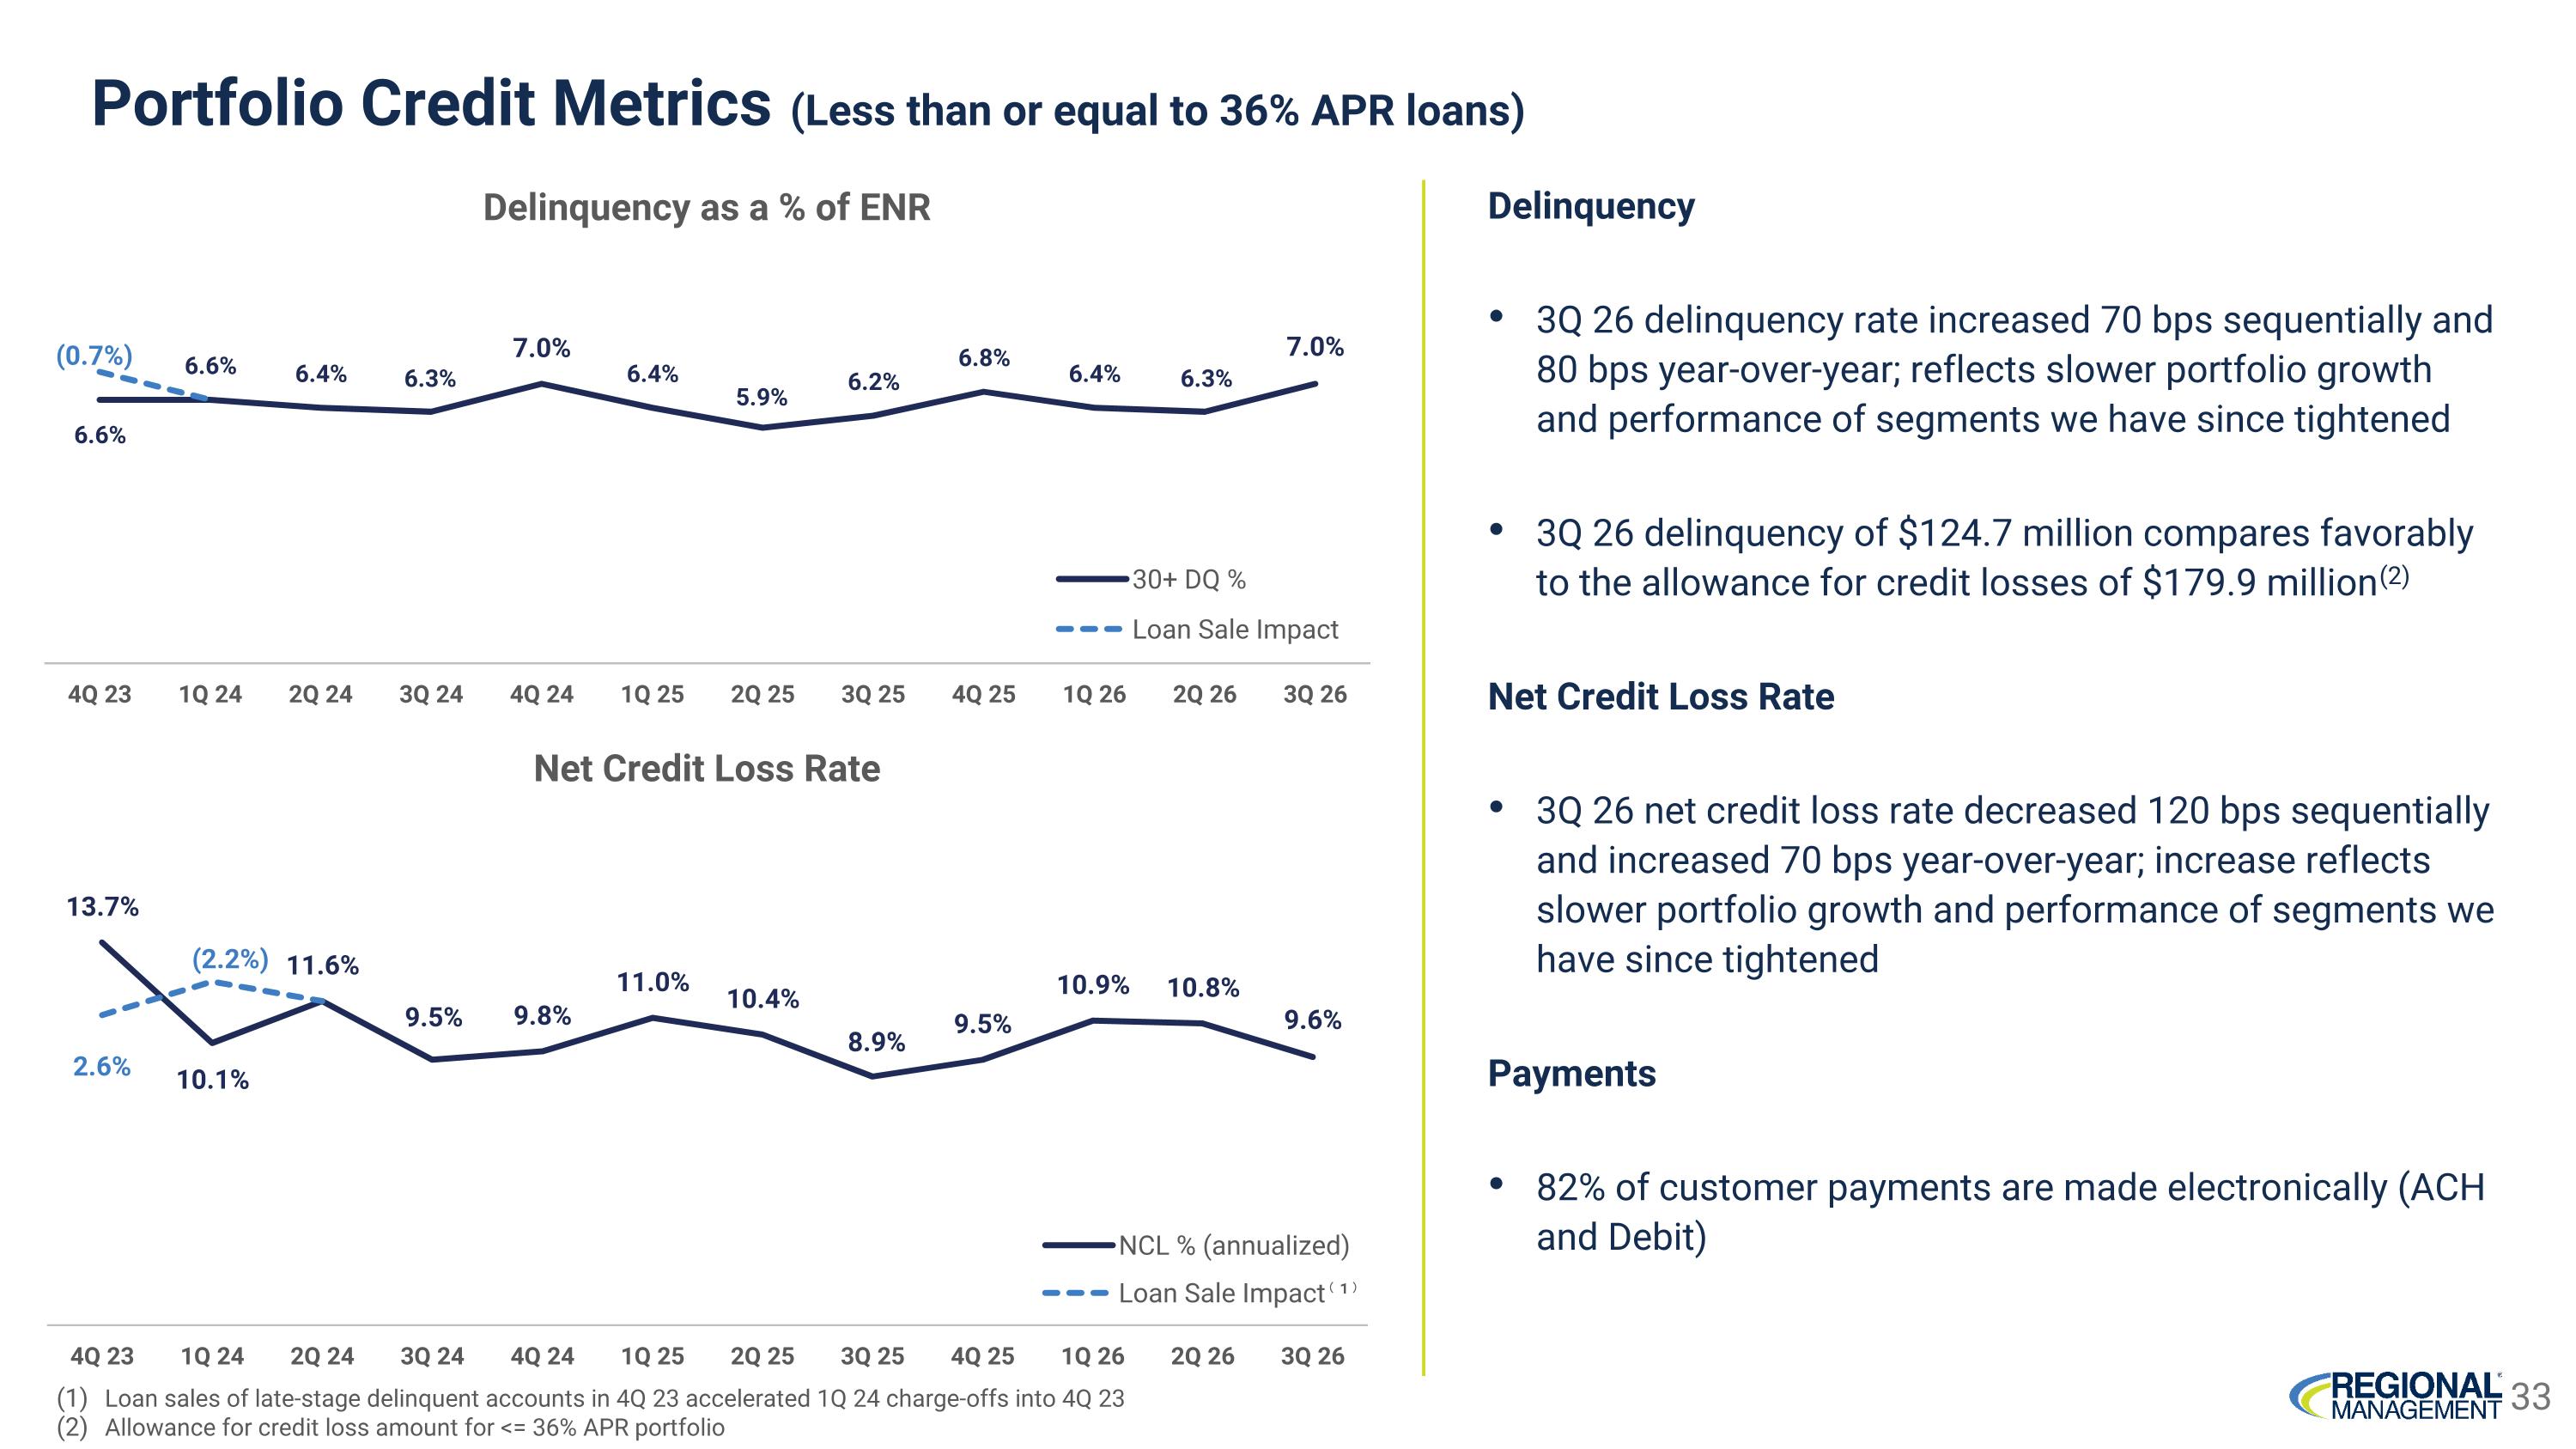
Portfolio Credit Metrics (Less than or equal to 36% APR loans) Loan sales of late-stage delinquent accounts in 4Q 23 accelerated 1Q 24 charge-offs into 4Q 23 Allowance for credit loss amount for <= 36% APR portfolio Delinquency 3Q 26 delinquency rate increased 70 bps sequentially and 80 bps year-over-year; reflects slower portfolio growth and performance of segments we have since tightened 3Q 26 delinquency of $124.7 million compares favorably to the allowance for credit losses of $179.9 million(2) Net Credit Loss Rate 3Q 26 net credit loss rate decreased 120 bps sequentially and increased 70 bps year-over-year; increase reflects slower portfolio growth and performance of segments we have since tightened Payments 82% of customer payments are made electronically (ACH and Debit)
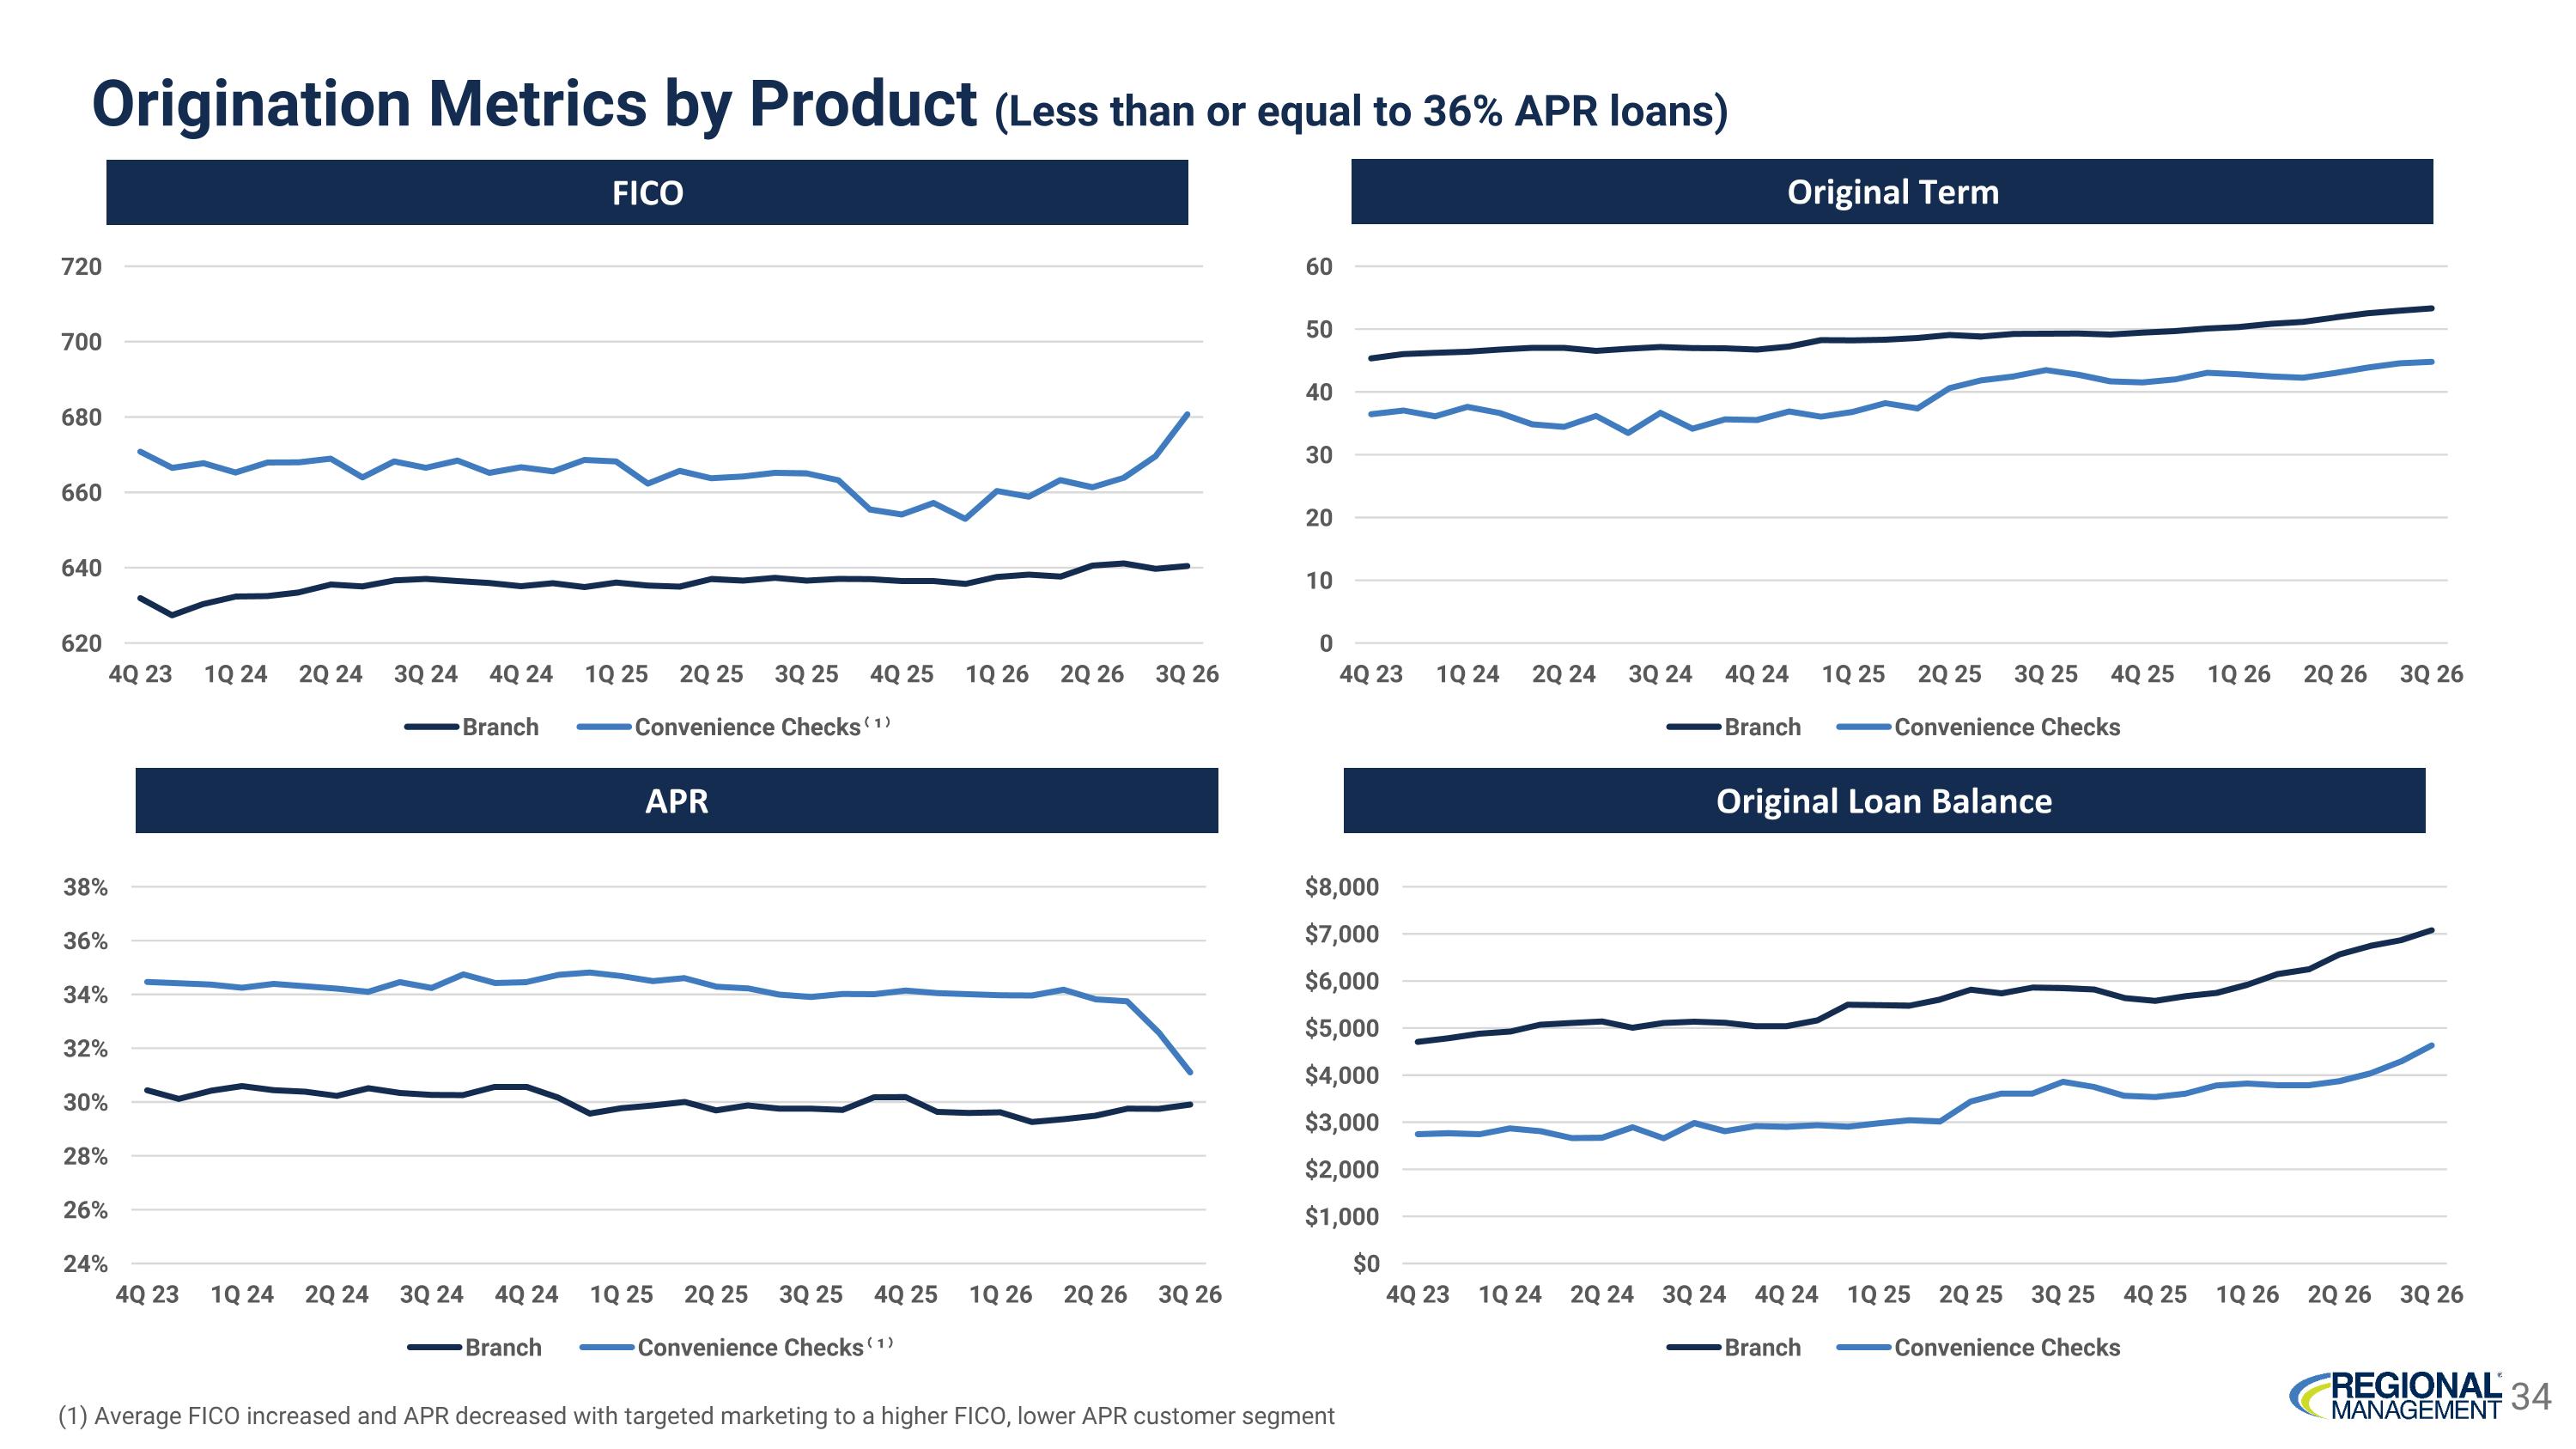
Origination Metrics by Product (Less than or equal to 36% APR loans) FICO Original Term APR Original Loan Balance (1) Average FICO increased and APR decreased with targeted marketing to a higher FICO, lower APR customer segment
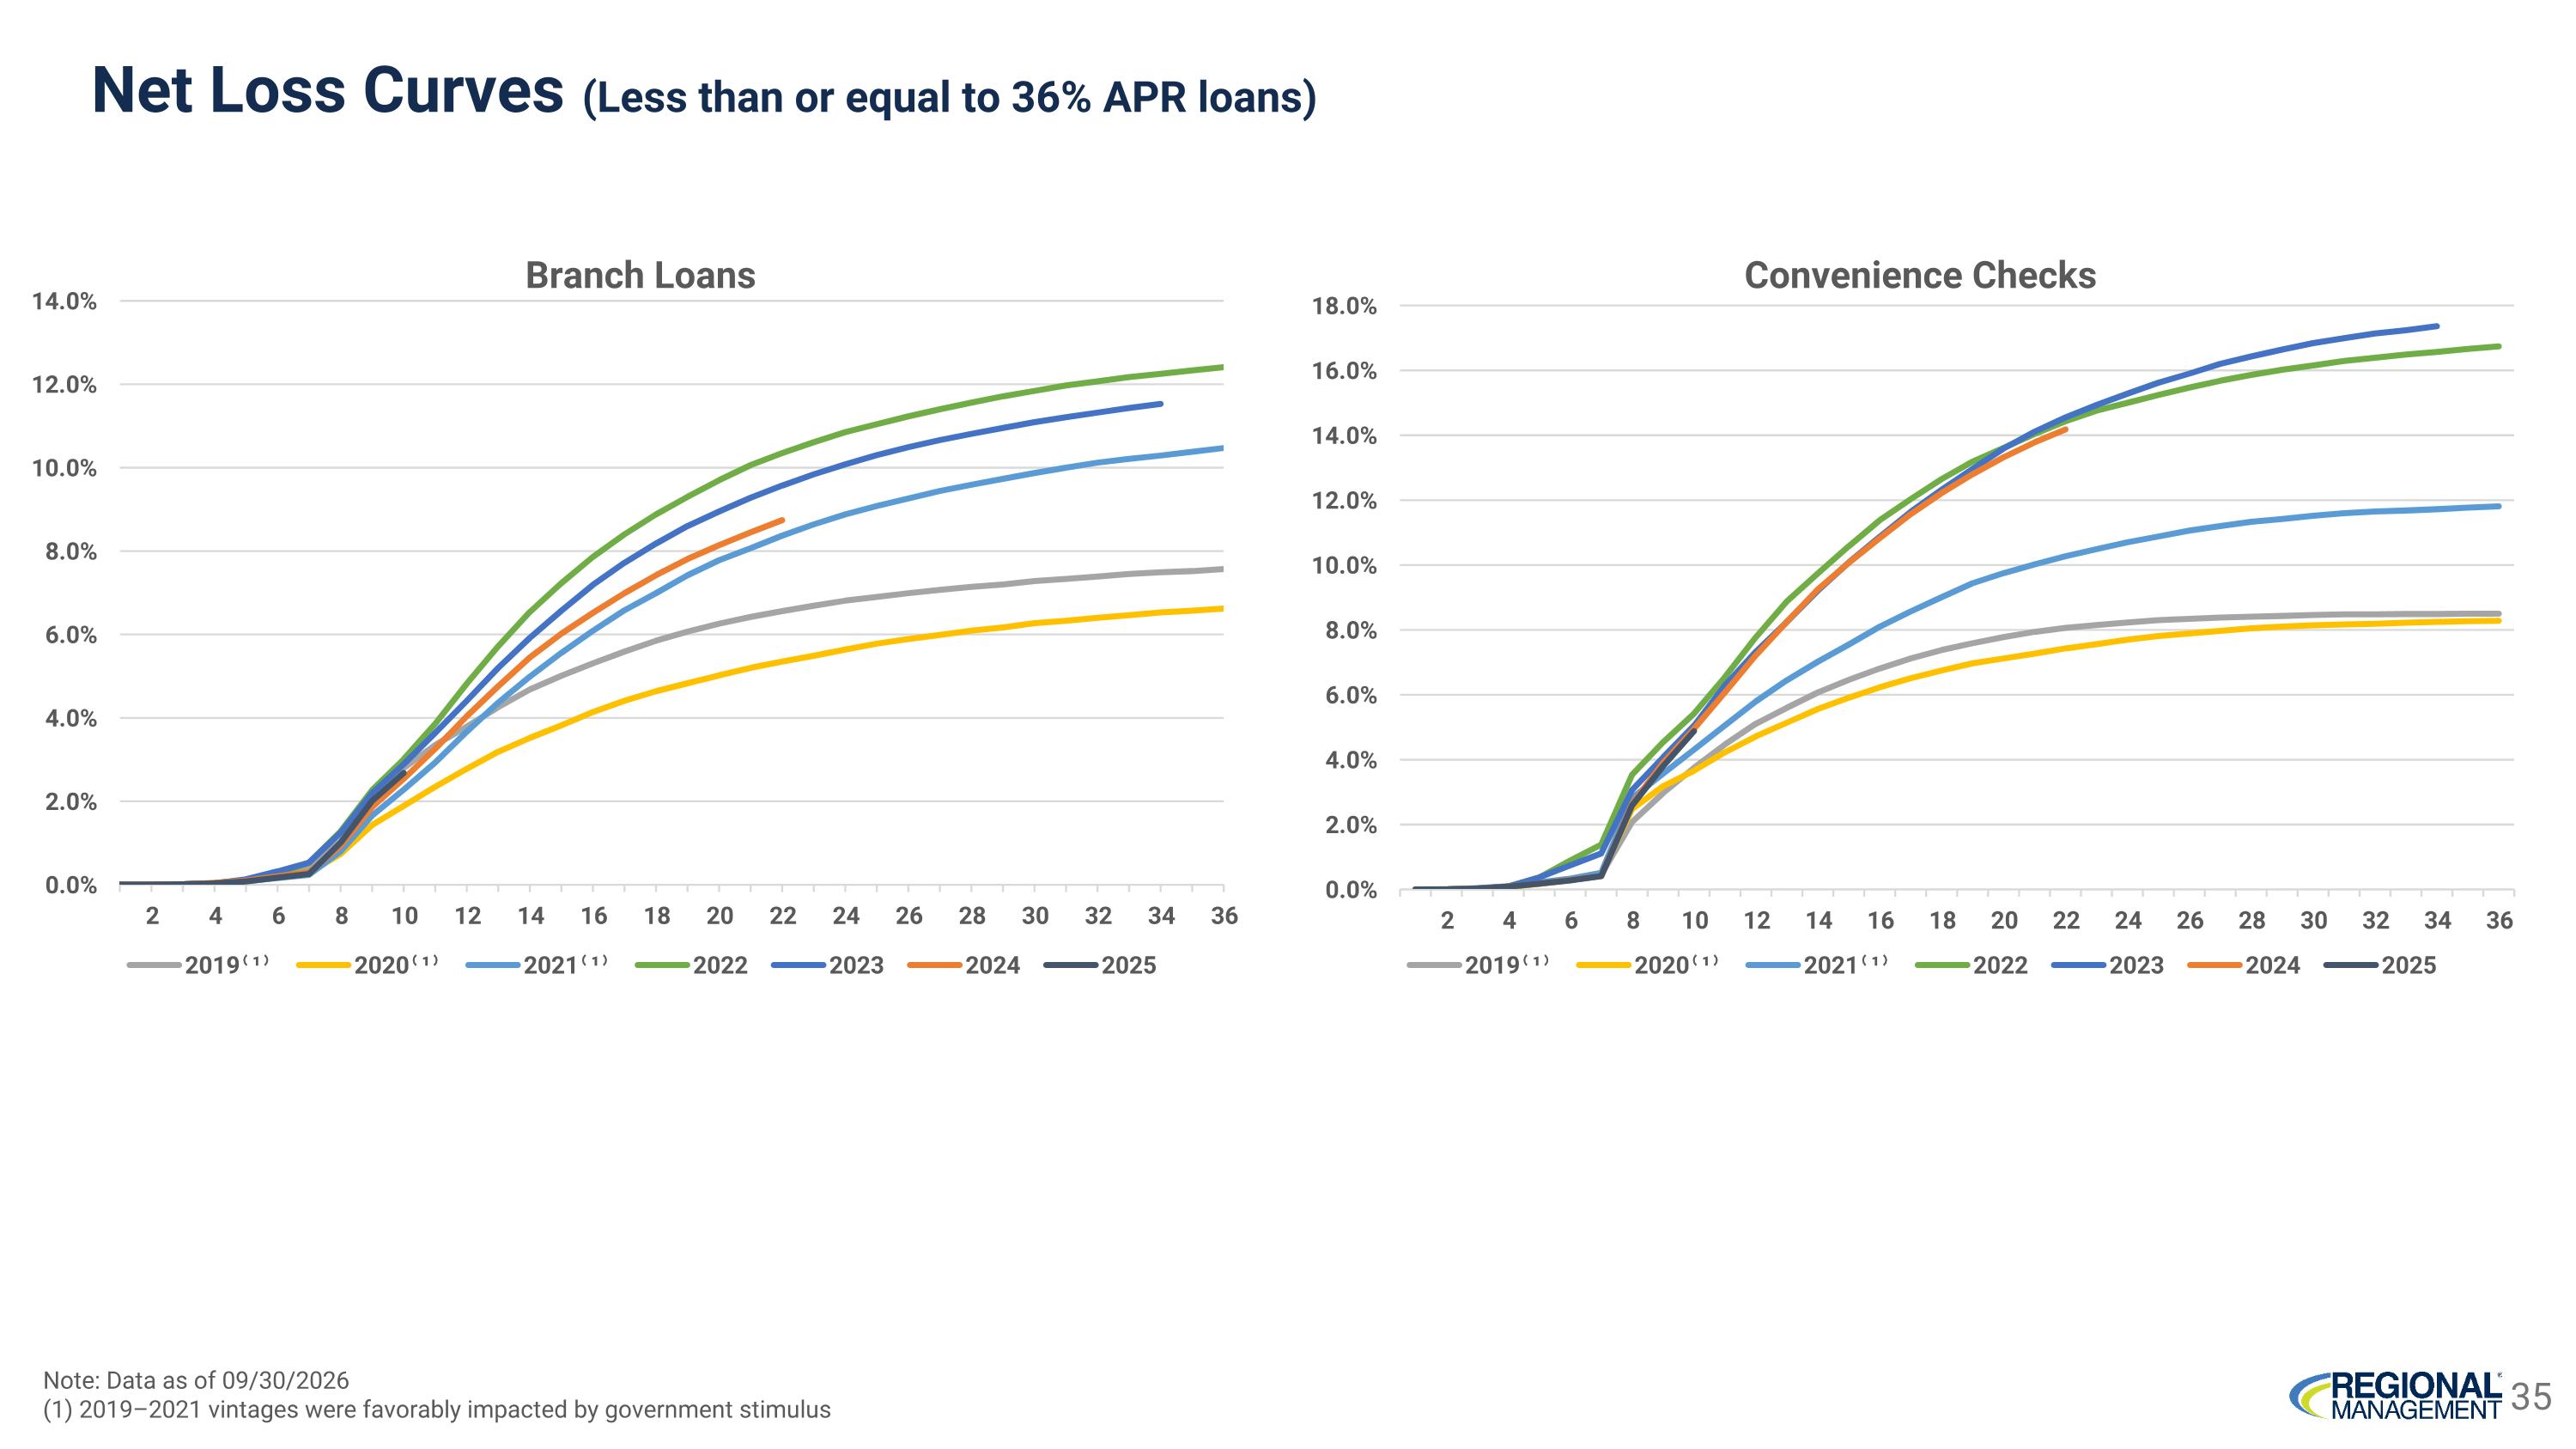
Net Loss Curves (Less than or equal to 36% APR loans) Note: Data as of 09/30/2026 (1) 2019–2021 vintages were favorably impacted by government stimulus
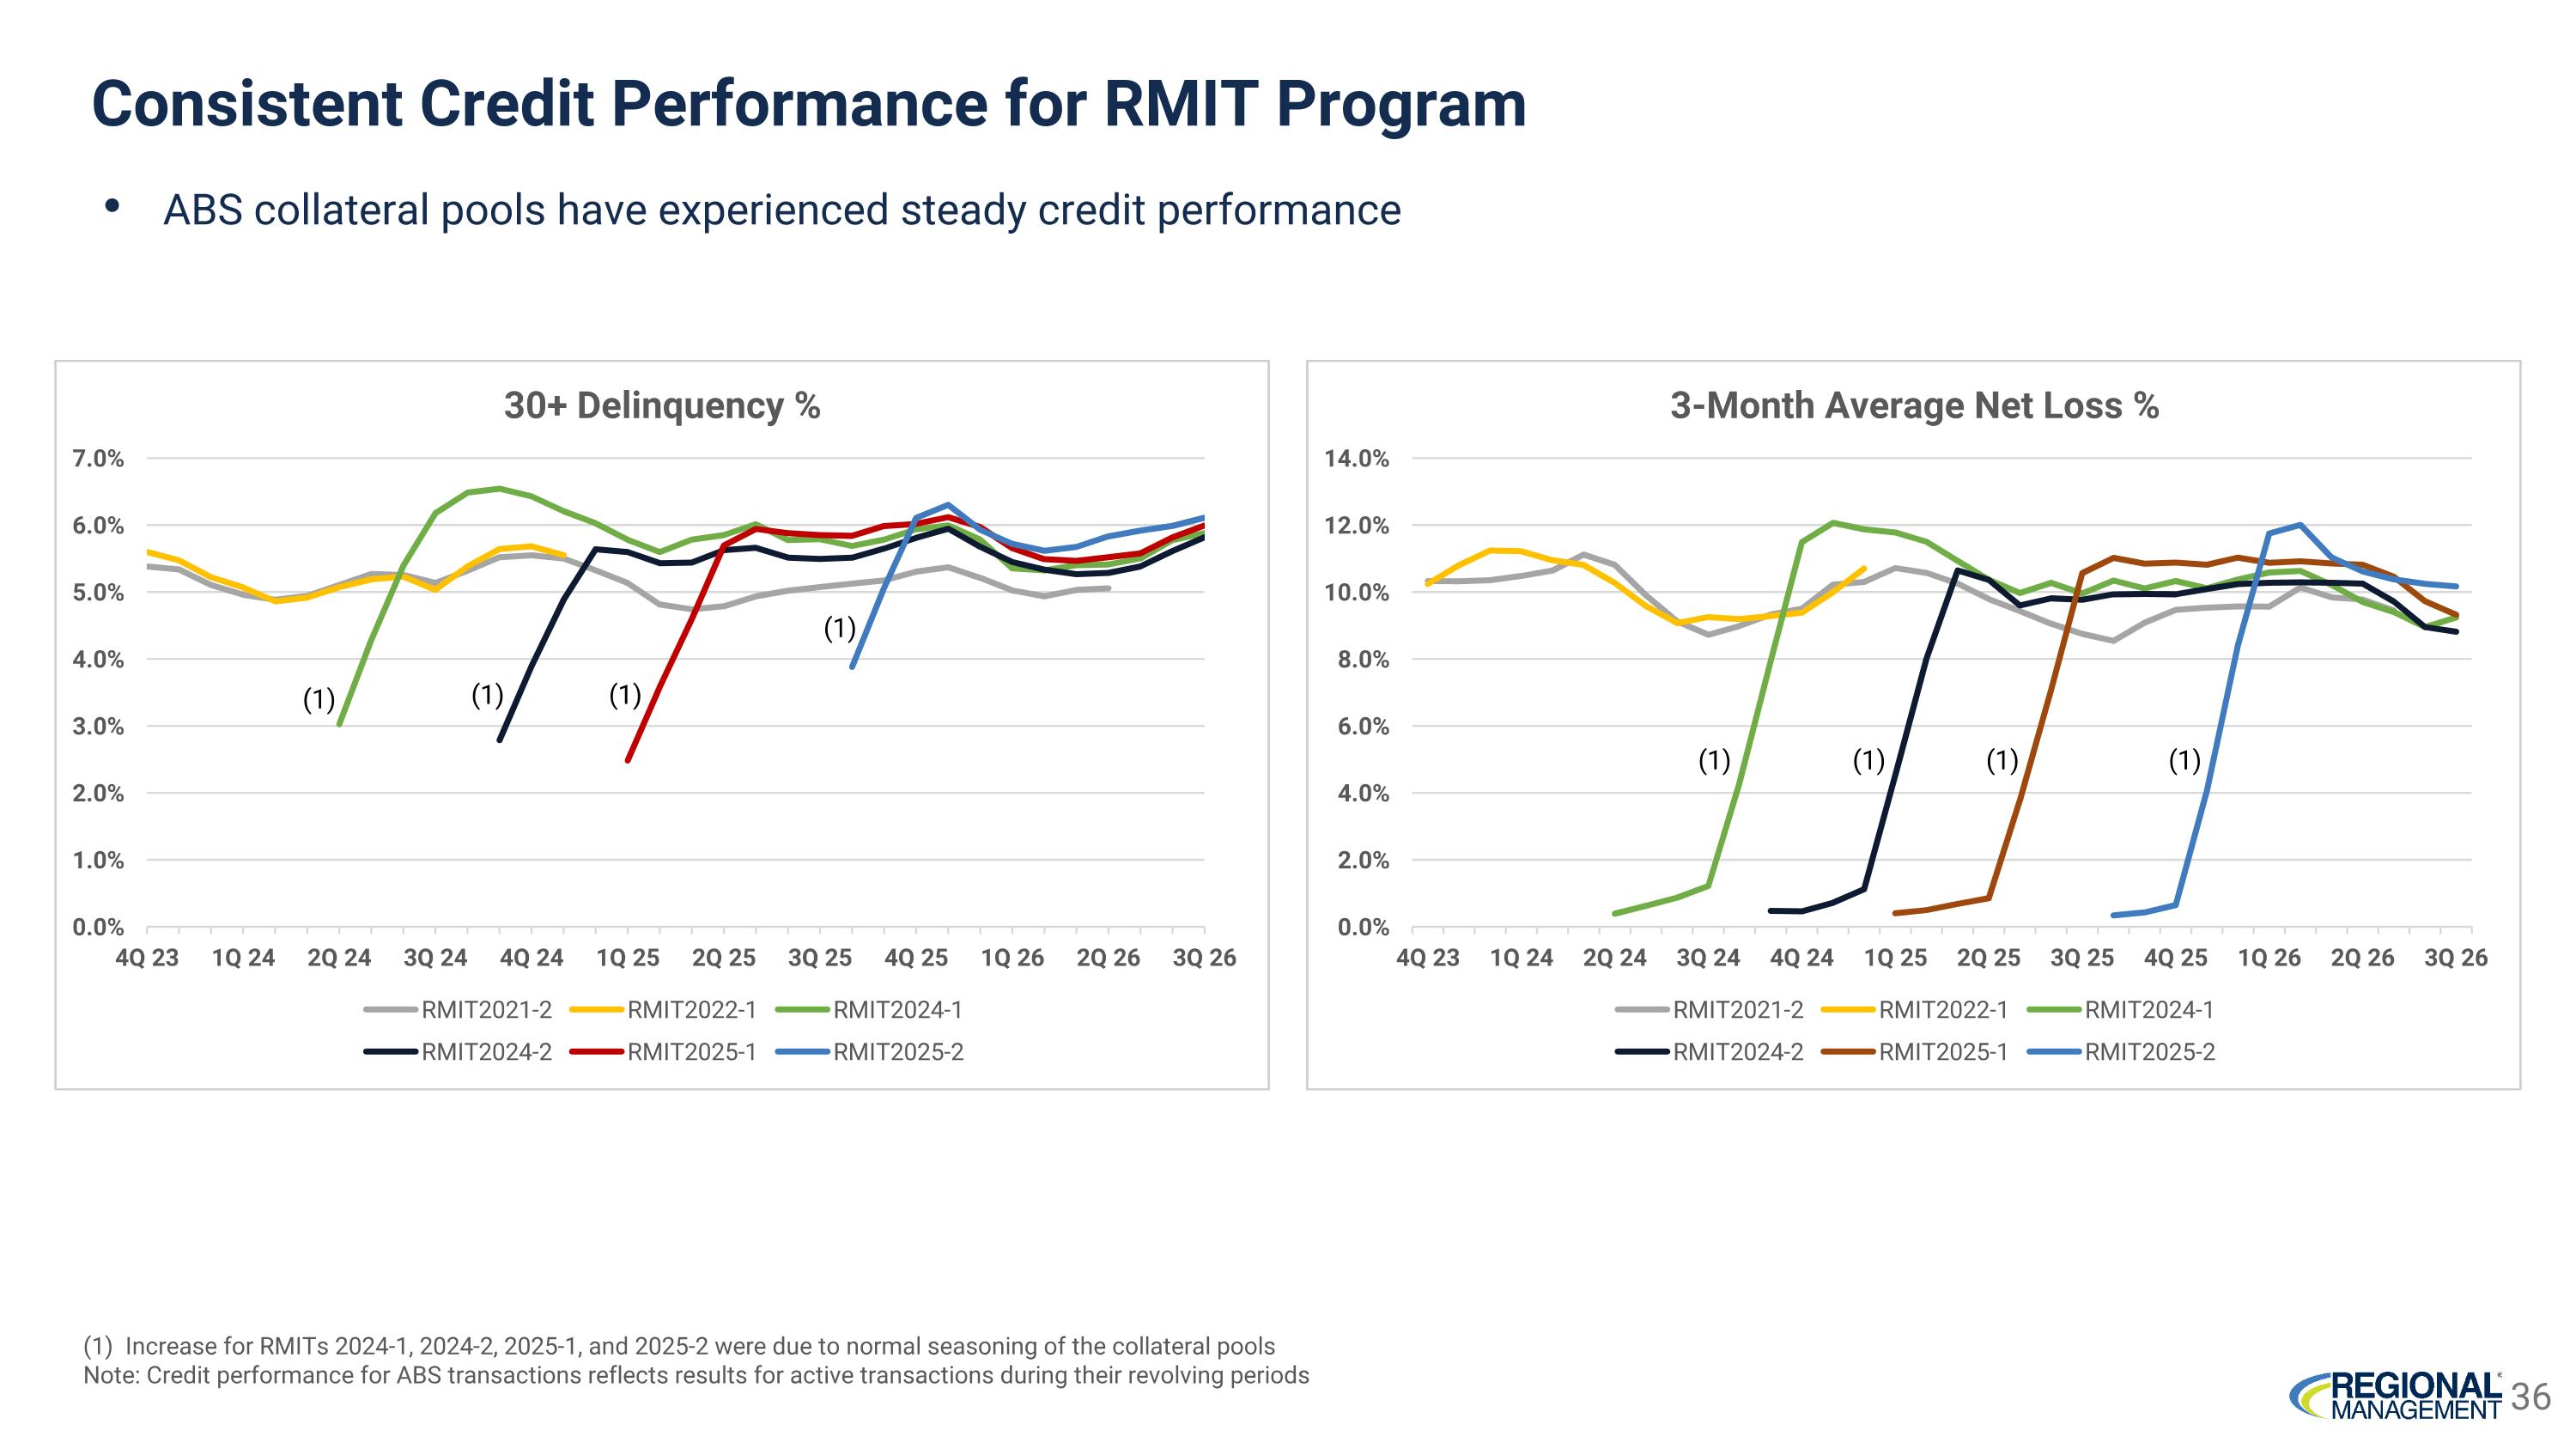
Consistent Credit Performance for RMIT Program (1) Increase for RMITs 2024-1, 2024-2, 2025-1, and 2025-2 were due to normal seasoning of the collateral pools Note: Credit performance for ABS transactions reflects results for active transactions during their revolving periods ABS collateral pools have experienced steady credit performance (1) (1) (1) (1) (1) (1) (1) (1)
Appendix
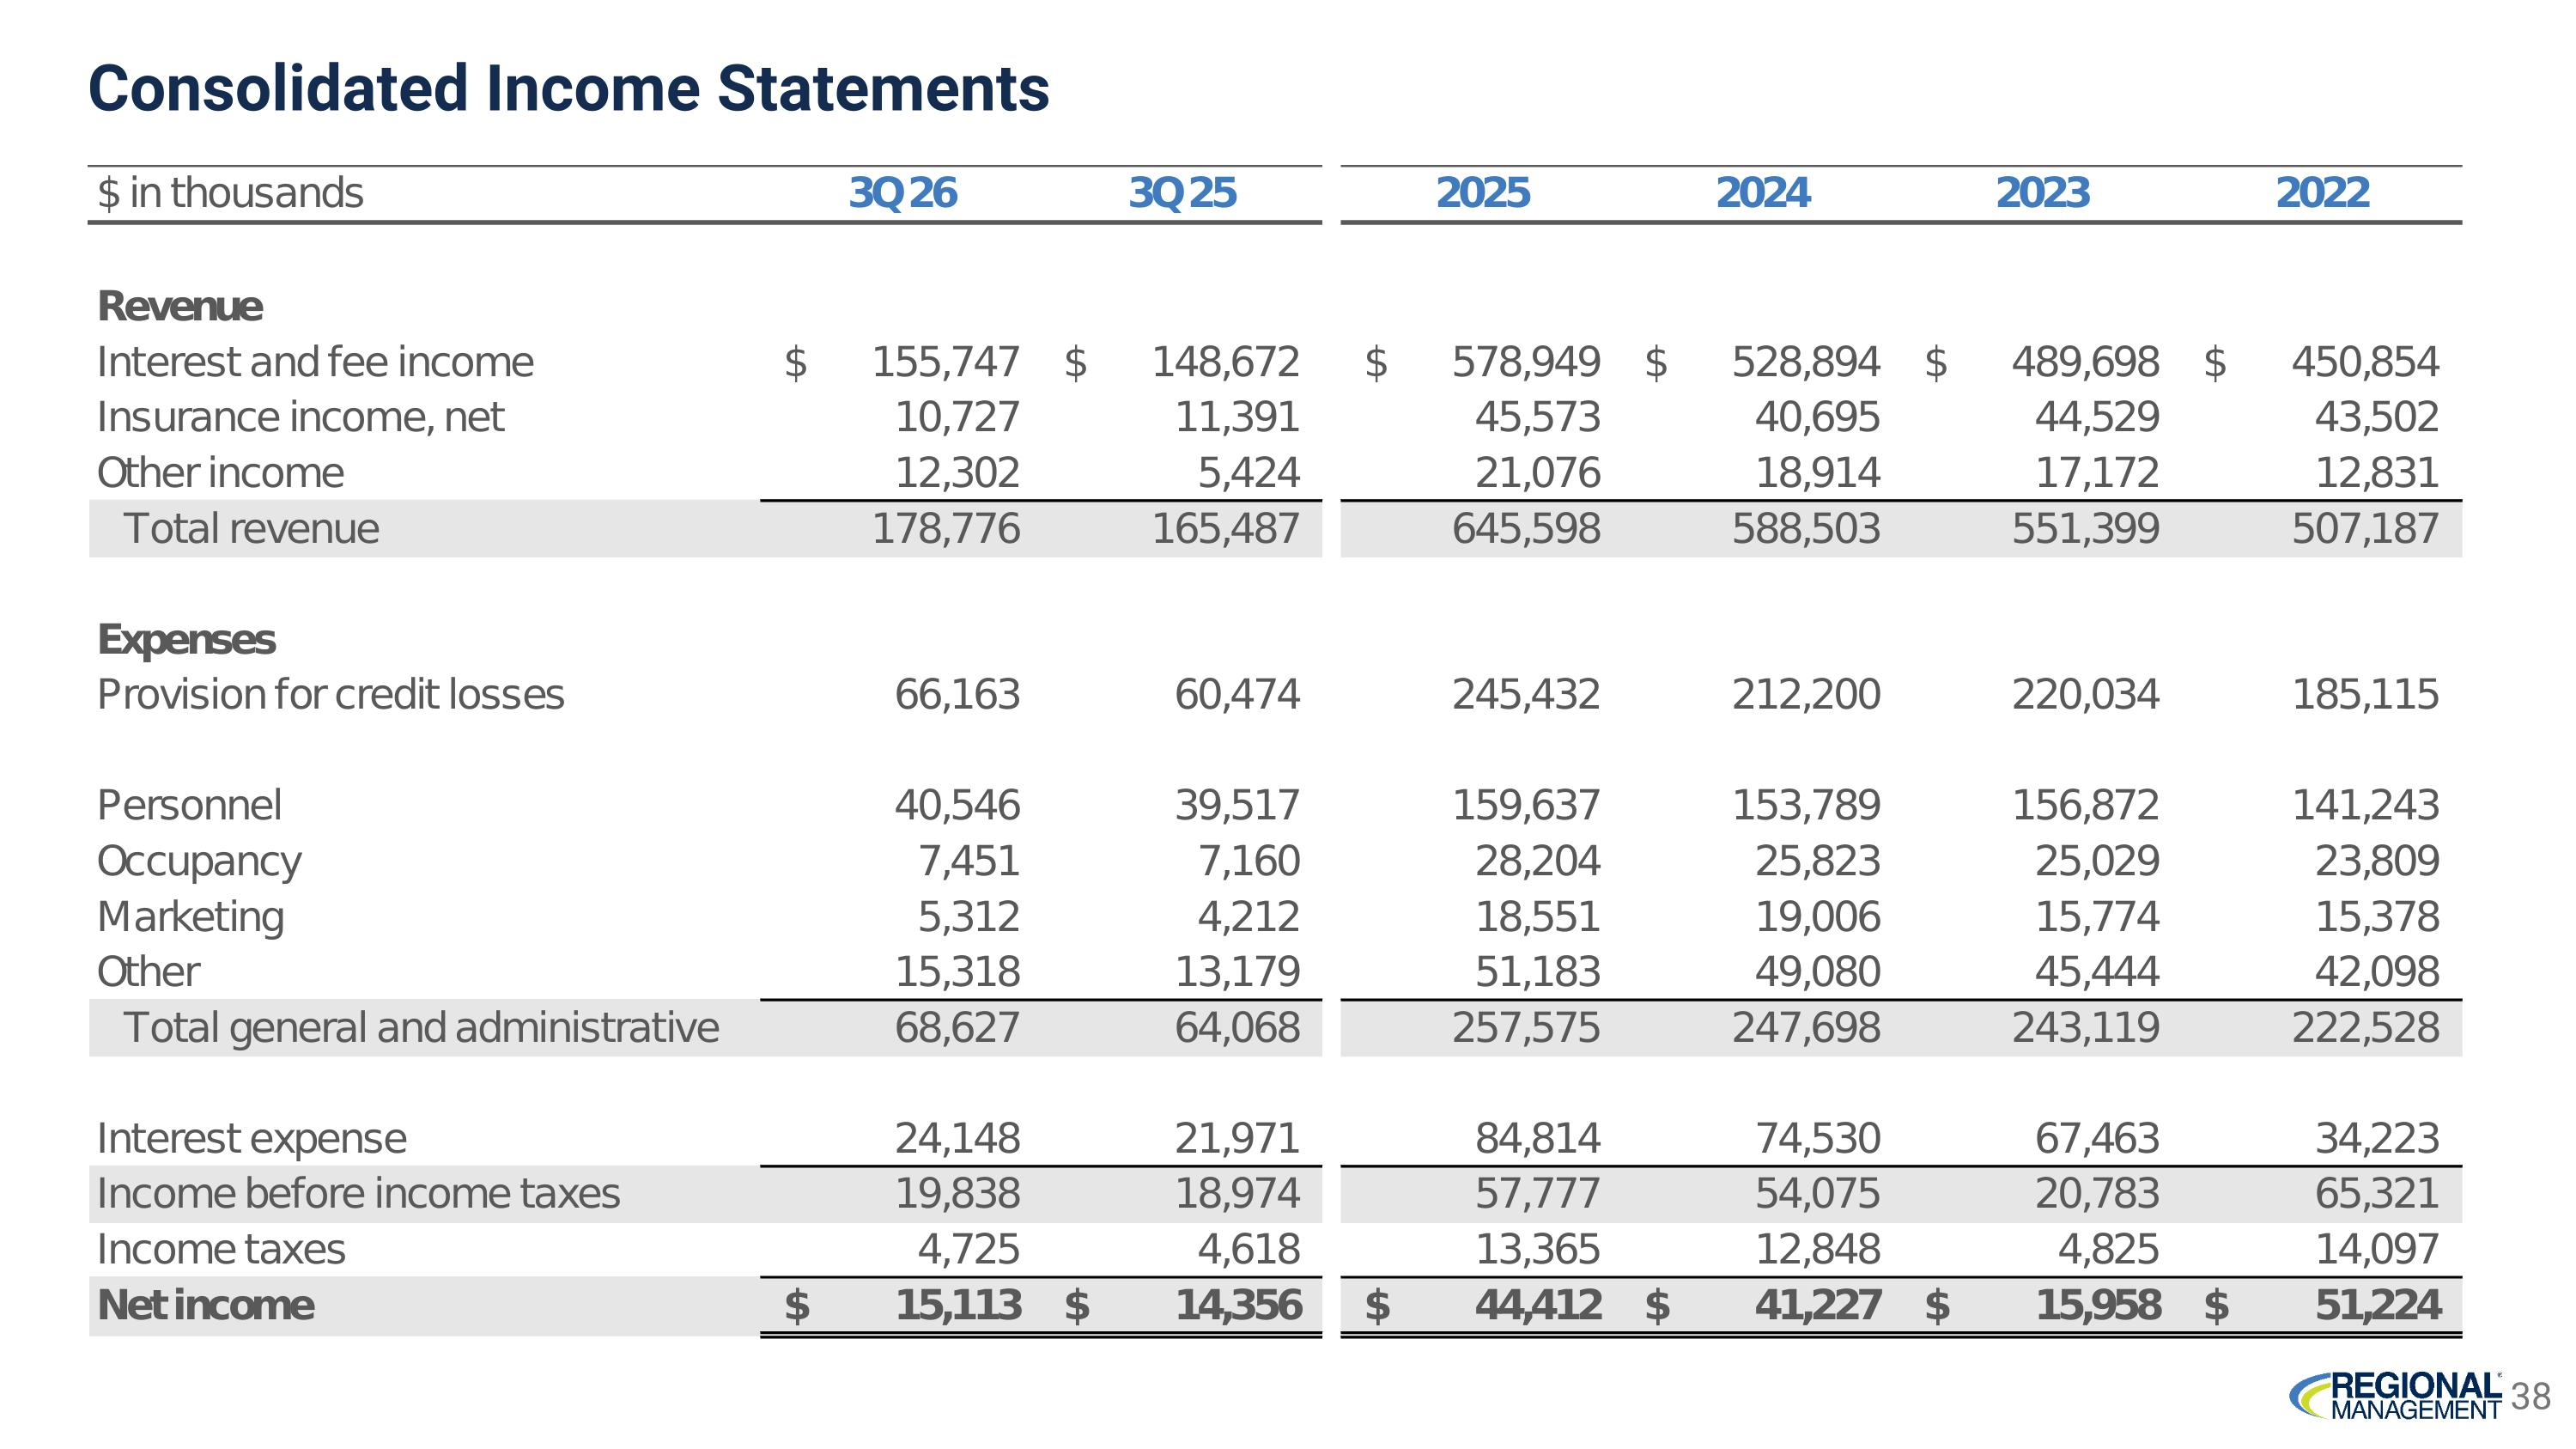
Consolidated Income Statements 38
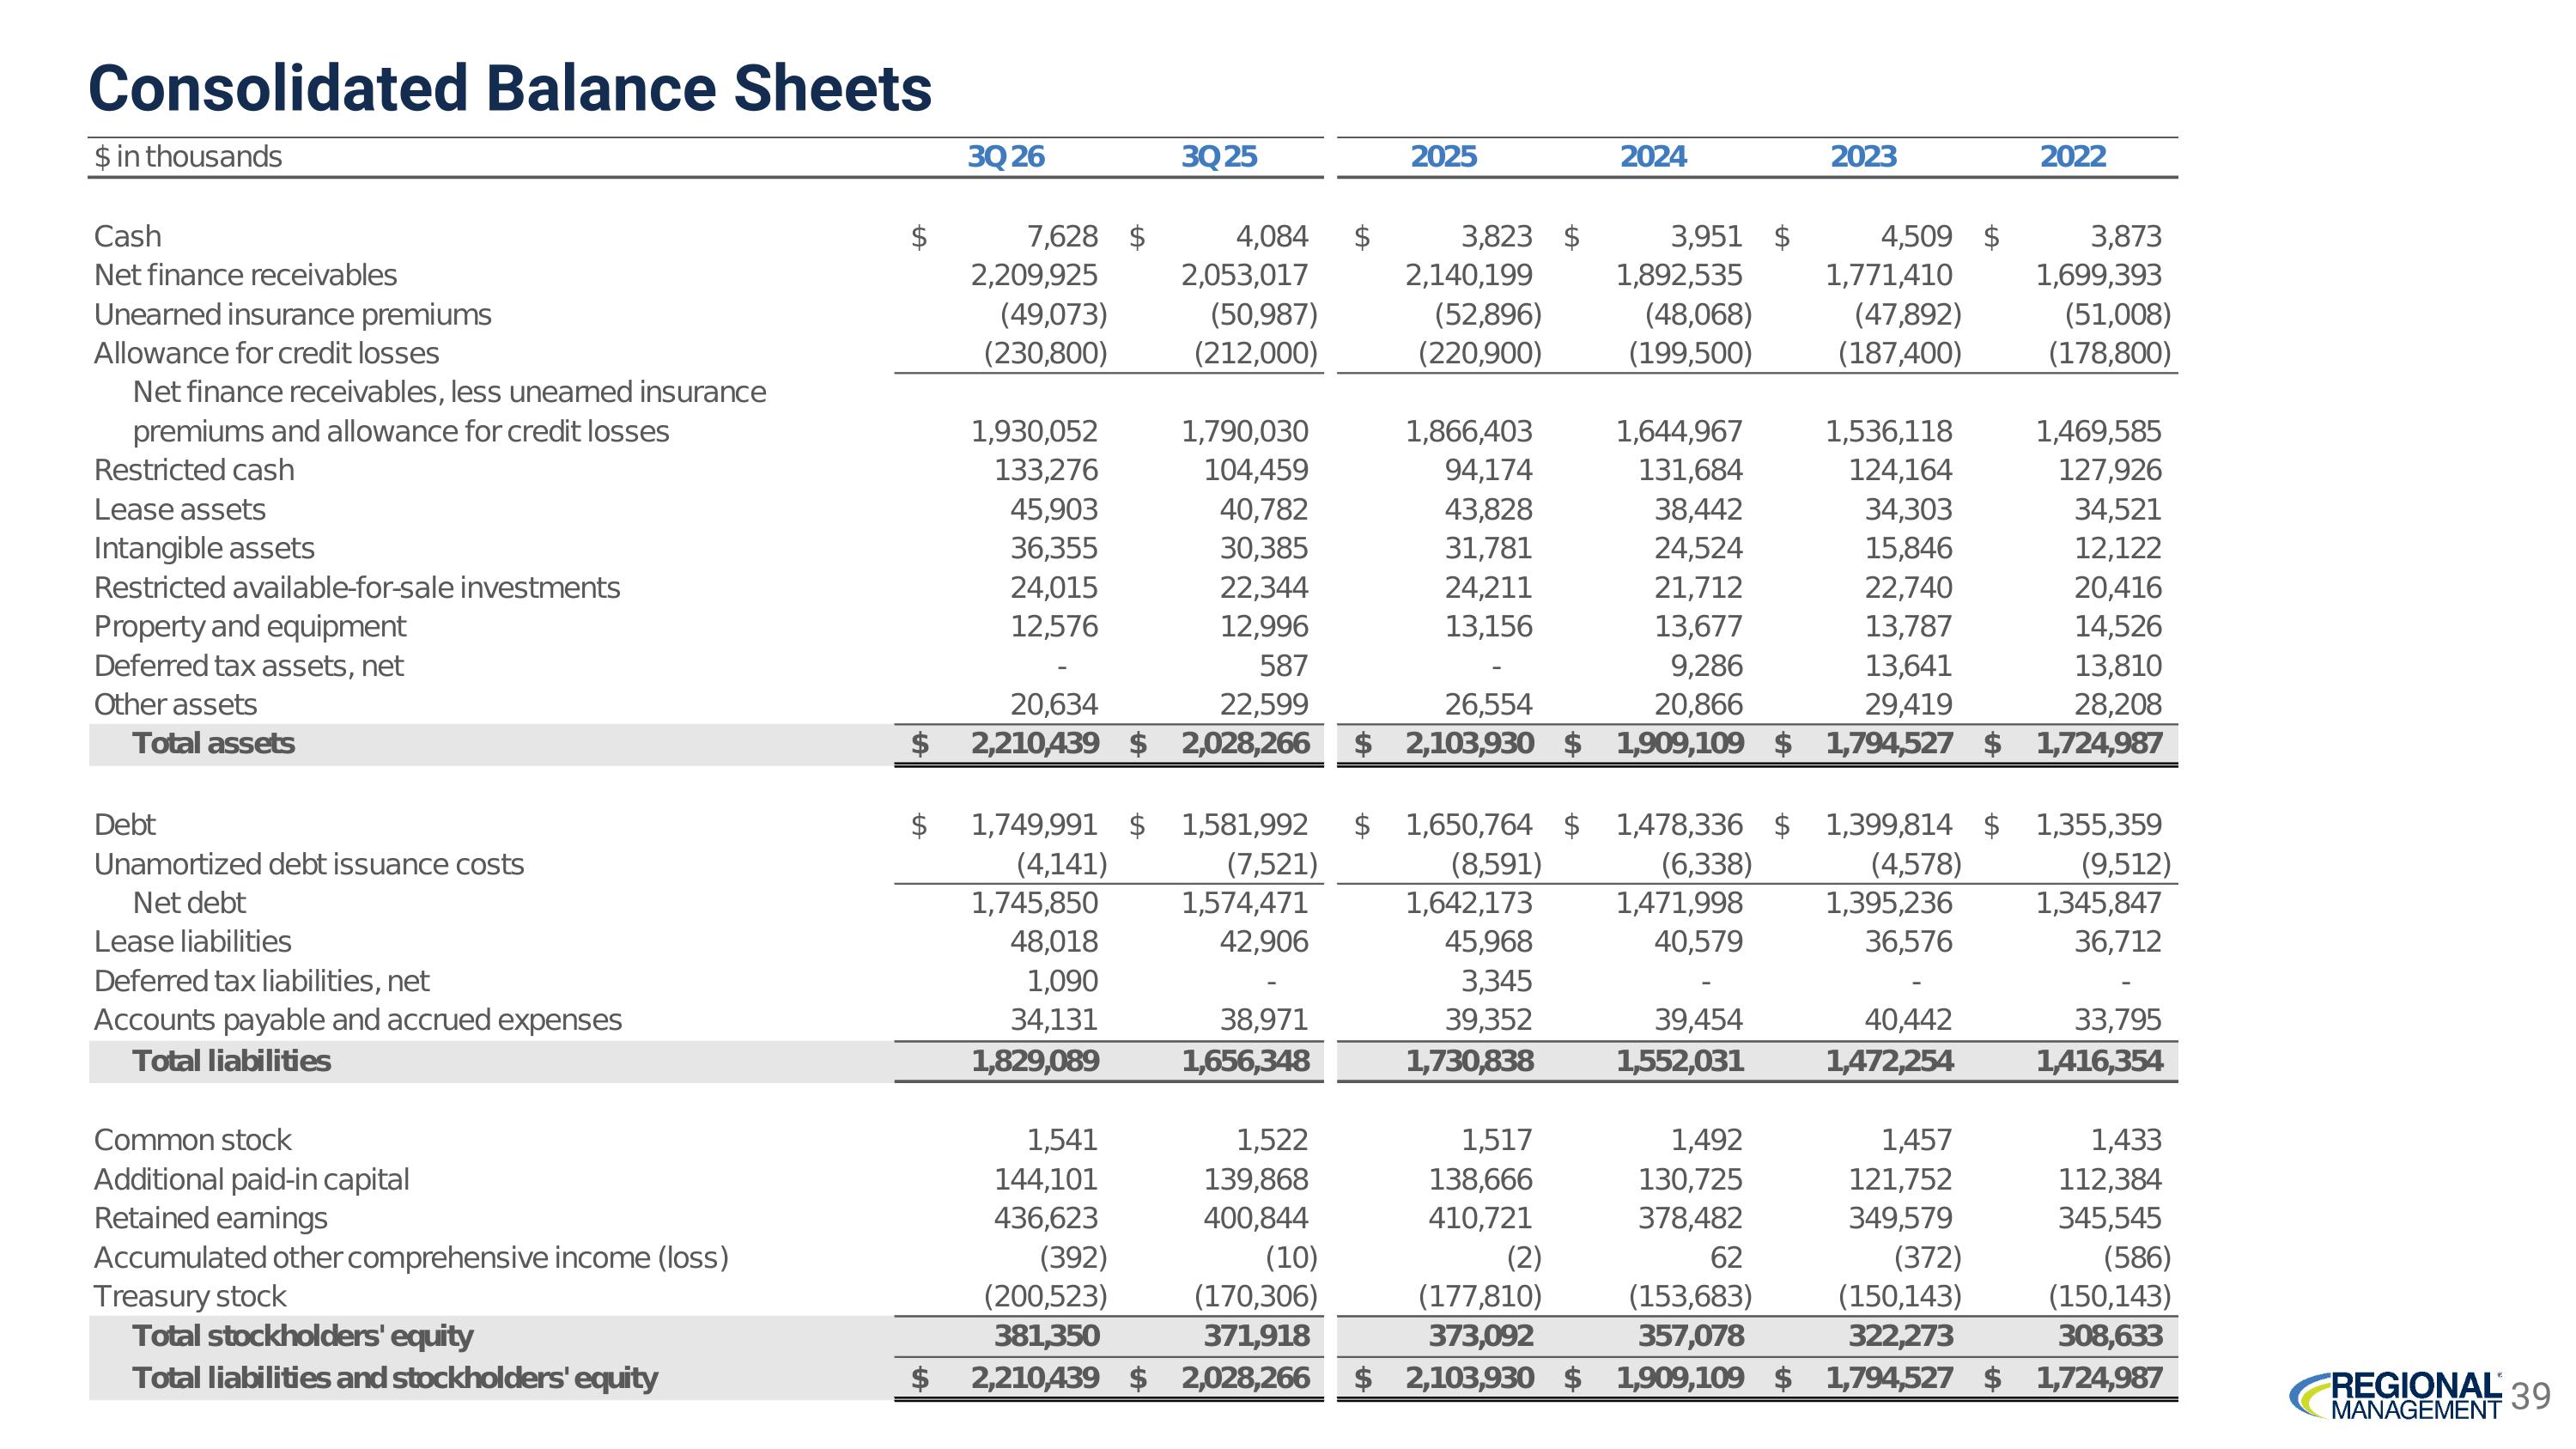
Consolidated Balance Sheets 39
Glossary Bps – basis points Delinquency rate (DQ %) – delinquent loans outstanding as a percentage of ending net finance receivables Efficiency ratio – general and administrative expenses as a percentage of total revenue ENR – ending net finance receivables Net credit loss rate (NCL %) – annualized net credit losses as a percentage of average net finance receivables Return on assets (ROA) – annualized net income as a percentage of average total assets Return on equity (ROE) – annualized net income as a percentage of average stockholders’ equity WAL – weighted average life 40