Management Discussion & Analysis
Management of Algonquin Power & Utilities Corp. ("AQN", the "Company" or the "Corporation") has prepared the following discussion and analysis to provide information to assist its securityholders' understanding of the financial results for the three and nine months ended September 30, 2026. This Management Discussion & Analysis ("MD&A") should be read in conjunction with AQN's unaudited interim condensed consolidated financial statements for the three and nine months ended September 30, 2026 and 2025. This MD&A should also be read in conjunction with AQN's audited consolidated financial statements for the years ended December 31, 2025 and 2024. This material is available on SEDAR+ at www.sedarplus.com, on EDGAR at www.sec.gov/edgar and on the AQN website at www.algonquinpower.com. Additional information about AQN, including the most recent Annual Information Form ("AIF"), can be found on SEDAR+ at www.sedarplus.com and on EDGAR at www.sec.gov/edgar.
Contents
| | | | | |
| Explanatory Notes | |
| Caution Concerning Forward-Looking Statements and Forward-Looking Information | |
| Caution Concerning Non-GAAP Measures | |
| Overview and Business Strategy | |
| |
| Significant Updates | |
| |
2026 Third Quarter Results From Operations | |
2026 Year-to-Date Results From Operations | |
| |
| |
| Regulated Services Group | |
| |
| Corporate Group | |
| Hydro Group | |
| |
| Discontinued Operations: Renewable Energy Group | |
| Non-GAAP Financial Measures | |
| |
| Summary of Property, Plant and Equipment Expenditures | |
| Liquidity and Capital Reserves | |
| Share-Based Compensation Plans | |
| Management Of Capital Structure | |
| Enterprise Risk Management | |
| Quarterly Financial Information | |
| |
| Disclosure Controls and Procedures | |
| |
| Critical Accounting Estimates and Policies | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 1 |
Explanatory Notes
Unless otherwise indicated, financial information provided for the three and nine months ended September 30, 2026 and 2025 has been prepared in accordance with generally accepted accounting principles in the United States ("U.S. GAAP"). As a result, the Company's financial information may not be comparable with financial information of other Canadian companies that provide financial information on another basis.
All monetary amounts are in U.S. dollars, except where otherwise noted. We denote any amounts denominated in Canadian dollars with "C$" immediately prior to the stated amount. Certain amounts in this MD&A may not total due to rounding.
Capitalized terms used herein and not otherwise defined have the meanings assigned to them in the Company's most recent AIF.
The term "rate base" is used in this document. Rate base is a measure specific to rate-regulated utilities that is not intended to represent any financial measure as defined by U.S. GAAP. The measure is used by the regulatory authorities in the jurisdictions where the Company's rate-regulated subsidiaries operate. The calculation of this measure may not be comparable to similarly-titled measures used by other companies.
Unless noted otherwise, this MD&A is based on information available to management as of November 6, 2026.
Renewables Business Sale
On January 8, 2025, the Company completed the previously announced sale of its renewable energy business (excluding hydro) (the "Renewables Sale") to a wholly-owned subsidiary of LS Power ("LS Buyer") for proceeds of approximately $2.1 billion, after subtracting taxes, transaction fees and other preliminary closing adjustments, including an adjustment for estimated remaining completion costs for in-construction assets. Approximately $1.95 billion of such proceeds were received upon the closing of the transaction and an additional approximately $150 million in proceeds were received subsequent to closing upon monetization of tax attributes on certain in-construction projects.
Additionally, the Company can receive up to $220 million in cash pursuant to an earn out agreement relating to certain wind assets (the "Earn Out"). The amount and timing of the ultimate net cash proceeds will be dependent on final completion costs for in-construction assets, the associated monetization of tax credits on certain of these projects (including, but not limited to, future events which could cause recapture of part or all of the tax attributes monetized and refund of the associated proceeds), and other final closing adjustments.
During the third quarter of 2024, the Company concluded that the consolidated assets within its former renewable energy group (excluding hydro) met the accounting requirements to be presented as "Held for Sale". As a result, the renewable energy group (excluding hydro) was classified as "discontinued operations" until closing of the Renewables Sale. The discontinued operations operated as a distinct segment and had no impact on the operations of the Regulated Services Group operating segment, other than sharing certain corporate support functions and benefiting from corporate debt and equity funding. This MD&A reflects the results of continuing operations, unless otherwise noted.
Sale of Chilean Operations
On August 28, 2026, AQN entered into an agreement to sell its wholly owned subsidiary, Liberty Holdings Chile SpA ("Suralis Holdco"), which indirectly holds the Company's approximately 64% ownership interest in Chilean water utility Suralis S.A. (“Suralis”), to a Chilean investment fund managed by Toesca S.A. Administradora General de Fondos (the "Buyer"). The sale subsequently closed on October 30, 2026. See Significant Updates - Sale of Chilean Operations.
Unless otherwise indicated, the information presented in this MD&A includes the results of Suralis Holdco. As a result of the sale of Suralis Holdco, the Company's Chilean operations were classified as held for sale as at September 30, 2026.
| | | | | | |
| | |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 2 | |
Caution Concerning Forward-Looking Statements and Forward-Looking Information
This document may contain statements that constitute "forward-looking information" within the meaning of applicable securities laws in each of the provinces and territories of Canada and the respective policies, regulations and rules under such laws or "forward-looking statements" within the meaning of the U.S. Private Securities Litigation Reform Act of 1995 (collectively, "forward-looking information"). The words "aims", "anticipates", "believes", "budget", "could", "estimates", "expects", "forecasts", "intends", "may", "might", "plans", "projects", "schedule", "seeks", "should", "strives", "targets", "will", "would", "pursue", "outlook" (and grammatical variations of such terms) and similar expressions are often intended to identify forward-looking information, although not all forward-looking information contains these identifying words. Specific forward-looking information in this document includes, but is not limited to, statements relating to: expected future investments and growth, earnings and results of operations; expectations regarding the timing and amount of the Earn Out in connection with the Renewables Sale; expectations regarding the proceeds from the earnout arrangement related to the sale of Suralis Holdco; the Company’s integrated customer solution technology platform; future plans and the expected outcomes thereof; liquidity, capital resources and operational requirements; sources of funding, including adequacy and availability of credit facilities, cash flows from operations, capital markets financing, and asset dispositions; potential acquisitions, dispositions, projects, initiatives or other transactions; financing plans; expectations regarding future macroeconomic conditions; expectations regarding the Company's corporate development activities and the results thereof; expectations regarding regulatory hearings, motions, decisions, orders, settlements, proposals, petitions, filings, appeals and approvals, including rate reviews, and the timing, impacts and outcomes thereof; expectations regarding the redemption of outstanding notes; expected future generation, capacity and production of the Company's energy facilities; expectations regarding future capital investments, including expected timing, investment plans, sources of funds and impacts; capital management plans and objectives; expectations regarding the outcome of legal claims and disputes, including as relates to the November 17, 2020 wildfire in California (the “Mountain View Fire”); expectations regarding the April 9, 2025 gas incident in Lexington, Missouri (the "Lexington Gas Incident"), including regulatory actions arising therefrom and availability of insurance coverage; strategy and goals; dividends to shareholders; share price appreciation; credit ratings from rating agencies; expectations regarding debt repayment and refinancing; the impact on the Company of actual or proposed laws, regulations and rules; accounting estimates; interest rates, including the anticipated effect of an increase thereof; financing costs; the expected impact of tariffs imposed by the U.S. and Canada and possible changes thereto; and currency exchange rates. All forward-looking information is given pursuant to the "safe harbour" provisions of applicable securities legislation.
The forecasts and projections that make up the forward-looking information contained herein are based on certain factors or assumptions which include, but are not limited to: the receipt of applicable regulatory approvals and requested rate decisions; the absence of material adverse regulatory decisions being received and the expectation of regulatory stability; the absence of any material equipment breakdown or failure; availability of financing including self-monetization transactions for U.S. federal tax credits on commercially reasonable terms; the stability of credit ratings of the Corporation and its subsidiaries; the absence of unexpected material liabilities or uninsured losses; the continued availability of commodity supplies and stability of commodity prices; the absence of interest rate increases or significant currency exchange rate fluctuations; the absence of significant operational, financial or supply chain disruptions or liability, including relating to additional import controls and tariffs; the continued ability to maintain systems and facilities to ensure their continued performance; the absence of a severe and prolonged downturn in general economic, credit, social or market conditions; the successful and timely development and construction of new projects; the absence of capital project or financing cost overruns; sufficient liquidity and capital resources; the continuation of long-term weather patterns and trends; the absence of significant counterparty defaults; the continued competitiveness of electricity pricing when compared with alternative sources of energy; the realization of the anticipated benefits of the Corporation's dispositions, acquisitions and joint ventures; the absence of a change in applicable laws, political conditions, public policies and directions by governments materially negatively affecting the Corporation; the ability to obtain, comply with and maintain licenses and permits; maintenance of adequate insurance coverage; the absence of material fluctuations in market energy prices; the absence of material disputes with taxation authorities or changes to applicable tax laws; continued maintenance of information technology infrastructure and the absence of a material breach of cybersecurity; the successful implementation and operation of new information technology systems and infrastructure; favourable relations with external stakeholders; favourable labour relations; that the Corporation will be able to successfully integrate newly acquired entities, and the absence of any material adverse changes to such entities prior to closing; the absence of undisclosed liabilities of entities being acquired; the absence of any significant indemnification claims arising from the Renewables Sale; the absence of any reputational harm to the Corporation as a result of the Renewables Sale and the announcement of the Redomicile; the absence of adverse reactions or changes in business relationships or relationships with employees following the Renewables Sale and the announcement of the Redomicile; and the ability of the Corporation to realize the anticipated benefits from the Renewables Sale and the Redomicile.
The forward-looking information contained herein is subject to risks, uncertainties and other factors that could cause actual results to differ materially from historical results or results anticipated by the forward-looking information. Factors which could cause results or events to differ materially from current expectations include, but are not limited to: changes in general economic, credit, social or market conditions; changes in customer energy usage patterns and energy demand; reductions in
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 3 |
the liquidity of energy markets; global climate change; the incurrence of environmental liabilities; natural disasters, diseases, pandemics, public health emergencies and other force majeure events and the collateral consequences thereof, including the disruption of economic activity, volatility in capital and credit markets and legislative and regulatory responses; critical equipment breakdown or failure; supply chain disruptions; the impact of existing import controls and tariffs and the imposition of additional import controls or tariffs; the failure of information technology infrastructure and other cybersecurity measures to protect against data, privacy and cybersecurity breaches; failure to successfully implement and operate, and cost overruns and delays in connection with, new information technology systems and infrastructure; physical security breach; the loss of key personnel and/or labour disruptions; seasonal fluctuations and variability in weather conditions and natural resource availability; reductions in demand for electricity, natural gas and water due to developments in technology; reliance on transmission systems owned and operated by third parties; issues arising with respect to land use rights and access to the Corporation's facilities; terrorist attacks; fluctuations in commodity and energy prices; capital expenditures; reliance on subsidiaries; the incurrence of an uninsured loss; a credit rating downgrade; an increase in financing costs or limits on access to credit and capital markets; inflation; increases and fluctuations in interest rates and failure to manage exposure to credit and financial instrument risk; currency exchange rate fluctuations; restricted financial flexibility due to covenants in existing credit agreements; an inability to refinance maturing debt on favourable terms; disputes with taxation authorities or changes to applicable tax laws; requirement for greater than expected contributions to post-employment benefit plans; default by a counterparty; inaccurate assumptions, judgments and/or estimates with respect to asset retirement obligations; failure to maintain required regulatory authorizations; changes in, or failure to comply with, applicable laws and regulations; failure of compliance programs; failure to dispose of assets (at all or at a competitive price) to fund the Company’s operations and strategic objectives; delays and cost overruns in the design and construction of projects; loss of key customers; a third party joint venture partner acting in a manner contrary to the Corporation’s interests; facilities being condemned or otherwise taken by governmental entities; increased external stakeholder activism adverse to the Corporation's interests; fluctuations in the price and liquidity of the Corporation's common shares and the Corporation's other securities; the failure to implement the Corporation's strategic objectives or achieve expected benefits relating to acquisitions, dispositions or other initiatives, including the Redomicile; and the possibility of adverse reactions or changes in business relationships or relationships with stakeholders resulting from the announcement of the Redomicile and the sale of Suralis Holdco. Although the Corporation has attempted to identify important factors that could cause actual actions, events or results to differ materially from those described in forward-looking information, there may be other factors that cause actions, events or results not to be as anticipated, estimated or intended. Some of these and other factors are discussed in more detail under the heading "Enterprise Risk Management" in this MD&A and in the Company’s MD&A for the three and twelve months ended December 31, 2025 (the "Annual MD&A") and under the heading "Enterprise Risk Factors" in the Corporation's most recent AIF.
Forward-looking information contained herein (including any financial outlook) is provided for the purposes of assisting the reader in understanding the Corporation and its business, operations, risks, financial performance, financial position and cash flows as at and for the periods indicated and to present information about management's current expectations and plans relating to the future, and the reader is cautioned that such information may not be appropriate for other purposes. Forward-looking information contained herein is made as of the date of this document and based on the plans, beliefs, estimates, projections, expectations, opinions and assumptions of management on the date hereof. There can be no assurance that forward-looking information will prove to be accurate, as actual results and future events could differ materially from those anticipated in such forward-looking information. Accordingly, readers should not place undue reliance on forward-looking information. While subsequent events and developments may cause the Corporation's views to change, the Corporation disclaims any obligation to update any forward-looking information or to explain any material difference between subsequent actual events and such forward-looking information, except to the extent required by applicable law. All forward-looking information contained herein is qualified by these cautionary statements.
Caution Concerning Non-GAAP Measures
AQN uses a number of financial measures to assess the performance of its business lines. Some measures are calculated in accordance with U.S. GAAP, while other measures do not have a standardized meaning under U.S. GAAP. These non-GAAP measures include non-GAAP financial measures and non-GAAP ratios, each as defined in Canadian National Instrument 52-112 Non-GAAP and Other Financial Measures Disclosure. AQN's method of calculating these measures may differ from methods used by other companies and therefore may not be comparable to similar measures presented by other companies.
The terms "Adjusted Net Earnings", "Earnings Before Interest and Taxes" ("EBIT"), and "Net Utility Sales", which are used throughout this MD&A, are non-GAAP financial measures. An explanation of each of these non-GAAP financial measures is set out below and a reconciliation to the most directly comparable U.S. GAAP measure, in each case, can be found in this MD&A. In addition, "Adjusted Net Earnings" is presented throughout this MD&A on a per common share basis. Adjusted Net Earnings per common share is a non-GAAP ratio and is calculated by dividing Adjusted Net Earnings by the weighted average number of common shares outstanding during the applicable period. As a pure-play regulated utility, as of the first quarter of 2025, the Company no longer presents "Adjusted Earnings Before Interest, Taxes, Depreciation and Amortization" or "Adjusted
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
Funds from Operations" as these metrics were relevant mainly to the Company's former renewable energy group (excluding hydro) that was sold in connection with the Renewables Sale.
AQN does not provide reconciliations for forward-looking non-GAAP financial measures as AQN is unable to provide a meaningful or accurate calculation or estimation of reconciling items and the information is not available without unreasonable effort. This is due to the inherent difficulty of forecasting the timing or amount of various events that have not yet occurred, are out of AQN's control and/or cannot be reasonably predicted, and that would impact the most directly comparable forward-looking U.S. GAAP financial measure. For these same reasons, AQN is unable to address the probable significance of the unavailable information. Forward-looking non-GAAP financial measures may vary materially from the corresponding U.S. GAAP financial measures.
EBIT
EBIT is a non-GAAP financial measure used by many investors to assess the Company's core operational profitability by measuring the profit generated from day-to-day business activities, excluding interest and tax expenses. AQN uses EBIT to assess its operating performance without the effects of (as applicable): income tax expense or recoveries, interest expense and earnings attributable to non-controlling interests. Earnings attributable to non-controlling interests includes Hypothetical Liquidation at Book Value ("HLBV") income (which represents the value of net tax attributes earned in the period from electricity generated by certain of AQN's U.S. wind power and U.S. solar generation facilities). AQN believes that presentation of this measure will enhance an investor's understanding of AQN's operating performance. EBIT is not intended to be representative of cash provided by operating activities or net earnings (each determined in accordance with U.S. GAAP, with net earnings being the most directly comparable U.S. GAAP financial measure) and can be impacted positively or negatively by these items. For a reconciliation of EBIT to net earnings attributable to common shareholders, see Non-GAAP Financial Measures starting on page 36 of this MD&A. For reconciliations of EBIT by business segments, see 2026 Third Quarter and Year-to-Date Regulated Services Group Net Earnings and Adjusted Net Earnings starting on page 18, Corporate Group Net Earnings and Adjusted Net Earnings on page 33 and Hydro Group Net Earnings and Adjusted Net Earnings on page 34 of this MD&A. Adjusted Net Earnings
Adjusted Net Earnings is a non-GAAP financial measure used by many investors to compare net earnings attributable to common shareholders from operations without the effects of certain volatile primarily non-cash items that generally have no current economic impact or items such as acquisition expenses or certain litigation expenses that are viewed as not directly related to a company’s operating performance. AQN uses Adjusted Net Earnings to assess its performance without the effects of (as applicable): gains or losses on foreign exchange, foreign exchange forward contracts, interest rate swaps, acquisition and transition costs, certain litigation expenses and write down of intangibles and property (including restructuring costs related to the Company's transition to a pure-play utility), plant and equipment, earnings or loss from discontinued operations, unrealized mark-to-market revaluation impacts, costs related to prior period adjustments due to changes in tax law, costs related to condemnation proceedings, gains and losses on disposition of assets, gains and losses on assets classified as held for sale, and other typically non-recurring or unusual items (including those related to the Mountain View Fire and the Lexington Gas Incident) as these are not reflective of the performance of the underlying business of AQN. AQN believes that analysis and presentation of net earnings or loss on this basis will enhance an investor’s understanding of the operating performance of its businesses. Adjusted Net Earnings is not intended to be representative of net earnings or loss determined in accordance with U.S. GAAP, and can be impacted positively or negatively by these items. For a reconciliation of Adjusted Net Earnings to net earnings attributable to common shareholders, see Non-GAAP Financial Measures starting on page 37, 2026 Third Quarter and Year-to-Date Regulated Services Group Net Earnings and Adjusted Net Earnings starting on page 18, Corporate Group Net Earnings and Adjusted Net Earnings on page 33 of this MD&A and Hydro Group Net Earnings and Adjusted Net Earnings on page 34 of this MD&A. The composition of Adjusted Net Earnings has been changed from that previously disclosed in the Annual MD&A to exclude one-time costs of arranging tax equity financing, costs related to management succession and executive retirement, changes in value of investments carried at fair value and prior period adjustments included in the gain (loss) from equity method investments not operated by the Company. Management believes this change better aligns the measure with industry practice and improves the metric's usefulness to investors. Comparative figures for this metric have been adjusted for the new composition.
Net Utility Sales
Net Utility Sales is a non-GAAP financial measure used by investors to identify utility revenue after commodity costs, either water, natural gas or electricity, where these commodity costs are generally included as a pass through in rates to its utility customers. AQN uses Net Utility Sales to assess its utility revenues without the effects of fluctuating commodity costs as such costs are predominantly passed through and paid for by utility customers. AQN believes that analysis and presentation of Net Utility Sales on this basis will enhance an investor's understanding of the revenue generation of the Regulated Services Group. It is not intended to be representative of revenue as determined in accordance with U.S. GAAP. For a reconciliation of
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 5 |
Net Utility Sales to revenue, see 2026 Third Quarter and Year-to-Date Regulated Services Group Net Earnings and Adjusted Net Earnings on page 18 of this MD&A. Overview and Business Strategy
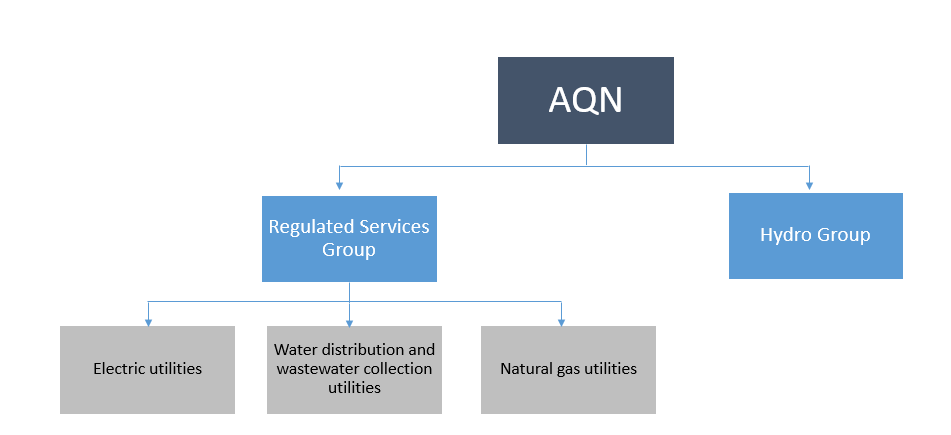
AQN is incorporated under the Canada Business Corporations Act. The Company's operations are organized across two business units consisting of (i) the Regulated Services Group, which primarily owns and operates a portfolio of regulated electric, water distribution and wastewater systems and natural gas utility systems and transmission operations in the United States, Canada and Bermuda and, prior to the closing of the sale of Suralis Holdco on October 30, 2026, held an interest in a water and wastewater utility system in Chile; and (ii) the Hydro Group, which consists of hydroelectric generation facilities located in Canada that were not sold as part of the Renewables Sale. Additionally, the Company has a corporate function, the Corporate Group, consisting of corporate debt and corporate and shared services that primarily support the Regulated Services Group and the Hydro Group. The Company’s former renewable energy group (excluding hydro) is reported as discontinued operations (see Note 18 to the unaudited interim condensed consolidated financial statements - Disposition of Renewable Energy Business) and was sold by the Company on January 8, 2025. The Company's business units align with how the Company assesses financial performance and makes decisions regarding resource allocations. Through its activities, the Company aims to drive growth in earnings and cash flows to support a sustainable dividend and share price appreciation. AQN strives to achieve these results while also seeking to maintain a business risk profile consistent with its investment grade credit ratings.
Summary Structure of the Business
The following chart depicts, in summary form, AQN's key operating business units. A more detailed description of AQN's organizational structure as of the date of the AIF can be found in the most recent AIF.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
Regulated Services Group
The Regulated Services Group primarily operates a diversified portfolio of regulated utility systems located in the United States, Canada and Bermuda. Additionally, prior to the closing of the sale of Suralis Holdco on October 30, 2026, the Regulated Services Group also held an interest in a water and wastewater utility in Chile (see Significant Updates - Sale of Chilean Operations). The Regulated Services Group served approximately 1,318,000 customer connections as at September 30, 2026 (using an average of 2.5 customers per connection, this translates into approximately 3,295,000 customers). The Regulated Services Group seeks to provide safe, high quality, and reliable services to its customers and to deliver stable and predictable earnings to AQN. The Regulated Services Group seeks to deliver long-term growth within its service territories, including through the pursuit of capital investment opportunities and other initiatives.
The Regulated Services Group's regulated electrical distribution utility systems and related generation assets are located in the U.S. states of Arkansas, California, Kansas, Missouri, Nevada, New Hampshire and Oklahoma, as well as in Bermuda, which together served approximately 343,000 electric customer connections as at September 30, 2026. The group also owns and operates generating assets with a gross capacity of approximately 2.0 GW and has investments in generating assets with approximately 0.3 GW of net generation capacity.
The Regulated Services Group's regulated water distribution and wastewater utility systems are located in the U.S. states of Arizona, Arkansas, California, Illinois, Missouri, New York, and Texas. Prior to the closing of the sale of Suralis Holdco on October 30, 2026, the Regulated Services Group also held an interest in a water and wastewater utility system in Chile. The group together served approximately 594,000 customer connections as at September 30, 2026.
The Regulated Services Group's regulated natural gas distribution utility systems are located in the U.S. states of Georgia, Illinois, Iowa, Massachusetts, Missouri, New Hampshire, and New York, and in the Canadian Province of New Brunswick, which together served approximately 381,000 natural gas customer connections as at September 30, 2026.
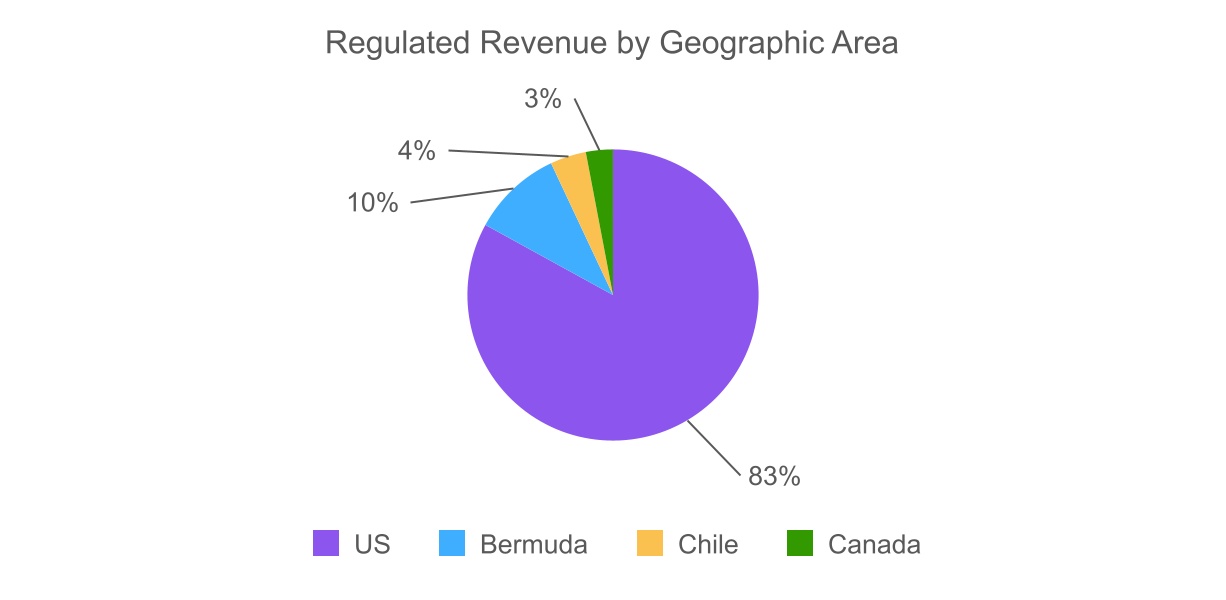
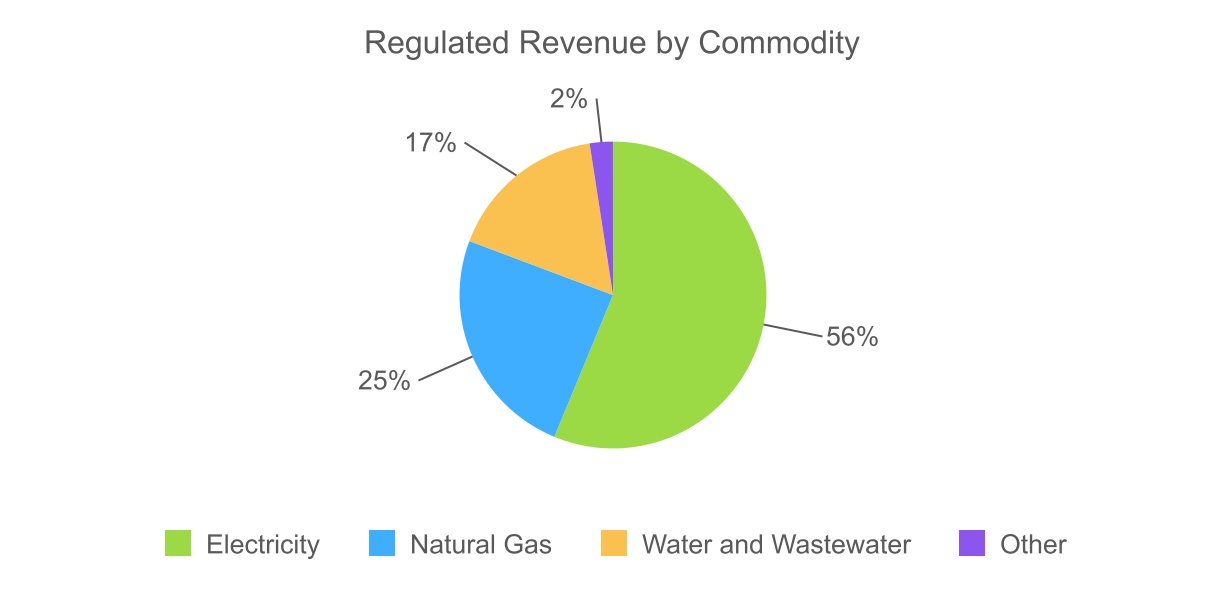
Below is a breakdown of the Regulated Services Group's Revenue by geographic area and by commodity for the nine months ended September 30, 2026.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 7 |
Hydro Group
The Hydro Group is comprised of 14 hydroelectric generating facilities located in the Canadian provinces of Alberta, Ontario, New Brunswick and Quebec with a combined gross generating capacity of approximately 112 MW and a net generating capacity of approximately 104 MW.
Corporate Group
The Corporate Group primarily consists of AQN’s corporate and shared services and corporate debt, in addition to certain ancillary investments.
The Company’s former renewable energy group (excluding hydro) is reported as "discontinued operations" and was sold by the Company on January 8, 2025.
Significant Updates
Sale of Chilean Operations
On August 28, 2026, AQN entered into an agreement to sell Suralis Holdco, which indirectly holds the Company's approximately 64% ownership interest in Suralis, to a Chilean investment fund managed by the Buyer. Suralis Holdco, together with its subsidiaries and the related assets and liabilities to be disposed of, are collectively referred to as the "Disposal Group".
Subsequent to quarter end, on October 30, 2026, the Company completed the sale for cash proceeds of approximately $126.4 million. Of this amount, approximately $12.3 million had previously been received as a deposit upon signing of the agreement on August 28, 2026, and was applied against the purchase price at closing, with the remaining approximately $114.1 million received at closing. Additionally, the Company may receive up to $1.5 million in additional cash consideration, pursuant to a contingent earnout arrangement, subject to certain regulatory outcomes and other contractual conditions.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
2026 Third Quarter Results From Operations
| | | | | | | | | | | |
Key Financial Information1 | Three months ended September 30, |
| (all dollar amounts in $ millions except per share information) | 2026 | 2025 | Change |
| Revenue | $ | 642.5 | | $ | 582.7 | | 10 | % |
| Net revenue | 491.8 | | 449.3 | | 9 | % |
| Net earnings attributable to shareholders | 60.4 | | 73.7 | | (18) | % |
| Net earnings attributable to common shareholders | 57.6 | | 71.0 | | (19) | % |
| | | |
| Net earnings attributable to common shareholders from continuing operations and discontinued operations | 57.0 | | 36.2 | | 57 | % |
Adjusted Net Earnings2 | 88.1 | | 69.0 | | 28 | % |
| Dividends declared to common shareholders | 50.3 | | 50.5 | | — | % |
| Weighted average number of common shares outstanding | 769,953,614 | | 768,226,488 | | |
| Per common share | | | |
| Basic and diluted net earnings | $ | 0.07 | | $ | 0.09 | | (22) | % |
| Basic and diluted net earnings from continuing operations and discontinued operations | $ | 0.07 | | $ | 0.05 | | 40 | % |
Adjusted Net Earnings2 | $ | 0.11 | | $ | 0.09 | | 22 | % |
| Dividends declared to common shareholders | $ | 0.07 | | $ | 0.07 | | — | % |
| | | | | |
| 1 | Reflects results of continuing operations unless marked otherwise (see Explanatory Notes). |
| 2 | See Caution Concerning Non-GAAP Measures. |
| |
For the three months ended September 30, 2026, AQN reported revenue of $642.5 million as compared to $582.7 million in the comparative period in 2025, an increase of $59.8 million. This increase was mainly driven by implementation of approved rates of $15.2 million at the Empire District (MO) Electric System, $1.6 million at the Empire District (KS) Electric System, $12.1 million at the CalPeco (CA) Electric System, $2.4 million at the New York (NY), Bella Vista (AZ), Beardsley (AZ), Cordes Lake (AZ) and Rio Rico (AZ) Water and Sewer Systems, and $20.4 million at the Empire District (MO) Electric System resulting from favourable weather in the third quarter of 2026.
The following tables outline the changes to Adjusted Net Earnings1 for the three months ended September 30, 2026 as compared to the same period in 2025, including the breakdown of net earnings attributable to common shareholders by the Company's main business units. The discussion following the tables explains the changes in net earnings attributable to common shareholders.
| | | | | | | | | | | |
Net earnings (loss) by business unit2 and Total Adjusted Net Earnings1 | Three months ended September 30, |
| (all dollar amounts in $ millions) | 2026 | 2025 | Change |
| Net earnings for Regulated Services Group | $ | 72.6 | | $ | 103.6 | | $ | (31.0) | |
| Net earnings for Hydro Group | 2.1 | | 3.3 | | $ | (1.2) | |
| Net loss for Corporate Group | (17.1) | | (35.9) | | $ | 18.8 | |
| Total net earnings attributable to common shareholders | 57.6 | | 71.0 | | (13.4) | |
| Add: Adjusted items | 30.5 | | (2.0) | | 32.5 | |
Total Adjusted Net Earnings1 | $ | 88.1 | | $ | 69.0 | | $ | 19.1 | |
| | | |
| | | |
| | | | | |
| 1 | See Caution Concerning Non-GAAP Measures. |
| 2 | Reflects results of continuing operations unless marked otherwise (see Explanatory Notes). |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 9 |
| | | | | | | | | | | | | | |
Change in net earnings (loss) and Adjusted Net Earnings1 Breakdown2 | Three months ended September 30, 2026 |
| (all dollar amounts in $ millions) | Regulated Services | Hydro | Corporate | Total |
| Change in net earnings attributable to common shareholders | | | | |
| Net earnings (loss) attributable to common shareholders - Prior period balances | $ | 103.6 | | $ | 3.3 | | $ | (35.9) | | $ | 71.0 | |
| | | | |
EBIT1,3 | | | | |
| Electricity | 11.4 | | — | | — | | 11.4 | |
| Natural Gas | (15.8) | | — | | — | | (15.8) | |
| Water | (4.0) | | — | | — | | (4.0) | |
| Other | (7.9) | | (1.0) | | 0.7 | | (8.2) | |
Total change in EBIT1 | (16.3) | | (1.0) | | 0.7 | | (16.6) | |
| | | | |
| Interest expense (income) | (21.8) | | — | | 16.9 | | (4.9) | |
| Income tax recovery (expense) | 4.1 | | (0.4) | | 1.3 | | 5.0 | |
| Net effect of non-controlling interests | 3.0 | | 0.2 | | — | | 3.2 | |
| Series A Preferred Share and Series D Preferred Share dividend | — | | — | | (0.1) | | (0.1) | |
| Total change in net earnings (loss) | (31.0) | | (1.2) | | 18.8 | | (13.4) | |
| | | | |
| Net earnings (loss) attributable to common shareholders - Current period balances | 72.6 | | 2.1 | | (17.1) | | 57.6 | |
| | | | |
Change in Adjusted Net Earnings1 | | | | |
Adjusted Net Earnings (Loss)1 - Prior period balance3 | 95.7 | | 3.3 | | (30.0) | | 69.0 | |
| Total change in net earnings (loss) | (31.0) | | (1.2) | | 18.8 | | (13.4) | |
Total change in adjusted items3 | 36.3 | | — | | (3.8) | | 32.5 | |
Adjusted Net Earnings (loss)1 - Current period balances | $ | 101.0 | | $ | 2.1 | | $ | (15.0) | | $ | 88.1 | |
| | | | | |
| 1 | See Caution Concerning Non-GAAP Measures. |
| 2 | Reflects results of continuing operations unless marked otherwise (see Explanatory Notes). |
| 3 | See 2026 Third Quarter and Year-to-Date Regulated Services Group Net Earnings and Adjusted Net Earnings, and Corporate Group Net Earnings and Adjusted Net Earnings. |
For the three months ended September 30, 2026, AQN reported net earnings attributable to common shareholders of $57.6 million and basic net earnings per common share of $0.07. During the comparative period in 2025, the Company reported net earnings attributable to common shareholders of $71.0 million and basic net earnings per common share of $0.09. The net earnings attributable to common shareholders decreased by $13.4 million and the basic net earnings per common share decreased by $0.02. These decreases were primarily driven by:
•A decrease of $31.0 million in the net earnings of the Regulated Services Group primarily due to:
–An increase of approximately $65.0 million, including:
–$28.3 million from the implementation of approved rates primarily at the Empire District (MO) Electric System and the CalPeco (CA) Electric System,
–a $20.4 million increase at the Empire District (MO) Electric System resulting from favourable weather in the third quarter of 2026,
–$16.3 million favourable impacts in other items including a decrease in income tax expense due to lower earnings before income taxes and favourable impact from the net effect of non-controlling interests due to higher wind production, resulting in higher HLBV income.
–These increases were more than offset by a decrease in net earnings of approximately $92.0 million, primarily due to:
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
–a $21.8 million increase in interest expense, mainly driven by the Senior Note Offering (as defined herein),
–$16.6 million of non-recoverable costs and additional accruals in connection with the Mountain View Fire,
–the non-recurrence of a $9.1 million gain recognized in 2025 on the settlement of a swap at the BELCO Electric System,
–an $8.3 million loss on net assets classified as held for sale related to the sale of Suralis Holdco,
–higher depreciation expense across the majority of utility systems and higher operating expenses primarily within gas utility systems, including costs related to gas safety excellence initiatives.
•Partially offset by a decrease of $18.8 million in the net loss for the Corporate Group primarily due to:
– the repayment on June 15, 2026 of $1,150.0 million of debt previously held at the Corporate Group, following the Senior Note Offering, resulting in lower interest expense at the Corporate Group.
For the three months ended September 30, 2026, AQN reported Adjusted Net Earnings per common share of $0.11 (see Caution Concerning Non-GAAP Measures). Adjusted Net Earnings increased by $19.2 million period over period (see Caution Concerning Non-GAAP Measures). This increase was primarily driven by the factors noted above, excluding the period-over-period impact of adjusted items of $32.5 million, primarily due to additional accruals of $16.6 million in connection with the Mountain View Fire, the non-recurrence of a $9.1 million gain on the settlement of a swap at the BELCO Electric System, and an $8.3 million loss on the net assets classified as held for sale relating to the sale of Suralis Holdco (see Reconciliation of Adjusted Net Earnings to Net Earnings).
For the three months ended September 30, 2026, cash provided by operating activities increased by $89.2 million as compared to the same period in 2025, primarily as a result of changes in working capital items of $69.7 million (see Note 16 to the unaudited interim condensed consolidated financial statements - Non-cash operating items) and a $12.6 million increase in depreciation and amortization. For the three months ended September 30, 2026 cash used by investing activities increased by $53.1 million as compared to the same period in 2025 mainly due to an increase of $63.7 million in additions to property, plant and equipment and intangible assets. For the three months ended September 30, 2026 cash provided by financing activities decreased by $32.3 million as compared to the same period in 2025 primarily due to $197.8 million of lower proceeds from the issuance of long-term debt, partially offset by $87.4 million of lower repayments of long-term debt and $71.0 million due to increased commercial paper usage.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
2026 Year-to-Date Results From Operations1
| | | | | | | | | | | | |
Key Financial Information1 | Nine months ended September 30, |
| (all dollar amounts in $ millions except per share information) | 2026 | 2025 | | Change |
| Revenue | $ | 1,978.8 | | $ | 1,802.9 | | | 10 | % |
| Net Revenue | 1,435.6 | | 1,326.3 | | | 8 | % |
| Net earnings attributable to shareholders | 153.6 | | 186.5 | | | (18) | % |
| Net earnings attributable to common shareholders | 145.6 | | 178.6 | | | |
| | | | |
| Net earnings attributable to common shareholders from continuing operations and discontinued operations | 141.6 | | 151.9 | | | (7) | % |
| | | | |
| | | | |
Adjusted Net Earnings2 | 216.9 | | 211.6 | | | |
| Dividends declared to common shareholders | 150.8 | | 151.3 | | | — | % |
| Weighted average number of common shares outstanding | 769,480,819 | | 767,986,630 | | | |
| Per common share | | | | |
| Basic and diluted net earnings | $ | 0.19 | | $ | 0.23 | | | (17) | % |
| Basic and diluted net earnings from continuing operations and discontinued operations | $ | 0.18 | | $ | 0.20 | | | |
| | | | |
Adjusted Net Earnings2 | $ | 0.28 | | $ | 0.28 | | | — | % |
| Dividends declared to common shareholders | $ | 0.20 | | $ | 0.20 | | | — | % |
| | | | |
| | | | |
| | | | |
| | | | | |
| |
| |
| 1 | Reflects results of continuing operations unless marked otherwise (see Explanatory Notes). |
| 2 | See Caution Concerning Non-GAAP Measures. |
For the nine months ended September 30, 2026, AQN reported revenue of $1,978.8 million as compared to $1,802.9 million in the comparative period, an increase of $175.9 million. This increase was mainly driven by the implementation of approved rates of $85.0 million at the CalPeco (CA) Electric System, $15.2 million at the Empire District (MO) Electric System, $1.6 million at the Empire District (KS) Electric System, $5.7 million at the New York (NY), Bella Vista (AZ), Beardsley (AZ), Cordes Lake (AZ) and Rio Rico (AZ) Water and Sewer Systems and $3.2 million at the Peach State Gas (GA) System, favourable weather of $11.2 million at Empire District (MO) Electric System as well as higher pass-through costs driven by increased commodity prices.
The following tables outline the changes to Adjusted Net Earnings1 for the nine months ended September 30, 2026 as compared to the same period in 2025, including the breakdown of net earnings attributable to common shareholders by the Company's main business units. The discussion following the tables explains the changes in net earnings attributable to common shareholders.
| | | | | | | | | | | |
Net earnings (loss) by business unit2 and Total Adjusted Net Earnings1 | Nine months ended September 30, |
| (all dollar amounts in $ millions) | 2026 | 2025 | Change |
| Net earnings for Regulated Services Group | $ | 222.0 | | $ | 271.1 | | $ | (49.1) | |
| Net earnings for Hydro Group | 7.3 | | 28.8 | | (21.5) | |
| Net loss for Corporate Group | (83.7) | | (121.3) | | 37.6 | |
| Total net earnings attributable to common shareholders | 145.6 | | 178.6 | | (33.0) | |
| Add: Adjusted items | 71.3 | | 33.0 | | 38.3 | |
Total Adjusted Net Earnings1 | $ | 216.9 | | $ | 211.6 | | $ | 5.3 | |
| | | |
| | | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 12 |
| | | | | | | | | | | | | | |
Change in net earnings and Adjusted Net Earnings1 Breakdown2 | Nine months ended September 30, 2026 |
| (all dollar amounts in $ millions) | Regulated Services | Hydro | Corporate | Total |
| Change in net earnings attributable to common shareholders | | | | |
| Net earnings (loss) attributable to common shareholders - Prior period balances | $ | 271.1 | | $ | 28.8 | | $ | (121.3) | | $ | 178.6 | |
| | | | |
EBIT1 | | | | |
| Electricity | 21.4 | | — | | — | | 21.4 | |
| Natural Gas | (51.2) | | — | | — | | (51.2) | |
| Water | 0.9 | | — | | — | | 0.9 | |
| Other | (3.1) | | (2.6) | | 13.0 | | 7.3 | |
Total change in EBIT1 | (32.0) | | (2.6) | | 13.0 | | (21.6) | |
| | | | |
| Interest expense | (34.5) | | 0.2 | | 18.9 | | (15.4) | |
| Income tax expense | 13.9 | | (19.3) | | 5.8 | | 0.4 | |
| Net effect of non-controlling interests | 3.5 | | 0.2 | | — | | 3.7 | |
| Series A Preferred Share and Series D Preferred Share dividend | — | | — | | (0.1) | | (0.1) | |
| Total change in net earnings | (49.1) | | (21.5) | | 37.6 | | (33.0) | |
| | | | |
| Net earnings (loss) attributable to common shareholders - Current period balances | 222.0 | | 7.3 | | (83.7) | | 145.6 | |
| | | | |
Change in Adjusted Net Earnings1 | | | | |
Adjusted Net Earnings (Loss)1 - Prior period balance3 | 266.8 | | 28.9 | | (84.1) | | 211.6 | |
| Total change in net earnings (loss) | (49.1) | | (21.5) | | 37.6 | | (33.0) | |
Total change in adjusted items3 | 59.5 | | — | | (21.2) | | 38.3 | |
Adjusted Net Earnings (loss)1 - Current period balances | $ | 277.2 | | $ | 7.4 | | $ | (67.7) | | $ | 216.9 | |
| | | | | |
| |
| |
| 1 | See Caution Concerning Non-GAAP Measures. |
| 2 | Reflects results of continuing operations unless marked otherwise (see Explanatory Notes). |
| 3 | See 2026 Third Quarter and Year-to-Date Regulated Services Group Net Earnings and Adjusted Net Earnings, and Corporate Group Net Earnings and Adjusted Net Earnings. |
For the nine months ended September 30, 2026, AQN reported net earnings attributable to common shareholders of $145.6 million and basic net earnings per common share of $0.19. During the comparative period in 2025, the Company reported net earnings attributable to common shareholders of $178.6 million and basic net earnings per common share of $0.23. The net earnings attributable to common shareholders decreased by $33.0 million, and basic net earnings per common share decreased by $0.04. The decreases were primarily driven by:
•A decrease of $49.1 million in the net earnings of the Regulated Services Group, primarily due to:
–an increase in EBIT (see Caution Concerning Non-GAAP Measures) from the Electric Systems of $21.4 million, primarily due to:
–$57.2 million from the implementation of approved rates, including $45.3 million at the CalPeco (CA) Electric System, which includes a $25.9 million net retroactive impact, and $11.2 million at the Empire District (MO) Electric System. The CalPeco (CA) Electric System amount excludes the related wildfire insurance expenses and corresponding recoveries through rates.
–an $11.2 million increase in net revenues due to favourable weather at the Empire District (MO) Electric System, and partially offset by;
–$33.8 million of higher non-recurring charges related to the Mountain View Fire, consisting of $17.2 million of previously incurred costs that were determined to be unrecoverable and $16.6 million of additional accruals in connection with the Mountain View Fire, and
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
–a $13.2 million unfavourable impact from other items, including higher operating and depreciation expenses, with the increase in depreciation expense primarily driven by sustaining and growth capital spending.
–a decrease in EBIT (see Caution Concerning Non-GAAP Measures) from the Gas Systems of $51.2 million, primarily due to:
–$36.9 million of higher expenses, including $24.8 million of higher operating expenses, mainly due to gas safety excellence initiatives and higher labour costs, and $12.1 million of higher non-recurring expenses primarily due to the Lexington Gas Incident, and
–$10.2 million of higher depreciation expense primarily due to non-recurrence of a deferral adjustment related to the EnergyNorth Gas (NH) System recorded in 2025,
–an increase in EBIT (see Caution Concerning Non-GAAP Measures) from the Water Systems of $0.9 million, primarily due to:
–$5.7 million from the implementation of approved rates, a $3.3 million favourable impact from the non-recurrence of a rate case adjustment recorded in 2025 at the Litchfield Park (AZ) Water and Sewer System, partially offset by:
–an $8.3 million loss on the net assets of the Disposal Group classified as held for sale (excluded from Adjusted Net Earnings (see Caution Concerning Non-GAAP Measures)).
–other items decreased net earnings by $20.2 million, primarily due to a $34.5 million increase in interest expense, including $23.5 million associated with the Senior Note Offering, partially offset by a $13.9 million decrease in income tax expense, primarily due to lower earnings before income taxes, with the decrease in tax expense partially offset by non-deductible costs related to the Mountain View Fire.
•A decrease of $21.5 million in the net earnings of the Hydro Group primarily due to the non-recurrence of a tax recovery of $15.9 million resulting from the tax basis step-up from Hydro Group’s reorganization in connection with the Renewables Sale.
•Partially offset by a decrease in the net loss of the Corporate Group of $37.6 million, primarily due to:
–a decrease of $18.9 million primarily due to lower interest expense following the repayment of $1,150.0 million of debt previously held at the Corporate Group, a $10.7 million decrease in net loss primarily due to lower foreign exchange losses and the non-recurrence of a $7.5 million foreign exchange loss recognized in 2025, and a $5.8 million increase in income tax recoveries, partially offset by $5.7 million of higher restructuring costs.
For the nine months ended September 30, 2026, AQN reported Adjusted Net Earnings per common share of $0.28 as compared to $0.28 per common share during the same period in 2025 (see Caution Concerning Non-GAAP Measures). Adjusted Net Earnings decreased by $5.4 million year over year (see Caution Concerning Non-GAAP Measures). This decrease was primarily driven by the factors noted above, excluding the period-over-period impact of adjusted items of $38.3 million, primarily due to higher restructuring costs of $14.6 million, $17.2 million of one-time, previously incurred Mountain View Fire costs that were determined to be unrecoverable, $16.6 million of additional accruals in connection with the Mountain View Fire, and an $8.3 million loss on the net assets classified as held for sale relating to the sale of Suralis Holdco, partially offset by $9.9 million of lower foreign exchange losses and $10.4 million of favourable income tax adjustments related to adjusted items (see Reconciliation of Adjusted Net Earnings to Net Earnings).
For the nine months ended September 30, 2026, cash provided by operating activities increased by $92.3 million as compared to the same period in 2025, primarily due to a $114.2 million increase in non-cash working capital items (see Note 16 to the unaudited interim condensed consolidated financial statements - Non-Cash Operating Items), partially offset by lower net earnings and other changes in non-cash operating items. For the nine months ended September 30, 2026, cash provided by investing activities decreased by $1,892.0 million as compared to the same period in 2025, primarily due to the non-recurring receipt of proceeds from the Renewables Sale in the prior period. For the nine months ended September 30, 2026, cash provided by financing activities increased by $1,883.2 million as compared to the same period in 2025 primarily due to the non-recurrence of debt repayments made in connection with the Renewables Sale in the prior year and increased commercial paper usage.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
REGULATED SERVICES GROUP
The Regulated Services Group primarily operates rate-regulated utilities that as of September 30, 2026 provided electric generation and transmission services as well as distribution services in the electric, natural gas and water and wastewater sectors to approximately 1,318,000 customer connections, which is an increase of approximately 21,300 customer connections as compared to September 30, 2025.
The Regulated Services Group seeks to deliver long-term growth within its service territories, including through the pursuit of capital investment opportunities and other initiatives.
| | | | | | | | | | | | | | | | | | | | | | | |
| Utility System Type | As at September 30, |
| 2026 | | 2025 |
| (all dollar amounts in $ millions) | Assets3 | Net Utility Sales1 | Total Customer Connections2 | | Assets3 | Net Utility Sales1 | Total Customer Connections2 |
| Electricity | $ | 5,641.4 | | $ | 820.7 | | 343,000 | | | $ | 5,504.0 | | $ | 712.6 | | 337,000 | |
| Natural Gas | 2,077.9 | | 273.7 | | 381,000 | | | 1,969.1 | | 278.4 | | 374,000 | |
| Water and Wastewater | 1,606.2 | | 287.6 | | 594,000 | | | 1,821.5 | | 282.5 | | 586,000 | |
| Other | 80.3 | | 25.0 | | | | 104.7 | | 22.9 | | |
| Other revenue | | 47.7 | | | | | 42.9 | | |
| Less: Cost of Sales | | (22.7) | | | | | (20.0) | | |
| Total | $ | 9,405.8 | | $ | 1,407.0 | | 1,318,000 | | | $ | 9,399.3 | | $ | 1,296.4 | | 1,297,000 | |
| | | | | | | |
| Accumulated Deferred Income Taxes Liability | $ | 999.5 | | | | | $ | 903.4 | | | |
| | | | | |
| 1 | Net Utility Sales for the nine months ended September 30, 2026 and 2025. See Caution Concerning Non-GAAP Measures. |
| 2 | Total Customer Connections represents the sum of all active and vacant customer connections. |
| 3 | Excludes assets held for sale of $308.5 million for 2026 and $324.3 million for 2025. |
The Regulated Services Group aggregates the performance of its utility operations by utility system type – electricity, natural gas, and water and wastewater systems.The electric distribution, generation and transmission systems are comprised of regulated electrical distribution utility systems that served approximately 343,000 customer connections in the U.S. States of Arkansas, California, Kansas, Missouri, New Hampshire and Oklahoma, as well as in Bermuda as at September 30, 2026.
The natural gas distribution systems are comprised of regulated natural gas distribution utility systems that served approximately 381,000 customer connections located in the U.S. States of Georgia, Illinois, Iowa, Massachusetts, Missouri, New Hampshire and New York, and in the Canadian Province of New Brunswick as at September 30, 2026.
The water and wastewater distribution systems are comprised of regulated water distribution and wastewater utility systems that served approximately 594,000 customer connections located in the U.S. States of Arizona, Arkansas, California, Illinois, Missouri, New York, and Texas, as well as in Chile, as at September 30, 2026.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 15 |
2026 Third Quarter and Year-to-Date Usage Results
| | | | | | | | | | | | | | |
| Electric Distribution Systems | Three months ended September 30, | Nine months ended September 30, |
| 2026 | 2025 | 2026 | 2025 |
| Average Active Electric Customer Connections For The Period | | | | |
| Residential | 281,000 | | 278,400 | | 280,400 | | 277,800 | |
| Commercial and industrial | 58,100 | | 55,700 | | 55,400 | | 55,600 | |
| Total Average Active Electric Customer Connections For The Period | 339,100 | | 334,100 | | 335,800 | | 333,400 | |
| | | | |
| Customer Usage (GW-hrs) | | | | |
| Residential | 895.4 | | 787.1 | | 2,248.1 | | 2,204.9 | |
| Commercial and industrial | 1,091.7 | | 1,062.8 | | 2,937.8 | | 2,933.3 | |
| Total Customer Usage (GW-hrs) | 1,987.1 | | 1,849.9 | | 5,185.9 | | 5,138.2 | |
For the three months ended September 30, 2026, the electric distribution systems' usage totaled 1,987.1 GW-hrs as compared to 1,849.9 GW-hrs for the same period in 2025, an increase of 137.2 GW-hrs or 7.4%. The increase in electricity consumption is primarily due to favourable weather conditions in the third quarter of 2026, as compared to 2025, at the Empire District Electric System.
For the nine months ended September 30, 2026, the electric distribution systems' usage totaled 5,185.9 GW-hrs as compared to 5,138.2 GW-hrs for the same period in 2025, an increase of 47.7 GW-hrs or 0.9%. The increase in electricity consumption is primarily due to slightly favourable weather conditions in the third quarter of 2026 as compared to the same period in 2025, at the Empire District Electric System.
| | | | | | | | | | | | | | |
| Natural Gas Distribution Systems | Three months ended September 30, | Nine months ended September 30, |
| 2026 | 2025 | 2026 | 2025 |
| Average Active Natural Gas Customer Connections For The Period | | | | |
| Residential | 318,900 | | 320,400 | | 321,400 | | 322,700 | |
| Commercial and industrial | 38,400 | | 38,800 | | 38,900 | | 39,300 | |
| Total Average Active Natural Gas Customer Connections For The Period | 357,300 | | 359,200 | | 360,300 | | 362,000 | |
| | | | |
| Customer Usage (MMBTU) | | | | |
| Residential | 1,162,817 | | 1,201,624 | | 13,796,460 | | 14,353,280 | |
| Commercial and industrial | 2,499,793 | | 2,523,707 | | 15,129,757 | | 15,485,615 | |
| Total Customer Usage (MMBTU) | 3,662,610 | | 3,725,331 | | 28,926,217 | | 29,838,895 | |
For the three months ended September 30, 2026, the natural gas distribution systems' usage totaled 3,662,610 MMBTU as compared to 3,725,331 MMBTU during the same period in 2025, a decrease of 62,721 MMBTU, or 1.7%. The decrease is primarily due to slightly unfavourable weather conditions across all gas systems.
For the nine months ended September 30, 2026, the natural gas distribution systems' usage totaled 28,926,217 MMBTU as compared to 29,838,895 MMBTU during the same period in 2025, a decrease of 912,678 MMBTU, or 3.1%. The decrease is primarily due to slightly unfavourable weather conditions across all gas systems.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 16 |
| | | | | | | | | | | | | | |
| Water and Wastewater Distribution Systems | Three months ended September 30, | Nine months ended September 30, |
| 2026 | 2025 | 2026 | 2025 |
| Average Active Customer Connections For The Period | | | | |
| Water distribution customer connections | 524,700 | | 520,400 | | 524,000 | | 518,500 | |
| Wastewater customer connections | 60,200 | | 58,700 | | 60,100 | | 58,600 | |
| Total Average Active Customer Connections For The Period | 584,900 | | 579,100 | | 584,100 | | 577,100 | |
| | | | |
| Gallons Provided (millions of gallons) | | | | |
| Water provided | 12,710 | | 12,737 | | 31,406 | | 31,407 | |
| Wastewater treated | 1,230 | | 920 | | 3,136 | | 2,767 | |
| Total Gallons Provided (millions of gallons) | 13,940 | | 13,657 | | 34,542 | | 34,174 | |
For the three months ended September 30, 2026, the water and wastewater distribution systems provided approximately 12,710 million gallons of water to customers and treated approximately 1,230 million gallons of wastewater. This is compared to 12,737 million gallons of water provided and 920 million gallons of wastewater treated during the same period in 2025, a decrease in total gallons provided of 27 million or 0.2% and an increase in total gallons treated of 310 million or 33.7%. The increase in wastewater treated is primarily due to higher usage at the Litchfield Park (AZ) Water and Sewer System.
For the nine months ended September 30, 2026, the water and wastewater distribution systems provided approximately 31,406 million gallons of water to customers and treated approximately 3,136 million gallons of wastewater. This is compared to 31,407 million gallons of water provided and 2,767 million gallons of wastewater treated during the same period in 2025, a decrease in total gallons provided of 1 million or 0.0% and an increase in total gallons treated of 369 million or 13.3%. The increase in wastewater treated is primarily due to higher usage at the Litchfield Park (AZ) Water and Sewer System.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 17 |
2026 Third Quarter and Year-to-Date Regulated Services Group Net Earnings and Adjusted Net Earnings
| | | | | | | | | | | | | | |
| | |
| Three months ended September 30, | Nine months ended September 30, |
| (all dollar amounts in $ millions) | 2026 | 2025 | 2026 | 2025 |
| Revenue | | | | |
| Regulated electricity distribution | $ | 417.8 | | $ | 360.8 | | $ | 1,096.9 | | $ | 983.2 | |
| Less: Regulated electricity purchased | (109.3) | | (96.6) | | (276.2) | | (270.6) | |
Net Utility Sales – electricity1 | 308.5 | | 264.2 | | 820.7 | | 712.6 | |
| Regulated gas distribution | 68.1 | | 67.6 | | 477.3 | | 423.3 | |
| Less: Regulated gas purchased | (17.0) | | (14.4) | | (203.6) | | (144.9) | |
Net Utility Sales – natural gas1 | 51.1 | | 53.2 | | 273.7 | | 278.4 | |
| Regulated water reclamation and distribution | 131.0 | | 129.9 | | 328.3 | | 323.6 | |
| Less: Regulated water production costs | (15.8) | | (14.9) | | (40.7) | | (41.1) | |
Net Utility Sales – water reclamation and distribution1 | 115.2 | | 115.0 | | 287.6 | | 282.5 | |
Other revenue2 | 17.6 | | 15.5 | | 47.7 | | 42.9 | |
| Less: Other Cost of Sales | (8.6) | | (7.5) | | (22.7) | | (20.0) | |
Net Utility Sales1,3 | 483.8 | | 440.4 | | 1,407.0 | | 1,296.4 | |
| Operating expenses | 217.7 | | 205.4 | | 672.2 | | 609.1 | |
| Depreciation and amortization | 105.3 | | 92.5 | | 315.3 | | 290.8 | |
| Loss on foreign exchange | 1.8 | | 0.6 | | 7.3 | | 6.4 | |
Add: Interest, dividend and other income | 8.2 | | 7.4 | | 27.2 | | 21.4 | |
Less: Other expenses | | | | |
| Pension and post-employment non-service (costs) recovery | 1.1 | | (1.3) | | (1.5) | | $ | (1.8) | |
| Other net losses | (31.8) | | (3.8) | | (65.1) | | $ | (14.1) | |
| Gain on derivative financial instruments | — | | 8.6 | | — | | $ | 9.2 | |
EBIT1,4 | 136.5 | | 152.8 | | 372.8 | | $ | 404.8 | |
| Interest expense | (58.0) | | (36.2) | | (139.9) | | (105.4) | |
| Income tax expense | (24.9) | | (29.0) | | (68.3) | | (82.2) | |
Net effect of non-controlling interests6 | 19.0 | | 16.0 | | 57.4 | | 53.9 | |
| Net earnings attributable to common shareholders | 72.6 | | 103.6 | | 222.0 | | 271.1 | |
| Add / (Less) Adjusted items: | | | | |
| Gain on derivative financial instruments | — | | (8.6) | | — | | (9.2) | |
Restructuring costs7 | 5.9 | | 0.4 | | 20.0 | | 0.8 | |
Mountain View Fire related costs7 | 16.6 | | — | | 33.8 | | — | |
Loss on net assets classified as held for sale7 | 8.3 | | — | | 8.3 | | — | |
| Loss on foreign exchange | 1.8 | | 0.6 | | 7.3 | | 6.4 | |
| Adjustment for taxes related to above | (4.2) | | (0.3) | | (14.2) | | (2.3) | |
Regulated Services Group Adjusted Net Earnings1,5 | $ | 101.0 | | $ | 95.7 | | $ | 277.2 | | $ | 266.8 | |
| | | | | |
| 1 | See Caution Concerning Non-GAAP Measures. |
| 2 | See Note 14 in the unaudited interim condensed consolidated financial statements. |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 18 |
| | | | | |
| 3 | This table contains a reconciliation of Net Utility Sales to revenue for the Regulated Services Group. The relevant sections of the table are derived from and should be read in conjunction with the unaudited interim condensed consolidated statement of operations and Note 14 in the unaudited interim condensed consolidated financial statements, "Segmented Information". This supplementary disclosure is intended to more fully explain disclosures related to Net Utility Sales and provides additional information related to the operating performance of the Regulated Services Group. Investors are cautioned that Net Utility Sales should not be construed as an alternative to revenue. |
| 4 | This table contains a reconciliation of EBIT to net earnings for the Regulated Services Group. The relevant sections of the table are derived from and should be read in conjunction with the unaudited interim condensed consolidated statement of operations and Note 14 in the unaudited interim condensed consolidated financial statements, "Segmented Information". This supplementary disclosure is intended to more fully explain disclosures related to EBIT and provides additional information related to the operating performance of the Regulated Services Group. Investors are cautioned that EBIT should not be construed as an alternative to net earnings. |
| 5 | This table contains a reconciliation of Adjusted Net Earnings to net earnings for the Regulated Services Group. The relevant sections of the table are derived from and should be read in conjunction with the unaudited interim condensed consolidated statement of operations and Note 14 in the unaudited interim condensed consolidated financial statements, "Segmented Information". This supplementary disclosure is intended to more fully explain disclosures related to Adjusted Net Earnings for the Regulated Services Group and provides additional information related to the operating performance of the Regulated Services Group. Investors are cautioned that Adjusted Net Earnings should not be construed as an alternative to net earnings. |
| 6 | Net effect of non-controlling interests primarily includes HLBV income from Empire Electric. |
| 7 | See Note 12 in the unaudited interim condensed consolidated financial statements. |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
2026 Third Quarter Regulated Services Group Operating Results
For the three months ended September 30, 2026, the Regulated Services Group reported revenue of $616.9 million (comprised of $417.8 million of regulated electricity distribution revenue, $68.1 million of regulated gas distribution revenue and $131.0 million of regulated water reclamation and distribution revenue) as compared to revenue of $558.3 million in the comparable period in the prior year (comprised of $360.8 million of regulated electricity distribution revenue, $67.6 million of regulated gas distribution revenue and $129.9 million of regulated water reclamation and distribution revenue).
For the three months ended September 30, 2026, the Regulated Services Group reported net earnings of $72.6 million as compared to $103.6 million for the comparable period in the prior year.
Highlights of the changes are summarized in the following table:
| | | | | |
| (all dollar amounts in $ millions) | Three months ended September 30, |
| Prior Period Net Earnings | $ | 103.6 | |
| |
Regulated Services Group EBIT1: | |
Electricity: Increase is primarily due to: –a $1.6 million impact from the implementation of approved rates at the Empire District (KS) Electric System –an $11.2 million impact from the implementation of approved rates at the Empire District (MO) Electric System, partially offset by $1.8 million of higher property tax expenses recovered through rates –a $12.1 million impact from the implementation of approved rates at the CalPeco (CA) Electric System, partially offset by $5.5 million of higher wildfire insurance expenses recovered through rates, which had previously been incurred by the Company and deferred under the Wildfire Expense Memorandum Account ("WEMA") mechanism –a $20.4 million impact from favourable weather conditions at the Empire District (MO) Electric System in the third quarter of 2026 compared to the same period in 2025
Partially offset by: –$16.6 million of additional accruals in connection with the Mountain View Fire at the CalPeco (CA) Electric System (excluded from the calculation of Adjusted Net Earnings (see Caution Concerning Non-GAAP Measures)) –$7.3 million of higher depreciation expense, including a $4.7 million increase related to depreciation of assets previously deferred through the Plant-in-Service Accounting (“PISA”) mechanism at the Empire District (MO) Electric System following the rate case, with the remaining increase primarily driven by sustaining and growth capital expenditures across the majority of the electric systems | 11.4 | |
Gas: Decrease is primarily due to: –$4.9 million of lower Gas System Enhancement Program ("GSEP") revenue due to timing of new rates at the New England (MA) Gas System –higher operating expenses of approximately $4.4 million, including $1.9 million related to gas safety excellence initiatives, with the remaining increase due to higher labour, employee benefits and maintenance costs and property taxes across most gas systems –the non-recurrence of a $7.1 million 2025 depreciation deferral adjustment related to the EnergyNorth Gas (NH) System –higher non-recurring gas remediation expenses of $1.4 million due to the Lexington Gas Incident (excluded from Adjusted Net Earnings (see Caution Concerning Non-GAAP Measures))
Partially offset by: –a $1.0 million impact from the implementation of approved rates at the Peach State (GA) Gas System | (15.8) | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 20 |
| | | | | |
| (all dollar amounts in $ millions) | Three months ended September 30, |
Water: Decrease is primarily due to: –an $8.3 million loss on the net assets of the Disposal Group classified as held for sale (excluded from the calculation of Adjusted Net Earnings (see Caution Concerning Non-GAAP Measures)) –a $1.3 million increase in depreciation expense across the majority of the water systems, primarily driven by sustaining and growth capital expenditures
Partially offset by: –a $2.4 million impact from the implementation of approved rates at the New York (NY), Bella Vista (AZ), Beardsley (AZ), Cordes Lake (AZ), Rio Rico (AZ), and Litchfield Park (AZ) Water and Sewer Systems –a $4.9 million favourable impact from a depreciation deferral adjustment at Litchfield Park (AZ) Water and Sewer System | (4.0) | |
Other: Decrease primarily due to a 2025 gain of $9.1 million on the settlement of a swap at the BELCO Electric system (excluded from the calculation of Adjusted Net Earnings (see Caution Concerning Non-GAAP Measures)) | (7.9) | |
| Interest expense: Increase primarily due to approximately $15.7 million of interest expense associated with the Senior Note Offering, which refinanced debt previously held at the Corporate Group with the remaining increase due to higher utilization of credit facilities. This increase was partially offset at the consolidated level by lower interest expense at the Corporate Group following the refinancing | (21.8) | |
| Income tax expense: Decrease primarily due to lower earnings before income taxes, partially offset by non-deductible costs related to the Mountain View Fire | 4.1 | |
| Net effect of non-controlling interests | 3.0 | |
| Current Period Net Earnings | $ | 72.6 | |
| | | | | |
| 1 | See Caution Concerning Non-GAAP Measures. |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
2026 Year-to-Date Regulated Services Group Operating Results
For the nine months ended September 30, 2026, the Regulated Services Group reported revenue of $1,902.5 million (comprised of $1,096.9 million of regulated electricity distribution revenue, $477.3 million of regulated natural gas distribution revenue and $328.3 million of regulated water reclamation and distribution revenue) as compared to revenue of $1,730.1 million in the same period in the prior year (comprised of $983.2 million of regulated electricity distribution revenue, $423.3 million of regulated gas distribution revenue and $323.6 million of regulated water reclamation and distribution revenue).
For the nine months ended September 30, 2026, the Regulated Services Group reported net earnings of $222.0 million as compared to $271.1 million in the comparable period in the prior year.
Highlights of the changes are summarized in the following table:
| | | | | |
| (all dollar amounts in $ millions) | Nine months ended September 30, |
| Prior Period Net Earnings | $ | 271.1 | |
| |
Regulated Services Group EBIT1: | |
Electricity: Increase is primarily due to: –a $1.6 million impact from the implementation of approved rates at the Empire Electric (KS) Electric System –an $11.2 million impact from the implementation of approved rates at the Empire District (MO) Electric System, partially offset by $1.8 million of higher property tax expenses recovered through rates –an $85.0 million impact from the implementation of approved rates at the CalPeco (CA) Electric System (including retroactive revenues to the first quarter of 2025 of $48.6 million), partially offset by $39.7 million higher wildfire insurance expenses recovered through rates (including retroactive expenses of $22.7 million relating to 2025), which had previously been incurred by the Company and deferred under the WEMA mechanism –a rate base reduction of $4.8 million at Granite State (NH) Electric System booked in the first quarter of 2025 related to the approval of a rate case –an $11.2 million favourable impact from favourable weather conditions at the Empire District (MO) Electric System Partially offset by: –$17.2 million of costs previously incurred related to the Mountain View Fire and deferred as a WEMA regulatory asset at the CalPeco (CA) Electric System that was determined to be unrecoverable and $16.6 million of additional accruals in connection with the Mountain View Fire at the CalPeco (CA) Electric System. Both of these items are non-recurring in nature and therefore excluded from Adjusted Net Earnings (see Caution Concerning Non-GAAP Measures) –higher depreciation expense of $14.4 million primarily due to a depreciation deferral adjustment of $4.8 million that Granite State (NH) Electric System recorded in 2025, a $4.7 million increase related to depreciation of assets previously deferred through PISA following the Empire District (MO) Electric System rate case, with the remaining increase across the majority of the electric systems primarily driven by sustaining and growth capital expenditures
| 21.4 | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 22 |
| | | | | |
| (all dollar amounts in $ millions) | Nine months ended September 30, |
Gas: Decrease is primarily due to: –a $5.7 million of lower GSEP revenue due to the timing of new rates at the New England (MA) Gas System –higher operating expenses of approximately $24.8 million, comprised of $8.3 million related to gas safety excellence initiatives and $16.5 million driven by higher labor, employee benefits, maintenance costs and property taxes, across most gas systems, including approximately $0.9 million of outage-related costs at the Midstates (MO) Gas System –higher other non-operating expenses primarily due to the absence of a $5.6 million favourable rate-case adjustment recorded in 2025 at the Empire (MO) Gas System related to the over-amortization of pension and other post-employment benefit balances –higher non-recurring gas remediation expenses of $6.5 million due to the Lexington Gas Incident (excluded from Adjusted Net Earnings (see Caution Concerning Non-GAAP Measures)) –a $10.2 million increase in depreciation expense primarily due to a depreciation deferral adjustment of $7.1 million related to the EnergyNorth Gas (NH) System recorded in 2025, with the remaining increase across the majority of gas systems driven by sustaining and growth capital expenditures Partially offset by: –a $3.0 million impact from the implementation of approved rates at the Peach State (GA) Gas System | (51.2) | |
Water: Increase is primarily due to: –a $5.7 million impact from the implementation of approved rates at the New York (NY), Bella Vista (AZ), Beardsley (AZ), Cordes Lake (AZ), Rio Rico (AZ) and Litchfield Park (AZ) Water and Sewer Systems –a rate case adjustment of $3.3 million at the Litchfield Park (AZ) Water and Sewer System booked in 2025 –higher net revenues of approximately $2.4 million at the Litchfield Park (AZ) and Rio Rico (AZ) Water and Sewer Systems from customer growth –a $4.9 million favourable impact from a depreciation deferral adjustment at the Litchfield Park (AZ) Water and Sewer System
Partially offset by: –a $3.1 million rate reduction at the Park Water (CA) and Apple Valley (CA) Water Systems retroactive to the third quarter of 2025 –a $4.3 million increase in depreciation expense across the majority of water systems, primarily driven by sustaining and growth capital expenditures –an $8.3 million loss on the net assets of the Disposal Group classified as held for sale (excluded from the calculation of Adjusted Net Earnings (see Caution Concerning Non-GAAP Measures)) | 0.9 | |
Other: Decrease primarily due to the non-recurrence of a $9.1 million gain recognized on the settlement of a swap at the BELCO Electric System (excluded from the calculation of Adjusted Net Earnings (see Caution Concerning Non-GAAP Measures)), partially offset by approximately $3.1 million of investment income earned on the proceeds from the Senior Note Offering and other favourable items | (3.1) | |
| Interest expense: Increase primarily due to $23.5 million of interest expense associated with the Senior Note Offering, which refinanced previously outstanding debt held at the Corporate Group with the remaining increase due to higher utilization of credit facilities. The increase related to the Senior Note Offering was substantially offset at the consolidated level by lower interest expense of $18.3 at the Corporate Group following the refinancing | (34.5) | |
| Income tax expense: Decrease primarily due to lower earnings before income taxes, partially offset by non-deductible costs related to the Mountain View Fire | 13.9 | |
| Net effect of non-controlling interests | 3.5 | |
| Current Period Net Earnings | $ | 222.0 | |
1 See Caution Concerning Non-GAAP Measures. | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
Regulatory Proceedings
The following table summarizes the major regulatory proceedings currently underway or completed or effective in 2026 within the Regulated Services Group.
| | | | | | | | | | | | | | | | |
| Utility | Jurisdiction | Regulatory Proceeding Type | Rate Request
(millions) | Current Status | | |
| Completed Rate Reviews: | | |
| CalPeco Electric | California | General Rate Case ("GRC") | $39.8 | On September 20, 2024, CalPeco Electric filed an application seeking a net adjustment in total customer rates of $39.8 million including $64.0 million in base revenues based on a return on equity ("ROE") of 11.00%, an equity ratio of 52.50% and current revenues at the time of filing. The requested base revenue adjustment was partially offset by the conclusion of $24.2 million of customer surcharge collections related to the 2022 general rate case, which were in effect at the time of filing and concluded in January 2025. On March 5, 2025, the Company filed a Motion for Interim Rate Relief and Request for Expedited Treatment in which it requested an interim rate recovery of 50.00% of its proposed base revenue requirement on a monthly basis beginning June 1, 2025 until issuance of a final decision in the proceeding. The Utility Reform Network ("TURN") and the Public Advocates Office ("Cal Advocates") opposed the Company’s request. On July 2, 2025, Cal Advocates, TURN and other intervenors in the proceeding filed testimony. Cal Advocates recommended an overall net adjustment in customer rates of $24.8 million. The Company served rebuttal testimony on July 24, 2025. Evidentiary hearings were held the week of September 15, 2025. On October 1, 2025, the Company submitted a joint motion requesting approval of a settlement agreement reached with majority of the Cal Advocates, TURN and other intervenors in the proceeding, which resolves all revenue requirement matters except ROE. The settlement agreement would result in a net adjustment in total customer rates of $24.8 million based on the Company's current authorized ROE of 10.00%. Legal briefs were filed on October 24, 2025. A proposed decision was issued on February 13, 2026 that would result in a net adjustment in total customer rates of $23.8 million (taking into account conclusion of $24.0 million in customer surcharge collections) and $48.6 million in base revenues based on a ROE of 9.75% and an equity ratio of 52.50%. The proposed decision adopts the settlement agreement provisions with the exception of rejecting the proposed fixed charge for residential customers. On March 19, 2026, the California Public Utilities Commission issued an order approving the proposed decision which results in an adjustment of $48.6 million in annualized base revenues based on a return on equity of 9.75% and an equity ratio of 52.50%, retroactive to January 1, 2025.
| | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 24 |
| | | | | | | | | | | | | | | | |
| Utility | Jurisdiction | Regulatory Proceeding Type | Rate Request
(millions) | Current Status | | |
| New England Natural Gas | Massachusetts | GRC | $55.8 | On June 13, 2025, New England Natural Gas filed an application seeking a rate adjustment of $55.8 million based on an ROE of 9.90% and an equity ratio of 53.00%. The request includes approximately $30.0 million of previously authorized GSEP rate base and a 5 year performance based ratemaking plan. A comprehensive settlement agreement was filed on January 30, 2026. The proposed settlement provides for a $45.3 million adjustment in distribution revenues, of which $27.4 million relates to prior investments under the GSEP and previously included in revenues. The settlement includes two rate base resets. The July 1, 2027 rate base reset would allow recovery of $13.0 million of 2026 pipeline safety investments, $6.7 million of Q4 2025 non-GSEP investments, and up to $13.3 million of 2026 non-GSEP, non-pipeline safety investments. The July 1, 2028 rate base reset would allow recovery of the remaining 2026 non-GSEP deferred additions (up to $13.3 million), $13.9 million of 2027 pipeline safety investments, up to $26.5 million of 2027 non-GSEP projects, and recovery of the 2026 non-GSEP deferred regulatory asset. The settlement reflects a capital structure of 47.10% debt and 52.90% equity, with an authorized ROE of 9.30%. The Pension Adjustment Factor would be rolled into base rates, with an approximately $9.5 million over-recovery credited to customers in 2026. In addition, $41.6 million of deferred GSEP costs would be recovered over 10 years through the GSEP beginning July 1, 2027, with carrying charges on the unrecovered balance at the Company’s money pool rate. The Company agreed to no further increase or redesign of base distribution rates before November 1, 2029. An order approving the settlement agreement was issued on March 27, 2026. New rates were effective April 1, 2026.
| | |
| St. Lawrence Gas | New York | GRC | $2.2 | On November 27, 2024, St. Lawrence Gas filed an application seeking a rate adjustment of $2.2 million based on an ROE of 9.90% and an equity ratio of 48.00%. On April 1, 2025, Staff of the New York Department of Public Service recommended a approximately $1.2 million decrease in rates. On April 22, 2025, the Company submitted rebuttal testimony requesting approximately $2.3 million. The Company filed notice and began confidential settlement negotiations on May 6, 2025. An unopposed Joint Proposal was filed on August 29, 2025 proposing a three-year rate plan ("Rate Plan") from November 1, 2025 through October 31, 2028 with unlevelized rate adjustments of $0.4 million in Rate Year 1, $1.9 million in Rate Year 2, and $1.6 million in Rate Year 3. Base rate adjustments would be levelized to reduce rate volatility to customers over the term of the Rate Plan. The Joint Proposal established ROE at 9.30%, and equity ratios of 46.00% in Rate Year 1, 47.00% in Rate Year 2, and 48.00% in Rate Year 3. The Rate Plan includes an Earnings Sharing Mechanism, gas safety and customer service performance metrics, customer programs to assist low income customers, and a three-year capital investment plan. The Joint Proposal also resolves the Company's outstanding Automated Meter Reading project petition providing funding to support the investment as part of the Rate Plan. The Joint Proposal includes provisions intended to further New York State's ability to meet the goals of the Climate Leadership and Community Protection Act. On January 22, 2026, the NYPSC approved the Joint Proposal.
| | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
| | | | | | | | | | | | | | | | |
| Utility | Jurisdiction | Regulatory Proceeding Type | Rate Request
(millions) | Current Status | | |
| Park Water | California | GRC | $9.3 | On January 2, 2024, Park Water filed an application seeking a rate adjustment of $9.3 million based on an ROE of 9.35% and an equity ratio of 57.00%. On July 24, 2024, the Public Advocates Office at CPUC filed testimony recommending a $2.4 million decrease in revenues for 2025. On September 23, 2024, the Company served rebuttal testimony seeking a $9.0 million rate adjustment. Legal briefs were filed in December 2024. On December 5, 2024, in the Cost of Capital proceeding for Small Class A Water Utilities, the CPUC issued an order increasing Park Water's ROE to 9.57%. On May 30, 2025, the CPUC authorized an interim rate adjustment of $0.9 million or 2.30%, effective July 1, 2025 and established an Interim Rate Memorandum Account to track differences between the interim rates and final rates approved. A proposed decision was issued on April 10, 2026 by the Administrative Law Judge recommending an adjustment in revenues of approximately $6.0 million or 14.31%. An alternate proposed decision was also issued on the same day by the assigned Commissioner's office, which recommends a rate adjustment of approximately $0.4 million or 1.06%. The Company filed comments on the proposed decisions on April 30, 2026. On May 13, 2026, a revised alternate proposed decision was issued, which recommended a decrease of $0.3 million or 0.70%. On May 14, 2026, the CPUC issued an order approving the revised alternate proposed decision, which authorizes a revenue requirement of $42.5 million based on a rate of return of 7.17%, which results in a revenue decrease of $0.3 million or 0.70% for the 2025 test year. On June 29, 2026, Park Water submitted a petition for modification to correct errors in the CPUC decision (D26-05-032) as certain adopted costs do not appear to be fully reflected in the authorized revenue requirement. The revenue requirement per the petition for modification is approximately $43.0 million, which would result in a rate increase of $0.2 million or 0.35%. On August 21, 2026, the CPUC issued a decision authorizing the revenue requirement included in the petition for modification and authorizing new rates to be retroactive to July 1, 2025.
| | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
| | | | | | | | | | | | | | | | |
| Utility | Jurisdiction | Regulatory Proceeding Type | Rate Request
(millions) | Current Status | | |
| Apple Valley Water | California | GRC | $3.1 | On January 2, 2024, Apple Valley Water filed an application seeking a rate adjustment of $3.1 million based on an ROE of 9.35% and an equity ratio of 57.00%. On July 24, 2024, the Public Advocates Office at the CPUC filed testimony recommending a $3.9 million decrease in revenues for 2025. On September 23, 2024, the Company served rebuttal testimony seeking a $2.9 million rate adjustment. Legal briefs were filed in December 2024. On December 5, 2024, in the Cost of Capital proceeding for Small Class A Water Utilities, the CPUC issued an order increasing Apple Valley Water’s ROE to 9.57%. On May 30, 2025, the CPUC authorized an interim rate adjustment of $0.7 million or 2.30%, effective July 1, 2025 and established an Interim Rate Memorandum Account to track differences between the interim rates and final rates approved. A proposed decision was issued on April 10, 2026 by the Administrative Law Judge recommending a rate adjustment of approximately $1.9 million or 7.17%. An alternate proposed decision was also issued on the same day by the assigned Commissioner's office, which recommends a decrease of approximately $2.2 million or 7.09% from present revenues. The Company filed comments on the proposed decisions on April 30, 2026. On May 13, 2026, a revised alternate proposed decision was issued, which recommended a decrease of approximately $2.4 million or 7.78%. On May 14, 2026, the CPUC issued an order approving the revised alternate proposed decision, which authorizes a revenue requirement of approximately $28.3 million based on a rate of return of 7.17%, which results in a revenue decrease of approximately $2.4 million or 7.78% for the 2025 test year. On June 29, 2026, Apple Valley Water submitted a petition for modification to correct errors in CPUC decision (D26-05-032) as certain adopted costs do not appear to be fully reflected in the authorized revenue requirement. The revenue requirement per the petition for modification is approximately $28.7 million, which would result in a rate decrease of approximately $2.0 million or 6.64%. On August 21, 2026, the CPUC issued a decision authorizing the revenue requirement included in the petition for modification and authorizing new rates to be retroactive to July 1, 2025.
| | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
| | | | | | | | | | | | | | | | |
| Utility | Jurisdiction | Regulatory Proceeding Type | Rate Request
(millions) | Current Status | | |
| Empire Electric | Missouri | GRC | $168.0 | On November 6, 2024, Empire Electric filed an application seeking a net rate adjustment of $92.1 million based on an ROE of 10.00% and an equity ratio of 53.10%. On February 3, 2025, Staff of the Missouri Public Service Commission ("MPSC") and the Office of the Public Counsel ("OPC") filed motions to dismiss the case. The Company withdrew its tariff sheets on February 26, 2025 and refiled revised tariff sheets on the same day seeking a base rate adjustment of $152.8 million. When considering the rebasing of test year revenues for fuel and purchased power costs and the energy efficiency cost recovery rate, the filing continues to seek a net rate adjustment of $92.1 million. On March 5, 2025, the MPSC suspended the new tariff sheets until January 2, 2026. On April 10, 2025, the MPSC approved a procedural schedule for the case and on April 23, 2025, the Commission extended the true-up period from September 30, 2024 to March 31, 2025. The Company’s final true-up position reflected an annual rate adjustment of approximately $168.0 million, primarily driven by projected higher natural gas costs required to operate its generating units. The MPSC Staff’s position supported an adjustment of about $128.0 million, while OPC recommended no adjustment, citing ongoing billing issues. To resolve these differences, the Company entered into a global non-unanimous stipulation agreement providing for a rate adjustment of $97.0 million, with the potential to earn an additional $13.7 million annually if certain billing and customer service metrics are met. OPC and Consumers Council of Missouri did not join the settlement, and as a result of their objections, a hearing was held during the week of October 13, 2025. During the hearing, settlement terms were presented as position statements from the signatories. On November 5, 2025, the MPSC deliberated on the case and requested amendments to incorporate customer satisfaction performance metrics. The original signatories of the non-unanimous stipulation agreement submitted performance metrics in December 2025. The Commission held an on the record proceeding on January 7, 2026 related to the performance metrics. On January 14, 2026, the Commission issued its Report and Order effective January 24, 2026 approving the settlement agreements which would allow for the $97.0 million to be phased in over 3 years once the performance metrics have been met for three consecutive months. The Company has the opportunity to record up to approximately $13.7 million annually in a regulatory asset, with recovery subject to review in a future rate case. On January 23, 2026, the Office of Public Counsel filed an application for rehearing and request for reconciliation. On February 5, 2026, the Commission issued an order denying the application for rehearing. On February 19, 2026, the Office of Public Counsel filed a Notice of Election to Not Appeal the Commission’s January 14 Report and Order. The Company submitted its third monthly filing stating that it has satisfied the terms of the Supplemental Stipulation for three consecutive months, which, under the Global Agreement, would permit implementation of a change in rates. In that filing, the Company identified limited deviations in each month, consistent with the provisions of the Supplemental Stipulation. On June 26, 2026 the Commission issued an Order scheduling an On-The-Record Proceeding for July 7, 2026 on the sole issue of whether the Company had met the three month performance metrics, and further suspended the tariff sheets until August 3, 2026. On July 15, 2026 the Commission issued an order finding that Empire met the customer service and billing metrics and authorized rates took effect August 3, 2026.
| | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
| | | | | | | | | | | | | | | | |
| Utility | Jurisdiction | Regulatory Proceeding Type | Rate Request
(millions) | Current Status | | |
| Empire Electric | Kansas | GRC | $15.8 | On December 31, 2025, Empire Electric filed an application to adjust its Kansas retail electric base rates of $15.8 million, or approximately 93.77%. If the Commission approves Empire's request to include the costs of its wind projects, in base rates, then a portion of the adjustment in base rates would be offset by an expected reduction in fuel costs of approximately $3.3 million per year, reducing the proposed adjustment in the residential customer's overall bill to 40.00%. The Company also proposed a three-year phase-in of rates. On May 6, 2026 Staff filed testimony which recommended rate adjustments of approximately $2.8 million in Year 1, $5.7 million in Year 2 and $8.5 million in Year 3. On June 3, 2026, the Company filed its Rebuttal Testimony indicating its revised revenue requirement adjustment is approximately $14.1 million. Additionally, the Company filed rebuttal testimony regarding the inappropriateness of the recommendation of a mandatory phase-in with no deferred revenue regulatory asset. On June 12, 2026 the parties filed a Joint Motion to Approve Unanimous Settlement Agreement which provides for an approximate $8.8 million rate adjustment be phased in over two years, the establishment of a deferred revenue regulatory asset account, and recovery of the Company's investment in its wind projects, along with the right to retain 50.00% of the revenue from the wind project in the first year of the phase-in. On July 21, 2026, the Commission approved the Unanimous Settlement. New rates took effect August 1, 2026.
| | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
| | | | | | | | | | | | | | | | |
| Utility | Jurisdiction | Regulatory Proceeding Type | Rate Request
(millions) | Current Status | | |
| Pending Rate Reviews: | | | | | |
| | | | | | |
Litchfield Park Water & Sewer | Arizona | GRC | $17.8 | On June 30, 2025, Litchfield Park Water & Sewer filed rate applications with the Arizona Corporation Commission ("ACC") for its water and wastewater systems, requesting a combined rate adjustment of $17.8 million. The request is based on an ROE of 10.80% and an equity ratio of 54.00%. As part of the application, the Company is seeking approval for the implementation of an annual formula rate based adjustment mechanism. On January 16, 2026, ACC Staff filed testimony which recommends a combined rate adjustment of $14.5 million based on an ROE of 9.45% and an equity ratio of 54.00%. The Company filed rebuttal testimony on February 25, 2026. On March 3, 2026, the Company and Commission Staff jointly submitted a settlement agreement that resolves all matters between the two parties and would result in a combined water and wastewater rate adjustment of $15.3 million based on an ROE of 9.75% and an equity ratio of 54.00%. On March 19, the Company and ACC Staff jointly submitted an updated formula rate proposal. The Residential Utility Consumer Office is not party to the settlement agreement. The ACC held hearings in March 2026 on the settlement agreement and the jointly filed a formula rate proposal. On July 24, 2026, the assigned Administrative Law Judge issued a Recommended Opinion and Order ("ROO") that adopts the key terms of the settlement agreement between the Company and Commission Staff and approves the formula rate proposal with certain changes. The ROO provides for a combined rate adjustment of $15.0 million based on a ROE of 9.75% and an equity ratio of 54.00%. On August 12, 2026, the ACC approved the ROO authorizing new rates effective September 1, 2026 and a combined rate adjustment of $14.9 million, based on a ROE of 9.40% and an equity ratio of 54.00%. On September 17, 2026, the Residential Utilities Consumers Office filed a motion for rehearing contesting the formula rates approval. That motion was administratively denied by operation of law as of October 7, 2026. | | |
| CalPeco Electric | California | Wildfire Expense Memorandum Application | $78.2 | On June 20, 2025, CalPeco Electric filed an application to recover $78.2 million in costs associated with the 2020 Mountain View Fire recorded in the WEMA. These costs include claim settlements in excess of Liberty’s wildfire insurance coverage, legal costs, and financing costs related to the Mountain View Fire. On December 12, 2025, Cal Advocates and Small Business Utility Advocates ("SBUA") filed testimony opposing the Company’s request. Cal Advocates did not put forward a specific disallowance proposal and SBUA proposed a full disallowance of Liberty's request. Liberty's rebuttal testimony was submitted on January 23, 2026, which revised the request to $77.4 million. Hearings were held February 10-11, 2026. Legal briefs were submitted on March 13, 2026 and April 3, 2026. On June 23, 2026, a proposed decision was issued by the Administrative Law Judge recommending recovery of approximately $58.1 million or 75.00% of the requested $77.4 million recorded in Liberty's WEMA. The proposed decision also recommended recovery over a five-year period, as opposed to Liberty's request for a three-year recovery period, and accordingly recommended up to approximately $3.4 million in additional financing costs to cover the longer recovery period. The Company filed comments on the proposed decision in July 2026. The proposed decision is expected to be on the agenda for the November 19, 2026 CPUC voting meeting. On October 7, 2026 Cal Advocates filed motions seeking to reopen the record to take notice of the Proposed Administrative Enforcement Order ("AEO") issued by the Commission’s Safety and Enforcement Division ("SED") on September 28, 2026 related to the Mountain View Fire recommending proposed penalties of approximately $16.0 million for alleged violations of General Order 95 Rule 31.1. On October 26, 2026, CalPeco filed a request for an evidentiary hearing on the proposed order, noting that the proposed order does not identify evidence sufficient to support the alleged violations, and the proposed penalty for the alleged violations is unsubstantiated, excessive, and unlawful.
| | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
| | | | | | | | | | | | | | | | |
| Utility | Jurisdiction | Regulatory Proceeding Type | Rate Request
(millions) | Current Status | | |
| Gold Canyon Sewer | Arizona | GRC | $1.7 | On June 30, 2026, Gold Canyon Sewer filed an application with the ACC requesting a rate adjustment of approximately $1.7 million. The request is based on an ROE of 10.60% and an equity ratio of 54.00%. On August 7, 2026, the Administrative Law Judge approved a procedural order providing for Staff and Intervenor direct testimony on issues other than rate design on January 19, 2027, company rebuttal February 19, 2027, surrebuttal March 12, 2027, and a hearing on March 30, 2027.
| | |
| Black Mountain Sewer | Arizona | GRC | $1.4 | On June 30, 2026, Black Mountain Sewer filed an application with the ACC requesting a rate adjustment of $1.4 million. The request is based on an ROE of 10.60% and an equity ratio of 54.00%. On August 7, 2026, the Administrative Law Judge approved a procedural order providing for Staff and Intervenor direct testimony on issues other than rate design on January 19, 2027, company rebuttal February 19, 2027, surrebuttal March 12, 2027, and a hearing on March 30, 2027.
| | |
| New York Water | NY | GRC | $38.1 | On May 29, 2026, New York Water filed an application with the New York State Public Service Commission requesting a revenue increase of $38.1 million. The request is based on an ROE of 10.00% and an equity ratio of 48.00%. On August 11, 2026, the Company updated its requested revenue increase to $37.6 million. Intervenor testimony was filed on October 1, 2026 with hearings scheduled to commence on November 2, 2026. Staff recommended a revenue increase of $12.6 million, partially determined using an ROE of 9.20% and an equity ratio of 48.00%. On October 27, 2026 New York Water filed a notice of impending settlement negotiations and a consent to a 60-day extension of the suspension period to June 29, 2027, subject to agreement with parties on a make whole provision to keep the Company in the same financial position that they would have been absent the extension. The ALJ subsequently vacated the scheduled November 2, 2026 hearing. The Commission must rule on the extension of the suspension period. | | |
| Energy North Natural Gas | NH | GRC | $35.8 | On July 30, 2026 EnergyNorth Natural Gas filed an application with the New Hampshire Public Utilities Commission ("NHPUC") requesting a revenue increase of $35.8 million. The request is based on an ROE of 10.25% and an equity ratio of 52.00%. On September 24, 2026, the NHPUC approved a procedural schedule, providing for New Hampshire Department of Energy ("DOE"), the Office of the Consumer Advocate ("OCA") and Intervenor testimony on March 29, 2027, Company rebuttal on May 17, 2027, filing of any settlement on June 4, 2027 and hearings from June 22 to July 1, 2027. On October 1, 2026 a Settlement Agreement on temporary rates was filed jointly with the DOE and the OCA. A hearing was held on the Temporary Rates Settlement Agreement on October 6, 2026. On October 30, 2026, the Commission scheduled a further hearing on temporary rates for November 19, 2026. | | |
| Empire Electric | Arkansas | GRC | $8.4 | On May 15, 2026, Empire Electric filed an application with the Arkansas Public Service Commission ("APSC") requesting a rate adjustment of $8.4 million. The request is based on an ROE of 10.00% and an equity ratio of 53.39%. The APSC hearing is scheduled for January 26, 2027.
| | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
| | | | | | | | | | | | | | | | |
| Utility | Jurisdiction | Regulatory Proceeding Type | Rate Request
(millions) | Current Status | | |
| Empire Electric | FERC | Incentive Request & Formula Rate Modification | $1.5 | On July 2, 2026, Empire Electric filed a request for transmission rate incentive treatment for its upcoming investment in a portfolio of electric transmission projects approved by the Southwest Power Pool ("SPP") in its 2024 Integrated Transmission Planning Assessment Report. These incentives include recovery of 100% of construction work in progress in rate base during the development of the projects and recovery of 100% of prudently incurred costs in the event the projects are cancelled or abandoned for reasons beyond Empire's control. On July 31, 2026, Empire requested that FERC modify its Transmission Formula Rate ("TFR") to transition to a projected formula from historical. This request seeks a 10.69% ROE with a 50 basis point Regional Transmission Organization Participation Adder for a total requested ROE of 11.19%. Empire also requested new depreciation rates and to change its rate year to a calendar year. On August 21, 2026, the Kansas Corporation Commission, and the Cities of Lockwood, Monett, and Mount Vernon, Missouri filed protests challenging the revisions to the transmission formula rate and protocols. On August 31, 2026, FERC issued an order authorizing the Abandoned Plant Incentive and CWIP Incentive for Empire Electric's investment in the SPP project portfolio. | | |
| Empire Electric | Oklahoma | GRC | $7.0 | On August 14, 2026, Empire Electric filed an application with the Oklahoma Corporation Commission ("OCC") requesting a rate adjustment of $7.0 million. The request is based on an ROE of 10.00% and an equity ratio of 54.75%. Intervenor testimony is due December 4, 2026 and the hearing is scheduled for February 2, 2027.
| | |
| Granite State Electric | New Hampshire | GRC | $12.3 | On October 6, 2026, Granite State Electric filed an application with the NHPUC requesting a rate adjustment of $12.3 million. The request is based on an ROE of 10.25% and an equity ratio of 52.00%. | | |
| Peach State Gas | Georgia | GRAM | $2.5 | On September 1, 2026, Peach State Gas filed its 2027 Georgia Rate Adjustment Mechanism with the Georgia Public Service Commission requesting a rate adjustment of $2.5 million, with new rates to be effective March 2027. The request is based on an ROE of 10.20% and an equity ratio of 56.00%.
| | |
| Empire Electric | Missouri | Large Load Tariff | N/A | On September 11, 2026, Empire Electric filed a Large Load tariff with the Missouri Public Service Commission, as required by Missouri Senate Bill 4. The proposed tariff is intended to support economic development and large-load investment while protecting existing customers by requiring large-load customers to pay their representative cost of service.
| | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |
CORPORATE GROUP NET EARNINGS AND ADJUSTED NET EARNINGS
Key financial information related to the Corporate Group is as follows:
| | | | | | | | | | | | | | |
2026 Third Quarter and Year-to-Date Corporate Group Net Loss and Adjusted Net Loss |
| Three months ended September 30, | Nine months ended September 30, |
| (all dollar amounts in $ millions) | 2026 | 2025 | 2026 | 2025 |
| Revenue | $ | 0.3 | | $ | 0.3 | | $ | 1.2 | | $ | 1.1 | |
| Operating expenses | 1.0 | | (0.9) | | 1.8 | | 3.0 | |
| Depreciation and amortization | 0.2 | | 0.3 | | 0.7 | | 0.7 | |
| Loss (Gain) on foreign exchange | 0.1 | | (2.9) | | (1.7) | | 9.0 | |
Add: Interest, dividend and other income | 3.5 | | 4.2 | | 10.1 | | 10.8 | |
| | | | |
Less: Other net gains (losses) | (1.9) | | (8.2) | | (17.8) | | (12.1) | |
| Gain (loss) on derivative financial instruments | — | | 0.1 | | — | | (7.4) | |
Corporate Group EBIT1,2 | 0.6 | | (0.1) | | (7.3) | | (20.3) | |
| Interest expense | (18.4) | | (35.3) | | (85.9) | | (104.8) | |
| Income tax recovery | 3.5 | | 2.2 | | 17.5 | | 11.7 | |
| Corporate Group Net Loss attributable to shareholders | (14.3) | | (33.2) | | (75.7) | | (113.4) | |
| Series A Preferred Share and Series D Preferred Share dividend | (2.8) | | (2.7) | | (8.0) | | (7.9) | |
| Corporate Group Net Loss attributable to common shareholders | (17.1) | | (35.9) | | (83.7) | | (121.3) | |
| Add / (Less): Adjusted items | | | | |
| Gain (loss) on derivative financial instruments | — | | (0.1) | | — | | 7.4 | |
Restructuring costs4 | 1.8 | | 9.2 | | 16.6 | | 21.2 | |
| | | | |
| Loss (Gain) on foreign exchange | 0.1 | | (2.9) | | (1.7) | | 9.0 | |
| Change in value of investments carried at fair value | — | | (0.1) | | — | | (0.1) | |
| Adjustment for taxes related to above | 0.2 | | (0.2) | | 1.1 | | (0.3) | |
Corporate Group Adjusted Net Loss1,3 | $ | (15.0) | | $ | (30.0) | | $ | (67.7) | | $ | (84.1) | |
| | | | | |
| 1 | See Caution Concerning Non-GAAP Measures. |
| 2 | This table contains a reconciliation of EBIT to net earnings for the Corporate Group. The relevant sections of the table are derived from and should be read in conjunction with the unaudited interim condensed consolidated statement of operations and Note 14 in the unaudited interim condensed consolidated financial statements, "Segmented Information". This supplementary disclosure is intended to more fully explain disclosures related to EBIT and provides additional information related to the operating performance of the Corporate Group. Investors are cautioned that EBIT should not be construed as an alternative to net earnings. |
| 3 | This table contains a reconciliation of Adjusted Net Earnings to net earnings for the Corporate Group. The relevant sections of the table are derived from and should be read in conjunction with the unaudited interim condensed consolidated statement of operations and Note 14 in the unaudited interim condensed consolidated financial statements, "Segmented Information". This supplementary disclosure is intended to more fully explain disclosures related to Adjusted Net Earnings for the Corporate Group and provides additional information related to the operating performance of the Corporate Group. Investors are cautioned that Adjusted Net Earnings should not be construed as an alternative to net earnings. |
| 4 | See Note 12 in the unaudited interim condensed consolidated financial statements. |
For the three and nine months ended September 30, 2026, the loss on derivative financial instruments was $nil and $0.1 million, compared to a loss of $nil and $7.4 million, respectively, in the same periods in 2025. The loss in the prior year period primarily related to the settlement of a C$300 million foreign exchange forward contract used to hedge underlying debt from the Company's former renewable energy group (excluding hydro).
For the three and nine months ended September 30, 2026, interest expense totaled $18.4 million and $85.9 million, compared to $35.3 million and $104.8 million, respectively, in the same periods in 2025. The decrease was primarily due to the repayment on June 15, 2026 of $1,150.0 million of debt previously held at the Corporate Group, following the Senior Note Offering, resulting in lower interest expense at the Corporate Group.
For the three months ended September 30, 2026, other losses totaled $1.9 million compared to $8.2 million, in the same period in 2025. The decrease was primarily related to a decrease in non-recurring costs (including third party consulting charges) in 2026. For the nine months ended September 30, 2026, other losses totaled $17.8 million compared to $12.1 million, in the same period in 2025. The increase was primarily related to non-recurring costs (including third party consulting charges).
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 33 |
HYDRO GROUP NET EARNINGS AND ADJUSTED EARNINGS
Key financial information related to the Hydro Group is as follows:
| | | | | | | | | | | | | | |
2026 Third Quarter and Year-to-Date Hydro Group Net Earnings1 and Adjusted Net Earnings2 |
| Three months ended September 30, | Nine months ended September 30, |
| (all dollar amounts in $ millions) | 2026 | 2025 | 2026 | 2025 |
| | | | |
| | | | |
| | | | |
| | | | |
| Revenue | $ | 7.6 | | $ | 8.4 | | $ | 27.1 | | $ | 28.1 | |
| Other revenue | 0.1 | | 0.2 | | 0.3 | | 0.7 | |
| | | | |
| Operating expenses | 2.3 | | 2.7 | | 8.4 | | 8.2 | |
| Depreciation and amortization | 1.8 | | 1.9 | | 5.5 | | 5.5 | |
| Loss on foreign exchange | — | | — | | 0.1 | | 0.2 | |
Add: Interest, dividend and other income | 0.1 | | — | | 0.1 | | 0.2 | |
Less: Other losses | — | | 0.7 | | (0.3) | | 0.7 | |
Hydro Group EBIT2 | 3.7 | | 4.7 | | 13.2 | | 15.8 | |
| Interest expense | (0.2) | | (0.2) | | (0.5) | | (0.7) | |
Income tax (expense) / recovery3 | (0.6) | | (0.2) | | (2.6) | | 16.7 | |
| Net earnings from non-controlling interest | (0.8) | | (1.0) | | (2.8) | | (3.0) | |
| Hydro Group net earnings attributable to common shareholders | 2.1 | | 3.3 | | 7.3 | | 28.8 | |
| Add / (Less): Adjusted items: | | | | |
| Loss on foreign exchange | — | | — | | 0.1 | | 0.2 | |
| Adjustment for taxes related to above | — | | — | | — | | (0.1) | |
| Hydro Group Adjusted Net Earnings | $ | 2.1 | | $ | 3.3 | | $ | 7.4 | | $ | 28.9 | |
| | | | | |
| 1 | This table contains a reconciliation of EBIT to net earnings for the Hydro Group. The relevant sections of the table are derived from and should be read in conjunction with the unaudited interim condensed consolidated statement of operations and Note 14 in the unaudited interim condensed consolidated financial statements, "Segmented Information". This supplementary disclosure is intended to more fully explain disclosures related to EBIT and provides additional information related to the operating performance of the Hydro Group. Investors are cautioned that EBIT should not be construed as an alternative to net earnings. |
| 2 | See Caution Concerning Non-GAAP Measures. |
| 3 | For the nine months ended September 30, 2026, income tax expense increased primarily because the comparable periods in 2025 included income tax recoveries of $15.9 million, resulting from the tax basis step-up from Hydro Group’s reorganization in connection with the Renewables Sale. |
| |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 34 |
DISCONTINUED OPERATIONS: RENEWABLE ENERGY GROUP
The former renewable energy group (excluding hydro), presented as discontinued operations, generated and sold electrical energy produced by its diverse portfolio of renewable power generation and clean power generation facilities located in the United States and Canada. The renewable energy group (excluding hydro) was sold by the Company on January 8, 2025.
Key financial information related to the discontinued operations is as follows:
| | | | | | | | | | | | | | |
2026 Third Quarter and Year-to-Date Discontinued Operations Results |
| Three months ended September 30, | Nine months ended September 30, |
| (all dollar amounts in $ millions) | 2026 | 2025 | 2026 | 2025 |
| Revenue | $ | — | | $ | — | | $ | — | | $ | 7.4 | |
| Operating loss | $ | — | | $ | — | | $ | — | | $ | (1.3) | |
| Net earnings (loss) attributable to AQN | $ | (0.6) | | $ | (34.8) | | $ | (4.0) | | $ | (26.7) | |
Due to the Renewables Sale, for the three and nine months ended September 30, 2026, the renewable energy group's facilities generated no operating revenue, compared to $nil and $7.4 million, respectively, in the corresponding period in 2025. The net loss attributable to the Company for the three and nine months ended September 30, 2026 were $0.6 million and $4.0 million, respectively, primarily reflecting closing and transition-related costs. This compares to net loss attributable to the Company of $34.8 million and $26.7 million, respectively, in the same period in 2025.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 35 |
NON-GAAP FINANCIAL MEASURES
Reconciliation of EBIT to Net Earnings
The following table is derived from and should be read in conjunction with the unaudited interim condensed consolidated statement of operations. This supplementary disclosure is intended to more fully explain disclosures related to EBIT of AQN and provides additional information related to the operating performance of AQN. Investors are cautioned that this measure should not be construed as an alternative to U.S. GAAP consolidated net earnings.
| | | | | | | | | | | | | | |
| Three months ended September 30, | Nine months ended September 30, |
| (all dollar amounts in $ millions) | 2026 | 2025 | 2026 | 2025 |
| Net earnings attributable to common shareholders | $ | 57.0 | | $ | 36.2 | | $ | 141.6 | | $ | 151.9 | |
| Add: Series A Preferred Share and Series D Preferred Share dividend | 2.8 | | 2.7 | | 8.0 | | 7.9 | |
| Net earnings attributable to shareholders | 59.8 | | 38.9 | | 149.6 | | 159.8 | |
| | | | |
| Add (deduct): | | | | |
| Income tax expense | 22.0 | | 27.0 | | 53.4 | | 53.8 | |
| Net effect of non-controlling interest | (18.2) | | (15.0) | | (54.6) | | (50.9) | |
| Earnings from discontinued operations, net of tax | 0.6 | | 34.8 | | 4.0 | | 26.7 | |
| Interest expense | 76.6 | | 71.7 | | 226.3 | | 210.9 | |
| EBIT | $ | 140.8 | | $ | 157.4 | | $ | 378.7 | | $ | 400.3 | |
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 36 |
Reconciliation of Adjusted Net Earnings to Net Earnings
The following table is derived from and should be read in conjunction with the unaudited interim condensed consolidated statement of operations. This supplementary disclosure is intended to more fully explain disclosures related to Adjusted Net Earnings of AQN and provides additional information related to the operating performance of AQN. Investors are cautioned that this measure should not be construed as an alternative to U.S. GAAP consolidated net earnings.
The following table shows the reconciliation of net earnings attributable to common shareholders to Adjusted Net Earnings of AQN exclusive of these items:
| | | | | | | | | | | | | | |
| Three months ended September 30, | Nine months ended September 30, |
| (all dollar amounts in $ millions except per share information) | 2026 | 2025 | 2026 | 2025 |
| Net earnings attributable to common shareholders | $ | 57.0 | | $ | 36.2 | | $ | 141.6 | | $ | 151.9 | |
| Add (deduct): | | | | |
| Loss from discontinued operations, net of tax | 0.6 | | 34.8 | | 4.0 | | 26.7 | |
| | | | |
| Gain on derivative financial instruments | — | | (8.7) | | — | | (1.8) | |
| | | | |
| | | | |
Restructuring costs1 | 7.7 | | 9.6 | | 36.6 | | 22.0 | |
Mountain View Fire related costs1 | 16.6 | | — | | 33.8 | | — | |
Loss on net assets classified as held for sale2 | 8.3 | | — | | 8.3 | | — | |
| | | | |
| Loss (Gain) on foreign exchange | 1.9 | | (2.3) | | 5.7 | | 15.6 | |
| | | | |
| | | | |
| | | | |
Change in value of investments carried at fair value3 | — | | (0.1) | | — | | (0.1) | |
| | | | |
| | | | |
| | | | |
| Adjustment for taxes related to above | (4.0) | | (0.5) | | (13.1) | | (2.7) | |
| Adjusted Net Earnings | $ | 88.1 | | $ | 69.0 | | $ | 216.9 | | $ | 211.6 | |
| Adjusted Net Earnings per common share | $ | 0.11 | | $ | 0.09 | | $ | 0.28 | | $ | 0.28 | |
| | | | | |
| |
| 1 | See Note 12 in the unaudited interim condensed Consolidated Financial Statements. |
| |
| 2 | See Note 19 in the unaudited interim condensed Consolidated Financial Statements. |
| 3 | See Note 5 in the unaudited interim condensed Consolidated Financial Statements. |
| |
For the three months ended September 30, 2026, Adjusted Net Earnings totaled $88.1 million as compared to $69.0 million for the same period in 2025, an increase of $19.1 million.
For the nine months ended September 30, 2026, Adjusted Net Earnings totaled $216.9 million as compared to $211.6 million for the same period in 2025, an increase of $5.3 million.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 37 |
SUMMARY OF PROPERTY, PLANT AND EQUIPMENT EXPENDITURES
| | | | | | | | | | | | | | |
| | |
| Three months ended September 30, | Nine months ended September 30, |
| (all dollar amounts in $ millions) | 2026 | 2025 | 2026 | 2025 |
| Regulated Services Group | | | | |
Sustaining1 | $ | 171.6 | | $ | 121.3 | | $ | 343.3 | | $ | 309.3 | |
| Growth | 34.3 | | 25.5 | | 102.5 | | 73.9 | |
| 205.9 | | 146.8 | | 445.8 | | 383.2 | |
| | | | |
| Hydro Group | 1.6 | | 1.7 | | 2.6 | | 2.9 | |
| | | | |
| Total Capital Expenditures | $ | 207.5 | | $ | 148.5 | | $ | 448.4 | | $ | 386.1 | |
| | | | | |
| 1 | Capital spend to support existing systems (e.g. asset replacements, safety & reliability projects). |
2026 Third Quarter Property, Plant and Equipment Expenditures
During the three months ended September 30, 2026, the Regulated Services Group made capital expenditures of $205.9 million as compared to $146.8 million during the same period in 2025. The increase of $59.1 million is mainly due to the timing of capital expenditures incurred. The Regulated Services Group's investments during the third quarter of 2026 were primarily related to the construction of transmission and distribution main replacements, work on new and existing substation assets, and initiatives relating to the safety and reliability of water, electric and natural gas systems.
During the three months ended September 30, 2026, the Hydro Group made capital expenditures of $1.6 million as compared to $1.7 million during the same period in 2025. The Hydro Group's investments in the third quarter of 2026 were primarily related to the replacement of capital components at existing operating facilities.
2026 Year-to-Date Property, Plant and Equipment Expenditures
During the nine months ended September 30, 2026, the Regulated Services Group incurred capital expenditures of $445.8 million as compared to $383.2 million during the same period in 2025. The increase of $62.6 million is mainly due to the timing of certain capital expenditures. The Regulated Services Group's investments year-to-date in 2026 were primarily related to the construction of transmission and distribution main replacements, work on new and existing substation assets, and initiatives relating to the safety and reliability of electric and natural gas systems.
During the nine months ended September 30, 2026, the Hydro Group made capital expenditures of $2.6 million as compared to $2.9 million during the same period in 2025. Investments year-to-date in 2026 were primarily related to the replacement of capital components at existing operating facilities.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 38 |
LIQUIDITY AND CAPITAL RESERVES
AQN has revolving credit and letter of credit facilities as well as separate credit facilities for the Regulated Services Group to manage liquidity and working capital requirements (collectively the "Bank Credit Facilities").
Bank Credit Facilities
The following table sets out the Bank Credit Facilities available to AQN and its operating groups as at September 30, 2026:
| | | | | | | | | | |
| | As at | | As at |
| | September 30, 2026 | | December 31, 2025 |
| (all dollar amounts in $ millions) | | Total | | Total |
Revolving and term credit facilities1 | | $ | 1,792.0 | | | $ | 1,850.0 | |
| Funds drawn on facilities / commercial paper issued | | (564.0) | | | (341.5) | |
| Letters of credit issued | | (36.8) | | | (34.1) | |
| Liquidity available under the facilities | | 1,191.2 | | | 1,474.4 | |
| Undrawn portion of uncommitted letter of credit facilities | | (1.7) | | | (62.4) | |
| Cash on hand | | 44.2 | | | 26.0 | |
Total Liquidity and Capital Reserves2 | | $ | 1,233.7 | | | $ | 1,438.0 | |
| | | | |
1 Includes a $17.0 million uncommitted standalone letter of credit facility for the Corporate Group compared to $75.0 million as at December 31, 2025. |
2Amounts as at September 30, 2026 and December 31, 2025 exclude liquidity associated with the Disposal Group classified as held for sale. |
Regulated Services Group
On September 14, 2026, the Regulated Services Group repaid $7.0 million aggregate principal amount of 7.99% First Mortgage Bonds due September 15, 2026.
As at September 30, 2026, the Regulated Services Group's $25.0 million senior unsecured revolving credit facility (the "Bermuda Credit Facility") had no amounts drawn. The Bermuda Credit Facility matures on July 10, 2027.
As at September 30, 2026, the Regulated Services Group's $1.0 billion senior unsecured revolving credit facility (the "Long-Term Regulated Services Credit Facility") had no amounts drawn and had $21.5 million of outstanding letters of credit. The Long-Term Regulated Services Credit Facility matures on November 13, 2030.
As at September 30, 2026, the Regulated Services Group had $564.0 million of commercial paper issued and outstanding.
Corporate Group
On September 1, 2026, the Corporate Group amended the size of its uncommitted standalone letter of credit facility from $14.6 million to $17.0 million. The Corporate Group has the ability to increase the facility as required with notice.
As at September 30, 2026, the Corporate Group's $750.0 million senior unsecured revolving credit facility (the "Corporate Credit Facility") had no amounts drawn and had no outstanding letters of credit. The Corporate Credit Facility matures on March 31, 2028.
As at September 30, 2026, the Company had issued $15.3 million of letters of credit from its $17.0 million uncommitted letter of credit facility.
Long-Term Debt
On April 17, 2026, the Regulated Services Group entered a $1.15 billion senior unsecured syndicated delayed draw term facility (the "Regulated Services Delayed Draw Term Facility") with a maturity date of April 17, 2028. On May 18, 2026, subsequent to the closing of the Senior Note Offering, the Regulated Services Delayed Draw Term Facility was terminated with no amounts drawn under its $1.15 billion of commitments.
On May 15, 2026, Liberty Utilities Co. ("LUCo") completed an offering (the "Senior Note Offering") of $650 million aggregate principal amount 5.10% senior notes due May 15, 2031 (the “2031 Notes”) and $500 million aggregate principal amount of 5.65% senior notes due May 15, 2036 (the “2036 Notes” and together with the 2031 Notes, the “Senior Notes”). The Senior Notes are unsecured and unsubordinated obligations of LUCo and rank equally with all of LUCo's existing and future unsecured and unsubordinated indebtedness and senior in right of payment to any existing and future LUCo subordinated indebtedness. LUCo used the net proceeds from the sale of the Senior Notes to repay an intercompany loan (including accrued interest) due to the Company and made an intercompany loan to Liberty Utilities (America) Co. (“LUA”). LUA subsequently used such funds
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 39 |
to repay existing amounts owing to the Company. On June 15, 2026, the Company used the funds, together with cash on hand, to fully repay its $1.15 billion aggregate principal amount of 5.365% notes due 2026 and to pay related fees and expenses.
Credit Ratings
AQN has a long-term consolidated corporate credit rating of BBB from Standard & Poor's Financial Services LLC, ("S&P"), a BBB rating from Morningstar DBRS ("DBRS") and a BBB issuer rating from Fitch Ratings Inc. ("Fitch").
LUCo has a corporate credit rating of BBB from S&P, a BBB issuer rating from Fitch and a Baa2 issuer rating from Moody's Investors Service, Inc. ("Moody's"). Debt issued by LUCo has a rating of BBB from S&P, BBB+ from Fitch and Baa2 from Moody's. Debt issued by Liberty Utilities Finance GP1 ("Liberty GP") has a rating of BBB (high) from DBRS, BBB+ from Fitch, BBB from S&P and Baa2 from Moody's. The Empire District Electric Company has an issuer rating of BBB from S&P and a Baa1 rating from Moody's. Liberty Utilities (Canada) LP, the parent company for the Canadian regulated utilities under the Regulated Services Group, has an issuer rating of BBB from DBRS. The fixed-rate securitized utility tariff bonds (series 2024-A) issued by Empire District Bondco, LLC have a rating of AAA (sf) from S&P and Moody's.
Contractual Obligations
Except for changes in scheduled principal repayments on long-term debt resulting from the Senior Note Offering completed during the second quarter of 2026, there were no material changes in the Company’s contractual obligations as at September 30, 2026 as compared to December 31, 2025. The following table presents the Company’s scheduled principal repayments on long-term debt as at September 30, 2026:
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| (all dollar amounts in $ millions) | Total | | Due in less
than 1 year | | Due in 1
to 3 years | | Due in 4
to 5 years | | Due after
5 years |
Principal repayments on debt obligations1,2,3 | $ | 6,554.1 | | | $ | 984.7 | | | $ | 929.4 | | | $ | 1,556.5 | | | $ | 3,083.5 | |
| | | | | | | | | |
| | | | | | | | | |
| 1 | Exclusive of deferred financing costs, bond premium/discount, and fair value adjustments at the time of issuance or acquisition. | | | | |
| 2 | The Company's subordinated unsecured notes have a maturity in 2079 and 2082, respectively. However, the Company currently anticipates repaying such notes in advance of maturity upon exercise of the Company's redemption rights in accordance with the terms of the applicable governing indenture. | | | | |
| 3 | Excludes amounts associated with the Disposal Group, classified as liabilities associated with assets held for sale. |
Equity
The common shares of AQN are publicly traded on the Toronto Stock Exchange and the New York Stock Exchange under the trading symbol "AQN". As at November 5, 2026, AQN had 769,990,872 issued and outstanding common shares.
AQN may issue an unlimited number of common shares. The holders of common shares are entitled to dividends, if and when declared; to one vote for each share at meetings of the holders of common shares; and to receive a pro rata share of any remaining property and assets of AQN upon liquidation, dissolution or winding up of AQN. All common shares are of the same class and with equal rights and privileges and are not subject to future calls or assessments.
AQN is also authorized to issue an unlimited number of preferred shares, issuable in one or more series, containing terms and conditions as approved by the board of directors of the Company (the "Board"). As at November 5, 2026, AQN had outstanding:
•4,800,000 Cumulative Rate Reset Preferred Shares, Series A, yielding 6.576% annually for the five-year period ending on December 31, 2028; and
•4,000,000 Cumulative Rate Reset Preferred Shares, Series D, yielding 6.853% annually for the five year period ending on March 31, 2029.
Declaration of 2026 Fourth Quarter Dividend of $0.0650 (C$0.0907) per Common Share
The Board has declared a fourth quarter 2026 dividend of $0.0650 per common share payable on January 15, 2027 to shareholders of record on December 31, 2026.
The Canadian dollar equivalent for the fourth quarter 2026 dividend is C$0.0907 per common share.
Changes in the level of dividends paid by AQN are at the discretion of the Board, with dividend levels being reviewed periodically by the Board in the context of AQN's financial performance and growth prospects.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 40 |
The previous four quarter U.S. and Canadian dollar equivalent dividends per common share have been as follows:
| | | | | | | | | | | | | | | | | |
| Q1 2026 | Q2 2026 | Q3 2026 | Q4 2026 | Total |
| U.S. dollar dividend | $ | 0.0650 | | $ | 0.0650 | | $ | 0.0650 | | $ | 0.0650 | | $ | 0.2600 | |
| Canadian dollar equivalent | C$ | 0.0888 | | C$ | 0.0886 | | C$ | 0.0912 | | C$ | 0.0907 | | C$ | 0.3593 | |
| | | | | |
Dividend Reinvestment Plan
Effective March 16, 2023, AQN suspended its shareholder dividend reinvestment plan (the "Reinvestment Plan") for registered holders of common shares of AQN. If the Company elects to reinstate the Reinvestment Plan in the future, shareholders who were enrolled in the Reinvestment Plan at its suspension and remain enrolled at reinstatement will automatically resume participation in the Reinvestment Plan.
As at September 30, 2026, 168,595,010 common shares representing approximately 22% of total common shares outstanding had been registered with the Reinvestment Plan.
SHARE-BASED COMPENSATION PLANS
As at September 30, 2026, the following share-based compensation awards were outstanding which may be exercised or settled, as applicable, for common shares of the Company:
| | | | | |
| Share-based compensation awards | Total |
| Options | 1,384,590 |
| |
| Performance and Restricted Share Units | 6,272,780 |
| Director's Deferred Share Units | 933,334 |
| Bonus Deferral Restricted Share Units | 64,009 |
AQN also has an Employee Share Purchase Plan (the "ESPP") which allows eligible employees to use a portion of their earnings to purchase common shares of AQN. As at September 30, 2026, a total of 4,778,868 common shares had been issued under the ESPP.MANAGEMENT OF CAPITAL STRUCTURE
AQN views its capital structure in terms of its debt and equity levels at its individual operating groups and at an overall company level.
AQN's objectives when managing capital are:
•to maintain its capital structure consistent with investment grade credit metrics appropriate to the sectors in which AQN operates;
•to maintain the utilities' capital structures consistent with capital structures approved by regulators in the jurisdictions in which the Company operates;
•to maintain appropriate debt and equity levels and to limit financial constraints on the use of capital;
•to have available capital to finance capital expenditures sufficient to maintain existing assets;
•to generate sufficient cash to fund sustainable dividends to shareholders as well as meet current tax and internal capital requirements; and
•to have appropriately sized revolving credit facilities available for ongoing investment in growth and development opportunities.
AQN monitors its cash position on a regular basis in an effort to have available funds to meet normal course capital and other expenditures.
ENTERPRISE RISK MANAGEMENT
The Corporation is subject to a number of risks and uncertainties, certain of which are described below. The risks discussed below are not intended to be a complete list of all risks that AQN, its subsidiaries and affiliates are encountering or may encounter. Please see the Company's most recent AIF and Annual MD&A available on SEDAR+ and EDGAR for a further discussion of risk factors to which the Company is subject. To the extent of any inconsistency, the risks discussed below are intended to provide an update on those that were previously disclosed.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 41 |
Risks Related to Changes in Laws and Regulations
The operations and activities of the Company, its subsidiaries and its business units are subject to the laws, regulations, orders and other requirements or actions of a variety of federal, state, provincial and local governments and courts, including regulatory commissions, environmental agencies and other regulatory bodies, which laws, regulations, decisions, orders, rules and other requirements affect the operations and activities of, and costs incurred by, the Company. The Company is accordingly subject to risks associated with: changing political conditions and changes in political leadership, changes in, modifications to, reinterpretations of or application of existing laws, rules, orders or regulations, the imposition of new laws, rules, orders or regulations (including the imposition of import controls and tariffs and the power of eminent domain), court decisions, and the taking of other action by governmental, judicial or regulatory authorities, including, but not limited to, a pause, reduction or elimination of relevant federal funding, incentives, credits or programs, revocation, lapse, limitation or non-renewal of utility franchises or other rights to provide utility services to existing or new customers, lack of approval of wildfire mitigation plans which could adversely affect the Company's ability to defend against wildfire litigation or obtain sufficient wildfire liability insurance, potential complaint and administrative proceedings, potential limitations on water rights used by utilities in providing service, eminent domain of assets, termination of contracts, actions to municipalize utility service areas or limitations on utility growth and/or expansions of service areas and anti-foreign ownership sentiment and actions resulting therefrom, any of which could adversely affect the Company's business, regulatory approvals, assets, results of operations and financial condition. If the Company or any of its subsidiaries or business units were found to be in violation of such applicable laws, regulations, orders or other requirements, they could be subject to significant penalties or legal actions and/or legal or regulatory decisions that could have a material impact on the Company.
Additionally, the jurisdictions in which the Company operates may be adversely affected by local, national and international political and economic developments. Such developments may include nationalization or expropriation initiatives, political instability, changes in government or governmental priorities, increased political or trade tensions between countries, legislation or policies affecting foreign ownership or investment, acts or threats of war, terrorism or other hostilities, actions taken by governments or regulatory bodies in response to such events, military actions or conflicts, including ongoing or escalating conflicts in the Middle East, which have resulted in disruption to commercial shipping lanes and contributed to volatility in global energy markets and broader inflationary pressures, and significant cybersecurity incidents originating from or directed at state or non‑state actors. Any such developments could disrupt economic conditions, impair the Company’s ability to operate or develop its assets, increase compliance or operating costs, cause supply chain disruptions, restrict access to capital or markets, or otherwise adversely affect the Company’s business, assets, results of operations, cash flows or financial condition. As a Canadian‑domiciled company with the majority of its operations and assets located in the United States, the Corporation may also be subject to heightened risks associated with foreign ownership or control, including the enactment or enforcement of U.S. federal, state or local laws, regulations or policies that could impose additional restrictions, conditions, review requirements or limitations on the Company or its utilities, which could adversely affect the Company’s operations, growth strategies or financial performance.
Treasury Risk Management
Capital Markets and Liquidity Risk
As at September 30, 2026, the Company and its subsidiaries had approximately $6.5 billion of long-term consolidated indebtedness. Management of the Company believes, based on its current expectations as to the Company's future performance, that the cash flow from operations, the funds available under its credit facilities, and its ability to access capital markets will be adequate to enable the Company to finance its operations, execute its business strategy and maintain an adequate level of liquidity. However, the Company's expected revenue and capital expenditures are only estimates. Moreover, actual cash flows from operations will depend on regulatory, market and other conditions that are beyond the Company's control and which may be impacted by the risk factors herein. As a result, there can be no assurance that management's expectations as to future performance will be realized.
The Company's ability to obtain additional debt or equity or issue other securities, on favourable terms or at all, may be adversely affected by negative perceptions of the Company, any adverse financial or operational performance, the price of the Common Shares of the Company, financial market disruptions, the failure or collapse of any financial institution, prevailing market views and perceptions, or other factors outside the Company's control. In addition, the Company may at times incur indebtedness in excess of its long-term leverage targets, in advance of raising the additional equity or similar securities necessary to repay such indebtedness and maintain its long-term leverage target. Any increase in the Company's leverage or degradation of key credit metrics below threshold levels could, among other things: limit the Company's ability to obtain additional financing for working capital, investments in subsidiaries, capital expenditures, debt service requirements, acquisitions and general corporate or other purposes; restrict the Company's flexibility and discretion to operate its business; limit the Company's ability to declare dividends or maintain prior dividend levels; require the Company to dedicate a portion of cash flows from operations to the payment of interest on its existing indebtedness, in which case such cash flows would not be available for other purposes; cause rating agencies to re-evaluate or downgrade the Company's existing credit
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 42 |
ratings; require the Company to post additional collateral security under some of its contracts and hedging arrangements; expose the Company to increased interest expense on borrowings at variable rates; limit the Company's ability to adjust to changing market conditions; place the Company at a competitive disadvantage compared to its competitors; make the Company vulnerable to any downturn in general economic conditions; render the Company unable to make expenditures that are important to its future growth strategies and require the Company to pursue alternative funding strategies.
The Company will need to refinance or reimburse amounts outstanding under the Company's existing consolidated indebtedness over time. There can be no assurance the Company will be successful in refinancing its indebtedness when necessary or that additional financing will be obtained when needed, on commercially reasonable terms or at all. In the event that the Company cannot refinance its indebtedness or raise additional indebtedness, or if the Company cannot refinance its indebtedness or raise additional indebtedness on terms that are no less favourable than the current terms, the Company's cash flows and ability to declare dividends or repay its indebtedness may be adversely affected.
The Company's ability to meet its debt service requirements will depend on its ability to generate cash in the future, which depends on many factors, including the Company's financial performance, debt service obligations, the realization of the anticipated benefits of any acquisition, disposition and investment activities, and working capital and capital expenditure requirements. In addition, the Company's ability to borrow funds in the future to make payments on outstanding debt will depend on the satisfaction of covenants in existing credit agreements and other agreements. A failure to comply with any covenants or obligations under the Company's consolidated indebtedness could result in a default under one or more such instruments, which, if not cured or waived, could result in the termination of dividends by the Company and permit acceleration of the relevant indebtedness. There can be no assurance that, if such indebtedness were to be accelerated, the Company's assets would be sufficient to repay such indebtedness in full. There can also be no assurance that the Company will generate cash flow in amounts sufficient to pay its outstanding indebtedness or to fund the Company's liquidity needs.
Interest Rate Risk
The Company is exposed to interest rate risk from certain outstanding variable interest indebtedness, as well as any new borrowings on existing and new credit facilities and other debt issuances. Fluctuations in interest rates may also impact the costs to obtain other forms of capital and the feasibility of planned growth initiatives.
In addition, for the Regulated Services Group, costs resulting from interest rate increases may not be recoverable in whole or in part, and "regulatory lag" may cause a time delay in the payment to the Regulated Services Group of any such costs that are recoverable.
As a result, fluctuations in interest rates could materially increase the Corporation's financing costs, limit the Corporation's options for financing or investment and adversely affect its results of operations, cash flows, key credit metrics, borrowing capacity and ability to implement its business strategy.
As at September 30, 2026, approximately 91% of debt outstanding in AQN and its subsidiaries was subject to a fixed rate of interest and, as a result, such debt is not subject to significant interest rate risk in the short-term time horizon.
Borrowings subject to variable interest rates can fluctuate significantly from month to month, quarter to quarter and year to year. AQN's target is to maintain a minimum of 90% fixed rate debt. As a result, the Company may hedge the interest rate risk on its variable interest rate borrowings from time to time.
Based on amounts outstanding as at September 30, 2026, the impact to interest expense on variable rate loans from changes in interest rates are as follows:
•the Corporate Credit Facility is subject to a variable interest rate and had no amounts outstanding as at September 30, 2026. As a result, a 100 basis point change in the variable rate charged would not impact interest expense;
•the Long-Term Regulated Services Credit Facility is subject to a variable interest rate and had no amounts outstanding as at September 30, 2026. As a result, a 100 basis point change in the variable rate charged would not impact interest expense;
•the Regulated Services Group's commercial paper program is subject to a variable interest rate and had $564.0 million outstanding as at September 30, 2026. As a result, a 100 basis point change in the variable rate charged would impact interest expense by $5.6 million annually;
•the Bermuda Credit Facility is subject to a variable interest rate and had no amounts outstanding as at September 30, 2026. As a result, a 100 basis point change in the variable rate charged would not impact interest expense.
In summary, a 100 basis point change in the variable interest rate would impact the interest expense of the Company by approximately $5.6 million annually.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 43 |
Tax Risk and Uncertainty
The Company is subject to income and other taxes primarily in the United States, Canada, and Bermuda. Changes in tax laws or interpretations or applications thereof, which may or may not have a retroactive effect, in the jurisdictions in which the Company does business could adversely affect the Company's results from operations, returns to shareholders, and cash flows. One or more taxing jurisdictions could seek to impose incremental or new taxes on the Company (or the Company could lose tax benefits to which it previously was entitled).
Operational Risk Management
Regulatory Risk
Profitability of AQN businesses is, in part, dependent on regulatory climates in the jurisdictions in which those businesses operate.
In the case of some of the Hydro Group’s hydroelectric facilities, water rights are owned by governments that reserve the right to control water levels, which may affect revenue. The failure to obtain all necessary licenses or permits for such facilities, including renewals thereof or modifications thereto, may result in an inability to operate the facility and could adversely affect cash generated from operating activities.
The Regulated Services Group’s facilities are subject to rate setting by its regulatory agencies. The Company operates utilities in 13 U.S. states, one Canadian province, and Bermuda and therefore is subject to regulation from 16 different regulatory agencies, including FERC. The time between the incurrence of costs and the granting of the rates to recover those costs by regulatory agencies is known as regulatory lag. Regulatory lag, inflationary effects and timing delays may impact the ability to recover expenses and/or capital costs, and profitability could be impacted. In order to mitigate this exposure, the Company seeks to obtain approval for regulatory constructs in the states in which it operates to allow for timely recovery of operating expenses and capital costs. A fundamental risk faced by a regulated utility is the disallowance by the utility’s regulator of operating expenses or capital costs for which recovery is sought through regulatory proceedings. The Company has invested significant capital in its utilities for which it is or will be seeking cost recovery. There is a risk that the utilities’ regulators may not approve, or may otherwise delay recovery, of some or all of the Company’s invested capital. In certain jurisdictions, the Company's utilities may be exposed to infrastructure-related responsibilities (including stormwater or climate adaptation systems) for which there is limited or no established cost recovery framework. In addition, as the Company recently updated its technology infrastructure systems, there is additional risk that financial data required for rate filings could be difficult to produce or the data is deemed unreliable for ratemaking purposes. Further, there is additional risk that customer billing services may be deemed inadequate and such customer billing concerns could negatively impact the risk of disallowance and/or regulatory lag and may result in additional administrative actions and complaint proceedings against the Company and its operating subsidiaries. In addition, capital investments that have become stranded may pose additional risk for cost recovery and could be subject to legislation or rulings that would impact the extent to which such costs could be recovered. Similarly, recovery of extraordinary fuel expenses may pose additional risk for cost recovery and could be subject to legislation or regulatory action that would impact the extent to which such costs could be recovered. Further, there is a risk that utility regulators may scrutinize the Company's allocation of shared costs. Certain regulatory mechanisms may require the Company to share operating cost and capital expenditure savings with customers, which could result in reductions to future customer rates. If the Company is unable to recover increased costs of operations or its investments in new facilities, or in the event of significant regulatory lag, the Company's results of operations could be adversely affected.
Furthermore, the economies of Canada and the United States each experienced a significant rise in the inflation rate in the post-pandemic era compared to recent historical inflation rates. While the inflation rate has subsided due, in part, to actions taken by the Bank of Canada and the U.S. Federal Reserve System, there remains uncertainty in the near-term outlook as to whether inflation will remain elevated. Increases in inflation raise the Company’s costs for labour, materials and services, and a failure to recover these increased costs could result in under-recovery. Cost recovery efforts could also face resistance from customers and other stakeholders especially in a rising cost environment, whether due to inflation or high fuel prices or otherwise, and/or in periods of economic decline or hardship. Significant increases in costs also could increase financing needs and otherwise adversely affect the Company’s business, financial position and results of operations.
In addition, there is a risk that the utility’s regulator will not approve the revenue requirements or rate adjustments requested in outstanding or future rate applications or will, on its own initiative, seek to reduce the existing revenue requirements or approved rates. Rate applications are subject to the utility regulator’s review process, usually involving participation from intervenors and other stakeholders that are involved in the case, and a public hearing process. There can be no assurance that resulting decisions or rate orders issued by the utility regulators will permit the Company to recover all costs actually incurred, costs of debt and income taxes, or to earn a particular return on equity.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 44 |
Condemnation Expropriation Proceedings
The Company's distribution systems could be subject to condemnation or other methods of taking by government entities under certain conditions (including, without limitation, Liberty Utilities (Apple Valley Ranchos Water) Corp., which has been the subject of a condemnation lawsuit filed by the Town of Apple Valley and Liberty Utilities (New York Water) Corp., which has received municipalization inquiries). There can be no assurance that the Corporation will receive fair market value for such assets or that the Corporation would not incur a loss.
Inflation Risk
AQN's profitability could be impacted by inflation increases above long-term averages. The Company's facilities are subject to rate setting by its regulatory agencies. The time between the incurrence of costs and the granting of the rates to recover those costs by regulatory agencies is known as regulatory lag. As a result of regulatory lag, inflationary effects and timing delays may impact the ability to recover expenses and/or capital costs, and profitability could be impacted. In the event of significant inflation, the impact of regulatory lag on the Company would be increased. In order to mitigate this exposure, the Company seeks to obtain approval for regulatory constructs in the states in which it operates to allow for timely recovery of operating expenses and capital costs.
Development and construction projects could experience a decrease in expected returns as a result of increased costs.
Tariff Risk
Changes in tariffs may adversely affect the capital expenditures required to maintain, develop or construct the Company’s projects or infrastructure. In 2025 and 2026, the U.S. government issued numerous executive orders imposing tariffs on goods from various countries around the world, including Canada, Mexico and China, as well as product-specific tariffs on various goods, such as steel, aluminum, copper and automobiles, and have indicated further measures may be under consideration. Many countries have similarly announced reciprocal or other tariffs impacting products manufactured or produced in the United States. New or existing trade agreements, including the ongoing review of the U.S.-Mexico-Canada Agreement, may also impact the tariff rate applicable to goods imported by the Company or its suppliers. Additionally, certain tariffs are subject to legal challenges. Accordingly, the situation is fluid and changes rapidly. Whether existing tariffs will be increased, decreased, or suspended altogether, as well as the imposition of additional tariffs by the U.S., the potential for further retaliation or tariff imposition by other countries, or any further adjustment to trade policies and tariffs and the timing thereof are difficult to predict at this time.
Tariffs may increase the cost of imported materials and equipment, disrupt supply chains, drive economic volatility, and create adverse capital and credit market conditions. The impact of tariffs on the cost of products and supplies used by the Company may increase the Company’s operating costs and elevate the cost of capital projects. Given the evolving nature of global trade policies, the Company cannot reasonably estimate the potential effects of current or future tariffs. Such effects could include project delays, cost increases, and other challenges to the execution of the Company’s strategic plans.
In addition, import restrictions, border delays and governmental seizures may also increase the cost of projects and result in construction and placed-in-service delays. These events could adversely affect the Company as a buyer and importer of goods, and ultimately impacts its expected returns, results of operations and cash flows.
Litigation Risks and Other Contingencies
AQN and certain of its subsidiaries are involved in various litigation, claims and other legal and regulatory proceedings that arise from time to time in the ordinary course of business. Any accruals for contingencies related to these items are recorded in the financial statements at the time it is concluded that a material financial loss is likely and the related liability is estimable. Anticipated recoveries under existing insurance policies are recorded when reasonably assured of recovery.
Mountain View Fire
On November 17, 2020, a wildfire now known as the Mountain View Fire occurred in the territory of Liberty Utilities (CalPeco Electric) LLC ("Liberty CalPeco"). The cause of the fire remains in dispute, and CAL FIRE has not yet released its final report. There were 22 lawsuits filed that name certain subsidiaries of the Company as defendants in connection with the Mountain View Fire, as well as a non-litigation claim brought by the U.S. Department of Agriculture seeking reimbursement for alleged fire suppression costs and a notice from the U.S. Bureau of Land Management seeking damages for the alleged burning of public lands without authorization. Fifteen lawsuits were brought by groups of individual plaintiffs and a Native American group alleging causes of action including negligence, inverse condemnation, nuisance, trespass and violations of Cal. Pub. Util. Code 2106 and Cal. Health and Safety Code 13007 (one of these 15 lawsuits also alleges the wrongful death of an individual and various subrogation claims on behalf of insurance companies). In six other lawsuits, insurance companies alleged inverse condemnation and negligence and seek recovery of amounts paid and to be paid to their insureds. In one other lawsuit, County of Mono, Antelope Valley Fire Protection District, and Bridgeport Indian Colony allege similar causes of action and seek damages for fire suppression costs, law enforcement costs, property and infrastructure damage, and other costs. Liberty CalPeco has resolved these 22 lawsuits and is in the process of obtaining dismissals with prejudice of said lawsuits.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 45 |
The trial date previously scheduled for April 15, 2025, was vacated. There are only two non-litigation claims remaining (one brought by the United States Department of Agriculture, and one brought by the Bureau of Land Management). The likelihood of success in these claims is uncertain. Liberty CalPeco is engaged in negotiations in an effort to try and resolve these claims short of litigation. The Company accrued and incurred estimated losses of $178.4 million for claims related to the Mountain View Fire, against which Liberty CalPeco has recorded recoveries through insurance of $116.0 million and WEMA of $71.5 million, which also includes legal expenses and carrying charges. On June 20, 2025, the Company filed an application seeking recovery of $78.2 million, comprising of the costs recorded to date in the WEMA and $6.7 million of forecasted legal expenses. On June 23, 2026, a proposed decision was issued by the Administrative Law Judge recommending recovery of approximately $58.1 million or 75% of the requested $77.4 million recorded. The proposed decision also recommends recovery over a five-year period, as opposed to Liberty CalPeco's request for a three-year recovery period, and accordingly recommends up to approximately $3.4 million in additional financing costs to cover the longer recovery period. Liberty CalPeco filed comments on the proposed decision in July 2026, and a commission vote on the decision is expected on November 19, 2026. The proposed decision resulted in a $17.2 million expense, which reduced earnings by the same amount. The estimate of losses is subject to change as additional information becomes available. The actual amount of losses may be higher or lower than these estimates. While the Company may incur a material loss in excess of the amount accrued, the Company cannot estimate the upper end of the range of reasonably possible losses that may be incurred. The Company has wildfire liability insurance that was applied up to applicable policy limits.
Apple Valley Condemnation Proceedings
On January 7, 2016, the Town of Apple Valley (the "Town") filed a lawsuit in California state court seeking to condemn the utility assets of Liberty Utilities (Apple Valley Ranchos Water) Corp. ("Liberty Apple Valley"). On May 7, 2021, the trial court issued a Tentative Statement of Decision denying the Town's attempt to take the Apple Valley water system by eminent domain. The ruling confirmed that Liberty Apple Valley's continued ownership and operation of the water system is in the best interest of the community. On October 14, 2021, the trial court issued the Final Statement of Decision. The trial court signed and entered an Order of Dismissal and Judgment on November 12, 2021. On January 7, 2022, the Town filed a notice of appeal of the judgment entered by the trial court. On August 2, 2022, the trial court issued a ruling awarding Liberty Apple Valley approximately $13.2 million in attorney's fees and litigation costs. The Town filed a notice of appeal of the fee award on August 22, 2022. On January 15, 2025, the California Court of Appeal issued a decision reversing the trial court's finding that the Town does not have a right to take the assets of Liberty Apple Valley and reversing the award of attorney's fees to Liberty Apple Valley. On February 21, 2025, Liberty Apple Valley filed a petition for review of the Court of Appeal decision with the California Supreme Court. On April 23, 2025, the California Supreme Court granted the petition for review. On August 24, 2026, the California Supreme Court issued its opinion and reversed the Court of Appeal on the applicable standard of review for utility condemnations in California and sustained the Trial Court rulings that the presumptions of public necessity and more necessary public use are rebuttable and Liberty Apple Valley was entitled to present evidence to rebut them at trial. The Supreme Court decision became final on September 23, 2026. The Supreme Court remanded the case to the Court of Appeal to reconsider certain remaining issues under the correct legal standard.
Lexington Gas Incident
On April 9, 2025, an explosion and fire occurred in Lexington, Missouri, destroying or damaging certain structures, including residences, served by the gas distribution system of The Empire District Gas Company. A minor died and two others suffered serious physical injuries. The National Transportation Safety Board is investigating. To date, eleven active lawsuits remain as well as other pre-litigation demands that have been asserted against a subsidiary of the Company and third party defendants which seek damages for personal injury and property damage. The Missouri Attorney General filed a petition for injunctive relief and civil penalties associated with the incident. This litigation has been resolved by a Consent Judgment which provides for a $0.03 million civil penalty and confirmation of Lexington asset mapping; the Consent Judgment has been approved by the court and all obligations under it have been satisfied. In addition, the MPSC opened an investigation docket into the Empire District Gas Company's compliance with pipeline safety requirements. Although there can be no assurance, the Company has insurance that is currently expected to apply up to applicable policy limits for personal injury and property damage litigation and claims. The Company has currently accrued and incurred estimated losses of $159.9 million for claims and other costs related to the incident, against which recoveries through insurance of $150.0 million have been recorded, reflecting amounts recovered and expected to be recovered. While the Company may incur a material loss in excess of the amount accrued, the Company cannot currently estimate the upper end of the range of reasonably possible losses that may be incurred. The estimate of losses is subject to change as additional information becomes available.
Technology Infrastructure Implementation Risk
The Company relies upon various information and operational technology infrastructure systems to carry out its business processes and operations. This subjects the Company to inherent costs and risks associated with maintaining, upgrading, replacing and changing information and operational technology systems. This includes impairment of its technology systems, potential disruption of operations, business process and internal control systems, substantial capital expenditures, demands
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 46 |
on management time and other risks of delays, and difficulties in upgrading, transitioning and integrating technology systems.
AQN and certain of its subsidiaries have completed the implementation of an integrated customer solution platform, which includes customer billing, enterprise resource planning systems and asset management systems. The transition of operations to these new technology systems, or deficiencies in the design or implementation of these systems, could materially adversely affect the Company's operations, including its ability to monitor its business, pay its suppliers, bill its customers, and record and report financial information accurately and on a timely basis; lead to higher than expected costs; lead to increased regulatory scrutiny or adverse regulatory consequences; or result in the failure to achieve the expected benefits. As a result, the Company's operations, financial condition, cash flows and results of operations could be adversely affected.
Redomicile Risk
The Company has announced its intention to redomicile the incorporation of the Company to the United States (the “Redomicile”). Management may be required to allocate substantial time and resources, and significant costs and taxes are expected to be incurred, to execute the Redomicile. Additionally, certain shareholders may be subject to adverse tax consequences in connection with the Redomicile. There is no assurance that the conditions to completion of the Redomicile will be satisfied or that the Company will ultimately complete the Redomicile or that, if completed, the Company will realize the expected benefits of the Redomicile. The fact that the Company is pursuing the Redomicile, and the dedication of substantial resources of the Company to the Redomicile, could have an adverse impact on the Company’s business, relationships with current and prospective employees, customers, suppliers, partners and other stakeholders, share price and operating results.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 47 |
QUARTERLY FINANCIAL INFORMATION
The following is a summary of unaudited quarterly financial information for each of the eight most recent quarters, the most recent of which ended September 30, 2026:
| | | | | | | | | | | | | | |
| 4th Quarter | 1st Quarter | 2nd Quarter | 3rd Quarter |
(all dollar amounts in $ millions except per share information)4 | 2025 | 2026 | 2026 | 2026 |
| Revenue | $ | 630.7 | | $ | 792.4 | | $ | 543.9 | | $ | 642.5 | |
| | | | |
| Net earnings attributable to common shareholders from continuing operations and discontinued operations | 18.4 | | 83.6 | | 1.0 | | 57.0 | |
| Net earnings attributable to common shareholders | 29.4 | | 83.1 | | 4.9 | | 57.6 | |
| Net earnings (loss) from discontinued operations | (11.0) | | 0.5 | | (3.9) | | (0.6) | |
| Net earnings per share from continuing operations and discontinued operations | 0.02 | | 0.11 | | — | | 0.07 | |
| Net earnings per share | 0.04 | | 0.11 | | 0.01 | | 0.07 | |
| Net loss per share from discontinued operations | (0.01) | | — | | (0.01) | | — | |
| Diluted net earnings per share | 0.02 | | 0.11 | | — | | 0.07 | |
Adjusted Net Earnings1 | 47.2 | | 99.6 | | 29.2 | | 88.1 | |
Adjusted Net Earnings per common share1 | 0.06 | | 0.13 | | 0.04 | | 0.11 | |
EBIT1 | 93.2 | | 169.0 | | 68.9 | | 140.8 | |
Total assets3 | 14,136.2 | | 14,049.9 | | 13,923.2 | | 14,093.4 | |
Long-term debt2,3 | 6,532.9 | | 6,686.0 | | 6,635.7 | | 6,500.3 | |
| Dividends declared per common share | $ | 0.07 | | $ | 0.07 | | $ | 0.07 | | $ | 0.07 | |
| | | | |
| 4th Quarter | 1st Quarter | 2nd Quarter | 3rd Quarter |
| 2024 | 2025 | 2025 | 2025 |
| Revenue | $ | 584.8 | | $ | 692.4 | | $ | 527.8 | | $ | 582.7 | |
| | | | |
| Net earnings (loss) attributable to common shareholders from continuing operations and discontinued operations | (189.1) | | 94.2 | | 21.5 | | 36.2 | |
| | | | |
| Net earnings (loss) attributable to common shareholders | (110.2) | | 92.8 | | 14.8 | | 71.0 | |
| Net earnings (loss) from discontinued operations | (78.9) | | 1.4 | | 6.7 | | (34.8) | |
| Net earnings (loss) per share from continuing operations and discontinued operations | (0.25) | | 0.12 | | 0.03 | | 0.05 | |
| Net earnings (loss) per share | (0.14) | | 0.12 | | 0.02 | | 0.09 | |
| Net earnings (loss) per share from discontinued operations | (0.10) | | — | | 0.01 | | (0.04) | |
| Diluted net earnings (loss) per share | (0.25) | | 0.12 | | 0.03 | | 0.05 | |
Adjusted Net Earnings1 | 42.5 | | 109.0 | | 33.6 | | 69.0 | |
Adjusted Net Earnings per common share1 | 0.06 | | 0.14 | | 0.04 | | 0.09 | |
EBIT1 | 115.8 | | 168.7 | | 74.2 | | 157.4 | |
Total assets3 | 16,961.7 | | 13,663.3 | | 13,693.4 | | 13,788.4 | |
Long-term debt2,3 | 8,047.5 | | 6,322.0 | | 6,328.8 | | 6,434.6 | |
| Dividends declared per common share | $ | 0.07 | | $ | 0.07 | | $ | 0.07 | | $ | 0.07 | |
| | | | | |
| 1 | See Caution Concerning Non-GAAP Measures. |
| 2 | Includes current portion of long-term debt and long-term debt. |
| 3 | Includes discontinued operations |
| 4 | Reflects results of continuing operations unless marked otherwise (see Explanatory Notes) |
Quarterly revenues have fluctuated between $527.8 million and $792.4 million over the prior two year period. A number of factors impact quarterly results, including acquisitions, dispositions (including the Renewables Sale), seasonal fluctuations and customer rates. In addition, a factor impacting revenues year over year is the fluctuation in the strength of the Canadian dollar relative to the U.S. dollar, which can result in significant changes in reported revenue from Canadian operations.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | 48 |
Quarterly net earnings (loss) attributable to common shareholders from continuing operations and discontinued operations have fluctuated between a loss of $189.1 million and earnings of $94.2 million over the prior two year period. Earnings have been impacted by non-cash factors such as impairment upon classification of the renewable energy group (excluding hydro) as held for sale, deferred tax recovery and expense, property, plant and equipment and mark-to-market gains and losses on financial instruments.
DISCLOSURE CONTROLS AND PROCEDURES
AQN's management carried out an evaluation as of September 30, 2026, under the supervision of and with the participation of AQN's Chief Executive Officer ("CEO") and Chief Financial Officer ("CFO"), of the effectiveness of the design and operations of AQN's disclosure controls and procedures (as defined in Rule 13a-15(e) and Rule 15d-15 (e) under the Securities Exchange Act of 1934, as amended (the "Exchange Act")). Based on that evaluation, the CEO and the CFO have concluded that as of September 30, 2026, AQN's disclosure controls and procedures are effective to provide reasonable assurance that information required to be disclosed by AQN in reports that it files or submits under the Exchange Act is recorded, processed, summarized, and reported within the time periods specified in rules and forms of the U.S. Securities and Exchange Commission, and is accumulated and communicated to management, including the CEO and CFO, as appropriate, to allow timely decisions regarding required disclosure.
Management Report on Internal Controls over Financial Reporting
Management, including the CEO and the CFO, is responsible for establishing and maintaining internal control over financial reporting. Management, as at the end of the period covered by this interim filing, designed internal controls over financial reporting to provide reasonable, but not absolute, assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with U.S. GAAP. The control framework management used to design the Company's internal control over financial reporting is that established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
Changes in Internal Controls over Financial Reporting
For the three months ended September 30, 2026, there has been no change in the Company's internal controls over financial reporting that has materially affected, or is reasonably likely to materially affect, the Company's internal controls over financial reporting.
Inherent Limitations on Effectiveness of Controls
Due to its inherent limitations, disclosure controls and procedures or internal control over financial reporting may not prevent or detect all misstatements based on error or fraud. Further, the effectiveness of internal control is subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with policies or procedures may change.
CRITICAL ACCOUNTING ESTIMATES AND POLICIES
AQN prepared its unaudited interim condensed consolidated financial statements in accordance with U.S. GAAP. The preparation of the unaudited interim condensed consolidated financial statements requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities, related amounts of revenues and expenses, and disclosure of contingent assets and liabilities. Significant areas requiring the use of management judgment relate to the scope of consolidated entities, useful lives and recoverability of assets, the measurement of deferred taxes and the recoverability of deferred tax assets, rate-regulation, unbilled revenue, pension and post-employment benefits, fair value of derivatives and fair value of assets and liabilities acquired in a business combination. Actual results may differ from these estimates.
AQN's significant accounting policies and new accounting standards are discussed in Notes 1 and 2, respectively, in the Company's unaudited interim condensed consolidated financial statements.
| | | | | |
| |
| Algonquin Power & Utilities Corp. - Management Discussion & Analysis | |