November 2026 Discussion Materials
Disclaimer This presentation has been prepared by GLC Advisors & Co., LLC (“GLC”) for the exclusive use of the party to whom GLC delivers this presentation, using information provided by the company that is the subject of such presentation (together with its subsidiaries and affiliates, the “Company”) and other publicly available information. GLC has not independently verified the information contained herein, nor does GLC make any representation or warranty, either express or implied, as to the accuracy, completeness or reliability of the information contained in this presentation. Any estimates or projections as to events that may occur in the future (including projections of revenue, expense, net income and stock performance) are based upon the best judgment of GLC from the information provided by the Company (including its advisors and representatives) and other publicly available information as of the date of this presentation. There is no guarantee that any of these estimates or projections will be achieved. Actual results will vary from the projections and such variations may be material. Nothing contained herein is, or shall be relied upon as, a promise or representation as to the past or future. GLC is not undertaking to provide any legal, regulatory, accounting, insurance, tax or other similar professional advice in this presentation. Nothing contained herein is, or shall be relied upon as, such advice. GLC and its affiliates expressly disclaim any and all liability relating or resulting from the use of this presentation. This presentation has been prepared solely for informational purposes and is not to be construed as a solicitation or an offer to buy or sell any securities or related financial instruments. No investment, divestment or other financial decisions or actions should be based solely on the information in this presentation and GLC is not, by making this report available, providing investment, legal, tax, financial, accounting or other advice to you or any other party. This material must not be copied, reproduced, distributed or passed to others at any time without the prior written consent of GLC.
Introduction Gogo has reached an economic agreement with well over 50% of its Original Term Loan B lenders for a 2.5 year maturity extension. The transaction is expected to close imminently The Original Term Loan B represents ~75% of Gogo’s outstanding debt, and the Company has agreed with an AHG of lenders on the economic terms of a maturity extension In exchange for the extension, the Company has agreed to an increased interest rate, one-time principal paydowns, and higher scheduled amortization, as outlined herein The Company is confident in its long-term story and would like to opportunistically address its remaining 2028 maturity of the $225mm Incremental Term Loan, ensuring a clear runway for management to continue to execute The Company’s $122mm revolver is undrawn. It has a maturity date of Dec. 2029, which springs to early 2028, 90 days before the April 2028 maturity of the Incremental Term Loan
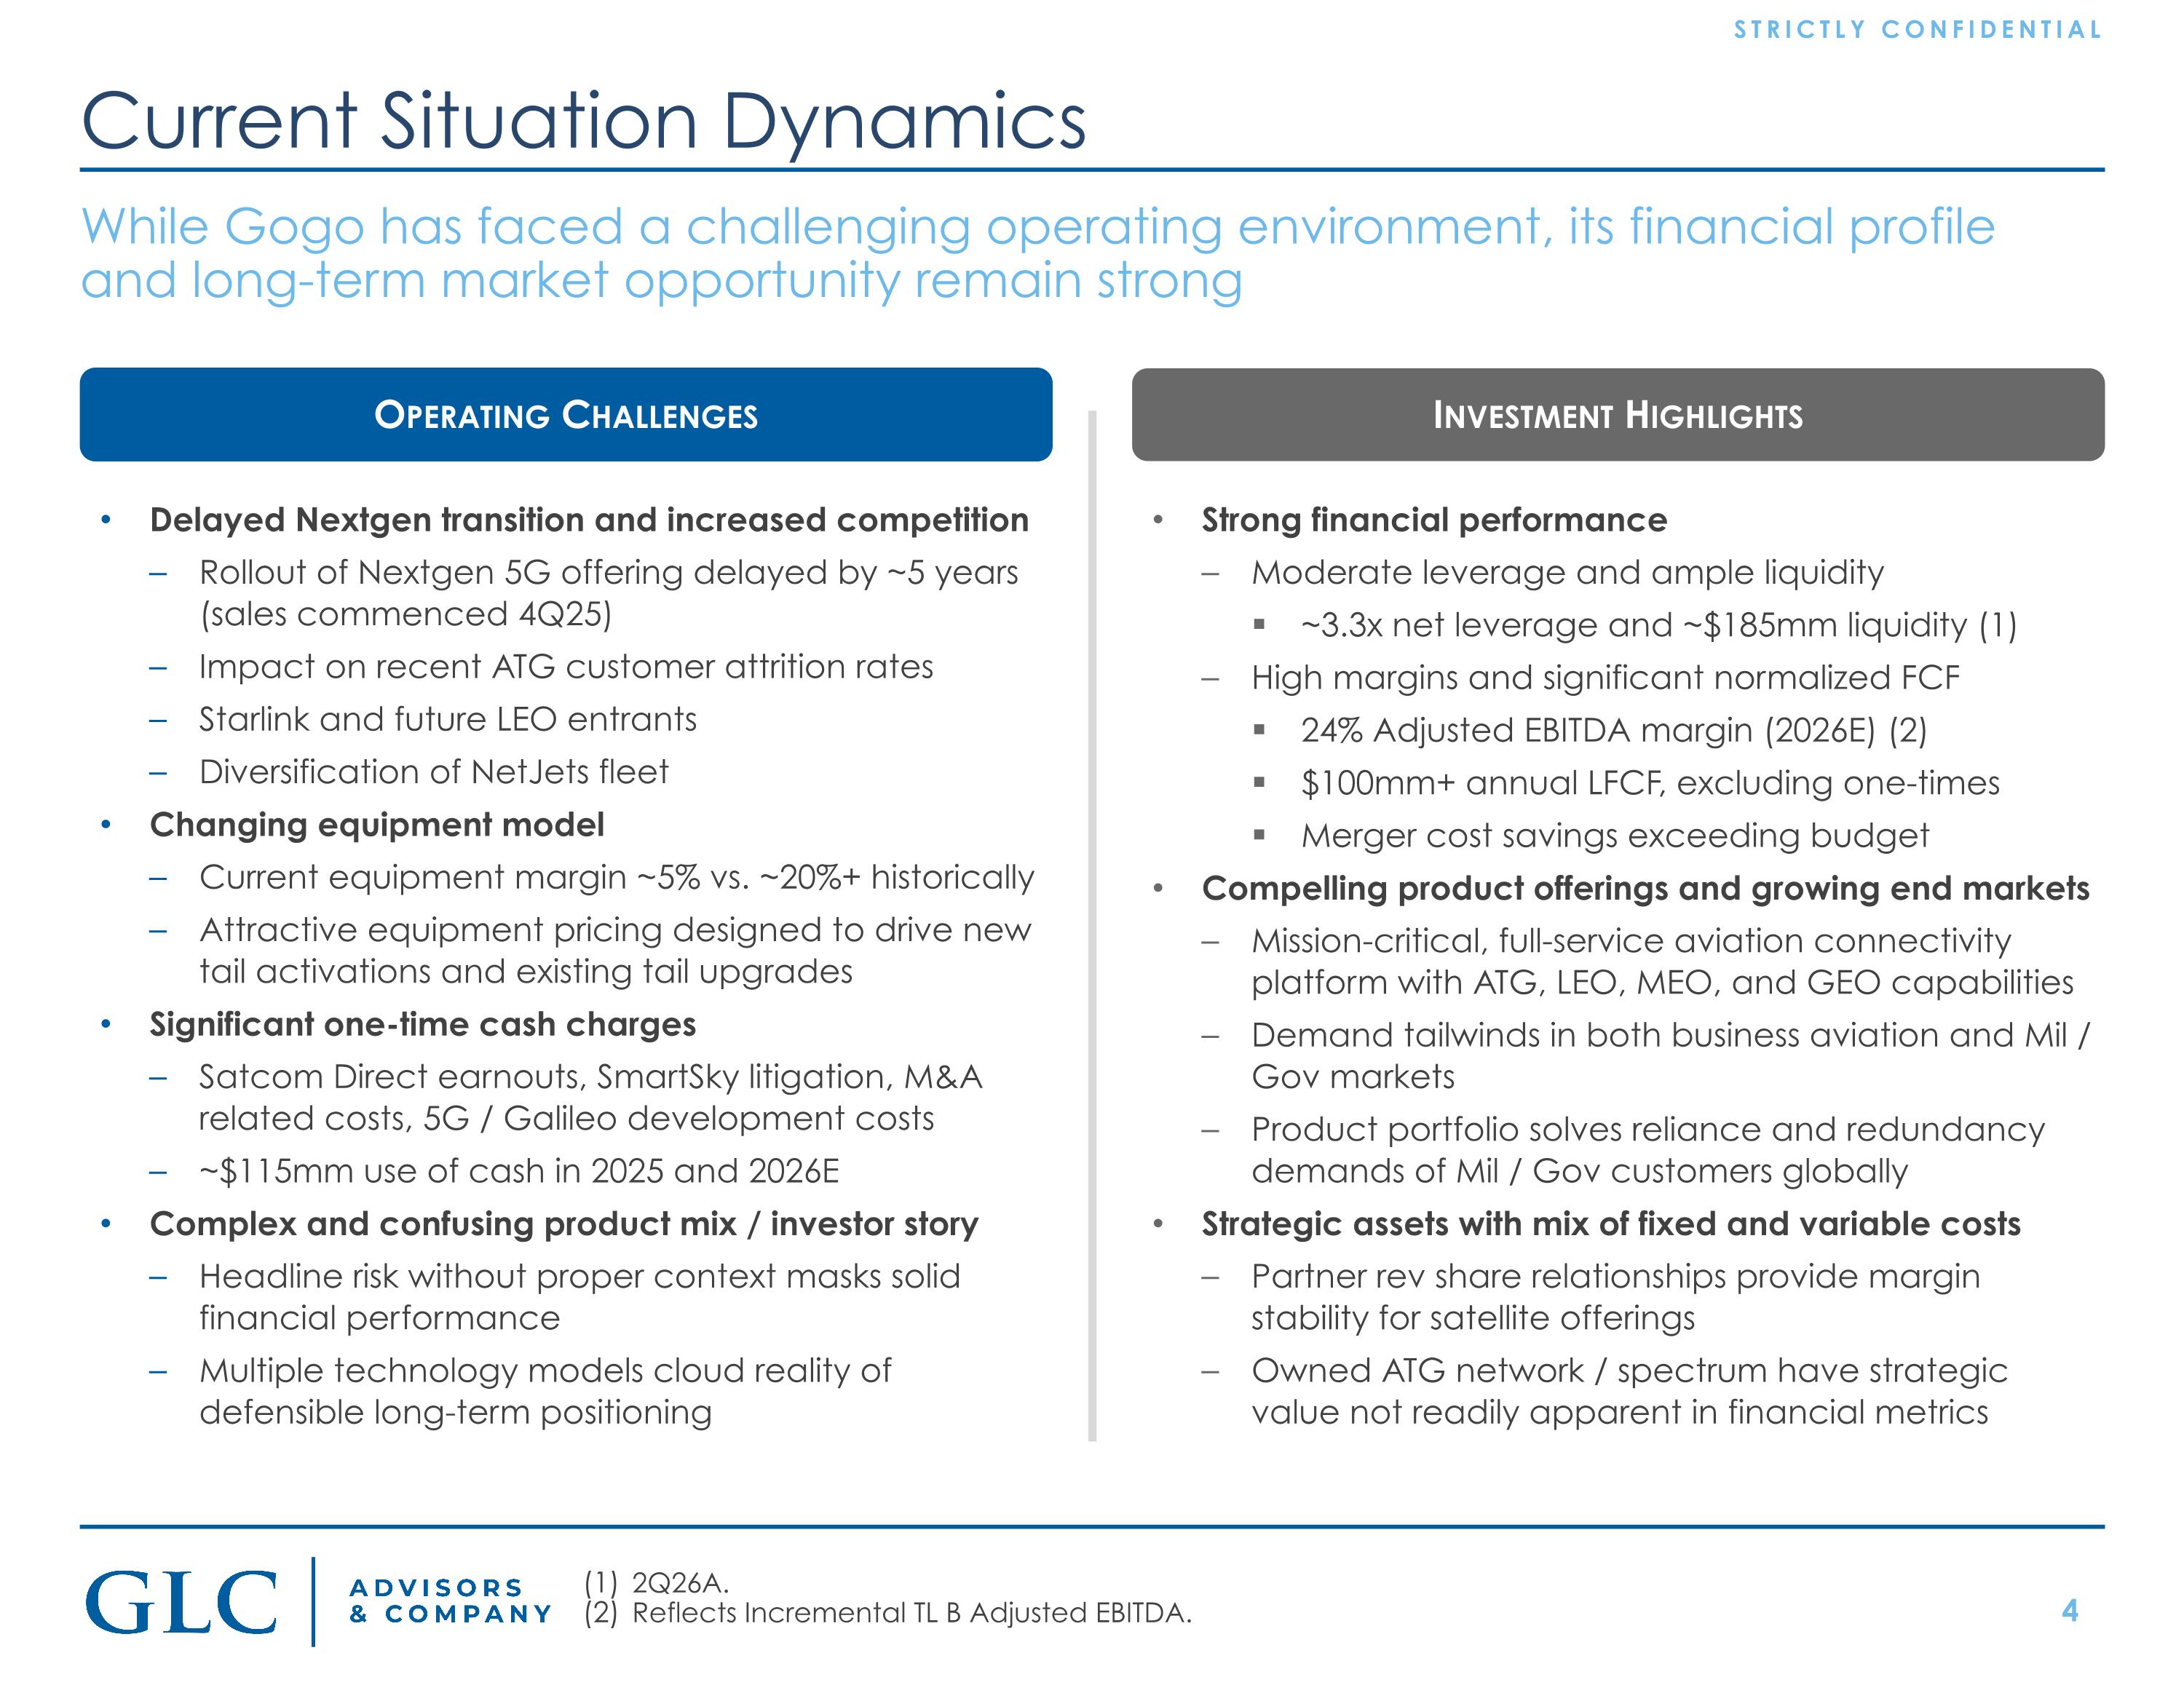
Current Situation Dynamics Investment Highlights Strong financial performance Moderate leverage and ample liquidity ~3.3x net leverage and ~$185mm liquidity (1) High margins and significant normalized FCF 24% Adjusted EBITDA margin (2026E) (2) $100mm+ annual LFCF, excluding one-times Merger cost savings exceeding budget Compelling product offerings and growing end markets Mission-critical, full-service aviation connectivity platform with ATG, LEO, MEO, and GEO capabilities Demand tailwinds in both business aviation and Mil / Gov markets Product portfolio solves reliance and redundancy demands of Mil / Gov customers globally Strategic assets with mix of fixed and variable costs Partner rev share relationships provide margin stability for satellite offerings Owned ATG network / spectrum have strategic value not readily apparent in financial metrics Operating Challenges While Gogo has faced a challenging operating environment, its financial profile and long-term market opportunity remain strong Delayed Nextgen transition and increased competition Rollout of Nextgen 5G offering delayed by ~5 years (sales commenced 4Q25) Impact on recent ATG customer attrition rates Starlink and future LEO entrants Diversification of NetJets fleet Changing equipment model Current equipment margin ~5% vs. ~20%+ historically Attractive equipment pricing designed to drive new tail activations and existing tail upgrades Significant one-time cash charges Satcom Direct earnouts, SmartSky litigation, M&A related costs, 5G / Galileo development costs ~$115mm use of cash in 2025 and 2026E Complex and confusing product mix / investor story Headline risk without proper context masks solid financial performance Multiple technology models cloud reality of defensible long-term positioning 2Q26A. Reflects Incremental TL B Adjusted EBITDA.
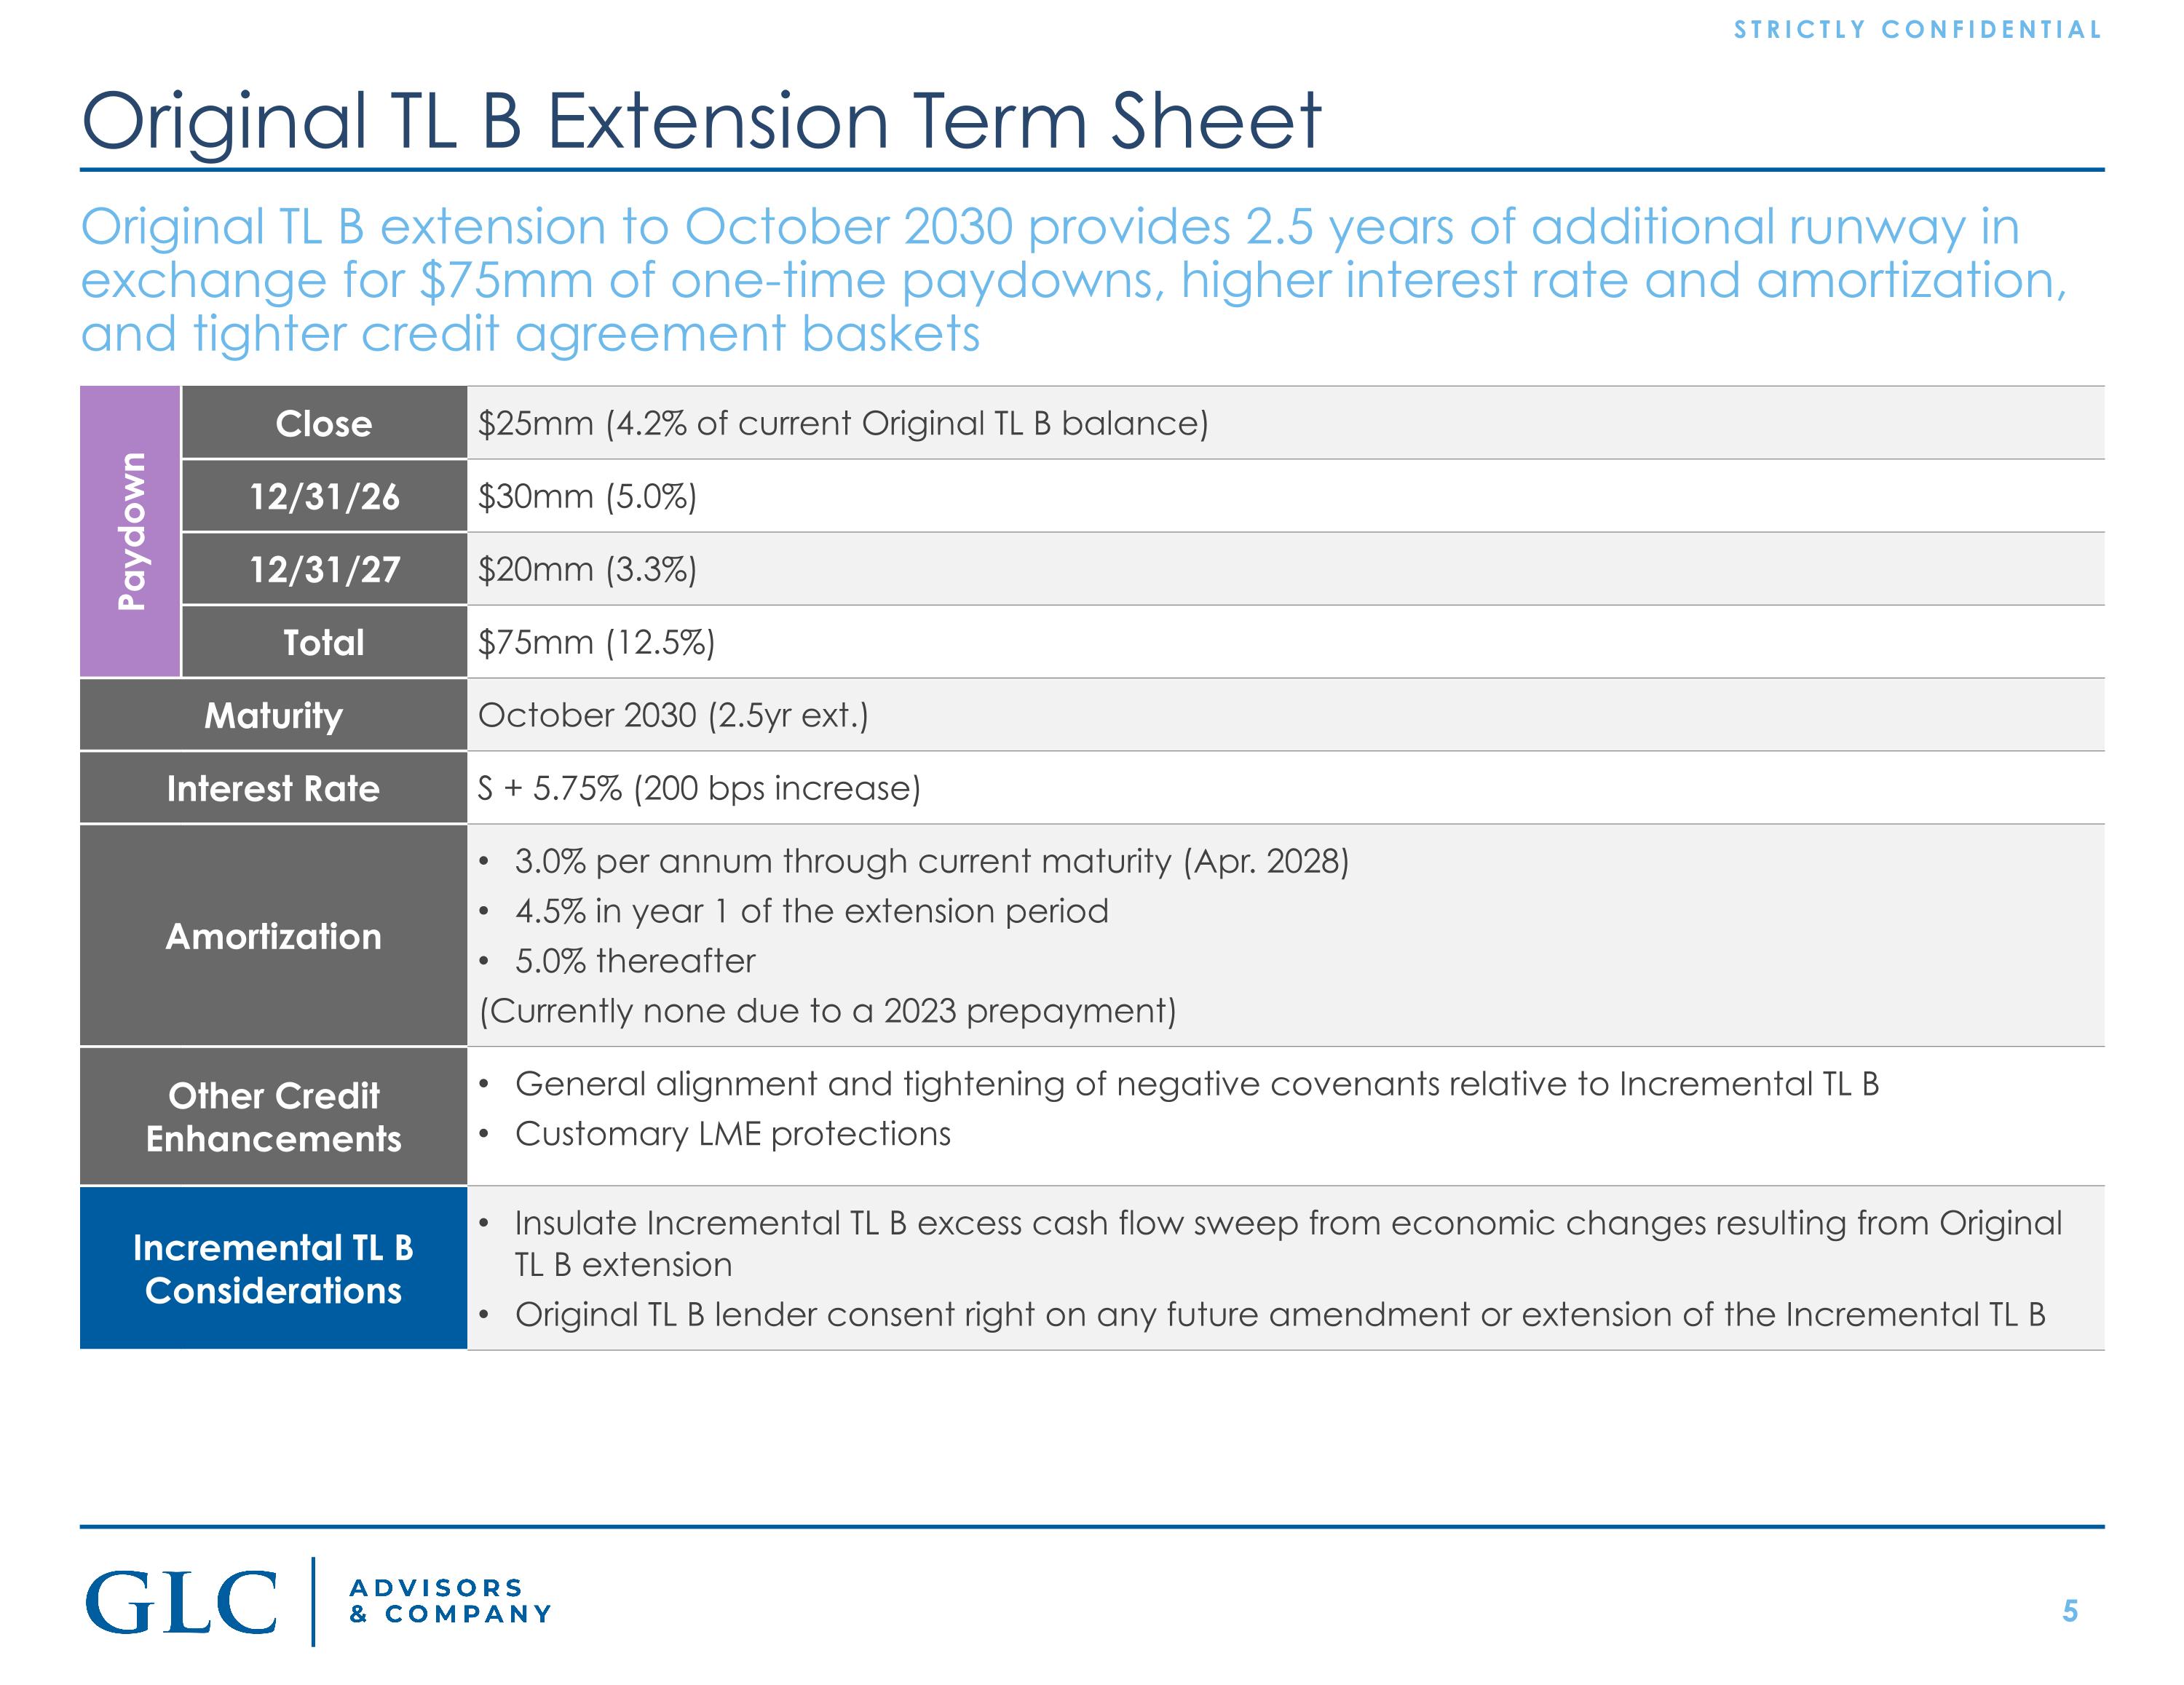
Paydown Close $25mm (4.2% of current Original TL B balance) 12/31/26 $30mm (5.0%) 12/31/27 $20mm (3.3%) Total $75mm (12.5%) Maturity October 2030 (2.5yr ext.) Interest Rate S + 5.75% (200 bps increase) Amortization 3.0% per annum through current maturity (Apr. 2028) 4.5% in year 1 of the extension period 5.0% thereafter (Currently none due to a 2023 prepayment) Other Credit Enhancements General alignment and tightening of negative covenants relative to Incremental TL B Customary LME protections Incremental TL B Considerations Insulate Incremental TL B excess cash flow sweep from economic changes resulting from Original TL B extension Original TL B lender consent right on any future amendment or extension of the Incremental TL B Original TL B Extension Term Sheet Original TL B extension to October 2030 provides 2.5 years of additional runway in exchange for $75mm of one-time paydowns, higher interest rate and amortization, and tighter credit agreement baskets
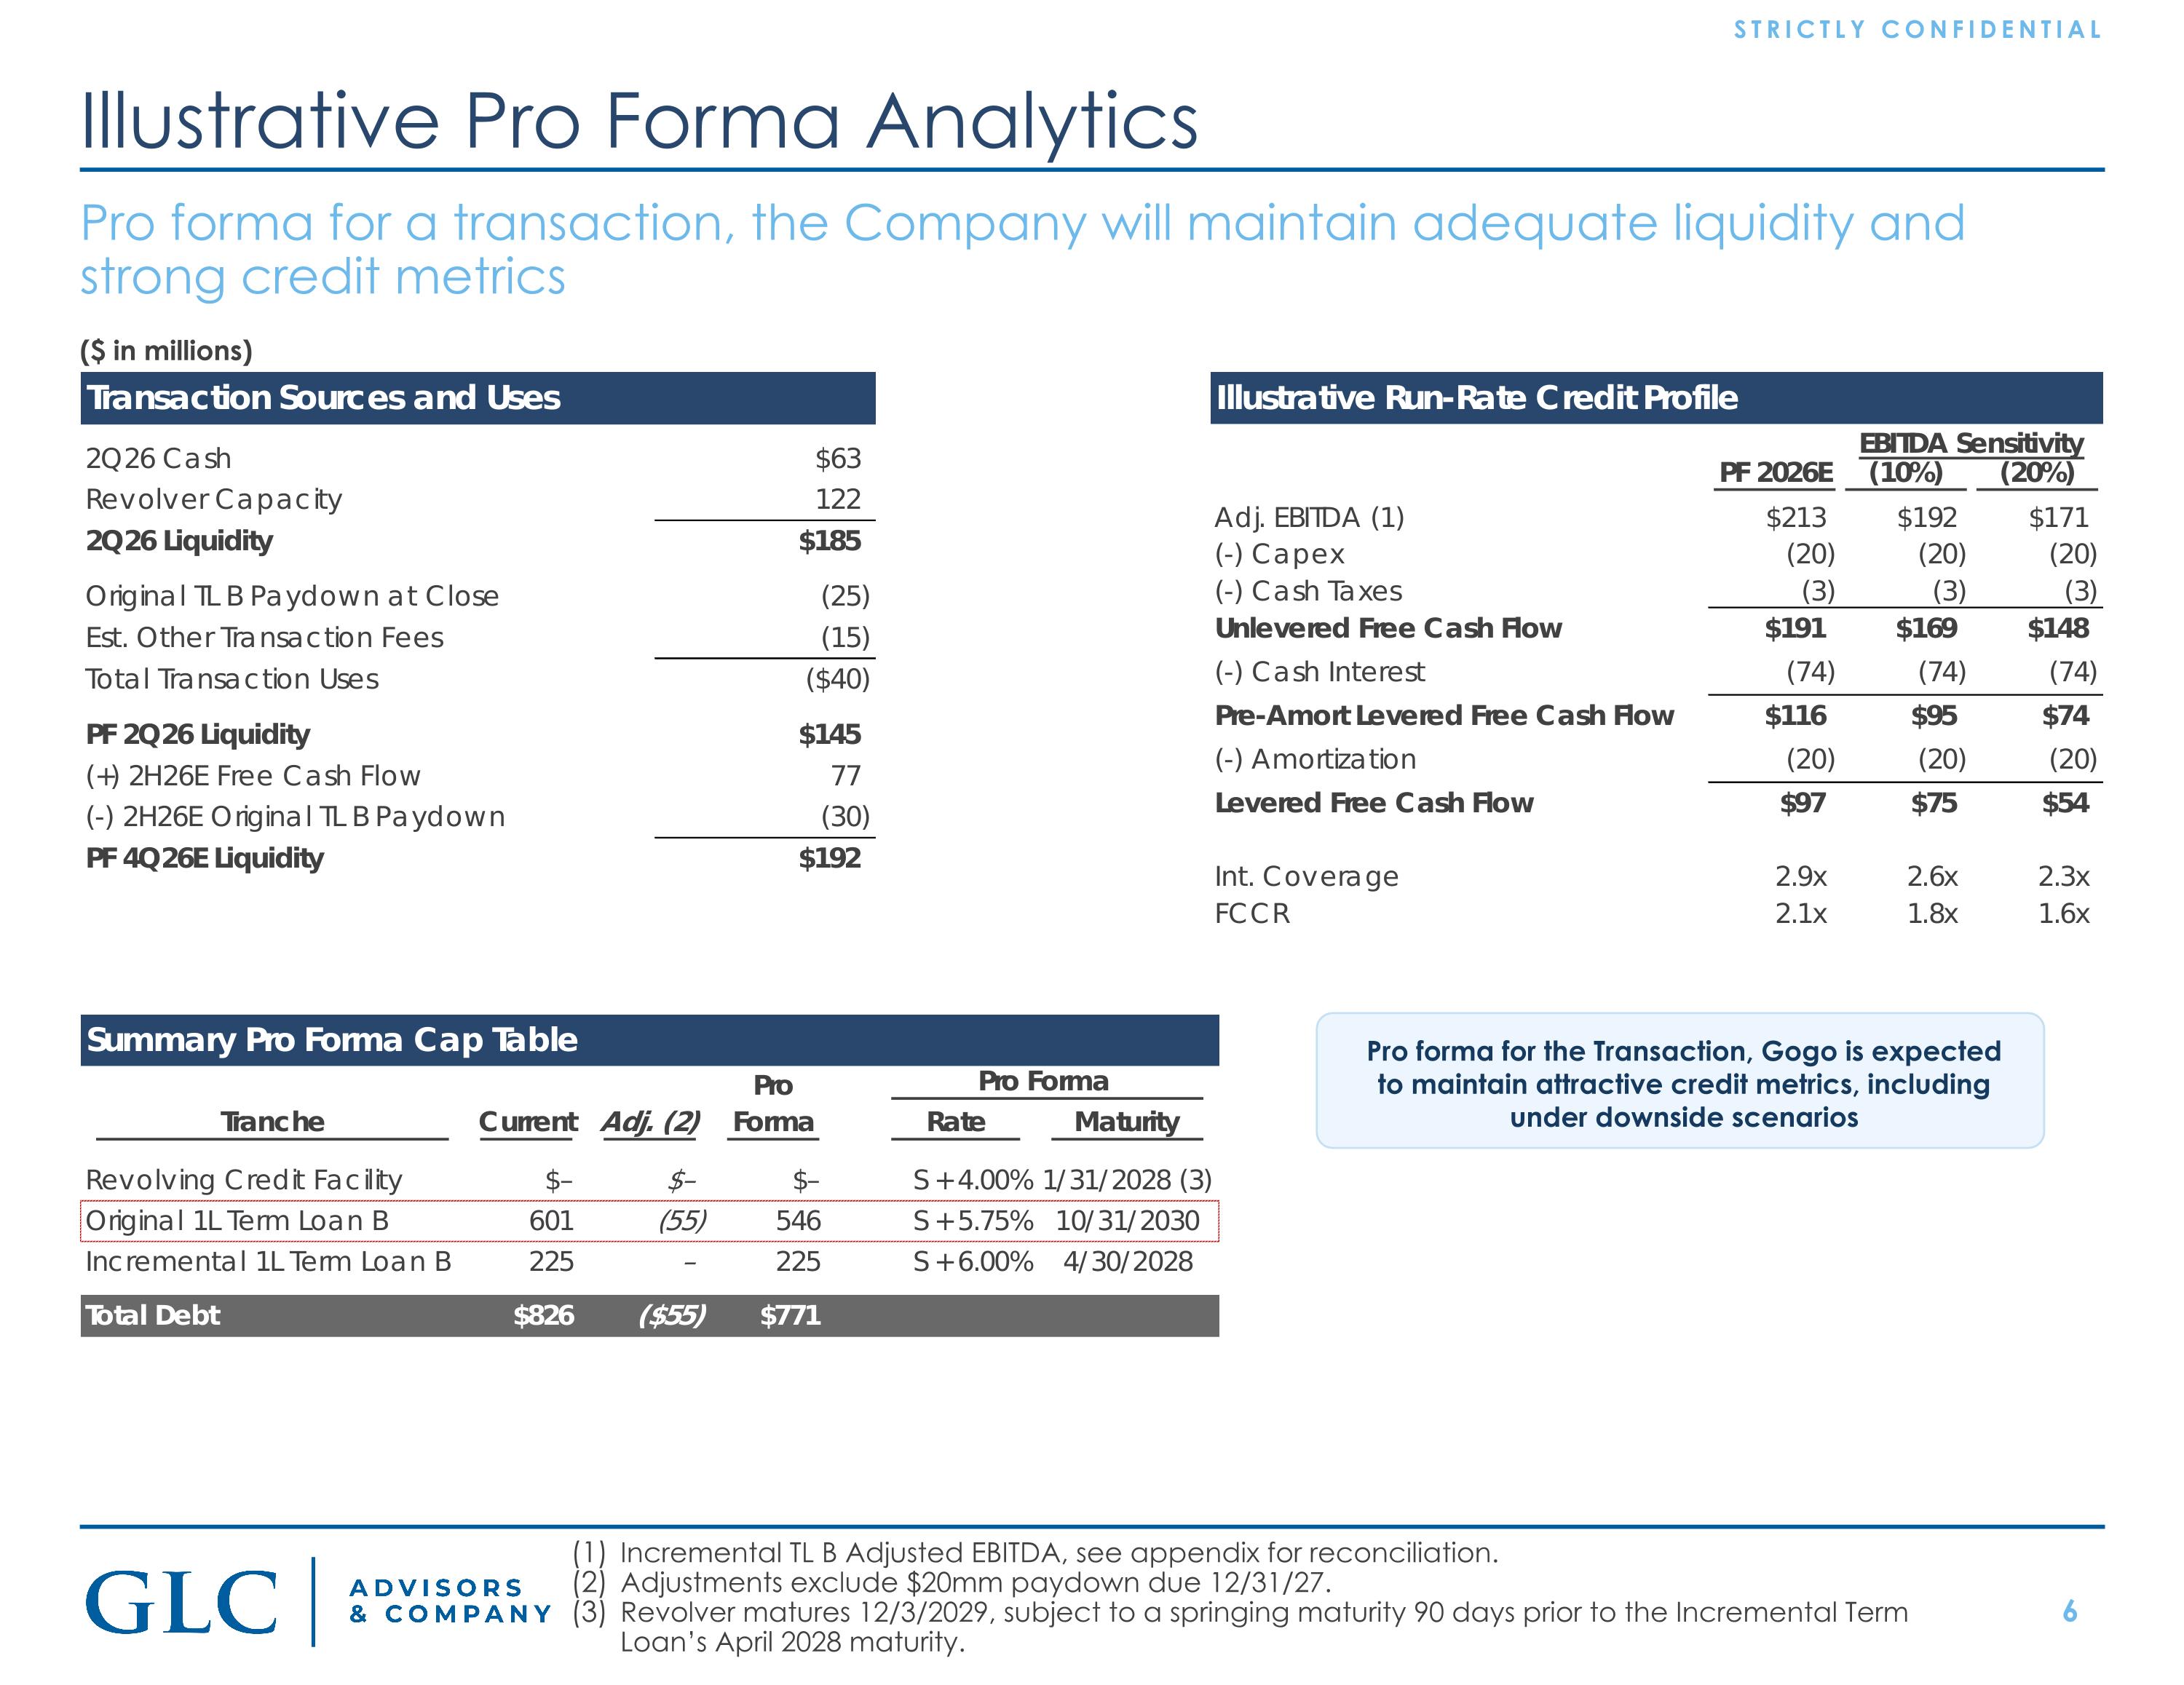
Illustrative Pro Forma Analytics Pro forma for the Transaction, Gogo is expected to maintain attractive credit metrics, including under downside scenarios Incremental TL B Adjusted EBITDA, see appendix for reconciliation. Adjustments exclude $20mm paydown due 12/31/27. Revolver matures 12/3/2029, subject to a springing maturity 90 days prior to the Incremental Term Loan’s April 2028 maturity. ($ in millions) Pro forma for a transaction, the Company will maintain adequate liquidity and strong credit metrics
Appendix
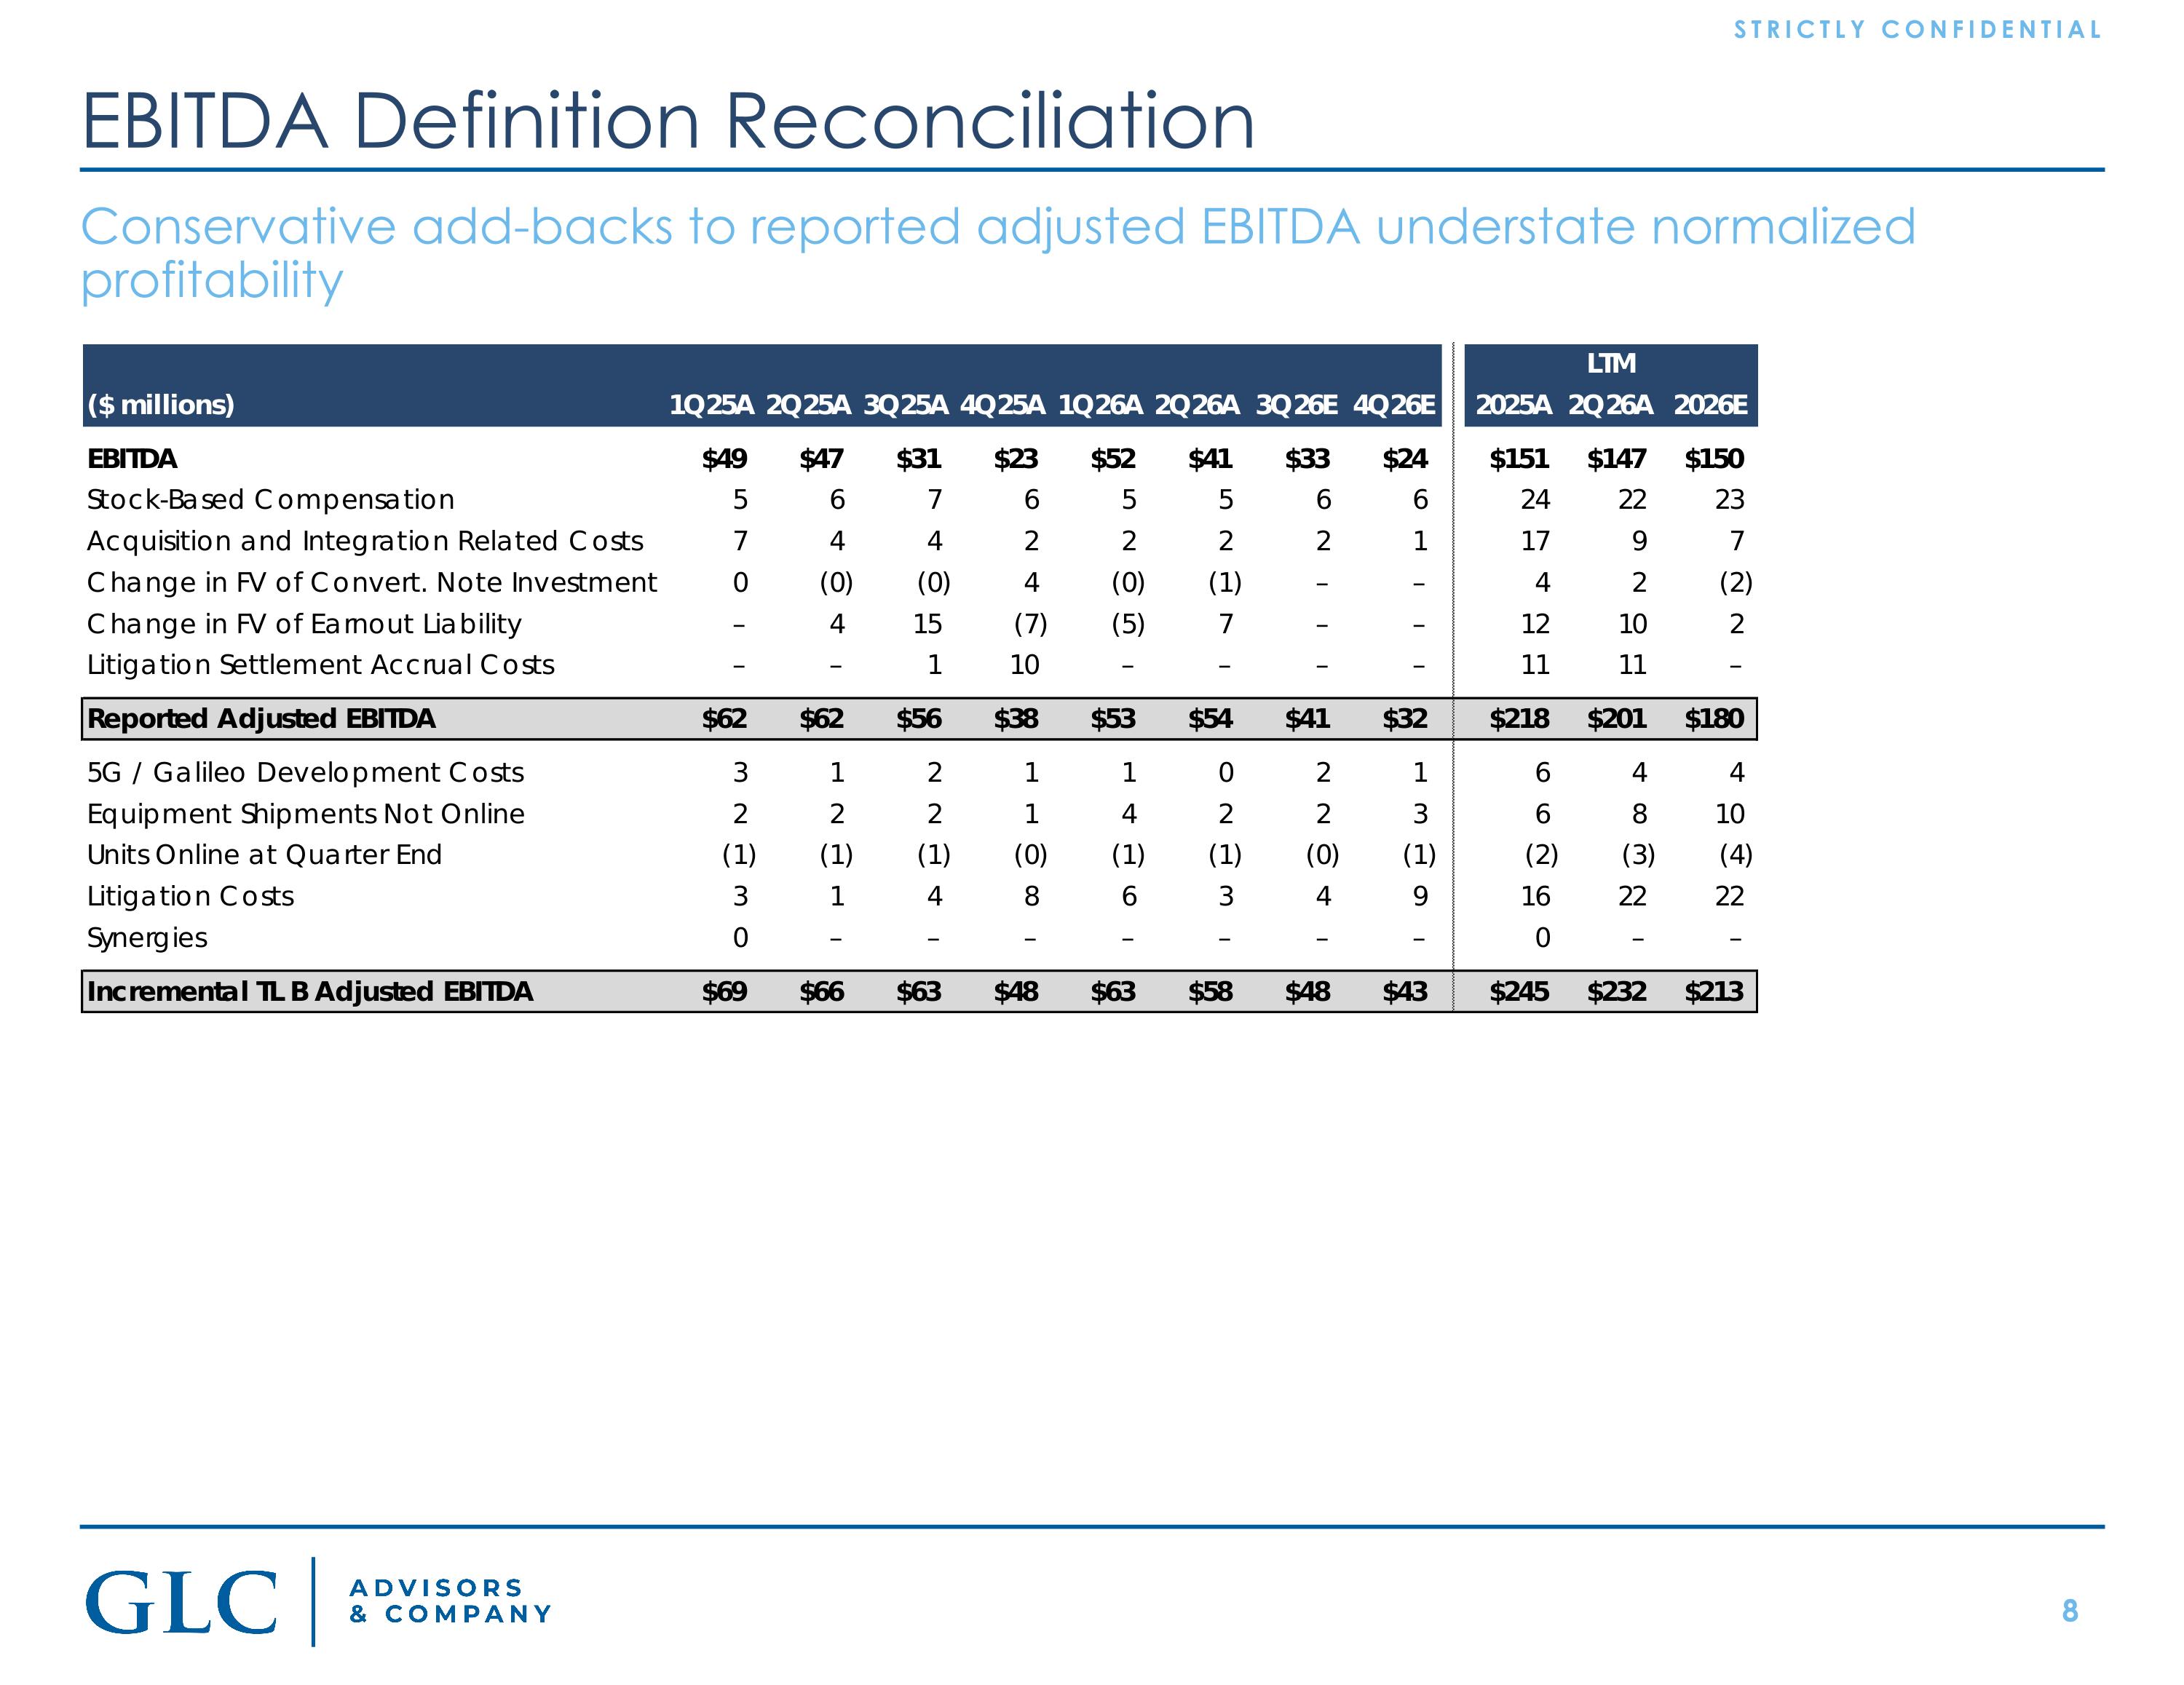
EBITDA Definition Reconciliation Conservative add-backs to reported adjusted EBITDA understate normalized profitability
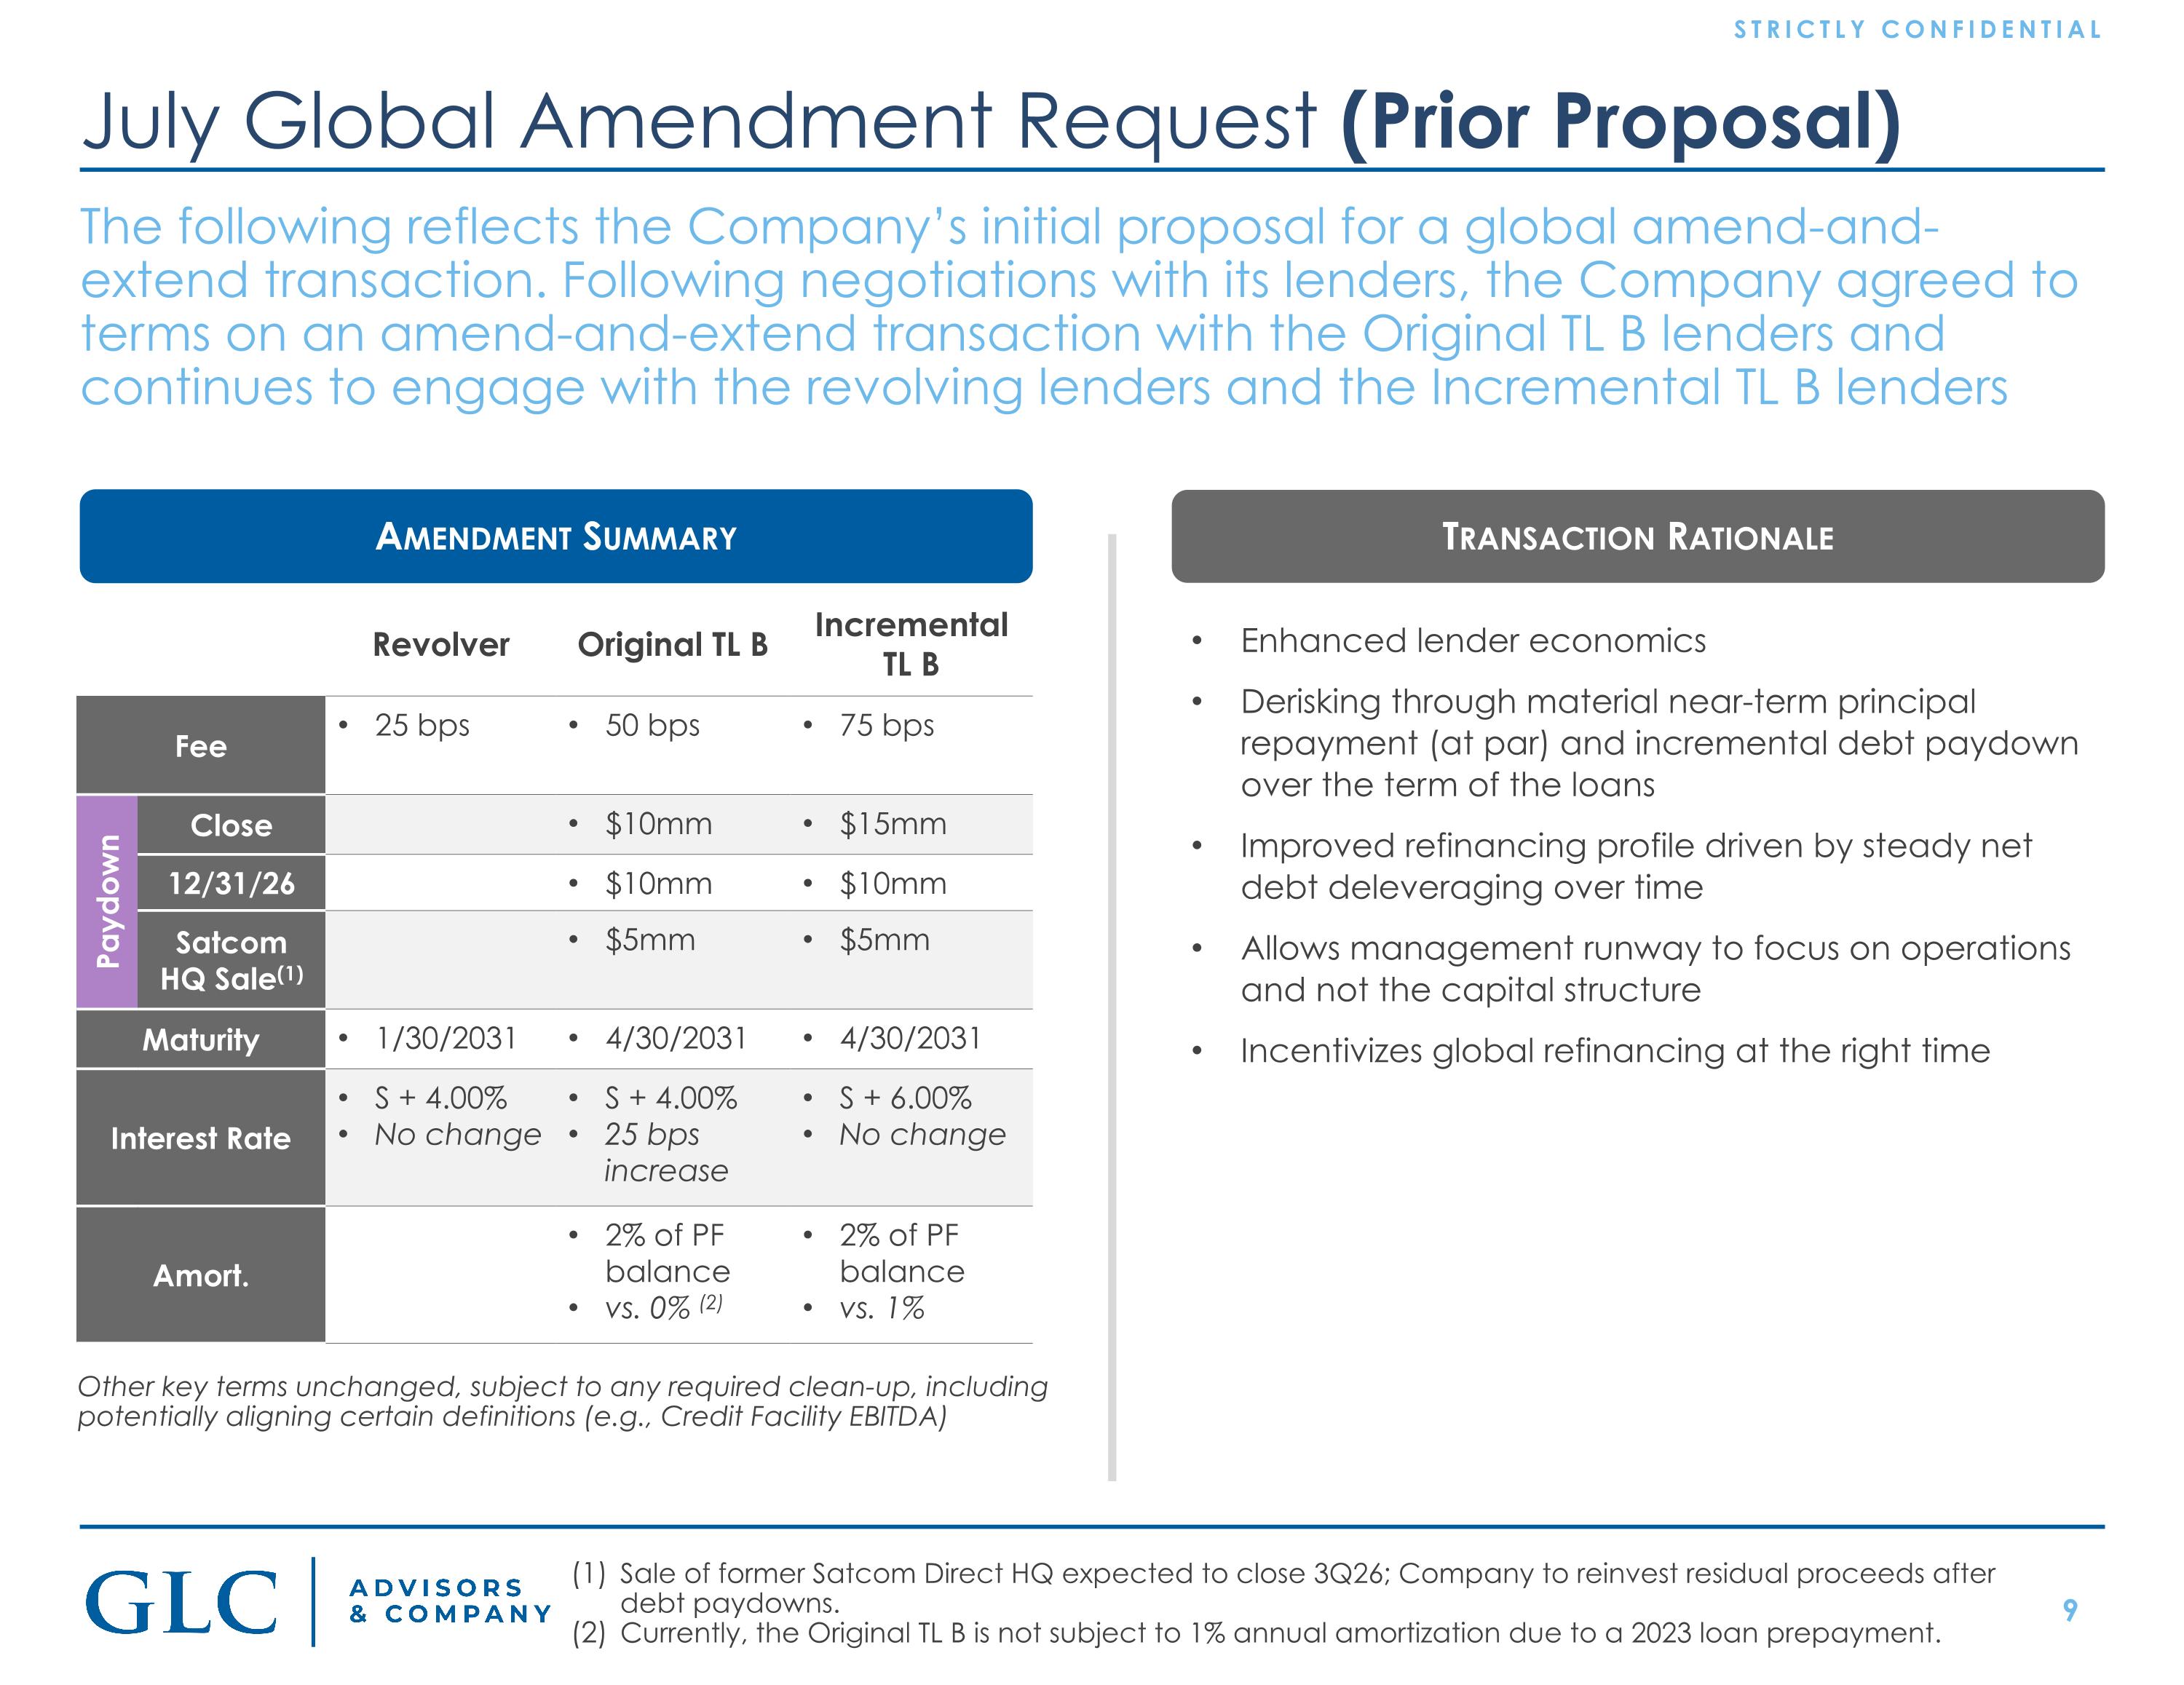
July Global Amendment Request (Prior Proposal) The following reflects the Company’s initial proposal for a global amend-and-extend transaction. Following negotiations with its lenders, the Company agreed to terms on an amend-and-extend transaction with the Original TL B lenders and continues to engage with the revolving lenders and the Incremental TL B lenders Transaction Rationale Enhanced lender economics Derisking through material near-term principal repayment (at par) and incremental debt paydown over the term of the loans Improved refinancing profile driven by steady net debt deleveraging over time Allows management runway to focus on operations and not the capital structure Incentivizes global refinancing at the right time Revolver Original TL B Incremental TL B Fee 25 bps 50 bps 75 bps Paydown Close $10mm $15mm 12/31/26 $10mm $10mm Satcom HQ Sale(1) $5mm $5mm Maturity 1/30/2031 4/30/2031 4/30/2031 Interest Rate S + 4.00% No change S + 4.00% 25 bps increase S + 6.00% No change Amort. 2% of PF balance vs. 0% (2) 2% of PF balance vs. 1% Amendment Summary Sale of former Satcom Direct HQ expected to close 3Q26; Company to reinvest residual proceeds after debt paydowns. Currently, the Original TL B is not subject to 1% annual amortization due to a 2023 loan prepayment. Other key terms unchanged, subject to any required clean-up, including potentially aligning certain definitions (e.g., Credit Facility EBITDA)