Natera, Inc. Q3’2026 Earnings Presentation November 5, 2026
2 Not for reproduction or further distribution. This presentation contains forward-looking statements under the meaning of the Private Securities Litigation Reform Act of 1995. All statements other than statements of historical facts contained in this presentation, including statements regarding our market opportunity, our anticipated products and launch schedules, our reimbursement coverage, our product costs and our gross margins, our commercial and strategic partnerships and potential acquisitions, our user experience, our clinical trials and studies, our strategies, our goals and general business and market conditions, are forward- looking statements. These forward-looking statements are subject to known and unknown risks and uncertainties that may cause actual results to differ materially, including: we face numerous uncertainties and challenges in achieving our financial projections and goals, including our long term projections of revenue; we may be unable to further increase the use and adoption of our products through our direct sales efforts or through our laboratory partners; we have incurred net losses since our inception and we anticipate that we will continue to incur net losses for the foreseeable future; our quarterly results may fluctuate from period to period; unless otherwise indicated, all financial data for the current and prior quarters are unaudited and subject to adjustment in connection with the completion of our quarterly and annual financial reporting processes; our estimates of market opportunity and forecasts of market growth may prove to be inaccurate; we may be unable to compete successfully with existing or future products or services offered by our competitors; we may engage in acquisitions, dispositions or other strategic transactions that may not achieve our anticipated benefits and could otherwise disrupt our business, cause dilution to our stockholders or reduce our financial resources; our products may not perform as expected; the results of our clinical studies may not support the use and reimbursement of our tests, particularly for microdeletions screening, and may not be able to be replicated in later studies required for regulatory approvals or clearances; if either of our primary CLIA-certified laboratories becomes inoperable, we will be unable to perform our tests and our business will be harmed; we rely on a limited number of suppliers or, in some cases, single suppliers, for some of our laboratory instruments and materials and may not be able to find replacements or immediately transition to alternative suppliers; if we are unable to successfully scale our operations, our business could suffer; the marketing, sale, and use of Panorama and our other products could result in substantial damages arising from product liability or professional liability claims that exceed our resources; we may be unable to expand, obtain or maintain third-party payer coverage and reimbursement for our tests, and we may be required to refund reimbursements already received; third-party payers may withdraw coverage or provide lower levels of reimbursement due to changing policies, billing complexities or other factors; we could incur substantial costs and delays complying with governmental regulations; litigation and other regulatory or governmental proceedings, related to our intellectual property or the commercialization of our tests, are costly, time- consuming, could result in our obligation to pay material judgments or incur material settlement costs, and could limit our ability to commercialize our tests; and any inability to effectively protect our proprietary technology could harm our competitive position or our brand. We discuss these and other risks and uncertainties in greater detail in the sections entitled “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in our periodic reports on Forms 10-K and 10-Q and in other filings we make with the SEC from time to time. Moreover, we operate in a very competitive and rapidly changing environment. New risks emerge from time to time. It is not possible for our management to predict all risks, nor can we assess the impact of all factors on our business or the extent to which any factor, or combination of factors, may cause actual results to differ materially from those contained in any forward-looking statement. In light of these risks, uncertainties and assumptions, the forward-looking events and circumstances discussed in this presentation may not occur and our actual results could differ materially and adversely from those anticipated or implied. As a result, you should not place undue reliance on our forward-looking statements. Except as required by law, we undertake no obligation to update publicly any forward-looking statements for any reason after the date of this presentation to conform these statements to actual results or to changes in our expectations. We file reports, proxy statements, and other information with the SEC. Such reports, proxy statements, and other information concerning us is available at http://www.sec.gov. Requests for copies of such documents should be directed to our Investor Relations department at Natera , Inc., 13011 McCallen Pass, Building A Suite 100, Austin, TX 78753. Our telephone number is (650) 980-9190. Safe-harbor statement
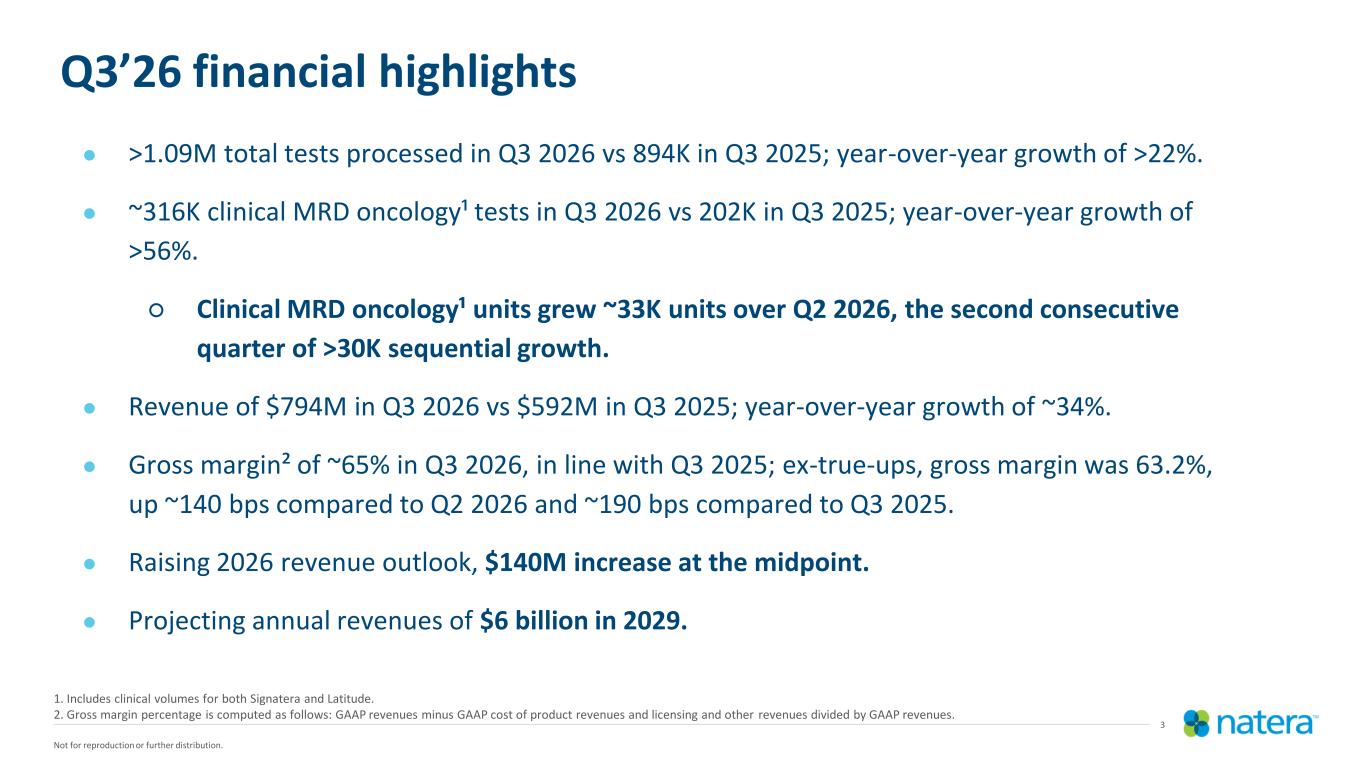
3 Not for reproduction or further distribution. Q3’26 financial highlights 1. Includes clinical volumes for both Signatera and Latitude. 2. Gross margin percentage is computed as follows: GAAP revenues minus GAAP cost of product revenues and licensing and other revenues divided by GAAP revenues. ● >1.09M total tests processed in Q3 2026 vs 894K in Q3 2025; year-over-year growth of >22%. ● ~316K clinical MRD oncology¹ tests in Q3 2026 vs 202K in Q3 2025; year-over-year growth of >56%. ○ Clinical MRD oncology¹ units grew ~33K units over Q2 2026, the second consecutive quarter of >30K sequential growth. ● Revenue of $794M in Q3 2026 vs $592M in Q3 2025; year-over-year growth of ~34%. ● Gross margin² of ~65% in Q3 2026, in line with Q3 2025; ex-true-ups, gross margin was 63.2%, up ~140 bps compared to Q2 2026 and ~190 bps compared to Q3 2025. ● Raising 2026 revenue outlook, $140M increase at the midpoint. ● Projecting annual revenues of $6 billion in 2029.
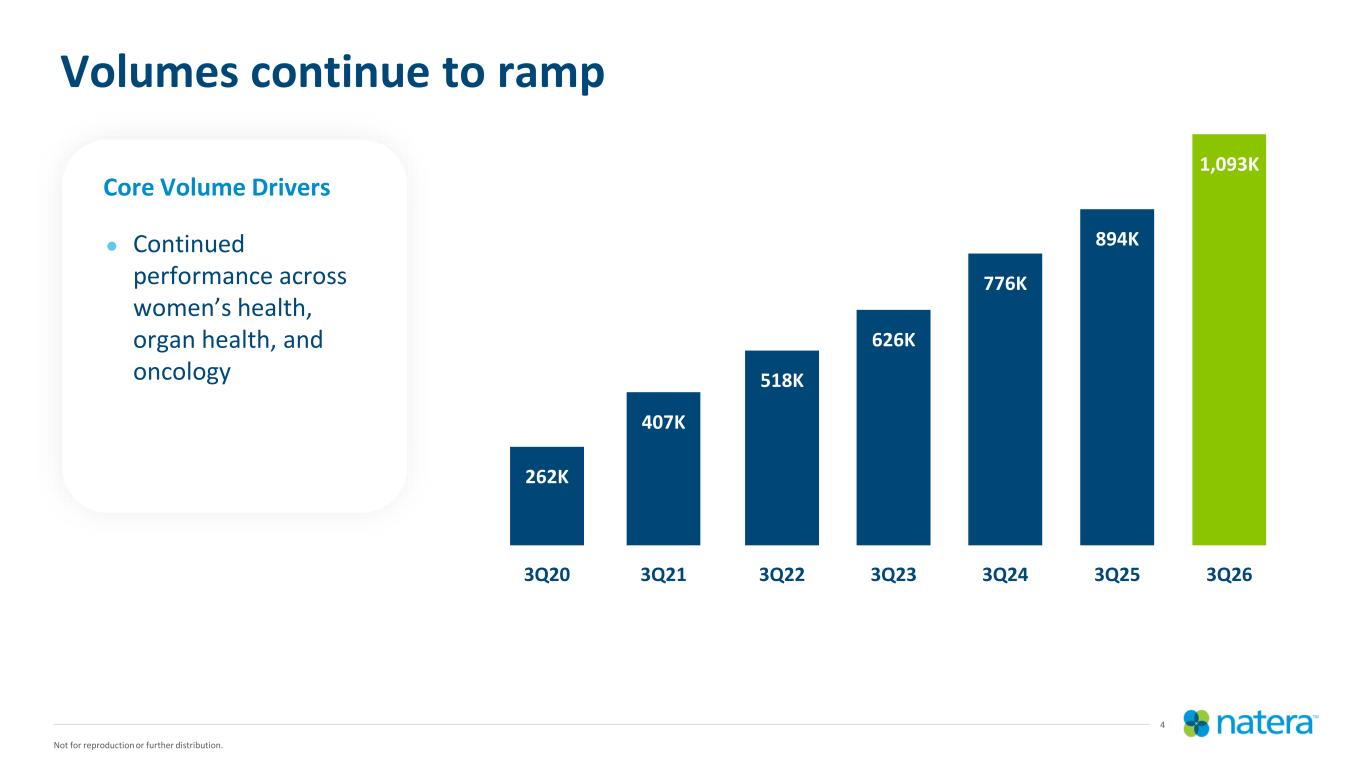
4 Not for reproduction or further distribution. Volumes continue to ramp Core Volume Drivers ● Continued performance across women’s health, organ health, and oncology 262K 3Q20 407K 3Q21 518K 3Q22 626K 3Q23 776K 3Q24 894K 3Q25 1,093K 3Q26
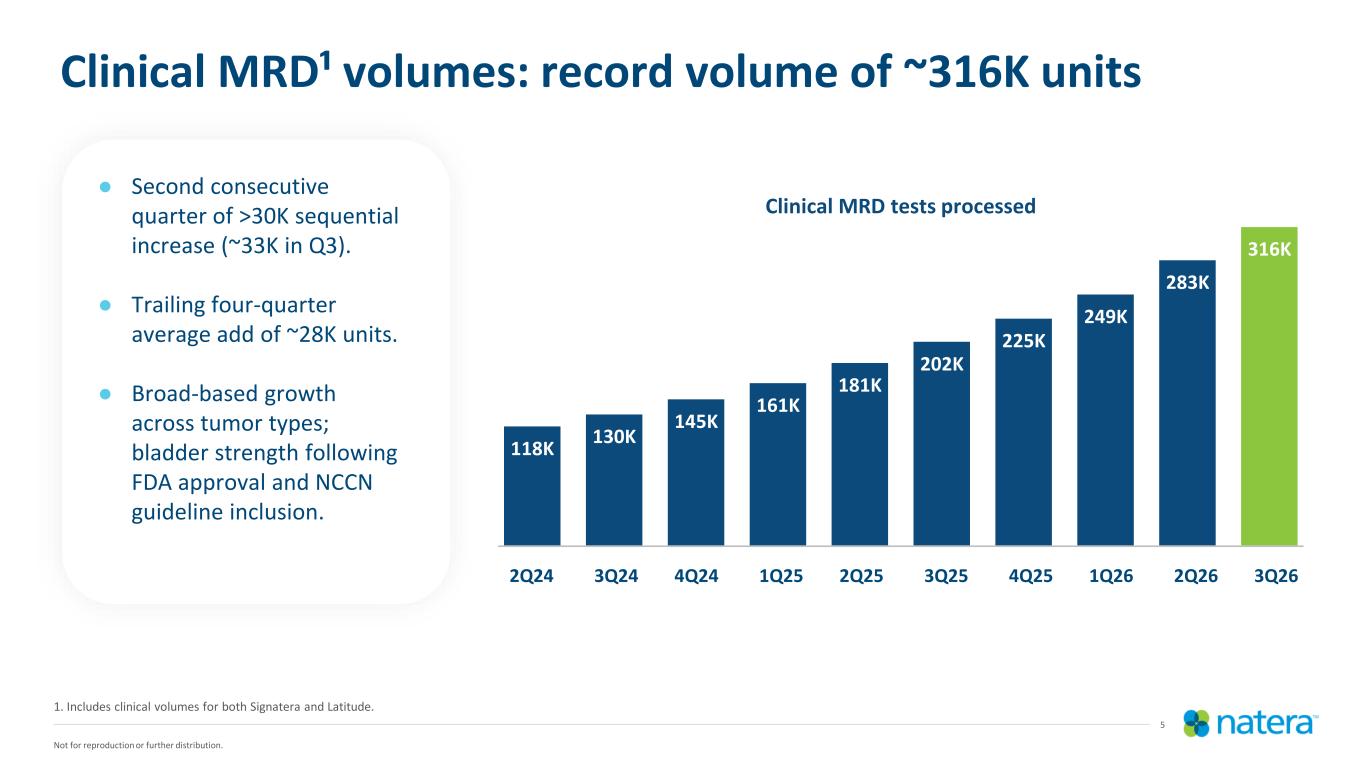
5 Not for reproduction or further distribution. 1. Includes clinical volumes for both Signatera and Latitude. Clinical MRD¹ volumes: record volume of ~316K units ● Second consecutive quarter of >30K sequential increase (~33K in Q3). ● Trailing four-quarter average add of ~28K units. ● Broad-based growth across tumor types; bladder strength following FDA approval and NCCN guideline inclusion. Clinical MRD tests processed 118K 130K 145K 161K 181K 202K 225K 249K 283K 316K 2Q24 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 3Q26
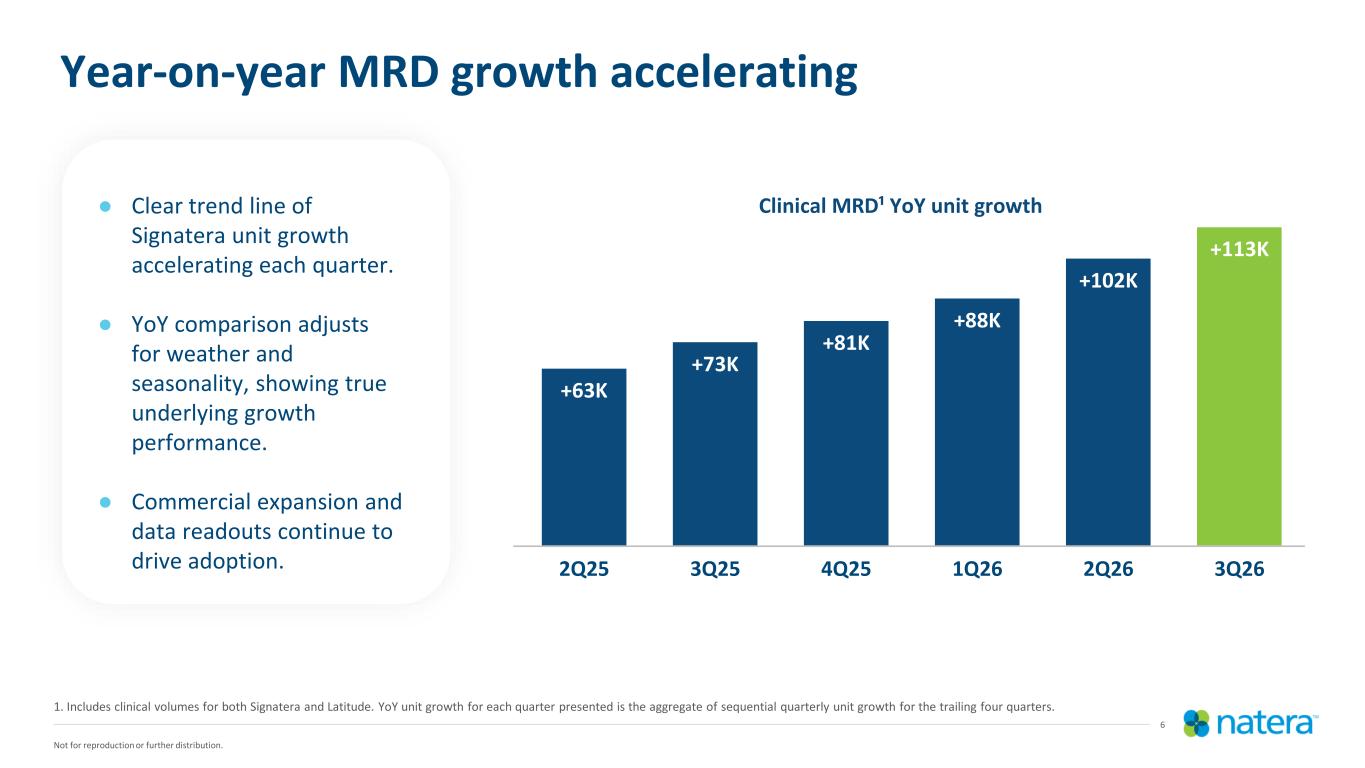
6 Not for reproduction or further distribution. 1. Includes clinical volumes for both Signatera and Latitude. YoY unit growth for each quarter presented is the aggregate of sequential quarterly unit growth for the trailing four quarters. Year-on-year MRD growth accelerating ● Clear trend line of Signatera unit growth accelerating each quarter. ● YoY comparison adjusts for weather and seasonality, showing true underlying growth performance. ● Commercial expansion and data readouts continue to drive adoption. Clinical MRD¹ YoY unit growth +63K +73K +81K +88K +102K +113K 2Q25 3Q25 4Q25 1Q26 2Q26 3Q26
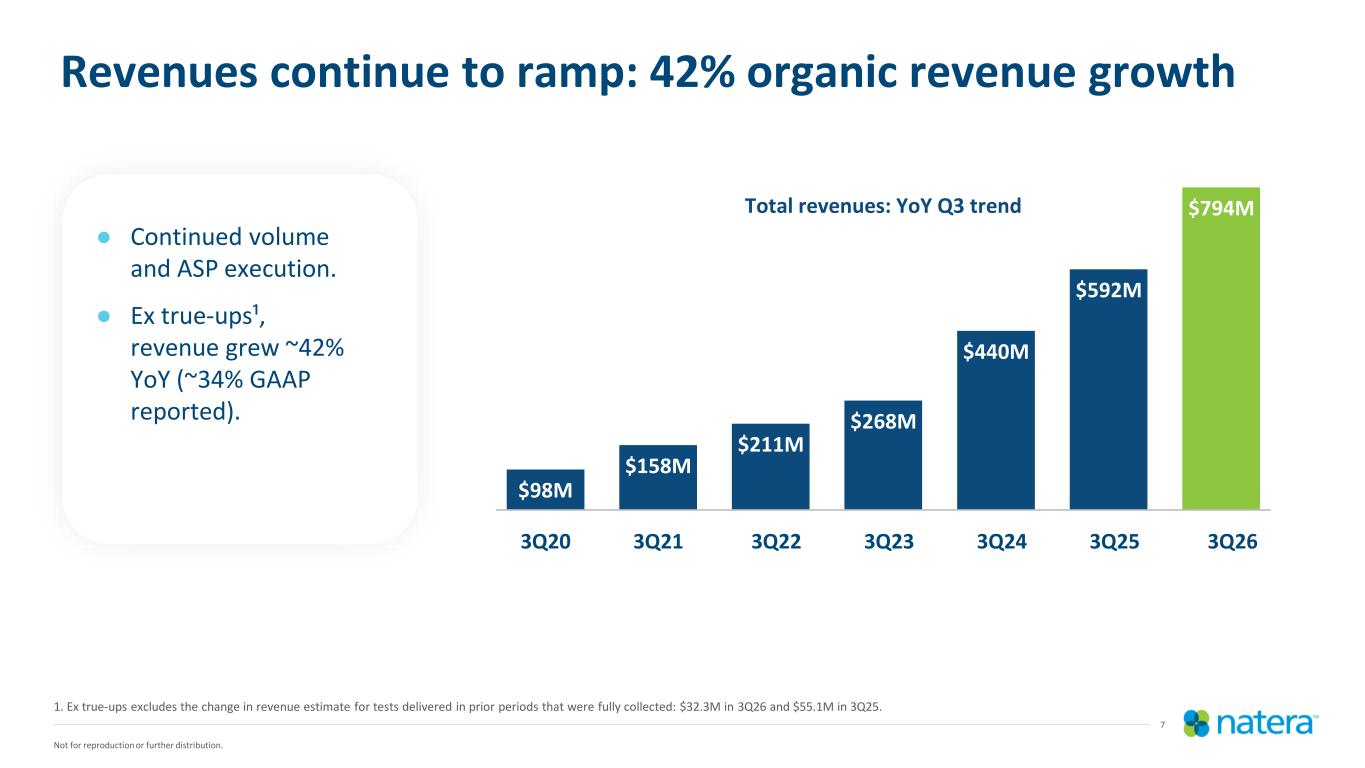
7 Not for reproduction or further distribution. 1. Ex true-ups excludes the change in revenue estimate for tests delivered in prior periods that were fully collected: $32.3M in 3Q26 and $55.1M in 3Q25. Revenues continue to ramp: 42% organic revenue growth ● Continued volume and ASP execution. ● Ex true-ups¹, revenue grew ~42% YoY (~34% GAAP reported). Total revenues: YoY Q3 trend $98M $158M $211M $268M $440M $592M $794M 3Q20 3Q21 3Q22 3Q23 3Q24 3Q25 3Q26
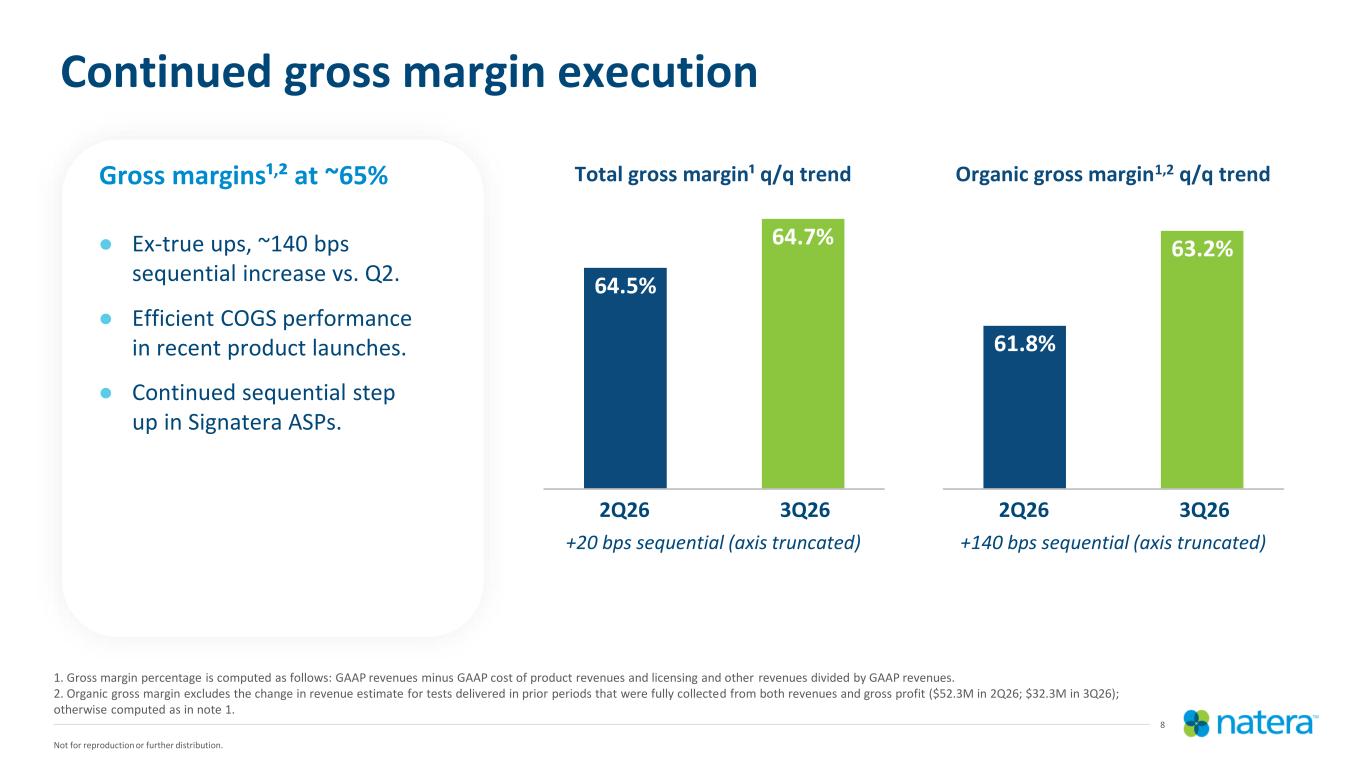
8 Not for reproduction or further distribution. 1. Gross margin percentage is computed as follows: GAAP revenues minus GAAP cost of product revenues and licensing and other revenues divided by GAAP revenues. 2. Organic gross margin excludes the change in revenue estimate for tests delivered in prior periods that were fully collected from both revenues and gross profit ($52.3M in 2Q26; $32.3M in 3Q26); otherwise computed as in note 1. Continued gross margin execution Gross margins¹,² at ~65% ● Ex-true ups, ~140 bps sequential increase vs. Q2. ● Efficient COGS performance in recent product launches. ● Continued sequential step up in Signatera ASPs. Total gross margin¹ q/q trend 2Q26 3Q26 +20 bps sequential (axis truncated) Organic gross margin1,2 q/q trend 2Q26 3Q26 +140 bps sequential (axis truncated) 64.5% 64.7% 61.8% 63.2%
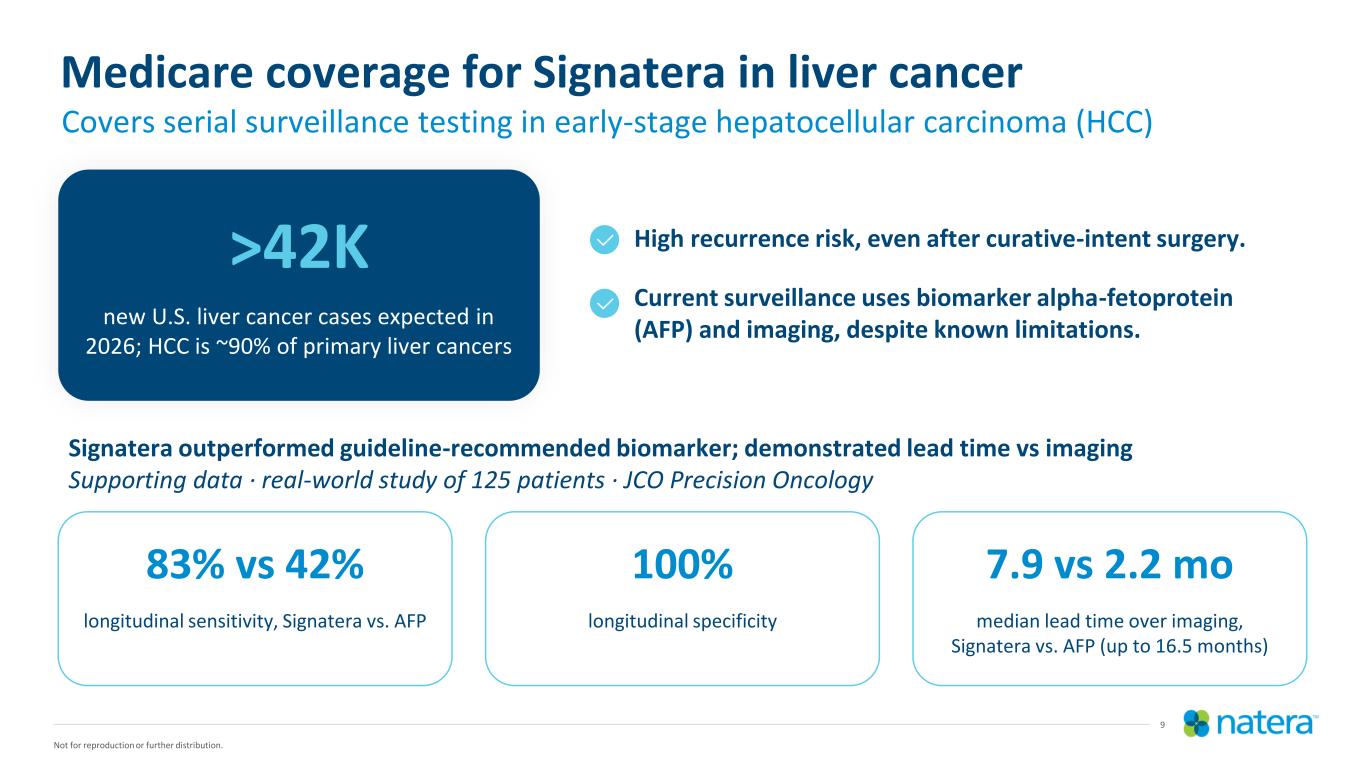
9 Not for reproduction or further distribution. Signatera outperformed guideline-recommended biomarker; demonstrated lead time vs imaging Supporting data · real-world study of 125 patients · JCO Precision Oncology Medicare coverage for Signatera in liver cancer Covers serial surveillance testing in early-stage hepatocellular carcinoma (HCC) 83% vs 42% longitudinal sensitivity, Signatera vs. AFP 100% longitudinal specificity 7.9 vs 2.2 mo median lead time over imaging, Signatera vs. AFP (up to 16.5 months) >42K new U.S. liver cancer cases expected in 2026; HCC is ~90% of primary liver cancers High recurrence risk, even after curative-intent surgery. Current surveillance uses biomarker alpha-fetoprotein (AFP) and imaging, despite known limitations.
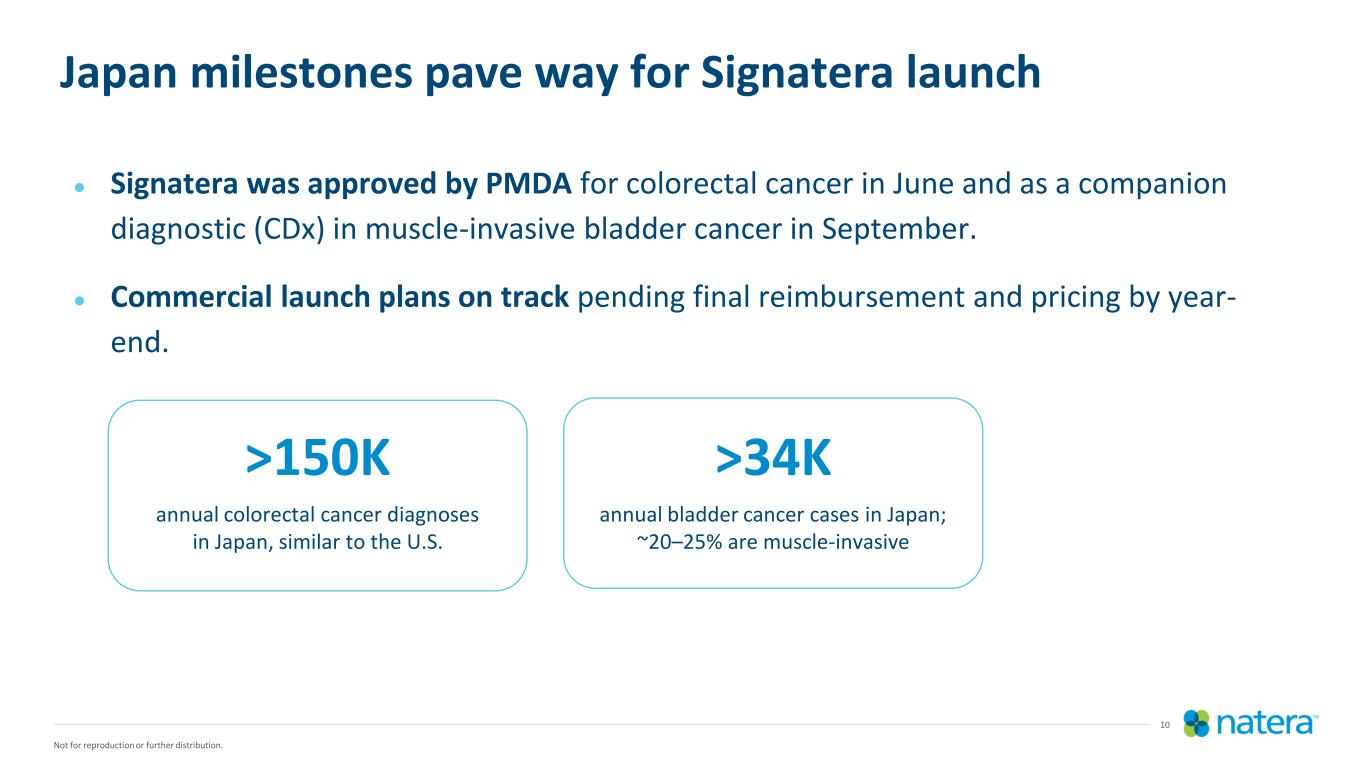
10 Not for reproduction or further distribution. ● Signatera was approved by PMDA for colorectal cancer in June and as a companion diagnostic (CDx) in muscle-invasive bladder cancer in September. ● Commercial launch plans on track pending final reimbursement and pricing by year- end. Japan milestones pave way for Signatera launch >150K annual colorectal cancer diagnoses in Japan, similar to the U.S. >34K annual bladder cancer cases in Japan; ~20–25% are muscle-invasive
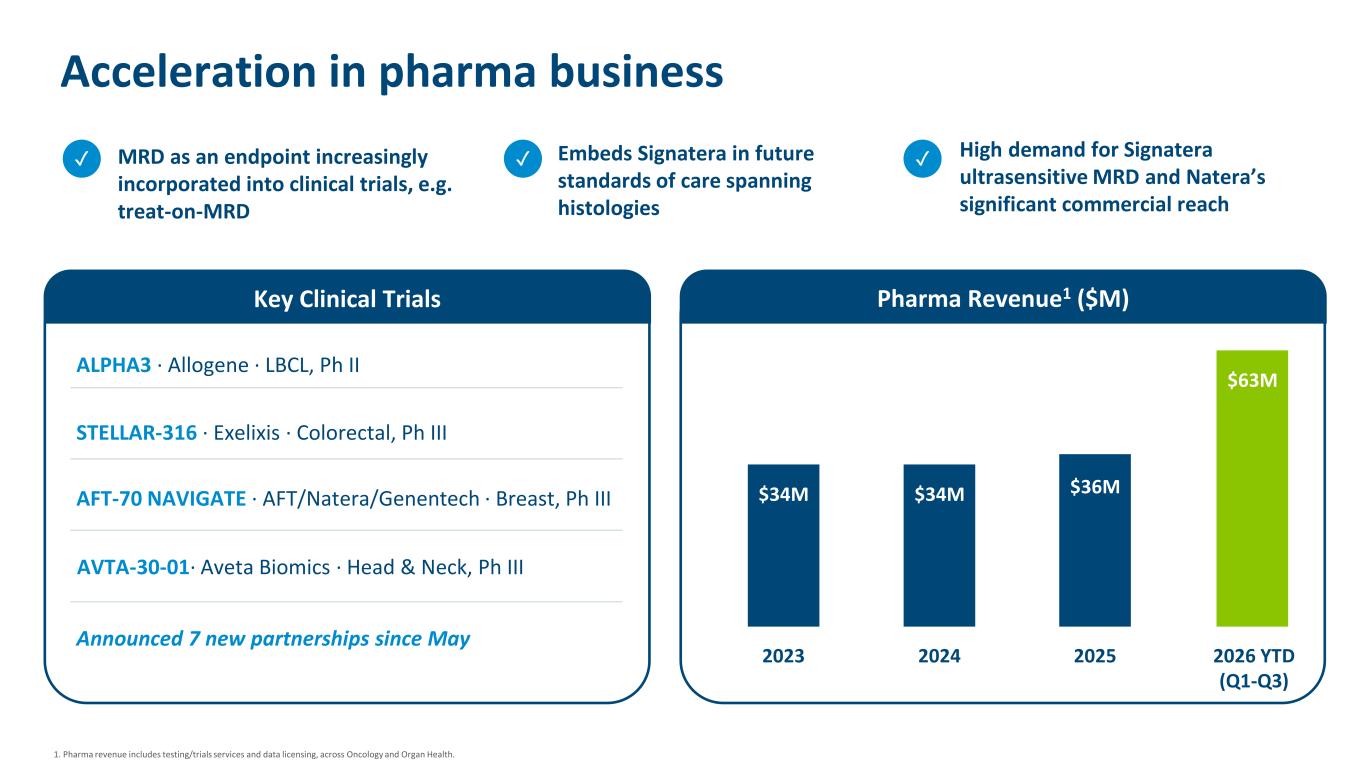
✓ MRD as an endpoint increasingly incorporated into clinical trials, e.g. treat-on-MRD ✓ ✓ Acceleration in pharma business Pharma revenue ($M) 1. Pharma revenue includes testing/trials services and data licensing, across Oncology and Organ Health. $34M 2023 $34M 2024 $36M 2025 $63M 2026 YTD (Q1-Q3) ALPHA3 · Allogene · LBCL, Ph II STELLAR-316 · Exelixis · Colorectal, Ph III AFT-70 NAVIGATE · AFT/Natera/Genentech · Breast, Ph III Announced 7 new partnerships since May Key Clinical Trials Pharma Revenue1 ($M) Embeds Signatera in future standards of care spanning histologies High demand for Signatera ultrasensitive MRD and Natera’s significant commercial reach AVTA-30-01· Aveta Biomics · Head & Neck, Ph III
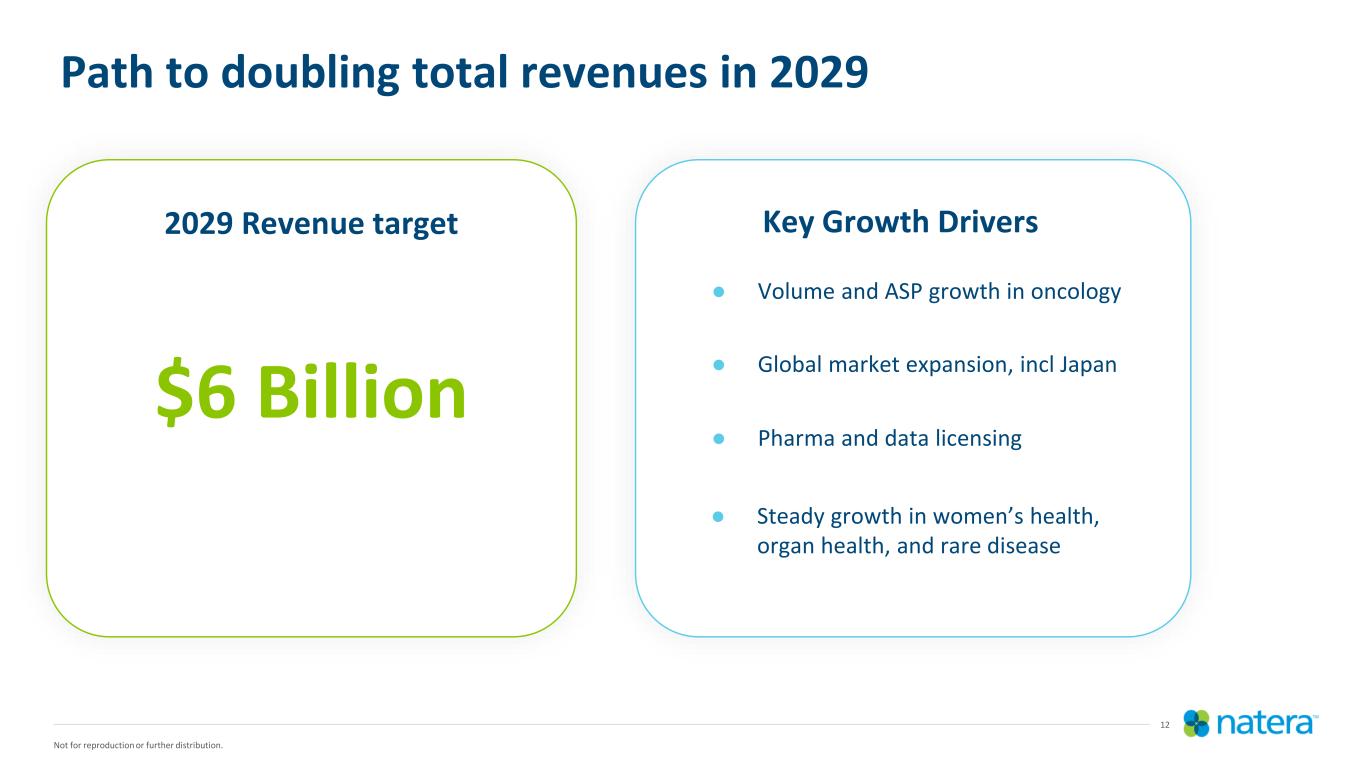
12 Not for reproduction or further distribution. ● Global market expansion, incl Japan ● Volume and ASP growth in oncology Path to doubling total revenues in 2029 ● Pharma and data licensing $6 Billion ● Steady growth in women’s health, organ health, and rare disease Key Growth Drivers2029 Revenue target
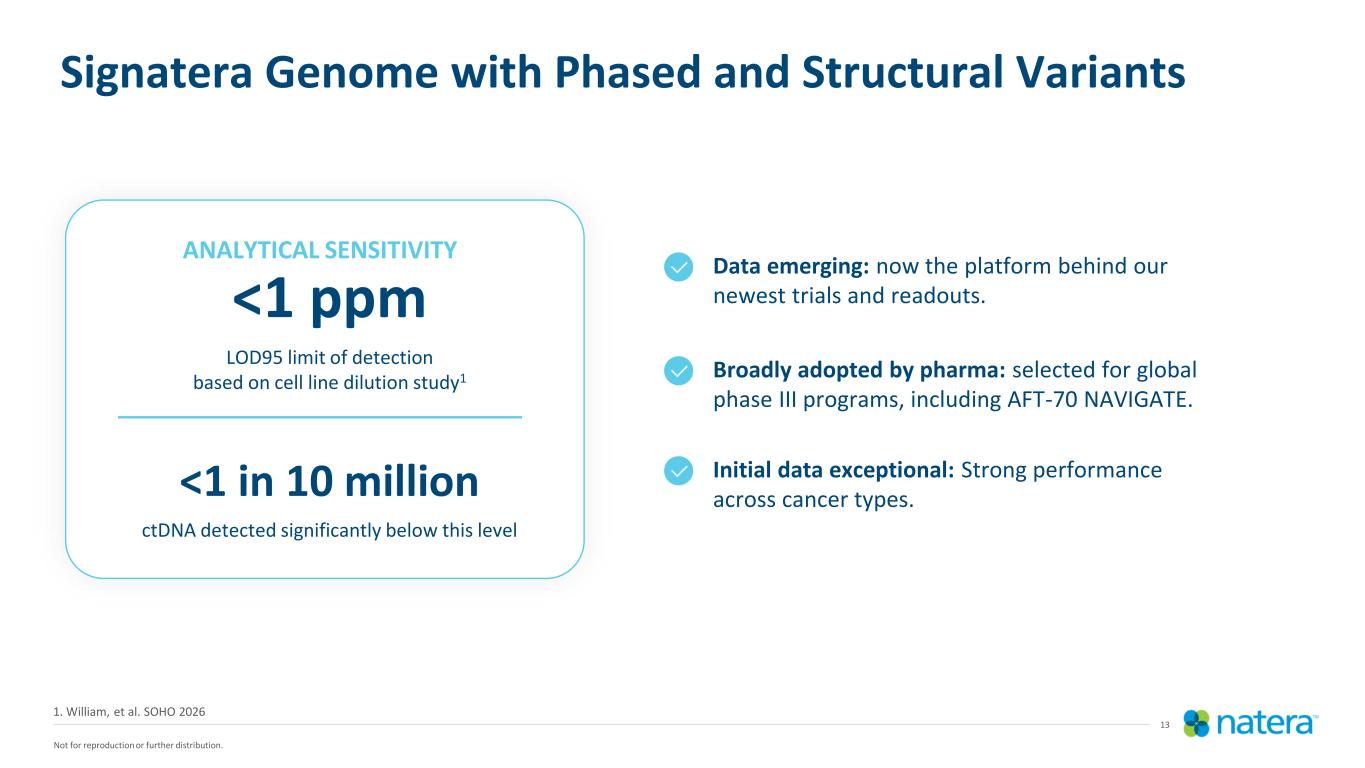
13 Not for reproduction or further distribution. Broadly adopted by pharma: selected for global phase III programs, including AFT-70 NAVIGATE. <1 ppm LOD95 limit of detection based on cell line dilution study1 <1 in 10 million ctDNA detected significantly below this level Data emerging: now the platform behind our newest trials and readouts. Initial data exceptional: Strong performance across cancer types. Signatera Genome with Phased and Structural Variants ANALYTICAL SENSITIVITY 1. William, et al. SOHO 2026
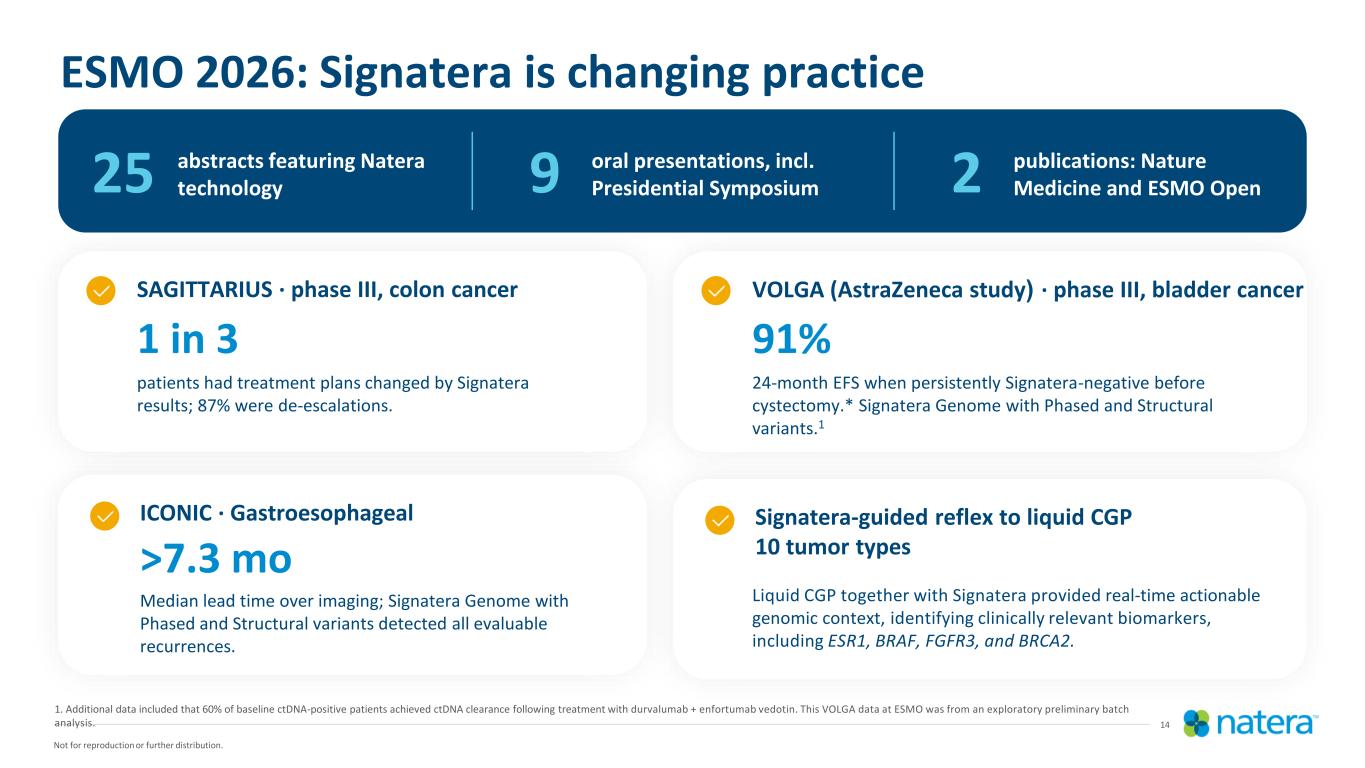
14 Not for reproduction or further distribution. ESMO 2026: Signatera is changing practice SAGITTARIUS · phase III, colon cancer VOLGA (AstraZeneca study) · phase III, bladder cancer 25 abstracts featuring Natera technology 9 oral presentations, incl. Presidential Symposium 2 publications: Nature Medicine and ESMO Open 1 in 3 patients had treatment plans changed by Signatera results; 87% were de-escalations. 91% 24-month EFS when persistently Signatera-negative before cystectomy.* Signatera Genome with Phased and Structural variants.1 ICONIC · Gastroesophageal >7.3 mo Median lead time over imaging; Signatera Genome with Phased and Structural variants detected all evaluable recurrences. Signatera-guided reflex to liquid CGP 10 tumor types Liquid CGP together with Signatera provided real-time actionable genomic context, identifying clinically relevant biomarkers, including ESR1, BRAF, FGFR3, and BRCA2. 1. Additional data included that 60% of baseline ctDNA-positive patients achieved ctDNA clearance following treatment with durvalumab + enfortumab vedotin. This VOLGA data at ESMO was from an exploratory preliminary batch analysis.
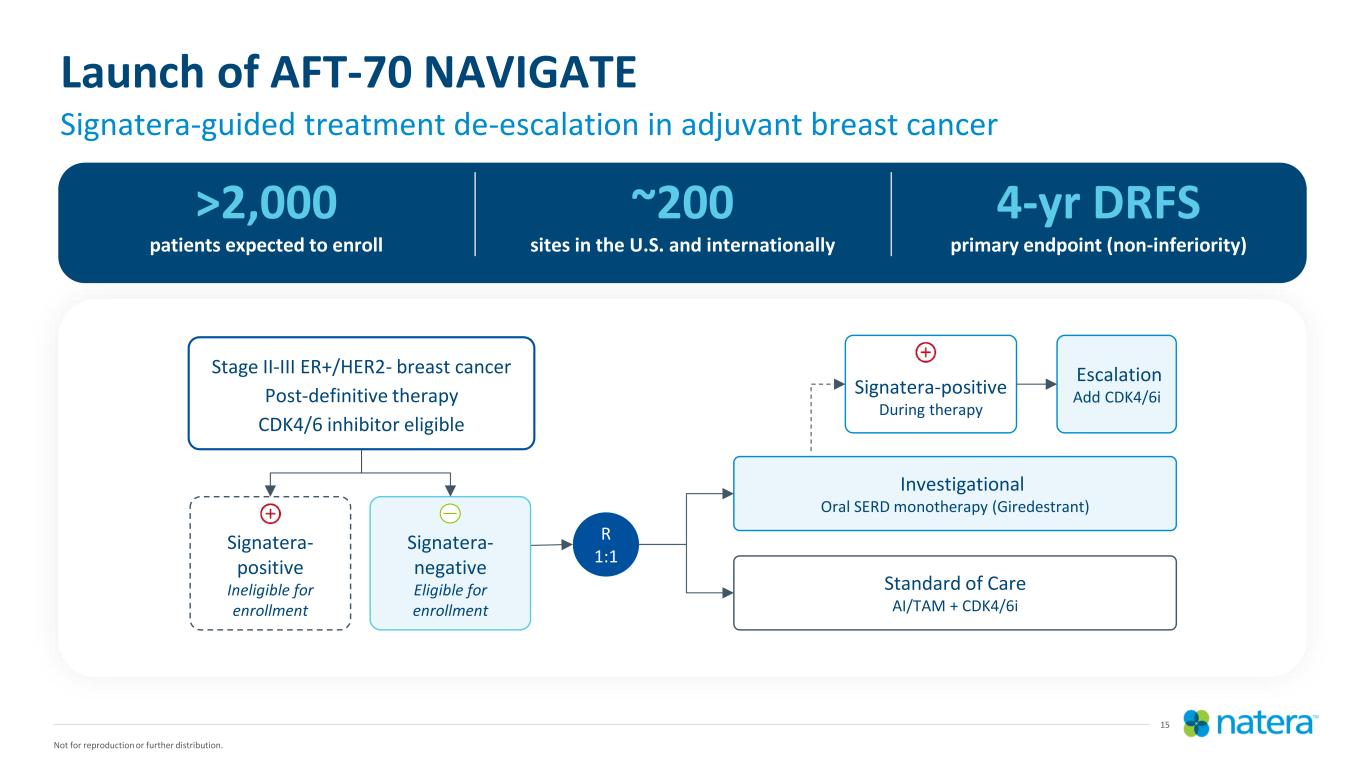
15 Not for reproduction or further distribution. Stage II-III ER+/HER2- breast cancer Post-definitive therapy CDK4/6 inhibitor eligible Signatera- negative Eligible for enrollment R 1:1 Standard of Care AI/TAM + CDK4/6i Investigational Oral SERD monotherapy (Giredestrant) Signatera-positive During therapy Escalation Add CDK4/6i Signatera- positive Ineligible for enrollment >2,000 patients expected to enroll ~200 sites in the U.S. and internationally 4-yr DRFS primary endpoint (non-inferiority) Launch of AFT-70 NAVIGATE Signatera-guided treatment de-escalation in adjuvant breast cancer
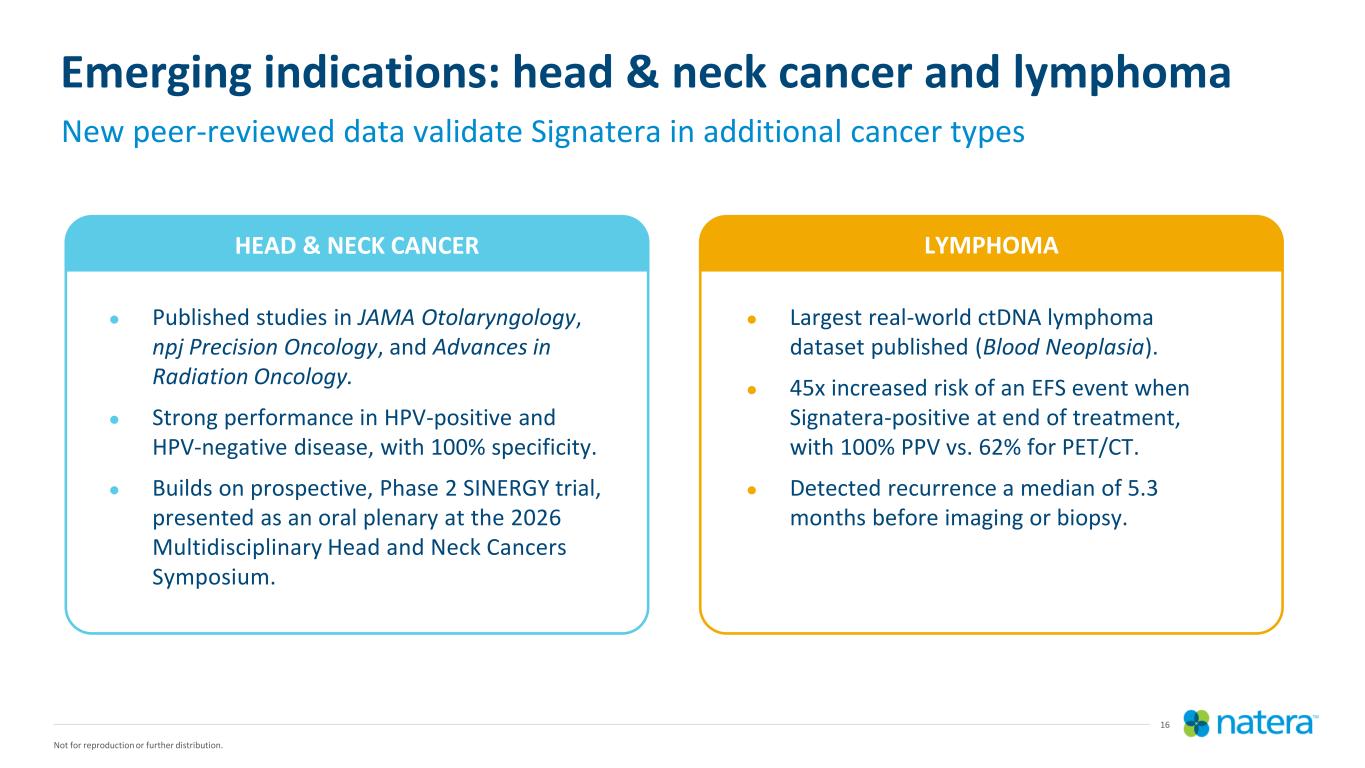
16 Not for reproduction or further distribution. HEAD & NECK CANCER LYMPHOMA Emerging indications: head & neck cancer and lymphoma New peer-reviewed data validate Signatera in additional cancer types ● Published studies in JAMA Otolaryngology, npj Precision Oncology, and Advances in Radiation Oncology. ● Strong performance in HPV-positive and HPV-negative disease, with 100% specificity. ● Builds on prospective, Phase 2 SINERGY trial, presented as an oral plenary at the 2026 Multidisciplinary Head and Neck Cancers Symposium. ● Largest real-world ctDNA lymphoma dataset published (Blood Neoplasia). ● 45x increased risk of an EFS event when Signatera-positive at end of treatment, with 100% PPV vs. 62% for PET/CT. ● Detected recurrence a median of 5.3 months before imaging or biopsy.
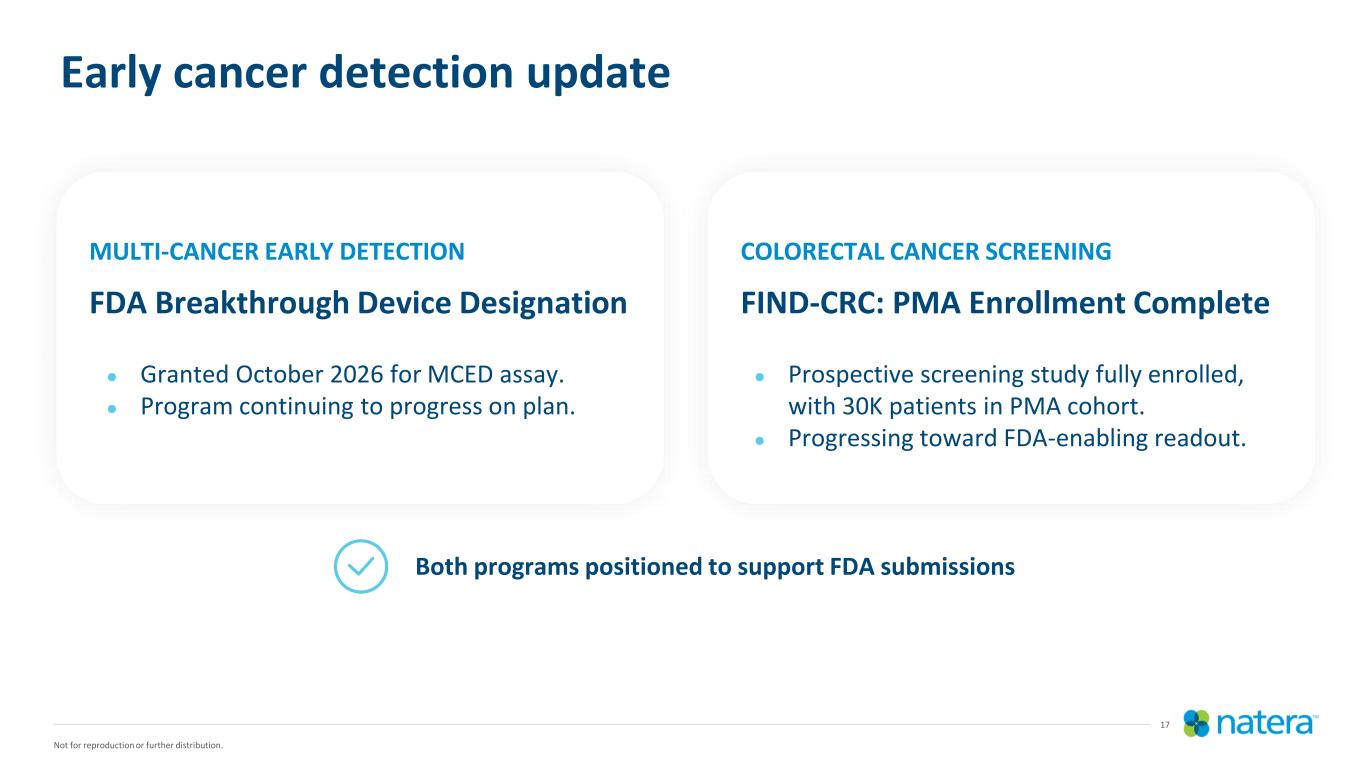
17 Not for reproduction or further distribution. Early cancer detection update COLORECTAL CANCER SCREENING FIND-CRC: PMA Enrollment Complete ● Prospective screening study fully enrolled, with 30K patients in PMA cohort. ● Progressing toward FDA-enabling readout. MULTI-CANCER EARLY DETECTION FDA Breakthrough Device Designation ● Granted October 2026 for MCED assay. ● Program continuing to progress on plan. Both programs positioned to support FDA submissions
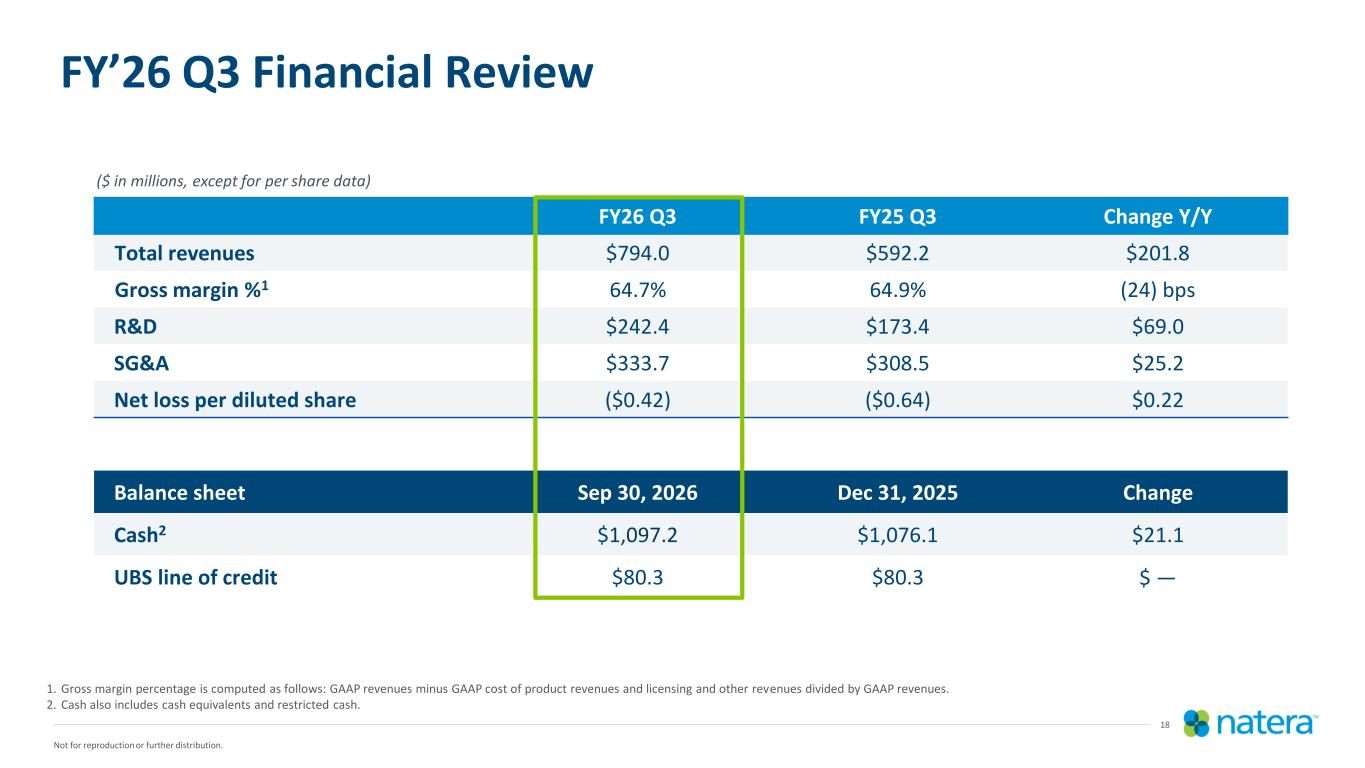
18 Not for reproduction or further distribution. FY’26 Q3 Financial Review ($ in millions, except for per share data) Balance sheet Sep 30, 2026 Dec 31, 2025 Change Cash2 $1,097.2 $1,076.1 $21.1 UBS line of credit $80.3 $80.3 $ — FY26 Q3 FY25 Q3 Change Y/Y Total revenues $794.0 $592.2 $201.8 Gross margin %1 64.7% 64.9% (24) bps R&D $242.4 $173.4 $69.0 SG&A $333.7 $308.5 $25.2 Net loss per diluted share ($0.42) ($0.64) $0.22 1. Gross margin percentage is computed as follows: GAAP revenues minus GAAP cost of product revenues and licensing and other revenues divided by GAAP revenues. 2. Cash also includes cash equivalents and restricted cash.
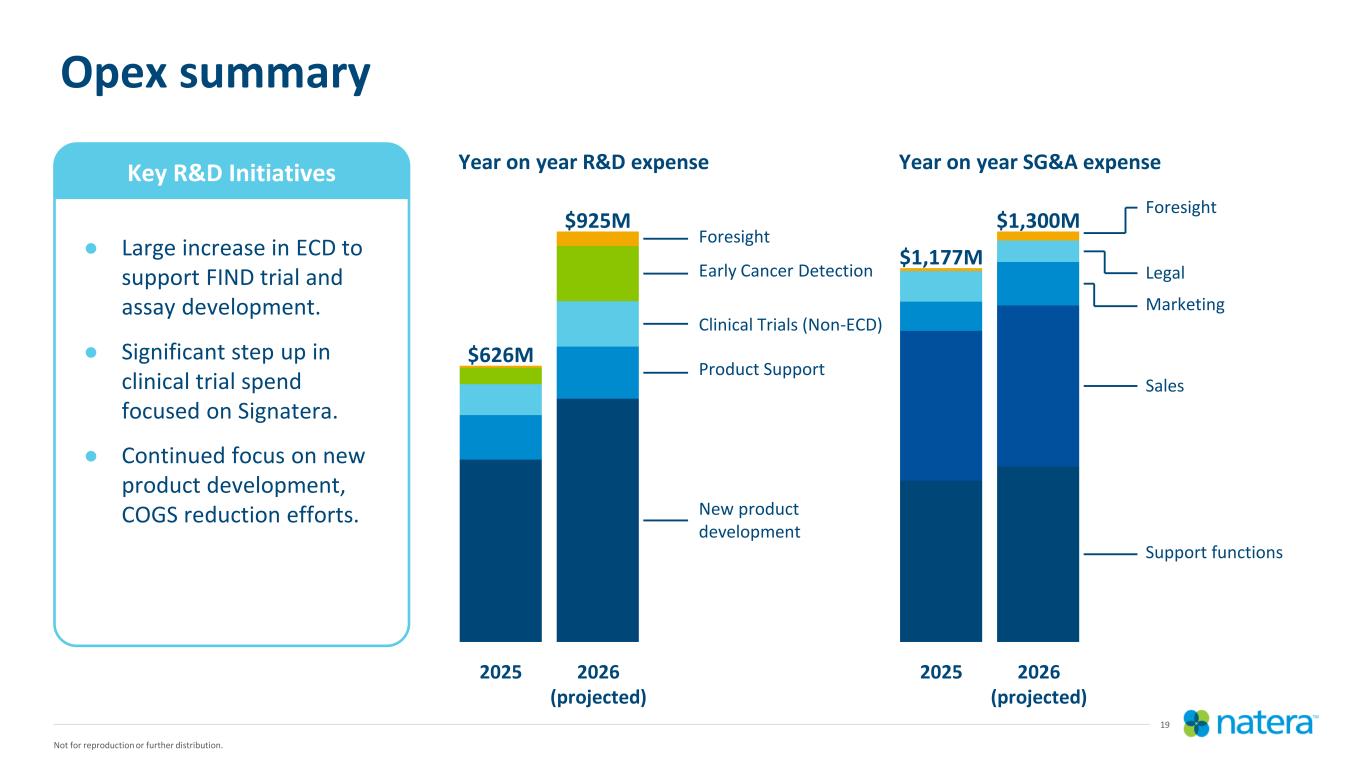
19 Not for reproduction or further distribution. Opex summary ● Large increase in ECD to support FIND trial and assay development. ● Significant step up in clinical trial spend focused on Signatera. ● Continued focus on new product development, COGS reduction efforts. Year on year R&D expense Year on year SG&A expense $626M $925M $1,177M $1,300M 2025 2026 (projected) 2025 New product development Product Support Clinical Trials (Non-ECD) Early Cancer Detection Foresight Support functions Sales Marketing Legal Foresight Key R&D Initiatives 2026 (projected)
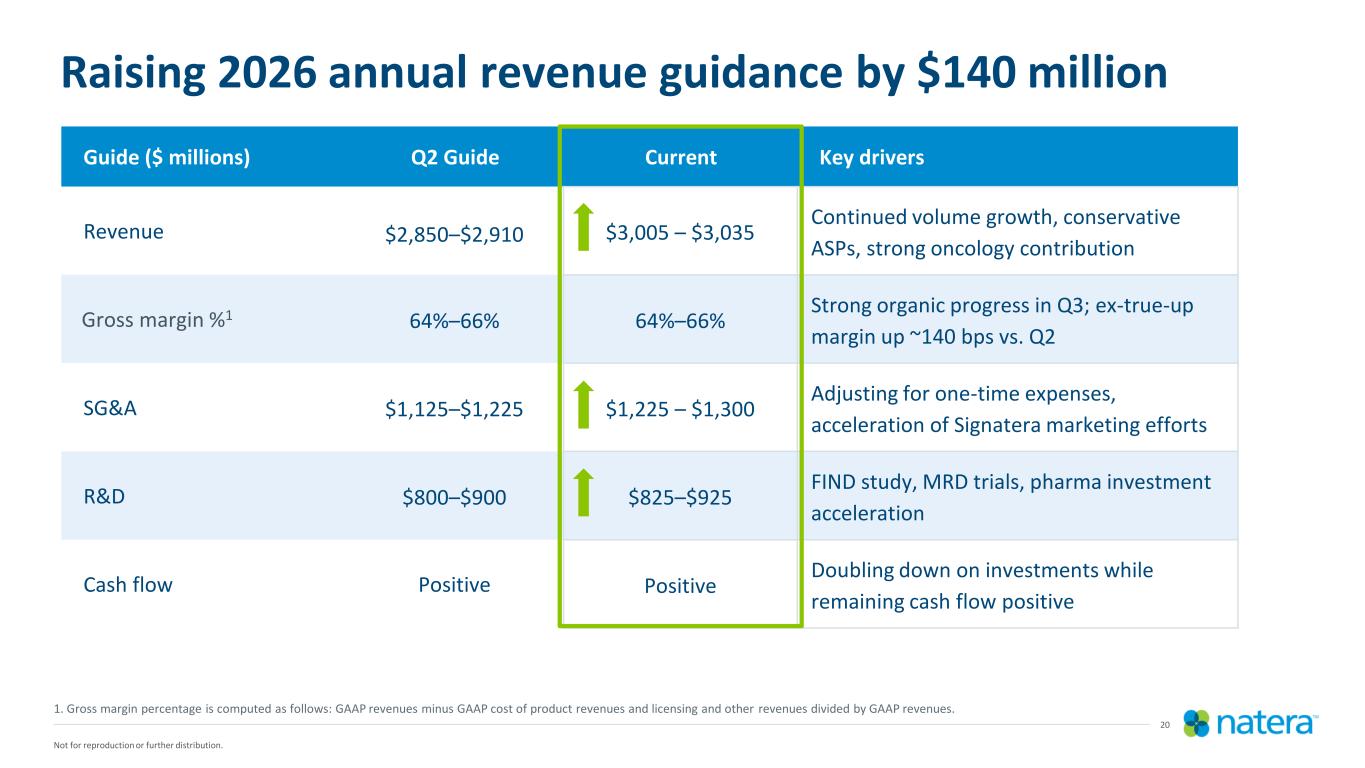
20 Not for reproduction or further distribution. 1. Gross margin percentage is computed as follows: GAAP revenues minus GAAP cost of product revenues and licensing and other revenues divided by GAAP revenues. Raising 2026 annual revenue guidance by $140 million Guide ($ millions) Q2 Guide Current Key drivers Revenue $2,850–$2,910 $3,005 – $3,035 Continued volume growth, conservative ASPs, strong oncology contribution Gross margin %1 64%–66% 64%–66% Strong organic progress in Q3; ex-true-up margin up ~140 bps vs. Q2 SG&A $1,125–$1,225 $1,225 – $1,300 Adjusting for one-time expenses, acceleration of Signatera marketing efforts R&D $800–$900 $825–$925 FIND study, MRD trials, pharma investment acceleration Cash flow Positive Positive Doubling down on investments while remaining cash flow positive
The tests described have been developed and their performance characteristics determined by the CLIA-certified laboratory performing the test. The tests have not been cleared or approved by the US Food and Drug Administration (FDA). Although FDA is exercising enforcement discretion of premarket review and other FDA legal requirements for laboratory-developed tests in the US, certification of the laboratory is required under CLIA to ensure the quality and validity of the tests. CAP accredited, ISO 13485 certified, and CLIA certified. © 2026 Natera, Inc. All Rights Reserved.