Exhibit
99.3
| October 28,
2026 |
|
| Due Diligence Narrative
Report |
|
| Clayton
Contact Information |
2 |
| Overview |
2 |
| Originators |
2 |
| Clayton’s Third
Party Review (“TPR”) Scope of Work |
3 |
| Review scope |
3 |
| # of Files
Reviewed |
3 |
| Loan Grading |
3 |
| TPR Component
Review Scope |
4 |
| Credit Review |
4 |
| Property Valuation
Review |
4 |
| Regulatory
Compliance Review |
5 |
| Data Integrity |
7 |
| Data Capture |
7 |
| Data Compare Results |
7 |
| Clayton Due Diligence
Results |
8 |
| Clayton Third Party
Reports Delivered |
9 |
| Appendix A: Credit Review
Scope |
10 |
| Appendix B: Origination
Appraisal Assessment |
13 |
| Appendix C: Regulatory
Compliance Review Scope |
16 |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 1 | October 28, 2026 |
CLAYTON CONTACT
INFORMATION
Client
Service Management:
| |
 |
Michael Santarsiere |
Client Service Director |
| |
|
|
Phone:
(813) 371-0280/E-mail: msantarsiere@clayton.com |
| | Joe
Ozment |
Vice President –
Client Services & Securitization |
| | | |
Phone:
(813) 261-0733/E-mail: jozment@clayton.com |
OVERVIEW
On behalf of NewRez LLC, Clayton Services
LLC (“Clayton”) conducted an independent third-party pre-securitization due diligence review of 27 residential loans. Rithm
Capital Corp. subsequently selected these loans for the NRMLT 2026-NQM12 transaction.
The loans referenced in this narrative report
were reviewed on a flow loan basis from June 2026 to August 2026. This narrative report provides information about the scope of work performed
by Clayton, and the results of Clayton’s review.
ORIGINATORS
Origination channels for the loans in this review:
|
Origination Channel |
Loan Count |
Percentage |
| Broker |
6 |
22.22% |
| Correspondent Flow with delegated underwriting |
21 |
77.78% |
| Total |
27 |
100.00% |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 2 | October 28, 2026 |
CLAYTON’S
THIRD PARTY REVIEW (“TPR”) SCOPE OF WORK
The scope of work for this transaction consisted
of a credit review, property valuation review, regulatory compliance review, and data integrity check.
| REVIEW SCOPE |
|
# OF FILES REVIEWED |
| Credit Review |
|
27 |
| Property Valuation Review |
|
27 |
| Regulatory Compliance Review |
|
25 |
| Data Integrity Check |
|
27 |
LOAN GRADING
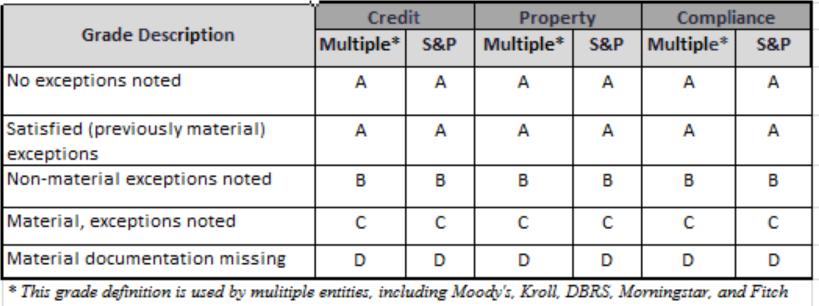
Each loan received an “initial”
and a “final” grade. The “initial” grade was assigned during the initial loan review. The “final”
grade takes into account additional information and supporting documentation that may have been provided by the originators to clear outstanding
conditions. Clayton’s loan grading is solely based on Clayton’s independent assessment of all guideline exceptions and compensating
factors for each of the component reviews. Clayton is providing a comprehensive loan-level analysis as part of this pre-securitization
reporting package that includes initial grades, final grades and detailed commentary on the rationale for any changes in grades and sets
forth compensating factors and waivers.
Clayton’s loan grading complied
with rating agency grading definitions published by Moody’s, Standard and Poor’s, Fitch, Morningstar, Kroll and DBRS.
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 3 | October 28, 2026 |
TPR COMPONENT REVIEW SCOPE
Clayton examined the selected loan
files with respect to the presence or absence of relevant documents, enforceability of mortgage loan documents, and accuracy and completeness
of data fields. Clayton relied on the accuracy of information contained in the loan documentation provided to Clayton.
CREDIT
REVIEW
Clayton’s Credit scope of review conducted on 27 loans
on this transaction included the following elements (for more detail, please refer to Appendix
A):
| · | Compared the loan documentation found in the loan file to the origination
guidelines; |
| · | Re-calculated LTV, CLTV, income, liabilities,
and debt-to-income ratios (DTI) and compared these against the stated seller origination guidelines; |
| · | Analyzed asset statements in order to determine that funds to close and
reserves were within origination guidelines; |
| · | Confirmed that credit scores (FICO) and credit histories were within origination
guidelines; |
| · | Evaluated for evidence of borrower’s willingness and ability to repay
the obligation; |
| · | Examined income, employment, assets, and occupancy status for reasonability; |
| · | Reviewed the occupancy, VOE and self/employed business documents within
the loan file, as applicable; |
| · | Listed the property type as Coop, as applicable; |
| · | Reviewed for condo warranty documentation, as applicable; |
PROPERTY
VALUATION REVIEW
Clayton’s Property Valuation scope of review conducted
included the following elements:
| · | Original Appraisal Assessment (27 loans) |
| - | Clayton
reviewed the original appraisal provided to determine whether the original appraisal was complete, thorough and the original appraised
value was reasonably supported. |
| - | For
more detail on the original appraisal review, please refer to Appendix B and to the guidelines
cited above. |
| · | Value Supported Analysis (27 loans) |
Clayton applied a cascade methodology
to determine if the original appraised value was reasonably supported when compared to an independent third party valuation product. Loans
were held to a -10% tolerance utilizing the following waterfall;
For further detail please refer to the NRMLT 2026-NQM12 Valuations
Summary Report
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 4 | October 28, 2026 |
REGULATORY COMPLIANCE REVIEW
Clayton’s regulatory compliance scope of review conducted
on 25 loans on this transaction included the elements summarized below. (For more detail, please refer to Appendix
C.)
Clayton utilized its proprietary FOCUS engine for regulatory
compliance testing.
The scope of the compliance review performed is summarized below:
| · | Tested
for certain applicable federal, state and local high cost and/or anti-predatory laws; |
| · | Tested
for state-specific consumer protection laws including late charge and prepayment penalty provisions; |
| · | Truth-in-lending/regulation
Z (TILA) testing included the following: |
| - | Notice
of Right to Cancel (Right of Rescission) adherence if applicable; |
| - | TIL
Disclosure Timing (3/7/3) and disclosure content; |
| - | TIL
APR and Finance charge tolerances; |
| - | Timeliness
of ARM Disclosures (if applicable); |
| - | Section
32 APR and Points and Fees Thresholds and prohibited practices; |
| - | Section
35 Higher Priced Mortgage Loans thresholds and applicable escrow and appraisal requirements; |
| - | Prohibited
Acts or Practices including Loan Originator compensation rules, NMLSR ID on documents, financing credit Insurance, mandatory arbitration
clauses, and NegAm Counseling; |
| - | Prepayment
Penalty restrictions; and |
| - | QM/ATR
Review: On applicable loans;, test compliance with applicable Qualified Mortgage (QM) and Ability to Repay (ATR) requirements
defined under the Dodd-Frank Wall Street Reform and Consumer Protection Act as promulgated by the Consumer Financial Protection Bureau
any loan subject to that regulation, as further described on Appendix C attached hereto. |
| - | TILA/RESPA
Integrated Disclosure Scope (‘Covered Loans’ with an Application Date => 10/3/2015); SFIG RMBS 3.0 TRID Compliance
Review Scope as further described on Appendix C attached hereto. |
| · | Real
Estate Settlement Procedures Act (RESPA) laws and regulations testing included the following, for loans other than ‘Covered
Loans’ and loans with an Application Date prior to 10/3/2015: |
| - | GFE
initial disclosure timing and content; |
| - | Confirmed
the file contains the final HUD1 Settlement Statement; |
| - | GFE
to HUD1 evaluation for 0% and 10% fee tolerances; |
| - | Homeownership
Counseling Notice; |
| - | Affiliated
Business Disclosure if applicable. |
OF NOTE: As of October 3, 2015 (“TRID Effective Date”),
Clayton commenced testing applicable loans subject to the TRID Effective date against a TRID scope of review that was based on outside
counsel’s interpretations of the published regulations as of the TRID Effective Date. Clayton’s scope was commercially reasonable
as it relates to a Third Party Review (“TPR”) firm’s role as TPR conducting an independent third-party pre-securitization
due diligence review (“Initial TRID Scope”). The Initial TRID Scope was created with guidance from outside counsel.
On, June 15th, 2016 SFIG published its RMBS 3.0 TRID
Compliance Review Scope © documentation, developed under the leadership of members from Third Party Review (“TPR”)
firms across the industry and SFIG’s RMBS 3.0 Due Diligence, Data and Disclosure Working Group. The RMBS 3.0 TRID Compliance
Review Scope was created with an aim to facilitate a uniform testing and risk identification standard as it would apply to an
assignee, as a result of a consistent Truth-In-Lending Act liability interpretation according to the understanding of prevailing
legal precedent and informal written guidance and webinars offered by the CFPB, as it applies to the Know Before You Owe / Truth In
Lending Act (“TILA) – Real Estate Settlement Procedures Act (“RESPA”) Integrated Disclosure
(“TRID”) Rule (78 FR 79730, as amended). RMBS 3.0 TRID Compliance Review Scope may be formally amended by the SFIG RMBS
3.0 Due Diligence, Data and Disclosure Working Group as clarifying regulations may be promulgated on a go forward basis, as well as
any binding judicial interpretations of the underlying law.
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 5 | October 28, 2026 |
Following the June 15th formal publication of
the RMBS 3.0 TRID Compliance Review Scope ©, Clayton reviewed prior testing results dating back to the TRID Effective Date, and applied
the enhanced RMBS 3.0 TRID Compliance Review Scope to such loans upon the affirmative election by Rithm Capital Corp.
Compliance Review (Business Purpose, Non-Owner Occupied)
Non-Owner Occupied Scope: Most consumer
protection laws are designed to afford protection to borrowers who are entering into a loan that will be secured by their residence. For
most high cost and higher-priced laws, as well as rescission, the only loans covered by the law are loans secured by the borrower’s
(or in the case of rescission a title holder’s) principal residence. Most other consumer protection laws extend to a borrower’s
secondary residence, which under TILA and RESPA is a residence that they occupy at least 2 weeks during the year. Further, if the loan
is for a business purpose it is often excluded from consumer protection laws regardless of occupancy, including TILA (whereas if it is
secured by non-owner occupied but for a personal, family or household purpose it is more likely to be covered).
Therefore, the list of laws that
Clayton tests that apply to a loan secured by non-owner occupied property for a business purpose is limited. Regulatory Compliance testing
of Business Purpose Loans consists of the following:
State and Federal High Cost and Higher-Priced:
| · | Cook
County High Cost Ordinance |
| · | Chicago
High Cost Ordinance |
Clayton currently tests the Chicago
and Cook County ordinances due to vague language around loans for a business purpose not related to the property. While the state of Illinois
has similar language, Clayton’s audit law firm determined that only principal residences should be tested for IL high cost.
Anti-predatory lending laws
| · | Virginia
Lender and Broker Act after 6/1/2008 |
| · | Minnesota
§58 on or after 8/1/2008 |
Prepayment Penalties and Late Charges in certain states
National Flood Insurance Program for 1-4 unit residential properties
(Transaction Date on or after 1/1/2016 for regulated lenders)
| · | Escrow
of insurance payments |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 6 | October 28, 2026 |
DATA INTEGRITY
Clayton utilized its proprietary FOCUS tool to determine
tape-to-file accuracy of 27 reviewed loans, by completing the following steps:
| · | Tape
data received from seller/client is stored in FOCUS; |
| · | Loan
reviewer collects validated loan data in FOCUS; |
| · | Each
received data point is compared to its counterpart collected data point; |
| · | Discrepancies
found during comparison are stored; |
| · | Each
discrepancy is reported in a Loan Level Tape Compare Upload. |
DATA CAPTURE
Clayton collected data fields required
to create American Securitization Forum (“ASF”) data tape. The file format was provided as part of the pre-securitization
reporting package. Additionally, Clayton captured rating agency required data points relating to ATR/QM determination, which is provided
in the reporting package.
DATA COMPARE RESULTS
Clayton provided Rithm Capital Corp. with
a copy of the Loan Level Tape Compare Upload which showed the differences between the data received from the sellers versus the data captured
by Clayton during the loan review in relation to the 27 loans reviewed.
|
Field Name |
# of Loans |
% Accuracy |
| Appraised Value |
4 |
85.19% |
| DTI (Back) |
3 |
88.89% |
| Loan Doc Type |
2 |
92.59% |
| Loan Purpose |
1 |
96.30% |
| Loan Term |
8 |
70.37% |
| Maturity Date |
3 |
88.89% |
| Occupancy |
2 |
92.59% |
| Product Type |
1 |
96.30% |
| Property Type |
5 |
81.48% |
| Representative Score |
1 |
96.30% |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 7 | October 28, 2026 |
CLAYTON DUE DILIGENCE
RESULTS
Below are the initial and final overall loan grades for this
review, as well as the credit, property valuation, and regulatory compliance
component review grades.
Initial and Final Overall Loan Grade Results
|
|
Overall Grade Migration |
| Initial |
| |
|
A |
B |
C |
D |
Total |
| A |
10 |
|
8 |
8 |
26 |
| B |
|
|
1 |
|
1 |
| C |
|
|
|
|
0 |
| D |
|
|
|
|
0 |
| Total |
10 |
0 |
9 |
8 |
27 |
The overall grade summary reflects the combination of the credit,
property valuation and regulatory compliance component reviews into one overall grade. The overall grade assigned is the most severe grade
from each of the component reviews.
Initial and Final Credit Component Grade
Results
|
|
Credit Grade Migration |
| Initial |
| Final |
|
A |
B |
C |
D |
Total |
| A |
11 |
|
8 |
7 |
26 |
| B |
|
|
1 |
|
1 |
| C |
|
|
|
|
0 |
| D |
|
|
|
|
0 |
| Total |
11 |
0 |
9 |
7 |
27 |
Initial and Final Property Valuation Grade
Results
|
|
Property Valuation Grade Migration |
| Initial |
| Final |
|
A |
B |
C |
D |
Total |
| A |
27 |
|
|
|
27 |
| B |
|
|
|
|
0 |
| C |
|
|
|
|
0 |
| D |
|
|
|
|
0 |
| Total |
27 |
0 |
0 |
0 |
27 |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 8 | October 28, 2026 |
Initial and Final Regulatory Compliance
Grade Results
|
|
Compliance Grade Migration |
| Initial |
| Final |
|
A |
B |
C |
D |
Total |
| A |
21 |
|
3 |
1 |
25 |
| B |
|
|
|
|
0 |
| C |
|
|
|
|
0 |
| D |
|
|
|
|
0 |
| Total |
21 |
0 |
3 |
1 |
25 |
*Compliance results may not tie to total loan count based on business
entity loans not being subject to a regulatory compliance review (2 loans in pool)
CLAYTON THIRD PARTY
REPORTS DELIVERED
Clayton furnished the following reports on this transaction:
| 6. | Loan Level Tape Compare |
| 7. | Waived Conditions Summary |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 9 | October 28, 2026 |
APPENDIX A: CREDIT
REVIEW SCOPE
For each mortgage loan, Clayton performed a guideline review
utilizing specific guidelines furnished at the time of the review.
| A. | Verified that the characteristics of the mortgage loan and borrower conformed to the Sponsor Acquisition
Criteria requirements including: |
| o | Property type and use eligibility; and if the
property type was a condominium or cooperative, assessed project adherence |
| o | Borrower eligibility, including: |
| - | Non-
occupant co-borrower |
| o | Transaction eligibility, including: |
| - | Loan
purpose - Occupancy |
| o | Noted any approved exceptions or waivers by
the originator and/or aggregator to guidelines; verified that approved exceptions included required, documented compensating factors |
| B. | As part of the guideline review, Clayton performed a credit
analysis during which various documents were examined, including: |
| o | Uniform Residential Loan Application reviewed to determine: |
| - | Initial
loan application was in the loan file and was signed by all borrowers |
| - | Final
loan application was in the loan file and was complete |
| - | Information
and debts disclosed on loan application aligned with related documentation in the loan file |
| o | Employment analyzed and verified through use of various documents, including: |
| - | Verbal
and/or written verifications of employments (VVOE, VOE) |
| - | Tax
transcripts (IRS Form 4506-T) |
| - | Other
documentation in loan file |
| - | Required
income documentation for all borrowers was present and within required time period |
| - | Documents
did not appear to have been altered or inconsistent |
| · | Signed
by all borrowers and processed by the originator |
| · | Compared
IRS tax transcripts to income documentation and noted any inconsistencies |
| - | Income
was recalculated and was documented with applicable documentation, including: |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 10 | October 28, 2026 |
| · | Other
documentation in loan file |
| - | Asset documentation required
to verify down payment, closing costs, prepaid items and reserves was present and within required timeframe, including: |
| · | Verification
of deposits (VOD) |
| · | Depository
account statements |
| · | Stock
or security account statements |
| · | Other
evidence of conveyance and transfer of funds, if a sale of assets was involved |
| · | Other
documentation in loan file |
| - | Asset
documents were reviewed to determine any large deposits and appropriate sourcing of funds |
| o | Credit
Report review included: |
| - | Complete
copy of report was in loan file |
| - | Report
was dated within required timeframe |
| - | All
borrowers were included in the report |
| - | Checked
any fraud alerts against related loan file documentation |
| - | Verified all disclosed mortgage
debt on credit report against the loan application (under the schedule of real estate owned) for accurate debt ratio calculation |
| - | Compared
liabilities listed on the credit report against the loan application for accurate debt ratio calculation |
| - | Captured
and utilized appropriate credit score for guideline review |
| o | Title
policy review included: |
| - | Title
interest – determined if |
| - | Appropriate
vestee(s) were listed on title policy |
| - | Amount
of coverage was greater than or equal to the original principal amount of the mortgage |
| - | Applicable
title endorsements were present |
| - | Checked for any encumbrances,
encroachments and other title exceptions affecting the lien identified through the title search; verified that each issues was addressed
in the transaction |
| - | Reviewed
the chain of title and duration of ownership by seller or borrower (whichever was applicable) |
| - | Captured
monthly tax payments in debt ratio calculation |
| o | HUD1
(Settlement Statement) review included: |
| - | Funds
to close identified and analyzed against borrower’s assets |
| - | Seller
contributions did not exceed maximum allowed |
| - | Subject
property, seller and borrower aligned with other loan documentation |
| - | Disbursements
and pay-offs included in debt ratio calculations |
| o | Hazard/Flood
insurance review included: |
| - | Verified
presence of required hazard insurance and flood insurance (if required) |
| - | Confirmed
that any required insurance was for the: |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 11 | October 28, 2026 |
| · | Life
of loan, if flood insurance required |
| - | Confirmed
that any required insurance minimum coverage amount and policy period |
| - | Reviewed
for evidence that any required insurance policy premium was paid |
| - | Confirmed
that the mortgagee clause listed the lender’s name and “it’s successors and assigns” |
| - | Confirmed
that the payment amount on any required insurance was included in the debt ratio calculation |
| o | Mortgage
Insurance review included: |
| - | Determined
if mortgage insurance is required |
| - | Captured
mortgage insurance name, certificate # and percentage guarantee (when required) |
| C. | For each mortgage loan, Clayton examined the mortgage or deed of trust for evidence of recordation. In
lieu of a copy of the mortgage or deed of trust with recording information, a copy of the mortgage or deed of trust that is stamped “true
and certified copy” by the escrow/settlement agent plus recording directions on closing instruction documentation was utilized as
evidence for recording. |
| D. | For each mortgage loan, Clayton utilized the results from an independent, third-party
fraud tool along with information in the loan file to identify and address any potential misrepresentations including: |
| - | Social
Security inconsistencies |
| - | Borrower
name variations |
| - | Borrower
address history |
| - | Subject
property ownership history |
| o | Licensing
– reviewed NMLS data for: |
| - | Mortgage
lender/originator |
| E. | Performed a DSCR review following the origination guidelines to arrive at a monthly property expense.
This number is used as the denominator to the monthly lease or estimated lease income. Clayton reviewed the applicable documentation and
data to arrive at this ratio, including: |
| o | Principal
and interest payment |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 12 | October 28, 2026 |
APPENDIX B: ORIGINATION
APPRAISAL ASSESSMENT
For each Mortgage Loan, Clayton performed the following origination
appraisal analysis:
| A. | Verified that the mortgage loan file contained an appraisal
report and that it met the following criteria: |
| o | Appraisal
report used standard GSE forms, appropriate to the property type: |
| − | FNMA
1004/FHLMC 70 – Uniform Residential Appraisal Report. Used for 1-unit properties, units in planned unit developments (detached
PUDs) and condominium projects that consist solely of detached dwelling (site condominium) |
| − | FNMA
1073/FHLMC 465 – Individual Condominium Report. Used to appraise a unit in a condominium project or a condominium unit in a PUD
(attached PUD) |
| − | FNMA
1025/FHLMC 72 – Small Residential Income Property Appraisal Report. Used for all two-to-four unit residential income properties,
including two-to-four unit properties in a PUD |
| − | FNMA
2090 – Individual Cooperative Appraisal Report. Used for individual cooperative units |
| − | FNMA
2000/FHLMC 1032 – One Unit Residential Appraisal Field Review |
| − | FNMA
2000a/FHLMC 1072 – Two to Four Unit Residential Appraisal Field Review |
| o | Appraisal
report was reasonably complete and included: |
| − | Appraisal
report form, certification, statement of limiting conditions and scope of work |
| − | Accurate
identification of the subject property |
| − | Accurate
identification of the subject loan transaction |
| − | Accurate
identification of the property type, in both land and improvements |
| − | All
required attachments including: |
| · | Subject
front, rear and street photos and valued features |
| · | Subject
interior photos – kitchen, all baths, main living area, updates/upgrades, deferred maintenance |
| · | Photos
of all comparable sales and listings |
| · | Exterior
sketch of property with dimensions |
| · | 1004MC
Market Conditions Report |
| − | Evidence
that appraisal report was made “As Is” or provided satisfactory evidence of completion for all material conditions |
| − | Appraisal
date met supplied Sponsor Acquisition Criteria |
| − | If
applicable to Sponsor Acquisition Criteria requirements, a second full appraisal was furnished and met Sponsor Acquisition Criteria |
| B. | Performed a general credibility assessment of the results of the appraisal per Title XI of FIRREA and
USPAP based on the following criteria: |
| − | Determined
that either the appraiser or supervisory appraiser was appropriately licensed by verifying the appraiser’s license included in
the appraisal. |
| − | Reviewed
for the presence of any “red flags” related to the mortgaged property that may have posed a risk to the property or occupants |
| − | Confirmed
that the appraiser’s certification is present and executed within the original appraisal. |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 13 | October 28, 2026 |
| C. | Reviewed and graded the appraisal valuation to the following
criteria: |
| o | Appraised value was reasonably supported. Utilized
the following review in making value supported determination: |
| − | Comps
used were located reasonably close to the subject property and if not the reason was satisfactorily explained |
| − | Comps
used were reasonably recent in transaction date and if not the reason was furnished |
| − | Comps
used were reasonably similar to the subject property and if not an explanation was supplied |
| − | Appraised
value of the subject was bracketed by the sales prices of the comps and if not the reason was furnished |
| − | Adjustments
were reviewed and appeared reasonable utilizing the 15% net/25% gross guideline. |
| o | Property was complete.
However, if the property was not 100% complete, then any unfinished portion had no material impact to the value, safety, soundness, structural
integrity, habitability or marketability of the subject property |
| o | Appraisal was reviewed
for any indication of property or marketability issues. Utilized the following key points in making determination: |
| − | Appraisal
was made on an “As Is” basis or provides satisfactory evidence of completion of all material conditions |
| − | Property
usage was reviewed for zoning compliance |
| − | Property
utilization was reviewed to determine it was “highest and best use” |
| − | Neighborhood
values were reviewed to determine if declining |
| − | Market
conditions were reviewed to determine indication of possible marketability issues: |
| − | Physical
condition of the property was reviewed to determine that the property condition was average or better |
| − | Style
of property was reviewed to determine if unique property |
| − | Any
health and safety issues were noted and/or remediated |
| − | Locational
and/or environmental concerns adequately addressed if present |
| D. | Property Eligibility Criteria – Clayton reviewed the
property to determine that the property met the client supplied eligibility requirements. Examples of ineligible property types may include: |
| o | 3 to 4 unit owner occupied properties |
| o | 2 to 4 unit second homes |
| o | Unwarrantable or limited review condominiums |
| o | Manufactured or mobile homes |
| o | Working farms, ranches or orchards |
| o | Properties subject to existing oil or gas leases |
| o | Properties located in Hawaii Lava Zones 1 and
2 |
| o | Properties exceeding Sponsor Acquisition Criteria
requirements for excess acreage |
| E. | Properties Affected by Disasters Criteria – Clayton reviewed the appraisal
date against any FEMA Declared Disaster Areas that were designated for Individual and/or Public Assistance due to a federal government
disaster declaration. |
| o | If the appraisal date
is before the FEMA Effective Date for any of the disasters listed, Clayton will specify whether or not there has been a property inspection
since the date listed, the latest inspection date, whether or not new damage has been indicated, and the amount of said damage. |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 14 | October 28, 2026 |
| o | The individuals performing
the aforementioned original appraisal assessment are not persons providing valuations for purposes of the Uniform Standards of Professional
Appraisal Practice (“USPAP”) or necessarily licensed as appraisers under Federal or State law, and the services being performed
by such persons do not constitute “appraisal reviews” for purposes of USPAP or Federal or State law. |
| o | Clayton makes no representation
or warranty as to the value of any mortgaged property, notwithstanding that Clayton may have reviewed valuation information for reasonableness |
| o | Clayton is not an ‘AMC’ (appraisal
management company) and therefore Clayton does not opine on the actual value of the underlying property |
| o | Clayton is not a ‘creditor’
within the meaning of ECOA or other lending laws and regulations, and therefore Clayton will not have any communication with or responsibility
to any individual consumer concerning property valuation. |
| o | Clayton does not check to see if the appraiser
is on the Freddie Mac exclusionary list |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 15 | October 28, 2026 |
APPENDIX C: REGULATORY
COMPLIANCE REVIEW SCOPE
This appendix provides an overview of Clayton’s
proprietary compliance system for 1-4 family residential mortgage loans in the due diligence process to determine, to the extent possible
and subject to the caveats below, whether the loans comply with federal, state and local laws. The Disclaimer section explains limitations
that you should be aware of. Additional details on the items listed below as well as Clayton’s state, county and municipal testing
can be provided upon request. The compliance engine is fully integrated into Clayton’s proprietary due diligence platform, FOCUS.
Federal Law
| A. | RESPA and Regulation X:
Loan level analysis on the following: |
| o | GFE/HUD1: confirm the correct version of the
GFE and HUD1 were properly completed under the Regulation X Final Rule that became mandatory on January 1, 2010 |
| o | Initial Good Faith Estimate, (GFE): timing and content of the initial disclosure |
| o | Final GFE: Verification that increases to fees
from the initial GFE were disclosed within 3 days of valid changed circumstance documentation within the loan file |
| o | Final HUD1 Settlement Statement: verify the
loan file contains the final HUD1 and the loan terms on the HUD1 correspond to the actual loan terms from the Note |
| o | Final GFE to HUD1 tolerance fee evaluation:
confirm the fees charged on the HUD1 do not exceed the Final GFE in the 0% or 10% fee tolerance categories, including a review for a Settlement
Service Provider List if the lender excludes fees that the borrower can shop for. |
| o | Affiliated Business Disclosure: if the loan
file indicates the lender or broker referred the borrower to a known affiliate, confirm the disclosure was provided to the borrower |
| o | Homeownership Counseling Notice: for loan applications
on or after 1/10/2014, confirm the notice was provided to the borrower within 3 days of application |
| B. | Truth in Lending Act and
Regulation Z - Loan level analysis on the following: |
| o | TIL Disclosure: Content of Disclosures –
perform an independent recalculation of the finance charges and APR to determine whether the amounts disclosed on the final TIL were within
allowable tolerances. Payment schedule accuracy, including under the Mortgage Disclosure Improvement Act for loans applications on or
after January 30, 2010. Additional disclosure content with a focus on the consistency of the prepayment penalty disclosure and assumption
policy with the note and security instrument. |
| o | Mortgage Disclosure Improvement Act, (3/7/3
rule): Confirm the timing of the initial TIL disclosure within 3 days of application, 7 days prior to consummation, and corrected TIL
disclosures provided at least 3 days prior to consummation for applications received on or after July 30, 2009 (Section 19) |
| o | ARM Disclosure: confirm these disclosures
are in the file within 3 days of application, or 3 days of the borrower discussing ARM programs identified within the loan file |
| o | Right of Rescission – Review the disclosure
form type, disclosure timing, disclosed dates, other material disclosures, and the loan disbursement (Section 23) |
| o | High Cost mortgage thresholds for points and fees (Section 32) |
| o | High Cost Prohibited Acts and Practices upon request (Section 33) |
| o | Higher Priced Mortgage
Loan thresholds for APR in relation to the APOR. Including Escrow and appraisal requirements (Section 35) |
| o | Prohibited Acts or Practices including testing
the Loan Originator compensation rules, NMLSR ID on documents, financing Credit Insurance, mandatory arbitration clauses, and NegAm Counseling
(Section 36) |
| o | ATR/QM Ability to Repay, aka Minimum Standards
for Transactions: for applications on or after 1/10/2014, confirm the loan file contains documentation to evidence the lender considered
and verified the borrower has the ability to repay in accordance with the ATR requirements This included identifying whether QM loans
met agency exemptions or were underwritten in accordance with Appendix Q. Non QM loans will be reviewed to ensure the lender documented
that they considered and verified the 8 underwriting factors as required for ATR compliance. This review also includes evaluating loans
against the new TILA prepayment penalty restrictions (Section 43) |
| o | TILA/RESPA Integrated Disclosures (“TRID”) |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 16 | October 28, 2026 |
| · | Test whether or not the loan is subject to
disclosure on TRID documents, the Loan Estimate (“LE”) and Closing Disclosure (“CD”) |
| · | Pre-application Requirement Testing: |
| · | Pre-application forms cannot look similar to the LE |
| · | Pre-application
forms must contain the required disclaimer (“Your actual rate, payment, and costs could be higher. Get an official Loan
Estimate before choosing a loan”). |
| · | The LE was delivered or placed in the mail
within 3 business days of the broker or lender receiving an application. |
| · | The
loan does not consummate (Clayton looks to the later of the note date or notary date) until the later of seven business days after
the LE is delivered or placed in the mail and three business days after the CD (or Corrected CD when a new three-day waiting period is
triggered) is received. |
| · | That a revised LE or CD is provided within
three business days of the lender having knowledge of the information that led to the change. |
| · | Zero and ten percent tolerance fees are only reset with a valid and timely
change of circumstance. |
| · | If a credit or refund is made, that it is sufficient to cover Clayton’s
calculated under-disclosure. |
| · | Payment Schedule Accuracy: |
| · | The number of columns and timing of changes
to payments as well as the mortgage insurance drop-off match Clayton’s calculated payment schedule. |
| · | Interest-only periods and final balloon payments are accurately completed. |
| · | The total of the principal and interest payment,
mortgage insurance and escrow amounts add up correctly. |
| · | When applicable, that the AIR and AP tables are consistent with Clayton’s
calculations. |
| · | Accuracy of the Loan Calculations |
| · | Total interest percentage |
| · | Compliance with the TRID rounding rules. |
| · | Compliance with specified formatting requirements. |
| · | Compliance with date entry requirements (such
as when a field, if not applicable, must be present and left blank). |
| · | Alphabetization of fees. |
| · | Title fees preceded by “Title –.” |
| · | Column
or similar limits such as four columns for Projected Payments and a maximum of thirteen Origination Charges on the LE. |
| · | Consistency within and across forms |
| · | Once a fee is disclosed it must remain substantially the same name across
disclosures. |
| · | Consistency between the Costs at Closing and
Calculating Cash to Close tables, for which there is a version for transactions with a seller and an optional, but not required, version
for transactions without a seller. They should be consistent within and across disclosures. |
| · | Where amounts in a table reference that they
are derived from another section of the form, that the amounts match the amount in the section referenced. |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 17 | October 28, 2026 |
| · | Escrow amounts disclosed
in the Projected Payments section tie out to the escrow amounts detailed in the Loan Disclosures section. |
| · | Completion
of the LE and CD |
| · | All required fields not specifically listed
herein are completed or left blank in accordance with TRID rules; creditor information, contact information, rate lock information, etc. |
| · | For areas where multiple options are provided,
such as Assumption, Negative Amortization and Liability after Foreclosure, only one option is indicated. |
| · | That there is either a signature or a Loan Acceptance statement on the form. |
| · | Clayton will capture if the borrower waived
their waiting period and the sufficiency of the waiver under TRID. However, based on past experience with clients, Clayton will also issue
an exception for the loan closing early. |
| · | Corrected
CD requiring a new waiting period |
| · | Whether the APR increased or decreased outside
of tolerance requiring a new waiting period and whether that waiting period was provided. For APR decreases Clayton will look to whether
the APR decreased due to a reduced finance charge, which will be considered to be within tolerance. |
| · | Whether the product or a product feature changed
which requires a new waiting period and whether that waiting period was provided. |
| · | Whether a prepayment
penalty was added requiring a new waiting period and whether that waiting period was provided. |
| · | Corrected CD’s provided with a post-close
refund. |
| · | Post-close CD’s
to correct numerical errors based on events (such as recording) occurring within 30 days of consummation. |
| · | Post-close CD’s to correct non-numerical
clerical errors required within 60 days of consummation. |
| · | Provision and timing of Your Home Loan Toolkit
(first lien, purchase-money loans) |
| · | Written List of Providers,
when there are items in in the Services You Can Shop For category (can impact fee tolerances) |
| · | Affiliated Business Disclosure (can impact fee
tolerances) |
| · | Outside
of Clayton’s default TRID scope: |
| · | Accuracy of the LE in terms of whether fees
are within the correct category and loan terms where we would need a Note to verify. More detailed testing will occur by comparing the
final CD to the Note terms. |
| · | Whether the Liability after Foreclosure selection is correct for the property
state. |
| · | Accuracy of the Aggregate Adjustment amount. |
| · | Presence and accuracy of the Seller’s Transaction columns of the Summaries
of Transactions section. |
| · | Accuracy of the Contact
Information for the lender, broker and settlement agent. Clayton will look for discrepancies across forms, but is not independently verifying
the information. |
| C. | FACTA - the Credit Score, Key Factors, and Notice
to Home Loan Applicant disclosures |
| D. | HMDA – Whether the loans is Rate Spread threshold
reportable. |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 18 | October 28, 2026 |
STATE, COUNTY and MUNICIPAL LAW
Clayton test whether a loan meets the thresholds for a higher-priced,
rate spread, subprime or nonprime mortgage loan, and
whether such loan meets regulatory requirements, in the following
states:
|
Higher-Priced |
| California |
Maryland |
New York |
| Connecticut |
Massachusetts (subprime ARMS to first time homebuyers) |
North Carolina |
| Maine |
Minnesota |
|
Clayton test whether a loan meets the thresholds for a high
cost or covered loan in the following states, counties and municipalities,
and also tests for compliance with provisions in such laws
that apply to all loans subject to high cost testing:
|
State/Local High Cost |
| Arkansas |
Maine |
Pennsylvania |
| California |
Maryland |
Rhode Island, including the Providence ordinance |
| Colorado |
Massachusetts |
South Carolina |
| Connecticut |
Nevada |
Tennessee |
| District of Columbia |
New Jersey |
Texas |
| Florida |
New Mexico |
Utah |
| Georgia |
New York |
Vermont
(High Rate, High Point law) |
| Illinois, including the Cook County and Chicago ordinances |
North Carolina |
Wisconsin |
| Indiana |
Ohio, including
Cleveland Heights ordinance |
|
| Kentucky |
Oklahoma |
|
Several states have laws that do not create a separate class
of high cost or higher-priced mortgage loans, but set APR or finance
charge ceilings and may also set forth similar anti-predatory
lending restrictions as found in high cost laws. Clayton tests for compliance with such laws in the following states:
| · | Minnesota
(Mortgage Originator and Service Licensing Act) |
| · | Puerto
Rico (Office Regulation 5722) |
| · | Texas
(Texas Finance Code) |
| · | West
Virginia (Residential Mortgage Lender, Broker and Servicer Act). |
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 19 | October 28, 2026 |
Clayton uses a module that reports to the client the factors
that the client can weigh to determine whether or not the loan is in the borrower’s interest, and also makes a mathematical determination
as to whether or not there is at least one benefit. This module is only used in the following states, where the laws or releases by the
regulators provide an indication of some standards that can be applied.
|
Borrower’s Interest |
| Maine |
Ohio |
South Carolina |
| Massachusetts |
Rhode Island |
|
Several states have laws that neither create a separate
class of high cost or higher-priced mortgage loan, nor impose a ceiling on the overall fees or APR, but nonetheless contain requirements
and restrictions on mortgage loans that may impact the assignee or the lien. Clayton tests for compliance with such laws, including late
charge and prepayment penalty provisions, in the following states and municipalities:
|
Consumer Protection |
| Alabama (the “Mini-code”) |
Nebraska (Mortgage Bankers Registration and Licensing Act and the Installment Loan Act) |
| Hawaii (Financial Services Loan Company Act) |
Nevada (AB 440 |
| Idaho (Residential Mortgage Practices Act) |
Ohio (Consumer Sales Practices Act; whether the loan is in Summit County) |
| Illinois (both versions of the Cook County Predatory Lending Database; Illinois Residential Mortgage Licensing Act) |
Texas (Article XVI, Section 50(a)(6) of the Texas Constitution) |
| Iowa (Consumer Credit Code) |
Utah (Consumer Credit Code) |
| Kansas (Consumer Credit Code) |
Virginia (Mortgage Lender and Broker Act) |
| Kentucky (HB 552) |
Washington (Consumer Loan Act and Responsible Mortgage Lending Act) |
| Maryland (DLLR Regulations, Commercial Law) |
West Virginia (Consumer Credit Protection Act) |
| Massachusetts (Attorney General regulations) |
Wyoming (Residential Mortgage Practices Act) |
| Michigan (Consumer Mortgage Protection Act) |
|
See attached Exhibit A - Consumer Protection Laws for additional
details on the specific components of the aforementioned Consumer Protection laws that are evaluated as part of the Clayton Compliance
Review Scope:
In addition to identifying whether Texas refinances are
cash out transactions subject to the Texas Constitution Article 16 Section 50(a)(6) requirements, Clayton reviews the title report to
confirm prior loans being refinanced are continuous purchase money and not (a)(6) loans. In the event a loan is determined to be a Texas
Home Equity loan, the underwriter reviews the loan images to
confirm the loan meets the Texas requirements including
maximum LTV/CLTV, 3% fee cap, product restrictions and the required disclosures were provided to the borrower in accordance with required
timelines.
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 20 | October 28, 2026 |
GSE Testing
Clayton can review loans to determine whether they comply
with Fannie Mae’s and Freddie Mac’s Points and Fees threshold tests. These fee limitations of 5% for all loans with application
dates prior to 1/10/2014 were reduced to 3% on Primary and Second Homes for applications on or after 1/10/2014. If requested, loans can
be reviewed to determine whether the loan is a residential mortgage transaction ineligible for delivery due to its APR or fees exceeding
the HOEPA thresholds. Clayton offers Lender Letter and non-traditional mortgage testing for Fannie Mae. (Note: Fannie Mae requires a non-disclosure
agreement between the client and Fannie Mae for Clayton to report these results.)
Disclaimer
Please be advised that Clayton has not determined whether
the Loans comply with federal, state or local laws, constitutional provisions, regulations or ordinances, including, but not limited to,
licensing and general usury laws that set rate and/or fee limitations, unless listed above. Clayton’s review is focused on issues
that raise concerns for secondary market investors and other assignees, based on potential for assignee liability, an adverse impact on
the lien, and regulatory, litigation and headline risk. Clayton’s review is not designed to fully test a lender’s compliance
with all applicable disclosure and licensing requirements. Furthermore, the findings reached by Clayton are dependent upon its receiving
complete and accurate data regarding the Loans from loan originators and other third parties. Please be further advised that Clayton and
its employees do not engage in the practice of law, and the findings set forth in the reports prepared by Clayton do not constitute legal
advice or opinions.
© 2026 Clayton Services LLC. All rights reserved.
This material is confidential and may not be copied, used, or
distributed without the written permission of Clayton Services LLC
| NRMLT 2026-NQM12 Due Diligence Narrative Report | Page | 21 | October 28, 2026 |