1 Earnings Supplement Third Quarter 2026 November 5, 2026
2 Forward-Looking Statements – Cautionary Language Certain statements made in this presentation and in other written or oral statements made by Lincoln or on Lincoln’s behalf are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 (“PSLRA”). A forward-looking statement is a statement that is not a historical fact and, without limitation, includes any statement that may predict, forecast, indicate or imply future results, performance or achievements. Forward-looking statements may contain words like: “anticipate,” “believe,” “estimate,” “expect,” “project,” “shall,” “will” and other words or phrases with similar meaning in connection with a discussion of future operating or financial performance, including the statements relating to our estimated impacts to operating income beginning in the fourth quarter of 2026 in connection with the Talcott reinsurance transaction and our estimated preferred stock dividend amounts through the fourth quarter of 2027. In particular, these include statements relating to future actions, trends in Lincoln’s businesses, prospective services or products, future performance or financial results. Lincoln claims the protection afforded by the safe harbor for forward-looking statements provided by the PSLRA. Forward-looking statements are subject to risks and uncertainties. Actual results could differ materially from those expressed in or implied by such forward-looking statements due to a variety of factors, including: • Weak general economic and business conditions that may affect demand for our products, account balances, investment results, guaranteed benefit liabilities, premium levels and claims experience; • Adverse global capital and credit market conditions that may affect our ability to raise capital, if necessary, and may cause us to realize impairments on investments and certain intangible assets, including goodwill and the valuation allowance against deferred tax assets, which may reduce future earnings and/or affect our financial condition and ability to raise additional capital or refinance existing debt as it matures; • The inability of our subsidiaries to pay dividends to the holding company in sufficient amounts, which could harm the holding company’s ability to meet its obligations; • Legislative, regulatory or tax changes, both domestic and foreign, that affect: the cost of, or demand for, our subsidiaries’ products; the required amount of reserves and/or surplus; our ability to conduct business; and our affiliate reinsurance arrangements; • Changes in tax law or the interpretation of or application of existing tax laws that could impact our tax costs and the products that we sell; • The impact of regulations adopted by the Securities and Exchange Commission (“SEC”), the Department of Labor or other federal or state regulators or self-regulatory organizations that could adversely affect our distribution model and sales of our products and result in additional disclosure and other requirements related to the sale and delivery of our products; • The impact of existing and emerging rules and regulations relating to privacy, cybersecurity and artificial intelligence (“AI”) that may lead to increased compliance costs, reputation risk and/or changes in business practices, and challenges with properly managing the use of AI that could result in reputational harm, competitive harm and legal liability; • Continued scrutiny and evolving expectations and regulations regarding ESG matters that may adversely affect our reputation and our investment portfolio; • Actions taken by reinsurers to raise rates on in-force business; • Declines in or sustained low interest rates causing a reduction in investment income, the interest margins of our businesses and demand for our products; • Increasing or sustained higher interest rates that may negatively affect our profitability, value of our investment portfolio and capital position and may cause policyholders to surrender annuity and life insurance policies, thereby causing realized investment losses; • The initiation of legal or regulatory proceedings against us, and the outcome of any legal or regulatory proceedings, such as: adverse actions related to present or past business practices common in businesses in which we compete; adverse decisions in significant actions including, but not limited to, actions brought by federal and state authorities and class action cases; new decisions that result in changes in law; and unexpected trial court rulings; • A decline or continued volatility in the equity markets causing a reduction in the sales of our subsidiaries’ products; a reduction of asset-based fees that our subsidiaries charge on various investment and insurance products; and an increase in liabilities related to guaranteed benefits, including riders on certain of our annuity products and secondary guarantees on certain variable universal life insurance products; • Ineffectiveness of our risk management policies and procedures, including our various hedging strategies; A deviation in actual experience regarding future policyholder behavior, mortality, morbidity, interest rates or equity market returns from the assumptions used in pricing our subsidiaries’ products and in establishing related insurance reserves, which may reduce future earnings; Changes in accounting principles that may affect our consolidated financial statements; • Lowering of one or more of our debt ratings issued by nationally recognized statistical rating organizations and the adverse effect such action may have on our ability to raise capital and on our liquidity and financial condition; • Lowering of one or more of the insurer financial strength ratings of our insurance subsidiaries and the adverse effect such action may have on the premium writings, policy retention and profitability of our insurance subsidiaries and liquidity; • Significant credit, accounting, fraud, corporate governance or other issues that may adversely affect the value of certain financial assets, as well as counterparties to which we are exposed to credit risk, requiring that we realize losses on financial assets; • Interruption in or failure of the telecommunication, information technology or other operational systems of the company or the third parties on whom we rely or failure to safeguard the confidentiality or privacy of sensitive data on such systems, including from cyberattacks or other breaches in security of such systems; • The effect of acquisitions and divestitures, including the inability to realize the anticipated benefits of acquisitions and dispositions of businesses and potential operating difficulties and unforeseen liabilities relating thereto, as well as the effect of restructurings, product withdrawals and other unusual items; • The inability to realize or sustain the benefits we expect from, greater than expected investments in, and the potential impact of efforts related to, our strategic initiatives; The adequacy and collectability of reinsurance that we have obtained; • Pandemics, acts of terrorism, war or other man-made and natural catastrophes that may adversely impact liabilities for policyholder claims and adversely affect our businesses and the cost and availability of reinsurance; • Competitive conditions, including pricing pressures, new product offerings and the emergence of new competitors, that may affect the level of premiums and fees that our subsidiaries can charge for their products; • The unknown effect on our subsidiaries’ businesses resulting from evolving market preferences and the changing demographics of our client base; and • The unanticipated loss of key management or wholesalers. The risks and uncertainties included here are not exhaustive. Our most recent Form 10-K, as well as other reports that we file with the SEC, include additional factors that could affect our businesses and financial performance. Moreover, we operate in a rapidly changing and competitive environment. New risk factors emerge from time to time, and it is not possible for management to predict all such risk factors. Further, it is not possible to assess the effect of all risk factors on our businesses or the extent to which any factor, or combination of factors, may cause actual results to differ materially from those contained in any forward-looking statements. Given these risks and uncertainties, investors should not place undue reliance on forward-looking statements as a prediction of actual results. In addition, Lincoln disclaims any obligation to correct or update any forward-looking statements to reflect events or circumstances that occur after the date of this presentation. The reporting of Risk-Based Capital (“RBC”) measures is not intended for the purpose of ranking any insurance company or for use in connection with any marketing, advertising or promotional activities.
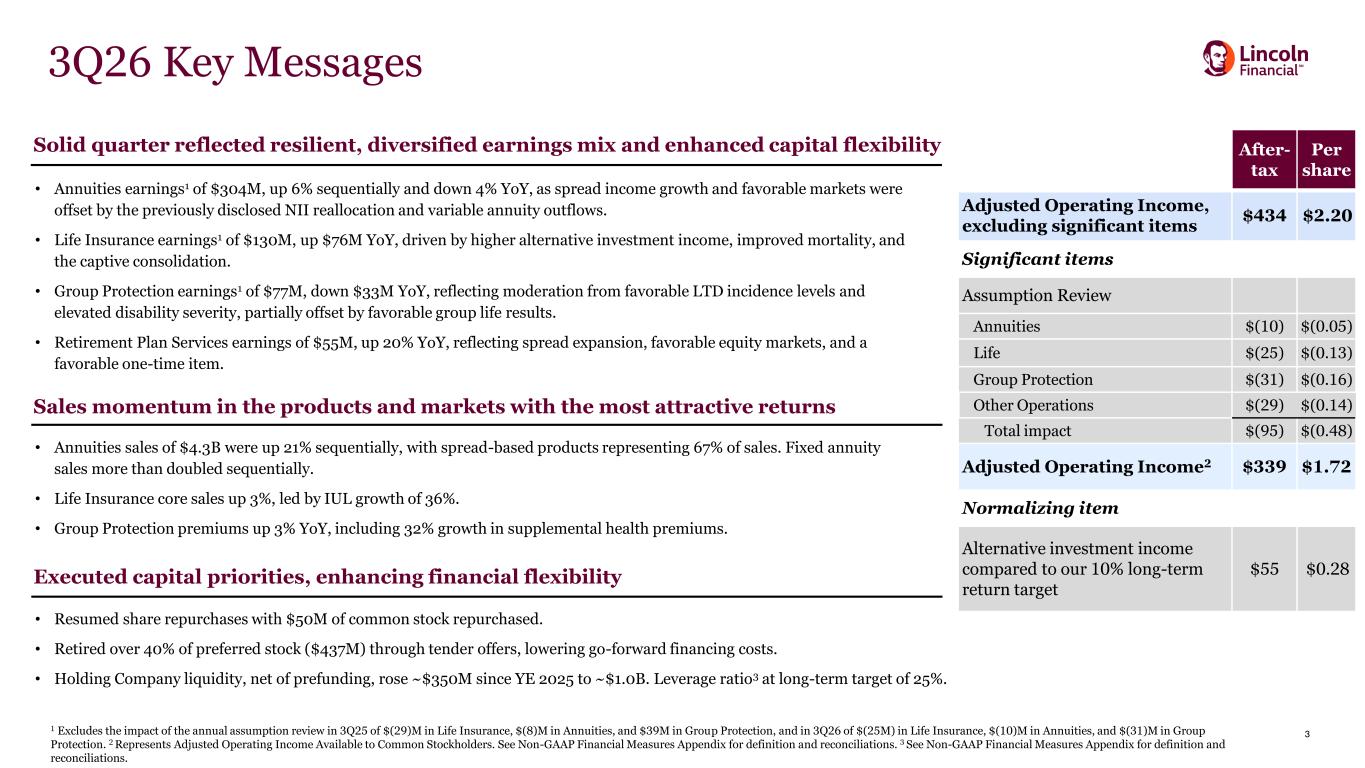
3 3Q26 Key Messages • Annuities sales of $4.3B were up 21% sequentially, with spread-based products representing 67% of sales. Fixed annuity sales more than doubled sequentially. • Life Insurance core sales up 3%, led by IUL growth of 36%. • Group Protection premiums up 3% YoY, including 32% growth in supplemental health premiums. • Annuities earnings1 of $304M, up 6% sequentially and down 4% YoY, as spread income growth and favorable markets were offset by the previously disclosed NII reallocation and variable annuity outflows. • Life Insurance earnings1 of $130M, up $76M YoY, driven by higher alternative investment income, improved mortality, and the captive consolidation. • Group Protection earnings1 of $77M, down $33M YoY, reflecting moderation from favorable LTD incidence levels and elevated disability severity, partially offset by favorable group life results. • Retirement Plan Services earnings of $55M, up 20% YoY, reflecting spread expansion, favorable equity markets, and a favorable one-time item. Sales momentum in the products and markets with the most attractive returns Executed capital priorities, enhancing financial flexibility • Resumed share repurchases with $50M of common stock repurchased. • Retired over 40% of preferred stock ($437M) through tender offers, lowering go-forward financing costs. • Holding Company liquidity, net of prefunding, rose ~$350M since YE 2025 to ~$1.0B. Leverage ratio3 at long-term target of 25%. 1 Excludes the impact of the annual assumption review in 3Q25 of $(29)M in Life Insurance, $(8)M in Annuities, and $39M in Group Protection, and in 3Q26 of $(25M) in Life Insurance, $(10)M in Annuities, and $(31)M in Group Protection. 2 Represents Adjusted Operating Income Available to Common Stockholders. See Non-GAAP Financial Measures Appendix for definition and reconciliations. 3 See Non-GAAP Financial Measures Appendix for definition and reconciliations. After- tax Per share Adjusted Operating Income, excluding significant items $434 $2.20 Significant items Assumption Review Annuities $(10) $(0.05) Life $(25) $(0.13) Group Protection $(31) $(0.16) Other Operations $(29) $(0.14) Total impact $(95) $(0.48) Adjusted Operating Income2 $339 $1.72 Normalizing item Alternative investment income compared to our 10% long-term return target $55 $0.28 Solid quarter reflected resilient, diversified earnings mix and enhanced capital flexibility
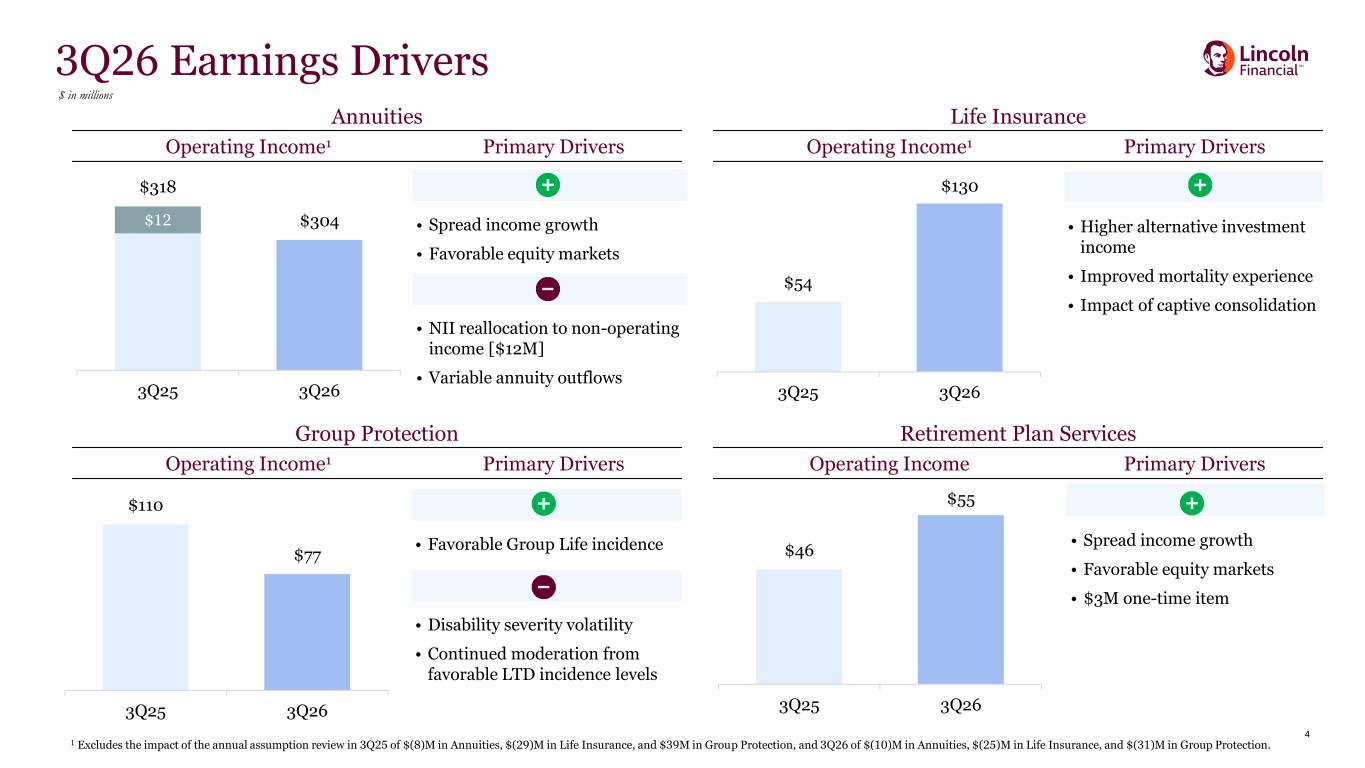
4 Annuities Life Insurance Operating Income1 Primary Drivers Operating Income1 Primary Drivers Group Protection Retirement Plan Services Operating Income1 Primary Drivers Operating Income Primary Drivers • Favorable Group Life incidence • Disability severity volatility • Continued moderation from favorable LTD incidence levels 3Q26 Earnings Drivers $ in millions • Spread income growth • Favorable equity markets • $3M one-time item • Higher alternative investment income • Improved mortality experience • Impact of captive consolidation 1 Excludes the impact of the annual assumption review in 3Q25 of $(8)M in Annuities, $(29)M in Life Insurance, and $39M in Group Protection, and 3Q26 of $(10)M in Annuities, $(25)M in Life Insurance, and $(31)M in Group Protection. • Spread income growth • Favorable equity markets • NII reallocation to non-operating income [$12M] • Variable annuity outflows $46 $55 3Q25 3Q26 $110 $77 3Q25 3Q26 $54 $130 3Q25 3Q26 $318 $304 3Q25 3Q26 $12
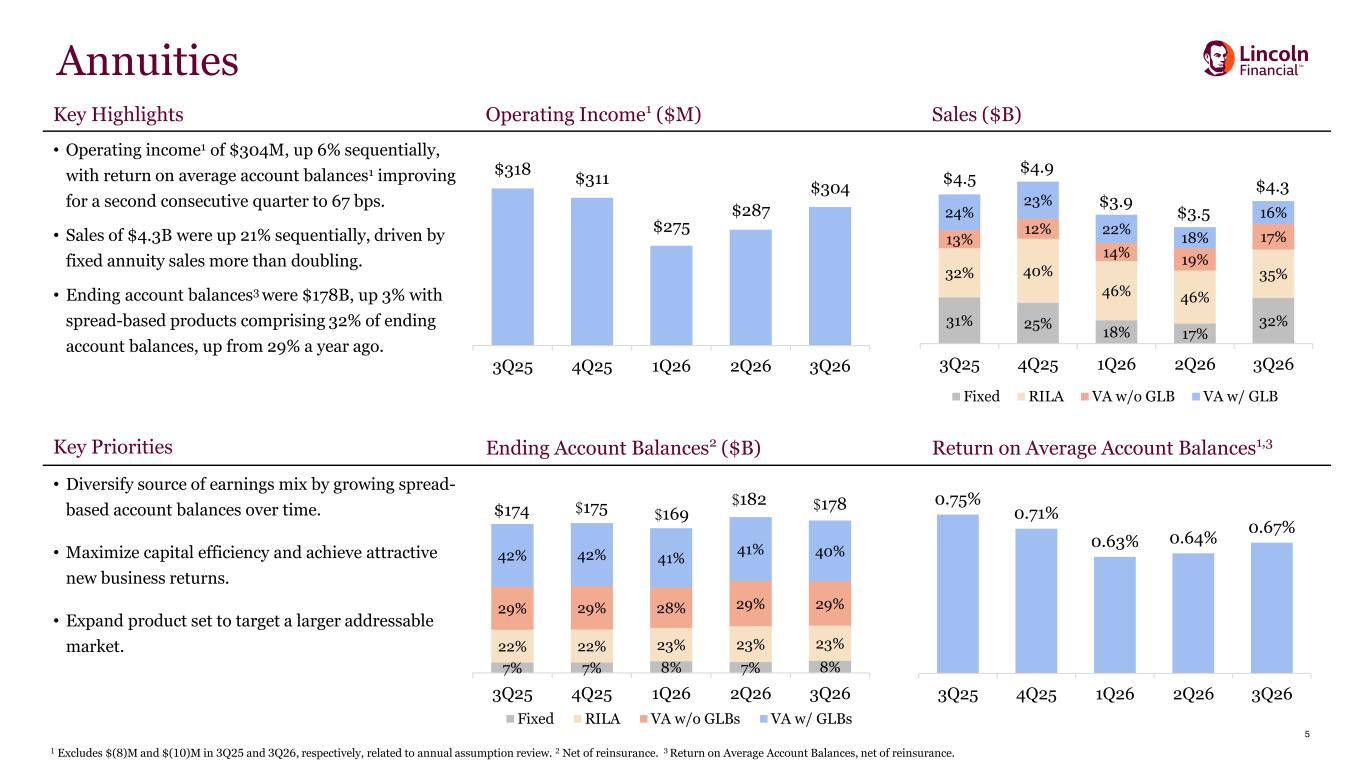
5 Annuities 1 Excludes $(8)M and $(10)M in 3Q25 and 3Q26, respectively, related to annual assumption review. 2 Net of reinsurance. 3 Return on Average Account Balances, net of reinsurance. Key Highlights Operating Income1 ($M) Sales ($B) • Operating income1 of $304M, up 6% sequentially, with return on average account balances1 improving for a second consecutive quarter to 67 bps. • Sales of $4.3B were up 21% sequentially, driven by fixed annuity sales more than doubling. • Ending account balances3 were $178B, up 3% with spread-based products comprising 32% of ending account balances, up from 29% a year ago. Key Priorities Ending Account Balances2 ($B) Return on Average Account Balances1,3 • Diversify source of earnings mix by growing spread- based account balances over time. • Maximize capital efficiency and achieve attractive new business returns. • Expand product set to target a larger addressable market. 7% 7% 8% 7% 8% 22% 22% 23% 23% 23% 29% 29% 28% 29% 29% 42% 42% 41% 41% 40% 3Q25 4Q25 1Q26 2Q26 3Q26 Fixed RILA VA w/o GLBs VA w/ GLBs $174 $175 $169 $182 $178 31% 25% 18% 17% 32% 32% 40% 46% 46% 35% 13% 12% 14% 19% 17% 24% 23% 22% 18% 16% 3Q25 4Q25 1Q26 2Q26 3Q26 Fixed RILA VA w/o GLB VA w/ GLB 0.75% 0.71% 0.63% 0.64% 0.67% 3Q25 4Q25 1Q26 2Q26 3Q26 $318 $311 $275 $287 $304 3Q25 4Q25 1Q26 2Q26 3Q26 $4.5 $4.9 $3.9 $3.5 $4.3
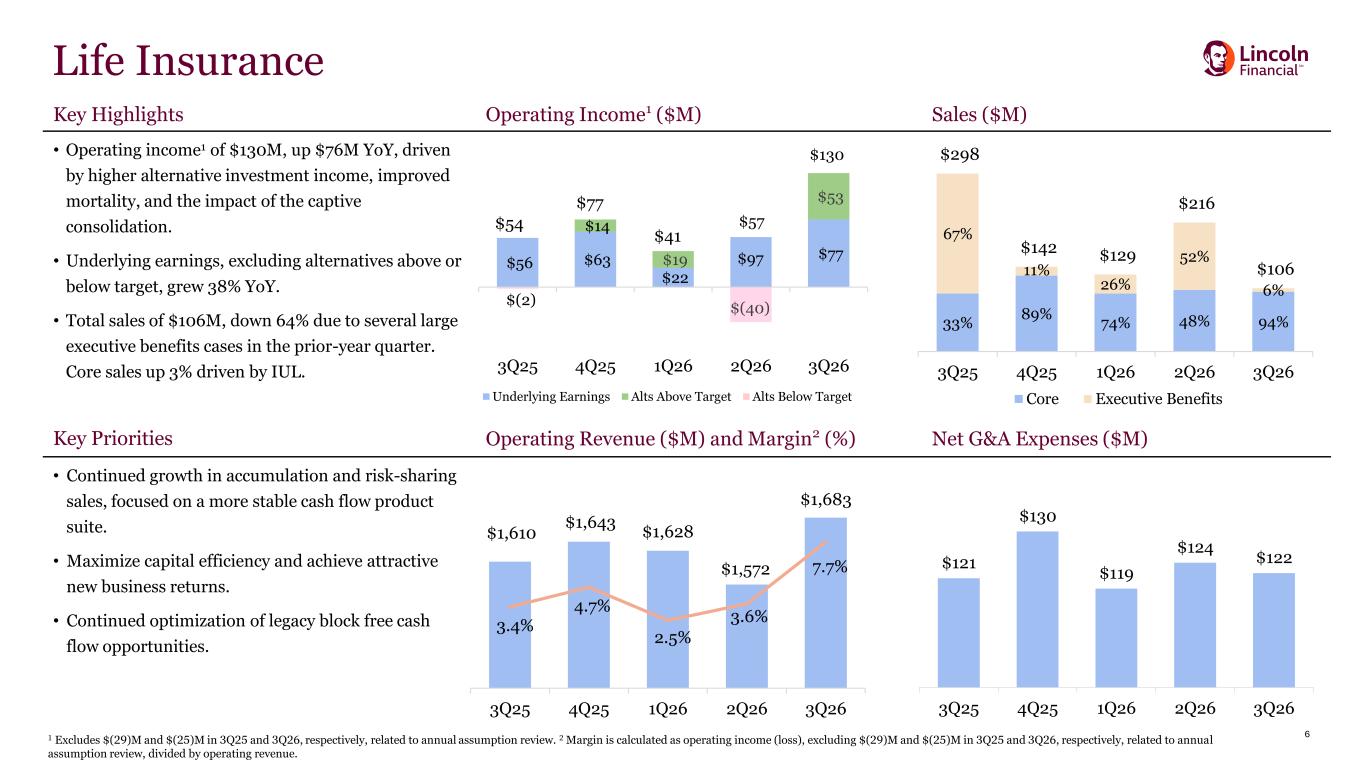
6 Key Highlights Operating Income1 ($M) Sales ($M) • Operating income1 of $130M, up $76M YoY, driven by higher alternative investment income, improved mortality, and the impact of the captive consolidation. • Underlying earnings, excluding alternatives above or below target, grew 38% YoY. • Total sales of $106M, down 64% due to several large executive benefits cases in the prior-year quarter. Core sales up 3% driven by IUL. Key Priorities Operating Revenue ($M) and Margin2 (%) Net G&A Expenses ($M) • Continued growth in accumulation and risk-sharing sales, focused on a more stable cash flow product suite. • Maximize capital efficiency and achieve attractive new business returns. • Continued optimization of legacy block free cash flow opportunities. 92% 91% 85% 80% 83% 8% 9% 15% 20% 17% 13% 8% 14% 19% 13% 19% 14% 1Q24 2Q24 3Q24 4Q24 1Q25 Underlying Earnings Alts Above Target Alts Below Target $56 $63 $22 $57 $77 $(2) $14 $19 $(40) $53 3Q25 4Q25 1Q26 2Q26 3Q26 $97 $130 Life Insurance 33% 89% 74% 48% 94% 67% 11% 26% 52% 6% $298 $142 $129 $216 $106 3Q25 4Q25 1Q26 2Q26 3Q26 Core Executive Benefits $54 $77 $121 $130 $119 $124 $122 3Q25 4Q25 1Q26 2Q26 3Q26 1 Excludes $(29)M and $(25)M in 3Q25 and 3Q26, respectively, related to annual assumption review. 2 Margin is calculated as operating income (loss), excluding $(29)M and $(25)M in 3Q25 and 3Q26, respectively, related to annual assumption review, divided by operating revenue. $1,610 $1,643 $1,628 $1,572 $1,683 3.4% 4.7% 2.5% 3.6% 7.7% -2.0% 0.0 % 2.0% 4.0% 6.0% 8.0% 10.0% 1400 1450 1500 1550 1600 1650 1700 3Q25 4Q25 1Q26 2Q26 3Q26 $41
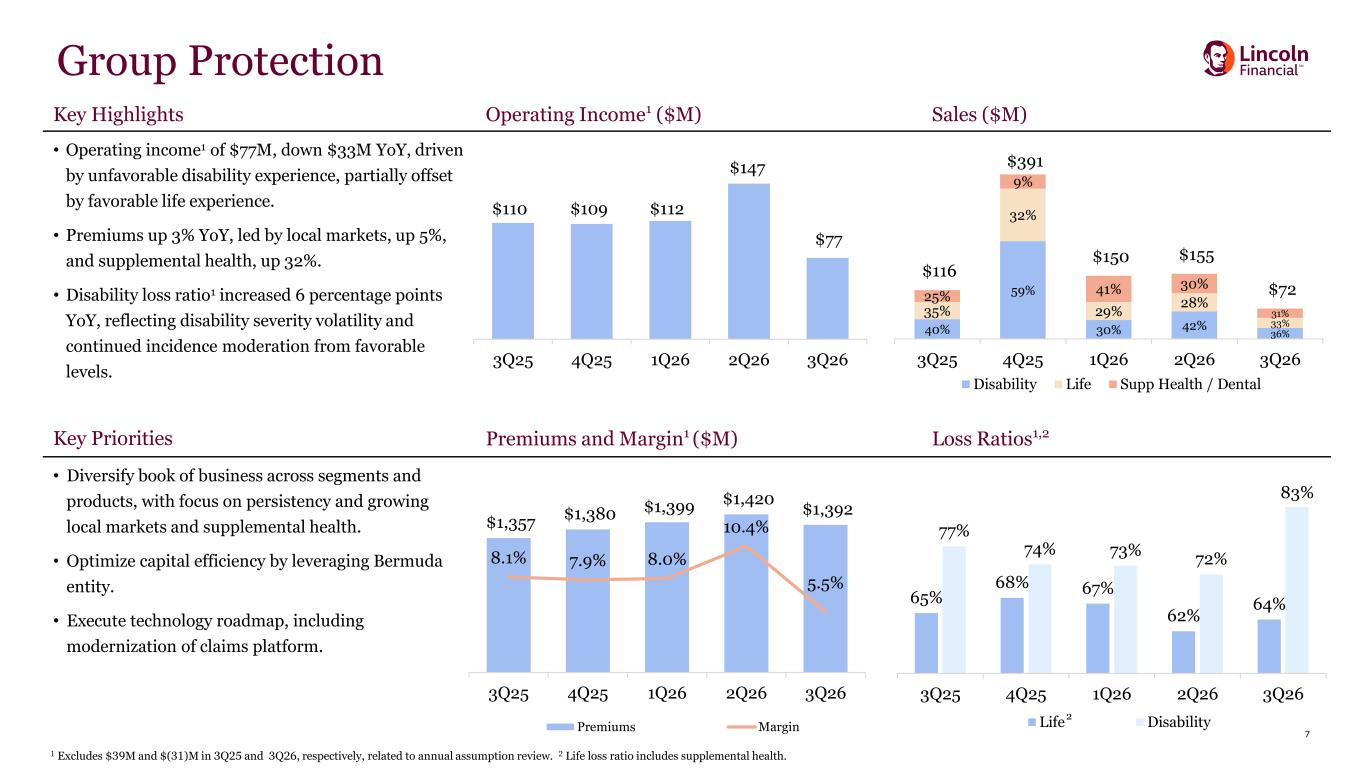
7 Key Highlights Operating Income1 ($M) Sales ($M) • Operating income1 of $77M, down $33M YoY, driven by unfavorable disability experience, partially offset by favorable life experience. • Premiums up 3% YoY, led by local markets, up 5%, and supplemental health, up 32%. • Disability loss ratio1 increased 6 percentage points YoY, reflecting disability severity volatility and continued incidence moderation from favorable levels. Key Priorities Premiums and Margin1 ($M) Loss Ratios1,2 • Diversify book of business across segments and products, with focus on persistency and growing local markets and supplemental health. • Optimize capital efficiency by leveraging Bermuda entity. • Execute technology roadmap, including modernization of claims platform. $1,357 $1,380 $1,399 $1,420 $1,392 8.1% 7.9% 8.0% 10.4% 5.5% 1.0% 3.0% 5.0% 7.0% 9.0% 11.0% 13.0% 15.0% $1,000 $1,050 $1,100 $1,150 $1,200 $1,250 $1,300 $1,350 $1,400 $1,450 $1,500 3Q25 4Q25 1Q26 2Q26 3Q26 Premiums Margin 65% 68% 67% 62% 64% 77% 74% 73% 72% 83% 3Q25 4Q25 1Q26 2Q26 3Q26 Life Disability 2 3Q25 4Q25 1Q26 2Q26 3Q26 $110 1 Excludes $39M and $(31)M in 3Q25 and 3Q26, respectively, related to annual assumption review. 2 Life loss ratio includes supplemental health. $109 $112 $147 $77 40% 59% 30% 42% 36% 35% 32% 29% 28% 33% 25% 9% 41% 30% 31% $116 $391 $150 $155 $72 3Q25 4Q25 1Q26 2Q26 3Q26 Disability Life Supp Health / Dental Group Protection
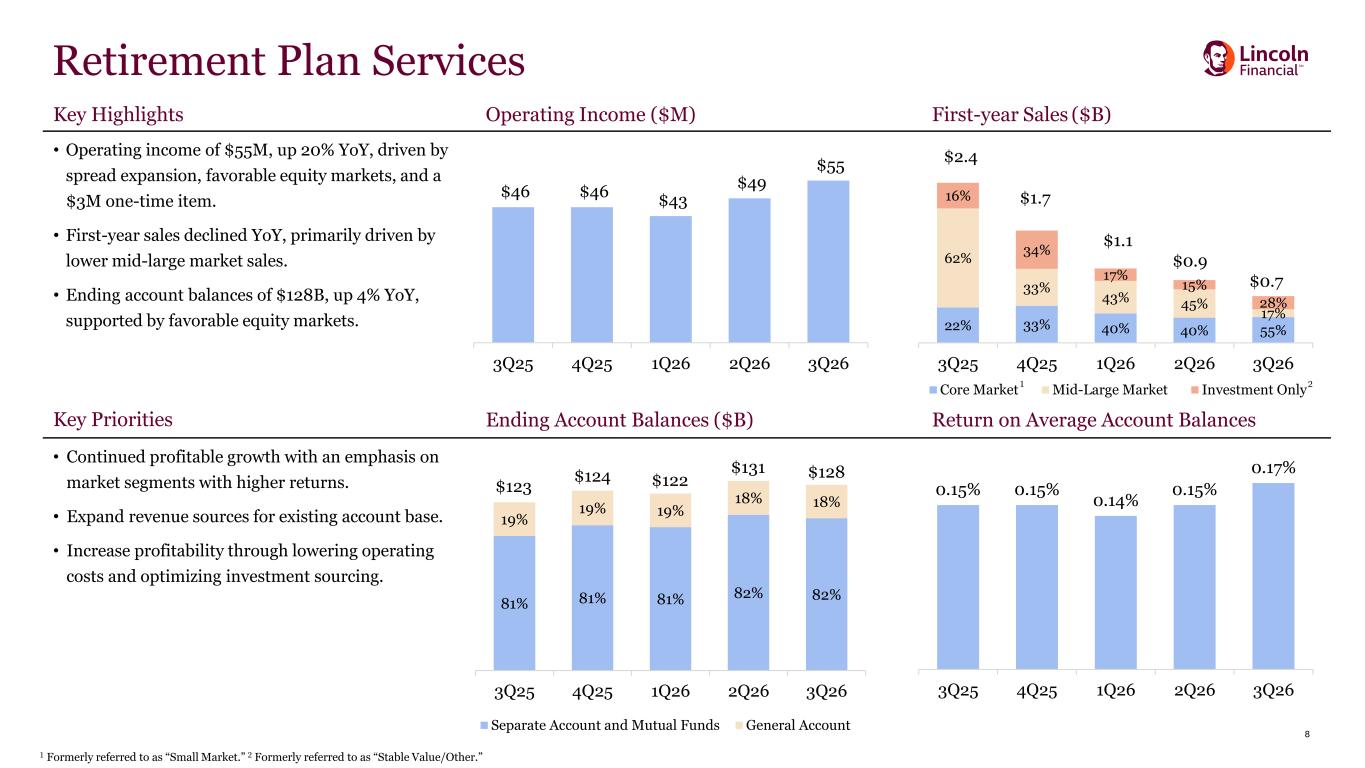
8 Key Highlights Operating Income ($M) First-year Sales ($B) • Operating income of $55M, up 20% YoY, driven by spread expansion, favorable equity markets, and a $3M one-time item. • First-year sales declined YoY, primarily driven by lower mid-large market sales. • Ending account balances of $128B, up 4% YoY, supported by favorable equity markets. Key Priorities Ending Account Balances ($B) Return on Average Account Balances • Continued profitable growth with an emphasis on market segments with higher returns. • Expand revenue sources for existing account base. • Increase profitability through lowering operating costs and optimizing investment sourcing. Retirement Plan Services 81% 81% 81% 82% 82% 19% 19% 19% 18% 18% 3Q25 4Q25 1Q26 2Q26 3Q26 Separate Account and Mutual Funds General Account $46 $46 $43 $49 $55 3Q25 4Q25 1Q26 2Q26 3Q26 0.15% 0.15% 0.14% 0.15% 0.17% 3Q25 4Q25 1Q26 2Q26 3Q26 22% 33% 40% 40% 55% 62% 33% 43% 45% 17% 16% 34% 17% 15% 28% 3Q25 4Q25 1Q26 2Q26 3Q26 Core Market Mid-Large Market Investment Only $0.9 $0.7 $2.4 $1.7 $1.1 1 Formerly referred to as “Small Market.” 2 Formerly referred to as “Stable Value/Other.” 1 2 $123 $124 $122 $131 $128
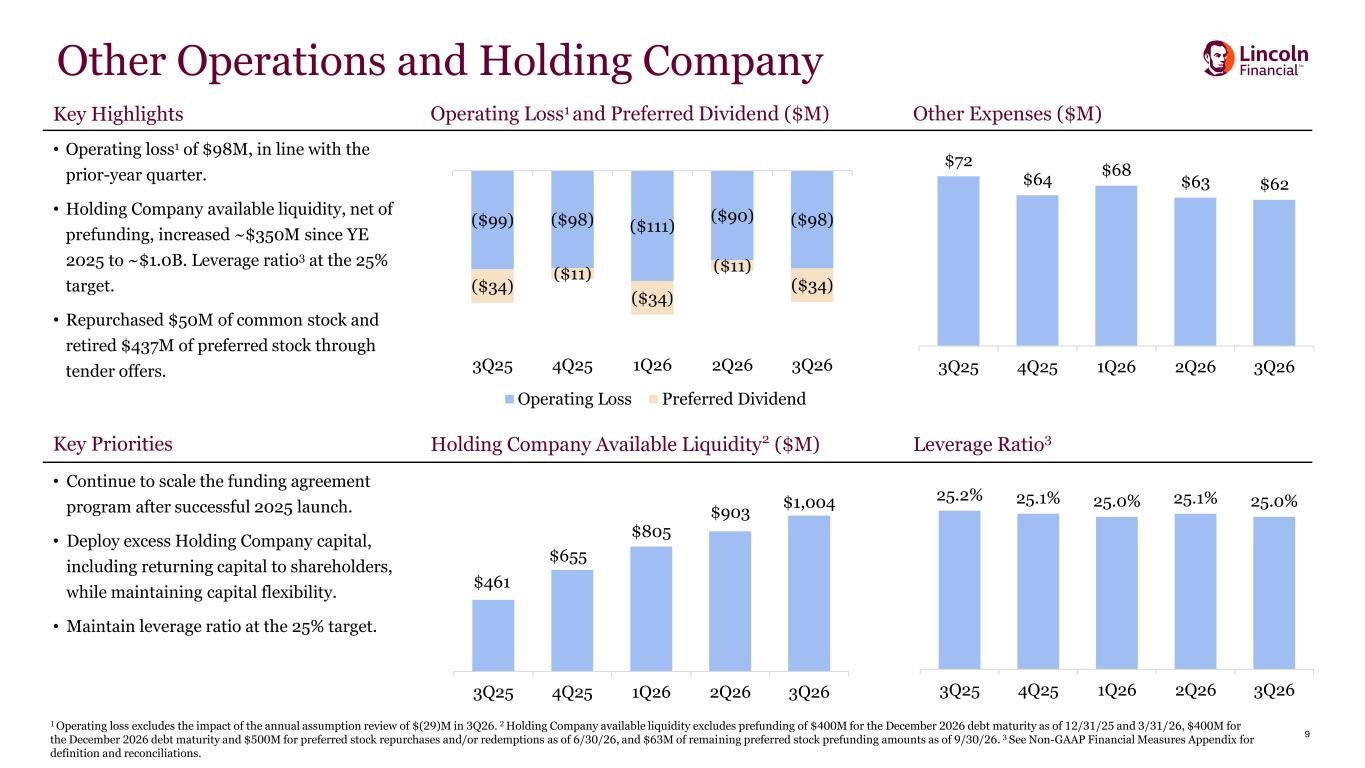
9 Key Highlights Operating Loss1 and Preferred Dividend ($M) Other Expenses ($M) • Operating loss1 of $98M, in line with the prior-year quarter. • Holding Company available liquidity, net of prefunding, increased ~$350M since YE 2025 to ~$1.0B. Leverage ratio3 at the 25% target. • Repurchased $50M of common stock and retired $437M of preferred stock through tender offers. Key Priorities Holding Company Available Liquidity2 ($M) Leverage Ratio3 • Continue to scale the funding agreement program after successful 2025 launch. • Deploy excess Holding Company capital, including returning capital to shareholders, while maintaining capital flexibility. • Maintain leverage ratio at the 25% target. Other Operations and Holding Company ($99) ($98) ($111) ($90) ($98) ($34) ($11) ($34) ($11) ($34) 3Q25 4Q25 1Q26 2Q26 3Q26 Operating Loss Preferred Dividend $461 $655 $805 $903 $1,004 3Q25 4Q25 1Q26 2Q26 3Q26 25.2% 25.1% 25.0% 25.1% 25.0% 3Q25 4Q25 1Q26 2Q26 3Q26 $72 $64 $68 $63 $62 3Q25 4Q25 1Q26 2Q26 3Q26 1 Operating loss excludes the impact of the annual assumption review of $(29)M in 3Q26. 2 Holding Company available liquidity excludes prefunding of $400M for the December 2026 debt maturity as of 12/31/25 and 3/31/26, $400M for the December 2026 debt maturity and $500M for preferred stock repurchases and/or redemptions as of 6/30/26, and $63M of remaining preferred stock prefunding amounts as of 9/30/26. 3 See Non-GAAP Financial Measures Appendix for definition and reconciliations.
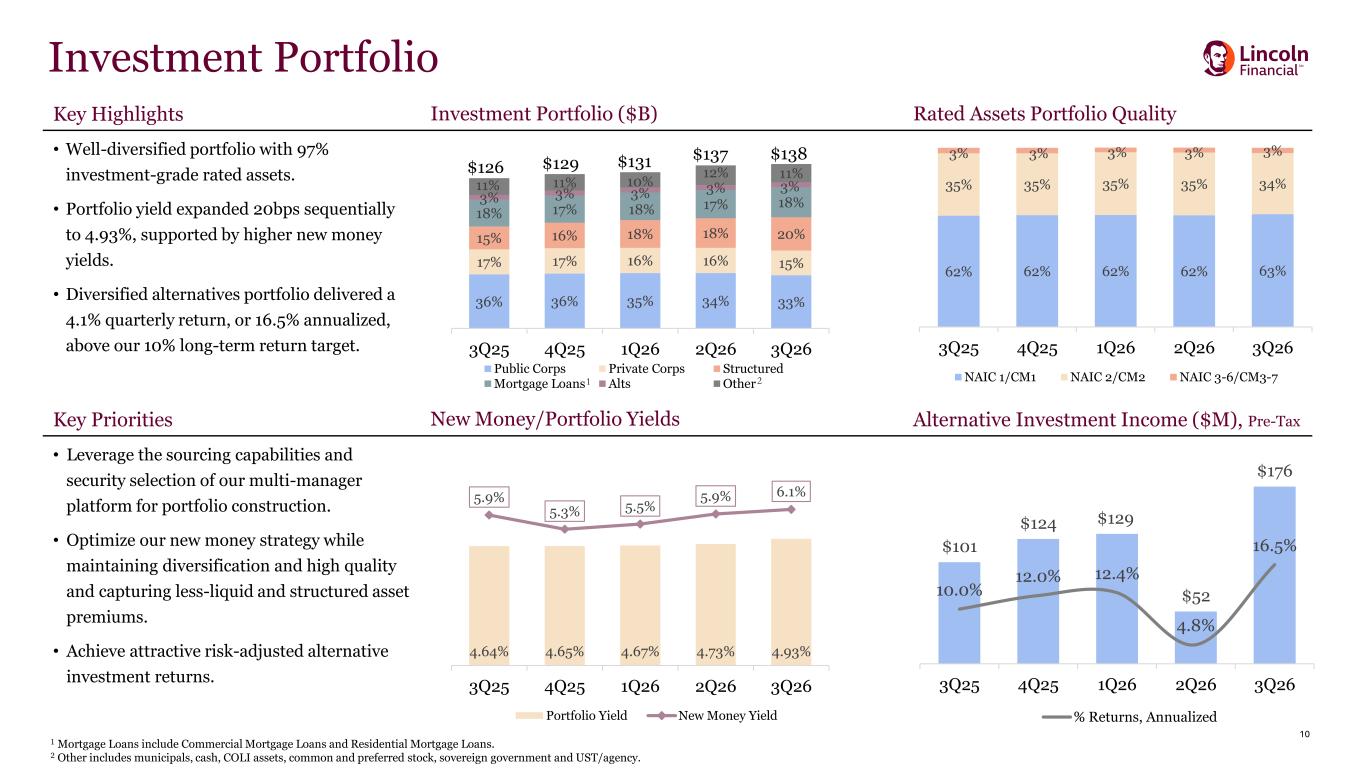
10 Key Highlights Investment Portfolio ($B) Rated Assets Portfolio Quality • Well-diversified portfolio with 97% investment-grade rated assets. • Portfolio yield expanded 20bps sequentially to 4.93%, supported by higher new money yields. • Diversified alternatives portfolio delivered a 4.1% quarterly return, or 16.5% annualized, above our 10% long-term return target. Key Priorities New Money/Portfolio Yields Alternative Investment Income ($M), Pre-Tax • Leverage the sourcing capabilities and security selection of our multi-manager platform for portfolio construction. • Optimize our new money strategy while maintaining diversification and high quality and capturing less-liquid and structured asset premiums. • Achieve attractive risk-adjusted alternative investment returns. 36% 36% 35% 34% 33% 17% 17% 16% 16% 15% 15% 16% 18% 18% 20% 18% 17% 18% 17% 18%3% 3% 3% 3% 3%11% 11% 10% 12% 11% 3Q25 4Q25 1Q26 2Q26 3Q26 Public Corps Private Corps Structured Mortgage Loans Alts Other 4.64% 4.65% 4.67% 4.73% 4.93% 5.9% 5.3% 5.5% 5.9% 6.1% 3Q25 4Q25 1Q26 2Q26 3Q26 Portfolio Yield New Money Yield 62% 62% 62% 62% 63% 35% 35% 35% 35% 34% 3% 3% 3% 3% 3% 3Q25 4Q25 1Q26 2Q26 3Q26 NAIC 1/CM1 NAIC 2/CM2 NAIC 3-6/CM3-7 $138 $126 $129 1 2 $131 1 Mortgage Loans include Commercial Mortgage Loans and Residential Mortgage Loans. 2 Other includes municipals, cash, COLI assets, common and preferred stock, sovereign government and UST/agency. $137 Investment Portfolio $101 $124 $129 $52 $176 10.0% 12.0% 12.4% 4.8% 16.5% 0 20 40 60 80 100 120 140 160 180 3Q25 4Q25 1Q26 2Q26 3Q26 % Returns, Annualized
11 Appendix
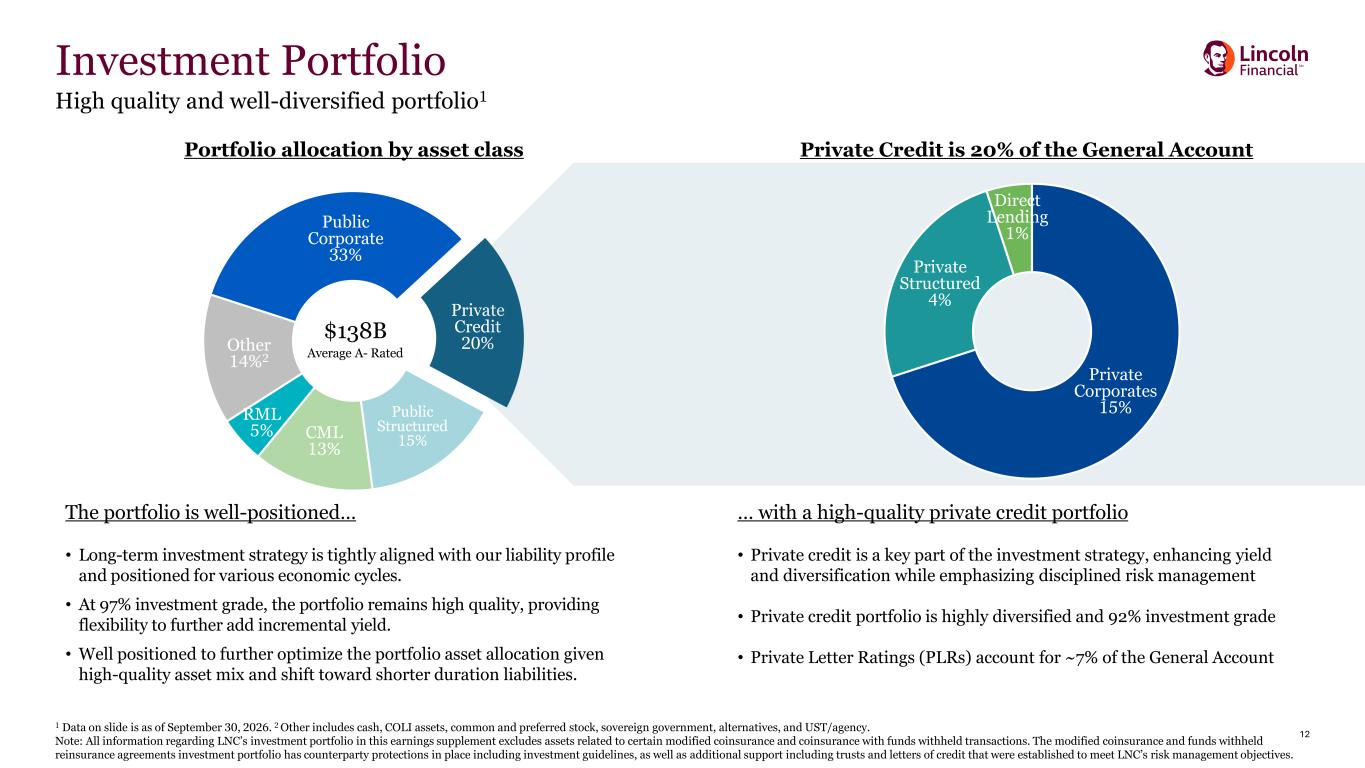
12 Public Corporate 33% Private Credit 20% Public Structured 15% CML 13% RML 5% Other 14%2 Investment Portfolio High quality and well-diversified portfolio1 $138B Average A- Rated Portfolio allocation by asset class 1 Data on slide is as of September 30, 2026. 2 Other includes cash, COLI assets, common and preferred stock, sovereign government, alternatives, and UST/agency. Note: All information regarding LNC’s investment portfolio in this earnings supplement excludes assets related to certain modified coinsurance and coinsurance with funds withheld transactions. The modified coinsurance and funds withheld reinsurance agreements investment portfolio has counterparty protections in place including investment guidelines, as well as additional support including trusts and letters of credit that were established to meet LNC’s risk management objectives. … with a high-quality private credit portfolio • Private credit is a key part of the investment strategy, enhancing yield and diversification while emphasizing disciplined risk management • Private credit portfolio is highly diversified and 92% investment grade • Private Letter Ratings (PLRs) account for ~7% of the General Account The portfolio is well-positioned… • Long-term investment strategy is tightly aligned with our liability profile and positioned for various economic cycles. • At 97% investment grade, the portfolio remains high quality, providing flexibility to further add incremental yield. • Well positioned to further optimize the portfolio asset allocation given high-quality asset mix and shift toward shorter duration liabilities. Private Credit is 20% of the General Account Private Corporates 15% Private Structured 4% Direct Lending 1%
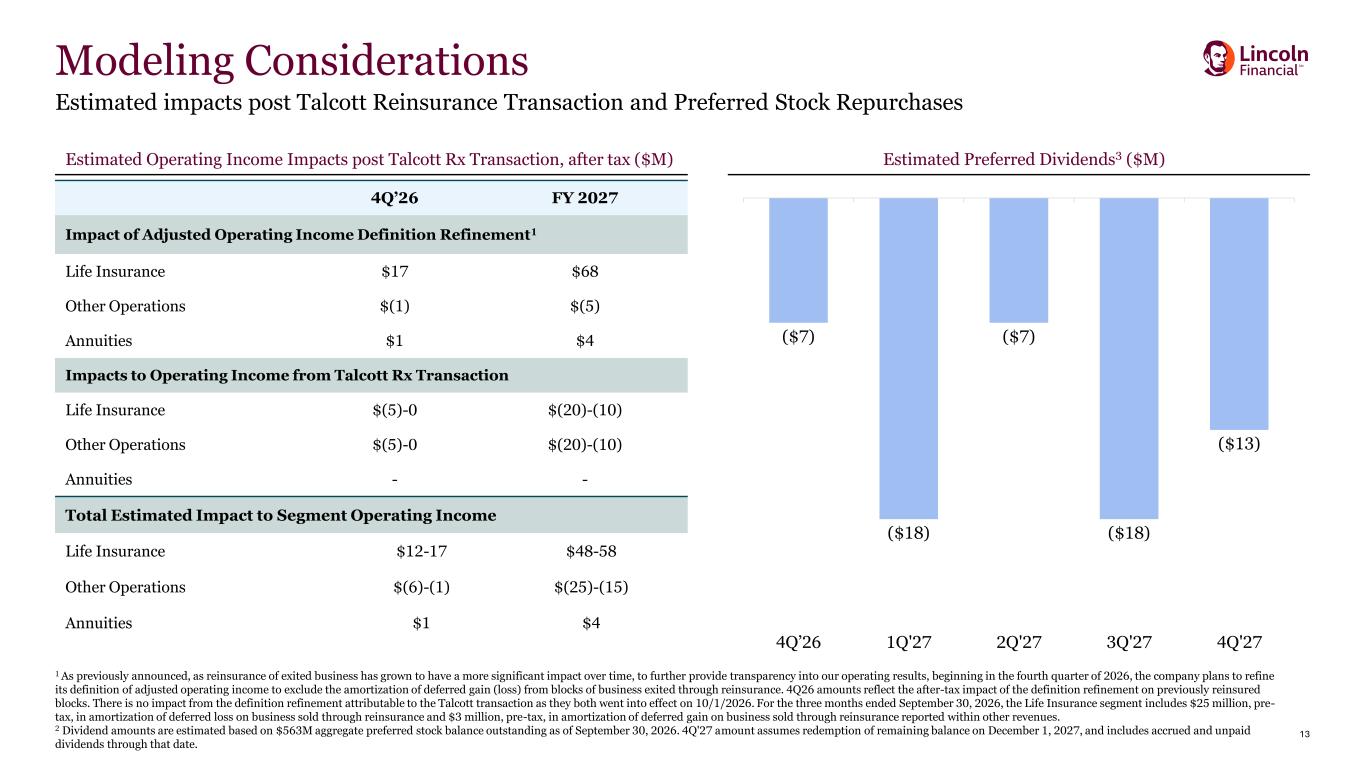
13 Modeling Considerations Estimated impacts post Talcott Reinsurance Transaction and Preferred Stock Repurchases Estimated Operating Income Impacts post Talcott Rx Transaction, after tax ($M) Estimated Preferred Dividends3 ($M) ($7) ($18) ($7) ($18) ($13) 4Q’26 1Q'27 2Q'27 3Q'27 4Q'27 4Q’26 FY 2027 Impact of Adjusted Operating Income Definition Refinement1 Life Insurance $17 $68 Other Operations $(1) $(5) Annuities $1 $4 Impacts to Operating Income from Talcott Rx Transaction Life Insurance $(5)-0 $(20)-(10) Other Operations $(5)-0 $(20)-(10) Annuities - - 1 As previously announced, as reinsurance of exited business has grown to have a more significant impact over time, to further provide transparency into our operating results, beginning in the fourth quarter of 2026, the company plans to refine its definition of adjusted operating income to exclude the amortization of deferred gain (loss) from blocks of business exited through reinsurance. 4Q26 amounts reflect the after-tax impact of the definition refinement on previously reinsured blocks. There is no impact from the definition refinement attributable to the Talcott transaction as they both went into effect on 10/1/2026. For the three months ended September 30, 2026, the Life Insurance segment includes $25 million, pre- tax, in amortization of deferred loss on business sold through reinsurance and $3 million, pre-tax, in amortization of deferred gain on business sold through reinsurance reported within other revenues. 2 Dividend amounts are estimated based on $563M aggregate preferred stock balance outstanding as of September 30, 2026. 4Q'27 amount assumes redemption of remaining balance on December 1, 2027, and includes accrued and unpaid dividends through that date. Total Estimated Impact to Segment Operating Income Life Insurance $12-17 $48-58 Other Operations $(6)-(1) $(25)-(15) Annuities $1 $4
14 Non-GAAP Financial Measures Appendix 2
15 Non-GAAP Financial Measures Non-GAAP Financial Measures Non-GAAP financial measures do not replace the most directly comparable GAAP measures. Reconciliations of the following non-GAAP financial measures to the most directly comparable GAAP financial measures or calculations of such measures, as applicable, are presented herein beginning on slide 17. Adjusted Income (Loss) From Operations Adjusted income (loss) from operations is GAAP net income (loss) excluding the effects of the following items, as applicable: • Items related to annuity product features, which include changes in market risk benefits (“MRBs”), changes in the fair value of the related hedge instruments inclusive of income allocated to support the cost of hedging or future benefits, and changes in the fair value of the embedded derivative liabilities and the associated index options for our indexed annuity products (collectively, “net annuity product features”); • Items related to life insurance product features, which include changes in the fair value of derivatives we hold as part of variable universal life insurance (“VUL”) hedging, changes in reserves resulting from benefit ratio unlocking associated with the impact of capital markets, and changes in the fair value of the embedded derivative liabilities of our indexed universal life insurance (“IUL”) contracts and the associated index options we hold to hedge them (collectively, “net life insurance product features”); • Credit loss-related adjustments on fixed maturity available-for-sale (“AFS”) securities, mortgage loans on real estate and reinsurance-related assets (“credit loss-related adjustments”); • Changes in the fair value of equity securities and certain other investments, the impact of certain derivatives, and realized gains (losses) on sales, disposals and impairments of financial assets (collectively, “investment gains (losses)”); • Changes in the fair value of reinsurance-related embedded derivatives, trading securities and mortgage loans on real estate electing the fair value option (“changes in the fair value of reinsurance-related embedded derivatives, trading securities and certain mortgage loans”); • Income (loss) from the initial adoption of new accounting standards, accounting policy changes and new regulations, including changes in tax law; • Income (loss) from reserve changes, net of related amortization, on business sold through reinsurance; • Losses from the impairment of intangible assets and gains (losses) on other non-financial assets; • Income (loss) from discontinued operations; • Other items, which include the following: certain legal and regulatory accruals; severance expense related to initiatives that realign the workforce; transaction, integration and other costs related to mergers and acquisitions including the acquisition or divestiture, through reinsurance or other means, of businesses or blocks of business, and certain other corporate initiatives; mark-to-market adjustment related to the LNC stock component of our deferred compensation plans (“deferred compensation mark-to-market adjustment”); gains (losses) on modification or early extinguishment of debt; and impacts from settlement or curtailment of defined benefit obligations; and • Income tax benefit (expense) related to the above pre-tax items, including the effect of tax adjustments such as changes to deferred tax valuation allowances. Adjusted income (loss) from operations available to common stockholders is defined as GAAP net income (loss) available to common stockholders excluding the effects of the items, as applicable, set forth in the definition of adjusted income (loss) from operations above and the impact of preferred stock repurchase premium. Management excludes the impact of preferred stock repurchase premium as it is not indicative of current operating fundamentals.
16 Non-GAAP Financial Measures, Cont’d Management believes that the use of the non-GAAP financial measures adjusted income (loss) from operations, adjusted income (loss) from operations available to common stockholders (or adjusted operating income) and adjusted income (loss) from operations per diluted share available to common stockholders is helpful to investors in evaluating the company’s performance. Management believes that excluding the following items from adjusted income (loss) from operations enhances understanding of the underlying trends and long-term performance of the company’s business. Management excludes “net annuity product features” as this adjustment primarily represents the difference between the valuation of reserves and the valuation of derivatives utilized for hedging our variable annuity and indexed annuity products, which can fluctuate significantly from period to period based on changes in equity markets and interest rates. This difference is due to the hedge focus on managing risks to statutory capital as opposed to the GAAP reserves. Management excludes “net life insurance product features” for similar reasons. In addition, management excludes “credit loss-related adjustments” and “investment gains (losses)” as the timing of changes in allowances or sales of credit-impaired investments depends largely on market credit cycles and can vary considerably from period to period and the timing of other sales of investments that would result in gains or losses is driven by market conditions, including interest rates, and other factors. Management excludes “changes in the fair value of reinsurance-related embedded derivatives, trading securities and certain mortgage loans” as this adjustment represents the economics of investments in underlying funds withheld portfolios supporting reinsurance agreements that have been transferred to third-party reinsurers, which is not indicative of our ongoing results. Finally, management excludes from adjusted income (loss) from operations certain additional items (as set forth in the definition above) that are not necessarily indicative of current operating fundamentals or future performance of the business segments, and, in most instances, decisions regarding these items do not necessarily relate to the operations of the individual segments. Management believes excluding these items better explains the results of the company’s ongoing businesses in a manner that allows for enhanced understanding of underlying trends, company performance and business fundamentals. Adjusted Stockholders' Equity Adjusted stockholders’ equity is stockholders’ equity, excluding accumulated other comprehensive income (loss) ("AOCI"), preferred stock, changes in MRBs, guaranteed living benefit (“GLB”) and guaranteed death benefit (“GDB”) hedge instruments gains (losses), and the difference between amounts recognized in net income (loss) on reinsurance-related embedded derivatives and the underlying asset portfolios (“reinsurance-related embedded derivatives and portfolio gains (losses)”). Management believes this metric is useful to investors to analyze our net worth because it eliminates the effect of market movements that can fluctuate significantly from period to period, primarily related to changes in equity markets and interest rates. Stockholders’ equity is the most directly comparable GAAP measure. Leverage Ratio Leverage ratio is a measure that we use to monitor the level of our debt relative to our total capitalization. Debt used in this metric reflects total debt and preferred stock adjusted for certain items. Total capitalization reflects debt used in the numerator of this ratio and stockholders' equity adjusted for certain items.
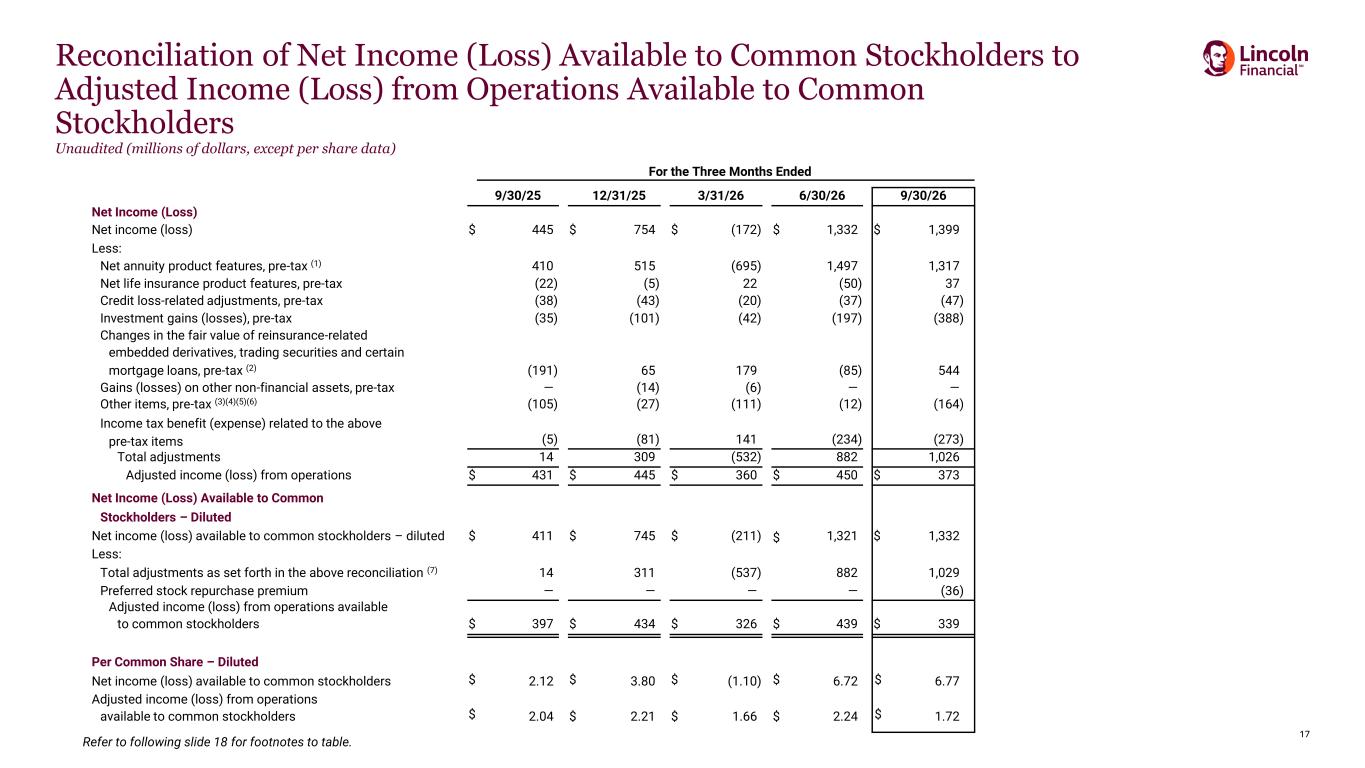
17 Reconciliation of Net Income (Loss) Available to Common Stockholders to Adjusted Income (Loss) from Operations Available to Common Stockholders Unaudited (millions of dollars, except per share data) For the Three Months Ended 9/30/25 12/31/25 3/31/26 6/30/26 9/30/26 Net Income (Loss) Net income (loss) $ 445 $ 754 $ (172) $ 1,332 $ 1,399 Less: Net annuity product features, pre-tax (1) 410 515 (695) 1,497 1,317 Net life insurance product features, pre-tax (22) (5) 22 (50) 37 Credit loss-related adjustments, pre-tax (38) (43) (20) (37) (47) Investment gains (losses), pre-tax (35) (101) (42) (197) (388) Changes in the fair value of reinsurance-related embedded derivatives, trading securities and certain mortgage loans, pre-tax (2) (191) 65 179 (85) 544 Gains (losses) on other non-financial assets, pre-tax — (14) (6) — — Other items, pre-tax (3)(4)(5)(6) (105) (27) (111) (12) (164) Income tax benefit (expense) related to the above pre-tax items (5) (81) 141 (234) (273) Total adjustments 14 309 (532) 882 1,026 Adjusted income (loss) from operations $ 431 $ 445 $ 360 $ 450 $ 373 Net Income (Loss) Available to Common Stockholders – Diluted Net income (loss) available to common stockholders – diluted $ 411 $ 745 $ (211) $ 1,321 $ 1,332 Less: Total adjustments as set forth in the above reconciliation (7) 14 311 (537) 882 1,029 Preferred stock repurchase premium — — — — (36) Adjusted income (loss) from operations available to common stockholders $ 397 $ 434 $ 326 $ 439 $ 339 Per Common Share – Diluted Net income (loss) available to common stockholders $ 2.12 $ 3.80 $ (1.10) $ 6.72 $ 6.77 Adjusted income (loss) from operations available to common stockholders $ 2.04 $ 2.21 $ 1.66 $ 2.24 $ 1.72 Refer to following slide 18 for footnotes to table.
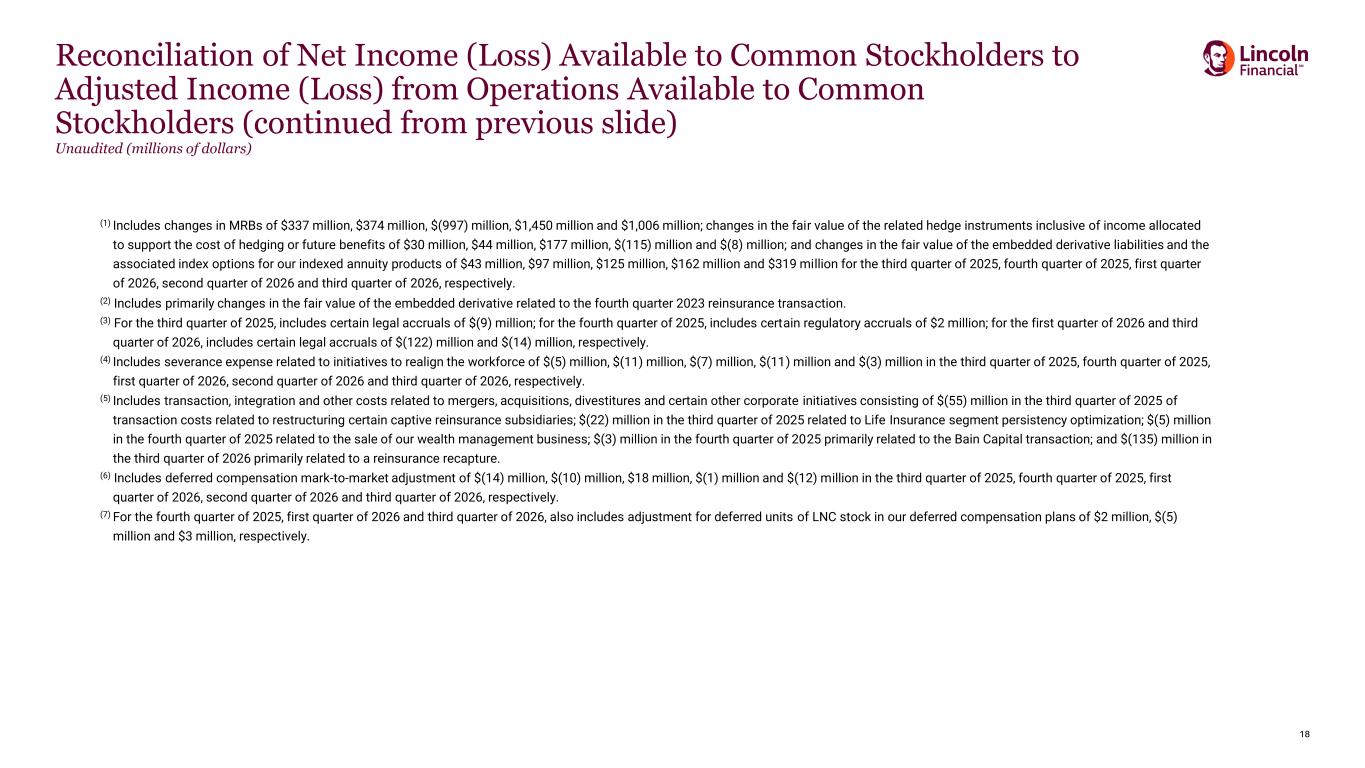
18 Reconciliation of Net Income (Loss) Available to Common Stockholders to Adjusted Income (Loss) from Operations Available to Common Stockholders (continued from previous slide) Unaudited (millions of dollars) (1) Includes changes in MRBs of $337 million, $374 million, $(997) million, $1,450 million and $1,006 million; changes in the fair value of the related hedge instruments inclusive of income allocated to support the cost of hedging or future benefits of $30 million, $44 million, $177 million, $(115) million and $(8) million; and changes in the fair value of the embedded derivative liabilities and the associated index options for our indexed annuity products of $43 million, $97 million, $125 million, $162 million and $319 million for the third quarter of 2025, fourth quarter of 2025, first quarter of 2026, second quarter of 2026 and third quarter of 2026, respectively. (2) Includes primarily changes in the fair value of the embedded derivative related to the fourth quarter 2023 reinsurance transaction. (3) For the third quarter of 2025, includes certain legal accruals of $(9) million; for the fourth quarter of 2025, includes certain regulatory accruals of $2 million; for the first quarter of 2026 and third quarter of 2026, includes certain legal accruals of $(122) million and $(14) million, respectively. (4) Includes severance expense related to initiatives to realign the workforce of $(5) million, $(11) million, $(7) million, $(11) million and $(3) million in the third quarter of 2025, fourth quarter of 2025, first quarter of 2026, second quarter of 2026 and third quarter of 2026, respectively. (5) Includes transaction, integration and other costs related to mergers, acquisitions, divestitures and certain other corporate initiatives consisting of $(55) million in the third quarter of 2025 of transaction costs related to restructuring certain captive reinsurance subsidiaries; $(22) million in the third quarter of 2025 related to Life Insurance segment persistency optimization; $(5) million in the fourth quarter of 2025 related to the sale of our wealth management business; $(3) million in the fourth quarter of 2025 primarily related to the Bain Capital transaction; and $(135) million in the third quarter of 2026 primarily related to a reinsurance recapture. (6) Includes deferred compensation mark-to-market adjustment of $(14) million, $(10) million, $18 million, $(1) million and $(12) million in the third quarter of 2025, fourth quarter of 2025, first quarter of 2026, second quarter of 2026 and third quarter of 2026, respectively. (7) For the fourth quarter of 2025, first quarter of 2026 and third quarter of 2026, also includes adjustment for deferred units of LNC stock in our deferred compensation plans of $2 million, $(5) million and $3 million, respectively.
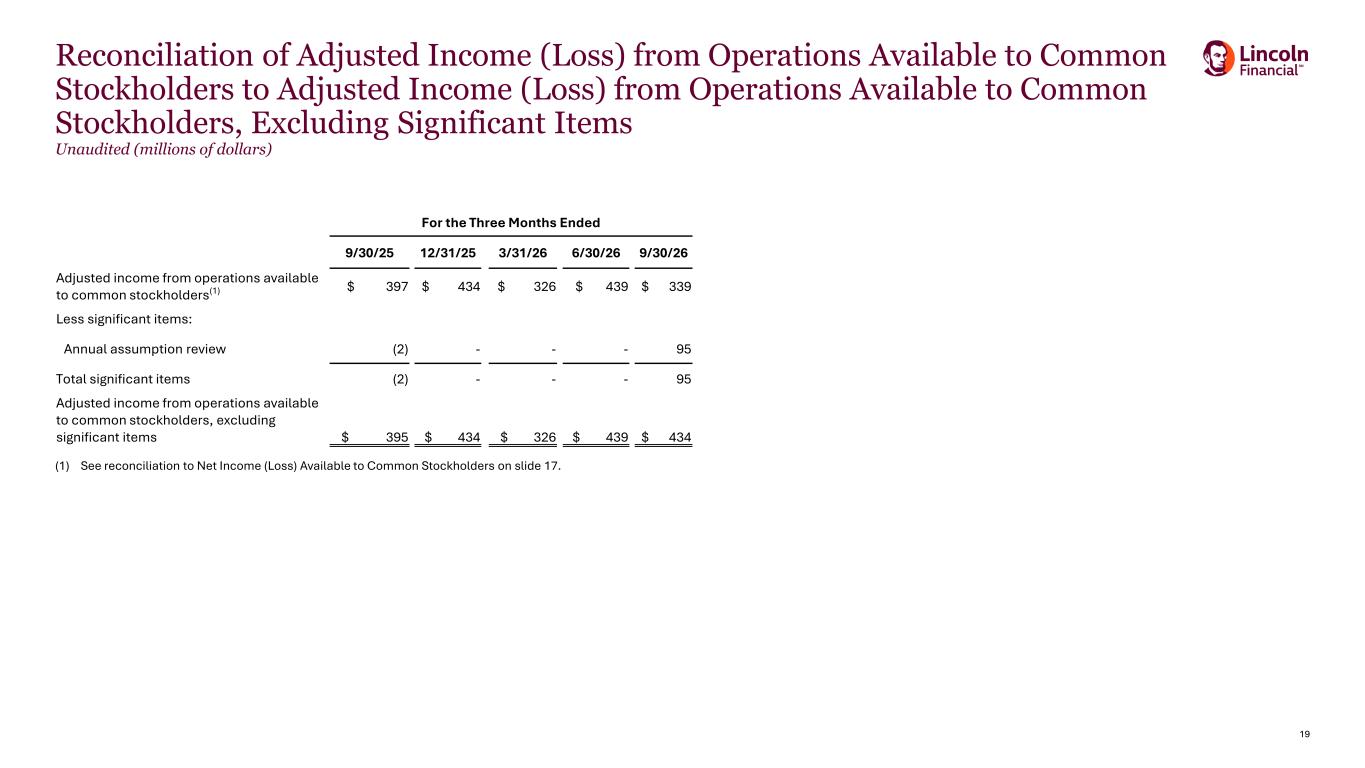
19 Reconciliation of Adjusted Income (Loss) from Operations Available to Common Stockholders to Adjusted Income (Loss) from Operations Available to Common Stockholders, Excluding Significant Items Unaudited (millions of dollars) (1) See reconciliation to Net Income (Loss) Available to Common Stockholders on slide 17. For the Three Months Ended 9/30/25 12/31/25 3/31/26 6/30/26 9/30/26 Adjusted income from operations available to common stockholders(1) $ 397 $ 434 $ 326 $ 439 $ 339 Less significant items: Annual assumption review (2) - - - 95 Total significant items (2) - - - 95 Adjusted income from operations available to common stockholders, excluding significant items $ 395 $ 434 $ 326 $ 439 $ 434
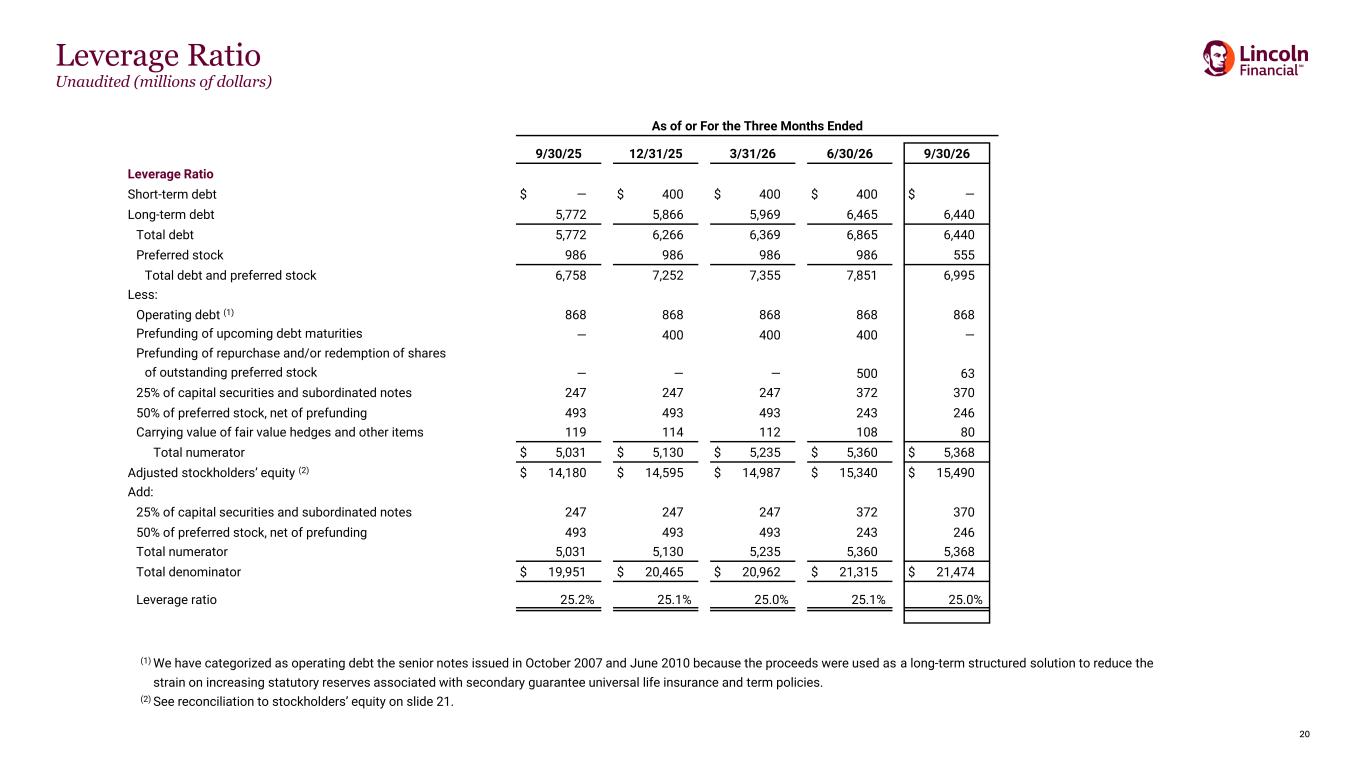
20 Leverage Ratio Unaudited (millions of dollars) As of or For the Three Months Ended 9/30/25 12/31/25 3/31/26 6/30/26 9/30/26 Leverage Ratio Short-term debt $ — $ 400 $ 400 $ 400 $ — Long-term debt 5,772 5,866 5,969 6,465 6,440 Total debt 5,772 6,266 6,369 6,865 6,440 Preferred stock 986 986 986 986 555 Total debt and preferred stock 6,758 7,252 7,355 7,851 6,995 Less: Operating debt (1) 868 868 868 868 868 Prefunding of upcoming debt maturities — 400 400 400 — Prefunding of repurchase and/or redemption of shares of outstanding preferred stock — — — 500 63 25% of capital securities and subordinated notes 247 247 247 372 370 50% of preferred stock, net of prefunding 493 493 493 243 246 Carrying value of fair value hedges and other items 119 114 112 108 80 Total numerator $ 5,031 $ 5,130 $ 5,235 $ 5,360 $ 5,368 Adjusted stockholders’ equity (2) $ 14,180 $ 14,595 $ 14,987 $ 15,340 $ 15,490 Add: 25% of capital securities and subordinated notes 247 247 247 372 370 50% of preferred stock, net of prefunding 493 493 493 243 246 Total numerator 5,031 5,130 5,235 5,360 5,368 Total denominator $ 19,951 $ 20,465 $ 20,962 $ 21,315 $ 21,474 Leverage ratio 25.2% 25.1% 25.0% 25.1% 25.0% (1) We have categorized as operating debt the senior notes issued in October 2007 and June 2010 because the proceeds were used as a long-term structured solution to reduce the strain on increasing statutory reserves associated with secondary guarantee universal life insurance and term policies. (2) See reconciliation to stockholders’ equity on slide 21.
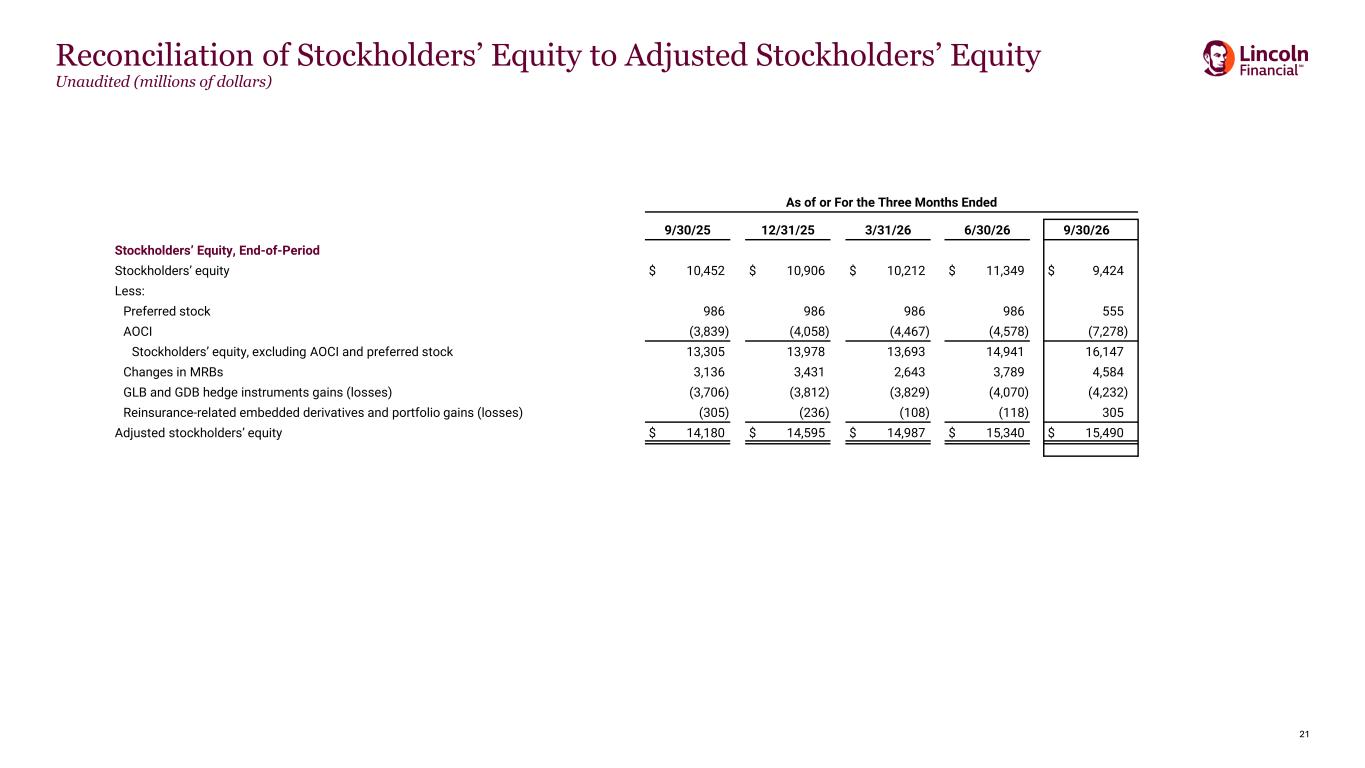
21 Reconciliation of Stockholders’ Equity to Adjusted Stockholders’ Equity Unaudited (millions of dollars) As of or For the Three Months Ended 9/30/25 12/31/25 3/31/26 6/30/26 9/30/26 Stockholders’ Equity, End-of-Period Stockholders’ equity $ 10,452 $ 10,906 $ 10,212 $ 11,349 $ 9,424 Less: Preferred stock 986 986 986 986 555 AOCI (3,839) (4,058) (4,467) (4,578) (7,278) Stockholders’ equity, excluding AOCI and preferred stock 13,305 13,978 13,693 14,941 16,147 Changes in MRBs 3,136 3,431 2,643 3,789 4,584 GLB and GDB hedge instruments gains (losses) (3,706) (3,812) (3,829) (4,070) (4,232) Reinsurance-related embedded derivatives and portfolio gains (losses) (305) (236) (108) (118) 305 Adjusted stockholders’ equity $ 14,180 $ 14,595 $ 14,987 $ 15,340 $ 15,490