Exhibit 99.2 ARRAY and Shoals Announce Transformative Merger, Creating Integrated Energy Infrastructure Platform November 4, 2026
Important Information and Disclaimers Non-GAAP Financial Measures This presentation includes certain financial measures that are not presented in accordance with U.S. Generally Accepted Accounting Principles (“GAAP”), including Adjusted EBITDA, Adjusted Gross Profit, Adjusted Gross Margin, Net Debt, Net Debt to Adjusted EBITDA and Adjusted General and Administrative Expenses. ARRAY and Shoals believe these non-GAAP financial measures provide useful information to investors regarding operating performance because they exclude certain items that management does not believe are indicative of ongoing operating results. The non-GAAP financial information is presented for supplemental informational purposes only and should not be considered a substitute for financial information presented in accordance with GAAP and may be different from similarly titled non-GAAP measures used by other companies. Shoals defines Adjusted EBITDA as net income plus/(minus) (i) interest expense, (ii) interest income, (iii) income tax expense, (iv) depreciation expense, (v) amortization of intangibles, (vi) equity-based compensation, (vii) gain (loss) on sale of asset, (viii) wire insulation shrinkback litigation expenses, (ix) plant optimization expenses, (x) shareholder litigation expenses, (xi) litigation settlement expense, net of insurance recoveries, and (xii) transaction, integration, and restructuring costs. Shoals and ARRAY define Adjusted EBITDA margin as Adjusted EBITDA as a percentage of revenue. ARRAY defines Adjusted EBITDA as net income (loss) to common stockholders plus (i) other income, net, (ii) gain on extinguishment of debts, net, (iii) foreign currency (gain) loss, net, (iv) preferred dividends and accretion, (v) interest expense, (vi) income tax expense, (vii) depreciation expense, (viii) amortization of intangibles, (ix) amortization of developed technology and backlog, (x) equity-based compensation, (xi) change in fair value of contingent consideration, (xii) certain legal expenses, and (xiii) acquisition-related expenses. ARRAY defines Adjusted Gross Profit as gross profit plus (i) amortization of developed technology and backlog and (ii) acquisition-related expenses. ARRAY defines Adjusted Gross Margin as Adjusted Gross Profit as a percentage of revenue. ARRAY defines Adjusted General and Administrative Expenses as general and administrative expense less (i) equity-based compensation, (ii) certain legal expenses, and (iii) acquisition-related expenses. ARRAY defines Net Debt as total debt less cash and cash equivalents and Net Debt to Adjusted EBITDA as Net Debt divided by pro forma Adjusted EBITDA for the applicable period. Shoals and ARRAY define pro forma Adjusted EBITDA as the combined Adjusted EBITDA of ARRAY and Shoals for the applicable period as if the proposed transaction had been completed at the beginning of that period. Pro forma Adjusted EBITDA has not been prepared in accordance with Article 11 of Regulation S-X. For more information regarding the use of these non-GAAP financial measures, please refer to the reconciliations on slides 26 – 29 and Shoals’ and ARRAY’s SEC filings. The companies are not providing a reconciliation of projected Adjusted EBITDA to net income, the most directly comparable GAAP financial measure, because certain information necessary to calculate such measure is not available without unreasonable effort, including items that are uncertain, depend on various factors and could have a material impact on GAAP results. Forward-Looking Statements This presentation contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements may be identified by words such as “anticipates,” “believes,” “could,” “continue,” “estimate,” “expects,” “intends,” “will,” “should,” “may,” “plan,” “predict,” “project,” “would” and similar expressions. These statements include, but are not limited to, statements regarding the expected benefits, timing and completion of the proposed transaction, ARRAY’s and Shoals' plans, objectives, expectations and intentions, the expected ownership of the combined company, the expected leadership and governance structure of the combined company, anticipated financial performance, expected synergies, capital structure actions, redemption of ARRAY’s preferred stock, strategic plans, customer benefits, growth opportunities, the anticipated timing of shareholder meetings and closing of the proposed transaction and other statements that are not historical facts. Forward-looking statements are based on current expectations and assumptions that are subject to risks and uncertainties, many of which are outside the control of ARRAY and Shoals. Actual results may differ materially from those expressed or implied by such forward-looking statements. Important risk factors that may cause such a difference include, but are not limited to: (i) the completion of the proposed transaction on the anticipated terms and timing, including obtaining shareholder and regulatory approvals, the anticipated tax treatment, redemption of ARRAY’s preferred stock, unforeseen liabilities, future capital expenditures, revenues, expenses, earnings, synergies, economic performance, indebtedness, financial condition, losses, future prospects, business and management strategies, expansion and growth of ARRAY’s and Shoals' businesses and the satisfaction of other conditions to the completion of the proposed transaction; (ii) the risk that governmental or regulatory approvals required for the proposed transaction may not be obtained or may result in the imposition of conditions that could adversely affect the combined company or the anticipated benefits of the proposed transaction; (iii) the risk that a condition to closing may not be satisfied, that an event, change or other circumstance could give rise to the termination of the proposed transaction, or that the proposed transaction may not be completed on the expected timeline or at all; (iv) failure to realize the anticipated benefits of the proposed transaction, including because of a delay in completing the transaction or because the businesses of ARRAY and Shoals are not integrated successfully on the anticipated timeline, or at all, or integration is more costly or difficult than expected; (v) the risk that anticipated cost savings and other synergies may not be fully realized or may take longer to realize than expected; (vi) ARRAY’s and Shoals' ability to implement their respective business strategies; (vii) pricing trends; (viii) potential litigation relating to the proposed transaction that could be instituted against ARRAY, Shoals or their respective directors and officers; (ix) the risk that disruptions from the proposed transaction will harm ARRAY’s or Shoals' businesses, including their current plans and operations, or divert management’s attention from ongoing business operations and opportunities; (x) the ability of ARRAY or Shoals to retain and hire key personnel; (xi) potential adverse reactions or changes to business, employee, customer or supplier relationships resulting from the announcement, pendency or completion of the proposed transaction; (xii) the risk that the announcement, pendency or completion of the proposed transaction could adversely affect the market price or long-term value of ARRAY’s or Shoals' common stock; (xiii) legislative, regulatory and economic developments affecting ARRAY’s and Shoals' businesses; (xiv) general economic and market developments and conditions, including changes in the solar industry, interest rates and access to capital; (xv) the evolving legal, regulatory and tax regimes under which ARRAY and Shoals operate; (xvi) potential business uncertainty, including changes to existing business relationships, during the pendency of the proposed transaction that could affect ARRAY’s or Shoals' financial performance; (xvii) restrictions during the pendency of the proposed transaction that may impact ARRAY’s or Shoals' ability to pursue certain business opportunities or strategic transactions; (xviii) the unpredictability and severity of catastrophic events, including acts of terrorism or the outbreak of war or hostilities, as well as ARRAY’s and Shoals' responses to any of the foregoing; and (xix) failure to receive the approval of the shareholders of ARRAY and Shoals. All such factors are difficult to predict, are beyond ARRAY’s and Shoals' control, and are subject to additional risks and uncertainties, including those detailed in ARRAY’s annual report on Form 10-K for the year ended December 31, 2025, quarterly reports on Form 10-Q, and current reports on Form 8-K that are available on its website at www.arraytechinc.com and on the website of the Securities and Exchange Commission at http://www.sec.gov, and those detailed in Shoals' annual report on Form 10-K for the year ended December 31, 2025, quarterly reports on Form 10-Q and current reports on Form 8-K that are available on its website at investors.shoals.com and on the SEC’s website at http://www.sec.gov. Forward-looking statements are based on the estimates and opinions of management at the time the statements are made. Neither ARRAY nor Shoals undertakes any obligation to update forward-looking statements, except as required by law. Readers are cautioned not to place undue reliance on these forward-looking statements that speak only as of the date hereof. No Offer or Solicitation This presentation is for informational purposes only and does not constitute an offer to buy or sell, the solicitation of an offer to buy or sell any securities or a solicitation of any vote or approval in any jurisdiction, nor shall there be any sale of securities in any jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of such jurisdiction. No offering of securities shall be made, except by means of a prospectus meeting the requirements of Section 10 of the U.S. Securities Act of 1933, as amended. Important Additional Information and Where to Find It In connection with the proposed transaction, ARRAY and Shoals expect to file a joint proxy statement with the SEC and ARRAY intends to file with the SEC a registration statement on Form S-4 that will include the joint proxy statement of ARRAY and Shoals and that will also constitute a prospectus of ARRAY. Each of ARRAY and Shoals may also file other relevant documents with the SEC regarding the proposed transaction. This presentation is not a substitute for the joint proxy statement/prospectus or registration statement or any other document that ARRAY or Shoals may file with the SEC. The definitive joint proxy statement/prospectus (if and when available) will be mailed to shareholders of ARRAY and Shoals. INVESTORS AND SECURITY HOLDERS ARE URGED TO READ THE REGISTRATION STATEMENT, JOINT PROXY STATEMENT/PROSPECTUS AND ANY OTHER RELEVANT DOCUMENTS THAT MAY BE FILED WITH THE SEC, AS WELL AS ANY AMENDMENTS OR SUPPLEMENTS TO THOSE DOCUMENTS, CAREFULLY AND IN THEIR ENTIRETY IF AND WHEN THEY BECOME AVAILABLE BECAUSE THEY CONTAIN OR WILL CONTAIN IMPORTANT INFORMATION ABOUT ARRAY, SHOALS AND THE PROPOSED TRANSACTION. Investors and shareholders will be able to obtain free copies of the registration statement and joint proxy statement/prospectus (if and when available) and other documents containing important information about ARRAY, Shoals and the proposed transaction, once such documents are filed with the SEC through the website maintained by the SEC at http://www.sec.gov. Copies of the registration statement and joint proxy statement/prospectus (if and when available) and other documents filed with the SEC by ARRAY may be obtained free of charge on ARRAY’s website at www.arraytechinc.com or, alternatively, by directing a request by mail to ARRAY’s Corporate Secretary at 701 Atrisco Vista Blvd, Albuquerque, New Mexico 87120. Copies of the registration statement and joint proxy statement/prospectus (if and when available) and other documents filed with the SEC by Shoals may be obtained free of charge on Shoals' website at investors.shoals.com or, alternatively, by directing a request by mail to Shoals' Corporate Secretary at 1500 Shoals Way, Portland, Tennessee 37148. Participants in the Solicitation ARRAY, Shoals and certain of their respective directors and executive officers may be deemed to be participants in the solicitation of proxies from shareholders in connection with the proposed transaction. Information regarding the directors and executive officers of ARRAY, including a description of their direct or indirect interests, by security holdings or otherwise, is set forth in ARRAY’s annual report on Form 10-K for the year ended December 31, 2025, including under the heading “Directors, Executive Officers and Corporate Governance,” and proxy statement for ARRAY’s 2026 Annual Meeting of Stockholders, which was filed with the SEC on April 7, 2026, including under the headings “Executive Officers,” “Board of Directors,” “Compensation of Directors” and “Security Ownership of Certain Beneficial Owners and Management.” To the extent holdings of ARRAY common stock by the directors and executive officers of ARRAY have changed from the amounts reflected therein, such changes have been or will be reflected on Initial Statements of Beneficial Ownership of Securities on Form 3 (“Form 3”), Statements of Changes in Beneficial Ownership on Form 4 (“Form 4”) or Annual Statements of Changes in Beneficial Ownership of Securities on Form 5 (“Form 5”), subsequently filed by ARRAY’s directors and executive officers with the SEC. Information about the directors and executive officers of Shoals, including a description of their direct or indirect interests, by security holdings or otherwise, is set forth in Shoals' annual report on Form 10-K for the year ended December 31, 2025, including under the heading “Directors, Executive Officers and Corporate Governance,” and proxy statement for Shoals' 2026 Annual Meeting of shareholders, which was filed with the SEC on March 20, 2026, including under the headings “Board Committees and Membership,” “Compensation of Non-Employee Directors,” “Compensation Discussion and Analysis” and “Security Ownership of Certain Beneficial Owners and Management.” To the extent holdings of Shoals common stock by the directors and executive officers of Shoals have changed from the amounts reflected therein, such changes have been or will be reflected on Forms 3, Forms 4 or Forms 5, subsequently filed by Shoals' directors and executive officers with the SEC. Other information regarding the participants in the proxy solicitations and a description of their direct and indirect interests, by security holdings or otherwise, will be contained in the registration statement and joint proxy statement/prospectus and other relevant materials to be filed with the SEC regarding the proposed transaction when such materials become available. Investors and security holders should read the registration statement and joint proxy statement/prospectus carefully when it becomes available before making any voting or investment decisions. You may obtain free copies of any of the documents referenced herein from ARRAY or Shoals using the sources indicated above. 2
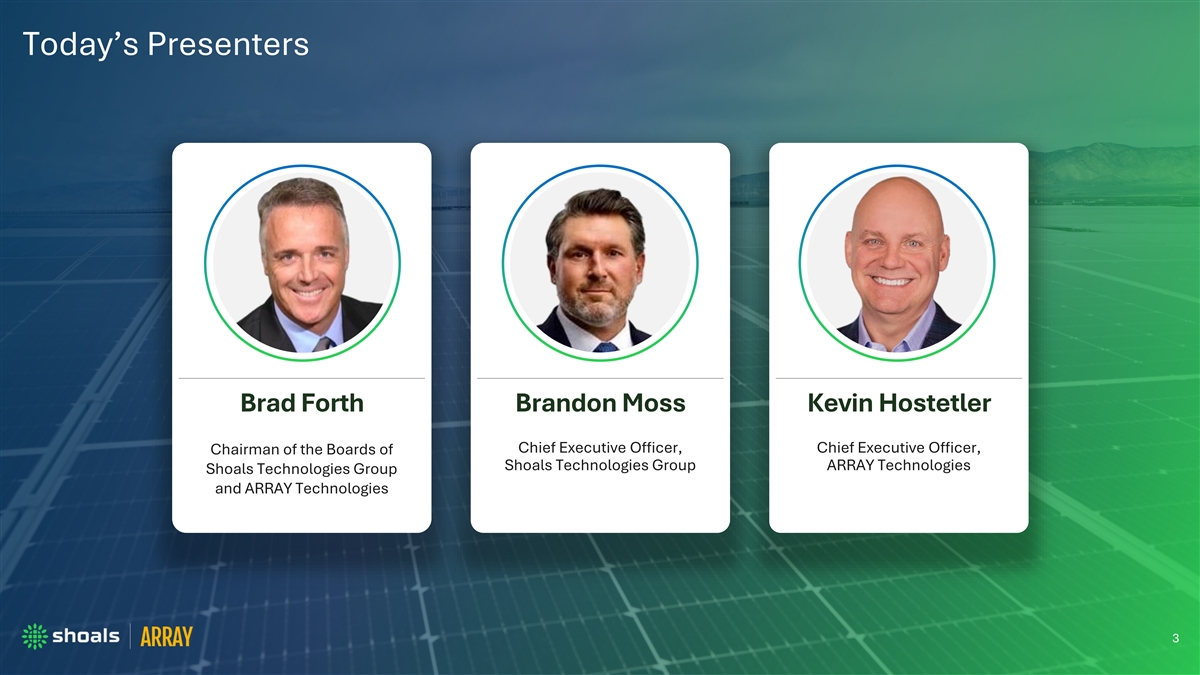
Today’s Presenters Brad Forth Brandon Moss Kevin Hostetler Chief Executive Officer, Chief Executive Officer, Chairman of the Boards of Shoals Technologies Group ARRAY Technologies Shoals Technologies Group and ARRAY Technologies 3
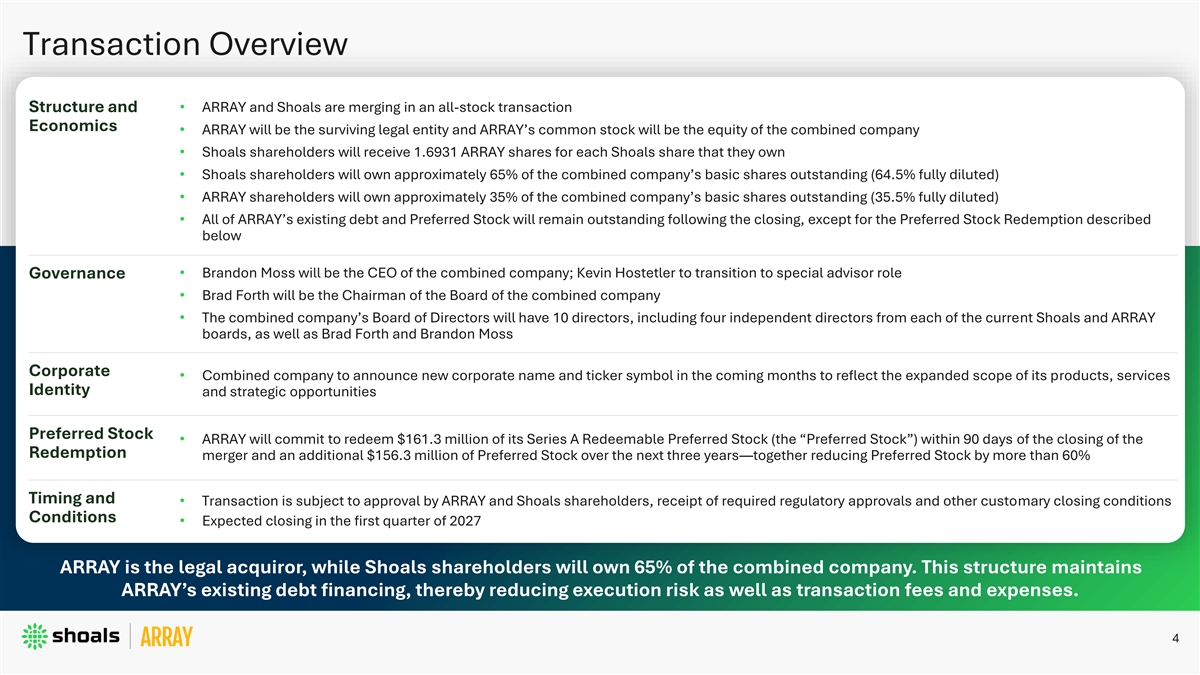
LW comment for the second bullet on the page: Should the legal entity be the parent entity since Shoals is merging into ARRAY merger sub (a Transaction Overview subsidiary of ARRAY) Structure and • ARRAY and Shoals are merging in an all-stock transaction Economics • ARRAY will be the surviving legal entity and ARRAY’s common stock will be the equity of the combined company • Shoals shareholders will receive 1.6931 ARRAY shares for each Shoals share that they own • Shoals shareholders will own approximately 65% of the combined company’s basic shares outstanding (64.5% fully diluted) • ARRAY shareholders will own approximately 35% of the combined company’s basic shares outstanding (35.5% fully diluted) • All of ARRAY’s existing debt and Preferred Stock will remain outstanding following the closing, except for the Preferred Stock Redemption described below • Brandon Moss will be the CEO of the combined company; Kevin Hostetler to transition to special advisor role Governance • Brad Forth will be the Chairman of the Board of the combined company • The combined company’s Board of Directors will have 10 directors, including four independent directors from each of the current Shoals and ARRAY boards, as well as Brad Forth and Brandon Moss Corporate • Combined company to announce new corporate name and ticker symbol in the coming months to reflect the expanded scope of its products, services Identity and strategic opportunities Preferred Stock • ARRAY will commit to redeem $161.3 million of its Series A Redeemable Preferred Stock (the “Preferred Stock”) within 90 days of the closing of the Redemption merger and an additional $156.3 million of Preferred Stock over the next three years—together reducing Preferred Stock by more than 60% Timing and • Transaction is subject to approval by ARRAY and Shoals shareholders, receipt of required regulatory approvals and other customary closing conditions Conditions • Expected closing in the first quarter of 2027 ARRAY is the legal acquiror, while Shoals shareholders will own 65% of the combined company. This structure maintains ARRAY’s existing debt financing, thereby reducing execution risk as well as transaction fees and expenses. 4
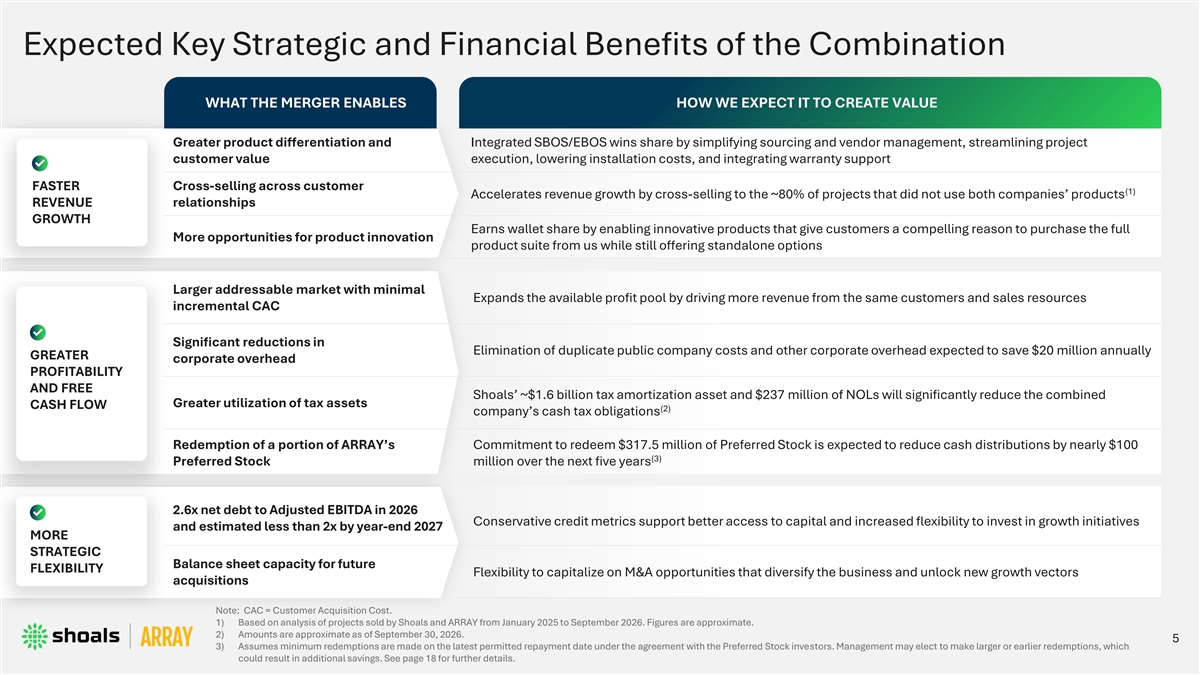
Expected Key Strategic and Financial Benefits of the Combination WHAT THE MERGER ENABLES HOW WE EXPECT IT TO CREATE VALUE Greater product differentiation and Integrated SBOS/EBOS wins share by simplifying sourcing and vendor management, streamlining project customer value execution, lowering installation costs, and integrating warranty support FASTER Cross-selling across customer (1) Accelerates revenue growth by cross-selling to the ~80% of projects that did not use both companies’ products REVENUE relationships GROWTH Earns wallet share by enabling innovative products that give customers a compelling reason to purchase the full More opportunities for product innovation product suite from us while still offering standalone options Larger addressable market with minimal Expands the available profit pool by driving more revenue from the same customers and sales resources incremental CAC Significant reductions in Elimination of duplicate public company costs and other corporate overhead expected to save $20 million annually GREATER corporate overhead PROFITABILITY AND FREE Shoals’ ~$1.6 billion tax amortization asset and $237 million of NOLs will significantly reduce the combined Greater utilization of tax assets CASH FLOW (2) company’s cash tax obligations Redemption of a portion of ARRAY’s Commitment to redeem $317.5 million of Preferred Stock is expected to reduce cash distributions by nearly $100 (3) Preferred Stock million over the next five years 2.6x net debt to Adjusted EBITDA in 2026 Conservative credit metrics support better access to capital and increased flexibility to invest in growth initiatives and estimated less than 2x by year-end 2027 MORE STRATEGIC Balance sheet capacity for future FLEXIBILITY Flexibility to capitalize on M&A opportunities that diversify the business and unlock new growth vectors acquisitions Note: CAC = Customer Acquisition Cost. 1) Based on analysis of projects sold by Shoals and ARRAY from January 2025 to September 2026. Figures are approximate. 2) Amounts are approximate as of September 30, 2026. 5 3) Assumes minimum redemptions are made on the latest permitted repayment date under the agreement with the Preferred Stock investors. Management may elect to make larger or earlier redemptions, which could result in additional savings. See page 18 for further details.
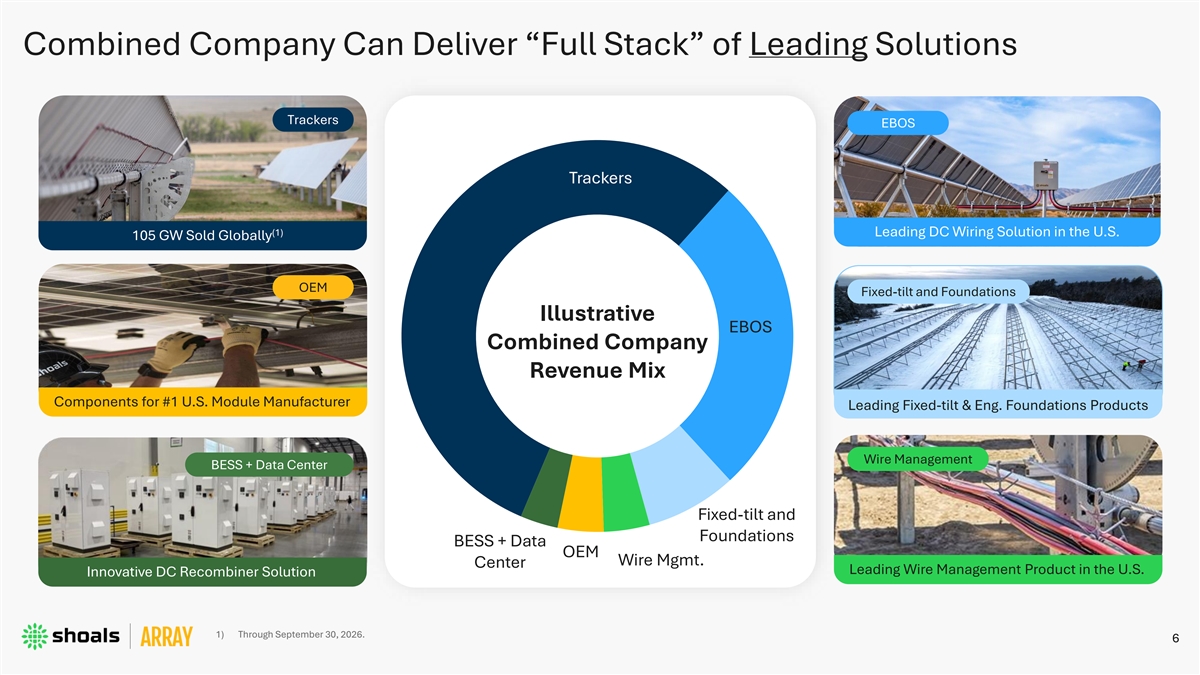
Combined Company Can Deliver “Full Stack” of Leading Solutions Trackers EBOS Trackers (1) Leading DC Wiring Solution in the U.S. 105 GW Sold Globally OEM Fixed-tilt and Foundations Illustrative EBOS Combined Company Revenue Mix Components for #1 U.S. Module Manufacturer Leading Fixed-tilt & Eng. Foundations Products Wire Management BESS + Data Center Fixed-tilt and Foundations BESS + Data OEM Wire Mgmt. Center Leading Wire Management Product in the U.S. Innovative DC Recombiner Solution 1) Through September 30, 2026. 6 6
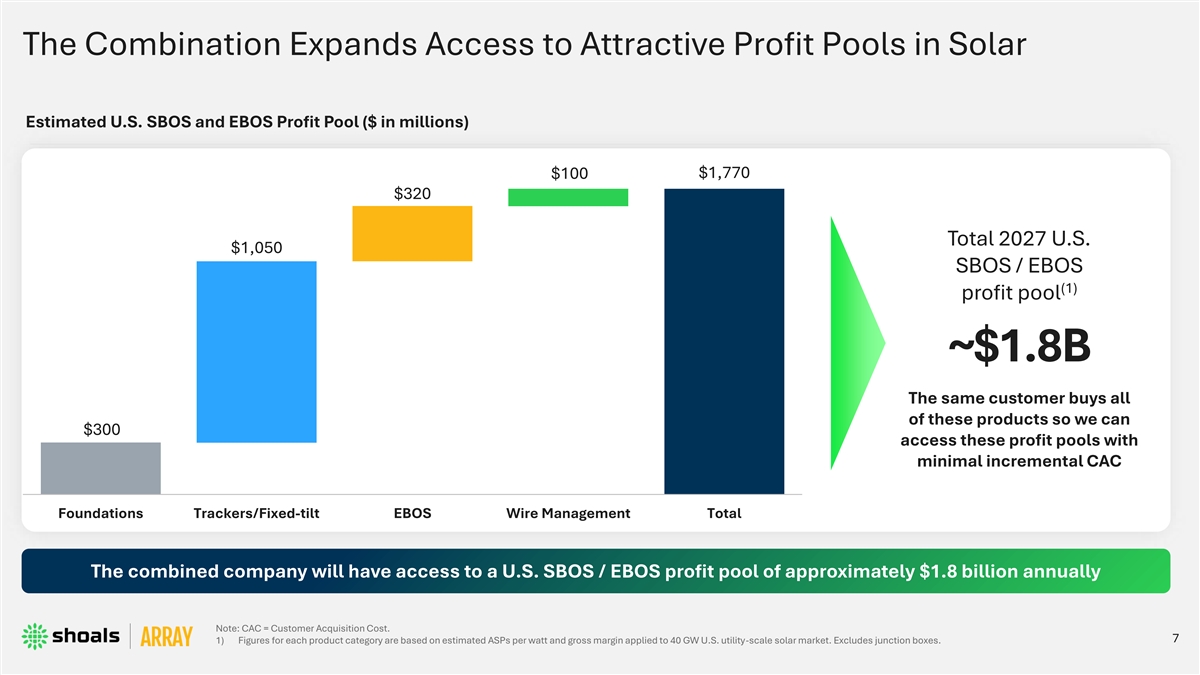
Note: ARRAY showed different TAM numbers at APA showcase in August ($4.3B utility scale tracker US TAM, $1.7B foundations, $150M+ wire The Combination Expands Access to Attractive Profit Pools in Solar management) Estimated U.S. SBOS and EBOS Profit Pool ($ in millions) $100 $1,770 $320 Total 2027 U.S. $1,050 SBOS / EBOS (1) profit pool ~$1.8B The same customer buys all of these products so we can $300 access these profit pools with minimal incremental CAC Foundations Trackers/Fixed-tilt EBOS Wire Management Total The combined company will have access to a U.S. SBOS / EBOS profit pool of approximately $1.8 billion annually Note: CAC = Customer Acquisition Cost. 7 1) Figures for each product category are based on estimated ASPs per watt and gross margin applied to 40 GW U.S. utility-scale solar market. Excludes junction boxes.
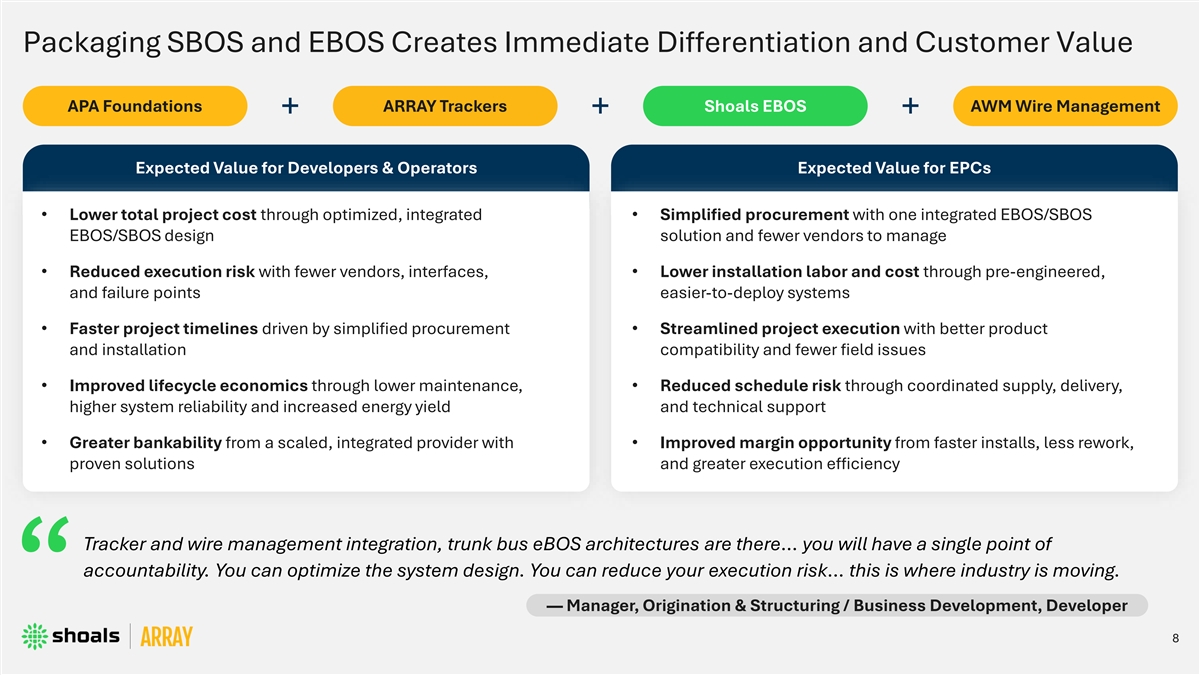
Packaging SBOS and EBOS Creates Immediate Differentiation and Customer Value APA Foundations ARRAY Trackers Shoals EBOS AWM Wire Management + + + Expected Value for Developers & Operators Expected Value for EPCs • Lower total project cost through optimized, integrated • Simplified procurement with one integrated EBOS/SBOS EBOS/SBOS design solution and fewer vendors to manage • Reduced execution risk with fewer vendors, interfaces, • Lower installation labor and cost through pre-engineered, and failure points easier-to-deploy systems • Faster project timelines driven by simplified procurement • Streamlined project execution with better product and installation compatibility and fewer field issues • Improved lifecycle economics through lower maintenance, • Reduced schedule risk through coordinated supply, delivery, higher system reliability and increased energy yield and technical support • Greater bankability from a scaled, integrated provider with • Improved margin opportunity from faster installs, less rework, proven solutions and greater execution efficiency Tracker and wire management integration, trunk bus eBOS architectures are there… you will have a single point of accountability. You can optimize the system design. You can reduce your execution risk… this is where industry is moving. — Manager, Origination & Structuring / Business Development, Developer “ 8
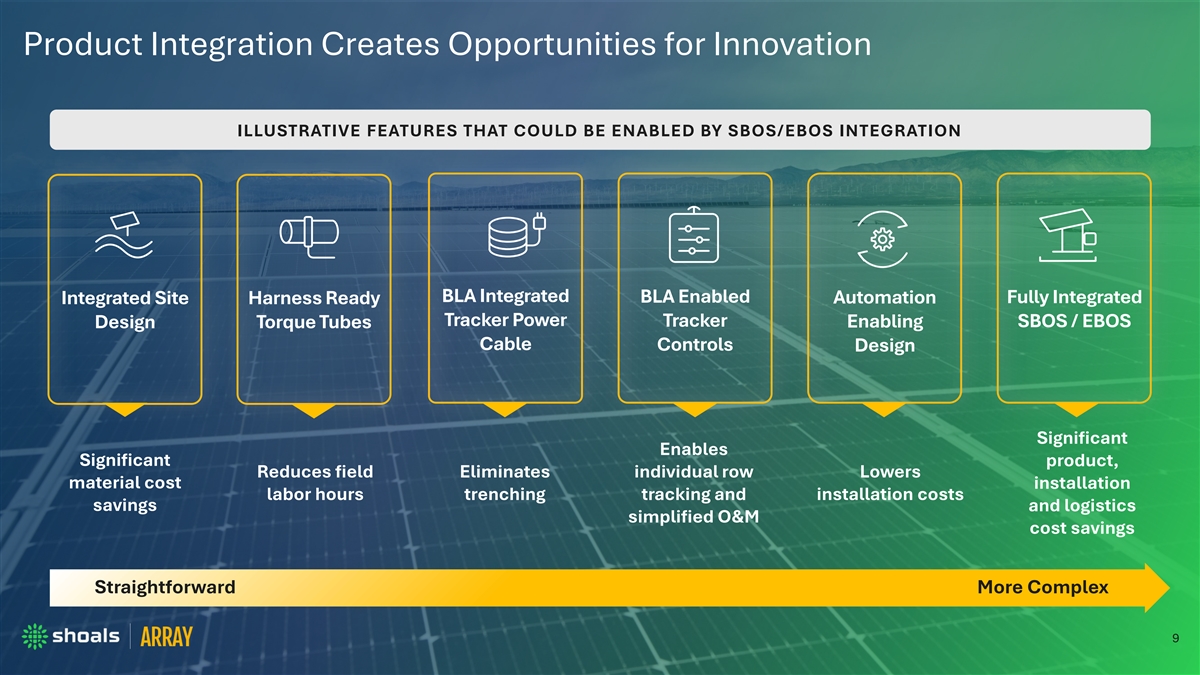
Product Integration Creates Opportunities for Innovation ILLUSTRATIVE FEATURES THAT COULD BE ENABLED BY SBOS/EBOS INTEGRATION BLA Integrated BLA Enabled Automation Fully Integrated Integrated Site Harness Ready Tracker Power Tracker Enabling SBOS / EBOS Design Torque Tubes Cable Controls Design Significant Enables Significant product, Reduces field Eliminates individual row Lowers material cost installation labor hours trenching tracking and installation costs savings and logistics simplified O&M cost savings Straightforward More Complex 9
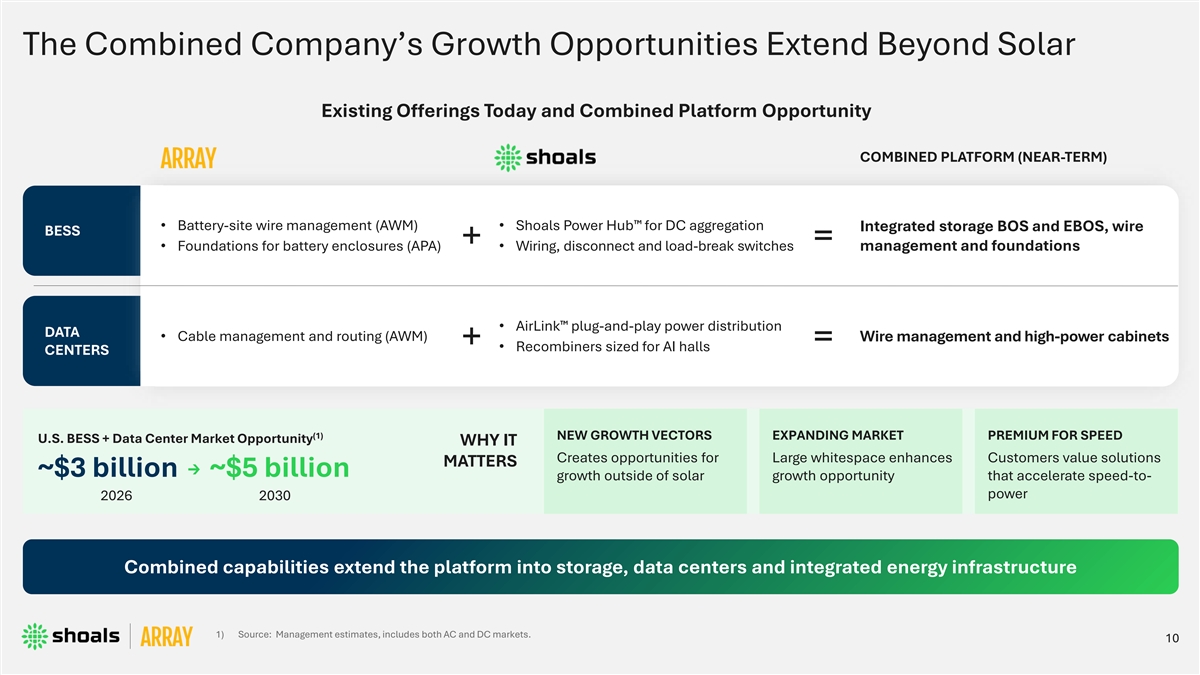
The Combined Company’s Growth Opportunities Extend Beyond Solar Existing Offerings Today and Combined Platform Opportunity COMBINED PLATFORM (NEAR-TERM) • Battery-site wire management (AWM)• Shoals Power Hub for DC aggregation Integrated storage BOS and EBOS, wire BESS + = • Foundations for battery enclosures (APA)• Wiring, disconnect and load-break switches management and foundations • AirLink plug-and-play power distribution DATA • Cable management and routing (AWM) Wire management and high-power cabinets + = • Recombiners sized for AI halls CENTERS (1) NEW GROWTH VECTORS EXPANDING MARKET PREMIUM FOR SPEED U.S. BESS + Data Center Market Opportunity WHY IT Creates opportunities for Large whitespace enhances Customers value solutions MATTERS ~$3 billion → ~$5 billion growth outside of solar growth opportunity that accelerate speed-to- power 2026 2030 Combined capabilities extend the platform into storage, data centers and integrated energy infrastructure 1) Source: Management estimates, includes both AC and DC markets. 10
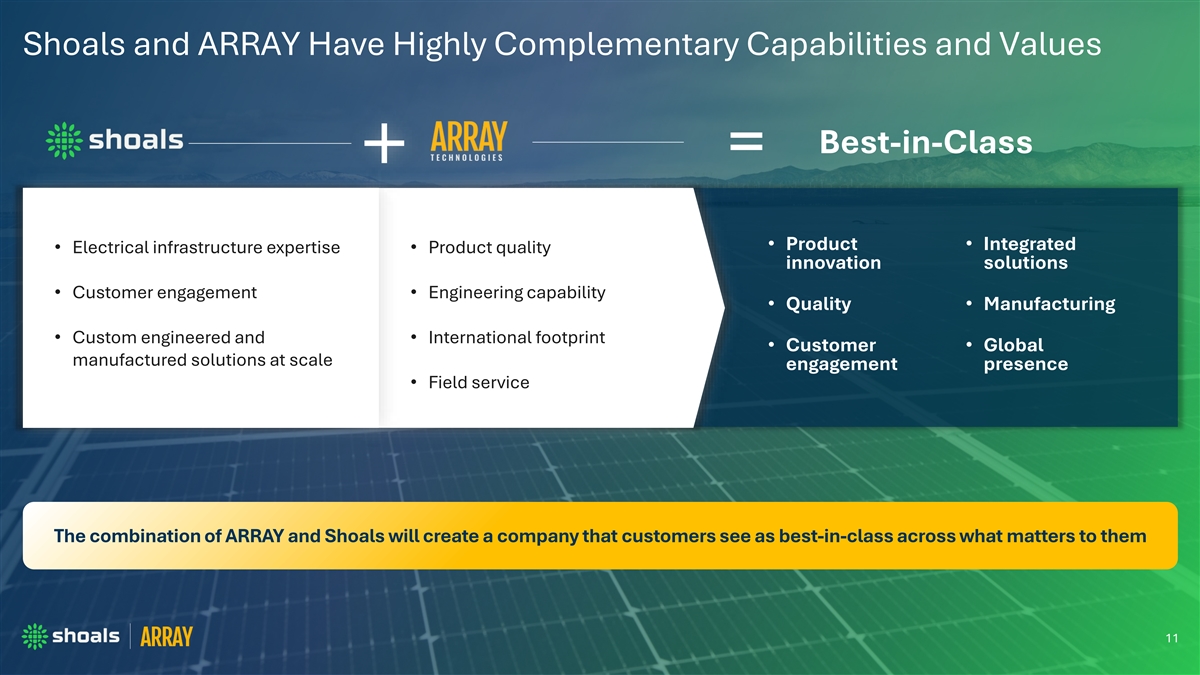
Shoals and ARRAY Have Highly Complementary Capabilities and Values Best-in-Class = • Product • Integrated • Electrical infrastructure expertise• Product quality innovation solutions • Customer engagement• Engineering capability • Quality• Manufacturing • Custom engineered and • International footprint • Customer • Global manufactured solutions at scale engagement presence • Field service The combination of ARRAY and Shoals will create a company that customers see as best-in-class across what matters to them 11
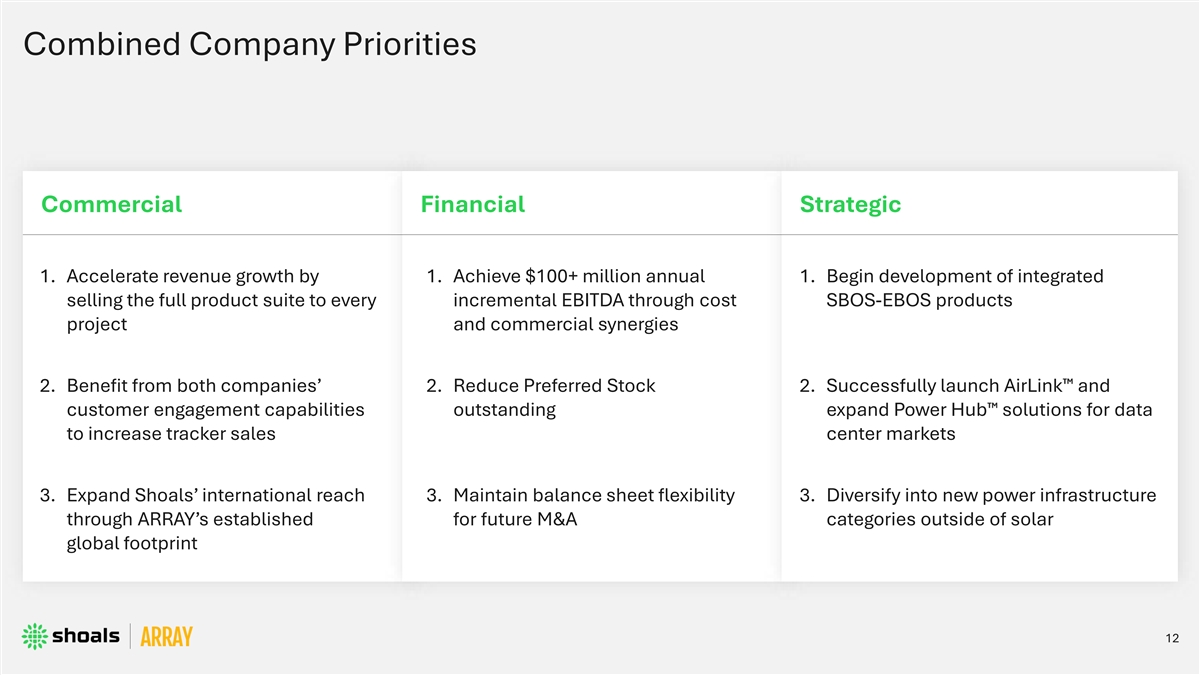
Combined Company Priorities Commercial Financial Strategic 1. Accelerate revenue growth by 1. Achieve $100+ million annual 1. Begin development of integrated selling the full product suite to every incremental EBITDA through cost SBOS-EBOS products project and commercial synergies 2. Benefit from both companies’ 2. Reduce Preferred Stock 2. Successfully launch AirLink and customer engagement capabilities outstanding expand Power Hub solutions for data to increase tracker sales center markets 3. Expand Shoals’ international reach 3. Maintain balance sheet flexibility 3. Diversify into new power infrastructure through ARRAY’s established for future M&A categories outside of solar global footprint 12
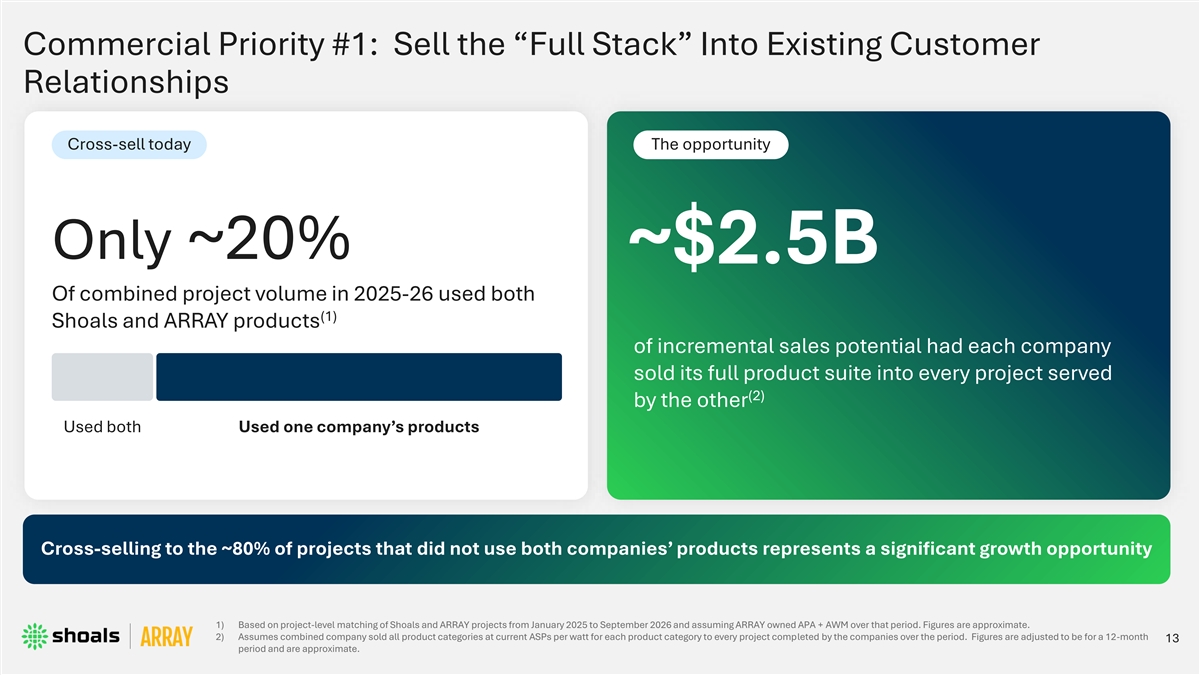
Commercial Priority #1: Sell the “Full Stack” Into Existing Customer Relationships Cross-sell today The opportunity Only ~20% ~$2.5B Of combined project volume in 2025-26 used both (1) Shoals and ARRAY products of incremental sales potential had each company sold its full product suite into every project served (2) by the other Used both Used one company’s products Cross-selling to the ~80% of projects that did not use both companies’ products represents a significant growth opportunity 1) Based on project-level matching of Shoals and ARRAY projects from January 2025 to September 2026 and assuming ARRAY owned APA + AWM over that period. Figures are approximate. 2) Assumes combined company sold all product categories at current ASPs per watt for each product category to every project completed by the companies over the period. Figures are adjusted to be for a 12-month 13 period and are approximate.
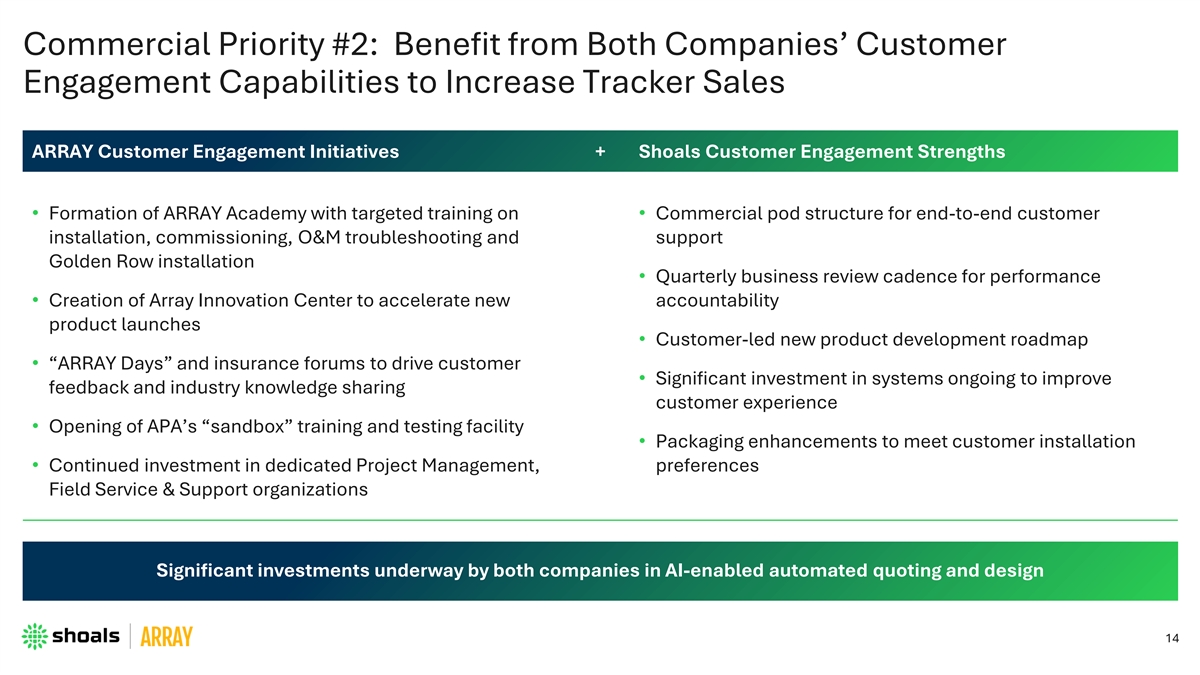
Commercial Priority #2: Benefit from Both Companies’ Customer Engagement Capabilities to Increase Tracker Sales ARRAY Customer Engagement Initiatives + Shoals Customer Engagement Strengths • Formation of ARRAY Academy with targeted training on • Commercial pod structure for end-to-end customer installation, commissioning, O&M troubleshooting and support Golden Row installation • Quarterly business review cadence for performance • Creation of Array Innovation Center to accelerate new accountability product launches • Customer-led new product development roadmap • “ARRAY Days” and insurance forums to drive customer • Significant investment in systems ongoing to improve feedback and industry knowledge sharing customer experience • Opening of APA’s “sandbox” training and testing facility • Packaging enhancements to meet customer installation • Continued investment in dedicated Project Management, preferences Field Service & Support organizations Significant investments underway by both companies in AI-enabled automated quoting and design 14
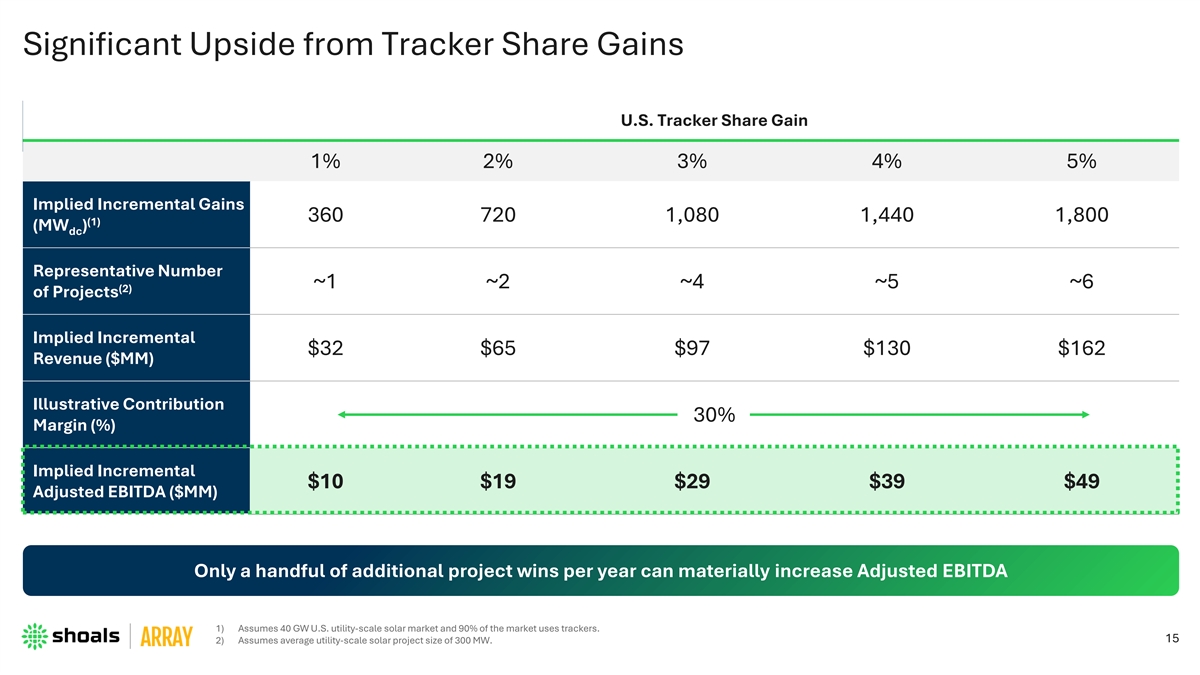
Significant Upside from Tracker Share Gains U.S. Tracker Share Gain 1% 2% 3% 4% 5% Implied Incremental Gains 360 720 1,080 1,440 1,800 (1) (MW ) dc Representative Number ~1 ~2 ~4 ~5 ~6 (2) of Projects Implied Incremental $32 $65 $97 $130 $162 Revenue ($MM) Illustrative Contribution 30% Margin (%) Implied Incremental $10 $19 $29 $39 $49 Adjusted EBITDA ($MM) Only a handful of additional project wins per year can materially increase Adjusted EBITDA 1) Assumes 40 GW U.S. utility-scale solar market and 90% of the market uses trackers. 15 2) Assumes average utility-scale solar project size of 300 MW.
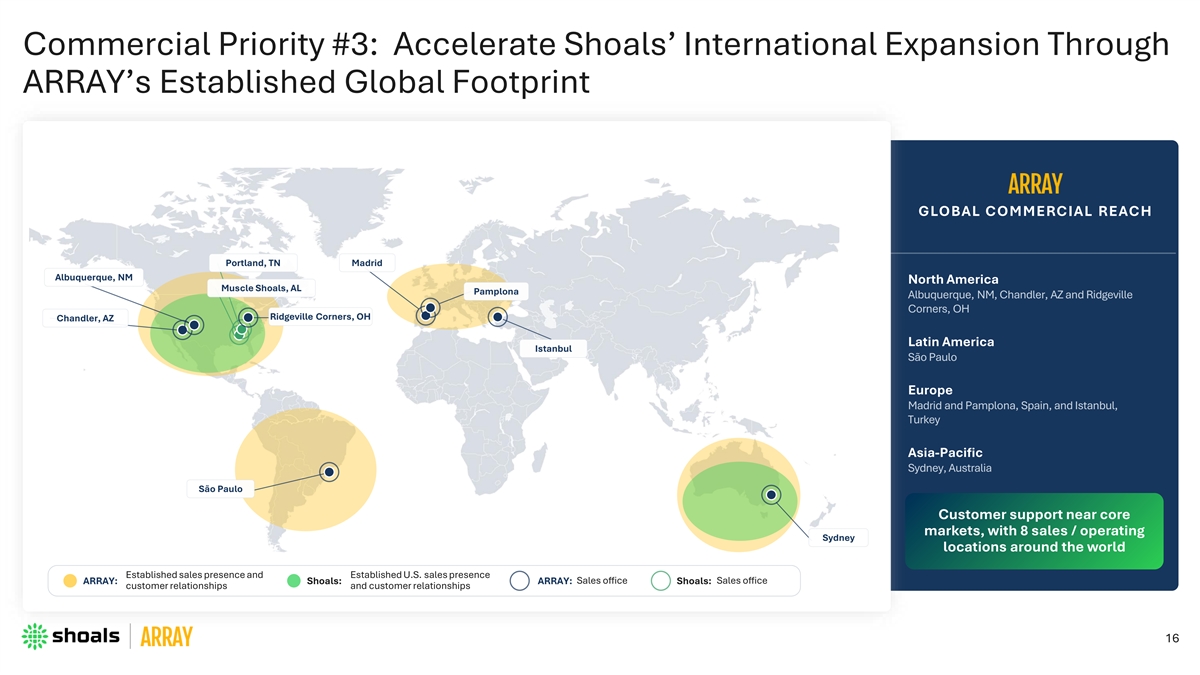
Commercial Priority #3: Accelerate Shoals’ International Expansion Through ARRAY’s Established Global Footprint GLOBAL COMMERCIAL REACH Portland, TN Madrid Albuquerque, NM North America Muscle Shoals, AL Pamplona Albuquerque, NM, Chandler, AZ and Ridgeville Corners, OH Ridgeville Corners, OH Chandler, AZ Latin America Istanbul São Paulo Europe Madrid and Pamplona, Spain, and Istanbul, Turkey Asia-Pacific Sydney, Australia São Paulo Customer support near core markets, with 8 sales / operating Sydney locations around the world Established sales presence and Established U.S. sales presence ARRAY: Shoals: ARRAY: Sales office Shoals: Sales office customer relationships and customer relationships 16
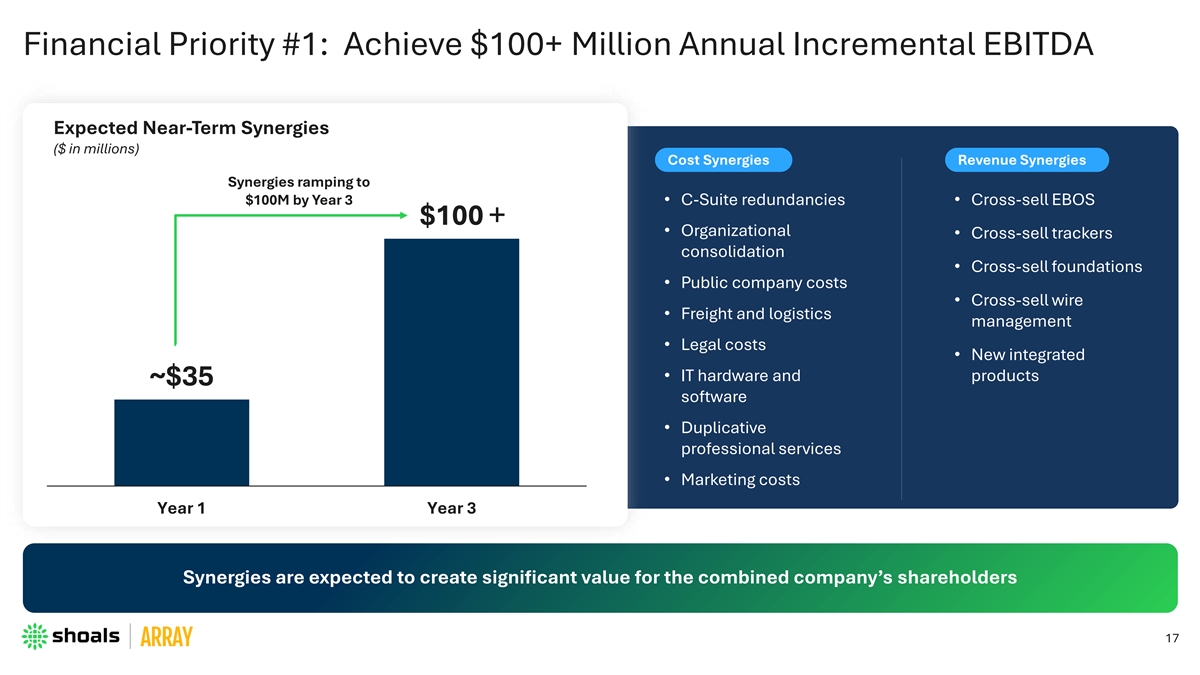
Financial Priority #1: Achieve $100+ Million Annual Incremental EBITDA Expected Near-Term Synergies ($ in millions) Cost Synergies Revenue Synergies Synergies ramping to $100M by Year 3• C-Suite redundancies• Cross-sell EBOS $100 + • Organizational • Cross-sell trackers consolidation • Cross-sell foundations • Public company costs • Cross-sell wire • Freight and logistics management • Legal costs • New integrated • IT hardware and products ~$35 software • Duplicative professional services • Marketing costs Year 1 Year 3 Synergies are expected to create significant value for the combined company’s shareholders 17
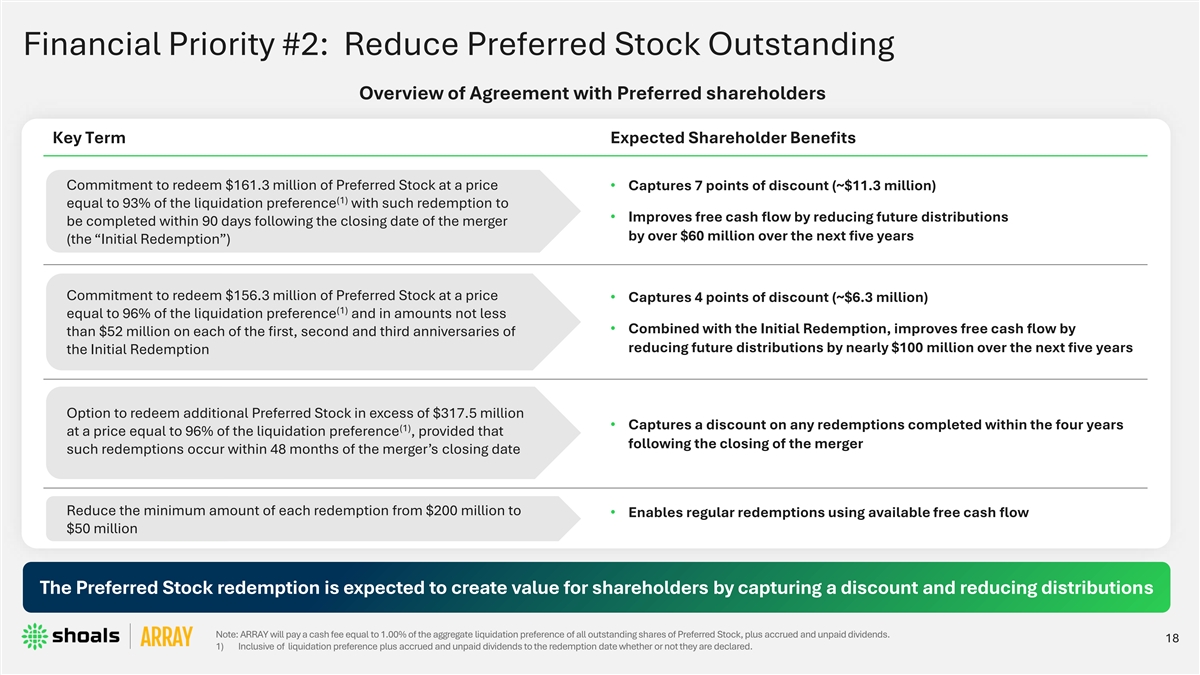
Financial Priority #2: Reduce Preferred Stock Outstanding Overview of Agreement with Preferred shareholders Key Term Expected Shareholder Benefits Commitment to redeem $161.3 million of Preferred Stock at a price • Captures 7 points of discount (~$11.3 million) (1) equal to 93% of the liquidation preference with such redemption to • Improves free cash flow by reducing future distributions be completed within 90 days following the closing date of the merger by over $60 million over the next five years (the “Initial Redemption”) Commitment to redeem $156.3 million of Preferred Stock at a price • Captures 4 points of discount (~$6.3 million) (1) equal to 96% of the liquidation preference and in amounts not less • Combined with the Initial Redemption, improves free cash flow by than $52 million on each of the first, second and third anniversaries of reducing future distributions by nearly $100 million over the next five years the Initial Redemption Option to redeem additional Preferred Stock in excess of $317.5 million • Captures a discount on any redemptions completed within the four years (1) at a price equal to 96% of the liquidation preference , provided that following the closing of the merger such redemptions occur within 48 months of the merger’s closing date Reduce the minimum amount of each redemption from $200 million to • Enables regular redemptions using available free cash flow $50 million The Preferred Stock redemption is expected to create value for shareholders by capturing a discount and reducing distributions Note: ARRAY will pay a cash fee equal to 1.00% of the aggregate liquidation preference of all outstanding shares of Preferred Stock, plus accrued and unpaid dividends. 18 1) Inclusive of liquidation preference plus accrued and unpaid dividends to the redemption date whether or not they are declared.
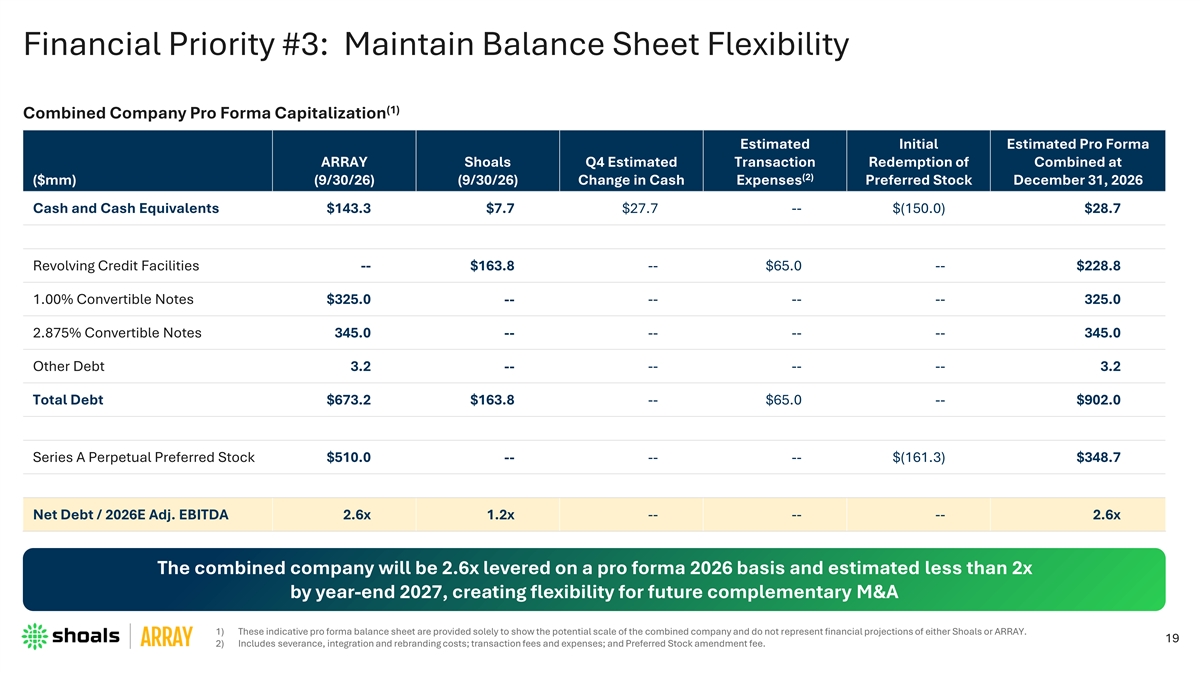
Financial Priority #3: Maintain Balance Sheet Flexibility (1) Combined Company Pro Forma Capitalization Estimated Initial Estimated Pro Forma ARRAY Shoals Q4 Estimated Transaction Redemption of Combined at (2) ($mm) (9/30/26) (9/30/26) Change in Cash Expenses Preferred Stock December 31, 2026 Cash and Cash Equivalents $143.3 $7.7 $27.7 -- $(150.0) $28.7 Revolving Credit Facilities -- $163.8 -- $65.0 -- $228.8 1.00% Convertible Notes $325.0 -- -- -- -- 325.0 2.875% Convertible Notes 345.0 -- -- -- -- 345.0 Other Debt 3.2 -- -- -- -- 3.2 Total Debt $673.2 $163.8 -- $65.0 -- $902.0 Series A Perpetual Preferred Stock $510.0 -- -- -- $(161.3) $348.7 Net Debt / 2026E Adj. EBITDA 2.6x 1.2x -- -- -- 2.6x The combined company will be 2.6x levered on a pro forma 2026 basis and estimated less than 2x by year-end 2027, creating flexibility for future complementary M&A 1) These indicative pro forma balance sheet are provided solely to show the potential scale of the combined company and do not represent financial projections of either Shoals or ARRAY. 19 2) Includes severance, integration and rebranding costs; transaction fees and expenses; and Preferred Stock amendment fee.
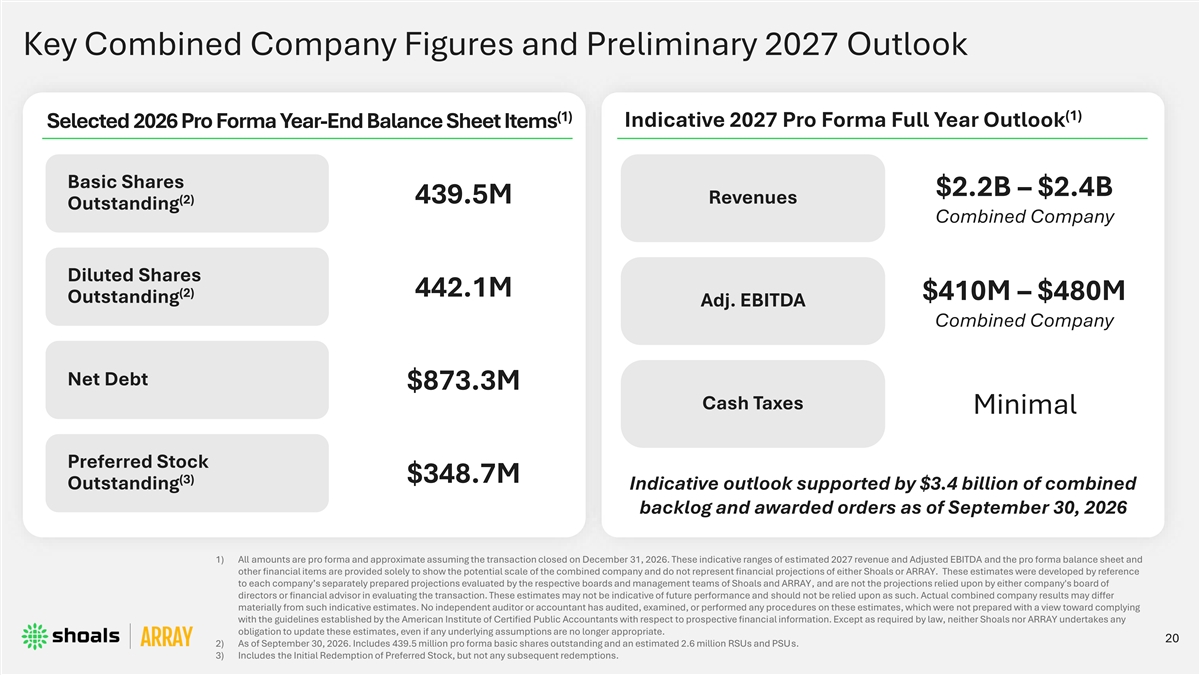
Key Combined Company Figures and Preliminary 2027 Outlook (1) (1) Indicative 2027 Pro Forma Full Year Outlook Selected 2026 Pro Forma Year-End Balance Sheet Items Basic Shares $2.2B – $2.4B (2) 439.5M Revenues Outstanding Combined Company Diluted Shares 442.1M (2) $410M – $480M Outstanding Adj. EBITDA Combined Company Net Debt $873.3M Cash Taxes Minimal Preferred Stock $348.7M (3) Outstanding Indicative outlook supported by $3.4 billion of combined backlog and awarded orders as of September 30, 2026 1) All amounts are pro forma and approximate assuming the transaction closed on December 31, 2026. These indicative ranges of estimated 2027 revenue and Adjusted EBITDA and the pro forma balance sheet and other financial items are provided solely to show the potential scale of the combined company and do not represent financial projections of either Shoals or ARRAY. These estimates were developed by reference to each company’s separately prepared projections evaluated by the respective boards and management teams of Shoals and ARRAY, and are not the projections relied upon by either company's board of directors or financial advisor in evaluating the transaction. These estimates may not be indicative of future performance and should not be relied upon as such. Actual combined company results may differ materially from such indicative estimates. No independent auditor or accountant has audited, examined, or performed any procedures on these estimates, which were not prepared with a view toward complying with the guidelines established by the American Institute of Certified Public Accountants with respect to prospective financial information. Except as required by law, neither Shoals nor ARRAY undertakes any obligation to update these estimates, even if any underlying assumptions are no longer appropriate. 20 2) As of September 30, 2026. Includes 439.5 million pro forma basic shares outstanding and an estimated 2.6 million RSUs and PSUs. 3) Includes the Initial Redemption of Preferred Stock, but not any subsequent redemptions.
Q3 Earnings 21
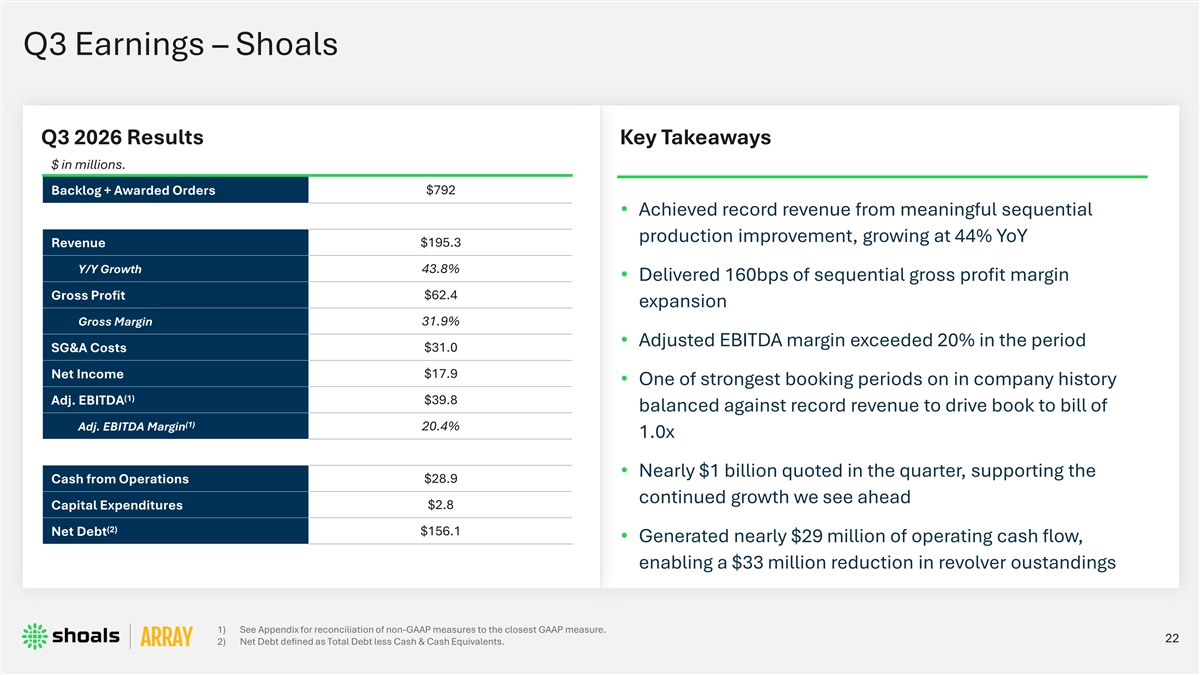
Q3 Earnings – Shoals Q3 2026 Results Key Takeaways $ in millions. Backlog + Awarded Orders $792 • Achieved record revenue from meaningful sequential production improvement, growing at 44% YoY Revenue $195.3 Y/Y Growth 43.8% • Delivered 160bps of sequential gross profit margin Gross Profit $62.4 expansion Gross Margin 31.9% • Adjusted EBITDA margin exceeded 20% in the period SG&A Costs $31.0 Net Income $17.9 • One of strongest booking periods on in company history (1) Adj. EBITDA $39.8 balanced against record revenue to drive book to bill of (1) 20.4% Adj. EBITDA Margin 1.0x • Nearly $1 billion quoted in the quarter, supporting the $28.9 Cash from Operations continued growth we see ahead $2.8 Capital Expenditures (2) $156.1 Net Debt • Generated nearly $29 million of operating cash flow, enabling a $33 million reduction in revolver oustandings 1) See Appendix for reconciliation of non-GAAP measures to the closest GAAP measure. 22 2) Net Debt defined as Total Debt less Cash & Cash Equivalents.
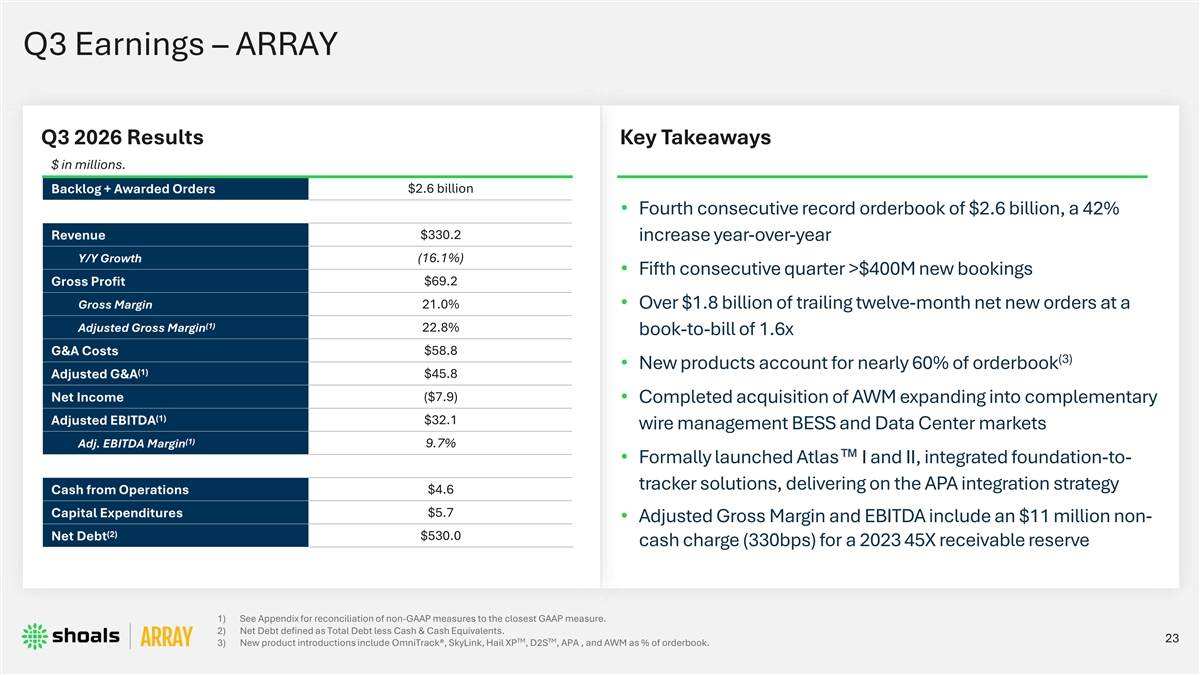
Q3 Earnings – ARRAY Q3 2026 Results Key Takeaways $ in millions. $2.6 billion Backlog + Awarded Orders • Fourth consecutive record orderbook of $2.6 billion, a 42% $330.2 Revenue increase year-over-year Y/Y Growth (16.1%) • Fifth consecutive quarter >$400M new bookings $69.2 Gross Profit Gross Margin 21.0%• Over $1.8 billion of trailing twelve-month net new orders at a (1) 22.8% Adjusted Gross Margin book-to-bill of 1.6x G&A Costs $58.8 (3) • New products account for nearly 60% of orderbook (1) Adjusted G&A $45.8 Net Income ($7.9) • Completed acquisition of AWM expanding into complementary (1) Adjusted EBITDA $32.1 wire management BESS and Data Center markets (1) Adj. EBITDA Margin 9.7% • Formally launched Atlas I and II, integrated foundation-to- tracker solutions, delivering on the APA integration strategy Cash from Operations $4.6 Capital Expenditures $5.7 • Adjusted Gross Margin and EBITDA include an $11 million non- (2) $530.0 Net Debt cash charge (330bps) for a 2023 45X receivable reserve 1) See Appendix for reconciliation of non-GAAP measures to the closest GAAP measure. 2) Net Debt defined as Total Debt less Cash & Cash Equivalents. TM TM 23 3) New product introductions include OmniTrack®, SkyLink, Hail XP , D2S , APA , and AWM as % of orderbook.
Q&A 24
Appendix 25
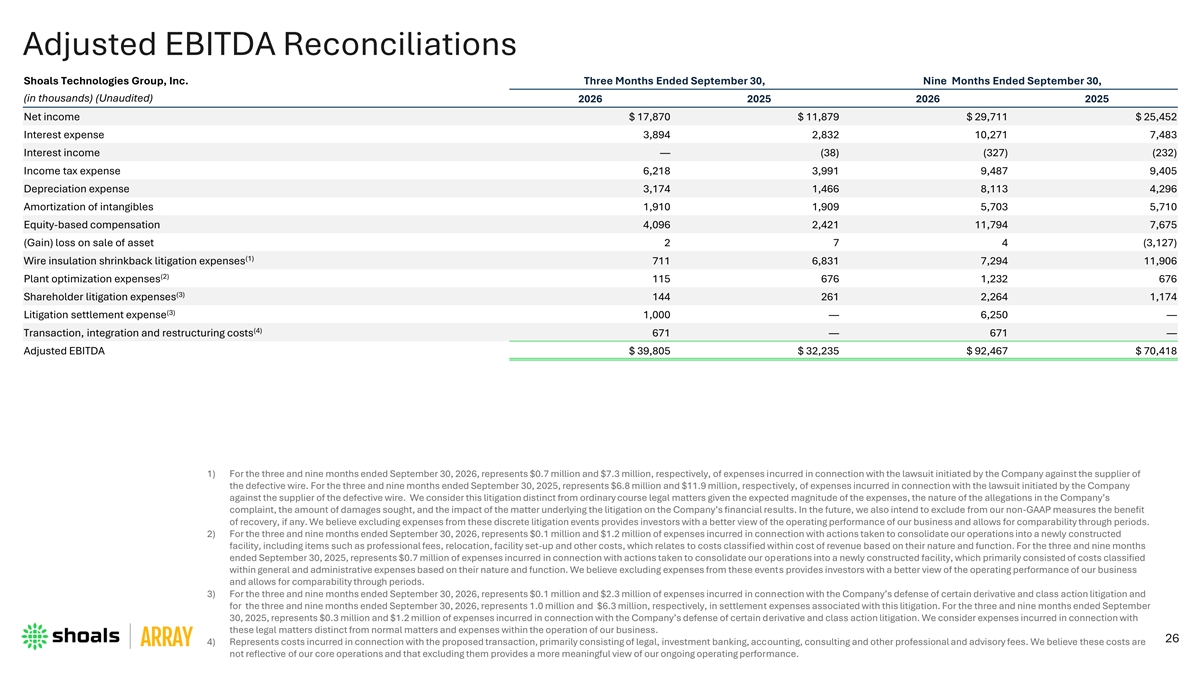
Adjusted EBITDA Reconciliations Shoals Technologies Group, Inc. Three Months Ended September 30, Nine Months Ended September 30, (in thousands) (Unaudited) 2026 2025 2026 2025 Net income $ 17,870 $ 11,879 $ 29,711 $ 25,452 Interest expense 3,894 2,832 10,271 7,483 Interest income — (38) (327) (232) Income tax expense 6,218 3,991 9,487 9,405 Depreciation expense 3,174 1,466 8,113 4,296 Amortization of intangibles 1,910 1,909 5,703 5,710 Equity-based compensation 4,096 2,421 11,794 7,675 (Gain) loss on sale of asset 2 7 4 (3,127) (1) Wire insulation shrinkback litigation expenses 711 6,831 7,294 11,906 (2) Plant optimization expenses 115 676 1,232 676 (3) Shareholder litigation expenses 144 261 2,264 1,174 (3) Litigation settlement expense 1,000 — 6,250 — (4) Transaction, integration and restructuring costs 671 — 671 — Adjusted EBITDA $ 39,805 $ 32,235 $ 92,467 $ 70,418 1) For the three and nine months ended September 30, 2026, represents $0.7 million and $7.3 million, respectively, of expenses incurred in connection with the lawsuit initiated by the Company against the supplier of the defective wire. For the three and nine months ended September 30, 2025, represents $6.8 million and $11.9 million, respectively, of expenses incurred in connection with the lawsuit initiated by the Company against the supplier of the defective wire. We consider this litigation distinct from ordinary course legal matters given the expected magnitude of the expenses, the nature of the allegations in the Company’s complaint, the amount of damages sought, and the impact of the matter underlying the litigation on the Company’s financial results. In the future, we also intend to exclude from our non-GAAP measures the benefit of recovery, if any. We believe excluding expenses from these discrete litigation events provides investors with a better view of the operating performance of our business and allows for comparability through periods. 2) For the three and nine months ended September 30, 2026, represents $0.1 million and $1.2 million of expenses incurred in connection with actions taken to consolidate our operations into a newly constructed facility, including items such as professional fees, relocation, facility set-up and other costs, which relates to costs classified within cost of revenue based on their nature and function. For the three and nine months ended September 30, 2025, represents $0.7 million of expenses incurred in connection with actions taken to consolidate our operations into a newly constructed facility, which primarily consisted of costs classified within general and administrative expenses based on their nature and function. We believe excluding expenses from these events provides investors with a better view of the operating performance of our business and allows for comparability through periods. 3) For the three and nine months ended September 30, 2026, represents $0.1 million and $2.3 million of expenses incurred in connection with the Company’s defense of certain derivative and class action litigation and for the three and nine months ended September 30, 2026, represents 1.0 million and $6.3 million, respectively, in settlement expenses associated with this litigation. For the three and nine months ended September 30, 2025, represents $0.3 million and $1.2 million of expenses incurred in connection with the Company’s defense of certain derivative and class action litigation. We consider expenses incurred in connection with these legal matters distinct from normal matters and expenses within the operation of our business. 26 4) Represents costs incurred in connection with the proposed transaction, primarily consisting of legal, investment banking, accounting, consulting and other professional and advisory fees. We believe these costs are not reflective of our core operations and that excluding them provides a more meaningful view of our ongoing operating performance.
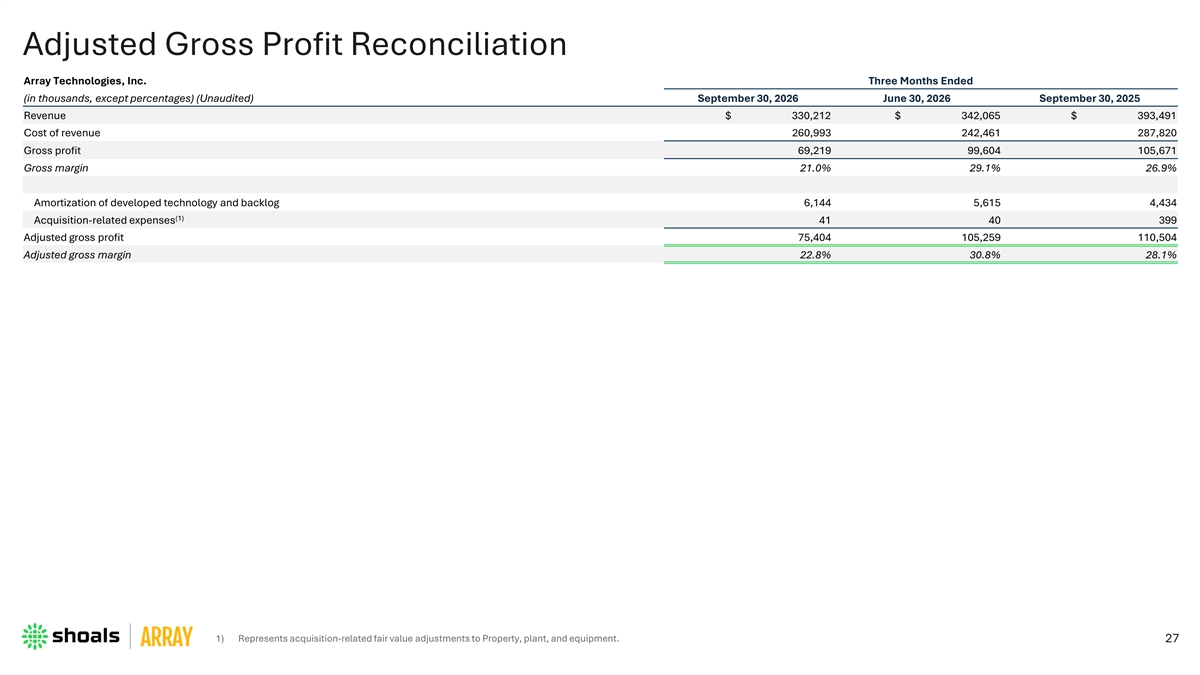
Adjusted Gross Profit Reconciliation Array Technologies, Inc. Three Months Ended (in thousands, except percentages) (Unaudited) September 30, 2026 June 30, 2026 September 30, 2025 Revenue $ 330,212 $ 342,065 $ 393,491 Cost of revenue 260,993 242,461 287,820 Gross profit 69,219 99,604 105,671 Gross margin 21.0% 29.1% 26.9% Amortization of developed technology and backlog 6,144 5,615 4,434 (1) Acquisition-related expenses 41 40 399 Adjusted gross profit 75,404 105,259 110,504 Adjusted gross margin 22.8% 30.8% 28.1% 1) Represents acquisition-related fair value adjustments to Property, plant, and equipment. 27
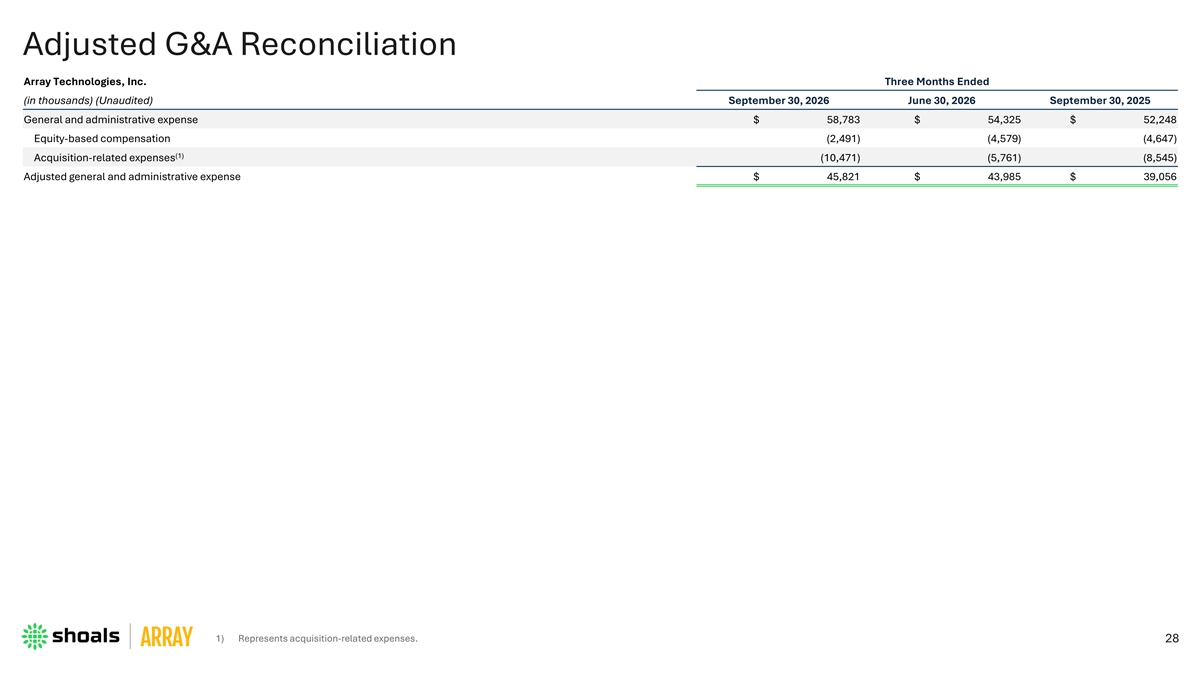
Adjusted G&A Reconciliation Array Technologies, Inc. Three Months Ended (in thousands) (Unaudited) September 30, 2026 June 30, 2026 September 30, 2025 General and administrative expense $ 58,783 $ 54,325 $ 52,248 Equity-based compensation (2,491) (4,579) (4,647) (1) Acquisition-related expenses (10,471) (5,761) (8,545) Adjusted general and administrative expense $ 45,821 $ 43,985 $ 39,056 1) Represents acquisition-related expenses. 28
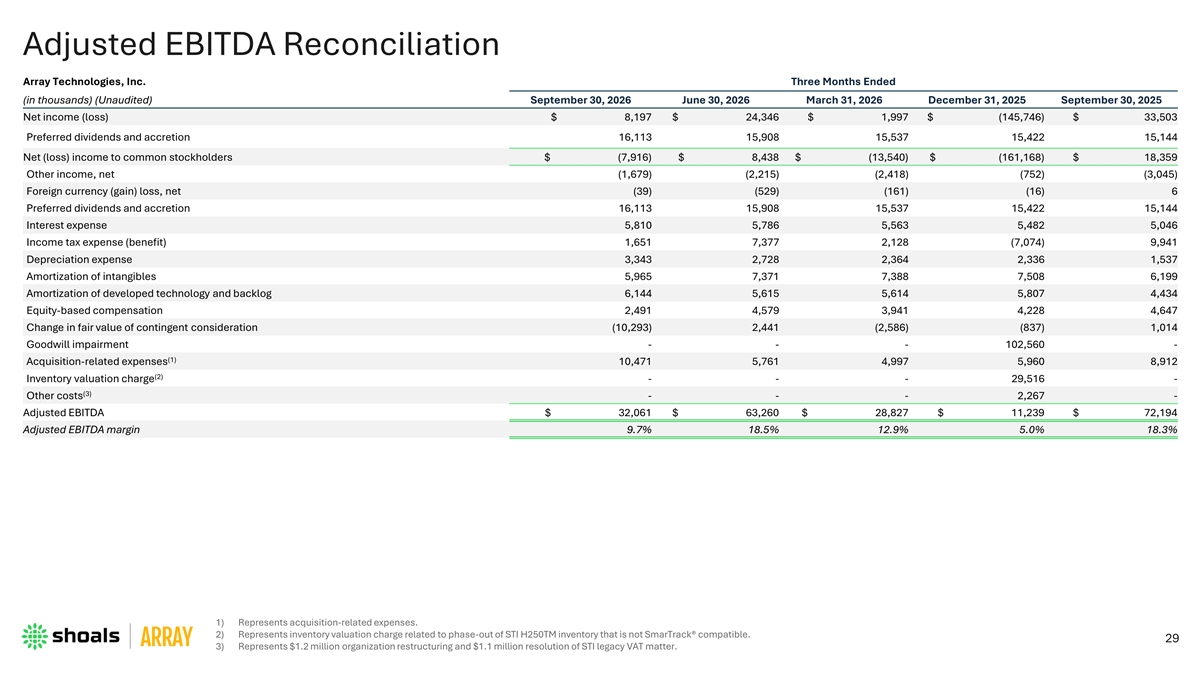
Adjusted EBITDA Reconciliation Array Technologies, Inc. Three Months Ended (in thousands) (Unaudited) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Net income (loss) $ 8,197 $ 24,346 $ 1,997 $ (145,746) $ 33,503 Preferred dividends and accretion 16,113 15,908 15,537 15,422 15,144 Net (loss) income to common stockholders $ (7,916) $ 8,438 $ (13,540) $ (161,168) $ 18,359 Other income, net (1,679) (2,215) (2,418) (752) (3,045) Foreign currency (gain) loss, net (39) (529) (161) (16) 6 Preferred dividends and accretion 16,113 15,908 15,537 15,422 15,144 Interest expense 5,810 5,786 5,563 5,482 5,046 Income tax expense (benefit) 1,651 7,377 2,128 (7,074) 9,941 Depreciation expense 3,343 2,728 2,364 2,336 1,537 Amortization of intangibles 5,965 7,371 7,388 7,508 6,199 Amortization of developed technology and backlog 6,144 5,615 5,614 5,807 4,434 Equity-based compensation 2,491 4,579 3,941 4,228 4,647 Change in fair value of contingent consideration (10,293) 2,441 (2,586) (837) 1,014 Goodwill impairment - - - 102,560 - (1) Acquisition-related expenses 10,471 5,761 4,997 5,960 8,912 (2) Inventory valuation charge - - - 29,516 - (3) Other costs - - - 2,267 - Adjusted EBITDA $ 32,061 $ 63,260 $ 28,827 $ 11,239 $ 72,194 Adjusted EBITDA margin 9.7% 18.5% 12.9% 5.0% 18.3% 1) Represents acquisition-related expenses. 2) Represents inventory valuation charge related to phase-out of STI H250TM inventory that is not SmarTrack® compatible. 29 3) Represents $1.2 million organization restructuring and $1.1 million resolution of STI legacy VAT matter.