1 Financial ResultsQ2 Fiscal 2027 Jaime A. Irick President and CEO Tom L. Barbato Chief Financial Officer NASDAQ: TRNS November 3, 2026 Exhibit 99.2
2 Safe Harbor Statement This presentation contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. All statements other than historical fact are forward-looking statements. Forward-looking statements are not statements of historical fact and thus are subject to risks, uncertainties and assumptions. Forward-looking statements are identified by words such as “may,” “potential,” “should,” “strategy,” “assuming,” “opportunity,” “will,” “expect,” “anticipate,” “believe,” “plan,” “outlook,” “continue,” and other similar expressions or variations thereof. All statements addressing operating performance, events or developments that Transcat expects or anticipates will occur in the future, including but not limited to statements relating to outlook, anticipated revenue, profit margins, sales operations, capital expenditures, cash flows, operating income, growth strategy, potential acquisitions, integration of acquired businesses, market position, customer preferences, and changes in market conditions in the industries in which Transcat operates are forward-looking statements. Forward-looking statements should be evaluated in light of important risk factors and uncertainties. These risk factors and uncertainties include those more fully described in Transcat’s Annual Report and Quarterly Reports filed with the Securities and Exchange Commission, including under the heading entitled “Risk Factors.” Should one or more of these risks or uncertainties materialize, or should any of the Company’s underlying assumptions prove incorrect, actual results may vary materially from those currently anticipated. In addition, undue reliance should not be placed on the Company’s forward-looking statements, which speak only as of the date they are made. Except as required by law, the Company disclaims any obligation to update, correct or publicly announce any revisions to any of the forward-looking statements contained in this news release, whether as the result of new information, future events or otherwise. This presentation includes some non-GAAP financial measures, which the Company believes are useful in evaluating our performance. You should not consider the presentation of this additional information in isolation or as a substitute for results prepared in accordance with GAAP. The Company has provided a discussion of these non- GAAP financial measures and reconciliations of comparable GAAP to non-GAAP measures in tables found in the Supplemental Information portion of this presentation. © 2026 Transcat Inc.
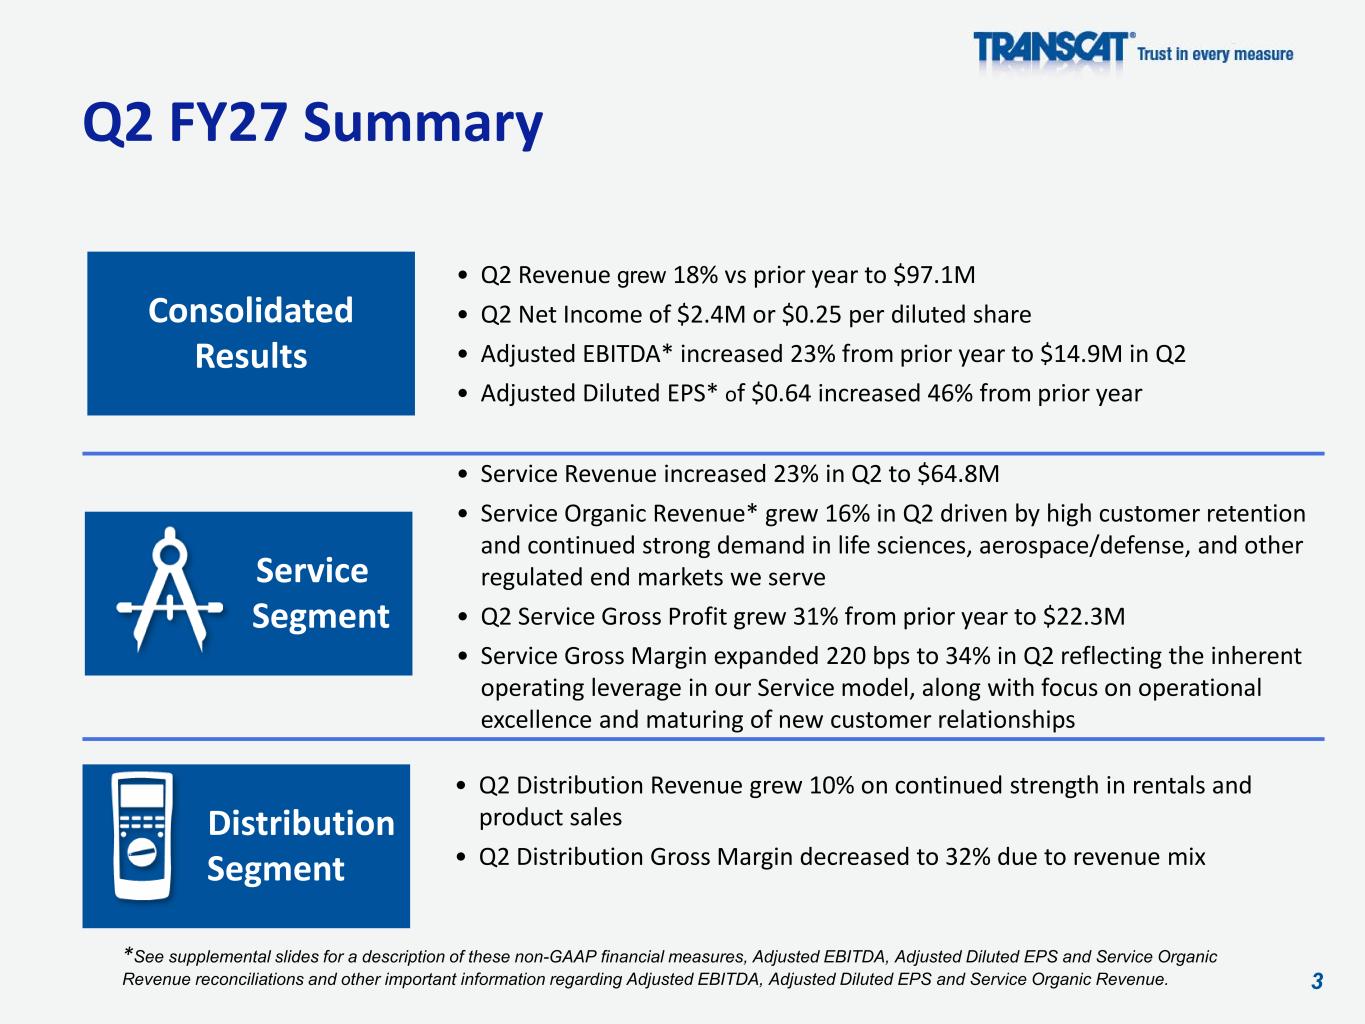
3 Q2 FY27 Summary Consolidated Results • Service Revenue increased 23% in Q2 to $64.8M • Service Organic Revenue* grew 16% in Q2 driven by high customer retention and continued strong demand in life sciences, aerospace/defense, and other regulated end markets we serve • Q2 Service Gross Profit grew 31% from prior year to $22.3M • Service Gross Margin expanded 220 bps to 34% in Q2 reflecting the inherent operating leverage in our Service model, along with focus on operational excellence and maturing of new customer relationships • Q2 Distribution Revenue grew 10% on continued strength in rentals and product sales • Q2 Distribution Gross Margin decreased to 32% due to revenue mix • Q2 Revenue grew 18% vs prior year to $97.1M • Q2 Net Income of $2.4M or $0.25 per diluted share • Adjusted EBITDA* increased 23% from prior year to $14.9M in Q2 • Adjusted Diluted EPS* of $0.64 increased 46% from prior year Service Segment Distribution Segment *See supplemental slides for a description of these non-GAAP financial measures, Adjusted EBITDA, Adjusted Diluted EPS and Service Organic Revenue reconciliations and other important information regarding Adjusted EBITDA, Adjusted Diluted EPS and Service Organic Revenue.
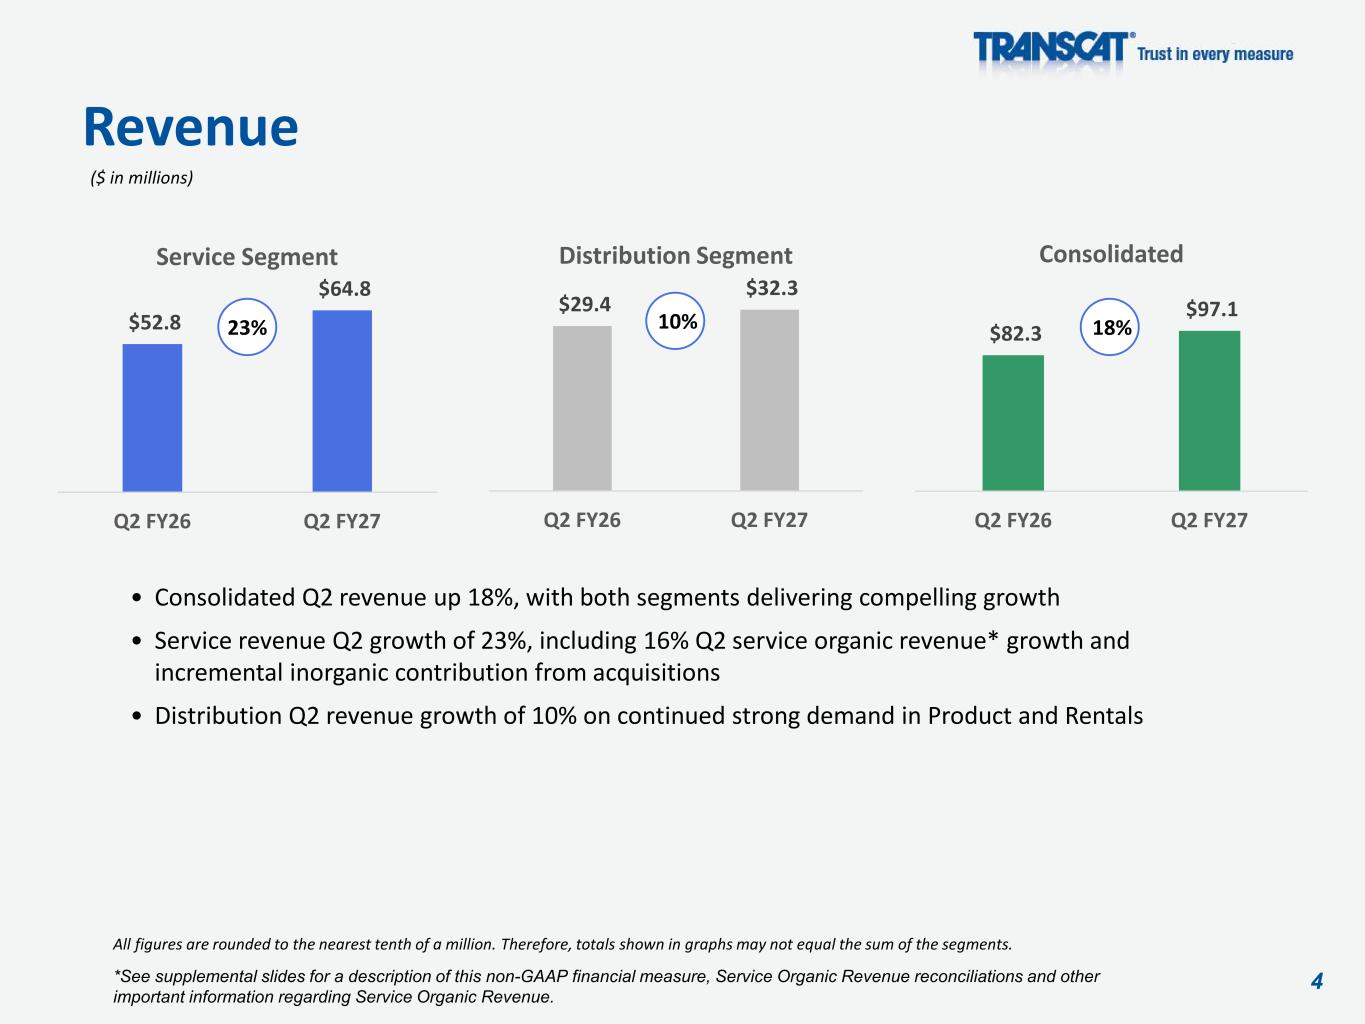
4 Revenue ($ in millions) All figures are rounded to the nearest tenth of a million. Therefore, totals shown in graphs may not equal the sum of the segments. *See supplemental slides for a description of this non-GAAP financial measure, Service Organic Revenue reconciliations and other important information regarding Service Organic Revenue. • Consolidated Q2 revenue up 18%, with both segments delivering compelling growth • Service revenue Q2 growth of 23%, including 16% Q2 service organic revenue* growth and incremental inorganic contribution from acquisitions • Distribution Q2 revenue growth of 10% on continued strong demand in Product and Rentals $52.8 $64.8 Q2 FY26 Q2 FY27 Service Segment $29.4 $32.3 Q2 FY26 Q2 FY27 Distribution Segment $82.3 $97.1 Q2 FY26 Q2 FY27 Consolidated 18%10%23%
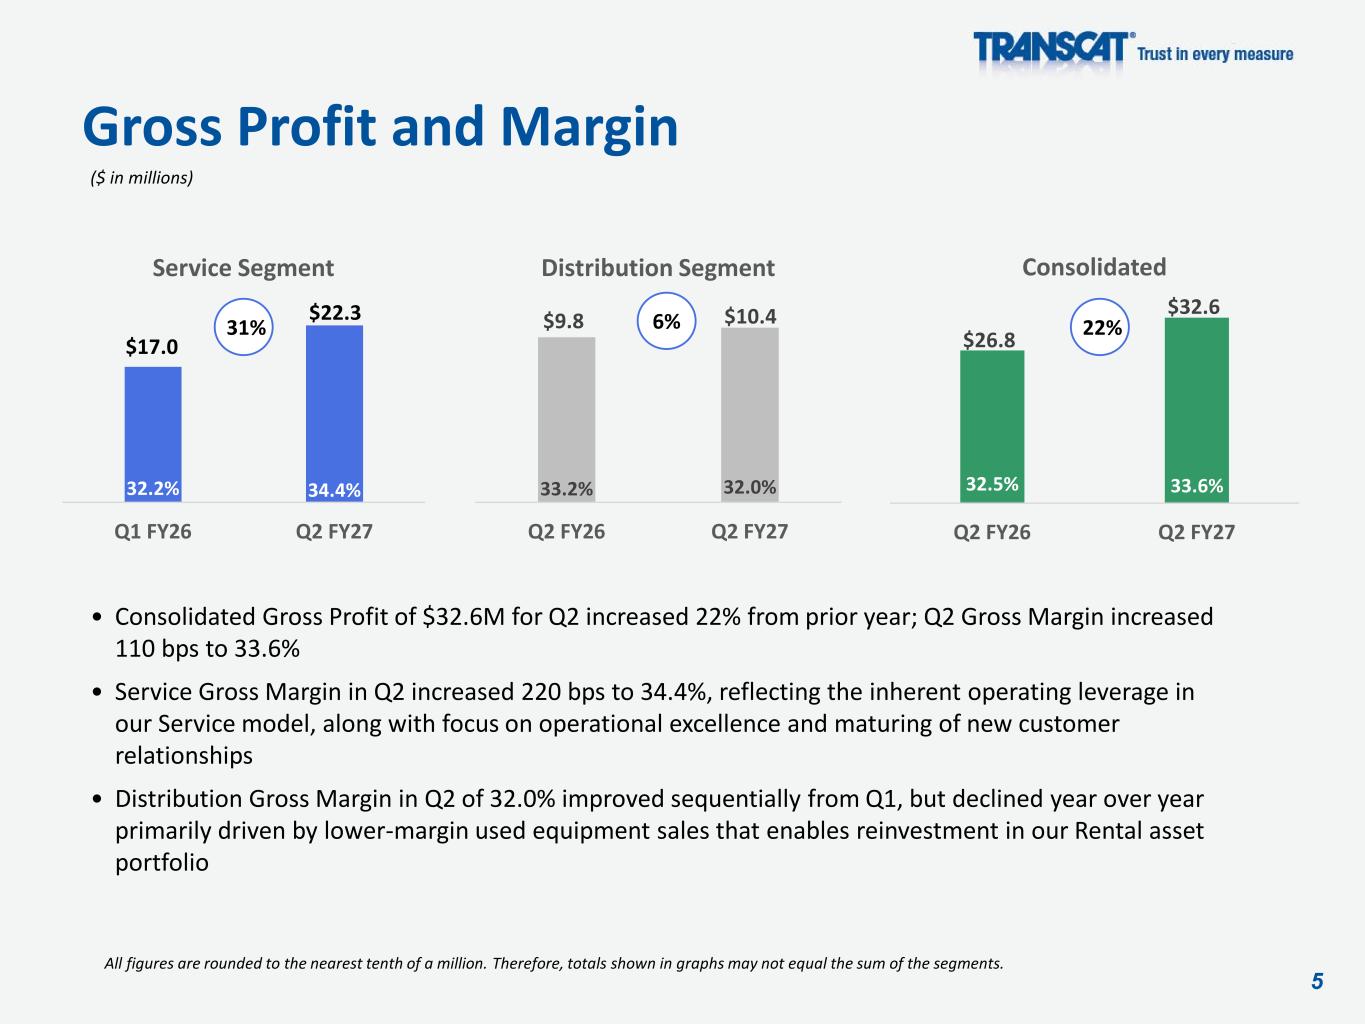
5 Gross Profit and Margin • Consolidated Gross Profit of $32.6M for Q2 increased 22% from prior year; Q2 Gross Margin increased 110 bps to 33.6% • Service Gross Margin in Q2 increased 220 bps to 34.4%, reflecting the inherent operating leverage in our Service model, along with focus on operational excellence and maturing of new customer relationships • Distribution Gross Margin in Q2 of 32.0% improved sequentially from Q1, but declined year over year primarily driven by lower-margin used equipment sales that enables reinvestment in our Rental asset portfolio All figures are rounded to the nearest tenth of a million. Therefore, totals shown in graphs may not equal the sum of the segments. ($ in millions) 32.2% 34.4% $17.0 $22.3 Q1 FY26 Q2 FY27 Service Segment 32.5% 33.6% $26.8 $32.6 Q2 FY26 Q2 FY27 Consolidated 33.2% 32.0% $9.8 $10.4 Q2 FY26 Q2 FY27 Distribution Segment 22%6%31%
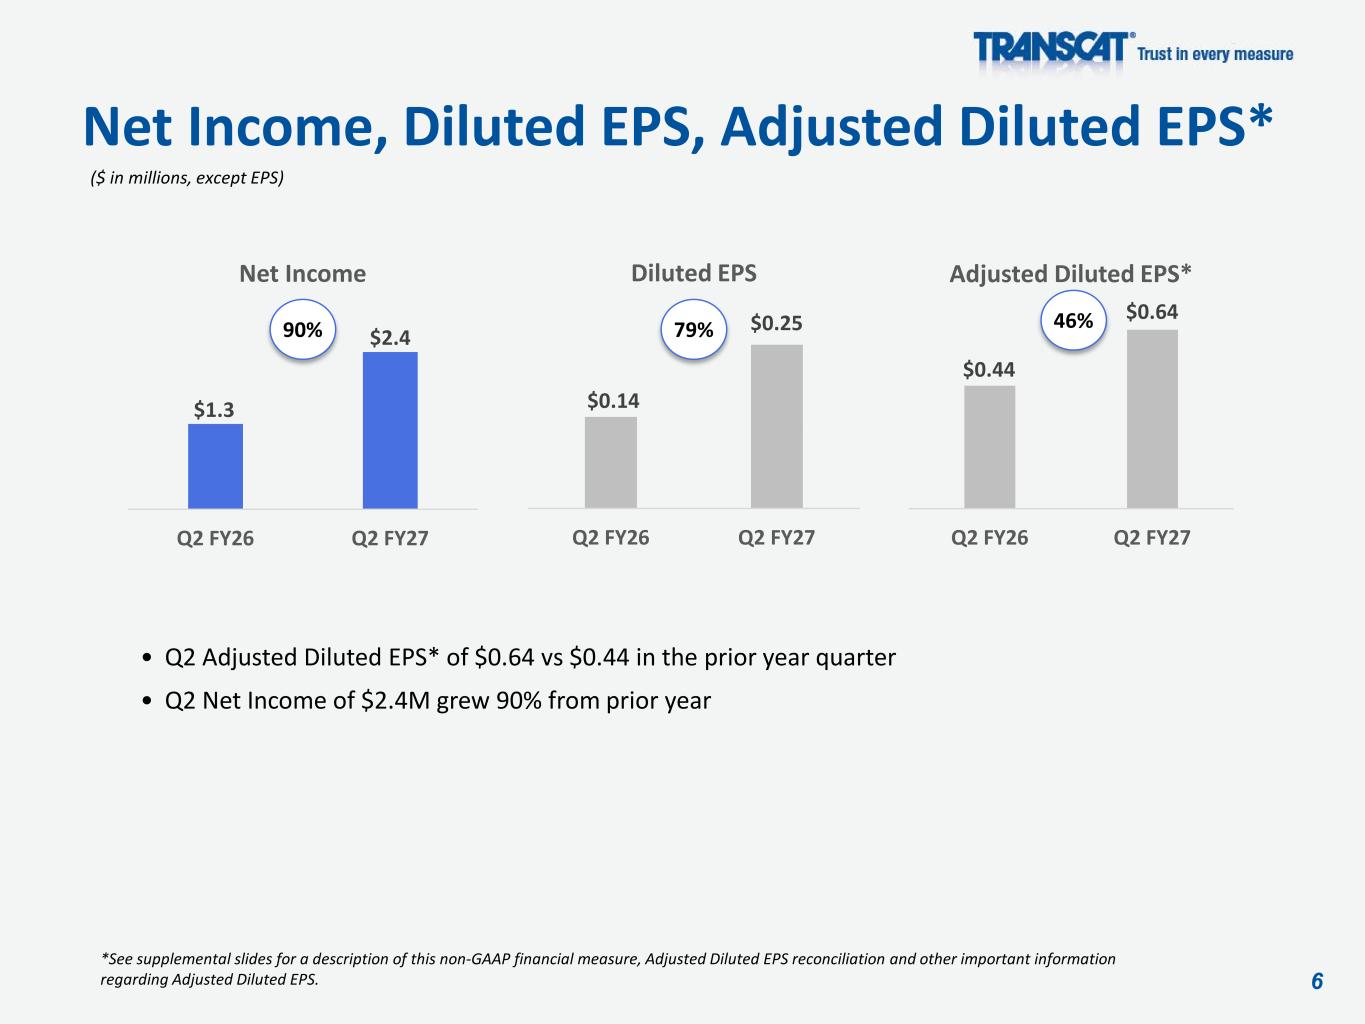
6 Net Income, Diluted EPS, Adjusted Diluted EPS* • Q2 Adjusted Diluted EPS* of $0.64 vs $0.44 in the prior year quarter • Q2 Net Income of $2.4M grew 90% from prior year ($ in millions, except EPS) *See supplemental slides for a description of this non-GAAP financial measure, Adjusted Diluted EPS reconciliation and other important information regarding Adjusted Diluted EPS. $1.3 $2.4 Q2 FY26 Q2 FY27 Net Income $0.14 $0.25 Q2 FY26 Q2 FY27 Diluted EPS $0.44 $0.64 Q2 FY26 Q2 FY27 Adjusted Diluted EPS* 90% 79% 46%
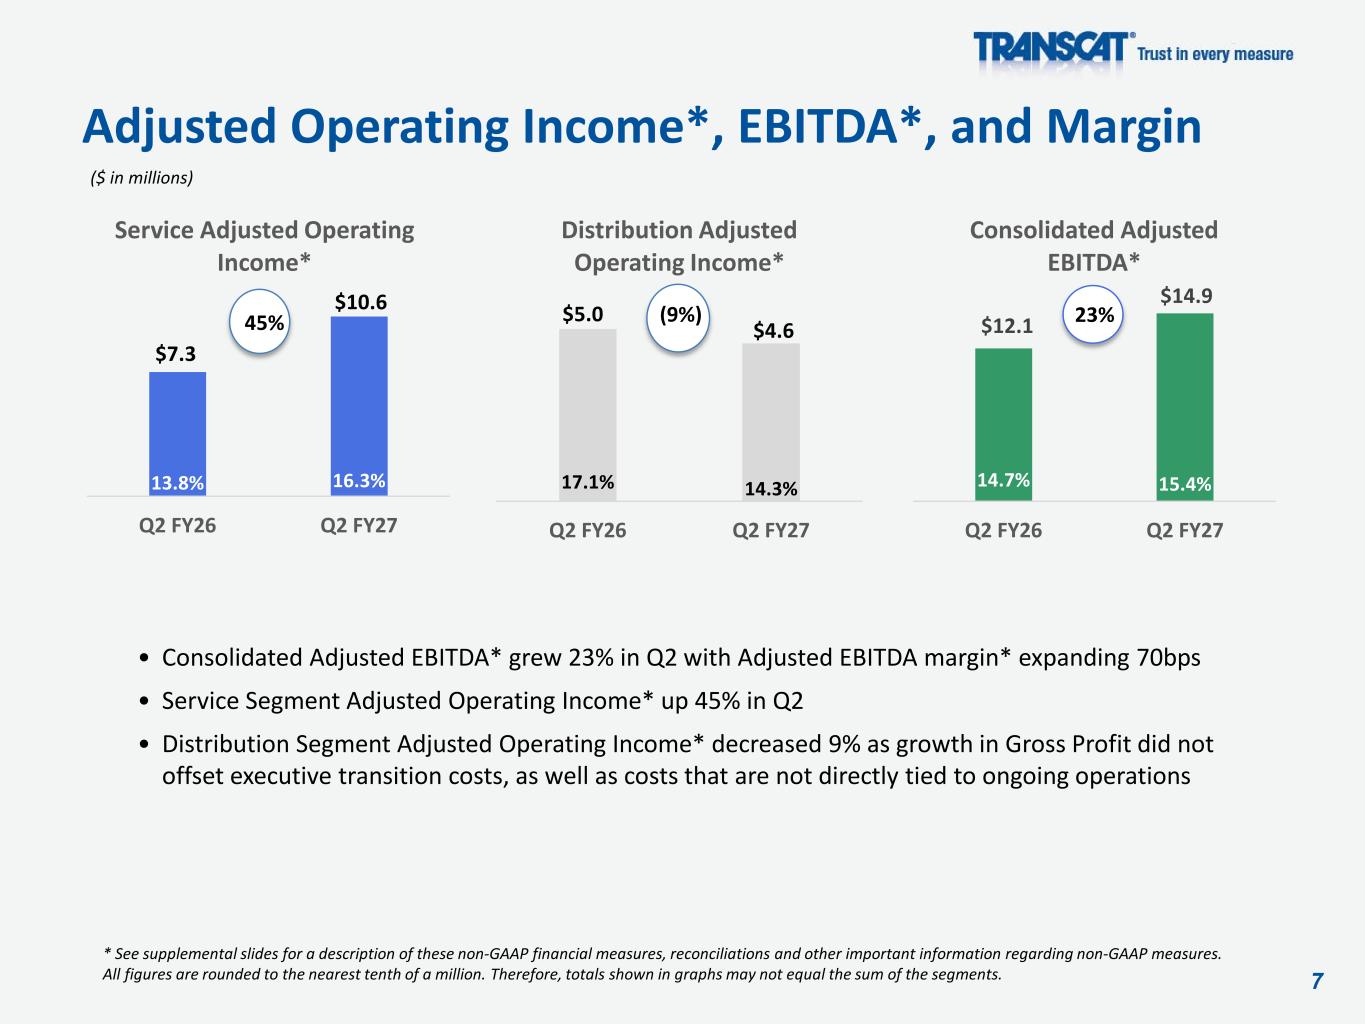
7 Adjusted Operating Income*, EBITDA*, and Margin ($ in millions) * See supplemental slides for a description of these non-GAAP financial measures, reconciliations and other important information regarding non-GAAP measures. All figures are rounded to the nearest tenth of a million. Therefore, totals shown in graphs may not equal the sum of the segments. • Consolidated Adjusted EBITDA* grew 23% in Q2 with Adjusted EBITDA margin* expanding 70bps • Service Segment Adjusted Operating Income* up 45% in Q2 • Distribution Segment Adjusted Operating Income* decreased 9% as growth in Gross Profit did not offset executive transition costs, as well as costs that are not directly tied to ongoing operations 13.8% 16.3% $7.3 $10.6 Q2 FY26 Q2 FY27 Service Adjusted Operating Income* 45% 14.7% 15.4% $12.1 $14.9 Q2 FY26 Q2 FY27 Consolidated Adjusted EBITDA* 17.1% 14.3% $5.0 $4.6 Q2 FY26 Q2 FY27 Distribution Adjusted Operating Income* (9%) 23%
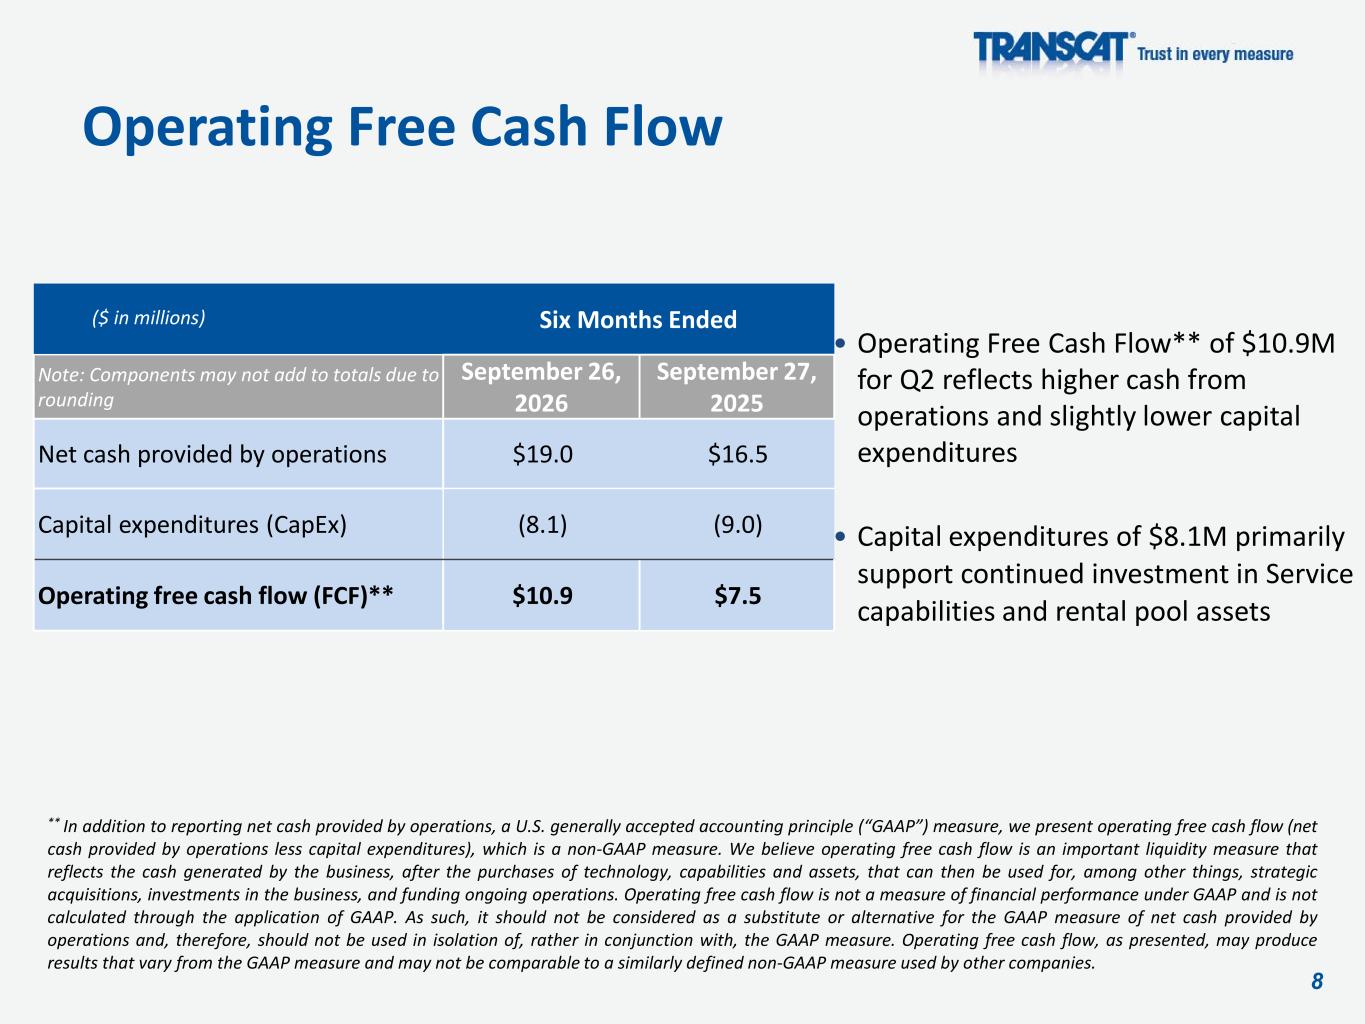
8 Operating Free Cash Flow ** In addition to reporting net cash provided by operations, a U.S. generally accepted accounting principle (“GAAP”) measure, we present operating free cash flow (net cash provided by operations less capital expenditures), which is a non-GAAP measure. We believe operating free cash flow is an important liquidity measure that reflects the cash generated by the business, after the purchases of technology, capabilities and assets, that can then be used for, among other things, strategic acquisitions, investments in the business, and funding ongoing operations. Operating free cash flow is not a measure of financial performance under GAAP and is not calculated through the application of GAAP. As such, it should not be considered as a substitute or alternative for the GAAP measure of net cash provided by operations and, therefore, should not be used in isolation of, rather in conjunction with, the GAAP measure. Operating free cash flow, as presented, may produce results that vary from the GAAP measure and may not be comparable to a similarly defined non-GAAP measure used by other companies. • Operating Free Cash Flow** of $10.9M for Q2 reflects higher cash from operations and slightly lower capital expenditures • Capital expenditures of $8.1M primarily support continued investment in Service capabilities and rental pool assets Six Months Ended Note: Components may not add to totals due to rounding September 26, 2026 September 27, 2025 Net cash provided by operations $19.0 $16.5 Capital expenditures (CapEx) (8.1) (9.0) Operating free cash flow (FCF)** $10.9 $7.5 ($ in millions)
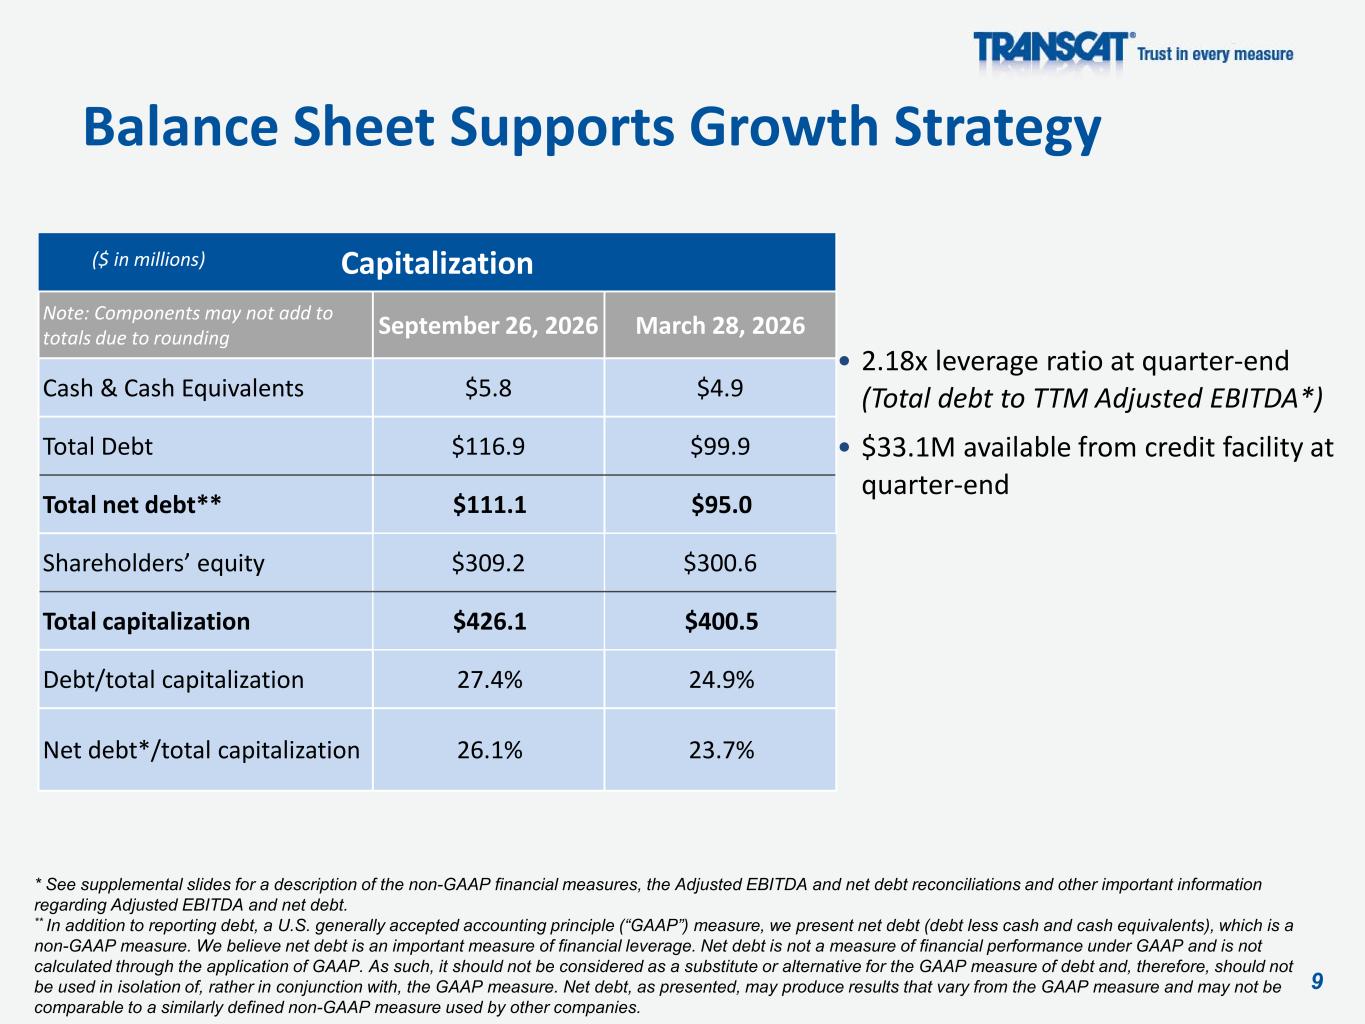
9 Balance Sheet Supports Growth Strategy • 2.18x leverage ratio at quarter-end (Total debt to TTM Adjusted EBITDA*) • $33.1M available from credit facility at quarter-end * See supplemental slides for a description of the non-GAAP financial measures, the Adjusted EBITDA and net debt reconciliations and other important information regarding Adjusted EBITDA and net debt. ** In addition to reporting debt, a U.S. generally accepted accounting principle (“GAAP”) measure, we present net debt (debt less cash and cash equivalents), which is a non-GAAP measure. We believe net debt is an important measure of financial leverage. Net debt is not a measure of financial performance under GAAP and is not calculated through the application of GAAP. As such, it should not be considered as a substitute or alternative for the GAAP measure of debt and, therefore, should not be used in isolation of, rather in conjunction with, the GAAP measure. Net debt, as presented, may produce results that vary from the GAAP measure and may not be comparable to a similarly defined non-GAAP measure used by other companies. Capitalization Note: Components may not add to totals due to rounding September 26, 2026 March 28, 2026 Cash & Cash Equivalents $5.8 $4.9 Total Debt $116.9 $99.9 Total net debt** $111.1 $95.0 Shareholders’ equity $309.2 $300.6 Total capitalization $426.1 $400.5 Debt/total capitalization 27.4% 24.9% Net debt*/total capitalization 26.1% 23.7% ($ in millions)
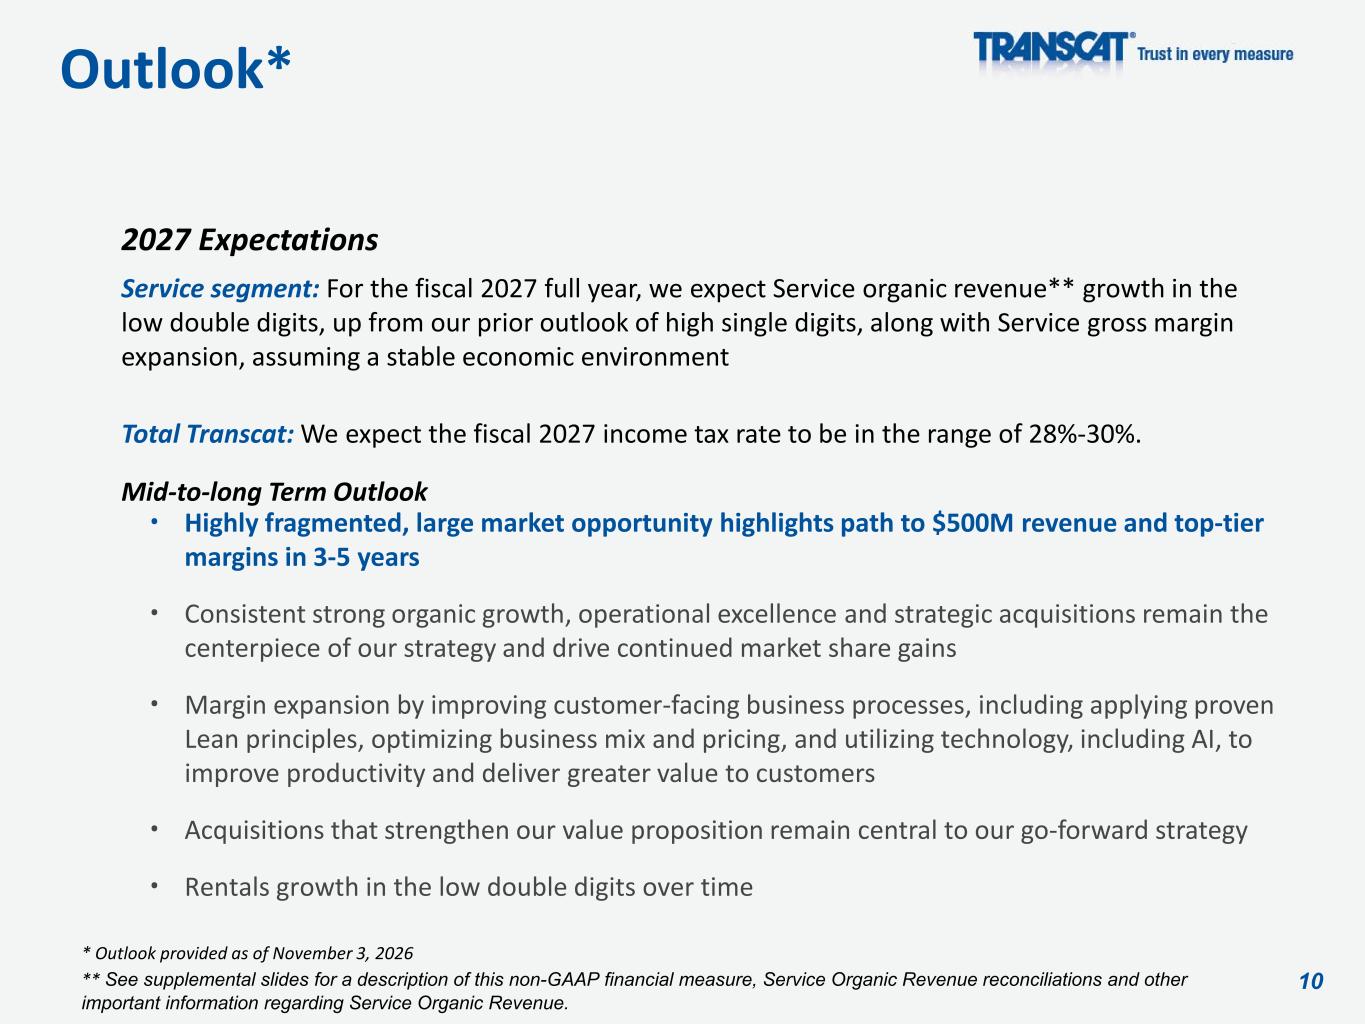
10 * Outlook provided as of November 3, 2026 ** See supplemental slides for a description of this non-GAAP financial measure, Service Organic Revenue reconciliations and other important information regarding Service Organic Revenue. Outlook* 2027 Expectations Service segment: For the fiscal 2027 full year, we expect Service organic revenue** growth in the low double digits, up from our prior outlook of high single digits, along with Service gross margin expansion, assuming a stable economic environment Total Transcat: We expect the fiscal 2027 income tax rate to be in the range of 28%-30%. Mid-to-long Term Outlook • Highly fragmented, large market opportunity highlights path to $500M revenue and top-tier margins in 3-5 years • Consistent strong organic growth, operational excellence and strategic acquisitions remain the centerpiece of our strategy and drive continued market share gains • Margin expansion by improving customer-facing business processes, including applying proven Lean principles, optimizing business mix and pricing, and utilizing technology, including AI, to improve productivity and deliver greater value to customers • Acquisitions that strengthen our value proposition remain central to our go-forward strategy • Rentals growth in the low double digits over time
11 Financial ResultsQ2 Fiscal 2027 NASDAQ: TRNS Questions & Answers TRANSCAT, INC 35 Vantage Point Drive Rochester, NY 14624 Investor Relations Chris Tyson Executive Vice President MZ Group - MZ North America 949-491-8235 TRNS@mzgroup us November 3, 2026
12 Conference Call and Webcast Playback • Replay Number: 1-844-512-2921 (US & Canada) 1-412-317-6671 (international) passcode: 11162777 Telephone replay available through Tuesday, November 17, 2026 • Webcast: https://viavid.webcasts.com/starthere.jsp?ei=1778889&tp_key=13ef016dde • Webcast / Presentation / Replay available at https://www.transcat.com/investor-relations
13 Supplemental Information
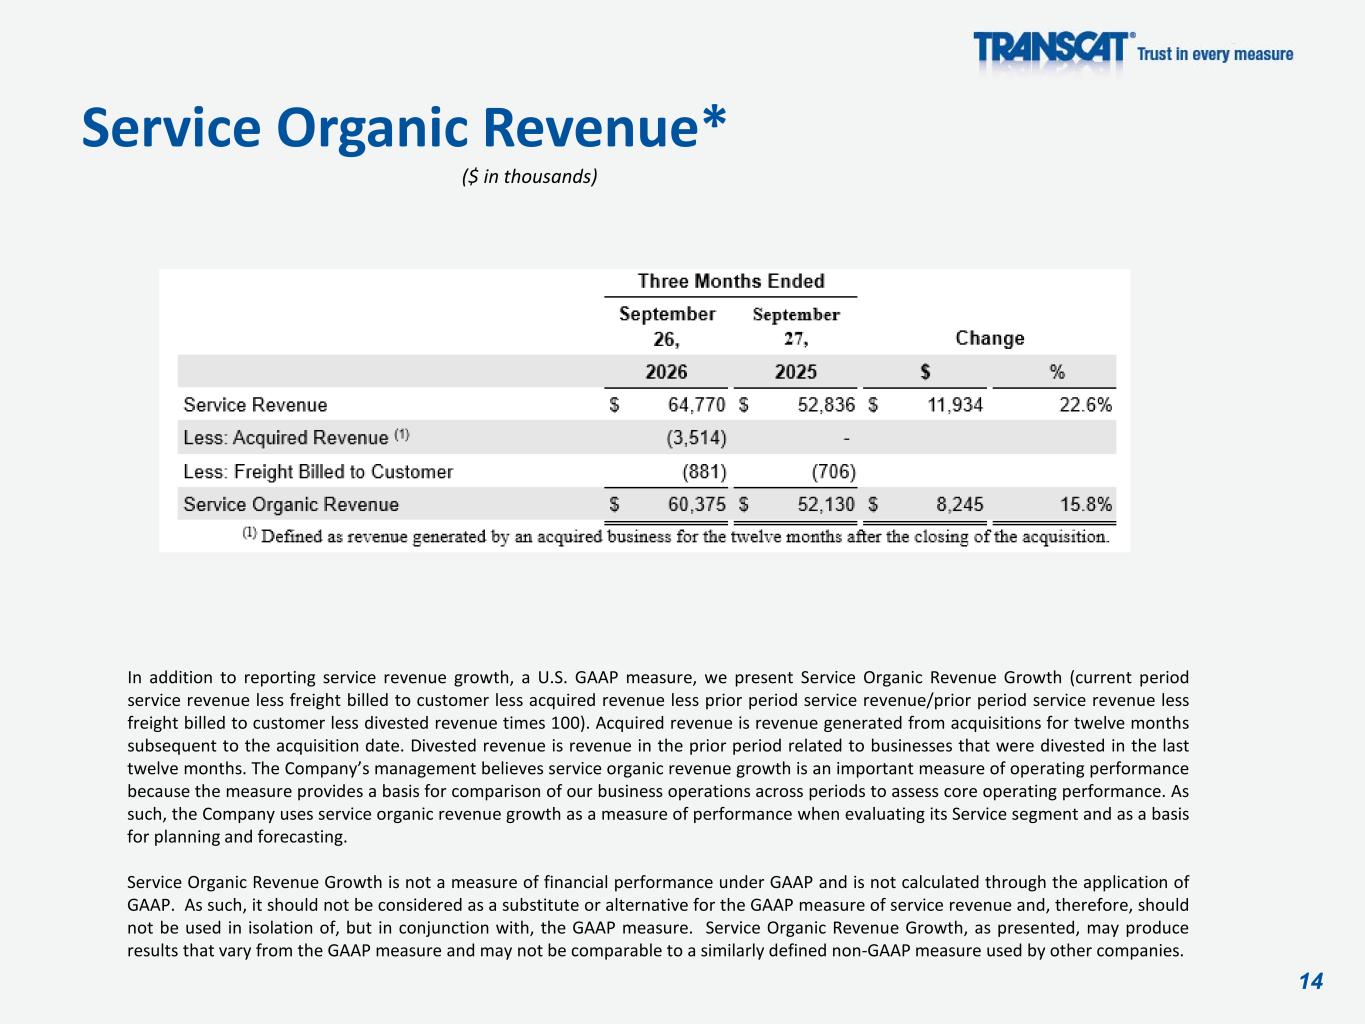
14 ($ in thousands) Service Organic Revenue* In addition to reporting service revenue growth, a U.S. GAAP measure, we present Service Organic Revenue Growth (current period service revenue less freight billed to customer less acquired revenue less prior period service revenue/prior period service revenue less freight billed to customer less divested revenue times 100). Acquired revenue is revenue generated from acquisitions for twelve months subsequent to the acquisition date. Divested revenue is revenue in the prior period related to businesses that were divested in the last twelve months. The Company’s management believes service organic revenue growth is an important measure of operating performance because the measure provides a basis for comparison of our business operations across periods to assess core operating performance. As such, the Company uses service organic revenue growth as a measure of performance when evaluating its Service segment and as a basis for planning and forecasting. Service Organic Revenue Growth is not a measure of financial performance under GAAP and is not calculated through the application of GAAP. As such, it should not be considered as a substitute or alternative for the GAAP measure of service revenue and, therefore, should not be used in isolation of, but in conjunction with, the GAAP measure. Service Organic Revenue Growth, as presented, may produce results that vary from the GAAP measure and may not be comparable to a similarly defined non-GAAP measure used by other companies.
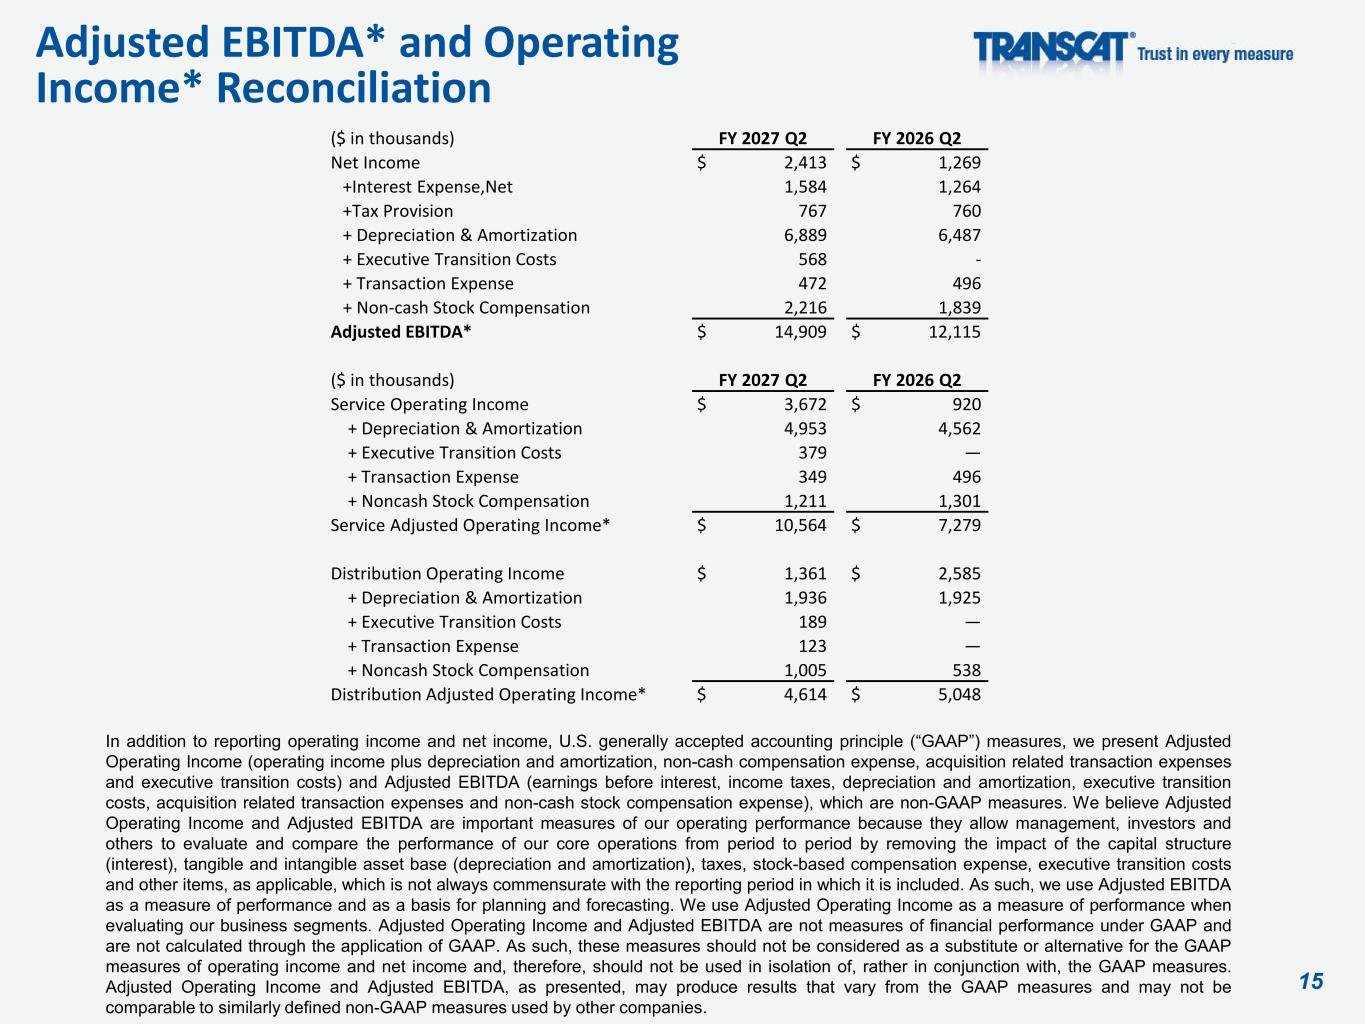
15 Adjusted EBITDA* and Operating Income* Reconciliation In addition to reporting operating income and net income, U.S. generally accepted accounting principle (“GAAP”) measures, we present Adjusted Operating Income (operating income plus depreciation and amortization, non-cash compensation expense, acquisition related transaction expenses and executive transition costs) and Adjusted EBITDA (earnings before interest, income taxes, depreciation and amortization, executive transition costs, acquisition related transaction expenses and non-cash stock compensation expense), which are non-GAAP measures. We believe Adjusted Operating Income and Adjusted EBITDA are important measures of our operating performance because they allow management, investors and others to evaluate and compare the performance of our core operations from period to period by removing the impact of the capital structure (interest), tangible and intangible asset base (depreciation and amortization), taxes, stock-based compensation expense, executive transition costs and other items, as applicable, which is not always commensurate with the reporting period in which it is included. As such, we use Adjusted EBITDA as a measure of performance and as a basis for planning and forecasting. We use Adjusted Operating Income as a measure of performance when evaluating our business segments. Adjusted Operating Income and Adjusted EBITDA are not measures of financial performance under GAAP and are not calculated through the application of GAAP. As such, these measures should not be considered as a substitute or alternative for the GAAP measures of operating income and net income and, therefore, should not be used in isolation of, rather in conjunction with, the GAAP measures. Adjusted Operating Income and Adjusted EBITDA, as presented, may produce results that vary from the GAAP measures and may not be comparable to similarly defined non-GAAP measures used by other companies. ($ in thousands) FY 2027 Q2 FY 2026 Q2 Net Income $ 2,413 $ 1,269 +Interest Expense,Net 1,584 1,264 +Tax Provision 767 760 + Depreciation & Amortization 6,889 6,487 + Executive Transition Costs 568 - + Transaction Expense 472 496 + Non-cash Stock Compensation 2,216 1,839 Adjusted EBITDA* $ 14,909 $ 12,115 ($ in thousands) FY 2027 Q2 FY 2026 Q2 Service Operating Income $ 3,672 $ 920 + Depreciation & Amortization 4,953 4,562 + Executive Transition Costs 379 — + Transaction Expense 349 496 + Noncash Stock Compensation 1,211 1,301 Service Adjusted Operating Income* $ 10,564 $ 7,279 Distribution Operating Income $ 1,361 $ 2,585 + Depreciation & Amortization 1,936 1,925 + Executive Transition Costs 189 — + Transaction Expense 123 — + Noncash Stock Compensation 1,005 538 Distribution Adjusted Operating Income* $ 4,614 $ 5,048
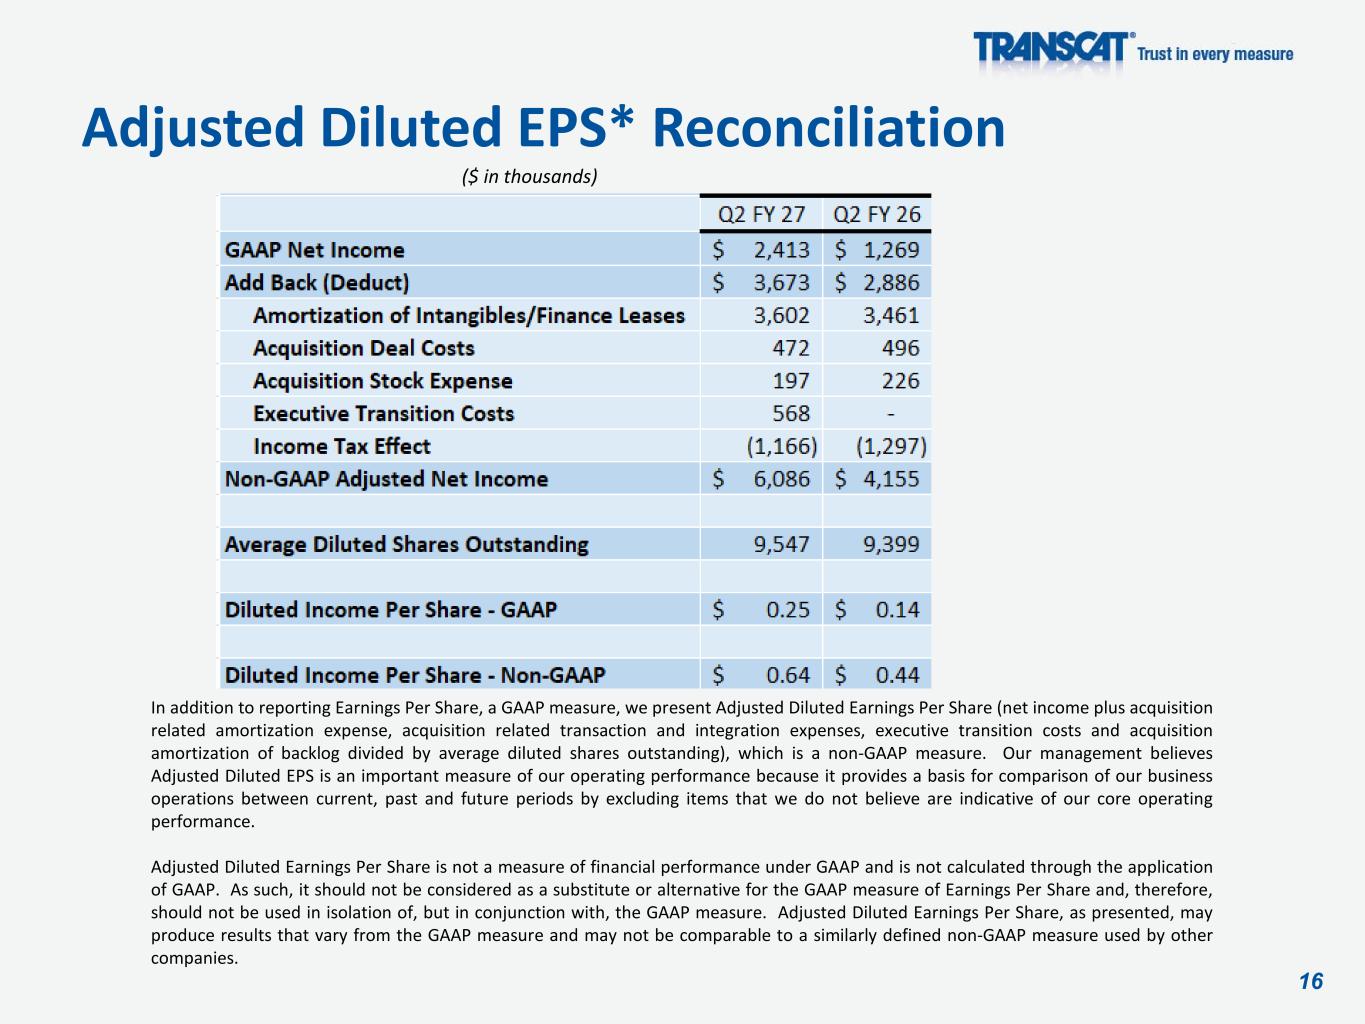
16 ($ in thousands) Adjusted Diluted EPS* Reconciliation In addition to reporting Earnings Per Share, a GAAP measure, we present Adjusted Diluted Earnings Per Share (net income plus acquisition related amortization expense, acquisition related transaction and integration expenses, executive transition costs and acquisition amortization of backlog divided by average diluted shares outstanding), which is a non-GAAP measure. Our management believes Adjusted Diluted EPS is an important measure of our operating performance because it provides a basis for comparison of our business operations between current, past and future periods by excluding items that we do not believe are indicative of our core operating performance. Adjusted Diluted Earnings Per Share is not a measure of financial performance under GAAP and is not calculated through the application of GAAP. As such, it should not be considered as a substitute or alternative for the GAAP measure of Earnings Per Share and, therefore, should not be used in isolation of, but in conjunction with, the GAAP measure. Adjusted Diluted Earnings Per Share, as presented, may produce results that vary from the GAAP measure and may not be comparable to a similarly defined non-GAAP measure used by other companies.