Quarterly Earnings Results Presentation Q3 2026 - November 2, 2026
2 PresBuilder Placeholder - Delete this box if you see it on a slide, but DO NOT REMOVE this box from the slide layout Forward Looking Statements This presentation contains certain forward-looking statements, including, but not limited to, certain plans, expectations, goals, projections, and statements, which are not historical facts and are subject to numerous assumptions, risks, and uncertainties. Statements that do not describe historical or current facts, including statements about beliefs and expectations, are forward-looking statements. All forward-looking statements are made in good faith by the company and are intended to qualify for the safe harbor from liability established by Section 27A of the Securities Act of 1933, Section 21E of the Securities Exchange Act of 1934, and the Private Securities Litigation Reform Act of 1995.You should not rely on these forward-looking statements as predictions of future events. Words such as "expect," "estimate," "project," "budget," "forecast," "anticipate," "intend," "plan," “target”, “goal”, "may," "will," "could," "should," "believes," "predicts," "potential," "continue," and similar expressions are intended to identify such forward-looking statements. These forward-looking statements include, without limitation, the Company’s expectations with respect to future performance. These forward-looking statements involve significant risks and uncertainties that could cause the actual results to differ materially from the expected results. Most of these factors are outside the Company's control and are difficult to predict. Factors that may cause such differences include, but are not limited to: (1) unfavorable economic conditions that may affect operations, financial condition and cash flows including spending on home renovation or construction projects, inflation, recessions, instability in the financial markets or credit markets; (2) increased supply chain costs, including tariffs, raw materials, sourcing, transportation and energy; (3) the highly competitive nature of the markets that we serve; (4) the ability to continue to innovate with new products and services; (5) seasonality; (6) large customer concentration; (7) the ability to recruit and retain qualified employees; (8) the outcome of any legal proceedings that may be instituted against the Company; (9) adverse changes in currency exchange rates; or (10) regulatory changes and potential legislation that could adversely impact financial results. The foregoing list of factors is not exclusive, and readers should also refer to those risks that are included in the Company’s filings with the Securities and Exchange Commission (“SEC”), including its Annual Report on Form 10-K for the fiscal year ended December 27, 2025 filed on February 17, 2026. Given these uncertainties, current or prospective investors are cautioned not to place undue reliance on any such forward looking statements. Except as required by applicable law, the Company does not undertake or accept any obligation or undertaking to release publicly any updates or revisions to any forward-looking statements in this communication to reflect any change in its expectations or any change in events, conditions or circumstances on which any such statement is based. Presentation of Non-GAAP Financial Measures In addition to the results provided in accordance with U.S. Generally Accepted Accounting Principles (“GAAP”) throughout this presentation the company has provided non-GAAP financial measures, which present results on a basis adjusted for certain items. The company uses these non-GAAP financial measures for business planning purposes and in measuring its performance relative to that of its competitors. The company believes that these non-GAAP financial measures are useful financial metrics to assess its operating performance from period-to-period by excluding certain items that the company believes are not representative of its core business. These non-GAAP financial measures are not intended to replace, and should not be considered superior to, the presentation of the company’s financial results in accordance with GAAP. The use of the non-GAAP financial measures terms may differ from similar measures reported by other companies and may not be comparable to other similarly titled measures. These non-GAAP financial measures are reconciled from the respective measures under GAAP in the appendix below. The company is not able to provide a reconciliation of the company’s non-GAAP financial guidance to the corresponding GAAP measures without unreasonable effort because of the inherent difficulty in forecasting and quantifying certain amounts necessary for such a reconciliation such as certain non-cash, nonrecurring or other items that are included in net income and EBITDA as well as the related tax impacts of these items and asset dispositions / acquisitions and changes in foreign currency exchange rates that are included in cash flow, due to the uncertainty and variability of the nature and amount of these future charges and costs.
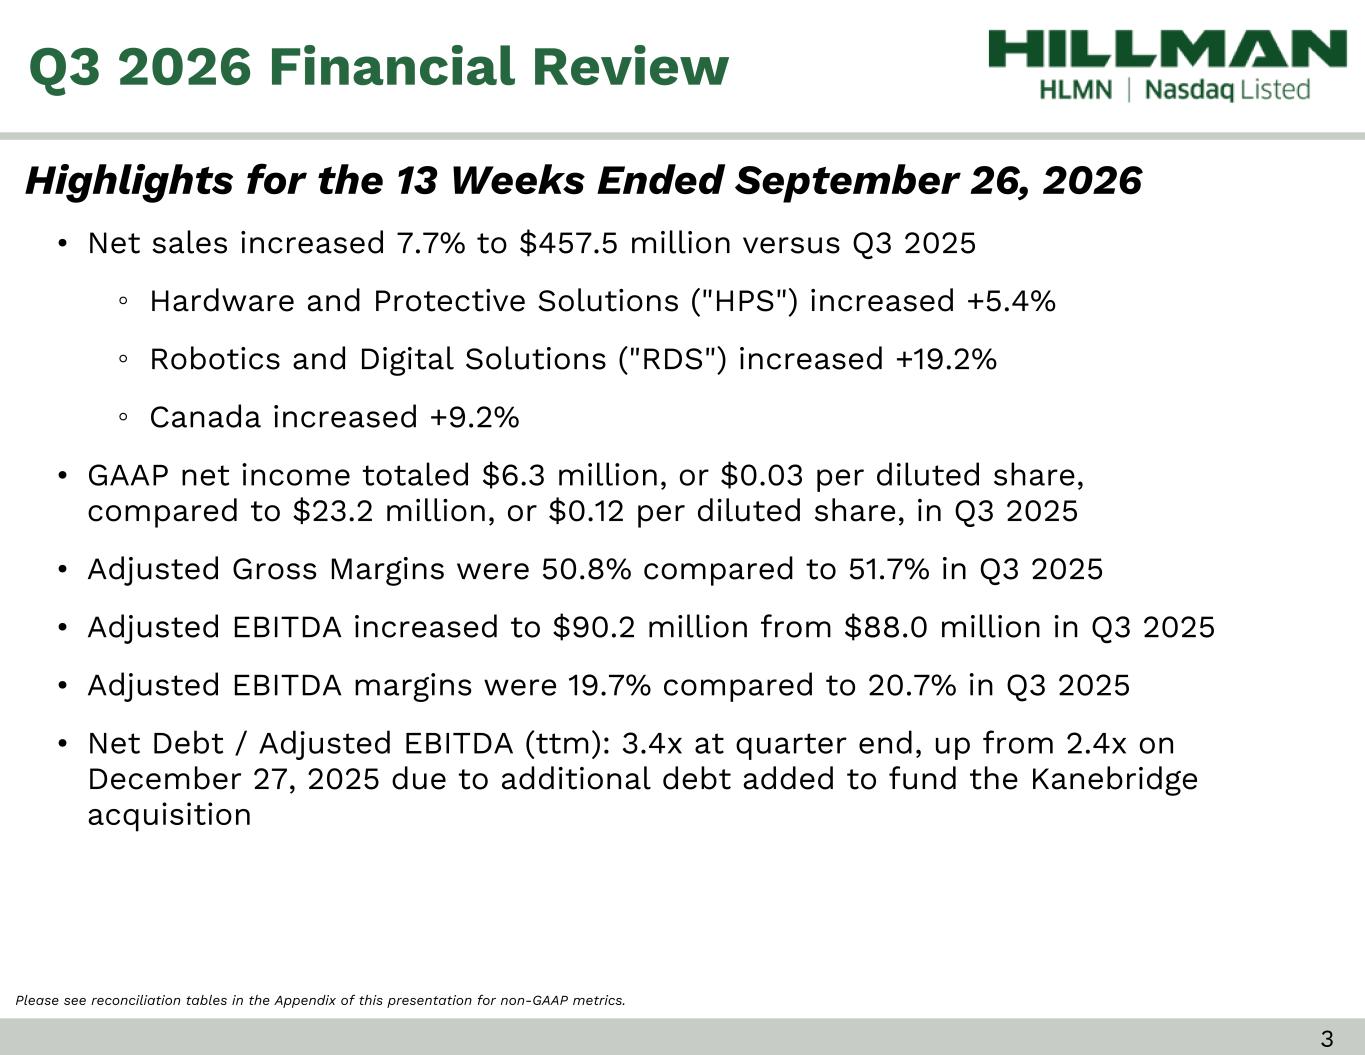
3 • Net sales increased 7.7% to $457.5 million versus Q3 2025 ◦ Hardware and Protective Solutions ("HPS") increased +5.4% ◦ Robotics and Digital Solutions ("RDS") increased +19.2% ◦ Canada increased +9.2% • GAAP net income totaled $6.3 million, or $0.03 per diluted share, compared to $23.2 million, or $0.12 per diluted share, in Q3 2025 • Adjusted Gross Margins were 50.8% compared to 51.7% in Q3 2025 • Adjusted EBITDA increased to $90.2 million from $88.0 million in Q3 2025 • Adjusted EBITDA margins were 19.7% compared to 20.7% in Q3 2025 • Net Debt / Adjusted EBITDA (ttm): 3.4x at quarter end, up from 2.4x on December 27, 2025 due to additional debt added to fund the Kanebridge acquisition Q3 2026 Financial Review Please see reconciliation tables in the Appendix of this presentation for non-GAAP metrics. Highlights for the 13 Weeks Ended September 26, 2026
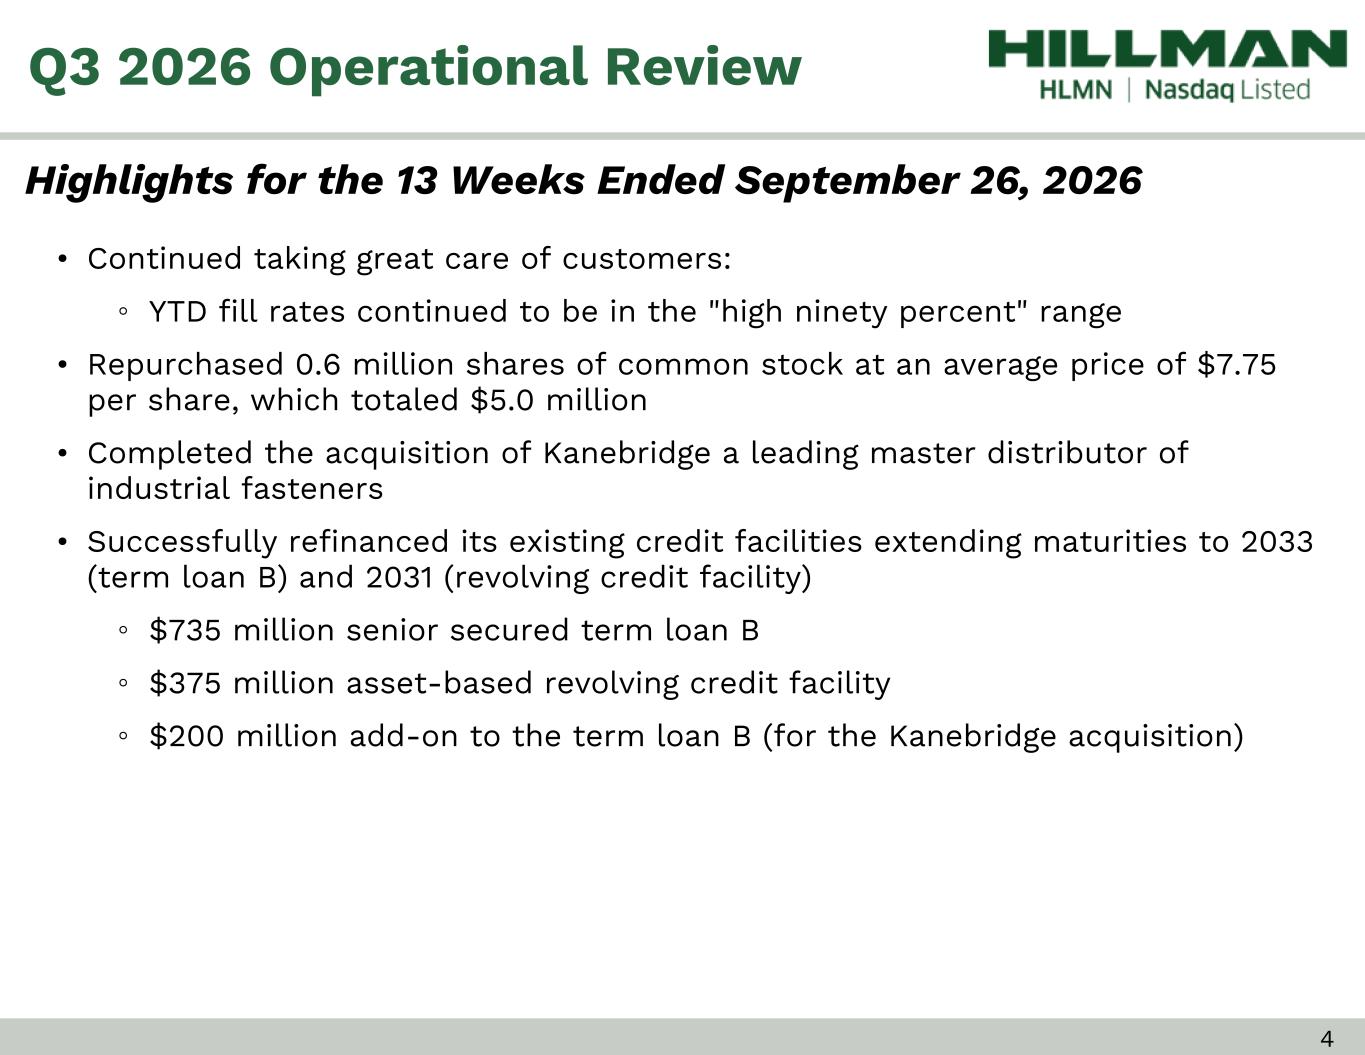
4 Q3 2026 Operational Review Highlights for the 13 Weeks Ended September 26, 2026 • Continued taking great care of customers: ◦ YTD fill rates continued to be in the "high ninety percent" range • Repurchased 0.6 million shares of common stock at an average price of $7.75 per share, which totaled $5.0 million • Completed the acquisition of Kanebridge a leading master distributor of industrial fasteners • Successfully refinanced its existing credit facilities extending maturities to 2033 (term loan B) and 2031 (revolving credit facility) ◦ $735 million senior secured term loan B ◦ $375 million asset-based revolving credit facility ◦ $200 million add-on to the term loan B (for the Kanebridge acquisition)
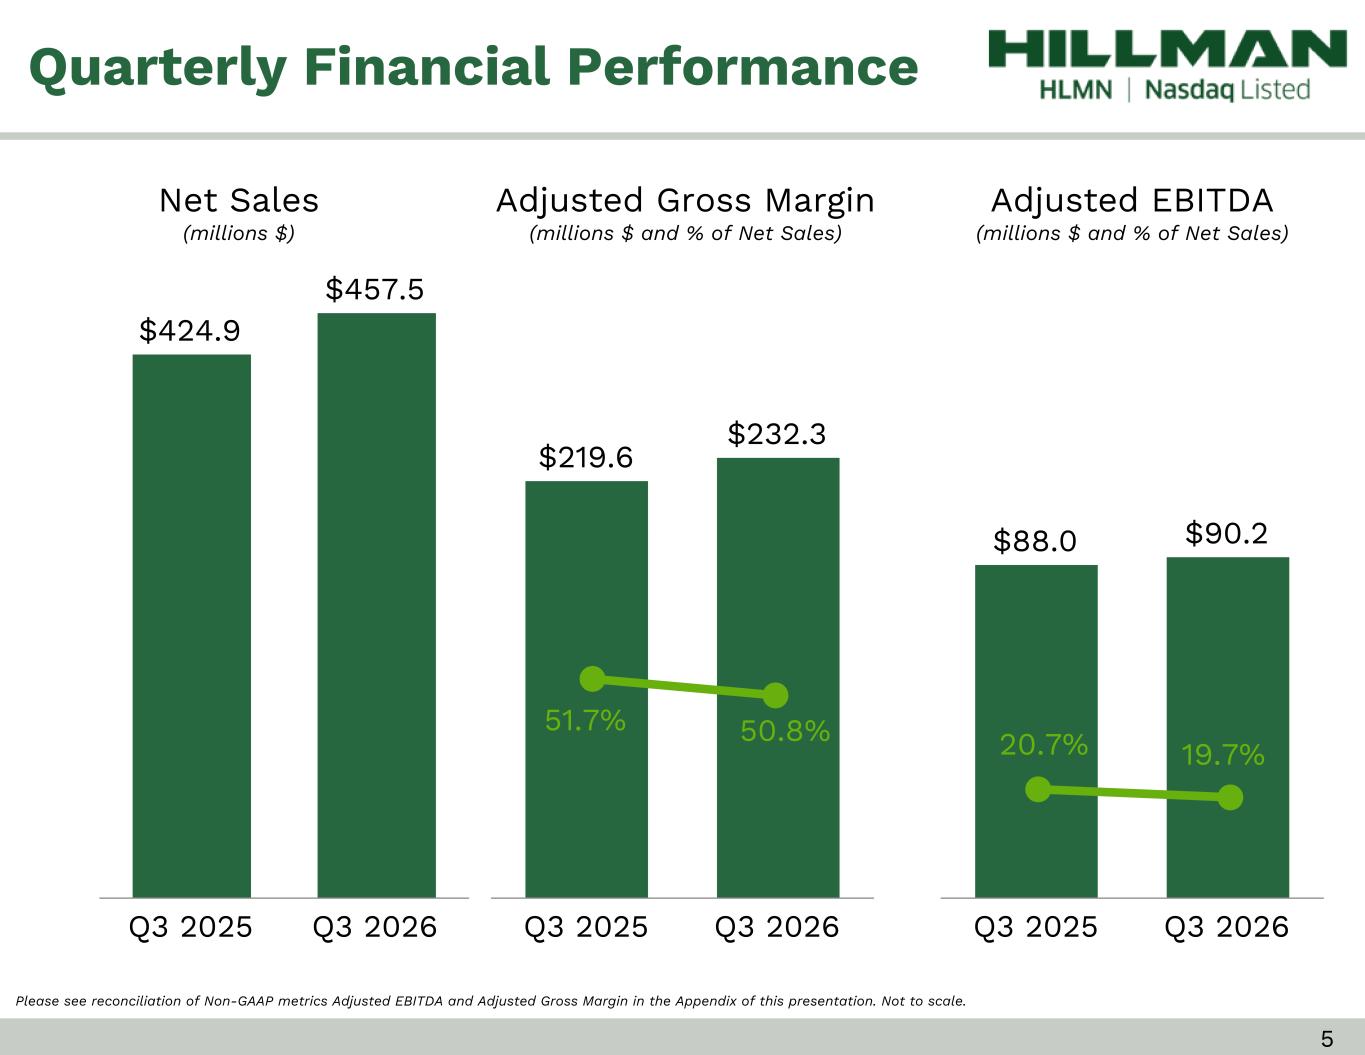
5 Quarterly Financial Performance Adjusted EBITDA (millions $ and % of Net Sales) Please see reconciliation of Non-GAAP metrics Adjusted EBITDA and Adjusted Gross Margin in the Appendix of this presentation. Not to scale. Net Sales (millions $) Adjusted Gross Margin (millions $ and % of Net Sales) $88.0 $90.2 Q3 2025 Q3 2026 19.7%20.7% $219.6 $232.3 Q3 2025 Q3 2026 $424.9 $457.5 Q3 2025 Q3 2026 50.8%51.7%
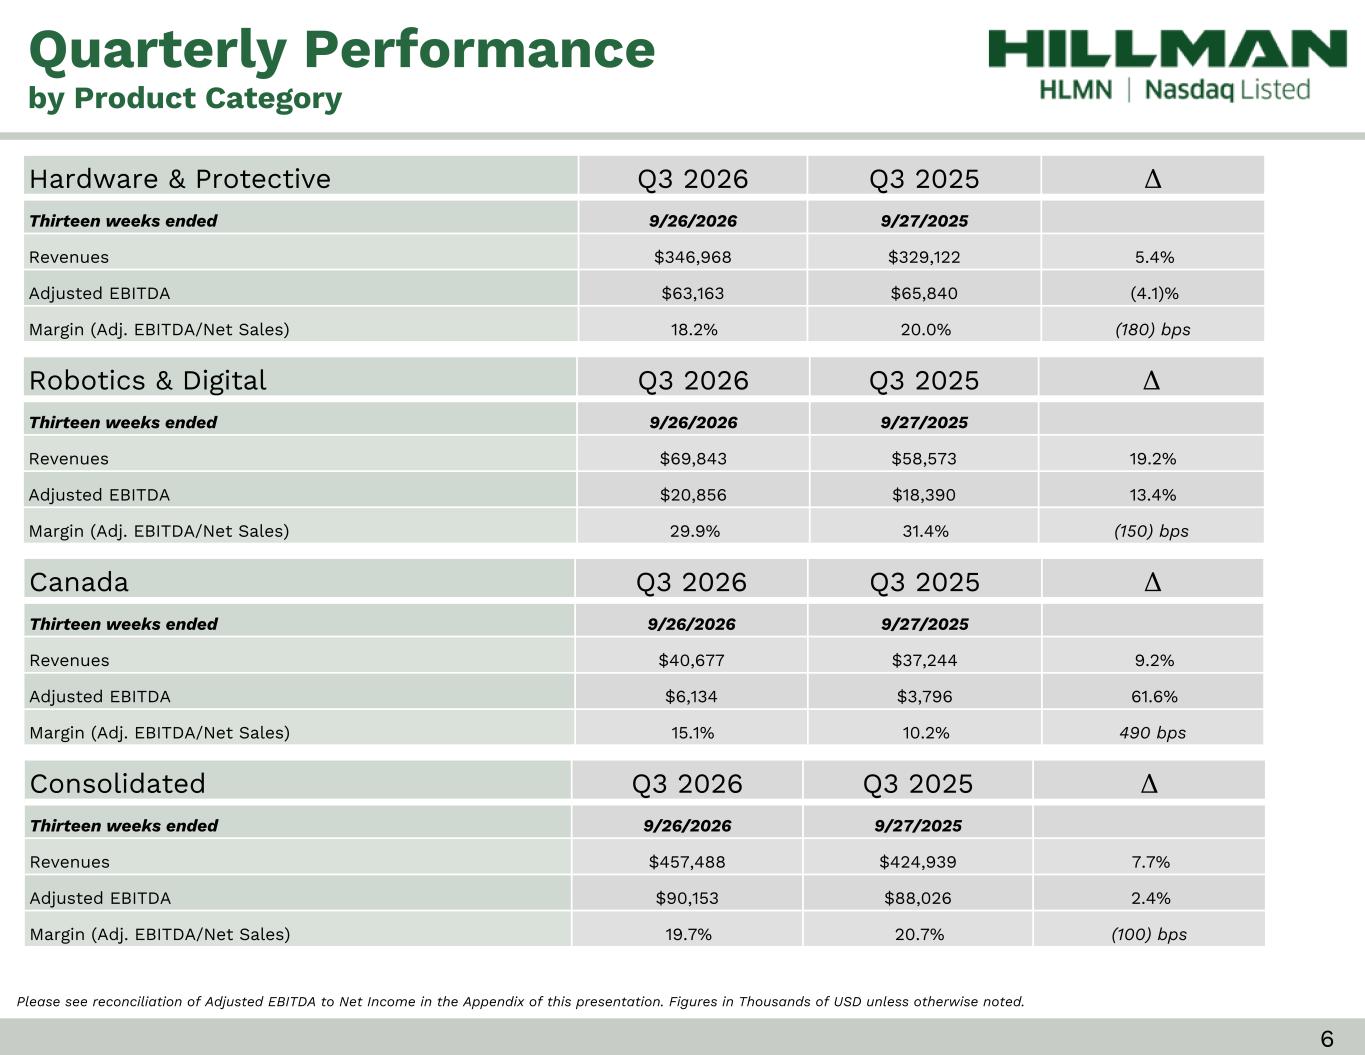
6 Hardware & Protective Q3 2026 Q3 2025 Δ Thirteen weeks ended 9/26/2026 9/27/2025 Revenues $346,968 $329,122 5.4% Adjusted EBITDA $63,163 $65,840 (4.1)% Margin (Adj. EBITDA/Net Sales) 18.2% 20.0% (180) bps Robotics & Digital Q3 2026 Q3 2025 Δ Thirteen weeks ended 9/26/2026 9/27/2025 Revenues $69,843 $58,573 19.2% Adjusted EBITDA $20,856 $18,390 13.4% Margin (Adj. EBITDA/Net Sales) 29.9% 31.4% (150) bps Canada Q3 2026 Q3 2025 Δ Thirteen weeks ended 9/26/2026 9/27/2025 Revenues $40,677 $37,244 9.2% Adjusted EBITDA $6,134 $3,796 61.6% Margin (Adj. EBITDA/Net Sales) 15.1% 10.2% 490 bps Consolidated Q3 2026 Q3 2025 Δ Thirteen weeks ended 9/26/2026 9/27/2025 Revenues $457,488 $424,939 7.7% Adjusted EBITDA $90,153 $88,026 2.4% Margin (Adj. EBITDA/Net Sales) 19.7% 20.7% (100) bps Quarterly Performance by Product Category Please see reconciliation of Adjusted EBITDA to Net Income in the Appendix of this presentation. Figures in Thousands of USD unless otherwise noted. • Top Row: ◦ 27 point height ◦ 16 font (work sans) ◦ 4 point white bottom line • First Column green ◦ Dark: CFD9D1 ◦ Light: D9E1DA • Other Columns gray ◦ Dark: D9D9D9 ◦ Light E0E0E0 ◦ 1 point white bottom and inside lines
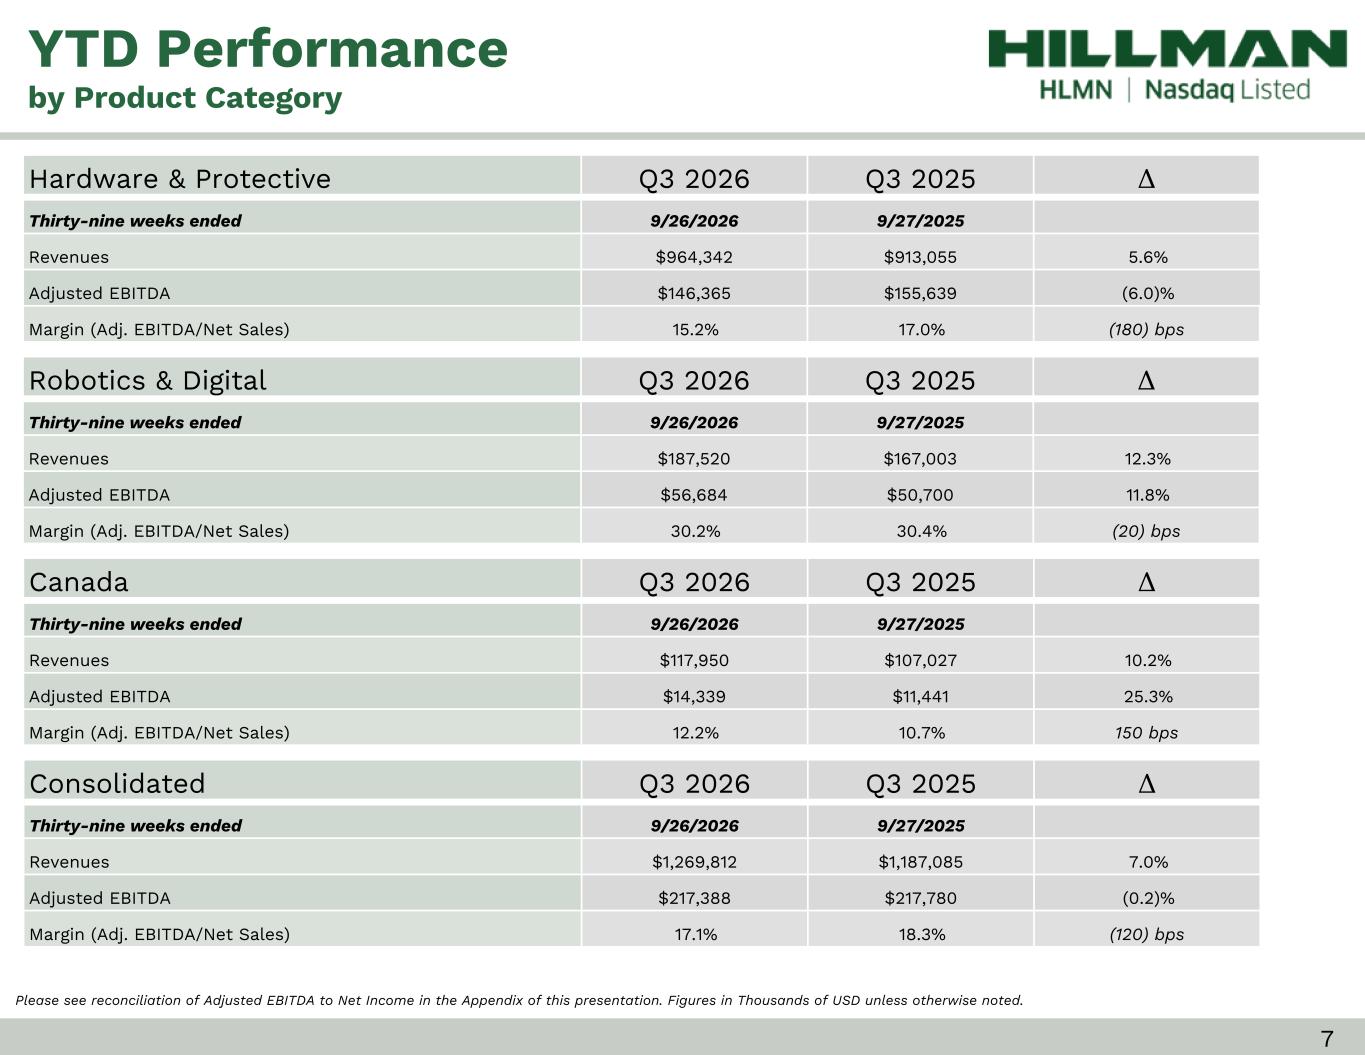
7 Hardware & Protective Q3 2026 Q3 2025 Δ Thirty-nine weeks ended 9/26/2026 9/27/2025 Revenues $964,342 $913,055 5.6% Adjusted EBITDA $146,365 $155,639 (6.0)% Margin (Adj. EBITDA/Net Sales) 15.2% 17.0% (180) bps Robotics & Digital Q3 2026 Q3 2025 Δ Thirty-nine weeks ended 9/26/2026 9/27/2025 Revenues $187,520 $167,003 12.3% Adjusted EBITDA $56,684 $50,700 11.8% Margin (Adj. EBITDA/Net Sales) 30.2% 30.4% (20) bps Canada Q3 2026 Q3 2025 Δ Thirty-nine weeks ended 9/26/2026 9/27/2025 Revenues $117,950 $107,027 10.2% Adjusted EBITDA $14,339 $11,441 25.3% Margin (Adj. EBITDA/Net Sales) 12.2% 10.7% 150 bps Consolidated Q3 2026 Q3 2025 Δ Thirty-nine weeks ended 9/26/2026 9/27/2025 Revenues $1,269,812 $1,187,085 7.0% Adjusted EBITDA $217,388 $217,780 (0.2)% Margin (Adj. EBITDA/Net Sales) 17.1% 18.3% (120) bps YTD Performance by Product Category Please see reconciliation of Adjusted EBITDA to Net Income in the Appendix of this presentation. Figures in Thousands of USD unless otherwise noted.
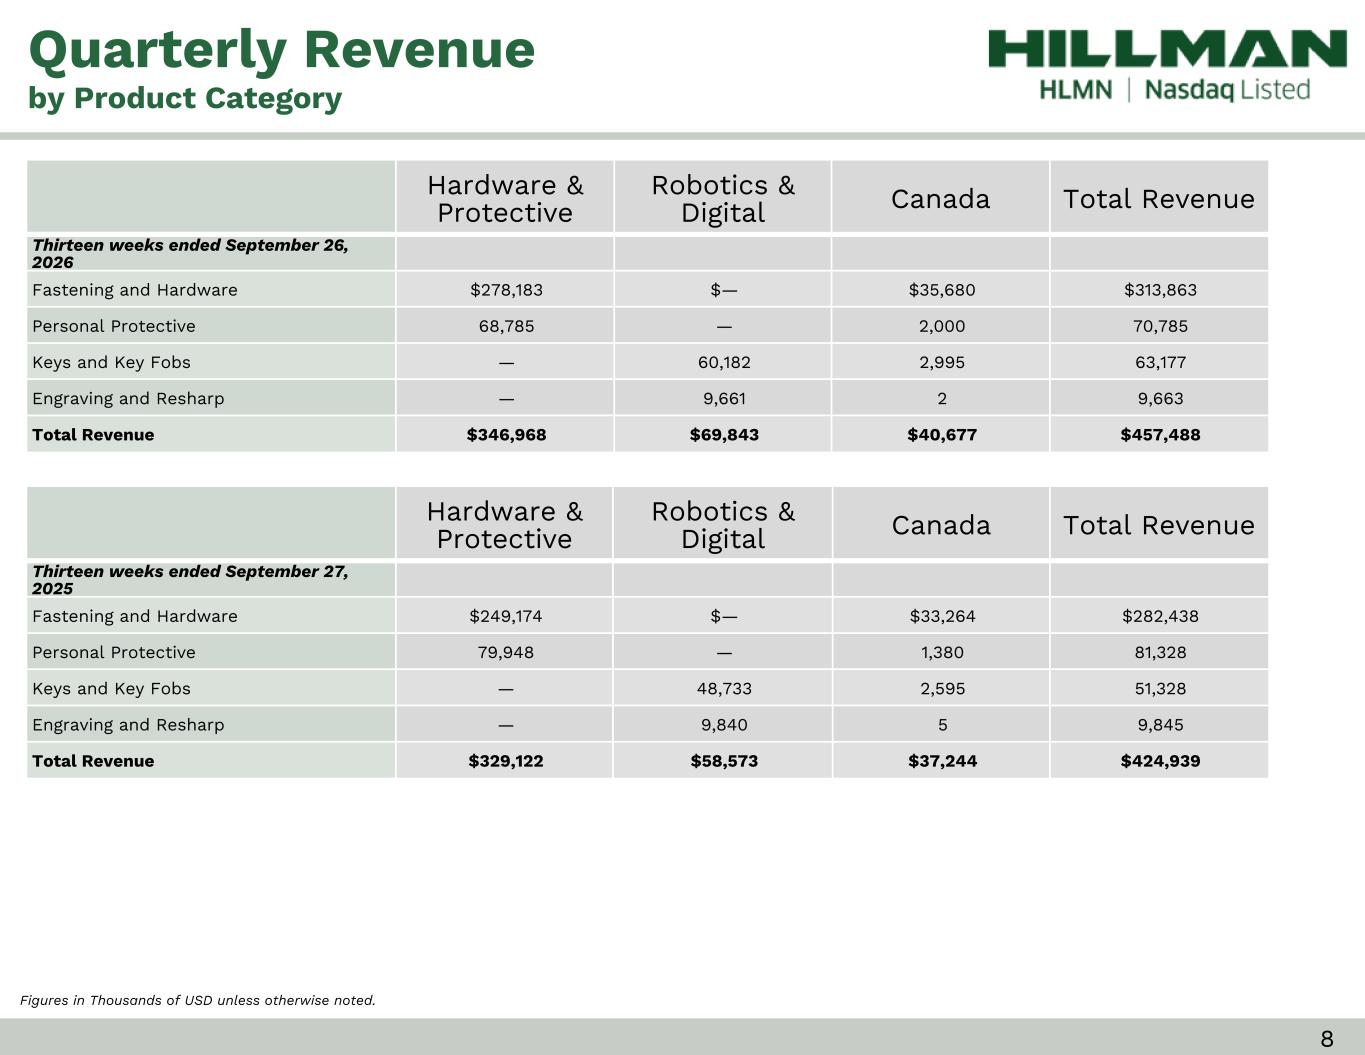
8 Hardware & Protective Robotics & Digital Canada Total Revenue Thirteen weeks ended September 26, 2026 Fastening and Hardware $278,183 $— $35,680 $313,863 Personal Protective 68,785 — 2,000 70,785 Keys and Key Fobs — 60,182 2,995 63,177 Engraving and Resharp — 9,661 2 9,663 Total Revenue $346,968 $69,843 $40,677 $457,488 Quarterly Revenue by Product Category Hardware & Protective Robotics & Digital Canada Total Revenue Thirteen weeks ended September 27, 2025 Fastening and Hardware $249,174 $— $33,264 $282,438 Personal Protective 79,948 — 1,380 81,328 Keys and Key Fobs — 48,733 2,595 51,328 Engraving and Resharp — 9,840 5 9,845 Total Revenue $329,122 $58,573 $37,244 $424,939 Figures in Thousands of USD unless otherwise noted.
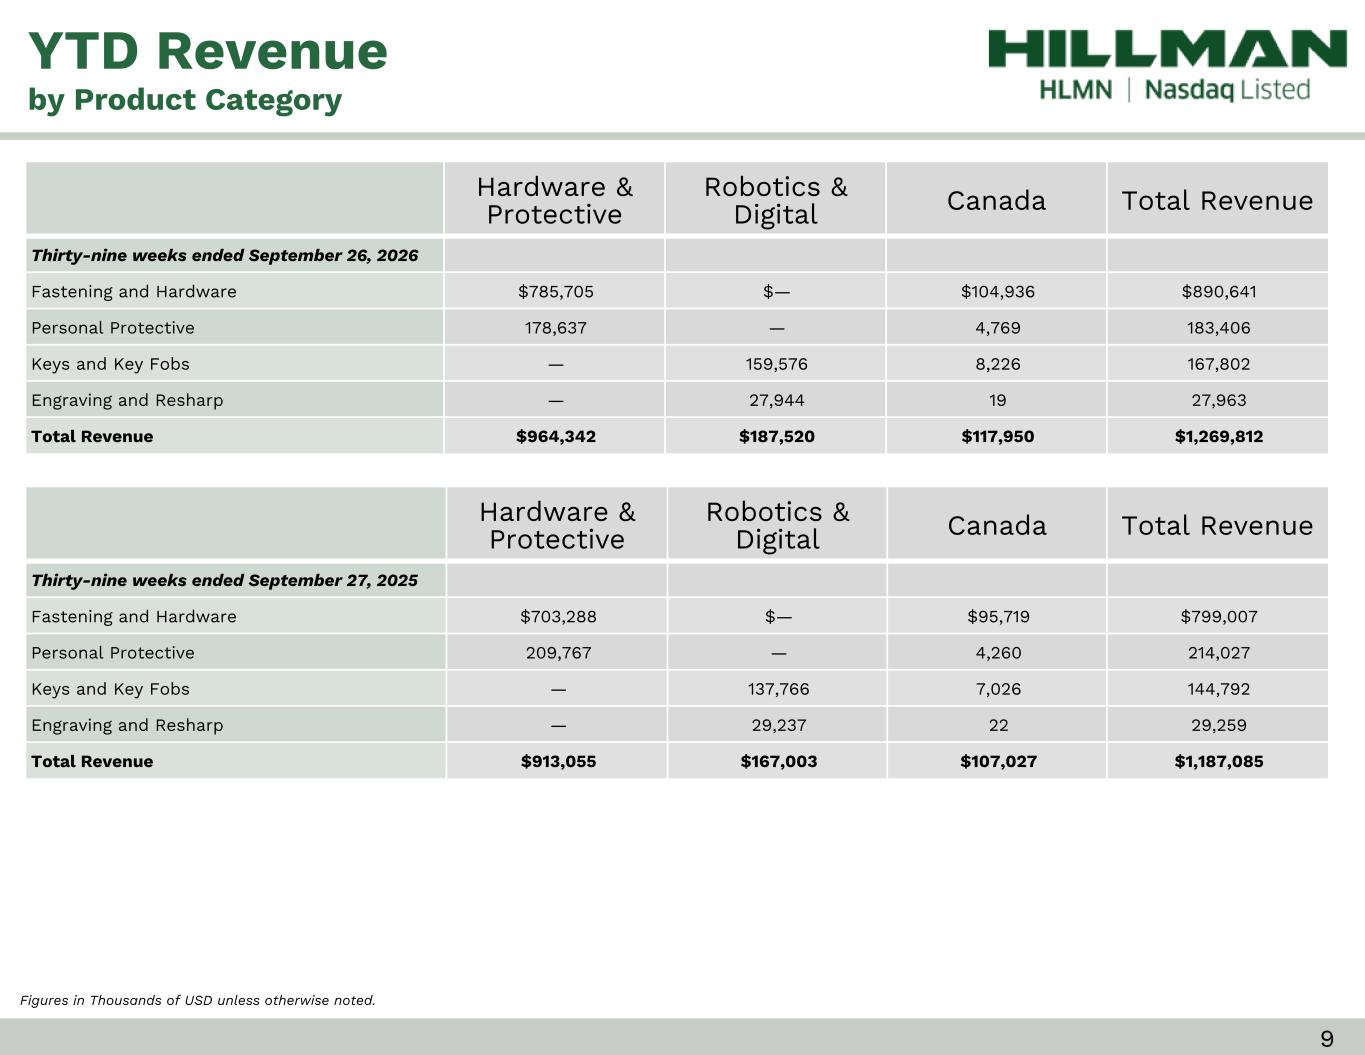
9 Hardware & Protective Robotics & Digital Canada Total Revenue Thirty-nine weeks ended September 26, 2026 Fastening and Hardware $785,705 $— $104,936 $890,641 Personal Protective 178,637 — 4,769 183,406 Keys and Key Fobs — 159,576 8,226 167,802 Engraving and Resharp — 27,944 19 27,963 Total Revenue $964,342 $187,520 $117,950 $1,269,812 YTD Revenue by Product Category Hardware & Protective Robotics & Digital Canada Total Revenue Thirty-nine weeks ended September 27, 2025 Fastening and Hardware $703,288 $— $95,719 $799,007 Personal Protective 209,767 — 4,260 214,027 Keys and Key Fobs — 137,766 7,026 144,792 Engraving and Resharp — 29,237 22 29,259 Total Revenue $913,055 $167,003 $107,027 $1,187,085 Figures in Thousands of USD unless otherwise noted.
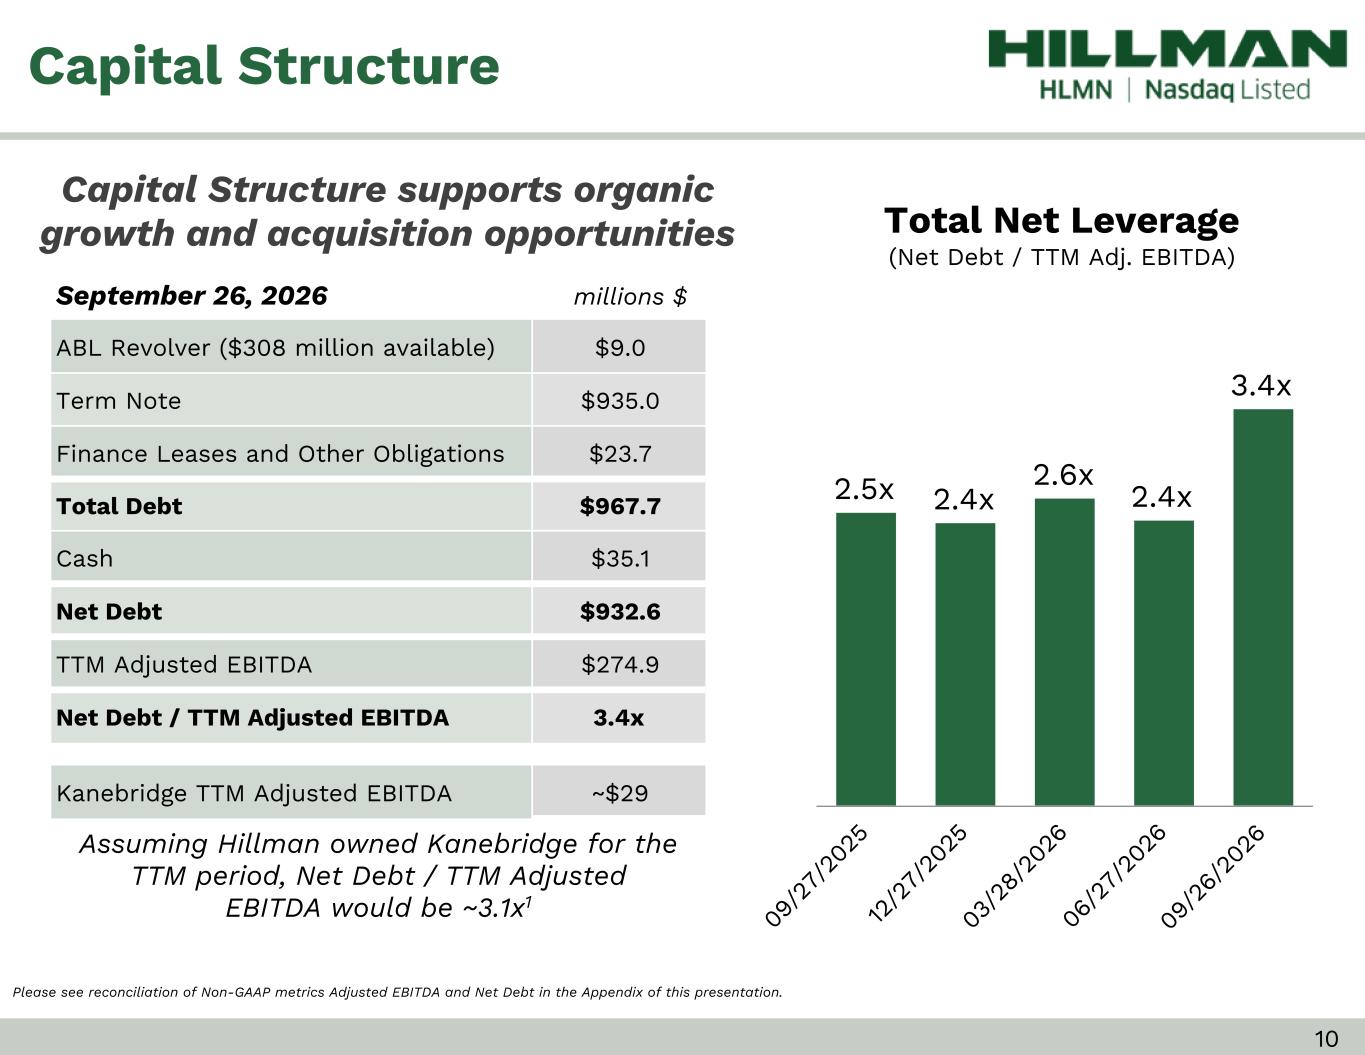
10 Total Net Leverage (Net Debt / TTM Adj. EBITDA) Capital Structure September 26, 2026 millions $ ABL Revolver ($308 million available) $9.0 Term Note $935.0 Finance Leases and Other Obligations $23.7 Total Debt $967.7 Cash $35.1 Net Debt $932.6 TTM Adjusted EBITDA $274.9 Net Debt / TTM Adjusted EBITDA 3.4x Please see reconciliation of Non-GAAP metrics Adjusted EBITDA and Net Debt in the Appendix of this presentation. 2.5x 2.4x 2.6x 2.4x 3.4x 09 /2 7/ 20 25 12 /2 7/ 20 25 03 /2 8/ 20 26 06 /2 7/ 20 26 09 /2 6/ 20 26 Capital Structure supports organic growth and acquisition opportunities Assuming Hillman owned Kanebridge for the TTM period, Net Debt / TTM Adjusted EBITDA would be ~3.1x1 Kanebridge TTM Adjusted EBITDA ~$29
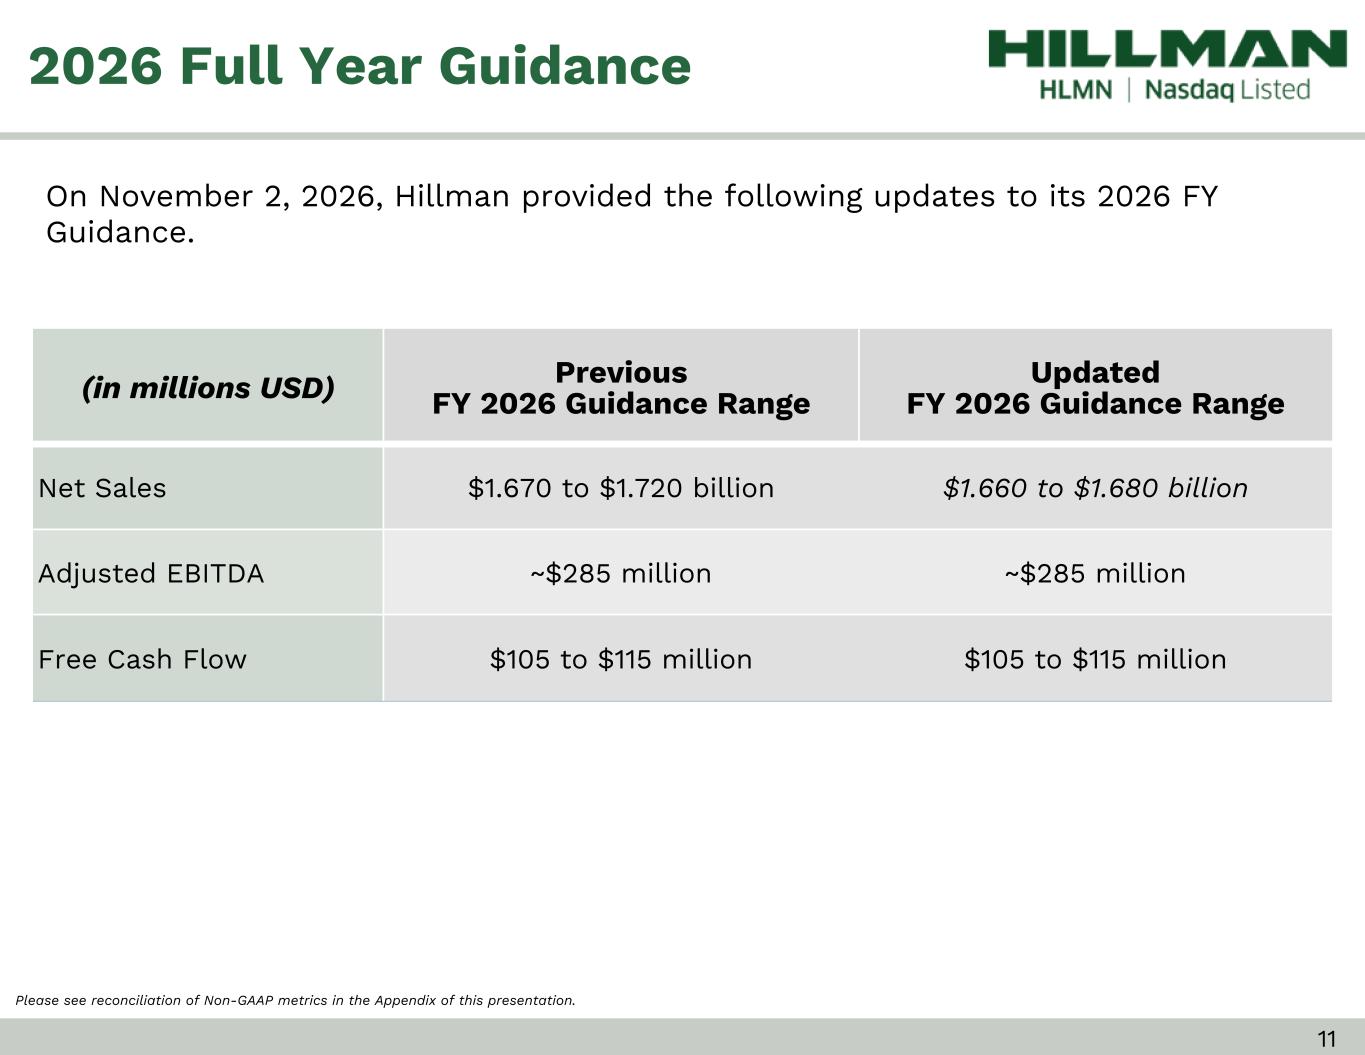
11 2026 Full Year Guidance (in millions USD) Previous FY 2026 Guidance Range Updated FY 2026 Guidance Range Net Sales $1.670 to $1.720 billion $1.660 to $1.680 billion Adjusted EBITDA ~$285 million ~$285 million Free Cash Flow $105 to $115 million $105 to $115 million On November 2, 2026, Hillman provided the following updates to its 2026 FY Guidance. Please see reconciliation of Non-GAAP metrics in the Appendix of this presentation.
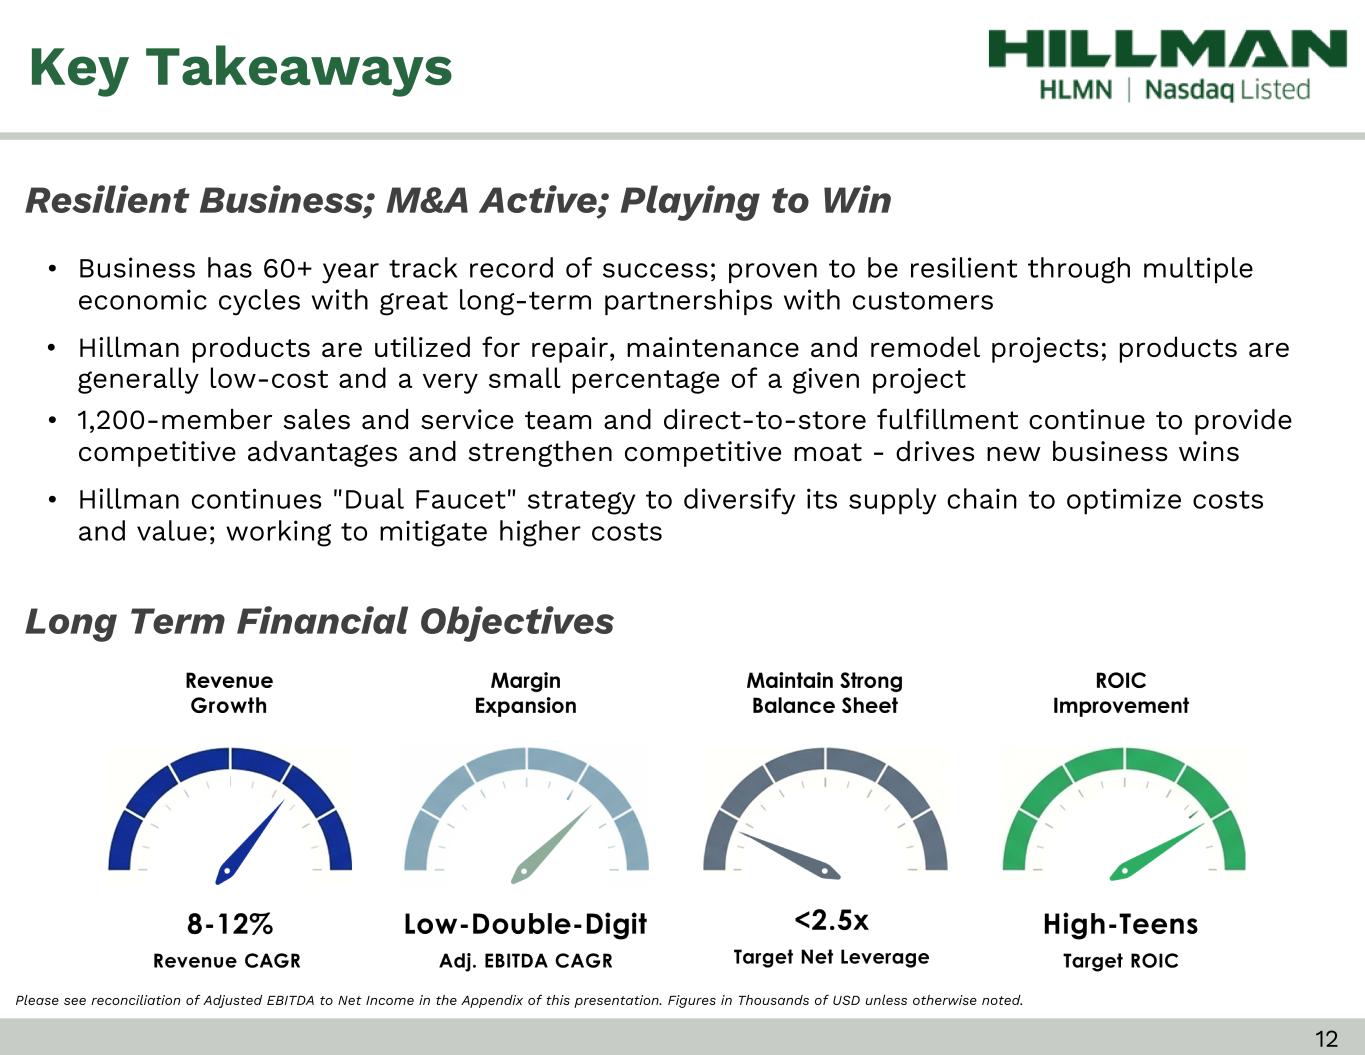
12 Key Takeaways Resilient Business; M&A Active; Playing to Win • Business has 60+ year track record of success; proven to be resilient through multiple economic cycles with great long-term partnerships with customers • Hillman products are utilized for repair, maintenance and remodel projects; products are generally low-cost and a very small percentage of a given project • 1,200-member sales and service team and direct-to-store fulfillment continue to provide competitive advantages and strengthen competitive moat - drives new business wins • Hillman continues "Dual Faucet" strategy to diversify its supply chain to optimize costs and value; working to mitigate higher costs Long Term Financial Objectives Please see reconciliation of Adjusted EBITDA to Net Income in the Appendix of this presentation. Figures in Thousands of USD unless otherwise noted.
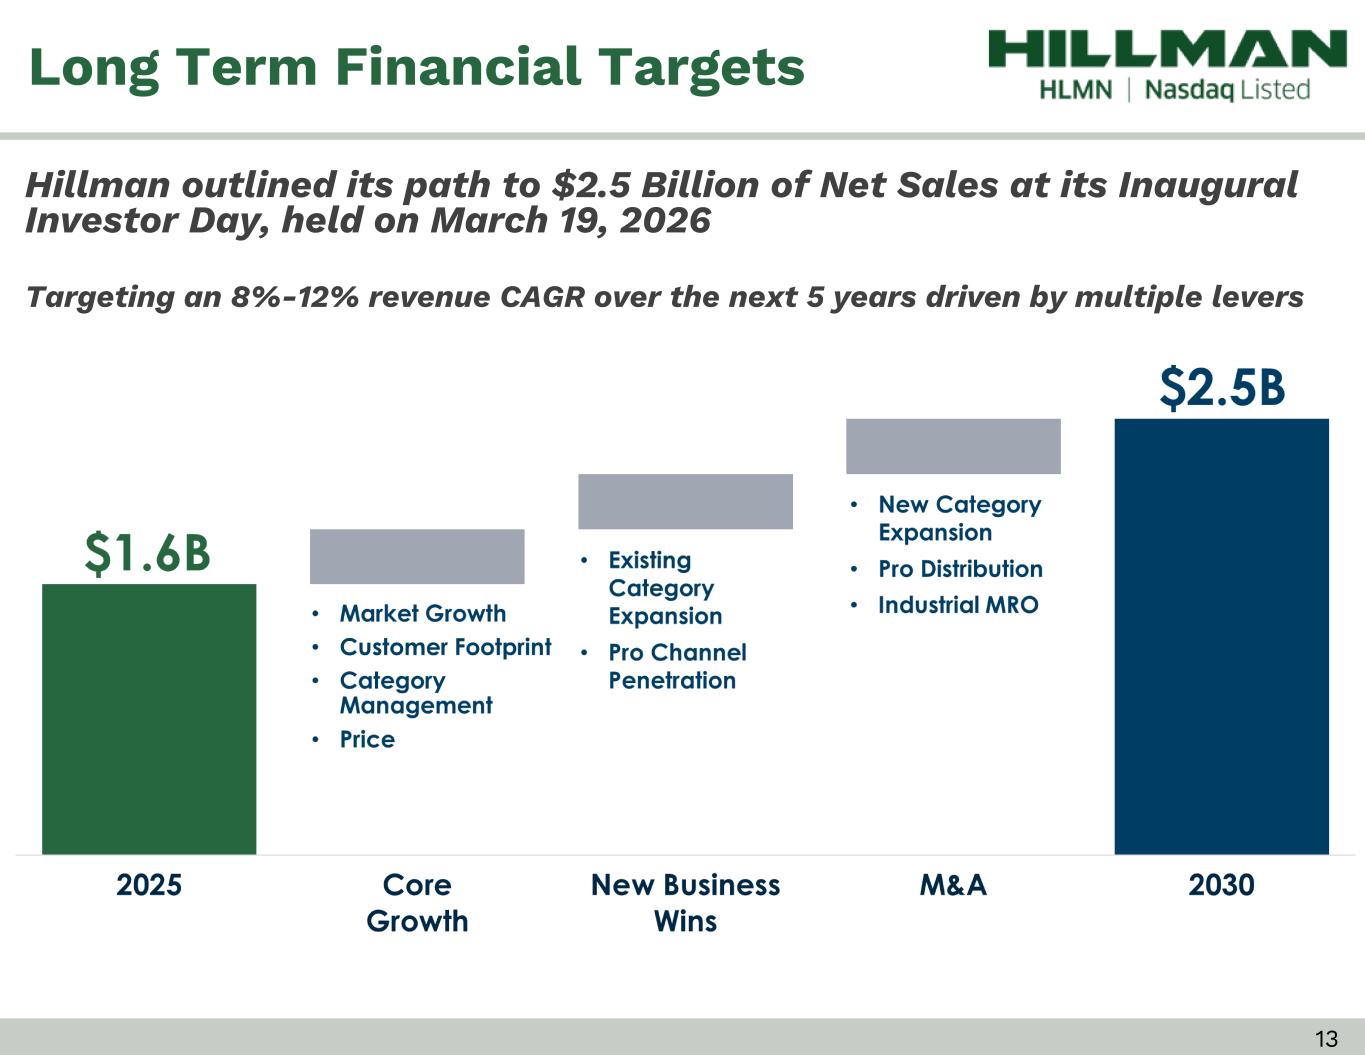
13 Long Term Financial Targets Hillman outlined its path to $2.5 Billion of Net Sales at its Inaugural Investor Day, held on March 19, 2026 Targeting an 8%-12% revenue CAGR over the next 5 years driven by multiple levers
Appendix
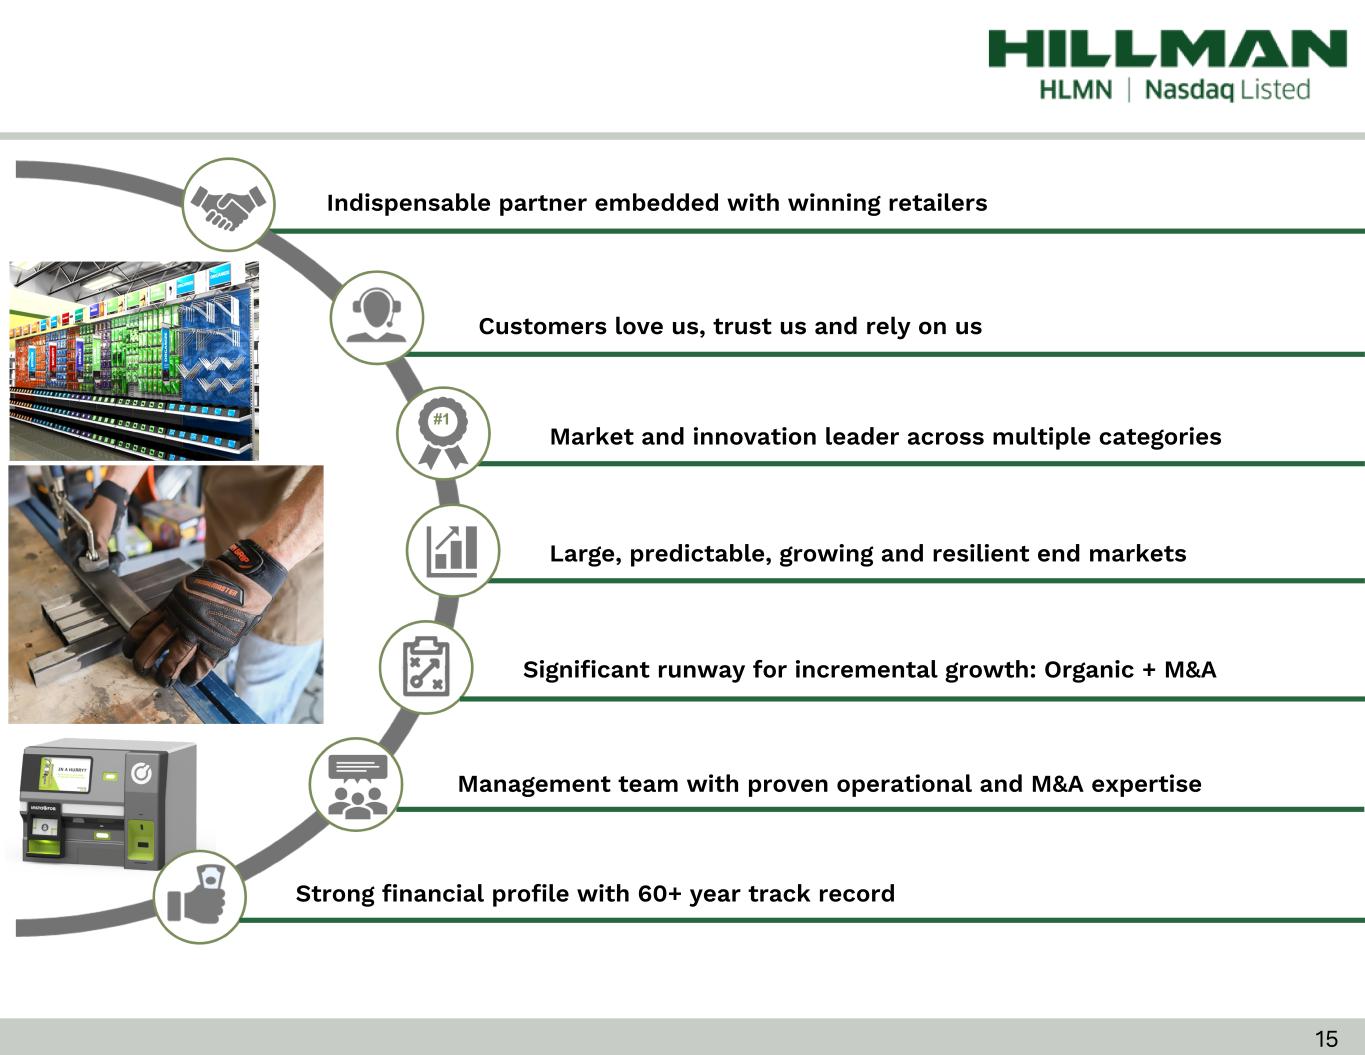
15 Investment Highlights Significant runway for incremental growth: Organic + M&A Management team with proven operational and M&A expertise Strong financial profile with 60+ year track record Market and innovation leader across multiple categories Indispensable partner embedded with winning retailers Customers love us, trust us and rely on us Large, predictable, growing and resilient end markets
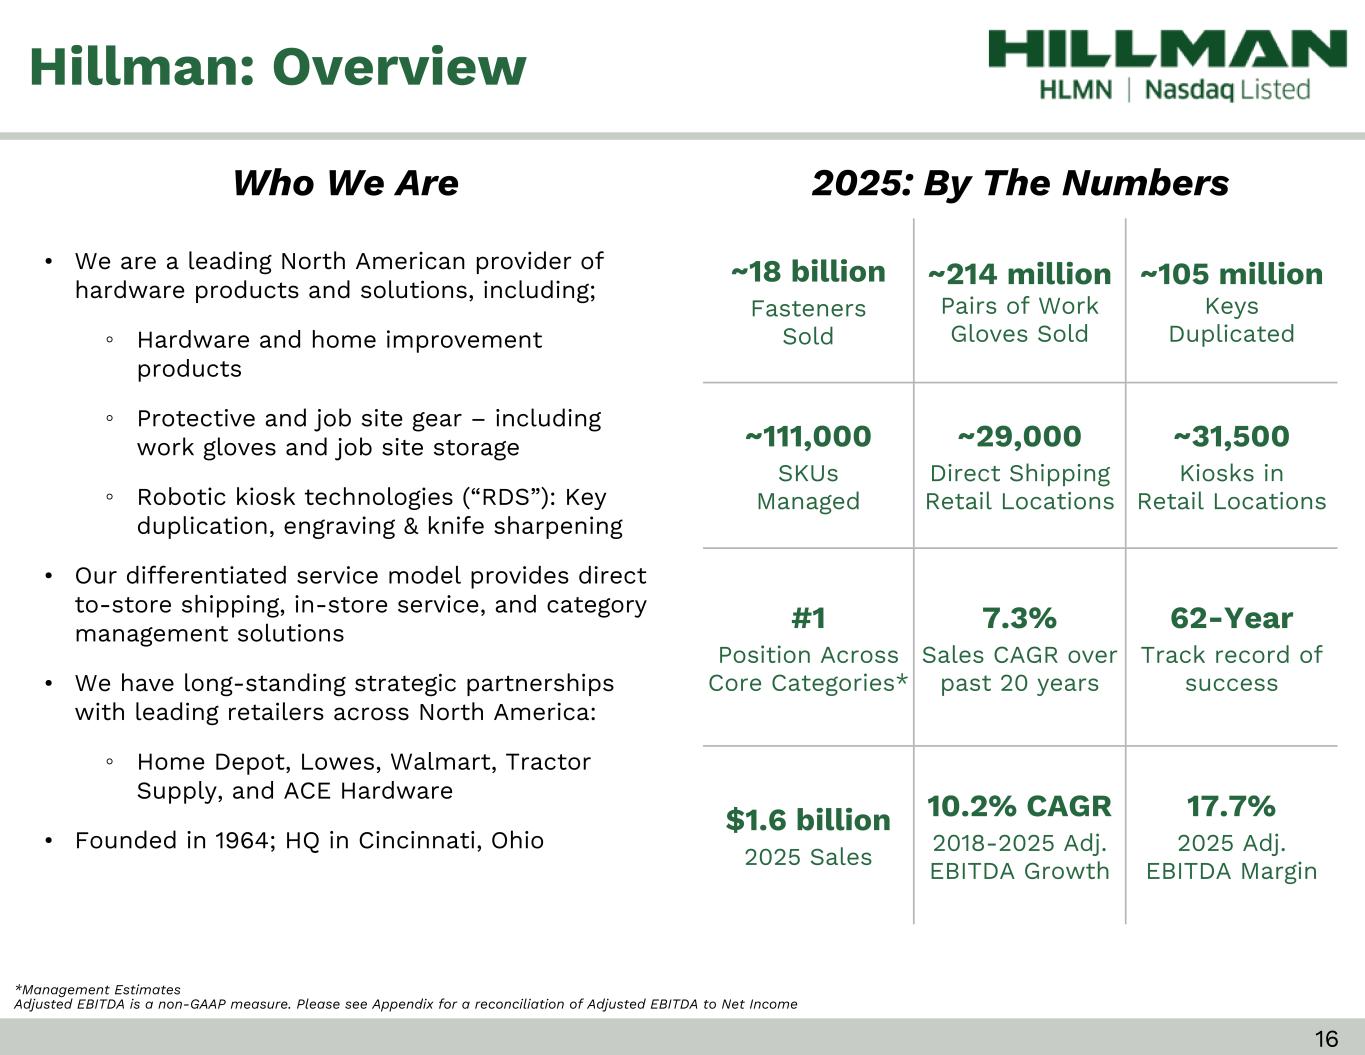
16 Hillman: Overview Who We Are *Management Estimates Adjusted EBITDA is a non-GAAP measure. Please see Appendix for a reconciliation of Adjusted EBITDA to Net Income ~18 billion Fasteners Sold ~214 million Pairs of Work Gloves Sold ~105 million Keys Duplicated ~111,000 SKUs Managed ~29,000 Direct Shipping Retail Locations ~31,500 Kiosks in Retail Locations #1 Position Across Core Categories* 7.3% Sales CAGR over past 20 years 62-Year Track record of success $1.6 billion 2025 Sales 10.2% CAGR 2018-2025 Adj. EBITDA Growth 17.7% 2025 Adj. EBITDA Margin 2025: By The Numbers • We are a leading North American provider of hardware products and solutions, including; ◦ Hardware and home improvement products ◦ Protective and job site gear – including work gloves and job site storage ◦ Robotic kiosk technologies (“RDS”): Key duplication, engraving & knife sharpening • Our differentiated service model provides direct to-store shipping, in-store service, and category management solutions • We have long-standing strategic partnerships with leading retailers across North America: ◦ Home Depot, Lowes, Walmart, Tractor Supply, and ACE Hardware • Founded in 1964; HQ in Cincinnati, Ohio
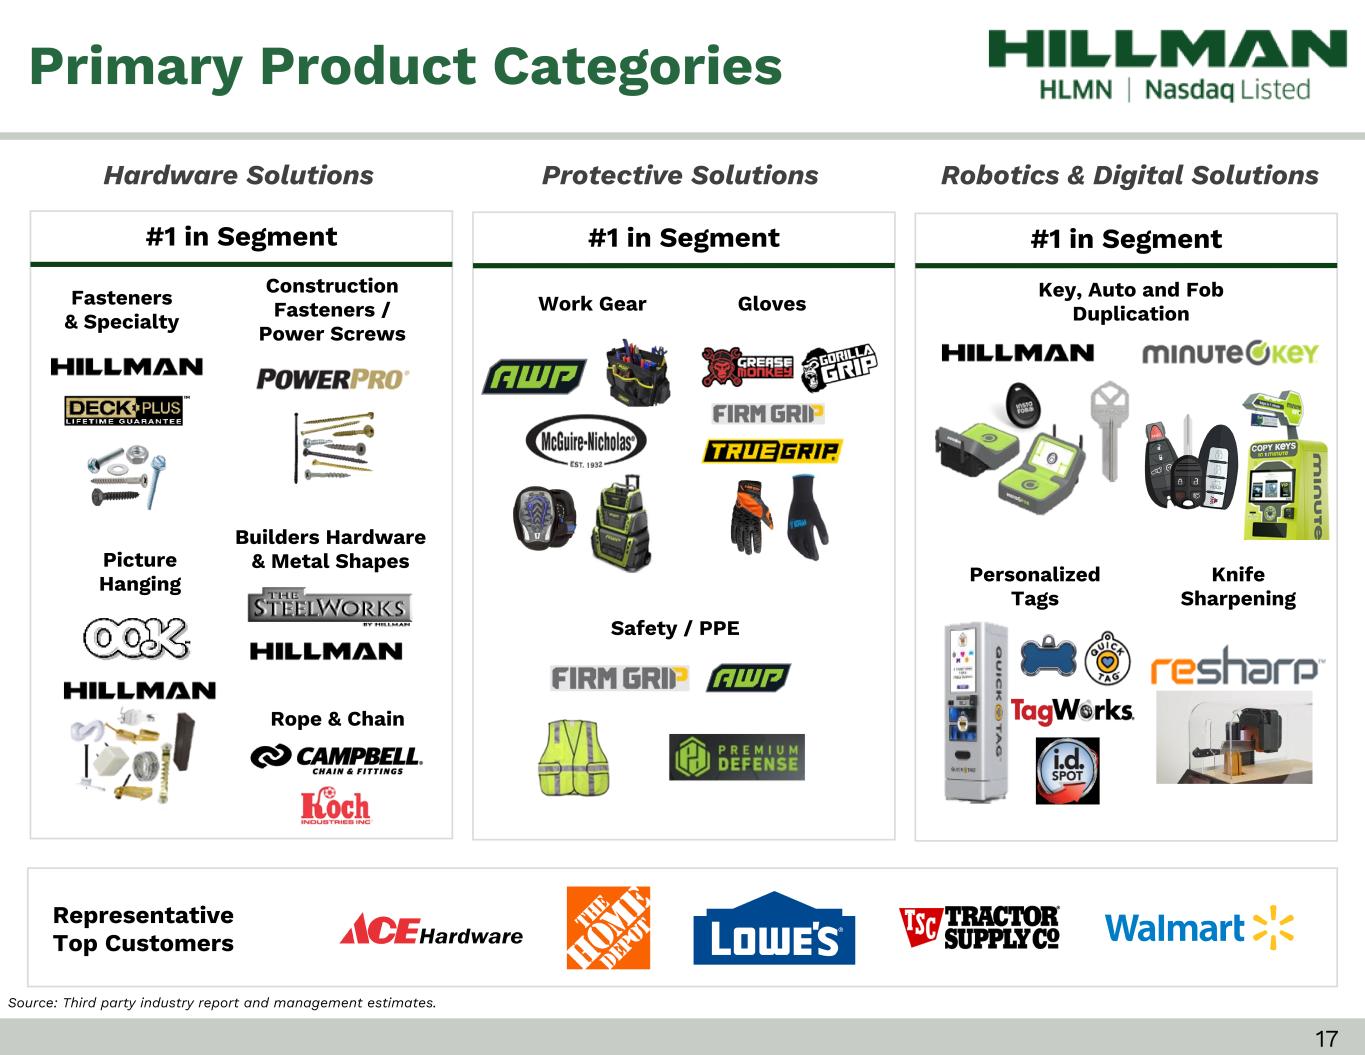
17 #1 in Segment Representative Top Customers #1 in Segment #1 in Segment Key, Auto and Fob Duplication Personalized Tags Knife Sharpening Fasteners & Specialty Gloves Builders Hardware & Metal Shapes Safety / PPE Construction Fasteners / Power Screws Work Gear Picture Hanging Source: Third party industry report and management estimates. Primary Product Categories Hardware Solutions Robotics & Digital SolutionsProtective Solutions Rope & Chain
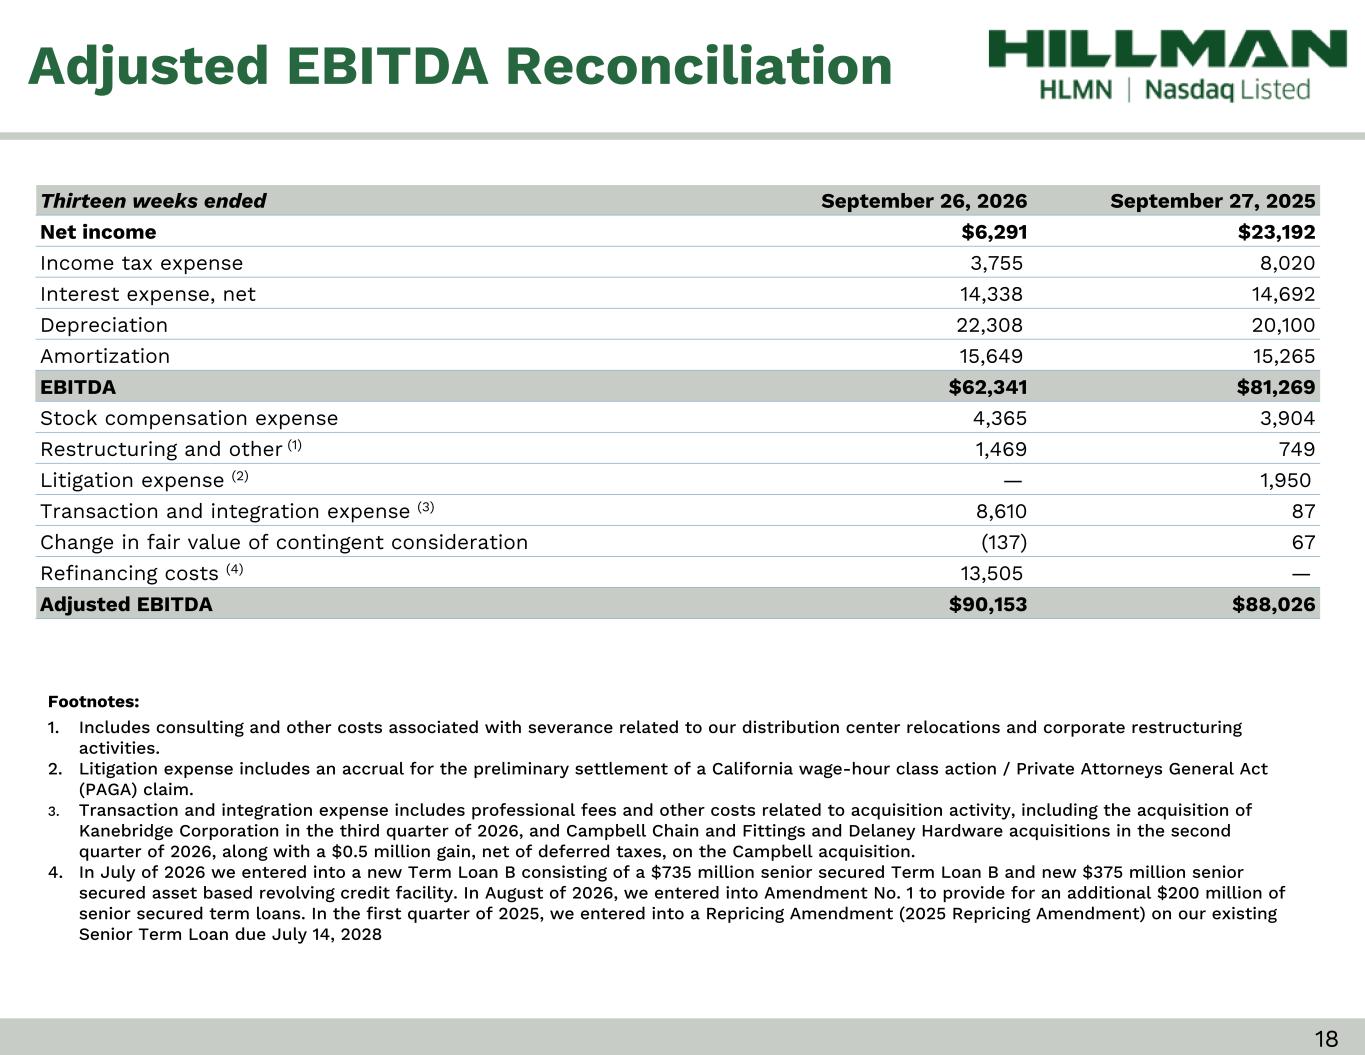
18 Thirteen weeks ended September 26, 2026 September 27, 2025 Net income $6,291 $23,192 Income tax expense 3,755 8,020 Interest expense, net 14,338 14,692 Depreciation 22,308 20,100 Amortization 15,649 15,265 EBITDA $62,341 $81,269 Stock compensation expense 4,365 3,904 Restructuring and other (1) 1,469 749 Litigation expense (2) — 1,950 Transaction and integration expense (3) 8,610 87 Change in fair value of contingent consideration (137) 67 Refinancing costs (4) 13,505 — Adjusted EBITDA $90,153 $88,026 Adjusted EBITDA Reconciliation Footnotes: 1. Includes consulting and other costs associated with severance related to our distribution center relocations and corporate restructuring activities. 2. Litigation expense includes an accrual for the preliminary settlement of a California wage-hour class action / Private Attorneys General Act (PAGA) claim. 3. Transaction and integration expense includes professional fees and other costs related to acquisition activity, including the acquisition of Kanebridge Corporation in the third quarter of 2026, and Campbell Chain and Fittings and Delaney Hardware acquisitions in the second quarter of 2026, along with a $0.5 million gain, net of deferred taxes, on the Campbell acquisition. 4. In July of 2026 we entered into a new Term Loan B consisting of a $735 million senior secured Term Loan B and new $375 million senior secured asset based revolving credit facility. In August of 2026, we entered into Amendment No. 1 to provide for an additional $200 million of senior secured term loans. In the first quarter of 2025, we entered into a Repricing Amendment (2025 Repricing Amendment) on our existing Senior Term Loan due July 14, 2028
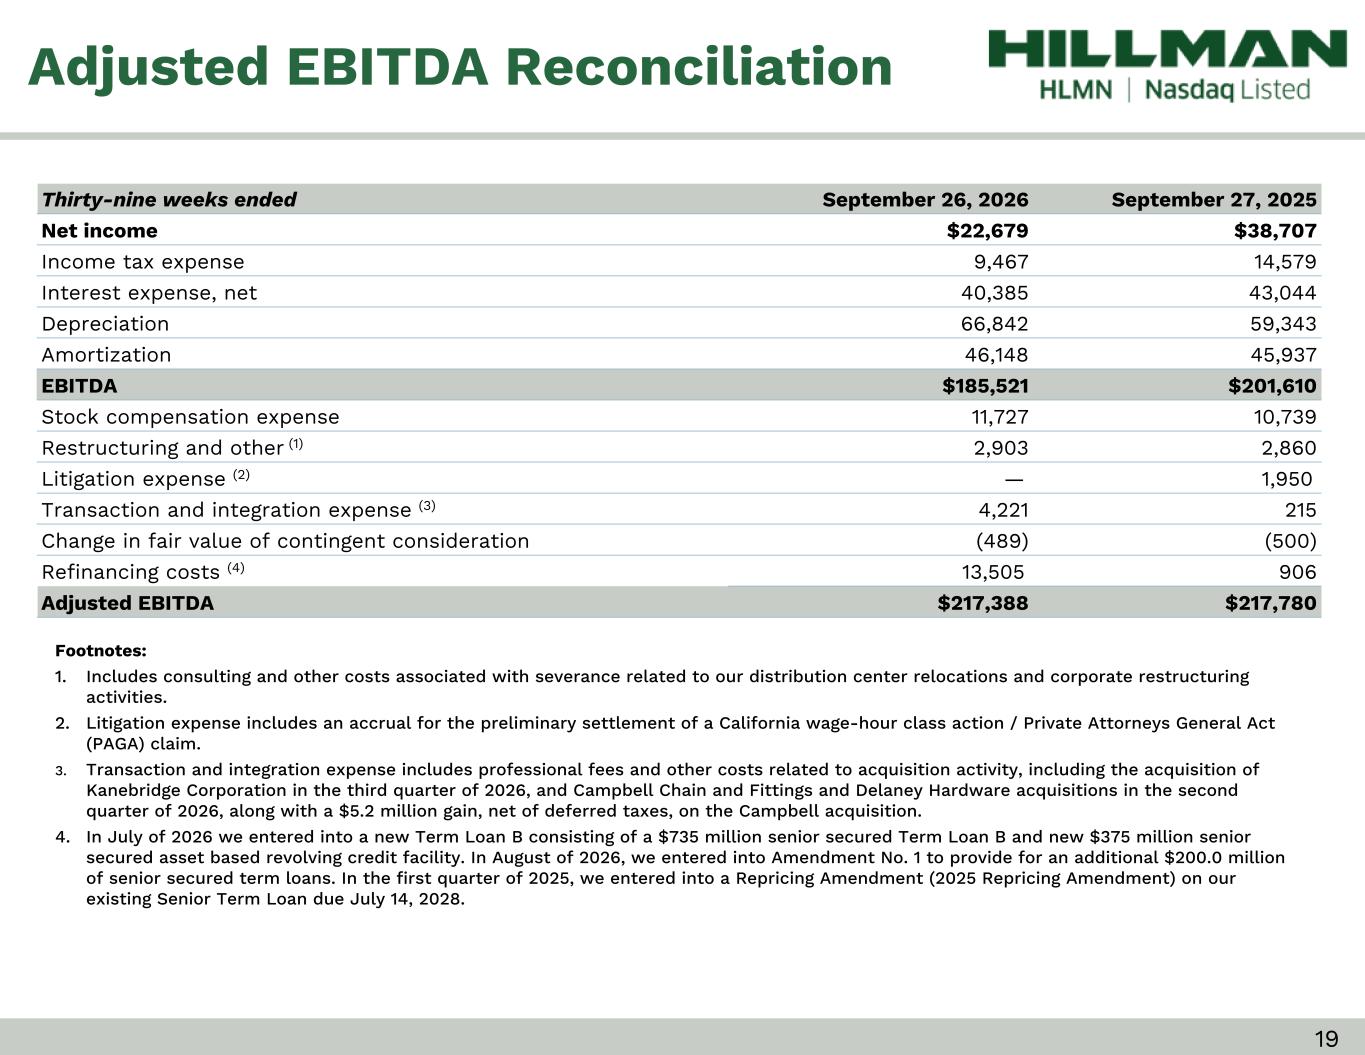
19 Thirty-nine weeks ended September 26, 2026 September 27, 2025 Net income $22,679 $38,707 Income tax expense 9,467 14,579 Interest expense, net 40,385 43,044 Depreciation 66,842 59,343 Amortization 46,148 45,937 EBITDA $185,521 $201,610 Stock compensation expense 11,727 10,739 Restructuring and other (1) 2,903 2,860 Litigation expense (2) — 1,950 Transaction and integration expense (3) 4,221 215 Change in fair value of contingent consideration (489) (500) Refinancing costs (4) 13,505 906 Adjusted EBITDA $217,388 $217,780 Adjusted EBITDA Reconciliation Footnotes: 1. Includes consulting and other costs associated with severance related to our distribution center relocations and corporate restructuring activities. 2. Litigation expense includes an accrual for the preliminary settlement of a California wage-hour class action / Private Attorneys General Act (PAGA) claim. 3. Transaction and integration expense includes professional fees and other costs related to acquisition activity, including the acquisition of Kanebridge Corporation in the third quarter of 2026, and Campbell Chain and Fittings and Delaney Hardware acquisitions in the second quarter of 2026, along with a $5.2 million gain, net of deferred taxes, on the Campbell acquisition. 4. In July of 2026 we entered into a new Term Loan B consisting of a $735 million senior secured Term Loan B and new $375 million senior secured asset based revolving credit facility. In August of 2026, we entered into Amendment No. 1 to provide for an additional $200.0 million of senior secured term loans. In the first quarter of 2025, we entered into a Repricing Amendment (2025 Repricing Amendment) on our existing Senior Term Loan due July 14, 2028.
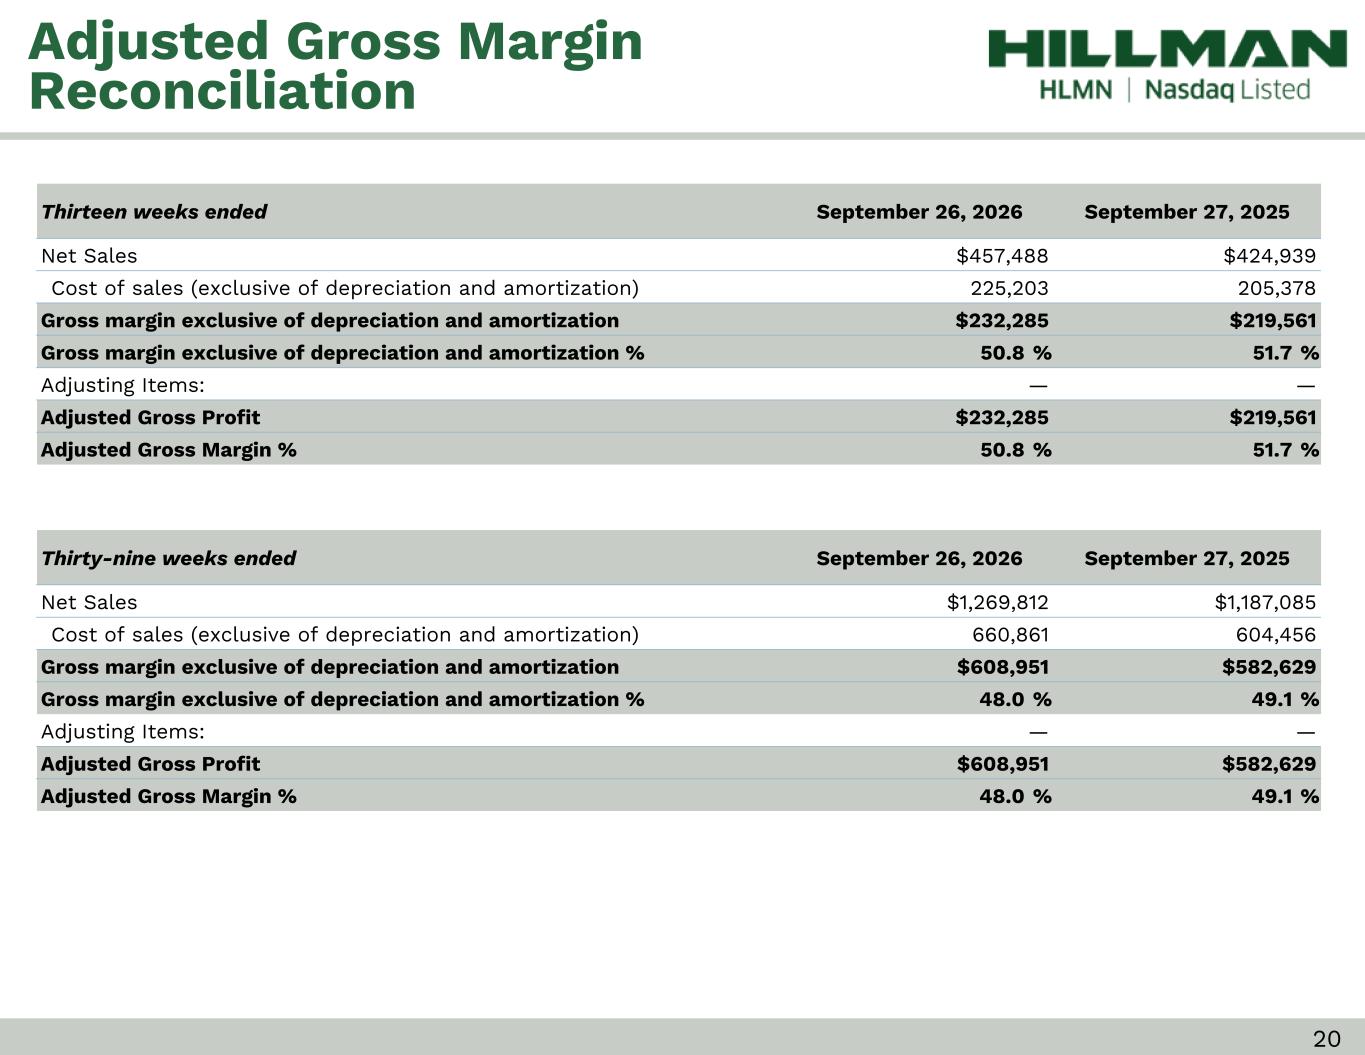
20 Thirteen weeks ended September 26, 2026 September 27, 2025 Net Sales $457,488 $424,939 Cost of sales (exclusive of depreciation and amortization) 225,203 205,378 Gross margin exclusive of depreciation and amortization $232,285 $219,561 Gross margin exclusive of depreciation and amortization % 50.8 % 51.7 % Adjusting Items: — — Adjusted Gross Profit $232,285 $219,561 Adjusted Gross Margin % 50.8 % 51.7 % Thirty-nine weeks ended September 26, 2026 September 27, 2025 Net Sales $1,269,812 $1,187,085 Cost of sales (exclusive of depreciation and amortization) 660,861 604,456 Gross margin exclusive of depreciation and amortization $608,951 $582,629 Gross margin exclusive of depreciation and amortization % 48.0 % 49.1 % Adjusting Items: — — Adjusted Gross Profit $608,951 $582,629 Adjusted Gross Margin % 48.0 % 49.1 % Adjusted Gross Margin Reconciliation
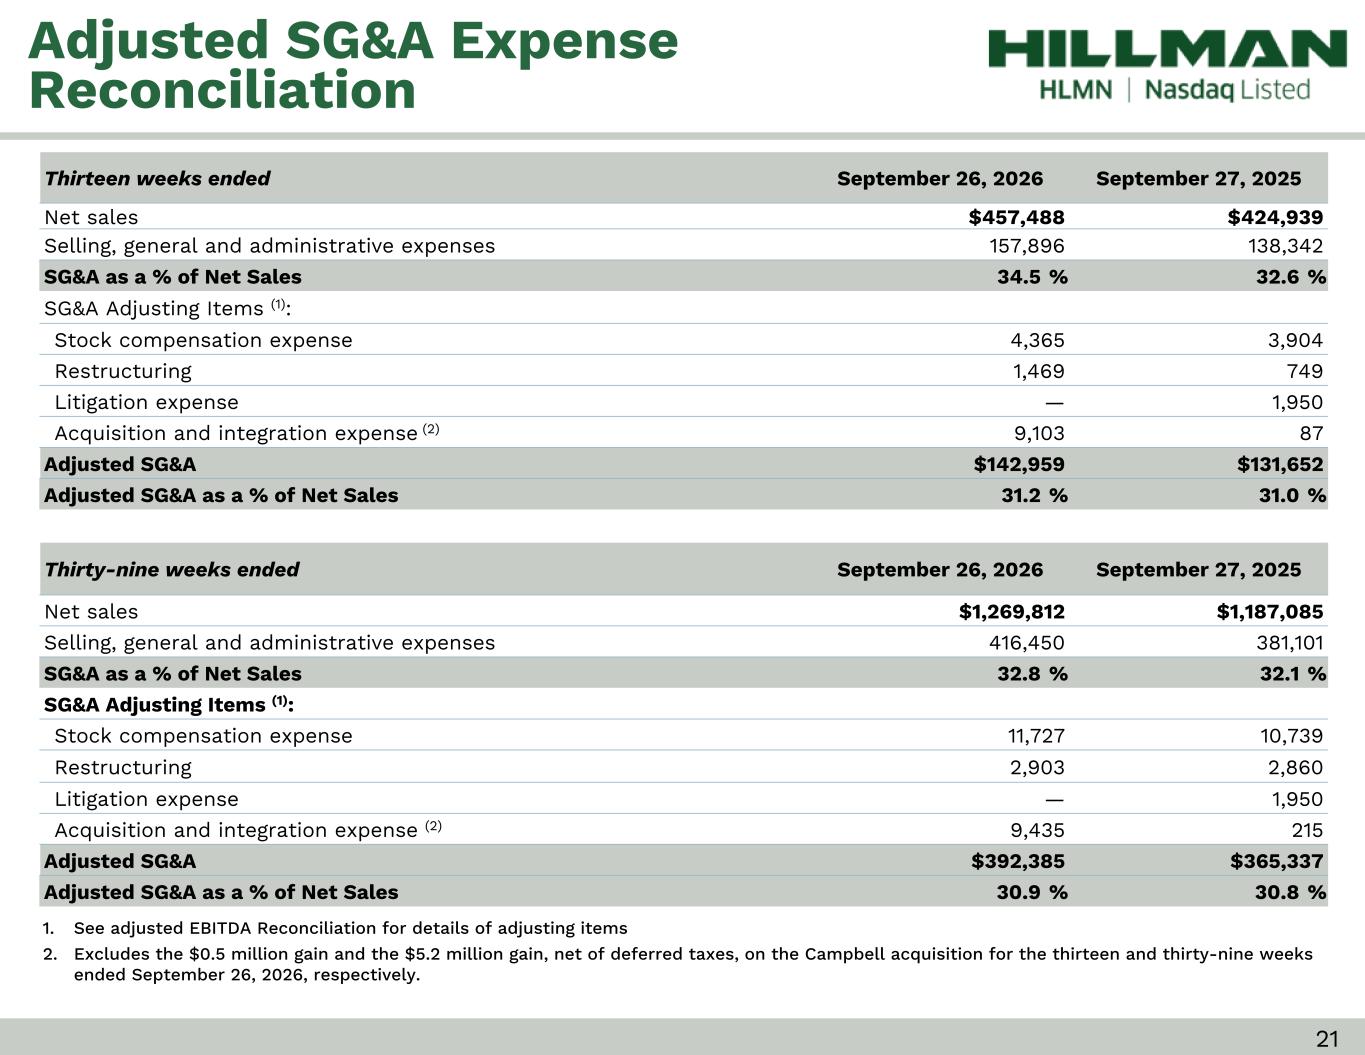
21 Thirteen weeks ended September 26, 2026 September 27, 2025 Net sales $457,488 $424,939 Selling, general and administrative expenses 157,896 138,342 SG&A as a % of Net Sales 34.5 % 32.6 % SG&A Adjusting Items (1): Stock compensation expense 4,365 3,904 Restructuring 1,469 749 Litigation expense — 1,950 Acquisition and integration expense (2) 9,103 87 Adjusted SG&A $142,959 $131,652 Adjusted SG&A as a % of Net Sales 31.2 % 31.0 % Thirty-nine weeks ended September 26, 2026 September 27, 2025 Net sales $1,269,812 $1,187,085 Selling, general and administrative expenses 416,450 381,101 SG&A as a % of Net Sales 32.8 % 32.1 % SG&A Adjusting Items (1): Stock compensation expense 11,727 10,739 Restructuring 2,903 2,860 Litigation expense — 1,950 Acquisition and integration expense (2) 9,435 215 Adjusted SG&A $392,385 $365,337 Adjusted SG&A as a % of Net Sales 30.9 % 30.8 % Adjusted SG&A Expense Reconciliation 1. See adjusted EBITDA Reconciliation for details of adjusting items 2. Excludes the $0.5 million gain and the $5.2 million gain, net of deferred taxes, on the Campbell acquisition for the thirteen and thirty-nine weeks ended September 26, 2026, respectively.
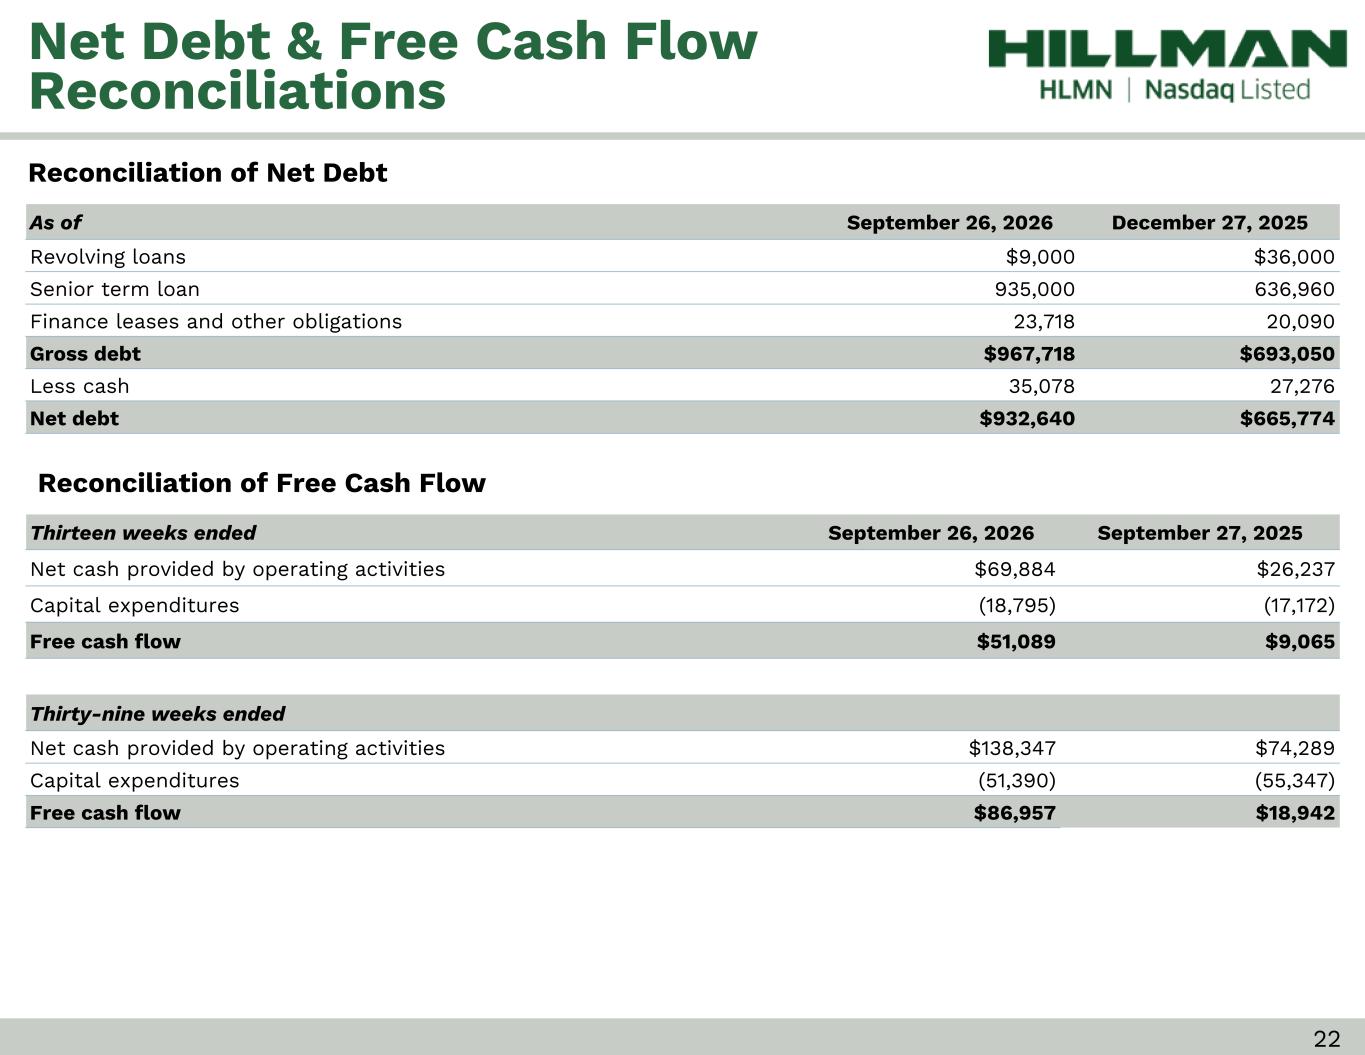
22 As of September 26, 2026 December 27, 2025 Revolving loans $9,000 $36,000 Senior term loan 935,000 636,960 Finance leases and other obligations 23,718 20,090 Gross debt $967,718 $693,050 Less cash 35,078 27,276 Net debt $932,640 $665,774 Net Debt & Free Cash Flow Reconciliations Thirteen weeks ended September 26, 2026 September 27, 2025 Net cash provided by operating activities $69,884 $26,237 Capital expenditures (18,795) (17,172) Free cash flow $51,089 $9,065 Thirty-nine weeks ended Net cash provided by operating activities $138,347 $74,289 Capital expenditures (51,390) (55,347) Free cash flow $86,957 $18,942 Reconciliation of Net Debt Reconciliation of Free Cash Flow
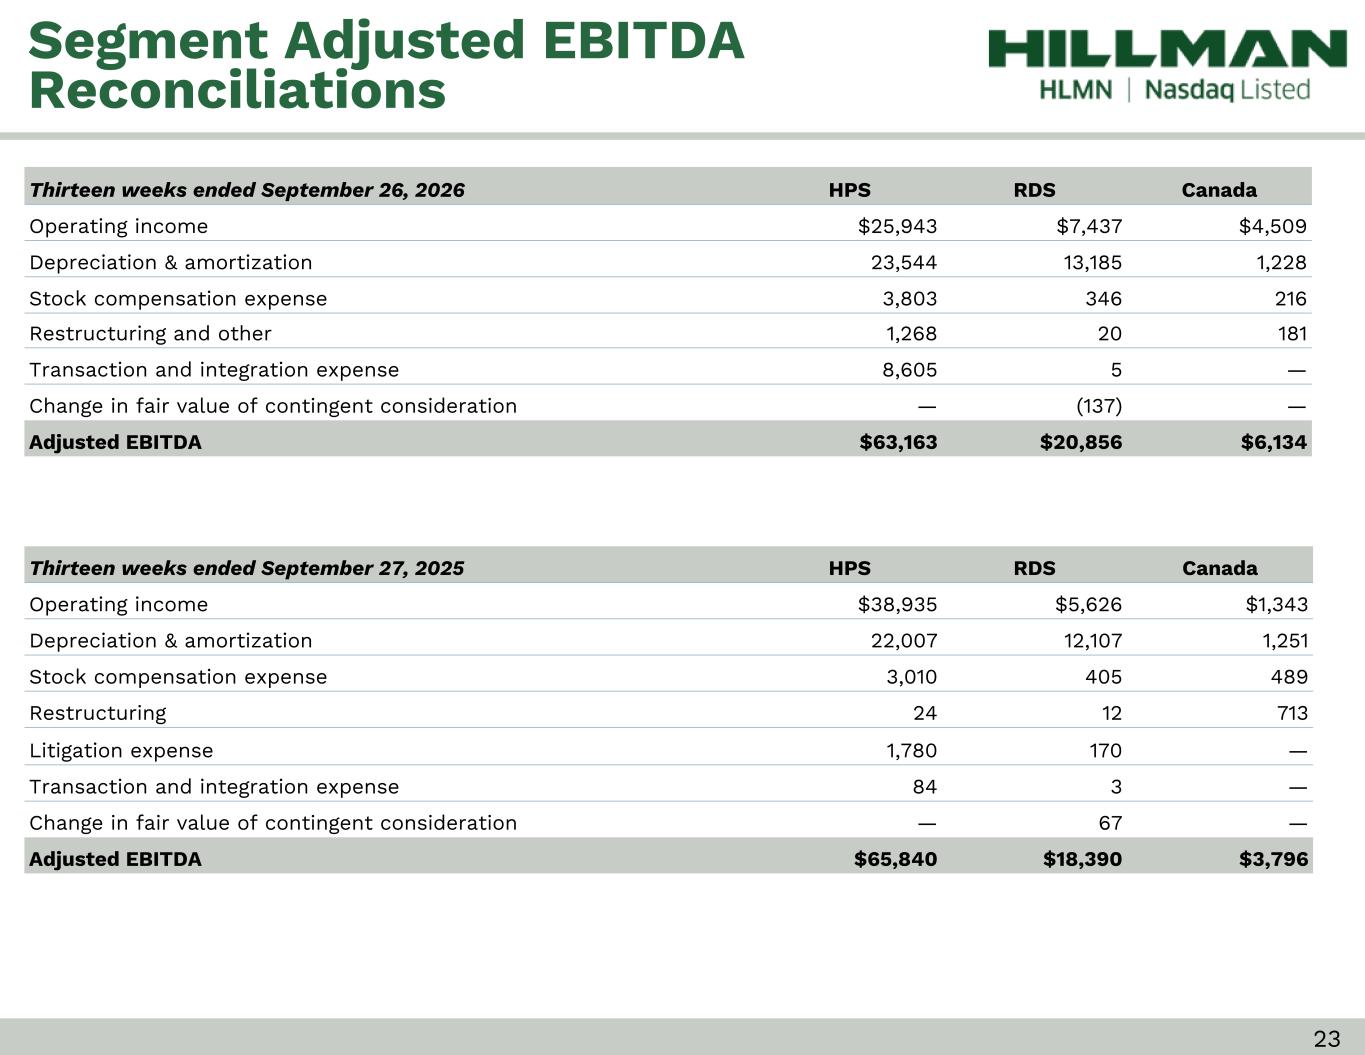
23 Thirteen weeks ended September 26, 2026 HPS RDS Canada Operating income $25,943 $7,437 $4,509 Depreciation & amortization 23,544 13,185 1,228 Stock compensation expense 3,803 346 216 Restructuring and other 1,268 20 181 Transaction and integration expense 8,605 5 — Change in fair value of contingent consideration — (137) — Adjusted EBITDA $63,163 $20,856 $6,134 Thirteen weeks ended September 27, 2025 HPS RDS Canada Operating income $38,935 $5,626 $1,343 Depreciation & amortization 22,007 12,107 1,251 Stock compensation expense 3,010 405 489 Restructuring 24 12 713 Litigation expense 1,780 170 — Transaction and integration expense 84 3 — Change in fair value of contingent consideration — 67 — Adjusted EBITDA $65,840 $18,390 $3,796 Segment Adjusted EBITDA Reconciliations
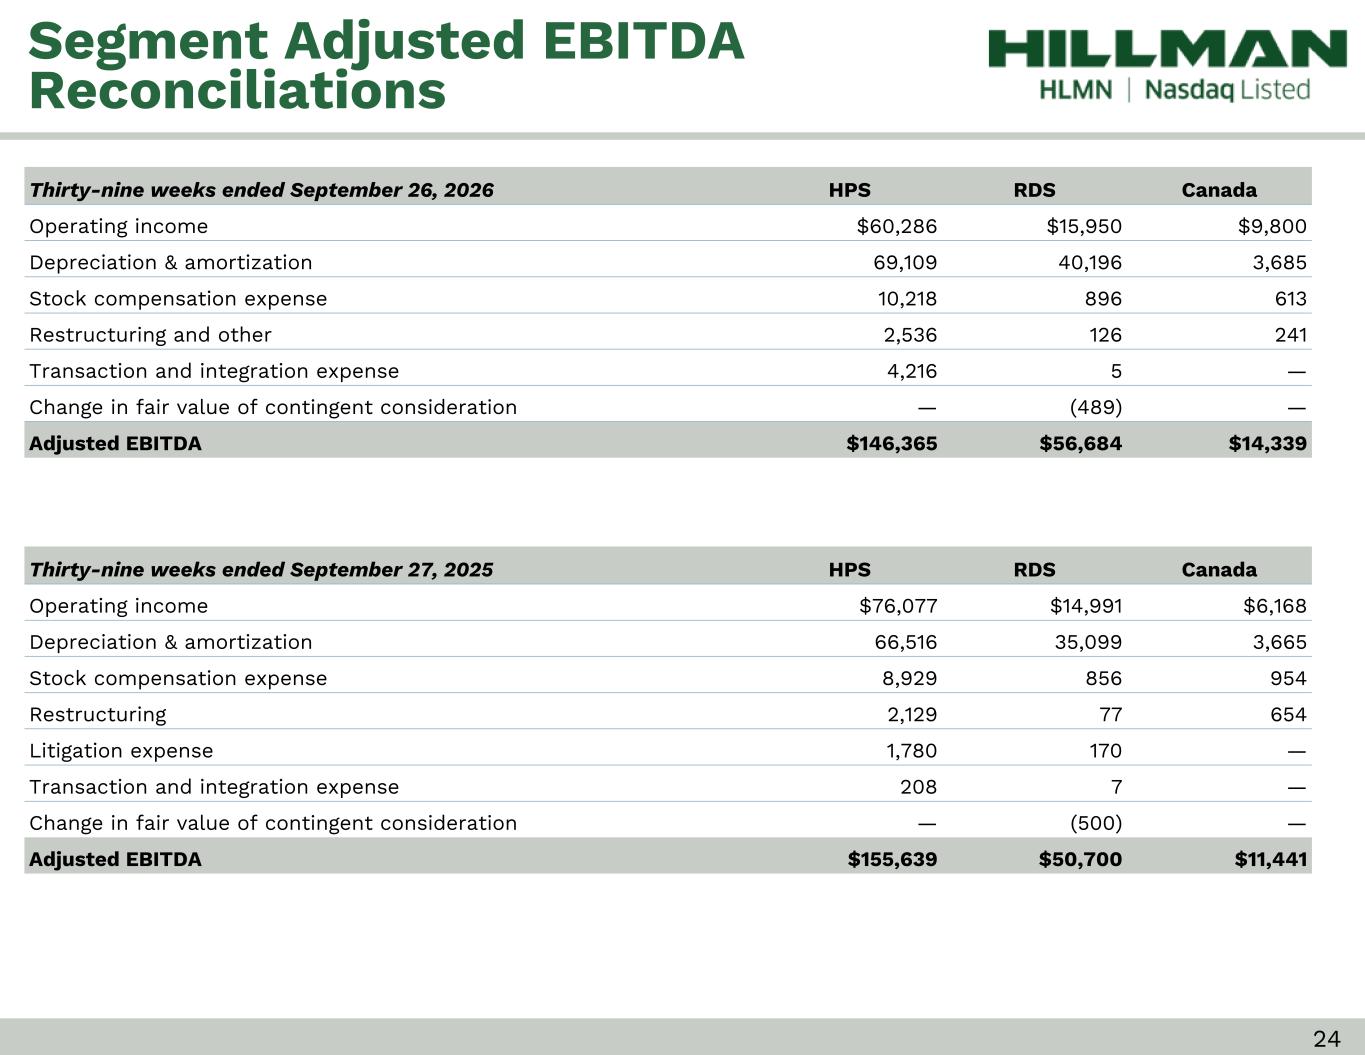
24 Thirty-nine weeks ended September 26, 2026 HPS RDS Canada Operating income $60,286 $15,950 $9,800 Depreciation & amortization 69,109 40,196 3,685 Stock compensation expense 10,218 896 613 Restructuring and other 2,536 126 241 Transaction and integration expense 4,216 5 — Change in fair value of contingent consideration — (489) — Adjusted EBITDA $146,365 $56,684 $14,339 Thirty-nine weeks ended September 27, 2025 HPS RDS Canada Operating income $76,077 $14,991 $6,168 Depreciation & amortization 66,516 35,099 3,665 Stock compensation expense 8,929 856 954 Restructuring 2,129 77 654 Litigation expense 1,780 170 — Transaction and integration expense 208 7 — Change in fair value of contingent consideration — (500) — Adjusted EBITDA $155,639 $50,700 $11,441 Segment Adjusted EBITDA Reconciliations