Exhibit 99.1
| 1 Financial Management Review 3Q26 | October 2026 Quarterly & Year- to-Date Report
| 2 Table of Contents Page 1. About Banco de Chile............................ 4 2. Corporate Governance.......................... 7 3. Business Strategy................................... 11 4. Business Environment........................... 27 5. Management Discussion & Analysis.... 34 6. Risk & Capital Management................. 67
| 3 Basis for Presentation This financial report, which accompanies our quarterly financial statements, has been prepared as requested by the Chilean Financial Market Commission (CMF) in the Compendium of Accounting Standards for Banks while being prepared in accordance with the IFRS Practice Statement 1 – Management Commentary as issued by the International Accounting Standards Board (IASB). Figures included in this report "Financial Management Review", for purposes of analysis, are based on both the financial statements and management information systems of Banco de Chile. Forward - Looking Information The information contained herein incorporates by reference statements comprising "forward-looking statements" that include statements regarding the intent, belief or current expectations of our directors and officers with respect to our future operating performance. Such statements include any forecasts, projections and descriptions of anticipated cost savings or other synergies. You should be aware that any such forward-looking statements are not guarantees of future performance and may involve risks and uncertainties, and that actual results may differ from those set forth in the forward-looking statements as a result of several factors (including, without limitations, the actions of competitors, future global economic conditions, market conditions, foreign exchange rates, and operating and financial risks related to managing growth and integrating acquired businesses), many of which are beyond our control. The occurrence of any such factors not currently expected by us would significantly alter the results set forth in these statements. Factors that could cause actual results to differ materially and adversely include, but are not limited to: changes in general economic, business or political or other conditions in Chile or changes in general economic or business conditions in Latin America; changes in capital markets in general that may affect policies or attitudes toward lending to Chile or Chilean companies; unexpected developments in certain existing litigation; increased costs; unanticipated increases in financing and other costs or the inability to obtain additional debt or equity financing on attractive terms; natural disasters or pandemics; the effect of tax laws or other kind of regulation on our business; other risk factors as reported in our form 20F filed with the U.S. SEC. Undue reliance should not be placed on such statements, which only address as of the date that they were made. Our independent public accountants have not examined or compiled the forward-looking statements and, accordingly, do not provide any assurance with respect to such statements. These cautionary statements should be considered in connection with any written or oral forward- looking statements that we may issue in the future. We do not undertake any obligation to release publicly any revisions to such forward-looking statements to reflect later events or circumstances or to reflect the occurrence of unanticipated events. Contacts Pablo Mejia Head of Investor Relations Investor Relations | Banco de Chile pmejiar@bancochile.cl Daniel Galarce Head of Financial Control & Capital Management Financial Control & Capital Area | Banco de Chile dgalarce@bancochile.cl
| 4 Section 1 About Banco de Chile
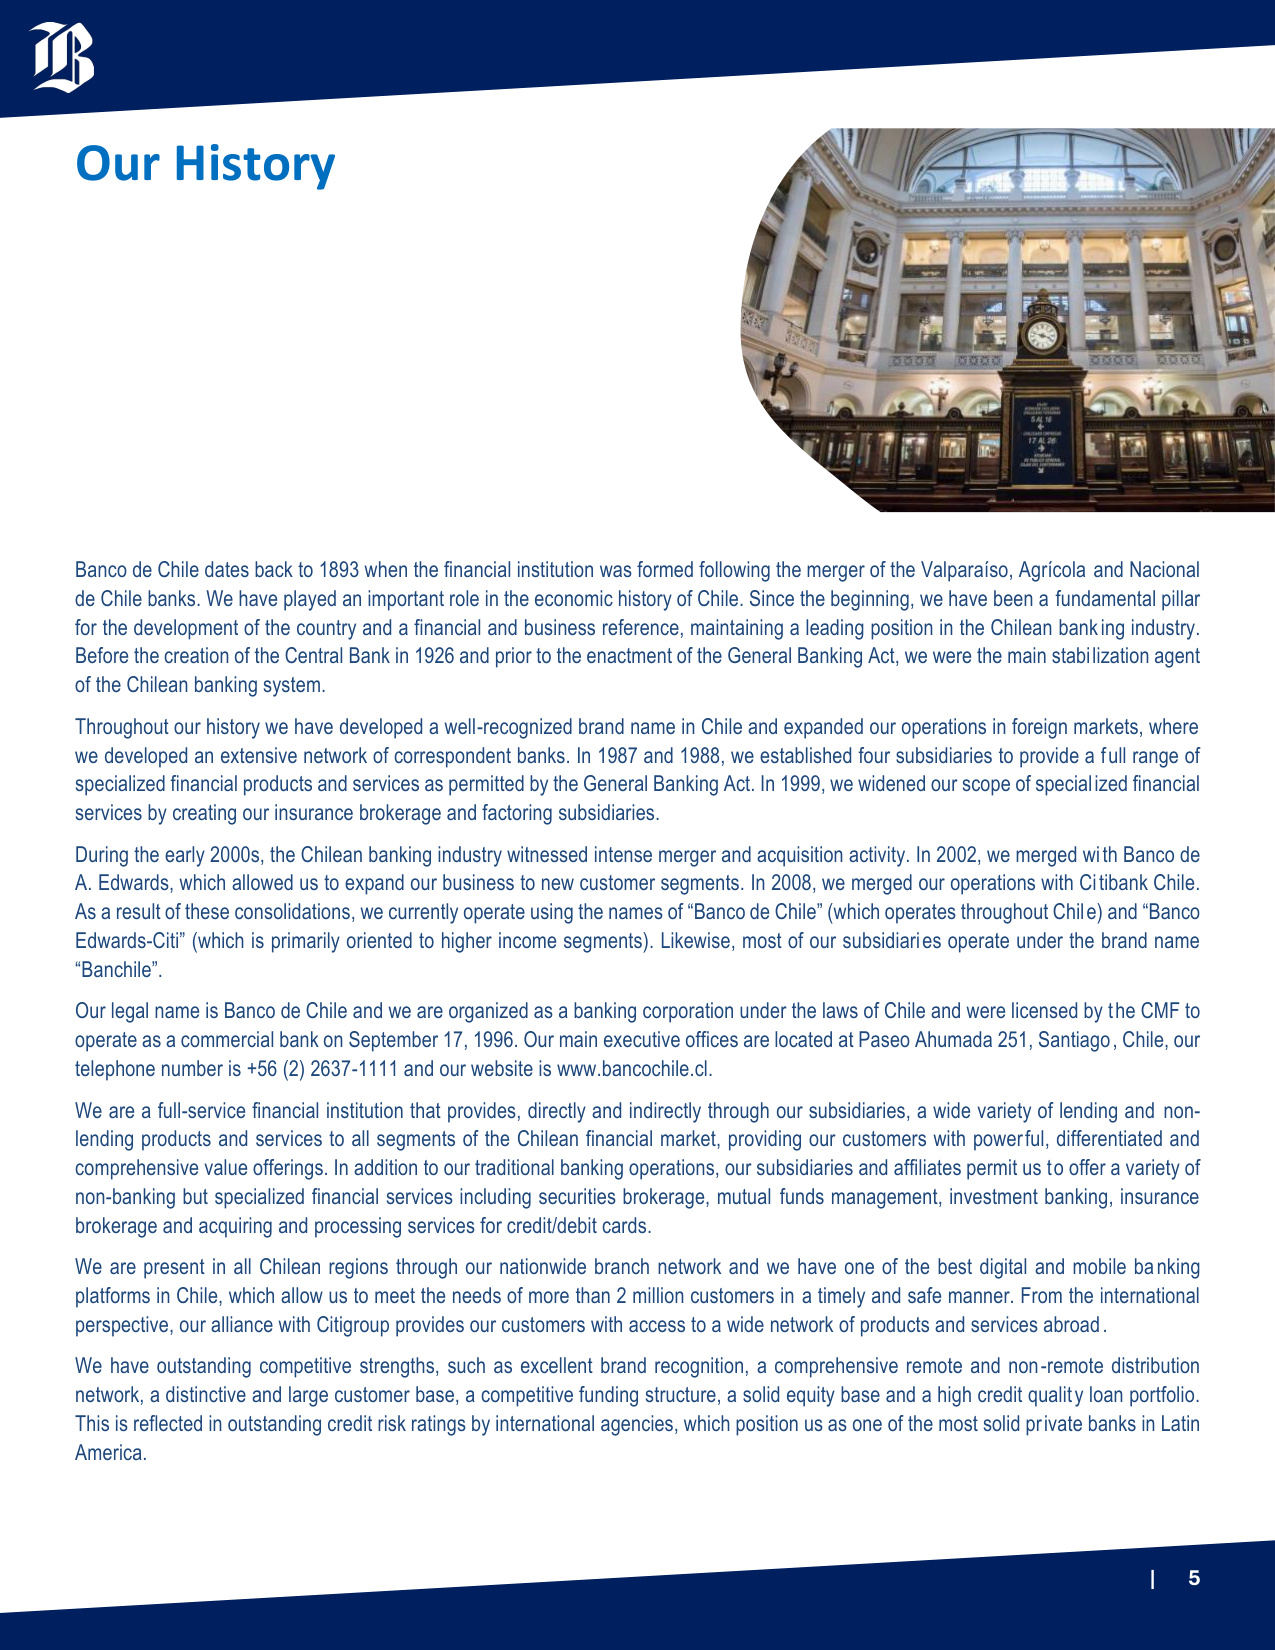
| 5 Our History Banco de Chile dates back to 1893 when the financial institution was formed following the merger of the Valparaíso, Agrícola and Nacional de Chile banks. We have played an important role in the economic history of Chile. Since the beginning, we have been a fundamental pillar for the development of the country and a financial and business reference, maintaining a leading position in the Chilean banking industry. Before the creation of the Central Bank in 1926 and prior to the enactment of the General Banking Act, we were the main stabilization agent of the Chilean banking system. Throughout our history we have developed a well-recognized brand name in Chile and expanded our operations in foreign markets, where we developed an extensive network of correspondent banks. In 1987 and 1988, we established four subsidiaries to provide a full range of specialized financial products and services as permitted by the General Banking Act. In 1999, we widened our scope of specialized financial services by creating our insurance brokerage and factoring subsidiaries. During the early 2000s, the Chilean banking industry witnessed intense merger and acquisition activity. In 2002, we merged with Banco de A. Edwards, which allowed us to expand our business to new customer segments. In 2008, we merged our operations with Citibank Chile. As a result of these consolidations, we currently operate using the names of "Banco de Chile" (which operates throughout Chile) and "Banco Edwards-Citi" (which is primarily oriented to higher income segments). Likewise, most of our subsidiaries operate under the brand name "Banchile". Our legal name is Banco de Chile and we are organized as a banking corporation under the laws of Chile and were licensed by the CMF to operate as a commercial bank on September 17, 1996. Our main executive offices are located at Paseo Ahumada 251, Santiago, Chile, our telephone number is +56 (2) 2637-1111 and our website is www.bancochile.cl. We are a full-service financial institution that provides, directly and indirectly through our subsidiaries, a wide variety of lending and non- lending products and services to all segments of the Chilean financial market, providing our customers with powerful, differentiated and comprehensive value offerings. In addition to our traditional banking operations, our subsidiaries and affiliates permit us to offer a variety of non-banking but specialized financial services including securities brokerage, mutual funds management, investment banking, insurance brokerage and acquiring and processing services for credit/debit cards. We are present in all Chilean regions through our nationwide branch network and we have one of the best digital and mobile banking platforms in Chile, which allow us to meet the needs of more than 2 million customers in a timely and safe manner. From the international perspective, our alliance with Citigroup provides our customers with access to a wide network of products and services abroad. We have outstanding competitive strengths, such as excellent brand recognition, a comprehensive remote and non-remote distribution network, a distinctive and large customer base, a competitive funding structure, a solid equity base and a high credit quality loan portfolio. This is reflected in outstanding credit risk ratings by international agencies, which position us as one of the most solid private banks in Latin America.
| 6 Financial Snapshot 3Q26 and 2026 YTD (In Millions of Ch$) Net Income 292,914 287,734 3Q25 3Q26 YoY Var. (1.8)% 926,725 946,929 2025 2026 YoY Var. +2.2% Operating Revenues 735,683 757,587 3Q25 3Q26 YoY Var. +3.0% 2,277,463 2,428,498 2025 2026 YoY Var. +6.6% Expected Credit Losses 79,560 96,392 3Q25 3Q26 YoY Var. +21.2% 266,080 375,650 2025 2026 YoY Var. +41.2% Operating Expenses 276,346 296,231 3Q25 3Q26 YoY Var. +7.2% 838,318 872,830 2025 2026 YoY Var. +4.1%
| 7 Section 2 Corporate Governance
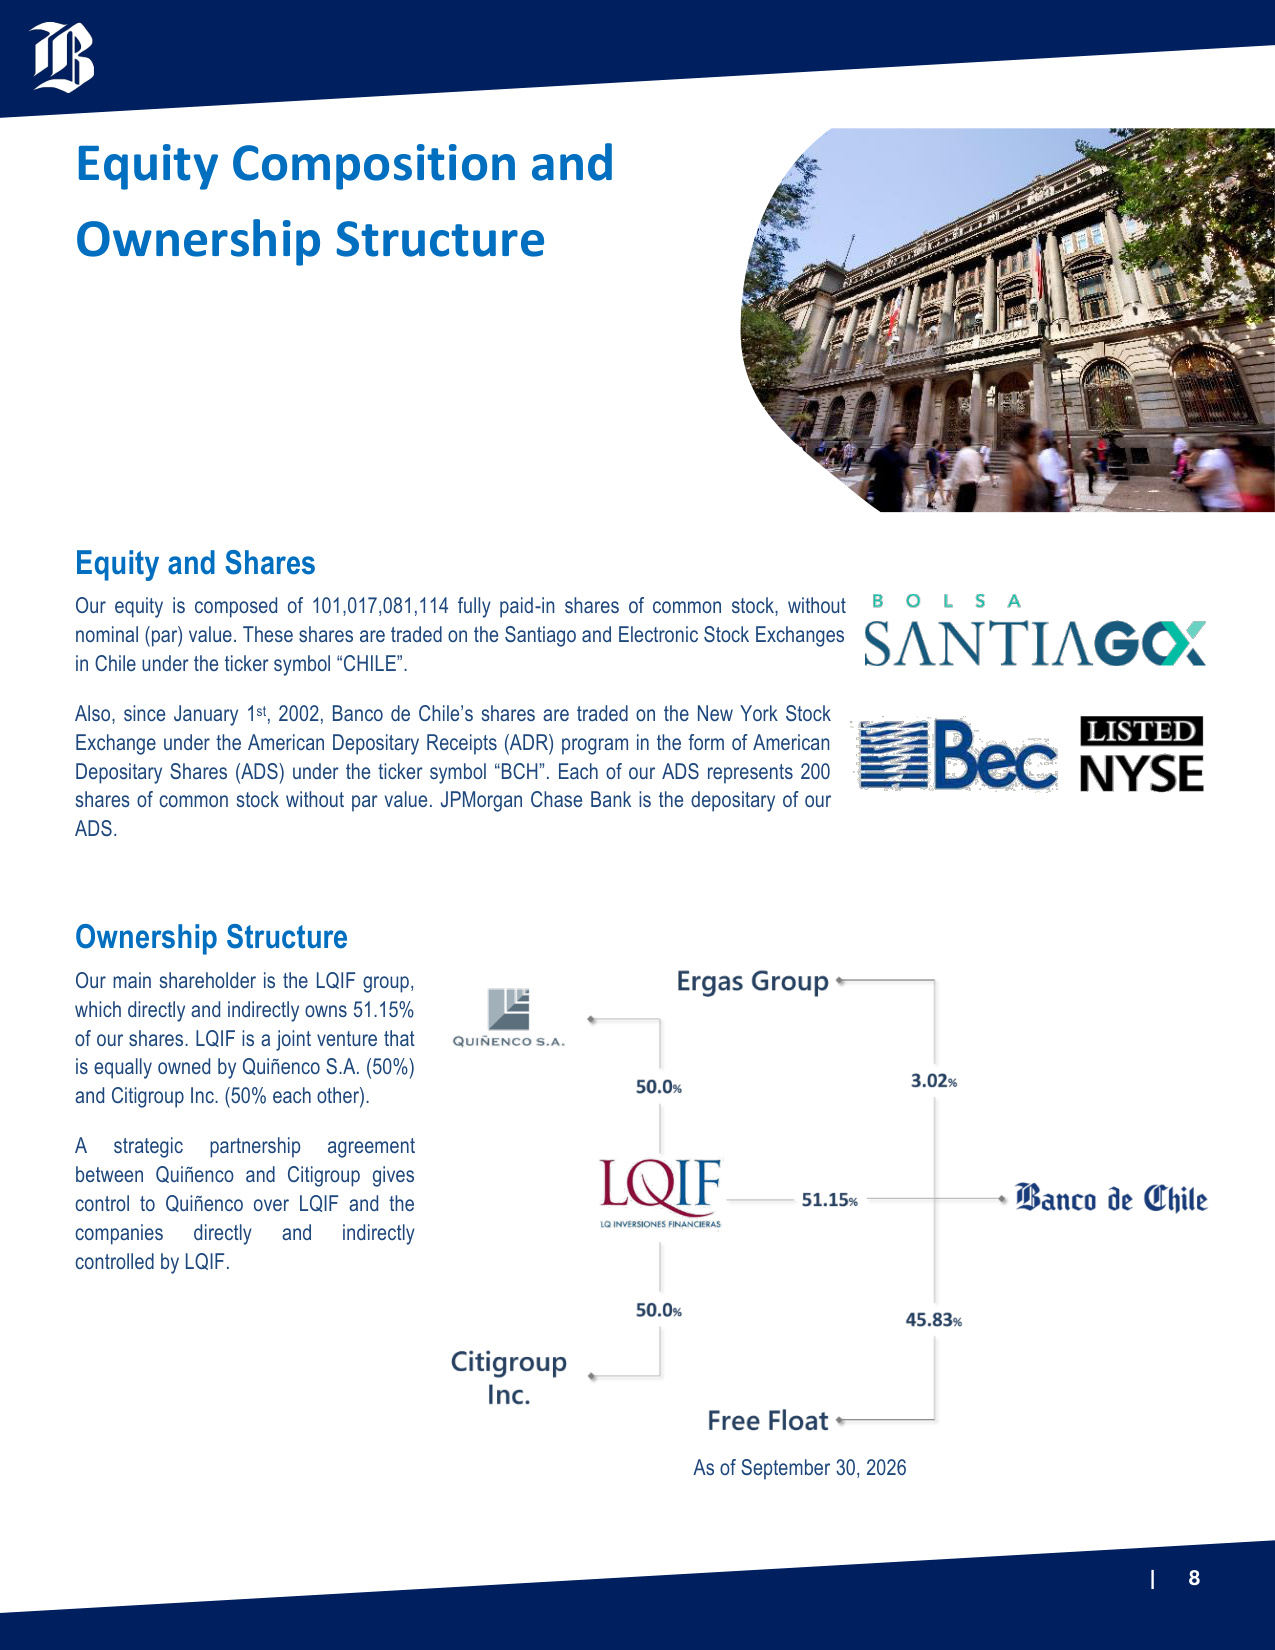
| 8 Equity Composition and Ownership Structure Equity and Shares Our equity is composed of 101,017,081,114 fully paid-in shares of common stock, without nominal (par) value. These shares are traded on the Santiago and Electronic Stock Exchanges in Chile under the ticker symbol "CHILE". Also, since January 1st, 2002, Banco de Chile's shares are traded on the New York Stock Exchange under the American Depositary Receipts (ADR) program in the form of American Depositary Shares (ADS) under the ticker symbol "BCH". Each of our ADS represents 200 shares of common stock without par value. JPMorgan Chase Bank is the depositary of our ADS. Ownership Structure Our main shareholder is the LQIF group, which directly and indirectly owns 51.15% of our shares. LQIF is a joint venture that is equally owned by Quiñenco S.A. (50%) and Citigroup Inc. (50% each other). A strategic partnership agreement between Quiñenco and Citigroup gives control to Quiñenco over LQIF and the companies directly and indirectly controlled by LQIF. As of September 30, 2026
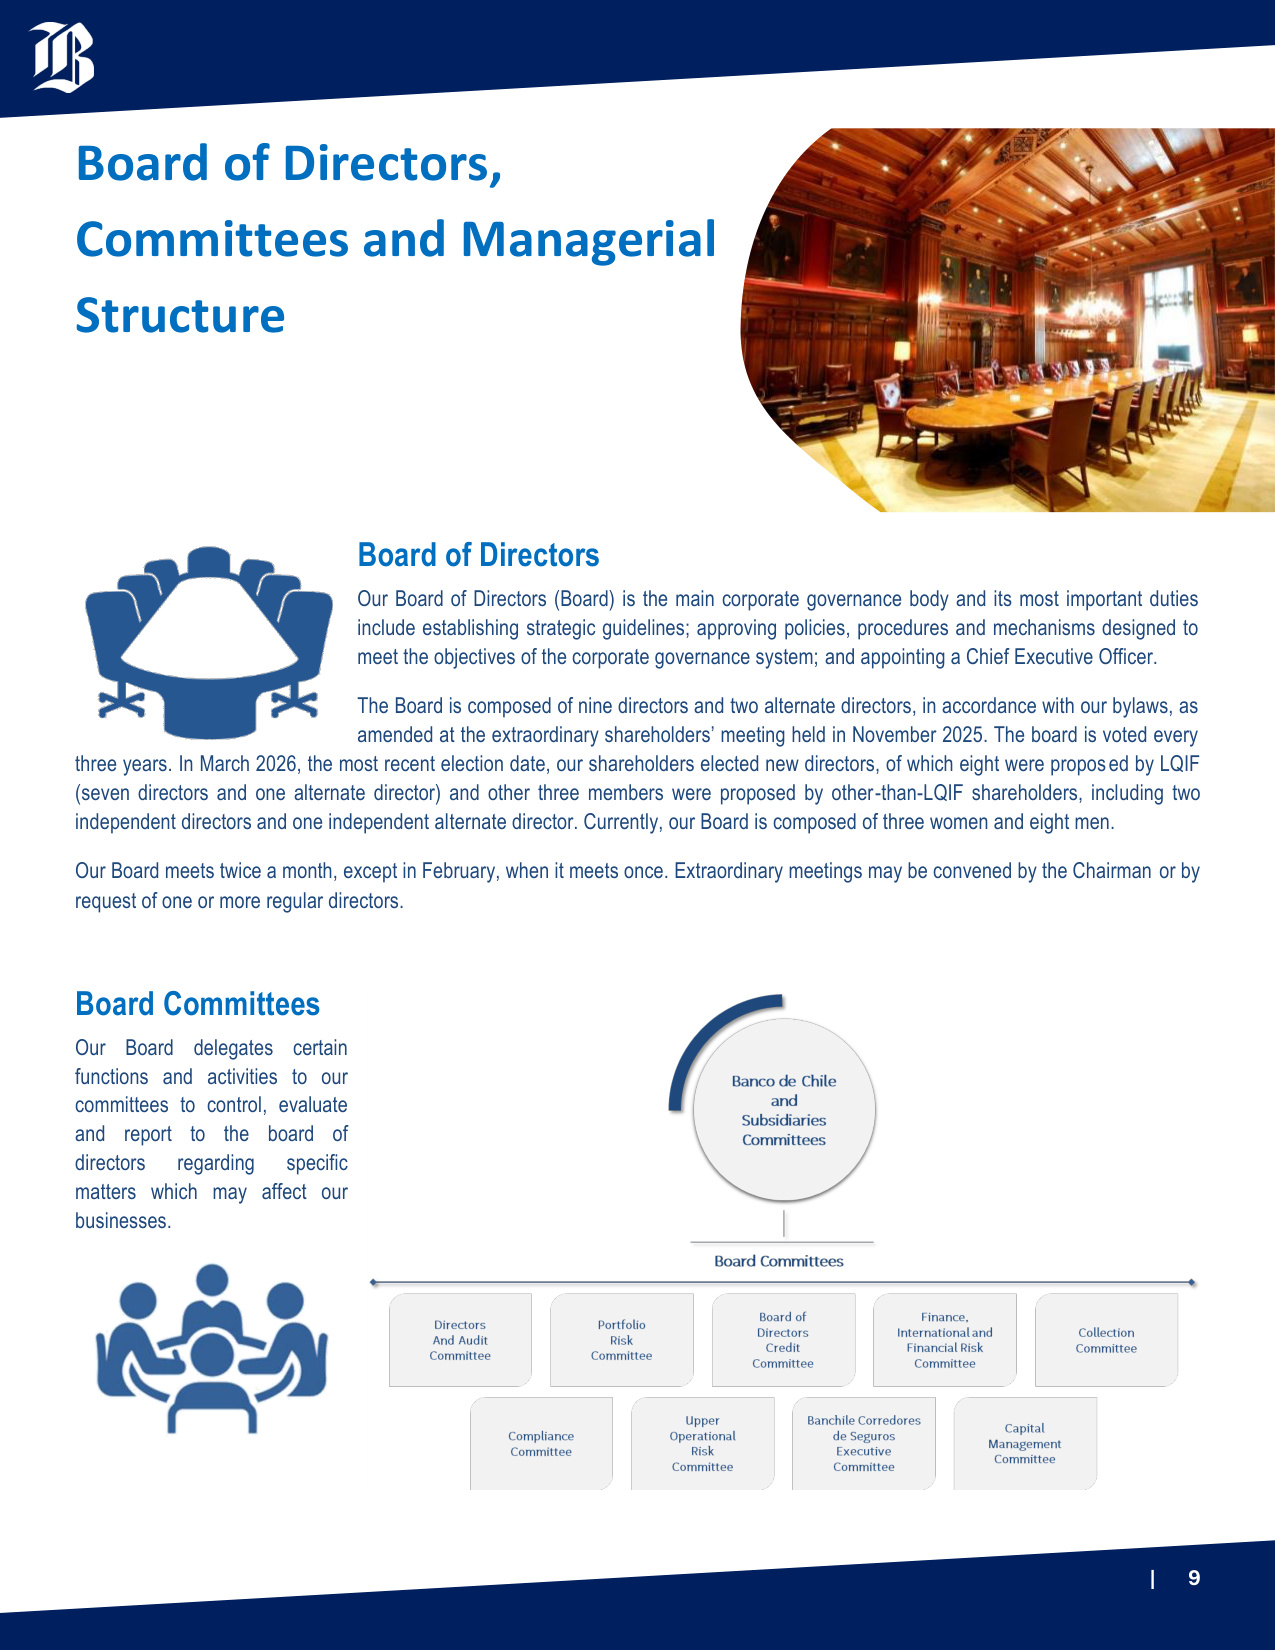
| 9 Board of Directors, Committees and Managerial Structure Board of Directors Our Board of Directors (Board) is the main corporate governance body and its most important duties include establishing strategic guidelines; approving policies, procedures and mechanisms designed to meet the objectives of the corporate governance system; and appointing a Chief Executive Officer. The Board is composed of nine directors and two alternate directors, in accordance with our bylaws, as amended at the extraordinary shareholders' meeting held in November 2025. The board is voted every three years. In March 2026, the most recent election date, our shareholders elected new directors, of which eight were proposed by LQIF (seven directors and one alternate director) and other three members were proposed by other-than-LQIF shareholders, including two independent directors and one independent alternate director. Currently, our Board is composed of three women and eight men. Our Board meets twice a month, except in February, when it meets once. Extraordinary meetings may be convened by the Chairman or by request of one or more regular directors. Board Committees Our Board delegates certain functions and activities to our committees to control, evaluate and report to the board of directors regarding specific matters which may affect our businesses.
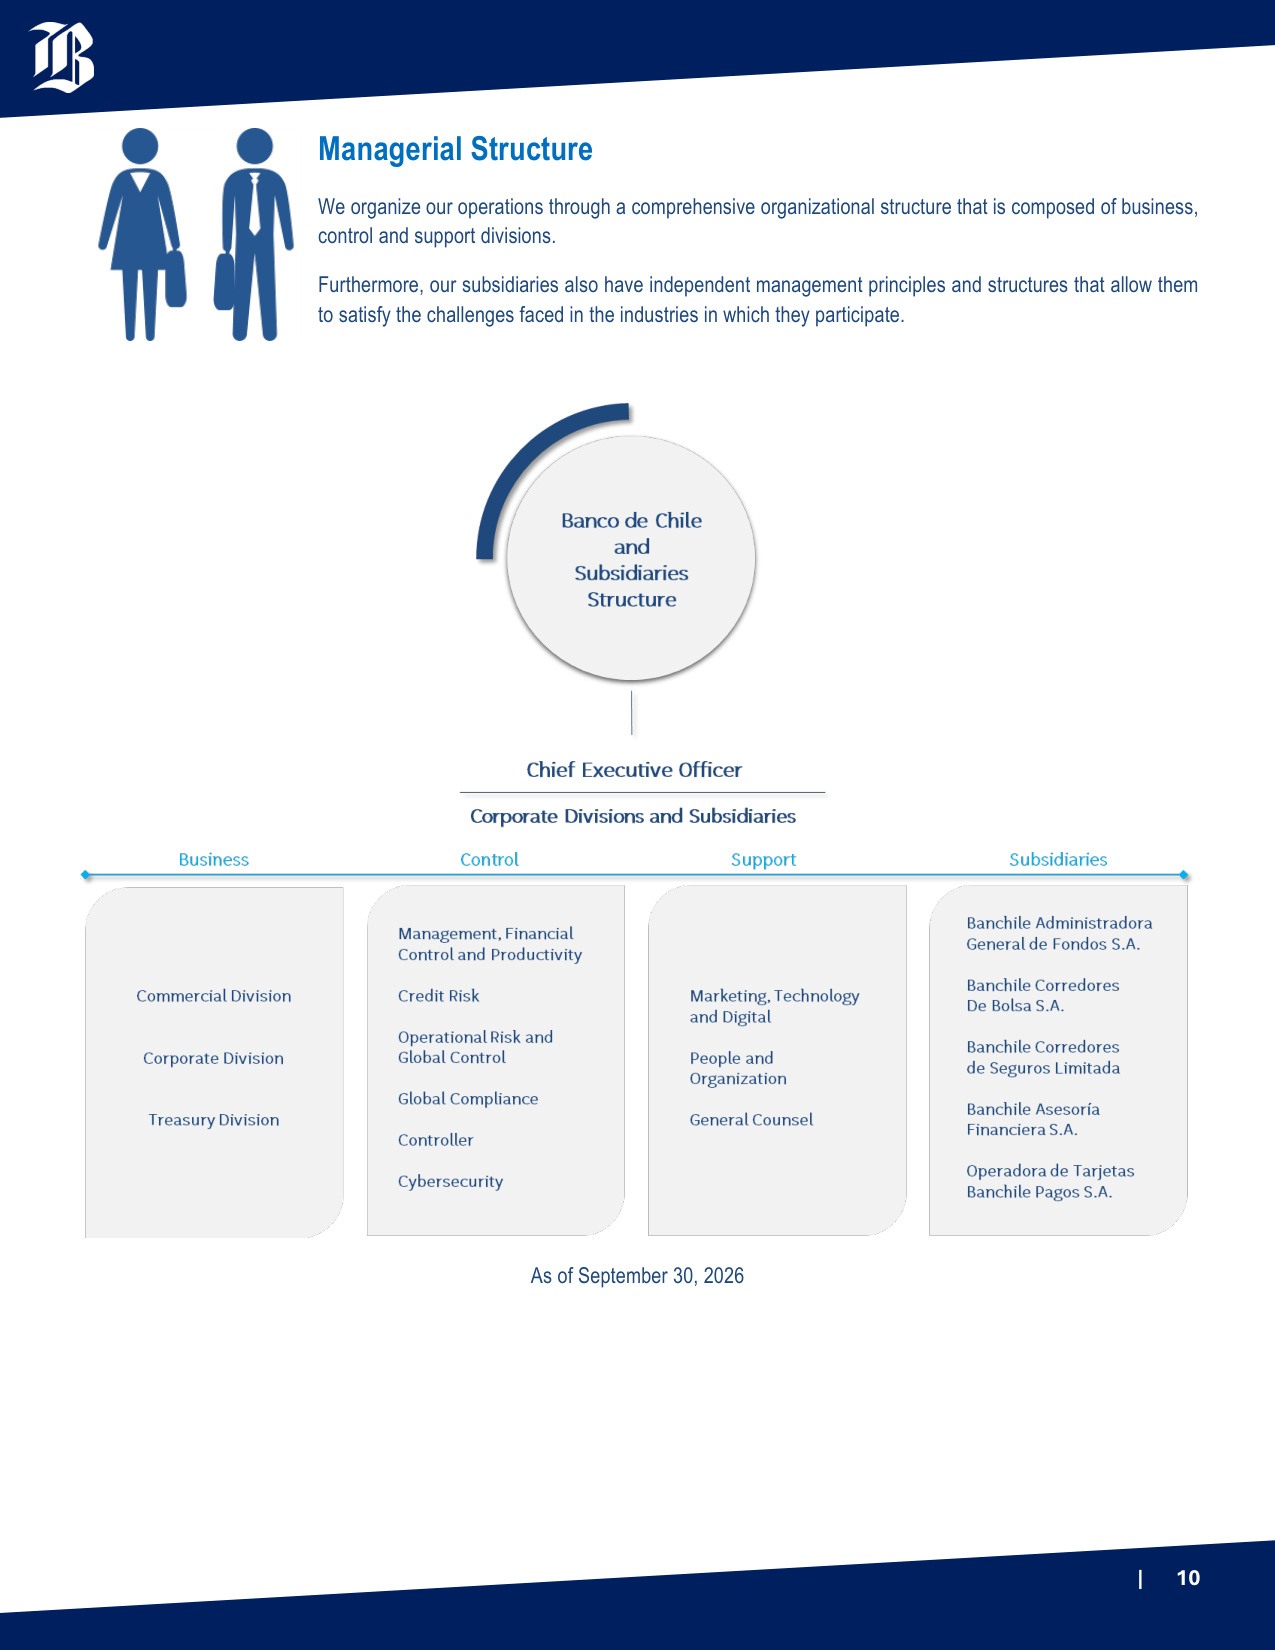
| 10 Managerial Structure We organize our operations through a comprehensive organizational structure that is composed of business, control and support divisions. Furthermore, our subsidiaries also have independent management principles and structures that allow them to satisfy the challenges faced in the industries in which they participate. As of September 30, 2026
| 11 Section 3 Business Strategy
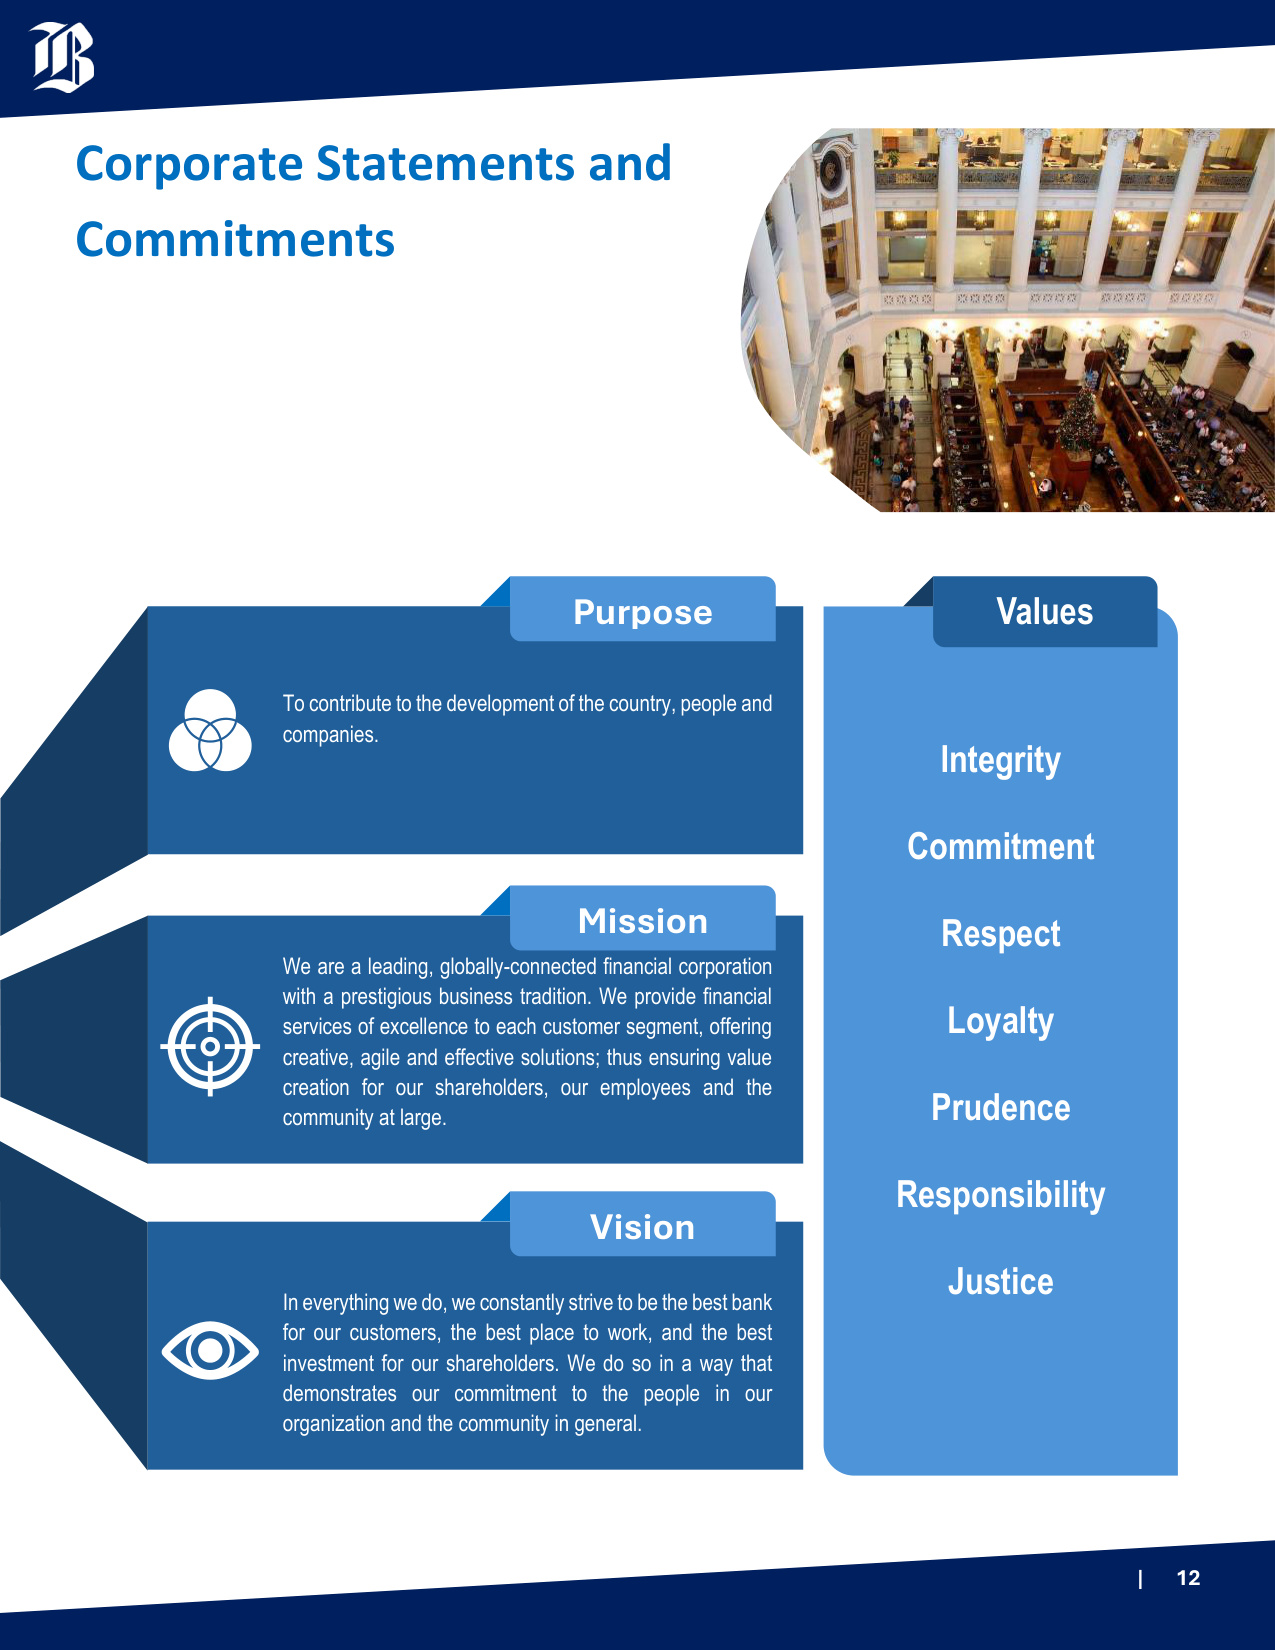
| 12 Corporate Statements and Commitments In everything we do, we constantly strive to be the best bank for our customers, the best place to work, and the best investment for our shareholders. We do so in a way that demonstrates our commitment to the people in our organization and the community in general. To contribute to the development of the country, people and companies. We are a leading, globally-connected financial corporation with a prestigious business tradition. We provide financial services of excellence to each customer segment, offering creative, agile and effective solutions; thus ensuring value creation for our shareholders, our employees and the community at large. Integrity Commitment Respect Loyalty Prudence Responsibility Justice Values Purpose Mission Vision
| 13 Our Customers We pursue to be the bank with the best service quality, offering innovative, simple and secure products and services designed to meet the needs and aspirations of each segment, with timely, agile and proactive service in order to build trusted and long-term relationships. To achieve this we strive to continuously develop always-available service channels that allow fluid and timely communication, while counting on employees devoted to customer service that also have digital knowledge. Our Staff We are certain that our team is a distinctive asset and a solid competitive advantage in the industry. This is based on their commitment, dedication and excellence. For this reason, we offer development and growth opportunities based on merit, providing competitive compensation and economic and welfare benefits. At the same time, we seek to promote a respectful, friendly and collaborative work environment in a place that has suitable technological tools and infrastructure. We build a homogeneous and distinctive culture, based on corporate commitments and values through the involvement in social activities, in order to become a Corporation distinguished as the best place to work and the best team in Chilean banking industry. Our Shareholders We honor our shareholders' confidence by maximizing the company's value, with responsibility, prudence and a long-term business vision. We deploy our business strategy based on appropriate risk management and a culture of operational excellence that allows us to project the sustainable leadership of the corporation. Our Community We are convinced that our success is linked to the sustainable development of our country and the community. That is why in our daily actions we reflect our commitment to community by supporting diverse initiatives to overcome adversity, through the development of internal policies and being present in emblematic solidarity crusades. We are committed to respecting diversity and inclusion, entrepreneurship, environmental care and equality and governance dimensions. Commitments
| 14 Stakeholder Engagement Banco de Chile keeps several communication channels open with our stakeholders in order to gather information to answer questions and manage concerns regarding different issues. We also actively participate in social media and count on specific channels dedicated to managing inquiries and requirements. Stakeholders Engagement Objectives Mechanisms and/or Channels of Communication Frequency Customers They are the reason for our existence and the center of all our decisions. • Offer excellent service characterized by integrity, personalization, agility and proactivity in order to build long-term, trust-based relationships. • Use permanently available service channels to keep customers informed in a timely and appropriate manner. • Provide differentiated financial solutions featuring quality, innovative products and services for each customer segment. • www.bancochile.cl • Branches and ATMs • Telephone banking service 600 637 37 37 • Mobile applications • Newsletter: Sustainability mass email • https://cl.linkedin.com/company/banco-de-chile • Twitter and Instagram:@bancodechile | @bancoedwards |@ayudaBancoChile • Facebook: bancodechile | bancoedwards Ongoing Monthly Ongoing Shareholders They share our purpose, trust in our project, and contribute financial resources for our operation. • Be the best investment option, maintaining a leading position by value of shares traded. • Promote operational efficiency and productivity in order to encourage prudent risk management based on integrity and transparency. • Shareholders' meeting • Annual Report & Form 20-F • Quarterly financial reports • Investor Relations: ir@bancochile.cl • Webcasts • Website Annual Quarterly Monthly Ongoing Employees They represent a distinctive asset for us, whose commitment, dedication, and excellence allow us to honor our purpose every day. • Offer merit-based development opportunities with competitive compensation and economic benefits. • Promote a respectful, polite work environment in a location equipped with the appropriate technology and infrastructure. • Intranet / Emails / SOY_DELCHILE Teams Group • Skills assessment • Counseling Program (Programa Orienta) • "Más Conectados" Platform • My Health Program (Programa Mi Salud) • Quality of Life Program / Active Chile Program • Bank of Points / Team meetings • Contact: comitedeetica@bancochile.cl apoyolaboral@bancochile.cl centroatencionpersonas@bancochile.cl Ongoing Community We are convinced that our success is linked to the sustainable development of the country and the community. • Promote financial education. • Strengthen and enhance inclusion and respect for diversity for a more equitable society with greater opportunities. • Manage the business in an environmentally respectful manner. • Address press requirements. • Support SMEs and entrepreneurs in developing their businesses. • Contact: sostenibilidad@bancochile.cl • www.bancochile.cl • prensa@bancochile.cl • www.bancochile.cl/saladeprensa • https://cl.linkedin.com/company/banco-de-chile • Twitter and Instagram:@bancodechile | @bancoedwards @ayudaBancoChile • Facebook: bancodechile | bancoedwards • Tik Tok: @fanaticosdelchile Ongoing Suppliers They enable us to carry out our operations and are part of our value chain. • Build long-term collaborative supplier relationships based on transparency, competition, efficiency, respect and objectivity. • Streamline and increase the effectiveness of processes for supplying goods and services. • Ensure that services are hired, and goods are acquired under market conditions. • proveedores@bancochile.cl • proveedores2@bancochile.cl • denunciasley20393@bancochile.cl • ARIBA platform. Ongoing
| 15 Competitive Landscape, Business Trends and Regulation The financial system in Chile consists of several industries, including Banking, Pension Funds, Insurance and Mutual Funds, with the Banking sector being the most relevant, with total loans representing approximately 73% of the Chilean GDP as of December 31, 2025. The Chilean banking industry, in turn, consists of 17 banks, 16 of which are privately-owned banks and one is a state-owned bank, namely, Banco Estado. Within the banking industry, we face significant and increasing competition in all market segments in which we operate. As a comprehensive commercial bank that offers a wide range of services to enterprises and individual customers, we deal with a variety of competitors, ranging from large private sector commercial banks to more specialized entities, such as "niche" banks. In addition, we face competition from other types of players, such as non-bank leasing, crowdfunding, factoring and automotive finance companies, fund managers and insurance companies within the savings product market, as well as insurance companies in the mortgage credit market. The Chilean banking industry has experienced increased levels of competition in recent years from domestic as well as foreign banks. It is worth mentioning that the progressive increase in competition has occurred in combination with the consolidation of industry through mergers and acquisitions, which have resulted in more comprehensive banking players that participate in all market segments. In this context, in recent years other non-traditional providers of financial services have emerged, such as e-commerce, local and foreign fintech companies, Telecom companies, like internet and mobile phone providers, and more recently some marketplaces that offer financing, directly to their customers or providers, which has resulted in the disintermediation of traditional banking service providers that have become increasingly challenged. In the retail market, we compete with other private sector Chilean banks, as well as with Banco Estado. Among private sector banks, we believe our strongest competitors in this market are Banco Santander Chile, Scotiabank Chile and BCI, which have developed diversified business strategies focused on both small and medium sized companies and middle-income segments of the Chilean population. In the wholesale market, our strongest competitors are Banco Santander Chile, BCI, Itaú and Scotiabank Chile. Likewise, our most relevant competitors in the high-income segment are Banco Santander Chile and Banco Bice, which use specialized business models that provide wealth management services and traditional banking services, just like us. Additionally, our subsidiaries compete with companies that offer non-banking specialized financial services in the higher-income individual segment and the middle market and corporate segment such as Larrain Vial, BTG Pactual, Moneda Patria Investments and Credicorp Capital, whose core businesses are securities brokerage, financial advisory and wealth management services. Other Chilean commercial entities also compete in these markets of specialized financial services, but they are less focused on such businesses. In the acquiring business, in which Banco de Chile started its own venture through the Banchile Pagos subsidiary, the main competitors are Transbank, Getnet and Mercado Pago. Chilean Financial Industry
| 16 Banco de Chile's strategy is continuously adapting to the evolution of the business environment. Below are the main elements and trends that currently characterize the business environment: Global Environment: • Normalization of both inflation and interest rates. • Climate change. • Armed conflicts and geopolitical reordering. • Disruption in international affairs and increased tensions in the world order. Local Environment: • Economic slowdown and subdued private investment. • Increased criminality. • New political cycle and expectations of economic boost. • Political fragmentation. • Strengthening consumer rights (data security). Banking Industry: • New technological capabilities (AI, Cloud, Cyber). • Regulatory pressure and progressive capital requirements. • Increased competition and widened competitive perimeter (Open Banking, Fintechs). • Sustainability and climate change. • Business model modernization, talent management, and IT strategies to adapt to the new environment. • More demanding and less loyal customers, with increased preference for a simple, customized, integrating and frictionless experience. • Optimization of the physical service network and consolidation of digital channels as the main way for interaction with customers. • Pressure on cybersecurity and data protection risks linked to the increase in digitalization. • Cost base optimization to mitigate increased competition and regulation. Key Trends in the Banking Business
| 17 Financial Market Commission (CMF) The CMF is responsible for regulating, supervising and sanctioning the operations, stability and development of the Chilean financial market (made up of listed companies, banks and financial institutions, insurance companies, insurance brokers, mutual funds and investment funds), promoting the participation of market agents and ensuring public confidence. To achieve this objective, the CMF must have a global and systemic vision, which allows the interests of investors and insured agents to be safeguarded. Regarding the specific powers of the CMF related to banking regulation, this entity authorizes the creation of new banks and has broad powers to interpret and enforce legal and regulatory requirements applicable to banks and financial institutions. Furthermore, in cases of noncompliance with its legal and regulatory requirements, the CMF has the ability to impose sanctions. In extreme cases, it can appoint, with the prior approval of the board of directors of the Central Bank, a provisional administrator to manage banks. It also has the mandate to approve any amendment to banks' bylaws. A bank's financial statements as of December 31 of each year must be audited and submitted to the CMF together with the report of its independent auditors. Also, banks are required by the CMF to include in mid-year financial statements (as of June 30 of every fiscal year) an auditor's interim review report on financial information in accordance with Chilean GAAP. In addition, banks are required to provide extensive information regarding their operations at various periodic intervals to the CMF by means of specialized reports associated with business-related risk, capital, products, debtors, transactions, distribution channels, among others. Central Bank The Central Bank is an autonomous legal entity created under the framework of the Chilean Constitution. It is subject to its Ley Orgánica Constitucional (the "Organic Constitutional Law") and the current Chilean Constitution. The Central Bank is directed and administered by a board of directors composed of five members appointed by the President of Chile, subject to Senate approval. The legal purpose of the Central Bank is to maintain the stability of the Chilean peso, that is, to keep inflation low and stable over time. It must also promote the stability and efficiency of the financial system, ensuring the normal functioning of internal and external payments. The agency regulates the amount of money and credit in circulation, executes international exchange operations and issues monetary, credit, financial and international exchange regulations. Securities and Exchange Commission (SEC) Since Banco de Chile has been listed on the New York Stock Exchange since January 1st, 2002, we are subject to regulation and supervision of the Securities and Exchange Commission. We are required to file with SEC the form 20F, including audited financial statements, as of December of each year in accordance with IFRS as issued by the International Accounting Standards Board. Regulatory Environment
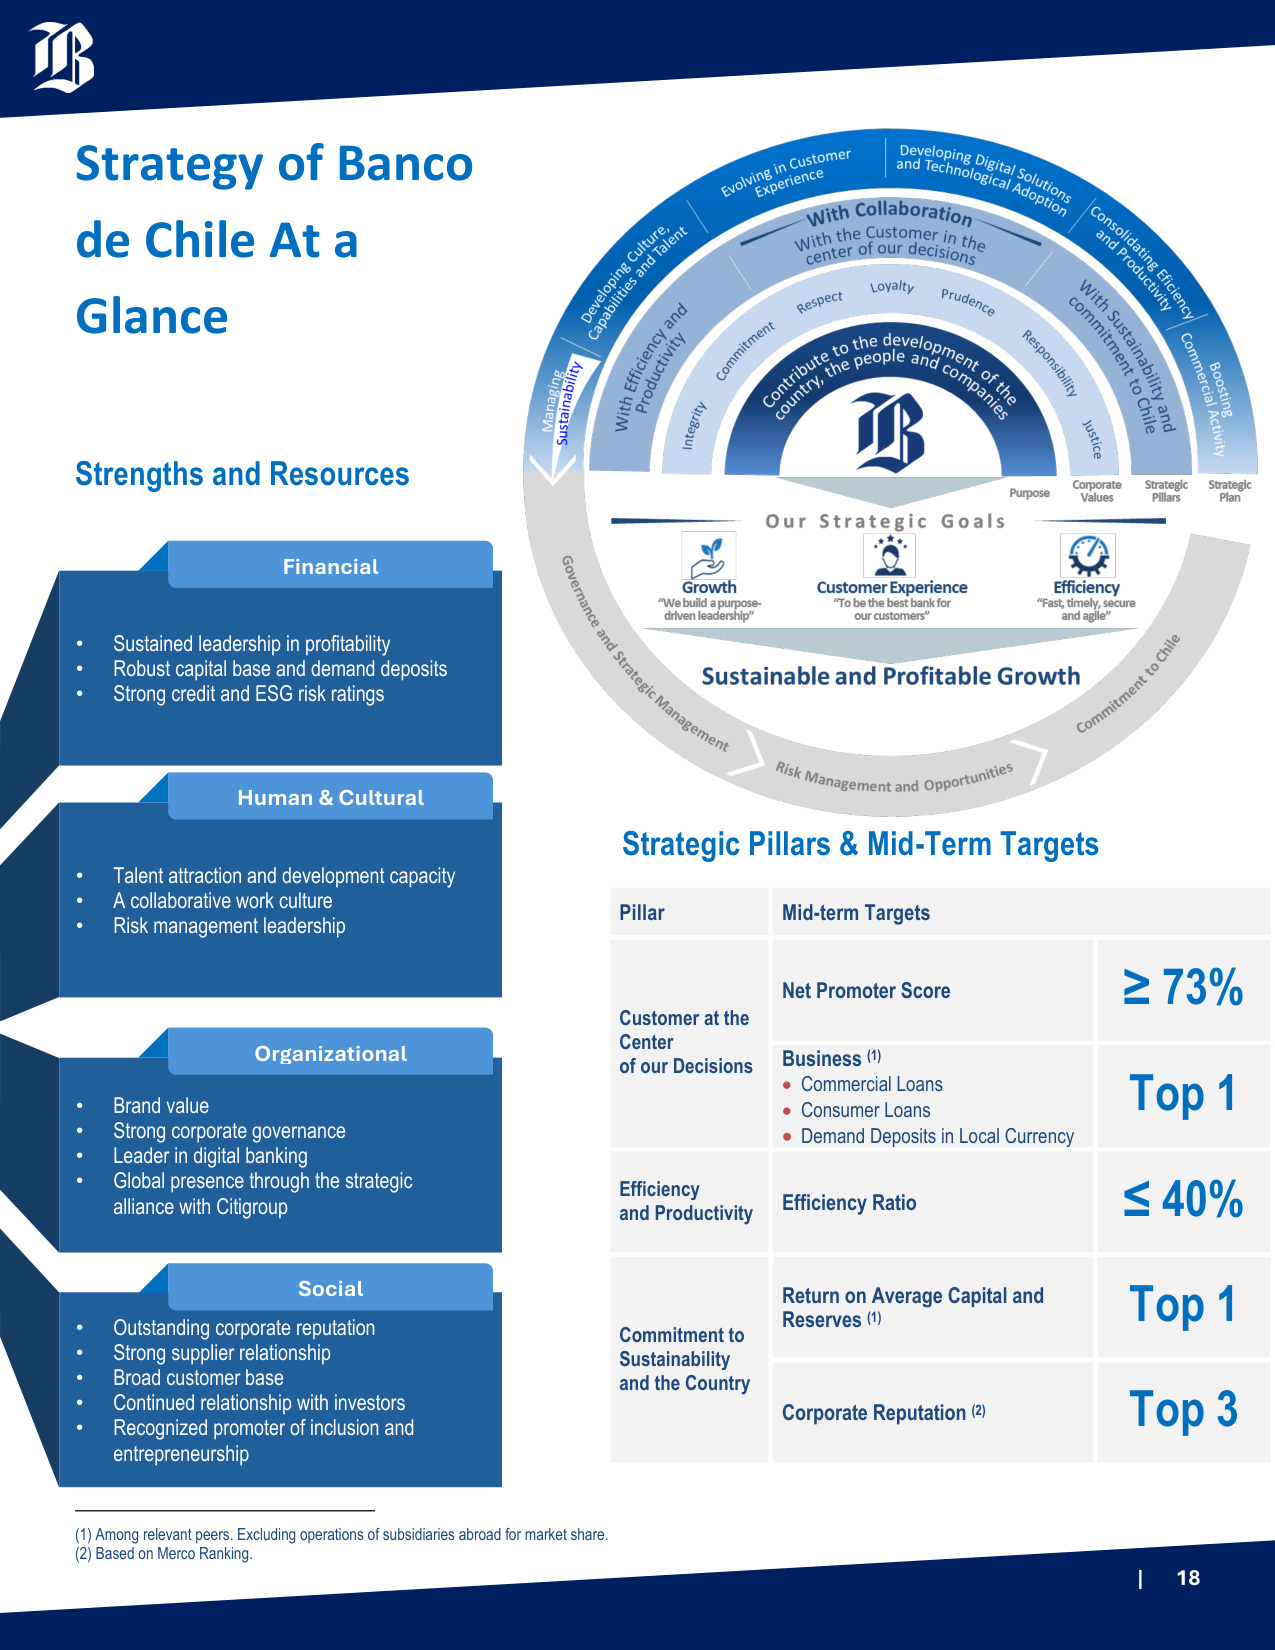
| 18 Strategy of Banco de Chile At a Glance Strengths and Resources Strategic Pillars & Mid-Term Targets (1) Among relevant peers. Excluding operations of subsidiaries abroad for market share. (2) Based on Merco Ranking. Pillar Mid-term Targets Customer at the Center of our Decisions Net Promoter Score ≥ 73% Business (1) • Commercial Loans • Consumer Loans • Demand Deposits in Local Currency Top 1 Efficiency and Productivity Efficiency Ratio ≤ 40% Commitment to Sustainability and the Country Return on Average Capital and Reserves (1) Top 1 Corporate Reputation (2) Top 3 • Outstanding corporate reputation • Strong supplier relationship • Broad customer base • Continued relationship with investors • Recognized promoter of inclusion and entrepreneurship • Sustained leadership in profitability • Robust capital base and demand deposits • Strong credit and ESG risk ratings • Talent attraction and development capacity • A collaborative work culture • Risk management leadership Financial Human & Cultural Social • Brand value • Strong corporate governance • Leader in digital banking • Global presence through the strategic alliance with Citigroup Organizational
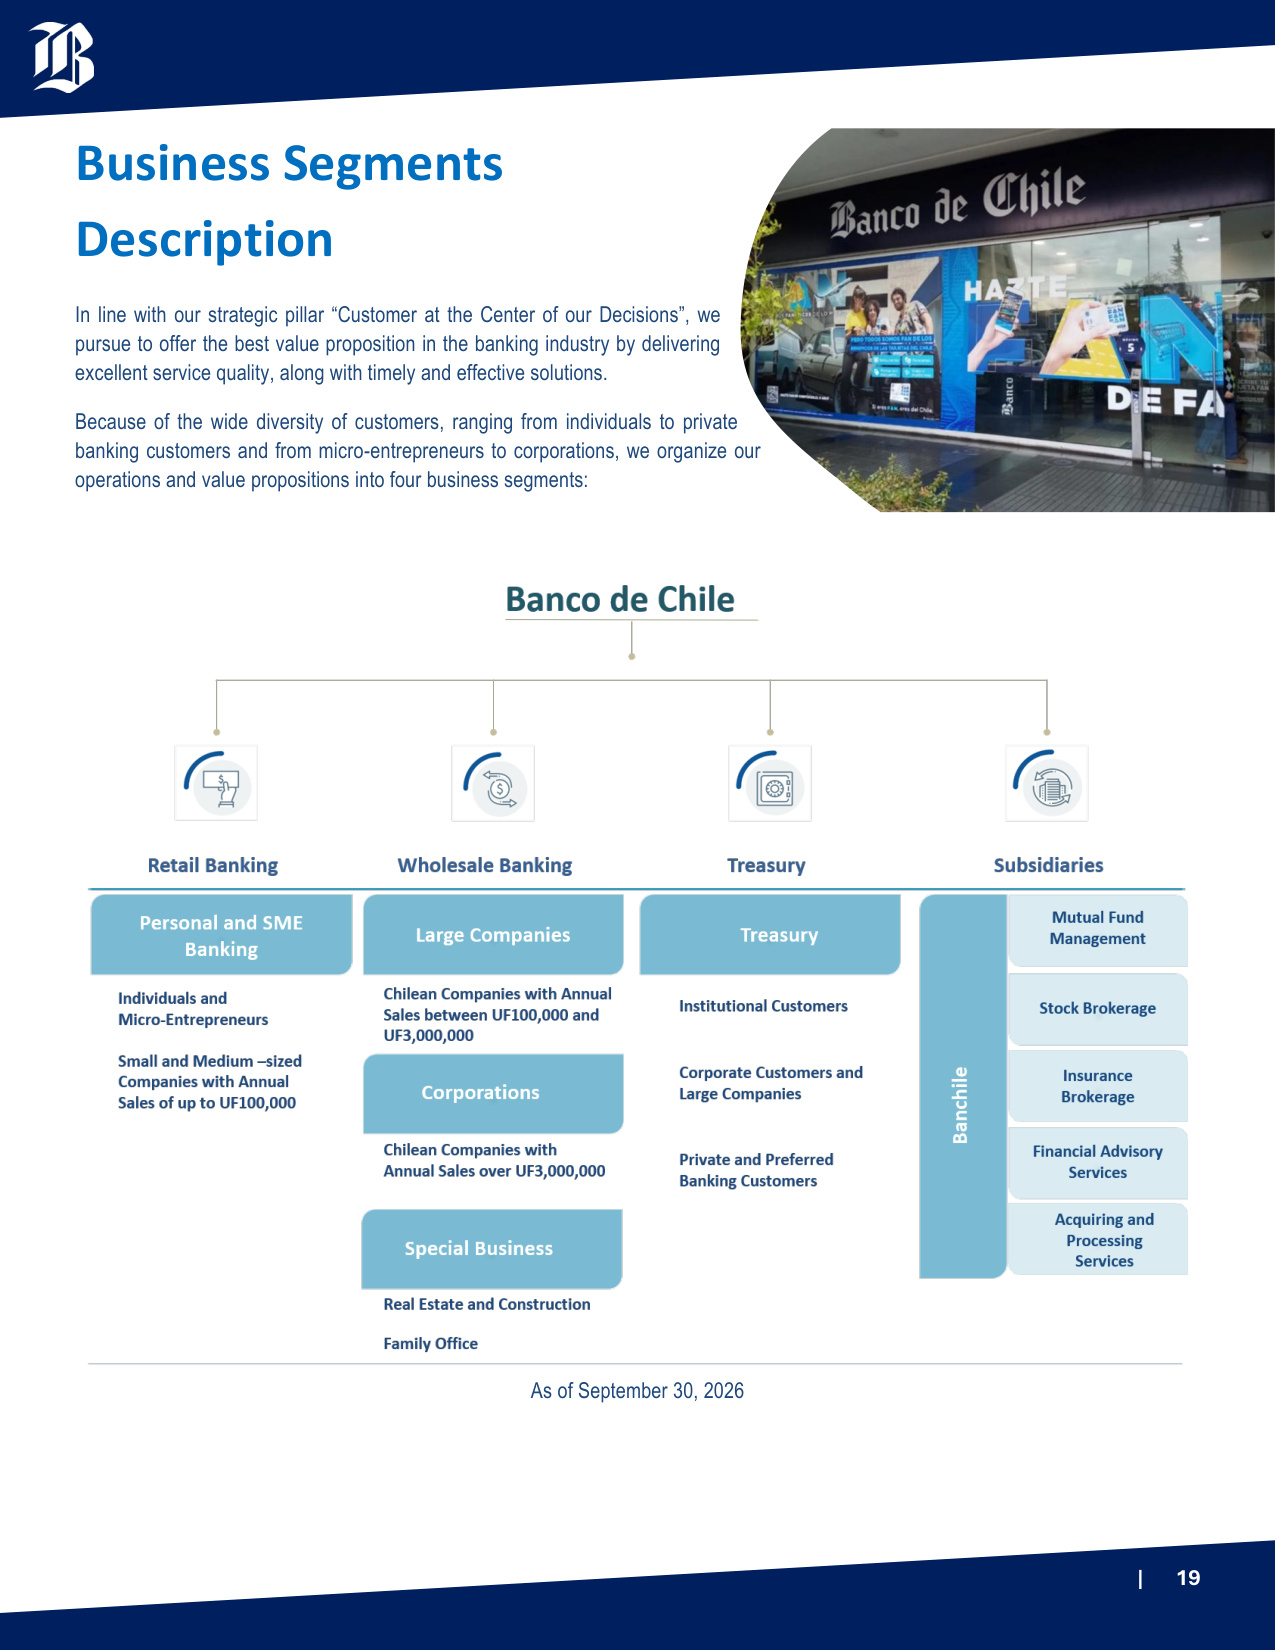
| 19 Business Segments Description In line with our strategic pillar "Customer at the Center of our Decisions", we pursue to offer the best value proposition in the banking industry by delivering excellent service quality, along with timely and effective solutions. Because of the wide diversity of customers, ranging from individuals to private banking customers and from micro-entrepreneurs to corporations, we organize our operations and value propositions into four business segments: As of September 30, 2026
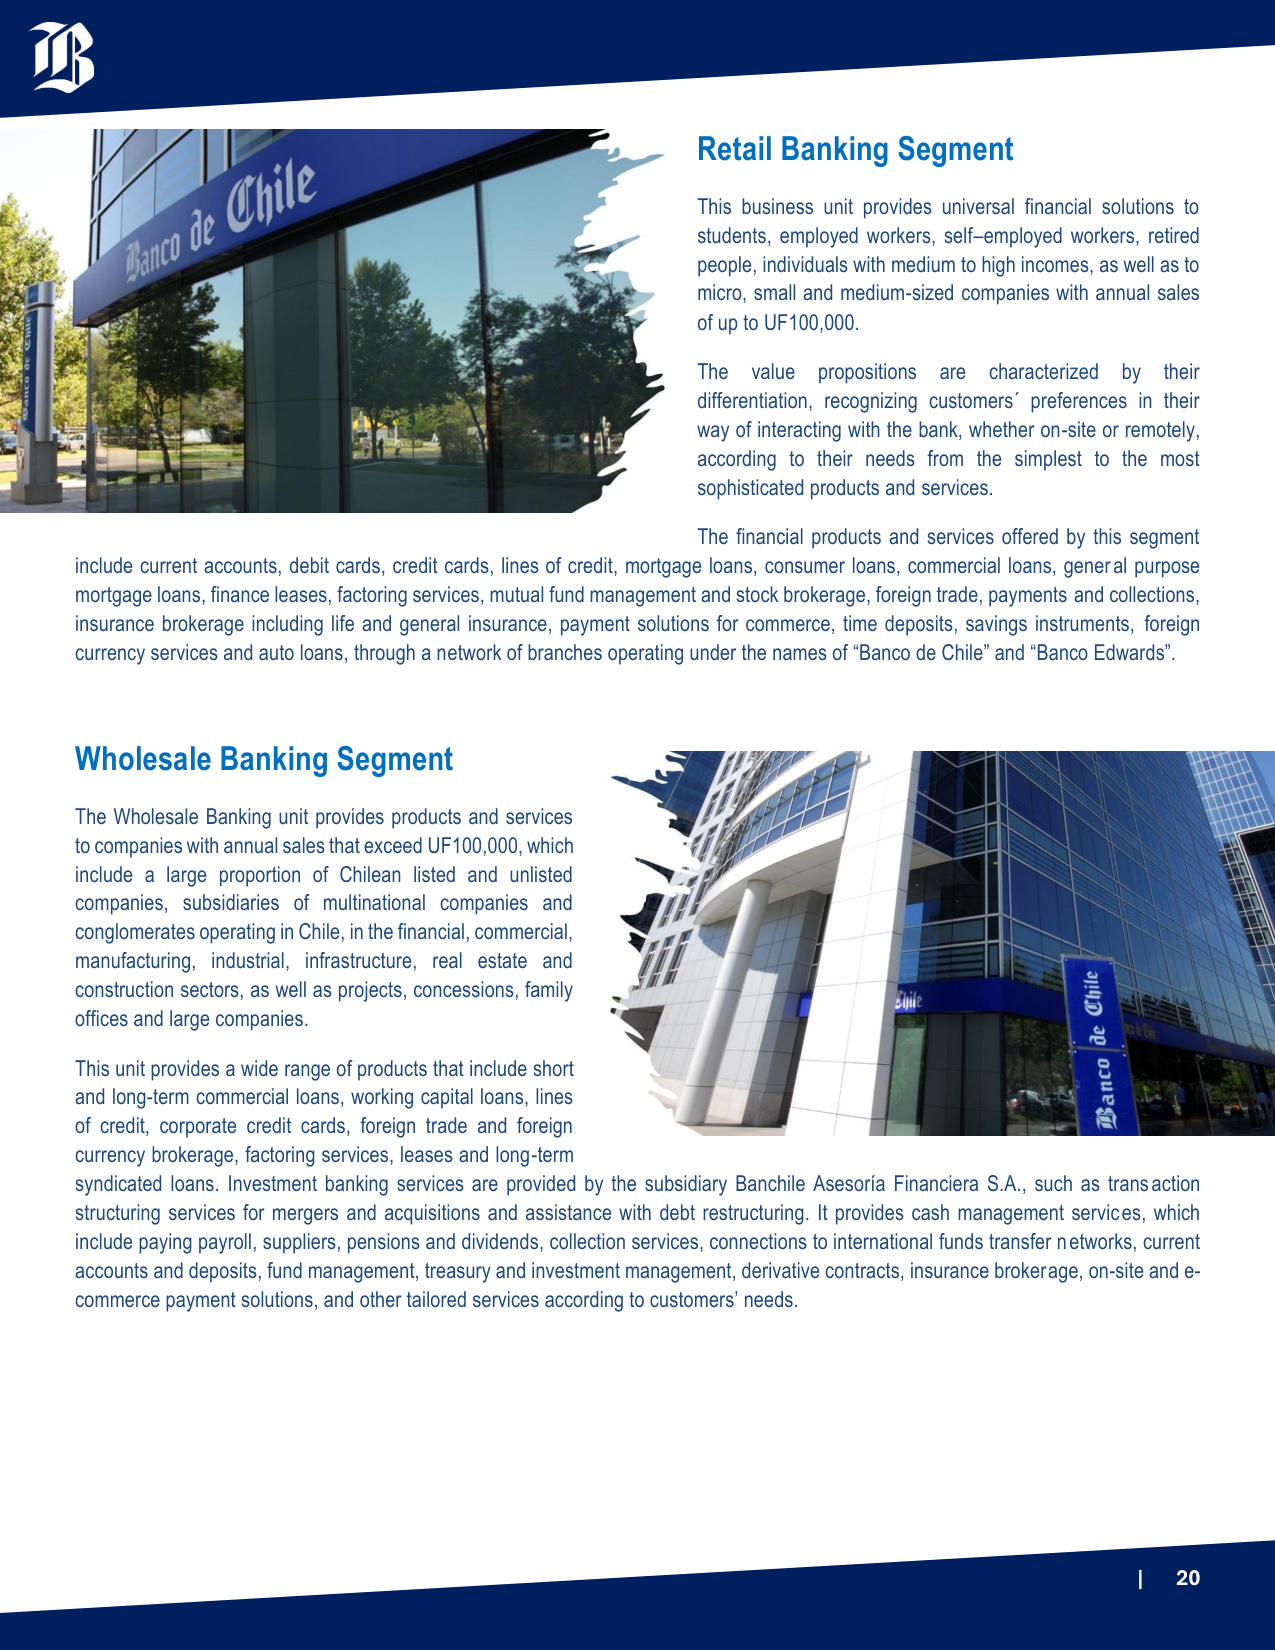
| 20 Retail Banking Segment This business unit provides universal financial solutions to students, employed workers, self–employed workers, retired people, individuals with medium to high incomes, as well as to micro, small and medium-sized companies with annual sales of up to UF100,000. The value propositions are characterized by their differentiation, recognizing customers´ preferences in their way of interacting with the bank, whether on-site or remotely, according to their needs from the simplest to the most sophisticated products and services. The financial products and services offered by this segment include current accounts, debit cards, credit cards, lines of credit, mortgage loans, consumer loans, commercial loans, general purpose mortgage loans, finance leases, factoring services, mutual fund management and stock brokerage, foreign trade, payments and collections, insurance brokerage including life and general insurance, payment solutions for commerce, time deposits, savings instruments, foreign currency services and auto loans, through a network of branches operating under the names of "Banco de Chile" and "Banco Edwards". Wholesale Banking Segment The Wholesale Banking unit provides products and services to companies with annual sales that exceed UF100,000, which include a large proportion of Chilean listed and unlisted companies, subsidiaries of multinational companies and conglomerates operating in Chile, in the financial, commercial, manufacturing, industrial, infrastructure, real estate and construction sectors, as well as projects, concessions, family offices and large companies. This unit provides a wide range of products that include short and long-term commercial loans, working capital loans, lines of credit, corporate credit cards, foreign trade and foreign currency brokerage, factoring services, leases and long-term syndicated loans. Investment banking services are provided by the subsidiary Banchile Asesoría Financiera S.A., such as transaction structuring services for mergers and acquisitions and assistance with debt restructuring. It provides cash management services, which include paying payroll, suppliers, pensions and dividends, collection services, connections to international funds transfer networks, current accounts and deposits, fund management, treasury and investment management, derivative contracts, insurance brokerage, on-site and e- commerce payment solutions, and other tailored services according to customers' needs.
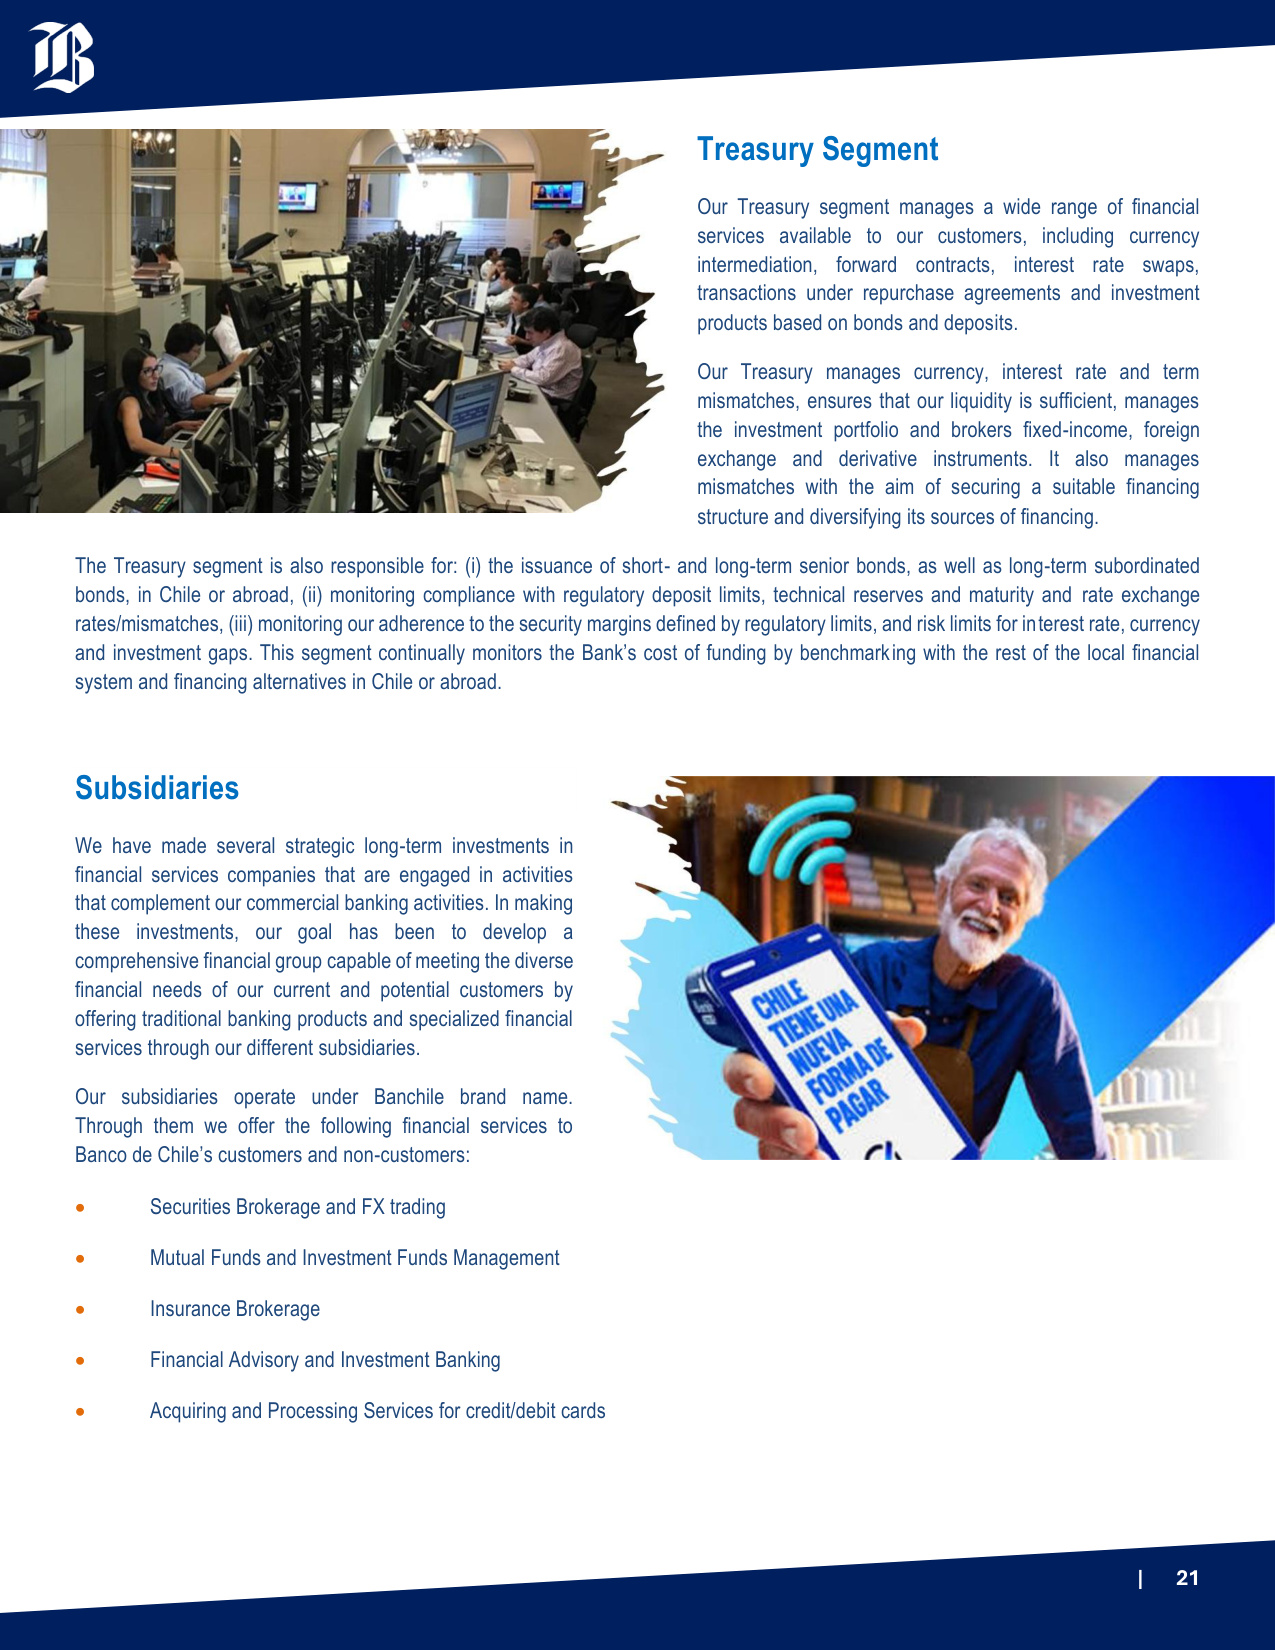
| 21 Treasury Segment Our Treasury segment manages a wide range of financial services available to our customers, including currency intermediation, forward contracts, interest rate swaps, transactions under repurchase agreements and investment products based on bonds and deposits. Our Treasury manages currency, interest rate and term mismatches, ensures that our liquidity is sufficient, manages the investment portfolio and brokers fixed-income, foreign exchange and derivative instruments. It also manages mismatches with the aim of securing a suitable financing structure and diversifying its sources of financing. The Treasury segment is also responsible for: (i) the issuance of short- and long-term senior bonds, as well as long-term subordinated bonds, in Chile or abroad, (ii) monitoring compliance with regulatory deposit limits, technical reserves and maturity and rate exchange rates/mismatches, (iii) monitoring our adherence to the security margins defined by regulatory limits, and risk limits for interest rate, currency and investment gaps. This segment continually monitors the Bank's cost of funding by benchmarking with the rest of the local financial system and financing alternatives in Chile or abroad. Subsidiaries We have made several strategic long-term investments in financial services companies that are engaged in activities that complement our commercial banking activities. In making these investments, our goal has been to develop a comprehensive financial group capable of meeting the diverse financial needs of our current and potential customers by offering traditional banking products and specialized financial services through our different subsidiaries. Our subsidiaries operate under Banchile brand name. Through them we offer the following financial services to Banco de Chile's customers and non-customers: • Securities Brokerage and FX trading • Mutual Funds and Investment Funds Management • Insurance Brokerage • Financial Advisory and Investment Banking • Acquiring and Processing Services for credit/debit cards
| 22 Snapshot on Strategic Advances Strategic Pillar Key Performance Indicator As of September 2026 Mid-Term Targets Customer at the Center of our Decisions Net Promoter Score 77.5% ≥ 73.0% Market Share in Business (1)3 Demand Deposits in Local Currency Top 1 Top 1 Commercial Loans Top 2 Top 1 Consumer Loans Top 2 Top 1 Efficiency and Productivity Cost-to-Income Ratio 35.9% ≤ 40.0% Sustainability and Commitment to Chile Return on Average Capital and Reserves (1) Top 2 Top 1 Corporate Reputation (2)(4) Top 4 Top 3 (1) Based on market shares as of August 31, 2026 (latest available information). Among relevant peers. Excluding operations of subsidiaries abroad for market share. (2) Based on 2025 Merco Ranking. Key Performance Indicators
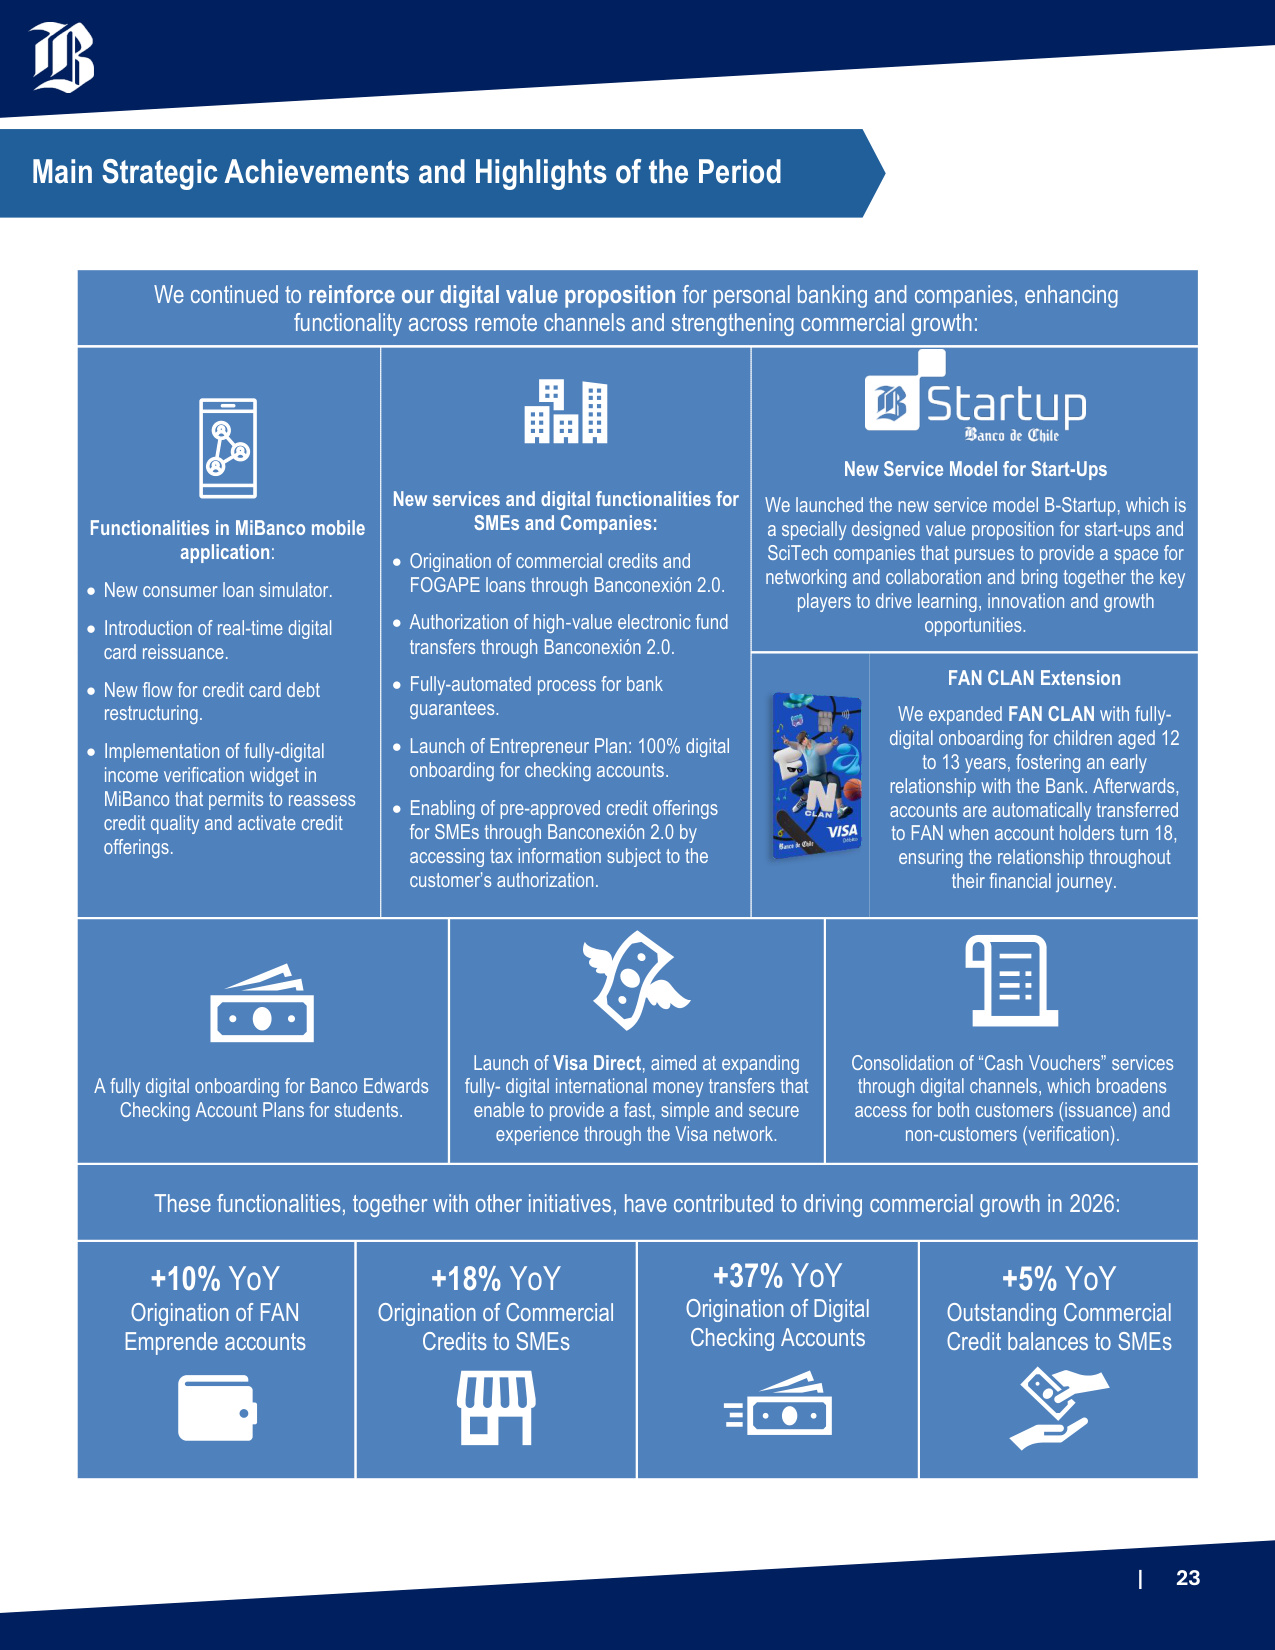
| 23 We continued to reinforce our digital value proposition for personal banking and companies, enhancing functionality across remote channels and strengthening commercial growth: Functionalities in MiBanco mobile application: • New consumer loan simulator. • Introduction of real-time digital card reissuance. • New flow for credit card debt restructuring. • Implementation of fully-digital income verification widget in MiBanco that permits to reassess credit quality and activate credit offerings. New services and digital functionalities for SMEs and Companies: • Origination of commercial credits and FOGAPE loans through Banconexión 2.0. • Authorization of high‑value electronic fund transfers through Banconexión 2.0. • Fully-automated process for bank guarantees. • Launch of Entrepreneur Plan: 100% digital onboarding for checking accounts. • Enabling of pre-approved credit offerings for SMEs through Banconexión 2.0 by accessing tax information subject to the customer's authorization. New Service Model for Start-Ups We launched the new service model B-Startup, which is a specially designed value proposition for start-ups and SciTech companies that pursues to provide a space for networking and collaboration and bring together the key players to drive learning, innovation and growth opportunities. FAN CLAN Extension We expanded FAN CLAN with fully- digital onboarding for children aged 12 to 13 years, fostering an early relationship with the Bank. Afterwards, accounts are automatically transferred to FAN when account holders turn 18, ensuring the relationship throughout their financial journey. A fully digital onboarding for Banco Edwards Checking Account Plans for students. Launch of Visa Direct, aimed at expanding fully- digital international money transfers that enable to provide a fast, simple and secure experience through the Visa network. Consolidation of "Cash Vouchers" services through digital channels, which broadens access for both customers (issuance) and non-customers (verification). These functionalities, together with other initiatives, have contributed to driving commercial growth in 2026: +10% YoY Origination of FAN Emprende accounts +18% YoY Origination of Commercial Credits to SMEs +37% YoY Origination of Digital Checking Accounts +5% YoY Outstanding Commercial Credit balances to SMEs Main Strategic Achievements and Highlights of the Period
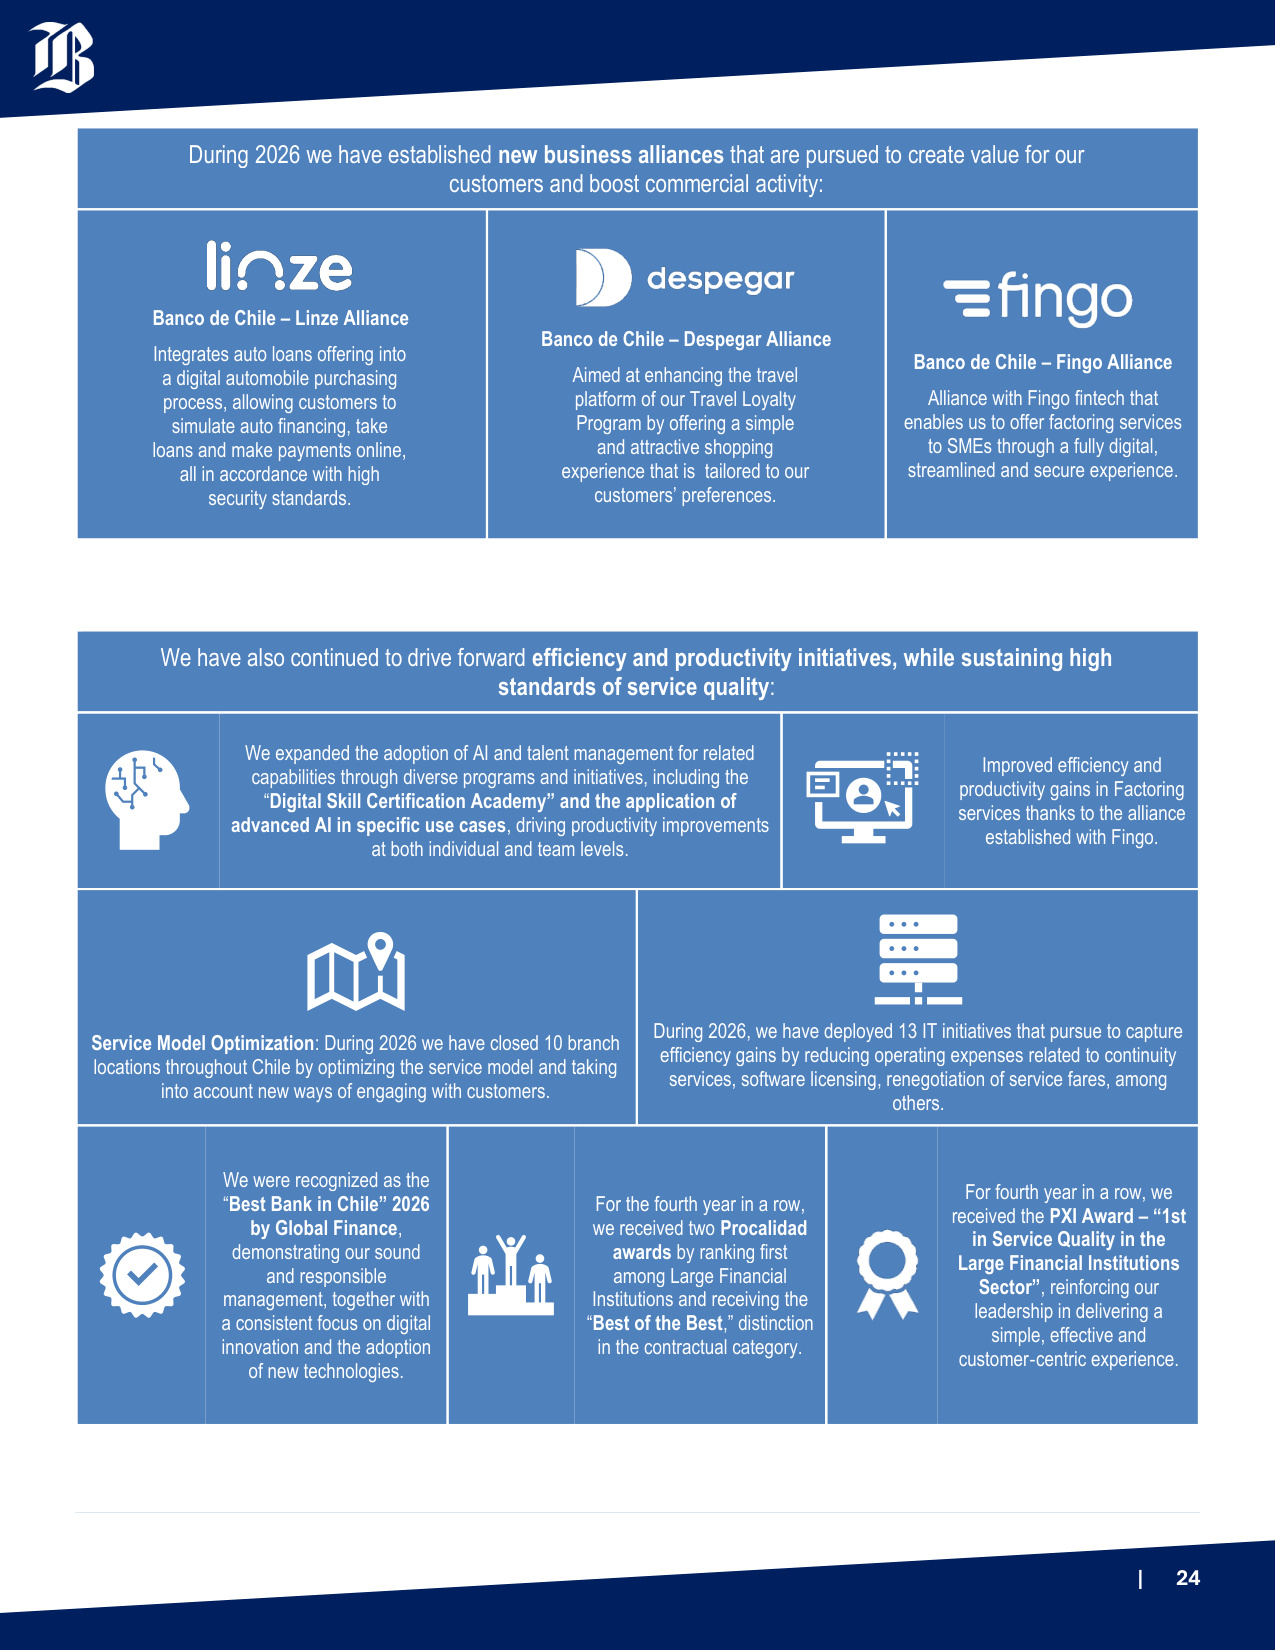
| 24 During 2026 we have established new business alliances that are pursued to create value for our customers and boost commercial activity: Banco de Chile – Linze Alliance Integrates auto loans offering into a digital automobile purchasing process, allowing customers to simulate auto financing, take loans and make payments online, all in accordance with high security standards. Banco de Chile – Despegar Alliance Aimed at enhancing the travel platform of our Travel Loyalty Program by offering a simple and attractive shopping experience that is tailored to our customers' preferences. Banco de Chile – Fingo Alliance Alliance with Fingo fintech that enables us to offer factoring services to SMEs through a fully digital, streamlined and secure experience. We have also continued to drive forward efficiency and productivity initiatives, while sustaining high standards of service quality: We expanded the adoption of AI and talent management for related capabilities through diverse programs and initiatives, including the "Digital Skill Certification Academy" and the application of advanced AI in specific use cases, driving productivity improvements at both individual and team levels. Improved efficiency and productivity gains in Factoring services thanks to the alliance established with Fingo. Service Model Optimization: During 2026 we have closed 10 branch locations throughout Chile by optimizing the service model and taking into account new ways of engaging with customers. During 2026, we have deployed 13 IT initiatives that pursue to capture efficiency gains by reducing operating expenses related to continuity services, software licensing, renegotiation of service fares, among others. We were recognized as the "Best Bank in Chile" 2026 by Global Finance, demonstrating our sound and responsible management, together with a consistent focus on digital innovation and the adoption of new technologies. For the fourth year in a row, we received two Procalidad awards by ranking first among Large Financial Institutions and receiving the "Best of the Best," distinction in the contractual category. For fourth year in a row, we received the PXI Award – "1st in Service Quality in the Large Financial Institutions Sector", reinforcing our leadership in delivering a simple, effective and customer‑centric experience.
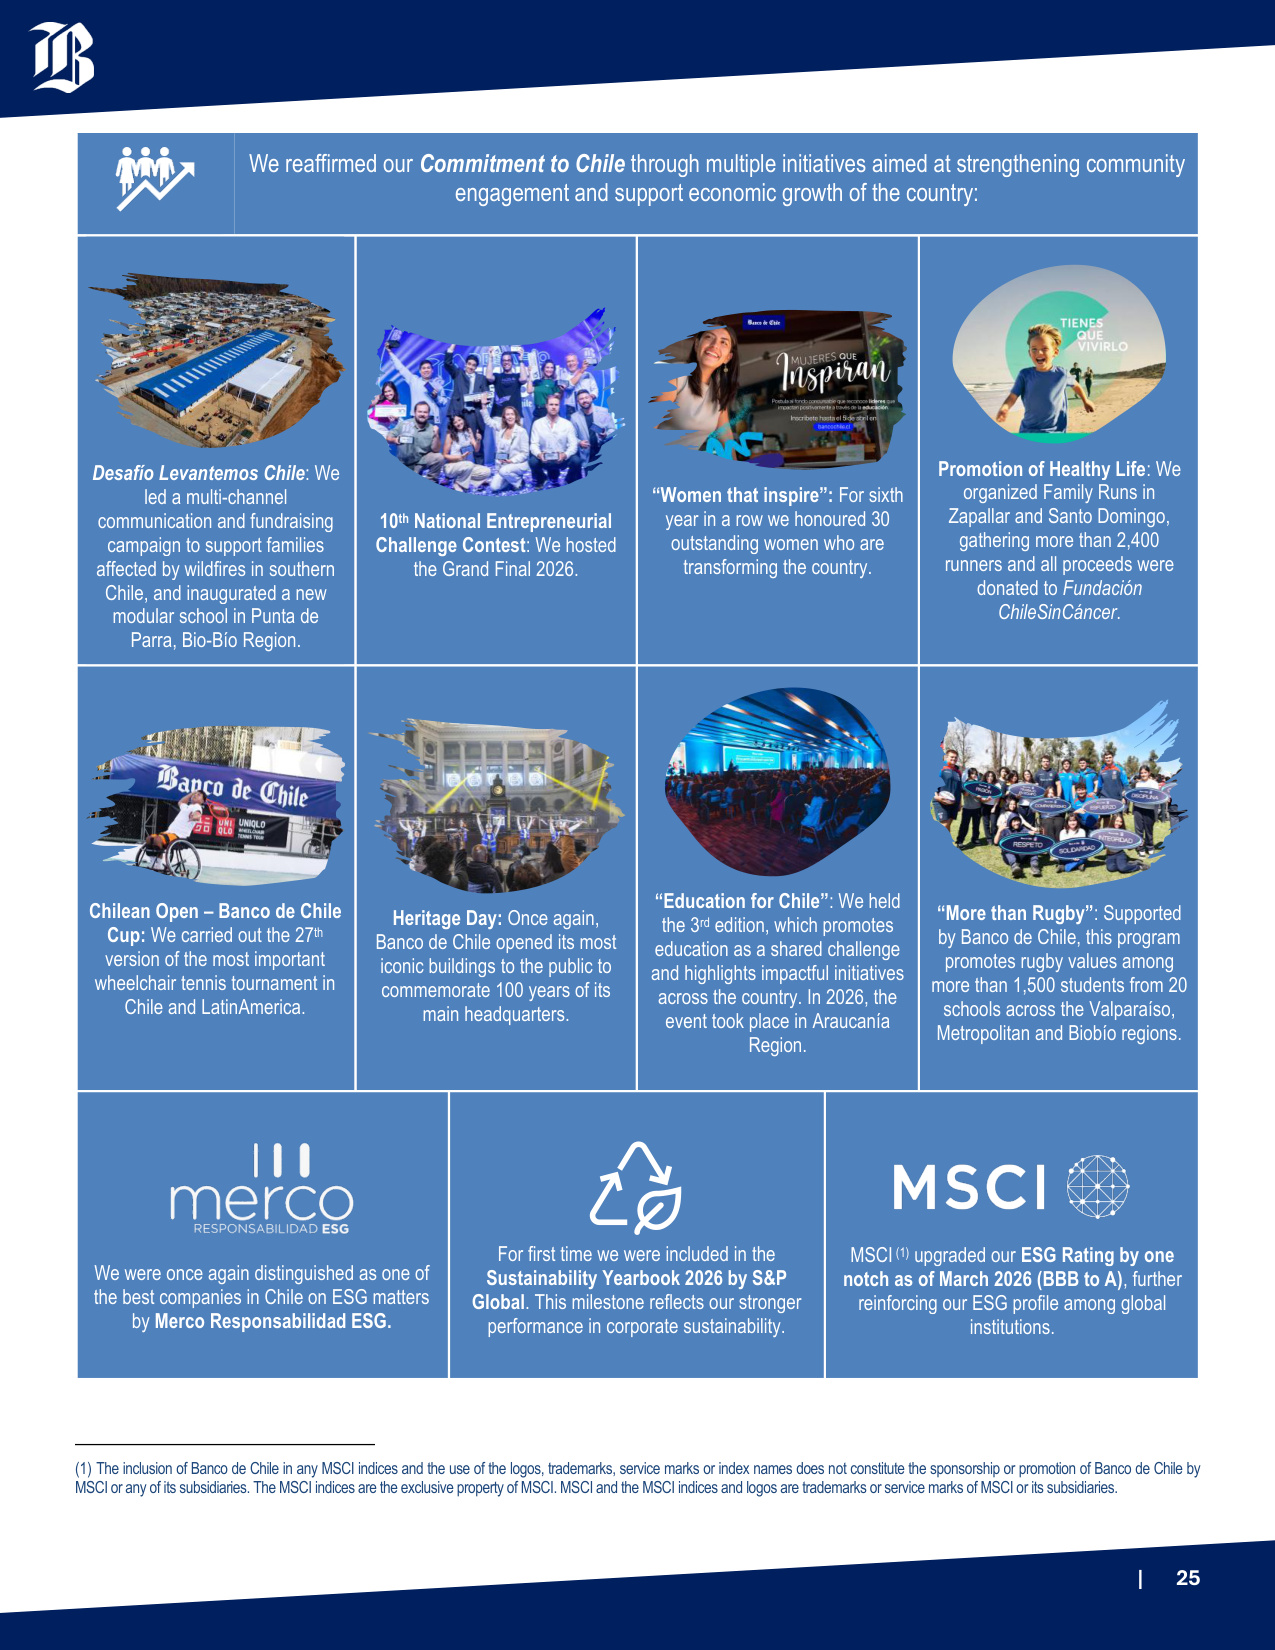
| 25 We reaffirmed our Commitment to Chile through multiple initiatives aimed at strengthening community engagement and support economic growth of the country: Desafío Levantemos Chile: We led a multi-channel communication and fundraising campaign to support families affected by wildfires in southern Chile, and inaugurated a new modular school in Punta de Parra, Bio-Bío Region. 10th National Entrepreneurial Challenge Contest: We hosted the Grand Final 2026. "Women that inspire": For sixth year in a row we honoured 30 outstanding women who are transforming the country. Promotion of Healthy Life: We organized Family Runs in Zapallar and Santo Domingo, gathering more than 2,400 runners and all proceeds were donated to Fundación ChileSinCáncer. Chilean Open – Banco de Chile Cup: We carried out the 27th version of the most important wheelchair tennis tournament in Chile and LatinAmerica. Heritage Day: Once again, Banco de Chile opened its most iconic buildings to the public to commemorate 100 years of its main headquarters. "Education for Chile": We held the 3rd edition, which promotes education as a shared challenge and highlights impactful initiatives across the country. In 2026, the event took place in Araucanía Region. "More than Rugby": Supported by Banco de Chile, this program promotes rugby values among more than 1,500 students from 20 schools across the Valparaíso, Metropolitan and Biobío regions. We were once again distinguished as one of the best companies in Chile on ESG matters by Merco Responsabilidad ESG. For first time we were included in the Sustainability Yearbook 2026 by S&P Global. This milestone reflects our stronger performance in corporate sustainability. MSCI (1) upgraded our ESG Rating by one notch as of March 2026 (BBB to A), further reinforcing our ESG profile among global institutions. (1) The inclusion of Banco de Chile in any MSCI indices and the use of the logos, trademarks, service marks or index names does not constitute the sponsorship or promotion of Banco de Chile by MSCI or any of its subsidiaries. The MSCI indices are the exclusive property of MSCI. MSCI and the MSCI indices and logos are trademarks or service marks of MSCI or its subsidiaries.
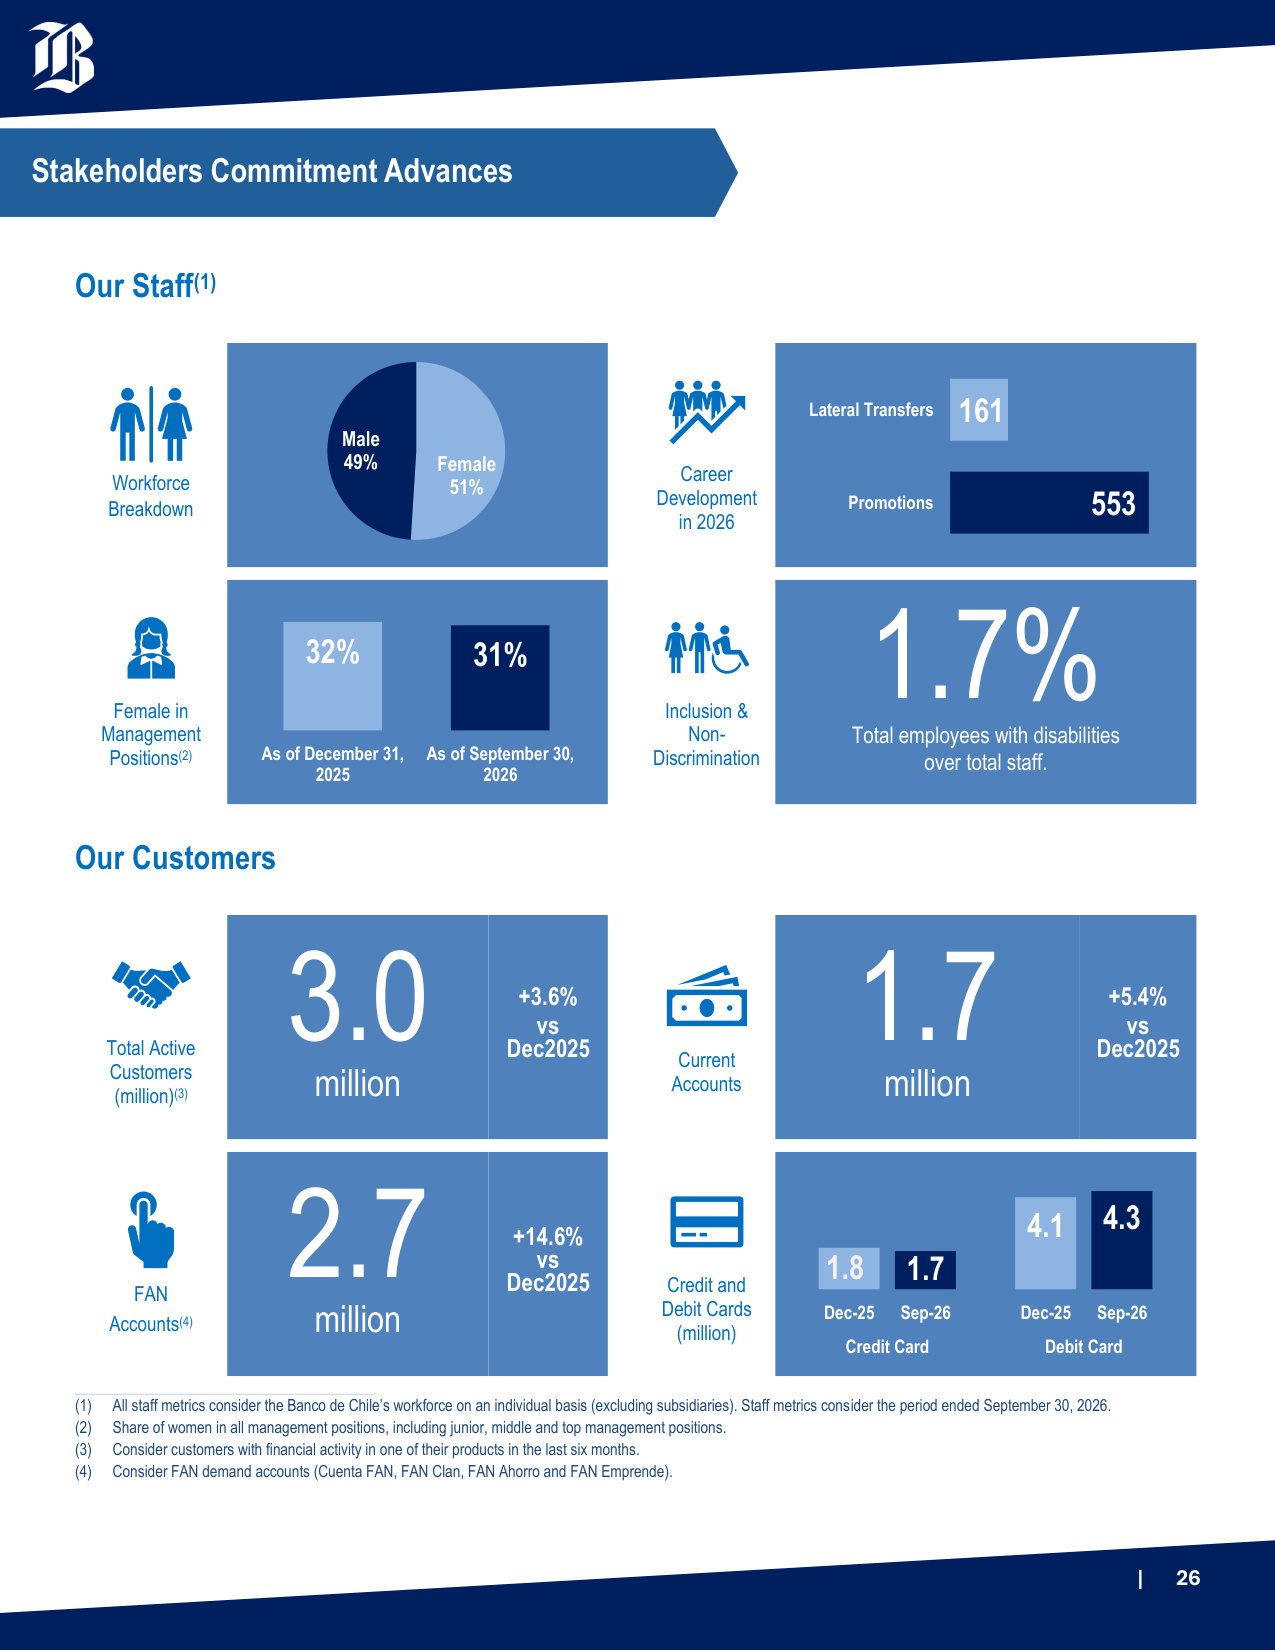
| 26 Our Staff(1) Workforce Breakdown Career Development in 2026 Female in Management Positions(2) Inclusion & Non- Discrimination 1.7% Total employees with disabilities over total staff. Our Customers Total Active Customers (million)(3) 3.0 million +3.6% vs Dec2025 Current Accounts 1.7 million +5.4% vs Dec2025 FAN Accounts(4) 2.7 million +14.6% vs Dec2025 Credit and Debit Cards (million) (1) All staff metrics consider the Banco de Chile's workforce on an individual basis (excluding subsidiaries). Staff metrics consider the period ended September 30, 2026. (2) Share of women in all management positions, including junior, middle and top management positions. (3) Consider customers with financial activity in one of their products in the last six months. (4) Consider FAN demand accounts (Cuenta FAN, FAN Clan, FAN Ahorro and FAN Emprende). Female 51% Male 49% 553 161 Promotions Lateral Transfers 32% 31% As of December 31, 2025 As of September 30, 2026 1.8 1.7 Dec-25 Sep-26 Credit Card 4.1 4.3 Dec-25 Sep-26 Debit Card Stakeholders Commitment Advances
| 27 Section 4 Business Environment
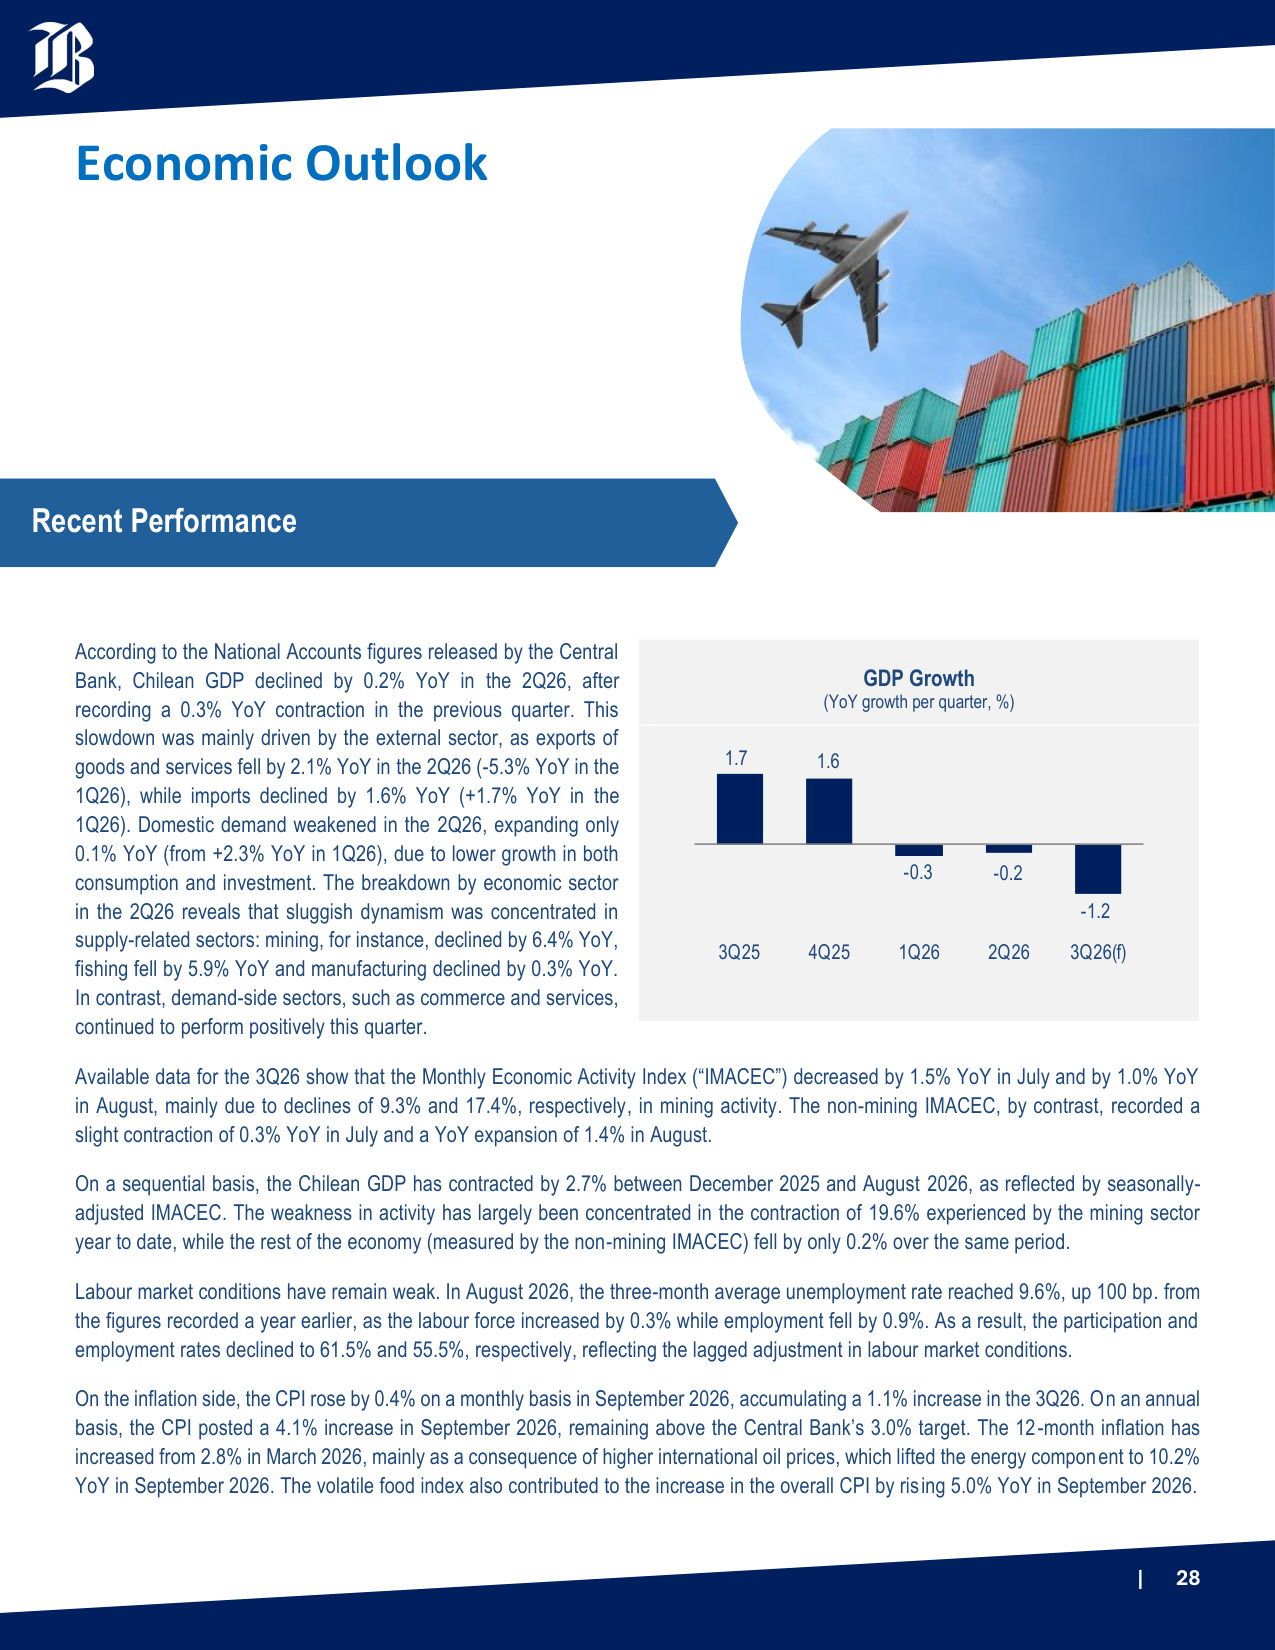
| 28 Economic Outlook According to the National Accounts figures released by the Central Bank, Chilean GDP declined by 0.2% YoY in the 2Q26, after recording a 0.3% YoY contraction in the previous quarter. This slowdown was mainly driven by the external sector, as exports of goods and services fell by 2.1% YoY in the 2Q26 (-5.3% YoY in the 1Q26), while imports declined by 1.6% YoY (+1.7% YoY in the 1Q26). Domestic demand weakened in the 2Q26, expanding only 0.1% YoY (from +2.3% YoY in 1Q26), due to lower growth in both consumption and investment. The breakdown by economic sector in the 2Q26 reveals that sluggish dynamism was concentrated in supply-related sectors: mining, for instance, declined by 6.4% YoY, fishing fell by 5.9% YoY and manufacturing declined by 0.3% YoY. In contrast, demand-side sectors, such as commerce and services, continued to perform positively this quarter. Available data for the 3Q26 show that the Monthly Economic Activity Index ("IMACEC") decreased by 1.5% YoY in July and by 1.0% YoY in August, mainly due to declines of 9.3% and 17.4%, respectively, in mining activity. The non-mining IMACEC, by contrast, recorded a slight contraction of 0.3% YoY in July and a YoY expansion of 1.4% in August. On a sequential basis, the Chilean GDP has contracted by 2.7% between December 2025 and August 2026, as reflected by seasonally- adjusted IMACEC. The weakness in activity has largely been concentrated in the contraction of 19.6% experienced by the mining sector year to date, while the rest of the economy (measured by the non-mining IMACEC) fell by only 0.2% over the same period. Labour market conditions have remain weak. In August 2026, the three-month average unemployment rate reached 9.6%, up 100 bp. from the figures recorded a year earlier, as the labour force increased by 0.3% while employment fell by 0.9%. As a result, the participation and employment rates declined to 61.5% and 55.5%, respectively, reflecting the lagged adjustment in labour market conditions. On the inflation side, the CPI rose by 0.4% on a monthly basis in September 2026, accumulating a 1.1% increase in the 3Q26. On an annual basis, the CPI posted a 4.1% increase in September 2026, remaining above the Central Bank's 3.0% target. The 12-month inflation has increased from 2.8% in March 2026, mainly as a consequence of higher international oil prices, which lifted the energy component to 10.2% YoY in September 2026. The volatile food index also contributed to the increase in the overall CPI by rising 5.0% YoY in September 2026. GDP Growth (YoY growth per quarter, %) 1.7 1.6 -0.3 -0.2 -1.2 3Q25 4Q25 1Q26 2Q26 3Q26(f) Recent Performance
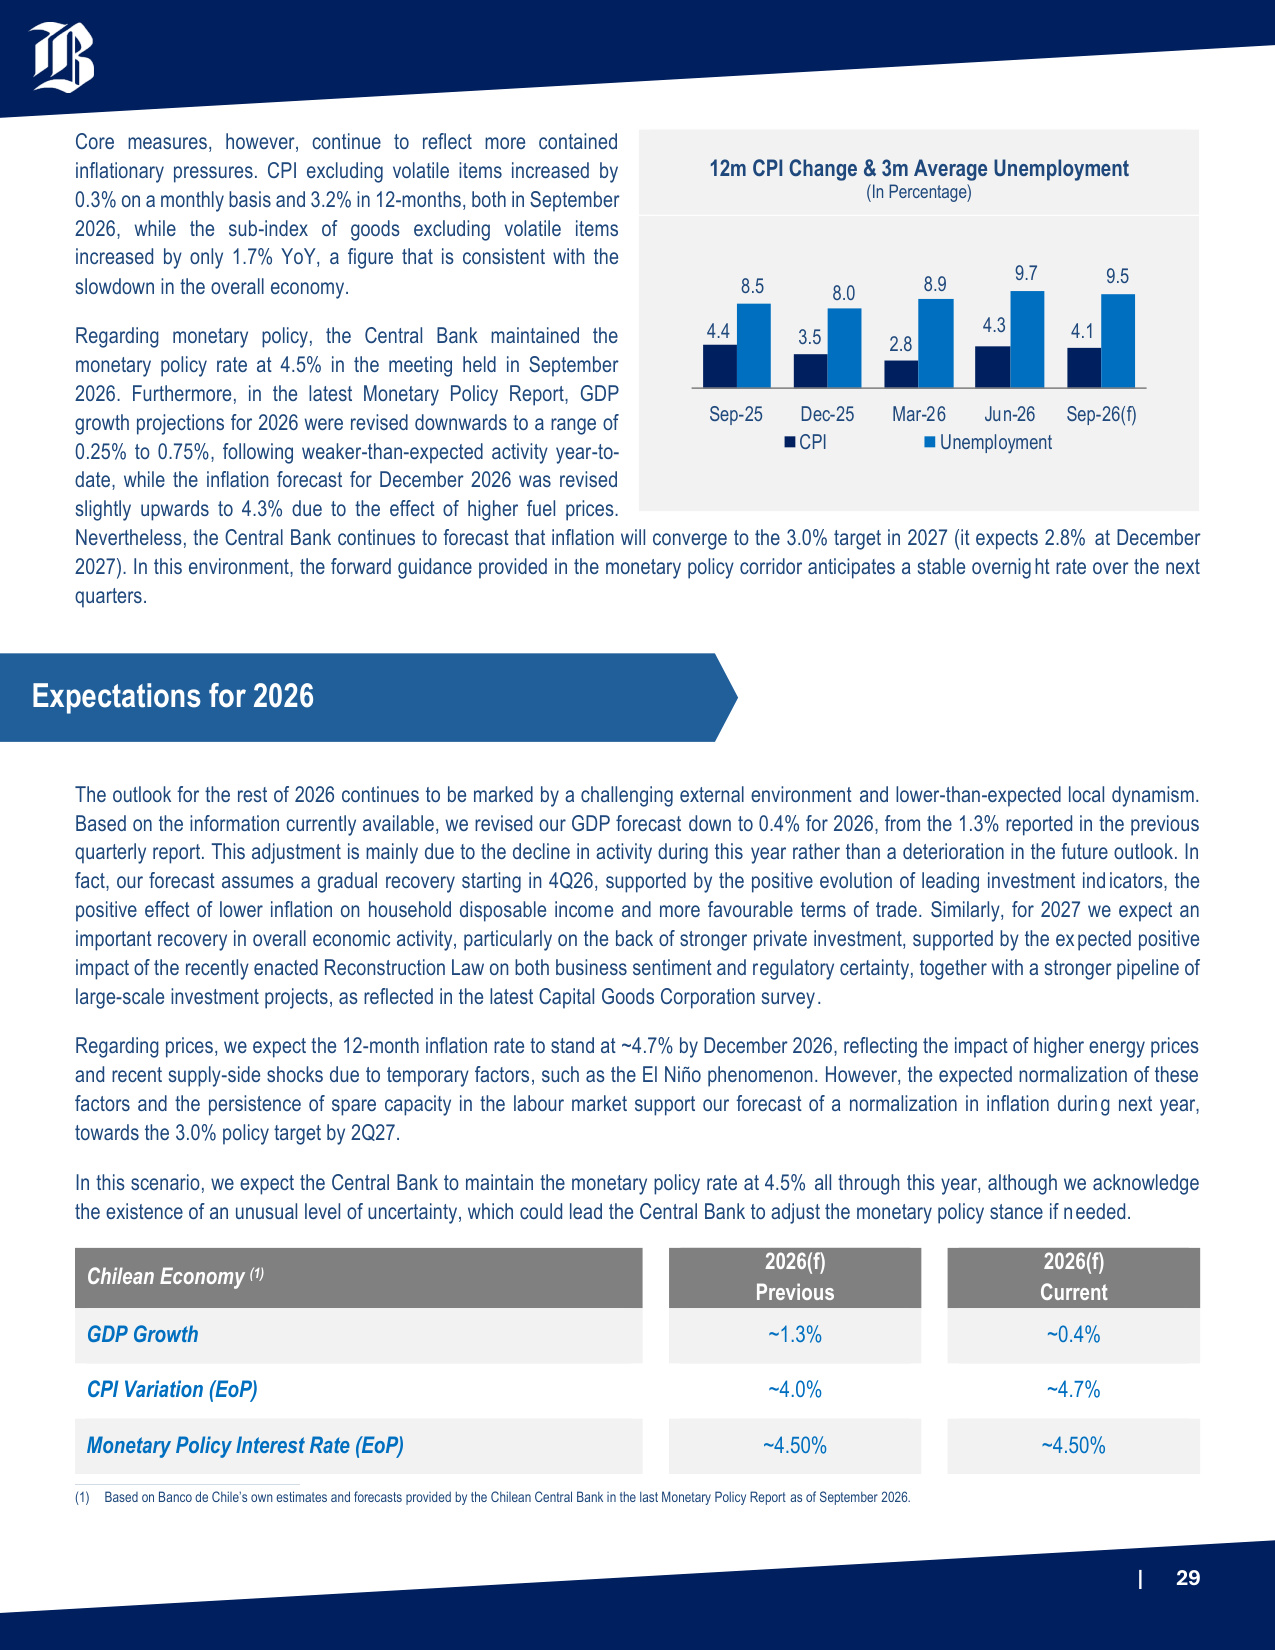
| 29 Core measures, however, continue to reflect more contained inflationary pressures. CPI excluding volatile items increased by 0.3% on a monthly basis and 3.2% in 12-months, both in September 2026, while the sub-index of goods excluding volatile items increased by only 1.7% YoY, a figure that is consistent with the slowdown in the overall economy. Regarding monetary policy, the Central Bank maintained the monetary policy rate at 4.5% in the meeting held in September 2026. Furthermore, in the latest Monetary Policy Report, GDP growth projections for 2026 were revised downwards to a range of 0.25% to 0.75%, following weaker-than-expected activity year-to- date, while the inflation forecast for December 2026 was revised slightly upwards to 4.3% due to the effect of higher fuel prices. Nevertheless, the Central Bank continues to forecast that inflation will converge to the 3.0% target in 2027 (it expects 2.8% at December 2027). In this environment, the forward guidance provided in the monetary policy corridor anticipates a stable overnight rate over the next quarters. The outlook for the rest of 2026 continues to be marked by a challenging external environment and lower-than-expected local dynamism. Based on the information currently available, we revised our GDP forecast down to 0.4% for 2026, from the 1.3% reported in the previous quarterly report. This adjustment is mainly due to the decline in activity during this year rather than a deterioration in the future outlook. In fact, our forecast assumes a gradual recovery starting in 4Q26, supported by the positive evolution of leading investment indicators, the positive effect of lower inflation on household disposable income and more favourable terms of trade. Similarly, for 2027 we expect an important recovery in overall economic activity, particularly on the back of stronger private investment, supported by the expected positive impact of the recently enacted Reconstruction Law on both business sentiment and regulatory certainty, together with a stronger pipeline of large-scale investment projects, as reflected in the latest Capital Goods Corporation survey. Regarding prices, we expect the 12-month inflation rate to stand at ~4.7% by December 2026, reflecting the impact of higher energy prices and recent supply-side shocks due to temporary factors, such as the El Niño phenomenon. However, the expected normalization of these factors and the persistence of spare capacity in the labour market support our forecast of a normalization in inflation during next year, towards the 3.0% policy target by 2Q27. In this scenario, we expect the Central Bank to maintain the monetary policy rate at 4.5% all through this year, although we acknowledge the existence of an unusual level of uncertainty, which could lead the Central Bank to adjust the monetary policy stance if needed. Chilean Economy (1) 2026(f) Previous 2026(f) Current GDP Growth ~1.3% ~0.4% CPI Variation (EoP) ~4.0% ~4.7% Monetary Policy Interest Rate (EoP) ~4.50% ~4.50% (1) Based on Banco de Chile's own estimates and forecasts provided by the Chilean Central Bank in the last Monetary Policy Report as of September 2026. 12m CPI Change & 3m Average Unemployment (In Percentage) 4.4 3.5 2.8 4.3 4.1 8.5 8.0 8.9 9.7 9.5 Sep-25 Dec-25 Mar-26 Jun-26 Sep-26(f) CPI Unemployment Expectations for 2026
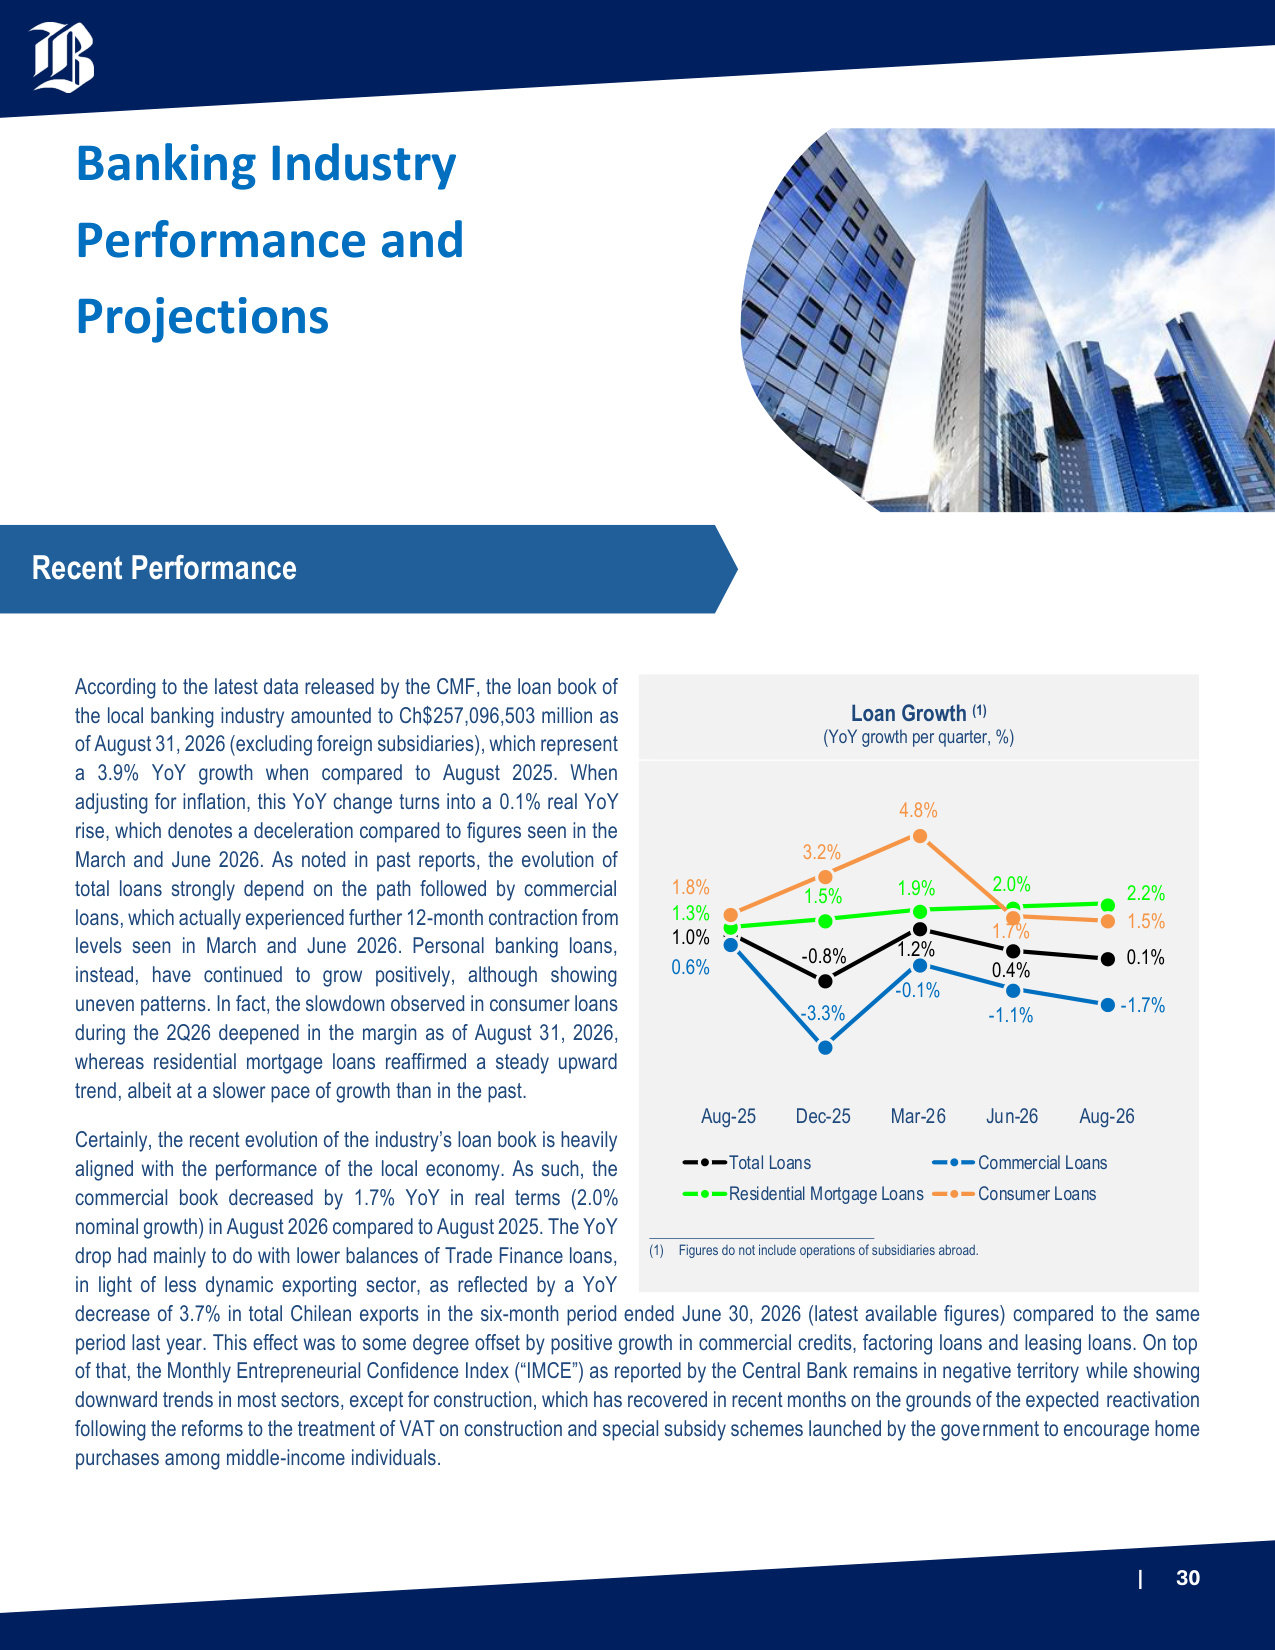
| 30 Banking Industry Performance and Projections According to the latest data released by the CMF, the loan book of the local banking industry amounted to Ch$257,096,503 million as of August 31, 2026 (excluding foreign subsidiaries), which represent a 3.9% YoY growth when compared to August 2025. When adjusting for inflation, this YoY change turns into a 0.1% real YoY rise, which denotes a deceleration compared to figures seen in the March and June 2026. As noted in past reports, the evolution of total loans strongly depend on the path followed by commercial loans, which actually experienced further 12-month contraction from levels seen in March and June 2026. Personal banking loans, instead, have continued to grow positively, although showing uneven patterns. In fact, the slowdown observed in consumer loans during the 2Q26 deepened in the margin as of August 31, 2026, whereas residential mortgage loans reaffirmed a steady upward trend, albeit at a slower pace of growth than in the past. Certainly, the recent evolution of the industry's loan book is heavily aligned with the performance of the local economy. As such, the commercial book decreased by 1.7% YoY in real terms (2.0% nominal growth) in August 2026 compared to August 2025. The YoY drop had mainly to do with lower balances of Trade Finance loans, in light of less dynamic exporting sector, as reflected by a YoY decrease of 3.7% in total Chilean exports in the six-month period ended June 30, 2026 (latest available figures) compared to the same period last year. This effect was to some degree offset by positive growth in commercial credits, factoring loans and leasing loans. On top of that, the Monthly Entrepreneurial Confidence Index ("IMCE") as reported by the Central Bank remains in negative territory while showing downward trends in most sectors, except for construction, which has recovered in recent months on the grounds of the expected reactivation following the reforms to the treatment of VAT on construction and special subsidy schemes launched by the government to encourage home purchases among middle-income individuals. Loan Growth (1) (YoY growth per quarter, %) 1.0% -0.8% 1.2% 0.4% 0.1% 0.6% -3.3% -0.1% -1.1% -1.7% 1.3% 1.5% 1.9% 2.0% 2.2% 1.8% 3.2% 4.8% 1.7% 1.5% Aug-25 Dec-25 Mar-26 Jun-26 Aug-26 Total Loans Commercial Loans Residential Mortgage Loans Consumer Loans (1) Figures do not include operations of subsidiaries abroad. Recent Performance
| 31 In Retail Banking, consumer loans increased 1.5% YoY in real terms (5.4% nominal) in August 2026, while Residential Mortgage loans recorded a YoY rise of 2.2% in real terms (6.0% nominal). The YoY change in consumer loans reaffirms the deceleration highlighted in previous reports, which has been observed in both installment loans and credit card loans. For both cases, the slowdown in household consumption has been the main underlying factor, as consumption of durable and non-durable goods, respectively, have steadily displayed lower growth rates than in 2025. Furthermore, the Consumer Confidence Index as reported by the Central Bank, has continued to decrease from the pickup seen in the 1Q26, given subdued economic growth and increased unemployment, as shown earlier in this report. Regarding residential mortgage loans, the gradual recovery observed over the last quarters has primarily been fostered governmental initiatives that pursue to revitalize the demand for housing among middle-income individuals, firstly for homes up to UF4,000 (~USD170,000) and more recently for homes up to UF6,000 (~USD250,000). Under this scheme, the state guarantees residential mortgage loans granted by commercial banks to individuals, subsidies the interest rate paid by debtors and also provides home purchasers with part of the down payment to ease credit granting conditions. Although these initiatives have been positive for both the housing market and residential mortgage loans, it is important to note that 12-month growth rates for these kinds of credits continue to be well below the expansion rates seen in the past, which has been the result of several dynamics working together, including elevated interest rates, higher-than-normal inflation in some periods, changes in the tax treatment for housing construction, and real wages growing well below housing prices. As for liabilities, Time Deposits managed by the industry reached Ch$124,367,836 million (excluding foreign subsidiaries) on August 31, 2026 and remained as the main funding source for the banking sector. This amount represents a 7.9% YoY rise (3.9% real) in relation to August 2025. In comparison with figures we saw last quarter, Time Deposits experienced an acceleration in 12-month growth, which appears to be directly linked to the slowdown observed in Demand Deposits over the same time frame. In fact, Demand Deposits handled by the entire system accounted for Ch$70,416,507 million (excluding foreign subsidiaries) on August 31, 2026, which denotes a 3.1% YoY increase (0.7% real contraction) compared to a year earlier, which seems to be associated with a combination of factors including increased unemployment, lower overall economic activity and deteriorated expectations of individual customers on the economic outlook while being below the ~6% average YoY growth rates seen in the 1H26. Nevertheless, given the moderate expansion of the industry's loan book, the reciprocity ratio of Demand Deposits to Total Loans continued to be above the ~25.0% levels seen before 2020 by reaching 27.4% in August 2026. In terms of long-term debt, the moderate expansion of the lending business –and the residential mortgage loans in particular– the need for this type of funding has remained subdued. Actually, on August 31, 2026 the Debt Issued by the industry (including regulatory capital instruments) totalled Ch$73,226,468 million, which was 0.1% below the level recorded a year earlier (a real contraction of 3.7% when adjusted for inflation). In regard to net income, the local industry recorded a bottom line of Ch$4,010,372 million in the eight-month period ended August 31, 2026, which represent a YoY rise of Ch$264,835 million or 7.1% when compared to the same period of 2025. As highlighted last quarter, this performance has been primarily driven by the temporary pickup in local inflation that benefited the CLF-indexed exposure held by the industry in the balance sheet, mostly associated with residential mortgage lending. Accordingly, operating revenues boosted Ch$934,640 million or 7.8% YoY compared to the eight-month period ended August 31, 2025, due to higher income from inflation-indexation and also net interest income on the net interest margin generated by the industry, together with increased net fee when compared to a year earlier. These positive effects were to some extent counterbalanced by: (i) a YoY increase of Ch$305,215 million or 5.8% in operating expenses, explained by the impact of the sale of the consumer lending portfolio formerly managed by the foreign subsidiary owned by one local player and, to a lesser degree, higher personnel expenses due to inflation indexation, (ii) credit loss expenses that increased Ch$210,284 million or 10.8% YoY following the net rise in additional provisions, given net allowance releases last year to address the implementation of the new provisioning model for the consumer loan portfolio, which was in part offset by a better performance in specific provisions, and (iii) higher income tax by Ch$154,306 million or 15.8% YoY owing to an exchange rate effect on operations carried out by a couple of players abroad.
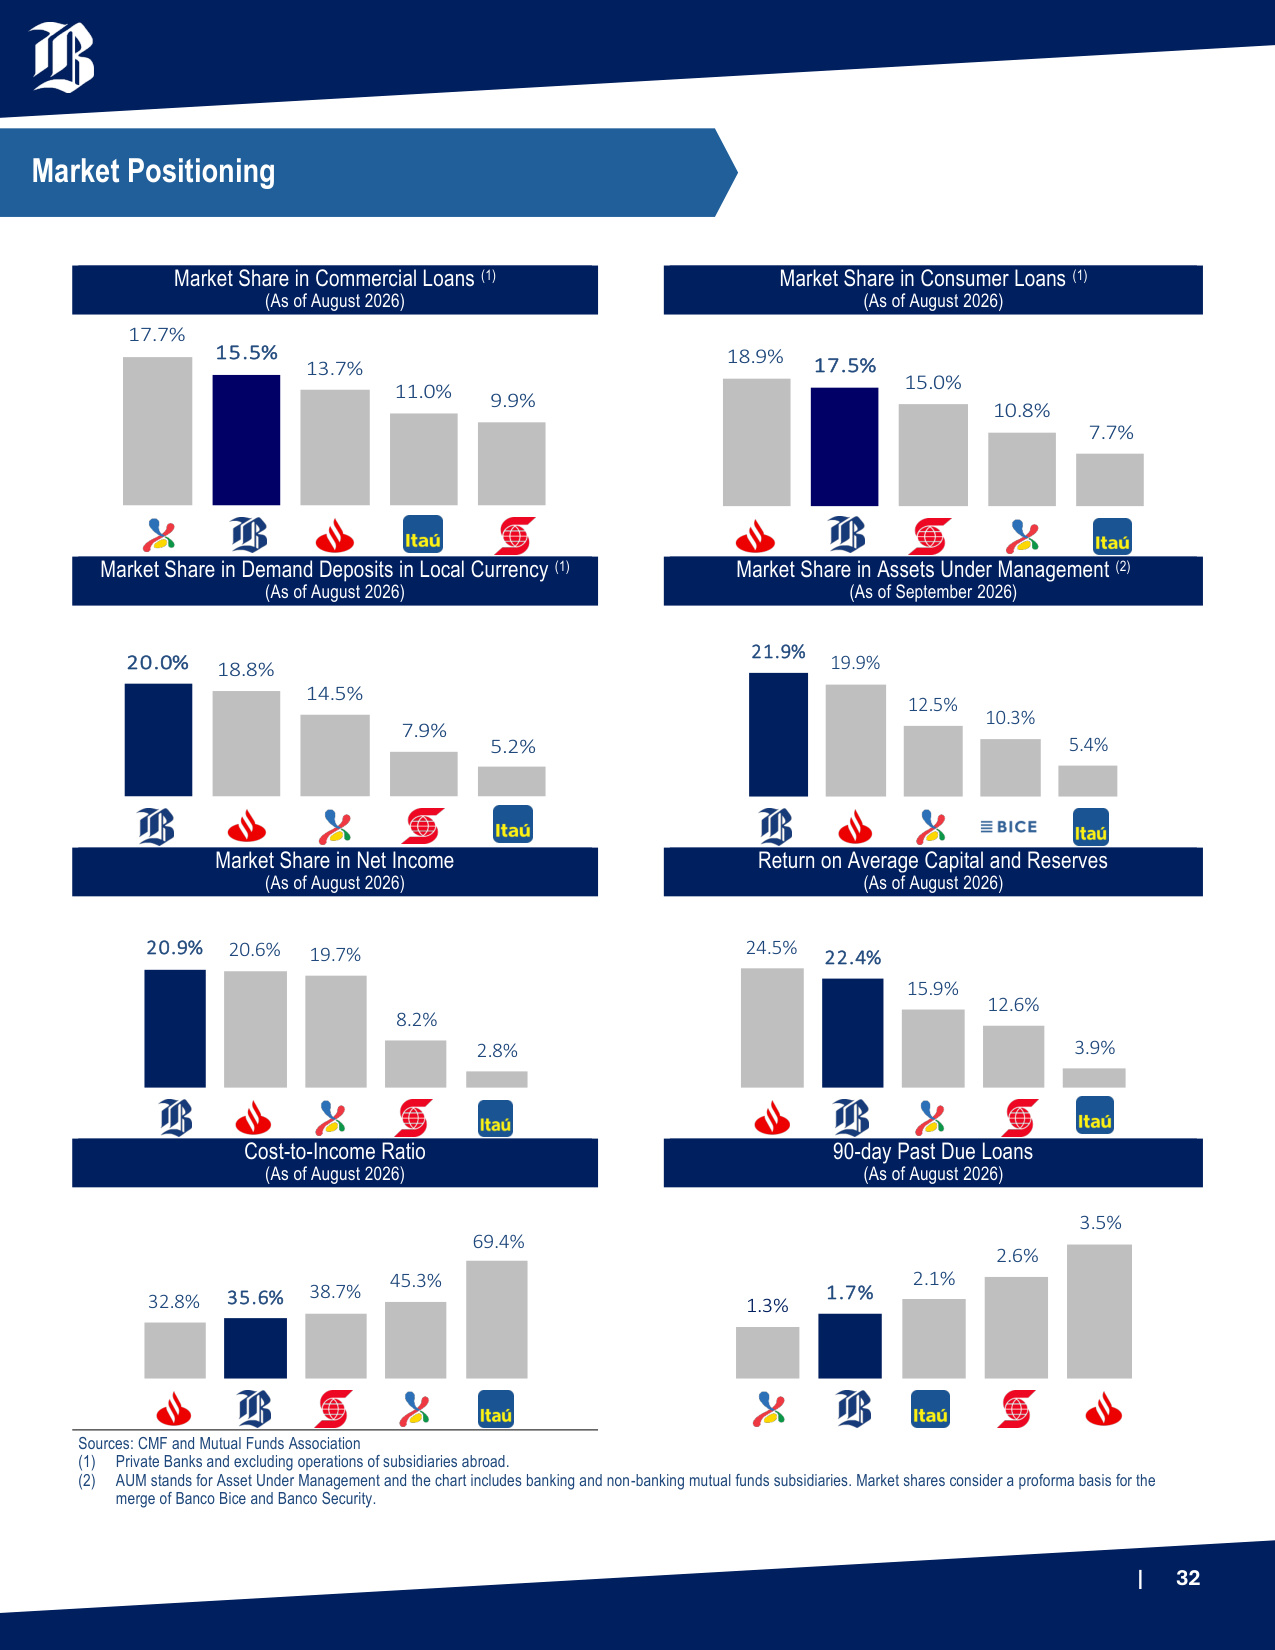
| 32 Market Share in Commercial Loans (1) (As of August 2026) Market Share in Consumer Loans (1) (As of August 2026) 17.7% 15.5% 13.7% 11.0% 9.9% 18.9% 17.5% 15.0% 10.8% 7.7% Market Share in Demand Deposits in Local Currency (1) (As of August 2026) Market Share in Assets Under Management (2) (As of September 2026) 20.0% 18.8% 14.5% 7.9% 5.2% 21.9% 19.9% 12.5% 10.3% 5.4% Market Share in Net Income (As of August 2026) Return on Average Capital and Reserves (As of August 2026) 20.9% 20.6% 19.7% 8.2% 2.8% 24.5% 22.4% 15.9% 12.6% 3.9% Cost-to-Income Ratio (As of August 2026) 90-day Past Due Loans (As of August 2026) 32.8% 35.6% 38.7% 45.3% 69.4% 1.3% 1.7% 2.1% 2.6% 3.5% Sources: CMF and Mutual Funds Association (1) Private Banks and excluding operations of subsidiaries abroad. (2) AUM stands for Asset Under Management and the chart includes banking and non-banking mutual funds subsidiaries. Market shares consider a proforma basis for the merge of Banco Bice and Banco Security. Market Positioning
| 33 Although we have revised expectations for the local economy, we have not modified our baseline scenario for the local banking industry significantly as mixed factors would be working together over the rest of the year. First of all, GDP growth for 2026 has sharply been revised downwards from 1.3% (last quarter) to 0.4% currently. However, the actual performance of the local economy has heavily been influenced by the mining industry, while other economic sectors have begun to show some modest signs of recovery. This could lead to a moderate cut in the lending activity for certain types of products, such as commercial loans. On the other hand, household consumption is slowing down but it continues to grow positively, while the housing market seems to be recovering moderately on the grounds of the support programs implemented by the Government. Accordingly, retail banking loans would continue to grow above inflation over the rest of the year. In addition, we revised our forecast for 12-month inflation upwards from 4.0% (last quarter) to 4.7% for December 2026. Based on these expectations, we now expect the industry's total book to grow ~5.0% YoY in nominal terms by December 2026 (above the ~4.0% expansion we forcasted last quarter). In terms of funding, at this point we expect the reciprocity ratio of Demand Deposits over Total Loans to decrease to levels in the range of 26% to 28% by December 2026 (from a range of 28% to 30% forecasted last quarter), provided that Demand Deposits appear to be slowing down in light of some macroeconomic factors including higher-than-expected inflation and increased unemployment. This, in turn, would promote the use of Time Deposits as a source of funding among banks, while Debt Issued will depend on long-term funding needs and the management of liquidity and interest rate risk in the banking book. Concerning net income, as we have revised our forecast for inflation upwards to 4.7% for December 2026 (from 4.0% last quarter) and the Central Bank is likely to keep the monetary policy interest rate at 4.5% (the same as last quarter), we have revised our estimate for industry's NIM to a range of 4.0% to 4.2% (from 3.6% to 3.8% last quarter) given the positive impact of increased inflation on the inflation-indexation exposure managed by the industry, whose revenues are part of the NIM. In terms of credit risk, to the extent some key macroeconomic indicators that affect customers' payment capacity, such as unemployment and overall economic activity, do not deteriorate further, we believe delinquency would stay at the upper boundary of the 2.3% to 2.4% range we forecasted last quarter, while credit loss expenses would also range from 1.2% to 1.3% (as a percentage of average loans) as we reported last quarter. Notwithstanding the above, we will closely monitor the aftermath of the conflict in the Strait of Hormuz in the coming quarters to adjust our forecast, if necessary. Banking Industry (1) FY2026 Previous FY2026 Current Nominal Loan Growth ~4.0% ~5.0% DDA / Total Loans 28% – 30% 26% – 28% Net Interest Margin 3.6% – 3.8% 4.0% – 4.2% CLE / Avg. Loans 1.2% – 1.3% 1.2% – 1.3% Past-Due Loans (>90d) 2.3% – 2.4% 2.3% – 2.4% (1) Based on Banco de Chile's own estimates. Expectations for 2026
| 34 Section 5 Management Discussion & Analysis
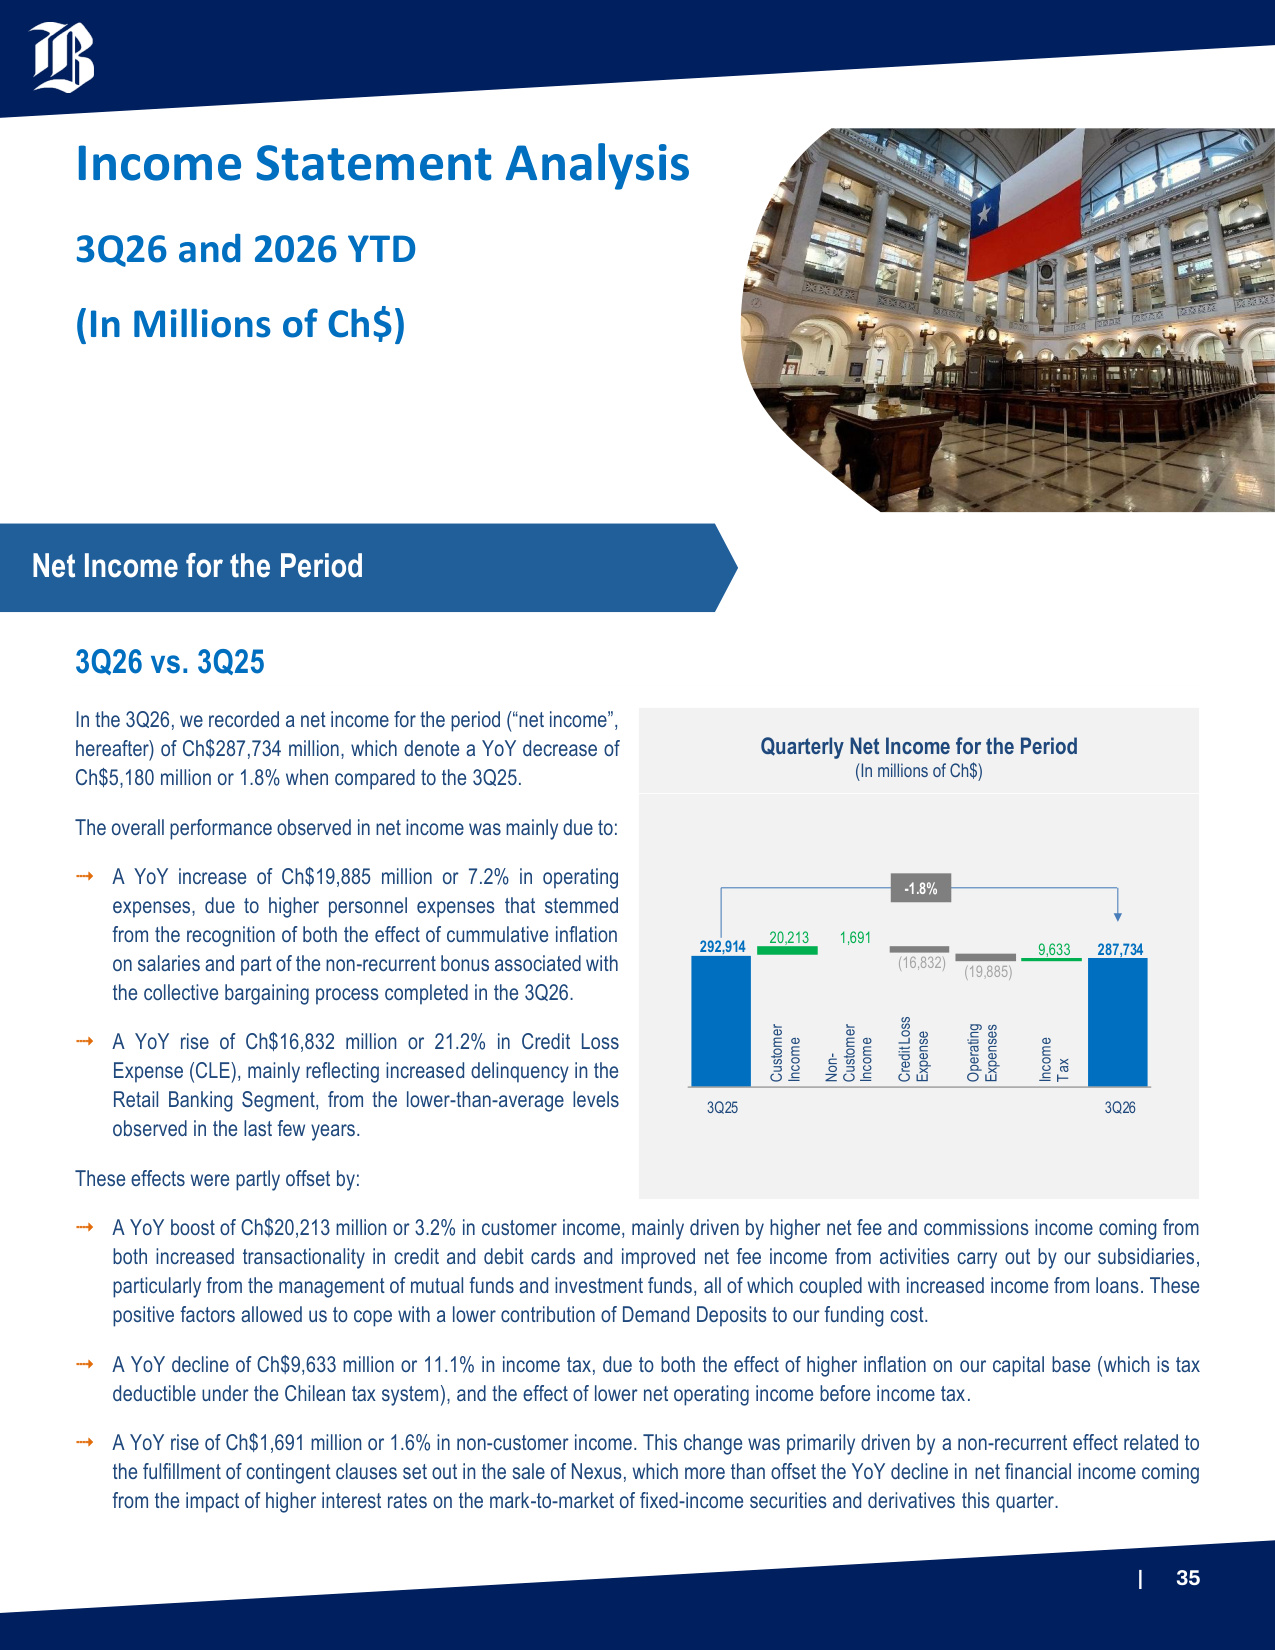
| 35 Income Statement Analysis 3Q26 and 2026 YTD (In Millions of Ch$) 3Q26 vs. 3Q25 In the 3Q26, we recorded a net income for the period ("net income", hereafter) of Ch$287,734 million, which denote a YoY decrease of Ch$5,180 million or 1.8% when compared to the 3Q25. The overall performance observed in net income was mainly due to: A YoY increase of Ch$19,885 million or 7.2% in operating expenses, due to higher personnel expenses that stemmed from the recognition of both the effect of cummulative inflation on salaries and part of the non-recurrent bonus associated with the collective bargaining process completed in the 3Q26. A YoY rise of Ch$16,832 million or 21.2% in Credit Loss Expense (CLE), mainly reflecting increased delinquency in the Retail Banking Segment, from the lower-than-average levels observed in the last few years. These effects were partly offset by: A YoY boost of Ch$20,213 million or 3.2% in customer income, mainly driven by higher net fee and commissions income coming from both increased transactionality in credit and debit cards and improved net fee income from activities carry out by our subsidiaries, particularly from the management of mutual funds and investment funds, all of which coupled with increased income from loans. These positive factors allowed us to cope with a lower contribution of Demand Deposits to our funding cost. A YoY decline of Ch$9,633 million or 11.1% in income tax, due to both the effect of higher inflation on our capital base (which is tax deductible under the Chilean tax system), and the effect of lower net operating income before income tax. A YoY rise of Ch$1,691 million or 1.6% in non-customer income. This change was primarily driven by a non-recurrent effect related to the fulfillment of contingent clauses set out in the sale of Nexus, which more than offset the YoY decline in net financial income coming from the impact of higher interest rates on the mark-to-market of fixed-income securities and derivatives this quarter. Quarterly Net Income for the Period (In millions of Ch$) 292,914 20,213 1,691 (16,832) (19,885) 9,633 287,734 3Q25 3Q26 -1.8% Non- Customer Income Income Tax Customer Income Credit Loss Expense Operating Expenses Net Income for the Period
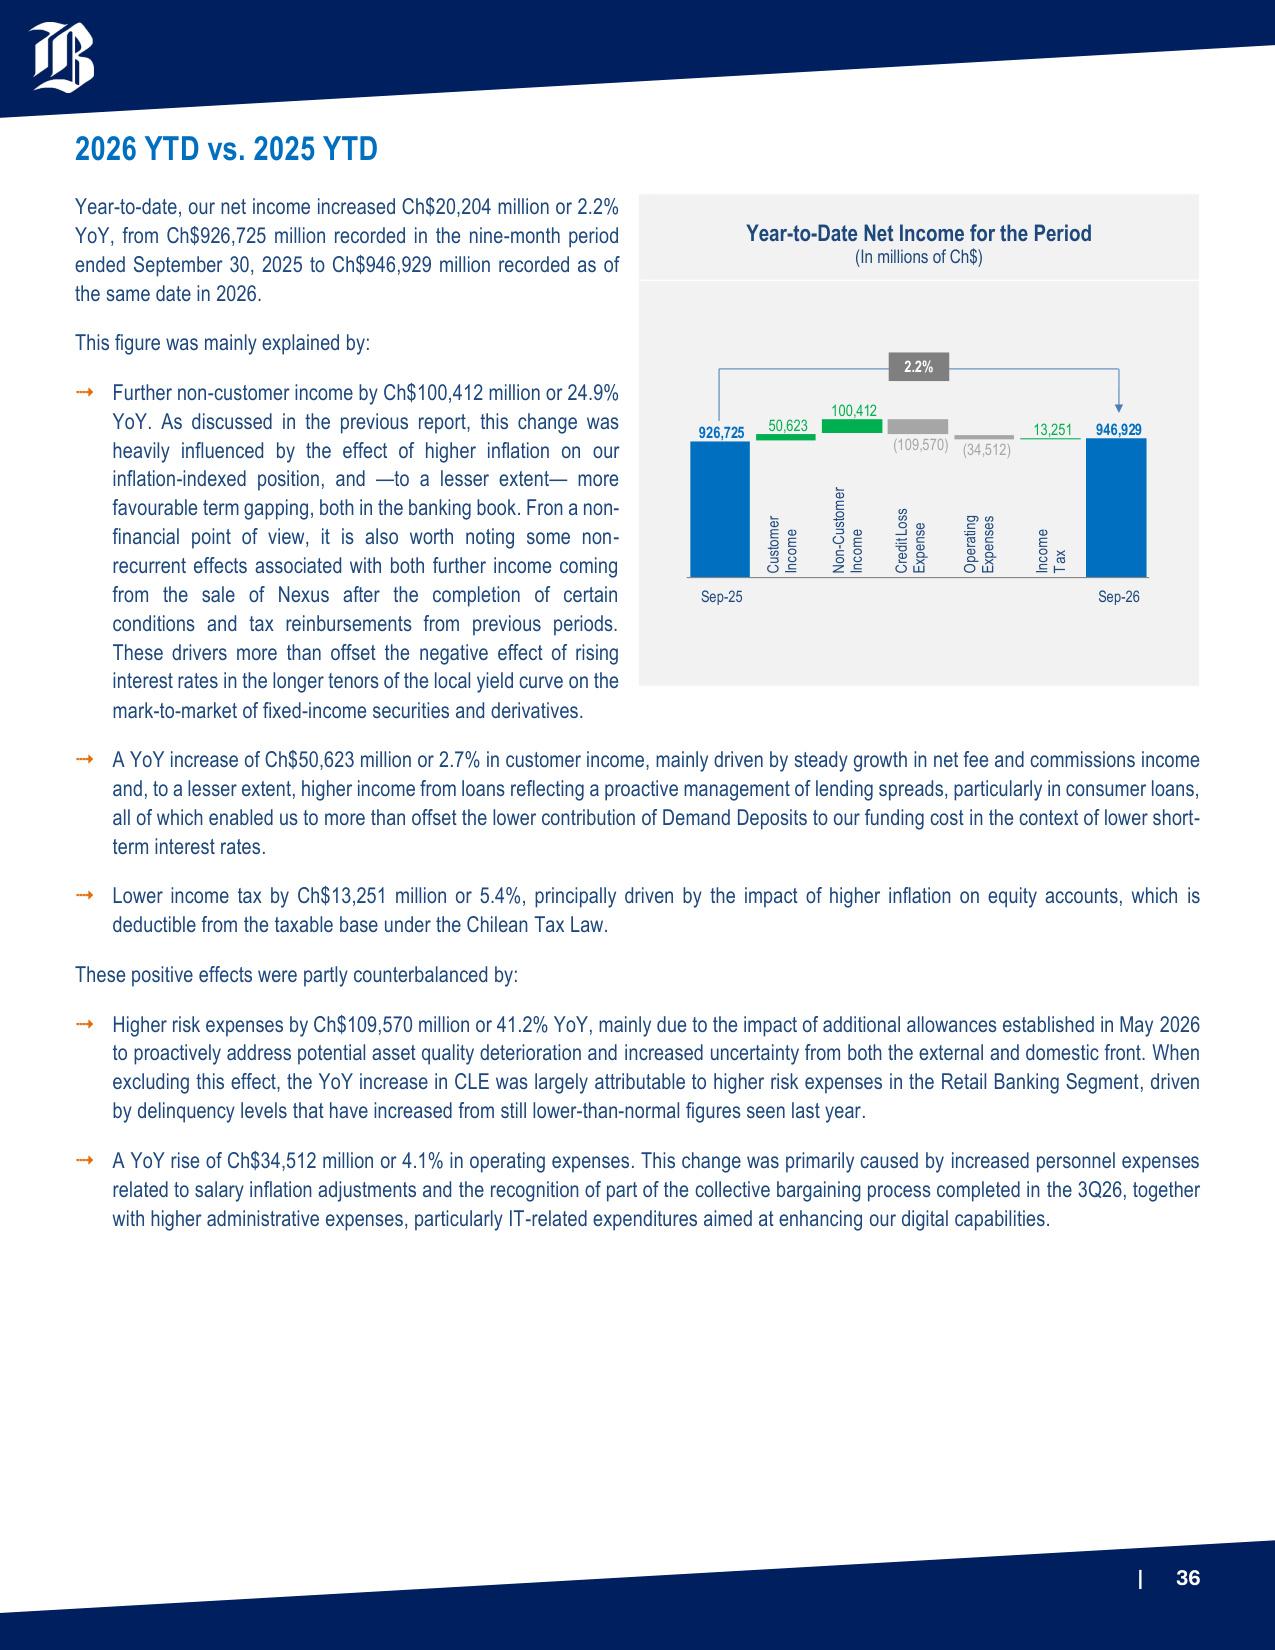
| 36 2026 YTD vs. 2025 YTD Year-to-date, our net income increased Ch$20,204 million or 2.2% YoY, from Ch$926,725 million recorded in the nine-month period ended September 30, 2025 to Ch$946,929 million recorded as of the same date in 2026. This figure was mainly explained by: Further non-customer income by Ch$100,412 million or 24.9% YoY. As discussed in the previous report, this change was heavily influenced by the effect of higher inflation on our inflation-indexed position, and —to a lesser extent— more favourable term gapping, both in the banking book. Fron a non- financial point of view, it is also worth noting some non- recurrent effects associated with both further income coming from the sale of Nexus after the completion of certain conditions and tax reinbursements from previous periods. These drivers more than offset the negative effect of rising interest rates in the longer tenors of the local yield curve on the mark-to-market of fixed-income securities and derivatives. A YoY increase of Ch$50,623 million or 2.7% in customer income, mainly driven by steady growth in net fee and commissions income and, to a lesser extent, higher income from loans reflecting a proactive management of lending spreads, particularly in consumer loans, all of which enabled us to more than offset the lower contribution of Demand Deposits to our funding cost in the context of lower short- term interest rates. Lower income tax by Ch$13,251 million or 5.4%, principally driven by the impact of higher inflation on equity accounts, which is deductible from the taxable base under the Chilean Tax Law. These positive effects were partly counterbalanced by: Higher risk expenses by Ch$109,570 million or 41.2% YoY, mainly due to the impact of additional allowances established in May 2026 to proactively address potential asset quality deterioration and increased uncertainty from both the external and domestic front. When excluding this effect, the YoY increase in CLE was largely attributable to higher risk expenses in the Retail Banking Segment, driven by delinquency levels that have increased from still lower-than-normal figures seen last year. A YoY rise of Ch$34,512 million or 4.1% in operating expenses. This change was primarily caused by increased personnel expenses related to salary inflation adjustments and the recognition of part of the collective bargaining process completed in the 3Q26, together with higher administrative expenses, particularly IT-related expenditures aimed at enhancing our digital capabilities. Year-to-Date Net Income for the Period (In millions of Ch$) 926,725 50,623 100,412 (109,570) (34,512) 13,251 946,929 Sep-25 Sep-26 Non-Customer Income Income Tax Customer Income Credit Loss Expense Operating Expenses 2.2%
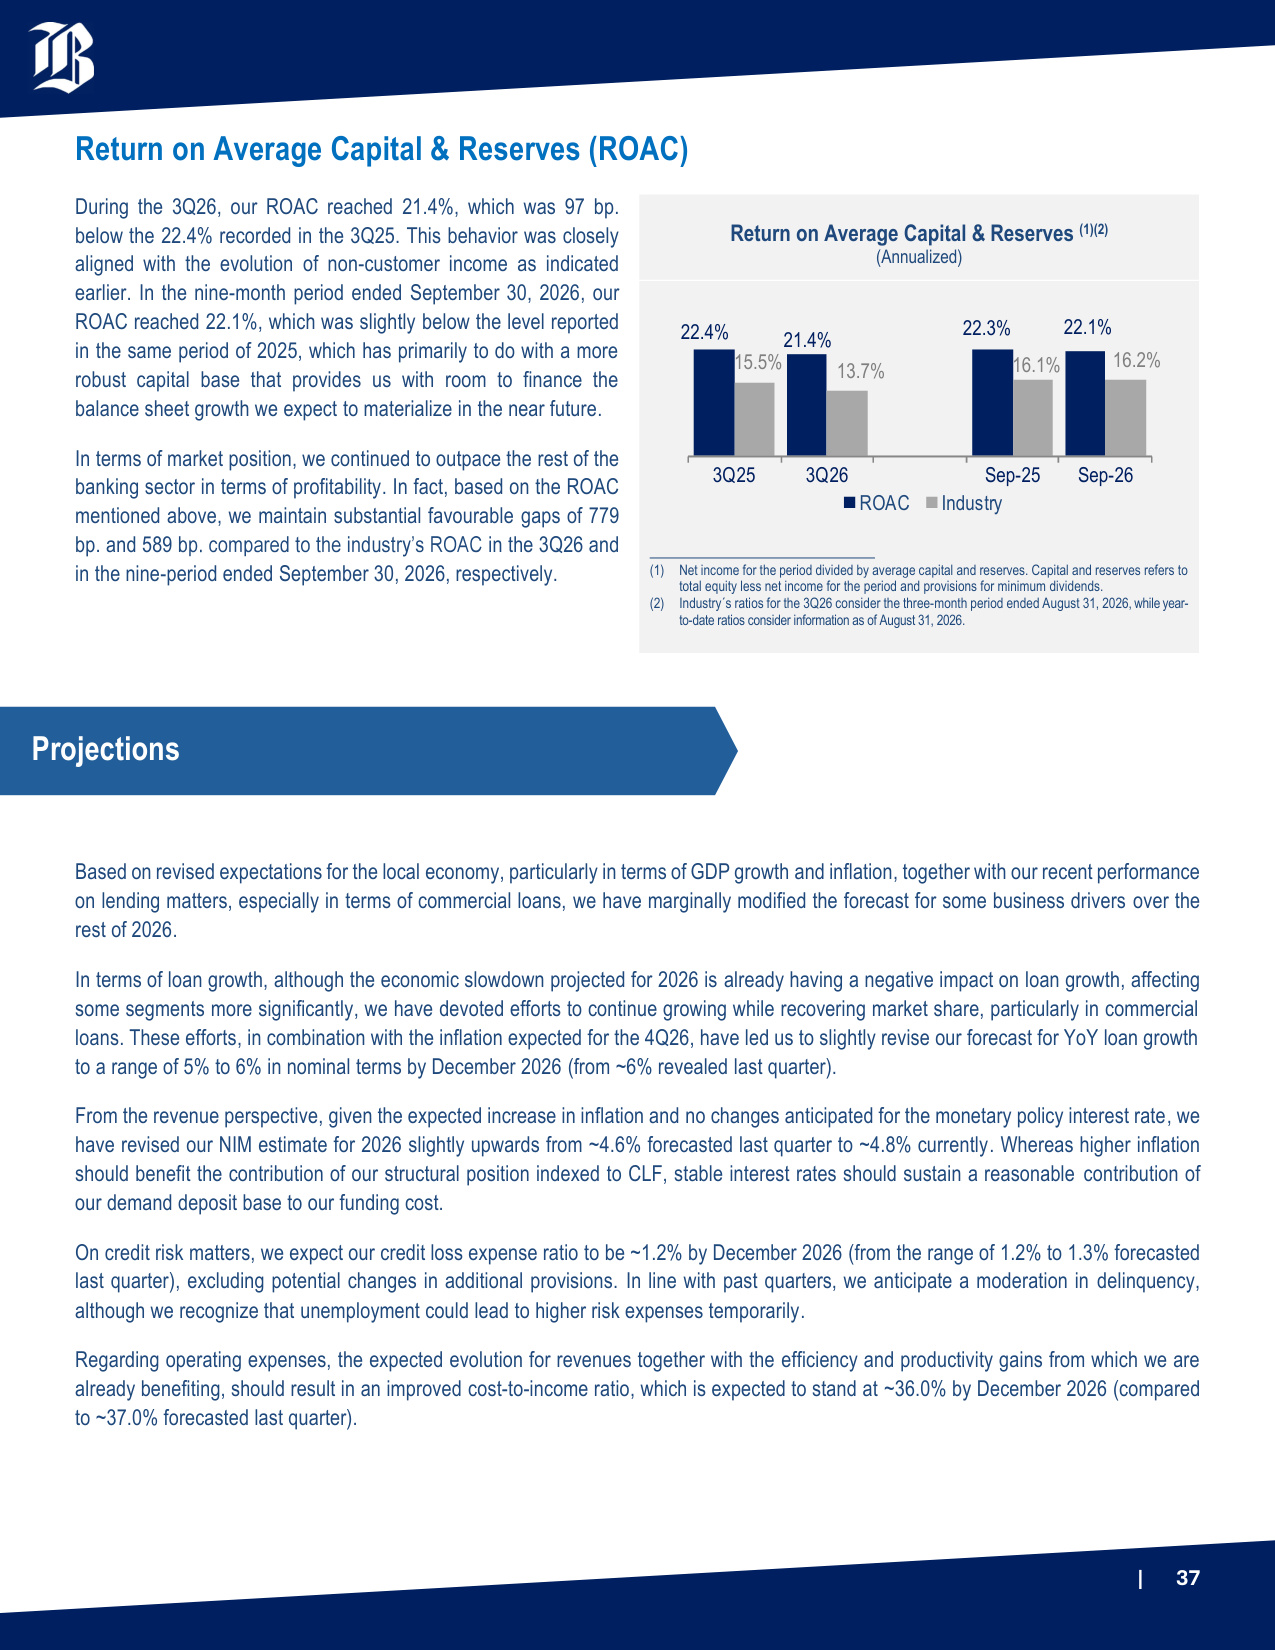
| 37 Return on Average Capital & Reserves (ROAC) During the 3Q26, our ROAC reached 21.4%, which was 97 bp. below the 22.4% recorded in the 3Q25. This behavior was closely aligned with the evolution of non-customer income as indicated earlier. In the nine-month period ended September 30, 2026, our ROAC reached 22.1%, which was slightly below the level reported in the same period of 2025, which has primarily to do with a more robust capital base that provides us with room to finance the balance sheet growth we expect to materialize in the near future. In terms of market position, we continued to outpace the rest of the banking sector in terms of profitability. In fact, based on the ROAC mentioned above, we maintain substantial favourable gaps of 779 bp. and 589 in the 3Q26 and in the nine-period ended September 30, 2026, respectively. Based on revised expectations for the local economy, particularly in terms of GDP growth and inflation, together with our recent performance on lending matters, especially in terms of commercial loans, we have marginally modified the forecast for some business drivers over the rest of 2026. In terms of loan growth, although the economic slowdown projected for 2026 is already having a negative impact on loan growth, affecting some segments more significantly, we have devoted efforts to continue growing while recovering market share, particularly in commercial loans. These efforts, in combination with the inflation expected for the 4Q26, have led us to slightly revise our forecast for YoY loan growth to a range of 5% to 6% in nominal terms by December 2026 (from ~6% revealed last quarter). From the revenue perspective, given the expected increase in inflation and no changes anticipated for the monetary policy interest rate, we have revised our NIM estimate for 2026 slightly upwards from ~4.6% forecasted last quarter to ~4.8% currently. Whereas higher inflation should benefit the contribution of our structural position indexed to CLF, stable interest rates should sustain a reasonable contribution of our demand deposit base to our funding cost. On credit risk matters, we expect our credit loss expense ratio to be ~1.2% by December 2026 (from the range of 1.2% to 1.3% forecasted last quarter), excluding potential changes in additional provisions. In line with past quarters, we anticipate a moderation in delinquency, although we recognize that unemployment could lead to higher risk expenses temporarily. Regarding operating expenses, the expected evolution for revenues together with the efficiency and productivity gains from which we are already benefiting, should result in an improved cost-to-income ratio, which is expected to stand at ~36.0% by December 2026 (compared to ~37.0% forecasted last quarter). Return on Average Capital & Reserves (1)(2) (Annualized) 22.4% 21.4% 22.3% 22.1% 15.5% 13.7% 16.1% 16.2% 3Q25 3Q26 Sep-25 Sep-26 ROAC Industry (1) Net income for the period divided by average capital and reserves. Capital and reserves refers to total equity less net income for the period and provisions for minimum dividends. (2) Industry´s ratios for the 3Q26 consider the three-month period ended August 31, 2026, while year- to-date ratios consider information as of August 31, 2026. Projections
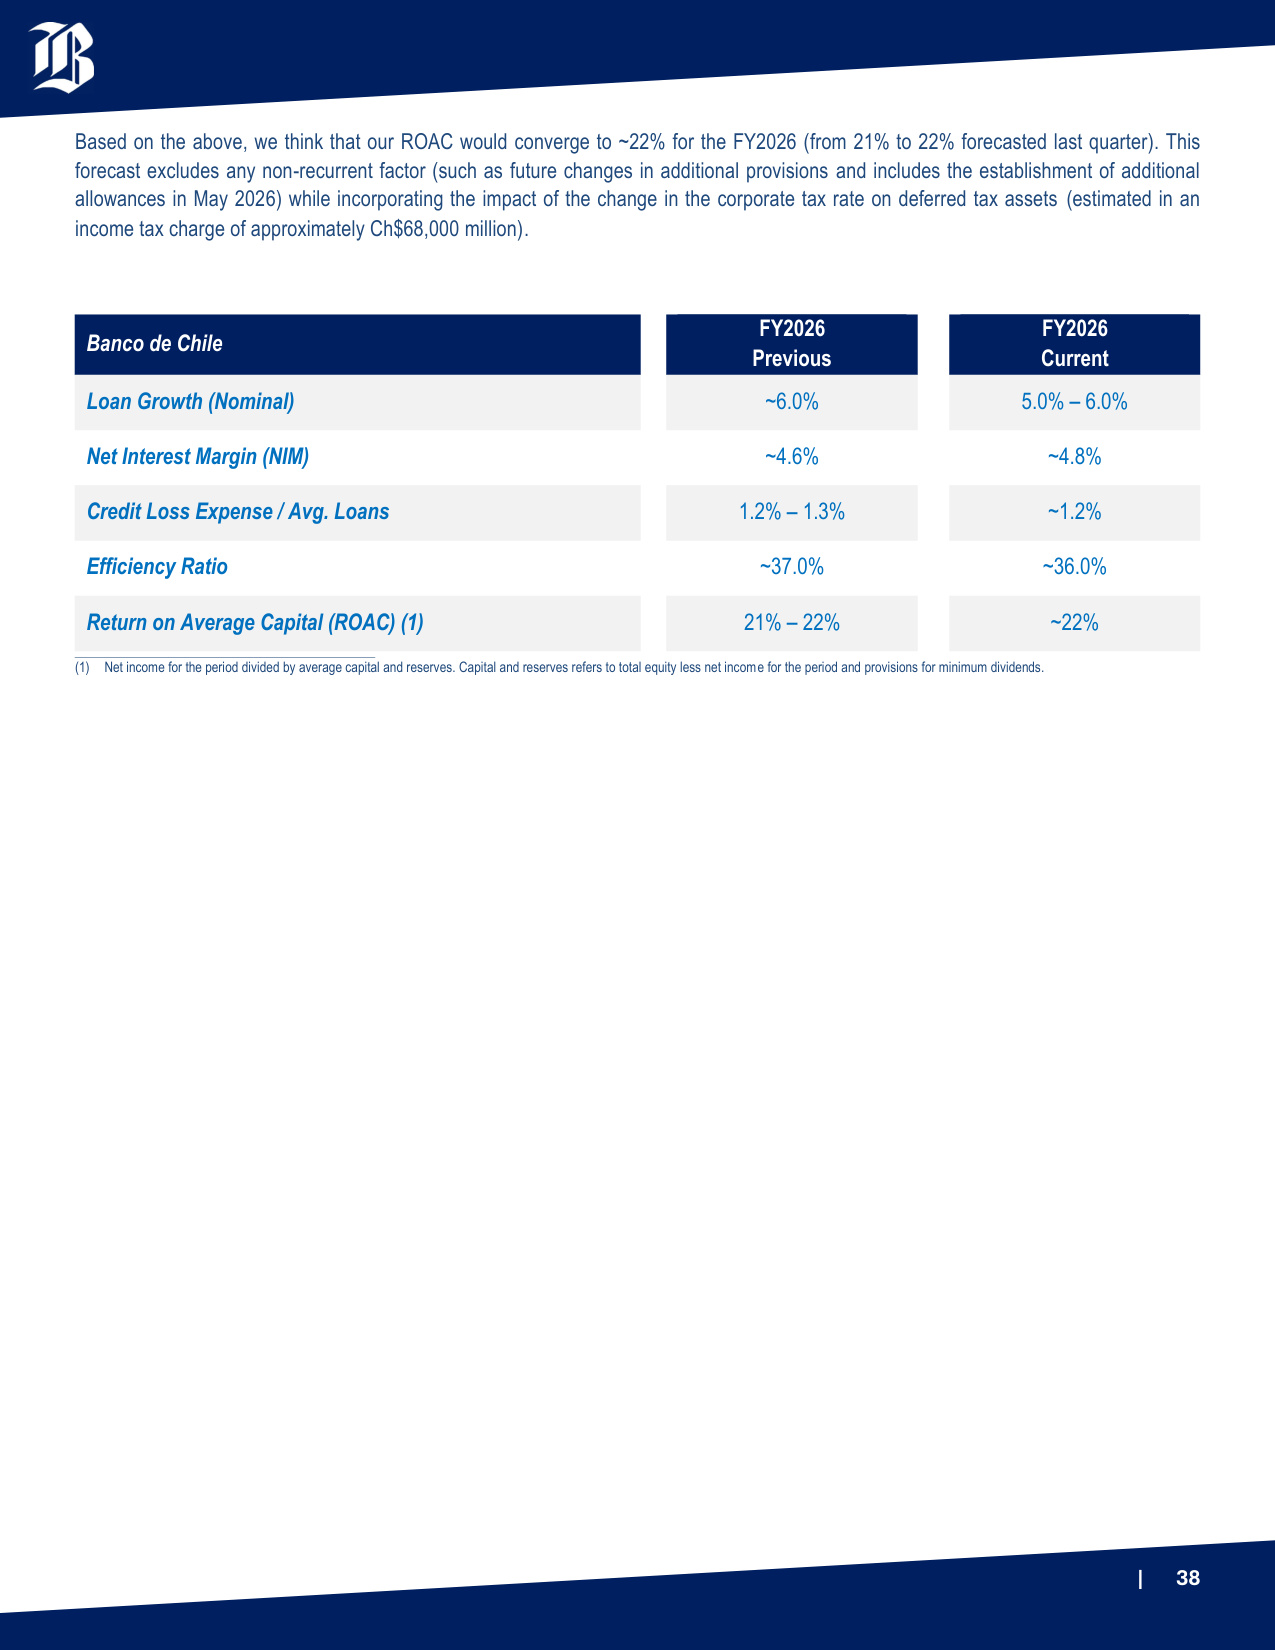
| 38 Based on the above, we think that our ROAC would converge to ~22% for the FY2026 (from 21% to 22% forecasted last quarter). This forecast excludes any non-recurrent factor (such as future changes in additional provisions and includes the establishment of additional allowances in May 2026) while incorporating the impact of the change in the corporate tax rate on deferred tax assets (estimated in an income tax charge of approximately Ch$68,000 million). Banco de Chile FY2026 Previous FY2026 Current Loan Growth (Nominal) ~6.0% 5.0% 6.0% Net Interest Margin (NIM) ~4.6% ~4.8% Credit Loss Expense / Avg. Loans 1.2% 1.3% ~1.2% Efficiency Ratio ~37.0% ~36.0% Return on Average Capital (ROAC) (1) 21% 22% ~22% (1) Net income for the period divided by average capital and reserves. Capital and reserves refers to total equity less net income for the period and provisions for minimum dividends.
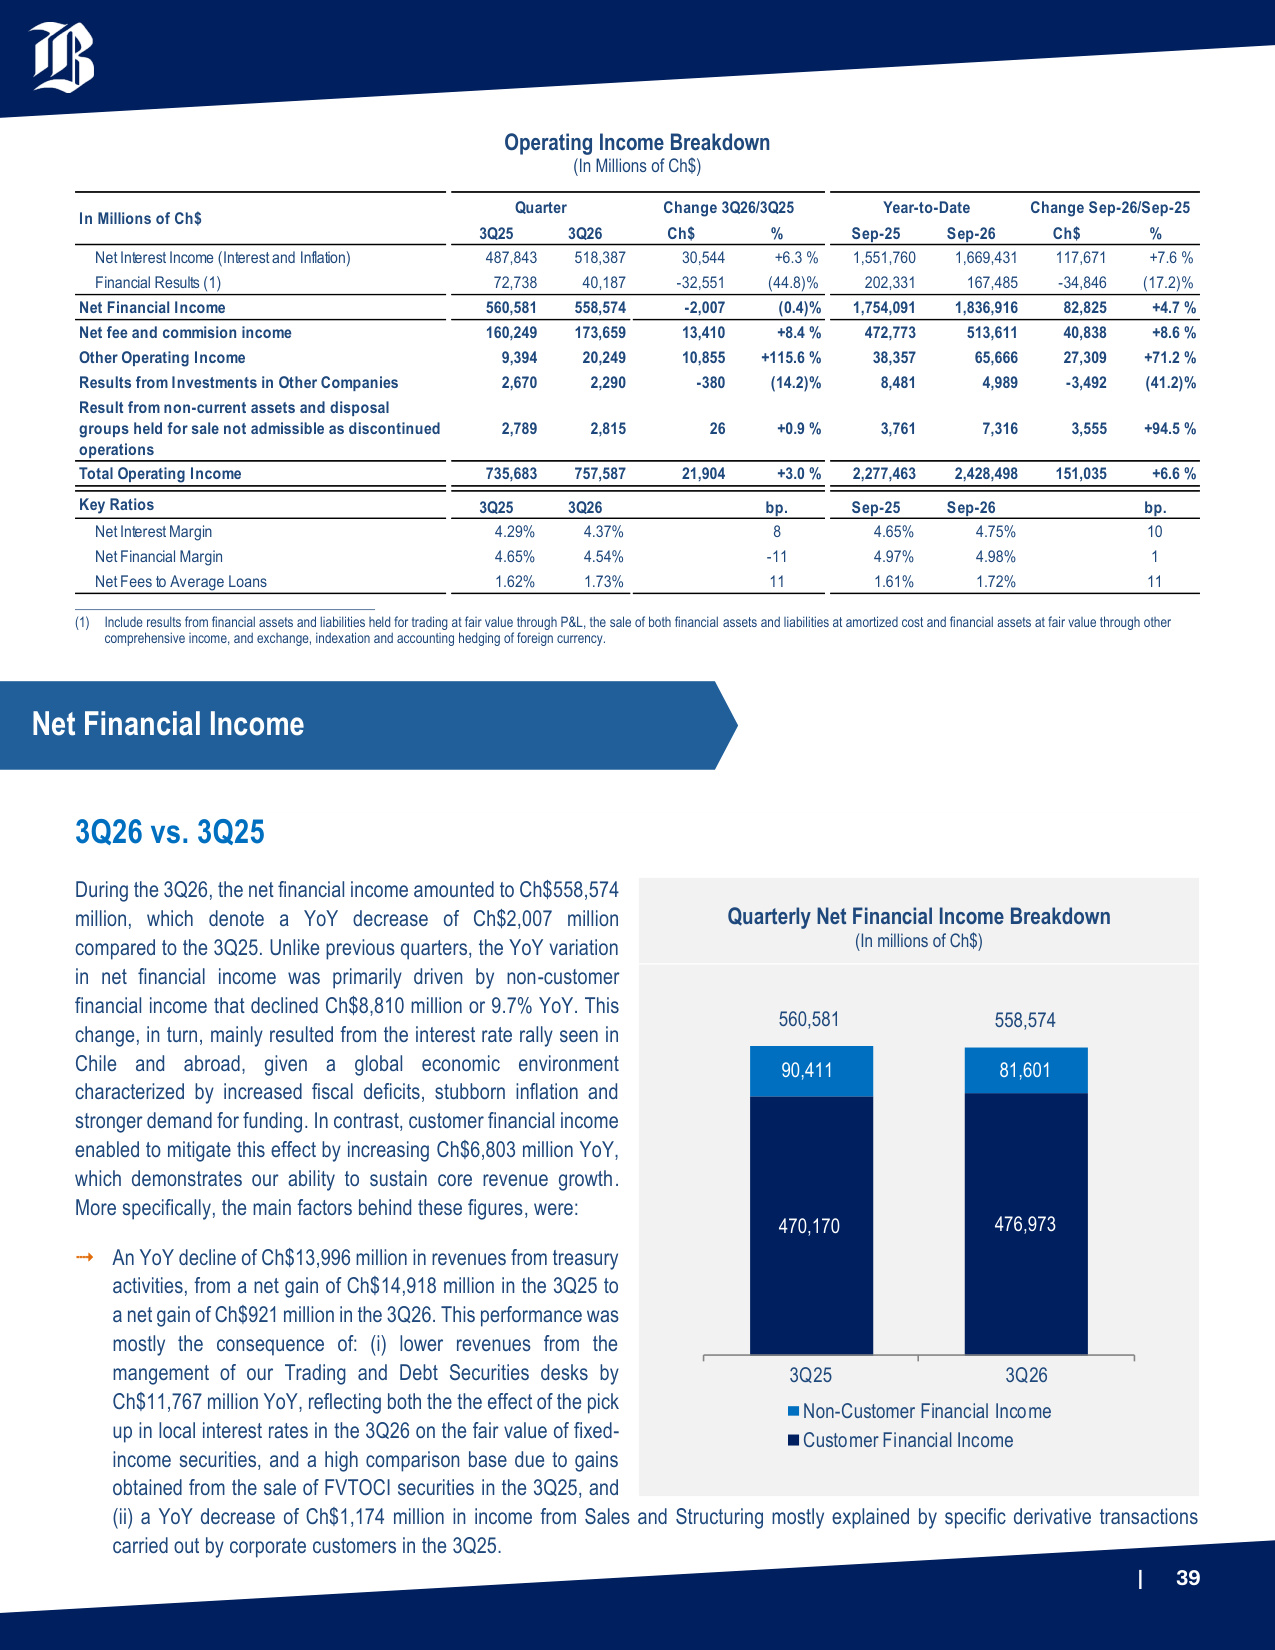
| 39 Operating Income Breakdown (In Millions of Ch$) 3Q25 3Q26 Ch$ % Sep-25 Sep-26 Ch$ % Net Interest Income (Interest and Inflation) 487,843 518,387 30,544 +6.3 % 1,551,760 1,669,431 117,671 +7.6 % Financial Results (1) 72,738 40,187 -32,551 (44.8)% 202,331 167,485 -34,846 (17.2)% Net Financial Income 560,581 558,574 -2,007 (0.4)% 1,754,091 1,836,916 82,825 +4.7 % Net fee and commision income 160,249 173,659 13,410 +8.4 % 472,773 513,611 40,838 +8.6 % Other Operating Income 9,394 20,249 10,855 +115.6 % 38,357 65,666 27,309 +71.2 % Results from Investments in Other Companies 2,670 2,290 -380 (14.2)% 8,481 4,989 -3,492 (41.2)% Result from non-current assets and disposal groups held for sale not admissible as discontinued operations 2,789 2,815 26 +0.9 % 3,761 7,316 3,555 +94.5 % Total Operating Income 735,683 757,587 21,904 +3.0 % 2,277,463 2,428,498 151,035 +6.6 % Key Ratios 3Q25 3Q26 bp. Sep-25 Sep-26 bp. Net Interest Margin 4.29% 4.37% 8 4.65% 4.75% 10 Net Financial Margin 4.65% 4.54% -11 4.97% 4.98% 1 Net Fees to Average Loans 1.62% 1.73% 11 1.61% 1.72% 11 Change Sep-26/Sep-25 In Millions of Ch$ Change 3Q26/3Q25 Year-to-Date Quarter (1) Include results from financial assets and liabilities held for trading at fair value through P&L, the sale of both financial assets and liabilities at amortized cost and financial assets at fair value through other comprehensive income, and exchange, indexation and accounting hedging of foreign currency. 3Q26 vs. 3Q25 During the 3Q26, the net financial income amounted to Ch$558,574 million, which denote a YoY decrease of Ch$2,007 million compared to the 3Q25. Unlike previous quarters, the YoY variation in net financial income was primarily driven by non-customer financial income that declined Ch$8,810 million or 9.7% YoY. This change, in turn, mainly resulted from the interest rate rally seen in Chile and abroad, given a global economic environment characterized by increased fiscal deficits, stubborn inflation and stronger demand for funding. In contrast, customer financial income enabled to mitigate this effect by increasing Ch$6,803 million YoY, which demonstrates our ability to sustain core revenue growth. More specifically, the main factors behind these figures, were: An YoY decline of Ch$13,996 million in revenues from treasury activities, from a net gain of Ch$14,918 million in the 3Q25 to a net gain of Ch$921 million in the 3Q26. This performance was mostly the consequence of: (i) lower revenues from the mangement of our Trading and Debt Securities desks by Ch$11,767 million YoY, reflecting both the the effect of the pick up in local interest rates in the 3Q26 on the fair value of fixed- income securities, and a high comparison base due to gains obtained from the sale of FVTOCI securities in the 3Q25, and (ii) a YoY decrease of Ch$1,174 million in income from Sales and Structuring mostly explained by specific derivative transactions carried out by corporate customers in the 3Q25. Quarterly Net Financial Income Breakdown (In millions of Ch$) 470,170 476,973 90,411 81,601 560,581 558,574 3Q25 3Q26 Non-Customer Financial Income Customer Financial Income Net Financial Income
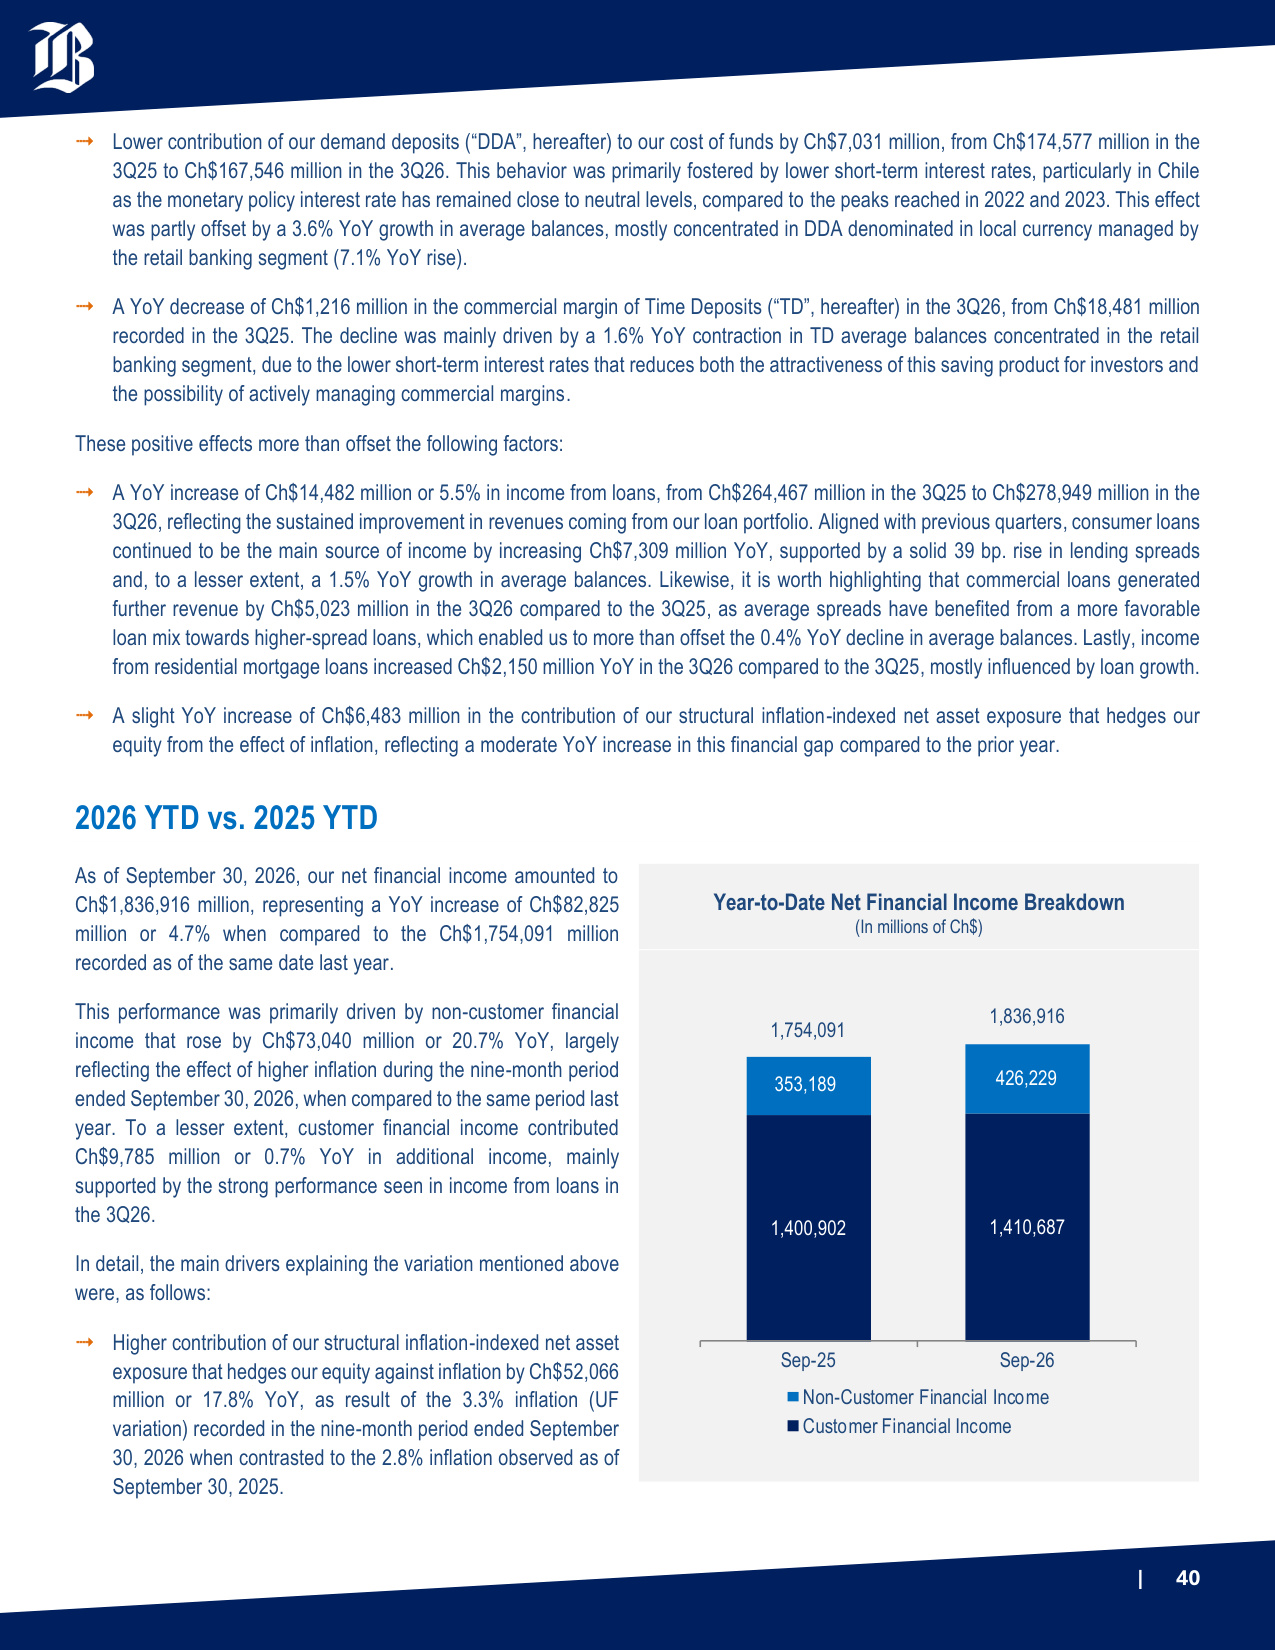
| 40 Lower contribution of our demand deposits ("DDA", hereafter) to our cost of funds by Ch$7,031 million, from Ch$174,577 million in the 3Q25 to Ch$167,546 million in the 3Q26. This behavior was primarily fostered by lower short-term interest rates, particularly in Chile as the monetary policy interest rate has remained close to neutral levels, compared to the peaks reached in 2022 and 2023. This effect was partly offset by a 3.6% YoY growth in average balances, mostly concentrated in DDA denominated in local currency managed by the retail banking segment (7.1% YoY rise). A YoY decrease of Ch$1,216 million in the commercial margin of Time Deposits ("TD", hereafter) in the 3Q26, from Ch$18,481 million recorded in the 3Q25. The decline was mainly driven by a 1.6% YoY contraction in TD average balances concentrated in the retail banking segment, due to the lower short-term interest rates that reduces both the attractiveness of this saving product for investors and the possibility of actively managing commercial margins. These positive effects more than offset the following factors: A YoY increase of Ch$14,482 million or 5.5% in income from loans, from Ch$264,467 million in the 3Q25 to Ch$278,949 million in the 3Q26, reflecting the sustained improvement in revenues coming from our loan portfolio. Aligned with previous quarters, consumer loans continued to be the main source of income by increasing Ch$7,309 million YoY, supported by a solid 39 bp. rise in lending spreads and, to a lesser extent, a 1.5% YoY growth in average balances. Likewise, it is worth highlighting that commercial loans generated further revenue by Ch$5,023 million in the 3Q26 compared to the 3Q25, as average spreads have benefited from a more favorable loan mix towards higher-spread loans, which enabled us to more than offset the 0.4% YoY decline in average balances. Lastly, income from residential mortgage loans increased Ch$2,150 million YoY in the 3Q26 compared to the 3Q25, mostly influenced by loan growth. A slight YoY increase of Ch$6,483 million in the contribution of our structural inflation-indexed net asset exposure that hedges our equity from the effect of inflation, reflecting a moderate YoY increase in this financial gap compared to the prior year. 2026 YTD vs. 2025 YTD As of September 30, 2026, our net financial income amounted to Ch$1,836,916 million, representing a YoY increase of Ch$82,825 million or 4.7% when compared to the Ch$1,754,091 million recorded as of the same date last year. This performance was primarily driven by non-customer financial income that rose by Ch$73,040 million or 20.7% YoY, largely reflecting the effect of higher inflation during the nine-month period ended September 30, 2026, when compared to the same period last year. To a lesser extent, customer financial income contributed Ch$9,785 million or 0.7% YoY in additional income, mainly supported by the strong performance seen in income from loans in the 3Q26. In detail, the main drivers explaining the variation mentioned above were, as follows: Higher contribution of our structural inflation-indexed net asset exposure that hedges our equity against inflation by Ch$52,066 million or 17.8% YoY, as result of the 3.3% inflation (UF variation) recorded in the nine-month period ended September 30, 2026 when contrasted to the 2.8% inflation observed as of September 30, 2025. Year-to-Date Net Financial Income Breakdown (In millions of Ch$) 1,400,902 1,410,687 353,189 426,229 1,754,091 1,836,916 Sep-25 Sep-26 Non-Customer Financial Income Customer Financial Income
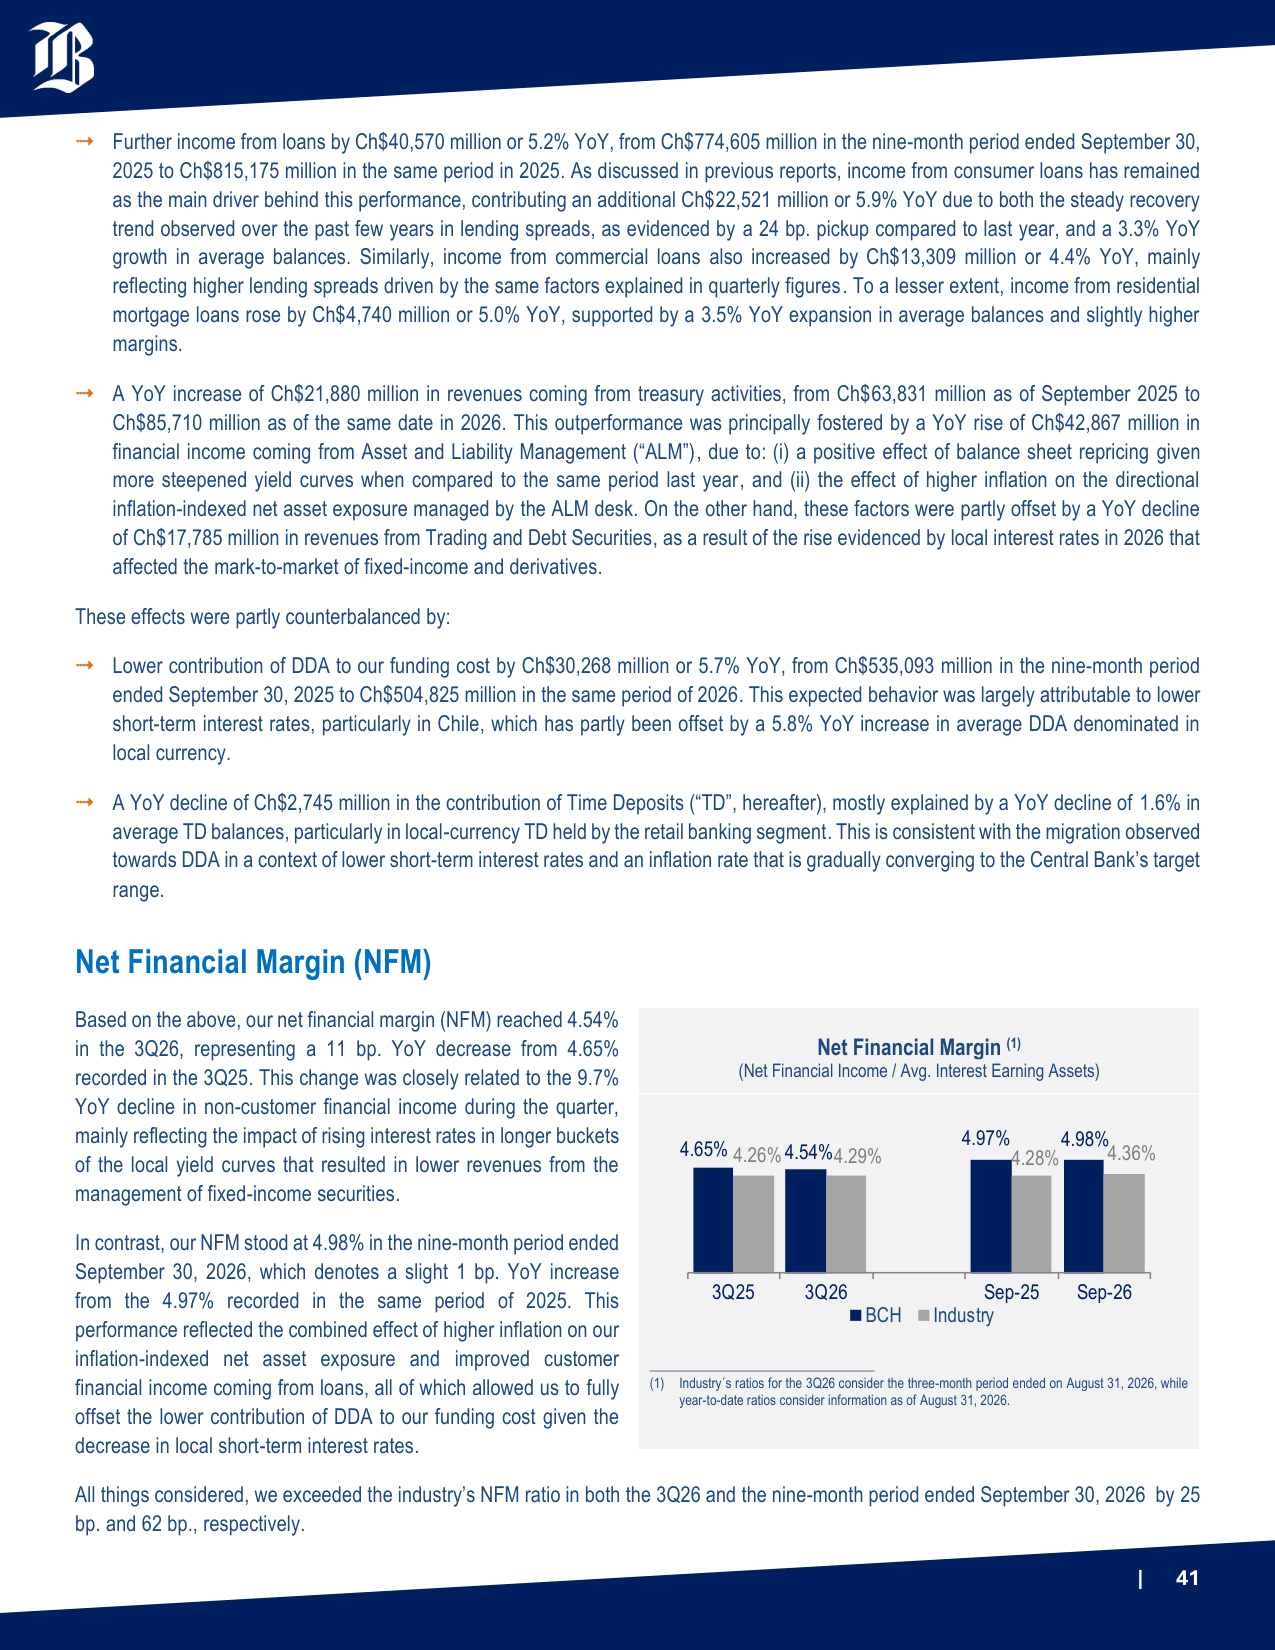
| 41 Further income from loans by Ch$40,570 million or 5.2% YoY, from Ch$774,605 million in the nine-month period ended September 30, 2025 to Ch$815,175 million in the same period in 2025. As discussed in previous reports, income from consumer loans has remained as the main driver behind this performance, contributing an additional Ch$22,521 million or 5.9% YoY due to both the steady recovery trend observed over the past few years in lending spreads, as evidenced by a 24 bp. pickup compared to last year, and a 3.3% YoY growth in average balances. Similarly, income from commercial loans also increased by Ch$13,309 million or 4.4% YoY, mainly reflecting higher lending spreads driven by the same factors explained in quarterly figures. To a lesser extent, income from residential mortgage loans rose by Ch$4,740 million or 5.0% YoY, supported by a 3.5% YoY expansion in average balances and slightly higher margins. A YoY increase of Ch$21,880 million in revenues coming from treasury activities, from Ch$63,831 million as of September 2025 to Ch$85,710 million as of the same date in 2026. This outperformance was principally fostered by a YoY rise of Ch$42,867 million in financial income coming from Asset and Liability Management ("ALM"), due to: (i) a positive effect of balance sheet repricing given more steepened yield curves when compared to the same period last year, and (ii) the effect of higher inflation on the directional inflation-indexed net asset exposure managed by the ALM desk. On the other hand, these factors were partly offset by a YoY decline of Ch$17,785 million in revenues from Trading and Debt Securities, as a result of the rise evidenced by local interest rates in 2026 that affected the mark-to-market of fixed-income and derivatives. These effects were partly counterbalanced by: Lower contribution of DDA to our funding cost by Ch$30,268 million or 5.7% YoY, from Ch$535,093 million in the nine-month period ended September 30, 2025 to Ch$504,825 million in the same period of 2026. This expected behavior was largely attributable to lower short-term interest rates, particularly in Chile, which has partly been offset by a 5.8% YoY increase in average DDA denominated in local currency. A YoY decline of Ch$2,745 million in the contribution of Time Deposits ("TD", hereafter), mostly explained by a YoY decline of 1.6% in average TD balances, particularly in local-currency TD held by the retail banking segment. This is consistent with the migration observed towards DDA in a context of lower short-term interest rates and an inflation rate that is gradually converging to the Central Bank's target range. Net Financial Margin (NFM) Based on the above, our net financial margin (NFM) reached 4.54% in the 3Q26, representing a 11 bp. YoY decrease from 4.65% recorded in the 3Q25. This change was closely related to the 9.7% YoY decline in non-customer financial income during the quarter, mainly reflecting the impact of rising interest rates in longer buckets of the local yield curves that resulted in lower revenues from the management of fixed-income securities. In contrast, our NFM stood at 4.98% in the nine-month period ended September 30, 2026, which denotes a slight 1 bp. YoY increase from the 4.97% recorded in the same period of 2025. This performance reflected the combined effect of higher inflation on our inflation-indexed net asset exposure and improved customer financial income coming from loans, all of which allowed us to fully offset the lower contribution of DDA to our funding cost given the decrease in local short-term interest rates. All things considered, we exceeded the industry's NFM ratio in both the 3Q26 and the nine-month period ended September 30, 2026 by 25 bp. and 62 bp., respectively. Net Financial Margin (1) (Net Financial Income / Avg. Interest Earning Assets) 4.65% 4.54% 4.97% 4.98% 4.26% 4.29% 4.28% 4.36% 3Q25 3Q26 Sep-25 Sep-26 BCH Industry (1) Industry´s ratios for the 3Q26 consider the three-month period ended on August 31, 2026, while year-to-date ratios consider information as of August 31, 2026.
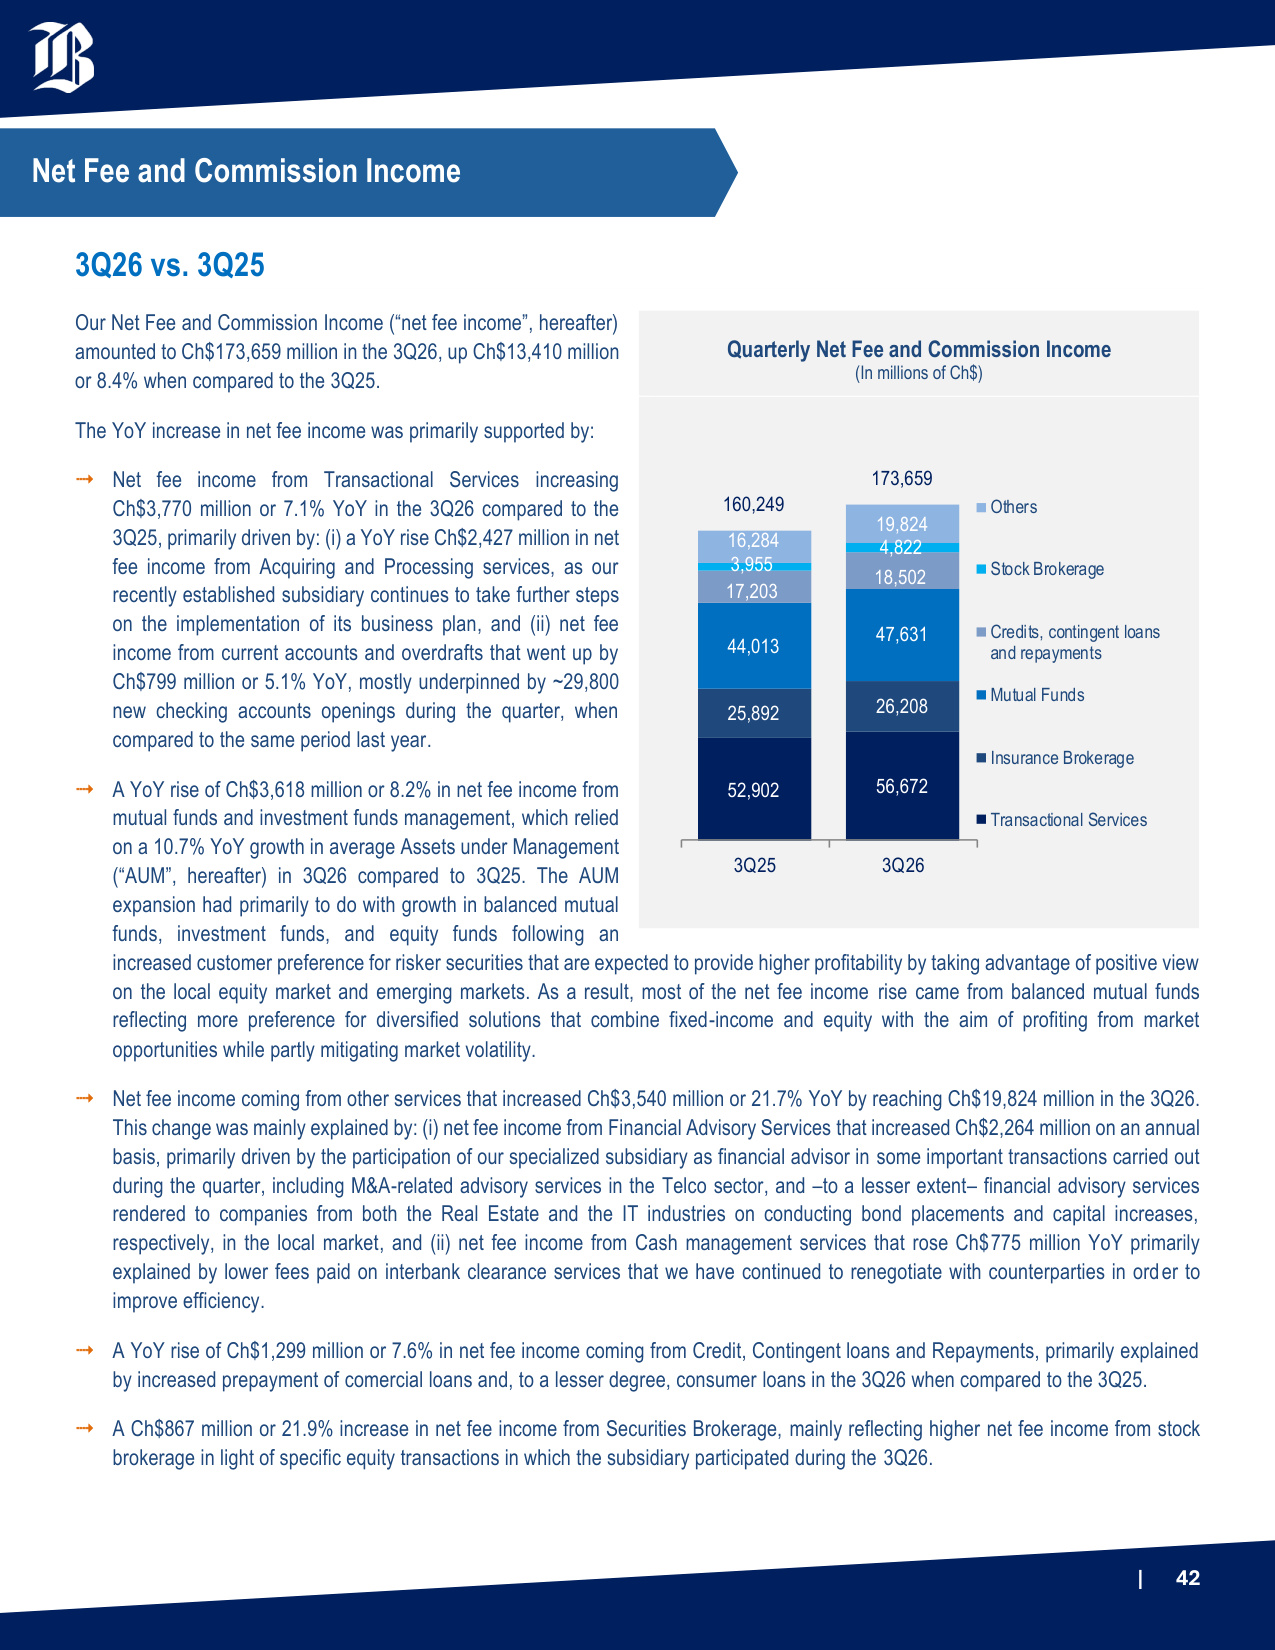
| 42 3Q26 vs. 3Q25 Our Net Fee and Commission Income ("net fee income", hereafter) amounted to Ch$173,659 million in the 3Q26, up Ch$13,410 million or 8.4% when compared to the 3Q25. The YoY increase in net fee income was primarily supported by: Net fee income from Transactional Services increasing Ch$3,770 million or 7.1% YoY in the 3Q26 compared to the 3Q25, primarily driven by: (i) a YoY rise Ch$2,427 million in net fee income from Acquiring and Processing services, as our recently established subsidiary continues to take further steps on the implementation of its business plan, and (ii) net fee income from current accounts and overdrafts that went up by Ch$799 million or 5.1% YoY, mostly underpinned by ~29,800 new checking accounts openings during the quarter, when compared to the same period last year. A YoY rise of Ch$3,618 million or 8.2% in net fee income from mutual funds and investment funds management, which relied on a 10.7% YoY growth in average Assets under Management ("AUM", hereafter) in 3Q26 compared to 3Q25. The AUM expansion had primarily to do with growth in balanced mutual funds, investment funds, and equity funds following an increased customer preference for risker securities that are expected to provide higher profitability by taking advantage of positive view on the local equity market and emerging markets. As a result, most of the net fee income rise came from balanced mutual funds reflecting more preference for diversified solutions that combine fixed-income and equity with the aim of profiting from market opportunities while partly mitigating market volatility. Net fee income coming from other services that increased Ch$3,540 million or 21.7% YoY by reaching Ch$19,824 million in the 3Q26. This change was mainly explained by: (i) net fee income from Financial Advisory Services that increased Ch$2,264 million on an annual basis, primarily driven by the participation of our specialized subsidiary as financial advisor in some important transactions carried out during the quarter, including M&A-related advisory services in the Telco sector, and –to a lesser extent– financial advisory services rendered to companies from both the Real Estate and the IT industries on conducting bond placements and capital increases, respectively, in the local market, and (ii) net fee income from Cash management services that rose Ch$775 million YoY primarily explained by lower fees paid on interbank clearance services that we have continued to renegotiate with counterparties in order to improve efficiency. A YoY rise of Ch$1,299 million or 7.6% in net fee income coming from Credit, Contingent loans and Repayments, primarily explained by increased prepayment of comercial loans and, to a lesser degree, consumer loans in the 3Q26 when compared to the 3Q25. A Ch$867 million or 21.9% increase in net fee income from Securities Brokerage, mainly reflecting higher net fee income from stock brokerage in light of specific equity transactions in which the subsidiary participated during the 3Q26. Quarterly Net Fee and Commission Income (In millions of Ch$) 52,902 56,672 25,892 26,208 44,013 47,631 17,203 18,502 3,955 4,822 16,284 19,824 160,249 173,659 3Q25 3Q26 Others Stock Brokerage Credits, contingent loans and repayments Mutual Funds Insurance Brokerage Transactional Services Net Fee and Commission Income
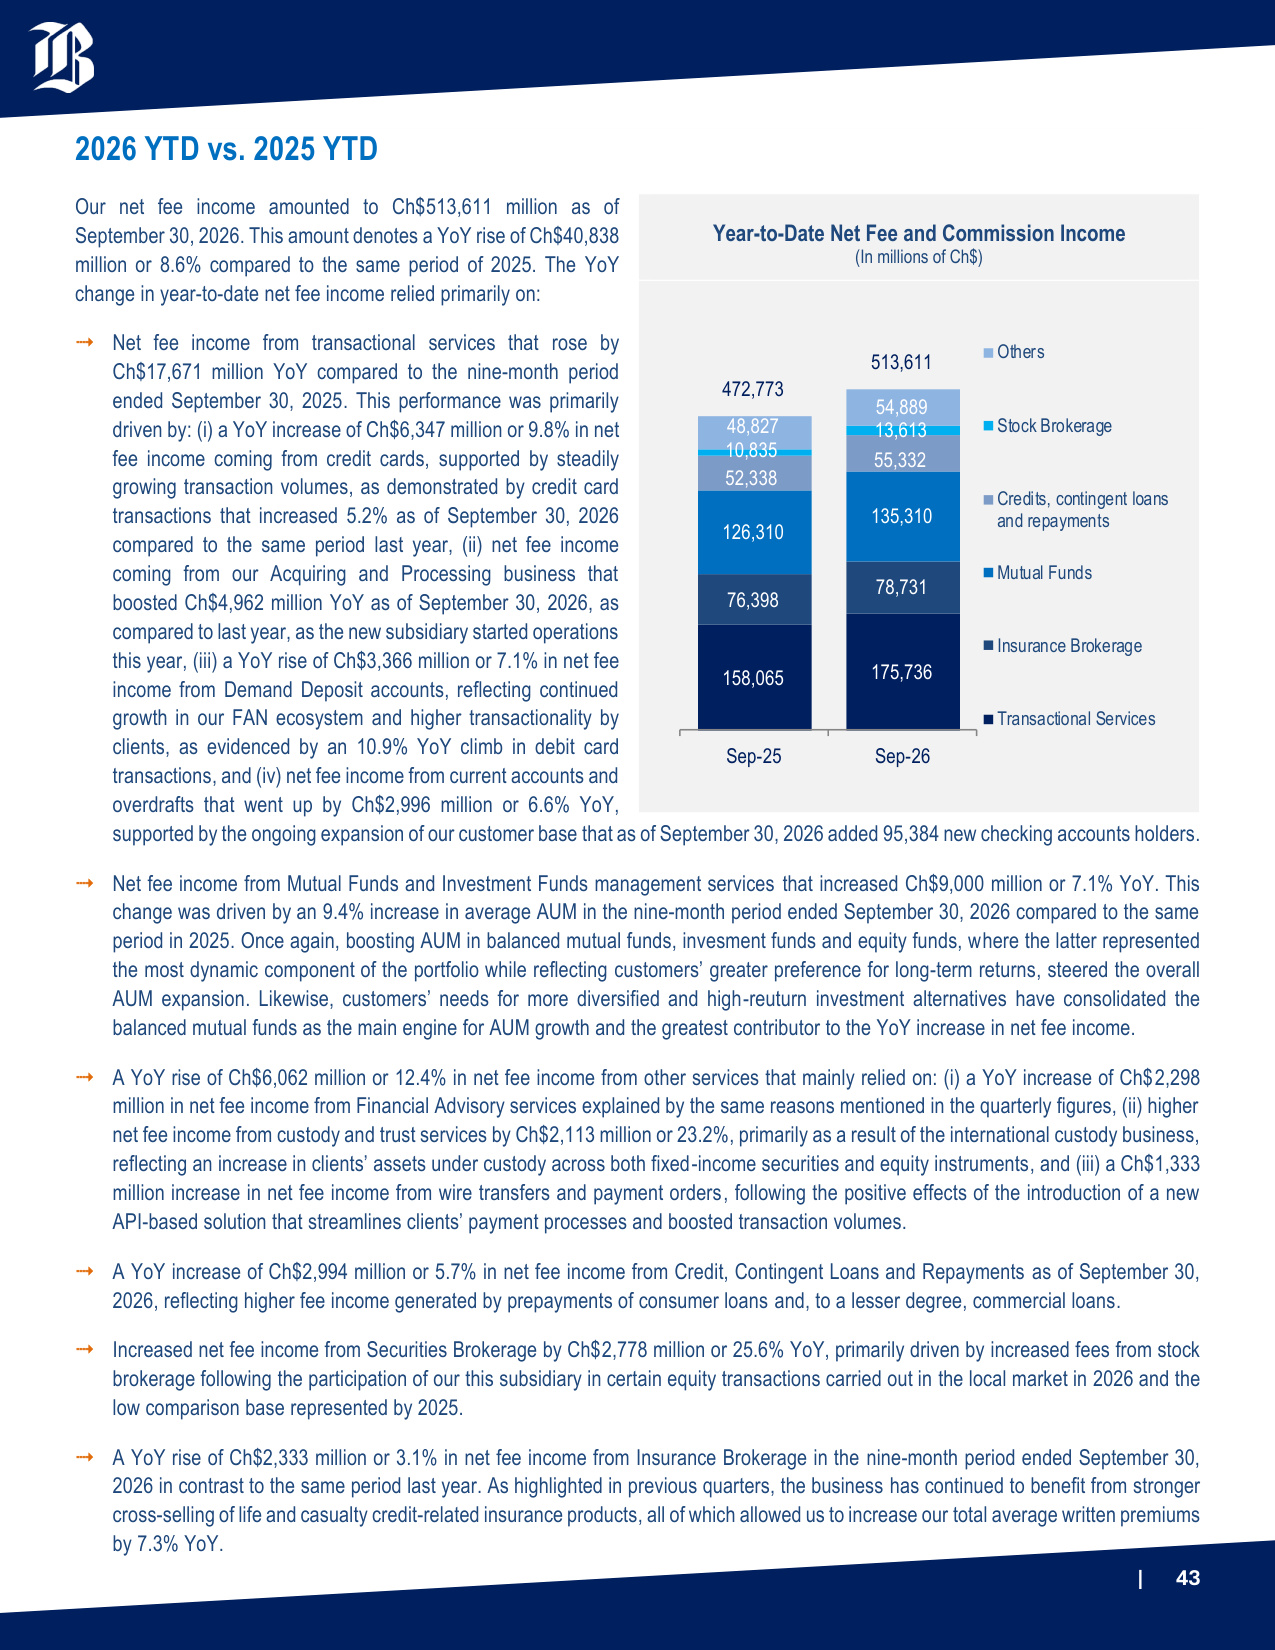
| 43 2026 YTD vs. 2025 YTD Our net fee income amounted to Ch$513,611 million as of September 30, 2026. This amount denotes a YoY rise of Ch$40,838 million or 8.6% compared to the same period of 2025. The YoY change in year-to-date net fee income relied primarily on: Net fee income from transactional services that rose by Ch$17,671 million YoY compared to the nine-month period ended September 30, 2025. This performance was primarily driven by: (i) a YoY increase of Ch$6,347 million or 9.8% in net fee income coming from credit cards, supported by steadily growing transaction volumes, as demonstrated by credit card transactions that increased 5.2% as of September 30, 2026 compared to the same period last year, (ii) net fee income coming from our Acquiring and Processing business that boosted Ch$4,962 million YoY as of September 30, 2026, as compared to last year, as the new subsidiary started operations this year, (iii) a YoY rise of Ch$3,366 million or 7.1% in net fee income from Demand Deposit accounts, reflecting continued growth in our FAN ecosystem and higher transactionality by clients, as evidenced by an 10.9% YoY climb in debit card transactions, and (iv) net fee income from current accounts and overdrafts that went up by Ch$2,996 million or 6.6% YoY, supported by the ongoing expansion of our customer base that as of September 30, 2026 added 95,384 new checking accounts holders. Net fee income from Mutual Funds and Investment Funds management services that increased Ch$9,000 million or 7.1% YoY. This change was driven by an 9.4% increase in average AUM in the nine-month period ended September 30, 2026 compared to the same period in 2025. Once again, boosting AUM in balanced mutual funds, invesment funds and equity funds, where the latter represented the most dynamic component of the portfolio while reflecting customers' greater preference for long-term returns, steered the overall AUM expansion. Likewise, customers' needs for more diversified and high-reuturn investment alternatives have consolidated the balanced mutual funds as the main engine for AUM growth and the greatest contributor to the YoY increase in net fee income. A YoY rise of Ch$6,062 million or 12.4% in net fee income from other services that mainly relied on: (i) a YoY increase of Ch$2,298 million in net fee income from Financial Advisory services explained by the same reasons mentioned in the quarterly figures, (ii) higher net fee income from custody and trust services by Ch$2,113 million or 23.2%, primarily as a result of the international custody business, reflecting an increase in clients' assets under custody across both fixed-income securities and equity instruments, and (iii) a Ch$1,333 million increase in net fee income from wire transfers and payment orders, following the positive effects of the introduction of a new API-based solution that streamlines clients' payment processes and boosted transaction volumes. A YoY increase of Ch$2,994 million or 5.7% in net fee income from Credit, Contingent Loans and Repayments as of September 30, 2026, reflecting higher fee income generated by prepayments of consumer loans and, to a lesser degree, commercial loans. Increased net fee income from Securities Brokerage by Ch$2,778 million or 25.6% YoY, primarily driven by increased fees from stock brokerage following the participation of our this subsidiary in certain equity transactions carried out in the local market in 2026 and the low comparison base represented by 2025. A YoY rise of Ch$2,333 million or 3.1% in net fee income from Insurance Brokerage in the nine-month period ended September 30, 2026 in contrast to the same period last year. As highlighted in previous quarters, the business has continued to benefit from stronger cross-selling of life and casualty credit-related insurance products, all of which allowed us to increase our total average written premiums by 7.3% YoY. Year-to-Date Net Fee and Commission Income (In millions of Ch$) 158,065 175,736 76,398 78,731 126,310 135,310 52,338 55,332 10,835 13,613 48,827 54,889 472,773 513,611 Sep-25 Sep-26 Others Stock Brokerage Credits, contingent loans and repayments Mutual Funds Insurance Brokerage Transactional Services
| 44 3Q26 vs. 3Q25 During the 3Q26, the Other Operating Income (including income from investments in other companies, result from non-current assets and disposal groups held for sale not admissible as discontinued operations and other operating income) increased Ch$10,501 million or 70.7% on a YoY basis, from the Ch$14,853 million recorded in the 3Q25 to Ch$25,354 million recorded in the 3Q26. Most of this rise had to do with YoY increase of Ch$10,855 million or 115.6% in other operating income, which in turn was primarily driven by a non-recurrent effect related to the fulfillment of contingent clauses once completed the migration of the credit card processing system, as set out in the sale of Nexus, a company that we formerly owned with other local banks and provided us with credit card processing services. 2026 YTD vs. 2025 YTD The Other Operating Income amounted to Ch$77,971 million in the nine-period ended September 30, 2026, denoting YoY growth of Ch$27,372 million or 54.1% when compared to the Ch$50,599 million recorded over the same period last year. This change was largely attributable to a YoY increase of Ch$27,309 million in other operating income, mainly due to: (i) a YoY rise of ~Ch$15,300 million associated with higher reimbursements of taxes paid in previous fiscal years recognized in 2026 when compared to 2025, and (ii) further other operating income by ~Ch$11,600 million arising from the same non-recurrent factor associated with the sale of Nexus as described above. In addition, result from non-current assets and disposal groups held for sale not admissible as discontinued operations increased by Ch$3,555 million during the year, stemming mainly from the sale of former branch locations closed in 2026 as part of our service model transformation process. These effects were partly offset by a YoY decrease of Ch$3,492 million in income from investments in other companies, from Ch$8,481 million in the nine-month period ended September 30, 2025 to Ch$4,989 million in the same period of 2026, mainly related to lower earnings from Transbank and Servipag this year. Other Operating Income
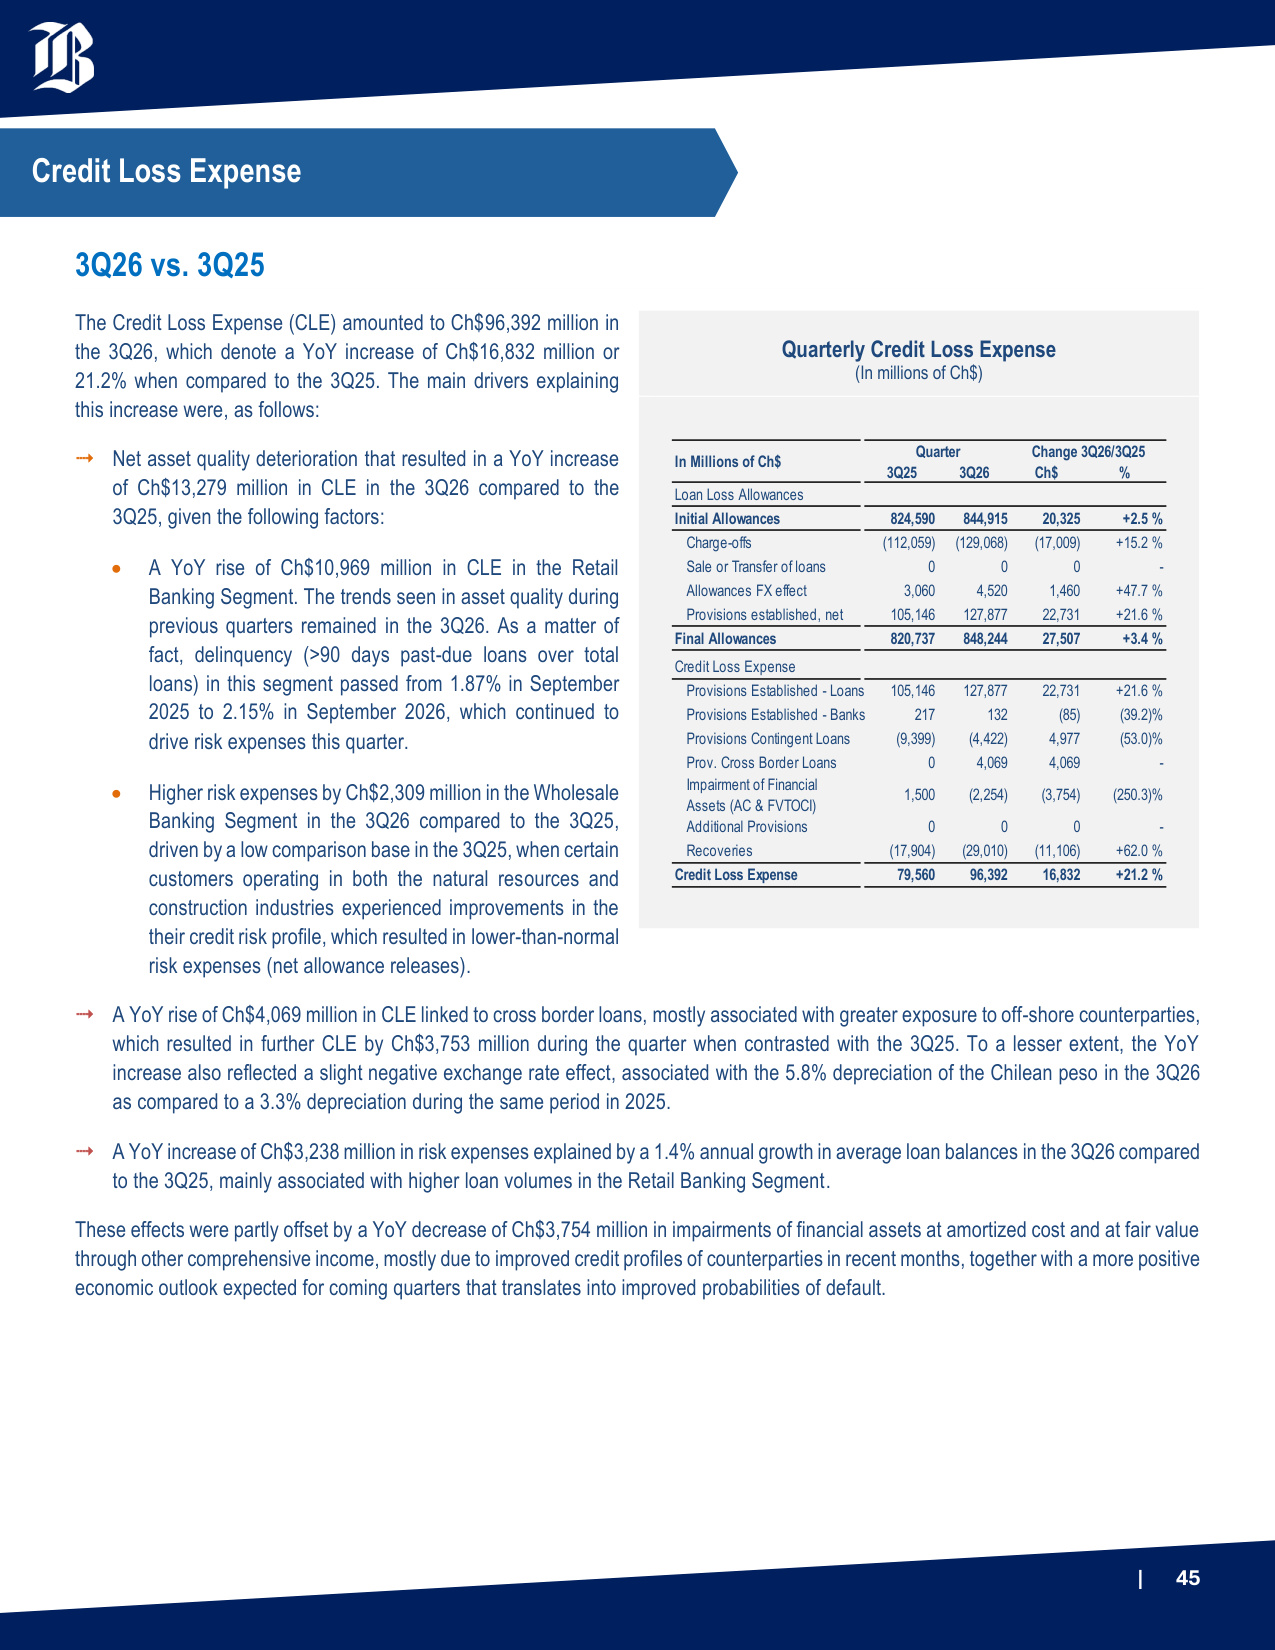
| 45 3Q26 vs. 3Q25 The Credit Loss Expense (CLE) amounted to Ch$96,392 million in the 3Q26, which denote a YoY increase of Ch$16,832 million or 21.2% when compared to the 3Q25. The main drivers explaining this increase were, as follows: Net asset quality deterioration that resulted in a YoY increase of Ch$13,279 million in CLE in the 3Q26 compared to the 3Q25, given the following factors: • A YoY rise of Ch$10,969 million in CLE in the Retail Banking Segment. The trends seen in asset quality during previous quarters remained in the 3Q26. As a matter of fact, delinquency (>90 days past-due loans over total loans) in this segment passed from 1.87% in September 2025 to 2.15% in September 2026, which continued to drive risk expenses this quarter. • Higher risk expenses by Ch$2,309 million in the Wholesale Banking Segment in the 3Q26 compared to the 3Q25, driven by a low comparison base in the 3Q25, when certain customers operating in both the natural resources and construction industries experienced improvements in the their credit risk profile, which resulted in lower-than-normal risk expenses (net allowance releases). A YoY rise of Ch$4,069 million in CLE linked to cross border loans, mostly associated with greater exposure to off-shore counterparties, which resulted in further CLE by Ch$3,753 million during the quarter when contrasted with the 3Q25. To a lesser extent, the YoY increase also reflected a slight negative exchange rate effect, associated with the 5.8% depreciation of the Chilean peso in the 3Q26 as compared to a 3.3% depreciation during the same period in 2025. A YoY increase of Ch$3,238 million in risk expenses explained by a 1.4% annual growth in average loan balances in the 3Q26 compared to the 3Q25, mainly associated with higher loan volumes in the Retail Banking Segment. These effects were partly offset by a YoY decrease of Ch$3,754 million in impairments of financial assets at amortized cost and at fair value through other comprehensive income, mostly due to improved credit profiles of counterparties in recent months, together with a more positive economic outlook expected for coming quarters that translates into improved probabilities of default. Quarterly Credit Loss Expense (In millions of Ch$) 3Q25 3Q26 Ch$ % Loan Loss Allowances Initial Allowances 824,590 844,915 20,325 +2.5 % Charge-offs (112,059) (129,068) (17,009) +15.2 % Sale or Transfer of loans 0 0 0 - Allowances FX effect 3,060 4,520 1,460 +47.7 % Provisions established, net 105,146 127,877 22,731 +21.6 % Final Allowances 820,737 848,244 27,507 +3.4 % Credit Loss Expense Provisions Established - Loans 105,146 127,877 22,731 +21.6 % Provisions Established - Banks 217 132 (85) (39.2)% Provisions Contingent Loans (9,399) (4,422) 4,977 (53.0)% Prov. Cross Border Loans 0 4,069 4,069 - Impairment of Financial Assets (AC & FVTOCI) 1,500 (2,254) (3,754) (250.3)% Additional Provisions 0 0 0 - Recoveries (17,904) (29,010) (11,106) +62.0 % Credit Loss Expense 79,560 96,392 16,832 +21.2 % In Millions of Ch$ Quarter Change 3Q26/3Q25 Credit Loss Expense
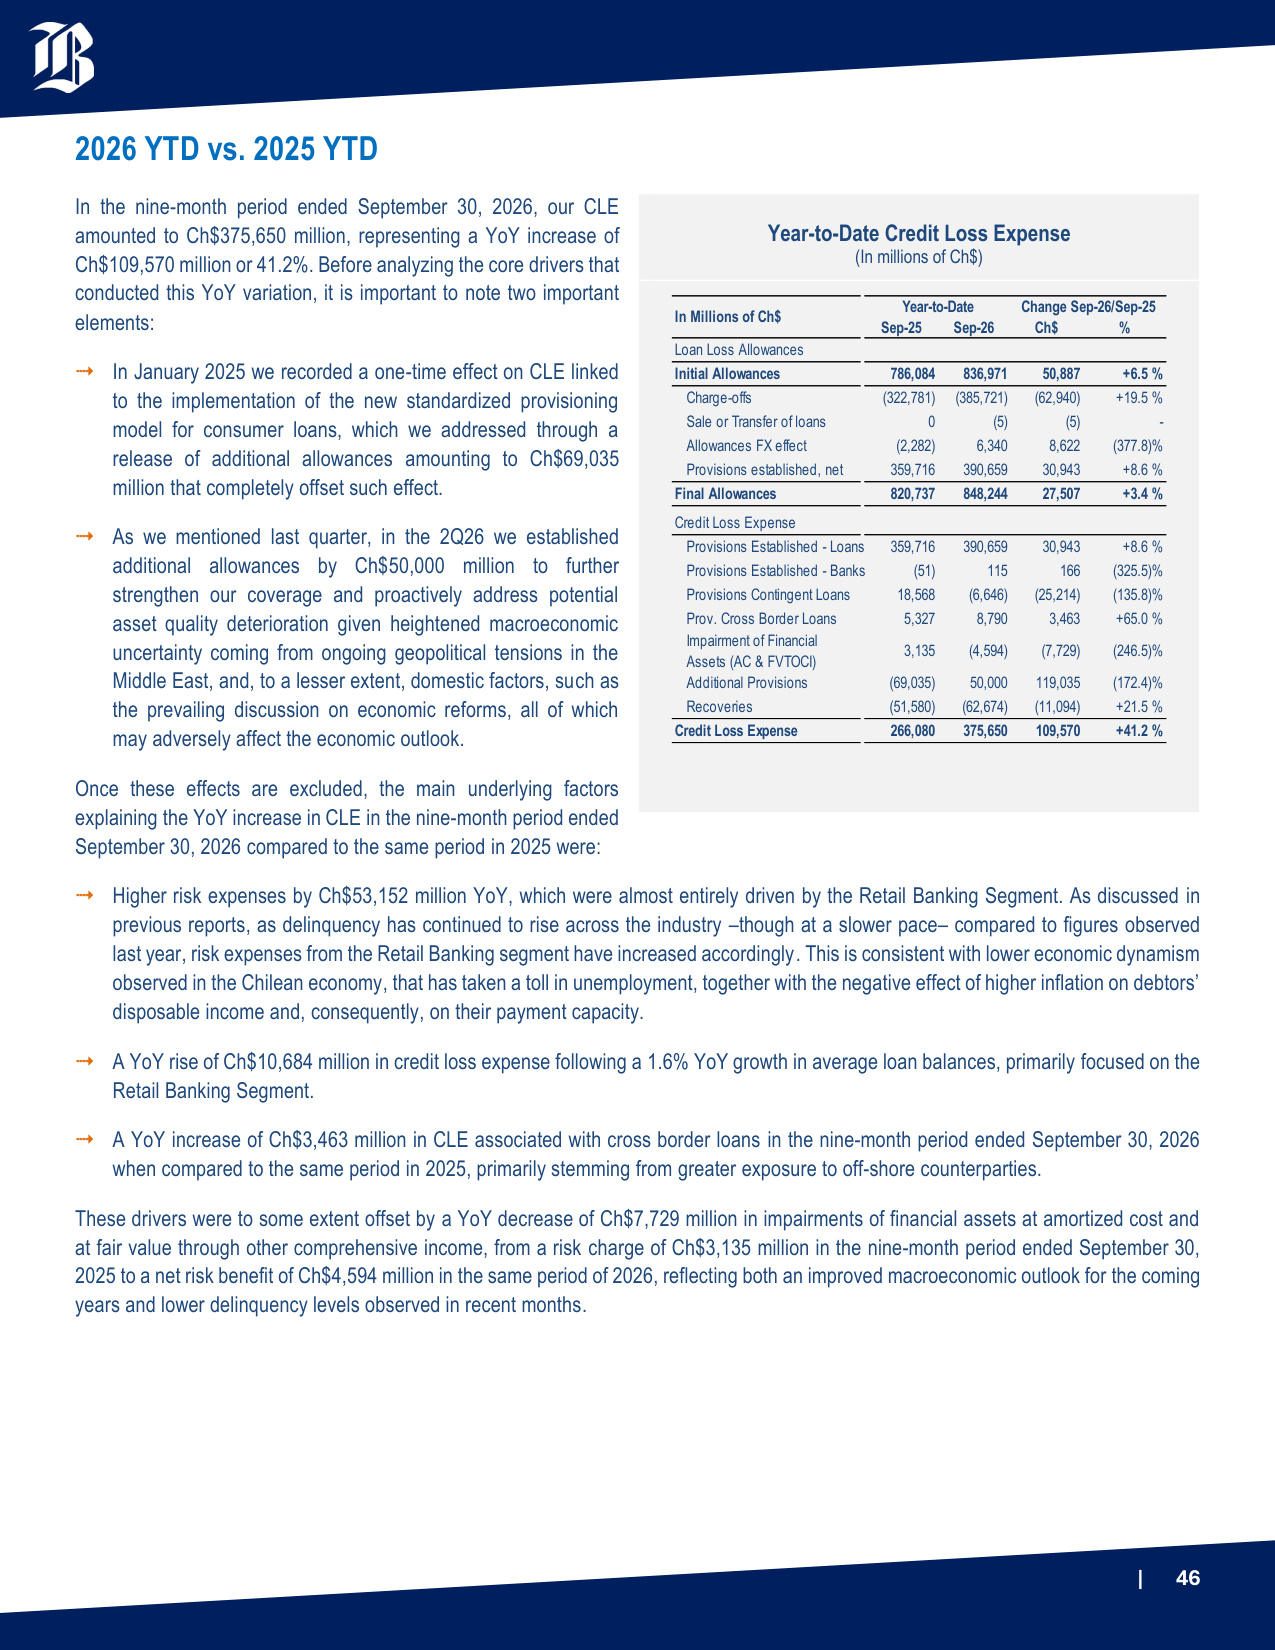
| 46 2026 YTD vs. 2025 YTD In the nine-month period ended September 30, 2026, our CLE amounted to Ch$375,650 million, representing a YoY increase of Ch$109,570 million or 41.2%. Before analyzing the core drivers that conducted this YoY variation, it is important to note two important elements: In January 2025 we recorded a one-time effect on CLE linked to the implementation of the new standardized provisioning model for consumer loans, which we addressed through a release of additional allowances amounting to Ch$69,035 million that completely offset such effect. As we mentioned last quarter, in the 2Q26 we established additional allowances by Ch$50,000 million to further strengthen our coverage and proactively address potential asset quality deterioration given heightened macroeconomic uncertainty coming from ongoing geopolitical tensions in the Middle East, and, to a lesser extent, domestic factors, such as the prevailing discussion on economic reforms, all of which may adversely affect the economic outlook. Once these effects are excluded, the main underlying factors explaining the YoY increase in CLE in the nine-month period ended September 30, 2026 compared to the same period in 2025 were: Higher risk expenses by Ch$53,152 million YoY, which were almost entirely driven by the Retail Banking Segment. As discussed in previous reports, as delinquency has continued to rise across the industry –though at a slower pace– compared to figures observed last year, risk expenses from the Retail Banking segment have increased accordingly. This is consistent with lower economic dynamism observed in the Chilean economy, that has taken a toll in unemployment, together with the negative effect of higher inflation on debtors' disposable income and, consequently, on their payment capacity. A YoY rise of Ch$10,684 million in credit loss expense following a 1.6% YoY growth in average loan balances, primarily focused on the Retail Banking Segment. A YoY increase of Ch$3,463 million in CLE associated with cross border loans in the nine-month period ended September 30, 2026 when compared to the same period in 2025, primarily stemming from greater exposure to off-shore counterparties. These drivers were to some extent offset by a YoY decrease of Ch$7,729 million in impairments of financial assets at amortized cost and at fair value through other comprehensive income, from a risk charge of Ch$3,135 million in the nine-month period ended September 30, 2025 to a net risk benefit of Ch$4,594 million in the same period of 2026, reflecting both an improved macroeconomic outlook for the coming years and lower delinquency levels observed in recent months. Year-to-Date Credit Loss Expense (In millions of Ch$) Sep-25 Sep-26 Ch$ % Loan Loss Allowances Initial Allowances 786,084 836,971 50,887 +6.5 % Charge-offs (322,781) (385,721) (62,940) +19.5 % Sale or Transfer of loans 0 (5) (5) - Allowances FX effect (2,282) 6,340 8,622 (377.8)% Provisions established, net 359,716 390,659 30,943 +8.6 % Final Allowances 820,737 848,244 27,507 +3.4 % Credit Loss Expense Provisions Established - Loans 359,716 390,659 30,943 +8.6 % Provisions Established - Banks (51) 115 166 (325.5)% Provisions Contingent Loans 18,568 (6,646) (25,214) (135.8)% Prov. Cross Border Loans 5,327 8,790 3,463 +65.0 % Impairment of Financial Assets (AC & FVTOCI) 3,135 (4,594) (7,729) (246.5)% Additional Provisions (69,035) 50,000 119,035 (172.4)% Recoveries (51,580) (62,674) (11,094) +21.5 % Credit Loss Expense 266,080 375,650 109,570 +41.2 % Change Sep-26/Sep-25 In Millions of Ch$ Year-to-Date
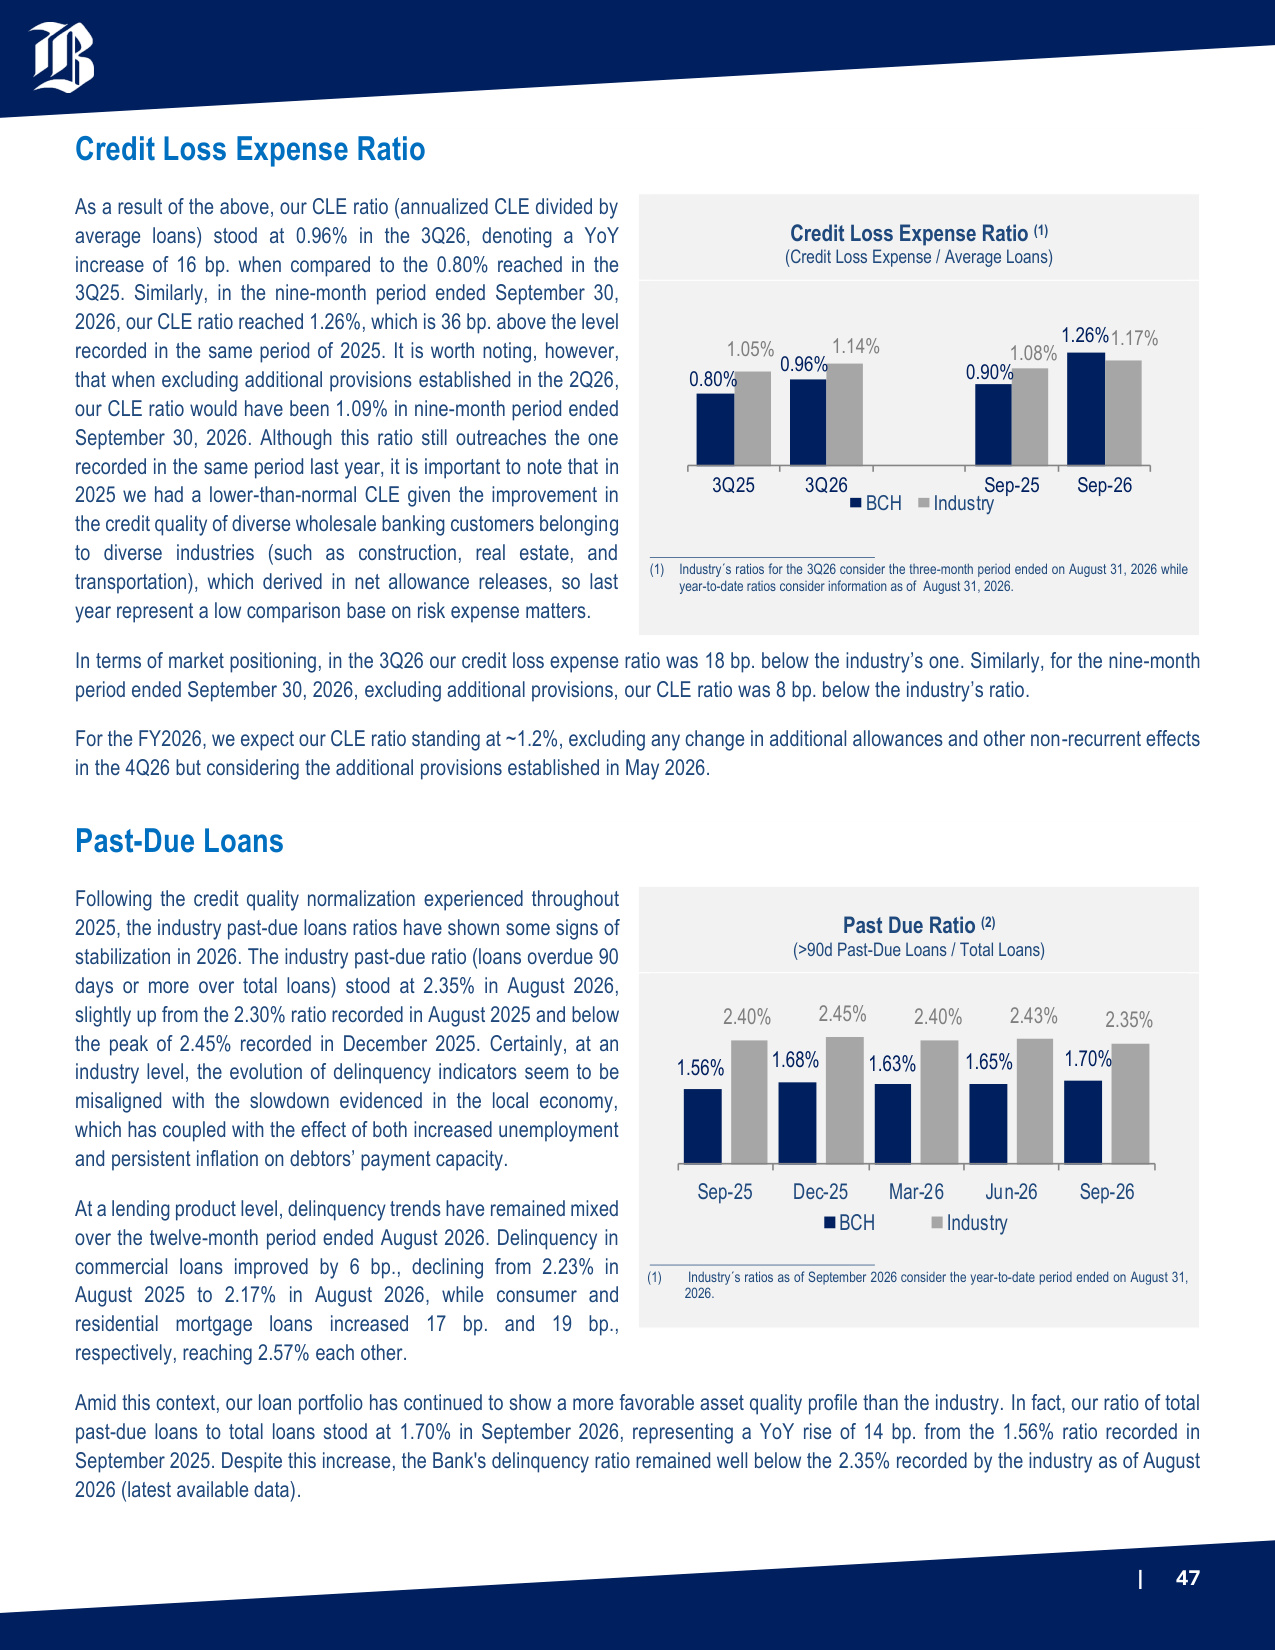
| 47 Credit Loss Expense Ratio As a result of the above, our CLE ratio (annualized CLE divided by average loans) stood at 0.96% in the 3Q26, denoting a YoY increase of 16 bp. when compared to the 0.80% reached in the 3Q25. Similarly, in the nine-month period ended September 30, 2026, our CLE ratio reached 1.26%, which is 36 bp. above the level recorded in the same period of 2025. It is worth noting, however, that when excluding additional provisions established in the 2Q26, our CLE ratio would have been 1.09% in nine-month period ended September 30, 2026. Although this ratio still outreaches the one recorded in the same period last year, it is important to note that in 2025 we had a lower-than-normal CLE given the improvement in the credit quality of diverse wholesale banking customers belonging to diverse industries (such as construction, real estate, and transportation), which derived in net allowance releases, so last year represent a low comparison base on risk expense matters. In terms of market positioning, in the 3Q26 our credit loss expense ratio was 18 bp. below the industry's one. Similarly, for the nine-month period ended September 30, 2026, excluding additional provisions, our CLE ratio was 8 bp. below the industry's ratio. For the FY2026, we expect our CLE ratio standing at ~1.2%, excluding any change in additional allowances and other non-recurrent effects in the 4Q26 but considering the additional provisions established in May 2026. Past-Due Loans Following the credit quality normalization experienced throughout 2025, the industry past-due loans ratios have shown some signs of stabilization in 2026. The industry past-due ratio (loans overdue 90 days or more over total loans) stood at 2.35% in August 2026, slightly up from the 2.30% ratio recorded in August 2025 and below the peak of 2.45% recorded in December 2025. Certainly, at an industry level, the evolution of delinquency indicators seem to be misaligned with the slowdown evidenced in the local economy, which has coupled with the effect of both increased unemployment and persistent inflation on debtors' payment capacity. At a lending product level, delinquency trends have remained mixed over the twelve-month period ended August 2026. Delinquency in commercial loans improved by 6 bp., declining from 2.23% in August 2025 to 2.17% in August 2026, while consumer and residential mortgage loans increased 17 bp. and 19 bp., respectively, reaching 2.57% each other. Amid this context, our loan portfolio has continued to show a more favorable asset quality profile than the industry. In fact, our ratio of total past-due loans to total loans stood at 1.70% in September 2026, representing a YoY rise of 14 bp. from the 1.56% ratio recorded in September 2025. Despite this increase, the Bank's delinquency ratio remained well below the 2.35% recorded by the industry as of August 2026 (latest available data). Credit Loss Expense Ratio (1) (Credit Loss Expense / Average Loans) 0.80% 0.96% 0.90% 1.26% 1.05% 1.14% 1.08% 1.17% 3Q25 3Q26 Sep-25 Sep-26 BCH Industry (1) Industry´s ratios for the 3Q26 consider the three-month period ended on August 31, 2026 while year-to-date ratios consider information as of August 31, 2026. Past Due Ratio (2) (>90d Past-Due Loans / Total Loans) 1.56% 1.68% 1.63% 1.65% 1.70% 2.40% 2.45% 2.40% 2.43% 2.35% Sep-25 Dec-25 Mar-26 Jun-26 Sep-26 BCH Industry (1) Industry´s ratios as of September 2026 consider the year-to-date period ended on August 31, 2026.
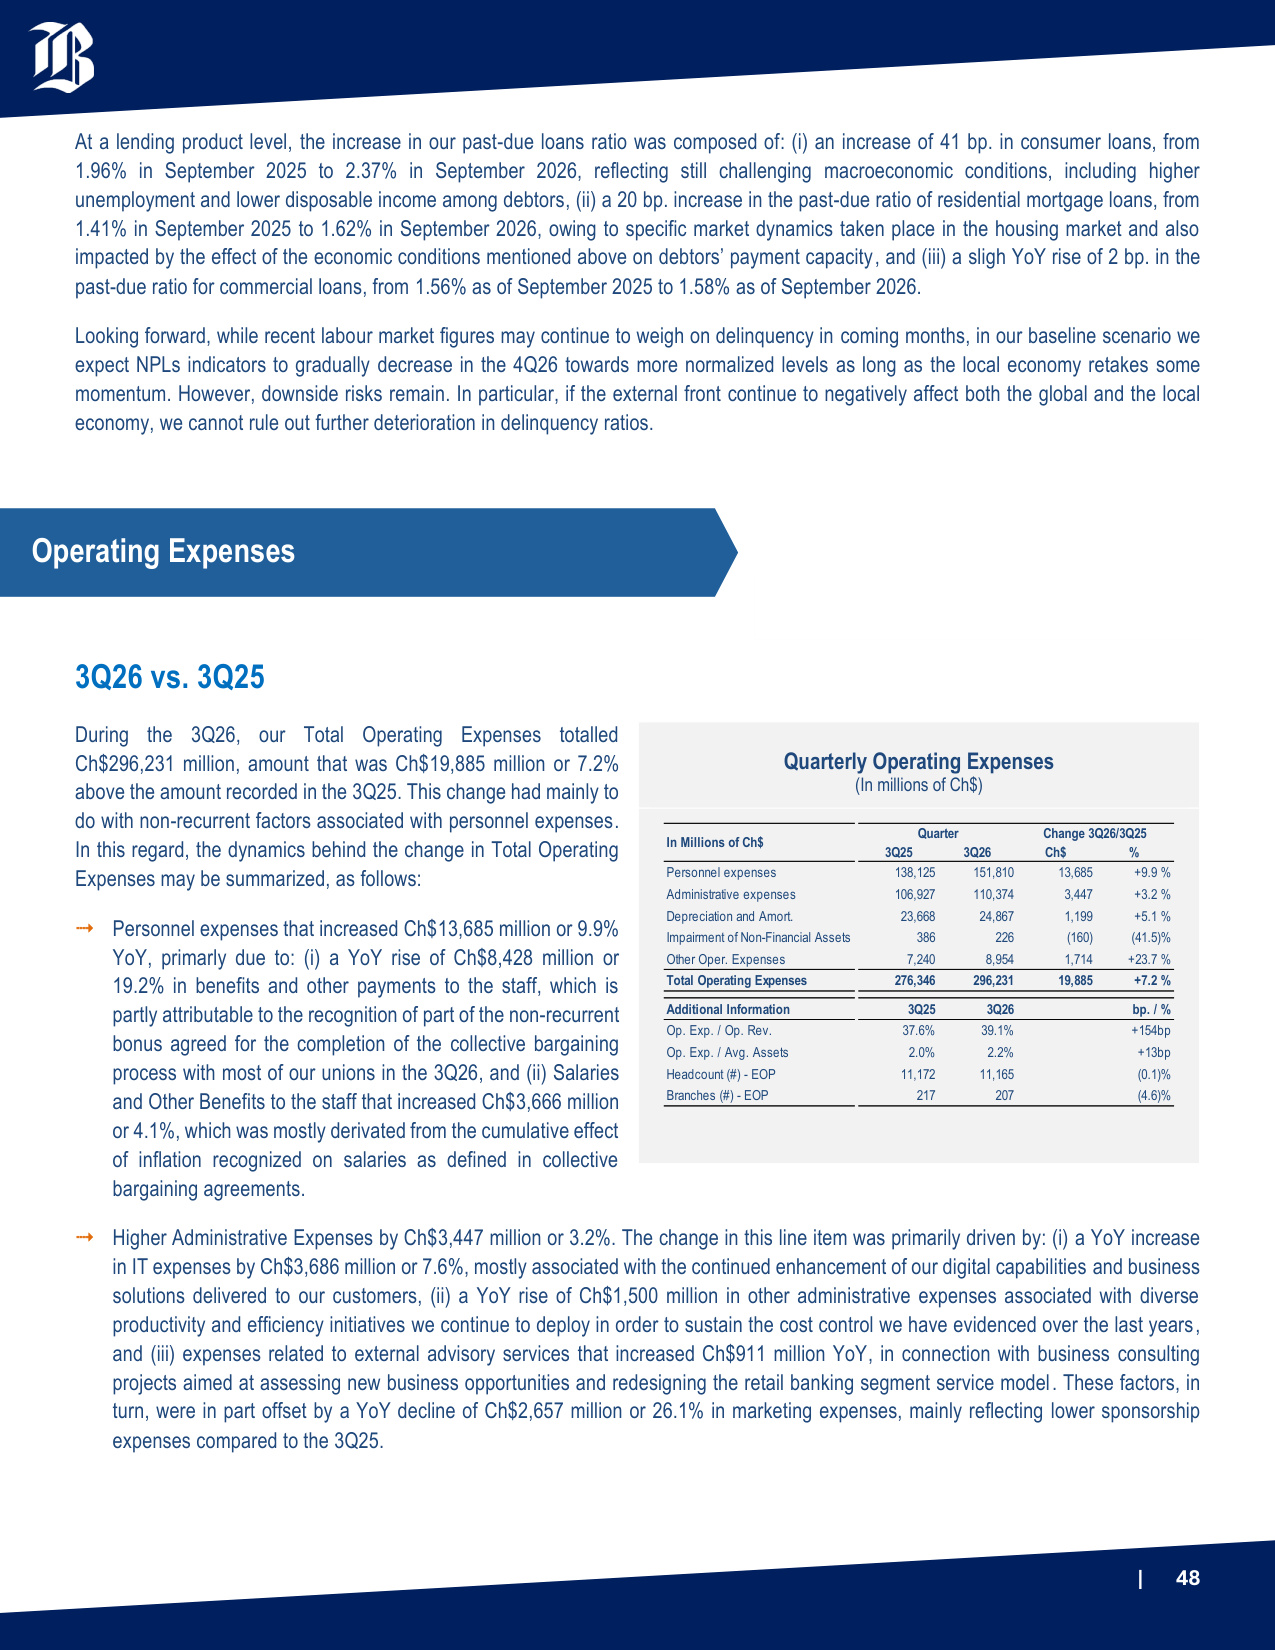
| 48 At a lending product level, the increase in our past-due loans ratio was composed of: (i) an increase of 41 bp. in consumer loans, from 1.96% in September 2025 to 2.37% in September 2026, reflecting still challenging macroeconomic conditions, including higher unemployment and lower disposable income among debtors, (ii) a 20 bp. increase in the past-due ratio of residential mortgage loans, from 1.41% in September 2025 to 1.62% in September 2026, owing to specific market dynamics taken place in the housing market and also impacted by the effect of the economic conditions mentioned above on debtors' payment capacity, and (iii) a sligh YoY rise of 2 bp. in the past-due ratio for commercial loans, from 1.56% as of September 2025 to 1.58% as of September 2026. Looking forward, while recent labour market figures may continue to weigh on delinquency in coming months, in our baseline scenario we expect NPLs indicators to gradually decrease in the 4Q26 towards more normalized levels as long as the local economy retakes some momentum. However, downside risks remain. In particular, if the external front continue to negatively affect both the global and the local economy, we cannot rule out further deterioration in delinquency ratios. 3Q26 vs. 3Q25 During the 3Q26, our Total Operating Expenses totalled Ch$296,231 million, amount that was Ch$19,885 million or 7.2% above the amount recorded in the 3Q25. This change had mainly to do with non-recurrent factors associated with personnel expenses. In this regard, the dynamics behind the change in Total Operating Expenses may be summarized, as follows: Personnel expenses that increased Ch$13,685 million or 9.9% YoY, primarly due to: (i) a YoY rise of Ch$8,428 million or 19.2% in benefits and other payments to the staff, which is partly attributable to the recognition of part of the non-recurrent bonus agreed for the completion of the collective bargaining process with most of our unions in the 3Q26, and (ii) Salaries and Other Benefits to the staff that increased Ch$3,666 million or 4.1%, which was mostly derivated from the cumulative effect of inflation recognized on salaries as defined in collective bargaining agreements. Higher Administrative Expenses by Ch$3,447 million or 3.2%. The change in this line item was primarily driven by: (i) a YoY increase in IT expenses by Ch$3,686 million or 7.6%, mostly associated with the continued enhancement of our digital capabilities and business solutions delivered to our customers, (ii) a YoY rise of Ch$1,500 million in other administrative expenses associated with diverse productivity and efficiency initiatives we continue to deploy in order to sustain the cost control we have evidenced over the last years, and (iii) expenses related to external advisory services that increased Ch$911 million YoY, in connection with business consulting projects aimed at assessing new business opportunities and redesigning the retail banking segment service model. These factors, in turn, were in part offset by a YoY decline of Ch$2,657 million or 26.1% in marketing expenses, mainly reflecting lower sponsorship expenses compared to the 3Q25. Quarterly Operating Expenses (In millions of Ch$) 3Q25 3Q26 Ch$ % Personnel expenses 138,125 151,810 13,685 +9.9 % Administrative expenses 106,927 110,374 3,447 +3.2 % Depreciation and Amort. 23,668 24,867 1,199 +5.1 % Impairment of Non-Financial Assets 386 226 (160) (41.5)% Other Oper. Expenses 7,240 8,954 1,714 +23.7 % Total Operating Expenses 276,346 296,231 19,885 +7.2 % Additional Information 3Q25 3Q26 bp. / % Op. Exp. / Op. Rev. 37.6% 39.1% +154bp Op. Exp. / Avg. Assets 2.0% 2.2% +13bp Headcount (#) - EOP 11,172 11,165 (0.1)% Branches (#) - EOP 217 207 (4.6)% In Millions of Ch$ Quarter Change 3Q26/3Q25 Operating Expenses
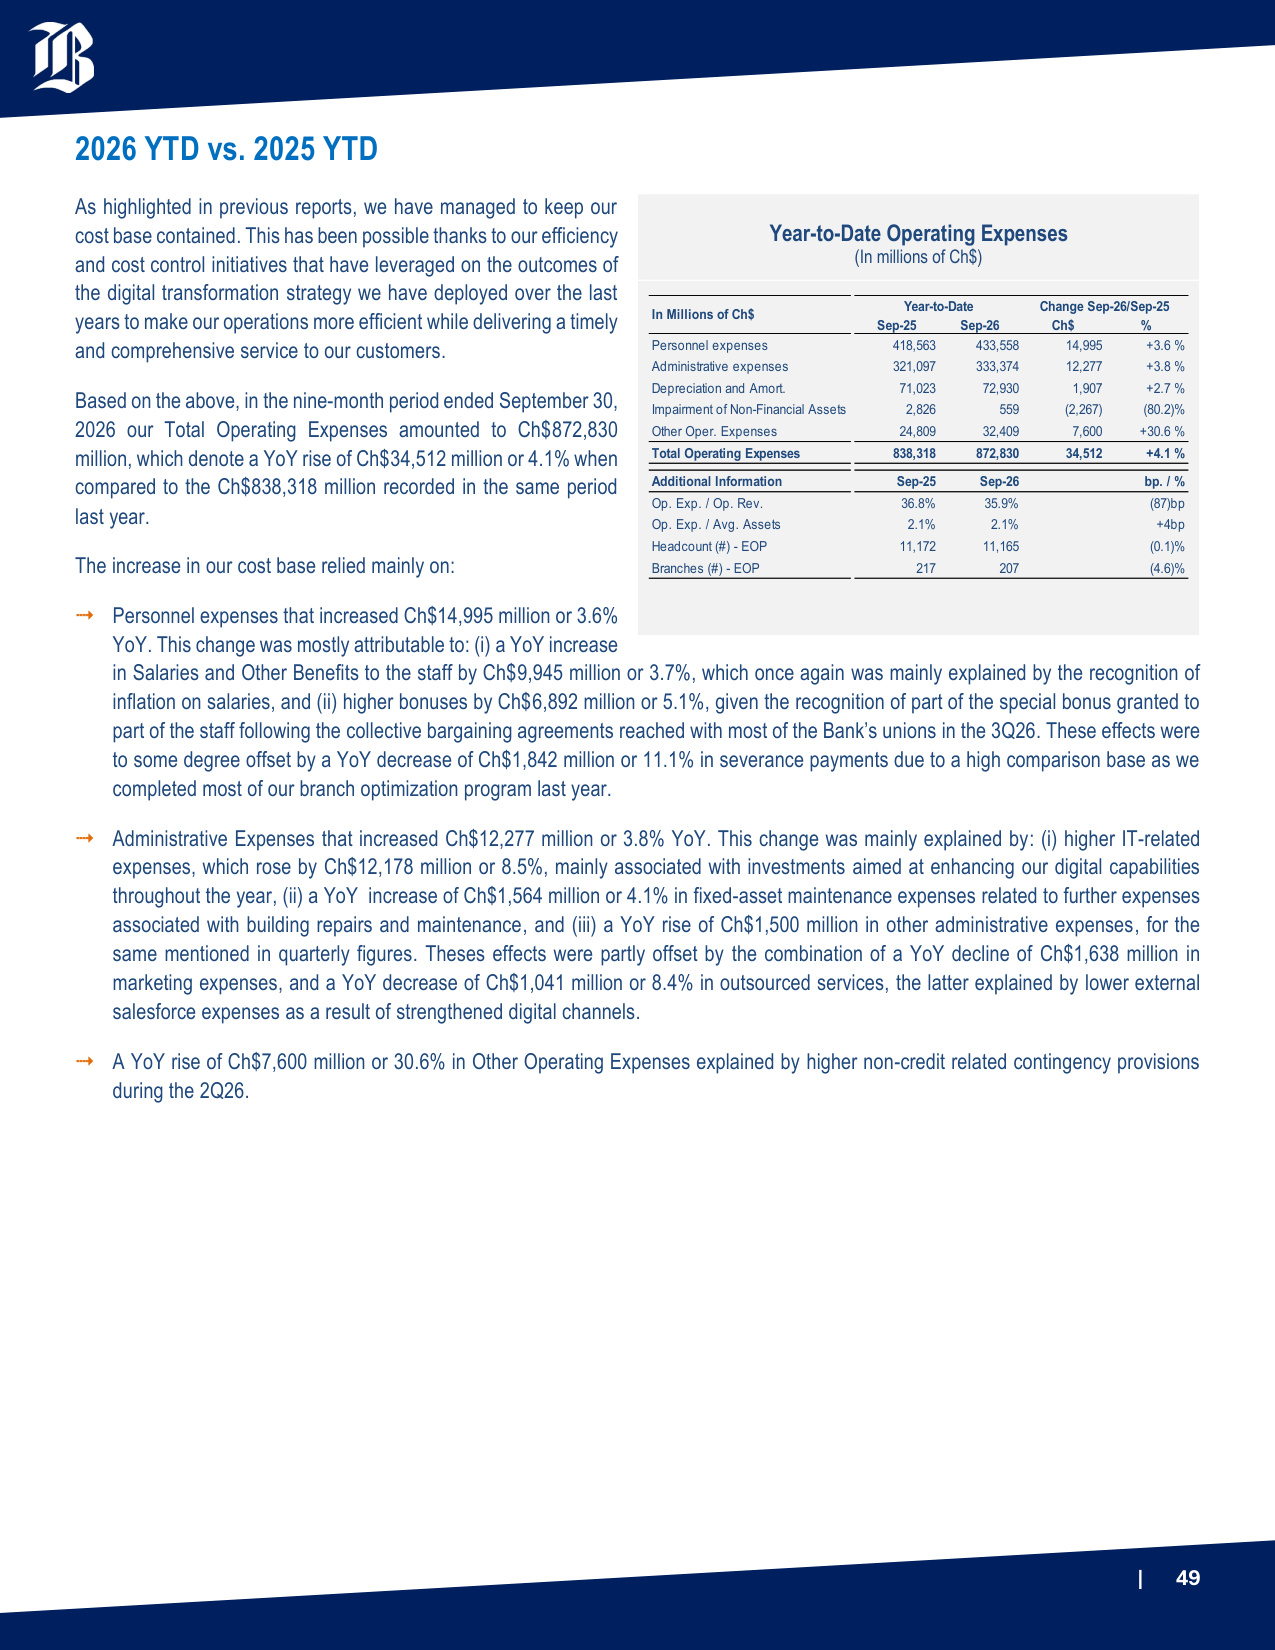
| 49 2026 YTD vs. 2025 YTD As highlighted in previous reports, we have managed to keep our cost base contained. This has been possible thanks to our efficiency and cost control initiatives that have leveraged on the outcomes of the digital transformation strategy we have deployed over the last years to make our operations more efficient while delivering a timely and comprehensive service to our customers. Based on the above, in the nine-month period ended September 30, 2026 our Total Operating Expenses amounted to Ch$872,830 million, which denote a YoY rise of Ch$34,512 million or 4.1% when compared to the Ch$838,318 million recorded in the same period last year. The increase in our cost base relied mainly on: Personnel expenses that increased Ch$14,995 million or 3.6% YoY. This change was mostly attributable to: (i) a YoY increase in Salaries and Other Benefits to the staff by Ch$9,945 million or 3.7%, which once again was mainly explained by the recognition of inflation on salaries, and (ii) higher bonuses by Ch$6,892 million or 5.1%, given the recognition of part of the special bonus granted to part of the staff following the collective bargaining agreements reached with most of the Bank's unions in the 3Q26. These effects were to some degree offset by a YoY decrease of Ch$1,842 million or 11.1% in severance payments due to a high comparison base as we completed most of our branch optimization program last year. Administrative Expenses that increased Ch$12,277 million or 3.8% YoY. This change was mainly explained by: (i) higher IT-related expenses, which rose by Ch$12,178 million or 8.5%, mainly associated with investments aimed at enhancing our digital capabilities throughout the year, (ii) a YoY increase of Ch$1,564 million or 4.1% in fixed-asset maintenance expenses related to further expenses associated with building repairs and maintenance, and (iii) a YoY rise of Ch$1,500 million in other administrative expenses, for the same mentioned in quarterly figures. Theses effects were partly offset by the combination of a YoY decline of Ch$1,638 million in marketing expenses, and a YoY decrease of Ch$1,041 million or 8.4% in outsourced services, the latter explained by lower external salesforce expenses as a result of strengthened digital channels. A YoY rise of Ch$7,600 million or 30.6% in Other Operating Expenses explained by higher non-credit related contingency provisions during the 2Q26. Year-to-Date Operating Expenses (In millions of Ch$) Sep-25 Sep-26 Ch$ % Personnel expenses 418,563 433,558 14,995 +3.6 % Administrative expenses 321,097 333,374 12,277 +3.8 % Depreciation and Amort. 71,023 72,930 1,907 +2.7 % Impairment of Non-Financial Assets 2,826 559 (2,267) (80.2)% Other Oper. Expenses 24,809 32,409 7,600 +30.6 % Total Operating Expenses 838,318 872,830 34,512 +4.1 % Additional Information Sep-25 Sep-26 bp. / % Op. Exp. / Op. Rev. 36.8% 35.9% (87)bp Op. Exp. / Avg. Assets 2.1% 2.1% +4bp Headcount (#) - EOP 11,172 11,165 (0.1)% Branches (#) - EOP 217 207 (4.6)% Year-to-Date Change Sep-26/Sep-25 In Millions of Ch$
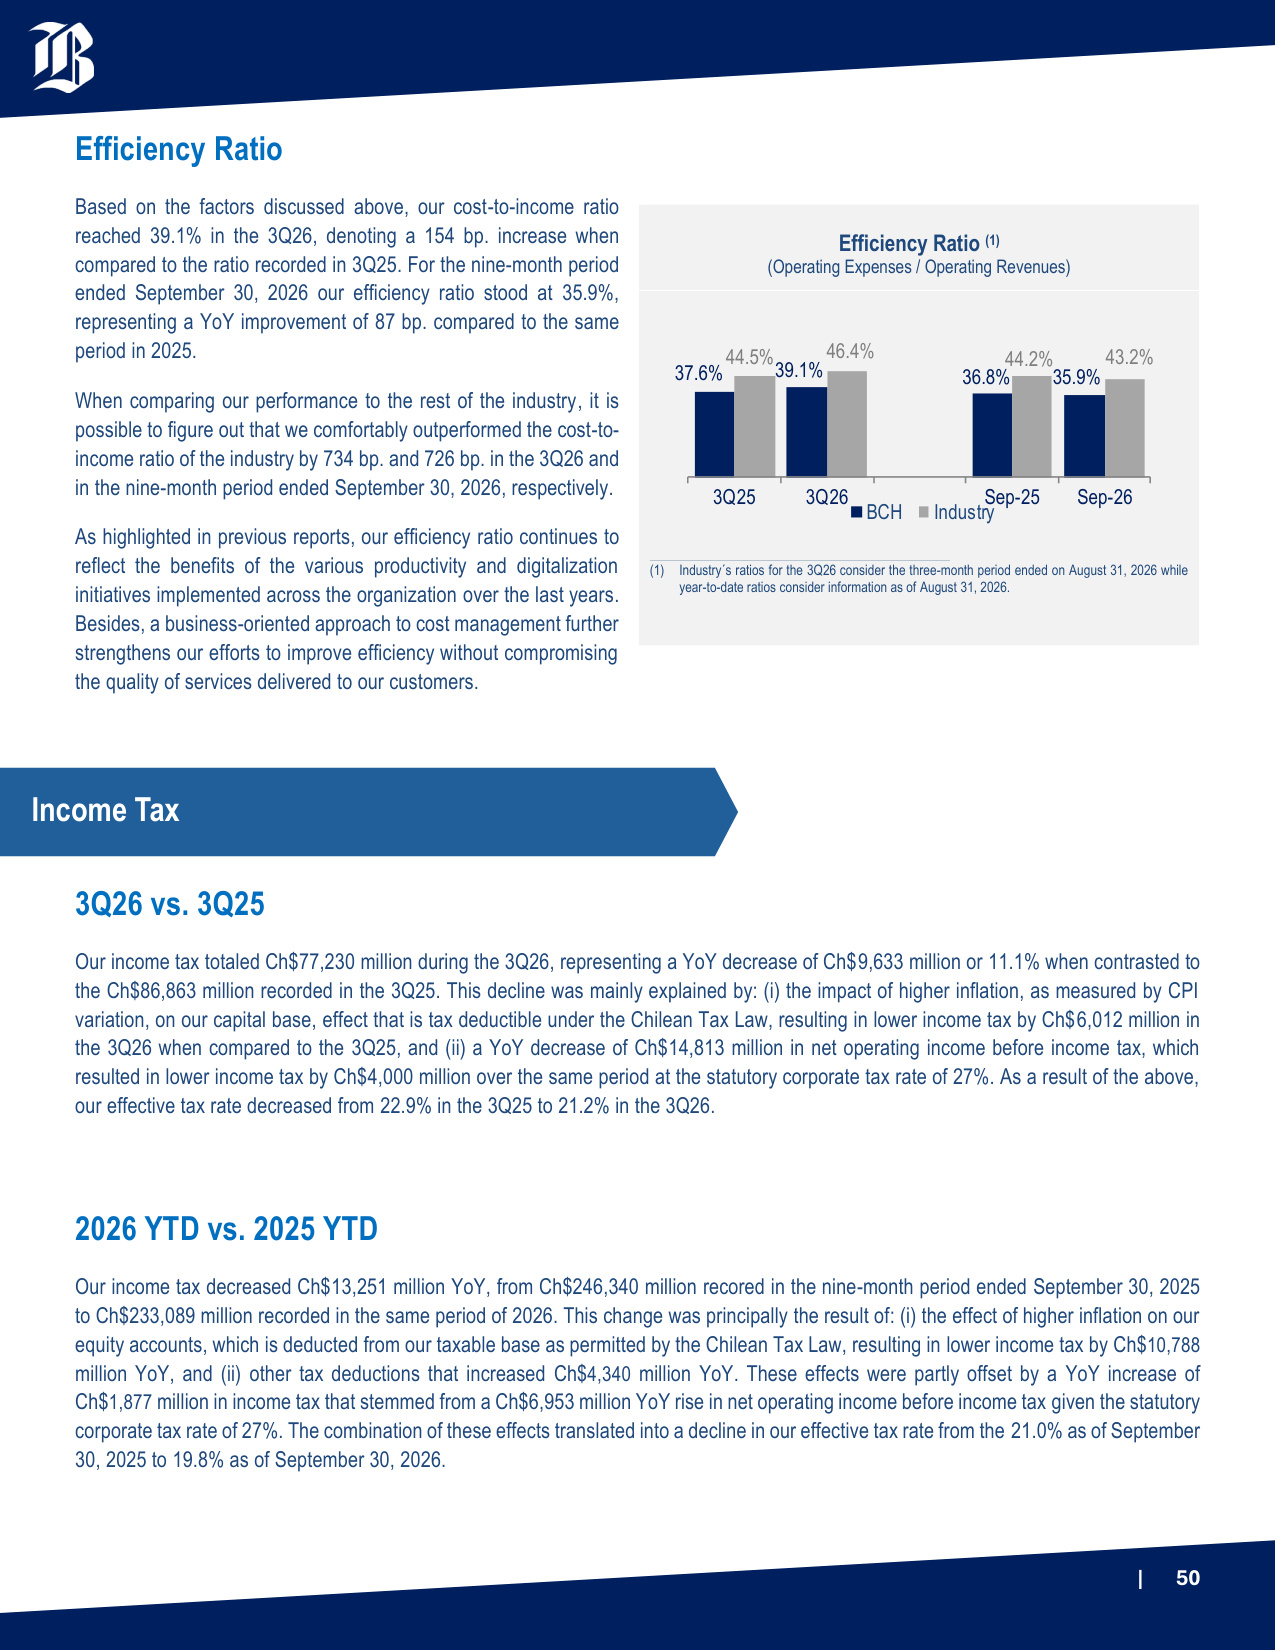
| 50 Efficiency Ratio Based on the factors discussed above, our cost-to-income ratio reached 39.1% in the 3Q26, denoting a 154 bp. increase when compared to the ratio recorded in 3Q25. For the nine-month period ended September 30, 2026 our efficiency ratio stood at 35.9%, representing a YoY improvement of 87 bp. compared to the same period in 2025. When comparing our performance to the rest of the industry, it is possible to figure out that we comfortably outperformed the cost-to- income ratio of the industry by 734 bp. and 726 bp. in the 3Q26 and in the nine-month period ended September 30, 2026, respectively. As highlighted in previous reports, our efficiency ratio continues to reflect the benefits of the various productivity and digitalization initiatives implemented across the organization over the last years. Besides, a business-oriented approach to cost management further strengthens our efforts to improve efficiency without compromising the quality of services delivered to our customers. 3Q26 vs. 3Q25 Our income tax totaled Ch$77,230 million during the 3Q26, representing a YoY decrease of Ch$9,633 million or 11.1% when contrasted to the Ch$86,863 million recorded in the 3Q25. This decline was mainly explained by: (i) the impact of higher inflation, as measured by CPI variation, on our capital base, effect that is tax deductible under the Chilean Tax Law, resulting in lower income tax by Ch$6,012 million in the 3Q26 when compared to the 3Q25, and (ii) a YoY decrease of Ch$14,813 million in net operating income before income tax, which resulted in lower income tax by Ch$4,000 million over the same period at the statutory corporate tax rate of 27%. As a result of the above, our effective tax rate decreased from 22.9% in the 3Q25 to 21.2% in the 3Q26. 2026 YTD vs. 2025 YTD Our income tax decreased Ch$13,251 million YoY, from Ch$246,340 million recored in the nine-month period ended September 30, 2025 to Ch$233,089 million recorded in the same period of 2026. This change was principally the result of: (i) the effect of higher inflation on our equity accounts, which is deducted from our taxable base as permitted by the Chilean Tax Law, resulting in lower income tax by Ch$10,788 million YoY, and (ii) other tax deductions that increased Ch$4,340 million YoY. These effects were partly offset by a YoY increase of Ch$1,877 million in income tax that stemmed from a Ch$6,953 million YoY rise in net operating income before income tax given the statutory corporate tax rate of 27%. The combination of these effects translated into a decline in our effective tax rate from the 21.0% as of September 30, 2025 to 19.8% as of September 30, 2026. Efficiency Ratio (1) (Operating Expenses / Operating Revenues) 37.6% 39.1% 36.8% 35.9% 44.5% 46.4% 44.2% 43.2% 3Q25 3Q26 Sep-25 Sep-26 BCH Industry (1) Industry´s ratios for the 3Q26 consider the three-month period ended on August 31, 2026 while year-to-date ratios consider information as of August 31, 2026. Income Tax
| 51 As anticipated in previous quarterly reports, the "National Reconstruction, Economic and Social Development" law was finally enacted on October 9, 2026. Among other measures, this law considers a gradual decline in the statutory corporate tax rate from the current 27% to 25.5% for 2027, 24% for 2028 and 23% for 2029 onwards. Since deferred taxes are measured by using the approved or substantially approved corporate tax rates as of the reporting date, as of September 30, 2026, no effects associated with this bill were recognized in our financial statements. However, the impact of this law will be recognized in October 2026 as an income tax charge approximately Ch$68,000 million. In coming years, our effective tax rate would be approximately three percentage points less than the new statutory corporate tax rates due to the impact of inflation on equity (assuming a ~3% inflation rate) and excluding any other non-recurrent tax deductions or surcharges.
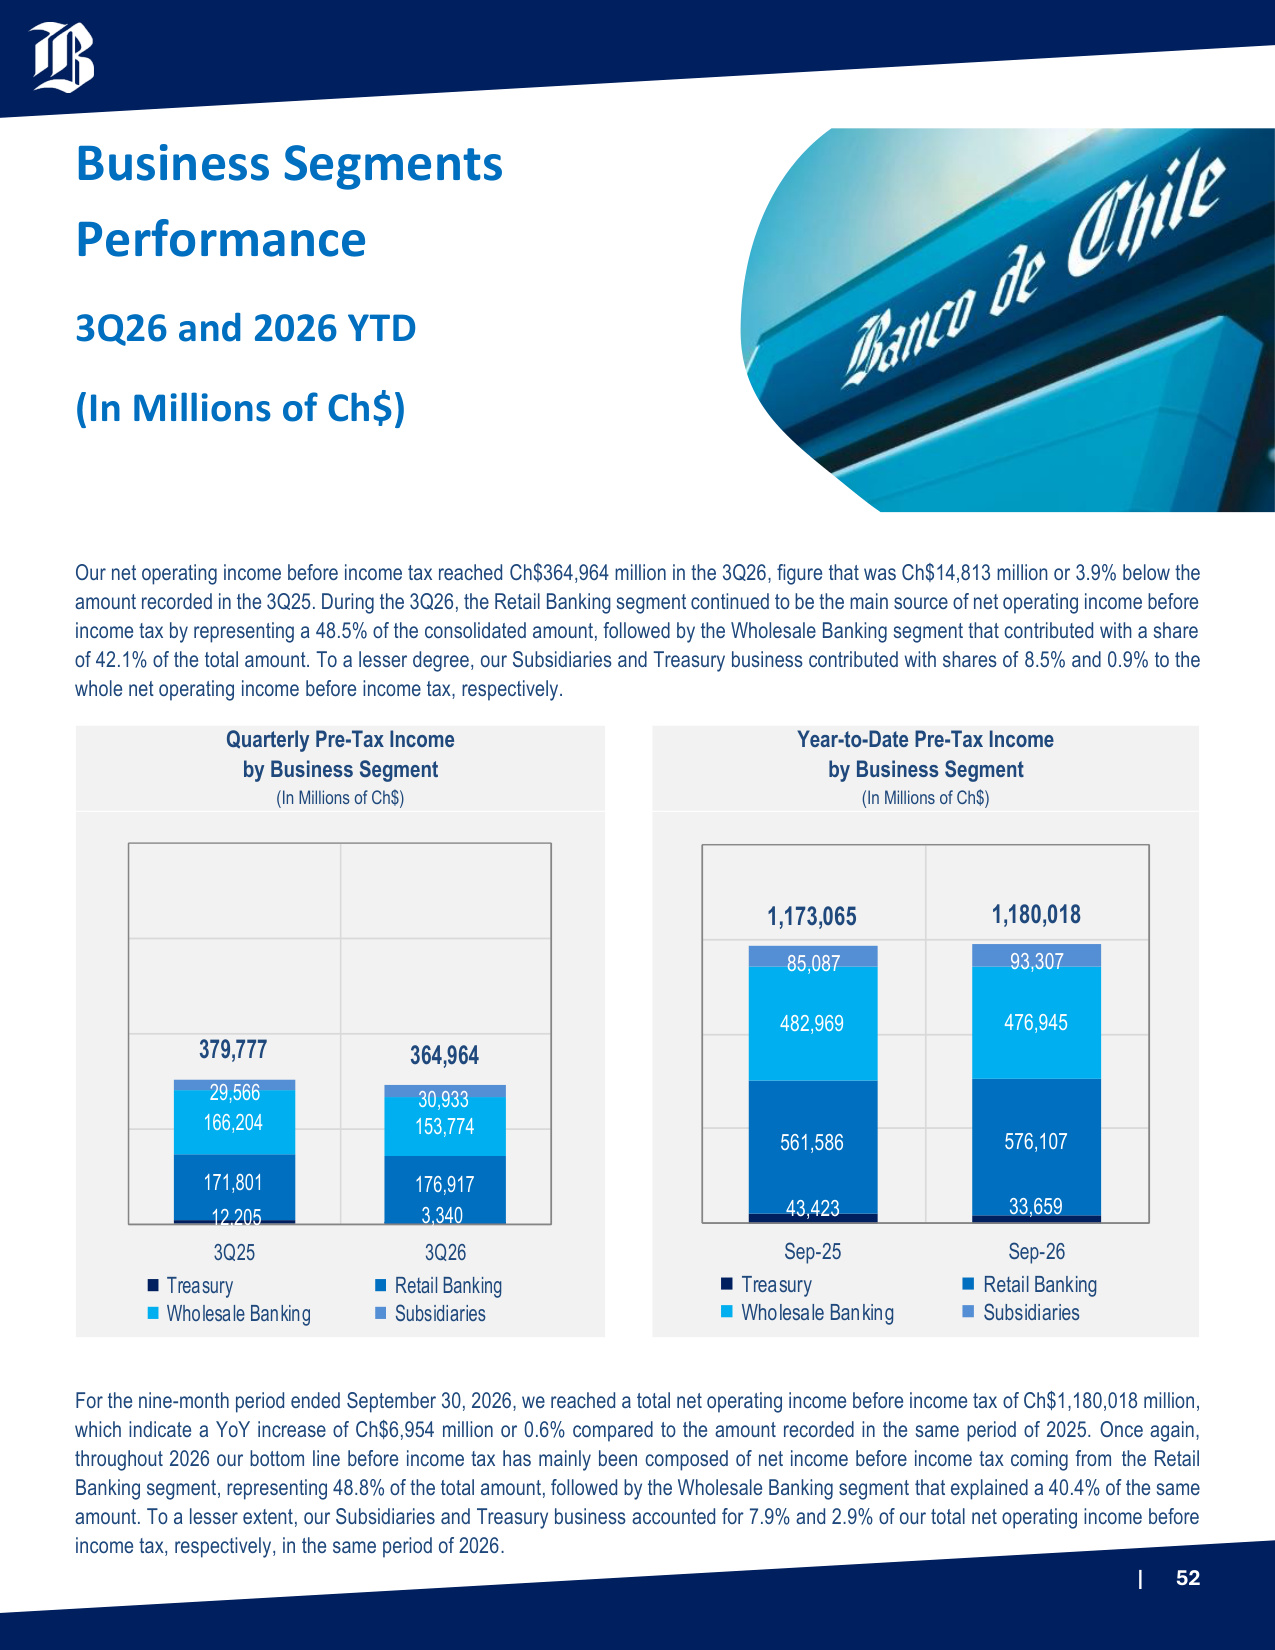
| 52 Business Segments Performance 3Q26 and 2026 YTD (In Millions of Ch$) Our net operating income before income tax reached Ch$364,964 million in the 3Q26, figure that was Ch$14,813 million or 3.9% below the amount recorded in the 3Q25. During the 3Q26, the Retail Banking segment continued to be the main source of net operating income before income tax by representing a 48.5% of the consolidated amount, followed by the Wholesale Banking segment that contributed with a share of 42.1% of the total amount. To a lesser degree, our Subsidiaries and Treasury business contributed with shares of 8.5% and 0.9% to the whole net operating income before income tax, respectively. Quarterly Pre-Tax Income by Business Segment (In Millions of Ch$) Year-to-Date Pre-Tax Income by Business Segment (In Millions of Ch$) 12,205 3,340 171,801 176,917 166,204 153,774 29,566 30,933 379,777 364,964 3Q25 3Q26 Treasury Retail Banking Wholesale Banking Subsidiaries 43,423 33,659 561,586 576,107 482,969 476,945 85,087 93,307 1,173,065 1,180,018 Sep-25 Sep-26 Treasury Retail Banking Wholesale Banking Subsidiaries For the nine-month period ended September 30, 2026, we reached a total net operating income before income tax of Ch$1,180,018 million, which indicate a YoY increase of Ch$6,954 million or 0.6% compared to the amount recorded in the same period of 2025. Once again, throughout 2026 our bottom line before income tax has mainly been composed of net income before income tax coming from the Retail Banking segment, representing 48.8% of the total amount, followed by the Wholesale Banking segment that explained a 40.4% of the same amount. To a lesser extent, our Subsidiaries and Treasury business accounted for 7.9% and 2.9% of our total net operating income before income tax, respectively, in the same period of 2026.
| 53 Retail Banking Segment We recorded a net operating income before income tax of Ch$176,917 million in the Retail Banking segment during the 3Q26. This amount denotes a YoY rise of Ch$5,116 million or 3.0% when compared to the 3Q25. This change was mainly explained by steady growth in total operating income that increased Ch$32,679 million or 7.0% YoY, which in turn was primarily fostered by the continued recovery of income from loans and, to a lesser degree, greater net fee income that principally came from transactional services, all allowing us to offset the lower contribution of DDA to our cost of funds given the prevailing interest rate scenario. On the other hand, the YoY increase in operating revenues was to some extent offset by: (i) a YoY rise of Ch$14,016 million or 14.6% in credit loss expense, primarily due to the impact of both the current economic slowdown and increased unemployment on delinquency in this business segment, and (ii) a YoY increase of Ch$13,546 million or 6.8% in operating expenses, principally due to increased personnel expenses following the recognition of both part of a special bonus granted to the staff for the completion of collective bargaining processes and the impact of inflation on salaries. In the nine-month period ended September 30, 2026, the Retail Banking segment reached net operating income before income tax of by Ch$576,107 million, which exceed by Ch$14,521 million or 2.6% the figure recorded in the same period last year. The main driver for this growth was the YoY boost of Ch$125,661 million or 8.8% in operating revenues, which in turn was rooted in: (i) higher income from loans particularly coming from a proactive management of lending spreads in consumer loans to individuals and commercial loans to SMEs, (ii) a YoY in revenues from the management of financial gaps that are partly allocated to this segment, given higher inflation and positive repricing, and (iii) greater net fee income, primarily related to transactional services. This factors allowed us to more than offset the lower contribution of demand deposits to our cost of funds for the same reasons mentioned above. On the other hand, the net increase in operating revenues also enabled us to more than counterbalance: (i) a YoY rise of Ch$91,144 million or 34.5% YoY in credit loss expenses, due to both increased additional provisions (set in the 2Q26) and higher delinquency in this segment, and (ii) a YoY surge of Ch$19,995 million or 3.3% in operating expenses, focused on personnel expenses as mentioned in the quarterly figures. Wholesale Banking Segment Our Wholesale Banking segment recorded net operating income before income tax by Ch$153,774 million in the 3Q26, which were Ch$12,430 million or 7.5% below the level reached in the 3Q25. This change mostly driven by the combination of the following factors: (i) a YoY increase of Ch$6,538 million or 36.0% in credit loss expense, owing to lower-than-normal risk expenses in the 3Q25 when some counterparties enhanced their risk profiles that resulted in net allowance releases, together with increased exposures to cross-border loans, (ii) total operating income that declined of Ch$3,215 million or 1.6% YoY, mostly driven by lower contribution of DDA managed by the segment to our funding cost that was partly offset by a YoY rise in net fee income, attributable to financial advisory and cash management services, and (iii) operating expenses that rose Ch$2,677 million or 5.2% YoY, mostly explained by the same factors affecting the cost base of the Retail Banking segment. In the nine-month period ended September 30, 2026, the Wholesale Banking segment recorded net operating income before income tax by Ch$476,945 million that were Ch$6,024 million or 1.2% below the amount recorded in the same period of 2025. The YoY variation in the pre-tax bottom line was primarily fostered by: (i) a YoY increase of Ch$26,124 million in credit loss expense due to the effect of additional provisions established in the 2Q26 that are partly allocated to this segment and greater exposure to cross border loans, and (ii) a YoY rise of Ch$8,189 million or 5.3% in operating expenses as a result of the recognition of part of the bonus granted to the staff for the completion of collective bargaining processes and inflation on salaries. These negative factors were in part offset by a YoY rise of Ch$28,289 million in total operating income generated by the segment that had largely to do with increased revenues from asset and liability management that are in part allocated to this segment and, to a lesser degree, higher net fee income owing to the same drivers mentioned in quarterly figures, which allowed us to counterbalance the lower contribution of DDA to our funding a a slight decrease in income from loans.
| 54 Treasury Segment During the 3Q26, the Treasury segment's net operating income before income tax amounted to Ch$3,340 million, representing a YoY decrease of Ch$8,865 million contrasted to the Ch$12,205 million reached in the 3Q25. This change resulted mainly from a Ch$12,757 million YoY decline in total operating revenues from our Debt Securities and Trading desks, mostly due to the negative effect of the sharp increase in local interest rates during the 3Q26 on the fair value of fixed-income securities, which coupled with a high comparison base stemming from marking-to-market gains obtained from the sale of FVOCI securities in the 3Q25. This effect was partly offset by a Ch$3,754 million YoY improvement in impairments of financial assets at amortized cost and at FVOCI, mainly reflecting improved counterparty credit profiles and a more favourable economic outlook expected for coming quarters, which translated into lower PDs. In the nine-month period ended September 30, 2026, the Treasury segment recorded a net operating income before income tax of Ch$33,659 million, representing a YoY decline of Ch$9,764 million or 22.5% contrasted to the same period in 2025. This performance was primarily explained by a Ch$16,965 million YoY decrease in total operating revenues from Ch$51,643 million recorded as of September 2025, mainly reflecting a Ch$13,004 million YoY decline in revenues from our Debt Securities desk for the same reasons explained in quarterly figures, and lower revenues by Ch$9,972 million from our Trading desk, primarily attributable to unfavourable movements in local interest rates during 2026, which resulted in negative fair value adjustments on fixed-income securities and derivatives, all of which more than offset higher revenues from term gapping and inflation-indexation that are partly allocated to this segment. The YoY decrease in total operating revenues was partly offset by a YoY improvement of Ch$7,729 million in impairments of financial assets at amortized cost and at FVOCI in 2026 when contrasted to 2025, mainly related to enhanced macroeconomic perspectives and delinquency during the year. Subsidiaries Net operating income before income tax from our subsidiaries amounted to Ch$30,933 million in the 3Q26, increasing Ch$1,367 million or 4.6% compared to the 3Q25. This performance was primarily driven by: (i) a Ch$2,380 million YoY in income before income tax from our Financial Advisory subsidiary, mainly due to its participation in M&A transactions in the Telco sector, as well as advisory services related to bond issuances and capital increases in the real estate and IT sectors, respectively, and (ii) a Ch$1,218 million YoY rise in pre-tax bottom line from our Mutual Funds and Investment Funds subsidiary, supported by a 10.7% YoY growth in average AUM in the 3Q26 compared to the 3Q25 driven by balanced mutual funds, investment funds and equity funds. These positive factors were partly offset by: (i) a Ch$1,002 million YoY decrease in net operating income before income tax generated by our Stock Brokerage subsidiary, mainly because of lower operating revenues owing to a net financial income decline related to the impact of rising interest rates on the mark-to-market of financial positions held by the company, and (ii) net operating losses of Ch$847 million at Banchile Pagos, which remains in the start-up phase. In the nine-month period ended September 30, 2026, our subsidiaries recorded net operating income before income tax by Ch$93,307 million, which exceeded by Ch$8,220 million or 9.7% the amount recorded in the same period of 2025. This performance was primarily driven by: (i) a Ch$4,648 million YoY increase in pre-tax bottom line generated by our Mutual Funds and Investment Funds subsidiary, largely attributable to higher net fee income as a result of a 9.4% expansion in average AUM in the nine-month period ended September 30, 2026 compared to the same period in 2025, driven by balanced mutual funds, investment funds and equity funds, with the latter exhibiting the strongest growth, (ii) a YoY increase of Ch$3,934 million in net operating income before income tax from our Stock Brokerage subsidiary, driven by higher brokerage fees as the subsidiary participated in specific equity transactions carried out in the local market, and (iii) a Ch$3,500 million YoY rise in the pre-tax bottom line of our Financial Advisory subsidiary, due to the same factors discussed above. These effects were in part offset by lower net operating income before income tax from Banchile Pagos by Ch$3,135 million, reflecting the current stage of development of this company.
| 55 Balance Sheet Analysis As of September 30, 2026 (In Millions of Ch$) As of September 30, 2026 we had total loans amounting to Ch$40,767,705 million, which represent a 2.9% nominal YoY expansion as compared to September 30, 2025 and a 4.0% nominal rise compared to December 2025. As highlighted last quarter, commercial loans have displayed a rebound from the figure seen in December 2025, which in turn has been rooted in some signs of dynamism in certain units of our Wholesale Banking Segment while enabling us to recover market share over the period. Likewise, as noted over the last quarters, SME lending continues to grow steadily in when setting aside the amortization of formerly granted Fogape loans. Furthermore, is important to recall that actual figures include the effect of a one-time change in the accounting presentation of credit card loans, which impacted loan growth for the whole portfolio. When excluding this effect, our loan portfolio would have grown 3.5% and 4.7% compared to September 2025 and December 2025, respectively. When looking at every lending product, it is possible to figure out that commercial loans grew 4.0% YoY in nominal terms when compared to September 30, 2025. More notably, these credits rose 7.8% contrasted to December 2025, which denotes an annualized growth rate of 10.5%. As mentioned, most of the expansion came from loan growth in the Wholesale Banking segment, particularly through the Corporate Banking Unit, based on improved business intelligence, and –to a lesser degree– from SME Banking, as demand for loans from these customers keep on picking up steadily, though at a moderate pace yet. In Personal Banking, loan growth has been more modest than for companies. Actually, Residential Mortgage loans increased 2.5% in nominal terms in September 2026 when compared to September 2025. Instead, consumer loans remained almost flat by recording a 0.1% YoY growth in September 2026. The dynamics explaining these behaviours are quite different. Whereas loan growth in Residential Mortgage loans has strongly been influenced by our aim of promoting a sustained improvement in lending spreads through selective growth in this product, the evolution of consumer loans had to do with a one-time effect associated with the migration of the credit card processing system that resulted in a revised accounting presentation, as we pointed out last quarter. Loan Portfolio Evolution (In Millions of Ch$ and %) 20,220,411 19,509,355 21,033,299 13,845,219 13,916,618 14,185,503 5,542,171 5,765,997 5,548,903 39,607,801 39,191,970 40,767,705 Sep-25 Dec-25 Sep-26 Commercial Loans Residential Mortgage Loans Consumer Loans +7.8% +1.9% +2.9% 52% 35% 14% (3.8)% +4.0% Loan Portfolio
| 56 Based on this change, early payments of credit card usage are inmediatly cleared against the credit card balance held by the debtor. Accordingly, once adopted the new processing system, our credit card loans and other demand deposits experienced a one-time decline (compared to prior figures) of approximately Ch$210,000 million in June 2026. Therefore, when adjusting the comparison base by this change ("proforma basis", hereafter), our total consumer loans would have grown 4.1% YoY in September 2026. Regarding the composition of our loan book, as of September 30, 2026, the portfolio continues to be primarily concentrated in loans handled by the Retail Banking segment that amounted to Ch$26,796,469 million, representing 65.7% of the whole portfolio, while loans managed by the Wholesale Banking segment accounted for Ch$13,971,237 million or 34.3% of the loan book as of the same date. Within the Retail Banking segment, Personal Banking loans represent 78.8% of the Retail Banking portfolio by totalling Ch$21,108,243 million, while the remaining share corresponds to SME loans for an amount of Ch$5,688,226 million or 21.2% of the Retail Banking segment book. In Wholesale Banking, in turn, loans provided to Corporations accounted for Ch$8,856,088 million or 63.4% of the segment's book, while loans handled by Large Companies amounted to Ch$5,115,149 million or 36.6% of the segment's portfolio. From the loan growth perspective, the book handled by the Retail Banking segment increased Ch$838,472 million or 3.2% YoY on a proforma basis in September 2026 (Ch$626,632 million or 2.4% actual) and Ch$555,477 million or 2.1% on a proforma basis (Ch$312,734 or 1.2% actual) compared to December 2025. The path followed by the Retail Banking portfolio has been influenced by expansions in both Personal Banking and SME Banking loans. As we have mentioned in the past, SME banking has shown a steady recovery in core lending over the last quarters, especially when setting aside the amortization of Fogape loans granted in the context of the pandemic. In Personal Banking loans, in turn, we are seeing mixed dynamics. Firstly, Residential Mortgage loans have experienced a slowdown over the last quarters as we are actively seeking for a balanced risk- return relationship for this lending product by giving priority to higher margins. In addition, consumer loans have continued to grow in line with inflation in both installment loans and credit card loans. The evolution of the Retail Banking loan book may be summarized, as follows: Personal Banking loans that, on a proforma basis, increased by Ch$595,419 million or 2.9% YoY in September 2026 (Ch$383,579 million or 1.9% actual) if contrasted to September 2025 and Ch$325,314 million or 1.6% (Ch$82,571 million or 0.4% actual) compared to December 2025. This expansion was steered by: • Residential Mortgage loans that grew Ch$340,284 million or 2.5% compared to a year earlier and Ch$268,885 million or 1.9% contrasted to December 2025 by reaching to Ch$14,185,503 million in September 2026. Although this lending product is growing below figures seen in the last decade across the industry, some state-backed schemes launched last year have slightly revitalized the demand for residential mortgage loans, thanks to subsidies on the interest rate paid by debtors and guarantees provided by the state to banks with the aim of both covering the credit risk involved and reducing the down payment for such loans for homes valued at up to UF6,000 (~USD250,000). Amid this environment, we have focused on growing selectively by taking advantage of our excellent customer knowledge and proximity, which has enabled us to improve lending spreads on new loans written by customers. Accordingly, in the nine-month period ended September 30, 2026 our origination of residential mortgage loans reached Ch$811,846 million, which denote a YoY decline of 30.2% when compared to the same period last year. Loans by Segment (In Millions of Ch$ and %) Retail Banking 26,796,469 65.7% Wholesale Banking 13,971,237 34.3% Individuals 21,108,243 51.8% SMEs 5,688,226 14.0% Large Companies 5,115,149 12.5% Corporate 8,856,088 21.7%
| 57 • Consumer loans that increased Ch$218,572 million or 4.1% YoY on a proforma basis (Ch$6,732 million or 0.1% actual rise) by reaching Ch$5,548,903 million in September 2026. When compared to December 2025, this amount represents a year-to-date increase of Ch$25,650 million or 0.5% proforma (Ch$217,094 million or 3.8% actual decline). This preformance was backed by: - Installment loans that increased Ch$125,833 million or 3.8% YoY in September 2026 by totalling Ch$3,434,746 million. This variation is aligned with the 12-month pace of growth of ~4% (nominal) we have consistently seen for this product over the last year, which is almost twofold the expansion rate seen in the 1H25. As highlighted last quarter we continuously attempt to reinforce the value proposition across all segments of individuals we serve, based on which we have entered into new alliances in order to widen our array of services. In this regard, it is worth noting our recently signed alliance with "Linze", which enables us to enter the Auto Loans market. This and other initiatives have positively impacted on our origination of installment loans that reached Ch$1,736,495 million in the nine-month period ended September 30, 2026, denoting a YoY increase of 4.3% compared to the same period in 2025. - Credit card loans that, on a proforma basis, grew Ch$94,093 million or 5.6% YoY by reaching Ch$1,826,957 million in September 2026 (Ch$117,747 million or 6.1% actual decline). As mentioned in previous reports, the reinforcement of our value offerings for credit cards has been one of our main objectives over the last years. As such, we have widened the benefits delivered to the credit card users through a more comprehensive loyalty program –that is continuously adding new alliances– while promoting the use of credit cards across all segments of individuals by means of sophisticated business intelligence tools without compromising asset quality at all. These actions have certainly supported the evolution of our credit card loans. SME Banking loans that reached Ch$5,688,226 million in September 2026, denoning a YoY climb of Ch$243,053 million or 4.5% compared to September 2025 and an increase of Ch$230,163 million or 4.2% in relation to December 2025. As we have pointed out in previous reports, borrowing from SMEs continues to grow steadily when excluding the amortization of Fogape loans. Actually, the underlying factors supporting growth in SME loans, include: (i) a YoY rise of Ch$557,437 million or 9.0% in Non-Fogape loans, based on our continuous focus on accompanying our SME customers throughout their life cycle to satisfy evolving customer needs, particularly in relation to remote interaction, while supporting them through diverse activities oriented to provide them with sophisticated entrepreneurial capabilities, and (ii) Fogape loans granted during or just after the COVID-19 pandemic, as an economic support measure, which recorded a YoY decline of Ch$249,328 million or 60.2% in September 2026. When compared to December 2025 SME core lending rose 7.1% in September 2026 (excluding Fogape loans), which also denotes an above-inflation growth rate rooted in the same dynamics noted earlier. In the Wholesale Banking segment, we have continued to see encouraging signs of recovery. The loan book managed by this segment amounted to Ch$13,971,237 million in September 2026, which represent a YoY rise of Ch$533,272 million or 4.0% compared to September 2025 and a notable year-to-date increase of Ch$1,263,002 million or 9.9% when contrasted to December 2025. This is particularly remarkable in light of the revised growth forecast provided by the Central Bank for private investment and GDP for 2026, which is in line with a slugggish business sentiment across the economy that has certainly taken a toll on borrowing from companies this year. In this regard, it is important to note that although the economic reactivation bill was passed by the Congress in August 2026, the measures addressed by the future law are not expected to have an immediate effect on economic growth but rather to pave the way for improved economic activity in the medium-term. Accordingly, since a more positive and clearer investment environment is expected from 2027 onwards, we expect wholesale lending to significantly reactivate during next year. Notwithstanding the above, the recent evolution of the Wholesale Banking loan book relied on mixed factors, including: Loans handled by our Corporate Banking Unit that increased Ch$534,810 million or 6.4% YoY by amounting to Ch$8,856,088 million as of September 30, 2026. This figure, in turn, represented a Ch$1,091,425 million or 14.1% year-to-date rise from the level recorded in December 2025. In September 2026 this banking unit performed positively in both: (i) Commercial Credits that rose Ch$483,936 million or 7.1% YoY when compared to September 2025, fostered by increased volumes of credits in the concessions, natural resources and retail industries, and (ii) Factoring loans that increased Ch$385,345 million or 89.9% YoY compared to September 2025, heavily concentrated in customers belonging to the natural resources industry, due to improved value offerings we have developed for this lending product across all business segments over the last years.
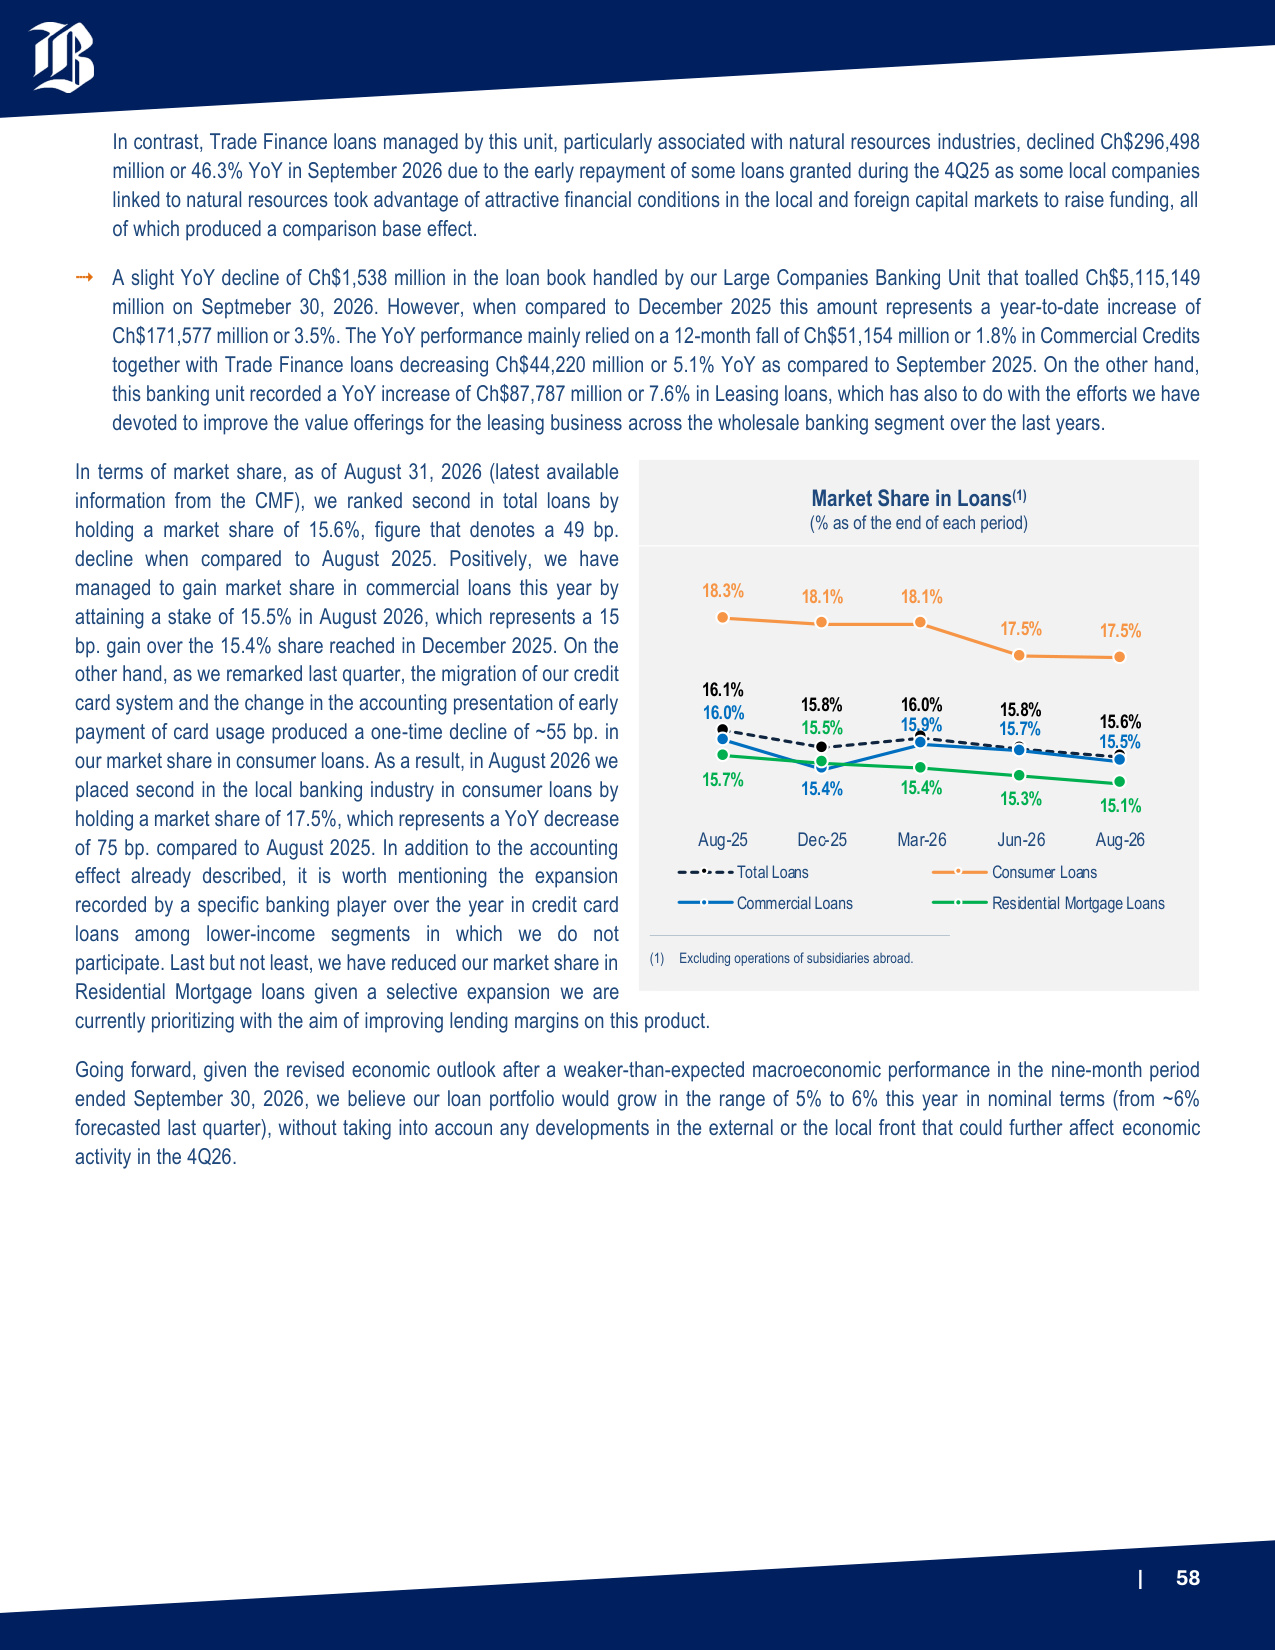
| 58 In contrast, Trade Finance loans managed by this unit, particularly associated with natural resources industries, declined Ch$296,498 million or 46.3% YoY in September 2026 due to the early repayment of some loans granted during the 4Q25 as some local companies linked to natural resources took advantage of attractive financial conditions in the local and foreign capital markets to raise funding, all of which produced a comparison base effect. A slight YoY decline of Ch$1,538 million in the loan book handled by our Large Companies Banking Unit that toalled Ch$5,115,149 million on Septmeber 30, 2026. However, when compared to December 2025 this amount represents a year-to-date increase of Ch$171,577 million or 3.5%. The YoY performance mainly relied on a 12-month fall of Ch$51,154 million or 1.8% in Commercial Credits together with Trade Finance loans decreasing Ch$44,220 million or 5.1% YoY as compared to September 2025. On the other hand, this banking unit recorded a YoY increase of Ch$87,787 million or 7.6% in Leasing loans, which has also to do with the efforts we have devoted to improve the value offerings for the leasing business across the wholesale banking segment over the last years. In terms of market share, as of August 31, 2026 (latest available information from the CMF), we ranked second in total loans by holding a market share of 15.6%, figure that denotes a 49 bp. decline when compared to August 2025. Positively, we have managed to gain market share in commercial loans this year by attaining a stake of 15.5% in August 2026, which represents a 15 bp. gain over the 15.4% share reached in December 2025. On the other hand, as we remarked last quarter, the migration of our credit card system and the change in the accounting presentation of early payment of card usage produced a one-time decline of ~55 bp. in our market share in consumer loans. As a result, in August 2026 we placed second in the local banking industry in consumer loans by holding a market share of 17.5%, which represents a YoY decrease of 75 bp. compared to August 2025. In addition to the accounting effect already described, it is worth mentioning the expansion recorded by a specific banking player over the year in credit card loans among lower-income segments in which we do not participate. Last but not least, we have reduced our market share in Residential Mortgage loans given a selective expansion we are currently prioritizing with the aim of improving lending margins on this product. Going forward, given the revised economic outlook after a weaker-than-expected macroeconomic performance in the nine-month period ended September 30, 2026, we believe our loan portfolio would grow in the range of 5% to 6% this year in nominal terms (from ~6% forecasted last quarter), without taking into accoun any developments in the external or the local front that could further affect economic activity in the 4Q26. Market Share in Loans(1) (% as of the end of each period) 16.1% 15.8% 16.0% 15.8% 15.6% 18.3% 18.1% 18.1% 17.5% 17.5% 16.0% 15.4% 15.9% 15.7% 15.5% 15.7% 15.5% 15.4% 15.3% 15.1% Aug-25 Dec-25 Mar-26 Jun-26 Aug-26 Total Loans Consumer Loans Commercial Loans Residential Mortgage Loans (1) Excluding operations of subsidiaries abroad.
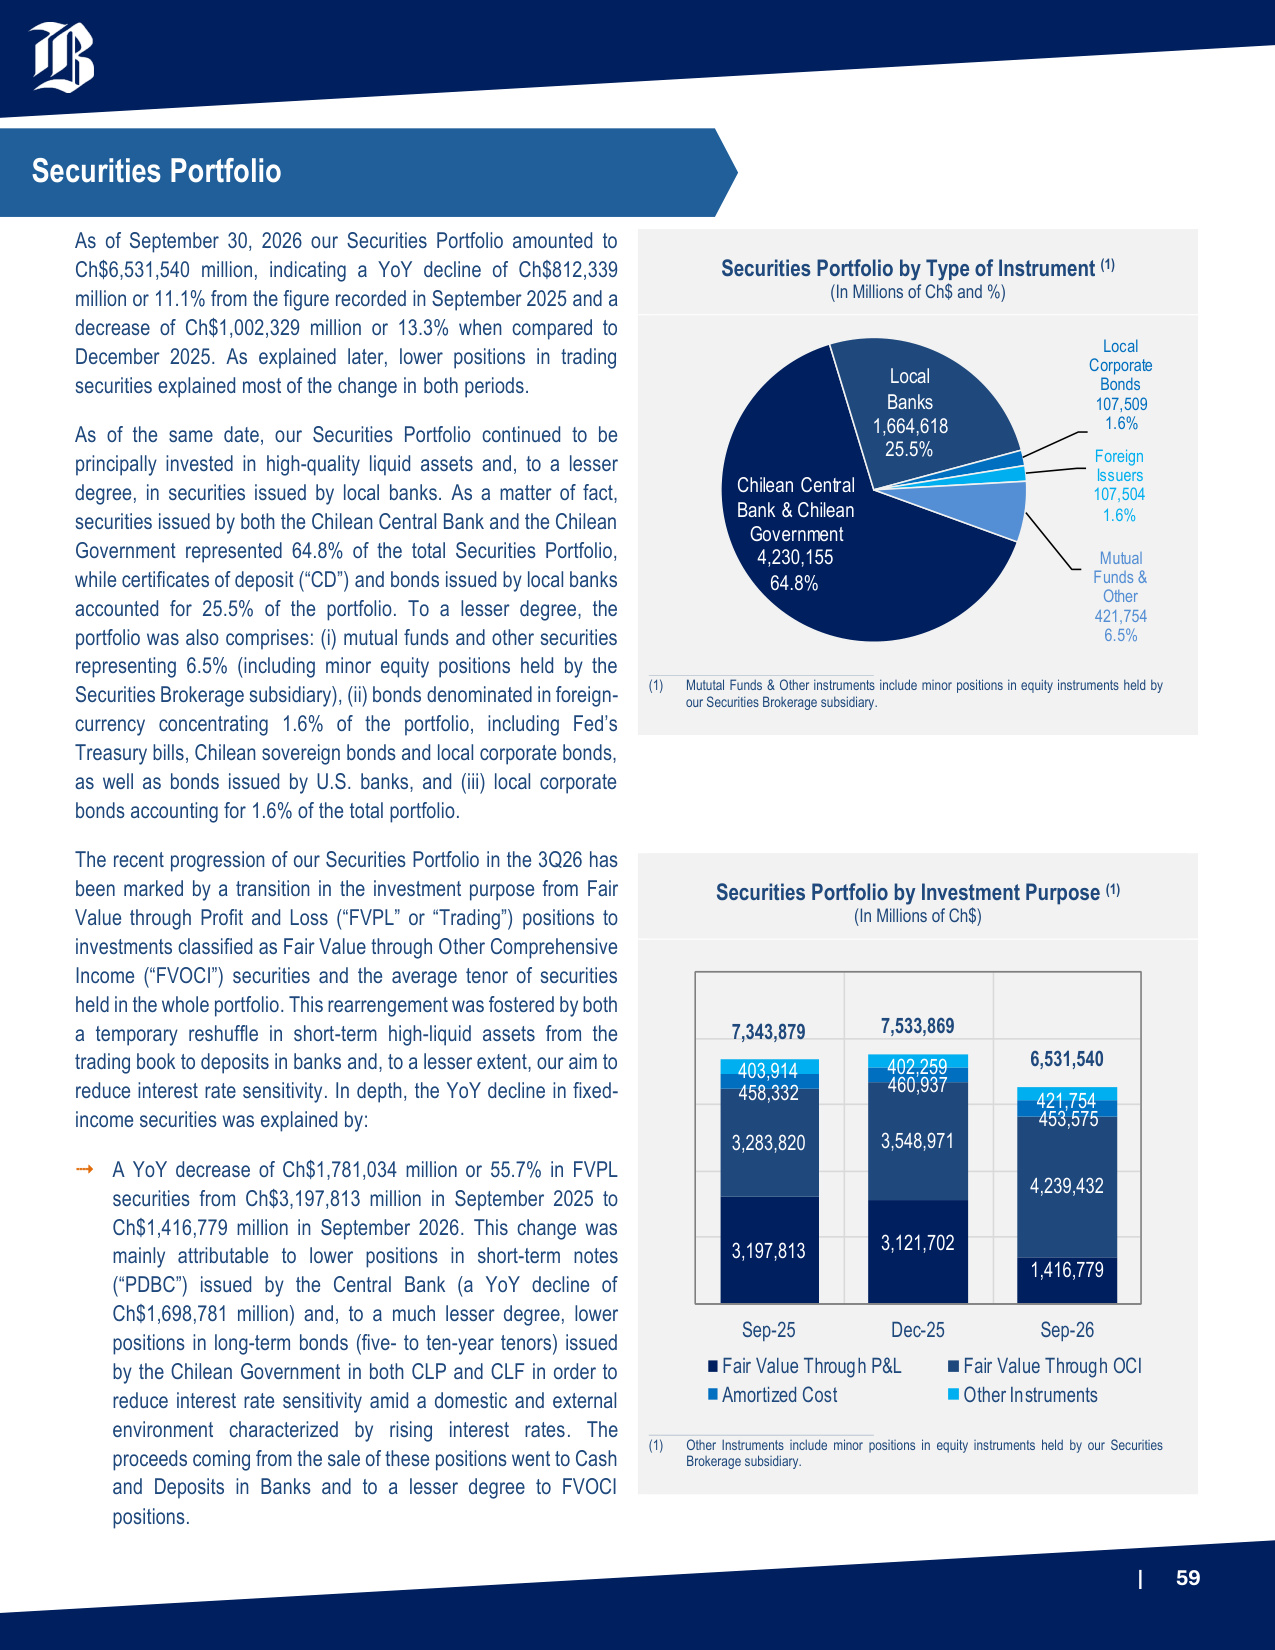
| 59 As of September 30, 2026 our Securities Portfolio amounted to Ch$6,531,540 million, indicating a YoY decline of Ch$812,339 million or 11.1% from the figure recorded in September 2025 and a decrease of Ch$1,002,329 million or 13.3% when compared to December 2025. As explained later, lower positions in trading securities explained most of the change in both periods. As of the same date, our Securities Portfolio continued to be principally invested in high-quality liquid assets and, to a lesser degree, in securities issued by local banks. As a matter of fact, securities issued by both the Chilean Central Bank and the Chilean Government represented 64.8% of the total Securities Portfolio, while certificates of deposit ("CD") and bonds issued by local banks accounted for 25.5% of the portfolio. To a lesser degree, the portfolio was also comprises: (i) mutual funds and other securities representing 6.5% (including minor equity positions held by the Securities Brokerage subsidiary), (ii) bonds denominated in foreign- currency concentrating 1.6% of the portfolio, including Fed's Treasury bills, Chilean sovereign bonds and local corporate bonds, as well as bonds issued by U.S. banks, and (iii) local corporate bonds accounting for 1.6% of the total portfolio. The recent progression of our Securities Portfolio in the 3Q26 has been marked by a transition in the investment purpose from Fair Value through Profit and Loss ("FVPL" or "Trading") positions to investments classified as Fair Value through Other Comprehensive Income ("FVOCI") securities and the average tenor of securities held in the whole portfolio. This rearrengement was fostered by both a temporary reshuffle in short-term high-liquid assets from the trading book to deposits in banks and, to a lesser extent, our aim to reduce interest rate sensitivity. In depth, the YoY decline in fixed- income securities was explained by: A YoY decrease of Ch$1,781,034 million or 55.7% in FVPL securities from Ch$3,197,813 million in September 2025 to Ch$1,416,779 million in September 2026. This change was mainly attributable to lower positions in short-term notes ("PDBC") issued by the Central Bank (a YoY decline of Ch$1,698,781 million) and, to a much lesser degree, lower positions in long-term bonds (five- to ten-year tenors) issued by the Chilean Government in both CLP and CLF in order to reduce interest rate sensitivity amid a domestic and external environment characterized by rising interest rates. The proceeds coming from the sale of these positions went to Cash and Deposits in Banks and to a lesser degree to FVOCI positions. Securities Portfolio by Type of Instrument (1) (In Millions of Ch$ and %) Chilean Central Bank & Chilean Government 4,230,155 64.8% Local Banks 1,664,618 25.5% Local Corporate Bonds 107,509 1.6% Foreign Issuers 107,504 1.6% Mutual Funds & Other 421,754 6.5% (1) Mututal Funds & Other instruments include minor positions in equity instruments held by our Securities Brokerage subsidiary. Securities Portfolio by Investment Purpose (1) (In Millions of Ch$) 3,197,813 3,121,702 1,416,779 3,283,820 3,548,971 4,239,432 458,332 460,937 453,575 403,914 402,259 421,754 7,343,879 7,533,869 6,531,540 Sep-25 Dec-25 Sep-26 Fair Value Through P&L Fair Value Through OCI Amortized Cost Other Instruments (1) Other Instruments include minor positions in equity instruments held by our Securities Brokerage subsidiary. Securities Portfolio
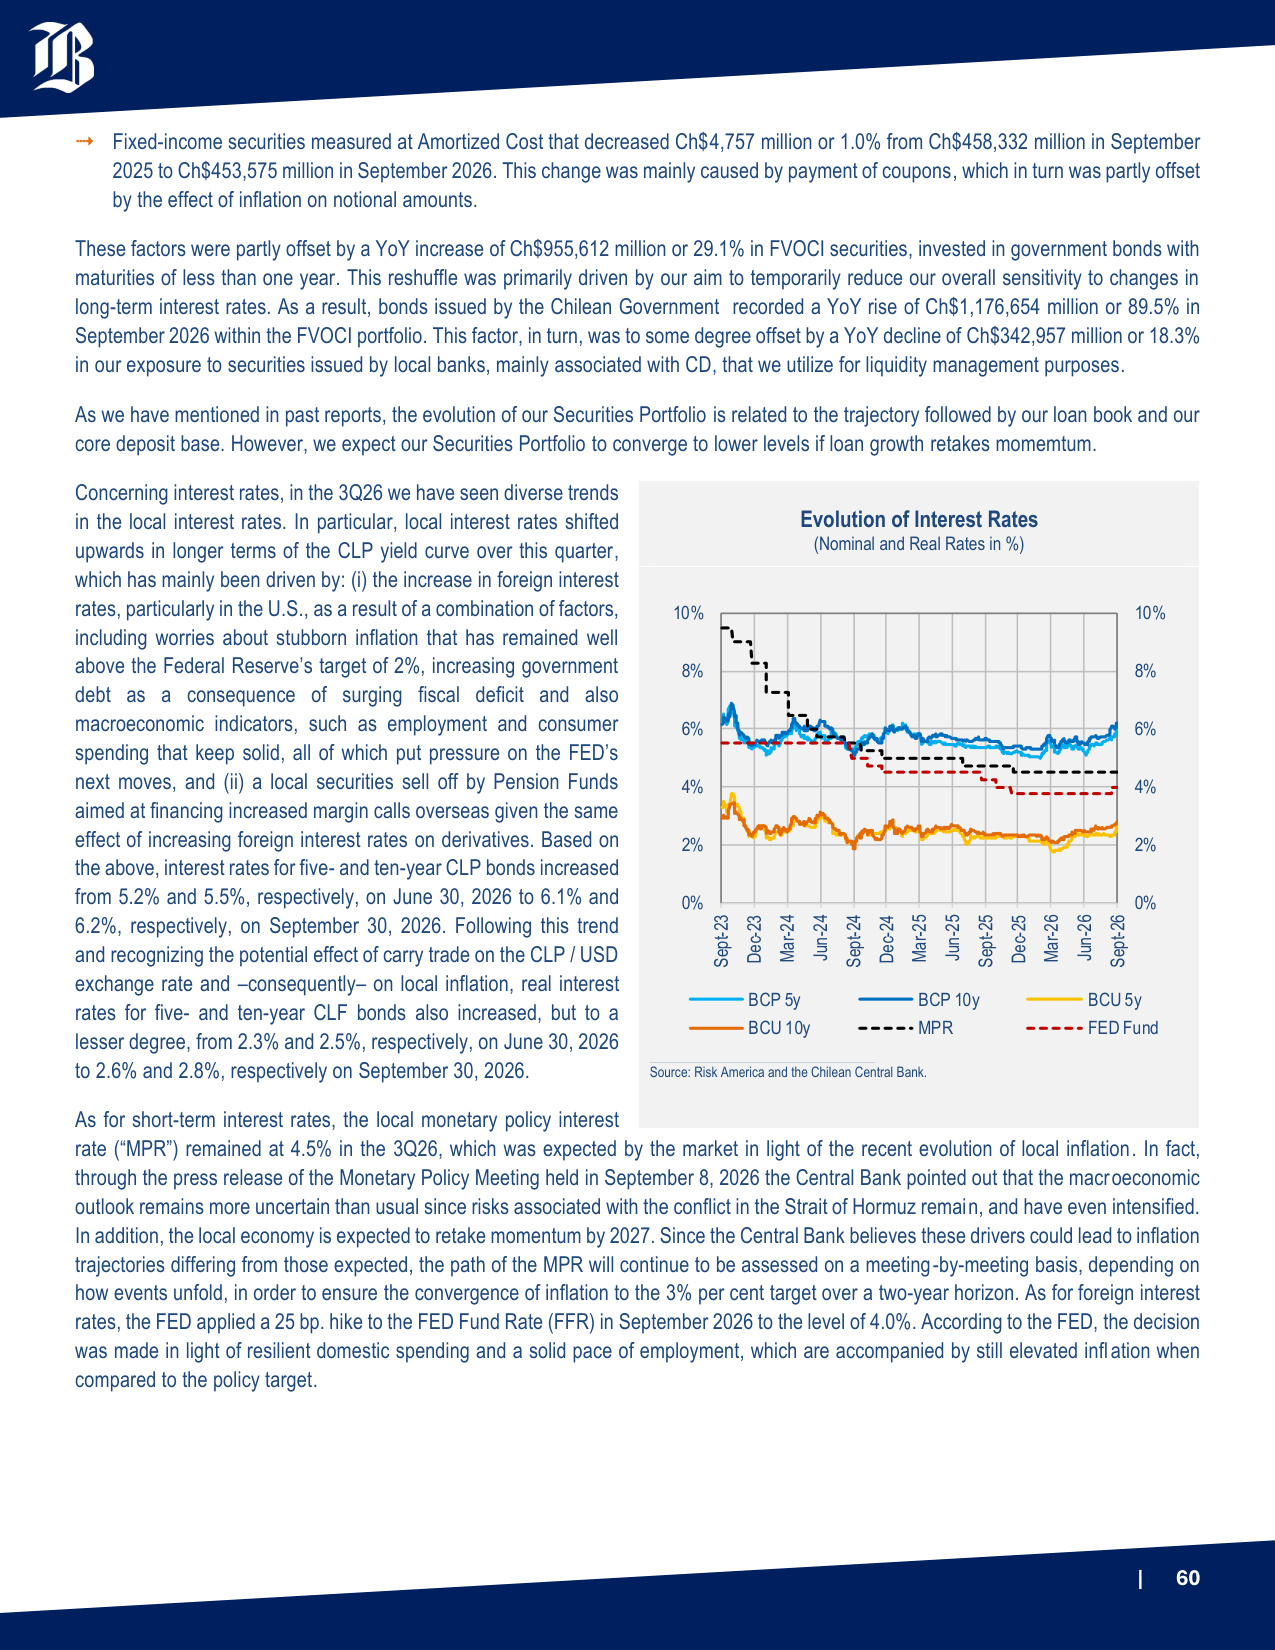
| 60 Fixed-income securities measured at Amortized Cost that decreased Ch$4,757 million or 1.0% from Ch$458,332 million in September 2025 to Ch$453,575 million in September 2026. This change was mainly caused by payment of coupons, which in turn was partly offset by the effect of inflation on notional amounts. These factors were partly offset by a YoY increase of Ch$955,612 million or 29.1% in FVOCI securities, invested in government bonds with maturities of less than one year. This reshuffle was primarily driven by our aim to temporarily reduce our overall sensitivity to changes in long-term interest rates. As a result, bonds issued by the Chilean Government recorded a YoY rise of Ch$1,176,654 million or 89.5% in September 2026 within the FVOCI portfolio. This factor, in turn, was to some degree offset by a YoY decline of Ch$342,957 million or 18.3% in our exposure to securities issued by local banks, mainly associated with CD, that we utilize for liquidity management purposes. As we have mentioned in past reports, the evolution of our Securities Portfolio is related to the trajectory followed by our loan book and our core deposit base. However, we expect our Securities Portfolio to converge to lower levels if loan growth retakes momemtum. Concerning interest rates, in the 3Q26 we have seen diverse trends in the local interest rates. In particular, local interest rates shifted upwards in longer terms of the CLP yield curve over this quarter, which has mainly been driven by: (i) the increase in foreign interest rates, particularly in the U.S., as a result of a combination of factors, including worries about stubborn inflation that has remained well above the Federal Reserve's target of 2%, increasing government debt as a consequence of surging fiscal deficit and also macroeconomic indicators, such as employment and consumer spending that keep solid, all of which put pressure on the FED's next moves, and (ii) a local securities sell off by Pension Funds aimed at financing increased margin calls overseas given the same effect of increasing foreign interest rates on derivatives. Based on the above, interest rates for five- and ten-year CLP bonds increased from 5.2% and 5.5%, respectively, on June 30, 2026 to 6.1% and 6.2%, respectively, on September 30, 2026. Following this trend and recognizing the potential effect of carry trade on the CLP / USD exchange rate and –consequently– on local inflation, real interest rates for five- and ten-year CLF bonds also increased, but to a lesser degree, from 2.3% and 2.5%, respectively, on June 30, 2026 to 2.6% and 2.8%, respectively on September 30, 2026. As for short-term interest rates, the local monetary policy interest rate ("MPR") remained at 4.5% in the 3Q26, which was expected by the market in light of the recent evolution of local inflation. In fact, through the press release of the Monetary Policy Meeting held in September 8, 2026 the Central Bank pointed out that the macroeconomic outlook remains more uncertain than usual since risks associated with the conflict in the Strait of Hormuz remain, and have even intensified. In addition, the local economy is expected to retake momentum by 2027. Since the Central Bank believes these drivers could lead to inflation trajectories differing from those expected, the path of the MPR will continue to be assessed on a meeting-by-meeting basis, depending on how events unfold, in order to ensure the convergence of inflation to the 3% per cent target over a two-year horizon. As for foreign interest rates, the FED applied a 25 bp. hike to the FED Fund Rate (FFR) in September 2026 to the level of 4.0%. According to the FED, the decision was made in light of resilient domestic spending and a solid pace of employment, which are accompanied by still elevated inflation when compared to the policy target. Evolution of Interest Rates (Nominal and Real Rates in %) 0% 2% 4% 6% 8% 10% 0% 2% 4% 6% 8% 10% Sept-23 Dec-23 Mar-24 Jun-24 Sept-24 Dec-24 Mar-25 Jun-25 Sept-25 Dec-25 Mar-26 Jun-26 Sept-26 BCP 5y BCP 10y BCU 5y BCU 10y MPR FED Fund Source: Risk America and the Chilean Central Bank.
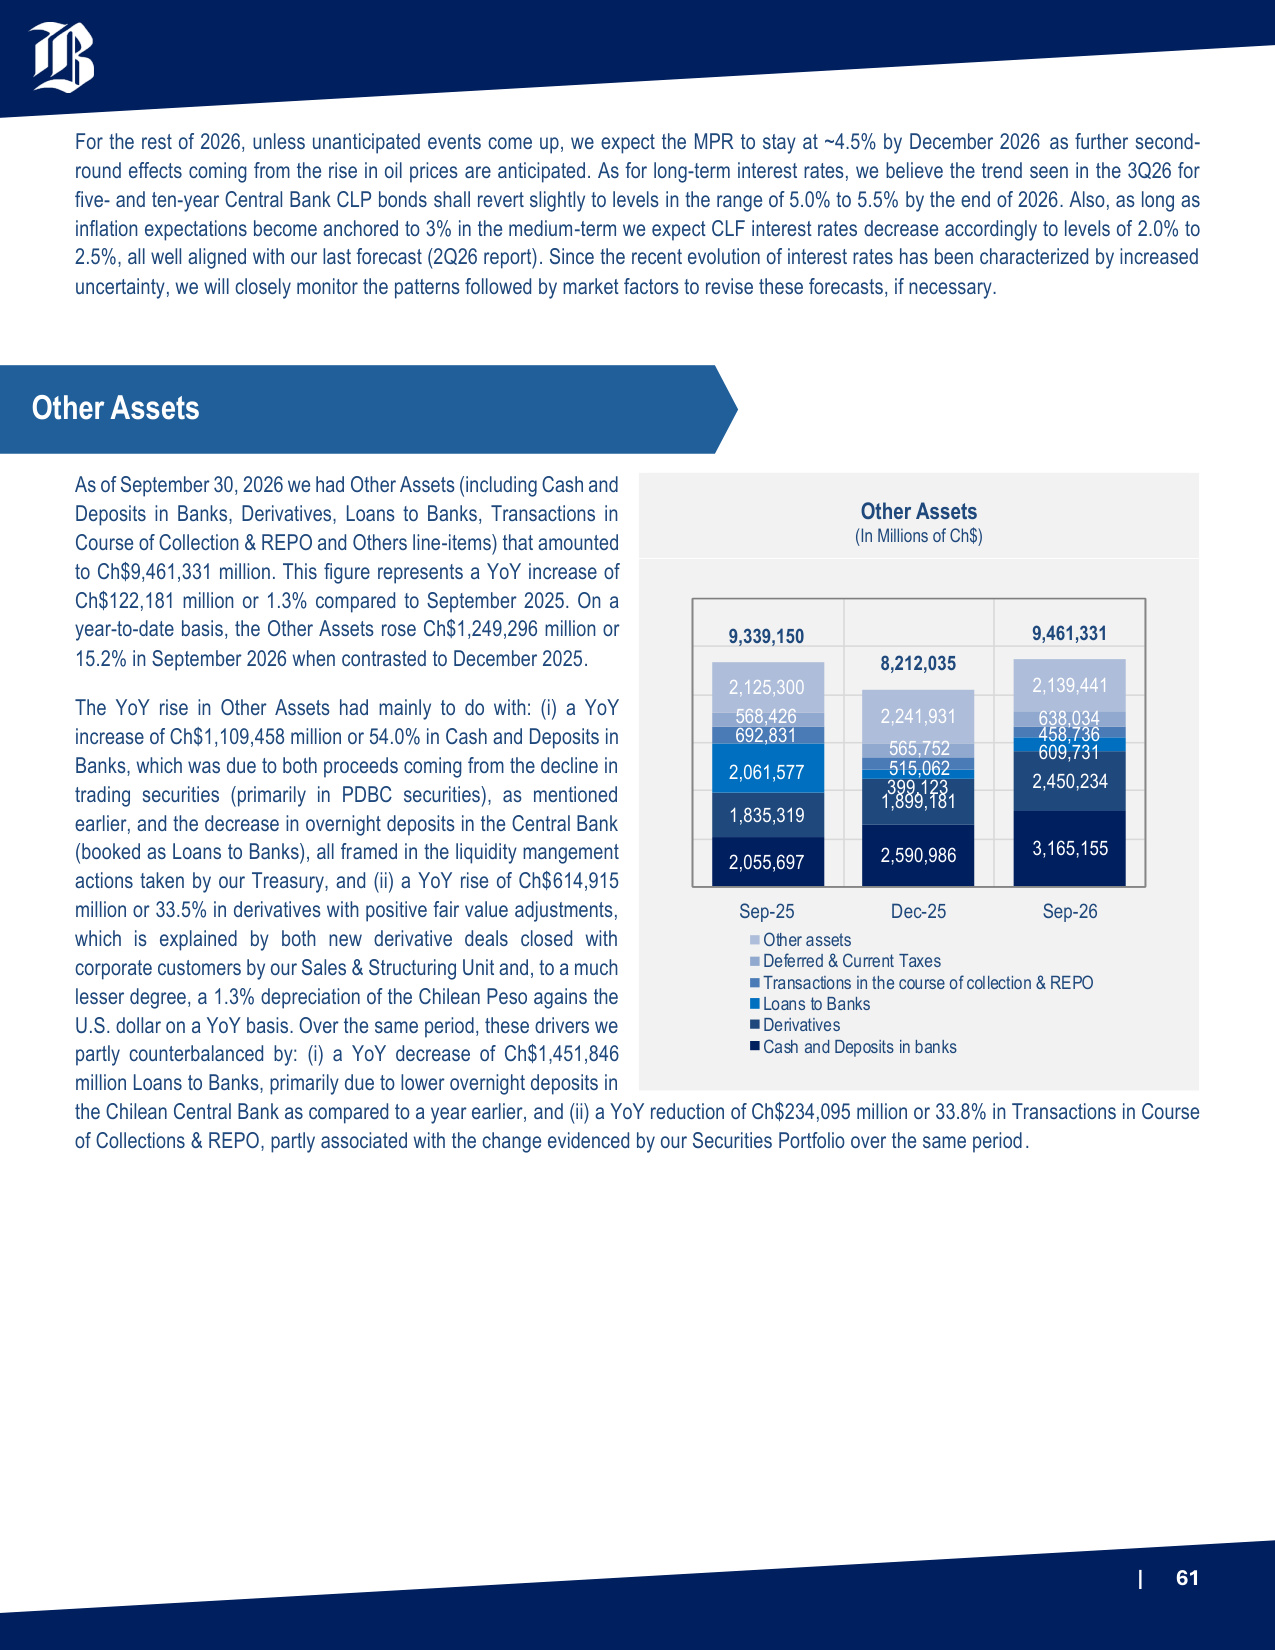
| 61 For the rest of 2026, unless unanticipated events come up, we expect the MPR to stay at ~4.5% by December 2026 as further second- round effects coming from the rise in oil prices are anticipated. As for long-term interest rates, we believe the trend seen in the 3Q26 for five- and ten-year Central Bank CLP bonds shall revert slightly to levels in the range of 5.0% to 5.5% by the end of 2026. Also, as long as inflation expectations become anchored to 3% in the medium-term we expect CLF interest rates decrease accordingly to levels of 2.0% to 2.5%, all well aligned with our last forecast (2Q26 report). Since the recent evolution of interest rates has been characterized by increased uncertainty, we will closely monitor the patterns followed by market factors to revise these forecasts, if necessary. As of September 30, 2026 we had Other Assets (including Cash and Deposits in Banks, Derivatives, Loans to Banks, Transactions in Course of Collection & REPO and Others line-items) that amounted to Ch$9,461,331 million. This figure represents a YoY increase of Ch$122,181 million or 1.3% compared to September 2025. On a year-to-date basis, the Other Assets rose Ch$1,249,296 million or 15.2% in September 2026 when contrasted to December 2025. The YoY rise in Other Assets had mainly to do with: (i) a YoY increase of Ch$1,109,458 million or 54.0% in Cash and Deposits in Banks, which was due to both proceeds coming from the decline in trading securities (primarily in PDBC securities), as mentioned earlier, and the decrease in overnight deposits in the Central Bank (booked as Loans to Banks), all framed in the liquidity mangement actions taken by our Treasury, and (ii) a YoY rise of Ch$614,915 million or 33.5% in derivatives with positive fair value adjustments, which is explained by both new derivative deals closed with corporate customers by our Sales & Structuring Unit and, to a much lesser degree, a 1.3% depreciation of the Chilean Peso agains the U.S. dollar on a YoY basis. Over the same period, these drivers we partly counterbalanced by: (i) a YoY decrease of Ch$1,451,846 million Loans to Banks, primarily due to lower overnight deposits in the Chilean Central Bank as compared to a year earlier, and (ii) a YoY reduction of Ch$234,095 million or 33.8% in Transactions in Course of Collections & REPO, partly associated with the change evidenced by our Securities Portfolio over the same period. Other Assets (In Millions of Ch$) 2,055,697 2,590,986 3,165,155 1,835,319 1,899,181 2,450,234 2,061,577 399,123 609,731 692,831 515,062 458,736 568,426 565,752 638,034 2,125,300 2,241,931 2,139,441 9,339,150 8,212,035 9,461,331 Sep-25 Dec-25 Sep-26 Other assets Deferred & Current Taxes Transactions in the course of collection & REPO Loans to Banks Derivatives Cash and Deposits in banks Other Assets
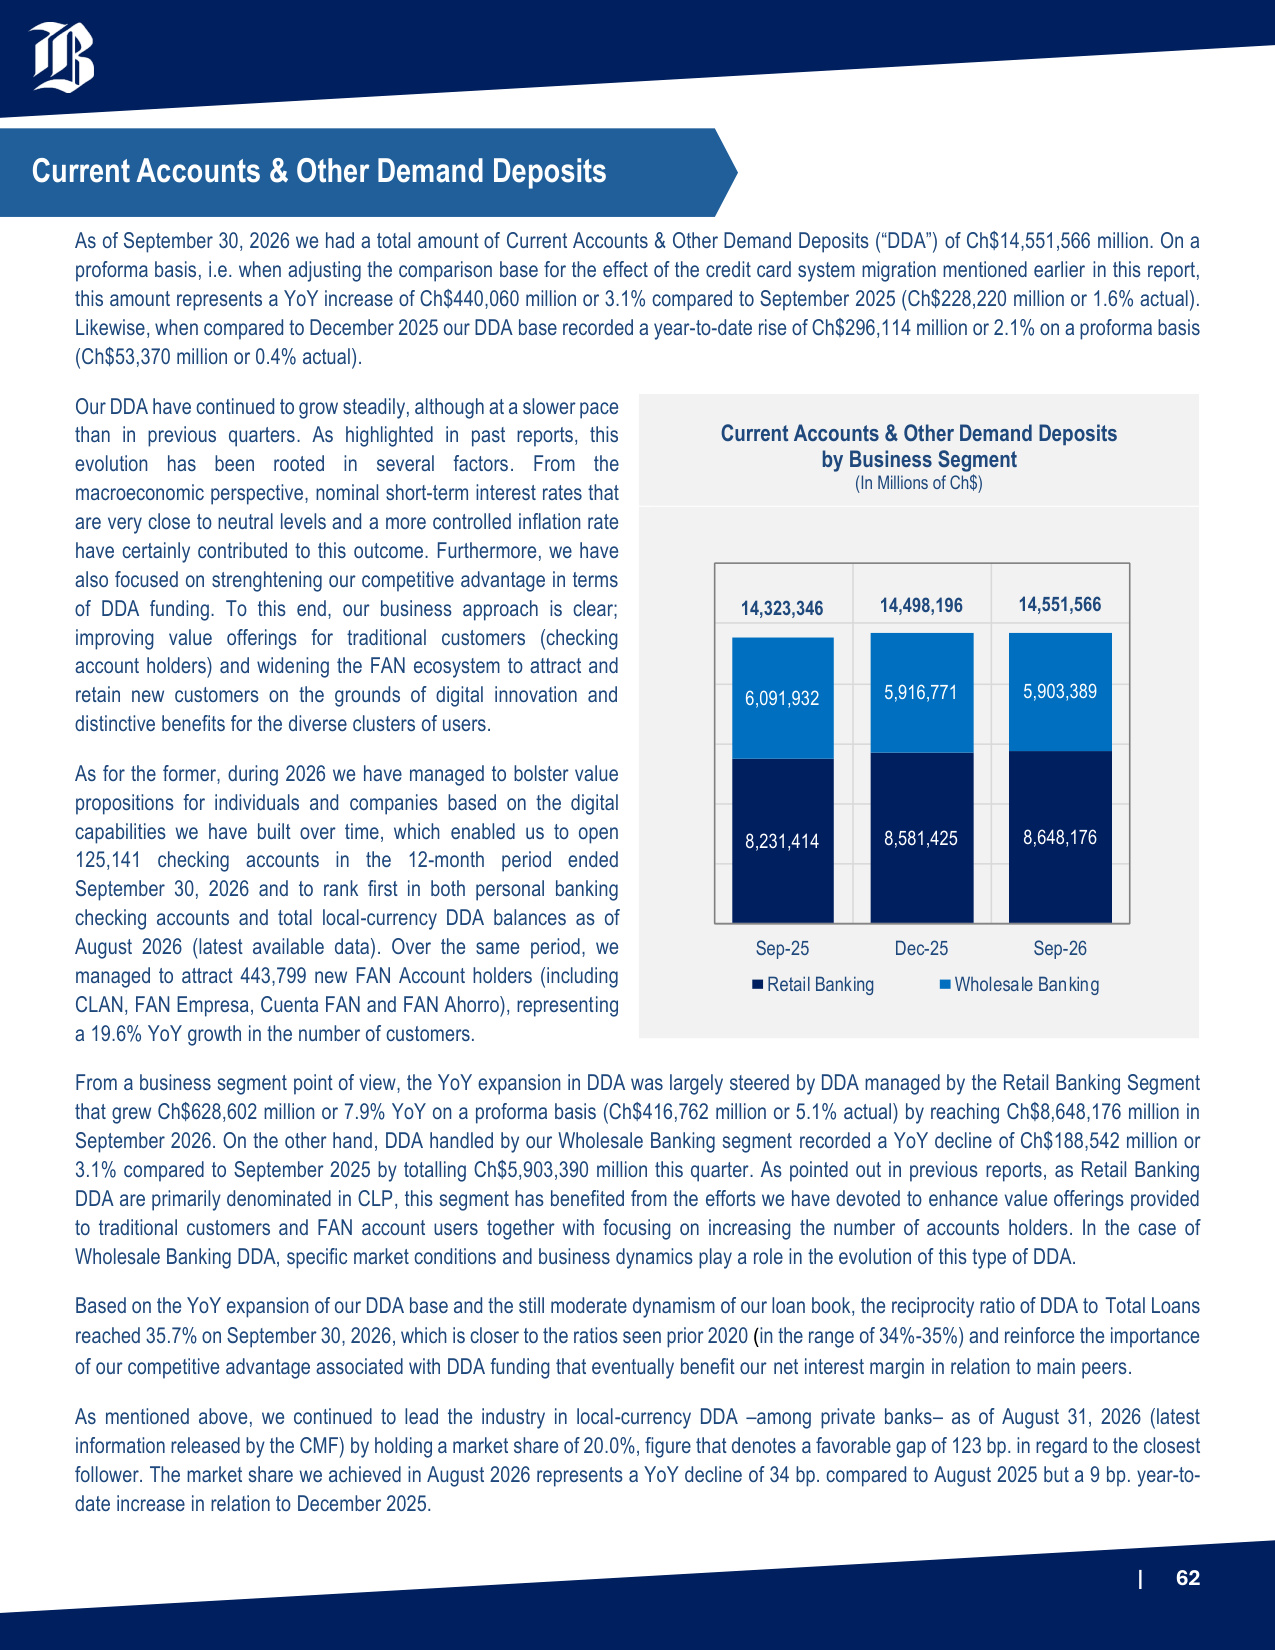
| 62 As of September 30, 2026 we had a total amount of Current Accounts & Other Demand Deposits ("DDA") of Ch$14,551,566 million. On a proforma basis, i.e. when adjusting the comparison base for the effect of the credit card system migration mentioned earlier in this report, this amount represents a YoY increase of Ch$440,060 million or 3.1% compared to September 2025 (Ch$228,220 million or 1.6% actual). Likewise, when compared to December 2025 our DDA base recorded a year-to-date rise of Ch$296,114 million or 2.1% on a proforma basis (Ch$53,370 million or 0.4% actual). Our DDA have continued to grow steadily, although at a slower pace than in previous quarters. As highlighted in past reports, this evolution has been rooted in several factors. From the macroeconomic perspective, nominal short-term interest rates that are very close to neutral levels and a more controlled inflation rate have certainly contributed to this outcome. Furthermore, we have also focused on strenghtening our competitive advantage in terms of DDA funding. To this end, our business approach is clear; improving value offerings for traditional customers (checking account holders) and widening the FAN ecosystem to attract and retain new customers on the grounds of digital innovation and distinctive benefits for the diverse clusters of users. As for the former, during 2026 we have managed to bolster value propositions for individuals and companies based on the digital capabilities we have built over time, which enabled us to open 125,141 checking accounts in the 12-month period ended September 30, 2026 and to rank first in both personal banking checking accounts and total local-currency DDA balances as of August 2026 (latest available data). Over the same period, we managed to attract 443,799 new FAN Account holders (including CLAN, FAN Empresa, Cuenta FAN and FAN Ahorro), representing a 19.6% YoY growth in the number of customers. From a business segment point of view, the YoY expansion in DDA was largely steered by DDA managed by the Retail Banking Segment that grew Ch$628,602 million or 7.9% YoY on a proforma basis (Ch$416,762 million or 5.1% actual) by reaching Ch$8,648,176 million in September 2026. On the other hand, DDA handled by our Wholesale Banking segment recorded a YoY decline of Ch$188,542 million or 3.1% compared to September 2025 by totalling Ch$5,903,390 million this quarter. As pointed out in previous reports, as Retail Banking DDA are primarily denominated in CLP, this segment has benefited from the efforts we have devoted to enhance value offerings provided to traditional customers and FAN account users together with focusing on increasing the number of accounts holders. In the case of Wholesale Banking DDA, specific market conditions and business dynamics play a role in the evolution of this type of DDA. Based on the YoY expansion of our DDA base and the still moderate dynamism of our loan book, the reciprocity ratio of DDA to Total Loans reached 35.7% on September 30, 2026, which is closer to the ratios seen prior 2020 (in the range of 34%-35%) and reinforce the importance of our competitive advantage associated with DDA funding that eventually benefit our net interest margin in relation to main peers. As mentioned above, we continued to lead the industry in local-currency DDA –among private banks– as of August 31, 2026 (latest information released by the CMF) by holding a market share of 20.0%, figure that denotes a favorable gap of 123 bp. in regard to the closest follower. The market share we achieved in August 2026 represents a YoY decline of 34 bp. compared to August 2025 but a 9 bp. year-to- date increase in relation to December 2025. Current Accounts & Other Demand Deposits by Business Segment (In Millions of Ch$) 8,231,414 8,581,425 8,648,176 6,091,932 5,916,771 5,903,389 14,323,346 14,498,196 14,551,566 Sep-25 Dec-25 Sep-26 Retail Banking Wholesale Banking Current Accounts & Other Demand Deposits
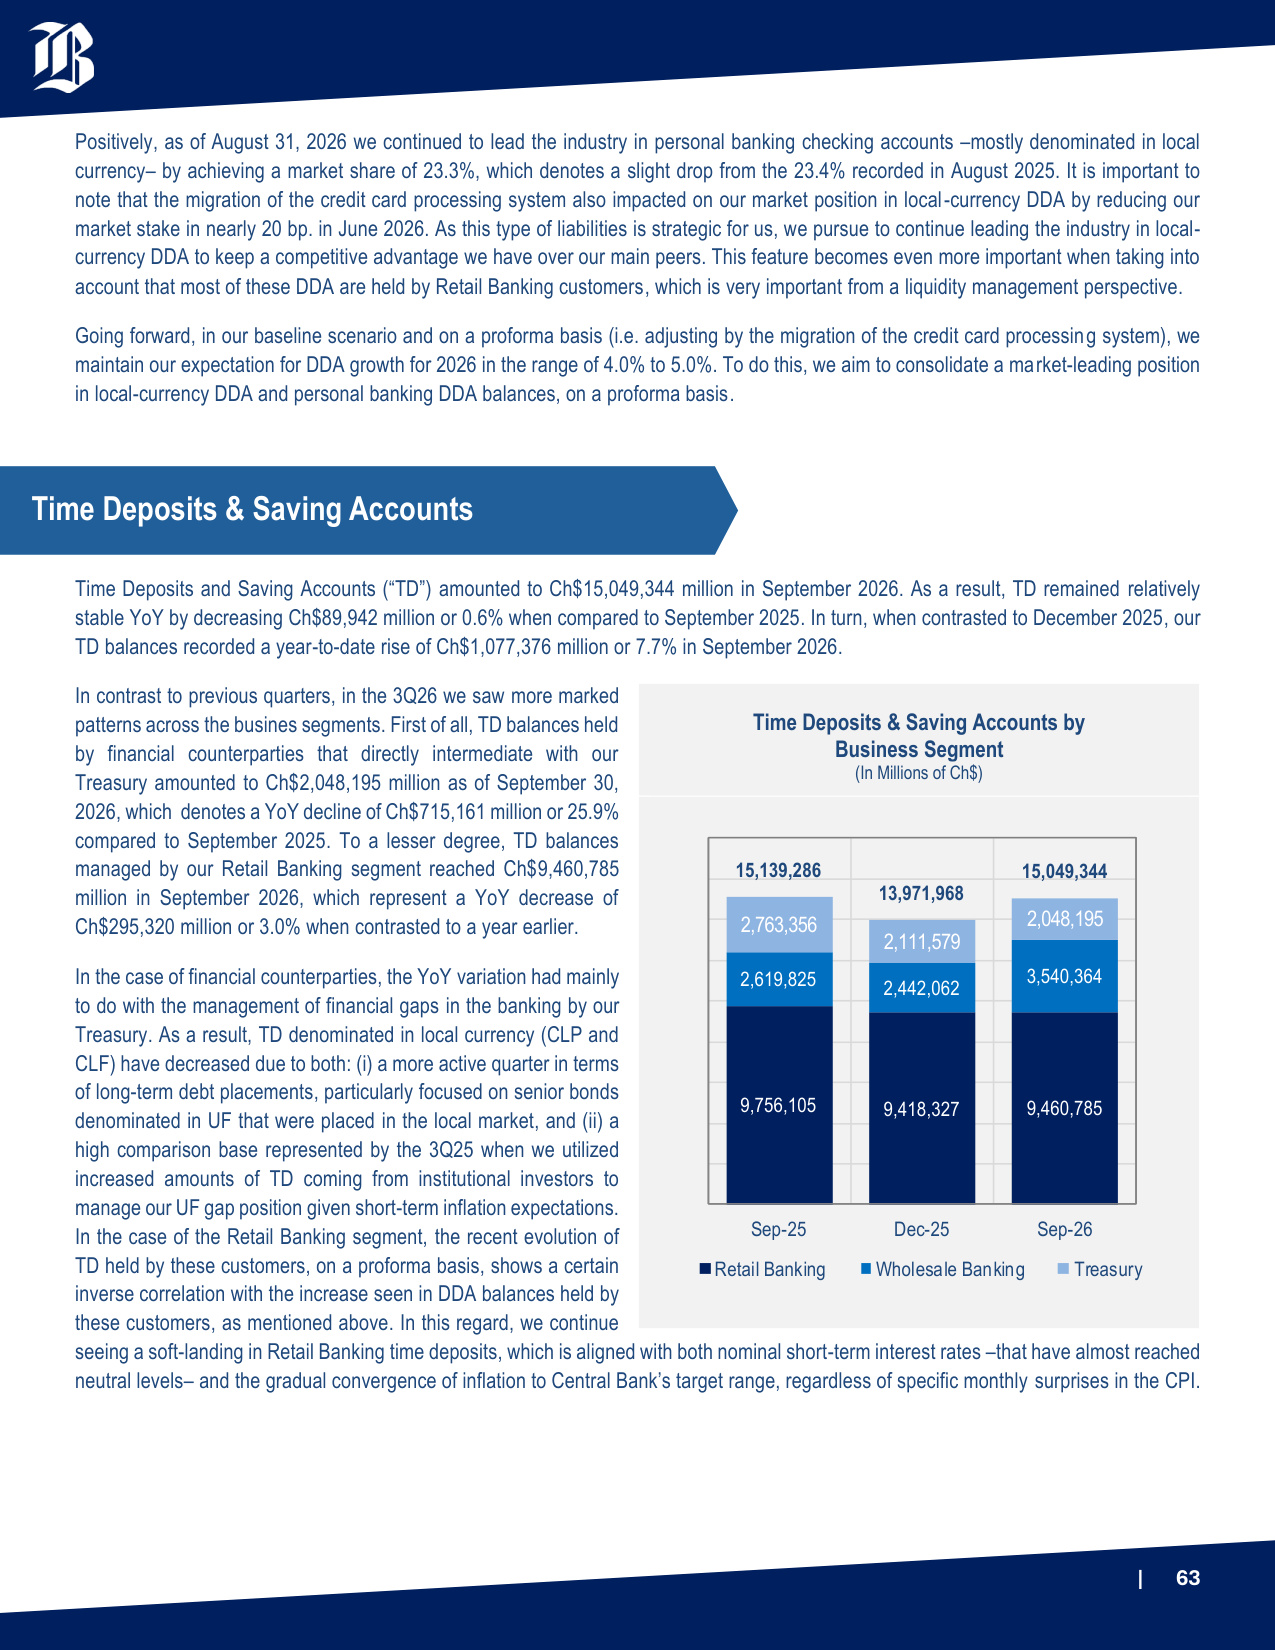
| 63 Positively, as of August 31, 2026 we continued to lead the industry in personal banking checking accounts –mostly denominated in local currency– by achieving a market share of 23.3%, which denotes a slight drop from the 23.4% recorded in August 2025. It is important to note that the migration of the credit card processing system also impacted on our market position in local-currency DDA by reducing our market stake in nearly 20 bp. in June 2026. As this type of liabilities is strategic for us, we pursue to continue leading the industry in local- currency DDA to keep a competitive advantage we have over our main peers. This feature becomes even more important when taking into account that most of these DDA are held by Retail Banking customers, which is very important from a liquidity management perspective. Going forward, in our baseline scenario and on a proforma basis (i.e. adjusting by the migration of the credit card processing system), we maintain our expectation for DDA growth for 2026 in the range of 4.0% to 5.0%. To do this, we aim to consolidate a market-leading position in local-currency DDA and personal banking DDA balances, on a proforma basis. Time Deposits and Saving Accounts ("TD") amounted to Ch$15,049,344 million in September 2026. As a result, TD remained relatively stable YoY by decreasing Ch$89,942 million or 0.6% when compared to September 2025. In turn, when contrasted to December 2025, our TD balances recorded a year-to-date rise of Ch$1,077,376 million or 7.7% in September 2026. In contrast to previous quarters, in the 3Q26 we saw more marked patterns across the busines segments. First of all, TD balances held by financial counterparties that directly intermediate with our Treasury amounted to Ch$2,048,195 million as of September 30, 2026, which denotes a YoY decline of Ch$715,161 million or 25.9% compared to September 2025. To a lesser degree, TD balances managed by our Retail Banking segment reached Ch$9,460,785 million in September 2026, which represent a YoY decrease of Ch$295,320 million or 3.0% when contrasted to a year earlier. In the case of financial counterparties, the YoY variation had mainly to do with the management of financial gaps in the banking by our Treasury. As a result, TD denominated in local currency (CLP and CLF) have decreased due to both: (i) a more active quarter in terms of long-term debt placements, particularly focused on senior bonds denominated in UF that were placed in the local market, and (ii) a high comparison base represented by the 3Q25 when we utilized increased amounts of TD coming from institutional investors to manage our UF gap position given short-term inflation expectations. In the case of the Retail Banking segment, the recent evolution of TD held by these customers, on a proforma basis, shows a certain inverse correlation with the increase seen in DDA balances held by these customers, as mentioned above. In this regard, we continue seeing a soft-landing in Retail Banking time deposits, which is aligned with both nominal short-term interest rates –that have almost reached neutral levels– and the gradual convergence of inflation to Central Bank's target range, regardless of specific monthly surprises in the CPI. Time Deposits & Saving Accounts by Business Segment (In Millions of Ch$) 9,756,105 9,418,327 9,460,785 2,619,825 2,442,062 3,540,364 2,763,356 2,111,579 2,048,195 15,139,286 13,971,968 15,049,344 Sep-25 Dec-25 Sep-26 Retail Banking Wholesale Banking Treasury Time Deposits & Saving Accounts
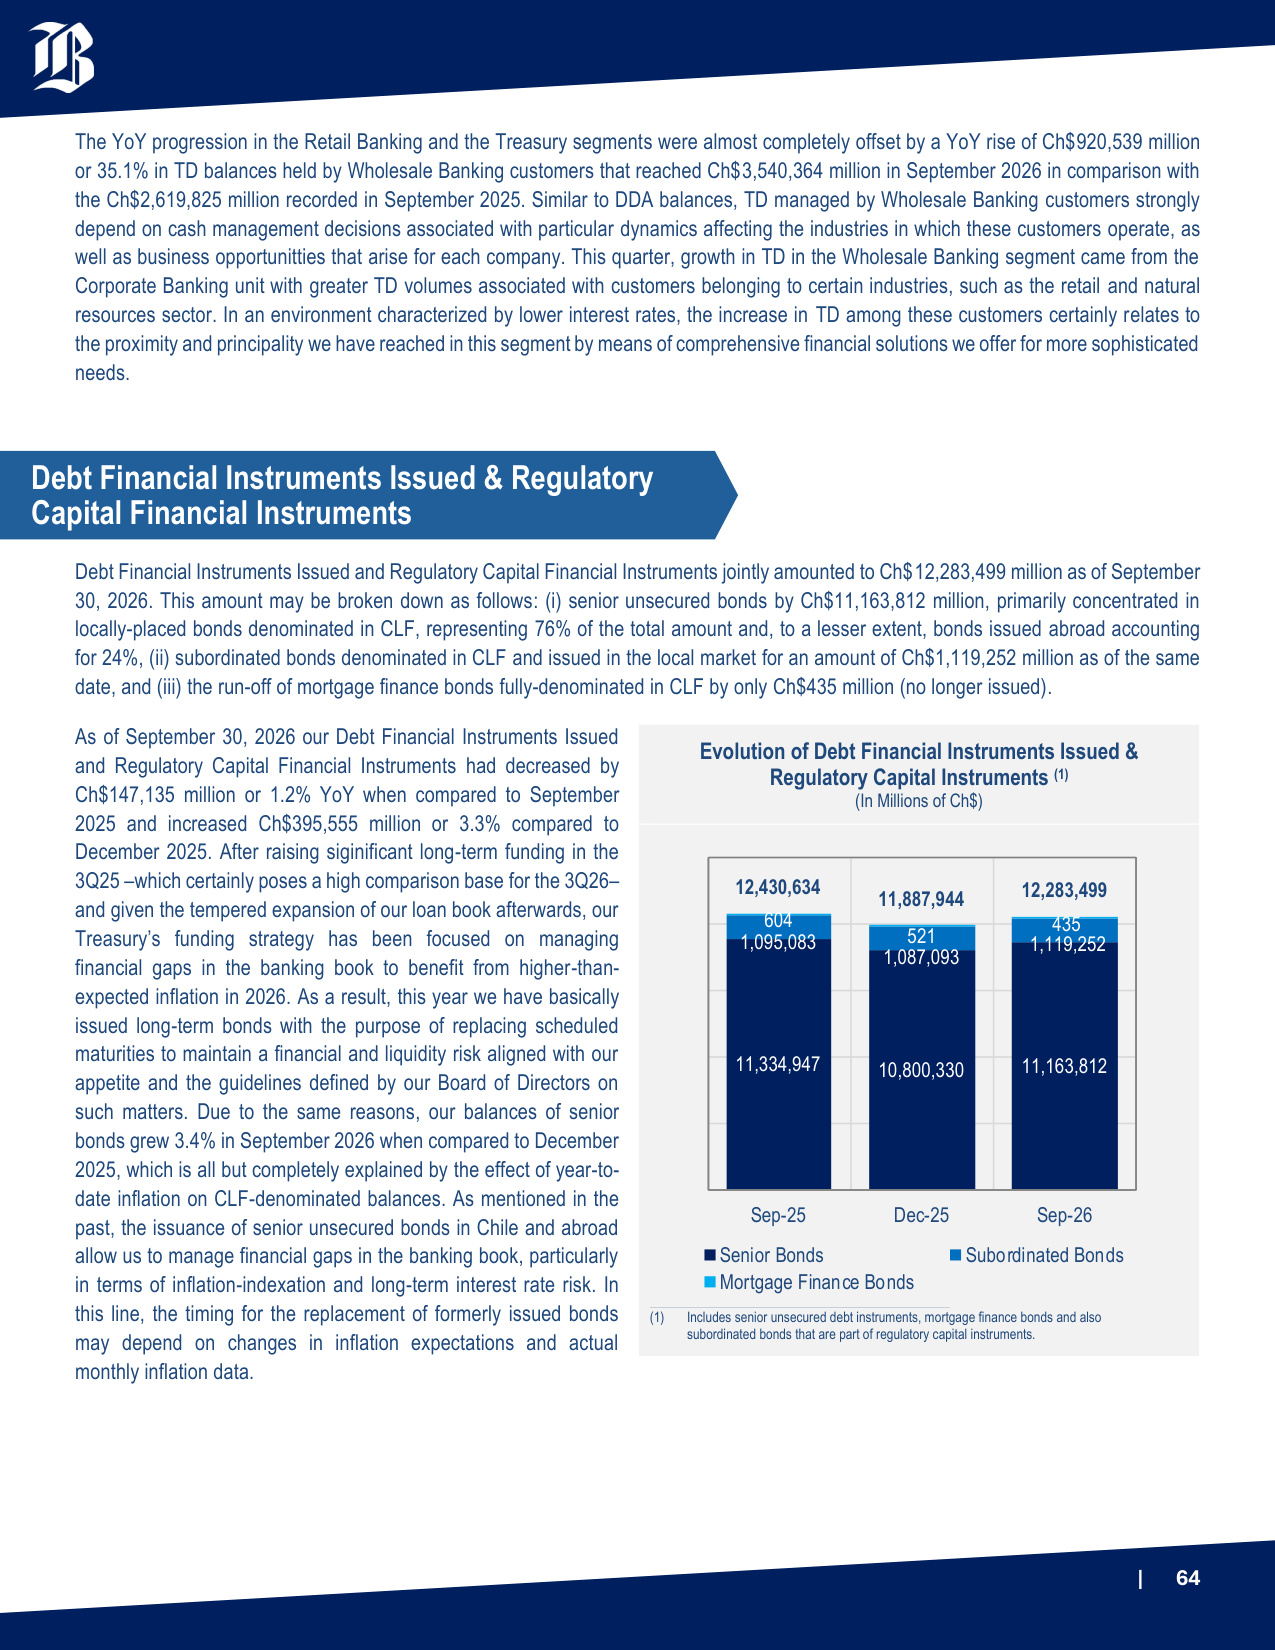
| 64 The YoY progression in the Retail Banking and the Treasury segments were almost completely offset by a YoY rise of Ch$920,539 million or 35.1% in TD balances held by Wholesale Banking customers that reached Ch$3,540,364 million in September 2026 in comparison with the Ch$2,619,825 million recorded in September 2025. Similar to DDA balances, TD managed by Wholesale Banking customers strongly depend on cash management decisions associated with particular dynamics affecting the industries in which these customers operate, as well as business opportunitties that arise for each company. This quarter, growth in TD in the Wholesale Banking segment came from the Corporate Banking unit with greater TD volumes associated with customers belonging to certain industries, such as the retail and natural resources sector. In an environment characterized by lower interest rates, the increase in TD among these customers certainly relates to the proximity and principality we have reached in this segment by means of comprehensive financial solutions we offer for more sophisticated needs. Debt Financial Instruments Issued and Regulatory Capital Financial Instruments jointly amounted to Ch$12,283,499 million as of September 30, 2026. This amount may be broken down as follows: (i) senior unsecured bonds by Ch$11,163,812 million, primarily concentrated in locally-placed bonds denominated in CLF, representing 76% of the total amount and, to a lesser extent, bonds issued abroad accounting for 24%, (ii) subordinated bonds denominated in CLF and issued in the local market for an amount of Ch$1,119,252 million as of the same date, and (iii) the run-off of mortgage finance bonds fully-denominated in CLF by only Ch$435 million (no longer issued). As of September 30, 2026 our Debt Financial Instruments Issued and Regulatory Capital Financial Instruments had decreased by Ch$147,135 million or 1.2% YoY when compared to September 2025 and increased Ch$395,555 million or 3.3% compared to December 2025. After raising siginificant long-term funding in the 3Q25 –which certainly poses a high comparison base for the 3Q26– and given the tempered expansion of our loan book afterwards, our Treasury's funding strategy has been focused on managing financial gaps in the banking book to benefit from higher-than- expected inflation in 2026. As a result, this year we have basically issued long-term bonds with the purpose of replacing scheduled maturities to maintain a financial and liquidity risk aligned with our appetite and the guidelines defined by our Board of Directors on such matters. Due to the same reasons, our balances of senior bonds grew 3.4% in September 2026 when compared to December 2025, which is all but completely explained by the effect of year-to- date inflation on CLF-denominated balances. As mentioned in the past, the issuance of senior unsecured bonds in Chile and abroad allow us to manage financial gaps in the banking book, particularly in terms of inflation-indexation and long-term interest rate risk. In this line, the timing for the replacement of formerly issued bonds may depend on changes in inflation expectations and actual monthly inflation data. Evolution of Debt Financial Instruments Issued & Regulatory Capital Instruments (1) (In Millions of Ch$) 11,334,947 10,800,330 11,163,812 1,095,083 1,087,093 1,119,252 604 521 435 12,430,634 11,887,944 12,283,499 Sep-25 Dec-25 Sep-26 Senior Bonds Subordinated Bonds Mortgage Finance Bonds (1) Includes senior unsecured debt instruments, mortgage finance bonds and also subordinated bonds that are part of regulatory capital instruments. Debt Financial Instruments Issued & Regulatory Capital Financial Instruments
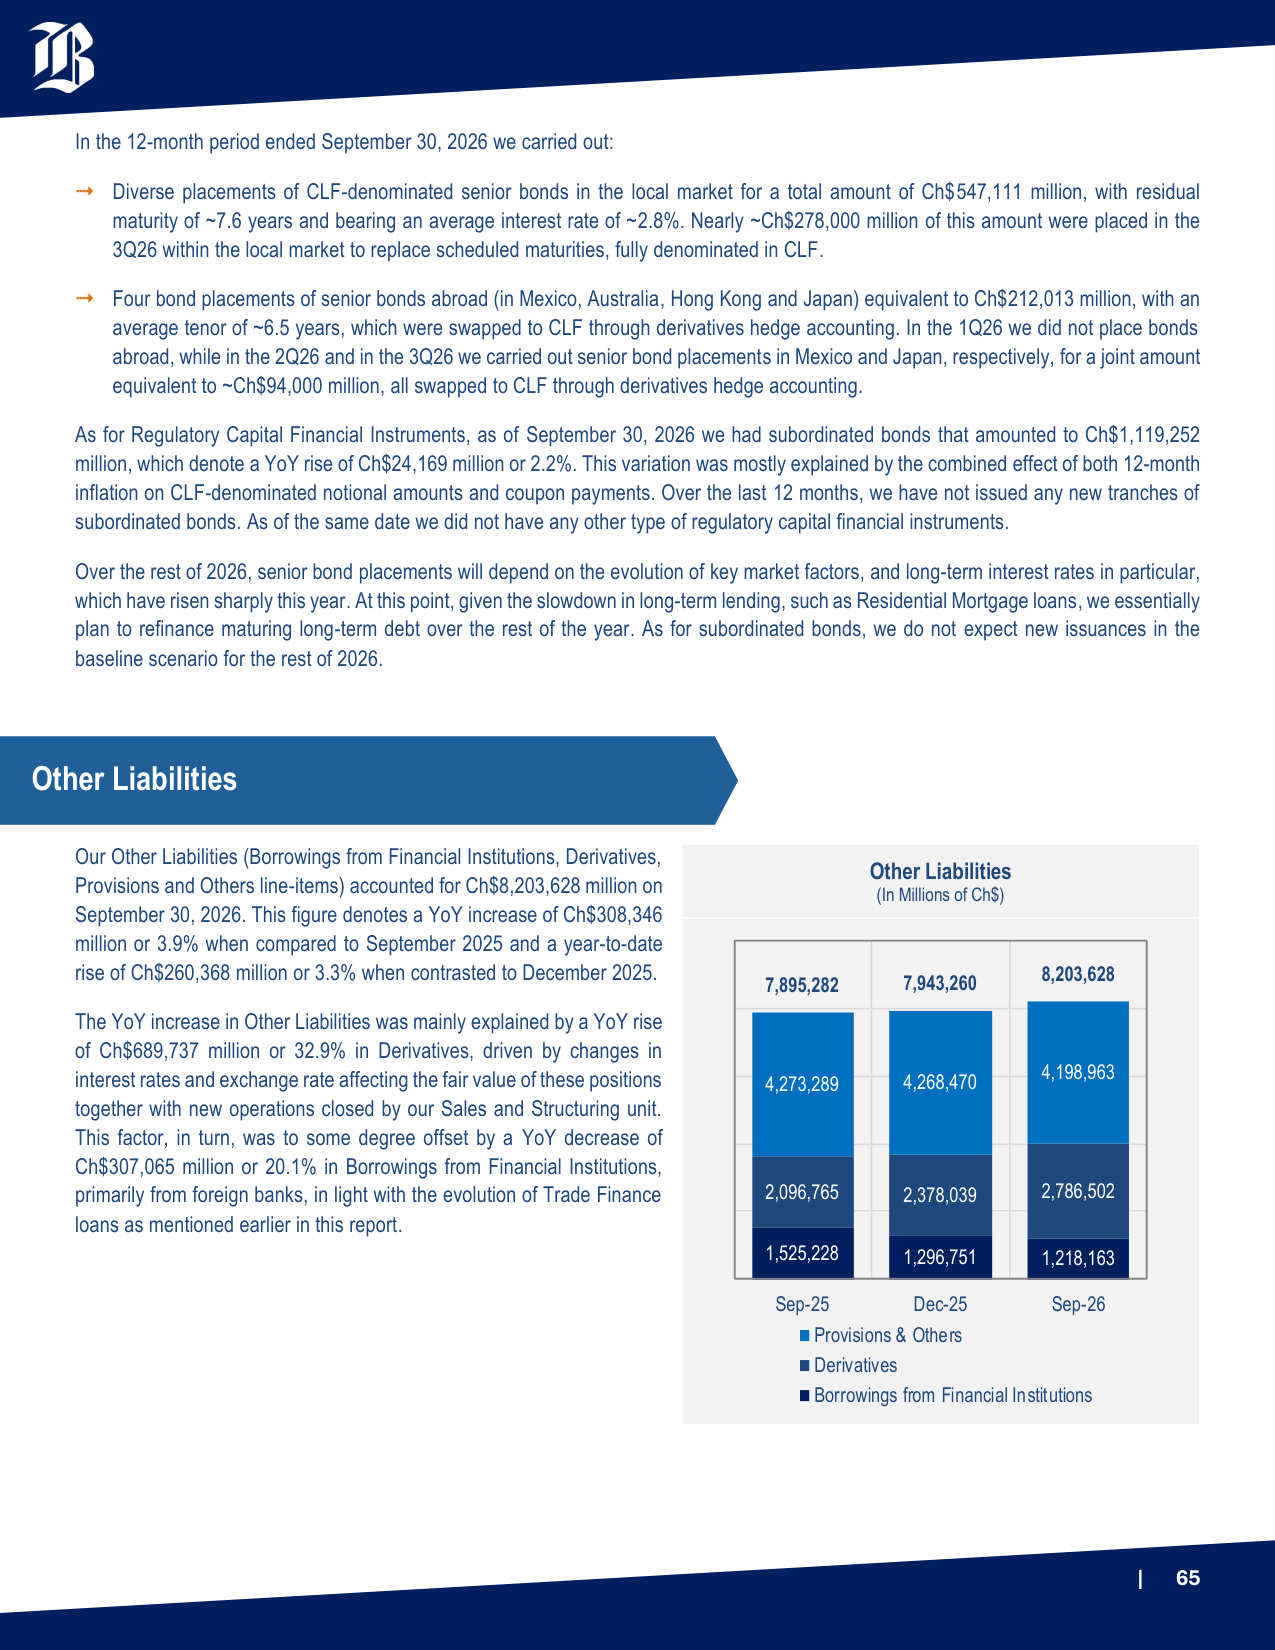
| 65 In the 12-month period ended September 30, 2026 we carried out: Diverse placements of CLF-denominated senior bonds in the local market for a total amount of Ch$547,111 million, with residual maturity of ~7.6 years and bearing an average interest rate of ~2.8%. Nearly ~Ch$278,000 million of this amount were placed in the 3Q26 within the local market to replace scheduled maturities, fully denominated in CLF. Four bond placements of senior bonds abroad (in Mexico, Australia, Hong Kong and Japan) equivalent to Ch$212,013 million, with an average tenor of ~6.5 years, which were swapped to CLF through derivatives hedge accounting. In the 1Q26 we did not place bonds abroad, while in the 2Q26 and in the 3Q26 we carried out senior bond placements in Mexico and Japan, respectively, for a joint amount equivalent to ~Ch$94,000 million, all swapped to CLF through derivatives hedge accounting. As for Regulatory Capital Financial Instruments, as of September 30, 2026 we had subordinated bonds that amounted to Ch$1,119,252 million, which denote a YoY rise of Ch$24,169 million or 2.2%. This variation was mostly explained by the combined effect of both 12-month inflation on CLF-denominated notional amounts and coupon payments. Over the last 12 months, we have not issued any new tranches of subordinated bonds. As of the same date we did not have any other type of regulatory capital financial instruments. Over the rest of 2026, senior bond placements will depend on the evolution of key market factors, and long-term interest rates in particular, which have risen sharply this year. At this point, given the slowdown in long-term lending, such as Residential Mortgage loans, we essentially plan to refinance maturing long-term debt over the rest of the year. As for subordinated bonds, we do not expect new issuances in the baseline scenario for the rest of 2026. Our Other Liabilities (Borrowings from Financial Institutions, Derivatives, Provisions and Others line-items) accounted for Ch$8,203,628 million on September 30, 2026. This figure denotes a YoY increase of Ch$308,346 million or 3.9% when compared to September 2025 and a year-to-date rise of Ch$260,368 million or 3.3% when contrasted to December 2025. The YoY increase in Other Liabilities was mainly explained by a YoY rise of Ch$689,737 million or 32.9% in Derivatives, driven by changes in interest rates and exchange rate affecting the fair value of these positions together with new operations closed by our Sales and Structuring unit. This factor, in turn, was to some degree offset by a YoY decrease of Ch$307,065 million or 20.1% in Borrowings from Financial Institutions, primarily from foreign banks, in light with the evolution of Trade Finance loans as mentioned earlier in this report. Other Liabilities (In Millions of Ch$) 1,525,228 1,296,751 1,218,163 2,096,765 2,378,039 2,786,502 4,273,289 4,268,470 4,198,963 7,895,282 7,943,260 8,203,628 Sep-25 Dec-25 Sep-26 Provisions & Others Derivatives Borrowings from Financial Institutions Other Liabilities
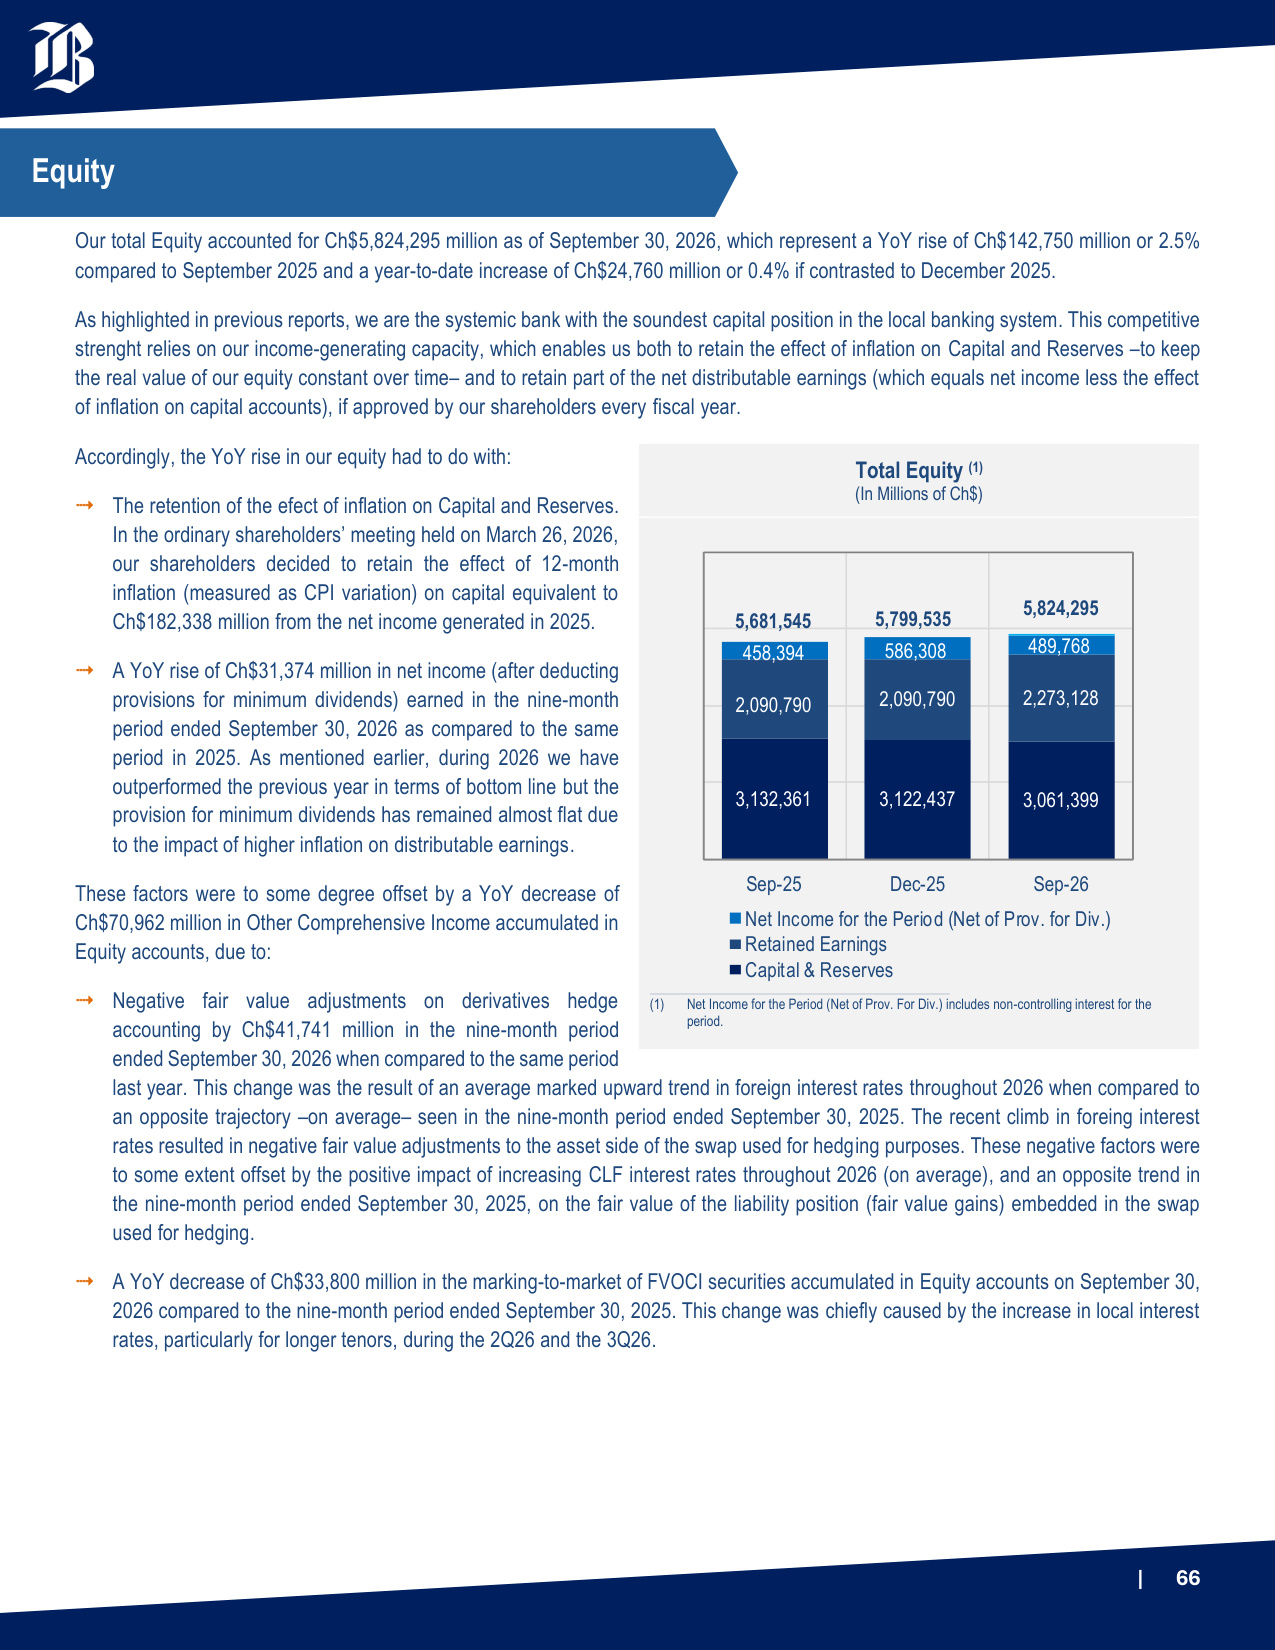
| 66 Our total Equity accounted for Ch$5,824,295 million as of September 30, 2026, which represent a YoY rise of Ch$142,750 million or 2.5% compared to September 2025 and a year-to-date increase of Ch$24,760 million or 0.4% if contrasted to December 2025. As highlighted in previous reports, we are the systemic bank with the soundest capital position in the local banking system. This competitive strenght relies on our income-generating capacity, which enables us both to retain the effect of inflation on Capital and Reserves –to keep the real value of our equity constant over time– and to retain part of the net distributable earnings (which equals net income less the effect of inflation on capital accounts), if approved by our shareholders every fiscal year. Accordingly, the YoY rise in our equity had to do with: The retention of the efect of inflation on Capital and Reserves. In the ordinary shareholders' meeting held on March 26, 2026, our shareholders decided to retain the effect of 12-month inflation (measured as CPI variation) on capital equivalent to Ch$182,338 million from the net income generated in 2025. A YoY rise of Ch$31,374 million in net income (after deducting provisions for minimum dividends) earned in the nine-month period ended September 30, 2026 as compared to the same period in 2025. As mentioned earlier, during 2026 we have outperformed the previous year in terms of bottom line but the provision for minimum dividends has remained almost flat due to the impact of higher inflation on distributable earnings. These factors were to some degree offset by a YoY decrease of Ch$70,962 million in Other Comprehensive Income accumulated in Equity accounts, due to: Negative fair value adjustments on derivatives hedge accounting by Ch$41,741 million in the nine-month period ended September 30, 2026 when compared to the same period last year. This change was the result of an average marked upward trend in foreign interest rates throughout 2026 when compared to an opposite trajectory –on average– seen in the nine-month period ended September 30, 2025. The recent climb in foreing interest rates resulted in negative fair value adjustments to the asset side of the swap used for hedging purposes. These negative factors were to some extent offset by the positive impact of increasing CLF interest rates throughout 2026 (on average), and an opposite trend in the nine-month period ended September 30, 2025, on the fair value of the liability position (fair value gains) embedded in the swap used for hedging. A YoY decrease of Ch$33,800 million in the marking-to-market of FVOCI securities accumulated in Equity accounts on September 30, 2026 compared to the nine-month period ended September 30, 2025. This change was chiefly caused by the increase in local interest rates, particularly for longer tenors, during the 2Q26 and the 3Q26. Total Equity (1) (In Millions of Ch$) 3,132,361 3,122,437 3,061,399 2,090,790 2,090,790 2,273,128 458,394 586,308 489,768 5,681,545 5,799,535 5,824,295 Sep-25 Dec-25 Sep-26 Net Income for the Period (Net of Prov. for Div.) Retained Earnings Capital & Reserves (1) Net Income for the Period (Net of Prov. For Div.) includes non-controlling interest for the period. Equity
| 67 Section 6 Risk & Capital Management
| 68 Approach to Risk Management Banco de Chile's risk profile ensures that its business can sustainably grow and is aligned with its strategic objectives in order to maximize value creation and guarantee its liquidity and capital adequacy. Global risk management takes into consideration the business segments served by the bank and its subsidiaries, which is approached from an integrated and differentiated perspective. The Bank's corporate governance relies on active participation by the board, in order to adequately manage risk, either directly or through committees composed of directors and senior management that have been described in the Corporate Governance section of this report. The board establishes the risk policies, the risk appetite framework, and the guidelines to develop, validate and monitor its models. It approves the provision models and annually issues an opinion on the adequacy of provisions. Management is responsible for establishing rules and procedures, and for controlling compliance with the board's instructions. The bank has integrated its capital and liquidity planning process into its strategic planning, in line with the risks inherent to its business, the financial and competitive environment, its business strategy, corporate values, and its risk governance, management and control systems. Its capital planning process is aligned with the regulator's requirements and incorporates Risk Weighted Asset calculations and stress tests for its credit, market and operational risks, and the integrated measurement of its financial and non-financial risks. The Credit Risk Division, the Operational Risk and Global Control Division and the Cybersecurity Division jointly manage risk. They form the corporate risk governance structure, and their highly experienced and specialized teams, together with a robust regulatory framework, secure optimal and effective management of the matters they address. The Credit Risk Division is responsible for credit risk during the loan origination, monitoring and recovery stages for both the Retail and Wholesale segments and, through the Market Risk Area, is also responsible for measuring, limiting, controlling and reporting on market risk, as well as defining valuation and management standards for the Bank's assets and liabilities. Risk Management Principles
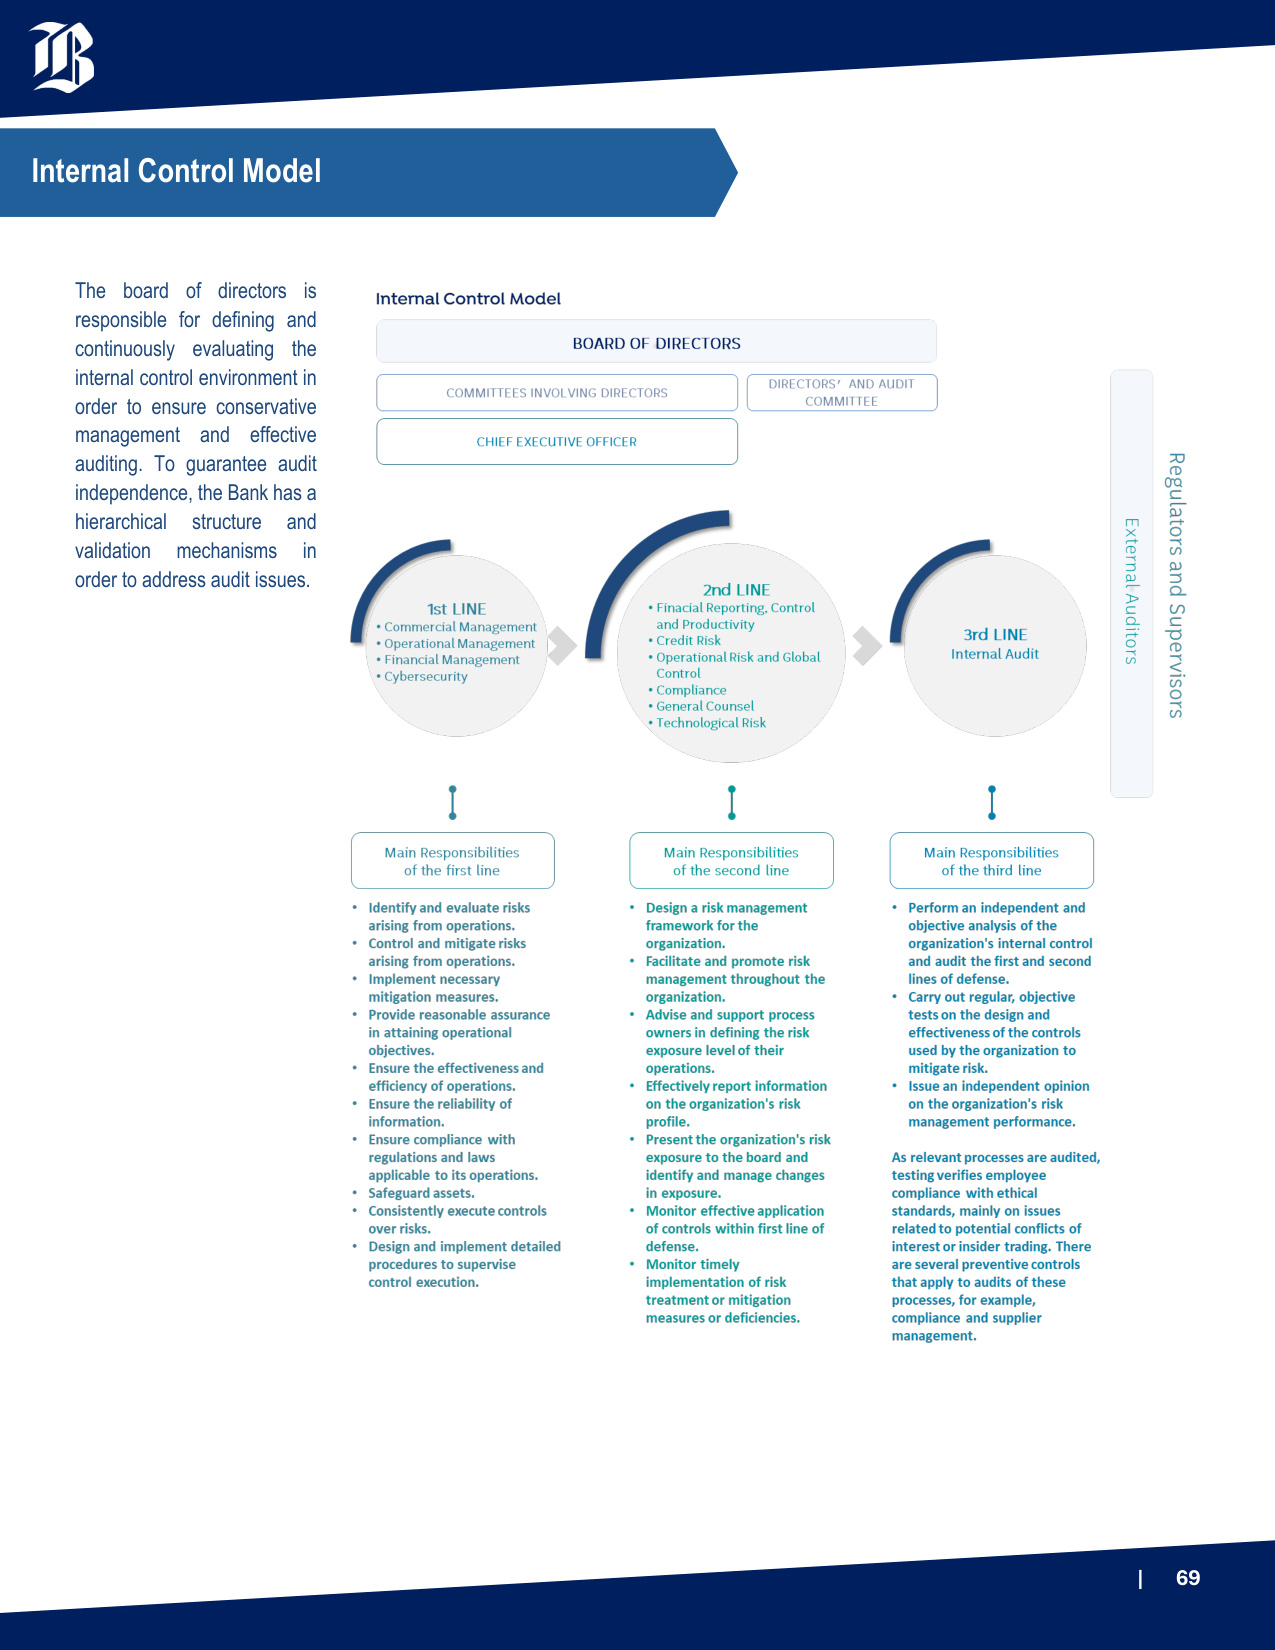
| 69 The board of directors is responsible for defining and continuously evaluating the internal control environment in order to ensure conservative management and effective auditing. To guarantee audit independence, the Bank has a hierarchical structure and validation mechanisms in order to address audit issues. Internal Control Model
| 70 The bank seeks an adequate risk-return and an appropriate risk balance, through careful credit risk management, which covers the loan origination, monitoring and recovery processes. It also continuously manages risk knowledge using an integral approach, in order to contribute to the business and anticipate threats that may damage its solvency or the quality of its loan portfolio, by developing a unique risk awareness culture throughout the corporation. This requires developing a risk management framework for the business segments served by the bank, responding to regulatory requirements and commercial dynamism, contributing to digital transformation, and contributing to the bank's businesses from a risk management perspective. It adopts a portfolio perspective that efficiently and proactively manages, resolves and controls the business approval process. The Bank integrates socio-environmental criteria into its evaluations for granting financing for domestic and regional projects that might generate such an impact, wherever executed. Projects must have all the permits, authorizations, licenses and studies required for their impacts in order to qualify for financing. For large customers, the bank also has specialized customer service units involved in the process of financing large-scale projects such as public works concessions that include building infrastructure and mining, power or real estate developments, all of which may have an environmental impact. Credit policies and processes are based on the following management principles, which use a specialized approach according to the characteristics of the bank's markets and segments, and acknowledge their peculiarities: • Perform a rigorous evaluation during the loan origination process • Implement a continuous, robust portfolio monitoring process • Develop credit risk modelling guidelines, covering regulatory and management aspects, for efficient decision making at each stage of the lending process. • Implement a timely, flexible, efficient collections structure • Efficiently manage teams, tools and information availability Our Credit Risk division uses these management principles to contribute to the business and anticipate threats that may affect solvency and portfolio quality, based on a segmentation by business, as follows: • Retail Banking Segment: Loan origination for these segments is mainly managed using risk evaluation scoring tools, supported by an appropriate credit attribution model, which is required to approve each transaction. These evaluations examine factors such as total borrowings, payment capacity and maximum acceptable exposure for the customer. • Wholesale Banking Segment: Origination management for this segment involves an individual assessment of the customer and, if it belongs to a group of companies, then this takes into consideration the bank's relationship with the rest of the group. This individual assessment considers income-generating capacity, financial capacity with emphasis on solvency, exposure levels, industry variables, an evaluation of the partners and management and aspects particular to the transaction, such as the financing structure, terms, products and any guarantees. Approach to Key Risks Credit Risk Credit risk assesses the probability that the counterparty in a credit transaction does not meet its contractual obligation because of payment incapacity or financial insolvency, and that leads to a potential loan loss.
| 71 The Bank separates this risk based on three types of market factors: spot prices, interest rates and option volatility. The Bank has a Market Risk Management policy, which is annually approved by the Board of Directors, where the types of internal limits and alerts are established, in addition to the regulatory ones, for the measurement of financial exposures and/or price risks. Measurement and control of the price risk, for management purposes, is carried out through several internal metrics and reports that differ from each other, depending on whether they are used for exposures in the Trading and Currency Book or for those belonging to the Banking Book. Regarding the internal tools designed for the Trading and Currency Book, the price risk management is deployed through the calculation and reporting of financial exposures through their sensitivities or greeks and the risk of the entire portfolio by means of the VaR model. Additionally, the Bank has established internal metrics for the management of the price risk of the Banking Book, defining limits and alerts for interest rate exposures. The Bank measures interest rate exposures through the Interest Rate Exposure (IRE) metric, and interest rate risk of the Banking Book using the EaR 12M (Earnings at Risk 12 months) methodology. In addition, internal policies establish the periodic carrying out of stress exercises on the positions of the Trading and Currency Book, and the Banking Book, which are used to contrast them against the maximum price risk tolerance defined by the Board of Directors. Limit usage and alert status are regularly reported to the respective business units. Likewise, the Bank's Senior Management is immediately notified in the case of excess limits or activation of alerts, including the monitoring of corrective action plans, if necessary. This information is reported monthly to the Finance, International and Financial Risk Committee and on a quarterly basis to the Board of Directors. The Bank has a Liquidity Risk Management Policy, reviewed and approved at least annually by the Board, which establishes the main guidelines for measuring, limiting, reporting and controlling liquidity risk. Funding liquidity is measured, reported and controlled by means of using internal metrics, including the Market Access Report (MAR). MAR limits are established to ensure that funding can be obtained and / or renewed in professional markets under normal business conditions, in different time horizons and currencies. The Bank also sets a minimum amount of highly liquid assets (or liquidity buffer), and a limit of the cross-currency funding position. Concentration ratios and other complementary metrics are also periodically measured, reported and controlled against warning levels. In addition, the Bank reports standardized metrics to regulators in accordance with their guidelines, such as the Liquidity Coverage Ratio (LCR) and the Net Stable Financing Ratio (NSFR). It also continuously monitors and tracks market variables and/or material events that could affect our liquidity position. In accordance with its Liquidity Risk Management Policy, the Bank performs regular stress testing in order to quantify its cash needs in the event of adverse scenarios of varying severity, which are contrasted against potentially available action plans detailed within the Liquidity Contingency Plan. These results are daily reported, monitored and controlled based on the maximum liquidity risk appetite defined by the Board. On the other hand, trading liquidity is assured by using limits with certain specific maturities based on the amounts that are normally traded in professional markets for interest rate exposure generated by debt instruments and derivatives. The same process is used to limit the Bank's overall exposure to each currency and to exchange rate volatility with varying maturities. Liquidity Risk Liquidity risk can arise either due to a reduction in the bank's funding capacity (funding liquidity risk) or a reduction in the traded value of its assets that can be liquidated or its market factors from derivatives held in its portfolios (transaction or trading liquidity risk). Price Risk Price risk can be defined as the risk of losses in the Trading and / or the Banking Book, arising from adverse movements in market factors.
| 72 These internal and regulatory metrics are regularly reported to the business units responsible for managing liquidity risk. Similarly, senior management is immediately notified if the limits are exceeded or triggers are breached, including, if necessary, monitoring of corrective action plans. Finally, the general status of liquidity risk is reported to the Asset and Liabilities Committee on a monthly basis and to the Board on a quarterly basis. Operational risk is inherent to all activities, products and systems, as well as strategic, business and support processes throughout the organization. All bank employees are appropriately responsible for the management and control of operational risks inherent to their duties, since these risks may result in direct or indirect financial losses. The bank controls and manages operational risk by developing a regulatory and governance framework adapted to the complexity of its business. The Operational Risk Policy defines a comprehensive management framework that includes identifying, evaluating, controlling, mitigating, monitoring and reporting these risks. This requires executing several processes as follows: • Process Assessment • Supplier Management • Fraud Management • Management of Operational Events and Operational Losses • Operational Risk Assessment for Projects • Control Testing • Risk Appetite Profile and Framework • Self-Assessment Matrix • Relations with External Entities and Corporate Training Plan Operational Risk Operational risk is the risk of loss resulting from deficiencies or failures in internal processes, staff or systems, or from external events. This definition includes legal risks and excludes strategic and reputation risks.
| 73 Being prepared to face any emergency is key to providing exceptional services to our customers. Therefore, we have developed a robust, consistent Business Continuity Plan to safeguard the bank and its subsidiaries. The objective of the plan is to establish general guidelines for ensuring the safety of our employees, protecting the organization's capital from catastrophic events, maintaining and updating documentation, and conducting training and testing. To comply with these guidelines, the bank has developed a strategy to meet this objective that covers the following areas: • Document Management • Business Continuity Testing • Crisis Management • Critical Supplier Management • Management of Alternative Sites • Relationship with Subsidiaries and External Organizations • Continuous Improvement • Training • Information Security Officer (ISO) Society is increasingly digitalized, so customer privacy and cybersecurity risk management is a priority for Banco de Chile. Therefore, the bank has developed a Strategic Cybersecurity Plan, which is aligned with the bank's business strategy. The main objectives of this plan are to protect customer and employee data, safeguard the bank's data, manage technological, cybersecurity and data security risks, and strengthen the risk prevention culture. This plan complies with the appropriate regulations, which include the Constitutional Law No. 21,096 on Personal Data Protection, the Protection of Privacy Law No. 19,628 (which will be replaced by Law No. 21,719 as of December 2026), the Cybersecurity Framework Law No. 21,663, and the provisions published in the Updated Compilation of Rules (RAN) issued by the CMF. This plan has been approved by senior management, who regularly receive associated progress reports. Data security and cybersecurity policies at Banco de Chile establish guidelines regarding the responsibility for and protection of data and its associated risk management, based on both regulatory aspects and international standards. These policies are reviewed annually and apply to employees, outsourced personnel, as well as suppliers and contractors of services who access its facilities or have access to bank and subsidiary data. The controls that protect this information and IT assets are defined by regulations, processes and the bank's internal procedures. Technological Risk, Cybersecurity and Data Protection Business Continuity Different situations that could affect the business continuity of the organization or the country, which requires to be constantly prepared to keep operating the products and services that are critical to its customers.
| 74 Banco de Chile knows that sound ethical management is essential for its industry leading position. Therefore, the bank has diverse protocols, systems and models to ensure ethical behavior of all its employees. The Code of Conduct is the key guideline and essential component of the bank's corporate ethics. It contains the general principles and instructions that guide the ethical-professional conduct of the employees, directors and board advisors. The purpose of the code is to safeguard the fundamental values to properly conduct the bank's business, in accordance with the bank's corporate philosophy. The Ethics Committee is responsible for overseeing its implementation within the bank. Preventing corruption and the use of the bank and its subsidiaries to engage in unlawful practices has been a concern over the last few decades for Banco de Chile. Awareness-raising measures and controls have been intensified during recent years, in order to prevent this kind of behavior. The bank has approved a Code of Conduct, a Prevention of Dishonest Practices Policy and a Handling Conflicts of Interest Policy, which describe the main roles and responsibilities to avoid that anything may be interpreted as a violation of ethical conduct or imply the risk of corruption or bribery. The Compliance Division, by means of its Regulatory Compliance Area and the Ethics Committee, are responsible for ensuring compliance with the conduct described in these policies. Its purpose is to manage the risks associated with models and their processes, so it relies on the model validation, model risk management and internal control functions. Model validation is responsible for performing an independent review of risk models, including risk-weighted assets and stress testing, during their construction and implementation stages. It validates compliance with board-approved guidelines and addresses aspects such as governance, data quality, modeling techniques, methodological and parametric implementation analysis and documentation. The results of these reviews are submitted to the respective committees. Model risk management is responsible for monitoring models and ensuring that they fulfill their life cycle status. The Model Risk Management Committee was created in July 2023 and is composed of members of the Bank' senior management. Model Risk and Internal Control Conduct Risk and Anti-Money Laundering
| 75 The Bank supervises and manages its capital adequacy based on the principles and objectives set forth in its Corporate Capital Management Policy and current risk appetite framework, ensuring that its capital base provides adequate coverage for the material risks of the business and complies with the requirements established by the CMF on this matter. Through its Policy, the Bank seeks to ensure the adequacy and quality of the Bank's capital, establish sufficient capital levels through the definition of internal capital targets, ensure that capital metrics meet the internal capital targets defined by the Bank in the short and medium term, establish periodic and timely reports to meet the objectives set on this matter and ensure the existence of a governance structure with clear roles and responsibilities within the organization. In terms of capital management, Banco de Chile is governed by, among others, the following principles: (i) ensuring the solvency of the Bank, without losing focus on the profitability of the capital invested by shareholders, (ii) considering capital as a scarce resource, so business and investment decisions should be oriented towards value creation by optimizing the capital invested, (iii) the Board of Directors is ultimately responsible for strategies and decisions that affect capital management, (iv) having a comprehensive capital management model that allows monitoring and control, (v) implementing an annual capital planning process, consistent and aligned with the definition of the risk appetite and strategic goals, and (vi) ensuring the accuracy, reasonability, quality and integrity of information related to capital management. Regarding Governance Structure, Banco de Chile has an adequate segregation of duties that allows activities related to business, control and monitoring, risk measurement and assessment, and capital adequacy, to be executed and reported with sufficient independence and in alignment with best risk and capital management practices. The key participants in the Bank's corporate governance structure for capital management are: • Board of Directors: Is the Bank's highest decision-making body, responsible for the supervision of capital management, including regulatory and internal compliance, through the approval of the Policy, the definition of general guidelines for capital management based on the risk profile assumed by the Bank, as well as the approval of internal targets and capital planning, the Risk Internal Assessment Measurement (RIA), the Risk Appetite Framework (RAF) and associated contingency plans, among other elements. • Capital Management Committee: Among other matters, the main function of Committee is to oversee and supervise capital management while being responsible for reviewing and proposing changes to the Policy, at least once a year; reviewing and approving governance documentation associated with capital management; ensuring that the Bank has sufficient capital to meet both its current needs and those arising from stress scenarios. Capital Management
| 76 Funding Concentration & Liquidity Position Our liquidity position has continued to be solid as shown by both the Liquidity Coverage Ratio (LCR) and the Net Stable Funding Ratio (NSFR), both remaining well above the prevailing regulatory limits of 100% for each metric, as defined by banking liquidity regulation. To achieve this position, we maintained high-quality liquid assets (HQLA) that averaged Ch$6,361 billion during the 3Q26, which explains the positive gap shown by the LCR in relation to both the regulatory and internal thresholds. From a composition standpoint, our HQLA continue to be primarily composed of fixed-income securities issued by the Chilean Government and other liquid assets. During the 3Q26, the evolution of the LCR was characterized by broadly stable HQLA levels, while fluctuations in the indicator were mainly driven by changes in 30-day net cash outflows, primarily reflecting movements in Time Deposits balances from financial counterparties. As for the NSFR, given our balance sheet structure and solid management of liquidity gaps, the relationship between available and required funding has remained stable over time. Liquidity Ratios: LCR and NSFR (In percentage as of each date, based on CMF C49 report) Liability Concentration by Counterparty (As percentage of Total Liabilities) 0% 50% 100% 150% 200% 250% 300% 350% 400% 450% 0% 50% 100% 150% 200% 250% 300% 350% 400% 450% Sep-24 Dec-24 Mar-25 Jun-25 Sep-25 Dec-25 Mar-26 Jun-26 Sep-26 LCR NSFR 41% 43% 16% Financial Counterparties Retail Counterparties Wholesale Non-Financial Counterparties From the funding concentration perspective, the composition of our deposit base remained relatively stable in 2026 in terms of types of instruments. In this regard, Time Deposits balances –as a percentage of total liabilities (i.e. excluding equity accounts)– showed a slight decrease from 30.4% in September 2025 to 30.0% in September 2026. Meanwhile, Demand Deposits as a percentage of total liabilities (excluding equity) increased in the margin YoY from 28.8% as of September 30, 2025 to 29.1% as of September 30, 2026. Recent Performance in Risk Management
| 77 Furthermore, given our persistent position in high-quality liquid assets, the funding from institutional counterparties remains below the funding from non-financial ones. Thus, we continue to present a well-balanced liability structure, as reflected in a 43% share of retail counterparties, a 41% share of financial counterparties and a 16% composed of wholesale non-financial counterparties. It is important to note that 59.8% of our liabilities with financial counterparties are concentrated in long-term bonds, representing a 24.5% of our total liabilities (excluding equity accounts) as of September 30, 2026 while being a stable source of funding regardless of the counterparty. Price Risk We continue to prudently manage our trading portfolio by focusing on providing our financial and corporate counterparties with competitive prices under the market-making activity and keeping price risk at bounded levels in the trading book. The Value-at-Risk (VaR) of our Trading Book averaged Ch$1,480 million for the nine-month period ended September 30, 2026, representing a 33.6% increase compared to the average VaR of Ch$1,108 million recorded in the same period of 2025. This was explained by increased positions in fixed-income instruments in CLP and CLF in 2026 when contrasted to 2025, together with heightened shocks in CLF derivatives resulting from significant interest rate shifts observed over the last quarters. Value-at-Risk Trading Book (1-day impact) (99% confidence level / Individual Basis) Earnings-at-Risk Banking Book (12-month impact) (99% confidence level / 3-month defeasance period / Individual Basis) In Millions of Ch$ Sep-25 Sep-26 Ch$ % Average 1,108 1,480 372 33.6% Maximum 1,906 2,400 495 26.0% Minimum 516 761 246 47.7% Year-to-Date Change In Millions of Ch$ Sep-25 Sep-26 Ch$ % Average 216,032 166,704 -49,328 -22.8% Maximum 228,919 181,733 -47,186 -20.6% Minimum 178,673 146,344 -32,329 -18.1% Year-to-Date Change In addition, the interest rate risk in the Banking Book, measured by the 12-month Earnings-at-Risk (EaR) metric, displayed a 22.8% YoY decrease from Ch$216,032 million on average for the nine-month period ended September 30, 2025 to Ch$166,704 million on average in the same period this year. This evolution was primarily driven by lower interest rate volatility during the period. Amid this backdrop, our net asset exposure to the CLF in the Banking Book reached Ch$9,110 billion in September 2026, amount that denotes an increase from the level recorded in the same period of 2025. Our current market view is that inflation in the local economy will remain above the Central Bank's mid-term target of 3.0% for a while as a consequence of persistent external inflationary pressures coming from ongoing global geopolitical uncertainty. As a result, inflation is expected to converge towards the target range set by the Central Bank at a slower pace than previously anticipated by local market agents. Inflation-Indexed Position in the Banking Book (In Billions of Ch$, End of Period) 8,511 8,982 9,694 8,955 8,339 8,841 8,853 9,053 9,110 Sep-24 Dec-24 Mar-25 Jun-25 Sep-25 Dec-25 Mar-26 Jun-26 Sep-26
| 78 It is worth mentioning that our CLF position in the banking book is composed of both our structural gap that hedges our shareholders' equity from the effect of inflation in the long-term and temporary directional positions taken by our Treasury to benefit from changes in short-term market expectations. Based on the revenues obtained from inflation indexation over the last quarters, we believe our strategy has more than offset the risk involved. Nevertheless, as mentioned in previous reports, we are continually assessing the expected track for inflation in order to change our exposure, if necessary. Operational Risk Regarding Operational Risk, we aim to keep a reasonable level of losses, by means of monitoring and controlling the proper functioning of our processes, personnel and internal systems, while also considering external issues. To achieve this goal, we operate through a Comprehensive Risk Management Framework, as well as a governance structure that addresses the complexity of our business model. As of September 30, 2026, we incurred net operational losses by Ch$15,503 million, which was primarily composed of: (i) losses associated with external fraud representing 73.0% of the total amount, (ii) losses related to Execution, Delivery and Process Management accounting for 15.8%, (iii) losses categorized as Work Practices and Safety in the Business Position representing 7.6%, and (iv) other effects that jointly explained 3.6%, including losses related to Business Interruption and System Failure, losses from Clients, Products & Business Practices as well as Damage to Physical Assets, and finally Internal Fraud. The amount of net operational losses recorded as of September 30, 2026 denotes a YoY increase of Ch$2,351 million or 17.9% when compared to the Ch$13,152 million recorded as of September 30, 2025. This change was conducted by specific drivers, as follows: A YoY growth of Ch$1,819 million or 19.2% in net losses related to External Fraud, explained by an increase in losses associated with electronic fraud, primarily in credit and debit card transactions. This effect was in part offset by lower losses associated with electronic funds transfer, due to a decrease in the occurrence of this type of events in the nine-month period ended September 30, 2026 compared to a year earlier. A YoY increase of Ch$1,179 million or 92.6% in net losses related to Execution, Delivery and Process Management, primarily driven by higher provisions associated with leasing operations, as well as losses from mass payment processes, compared to 2025. To mitigate these risks, we have implemented certain measures aimed at strengthening the control environment, automated execution of controls in the mass payment process, and the centralization of activities and the reassessment of roles and responsibilities. Net Operational Losses by Type (In Millions of Ch$ / Net of Recoveries) 11,312 2,452 1,180 144 120 293 3 9,493 1,273 1,162 331 444 365 84 0 5,000 10,000 15,000 20,000 External Fraud Execution, Delivery and Process Management Work Practices and Safety in the Business Position Customers, Products and Business Practices Damage to physical assets Business Interruption and System Failure Internal Fraud As of September 30, 2025 As of September 30, 2026
| 79 These effects were partly counterbalanced by: Lower net losses associated with the Damage to Physical Assets category by Ch$324 million or 73.0% YoY, due to a YoY decrease in expenses related to fixed-asset repairs as a result of certain operational events affecting commercial infrastructure, particularly ATMs and branches, that occurred last year. A YoY decrease of Ch$187 million or 56.6% associated with the Clients, Products and Business Practices category, mainly due to lower spending on legal contingenies compared to last year. A YoY decline of Ch$72 million or 19.8% in net operational losses associated with Business Disruption and System Failures, primarily driven by initiatives aimed at strengthening our system control through improvements in system settings. Capital Adequacy On September 30, 2026, we had a Total Capital Ratio of 17.9%, which was 9 bp. below the ratio recorded on the same date in 2025. Similarly, both the CET1 ratio and the Tier 1 ratio amounted to 14.1% in September 2026, representing a 10 bp. YoY decline compared to September 2025. These YoY variations were mainly driven by a YoY expansion of Ch$1,039,522 million or 2.7% in risk-weighted assets ("RWA", hereafter), from Ch$39,199,658 million on September 30, 2025 to Ch$40,239,180 million on September 30, 2026. This effect, however, was partly offset by a 2.1% YoY increase in Total Regulatory Capital. In the case of RWA, the YoY increase was mostly attributable to: (i) a Ch$954,693 million or 2.9% YoY increase in Credit-RWA, mainly driven by growth in commercial loans resulting from commercial efforts deployed in the 3Q26 to regain market share across the financial services, retail and natural resources sectors and a low comparison base as represented by September 2025, (ii) Operational-RWA that rose Ch$76,070 million or 1.8% YoY, mainly due to the impact of increased net fee income over the last three years based on the business indicator of the standardized model used in Chile, and (iii) a slight YoY pick up of Ch$8,759 million or 0.5% in Market-RWA, primarily as a consequence of a decrease in the exposure to trading securities in the 3Q26 compared to previous quarters. Regarding our capital base, on September 30, 2026, both our CET1 Capital and Tier1 Capital amounted to Ch$5,678,634 million, which exceeded by Ch$108,035 million or 1.9% the amount recorded a year earlier. This change was primarily explained earnings retention associated with the impact of inflation on equity accounts coming from the net income earned in 2025, which was to some degree offset by higher regulatory adjustments to CET1 capital as a result of the end of the phase-in period for such adjustments starting December 2025. Likewise, our Total Regulatory Capital accounted for Ch$7,192,931 million on September 30, 2026, which represent a YoY rise of Ch$150,681 million or 2.1% compared to September 2025 on the grounds of the above-mentioned increase in CET1 Capital, together with a YoY increase of Ch$42,647 million or 2.9% in Tier2 Capital owing to both the effect of inflation on subordinated bonds denominated in CLF and slightly higher additional provisions computed as Tier2 Capital. Capital Adequacy Ratios (As Percentage as of Each Date) 9.7% 14.2% 14.2% 18.0% 9.8% 14.1% 14.1% 17.9% +14 bp (10) bp (10) bp (9) bp (100, 00) bp (80,00) bp (60,00) bp (40,00) bp (20,00) bp +0 bp 0.0% 5.0% 10 .0 % 15 .0 % 20 .0 % 25 .0 % Common Equity Tier 1 Total Assets Common Equity Tier 1 RWA Tier 1 Capital RWA Total Capital RWA Sep-25 Sep-26
| 80 Based on the above, on September 30, 2026 we fully complied with all mandatory limits (including buffers and additional capital requirements, if any) of: (i) 3.0% for the leverage ratio, (ii) 8.75% for the CET1 ratio, (iii) 10.25% for the Tier1 ratio, and (iv) 12.25% for the Total Capital ratio, which include both minimum legal capital requirements and additional requirements: (i) a counter-cyclical buffer of 0.5% over RWA that will increase to 1.0% starting May 2028 as defined by the Central Bank in May 2026, (ii) a conservation buffer of 2.5% over RWA, and (iii) a systemic capital charge of 1.25% over RWA assigned to us and reaffirmed by the CMF on March 27, 2026. Finally, on September 11, 2026, the CMF published the final modifications to the standardized methodology for the measurement of Market- RWA (RAN 21-7), which introduced the chance for banks to measure the interest rate risk in the trading book based on duration instead of maturity. On the same date, the chilean regulator also published for public comment a new set of amendments for the same methodology that pursue to give banks the possibility of excluding certain derivative positions showing opposed exposures to the same market factors and tenors. According to the CMF, banks could reduce Market-RWA by approximately 35%. The comment period for this proposal ended on October 20, 2026 and the final rules are still pending of publication. Regarding the set of amendments to the corporate governance on capital and risk management matters, together with the introduction of a formal Recovery Planning process, no final rules have been published by the CMF yet. Credit Risk Ratings Our credit ratings determine the cost and terms upon which we are able to raise funding. Rating agencies evaluate us by considering diverse factors, including the financial strength, the business environment and the economic backdrop. International Credit Ratings MOODY'S Long-Term Short-Term Foreign Currency A2 P-1 Outlook Stable STANDARD & POOR'S Long-Term Short-Term Foreign Currency A A-1 Outlook Stable Local Credit Ratings HUMPHREYS Long-Term Short-Term Deposits AAA 1+ Level Outlook Stable FELLER RATE Long-Term Short-Term Deposits AAA 1+ Level Outlook Stable
| 81 Appendix Selected Financial Data
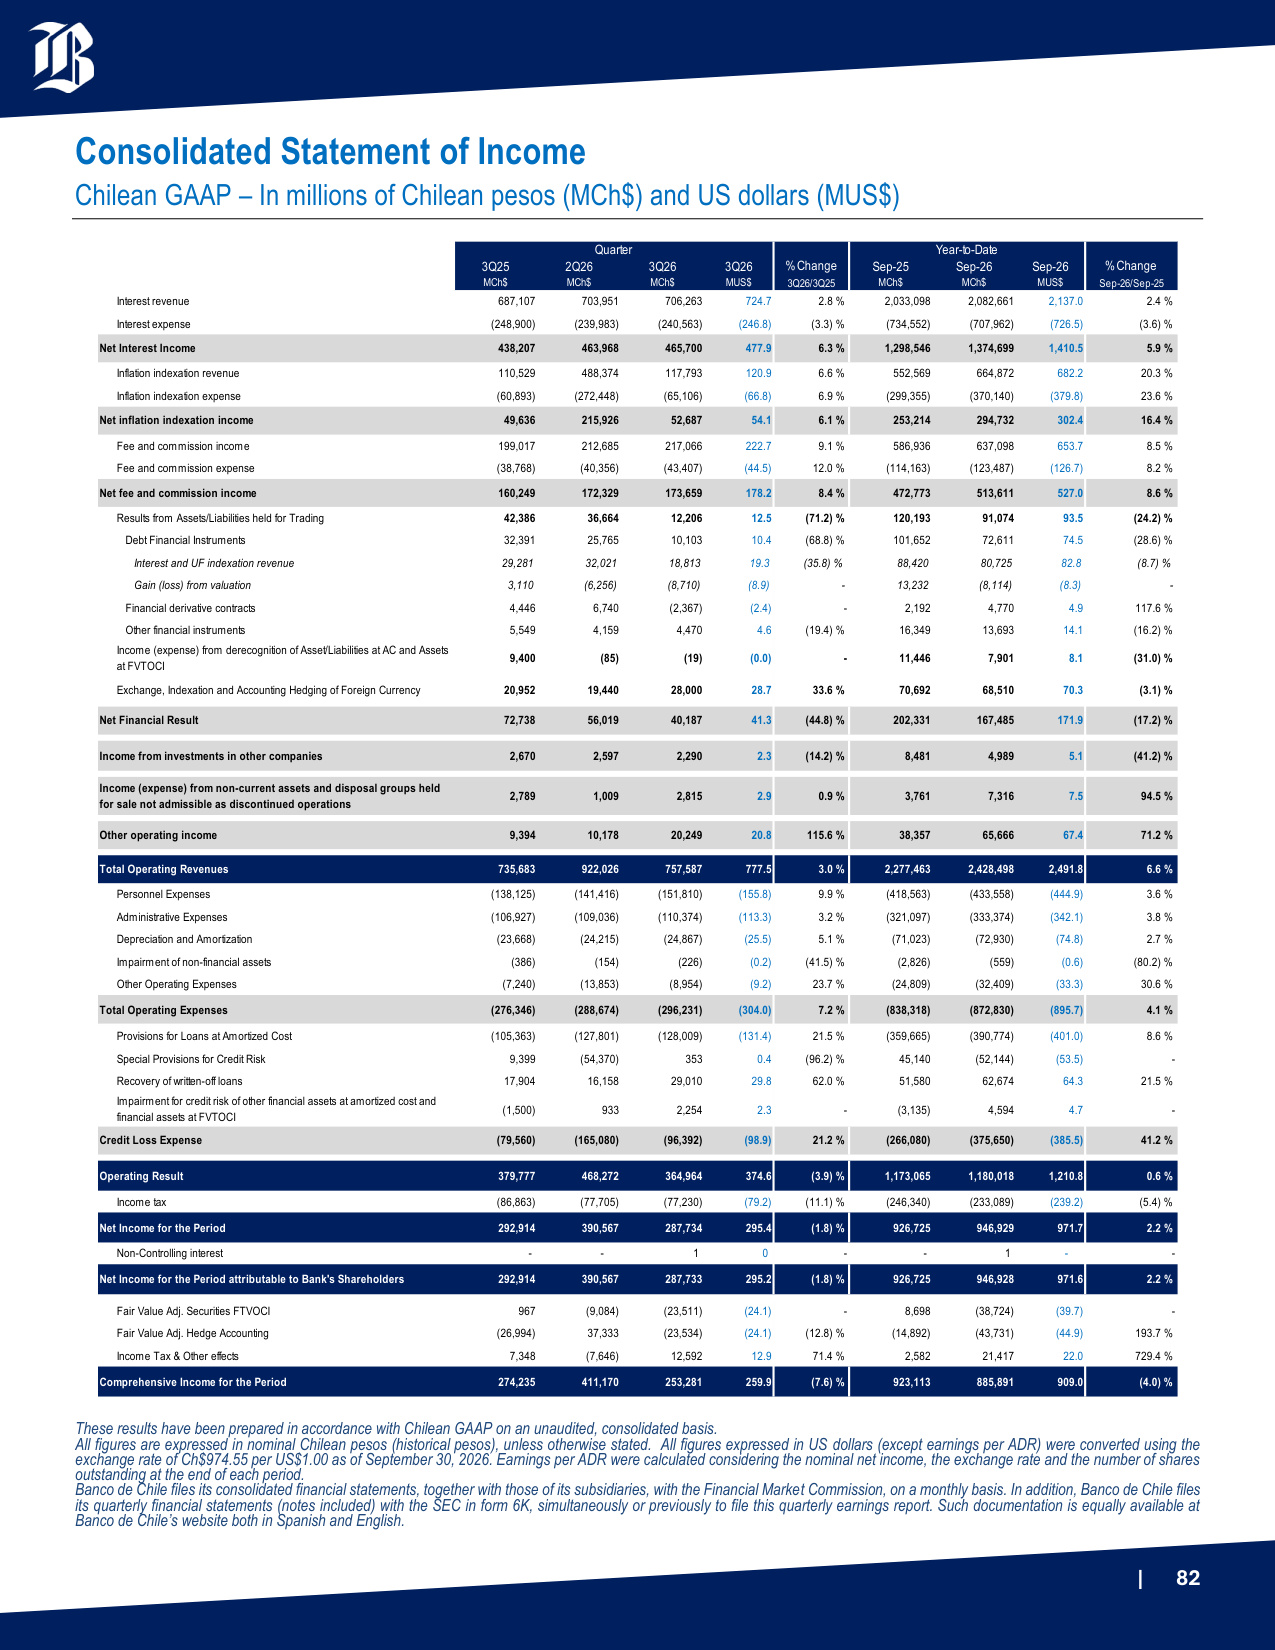
| 82 Consolidated Statement of Income Chilean GAAP – In millions of Chilean pesos (MCh$) and US dollars (MUS$) 3Q25 2Q26 3Q26 3Q26 % Change Sep-25 Sep-26 Sep-26 % Change MCh$ MCh$ MCh$ MUS$ 3Q26/3Q25 MCh$ MCh$ MUS$ Sep-26/Sep-25 Interest revenue 687,107 703,951 706,263 724.7 2.8 % 2,033,098 2,082,661 2,137.0 2.4 % Interest expense (248,900) (239,983) (240,563) (246.8) (3.3) % (734,552) (707,962) (726.5) (3.6) % Net Interest Income 438,207 463,968 465,700 477.9 6.3 % 1,298,546 1,374,699 1,410.5 5.9 % Inflation indexation revenue 110,529 488,374 117,793 120.9 6.6 % 552,569 664,872 682.2 20.3 % Inflation indexation expense (60,893) (272,448) (65,106) (66.8) 6.9 % (299,355) (370,140) (379.8) 23.6 % Net inflation indexation income 49,636 215,926 52,687 54.1 6.1 % 253,214 294,732 302.4 16.4 % Fee and commission income 199,017 212,685 217,066 222.7 9.1 % 586,936 637,098 653.7 8.5 % Fee and commission expense (38,768) (40,356) (43,407) (44.5) 12.0 % (114,163) (123,487) (126.7) 8.2 % Net fee and commission income 160,249 172,329 173,659 178.2 8.4 % 472,773 513,611 527.0 8.6 % Results from Assets/Liabilities held for Trading 42,386 36,664 12,206 12.5 (71.2) % 120,193 91,074 93.5 (24.2) % Debt Financial Instruments 32,391 25,765 10,103 10.4 (68.8) % 101,652 72,611 74.5 (28.6) % Interest and UF indexation revenue 29,281 32,021 18,813 19.3 (35.8) % 88,420 80,725 82.8 (8.7) % Gain (loss) from valuation 3,110 (6,256) (8,710) (8.9) - 13,232 (8,114) (8.3) - Financial derivative contracts 4,446 6,740 (2,367) (2.4) - 2,192 4,770 4.9 117.6 % Other financial instruments 5,549 4,159 4,470 4.6 (19.4) % 16,349 13,693 14.1 (16.2) % Income (expense) from derecognition of Asset/Liabilities at AC and Assets at FVTOCI 9,400 (85) (19) (0.0) - 11,446 7,901 8.1 (31.0) % Exchange, Indexation and Accounting Hedging of Foreign Currency 20,952 19,440 28,000 28.7 33.6 % 70,692 68,510 70.3 (3.1) % Net Financial Result 72,738 56,019 40,187 41.3 (44.8) % 202,331 167,485 171.9 (17.2) % Income from investments in other companies 2,670 2,597 2,290 2.3 (14.2) % 8,481 4,989 5.1 (41.2) % Income (expense) from non-current assets and disposal groups held for sale not admissible as discontinued operations 2,789 1,009 2,815 2.9 0.9 % 3,761 7,316 7.5 94.5 % Other operating income 9,394 10,178 20,249 20.8 115.6 % 38,357 65,666 67.4 71.2 % Total Operating Revenues 735,683 922,026 757,587 777.5 3.0 % 2,277,463 2,428,498 2,491.8 6.6 % Personnel Expenses (138,125) (141,416) (151,810) (155.8) 9.9 % (418,563) (433,558) (444.9) 3.6 % Administrative Expenses (106,927) (109,036) (110,374) (113.3) 3.2 % (321,097) (333,374) (342.1) 3.8 % Depreciation and Amortization (23,668) (24,215) (24,867) (25.5) 5.1 % (71,023) (72,930) (74.8) 2.7 % Impairment of non-financial assets (386) (154) (226) (0.2) (41.5) % (2,826) (559) (0.6) (80.2) % Other Operating Expenses (7,240) (13,853) (8,954) (9.2) 23.7 % (24,809) (32,409) (33.3) 30.6 % Total Operating Expenses (276,346) (288,674) (296,231) (304.0) 7.2 % (838,318) (872,830) (895.7) 4.1 % Provisions for Loans at Amortized Cost (105,363) (127,801) (128,009) (131.4) 21.5 % (359,665) (390,774) (401.0) 8.6 % Special Provisions for Credit Risk 9,399 (54,370) 353 0.4 (96.2) % 45,140 (52,144) (53.5) - Recovery of written-off loans 17,904 16,158 29,010 29.8 62.0 % 51,580 62,674 64.3 21.5 % Impairment for credit risk of other financial assets at amortized cost and financial assets at FVTOCI (1,500) 933 2,254 2.3 - (3,135) 4,594 4.7 - Credit Loss Expense (79,560) (165,080) (96,392) (98.9) 21.2 % (266,080) (375,650) (385.5) 41.2 % Operating Result 379,777 468,272 364,964 374.6 (3.9) % 1,173,065 1,180,018 1,210.8 0.6 % Income tax (86,863) (77,705) (77,230) (79.2) (11.1) % (246,340) (233,089) (239.2) (5.4) % Net Income for the Period 292,914 390,567 287,734 295.4 (1.8) % 926,725 946,929 971.7 2.2 % Non-Controlling interest - - 1 0 - - 1 - - Net Income for the Period attributable to Bank's Shareholders 292,914 390,567 287,733 295.2 (1.8) % 926,725 946,928 971.6 2.2 % Fair Value Adj. Securities FTVOCI 967 (9,084) (23,511) (24.1) - 8,698 (38,724) (39.7) - Fair Value Adj. Hedge Accounting (26,994) 37,333 (23,534) (24.1) (12.8) % (14,892) (43,731) (44.9) 193.7 % Income Tax & Other effects 7,348 (7,646) 12,592 12.9 71.4 % 2,582 21,417 22.0 729.4 % Comprehensive Income for the Period 274,235 411,170 253,281 259.9 (7.6) % 923,113 885,891 909.0 (4.0) % Quarter Year-to-Date These results have been prepared in accordance with Chilean GAAP on an unaudited, consolidated basis. All figures are expressed in nominal Chilean pesos (historical pesos), unless otherwise stated. All figures expressed in US dollars (except earnings per ADR) were converted using the exchange rate of Ch$974.55 per US$1.00 as of September 30, 2026. Earnings per ADR were calculated considering the nominal net income, the exchange rate and the number of shares outstanding at the end of each period. Banco de Chile files its consolidated financial statements, together with those of its subsidiaries, with the Financial Market Commission, on a monthly basis. In addition, Banco de Chile files its quarterly financial statements (notes included) with the SEC in form 6K, simultaneously or previously to file this quarterly earnings report. Such documentation is equally available at Banco de Chile's website both in Spanish and English.
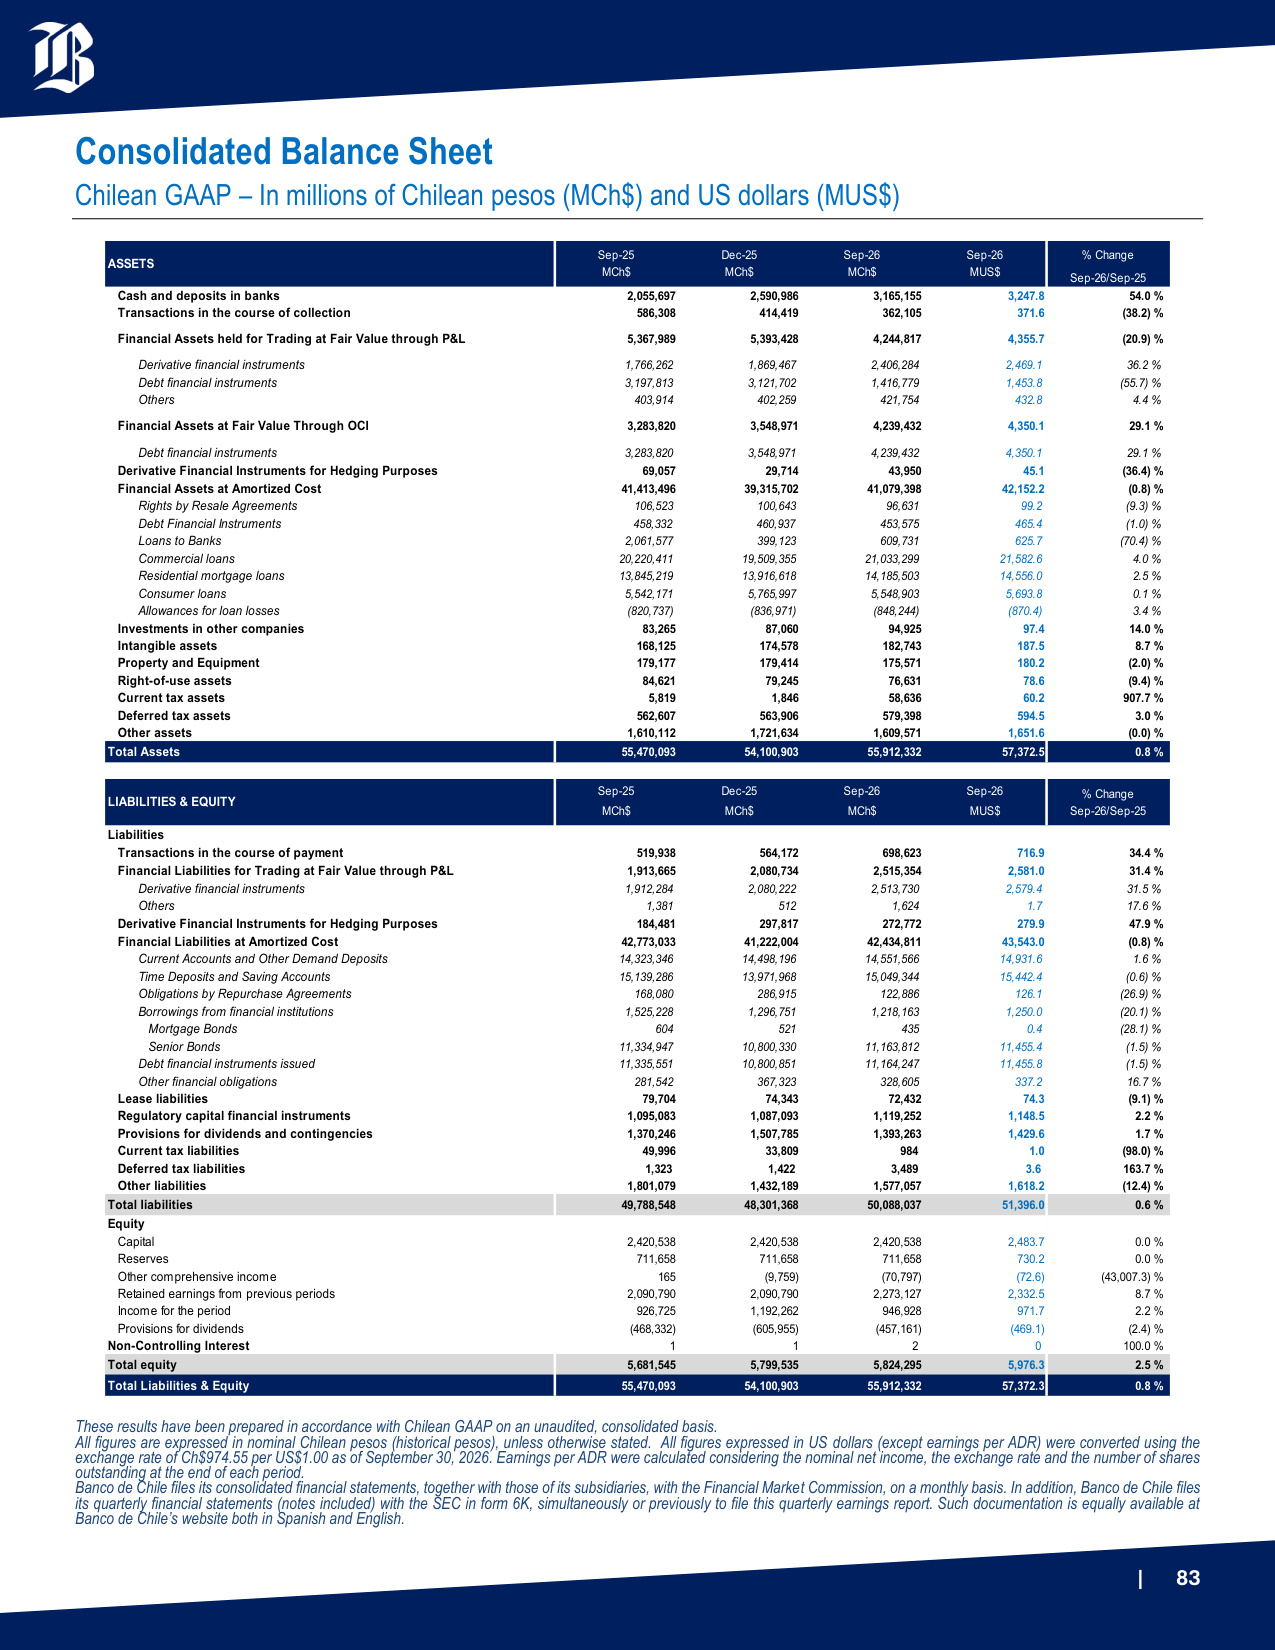
| 83 Consolidated Balance Sheet Chilean GAAP – In millions of Chilean pesos (MCh$) and US dollars (MUS$) Sep-25 Dec-25 Sep-26 Sep-26 MCh$ MCh$ MCh$ MUS$ Sep-26/Sep-25 Cash and deposits in banks 2,055,697 2,590,986 3,165,155 3,247.8 54.0 % Transactions in the course of collection 586,308 414,419 362,105 371.6 (38.2) % Financial Assets held for Trading at Fair Value through P&L 5,367,989 5,393,428 4,244,817 4,355.7 (20.9) % Derivative financial instruments 1,766,262 1,869,467 2,406,284 2,469.1 36.2 % Debt financial instruments 3,197,813 3,121,702 1,416,779 1,453.8 (55.7) % Others 403,914 402,259 421,754 432.8 4.4 % Financial Assets at Fair Value Through OCI 3,283,820 3,548,971 4,239,432 4,350.1 29.1 % Debt financial instruments 3,283,820 3,548,971 4,239,432 4,350.1 29.1 % Derivative Financial Instruments for Hedging Purposes 69,057 29,714 43,950 45.1 (36.4) % Financial Assets at Amortized Cost 41,413,496 39,315,702 41,079,398 42,152.2 (0.8) % Rights by Resale Agreements 106,523 100,643 96,631 99.2 (9.3) % Debt Financial Instruments 458,332 460,937 453,575 465.4 (1.0) % Loans to Banks 2,061,577 399,123 609,731 625.7 (70.4) % Commercial loans 20,220,411 19,509,355 21,033,299 21,582.6 4.0 % Residential mortgage loans 13,845,219 13,916,618 14,185,503 14,556.0 2.5 % Consumer loans 5,542,171 5,765,997 5,548,903 5,693.8 0.1 % Allowances for loan losses (820,737) (836,971) (848,244) (870.4) 3.4 % Investments in other companies 83,265 87,060 94,925 97.4 14.0 % Intangible assets 168,125 174,578 182,743 187.5 8.7 % Property and Equipment 179,177 179,414 175,571 180.2 (2.0) % Right-of-use assets 84,621 79,245 76,631 78.6 (9.4) % Current tax assets 5,819 1,846 58,636 60.2 907.7 % Deferred tax assets 562,607 563,906 579,398 594.5 3.0 % Other assets 1,610,112 1,721,634 1,609,571 1,651.6 (0.0) % Total Assets 55,470,093 54,100,903 55,912,332 57,372.5 0.8 % Sep-25 Dec-25 Sep-26 Sep-26 MCh$ MCh$ MCh$ MUS$ Sep-26/Sep-25 Liabilities Transactions in the course of payment 519,938 564,172 698,623 716.9 34.4 % Financial Liabilities for Trading at Fair Value through P&L 1,913,665 2,080,734 2,515,354 2,581.0 31.4 % Derivative financial instruments 1,912,284 2,080,222 2,513,730 2,579.4 31.5 % Others 1,381 512 1,624 1.7 17.6 % Derivative Financial Instruments for Hedging Purposes 184,481 297,817 272,772 279.9 47.9 % Financial Liabilities at Amortized Cost 42,773,033 41,222,004 42,434,811 43,543.0 (0.8) % Current Accounts and Other Demand Deposits 14,323,346 14,498,196 14,551,566 14,931.6 1.6 % Time Deposits and Saving Accounts 15,139,286 13,971,968 15,049,344 15,442.4 (0.6) % Obligations by Repurchase Agreements 168,080 286,915 122,886 126.1 (26.9) % Borrowings from financial institutions 1,525,228 1,296,751 1,218,163 1,250.0 (20.1) % Mortgage Bonds 604 521 435 0.4 (28.1) % Senior Bonds 11,334,947 10,800,330 11,163,812 11,455.4 (1.5) % Debt financial instruments issued 11,335,551 10,800,851 11,164,247 11,455.8 (1.5) % Other financial obligations 281,542 367,323 328,605 337.2 16.7 % Lease liabilities 79,704 74,343 72,432 74.3 (9.1) % Regulatory capital financial instruments 1,095,083 1,087,093 1,119,252 1,148.5 2.2 % Provisions for dividends and contingencies 1,370,246 1,507,785 1,393,263 1,429.6 1.7 % Current tax liabilities 49,996 33,809 984 1.0 (98.0) % Deferred tax liabilities 1,323 1,422 3,489 3.6 163.7 % Other liabilities 1,801,079 1,432,189 1,577,057 1,618.2 (12.4) % Total liabilities 49,788,548 48,301,368 50,088,037 51,396.0 0.6 % Equity Capital 2,420,538 2,420,538 2,420,538 2,483.7 0.0 % Reserves 711,658 711,658 711,658 730.2 0.0 % Other comprehensive income 165 (9,759) (70,797) (72.6) (43,007.3) % Retained earnings from previous periods 2,090,790 2,090,790 2,273,127 2,332.5 8.7 % Income for the period 926,725 1,192,262 946,928 971.7 2.2 % Provisions for dividends (468,332) (605,955) (457,161) (469.1) (2.4) % Non-Controlling Interest 1 1 2 0 100.0 % Total equity 5,681,545 5,799,535 5,824,295 5,976.3 2.5 % Total Liabilities & Equity 55,470,093 54,100,903 55,912,332 57,372.3 0.8 % ASSETS % Change LIABILITIES & EQUITY % Change These results have been prepared in accordance with Chilean GAAP on an unaudited, consolidated basis. All figures are expressed in nominal Chilean pesos (historical pesos), unless otherwise stated. All figures expressed in US dollars (except earnings per ADR) were converted using the exchange rate of Ch$974.55 per US$1.00 as of September 30, 2026. Earnings per ADR were calculated considering the nominal net income, the exchange rate and the number of shares outstanding at the end of each period. Banco de Chile files its consolidated financial statements, together with those of its subsidiaries, with the Financial Market Commission, on a monthly basis. In addition, Banco de Chile files its quarterly financial statements (notes included) with the SEC in form 6K, simultaneously or previously to file this quarterly earnings report. Such documentation is equally available at Banco de Chile's website both in Spanish and English.
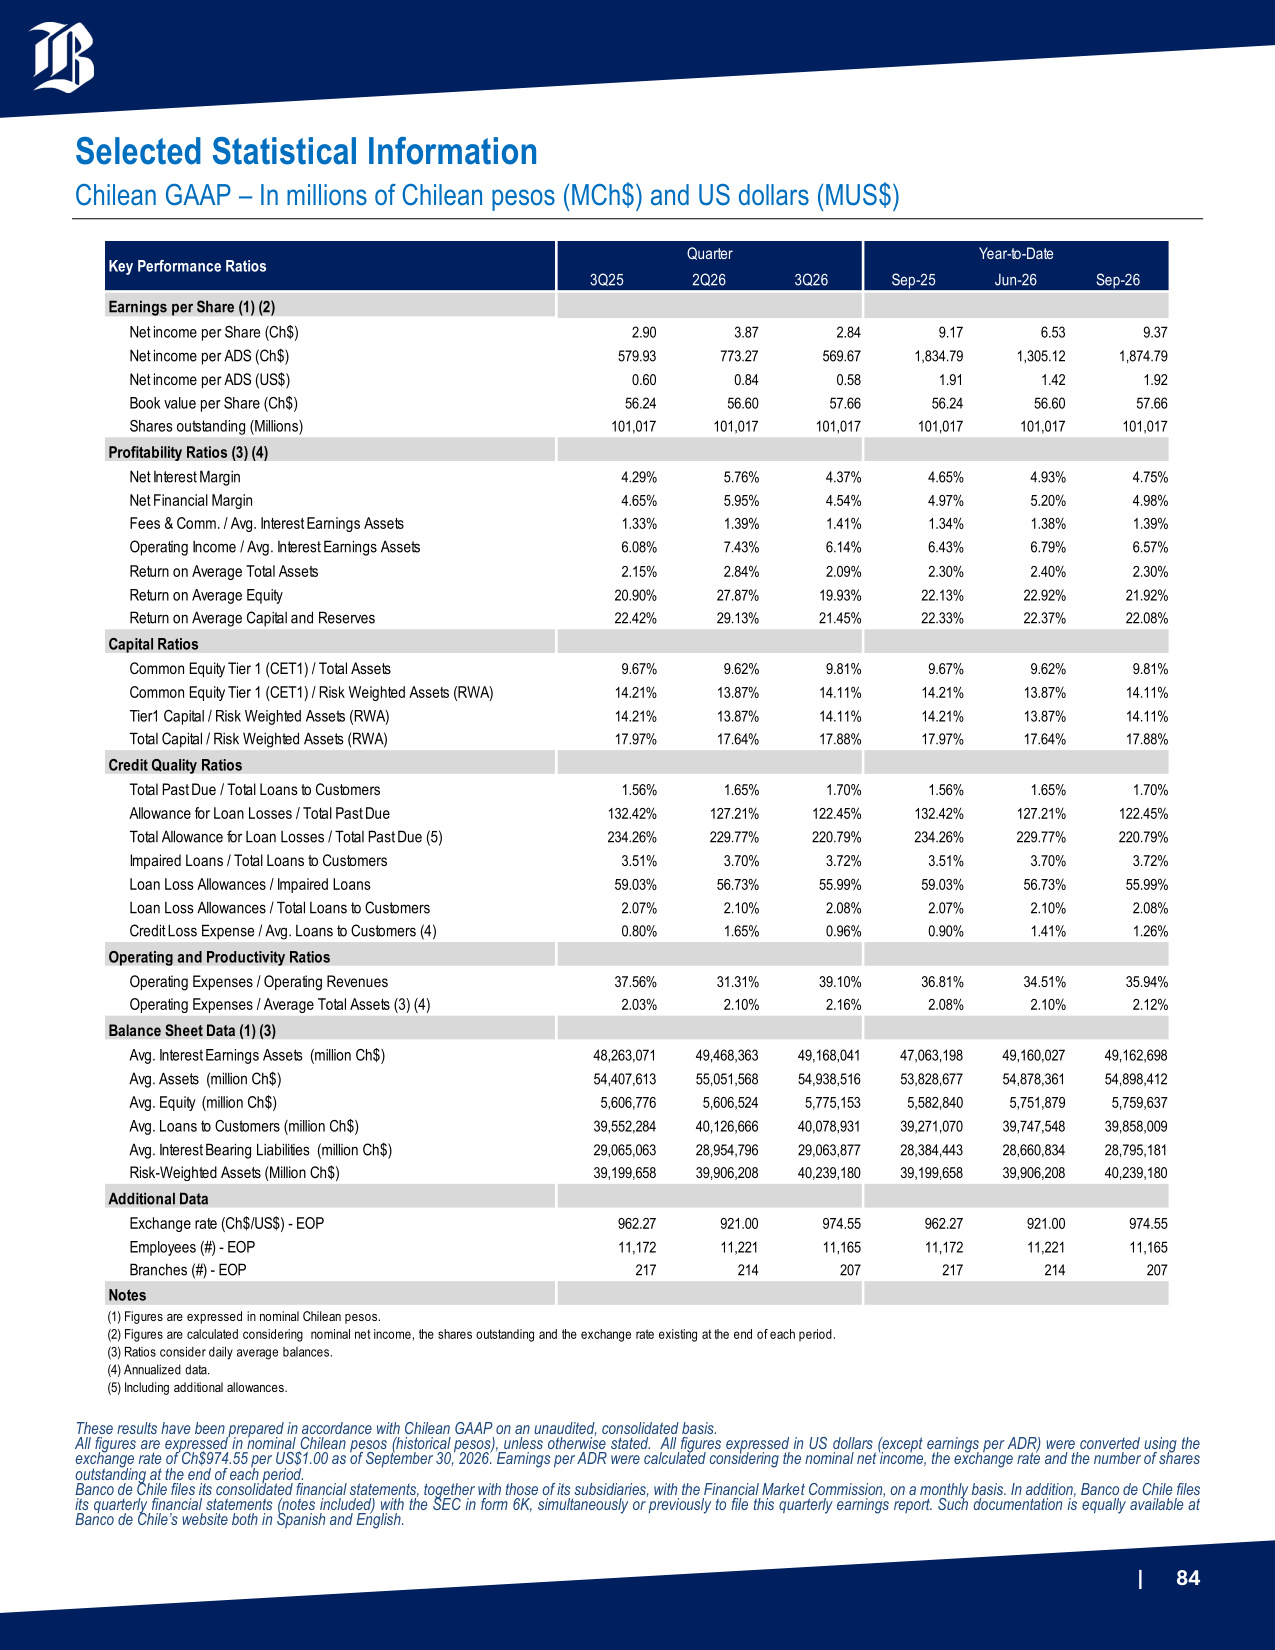
| 84 Selected Statistical Information Chilean GAAP – In millions of Chilean pesos (MCh$) and US dollars (MUS$) 3Q25 2Q26 3Q26 Sep-25 Jun-26 Sep-26 Earnings per Share (1) (2) Net income per Share (Ch$) 2.90 3.87 2.84 9.17 6.53 9.37 Net income per ADS (Ch$) 579.93 773.27 569.67 1,834.79 1,305.12 1,874.79 Net income per ADS (US$) 0.60 0.84 0.58 1.91 1.42 1.92 Book value per Share (Ch$) 56.24 56.60 57.66 56.24 56.60 57.66 Shares outstanding (Millions) 101,017 101,017 101,017 101,017 101,017 101,017 Profitability Ratios (3) (4) Net Interest Margin 4.29% 5.76% 4.37% 4.65% 4.93% 4.75% Net Financial Margin 4.65% 5.95% 4.54% 4.97% 5.20% 4.98% Fees & Comm. / Avg. Interest Earnings Assets 1.33% 1.39% 1.41% 1.34% 1.38% 1.39% Operating Income / Avg. Interest Earnings Assets 6.08% 7.43% 6.14% 6.43% 6.79% 6.57% Return on Average Total Assets 2.15% 2.84% 2.09% 2.30% 2.40% 2.30% Return on Average Equity 20.90% 27.87% 19.93% 22.13% 22.92% 21.92% Return on Average Capital and Reserves 22.42% 29.13% 21.45% 22.33% 22.37% 22.08% Capital Ratios Common Equity Tier 1 (CET1) / Total Assets 9.67% 9.62% 9.81% 9.67% 9.62% 9.81% Common Equity Tier 1 (CET1) / Risk Weighted Assets (RWA) 14.21% 13.87% 14.11% 14.21% 13.87% 14.11% Tier1 Capital / Risk Weighted Assets (RWA) 14.21% 13.87% 14.11% 14.21% 13.87% 14.11% Total Capital / Risk Weighted Assets (RWA) 17.97% 17.64% 17.88% 17.97% 17.64% 17.88% Credit Quality Ratios Total Past Due / Total Loans to Customers 1.56% 1.65% 1.70% 1.56% 1.65% 1.70% Allowance for Loan Losses / Total Past Due 132.42% 127.21% 122.45% 132.42% 127.21% 122.45% Total Allowance for Loan Losses / Total Past Due (5) 234.26% 229.77% 220.79% 234.26% 229.77% 220.79% Impaired Loans / Total Loans to Customers 3.51% 3.70% 3.72% 3.51% 3.70% 3.72% Loan Loss Allowances / Impaired Loans 59.03% 56.73% 55.99% 59.03% 56.73% 55.99% Loan Loss Allowances / Total Loans to Customers 2.07% 2.10% 2.08% 2.07% 2.10% 2.08% Credit Loss Expense / Avg. Loans to Customers (4) 0.80% 1.65% 0.96% 0.90% 1.41% 1.26% Operating and Productivity Ratios Operating Expenses / Operating Revenues 37.56% 31.31% 39.10% 36.81% 34.51% 35.94% Operating Expenses / Average Total Assets (3) (4) 2.03% 2.10% 2.16% 2.08% 2.10% 2.12% Balance Sheet Data (1) (3) Avg. Interest Earnings Assets (million Ch$) 48,263,071 49,468,363 49,168,041 47,063,198 49,160,027 49,162,698 Avg. Assets (million Ch$) 54,407,613 55,051,568 54,938,516 53,828,677 54,878,361 54,898,412 Avg. Equity (million Ch$) 5,606,776 5,606,524 5,775,153 5,582,840 5,751,879 5,759,637 Avg. Loans to Customers (million Ch$) 39,552,284 40,126,666 40,078,931 39,271,070 39,747,548 39,858,009 Avg. Interest Bearing Liabilities (million Ch$) 29,065,063 28,954,796 29,063,877 28,384,443 28,660,834 28,795,181 Risk-Weighted Assets (Million Ch$) 39,199,658 39,906,208 40,239,180 39,199,658 39,906,208 40,239,180 Additional Data Exchange rate (Ch$/US$) - EOP 962.27 921.00 974.55 962.27 921.00 974.55 Employees (#) - EOP 11,172 11,221 11,165 11,172 11,221 11,165 Branches (#) - EOP 217 214 207 217 214 207 Notes (1) Figures are expressed in nominal Chilean pesos. (2) Figures are calculated considering nominal net income, the shares outstanding and the exchange rate existing at the end of each period. (3) Ratios consider daily average balances. (4) Annualized data. (5) Including additional allowances. Quarter Year-to-Date Key Performance Ratios These results have been prepared in accordance with Chilean GAAP on an unaudited, consolidated basis. All figures are expressed in nominal Chilean pesos (historical pesos), unless otherwise stated. All figures expressed in US dollars (except earnings per ADR) were converted using the exchange rate of Ch$974.55 per US$1.00 as of September 30, 2026. Earnings per ADR were calculated considering the nominal net income, the exchange rate and the number of shares outstanding at the end of each period. Banco de Chile files its consolidated financial statements, together with those of its subsidiaries, with the Financial Market Commission, on a monthly basis. In addition, Banco de Chile files its quarterly financial statements (notes included) with the SEC in form 6K, simultaneously or previously to file this quarterly earnings report. Such documentation is equally available at Banco de Chile's website both in Spanish and English.