Exhibit 99.1
BANCO DE CHILE AND SUBSIDIARIES
INDEX
| I. | Interim Consolidated Statements of Financial Position |
| II. | Interim Consolidated Statements of Income |
| III. | Interim Consolidated Statements of Other Comprehensive Income |
| IV. | Interim Consolidated Statements of Cash Flows |
| V. | Interim Consolidated Statements of Changes in Equity |
| VI. | Notes to the Interim Consolidated Financial Statements |
| MCh$ | = | Millions of Chilean pesos |
| BCh$ | = | Billions of Chilean pesos |
| MUS$ | = | Millions of U.S. dollars |
| ThUS$ | = | Thousands of U.S. dollars |
| UF or CLF | = | Unidad de Fomento (The UF is an inflation-indexed, Chilean peso denominated monetary unit set daily in advance on the basis of the previous month’s inflation rate). |
| Ch$ or CLP | = | Chilean pesos |
| US$ or USD | = | U.S. dollar |
| JPY | = | Japanese yen |
| EUR | = | Euro |
| HKD | = | Hong Kong dollar |
| CHF | = | Swiss Franc |
| PEN | = | Peruvian sol |
| AUD | = | Australian dollar |
| NOK | = | Norwegian krone |
| MXN | = | Mexican peso |
| IFRS | = | International Financial Reporting Standards |
| IAS | = | International Accounting Standards |
| RAN | = | Updated Standards Compilation issued by the Chilean Financial Market Commission (“CMF”) |
| IFRIC | = | International Financial Reporting Interpretations Committee |
| SIC | = | Standards Interpretation Committee |
BANCO DE CHILE AND SUBSIDIARIES
INDEX
i
BANCO DE CHILE AND SUBSIDIARIES
INTERIM CONSOLIDATED STATEMENTS OF FINANCIAL POSITION
As of September 30, 2026 and December 31, 2025
| September | December | ||||||||||
| Notes | 2026 | 2025 | |||||||||
| MCh$ | MCh$ | ||||||||||
| ASSETS | |||||||||||
| Cash and deposits in banks | 7 | 3,165,155 | 2,590,986 | ||||||||
| Transactions in the course of collection | 7 | 362,105 | 414,419 | ||||||||
| Financial assets held for trading at fair value through profit or loss: | |||||||||||
| Derivative financial instruments | 8 | 2,406,284 | 1,869,467 | ||||||||
| Debt financial instruments | 8 | 1,416,779 | 3,121,702 | ||||||||
| Others | 8 | 421,754 | 402,259 | ||||||||
| Non-trading financial assets mandatorily measured at fair value through profit or loss | 9 | — | — | ||||||||
| Financial assets designated at fair value through profit or loss | 10 | — | — | ||||||||
| Financial assets at fair value through other comprehensive income: | |||||||||||
| Debt financial instruments | 11 | 4,239,432 | 3,548,971 | ||||||||
| Others | 11 | — | — | ||||||||
| Derivative financial instruments for hedging purposes | 12 | 43,950 | 29,714 | ||||||||
| Financial assets at amortized cost: | |||||||||||
| Rights by resale agreements | 13 | 96,631 | 100,643 | ||||||||
| Debt financial instruments | 13 | 453,575 | 460,937 | ||||||||
| Loans to Banks | 13 | 609,731 | 399,123 | ||||||||
| Commercial loans | 13 | 20,658,046 | 19,137,460 | ||||||||
| Residential mortgage loans | 13 | 14,139,811 | 13,874,507 | ||||||||
| Consumer loans | 13 | 5,121,604 | 5,343,032 | ||||||||
| Investments in other companies | 14 | 94,925 | 87,060 | ||||||||
| Intangible assets | 15 | 182,743 | 174,578 | ||||||||
| Property and equipment | 16 | 175,571 | 179,414 | ||||||||
| Right-of-use assets | 17 | 76,631 | 79,245 | ||||||||
| Current tax assets | 18 | 58,636 | 1,846 | ||||||||
| Deferred tax assets | 18 | 579,398 | 563,906 | ||||||||
| Other assets | 19 | 1,579,624 | 1,696,031 | ||||||||
| Non-current assets and disposal groups held for sale | 20 | 29,947 | 25,603 | ||||||||
| TOTAL ASSETS | 55,912,332 | 54,100,903 | |||||||||
The accompanying notes 1 to 49 are an integral part of these interim consolidated financial statements
1
BANCO DE CHILE AND SUBSIDIARIES
INTERIM CONSOLIDATED STATEMENTS OF FINANCIAL POSITION
As of September 30, 2026 and December 31, 2025
| September | December | ||||||||||
| Notes | 2026 | 2025 | |||||||||
| MCh$ | MCh$ | ||||||||||
| LIABILITIES | |||||||||||
| Transactions in the course of payments | 7 | 698,623 | 564,172 | ||||||||
| Financial liabilities held for trading at fair value through profit or loss: | |||||||||||
| Derivative financial instruments | 21 | 2,513,730 | 2,080,222 | ||||||||
| Others | 21 | 1,624 | 512 | ||||||||
| Financial liabilities designated as at fair value through profit or loss | 10 | — | — | ||||||||
| Derivative financial instruments for hedging purposes | 12 | 272,772 | 297,817 | ||||||||
| Financial liabilities at amortized cost: | |||||||||||
| Current accounts and other demand deposits | 22 | 14,551,566 | 14,498,196 | ||||||||
| Time deposits and saving accounts | 22 | 15,049,344 | 13,971,968 | ||||||||
| Obligations by repurchase agreements | 22 | 122,886 | 286,915 | ||||||||
| Borrowings from financial institutions | 22 | 1,218,163 | 1,296,751 | ||||||||
| Debt financial instruments issued | 22 | 11,164,247 | 10,800,851 | ||||||||
| Other financial obligations | 22 | 328,605 | 367,323 | ||||||||
| Lease liabilities | 17 | 72,432 | 74,343 | ||||||||
| Regulatory capital financial instruments | 23 | 1,119,252 | 1,087,093 | ||||||||
| Provision for contingencies | 24 | 161,029 | 180,548 | ||||||||
| Provision for dividends | 25 | 457,161 | 605,955 | ||||||||
| Special provisions for credit risk | 26 | 775,073 | 721,282 | ||||||||
| Current tax liabilities | 18 | 984 | 33,809 | ||||||||
| Deferred tax liabilities | 18 | 3,489 | 1,422 | ||||||||
| Other liabilities | 27 | 1,577,057 | 1,432,189 | ||||||||
| Liabilities included in disposal groups held for sale | 20 | — | — | ||||||||
| TOTAL LIABILITIES | 50,088,037 | 48,301,368 | |||||||||
| EQUITY | |||||||||||
| Capital | 28 | 2,420,538 | 2,420,538 | ||||||||
| Reserves | 28 | 711,658 | 711,658 | ||||||||
| Accumulated other comprehensive income | |||||||||||
| Items that are not reclassified in profit and loss | 28 | 11,576 | 6,894 | ||||||||
| Items that can be reclassified to profit and loss | 28 | (82,373 | ) | (16,653 | ) | ||||||
| Retained earnings from previous period | 28 | 2,273,127 | 2,090,790 | ||||||||
| Income for the period | 28 | 946,928 | 1,192,262 | ||||||||
| Less: Provision for dividends | 28 | (457,161 | ) | (605,955 | ) | ||||||
| Bank´s Shareholders | 28 | 5,824,293 | 5,799,534 | ||||||||
| Non-controlling interests | 28 | 2 | 1 | ||||||||
| TOTAL EQUITY | 5,824,295 | 5,799,535 | |||||||||
| TOTAL LIABILITIES AND EQUITY | 55,912,332 | 54,100,903 | |||||||||
The accompanying notes 1 to 49 are an integral part of these interim consolidated financial statements
2
BANCO DE CHILE AND SUBSIDIARIES
INTERIM CONSOLIDATED STATEMENTS OF INCOME
For the period ended September 30, 2026 and 2025,
| For the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | |||||||||||||||||
| Notes | 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||
| Interest revenue | 30 | 2,082,661 | 2,033,098 | 706,263 | 687,107 | ||||||||||||||
| Interest expense | 30 | (707,962 | ) | (734,552 | ) | (240,563 | ) | (248,900 | ) | ||||||||||
| Net interest income | 1,374,699 | 1,298,546 | 465,700 | 438,207 | |||||||||||||||
| Inflation indexation revenue | 31 | 664,872 | 552,569 | 117,793 | 110,529 | ||||||||||||||
| Inflation indexation expense | 31 | (370,140 | ) | (299,355 | ) | (65,106 | ) | (60,893 | ) | ||||||||||
| Net inflation indexation income | 294,732 | 253,214 | 52,687 | 49,636 | |||||||||||||||
| Fee and commission income | 32 | 637,098 | 586,936 | 217,066 | 199,017 | ||||||||||||||
| Fee and commission expense | 32 | (123,487 | ) | (114,163 | ) | (43,407 | ) | (38,768 | ) | ||||||||||
| Net fee and commission income | 513,611 | 472,773 | 173,659 | 160,249 | |||||||||||||||
| Financial result for: | |||||||||||||||||||
| Financial assets and liabilities held for trading | 33 | 91,074 | 120,193 | 12,206 | 42,386 | ||||||||||||||
| Non-trading financial assets mandatorily measured at fair value through profit or loss | 33 | — | — | — | — | ||||||||||||||
| Financial assets and liabilities designated as at fair value through profit or loss | 33 | — | — | — | — | ||||||||||||||
| Income (expense) from derecognition of financial assets and liabilities at amortized cost and financial assets at FVTOCI | 33 | 7,901 | 11,446 | (19 | ) | 9,400 | |||||||||||||
| Exchange, indexation and accounting hedging of foreign currency | 33 | 68,510 | 70,692 | 28,000 | 20,952 | ||||||||||||||
| Reclassification of financial assets for changes in the business model | 33 | — | — | — | — | ||||||||||||||
| Other financial result | 33 | — | — | — | — | ||||||||||||||
| Net Financial Result | 33 | 167,485 | 202,331 | 40,187 | 72,738 | ||||||||||||||
| Income from investments in other companies | 34 | 4,989 | 8,481 | 2,290 | 2,670 | ||||||||||||||
| Income (expense) from non-current assets and disposal groups held for sale not admissible as discontinued operations | 35 | 7,316 | 3,761 | 2,815 | 2,789 | ||||||||||||||
| Other operating income | 36 | 65,666 | 38,357 | 20,249 | 9,394 | ||||||||||||||
| TOTAL OPERATING INCOME | 2,428,498 | 2,277,463 | 757,587 | 735,683 | |||||||||||||||
| Personnel expenses | 37 | (433,558 | ) | (418,563 | ) | (151,810 | ) | (138,125 | ) | ||||||||||
| Administrative expenses | 38 | (333,374 | ) | (321,097 | ) | (110,374 | ) | (106,927 | ) | ||||||||||
| Depreciation and amortization | 39 | (72,930 | ) | (71,023 | ) | (24,867 | ) | (23,668 | ) | ||||||||||
| Impairment of non-financial assets | 40 | (559 | ) | (2,826 | ) | (226 | ) | (386 | ) | ||||||||||
| Other operating expenses | 36 | (32,409 | ) | (24,809 | ) | (8,954 | ) | (7,240 | ) | ||||||||||
| TOTAL OPERATING EXPENSES | (872,830 | ) | (838,318 | ) | (296,231 | ) | (276,346 | ) | |||||||||||
| OPERATING RESULT BEFORE CREDIT LOSSES | 1,555,668 | 1,439,145 | 461,356 | 459,337 | |||||||||||||||
The accompanying notes 1 to 49 are an integral part of these interim consolidated financial statements
3
BANCO DE CHILE AND SUBSIDIARIES
INTERIM CONSOLIDATED STATEMENTS OF INCOME
For the period ended September 30, 2026 and 2025,
| For the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||||
| Notes | 2026 | 2025 | 09.30.2026 | 09.30.2025 | ||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||
| Credit loss expense for: | ||||||||||||||||||
| Provisions for credit risk of loans to banks and loans to customers | 41 | (390,774 | ) | (359,665 | ) | (128,009 | ) | (105,363 | ) | |||||||||
| Special provisions for credit risk | 41 | (52,144 | ) | 45,140 | 353 | 9,399 | ||||||||||||
| Recovery of written-off credits | 41 | 62,674 | 51,580 | 29,010 | 17,904 | |||||||||||||
| Impairments for credit risk of other financial assets at amortized cost and financial assets at FVTOCI | 41 | 4,594 | (3,135 | ) | 2,254 | (1,500 | ) | |||||||||||
| Credit loss expense | 41 | (375,650 | ) | (266,080 | ) | (96,392 | ) | (79,560 | ) | |||||||||
| NET OPERATING INCOME | 1,180,018 | 1,173,065 | 364,964 | 379,777 | ||||||||||||||
| Income from continuing operations before income tax | 1,180,018 | 1,173,065 | 364,964 | 379,777 | ||||||||||||||
| Income tax | 18 | (233,089 | ) | (246,340 | ) | (77,230 | ) | (86,863 | ) | |||||||||
| Income from continuing operations after income tax | 946,929 | 926,725 | 287,734 | 292,914 | ||||||||||||||
| Income from discontinued operations before income tax | — | — | — | — | ||||||||||||||
| Income tax from discontinued operations | 18 | — | — | — | — | |||||||||||||
| Income from discontinued operations after income tax | 42 | — | — | — | — | |||||||||||||
| NET INCOME FOR THE PERIOD | 28 | 946,929 | 926,725 | 287,734 | 292,914 | |||||||||||||
| Attributable to: | ||||||||||||||||||
| Bank´s Shareholders | 28 | 946,928 | 926,725 | 287,733 | 292,914 | |||||||||||||
| Non-controlling interests | 1 | — | 1 | — | ||||||||||||||
| Earnings per share: | $ | $ | $ | $ | ||||||||||||||
| Basic earnings | 28 | 9.37 | 9.17 | 2.84 | 2.90 | |||||||||||||
| Diluted earnings | 28 | 9.37 | 9.17 | 2.84 | 2.90 | |||||||||||||
The accompanying notes 1 to 49 are an integral part of these interim consolidated financial statements
4
BANCO DE CHILE AND SUBSIDIARIES
INTERIM CONSOLIDATED STATEMENTS OF OTHER COMPREHENSIVE INCOME
For the period ended September 30, 2026 and 2025
| For the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||||
| Notes | 2026 | 2025 | 09.30.2026 | 09.30.2025 | ||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||
| NET INCOME FOR THE PERIOD | 28 | 946,929 | 926,725 | 287,734 | 292,914 | |||||||||||||
| ITEMS THAT WILL NOT BE RECLASSIFIED TO PROFIT OR LOSS | ||||||||||||||||||
| Re-measurement of the liability (asset) for net defined benefits and actuarial results for other employee benefit plans | 28 | 53 | (62 | ) | — | — | ||||||||||||
| Fair value changes of equity instruments designated as at FVTOCI | 28 | 6,325 | (125 | ) | 3,222 | 117 | ||||||||||||
| Fair value changes of financial liabilities designated as at fair value through profit or loss attributable to changes in the credit risk of the financial liability | 28 | — | — | — | — | |||||||||||||
| Others | 28 | — | — | — | — | |||||||||||||
| OTHER COMPREHENSIVE INCOME THAT WILL NOT BE RECLASSIFIED TO PROFIT OR LOSS BEFORE TAX | 6,378 | (187 | ) | 3,222 | 117 | |||||||||||||
| Income tax on other comprehensive income that will not be reclassified to profit or loss | 28 | (1,696 | ) | (459 | ) | (864 | ) | (28 | ) | |||||||||
| TOTAL OTHER COMPREHENSIVE INCOME THAT WILL NOT BE RECLASSIFIED TO INCOME AFTER TAXES | 28 | 4,682 | (646 | ) | 2,358 | 89 | ||||||||||||
| ITEMS THAT CAN BE RECLASSIFIED TO PROFIT OR LOSS | ||||||||||||||||||
| Fair value changes of financial assets at FVTOCI | 28 | (38,724 | ) | 8,698 | (23,511 | ) | 967 | |||||||||||
| Cash flow hedges | 28 | (43,731 | ) | (14,892 | ) | (23,534 | ) | (26,994 | ) | |||||||||
| Participation in other comprehensive income of entities registered under the equity method | 28 | 27 | 58 | 42 | 32 | |||||||||||||
| OTHER COMPREHENSIVE INCOME THAT WILL BE RECLASSIFIED TO INCOME BEFORE TAXES | (82,428 | ) | (6,136 | ) | (47,003 | ) | (25,995 | ) | ||||||||||
| Income tax on other comprehensive income that can be reclassified in profit or loss | 28 | 16,708 | 3,170 | 10,192 | 7,227 | |||||||||||||
| TOTAL OTHER COMPREHENSIVE INCOME THAT WILL BE RECLASSIFIED TO PROFIT OR LOSS AFTER TAX | 28 | (65,720 | ) | (2,966 | ) | (36,811 | ) | (18,768 | ) | |||||||||
| TOTAL OTHER COMPREHENSIVE INCOME FOR THE PERIOD | 28 | (61,038 | ) | (3,612 | ) | (34,453 | ) | (18,679 | ) | |||||||||
| CONSOLIDATED COMPREHENSIVE INCOME FOR THE PERIOD | 885,891 | 923,113 | 253,281 | 274,235 | ||||||||||||||
| Attributable to: | ||||||||||||||||||
| Bank´s Shareholders | 885,890 | 923,113 | 253,280 | 274,235 | ||||||||||||||
| Non-controlling interests | 1 | — | 1 | — | ||||||||||||||
The accompanying notes 1 to 49 are an integral part of these interim consolidated financial statements
5
BANCO DE CHILE AND SUBSIDIARIES
INTERIM CONSOLIDATED STATEMENTS OF CASH FLOWS
For the period
ended September 30, 2026 and 2025
| September | September | |||||||||
| Notes | 2026 | 2025 | ||||||||
| MCh$ | MCh$ | |||||||||
| CASH FLOW FROM OPERATING ACTIVITIES: | ||||||||||
| Net operating income, before income tax | 1,180,018 | 1,173,065 | ||||||||
| Income tax | 18 | (233,089 | ) | (246,340 | ) | |||||
| Net income for the period | 946,929 | 926,725 | ||||||||
| Debit (credits) to profit or (loss) that do not represent movements in cash flows: | ||||||||||
| Depreciation and amortization | 39 | 72,930 | 71,023 | |||||||
| Impairment of non-financial assets | 40 | 559 | 2,826 | |||||||
| Allowances established for credit risk | 394,970 | 368,127 | ||||||||
| Provisions for contingent loans | 41 | (6,646 | ) | 18,568 | ||||||
| Additional provisions | 41 | 50,000 | (69,035 | ) | ||||||
| Fair value of debt financial instruments held for trading at FVTPL | 9,115 | (4,034 | ) | |||||||
| Change in deferred tax assets and liabilities | 18 | (10,220 | ) | (5,914 | ) | |||||
| Net gain from investments in associates and joint ventures | 34 | (4,414 | ) | (8,041 | ) | |||||
| Net gain on sale of assets received in payments | (1,279 | ) | (1,527 | ) | ||||||
| Net gain on sale of property and equipment | 35 | (6,597 | ) | (6,182 | ) | |||||
| Write-off assets received in lieu of payment or foreclosed at judicial auction | 35 | 10,981 | 12,269 | |||||||
| Other debits (credits) that do not represent cash flows | 2,124 | 14,047 | ||||||||
| Net change in exchange rates, interest, indexation and fees accrued on assets and liabilities | 472,410 | 514,218 | ||||||||
| Changes due to (increase) decrease in assets and liabilities affecting the operating flow: | ||||||||||
| Net (increase) decrease in loans to banks | (213,160 | ) | (1,401,140 | ) | ||||||
| Net (increase) decrease in loans to customers | (1,832,007 | ) | (1,025,666 | ) | ||||||
| Net (increase) decrease of debt financial instruments held for trading at FVTPL | 131,749 | (150,724 | ) | |||||||
| Net (increase) decrease in other assets and liabilities | (12,844 | ) | 553,377 | |||||||
| Increase (decrease) in deposits and other demand deposits | 52,344 | 61,469 | ||||||||
| Increase (decrease) in repurchase agreements | (161,540 | ) | 62,931 | |||||||
| Increase (decrease) in deposits and other time deposits | 1,069,140 | 984,656 | ||||||||
| Sale of assets received in lieu of payment | 19,986 | 21,783 | ||||||||
| Increase (decrease) in obligations with foreign banks | (173,443 | ) | 451,830 | |||||||
| Increase (decrease) in other financial obligations | (46,898 | ) | (4,959 | ) | ||||||
| Increase (decrease) in obligations with the Central Bank of Chile | — | — | ||||||||
| Net increase (decrease) of debt financial instruments at FVTOCI | (726,125 | ) | (1,193,542 | ) | ||||||
| Net (increase) decrease of financial instruments at amortized cost | 11,466 | 380,110 | ||||||||
| Total net cash (used in) from operating activities | 49,530 | 573,195 | ||||||||
| CASH FLOW FROM INVESTING ACTIVITIES: | ||||||||||
| Leasehold improvements | 17 | (182 | ) | (489 | ) | |||||
| Property and equipment purchase | 16 | (15,650 | ) | (11,831 | ) | |||||
| Property and equipment sale | 10,022 | 8,515 | ||||||||
| Sale of investments in companies | — | — | ||||||||
| Acquisition of intangibles | 15 | (42,352 | ) | (39,685 | ) | |||||
| Dividend received of investments in companies | 3,324 | 3,814 | ||||||||
| Total net cash used in investing activities | (44,838 | ) | (39,676 | ) | ||||||
| CASH FLOW FROM FINANCING ACTIVITIES: | ||||||||||
| Attributable to the interest of the owners: | ||||||||||
| Redemption and payment of interest of mortgage finance bonds of credit | (86 | ) | (264 | ) | ||||||
| Redemption and payment of interest on senior bonds | (1,684,131 | ) | (1,120,245 | ) | ||||||
| Redemption and payment of interest on subordinated bonds | (30,352 | ) | (29,488 | ) | ||||||
| Senior bonds issuance | 22 | 1,452,513 | 2,331,480 | |||||||
| Subordinated bonds issuance | — | — | ||||||||
| Payment of ordinary share dividends | 28 | (1,009,925 | ) | (995,380 | ) | |||||
| Principal and interest payments for obligations under lease contracts | 17 | (22,570 | ) | (23,239 | ) | |||||
| Attributable to non-controlling interest: | ||||||||||
| Dividend payment and/or withdrawals of paid-in capital related to the subsidiaries corresponding to the non-controlling interest | — | — | ||||||||
| Total net cash used in financing activities | (1,294,551 | ) | 162,864 | |||||||
| INCREASE (DECREASE) IN CASH AND CASH EQUIVALENTS FOR THE PERIOD | (1,289,859 | ) | 696,383 | |||||||
| Effect of exchange rate fluctuations on cash and cash equivalents | 125,542 | (21,144 | ) | |||||||
| Cash and cash equivalents at the beginning of the period | 7 | 5,322,146 | 4,489,586 | |||||||
| Cash and cash equivalents at the end of the period | 7 | 4,157,829 | 5,164,825 | |||||||
| September | September | |||||||
| 2026 | 2025 | |||||||
| Interest operating cash flow: | MCh$ | MCh$ | ||||||
| Interest and indexation received | 2,575,572 | 2,632,071 | ||||||
| Interest and indexation paid | (1,037,088 | ) | (975,524 | ) | ||||
The accompanying notes 1 to 49 are an integral part of these interim consolidated financial statements
6
BANCO DE CHILE AND SUBSIDIARIES
INTERIM CONSOLIDATED STATEMENTS OF CASH FLOWS
For the period ended September 30, 2026 and 2025
Reconciliation of liabilities arising from financing activities:
| Changes from non-cash Flow items | ||||||||||||||||||||||||||||
| 12.31.2025 | Net Cash Flow | Acquisition / (Disposals) | Foreign currency | UF Movement | Changes other than Cash | 09.30.2026 | ||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||
| Mortgage finance bonds | 521 | (86 | ) | — | — | — | — | 435 | ||||||||||||||||||||
| Bonds | 11,887,423 | (261,970 | ) | — | 228,956 | 428,655 | — | 12,283,064 | ||||||||||||||||||||
| Dividends paid | 605,955 | (1,009,925 | ) | — | — | — | 861,131 | 457,161 | ||||||||||||||||||||
| Obligations for lease contracts | 74,343 | (22,570 | ) | 17,263 | — | 3,396 | — | 72,432 | ||||||||||||||||||||
| Dividend payment and/or withdrawals of paid-in capital in respect of the subsidiaries corresponding to the non-controlling interest | — | — | — | — | — | — | — | |||||||||||||||||||||
| Total liabilities from financing activities | 12,568,242 | (1,294,551 | ) | 17,263 | 228,956 | 432,051 | 861,131 | 12,813,092 | ||||||||||||||||||||
| Changes from non-cash Flow items | ||||||||||||||||||||||||||||
| 12.31.2024 | Net Cash Flow | Acquisition / (Disposals) | Foreign currency | UF Movement | Changes other than Cash | 09.30.2025 | ||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||
| Mortgage finance bonds | 850 | (264 | ) | — | — | 18 | — | 604 | ||||||||||||||||||||
| Bonds | 10,758,098 | 1,181,747 | — | 28,070 | 462,115 | — | 12,430,030 | |||||||||||||||||||||
| Dividends paid | 597,228 | (995,380 | ) | — | — | — | 866,484 | 468,332 | ||||||||||||||||||||
| Obligations for lease contracts | 91,429 | (23,239 | ) | 7,782 | — | 3,732 | — | 79,704 | ||||||||||||||||||||
| Dividend payment and/or withdrawals of paid-in capital in respect of the subsidiaries corresponding to the non-controlling interest | — | — | — | — | — | — | — | |||||||||||||||||||||
| Total liabilities from financing activities | 11,447,605 | 162,864 | 7,782 | 28,070 | 465,865 | 866,484 | 12,978,670 | |||||||||||||||||||||
The accompanying notes 1 to 49 are an integral part of these interim consolidated financial statements
7
BANCO DE CHILE AND SUBSIDIARIES
INTERIM CONSOLIDATED STATEMENTS OF CHANGES IN EQUITY
For the period between January 1, and September 30, 2026 and 2025
| Attributable to shareholders of the Bank | |||||||||||||||||||||||||||||||
| Note | Capital | Reserves | Accumulated other comprehensive income | Retained earnings from previous years and income (loss) for the year | Total | Non-controlling interests | Total Equity | ||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Balances as of January 1, 2025 | 2,420,538 | 709,742 | 3,777 | 2,488,942 | 5,622,999 | 2 | 5,623,001 | ||||||||||||||||||||||||
| Dividends distributed and paid | 28 | — | — | — | (995,380 | ) | (995,380 | ) | (1 | ) | (995,381 | ) | |||||||||||||||||||
| Application of provision for payment of common stock dividends | — | — | — | 597,228 | 597,228 | — | 597,228 | ||||||||||||||||||||||||
| Provision for payment of common stock dividends | — | — | — | (468,332 | ) | (468,332 | ) | — | (468,332 | ) | |||||||||||||||||||||
| Subtotal: transactions with owners during the period | — | — | — | (866,484 | ) | (866,484 | ) | (1 | ) | (866,485 | ) | ||||||||||||||||||||
| Net Income for the period 2025 | 28 | — | — | — | 926,725 | 926,725 | — | 926,725 | |||||||||||||||||||||||
| Other comprehensive income for the period | 28 | — | 1,916 | (3,612 | ) | — | (1,696 | ) | — | (1,696 | ) | ||||||||||||||||||||
| Subtotal: Comprehensive income for the period | — | 1,916 | (3,612 | ) | 926,725 | 925,029 | — | 925,029 | |||||||||||||||||||||||
| Balances as of September 30, 2025 | 2,420,538 | 711,658 | 165 | 2,549,183 | 5,681,544 | 1 | 5,681,545 | ||||||||||||||||||||||||
| Dividends distributed and paid | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Application of provision for payment of common stock dividends | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Provision for payment of common stock dividends | — | — | — | (137,623 | ) | (137,623 | ) | — | (137,623 | ) | |||||||||||||||||||||
| Subtotal: transactions with owners during the period | — | — | — | (137,623 | ) | (137,623 | ) | — | (137,623 | ) | |||||||||||||||||||||
| Net Income for the period 2025 | — | — | — | 265,537 | 265,537 | — | 265,537 | ||||||||||||||||||||||||
| Other comprehensive income for the period | — | — | (9,924 | ) | — | (9,924 | ) | — | (9,924 | ) | |||||||||||||||||||||
| Subtotal: Comprehensive income for the period | — | — | (9,924 | ) | 265,537 | 255,613 | — | 255,613 | |||||||||||||||||||||||
| Balances as of December 31, 2025 | 2,420,538 | 711,658 | (9,759 | ) | 2,677,097 | 5,799,534 | 1 | 5,799,535 | |||||||||||||||||||||||
| Dividends distributed and paid | 28 | — | — | — | (1,009,925 | ) | (1,009,925 | ) | — | (1,009,925 | ) | ||||||||||||||||||||
| Application of provision for payment of common stock dividends | 28 | — | — | — | 605,955 | 605,955 | — | 605,955 | |||||||||||||||||||||||
| Provision for payment of common stock dividends | 28 | — | — | — | (457,161 | ) | (457,161 | ) | — | (457,161 | ) | ||||||||||||||||||||
| Subtotal: transactions with owners during the period | — | — | — | (861,131 | ) | (861,131 | ) | — | (861,131 | ) | |||||||||||||||||||||
| Net Income for the period 2026 | 28 | — | — | — | 946,928 | 946,928 | 1 | 946,929 | |||||||||||||||||||||||
| Other comprehensive income for the period | 28 | — | — | (61,038 | ) | — | (61,038 | ) | — | (61,038 | ) | ||||||||||||||||||||
| Subtotal: Comprehensive income for the period | — | — | (61,038 | ) | 946,928 | 885,890 | 1 | 885,891 | |||||||||||||||||||||||
| Balances as of September 30, 2026 | 2,420,538 | 711,658 | (70,797 | ) | 2,762,894 | 5,824,293 | 2 | 5,824,295 | |||||||||||||||||||||||
The accompanying notes 1 to 49 are an integral part of these interim consolidated financial statements
8
BANCO DE CHILE AND SUBSIDIARIES
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS
As of September 30, 2026 and 2025 and December 31, 2025
| 1. | Company information: |
Banco de Chile (“The Bank”) has been authorized to operate as a commercial bank since September 17, 1996, being, in conformity with the stipulations of article 25 of Law No. 19,396, the legal successor of Banco de Chile resulting from the merger of the Banco Nacional de Chile, Banco Agrícola and Banco de Valparaiso, which was incorporated by public deed dated October 28, 1893, granted before the Notary Public of Santiago, Mr. Eduardo Reyes Lavalle, and authorized by Supreme Decree of dated November 28, 1893.
The Bank is a Corporation organized under the laws of the Republic of Chile, regulated by the Chilean Commission for the Financial Market (“CMF”). Since 2001, it is subject to the supervision of the Securities and Exchange Commission of the United States of America (“SEC”), in consideration of the fact that the Bank is registered on the New York Stock Exchange (“NYSE”), through a program of American Depositary Receipt (“ADR”).
Banco de Chile offers a broad range of banking services to its customers, ranging from individuals to large corporations. Additionally, the Bank offers international as well as treasury banking services, in addition to those offered by subsidiaries that include securities brokerage, mutual fund and investment management, insurance brokerage and financial advisory services.
Banco de Chile’s registered office is located at Ahumada 251, Santiago, Chile and its website is www.bancochile.cl.
9
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies: |
| (a) | Legal Provisions: |
Decree Law No. 3,538 of 1980, according to the text superseded by the first article of Law No. 21,000 that “Creates the Financial Market Commission”, provides in number 6 of its article 5 that the Financial Market Commission (“CMF”) may “set the standards for the preparation and presentation of reports, balance sheets, statements of situation and other financial statements of the audited entities and determine the principles under which they must keep their accounting records”.
According to the current legal framework, banks must use the accounting principles established by the CMF and in everything that is not dealt with by it or in contravention of its instructions, they must adhere to the generally accepted accounting principles, which correspond to the technical standards issued by the Colegio de Contadores de Chile A.G., coinciding with the Accounting Standards of International Financial Reporting Standards (“IFRS”) issued by the International Accounting Standards Board (“IASB”). Should any discrepancy exist between accounting principles generally accepted in Chile and the accounting standards issued by the CMF, the latter shall prevail.
The notes to the Interim Consolidated Financial Statements contain additional information to that presented in the Interim Consolidated Statement of Financial Position, Interim Consolidated Statement of Income, Interim Consolidated Statement of Other Comprehensive Income, Interim Consolidated Statement of Cash Flows and Interim Consolidated Statement of Changes in Equity. They provide narrative descriptions or disaggregation of such statements in a clear, relevant, reliable and comparable manner.
| (b) | Basis of Consolidation: |
The Interim Consolidated Financial Statements of Banco de Chile for the period ended September 30, 2026 and 2025 and December 31, 2025, have been consolidated with its subsidiaries. The Interim Consolidated Financial Statements have been prepared using consistent accounting policies for similar transactions and other events, in equivalent circumstances.
Significant intercompany transactions and balances (assets and liabilities, equity, income, expenses and cash flows) generated from operations performed between the Bank and its subsidiaries have been eliminated in the consolidation process. The non-controlling interest corresponding to the participation percentage of third parties in subsidiaries, which the Bank does not own directly or indirectly, has been recognized and is shown separately in the consolidated shareholders’ equity and consolidated income statement of the Bank.
10
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| − | Subsidiaries: |
Interim Consolidated Financial Statements for the period ended September 30, 2026 and 2025 and December 31, 2025 include the Financial Statements of the Bank and its subsidiaries in accordance with IFRS 10 “Consolidated Financial Statements”.
The entities controlled by the Bank and consolidated are detailed as follows:
| Ownership interest | |||||||||||||||||||||||||||||||||||
| Direct | Indirect | Total | |||||||||||||||||||||||||||||||||
| Functional | September | December | September | December | September | December | |||||||||||||||||||||||||||||
| Rut | Subsidiaries | Country | Currency | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||
| % | % | % | % | % | % | ||||||||||||||||||||||||||||||
| 96,767,630-6 | Banchile Administradora General de Fondos S.A. | Chile | Ch$ | 99.98 | 99.98 | 0.02 | 0.02 | 100.00 | 100.00 | ||||||||||||||||||||||||||
| 96,543,250-7 | Banchile Asesoría Financiera S.A. | Chile | Ch$ | 99.96 | 99.96 | — | — | 99.96 | 99.96 | ||||||||||||||||||||||||||
| 77,191,070-K | Banchile Corredores de Seguros Ltda. | Chile | Ch$ | 99.83 | 99.83 | 0.17 | 0.17 | 100.00 | 100.00 | ||||||||||||||||||||||||||
| 96,571,220-8 | Banchile Corredores de Bolsa S.A. | Chile | Ch$ | 99.70 | 99.70 | 0.30 | 0.30 | 100.00 | 100.00 | ||||||||||||||||||||||||||
| 77,955,969-6 | Operadora de Tarjetas Banchile Pagos S.A. | Chile | Ch$ | 99.90 | 99.90 | 0.10 | 0.10 | 100.00 | 100.00 | ||||||||||||||||||||||||||
| − | Investments in associates and joint ventures: |
Associated entities are those over which the Bank has the ability to exercise significant influence, without having control over the associate.
Investments in associates where the entity has significant influence are accounted for using the equity method of accounting (Note 14 Investments in other companies).
Joint Ventures are joint arrangements whereby the parties that have joint control of the arrangement have rights to the net assets of the arrangement. Joint control exists only when decisions about the relevant activities require the unanimous consent of the parties sharing control.
Investments defined as a “Joint Venture” are recognized using the equity method of accounting.
The investment in other companies that, for its characteristics, is defined as “Joint Venture” is Servipag Ltda.
| − | Minority investments in other companies: |
On initial recognition, the Bank and subsidiaries may make an irrevocable election to present in other comprehensive income subsequent changes in the fair value of an investment in an equity instrument that is not held for trading and is not contingent consideration recognized by an acquirer in a business combination to which IFRS 3 is applied.
11
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| − | Fund management: |
The Bank and its subsidiaries manage and administer assets held in mutual funds and other investment products on behalf of investors, receiving compensation in line with the services provided and in accordance with market conditions. Managed resources are owned by third parties and, therefore, not included in the Consolidated Statements of Financial Position.
In accordance with IFRS 10, for consolidation purposes it is necessary to assess the role of the Bank and its subsidiaries with respect to the funds they manage, to determine whether that role is Agent or Principal.
The Bank and its subsidiaries manage investments and mutual funds on behalf and for the benefit of investors, acting only as an Agent in this relationship. Under this category, and as per the aforementioned regulation, it does not control such funds when exercising their authority to make decisions. Accordingly, as of September 30, 2026 and 2025 acting as agents, are not controlled and therefore not consolidated by the Bank or its subsidiaries.
| (c) | Non-controlling interest: |
Non-controlling interest represents the share of losses, income and net assets that the Bank does not control, either directly or indirectly. It is presented as a separate item in the Consolidated Statements of Income and the Consolidated Statements of Financial Position.
| (d) | Use of Estimates and Judgment: |
The preparation of Interim Consolidated Financial Statements requires Management to make judgments, estimations and assumptions that affect the application of accounting policies and the valuation of assets, liabilities, income and expenses presented. Actual results could differ from these estimated amounts. The estimates made refer to:
| - | Impairment losses on assets and liabilities (Notes 11, 13, 15, 16, 17 and 40); |
| - | Allowance for credit losses (Notes 13, 26 and 41); |
| - | Expenses for amortization of intangible assets, depreciation of property and equipment and leased assets and lease liabilities (Notes 15, 16 and 17); |
| - | Current and deferred taxes (Note 18); |
| - | Provision for contingencies (Note 24); |
| - | Contingencies and commitments (Note 29); |
| - | Fair value of financial assets and liabilities (Notes 8, 11, 12, 21 and 44). |
Estimates and relevant assumptions are regularly reviewed by Management in order to quantify certain assets, liabilities, revenue, expenses and commitments.
During the period ended September 30, 2026, there have been no significant changes in the estimates made.
12
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| (e) | Financial Assets: |
The classification, measurement and presentation of financial assets has been performed based on the standards issued by the CMF in the Compendium of Accounting Standards for Banks or “CNCB” (per its Spanish acronym), considering the criteria described below:
Classification of financial assets:
On initial recognition, a financial asset is classified within the following categories: Financial assets held for trading at fair value through profit or loss; Non-trading financial assets mandatorily measured at fair value through profit or loss; Financial assets designated as at fair value through profit or loss; Financial assets at fair value through other comprehensive income and Financial assets at amortized cost.
The criteria for classifying financial assets, which includes the standards defined in IFRS 9, depends on the business model with which the entity manages the assets and the contractual characteristics of the cash flows, commonly known as the “Solely Payments of Principal and Interest” (SPPI) criterion.
The measurement of these assets should reflect how the Bank manages groups of financial assets and does not depend on the intent for an individual instrument.
A financial asset shall be measured at amortized cost if both of the following conditions are met:
| - | The financial asset is held within a business model whose objective is to hold financial assets to collect contractual cash flows and |
| - | The contractual terms of the financial asset give rise on specified dates to cash flows that are solely payments of principal and interest on the principal amount outstanding. |
A financial asset shall be measured at fair value through other comprehensive income if the following two conditions are met:
| - | It is held within a business model whose objective is achieved by both collecting contractual cash flows and selling financial assets and |
| - | The contractual terms of the financial asset give rise on specified dates to cash flows that are solely payments of principal and interest on the principal amount outstanding. |
A financial asset will be classified at fair value through profit or loss whenever, due to the business model or the characteristics of its contractual cash flows, it is not appropriate to classify it in any of the other categories described above.
13
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
Measurement of financial assets:
Initial recognition:
Financial assets are initially recognized at fair value plus, in the case of a financial asset that is not carried at fair value through profit or loss, the transaction costs that are directly attributable to its acquisition or issuance, using the Effective Interest Rate method (EIT). The calculation of the effective interest rate includes all fees, commissions and other items paid or received that are part of the effective interest rate. Transaction costs include incremental costs that are directly attributable to the acquisition or issuance of a financial asset.
Subsequent measurement:
All variations in the value of financial assets due to the accrual of interest and items treated as interest are recorded in “Interest income” or “Interest expense” of the Consolidated Statement of Income for the year in which the accrual occurred, except for trading derivatives that are not part of accounting hedges.
Changes in the valuations that occur subsequent to initial registration for reasons other than those mentioned in the preceding paragraph, are treated as described below, based on the categories in which the financial assets are classified.
Financial assets held for trading at fair value through profit or loss, Non-trading financial assets mandatorily measured at fair value through profit or loss and financial assets designated as at fair value through profit or loss:
The caption “Financial assets held for trading at fair value through profit or loss” will record financial assets whose business model aims to generate profits through purchases and sales or to generate results at short-term.
The financial assets recorded under “Non-trading Financial assets mandatorily measured at fair value through profit or loss” are assigned to a business model whose objective is achieved by obtaining contractual cash flows and/or selling financial assets but where the cash flows contracts have not met the conditions of the SPPI test.
The caption “Financial assets designated as at fair value through profit or loss” will classify financial assets only when such designation eliminates or significantly reduces the inconsistency in the measurement or in the recognition that would arise from valuing or recognizing the assets on a different basis.
The assets recorded in these items are valued after their acquisition at their fair value and changes in their value are recorded, at their net amount, under “Financial assets and liabilities held for trading”, “Non-trading financial assets and liabilities mandatorily measured at fair value through profit or loss” and “Financial assets and liabilities designated as at fair value through profit or loss” of the Consolidated Statement of Income. Variations originated from differences are recorded under “Foreign currency changes, UF indexation and accounting hedge” in the Consolidated Statement of Income.
14
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
Financial assets at fair value through other comprehensive income:
| − | Debt financial instruments: |
The assets recorded in this item are measured at their fair value, interest income and indexation of these instruments, as well as exchange differences and impairment arising, are recorded in the Consolidated Statement of Income, whereas subsequent variations in their valuation are temporarily recorded (for its amount net of taxes) in “Changes in the fair value of financial assets at fair value through other comprehensive income” of the Consolidated Statements of Other Comprehensive Income.
The amounts recorded in “Changes in the fair value of financial assets at fair value through other comprehensive income” continue to be part of the Bank’s consolidated equity until the asset is derecognized in the consolidated balance. Should these assets be sold, the resulting gain or loss is recognized in “Financial result for derecognizing financial assets and liabilities at amortized cost and financial assets at fair value through other comprehensive income” in the Consolidated Statement of Income.
Net impairment losses on financial assets at fair value through other comprehensive income occurred during the year are recorded in “Impairment due to credit risk of other financial assets at amortized cost and financial assets at fair value through other comprehensive income” in the Consolidated Statement of Income.
| − | Equity financial instruments: |
On initial recognition, the Bank may make the irrevocable decision to present subsequent changes in fair value in other comprehensive income. Subsequent variations in this valuation will be recognized in “Changes in fair value of equity instruments designated as at fair value through other comprehensive income.” The dividends received from these investments are recorded in “Income from investments in companies” in the Consolidated Statement of Income. These instruments are not subject to the impairment model of IFRS 9.
| − | Financial assets at amortized cost: |
The assets recorded in this item of the Consolidated Statement of Financial Position are measured after their acquisition at their “amortized cost”, in accordance with the effective interest method. They are subdivided according to the following:
| - | Rights by resale agreements (Note 13 (a)). |
| - | Debt financial instruments (Note 13 (b)). |
| - | Loans to Banks (Note 13 (c)). |
| - | Loans to customers (Note 13 (d)). |
Losses due to impairment of these assets generated in each year are recorded in “Provisions for credit risk of loans to banks and loans to customers” and “Impairments for credit risk of other financial assets at amortized cost and financial assets at FVTOCI” in the Consolidated Statement of Income.
15
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| − | Rights and Obligations by repurchase agreements: |
Resale agreement operations are carried out as a form of investment. Under these agreements, financial instruments are purchased, which are included as assets in “Rights by resale agreements” which are valued according to the interest rate of the agreement through the amortized cost method. In accordance with current regulations, the Bank does not record as its own portfolio those papers purchased under resale agreements.
Repurchase agreement operations are also performed as a form of financing, which are included as liabilities in “Obligations by repurchase agreements”. In this regard, the investments that are sold subject to a repurchase obligation and that are used as collateral for the loan correspond to financial debt securities. The obligation to repurchase the investment is classified in liabilities as “Obligations by repurchase agreements” and is measured according to the interest rate of the agreement.
| − | Debt financial instruments at amortized cost: |
These instruments are recorded at their cost plus accrued interest and UF indexation, less the allowances for impairment made when their recorded amount is higher than the estimated amount of recovery and their interest and UF indexation of debt financial instrument at amortized cost are included in “Interest income” and “UF indexation income”.
| − | Loans to Banks: |
This item shows the balances of operations with local and foreign banks, including the Central Bank of Chile and foreign Central Banks.
| − | Loans to customers: |
Loans from customers include generated and acquired relate to non-derivative financial assets with fixed or determinable payments that are not quoted in an active market and which the Bank does not intend to sell immediately or in the short-term.
| (i) | Valuation method |
They are initially measured at cost plus incremental transaction costs and income, and subsequently measured at amortized cost, using the effective interest rate method, less any impairment loss, except when the Bank defines certain loans as hedged items, measured at fair value through profit or loss as described in letter (p) of this note.
| (ii) | Lease contracts |
These are included under the item “Loans to customers” correspond to regular lease payments for contracts which meet the definition to be classified as financial leases and are presented at their nominal value net of unearned interest as of each year-end.
16
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| (iii) | Factoring transactions |
They are measured for the amounts disbursed by the Bank in exchange for invoices or other commercial instruments representing credits, with or without responsibility of the grantor, received in discount. Price differences between the amounts disbursed and the nominal value of the credits are recorded in profit or loss as interest income, through the effective interest method, during the financing period. In those cases where the transfer of these instruments was made without responsibility of the grantor, the Bank assumes the insolvency risks of those required to pay.
| (f) | Allowances for credit losses: |
The Bank permanently evaluates the entire portfolio of loans and contingent loans, with the aim of establishing the necessary and sufficient provisions in a timely manner to cover the expected losses associated with the characteristics of the debtors and their credits, based on the payment and subsequent recovery.
Allowances are required to cover the risk of loan losses have been established in accordance with the instructions issued by the CMF. The loans are presented net of those allowances and, in the case of contingent loans are shown in liabilities under the item “Special provisions for credit risk”
In accordance with CMF’s instructions, models or methods are used based on an individual and collective analysis of debtors, to establish the allowance for loan losses. The Bank’s Board of Directors approves such models, as well as the amendments to their design and application.
| (i) | Allowance for individual evaluations. |
An individual analysis of debtors is applied to companies that are of such significance with respect to size, complexity or level of exposure to the bank, that they must be analyzed in depth.
Likewise, the analysis of borrowers focuses on its creditworthiness related to the capacity and willingness to meet their credit obligations, through sufficient and reliable information, and should also be analyzed with respect to guarantees, terms, interest rates, currency and indexation, etc.
For the purposes of establishing the allowances, banks must assess the creditworthiness and classify debtors and their transactions referred to contingent loans, in the related categories with the prior allocation to one of the following three portfolio categories: Normal, Substandard and Non-performing loans.
17
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| − | Normal Loans and Substandard Loans: |
Normal performing loans: includes those debtors whose payment capacity allows them to meet their obligations and commitments, and according to the evaluation of their economic and financial position no change in this condition are displayed. Loans classified in categories A1 through A6.
Substandard loans: includes all borrowers with insufficient payment capacity or significant deterioration of payment capacity that may be reasonably expected not to comply with all principal and interest payments obligations set forth in the credit agreement, showing a low flexibility to meet its financial obligations at short-term.
The Substandard Portfolio also includes those debtors who have shown past due amounts over 30 days recently. The classifications assigned to this portfolio are categories B1 to B4 of the rating scale.
As a result of individual analysis of the debtors, the Bank must classify them in the following categories, assigning, subsequently, the percentage of probability of default and loss given default resulting in the following percentage of expected loss:
| Type of portfolio | Category of debtors |
Probability of default (%) PD |
Loss given default (%) LGD |
Expected loss (%) EL | ||||
| Normal Loans | A1 | 0.04 | 90.0 | 0.03600 | ||||
| A2 | 0.10 | 82.5 | 0.08250 | |||||
| A3 | 0.25 | 87.5 | 0.21875 | |||||
| A4 | 2.00 | 87.5 | 1.75000 | |||||
| A5 | 4.75 | 90.0 | 4.27500 | |||||
| A6 | 10.00 | 90.0 | 9.00000 | |||||
| Substandard Loans | B1 | 15.00 | 92.5 | 13.87500 | ||||
| B2 | 22.00 | 92.5 | 20.35000 | |||||
| B3 | 33.00 | 97.5 | 32.17500 | |||||
| B4 | 45.00 | 97.5 | 43.87500 |
Allowances for Normal and Substandard Loans:
To determine the amount of allowances to be made for normal and substandard portfolios, the exposure subject to the allowances should be estimated previously, applying the related loss percentages, which consist of probability of default (PD) and loss given default (LGD) established for the category in which the debtor and/or guarantor belong, as appropriate.
The exposure subject to allowances relates to loans plus contingent loans minus the amounts to be recovered by way of the foreclosure of financial or real guarantees of the operations. Loans mean the carrying amount of loans and accounts receivable of the related debtor, whereas for contingent loans, the value resulting from applying that indicated in No. 3 of Chapter B-3 of the CNCB.
18
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
For real guarantees, the Bank must demonstrate that the value assigned to this deduction reasonably reflects the value that it would obtain from the sale of the assets or equity instruments. Also, in qualifying cases, the direct debtor’s credit risk may be substituted for the creditworthiness of the guarantor. In no event may the guaranteed securities be discounted from the amount of the exposure, as this procedure is only applicable when related to financial or real guarantees.
For calculation purposes, the following must be considered:
Provision debtor = (ESA-GE) x (PDdebtor /100) x (LGDdebtor /100) + GE x (PDguarantor /100) x (LGDguarantor /100)
Where:
| ESA = | Exposure subject to allowances, (Loans + Contingent Loans) – Financial or real guarantees |
| GE = | Guaranteed exposure |
However, the Bank must maintain a minimum provision level of 0.50% over normal portfolio and contingent loans.
| − | Non-performing loans: |
The non- performing portfolio includes the debtors and their loans whose recovery is considered remote, as they show impaired or no payment capacity. This category comprises all debtors who have stopped paying their creditors or with visible evidence that they will stop doing so, as well as those for which a forced restructuring of their debts is necessary, reducing the obligation or postponing the payment of the principal or interest and, in addition, any debtor that has 90 days overdue or more in the payment of interest or principal of any loan. This portfolio is composed of the debtors belonging to categories C1 to C6 of the rating scale and all loans, including 100% of the amount of contingent loans, held by those same debtors.
For purposes recognizing the allowances on non- performing loans, the Bank has allowance percentages to be applied to the amount of exposure, which relates to the amount of loans and contingent loans kept by the same debtor. To apply that percentage, an expected loss rate must be estimated, deducting from the exposure amount the recoverable amounts through the execution of financial or real guarantees supporting the transaction and, in the event specific background substantiate it, deducting the present value of recoveries that may be obtained performing collection actions, net of expenses associated with them. Such loss percentage must be categorized in one of the six levels defined by the range of expected actual losses by the Bank for all transactions from the same debtor.
19
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
These categories, their loss range as estimated by the Bank and the percentages of allowances that must be applied on the amount of exposures, are listed in the following table:
| Type of portfolio | Risk Scale | Expected Loss Range | Allowance (%) | |||||
| Non-performing loans | C1 | Up to 3% | 2 | |||||
| C2 | More than 3% up to 20% | 10 | ||||||
| C3 | More than 20% up to 30% | 25 | ||||||
| C4 | More than 30 % up to 50% | 40 | ||||||
| C5 | More than 50% up to 80% | 65 | ||||||
| C6 | More than 80% | 90 |
For calculation purposes, the following must be considered:
| Expected Loss Rate | = (E−R)/E | |
| Allowance | = E × (AP/100) |
Where:
| E | = Exposure Amount |
| R | = Recoverable Amount |
| AP | = Allowance Percentage (according to the category in which the Expected Loss Rate should be assigned). |
All of the loans debtors must remain in the Default Portfolio until there is a normalization of their capacity or payment behavior, without prejudice to punishment of each particular credit that meets the condition indicated in Title II of Chapter B-2 of the Compendium of Accounting Standards for Banks. To remove a debtor from the Default Portfolio, once the circumstances that lead to classification in this portfolio according to these regulations have been overcome, at least the following cumulative conditions must be met:
| - | No obligation of the debtor with the bank are more than 30 calendar days overdue. |
| - | No new refinances agreements have been granted to pay their obligations. |
| - | At least one of the payments includes amortization of capital. |
| - | If the debtor has any loan with partial payment periods less than six months, they have already made two payments. |
| - | If the debtor must pay monthly fees for one or more loans, at least, four consecutive dues have been paid. |
| - | The debtor does not have direct debts unpaid in the CMF compiled information, except in the case of insignificant amounts are involved. |
20
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| (ii) | Allowances for group assessment. |
Group assessments are relevant for residential and consumer mortgage loan exposures, in addition to commercial exposures related to student loans and exposures with debtors that simultaneously meet the following conditions:
| - | The Bank has an aggregate exposure to a single counterparty of less than 20,000 UF. The aggregate exposure should require gross provisions or other mitigations factors. In addition, for its computation, mortgage loans must be excluded. In the case of off-balance sheet items, the gross amount is calculated by applying the credit conversion factors, defined in chapter B-3 of the CNCB. To determine the aggregate exposure, the bank must consider the definition of corporate group established in Title II of Chapter 12-16 of the Actualized Standards Compilation. |
Banks must maintain a complete and permanent monitoring of all operations with entities belonging to business groups. Considering the potential costs of forming groups for all debtors, the bank must at least maintain control and forming groups, if applicable, for all debtors who maintain a current exposure greater than a minimum amount established by the banking institution which may not be greater than 1% of its effective equity at the time the definition of the group portfolio is made.
| - | Each aggregate exposure to a single counterparty does not exceed 0.2% of the total commercial group portfolio. To avoid circular calculations, the criteria will be checked only once. |
For the remaining commercial credit exposures, the individual analysis model of the debtors must be applied.
The determination of the type of analysis (group or individual) must be carried out at the global consolidated level, once a year, or after significant adjustments in the Bank’s portfolio, such as mergers, acquisitions, purchases or significant portfolio sales.
To determine allowances, group assessment requires the creation of loan groups with similar characteristics in terms of debtors types and agreed terms, to establish technically based estimates by prudential criteria and following both the payment behavior of the group in question and the recoveries concerned of defaulted loans and consequently provide the necessary provisions to cover the portfolio risk.
To determine its allowances, the Bank segments its debtors into homogeneous groups, according described above, associating to each group with a determined probability of default and a recovery percentage based in a historic analysis. The amount of provisions to register it will be obtained multiplied the total loans of respective group by the percentages of estimated default and of loss given the default, the estimated losses must be related to the type of portfolio and the term of the operations.
The Bank discriminates between provisions on the normal portfolio and on the portfolio in default, and those that protect the risks of contingent credits associated with those portfolios.
21
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| − | Standard method of provisions for group portfolio. |
The standard methodologies presented below establish the variables and parameters that determine the provision factor for each type of portfolio that the CMF has defined as representative, according to the common characteristics shared by the operations that comprise them.
| (a) | Residential mortgage portfolio |
The provision factor applicable, represented by expected loss over the mortgage loans, will depend on the past due of each credit and the relation, at the end of month, between outstanding capital and the value of the mortgage collateral (PVG), according to the following table:
| Allowances factor applicable according to delinquency and CMG | ||||||||||||
| CMG section | Days of default at the end of the month | |||||||||||
| Concept | 0 | 1-29 | 30-59 | 60-89 | Non-performing Portfolio | |||||||
| CMG ≤ 40% | PD (%) | 1.0916 | 21.3407 | 46.0536 | 75.1614 | 100.0000 | ||||||
| LGD (%) | 0.0225 | 0.0441 | 0.0482 | 0.0482 | 0.0537 | |||||||
| EAD (%) | 0.0002 | 0.0094 | 0.0222 | 0.0362 | 0.0537 | |||||||
| 40% < CMG≤ 80% | PD (%) | 1.9158 | 27.4332 | 52.0824 | 78.9511 | 100.0000 | ||||||
| LGD (%) | 2.1955 | 2.8233 | 2.9192 | 2.9192 | 3.0413 | |||||||
| EAD (%) | 0.0421 | 0.7745 | 1.5204 | 2.3047 | 3.0413 | |||||||
| 80% < CMG≤ 90% | PD (%) | 2.5150 | 27.9300 | 52.5800 | 79.6952 | 100.0000 | ||||||
| LGD (%) | 21.5527 | 21.6600 | 21.9200 | 22.1331 | 22.2310 | |||||||
| EAD (%) | 0.5421 | 6.0496 | 11.5255 | 17.6390 | 22.2310 | |||||||
| CMG > 90% | PD (%) | 2.7400 | 28.4300 | 53.0800 | 80.3677 | 100.0000 | ||||||
| LGD (%) | 27.2000 | 29.0300 | 29.5900 | 30.1558 | 30.2436 | |||||||
| EAD (%) | 0.7453 | 8.2532 | 15.7064 | 24.2355 | 30.2436 | |||||||
Where:
| PD | : | Probability of default |
| LGD | : | Loss given default |
| EAD | : | Exposure at default |
| CMG | : | Outstanding loan capital /Mortgage Guarantee value |
| (b) | Commercial portfolio |
To determine these allowances, the Bank considers the standard methods presented below, as applicable to commercial leasing operations or other types of commercial loans. Then, the applicable provision factor will be assigned considering the parameters defined for each method.
22
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| ● | Commercial Leasing Operations |
The provision factor applies to the current value of commercial leasing operations (including the purchase option) and will depends on the default of each operation, the type of leased asset and the relationship between the current value of each operation and the leased asset value (PVB) at each month-end, as indicated in the following tables:
| Probability of default (PD) applicable according to default and type of asset (%) | ||||
| Days of default of the operation at the month-end | Type of asset | |||
| Real estate | Non-real estate | |||
| 0 | 0.79 | 1.61 | ||
| 1-29 | 7.94 | 12.02 | ||
| 30-59 | 28.76 | 40.88 | ||
| 60-89 | 58.76 | 69.38 | ||
| Portfolio in default | 100.00 | 100.00 | ||
| Loss given the default (LGD) applicable according to PVB section and type of asset (%) | ||||
| PVB = Current value of the operation / Value of the leased asset | ||||
| PVB section | Real estate | Non-real estate | ||
| PVB ≤ 40% | 0.05 | 18.20 | ||
| 40% < PVB ≤ 50% | 0.05 | 57.00 | ||
| 50% < PVB ≤ 80% | 5.10 | 68.40 | ||
| 80% < PVB ≤ 90% | 23.20 | 75.10 | ||
| PVB > 90% | 36.20 | 78.90 | ||
The determination of the PVB relationship is made considering the appraisal value expressed in UF for real estate and in Chilean pesos for non-real estate, recorded at the time of the respective loan granting, taking into account possible situations that may be causing temporary increases in the assets prices at that time.
| ● | Generic commercial loans and factoring |
For the factoring operations and other commercial loans, other than those indicated above, the provision factor, applicable to the amount of the placement and the exposure of the contingent loan risk, will depends on the default of each operation and the relationship that exists at the end of each month, between the obligations that the debtor has with the bank and the value of the collateral that protect them (PTVG), as indicated in the following tables:
| Probability of default (PD) applicable according to default and PTVG section (%) | |||||||||
| Days of default at the month-end | With collateral | Without collateral | |||||||
| PTVG≤100% | PTVG>100% | ||||||||
| 0 | 1.86 | 2.68 | 4.91 | ||||||
| 1-29 | 11.60 | 13.45 | 22.93 | ||||||
| 30-59 | 25.33 | 26.92 | 45.30 | ||||||
| 60-89 | 41.31 | 41.31 | 61.63 | ||||||
| Portfolio in default | 100.00 | 100.00 | 100.00 | ||||||
23
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| Loss given the default (LGD) applicable according to PTVG section (%) | ||||||||
| Collateral (with / without) | PTVG section | Generic commercial operations or factoring without the responsibility of the transferor | Factoring
with the responsibility of the transferor |
|||||
| With collateral | PTVG ≤ 60% | 5.00 | 3.20 | |||||
| 60% < PTVG≤ 75% | 20.30 | 12.80 | ||||||
| 75% < PTVG ≤ 90% | 32.20 | 20.30 | ||||||
| 90% < PTVG | 43.00 | 27.10 | ||||||
| Without collateral | 56.90 | 35.90 | ||||||
The collaterals used for the purposes of calculating the PTVG relationship of this method may be specific or general, including those that are simultaneously specific and general. Collateral can only be considered if, according to the respective coverage clauses, it was constituted in the first degree of preference in favor of the Bank and only guarantees the debtor’s credits with respect to which it is imputed (not shared with other debtors).
The invoices assigned in the factoring operations will not be considered for purposes of calculating the PTVG. The excess of collateral associated with mortgage loans referred to in numeral 3.1.1 Residential mortgage portfolio in Chapter B-1 of CNCB may be considered, computed as the difference between 80% of the property commercial value, according to with the conditions set out in that framework, and the mortgage loan that guarantees.
For the calculation of the PTVG ratio, the following considerations must be taken into account:
| i. | Transactions with specific collaterals: when the debtor granted specific collateral for generic commercial loans and factoring, the PTVG ratio is calculated independently for each covered transaction, such as the division between the amount of the loans and the contingent loans exposure and the collateral’s value of the covered product. |
| ii. | Transactions with general collaterals: when the debtor granted general or general and specific collaterals, the Bank calculates the respective PTVG, jointly for all generic commercial loans and factoring and not contemplated in the preceding paragraph i), as the quotient between the sum of the amounts of the loans and exposures of contingent loans and the general, or general and specific collateral that, according to the scope of the remaining coverage clauses, safeguard the loans considered in the numerator aforementioned coverage ratio. |
24
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
The amounts of the guarantees used in the PTVG ratio of numerals i) and ii), different from those associated with excess guarantees from mortgage loans to which the residential mortgage portfolio refers, must be determined according to:
| - | The last valuation of the collateral, be it appraisal or fair value, according to the type of real guarantee in question. For the determination of fair value, the criteria indicated in Chapter 7-12 (Fair Value of Financial Instruments) of the RAN should be considered. |
| - | Possible situations that could be causing temporary increases in the values of the collaterals. |
| - | Limitations on the amount of coverage established in their respective clauses. |
| (c) | Consumer Portfolio |
The allowance factor, represented by the expected loss (EL), corresponds to the probability of default (PD) together with the loss given the default occurred (LGD). This factor is applied uniformly to all contingent consumer loans and consumer credits held by the debtor with the bank and its subsidiaries established in Chile, including consumer leasing transactions. In the case of contingent transactions, the exposure measure is calculated according to the provisions established in Chapter B-3 of the CNC will be considered.
To define the value of the PD, the following factors are calculated for each debtor:
| ● | Bank default rate: This corresponds to the maximum default rate (in days) for the consumer portfolio, including consumer leasing transactions, that the debtor has with the bank at the end of the month for which provisions are being determined. For clients with more than one transaction, the maximum value obtained from all of them is used. This variable is measured by considering all entities that comprise the institution’s overall consolidated level. |
| ● | 30 days in default in the financial system: This variable applies to whether the debtor has at least one direct debt in default for 30 days or more in any of the three months prior to the date on which the provisions are calculated. This variable is calculated based on the debtor’s defaults with all credit providers for which information is available. This variable includes the list of debtors reported by the CMF, as well as the bank itself at a global consolidated level, and the various financial products. It excludes only loans subject to a communication ban under Law No. 19,628 on the Protection of Privacy. |
| ● | Having a mortgage Loan: This variable determines whether the borrower has a current mortgage loan in the financial system. In this case, the bank uses the most recent information available at the date the provisions are being calculated, considering the list of borrowers reported by the CMF, in addition to the bank’s own consolidated data. |
25
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
The table of factors considered to define the PD is as follows:
| With a mortgage loan for housing in the system | No mortgage loan for housing in the system | |||||||||||
| Maximum default level in the month and bank (range in days that includes extremes | No default greater than 30 days in the system |
With a default greater than 30 days in the system |
No
default greater than 30 days in the system |
With a default greater than 30 days in the system |
||||||||
| 0 and 7 | 3.3 | % | 14.6 | % | 6.6 | % | 19.8 | % | ||||
| 8 and 30 | 20.4 | % | 41.6 | % | 30.6 | % | 48.5 | % | ||||
| 31 and 60 | 50.2 | % | 63.0 | % | 65.1 | % | 66.3 | % | ||||
| 61 and 89 | 62.6 | % | 81.7 | % | 72.3 | % | 86.9 | % | ||||
In the event that the debtor is in default, the assigned LGD will be 100%.
To determine the value of the LGD, it is determined whether the debtor has a mortgage loan for the home in the system as defined for the value of the PD, and the type of loan involved.
The LGD to be used is defined according to the following table:
| Automotive leasing and credit operations | Credits in installments | Credit cards and lines, and other consumer products | ||||||||||
| With a mortgage loan for housing in the system | 33.2 | % | 47.7 | % | 49.5 | % | ||||||
| No mortgage loan for housing in the system | 33.2 | % | 56.6 | % | 60.3 | % | ||||||
The allocation of the LGD value is carried out according to the following guidelines:
| ● | “Automotive leasing and credit operations” will be considered those loans where the transaction is intended to finance the acquisition of private vehicles, which remain as collateral (pledge) in favor of the institution. Consumer financial leasing operations are also considered in this category. |
| ● | “Installment Credits” will correspond to those registered in the item Consumer Credits in Installments of Chapter C-3 of the CNC, to the extent that these have been granted upon signing of a promissory note that clearly establishes the amount of capital, term, rate and number of installments, without a predefined use of the funds (free disposal) and does not correspond to the previous category. |
| ● | If a loan does not fall under either of the two previous definitions, but is classified as consumer loans, the LGD value assigned to the “Credit cards and lines, and other consumer loans” category must be applied. |
26
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| − | Portfolio in default. |
Includes all placements and 100% of the amount of the contingent loans, of the debtors that the closing of a month presents a delay equal to or greater than 90 days in the payment of the interest of the capital of any credit. It will also include debtors who are granted a credit to leave an operation that has more than 60 days of delay in their payment, as well as those debtors who were subject to forced restructuring or partial forgiveness of a debt.
They may exclude from the portfolio in default: a) mortgage loans for housing, which delinquent less than 90 days, unless the debtor has another loan of the same type with greater delinquency; and, b) credits for financing higher studies of Law No. 20,027, which do not yet present the non-compliance conditions indicated in Circular No. 3,454 of December 10, 2008.
All credits of the debtor must be kept in the Default Portfolio until there is a normalization of their ability or payment behavior, without prejudice to punishment of each particular credit that meets the condition indicated in Title II of Chapter B-2 of the CNCB. To remove a debtor from the Default Portfolio, once the circumstances that lead to classification in this portfolio according to the present rules have been overcome, at least the following copulative conditions must be met:
| - | No obligation of the debtor with the bank with more than 30 calendar days overdue. |
| - | No new refinances granted to pay its obligations. |
| - | At least one of the payments includes amortization of capital. |
| - | If the debtor has a credit with partial payment periods less than six months, has already made two payments. |
| - | If the debtor must pay monthly fees for one or more credits, has paid four consecutive dues. |
| - | The debtor does not appear with unpaid debts direct according to the information recast by CMF, except for insignificant amounts. |
| (iii) | Impaired portfolio. |
The impaired portfolio includes the following assets, according to Chapter B-1 of the CNCB of the CMF:
| - | In case of individually assessed debtors, includes credits from “Non-performing loans” and those classified in categories B3 and B4 of “Substandard Portfolio”. |
| - | These debtors subject to collective assessment includes all credits of the “Non- performing loans”. |
| (iv) | Charge-offs. |
Generally, the charge-offs are produced when the contractual rights on cash flows end. In case of loans, even if the above does not happen, it will proceed to charge-offs the respective asset balances.
The charge-off refers to derecognition of the assets in the Consolidated Statement of Financial Position, related to the respective transaction and, therefore, the part that could not be past-due if a loan is payable in installments, or a lease.
27
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| − | Charge-offs of loans to customers |
The charge-off must be made using the credit risk provisions constituted, regardless of the reason for which the charge-off occurred.
Write-offs for loans to customers and accounts receivable, other than from leasing operations, should be made in the following circumstances, whichever occurs first:
| - | The Bank, based on all available information, concludes that will not obtain any cash flow of the credit recorded as an asset. |
| - | When the debt without executive title expires 90 days after it was recorded in asset. |
| - | At the expiration of the statute of limitations for actions to demand payment through an executive trial, or at the time of rejection or abandonment of the execution of the judgment by final court resolution. |
| - | When past-due term of a transaction reaches the charge-off term disposed below: |
| Type of Loan | Term | |
| Consumer loans - secured and unsecured | 6 months | |
| Other transactions - unsecured | 24 months | |
| Commercial loans - secured | 36 months | |
| Residential mortgage loans | 48 months |
The term corresponds to the time elapsed from the date on which the payment of all or part of the obligation that is in default became enforceable.
| − | Charge-offs of lease operations |
These assets must be charge-offs against the following circumstances, whichever occurs first:
| - | The Bank concludes that there is no possibility of the rent recoveries and the value of the property cannot be considered for purposes of recovery of the contract, either because the lessee has not the asset, for the property’s conditions, for expenses that involve its recovery, transfer and maintenance, due to technological obsolescence or absence of a history of your location and current situation. |
| - | When it complies the prescription term of actions to demand the payment through executory or upon rejection or abandonment of executory by court. |
| - | When a contract has been in default reach the period of time indicated below: |
| Type of Loan | Term | |
| Consumer leases | 6 months | |
| Other non-real estate lease transactions | 12 months | |
| Real estate leases (commercial or residential) | 36 months |
The term corresponds to the time elapsed from the date on which the payment of all or part of the obligation that is in default became enforceable.
28
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| (v) | Recovery of written-off loans |
Subsequent payments obtained for transactions written-off are recognized directly as profit or loss in the Consolidated Statement of Income under the item “Recovery of written-off loans”.
In the event that there are recoveries in assets, revenue will be recognized in profit or loss for the amount by which they are incorporated into the asset. The same criterion will be followed if the leased assets are recovered after the write-off of a leasing transaction, when such assets are incorporated into the assets.
Any renegotiation of a loan written-off does not give rise to revenue, as long as the transaction continues to be impaired, and the actual payments received will be treated as recoveries of loans written-off.
Consequently, the renegotiated loan will be re-entered as an asset if it ceases to be impaired, also recognizing the income from the activation as recovery of loans written-off.
The same criterion should apply in the event that a loan is granted to repay a loan written-off.
| (g) | Impairment for credit risk on financial assets at amortized cost and financial assets at fair value through other comprehensive income (FVTOCI): |
In accordance with Chapter A-2 of the CNCB of the CMF, the impairment model of IFRS 9 will not be applied to loans in the category “Financial assets at amortized cost” (“Loans to Banks” and “Loans to customers”), nor on “Contingent loans”, since the criteria for these instruments are defined in Chapter B-1 to B-3 of the CNCB.
For the rest of the financial assets measured at Amortized Cost or FVTOCI, the model on which impairment losses must be calculated corresponds to one of Expected Credit Loss (ECL) as established in IFRS 9.
Debt financial instruments whose subsequent valuation measurement is at amortized cost or at FVTOCI will be subject to impairment due to credit risk. On the contrary, those instruments at fair value through profit or loss do not require this measurement.
The measurement of impairment is performed in accordance with a general impairment model that is based on the existence of 3 possible stages of the financial asset, the existence or not of a significant increase in credit risk and the condition of impairment. The 3 stages determine the amount of impairment that will be recognized as an expected credit loss, as well as the interest income that will be recorded at each reporting date. Below, each stage is listed:
Stage 1: Incorporates financial assets whose credit risk has not increased significantly since initial recognition. Expected credit losses are recognized to 12-month. Interest is recognized based on the gross amount in the balance sheet.
Stage 2: Incorporates financial assets whose credit risk has increased significantly since initial recognition. Expected credit losses are recognized throughout the life of the financial asset. Interest is recognized based on the gross amount in the balance sheet.
29
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
Stage 3: Incorporates impaired financial assets. Expected credit losses are recognized throughout the life of the financial asset. Interest is recognized based on the net amount (gross amount on the balance sheet less allowance for credit risk).
| − | Impairment of debt financial instruments measured at fair value through other comprehensive income. |
The Bank applies the value impairment requirements for the recognition and measurement of an impairment loss allowance account to financial assets that are measured at fair value through other comprehensive income in accordance with IFRS 9. This impairment loss allowance account is recognized in Other Comprehensive Income (OCI) and does not reduce the carrying amount of the financial asset in the Consolidated Statement of Financial Position. The cumulative loss recognized in OCI is recycled in profit or loss when derecognizing the financial assets.
| (h) | Financial liabilities: |
Classification of financial liabilities:
Financial liabilities are classified in the following categories:
| - | Financial liabilities at amortized cost. |
| - | Financial liabilities held for trading at fair value through profit or loss: Financial instruments are recorded in this item when the Bank’s objective is to generate profits through purchases and sales with these instruments. This item includes financial derivative instruments held for trading that are liabilities, which will be measured subsequently at fair value. |
| - | Financial liabilities designated at fair value through profit or loss: The Bank has the option to irrevocably designate, at the time of initial recognition, a financial liability as measured at fair value through profit or loss if the application of this criterion eliminates or significantly reduces inconsistencies in the measurement or recognition, or if it is a group of financial liabilities, or a group of financial assets and liabilities, that is managed, and its performance evaluated, based on fair value in line with a risk management or investment strategy. |
Measurement of financial liabilities:
Initial measurement:
They are initially recorded at fair value, less transaction costs that are directly attributable to their issuance. Variations in the value of financial liabilities due to the accrual of interest, UF indexation and similar concepts are recorded under the items “Interest expenses” and “Inflation indexation expense” of the Consolidated Statement of Income for the period in which the accrual occurred (see Note 30 and 31).
30
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
Subsequent measurement:
The changes in the measurements that will occur after the initial registration due to reasons other than those mentioned in the previous paragraph, are treated as described below, based on the categories in which the financial liabilities are classified.
Financial liabilities at amortized cost:
The liabilities recorded in this item are measured after their acquisition at their amortized cost, which is determined in accordance with the effective interest rate method (EIR).
| (i) | Derecognition of financial assets and liabilities: |
The Bank and its subsidiaries derecognize a financial asset in its Statement of Financial Position, when the contractual rights to the cash flows from the financial asset expire or when it transfers the rights to receive contractual cash flows of the financial asset are transferred during a transaction in which all ownership risks and rewards of the financial asset are transferred. Any portion of transferred financial assets that is created or retained by the Bank is recognized as a separate asset or liability.
When the Bank transfers a financial asset, it assesses to what extent it has retained the risks and rewards of the ownership. In this case:
| − | If substantially all risks and rewards of ownership of the financial asset have been transferred, it is derecognized, and any rights or obligations created or retained upon transfer are recognized separately as assets or liabilities. |
| − | If substantially all risks and rewards of ownership of the financial asset have been retained, the Bank continues to recognize it. |
| − | If substantially all risks and rewards of ownership of the financial asset are neither transferred nor retained, the Bank will determine if it has retained control of the financial asset. In this case: |
| - | If the Bank has not retained control, the financial asset will be derecognized, and any rights or obligations created or retained upon transfer will be recognized separately as assets or liabilities. |
| - | If the Bank has retained control, it will continue to recognize the financial asset in the Consolidated Statement of Financial Position for an amount equal to its exposure to changes in value that can experience and recognize a financial liability associated to the transferred financial asset. |
The Bank derecognizes a financial liability (or a portion thereof) from its Consolidated Statement of Financial Position if, and only if, it has extinguished or, in other words, when the obligation specified in the corresponding contract has been paid or settled or has expired.
31
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| (j) | Offset of financial assets and liabilities: |
Financial assets and liabilities are offset, so that their net amount is presented in the Consolidated Statement of Financial Position, and only when the Bank has a legally enforceable right to set off the recognized amounts and intends to settle on a net basis, or to realize the asset and settle the liability simultaneously.
Income and expenses are shown net only if accounting standards allow such treatment, or in the case of gains and losses arising from a group of similar transactions such as the Bank’s trading and foreign exchange activity.
| (k) | Functional currency: |
The items included in the Financial Statements of each of the entities of Banco de Chile and its subsidiaries are presented using the currency of the primary economic environment in which it operates (functional currency). The functional currency of Banco de Chile is the Chilean peso, which is also the currency used to present the entity’s consolidated financial statements.
| (l) | Foreign currency transactions: |
Transactions in currencies other than the functional currency are considered to be in foreign currency and are initially recorded at the exchange rate of the functional currency on the transaction date. Monetary assets and liabilities denominated in foreign currencies are converted using the exchange rate of the functional currency as of the date of the Statement of Financial Position, for profit or loss the exchange rate corresponding to each month-end is applied. All differences are recorded as a debit or credit to profit or loss.
As of September 30, 2026 and 2025, the Bank and its subsidiaries applied the exchange rate of accounting representation according to the standards issued by the Chilean CMF, for which the assets in dollars are shown at their equivalent value in Chilean pesos calculated using the following market exchange rate Ch$ 974.55 per US$1 (Ch$962.27 per US$1 as of September 30, 2025).
As of September 30, 2026, the amount of Ch$ 68,510 million corresponds to the net income from exchange, indexation and accounting hedging of foreign currency (net gain of Ch$70,692 million as of September 30, 2025) shown in the Consolidated Statements of Income, includes the result from foreign currency exchange operations, indexation and accounting hedges, including the translation of assets and liabilities in foreign currency or indexed to exchange rate.
32
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| (m) | Operating Segments: |
The Bank discloses information by segment in accordance with IFRS 8 (Note 6). The Bank’s operating segments are determined based on its different business units, considering the following:
| - | That it conducts business activities from which income is obtained and expenses are incurred (including income and expense from transactions with other components of the same entity). |
| - | That its operating results are regularly reviewed by the entity’s highest decision-making authority for operating decisions, to decide on the resources to be allocated to the segment and assess its performance; and |
| - | For which financial information is available about the segment which is differentiated. |
| (n) | Statement of cash flows: |
The Consolidated Statement of Cash Flows shows the changes in cash and cash equivalents derived from operating, investing and financing activities, during the year. The Bank uses the indirect method for the preparation of the statement of cash flows.
For the preparation of Consolidated Financial Statements of Cash Flow, the following concepts are considered:
| - | Cash and cash equivalents: corresponds to the item “Cash and deposits in banks”, plus (minus) the net balance corresponding to transactions pending settlement that are shown in the Consolidated Statement of Financial Position, plus other cash equivalents such as investments in short-term debt financial instruments that meet the criteria to be considered “cash equivalents”, for which they must have an original maturity of 90 days or less from the date of acquisition, be highly liquid, readily convertible into known amounts of cash from the date of the initial investment, and that the financial instruments are exposed to an insignificant risk of changes in value. |
| - | Operating activities: correspond to the principal revenue-producing activities of the Bank and other activities that are not investing or financing activities. |
| - | Investing activities: correspond to the acquisition and disposal of long-term assets and other investments not included in cash and cash equivalents. |
| - | Financing activities: corresponds to the activities that result in changes in the size and composition of the contributed equity and of liabilities that are not part of operating and investing activities. |
33
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| (o) | Financial derivative instruments: |
A “Financial Derivative” is a financial instrument whose value changes in response to changes in an observable market variable (such as an interest rate, exchange rate, the price of a financial instrument or a market index, including credit ratings), whose initial investment is very small in relation to other financial instruments with a similar response to changes in market conditions and which is generally settled at a future date.
The Bank maintains contracts of derivative financial instruments, to hedge the foreign currency and interest rate risk exposures. These contracts are initially recognized in the Consolidated Statement of Financial Position at their cost (including the transactions costs) and subsequently measured at fair value. Derivative contracts are stated as an asset when their fair value is positive and as a liability when it is negative under the item “Financial derivative instruments”.
Changes in fair value of derivative contracts held for trading are included under the caption “Financial Assets and Liabilities held for Trading”, on the Consolidated Statement of Income.
Additionally, the Bank includes in the measurement of the derivatives “Counterparty Credit Risk Adjustments, including: “CVA” or Credit Valuation Adjustment to reflect the counterparty credit risk in determining the fair value, as well as the “DVA” o Debit Valuation Adjustment to reflect the Bank’s own credit risk. Likewise, the Bank incorporates “Financing Adjustment”, also called “FVA” or Funding Valuation Adjustment, which captures the expected cost (or benefit) of financing (reinvesting) the cash flows of the derivative, with respect to a reference discount rate, when there are no collaterals (or they are imperfect).
Certain embedded derivatives in other financial instruments are treated as separate derivatives when their risk and characteristics are not closely related to those of the host contract and it is not measured at fair value with the related unrealized gains and losses included in profit or loss.
| (p) | Derivative instruments for accounting hedges: |
The Bank has opted to continue applying the hedge accounting requirements included in IAS 39 when adopting IFRS 9.
At the date of entering into a derivative contract, it must be designated by the Bank as a derivative instrument for trading or for hedge accounting purposes.
If the derivative instrument is classified for hedging purposes, it may be:
| - | A fair value hedge of existing assets or liabilities or firm commitments. |
| - | A cash flow hedge related to existing assets or liabilities or expected transactions. |
A hedge relationship for hedge accounting must meet all the following conditions:
| - | At the inception of the hedge, the hedging relationship has been formally documented. |
| - | the hedge is expected to be highly effective. |
| - | the effectiveness of the hedge can be measured reliably. |
| - | the hedge is highly effective in relation to the hedged risk, on a continuous basis throughout the entire hedging relationship. |
34
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
The Bank presents and measures individual hedges (where there is a specific identification of hedged item and hedged instruments) by classification, according to the following criteria:
Fair value hedges: Changes in the fair value of a derivative hedging instrument, designated as a fair value hedge, are recognized in income under the lines “Net interest income” and “Net indexation income” and/or “Foreign currency changes, UF indexation and accounting hedge”, depending on the type of risk covered. The hedged item is also presented at fair value in relation to the risk being hedged; gains or losses attributable to the hedged risk are recognized in income under the lines “Net interest income” and “Net inflation indexation income” and adjust the book value of the item subject to the hedge.
Cash flow hedge: Changes in the fair value of financial instruments derivative designated like “cash flow hedge” are recognized in “Cash flow accounting hedge” included in the Consolidated Other Comprehensive Income, to the extent that hedge is effective and hedge is reclassified to income in the item “Net interest income” and “Net inflation indexation income” and/or “Foreign currency changes, UF indexation and accounting hedge”, when hedged item affects the income of the Bank produced for the “interest rate risk” or “foreign exchange risk”, respectively. If the hedge is not effective, the changes in the fair value are recognized directly in the results of the year under the caption “Other financial result”.
If the hedging instrument no longer meets the criteria for cash flow hedge accounting, it expires or is sold, it is suspended or exercised, this hedge is discontinued prospectively. Accumulated gains or losses recognized previously in the equity are maintained there until forecasted transactions occur, in that moment will be recognized in Consolidated Statement of Income (in the item “Net interest income” and “Net inflation indexation income” and/or “Foreign currency changes, UF indexation and accounting hedge”, depend of the hedge), lesser than it foresees that the transaction will not execute, in this case it will be recognized immediately in Consolidated Statement of Income (in the item “Net interest income” and “Net inflation indexation income” and/or “Foreign currency changes, UF indexation and accounting hedge”, depending on the hedge).
| (q) | Intangible Assets: |
Intangible assets (Note 15) are initially recognized at their acquisition cost and are subsequently measured at their cost less any accumulated amortization or less any accumulated impairment loss.
Software or computer programs acquired or generated internally by the Bank and its subsidiaries are accounted for at cost less accumulated amortization and impairment losses.
The subsequent expense in software assets is capitalized only when it increases the future economic benefit for the specific asset. All other expenses are recorded as an expense as incurred.
Amortization is recognized in profit or loss on the straight-line amortization method based considering the estimated useful lives of the software, from the date on which they are available for use. The estimated useful life of software is a maximum of 6 years.
35
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| (r) | Property and equipment: |
Property and equipment (Note 16) includes the amount of land, real estate, furniture, IT hardware and equipment and other installations owned by the consolidated entities and which are for own use. These assets are stated at historical cost less depreciation and accumulated impairment. This cost includes expenditures that are directly attributed to the acquisition of the asset.
Depreciation is recognized in the Consolidated Statements of Income on a straight-line basis over the estimated useful lives of each part of the item of property and equipment.
The estimated average useful lives for the periods 2026 and 2025 are as follows:
| - | Buildings | 50 years | |
| - | Facilities | 10 years | |
| - | Equipment | 5 years | |
| - | Furniture | 5 years |
Maintenance expenses related to those assets held for own uses are recognized as expenses in the year in which they are incurred.
| (s) | Current taxes and deferred taxes: |
The income tax provision of the Bank and its subsidiaries has been determined in conformity with current tax regulations.
The Bank and its subsidiaries recognize, when appropriate, deferred tax assets and liabilities for future estimates of tax effects from temporary differences between the carrying value and tax basis of assets and liabilities. Deferred tax assets and liabilities are measured in accordance with current Chilean tax legislation, at the tax rates that are expected to be applied in the year in which the deferred tax assets and liabilities are to be realized or settled. Future effects from changes in tax legislation or income tax rate are recognized in deferred taxes starting from the date in which the law approving such changes is enacted or substantially enacted (Note 18).
Deferred tax assets are recognized only to the extent that it is probable that future taxable profits will be available against which the temporary difference can be utilized to recover temporary difference deductions. According to instructions from the Chilean CMF, deferred taxes are presented in the Consolidated Statement of Financial Position according with IAS 12 “Income Taxes”.
36
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| (t) | Provisions, contingent assets and liabilities: |
Provisions are liabilities involving uncertainty about their amount or maturity. They are recorded in the Consolidated Statement of Financial Position when the following requirements are jointly met:
| - | as a result of a past event, the Bank has a present or constructive obligation; |
| - | it is probable that at the reporting date an outflow of economic benefits will be required from the Bank or its subsidiaries to settle the obligation; and |
| - | the amount of such resources can be estimated reliably. |
A contingent asset or liability is any right or obligation arising from past events whose existence will be confirmed by one or more uncertain future events which are not within the control of the Bank.
Contingent loans are understood as operations or commitments in which the Bank assumes a credit risk by committing itself to third parties, in the event of a future event, to make a payment or disbursement that must be recovered from its customers.
The following are classified as contingent loans in off-balance sheet information:
| - | Undrawn credit lines: Considers the unused amounts of lines of credit that allow customers to use credit without previous decisions by the Bank. |
| - | Undrawn credit lines with immediate termination: Considers those undrawn credit lines, defined in the preceding paragraph, that the Bank can unconditionally cancel at any time and without prior notice, or whose automatic cancellation is considered in the event of impairment of the debtor’s creditworthiness, as permitted by the current legal framework and the contractual conditions established between the parties. |
| - | Contingent loans linked to CAE: Correspond to loan commitments granted in accordance with Law No. 20,027 (“CAE”). |
| - | Letters of credit for goods circulation operations: Considers the commitments that arise, both to the issuing bank and to the confirming bank, from self-settled commercial letters of credit with a maturity period of less than 1 year, arising from goods circulation operations (e.g., confirmed foreign or documentary letters of credit). Includes documentary letters of credit issued by the Bank, which have not yet been negotiated. |
| - | Debt purchase commitments in local currency abroad: Note issuance facility (NIF) and revolving underwriting facility (RUF) are considered. |
37
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| - | Transactions related to contingent events: Guarantee bonds with promissory notes referred to in Chapter 8-11 of the Updated Standards Compilation are considered. |
| - | Guarantees and sureties: Includes guarantees, sureties and standby letters of credit referred to in Chapter 8-10 of the Updated Standards Compilation. In addition, it includes the payment guarantees of buyers in factoring operations, as indicated in Chapter 8-38 of such Compilation. |
| - | Other loan commitments: It includes the unplaced amounts of committed loans that are to be disbursed on an agreed future date or triggered by events contractually defined with the customer, as is the case with irrevocable credit lines tied to the progress of projects (for provisions purposes, both the gross exposure referred to in No. 3 and future increases in the amount of guarantees associated with committed disbursements must be considered). |
Exposure to credit risk on contingent loans:
To calculate allowances for contingent loans, the amount of exposure to be considered will be equivalent to the percentage of the amounts of the contingent loans indicated below:
| Type of contingent loan | Credit Conversion Factor | |||
| Undrawn credit lines with immediate termination | 10 | % | ||
| Contingent loans linked to CAE | 15 | % | ||
| Letters of credit for goods circulation operations | 20 | % | ||
| Other undrawn credit lines | 40 | % | ||
| Debt purchase commitments in local currency abroad | 50 | % | ||
| Transactions related to contingent events | 50 | % | ||
| Guarantees and sureties | 100 | % | ||
| Other credit commitments | 100 | % | ||
| Other contingent loans | 100 | % | ||
When dealing with transactions performed with customers with overdue loans, that exposure shall be equivalent to 100% of their contingent loans.
| (u) | Provisions for minimum dividends: |
In accordance with the CNCB issued by the CMF, the Bank records within liabilities the portion of net income for the year that should be distributed to comply with the Shareholders’ Corporations Law or its dividend policy. For such purposes, the Bank establishes a provision in a complementary equity account within retained earnings (Note 25).
For the purposes of calculating the provision for minimum dividends, the distributable net income is considered, which is defined as the amount resulting from reducing or adding to the net income for the year, the adjustment of the value of the paid-in capital and reserves, for the effects of the variation in the Consumer Price Index.
38
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| (v) | Employee benefits: |
Employee benefits are all forms of consideration granted by an entity in exchange for services provided by employees or severance pay.
Short-term employee benefits are employee benefits (other than termination benefits) that are expected to be settled in full before twelve months after the end of the annual reporting period in which the employees have rendered the related services (Note 24 letter (c)).
| - | Accrued vacations |
The annual costs of vacations and staff benefits are recognized on an accrual basis.
| - | Other short-term benefits |
The entity considers for its employees an annual incentive plan for meeting objectives and individual contribution to the entity’s results, which are eventually delivered, consisting of a certain number or portion of monthly salaries and are accrued for based on the estimated amount to be distributed.
Other long-term employee benefits are all employee benefits other than short-term employee benefits, post-employment benefits, and termination benefits.
| (w) | Earnings per share: |
The basic earnings per share is determined by dividing the net income attributed to the Bank’s owners in a period and the weighted average number of shares outstanding during that period.
Diluted earnings per share are determined similarly to basic earnings, but the weighted average number of outstanding shares is adjusted to take into account the potential dilutive effect of the options on shares, warrants and convertible debt. At the end of the periods ended September 30, 2026 and 2025 there are no concepts that should be adjusted.
| (x) | Interest revenue and expense and UF indexation: |
Interest income and expenses and UF indexation (Notes 30 and 31) are recognized in the Consolidated Statement of Income using the effective interest rate method. The effective interest rate is the rate which exactly discounts estimated future cash payments or receipts through the expected life of the financial instrument (or, where appropriate, in a shorter period), to the carrying amount of the financial asset or financial liability. To calculate the effective interest rate, the Bank determines cash flows by taking into account all contractual conditions of the financial instrument, excluding future credit losses.
The effective interest rate calculation includes all fees and other amounts paid or received that are part of the effective interest rate. Transaction costs include incremental costs that are directly attributable to the acquisition or issuance of a financial asset or liability.
In the case of the impaired portfolio and current loans with a high risk of recoverability of Loans to customers, the Bank has applied a conservative position of discontinuing the accrual of interest and UF indexation on an accrual basis in the Consolidated Statement of Income, when the loan or one of its payments has been 90 days past due.
39
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| (y) | Fee and commission income and expenses: |
Fee and commission income and expenses (Note 32) are recognized in the Consolidated Statement of Income using the criteria established in IFRS 15 “Revenue from Contracts with Customers”.
In accordance with IFRS 15, revenue is recognized based on the contractual terms agreed upon with customers. Such revenue is recognized when, or as, a performance obligation is satisfied through the transfer of the committed goods or services to the customer, or when control of those goods or services is transferred to the customer.
Under IFRS 15, revenue recognition must be determined based on the nature of the committed goods or services. The most significant recognition criteria include the following:
| − | Those that correspond to a singular act, when the act that originates them takes place. |
| − | Those that originate in transactions or services that are extended over time, during the life of such transactions or services. |
| − | Commissions on loan commitments and other fees related to loan transactions are deferred (together with the incremental costs directly related to the placement) and recognized as an adjustment to the effective interest rate of the placement. For loan commitments, when there is no certainty of the date of effective placement, fees and commissions are recognized in the period of the commitment that originates it on a straight-line basis. |
The fees registered as income by the Bank correspond mainly to:
| − | Commissions for loan prepayment: These commissions are accrued at the time the loans are prepaid. |
| − | Commissions for lines of credit and overdrafts: These commissions are accrued in the period related to the granting of lines of credit and overdrafts in current accounts. |
| − | Commissions for guarantee and letters of credit: These commissions are accrued in the period related to the granting by the Bank of payment guarantees for real or contingent obligations of third parties. |
| − | Commissions for card services: Correspond to commissions accrued for the period, related to the use of credit cards, debit cards and other. |
| − | Commissions for account management: Includes commissions that accrue in the period related to the maintenance of current accounts and other deposit accounts. |
| − | Commissions for collections and payments: Includes commissions generated by the collection and payment services provided by the Bank. |
| − | Commissions for intermediation and management of securities: correspond to income from brokerage service, placements, administration and custody of securities. |
| − | Remuneration for management of mutual funds, investment funds or others: corresponds to the commissions from the General Fund Administrator for the administration of third-party funds. |
| − | Remuneration for brokerage and insurance consulting services: includes income from brokerage and insurance advice by the Bank or its subsidiaries is included. |
| − | Commissions for factoring operation services: include commissions for factoring operations services performed by the Bank. |
40
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| − | Commissions for financial consulting services: includes commissions for financial advisory services performed by the Bank and its subsidiary. |
| − | Other commissions received: includes income generated from foreign currency exchange, issuance bank guarantees, issuance of bank check, use of distribution channels, agreement on the use of a brand and placement of financial products and cash transfers, and recognition of payments associated with commercial alliances, among others. |
Commission expenses include:
| − | Commissions for card operations: includes commissions paid for credit and debit card operations. |
| − | Commissions for licensing the use of card brands. |
| − | Expenses for obligations of loyalty and merits programs for card customers. |
| − | Commissions for operations with securities: includes commissions for deposit and custody of securities and brokerage of securities. |
| − | Other commissions for services received: includes commissions for guarantees and sureties of Bank obligations, for foreign trade operations, for correspondent banks in the country and abroad, for ATMs and electronic fund transfer services. |
| − | Commissions for compensation of large value payments: corresponds to commissions paid to entities such as ComBanc, CCLV Contraparte Central, etc. |
| (z) | Impairment of non-financial assets: |
The carrying amounts of the non-financial assets of the Bank and its subsidiaries, are reviewed throughout the year and especially at each reporting date, to determine if any indication of impairment exists. If such indication exists, then the recoverable amount of the asset is estimated.
| (aa) | Financial and operating leases: |
| − | The Bank acting as lessor |
Assets leased to customers under agreements which transfer substantially all the risks and rewards of ownership, with or without ultimate legal title, are classified as finance leases. When assets held are subject to a finance lease, the leased assets are derecognized and a receivable is recognized which is equal to the present value of the minimum lease payments, discounted at the interest rate implicit in the lease. Initial direct costs incurred in negotiating and arranging a finance lease are incorporated into the receivable through the discount rate applied to the lease. Finance lease income is recognized over the lease term based on a pattern reflecting a constant periodic rate of return on the net investment in the finance lease.
Assets leased to customers under agreements, which do not transfer substantially all the risks, and rewards of ownership are classified as operating leases.
The leased investment properties, under the operating lease modality, are included in the Consolidated Statement of Financial Position as “Other assets” and depreciation is determined on the book value of these assets, applying a proportion of the value in a systematic way on the economic use of the estimated useful life. Lease income is recognized on a straight-line basis over the lease term.
41
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| − | The Bank acting as lessee |
A contract is, or contains a lease, if one party has the right to control the use of an identified asset for a period of time in exchange for a regular payment (Note 17).
On the date of commencement of a lease, a right-to-use assets leased is determined at cost, which includes the amount of the initial measurement of the lease liability plus other disbursements made.
The amount of the lease liability is measured at the present value of future lease payments that have not been paid on that date, which are discounted using the Bank’s incremental financing interest rate.
The right-of-use asset is measured using the cost model, less accumulated depreciation and accumulated impairment losses, depreciation of the right-of-use asset, is recognized in the Consolidated Statements of Income on a straight-line depreciation basis from the commencement date and until the end of the lease term.
The monthly variation of the UF for the contracts established in such monetary unit should be treated as a remeasurement; accordingly, the UF indexation modifies the value of the lease liability, and simultaneously, the amount of the right-of-use asset must be adjusted by this effect.
Subsequent to the commencement date, the lease liability is measured by reducing the carrying amount to reflect the lease payments made and the modifications to the lease.
In accordance with IFRS 16 “Leases” the Bank does not apply this rule to contracts whose term is 12 months or less and those that contain an underlying asset of low value. In these cases, payments are recognized as a lease expense.
| (ab) | Additional allowances: |
In accordance with the standards issued by the CMF, banks could record additional allowances for its individually evaluated loan portfolio, taking into consideration the expected impairment of this portfolio. The calculation of this allowance is performed based on the Bank’s historical experience and considering possible future adverse macroeconomic conditions or circumstances that could affect a specific sector.
Allowances made in order to prevent the risk of macroeconomic fluctuations should anticipate situations of reversal of expansive economic cycles that, in the future, could result in a worsening of the conditions and, function as a countercyclical mechanism for accumulating additional allowances when the scenario is favorable and release or allocate them to specific allowances when environmental conditions deteriorate.
Accordingly, additional allowances must always correspond to general allowances on commercial, consumer or mortgage loans, or segments identified, and in no case may be used to offset weaknesses in the models used by the Bank (Note 26).
As of September 30, 2026, the balance of additional allowances amounts to Ch$681,217 million (Ch$631,217 million as of December 2025), which are presented in the caption “Special provisions for Credit risk” in Liabilities in the Consolidated Statement of Financial Position.
42
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 2. | Summary of Significant Accounting Policies, continued: |
| (ac) | Fair value measurement: |
“Fair value” is understood as the amount that would be received to sell an asset or paid to transfer a liability in an orderly transaction between participants in a principal (or more advantageous) market at the measurement date under current market conditions, regardless of whether that price is directly observable or estimated using another valuation technique. The most objective and usual reference of fair value is the price that would be paid in an active, transparent and deep market (“quoted price” or “market price”).
When available, the Bank estimates the fair value of an instrument using quoted prices in an active market for that instrument. A market is considered active if quoted prices are readily and regularly available and represent actual and regularly occurring market transactions on an arm’s length basis.
If a market for a financial instrument is not active, the Bank establishes fair value using a valuation technique. These valuation techniques include the use of recent market transactions between knowledgeable, willing parties in an arm’s length transaction, if available, as well as references to the fair value of other instruments that are substantially the same, discounted cash flows and options pricing models.
The selected valuation technique makes maximum use of information obtained in the market, using the least possible amount of data estimated by the Bank, incorporates all the factors that market participants would consider to establish the price, and will be consistent with generally accepted economic methodologies for calculating the price of financial instruments. The variables used by the valuation technique reasonably represent market expectations and reflect the return-risk factors inherent to the financial instrument. Periodically, the Bank calibrates the valuation techniques and tests it for validity using prices from observable current market transaction in the same instrument or based on available observable market information.
The best evidence of the fair value of a financial instrument at initial recognition is the transaction price (i.e., the fair value of the consideration given or received) unless the fair value of that instrument is evidenced by comparison with other observable current market transactions in the same instrument (i.e. without modification or repackaging) or based on a valuation technique whose variables include only data from observable markets. However, when transaction price provides the best evidence of fair value at initial recognition, the financial instrument is initially measured at the transaction price and any difference between this price and the value initially obtained from a valuation model is subsequently recognized in profit or loss.
Note that the Bank has financial assets and liabilities that offset each other’s market risks, based on which average market prices are used as a basis for determining their fair value.
Then, the fair value estimates obtained from models are adjusted for any other factors, such as liquidity risk or model uncertainties; to the extent that the Bank believes that a third-party market participant would take them into account in pricing a transaction.
The Bank’s fair value disclosures are included in Note 44.
43
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 3. | New Accounting Pronouncements Issued and Adopted, or Issued that have not yet been Adopted: |
Standards approved and/or amended by the International Accounting Standards Board (IASB) and by the Financial Market Commission (CMF):
Standards and interpretations that have been adopted in these Consolidated Financial Statements.
As of the date of issuance of these Interim Consolidated Financial Statements, the new accounting pronouncements issued by both the IASB and the CMF, which have been adopted by the Bank and its subsidiaries, are detailed below:
| - | Accounting standards issued by IASB. |
IFRS 9 and IFRS 7 Financial Instruments: Classification and Measurement
In May 2024, the IASB issued amendments to the classification and measurement requirements of IFRS 9, “Financial Instruments”, and to the disclosure requirements of IFRS 7, “Financial Instruments: Disclosures”, as follows:
Derecognition of financial liabilities settled by electronic transfer.
The amendment allows an entity to consider that a financial liability (or part of it) that is settled using an electronic payment system is cancelled, expires or the liability otherwise qualifies for derecognition before the settlement date, if certain specified criteria are met. An entity that chooses to apply the deregistration option would be required to apply it to all settlements made through the same electronic payment system.
Classification of financial assets
The amendment provides guidance on how an entity can evaluate whether the contractual cash flows of a financial asset are consistent with a basic loan agreement, for classification and measurement purposes.
The amendment also improves the description of the term “non-recourse”, meaning that a financial asset has “non-recourse” features if an entity’s ultimate right to receive cash flows is contractually limited to the cash flows generated by specific assets.
Disclosures
For investments in equity financial instruments designated at fair value through other comprehensive income, an entity is required to disclose the fair value gain or loss presented in other comprehensive income during the period, showing separately the fair value gain or loss that relates to investments derecognized in the period and the fair value gain or loss that relates to investments held at the end of the period.
Additional disclosures are required for financial assets and liabilities with contractual terms that reference a contingent event (including those that are linked to Environmental, Social and Governance factor (ESG)).
The amendments are effective for annual periods beginning on or after January 1, 2026.
The Bank had no impact on the implementation of this new standard.
44
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 3. | New Accounting Pronouncements Issued and Adopted, or Issued that have not yet been Adopted, continued: |
New Standards and interpretations issued but not yet effective:
The following is a summary of new standards, interpretations and improvements to the International Financial Reporting Standards (IFRS Accounting Standards) issued by the International Accounting Standards Board (IASB) and the CMF that are not yet effective as of September 30, 2026:
| - | Accounting standards issued by IASB. |
IAS 28 Investments in Associates and Joint Ventures and IFRS 10 Consolidated Financial Statements.
In September 2014, the IASB issued this amendment, which clarifies the scope of the gains and losses recognized in a transaction, that involves an associate or joint venture, and that this depends on whether the asset sold, or contribution constitutes a business. Accordingly, the IASB concluded that all gains or losses must be recognized against loss of control of a business.
Likewise, the gains or losses resulting from the sale or contribution of a subsidiary that does not constitute a business (definition of IFRS 3) to an associate or joint venture must be recognized only to the extent of unrelated interests in the associate or joint venture.
During December 2015, the IASB agreed to set the effective date of this amendment in the future, allowing its immediate adoption.
Banco de Chile and its subsidiaries will have no impact on the Consolidated Financial Statements as a result of the application of this amendment.
IFRS 18 – Presentation and Disclosure in Financial Statements.
In April 2024, IASB issued a new accounting standard, IFRS 18 Presentation and Disclosure in Financial Statements, replacing the IAS 1 Presentation of Financial Statements.
This new standard aims to improve the usefulness of the information presented and disclosures so that the comparability of the financial information is enhanced, complying with the qualitative characteristics defined in the conceptual framework of the International Financial Reporting Standards (IFRS).
According to the information provided by IASB, the standard introduces three new requirements:
| - | Improving the comparability of the statement of income. |
| - | Higher transparency in measuring performance defined by Management. |
| - | More useful grouping of the information in the financial statements. |
The standard will be effective for annual accounting periods beginning on or after January 1, 2027.
Because these Consolidated Financial Statements are prepared in accordance with the standards issued by the CMF as defined in CNCB, the adoption of this standard is conditional upon the amendment of the CNCB.
45
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 3. | New Accounting Pronouncements Issued and Adopted, or Issued that have not yet been Adopted, continued: |
IFRS 19 – Subsidiaries without Public Accountability: Disclosures
In May 2024, the IASB issued the new accounting standard IFRS 19 Subsidiaries without Public Accountability: Disclosures, which will become effective on January 1, 2027 where early application is permitted.
This new standard allows to save preparation costs of the financial statements of subsidiaries without public accountability, making possible to disclose less information and adapt the financial statements to the needs of the users when certain conditions are met.
The standard establishes that a subsidiary has public accountability if:
| - | It has debt instruments or capital that is subject to trade on a public market or if it is in the process of issuing such instruments to negotiate on a public market; or |
| - | Manages fiduciary assets for a broad group of outsiders as one of its principal businesses. |
A subsidiary is eligible and can apply IFRS 19 in its consolidated, separate or stand-alone financial statements if:
| - | It has no public accountability; and |
| - | Its ultimate Parent or any other intermediate Parent issued consolidated financial statements that are available for public use and comply with IFRS. |
This new standard will not have an impact on the Consolidated Financial Statements.
| 4. | Changes in Accounting Policies |
During the period ended September 30, 2026, there have been no material changes in accounting policies affecting the presentation of these Interim Consolidated Financial Statements.
46
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 5. | Relevant Events: |
| (a) | During the period 2026, Banco de Chile has reported as an essential event the following placements in the local market of senior, dematerialized and bearer bonds issued by Banco de Chile and registered with the Securities Registry of the Financial Market Commission: |
| Date | Registration number in the Securities Registry | Series | Amount | Currency | Maturity date | Average rate | ||||||||||
| January 8, 2026 (*) | 20240002 | HW | 750,000 | UF | 06/01/2044 | 2.93 | % | |||||||||
| January 12, 2026 (*) | 20240002 | HW | 100,000 | UF | 06/01/2044 | 2.92 | % | |||||||||
| January 14, 2026 | 11/2022 | FU | 500,000 | UF | 11/01/2032 | 2.81 | % | |||||||||
| January 14, 2026 | 11/2022 | GG | 350,000 | UF | 05/01/2035 | 2.89 | % | |||||||||
| January 14, 2026 (*) | 20240002 | HW | 300,000 | UF | 06/01/2044 | 2.91 | % | |||||||||
| January 15, 2026 | 11/2022 | FU | 500,000 | UF | 11/01/2032 | 2.78 | % | |||||||||
| January 15, 2026 (*) | 20240002 | HH | 400,000 | UF | 12/01/2036 | 2.87 | % | |||||||||
| January 15, 2026 (*) | 20240002 | HW | 50,000 | UF | 06/01/2044 | 2.89 | % | |||||||||
| February 10, 2026 | 11/2022 | FG | 860,000 | UF | 11/01/2030 | 2.59 | % | |||||||||
| March 5, 2026 | 11/2022 | FG | 1,000,000 | UF | 11/01/2030 | 2.51 | % | |||||||||
| June 30, 2026 | 11/2022 | FG | 310,000 | UF | 11/01/2030 | 2.82 | % | |||||||||
| July 1, 2026 | 11/2022 | FG | 400,000 | UF | 11/01/2030 | 2.82 | % | |||||||||
| July 2, 2026 | 11/2022 | GA | 250,000 | UF | 05/01/2034 | 3.03 | % | |||||||||
| July 6, 2026 | 11/2022 | FG | 880,000 | UF | 11/01/2030 | 2.81 | % | |||||||||
| July 7, 2026 | 11/2022 | FG | 300,000 | UF | 11/01/2030 | 2.80 | % | |||||||||
| July 8, 2026 | 11/2022 | FG | 250,000 | UF | 11/01/2030 | 2.74 | % | |||||||||
| July 20, 2026 | 11/2022 | GA | 425,000 | UF | 05/01/2034 | 2.95 | % | |||||||||
| July 22, 2026 | 11/2022 | GA | 125,000 | UF | 05/01/2034 | 2.95 | % | |||||||||
| August 21, 2026 | 11/2022 | FT | 1,300,000 | UF | 10/01/2032 | 2.92 | % | |||||||||
| August 27, 2026 | 11/2022 | FT | 1,100,000 | UF | 10/01/2032 | 2.92 | % | |||||||||
| September 3, 2026 | 11/2022 | FT | 400,000 | UF | 10/01/2032 | 2.88 | % | |||||||||
| September 4, 2026 | 11/2022 | FT | 466,000 | UF | 10/01/2032 | 2.86 | % | |||||||||
| September 4, 2026 (*) | 20240002 | HC | 900,000 | UF | 08/01/2034 | 2.98 | % | |||||||||
| (*) | The bonds have been registered under the Automatic Registration modality, with the registration number dated April 5, 2024. |
| (b) | On January 21, 2026, Banco de Chile reported that Mr. Francisco Pérez Mackenna submitted his resignation from the positions of Regular Director and Vice Chairman of Banco de Chile, effective January 31, 2026, which was accepted by the Board of Directors. Likewise, the Board agreed to appoint Mr. Óscar Hasbún Martínez as Regular Director, replacing Mr. Francisco Pérez Mackenna, effective February 1, 2026 and until the next Annual General Shareholders’ Meeting. Finally, the Board agreed to appoint Regular Director Mr. Jean-Paul Luksic Fontbona as Vice Chairman of the Board, effective February 1, 2026. |
47
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 5. | Relevant Events, continued: |
| (c) | On January 29, 2026, the Board of Directors of Banco de Chile agreed to convene an Ordinary Shareholders’ Meeting for March 26, 2026 in order to propose, among other matters, the following distribution of profits for the year ended on December 31, 2025: |
| a) | Deduct and withhold from the net income of the year, an amount equivalent to the effect of inflation of the paid capital and reserves according to the variation of the Consumer Price Index that occurred between November 2024 and November 2025, amounting to Ch$182,336,381,737 which will be added to retained earnings from previous periods. |
| b) | Distribute in the form of dividend the remaining profit, corresponding to a dividend of Ch$9.99757030464 to each of the 101,017,081,114 shares of the Bank. |
Consequently, it will be proposed a distribution as dividend of 84.7% of the profits for the year ended December 31, 2025.
Additionally, in accordance with the Bank’s Bylaws, and considering the amendment to Article Eight approved at the Extraordinary Shareholders’ Meeting held on November 10, 2025, the election of the Board of Directors to take place at the upcoming Ordinary Shareholders’ Meeting on March 26, 2026 will require the appointment of nine Principal Directors, as well as two Alternate Directors.
| (d) | On March 6, 2026, the subsidiary Banchile Administradora de Fondos S.A. reported that Mr. José Luis Vizcarra Villalobos submitted his resignation from his position as Director of Banchile Administradora General de Fondos S.A. |
| (e) | On March 12, 2026, the subsidiary Banchile Administradora de Fondos S.A. reported that Mr. Andrés Ergas Heymann submitted his resignation from his position as Director of Banchile Administradora General de Fondos S.A. |
| (f) | On March 12, 2026, Banco de Chile reported that Mr. Andrés Ergas Heymann submitted his resignation from his position as Regular Director of Banco de Chile. At the Ordinary Meeting of the Board of Directors held on the same date, the Board of Directors of Banco de Chile acknowledged and accepted said resignation. |
Likewise, and in accordance with the provisions of Article Eight of the Bank’s Bylaws, the First Alternate Independent Director, Mr. Paul Furst Gwinner, assumed the position of Regular Independent Director.
| (g) | On March 26, 2026, Banco de Chile reported that, at the Ordinary Shareholders’ Meeting, the Board of Directors was fully renewed, as the legal and bylaw-mandated three-year term of office of the outgoing Board of Directors had expired. |
48
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 5. | Relevant Events, continued: |
Following the corresponding vote held at said meeting, the following individuals were elected as Directors of the Bank for a new three-year term:
| Regular Directors: | Hernán Büchi Buc | |
| Vivianne Caumont | ||
| Julio Santiago Figueroa | ||
| Paul Furst Gwinner (Independent) | ||
| Pablo Granifo Lavín | ||
| Oscar Hasbún Martínez | ||
| Ana Holuigue Barros (Independent) | ||
| Patricio Jottar Nasrallah | ||
| Jean-Paul Luksic Fontbona |
| First Alternate Director: | Nicolás Lewin Muñoz (Independent) | |
| Second Alternate Director: | Sandra Marta Guazzotti |
Furthermore, at an Ordinary Meeting of the Board of Directors held on the same date, the following appointments and designations were agreed upon:
| Chairman: | Pablo Granifo Lavín | |
| Vice Chairman: | Jean-Paul Luksic Fontbona | |
| Vice Chairman: | Julio Santiago Figueroa |
| (h) | On April 27, 2026, the subsidiary Operadora de Tarjetas Banchile Pagos S.A. reported that, at an extraordinary meeting of its Board of Directors, the resignation submitted by its General Manager, Mr. Rodrigo Devía González, was acknowledged, which will become effective on April 30, 2026. |
At the same meeting of the Board of Directors, it was resolved to appoint Mr. Felipe Pérez González as General Manager of the Company, effective as of May 1, 2026. Mr. Pérez González currently serves as the Company’s Commercial Manager.
| (i) | During the period 2026 Banco de Chile has reported as an essential fact the following placements in the foreign market, issued under its Medium Term Notes Program (“MTN”): |
| Date | Amount | Currency | Maturity date | Average rate | ||||||||
| May 12, 2026 | 700,000,000 | MXN | 05/11/2033 | TIIE (28 days) + 0.95% | ||||||||
| July 21, 2026 | 10,000,000,000 | JPY | 07/30/2029 | 2.32% | ||||||||
| (j) | On August 24, 2026 , the subsidiary Banchile Administradora General de Fondos S.A. reported that its Board of Directors had agreed to amend the Policy on Ordinary Course Transactions. The updated policy is available to interested parties and the general public at the offices of Banchile Administradora General de Fondos S.A. and in the “Regulatory and Financial Information” section of the website www.banchileinversiones.cl. |
| (k) | On August 27, 2026, the Board of Directors of Banco de Chile announced an amendment to the Policy on Ordinary Course Transactions. The updated policy is available to interested parties and the general public at the Bank’s offices and on the website www.bancochile.cl, under “Our Bank/Corporate Governance.” |
49
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 6. | Business Segments: |
For management purposes, the Bank is organized into four segments, which are defined based on the types of products and services offered, and the type of client in which focuses as described below:
Retail Banking:
This segment focuses on individuals and small and medium-sized companies (SMEs) with annual sales up to UF 100,000, where the product offering focuses primarily on consumer loans, commercial loans, checking accounts, credit cards, credit lines and residential mortgage loans.
Wholesale Banking:
This segment focused on corporate clients and large companies, whose annual revenue exceed UF 100,000, where the product offering focuses primarily on commercial loans, checking accounts and liquidity management services, debt instruments, foreign trade, derivative contracts and leases.
Treasury:
This segment includes revenues associated with the management of the investment portfolio and the business of financial transactions and currency trading.
Transactions with customers performed by the Treasury are reflected in the respective aforementioned segments. These products are highly transaction-focused and include foreign exchange transactions, derivatives and financial instruments in general, among others.
Subsidiaries:
Corresponds to the businesses generated by the companies controlled by the Bank, which perform banking business support activities. Companies comprising this segment are:
| - | Banchile Administradora General de Fondos S.A. | |
| - | Banchile Asesoría Financiera S.A. | |
| - | Banchile Corredores de Seguros Ltda. | |
| - | Banchile Corredores de Bolsa S.A. | |
| - | Operadora de Tarjetas Banchile Pagos S.A. |
50
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 6. | Business Segments, continued: |
The financial information used to measure the performance of the Bank’s business segments is not comparable with similar information from other financial institutions because each institution relies on its own definitions. The accounting policies applied to the segments are the same as those described in the summary of accounting policies. The Bank obtains the majority of the results from: interest, indexation and fees and commissions and financial transaction and changes, discounting provisions for credit risk and operating expenses. Management relies mainly on these concepts to evaluate the performance of the segments and make decisions about the goals and allocations of resources of each unit. Although the results of the segments reconcile with those of the Bank at the total level, this is not necessarily the case in terms of the different concepts, because management is measured and controlled individually and not on a consolidated basis, applying the following criteria:
| · | The net interest margin of loans and deposits is obtained by aggregating the net financial margins of each individual operation of credit and deposit transactions performed by the bank. For these purposes, the volume of each operation and its contribution margin are considered, which in turn corresponds to the difference between the effective rate of the customer and the internal transfer price established according to each transaction´s term and currency of each operation. Additionally, the net margin includes the result of interest and indexation from the accounting hedges. |
| · | Allowance for credit risk is determined at the customer and counterparty level based on the characteristics of each of their operations. Additional allowances are assigned to the different business segments based on the credit risk weighted assets of each segment. |
| · | The capital and financial impacts on profit or loss have been assigned to each segment based on the risk-weighted assets. |
| · | Operating expenses are reflected at the level of the different functional areas of the Bank. Then, for the business segment purposes, the allocation of expenses from functional areas is done using different allocation criteria, at the level of the different concepts and expense items. |
Taxes are managed at a corporate level and are not allocated to business segments.
For the periods ended September 30, 2026 and 2025 there was no income from transactions with a customer or counterparty that accounted for 10% or more of the Bank’s total revenues.
51
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 6. | Business Segments, continued: |
The following table presents the income by segment for the periods ended September 30, 2026 and 2025 for each of the segments defined above:
| Retail Banking | Wholesale Banking | Treasury | Subsidiaries | Subtotal | Consolidation adjustment | Total | ||||||||||||||||||||||||||||||||||||||||||||||||||
| September | September | September | September | September | September | September | September | September | September | September | September | September | September | |||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||||||||
| Net interest income and UF indexation | 1,195,356 | 1,115,811 | 529,388 | 511,269 | (56,948 | ) | (75,068 | ) | (20 | ) | (1,166 | ) | 1,667,776 | 1,550,846 | 1,655 | 914 | 1,669,431 | 1,551,760 | ||||||||||||||||||||||||||||||||||||||
| Net fee and commission income | 290,059 | 268,050 | 76,407 | 72,606 | 4,257 | 3,013 | 144,527 | 148,094 | 515,250 | 491,763 | (1,639 | ) | (18,990 | ) | 513,611 | 472,773 | ||||||||||||||||||||||||||||||||||||||||
| Profit (loss) of financial operations | 389 | 319 | 12,368 | 12,960 | 72,875 | 100,308 | 14,998 | 18,966 | 100,630 | 132,553 | (1,655 | ) | (914 | ) | 98,975 | 131,639 | ||||||||||||||||||||||||||||||||||||||||
| Foreign currency changes, indexation and accounting hedge | 11,541 | 6,276 | 24,090 | 24,471 | 10,163 | 20,480 | 22,716 | 19,465 | 68,510 | 70,692 | — | — | 68,510 | 70,692 | ||||||||||||||||||||||||||||||||||||||||||
| Other income | 54,818 | 32,608 | 20,850 | 13,412 | 4,304 | 2,791 | 5,542 | 4,493 | 85,514 | 53,304 | (12,532 | ) | (11,186 | ) | 72,982 | 42,118 | ||||||||||||||||||||||||||||||||||||||||
| Income from investments in other companies | 2,954 | 6,393 | 1,436 | 1,532 | 27 | 119 | 572 | 437 | 4,989 | 8,481 | — | — | 4,989 | 8,481 | ||||||||||||||||||||||||||||||||||||||||||
| Total operating income | 1,555,117 | 1,429,457 | 664,539 | 636,250 | 34,678 | 51,643 | 188,335 | 190,289 | 2,442,669 | 2,307,639 | (14,171 | ) | (30,176 | ) | 2,428,498 | 2,277,463 | ||||||||||||||||||||||||||||||||||||||||
| Personnel expenses | (299,696 | ) | (277,108 | ) | (83,147 | ) | (79,310 | ) | (3,095 | ) | (2,923 | ) | (47,636 | ) | (59,238 | ) | (433,574 | ) | (418,579 | ) | 16 | 16 | (433,558 | ) | (418,563 | ) | ||||||||||||||||||||||||||||||
| Administrative expenses | (237,320 | ) | (246,338 | ) | (69,235 | ) | (65,424 | ) | (2,010 | ) | (1,728 | ) | (38,122 | ) | (36,990 | ) | (346,687 | ) | (350,480 | ) | 13,313 | 29,383 | (333,374 | ) | (321,097 | ) | ||||||||||||||||||||||||||||||
| Depreciation and amortization | (59,975 | ) | (59,075 | ) | (5,835 | ) | (6,485 | ) | (359 | ) | (408 | ) | (6,761 | ) | (5,055 | ) | (72,930 | ) | (71,023 | ) | — | — | (72,930 | ) | (71,023 | ) | ||||||||||||||||||||||||||||||
| Impairment of non-financial assets | (4 | ) | (273 | ) | (2 | ) | (5 | ) | — | — | (553 | ) | (2,548 | ) | (559 | ) | (2,826 | ) | — | — | (559 | ) | (2,826 | ) | ||||||||||||||||||||||||||||||||
| Other operating expenses | (26,827 | ) | (21,033 | ) | (4,350 | ) | (3,156 | ) | (149 | ) | (26 | ) | (1,925 | ) | (1,371 | ) | (33,251 | ) | (25,586 | ) | 842 | 777 | (32,409 | ) | (24,809 | ) | ||||||||||||||||||||||||||||||
| Total operating expenses | (623,822 | ) | (603,827 | ) | (162,569 | ) | (154,380 | ) | (5,613 | ) | (5,085 | ) | (94,997 | ) | (105,202 | ) | (887,001 | ) | (868,494 | ) | 14,171 | 30,176 | (872,830 | ) | (838,318 | ) | ||||||||||||||||||||||||||||||
| Expenses for credit losses (*) | (355,188 | ) | (264,044 | ) | (25,025 | ) | 1,099 | 4,594 | (3,135 | ) | (31 | ) | — | (375,650 | ) | (266,080 | ) | — | — | (375,650 | ) | (266,080 | ) | |||||||||||||||||||||||||||||||||
| Net operating income | 576,107 | 561,586 | 476,945 | 482,969 | 33,659 | 43,423 | 93,307 | 85,087 | 1,180,018 | 1,173,065 | — | — | 1,180,018 | 1,173,065 | ||||||||||||||||||||||||||||||||||||||||||
| Income taxes | (233,089 | ) | (246,340 | ) | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net income after taxes | 946,929 | 926,725 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (*) | As of September 30, 2026, the retail and wholesale banking segments include additional provisions allocated based on their risk-weighted assets of Ch$26,244 million and Ch$23,756 million, respectively. |
52
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 6. | Business Segments, continued: |
For comparative purposes, the 2025 figures include certain minor reclassifications of some line items.
The following table presents assets and liabilities as of September 30, 2026 and December 31, 2025 by each segment defined above:
| Retail Banking | Wholesale Banking | Treasury | Subsidiaries | Subtotal | Consolidation adjustment | Total | ||||||||||||||||||||||||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | September | December | September | December | September | December | |||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||||||||
| Assets | 26,152,501 | 25,819,643 | 13,768,280 | 12,536,827 | 14,234,072 | 14,154,573 | 1,361,937 | 1,285,572 | 55,516,790 | 53,796,615 | (242,492 | ) | (261,464 | ) | 55,274,298 | 53,535,151 | ||||||||||||||||||||||||||||||||||||||||
| Current and deferred taxes | 638,034 | 565,752 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | 55,912,332 | 54,100,903 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities | 18,255,287 | 17,893,540 | 11,459,680 | 10,543,300 | 19,516,704 | 19,062,619 | 1,094,385 | 1,028,142 | 50,326,056 | 48,527,601 | (242,492 | ) | (261,464 | ) | 50,083,564 | 48,266,137 | ||||||||||||||||||||||||||||||||||||||||
| Current and deferred taxes | 4,473 | 35,231 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities | 50,088,037 | 48,301,368 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
53
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 7. | Cash and Cash Equivalents: |
The detail of the balances included in cash and cash equivalents is as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Cash and deposits in banks: | ||||||||
| Cash | 954,001 | 900,264 | ||||||
| Deposit in Chilean Central Bank (*) | 1,265,623 | 1,347,525 | ||||||
| Deposit in foreign Central Banks | — | — | ||||||
| Deposits in domestic banks | 4,467 | 8,862 | ||||||
| Deposits in abroad banks | 941,064 | 334,335 | ||||||
| Subtotal – Cash and deposits in banks | 3,165,155 | 2,590,986 | ||||||
| Net transactions in the course of settlement (**) | (336,518 | ) | (149,753 | ) | ||||
| Cash equivalents (***) | 1,329,192 | 2,880,913 | ||||||
| Total cash and cash equivalents | 4,157,829 | 5,322,146 | ||||||
The detail of the balances included under net ongoing clearance operations is as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Assets | ||||||||
| Documents drawn on other banks (clearing) | 114,019 | 115,967 | ||||||
| Funds receivable | 248,086 | 298,452 | ||||||
| Subtotal - assets | 362,105 | 414,419 | ||||||
| Liabilities | ||||||||
| Funds payable | (698,623 | ) | (564,172 | ) | ||||
| Subtotal - liabilities | (698,623 | ) | (564,172 | ) | ||||
| Net transactions in the course of settlement | (336,518 | ) | (149,753 | ) | ||||
| (*) | The level of funds in cash and in the Central Bank of Chile responds to regulations on reserve requirements that the bank must maintain on average in monthly periods. |
| (**) | Trading operations pending settlement correspond to transactions in which only the settlement remains that will increase or decrease the funds in the Central Bank of Chile or in banks in foreign countries, normally within a period ranging between 12 or 24 business hours. |
| (***) | Refers to financial instruments that meet the criteria to be considered as “cash equivalents” as defined by IAS 7, i.e., to qualify as “cash equivalents” investments in debt financial instruments must be: short-term with an original maturity of 90 days or less from the date of acquisition, highly liquid, readily convertible to known amounts of cash from the date of initial investment, and that the financial instruments are exposed to an insignificant risk of changes in their value. |
54
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 8. | Financial Assets Held for Trading at Fair Value through Profit or Loss: |
The detail of this line item is as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Financial derivative instruments | 2,406,284 | 1,869,467 | ||||||
| Debt Financial Instruments | 1,416,779 | 3,121,702 | ||||||
| Others | 421,754 | 402,259 | ||||||
| Total | 4,244,817 | 5,393,428 | ||||||
| (a) | The Bank as of September 30, 2026 and December 31, 2025, maintains the following asset portfolio of derivative instruments: |
| Notional amount of contract with final expiration date in | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| On Demand | Up to 1 month | Over 1 month and up to 3 months | Over 3 months and up to 12 months | Over 1 year and up to 3 years | Over 3 years and up to 5 years | Over 5 years | Total | Fair Value Assets | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | September | December | September | December | September | December | September | December | September | December | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Currency forward | — | — | 7,700,280 | 6,451,389 | 4,146,074 | 3,453,741 | 5,958,513 | 3,453,928 | 624,456 | 658,475 | 65,557 | 3,028 | 17,001 | — | 18,511,881 | 14,020,561 | 632,805 | 377,810 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest rate swap | — | — | 2,530,246 | 384,202 | 1,485,207 | 2,758,114 | 6,931,390 | 7,746,942 | 7,858,170 | 7,089,417 | 5,201,105 | 4,497,481 | 4,593,755 | 4,088,342 | 28,599,873 | 26,564,498 | 724,037 | 451,124 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest rate and cross currency swap | — | — | 71,861 | 227,581 | 275,182 | 556,735 | 1,399,733 | 1,527,659 | 2,890,989 | 2,396,969 | 2,592,151 | 2,170,585 | 2,802,942 | 2,529,413 | 10,032,858 | 9,408,942 | 1,045,780 | 1,037,686 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Call currency options | — | — | 15,120 | 5,591 | 74,309 | 28,062 | 36,765 | 57,525 | 731 | — | — | — | — | — | 126,925 | 91,178 | 3,538 | 332 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Put currency options | — | — | 4,250 | 14,679 | 30,502 | 18,722 | 8,286 | 29,583 | — | — | — | — | — | — | 43,038 | 62,984 | 124 | 2,515 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total | — | — | 10,321,757 | 7,083,442 | 6,011,274 | 6,815,374 | 14,334,687 | 12,815,637 | 11,374,346 | 10,144,861 | 7,858,813 | 6,671,094 | 7,413,698 | 6,617,755 | 57,314,575 | 50,148,163 | 2,406,284 | 1,869,467 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
55
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 8. | Financial Assets Held for Trading at Fair Value through Profit or Loss, continued: |
| b) | The detail of Debt Financial Instruments is the following: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Instruments issued by the Chilean Government and Central Bank of Chile | ||||||||
| Debt financial instruments from the Central Bank of Chile | 822,188 | 2,388,127 | ||||||
| Bonds and Promissory notes from the General Treasury of the Republic | 463,516 | 410,202 | ||||||
| Other fiscal debt financial instruments | — | — | ||||||
| Other Instruments Issued in Chile | ||||||||
| Debt financial instruments from other domestic banks | 131,075 | 277,354 | ||||||
| Bonds and trade effects from domestic companies | — | — | ||||||
| Other debt financial instruments issued in the country | — | — | ||||||
| Instruments Issued Abroad | ||||||||
| Financial instruments from foreign governments or Central Banks | — | — | ||||||
| Financial debt instruments from foreign goverments and fiscal entities | — | 46,019 | ||||||
| Debt financial instruments from other foreign banks | — | — | ||||||
| Bonds and trade effects from foreign companies | — | — | ||||||
| Total | 1,416,779 | 3,121,702 | ||||||
Under Instruments issued by the Chilean Government and Central Bank of Chile are classified instruments sold under repurchase agreements to customers and financial institutions of Ch$23,350 million as of September 30, 2026 (Ch$62,046 million as of December 31, 2025). The repurchase agreements have an average maturity of 1 day at the end September 30, 2026 (2 days in December 2025).
Under Other financial debt securities issued in Chile are included instruments sold under repurchase agreements to customers and financial institutions by an amount of Ch$67,450 million as of September 30, 2026 (Ch$151,169 million in December 2025). The repurchase agreements have an average maturity of 4 days at the end of the period 2026 (4 days in December 2025).
Additionally, the Bank has investments in own-issued letters of credit for an amount equivalent to Ch$338 million as of September 30, 2026 (Ch$474 million in December 2025), which are presented as a reduction of the liability item “Debt Financial Instruments Issued”.
56
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 8. | Financial Assets Held for Trading at Fair Value through Profit or Loss, continued: |
| c) | The detail of other financial instruments is as follows: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Mutual fund investments | ||||||||
| Funds managed by related companies | 417,079 | 400,222 | ||||||
| Funds managed by third-party | — | — | ||||||
| Equity instruments | ||||||||
| Domestic equity instruments | 2,177 | 619 | ||||||
| Foreign equity instruments | — | — | ||||||
| Loans originated and acquired by the entity | — | — | ||||||
| Others | 2,498 | 1,418 | ||||||
| Total | 421,754 | 402,259 | ||||||
| 9. | Non-trading Financial Assets mandatorily measured at Fair Value through Profit or Loss: |
As of September 30, 2026 and December 31, 2025, the Bank does not hold any non-trading financial assets mandatorily measured at fair value through profit or loss.
| 10. | Financial Assets and Liabilities designated as at Fair Value through Profit or Loss: |
As of September 30, 2026 and December 31, 2025, the Bank does not hold financial assets and liabilities designated as at fair value through profit or loss.
57
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 11. | Financial Assets at Fair Value through Other Comprehensive Income: |
The item detail is as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Debt Financial Instruments | 4,239,432 | 3,548,971 | ||||||
| Others | — | — | ||||||
| Total | 4,239,432 | 3,548,971 | ||||||
| (a) | As of September 30, 2026 and December 31, 2025, the detail of debt financial instruments is as follows: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Instruments issued by the Chilean Government and Central Bank of Chile | ||||||||
| Debt financial instruments from the Central Bank of Chile | — | — | ||||||
| Bonds and Promissory notes from the General Treasury of the Republic | 2,490,868 | 1,174,234 | ||||||
| Other fiscal debt financial instruments | 9 | 72 | ||||||
| Other Instruments Issued in Chile | ||||||||
| Debt financial instruments from other domestic banks | 1,533,543 | 2,234,247 | ||||||
| Bonds and trade effects from domestic companies | 107,509 | 104,679 | ||||||
| Other debt financial instruments issued in the country | — | — | ||||||
| Instruments Issued Abroad | ||||||||
| Financial instruments from foreign Central Banks | — | — | ||||||
| Financial instruments from foreign governments and fiscal entities | 26,013 | 35,739 | ||||||
| Debt financial instruments from other foreign banks | 54,914 | — | ||||||
| Bonds and trade effects from foreign companies | 26,576 | — | ||||||
| Other debt financial instruments issued abroad | — | — | ||||||
| Total | 4,239,432 | 3,548,971 | ||||||
Instruments issued by the Chilean Government and Central Bank of Chile include instruments sold under repurchase agreements to clients and financial institutions for an amount of Ch$4,841 million in September 2026 (Ch$43,599 million in December 2025). The repurchase agreements have an average maturity of 3 days in September 2026 (5 days in December 2025).
Under the same item, instruments that guarantee margins for cleared derivatives transactions are classified through Comder Contraparte Central S.A. for an amount of Ch$68,789 million as of September 30, 2026 (Ch$20,714 million as of December 31, 2025).
58
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 11. | Financial Assets at Fair Value through Other Comprehensive Income, continued: |
As of September 30, 2026 the accumulated credit impairment for debt instruments at fair value through other comprehensive income amounted to Ch$2,212 million (Ch$6,979 million as of December 31, 2025).
| (b) | The analysis of changes in fair value and expected losses from debt instruments measured at fair value is detailed as follows: |
| Stage 1 Individual | Stage 2 Individual | Stage 3 Individual | Total | |||||||||||||||||||||||||||||
| Fair value | Impairment | Fair value | Impairment | Fair value | Impairment | Fair value | Impairment | |||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Balance as of January 1, 2025 | 2,088,345 | 4,226 | — | — | — | — | 2,088,345 | 4,226 | ||||||||||||||||||||||||
| Net change in balance | 1,454,573 | 2,753 | — | — | — | — | 1,454,573 | 2,753 | ||||||||||||||||||||||||
| Change in fair value | 6,053 | — | — | — | — | — | 6,053 | — | ||||||||||||||||||||||||
| Transfer to Stage 1 | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Transfer to Stage 2 | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Transfer to Stage 3 | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Impact due to transfer between stages | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Balance as of December 31, 2025 | 3,548,971 | 6,979 | — | — | — | — | 3,548,971 | 6,979 | ||||||||||||||||||||||||
| Balance as of January 1, 2026 | 3,548,971 | 6,979 | — | — | — | — | 3,548,971 | 6,979 | ||||||||||||||||||||||||
| Net change in balance | 724,418 | (4,767 | ) | — | — | — | — | 724,418 | (4,767 | ) | ||||||||||||||||||||||
| Change in fair value | (33,957 | ) | — | — | — | — | — | (33,957 | ) | — | ||||||||||||||||||||||
| Transfer to Stage 1 | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Transfer to Stage 2 | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Transfer to Stage 3 | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Impact due to transfer between stages | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Balance as of September 30, 2026 | 4,239,432 | 2,212 | — | — | — | — | 4,239,432 | 2,212 | ||||||||||||||||||||||||
| (c) | Realized and unrealized gains and losses: |
As of September 30, 2026, the portfolio of debt financial instruments includes an accumulated unrealized loss of Ch$25,440 million (unrealized gain of Ch$13,284 million as of December 31, 2025), recorded as an equity valuation adjustment.
Gross realized gains and losses on the sale of debt financial instruments, as of September 30, 2026 and 2025 are reported under “Net Financial Result” (See Note 33).
The changes in realized gains and losses at the end of both periods are detailed as follows:
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Unrealized gains (losses) | (30,828 | ) | 21,846 | |||||
| Realized losses (gains) reclassified to income | (7,896 | ) | (13,148 | ) | ||||
| Subtotal | (38,724 | ) | 8,698 | |||||
| Income tax on other comprehensive income | 4,901 | (851 | ) | |||||
| Net effect on equity | (33,823 | ) | 7,847 | |||||
59
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 12. | Derivative financial instruments for hedging purposes: |
| (a.1) | As of September 30, 2026 and December 31, 2025, the Bank has the following asset portfolio of financial derivative instruments for accounting hedging purposes: |
| Notional amount of contract with final expiration date in | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| On Demand | Up to 1 month | Over 1 month and up to 3 months | Over 3 months and up to 12 months | Over 1 year and up to 3 years | Over 3 years and up to 5 years | Over 5 years | Total | Fair
value Assets | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | September | December | September | December | September | December | September | December | September | December | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Derivatives held for fair value hedges | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash flow hedge derivatives | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest rate swap and cross currency swap | — | — | — | — | — | — | 179,214 | — | 137,674 | 215,715 | — | — | 192,500 | 107,073 | 509,388 | 322,788 | 43,950 | 29,714 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total | — | — | — | — | — | — | 179,214 | — | 137,674 | 215,715 | — | — | 192,500 | 107,073 | 509,388 | 322,788 | 43,950 | 29,714 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (a.2) | As of September 30, 2026 and December 31, 2025, the Bank has the following debt portfolio of financial derivative instruments for accounting hedging purposes: |
| Notional amount of contract with final expiration date in | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| On Demand | Up to 1 month | Over 1 month and up to 3 months | Over 3 months and up to 12 months | Over 1 year and up to 3 years | Over 3 years and up to 5 years | Over 5 years | Total | Fair
value | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | September | December | September | December | September | December | September | December | September | December | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Derivatives held for fair value hedges | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash flow hedge derivatives | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest rate swap and cross currency swap | — | — | — | — | — | — | 151,040 | — | 50,294 | 230,019 | 524,045 | 254,545 | 1,090,057 | 1,350,496 | 1,815,436 | 1,835,060 | 272,772 | 297,817 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total | — | — | — | — | — | — | 151,040 | — | 50,294 | 230,019 | 524,045 | 254,545 | 1,090,057 | 1,350,496 | 1,815,436 | 1,835,060 | 272,772 | 297,817 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
60
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 12. | Derivative financial instruments for hedging purposes, continued: |
| (b) | Fair value Hedges: |
As of September 30, 2026 and December 31, 2025, no fair value hedges are held.
| (c) | Cash flow Hedges: |
| (c.1) | The Bank uses cross currency swaps to hedge the risk from variability of cash flows attributable to changes in the interest rates and foreign exchange of foreign banks obligations and bonds issued abroad in US dollars, Hong Kong dollars, Swiss Franc, Japanese yen, Peruvian sol, Australian dollars, Euros, Norwegian kroner and Mexican pesos. The cash flows of the cross currency swaps equal the cash flows of the hedged items, which modify uncertain cash flows to known cash flows derived from a fixed interest rate. |
Additionally, these cross currency swap contracts are used to hedge the risk from variability of the Unidad de Fomento (“UF”) in assets flows denominated in UF until a nominal amount equal to the portion notional of the hedging instrument UF, whose daily indexation impact the line item “Interest Revenue” of the Statement of Income.
61
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 12. | Derivative financial instruments for hedging purposes, continued: |
| (c) | Cash flow Hedges, continued: |
| (c.2) | Below are the cash flows from bonds issued abroad objects of this hedge and the cash flows of the asset part of the derivative instrument: |
| On Demand | Up to 1 month | Over 1 month and up to 3 months | Over 3 months and up to 12 months | Over 1 year and up to 3 years | Over 3 years and up to 5 years | Over 5 years | Total | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | September | December | September | December | September | December | September | December | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||||||||||||||
| Hedged item | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Outflows: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate Bond | — | — | (6,170 | ) | (1,017 | ) | (18,092 | ) | (9,291 | ) | (395,731 | ) | (52,425 | ) | (325,810 | ) | (572,565 | ) | (559,822 | ) | (297,431 | ) | (1,336,176 | ) | (1,437,654 | ) | (2,641,801 | ) | (2,370,383 | ) | ||||||||||||||||||||||||||||||||||
| Hedging instrument | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Inflows: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cross Currency Swap | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net cash flows | — | — | 6,170 | 1,017 | 18,092 | 9,291 | 395,731 | 52,425 | 325,810 | 572,565 | 559,822 | 297,431 | 1,336,176 | 1,437,654 | 2,641,801 | 2,370,383 | ||||||||||||||||||||||||||||||||||||||||||||||||
| — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| (c.3) | Below are the cash flows from underlying assets and the cash flows of the liability part of the derivative instrument: |
| On Demand | Up to 1 month | Over 1 month and up to 3 months | Over 3 months and up to 12 months | Over 1 year and up to 3 years | Over 3 years and up to 5 years | Over 5 years | Total | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | September | December | September | December | September | December | September | December | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||||||||||||||
| Hedged item | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Inflows: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash flows in CLF | — | — | 4,309 | 2,270 | 12,628 | 2,881 | 361,691 | 41,030 | 269,750 | 527,973 | 590,674 | 320,395 | 1,360,146 | 1,549,936 | 2,599,198 | 2,444,485 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Hedging instrument | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Outflows: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cross Currency Swap | — | — | (4,309 | ) | (2,270 | ) | (12,628 | ) | (2,881 | ) | (361,691 | ) | (41,030 | ) | (269,750 | ) | (527,973 | ) | (590,674 | ) | (320,395 | ) | (1,360,146 | ) | (1,549,936 | ) | (2,599,198 | ) | (2,444,485 | ) | ||||||||||||||||||||||||||||||||||
| Net cash flows | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
62
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 12. | Derivative financial instruments for hedging purposes, continued: |
| (c) | Cash flow Hedges, continued: |
With respect to CLF assets hedged; these are revalued monthly according to the variation of the UF, which is equivalent to monthly reinvest the assets until maturity of the relationship hedging.
| (c.4) | The unrealized results generated during the period 2026 by those derivative contracts that composed the hedging instruments in this cash flow hedging strategy, have been recorded with a charge to equity amounting to Ch$43,731 million (charge to equity of Ch$14,892 million in September 2025). The net effect of taxes charge to equity amounts to Ch$31,924 million (a charge to equity of Ch$10,871 million during the period 2025). |
The accumulated balance for this concept as of September 30, 2026 corresponds to a charge to equity amounted to Ch$84,469 million (charge to equity of Ch$40,738 million as of December 31, 2025).
| (c.5) | The effect of the cash flow hedging derivatives that offset the result of the hedged instruments corresponds to a credit to income of Ch$95,331 million during the period 2026 (charge to results for Ch$20,149 million during September 2025). |
| (c.6) | As of September 30, 2026 and 2025, there is not any inefficiency in the cash flow hedge, because both, hedged item and hedge instruments, are mirrors of each other, it means that all variation of value attributable to rate and revaluation components are netted totally. |
| (c.7) | As of September 30, 2026 and 2025, the Bank had no hedges of net investments in foreign businesses. |
| 13. | Financial assets at amortized cost: |
The item detail is as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Rights by resale agreements | 96,631 | 100,643 | ||||||
| Debt financial instruments | 453,575 | 460,937 | ||||||
| Loans to Banks | 609,731 | 399,123 | ||||||
| Loans to customers: | ||||||||
| Commercial loans | 21,033,299 | 19,509,355 | ||||||
| Residential mortgage loans | 14,185,503 | 13,916,618 | ||||||
| Consumer loans | 5,548,903 | 5,765,997 | ||||||
| Allowances established for credit risk (*) | ||||||||
| Commercial loans allowances | (375,253 | ) | (371,895 | ) | ||||
| Residential mortgage loans allowances | (45,692 | ) | (42,111 | ) | ||||
| Consumer loans allowances | (427,299 | ) | (422,965 | ) | ||||
| Total | 41,079,398 | 39,315,702 | ||||||
| (*) | In addition to these allowances for credit losses, country risk allowances are to cover foreign operations and additional allowances agreed by the Board of Directors are maintained, which are presented in liabilities under the line item Special allowances for credit losses (See Note 26). |
63
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (a) | Rights by resale agreements: |
The Bank provides financing to its customers through rights by resale agreements, in which the financial instrument serves as collateral. As of September 30, 2026 and December 31, 2025, the detail is as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Transaction with domestic banks | — | — | ||||||
| Transaction with foreign banks | — | — | ||||||
| Transaction with other domestic entities | ||||||||
| Resale agreements | 96,631 | 100,643 | ||||||
| Rights from securities lending | — | — | ||||||
| Transaction with other foreign entities | — | — | ||||||
| Accumulated Impairment Value of Financial Assets at Amortized Cost Rights by resale agreements | — | — | ||||||
| Total | 96,631 | 100,643 | ||||||
The Bank and its subsidiaries have received financial instruments that they can sell or give as collateral in case the owner of these instruments enters into default or in bankruptcy. As of September 30, 2026, the fair value of the instruments received amounts to Ch$95,141 million (Ch$107,060 million in December 2025).
| (b) | Debt financial instruments: |
At the end of each period, the balances presented under this line are detailed follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Instruments issued by the Chilean Government and Central Bank of Chile | ||||||||
| Debt financial instruments from the Central Bank of Chile | — | — | ||||||
| Bonds and promissory notes from the General Treasury of the Republic | 453,625 | 460,956 | ||||||
| Other fiscal debt financial instruments | — | — | ||||||
| Other Financial Instruments issued in Chile | — | — | ||||||
| Financial Instruments issued Abroad | — | — | ||||||
| Accumulated Impairment Value of Financial Assets at Amortized Cost Debt Financial Instruments | ||||||||
| Financial assets with no significant increase in credit risk since initial recognition (stage 1) | (50 | ) | (19 | ) | ||||
| Financial assets with a significant increase in credit risk since initial recognition, but without credit impairment (stage 2) | — | — | ||||||
| Financial assets with credit impairment (stage 3) | — | — | ||||||
| Total | 453,575 | 460,937 | ||||||
64
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (c) | Loans to Banks: At the end of each period, the balances presented under this item are as follows: |
| Assets before allowances | Allowances established | |||||||||||||||||||||||||||||||||||
| As of September 30, 2026 | Normal Portfolio Individual Evaluation | Substandard Portfolio Individual Evaluation | Non-performing Portfolio Individual Evaluation | Total | Normal Portfolio Individual Evaluation | Substandard Portfolio Individual Evaluation | Non-performing Portfolio Individual Evaluation | Total | Net Financial Asset | |||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||
| Domestic Banks | ||||||||||||||||||||||||||||||||||||
| Interbank loans of liquidity | 200,000 | — | — | 200,000 | (72 | ) | — | — | (72 | ) | 199,928 | |||||||||||||||||||||||||
| Commercial Interbank loans | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Overdrafts on current accounts | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Chilean exports foreign trade loans | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Chilean imports foreign trade loans | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Credits with third countries | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Non-transferable deposits in domestic banks | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other debts with domestic banks | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Foreign Banks | ||||||||||||||||||||||||||||||||||||
| Interbank loans of liquidity | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Commercial interbank loans | 257,310 | — | — | 257,310 | (563 | ) | — | — | (563 | ) | 256,747 | |||||||||||||||||||||||||
| Overdrafts on current accounts | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Chilean exports foreign trade loans | 153,250 | — | — | 153,250 | (194 | ) | — | — | (194 | ) | 153,056 | |||||||||||||||||||||||||
| Chilean imports foreign trade loans | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Foreign trade loans between third countries | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Current account deposits with foreign banks for derivatives transactions | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other non-transferable deposits with foreign banks | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other loans with foreign banks | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Subtotal Domestic and Foreign banks | 610,560 | — | — | 610,560 | (829 | ) | — | — | (829 | ) | 609,731 | |||||||||||||||||||||||||
| Central Bank of Chile | ||||||||||||||||||||||||||||||||||||
| Deposits in foreign current accounts for derivative transactions with a counterparty | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other deposits not available | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other receivables | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Foreign Central Banks | ||||||||||||||||||||||||||||||||||||
| Deposits in foreign current accounts for derivatives transactions | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other deposits not available | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other receivables | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Subtotal Central Bank of Chile and Foreign Central Banks | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Total | 610,560 | — | — | 610,560 | (829 | ) | — | — | (829 | ) | 609,731 | |||||||||||||||||||||||||
65
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (c) | Loans to Banks, continued: |
| Assets before allowances | Allowances established | |||||||||||||||||||||||||||||||||||
| As of December 31, 2025 | Normal Portfolio Individual Evaluation | Substandard Portfolio Individual Evaluation | Non-performing Portfolio Individual Evaluation | Total | Normal Portfolio Individual Evaluation | Substandard Portfolio Individual Evaluation | Non-performing Portfolio Individual Evaluation | Total | Net Financial Asset | |||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||
| Domestic Banks | ||||||||||||||||||||||||||||||||||||
| Interbank loans of liquidity | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Commercial Interbank loans | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Overdrafts on current accounts | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Chilean exports foreign trade loans | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Chilean imports foreign trade loans | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Credits with third countries | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Non-transferable deposits in domestic banks | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other debts with domestic banks | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Foreign Banks | ||||||||||||||||||||||||||||||||||||
| Interbank loans of liquidity | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Commercial interbank loans | 204,397 | — | — | 204,397 | (447 | ) | — | — | (447 | ) | 203,950 | |||||||||||||||||||||||||
| Overdrafts on current accounts | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Chilean exports foreign trade loans | 195,395 | — | — | 195,395 | (222 | ) | — | — | (222 | ) | 195,173 | |||||||||||||||||||||||||
| Chilean imports foreign trade loans | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Foreign trade loans between third countries | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Current account deposits with foreign banks for derivatives transactions | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other non-transferable deposits with foreign banks | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other loans with foreign banks | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Subtotal Domestic and Foreign banks | 399,792 | — | — | 399,792 | (669 | ) | — | — | (669 | ) | 399,123 | |||||||||||||||||||||||||
| Central Bank of Chile | ||||||||||||||||||||||||||||||||||||
| Deposits in foreign current accounts for derivative transactions with a counterparty | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other deposits not available | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||
| Other receivables | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Foreign Central Banks | ||||||||||||||||||||||||||||||||||||
| Deposits in foreign current accounts for derivatives transactions | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other deposits not available | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Other receivables | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Subtotal Central Bank of Chile and Foreign Central Banks | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||
| Total | 399,792 | — | — | 399,792 | (669 | ) | — | — | (669 | ) | 399,123 | |||||||||||||||||||||||||
66
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (d) | Loans to customers: at the end of each period, the balances presented under this line item are detailed as follows: |
| Assets before allowances | Allowances established | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans to Customers | Normal
Portfolio Evaluation | Substandard Portfolio Evaluation | Non-performing
Portfolio Evaluation | Normal
Portfolio Evaluation | Substandard
Portfolio Evaluation | Non-performing Portfolio Evaluation | Sub | Deductible
guarantees Fogape | Net
Financial | |||||||||||||||||||||||||||||||||||||||||||||||||||
| as of September 30, 2026 | Individual | Group | Individual | Individual | Group | Total | Individual | Group | Individual | Individual | Group | Total | Covid-19 | Total | Asset | |||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||||||||||||||||||
| Commercial loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial loans | 11,427,276 | 3,921,276 | 195,639 | 217,353 | 394,364 | 16,155,908 | (93,190 | ) | (29,247 | ) | (3,046 | ) | (48,358 | ) | (80,518 | ) | (254,359 | ) | (1,393 | ) | (255,752 | ) | 15,900,156 | |||||||||||||||||||||||||||||||||||||
| Chilean exports foreign trade loans | 654,338 | 3,263 | 12,058 | 14,036 | 53 | 683,748 | (21,736 | ) | (81 | ) | (454 | ) | (3,235 | ) | (30 | ) | (25,536 | ) | — | (25,536 | ) | 658,212 | ||||||||||||||||||||||||||||||||||||||
| Accrediting foreign trade loans negotiated in terms of Chilean imports | 82 | — | — | — | — | 82 | (7 | ) | — | — | — | — | (7 | ) | — | (7 | ) | 75 | ||||||||||||||||||||||||||||||||||||||||||
| Chilean imports foreign trade loans | 533,447 | 46,528 | 4,233 | 4,614 | 1,791 | 590,613 | (19,936 | ) | (1,351 | ) | (306 | ) | (2,572 | ) | (992 | ) | (25,157 | ) | — | (25,157 | ) | 565,456 | ||||||||||||||||||||||||||||||||||||||
| Foreign trade credits for operations with third countries | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Current account debtors | 87,475 | 89,489 | 6,171 | 4,389 | 2,412 | 189,936 | (3,037 | ) | (2,156 | ) | (656 | ) | (2,592 | ) | (1,138 | ) | (9,579 | ) | — | (9,579 | ) | 180,357 | ||||||||||||||||||||||||||||||||||||||
| Credit card debtors | 29,323 | 87,256 | 1,479 | 1,457 | 13,249 | 132,764 | (1,184 | ) | (3,058 | ) | (204 | ) | (958 | ) | (7,278 | ) | (12,682 | ) | — | (12,682 | ) | 120,082 | ||||||||||||||||||||||||||||||||||||||
| Factoring transactions | 1,008,906 | 35,633 | 4,476 | 96 | 18 | 1,049,129 | (15,397 | ) | (737 | ) | (512 | ) | (86 | ) | (6 | ) | (16,738 | ) | — | (16,738 | ) | 1,032,391 | ||||||||||||||||||||||||||||||||||||||
| Commercial lease transactions (1) | 1,788,601 | 298,303 | 30,665 | 41,751 | 13,439 | 2,172,759 | (3,715 | ) | (2,079 | ) | (179 | ) | (15,518 | ) | (2,619 | ) | (24,110 | ) | — | (24,110 | ) | 2,148,649 | ||||||||||||||||||||||||||||||||||||||
| Student loans | — | 41,711 | — | — | 3,356 | 45,067 | — | (1,986 | ) | — | — | (2,348 | ) | (4,334 | ) | — | (4,334 | ) | 40,733 | |||||||||||||||||||||||||||||||||||||||||
| Other loans and accounts receivable | 8,701 | 764 | 112 | 2,787 | 929 | 13,293 | (244 | ) | (1 | ) | (19 | ) | (745 | ) | (349 | ) | (1,358 | ) | — | (1,358 | ) | 11,935 | ||||||||||||||||||||||||||||||||||||||
| Subtotal | 15,538,149 | 4,524,223 | 254,833 | 286,483 | 429,611 | 21,033,299 | (158,446 | ) | (40,696 | ) | (5,376 | ) | (74,064 | ) | (95,278 | ) | (373,860 | ) | (1,393 | ) | (375,253 | ) | 20,658,046 | |||||||||||||||||||||||||||||||||||||
| Residential mortgage loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans secured by mortgage finance bonds | — | 647 | — | — | 105 | 752 | — | (1 | ) | — | — | (6 | ) | (7 | ) | — | (7 | ) | 745 | |||||||||||||||||||||||||||||||||||||||||
| Endorsable mortgage mutual loans | — | 6,818 | — | — | 229 | 7,047 | — | (12 | ) | — | — | (13 | ) | (25 | ) | — | (25 | ) | 7,022 | |||||||||||||||||||||||||||||||||||||||||
| Mortgage mutual financed by mortgage bonds | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Other mortgage mutual loans | — | 13,585,453 | — | — | 431,640 | 14,017,093 | — | (16,699 | ) | — | — | (27,570 | ) | (44,269 | ) | — | (44,269 | ) | 13,972,824 | |||||||||||||||||||||||||||||||||||||||||
| Residential lease transactions (1) | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Other loans and accounts receivable | — | 147,636 | — | — | 12,975 | 160,611 | — | (193 | ) | — | — | (1,198 | ) | (1,391 | ) | — | (1,391 | ) | 159,220 | |||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 13,740,554 | — | — | 444,949 | 14,185,503 | — | (16,905 | ) | — | — | (28,787 | ) | (45,692 | ) | — | (45,692 | ) | 14,139,811 | |||||||||||||||||||||||||||||||||||||||||
| Consumer loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Consumer loans in installments | — | 3,174,755 | — | — | 259,991 | 3,434,746 | — | (146,893 | ) | — | — | (138,838 | ) | (285,731 | ) | — | (285,731 | ) | 3,149,015 | |||||||||||||||||||||||||||||||||||||||||
| Current account debtors | — | 267,339 | — | — | 17,365 | 284,704 | — | (17,253 | ) | — | — | (10,011 | ) | (27,264 | ) | — | (27,264 | ) | 257,440 | |||||||||||||||||||||||||||||||||||||||||
| Credit card debtors | — | 1,783,145 | — | — | 43,812 | 1,826,957 | — | (88,286 | ) | — | — | (25,260 | ) | (113,546 | ) | — | (113,546 | ) | 1,713,411 | |||||||||||||||||||||||||||||||||||||||||
| Consumer lease transactions (1) | — | 1,117 | — | — | 84 | 1,201 | — | (24 | ) | — | — | (28 | ) | (52 | ) | — | (52 | ) | 1,149 | |||||||||||||||||||||||||||||||||||||||||
| Other loans and accounts receivable | — | 6 | — | — | 1,289 | 1,295 | — | (2 | ) | — | — | (704 | ) | (706 | ) | — | (706 | ) | 589 | |||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 5,226,362 | — | — | 322,541 | 5,548,903 | — | (252,458 | ) | — | — | (174,841 | ) | (427,299 | ) | — | (427,299 | ) | 5,121,604 | |||||||||||||||||||||||||||||||||||||||||
| Total | 15,538,149 | 23,491,139 | 254,833 | 286,483 | 1,197,101 | 40,767,705 | (158,446 | ) | (310,059 | ) | (5,376 | ) | (74,064 | ) | (298,906 | ) | (846,851 | ) | (1,393 | ) | (848,244 | ) | 39,919,461 | |||||||||||||||||||||||||||||||||||||
| (1) | In this item, the Bank finances for its customers the acquisition of movable and immovable property through financial lease contracts. As of September 30, 2026, Ch$1,080,953 million correspond to finance leases on real estate assets and Ch$1,093,007 million correspond to finance leases on movable property. |
67
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (d) | Loans to Customers, continued: |
| Assets before allowances | Allowances established | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans to Customers | Normal
Portfolio Evaluation | Substandard Portfolio Evaluation | Non-performing
Portfolio Evaluation | Normal
Portfolio Evaluation | Substandard
Portfolio Evaluation | Non-performing Portfolio Evaluation | Sub | Deductible
guarantees Fogape | Net
Financial | |||||||||||||||||||||||||||||||||||||||||||||||||||
| As of December 31, 2025 | Individual | Group | Individual | Individual | Group | Total | Individual | Group | Individual | Individual | Group | Total | Covid-19 | Total | Asset | |||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||||||||||||||||||
| Commercial loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial loans | 10,420,557 | 3,864,529 | 175,300 | 214,874 | 354,171 | 15,029,431 | (86,198 | ) | (27,878 | ) | (2,224 | ) | (63,700 | ) | (74,211 | ) | (254,211 | ) | (1,337 | ) | (255,548 | ) | 14,773,883 | |||||||||||||||||||||||||||||||||||||
| Chilean exports foreign trade loans | 614,551 | 2,558 | 12,342 | 13,881 | 133 | 643,465 | (17,574 | ) | (57 | ) | (3,000 | ) | (3,537 | ) | (76 | ) | (24,244 | ) | — | (24,244 | ) | 619,221 | ||||||||||||||||||||||||||||||||||||||
| Accrediting foreign trade loans negotiated in terms of Chilean imports | 273 | — | — | — | — | 273 | (24 | ) | — | — | — | — | (24 | ) | — | (24 | ) | 249 | ||||||||||||||||||||||||||||||||||||||||||
| Chilean imports foreign trade loans | 469,042 | 43,692 | 6,600 | 4,143 | 2,213 | 525,690 | (18,896 | ) | (1,228 | ) | (625 | ) | (2,786 | ) | (1,250 | ) | (24,785 | ) | — | (24,785 | ) | 500,905 | ||||||||||||||||||||||||||||||||||||||
| Foreign trade credits for operations with third countries | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Current account debtors | 83,206 | 89,653 | 5,408 | 2,654 | 2,413 | 183,334 | (3,003 | ) | (2,144 | ) | (526 | ) | (1,657 | ) | (1,134 | ) | (8,464 | ) | — | (8,464 | ) | 174,870 | ||||||||||||||||||||||||||||||||||||||
| Credit card debtors | 28,769 | 91,388 | 1,106 | 1,380 | 12,175 | 134,818 | (1,194 | ) | (3,098 | ) | (144 | ) | (963 | ) | (6,649 | ) | (12,048 | ) | — | (12,048 | ) | 122,770 | ||||||||||||||||||||||||||||||||||||||
| Factoring transactions | 794,379 | 35,559 | 3,901 | 118 | 11 | 833,968 | (13,041 | ) | (840 | ) | (315 | ) | (90 | ) | (4 | ) | (14,290 | ) | — | (14,290 | ) | 819,678 | ||||||||||||||||||||||||||||||||||||||
| Commercial lease transactions (1) | 1,714,548 | 296,688 | 28,165 | 42,154 | 14,238 | 2,095,793 | (3,718 | ) | (1,759 | ) | (118 | ) | (15,409 | ) | (2,733 | ) | (23,737 | ) | (135 | ) | (23,872 | ) | 2,071,921 | |||||||||||||||||||||||||||||||||||||
| Student loans | — | 44,179 | — | — | 3,088 | 47,267 | — | (2,044 | ) | — | — | (2,152 | ) | (4,196 | ) | — | (4,196 | ) | 43,071 | |||||||||||||||||||||||||||||||||||||||||
| Other loans and accounts receivable | 8,407 | 728 | 126 | 4,907 | 1,148 | 15,316 | (250 | ) | (1 | ) | (15 | ) | (3,770 | ) | (388 | ) | (4,424 | ) | — | (4,424 | ) | 10,892 | ||||||||||||||||||||||||||||||||||||||
| Subtotal | 14,133,732 | 4,468,974 | 232,948 | 284,111 | 389,590 | 19,509,355 | (143,898 | ) | (39,049 | ) | (6,967 | ) | (91,912 | ) | (88,597 | ) | (370,423 | ) | (1,472 | ) | (371,895 | ) | 19,137,460 | |||||||||||||||||||||||||||||||||||||
| Residential mortgage loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans secured by mortgage finance bonds | — | 694 | — | — | 112 | 806 | — | (2 | ) | — | — | (6 | ) | (8 | ) | — | (8 | ) | 798 | |||||||||||||||||||||||||||||||||||||||||
| Endorsable mortgage mutual loans | — | 8,318 | — | — | 286 | 8,604 | — | (7 | ) | — | — | (23 | ) | (30 | ) | — | (30 | ) | 8,574 | |||||||||||||||||||||||||||||||||||||||||
| Mortgage mutual financed with mortgage bonds | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Other mortgage mutual loans | — | 13,351,528 | — | — | 394,437 | 13,745,965 | — | (15,922 | ) | — | — | (24,931 | ) | (40,853 | ) | — | (40,853 | ) | 13,705,112 | |||||||||||||||||||||||||||||||||||||||||
| Residential lease transactions (1) | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Other loans and accounts receivable | — | 149,607 | — | — | 11,636 | 161,243 | — | (199 | ) | — | — | (1,021 | ) | (1,220 | ) | — | (1,220 | ) | 160,023 | |||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 13,510,147 | — | — | 406,471 | 13,916,618 | — | (16,130 | ) | — | — | (25,981 | ) | (42,111 | ) | — | (42,111 | ) | 13,874,507 | |||||||||||||||||||||||||||||||||||||||||
| Consumer loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Consumer loans in installments | — | 3,135,509 | — | — | 240,022 | 3,375,531 | — | (147,737 | ) | — | — | (130,692 | ) | (278,429 | ) | — | (278,429 | ) | 3,097,102 | |||||||||||||||||||||||||||||||||||||||||
| Current account debtors | — | 277,151 | — | — | 15,646 | 292,797 | — | (17,142 | ) | — | — | (8,999 | ) | (26,141 | ) | — | (26,141 | ) | 266,656 | |||||||||||||||||||||||||||||||||||||||||
| Credit card debtors | — | 2,056,286 | — | — | 38,747 | 2,095,033 | — | (95,237 | ) | — | — | (22,337 | ) | (117,574 | ) | — | (117,574 | ) | 1,977,459 | |||||||||||||||||||||||||||||||||||||||||
| Consumer lease transactions (1) | — | 1,142 | — | — | 57 | 1,199 | — | (19 | ) | — | — | (19 | ) | (38 | ) | — | (38 | ) | 1,161 | |||||||||||||||||||||||||||||||||||||||||
| Other loans and accounts receivable | — | 44 | — | — | 1,393 | 1,437 | — | (11 | ) | — | — | (772 | ) | (783 | ) | — | (783 | ) | 654 | |||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 5,470,132 | — | — | 295,865 | 5,765,997 | — | (260,146 | ) | — | — | (162,819 | ) | (422,965 | ) | — | (422,965 | ) | 5,343,032 | |||||||||||||||||||||||||||||||||||||||||
| Total | 14,133,732 | 23,449,253 | 232,948 | 284,111 | 1,091,926 | 39,191,970 | (143,898 | ) | (315,325 | ) | (6,967 | ) | (91,912 | ) | (277,397 | ) | (835,499 | ) | (1,472 | ) | (836,971 | ) | 38,354,999 | |||||||||||||||||||||||||||||||||||||
| (1) | In this item, the Bank finances for its customers the acquisition of movable and immovable property through financial lease contracts. As of December 31, 2025, Ch$1,032,905 million correspond to finance leases on real estate assets and Ch$1,064,087 million correspond to finance leases on movable property |
68
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (e) | Contingent loan: At the close of each reporting period, the contingent credit risk exposure is as follows: |
| Outstanding exposure before provisions | Provisions established | Net exposure | ||||||||||||||||||||||||||||||||||||||||||||||||||
| As of September 30, | Normal Portfolio Evaluation | Substandard Portfolio Evaluation | Non-performing Portfolio Evaluation | Normal
Portfolio Evaluation | Substandard Portfolio Evaluation | Non-performing Portfolio Evaluation | for
credit risk of contingent | |||||||||||||||||||||||||||||||||||||||||||||
| 2026 | Individual | Group | Individual | Individual | Group | Total | Individual | Group | Individual | Individual | Group | Total | Loans | |||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||||||||||||
| Guarantees and sureties | 300,506 | 651 | — | — | — | 301,157 | (3,990 | ) | (6 | ) | — | — | — | (3,996 | ) | 297,161 | ||||||||||||||||||||||||||||||||||||
| Letters of credit for goods circulation operations | 732,640 | 296 | — | — | — | 732,936 | (926 | ) | (2 | ) | — | — | — | (928 | ) | 732,008 | ||||||||||||||||||||||||||||||||||||
| Debt purchase commitments in local currency abroad | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||
| Transactions related to contingent events | 2,824,390 | 66,810 | 13,054 | 6,240 | 408 | 2,910,902 | (26,558 | ) | (695 | ) | (613 | ) | (3,282 | ) | (226 | ) | (31,374 | ) | 2,879,528 | |||||||||||||||||||||||||||||||||
| Undrawn credit lines with immediate termination | 1,707,414 | 10,509,389 | 8,135 | 1,559 | 6,486 | 12,232,983 | (3,285 | ) | (34,730 | ) | (126 | ) | (856 | ) | (3,535 | ) | (42,532 | ) | 12,190,451 | |||||||||||||||||||||||||||||||||
| Undrawn credit lines | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||
| Other irrevocable loan commitments | 131,458 | — | — | — | — | 131,458 | (684 | ) | — | — | — | — | (684 | ) | 130,774 | |||||||||||||||||||||||||||||||||||||
| Other contingent loans | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||
| Total | 5,696,408 | 10,577,146 | 21,189 | 7,799 | 6,894 | 16,309,436 | (35,443 | ) | (35,433 | ) | (739 | ) | (4,138 | ) | (3,761 | ) | (79,514 | ) | 16,229,922 | |||||||||||||||||||||||||||||||||
| Outstanding exposure before provisions | Provisions established | Net exposure | ||||||||||||||||||||||||||||||||||||||||||||||||||
| As of December 31, | Normal
Portfolio Evaluation | Substandard Portfolio Evaluation | Non-performing Portfolio Evaluation | Normal
Portfolio Evaluation | Substandard Portfolio Evaluation | Non-performing Portfolio Evaluation | for
credit risk of contingent | |||||||||||||||||||||||||||||||||||||||||||||
| 2025 | Individual | Group | Individual | Individual | Group | Total | Individual | Group | Individual | Individual | Group | Total | loans | |||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||||||||||||
| Guarantees and sureties | 288,155 | 555 | — | — | — | 288,710 | (4,410 | ) | (4 | ) | — | — | — | (4,414 | ) | 284,296 | ||||||||||||||||||||||||||||||||||||
| Letters of credit for goods circulation operations | 449,025 | 395 | 339 | — | — | 449,759 | (690 | ) | (2 | ) | (21 | ) | — | — | (713 | ) | 449,046 | |||||||||||||||||||||||||||||||||||
| Debt purchase commitments in local currency abroad | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||
| Transactions related to contingent events | 3,062,574 | 65,077 | 32,556 | 12,653 | 401 | 3,173,261 | (28,987 | ) | (668 | ) | (2,818 | ) | (5,749 | ) | (171 | ) | (38,393 | ) | 3,134,868 | |||||||||||||||||||||||||||||||||
| Undrawn credit lines with immediate termination | 1,644,538 | 9,795,652 | 6,174 | 1,160 | 6,258 | 11,453,782 | (2,991 | ) | (32,626 | ) | (85 | ) | (747 | ) | (3,485 | ) | (39,934 | ) | 11,413,848 | |||||||||||||||||||||||||||||||||
| Undrawn credit lines | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||
| Other irrevocable loan commitments | 69,191 | — | — | — | — | 69,191 | (1,059 | ) | — | — | — | — | (1,059 | ) | 68,132 | |||||||||||||||||||||||||||||||||||||
| Other contingent loans | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||
| Total | 5,513,483 | 9,861,679 | 39,069 | 13,813 | 6,659 | 15,434,703 | (38,137 | ) | (33,300 | ) | (2,924 | ) | (6,496 | ) | (3,656 | ) | (84,513 | ) | 15,350,190 | |||||||||||||||||||||||||||||||||
69
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (f) | Allowances: |
Summary of changes in loans to banks allowances constituted by credit risk portfolio in the period:
| Changes in allowances established by portfolio in the period | ||||||||||||||||
| Individual Evaluation | ||||||||||||||||
| Loans to Banks | Normal Portfolio | Substandard Portfolio | Non-performing Portfolio | Total | ||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Balance as of January 1, 2026 | 669 | — | — | 669 | ||||||||||||
| Allowances established/ released: | ||||||||||||||||
| Change in measurement without portfolio reclassification during the period | 26 | — | — | 26 | ||||||||||||
| Change in measurement without portfolio reclassification from the beginning to the end of the period (portfolio from (-) until (+)): | ||||||||||||||||
| Transfer from Normal individual to Substandard | — | — | — | — | ||||||||||||
| Transfer from Normal individual to Non-performing individual | — | — | — | — | ||||||||||||
| Transfer from Substandard to Non-performing individual | — | — | — | — | ||||||||||||
| Transfer from Substandard to Normal individual | — | — | — | — | ||||||||||||
| Transfer from Non-performing individual to Substandard | — | — | — | — | ||||||||||||
| Transfer from Non-performing individual to Normal individual | — | — | — | — | ||||||||||||
| New credits originated | 1,072 | — | — | 1,072 | ||||||||||||
| New credits for conversion of contingent to loan | — | — | — | — | ||||||||||||
| New credits purchased | — | — | — | — | ||||||||||||
| Sales or transfers of credits | — | — | — | — | ||||||||||||
| Payment of credit | (1,681 | ) | — | — | (1,681 | ) | ||||||||||
| Provisions for write-offs | — | — | — | — | ||||||||||||
| Recovery of written-off loans | — | — | — | — | ||||||||||||
| Foreign exchange differences | 45 | — | — | 45 | ||||||||||||
| Other changes in allowances | 698 | — | — | 698 | ||||||||||||
| Balance as of September 30, 2026 | 829 | — | — | 829 | ||||||||||||
| Changes in allowances established by portfolio in the year | ||||||||||||||||
| Individual Evaluation | ||||||||||||||||
| Loans to Banks | Normal Portfolio | Substandard Portfolio | Non-performing Portfolio | Total | ||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Balance as of January 1, 2025 | 888 | — | — | 888 | ||||||||||||
| Allowances established/ released: | ||||||||||||||||
| Change in measurement without portfolio reclassification during the year | (64 | ) | — | — | (64 | ) | ||||||||||
| Change in measurement without portfolio reclassification from the beginning to the end of the year (portfolio from (-) until (+)): | ||||||||||||||||
| Transfer from Normal individual to Substandard | — | — | — | — | ||||||||||||
| Transfer from Normal individual to Non-performing individual | — | — | — | — | ||||||||||||
| Transfer from Substandard to Non-performing individual | — | — | — | — | ||||||||||||
| Transfer from Substandard to Normal individual | — | — | — | — | ||||||||||||
| Transfer from Non-performing individual to Substandard | — | — | — | — | ||||||||||||
| Transfer from Non-performing individual to Normal individual | — | — | — | — | ||||||||||||
| New credits originated | 1,807 | — | — | 1,807 | ||||||||||||
| New credits for conversion of contingent to loan | — | — | — | — | ||||||||||||
| New credits purchased | — | — | — | — | ||||||||||||
| Sales or transfers of credits | — | — | — | — | ||||||||||||
| Payment of credit | (2,653 | ) | — | — | (2,653 | ) | ||||||||||
| Provisions for write-offs | — | — | — | — | ||||||||||||
| Recovery of written-off loans | — | — | — | — | ||||||||||||
| Foreign exchange differences | (68 | ) | — | — | (68 | ) | ||||||||||
| Other changes in allowances | 759 | — | — | 759 | ||||||||||||
| Balance as of December 31, 2025 | 669 | — | — | 669 | ||||||||||||
70
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (f) | Allowances, continued: |
Summary of changes in commercial loan allowances constituted by credit risk portfolio in the period:
| Changes in allowances established by portfolio in the period | ||||||||||||||||||||||||||||||||
| Normal
Portfolio Evaluation | Substandard Portfolio Evaluation | Non-performing
Portfolio Evaluation | Deductible guarantees Fogape | |||||||||||||||||||||||||||||
| Commercial loans | Individual | Group | Individual | Individual | Group | Sub total | Covid-19 | Total | ||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Balance as of January 1, 2026 | 143,898 | 39,049 | 6,967 | 91,912 | 88,597 | 370,423 | 1,472 | 371,895 | ||||||||||||||||||||||||
| Allowance established/ released: | ||||||||||||||||||||||||||||||||
| Change in measurement without portfolio reclassification during the period | (3,509 | ) | 18,773 | (456 | ) | (1,691 | ) | 3,141 | 16,258 | — | 16,258 | |||||||||||||||||||||
| Change in measurement without portfolio reclassification from the beginning to the end of the period (portfolio from (-) until (+)): | ||||||||||||||||||||||||||||||||
| Transfer from Normal individual to Substandard | (2,620 | ) | — | 4,413 | — | — | 1,793 | — | 1,793 | |||||||||||||||||||||||
| Transfer from Normal individual to Non-performing individual | (31 | ) | — | — | 610 | — | 579 | — | 579 | |||||||||||||||||||||||
| Transfer from Substandard to Non-performing individual | — | — | (2,601 | ) | 8,501 | — | 5,900 | — | 5,900 | |||||||||||||||||||||||
| Transfer from Substandard to Normal individual | 347 | — | (359 | ) | — | — | (12 | ) | — | (12 | ) | |||||||||||||||||||||
| Transfer from Non-performing individual to Substandard | — | — | 108 | (282 | ) | — | (174 | ) | — | (174 | ) | |||||||||||||||||||||
| Transfer from Non-performing individual to Normal individual | 22 | — | — | (316 | ) | — | (294 | ) | — | (294 | ) | |||||||||||||||||||||
| Transfer from Normal group to Non-performing group | — | (11,550 | ) | — | — | 29,757 | 18,207 | — | 18,207 | |||||||||||||||||||||||
| Transfer from Non-performing group to Normal group | — | 216 | — | — | (3,935 | ) | (3,719 | ) | — | (3,719 | ) | |||||||||||||||||||||
| Transfer from Individual (normal, substandard, Non-performing) to Group (normal, Non-performing) | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Transfer from Group (normal, Non-performing) to Individual (normal, substandard, Non-performing) | 853 | (722 | ) | 153 | 8 | (320 | ) | (28 | ) | — | (28 | ) | ||||||||||||||||||||
| New credits originated | 183,940 | 20,788 | 5,031 | 19,211 | 9,533 | 238,503 | — | 238,503 | ||||||||||||||||||||||||
| New credits for conversion of contingent to loan | 10,060 | 8,137 | 1,113 | 1,373 | 867 | 21,550 | — | 21,550 | ||||||||||||||||||||||||
| New credits purchased | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Sales or transfers of credits | — | — | — | (5 | ) | — | (5 | ) | — | (5 | ) | |||||||||||||||||||||
| Payment of credit | (179,068 | ) | (34,168 | ) | (9,141 | ) | (29,935 | ) | (14,497 | ) | (266,809 | ) | — | (266,809 | ) | |||||||||||||||||
| Provisions for write-offs | — | — | — | (16,479 | ) | (18,031 | ) | (34,510 | ) | — | (34,510 | ) | ||||||||||||||||||||
| Recovery of written-off loans | — | 30 | — | 8 | 29 | 67 | — | 67 | ||||||||||||||||||||||||
| Changes to models and assumptions | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Foreign exchange differences | 4,554 | 143 | 148 | 1,149 | 137 | 6,131 | — | 6,131 | ||||||||||||||||||||||||
| Other changes in allowances | — | — | — | — | — | — | (79 | ) | (79 | ) | ||||||||||||||||||||||
| Balance as of September 30, 2026 | 158,446 | 40,696 | 5,376 | 74,064 | 95,278 | 373,860 | 1,393 | 375,253 | ||||||||||||||||||||||||
71
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (f) | Allowances, continued: |
| Changes in allowances established by portfolio in the year | ||||||||||||||||||||||||||||||||
| Normal
Portfolio Evaluation | Substandard Portfolio Evaluation | Non-performing Portfolio Evaluation | Deductible
guarantees Fogape | |||||||||||||||||||||||||||||
| Commercial loans | Individual | Group | Individual | Individual | Group | Sub total | Covid-19 | Total | ||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Balance as of January 1, 2025 | 158,335 | 37,200 | 4,448 | 86,715 | 90,436 | 377,134 | 3,161 | 380,295 | ||||||||||||||||||||||||
| Allowance established/ released: | ||||||||||||||||||||||||||||||||
| Change in measurement without portfolio reclassification during the year | (1,816 | ) | 21,804 | 3,241 | 20,276 | 5,242 | 48,747 | — | 48,747 | |||||||||||||||||||||||
| Change in measurement without portfolio reclassification from the beginning to the end of the year (portfolio from (-) until (+)): | ||||||||||||||||||||||||||||||||
| Transfer from Normal individual to Substandard | (3,266 | ) | — | 6,327 | — | — | 3,061 | — | 3,061 | |||||||||||||||||||||||
| Transfer from Normal individual to Non-performing individual | (164 | ) | — | — | 1,934 | — | 1,770 | — | 1,770 | |||||||||||||||||||||||
| Transfer from Substandard to Non-performing individual | — | — | (3,941 | ) | 13,409 | — | 9,468 | — | 9,468 | |||||||||||||||||||||||
| Transfer from Substandard to Normal individual | 408 | — | (677 | ) | — | — | (269 | ) | — | (269 | ) | |||||||||||||||||||||
| Transfer from Non-performing individual to Substandard | — | — | 16 | (469 | ) | — | (453 | ) | — | (453 | ) | |||||||||||||||||||||
| Transfer from Non-performing individual to Normal individual | 11 | — | — | (149 | ) | — | (138 | ) | — | (138 | ) | |||||||||||||||||||||
| Transfer from Normal group to Non-performing group | — | (15,019 | ) | — | — | 39,548 | 24,529 | — | 24,529 | |||||||||||||||||||||||
| Transfer from Non-performing group to Normal group | — | 629 | — | — | (9,650 | ) | (9,021 | ) | — | (9,021 | ) | |||||||||||||||||||||
| Transfer from Individual (normal, substandard, Non-performing) to Group (normal, Non-performing) | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Transfer from Group (normal, Non-performing) to Individual (normal, substandard, Non-performing) | 979 | (1,020 | ) | 162 | 75 | (144 | ) | 52 | — | 52 | ||||||||||||||||||||||
| New credits originated | 238,733 | 27,077 | 6,154 | 5,271 | 13,566 | 290,801 | — | 290,801 | ||||||||||||||||||||||||
| New credits for conversion of contingent to loan | 16,264 | 10,278 | 1,076 | 1,690 | 1,123 | 30,431 | — | 30,431 | ||||||||||||||||||||||||
| New credits purchased | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Sales or transfers of credits | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Payment of credit | (260,129 | ) | (41,785 | ) | (9,566 | ) | (22,118 | ) | (26,068 | ) | (359,666 | ) | — | (359,666 | ) | |||||||||||||||||
| Provisions for write-offs | — | — | — | (13,218 | ) | (25,396 | ) | (38,614 | ) | — | (38,614 | ) | ||||||||||||||||||||
| Recovery of written-off loans | — | 20 | — | — | 119 | 139 | — | 139 | ||||||||||||||||||||||||
| Changes to models and assumptions | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Foreign exchange differences | (5,457 | ) | (135 | ) | (273 | ) | (1,504 | ) | (179 | ) | (7,548 | ) | — | (7,548 | ) | |||||||||||||||||
| Other changes in allowances | — | — | — | — | — | — | (1,689 | ) | (1,689 | ) | ||||||||||||||||||||||
| Balance as of December 31, 2025 | 143,898 | 39,049 | 6,967 | 91,912 | 88,597 | 370,423 | 1,472 | 371,895 | ||||||||||||||||||||||||
72
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (f) | Allowances, continued: |
Summary of changes in residential allowances for residential mortgage loans established by credit risk portfolio in the period:
| Changes in allowances established by portfolio in the period | ||||||||||||
| Group Evaluation | ||||||||||||
| Residential mortgage loans | Normal Portfolio | Non-performing Portfolio | Total | |||||||||
| MCh$ | MCh$ | MCh$ | ||||||||||
| Balance as of January 1, 2026 | 16,130 | 25,981 | 42,111 | |||||||||
| Allowances established/ released: | ||||||||||||
| Change in measurement without portfolio reclassification during the period | 2,948 | 1,082 | 4,030 | |||||||||
| Change in measurement without portfolio reclassification from the beginning to the end of the period (portfolio from (-) until (+)): | ||||||||||||
| Transfer from Normal group to Non-performing group | (2,707 | ) | 6,815 | 4,108 | ||||||||
| Transfer from Non-performing group to Normal group | 260 | (1,066 | ) | (806 | ) | |||||||
| New credits originated | 898 | 24 | 922 | |||||||||
| New credits purchased | — | — | — | |||||||||
| Sales or transfers of credits | — | — | — | |||||||||
| Payment of credit | (624 | ) | (2,859 | ) | (3,483 | ) | ||||||
| Provisions for write-offs | — | (1,190 | ) | (1,190 | ) | |||||||
| Recovery of written-off loans | — | — | — | |||||||||
| Changes to models and assumptions | — | — | — | |||||||||
| Foreign exchange differences | — | — | — | |||||||||
| Other changes in allowances | — | — | — | |||||||||
| Balance as of September 30, 2026 | 16,905 | 28,787 | 45,692 | |||||||||
| Changes in allowances established by portfolio in the year | ||||||||||||
| Group Evaluation | ||||||||||||
| Residential mortgage loans | Normal Portfolio | Non-performing Portfolio | Total | |||||||||
| MCh$ | MCh$ | MCh$ | ||||||||||
| Balance as of January 1, 2025 | 15,859 | 22,541 | 38,400 | |||||||||
| Allowances established/ released: | ||||||||||||
| Change in measurement without portfolio reclassification during the year | 3,623 | 767 | 4,390 | |||||||||
| Change in measurement without portfolio reclassification from the beginning to the end of the year (portfolio from (-) until (+)): | ||||||||||||
| Transfer from Normal group to Non-performing group | (4,418 | ) | 10,190 | 5,772 | ||||||||
| Transfer from Non-performing group to Normal group | 535 | (2,015 | ) | (1,480 | ) | |||||||
| New credits originated | 1,496 | 10 | 1,506 | |||||||||
| New credits purchased | — | — | — | |||||||||
| Sales or transfers of credits | — | — | — | |||||||||
| Payment of credit | (965 | ) | (4,700 | ) | (5,665 | ) | ||||||
| Provisions for write-offs | — | (812 | ) | (812 | ) | |||||||
| Recovery of written-off loans | — | — | — | |||||||||
| Changes to models and assumptions | — | — | — | |||||||||
| Foreign exchange differences | — | — | — | |||||||||
| Other changes in allowances | — | — | — | |||||||||
| Balance as of December 31, 2025 | 16,130 | 25,981 | 42,111 | |||||||||
73
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (f) | Allowances, continued: |
Summary of changes in allowances for consumer loans established by credit risk portfolio in the period:
| Changes in allowances established by portfolio in the period | ||||||||||||
| Group Evaluation | ||||||||||||
| Consumer loans | Normal Portfolio | Non-performing Portfolio | Total | |||||||||
| MCh$ | MCh$ | MCh$ | ||||||||||
| Balance as of January 1, 2026 | 260,146 | 162,819 | 422,965 | |||||||||
| Allowances established/ released: | ||||||||||||
| Change in measurement without portfolio reclassification during the period | 175,752 | 45,710 | 221,462 | |||||||||
| Change in measurement without portfolio reclassification from the beginning to the end of the period (portfolio from (-) until (+)): | ||||||||||||
| Transfer from Normal group to Non-performing group | (134,412 | ) | 159,949 | 25,537 | ||||||||
| Transfer from Non-performing group to Normal group | 4,022 | (22,390 | ) | (18,368 | ) | |||||||
| New credits originated | 68,865 | 74,116 | 142,981 | |||||||||
| New credits for conversion of contingent to loan | 117,928 | 1,211 | 119,139 | |||||||||
| New credits purchased | — | — | — | |||||||||
| Sales or transfers of credits | — | — | — | |||||||||
| Payment of credit | (241,050 | ) | (77,242 | ) | (318,292 | ) | ||||||
| Provisions for write-offs | — | (169,394 | ) | (169,394 | ) | |||||||
| Recovery of written-off loans | 1,028 | — | 1,028 | |||||||||
| Changes to models and assumptions | — | — | — | |||||||||
| Foreign exchange differences | 179 | 62 | 241 | |||||||||
| Other changes in allowances | — | — | — | |||||||||
| Balance as of September 30, 2026 | 252,458 | 174,841 | 427,299 | |||||||||
| Changes in allowances established by portfolio in the year | ||||||||||||
| Group Evaluation | ||||||||||||
| Consumer loans | Normal Portfolio | Non-performing Portfolio | Total | |||||||||
| MCh$ | MCh$ | MCh$ | ||||||||||
| Balance as of January 1, 2025 | 200,057 | 167,332 | 367,389 | |||||||||
| Allowances established/ released: | ||||||||||||
| Change in measurement without portfolio reclassification during the year | 189,896 | 49,430 | 239,326 | |||||||||
| Change in measurement without portfolio reclassification from the beginning to the end of the year (portfolio from (-) until (+)): | ||||||||||||
| Transfer from Normal group to Non-performing group | (155,357 | ) | 187,954 | 32,597 | ||||||||
| Transfer from Non-performing group to Normal group | 6,242 | (38,151 | ) | (31,909 | ) | |||||||
| New credits originated | 89,298 | 89,118 | 178,416 | |||||||||
| New credits for conversion of contingent to loan | 168,066 | 1,658 | 169,724 | |||||||||
| New credits purchased | — | — | — | |||||||||
| Sales or transfers of credits | — | — | — | |||||||||
| Payment of credit | (282,980 | ) | (92,752 | ) | (375,732 | ) | ||||||
| Provisions for write-offs | — | (194,440 | ) | (194,440 | ) | |||||||
| Recovery of written-off loans | 1,160 | — | 1,160 | |||||||||
| Changes to models and assumptions | 43,987 | (7,328 | ) | 36,659 | ||||||||
| Foreign exchange differences | (223 | ) | (2 | ) | (225 | ) | ||||||
| Other changes in allowances | — | — | — | |||||||||
| Balance as of December 31, 2025 | 260,146 | 162,819 | 422,965 | |||||||||
74
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (f) | Allowances, continued: |
Summary of changes in provisions for contingent credit losses established by credit risk portfolio in the period:
| Changes in provisions established by portfolio in the period | ||||||||||||||||||||||||
| Normal
Portfolio Evaluation | Substandard Portfolio Evaluation | Non-performing
Portfolio Evaluation | ||||||||||||||||||||||
| Contingent loan exposure | Individual | Group | Individual | Individual | Group | Total | ||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||
| Balance as of January 1, 2026 | 38,137 | 33,300 | 2,924 | 6,496 | 3,656 | 84,513 | ||||||||||||||||||
| Provisions established / released: | ||||||||||||||||||||||||
| Change in measurement without portfolio reclassification during the period | 430 | 13,825 | 114 | 1,244 | 1,757 | 17,370 | ||||||||||||||||||
| Change in measurement without portfolio reclassification from the beginning to the end of the period (portfolio from (-) until (+)): | ||||||||||||||||||||||||
| Transfer from Normal individual to Substandard | (238 | ) | — | 425 | — | — | 187 | |||||||||||||||||
| Transfer from Normal individual to Non-performing individual | — | — | — | 62 | — | 62 | ||||||||||||||||||
| Transfer from Substandard to Non-performing individual | — | — | (19 | ) | 523 | — | 504 | |||||||||||||||||
| Transfer from Substandard to Normal individual | 25 | — | (41 | ) | — | — | (16 | ) | ||||||||||||||||
| Transfer from Non-performing individual to Substandard | — | — | 1 | (32 | ) | — | (31 | ) | ||||||||||||||||
| Transfer from Non-performing individual to Normal individual | — | — | — | (15 | ) | — | (15 | ) | ||||||||||||||||
| Transfer from Normal group to Non-performing group | — | (177 | ) | — | — | 2,629 | 2,452 | |||||||||||||||||
| Transfer from Non-performing group to Normal group | — | 5 | — | — | (666 | ) | (661 | ) | ||||||||||||||||
| Transfer from Individual (normal, substandard, Non-performing) to Group (normal, Non-performing) | — | — | — | — | — | — | ||||||||||||||||||
| Transfer from Group (normal, non-performing) to Individual (normal, substandard, non-performing) | 138 | (70 | ) | 1 | — | — | 69 | |||||||||||||||||
| New contingent loan granted | 23,101 | 1,763 | 1,137 | 61 | 80 | 26,142 | ||||||||||||||||||
| Contingent credits for conversion | (1,279 | ) | (9,480 | ) | (120 | ) | (1,070 | ) | (1,227 | ) | (13,176 | ) | ||||||||||||
| Changes to models and assumptions | — | — | — | — | — | — | ||||||||||||||||||
| Foreign exchange differences | 573 | 1,072 | — | 2 | — | 1,647 | ||||||||||||||||||
| Other changes in allowances | (25,444 | ) | (4,805 | ) | (3,683 | ) | (3,133 | ) | (2,468 | ) | (39,533 | ) | ||||||||||||
| Balance as of September 30, 2026 | 35,443 | 35,433 | 739 | 4,138 | 3,761 | 79,514 | ||||||||||||||||||
| Changes in provisions constituted by portfolio in the year | ||||||||||||||||||||||||
| Normal Portfolio Evaluation | Substandard Portfolio Evaluation | Non-performing
Portfolio Evaluation | ||||||||||||||||||||||
| Contingent loan exposure | Individual | Group | Individual | Individual | Group | Total | ||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||
| Balance as of January 1, 2025 | 41,208 | 5,343 | 2,894 | 14,400 | 3,692 | 67,537 | ||||||||||||||||||
| Provisions established / released: | ||||||||||||||||||||||||
| Change in measurement without portfolio reclassification during the year | 1,492 | 16,043 | 285 | 3,474 | 1,962 | 23,256 | ||||||||||||||||||
| Change in measurement without portfolio reclassification from the beginning to the end of the year (portfolio from (-) until (+)): | ||||||||||||||||||||||||
| Transfer from Normal individual to Substandard | (272 | ) | — | 599 | — | — | 327 | |||||||||||||||||
| Transfer from Normal individual to Non-performing individual | (1 | ) | — | — | 69 | — | 68 | |||||||||||||||||
| Transfer from Substandard to Non-performing individual | — | — | (172 | ) | 1,242 | — | 1,070 | |||||||||||||||||
| Transfer from Substandard to Normal individual | 173 | — | (374 | ) | — | — | (201 | ) | ||||||||||||||||
| Transfer from Non-performing individual to Substandard | — | — | 1 | (53 | ) | — | (52 | ) | ||||||||||||||||
| Transfer from Non-performing individual to Normal individual | — | — | — | (36 | ) | — | (36 | ) | ||||||||||||||||
| Transfer from Normal group to Non-performing group | — | (301 | ) | — | — | 3,427 | 3,126 | |||||||||||||||||
| Transfer from Non-performing group to Normal group | — | 17 | — | — | (1,836 | ) | (1,819 | ) | ||||||||||||||||
| Transfer from Individual (normal, substandard, Non-performing) to Group (normal, Non-performing) | — | — | — | — | — | — | ||||||||||||||||||
| Transfer from Group (normal, non-performing) to Individual (normal, substandard, non-performing) | 67 | (49 | ) | 20 | — | — | 38 | |||||||||||||||||
| New contingent loan granted | 32,199 | 2,575 | 8,550 | 138 | 320 | 43,782 | ||||||||||||||||||
| Contingent credits for conversion | (2,036 | ) | (5,941 | ) | (23 | ) | (1,448 | ) | (1,508 | ) | (10,956 | ) | ||||||||||||
| Changes to models and assumptions | — | 27,208 | — | — | 531 | 27,739 | ||||||||||||||||||
| Foreign exchange differences | (682 | ) | (1,021 | ) | (12 | ) | (20 | ) | (147 | ) | (1,882 | ) | ||||||||||||
| Other changes in allowances | (34,011 | ) | (10,574 | ) | (8,844 | ) | (11,270 | ) | (2,785 | ) | (67,484 | ) | ||||||||||||
| Balance as of December 31, 2025 | 38,137 | 33,300 | 2,924 | 6,496 | 3,656 | 84,513 | ||||||||||||||||||
75
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| g) | Economic activity sector: |
At the closing of each reporting period, the composition of economic activity for loans, contingent loans exposure and provisions constituted are as follows:
| Credit and Contingent loans Exposure | Allowances Established | |||||||||||||||||||||||||||||||||||||||||||||||
| Domestic loans | Foreign loans | Total | Total | Domestic loans | Foreign loans | Total | Total | |||||||||||||||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | September | December | September | December | |||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||
| Loans to Banks | 200,000 | — | 410,560 | 399,792 | 610,560 | 399,792 | (72 | ) | — | (757 | ) | (669 | ) | (829 | ) | (669 | ) | |||||||||||||||||||||||||||||||
| Commercial loans | ||||||||||||||||||||||||||||||||||||||||||||||||
| Agriculture and livestock | 937,715 | 792,012 | — | — | 937,715 | 792,012 | (19,018 | ) | (14,497 | ) | — | — | (19,018 | ) | (14,497 | ) | ||||||||||||||||||||||||||||||||
| Fruit | 738,251 | 659,003 | — | — | 738,251 | 659,003 | (12,838 | ) | (10,315 | ) | — | — | (12,838 | ) | (10,315 | ) | ||||||||||||||||||||||||||||||||
| Forestry | 72,931 | 83,379 | — | — | 72,931 | 83,379 | (4,261 | ) | (6,035 | ) | — | — | (4,261 | ) | (6,035 | ) | ||||||||||||||||||||||||||||||||
| Fishing | 15,174 | 31,154 | — | — | 15,174 | 31,154 | (566 | ) | (1,837 | ) | — | — | (566 | ) | (1,837 | ) | ||||||||||||||||||||||||||||||||
| Mining | 174,234 | 245,015 | — | — | 174,234 | 245,015 | (2,214 | ) | (2,548 | ) | — | — | (2,214 | ) | (2,548 | ) | ||||||||||||||||||||||||||||||||
| Oil and natural gas | 471 | 111 | — | — | 471 | 111 | (10 | ) | (7 | ) | — | — | (10 | ) | (7 | ) | ||||||||||||||||||||||||||||||||
| Product manufacturing industry: | ||||||||||||||||||||||||||||||||||||||||||||||||
| Food, beverages and tobacco | 713,530 | 715,555 | — | — | 713,530 | 715,555 | (13,264 | ) | (10,827 | ) | — | — | (13,264 | ) | (10,827 | ) | ||||||||||||||||||||||||||||||||
| Textile, leather goods and footwear | 22,633 | 23,912 | — | — | 22,633 | 23,912 | (664 | ) | (597 | ) | — | — | (664 | ) | (597 | ) | ||||||||||||||||||||||||||||||||
| Wood and furniture | 57,650 | 83,497 | — | — | 57,650 | 83,497 | (2,811 | ) | (3,069 | ) | — | — | (2,811 | ) | (3,069 | ) | ||||||||||||||||||||||||||||||||
| Cellulose, paper and printing | 45,119 | 17,199 | — | — | 45,119 | 17,199 | (875 | ) | (671 | ) | — | — | (875 | ) | (671 | ) | ||||||||||||||||||||||||||||||||
| Chemicals and petroleum products | 299,923 | 167,865 | — | — | 299,923 | 167,865 | (8,462 | ) | (6,228 | ) | — | — | (8,462 | ) | (6,228 | ) | ||||||||||||||||||||||||||||||||
| Metal, non-metal, machinery or others | 596,222 | 511,841 | — | — | 596,222 | 511,841 | (10,516 | ) | (10,139 | ) | — | — | (10,516 | ) | (10,139 | ) | ||||||||||||||||||||||||||||||||
| Electricity, gas and water | 259,248 | 238,995 | — | 1,366 | 259,248 | 240,361 | (3,188 | ) | (2,989 | ) | — | (58 | ) | (3,188 | ) | (3,047 | ) | |||||||||||||||||||||||||||||||
| Residential construction | 175,237 | 174,440 | — | — | 175,237 | 174,440 | (4,135 | ) | (5,100 | ) | — | — | (4,135 | ) | (5,100 | ) | ||||||||||||||||||||||||||||||||
| Non-residential constructions (office, civil engineering) | 869,877 | 493,346 | — | — | 869,877 | 493,346 | (8,998 | ) | (8,128 | ) | — | — | (8,998 | ) | (8,128 | ) | ||||||||||||||||||||||||||||||||
| Wholesale | 1,768,313 | 1,489,446 | 1,501 | — | 1,769,814 | 1,489,446 | (47,338 | ) | (45,131 | ) | (64 | ) | — | (47,402 | ) | (45,131 | ) | |||||||||||||||||||||||||||||||
| Retail, restaurants and hotels | 1,167,340 | 1,043,462 | — | — | 1,167,340 | 1,043,462 | (46,215 | ) | (42,420 | ) | — | — | (46,215 | ) | (42,420 | ) | ||||||||||||||||||||||||||||||||
| Transport and storage | 967,869 | 1,036,044 | — | — | 967,869 | 1,036,044 | (30,806 | ) | (31,049 | ) | — | — | (30,806 | ) | (31,049 | ) | ||||||||||||||||||||||||||||||||
| Communications | 230,952 | 198,462 | — | — | 230,952 | 198,462 | (2,752 | ) | (3,233 | ) | — | — | (2,752 | ) | (3,233 | ) | ||||||||||||||||||||||||||||||||
| Financial services | 3,103,752 | 2,806,363 | — | 36,163 | 3,103,752 | 2,842,526 | (29,127 | ) | (25,757 | ) | — | (633 | ) | (29,127 | ) | (26,390 | ) | |||||||||||||||||||||||||||||||
| Business services | 2,614,411 | 2,274,095 | — | — | 2,614,411 | 2,274,095 | (53,303 | ) | (53,104 | ) | — | — | (53,303 | ) | (53,104 | ) | ||||||||||||||||||||||||||||||||
| Real estate services | 3,707,820 | 3,533,269 | 1,255 | 2,323 | 3,709,075 | 3,535,592 | (16,221 | ) | (20,968 | ) | (3 | ) | (5 | ) | (16,224 | ) | (20,973 | ) | ||||||||||||||||||||||||||||||
| Student loans | 45,067 | 47,266 | — | — | 45,067 | 47,266 | (4,335 | ) | (4 | ) | — | — | (4,335 | ) | (4 | ) | ||||||||||||||||||||||||||||||||
| Government administration, defense and police force | 205 | 26,103 | — | — | 205 | 26,103 | (5 | ) | (273 | ) | — | — | (5 | ) | (273 | ) | ||||||||||||||||||||||||||||||||
| Social and personal services and other community services | 2,446,599 | 2,777,669 | — | — | 2,446,599 | 2,777,669 | (53,264 | ) | (66,273 | ) | — | — | (53,264 | ) | (66,273 | ) | ||||||||||||||||||||||||||||||||
| Subtotal | 21,030,543 | 19,469,503 | 2,756 | 39,852 | 21,033,299 | 19,509,355 | (375,186 | ) | (371,199 | ) | (67 | ) | (696 | ) | (375,253 | ) | (371,895 | ) | ||||||||||||||||||||||||||||||
| Residential mortgage loans | 14,185,503 | 13,916,618 | — | — | 14,185,503 | 13,916,618 | (45,692 | ) | (42,111 | ) | — | — | (45,692 | ) | (42,111 | ) | ||||||||||||||||||||||||||||||||
| Consumer loans | 5,548,903 | 5,765,997 | — | — | 5,548,903 | 5,765,997 | (427,299 | ) | (422,965 | ) | — | — | (427,299 | ) | (422,965 | ) | ||||||||||||||||||||||||||||||||
| Contingent loan exposure | 16,309,436 | 15,434,703 | — | — | 16,309,436 | 15,434,703 | (79,514 | ) | (84,513 | ) | — | — | (79,514 | ) | (84,513 | ) | ||||||||||||||||||||||||||||||||
76
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (h) | Residential mortgage loans and their allowances established by outstanding loan principal owed to value of mortgage collateral (PVG) and past due, respectively: |
As of September 30, 2026
| Loan Tranche / | Residential mortgage loans (MCh$) | Allowances established of Residential mortgage loans (MCh$) | ||||||||||||||||||||||||||||||||||||||||||||||
| Guarantee | Days in default at the end of the period | Days in default at the end of the period | ||||||||||||||||||||||||||||||||||||||||||||||
| Value (%) | 0 | 1 to 29 | 30 to 59 | 60 to 89 | > = 90 | Total | 0 | 1 to 29 | 30 to 59 | 60 to 89 | > = 90 | Total | ||||||||||||||||||||||||||||||||||||
| PVG <=40% | 2,312,784 | 50,257 | 22,541 | 9,812 | 24,644 | 2,420,038 | (1,985 | ) | (820 | ) | (664 | ) | (383 | ) | (1,374 | ) | (5,226 | ) | ||||||||||||||||||||||||||||||
| 40% < PVG <= 80% | 10,057,983 | 265,805 | 126,880 | 58,179 | 194,356 | 10,703,203 | (11,792 | ) | (4,724 | ) | (4,085 | ) | (2,221 | ) | (11,707 | ) | (34,529 | ) | ||||||||||||||||||||||||||||||
| 80% < PVG <= 90% | 781,404 | 10,900 | 4,907 | 1,925 | 8,139 | 807,275 | (1,816 | ) | (409 | ) | (298 | ) | (186 | ) | (1,344 | ) | (4,053 | ) | ||||||||||||||||||||||||||||||
| PVG > 90% | 251,198 | 664 | 912 | 39 | 2,174 | 254,987 | (1,326 | ) | (27 | ) | (43 | ) | (11 | ) | (477 | ) | (1,884 | ) | ||||||||||||||||||||||||||||||
| Total | 13,403,369 | 327,626 | 155,240 | 69,955 | 229,313 | 14,185,503 | (16,919 | ) | (5,980 | ) | (5,090 | ) | (2,801 | ) | (14,902 | ) | (45,692 | ) | ||||||||||||||||||||||||||||||
As of December 31, 2025
| Loan Tranche / | Residential mortgage loans (MCh$) | Allowances established of Residential mortgage loans (MCh$) | ||||||||||||||||||||||||||||||||||||||||||||||
| Guarantee | Days in default at the end of the year | Days in default at the end of the year | ||||||||||||||||||||||||||||||||||||||||||||||
| Value (%) | 0 | 1 to 29 | 30 to 59 | 60 to 89 | > = 90 | Total | 0 | 1 to 29 | 30 to 59 | 60 to 89 | > = 90 | Total | ||||||||||||||||||||||||||||||||||||
| PVG <=40% | 2,150,230 | 46,627 | 20,991 | 8,964 | 20,074 | 2,246,886 | (1,715 | ) | (647 | ) | (597 | ) | (361 | ) | (1,090 | ) | (4,410 | ) | ||||||||||||||||||||||||||||||
| 40% < PVG <= 80% | 9,949,544 | 264,207 | 116,564 | 54,478 | 185,737 | 10,570,530 | (10,739 | ) | (4,196 | ) | (3,651 | ) | (2,269 | ) | (11,026 | ) | (31,881 | ) | ||||||||||||||||||||||||||||||
| 80% < PVG <= 90% | 779,994 | 11,420 | 3,879 | 1,987 | 8,982 | 806,262 | (1,702 | ) | (402 | ) | (281 | ) | (180 | ) | (1,456 | ) | (4,021 | ) | ||||||||||||||||||||||||||||||
| PVG > 90% | 289,177 | 544 | 994 | 288 | 1,937 | 292,940 | (1,227 | ) | (50 | ) | (46 | ) | (31 | ) | (445 | ) | (1,799 | ) | ||||||||||||||||||||||||||||||
| Total | 13,168,945 | 322,798 | 142,428 | 65,717 | 216,730 | 13,916,618 | (15,383 | ) | (5,295 | ) | (4,575 | ) | (2,841 | ) | (14,017 | ) | (42,111 | ) | ||||||||||||||||||||||||||||||
77
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (i) | Loans to Banks and Commercial loans and their allowances established by classification category: |
The concentration of loans to banks and commercial loans and their allowances established by classification category is as follows:
| Individual Evaluation | Group Evaluation | Portfolio | Provisions of deductible guarantees | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Normal Portfolio | Substandard Portfolio | Non-performing Portfolio | Portfolio | Non- | Fogape | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| As of September 30, | A1 | A2 | A3 | A4 | A5 | A6 | Subtotal | B1 | B2 | B3 | B4 | Subtotal | C1 | C2 | C3 | C4 | C5 | C6 | Subtotal | Total | Normal | performing | Total | Total | Covid 19 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans to Banks | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interbank loans of liquidity | 200,000 | — | — | — | — | — | 200,000 | — | — | — | — | — | — | — | — | — | — | — | — | 200,000 | — | — | — | 200,000 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial interbank loans | — | — | 257,310 | — | — | — | 257,310 | — | — | — | — | — | — | — | — | — | — | — | — | 257,310 | — | — | — | 257,310 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Overdrafts on current accounts | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Chilean exports foreign trade loans | 58 | 103,511 | 49,681 | — | — | — | 153,250 | — | — | — | — | — | — | — | — | — | — | — | — | 153,250 | — | — | — | 153,250 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Chilean imports foreign trade loans | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Foreign trade loans between third countries | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Current account deposits with foreign banks for derivative transactions | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other non-transferable deposits in banks | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other loans with banks | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | 200,058 | 103,511 | 306,991 | — | — | — | 610,560 | — | — | — | — | — | — | — | — | — | — | — | — | 610,560 | — | — | — | 610,560 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Allowances established | 72 | 85 | 672 | — | — | — | 829 | — | — | — | — | — | — | — | — | — | — | — | — | 829 | — | — | — | 829 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| % Allowances established | 0.04 | % | 0.08 | % | 0.22 | % | — | — | — | 0.14 | % | — | — | — | — | — | — | — | — | — | — | — | — | 0.14 | % | — | — | — | 0.14 | % | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial loans | — | 1,606,058 | 1,856,225 | 1,941,630 | 4,071,141 | 1,952,222 | 11,427,276 | 127,075 | 50,447 | 14,825 | 3,292 | 195,639 | 103,898 | 36,734 | 18,376 | 26,522 | 4,947 | 26,876 | 217,353 | 11,840,268 | 3,921,276 | 394,364 | 4,315,640 | 16,155,908 | 1,393 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Chilean exports foreign trade loans | — | 52,801 | 73,640 | 93,687 | 253,216 | 180,994 | 654,338 | 3,855 | 501 | 1,742 | 5,960 | 12,058 | 8,795 | 582 | — | 2,384 | — | 2,275 | 14,036 | 680,432 | 3,263 | 53 | 3,316 | 683,748 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Accrediting foreign trade loans negotiated in terms of Chilean imports | — | — | — | — | — | 82 | 82 | — | — | — | — | — | — | — | — | — | — | — | — | 82 | — | — | — | 82 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Chilean imports foreign trade loans | — | 12,965 | 77,744 | 111,156 | 156,206 | 175,376 | 533,447 | 3,805 | 428 | — | — | 4,233 | 1,076 | — | — | 917 | 701 | 1,920 | 4,614 | 542,294 | 46,528 | 1,791 | 48,319 | 590,613 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Foreign trade loans between third countries | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Current account debtors | — | 9 | 11,135 | 25,827 | 31,929 | 18,575 | 87,475 | 4,334 | 1,274 | 298 | 265 | 6,171 | 507 | 184 | 51 | 1,161 | 605 | 1,881 | 4,389 | 98,035 | 89,489 | 2,412 | 91,901 | 189,936 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Credit card debtors | — | 644 | 2,267 | 4,164 | 10,794 | 11,454 | 29,323 | 1,084 | 270 | 88 | 37 | 1,479 | 214 | 99 | 36 | 78 | 93 | 937 | 1,457 | 32,259 | 87,256 | 13,249 | 100,505 | 132,764 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Factoring transactions | — | 469,635 | 200,535 | 51,045 | 166,253 | 121,438 | 1,008,906 | 4,473 | 3 | — | — | 4,476 | — | — | — | — | — | 96 | 96 | 1,013,478 | 35,633 | 18 | 35,651 | 1,049,129 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial lease transactions | — | 42,880 | 91,700 | 340,385 | 710,870 | 602,766 | 1,788,601 | 20,970 | 4,875 | 2,885 | 1,935 | 30,665 | 6,482 | 5,072 | 2,172 | 16,257 | 11,026 | 742 | 41,751 | 1,861,017 | 298,303 | 13,439 | 311,742 | 2,172,759 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Student loans | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | 41,711 | 3,356 | 45,067 | 45,067 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other loans and accounts receivable | — | 588 | 1,913 | 1,510 | 2,655 | 2,035 | 8,701 | 52 | 27 | 4 | 29 | 112 | 1,516 | 7 | 11 | 783 | 101 | 369 | 2,787 | 11,600 | 764 | 929 | 1,693 | 13,293 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 2,185,580 | 2,315,159 | 2,569,404 | 5,403,064 | 3,064,942 | 15,538,149 | 165,648 | 57,825 | 19,842 | 11,518 | 254,833 | 122,488 | 42,678 | 20,646 | 48,102 | 17,473 | 35,096 | 286,483 | 16,079,465 | 4,524,223 | 429,611 | 4,953,834 | 21,033,299 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Allowances established | — | 1,283 | 3,798 | 23,202 | 60,661 | 69,502 | 158,446 | 3,902 | 962 | 366 | 146 | 5,376 | 2,450 | 4,268 | 5,161 | 19,241 | 11,358 | 31,586 | 74,064 | 237,886 | 40,696 | 95,278 | 135,974 | 373,860 | 1,393 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| % Allowances established | — | 0.06 | % | 0.16 | % | 0.90 | % | 1.12 | % | 2.27 | % | 1.02 | % | 2.36 | % | 1.66 | % | 1.84 | % | 1.27 | % | 2.11 | % | 2.00 | % | 10.00 | % | 25.00 | % | 40.00 | % | 65.00 | % | 90.00 | % | 25.85 | % | 1.48 | % | 0.90 | % | 22.18 | % | 2.74 | % | 1.78 | % | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||
78
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (i) | Loans to Banks and Commercial loans and their allowances established by classification category, continued: |
| Individual Evaluation | Group Evaluation | Provisions
of deductible guarantees | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Normal Portfolio | Substandard Portfolio | Non-performing Portfolio | Portfolio | Portfolio | Fogape | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| As of December 31, 2025 | A1 | A2 | A3 | A4 | A5 | A6 | Subtotal | B1 | B2 | B3 | B4 | Subtotal | C1 | C2 | C3 | C4 | C5 | C6 | Subtotal | Total | Normal | Non-performing | Total | Total | Covid 19 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans to Banks | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interbank loans of liquidity | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial interbank loans | — | — | 204,397 | — | — | — | 204,397 | — | — | — | — | — | — | — | — | — | — | — | — | 204,397 | — | — | — | 204,397 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Overdrafts on current accounts | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Chilean exports foreign trade loans | 21,658 | 121,875 | 51,862 | — | — | — | 195,395 | — | — | — | — | — | — | — | — | — | — | — | — | 195,395 | — | — | — | 195,395 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Chilean imports foreign trade loans | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Foreign trade loans between third countries | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Current account deposits with foreign banks for derivative transactions | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other non-transferable deposits in banks | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other loans with banks | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | 21,658 | 121,875 | 256,259 | — | — | — | 399,792 | — | — | — | — | — | — | — | — | — | — | — | — | 399,792 | — | — | — | 399,792 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Allowances established | 8 | 101 | 560 | — | — | — | 669 | — | — | — | — | — | — | — | — | — | — | — | — | 669 | — | — | — | 669 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| % Allowances established | 0.04 | % | 0.08 | % | 0.22 | % | — | — | — | 0.17 | % | — | — | — | — | — | — | — | — | — | — | — | — | 0.17 | % | — | — | — | 0.17 | % | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial loans | — | 1,153,508 | 1,728,748 | 1,785,471 | 3,797,965 | 1,954,865 | 10,420,557 | 80,779 | 53,741 | 30,679 | 10,101 | 175,300 | 81,076 | 39,461 | 18,204 | 25,097 | 9,558 | 41,478 | 214,874 | 10,810,731 | 3,864,529 | 354,171 | 4,218,700 | 15,029,431 | 1,337 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Chilean exports foreign trade loans | — | 6,283 | 174,057 | 82,591 | 214,240 | 137,380 | 614,551 | 3,328 | 2,066 | 1,517 | 5,431 | 12,342 | 9,032 | 538 | — | 472 | 1,366 | 2,473 | 13,881 | 640,774 | 2,558 | 133 | 2,691 | 643,465 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Accrediting foreign trade loans negotiated in terms of Chilean imports | — | — | — | — | — | 273 | 273 | — | — | — | — | — | — | — | — | — | — | — | — | 273 | — | — | — | 273 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Chilean imports foreign trade loans | — | 5,112 | 70,520 | 87,286 | 131,969 | 174,155 | 469,042 | 5,534 | 1,066 | — | — | 6,600 | — | — | — | 886 | 1,999 | 1,258 | 4,143 | 479,785 | 43,692 | 2,213 | 45,905 | 525,690 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Foreign trade loans between third countries | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Current account debtors | — | 6 | 10,302 | 14,009 | 34,429 | 24,460 | 83,206 | 3,529 | 1,301 | 291 | 287 | 5,408 | 580 | 141 | 32 | 131 | 89 | 1,681 | 2,654 | 91,268 | 89,653 | 2,413 | 92,066 | 183,334 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Credit card debtors | — | 337 | 1,625 | 4,112 | 11,307 | 11,388 | 28,769 | 725 | 285 | 84 | 12 | 1,106 | 124 | 103 | 27 | 77 | 125 | 924 | 1,380 | 31,255 | 91,388 | 12,175 | 103,563 | 134,818 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Factoring transactions | — | 332,348 | 155,891 | 41,115 | 146,837 | 118,188 | 794,379 | 3,352 | 549 | — | — | 3,901 | — | 20 | — | — | — | 98 | 118 | 798,398 | 35,559 | 11 | 35,570 | 833,968 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial lease transactions | — | 42,246 | 98,668 | 329,583 | 698,835 | 545,216 | 1,714,548 | 17,936 | 4,005 | 2,151 | 4,073 | 28,165 | 4,635 | 8,868 | 1,512 | 15,394 | 10,707 | 1,038 | 42,154 | 1,784,867 | 296,688 | 14,238 | 310,926 | 2,095,793 | 135 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Student loans | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | 44,179 | 3,088 | 47,267 | 47,267 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other loans and accounts receivable | — | 744 | 1,680 | 1,303 | 2,503 | 2,177 | 8,407 | 73 | 45 | 2 | 6 | 126 | 225 | 10 | 81 | 381 | 788 | 3,422 | 4,907 | 13,440 | 728 | 1,148 | 1,876 | 15,316 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 1,540,584 | 2,241,491 | 2,345,470 | 5,038,085 | 2,968,102 | 14,133,732 | 115,256 | 63,058 | 34,724 | 19,910 | 232,948 | 95,672 | 49,141 | 19,856 | 42,438 | 24,632 | 52,372 | 284,111 | 14,650,791 | 4,468,974 | 389,590 | 4,858,564 | 19,509,355 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Allowances established | — | 1,035 | 3,616 | 20,130 | 53,536 | 65,581 | 143,898 | 2,838 | 1,225 | 222 | 2,682 | 6,967 | 1,914 | 4,914 | 4,964 | 16,975 | 16,010 | 47,135 | 91,912 | 242,777 | 39,049 | 88,597 | 127,646 | 370,423 | 1,472 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| % Allowances established | — | 0.07 | % | 0.16 | % | 0.86 | % | 1.06 | % | 2.21 | % | 1.02 | % | 2.46 | % | 1.94 | % | 0.64 | % | 13.47 | % | 2.99 | % | 2.00 | % | 10.00 | % | 25.00 | % | 40.00 | % | 65.00 | % | 90.00 | % | 32.35 | % | 1.66 | % | 0.87 | % | 22.74 | % | 2.63 | % | 1.90 | % | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||
79
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (j) | Loans and their allowances for loan losses by tranches of days past-due: |
The concentration of credit risk by days past due is as follows;
| Financial assets before allowances | Allowances established | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Substandard | Non-performing | Substandard | Non-performing | Deductible | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Normal Portfolio | Portfolio | Portfolio | Normal Portfolio | Portfolio | Portfolio | guarantees | Net | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Evaluation | Evaluation | Evaluation | Sub | Evaluation | Evaluation | Evaluation | Sub | Fogape | Financial | |||||||||||||||||||||||||||||||||||||||||||||||||||
| As of September 30, 2026 | Individual | Group | Individual | Individual | Group | Total | Individual | Group | Individual | Individual | Group | Total | Covid-19 | Total | Assets | |||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||||||||||||||||||
| Loans to Banks | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 0 days | 523,202 | — | — | — | — | 523,202 | (757 | ) | — | — | — | — | (757 | ) | — | (757 | ) | |||||||||||||||||||||||||||||||||||||||||||
| 1 to 29 days | 87,358 | — | — | — | — | 87,358 | (72 | ) | — | — | — | — | (72 | ) | — | (72 | ) | |||||||||||||||||||||||||||||||||||||||||||
| 30 to 59 days | — | — | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||
| 60 to 89 days | — | — | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||
| > = 90 days | — | — | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | 610,560 | — | — | — | — | 610,560 | (829 | ) | — | — | — | — | (829 | ) | — | (829 | ) | 609,731 | ||||||||||||||||||||||||||||||||||||||||||
| Commercial loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 0 days | 15,402,076 | 4,306,796 | 210,260 | 127,758 | 103,391 | 20,150,281 | (156,115 | ) | (30,580 | ) | (4,376 | ) | (38,981 | ) | (18,892 | ) | (248,944 | ) | (1,393 | ) | (250,337 | ) | ||||||||||||||||||||||||||||||||||||||
| 1 to 29 days | 132,556 | 149,690 | 31,292 | 29,077 | 41,085 | 383,700 | (2,188 | ) | (4,957 | ) | (645 | ) | (3,159 | ) | (7,459 | ) | (18,408 | ) | — | (18,408 | ) | |||||||||||||||||||||||||||||||||||||||
| 30 to 59 days | 3,516 | 51,890 | 9,697 | 16,589 | 37,126 | 118,818 | (143 | ) | (3,520 | ) | (320 | ) | (2,850 | ) | (6,237 | ) | (13,070 | ) | — | (13,070 | ) | |||||||||||||||||||||||||||||||||||||||
| 60 to 89 days | 1 | 15,847 | 3,584 | 6,831 | 21,625 | 47,888 | — | (1,639 | ) | (35 | ) | (1,375 | ) | (4,053 | ) | (7,102 | ) | — | (7,102 | ) | ||||||||||||||||||||||||||||||||||||||||
| > = 90 days | — | — | — | 106,228 | 226,384 | 332,612 | — | — | — | (27,699 | ) | (58,637 | ) | (86,336 | ) | — | (86,336 | ) | ||||||||||||||||||||||||||||||||||||||||||
| Subtotal | 15,538,149 | 4,524,223 | 254,833 | 286,483 | 429,611 | 21,033,299 | (158,446 | ) | (40,696 | ) | (5,376 | ) | (74,064 | ) | (95,278 | ) | (373,860 | ) | (1,393 | ) | (375,253 | ) | 20,658,046 | |||||||||||||||||||||||||||||||||||||
| Residential mortgage loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 0 days | — | 13,314,806 | — | — | 88,563 | 13,403,369 | — | (10,972 | ) | — | — | (5,947 | ) | (16,919 | ) | — | (16,919 | ) | ||||||||||||||||||||||||||||||||||||||||||
| 1 to 29 days | — | 279,648 | — | — | 47,978 | 327,626 | — | (3,015 | ) | — | — | (2,965 | ) | (5,980 | ) | — | (5,980 | ) | ||||||||||||||||||||||||||||||||||||||||||
| 30 to 59 days | — | 105,741 | — | — | 49,499 | 155,240 | — | (1,974 | ) | — | — | (3,116 | ) | (5,090 | ) | — | (5,090 | ) | ||||||||||||||||||||||||||||||||||||||||||
| 60 to 89 days | — | 40,359 | — | — | 29,596 | 69,955 | — | (944 | ) | — | — | (1,857 | ) | (2,801 | ) | — | (2,801 | ) | ||||||||||||||||||||||||||||||||||||||||||
| > = 90 days | — | — | — | — | 229,313 | 229,313 | — | — | — | — | (14,902 | ) | (14,902 | ) | — | (14,902 | ) | |||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 13,740,554 | — | — | 444,949 | 14,185,503 | — | (16,905 | ) | — | — | (28,787 | ) | (45,692 | ) | — | (45,692 | ) | 14,139,811 | |||||||||||||||||||||||||||||||||||||||||
| Consumer loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 0 days | — | 4,964,283 | — | — | 88,544 | 5,052,827 | — | (186,864 | ) | — | — | (47,257 | ) | (234,121 | ) | — | (234,121 | ) | ||||||||||||||||||||||||||||||||||||||||||
| 1 to 29 days | — | 165,793 | — | — | 37,334 | 203,127 | — | (27,608 | ) | — | — | (19,830 | ) | (47,438 | ) | — | (47,438 | ) | ||||||||||||||||||||||||||||||||||||||||||
| 30 to 59 days | — | 66,666 | — | — | 36,791 | 103,457 | — | (23,983 | ) | — | — | (19,603 | ) | (43,586 | ) | — | (43,586 | ) | ||||||||||||||||||||||||||||||||||||||||||
| 60 to 89 days | — | 29,620 | — | — | 29,076 | 58,696 | — | (14,003 | ) | — | — | (15,866 | ) | (29,869 | ) | — | (29,869 | ) | ||||||||||||||||||||||||||||||||||||||||||
| > = 90 days | — | — | — | — | 130,796 | 130,796 | — | — | — | — | (72,285 | ) | (72,285 | ) | — | (72,285 | ) | |||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 5,226,362 | — | — | 322,541 | 5,548,903 | — | (252,458 | ) | — | — | (174,841 | ) | (427,299 | ) | — | (427,299 | ) | 5,121,604 | |||||||||||||||||||||||||||||||||||||||||
| Total Loans | 16,148,709 | 23,491,139 | 254,833 | 286,483 | 1,197,101 | 41,378,265 | (159,275 | ) | (310,059 | ) | (5,376 | ) | (74,064 | ) | (298,906 | ) | (847,680 | ) | (1,393 | ) | (849,073 | ) | 40,529,192 | |||||||||||||||||||||||||||||||||||||
80
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (j) | Loans and their allowances for loan losses by number of days past-due, continued: |
| Financial assets before allowances | Allowances established | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Substandard | Non-performing | Substandard | Non-performing | Deductible | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Normal Portfolio | Portfolio | Portfolio | Normal Portfolio | Portfolio | Portfolio | guarantees | Net | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Evaluation | Evaluation | Evaluation | Sub | Evaluation | Evaluation | Evaluation | Sub | Fogape | Financial | |||||||||||||||||||||||||||||||||||||||||||||||||||
| As of December 31, 2025 | Individual | Group | Individual | Individual | Group | Total | Individual | Group | Individual | Individual | Group | Total | Covid-19 | Total | Assets | |||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||||||||||||||||||
| Loans to Banks | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 0 days | 275,178 | — | — | — | — | 275,178 | (572 | ) | — | — | — | — | (572 | ) | — | (572 | ) | |||||||||||||||||||||||||||||||||||||||||||
| 1 to 29 days | 124,614 | — | — | — | — | 124,614 | (97 | ) | — | — | — | — | (97 | ) | — | (97 | ) | |||||||||||||||||||||||||||||||||||||||||||
| 30 to 59 days | — | — | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||
| 60 to 89 days | — | — | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||
| > = 90 days | — | — | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | 399,792 | — | — | — | — | 399,792 | (669 | ) | — | — | — | — | (669 | ) | — | (669 | ) | 399,123 | ||||||||||||||||||||||||||||||||||||||||||
| Commercial loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 0 days | 13,955,276 | 4,239,684 | 194,788 | 87,612 | 96,021 | 18,573,381 | (141,443 | ) | (29,281 | ) | (6,044 | ) | (24,797 | ) | (18,010 | ) | (219,575 | ) | (1,464 | ) | (221,039 | ) | ||||||||||||||||||||||||||||||||||||||
| 1 to 29 days | 167,480 | 162,816 | 27,547 | 41,729 | 36,686 | 436,258 | (2,223 | ) | (5,252 | ) | (617 | ) | (6,906 | ) | (6,386 | ) | (21,384 | ) | (2 | ) | (21,386 | ) | ||||||||||||||||||||||||||||||||||||||
| 30 to 59 days | 10,972 | 51,881 | 9,409 | 14,562 | 38,309 | 125,133 | (232 | ) | (3,071 | ) | (211 | ) | (3,211 | ) | (6,560 | ) | (13,285 | ) | (3 | ) | (13,288 | ) | ||||||||||||||||||||||||||||||||||||||
| 60 to 89 days | 4 | 14,593 | 1,204 | 11,781 | 21,858 | 49,440 | — | (1,445 | ) | (95 | ) | (1,734 | ) | (4,372 | ) | (7,646 | ) | — | (7,646 | ) | ||||||||||||||||||||||||||||||||||||||||
| > = 90 days | — | — | — | 128,427 | 196,716 | 325,143 | — | — | — | (55,264 | ) | (53,269 | ) | (108,533 | ) | (3 | ) | (108,536 | ) | |||||||||||||||||||||||||||||||||||||||||
| Subtotal | 14,133,732 | 4,468,974 | 232,948 | 284,111 | 389,590 | 19,509,355 | (143,898 | ) | (39,049 | ) | (6,967 | ) | (91,912 | ) | (88,597 | ) | (370,423 | ) | (1,472 | ) | (371,895 | ) | 19,137,460 | |||||||||||||||||||||||||||||||||||||
| Residential mortgage loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 0 days | — | 13,093,896 | — | — | 75,049 | 13,168,945 | — | (10,442 | ) | — | — | (4,941 | ) | (15,383 | ) | — | (15,383 | ) | ||||||||||||||||||||||||||||||||||||||||||
| 1 to 29 days | — | 282,937 | — | — | 39,861 | 322,798 | — | (2,864 | ) | — | — | (2,431 | ) | (5,295 | ) | — | (5,295 | ) | ||||||||||||||||||||||||||||||||||||||||||
| 30 to 59 days | — | 99,433 | — | — | 42,995 | 142,428 | — | (1,888 | ) | — | — | (2,687 | ) | (4,575 | ) | — | (4,575 | ) | ||||||||||||||||||||||||||||||||||||||||||
| 60 to 89 days | — | 33,881 | — | — | 31,836 | 65,717 | — | (936 | ) | — | — | (1,905 | ) | (2,841 | ) | — | (2,841 | ) | ||||||||||||||||||||||||||||||||||||||||||
| > = 90 days | — | — | — | — | 216,730 | 216,730 | — | — | — | — | (14,017 | ) | (14,017 | ) | — | (14,017 | ) | |||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 13,510,147 | — | — | 406,471 | 13,916,618 | — | (16,130 | ) | — | — | (25,981 | ) | (42,111 | ) | — | (42,111 | ) | 13,874,507 | |||||||||||||||||||||||||||||||||||||||||
| Consumer loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 0 days | — | 5,181,589 | — | — | 81,810 | 5,263,399 | — | (195,078 | ) | — | — | (44,061 | ) | (239,139 | ) | — | (239,139 | ) | ||||||||||||||||||||||||||||||||||||||||||
| 1 to 29 days | — | 197,891 | — | — | 31,921 | 229,812 | — | (29,756 | ) | — | — | (17,575 | ) | (47,331 | ) | — | (47,331 | ) | ||||||||||||||||||||||||||||||||||||||||||
| 30 to 59 days | — | 64,450 | — | — | 39,232 | 103,682 | — | (22,994 | ) | — | — | (21,719 | ) | (44,713 | ) | — | (44,713 | ) | ||||||||||||||||||||||||||||||||||||||||||
| 60 to 89 days | — | 26,202 | — | — | 26,112 | 52,314 | — | (12,318 | ) | — | — | (14,494 | ) | (26,812 | ) | — | (26,812 | ) | ||||||||||||||||||||||||||||||||||||||||||
| > = 90 days | — | — | — | — | 116,790 | 116,790 | — | — | — | — | (64,970 | ) | (64,970 | ) | — | (64,970 | ) | |||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 5,470,132 | — | — | 295,865 | 5,765,997 | — | (260,146 | ) | — | — | (162,819 | ) | (422,965 | ) | — | (422,965 | ) | 5,343,032 | |||||||||||||||||||||||||||||||||||||||||
| Total Loans | 14,533,524 | 23,449,253 | 232,948 | 284,111 | 1,091,926 | 39,591,762 | (144,567 | ) | (315,325 | ) | (6,967 | ) | (91,912 | ) | (277,397 | ) | (836,168 | ) | (1,472 | ) | (837,640 | ) | 38,754,122 | |||||||||||||||||||||||||||||||||||||
81
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 13. | Financial assets at amortized cost, continued: |
| (k) | Finance lease contracts: |
The cash flows to be received by the Bank from finance lease contracts have the following maturities:
| Total receivable | Unearned income | Net lease receivable (*) | ||||||||||||||||||||||
| September | December | September | December | September | December | |||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||
| Due within one year | 732,881 | 710,040 | (104,657 | ) | (103,108 | ) | 628,224 | 606,932 | ||||||||||||||||
| Due after 1 year but within 2 years | 566,441 | 535,475 | (76,464 | ) | (75,325 | ) | 489,977 | 460,150 | ||||||||||||||||
| Due after 2 years but within 3 years | 376,400 | 352,493 | (49,129 | ) | (47,794 | ) | 327,271 | 304,699 | ||||||||||||||||
| Due after 3 years but within 4 years | 240,714 | 246,887 | (32,260 | ) | (31,701 | ) | 208,454 | 215,186 | ||||||||||||||||
| Due after 4 years but within 5 years | 153,654 | 152,099 | (23,001 | ) | (21,669 | ) | 130,653 | 130,430 | ||||||||||||||||
| Due after 5 years | 430,539 | 414,606 | (48,811 | ) | (47,937 | ) | 381,728 | 366,669 | ||||||||||||||||
| Total | 2,500,629 | 2,411,600 | (334,322 | ) | (327,534 | ) | 2,166,307 | 2,084,066 | ||||||||||||||||
| (*) | The net lease receivable does not include past-due portfolio totaling Ch$7,653 million as of September 30, 2026 (Ch$12,926 million in December 2025). |
The Bank maintains financial lease operations associated with movable assets, vehicles, industrial machinery, transportation equipment and real estate. These leases contracts have an average term between 1 and 12 years.
| (l) | Purchase of loan portfolio: |
During the period ended as of September 30, 2026 and December 31, 2025 no portfolio purchases were made.
| (m) | Sale or transfer of loans: |
During the period 2026, the following sales or transfer of loans were made:
| September 2026 | ||||||||||||||||
| Carrying amount | Allowances | Sale price | Effect on income (loss) gain |
|||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Sale or transfer of current loans | 289 | 5 | 289 | 5 | ||||||||||||
| Sale or transfer of written – off loans | — | — | — | — | ||||||||||||
| Total | 289 | 5 | 289 | 5 | ||||||||||||
As of September 30, 2025, no sales or transfers of loans from the loan portfolio have been made.
| (n) | Securitization of own assets: |
During the period 2026 and the year 2025, there are not securitization transactions executed involving its own assets.
82
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 14. | Investments in Other companies: |
| (a) | At the end of each period, investments are presented according to the following detail: |
| % Ownership Interest | Assets | |||||||||||||||||
| September | December | September | December | |||||||||||||||
| Company | Shareholder | 2026 | 2025 | 2026 | 2025 | |||||||||||||
| % | % | MCh$ | MCh$ | |||||||||||||||
| Associates | ||||||||||||||||||
| Transbank S.A. | Banco de Chile | 26.16 | 26.16 | 44,695 | 44,601 | |||||||||||||
| Redbanc S.A. | Banco de Chile | 38.13 | 38.13 | 7,889 | 6,685 | |||||||||||||
| Centro de Compensación Automatizado S.A. | Banco de Chile | 33.33 | 33.33 | 5,987 | 6,296 | |||||||||||||
| Sociedad Interbancaria de Depósitos de Valores S.A. | Banco de Chile | 26.81 | 26.81 | 3,349 | 3,078 | |||||||||||||
| Administrador Financiero de Transantiago S.A. | Banco de Chile | 20.00 | 20.00 | 1,935 | 2,101 | |||||||||||||
| Servicios de Infraestructura de Mercado OTC S.A. | Banco de Chile | 12.33 | 12.33 | 1,844 | 1,861 | |||||||||||||
| Sociedad Operadora de la Cámara de Compensación de Pagos de Alto Valor S.A. | Banco de Chile | 15.00 | 15.00 | 1,589 | 1,511 | |||||||||||||
| Subtotal Associates | 67,288 | 66,133 | ||||||||||||||||
| Joint Venture | ||||||||||||||||||
| Servipag Ltda. | Banco de Chile | 50.00 | 50.00 | 10,072 | 9,695 | |||||||||||||
| Subtotal Joint Venture | 10,072 | 9,695 | ||||||||||||||||
| Subtotal | 77,360 | 75,828 | ||||||||||||||||
| Minority Investments | ||||||||||||||||||
| Holding Bursátil Regional S.A. (1) | Banchile Corredores de Bolsa | 13,911 | 8,387 | |||||||||||||||
| Banco Latinoamericano de Comercio Exterior S.A. (Bladex) (1) | Banco de Chile | 3,187 | 2,386 | |||||||||||||||
| Bolsa Electrónica de Chile, Bolsa de Valores (1) | Banchile Corredores de Bolsa | 349 | 349 | |||||||||||||||
| Sociedad de Telecomunicaciones Financieras Interbancarias Mundiales (Swift) | Banco de Chile | 110 | 102 | |||||||||||||||
| CCLV Contraparte Central S.A. | Banchile Corredores de Bolsa | 8 | 8 | |||||||||||||||
| Subtotal Minority Investments | 17,565 | 11,232 | ||||||||||||||||
| Total | 94,925 | 87,060 | ||||||||||||||||
| (1) | Investments in shares have been irrevocably designated as at fair value through other comprehensive income and, therefore, are recorded at market value in accordance with IFRS 9. |
| (b) | Changes in investments in companies recorded under the equity method in the period 2026 and 2025 is detailed as follows: |
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Balance as of January 1, | 75,828 | 67,277 | ||||||
| Acquisition of investments in companies | — | — | ||||||
| Participation in net income | 4,414 | 8,041 | ||||||
| Dividends received | (2,749 | ) | (3,374 | ) | ||||
| Reclassification to non-current assets for sale | — | — | ||||||
| Other | (133 | ) | 58 | |||||
| Total | 77,360 | 72,002 | ||||||
| (c) | During the period ended September 30, 2026 and 2025, no impairment has been recorded in these investments. |
83
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 14. | Investments in other companies, continued: |
| (d) | Summarized Financial Information of Associates and Joint Ventures |
| Associates | Joint Venture | |||||||||||||||||||||||||||||||
| September 2026 | Centro de Compensación Automatizado S.A. |
Sociedad Operadora de la Cámara de Compensación de Pagos de Alto Valor S.A. |
Sociedad Interbancaria de Depósito de Valores S.A. |
Redbanc S.A. |
Transbank S.A. |
Administrador Financiero de Transantiago S.A. |
Servicios de Infraestructura de Mercado OTC S.A. |
Servipag Ltda. |
||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Current assets | 6,165 | 1,713 | 199 | 21,030 | 1,647,306 | 63,878 | 6,531 | 102,719 | ||||||||||||||||||||||||
| Non-current assets | 15,545 | 10,033 | 12,295 | 10,255 | 99,748 | 791 | 13,251 | 16,562 | ||||||||||||||||||||||||
| Total Assets | 21,710 | 11,746 | 12,494 | 31,285 | 1,747,054 | 64,669 | 19,782 | 119,281 | ||||||||||||||||||||||||
| Current liabilities | 3,764 | 1,298 | — | 10,820 | 1,547,391 | 53,036 | 4,514 | 93,653 | ||||||||||||||||||||||||
| Non-current liabilities | 491 | 167 | — | 81 | 28,789 | 2,461 | 311 | 5,485 | ||||||||||||||||||||||||
| Total Liabilities | 4,255 | 1,465 | — | 10,901 | 1,576,180 | 55,497 | 4,825 | 99,138 | ||||||||||||||||||||||||
| Equity | 17,455 | 10,281 | 12,494 | 20,384 | 170,874 | 9,172 | 14,948 | 20,143 | ||||||||||||||||||||||||
| Minority interest | — | — | — | — | — | — | 9 | — | ||||||||||||||||||||||||
| Total Liabilities and Equity | 21,710 | 11,746 | 12,494 | 31,285 | 1,747,054 | 64,669 | 19,782 | 119,281 | ||||||||||||||||||||||||
| Operating income | 15,457 | 5,089 | 3 | 40,160 | 560,890 | 3,603 | 5,039 | 26,906 | ||||||||||||||||||||||||
| Operating expenses | (9,437 | ) | (4,106 | ) | (25 | ) | (36,428 | ) | (478,314 | ) | (1,783 | ) | (5,534 | ) | (26,460 | ) | ||||||||||||||||
| Other income (expenses) | 645 | 345 | 1,646 | 225 | (82,064 | ) | 350 | 442 | 586 | |||||||||||||||||||||||
| Income before tax | 6,665 | 1,328 | 1,624 | 3,957 | 512 | 2,170 | (53 | ) | 1,032 | |||||||||||||||||||||||
| Income tax | (1,581 | ) | (281 | ) | — | (918 | ) | 462 | (496 | ) | 71 | (278 | ) | |||||||||||||||||||
| Income (loss) for the period | 5,084 | 1,047 | 1,624 | 3,039 | 974 | 1,674 | 18 | 754 | ||||||||||||||||||||||||
| Associates | Joint Venture | |||||||||||||||||||||||||||||||
| December 2025 | Centro de Compensación Automatizado S.A. |
Sociedad Operadora de la Cámara de Compensación de Pagos de Alto Valor S.A. |
Sociedad Interbancaria de Depósito de Valores S.A. |
Redbanc S.A. |
Transbank S.A. |
Administrador Financiero de Transantiago S.A. |
Servicios de Infraestructura de Mercado OTC S.A. |
Servipag Ltda. |
||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Current assets | 11,318 | 1,948 | 113 | 17,683 | 1,510,782 | 62,043 | 23,022 | 75,456 | ||||||||||||||||||||||||
| Non-current assets | 11,014 | 9,512 | 11,382 | 12,516 | 126,168 | 814 | 12,510 | 19,150 | ||||||||||||||||||||||||
| Total Assets | 22,332 | 11,460 | 11,495 | 30,199 | 1,636,950 | 62,857 | 35,532 | 94,606 | ||||||||||||||||||||||||
| Current liabilities | 3,816 | 1,599 | 608 | 12,896 | 1,437,807 | 51,445 | 19,976 | 69,469 | ||||||||||||||||||||||||
| Non-current liabilities | 229 | 259 | — | 108 | 29,243 | 1,659 | 536 | 5,748 | ||||||||||||||||||||||||
| Total Liabilities | 4,045 | 1,858 | 608 | 13,004 | 1,467,050 | 53,104 | 20,512 | 75,217 | ||||||||||||||||||||||||
| Equity | 18,287 | 9,602 | 10,887 | 17,195 | 169,900 | 9,753 | 15,011 | 19,389 | ||||||||||||||||||||||||
| Minority interest | — | — | — | — | — | — | 9 | — | ||||||||||||||||||||||||
| Total Liabilities and Equity | 22,332 | 11,460 | 11,495 | 30,199 | 1,636,950 | 62,857 | 35,532 | 94,606 | ||||||||||||||||||||||||
| Operating income | 23,082 | 7,748 | 2 | 63,621 | 895,308 | 5,236 | 8,782 | 42,073 | ||||||||||||||||||||||||
| Operating expenses | (15,635 | ) | (6,054 | ) | (54 | ) | (59,339 | ) | (725,117 | ) | (2,654 | ) | (9,302 | ) | (39,118 | ) | ||||||||||||||||
| Other income (expenses) | 602 | 364 | 2,045 | 137 | (142,240 | ) | 696 | 741 | 839 | |||||||||||||||||||||||
| Income before tax | 8,049 | 2,058 | 1,993 | 4,419 | 27,951 | 3,278 | 221 | 3,794 | ||||||||||||||||||||||||
| Income tax | (2,027 | ) | (477 | ) | — | (1,064 | ) | (5,853 | ) | (773 | ) | 34 | (920 | ) | ||||||||||||||||||
| Income for the year | 6,022 | 1,581 | 1,993 | 3,355 | 22,098 | 2,505 | 255 | 2,874 | ||||||||||||||||||||||||
84
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 15. | Intangible Assets: |
| (a) | The composition of intangible assets as of September 30, 2026 and December 31, 2025, are as follows: |
| Average useful Life | Average remaining amortization | Gross balance | Accumulated Amortization | Net balance | ||||||||||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | September | December | |||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||
| Years | Years | Years | Years | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||
| Other independently originated intangible assets | 6 | 6 | 4 | 4 | 475,858 | 433,543 | (293,115 | ) | (258,965 | ) | 182,743 | 174,578 | ||||||||||||||||||||||||||||
| Total | 475,858 | 433,543 | (293,115 | ) | (258,965 | ) | 182,743 | 174,578 | ||||||||||||||||||||||||||||||||
| (b) | Changes in intangible assets during the period ended September 30, 2026 and December 31, 2025, are detailed as follows: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Gross Balance | ||||||||
| Balance as of January 1, | 433,543 | 379,546 | ||||||
| Acquisition | 42,352 | 58,597 | ||||||
| Disposals/ write-downs | (11 | ) | (9,474 | ) | ||||
| Transfers | (26 | ) | 5,567 | |||||
| Impairment (*) | — | (693 | ) | |||||
| Total | 475,858 | 433,543 | ||||||
| Accumulated Amortization | ||||||||
| Balance as of January 1, | (258,965 | ) | (220,990 | ) | ||||
| Amortization for the period (**) | (34,161 | ) | (41,453 | ) | ||||
| Disposals/ write-downs | 11 | 8,304 | ||||||
| Transfers | — | (5,055 | ) | |||||
| Impairment (*) | — | 229 | ||||||
| Total | (293,115 | ) | (258,965 | ) | ||||
| Balance Net | 182,743 | 174,578 | ||||||
| (*) | See Note 40 Impairment of non-financial assets. |
| (**) | See Note 39 Depreciation and Amortization. |
| (c) | As of September 30, 2026, the Bank records Ch$16,969 million (Ch$18,157 million as of December 31, 2025) of assets associated with technological developments in progress. |
| (d) | As of September 30, 2026 and December 31, 2025, there are no restrictions on the Bank’s intangible assets. Also, there are no intangible assets held as collateral for the fulfillment of obligations. |
85
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 16. | Property and equipment: |
| (a) | The properties and equipment as of September 30, 2026 and December 31, 2025 are composed of the following: |
| Average useful Life | Average remaining depreciation | Gross balance | Accumulated Depreciation | Net balance | ||||||||||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | September | December | |||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||
| Years | Years | Years | Years | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||
| Class of property and equipment: | ||||||||||||||||||||||||||||||||||||||||
| Land and Buildings | 25 | 25 | 17 | 17 | 323,860 | 324,366 | (180,340 | ) | (175,899 | ) | 143,520 | 148,467 | ||||||||||||||||||||||||||||
| Equipment | 5 | 5 | 4 | 3 | 266,418 | 259,367 | (244,532 | ) | (236,924 | ) | 21,886 | 22,443 | ||||||||||||||||||||||||||||
| Others | 7 | 7 | 5 | 4 | 63,181 | 60,170 | (53,016 | ) | (51,666 | ) | 10,165 | 8,504 | ||||||||||||||||||||||||||||
| Total | 653,459 | 643,903 | (477,888 | ) | (464,489 | ) | 175,571 | 179,414 | ||||||||||||||||||||||||||||||||
| (b) | The changes in properties and equipment as of September 30, 2026 and December 31, 2025, are as follows: |
| September 2026 | ||||||||||||||||
| Land and Buildings | Equipment | Others | Total | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Gross Balance | ||||||||||||||||
| Balance as of January 1, 2026 | 324,366 | 259,367 | 60,170 | 643,903 | ||||||||||||
| Reclassification | — | — | — | — | ||||||||||||
| Additions | 4,811 | 7,194 | 3,645 | 15,650 | ||||||||||||
| Disposals and sales for the period | (5,317 | ) | (137 | ) | (499 | ) | (5,953 | ) | ||||||||
| Transfers | — | — | (129 | ) | (129 | ) | ||||||||||
| Impairment (**) | — | (6 | ) | (6 | ) | (12 | ) | |||||||||
| Total | 323,860 | 266,418 | 63,181 | 653,459 | ||||||||||||
| Accumulated Depreciation | ||||||||||||||||
| Balance as of January 1, 2026 | (175,899 | ) | (236,924 | ) | (51,666 | ) | (464,489 | ) | ||||||||
| Reclassification | — | — | — | — | ||||||||||||
| Depreciation for the period (*) | (6,943 | ) | (7,746 | ) | (1,826 | ) | (16,515 | ) | ||||||||
| Disposals and sales of the period | 2,502 | 137 | 476 | 3,115 | ||||||||||||
| Transfers | — | 1 | — | 1 | ||||||||||||
| Total | (180,340 | ) | (244,532 | ) | (53,016 | ) | (477,888 | ) | ||||||||
| Balance as of September 30, 2026 | 143,520 | 21,886 | 10,165 | 175,571 | ||||||||||||
| December 2025 | ||||||||||||||||
| Land and Buildings | Equipment | Others | Total | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Gross Balance | ||||||||||||||||
| Balance as of January 1, 2025 | 327,862 | 261,142 | 63,198 | 652,202 | ||||||||||||
| Reclassification | 1,222 | 309 | (1,531 | ) | — | |||||||||||
| Additions | 6,161 | 9,854 | 1,922 | 17,937 | ||||||||||||
| Disposals and sales for the year | (10,853 | ) | (6,138 | ) | (3,413 | ) | (20,404 | ) | ||||||||
| Transfers | — | (5,567 | ) | — | (5,567 | ) | ||||||||||
| Impairment | (26 | ) | (233 | ) | (6 | ) | (265 | ) | ||||||||
| Total | 324,366 | 259,367 | 60,170 | 643,903 | ||||||||||||
| Accumulated Depreciation | ||||||||||||||||
| Balance as of January 1, 2025 | (173,132 | ) | (236,146 | ) | (53,851 | ) | (463,129 | ) | ||||||||
| Reclassification | (1,150 | ) | (173 | ) | 1,323 | — | ||||||||||
| Depreciation for the year | (9,807 | ) | (11,379 | ) | (2,458 | ) | (23,644 | ) | ||||||||
| Disposals and sales for the year | 8,190 | 5,719 | 3,320 | 17,229 | ||||||||||||
| Transfers | — | 5,055 | — | 5,055 | ||||||||||||
| Total | (175,899 | ) | (236,924 | ) | (51,666 | ) | (464,489 | ) | ||||||||
| Balance as of December 31, 2025 | 148,467 | 22,443 | 8,504 | 179,414 | ||||||||||||
| (*) | See Note 39 Depreciation and Amortization. |
| (**) | See Note 40 Impairment of non-financial assets. |
86
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 16. | Property and equipment, continued: |
| (c) | As of September 30, 2026, the Bank records Ch$14,082 million (Ch$10,920 million as of December 31, 2025) in assets under commissioning. |
| (d) | As of September 30, 2026 and December 31, 2025, there are no restrictions on property and equipment of the Bank and its subsidiaries. Furthermore, there are no property and equipment held as collateral for the fulfillment of obligations. |
| 17. | Right-of-use assets and Lease liabilities: |
| (a) | The detail of the right-of-use assets as of September 30, 2026 and December 31, 2025, is as follows: |
| Gross Balance | Accumulated Depreciation | Net Balance | ||||||||||||||||||||||
| September | December | September | December | September | December | |||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||
| Categories | ||||||||||||||||||||||||
| Buildings | 123,908 | 111,839 | (70,129 | ) | (62,144 | ) | 53,779 | 49,695 | ||||||||||||||||
| Floor space for ATMs | 42,006 | 41,026 | (25,057 | ) | (18,040 | ) | 16,949 | 22,986 | ||||||||||||||||
| Improvements to leased property | 28,603 | 28,562 | (22,700 | ) | (21,998 | ) | 5,903 | 6,564 | ||||||||||||||||
| Total | 194,517 | 181,427 | (117,886 | ) | (102,182 | ) | 76,631 | 79,245 | ||||||||||||||||
| (b) | The changes of the rights over leased assets as of September 30, 2026 and December 31, 2025, is as follows: |
| September 2026 | ||||||||||||||||
| Buildings | Floor space for ATMs | Improvements to leased property | Total | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Gross Balance | ||||||||||||||||
| Balance as of January 1, 2026 | 111,839 | 41,026 | 28,562 | 181,427 | ||||||||||||
| Additions | 18,593 | 1,088 | 182 | 19,863 | ||||||||||||
| Write-downs | (6,524 | ) | (108 | ) | (141 | ) | (6,773 | ) | ||||||||
| Remeasurement | — | — | — | — | ||||||||||||
| Other incremental | — | — | — | — | ||||||||||||
| Total | 123,908 | 42,006 | 28,603 | 194,517 | ||||||||||||
| Accumulated Depreciation | ||||||||||||||||
| Balance as of January 1, 2026 | (62,144 | ) | (18,040 | ) | (21,998 | ) | (102,182 | ) | ||||||||
| Depreciation of the period (*) | (14,091 | ) | (7,105 | ) | (798 | ) | (21,994 | ) | ||||||||
| Write-downs | 6,153 | 88 | 96 | 6,337 | ||||||||||||
| Other incremental | (47 | ) | — | — | (47 | ) | ||||||||||
| Total | (70,129 | ) | (25,057 | ) | (22,700 | ) | (117,886 | ) | ||||||||
| Balance as of September 30, 2026 | 53,779 | 16,949 | 5,903 | 76,631 | ||||||||||||
| (*) | See Note 39 Depreciation and Amortization. |
87
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 17. | Right-of-use assets and Lease liabilities, continued: |
| December 2025 | ||||||||||||||||
| Buildings | Floor space for ATMs | Improvements to leased property | Total | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Gross Balance | ||||||||||||||||
| Balance as of January 1, 2025 | 126,655 | 36,080 | 28,783 | 191,518 | ||||||||||||
| Additions | 8,256 | 5,239 | 765 | 14,260 | ||||||||||||
| Disposals | (22,850 | ) | (293 | ) | (986 | ) | (24,129 | ) | ||||||||
| Remeasurement | (222 | ) | — | — | (222 | ) | ||||||||||
| Other increases | — | — | — | — | ||||||||||||
| Total | 111,839 | 41,026 | 28,562 | 181,427 | ||||||||||||
| Accumulated Depreciation | ||||||||||||||||
| Balance as of January 1, 2025 | (63,657 | ) | (9,307 | ) | (21,675 | ) | (94,639 | ) | ||||||||
| Depreciation of the year | (19,581 | ) | (9,026 | ) | (1,049 | ) | (29,656 | ) | ||||||||
| Disposals | 21,321 | 293 | 726 | 22,340 | ||||||||||||
| Other increases | (227 | ) | — | — | (227 | ) | ||||||||||
| Total | (62,144 | ) | (18,040 | ) | (21,998 | ) | (102,182 | ) | ||||||||
| Balance as of December 31, 2025 | 49,695 | 22,986 | 6,564 | 79,245 | ||||||||||||
| (c) | Future maturities (including unearned interest) of the lease liabilities as of September 30, 2026 and December 31, 2025 are detailed as follows: |
| September 2026 | ||||||||||||||||||||||||||||||||
| On Demand | Up to 1 month | Over 1 month up to 3 months | Over 3 months up to 12 months | Over 1 year and up to 3 years | Over 3 years and up to 5 years | Over 5 years | Total | |||||||||||||||||||||||||
| Lease associated to: | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||
| Buildings | — | 1,634 | 3,277 | 13,057 | 22,482 | 9,322 | 7,049 | 56,821 | ||||||||||||||||||||||||
| ATMs | — | 837 | 1,671 | 7,162 | 9,055 | 389 | 4 | 19,118 | ||||||||||||||||||||||||
| Total | — | 2,471 | 4,948 | 20,219 | 31,537 | 9,711 | 7,053 | 75,939 | ||||||||||||||||||||||||
| December 2025 | ||||||||||||||||||||||||||||||||
| On Demand | Up to 1 month | Over 1 month up to 3 months | Over 3 months up to 12 months | Over 1 year and up to 3 years | Over 3 years and up to 5 years | Over 5 years | Total | |||||||||||||||||||||||||
| Lease associated to: | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||
| Buildings | — | 1,551 | 3,099 | 10,731 | 19,628 | 10,676 | 7,399 | 53,084 | ||||||||||||||||||||||||
| ATMs | — | 802 | 1,603 | 7,206 | 15,062 | 733 | 20 | 25,426 | ||||||||||||||||||||||||
| Total | — | 2,353 | 4,702 | 17,937 | 34,690 | 11,409 | 7,419 | 78,510 | ||||||||||||||||||||||||
88
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 17. | Right-of-use assets and Lease liabilities, continued: |
The Bank and its subsidiaries record contracts with certain renewal options and for which there is reasonable certainty that such option will be exercised. In such cases, the lease term used to measure the liability and assets corresponds to an estimate of future renewals.
| (d) | The changes in the obligations for lease liabilities and the cash flows for the periods 2026 and 2025 are detailed as follows: |
| Lease liability | Total cash flow for the period | |||
| MCh$ | ||||
| Balances as of January 1, 2025 | 91,429 | |||
| Liabilities for new lease agreements | 8,795 | |||
| Interest accrual expenses | 1,621 | |||
| Payments of principal and interests | (23,239 | ) | ||
| Remeasurement | (222 | ) | ||
| Derecognized contracts | (791 | ) | ||
| Indexation | 2,111 | |||
| Balances as of September 30, 2025 | 79,704 | |||
| Liabilities for new lease agreements | 2,156 | |||
| Interest accrual expenses | 491 | |||
| Payments of principal and interests | (7,658 | ) | ||
| Remeasurement | — | |||
| Derecognized contracts | (777 | ) | ||
| Indexation | 427 | |||
| Balances as of December 31, 2025 | 74,343 | |||
| Liabilities for new lease agreements | 17,648 | |||
| Interest accrual expenses | 1,362 | |||
| Payments of principal and interests | (22,570 | ) | ||
| Remeasurement | — | |||
| Derecognized contracts | (384 | ) | ||
| Indexation | 2,033 | |||
| Balances as of September 30, 2026 | 72,432 | |||
| (e) | The future cash flows related to short-term lease agreements in force as of September 30, 2026 correspond to Ch$3,237 million (Ch$5,071 million as of December 31, 2025). |
| (f) | As of September 30, 2026, the minimum future rental income to be received from operating leases amounts to Ch$22,668 million (Ch$19,926 million as of December 31, 2025). |
89
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 18. | Taxes: |
| (a) | Current Taxes: |
The Bank and its subsidiaries at the end of each period, have constituted a provision for first category income tax, which was determined based on current tax regulations, and has been reflected in the Interim Statement of Financial Position net of taxes to be recovered or payable, as applicable, as of September 30, 2026 and December 31, 2025 according to the following detail:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Income tax | (238,493 | ) | (325,028 | ) | ||||
| Previous year tax | — | — | ||||||
| Less: | ||||||||
| Monthly prepaid taxes | 290,229 | 286,874 | ||||||
| Credit for training expenses | 1,422 | 1,920 | ||||||
| Others | 4,494 | 4,271 | ||||||
| Total tax (payable) receivable, net | 57,652 | (31,963 | ) | |||||
| Income tax rate | 27 | % | 27 | % | ||||
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Current tax assets | 58,636 | 1,846 | ||||||
| Current tax liabilities | (984 | ) | (33,809 | ) | ||||
| Total tax (payable) receivable, net | 57,652 | (31,963 | ) | |||||
| (b) | Income Tax: |
The effect of the tax expense during the periods between January 1 and September 30, 2026 and 2025, is composed of the following:
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Income tax expense: | ||||||||
| Current year tax | 250,300 | 256,825 | ||||||
| Previous year tax | (538 | ) | (3,710 | ) | ||||
| Subtotal | 249,762 | 253,115 | ||||||
| (Credit) debit for deferred taxes: | ||||||||
| Origin and (reversal) of temporary differences | (10,220 | ) | (5,914 | ) | ||||
| Subtotal | (10,220 | ) | (5,914 | ) | ||||
| Others | (6,453 | ) | (861 | ) | ||||
| Net debit to income for income taxes | 233,089 | 246,340 | ||||||
90
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 18. | Taxes, continued: |
| (c) | Reconciliation of effective tax rate: |
The following table reconciles the income tax rate to the effective rate applied to determine the Bank’s income tax expense as of September 30, 2026 and 2025:
| September 2026 | September 2025 | |||||||||||||||
| Tax rate | Tax rate | |||||||||||||||
| % | MCh$ | % | MCh$ | |||||||||||||
| Income tax calculated on net income before tax | 27.00 | 318,605 | 27.00 | 316,728 | ||||||||||||
| Additions or deductions | (1.28 | ) | (15,068 | ) | (1.35 | ) | (15,814 | ) | ||||||||
| Tax price-level adjustment | (5.48 | ) | (64,685 | ) | (4.59 | ) | (53,897 | ) | ||||||||
| Other | (0.49 | ) | (5,763 | ) | (0.06 | ) | (677 | ) | ||||||||
| Effective rate and income tax expense | 19.75 | 233,089 | 21.00 | 246,340 | ||||||||||||
| (d) | Effect of deferred taxes on income and equity: |
The Bank and its subsidiaries have recorded the effects of deferred taxes in their Interim Consolidated Financial Statements. Debit and credit differences as of September 30, 2026 are detailed as follows:
| Balances as of December 31, |
Effect on | Balances as of September 30, |
||||||||||||||
| 2025 | Income | Equity | 2026 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Debit Differences: | ||||||||||||||||
| Allowances for loan losses | 372,091 | 13,962 | — | 386,053 | ||||||||||||
| Provision for employee expenses | 21,435 | (2,586 | ) | — | 18,849 | |||||||||||
| Provision disposal undrawn credit lines | 10,900 | 584 | — | 11,484 | ||||||||||||
| Accrued vacations | 11,674 | 142 | — | 11,816 | ||||||||||||
| Accrued interests and indexation of impaired portfolio | 16,587 | 1,724 | — | 18,311 | ||||||||||||
| Provision for staff severance indemnity payments | 979 | (382 | ) | (14 | ) | 583 | ||||||||||
| Provision for credit card expenses | 10,208 | (1,667 | ) | — | 8,541 | |||||||||||
| Provision for accrued expenses | 9,131 | 2,970 | — | 12,101 | ||||||||||||
| Adjustment for valuation of investments and equity instruments at fair value through OCI | — | — | 2,310 | 2,310 | ||||||||||||
| Leases | 126,124 | 4,903 | — | 131,027 | ||||||||||||
| Unearned income | 3,489 | (277 | ) | — | 3,212 | |||||||||||
| Exchange rate difference | — | 1,368 | — | 1,368 | ||||||||||||
| Property and equipment valuation difference | 9,588 | 2,375 | — | 11,963 | ||||||||||||
| Other adjustments | 28,900 | 1,510 | — | 30,410 | ||||||||||||
| Total Debit Differences | 621,106 | 24,626 | 2,296 | 648,028 | ||||||||||||
| Credit Differences: | ||||||||||||||||
| Intangible assets (software and others) | 28,573 | 1,549 | — | 30,122 | ||||||||||||
| Adjustment for valuation of investments and equity instruments at fair value through OCI | 909 | — | (909 | ) | — | |||||||||||
| Transitory assets | 9,607 | 9,912 | — | 19,519 | ||||||||||||
| Loans accrued to effective rate | 2,211 | (145 | ) | — | 2,066 | |||||||||||
| Prepaid expenses | 2,561 | 10,241 | — | 12,802 | ||||||||||||
| Exchange rate difference | 6,717 | (6,717 | ) | — | — | |||||||||||
| Capitalized bond placement expense | 4,911 | (266 | ) | — | 4,645 | |||||||||||
| Other adjustments | 3,133 | (168 | ) | — | 2,965 | |||||||||||
| Total Credit Differences | 58,622 | 14,406 | (909 | ) | 72,119 | |||||||||||
| Total Debit (Credit), net | 562,484 | 10,220 | 3,205 | 575,909 | ||||||||||||
91
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 18. | Taxes, continued: |
| (d) | Effect of deferred taxes on income and equity, continued: |
Reconciliation to Statement of Financial Position:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Deferred tax assets | 579,398 | 563,906 | ||||||
| Deferred tax liabilities | (3,489 | ) | (1,422 | ) | ||||
| Total deferred taxes | 575,909 | 562,484 | ||||||
Debit and credit differences as of December 31, 2025 are detailed as follows:
| Balances as of December 31, |
Effect on | Balances as of December 31, |
||||||||||||||
| 2024 | Income | Equity | 2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Debit Differences: | ||||||||||||||||
| Allowances for loan losses | 384,945 | (12,854 | ) | — | 372,091 | |||||||||||
| Provision for employee expenses | 24,636 | (3,201 | ) | — | 21,435 | |||||||||||
| Provision disposal undrawn credit lines | 3,237 | 7,663 | — | 10,900 | ||||||||||||
| Accrued vacations | 11,562 | 112 | — | 11,674 | ||||||||||||
| Accrued interests and indexation of impaired portfolio | 16,534 | 53 | — | 16,587 | ||||||||||||
| Provision for staff severance indemnity payments | 1,004 | (42 | ) | 17 | 979 | |||||||||||
| Provision for credit card expenses | 10,968 | (760 | ) | — | 10,208 | |||||||||||
| Provision for accrued expenses | 10,231 | (1,100 | ) | — | 9,131 | |||||||||||
| Adjustment for valuation of investments and equity instruments at fair value through OCI | 475 | — | (475 | ) | — | |||||||||||
| Leases | 110,943 | 15,181 | — | 126,124 | ||||||||||||
| Unearned income | 4,114 | (625 | ) | — | 3,489 | |||||||||||
| Property and equipment valuation difference | 6,800 | 2,788 | — | 9,588 | ||||||||||||
| Other adjustments | 23,483 | 5,417 | — | 28,900 | ||||||||||||
| Total Debit Differences | 608,932 | 12,632 | (458 | ) | 621,106 | |||||||||||
| Credit Differences: | ||||||||||||||||
| Intangible (software and others) | 24,998 | 3,575 | — | 28,573 | ||||||||||||
| Adjustment for valuation of investments and equity instruments at fair value through OCI | — | — | 909 | 909 | ||||||||||||
| Transitory assets | 9,726 | (119 | ) | — | 9,607 | |||||||||||
| Loans accrued to effective rate | 2,333 | (122 | ) | — | 2,211 | |||||||||||
| Prepaid expenses | 6,400 | (3,839 | ) | — | 2,561 | |||||||||||
| Exchange rate difference | 801 | 5,916 | — | 6,717 | ||||||||||||
| Capitalized bond placement expense | 4,895 | 16 | — | 4,911 | ||||||||||||
| Other adjustments | 3,116 | 17 | — | 3,133 | ||||||||||||
| Total Credit Differences | 52,269 | 5,444 | 909 | 58,622 | ||||||||||||
| Total Debit(Credit), net | 556,663 | 7,188 | (1,367 | ) | 562,484 | |||||||||||
92
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 18. | Taxes, continued: |
| (e) | For the purposes of complying with the Circular No. 47 issued by the Chilean Internal Revenue Service (SII) and No. 3,478 issued by the CMF, dated August 18, 2009 the changes and effects generated by the application of Article 31, No. 4 of the Income Tax Law are detailed below. |
As the circular requires, the information corresponds only to the Bank’s loan operations and does not consider operations of subsidiary entities that are consolidated in these Interim Consolidated Financial Statements.
| Assets at tax value | ||||||||||||||||||||
| (e.1) Loans to Banks and Loans to customers as of September 30, 2026 | Book value assets (*) | Assets at tax value | Past-due loans with guarantees | Past-due loans without guarantees | Total Past-due loans | |||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||
| Loans to Banks | 609,731 | 610,560 | — | — | — | |||||||||||||||
| Commercial loans | 17,485,153 | 17,878,511 | 55,592 | 90,638 | 146,230 | |||||||||||||||
| Consumer loans | 5,120,455 | 5,668,455 | 1,782 | 47,281 | 49,063 | |||||||||||||||
| Residential mortgage loans | 14,139,811 | 14,198,489 | 20,278 | 2,087 | 22,365 | |||||||||||||||
| Total | 37,355,150 | 38,356,015 | 77,652 | 140,006 | 217,658 | |||||||||||||||
| Assets at tax value | ||||||||||||||||||||
| (e.1) Loans to Banks and Loans to customers as of December 31, 2025 | Book value assets (*) | Assets at tax value | Past-due loans with guarantees | Past-due loans without guarantees | Total Past-due loans | |||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||
| Loans to Banks | 399,123 | 399,792 | — | — | — | |||||||||||||||
| Commercial loans | 16,245,986 | 16,638,563 | 52,050 | 99,694 | 151,744 | |||||||||||||||
| Consumer loans | 5,341,871 | 5,876,928 | 1,257 | 42,149 | 43,406 | |||||||||||||||
| Residential mortgage loans | 13,874,507 | 13,929,216 | 17,187 | 1,943 | 19,130 | |||||||||||||||
| Total | 35,861,487 | 36,844,499 | 70,494 | 143,786 | 214,280 | |||||||||||||||
| (*) | In accordance with the aforementioned Circular and the instructions from the SII, the value of assets in the Financial Statements are presented on a stand-alone basis (only considering Banco de Chile) net of allowance for loan losses and do not include lease and factoring operations. |
93
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 18. | Taxes, continued: |
| (e.2) Allowances on past-due loans | Balance as of January 1, 2026 |
Write-offs against provisions |
Allowances established |
Allowances released |
Balance as of September 30, 2026 |
|||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||
| Commercial loans | 99,694 | (46,338 | ) | 85,099 | (47,817 | ) | 90,638 | |||||||||||||
| Consumer loans | 42,150 | (295,470 | ) | 314,380 | (13,779 | ) | 47,281 | |||||||||||||
| Residential mortgage loans | 1,944 | (3,133 | ) | 4,794 | (1,518 | ) | 2,087 | |||||||||||||
| Total | 143,788 | (344,941 | ) | 404,273 | (63,114 | ) | 140,006 | |||||||||||||
| (e.2) Allowances on past-due loans | Balance as of January 1, 2025 |
Write-offs against provisions |
Allowances established |
Allowances released |
Balance as of December 31, 2025 |
|||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||
| Commercial loans | 94,025 | (52,371 | ) | 108,970 | (50,930 | ) | 99,694 | |||||||||||||
| Consumer loans | 34,500 | (304,661 | ) | 341,290 | (28,979 | ) | 42,150 | |||||||||||||
| Residential mortgage loans | 685 | (2,049 | ) | 4,486 | (1,178 | ) | 1,944 | |||||||||||||
| Total | 129,210 | (359,081 | ) | 454,746 | (81,087 | ) | 143,788 | |||||||||||||
| September | December | |||||||
| (e.3) Write-offs and recoveries | 2026 | 2025 | ||||||
| MCh$ | MCh$ | |||||||
| Write-offs, Art. 31 No. 4 second subparagraph | 35,507 | 34,158 | ||||||
| Write-offs resulting in allowances released | 25 | 299 | ||||||
| Recovery or renegotiation of written-off loans | 1,892 | 1,773 | ||||||
| September | December | |||||||
| (e.4) Application of Art. 31 No. 4 first & third subsections of the income tax law | 2026 | 2025 | ||||||
| MCh$ | MCh$ | |||||||
| Write-offs in accordance with first subparagraph | — | — | ||||||
| Write-offs in accordance with third subparagraph | 25 | 299 | ||||||
94
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 19. | Other Assets: |
At the end of each period, this line item is composed of the following:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Cash collateral provided for derivative financial transactions | 483,011 | 463,266 | ||||||
| Debtors from brokerage of financial instruments | 410,084 | 419,167 | ||||||
| Accounts receivable from third parties | 328,540 | 170,185 | ||||||
| Prepaid expenses | 113,563 | 39,416 | ||||||
| Assets to be leased out as lessor (*) | 94,531 | 134,283 | ||||||
| Accounts receivable from the General Treasury of the Republic and other fiscal organizations | 64,196 | 406,395 | ||||||
| Income from regular activities from contracts with customers | 33,412 | 22,350 | ||||||
| Other provided cash collateral | 22,950 | 11,836 | ||||||
| Investment properties | 10,237 | 11,049 | ||||||
| Pending transactions | 2,512 | 3,364 | ||||||
| Accumulated impairment in respect of other assets receivable | (2,913 | ) | (2,638 | ) | ||||
| Other Assets | 19,501 | 17,358 | ||||||
| Total | 1,579,624 | 1,696,031 | ||||||
| (*) | Correspond to fixed assets to be delivered under the financial lease modality. |
95
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 20. | Non-current assets and disposal groups held for sale and liabilities included in disposal groups for sale: |
| (a) | At the end of each period, the item is composed as follows: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Assets received in lieu of payment or awarded at judicial sale (*) | ||||||||
| Assets awarded in judicial auction | 23,584 | 22,571 | ||||||
| Assets received in lieu of payment | 4,171 | 2,054 | ||||||
| Provision for assets received in lieu of payment or awarded | (67 | ) | (35 | ) | ||||
| Non-current assets for sale | ||||||||
| Investments in other companies | — | — | ||||||
| Assets for recovery of assets transferred in financial leasing operations | 2,259 | 1,013 | ||||||
| Disposal groups held for sale | — | — | ||||||
| Total | 29,947 | 25,603 | ||||||
| (*) | Assets received in lieu of payment refer to assets accepted as payment for past-due or written-off debts owed by customers. The assets acquired as such do not exceed 20% of the Bank’s effective equity. |
| (b) | Changes in the provision for assets received in lieu of payment during the period 2026 and 2025 are detailed as follows: |
| Provision for assets received in lieu of payment | MCh$ | |||
| Balance as of January 1, 2025 | 82 | |||
| Provisions used | (1,913 | ) | ||
| Provisions established | 1,872 | |||
| Provisions released | — | |||
| Balance as of September 30, 2025 | 41 | |||
| Provisions used | (754 | ) | ||
| Provisions established | 748 | |||
| Provisions released | — | |||
| Balance as of December 31, 2025 | 35 | |||
| Provisions used | (1,906 | ) | ||
| Provisions established | 1,938 | |||
| Provisions released | — | |||
| Balance as of September 30, 2026 | 67 | |||
| (c) | The Bank does not record liabilities included in the disposal group for sale during the periods September 2026 and December 2025. |
96
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 21. | Financial liabilities held for trading at fair value through profit or loss: |
The detail of this line item is as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Financial derivative contracts | 2,513,730 | 2,080,222 | ||||||
| Others | 1,624 | 512 | ||||||
| Total | 2,515,354 | 2,080,734 | ||||||
| a) | As of September 30, 2026 and December 31, 2025, the Bank maintains the following debt portfolio of derivative instruments: |
| Notional amount of contract with final expiration date in | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| On Demand | Up to 1 month | Over 1 month and up to 3 months | Over 3 months and up to 12 months | Over 1 year and up to 3 years | Over 3 years and up to 5 years | Over 5 years | Total | Fair value Liabilities | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | September | December | September | December | September | December | September | December | September | December | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Currency forward | — | — | 7,826,681 | 7,393,965 | 3,350,184 | 3,560,210 | 6,034,402 | 3,716,879 | 600,666 | 659,862 | 65,559 | 50,930 | — | — | 17,877,492 | 15,381,846 | 591,900 | 456,184 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest rate swap | — | — | 1,058,372 | 3,093,258 | 1,177,675 | 2,016,845 | 7,699,603 | 7,398,940 | 7,168,324 | 7,351,083 | 4,527,638 | 4,073,662 | 3,901,578 | 3,779,852 | 25,533,190 | 27,713,640 | 587,514 | 414,907 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest rate swap and cross currency swap | — | — | 164,277 | 151,577 | 713,950 | 369,984 | 1,529,327 | 1,700,333 | 3,497,965 | 3,071,039 | 3,507,319 | 2,631,798 | 4,180,203 | 3,375,877 | 13,593,041 | 11,300,608 | 1,330,874 | 1,206,802 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Currency call options | — | — | 9,401 | 12,533 | 23,681 | 18,722 | 17,739 | 33,332 | — | — | — | — | — | — | 50,821 | 64,587 | 2,788 | 870 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Currency put options | — | — | 12,607 | 5,783 | 36,108 | 7,611 | 38,711 | 21,870 | 731 | — | — | — | — | — | 88,157 | 35,264 | 654 | 1,459 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total | — | — | 9,071,338 | 10,657,116 | 5,301,598 | 5,973,372 | 15,319,782 | 12,871,354 | 11,267,686 | 11,081,984 | 8,100,516 | 6,756,390 | 8,081,781 | 7,155,729 | 57,142,701 | 54,495,945 | 2,513,730 | 2,080,222 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| b) | Other instruments or financial liabilities: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Current accounts and other demand deposits | — | — | ||||||
| Savings accounts and other time deposits | — | — | ||||||
| Debt instruments issued | — | — | ||||||
| Others | 1,624 | 512 | ||||||
| Total | 1,624 | 512 | ||||||
97
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 22. | Financial liabilities at amortized cost: |
The detail of this line item is as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Current accounts and other demand deposits | 14,551,566 | 14,498,196 | ||||||
| Time deposits and saving accounts | 15,049,344 | 13,971,968 | ||||||
| Obligations by repurchase agreements | 122,886 | 286,915 | ||||||
| Borrowings from financial institutions | 1,218,163 | 1,296,751 | ||||||
| Debt financial instruments issued | 11,164,247 | 10,800,851 | ||||||
| Other financial obligations | 328,605 | 367,323 | ||||||
| Total | 42,434,811 | 41,222,004 | ||||||
| (a) | Current accounts and other demand deposits: |
At the end of each period, the composition of current accounts and other demand deposits is as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Current accounts | 11,944,249 | 11,775,903 | ||||||
| Other demand obligations | 1,324,080 | 1,507,373 | ||||||
| Demand deposits accounts | 771,023 | 724,359 | ||||||
| Other demand deposits | 512,214 | 490,561 | ||||||
| Total | 14,551,566 | 14,498,196 | ||||||
| (b) | Time deposits and saving accounts: |
At the end of each period, the composition of time deposits and saving accounts is as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Time deposits | 14,583,741 | 13,546,479 | ||||||
| Term savings accounts | 446,479 | 405,689 | ||||||
| Other term balances payable | 19,124 | 19,800 | ||||||
| Total | 15,049,344 | 13,971,968 | ||||||
98
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 22. | Financial liabilities at amortized cost, continued: |
| (c) | Obligations by repurchase agreements: |
The Bank obtains financing by selling financial instruments and agreeing to repurchase them in the future, plus interest at a rate established previously. As of September 30, 2026 and December 31, 2025 the repurchase agreements are detailed as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Transaction with domestic banks | — | — | ||||||
| Transaction with foreign banks | — | — | ||||||
| Transaction with other domestic entities | ||||||||
| Repurchase agreements | 122,886 | 286,915 | ||||||
| Transaction with other foreign entities | — | — | ||||||
| Total | 122,886 | 286,915 | ||||||
The fair value of the financial instruments delivered as collateral by the Bank and its subsidiaries, in sales transactions with repurchase agreement and securities lending as of September 30, 2026 amounts to Ch$123,208 million (Ch$284,572 million in December 2025). In the event that the Bank and its subsidiaries enter into default or bankruptcy, the counterparty is authorized to sell or deliver these investments as collateral.
| (d) | Borrowings from Financial Institutions: |
At the end of each period, borrowings from financial institutions are detailed as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Foreign banks | ||||||||
| Foreign trade financing | ||||||||
| Bank of America, N.A. | 270,393 | 238,925 | ||||||
| Caixabank S.A. | 201,627 | 147,091 | ||||||
| Citibank N.A. | 175,563 | 137,114 | ||||||
| JP Morgan Chase Bank, N.A. | 174,928 | 168,329 | ||||||
| The Bank of New York Mellon | 151,204 | 85,533 | ||||||
| Zuercher Kantonalbank | 86,206 | 108,803 | ||||||
| Commerzbank AG | 3,699 | 839 | ||||||
| Standard Chartered Bank | 3,522 | 2,086 | ||||||
| Wells Fargo Bank, N.A. | 118 | 50 | ||||||
| MUFG Bank, LTD. | 105 | — | ||||||
| HSBC Bank | — | 208,465 | ||||||
| Standard Chartered Bank (Hong Kong) Limited | — | 63,261 | ||||||
| Borrowings and other obligations | ||||||||
| Wells Fargo Bank, N.A. | 149,003 | 136,255 | ||||||
| Citibank N.A. United States | 1,795 | — | ||||||
| Subtotal foreign banks | 1,218,163 | 1,296,751 | ||||||
| Total | 1,218,163 | 1,296,751 | ||||||
99
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 22. | Financial liabilities at amortized cost, continued: |
| (e) | Debt financial instruments issued: |
At the end of each period, the composition of debt financial instruments issued as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Mortgage finance bonds | ||||||||
| Mortgage finance bonds for housing | 435 | 521 | ||||||
| Mortgage finance bonds for general purposes | — | — | ||||||
| Bonds | ||||||||
| Senior Bonds | 11,163,812 | 10,800,330 | ||||||
| Mortgage bonds | — | — | ||||||
| Total | 11,164,247 | 10,800,851 | ||||||
During the period ended September 30, 2026 Banco de Chile has placed bonds for Ch$1,452,513 million, which corresponds to Short-Term Bonds and Long-Term Bonds for amounts of Ch$872,081 and Ch$580,432 million respectively, according to the following details:
Short-term Bonds
Counterparty | Currency | Amount MCh$ | Annual interest rate % | Date of issuance | Maturity date |
|||||||||||
| Wells Fargo Bank | USD | 90,487 | 3.91 | 01-02-2026 | 07-10-2026 | |||||||||||
| Wells Fargo Bank | USD | 86,531 | 3.95 | 02-05-2026 | 08-10-2026 | |||||||||||
| Wells Fargo Bank | USD | 45,276 | 4.01 | 05-05-2026 | 08-05-2026 | |||||||||||
| Bank Of America Na New York | USD | 4,467 | 4.00 | 05-06-2026 | 06-08-2026 | |||||||||||
| Bank Of America Na New York | USD | 44,759 | 4.04 | 05-27-2026 | 07-27-2026 | |||||||||||
| Bank Of America Na New York | USD | 26,855 | 4.05 | 05-27-2026 | 07-29-2026 | |||||||||||
| Wells Fargo Bank | USD | 89,518 | 4.07 | 05-27-2026 | 09-01-2026 | |||||||||||
| Bank Of America Na New York | USD | 22,380 | 4.07 | 05-27-2026 | 09-02-2026 | |||||||||||
| Bank Of America Na New York | USD | 44,759 | 4.07 | 05-27-2026 | 08-28-2026 | |||||||||||
| Wells Fargo Bank | USD | 46,208 | 4.16 | 06-26-2026 | 10-01-2026 | |||||||||||
| Bank Of America Na New York | USD | 4,627 | 4.15 | 07-01-2026 | 09-29-2026 | |||||||||||
| Bank Of America Na New York | USD | 41,640 | 4.12 | 07-01-2026 | 08-31-2026 | |||||||||||
| Citibank N.A. | USD | 10,787 | 4.15 | 08-28-2026 | 11-27-2026 | |||||||||||
| Citibank N.A. | USD | 44,460 | 4.41 | 09-01-2026 | 08-31-2027 | |||||||||||
| Citibank N.A. | USD | 9,173 | 4.12 | 09-01-2026 | 11-30-2026 | |||||||||||
| Wells Fargo Bank | USD | 96,208 | 4.61 | 09-23-2026 | 01-25-2027 | |||||||||||
| Bank Of America Na New York | USD | 48,105 | 4.61 | 09-23-2026 | 02-23-2027 | |||||||||||
| Citibank N.A. | USD | 9,616 | 4.54 | 09-25-2026 | 01-25-2027 | |||||||||||
| Citibank N.A. | USD | 9,616 | 4.97 | 09-25-2026 | 09-24-2027 | |||||||||||
| Citibank N.A. | USD | 96,609 | 4.32 | 09-28-2026 | 11-03-2026 | |||||||||||
| Total | 872,081 | |||||||||||||||
100
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 22. | Financial liabilities at amortized cost, continued: |
Long-Term Bonds
| Series | Currency | Amount MCh$ | Terms Years | Annual interest rate % | Date of issuance | Maturity date |
|||||||||||||
| BCHIHW1223 | UF | 32,293 | 18 | 2.93 | 01-08-2026 | 06-01-2044 | |||||||||||||
| BCHIHW1223 | UF | 4,312 | 18 | 2.92 | 01-12-2026 | 06-01-2044 | |||||||||||||
| BCHIFU0522 | UF | 19,723 | 6 | 2.81 | 01-14-2026 | 11-01-2032 | |||||||||||||
| BCHIGG1121 | UF | 13,776 | 9 | 2.89 | 01-14-2026 | 05-01-2035 | |||||||||||||
| BCHIHW1223 | UF | 12,953 | 18 | 2.91 | 01-14-2026 | 06-01-2044 | |||||||||||||
| BCHIFU0522 | UF | 19,759 | 6 | 2.78 | 01-15-2026 | 11-01-2032 | |||||||||||||
| BCHIHH1223 | UF | 16,880 | 10 | 2.87 | 01-15-2026 | 12-01-2036 | |||||||||||||
| BCHIHW1223 | UF | 2,165 | 18 | 2.89 | 01-15-2026 | 06-01-2044 | |||||||||||||
| BCHIFG0522 | UF | 34,396 | 4 | 2.59 | 02-10-2026 | 11-01-2030 | |||||||||||||
| BCHIFG0522 | UF | 40,329 | 4 | 2.51 | 03-05-2026 | 11-01-2030 | |||||||||||||
| BCHIFG0522 | UF | 12,596 | 4 | 2.82 | 06-30-2026 | 11-01-2030 | |||||||||||||
| BCHIFG0522 | UF | 16,255 | 4 | 2.82 | 07-01-2026 | 11-01-2030 | |||||||||||||
| BCHIGA1121 | UF | 10,022 | 8 | 3.03 | 07-02-2026 | 05-01-2034 | |||||||||||||
| BCHIFG0522 | UF | 35,800 | 4 | 2.81 | 07-06-2026 | 11-01-2030 | |||||||||||||
| BCHIFG0522 | UF | 12,212 | 4 | 2.80 | 07-07-2026 | 11-01-2030 | |||||||||||||
| BCHIFG0522 | UF | 10,202 | 4 | 2.74 | 07-08-2026 | 11-01-2030 | |||||||||||||
| BCHIGA1121 | UF | 17,163 | 8 | 2.95 | 07-20-2026 | 05-01-2034 | |||||||||||||
| BCHIGA1121 | UF | 5,049 | 8 | 2.95 | 07-22-2026 | 05-01-2034 | |||||||||||||
| BCHIFT0422 | UF | 52,727 | 6 | 2.92 | 08-21-2026 | 10-01-2032 | |||||||||||||
| BCHIFT0422 | UF | 44,635 | 6 | 2.92 | 08-27-2026 | 10-01-2032 | |||||||||||||
| BCHIFT0422 | UF | 16,279 | 6 | 2.88 | 09-03-2026 | 10-01-2032 | |||||||||||||
| BCHIFT0422 | UF | 18,992 | 6 | 2.86 | 09-04-2026 | 10-01-2032 | |||||||||||||
| BCHIHC0224 | UF | 38,235 | 8 | 2.98 | 09-04-2026 | 08-01-2034 | |||||||||||||
| Subtotal | 486,753 | ||||||||||||||||||
| BONO MXN | MXN | 36,434 | 7 | TIIE (28 días) + 0.95% | 05-12-2026 | 05-11-2033 | |||||||||||||
| BONO JPY | JPY | 57,245 | 3 | 2.32 | 07-21-2026 | 07-30-2029 | |||||||||||||
| Subtotal | 93,679 | ||||||||||||||||||
| Total | 580,432 | ||||||||||||||||||
During the year ended December 31, 2025 Banco de Chile has placed bonds for Ch$2,742,341 million, which corresponds to Short-Term Bonds and Long-Term Bonds for amounts of Ch$819,195 and Ch$1,923,146 million respectively, according to the following details:
Short-term Bonds
Counterparty | Currency | Amount MCh$ | Annual interest rate % | Date of issuance | Maturity date |
|||||||||||
| Wells Fargo Bank | USD | 98,630 | 4.68 | 01/27/2025 | 05/02/2025 | |||||||||||
| Wells Fargo Bank | USD | 98,630 | 4.65 | 01/27/2025 | 08/01/2025 | |||||||||||
| Wells Fargo Bank | USD | 92,519 | 4.55 | 03/07/2025 | 04/07/2025 | |||||||||||
| Wells Fargo Bank | USD | 9,252 | 4.45 | 03/07/2025 | 09/05/2025 | |||||||||||
| Wells Fargo Bank | USD | 93,634 | 4.60 | 06/25/2025 | 10/01/2025 | |||||||||||
| Wells Fargo Bank | USD | 93,062 | 4.55 | 06/26/2025 | 11/03/2025 | |||||||||||
| Wells Fargo Bank | USD | 4,653 | 4.55 | 06/26/2025 | 07/31/2025 | |||||||||||
| Wells Fargo Bank | USD | 96,646 | 4.45 | 08/05/2025 | 12/08/2025 | |||||||||||
| Wells Fargo Bank | USD | 94,372 | 4.10 | 10/28/2025 | 02/06/2026 | |||||||||||
| Wells Fargo Bank | USD | 46,310 | 4.20 | 11/26/2025 | 12/29/2025 | |||||||||||
| Wells Fargo Bank | USD | 91,487 | 4.01 | 12/29/2025 | 04/02/2026 | |||||||||||
| Total | 819,195 | |||||||||||||||
101
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 22. | Financial liabilities at amortized cost, continued: |
| (e) | Debt financial instruments issued, continued: |
Long-Term Bonds
| Series | Currency | Amount MCh$ | Terms | Annual interest rate % | Date of issuance | Maturity date |
||||||||||||||
| BCHIFC0721 | UF | 22,830 | 5 | 2.97 | 03/17/2025 | 01/01/2030 | ||||||||||||||
| BCHIFC0721 | UF | 11,422 | 5 | 2.97 | 03/20/2025 | 01/01/2030 | ||||||||||||||
| BCHIFC0721 | UF | 40,001 | 5 | 2.97 | 03/21/2025 | 01/01/2030 | ||||||||||||||
| BCHIFC0721 | UF | 30,548 | 5 | 2.96 | 04/01/2025 | 01/01/2030 | ||||||||||||||
| BCHIFO0721 | UF | 34,577 | 7 | 2.92 | 04/03/2025 | 01/01/2032 | ||||||||||||||
| BCHIFH1221 | UF | 33,047 | 6 | 2.84 | 04/15/2025 | 12/01/2030 | ||||||||||||||
| BCHIGG1121 | UF | 38,413 | 10 | 3.03 | 04/17/2025 | 05/01/2035 | ||||||||||||||
| BCHIHD0424 | UF | 81,115 | 10 | 3.03 | 04/17/2025 | 10/01/2034 | ||||||||||||||
| BCHIFH1221 | UF | 11,679 | 6 | 2.92 | 05/07/2025 | 12/01/2030 | ||||||||||||||
| BCHIGG1121 | UF | 5,712 | 10 | 3.03 | 05/09/2025 | 05/01/2035 | ||||||||||||||
| BCHIHN1223 | UF | 12,517 | 15 | 3.06 | 05/09/2025 | 12/01/2039 | ||||||||||||||
| BCHIFA0222 | UF | 22,900 | 3 | 2.77 | 05/30/2025 | 08/01/2028 | ||||||||||||||
| BCHIFH1221 | UF | 9,575 | 6 | 3.06 | 05/30/2025 | 12/01/2030 | ||||||||||||||
| BCHIFH1221 | UF | 13,407 | 6 | 3.06 | 06/02/2025 | 12/01/2030 | ||||||||||||||
| BCHIFH1221 | UF | 9,581 | 6 | 3.05 | 06/02/2025 | 12/01/2030 | ||||||||||||||
| BCHIFH1221 | UF | 8,667 | 6 | 3.04 | 06/03/2025 | 12/01/2030 | ||||||||||||||
| BCHIFH1221 | UF | 4,145 | 6 | 3.04 | 06/06/2025 | 12/01/2030 | ||||||||||||||
| BCHIFH1221 | UF | 25,567 | 6 | 3.04 | 06/10/2025 | 12/01/2030 | ||||||||||||||
| BCHIFO0721 | UF | 19,306 | 7 | 3.06 | 06/10/2025 | 01/01/2032 | ||||||||||||||
| BCHIGG1121 | UF | 23,174 | 10 | 3.15 | 07/03/2025 | 05/01/2035 | ||||||||||||||
| BCHICI0815 | UF | 19,989 | 8 | 3.14 | 07/09/2025 | 02/01/2033 | ||||||||||||||
| BCHICG0815 | UF | 49,639 | 7 | 3.14 | 07/10/2025 | 08/01/2032 | ||||||||||||||
| BCHICH1215 | UF | 15,721 | 8 | 3.14 | 07/10/2025 | 12/01/2032 | ||||||||||||||
| BCHICI0815 | UF | 5,996 | 8 | 3.14 | 07/10/2025 | 02/01/2033 | ||||||||||||||
| BCHIHW1223 | UF | 65,578 | 19 | 3.21 | 07/15/2025 | 06/01/2044 | ||||||||||||||
| BCHIGB0322 | UF | 8,589 | 9 | 3.18 | 07/17/2025 | 09/01/2034 | ||||||||||||||
| BCHIGB0322 | UF | 9,557 | 9 | 3.16 | 07/18/2025 | 09/01/2034 | ||||||||||||||
| BCHIGB0322 | UF | 5,747 | 9 | 3.13 | 07/21/2025 | 09/01/2034 | ||||||||||||||
| BCHIGB0322 | UF | 19,187 | 9 | 3.11 | 07/22/2025 | 09/01/2034 | ||||||||||||||
| BCHIGG1121 | UF | 5,718 | 10 | 3.11 | 07/22/2025 | 05/01/2035 | ||||||||||||||
| BCHIHW1223 | UF | 18,489 | 19 | 3.19 | 07/22/2025 | 06/01/2044 | ||||||||||||||
| BCHIGG1121 | UF | 3,870 | 10 | 2.99 | 08/22/2025 | 05/01/2035 | ||||||||||||||
| BCHIHN1223 | UF | 22,894 | 15 | 3.06 | 08/27/2025 | 12/01/2039 | ||||||||||||||
| BCHIGG1121 | UF | 15,519 | 10 | 3.01 | 09/04/2025 | 05/01/2035 | ||||||||||||||
| BCHIHW1223 | UF | 8,374 | 19 | 3.12 | 09/04/2025 | 06/01/2044 | ||||||||||||||
| BCHIGA1121 | UF | 38,815 | 9 | 3.05 | 09/05/2025 | 05/01/2034 | ||||||||||||||
| BCHIGD0721 | UF | 153,769 | 10 | 3.09 | 09/05/2025 | 01/01/2035 | ||||||||||||||
| BCHIHI1223 | UF | 206,194 | 12 | 3.13 | 09/05/2025 | 06/01/2037 | ||||||||||||||
| BCHIGA1121 | UF | 31,211 | 9 | 2.99 | 09/11/2025 | 05/01/2034 | ||||||||||||||
| BCHIGA1121 | UF | 1,951 | 9 | 2.99 | 09/15/2025 | 05/01/2034 | ||||||||||||||
| BCHIHW1223 | UF | 23,076 | 19 | 3.12 | 09/15/2025 | 06/01/2044 | ||||||||||||||
| BCHIHN1223 | UF | 41,978 | 14 | 3.03 | 09/16/2025 | 12/01/2039 | ||||||||||||||
| BCHIFU0522 | UF | 64,527 | 7 | 2.91 | 09/17/2025 | 11/01/2032 | ||||||||||||||
| BCHIGA1121 | UF | 21,475 | 9 | 2.99 | 09/17/2025 | 05/01/2034 | ||||||||||||||
| BCHIFU0522 | UF | 31,288 | 7 | 2.91 | 09/22/2025 | 11/01/2032 | ||||||||||||||
| BCHIGA1121 | UF | 5,862 | 9 | 2.98 | 09/22/2025 | 05/01/2034 | ||||||||||||||
| BCHIHH1223 | UF | 87,021 | 11 | 3.08 | 09/22/2025 | 12/01/2036 | ||||||||||||||
| BCHIHH1223 | UF | 66,367 | 11 | 3.07 | 09/23/2025 | 12/01/2036 | ||||||||||||||
| BCHIFU0522 | UF | 5,873 | 7 | 2.90 | 09/25/2025 | 11/01/2032 | ||||||||||||||
| BCHIGA1121 | UF | 25,525 | 9 | 2.99 | 10/28/2025 | 05/01/2034 | ||||||||||||||
| BCHIHW1223 | UF | 6,410 | 19 | 3.03 | 10/28/2025 | 06/01/2044 | ||||||||||||||
| BCHIHW1223 | UF | 12,850 | 19 | 3.02 | 10/30/2025 | 06/01/2044 | ||||||||||||||
| BCHIFU0522 | UF | 15,573 | 7 | 2.89 | 11/06/2025 | 11/01/2032 | ||||||||||||||
| Subtotal | 1,572,815 | |||||||||||||||||||
102
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 22. | Financial liabilities at amortized cost, continued: |
| (e) | Debt financial instruments issued, continued: |
Long-Term Bonds
| Series | Currency | Amount MCh$ | Terms Years | Annual interest rate % | Date of issuance | Maturity date | |||||||||||
| BONO CHF | CHF | 115,739 | 6 | 1.1875 | 06/17/2025 | 07/15/2031 | |||||||||||
| BONO JPY | JPY | 65,260 | 5 | 1.635 | 06/18/2025 | 06/27/2030 | |||||||||||
| BONO MXN | MXN | 50,998 | 5 | TIIE (28 days) + 1.05 | 07/09/2025 | 07/17/2030 | |||||||||||
| BONO AUD | AUD | 43,101 | 10 | BBSW3M +1.28 | 10/22/2025 | 10/30/2035 | |||||||||||
| BONO HKD | HKD | 75,233 | 7 | 3.735 | 10/30/2025 | 11/12/2032 | |||||||||||
| Subtotal | 350,331 | ||||||||||||||||
| Total | 1,923,146 | ||||||||||||||||
As of September 30, 2026 and December 31, 2025, the Bank has not presented defaults in the payment of principal and interest on its debt instruments. Likewise, there have been no breaches of covenants and other commitments associated with the debt instruments issued.
| (f) | Other Financial Obligations: |
At the end of each period, the composition of other financial obligations is as follows:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Other financial obligations in Chile | 328,605 | 367,323 | ||||||
| Other financial obligations with the public sector | — | — | ||||||
| Total | 328,605 | 367,323 | ||||||
| 23. | Regulatory capital financial instruments: |
| a) | At the end of each period, this item is composed as follows: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Subordinated bonds | ||||||||
| Subordinated bonds with transitory recognition | — | — | ||||||
| Subordinated bonds | 1,119,252 | 1,087,093 | ||||||
| Bonds with no fixed term of maturity | — | — | ||||||
| Preferred shares | — | — | ||||||
| Total | 1,119,252 | 1,087,093 | ||||||
| b) | Issuances of regulatory capital financial instruments in the period: |
As of September 30, 2026 and December 31, 2025, no issues of regulatory capital financial instruments have been made.
103
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 23. | Regulatory capital financial instruments, continued: |
| c) | Changes in regulatory capital financial instruments: |
| Subordinated bonds | Bonds with no fixed term of maturity | Preferred shares | ||||||||||
| MCh$ | MCh$ | MCh$ | ||||||||||
| Balance as of January 1, 2025 | 1,068,879 | — | — | |||||||||
| New issuances performed | — | — | — | |||||||||
| Transaction costs | — | — | — | |||||||||
| Amortization of transaction costs | — | — | — | |||||||||
| Accrued interest | 35,283 | — | — | |||||||||
| Acquisition or redemption by the issuer | — | — | — | |||||||||
| Modification of the issuance conditions | — | — | — | |||||||||
| Interest and UF indexation payments to the holder | (43,392 | ) | — | — | ||||||||
| Principal payments to the holder | (9,552 | ) | — | — | ||||||||
| Accrued UF indexation | 35,875 | — | — | |||||||||
| Exchange rate differences | — | — | — | |||||||||
| Depreciation | — | — | — | |||||||||
| Repricing | — | — | — | |||||||||
| Expiration | — | — | — | |||||||||
| Conversion to common shares | — | — | — | |||||||||
| Balance as of December 31, 2025 | 1,087,093 | — | — | |||||||||
| Balance as of January 1, 2026 | 1,087,093 | — | — | |||||||||
| New issuances performed | — | — | — | |||||||||
| Transaction costs | — | — | — | |||||||||
| Amortization of transaction costs | — | — | — | |||||||||
| Accrued interest | 26,780 | — | — | |||||||||
| Acquisition or redemption by the issuer | — | — | — | |||||||||
| Modification of the issuance conditions | — | — | — | |||||||||
| Interest and UF indexation payments to the holder | (24,432 | ) | — | — | ||||||||
| Principal payments to the holder | (5,920 | ) | — | — | ||||||||
| Accrued UF indexation | 35,731 | — | — | |||||||||
| Exchange rate differences | — | — | — | |||||||||
| Depreciation | — | — | — | |||||||||
| Repricing | — | — | — | |||||||||
| Expiration | — | — | — | |||||||||
| Conversion to common shares | — | — | — | |||||||||
| Balance as of September 30, 2026 | 1,119,252 | — | — | |||||||||
104
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 23. | Regulatory capital financial instruments, continued: |
| d) | Below is the detail of the subordinated bonds owed as of September 30, 2026 and December 31, 2025: |
| September 2026 | ||||||||||||||||||
| Series | Currency | Issuance currency amount | Interest rate % | Registration date | Maturity date | Balance owed MCh$ | ||||||||||||
| C1 | UF | 300,000 | 7.5 | 12/06/1999 | 01/01/2030 | 3,404 | ||||||||||||
| C1 | UF | 200,000 | 7.4 | 12/06/1999 | 01/01/2030 | 2,271 | ||||||||||||
| C1 | UF | 530,000 | 7.1 | 12/06/1999 | 01/01/2030 | 6,044 | ||||||||||||
| C1 | UF | 300,000 | 7.1 | 12/06/1999 | 01/01/2030 | 3,422 | ||||||||||||
| C1 | UF | 50,000 | 6.5 | 12/06/1999 | 01/01/2030 | 575 | ||||||||||||
| C1 | UF | 450,000 | 6.6 | 12/06/1999 | 01/01/2030 | 5,178 | ||||||||||||
| F | UF | 1,000,000 | 5.0 | 11/28/2008 | 11/01/2033 | 40,613 | ||||||||||||
| F | UF | 1,500,000 | 5.0 | 11/28/2008 | 11/01/2033 | 60,920 | ||||||||||||
| F | UF | 759,000 | 4.5 | 11/28/2008 | 11/01/2033 | 31,727 | ||||||||||||
| F | UF | 241,000 | 4.5 | 11/28/2008 | 11/01/2033 | 10,074 | ||||||||||||
| F | UF | 4,130,000 | 4.2 | 11/28/2008 | 11/01/2033 | 175,164 | ||||||||||||
| F | UF | 1,000,000 | 4.3 | 11/28/2008 | 11/01/2033 | 42,412 | ||||||||||||
| F | UF | 70,000 | 4.2 | 11/28/2008 | 11/01/2033 | 2,976 | ||||||||||||
| F | UF | 4,000,000 | 3.9 | 11/28/2008 | 11/01/2033 | 173,651 | ||||||||||||
| F | UF | 2,300,000 | 3.8 | 11/28/2008 | 11/01/2033 | 100,142 | ||||||||||||
| G | UF | 600,000 | 4.0 | 11/29/2011 | 11/01/2036 | 24,546 | ||||||||||||
| G | UF | 50,000 | 4.0 | 11/29/2011 | 11/01/2036 | 2,046 | ||||||||||||
| G | UF | 80,000 | 3.9 | 11/29/2011 | 11/01/2036 | 3,291 | ||||||||||||
| G | UF | 450,000 | 3.9 | 11/29/2011 | 11/01/2036 | 18,529 | ||||||||||||
| G | UF | 160,000 | 3.9 | 11/29/2011 | 11/01/2036 | 6,588 | ||||||||||||
| G | UF | 1,000,000 | 2.7 | 11/29/2011 | 11/01/2036 | 45,518 | ||||||||||||
| G | UF | 300,000 | 2.7 | 11/29/2011 | 11/01/2036 | 13,656 | ||||||||||||
| G | UF | 1,360,000 | 2.6 | 11/29/2011 | 11/01/2036 | 62,057 | ||||||||||||
| I | UF | 900,000 | 1.0 | 11/29/2011 | 11/01/2040 | 51,164 | ||||||||||||
| J | UF | 1,400,000 | 1.0 | 11/29/2011 | 11/01/2042 | 81,441 | ||||||||||||
| J | UF | 1,500,000 | 1.0 | 11/29/2011 | 11/01/2042 | 87,366 | ||||||||||||
| J | UF | 1,100,000 | 1.0 | 11/29/2011 | 11/01/2042 | 64,477 | ||||||||||||
| Total subordinated bonds owed | 1,119,252 | |||||||||||||||||
105
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 23. | Regulatory capital financial instruments, continued: |
| December 2025 | ||||||||||||||||||
| Series | Currency | Issuance currency amount | Interest rate % | Registration date | Maturity date | Balance owed MCh$ | ||||||||||||
| C1 | UF | 300,000 | 7.5 | 12/06/1999 | 01/01/2030 | 4,167 | ||||||||||||
| C1 | UF | 200,000 | 7.4 | 12/06/1999 | 01/01/2030 | 2,780 | ||||||||||||
| C1 | UF | 530,000 | 7.1 | 12/06/1999 | 01/01/2030 | 7,404 | ||||||||||||
| C1 | UF | 300,000 | 7.1 | 12/06/1999 | 01/01/2030 | 4,193 | ||||||||||||
| C1 | UF | 50,000 | 6.5 | 12/06/1999 | 01/01/2030 | 706 | ||||||||||||
| C1 | UF | 450,000 | 6.6 | 12/06/1999 | 01/01/2030 | 6,350 | ||||||||||||
| D1 | UF | 2,000,000 | 3.6 | 06/20/2002 | 04/01/2026 | 3,626 | ||||||||||||
| F | UF | 1,000,000 | 5.0 | 11/28/2008 | 11/01/2033 | 38,760 | ||||||||||||
| F | UF | 1,500,000 | 5.0 | 11/28/2008 | 11/01/2033 | 58,140 | ||||||||||||
| F | UF | 759,000 | 4.5 | 11/28/2008 | 11/01/2033 | 30,367 | ||||||||||||
| F | UF | 241,000 | 4.5 | 11/28/2008 | 11/01/2033 | 9,642 | ||||||||||||
| F | UF | 4,130,000 | 4.2 | 11/28/2008 | 11/01/2033 | 167,899 | ||||||||||||
| F | UF | 1,000,000 | 4.3 | 11/28/2008 | 11/01/2033 | 40,653 | ||||||||||||
| F | UF | 70,000 | 4.2 | 11/28/2008 | 11/01/2033 | 2,853 | ||||||||||||
| F | UF | 4,000,000 | 3.9 | 11/28/2008 | 11/01/2033 | 166,840 | ||||||||||||
| F | UF | 2,300,000 | 3.8 | 11/28/2008 | 11/01/2033 | 96,242 | ||||||||||||
| G | UF | 600,000 | 4.0 | 11/29/2011 | 11/01/2036 | 23,505 | ||||||||||||
| G | UF | 50,000 | 4.0 | 11/29/2011 | 11/01/2036 | 1,959 | ||||||||||||
| G | UF | 80,000 | 3.9 | 11/29/2011 | 11/01/2036 | 3,153 | ||||||||||||
| G | UF | 450,000 | 3.9 | 11/29/2011 | 11/01/2036 | 17,751 | ||||||||||||
| G | UF | 160,000 | 3.9 | 11/29/2011 | 11/01/2036 | 6,311 | ||||||||||||
| G | UF | 1,000,000 | 2.7 | 11/29/2011 | 11/01/2036 | 43,916 | ||||||||||||
| G | UF | 300,000 | 2.7 | 11/29/2011 | 11/01/2036 | 13,175 | ||||||||||||
| G | UF | 1,360,000 | 2.6 | 11/29/2011 | 11/01/2036 | 59,884 | ||||||||||||
| I | UF | 900,000 | 1.0 | 11/29/2011 | 11/01/2040 | 49,827 | ||||||||||||
| J | UF | 1,400,000 | 1.0 | 11/29/2011 | 11/01/2042 | 79,235 | ||||||||||||
| J | UF | 1,500,000 | 1.0 | 11/29/2011 | 11/01/2042 | 85,004 | ||||||||||||
| J | UF | 1,100,000 | 1.0 | 11/29/2011 | 11/01/2042 | 62,751 | ||||||||||||
| Total subordinated bonds owed | 1,087,093 | |||||||||||||||||
| 24. | Provision for contingencies: |
| (a) | At the end of each period, this line item is composed of the following: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Provisions for employee benefit obligations | 126,670 | 140,153 | ||||||
| Provisions for customer loyalty program and merit program obligations | 31,635 | 37,806 | ||||||
| Provisions for lawsuits and litigation | 2,480 | 2,037 | ||||||
| Provisions for operational risk | 244 | 552 | ||||||
| Provisions of a foreign bank branch for profit remittances to its parent company | — | — | ||||||
| Provisions for restructuring plans | — | — | ||||||
| Other provisions for other contingencies | — | — | ||||||
| Total | 161,029 | 180,548 | ||||||
106
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 24. | Provision for contingencies, continued; |
| (b) | The following table shows the changes in provisions during the periods 2026 and 2025: |
| Provisions for employee benefit obligations | Provisions of a foreign bank branch for profit remittances to its parent company | Provisions for restructuring plans | Provisions for lawsuits and litigation | Provisions for obligations of customer loyalty and merit programs | Provisions for operational risk | Other provisions for other contingencies | Total | |||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Balances as of January 1, 2025 | 151,633 | — | — | 1,592 | 40,621 | 907 | — | 194,753 | ||||||||||||||||||||||||
| Provisions established | 77,128 | — | — | 535 | — | 253 | — | 77,916 | ||||||||||||||||||||||||
| Provisions used | (98,280 | ) | — | — | (75 | ) | — | (644 | ) | — | (98,999 | ) | ||||||||||||||||||||
| Provisions released | — | — | — | (104 | ) | (201 | ) | (76 | ) | — | (381 | ) | ||||||||||||||||||||
| Balances as of September 30, 2025 | 130,481 | — | — | 1,948 | 40,420 | 440 | — | 173,289 | ||||||||||||||||||||||||
| Provisions established | 31,181 | — | — | 122 | — | 173 | — | 31,476 | ||||||||||||||||||||||||
| Provisions used | (21,509 | ) | — | — | (33 | ) | — | (51 | ) | — | (21,593 | ) | ||||||||||||||||||||
| Provisions released | — | — | — | — | (2,614 | ) | (10 | ) | — | (2,624 | ) | |||||||||||||||||||||
| Balances as of December 31, 2025 | 140,153 | — | — | 2,037 | 37,806 | 552 | — | 180,548 | ||||||||||||||||||||||||
| Provisions established | 82,505 | — | — | 715 | — | 81 | — | 83,301 | ||||||||||||||||||||||||
| Provisions used | (95,988 | ) | — | — | (188 | ) | — | (106 | ) | — | (96,282 | ) | ||||||||||||||||||||
| Provisions released | — | — | — | (84 | ) | (6,171 | ) | (283 | ) | — | (6,538 | ) | ||||||||||||||||||||
| Balances as of September 30, 2026 | 126,670 | — | — | 2,480 | 31,635 | 244 | — | 161,029 | ||||||||||||||||||||||||
| (c) | Provisions for employee benefit obligations: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Provision for short-term employee benefits | 120,145 | 131,763 | ||||||
| Provision for benefits to employees for contract termination | 6,525 | 8,390 | ||||||
| Provision for benefits to post-employment employees | — | — | ||||||
| Provision for long-term employee benefits | — | — | ||||||
| Provision for share-based employee benefits | — | — | ||||||
| Provision for obligations for defined contribution post-employment plans | — | — | ||||||
| Provision for obligations for post-employment defined benefit plans | — | — | ||||||
| Provision for other employee obligations | — | — | ||||||
| Total | 126,670 | 140,153 | ||||||
107
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 24. | Provision for contingencies, continued; |
| (d) | Provision for short-term employee benefits: |
| (i) | Compliance bonuses provision: |
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Balances as of January 1 | 67,352 | 68,356 | ||||||
| Net provisions established | 42,228 | 40,422 | ||||||
| Provisions used | (55,526 | ) | (54,878 | ) | ||||
| Total | 54,054 | 53,900 | ||||||
| (ii) | Vacation provision: |
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Balances as of January 1 | 43,238 | 42,824 | ||||||
| Net provisions established | 4,874 | 4,752 | ||||||
| Provisions used | (4,349 | ) | (5,293 | ) | ||||
| Total | 43,763 | 42,283 | ||||||
| (iii) | Provision of other benefits to personnel: |
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Balances as of January 1 | 21,173 | 32,125 | ||||||
| Net provisions established | 35,153 | 31,550 | ||||||
| Provisions used | (33,998 | ) | (37,766 | ) | ||||
| Total | 22,328 | 25,909 | ||||||
| (e) | Provision for benefits to employees for contract termination: |
| (i) | Changes of the provision for employee benefits due to the termination of the employment contract: |
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Present value of the obligations at the beginning of the period | 8,390 | 8,328 | ||||||
| Increase in provision | 303 | 342 | ||||||
| Benefit paid | (2,115 | ) | (343 | ) | ||||
| Effect of change in actuarial factors | (53 | ) | 62 | |||||
| Total | 6,525 | 8,389 | ||||||
108
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 24. | Provision for contingencies, continued; |
| (e) | Provision for benefits to employees for contract termination, continued: |
| (ii) | Net benefits expenses: |
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Increase (decrease) in provisions | (55 | ) | (114 | ) | ||||
| Interest cost of benefits obligations | 358 | 456 | ||||||
| Effect of change in actuarial factors | (53 | ) | 62 | |||||
| Net benefits expenses | 250 | 404 | ||||||
| (iii) | Factors used in the calculation of the provision: |
The main assumptions used in the determination of staff severance indemnity payment obligations for the Bank’s plan are shown below:
September
30, | December 31, 2025 | |||||||
| % | % | |||||||
| Discount rate | 5.71 | 5.71 | ||||||
| Salary increase rate | 4.47 | 5.50 | ||||||
| Probability of payment | 99.99 | 99.99 | ||||||
The most recent actuarial valuation of the staff severance indemnities provision was performed during the first quarter of 2026.
| (f) | Share-based compensation programs: |
As of September 30, 2026 and December 31, 2025, the Bank and its subsidiaries do not have a share-based compensation plan.
109
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 25. | Provision for dividends: |
| (a) | The detail of this line item is as follows: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Provisions for dividends | 457,161 | 605,955 | ||||||
| Provisions for payment of interest on bonds with no fixed maturity term | — | — | ||||||
| Provision for reappreciation of bonds without a fixed term of maturity | — | — | ||||||
| Total | 457,161 | 605,955 | ||||||
| (b) | Changes at the end of each period are detailed as follows: |
| Provisions for dividends | Provisions for payment of interest on bonds with no fixed maturity term | Provision for reappreciation of bonds without a fixed term of maturity | Total | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Balances as of January 1, 2025 | 597,228 | — | — | 597,228 | ||||||||||||
| Provisions established | 468,332 | — | — | 468,332 | ||||||||||||
| Provisions used | (597,228 | ) | — | — | (597,228 | ) | ||||||||||
| Provisions released | — | — | — | — | ||||||||||||
| Balances as of September 30, 2025 | 468,332 | — | — | 468,332 | ||||||||||||
| Provisions established | 137,623 | — | — | 137,623 | ||||||||||||
| Provisions used | — | — | — | — | ||||||||||||
| Provisions released | — | — | — | — | ||||||||||||
| Balances as of December 31, 2025 | 605,955 | — | — | 605,955 | ||||||||||||
| Provisions established | 457,161 | — | — | 457,161 | ||||||||||||
| Provisions used | (605,955 | ) | — | — | (605,955 | ) | ||||||||||
| Provisions released | — | — | — | — | ||||||||||||
| Balances as of September 30, 2026 | 457,161 | — | — | 457,161 | ||||||||||||
110
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 26. | Special provisions for credit risk: |
| a) | At the end of each period, this item is composed as follows: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Additional loan provisions | 681,217 | 631,217 | ||||||
| Provisions for credit risk for contingent loans (*) | 79,514 | 84,513 | ||||||
| Provisions for country risk for transactions with debtors with residence abroad | 14,342 | 5,552 | ||||||
| Special provisions for loans abroad | — | — | ||||||
| Provisions for adjustments to the minimum provision required for normal portfolio with individual evaluation | — | — | ||||||
| Provisions established by credit risk because of additional prudential requirements | — | — | ||||||
| Total | 775,073 | 721,282 | ||||||
| (*) | Changes in provisions for credit risk for contingent loans are disclosed in Note 13 letter (f). |
| b) | Changes in provisions for special credit risk are detailed as follows: |
| Additional loan provisions | Provisions for credit risk for contingent loans | Provisions for country risk for transactions with debtors with residence abroad | Total | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Balances as of January 1, 2025 | 700,252 | 67,537 | 6,395 | 774,184 | ||||||||||||
| Provisions established | — | 18,568 | 5,327 | 23,895 | ||||||||||||
| Provisions used | — | — | — | — | ||||||||||||
| Provisions released | (69,035 | ) | — | — | (69,035 | ) | ||||||||||
| Foreign exchange differences | — | (419 | ) | — | (419 | ) | ||||||||||
| Balances as of September 30, 2025 | 631,217 | 85,686 | 11,722 | 728,625 | ||||||||||||
| Provisions established | — | 290 | — | 290 | ||||||||||||
| Provisions used | — | — | — | — | ||||||||||||
| Provisions released | — | — | (6,170 | ) | (6,170 | ) | ||||||||||
| Foreign exchange differences | — | (1,463 | ) | — | (1,463 | ) | ||||||||||
| Balances as of December 31, 2025 | 631,217 | 84,513 | 5,552 | 721,282 | ||||||||||||
| Provisions established | 50,000 | — | 8,790 | 58,790 | ||||||||||||
| Provisions used | — | — | — | — | ||||||||||||
| Provisions released | — | (6,646 | ) | — | (6,646 | ) | ||||||||||
| Foreign exchange differences | — | 1,647 | — | 1,647 | ||||||||||||
| Balances as of September 30, 2026 | 681,217 | 79,514 | 14,342 | 775,073 | ||||||||||||
111
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 27. | Other Liabilities: |
At the end of each period, this line item is composed of the following:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Accounts payable to third parties | 629,088 | 435,717 | ||||||
| Creditors for intermediation of financial instruments | 410,263 | 417,372 | ||||||
| Obligations for mortgage loans granted to be remitted to other banks and/or real estate companies | 248,969 | 287,820 | ||||||
| Cash guarantees received for derivative financial transactions | 154,513 | 190,440 | ||||||
| Securities to be settled | 36,928 | — | ||||||
| Liability for income from regular activities from contracts with customers | 33,327 | 37,812 | ||||||
| Agreed dividends payable | 19,537 | 16,792 | ||||||
| VAT liability | 4,975 | 4,317 | ||||||
| Outstanding transactions | 2,498 | 1,858 | ||||||
| Other cash guarantees received | 632 | 573 | ||||||
| Other liabilities | 36,327 | 39,488 | ||||||
| Total | 1,577,057 | 1,432,189 | ||||||
112
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 28. | Equity: |
| (a) | Capital: |
| (i) | Authorized, subscribed and paid shares: |
As of September 30, 2026, the paid-in capital of Banco de Chile is represented by 101,017,081,114 registered shares (101,017,081,114 shares as of December 31, 2025), with no par value, subscribed and fully paid.
| As of September 30, 2026 | ||||||||
| Name of the company or shareholders | Number of Shares | Ownership % | ||||||
| LQ Inversiones Financieras S.A. | 46,815,289,329 | 46.344 | % | |||||
| Banchile Corredores de Bolsa S.A. | 5,480,233,759 | 5.425 | % | |||||
| Inversiones LQ-SM Limitada | 4,854,988,014 | 4.806 | % | |||||
| Banco de Chile on behalf of State Street | 3,968,120,449 | 3.928 | % | |||||
| Banco Santander on behalf of non-resident third parties | 3,134,207,754 | 3.103 | % | |||||
| Banco de Chile on behalf of non-resident third parties | 2,524,628,806 | 2.499 | % | |||||
| Banco de Chile on behalf of Citibank New York | 2,495,154,235 | 2.470 | % | |||||
| JP Morgan Chase Bank | 2,041,471,308 | 2.021 | % | |||||
| Banco Santander Chile | 1,943,904,261 | 1.924 | % | |||||
| Ever Chile SPA | 1,888,369,814 | 1.869 | % | |||||
| Ever 1 BAE SPA | 1,166,584,950 | 1.155 | % | |||||
| Bice Inversiones Corredora de Bolsa | 1,034,124,880 | 1.024 | % | |||||
| Larraín Vial S.A. Corredora de Bolsa | 998,092,630 | 0.988 | % | |||||
| Inversiones Avenida Borgoño Limitada | 882,604,102 | 0.874 | % | |||||
| A.F.P Habitat S.A. Fondo A | 810,296,382 | 0.802 | % | |||||
| Santander Corredores de Bolsa Limitada | 756,804,928 | 0.749 | % | |||||
| BCI Corredores de Bolsa S.A. | 683,261,942 | 0.677 | % | |||||
| A.F.P Cuprum S.A. Fondo A | 677,129,386 | 0.670 | % | |||||
| A.F.P Capital S.A. Fondo de Pensión A | 574,494,159 | 0.569 | % | |||||
| BTG Pactual Chile S.A. Corredores de Bolsa | 568,453,996 | 0.563 | % | |||||
| Subtotal | 83,298,215,084 | 82.460 | % | |||||
| Other shareholders | 17,718,866,030 | 17.540 | % | |||||
| Total | 101,017,081,114 | 100.000 | % | |||||
113
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 28. | Equity, continued: |
| (a) | Capital, continued: |
| (i) | Authorized, subscribed and paid shares, continued: |
| As of December 31, 2025 | ||||||||
| Name of the company or shareholders | Number of Shares | Ownership % | ||||||
| LQ Inversiones Financieras S.A. | 46,815,289,329 | 46.344 | % | |||||
| Banchile Corredores de Bolsa S.A. | 5,298,295,922 | 5.245 | % | |||||
| Inversiones LQ-SM Limitada | 4,854,988,014 | 4.806 | % | |||||
| Banco de Chile on behalf of State Street | 4,368,739,111 | 4.325 | % | |||||
| Banco Santander on behalf of foreign investors | 3,959,115,077 | 3.919 | % | |||||
| JP Morgan Chase Bank | 2,719,097,108 | 2.692 | % | |||||
| Banco de Chile on behalf of non-resident third parties | 2,355,382,741 | 2.332 | % | |||||
| Banco Santander Chile | 1,926,817,275 | 1.907 | % | |||||
| Ever Chile SPA | 1,888,369,814 | 1.869 | % | |||||
| Banco de Chile on behalf of Citibank New York | 1,663,309,364 | 1.647 | % | |||||
| Ever 1 BAE SPA | 1,166,584,950 | 1.155 | % | |||||
| Larraín Vial S.A. Corredora de Bolsa | 1,000,886,079 | 0.991 | % | |||||
| Inversiones Avenida Borgoño Limitada | 882,604,102 | 0.874 | % | |||||
| BCI Corredores de Bolsa S.A. | 779,379,823 | 0.772 | % | |||||
| A.F.P Habitat S.A. for A Fund | 758,929,122 | 0.751 | % | |||||
| Santander Corredores de Bolsa Limitada | 703,730,776 | 0.697 | % | |||||
| A.F.P Cuprum S.A. for A Fund | 635,579,418 | 0.629 | % | |||||
| Banco de Chile on behalf of Citibank London | 549,822,754 | 0.544 | % | |||||
| Valores Security S.A. Corredores de Bolsa | 527,069,658 | 0.522 | % | |||||
| A.F.P Capital S.A. Pension Fund A | 518,556,321 | 0.513 | % | |||||
| Subtotal | 83,372,546,758 | 82.534 | % | |||||
| Other shareholders | 17,644,534,356 | 17.466 | % | |||||
| Total | 101,017,081,114 | 100.000 | % | |||||
114
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 28. | Equity, continued: |
| (a) | Capital, continued: |
| (ii) | Shares: |
The following table shows the share movements from December 31, 2025 to September 30, 2026:
| Total | ||||
Ordinary Shares | ||||
| Total shares as of December 31, 2025 | 101,017,081,114 | |||
| Total shares as of September 30, 2026 | 101,017,081,114 | |||
| (b) | Approval and payment of dividends: |
At the Bank´s Ordinary Shareholders’ Meeting held on March 26, 2026, the distribution and payment of dividend No. 214 of Ch$9.99757030464 per share of the Banco de Chile was approved, with debit to the net distributable income for the year ended December 31, 2025. Dividends paid during 2026 amounted to Ch$1,009,925 million.
At the Bank´s Ordinary Shareholders’ Meeting held on March 27, 2025, the distribution and payment of dividend No. 213 of Ch$9.85357420889 per share of the Banco de Chile was approved, with debit to the net distributable income for the year ended December 31, 2024. Dividends paid during 2025 amounted to Ch$995,380 million.
| (c) | Provision for minimum dividends: |
The Board of Directors of Banco de Chile agreed for the purposes of minimum dividends, to establish a provision of 60% of the net income resulting from reducing or adding to the net income for the related year, the adjustment of the amount of paid-in capital and reserves as a result of variations in the Consumer Price Index (CPI) between the month prior to the current month and November of prior year. The amount to be reduced from net income for the period ended September 30, 2026 was Ch$184,993 million (Ch$182,337 million as of December 31, 2025).
As indicated, as of September 30, 2026, the amount of the net income determined in accordance with the preceding paragraph is equivalent to Ch$761,935 million (Ch$1,009,925 million as of December 31, 2025). Consequently, the Bank recorded a provision for minimum dividends under “Provision for dividends” as of September 30 of Ch$457,161 million (Ch$605,955 million in December 2025), which reflects as a counterpart an equity reduction for the same amount.
115
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 28. | Equity, continued: |
| (d) | Earnings per share: |
| (i) | Basic earnings per share: |
Basic earnings per share are determined by dividing the net income attributable to the Bank ordinary shareholders in a year between the weighted average number of shares outstanding during that year, excluding the average number of own shares held throughout the year.
| (ii) | Diluted earnings per share: |
In order to calculate the diluted earnings per share, both the amount of income attributable to common shareholders and the weighted average number of shares outstanding, net of own shares, must be adjusted for all the inherent dilutive effects to the potential common shares (stock options, warrants and convertible debt).
Accordingly, the basic and diluted earnings per share as of September 30, 2026 and 2025 were determined as follows:
| September | September | |||||||
| 2026 | 2025 | |||||||
| Basic earnings per share: | ||||||||
| Net profits attributable to bank´s shareholders (in millions of Chilean pesos) | 946,928 | 926,725 | ||||||
| Weighted average number of ordinary shares | 101,017,081,114 | 101,017,081,114 | ||||||
| Earning per shares (in Chilean pesos) | 9.37 | 9.17 | ||||||
| Diluted earnings per share: | ||||||||
| Net profits attributable to bank´s shareholders (in millions of Chilean pesos) | 946,928 | 926,725 | ||||||
| Weighted average number of ordinary shares | 101,017,081,114 | 101,017,081,114 | ||||||
| Assumed conversion of convertible debt | — | — | ||||||
| Adjusted number of shares | 101,017,081,114 | 101,017,081,114 | ||||||
| Diluted earnings per share (in Chilean pesos) | 9.37 | 9.17 | ||||||
As of September 30, 2026 and 2025, the Bank does not have instruments that generate dilutive effects.
116
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 28. | Equity, continued: |
| (e) | Other comprehensive income: |
The detail of and changes in accumulated other comprehensive income as of September 30, 2026 and 2025:
| Items that will not be reclassified to profit or loss | Items that can be reclassified to profit or loss | |||||||||||||||||||||||||||||||||||||||
| New measurements of net defined benefit liability and actuarial results for other employee benefit plans | Fair value changes of equity instruments designated as at FVTOCI | Income tax | Subtotal | Fair value changes of financial assets at FVTOCI | Cash flow accounting hedge | Participation in other comprehensive income of entities registered under the equity method | Income tax | Subtotal | Total | |||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||
| Opening balances as of January 1, 2025 | (298 | ) | 9,456 | (1,606 | ) | 7,552 | 4,478 | (12,397 | ) | (48 | ) | 4,192 | (3,775 | ) | 3,777 | |||||||||||||||||||||||||
| Other comprehensive income for the period | (62 | ) | (125 | ) | (459 | ) | (646 | ) | 8,698 | (14,892 | ) | 58 | 3,170 | (2,966 | ) | (3,612 | ) | |||||||||||||||||||||||
| Balances as of September 30, 2025 | (360 | ) | 9,331 | (2,065 | ) | 6,906 | 13,176 | (27,289 | ) | 10 | 7,362 | (6,741 | ) | 165 | ||||||||||||||||||||||||||
| Opening balances as of January 1, 2026 | (360 | ) | 9,308 | (2,054 | ) | 6,894 | 13,284 | (40,738 | ) | (107 | ) | 10,908 | (16,653 | ) | (9,759 | ) | ||||||||||||||||||||||||
| Other comprehensive income for the period | 53 | 6,325 | (1,696 | ) | 4,682 | (38,724 | ) | (43,731 | ) | 27 | 16,708 | (65,720 | ) | (61,038 | ) | |||||||||||||||||||||||||
| Balances as of September 30, 2026 | (307 | ) | 15,633 | (3,750 | ) | 11,576 | (25,440 | ) | (84,469 | ) | (80 | ) | 27,616 | (82,373 | ) | (70,797 | ) | |||||||||||||||||||||||
| (f) | Retained earnings from previous years: |
During the year 2026, the Ordinary Shareholders Meeting of Banco de Chile agreed to deduct and withhold from the year 2025 liquid income, an amount equivalent to the value effect of the monetary unit of paid capital and reserves according to the variation in the Consumer Price Index, which occurred between November 2024 and November 2025, amounting to Ch$182,337 million.
117
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 29. | Contingencies and Commitments: |
| (a) | The Bank and its subsidiaries have exposures associated with contingent loans and other liabilities according to the following detail: |
| (a.1) | Contingent loans: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Guarantees and sureties | ||||||||
| Guarantees and sureties in domestic currency | — | — | ||||||
| Guarantees and sureties in foreign currency | 301,157 | 288,710 | ||||||
| Letters of credit for goods circulation operations | 732,936 | 449,759 | ||||||
| Debt purchase commitments in local currency abroad | — | — | ||||||
| Transactions related to contingent events | ||||||||
| Transactions related to contingent events in domestic currency | 2,382,265 | 2,563,484 | ||||||
| Transactions related to contingent events in foreign currency | 528,637 | 609,777 | ||||||
| Undrawn credit lines with immediate termination | ||||||||
| Balance of lines of credit and agreed overdraft in current account – commercial loans | 1,810,604 | 1,764,560 | ||||||
| Balance of lines of credit on credit card – commercial loans | 412,368 | 370,983 | ||||||
| Balance of lines of credit and agreed overdraft in current account – consumer loans | 1,492,227 | 1,501,358 | ||||||
| Balance of lines of credit on credit card – consumer loans | 8,517,784 | 7,816,881 | ||||||
| Balance of lines of credit and agreed overdraft in current account – loans to banks | — | — | ||||||
| Undrawn credit lines | — | — | ||||||
| Other commitments | ||||||||
| Credits for higher studies Law No. 20,027 (CAE) | — | — | ||||||
| Other irrevocable loan commitments | 131,458 | 69,191 | ||||||
| Other credit commitments | — | — | ||||||
| Total | 16,309,436 | 15,434,703 | ||||||
| (a.2) | Responsibilities assumed to meet customer needs: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Transactions on behalf of third parties | ||||||||
| Collections | 106,706 | 138,556 | ||||||
| Placement or sale of financial instruments | — | — | ||||||
| Transferred financial assets managed by the bank | — | — | ||||||
| Third-party resources managed by the bank | 2,060,323 | 1,635,950 | ||||||
| Subtotal | 2,167,029 | 1,774,506 | ||||||
| Securities custody | ||||||||
| Securities safekept by a banking subsidiary | 10,781,271 | 9,719,621 | ||||||
| Securities safekept by the bank | 4,196,949 | 4,438,522 | ||||||
| Securities safekept deposited in another entity | 35,445,827 | 29,035,809 | ||||||
| Securities issued by the bank | — | — | ||||||
| Subtotal | 50,424,047 | 43,193,952 | ||||||
| Total | 52,591,076 | 44,968,458 | ||||||
118
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 29. | Contingencies and Commitments, continued: |
| (b) | Lawsuits and legal proceedings: |
| (b.1) | Normal judicial contingencies in the industry: |
At the date of issuance of these Interim Consolidated Financial Statements, there are legal actions filed against the Bank related with the ordinary course operations. As of September 30, 2026, the Bank maintain provisions for judicial contingencies amounting to Ch$2,480 million (Ch$2,037 million as of December 2025), which are part of the item “Provision for contingencies” in the Statement of Financial Position.
The estimated end dates of the respective legal contingencies are as follows:
| As of September 30, 2026 | ||||||||||||||||||||||||
| 2026 | 2027 | 2028 | 2029 | 2030 | Total | |||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||
| Legal contingencies | 461 | 1,400 | 619 | — | — | 2,480 | ||||||||||||||||||
| (b.2) | Contingencies for significant lawsuits: |
As of September 30, 2026 and December 31, 2025, there are not significant lawsuits in court that affect or may affect these Interim Consolidated Financial Statements.
| (c) | Guarantees granted by operations: |
| i. | In subsidiary Banchile Administradora General de Fondos S.A.: |
In compliance with Article No, 12 of Law No. 20,712, Banchile Administradora General de Fondos S.A., has designated Banco de Chile as the representative of the beneficiaries of the guarantees it has established, and in such role the Bank has issued bank guarantees totaling UF 5,601,966 maturing January 7, 2027. The subsidiary took out an insurance policy with Solunion Chile Seguros de Créditos S.A. for the Real Estate Funds for a guaranteed amount of UF 419,500.
As of September 30, 2026 and 2025, the Bank has not guaranteed mutual funds.
| ii. | In subsidiary Banchile Corredores de Bolsa S.A.: |
For the purposes of ensuring proper and full compliance with all of its obligations as broker-dealer entity, in conformity with the provisions from Article 30 and subsequent of Law No. 18,045 on Securities Markets, the subsidiary established a guarantee in an insurance policy of UF 20,000, insured by Solunion Chile Seguros de Créditos S.A., maturing on April 22, 2028, whereby the Securities Exchange of the Santiago Stock Exchange was appointed as the subsidiary’s creditor representative.
119
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 29. | Contingencies and Commitments, continued: |
| (c) | Guarantees granted by operations, continued: |
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Guarantees: | ||||||||
| Shares received as collateral for simultaneous operations: | ||||||||
| Santiago Securities Exchange, Stock Exchange | 4,497 | 23,244 | ||||||
| Electronic Chilean Securities Exchange, Stock Exchange | 34,513 | 37,559 | ||||||
| Fixed income securities delivered to guarantee CCLV system: | ||||||||
| Santiago Securities Exchange, Stock Exchange | 10,741 | 9,840 | ||||||
| Fixed income securities as collateral for the Santiago Stock Exchange | 2,248 | 2,148 | ||||||
| Shares delivered to guarantee equity lending and short-selling: | ||||||||
| Santiago Securities Exchange, Stock Exchange | 1,614 | — | ||||||
| Cash guarantees received for operations with derivatives | 1,125 | 8,477 | ||||||
| Cash guarantees for operations with derivatives | 11,108 | 2 | ||||||
| Equity securities received for operations with derivatives: | ||||||||
| Electronic Chilean Securities Exchange, Stock Exchange | 241 | — | ||||||
| Depósito Central de Valores S.A. | 4,277 | 1,635 | ||||||
| Total | 70,364 | 82,905 | ||||||
In conformity with the internal regulation of the stock exchanges in which it participates, and for the purpose of ensuring its proper performance, the subsidiary Banchile Corredores de Bolsa S.A maintains in favor of the Santiago Stock Exchange a guarantee in fixed income financial instruments equivalent to Ch$2,248 million. It also maintains a pledge in favor of the Electronic Stock Exchange for three hundred thousand shares of said institution.
Banchile Corredores de Bolsa S.A. keeps an insurance policy current with Chubb Seguros Chile S.A. that expires June 30, 2027, this considers matters of employee fidelity, physical losses, falsification or adulteration, and currency fraud with a coverage amount equivalent to US$20,000,000.
It also provided a bank guarantee in the amount of UF 511,100 for the benefits of investors in portfolio management contracts. This bank guarantee is revaluated in UF to fixed term, non-endorsable and has a maturity date of January 7, 2027.
It also provided a cash guarantee in the amount of US$122,494.32 for the purpose of complying with the obligations to Pershing, for any operations conducted through that broker, additionally, there are US$934,083.83 for variable income operations.
120
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 29. | Contingencies and Commitments, continued: |
| (c) | Guarantees granted by operations, continued: |
A guarantee of UF 10,000 has been constituted, to guarantee compliance with the investment portfolio management service contract. Such guarantee corresponds to a non-endorsable fixed-term readjustable bond in UF issued by Banco de Chile effective through January 27, 2028.
| iii. | In subsidiary Banchile Corredores de Seguros Ltda.: |
According to established in article 58, letter D of D.F.L. 251, as of September 30, 2026 the entity maintains two insurance policies effective from April 15, 2026 to April 14, 2027 which protect it against potential damages caused by infractions of the law, regulations and complementary rules that regulate insurance brokers, especially when the non-compliance comes from acts, errors or omissions of the broker, its representatives, agents or dependents that participate in the intermediation.
The policies contracted are:
| Matter insured | Amount insured (UF) | |||
| Errors and omissions liability policy | 500 | |||
| Civil responsibility policy | 60,000 | |||
| (d) | Exempt Resolution No. 270 dated October 30, 2014, the Superintendency of Securities and Insurance (current Commission for the Financial Market) imposed a fine of UF 50,000 to Banchile Corredores de Bolsa S.A. for violations of the second paragraph of article 53 of the Securities Market Law, said company filed a claim with the competent Civil Court requesting the annulment of the fine. On December 10, 2019, a judgement in the case was issued reducing the fine to the amount of UF 7,500, which was confirmed in the second instance by the Illustrious Court of Appeals of Santiago. The intervening parties filed cassation appeals in form and substance before the Supreme Court against the sentence in second instance. On August 13, 2024 the Supreme Court ordered the hearing of the case, which is pending as of this date. |
The company has not made provisions considering that the Bank’s legal advisors in charge of the procedure estimate that there are solid grounds that the claim filed by Banchile Corredores de Bolsa S.A. can be accepted.
121
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 30. | Interest Revenue and Expenses: |
| (a) | At the end of the period, the summary of interest is as follows: |
| For
the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Interest revenue | 2,082,661 | 2,033,098 | 706,263 | 687,107 | ||||||||||||
| Interest expenses | (707,962 | ) | (734,552 | ) | (240,563 | ) | (248,900 | ) | ||||||||
| Total net interest income | 1,374,699 | 1,298,546 | 465,700 | 438,207 | ||||||||||||
| (b) | The composition of interest revenue is as follows: |
| For
the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Financial assets at amortized cost: | ||||||||||||||||
| Rights by resale agreements | 4,667 | 3,814 | 1,417 | 1,180 | ||||||||||||
| Debt financial instruments | 8,403 | 9,306 | 2,761 | 2,818 | ||||||||||||
| Loans to Banks | 19,787 | 32,120 | 5,872 | 9,410 | ||||||||||||
| Commercial loans | 916,789 | 933,173 | 311,787 | 314,432 | ||||||||||||
| Residential mortgage loans | 363,972 | 338,380 | 123,470 | 115,593 | ||||||||||||
| Consumer Loans | 628,863 | 617,930 | 210,958 | 207,414 | ||||||||||||
| Other financial instruments | 30,771 | 36,099 | 11,787 | 12,193 | ||||||||||||
| Financial assets at fair value through other comprehensive income: | ||||||||||||||||
| Debt financial instruments | 137,955 | 89,760 | 50,064 | 35,760 | ||||||||||||
| Other financial instruments | — | — | — | — | ||||||||||||
| Income of accounting hedges on interest rate risk | (28,546 | ) | (27,484 | ) | (11,853 | ) | (11,693 | ) | ||||||||
| Total | 2,082,661 | 2,033,098 | 706,263 | 687,107 | ||||||||||||
| (b.1) | At the end of the period, the stock of interest not recognized in income is as follows: |
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Commercial loans | 37,321 | 37,996 | ||||||
| Residential mortgage loans | 10,984 | 8,243 | ||||||
| Consumer Loans | 4,413 | 3,735 | ||||||
| Total | 52,718 | 49,974 | ||||||
122
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 30. | Interest Revenue and Expenses, continued: |
| (c) | The composition of interest expenses is as follows: |
| For
the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Financial liabilities at amortized cost: | ||||||||||||||||
| Current accounts and other demand deposits | 1,067 | 830 | 461 | 341 | ||||||||||||
| Time deposits and saving accounts | 441,368 | 484,609 | 152,091 | 162,956 | ||||||||||||
| Obligations by repurchase agreements | 5,528 | 5,690 | 1,479 | 1,785 | ||||||||||||
| Borrowings from financial institutions | 39,200 | 46,248 | 13,649 | 15,699 | ||||||||||||
| Debt financial instruments issued | 234,708 | 209,845 | 80,050 | 74,753 | ||||||||||||
| Other financial obligations | — | — | — | — | ||||||||||||
| Lease liabilities | 1,362 | 1,621 | 452 | 508 | ||||||||||||
| Regulatory capital financial instruments | 26,780 | 26,393 | 9,057 | 8,882 | ||||||||||||
| Income of accounting hedges of interest rate risk | (42,051 | ) | (40,684 | ) | (16,676 | ) | (16,024 | ) | ||||||||
| Total | 707,962 | 734,552 | 240,563 | 248,900 | ||||||||||||
| (d) | As of September 30, 2026 and 2025, the Bank uses cross currency swaps to hedge the risk of variability of obligations flows with foreign banks and bonds issued in foreign currency. |
| For the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||||||||||||||||||||||||||||||||||
| Income | Expense | Total | Income | Expense | Total | Income | Expense | Total | Income | Expense | Total | |||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||
| Gain from fair value accounting hedges | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||
| Loss from fair value accounting hedges | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||
| Gain from cash flow accounting hedges | 26,342 | 73,655 | 99,997 | 63,132 | 112,807 | 175,939 | 12,396 | 31,728 | 44,124 | 8,164 | 29,475 | 37,639 | ||||||||||||||||||||||||||||||||||||
| Loss from cash flow accounting hedges | (54,888 | ) | (31,604 | ) | (86,492 | ) | (90,616 | ) | (72,123 | ) | (162,739 | ) | (24,249 | ) | (15,052 | ) | (39,301 | ) | (19,857 | ) | (13,451 | ) | (33,308 | ) | ||||||||||||||||||||||||
| Net gain on hedge item adjustment | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||
| Total | (28,546 | ) | 42,051 | 13,505 | (27,484 | ) | 40,684 | 13,200 | (11,853 | ) | 16,676 | 4,823 | (11,693 | ) | 16,024 | 4,331 | ||||||||||||||||||||||||||||||||
123
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 31. | Inflation indexation revenue and expense: |
| (a) | At the end of the period, the summary of inflation indexation is as follows: |
| For the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Inflation indexation revenue | 664,872 | 552,569 | 117,793 | 110,529 | ||||||||||||
| Inflation indexation expense | (370,140 | ) | (299,355 | ) | (65,106 | ) | (60,893 | ) | ||||||||
| Total net inflation indexation income | 294,732 | 253,214 | 52,687 | 49,636 | ||||||||||||
| (b) | The composition of Inflation indexation revenue is as follows |
| For the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Financial assets at amortized cost: | ||||||||||||||||
| Rights by resale agreements | — | — | — | — | ||||||||||||
| Debt financial instruments | 4,977 | 11,026 | 884 | 825 | ||||||||||||
| Loans to Banks | — | — | — | — | ||||||||||||
| Commercial loans | 253,214 | 209,894 | 43,931 | 42,529 | ||||||||||||
| Residential mortgage loans | 455,662 | 367,705 | 81,558 | 76,256 | ||||||||||||
| Consumer Loans | 715 | 773 | 113 | 143 | ||||||||||||
| Other financial instruments | 1,490 | 2,039 | 460 | 515 | ||||||||||||
| Financial assets at fair value through other comprehensive income: | ||||||||||||||||
| Debt financial instruments | 22,009 | 18,282 | 4,227 | 2,752 | ||||||||||||
| Other financial instruments | — | — | — | — | ||||||||||||
| Income of accounting hedges on interest rate risk | (73,195 | ) | (57,150 | ) | (13,380 | ) | (12,491 | ) | ||||||||
| Total | 664,872 | 552,569 | 117,793 | 110,529 | ||||||||||||
| (b.1) | At the end of the period, the stock of inflation indexation not recognized in results is detailed as follows: |
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Commercial loans | 4,575 | 4,099 | ||||||
| Residential mortgage loans | 11,224 | 8,636 | ||||||
| Consumer Loans | 9 | 10 | ||||||
| Total | 15,808 | 12,745 | ||||||
124
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 31. | Inflation indexation revenue and expense, continued: |
| (c) | The composition of Inflation indexation expense is as follows: |
| For the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Financial liabilities at amortized cost: | ||||||||||||||||
| Current accounts and other demand deposits | 13,159 | 13,890 | 2,086 | 2,384 | ||||||||||||
| Time deposits and saving accounts | 47,153 | 46,321 | 8,951 | 8,895 | ||||||||||||
| Obligations by repurchase agreements | — | — | — | — | ||||||||||||
| Borrowings from financial institutions | — | — | — | — | ||||||||||||
| Debt financial instruments issued | 274,097 | 209,845 | 47,722 | 43,654 | ||||||||||||
| Other financial obligations | — | — | — | — | ||||||||||||
| Regulatory capital financial instruments | 35,731 | 29,299 | 6,347 | 5,960 | ||||||||||||
| Income of accounting hedges of UF, IVP, IPC indexation risk | — | — | — | — | ||||||||||||
| Total | 370,140 | 299,355 | 65,106 | 60,893 | ||||||||||||
| (d) | As of September 30, 2026 and 2025, the Bank uses cross currency swaps to hedge the risk of variability of obligations flows with foreign banks and bonds issued in foreign currency. |
| For the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||||||||||||||||||||||||||||||||||
| Income | Expense | Total | Income | Expense | Total | Income | Expense | Total | Income | Expense | Total | |||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||
| Gain from fair value accounting hedges | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||
| Loss from fair value accounting hedges | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||
| Gain from cash flow accounting hedges | 1,189 | — | 1,189 | 6,766 | — | 6,766 | — | — | — | 5,075 | — | 5,075 | ||||||||||||||||||||||||||||||||||||
| Loss from cash flow accounting hedges | (74,384 | ) | — | (74,384 | ) | (63,916 | ) | — | (63,916 | ) | (13,380 | ) | — | (13,380 | ) | (17,566 | ) | — | (17,566 | ) | ||||||||||||||||||||||||||||
| Net gain on hedge item adjustment | — | — | — | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||
| Total | (73,195 | ) | — | (73,195 | ) | (57,150 | ) | — | (57,150 | ) | (13,380 | ) | — | (13,380 | ) | (12,491 | ) | — | (12,491 | ) | ||||||||||||||||||||||||||||
125
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 32. | Fee and commission income and expense: |
The fee and commission income and expense that are shown in the Interim Consolidated Statement of Income for the period are as follows:
| For the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Fee and commission income and services rendered | ||||||||||||||||
| Commissions from debit and credit card services | 215,466 | 189,812 | 71,452 | 63,128 | ||||||||||||
| Remuneration from administration of mutual funds, investment funds or others | 135,310 | 126,310 | 47,631 | 44,013 | ||||||||||||
| Account management fees | 59,827 | 56,712 | 20,535 | 19,843 | ||||||||||||
| Commissions from collections, recoveries and payments | 52,707 | 54,718 | 17,882 | 18,075 | ||||||||||||
| Commissions from guarantees and letters of credit | 31,878 | 32,210 | 10,850 | 11,000 | ||||||||||||
| Brand use agreement | 25,549 | 24,104 | 8,447 | 8,117 | ||||||||||||
| Commissions from trading and securities management | 24,114 | 17,829 | 8,212 | 6,325 | ||||||||||||
| Insurance not related to the granting of credits to natural persons | 19,447 | 19,318 | 6,555 | 6,490 | ||||||||||||
| Commissions from credit prepayments | 15,235 | 12,362 | 5,680 | 4,317 | ||||||||||||
| Use of distribution channel | 14,334 | 15,343 | 4,868 | 5,291 | ||||||||||||
| Insurance related to the granting of credits to natural persons | 7,035 | 6,266 | 2,230 | 2,077 | ||||||||||||
| Insurance not related to the granting of credits to legal entities | 5,737 | 5,178 | 1,847 | 1,825 | ||||||||||||
| Financial advisory services | 3,802 | 1,504 | 2,390 | 127 | ||||||||||||
| Commissions from lines of credit and overdrafts on current account | 3,667 | 3,680 | 1,255 | 1,224 | ||||||||||||
| Insurance related to the granting of credits to legal entities | 1,934 | 1,587 | 649 | 548 | ||||||||||||
| Commissions from factoring operations services | 946 | 968 | 330 | 342 | ||||||||||||
| Loan commissions with letters of credit | 4 | 17 | 1 | 5 | ||||||||||||
| Other commission earned | 20,106 | 19,018 | 6,252 | 6,270 | ||||||||||||
| Total | 637,098 | 586,936 | 217,066 | 199,017 | ||||||||||||
| Fee and commission expense and services received | ||||||||||||||||
| Commissions from card transactions | (47,033 | ) | (48,357 | ) | (15,370 | ) | (15,341 | ) | ||||||||
| Expenses due to obligations on loyalty programs and merits for cardholders | (33,094 | ) | (26,100 | ) | (12,413 | ) | (9,936 | ) | ||||||||
| Interbank transactions | (16,508 | ) | (20,648 | ) | (5,683 | ) | (7,280 | ) | ||||||||
| Commissions from use of card brands license | (7,253 | ) | (7,589 | ) | (2,949 | ) | (2,216 | ) | ||||||||
| Other fees for services related to the credit card system and payment cards with funds provision as a means of payment | (6,699 | ) | (24 | ) | (2,895 | ) | (24 | ) | ||||||||
| Commissions from securities transaction | (6,405 | ) | (4,369 | ) | (1,973 | ) | (1,480 | ) | ||||||||
| Collections and payments | (2,667 | ) | (3,025 | ) | (831 | ) | (996 | ) | ||||||||
| Other commissions from services received | (3,828 | ) | (4,051 | ) | (1,293 | ) | (1,495 | ) | ||||||||
| Total | (123,487 | ) | (114,163 | ) | (43,407 | ) | (38,768 | ) | ||||||||
| Total Net | 513,611 | 472,773 | 173,659 | 160,249 | ||||||||||||
126
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 33. | Net Financial Result: |
| (a) | The amount of net financial result shown in the Interim Consolidated Income Statement for the period corresponds to the following concepts: |
| For the nine-month period ended September 30 | 07.01.2026 to | 07.01.2025 to | ||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Financial result from: | ||||||||||||||||
| Financial assets held for trading at fair value through profit or loss: | ||||||||||||||||
| Financial derivative contracts | 3,877,079 | 1,663,993 | 1,670,792 | 680,084 | ||||||||||||
| Debt Financial Instruments | 72,611 | 101,652 | 10,103 | 32,391 | ||||||||||||
| Other financial instruments | 14,575 | 16,647 | 4,463 | 5,522 | ||||||||||||
| Financial liabilities held for trading at fair value through profit or loss: | ||||||||||||||||
| Financial derivative contracts | (3,872,308 | ) | (1,661,801 | ) | (1,673,157 | ) | (675,638 | ) | ||||||||
| Other financial instruments | (883 | ) | (298 | ) | 5 | 27 | ||||||||||
| Subtotal | 91,074 | 120,193 | 12,206 | 42,386 | ||||||||||||
| Non-trading financial assets mandatorily measured at fair value through profit or loss: | ||||||||||||||||
| Debt Financial Instruments | — | — | — | — | ||||||||||||
| Other financial instruments | — | — | — | — | ||||||||||||
| Financial assets designated as at fair value through profit or loss: | ||||||||||||||||
| Debt Financial Instruments | — | — | — | — | ||||||||||||
| Other financial instruments | — | — | — | — | ||||||||||||
| Financial liabilities designated as at fair value through profit or loss: | ||||||||||||||||
| Current accounts and other demand deposits and time deposits and savings accounts | — | — | — | — | ||||||||||||
| Debt instruments issued | — | — | — | — | ||||||||||||
| Others | — | — | — | — | ||||||||||||
| Derecognition of financial assets and liabilities at amortized cost and financial assets at fair value through other comprehensive income: | ||||||||||||||||
| Financial assets at amortized cost | 5 | (1,702 | ) | — | — | |||||||||||
| Financial assets at fair value through other comprehensive income | 7,896 | 13,148 | (19 | ) | 9,400 | |||||||||||
| Financial liabilities at amortized cost | — | — | — | — | ||||||||||||
| Regulatory capital financial instruments | — | — | — | — | ||||||||||||
| Subtotal | 7,901 | 11,446 | (19 | ) | 9,400 | |||||||||||
| Exchange, indexation and accounting hedging of foreign currency: | ||||||||||||||||
| Gain (loss) from foreign currency exchange | (100,190 | ) | 52,731 | (101,847 | ) | (55,647 | ) | |||||||||
| Gain (loss) from indexation for exchange rate | 13,679 | (5,840 | ) | 10,963 | 4,431 | |||||||||||
| Net gain (loss) from derivatives in accounting hedges of foreign currency risk | 155,021 | 23,801 | 118,884 | 72,168 | ||||||||||||
| Subtotal | 68,510 | 70,692 | 28,000 | 20,952 | ||||||||||||
| Reclassification of financial assets for changes to business models: | ||||||||||||||||
| From financial assets at amortized cost to financial assets held for trading at fair value through profit or loss | — | — | — | — | ||||||||||||
| From financial assets at fair value through other comprehensive income to financial assets held for trading at fair value through profit or loss | — | — | — | — | ||||||||||||
| Modifications of financial assets and liabilities: | ||||||||||||||||
| Financial assets at amortized cost | — | — | — | — | ||||||||||||
| Financial assets at fair value through other comprehensive income | — | — | — | — | ||||||||||||
| Financial liabilities at amortized cost | — | — | — | — | ||||||||||||
| Lease liabilities | — | — | — | — | ||||||||||||
| Regulatory capital financial instruments | — | — | — | — | ||||||||||||
| Ineffective accounting hedges: | ||||||||||||||||
| Gain (loss) from ineffective cash flow accounting hedges | — | — | — | — | ||||||||||||
| Gain (loss) from ineffective accounting hedges of net investment abroad | — | — | — | — | ||||||||||||
| Other type of accounting hedges: | ||||||||||||||||
| Hedges of other types of financial assets | — | — | — | — | ||||||||||||
| Total | 167,485 | 202,331 | 40,187 | 72,738 | ||||||||||||
127
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 33. | Net Financial Result, continued: |
| (b) | The detail of the income (expense) associated with the changes in allowances for credit losses on loans and contingent loans denominated in foreign currency, which is reflected in “Exchange, indexation and accounting hedging of foreign currency”. |
| For
the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Loans to Banks | (45 | ) | 28 | (36 | ) | (19 | ) | |||||||||
| Commercial loans | (6,131 | ) | 2,222 | (4,400 | ) | (2,968 | ) | |||||||||
| Residential mortgage loans | — | — | — | — | ||||||||||||
| Consumer loans | (241 | ) | 60 | (152 | ) | (92 | ) | |||||||||
| Contingent loans | (1,647 | ) | 419 | (1,203 | ) | (734 | ) | |||||||||
| Total | (8,064 | ) | 2,729 | (5,791 | ) | (3,813 | ) | |||||||||
| 34. | Income from investments in other companies: |
The income obtained from investments in companies detailed in Note 14 corresponds to the following:
| September | September | |||||||||
| Shareholder | 2026 | 2025 | ||||||||
| MCh$ | MCh$ | |||||||||
| Income attributable to investments in other companies: | ||||||||||
| Associates | ||||||||||
| Centro de Compensación Automatizado S.A. | Banco de Chile | 1,694 | 1,415 | |||||||
| Redbanc S.A. | Banco de Chile | 1,159 | 952 | |||||||
| Sociedad Interbancaria de Depósitos de Valores S.A. | Banco de Chile | 435 | 382 | |||||||
| Administrador Financiero de Transantiago S.A. | Banco de Chile | 335 | 341 | |||||||
| Transbank S.A. | Banco de Chile | 255 | 3,958 | |||||||
| Sociedad Operadora de la Cámara de Compensación de Pagos de Alto Valor S.A. | Banco de Chile | 157 | 170 | |||||||
| Servicios de Infraestructura de Mercado OTC S.A. | Banco de Chile | 2 | 58 | |||||||
| Subtotal Associates | 4,037 | 7,276 | ||||||||
| Joint Ventures | ||||||||||
| Servipag Ltda. | Banco de Chile | 377 | 765 | |||||||
| Subtotal Joint Ventures | 377 | 765 | ||||||||
| Subtotal | 4,414 | 8,041 | ||||||||
| Minority Investments | ||||||||||
| Holding Bursátil Regional S.A. | Banchile Corredores de Bolsa | 431 | 315 | |||||||
| Banco Latinoamericano de Comercio Exterior S.A. (Bladex) | Banco de Chile | 112 | 108 | |||||||
| Bolsa Electrónica de Chile, Bolsa de Valores | Banchile Corredores de Bolsa | 29 | 16 | |||||||
| CCLV Contraparte Central S.A. | Banchile Corredores de Bolsa | 3 | 1 | |||||||
| Subtotal Minority Investments | 575 | 440 | ||||||||
| Total Investments in other companies | 4,989 | 8,481 | ||||||||
128
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 35. | Income (expense) from non-current assets and disposal groups held for sale not admissible as discontinued operations: |
The composition of the results of non-current assets and disposal groups not eligible as discontinued operations during the periods 2026 and 2025 is as follows:
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Net income from assets received in payment or awarded in judicial auction | ||||||||
| Gain (loss) on sale of assets received in lieu of payment or awarded in judicial auction | 13,818 | 11,527 | ||||||
| Other income from assets received in lieu of payment or awarded in judicial auction | 6 | 51 | ||||||
| Provisions for adjustments to net realizable value of assets received in lieu of payment or awarded in judicial auction | (1,890 | ) | (1,939 | ) | ||||
| Write-off of assets received in lieu of payment or awarded in judicial auction | (10,981 | ) | (12,269 | ) | ||||
| Expenses to maintain assets received in lieu of payment or awarded in judicial auction | (1,761 | ) | (1,284 | ) | ||||
| Non-current assets held for sale | ||||||||
| Investments in other companies | — | — | ||||||
| Intangible assets | — | — | ||||||
| Property and equipment | 6,597 | 6,182 | ||||||
| Assets for recovery of assets transferred in financial lease operations | 1,527 | 1,493 | ||||||
| Other assets | — | — | ||||||
| Disposal groups held for sale | — | — | ||||||
| Total | 7,316 | 3,761 | ||||||
| 36. | Other operating Income and Expenses: |
| a) | During the periods 2026 and 2025, the Bank and its subsidiaries record other operating income, detailed as follows: |
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Indexation of tax refunds from previous years | 26,410 | 11,110 | ||||||
| Expense recovery | 19,234 | 20,298 | ||||||
| Income from migration contract fulfillment | 11,561 | — | ||||||
| Income from investment property | 5,534 | 5,222 | ||||||
| Indexation of monthly tax provisional payments | 2,357 | 1,323 | ||||||
| Other income | 570 | 404 | ||||||
| Total | 65,666 | 38,357 | ||||||
129
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 36. | Other operating Income and Expenses, continued: |
| b) | During the periods 2026 and 2025, the Bank and its subsidiaries present other operating expenses, according to the following: |
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Write-offs for operating risks | 23,148 | 19,897 | ||||||
| Provisions for lawsuits, litigation and contingencies | 6,443 | 356 | ||||||
| Expense in insurance premiums to cover operational risk events | 4,628 | 4,707 | ||||||
| Card administration | 3,041 | 3,160 | ||||||
| Expenses for financial lease loan operations | 1,677 | 3,357 | ||||||
| Legal expenses and lawsuits | 1,456 | 1,545 | ||||||
| Expenses for write-off of leased assets recoveries | 608 | 276 | ||||||
| Write-offs for commercial decisions | 557 | 509 | ||||||
| Appraisal expense | 265 | 248 | ||||||
| Life insurance | 262 | 233 | ||||||
| Renegotiated loan insurance premium | 127 | 147 | ||||||
| (Release) expense on provisions for operational risk | (109 | ) | (468 | ) | ||||
| Provision for pending operations | (252 | ) | 589 | |||||
| Expense recovery from operational risk events | (10,278 | ) | (10,184 | ) | ||||
| Other expenses | 836 | 437 | ||||||
| Total | 32,409 | 24,809 | ||||||
| 37. | Personnel expenses: |
The composition of the expense for employee benefit obligations during the periods 2026 and 2025 is as follows:
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Expenses for short-term employee benefits | 409,843 | 393,277 | ||||||
| Expenses for employee benefits due to termination of employment contract | 14,677 | 16,519 | ||||||
| Training expenses | 3,119 | 2,535 | ||||||
| Expenses for nursery and kindergarten | 1,016 | 1,146 | ||||||
| Other personnel expenses | 4,903 | 5,086 | ||||||
| Total | 433,558 | 418,563 | ||||||
130
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 38. | Administrative expenses: |
This item is composed as follows:
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| General administrative expenses | ||||||||
| Information technology and communications | 129,997 | 118,824 | ||||||
| Maintenance and repair of property and equipment | 39,719 | 38,154 | ||||||
| Surveillance and securities transport services | 8,000 | 8,016 | ||||||
| External advisory services and professional services fees | 6,979 | 6,852 | ||||||
| External financial information and fraud prevention service | 6,544 | 6,520 | ||||||
| Office supplies | 6,131 | 6,836 | ||||||
| Legal and notary expenses | 5,721 | 5,106 | ||||||
| Energy, heating and other utilities | 5,028 | 5,063 | ||||||
| Donations | 3,484 | 2,071 | ||||||
| Other expenses of obligations for lease contracts | 3,219 | 2,982 | ||||||
| External service of documentation custody | 3,150 | 3,427 | ||||||
| Insurance premiums except to cover operational risk events | 2,998 | 2,853 | ||||||
| Postal box, mail, postage and home delivery services | 2,990 | 3,090 | ||||||
| Expenses for short-term leases | 2,762 | 3,798 | ||||||
| Representation and travel expenses | 2,597 | 2,413 | ||||||
| Card embossing service | 1,760 | 1,698 | ||||||
| Fees for other technical reports | 748 | 617 | ||||||
| Fees for review and audit of the financial statements by the external auditor | 748 | 693 | ||||||
| Expenses for leases low value | 326 | 413 | ||||||
| Title classification fees | 191 | 77 | ||||||
| Fines applied by other agencies | 62 | 28 | ||||||
| Other general administrative expenses | 15,784 | 14,193 | ||||||
| Outsourced services | ||||||||
| Technological developments expenses, certification and technology testing | 14,994 | 15,726 | ||||||
| Data processing | 10,395 | 8,658 | ||||||
| External credit evaluation service | 2,763 | 4,298 | ||||||
| Sales service, marketing, distribution for products, quality control customer service | 1,830 | 717 | ||||||
| External collection service | 1,654 | 2,931 | ||||||
| External human resources administration services and supply of external personnel | 1,458 | 1,511 | ||||||
| External cleaning service, cafeteria, custody of files and documents, storage of furniture and equipment | 225 | 265 | ||||||
| Other outsourced services | 1,462 | 985 | ||||||
| Board of Director’s expenses | ||||||||
| Board of Directors’ remuneration | 2,566 | 2,681 | ||||||
| Other Board of directors’ expenses | 7 | 72 | ||||||
| Advertising | 27,656 | 29,294 | ||||||
| Taxes, contribution payments and other legal charges | ||||||||
| Contribution to the banking regulator | 11,640 | 11,015 | ||||||
| Property taxes | 3,968 | 5,553 | ||||||
| Taxes other than income tax | 2,368 | 2,214 | ||||||
| Municipal patents | 1,412 | 1,406 | ||||||
| Other legal charges | 38 | 47 | ||||||
| Total | 333,374 | 321,097 | ||||||
131
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 39. | Depreciation and Amortization: |
The amounts corresponding to debits to profit or loss for depreciation and amortization during the periods 2026 and 2025, are detailed as follows:
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Amortization of intangibles assets | ||||||||
| Other intangible assets arising from business combinations | — | — | ||||||
| Other independently originated intangible assets | 34,161 | 30,604 | ||||||
| Depreciation of property and equipment | ||||||||
| Buildings and land | 6,943 | 7,347 | ||||||
| Other property and equipment | 9,572 | 10,482 | ||||||
| Depreciation and impairment of leased assets | ||||||||
| Buildings and land | 21,196 | 21,532 | ||||||
| Other property and equipment | — | — | ||||||
| Depreciation for improvements in leased real estate as right-to-use lease assets | 798 | 790 | ||||||
| Amortization for the right-to-use other intangible assets under lease | — | — | ||||||
| Depreciation of other assets for investment properties | 260 | 268 | ||||||
| Amortization of other assets per activity income asset | — | — | ||||||
| Total | 72,930 | 71,023 | ||||||
| 40. | Impairment of non-financial assets: |
As of September 30, 2026 and 2025, the detail of the line item for impairment of non-financial assets is composed as follows:
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Impairment of intangible assets | — | 19 | ||||||
| Impairment of property and equipment | 11 | 259 | ||||||
| Impairment of assets from revenue from contracts with customers | 548 | 2,548 | ||||||
| Total | 559 | 2,826 | ||||||
132
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 41. | Credit loss expense: |
| (a) | The composition is as follows: |
| For the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Expense of allowances established for credit risk | 390,774 | 359,665 | 128,009 | 105,363 | ||||||||||||
| Expense (release) of special provisions for credit risk | 52,144 | (45,140 | ) | (353 | ) | (9,399 | ) | |||||||||
| Recovery of written-off loans | (62,674 | ) | (51,580 | ) | (29,010 | ) | (17,904 | ) | ||||||||
| Impairments for credit risk of other financial assets at amortized cost and financial assets at FVTOCI | (4,594 | ) | 3,135 | (2,254 | ) | 1,500 | ||||||||||
| Total | 375,650 | 266,080 | 96,392 | 79,560 | ||||||||||||
| (b) | Summary of the expense of allowances constituted for credit risk and expense for credit losses: |
| Expense of allowances constituted in the period | ||||||||||||||||||||||||||||||||
| Normal Portfolio | Substandard Portfolio | Non-Performing Portfolio | Deductible guarantees | |||||||||||||||||||||||||||||
| Evaluation | Evaluation | Evaluation | Fogape | |||||||||||||||||||||||||||||
| As of September 30, 2026 | Individual | Group | Individual | Individual | Group | Subtotal | Covid-19 | Total | ||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Loans to Banks | ||||||||||||||||||||||||||||||||
| Allowances established | 115 | — | — | — | — | 115 | — | 115 | ||||||||||||||||||||||||
| Allowances released | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Subtotal | 115 | — | — | — | — | 115 | — | 115 | ||||||||||||||||||||||||
| Commercial loans | ||||||||||||||||||||||||||||||||
| Allowances established | 9,898 | 1,558 | — | 6,262 | 52,942 | 70,660 | — | 70,660 | ||||||||||||||||||||||||
| Allowances released | — | — | (1,726 | ) | — | — | (1,726 | ) | (79 | ) | (1,805 | ) | ||||||||||||||||||||
| Subtotal | 9,898 | 1,558 | (1,726 | ) | 6,262 | 52,942 | 68,934 | (79 | ) | 68,855 | ||||||||||||||||||||||
| Residential mortgage loans | ||||||||||||||||||||||||||||||||
| Allowances established | — | 776 | — | — | 12,590 | 13,366 | — | 13,366 | ||||||||||||||||||||||||
| Allowances released | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Subtotal | — | 776 | — | — | 12,590 | 13,366 | — | 13,366 | ||||||||||||||||||||||||
| Consumer loans | ||||||||||||||||||||||||||||||||
| Allowances established | — | — | — | — | 316,364 | 316,364 | — | 316,364 | ||||||||||||||||||||||||
| Allowances released | — | (7,926 | ) | — | — | — | (7,926 | ) | — | (7,926 | ) | |||||||||||||||||||||
| Subtotal | — | (7,926 | ) | — | — | 316,364 | 308,438 | — | 308,438 | |||||||||||||||||||||||
| Expense (release) of provisions for credit risk | 10,013 | (5,592 | ) | (1,726 | ) | 6,262 | 381,896 | 390,853 | (79 | ) | 390,774 | |||||||||||||||||||||
| Recovery of written-off loans | ||||||||||||||||||||||||||||||||
| Loans to Banks | — | |||||||||||||||||||||||||||||||
| Commercial loans | (16,238 | ) | ||||||||||||||||||||||||||||||
| Residential mortgage loans | (3,848 | ) | ||||||||||||||||||||||||||||||
| Consumer loans | (42,588 | ) | ||||||||||||||||||||||||||||||
| Subtotal | (62,674 | ) | ||||||||||||||||||||||||||||||
| Loan credit loss expenses | 328,100 | |||||||||||||||||||||||||||||||
133
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 41. | Credit loss expense, continued: |
| (b) | Summary of the expense of allowances constituted for credit risk and expense for credit losses, continued; |
| Expense of allowances constituted in the period | ||||||||||||||||||||||||||||||||
| Normal Portfolio | Substandard Portfolio | Non-Performing Portfolio | Deductible guarantees | |||||||||||||||||||||||||||||
| Evaluation | Evaluation | Evaluation | Fogape | |||||||||||||||||||||||||||||
| As of September 30, 2025 | Individual | Group | Individual | Individual | Group | Subtotal | Covid-19 | Total | ||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Loans to Banks | ||||||||||||||||||||||||||||||||
| Allowances established | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Allowances released | (51 | ) | — | — | — | — | (51 | ) | — | (51 | ) | |||||||||||||||||||||
| Subtotal | (51 | ) | — | — | — | — | (51 | ) | — | (51 | ) | |||||||||||||||||||||
| Commercial loans | ||||||||||||||||||||||||||||||||
| Allowances established | — | 1,882 | 2,480 | 12,377 | 45,579 | 62,318 | — | 62,318 | ||||||||||||||||||||||||
| Allowances released | (1,898 | ) | — | — | — | — | (1,898 | ) | (1,610 | ) | (3,508 | ) | ||||||||||||||||||||
| Subtotal | (1,898 | ) | 1,882 | 2,480 | 12,377 | 45,579 | 60,420 | (1,610 | ) | 58,810 | ||||||||||||||||||||||
| Residential mortgage loans | ||||||||||||||||||||||||||||||||
| Allowances established | — | — | — | — | 8,936 | 8,936 | — | 8,936 | ||||||||||||||||||||||||
| Allowances released | — | (381 | ) | — | — | — | (381 | ) | — | (381 | ) | |||||||||||||||||||||
| Subtotal | — | (381 | ) | — | — | 8,936 | 8,555 | — | 8,555 | |||||||||||||||||||||||
| Consumer loans | ||||||||||||||||||||||||||||||||
| Allowances established | — | 48,698 | — | — | 243,653 | 292,351 | — | 292,351 | ||||||||||||||||||||||||
| Allowances released | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Subtotal | — | 48,698 | — | — | 243,653 | 292,351 | — | 292,351 | ||||||||||||||||||||||||
| Expense (release) of provisions for credit risk | (1,949 | ) | 50,199 | 2,480 | 12,377 | 298,168 | 361,275 | (1,610 | ) | 359,665 | ||||||||||||||||||||||
| Recovery of written-off credits | ||||||||||||||||||||||||||||||||
| Loans to Banks | — | |||||||||||||||||||||||||||||||
| Commercial loans | (12,056 | ) | ||||||||||||||||||||||||||||||
| Residential mortgage loans | (5,898 | ) | ||||||||||||||||||||||||||||||
| Consumer loans | (33,626 | ) | ||||||||||||||||||||||||||||||
| Subtotal | (51,580 | ) | ||||||||||||||||||||||||||||||
| Loan credit loss expenses | 308,085 | |||||||||||||||||||||||||||||||
134
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 41. | Credit loss expense, continued: |
| (c) | Summary of expense for special provisions for credit risk: |
| For the nine-month period ended September 30, | 07.01.2026 to | 07.01.2025 to | ||||||||||||||
| 2026 | 2025 | 09.30.2026 | 09.30.2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Expenses (release) of provisions for contingent loans: | ||||||||||||||||
| Loans to Banks | — | — | — | — | ||||||||||||
| Commercial loans | (7,834 | ) | (10,591 | ) | (4,728 | ) | (9,809 | ) | ||||||||
| Consumer loans | 1,188 | 29,159 | 306 | 410 | ||||||||||||
| Expenses from provisions for country risk for transactions with debtors with residence abroad | 8,790 | 5,327 | 4,069 | — | ||||||||||||
| Expense of special provisions for loans abroad | — | — | — | — | ||||||||||||
| Expenses of additional loan provisions: | ||||||||||||||||
| Commercial loans | 50,000 | (69,035 | ) | — | — | |||||||||||
| Residential mortgage loans | — | — | — | — | ||||||||||||
| Consumer loans | — | — | — | — | ||||||||||||
| Expense of other special provisions established for credit risk | 52,144 | (45,140 | ) | (353 | ) | (9,399 | ) | |||||||||
| 42. | Income from discontinued operations: |
As of September 30, 2026 and 2025, the Bank does not record income from discontinued operations.
| 43. | Related Party Disclosures: |
Related parties are considered to be those persons or legal entities who are in positions to directly or indirectly have significant influence through their ownership or management of the Bank and its subsidiaries, as set out in the Compendium of Accounting Standards for Banks and Chapter 12-4 of the current Compilation of Standards issued by the CMF.
Accordingly, the Bank has considered as related parties those persons or legal entities who have a direct participation or through third parties on Bank ownership, where such ownership exceeds 5% of the shares, as well as persons who, regardless of ownership, have authority and responsibility for planning, management and control of the activities of the entity or its subsidiaries. Companies in which the parties related by ownership or management of the Bank have a share which reaches or exceeds 5%, or has the position of director, general manager or equivalent are considered related parties.
135
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 43. | Related Party Disclosures, continued: |
| (a) | Assets and liabilities with related parties: |
| Related Party Type | ||||||||||||||||||||
Type of current assets and liabilities with related parties As of September 30, 2026 | Parent Entity | Other Legal Entity | Key Personnel of the Consolidated Bank | Other Related Parties | Total | |||||||||||||||
| ASSETS | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||
| Financial assets held for trading at fair value through profit or loss: | ||||||||||||||||||||
| Derivative Financial Instruments | — | 279,496 | — | — | 279,496 | |||||||||||||||
| Debt financial instruments | — | — | — | — | — | |||||||||||||||
| Other financial instruments | — | 184 | — | — | 184 | |||||||||||||||
| Non-trading financial assets mandatorily measured at fair value through profit or loss | — | — | — | — | — | |||||||||||||||
| Financial assets designated as at fair value through profit or loss | — | — | — | — | — | |||||||||||||||
| Financial assets at fair value through other comprehensive income | — | 35,493 | — | — | 35,493 | |||||||||||||||
| Derivative financial instruments for hedging purposes | — | 3,651 | — | — | 3,651 | |||||||||||||||
| Financial assets at amortized cost: | ||||||||||||||||||||
| Rights by resale agreements | — | — | — | — | — | |||||||||||||||
| Debt financial instruments | — | — | — | — | — | |||||||||||||||
| Commercial loans | — | 235,668 | 1,879 | 10,605 | 248,152 | |||||||||||||||
| Residential mortgage loans | — | — | 16,563 | 61,358 | 77,921 | |||||||||||||||
| Consumer Loans | — | — | 1,690 | 9,903 | 11,593 | |||||||||||||||
| Allowances established – loans | (1,545 | ) | (76 | ) | (446 | ) | (2,067 | ) | ||||||||||||
| Other assets | 17 | 228,325 | 1 | 19 | 228,362 | |||||||||||||||
| Contingent loans | — | 119,234 | 3,837 | 17,985 | 141,056 | |||||||||||||||
| LIABILITIES | ||||||||||||||||||||
| Financial liabilities held for trading at fair value through profit or loss: | ||||||||||||||||||||
| Derivative Financial Instruments | — | 260,822 | — | — | 260,822 | |||||||||||||||
| Financial liabilities designated as at fair value through profit or loss | — | — | — | — | — | |||||||||||||||
| Derivative financial instruments for hedging purposes | — | 19,137 | — | — | 19,137 | |||||||||||||||
| Financial liabilities at amortized cost: | ||||||||||||||||||||
| Current accounts and other demand deposits | 144 | 118,964 | 2,017 | 5,723 | 126,848 | |||||||||||||||
| Time deposits and saving accounts | 94,638 | 246,452 | 2,800 | 16,872 | 360,762 | |||||||||||||||
| Obligations by repurchase agreements | — | — | — | — | — | |||||||||||||||
| Borrowings from financial institutions | — | 177,358 | — | — | 177,358 | |||||||||||||||
| Debt financial instruments issued | — | — | — | — | — | |||||||||||||||
| Other financial obligations | — | — | — | — | — | |||||||||||||||
| Lease liabilities | — | 6,093 | — | — | 6,093 | |||||||||||||||
| Other liabilities | — | 285,537 | 405 | 120 | 286,062 | |||||||||||||||
136
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 43. | Related Party Disclosures, continued: |
| (a) | Assets and liabilities with related parties, continued: |
| Related Party Type | ||||||||||||||||||||
Type of current assets and liabilities with related parties As of December 31, 2025 | Parent Entity | Other Legal Entity | Key Personnel of the Consolidated Bank | Other Related Parties | Total | |||||||||||||||
| ASSETS | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||
| Financial assets held for trading at fair value through profit or loss: | ||||||||||||||||||||
| Derivative Financial Instruments | — | 231,036 | — | — | 231,036 | |||||||||||||||
| Debt financial instruments | — | — | — | — | — | |||||||||||||||
| Other financial instruments | — | 20 | — | — | 20 | |||||||||||||||
| Non-trading financial assets mandatorily measured at fair value through profit or loss | — | — | — | — | — | |||||||||||||||
| Financial assets designated as at fair value through profit or loss | — | — | — | — | — | |||||||||||||||
| Financial assets at fair value through other comprehensive income | — | 33,856 | — | — | 33,856 | |||||||||||||||
| Derivative financial instruments for hedging purposes | — | — | — | — | — | |||||||||||||||
| Financial assets at amortized cost: | ||||||||||||||||||||
| Rights by resale agreements | — | — | — | — | — | |||||||||||||||
| Debt financial instruments | — | — | — | — | — | |||||||||||||||
| Commercial loans | 189,539 | 1,928 | 10,553 | 202,020 | ||||||||||||||||
| Residential mortgage loans | — | — | 15,440 | 62,685 | 78,125 | |||||||||||||||
| Consumer Loans | — | — | 1,756 | 10,639 | 12,395 | |||||||||||||||
| Allowances established – loans | — | (1,562 | ) | (61 | ) | (438 | ) | (2,061 | ) | |||||||||||
| Other assets | 17 | 285,355 | 8 | 95 | 285,475 | |||||||||||||||
| Contingent loans | — | 167,862 | 3,401 | 16,776 | 188,039 | |||||||||||||||
| LIABILITIES | ||||||||||||||||||||
| Financial liabilities held for trading at fair value through profit or loss: | ||||||||||||||||||||
| Derivative Financial Instruments | — | 303,280 | — | — | 303,280 | |||||||||||||||
| Financial liabilities designated as at fair value through profit or loss | — | — | — | — | — | |||||||||||||||
| Derivative financial instruments for hedging purposes | — | 19,931 | — | — | 19,931 | |||||||||||||||
| Financial liabilities at amortized cost: | ||||||||||||||||||||
| Current accounts and other demand deposits | 300 | 168,799 | 2,281 | 6,105 | 177,485 | |||||||||||||||
| Time deposits and saving accounts | 45,379 | 132,812 | 3,181 | 17,594 | 198,966 | |||||||||||||||
| Obligations by repurchase agreements | — | 750 | — | — | 750 | |||||||||||||||
| Borrowings from financial institutions | — | 137,114 | — | — | 137,114 | |||||||||||||||
| Debt financial instruments issued | — | — | — | — | — | |||||||||||||||
| Other financial obligations | — | — | — | — | — | |||||||||||||||
| Lease liabilities | — | 7,036 | — | — | 7,036 | |||||||||||||||
| Other liabilities | — | 225,578 | 556 | 2 | 226,136 | |||||||||||||||
137
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 43. | Related Party Disclosures, continued: |
| (b) | Income and expenses from related party transactions (*): |
| As of September 30, 2026 | Parent Entity | Other Legal Entity | Key personnel of the consolidated Bank | Other Related parties | Total | |||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||
| Interest revenue | — | 9,806 | 478 | 2,246 | 12,530 | |||||||||||||||
| Inflation indexation revenue | — | 2,000 | 606 | 2,948 | 5,554 | |||||||||||||||
| Fee and commission income | 133 | 68,839 | 48 | 57 | 69,077 | |||||||||||||||
| Net Financial result | — | 58,476 | — | — | 58,476 | |||||||||||||||
| Other income | — | — | — | — | — | |||||||||||||||
| Total Income | 133 | 139,121 | 1,132 | 5,251 | 145,637 | |||||||||||||||
| Interest expense | 2,241 | 5,499 | 119 | 549 | 8,408 | |||||||||||||||
| Inflation indexation expense | — | — | — | — | — | |||||||||||||||
| Fee and commission expense | — | 21,858 | — | — | 21,858 | |||||||||||||||
| Expenses credit losses (gains) | — | 123 | 7 | (92 | ) | 38 | ||||||||||||||
| Personnel expenses | — | 95 | 31,117 | 68,476 | 99,688 | |||||||||||||||
| Administrative expenses | — | 8,174 | 2,627 | 9 | 10,810 | |||||||||||||||
| Other expenses | — | 2 | 8 | 26 | 36 | |||||||||||||||
| Total Expenses | 2,241 | 35,751 | 33,878 | 68,968 | 140,838 | |||||||||||||||
| As of September 30, 2025 | Parent Entity | Other Legal Entity | Key personnel of the consolidated Bank | Other Related parties | Total | |||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||
| Interest revenue | — | 15,556 | 401 | 2,214 | 18,171 | |||||||||||||||
| Inflation indexation revenue | — | 1,732 | 459 | 1,904 | 4,095 | |||||||||||||||
| Fee and commission income | 129 | 68,989 | 40 | 42 | 69,200 | |||||||||||||||
| Net Financial result | — | 312 | — | — | 312 | |||||||||||||||
| Other income | — | — | — | — | — | |||||||||||||||
| Total Income | 129 | 86,589 | 900 | 4,160 | 91,778 | |||||||||||||||
| Interest expense | 6,084 | 3,769 | 117 | 664 | 10,634 | |||||||||||||||
| Inflation indexation expense | — | — | 5 | 5 | 10 | |||||||||||||||
| Fee and commission expense | — | 21,763 | — | — | 21,763 | |||||||||||||||
| Expenses credit losses (gains) | — | 255 | 31 | 149 | 435 | |||||||||||||||
| Personnel expenses | — | 90 | 29,448 | 63,895 | 93,433 | |||||||||||||||
| Administrative expenses | — | 8,006 | 2,830 | 42 | 10,878 | |||||||||||||||
| Other expenses | — | 13 | 6 | 16 | 35 | |||||||||||||||
| Total Expenses | 6,084 | 33,896 | 32,437 | 64,771 | 137,188 | |||||||||||||||
| (*) | This does not constitute a Statement of Income from operations with related parties since the assets with these parties are not necessarily equal to the liabilities and in each of them the total income and expenses are reflected and not those corresponding to matched operations. |
138
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 43. | Related Party Disclosures, continued: |
| (c) | Transactions with related parties: Individual transactions in the period with related parties that are legal entities, which do not correspond to the usual operations of the line of business performed with customers in general and when such individual transactions consider a transfer of resources, services or obligations higher than UF 2,000 are detailed below. |
As of September 30, 2026
| Nature of the | Transaction description | Transactions under equivalent conditions to those transactions | Effect on | Effect on the statement of Financial position | ||||||||||||||||||||||||||
| Company name | relationship with the Bank | Type
of service | Term | Renewal conditions | conducted on an arm’s length basis | Amount MCh$ | Income MCh$ | Expenses MCh$ | Accounts receivable MCh$ | Accounts payable MCh$ | ||||||||||||||||||||
| Servipag Ltda. | Joint venture | Collection services | 30 days | Contract | Yes | 2,669 | — | 2,669 | — | 305 | ||||||||||||||||||||
| IT support services | 30 days | Contract | Yes | 338 | — | 338 | — | — | ||||||||||||||||||||||
| IT project services | 30 days | Contract | Yes | 102 | — | 102 | — | — | ||||||||||||||||||||||
| Software development service | 30 days | Contract | Yes | 90 | — | 90 | — | — | ||||||||||||||||||||||
| Enex S.A. | Other related parties | Rent spaces for ATM | 30 days | Contract | Yes | 1,675 | — | 1,675 | — | 384 | ||||||||||||||||||||
| Advertising services | 30 days | Contract | Yes | 108 | — | 108 | — | — | ||||||||||||||||||||||
| Redbanc S.A. | Associates | Electronic transaction management | 30 days | Contract | Yes | 13,578 | — | 13,578 | — | 1,555 | ||||||||||||||||||||
| IT services | 30 days | Contract | Yes | 338 | — | 338 | — | — | ||||||||||||||||||||||
| IT project services | 30 days | Contract | Yes | 113 | — | 113 | — | — | ||||||||||||||||||||||
| Fraud prevention services | 30 days | Contract | Yes | 92 | — | 92 | — | — | ||||||||||||||||||||||
| Depósito Central de Valores S.A. | Other related parties | Custodial services | 30 days | Contract | Yes | 985 | — | 985 | — | 96 | ||||||||||||||||||||
| Quality control and custodial services | 30 days | Contract | Yes | 856 | — | 856 | — | — | ||||||||||||||||||||||
| CCLV Contraparte Central S.A. | Minority investments | Brokerage commission | 30 days | Contract | Yes | 261 | — | 261 | — | 26 | ||||||||||||||||||||
| Manantial S.A. | Other related parties | General expenses | 30 days | Contract | Yes | 306 | — | 306 | — | — | ||||||||||||||||||||
| Sociedad Operadora de la Cámara de Compensación de Pagos de Alto Valor S.A. | Associates | Collection services | 30 days | Contract | Yes | 766 | — | 766 | — | 88 | ||||||||||||||||||||
| Canal 13 | Other related parties | Advertising services | 30 days | Contract | Yes | 1,023 | — | 1,023 | — | 449 | ||||||||||||||||||||
| Comder Contraparte Central S.A. | Other related parties | Securities clearing services | 30 days | Contract | Yes | 671 | — | 671 | — | — | ||||||||||||||||||||
| Citigroup Global Markets INC | Other related parties | Brokerage commission | 30 days | Contract | Yes | 403 | — | 403 | — | 94 | ||||||||||||||||||||
| Bolsa de Comercio de Santiago, Bolsa de Valores | Minority investments | Brokerage commission | 30 days | Contract | Yes | 210 | — | 210 | — | 31 | ||||||||||||||||||||
| Bolsa Electrónica de Chile, Bolsa de Valores | Minority investments | Brokerage commission | 30 days | Contract | Yes | 155 | — | 155 | — | 31 | ||||||||||||||||||||
| Service of financial information | 30 days | Contract | Yes | 84 | — | 84 | — | — | ||||||||||||||||||||||
| Holding Bursátil Regional S.A. | Minority investments | Service of financial information | 30 days | Contract | Yes | 265 | — | 265 | — | 7 | ||||||||||||||||||||
| IT support services | 30 days | Contract | Yes | 138 | — | 138 | — | — | ||||||||||||||||||||||
| Brokerage commission | 30 days | Contract | Yes | 91 | — | 91 | — | — | ||||||||||||||||||||||
| DCV Registros S.A. | Other related parties | IT services | 30 days | Contract | Yes | 273 | — | 273 | — | — | ||||||||||||||||||||
| Transbank S.A. | Associates | Card processing | 30 days | Contract | Yes | 419 | — | 419 | — | 56 | ||||||||||||||||||||
| Exchange commission | 30 days | Contract | Yes | 57,182 | 57,182 | — | — | — | ||||||||||||||||||||||
| Inmobiliaria Consultora y Operadora IF SPA | Other related parties | Advertising services | 30 days | Contract | Yes | 115 | — | 115 | — | 24 | ||||||||||||||||||||
| Centro de Compensación Automatizado S.A. | Associates | Transfer services | 30 days | Contract | Yes | 2,185 | — | 2,185 | — | 261 | ||||||||||||||||||||
| Collection services | 30 days | Contract | Yes | 122 | — | 122 | — | — | ||||||||||||||||||||||
| Citibank N.A. | Other related parties | Connectivity business commissions | Quarterly | Contract | Yes | 6,382 | 6,382 | — | 2,532 | — | ||||||||||||||||||||
| Plaza Oeste SPA | Other related parties | Financial lease agreements | 30 days | Contract | Yes | 105 | — | 105 | — | 512 | ||||||||||||||||||||
| Common area expenses | 30 days | Contract | Yes | 339 | — | 339 | — | — | ||||||||||||||||||||||
| Rents | 30 days | Contract | Yes | 83 | — | 83 | — | — | ||||||||||||||||||||||
| Plaza del Trébol SPA | Other related parties | Financial lease agreements | 30 days | Contract | Yes | 157 | — | 157 | — | 188 | ||||||||||||||||||||
| Common area expenses | 30 days | Contract | Yes | 157 | — | 157 | — | — | ||||||||||||||||||||||
| Nuevos Desarrollos S.A. | Other related parties | Financial lease agreements | 30 days | Contract | Yes | 89 | — | 89 | — | 261 | ||||||||||||||||||||
| Plaza Vespucio SPA | Other related parties | Financial lease agreements | 30 days | Contract | Yes | 97 | — | 97 | — | 73 | ||||||||||||||||||||
| Plaza La Serena SPA | Other related parties | Financial lease agreements | 30 days | Contract | Yes | 198 | — | 198 | — | 207 | ||||||||||||||||||||
| Inmobiliaria Mall Calama S.A. | Other related parties | Financial lease agreements | 30 days | Contract | Yes | 28 | — | 28 | — | 122 | ||||||||||||||||||||
139
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 43. | Related Party Disclosures, continued: |
| (c) | Transactions with related parties, continued: |
As of December 31, 2025
| Nature of the | Transaction description | Transactions under equivalent conditions to those transactions | Effect on | Effect on the statement of Financial position | ||||||||||||||||||||||||||
| Company name | relationship with the Bank | Type of service | Term | Renewal conditions | conducted on an arm’s length basis | Amount MCh$ | Income MCh$ | Expenses MCh$ | Accounts receivable MCh$ | Accounts payable MCh$ | ||||||||||||||||||||
| Servipag Ltda. | Joint venture | Collection services | 30 days | Contract | Yes | 4,010 | — | 4,010 | — | 328 | ||||||||||||||||||||
| IT support services | 30 days | Contract | Yes | 296 | — | 296 | — | — | ||||||||||||||||||||||
| Software development service | 30 days | Contract | Yes | 85 | — | 85 | — | — | ||||||||||||||||||||||
| IT project services | 30 days | Contract | Yes | 94 | — | 94 | — | — | ||||||||||||||||||||||
| Bolsa de Comercio de Santiago, Bolsa de Valores | Minority investments | Brokerage commission | 30 days | Contract | Yes | 292 | — | 292 | — | — | ||||||||||||||||||||
| Manantial S.A. | Other related parties | General expenses | 30 days | Contract | Yes | 329 | — | 329 | — | — | ||||||||||||||||||||
| Universidad Del Desarrollo | Other related parties | Advertising services | 30 days | Contract | Yes | 336 | — | 336 | — | 336 | ||||||||||||||||||||
| Enex S.A. | Other related parties | Rent spaces for ATM | 30 days | Contract | Yes | 2,257 | — | 2,257 | — | 570 | ||||||||||||||||||||
| Advertising services | 30 days | Contract | Yes | 132 | — | 132 | — | — | ||||||||||||||||||||||
| Redbanc S.A. | Associates | Electronic transaction management services | 30 days | Contract | Yes | 19,080 | — | 19,080 | — | 1,609 | ||||||||||||||||||||
| IT project services | 30 days | Contract | Yes | 207 | — | 207 | — | — | ||||||||||||||||||||||
| IT services | 30 days | Contract | Yes | 190 | — | 190 | — | — | ||||||||||||||||||||||
| Depósito Central de Valores S.A. | Other related parties | Quality control and custodial services | 30 days | Contract | Yes | 764 | — | 764 | — | 22 | ||||||||||||||||||||
| Custodial services | 30 days | Contract | Yes | 1,178 | — | 1,178 | — | — | ||||||||||||||||||||||
| CCLV Contraparte Central S.A. | Minority investments | Brokerage commission | 30 days | Contract | Yes | 325 | — | 325 | — | — | ||||||||||||||||||||
| Sociedad Operadora de la Cámara de Compensación de Pagos de Alto Valor S.A. | Associates | Collection services | 30 days | Contract | Yes | 943 | — | 943 | — | 91 | ||||||||||||||||||||
| Inmobiliaria e Inversiones Capitolio S.A. | Other related parties | Leases | 30 days | Contract | Yes | 83 | — | 83 | — | — | ||||||||||||||||||||
| Fundación Teleton | Other related parties | Advertising services | 30 days | Contract | Yes | 577 | — | 577 | — | 268 | ||||||||||||||||||||
| Donations | 30 days | Contract | Yes | 1,590 | — | 1,590 | — | — | ||||||||||||||||||||||
| Canal 13 | Other related parties | Advertising services | 30 days | Contract | Yes | 131 | — | 131 | — | — | ||||||||||||||||||||
| La Barra S.A. | Other related parties | Advertising services | 30 days | Contract | Yes | 96 | — | 96 | — | — | ||||||||||||||||||||
| Bolsa Electrónica de Chile, Bolsa de Valores | Minority investments | Brokerage commission | 30 days | Contract | Yes | 189 | — | 189 | — | 7 | ||||||||||||||||||||
| Service of financial information | 30 days | Contract | Yes | 95 | — | 95 | — | — | ||||||||||||||||||||||
| Citibank N.A. Reino Unido | Other related parties | Service of financial information | 30 days | Contract | Yes | 106 | — | 106 | — | — | ||||||||||||||||||||
| Comder Contraparte Central S.A. | Other related parties | Securities clearing services | 30 days | Contract | Yes | 769 | — | 769 | — | — | ||||||||||||||||||||
| Citigroup Global Markets INC | Other related parties | Brokerage commission | 30 days | Contract | Yes | 369 | — | 369 | — | 50 | ||||||||||||||||||||
| DCV Registros S.A. | Other related parties | IT services | 30 days | Contract | Yes | 258 | — | 258 | — | — | ||||||||||||||||||||
| Transbank S.A. | Associates | Card processing | 30 days | Contract | Yes | 631 | — | 631 | — | 110 | ||||||||||||||||||||
| Exchange commission | 30 days | Contract | Yes | 77,727 | 77,727 | — | — | — | ||||||||||||||||||||||
| Centro de Compensación Automatizado S.A. | Associates | Transfer services | 30 days | Contract | Yes | 2,850 | — | 2,850 | — | 255 | ||||||||||||||||||||
| Fraud prevention services | 30 days | Contract | Yes | 344 | — | 344 | — | — | ||||||||||||||||||||||
| Collection services | 30 days | Contract | Yes | 147 | — | 147 | — | — | ||||||||||||||||||||||
| Artikos Chile S.A. | Other related parties | IT services | 30 days | Contract | Yes | 280 | — | 280 | — | — | ||||||||||||||||||||
| IT support services | 30 days | Contract | Yes | 236 | — | 236 | — | — | ||||||||||||||||||||||
| Citibank N.A. | Other related parties | Connectivity business commissions | Quarterly | Contract | Yes | 7,991 | 7,991 | — | 3,362 | — | ||||||||||||||||||||
| Desarrollos e Inversiones Internacionales SpA | Other related parties | Common area expenses | 30 days | Contract | Yes | 101 | — | 101 | — | 13 | ||||||||||||||||||||
| Plaza Oeste SPA | Other related parties | Common area expenses | 30 days | Contract | Yes | 167 | — | 167 | — | 50 | ||||||||||||||||||||
| Financial lease agreements | 30 days | Contract | Yes | 250 | — | 250 | — | 592 | ||||||||||||||||||||||
| Plaza del Trébol SPA | Other related parties | Common area expenses | 30 days | Contract | Yes | 106 | — | 106 | — | 127 | ||||||||||||||||||||
| Financial lease agreements | 30 days | Contract | Yes | 256 | — | 256 | — | 19 | ||||||||||||||||||||||
| Nuevos Desarrollos S.A. | Other related parties | Financial lease agreements | 30 days | Contract | Yes | 193 | — | 193 | — | 335 | ||||||||||||||||||||
| Plaza Vespucio SPA | Other related parties | Financial lease agreements | 30 days | Contract | Yes | 133 | — | 133 | — | 32 | ||||||||||||||||||||
| Plaza Tobalaba SPA | Other related parties | Financial lease agreements | 30 days | Contract | Yes | 133 | — | 133 | — | — | ||||||||||||||||||||
| Plaza La Serena SPA | Other related parties | Financial lease agreements | 30 days | Contract | Yes | 257 | — | 257 | — | 385 | ||||||||||||||||||||
| Inmobiliaria Mall Calama S.A. | Other related parties | Financial lease agreements | 30 days | Contract | Yes | 148 | — | 148 | — | — | ||||||||||||||||||||
140
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 43. | Related Party Disclosures, continued: |
| (d) | Payments to the Board of Directors and to key personnel of the management of the Bank and its subsidiaries: |
| September | September | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Board of Directors: | ||||||||
| Payment of remuneration and allowances of the Board of Directors - Bank and its subsidiaries | 2,566 | 2,681 | ||||||
| Other Board of Director’s expenses | 7 | 72 | ||||||
| Key Personnel of the Management of the Bank and its Subsidiaries: | ||||||||
| Payment for short-term employee benefits | 29,069 | 28,136 | ||||||
| Payment for severance | 2,048 | 1,312 | ||||||
| Payment for post-employment benefits to employees | — | — | ||||||
| Payment for long-term employee benefits | — | — | ||||||
| Payment for employees based on shares or equity instruments | — | — | ||||||
| Payment for obligations for defined contribution post-employment plans | — | — | ||||||
| Payment for obligations for post-employment defined benefit plans | — | — | ||||||
| Payment for other staff obligations | — | — | ||||||
| Subtotal | 31,117 | 29,448 | ||||||
| Total | 33,690 | 32,201 | ||||||
| (e) | Composition of the Board of Directors and key personnel of the Management of the Bank and its subsidiaries: |
| September | September | |||||||
| 2026 | 2025 | |||||||
| No. Executives | ||||||||
| Board of Directors: Directors – Bank and its subsidiaries | 15 | 17 | ||||||
| Key Personnel of the Management of the Bank and its Subsidiaries: | ||||||||
| CEO – Bank | 1 | 1 | ||||||
| CEOs – Subsidiaries | 5 | 5 | ||||||
| Division / Area Managers – Bank | 77 | 75 | ||||||
| Division / Area Managers – Subsidiaries | 34 | 29 | ||||||
| Subtotal | 117 | 110 | ||||||
| Total | 132 | 127 | ||||||
141
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 44. | Fair Value of Financial Assets and Liabilities: |
Banco de Chile and its subsidiaries have defined a corporate framework for valuation and control related with the process to the fair value measurement.
Within the established framework includes the Product Control Unit, which is independent of the business areas and reports to the Division Manager Management, Financial Control and Productivity. This function befalls to the Financial Control, Treasury and Capital Manager, through the Financial Risk Information and Control Section, is responsible for independent verification of price and results of trading (including derivatives) and investment operations and all fair value measurements.
To achieve the appropriate measurements and controls, the Bank and its subsidiaries, take into account at least the following aspects:
| (i) | Industry standard valuation. |
To value financial instruments, the Bank uses industry standard modeling; quota value, share price, discounted cash flows and valuation of options through Black-Scholes-Merton, according to the case.
The input parameters for the valuation of fixed income instruments and options correspond to rates, prices and volatility levels for different terms and market factors that are traded in the national and international market and that are provided by the main sources of the market.
In the case of the valuation of derivatives under a CSA (Credit Support Annex Discounting) agreement, the rates used to discount the flows correspond to the CSA Discounting methodology, where the discount factors used depend on the collateral agreement that exists with each counterparty.
| (ii) | Quoted prices in active markets. |
The fair value for instruments with quoted prices in active markets is determined using daily quotes from electronic systems information (such as Santiago Stock Exchange, Bloomberg, LVA and Risk America, etc.). This quote represents the price at which these instruments are regularly traded in the financial markets.
| (iii) | Valuation techniques. |
If no specific quotes are available for the instrument to be valued, valuation techniques will be used to determine the fair value.
Due to, in general, the valuation models require a set of market parameters as inputs, the aim is to maximize information based on observable or price-related quotations for similar instruments in active markets. To the extent there is no information in direct from the markets, data from external suppliers of information, prices of similar instruments and historical information are used to validate the valuation parameters.
142
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 44. | Fair Value of Financial Assets and Liabilities, continued: |
| (iv) | Fair value adjustments. |
Part of the fair value process considers four adjustments to the market value, calculated based on the market parameters, including a liquidity adjustment, a Bid/Offer adjustment, an adjustment for derivative credit risk (CVA and DVA), and an adjustment for the funding of the derivative cash flows (FVA). Likewise, for certain fixed income instruments held in investment portfolios measured at fair value through other comprehensive income or at amortized cost, the portion of the fair value adjustment explained by impairment due to counterparty credit risk is determined.
The calculation of the liquidity adjustment considers the size of the position in each factor, the liquidity of each factor, the relative size of Bank with respect to the market, and the liquidity observed in transactions recently carried out in the market. In turn, the Bid/Offer adjustment, represents the impact on the valuation of an instrument depending on whether the position corresponds to a long (bought) or a short (sold). To calculate this adjustment is used the direct quotes from active markets or indicative prices or derivatives of similar assets depending on the instrument, considering the Bid, Mid and Offer, respectively. Finally, the adjustment made for CVA and DVA for derivatives corresponds to the credit risk recognition of the issuer, either of the counterparty (CVA) or of Banco de Chile (DVA). Similarly, the determination of credit risk impairment is determined based on the counterparty risk implicit in the instrument’s market rate. Finally, the FVA adjustment for derivatives corresponds to a value adjustment that reflects the expected cost (or benefit) of financing (reinvesting) the cash flows of the derivative, with respect to a reference discount rate, when there are no collaterals, or this one is imperfect.
Note that there is also the concept of COLVA for derivatives, which is a valuation adjustment if a derivative is valued using parameters other than those used in the CSA Discounting methodology. The Bank uses CSA Discounting as the valuation methodology, COLVA is already part of the derivative’s Mark-to-Market (MTM), and no additional adjustment is required for this concept. However, the Bank measures COLVA for internal management purposes, relative to a SOFR Discounting scenario (scenario where all derivatives have USD SOFR collateral).
Liquidity value adjustments are made to trading instruments (including derivatives) only, while Bid/Offer adjustments are made for trading instruments and financial instruments at fair value through other comprehensive income. Adjustments for CVA/DVA/FVA/COLVA are made only for derivatives. Also, credit risk impairment is computed only for fixed income instruments measured at fair value through other comprehensive income measured at amortized cost.
143
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 44. | Fair Value of Financial Assets and Liabilities, continued: |
| (v) | Fair value control. |
A process of independent verification of prices and interest rates is executed daily, in order to control that the market parameters used by the Bank in the valuation of the financial instruments relating to the current state of the market and from them the best estimate derived of the fair value. The objective of this process is to control those the official market parameters provided by the respective business areas, before being entered into the valuation, are within acceptable ranges of differences when compared to the same set of parameters prepared independently by the Financial Risk Information and Control Section. As a result, value differences are obtained at the level of currency, product and portfolio. In the event significant differences exist, these differences are scaled according to the amount of individual materiality of each market factor and aggregated at the portfolio level, according to the grouping levels within previously defined ranges. These ranges are approved by the Finance, International and Financial Risk Committee.
Complementary and in parallel, the Financial Risk Information and Control Section generates and reports daily Profit and Loss (“P&L”) and Exposure to Market Risks, which allow for proper control and consistency of the parameters used in the valuation.
| (vi) | Judgmental analysis and information to Management. |
Cases, where there are no market quotations for the instrument to be valued and there are no prices for similar transactions instruments or indicative parameters, a specific control and a reasoned analysis must be carried out in order to estimate the fair value of the operation. Within the valuation framework described in the Reasonable Value Policy (and its procedure) approved by the Board of Directors of the Bank, a required level of approval is set in order to carry out transactions where market information is not available, or it is not possible to infer prices or rates from it.
| (a) | Hierarchy of instruments valued at Fair value: |
Banco de Chile and its subsidiaries, classify all the financial instruments among the following levels:
| Level 1: | These are financial instruments whose fair value is calculated at quoted prices (unadjusted) in extracted from liquid and deep markets. For these instruments there are quotes or prices (return internal rates, quote value, price) the observable market, so that assumptions are not required to determine the value. | |
| In this level, the following instruments are considered: currency futures, debt instruments issued by the Treasury and the Central Bank of Chile, which belong to benchmarks, mutual fund investments and equity shares. | ||
| For the instruments of the Central Bank of Chile and the General Treasury of the Republic, all those mnemonics belonging to a Benchmark, in other words corresponding to one of the following categories published by the Santiago Stock Exchange, will be considered as Level 1: Pesos-02, Pesos-03, Pesos-04, Pesos-05, Pesos-07, Pesos-10, Pesos-20, UF-02, UF-03, UF-04, UF-05, UF-07, UF-10, UF-20, UF-30. |
144
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 44. | Fair Value of Financial Assets and Liabilities, continued: |
A Benchmark corresponds to a group of mnemonics that are similar in duration and are traded in an equivalent way, i.e., the price (return internal rates in this case) obtained is the same for all the instruments that make up a Benchmark. This feature defines a greater depth of market, with daily quotations that allow classifying these instruments as Level 1.
In the case of debt issued by the Chilean Government, the internal rate of return of the market is used to discount all flows to present value. In the case of mutual funds and equity shares, the current market price per share, which multiplied by the number of instruments results in the fair value.
The preceding described valuation methodology is equivalent to the one used by the Santiago Stock Exchange and correspond to the standard methodology used in the market.
| Level 2: | They are financial instruments whose fair value is calculated based on prices other than in quoted in Level 1 that are observable for the asset or liability, directly (that is, as prices or internal rates of return) or indirectly (that is, derived from prices or internal rates of return from similar instruments). These categories include: |
| a) | Quoted prices for similar assets or liabilities in active markets. |
| b) | Quoted prices for identical or similar assets or liabilities in markets that are not active. |
| c) | Inputs data other than quoted prices that are observable for the asset or liability. |
| d) | Inputs data corroborated by the market. |
At this level there are mainly derivatives instruments, debt issued by banks, debt issues of Chilean and foreign companies, issued in Chile or abroad, mortgage claims, financial brokerage instruments and some issuances by the Central Bank of Chile and the General Treasury of the Republic, which do not belong to benchmarks.
The technique used for derivative valuation depends on whether the instrument is impacted by volatility as a relevant market factor. Accordingly, for options, the Black-Scholes-Merton formula is applied, as it incorporates volatility, whereas for other derivatives, such as forwards and swaps, the discounted cash flow method is used.
For the remaining instruments at this level, as for debt issues of level 1, the valuation is done through cash flows model by using an internal rate of return that can be derived or estimated from internal rates of return of similar securities as mentioned above.
If there is no observable price for an instrument in a specific term, the price will be inferred from the interpolation between periods that have observable quoted price in active markets. These models incorporate various market variables, including the credit quality of counterparties, exchange rates and interest rate curves.
145
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 44. | Fair Value of Financial Assets and Liabilities, continued: |
Valuation Techniques and Inputs for Level 2 Instrument:
|
Type of Financial Instrument |
Valuation Method | Description: Inputs and Sources |
|
Local Bank and Corporate Bonds |
Discounted cash flows model
|
Prices (internal rates of return) are provided by third party price providers that are widely used in the Chilean market.
Model is based on a Base Yield (Central Bank Bonds or the General Treasury of the Republic) and issuer spread.
The model is based on daily prices and risk/maturity similarities between Instruments. |
|
Offshore Bank and Corporate Bonds |
Prices are provided by third party price providers that are widely used in the Chilean market.
Model is based on daily prices. | |
|
Local Central Bank and Treasury Bonds |
Prices (internal rates of return) are provided by third party price providers that are widely used in the Chilean market.
Model is based on daily prices. | |
|
Mortgage Notes |
Prices (internal rates of return) are provided by third party price providers that are widely used in the Chilean market.
Model is based on a Base Yield (Central Bank Bonds or the General Treasury of the Republic) and issuer spread.
The model takes into consideration daily prices and risk/maturity similarities between instruments. | |
|
Time Deposits |
Prices (internal rates of return) are provided by third party price providers that are widely used in the Chilean market.
Model is based on daily prices and considers risk/maturity similarities between instruments. | |
|
Cross Currency Swaps, Interest Rate Swaps, FX Forwards, Inflation Forwards |
Forward Points, Inflation forecast and local swap rates are provided by market brokers that are widely used in the Chilean market.
Offshore rates and spreads are obtained from third party price providers that are widely used in the Chilean market.
Zero Coupon rates are calculated by using the bootstrapping method over swap rates.
| |
| FX Options |
Black-Scholes Model |
Prices for volatility surface estimates are obtained from market brokers that are widely used in the Chilean market. |
146
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 44. | Fair Value of Financial Assets and Liabilities, continued: |
| Level 3: | These are financial instruments whose fair value is determined using non-observable inputs data neither for the assets or liabilities under analysis nor for similar instruments. An adjustment to an input that is significant to the entire measurement can result in a fair value measurement classified within Level 3 of the fair value hierarchy, if the adjustment uses significant non-observable data entry. | |
| The instruments likely to be classified as level 3 are mainly Corporate Debt by Chilean and foreign companies, issued both in Chile and abroad. |
Valuation Techniques and Inputs for Level 3 Instrument:
| Type of Financial Instrument | Valuation Method | Description: Inputs and Sources |
|
Local Bank and Corporate Bonds |
Discounted cash flows model
|
Since inputs for these types of securities are not observable by the market, we model interest rate of returns for them based on a Base Yield (Central Bank Bonds or the General Treasury of the Republic) and issuer spread. These inputs (base yield and issuer spread) are provided on a daily basis by third party price providers that are widely used in the Chilean market. |
| Offshore Bank and Corporate Bonds |
Since inputs for these types of securities are not observable by the market, we model interest rate of returns for them based on a Base Yield and issuer spread. These inputs (base yield and issuer spread) are provided on a weekly basis by third party price providers that are widely used in the Chilean market.
|
147
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 44. | Fair Value of Financial Assets and Liabilities, continued: |
| (b) | Level chart: |
The following table shows the classification by levels, for financial instruments registered at fair value.
| Level 1 | Level 2 | Level 3 | Total | |||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | |||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Financial Assets | ||||||||||||||||||||||||||||||||
| Financial Assets held for trading at fair value through profit or loss | ||||||||||||||||||||||||||||||||
| Financial Derivative contracts: | ||||||||||||||||||||||||||||||||
| Forwards | — | — | 632,805 | 377,810 | — | — | 632,805 | 377,810 | ||||||||||||||||||||||||
| Swaps | — | — | 1,769,817 | 1,488,810 | — | — | 1,769,817 | 1,488,810 | ||||||||||||||||||||||||
| Call Options | — | — | 3,538 | 332 | — | — | 3,538 | 332 | ||||||||||||||||||||||||
| Put Options | — | — | 124 | 2,515 | — | — | 124 | 2,515 | ||||||||||||||||||||||||
| Futures | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Subtotal | — | — | 2,406,284 | 1,869,467 | — | — | 2,406,284 | 1,869,467 | ||||||||||||||||||||||||
| Debt Financial Instruments: | ||||||||||||||||||||||||||||||||
| From the Chilean Government and Central Bank | 174,354 | 289,581 | 1,111,350 | 2,508,748 | — | 1,285,704 | 2,798,329 | |||||||||||||||||||||||||
| Other debt financial instruments issued in Chile | — | — | 109,944 | 263,104 | 21,131 | 14,250 | 131,075 | 277,354 | ||||||||||||||||||||||||
| Financial debt instruments issued Abroad | — | — | — | 46,019 | — | — | — | 46,019 | ||||||||||||||||||||||||
| Subtotal | 174,354 | 289,581 | 1,221,294 | 2,817,871 | 21,131 | 14,250 | 1,416,779 | 3,121,702 | ||||||||||||||||||||||||
| Others | 421,754 | 402,259 | — | — | 421,754 | 402,259 | ||||||||||||||||||||||||||
| Subtotal | 596,108 | 691,840 | 3,627,578 | 4,687,338 | 21,131 | 14,250 | 4,244,817 | 5,393,428 | ||||||||||||||||||||||||
| Financial Assets at fair value through Other Comprehensive Income | ||||||||||||||||||||||||||||||||
| Debt Financial Instruments: (1) | ||||||||||||||||||||||||||||||||
| From the Chilean Government and Central Bank | 739,462 | 604,907 | 1,751,415 | 569,399 | — | — | 2,490,877 | 1,174,306 | ||||||||||||||||||||||||
| Other debt financial instruments issued in Chile | — | — | 1,594,493 | 2,285,253 | 46,559 | 53,673 | 1,641,052 | 2,338,926 | ||||||||||||||||||||||||
| Financial debt instruments issued Abroad | — | — | 107,503 | 35,739 | — | — | 107,503 | 35,739 | ||||||||||||||||||||||||
| Subtotal | 739,462 | 604,907 | 3,453,411 | 2,890,391 | 46,559 | 53,673 | 4,239,432 | 3,548,971 | ||||||||||||||||||||||||
| Financial Derivative contracts for hedging purposes | ||||||||||||||||||||||||||||||||
| Forwards | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Swaps | — | — | 43,950 | 29,714 | — | — | 43,950 | 29,714 | ||||||||||||||||||||||||
| Call Options | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Put Options | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Futures | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Subtotal | — | — | 43,950 | 29,714 | — | — | 43,950 | 29,714 | ||||||||||||||||||||||||
| Total | 1,335,570 | 1,296,747 | 7,124,939 | 7,607,443 | 67,690 | 67,923 | 8,528,199 | 8,972,113 | ||||||||||||||||||||||||
| Financial Liabilities | ||||||||||||||||||||||||||||||||
| Financial liabilities held for trading at fair value through profit or loss: | ||||||||||||||||||||||||||||||||
| Financial Derivative contracts: | ||||||||||||||||||||||||||||||||
| Forwards | — | — | 591,900 | 456,184 | — | — | 591,900 | 456,184 | ||||||||||||||||||||||||
| Swaps | — | — | 1,918,388 | 1,621,709 | — | — | 1,918,388 | 1,621,709 | ||||||||||||||||||||||||
| Call Options | — | — | 2,788 | 870 | — | — | 2,788 | 870 | ||||||||||||||||||||||||
| Put Options | — | — | 654 | 1,459 | — | — | 654 | 1,459 | ||||||||||||||||||||||||
| Futures | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Subtotal | — | — | 2,513,730 | 2,080,222 | — | — | 2,513,730 | 2,080,222 | ||||||||||||||||||||||||
| Others | — | — | 1,624 | 512 | — | — | 1,624 | 512 | ||||||||||||||||||||||||
| Financial derivative contracts for hedging purposes | ||||||||||||||||||||||||||||||||
| Forwards | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Swaps | — | — | 272,772 | 297,817 | — | — | 272,772 | 297,817 | ||||||||||||||||||||||||
| Call Options | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Put Options | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Futures | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Subtotal | — | — | 272,772 | 297,817 | — | — | 272,772 | 297,817 | ||||||||||||||||||||||||
| Total | — | — | 2,788,126 | 2,378,551 | — | — | 2,788,126 | 2,378,551 | ||||||||||||||||||||||||
| (1) | As of September 30, 2026, 100% of instruments of Level 3 have denomination “Investment Grade”. Also, 100% of total of these financial instruments correspond to domestic issuers. |
148
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 44. | Fair Value of Financial Assets and Liabilities, continued: |
| (c) | Level 3 reconciliation: |
The following table shows the reconciliation between the balances at the beginning and at the end of period for those instruments classified in Level 3, whose fair value is reflected in the Interim Consolidated Financial Statements:
| September 2026 | ||||||||||||||||||||||||||||||||
| Balance as of January 1, 2026 | Gain (Loss) Recognized in Income (1) | Gain (Loss) Recognized in Equity (2) | Purchases | Sales | Transfer from Level 1 and 2 | Transfer to Level 1 and 2 | Balance as of September 30, 2026 | |||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Financial Assets held for trading at fair value through profit or loss | ||||||||||||||||||||||||||||||||
| Debt Financial Instruments: | ||||||||||||||||||||||||||||||||
| Other debt financial instruments issued in Chile | 14,250 | — | — | 10,717 | (3,836 | ) | — | — | 21,131 | |||||||||||||||||||||||
| Subtotal | 14,250 | — | — | 10,717 | (3,836 | ) | — | — | 21,131 | |||||||||||||||||||||||
| Financial Assets at fair value through Other Comprehensive Income | ||||||||||||||||||||||||||||||||
| Debt Financial Instruments: | ||||||||||||||||||||||||||||||||
| Other debt financial instruments issued in Chile | 53,673 | (866 | ) | 232 | — | — | 18,476 | (24,956 | ) | 46,559 | ||||||||||||||||||||||
| Subtotal | 53,673 | (866 | ) | 232 | — | — | 18,476 | (24,956 | ) | 46,559 | ||||||||||||||||||||||
| Total | 67,923 | (866 | ) | 232 | 10,717 | (3,836 | ) | 18,476 | (24,956 | ) | 67,690 | |||||||||||||||||||||
| December 2025 | ||||||||||||||||||||||||||||||||
| Balance as of January 1, 2025 | Gain (Loss) Recognized in Income (1) | Gain (Loss) Recognized in Equity (2) | Purchases | Sales | Transfer from Level 1 and 2 | Transfer to Level 1 and 2 | Balance as of December 31, 2025 | |||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Financial Assets held for trading at fair value through profit or loss | ||||||||||||||||||||||||||||||||
| Debt Financial Instruments: | ||||||||||||||||||||||||||||||||
| Other debt financial instruments issued in Chile | 11,273 | 274 | — | 15,952 | (5,698 | ) | — | (7,551 | ) | 14,250 | ||||||||||||||||||||||
| Subtotal | 11,273 | 274 | — | 15,952 | (5,698 | ) | — | (7,551 | ) | 14,250 | ||||||||||||||||||||||
| Financial Assets at fair value through Other Comprehensive Income | ||||||||||||||||||||||||||||||||
| Debt Financial Instruments: | ||||||||||||||||||||||||||||||||
| Other debt financial instruments issued in Chile | 71,922 | 1,225 | 473 | — | (44,801 | ) | 61,899 | (37,045 | ) | 53,673 | ||||||||||||||||||||||
| Subtotal | 71,922 | 1,225 | 473 | — | (44,801 | ) | 61,899 | (37,045 | ) | 53,673 | ||||||||||||||||||||||
| Total | 83,195 | 1,499 | 473 | 15,952 | (50,499 | ) | 61,899 | (44,596 | ) | 67,923 | ||||||||||||||||||||||
| (1) | Recorded in income under item “Net Financial Result”. |
| (2) | Recorded in equity under item “Accumulated other comprehensive income”. |
149
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 44. | Fair Value of Financial Assets and Liabilities, continued: |
| (d) | Sensitivity of instruments classified in Level 3 to changes in key assumptions of models: |
The following table shows the sensitivity, by type of instrument, of those instruments classified in Level 3 using alternative in key valuation assumptions:
| As of September 30, 2026 | As of December 31, 2025 | |||||||||||||||
| Level 3 | Sensitivity to changes in key assumptions of models | Level 3 | Sensitivity to changes in key assumptions of models | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Financial Assets held for trading at fair value through profit or loss | ||||||||||||||||
| Debt Financial Instruments: | ||||||||||||||||
| Other debt financial instruments issued in Chile | 21,131 | (10 | ) | 14,250 | (15 | ) | ||||||||||
| Subtotal | 21,131 | (10 | ) | 14,250 | (15 | ) | ||||||||||
| Financial Assets at fair value through Other Comprehensive Income | ||||||||||||||||
| Debt Financial Instruments: | ||||||||||||||||
| Other debt financial instruments issued in Chile | 46,559 | (1,072 | ) | 53,673 | (1,652 | ) | ||||||||||
| Subtotal | 46,559 | (1,072 | ) | 53,673 | (1,652 | ) | ||||||||||
| Total | 67,690 | (1,082 | ) | 67,923 | (1,667 | ) | ||||||||||
With the purpose of determining the sensitivity of the financial investments to changes in significant market factors, the Bank has made alternative calculations at fair value, changing those key parameters for the valuation and which are not directly observable in screens. In the case of the financial assets listed in the table above, which correspond to Bank Bonds and Corporate Bonds, it was considered that, since there are no current observables prices, the input prices will be based on brokers’ quotes. The prices are usually calculated as a base rate plus a spread. For Local Bonds it was determined to apply a 10% impact on the price. The 10% impact is considered reasonable, taking into account the market performance of these instruments and comparing it against the bid/offer adjustment that is provisioned by these instruments.
150
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 44. | Fair Value of Financial Assets and Liabilities, continued: |
| (e) | Other assets and liabilities: |
The following table summarizes the fair values of the Bank’s main financial assets and liabilities that are not recorded at fair value in the Consolidated Statement of Financial Position. The values shown in this note are not attempt to estimate the value of the Bank’s income-generating assets, nor forecast their future behavior. The estimated fair value is as follows:
| Book Value | Estimated Fair Value | |||||||||||||||
| September | December | September | December | |||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| Assets | ||||||||||||||||
| Cash and deposits in banks | 3,165,155 | 2,590,986 | 3,165,155 | 2,590,986 | ||||||||||||
| Transactions in the course of collection | 362,105 | 414,419 | 362,105 | 414,419 | ||||||||||||
| Subtotal | 3,527,260 | 3,005,405 | 3,527,260 | 3,005,405 | ||||||||||||
| Financial assets at amortized cost: | ||||||||||||||||
| Rights by resale agreements | 96,631 | 100,643 | 96,631 | 100,643 | ||||||||||||
| Debt financial instruments | 453,575 | 460,937 | 425,581 | 435,196 | ||||||||||||
| Loans to Banks: | ||||||||||||||||
| Domestic banks | 199,928 | — | 199,928 | — | ||||||||||||
| Central Bank of Chile | — | — | — | — | ||||||||||||
| Foreign banks | 409,803 | 399,123 | 404,367 | 397,340 | ||||||||||||
| Subtotal | 1,159,937 | 960,703 | 1,126,507 | 933,179 | ||||||||||||
| Loans to customers, net: | ||||||||||||||||
| Commercial loans | 20,658,046 | 19,137,460 | 20,400,767 | 18,835,985 | ||||||||||||
| Residential mortgage loans | 14,139,811 | 13,874,507 | 14,428,407 | 13,957,541 | ||||||||||||
| Consumer loans | 5,121,604 | 5,343,032 | 5,183,750 | 5,436,873 | ||||||||||||
| Subtotal | 39,919,461 | 38,354,999 | 40,012,924 | 38,230,399 | ||||||||||||
| Total | 44,606,658 | 42,321,107 | 44,666,691 | 42,168,983 | ||||||||||||
| Liabilities | ||||||||||||||||
| Transactions in the course of payment | 698,623 | 564,172 | 698,623 | 564,172 | ||||||||||||
| Financial liabilities at amortized cost: | ||||||||||||||||
| Current accounts and other demand deposits | 14,551,566 | 14,498,196 | 14,551,566 | 14,498,196 | ||||||||||||
| Time deposits and saving accounts | 15,049,344 | 13,971,968 | 15,049,552 | 13,965,200 | ||||||||||||
| Obligations by repurchase agreements | 122,886 | 286,915 | 122,886 | 286,915 | ||||||||||||
| Borrowings from financial institutions | 1,218,163 | 1,296,751 | 1,204,864 | 1,278,009 | ||||||||||||
| Debt financial instruments issued: | ||||||||||||||||
| Mortgage finance bonds for residential purposes | 435 | 521 | 478 | 578 | ||||||||||||
| Mortgage finance bonds for general purposes | — | — | — | — | ||||||||||||
| Bonds | 11,163,812 | 10,800,330 | 10,933,199 | 10,725,466 | ||||||||||||
| Other financial obligations | 328,605 | 367,323 | 328,605 | 367,323 | ||||||||||||
| Subtotal | 42,434,811 | 41,222,004 | 42,191,150 | 41,121,687 | ||||||||||||
| Regulatory capital financial instruments: | ||||||||||||||||
| Subordinate bonds | 1,119,252 | 1,087,093 | 1,039,001 | 1,055,062 | ||||||||||||
| Total | 44,252,686 | 42,873,269 | 43,928,774 | 42,740,921 | ||||||||||||
Other financial assets and liabilities not measured at their fair value, but for which a fair value is estimated, even if not managed based on such value, include assets and liabilities such as placements, deposits and other time deposits, debt issued, and other financial assets and obligations with different maturities and characteristics. The fair value of these assets and liabilities is calculated using the Discounted Cash Flow model and the use of various data sources such as yield curves, credit risk spreads, etc. In addition, due to some of these assets and liabilities are not traded on the market, periodic reviews and analyzes are required to determine the suitability of the inputs and determined fair values.
151
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 44. | Fair Value of Financial Assets and Liabilities, continued: |
| (f) | Levels of other assets and liabilities: |
The following table shows the estimated fair value of financial assets and liabilities not measured at their fair value, as of September 30, 2026 and December 31, 2025:
| Level 1 Estimated fair value | Level 2 Estimated fair value | Level 3 Estimated fair value | Total Estimated fair value | |||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | |||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||
| Cash and deposits in banks | 3,165,155 | 2,590,986 | — | — | — | — | 3,165,155 | 2,590,986 | ||||||||||||||||||||||||
| Transactions in the course of collection | 362,105 | 414,419 | — | — | — | — | 362,105 | 414,419 | ||||||||||||||||||||||||
| Subtotal | 3,527,260 | 3,005,405 | — | — | — | — | 3,527,260 | 3,005,405 | ||||||||||||||||||||||||
| Financial assets at amortized cost: | ||||||||||||||||||||||||||||||||
| Rights by resale agreements | 96,631 | 100,643 | — | — | — | — | 96,631 | 100,643 | ||||||||||||||||||||||||
| Debt financial instruments | 425,581 | 435,196 | — | — | — | — | 425,581 | 435,196 | ||||||||||||||||||||||||
| Loans to Banks: | ||||||||||||||||||||||||||||||||
| Domestic banks | 199,928 | — | — | — | — | — | 199,928 | — | ||||||||||||||||||||||||
| Central Bank of Chile | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Foreign banks | — | — | — | — | 404,367 | 397,340 | 404,367 | 397,340 | ||||||||||||||||||||||||
| Subtotal | 722,140 | 535,839 | — | — | 404,367 | 397,340 | 1,126,507 | 933,179 | ||||||||||||||||||||||||
| Loans to customers, net: | ||||||||||||||||||||||||||||||||
| Commercial loans | — | — | — | — | 20,400,767 | 18,835,985 | 20,400,767 | 18,835,985 | ||||||||||||||||||||||||
| Residential mortgage loans | — | — | — | — | 14,428,407 | 13,957,541 | 14,428,407 | 13,957,541 | ||||||||||||||||||||||||
| Consumer loans | — | — | — | — | 5,183,750 | 5,436,873 | 5,183,750 | 5,436,873 | ||||||||||||||||||||||||
| Subtotal | — | — | — | — | 40,012,924 | 38,230,399 | 40,012,924 | 38,230,399 | ||||||||||||||||||||||||
| Total | 4,249,400 | 3,541,244 | — | — | 40,417,291 | 38,627,739 | 44,666,691 | 42,168,983 | ||||||||||||||||||||||||
| Liabilities | ||||||||||||||||||||||||||||||||
| Transactions in the course of payment | 698,623 | 564,172 | — | — | — | — | 698,623 | 564,172 | ||||||||||||||||||||||||
| Financial liabilities at amortized cost: | ||||||||||||||||||||||||||||||||
| Current accounts and other demand deposits | 14,551,566 | 14,498,196 | — | — | — | — | 14,551,566 | 14,498,196 | ||||||||||||||||||||||||
| Time deposits and saving accounts | — | — | — | — | 15,049,552 | 13,965,200 | 15,049,552 | 13,965,200 | ||||||||||||||||||||||||
| Obligations by repurchase agreements | 122,886 | 286,915 | — | — | — | — | 122,886 | 286,915 | ||||||||||||||||||||||||
| Borrowings from financial institutions | — | — | — | — | 1,204,864 | 1,278,009 | 1,204,864 | 1,278,009 | ||||||||||||||||||||||||
| Debt financial instruments issued: | ||||||||||||||||||||||||||||||||
| Mortgage finance bonds for residential purposes | — | — | 478 | 578 | — | — | 478 | 578 | ||||||||||||||||||||||||
| Mortgage finance bonds for general purposes | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||
| Bonds | — | — | 10,933,199 | 10,725,466 | — | — | 10,933,199 | 10,725,466 | ||||||||||||||||||||||||
| Other financial obligations | — | — | — | — | 328,605 | 367,323 | 328,605 | 367,323 | ||||||||||||||||||||||||
| Subtotal | 14,674,452 | 14,785,111 | 10,933,677 | 10,726,044 | 16,583,021 | 15,610,532 | 42,191,150 | 41,121,687 | ||||||||||||||||||||||||
| Regulatory capital financial instruments: | ||||||||||||||||||||||||||||||||
| Subordinate bonds | — | — | — | — | 1,039,001 | 1,055,062 | 1,039,001 | 1,055,062 | ||||||||||||||||||||||||
| Total | 15,373,075 | 15,349,283 | 10,933,677 | 10,726,044 | 17,622,022 | 16,665,594 | 43,928,774 | 42,740,921 | ||||||||||||||||||||||||
152
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 44. | Fair Value of Financial Assets and Liabilities, continued: |
| (f) | Levels of other assets and liabilities, continued: |
The Bank determines the fair value of these assets and liabilities according to the following:
| · | Short-term assets and liabilities: For assets and liabilities with short-term maturity, it is assumed that the book values approximate to their fair value. This assumption is applied to the following assets and liabilities: |
| Assets: | Liabilities: | |||
| - | Cash and deposits in banks | - | Current accounts and other demand deposits | |
| - | Transactions in the course of collection | - | Transactions in the course of payments | |
| - | Rights by resale agreements | - | Obligations by repurchase agreements | |
| - | Loans to domestic banks (including the Central Bank of Chile) | |||
| · | Loans to Customers and Advances to foreign banks: Fair value is determined by using the discounted cash flow model and internally generated discount rates, based on internal transfer rates derived from our internal transfer price process. Once the present value is determined, we deduct the related loan loss allowances to incorporate the credit risk associated with each contract or loan. As we use internally generated parameters for valuation purposes, we categorize these instruments in Level 3. |
| · | Debt financial instruments at amortized cost: The fair value is calculated with the methodology of the Stock Exchange, using the IRR observed in the market. Because the instruments that are in this category correspond to General Treasury of the Republic bonds that are Benchmark, they are classified in Level 1. |
| · | Mortgage finance bonds and Bonds: To determine the present value of contractual cash flows, we apply the discounted cash flow model by using market interest rates that are available in the market, either for the instruments under valuation or instruments with similar features that fit valuation needs in terms of currency, maturities and liquidity. The market interest rates are obtained from third party price providers widely used by the market. As a result of the valuation technique and the quality of inputs (observable) used for valuation, we categorize these financial liabilities in Level 2. |
| · | Saving Accounts, Time Deposits, Borrowings from Financial Institutions (including the Central Bank of Chile), Subordinated Bonds and Other borrowings financial: The discounted cash flow model is used to obtain the present value of committed cash flows by applying a bucket approach and average adjusted discount rates that derived from both market rates for instruments with similar features and our internal transfer price process. As we use internally generated parameters and/or apply significant judgmental analysis for valuation purposes, we categorize these financial liabilities in Level 3. |
153
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 45. | Maturity according to their remaining Terms of Financial Assets and Liabilities: |
The table below details the main financial assets and liabilities grouped in accordance with their remaining maturity, including capitals and accrued interest as of September 30, 2026 and December 31, 2025. As these are for trading and financial instrument at fair value through other comprehensive income are included at their fair value:
| September 2026 | ||||||||||||||||||||||||||||||||||||||||
| On demand | Up to 1 month | Over 1 month and up to 3 months |
Over 3 month and up to 12 months |
Subtotal up to 1 year |
Over 1 year and up to 3 years |
Over 3 years and up to 5 years |
Over 5 years |
Subtotal over 1 year |
Total | |||||||||||||||||||||||||||||||
| Assets | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||
| Cash and deposits in banks | 3,165,155 | — | — | — | 3,165,155 | — | — | — | — | 3,165,155 | ||||||||||||||||||||||||||||||
| Transactions in the course of collection | — | 362,105 | — | — | 362,105 | — | — | — | — | 362,105 | ||||||||||||||||||||||||||||||
| Financial assets held for trading at fair value through profit or loss: | ||||||||||||||||||||||||||||||||||||||||
| Derivative contracts financial | — | 227,446 | 229,146 | 424,852 | 881,444 | 477,051 | 589,809 | 457,980 | 1,524,840 | 2,406,284 | ||||||||||||||||||||||||||||||
| Debt financial instruments | — | 1,416,779 | — | — | 1,416,779 | — | — | — | — | 1,416,779 | ||||||||||||||||||||||||||||||
| Others | — | 421,754 | — | — | 421,754 | — | — | — | — | 421,754 | ||||||||||||||||||||||||||||||
| Financial assets at fair value through other comprehensive income | — | 134,002 | 667,791 | 1,233,681 | 2,035,474 | 1,110,266 | 230,664 | 863,028 | 2,203,958 | 4,239,432 | ||||||||||||||||||||||||||||||
| Derivative contracts financial for hedging purposes | — | — | — | 11,993 | 11,993 | 7,749 | — | 24,208 | 31,957 | 43,950 | ||||||||||||||||||||||||||||||
| Financial assets at amortized cost: | ||||||||||||||||||||||||||||||||||||||||
| Rights by resale agreements | — | 35,661 | 58,684 | 2,286 | 96,631 | — | — | — | — | 96,631 | ||||||||||||||||||||||||||||||
| Debt financial instruments (*) | — | — | — | — | — | 135,725 | 317,900 | — | 453,625 | 453,625 | ||||||||||||||||||||||||||||||
| Loans to Banks (**) | — | 351,824 | 1,426 | 257,310 | 610,560 | — | — | — | — | 610,560 | ||||||||||||||||||||||||||||||
| Loans to customers (**) | — | 5,671,609 | 3,345,884 | 6,424,703 | 15,442,196 | 7,454,183 | 4,806,166 | 13,065,160 | 25,325,509 | 40,767,705 | ||||||||||||||||||||||||||||||
| Total financial assets | 3,165,155 | 8,621,180 | 4,302,931 | 8,354,825 | 24,444,091 | 9,184,974 | 5,944,539 | 14,410,376 | 29,539,889 | 53,983,980 | ||||||||||||||||||||||||||||||
| September 2026 | ||||||||||||||||||||||||||||||||||||||||
| On demand | Up to 1 month | Over 1 month and up to 3 months |
Over 3 month and up to 12 months |
Subtotal up to 1 year |
Over 1 year and up to 3 years |
Over 3 years and up to 5 years |
Over 5 years |
Subtotal over 1 year |
Total | |||||||||||||||||||||||||||||||
| Liabilities | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||
| Transactions in the course of payment | — | 698,623 | — | — | 698,623 | — | — | — | — | 698,623 | ||||||||||||||||||||||||||||||
| Financial liabilities held for trading at fair value through profit or loss: | ||||||||||||||||||||||||||||||||||||||||
| Derivative contracts financial | — | 225,311 | 233,353 | 451,788 | 910,452 | 572,003 | 579,562 | 451,713 | 1,603,278 | 2,513,730 | ||||||||||||||||||||||||||||||
| Others | — | 1,216 | 408 | — | 1,624 | — | — | — | — | 1,624 | ||||||||||||||||||||||||||||||
| Derivative contracts financial for hedging purposes | — | — | — | 1,088 | 1,088 | 2,373 | 79,450 | 189,861 | 271,684 | 272,772 | ||||||||||||||||||||||||||||||
| Financial liabilities at amortized cost: | ||||||||||||||||||||||||||||||||||||||||
| Current accounts and other demand deposits | 14,551,566 | — | — | — | 14,551,566 | — | — | — | — | 14,551,566 | ||||||||||||||||||||||||||||||
| Time deposits and saving accounts (***) | — | 8,680,964 | 2,629,649 | 3,262,415 | 14,573,028 | 27,951 | 1,137 | 749 | 29,837 | 14,602,865 | ||||||||||||||||||||||||||||||
| Obligations by repurchase agreements | — | 121,970 | 916 | — | 122,886 | — | — | — | — | 122,886 | ||||||||||||||||||||||||||||||
| Borrowings from financial institutions | — | 207,203 | 73,041 | 787,774 | 1,068,018 | 150,145 | — | — | 150,145 | 1,218,163 | ||||||||||||||||||||||||||||||
| Debt financial instruments issued: | ||||||||||||||||||||||||||||||||||||||||
| Mortgage finance bonds | — | 10 | 26 | 29 | 65 | 83 | 71 | 216 | 370 | 435 | ||||||||||||||||||||||||||||||
| Bonds | — | 399,076 | 415,392 | 1,298,901 | 2,113,369 | 2,160,998 | 1,736,724 | 5,152,721 | 9,050,443 | 11,163,812 | ||||||||||||||||||||||||||||||
| Other financial obligations | — | 328,605 | — | — | 328,605 | — | — | — | — | 328,605 | ||||||||||||||||||||||||||||||
| Lease liabilities | — | 2,348 | 4,703 | 19,239 | 26,290 | 30,084 | 9,299 | 6,759 | 46,142 | 72,432 | ||||||||||||||||||||||||||||||
| Regulatory capital financial instruments | — | — | 99,881 | 5,349 | 105,230 | 12,241 | 3,309 | 998,472 | 1,014,022 | 1,119,252 | ||||||||||||||||||||||||||||||
| Total financial liabilities | 14,551,566 | 10,665,326 | 3,457,369 | 5,826,583 | 34,500,844 | 2,955,878 | 2,409,552 | 6,800,491 | 12,165,921 | 46,666,765 | ||||||||||||||||||||||||||||||
| Mismatch | (11,386,411 | ) | (2,044,146 | ) | 845,562 | 2,528,242 | (10,056,753 | ) | 6,229,096 | 3,534,987 | 7,609,885 | 17,373,968 | 7,317,215 | |||||||||||||||||||||||||||
| (*) | These balances are presented without deduction of impairment, which amount to Ch$50 million. |
| (**) | These balances are presented without deduction of their respective related allowances, which amount to Ch$848,244 million for loans to customers and Ch$829 million for borrowings from financial institutions. |
| (***) | Excludes term saving accounts, which amount to Ch$446,479 million. |
154
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 45. | Maturity according to their remaining Terms of Financial Assets and Liabilities, continued: |
| December 2025 | ||||||||||||||||||||||||||||||||||||||||
| On demand | Up to 1 month | Over 1 month and up to 3 months |
Over 3 month and up to 12 months |
Subtotal up to 1 year |
Over 1 year and up to 3 years |
Over 3 years and up to 5 years |
Over 5 years |
Subtotal over 1 year |
Total | |||||||||||||||||||||||||||||||
| Assets | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||
| Cash and deposits in banks | 2,590,986 | — | — | — | 2,590,986 | — | — | — | — | 2,590,986 | ||||||||||||||||||||||||||||||
| Transactions in the course of collection | — | 414,419 | — | — | 414,419 | — | — | — | — | 414,419 | ||||||||||||||||||||||||||||||
| Financial assets held for trading at fair value through profit or loss: | ||||||||||||||||||||||||||||||||||||||||
| Derivative contracts financial | — | 167,124 | 136,487 | 323,653 | 627,264 | 398,808 | 386,942 | 456,453 | 1,242,203 | 1,869,467 | ||||||||||||||||||||||||||||||
| Debt financial instruments | — | 3,121,702 | — | — | 3,121,702 | — | — | — | — | 3,121,702 | ||||||||||||||||||||||||||||||
| Others | — | 402,259 | — | — | 402,259 | — | — | — | — | 402,259 | ||||||||||||||||||||||||||||||
| Financial assets at fair value through other comprehensive income | — | 71,180 | 341,097 | 1,162,592 | 1,574,869 | 1,339,478 | 218,817 | 415,807 | 1,974,102 | 3,548,971 | ||||||||||||||||||||||||||||||
| Derivative contracts financial for hedging purposes | — | — | — | — | — | 9,670 | — | 20,044 | 29,714 | 29,714 | ||||||||||||||||||||||||||||||
| Financial assets at amortized cost: | ||||||||||||||||||||||||||||||||||||||||
| Rights by resale agreements | — | 79,029 | 20,337 | 1,277 | 100,643 | — | — | — | — | 100,643 | ||||||||||||||||||||||||||||||
| Debt financial instruments (*) | — | — | 8,620 | — | 8,620 | 133,217 | 319,119 | — | 452,336 | 460,956 | ||||||||||||||||||||||||||||||
| Loans to Banks (**) | — | 186,241 | 8,838 | 204,713 | 399,792 | — | — | — | — | 399,792 | ||||||||||||||||||||||||||||||
| Loans to customers (**) | — | 5,567,445 | 2,215,757 | 7,141,898 | 14,925,100 | 7,033,442 | 4,612,946 | 12,620,482 | 24,266,870 | 39,191,970 | ||||||||||||||||||||||||||||||
| Total financial assets | 2,590,986 | 10,009,399 | 2,731,136 | 8,834,133 | 24,165,654 | 8,914,615 | 5,537,824 | 13,512,786 | 27,965,225 | 52,130,879 | ||||||||||||||||||||||||||||||
| December 2025 | ||||||||||||||||||||||||||||||||||||||||
| On demand | Up to 1 month | Over 1 month and up to 3 months |
Over
3 month and up to 12 months |
Subtotal
up to 1 year |
Over
1 year and up to 3 years |
Over
3 years and up to 5 years |
Over 5 years |
Subtotal
over 1 year |
Total | |||||||||||||||||||||||||||||||
| Liabilities | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||
| Transactions in the course of payment | — | 564,172 | — | — | 564,172 | — | — | — | — | 564,172 | ||||||||||||||||||||||||||||||
| Financial liabilities held for trading at fair value through profit or loss: | ||||||||||||||||||||||||||||||||||||||||
| Derivative contracts financial | — | 206,193 | 136,315 | 350,100 | 692,608 | 546,890 | 381,826 | 458,898 | 1,387,614 | 2,080,222 | ||||||||||||||||||||||||||||||
| Others | — | 203 | 309 | — | 512 | — | — | — | — | 512 | ||||||||||||||||||||||||||||||
| Derivative contracts financial for hedging purposes | — | — | — | — | — | 4,363 | 53,287 | 240,167 | 297,817 | 297,817 | ||||||||||||||||||||||||||||||
| Financial liabilities at amortized cost: | ||||||||||||||||||||||||||||||||||||||||
| Current accounts and other demand deposits | 14,498,196 | — | — | — | 14,498,196 | — | — | — | — | 14,498,196 | ||||||||||||||||||||||||||||||
| Time deposits and saving accounts (***) | — | 8,929,347 | 2,863,533 | 1,765,508 | 13,558,388 | 6,467 | 793 | 631 | 7,891 | 13,566,279 | ||||||||||||||||||||||||||||||
| Obligations by repurchase agreements | — | 286,915 | — | — | 286,915 | — | — | — | — | 286,915 | ||||||||||||||||||||||||||||||
| Borrowings from financial institutions | — | 64,758 | 322,064 | 773,675 | 1,160,497 | 136,254 | — | — | 136,254 | 1,296,751 | ||||||||||||||||||||||||||||||
| Debt financial instruments issued: | ||||||||||||||||||||||||||||||||||||||||
| Mortgage finance bonds | — | 53 | 34 | 20 | 107 | 83 | 89 | 242 | 414 | 521 | ||||||||||||||||||||||||||||||
| Bonds | — | 85,903 | 412,740 | 1,120,727 | 1,619,370 | 2,516,201 | 1,715,429 | 4,949,330 | 9,180,960 | 10,800,330 | ||||||||||||||||||||||||||||||
| Other financial obligations | — | 367,323 | — | — | 367,323 | — | — | — | — | 367,323 | ||||||||||||||||||||||||||||||
| Lease liabilities | — | 2,217 | 4,435 | 16,917 | 23,569 | 32,855 | 10,827 | 7,092 | 50,774 | 74,343 | ||||||||||||||||||||||||||||||
| Regulatory capital financial instruments | — | 2,153 | — | 105,722 | 107,875 | 11,039 | 9,241 | 958,938 | 979,218 | 1,087,093 | ||||||||||||||||||||||||||||||
| Total financial liabilities | 14,498,196 | 10,509,237 | 3,739,430 | 4,132,669 | 32,879,532 | 3,254,152 | 2,171,492 | 6,615,298 | 12,040,942 | 44,920,474 | ||||||||||||||||||||||||||||||
| Mismatch | (11,907,210 | ) | (499,838 | ) | (1,008,294 | ) | 4,701,464 | (8,713,878 | ) | 5,660,463 | 3,366,332 | 6,897,488 | 15,924,283 | 7,210,405 | ||||||||||||||||||||||||||
| (*) | These balances are presented without deduction of impairment, which amount to Ch$19 million. |
| (**) | These balances are presented without deduction of their respective related allowances, which amount to Ch$836,971 million for loans to customers and Ch$669 million for borrowings from financial institutions. |
| (***) | Excludes term saving accounts, which amount to Ch$405,689 million. |
155
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 46. | Financial and Non-Financial Assets and Liabilities by Currency: |
| As of September 30, 2026 | CLP | CLF | FX Indexation | USD | COP | GBP | EUR | CHF | JPY | CNY | Others | TOTAL | ||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||||||||||||||||||
| Financial assets | 24,432,006 | 23,124,530 | 204,023 | 5,089,961 | — | 37,309 | 168,921 | 5,924 | 31,110 | 22,168 | 18,905 | 53,134,857 | ||||||||||||||||||||||||||||||||||||
| Non-Financial assets | 2,132,518 | 11,920 | 5,289 | 623,179 | — | — | 4,568 | — | — | — | 1 | 2,777,475 | ||||||||||||||||||||||||||||||||||||
| Total Assets | 26,564,524 | 23,136,450 | 209,312 | 5,713,140 | — | 37,309 | 173,489 | 5,924 | 31,110 | 22,168 | 18,906 | 55,912,332 | ||||||||||||||||||||||||||||||||||||
| Liabilities | ||||||||||||||||||||||||||||||||||||||||||||||||
| Financial liabilities | 27,986,399 | 11,091,812 | 338 | 6,297,685 | — | 1,929 | 136,516 | 268,783 | 311,156 | 2,274 | 1,016,352 | 47,113,244 | ||||||||||||||||||||||||||||||||||||
| Non-Financial liabilities | 2,349,798 | 269,284 | 1,766 | 340,204 | — | 51 | 13,548 | 14 | 12 | 4 | 112 | 2,974,793 | ||||||||||||||||||||||||||||||||||||
| Total Liabilities | 30,336,197 | 11,361,096 | 2,104 | 6,637,889 | — | 1,980 | 150,064 | 268,797 | 311,168 | 2,278 | 1,016,464 | 50,088,037 | ||||||||||||||||||||||||||||||||||||
| Mismatch of Financial Assets and Liabilities (*) | (3,554,393 | ) | 12,032,718 | 203,685 | (1,207,724 | ) | — | 35,380 | 32,405 | (262,859 | ) | (280,046 | ) | 19,894 | (997,447 | ) | 6,021,613 | |||||||||||||||||||||||||||||||
| (*) | This value does not consider non-financial assets and liabilities and the notional values of derivative instruments, which are disclosed at fair value. |
| As of December 31, 2025 | CLP | CLF | FX Indexation | USD | COP | GBP | EUR | CHF | JPY | CNY | Others | TOTAL | ||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||||||||||||||||||
| Financial assets | 24,174,985 | 22,931,512 | 187,136 | 3,762,611 | — | 18,278 | 148,857 | 4,009 | 13,147 | 29,502 | 23,183 | 51,293,220 | ||||||||||||||||||||||||||||||||||||
| Non-Financial assets | 2,271,476 | 7,822 | 1,209 | 526,132 | — | 21 | 955 | 68 | — | — | — | 2,807,683 | ||||||||||||||||||||||||||||||||||||
| Total Assets | 26,446,461 | 22,939,334 | 188,345 | 4,288,743 | — | 18,299 | 149,812 | 4,077 | 13,147 | 29,502 | 23,183 | 54,100,903 | ||||||||||||||||||||||||||||||||||||
| Liabilities | ||||||||||||||||||||||||||||||||||||||||||||||||
| Financial liabilities | 26,552,935 | 11,209,717 | 252 | 6,018,272 | — | 6,079 | 129,357 | 262,499 | 232,405 | 18,817 | 895,830 | 45,326,163 | ||||||||||||||||||||||||||||||||||||
| Non-Financial liabilities | 2,392,309 | 303,470 | 1,687 | 274,452 | — | 5 | 2,573 | 571 | 12 | 3 | 123 | 2,975,205 | ||||||||||||||||||||||||||||||||||||
| Total Liabilities | 28,945,244 | 11,513,187 | 1,939 | 6,292,724 | — | 6,084 | 131,930 | 263,070 | 232,417 | 18,820 | 895,953 | 48,301,368 | ||||||||||||||||||||||||||||||||||||
| Mismatch of Financial Assets and Liabilities (*) | (2,377,950 | ) | 11,721,795 | 186,884 | (2,255,661 | ) | — | 12,199 | 19,500 | (258,490 | ) | (219,258 | ) | 10,685 | (872,647 | ) | 5,967,057 | |||||||||||||||||||||||||||||||
| (*) | This value does not consider non-financial assets and liabilities and the notional values of derivative instruments, which are disclosed at fair value. |
156
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report: |
| (1) | Introduction: |
Banco de Chile seeks to maintain a risk profile that ensures the sustainable growth that is aligned with its strategic objectives, maximizing value creation and guarantee its long-term solvency. The Overall risk management takes into consideration the different business segments to which the Bank, being approached from a comprehensive and differentiated perspective.
Our risk management policies are established to identify and analyze the risks faced by the Bank, set appropriate risk limits, alerts and controls, monitor risks and compliance with limits and alerts in order to perform the necessary action plans. Through its administration policies and procedures, the Bank develops a disciplined and constructive control environment. Policies as well as risk management standards, procedures and systems are regularly reviewed, and with strict adherence to compliance with the current regulatory framework.
For such purposes, the Bank has teams with extensive experience and knowledge in each area associated with risks, ensuring comprehensive and consolidated management of such risks, including the Bank and its subsidiaries.
| (a) | Risk Management Structure |
Credit, Market and Operational Risk Management are at all levels within the Organization, with a Corporate Governance structure that recognizes the significance of the different risk areas that exist.
The Bank’s Board of Directors as the maximum authority is responsible for establishing risk policies, the Risk Appetite Framework, and the guidelines for the measurement criteria and follow up of risks. Also, it approves the risk limits and contingency plans for each of the risks. Moreover, it approves the following policies: Credit risk policy, policy for complex products and services, operational risk policy, business continuation policy, outsourcing policy, investments in debt instruments policy, market risk policy and liquidity risk policy. Likewise, it approves the internal provision, credit risk, market and operational stress testing models. Additional allowances Policy and pronounces annually on the adequacy of allowances. Additionally, it approves the capital management policy for the monitoring, control, administration and the management of the bank´s capital. Also, it confirms the strategies, functional structure and comprehensive management model of Operational Risk and guarantees the consistency of this model with the Bank’s strategy and proper implementation of the model within the organization. Accordingly, it has approved the risk management policy of the model together with the development framework, validation, implementation, integration and follows up on the models. Furthermore, it establishes the Subsidiary Risk Control Policy, describing the supervision scheme that the Bank applies to the relevant subsidiaries to control the risks that affect them. Management is responsible both for the establishment of standards and associated procedures as well as for the control and compliance with that agreed by the Board of Directors, ensuring that there is consistency between the criteria applied by the Bank and its subsidiaries, maintaining strict coordination at the corporate level and informing the Board of Directors at the defined instances.
The Bank’s Corporate Governance considers the active participation of the Board, acting directly or through different committees made up of Directors and Senior Management. It is permanently informed and becomes aware of the evolution of the different risk management areas, participating through its Finance, International and Financial Risk, Credit, Portfolio Risk Committee, Higher Committee on Operational Risk and Capital Management, in which the status of credit, market and operational risks and the Bank’s capital management are reviewed.
157
| 47. | Risk Management and Report, continued: |
In addition to the Board Committees, the Bank’s Management has several specialized committees, including the Internal Models and Integration Strategies Committee (formerly the Technical Committee for the Supervision and Development of Internal Models), whose name was changed to reflect its role in overseeing the development, integration and monitoring of internal credit risk methodologies; the Model Risk Management Committee; and the Operational Risk Committee, which address specific matters related to risk management.
The following sections describe the different committees of Directors and Administration previously mentioned.
Risk management is carried out jointly by the Credit Risk Division and the Operational Risk and Global Control Division, which together form the risk corporate governance structure. These divisions are supported by highly experienced and specialized teams, as well as a robust regulatory framework, enabling optimal and effective management of matters within their respective areas of responsibility.
These divisions contribute to the effective governance of the Corporation’s principal risks, with the objective of optimizing the risk–return relationship, safeguarding business continuity, and strengthening a robust risk culture. This approach is implemented through the identification, assessment, and management of potential losses arising from counterparties’ failure to meet their obligations, exposure to changes in market risk factors, or the inadequacy or failure of processes, personnel, and/or internal systems, as well as from external events, thereby contributing comprehensively to sound capital management.
Likewise, these divisions continually manage risk knowledge from a comprehensive approach, in order to contribute to the business anticipating threats that may damage the solvency and quality of the portfolio, promoting a unified and cross-functional risk culture across the Corporation through training and permanent education.
Within the Credit Risk Division, the Bank’s risk functions are integrated as follows, ensuring, at the same time, the correct segregation of functions and independence:
| - | Market Risk: Is responsible for developing the function of measuring, limiting, controlling and reporting market risk, along with defining valuation standards and managing the Bank’s assets and liabilities. Moreover, this management is responsible for taking care of the compliance of market risk management policies, liquidity management, investment in debt instruments approved by the board and to communicate promptly the status of market risks in detail accordingly. | |
| - | Wholesale Credit Risk Admission: is responsible for managing, resolving and controlling the approval process of businesses related to the Wholesale segment portfolio, including specific sectors and products for this portfolio, ensuring coherence, compliance and consistency of policies. of credit risk both in the bank and in its subsidiaries. | |
| - | Retail Admission, Regulations and Risk Transformation: Responsible for defining the credit risk management framework, both for reactive and proactive retail origination, within the defined regulatory scope and risk appetite established by the Bank. Also, the maintenance and implementation of all credit risk strategies associated with the automatic evaluation. | |
| Manages the regulatory body, policies, standards and procedures of credit risk, adapting the established requirements and processes, for all segments transversally in the Bank. Likewise, it carries out reviews of the quality of the credit process applied to retail banks and the continuous training of executives. | ||
| - | Special Asset Management: is responsible for the collection of credits from all of the Bank’s customer segments, with differentiated management in accordance with institutional policies. |
In addition, it is responsible for managing the sale of assets recovered by the Bank, coming from credit recovery processes.
158
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| - | Risk Management Monitoring, Reporting and Control: is responsible for managing and reporting credit risk, especially through monitoring the main portfolio indicators and in-depth analysis of situations and scenarios of special attention, timely detecting problems that may affect certain products, debtors or sectors, with the aim of minimizing the risk assumed and anticipating situations that could lead to credit losses. In addition, it monitors model performance and reports the results to the appropriate governance bodies. |
Likewise, it provides information to the different government bodies and areas involved in the decision-making process and contributes to providing effective governance to the Corporate Credit Risk Division projects, ensuring regulatory compliance and the correct execution of the projects. Themselves, as well as being responsible for the management control of the Corporate Risk Division.
| - | Risk Models: is responsible for developing, maintaining and updating credit risk models, whether for regulatory or management uses, in accordance with local and international regulations, determining the functional specifications and the most appropriate statistical techniques for the development of the required models. These models are immersed in the measurement and management of model risk carried out by the Model Risk and Internal Control Management, and presented to the corresponding government bodies, such as the Technical Committee for the Supervision of Internal Models and strategies of integration, the Portfolio Risk Committee or the Board of Directors, as appropriate. |
Additionally, this Area is responsible for managing the process of calculating provisions for credit risk, ensuring the correct execution of the processes and analysis of the results obtained.
The Operational Risk and Global Control Division is responsible for the areas of Operational Risk, Business Continuity, Model Risk, Internal Control, and Technology Risk. It is charged with managing and overseeing the implementation of policies, standards, and procedures related to each of these areas across the Bank and its Subsidiaries. To fulfill these responsibilities, the Division maintains a specialized organizational structure composed of various units dedicated to the different risk areas under its oversight. Within this framework, the Operational Risk Management Department is responsible for ensuring the effective identification and management of operational risks, fostering a risk-aware culture focused on preventing financial losses, continuously improving process quality, and strengthening the Bank’s enterprise-wide risk management framework. These efforts are aligned with Basel III regulatory requirements and the Bank’s strategic business objectives.
Likewise, the Business Continuity Management is responsible for the management, control, and administration of recovery strategies in contingency situations. In addition, it ensures the Bank’s operational resilience by maintaining the crisis-management governance model, guaranteeing the continuity of critical services and operations, particularly those related to critical payment products and services. This model is strengthened through a comprehensive resilience framework that includes ongoing training programs, plan updates, and controlled testing to validate the effectiveness of the strategies against disruptive events that may impact the Bank, thereby reinforcing its capacity to respond safely and efficiently. Additionally, the structure includes the role and responsibilities of the Information Security Officer (ISO), who operates independently from the Cybersecurity Division. The ISO’s function is to design and implement controls by monitoring the activities carried out by the organizational units responsible for information security, cybersecurity, and technology risk within the Bank and its subsidiaries.
159
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
Also within its structure is the Model Risk and Internal Control, which is responsible for managing risks associated with models and processes. To carry out these responsibilities, it relies on model validation, model risk management, and internal control functions. In this capacity, it performs independent reviews of models and methodologies within its scope, assessing data quality, modeling techniques, compliance with regulatory requirements, their integration within the organization, and the adequacy of supporting documentation. In addition, it monitors each stage of the model and methodology lifecycle within its scope, with the ultimate objective of establishing mechanisms that enable the measurement and management of the level of model risk to which the Bank is exposed.
Furthermore, it is responsible for conducting an independent assessment of the internal control environment. To this end, it employs procedures based on the COSO 2013 Framework (Committee of Sponsoring Organizations of the Treadway Commission), which comprises five components: control environment, risk assessment, control activities, information and communication, and monitoring activities. These efforts support compliance with both local and international regulatory requirements, including the updated compilation of regulations issued by the Financial Market Commission (CMF) and Section 404 of the Sarbanes-Oxley Act, respectively.
With respect to Technology Risk, the Operational Risk and Global Control Division is responsible for managing technology risk, information security risk, and cybersecurity risk, taking into consideration the threats, vulnerabilities, and scenarios that could compromise the Bank’s services and processes. This responsibility is carried out through the identification, assessment, monitoring, and reporting of risk exposures, including the estimation of the likelihood and potential impact of risk events. These activities strengthen the internal control framework, promote the implementation of risk treatment measures, and contribute to operational resilience, regulatory compliance, and the protection of information with respect to its confidentiality, integrity, and availability across the various areas of work.
Additionally, the Bank has the Cybersecurity Division, which is responsible for defining, implementing and reporting the progress of the Strategic Cybersecurity Plan in line with the Bank’s business strategy, with one of its main focuses being to protect internal information, of its clients and collaborators.
This Division consists of the Governance and Identity Management, the Cyber Defense Management and the Threat and Cybersecurity Management. The Cybersecurity Management and Subsidiaries Control Department is also part of the division, as a control unit. Section 5 of this Note describes the responsibilities of the indicated Managements.
Committees of Directors and Bank Administration
| (i) | Finance, International and Financial Risk Committee |
In general terms, the objectives of this committee are to monitor and continuously review the liquidity status and trends in the most important financial positions, as well as the associated results, and the price and liquidity risks that will be generated. Some of its specific functions include, the review of the proposal to the Board of Directors of the Risk Appetite Framework (RAF), the Financing Plan and the structure of limits and alerts for price and liquidity risks, reviewing and approving the Comprehensive Risk Measurement (CRM) for subsequent due review in the Capital Management Committee and approval by the Board of Directors, the design of policies and procedures related to the establishment of limits and alerts for price risk and liquidity risk; reviewing the evolution of financial positions and market risks; monitoring limit excesses and alert activations; ensuring adequate identification of risk factors in financial positions; ensuring that the price and liquidity risk management guidelines in the Bank’s subsidiaries are consistent with those of the Bank, and that these are reflected in its own policies and procedures.
160
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (ii) | Credit Committees |
The credit approval process is performed mainly through several credit committees, which are composed of qualified professionals and with the sufficient powers to make the decisions required.
Each committee defines the terms and conditions under which the Bank accepts counterparty risks, and the Credit Risk Division participates independently and autonomously of the commercial areas. They are constituted according to the commercial segments and the amounts be approved and have different meeting periodicities.
Within the Bank´s risk management structure, the maximum approval instance is the Director´s Credit Committee. Its functions are to resolve all credit transactions associated with customers and economic groups with approved lines of credit in excess of UF750,000, and to approve all credit transactions where the bank’s internal regulations require approval from this Committee, except for any special powers delegated by the Board of Directors to Management.
| (iii) | Portfolio Risk Committee |
Among other duties, the Portfolio Risk Committee must understand the composition, concentration and risks attached to the bank’s loan portfolio, from a global, sectoral and business unit perspective, review and approve the comprehensive risk measurement (CRM) and the Credit Risk Appetite Framework (RAF) in the area of credit risk; It must review the main debtors, their delinquency, past-due portfolio and impairment indicators, together with the write-offs and loan portfolio allowances for each segment. It must propose differentiated management strategies, as well as analyzing and agreeing on the and analyze credit policy proposals that will be approved by the board of directors. This committee also reviews and confirms the approvals of management models and methodologies Also, this committee is responsible for reviewing and ratifying the approvals of management models and methodologies previously conducted by the Technical Committee for the Supervision of Internal Models and strategies of integration, as well as proposing the regulatory models and methodologies for final approval by the Board of Directors.
| (iv) | Collection Committee |
The purpose of the Collection Committee is fundamentally to ensure the ongoing and proper monitoring of credit collection activities. In particular, it focuses on reviewing the results and evolution of the amounts assigned to collection across the different delinquency stages of each product, as well as the productivity and recovery performance of the various banking segments.
161
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (v) | Senior Operational Risk Committee |
The Senior Operational Risk Committee reviews and has the authority to approve the necessary changes to the processes, controls and information systems supporting Banco de Chile’s operations, with the aim of mitigating operational risks and ensuring that the various areas appropriately manage and control such risks. The Committee also reviews and approves the Bank’s Comprehensive Operational Risk Management Model, including matters related to Business Continuity, Information Security, Cybersecurity and Suppliers. In this context, it monitors exposure to operational risks, reviews and approves the Risk Appetite and Risk Measurement Frameworks, assesses relevant events and mitigation plans, and oversees regulatory compliance. In addition, it periodically reports to the Board of Directors on the Bank’s risk profile and the effectiveness of its risk management. The Committee verifies the consistency of the policies related to these matters, both at the Bank and its Subsidiaries, and oversees corrective actions in response to deviations or contingency scenarios that may affect the Subsidiaries and/or the Bank.
| (vi) | Capital Management Committee |
The main purpose of this committee is to assess, monitor and review capital adequacy in accordance with the principles in the bank’s capital management policy and its risk framework, to ensure that capital resources are adequately managed, the CMF’s principles are respected, and the bank’s medium-term sustainability.
| (vii) | Technical Committee for the Supervision of Internal Models and Strategies of Integration |
Among other responsibilities, this Committee is responsible for establishing, analyzing and ensuring compliance with the methodological guidelines for the development and monitoring of credit risk models, for both regulatory and internal management purposes; analyzing the criteria adopted; and reviewing and approving methodologies for monitoring internal models, which must be submitted to the Credit Risk Committee for final ratification. The Committee also reviews and approves the integration strategies for internal credit risk methodologies, including any subsequent adjustments or modifications. The guidelines must be submitted to the Credit Risk Committee and, where applicable, to the Board of Directors for final approval. In the case of regulatory models, this Committee’s role is limited to reviewing such models, while approval rests with the Credit Risk Committee and, subsequently, the Board of Directors.
162
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (viii) | Model Risk Management Committee |
Its main function is to establish and oversee the institution-wide model risk management framework. Among other responsibilities, this committee reviews and discusses the identification and assessment of model risks based on aggregated results, provides guidelines and verifies the consistency of policies with subsidiaries, ensures the updating of the institutional inventory of models and methodologies, reviews the status of observations and action plans, and submits the Model Risk Management Policy to the Board of Directors for review and approval.
| (ix) | Operational Risk Committee |
The Committee is empowered to implement the necessary changes to the processes, controls and information systems supporting Banco de Chile’s operations, with the aim of mitigating operational risks and ensuring that the various areas appropriately manage and control such risks. The Committee’s objective is to oversee the Bank’s comprehensive operational risk management, including matters related to Business Continuity, Information Security and Suppliers. To this end, it monitors risk exposure, promotes a culture of operational risk management and compliance with the applicable regulatory framework, reviews the Risk Appetite and Risk Measurement Frameworks, assesses relevant events and mitigation plans, and monitors initiatives aimed at strengthening the Bank’s resilience and operational continuity.
| (b) | Internal Audit |
The risk management processes of the entire Bank are permanently audited by the Internal Audit Area, which examines the sufficiency of the procedures and their compliance. Internal Audit discusses the results of all evaluations with Management and reports its findings and recommendations to the Board of Directors through the Audit Committee.
163
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (c) | Measurement Methodology |
Regarding Credit Risk, loan loss provision and write offs are the fundamental metrics of the credit quality of our portfolio.
Banco de Chile permanently evaluates its loan portfolio, timely recognizing its risks. The Bank has a set of guidelines for the generation of credit risk models, covering management models (reactive and proactive admission models and collection models), provision models (both under local regulations in accordance with the instructions issued by the CMF, as well as under IFRS criteria) which are incorporated into the Bank’s risk management framework, and stress tests that are part of the Bank’s effective equity self-assessment process. The Board of Directors approves these guidelines, and the models developed.
For the purposes of covering losses in the event of customers payment default, the Bank determines the level of allowances that must be established based on the following:
| - | Individual evaluation: mainly applies to the Bank’s portfolio of legal persons that, due to their size, complexity or indebtedness, requires a more detailed level of knowledge and a case-by-case analysis. Each debtor is assigned one of the 16 risk categories defined by the CMF, to establish the allowances in a timely and appropriate manner. The review of the portfolio risk classifications is carried out permanently considering the financial situation, payment behavior and the environment of each client. |
| - | Group evaluation mainly applies to the portfolio of natural persons and smaller companies. These assessments are carried out monthly through statistical models that allow estimating the level of allowances necessary to cover the portfolio risk; for commercial, consumer and mortgage portfolios, these results are compared with the standard models provided by the regulator, with the resulting allowance being the largest between both methods. The consistency analysis of the models is conducted through an independent validation of the unit that develops them and, subsequently, through the analysis of retrospective tests that allow the comparison of the actual losses to expected losses. |
To validate the quality and robustness of the risk assessment processes, the Bank annually performs a test of the adequacy of allowances for the total loan portfolio, verifying that the allowances established are adequate to cover the losses that could arise from credit operations granted. The result of this analysis is presented to the Board of Directors, which provides its view on the adequacy of the allowances in each year.
164
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
Banco de Chile establishes additional allowances with the objective of protecting itself from the risk of unpredictable economic fluctuations that may affect the macroeconomic environment or the situation of a specific economic sector. At least once a year, the amount of additional allowances to be or released is annually proposed to the Portfolio Risk Committee and subsequently to the Board of Directors for approval.
During May 2026, the Bank established additional loan loss allowances, taking into consideration various forward-looking analyses, economic cycle expectations, and local macroeconomic projections, as the key factors.
The monitoring and control of risks are performed mainly based on limits established by the Board of Directors. These limits reflect the Bank’s business and market strategy, as well as the level of risk that it is willing to accept, with additional emphasis on the industries selected.
The Bank develops its capital planning process on a comprehensive basis with its strategic planning, in line with the risks inherent to its activity, the economic and competitive environment, its business strategy, corporate values, as well as its governance, management and risk control. As part of the capital planning process and, in line with that required by the regulator, Risk-Weighted Assets and stress tests are obtained in the dimensions of credit, market and operational risk, as well as the Comprehensive Measurement of risks.
The Bank annually reviews and updates its Risk Appetite Framework, approved by the Board of Directors, that allows the Bank to identify, evaluate, measure, mitigate and control proactively and in advance all relevant risks that could materialize in the normal course of its business. For such purpose, the Bank uses different management tools and defines an adequate structure of alerts and limits, which are part of such Framework allowing it to constantly monitor the performance of different indicators and implement timely corrective actions, in the cases those are needed. The result of these activities is part of the annual self-assessment report of effective equity approved by the Board of Directors and reported to the CMF.
165
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (2) | Credit Risk: |
Credit risk considers the likelihood that the counterparty in the credit operation will not be able to fulfill its contractual obligation due to inability or financial insolvency, and this leads to a potential credit loss.
The Bank seeks an adequate risk-return relation, and an appropriate balance of the risks assumed, through permanent credit risk management considering the processes of admission, monitoring and recovery of the loans granted. It establishes the risk management framework for the different business segments it serves, responding to regulatory demands and commercial dynamism, being part of the digital transformation and contributing from a risk perspective to the various businesses addressed, through a vision of the portfolio that allows managing, resolving and controlling the business approval and monitoring process in an efficient and proactive manner.
In the business segments, the application of additional management processes is taken into consideration, to the extent required, for those financing requests that that will have a greater exposure to environmental and/or social risks.
The Bank integrates the socio-environmental criteria in its evaluations for the granting of financing destined to the development of projects, whether national or regional, and that can generate an impact of this type, where they are executed. For the financing of projects, they must have the corresponding permits, authorizations, patents and studies, according to the impact they generate. In addition, the Bank has specialized units for serving large clients, through which the financing of project development is concentrated, including those of Public Works concessions that contemplate the construction of infrastructure, mining, electrical and real estate developments that can generate an environmental impact.
The Bank has the development of climate change risk heat maps, addressing both Physical Risks at the level of the country’s geographic zones and Transition Risks at the level of economic sectors. Likewise, within the framework of the regulatory provisions set forth in General rule NCG 519, the Bank is making progress across various areas in preparation for its forthcoming entry into force.
166
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
Credit policies and processes materialize in the following management principles, which are addressed with a specialized approach according to the characteristics of the different markets and segments to which services are provided, recognizing the singularities of each one of them:
| 1. | Apply a rigorous evaluation in the admission process, based on established credit policies, standards and procedures, together with the availability of sufficient and accurate information. Accordingly, the Bank needs to analyze the generation of flows and solvency of the customer to meet its payment commitments and, when the characteristics of the operation merit it, must constitute adequate guarantees must be constituted that allow mitigating the risk assumed with the customer. |
| 2. | Have permanent and robust portfolio tracking processes, through procedures and systems that alert both the potential indications of impairment of clients, with respect to the conditions of origin, and also the possible business opportunities with those that present a better payments quality and behavior. |
| 3. | Develop credit risk modeling guidelines, in regulatory aspects and management, for efficient decision-making at different stages of the credit process. |
| 4. | Have a collection structure with timely, agile and effective processes that allow management to be performed in accordance with the different types of customers and the types of breaches that arise, always in strict adherence to the regulatory framework and the Bank’s reputational definitions. |
| 5. | Maintain an efficient administration in the organization of teams, tools and availability of information that allow the Bank to have optimal credit risk management. |
Based on these management principles, the Credit Risk Division contributes to the business and anticipates threats that may affect the solvency and quality of the portfolio, delivering timely responses to customers, maintaining the solid foundations that characterize the Bank’s portfolio in its different segments. and products.
The credit risk management process consists of the stages of Admission, Monitoring and Recovery or Collection for the retail and wholesale business segments to which the Bank provides services.
| (a) | Admission: |
In the retail segments, admission management performed mainly through a risk evaluation that uses scoring tools and credit attribution to approve each transaction. These evaluations, for natural persons without a business line and clients in the SME segment, take into consideration the level of indebtedness, the payment capacity and the maximum acceptable exposure for the customer, through information on payment behavior, indebtedness in the financial system and business and financial information, as applicable.
Additionally, the bank has proactive admission processes for a diverse portfolio of customers. These consist of mass evaluation of customers through statistical models of eligibility and payment capacity, generating credit offers aligned with the strategies defined. This results in having preapproved loan offers available through multiple channels taking into consideration the business plan and the relation between risk and return.
167
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
In the wholesale segments, the credit approval process is conducted through a case-by-case assessment of each customer, also taking into consideration the relationship of the rest of the group with the Bank and, where applicable, the customer’s economic group. This assessment considers, among other factors, earnings generation capacity, financial condition, with particular emphasis on capital adequacy, exposure levels, industry-related variables, an assessment of the shareholders and management, and transaction-specific aspects such as financing structure, tenor, products and any collateral provided. The process is supported by a Rating Model applicable to the economic sectors in which the Bank operates, which contributes to greater consistency in the assessment of the customer and its economic group and also determines the level of delegated authority required for approval of the credit risk exposure.
There are also specialized areas of segments that by their nature need the knowledge of an expert, such as real estate, construction, agriculture, finance, international, among others. These experts support the preparation of the transactions having certain tools designed to meet the needs of the specific characteristics of the businesses and their related risks.
| (b) | Follow Up: |
From granting a loan until its full extinction, it is necessary to have a follow up of the behavior and financial position of the debtor with an emphasis on its payment capacity, as the situation of the customer and associated risk change over time. Portfolio monitoring allows the bank to act proactively if indications of overall impairment are noted or if the debtor’s ability to meet its obligations is affected.
In the follow up function, methodologies and tools for the different segments in which the bank operates, have been developed, which allow a proper management of its credit portfolio.
In the retail segments, the control and follow up concentrate on monitoring the main indicators of the portfolio and analysis of the groups, reported in the management reports, generating significant information for the decision making process in different instances defined. In addition, special follow ups are generated according to the significant events in the environment.
In the wholesale segments, a permanent follow up is performed through management tools at individual level taking into consideration the business segments, and economic sectors. Through this process the alarms are generated that guarantee the proper and timely recognition of the risk in the individual portfolio. The specific and the special conditions established in the admission stage are monitored, including financial covenants, coverage of certain guarantees and conditions imposed at the time of the approval.
Additionally, in the Admission area, simultaneous follow up tasks are perform that allow the Bank to monitor the evolution of the transactions from the beginning until recovery, with the purpose of making sure that the portfolio´s risks are properly and timely, and proactively managing the cases posing higher risks.
168
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (c) | Recovery or collection: |
The Bank has specific regulations related to customer collection and normalization, which ensure the quality of the portfolio in accordance with credit policies, and the desired risk appetite framework and strict adherence to the current regulatory framework. Through collection management, customers with temporary cash flow problems are favored, debt normalization plans are proposed for viable customers, so that it is possible to maintain the relationship in the long term once their situation is regularized. The recovery of assets at risk is maximized and the necessary collection actions are conducted, in a timely manner, to ensure the recovery of debts or reduce the potential loss.
In the retail segments, the Bank defines refinancing criteria through the establishment of predefined renegotiation guidelines to resolve the debt issues of viable customers with payment intentions, maintaining an adequate risk-return ratio, along with the incorporation of robust tools for differentiated collection management.
In the wholesale segments, when detecting customers that show indications of impairment or default of any type or condition, the commercial area to which the client belongs, together with the Credit Risk Division, establish action plans for their regularization. For cases of higher complexity where specialized management is required, the Special Asset Management, area is directly in charge of collection management, establishing action plans and negotiations based on the characteristics of each customer.
169
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (d) | Portfolio Concentration: |
The maximum exposure to credit risk, by customer or counterparty, without taking into account guarantees or other credit enhancements as of September 30, 2026 and December 31, 2025, does not exceed 10% of the Bank’s effective equity.
The following tables show credit risk exposure per balance sheet item, including derivatives, detailed by both geographic region and industry sector as of September 30, 2026:
| Chile | United States | England | Brazil | Others | Total | |||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||
| Financial Assets | ||||||||||||||||||||||||
| Cash and deposits in banks | 2,224,091 | 831,797 | 26,868 | 9 | 82,390 | 3,165,155 | ||||||||||||||||||
| Financial assets held for trading at fair value through profit or loss: | ||||||||||||||||||||||||
| Derivative contracts financial | ||||||||||||||||||||||||
| Forwards (*) | 457,080 | 3,829 | 110,685 | — | 61,211 | 632,805 | ||||||||||||||||||
| Swaps (**) | 729,142 | 104,115 | 746,383 | — | 190,177 | 1,769,817 | ||||||||||||||||||
| Call Options | 3,538 | — | — | — | — | 3,538 | ||||||||||||||||||
| Put Options | 124 | — | — | — | — | 124 | ||||||||||||||||||
| Futures | — | — | — | — | — | — | ||||||||||||||||||
| Subtotal | 1,189,884 | 107,944 | 857,068 | — | 251,388 | 2,406,284 | ||||||||||||||||||
| Debt Financial Instruments | ||||||||||||||||||||||||
| From the Chilean Government and Central Bank | 1,285,704 | — | — | — | — | 1,285,704 | ||||||||||||||||||
| Other debt financial instruments issued in Chile | 131,075 | — | — | — | — | 131,075 | ||||||||||||||||||
| Financial debt instruments issued Abroad | — | — | — | — | — | — | ||||||||||||||||||
| Subtotal | 1,416,779 | — | — | — | — | 1,416,779 | ||||||||||||||||||
| Other Financial Instruments | ||||||||||||||||||||||||
| Investments in mutual funds | 417,079 | — | — | — | — | 417,079 | ||||||||||||||||||
| Equity instruments | 2,177 | — | — | — | — | 2,177 | ||||||||||||||||||
| Others | 1,910 | 588 | — | — | — | 2,498 | ||||||||||||||||||
| Subtotal | 421,166 | 588 | — | — | — | 421,754 | ||||||||||||||||||
| Financial Assets at fair value through other comprehensive income: | ||||||||||||||||||||||||
| Debt Financial Instruments | ||||||||||||||||||||||||
| From the Chilean Government and Central Bank | 2,490,877 | — | — | — | — | 2,490,877 | ||||||||||||||||||
| Other debt financial instruments issued in Chile | 1,641,052 | — | — | — | — | 1,641,052 | ||||||||||||||||||
| Financial debt instruments issued Abroad | — | 107,503 | — | — | — | 107,503 | ||||||||||||||||||
| Subtotal | 4,131,929 | 107,503 | — | — | — | 4,239,432 | ||||||||||||||||||
| Derivative financial instruments for hedging purposes | ||||||||||||||||||||||||
| Forwards | ||||||||||||||||||||||||
| Swaps | — | 11,599 | 30,521 | — | 1,830 | 43,950 | ||||||||||||||||||
| Call Options | — | — | — | — | — | — | ||||||||||||||||||
| Put Options | — | — | — | — | — | — | ||||||||||||||||||
| Futures | — | — | — | — | — | — | ||||||||||||||||||
| Subtotal | — | 11,599 | 30,521 | — | 1,830 | 43,950 | ||||||||||||||||||
| Financial assets at amortized cost: | ||||||||||||||||||||||||
| Rights by resale agreements | ||||||||||||||||||||||||
| 96,631 | — | — | — | — | 96,631 | |||||||||||||||||||
| Debt Financial Instruments | ||||||||||||||||||||||||
| From the Chilean Government and Central Bank | ||||||||||||||||||||||||
| Subtotal | 453,625 | — | — | — | — | 453,625 | ||||||||||||||||||
| 453,625 | — | — | — | — | 453,625 | |||||||||||||||||||
| Loans to Banks | ||||||||||||||||||||||||
| Central Bank of Chile | ||||||||||||||||||||||||
| Domestic banks | — | — | — | — | — | — | ||||||||||||||||||
| Foreign Banks (***) | 200,000 | — | — | — | — | 200,000 | ||||||||||||||||||
| Subtotal | — | — | — | 257,310 | 153,250 | 410,560 | ||||||||||||||||||
| 200,000 | — | — | 257,310 | 153,250 | 610,560 | |||||||||||||||||||
| Loans to Customers | ||||||||||||||||||||||||
| Commercial loans | ||||||||||||||||||||||||
| Residential mortgage loans | 21,030,542 | — | — | — | 2,757 | 21,033,299 | ||||||||||||||||||
| Consumer loans | 14,185,503 | — | — | — | — | 14,185,503 | ||||||||||||||||||
| Subtotal | 5,548,903 | — | — | — | — | 5,548,903 | ||||||||||||||||||
| 40,764,948 | — | — | — | 2,757 | 40,767,705 | |||||||||||||||||||
| (*) | Others includes: France of Ch$42,026 million, Switzerland of Ch$2,920 million, Spain of Ch$16,236 million and Belgium of Ch$29 million. |
| (**) | Others includes: France of Ch$110,626 million, Spain of Ch$14,167 million and Canada of Ch$65,384 million. |
| (***) | Others includes: China of Ch$86,442 million, South Korea of Ch$17,675 million and Switzerland of Ch$49,133. |
170
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| Central Bank of Chile | Government | Retail (Individuals) | Financial Services | Trade | Manufacturing | Mining | Electricity, Gas and Water | Agriculture and Livestock | Fishing | Transportation and
| Construction | Services | Others | Total | ||||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||||||||||||||||||
| Cash and deposits in banks | 1,265,623 | — | — | 1,899,532 | — | — | — | — | — | — | — | — | — | — | 3,165,155 | |||||||||||||||||||||||||||||||||||||||||||||
| Financial Assets held for trading at fair value through profit or loss: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Derivative contracts Financial | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Forwards | — | — | — | 573,587 | 7,397 | 9,962 | 405 | 1,331 | 7,419 | 48 | 11,819 | 13 | 20,824 | — | 632,805 | |||||||||||||||||||||||||||||||||||||||||||||
| Swaps | — | — | — | 1,688,031 | 180 | 716 | — | 14,450 | 2,066 | 736 | 29,836 | 3,322 | 30,480 | — | 1,769,817 | |||||||||||||||||||||||||||||||||||||||||||||
| Call Options | — | — | — | 538 | 481 | 956 | — | — | 1,001 | — | 266 | — | 296 | — | 3,538 | |||||||||||||||||||||||||||||||||||||||||||||
| Put Options | — | — | — | 53 | 29 | 41 | — | — | — | — | — | — | 1 | — | 124 | |||||||||||||||||||||||||||||||||||||||||||||
| Futures | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | — | — | 2,262,209 | 8,087 | 11,675 | 405 | 15,781 | 10,486 | 784 | 41,921 | 3,335 | 51,601 | — | 2,406,284 | |||||||||||||||||||||||||||||||||||||||||||||
| Debt Financial Instruments | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| From the Chilean Government and Central Bank | 822,188 | 463,516 | — | — | — | — | — | — | — | — | — | — | — | — | 1,285,704 | |||||||||||||||||||||||||||||||||||||||||||||
| Other debt financial instruments issued in Chile | — | — | — | 131,075 | — | — | — | — | — | — | — | — | — | — | 131,075 | |||||||||||||||||||||||||||||||||||||||||||||
| Financial debt instruments issued Abroad | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | 822,188 | 463,516 | — | 131,075 | — | — | — | — | — | — | — | — | — | — | 1,416,779 | |||||||||||||||||||||||||||||||||||||||||||||
| Other Financial Instruments | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Investments in mutual funds | — | — | — | 417,079 | — | — | — | — | — | — | — | — | — | — | 417,079 | |||||||||||||||||||||||||||||||||||||||||||||
| Equity instruments | — | — | — | 2,177 | — | — | — | — | — | — | — | — | — | — | 2,177 | |||||||||||||||||||||||||||||||||||||||||||||
| Others | — | — | — | 2,498 | — | — | — | — | — | — | — | — | — | — | 2,498 | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | — | — | 421,754 | — | — | — | — | — | — | — | — | — | — | 421,754 | |||||||||||||||||||||||||||||||||||||||||||||
| Financial Assets at fair value through Other Comprehensive Income | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt Financial Instruments | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| From the Chilean Government and Central Bank | — | 2,490,877 | — | — | — | — | — | — | — | — | — | — | — | — | 2,490,877 | |||||||||||||||||||||||||||||||||||||||||||||
| Other debt financial instruments issued in Chile | — | — | — | 1,550,856 | — | — | — | 12,107 | — | — | — | — | 78,089 | — | 1,641,052 | |||||||||||||||||||||||||||||||||||||||||||||
| Financial debt instruments issued Abroad | — | — | — | 107,503 | — | — | — | — | — | — | — | — | — | — | 107,503 | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 2,490,877 | — | 1,658,359 | — | — | — | 12,107 | — | — | — | — | 78,089 | — | 4,239,432 | |||||||||||||||||||||||||||||||||||||||||||||
| Derivative financial instruments for hedging purposes | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Forwards | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Swaps | — | — | — | 43,950 | — | — | — | — | — | — | — | — | — | — | 43,950 | |||||||||||||||||||||||||||||||||||||||||||||
| Call Options | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Put Options | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Futures | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | — | — | 43,950 | — | — | — | — | — | — | — | — | — | — | 43,950 | |||||||||||||||||||||||||||||||||||||||||||||
| Financial assets at amortized cost (*) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Rights by resale agreements | — | — | — | 94,110 | — | — | — | — | — | — | — | — | 2,521 | — | 96,631 | |||||||||||||||||||||||||||||||||||||||||||||
| Debt financial instruments | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| From the Chilean Government and Central Bank | — | 453,625 | — | — | — | — | — | — | — | — | — | — | — | — | 453,625 | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 453,625 | — | — | — | — | — | — | — | — | — | — | — | — | 453,625 | |||||||||||||||||||||||||||||||||||||||||||||
| Loans to Banks | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Central Bank of Chile | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Domestic banks | — | — | — | 200,000 | — | — | — | — | — | — | — | — | — | — | 200,000 | |||||||||||||||||||||||||||||||||||||||||||||
| Foreign banks | — | — | — | 410,560 | — | — | — | — | — | — | — | — | — | — | 410,560 | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | — | — | 610,560 | — | — | — | — | — | — | — | — | — | — | 610,560 | |||||||||||||||||||||||||||||||||||||||||||||
| (*) | Economic activity of Loans to customers disclosed in Note 13 letter (g). |
171
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
The following tables show credit risk exposure per balance sheet item, including derivatives, detailed by both geographic region and industry sector as of December 31, 2025:
| Chile | United States | England | Brazil | Others | Total | |||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||
| Financial Assets | ||||||||||||||||||||||||
| Cash and deposits in banks | 2,256,651 | 279,035 | 7,971 | 8 | 47,321 | 2,590,986 | ||||||||||||||||||
| Financial assets held for trading at fair value through profit or loss: | ||||||||||||||||||||||||
| Derivative contracts financial | ||||||||||||||||||||||||
| Forwards (*) | 219,698 | 9,347 | 73,114 | — | 75,651 | 377,810 | ||||||||||||||||||
| Swaps (**) | 683,270 | 118,530 | 575,343 | — | 111,667 | 1,488,810 | ||||||||||||||||||
| Call Options | 332 | — | — | — | — | 332 | ||||||||||||||||||
| Put Options | 2,515 | — | — | — | — | 2,515 | ||||||||||||||||||
| Futures | — | — | — | — | — | — | ||||||||||||||||||
| Subtotal | 905,815 | 127,877 | 648,457 | — | 187,318 | 1,869,467 | ||||||||||||||||||
| Debt Financial Instruments | ||||||||||||||||||||||||
| From the Chilean Government and Central Bank | 2,798,329 | — | — | — | — | 2,798,329 | ||||||||||||||||||
| Other debt financial instruments issued in Chile | 277,354 | — | — | — | — | 277,354 | ||||||||||||||||||
| Financial debt instruments issued Abroad | — | 46,019 | — | — | — | 46,019 | ||||||||||||||||||
| Subtotal | 3,075,683 | 46,019 | — | — | — | 3,121,702 | ||||||||||||||||||
| Other Financial Instruments | ||||||||||||||||||||||||
| Investments in mutual funds | 400,222 | — | — | — | — | 400,222 | ||||||||||||||||||
| Equity instruments | 619 | — | — | — | — | 619 | ||||||||||||||||||
| Others | 616 | 802 | — | — | — | 1,418 | ||||||||||||||||||
| Subtotal | 401,457 | 802 | — | — | — | 402,259 | ||||||||||||||||||
| Financial Assets at fair value through other comprehensive income: | ||||||||||||||||||||||||
| Debt Financial Instruments | ||||||||||||||||||||||||
| From the Chilean Government and Central Bank | 1,174,306 | — | — | — | — | 1,174,306 | ||||||||||||||||||
| Other debt financial instruments issued in Chile | 2,338,926 | — | — | — | — | 2,338,926 | ||||||||||||||||||
| Financial debt instruments issued Abroad | — | 35,739 | — | — | — | 35,739 | ||||||||||||||||||
| Subtotal | 3,513,232 | 35,739 | — | — | — | 3,548,971 | ||||||||||||||||||
| Derivative financial instruments for hedging purposes | ||||||||||||||||||||||||
| Forwards | — | — | — | — | — | — | ||||||||||||||||||
| Swaps | — | 7,130 | 22,584 | — | — | 29,714 | ||||||||||||||||||
| Call Options | — | — | — | — | — | — | ||||||||||||||||||
| Put Options | — | — | — | — | — | — | ||||||||||||||||||
| Futures | — | — | — | — | — | — | ||||||||||||||||||
| Subtotal | — | 7,130 | 22,584 | — | — | 29,714 | ||||||||||||||||||
| Financial assets at amortized cost: | ||||||||||||||||||||||||
| Rights by resale agreements | 100,643 | — | — | — | — | 100,643 | ||||||||||||||||||
| Debt Financial Instruments | ||||||||||||||||||||||||
| From the Chilean Government and Central Bank | 460,956 | — | — | — | — | 460,956 | ||||||||||||||||||
| Subtotal | 460,956 | — | — | — | — | 460,956 | ||||||||||||||||||
| Loans to Banks | ||||||||||||||||||||||||
| Central Bank of Chile | — | — | — | — | — | — | ||||||||||||||||||
| Domestic banks | — | — | — | — | — | — | ||||||||||||||||||
| Foreign Banks (***) | — | 5,024 | — | 204,397 | 190,371 | 399,792 | ||||||||||||||||||
| Subtotal | — | 5,024 | — | 204,397 | 190,371 | 399,792 | ||||||||||||||||||
| Loans to customers | ||||||||||||||||||||||||
| Commercial loans | 19,469,504 | — | — | — | 39,851 | 19,509,355 | ||||||||||||||||||
| Residential mortgage loans | 13,916,618 | — | — | — | — | 13,916,618 | ||||||||||||||||||
| Consumer loans | 5,765,997 | — | — | — | — | 5,765,997 | ||||||||||||||||||
| Subtotal | 39,152,119 | — | — | — | 39,851 | 39,191,970 | ||||||||||||||||||
| (*) | Others includes: France of Ch$70,734 million, Switzerland of Ch$4,917 million. |
| (**) | Others includes: France of Ch$38,116 million, Spain of Ch$26,711 million and Canada of Ch$46,840 million. |
| (***) | Others includes: China of Ch$122,586 million, South Korea of Ch$6,794, Peru of Ch$473 million, Netherlands of Ch$36,303 million, Singapore of Ch$21,658 million and India of Ch$2,557 million. |
172
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| Central Bank of Chile | Government | Retail (Individuals) | Financial Services | Trade | Manufacturing | Mining | Electricity, Gas and Water | Agriculture and Livestock | Fishing | Transportation and Telecom | Construction | Services | Others | Total | ||||||||||||||||||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||||||||||||||||||||||||||
| Cash and deposits in banks | 1,347,525 | — | — | 1,243,461 | — | — | — | — | — | — | — | — | — | — | 2,590,986 | |||||||||||||||||||||||||||||||||||||||||||||
| Financial Assets held for trading at fair value through profit or loss: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Derivative contracts Financial | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Forwards | — | — | — | 336,264 | 13,248 | 6,864 | 1,297 | 586 | 1,437 | — | 8,506 | 5,667 | 3,941 | — | 377,810 | |||||||||||||||||||||||||||||||||||||||||||||
| Swaps | — | — | 8 | 1,412,893 | 2,596 | 3,106 | — | 17,419 | 4,405 | 33 | 34,024 | 2,654 | 11,672 | — | 1,488,810 | |||||||||||||||||||||||||||||||||||||||||||||
| Call Options | — | — | — | 58 | 204 | 13 | — | — | 57 | — | — | — | — | — | 332 | |||||||||||||||||||||||||||||||||||||||||||||
| Put Options | — | — | — | 425 | 1,866 | 199 | — | — | — | 16 | — | 8 | 1 | — | 2,515 | |||||||||||||||||||||||||||||||||||||||||||||
| Futures | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | — | 8 | 1,749,640 | 17,914 | 10,182 | 1,297 | 18,005 | 5,899 | 49 | 42,530 | 8,329 | 15,614 | — | 1,869,467 | |||||||||||||||||||||||||||||||||||||||||||||
| Debt Financial Instruments | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| From the Chilean Government and Central Bank | 2,388,127 | 410,202 | — | — | — | — | — | — | — | — | — | — | — | — | 2,798,329 | |||||||||||||||||||||||||||||||||||||||||||||
| Other debt financial instruments issued in Chile | — | — | — | 277,354 | — | — | — | — | — | — | — | — | — | — | 277,354 | |||||||||||||||||||||||||||||||||||||||||||||
| Financial debt instruments issued Abroad | — | 46,019 | — | — | — | — | — | — | — | — | — | — | — | — | 46,019 | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | 2,388,127 | 456,221 | — | 277,354 | — | — | — | — | — | — | — | — | — | — | 3,121,702 | |||||||||||||||||||||||||||||||||||||||||||||
| Other Financial Instruments | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Investments in mutual funds | — | — | — | 400,222 | — | — | — | — | — | — | — | — | — | — | 400,222 | |||||||||||||||||||||||||||||||||||||||||||||
| Equity instruments | — | — | — | 619 | — | — | — | — | — | — | — | — | — | — | 619 | |||||||||||||||||||||||||||||||||||||||||||||
| Others | — | — | — | 1,418 | — | — | — | — | — | — | — | — | — | — | 1,418 | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | — | — | 402,259 | — | — | — | — | — | — | — | — | — | — | 402,259 | |||||||||||||||||||||||||||||||||||||||||||||
| Financial Assets at fair value through Other Comprehensive Income | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt Financial Instruments | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| From the Chilean Government and Central Bank | — | 1,174,306 | — | — | — | — | — | — | — | — | — | — | — | — | 1,174,306 | |||||||||||||||||||||||||||||||||||||||||||||
| Other debt financial instruments issued in Chile | — | — | — | 2,254,319 | 6,658 | — | — | 11,727 | 38,011 | — | — | — | 28,211 | — | 2,338,926 | |||||||||||||||||||||||||||||||||||||||||||||
| Financial debt instruments issued Abroad | — | — | — | 35,739 | — | — | — | — | — | — | — | — | — | — | 35,739 | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 1,174,306 | — | 2,290,058 | 6,658 | — | — | 11,727 | 38,011 | — | — | — | 28,211 | — | 3,548,971 | |||||||||||||||||||||||||||||||||||||||||||||
| Derivative financial instruments for hedging purposes | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Forwards | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Swaps | — | — | — | 29,714 | — | — | — | — | — | — | — | — | — | — | 29,714 | |||||||||||||||||||||||||||||||||||||||||||||
| Call Options | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Put Options | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Futures | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | — | — | 29,714 | — | — | — | — | — | — | — | — | — | — | 29,714 | |||||||||||||||||||||||||||||||||||||||||||||
| Financial assets at amortized cost (*) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Rights by resale agreements | — | — | — | 98,266 | — | — | — | — | — | — | — | — | 2,377 | — | 100,643 | |||||||||||||||||||||||||||||||||||||||||||||
| Debt financial instruments | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| From the Chilean Government and Central Bank | — | 460,956 | — | — | — | — | — | — | — | — | — | — | — | — | 460,956 | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | 460,956 | — | — | — | — | — | — | — | — | — | — | — | — | 460,956 | |||||||||||||||||||||||||||||||||||||||||||||
| Loans to Banks | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Central Bank of Chile | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Domestic banks | — | — | — | — | — | — | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Foreign banks | — | — | — | 399,792 | — | — | — | — | — | — | — | — | — | — | 399,792 | |||||||||||||||||||||||||||||||||||||||||||||
| Subtotal | — | — | — | 399,792 | — | — | — | — | — | — | — | — | — | — | 399,792 | |||||||||||||||||||||||||||||||||||||||||||||
| (*) | Economic activity of Loans to customers disclosed in Note 13 letter (g). |
173
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (e) | Collateral and Other Credit Enhancements: |
The amount and type of collateral required depends on the counterparty’s credit risk assessment.
The Bank has guidelines regarding the acceptability of types of collateral and valuation parameters.
The main types of collateral obtained are:
| ● | For commercial loans: Residential and non-residential real estate, liens and inventory. |
| ● | For consumer loans and residential mortgage loans for housing: Mortgage loans on residential property. |
The Bank also obtains collateral from parent companies for loans granted to their subsidiaries.
Management makes sure its collateral is acceptable in accordance with to both external standards and internal policies guidelines and parameters. The Bank has approximately 256,025 collateral constituted as of September 30, 2026 (255,927 in December 2025), the majority of which consist of real estate. The following table contains guarantees value:
| Guarantee | ||||||||||||||||||||||||
| September 2026 | Loans | Mortgages | Pledges | Securities | Warrants | Total | ||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||
| Corporate Lending | 16,079,402 | 3,976,306 | 216,753 | 513,089 | 3,395 | 4,709,543 | ||||||||||||||||||
| Small Business Lending | 4,953,897 | 3,590,956 | 13,329 | 12,398 | — | 3,616,683 | ||||||||||||||||||
| Consumer Lending | 5,548,903 | 387,161 | 457 | 2,440 | — | 390,058 | ||||||||||||||||||
| Mortgage Lending | 14,185,503 | 13,657,389 | 61 | — | — | 13,657,450 | ||||||||||||||||||
| Total | 40,767,705 | 21,611,812 | 230,600 | 527,927 | 3,395 | 22,373,734 | ||||||||||||||||||
| Guarantee | ||||||||||||||||||||||||
| December 2025 | Loans | Mortgages | Pledges | Securities | Warrants | Total | ||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||
| Corporate Lending | 14,650,675 | 3,943,491 | 132,773 | 471,893 | 3,086 | 4,551,243 | ||||||||||||||||||
| Small Business Lending | 4,858,680 | 3,465,683 | 15,860 | 10,592 | — | 3,492,135 | ||||||||||||||||||
| Consumer Lending | 5,765,997 | 367,490 | 439 | 2,361 | — | 370,290 | ||||||||||||||||||
| Mortgage Lending | 13,916,618 | 13,457,848 | 63 | — | — | 13,457,911 | ||||||||||||||||||
| Total | 39,191,970 | 21,234,512 | 149,135 | 484,846 | 3,086 | 21,871,579 | ||||||||||||||||||
The Bank also uses mitigating tactics for credit risk on derivative transactions. Through date, the following mitigating tactics are used:
| ● | Accelerating transactions and net payment using market values at the date of default of one of the parties. |
| ● | Option for both parties to terminate early any transactions with a counterparty at a given date, using market values as of the respective date. |
Margins established with time deposits by customers who have FX forwards with the subsidiary Banchile Corredores de Bolsa S.A.
174
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (e) | Collateral and Other Credit Enhancements, continued: |
The value of the guarantees that the Bank holds related to the loans individually classified as impaired as of September 30, 2026 and December 31, 2025 amounted Ch$198,251 million and Ch$190,093 million, respectively.
The value guarantees related to past due loans but no impaired as of September 30, 2026 and December 31, 2025 amounted Ch$566,523 million and Ch$545,626 million respectively.
| (f) | Credit Quality by Asset Class: |
The Bank determines the credit quality of financial assets using internal credit ratings. The rating process is linked to the Bank’s approval and monitoring processes and is performed in accordance with risk categories established by current standards. Credit quality is continuously updated based on any favorable or unfavorable developments for customers or their environments, considering aspects such as commercial and payment behavior as well as financial information.
The Bank also conducts reviews focused on companies that are involved in specific economic sectors, which are affected either by macroeconomic variables or variables of the sector. In this way, it is possible to timely establish the necessary and sufficient level of provisions to cover the losses due to the possible non-recoverability of the loans granted.
The credit quality by asset class for Consolidated Statements of Financial Position sheet items, based on the Bank’s credit rating system, is presented in Note 13 letter (d).
Below is the detail of the default but not impaired portfolio:
| Past due but not impaired (*) | ||||||||||||||||
| 1 to 29 days | 30 to 59 days | 60 to 89 days | 90 or more days | |||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||
| September 2026 | 845,513 | 234,900 | 89,251 | — | ||||||||||||
| December 2025 | 875,016 | 233,505 | 75,726 | — | ||||||||||||
| (*) | These amounts include the overdue portion and the remaining balance of loans in default. |
| (g) | Assets Received in Lieu of Payment: |
The Bank has received assets in lieu of payment totaling Ch$27,755 million and Ch$24,625 million as of September 30, 2026 and December 31, 2025, respectively, the majority of which are properties. All these assets are managed for sale.
175
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (h) | Renegotiated Assets: |
The loans are presented as renegotiated in the statement of financial position correspond to those in which the related financial commitments have been restructured and the Bank assesses the probability of recovery as sufficiently high.
The table below provides the detail of the carrying amounts of loans with renegotiated terms by financial asset class:
| September | December | |||||||
| 2026 | 2025 | |||||||
| Financial Assets | MCh$ | MCh$ | ||||||
| Loans to Banks | ||||||||
| Central Bank of Chile | — | — | ||||||
| Domestic banks | — | — | ||||||
| Foreign banks | — | — | ||||||
| Subtotal | — | — | ||||||
| Loans to customers, net | ||||||||
| Commercial loans | 486,008 | 504,756 | ||||||
| Residential mortgage loans | 346,075 | 322,610 | ||||||
| Consumer loans | 409,398 | 365,996 | ||||||
| Subtotal | 1,241,481 | 1,193,362 | ||||||
| Total renegotiated financial assets | 1,241,481 | 1,193,362 | ||||||
| (i) | Compliance with credit limits granted to related debtors: |
Below are detailed the figures for compliance with the credit limit granted to debtors related to the ownership or management of the Bank and subsidiaries, in accordance with the Article 84 No. 2 of the General Banking Law, which establishes that in no case the total of these credits may exceed the amount of its Total or Regulatory Capital:
| September | December | |||||||
| 2026 | 2025 | |||||||
| MCh$ | MCh$ | |||||||
| Total related debt | 565,345 | 571,097 | ||||||
| Consolidated Total or Regulatory Capital | 7,192,931 | 7,115,175 | ||||||
| Limit used % | 7.86 | % | 8.03 | % | ||||
176
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk: |
Market Risk refers to the loss that the Bank could face due to a liquidity shortage to make the payments, or to close financial transactions in a timely manner (Liquidity Risk), or due to adverse movements in the values of market variables (Price Risk). For its proper management, the guidelines of the Liquidity Risk Management Policy and the Market Risk Management Policy are considered, both are subject to review, by the Market Risk Manager and approval by the Bank’s Board of Directors, at least annually.
| a) | Liquidity Risk: |
Liquidity Risk Measurement and Limits
The Bank manages the Liquidity Risk in accordance with the established on the Liquidity Risk Management Policy, managing separately for each sub-category thereof; this is for Trading Liquidity Risk and Funding Liquidity Risk.
Trading Liquidity Risk is the inability to close, at current market prices, the financial positions opened mainly from the Trading Book (which is daily valued at market prices and the value differences instantly reflected in the Statement of Income). This risk is controlled by establishing limits on the positions amounts of the Trading Book in accordance with that is estimated to be closed in a short time period. Additionally, the Bank incorporates a negative impact on the Statement of Income whenever it believes that the size of a certain position in the Trading Book exceeds the reasonable amount, negotiated in the secondary markets, which would allow the exposure to be offset without altering market prices.
Funding Liquidity Risk refers to the Bank’s inability to obtain sufficient cash to meet its immediate obligations. This risk is managed by a minimum amount of highly liquid assets called liquidity buffer, and establishing limits and controls of internal metrics, among which the Market Access Report (“MAR”) stands out, which estimates the amount of funding that the Bank would need from wholesale financial counterparties, for the next 30 and 90 days in each of the significant currencies in the balance sheet, to face a cash need as a result of the transaction under business as usual conditions.
177
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (a) | Liquidity Risk, continued: |
The use of September within 2026 is shown below (LCCY = local currency; FCCY = foreign currency):
MAR LCCY + FCCY BCh$ | MAR FCCY MUS$ | |||||||||||||
| 1 - 30 days | 1 - 90 days | 1 - 30 days | ||||||||||||
| Maximum | 3,488 | 5,370 | Maximum | 1,881 | ||||||||||
| Minimum | 684 | 3,026 | Minimum | 273 | ||||||||||
| Average | 1,977 | 4,273 | Average | 1,157 | ||||||||||
The Bank also monitors the amount of assets denominated in local currency that is financed by liabilities denominated in foreign currency, including all tenors and the cash flows generated by full delivery derivatives payments. This metric is referred to as Cross Currency Funding. The bank oversees and limits this amount to take precautions against not only Banco de Chile’s event but also against a systemic adverse environment generated by a country risk event that might trigger lack of foreign currency funding.
The use of Cross Currency Funding within year 2026 is illustrated below:
Cross Currency Funding MUS$ | ||||
| Maximum | 4,384 | |||
| Minimum | 2,573 | |||
| Average | 3,496 | |||
The Bank establishes thresholds that alert behaviors outside the expected ranges at a normal or prudent level of operation, in order to protect other dimensions of liquidity risk such as, for example, maturities concentration of fund providers, the diversification of sources of funds either by type of counterparty or type of product, among others.
The evolution over time of the statement of financial ratios of the Bank is monitored in order to detect structural changes in the characteristics of the balance sheet, such as those presented in the following table and whose relevant values of use during the year 2026 are shown below:
| Funding Financial Counterparties / Assets | Deposits/ Loans | |||||||
| Maximum | 39 | % | 65 | % | ||||
| Minimum | 37 | % | 61 | % | ||||
| Average | 38 | % | 62 | % | ||||
178
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (a) | Liquidity Risk, continued: |
Additionally, certain market index, prices and monetary decisions made by the Central Bank of Chile are monitored to detect structural changes in market conditions that can trigger a liquidity shortage or even a financial crisis.
Furthermore, the Liquidity Risk Management Policy requires the regular performance of stress tests periodically which are controlled against potentially accessible action plans in each modeled scenario, according with the guidelines established in the Liquidity Contingency Plan. This process is essential in determining the Bank´s liquidity risk appetite.
The Bank measures and controls the mismatch of cash flows under regulatory standards with the C46 index report, which represents the net cash flows expected over time because of the contractual maturity of almost all assets and liabilities. Additionally, the Commission for the Financial Market (hereinafter, “CMF”) authorized Banco de Chile, among others, to report the adjusted C46 index. This allows the Bank to report, in addition to the regular C46 index, outflow behavior assumptions of certain specific elements of the liability, such as demand deposits and time deposits. In addition, the regulator also requires some rollover assumptions for the loan portfolio.
Through the present date, the CMF establishes the following provisions for the C46 index:
Foreign Currency balance sheet items: 1-30 days, Regulatory Limit C46 index < 1 x Tier-1 Capital
The levels of use of this index during the year 2026 are shown illustrated below:
Adjusted C46 CCY and FCCY as part of Basic Capital | Adjusted C46 FCCY as part of | |||||||||||
| 1 - 30 days | 1 - 90 days | 1 - 30 days | ||||||||||
| Maximum | 0.17 | 0.14 | 0.41 | |||||||||
| Minimum | (0.22 | ) | (0.11 | ) | 0.16 | |||||||
| Average | 0.02 | (0.01 | ) | 0.28 | ||||||||
| Regulatory Limit | N/A | N/A | 1.0 | |||||||||
179
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (a) | Liquidity Risk, continued: |
The individual and consolidated term liquidity gap are presented below:
QUARTERLY STATEMENT OF INDIVIDUAL LIQUIDITY SITUATION
AS OF SEPTEMBER 30, 2026 CONTRACTUAL BASIS
Amounts in MCh$
| CONSOLIDATED CURRENCY | From 0 to 7 days | From 0 to 15 days | From 0 to 30 days | From 0 to 90 days | ||||||||||||
| Cash flow receivable (assets) and income | 7,988,397 | 11,690,700 | 12,935,775 | 16,821,491 | ||||||||||||
| Cash flow payable (liabilities) and expenses | 20,668,100 | 22,776,071 | 26,376,170 | 29,607,599 | ||||||||||||
| Liquidity Gap | 12,679,703 | 11,085,371 | 13,440,395 | 12,786,108 | ||||||||||||
| FOREIGN CURRENCY | From 0 to 7 days | From 0 to 15 days | From 0 to 30 days | From 0 to 90 days | ||||||||||||
| Cash flow receivable (assets) and income | 1,231,645 | 1,291,020 | 1,384,585 | 1,387,088 | ||||||||||||
| Cash flow payable (liabilities) and expenses | 2,644,323 | 2,895,991 | 3,478,919 | 4,179,961 | ||||||||||||
| Liquidity Gap | 1,412,678 | 1,604,971 | 2,094,334 | 2,792,873 | ||||||||||||
| Limits: | ||||||||||||||||
| One time capital | 5,678,634 | |||||||||||||||
| AVAILABLE MARGIN (*) | 3,584,300 | |||||||||||||||
| * | In the limit up to 30 days, in foreign currency, the Bank has an available margin of Ch$3,584,299,931,681. |
QUARTERLY STATEMENT OF INDIVIDUAL LIQUIDITY SITUATION
AS OF SEPTEMBER 30, 2026 ADJUSTED BASIS
Amounts in MCh$
| CONSOLIDATED CURRENCY | From 0 to 7 days | From 0 to 15 days | From 0 to 30 days | From 0 to 90 days | ||||||||||||
| Cash flow receivable (assets) and income | 7,518,460 | 10,851,668 | 11,462,562 | 13,956,762 | ||||||||||||
| Cash flow payable (liabilities) and expenses | 10,206,788 | 10,943,533 | 12,429,193 | 14,251,763 | ||||||||||||
| Liquidity Gap | 2,688,328 | 91,865 | 966,631 | 295,001 | ||||||||||||
| FOREIGN CURRENCY | From 0 to 7 days | From 0 to 15 days | From 0 to 30 days | From 0 to 90 days | ||||||||||||
| Cash flow receivable (assets) and income | 1,085,274 | 1,076,674 | 855,774 | 486,700 | ||||||||||||
| Cash flow payable (liabilities) and expenses | 1,790,746 | 1,969,149 | 2,399,614 | 2,993,060 | ||||||||||||
| Liquidity Gap | 705,472 | 892,475 | 1,543,840 | 2,506,360 | ||||||||||||
| Limits: | ||||||||||||||||
| One time capital | 5,678,634 | |||||||||||||||
| AVAILABLE MARGIN (*) | 4,134,794 | |||||||||||||||
| * | In the limit up to 30 days, in foreign currency, the Bank has an available margin of Ch$4,134,794,225,330. |
180
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (a) | Liquidity Risk, continued: |
QUARTERLY STATEMENT OF CONSOLIDATED LIQUIDITY SITUATION
AS OF SEPTEMBER 30, 2026 CONTRACTUAL BASIS
Amounts in MCh$
| CONSOLIDATED CURRENCY | From 0 to 7 days | From 0 to 15 days | From 0 to 30 days | From 0 to 90 days | ||||||||||||
| Cash flow receivable (assets) and income | 9,052,917 | 12,767,873 | 14,018,381 | 17,963,759 | ||||||||||||
| Cash flow payable (liabilities) and expenses | 21,586,911 | 23,697,560 | 27,297,971 | 30,530,322 | ||||||||||||
| Liquidity Gap | 12,533,994 | 10,929,687 | 13,279,590 | 12,566,563 | ||||||||||||
| FOREIGN CURRENCY | From 0 to 7 days | From 0 to 15 days | From 0 to 30 days | From 0 to 90 days | ||||||||||||
| Cash flow receivable (assets) and income | 1,231,713 | 1,291,088 | 1,384,653 | 1,387,156 | ||||||||||||
| Cash flow payable (liabilities) and expenses | 2,644,323 | 2,895,991 | 3,478,919 | 4,180,030 | ||||||||||||
| Liquidity Gap | 1,412,610 | 1,604,903 | 2,094,266 | 2,792,874 | ||||||||||||
| Limits: | ||||||||||||||||
| One time capital | 5,678,634 | |||||||||||||||
| AVAILABLE MARGIN (*) | 3,584,368 | |||||||||||||||
| * | In the limit up to 30 days, in foreign currency, the Bank has an available margin of Ch$3,584,367,853,197. |
QUARTERLY STATEMENT OF CONSOLIDATED LIQUIDITY SITUATION
AS OF SEPTEMBER 30, 2026 ADJUSTED BASIS
Amounts in MCh$
| CONSOLIDATED CURRENCY | From 0 to 7 days | From 0 to 15 days | From 0 to 30 days | From 0 to 90 days | ||||||||||||
| Cash flow receivable (assets) and income | 8,582,981 | 11,928,840 | 12,545,168 | 15,099,030 | ||||||||||||
| Cash flow payable (liabilities) and expenses | 11,125,599 | 11,865,022 | 13,350,994 | 15,174,486 | ||||||||||||
| Liquidity Gap | 2,542,618 | (63,818 | ) | 805,826 | 75,456 | |||||||||||
| FOREIGN CURRENCY | From 0 to 7 days | From 0 to 15 days | From 0 to 30 days | From 0 to 90 days | ||||||||||||
| Cash flow receivable (assets) and income | 1,085,342 | 1,076,742 | 855,842 | 486,768 | ||||||||||||
| Cash flow payable (liabilities) and expenses | 1,790,746 | 1,969,149 | 2,399,614 | 2,993,129 | ||||||||||||
| Liquidity Gap | 705,404 | 892,407 | 1,543,772 | 2,506,361 | ||||||||||||
| Limits: | ||||||||||||||||
| One time capital | 5,678,634 | |||||||||||||||
| AVAILABLE MARGIN (*) | 4,134,862 | |||||||||||||||
| * | In the limit up to 30 days, in foreign currency, the Bank has an available margin of Ch$4,134,862,146,848. |
181
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (a) | Liquidity Risk, continued: |
Liquid Assets Consolidated Balance Statement as of September 30, 2026, values in BCh$
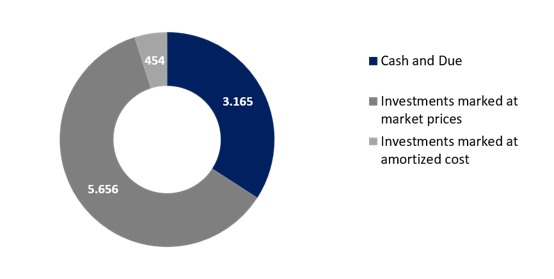
Source: Financial Statements Banco de Chile as of September 30, 2026
Additionally, the regulatory entities have introduced other metrics that the Bank uses in its management, such as the Liquidity Coverage Ratio (“LCR”) and Net Stable Funding Ratio (“NSFR”), using assumptions similar to those used in the international banking. For the both LCR and NSFR indicators, the minimum level required is 1 time (100%), evolution of the LCR and NSFR metrics during the year 2026 are shown below:
| LCR | NSFR | |||||||
| Maximum | 2.85 | 1.20 | ||||||
| Minimum | 1.65 | 1.18 | ||||||
| Average | 2.03 | 1.19 | ||||||
| Regulatory Limit | 1.00 | 1.00 | ||||||
182
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (a) | Liquidity Risk, continued: |
The contractual maturity profile of the financial liabilities of Banco de Chile and its subsidiaries (consolidated basis), as of September 2026 and December 2025, is as follows:
Up to 1 month | 1 to 3 months | 3 to 12 months | 1 to 3 years | 3 to 5 years | Over 5 years | Total | ||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||
| Liabilities as of September 30, 2026 | ||||||||||||||||||||||||||||
| Transactions in the course of payment | 698,623 | — | — | — | — | — | 698,623 | |||||||||||||||||||||
| Full delivery derivative transactions | 1,141,600 | 935,023 | 1,110,962 | 1,422,853 | 1,570,823 | 1,221,165 | 7,402,426 | |||||||||||||||||||||
| Financial liabilities at amortized cost: | ||||||||||||||||||||||||||||
| Current accounts and other demand deposits | 14,551,566 | — | — | — | — | — | 14,551,566 | |||||||||||||||||||||
| Time deposits and saving accounts | 9,104,767 | 2,658,829 | 3,363,560 | 29,500 | 1,137 | 764 | 15,158,557 | |||||||||||||||||||||
| Obligations by repurchase agreements | 122,020 | — | — | — | — | — | 122,020 | |||||||||||||||||||||
| Borrowings from financial institutions | 205,998 | 73,104 | 798,821 | 150,676 | — | — | 1,228,599 | |||||||||||||||||||||
| Debt financial instruments issued (all currencies) | 235,334 | 406,363 | 1,539,317 | 2,632,729 | 2,191,557 | 5,908,294 | 12,913,594 | |||||||||||||||||||||
| Other financial obligations | 328,605 | — | — | — | — | — | 328,605 | |||||||||||||||||||||
| Regulatory capital financial instruments (subordinated bonds) | — | 20,542 | 27,253 | 95,590 | 85,523 | 1,167,662 | 1,396,570 | |||||||||||||||||||||
| Total (excluding non-delivery derivative transactions) | 26,388,513 | 4,093,861 | 6,839,913 | 4,331,348 | 3,849,040 | 8,297,885 | 53,800,560 | |||||||||||||||||||||
| Non-delivery derivative transactions | 715,256 | 487,053 | 1,605,786 | 1,438,489 | 1,286,838 | 2,354,299 | 7,887,721 | |||||||||||||||||||||
Up to 1 month | 1 to 3 months | 3 to 12 months | 1 to 3 years | 3 to 5 years | Over 5 years | Total | ||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||
| Liabilities as of December 31, 2025 | ||||||||||||||||||||||||||||
| Transactions in the course of payment | 564,172 | — | — | — | — | — | 564,172 | |||||||||||||||||||||
| Full delivery derivative transactions | 490,271 | 369,130 | 724,294 | 1,153,074 | 1,027,445 | 1,247,938 | 5,012,152 | |||||||||||||||||||||
| Financial liabilities at amortized cost: | ||||||||||||||||||||||||||||
| Current accounts and other demand deposits | 14,498,196 | — | — | — | — | — | 14,498,196 | |||||||||||||||||||||
| Time deposits and saving accounts | 9,316,902 | 2,897,857 | 1,813,808 | 6,587 | 793 | 646 | 14,036,593 | |||||||||||||||||||||
| Obligations by repurchase agreements | 287,110 | — | — | — | — | — | 287,110 | |||||||||||||||||||||
| Borrowings from financial institutions | 64,372 | 318,830 | 778,352 | 135,060 | — | — | 1,296,614 | |||||||||||||||||||||
| Debt financial instruments issued (all currencies) | 18,708 | 370,475 | 1,289,167 | 3,015,473 | 2,119,402 | 5,738,729 | 12,551,954 | |||||||||||||||||||||
| Other financial obligations | 367,323 | — | — | — | — | — | 367,323 | |||||||||||||||||||||
| Regulatory capital financial instruments (subordinated bonds) | 3,247 | — | 46,655 | 92,486 | 89,240 | 1,149,624 | 1,381,252 | |||||||||||||||||||||
| Total (excluding non-delivery derivative transactions) | 25,610,301 | 3,956,292 | 4,652,276 | 4,402,680 | 3,236,880 | 8,136,937 | 49,995,366 | |||||||||||||||||||||
| Non-delivery derivative transactions | 479,836 | 675,990 | 775,896 | 1,529,409 | 1,014,770 | 2,214,460 | 6,690,361 | |||||||||||||||||||||
183
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (b) | Price Risk: |
The Price Risk measurement and management processes are carried out in accordance with the established on the Market Risk Management Policy, by using internal metrics developed by the Bank, both for the Trading Book and for the Banking Book (the Banking Book includes all balance sheet items, including those in the Trading Book but in such case these are reported at an interest rate adjustment term of one day, thus not generating accrual interest rate risk). In addition, the portfolio recorded under the Fair Value Through Other Comprehensive Income (hereinafter FVTOCI) is considered, which is a sub-set of the Banking Book, which given its nature is relevant to measure it independently. In addition, the Bank reports metrics to regulatory entities according to the models defined by them.
The Bank has established internal limits for the exposures of the Trading Book. In fact, FX positions (FX delta), interest rate sensitivities generated by the derivatives and debt securities portfolios (DV01 or also referred as to rho) and the FX options volatility sensitivity (vega) are measured, reported and controlled against their limits. Limits are established on an aggregate basis but also for some specific tenor points. The use of these limits is daily monitored, controlled and reported by independent control functions to the senior management of the bank. The internal governance framework also establishes that these limits must be approved by the Board of Directors and reviewed at least annually.
The Bank measures and controls the risk for the Trading Book portfolios using the Value-at-Risk (VaR). The model uses a 99% confidence level, and the most recent one-year observed rates, prices and yields data.
The use of VaR within the year 2026 is shown below:
Value-at-Risk 99% one-day confidence level | ||||
| MCh$ | ||||
| Maximum | 2,400 | |||
| Minimum | 761 | |||
| Average | 1,480 | |||
Additionally, the Bank performs measuring, limiting, controlling and reporting interest rate exposures and risks for the Banking Book using internally developed methodologies based on the differences in the amounts of assets and liabilities considering the interest rate adjustment dates. Exposures are measured according to the Interest Rate Exposure or IRE metric and their related risks using the Earnings-at-Risk or EaR metric for short-term measurements and metrics such as Delta EVE sensitivities (Economic Value of Equity) and Delta EVE VaR for long-term measurements. Within these metrics, Prepayment Risk is considered, which corresponds to the customer’s ability to pay, fully or partially, their debt before maturity. For such purposes, a loan flow allocation model is generated with exposure to interest rate fluctuations, according to their prepayment behavior, finally reflecting a decrease in their average maturity term.
184
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (b) | Price Risk, continued: |
The use of EaR within the year 2026 is shown below:
12- months Earnings-at-Risk 99% confidence level 3 months closing period | ||||
| MCh$ | ||||
| Maximum | 181,733 | |||
| Minimum | 146,344 | |||
| Average | 166,704 | |||
The regulatory risk measurement for the Trading Book (Market Risk Weighted Assets report or MRWA) is prepared using guidelines provided by the Central Bank of Chile (hereinafter, “BCCh”) and the CMF. The aforementioned methodologies estimate the potential loss that the bank may incur considering standardized fluctuations of the value of market factors such as FX rates, interest rates and volatilities that may adversely impact the value of FX spot positions, interest rate exposures, and volatility exposures, respectively. Interest rates changes are provided by the regulatory entity; moreover, correlation factors and very conservative term are included to explain non-parallel changes in the yield curve.
The risk measurement for the Banking Book, according to regulatory guidelines (RMLB report per its Spanish acronym), because of interest rate fluctuations is carried out through the use of standardized methodologies provided by regulatory entities (BCCh and CMF). The report includes models for reporting interest rate gaps and how their value varies, according to rate fluctuations that are defined by the scenarios provided by the regulations. In addition to this, the regulatory entity has requested banks to establish internal limits, separately for short-term and long-term balances, NII and EVE respectively, for these regulatory measurements.
The results effectively realized during the month for trading activities are controlled against defined loss levels and if these levels are exceeded, senior management is notified to evaluate potential corrective actions.
Finally, the Market Risk Management Policy of Banco de Chile required the performance of daily stress tests for the Trading Book and monthly for the Banking Book. Additionally, the stress test for the FVTOCI portfolio is included, which is reported daily. The output of the stress testing process is monitored against corresponding alert levels; in the case those triggers are breached, the senior management is notified to implement further actions, if necessary. Additionally, these book tests are a fundamental part of establishing the Bank’s price risk appetite framework.
185
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (b) | Price Risk, continued: |
Up to 1 month | 1 to 3 months | 3 to 12 months | 1 to 3 years | 3 to 5 years | Over 5 years | Total | ||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||
| Assets as of September 30, 2026 | ||||||||||||||||||||||||||||
| Cash and deposits in banks | 3,151,395 | — | — | — | — | — | 3,151,395 | |||||||||||||||||||||
| Transactions in the course of collection | 343,317 | — | — | — | — | — | 343,317 | |||||||||||||||||||||
| Financial assets at fair value through other comprehensive income: | ||||||||||||||||||||||||||||
| Debt financial instruments | 276,440 | 1,024,344 | 1,490,224 | 866,927 | 292,923 | 288,574 | 4,239,432 | |||||||||||||||||||||
| Derivative financial instruments for hedging purposes | 6,168 | 12,521 | 388,845 | 316,323 | 584,591 | 843,660 | 2,152,108 | |||||||||||||||||||||
| Financial assets at amortized cost: | ||||||||||||||||||||||||||||
| Rights by resale agreements | 10,023 | — | — | — | — | — | 10,023 | |||||||||||||||||||||
| Debt financial instruments | 1,203 | — | 12,183 | 162,578 | 314,256 | — | 490,220 | |||||||||||||||||||||
| Loans to Banks | 351,854 | 1,435 | 265,944 | — | — | — | 619,233 | |||||||||||||||||||||
| Loans to customers, net | 3,851,396 | 3,638,139 | 7,537,890 | 9,438,673 | 6,044,564 | 16,305,363 | 46,816,025 | |||||||||||||||||||||
| Total Assets | 7,991,796 | 4,676,439 | 9,695,086 | 10,784,501 | 7,236,334 | 17,437,597 | 57,821,753 | |||||||||||||||||||||
Up to 1 month | 1 to 3 months | 3 to 12 months | 1 to 3 years | 3 to 5 years | Over 5 years | Total | ||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||
| Assets as of December 31, 2025 | ||||||||||||||||||||||||||||
| Cash and deposits in banks | 2,574,653 | — | — | — | — | — | 2,574,653 | |||||||||||||||||||||
| Transactions in the course of collection | 398,870 | — | — | — | — | — | 398,870 | |||||||||||||||||||||
| Financial assets at fair value through other comprehensive income: | ||||||||||||||||||||||||||||
| Debt financial instruments | 122,687 | 364,977 | 1,694,489 | 1,037,150 | 177,600 | 151,991 | 3,548,894 | |||||||||||||||||||||
| Derivative financial instruments for hedging purposes | 1,530 | 7,885 | 40,255 | 564,015 | 298,745 | 1,057,656 | 1,970,086 | |||||||||||||||||||||
| Financial assets at amortized cost: | ||||||||||||||||||||||||||||
| Rights by resale agreements | 57,023 | — | — | — | — | — | 57,023 | |||||||||||||||||||||
| Debt financial instruments | — | 14,089 | 7,859 | 162,583 | 321,295 | — | 505,826 | |||||||||||||||||||||
| Loans to Banks | 186,284 | 8,892 | 208,407 | — | — | — | 403,583 | |||||||||||||||||||||
| Loans to customers, net | 5,578,003 | 2,465,737 | 8,212,752 | 8,924,482 | 5,793,296 | 16,143,007 | 47,117,277 | |||||||||||||||||||||
| Total Assets | 8,919,050 | 2,861,580 | 10,163,762 | 10,688,230 | 6,590,936 | 17,352,654 | 56,576,212 | |||||||||||||||||||||
186
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (b) | Price Risk, continued: |
Up to 1 month | 1 to 3 months | 3 to 12 months | 1 to 3 years | 3 to 5 years | Over 5 years | Total | ||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||
| Liabilities as of September 30, 2026 | ||||||||||||||||||||||||||||
| Transactions in the course of payment | 679,906 | — | — | — | — | — | 679,906 | |||||||||||||||||||||
| Derivative financial instruments for hedging purposes | 4,323 | 6,984 | 363,631 | 276,857 | 664,015 | 1,227,181 | 2,542,991 | |||||||||||||||||||||
| Financial liabilities at amortized cost: | ||||||||||||||||||||||||||||
| Current accounts and other demand deposits | 14,584,909 | — | — | — | — | — | 14,584,909 | |||||||||||||||||||||
| Time deposits and saving accounts | 9,104,767 | 2,658,829 | 3,363,560 | 29,500 | 1,137 | 764 | 15,158,557 | |||||||||||||||||||||
| Obligations by repurchase agreements | 4,852 | — | — | — | — | — | 4,852 | |||||||||||||||||||||
| Borrowings from financial institutions | 205,998 | 73,104 | 798,821 | 150,676 | — | — | 1,228,599 | |||||||||||||||||||||
| Debt financial instruments issued (*) | 235,334 | 406,363 | 1,539,317 | 2,632,729 | 2,191,557 | 5,908,294 | 12,913,594 | |||||||||||||||||||||
| Other financial obligation | 322,864 | — | — | — | — | — | 322,864 | |||||||||||||||||||||
| Regulatory capital financial instruments (subordinated bonds) | — | 20,542 | 27,253 | 95,590 | 85,523 | 1,167,662 | 1,396,570 | |||||||||||||||||||||
| Total liabilities | 25,142,953 | 3,165,822 | 6,092,582 | 3,185,352 | 2,942,232 | 8,303,901 | 48,832,842 | |||||||||||||||||||||
Up to 1 month | 1 to 3 months | 3 to 12 months | 1 to 3 years | 3 to 5 years | Over 5 years | Total | ||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | ||||||||||||||||||||||
| Liabilities as of December 31, 2025 | ||||||||||||||||||||||||||||
| Transactions in the course of payment | 571,023 | — | — | — | — | — | 571,023 | |||||||||||||||||||||
| Derivative financial instruments for hedging purposes | 2,252 | 2,021 | 29,606 | 535,849 | 354,597 | 1,481,648 | 2,405,973 | |||||||||||||||||||||
| Financial liabilities at amortized cost: | ||||||||||||||||||||||||||||
| Current accounts and other demand deposits | 14,526,894 | — | — | — | — | — | 14,526,894 | |||||||||||||||||||||
| Time deposits and saving accounts | 9,316,902 | 2,897,857 | 1,813,808 | 6,587 | 793 | 646 | 14,036,593 | |||||||||||||||||||||
| Obligations by repurchase agreements | 43,509 | — | — | — | — | — | 43,509 | |||||||||||||||||||||
| Borrowings from financial institutions | 64,372 | 318,830 | 778,352 | 135,060 | — | — | 1,296,614 | |||||||||||||||||||||
| Debt financial instruments issued (*) | 18,708 | 370,475 | 1,289,167 | 3,015,473 | 2,119,402 | 5,738,729 | 12,551,954 | |||||||||||||||||||||
| Other financial obligation | 363,649 | — | — | — | — | — | 363,649 | |||||||||||||||||||||
| Regulatory capital financial instruments (subordinated bonds) | 3,247 | — | 46,655 | 92,486 | 89,240 | 1,149,624 | 1,381,252 | |||||||||||||||||||||
| Total liabilities | 24,910,556 | 3,589,183 | 3,957,588 | 3,785,455 | 2,564,032 | 8,370,647 | 47,177,461 | |||||||||||||||||||||
| (*) | Amounts shown here are different from those reported in the liabilities report, which is part of the liquidity analysis, due to differences in the treatment of mortgage bonds issued by the Bank in both reports. |
187
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (b) | Price Risk, continued: |
Price Risk Sensitivity Analysis
The Bank uses stress tests as the main sensitivity analysis tool for Price Risk. The analysis is implemented for the Trading Book, Banking Book and the FVTOCI portfolio separately. The Bank has adopted this tool as it is considered more useful than fluctuations in business as usual scenario, such as VaR or EaR, given that:
| (i) | The financial crisis shows market factors fluctuations that are materially larger than those used in the VaR with 99% of confidence level or EaR with 99% of confidence level. |
| (ii) | The financial crisis also shows that correlations between these fluctuations are materially different from those used in the VaR calculation, since a crisis precisely indicates severe disconnections between the behaviors of market factors fluctuations with respect to the patterns observed under normal conditions. |
| (iii) | Trading liquidity dramatically diminishes during financial distress and especially in emerging markets. Therefore, the overnight VaR number might not be representative of the loss for trading portfolios in such environment since closing exposures period may exceed one business day. This may also happen when calculating EaR, even considering three months as the closing period. |
The impacts are determined through mathematical simulations of fluctuations in the values of market factors, and, estimating the changes of the economic and /or accounting value of the financial positions.
188
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (b) | Price Risk, continued: |
To comply with IFRS 9, the following exercise was included illustrating an estimation of the impact of extreme but reasonable fluctuations of interest rates, swaps yields, FX rates and exchange volatility, which are used for valuing Trading Book, Banking Book and the FVTOCI portfolio. Because the Bank’s portfolio includes positions denominated in nominal and real interest rates, these fluctuations must be aligned with extreme but realistic Chilean inflation changes forecasts.
For the Trading Book, the exercise is implemented by multiplying the sensitivity by the fluctuations obtained as the results of mathematical simulations over a two-week time horizon and using the maximum historical volatility, within a significant period of time, in each of the market factor present. In the case of the FVTOCI portfolio a four-week time horizon is used due to liquidity constrains; Banking Book impacts are estimated by multiplying cumulative gaps by forward interest rates fluctuations modeled over a three-month time horizon and using the maximum historical volatility of interest fluctuations but limited by maximum fluctuations and / or levels observed within a significant period of time. It is relevant to note that the methodology might ignore some portion of the interest rates convexity, since it is not captured properly when large fluctuations are modeled. Because of the magnitude of the changes, the methodology may be reasonable enough for the purposes and scope of the analysis.
The following table illustrates the fluctuations resulting from the main market factors in the maximum stress test exercise, or more adverse, for the Trading Book.
The directions or signs of these fluctuations related to those that generate the most adverse impact in the aggregate level.
Average Fluctuations of Market Factors for Maximum Stress Scenario
Trading Book
| CLP Derivatives (bps) | CLP Bonds (bps) | CLF Derivatives (bps) | CLF Bonds (bps) | USD Offshore SOFR Derivatives (bps) | Spread USD SOFR/CAM Derivatives (bps) | |||||||||||||||||||
| Lower than 1 year | (30 | ) | 9 | (22 | ) | 22 | 2 | (83 | ) | |||||||||||||||
| Higher than 1 year | (43 | ) | 138 | (31 | ) | 143 | 4 | (49 | ) | |||||||||||||||
bps = basis points.
189
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (b) | Price Risk, continued: |
The worst impact on the Bank’s Trading Book as of September 30, 2026, as a result of the simulation process described above, is as follows:
| Most Adverse Stress Scenario P&L
Impact Trading Book (MCh$) | ||||
| CLP Interest Rate | (14,894 | ) | ||
| Derivatives | (2,777 | ) | ||
| Debt instruments | (12,117 | ) | ||
| CLF Interest Rate | (10,888 | ) | ||
| Derivatives | (733 | ) | ||
| Debt instruments | (10,155 | ) | ||
| Interest rate US SOFR | (70 | ) | ||
| SOFR/CAM interest rate spread | (2,672 | ) | ||
| Total Interest rates | (28,524 | ) | ||
| Banking spread | — | |||
| Total FX and FX Options | 424 | |||
| Total | (28,100 | ) | ||
The modeled scenario would generate losses in the Trading Book of Ch$28,100 million. Such fluctuations would not result in material losses compared to Basic Capital or to the P&L estimate for the next 12-months.
The impact on the Banking Book as of September 30, 2026, which does not necessarily mean a net loss (gain) but a lower (higher) net income from funds generation (resulting in the generation of the net interest rate), is shown below:
|
Most Adverse Stress Scenario 12-Month Revenue | ||||
| Impact by Base Interest Rate shocks | (361,494 | ) | ||
| Impact due to Spreads Shocks | (9,061 | ) | ||
| Higher / (Lower) Net revenues | (370,555 | ) | ||
190
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (3) | Market Risk, continued: |
| (b) | Price Risk, continued: |
The impact on the FVTOCI portfolio is detailed in the tables below. First there are the main fluctuation in the market factors, due to the scenarios provided for the stress test meltdown (more adverse), for this portfolio.
The signs of the variations below, correspond to the ones that generate the most adverse impact.
Average Fluctuations of Market Factors for Maximum Stress Scenario FVTOCI Portfolio | ||||||||||||||||
| CLP Bonds (bps) | CLF Bonds (bps) | USD Offshore SOFR Derivatives (bps) | Spread USD SOFR/CAM Derivatives (bps) | |||||||||||||
| Lower than 1 year | 97 | 155 | (4 | ) | 40 | |||||||||||
| Higher than 1 year | 196 | 225 | 10 | 21 | ||||||||||||
bps = basis points
The worst impact on the Bank’s FVTOCI portfolio as of September 30, 2026, as a result of the simulation process described above, is as follows:
| Most Adverse Stress Scenario P&L Impact FVTOCI portfolio (MCh$) | ||||
| CLP Debt Instrument | (77,056 | ) | ||
| CLF Debt Instrument | (77,559 | ) | ||
| Interest rate US SOFR | (620 | ) | ||
| Banking spread | (4,927 | ) | ||
| Corporative spread | (2,509 | ) | ||
| Total | (162,671 | ) | ||
The modeled for the FVTOCI Portfolio would generate potential impacts on equity accounts for Ch$162,671 million.
The main negative impact on the Trading Book would occur because of an increase in rates on debt instruments in CLP and CLF over 1 year, while in the case of the FVTOCI portfolio the main impact comes from upward fluctuations in interest rates of debt instruments in CLP and CLF greater than 1 year. the lowest potential earnings over the next 12 months in the banking book would occur under a scenario characterized by a sharp decline in inflation rates and a moderate decrease in nominal interest rates.
191
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (4) | Other Information related to Financial Risks: |
Offsetting of financial assets and liabilities:
The Bank trades financial derivatives with foreign counterparties using ISDA Master Agreement (International Swaps and Derivatives Association, Inc.), under legal jurisdiction of the City of New York – USA or London – United Kingdom. Legal framework in these jurisdictions, along with documentation mentioned, it allows Banco de Chile the right to anticipate the maturity of the transaction and then, offset the net value of those transactions in case of default of counterparty. Additionally, the Bank has negotiated with these counterparties an additional annex (CSA Credit Support Annex), that includes other credit mitigating, such as entering margins on a certain amount of net value of transactions, early termination (optional or mandatory) of transactions at certain dates in the future, coupon adjustment of transaction in exchange for payment of the debtor counterpart over a certain threshold amount, etc.
Below are detail the contracts susceptible to offset:
| Fair Value | Negative Fair Value of contracts with right to offset | Positive Fair Value of contracts with right to offset | Financial Collateral | Net Fair Value | ||||||||||||||||||||||||||||||||||||
| September | December | September | December | September | December | September | December | September | December | |||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||
| MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | MCh$ | |||||||||||||||||||||||||||||||
| Derivative financial assets | 2,450,234 | 1,899,181 | (968,557 | ) | (715,643 | ) | (1,013,092 | ) | (839,686 | ) | (157,699 | ) | (172,966 | ) | 310,886 | 170,886 | ||||||||||||||||||||||||
| Derivative financial liabilities | 2,786,502 | 2,378,039 | (968,557 | ) | (715,643 | ) | (1,013,092 | ) | (839,686 | ) | (448,022 | ) | (456,594 | ) | 356,831 | 366,116 | ||||||||||||||||||||||||
192
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (5) | Operational risk: |
One of the Bank’s objectives is to monitor, control and maintain at adequate levels, the risk of losses resulting from a lack of adequacy or a failure of processes, personnel and/or internal systems, or due to external events. This definition includes legal risk and excludes strategic and reputational risk.
Operational risk is inherent to all activities, products, and systems, and is transversal to the entire organization, encompassing its strategic, business, and support processes. All Bank collaborators are responsible, within their respective areas of responsibility, for managing and controlling the operational risk inherent in their activities, as its materialization can generate direct or indirect financial losses.
To face this risk, the Bank has defined a Regulatory Framework and a governance structure according to the volume and complexity of its activities. The Operational Risk and Global Control Division administer the management of this risk, through the establishment of an Operational Risk Management. Likewise, the “Superior Committee for Operational Risk” and the “Committee for Operational Risk” supervise it.
The Operational Risk Policy defines a comprehensive management model based on four main processes that ensure an adequate control environment in the organization.
These processes are implemented in the different areas of Operational Risk action, using various management and control tools.
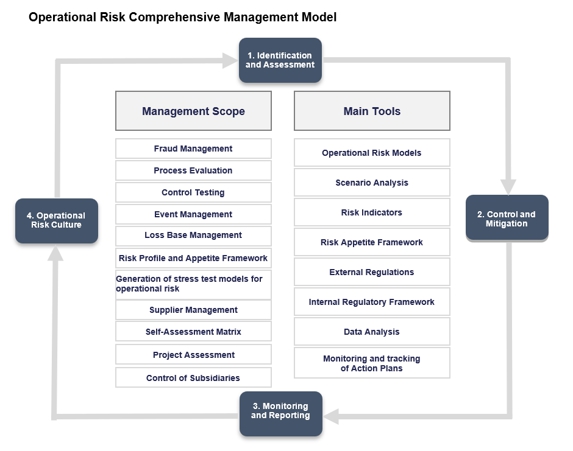
193
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (5) | Operational risk, continued: |
The aforementioned processes correspond to:
1. Identification and Evaluation: At Banco de Chile, this process considers internal and external factors, which allows us to better understand operational risk, and thus allocate resources and define strategies efficiently and effectively.
The Bank promotes the use of methodologies and procedures with the objective of guaranteeing an adequate identification and evaluation of these risks, both inherent and residual. These are executed with a frequency that allows knowing the operational risks in a timely manner.
2. Control and Mitigation: Determination of acceptable risk levels and mitigation actions to be applied in case of deviation from these levels. This process aims to maintain risk at adequate levels.
Banco de Chile will execute a set of control and mitigation tools in the different areas of management, which will make it possible to alert deviations in exposure to operational risk, where mitigation measures will be evaluated to solve them.
3. Monitoring and Reporting: This process aims to guarantee the monitoring of the main risks and inform the different interested parties.
At Banco de Chile, monitoring and reporting will consider information related to the different areas of management. If necessary, the results of the monitoring activities will be included in the relevant government instances.
4. Operational Risk Culture: The Operational Risk Management plans operational risk culture programs, aimed at raising awareness and training Bank employees in risk identification, control effectiveness, and event detection in their normal operating activities, so that each collaborator contributes to reduce the occurrence of risk events and mitigate their impact on the business.
Additionally, the comprehensive management of Operational Risk considers the following areas:
| − | Fraud Management |
| − | Process Assessment |
| − | Testing of Controls |
| − | Event Management |
| − | Loss Base Management |
| − | Profile and Risk Appetite Framework |
| − | Execution of Stress Test Models for Operational Risk |
| − | Supplier Management |
| − | Risk Management Self-Assessment Matrix |
| − | Operational Risk Assessment for Projects |
| − | Subsidiary Control |
194
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (5) | Operational risk, continued: |
All areas mentioned above, together with the corresponding Regulatory Framework and governance structure, perform the overall management of Operational Risk. In this way, Banco de Chile and its Subsidiaries ensure an adequate environment for the management of operational risk.
Below is the exposure to net loss, gross loss and recoveries due to operational risk events as of September 30, 2026 and 2025:
| September 2026 | September 2025 | |||||||||||||||||||||||
| Category | Lost gross MCh$ | Recoveries MCh$ | Lost net MCh$ | Lost gross MCh$ | Recoveries MCh$ | Lost net MCh$ | ||||||||||||||||||
| Internal fraud | 3 | — | 3 | 85 | (1 | ) | 84 | |||||||||||||||||
| External fraud | 21,477 | (10,165 | ) | 11,312 | 19,693 | (10,200 | ) | 9,493 | ||||||||||||||||
| Work practices and safety in the business position | 1,184 | (4 | ) | 1,180 | 1,162 | — | 1,162 | |||||||||||||||||
| Customers, products and business practices | 164 | (20 | ) | 144 | 331 | — | 331 | |||||||||||||||||
| Damage to physical assets | 199 | (79 | ) | 120 | 458 | (14 | ) | 444 | ||||||||||||||||
| Business interruption and system failures | 339 | (46 | ) | 293 | 370 | (5 | ) | 365 | ||||||||||||||||
| Execution, delivery and process management | 2,509 | (58 | ) | 2,451 | 1,397 | (124 | ) | 1,273 | ||||||||||||||||
| Total | 25,875 | (10,372 | ) | 15,503 | 23,496 | (10,344 | ) | 13,152 | ||||||||||||||||
Technology Risk
The Bank’s objective is to manage technology risk, information security risk, and cybersecurity risk in order to safeguard the confidentiality, integrity, and availability of information. This is achieved through the identification, assessment, monitoring, and reporting of risk exposures, taking into account the likelihood of occurrence and the potential impact of events that could affect the achievement of business objectives. The key areas of risk management include:
Assessment of Information and Technology Assets within Processes, Regulatory Compliance, and Emerging Risks
Security Testing Assessments
Compliance with the SWIFT Customer Security Controls Framework (CSCF)
Assessment of Technology Projects and Changes
Assessment of Cyber Risk Exposure Related to Third-Party Providers
Risk Profile and Risk Appetite Framework Subsidiary Alignment and Compliance Controls
Control of Technology Infrastructure Vulnerabilities
In addition, Technology Risk management enables the Bank to proactively address threats, vulnerabilities, and exposure scenarios that could affect its operations. To this end, the Bank applies a continuous assessment methodology to the technological components supporting its business, operational support, and strategic processes. This approach facilitates the identification of improvement opportunities, the implementation of mitigation measures, and the strengthening of the organization’s operational resilience.
195
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
| (5) | Operational risk, continued: |
Cybersecurity
The Identity Governance Management is responsible for developing, implementing, and improving the identity and access management strategy, protecting data while ensuring operational efficiency and regulatory compliance. It implements IAM technologies and collaborates with all areas of the Corporation, promoting automation and the continuous improvement of access controls. The Cyber Defense Management is responsible for proactively protecting, monitoring, containing and eliminating threats and vulnerabilities through automated containment measures, and for managing incidents of cyberscurity assertively and in a timely manner, with the objective of safeguarding the Corporation’s information assets based on the prevailing threat landscape.
In addition, the Cybersecurity Threat Management Division is responsible for identifying, analyzing and anticipating threats that may affect the Corporation through Cyber Intelligence, Cybersecurity Architecture and Application Security capabilities. Its role is to generate actionable intelligence to support decision-making, define and implement security architectures and controls, and embed security from the design and development stages of solutions. It also leads threat assessment, detection and validation capabilities, as well as vulnerability identification, proactively contributing to strengthening the resilience and protection of the Corporation’s critical assets. This is achieved through the implementation of structured cybersecurity processes designed to continuously strengthen the protection of Banco de Chile’s technology assets by integrating security throughout the entire lifecycle of digital solutions and capabilities, with the aim of reducing exposure to various threats and contributing to secure and resilient business operations.
Finally, the Cybersecurity Management and Subsidiary Oversight Division is responsible for managing the cybersecurity and information protection strategy, as well as cybersecurity processes, policies, standards and procedures, through a comprehensive approach that supports risk management and safeguards the confidentiality, integrity and availability of information. It is also responsible for the execution of cybersecurity initiatives, projects and budget. In its Subsidiary Oversight role, the Division maintains a communication channel with the Information Security Officer of each respective subsidiary to ensure compliance with cybersecurity guidelines through advisory services, support, training and consulting.
Business Continuity Management
To ensure compliance with objectives related to customer service delivery, the bank has a Business Continuity Management, which, through its Policy and Standard, establishes guidelines to manage, control, and administer recovery strategies in contingency situations. It maintains the crisis governance model and ensures the continuity of critical services and operations related to the payment chain through a resilient, comprehensive model that includes plans and controlled tests to mitigate the impact of disruptive events that may affect the bank. Additionally, the role and responsibilities of the Information Security Officer (ISO) are defined, operating independently from the Cybersecurity Division. The ISO’s function is to design and implement controls by monitoring the tasks performed by the organizational units responsible for information security, cybersecurity, and technology risk within the Bank and its subsidiaries.
196
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 47. | Risk Management and Report, continued: |
That is why Business Continuity has available methodologies and controls that contribute to the application of the comprehensive model within the corporation, mainly represented in the following management areas:
| − | Document Management: It consists of carrying out methodological processes of updating the documentation that supports Business Continuity in operational and technological areas, with the aim of keeping the strategy implemented in the Bank up to date and in accordance with the guidelines of Business Continuity Management (BCM). |
| − | Business Continuity Tests: It refers to annually scheduled contingency simulations that address the five risk scenarios defined for the Bank (Failure in Technology Infrastructure, Failure in Physical Infrastructure, Massive Absence of Personnel, Failure in Critical Supplier Service and Cybersecurity). These test, allow to maintain constant training and integration of critical personnel operating the payment chain, under the defined contingency procedures that support the Bank’s critical products and services. |
| − | Crisis Management: Internal process of the Bank that maintains and trains the key executive roles associated with the Crisis Groups in conjunction with the main recovery strategies and structures defined in the BCM model. In this way, it constantly strengthens the different areas necessary for preparation, execution and monitoring, that will allow facing crisis events in the Bank. |
| − | Critical Supplier Management: This involves the management, control and testing of Business Continuity Plans implemented by the suppliers involved in the processing of critical products and services for the Bank, associated with the risk scenarios established in direct relation to the contracted service. |
| − | Alternative Site Management: It involves the ongoing management and monitoring of secondary physical locations for the Bank’s critical units, with the aim of ensuring the continuity of operations in the event of a failure at the primary site. The objective is to safeguard and maintain the operational and technological capabilities of the alternate sites, reducing recovery times and ensuring effective activation whenever required. |
| − | Relations with subsidiaries and External Entities: It consists of the permanent control, management and leveling on the compliance of Subsidiaries under the methodology and strategic lines established by the Bank in crisis environments and Business Continuity Management. It also includes the global management with the requirements of internal and external regulators. |
| − | Continuous Improvement: considers the application of processes, automation and the adaptation of resources used in the internal processes of the Business Continuity Model, with the objective of improving response in the delivery and analysis of information in contingencies, strengthening the managed processes of the BCM. |
| − | Training: It includes the development and implementation of processes and training activities under different learning methodologies to strengthen and empower employees on the areas of the Business Continuity Model. |
| − | Cybersecurity Control: Design and implement independent controls by monitoring the tasks carried out by the organizational units responsible for the Bank’s information security, cybersecurity and technological risk. |
The management and unification of the described areas, together with the compliance of the implemented regulations and the structured governability, constitute the Business Continuity Model of the Banco de Chile.
197
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 48. | Information on Regulatory Capital and Capital Adequacy Ratios: |
Requirements and Capital Management:
The main objectives of the Bank’s capital management are to ensure the adequacy and quality of its capital, at a consolidated level, based on the adequate management of the risks it faces in its operations, establishing sufficient capital levels, through the definition of internal objectives, that supports both the business strategy in both normal and stress scenarios in the short and medium term, thus ensuring compliance with regulatory requirements, coverage of its material risks, a sound credit classification and the generation of adequate capital headroom. During 2026, the Bank has met the required capital requirements and its internal adequacy objectives.
As part of its Capital Management Policy, the Bank has established capital adequacy alerts and limits approved by the Board of Directors, which are monitored by the governance structures that the Bank has established for these purposes, including the Capital Management Committee. During 2026, none of the internal alerts defined by the Bank were activated as part of the Capital Risk Appetite Framework. In this sense, the Bank manages capital based on its strategic objectives, its risk profile and its ability to generate cash flows, as well as the economic and business context in which it operates. If it requires strengthening its capital structure, the Bank may, among other options, propose to its shareholders meeting modifications to the dividend payment ratio, as well as issue basic capital, additional tier 1 capital or tier 2 capital instruments.
Capital Requirements
In accordance with the General Banking Law, the effective equity of a bank may not be less than 8% of its risk-weighted assets (RWA), net of required provisions. Additionally, it establishes that the Basic Capital may not be less than 4.5% of its RWA or 3% of its total assets, net of required provisions. Regarding Tier 1 capital, corresponding to the sum of Basic Capital and Additional Tier 1 Capital, the latter in the form of bonds with no maturity date and preferred shares, the requirements establish that it may not be less than 6% of their RWAs, net of required provisions. Likewise, banking entities must comply, as established by current regulations or regulators, with buffers and capital charges, such as the conservation buffer, the countercyclical buffer and capital charges by the systemically important buffer and/or Pillar 2.
On May, 2023, the Central Bank reported that its board agreed to activate the counter-cyclical core capital buffer for banks, at a local banking industry level, equivalent to 0.5% of the risk-weighted assets of banking institutions, effective beginning in May 2024. In the monetary policy meeting of May 2026 the Central Bank decided to raise the requirement from 0.5% to 1% of risk-weighted assets, with the new requirement becoming effective in May 2028.
On January 17, 2025 the CMF communicated that, as a result of the supervisory process, it decided to maintain the additional capital requirement for Pillar 2 effective on that date for the equivalent to 0.13% of the RWA, which was fully constituted in June 2025. On January 16, 2026, as a result of the supervisory process, the CMF resolved and communicated the removal of the additional Pillar 2 requirement for Banco de Chile.
On March 27, 2026, the CMF reported the result of the annual review of the systemic importance rating for local banks, maintaining an additional basic capital charge of 1.25% of the RWA for Banco de Chile.
As of December 1, 2025, the phased implementation of requirements for systemic banks and the gradual adjustments to regulatory capital have been fully completed. From this date onward, the only remaining transitional measure relates to the continued recognition of subordinated bonds issued by banking subsidiaries as effective equity.
198
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 48. | Information on Regulatory Capital and Capital Adequacy Ratios, continued: |
Information on regulatory capital and capital adequacy indicators is presented below:
| Total assets, risk-weighted assets and components of the effective equity components under to Basel III |
Local and Overall consolidated |
Local and Overall consolidated |
||||||||||||
| Item No. | Item description | Note | September 30, 2026 |
December 31, 2025 |
||||||||||
| MCh$ | MCh$ | |||||||||||||
| 1 | Total assets as per to the statement of financial position | 55,912,332 | 54,100,903 | |||||||||||
| 2 | Non-consolidated investment in subsidiaries | a | — | — | ||||||||||
| 3 | Assets discounted from regulatory capital, other than item 2 | b | 2,637,828 | 2,069,627 | ||||||||||
| 4 | Derivative credit equivalents | c | 1,433,449 | 1,070,598 | ||||||||||
| 5 | Contingent loans | d | 3,189,345 | 3,110,749 | ||||||||||
| 6 | Assets generated by the intermediation of financial instruments | e | — | — | ||||||||||
| 7 | = (1-2-3+4+5-6) Total assets for regulatory purposes | 57,897,298 | 56,212,623 | |||||||||||
| 8.a | Credit risk weighted assets, estimated according to the standard methodology (CRWA) | f | 34,346,427 | 33,093,851 | ||||||||||
| 8.b | Credit risk weighted assets, estimated according to internal methodologies (CRWA) | f | — | — | ||||||||||
| 9 | Market risk weighted assets (MRWA) | h | 1,638,415 | 1,712,039 | ||||||||||
| 10 | Operational risk weighted assets (ORWA) | g | 4,254,339 | 4,112,856 | ||||||||||
| 11.a | = (8.a/8.b+9+10) Risk-weighted assets (RWA) | 40,239,181 | 38,918,746 | |||||||||||
| 11.b | = (8.a/8.b+9+10) Risk-weighted assets, after application of the output floor (RWA) | 40,239,181 | 38,918,746 | |||||||||||
| 12 | Owner’s equity | 5,824,293 | 5,799,534 | |||||||||||
| 13 | Non-controlling interest | i | 2 | 1 | ||||||||||
| 14 | Goodwill | j | — | — | ||||||||||
| 15 | Excess minority investments | k | — | — | ||||||||||
| 16 | = (12+13-14-15) Core Tier 1 Capital (CET1) | 5,824,295 | 5,799,535 | |||||||||||
| 17 | Additional deductions to core tier 1 capital, other than item 2 | l | 145,661 | 155,410 | ||||||||||
| 18 | = (16-17-2) Core Tier 1 Capital (CET1) | 5,678,634 | 5,644,125 | |||||||||||
| 19 | Voluntary (additional) provisions as additional Tier 1 capital (AT1) | m | — | — | ||||||||||
| 20 | Subordinated bonds imputed as additional tier 1 capital (AT1) | m | — | — | ||||||||||
| 21 | Preferred shares allocated to additional tier 1 capital (AT1) | — | — | |||||||||||
| 22 | Bonds without a fixed term of maturity imputed to additional tier 1 capital (AT1) | — | — | |||||||||||
| 23 | Discounts on AT1 | l | — | — | ||||||||||
| 24 | = (19+20+21+22-23) Additional Tier 1 Capital (AT1) | — | — | |||||||||||
| 25 | = (18+24) Tier 1 Capital | 5,678,634 | 5,644,125 | |||||||||||
| 26 | Voluntary provisions (additional) imputed as Tier 2 capital (T2) | n | 429,330 | 413,673 | ||||||||||
| 27 | Subordinated bonds imputed as Tier 2 capital (T2) | n | 1,084,967 | 1,057,377 | ||||||||||
| 28 | = (26+27) Equivalent tier 2 capital (T2) | 1,514,297 | 1,471,050 | |||||||||||
| 29 | Discounts applied to T2 | l | — | — | ||||||||||
| 30 | = (28-29) Tier 2 capital (T2) | 1,514,297 | 1,471,050 | |||||||||||
| 31 | = (25+30) Effective equity | 7,192,931 | 7,115,175 | |||||||||||
| 32 | Additional basic capital required for the constitution of the conservation buffer | o | 1,005,979 | 972,969 | ||||||||||
| 33 | Additional basic capital required to set up the countercyclical buffer | p | 201,196 | 194,594 | ||||||||||
| 34 | Additional basic capital required for banks qualified as systemic | q | 502,990 | 486,484 | ||||||||||
| 35 | Additional capital required for the evaluation of the adequacy of effective equity (Pillar 2) | r | — | 37,946 | ||||||||||
| a) | Relates to the value of the investment in subsidiaries that are not consolidated. Applies only in the local consolidation when the bank has foreign subsidiaries, subtracting totally its value in assets and CET1. |
| b) | Relates to the value of the asset items that are subtracted from the regulatory capital, in accordance with the paragraph(a) of title N°3 of chapter 21-30 of the RAN. |
199
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 48. | Information on Regulatory Capital and Capital Adequacy Ratios, continued: |
| c) | Relates to the credit equivalents of the derivative instruments, in accordance with the paragraph (b) of title N°3 of chapter 21-30 of the RAN. |
| d) | Relates to the contingent exposure according to the paragraph c) of the title N°3 of chapter 21-30 of the RAN. |
| e) | Relates to the intermediation of financial instrument assets in the name of the bank on behalf of third parties that are consolidated as established in the paragraph d) of the title N°3 of chapter 21-30 of the RAN. |
| f) | Relates to the estimated credit risk weighted assets according to the chapter 21-6 of RAN. If the bank does not have the authorization to apply internal methodologies, needs to inform the field 8.b as zero. |
| g) | Relates to the estimated market risk weighted assets according to the chapter 21-7 of the RAN. |
| h) | Relates to the estimated operational risk weighted assets according to the chapter 21-8 of the RAN. |
| i) | Relates to to the non-controlling interest, depending on the level of consolidation, up to 20% of the owners’ assets. |
| j) | Assets that correspond to goodwill. |
| k) | Relates to to the balances of investment assets in non-business support companies that do not participate in the consolidation, above 5% of the owners’ equity. |
| l) | For CET1 and T2, banks must estimate the equivalent value for each tier of capital, as well as that obtained by fully applying Chapter 21-1 of the RAN. Then, the difference between the equivalent value and the fully applied value must be weighted by the discount factor in force on the reporting date according to the transitional provisions of Chapter 21-1 of the RAN and reported in this row. For of the AT1, discounts are applied directly if any |
| m) | Provisions and subordinated bonds allocated to additional tier 1 capital (AT1), as established in Chapter 21-2 of the RAN. |
| n) | Provisions and subordinated bonds allocated to the equivalent definition of tier 2 capital (T2), as established in Chapter 21-1 of the RAN. |
| o) | Relates to the additional basic capital (CET1) for the constitution of the conservation buffer, as established in Chapter 21-12 of the RAN. |
| p) | Relates to the additional basic capital (CET1) for the constitution of the countercyclical buffer, as established in Chapter 21-12 of the RAN. |
| q) | Relates to the additional basic capital (CET1) for banks qualified as systemic banks, as established in Chapter 21-11 of the RAN. |
| r) | Relates to the additional capital for the evaluation of the sufficiency of the effective equity (Pillar 2) of the bank, as established in Chapter 21-13 of the RAN. |
200
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 48. | Information on Regulatory Capital and Capital Adequacy Ratios, continued: |
| Local and Overall consolidated | Local and Overall consolidated | ||||||||||||
| Capital Adequacy Ratios and Regulatory Compliance according to Basel III | September 30, 2026 | December
31, 2025 | |||||||||||
| Item No. | Item description (*) | Note | % | % | |||||||||
| 1 | Leverage Ratio (T1 I18/T1 I7) | 9.81 | % | 10.04 | % | ||||||||
| 1.a | Leverage Ratio that the bank must meet, considering the minimum requirements | a | 3 | % | 3 | % | |||||||
| 2 | CET 1 Capital Ratio (T1 I18/T1 I11.b) | 14.11 | % | 14.50 | % | ||||||||
| 2.a | CET 1 Capital Ratio that the bank must meet, considering the minimum requirements | a | 5.75 | % | 5.82 | % | |||||||
| 2.b | Capital buffer shortfall | b | — | — | |||||||||
| 3 | Tier 1 Capital Ratio (T1 I25/T1 I11.b) | 14.11 | % | 14.50 | % | ||||||||
| 3.a | Tier 1 Capital Ratio that the bank must meet, considering the minimum requirements | a | 7.25 | % | 7.35 | % | |||||||
| 4 | Regulatory Capital Ratio (T1 I31/T1 I11.b) | 17.88 | % | 18.28 | % | ||||||||
| 4.a | Regulatory Capital Ratio that the bank must meet, considering the minimum requirements | a | 9.25 | % | 9.38 | % | |||||||
| 4.b | Regulatory Capital Ratio that the bank must meet, considering the charge for article 35 bis | c | N/A | N/A | |||||||||
| 4.c | Regulatory Capital Ratio that the bank must meet, considering the minimum requirements, conservation buffer and countercyclical buffer | b | 12.25 | % | 12.38 | % | |||||||
| 5 | Credit rating | d | A | A | |||||||||
| Regulatory compliance for Capital Adequacy | |||||||||||||
| 6 | Additional provisions computed in Tier 2 capital (T2) in relation to CRWA (T1 I26/T1 I8.a) | e | 1.25 | % | 1.25 | % | |||||||
| 7 | Subordinated bonds computed as Tier 2 capital (T2) in relation to CET 1 Capital | f | 18.63 | % | 18.23 | % | |||||||
| 8 | Additional Tier 1 Capital (AT1) in relation to CET 1 Capital (T1 I24/T1 I18) | g | — | — | |||||||||
| 9 | Voluntary (additional) provisions and subordinated bonds computed as AT1 in relation to RWAs ((T1 I19+T1 I20)/T1 I11.b) | h | N/A | N/A | |||||||||
| (*) | T1 Ix: corresponds to item x of the previous table. |
| a) | In the case of the leverage indicator, the requirement is 3% without prejudice to the additional requirements for systemic banks that could be set according to the provisions of Chapter 21-30 of the RAN. |
In the case of core capital, the bank considers a charge of 4.5% of risk-weighted assets (RWA) plus the systemic charge and Pillar 2 requirements.
In Tier 1 capital, a value of 6% plus the systemic bank charge and Pillar 2 charge is considered the minimum requirement.
For effective equity, 8% of the RWA is considered, adding to this value the additional charges for systemic bank and Pillar 2.
The systemic bank requirements for Banco de Chile are equivalent to 1.25%. No charge for Pillar 2 as of September 30, 2026 (0.13% as of December 31, 2025 which is covered by 56.3% with basic capital).
| b) | The capital buffer deficit must be estimated according to the provisions of Chapter 21-12 of the RAN. This value defines the restriction on the distribution of dividends, as provided in the Chapter mentioned above. |
In the case of effective equity, the requirement of 100% of the conservation buffer of 2.5% and a counter-cyclical capital charge are added to the value reported in note 4.a). of 0.5%.
| c) | It corresponds to the effective equity requirement in force by article 35 bis of the General Banking Law. |
| d) | It corresponds to the solvency classification as established in article 61 of the general banking law. |
| e) | Limit is equivalent to 1.25% when using standard methodology for determining CRWAs. |
| f) | Limit is equivalent to 50% of the basic capital, considering the discounts applied to these instruments according to Chapter 21-1 of the RAN. |
| g) | Additional Tier 1 capital cannot exceed 1/3 of core capital. |
| h) | Additional provisions and subordinated bonds could be temporarily allocated until November 2023 to AT 1 for up to 1% of the RWA as of December 1, 2021. This value decreased annually by 0.5% in accordance with the transitional provisions of Chapter 21-2 of the RAN. |
201
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 49. | Subsequent Events: |
| (a) | On October 9, 2026, The President of the Republic enacted the National Reconstruction and Economic and Social Development Law, which was published in the official Gazette on October 17, 2026. Among other matters, the Law provides for a gradual reduction, over a three-year period, in the First Category Income Tax rate from 27% to 23%. |
In accordance with IAS 12 “Income Taxes,” deferred tax assets and liabilities are measured using the tax rates that have been enacted or substantively enacted by the end of the reporting period. Since the aforementioned Law was enacted after September 30, 2026, these financial statements do not recognize the effects associated with such Law. However, considering the gradual implementation of the new tax rates and the estimated reversal periods of the temporary differences giving rise to deferred tax assets and liabilities, the Bank estimated that the remeasurement of deferred tax assets and liabilities will result in a net charge to income for October 2026 of approximately Ch$68,000 million.
| (b) | On October 19, 2026, the subsidiary Banchile Corredores de Bolsa S.A. reported that its Board of Directors had agreed to amend its Ordinary Course of Business Transactions Policy. |
The updated text of the aforementioned policy is available to interested parties and the general public at the offices of Banchile Corredores de Bolsa S.A. and in the “Regulatory and Financial Information” section of the Banchile Inversiones website at www.banchileinversiones.cl.
| (c) | On October 29, 2026, Banco de Chile reported as a Material Event that, at an Ordinary Board Meeting held on the same date, Mr. Eduardo Ebensperger Orrego submitted his resignation as Chief Executive Officer of Banco de Chile for consideration by the Board of Directors, effective April 2, 2027. |
At said meeting, the Board of Directors resolved to accept the aforementioned resignation, effective as of the date indicated above, and expressed its recognition and appreciation for Mr. Ebensperger’s service and contribution to the Bank during his more than ten years serving as Chief Executive Officer. The Board also expressed its appreciation for the advance notice with which the resignation was communicated, which contributes to strengthening continuity in the Bank’s executive leadership.
Finally, at the aforementioned meeting, the Board of Directors resolved to appoint Mr. Hernán Arellano Salas as Chief Executive Officer of the Bank, effective April 3, 2027.
The Interim Consolidated Financial Statements of Banco de Chile for the period ended September 30, 2026 were approved by the Directors on October 29, 2026.
202
NOTES TO THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS, continued
| 49. | Subsequent Events: |
In Management's opinion, there are no other significant subsequent events that affect or could affect the Interim Consolidated Financial Statements of Banco de Chile and its subsidiaries between September 30, 2026 and the date of issuance of these Interim Consolidated Financial Statements.
| /s/ Héctor Hernández G. | /s/ Eduardo Ebensperger O. | |
| Héctor Hernández G. | Eduardo Ebensperger O. | |
| General Accounting Manager | Chief Executive Officer |
203