1
INTEGRATED ANNUAL REPORT FOR THE 20-F 2026
2
Contents
Section | Page |
Delivering profitable ounces | |
Sustainability performance | |
Illegal mining and unauthorised access | |
Air quality | |
Governance | |
Board committees | |
3
Harmony in focus
Harmony is a resilient gold and copper producer operating in South
Africa, Australia and Papua New Guinea.
Established on 25 August 1950 with our first mine in South Africa’s Free State province, Harmony has
demonstrated adaptability and operational resilience for 76 years, making us South Africa's largest gold producer
by volume and the world’s leader in gold tailings reclamation. We are anchored in gold but adding quality copper
through the high-grade, underground CSA copper mine and high-margin open-pit Eva Copper Project under
construction, both located in Australia. Headquartered in Randfontein, South Africa, we are dual-listed on the
JSE (HAR) and NYSE (HMY) with a long-standing commitment to responsible mining and sustainable value
creation.
Who we are Mining with Purpose sets our intent, our values guide how we decide and behave, and our leadership philosophy is what carries both from the boardroom to the rock face. | ||||||
Mining with Purpose Safety above all: The wellbeing of every Harmonite is our number one, non-negotiable value. | |||||
Profitable company | Environmental stewardship | Good governance | Lasting value | ||
Safe, organic growth and value-accretive acquisitions | Responsible management of resources and environmental impacts | Integrity and accountability woven into everything we do | Long-term economic and social benefit for host countries | ||
Our values Principle-centred, guiding our decision-making, behaviour and culture. | ||||||
Safety | Achievement | Accountable | Connected | Honesty | ||
No matter the circumstances, safety is our main priority. | Achievement is core, driven by purpose, resilience and courage. | Our compass for delivering on our commitments. | Unity in diversity, inclusion in action. | We build trust with clear, courageous and authentic honesty. | ||
Leadership philosophy Effective leadership creates an environment where people feel respected, trusted, safe, valued and inspired to turn purpose into performance, every day. | |||||
Safety and health | Our values | Our people | Operational excellence | ||
Safety comes first in everything we do. | We live by our values – always. They shape how we work together and lead diverse teams in a high- performing and inclusive environment. | By valuing and empowering our people, we create meaningful impact. | We take ownership of our business, stay connected to our operations and adapt to change to deliver sustainable results. | ||
4
What we do Safe, predictable production is the foundation of Harmony’s success. Driven by strong leadership, disciplined planning, operational excellence, effective orebody management and low-cost Reserve conversion, we create value through our core business activities. | |||||||||||||
Exploration and resource development | Development and capital projects | Underground and open-pit mining | Processing and tailings retreatment | Sales and logistics | Responsible stewardship | ||||||||
•Systematic drilling to extend Mineral Resources •Focus on gold and copper growth •Permitting and studies to extend life of mine. | •Capital directed to our asset portfolios for best return (extend life of mine and improve grade) •Disciplined project execution. | •Safe extraction across operations •Productivity and grade optimisation. | •World-class CIL/CIP and gravity circuits •Circular economy leader through tailings retreatment •Copper flotation and concentrate production. | •Gold sold to gold markets and the Australian Bullion Corporation •Copper concentrate sold to Glencore •Diversified revenue streams including by-product revenue. | •Safety-first culture •Advancing renewable energy •Social value creation and community development •Responsible mine closure and legacy planning. | ||||||||
How we create value A decade of disciplined investment | ||||||||||
2016 Hidden Valley (acquired remaining 50%) Open-pit gold (Papua New Guinea) | 2020 Mponeng Underground gold (South Africa) | 2022 Eva Copper Open-pit project (Australia) | u | |||||||
2018 Moab Khotsong Underground gold (South Africa) | 2016 Mine Waste Solutions Surface retreatment gold (South Africa) | 2025 CSA Underground, high-grade copper (Australia) | ||||||||
16 operations, 3 continents | ||
SA | South Africa | |
PNG | Papua New Guinea | |
AUS | Australia | |
Production | ||
Gold | Copper | |
By-products: silver and uranium | ||
Our strategy: To produce safe, profitable ounces and improve margins through operational excellence and value-accretive acquisitions. | |||||||||||||||
Pillar 1 | Pillar 2 | Pillar 3 | Pillar 4 | ||||||||||||
Responsible stewardship | + | Operational excellence | + | Effective capital allocation | = | Cash certainty | |||||||||
Sustainability is embedded in our strategy – responsible mining today and a copper- enabled low-carbon transition tomorrow. | |||||||||||||||
Shared value: A clear, disciplined strategy to deliver sustainable long-term value through commodity cycles | |||||
Stakeholder | Expectation | Value delivered | |||
Investors and financiers | Returns | Cash flow, dividends and long-term value | |||
Employees, contractors and unions | Safe work | Jobs, growth and wellbeing | |||
Communities, traditional leaders and NGOs | Development | Infrastructure and improved livelihoods | |||
Governments and regulators | Compliance | Taxes and economic contribution | |||
Suppliers | Partnerships | Sustainable value chains and local procurement | |||
Where we’re going FY26 was a defining year in Harmony's evolution towards a diversified gold and copper producer. Gold is the foundation of the company, generating the cash flows that have supported our growth for close to eight decades. Copper is now adding an important new dimension to that foundation, providing greater diversification, increased resilience and exposure to long-term structural demand. | ||||
Up to 2025 | 2026 and 2030 | Beyond 2030 | ||
Our focus was on strengthening portfolio quality through disciplined acquisitions and strategic investment. Today, we are a different company from a decade ago, with a high-quality gold portfolio, a growing copper business and a stronger platform for the future. | Our next phase is execution, delivering and unlocking the value already embedded in our portfolio. Through disciplined capital allocation, operational excellence and the successful delivery of our growth projects, we will convert asset quality into stronger earnings, cash generation and shareholder returns. | We expect a meaningful cash flow inflection as our major growth projects are completed, margins improve, real unit costs decline and free cash flow expands. | ||
5
Our leadership
Board of directors
Directors as at 30 June 2026.
Committees: | Audit and risk | Remuneration | Investment | Social and ethics | Nomination | Technical |
Gender diversity | ||||
5 women (33%) | ||||
10 men (67%) | ||||
Board leadership | Executive directors | Independent non-executive directors | |||||||||||
Dr Patrice Motsepe (64) Non-executive chairman BA, LLB, Doctor of Commerce (Honoris Causa), Doctor of Management and Commerce (Honoris Causa) Appointed 23 September 2003 Member: Nomination | Beyers Nel (49) Chief executive officer BEng Mining Engineering, MBA (cum laude), DPMM, BLDP, CPBPM, Mine Manager’s Certificate of Competency Joined Harmony in 2003 and appointed chief executive officer on 1 January 2025 | Bongani Nqwababa (60) BAcc (hons), FCA, MBA Appointed 18 May 2022 Chairperson: Investment Member: Remuneration; Audit and risk | Zanele Matlala (63) BCom, BCompt (hons), CA(SA) Appointed 17 January 2025 Chairperson: Social and ethics Member: Audit and risk | Martin Prinsloo (57) CA(SA) Appointed 18 May 2022 Chairperson: Audit and risk Member: Technical; Investment | |||||||||
Karabo Nondumo (48) Independent non-executive deputy chairperson BAcc, HDip Accounting, CA(SA) Appointed 3 May 2013 Member: Investment; Nomination; Social and ethics | Boipelo Lekubo (43) Financial director BCom (hons), CA(SA) Joined Harmony in June 2017 and appointed financial director on 3 March 2020 | Given Sibiya (58) BCom, BAcc, CA(SA) Appointed 13 May 2019 Chairperson: Remuneration Member: Social and ethics; Audit and risk | Mametja Moshe (46) BCom, BCom (hons), CA(SA), MBA Appointed 17 January 2025 Member: Audit and risk; Social and ethics | Dr Mavuso Msimang (85) MBA Project Management, BSc Appointed 26 March 2011 Member: Social and ethics; Nomination | |||||||||
Faan Lombard (69) Lead independent non-executive director CA(SA) Appointed 14 August 2025 Chairperson: Nomination Member: Audit and risk | Dr Mashego Mashego (62) Executive director BA Education, BA (hons) Human Resources Management, MPhil, Joint Management Development Programme, Global Executive Development Programme Joined Harmony in 2005 and appointed executive director on 24 February 2010 | Peter Turner (69) NHD Mechanical Engineering, Mine Manager’s Certificates Metalliferous Mines, Mechanical Engineers Certificate Metalliferous Mines, CPIR, MDP, EDP Appointed 19 February 2021 Chairperson: Technical Member: Investment | Vishnu Pillay (69) BSc (hons), MSc Appointed 8 May 2013 Member: Technical; Investment; Nomination; Remuneration | Mangisi Gule (74) BA (hons), PDM Appointed 17 January 2025 Member: Remuneration | |||||||||

Racial diversity | ||||
HDSA | 11 | |||
Other | 4 | |||
Tenure | ||||
8 | 1 – 5 years | |||
2 | 6 – 10 years | |||
5 | 10+ years | |||

Independence | ||
73% Independent non-executives 7% Non-executives 20% Executives | ||
As at 30 June 2026 | ||

6
Executive management
Harmony’s executive management team comprises the chief executive officer, financial director and an executive director (see previous page). Together with six prescribed officers, they serve as the group
executive committee. This committee is supported by four corporate executives, who make up the group chief executive’s office.
There are also regional executive committees for South Africa and Australasia.
Prescribed Officers | Corporate executives | |||||||||||
Floyd Masemula (46) Deputy chief executive officer BEng Mining Engineering, MBA, PGDip Management Practice, MDP, Mine Manager’s Certificate of Competency | Johannes van Heerden (54) Chief development officer BCompt (hons), CA(SA) | Marian van der Walt (53) Chief corporate officer MBA (Oxford) (cum laude), BCom Law, LLB, HDip Tax, NDip Corporate Governance, NDip Insolvency Law, Certificate in Business Leadership and Investor Relations (UK) | Besky Maluleka-Ngunjiri (50) Chief audit executive MBA (cum laude), BCompt (hons), CTA, CIA, CCSA | Dr Hendrik Kotze (61) Executive: Chief technology and information officer PhD XaaS and Systemic Risk, MBA, BCom Commercial Computer Science | ||||||||
Anton Buthelezi (62) Chief people officer NDip Human Resource Management, Btech Labour Relations Management), AdvDip Labour Law, Certificate in Business Leadership | Jaco Boshoff (57) Chief operating officer: Australasia BSc (hons), MSc, MBA, Certification in Business Leadership, PrSciNat | Dr Urishanie Govender (56) Chief sustainability officer PhD Business Leadership, Masters in Business Leadership (cum laude) and Chemistry, PrSciNat | Herman Perry (54) Executive: Chief financial officer BCom (hons), CA(SA) | Shela Mohatla (41) Executive: Group company secretary MBA, FCG (CGISA), BAdmin IR, PGDip Corporate Law, PMD, CertDir® | ||||||||


7
Business model
Harmony's business model is a resilient, evolving system: a gold foundation built on consistent delivery, now enriched by high-grade
copper assets that position the group to capitalise on one of the most compelling structural demand stories in global commodities.
FY26 marks the first financial year in which Harmony's business model spans three continents and two primary commodities.
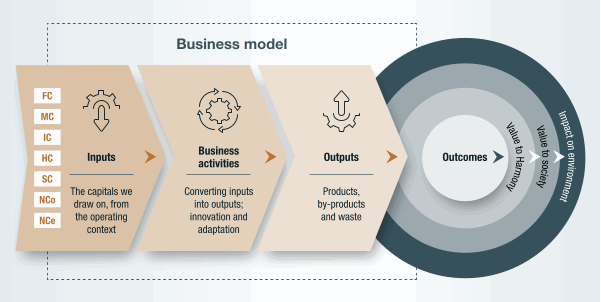
Our business model is the system
through which our business activities
transform the resources and
relationships on which we rely into
products and by-products. These
outputs create, preserve or erode value
for our business and stakeholders over
the short, medium and long term. This
enables us to Mine with purpose as we
execute our strategy, guided by good
governance practices and effective
leadership. We adapt our business
model and strategy to remain
responsive to the external factors that
influence our ability to generate value
over time. These factors include our
operating context, risks and
opportunities, stakeholder relationships
and the broader factors that influence
our ability to generate value over time.
Over the past decade we have adapted
our business model to reduce
concentration risk and improve
resilience through commodity cycles.
This was shaped by Harmony’s
geographic diversification (from a two-
jurisdiction gold producer to a three-
jurisdiction, multi-commodity group)
and the focal shift toward higher-grade,
longer-life assets within a more
diversified and balanced portfolio. Our
systematic hedging programme and
capital allocation framework enable us
to deploy capital where it will best
enhance shareholder value.
Shared resources | ||||||||||
We recognise that some of the resources we use and rely on are shared with the people and natural ecosystems in and around the locations in which we operate. Our orebodies are located across eight local municipalities in the Free State, North West and Gauteng provinces of South Africa, the Morobe Province in Papua New Guinea and Queensland and New South Wales in Australia. | Within these communities, we rely on and share water from the same catchment areas, electricity from the same power grids and transport systems such as roads and railways. These shared resources are also used by our workforce and their dependants who live in our host and labour-sending communities. The land and tailings facilities we manage will remain with those communities long after our mining rights have expired. | We therefore do not own or control the social, relationship and broader environmental resources on which we depend and continued access to these shared resources depends on the relationships we maintain with the stakeholders impacted by our activities, positively or negatively. | ||||||||
8
Inputs | Our six capitals are not independent inputs. Each is used to sustain or grow the others, and a constraint in one cascades through the value creation process. We actively manage these interdependencies, tracking how changes in availability, quality and affordability affect our resilience over the short, medium and long term. | How we define natural capital We define natural capital as the mineral deposits, water, land and energy resources our operations use. The orebody (Mineral Resource) is finite and non-renewable. Extracting it produces our gold, copper, silver and uranium, creating value across the other capitals. Individual orebodies will always decline because we do not replace what we mine. Reserves added through exploration and acquisition are a portfolio-level replacement, not a restoration of what has been depleted. The environment (water, land, air, biodiversity and climate) is a largely renewable and manageable set of natural systems around our operations. Value is created, preserved or eroded through the quality of our stewardship: rehabilitation, tailings retreatment and the circular economy, water recycling, renewable energy and biodiversity protection. | |||||||
Financial capital | Manufactured capital | Intellectual capital | Human capital | Social capital | Natural capital (orebody) | Natural capital (environment) | ||
Resources and relationships we use and impact | ||||||||
•Three funding sources: internally generated cash flows (primary), equity and debt capital and debt facilities •CSA bridge facility sized for short- term repayment, preserving capacity for our major projects. | •Diversified asset base across three jurisdictions: •nine South African underground gold mines •South African surface retreatment and open-pit operations •Hidden Valley open-pit in Papua New Guinea •the CSA mine in New South Wales, Australia, and •Eva Copper Project in Queensland, Australia, a greenfield asset under active construction •Solar PV plants include Sungazer 1 (30MW at the Tshepong operations) and Sungazer 2 (100MW at Moab Khotsong, under construction), with the latter representing one of Africa's largest solar projects in the mining industry. | •Mining rights across all operations •Deep-level, hard-rock mining expertise: geotechnical, ground support and extreme-depth mechanisation •IT and business optimisation systems: the shaft call factor (SCF) programme, TMM and collision prevention systems •Operating know-how: integrating and optimising acquired underground mines, and a growing geological understanding of CSA from our 24-month drilling programme •Proprietary frameworks: Thibakotsi (culture and safety ownership), decarbonisation, rehabilitation, water, governance and stakeholder engagement •An employee value proposition for critical skills, backed by a five-year South African wage agreement for cost and industrial relations stability •Capital management: capital allocation, systematic hedging and dividend policy. | •A workforce of over 50 000 employees and contractors •86% of South African employees come from host communities, Papua New Guinea nationals make up over 87%of the permanent workforce there, and CSA’s workforce is drawn from the Cobar region. | •Decades-deep community relationships: Harmony is the dominant employer in several South African towns and the primary formal employer in the Hidden Valley region, while CSA has a 150-year operating history in Cobar •Established regulatory relationships across three jurisdictions and multiple government tiers, built through consistent, transparent engagement •B-BBEE compliance in South Africa, a structural prerequisite for mining licences and community acceptance •Local and regional supply chains that reduce cost, create community value and reinforce our social licence •Long-standing capital provider relationships across equity, bonds and banks. | •A globally significant gold Mineral Resource and Reserve base plus a CSA copper resource of 1.1Mt at 4.61% Cu •The world's largest tailings retreatment operation (MWS) transforms historical environmental liabilities into productive output – a unique circular economy position. | •Land, water and air access rights across all jurisdictions. The regulatory relationships governing these are as important as physical availability •Access to water resources and infrastructure across all jurisdictions, with water availability, quality and regulatory access increasingly influencing operational resilience •Water recycling systems, treatment facilities and storage infrastructure that support mining, processing and tailings operations •CSA's high-grade mineralogy requires lower energy and reagent inputs per tonne of copper produced relative to most comparable operations •Growing renewable energy infrastructure (Sungazer 1 and Sungazer 2) that progressively reduces grid electricity dependence. | ||
Interdependencies and resource constraints | ||||||||
•Financial capital funds every other capital. Our dual JSE/NYSE listing and investment-grade creditworthiness underpin access to growth funding •Eva Copper, the CSA acquisition, the South African extensions and the renewables build-out are running simultaneously, constraining near- term free cash flow in exchange for a higher-quality and more diversified portfolio in the long term •We remain exposed to factors outside our control: the gold and copper price, inflation, electricity tariffs and access to capital markets. | •Beyond growth capital, we invest continuously to maintain and modernise operations so they run safely •Deep-level South African assets require permanent sustaining capital. •Moab Khotsong enters a planned multi-year lower-production phase while the orebody life and quality are extended •CSA and Eva Copper are shifting the asset mix towards copper and tier- one jurisdiction assets. | •Intellectual capital is deployed across every other capital, including our capital allocation framework, which weighs each investment across the group’s asset portfolio by grade, risk and expected return •CSA requires new geological and regulatory knowledge, and embedding Harmony’s safety culture there is a multi- year process •Culture transformation towards zero harm takes time and draws on human, financial, manufactured and social and relationship capital •Securing mining rights and leases is increasingly complex in a shifting political, social and environmental landscape •Simultaneous transformational programmes place material demands on finite senior management capacity. | •Safety, health and wellbeing require sustained social and financial investment. Culture transformation responds directly to the risk of injury or loss of life in deep-level hard-rock mining •Diversifying our workforce remains an ongoing priority, with women still underrepresented in certain roles and levels despite continued progress in improving workforce diversity •Skilled deep-level mining professionals are scarce industry- wide, intensifying competition for talent. | •Trust and credibility in the diverse regions where we operate sustain our social licence. Operational incidents or perceived failures of accountability could erode it •Our reputation as a responsible miner depends on how we manage the resources we share, requiring financial, intellectual and human capital investment •Managing distinct legal, cultural and regulatory relationships across three jurisdictions adds structural complexity to every decision. | •Limited life-of-mines and depleting Ore Reserves could constrain long- term value creation. Continuous exploration and resource conversion are permanent, non-negotiable requirements. | •Protecting the natural resources we rely on depends on financial and manufactured capital and affects our human and social and relationship capital •Mining is energy intensive, and our emissions largely reflect the carbon intensity of the electricity we use. Shifting to renewable energy is therefore central to our net-zero 2045 ambition, which will require sustained investment over decades •Water is increasingly constrained in the semi-arid Cobar Basin and in South Africa. Our water use licences and recycling infrastructure are strategic assets •Mine closure and rehabilitation obligations across all jurisdictions are a long-term natural capital liability requiring continuous provisioning. | ||
9
Business activities | Our business activities are guided by our four strategic pillars, enabling informed decision-making to improve and sustain our business model over time. | Every strategic decision in FY26, including the acquisition of MAC Copper, Eva Copper construction, the South African mine-life extensions, the enhanced dividend policy and the modifications to the renewable energy programme, was aimed at strengthening one or more elements of the business model. | |||||||
We use our inputs to conduct: | ||||||||||||
Exploration and resource development | è | Development and capital projects | è | Underground and open-pit mining | è | Processing and tailings retreatment | è | Sales and logistics | è | Responsible stewardship | ||
How we organise our business activities is itself a source of value. Rather than managing our assets as a single pool, we group them into distinct portfolios. Each asset portfolio plays a distinct role in delivering our business activities, contributing to Harmony’s evolution from a gold producer to a diversified gold and copper company. | |||||||||||||||||
Gold foundation: underground high-reserve grade | Gold foundation: underground lower- reserve grade | Gold foundation: surface and retreatment | Strategic copper | Gold and copper growth | |||||||||||||
Outputs | Our business activities produce the following key outputs: | |||||
Primary products | By-products | Waste and emissions | ||||||||||||||||||||||
Gold | Copper | Silver | Uranium | Tailings | Hazardous waste to landfill | GHG emissions | ||||||||||||||||||
FY26 actual | FY26 actual | FY26 actual | FY26 actual | FY26 actual | FY26 actual | FY26 actual | ||||||||||||||||||
1.43Moz | 18 207t (eight months) | 2.27Moz | 419.54klb | Tailings generated through mining and processing are managed through approved storage facilities and operational controls. Harmony also reprocesses historical tailings, converting legacy waste into productive output and reducing environmental liabilities. | Hazardous waste sent to landfill increased to 805t in FY26 (FY25: 558t), but remains significantly lower than the 1 261t recorded in FY24. Harmony continues to apply the waste hierarchy, prioritising waste reduction, reuse, recycling and resource recovery before disposal. | Total scope 1 and 2 emissions, excluding biogenic emissions from land clearing, increased to 4.82MtCO₂e due to higher activity, increased electricity and diesel consumption, a higher Eskom grid emission factor, and the inclusion of Australian operations. | ||||||||||||||||||
FY25 (comparative) | FY25 (comparative) | FY25 (comparative) | FY25 (comparative) | |||||||||||||||||||||
1.48Moz | N/A | 3.14Moz | 488.05klb | |||||||||||||||||||||
FY27 full-year guidance | FY27 full-year guidance | Silver and uranium by-product revenue provide additional margin support through operating cost offsets | ||||||||||||||||||||||
1.3 – 1.4Moz | 28 000 – 30 000t | |||||||||||||||||||||||
10
Outcomes | Our four strategic pillars translate our purpose into outcomes across the six capitals. We report on our performance so that stakeholders can make an informed assessment of how Harmony creates, preserves and erodes value within its economic, social and environmental context over the short, medium and long term. We are deliberately maximising the value returned to all capitals for each ounce we mine. | The analysis below is supported by detailed information in the Delivering our strategy section. | |||||||
▲ Value created — net increase in a capital over time | ¢ Value preserved — maintained a capital over time | ▼ Value eroded — net decrease in a capital over time |
Net outcome | Value created | Value preserved | Value eroded | |||
Financial capital | ▲ Value created: Record free cash flow, earnings and dividends achieved with copper growth funded through a bridge loan, outweighing acquisition and financing costs while preserving balance sheet strength. | •Revenue increased by 34.3% to R99.2 billion (US$5.9 billion) •Copper added as a new revenue stream •Record adjusted free cash flow of R17.1 billion (US$1.0 billion), up 53.9% •Record full-year dividend of R8.2 billion (US$503 million) (1 280 SA cents per share) declared under the enhanced dividend policy. | •All major capital commitments funded from existing cash, internally generated cash flows and debt facilities •Net debt to EBITDA was 0.02x after the R17.5 billion (US$1.0 billion) MAC Copper acquisition, with year-end liquidity of R17.1 billion •Debt facilities refinanced and expanded, introducing A$ funding aligned to the Australasia growth. | •All-in sustaining costs increased 13.2% to R1 191 698/ kg (US$2 195/oz) on a lower production base and sustained inflationary pressure •Realised gold hedge losses of R9.6 billion (US$571 million) on the settlement of legacy positions in a higher spot price environment •The all-cash MAC Copper acquisition, alongside capital investments, moved the group from net cash of R11.1 billion to modest debt of R852 million. | ||
Manufactured capital | ▲ Value created: We expanded our portfolio investment while modernising and diversifying our asset base faster than existing infrastructure depreciated. | •The CSA acquisition established Harmony as an Australian copper producer •Eva Copper Project (R4.6 billion) moved into construction phase with plant construction ramping up (secured major amendment to environment permit) •Sungazer 2, a 100MW solar plant at Moab Khotsong, is progressing through construction and commissioning activities •Kareerand TSF extension complete, extending Mine Waste Solutions’ life of mine to 13 years. | •CSA shaft steelwork replacement completed and ventilation project remains on track, improving long- term infrastructure reliability •Ageing deep-level South African infrastructure continues to require sustaining capital (R8.3 billion) •Mponeng Extension Project on schedule and Moab Khotsong Zaaiplaats Extension Project advancing, sustaining the production profile of our South African high-grade portfolio as existing mining areas deplete •Tshepong North life of mine extended from six to 15 years (project approved in FY27). | •Moab Khotsong enters a planned multi-year lower- production phase (gold gap) •CSA revenue was affected by a planned one-month shaft steelwork stoppage. | ||
Intellectual capital | ¢ Value preserved: Our core operating disciplines were maintained while extending our know-how to our copper footprint. | •Deep underground mining capabilities applied systematically to CSA and meaningful cost efficiencies at CSA since acquisition, achieving a 77% reduction in corporate and services costs on an A$/lb basis. •Wire the Mine project achieved the first underground video call from 3 700m at Mponeng, marking a significant step towards fully connected, digitally enabled mining •Embedded sustainability framework, enhancing strategic thinking, inclusive of climate resilience and community partnerships. | •All mining rights and leases retained across the three jurisdictions •MSCI ESG rating upgraded to “A”, a ninth consecutive year in the FTSE4Good Index Series and a CDP water score of “A-” •Adapted Eva Copper construction activities following the discovery of a protected species •Cybersecurity maturity advanced from preventative controls towards a zero trust model, with monitoring and threat detection extended into operational technology environments. | |||
Human capital | ▼ Value eroded: Zero harm is our overriding human capital goal. Any loss of life is an erosion of value, which we continue to deliberately address through our extensive safety risk management and culture transformation programmes. | •Inclusive of CSA, workforce increased 7% to more than 50 000 employees and contractors •Lowest recorded group LTIFR of 5.05 (FY25: 5.39), with six of nine underground mines exceeding one million loss-of-life-free shifts •37 000 employees and contractors completed safety training and 23 million critical controls were monitored across operations •Group tuberculosis incidence more than halved since FY23 to 287 per 100 000, supported by community outreach reaching 4 756 people. | •The five-year South African wage agreement, covering 94% of employees, entered its third year with no strikes or labour-related stoppages •Zero loss of life recorded at the Papua New Guinea and Australian operations and post year-end, Kusasalethu achieved a safety milestone of three million loss-of-life- free shifts •In South Africa, Thibakotsi implementation reached 84%, while the Building Blue culture programme was launched across Australasia. | •The tragic loss of six colleagues (FY25: 11) represents an irreversible erosion of value that no other outcome offsets •Despite improvements in our LTIFR measure, lost-time injuries erode value •Occupational health exposures remain an area of focus: 98 (FY25: 102) early noise-induced hearing loss cases identified and 73% (FY25: 78%) of silica readings met the 0.03mg/m³ milestone (our target is 95%). | ||
11
Net outcome | Value created | Value preserved | Value eroded | |||
Social capital | ¢ Value preserved: We have upheld stakeholder trust and our reputation as a responsible miner. We deliver shareholder returns, invest in our workforce, maintain regulatory confidence, create local economic participation and honour our community-based commitments. | •R10.9 billion (US$929 million) paid in taxes and royalties to host governments and a record R8.2 billion returned to shareholders •R190 million (US$11.2 million) invested in community development across the three jurisdictions, including R54 million (US$3.2 million) against fourth-generation SLP commitments •Eva Copper generated tangible regional economic value, with local businesses securing 28% of project expenditure against a 20% target, while R237 million (A$20.7 million) in Queensland Government funding was received to support the project's development •Hidden Valley’s greenhire programme employed and trained 127 people, taking participation to 656 since inception; over 40% of employees come from local communities. | •Stakeholder relationships were maintained across South Africa, Papua New Guinea and Australia, with concerns, complaints and grievances received declining from 120 to 79 •Constructive union, landowner and community partnerships maintained, including the negotiation and approval of a new community development agreement at Hidden Valley •Our response to a protected species find at Eva Copper, including regulatory engagement and adapting project activities, demonstrated our approach to responsible environmental management. | •Legacy socio-economic challenges – unemployment, inequality and organised illegal mining – continue to pressure relationships in host regions •Third-generation SLP backlog projects remained outstanding, delayed by agreement timelines community protest action and contractor performance. | ||
Natural capital (orebody) | ▼ Value eroded: We erode natural resources through our core business activities. We maximise the value transformed out of each unit mined (value over volume) and, at portfolio level, replace and upgrade the reserve base through exploration and diversification. | •Not applicable. An orebody is a finite, natural endowment we can only responsibly draw down from. | •Portfolio-level replacement rather than preservation: gold Mineral Reserves rose 1.7% to 27.4Moz •Copper Mineral Resources increased 18.5% to 7.4Mt and Reserves rose 70.7% to 4.0Mt, driven by Eva Copper and CSA •CSA drilling confirmed orebody extension potential, while the approved extension of Hidden Valley to 2030 supports longer-term production. •Through our surface retreatment operations, we continue to convert historic tailings into production, unlocking value without new extraction. | •Production of 44 464kg (1.43Moz) of gold and 18 207 tonnes (40.1Mlb) of copper permanently removed from our orebodies •Gold Mineral Resources were 106.8Moz down 1.8%, including 2.1Moz depleted through mining during the year •Continuous exploration and reserve conversion remain a permanent, non-negotiable cost because the business model irreversibly consumes ore reserves. | ||
Natural capital (environment) | ▼ Value eroded: Mining activities impact land, biodiversity and natural systems. We seek to avoid and minimise these impacts, progressively rehabilitate disturbed areas and manage unavoidable impacts responsibly. We are also working to reduce the emissions associated with our operations. | •Sungazer 1 (30MW) is operational and Sungazer 2 (100MW) is nearing commissioning, progressing our ambition for approximately 800MW of renewable energy capacity •Phytoremediation woodland at Kareerand completed on 60 hectares, with a further 18 500 trees established across Free State tailings facilities •The 10Ml/day TauTona reverse osmosis plant was commissioned, treating fissure water for reuse and reducing reliance on external potable supply. | •78.0% of water recycled, preserving our natural resources •Harmony managed 87 existing tailings storage facilities – South African facilities are managed with reference to SANS 10286, Australasia facilities follow ANCOLD guidance and Hidden Valley adopts layered assurance elements of GISTM •Zero environmental fines or directives recorded in FY26. | •Greenhouse gas emissions remain a consequence of energy-intensive mining •Energy use and emissions rose, reflecting higher electricity consumption and Eskom’s grid emission factor in South Africa, as well as the addition of CSA mine and Eva Copper to the group energy and emissions inventory. We are reviewing our SBTi- approved targets to reflect our revised portfolio and emissions profile •Land disturbed by mining activities increased with CSA and Eva Copper, and closure and rehabilitation obligations remain a long-term natural capital liability. | ||
▲ Value created — net increase in a capital over time | ¢ Value preserved — maintained a capital over time | ▼ Value eroded — net decrease in a capital over time |
Harmony enters FY27 with a robust balance sheet and a high-margin gold portfolio that remains the cash-generative foundation of the business. A growing copper platform provides diversification and a pathway towards approximately 100 000 tonnes of annual copper production over the next three to five years, demonstrating how the business model supports disciplined delivery, portfolio progression and enduring value. | ||||
12
Operating context
Harmony's ability to create and preserve value is influenced by
external factors that shape the markets, jurisdictions and the
communities in which we operate. These factors inform our
strategic priorities, capital allocation decisions, operational
plans, principal risks and growth opportunities.
Overview
During FY26, the operating environment was characterised by strong gold and copper prices,
growing demand for copper, geopolitical uncertainty, evolving regulatory and sustainability
expectations, increasing cybersecurity threats, energy and water security challenges, and rising
stakeholder expectations. While these factors create uncertainty, they also present opportunities to
strengthen resilience, enhance portfolio quality and support long-term value creation.
Harmony assesses these developments through its four strategic pillars and its risk appetite and
tolerance framework. This approach guides decision-making by balancing responsible
stewardship, operational excellence, cash certainty and effective capital allocation with sustainable
growth and shareholder returns.
External drivers shaping Harmony’s value creation
1 | |||||
Economic and market conditions | Commodity prices and cycles, inflation, exchange rates and capital market conditions | ||||
2 | |||||
Political, regulatory and governance environment | Geopolitical tension, country policies, permitting, legislation and disclosure expectations | ||||
3 | |||||
Social and stakeholder environment | Communities, labour, safety expectations, social licence, illegal mining and security | ||||
4 | |||||
Natural environment and resource security | Climate change, energy, water, biodiversity and infrastructure resilience | ||||
5 | |||||
Technology, cybersecurity and innovation | Digitalisation, automation, AI, cyber threats and operational technology exposure | ||||
6 | |||||
Labour, skills and competitive dynamics | Competition for talent, specialist skills, capital, high-quality copper exposure and critical inputs | ||||
13
Economic and market conditions
The gold price environment remained supportive throughout FY26, strengthening earnings, free
cash flow and capital allocation flexibility. At the same time, long-term electrification, energy
transition and infrastructure development trends continued to support demand for copper and
other critical minerals. This environment reinforces Harmony's strategy of building a diversified gold
and copper portfolio. The integration of CSA mine and continued advancement of Eva Copper
expand the group's exposure to copper whilst enhancing earnings diversification, growth
optionality and portfolio resilience.
While elevated commodity prices supported financial performance, inflationary pressures, foreign
exchange volatility, labour costs, fuel markets and project-related input costs continued to influence
margins and project economics. The group's focus on disciplined capital allocation, conservative
planning assumptions and portfolio quality remains essential to maintaining resilience across
commodity cycles.
SA | South Africa | ||
Elevated gold prices support cash generation, although margins remain sensitive to electricity, labour, consumables and sustaining capital costs. Mature orebodies and reserve replacement remain structural industry challenges. | |||
PNG | Papua New Guinea | ||
Performance is influenced by commodity prices, power costs, logistics, foreign exchange availability and project development opportunities, including Wafi-Golpu. | |||
AUS | Australia | ||
CSA mine strengthens copper exposure and geographic diversification, while the Eva Copper Project provides a significant long-term growth opportunity. | |||
Harmony’s response
Maintain conservative planning assumptions, a structured hedging programme, disciplined capital
allocation, portfolio diversification and reserve replacement focus.
Political, regulatory and governance environment
The geopolitical environment remained volatile during FY26, influencing supply chains, logistics
costs, energy markets and capital flows. At the same time, geopolitical uncertainty continued to
reinforce gold's role as a safe-haven asset and strengthen the strategic importance of copper in
support of the global energy transition.
Mining companies also face increasing regulatory scrutiny, evolving sustainability disclosure
expectations and changing policy frameworks across jurisdictions. Harmony's diversified asset
base provides resilience, while ongoing engagement with governments, regulators, industry
associations and stakeholders supports regulatory compliance, investment certainty and
responsible growth.
SA | South Africa | ||
Regulatory reform, infrastructure constraints and illegal mining continue to influence the operating environment. | |||
PNG | Papua New Guinea | ||
Mining law reforms, permitting requirements, foreign exchange constraints and stakeholder engagement remain important considerations. | |||
AUS | Australia | ||
A stable mining jurisdiction, although environmental, permitting and climate- related expectations continue to evolve. | |||
Harmony’s response
Maintain active government engagement, industry participation, regulatory monitoring, legal
oversight, compliance discipline and staged project governance.
Social and stakeholder environment
Maintaining trust with employees, communities, governments, investors and organised labour is
fundamental to Harmony's long-term success and social licence to operate. Across all
jurisdictions, expectations continue to rise regarding safety performance, environmental
stewardship, local economic participation, community development and transparent stakeholder
engagement.
Safety remains Harmony's foremost responsibility and a foundational requirement for sustainable
value creation. Strong stakeholder relationships support operational stability, project development,
workforce engagement and long-term growth opportunities. Conversely, community
dissatisfaction, labour instability, criminal activity or declining stakeholder trust have the potential to
affect operational continuity and project execution.
SA | South Africa | ||
Community expectations, labour dynamics and illegal mining remain key external factors. | |||
PNG | Papua New Guinea | ||
Community relationships, benefit-sharing arrangements and local participation are central to future growth opportunities. | |||
AUS | Australia | ||
Workforce availability, cultural heritage expectations and contractor management remain key focus areas. | |||
Harmony’s response
Strengthen safety leadership, community engagement, labour stability, security capability,
contractor oversight and social performance discipline.
14
Natural environment and resource security
Reliable access to energy, water and other natural resources remains essential to operational
continuity, cost competitiveness and long-term sustainability. Climate change, infrastructure
resilience, biodiversity considerations and evolving environmental expectations continue to
influence operating conditions across all jurisdictions.
SA | South Africa | ||
Energy security, water availability, severe weather and ageing public infrastructure remain important considerations. | |||
PNG | Papua New Guinea | ||
Rainfall intensity, terrain, power reliability and environmental management requirements shape operating conditions. | |||
AUS | Australia | ||
Water availability, climate resilience and infrastructure reliability remain important to ongoing operations and project development. | |||
Harmony’s response
Harmony's response includes investment in renewable energy, water stewardship, climate
resilience, environmental management and infrastructure reliability. These initiatives are intended
not only to mitigate risk, but also to improve operational resilience, reduce long-term cost
exposure and strengthen stakeholder confidence.
Technology, cybersecurity and innovation
Technology continues to create opportunities to improve safety, productivity, asset reliability,
operational planning and project execution. Digitalisation, automation, advanced analytics and
emerging artificial intelligence applications have the potential to enhance operational performance
and decision-making across the group.
At the same time, the increasing integration of digital technologies and operational systems
heightens cybersecurity risks. Cybersecurity therefore remains a key strategic focus, with Harmony
continuing to strengthen cyber resilience, operational technology protection, vendor assurance
and technology governance.
Harmony’s response
Increase cyber resilience, governance oversight, operational technology protection, vendor
assurance, maintenance discipline and targeted technology adoption.
Labour, skills and competitive dynamics
Competition for skilled employees, project capability, contractor capacity and investment capital
remains an important feature of the mining industry. Success increasingly depends on operational
excellence, portfolio quality, disciplined execution and the ability to attract and retain critical
technical, engineering, project and digital skills.
Harmony's growing copper exposure established South African gold platform and disciplined
growth strategy position the group competitively. Continued investment in leadership
development, succession planning, employee value propositions and organisational capability
remains essential to supporting future growth and operational performance.
Harmony’s response
Strengthen employee value proposition, succession, capability building, project governance,
contractor management and portfolio quality discipline.
Strategic implications
The external environment continues to create both risks and opportunities for Harmony. Strong
commodity fundamentals, growing copper demand, technological innovation and portfolio
diversification opportunities support long-term growth. At the same time, geopolitical uncertainty,
regulatory change, resource security, climate-related impacts and cybersecurity threats require
ongoing management focus.
Through its diversified portfolio, disciplined capital allocation framework, strong balance sheet and
integrated approach to risk management, Harmony seeks to strengthen resilience, capture
emerging opportunities and create sustainable value for shareholders and stakeholders over the
short, medium and long term. The table below links each external driver to our strategic response,
the value outcome we seek and the strategic risks we manage.
External environment category | Linked strategic risk themes | |||||
Economic and market conditions | •Commodity price and foreign exchange volatility •Replacing the depleting ore reserve base •Not achieving operational plans at critical operations. | |||||
Political, regulatory and governance context | •Political tensions – geopolitical and local •Supply chain disruption •Regulatory and policy uncertainty •Project execution and funding ability. | |||||
Social and stakeholder environment | •Safety and health •Trackless mobile machinery •Water security – infrastructure, management and licensing •Illegal mining and security. | |||||
Natural environment and resource security | •Impact of climate change •Water security – infrastructure, management and licensing •Security of electricity and energy supply •Replacing the depleting ore reserve base. | |||||
Technology, cybersecurity and innovation | •Cybersecurity and digital resilience •Trackless mobile machinery. | |||||
Labour, skills and competitive dynamics | •Retaining key skills and experience •Project execution and funding ability •Not achieving operational plans at critical operations. | |||||
15
Risk and opportunity management
Managing risk to create sustainable value: Harmony's approach to risk and opportunity management supports the delivery of our
strategy, the protection of our people and assets, and the creation of sustainable long-term value for shareholders and other
stakeholders. Risk management is embedded in strategic planning, capital allocation, operational execution and project development,
enabling informed decision-making in a dynamic operating environment.
The board oversees the group's strategic risks and
opportunities, ensuring that key matters are considered in
strategic decisions and that the company operates within its
approved risk appetite. Supported by the audit and risk
committee, technical committee and executive management,
the board continuously monitors factors that could influence
Harmony's ability to achieve its strategic objectives, deliver
operational performance and maintain financial resilience.
Harmony's enterprise risk management framework aligns with
ISO 31000 and the principles of the King Report. The
framework supports a consistent and integrated approach to
identifying, assessing, managing and monitoring risks and
opportunities across the group's operations, projects and
growth initiatives.
While risk management seeks to reduce potential adverse
impacts, it also enables Harmony to identify opportunities to
improve operational performance, strengthen resilience,
optimise capital allocation and enhance both long-term
competitiveness and shareholder value. This is particularly
relevant as Harmony advances its copper strategy,
progresses major growth projects and continues investing in
operational excellence and renewable energy initiatives.
Our strategic risks and opportunities
The board reviews Harmony's strategic risks and
opportunities throughout the year as part of its oversight of
performance, capital allocation, sustainability and growth.
These represent the most significant factors that could affect
the group's ability to create sustainable value over the medium
and long term.
The risk environment continues to evolve in response to
changing operating conditions, regulatory developments,
technological disruption, climate-related challenges and
geopolitical uncertainty. During FY26, particular focus was
placed on safety and health performance, operational delivery,
energy security, water stewardship, cybersecurity, project
execution and the successful development of Harmony's
growth pipeline.
Harmony's strategic risks are interconnected and are
managed through integrated governance, disciplined
operational execution and targeted mitigation strategies. Risk
management is integrated with Harmony's four strategic
pillars, responsible stewardship, operational excellence,
effective capital allocation and cash certainty. Effective
management of these risks supports operational continuity,
financial performance, strategic flexibility and long-term
resilience.
Equally, many of these risks create opportunities. The
continued advancement of our Eva Copper Project, the
contribution from CSA, renewable energy investments,
reserve replacement initiatives and ongoing operational
improvements position Harmony to enhance portfolio quality,
diversify earnings and strengthen returns through commodity
cycles.
Governance and oversight
The board retains ultimate accountability for risk governance.
Through the audit and risk committee and technical
committee, the board oversees Harmony's risk profile, risk
appetite, emerging risks and the effectiveness of risk
management processes.
Executive management is responsible for implementing the
risk management framework, embedding risk-based decision-
making and ensuring that key risks and opportunities are
actively managed. Accountability for specific risks rests with
designated risk owners across the business, supported by
specialist functions including risk, compliance, sustainability,
technology, finance and internal audit.
Harmony applies a combined assurance model to provide
confidence over the effectiveness of risk management and
internal controls. Internal audit, risk management, compliance
and management assurance activities provide coordinated
oversight of strategic risks and support the board's
assessment of organisational resilience and control
effectiveness.
Risk prioritisation
Harmony applies an integrated approach to risk assessment
and identification of key matters. Strategic risks are identified
through structured assessments across the group and are
considered in the context of both their potential impact on
enterprise value and their broader impacts on people,
communities and the environment.
Strategic risks, reflecting those matters considered most likely
to influence the group's long-term sustainability,
competitiveness, operational performance and value creation,
are reviewed regularly by management, executive committees
and the board to ensure that emerging developments,
changes in exposure and management effectiveness are
appropriately reflected.
Risk appetite and tolerance framework
Harmony's risk appetite and tolerance framework (RATF)
guides how the board and management evaluate risk when
pursuing Harmony’s strategic objectives. The framework
recognises that creating sustainable shareholder value
requires taking considered risk while maintaining appropriate
safeguards around the areas most critical to long-term
success.
The RATF provides a structured basis for decision-making
across strategy, operations, capital allocation and project
development. It enables the board to distinguish between risks
that are acceptable in pursuit of growth and value creation and
those that require mitigation, transfer or avoidance. The
framework supports disciplined capital deployment, operational
resilience and long-term sustainability while remaining aligned
with Harmony's strategic priorities.
Harmony maintains zero tolerance for the loss of life and a low
tolerance for risks that could result in significant environmental
harm, significant regulatory breaches or impairment of its
licence to operate. The group is prepared to accept measured
levels of risk in support of exploration, project development,
acquisitions and other initiatives that enhance the quality and
sustainability of the portfolio and are expected to generate
attractive long-term returns.
The framework is anchored by four strategic pillars, each
supported by a board-approved risk statement that informs
decision-making throughout the business: responsible
stewardship, operational excellence, cash certainty and
effective capital allocation. Together, these principles ensure
that risk management supports strategy execution and value
creation rather than functioning solely as a governance
process.
16
Key matters affecting our business and strategy
Harmony operates in a complex and evolving business environment. The matters described in this section reflect key factors that influence our strategy, financial position and performance, operations and
prospects. These matters inform our strategic priorities, risk management and allocation of resources and should be considered together with the principal risks and opportunities facing the group.
The matters described below provide context for understanding how developments in Harmony's operating environment influence our strategy, risk management, capital allocation and operational priorities.
Key matters affecting our business and strategy
The matters below represent key factors that affect, or could affect, Harmony's business, strategy, operations, financial performance and prospects. They are interconnected and are considered as part of
Harmony's strategy, enterprise risk management, capital allocation and operational planning processes. The order in which the matters are presented does not indicate their relative importance, likelihood or
potential magnitude.
Key matters | Key matters (continued) | ||
Safety | Energy and electricity management | ||
Commodity price and exchange rate fluctuations | Management of illegal mining and unauthorised access | ||
Geopolitical and economic volatility | Retaining key skills and skills development | ||
Depleting ore reserves | Capital allocation | ||
Execution of multiple, significant projects | Governance excellence | ||
Water management | Social licence to operate | ||
Operational excellence and resilience | Sound labour relations | ||
TSF and waste management | Regulatory, legislative and policy uncertainty | ||
Critical infrastructure vulnerability | Post-closure sustainability | ||
Health | Innovation, technology and digitalisation | ||
Supply chain management | Sustainable communities | ||
Climate change and energy | Biodiversity, land use and environmental degradation | ||
Cybersecurity |
17
Detailed analysis
The table below shows why each matter affects value creation, which capitals are affected, linked strategic risks and opportunities, relevant time horizons and where further detail can be found on how we
manage each matter.
Time horizon key: | ST | short term (up to 12 months) | MT | medium term (more than one year up to four years) | LT | long term (more than four years) |
Key matter | Why it matters to Harmony | Related strategic risks and opportunities | Time horizon | ||||||||
Safety | Deep-level underground mining is inherently hazardous, with daily exposure to seismic events, fall- of-ground, equipment incidents and occupational health hazards. Loss of life and serious injury inflict irreversible harm on employees, families and communities and can trigger operational stoppages, regulatory scrutiny, legal liability and consequences for our licence to operate. | •Safety and health •Not achieving operational plans at critical operations. | ST MT LT | ||||||||
Commodity price and exchange rate fluctuations | Movements in gold and copper prices, together with rand, PGK and A$ volatility, directly affect revenue realisation, cost structures and the viability of marginal ounces, with knock-on effects on cash generation, margins and funding capacity. | •Commodity price and foreign exchange volatility •Political tensions – geopolitical and local. | ST MT LT | ||||||||
Geopolitical and economic volatility | Operating across three jurisdictions exposes Harmony to distinct political and macro-economic risk profiles. Trade disputes, regulatory uncertainty, sovereign credit dynamics and heightened geopolitical tensions affect the cost of capital, input costs, supply chain reliability, investor confidence and the commercial viability of projects. | •Political tensions – geopolitical and local •Commodity price and foreign exchange volatility •Supply chain disruption •Regulatory and policy uncertainty. | ST MT LT | ||||||||
Depleting ore reserves | Continuous replacement of Mineral Reserves is fundamental to Harmony’s business model. Failure to replenish reserves shortens life of mine, constrains future production volumes and threatens long-term sustainability, investor confidence and Harmony’s economic contribution to host communities. | •Replacing the depleting ore reserve base •Project execution and funding ability. | MT LT | ||||||||
Execution of multiple, significant projects | Delays or cost overruns on Harmony’s major projects impair the expected returns and production build-up from the growth pipeline, delay value delivery to shareholders and erode investor confidence in management’s ability to execute strategy at scale. | •Project execution and funding ability •Retaining key skills and experience •Trackless mobile machinery. | MT LT | ||||||||
Water management | Water is a critical input for mining and processing. Scarcity, regulatory restrictions or licence non- compliance can constrain production, and poor management can lead to environmental and community impacts that undermine Harmony's licence to operate. | •Water security – infrastructure, management and licensing. | MT LT | ||||||||
18
Key matter | Effect on value creation | Strategic risks and opportunities | Time horizon | ||||||||
Operational excellence and resilience | Operational underperformance impairs revenue, cost efficiency, asset utilisation and continuity. Failures in safety, infrastructure or planning can also trigger environmental incidents, injuries and disruptions to community relations, with consequences that extend beyond the initial event. | •Not achieving operational plans at critical operations •Security of electricity and energy supply •Illegal mining and security •Supply chain disruption •Water security – infrastructure, management and licensing •Replacing the depleting ore reserve base. | ST MT LT | ||||||||
TSF and waste management | Tailings storage facility failure poses severe risks to human life, the environment and Harmony’s financial position through liability, remediation costs and potential licence withdrawal. Safe design, monitoring and management of TSFs are non-negotiable operational and regulatory requirements. | •Impact of climate change •Regulatory and policy uncertainty •Water security – infrastructure, management and licensing. | ST MT LT | ||||||||
Critical infrastructure vulnerability | Deteriorating public and private infrastructure (for example, unreliable potable water in South Africa, ageing electricity infrastructure and poor road conditions, such as at the Kumalu River crossing in Papua New Guinea) imposes additional self-provisioning costs, disrupts operational continuity and raises community expectations for Harmony to fill infrastructure delivery gaps. | •Water security – infrastructure, management and licensing •Security of electricity and energy supply. | ST MT | ||||||||
Health | Occupational health hazards include silica dust, noise-induced hearing loss, heat stress, radiation and disease risk in endemic areas (HIV/Aids and tuberculosis). These can reduce productivity, drive absenteeism and cause loss of experienced personnel. Harmony’s healthcare presence in remote host communities also supports its licence to operate and its ability to attract and retain talent. | •Safety and health •Not achieving operational plans at critical operations •Retaining key skills and experience. | ST MT LT | ||||||||
Supply chain management | Shortages and extended lead times for strategic spares, critical consumables (sulphuric acid, cyanide, oxygen), reagents and large-scale mining equipment can disrupt production and delay capital projects. Single-source or foreign-sourced supply, Papua New Guinea foreign exchange constraints and geopolitical pressure further heighten exposure and cost risk. | •Supply chain disruption •Political tensions – geopolitical and local •Project execution and funding ability. | ST MT | ||||||||
Climate change and energy | Physical and transition climate risks affect assets, operations, cost structures and long-term viability. Carbon pricing, regulatory requirements and changing physical conditions may affect operating and capital costs, access to capital, asset resilience and long-term planning. | •Impact of climate change •Security of electricity and energy supply •Regulatory and policy uncertainty. | ST MT LT | ||||||||
19
Key matter | Effect on value creation | Strategic risks and opportunities | Time horizon | ||||||||
Cybersecurity | An information security compromise or data breach threatens operational continuity, exposes Harmony to financial loss, damages sensitive data assets and undermines stakeholder trust. This risk increases as digitalisation across mining operations expands the potential for cyber attacks. | •Cybersecurity and digital resilience. | ST MT | ||||||||
Energy and electricity management | Energy is a critical and costly input for Harmony's deep-level mining operations, which are significantly more energy-intensive than surface mines. Unreliable electricity supply in South Africa and Papua New Guinea, above-inflation tariff increases and continued reliance on coal-fired grid electricity affect operating costs, resilience and the group’s emissions profile. | •Security of electricity and energy supply •Impact of climate change. | ST MT LT | ||||||||
Management of illegal mining and unauthorised access | Illegal mining in South Africa creates safety risks for employees and illegal miners alike, causes asset damage and gold theft, impairs community relations and Harmony’s licence to operate. | •Illegal mining and security •Safety and health. | ST MT | ||||||||
Retaining key skills and skills development | Deep-level mining depends on highly specialised technical skills, from rock mechanics and mine planning to metallurgy, engineering and ore reserve management. These skills take years to develop and are in limited global supply. Skills shortages, workforce ageing, competition from other sectors and accelerating technology adoption raise the risk of capability loss, productivity decline and reduced innovation capacity. | •Retaining key skills and experience •Not achieving operational plans at critical operations •Project execution and funding ability •Cybersecurity and digital resilience •Trackless mobile machinery. | ST MT LT | ||||||||
Capital allocation | Capital allocation determines how Harmony's funds are deployed across sustaining capital, growth projects, shareholder returns and transition opportunities. Poor allocation destroys shareholder value and constrains Harmony’s ability to develop future production, diversify the portfolio and respond to emerging opportunities. | •Replacing the depleting ore reserve base •Project execution and funding ability •Security of electricity and energy supply •Impact of climate change. | ST MT LT | ||||||||
Governance excellence | Robust governance underpins stakeholder trust, our licence to operate and the quality of strategic decision-making. Governance failures can expose Harmony to fines, litigation and reputational damage. Strong governance supports disciplined execution, risk oversight and accountability across the business. | •Regulatory and policy uncertainty. | ST MT LT | ||||||||
20
Key matter | Effect on value creation | Strategic risks and opportunities | Time horizon | ||||||||
Social licence to operate | Ongoing legitimacy of operations depends on trust with host communities, traditional authorities, landowners and governments. Failure to meet SLP commitments, agreement-based obligations or address community grievances can trigger unrest, legal action, reputational damage and, ultimately, disruption to operations. | •Regulatory and policy uncertainty •Illegal mining and security •Political tensions – geopolitical and local •Retaining key skills and experience. | ST MT LT | ||||||||
Sound labour relations | Stable employee relations are essential for operational continuity. Poor relations raise the risk of strikes, reduced productivity, workforce turnover and reputational damage, while strong relations support engagement, safety performance and consistent execution of strategy. | •Not achieving operational plans at critical operations •Retaining key skills and experience. | ST MT LT | ||||||||
Regulatory, legislative and policy uncertainty | South Africa's draft Mineral Resources Development Amendment Bill and the Climate Change Act 22 of 2024, Papua New Guinea's proposed 2025 Mining Act and evolving regulatory and disclosure requirements in Australia, among other evolving frameworks, create compliance, cost, licence and reputational risks across Harmony’s three operating jurisdictions. | •Regulatory and policy uncertainty •Political tensions – geopolitical and local •Impact of climate change. | ST MT LT | ||||||||
Post-closure sustainability | Inadequate planning for mine closure creates long-term rehabilitation liabilities, environmental legacy risks and social risks linked to loss of livelihoods in host communities. Sound provisioning, progressive rehabilitation and community transition planning are key to responsible outcomes. | •Illegal mining and security •Political tensions – geopolitical and local. | LT | ||||||||
Innovation, technology and digitalisation | Adoption of trackless mobile machinery, artificial intelligence, data analytics and digital tools supports productivity, cost reduction, safety and data-driven decision-making. Failure to adopt relevant technologies risks competitive disadvantage and erosion of Harmony’s operating knowledge base and know‑how. | •Not achieving operational plans at critical operations •Retaining key skills and experience •Cybersecurity and digital resilience. | ST MT LT | ||||||||
Sustainable communities | The long-term viability of operations can be affected by relationships with host communities and the social and economic effects of mining activities. Community dissatisfaction, unmet commitments or adverse community impacts may result in disruption, additional costs, reputational damage or loss of support for current and future operations. Community investment, local procurement, employment and post-closure planning form part of Harmony's approach to managing these risks. | •Water security – infrastructure, management and licensing. | MT LT | ||||||||
Biodiversity, land use and environmental degradation | Mining activities affect ecosystems through land disturbance, water use and emissions. Biodiversity loss or other environmental impacts may result in additional permitting requirements, remediation obligations, project delays, increased costs, regulatory action or adverse effects on community support for our operations. | •Water security – infrastructure, management and licensing •Impact of climate change. | MT LT | ||||||||
Looking ahead
These matters will continue to be assessed as Harmony's operational footprint and portfolio evolve. Changes in our operations, projects, regulatory environment and other external conditions may affect their
significance to the Group over time.
21
Strategy
Harmony’s strategy is centred on delivering safe, profitable and predictable production, generating strong cash flows and allocating
capital in a disciplined manner to support a high-margin, durable gold and copper business, while creating long-term value for our
stakeholders.
Our strategic decisions are informed by embedded enterprise risk management, stakeholder
engagement and our evolving business model as we integrate copper as a strategic commodity
alongside gold. Our four strategic pillars and an integrated portfolio of operations and projects
enable us to execute our strategy consistently and effectively. We also consider the trade-offs
inherent in our decision-making alongside the six capitals we use to create, preserve or erode
value over the short, medium and long term.
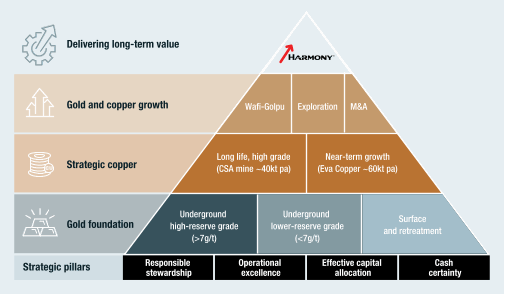
Our asset portfolio is built from the bottom up:
•Gold foundation – a foundation that generates cash today; gold remains Harmony's foundation,
supported by a combination of underground, surface, and retreatment operations
•Strategic copper – the middle layer, adding meaningful copper growth through CSA and Eva
Copper, adds durability and diversification, and
•Gold and copper growth – the apex, including the Tier 1 Wafi-Golpu copper-gold project,
holding longer-dated optionality.
Our operational and investment plans continue to strengthen the foundation of our business
through disciplined investment in our high-quality gold assets while expanding our exposure to
copper. This growing gold and copper portfolio enhances optionality, supports a long pipeline of
organic growth opportunities and reinforces our ability to generate sustainable cash flows and
attractive returns. Details on each strategic pillar are available on the following page. The board
approves and oversees our strategy and capital allocation.
How stakeholder insights shaped our strategy
Stakeholder engagement is a core input into our strategy.
Strategy in context
Our strategy responds to factors largely beyond our control: commodity prices and exchange
rates, growing copper demand, maturing South African orebodies, energy and climate pressures,
rising regulatory and stakeholder expectations, and competition for skills and technology. Our four
strategic pillars also anchor our risk appetite and tolerance framework, each supported
by a board-approved risk statement.
Strategic pillars and resource allocation
Our gold foundation delivers robust cash flows, copper growth enhances resilience over the next
three to five years, and longer-dated options such as Wafi-Golpu could extend value well beyond
2036. What makes the structure work is the four strategic pillars beneath it: without responsible
stewardship and operational excellence there is no reliable foundation, and without effective capital
allocation and cash certainty there is nothing with which to build the levels above. Together they
create sustainable value for shareholders and broader stakeholders, preserve the financial flexibility
to respond to changing markets, and inform decisions across the portfolio – including how we
allocate capital, which is set out later in this chapter. The table overleaf shows how we aim to
deliver each pillar and the capitals we draw on to do so.
22
Resource allocation | |||||||||||
Strategic pillar | What we want to achieve | How we achieve this | FC | MC | IC | HC | SC | NCo | NCe | Key trade-off considerations in allocating resources | |
Responsible stewardship | •Protect people, communities and the environment while strengthening trust •Maintaining social licence, resilience and responsible growth. | •Embed a proactive safety culture through Thibakotsi and critical control management •Advance sustainability framework priorities, including decarbonisation and responsible project development •Engage constructively with employees, communities, regulators, investors and host governments. | D | E | D | D | E | E | •We prioritise safety, community wellbeing, compliance and environmental protection alongside short-term financial return expectations •This means accepting a trade-off in financial capital to preserve and grow our human, natural, and social and relationship capital •In FY26 this included R190 million invested in community projects and the continued operation of certain South African underground assets for the employment and household income they sustain, despite margin pressures. | ||
Operational excellence | •Safe, predictable and profitable production. | •Deliver safe, predictable production across gold and copper operations •Optimise grades, costs, infrastructure reliability and mining flexibility •Execute life-extension and productivity projects while strengthening digital enabled operating capabilities. | D | E | D | D | D | E | •We balance short-term production against long-term flexibility and mine life, as seen across our projects. At Moab Khotsong, we are accepting lower production from FY27 to FY31 to develop the Zaaiplaats extension, which will return the mine to steady-state production and extend its life. Lower production has been offset by copper production at CSA •We also weigh sustaining capital expenditure against retaining cash for growth and distribution to shareholders. | ||
Effective capital allocation | •Portfolio quality, margin expansion and long-term growth •Low cost Mineral Reserve conversion •Maintain robust, flexible balance sheet •Meaningful shareholder returns. | •Direct capital towards high-quality, higher- grade, longer-life and lower-risk assets •Fund major projects from internally generated cash flows and capital-efficient funding structures •Apply investment criteria covering safety, sustainability, margin improvement, life of mine, affordability and returns above cost of capital •Maintain a prudent balance sheet by targeting net debt to EBITDA below 1.0x through the cycle and optimising the capital structure to support long-term value creation. Further details on how we allocate capital can be found overleaf. | D | L | D | D | L | L | •We balance shareholder returns against reinvestment in operations, growth funding and balance sheet resilience •Capital is prioritised towards projects that improve portfolio quality and durability, even where the benefits emerge over longer time horizons •FY27 is a deliberate investment year: advancing Eva Copper, CSA optimisation, the South African life-of-mine extensions and the renewables build-out concurrently constrains near-term free cash flow in exchange for a higher-quality, more diversified and long-life portfolio •Copper growth creates financial and manufactured capital but increases energy use, emissions and land disturbance, which we address through the renewable energy programme and progressive rehabilitation. | ||
Cash certainty | •Consistent delivery, cost discipline, investment in higher-quality and higher- margin operations •Consistent hedging policy alongside balance sheet strength. | •Generate free cash flow through operational delivery and cost discipline •Maintain balance sheet strength and liquidity •Board approved hedging strategy •Fund operational requirements, growth priorities and sustainable shareholder returns. | D | D | •Our hedging programme locks in margins to protect against market risk at the opportunity cost of reduced upside when prices rise •In FY26, realised gold hedge losses of R9.6 billion on legacy positions were more than offset by higher spot prices on unhedged production. | ||||||
D | Deployed: resources allocated as an input to the pillar | E | Enhanced: resources built or protected by the pillar (outcome) | L | Leveraged: existing resources drawn on as an enabler |
23
How we allocate capital
Every rand or dollar invested in this business competes for risk-adjusted, per-share returns. Our capital allocation framework follows a deliberate hierarchy. We first preserve and protect our existing value base
through investment in our people, assets and operational sustainability. We then improve the portfolio by extending mine lives, increasing quality and enhancing cash-generating capacity. Only thereafter do
we fund growth opportunities for sustainable long-term value creation.
Maintaining adequate liquidity and keeping net debt to EBITDA below 1.0x and remaining fundable through commodity cycles ensures that the balance sheet remains robust. All of these are done alongside
rewarding shareholders under our enhanced dividend policy, which allows up to 50% of net free cash flow after all capital expenditure, to be returned to shareholders, subject to leverage levels and board
discretion.
Cash generation | è | 1 | Balance sheet strength | |||||||||||||||||||||||
Protect the base | Non-negotiable | |||||||||||||||||||||||||
Safety, asset integrity, mining flexibility and sustaining capital protect reliable production. | Liquidity Maintain sufficient cash and undrawn facilities | Leverage Protect covenant and maintain net debt to EBITDA <1.0x | Downside resilience Remain fundable through commodity cycles | |||||||||||||||||||||||
2 | ||||||||||||||||||||||||||
Improve the quality and duration of the portfolio | Value enhancing | |||||||||||||||||||||||||
Reserve conversion, grade and margin enhancement and life-of-mine extension. | ||||||||||||||||||||||||||
3 | ||||||||||||||||||||||||||
Fund disciplined growth | Risk adjusted | |||||||||||||||||||||||||
Approved organic projects first; inorganic growth only when demonstrably value accretive. | ||||||||||||||||||||||||||
Return proportion of remaining free cash to shareholders | ||||||||||||||||||||||||||
Base dividend plus performance dividend | Applies to every decision | |||||||||||||||||||||||||
Harmony's capital allocation framework | ||||||||||||||||||||||||||
24
Protect the base
Safety, asset integrity, mining flexibility and sustaining capital
receive the first allocation of capital and are non-negotiable.
This spend safeguards our people, keeps our mines reliable
and protects the cash flows that fund everything above it.
For FY27, about 20% of planned capital protects the base.
Improve quality and duration of the portfolio
We then invest to make the portfolio better, not simply bigger.
Low‑cost reserve conversion, grade and margin enhancement
and life-of-mine extension at our existing underground
operations remain our lowest-cost route to converting Mineral
Resources into economically viable Mineral Reserves. These
brownfield extension projects generate positive net present
values and internal rates of return above our hurdle rates. In
South Africa, our Mponeng, Moab Khotsong, Tshepong North
and Doornkop extension projects alone are converting
approximately 9.8Moz to Reserves at IRRs of between 30%
and 65%, while leveraging existing skills and infrastructure,
which limits execution risk. They are also sustainable mining in
practice: extending the life of an operation sustains the
livelihoods of the employees, host communities and suppliers
who depend on it. In Australia, the CSA mine, now fully
integrated, is being optimised through a 24-month
programme anchored by the capital ventilation project. For
FY27, about 40% of planned capital is focused on improving
the quality and extending the life of our existing operations.
Fund disciplined growth
Next we consider additional growth. Organic growth projects
still offer the most cost effective method of adding reserves to
the portfolio. Greenfield and inorganic opportunities must
demonstrate compelling, risk-adjusted value creation and
satisfy our strict investment criteria before capital is
committed. Planned capital funds the greenfield Eva Copper
Project. Longer-dated optionality, in particular Wafi-Golpu,
exploration and value-accretive mergers and acquisitions,
remains subject to the same discipline. For FY27 the
remaining 40% of planned capital is being spent to develop
the Eva Copper Project.
A deliberate investment year
FY27 is, by design, an investment year. Funded, again from
internally generated cash flows and capital-efficient funding
structures.
Business | Scope | Capital expenditure guidance* |
Gold | All operations | R14.4 billion |
Copper | CSA | R2.1 billion |
Eva Copper Project** | US$650 million – US$680 million |
*Excludes renewable energy projects and Wafi-Golpu.
**Subject to securing environmental approvals.
FY26 capital expenditure and the funding of the MAC Copper
acquisition are set out in the Financial director’s report. The
strategy is set and the pipeline is defined. The focus now is on
execution.
Investment criteria
The investment criteria below translate our broader capital
allocation priorities into specific, measurable tests. Each
prospective investment (acquisition or project) is screened
against our investment criteria, allowing for disciplined,
sustainability-aligned and value-accretive capital allocation.
Investment criterion | Test applied | |||
Lower-risk profile | All ESG factors considered, especially safety and the impact of climate change. | |||
Improving margins | Preference for larger, higher-margin assets to improve portfolio quality; AISC of less than US$1 750/oz. | |||
Improve production profile | Permitted, near-term production preferred; 10‑year LoM or longer at >100 000oz per annum in regions where we operate; 10-year LoM or longer at >150 000oz per annum in new areas outside operating hubs. | |||
Affordability | Capital intensity versus cash flows must remain manageable. | |||
Generating returns | Acquisitions and projects must deliver returns exceeding the regional cost of capital while compensating for risk. |
25
Tracking our performance against our strategy
Our four strategic pillars provide the framework against which we set targets and measure delivery. For each pillar, we report FY26 outcomes against the targets, guidance and commitments we set, including
those we did not meet, followed by our short, medium and long-term objectives.
Legend | Achieved | Partly achieved or progressing | Not achieved | |||||||||
Responsible stewardship
FY26 performance against targets and guidance
Performance area | Result | FY26 outcome | ||||
Safety frequency rate | Lowest-ever group LTIFR of 5.05 per million hours worked (FY25: 5.39; FY24: 5.53) | |||||
Loss of life | Six colleagues tragically lost (FY25: 11; FY24: 7) against our zero-harm target – the outcome we most need to change | |||||
Water and environment | 78.0% of water recycled (FY25: 72.7%) and zero environmental fines, directives or unauthorised discharges | |||||
Energy transition | Sungazer 1 operating and Sungazer 2 nearing commissioning, although energy use and emissions rose with CSA and Eva Copper Project | |||||
Communities and social licence | R190 million invested in community development; grievances received fell from 120 to 79, but the third-generation SLP backlog and the OECD specific instance relating to Wafi-Golpu remain open |
Forward-looking strategic objectives
Short term – FY27 operational delivery cycle | |||
•Maintain our focus on our safety frequency rate •Continue Thibakotsi culture transformation and roll out the Australasian safety maturity assessment •Sungazer 2 (100MW, Moab Khotsong) to progress through construction and commissioning activities •Refresh emissions reduction targets and transition pathway with the SBTi •Complete the third-generation SLP backlog and transition the Hidden Valley MoA to a Community Development Agreement •Maintain partner-of-choice relationships in South Africa, Australia and Papua New Guinea. | |||
Medium term – FY28 to FY30 project execution cycle | |||
•Advance the renewable energy programme towards approximately 800MW, funded through ring‑fenced green loan facilities •Deliver the Eva Copper Kalkadoon and Indigenous procurement plan and formalise ESG screening of suppliers. | |||
Long term – FY31+ portfolio transformation horizon | |||
•Reduce scope 1 and 2 emissions by 63% by FY36 (FY21 baseline) aligned with our 2045 net-zero ambition •Reduce potable water dependence by 80% by FY34 (FY16 baseline) •Be recognised as a leading, responsible miner and partner of choice in South Africa, Papua New Guinea and Australia. | |||
26
Operational excellence
FY26 performance against targets and guidance
Performance area | Result | FY26 outcome | ||||
Gold production | Guidance met for the 11th consecutive year at 44 464kg (1.43Moz), 3% lower in line with plan (FY25: 1.48Moz) | |||||
Gold underground grade | Recovered grade of 5.83g/t (FY25: 6.27g/t), above guidance of >5.80g/t | |||||
Gold AISC | R1 191 698/kg, up 13% on a lower production base but within guidance of R1 150 000/kg to R1 220 000/kg | |||||
Copper production and cost | First year as a copper producer: 18 207t from CSA at the upper end of guidance; 3.75% recovered grade and C1 cost of US$2.47/lb, well below guidance | |||||
CSA integration | Completed within eight months, despite a planned shaft steelwork stoppage | |||||
Zaaiplaats project | Progressing, with contractor-related delays incorporated into Moab Khotsong life-of-mine plans |
Forward-looking strategic objectives
Short term – FY27 operational delivery cycle | |||
•Mark the 12th consecutive year of meeting gold production guidance •Achieve FY27 gold production guidance of 1.3Moz to 1.4Moz and maintain underground recovered grade at about 5.6g/t and gold AISC within R1 300 000/kg to R1 395 000/kg •Achieve copper guidance of 28 000 to 30 000 tonnes and cost guidance (C1 cash cost) between US$2.55/lb to US$2.65/lb from CSA. | |||
Medium term – FY28 to FY30 project execution cycle | |||
•Complete Mponeng and Moab Khotsong extension projects, achieving steady-state production of ~250 000oz and >200 000oz respectively •Complete CSA optimisation and re-establish full mining flexibility •Reach approximately 40 000 tonnes a year of copper at CSA by FY29 •First copper production from Eva Copper in the second half of calendar 2028, within the approved capital estimate of US$1.55 billion to US$1.75 billion •Build total copper production capacity towards approximately 100 000 tonnes a year once Eva Copper is in production. | |||
Long term – FY31+ portfolio transformation horizon | |||
•Sustain a flat to growing gold-equivalent production profile, with copper contributing an increasing share •Shift the production split from ~84% South Africa/16% Australasia to approximately 70%/30% by FY36 (based on FY27 planning parameters). | |||
Effective capital allocation
FY26 performance against targets and guidance
Performance area | Result | FY26 outcome | ||||
Capital expenditure | R17.1 billion (US$1.0 billion) – R8.3 billion sustaining, R4.1 billion growth and R4.6 billion Eva Copper – funded from internally generated cash flows and capital-efficient funding structures | |||||
Copper acquisition | R17.5 billion (US$1.0 billion) MAC Copper acquisition completed on 24 October 2025 | |||||
Eva Copper Project | Advanced into construction following the November 2025 final investment decision | |||||
South African extension projects | Mponeng, Moab Khotsong and Doornkop extensions progressed and Tshepong North approved; together converting ~9.8Moz at IRRs of 30% to 65% | |||||
Mineral Resources and Reserves | Copper Mineral Resources up 18.5% to 7.4Mt and Reserves up 71% to 4.0Mt; gold Reserves up 1.7% to 27.4Moz, but gold Resources declined 1.8% with 2.1Moz depleted | |||||
Life-of-mine extension | Kareerand TSF extension completed, adding more than 14 years to Mine Waste Solutions |
Forward-looking strategic objectives
Short term – FY27 operational delivery cycle | |||
•Allocate ~20% of planned capital to protect the base, ~40% to improve portfolio quality and ~40% to Eva Copper •Advance Eva Copper Project responsibly and sustainably •Progress CSA optimisation and ventilation infrastructure •Continue the Mponeng, Moab Khotsong (Zaaiplaats), Tshepong North and Doornkop (212 level ore handling) projects and commission the Mispah pump station at MWS •Progress Hidden Valley Stage 9 and TSF3, and Free State and West Wits retreatment feasibility studies. | |||
Medium term – FY28 to FY30 project execution cycle | |||
•Complete the Wafi-Golpu special mining lease process and progress towards FID, pending Papua New Guinea Government approval •Extend life of mine at Hidden Valley beyond FY30 through Stage 9 and TSF3 approvals (environmental permit amendment confirmed). | |||
Long term – FY31+ portfolio transformation horizon | |||
•Bring Wafi-Golpu into production (targeted average of 180kt copper and 250 000oz gold a year, 100% basis, 2018 feasibility study) •Realise Free State and West Wits surface retreatment expansion projects, including 5.7Moz from old Free State tailings dams (feasibility studies underway). | |||
27
Cash certainty
FY26 performance against targets and guidance
Performance area | Result | FY26 outcome | ||||
Revenue | Record revenue of R99.2 billion, up 34% | |||||
Free cash flow | Record adjusted free cash flow of R17.1 billion, up 54% | |||||
Earnings | Headline earnings per share up 87% to 4 363 SA cents | |||||
Shareholder returns | Record full-year dividend of R8.2 billion (1 280 SA cents per share) declared under the enhanced dividend policy | |||||
Balance sheet and liquidity | Net debt of R852 million (FY25: net cash of R11.1 billion) after the MAC Copper acquisition; net debt to EBITDA of 0.02x, within the 1x covenant; liquidity of R17.1 billion | |||||
Hedging | Realised gold hedge losses of R9.6 billion on the settlement of legacy positions, more than offset by higher spot prices on unhedged production |
Forward-looking strategic objectives
Short term – FY27 operational delivery cycle | |||
•Return to a net cash position •Continue disciplined hedging aimed at margin protection •Sustain shareholder returns in line with policy and cash flow generation •Plan conservatively, using a gold price of R1 850 000/kg for FY27. | |||
Medium term – FY28 to FY30 project execution cycle | |||
•Fund Eva Copper Project construction from internally generated cash flows and capital-efficient funding structures. | |||
Long term – FY31+ portfolio transformation horizon | |||
•Realise the expected cash flow inflection beyond 2030 as margins strengthen, real unit costs decline and free cash flow expands. | |||
Strategic outlook
Key projects portfolio: securing long-term value creation
Ongoing investment across our operations is designed to improve margins, extend mine lives and
ensure that Harmony produces gold and copper for decades to come. The projects below
demonstrate how current capital allocation decisions support the long-term evolution of the
portfolio.
Project / asset | Strategic value | Project phase | Status | |||||||||||
Mponeng extension | High-grade gold foundation and long-term cash-flow durability. | Execution | On schedule; life of mine extended to about 20 years. | |||||||||||
Moab Khotsong extension (Zaaiplaats) | Replaces maturing production and preserves high-grade SA gold exposure. | Execution | Progressing, with contractor- related delays incorporated into life-of-mine plans; 18-year life. | |||||||||||
Eva Copper | Core medium-term copper growth project in a tier-one jurisdiction. | Execution | Construction progressing; long- lead equipment secured and major contracts awarded. | |||||||||||
CSA mine | Immediate copper production, Australian diversification and path to 40 000 tonnes a year. | Operating – optimisation | Integration complete; capital ventilation project on schedule. | |||||||||||
Doornkop (212 level) | Extends the orebody at depth and improves margins. | Execution | On track, supporting a 15-year life of mine. | |||||||||||
Tshepong North extension | Sustains production above 3 000kg a year from existing infrastructure. | Execution (approved FY27) | Approved, extending life of mine from six to 15 years. | |||||||||||
Hidden Valley extension | International gold production and Papua New Guinea platform optionality. | Feasibility | Stage 9 fully permitted; studies underway to extend beyond FY30. | |||||||||||
Wafi-Golpu | Long-term copper-gold option with scale and transformation potential. | Permitting | Special mining lease engagement with the Papua New Guinea Government ongoing, with joint- venture partner Newmont. | |||||||||||
28
Harmony now guides production in gold and copper rather than gold-equivalent ounces, reflecting
the increasing role of copper in our portfolio. The graph below nevertheless includes gold-
equivalent production to illustrate the combined contribution of our current assets and growth
projects and the resulting flat to growing production profile over time.
The profile demonstrates the evolution of our portfolio, with gold continuing to provide a strong
foundation while copper contributes an increasing share of future production. This supports our
focus on value enhancement through disciplined investment in high-grade, long-life gold and
copper assets.
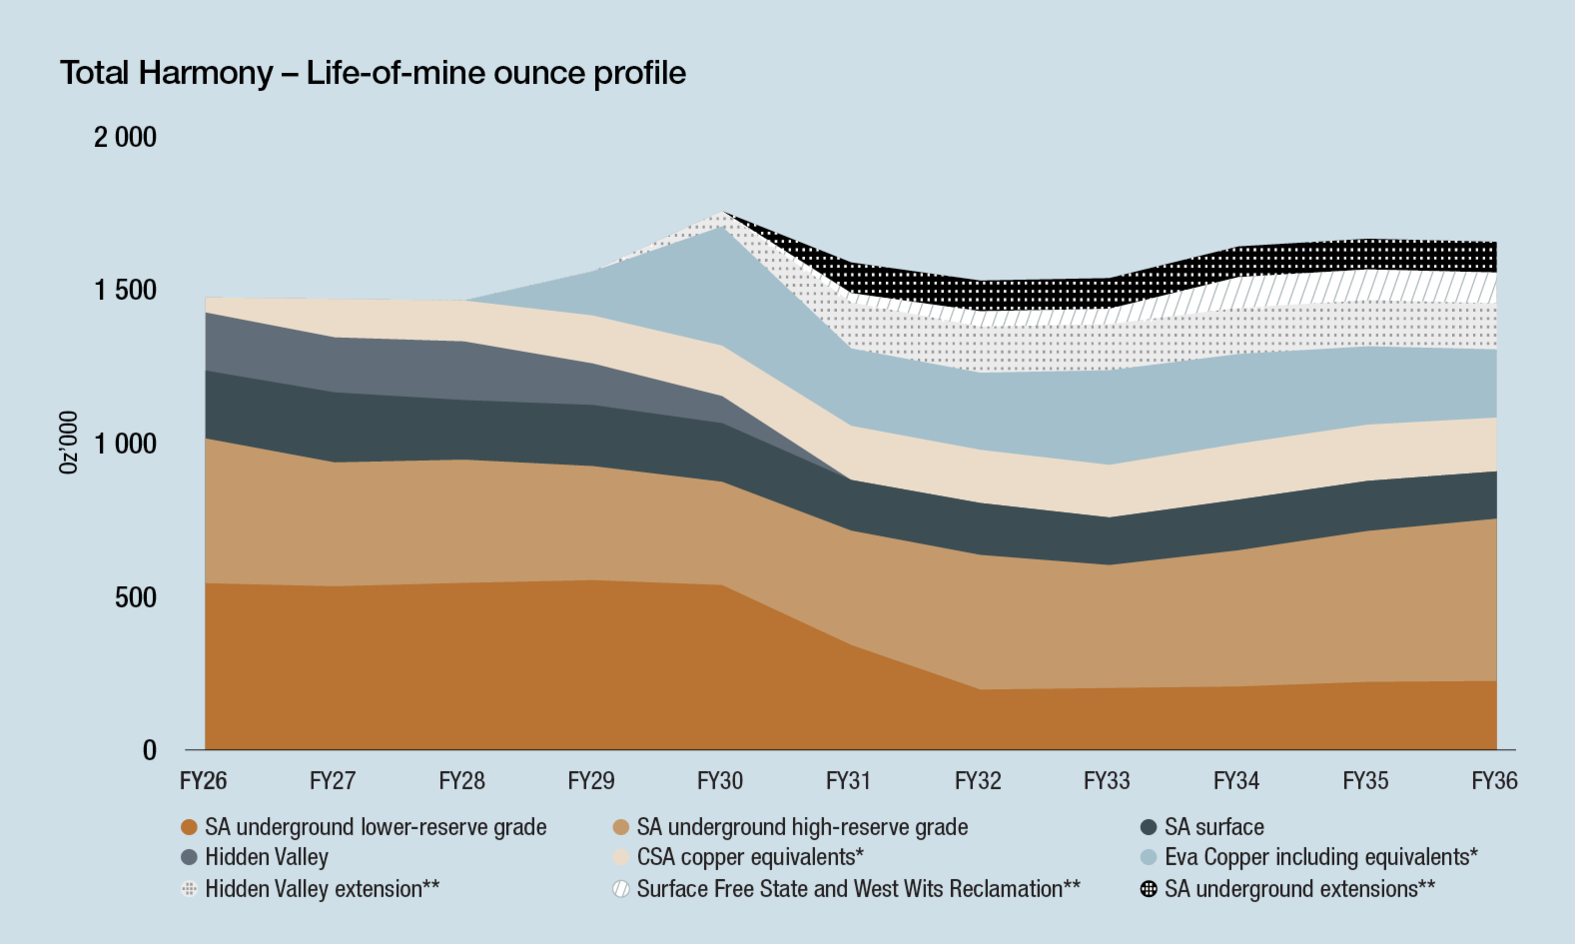
*Gold equivalent ounces are calculated assuming US$2 915/oz Au, US$4.78/lb Cu, US$38.90/oz Ag,
assuming a 100% recovery for all metals.
**Conceptual studies, not yet been approved.
Harmony’s competitive landscape and market positioning
From 2026 to 2030, our focus shifts from acquiring assets to executing the projects outlined
above, subject to capital availability and the outstanding environmental and regulatory approvals.
Beyond 2030, we expect a cash inflection point as our capital-expenditure-intensive Eva Copper
Project is completed, real unit costs decline and free cash flow expands. Our ability to operate
some of the world’s deepest and most complex orebodies, supported by longstanding gold-
mining capabilities and disciplined cost control, contributed to a record 42% gold AISC margin in
FY26 (FY22: 7%).
Availability of the capitals we depend on
Delivering this outlook depends on the continued availability, quality and affordability of the capitals
we rely on, notably scarce deep-level mining and project skills, water, reliable and affordable
energy, and finite senior management capacity.
Our eleven-year record of meeting gold production guidance, net debt to EBITDA of 0.02x and
R17.1 billion in available liquidity provides financial resilience. Realising the full value of our portfolio
depends on disciplined project execution, funding availability, permitting outcomes and commodity
market conditions. Key risks include execution and funding capacity, replacement of the depleting
ore reserve base, regulatory and policy uncertainty, including the Wafi-Golpu special mining lease
and Eva Copper federal environmental approvals, and commodity price and foreign exchange
volatility.
Remuneration-linked performance drivers
Harmony’s reward strategy supports the delivery of business strategy, risk-adjusted performance
and long-term value creation. Short and long-term incentive measures are linked to a balanced
scorecard that includes safety, operational, financial, sustainability and strategic delivery measures.
29
Performance by operation
Our gold foundation of high-grade and lower-grade underground mines, complemented by surface, retreatment and open-pit
operations including Hidden Valley, generates the cash that sustains the business today. Building on that foundation, our newly
acquired CSA mine and the Eva Copper Project add meaningful copper growth, diversifying us further by geography and commodity.
As a geographically diversified gold and copper producer, Harmony continues to evolve its portfolio to enhance resilience, flexibility and long-term value creation. Spanning three regions and multiple mining methods, our asset portfolio combines cash-generating operations with strategically positioned growth projects across both gold and copper. | ||
Asset portfolio Harmony is building a stronger, more resilient and future-focused business. By optimising operations, pursuing value-accretive growth, diversifying the portfolio and securing robust free cash flow, we create enduring profitability and long-term shareholder value. Each portfolio plays a distinct role in the business model and contributes to Harmony's transformation into a high-quality, geographically diversified gold and copper producer. | |||
Gold foundation: underground high-reserve grade | |||
Long-life, high-grade cash engines at more than 7g/t, securing short and long-term free cash flow. | |||
Gold foundation: underground lower-reserve grade | |||
Optimised for free cash generation at less than 7g/t; support Harmony’s social licence and funds the project pipeline. | |||
Gold foundation: surface and retreatment | |||
Lower-risk, high-margin ounces with attractive ESG and cash characteristics. | |||
Strategic copper | |||
Adding meaningful copper growth through CSA and Eva Copper Project; adds durability and diversification. | |||
Gold and copper growth | |||
Includes the Tier 1 Wafi-Golpu copper-gold project, holding strategic optionality. | |||
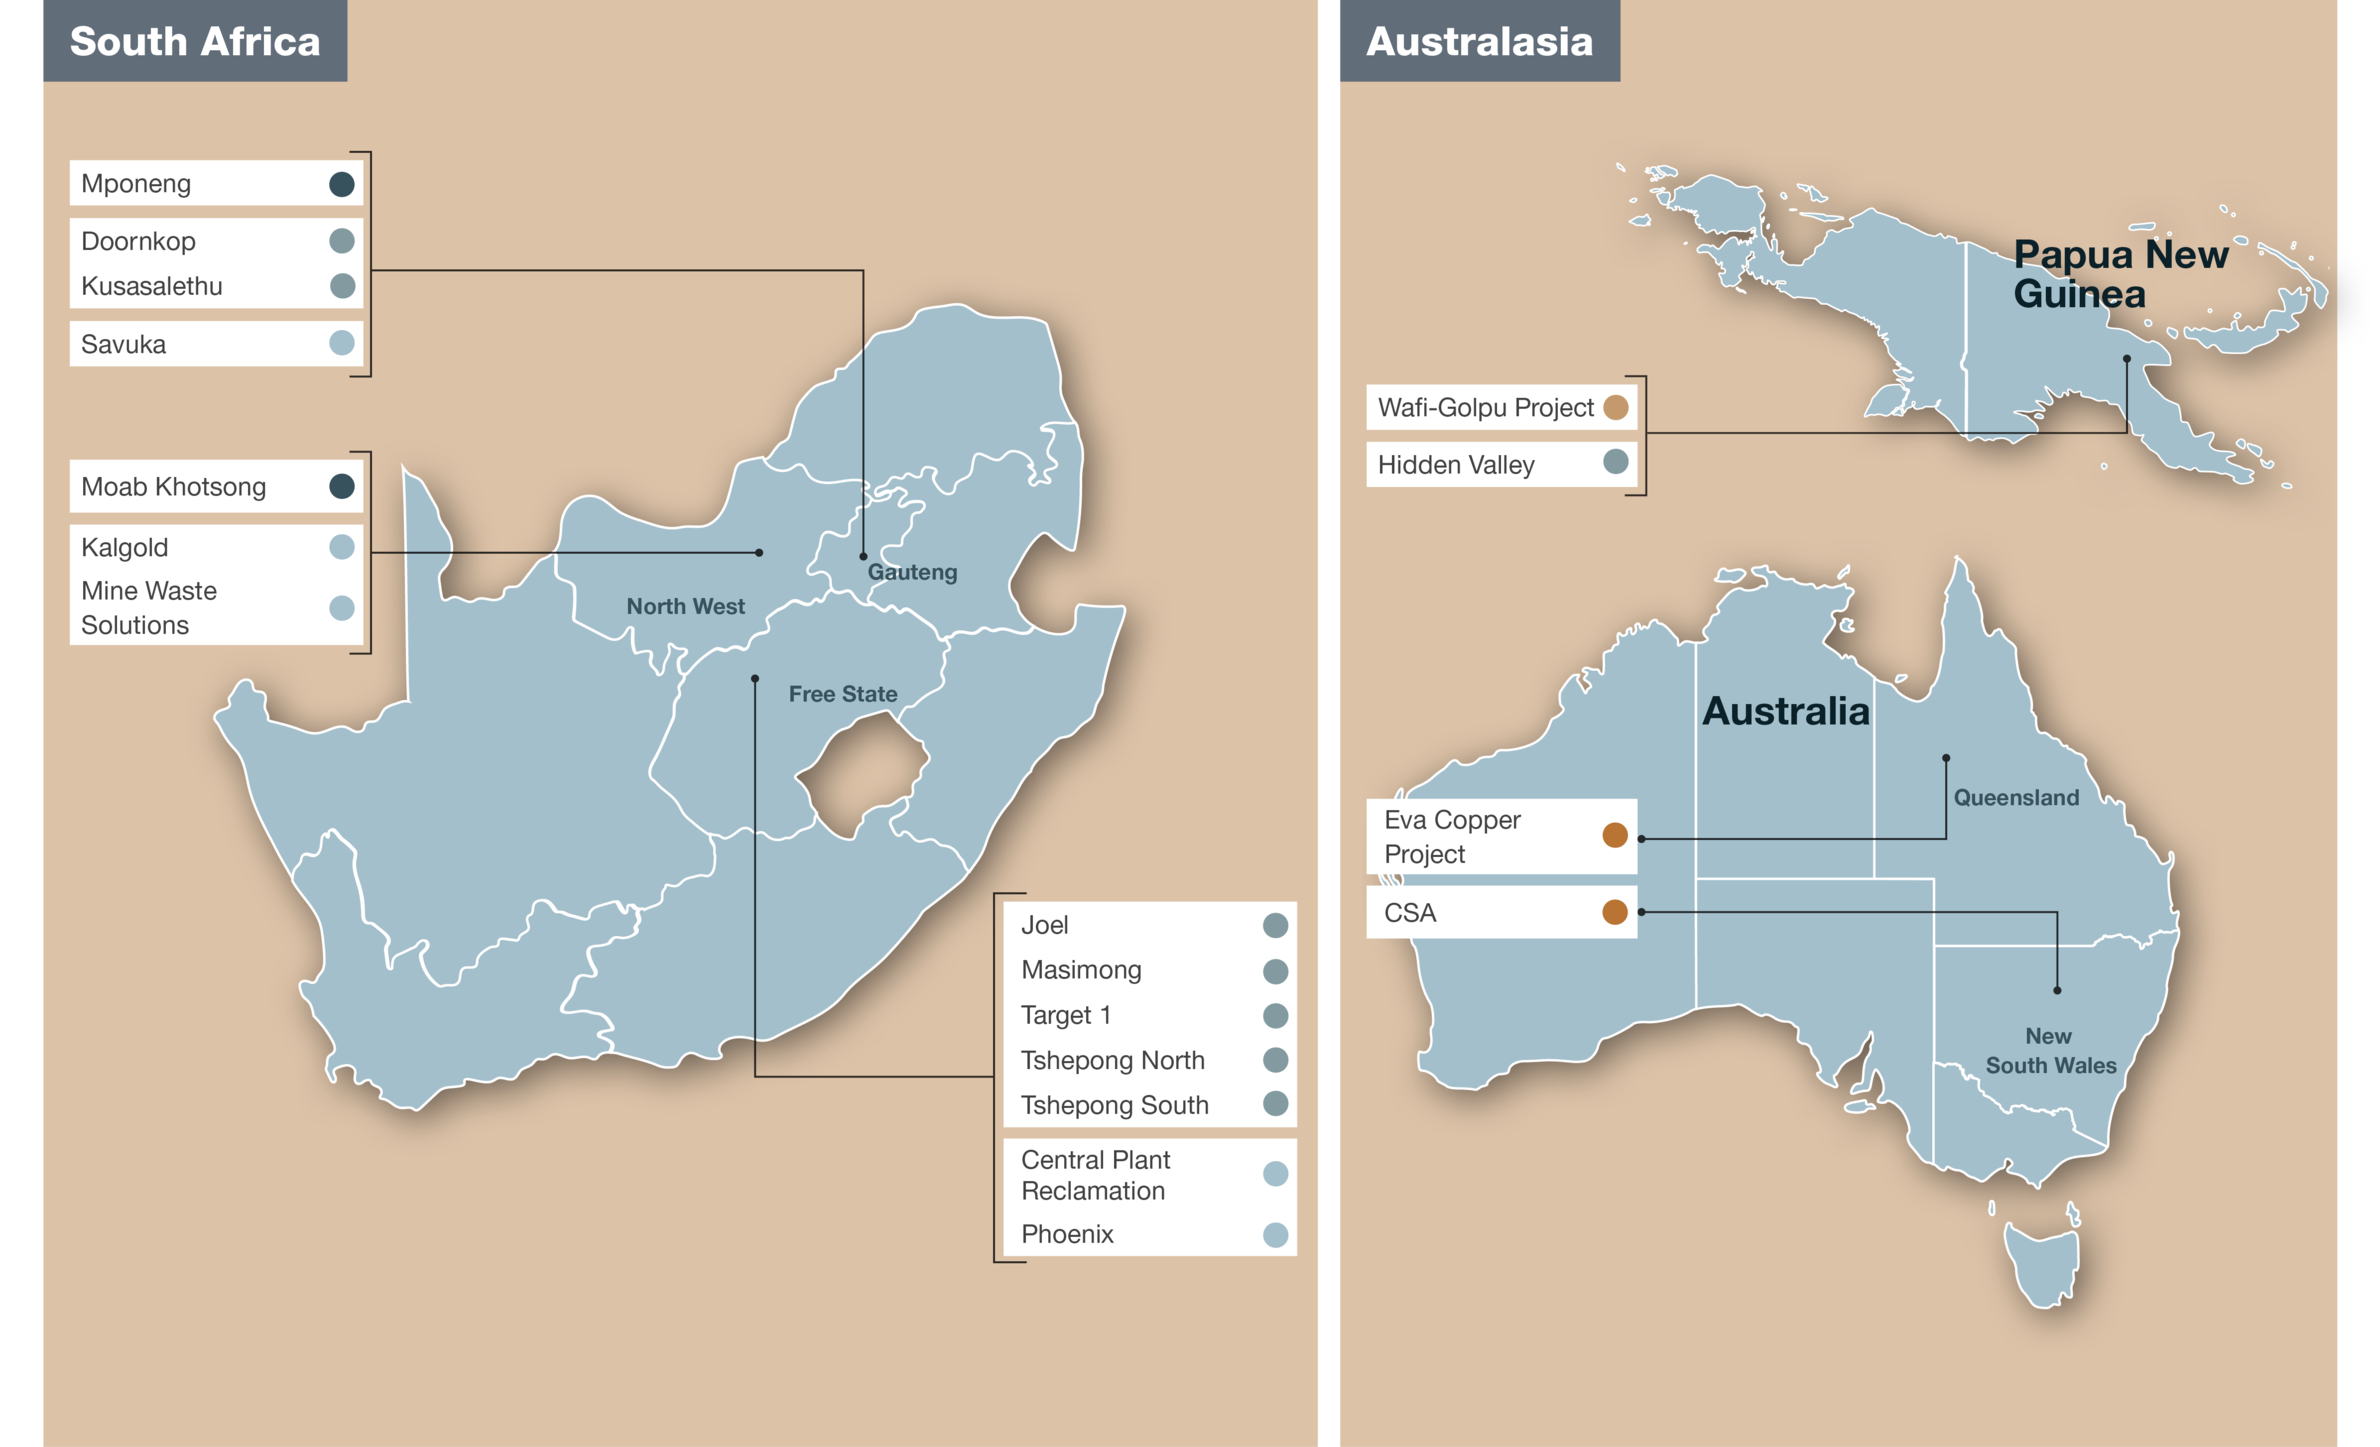
30
Our approach
Rooted in responsible mining, we Mine with Purpose – creating shared value where safety, operational excellence and sustainability are non-negotiable. A safe mine is a profitable mine.
Our strategic pillars: | Responsible stewardship | Operational excellence | Effective capital allocation | Cash certainty | |||||||||||||||||||||||
Our key operational metrics: Guided by both our responsible stewardship and operational excellence strategic pillars, operational performance is assessed through four headline metrics, supported by programme focus areas and the wider integrated reporting context. | Value outcome Disciplined operational delivery that protects people, sustains assets and supports cash certainty. Inputs and outcomes feed back into the next cycle. | |||||||||||||||||||||||||||
Safety People and critical controls | Grade Quality of production base | Costs Cost discipline and productivity | Production Delivery against plan | |||||||||||||||||||||||||
Key focus areas of our operational excellence programme | ||||||||||||||||
Safety and health | Cost management | Capital allocation | Grade management and mining flexibility | |||||||||||||
•Journey to proactive safety •Risk management and critical controls •Bottom-up safety transformation. | •Focused cost management and project delivery •Improved productivity | •Prioritised capital for growth and to sustain the business. | •Limit mining below cut-off grade •Flexibility built into mine plans. | |||||||||||||
Key stakeholders: Employees and unions | Key stakeholders: Investors and financiers; Suppliers | Key stakeholders: Investors and financiers; Suppliers | Key stakeholders: Investors and financiers | |||||||||||||
Key risks: Safety and health; Trackless mobile machinery | Key risks: Not achieving operational plans at critical operations | Key risks: Replacing the depleting ore reserve base; Unsuccessful project execution and funding ability | Key risks: Replacing the depleting ore reserve base; Not achieving operational plans at critical operations | |||||||||||||
Infrastructure maintenance | Environmental management | Social management | The trade-off we made this year Higher sustaining capital and lower planned volume – financial capital drawn down – to protect infrastructure, grade and safety performance. We hold mining below cut-off grade to a limit, accepting less volume today to preserve reserve quality and margin tomorrow. | |||||||||||||
•Fewer unplanned stoppages •Reliable, well-maintained assets. | •Water recycling •Decarbonisation •Tailings management. | •Community engagement •Social upliftment. | ||||||||||||||
Key stakeholders: Suppliers | Key stakeholders: Governments and regulators | Key stakeholders: Communities and NGOs; Employees and unions | ||||||||||||||
Key risks: Not achieving operational plans at critical operations; Security of electricity and energy supply | Key risks: Water security – infrastructure, management and licensing; Impact of climate change; Security of electricity and energy supply | Key risks: Water security – infrastructure, management and licensing | ||||||||||||||
Governance – the board’s technical committee and social and ethics committee direct and oversee every focus area above | ||||||||||||||||
31
Safety and operational risk management
Managing safety risks: Safety is a key risk for Harmony.
As such, it is imperative to ensure safe production, prevent loss-
of-life incidents and embed a proactive safety culture across all
our operations. We have adopted global best practice safety
standards via a four-layered approach. The approach is based on
risk management, implemented modernised safety systems and
an intensified focus on leadership development and training to
address behaviour to achieve our goal of ensuring that each
employee returns home safely every day.
Managing operational risks: Operational risk management is
an integral part of our business and operating strategy. It entails
managing risks effectively while working productively. Our risk-
based approach helps ensure that all supporting systems are
functioning efficiently. Safety hazards and operational business
risks are identified and dealt with continuously at each of our
operations.
Harmony’s top operational risks are:
•Loss of life/safety
•Security of electricity power supply and the impact of
higher electricity costs
•Not achieving operational objectives at our critical operations
•Unsuccessful project execution
•Supply chain disruptions.
Our performance
The safety and health of our employees and their families is, and
will always be, the heart of everything we do at Harmony. Safety
is not simply a rule we follow – it is a deeply held value woven
into our culture and our conscience.
This year, we suffered the loss of six of our colleagues that did
not return home, and the grief we carry is profound. Behind each
of these tragedies is a family shattered, a community forever
changed, and a workplace left with an irreplaceable void.
We mourn each person deeply, and we hold their loved ones in
our hearts. We acknowledge that working in some of the deepest
mines in the world carries extraordinary risk, and with that comes
an extraordinary responsibility – one we do not take lightly.
We owe it to every employee, and to those we have lost, to do
better. That is why we remain steadfast in our commitment to
a proactive and compassionate approach to safety.
We continue to invest meaningfully in the infrastructure, systems,
and human support needed to ensure that every single person
who comes to work feels protected, valued, and empowered. We
will not rest until every workplace is as safe as it can possibly be –
because every life matters deeply to us. Group lost-time injury
frequency rate (per million hours worked) (LTIFR) for FY26
decreased to 5.05 per million hours worked (FY25: 5.39 per
million hours worked).
FY26 marked another standout year for Harmony, highlighted by
the strategic acquisition of MAC Copper’s CSA mine, on-target
guidance delivery, and robust adjusted free cash flows driven by
sustained gold price strength. Group gold production declined as
planned 3% to 44 464kg (1.43Moz), down from 46 023kg
(1.48Moz) in FY25. The reduction was primarily attributable to
lower output at Moab Khotsong, Mponeng, and Kusasalethu,
though production remained within the guided range of 1.4Moz to
1.5Moz. The average underground recovered grade fell 7% to
5.83g/t from 6.27g/t in FY25, with most operations reporting lower
grades – Tshepong North and Masimong being the notable
exceptions.
Gold revenue reached a record R91 932 million in FY26, a
30% increase from R70 732 million in FY25, driven entirely by
stronger gold prices. The average gold price received rose 35% to
R2 069 710/kg (FY25: R1 529 358/kg), reflecting a meaningful
45% uplift in the US dollar price to US$3 811/oz (FY25: US$2
620/oz). Group all-in sustaining cost rose 13% to R1 191 698/kg
(FY25: R1 053 189/kg), yet remained within the guided range of
R1 150 000/kg to R1 220 000/kg. The increase was driven by
lower planned production volumes, higher sustaining capital, and
elevated cash operating costs resulting from annual wage
increases, above-inflation electricity tariff hikes as well as higher
government royalties. Production profit grew by 59% to R48 184
million, up from R30 214 million in FY25.
Group operational capital expenditure for gold assets increased
10% year-on-year to R12 118 million (FY25: R10 998 million),
largely driven by equipment replacement and deferred stripping
capital. Abnormal expenditure climbed 42% to R1 727 million
(FY25: R1 213 million), reflecting increased spend across most
operations. Deferred stripping capital rose by 60% to R1 171
million from R730 million in FY25, mainly at Hidden Valley and
Kalgold.
Since the date of acquisition, CSA mine has produced 18 207
tonnes of copper, generating revenue of R3 501 million at a C1 cost
of US$2.47/lb. The operation contributed production profit of
R1 876 million and recorded capital expenditure of R1 049 million.
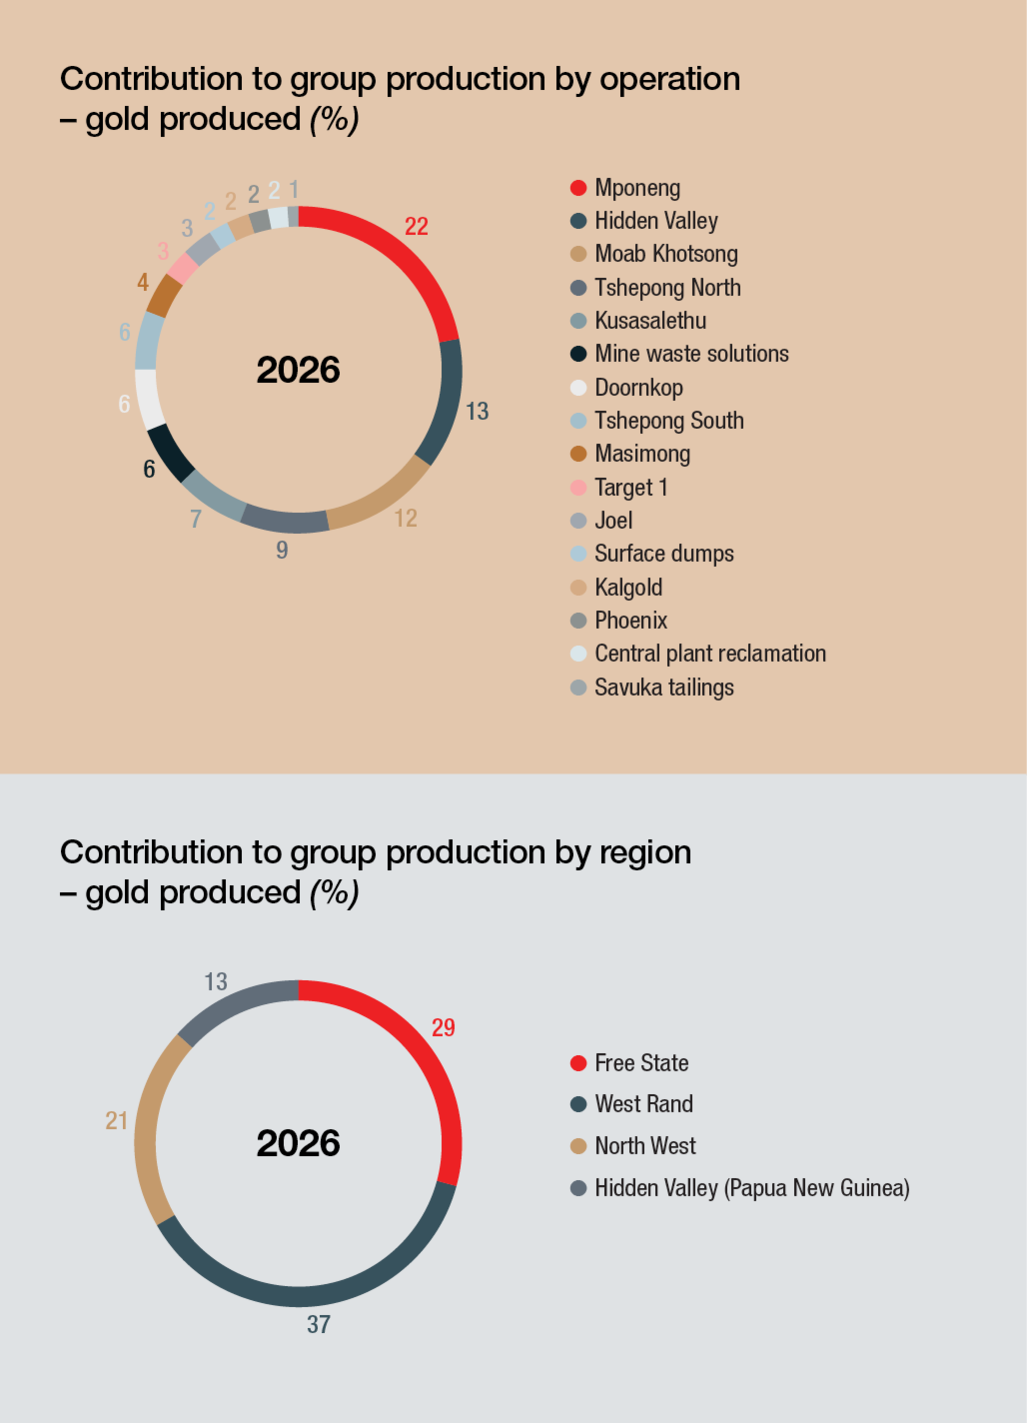
32
Group adjusted free cash flow reached a new record high in FY26, rising 54% to R17 148 million from R11 142 million in FY25, supported by a stronger gold price. Correspondingly, group adjusted free cash
flow margins expanded by 13% in FY26, improving to 18% from 16% recorded in the prior financial year.
FY26 focus areas and actions | How we performed | ||||
Continue embedding a proactive safety culture | The LTIFR in FY26 for our South African operations improved 11% to 5.06 per million hours from 5.69 per million hours in FY25. | ||||
Ensure we meet our operational plans and generate free cash flow | We met all guidance metrics and achieved record high adjusted free cash flows, generating R17.1 billion for FY26. | ||||
Continue to pursue organic brownfields growth strategy | We pursued brownfield exploration at Hidden Valley and Kalgold to optimise existing open-pit operations, with brownfield exploration at our underground operations in South Africa. | ||||
Continue to ensure major project execution and capital spend are aligned to plan | Good progress continues to be made on both the Mponeng life-of-mine extension and Zaaiplaats projects. The Kareerand extension project has been brought to a successful completion, while the Tshepong North life-of-mine extension project has received formal approval. Combined capital expenditure came in at R4.1 billion, excluding renewable energy costs, marginally below guidance. | ||||
Continue to drive down unit costs by improving our safety performance, delivering on our production plans and increasing the productivity of our mining teams | Group gold assets all-in sustaining cost rose by 13% to R1 191 698/kg, in line with planning and guidance. | ||||
Gold assets – key operational metrics FY26 – year-on-year (YoY) comparison
Unit | YoY move | YoY % | FY26 | FY25 | |||||
Gold price | (R/kg) | é | 35 | 2 069 710 | 1 529 358 | Higher average gold price received YoY reflected in higher gold revenue. | |||
Underground yield | (g/t) | ê | (7) | 5.83 | 6.27 | Reflecting lower grades across most operations as guided. Tshepong North improved 19% YoY to 5.13g/t. | |||
Margin | (%) | é | 44 | 39 | 27 | Margin increased YoY mainly due to the higher gold price. | |||
Gold produced | (kg) | ê | (3) | 44 464 | 46 023 | Lower in line with plan, mainly at Moab Khotsong, Mponeng and surface sources. Tshepong North and Hidden Valley delivered exceptional performances increasing YoY. | |||
Gold foundation: Underground high-reserve grade | (kg) | ê | (11) | 14 743 | 16 554 | Moab Khotsong lower grades at 6.93g/t. Mponeng lower following record FY25. | |||
Gold foundation: Underground lower-reserve grade | (kg) | é | 3 | 16 937 | 16 487 | Increase mainly driven by exceptional performance from Tshepong North with Doornkop and Masimong also recording increased production. | |||
Gold foundation: Surface and retreatment (South Africa) | (kg) | ê | (13) | 6 880 | 7 875 | Lower production across most operations due to various operational challenges. | |||
Gold foundation: Surface and retreatment (Hidden Valley) | (kg) | é | 16 | 5 904 | 5 107 | Excellent performance from Hidden Valley driven by a higher recovered grade at 1.59g/t. | |||
All-in sustaining cost | (R/kg) | é | (13) | 1 191 698 | 1 053 189 | Increase driven by lower production, higher sustaining capex and inflationary pressures on cash cost. |
Tiered asset portfolio
Through our reconfigured asset portfolio, built from the bottom up, Harmony is building a stronger, more resilient and future-focused business. By optimising operations, pursuing value-accretive growth,
diversifying the portfolio and securing robust free cash flow, we create enduring profitability and long-term shareholder value. Each portfolio plays a distinct role in the business model and contributes to
Harmony’s transformation into a high-quality, geographically diversified gold and copper producer.
33
FY27 outlook
Gold assets
In the next financial year, gold production is estimated to be between 1.3Moz and 1.4Moz at an
all‑in sustaining cost of between R1 300 000/kg and R1 395 000/kg. Underground recovered
grade is expected to be approximately 5.60g/t.
We are looking forward to some exciting growth opportunities:
•The Zaaiplaats project will continue to be a focus area for Moab Khotsong with steady progress
•Mponeng will continue with the life-of-mine extension project
•Tshepong North life-of-mine extension has been approved by the board and will commence in
FY27.
Harmony has numerous exploration drilling programmes running in South Africa that will
continue into FY27.
Copper assets
Copper production from CSA mine for FY27 is estimated to be between 28 000t and 30 000t at a
C1 cost of between US$2.55/lb and US$2.65/lb. Recovered grade is expected to be
approximately 3.5%.
We see significant growth potential on the horizon. The Eva Copper Project is in progress and will
continue in FY27 with significant capital investment of between US$650 million to US$680 million.
Looking forward
Key focus areas and actions in FY27 include:
•Continue to embed a real risk reduction safety culture towards zero harm
•Ensure we meet our operational plans and generate free cash flow
•Continue to pursue organic brownfields growth opportunities
•Continue to ensure major project execution and capital spend are aligned to plan
•Continue to drive down unit costs by improving our safety performance, delivering on
our production plans, increasing the productivity of our mining teams.
See overleaf for graphs illustrating forecast group growth capital expenditure to FY29 and
capital expenditure by operation for FY27.
FY27 production and capital guidance
Gold production | Capital expenditure1 | Life of mine | |||
Gold assets | (oz) | (Rm) | (years) | ||
Moab Khotsong | 117 400 – 125 500 | 1 997 | 18 | ||
Mponeng | 265 600 – 295 100 | 3 122 | 20 | ||
Tshepong North | 100 100 – 106 100 | 1 195 | 15 | ||
Tshepong South | 74 600 – 78 500 | 585 | 4 | ||
Doornkop | 74 600 – 82 400 | 1 413 | 15 | ||
Joel | 50 200 – 52 900 | 343 | 5 | ||
Target 1 | 52 500 – 55 900 | 458 | 5 | ||
Kusasalethu | 107 300 – 114 000 | 626 | 4 | ||
Masimong | 49 400 – 52 000 | 322 | 3 | ||
Underground operations – total2 | 10 061 | ||||
South African surface operations (tailings and waste rock dumps) | 95 400 – 98 700 | 552 | 9+ | ||
Mine Waste Solutions (MWS) | 93 000 – 93 000 | 215 | 13 | ||
Kalgold | 37 500 – 40 000 | 75 | 12 | ||
Hidden Valley3 | 167 800 – 174 200 | 3 472 | 4 | ||
Other international | 70 | ||||
Total | 1.3 – 1.4Moz | 14 445 | |||
1Excludes renewables.
2At an underground recovered grade of ~5.60g/t.
3Includes capitalised stripping costs.
Copper production | Capital expenditure4 | Life of mine | |||
Copper assets | (t) | (Rm) | (years) | ||
CSA5 | 28 000 – 30 000 | 2 109 | 19 | ||
4Excludes Eva Copper and Wafi-Golpu.
5At a recovered grade of ~3.5%.
34
Forecast capital expenditure to FY29 and capital expenditure by operation for FY27
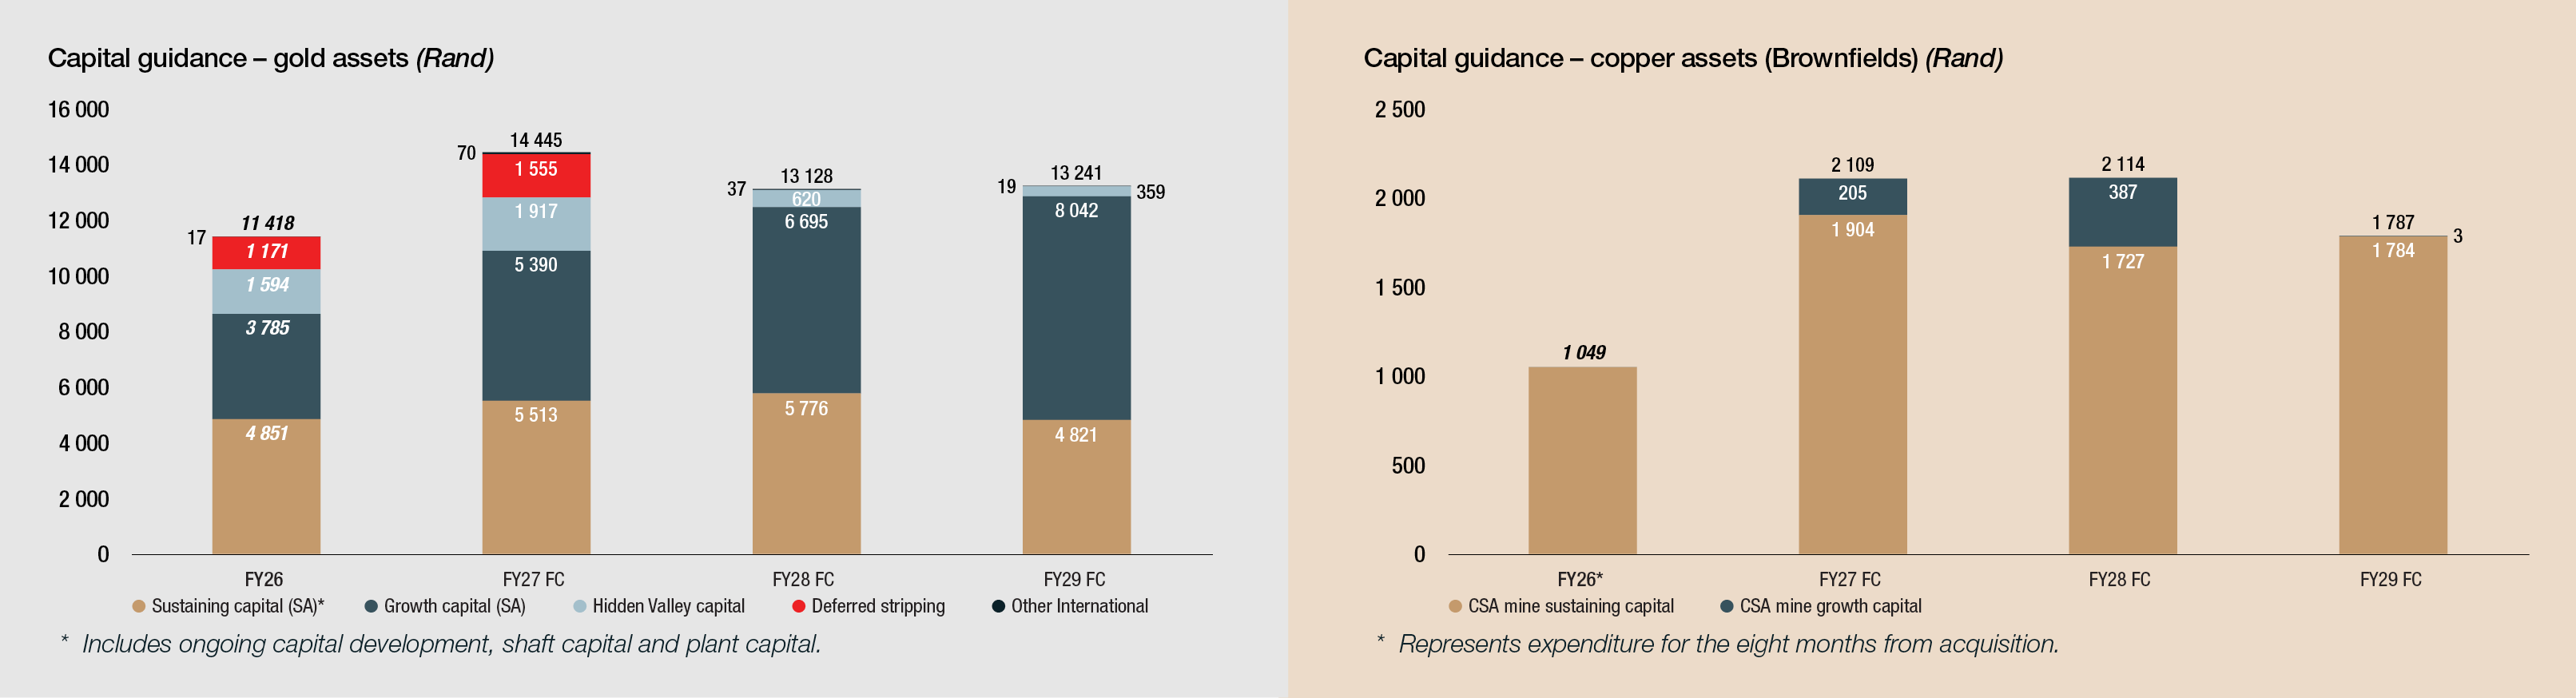
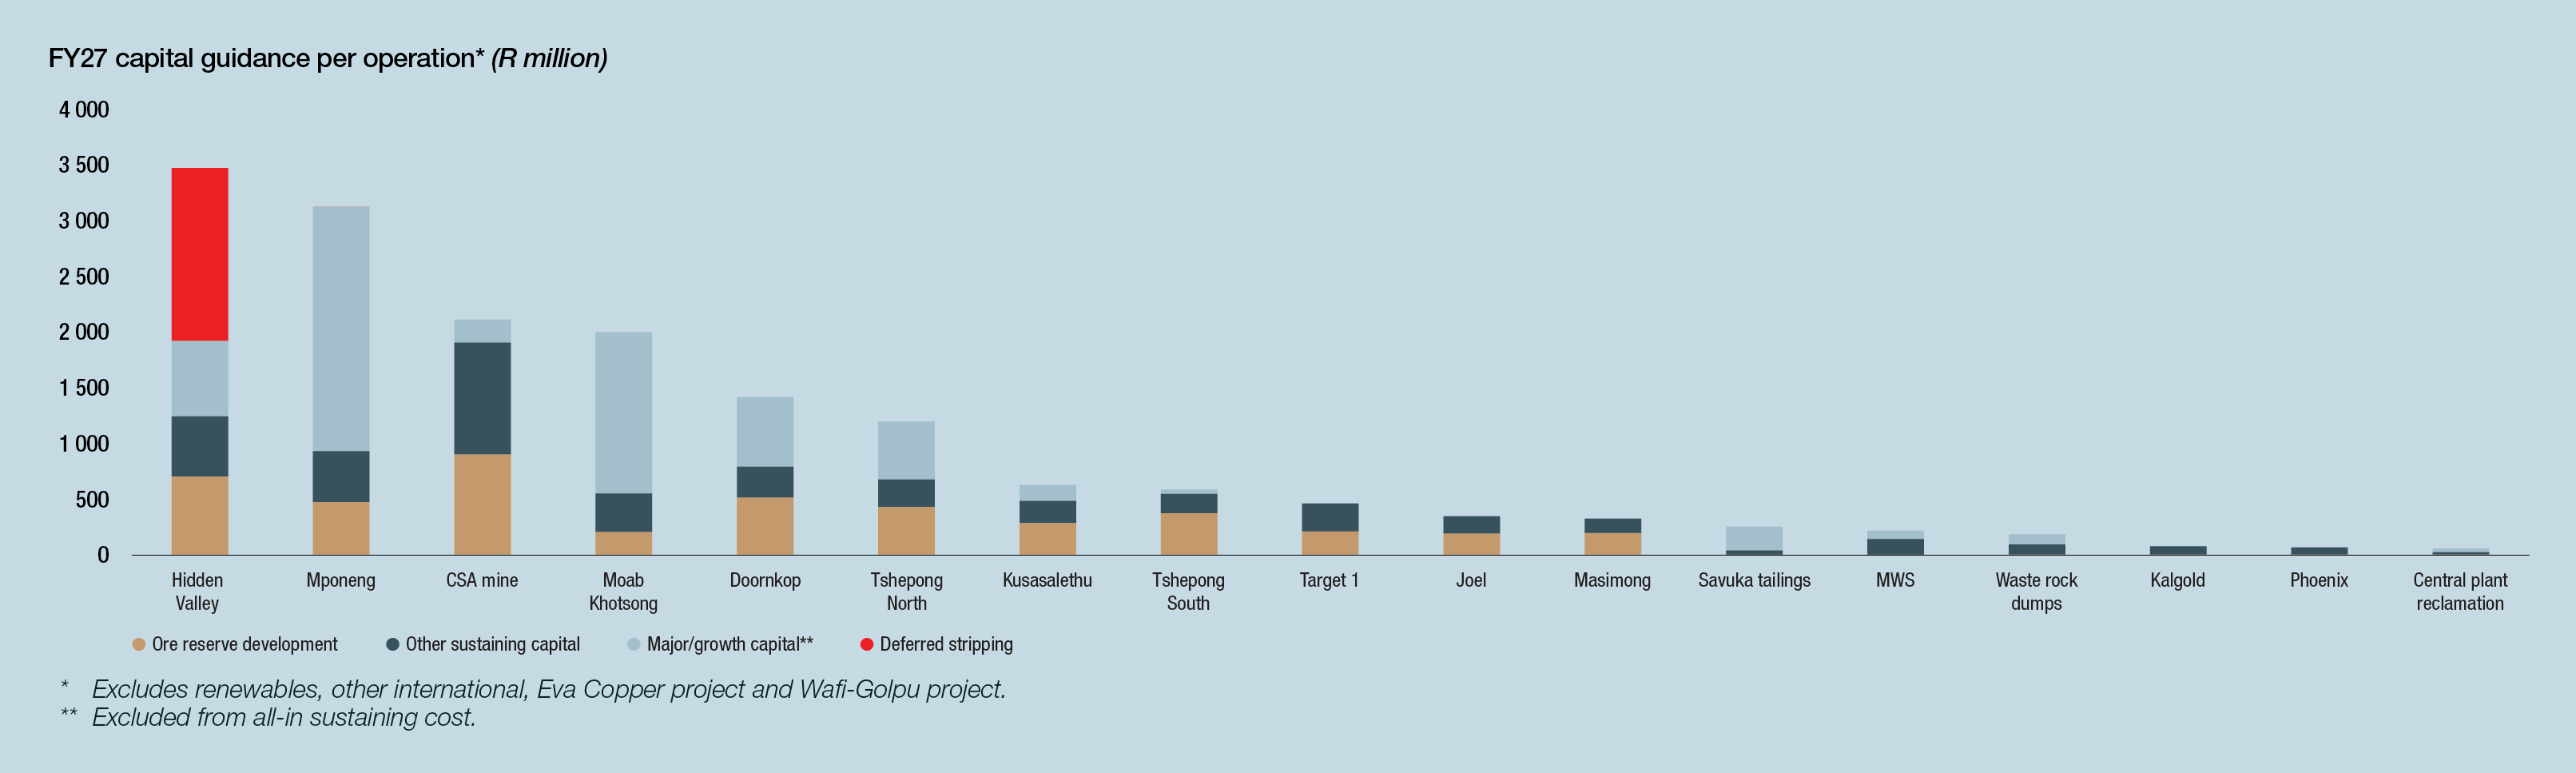
35
Gold foundation
Our South African underground mines are grouped by our
high reserve grade operations consisting of Mponeng and
Moab Khotsong and our lower reserve grade operations
consisting of the remainder of our South African underground
operations.
Gold foundation: Underground high-reserve
grade
Gold production at our high-grade mines declined 11% year-
on-year to 14 743kg (473 997oz). This reflects reduced output
from Mponeng, which came off a record performance in
FY25, as well as a planned decrease in production from Moab
Khotsong. At Moab Khotsong, we are now in the anticipated
"gold gap" as mining activity progressively shifts to
replacement mining areas. The recovered grade across these
operations fell 9%, from 9.89g/t in FY25 to 8.97g/t in the
current year. Moab Khotsong experienced the steeper grade
decline as access to high-grade areas reduced, dropping
16% to 6.93g/t compared to 8.21g/t in FY25, while
Mponeng’s grade eased 5% to 10.67g/t from an exceptional
11.27g/t the prior year. Total ore milled across these
operations decreased by 2% for FY26 relative to the previous
financial year, driven primarily by a 3% reduction at Mponeng.
Despite lower production, these mines made a meaningful
contribution to group performance, delivering 32% of group
adjusted free cash flow for FY26 at R11.6 billion (US$690
million), up from R8.8 billion (US$486 million) in FY25.
Gold foundation: Underground lower-reserve
grade
Our lower-grade operations delivered a solid 3% increase in
gold production for FY26, reaching 16 937kg (544 537oz).
The performance was underpinned by an outstanding
contribution from Tshepong North, with Doornkop, Masimong,
and Target 1 also recording year-on-year production gains.
The combination of higher gold prices and improved
operational output translated into a notable financial result,
with these operations generating adjusted free cash flow of
R8.8 billion (US$521 million) for FY26, a 283% increase
compared to the R2.3 billion (US$126 million) achieved
in FY25.
Surface and retreatment
South African operations
Gold production declined 13% year-on-year to 6 880kg
(221 199oz) in FY26, compared to 7 875kg (253 187oz) in
FY25. The majority of operations experienced lower output
due to various operational challenges, with Central Plant
Reclamation being the sole exception. Notwithstanding the
drop in gold production, the significantly higher gold price
achieved during the year drove adjusted free cash flow up by
53% to R6.6 billion (US$390 million) in FY26, from R4.3 billion
(US$237 million) in the prior year.
Australasian operations
Hidden Valley delivered another exceptional performance in
FY26 with gold production up 16% to 5 904kg (189 818oz),
compared with 5 107kg (164 193oz) in FY25. The recovered
grade improved by 18% year-on-year to 1.59g/t (FY25: 1.35g/
t), partially offset by a marginal decline in ore milled volumes.
Total ore milled for FY26 was 3.72 million tonnes, broadly in
line with the prior year (FY25: 3.79 million tonnes).
Silver production declined 36% to 60 208kg (1 935 725oz)
from 93 772kg (3 014 838oz) in FY25. Despite this, silver
revenue rose significantly to R2.1 billion (FY25: R1.7 billion),
driven by a 109% increase in the price received, which
climbed to US$65.34/oz from US$31.29/oz in the prior year.
Adjusted free cash flow surged 121% to R8.4 billion
(US$497 million) from R3.8 billion (US$207 million) in FY25,
representing another outstanding operational and financial
outcome for the operation.
Strategic copper
In FY26, Harmony expanded its portfolio through the
acquisition of MAC Copper, gaining ownership of the CSA
mine in Australia. Following the handover in October 2025, the
company directed its efforts toward addressing core
operational mining challenges, with the goal of establishing a
reliable and consistent production performance base. From
acquisition to financial year end, the mine produced 18 207
tonnes of copper at a recovered grade of 3.75%. Over this
period, CSA mine contributed production profit of R1 876
million (US$111 million), underscoring its value as a
meaningful addition to Harmony’s asset base.
Gold and copper growth
The Tier 1 Wafi-Golpu Project remains a significant long-life
copper-gold opportunity and an important source of longer-
term optionality, with engagement on the special mining lease
continuing.
36
Moab Khotsong
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 5 196 | 5 108 | 5 438 | ||
Contractors | 1 116 | 1 124 | 1 061 | ||
Total | 6 312 | 6 232 | 6 499 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 748 | 753 | 822 | |
(000t) (imperial) | 825 | 830 | 906 | ||
Gold produced | (kg) | 5 182 | 6 184 | 6 599 | |
(oz) | 166 605 | 198 820 | 212 162 | ||
Gold sold | (kg) | 5 211 | 6 178 | 6 650 | |
(oz) | 167 537 | 198 627 | 213 803 | ||
Grade | (g/t) | 6.93 | 8.21 | 8.03 | |
(oz/t) | 0.202 | 0.240 | 0.234 | ||
Productivity | (g/TEC) | 87.52 | 102.63 | 101.44 | |
Development results | |||||
– Total metres (excluding capital metres) | 2 432 | 3 058 | 4 663 | ||
– Reef metres | 340 | 649 | 1 328 | ||
– Capital metres | 2 079 | 2 445 | 2 960 | ||
Financial | |||||
Revenue | (Rm) | 10 775 | 9 455 | 8 108 | |
(US$m) | 638 | 521 | 434 | ||
Average gold price received | (R/kg) | 2 067 692 | 1 530 503 | 1 219 199 | |
(US$/oz) | 3 808 | 2 622 | 2 028 | ||
Cash operating cost4 | (Rm) | 6 190 | 5 238 | 4 623 | |
(US$m) | 366 | 289 | 249 | ||
Production profit4 | (Rm) | 4 668 | 4 220 | 3 461 | |
(US$m) | 276 | 232 | 185 | ||
Capital expenditure | (Rm) | 2 380 | 2 427 | 1 330 | |
(US$m) | 141 | 134 | 71 | ||
Adjusted free cash flow1, 4 | (Rm) | 2 205 | 1 791 | 2 155 | |
(US$m) | 131 | 99 | 115 | ||
Cash operating cost4 | (R/kg) | 1 194 477 | 846 963 | 700 614 | |
(US$/oz) | 2 200 | 1 451 | 1 165 | ||
All-in sustaining cost4 | (R/kg) | 1 302 718 | 951 955 | 800 169 | |
(US$/oz) | 2 399 | 1 631 | 1 331 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | 2 | 2 | – | ||
Lost-time injury frequency rate | (per million hours worked) | 3.74 | 3.72 | 5.36 | |
Environment2 | |||||
Electricity consumption | (GWh) | 796 | 740 | 774 | |
Water consumption – primary activities | (Ml) | 7 191 | 7 056 | 7 982 | |
Greenhouse gas emissions | (000tCO2e) | 861 | 771 | 776 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 1.06 | 0.98 | 0.94 | |
– Water | (000m3/t) | 0.01 | 9.37 | 9.71 | |
– Greenhouse gas emissions | (tCO2e/t) | 1.15 | 1.02 | 0.94 | |
Number of reportable environmental incidents3 | – | – | – | ||
Community | |||||
Local economic development | (Rm) | 30 | 25 | 30 | |
Training and development | (Rm) | 74 | 109 | 115 |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
2Figures include Nufcor.
3Figures include reportable incidents in Zaaiplaats.
4Figures for FY24 and FY25 restated.
37
Overview of operations
Moab Khotsong is a deep-level mine near the towns of Orkney
and Klerksdorp, some 180km south-west of Johannesburg.
The mine, which began producing in 2003, was acquired from
AngloGold Ashanti Limited in March 2018.
Mining is based on a scattered-mining method, together with
an integrated backfill support system that incorporates bracket
pillars. The geology at Moab Khotsong is structurally complex,
with large fault-loss areas between the three mining areas (top
mine (Great Noligwa), middle mine and lower mine (growth project
and Zaaiplaats project in execution phase)). The mine exploits the
Vaal Reef as its primary orebody. The economic reef horizons are
mined between 1 791m and 3 052m below surface. Ore mined is
processed at the Noligwa gold plant. The plant uses the reverse
gold-leach method, with gold and uranium being recovered
through gold cyanide and acid uranium leaching.
Salient features for FY26
•Regrettably, two lives were lost at Moab Khotsong during
FY26.
•The LTIFR remained almost unchanged at 3.74 per million
hours worked in FY26 (FY25: 3.72 per million hours worked)
•Gold production declined by 16% to 5 182kg (166 605oz),
down from 6 184kg (198 820oz) recorded in FY25 and is the
group’s third-largest gold producer, contributing 12% of total
group production
•Ore milled was broadly in line with the prior year, decreasing
marginally to 748 000 tonnes in FY26 (FY25: 753 000 tonnes)
•The recovered grade fell 16% to 6.93g/t in FY26 (FY25: 8.21g/
t), primarily driven by unplanned changes in the mining
sequence, reduced mining flexibility and lower face grades
experienced during the year, all of which collectively
contributed to the lower recovery performance
•Driven by consistently higher gold prices, revenue received
increased by 14% to R10 775 million (FY25: R9 455 million).
The average gold price received rose sharply by 35% to
R2 067 692/kg (FY25: R1 530 503/kg), which helped
compensate for a decline in gold production volumes
•Cash operating costs rose by 18% to R6 190 million (FY25:
R5 238 million), reflecting the combined pressure of annual
wage adjustments, higher electricity tariffs, inflationary
increases on consumables and contractor services, and
reduced uranium sales. Uranium revenue, treated as a by-
product credit to cost, declined by 31% to R566 million (FY25:
R822 million). This was driven by lower sales volumes of 396
000lb, representing a 30% decrease compared to the 566
000lb sold in FY25. Royalties payable under the Mineral and
Petroleum Resources Development Act (MPRDA) increased by
27% to R405 million (FY25: R319 million), largely as a result of
higher revenue and improved profitability
•Capital expenditure, excluding renewables, increased by 17%
to R1 663 million, compared to R1 423 million in FY25. Of this,
71% (equivalent to R1 182 million) was directed toward major
capital projects, predominantly the Zaaiplaats project, while
R197 million was allocated to ongoing development activities.
An additional R716 million was invested in the renewable
energy project earmarked to benefit the Moab Khotsong
operation
•Moab Khotsong delivered an adjusted free cash flow
contribution of R2 205 million, representing a 23%
improvement over the R1 791 million reported in FY25.
Key indicators for FY27
•18-year life of mine
•Production guidance of between 117 400oz and 125 500oz
•Capital expenditure, excluding renewables, of approximately
R1 997 million, mainly for the Zaaiplaats major project and
ongoing development.
Our focus areas in FY27 To maintain production stability and optimise the life-of-mine extension capital project (Zaaiplaats) to reduce the gold gap. | |||
38
Mponeng
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 4 762 | 4 753 | 4 710 | ||
Contractors | 1 549 | 1 334 | 780 | ||
Total | 6 311 | 6 087 | 5 490 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 896 | 920 | 880 | |
(000t) (imperial) | 987 | 1 015 | 971 | ||
Gold produced | (kg) | 9 561 | 10 370 | 8 751 | |
(oz) | 307 392 | 333 402 | 281 350 | ||
Gold sold | (kg) | 9 503 | 10 454 | 8 648 | |
(oz) | 305 528 | 336 104 | 278 039 | ||
Grade | (g/t) | 10.67 | 11.27 | 9.94 | |
(oz/t) | 0.311 | 0.328 | 0.290 | ||
Productivity | (g/TEC) | 159.25 | 173.97 | 151.59 | |
Development results | |||||
– Total metres (excluding capital metres) | 5 632 | 6 335 | 7 142 | ||
– Reef metres | 1 140 | 1 556 | 1 379 | ||
– Capital metres | 2 077 | 1 295 | – | ||
Financial | |||||
Revenue | (Rm) | 19 571 | 16 079 | 10 577 | |
(US$m) | 1 159 | 886 | 566 | ||
Average gold price received | (R/kg) | 2 059 459 | 1 538 051 | 1 223 096 | |
(US$/oz) | 3 793 | 2 635 | 2 035 | ||
Cash operating cost2 | (Rm) | 7 981 | 7 003 | 5 883 | |
(US$m) | 473 | 386 | 315 | ||
Production profit2 | (Rm) | 11 721 | 9 033 | 4 770 | |
(US$m) | 694 | 498 | 255 | ||
Capital expenditure | (Rm) | 2 146 | 2 043 | 890 | |
(US$m) | 127 | 113 | 48 | ||
Adjusted free cash flow1, 2 | (Rm) | 9 444 | 7 032 | 3 805 | |
(US$m) | 559 | 387 | 203 | ||
Cash operating cost2 | (R/kg) | 834 795 | 675 351 | 672 238 | |
(US$/oz) | 1 537 | 1 157 | 1 119 | ||
All-in sustaining cost2 | (R/kg) | 957 526 | 804 307 | 786 553 | |
(US$/oz) | 1 763 | 1 378 | 1 308 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | 3 | 2 | 2 | ||
Lost-time injury frequency rate | (per million hours worked) | 6.70 | 6.12 | 8.37 | |
Environment | |||||
Electricity consumption | (GWh) | 1 067 | 1 014 | 932 | |
Water consumption – primary activities | (Ml) | 3 939 | 5 976 | 5 977 | |
Greenhouse gas emissions | (000tCO2e) | 1 154 | 1 057 | 933 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 1.19 | 1.10 | 1.06 | |
– Water | (000m3/t) | – | 6.49 | 6.79 | |
– Greenhouse gas emissions | (tCO2e/t) | 1.29 | 1.15 | 1.06 | |
Number of reportable environmental incidents | – | – | – | ||
Community | |||||
Local economic development | (Rm) | 16 | 17 | 24 | |
Training and development | (Rm) | 100 | 86 | 78 |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
2Figures for FY24 and FY25 restated.
39
Overview of operations
Mponeng is a deep-level mine near the town of Carletonville,
some 90km south-west of Johannesburg. The mine, which began
producing in 1986, was acquired from AngloGold Ashanti Limited
in October 2020.
The orebody is extracted mostly by breast-mining methods, with
associated waste mining in addition to the reef being extracted.
The dilution from these waste sources is captured and
incorporated in the tonnage calculation, with historical performance
being the benchmark. The mine exploits the Ventersdorp Contact
Reef as its primary orebody.
The economic reef horizons are mined between 3 160m and
3 740m below surface. Ore mined is processed at the Mponeng
gold plant. The plant uses the conventional gold-leach method,
with gold recovered through carbon-in-pulp technology.
Salient features for FY26
•Regrettably, three lives were lost at Mponeng during FY26.
•The lost-time injury frequency rate deteriorated by 9% to
6.70 per million hours worked in FY26, compared to 6.12 per
million hours worked in FY25
•Mponeng remained the group’s leading gold producer,
accounting for 22% of total production. Gold production
declined by 8% in FY26 to 9 561kg (307 392oz), following an
exceptional performance in FY25 which yielded 10 370kg
(333 402oz)
•Ore milled totalled 896 000 tonnes in FY26, reflecting a 3%
decrease from the 920 000 tonnes recorded in FY25
•The recovered grade fell to 10.67g/t, easing from the high
of 11.27g/t achieved during the prior year’s exceptional
performance
•Revenue grew by 22% to R19 571 million (FY25: R16 079
million), driven primarily by a stronger gold price received.
The average gold price received rose 34% to R2 059 459/kg
(FY25: R1 538 051/kg)
•Cash operating costs increased 14% year-on-year to
R7 981 million (FY25: R7 003 million), reflecting the impact of
annual wage settlements, higher electricity tariffs, and broader
inflationary pressures. MPRDA royalties rose sharply by 45% to
R1 075 million (FY25: R740 million), largely as a result of the
growth in revenue and profitability
•Capital expenditure edged up 5% to R2 146 million (FY25:
R2 043 million). Major capital expenditure increased 32% to
R1 218 million (FY25: R924 million), with the bulk of spending
directed towards the life-of-mine extension project. Ongoing
development activities accounted for R490 million of total
capital spend
•Mponeng once again led the portfolio as the single largest
contributor to adjusted free cash flow, generating R9 444
million, a notable improvement on the R7 032 million reported
in FY25.
Key indicators for FY27
•20-year life of mine
•Production guidance of between 265 600oz and 295 100oz
•Capital expenditure of approximately R3 122 million, mainly
for the life-of-mine extension project, Ice plant and ongoing
development.
Our focus areas in FY27 Grade management remains a key deliverable and focus area. Iceberg management a key priority with minable face length well managed. Infrastructure maintenance at Mponeng remains a priority and ensuring redundancy a key deliverable. Capital transition to the hybrid model commenced with staffing a key enabler to support output. | |||
40
Tshepong North
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 3 534 | 3 391 | 3 457 | ||
Contractors | 498 | 374 | 317 | ||
Total | 4 032 | 3 765 | 3 774 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 776 | 673 | 726 | |
(000t) (imperial) | 856 | 743 | 800 | ||
Gold produced | (kg) | 3 977 | 2 900 | 3 248 | |
(oz) | 127 864 | 93 237 | 104 426 | ||
Gold sold | (kg) | 3 986 | 2 905 | 3 196 | |
(oz) | 128 153 | 93 397 | 102 754 | ||
Grade | (g/t) | 5.13 | 4.31 | 4.47 | |
(oz/t) | 0.149 | 0.125 | 0.131 | ||
Productivity | (g/TEC) | 95.89 | 71.06 | 79.05 | |
Development results | |||||
– Total metres (excluding capital metres) | 8 173 | 7 129 | 8 085 | ||
– Reef metres | 1 011 | 1 368 | 1 124 | ||
– Capital metres | 436 | 379 | – | ||
Financial | |||||
Revenue | (Rm) | 8 343 | 4 447 | 3 877 | |
(US$m) | 494 | 245 | 207 | ||
Average gold price received | (R/kg) | 2 093 050 | 1 530 731 | 1 213 187 | |
(US$/oz) | 3 854 | 2 623 | 2 018 | ||
Cash operating cost2 | (Rm) | 3 830 | 3 108 | 2 883 | |
(US$m) | 227 | 171 | 154 | ||
Production profit2 | (Rm) | 4 568 | 1 349 | 1 040 | |
(US$m) | 270 | 74 | 56 | ||
Capital expenditure | (Rm) | 838 | 695 | 559 | |
(US$m) | 50 | 38 | 30 | ||
Adjusted free cash flow1, 2 | (Rm) | 3 675 | 644 | 435 | |
(US$m) | 218 | 35 | 23 | ||
Cash operating cost2 | (R/kg) | 963 025 | 1 071 725 | 887 724 | |
(US$/oz) | 1 773 | 1 836 | 1 477 | ||
All-in sustaining cost2 | (R/kg) | 1 143 151 | 1 300 791 | 1 082 209 | |
(US$/oz) | 2 105 | 2 229 | 1 800 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | – | – | 1 | ||
Lost-time injury frequency rate | (per million hours worked) | 3.49 | 4.85 | 4.13 | |
Environment | |||||
Electricity consumption | (GWh) | 266 | 273 | 247 | |
Water consumption – primary activities | (Ml) | 1 187 | 1 119 | 1 039 | |
Greenhouse gas emissions | (000tCO2e) | 263 | 248 | 248 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 0.34 | 0.41 | 0.34 | |
– Water | (000m3/t) | 1.53 | 1.66 | 1.43 | |
– Greenhouse gas emissions | (tCO2e/t) | 0.34 | 0.39 | 0.34 | |
Number of reportable environmental incidents | – | – | – | ||
Community | |||||
Local economic development | (Rm) | 14 | 15 | 20 | |
Training and development | (Rm) | 62 | 76 | 71 |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
2Figures for FY24 and FY25 restated.
41
Overview of operations
Tshepong North is a deep-level underground mining operation
in the Free State, near the town of Welkom, some 250km
from Johannesburg. Tshepong North is a mature underground
operation that uses conventional undercut mining in the Basal
Reef while the B Reef is exploited as a high-grade secondary reef.
Ore mined is processed at the Harmony One plant, with gold
recovered using the gold cyanide leaching process.
Salient features for FY26
•Reached 2.7 million loss-of-life free shifts during FY26
•The lost-time injury frequency rate improved 28% to 3.49 per
million hours worked (FY25: 4.85 per million hours worked)
•An exceptional year with gold production surging 37% to
3 977kg (127 864oz), up from 2 900kg (93 237oz) in FY25
•Ore milled increased by 15% to 776 000 tonnes, compared
to 673 000 tonnes in the prior year
•The operation benefitted from higher average mining grades,
which drove the recovered grade 19% higher to 5.13g/t,
against 4.31g/t recorded in FY25
•Revenue grew significantly by 88% to R8 343 million (FY25:
R4 447 million), underpinned by the increase in production
volumes and a 37% rise in the average gold price received
to R2 093 050/kg (FY25: R1 530 731/kg)
•Cash operating costs rose 23% to R3 830 million, compared
to R3 108 million in FY25, driven primarily by annual wage
adjustments, higher electricity tariffs, and increased MPRDA
royalties. Royalties saw a significant surge of 263% to
R356 million (FY25: R98 million), reflecting the substantial
growth in revenue and profits during the period
•Capital expenditure for FY26 rose by 21% year-on-year to
R838 million (FY25: R695 million), driven primarily by ongoing
development activities and capital investment directed toward
the life-of-mine extension project. Of the total expenditure,
R403 million was allocated to ongoing development costs
•Adjusted free cash flow saw a substantial improvement,
increasing to R3 675 million (FY25: R644 million), reflecting
the strong operational performance during the period.
Key indicators for FY27
•15-year life of mine
•Production guidance of between 100 100oz and 106 100oz
•Capital expenditure of approximately R1 195 million, mainly for
the life-of-mine extension project and ongoing development.
Our focus areas in FY27 Continue building on strong operational momentum while advancing our systems-based approach to safety culture and risk management, thereby positioning the operation as a benchmark for sustained, responsible production. | |||
42
Tshepong South
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 3 049 | 3 115 | 3 137 | ||
Contractors | 406 | 359 | 353 | ||
Total | 3 455 | 3 474 | 3 490 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 444 | 448 | 465 | |
(000t) (imperial) | 489 | 494 | 512 | ||
Gold produced | (kg) | 2 541 | 2 739 | 3 129 | |
(oz) | 81 694 | 88 061 | 100 599 | ||
Gold sold | (kg) | 2 533 | 2 737 | 3 082 | |
(oz) | 81 437 | 87 997 | 99 088 | ||
Grade | (g/t) | 5.72 | 6.11 | 6.73 | |
(oz/t) | 0.167 | 0.178 | 0.196 | ||
Productivity | (g/TEC) | 69.86 | 74.38 | 84.04 | |
Development results | |||||
– Total metres (excluding capital metres) | 3 927 | 4 328 | 5 965 | ||
– Reef metres | 1 193 | 787 | 1 055 | ||
– Capital metres | 2 441 | 2 380 | 2 116 | ||
Financial | |||||
Revenue | (Rm) | 5 191 | 4 233 | 3 734 | |
(US$m) | 307 | 233 | 200 | ||
Average gold price received | (R/kg) | 2 049 445 | 1 546 491 | 1 211 447 | |
(US$/oz) | 3 774 | 2 650 | 2 015 | ||
Cash operating cost2 | (Rm) | 3 325 | 2 941 | 2 614 | |
(US$m) | 197 | 162 | 140 | ||
Production profit2 | (Rm) | 1 851 | 1 314 | 1 163 | |
(US$m) | 110 | 72 | 62 | ||
Capital expenditure | (Rm) | 610 | 570 | 527 | |
(US$m) | 36 | 31 | 28 | ||
Adjusted free cash flow1, 2 | (Rm) | 1 256 | 722 | 592 | |
(US$m) | 74 | 40 | 32 | ||
Cash operating cost2 | (R/kg) | 1 308 370 | 1 073 777 | 835 470 | |
(US$/oz) | 2 409 | 1 840 | 1 390 | ||
All-in sustaining cost2 | (R/kg) | 1 563 665 | 1 258 086 | 1 004 036 | |
(US$/oz) | 2 880 | 2 155 | 1 671 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | – | – | 1 | ||
Lost-time injury frequency rate | (per million hours worked) | 4.78 | 6.04 | 5.57 | |
Environment | |||||
Electricity consumption | (GWh) | 295 | 251 | 251 | |
Water consumption – primary activities | (Ml) | 1 816 | 1 316 | 1 316 | |
Greenhouse gas emissions | (000tCO2e) | 277 | 251 | 251 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 0.66 | 0.67 | 0.54 | |
– Water | (000m3/t) | – | 4.02 | 2.83 | |
– Greenhouse gas emissions | (tCO2e/t) | 0.62 | 0.60 | 0.54 | |
Number of reportable environmental incidents | – | – | – | ||
Community | |||||
Local economic development | (Rm) | 10 | 12 | 16 | |
Training and development | (Rm) | 62 | 74 | 62 |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
2Figures for FY24 and FY25 restated.
43
Overview of operations
Tshepong South is located in the Free State, near the town of
Welkom, some 250km from Johannesburg. Tshepong South
exploits the Basal Reef with the B Reef mined as a high-grade
secondary reef and uses the conventional undercut and opencut
mining method. Rock from Tshepong South is transported via
a railveyor system to Nyala shaft, from where it is hoisted to
surface. Mining is conducted at depths of 1 500m to 2 300m.
Ore mined is processed at the Harmony One plant, with gold
recovered using the gold cyanide leaching process.
Salient features for FY26
•Achieved 1.9 million loss-of-life free shifts during FY26
•The lost-time injury frequency rate improved by 21% to 4.78
per million hours worked, compared to 6.04 per million hours
worked in FY25
•Gold production decreased by 7% to 2 541kg (81 694oz),
against 2 739kg (88 061oz) in FY25
•Ore milled for the year was marginally lower at 444 000 tonnes,
compared to 448 000 tonnes in FY25
•The recovered grade of 5.72g/t was 6% lower than the
6.11g/t recorded in FY25, impacted by challenging mining
conditions and elevated seismic activity, which necessitated
the redeployment of crews to lower-risk areas, ultimately
affecting the overall mining mix
•Revenue increased by 23% to R5 191 million (FY25:
R4 233 million), driven by a 33% increase in the average gold price
received to R2 049 445/kg (FY25: R1 546 491/kg)
•Cash operating costs rose by 13% to R3 325 million (FY25:
R2 941 million), driven primarily by annual wage increases and
higher electricity tariffs, while consumables and contractor
costs remained well contained, with increases tracking below
inflation. MPRDA royalties also contributed to the overall cost
increase, surging 127% to R216 million (FY25: R95 million),
reflecting the impact of stronger revenue and improved
profitability
•Capital expenditure increased by 7% to R610 million
(FY25: R570 million), largely directed towards ongoing mine
development as well as the B Reef and chairlift major capital
projects, with R302 million allocated specifically to ongoing
development activities
•Adjusted free cash flow improved significantly, climbing
74% to R1 256 million compared to R722 million in FY25.
Key indicators for FY27
•Four-year life of mine
•Production guidance of between 74 600oz and 78 500oz
•Capital expenditure of approximately R585 million, of which
R370 million is primarily allocated to ongoing development.
Our focus areas in FY27 Focus on operational resilience and reliability, with targeted investment in B Reef exploration to both the Northern and Southern blocks whilst at the same time maintaining consistent, quality-driven output through FY27. | |||
44
Doornkop
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 3 182 | 3 224 | 3 474 | ||
Contractors | 865 | 760 | 678 | ||
Total | 4 047 | 3 984 | 4 152 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 856 | 742 | 815 | |
(000t) (imperial) | 945 | 818 | 900 | ||
Gold produced | (kg) | 2 851 | 2 720 | 3 470 | |
(oz) | 91 662 | 87 450 | 111 562 | ||
Gold sold | (kg) | 2 815 | 2 730 | 3 469 | |
(oz) | 90 505 | 87 772 | 111 531 | ||
Grade | (g/t) | 3.33 | 3.67 | 4.26 | |
(oz/t) | 0.097 | 0.107 | 0.124 | ||
Productivity | (g/TEC) | 71.20 | 64.54 | 79.63 | |
Development results | |||||
– Total metres (excluding capital metres) | 8 709 | 9 443 | 8 836 | ||
– Reef metres | 1 605 | 1 539 | 1 798 | ||
– Capital metres | 1 460 | 843 | 2 894 | ||
Financial | |||||
Revenue | (Rm) | 5 834 | 4 158 | 4 198 | |
(US$m) | 345 | 229 | 225 | ||
Average gold price received | (R/kg) | 2 072 397 | 1 523 087 | 1 210 252 | |
(US$/oz) | 3 816 | 2 609 | 2 013 | ||
Cash operating cost2 | (Rm) | 3 476 | 3 165 | 3 061 | |
(US$m) | 206 | 174 | 164 | ||
Production profit2 | (Rm) | 2 410 | 913 | 1 151 | |
(US$m) | 143 | 50 | 62 | ||
Capital expenditure | (Rm) | 1 091 | 914 | 687 | |
(US$m) | 65 | 50 | 37 | ||
Adjusted free cash flow1, 2 | (Rm) | 1 267 | 79 | 451 | |
(US$m) | 75 | 4 | 24 | ||
Cash operating cost2 | (R/kg) | 1 219 067 | 1 163 565 | 882 010 | |
(US$/oz) | 2 245 | 1 994 | 1 467 | ||
All-in sustaining cost2 | (R/kg) | 1 482 134 | 1 440 593 | 1 033 627 | |
(US$/oz) | 2 729 | 2 468 | 1 719 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | – | 2 | 1 | ||
Lost-time injury frequency rate | (per million hours worked) | 5.95 | 6.75 | 7.58 | |
Environment | |||||
Electricity consumption | (GWh) | 259 | 258 | 249 | |
Water consumption – primary activities | (Ml) | 459 | 668 | 864 | |
Greenhouse gas emissions | (000tCO2e) | 281 | 269 | 253 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 0.30 | 0.31 | 0.31 | |
– Water | (000m3/t) | – | 0.90 | 1.06 | |
– Greenhouse gas emissions | (tCO2e/t) | 0.33 | 0.36 | 0.31 | |
Number of reportable environmental incidents | – | – | – | ||
Community | |||||
Local economic development | (Rm) | 13 | 9 | 5 | |
Training and development | (Rm) | 78 | 86 | 84 |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
2Figures for FY24 and FY25 restated.
45
Overview of operations
Doornkop is a deep-level single-shaft operation in Gauteng,
some 30km west of Johannesburg, on the northern rim of the
Witwatersrand Basin. While a mature operation, it still has
15 years life of mine remaining.
The operation focuses on narrow-reef conventional mining of the
South Reef gold-bearing conglomerate. Mining is undertaken to a
depth of 2 219m below surface. Ore is processed at the
Doornkop plant, which uses the carbon-in-pulp process to
extract gold.
Salient features for FY26
•Achieved 1.45 million loss-of-life free shifts during FY26
•The lost-time injury frequency rate (LTIFR) improved by 12%
to 5.95 per million hours worked, compared to 6.75 per million
hours worked in FY25
•Gold production increased by 5% year-on-year to 2 851kg
(91 662oz), up from 2 720kg (87 450oz) recorded in FY25
•Ore milled of 856 000 tonnes was 15% higher than the
742 000 tonnes processed in FY25, offsetting the impact
of a lower recovered grade
•The recovered grade declined by 9% to 3.33g/t, compared
to 3.67g/t in the prior year
•Revenue increased by 40% to R5 834 million, compared to
R4 158 million in FY25. This growth was driven by both higher
gold production and a significantly stronger gold price received,
which rose 36% to R2 072 397/kg in FY26 from R1 523 087/
kg in the prior year
•Cash operating costs rose by 10% to R3 476 million (FY25:
R3 165 million), driven primarily by annual wage increases and
higher electricity tariffs. Consumables costs were well
managed, declining year-on-year, while contractor costs grew
at a rate below inflation. MPRDA royalties increased sharply by
141% to R190 million, up from R79 million in FY25, reflecting
improved profitability and higher revenue
•Capital expenditure increased by 19% to R1 091 million from
R914 million in FY25, underpinned by ongoing development
activity and major project capital investment related to the
207/212 level project. Of the total spend, R460 million was
allocated to ongoing development and R452 million to the
major capital project
•Adjusted free cash flow improved significantly to R1 267 million,
compared to R79 million in FY25, reflecting the strong gold
price as well as operational and financial performance achieved
during the period.
Key indicators for FY27
•15-year life of mine
•Production guidance of between 74 600oz and 82 400oz
•Capital expenditure of approximately R1 413 million, mainly for
ongoing development and the 207/212 level major project.
Our focus areas in FY27 Development ramp-up well on track. Maintaining the iceberg and ensure minable face length remains on plan with proper execution strategies on equipping embedded. Capital on plan. | |||
46
Joel
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 1 819 | 1 757 | 1 729 | ||
Contractors | 488 | 285 | 198 | ||
Total | 2 307 | 2 042 | 1 927 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 376 | 374 | 401 | |
(000t) (imperial) | 415 | 412 | 442 | ||
Gold produced | (kg) | 1 399 | 1 634 | 1 733 | |
(oz) | 44 979 | 52 534 | 55 718 | ||
Gold sold | (kg) | 1 398 | 1 639 | 1 708 | |
(oz) | 44 948 | 52 695 | 54 914 | ||
Grade | (g/t) | 3.72 | 4.37 | 4.32 | |
(oz/t) | 0.108 | 0.128 | 0.126 | ||
Productivity | (g/TEC) | 62.00 | 75.16 | 79.45 | |
Development results | |||||
– Total metres (excluding capital metres) | 3 672 | 3 183 | 3 194 | ||
– Reef metres | 963 | 947 | 935 | ||
– Capital metres | – | – | – | ||
Financial | |||||
Revenue | (Rm) | 2 873 | 2 484 | 2 079 | |
(US$m) | 170 | 137 | 111 | ||
Average gold price received | (R/kg) | 2 054 844 | 1 515 661 | 1 216 923 | |
(US$/oz) | 3 784 | 2 597 | 2 024 | ||
Cash operating cost2 | (Rm) | 2 107 | 1 867 | 1 692 | |
(US$m) | 125 | 103 | 90 | ||
Production profit2 | (Rm) | 767 | 620 | 414 | |
(US$m) | 45 | 34 | 22 | ||
Capital expenditure | (Rm) | 330 | 270 | 236 | |
(US$m) | 20 | 15 | 13 | ||
Adjusted free cash flow1, 2 | (Rm) | 436 | 347 | 151 | |
(US$m) | 26 | 19 | 8 | ||
Cash operating cost2 | (R/kg) | 1 505 998 | 1 142 605 | 976 319 | |
(US$/oz) | 2 773 | 1 958 | 1 624 | ||
All-in sustaining cost2 | (R/kg) | 1 791 547 | 1 343 321 | 1 146 079 | |
(US$/oz) | 3 299 | 2 301 | 1 906 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | – | 4 | – | ||
Lost-time injury frequency rate | (per million hours worked) | 2.49 | 3.97 | 4.70 | |
Environment | |||||
Electricity consumption | (GWh) | 109 | 107 | 101 | |
Water consumption – primary activities | (Ml) | 892 | 1 045 | 982 | |
Greenhouse gas emissions | (000tCO2e) | 119 | 112 | 101 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 0.29 | 0.29 | 0.25 | |
– Water | (000m3/t) | – | 2.79 | 2.45 | |
– Greenhouse gas emissions | (tCO2e/t) | 0.32 | 0.30 | 0.25 | |
Number of reportable environmental incidents | – | – | – | ||
Community | |||||
Local economic development | (Rm) | 6 | 8 | 7 | |
Training and development | (Rm) | 32 | 34 | 28 |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
2Figures for FY24 and FY25 restated.
47
Overview of operations
Joel is a twin-shaft mining operation in the Free State, some
290km south-west of Johannesburg, on the southern edge of the
Witwatersrand Basin.
A pre-developed scattered-mining system is used. This enables
unpay and geologically complex areas to be left unmined, while
considering the overall panel configuration and stability of footwall
development. This allows for mining to be selective, based on the
proven Mineral Reserve during the development phase. The primary
economic reef mined is the narrow tabular Beatrix Reef deposit,
accessed via conventional grid development. Mining is currently
being conducted to a depth of 1 379m below collar. As the Joel
plant was decommissioned in FY19, ore mined is now processed
at the Harmony One plant.
Salient features for FY26
•The operation achieved a loss-of-life free year, recording
570 000 loss-of-life free shifts
•The lost-time injury frequency rate improved significantly in
FY26, recording a 37% improvement to 2.49 per million hours
worked, compared to 3.97 per million hours worked in FY25
•Gold production declined by 14% to 1 399kg (44 979oz), down
from 1 634kg (52 534oz) in FY25. This decrease was
attributable to a combination of factors, including mining and
ventilation-related challenges, lower face grades, and below-
expected plant recovery performance, all of which collectively
impacted overall gold output
•Ore milled remained relatively stable, increasing marginally
to 376 000 tonnes, compared to 374 000 tonnes in FY25
•The recovered grade of 3.72g/t represented a 15% decline
against the 4.37g/t achieved in FY25
•Revenue grew by 16% to R2 873 million, up from R2 484
million in FY25, despite lower production levels. This
improvement was driven by a stronger gold price received,
which rose 36% to R2 054 844/kg compared to R1 515 661/
kg in FY25
•Cash operating costs increased by 13% to R2 107 million
(FY25: R1 867 million), largely reflecting annual wage and
electricity tariff increases, alongside inflationary pressures on
consumables and contractor costs. MPRDA royalties more
than doubled, rising 120% to R121 million from R55 million in
the prior year
•Capital expenditure increased by 22% to R330 million (FY25:
R270 million), with ongoing development activities accounting
for R188 million of the total spend
•Adjusted free cash flow improved by 26% to R436 million,
compared to R347 million recorded in FY25.
Key indicators for FY27
•Five-year life of mine
•Production guidance of between 50 200oz and 52 900oz
•Capital expenditure of approximately R343 million, mainly
for ongoing development.
Our focus areas in FY27 Prioritise grade optimisation to enhance recovery efficiency, while maintaining the operation’s strong safety performance. | |||
48
Target 1
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 1 679 | 1 626 | 1 569 | ||
Contractors | 495 | 435 | 436 | ||
Total | 2 174 | 2 061 | 2 005 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 406 | 391 | 462 | |
(000t) (imperial) | 447 | 432 | 510 | ||
Gold produced | (kg) | 1 409 | 1 387 | 1 859 | |
(oz) | 45 301 | 44 593 | 59 769 | ||
Gold sold | (kg) | 1 392 | 1 415 | 1 854 | |
(oz) | 44 755 | 45 492 | 59 608 | ||
Grade | (g/t) | 3.47 | 3.55 | 4.02 | |
(oz/t) | 0.101 | 0.103 | 0.117 | ||
Productivity | (g/TEC) | 60.02 | 62.93 | 88.65 | |
Development results | |||||
– Total metres (excluding capital metres) | 2 126 | 1 759 | 1 915 | ||
– Reef metres | 172 | 233 | 13 | ||
– Capital metres | – | – | – | ||
Financial | |||||
Revenue | (Rm) | 2 865 | 2 161 | 2 262 | |
(US$m) | 170 | 119 | 121 | ||
Average gold price received | (R/kg) | 2 058 047 | 1 527 507 | 1 219 817 | |
(US$/oz) | 3 790 | 2 617 | 2 029 | ||
Cash operating cost2 | (Rm) | 2 719 | 2 510 | 2 361 | |
(US$m) | 161 | 138 | 126 | ||
Production profit2 | (Rm) | 176 | (374) | (96) | |
(US$m) | 10 | (21) | (5) | ||
Capital expenditure | (Rm) | 402 | 491 | 488 | |
(US$m) | 24 | 27 | 26 | ||
Adjusted free cash flow1, 2 | (Rm) | (257) | (839) | (587) | |
(US$m) | (15) | (46) | (31) | ||
Cash operating cost2 | (R/kg) | 1 930 013 | 1 809 603 | 1 269 885 | |
(US$/oz) | 3 554 | 3 100 | 2 112 | ||
All-in sustaining cost2 | (R/kg) | 2 268 356 | 2 202 435 | 1 562 353 | |
(US$/oz) | 4 177 | 3 773 | 2 599 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | 1 | – | – | ||
Lost-time injury frequency rate | (per million hours worked) | 9.17 | 10.26 | 6.24 | |
Environment | |||||
Electricity consumption | (GWh) | 217 | 224 | 233 | |
Water consumption – primary activities | (Ml) | 690 | 777 | 590 | |
Greenhouse gas emissions | (000tCO2e) | 238 | 237 | 236 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 0.53 | 0.57 | 0.50 | |
– Water | (000m3/t) | – | 1.99 | 1.28 | |
– Greenhouse gas emissions | (tCO2e/t) | 0.59 | 0.61 | 0.51 | |
Number of reportable environmental incidents | – | – | – | ||
Community | |||||
Local economic development | (Rm) | 8 | 8 | 11 | |
Training and development | (Rm) | 47 | 59 | 63 |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
2Figures for FY24 and FY25 restated.
49
Overview of operations
Target 1 is an advanced, single-shaft, deep-level mine in the
Free State, some 270km south-west of Johannesburg. It has
a planned life of mine of five years.
While most of the ore extracted comes from mechanised
mining (massive mining techniques), conventional stoping is
still employed primarily to destress areas ahead of mechanised
mining. The gold mineralisation currently exploited is contained in
a succession of Elsburg and Dreyerskuil quartz pebble
conglomerate reefs. These reefs are mined to a depth of around 2
300m below surface. Ore mined is milled and processed at the
Target plant, with gold recovered by means of gold cyanide
leaching.
Salient features for FY26
•Regrettably, one life was lost at Target during FY26
•The lost-time injury frequency rate improved 11% from 10.26
per million hours worked in FY25 to 9.17 per million hours
worked in FY26
•Gold production grew by 2% year-on-year, increasing to
1 409kg (45 301oz) from 1 387kg (44 593oz) in FY25. While
the operation delivered an encouraging performance during the
first half of the financial year, the second half was impacted by
operational challenges that weighed on full-year production
•Ore milled increased by 4% to 406 000 tonnes, compared to
391 000 tonnes in FY25
•The recovered grade of 3.47g/t was marginally lower, declining
by 2% relative to the 3.55g/t recorded in FY25
•Revenue grew strongly by 33% to R2 865 million in FY26
(FY25: R2 161 million), supported by consistent production
performance and a favourable gold price environment. The gold
price received rose 35% year-on-year, climbing from R1 527
507/kg in FY25 to R2 058 047/kg in FY26
•Cash operating costs rose by 8% to R2 719 million (FY25:
R2 510 million), driven primarily by annual wage adjustments
and increases in electricity tariffs. Notably, consumable costs
declined on a year-on-year basis, while contractor costs grew
at a rate well below inflation, partially offsetting the overall cost
pressures
•Capital expenditure reduced to R402 million (FY25: R491
million), reflecting disciplined spending directed largely toward
ongoing development activities and the replacement of
equipment. Of the total capital deployed, R217 million was
allocated specifically to ongoing development.
Key indicators for FY27
•Five-year life of mine
•Production guidance of between 52 500oz and 55 900oz
•Capital expenditure of approximately R458 million, mainly
for ongoing development and equipment replacement.
Our focus areas in FY27 Maintain a disciplined focus on grade and quality improvement as part of an ongoing operational review, with safety and risk management remaining a key priority. | |||
50
Kusasalethu
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 3 594 | 3 499 | 3 502 | ||
Contractors | 557 | 473 | 466 | ||
Total | 4 151 | 3 972 | 3 968 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 520 | 544 | 584 | |
(000t) (imperial) | 573 | 599 | 644 | ||
Gold produced | (kg) | 3 198 | 3 629 | 3 842 | |
(oz) | 102 818 | 116 675 | 123 523 | ||
Gold sold | (kg) | 3 159 | 3 658 | 3 795 | |
(oz) | 101 563 | 117 607 | 122 011 | ||
Grade | (g/t) | 6.15 | 6.67 | 6.58 | |
(oz/t) | 0.179 | 0.195 | 0.192 | ||
Productivity | (g/TEC) | 70.82 | 82.17 | 88.27 | |
Development results | |||||
– Total metres (excluding capital metres) | 4 008 | 2 993 | 2 724 | ||
– Reef metres | 586 | 535 | 472 | ||
– Capital metres | – | – | – | ||
Financial | |||||
Revenue | (Rm) | 6 465 | 5 594 | 4 638 | |
(US$m) | 383 | 308 | 248 | ||
Average gold price received | (R/kg) | 2 046 390 | 1 529 149 | 1 222 101 | |
(US$/oz) | 3 769 | 2 620 | 2 033 | ||
Cash operating cost2 | (Rm) | 4 503 | 3 960 | 3 720 | |
(US$m) | 267 | 218 | 199 | ||
Production profit2 | (Rm) | 2 001 | 1 594 | 956 | |
(US$m) | 118 | 88 | 51 | ||
Capital expenditure | (Rm) | 371 | 461 | 226 | |
(US$m) | 22 | 25 | 12 | ||
Adjusted free cash flow1, 2 | (Rm) | 1 591 | 1 172 | 692 | |
(US$m) | 94 | 65 | 37 | ||
Cash operating cost2 | (R/kg) | 1 407 929 | 1 091 327 | 968 372 | |
(US$/oz) | 2 593 | 1 870 | 1 611 | ||
All-in sustaining cost2 | (R/kg) | 1 576 000 | 1 254 661 | 1 061 766 | |
(US$/oz) | 2 902 | 2 150 | 1 766 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | – | – | 2 | ||
Lost-time injury frequency rate | (per million hours worked) | 7.75 | 8.86 | 9.89 | |
Environment | |||||
Electricity consumption | (GWh) | 526 | 523 | 542 | |
Water consumption – primary activities | (Ml) | 1 544 | 2 215 | 3 020 | |
Greenhouse gas emissions | (000tCO2e) | 568 | 544 | 542 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 1.01 | 0.96 | 0.93 | |
– Water | (000m3/t) | 2.97 | 4.07 | 5.17 | |
– Greenhouse gas emissions | (tCO2e/t) | 1.09 | 1.00 | 0.93 | |
Number of reportable environmental incidents | – | – | – | ||
Community | |||||
Local economic development | (Rm) | 21 | 10 | 12 | |
Training and development | (Rm) | 21 | 18 | 16 |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
2Figures for FY24 and FY25 restated.
51
Overview of operations
Kusasalethu is a mature, deep-level mine 90km west of
Johannesburg, near the border of Gauteng and North West
provinces. Mining is at a depth of 3 388m with four years’
life of mine remaining.
The mine comprises twin vertical and twin sub-vertical shaft
systems and uses conventional mining methods in a sequential
grid layout. It exploits the Ventersdorp Contact Reef as its primary
orebody. Ore mined is treated at the Mponeng plant.
Salient features for FY26
•The operation recorded 2.9 million loss-of-life free shifts during
the year and post year-end, achieved the safety milestone of
three million loss-of-life free shifts, reflecting a continued
commitment to workforce safety
•The lost-time injury frequency rate improved by 13%, declining
to 7.75 per million hours worked in FY26, compared to 8.86
per million hours worked in FY25
•Gold production for the year totalled 3 198kg (102 818oz),
representing a 12% decrease against the 3 629kg (116 675oz)
produced in FY25. Production was periodically constrained
by geological and mining-related challenges, which
necessitated the unplanned redeployment of crews and
adversely impacted overall output
•Ore milled declined by 4% to 520 000 tonnes, compared to
544 000 tonnes in the prior year
•The recovered grade decreased by 8% to 6.15g/t, from 6.67g/t
recorded in FY25
•Notwithstanding the lower production, gold revenue increased
by 16% to R6 465 million (FY25: R5 594 million), underpinned
by a significantly higher gold price. The average gold price
received rose by 34% to R2 046 390/kg, up from R1 529 149/
kg in FY25
•Cash operating costs increased by 14% to R4 503 million
(FY25: R3 960 million), driven primarily by annual wage and
electricity tariff increases, inflationary pressures on
consumables and contractor costs, and higher MPRDA
royalties. Notably, royalties surged 96% year-on-year to R208
million (FY25: R106 million)
•Capital expenditure declined 19% to R371 million (FY25:
R461 million), with R252 million directed toward ongoing
development activities
•Adjusted free cash flow improved strongly, rising 36% to
R1 591 million (FY25: R1 172 million).
Key indicators for FY27
•Four-year life of mine
•Production guidance of between 107 300oz and 114 000oz
•Capital expenditure of approximately R626 million, mainly for
ongoing development.
Our focus areas in FY27 Development ramp-up well on track. Maintaining the iceberg and ensure minable face length remains on plan with proper execution strategies on equipping. New raise lines with double shift blasting implemented to fast-track raise holing dates paying off. Organic growth opportunities linked to the exploration strategies critical to understand the grade model beyond BV 78. | |||
52
Masimong
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 1 933 | 1 923 | 1 945 | ||
Contractors | 285 | 166 | 148 | ||
Total | 2 218 | 2 089 | 2 093 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 415 | 424 | 473 | |
(000t) (imperial) | 458 | 468 | 523 | ||
Gold produced | (kg) | 1 562 | 1 478 | 1 780 | |
(oz) | 50 219 | 47 519 | 57 229 | ||
Gold sold | (kg) | 1 563 | 1 483 | 1 756 | |
(oz) | 50 251 | 47 679 | 56 457 | ||
Grade | (g/t) | 3.76 | 3.49 | 3.76 | |
(oz/t) | 0.110 | 0.102 | 0.109 | ||
Productivity | (g/TEC) | 66.71 | 64.41 | 77.75 | |
Development results | |||||
– Total metres (excluding capital metres) | 2 869 | 2 652 | 2 474 | ||
– Reef metres | 745 | 937 | 640 | ||
– Capital metres | – | – | – | ||
Financial | |||||
Revenue | (Rm) | 3 231 | 2 245 | 2 137 | |
(US$m) | 191 | 124 | 114 | ||
Average gold price received | (R/kg) | 2 067 183 | 1 513 550 | 1 216 723 | |
(US$/oz) | 3 807 | 2 593 | 2 024 | ||
Cash operating cost2 | (Rm) | 2 305 | 1 966 | 1 887 | |
(US$m) | 136 | 108 | 101 | ||
Production profit2 | (Rm) | 943 | 271 | 280 | |
(US$m) | 56 | 15 | 15 | ||
Capital expenditure | (Rm) | 89 | 111 | 44 | |
(US$m) | 5 | 6 | 2 | ||
Adjusted free cash flow1, 2 | (Rm) | 837 | 167 | 206 | |
(US$m) | 50 | 9 | 11 | ||
Cash operating cost2 | (R/kg) | 1 475 458 | 1 330 370 | 1 059 843 | |
(US$/oz) | 2 717 | 2 279 | 1 763 | ||
All-in sustaining cost2 | (R/kg) | 1 530 548 | 1 448 902 | 1 124 542 | |
(US$/oz) | 2 819 | 2 482 | 1 871 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | – | – | – | ||
Lost-time injury frequency rate | (per million hours worked) | 4.82 | 4.43 | 3.20 | |
Environment | |||||
Electricity consumption | (GWh) | 152 | 142 | 140 | |
Water consumption – primary activities | (Ml) | 603 | 676 | 647 | |
Greenhouse gas emissions | (000tCO2e) | – | 148 | 140 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 0.37 | 0.34 | 0.30 | |
– Water | (000m3/t) | – | 1.60 | 1.37 | |
– Greenhouse gas emissions | (tCO2e/t) | – | 0.35 | 0.30 | |
Number of reportable environmental incidents | – | – | – | ||
Community | |||||
Local economic development | (Rm) | 5 | 8 | 11 | |
Training and development | (Rm) | 37 | 38 | 34 |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
2Figures for FY24 and FY25 restated.
53
Overview of operations
Masimong is a deep-level mine in the Free State, near Welkom,
some 260km from Johannesburg. The operation is close to the
end of its mine life, with three years of mining left. Masimong
is a mine that reflects the effectiveness of Harmony’s business
model.
The Masimong complex comprises two shafts with 5 shaft used
as the operating shaft and 4 shaft for ventilation, pumping and
a second escape outlet. Masimong exploits the Basal Reef and
B Reef, using a conventional tabular narrow-reef stoping method.
Mining is conducted at a depth of 1 650m to 2 010m below collar.
Ore mined is processed at the nearby Harmony One plant.
Salient features for FY26
•The operation achieved 4.8 million loss-of-life free shifts during
FY26
•However, the lost-time injury frequency rate (LTIFR) regressed
9%, rising to 4.82 per million hours worked (FY25: 4.43 per
million hours worked)
•Gold production grew by 6% year-on-year to 1 562kg
(50 219oz), compared to 1 478kg (47 519oz) in FY25
•Ore milled was marginally lower at 415 000 tonnes (FY25:
424 000 tonnes), while the recovered grade improved by
8% to 3.76g/t from 3.49g/t in the prior year
•Gold revenue increased by 44% to R3 231 million (FY25:
R2 245 million), supported by higher production volumes and
a 37% increase in the gold price to R2 067 183/kg (FY25:
R1 513 550/kg)
•Cash operating costs rose by 17% to R2 305 million (FY25:
R1 966 million), primarily driven by annual wage increases and
higher electricity tariffs. MPRDA royalties surged 188% to
R161 million (FY25: R56 million)
•Capital expenditure decreased to R89 million (FY25:
R111 million), largely directed towards equipment replacement.
Key indicators for FY27
•Three-year life of mine
•Production guidance of between 49 400oz and 52 000oz
•Capital expenditure of approximately R322 million. A total of
R193 million is planned towards on-going development due to
the extension in life of mine. The remainder being planned for
equipment and plant maintenance.
Our focus areas in FY27 Advance development activity to unlock further ore access, supported by continued investment in workforce capability and sustained safety leadership. Aggressively drive exploration in the 1550 and Saaiplaas blocks to unlock the envisaged organic growth potential. | |||
54
Mine Waste Solutions (tailings retreatment)
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 554 | 544 | 516 | ||
Contractors | 1 140 | 1 633 | 1 880 | ||
Total | 1 694 | 2 177 | 2 396 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 24 986 | 23 054 | 22 655 | |
(000t) (imperial) | 27 552 | 25 423 | 24 982 | ||
Gold produced | (kg) | 2 680 | 2 996 | 3 770 | |
(oz) | 86 164 | 96 323 | 121 207 | ||
Gold sold | (kg) | 2 670 | 3 057 | 3 742 | |
(oz) | 85 843 | 98 284 | 120 309 | ||
Grade | (g/t) | 0.107 | 0.130 | 0.166 | |
(oz/t) | 0.003 | 0.004 | 0.005 | ||
Productivity | (g/TEC) | 232.31 | 288.35 | 481.06 | |
Financial | |||||
Revenue1 | (Rm) | 5 507 | 4 458 | 4 016 | |
(US$m) | 326 | 246 | 215 | ||
Average gold price received | (R/kg) | 2 062 407 | 1 430 061 | 986 777 | |
(US$/oz) | 3 798 | 2 450 | 1 641 | ||
Cash operating cost3 | (Rm) | 2 459 | 2 205 | 2 058 | |
(US$m) | 146 | 121 | 110 | ||
Production profit3 | (Rm) | 3 073 | 2 237 | 1 966 | |
(US$m) | 182 | 123 | 105 | ||
Capital expenditure | (Rm) | 674 | 1 061 | 1 463 | |
(US$m) | 40 | 58 | 78 | ||
Adjusted free cash flow2, 3 | (Rm) | 2 373 | 1 105 | 172 | |
(US$m) | 140 | 61 | 9 | ||
Cash operating cost3 | (R/kg) | 917 667 | 736 108 | 545 991 | |
(US$/oz) | 1 690 | 1 261 | 908 | ||
All-in sustaining cost3 | (R/kg) | 998 921 | 794 566 | 606 396 | |
(US$/oz) | 1 840 | 1 361 | 1 009 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | – | – | – | ||
Lost-time injury frequency rate | (per million hours worked) | 4.52 | 5.41 | 4.04 | |
Environment | |||||
Electricity consumption | (GWh) | 238 | 224 | 212 | |
Water consumption – primary activities | (Ml) | 5 343 | 5 710 | 5 744 | |
Greenhouse gas emissions | (000tCO2e) | 265 | 244 | 222 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 0.01 | 0.01 | 0.01 | |
– Water | (000m3/t) | – | 0.25 | 0.25 | |
– Greenhouse gas emissions | (tCO2e/t) | 0.01 | 0.01 | 0.01 | |
Number of reportable environmental incidents | – | – | – | ||
Community | |||||
Local economic development | (Rm) | – | – | – | |
Training and development | (Rm) | 16 | 15 | 11 |
1Includes a non-cash consideration for the streaming arrangement with Franco-Nevada.
2Adjusted free cash flow = revenue – Franco-Nevada non-cash consideration – cash operating cost – capital
expenditure as per operating results.
3Figures for FY24 and FY25 restated.
55
Overview of operations
Mine Waste Solutions (MWS) is a tailings retreatment operation
near Klerksdorp in the North West province. It reprocesses low-
grade material from tailings storage facilities scattered across the
Vaal River and Stilfontein area to reduce the tailings footprint.
The operation was acquired from AngloGold Ashanti Limited
in October 2020.
Harmony’s subsidiary, Chemwes Proprietary Limited, the owner
of Mine Waste Solutions, had a contract with Franco-Nevada
Barbados (Franco-Nevada) where Franco-Nevada was entitled
to receive 25% of all the gold produced through Mine Waste
Solutions.
On 23 October 2024, Harmony fulfilled all its obligations
stemming from the streaming agreement with Franco-Nevada.
From this date onwards, all gold revenue generated was based
on quoted market prices.
Salient features for FY26
•The lost-time injury frequency rate at Mine Waste Solutions
improved to 4.52 per million hours worked (FY25: 5.41 per
million hours worked)
•Gold production declined by 11% to 2 680kg (86 164oz),
compared to 2 996kg (96 323oz) in FY25, primarily due to the
industry-wide cyanide supply shortage that severely disrupted
operations during the December 2025 quarter and continued to
impact the March 2026 quarter. Production losses were further
compounded by adverse weather conditions, Eskom power
failures and broader operational challenges throughout FY26
•Ore processed increased by 8% to 24.99 million tonnes, up
from 23.05 million tonnes in FY25
•The recovered grade was negatively impacted by the
aforementioned challenges, declining 18% to 0.107g/t from
0.130g/t in FY25
•Despite lower production, revenue grew by 24% to R5 507
million (FY25: R4 458 million), underpinned by a 44% increase in
the gold price received, which rose to R2 062 407/kg from R1
430 061/kg in FY25. It is noted that FY25 pricing was still
partially suppressed by the Franco-Nevada contract, which
concluded in October 2024
•Cash operating costs rose by 12% to R2 459 million (FY25:
R2 205 million), driven primarily by annual wage and electricity
tariff increases, alongside inflationary pressures on
consumables and contractor costs
•Capital expenditure decreased significantly by 36% to
R674 million, compared to R1 061 million in FY25, largely
reflecting the completion of the Kareerand expansion project
•Adjusted free cash flow improved substantially to R2 373
million, more than doubling from R1 105 million recorded in
FY25.
Key indicators for FY27
•13-year life of mine
•Production guidance of approximately 93 000oz
•Capital expenditure of approximately R215 million, mainly for
plant capital and significantly lower than previous years due
to the completion of the Kareerand extension project.
Our focus areas in FY27 The focus in the new year is to ensure operational excellence in all aspects of the business and achievement of the strategic plan. | |||
56
Kalgold
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 268 | 258 | 266 | ||
Contractors | 645 | 485 | 475 | ||
Total | 913 | 743 | 741 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 1 467 | 1 464 | 1 492 | |
(000t) (imperial) | 1 618 | 1 614 | 1 645 | ||
Gold produced | (kg) | 1 109 | 1 236 | 1 425 | |
(oz) | 35 655 | 39 738 | 45 815 | ||
Gold sold | (kg) | 1 144 | 1 206 | 1 423 | |
(oz) | 36 781 | 38 774 | 45 750 | ||
Grade | (g/t) | 0.76 | 0.84 | 0.96 | |
(oz/t) | 0.022 | 0.025 | 0.028 | ||
Productivity | (g/TEC) | 119.42 | 137.01 | 186.71 | |
Financial | |||||
Revenue | (Rm) | 2 345 | 1 842 | 1 730 | |
(US$m) | 139 | 101 | 93 | ||
Average gold price received | (R/kg) | 2 049 684 | 1 527 460 | 1 216 047 | |
(US$/oz) | 3 775 | 2 617 | 2 023 | ||
Cash operating cost2 | (Rm) | 1 259 | 1 198 | 1 057 | |
(US$m) | 75 | 66 | 57 | ||
Production profit2 | (Rm) | 1 060 | 677 | 676 | |
(US$m) | 63 | 37 | 36 | ||
Capital expenditure | (Rm) | 397 | 150 | 263 | |
(US$m) | 24 | 8 | 14 | ||
Adjusted free cash flow1, 2 | (Rm) | 712 | 479 | 408 | |
(US$m) | 42 | 26 | 22 | ||
Cash operating cost2 | (R/kg) | 1 135 153 | 969 049 | 741 817 | |
(US$/oz) | 2 090 | 1 660 | 1 234 | ||
All-in sustaining cost2 | (R/kg) | 1 534 775 | 1 120 104 | 949 461 | |
(US$/oz) | 2 826 | 1 919 | 1 579 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | – | – | – | ||
Lost-time injury frequency rate | (per million hours worked) | 0.60 | 3.54 | 1.46 | |
Environment | |||||
Electricity consumption | (GWh) | 50 | 53 | 54 | |
Water consumption – primary activities | (Ml) | 276 | 260 | 285 | |
Greenhouse gas emissions | (000tCO2e) | 77 | 73 | 73 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 0.03 | 0.04 | 0.04 | |
– Water | (000m3/t) | – | 0.18 | 0.19 | |
– Greenhouse gas emissions | (tCO2e/t) | 0.05 | 0.05 | 0.05 | |
Number of reportable environmental incidents | – | – | – | ||
Community | |||||
Local economic development | (Rm) | 1 | 3 | 2 | |
Training and development | (Rm) | 12 | 15 | 10 |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure ± impact of run-of-mine costs
as per operating results.
2Figures for FY24 and FY25 restated.
57
Overview of operations
Kalgold is a long-life, open-pit gold mine on the Kraaipan
Greenstone Belt, 55km south-west of Mahikeng in North
West province.
Mining takes place from the A-zone pit, Watertank pit, Henry’s pit
as well as Windmill pit. Mined ore is processed at the carbon-in-
leach Kalgold plant.
Salient features for FY26
•Kalgold maintained its loss-of-life free record in FY26
•The lost-time injury frequency rate improved significantly to
0.60 per million hours worked (FY25: 3.54 per million hours
worked)
•Gold production declined by 10% to 1 109kg (35 655oz),
compared to 1 236kg (39 738oz) in FY25. This was primarily
attributable to the industry-wide cyanide shortage experienced
during the December 2025 quarter, as well as inclement
weather during the June 2026 quarter, which restricted access
to high-grade blocks and negatively impacted recovered
grades
•Ore milled remained broadly in line with FY25 at 1.467 million
tonnes (FY25: 1.464 million tonnes)
•The recovered grade of 0.76g/t was 10% lower than the 0.84g/t
recorded in the prior year, reflecting the constraints noted
above
•Notwithstanding the lower production, gold revenue increased
by 27% to R2 345 million (FY25: R1 842 million), supported by
a materially higher gold price received. The gold price received
rose by 34% to R2 049 684/kg (FY25: R1 527 460/kg)
•Cash operating costs increased by 5% to R1 259 million (FY25:
R1 198 million), driven primarily by annual wage and electricity
tariff increases, partially offset by higher deferred stripping
credits
•Capital expenditure increased to R397 million (FY25:
R150 million), largely reflecting higher capitalised stripping of
R335 million compared to R114 million in FY25
•Adjusted free cash flow grew by 49% to R712 million (FY25:
R479 million).
Key indicators for FY27
•12-year life of mine
•Production guidance of between 37 500oz and 40 000oz
•Capital expenditure of approximately R75 million, mainly
for plant capital.
Our focus areas in FY27 To maintain steady production execution from all four pits and sustain the prospecting exploration drilling of the D-Zone Area for the operation’s organic growth. | |||
58
Phoenix (tailings retreatment)
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 86 | 88 | 86 | ||
Contractors | 370 | 355 | 261 | ||
Total | 456 | 443 | 347 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 5 293 | 5 857 | 6 067 | |
(000t) (imperial) | 5 836 | 6 459 | 6 691 | ||
Gold produced | (kg) | 780 | 954 | 923 | |
(oz) | 25 078 | 30 673 | 29 674 | ||
Gold sold | (kg) | 780 | 960 | 905 | |
(oz) | 25 078 | 30 865 | 29 096 | ||
Grade | (g/t) | 0.147 | 0.163 | 0.152 | |
(oz/t) | 0.004 | 0.005 | 0.004 | ||
Productivity | (g/TEC) | 331.71 | 443.92 | 449.21 | |
Financial | |||||
Revenue | (Rm) | 1 780 | 1 570 | 1 140 | |
(US$m) | 105 | 86 | 61 | ||
Average gold price received | (R/kg) | 2 282 378 | 1 635 717 | 1 259 294 | |
(US$/oz) | 4 203 | 2 802 | 2 095 | ||
Cash operating cost2 | (Rm) | 639 | 571 | 546 | |
(US$m) | 38 | 31 | 29 | ||
Production profit2 | (Rm) | 1 145 | 999 | 603 | |
(US$m) | 68 | 55 | 32 | ||
Capital expenditure | (Rm) | 89 | 116 | 14 | |
(US$m) | 5 | 6 | 1 | ||
Adjusted free cash flow1, 2 | (Rm) | 1 052 | 884 | 580 | |
(US$m) | 62 | 49 | 31 | ||
Cash operating cost2 | (R/kg) | 819 669 | 598 034 | 591 753 | |
(US$/oz) | 1 509 | 1 025 | 984 | ||
All-in sustaining cost2 | (R/kg) | 930 533 | 721 679 | 617 062 | |
(US$/oz) | 1 714 | 1 236 | 1 026 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | – | 1 | – | ||
Lost-time injury frequency rate | (per million hours worked) | – | 2.16 | – | |
Environment | |||||
Electricity consumption | (GWh) | 36 | 42 | 40 | |
Water consumption – primary activities | (Ml) | 574 | 314 | 98 | |
Greenhouse gas emissions | (000tCO2e) | 39 | 44 | 40 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 0.01 | 0.01 | 0.01 | |
– Water | (000m3/t) | – | 0.05 | 0.02 | |
– Greenhouse gas emissions | (tCO2e/t) | 0.01 | 0.01 | 0.01 | |
Number of reportable environmental incidents | – | – | – |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
2Figures for FY24 and FY25 restated.
59
Overview of operations
Phoenix is a tailings retreatment operation in Virginia, Free State.
It retreats tailings from Harmony’s tailings storage facilities in the
Free State region to extract any residual gold, using the Saaiplaas
plant. It is 100% owned by the black economic empowerment
company, Tswelopele Beneficiation Operation Proprietary Limited,
of which Harmony is a 77% shareholder.
Salient features for FY26
•The operation achieved a loss-of-life free year
•Gold production declined by 18% to 780kg (25 078oz)
compared to 954kg (30 673oz) in FY25, although this was
consistent with planned production targets
•Ore processed totalled 5.3 million tonnes, a 10% reduction
from the 5.9 million tonnes processed in FY25
•The recovered grade fell 10% to 0.147g/t, from 0.163g/t
recorded in the prior year
•Revenue grew by 13% to R1 780 million (FY25: R1 570 million),
as a significantly higher gold price received more than offset the
decline in production volumes. The gold price received
increased by 40% to R2 282 378/kg, up from R1 635 717/kg
in FY25
•The lower production volumes resulted in all-in sustaining costs
rising 29% to R930 533/kg (FY25: R721 679/kg). Cash
operating costs increased by 12% from R571 million to R639
million, driven primarily by annual wage and electricity tariff
increases, as well as higher water, maintenance, and security
costs
•Capital expenditure decreased to R89 million (FY25: R116
million), with spend directed mainly towards establishing the
FSS6 feed source and plant maintenance activities
•Phoenix generated adjusted free cash of R1 052 million,
representing a 19% increase over the R884 million recorded
in FY25.
Key indicators for FY27
•Four-year life of mine
•Production guidance of approximately 25 200oz
•Capital expenditure of approximately R64 million, mainly
towards plant capital.
Our focus areas in FY27 Focus on operational excellence throughout the value chain of the business. | |||
60
Central Plant Reclamation (tailings retreatment)
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 93 | 88 | 96 | ||
Contractors | 295 | 183 | 154 | ||
Total | 388 | 271 | 250 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 3 729 | 3 912 | 3 936 | |
(000t) (imperial) | 4 112 | 4 313 | 4 340 | ||
Gold produced | (kg) | 674 | 646 | 615 | |
(oz) | 21 670 | 20 770 | 19 773 | ||
Gold sold | (kg) | 668 | 655 | 609 | |
(oz) | 21 476 | 21 059 | 19 580 | ||
Grade | (g/t) | 0.181 | 0.165 | 0.156 | |
(oz/t) | 0.005 | 0.005 | 0.005 | ||
Productivity | (g/TEC) | 334.32 | 323.90 | 306.51 | |
Financial | |||||
Revenue | (Rm) | 1 380 | 1 013 | 741 | |
(US$m) | 82 | 56 | 40 | ||
Average gold price received | (R/kg) | 2 066 448 | 1 547 217 | 1 216 856 | |
(US$/oz) | 3 806 | 2 651 | 2 024 | ||
Cash operating cost2 | (Rm) | 361 | 362 | 359 | |
(US$m) | 21 | 20 | 19 | ||
Production profit2 | (Rm) | 1 023 | 645 | 386 | |
(US$m) | 61 | 36 | 21 | ||
Capital expenditure | (Rm) | 74 | 20 | 36 | |
(US$m) | 4 | 1 | 2 | ||
Adjusted free cash flow1, 2 | (Rm) | 945 | 631 | 346 | |
(US$m) | 56 | 35 | 19 | ||
Cash operating cost2 | (R/kg) | 535 276 | 560 782 | 583 728 | |
(US$/oz) | 986 | 961 | 971 | ||
All-in sustaining cost2 | (R/kg) | 578 135 | 594 696 | 646 595 | |
(US$/oz) | 1 065 | 1 019 | 1 076 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | – | – | – | ||
Lost-time injury frequency rate | (per million hours worked) | 4.89 | 2.38 | – | |
Environment | |||||
Electricity consumption | (GWh) | 22 | 24 | 24 | |
Water consumption – primary activities | (Ml) | 209 | 224 | 178 | |
Greenhouse gas emissions | (000tCO2e) | 26 | 27 | 27 | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | 0.01 | 0.01 | 0.01 | |
– Water | (000m3/t) | – | 0.06 | 0.05 | |
– Greenhouse gas emissions | (tCO2e/t) | 0.01 | 0.01 | 0.01 | |
Number of reportable environmental incidents | – | – | – |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
2Figures for FY24 and FY25 restated.
61
Overview of operations
Central Plant Reclamation is a tailings retreatment operation near
Welkom in the Free State. Originally built to process waste rock
dumps, it was converted into a tailings retreatment facility in FY17.
Salient features for FY26
•Central Plant Reclamation continued to uphold its strong safety
record during the period
•Gold production rose 4% year-on-year to 674kg (21 670oz),
up from 646kg (20 770oz) in FY25
•Ore processed declined 5%, which totalled 3.7 million tonnes
compared to 3.9 million tonnes in the prior year
•The recovered grade improved by 10% to 0.181g/t, from
0.165g/t previously
•Revenue grew significantly, increasing 36% to R1 380 million
from R1 013 million in FY25, driven by both higher gold
production and a stronger gold price received. The gold price
realised rose 34% to R2 066 448/kg, compared to R1 547 217/
kg in the prior year
•The all-in sustaining cost improved by 3% to R578 135/kg
(FY25: R594 696/kg), reflecting the benefit of higher gold
production. Cash costs remained largely stable at R361 million,
broadly in line with the R362 million recorded in FY25
•Capital expenditure increased substantially from R20 million in
FY25 to R74 million, predominantly directed towards the FSS3
feed source and plant maintenance
•Adjusted free cash flow increased by 50% to R945 million,
compared to R631 million in the prior year.
Key indicators for FY27
•Nine-year life of mine
•Production guidance of approximately 17 700oz
•Capital expenditure of approximately R56 million,
mainly towards the FSS3 feed source and plant capital.
Our focus areas in FY27 Focus on operational excellence throughout the value chain of the business. | |||
62
Savuka (tailings retreatment)
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 104 | 100 | 100 | ||
Contractors | 197 | 140 | 140 | ||
Total | 301 | 240 | 240 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 3 700 | 3 669 | 4 019 | |
(000t) (imperial) | 4 079 | 4 046 | 4 431 | ||
Gold produced | (kg) | 566 | 568 | 609 | |
(oz) | 18 198 | 18 261 | 19 579 | ||
Gold sold | (kg) | 561 | 560 | 615 | |
(oz) | 18 036 | 18 004 | 19 773 | ||
Grade | (g/t) | 0.153 | 0.155 | 0.152 | |
(oz/t) | 0.004 | 0.005 | 0.004 | ||
Productivity1 | (g/TEC) | 249.36 | 250.13 | 272.98 | |
Financial | |||||
Revenue | (Rm) | 1 157 | 861 | 753 | |
(US$m) | 69 | 47 | 40 | ||
Average gold price received | (R/kg) | 2 062 868 | 1 538 107 | 1 223 769 | |
(US$/oz) | 3 799 | 2 635 | 2 036 | ||
Cash operating cost3 | (Rm) | 389 | 391 | 355 | |
(US$m) | 23 | 22 | 19 | ||
Production profit3 | (Rm) | 772 | 476 | 393 | |
(US$m) | 46 | 26 | 21 | ||
Capital expenditure | (Rm) | 141 | 48 | 21 | |
(US$m) | 8 | 3 | 1 | ||
Adjusted free cash flow2, 3 | (Rm) | 628 | 422 | 377 | |
(US$m) | 37 | 23 | 20 | ||
Cash operating cost3 | (R/kg) | 686 528 | 687 907 | 583 368 | |
(US$/oz) | 1 264 | 1 179 | 970 | ||
All-in sustaining cost3 | (R/kg) | 925 701 | 773 489 | 617 754 | |
(US$/oz) | 1 705 | 1 325 | 1 028 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
Safety | |||||
Loss of life | – | – | – | ||
Lost-time injury frequency rate | (per million hours worked) | – | 2.48 | – | |
1FY24 figure restated.
2Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
3Figures for FY24 and FY25 restated.
63
Overview of operations
Savuka plant is situated near the town of Carletonville and was
acquired from AngloGold Ashanti Limited in October 2020.
The plant originally treated both waste rock and tailings, but
was converted to a tailings treatment facility in October 2021
when the milling section of the plant was decommissioned.
Salient features for FY26
•The operation sustained its strong safety record throughout the
period
•Gold production remained broadly stable year-on-year at
566kg (18 198oz), compared to 568kg (18 261oz) in the prior
year
•Ore processed increased marginally to 3.700 million tonnes,
up from 3.669 million tonnes in FY25
•The recovered grade was 1% lower at 0.153g/t when
compared to the 0.155g/t in FY25
•Gold revenue grew 34% to R1 157 million (FY25: R861 million),
driven by a 34% increase in the average gold price received,
which rose from R1 538 107/kg to R2 062 868/kg
•The all-in sustaining cost increased by 20% to R925 701/kg
(FY25: R773 489/kg), largely reflecting a significant rise in plant
capital expenditure. Cash costs, however, remained well
controlled, edging slightly lower to R389 million from R391
million in FY25
•Sustaining capital expenditure increased by R93 million to
R141 million (FY25: R48 million), with the majority allocated to
the 7A/7B deposition project and plant maintenance activities.
Key indicators for FY27
•Six-year life of mine
•Production guidance of approximately 16 700oz
•Capital expenditure of approximately R251 million, mainly
for the Mponeng lower compartment project and plant capital.
Our focus areas in FY27 Awaiting the new authorised TSF height and implementation of the plan to divert Savuka residue to Mponeng TSF. | |||
64
Waste rock dumps
FY26 | FY25 | FY24 | |||
Operational | |||||
Volumes milled | (000t) (metric) | 3 072 | 3 885 | 4 162 | |
(000t) (imperial) | 3 387 | 4 285 | 4 590 | ||
Gold produced | (kg) | 1 071 | 1 475 | 1 724 | |
(oz) | 34 434 | 47 422 | 55 429 | ||
Gold sold | (kg) | 1 075 | 1 458 | 1 718 | |
(oz) | 34 561 | 46 875 | 55 235 | ||
Grade | (g/t) | 0.349 | 0.380 | 0.414 | |
(oz/t) | 0.010 | 0.011 | 0.012 | ||
Financial | |||||
Revenue | (Rm) | 2 220 | 2 208 | 2 100 | |
(US$m) | 131 | 122 | 112 | ||
Average gold price received | (R/kg) | 2 064 738 | 1 514 674 | 1 222 494 | |
(US$/oz) | 3 802 | 2 595 | 2 034 | ||
Cash operating cost | (Rm) | 1 287 | 1 431 | 1 395 | |
(US$m) | 76 | 79 | 75 | ||
Production profit | (Rm) | 930 | 773 | 712 | |
(US$m) | 55 | 43 | 38 | ||
Capital expenditure | (Rm) | 54 | – | 4 | |
(US$m) | 3 | – | – | ||
Adjusted free cash flow1 | (Rm) | 878 | 778 | 700 | |
(US$m) | 52 | 43 | 37 | ||
Cash operating cost | (R/kg) | 1 202 044 | 969 849 | 809 415 | |
(US$/oz) | 2 214 | 1 662 | 1 346 | ||
All-in sustaining cost | (R/kg) | 1 249 799 | 984 564 | 810 746 | |
(US$/oz) | 2 302 | 1 687 | 1 349 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | – | – | – | ||
Lost-time injury frequency rate | (per million hours worked) | – | – | – | |
Environment | |||||
Electricity consumption | (GWh) | * | * | * | |
Water consumption – primary activities | (Ml) | * | * | * | |
Greenhouse gas emissions | (000tCO2e) | * | * | * | |
Intensity data per tonne treated | |||||
– Energy | (MWh/t) | * | * | * | |
– Water | (000m3/t) | * | * | * | |
– Greenhouse gas emissions | (tCO2e/t) | * | * | * | |
Number of reportable environmental incidents | – | – | – |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure as per operating results.
*Electricity and water consumption and related emission and intensity data for the respective plants at which
the waste rock dumps are processed are accounted for as part of the primary operation’s environmental
results.
65
Overview of operations
Production from processing surface rock dumps, situated across
Harmony’s operations, depends entirely on the availability of
spare mill capacity at the various operational plants. At the end of
FY25 Kusasalethu plant (near the border of Gauteng and North
West provinces) ceased milling waste rock and no longer
produces gold. The plant now receives tailings from the Savuka
plant to produce backfill material, which is used to provide ground
support in active stoping areas. Waste rock dumps near Orkney
(acquired with Moab Khotsong operations) is treated at the
Noligwa plant. Milling of waste rock dumps at the Doornkop plant
in Gauteng began in FY18. Waste rock dumps and tailings
facilities acquired with Mponeng are treated at Mponeng and
Savuka plants respectively. Surface ore treated at Kopanang
plant was unprofitable and closed during the first quarter of FY22.
The plant is currently on care and maintenance.
Salient features for FY26
•Gold production declined 27% to 1 071kg (34 434oz),
compared to 1 475kg (47 422oz) in FY25. Performance across
these operations were impacted by the depletion of ore
sources, below-plan delivered grades at certain sites, milling
constraints, and delays in the commissioning of the conveyor
belt at the Loraine 1 waste rock feed source
•Ore milled decreased by 21% to 3.1 million tonnes, down from
3.9 million tonnes in FY25
•The recovered grade declined 8% to 0.349g/t, from 0.380g/t
recorded in FY25
•Despite lower production volumes, gold revenue increased
marginally to R2 220 million (FY25: R2 208 million), supported by
a higher gold price received. The average gold price received
rose 36% to R2 064 738/kg, compared to R1 514 674/kg in
FY25
•The impact of reduced production drove the all-in sustaining
cost 27% higher to R1 249 799/kg (FY25: R984 564/kg). Cash
cost, however, decreased by 10%, reflecting lower throughput
volumes.
Our focus areas in FY27 Our priority is to continue safe, profitable production by maintaining costs and improving mining efficiencies. | |||
66
Papua New Guinea
Hidden Valley
FY26 | FY25 | FY24 | |||
Number of employees | |||||
Permanent | 1 489 | 1 416 | 1 387 | ||
Contractors | 730 | 950 | 696 | ||
Total | 2 219 | 2 366 | 2 083 | ||
Operational | |||||
Volumes milled | (000t) (metric) | 3 720 | 3 787 | 3 360 | |
(000t) (imperial) | 4 102 | 4 177 | 3 705 | ||
Gold produced | (kg) | 5 904 | 5 107 | 5 101 | |
(oz) | 189 818 | 164 193 | 164 000 | ||
Gold sold | (kg) | 5 960 | 5 098 | 5 052 | |
(oz) | 191 619 | 163 905 | 162 425 | ||
Grade | (g/t) | 1.59 | 1.35 | 1.52 | |
(oz/t) | 0.046 | 0.039 | 0.044 | ||
Financial | |||||
Revenue | (Rm) | 12 397 | 7 923 | 6 181 | |
(US$m) | 734 | 436 | 331 | ||
Average gold price received | (R/kg) | 2 079 976 | 1 554 096 | 1 223 409 | |
(US$/oz) | 3 830 | 2 663 | 2 035 | ||
Cash operating cost | (Rm) | 1 264 | 2 344 | 2 435 | |
(US$m) | 75 | 129 | 130 | ||
Production profit | (Rm) | 11 077 | 5 467 | 3 933 | |
(US$m) | 656 | 301 | 210 | ||
Capital expenditure | (Rm) | 2 431 | 1 620 | 1 541 | |
(US$m) | 144 | 89 | 82 | ||
Adjusted free cash flow1 | (Rm) | 8 403 | 3 766 | 2 188 | |
(US$m) | 497 | 207 | 117 | ||
Cash operating cost | (R/kg) | 214 049 | 458 928 | 477 360 | |
(US$/oz) | 394 | 786 | 794 | ||
All-in sustaining cost | (R/kg) | 658 503 | 868 228 | 814 375 | |
(US$/oz) | 1 208 | 1 486 | 1 352 | ||
Average exchange rate | (R/US$) | 16.89 | 18.15 | 18.70 | |
FY26 | FY25 | FY24 | |||
Safety | |||||
Loss of life | – | – | – | ||
Lost-time injury frequency rate | (per million hours worked) | 0.17 | – | 0.34 | |
Environment | |||||
Electricity consumption2 | (GWh) | 132 | 139 | 129 | |
Water consumption – primary activities | (Ml) | 2 110 | 2 047 | 2 112 | |
Greenhouse gas emissions3 | (000tCO2e) | 161 | 184 | 179 | |
Intensity data per tonne treated | |||||
– Energy4 | (MWh/t) | 0.04 | 0.04 | 0.04 | |
– Water | (000m3/t) | 0.57 | 0.54 | 0.63 | |
– Greenhouse gas emissions | (tCO2e/t) | 0.04 | 0.05 | 0.05 | |
Number of reportable environmental incidents | – | – | – |
1Adjusted free cash flow = revenue – cash operating cost – capital expenditure ± impact of run-of-mine costs
as per operating results.
2Electricity consumption includes both self-generated and grid-purchased.
3Inclusive of scope 1 (direct) and scope 2 (indirect from purchased electricity) emissions.
4Represents electricity only.
67
Overview of operations
The Hidden Valley mine is an open-pit gold and silver operation
in Morobe Province, Papua New Guinea, some 210km north-
west of Port Moresby. The mine is located at elevations of
1 700m to 2 800m above sea level in steep mountainous and
forested terrain that receives around 3 000mm of rainfall per year.
The major gold and silver deposits of Hidden Valley are in the
Morobe Granodiorite of the Wau Graben.
Crushed ore is conveyed from the pit via a 5.5km overland pipe
conveyor and treated at the Hidden Valley processing plant, using
a two-stage crushing circuit followed by a semi-autogenous
grinding mill, gravity, counter current decantation/Merrill Crowe
circuit for silver and a carbon-in-leach circuit for gold.
Salient features for FY26
•Hidden Valley continued its outstanding safety record,
achieving a tenth consecutive year without any loss-of-life
incidents and surpassing 5.1 million loss-of-life free shifts
•Gold production rose 16% year-on-year to 5 904kg (189
818oz), up from 5 107kg (164 193oz) in FY25
•Ore milled came in marginally lower at 3.7 million tonnes,
compared to 3.8 million tonnes in the prior year
•The recovered grade improved significantly by 18% to 1.59g/t
from 1.35g/t in FY25
•Revenue surged 56% to R12 397 million (FY25: R7 923 million),
driven by both higher production volumes and a 34% increase
in the gold price received, which rose to R2 079 976/kg from
R1 554 096/kg in FY25
•All-in sustaining cost declined 24% to R658 503/kg
(FY25: R868 228/kg), reflecting the benefits of increased
production, lower operating costs boosted by higher silver
credits attributable to improved silver prices
•Total capital expenditure increased 50% to R2 431 million from
R1 620 million in FY25, primarily driven by capitalised stripping
activities and equipment replacement
•Hidden Valley once again ranked as the second-largest
individual mine contributor to adjusted free cash flow,
generating R8 403 million for the period, compared to R3 766
million in FY25.
Key indicators for FY27
•Four-year life of mine
•Production guidance of between 167 800oz and 174 200oz
•Capital expenditure of approximately R3 472 million, mainly
for deferred stripping capital, tailings storage facility and plant
maintenance.
Our focus areas in FY27 Our focus is on safe, environmentally responsible, margin- focused production against plan and progressing of project studies for life-of-mine extension. | |||
68
Exploration and projects
Harmony prioritises the successful execution of multiple, significant projects to sustain the profitability of operational mines and
secure long-term value creation for our business and stakeholders. We achieve this by investing in major projects, including the
extension of our assets, TSF reclamation, renewable energy and copper growth. We also actively invest in greenfield and brownfield
exploration to mitigate the risk of a depleting Mineral Reserve base. This drives short to medium-term organic Mineral Reserve
replacement and growth to support our goal of increasing quality ounces.
Optimal long-term value creation and margin expansion |
Exploration | ||||
Regional Eva Copper portfolio drilling | ||||
Kalgold drilling – brownfields | ||||
CSA mine extension drilling | ||||
Studies | ||||
Free State surface re-mining | ||||
West Wits surface re-mining | ||||
Kusasalethu extension | ||||
TauTona CLR1 pillar | ||||
Hidden Valley (stage 9) | ||||
1Carbon Leader Reef.
Permitting | ||||
Wafi-Golpu Project copper-gold: •Gold: 0.86g/t •Copper: 1.1% •Framework memorandum of understanding signed •Mining development contract negotiation in progress •Special mining lease to follow. | ||||
Kerimenge CIL2 and heap leach study | ||||
2Carbon-in-leach.
Execution | |||||||
Gold life extension | Copper growth | ||||||
Moab Khotsong extension (Zaaiplaats) | Eva Copper Project | ||||||
Mponeng extension (including TauTona VCR3 Pillar) | CSA Deeps extension study | ||||||
Hidden Valley (TSF3) | |||||||
Doornkop 212L | |||||||
Tshepong North extension | |||||||
3Ventersdorp Contact Reef.
Exploration
Our exploration strategy is to predominantly pursue brownfields exploration targets close to existing infrastructure. In addition to reviewing exploration opportunities as part of our new business strategy,
our priorities for FY26 as part of our exploration programme included:
Kalgold drilling | Eva Copper drilling | CSA drilling | ||||||||||
Exploration is aimed at improving the understanding of the potential to develop the Kraaipan Greenstone Belt into a new mineralised province with multiple mining centres. The Prospecting Right for the D Zone South exploration drilling was granted and executed by the DMPR in March 2026. The Torque Exploration crew and drill rig were mobilised in April and reverse circulation (RC) drilling commenced in May 2026. The current Phase I drilling is a Resource Definition exploration programme, consisting of 36 boreholes comprising 3 200m of drilling. At the end of FY26, 19 boreholes had been completed, totalling 1 632m of drilling. | The project was acquired in December 2022. In FY26, drilling comprised 114 holes for 20 133m. The drilling was undertaken as part of the Eva feasibility study update. It was designed to increase confidence in the Mineral Resource base and support various study elements. Initial drilling on the exploration permits during the year comprised 41 holes for 9 428m. An updated resource model was developed and declared. | Exploration activities focused on brownfield copper opportunities close to existing mine infrastructure and regional target generation across the broader tenement package. Near-mine target evaluation and Mineral Resource extension drilling progressed during FY26, comprising three drill holes over 3 588m. The QTS mine life extension project advanced during the year, with drilling confirming the presence of alteration and mineralisation along strike of the QTS South ore system. Regional exploration activities included the acquisition of geophysical data sets and target-generation work across the CSA tenement package. Fixed- loop electromagnetic and airborne magnetic surveys were completed, supporting the identification and prioritisation of exploration targets across the holding. | ||||||||||
69
Projects
Approach
Harmony recognises the complexity and inherent risks associated with managing multiple large-
scale projects concurrently across its operations. Our project execution management system
provides operational guidelines that standardise our approach throughout project phases (ideation,
concept studies, prefeasibility studies, feasibility studies, operational readiness and execution). The
system allows us to define processes, set execution standards, track performance, manage
resources and implement changes where required. Project managers use the system to monitor
progress continuously and report to operational teams and the Harmony executives on a daily,
weekly and monthly basis. Key deliverables are established for each project phase, aligned with
Harmony’s strategic goals and risk appetite. This approach promotes operational excellence and
incorporates rigorous governance requirements to address the complexities of multiple projects.
Harmony’s Central Projects Management Office (CPMO) drives the successful execution of project
management.
Governance
Our governance framework provides key policies, standards, procedures, guidelines and
templates aligned with Harmony’s investment approach and best practices. The CPMO monitors
progress, performance and adherence to governance on a monthly basis, through steering
committee meetings and project metrics. The group executive team monitors progress and
performance on a quarterly basis. In addition, Harmony’s internal audit function conducts annual
audits into the CPMO activities. Harmony is pioneering the deployment of standardised reporting
and template tools across selected pilot sites, designed to streamline project management
processes and enable best practice adoption. These tools are designed to enhance accuracy and
efficiency, enabling adherence to industry standards to manage cost, time and scope. We conduct
training to provide project managers with a clear and concise understanding for efficient
application.
Risk management
Project execution risk management is an integral part of our business and operating strategy,
allowing for a safe working environment that remains profitable. We include critical operational
risks in our strategic risk register, which is reviewed by our group executive committee and the
board’s technical, and audit and risk committees. We also include site-specific issues in
operational risk registers. Harmony’s top exploration and project-related risks include:
•Safety and health
•Unsuccessful project execution
•Not achieving operational objectives at our critical operations
•Security of electricity power supply and the impact of higher electricity costs
•Supply chain disruptions (including supply of goods, availability and increasing costs).
70
Key projects
We have identified substantial opportunities in our existing portfolio through exploration and
brownfield projects that will extend the life of some of our larger and higher-grade assets, adding
lower-risk, higher-margin ounces to Harmony’s portfolio. Each project brings multiple benefits to
Harmony and exceeds all our minimum criteria for allocating capital.
The salient features of our key projects are:
South Africa | ||||||||
Mining projects in execution | ||||||||
Moab Khotsong – Zaaiplaats Project | ||||||||
Status | Board-approved FY21, mining 101L to 114L | |||||||
Scope | Three new declines and associated infrastructure below 101 level | |||||||
FY26 progress | 2 081m developed. The decline system reached the first production horizon at 103 level. Trackless mobile machinery (TMM) commissioning achieved, infrastructure construction ongoing | |||||||
FY27 plans | Complete permanent TMM workshops, install material decline winder, progress conveyor system | |||||||
Mponeng extension (including TauTona VCR Pillar) | ||||||||
TauTona VCR Pillar | Board-approved extraction of shaft pillar VCR orebody sections | |||||||
LoM extension | Board-approved carbon leader reef and VCR mining below 120 level/126 level via trackless ramps and twin decline systems | |||||||
FY26 progress | Opening-up and rehabilitation activities continued, Integrated Owners’ Model rolled out | |||||||
FY27 plans | Continue development, support/equipping, trackless workshop commissioning | |||||||
South Africa continued | ||||||||
Doornkop 212 level | ||||||||
Scope | Extend mining to depth with new ore handling system, shaft infrastructure upgrades | |||||||
Key components | Construct new ore-handling system, DK1A shaft conversion to intake, split refrigeration plan, integrated electrical infrastructure. Upgrade water management infrastructure | |||||||
FY26 progress | Production on 212 level recovered following dewatering upgrades. Development achieved 1 442m. The surface fan upgrade and TMM workshop were completed. Phase 1 of the overhead power line was completed and Phase 2 commenced | |||||||
FY27 plans | Construct three silos and commence installation of the conveyor belts. Complete the new fan changeover, 207 and 212 level dams and Phase 2 of the overhead line. Progress the DK1A intake conversion and split-cooling solution. Continue exploration drilling for resource definition | |||||||
Tshepong North extension | ||||||||
Scope | Extend Tshepong’s economic life through the sub-75 decline and associated infrastructure | |||||||
FY26 progress | Feasibility study completed confirming economic viability. Capital budget for FY27 approved by the board | |||||||
FY27 plans | Progress cooling infrastructure programme, establish conventional mining development operation | |||||||
MWS – Mispah tailings dam retreatment | ||||||||
Objective | Construct Mispah pump station to treat Mispah 1 TSF through MWS | |||||||
FY26 progress | Commissioning of the Mispah pump station was achieved for June 2026, with production from July 2026 | |||||||
FY27 plans | Progressively ramp up reclamation volume during the first quarter of FY27 | |||||||
71
 | Papua New Guinea | |||||||
Hidden Valley LoM extension study | ||||||||
Objective | Convert remaining Stage 9 resources and assess third TSF | |||||||
FY26 progress | Environmental permit for the third TSF has been granted, mining lease extended to 2040 and feasibility study advanced | |||||||
FY27 plans | Complete the feasibility study and progress to Final Investment Decision | |||||||
Kerimenge study | ||||||||
Status | Prefeasibility study completed in 2026 | |||||||
Options | Heap leach processing and integration with Hidden Valley CIL processing | |||||||
Integration | Now rolled into Hidden Valley LoM extension study | |||||||
FY27 plans | Complete the Environmental Impact Assessment and submit the Mining Lease application | |||||||
Wafi-Golpu Project (Harmony 50%) | ||||||||
Status | Greenfield undeveloped deep-level block cave mine in permitting phase | |||||||
Mining method | Block cave with multi-cave options (BC44, BC42, BC40) | |||||||
Operating life | >28 years (potential to extend to 40 years) | |||||||
Current status | Environment permit granted December 2020; special mining lease negotiations ongoing with PNG State | |||||||
Next steps | Re-establish project delivery capability, validate 2018 feasibility study, commence early works | |||||||
| Australia | |||||||
Eva Copper Project | ||||||||
Status | Key approvals secured, federal approvals progressing | |||||||
Scope | Multiple open-pits with purpose-built copper concentrator | |||||||
Current work | The project has moved into execution, with site establishment under way and process plant construction advancing. During FY26, a northern blue-tongued skink, a species listed as critically endangered, was identified during clearing activities within the project area. Further environmental studies, assessments and regulatory approvals have been advanced in response and construction sequencing modified. First production is targeted for the second half of calendar 2028, subject to timely receipt of federal environmental approvals | |||||||
Team | Experienced project team established in Brisbane and Cloncurry | |||||||
Permits | Key approvals secured; federal approvals progressing | |||||||
CSA Deeps extension study | ||||||||
Scope | Evaluate depth extensions to the QTS orebodies to add additional copper tonnes and extend mine life | |||||||
Status | Ongoing concept study evaluating depth extensions to the QTS orebodies, with resource definition and assessment of deeper, undrilled portions of the orebody | |||||||
72
Sustainability performance
Guided by our sustainability framework, we continue to enhance how we identify, understand and respond to the sustainability
matters that affect our business, stakeholders and long-term value creation. Our performance chapters bring together our key
sustainability and climate-related impacts, risks and opportunities (IROs), management responses, initiatives, metrics and targets to
show how we are progressing our sustainability priorities.
Understanding our approach
During FY26, Harmony introduced key sustainability-related impacts, risks and opportunities (IROs) to provide a more structured view of the matters most relevant to our business and stakeholders. The IROs
provide a more granular view of sustainability-related matters, helping to identify the pathways through which they may affect our business, stakeholders and long-term value creation.
Sustainability-related impacts, risks and opportunities discussed in this section have been identified using Harmony’s broader sustainability and stakeholder assessment processes. Their inclusion does not
necessarily indicate that each matter is material to Harmony or its investors under US federal securities laws. Matters considered material under US federal securities laws are addressed in the applicable
sections of the Form 20-F.
These performance chapters bring together management responses, initiatives, metrics and targets associated with these matters, laying the foundation for stronger alignment between IROs and performance
reporting over time.
Assessing our performance
Harmony has an established approach to measuring and benchmarking sustainability performance. We use internal metrics and targets alongside external assessments to track progress, support
accountability and identify areas for improvement.
Our performance is independently benchmarked through assessments including FTSE4Good, CDP, MSCI and Sustainalytics. These assessments provide additional perspectives on our sustainability
performance, risk management and disclosure practices and complement the metrics and targets used across the business.
Our KPIs, metrics and targets
KPIs are central to driving our shared strategic and sustainability objectives, enabling consistent progress tracking, performance evaluation and accountability across the business. Our five-year targets (FY23
– FY27) span the environmental, social and governance dimensions of our business and address key areas of significance to Harmony and our stakeholders.
Our group environmental policy has been updated, reaffirming the group’s commitment to environmental stewardship and responsible mining. Our environmental targets address important aspects including:
•GHG emissions and renewable energy
•Potable water consumption and water management
•Waste and hazardous materials
•Ecological impacts.
Our social targets focus on the safety, health and upliftment of our people and communities, including:
•Achieving zero harm and preventing significant injuries and loss of life
•Preventing occupational disease
•Delivering high-impact legacy projects in our South African regions
•Building a more diverse and inclusive workforce.
Our governance targets reinforce board independence and accountability and support the integration of sustainability considerations into how we lead, oversee and reward performance.
Note on future focus sections included in each chapter/IRO
The ‘Future focus’ sections describe management’s current priorities and intended actions and should be read with the Form 20-F’s cautionary statement about forward-looking statements.
73
Safety
Key matters: Safety Potential impacts on society, the environment and the economy: Safety incidents can cause serious or lasting harm to employees and contractors, their families and communities. Effective safety risk management protects people from harm and supports the right to a safe and healthy working environment. Matters that could impact Harmony: Managing safety effectively requires ongoing investment of time, effort and financial resources. Serious safety incidents can disrupt operations, increase costs and regulatory exposure, affect workforce availability and damage relationships with employees, contractors, regulators, investors and lenders. | ||
Sustainability framework | Safety, health and wellbeing: Pursue our goal of zero harm through a strong safety culture and supporting systems promoting employee physical and psychological health, safety and wellbeing. | ||
Strategic risk and opportunity | Risk: Safety and health Safety and health performance underpins operational continuity, workforce productivity and Harmony’s licence to operate. Opportunity: Culture, leadership and investment Strong safety culture, leadership and investment can enhance operational discipline, workforce engagement, regulator confidence and long-term operational sustainability. | ||
Everyone has a fundamental right to a safe working environment.
Our objective is to achieve zero harm through active leadership, effective management of consistent risks and controls, and a workforce
that takes ownership of safety.
Safety impacts, risks and opportunities (IROs)
Prevention of serious injuries and loss of life | Safety leadership, accountability and workforce ownership | |||||||
Through proactive risk management, we seek to prevent harm and maintain a safe working environment. Robust monitoring, verification and assurance processes help confirm that critical safety controls are operating as intended, reducing the risk of fatal or catastrophic events and providing confidence that critical controls remain effective in practice. | We seek to foster a proactive safety culture by empowering employees to identify hazards, speak up, escalate concerns and take action before harm occurs. Visible leadership, accountability, psychological safety, recognition and learning from incidents help strengthen shared responsibility for safety and support safer decisions and behaviours across our workplaces. | |||||||
The combination of a proactive safety culture and robust control and safety management systems applicable to 100% of our workforce, provides a unified prevention system designed to eliminate loss of life (fatalities), serious injuries, and high-potential safety events. | ||||||||
Regional context
South Africa Our large, established workforce operates across deep-level mines, surface operations, plants and services. Long-standing workforce structures and employee representation arrangements help facilitate engagement on safety matters at all organisational levels. Our Thibakotsi programme provides the key framework for strengthening leadership, personal accountability, workforce empowerment and learning across the region. | Papua New Guinea Our portfolio includes the operating Hidden Valley mine, the Wafi-Golpu Project and exploration activities. Remote locations and rostered work arrangements require ongoing focus on workforce wellbeing, fatigue management and maintaining strong workforce connections. Visible leadership, clear communication and regular engagement help reinforce shared expectations and workforce ownership of safety across employees, contractors and project teams. | Australia Australia’s workforce spans an operating underground mine, a major construction project and exploration activities. As Harmony expands its presence in the region, maintaining consistent safety expectations and workforce engagement across these activities remains a priority. We are progressively aligning leadership practices, workforce participation and psychosocial risk management approaches to support a strong safety culture across our operations and projects. | ||||||||
Performance snapshot
Group Loss of life 6 (FY25: 11) | Group LTIFR 5.05 (FY25: 5.39) | Full-time and contractor employees who completed safety training (South Africa) 37 000 (FY25: 36 000) | Specialist inspections conducted and digitally captured (South Africa) 117 000 (FY25: 113 000) | Line inspections conducted and digitally captured (South Africa) 2.5 million (FY25: 2.4 million) | Controls monitored cumulatively across South Africa operations 23 million (FY25: 22 million) | |||||||||||||||||
Every loss is deeply felt. We remember the colleagues who passed away during FY26 and honour the contribution each made to our
operations, our teams and the broader Harmony community. We extend our heartfelt condolences to their families, friends and
colleagues.
74
How we manage safety IROs
1 | Prevention of serious injuries and loss of life | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Mining operations can expose employees and contractors to hazards that may result in serious injury or loss of life. The risks associated with these hazards are influenced by identification and verification of critical controls, effective contractor and workforce risk management, learning from events, and managing changes in the workplace as they occur. | Potential impacts on society and the economy Where safety risks are not effectively identified and managed, serious injuries and loss of life may occur, resulting in profound impacts on employees, contractors, families and local communities. Such incidents can contribute to loss of household income, increased reliance on healthcare and social support systems, reduced economic participation and diminished confidence in the mining sector’s ability to create shared value responsibly. | Potential operational effect on Harmony Failure to effectively manage critical risks may result in loss of life, serious injuries and high- potential incidents, leading to operational disruptions, regulatory action and production losses. Such events may negatively affect workforce morale, stakeholder trust, attraction of new talent and Harmony’s social licence to operate, while necessitating extensive incident response, investigation and remediation efforts. | Potential financial effect on Harmony Significant safety incidents may result in direct and indirect costs, including medical treatment, compensation, legal proceedings, regulatory penalties and increased insurance costs. Production losses arising from regulatory stoppages may further affect profitability, cash flow, access to capital and Harmony’s long-term ability to create shareholder value. Investment in safety leadership and critical controls strengthens operational discipline and resilience. | |||||||||||
Our approach
Our primary objective is to safeguard our people by identifying our
highest consequence hazards and establishing controls to
prevent loss of life and serious harm. We pursue this objective
through an integrated approach that combines risk management,
with a strong focus on critical controls, technology, safety
behaviours, culture and leadership accountability.
Identifying and assessing critical safety risks
To identify critical hazards and significant unwanted events,
understand how they could arise and determine the controls
required to manage them, we use a four-layered risk approach:
Baseline assessments establish the broader hazard profile |
Issue-based assessments, including bow-tie analysis, examine threats, consequences and critical controls |
Task-based assessments define controls for specific work |
Continuous risk assessment tests whether conditions or exposure have changed before and during work |
These processes are applied through regional and operational
arrangements and inform risk registers, work planning, control
ownership and escalation. Together, they support early
identification of change and help keep risk assessments
and controls relevant to the work being undertaken.
Managing critical safety risks
Critical controls: identification, implementation and verification
Our critical control management process supports the
identification, implementation and verification of controls designed
to prevent significant unwanted events or minimise their impact
should they occur. Their effectiveness relies on a culture of
leadership, accountability and workforce ownership. A strong
safety culture encourages our people to comply with all controls,
identify change in the risk profile or task as it occurs, and feel safe
to stop and escalate concerns as they feel necessary (see IRO2).
Hazards are eliminated or exposure designed out wherever
practicable before relying on controls dependent on human action.
Technology is used where proportionate to a hazard, removing
people from hazardous situations, reducing exposure,
strengthening engineering controls or improving monitoring of
conditions and control performance. These technologies
complement planning, supervision, field verification and workforce
intervention.
Critical controls are supported through work planning,
competency management, contractor oversight and escalation
processes. At site level, risk assessments, permits, inductions,
pre-start meetings and inspections help translate controls into
safe work practices.
Controls are categorised based on their position in the hierarchy
of controls and their survivability, availability and reliability.
Verification and assurance activities, including control and permit
checks, inspections, audits and reviews, are used to confirm that
key controls are in place and functioning as intended. Findings
are escalated through governance structures and tracked to
closure. Verification methods are tailored to each asset’s hazards,
regulatory requirements, infrastructure and development stages.
Examples of technology-enabled controls and monitoring include:
•Collision avoidance and proximity detection systems
•Fatigue and operator alertness systems
•Missing person location capability
•Proactive identification and management of structural defects
•Advanced access control technologies on rail-bound equipment
and winches.
75
Safety leadership and critical risk management framework
ç | Governance and oversight | ç | ||||||||||||||||||||||||
Through management and oversight processes, we set expectations and accountabilities, support culture and leadership programmes, oversee critical risks and control performance, and monitor corrective actions. | ||||||||||||||||||||||||||
Train, develop, engage and communicate We build competence and risk awareness through training and development, while engaging employees, contractors and relevant stakeholders to identify hazards, surface concerns, share information and support timely action through workforce participation, contractor coordination, regulatory engagement and cross-site learning. | è | Principles and expectations | Leadership visibility and control ownership | Performance monitoring, reporting and assurance | Escalation and corrective action | ç | Learn and improve We use lessons from incidents and high-potential events, control verification activities, assurance and audit findings, emergency exercises, changing operating conditions and other operational insights to continually strengthen risk assessments, controls, procedures, training and verification processes. | |||||||||||||||||||
Safety behaviours, culture and leadership accountability | ||||||||||||||||||||||||||
Strengthening safety ownership through visible leadership, psychological safety and accountability so that people consistently apply controls, halt work if controls are ineffective, and take action before harm occurs. | ||||||||||||||||||||||||||
Identifying, managing and monitoring critical safety risks | ||||||||||||||||||||||||||
Identify and assess | Identify critical hazards, significant unwanted events and control pathways through risk assessments, risk register and, where used, bow-tie analysis. | |||||||||||||||||||||||||
⇓ | ||||||||||||||||||||||||||
Design controls, define performance, implement | Define critical controls, performance requirements and supporting technologies to prevent loss of life and serious harm, and assign ownership and accountability. | |||||||||||||||||||||||||
⇃⇂ | ||||||||||||||||||||||||||
Verify and assure | Verify controls are present, effective and performing against defined standards through inspections, audits and field verification. | |||||||||||||||||||||||||
⇃⇂ | ||||||||||||||||||||||||||
Monitor and intervene | Use digital tools, monitoring systems and operational oversight to improve control effectiveness, enhance visibility of risk and support timely intervention. | |||||||||||||||||||||||||
⇃⇂ | ||||||||||||||||||||||||||
Prepare and respond | Maintain emergency and crisis management arrangements suited to site risks, including response capability, exercises and mutual aid where appropriate. | |||||||||||||||||||||||||
é | ||||||||||||||||||||||||||
Regional and operational implementation | ||||||||||||||||||||||||||
è | Our regions and operations translate group-level safety expectations into risk-management processes, critical controls, verification methods and implementation priorities that reflect each asset’s hazards, regulatory setting, infrastructure, operating context and stage of development. | è | ||||||||||||||||||||||||
76
Monitoring critical safety risks
Critical control verifications provide early warning of potential
control degradation, while the close-out of significant findings
from incident investigations and verification failures strengthens
critical controls and supports safety risk reduction.
At our South African operations, selected leading indicators linked
to critical controls, including the outcomes of critical control
verifications, are digitally monitored to provide visibility of control
performance and support timely intervention where required.
Examples of monitoring and reporting tools include:
•Digital capture of inspections, incidents and corrective actions
•Safety dashboards and management reporting
•Geotechnical and other real-time hazard monitoring
•Vehicle and fleet tracking and monitoring.
Learning and continual improvement
To drive continual improvement, we implement:
•Root cause analysis: Examining immediate, underlying and
systemic factors, including whether controls were absent,
ineffective, bypassed or insufficient
•Informed corrective action: Using investigation findings,
assurance results and industry learnings to revise risk
assessments, controls, procedures, training and assurance
activities
•Shared learning: applying regional review and notification
processes to share significant incident learnings across
operations and our regions
•Accountability and closure: assigning ownership, closing
actions within agreed timeframes and confirming changes
address identified factors.
Engagement and communication
Engagement and communication support the consistent
application of safety requirements across the business.
Examples of our engagement and communication channels
include:
•Pre-start meetings, toolbox talks and inductions
•Leadership interactions and safety conversations, including
visible field engagement and opportunities for employees and
contractors to raise concerns
•Safety committees, employee representative arrangements and
feedback mechanisms that support workforce consultation,
participation and speak-up culture
•Contractor forums and coordination meetings to align safety
expectations, review performance and assign actions across
organisational interfaces
•Incident notifications, safety alerts and learning forums to
communicate significant incidents, high-potential events,
regulatory developments and relevant industry learnings
•Regulatory engagement, inspections and site visits
•Emergency response and community engagement where
significant safety events could affect external responders,
neighbouring operations, families or nearby communities.
Governance
Safety is embedded throughout Harmony’s management
structures. Group safety principles and standards establish
expectations for risk management, critical controls, leadership
and workforce behaviours, while regional executives and
operational leaders are accountable for implementation and
performance within their areas of responsibility. The board and its
committees oversee safety performance, critical risks, significant
incidents and the effectiveness of culture and leadership
initiatives. Critical risks, control performance, assurance findings
and corrective actions are monitored through management
processes, with key matters escalated and tracked to closure.
FY26 notable safety improvements
Learning from critical risks and high potential incidents
Harmony group
For our South Africa region, we implemented a series of themed
safety campaigns during FY26, which focused on critical risks
identified through Harmony’s risk management processes and
emerging industry trends. These campaigns have been reinforced
through critical control verification conducted by supervisors and
operational teams, promoting continuous engagement,
accountability and risk awareness at all levels of the organisation.
In Australasia, a High-Potential Incident Management Review
was established. This provides a structured forum to review
investigation findings, identify recurring themes, share lessons
learned and track corrective actions to closure. Significant
incident and high-potential incident review processes were also
embedded at site level, including within Hidden Valley’s weekly
leadership meetings, where investigation findings are assessed
against the site’s critical risk register and verification processes to
ensure critical controls remain current and effective. These
reviews are supported by notification alerts covering significant
and high-potential incidents, regulatory safety matters and
relevant industry events, enabling timely communication and
shared learning across the region.
Fleet monitoring and collision prevention technologies
Harmony group
In South Africa, we continued the implementation of the Collision
Prevention System (CPS) in line with the Mine Health and Safety
Council’s level 9 requirements. By August 2026, overall
commissioning across the South African operations reached
97.1%, with Moab Khotsong, Tshepong and Kalgold achieving
full (100%) commissioning status. The phased rollout of CPS
technology is a key component of Harmony’s drive to eliminate
vehicle-related incidents by improving vehicle-to-vehicle and
vehicle-to-pedestrian interaction management, strengthening
situational awareness, and enhancing operational safety across
the group’s underground and surface mining operations.
At Hidden Valley, fatigue monitoring and collision avoidance
system coverage continued to expand across Hidden Valley’s
mining fleet and other vehicles, alongside improvements to
surveillance system alerts.
At Eva Copper, we introduced vehicle fleet tracking, and we are
investigating collision avoidance monitoring for the mining fleet
and other site vehicles as part of operational readiness.
At CSA mine, planning was undertaken for the installation of laser
warning systems on the Jumbo mobile equipment fleet in FY27.
This is in response to industry learnings from the loss of life at
another Australian mine in 2026.
77
Strengthening key risk oversight processes
Hidden Valley, Papua New Guinea
Hidden Valley strengthened its existing critical risk oversight by
introducing a more structured 12-month rolling risk management
plan. The plan identifies critical risks, assigns risk owners and
schedules verification checks for associated controls.
External safety governance audits provide an additional source
of assurance, with findings assigned for corrective action and
improvement. Weekly and quarterly regulatory mine inspections
also support the site’s assessment of compliance with Mineral
Resources Authority requirements and identify matters requiring
attention. Together, these processes strengthen accountability for
critical risks, provide greater visibility of control performance and
support the timely escalation and close-out of findings.
Adopting Harmony’s critical controls, with data
improvements to drive better insights
CSA mine, Australia
When Harmony acquired the CSA mine in October 2025, the
site’s lost-time injury frequency rate (LTIFR) and all-injury
frequency rate (AIFR) did not meet Harmony’s safety performance
expectations. This highlighted the need for sustained
improvement effort, leading to the commencement of a multi-year
improvement programme focused on strengthening safety
systems, critical controls, leadership and culture.
During our first eight months of ownership, this included:
•People and processes: We reviewed injury management,
onboarded nurse practitioners for rehabilitation and return-to-
work, and operational leaders completed Harmony’s Building
Blue leadership programme
•Culture assessment: We engaged DSS+ to run a Bradley
Curve safety culture maturity assessment in the second quarter
of FY27, and findings will inform a 36-month safety roadmap
•Data and systems: We have consolidated and standardised
safety data, introduced automated reporting, and centralised
incident, injury, corrective action, inspection and regulatory
information in the current safety management system to
improve visibility of trends, action status and priority areas
•Dedicated resourcing: we assigned a site-based risk
resource to strengthen critical risk management and control
processes.
Strengthening critical controls for rail equipment
TauTona and Tshepong North, South Africa
Harmony progressed the implementation of ID card-based
access control systems across the rail-bound equipment (RBE)
fleet. The technology was successfully installed and tested on
battery-electric RBE controllers at TauTona mine’s 112 Level.
Following targeted design enhancements, the system has
demonstrated reliable performance and is being expanded to
locomotives operating between Mponeng and TauTona as part of
a broader validation programme.
In parallel, ID-based access control for locomotive controllers was
successfully tested at the Tshepong North surface training centre.
Planning for operational deployment is underway, with
implementation activities aligned to the required locomotive
modifications. Once fully deployed, the technology will provide
an additional layer of control by preventing unauthorised
operation of rail-bound equipment.
ID card pilot programme for winch access control
Kusasalethu mine, South Africa
Harmony is piloting an ID card access system for winches at
Kusasalethu mine. Initial testing on the 106/24 raise line has
yielded positive results, with no significant technical challenges
identified. The next phase includes training facilitators and
operators to support wider implementation across additional raise
lines.
Aligning project and partner stakeholders on safety
and health
Eva Copper, Australia
With Harmony reaching financial investment decision on Eva
Copper in November 2025, the project is in the construction
phase. This has brought increased activity and a growing
workforce across multiple project partners and contractors onto
the site. Harmony introduced a weekly safety and health meeting
to coordinate safety matters across participating organisations.
The meeting provides a regular forum to align safety expectations,
discuss current and upcoming work, identify hazards and interface
risks and control measures, share relevant information and assign
follow-up actions. Establishing this routine early in construction
supports coordinated planning and helps clarify responsibilities as
activities, workforce numbers and contractor interfaces increase.
Commencing the journey towards a regional safety
management system
Australasia operations
We are building the foundation for a regional digital safety platform
across Australia and Papua New Guinea. Sites currently use
different digital platforms, reflecting their varied operating histories
and development stages. Work is also underway to review and
standardise leading safety indicators across Australasia,
supporting greater consistency in how safety performance is
monitored and assessed.
In FY26, we defined regional requirements and progressed
selection and design of a platform to improve consistency,
accessibility and visibility of safety information.
The selected digital safety platform will support more consistent
capture and analysis of injury, incident, inspection, audit, medical,
health, hygiene, risk and corrective action data. Planned
capabilities include mobile reporting for inspections, field
interactions and audits, plus dashboards for clearer performance
visibility.
We are also designing data-lake and Power BI capabilities to
consolidate regional information and enable more timely analysis.
The six-month implementation plan commenced in the first
quarter of FY27.
Managing seismic hazards in deep underground
mining
Mponeng, South Africa
During the year, Mponeng mine continued to implement long-hole
blasting to mitigate against stress build up and associated
seismic hazard. At the world’s deepest operating mine, reaching
depths of approximately 4km below surface, the technique
extends conventional preconditioning practices by using
strategically designed long holes to access and treat highly
stressed rock masses and identified seismic source zones ahead
of mining activities. Hole configurations are tailored to site-specific
geological conditions, seismic risk assessments and rock
engineering requirements to target high-risk areas.
Long-hole blasting aims to release the stored rock mass energy
to reduce the likelihood and severity of strain bursts, face
ejections and other rock-related incidents.
78
Performance and effectiveness
Group LTIFR for FY26 was 5.05 per million hours worked, representing our lowest recorded LTIFR and a 6.3% improvement on the prior year. This achievement reflects the dedication, hard work and
commitment of thousands of employees and leaders across our operations.
Group | South Africa | Papua New Guinea | Australia | ||
Loss-of-life injury frequency rate | 0.06 (FY25: 0.11) | 0.06 (FY25: 0.12) | 0 (FY25: 0) | 0 (FY25: 0) | |
Lost-time injury frequency rate | 5.05 (FY25: 5.39) | 5.06 (FY25: 5.69) | 0.45 (FY25: 0.00) | 17.36 (FY25: 4.44) |
South Africa
Despite the improvement in our LTIFR, we tragically lost six employees (FY25: 11) at our South African operations against our objective of zero loss of life. All Harmony initiatives are guided by this objective
and all learnings are applied to eliminate loss of life at Harmony.
Causes of loss-of-life | Main contributors to LTIFR | Mitigation measures | ||||||
•Seismic-induced fall-of-ground •Falling material •Electricity •Trucks, tramming and transport •Tools, machinery and equipment. | •Slip-and-fall incidents (main contributor) •Material handling •Tools, machinery and equipment •Foreign body •Gravity-induced fall of ground •Seismic-induced fall of ground •Struck-by incidents •Rolling rock •Falling material •Trucks, tramming and transport. | •Group standards for shaft safety devices reviewed and compliance monitoring enhanced •Strengthened workplace examination and making-safe requirements, with workplace audits and defined remedial action plans •Aligned all electrical installation drawings with original equipment manufacturer designs and reinforced hazard identification and risk assessment, permit to work, and stop, look, assess and manage processes with all electricians •Engineering controls implemented to initiate an immediate response to leading indicators •Refresher training for all Miners and Competent A personnel on strata control and safe workplace declaration •Start-up risk assessment processes reviewed and strengthened; trigger action response plans reinforced. | ||||||
Loss-of-life and serious injury compensation
Bereaved families receive compensation as soon as possible after the loss of an employee’s life at our operations. | Our focus is on supporting the family and colleagues affected by the loss. This includes maintaining direct contact with the bereaved family, offering practical and emotional support where appropriate, and paying our respects through memorial and funeral services. | ||||
Compensation includes: •Funeral services, coffins and mourner transportation •An on-mine memorial service with accommodation while attending to the deceased person’s affairs •R80 000 Mineworkers Provident Fund advance •R50 000 Harmony donation •Enrolment of children in the Harmony Education Fund •Offer of employment at underground entry level to a family member •Housing support (R250 000 once-off benefit to immediate family members who are registered as the employee’s dependents and share a primary residence with the employee). | Compensation for serious injury on duty includes: •Lump sum or monthly payments (based on the Compensation for Occupational Injuries and Diseases Act disability rating) •Alternative employment (if available) •Two weeks’ termination payment of R100 000 from 1 July 2026, per completed consecutive year of service (if alternative work is not available) •Employment offer, based on available underground vacancies at entry level, to an immediate family member •TEBA home-based care for medically incapacitated employees •The company makes homes accessible and user-friendly for paraplegics. | ||||
79
Underground operations
LTIFR performance has improved over time, supported by a
continued focus on workplace standards and risk
management across our underground operations.
Six of our nine underground mines completed more than one
million shifts without a loss of life during FY26. Masimong
achieved four million loss of life-free shifts, while Kusasalethu,
Tshepong and Target each exceeded two million loss of life-
free shifts. Phakisa, Moab Khotsong, Doornkop and Mponeng
each surpassed one million loss-of-life-free shifts.
The highest number of loss of life-free shifts and injury-free
days achieved by each operation during FY26 are presented
below.
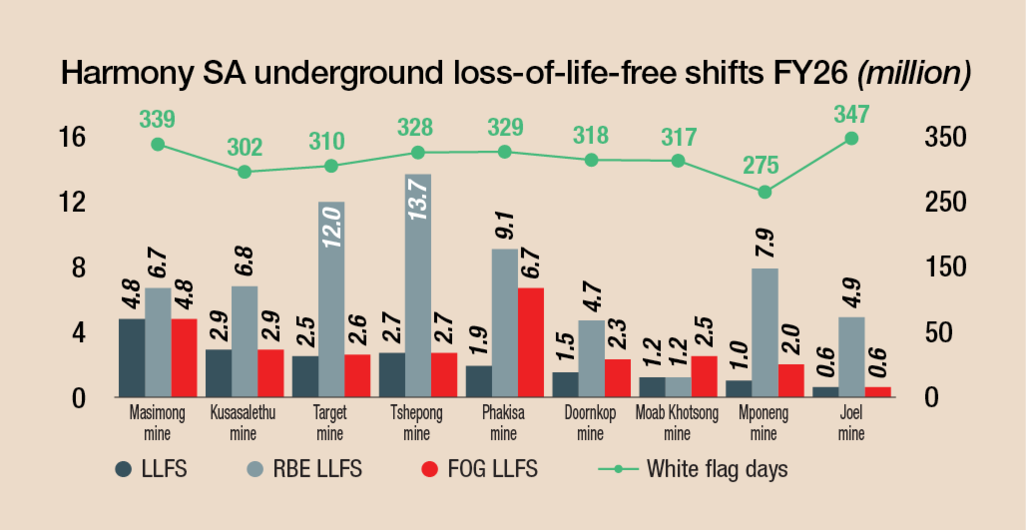
Surface operations
Of our 24 surface operations, 14 recorded more than
one million fatality-free hours worked in FY26.
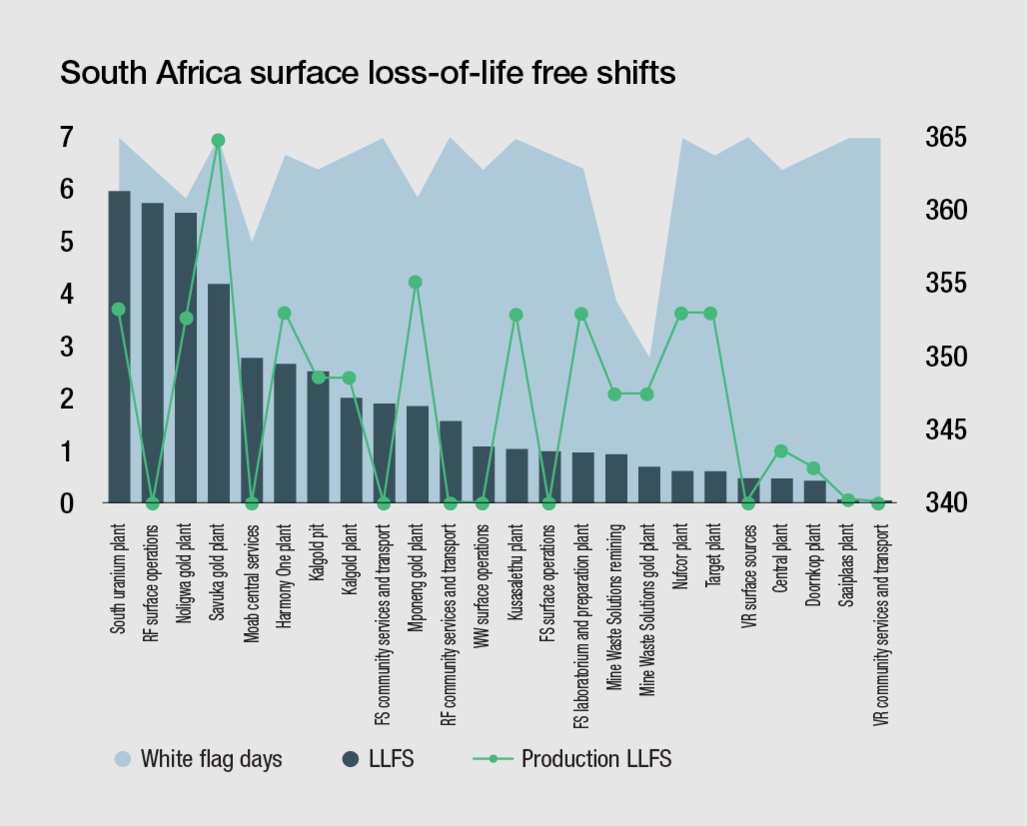
Along with the reduction in the LTIFR, our performance has
shown significant improvement:
Reportable injury frequency rate (RIFR) | ||
decreased by 8.0% to 3.34 (FY25: 3.63) | ||
Rail-bound equipment injury frequency rate (RBEIFR) | ||
decreased by 24.2% to 0.25 (FY25: 0.33) | ||
Mines that achieved RBE loss-of-life-free shift millionaire status: •Tshepong (13 million) •Phakisa (9 million) •Mponeng (7 million) •Kusasalethu (6 million) •Doornkop (4 million) •Moab Khotsong (1 million). | ||
Fall-of-ground injury frequency rate (FOGIFR) | ||
decreased by 12.3% to 1.00 (FY25: 1.14) | ||
•Doornkop, Kusasalethu, Moab Khotsong and Tshepong mines all recorded 2 million fall-of-ground loss-of-life-free shifts •Phakisa mine recorded 6 million fall-of-ground loss-of-life- free shifts. | ||
Safety performance continued to improve alongside efforts to
strengthen critical control management, enhance visibility of
leading indicators through integrated reporting and reinforce
safe behaviours through the accountability model. Visible Felt
Leadership engagements and coaching continued to support
accountability, hazard awareness and risk-based decision-
making across operations.
Fall-of-ground LTIFR decreased from 1.51 in FY21 to 1.00 in
FY26, representing a 34% reduction over the period. While
performance deteriorated temporarily in FY24, the overall
downward trend has been maintained. This improvement is
consistent with ongoing efforts to strengthen ground control
practices, workplace standards and risk management.
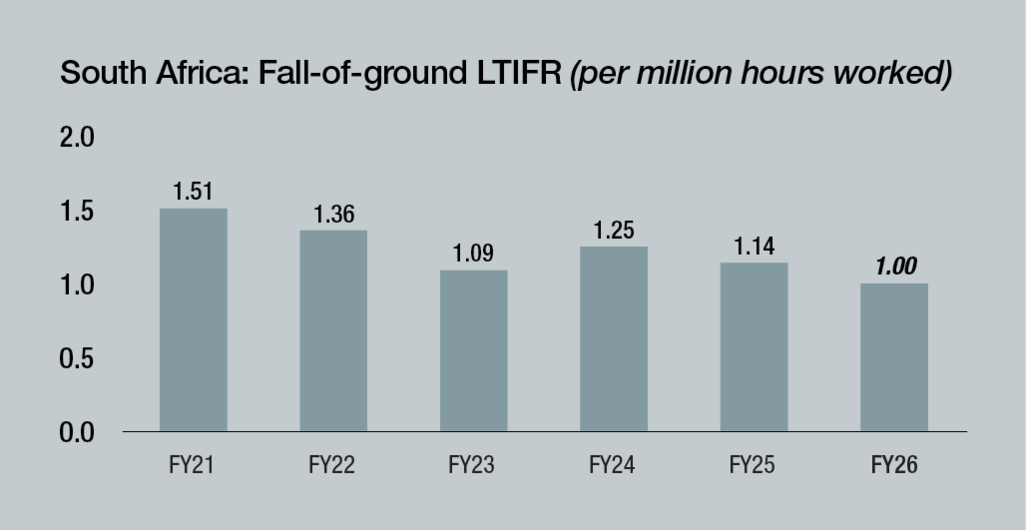
80
Leading indicators monitored in FY26
Metric | Definition/calculation | Target type and year | FY26 | FY25 | FY24 | FY23 | FY22 | |
Close-out of A Hazard fatal risk control findings | Percentage close-out of A Hazard fatal risk control findings for South Africa. | Harmony-defined leading indicator | 100 | 96.5 | 98.8 | 99.7 | 99.6 |
Critical control verification confirmed that 99.9% of assessed controls were operating effectively. In addition, 68% of critical control actions were closed by their due dates, with the remainder requiring
extensions due to their complexity.
2.5 million (FY25: 2.4 million) line inspections conducted and digitally captured CAT 4-8 employees, contractors, all supervisory levels and management | 117 000 (FY25: 113 000) specialists inspections (safety, occupational hygiene and strata controls) conducted and digitally captured | |||||
1 271 (FY25: 8311) high-risk engineering tasks verified prior to conducting work | 978 000 (FY25: 886 000) planned maintenance tasks completed | |||||
37 000 (FY25: 36 000) full-time and contractor employees completed safety training (on-boarding and refresher) | ||||||
1 The FY25 Sustainability report incorrectly reported this metric as 83. The figure has been corrected to 831. | ||||||
81
Papua New Guinea
We recorded a lost-time injury frequency rate of 0.45 per million hours worked (FY25: 0.00), as a
result of experiencing three lost-time injuries during the year. These involved two fall-related incidents
resulting in leg injuries and a contact incident resulting in a hand injury. In response, we increased our
focus on field observations, pre-work planning and hazard awareness. Hidden Valley mine has
maintained a loss-of-life free record since 2015.
Leading safety indicators in Papua New Guinea include visible felt safety leadership, operator and
field critical control checks (OCCCs and FCCCs), system verification checks (SVCs), and near miss
and high potential near miss reporting and investigations.
Australia
We recorded a lost-time injury frequency rate of 17.36 per million hours worked (FY25: 4.44). FY26
was a period of significant change in the Australian region, including the transition of the Eva Copper
Project into construction and the acquisition of CSA mine in October 2025. Lost-time injuries across
the region were primarily associated with trips and falls, body stressing and contact with equipment.
At CSA mine, safety performance improved during the second half of FY26, with LTIFR reducing from
16.3 to 10.7 and TRIFR from 33.3 to 30.6 since January 2026, supported by Harmony initiatives
focused on safety systems, critical controls, leadership and culture.
At the Eva Copper Project, lost-time injuries were associated with a trip-and-fall incident resulting
in a hand injury, a knee injury related to body stressing, and a finger injury caused by contact with
equipment. These incidents occurred as activity at Eva Copper increased with the mobilisation and
commencement of project and construction activities. In response, the project increased its focus
on standardised work practices, field observations and pre-task planning.
Lost-time injuries experienced by our Australian exploration division related to body stressing (leg
injury) and contact with equipment (back injury).
Leading safety indicators in Australia include visible felt safety leadership, critical control and system
verification checks, planned observations at CSA mine, and near miss and high potential near miss
reporting and investigations.
Future focus
Harmony group •Enhance CEO visibility on critical controls for high risk workplaces and drive systemic close-out on actions across the business •Strengthen the effectiveness of our critical control management programme through enhanced control and control monitoring, verification and reporting of critical control performance indicators •Introduce a lifesaving rules and behaviours programme across the Harmony group. South Africa •Empower frontline worker and contractor to report on workplace safety using core app •Strengthen real risk reduction by deploying sensor in key equipment and locations for real time monitoring and digital reporting •Develop near real-time dashboard linked to entry examination and pre-use checklists •Promote psychological safety to support risk response from frontline level to executive level •Entrench learning from incidents and support continuous improvement in safety by tracking actions and their close out •Continue to build capacity by including Harmony Leadership philosophy and expectations in supervisory training and leadership development initiatives •Entrench accountability model through recognition of good behaviours and corrective steps for at risk behaviours •Implement and embed the Thibakotsi Culture Transformation Framework to strengthen team trust, situational awareness, and collaborative performance. Australasia •Incorporate controls for hazards with the potential to cause loss of life and drawing on high- reliability organisational principles, human and organisational performance practices, and ICMM guidance for Australasia •Continue implementation and adoption of regional digital safety platform across Australia and Papua New Guinea •Establish a regional critical control standard to guide our operations on performance standards for loss of life hazards •Strengthen critical control and system verification checks in the field and make escalation clearer when controls are missing or not effective at Hidden Valley mine •Introduce and embed Harmony’s critical controls management at the Eva Copper Project and Exploration Australasia •Introduce and embed our critical controls at CSA mine with additional risk capacity enabling improved planning, execution and assurance •Review and standardisation of leading indicators for Australasia. | |||
82
How we manage safety IROs
2 | Safety leadership, accountability and workforce ownership | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers This IRO is driven by the organisational and cultural conditions that influence how people identify, respond to and learn from risk. They include visible and consistent leadership; whether production pressure influences decisions at the work face; whether employees and contractors feel able to raise a concern or stop unsafe work; the fairness of accountability; supervisory capability; and willingness to report openly and learn. | Potential impacts on society and the economy A loss of life or serious injury is irreversible, resulting in loss-of-life, permanent disability and trauma that extends beyond the individual to families, colleagues and communities. Where an employee is the primary earner in an extended household, the impacts can also include the loss of income, care and stability for dependants who rely on that individual. A healthy culture supports a proactive approach to safety by encouraging people to identify and escalate hazards, speak up when concerns arise and intervene when work cannot be performed safely. | Potential operational effect on Harmony Where leadership commitment or accountability is inconsistent, unsafe practices and control deviations may persist. Failure to report near-misses and high-potential incidents can limit opportunities to identify underlying causes, learn and take preventive action before a more serious incident occurs. A strong safety culture encourages reporting and learning, helping keep people safe and improve safety performance, standards and practices. | Potential financial effect on Harmony Strong safety performance can reduce disruption and production losses, improve operational efficiency and strengthen workforce attraction and retention. Achieving this requires sustained investment in leadership development, supervisory capability, training, workforce and organised labour engagement, contractor management and assurance. Poor safety performance may increase remediation, regulatory and insurance costs and affect Harmony’s reputation and licence to operate. | |||||||||||
Our approach
Harmony’s leadership philosophy
Leadership is about consistency, service, accountability and
empowerment. Leaders can create an environment where people
feel respected, trusted, safe and valued, and where they are
encouraged to participate, raise concerns and contribute to safer
outcomes.
Leaders shape safety culture through their decisions, operational
priorities, field presence and response to concerns. We support
leaders, supervisors and middle managers through formal
training, coaching, leadership development and operational
engagement activities that strengthen risk-based decision-
making, safety conversations and intervention when conditions
are unsafe. Employees and contractors are expected to
understand the hazards associated with their work, apply
required controls, remain alert to changing conditions and stop or
escalate to supervision when it cannot be performed safely.
Leaders are responsible for establishing safe systems of work,
providing appropriate resources and supervision, and responding
when controls are absent or ineffective.
We combine recognition of positive safety behaviours with timely,
fair and proportionate intervention where behaviours or control
requirements do not meet expectations. Ownership of identified
deviations and corrective actions is assigned and actions are
monitored to closure. This approach aims to reinforce
responsibility and follow-through without discouraging good-faith
reporting or weakening workforce trust.
Managing psychosocial risks
We identify and manage work-related factors that may cause
psychosocial or physical harm, including job demands, fatigue,
remote or isolated work, poor support, harmful workplace
behaviours and organisational change.
In Australasia, we apply risk-management processes to assess
these hazards and implement controls suited to the work and
operating context. In South Africa this work is gaining momentum
and will be implemented in FY27.
83
Culture insights and improvement
We use workforce feedback, culture diagnostics, leadership
observations and behavioural information to identify opportunities for
improvement and inform operation-specific priorities. These insights
are considered alongside safety performance information, risk
indicators and control effectiveness measures described under
IRO 1.
In South Africa, the Thibakotsi culture transformation journey
provides a structured framework for measuring and strengthening
the human and organisational conditions that support safe work.
Collaboration and partnerships
We engage with employees and contractors to inform actions that
support safe production and strengthen our alignment with our
safety expectations.
In South Africa, we are an active member of the Harmony
Tripartite, a multi-stakeholder task team supported by the
Minerals Council South Africa and established to achieve zero
harm through a proactive caring culture that supports employees’
safety, health and wellbeing.
Our South African collaboration includes:
•Monthly alignment meetings
•Leading the Tripartite culture transformation workstream
•Participation in the Mandela Mining Precinct
•Participation in Minerals Council CEO safety interventions.
In Australasia, we collaborate with regulators, neighbouring
operations and industry bodies to strengthen safety performance
and capability. This includes engagement with the Mineral
Resources Authority in Papua New Guinea, mining safety
regulators in Queensland and New South Wales, neighbouring
mining operations and industry associations including AusIMM
and Australian Resources and Energy Employer Association.
FY26 progress and achievements
Advancing culture transformation
Thibakotsi, South Africa
Our focus is shifting towards organisational sustainability,
accountability and the integration of risk management into
everyday work practices. This includes embedding safety culture
principles in operational routines and multidisciplinary activities,
strengthening governance and quality assurance of culture
transformation initiatives, and maintaining the behavioural
standards expected of employees and contractors.
Empowering leadership
Further work during FY26 focused on continuous improvement of existing Thibakotsi initiatives, including middle management
supervisory empowerment and frontline empowerment, integrating risk propensity, learning from incidents, accountability model
and personal ownership into the learning and development programmes.
Sustained Thibakotsi team training
In FY26, we developed a Harmony-owned frontline empowerment delivery methodology to transition delivery of Thibakotsi team training
from an external provider to an internal line-owned delivery. This shift is intended to strengthen line management ownership, improve
consistency in how the programme is delivered and build internal capability to sustain it over time.
Integrating our reporting approach
The intent of integrated, automated reporting approach is to bring together culture diagnostics, leadership feedback, behavioural
observations and selected leading indicators to improve visibility of implementation and guide more targeted organisational effectiveness
improvement support across mines, plants and services.
The Thibakotsi journey unpacked
Proactive culture/Live longer | ||||||||||||||||
Leader | Initiative | Business improvement | Optimisation | |||||||||||||
Develop myself | Visible felt leadership: approach, training, coaching and feedback | Visible felt leadership established at all operations | Embed a new way of work – linked to our values | |||||||||||||
Leadership assessments and leadership development programmes | Effective, efficient and mature leadership | |||||||||||||||
Develop others | Engagement and tactics for middle management and supervisors | Engaged and empowered middle management and supervisors | ||||||||||||||
Risk propensity assessments and training | Improved employee and team risk profiles | |||||||||||||||
Learning from incidents: closing the loop and organisational learning | Learning from incidents processes established | |||||||||||||||
Take people along | Bottom-up interventions: safety transformation with training and impact measurement | Improved operational safety and production indicators | ||||||||||||||
Employee engagement tactics | Engaged employees at all operations | Underpinned by the Harmony values | ||||||||||||||
Change management, including stakeholder engagement, communication, evaluation and audit of key action items | ||||||||||||||||
84
Improving our safety culture
Using insights to target improvement, South Africa
We recognise that culture transformation requires sustained effort
and continuous reinforcement and have continued monitored
progress through a series of culture diagnostics every three years.
The next culture diagnostic is scheduled for 2027.
The diagnostic and subsequent validation workshops provide
valuable perspectives on workforce perceptions, leadership
effectiveness, accountability, engagement and organisational
resilience. These findings continue to inform leadership
development, workforce engagement and risk response activities,
supporting the management of identified risks and integration of
lessons learned across the business.
During FY26, we continued to apply findings from the most recent
diagnostic assessment through the Thibakotsi programme. The
assessment highlighted progress in embedding the desired
culture and identified a strong sense of job security and
confidence in Harmony’s long-term sustainability, reinforcing the
values of purpose, pride and personal ownership that underpin
the Thibakotsi journey.
Snapshot of our FY24 culture diagnostic findings:
23 517 responses received across all organisational levels, representing a 54% participation rate | Implementation of Thibakotsi improved to 84% (FY25: 79%) | |||||
Overall entropy score of 12% reflects a relatively healthy organisational culture, while also highlighting opportunities for targeted intervention in specific departments | ||||||
Leadership 360 Programme
South Africa
We progressed Leadership 360 assessments and leadership
development to strengthen leadership and supervisory capability
across our South African operations. Harmony-developed
programmes for middle management, supervisors and frontline
leaders provide consistent content and seek to equip line leaders
to facilitate development within their teams.
Turning safety culture insights into a structured
improvement roadmap
Hidden Valley, Papua New Guinea
Harmony completed an independent safety culture maturity
assessment with DSS+ to identify strengths and opportunities to
further reinforce safety culture at Hidden Valley. The findings
informed a 36‑month improvement roadmap, with priority actions
incorporated into the operation’s 12‑month safety plan.
While Hidden Valley continues to deliver strong safety outcomes,
the assessment highlighted opportunities to further strengthen
workforce ownership, learning and shared accountability for
safety. Key improvement initiatives include aligning leaders on the
current and desired future safety culture, conducting a workforce
safety perception survey, reviewing the assessment findings
through facilitated workshops, and refining the site’s safety
improvement strategy. Progress against the roadmap is reviewed
through monthly leadership meetings and monitored as part of
the site’s ongoing improvement programme.
Strengthening frontline safety leadership and
communication as we embark on construction
Eva Copper, Australia
As construction activity, workforce numbers and project-partner
interfaces increased, Eva Copper held safety reset forums to
reinforce expected behaviours, clarify responsibilities and align the
site workforce on safety requirements. The project also
progressed its Supervisor Appointment Programme to strengthen
frontline leadership and support consistent supervision across
construction activities.
We expanded our safety communication mechanisms through a
new weekly safety and health meeting and workforce bulletin,
supporting alignment among project partners and the consistent
communication of emerging hazards and incident learnings
across the workforce.
Advancing safety leadership and culture following
acquisition
CSA mine, Australia
Alongside improvements to systems and risk management, the
site increased visible felt leadership interactions and invested in
building supervisor and middle-management capability to support
clearer expectations, stronger safety conversations and more
timely coaching when risks or at-risk behaviours are identified.
A stronger emphasis was also placed on accountability and
workforce participation. Through safety observations, inductions,
leadership messaging, field engagements and recognition of
positive safety behaviours, employees and contractors were
encouraged to take ownership of safety outcomes and reinforce
the standards expected across the operation. Preparations also
commenced for the implementation of a regionally aligned
Lifesaving Behaviours programme.
The site also reintroduced its safety committee following
Harmony’s acquisition, providing a formal forum for worker
consultation on significant incidents, behavioural safety, corrective
actions and the zero-harm objective.
Strengthening psychosocial risk management
Australasia region
The Australasia region is progressing structured approaches to
identify psychosocial hazards, assess exposure and implement
controls through work design, leadership action and operational
risk management. During FY26, CSA mine completed a
psychosocial risk assessment, participated in industry forums and
workshops, delivered a psychosocial safety presentation at the
New South Wales Mine Managers Conference, completed visual
literacy training and undertook internal and external culture
surveys. Survey findings are being analysed to inform education
and improvement initiatives in FY27.
85
Performance and effectiveness
Group safety outcomes, including loss of life, loss-of-life
frequency rate and LTIFR provide important context for assessing
the effectiveness of our overall safety approach. However, these
measures do not isolate the contribution of behaviour, culture and
accountability.
In South Africa, the progressive implementation of the Thibakotsi
safety culture transformation programme reached 84% during
FY26, exceeding the 75% level identified as the inflection point for
a healthy safety culture.
In Papua New Guinea and Australia, Visible Felt Safety Leadership
(VFSL) remains a key behavioural safety programme, combining
leadership engagement and workplace observations to reinforce
safe behaviours and identify opportunities for improvement.
These programmes are supported by critical control verification,
near miss and high potential near miss reporting and
investigation, and site-specific initiatives such as planned safety
observations at CSA mine. Work is underway in Australasia to
review and standardise leading safety indicators, supporting
greater consistency in how safety performance is monitored
across the region. This work complements the development of
the regional safety management system and digital safety
platform.
Future focus
•Conduct the next culture diagnostic in 2027 and incorporate findings into continuous improvement programmes •Progress Hidden Valley’s safety culture improvement roadmap and related workforce engagement initiatives •Continue developing leadership and supervisory capability to strengthen workforce ownership and accountability •Standardise leading safety indicators and further develop regional safety management and digital safety systems. | |||
86
Health and wellbeing
Key matters: Health Potential impacts on society, the environment and the economy: Occupational exposures can cause acute and chronic illness, while communicable and non-communicable diseases can affect the health and wellbeing of our workforce and surrounding communities. These impacts can affect quality of life, livelihoods and, in some cases, have lasting consequences for individuals and families. Matters that could impact Harmony: Supporting workforce health requires ongoing resources for healthcare, occupational health and preventative programmes. Workforce ill health can increase absenteeism, reduce workforce availability and productivity, and increase healthcare costs, while occupational and chronic disease can create longer-term compensation, medical and litigation liabilities. | ||
Sustainability framework | Safety, health and wellbeing: Pursue our goal of zero harm through a strong safety culture and supporting systems promoting employee physical and psychological health, safety and wellbeing. | ||
Strategic risk and opportunity | Risk: Safety and health Safety and health performance underpins operational continuity, workforce productivity and Harmony’s licence to operate. Opportunity: Culture, leadership and investment Strong culture, leadership and investment in safety, health and wellbeing strengthen operational discipline, workforce resilience and engagement, regulator confidence and long-term operational sustainability. | ||
The health and wellbeing of our employees are fundamental to safe, resilient and
productive operations.
Good health supports our people’s quality of life and capacity to participate fully in work and life. Occupational health, communicable
diseases, and physical or psychological health conditions may cause acute or chronic illness, reduced capacity and lasting harm. These
effects may extend to families and communities, while ill health can reduce employee availability and affect long-term business
performance. Our occupational health management system is applicable to 100% of our workforce to prevent and reduce exposures.
Health and wellbeing impacts, risks and opportunities (IROs)
Workforce health | Occupational disease | Communicable disease | Non-communicable disease and wellbeing | |||||||||||||||
Workforce health affects workers’ quality of life and long-term health outcomes, and shapes fitness for work, workforce availability and operational continuity. Poorly managed, it drives absenteeism, turnover, future compensation and liability exposure; managed well, it supports retention, capability and continuity of operations. This IRO arises through three inter- related pathways, being IROs 2, 3 and 4. | Mining and processing activities can expose employees and contractors to physical, chemical, biological, ergonomic and psychosocial hazards. Unmanaged, these exposures cause acute illness and chronic, often irreversible, occupational disease – including conditions with long latency that manifest years after exposure. Managing them requires controls applied in accordance with the hierarchy of control, and verified through exposure monitoring and health surveillance. Work exposures also influence susceptibility to communicable and chronic disease, connecting IRO 2 to IROs 3 and 4. | Workers and host communities are affected by airborne, vector-borne and blood-borne diseases with exposure shaped by regional disease burdens, workforce mobility and operating context. Workforce mobility carries disease risk between operations, home and host communities in both directions, thus control measures must extend beyond the workplace. Communicable disease risk is shaped by both workplace exposures and individual health status, connecting IRO 3 to IROs 2 and 4. | Modifiable risk factors – including physical inactivity, nutrition and substance use – contribute to chronic conditions such as cardiovascular disease, diabetes and mental ill health. An ageing workforce, remote operating conditions and camp-based living can compound these risks and limit access to primary care. Together they affect wellbeing, fitness for work and long-term workforce availability. Chronic conditions are influenced by work exposures and in turn affect susceptibility to communicable disease, connecting IRO 2 and 3. | |||||||||||||||

1
2
3
4
Performance snapshot
Total healthcare expenditure R1.1 billion (FY25: R1.1 billion) | Medical examinations conducted 83 494 in South Africa (FY25: 72 039) 18 808 across our Australasian operations (FY25: 21 336) | Chronic disease management Approximately 71% of our South African employees and 14% of our Papua New Guinea employees enrolled in chronic disease management | Available shifts (South Africa) Health absenteeism declined for the fifth consecutive year 7.2% (FY25: 7.3%) | |||||||||||
87
Regional context
South Africa | Papua New Guinea | Australia | ||||||||||||
Health burden | South Africa faces a complex burden of health risks. Communicable diseases, particularly HIV and tuberculosis, remain significant public health challenges. Non-communicable diseases including cardiovascular disease, diabetes, cancer and chronic respiratory disease are also major contributors to morbidity and mortality. Mental-ill health, occupational disease and workplace injury remain important workforce considerations. Health outcomes are further influenced by socio-economic inequality, variable access to healthcare, and lifestyle risk factors including tobacco use, harmful alcohol consumption, poor nutrition and physical inactivity. | Papua New Guinea carries a high burden of communicable disease, including malaria, tuberculosis, HIV, and water and food-borne illnesses. Non-communicable diseases such as cardiovascular disease, diabetes and cancer are increasing in prevalence. Mental health challenges, occupational health risks, and limited access to healthcare services continue to affect population health outcomes. These pressures are compounded by poor sanitation, malnutrition, maternal and child health challenges, and widespread betel nut and tobacco use. | Australia’s principal health burdens include non-communicable diseases such as cardiovascular disease, cancer, diabetes and respiratory conditions, alongside mental-ill health and an ageing population. Occupational injury, musculoskeletal disorders and chronic disease management remain important workforce health considerations. Persistent health inequities experienced by Aboriginal and Torres Strait Islander peoples, particularly in regional and remote communities, continue to influence access to care and health outcomes. Lifestyle risk factors including obesity, alcohol use and physical inactivity also contribute significantly to disease burden. | |||||||||||
Healthcare access | Access to health care is uneven and closely tied to socio-economic circumstance. Services are concentrated in urban centres, and mine health facilities carry a substantial share of workforce care. | Geographic isolation, health workforce constraints and limited infrastructure can increase vulnerability and delay diagnosis, treatment and continuity of care. | Distance and roster patterns constrain access to routine primary care, and workers on residential or fly-in-fly-out arrangements may have limited continuity with a regular provider. | |||||||||||
Regulatory framework | Occupational health is regulated under the Mine Health and Safety Act 29 of 1996, supported by tripartite industry milestones set through the Mine Health and Safety Council. | Occupational health is regulated under the Mining (Safety) Act 1977. Where PNG regulation does not address a matter or does not set a standard, we apply the equivalent Australian requirement as our minimum. | Occupational health is regulated in New South Wales under the Work Health and Safety Act 2011 and the Work Health and Safety (Mines and Petroleum Sites) Act 2013, and in Queensland under the Work Health and Safety Act 2011. | |||||||||||
How we manage health and wellbeing IROs
1 | Workforce health | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Occupational exposure compounds susceptibility to communicable disease, and chronic conditions worsen the course of both. The health of our people is shaped by the three interrelated pathways: occupational exposure; communicable diseases; and non-communicable disease and wellbeing. Each pathway reflects a different relationship between our operations and workforce health, and a different balance of prevention, mitigation and support. Mining depth, operating environment, employee demographics and access to healthcare may intensify these drivers. | Potential impact on society and the economy These exposures and conditions may cause acute or chronic illness, irreversible occupational disease, reduced physical or cognitive capacity, diminished quality of life and, in severe cases, premature death. Consequences may extend to broader family networks through lost income and increased care responsibilities, and to communities through pressure on health services and the loss of skills and earning capacity. Where communicable disease is present in our workforce, transmission may extend into our host communities. | Potential operational effect on Harmony Worker ill health may increase absenteeism and prolonged sick leave, constrain worker deployment, delay safe return to work and reduce labour availability, with disproportionate effect where output depends on complete crews. Reduced physical or cognitive capacity may also increase the potential for safety incidents in high-risk operating environments and place additional demands on operational and health teams. Ill health removes experienced people from the workforce, and that loss concentrates among those whose accumulated exposure and age make them most susceptible – the workers carrying the deepest operational knowledge. Effective prevention and early intervention can support healthier people, workforce availability and operational resilience. | Potential financial effect on Harmony Harmony incurs substantial expenditure to prevent and manage employee ill health and reduce its wider financial consequences. Without effective prevention, early detection, treatment and rehabilitation, health conditions may raise unit costs through lost production and reduced worker productivity. They may also increase compensation, health benefit, litigation and regulatory liabilities and require further investment in exposure controls, operational infrastructure and healthcare capacity. As many occupational diseases have long latency, current liabilities largely reflect historical exposure, and the effect of controls applied today is realised over decades rather than reporting periods. | |||||||||||
88
Our approach
Health is managed as a single topic across the three aforementioned interrelated pathways to effectively cover worker health and wellbeing. As exposure in one pathway influences vulnerability in another, we
managed them together rather than as exclusively separate programmes.
Group-wide, our approach follows a consistent sequence: preventing and controlling exposure at the source, detecting health conditions early through medical surveillance and screening, providing
appropriate treatment and ongoing management and supporting rehabilitation and safe return to work.
How these commitments are delivered differs by region. Workforce scale, disease burden, regulatory framework and the availability of external healthcare shape whether care is provided directly, through
contracted providers, or through national health systems. The regional delivery models set out below describe those arrangements.
Our regional delivery models | ||||||||||||||
South Africa | Papua New Guinea | Australia | ||||||||||||
Workforce coverage | 46 685 | 2 459 | 1 381 | |||||||||||
Model | Fully integrated in-house health service | On-site clinic with off-site referral capability | On-site emergency and fitness-for-work capability, with external service delivery | |||||||||||
On-site clinical team | Full time medical practitioners, nurses and support teams providing 24-hour care | Full time medical practitioners, nurses and support staff, with 24‑hour emergency cover | Nurse or paramedic providing 24-hour emergency cover | |||||||||||
Scope of on-site care | Emergency response, occupational medicine and primary healthcare delivered in full, integrated with occupational hygiene monitoring, health surveillance and fitness-for-work assessment | Emergency response, occupational health and primary healthcare, including day treatment and management of minor illness and injury, within the clinic’s defined scope of practice | Emergency response, fitness-for-work assessment including return to duty, and alcohol and other drug testing, and first line care for minor illness and injury. All other occupational and primary healthcare is delivered offsite | |||||||||||
External care and referral | Referral to external specialists and hospitals | External inpatient and outpatient care. Definitive care depends on referral or medical evacuation | Occupational health services, health surveillance and treatment delivered through contracted providers or the Australian health system | |||||||||||
Healthcare benefits | Company-funded healthcare benefits or medical scheme arrangements, depending on employee category | Employer-funded medical insurance | Access to employee-discounted private health insurance | |||||||||||
Health system and community interface | Harmony partners with provincial and district health authorities on health outreach programmes that address the burden of disease among employees and surrounding communities | Harmony works with provincial and district health authorities to support community health outreach and to extend continuity of care for our people when they are away from site | State-based notifiable disease reporting, coordination with state-based emergency services and regional hospitals for emergency response management and engagement with local health services | |||||||||||
89
ç | è | |||||||||||||||||||||||||||||
Occupational health exposures | Fatigue and mental health | Non-communicable disease and wellbeing | ||||||||||||||||||||||||||||
ê | ê | |||||||||||||||||||||||||||||
 | ||||||||||||||||||||||||||||||
Noise exposure | Loss of hearing | Financial distress | ||||||||||||||||||||||||||||
Airborne pollutant exposure | Occupational lung diseases | •Heart attacks •Diabetes | •Cancer •Hypertension | Lifestyle issues | ||||||||||||||||||||||||||
Ergonomic and machinery | Musculoskeletal (bones, muscles, joints) | Trauma cases (motor vehicle accidents, injuries outside of work and gender based violence) | ||||||||||||||||||||||||||||
Thermal exposure | Heat-related disorders | Communicable disease | ||||||||||||||||||||||||||||
ê | ||||||||||||||||||||||||||||||
Radiation exposure | Radiation-related disorders | Weakened immune system increasing other health risks | HIV, tuberculosis, malaria | |||||||||||||||||||||||||||
Our integrated response across all three pathways | ||||||||||||||||
Prevent and control | Detect early | Treat and manage | Rehabilitate and support recovery | Monitor and improve | ||||||||||||
Governance
The board oversees workforce health through the social and
ethics committee. Oversight is supported by quarterly reporting
on health risks, programme performance, leading and lagging
indicators, and workforce health outcomes. Health and safety
performance forms part of executive and eligible management
variable remuneration, reinforcing accountability for worker health
and safety outcomes. Regional executives are accountable for
implementing Harmony’s health strategy in line with local health
needs, operating conditions and regulatory requirements.
Operational teams are responsible for delivering occupational
health programmes, medical surveillance, healthcare services and
wellbeing initiatives. Workers participate in health governance
through health and safety committees at each operation,
providing a formal mechanism for consultation, hazard
identification and input into programme design. Health risks and
performance are monitored through risk registers, performance
reporting, health information systems, internal audits and
corrective actions processes. Delivery is supported by
collaboration across health, occupational hygiene, human
resources and operational teams.
90
How we manage health and wellbeing IROs
2 | Occupational disease | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Occupational health risk is influenced by mining method, orebody characteristics and work design, with exposure levels shaped by factors such as depth, ventilation and refrigeration capacity, equipment selection and condition, process enclosure, and the duration and frequency of exposure. Health risks arise where workers are exposed to hazardous agents including respirable crystalline silica, diesel particulate matter, noise, heat, ionising radiation and solar ultraviolet radiation. The risk profile can change over time as operations deepen, infrastructure ages, mining conditions evolve and environmental temperatures increase. The effectiveness of controls is assessed through exposure monitoring, health surveillance and verification of critical controls. | Potential impacts on society (our workforce) Occupational disease can result in permanent impairment, chronic illness, reduced quality of life and premature mortality. Many occupational health conditions are irreversible and may not be diagnosed until years or decades after exposure, limiting opportunities for early intervention. Health impacts can reduce functional capacity, fitness for work and long- term employability, while conditions such as hearing loss, heat illness and fatigue may also increase safety risks. The consequences often extend beyond affected workers through reduced household income, impacts on dependants and diminished wellbeing, reinforcing the importance of preventing exposure and maintaining effective controls. | Potential operational effect on Harmony Occupational health risks vary across asset types, mining methods and operating environments. While hazards such as noise, fatigue and psychosocial factors are relevant across operations, exposures to respirable crystalline silica, diesel particulate matter, heat and ionising radiation are generally more significant in underground environments, where risk is influenced by depth, ventilation capacity and fleet composition. Solar ultraviolet radiation is a key exposure for workers in surface and open-pit operations. Workforce mobility, including the movement of employees and contractors between operations, can also contribute to cumulative exposure profiles. If not effectively managed, occupational health risks may affect workforce availability, productivity and overall operational performance. Infectious disease risks are considered separately under IRO 3. | Potential financial effect on Harmony Occupational disease can create long-term financial exposure through compensation obligations, healthcare and rehabilitation costs, claims management and regulatory compliance requirements. Due to the often lengthy latency period associated with occupational diseases, current liabilities may arise from historical exposures, while present- day exposures can generate future obligations that are not immediately reflected in performance outcomes. Maintaining effective controls requires ongoing investment in ventilation and refrigeration infrastructure, fleet modernisation, emissions reduction technologies and occupational health programmes. Failure to adequately manage exposures may increase future liabilities, constrain operational performance and adversely affect Harmony’s reputation and social licence to operate. | |||||||||||
Our approach
We manage occupational health risks through a risk-based
framework that identifies hazards, assesses exposure,
implements controls and verifies their effectiveness. Controls are
applied in accordance with the hierarchy of control, prioritising
elimination, substitution and engineering controls wherever
practicable, supported by administrative controls and personal
protective equipment where required.
Our approach aligns with the principles of ISO 45001 and the
ICMM Performance Expectations. Group standards establish
minimum requirements across the portfolio, with the more
stringent requirement applied where local and group requirements
differ. Operational teams manage site-specific risks with oversight
from regional and group health functions.
These requirements apply to employees and contractors.
Occupational health programmes include exposure assessment,
health surveillance and control assurance activities, with
continued focus on achieving consistent contractor coverage
across the portfolio.
Performance is assessed using both leading and lagging
indicators, including exposure data, control verification, health
surveillance outcomes and occupational illness trends. Where
exposure baselines for a hazard have not yet been established,
targeted monitoring programmes are implemented and progress
is reported transparently.
91
Respirable crystalline silica | Noise | Heat | Diesel particulate matter | |||||||||||
Water suppression, extraction, ventilation and enclosure at source; work methods and exposure duration limits; fit-tested respiratory protection for residual exposure. | Equipment selection, maintenance, silencers and acoustic enclosures at source; access and time controls to limit exposure duration; fit-verified hearing protection. | Ventilation and refrigeration at depth; work scheduling, work-rest arrangements, hydration and thermal work limits at surface. | Fleet renewal and electrification where practicable; engine maintenance, fuel and after‑treatment selection; ventilation design and idling controls. | |||||||||||
Ionising radiation | Metal fume | Solar ultraviolet radiation | Psychosocial risk | |||||||||||
Ventilation and dust control; sealed source management and registers; dose limits, with personnel reassigned where they approach Harmony’s internal exposure thresholds. | Water suppression, extraction, ventilation and enclosure at source; work methods and exposure duration limits; fit-tested respiratory protection for residual exposure. | Solar ultraviolet radiation exposure is managed through shade, task planning, UV-protective clothing, eye protection, sunscreen, awareness training and referral for skin checks where required. | Supportive leadership, clear roles, workload and fatigue management, counselling support, early reporting and financial wellness support in the form of financial literacy initiatives. | |||||||||||
FY26 progress and achievements
Region-wide equipment review to strengthen noise
controls
South African operations
We continued the provision and monitoring of personalised
hearing protection while progressing hearing-conservation
measures. In FY26, provision of personalised hearing devices
reached 99% of employees and 77% of contractors. In South
Africa, an audit also identified some pieces of equipment
operating above 104dBA. To meet the revised industry milestone
for December 2034, noise from individual pieces of equipment
and process equipment must not exceed 104dBA. This reinforces
the need to sustain engineering controls, address equipment-
related noise and continue to strengthen hearing conservation
measures.
Progress towards the revised industry silica dust
milestone
South African operations
We continue investing in dust suppression, ventilation
improvements and real-time monitoring to strengthen control
of respirable silica exposure and support progress towards the
revised industry milestone. Operations are applying Mining
Industry Occupational Safety and Health Initiatives to strengthen
the adoption of best practices in mitigating the risk of exposure to
respirable crystalline silica.
Addressing legacy occupational disease claims
The Tshiamiso Trust independently administers compensation
under the R5.2 billion silicosis and tuberculosis class-action
settlement between Harmony, five other gold mining companies
and affected mineworkers. Harmony participated in the
settlement and establishment of the trust and supports current
and former mineworkers through medical examinations, tracing
and claims assistance.
In FY26, the trust paid R160 million to 1 525 current and former
Harmony mineworkers. To date, the trust has paid R1.1 billion to
11 535 current and former Harmony mineworkers.
Separately, South Africa’s statutory occupational disease
compensation fund, administered by the Compensation
Commissioner for Occupational Diseases, paid R162 million
to 1 583 current and former Harmony mineworkers in FY26.
92
Sharing our healthcare delivery experience
South African operations
During the year, we were proud to host government health
officials from Liberia and Bangladesh at Doornkop Mine’s Medical
Hub for a benchmarking visit facilitated with the Medical Bureau
for Occupational Diseases. Through the Joint Learning Network
for Universal Health Coverage, we shared insights from
Harmony’s health-service delivery and governance arrangements,
including our contracting models, collaboration frameworks and
partnerships. The visit enabled practical knowledge exchange and
consideration of approaches that could be adapted and tested in
other country contexts to strengthen sustainable health
interventions and improve employee and community health
outcomes.
Responding to thermal exposure and identification
of capital requirements
South African operations
We conducted a comprehensive review of our cooling
infrastructure at deep-level mines, initiated due to the increase
in heat cases, ageing ventilation infrastructure and rising ambient
temperatures. Our findings are informing FY26 and FY27 capital
allocation decisions, which will enable us to control heat exposure
more effectively. Further, refrigeration upgrades at Tshepong and
Mponeng mines, together with new cooling infrastructure at
Doornkop mine, have been approved.
Broadening our exposure surveillance above-ground
South African operations
We began extending occupational hygiene surveillance across surface and open-cut operations to better characterise exposure to solar
UV, diesel particulate matter and whole-body vibration and establish a stronger basis for future control and reporting.
Managing radiation exposure
South African operations
We strengthened the monthly monitoring of employees approaching administrative exposure limits by relocating them to less exposed
areas or, in severe cases, moving them to surface work.
Digital health landscape | ||
The group has invested significantly in healthcare technology to improve efficiency and outcomes. Electronic health records (EHR) are integrated across all facilities, supporting continuity of care and enabling data-driven decision-making. Additionally, digital capabilities include appointment scheduling and real-time data analytics dashboards that track health trends and cost drivers are in the process of being scaled up. AI-assisted chest X-ray screening that enhances tuberculosis detection is being explored, while a picture, archiving and communication system for digital radiology has been deployed across South African operations. Future prospects are automated medicine dispensing, biometric patient identification, and telehealth consultations for specialist referrals. | ||
93
Performance and effectiveness
Goal | Key controls | South Africa | Papua New Guinea | Australia | Trend | ||||||||||||
Noise-induced hearing loss (NIHL) | |||||||||||||||||
South Africa: •By December 2034, equipment noise should not exceed 104dB(A) •No novice NIHL cases among people previously unexposed to occupational noise before December 2024. Australasia: •Eliminate new cases of noise- induced hearing loss. | Equipment selection and maintenance; silencers, screens and acoustic enclosures; access and exposure-duration controls; personalised, fit-verified hearing protection; audiometric surveillance. | •Nine pieces of equipment are above the new milestone of 104dB(A). The overall noise clipper usage is above 95% across all operations •The number of employees with early NIHL decreased to 98 (FY25: 102) and those compensated for NIHL to 61 (FY25: 111) •On track to achieve goal. Since January 2025, zero reported cases of standard threshold shift cases exceeding 25dB(A) from baseline. | •No new NIHL cases diagnosed •Individual fit testing of hearing protectors is being expanded into Papua New Guinea. | •No new NIHL cases diagnosed. | Improving | ||||||||||||
Radiation | |||||||||||||||||
South Africa: •Prevent employee overexposure to radiation – below 20mSv in one year and 95mSv in five years. Australasia: •Keep occupational doses as low as reasonably achievable and well within regulatory limits. | Ventilation and dust control; sealed-source management and registers; personal dose monitoring; administrative limits; reassignment where limits are approached; site risk assessments. | •Two employees (FY25: 24 employees) are on surface after exceeding Harmony’s 95mSv over a five-year period administrative limit •A further 12 employees were identified as approaching administrative control limits in 2026, with three reassigned to lower-risk areas and remaining nine employees under review for reassignment. | •No doses exceeded 20mSv/yr or 95mSv/5yr •Hidden Valley radiation risk assessment underway •Personal monitoring established for any potential dose above 1mSv/yr. | •No doses exceeded 20mSv/yr or 95mSv/5yr •CSA mine completed radiation risk assessment •Personal monitoring established for any potential dose above 1mSv/yr. | Improving | ||||||||||||
Respirable crystalline silica and silicosis | |||||||||||||||||
South Africa (Industry milestone): •By December 2034, 95% of individual exposure results should be below 0.03mg/m³ •No novice pneumoconiosis cases among people previously unexposed to mining dust before December 2024. Australasia: •Eliminate new cases of silica-related disease, including silicosis, lung cancer and chronic obstructive pulmonary disease. | Water suppression, extraction, ventilation and enclosure; work- method and exposure-duration controls; fit-tested respiratory protection; exposure monitoring; medical surveillance; engineering-control verification. | •Most metallurgical plants and one- third of our South African mines exceeded our 95% target •73% of exposure results were below the milestone, down from 78% in FY25 •Zero novice pneumoconiosis diagnoses, unchanged from FY25 •Engineering-control compliance was 95%. | •No cases diagnosed •The Australian standard is applied as the regional minimum, including in Papua New Guinea, with adjustment for extended rosters. | •No cases diagnosed •Exposure profiles are being assessed against both the current standard and a possible future 0.025mg/m³ standard. | Improving (South Africa) Maintained (Papua New Guinea) Baseline being assessed (Australia) | ||||||||||||
94
Goal | Key controls | South Africa | Papua New Guinea | Australia | Trend | ||||||||||||
Thermal stress and heat-related illness | |||||||||||||||||
South Africa: •Compliance with thermal stress management criteria including intake wet-bulb specifications and thermal work limit based risk management (Industry milestone). Australasia: •Prevent heat-related illnesses and heat strain. | Ventilation and refrigeration at depth; work scheduling; work- rest arrangements; hydration; thermal work limits; acclimatisation; heat-tolerance screening and medical review. | •64% of cross-cuts were below the 26°C wet-bulb threshold •Cooling infrastructure was reviewed, with refrigeration upgrades approved at Tshepong and Mponeng and new cooling infrastructure approved at Doornkop. | •Zero heat-related illness events. | •Twelve heat-related illness events. | Improving (South Africa) Maintained (Papua New Guinea) Baseline being assessed (Australia) | ||||||||||||
Solar ultraviolet exposure | |||||||||||||||||
Australasia: •Eliminate occupationally caused skin cancer. | Shade; task planning and scheduling; ultraviolet-protective clothing and eye protection; sunscreen; awareness training; skin-check referrals; shade and cabin-design assessment. | •South Africa began extending surface and open-cut surveillance to characterise solar ultraviolet radiation exposure. | •Zero cases of occupational skin cancer across the region. | •Zero cases of occupational skin cancer across the region. | Baseline developing | ||||||||||||
Psychosocial hazards | |||||||||||||||||
Group: •Prevent psychological injury caused by work. | Supportive leadership; clear roles; workload and fatigue management; risk assessment; counselling support; early reporting; financial-wellness support; management. | •Commencing an effective collaboration framework that aims at addressing workplace drivers of psychosocial risks. | •Zero psychological injury claims •Australasian approach applies psychosocial-risk requirements as the minimum standard in Papua New Guinea. | •Zero psychological injury claims •One site with completed psychosocial risk assessment. | Baseline developing | ||||||||||||
Future focus
•Harmony will accelerate progress towards the December 2034 milestones, targeting 95% silica compliance at 0.03mg/m³, managing of equipment above 104dBA, and zero NIHL or silicosis cases among novice workers •Continually assess the root cause of heat cases with increases investigated further through strengthened acclimatisation and Thermal Work Limit protocols •Medically enhance the detection capabilities of all conditions, relying on available technological advances. | |||
95
3 | Communicable diseases | I | R | O | SA | PNG | |||||||||||||
Impact, risk and opportunity drivers Communicable disease risk is influenced by disease prevalence, workforce mobility, living conditions, access to healthcare, public health system capacity, water and sanitation infrastructure, and travel to and from endemic regions. Exposure patterns are also shaped by interactions between employees, contractors, accommodation facilities and host communities, which can affect the potential for disease transmission and outbreak management. | Potential impacts on society (our workforce) Communicable diseases can result in serious or chronic illness, reduced quality of life, loss of work capacity, and in severe cases, premature death. Some conditions require long-term treatment and clinical management, while others can cause serious acute illness. The impacts of communicable disease often extend beyond affected individuals through lost income, increased caregiving responsibilities and broader social and economic effects on workers, their families and communities. | Potential operational effect on Harmony The significance of communicable disease risks varies across regions and operating environments. HIV and tuberculosis are most significant in South Africa and Papua New Guinea, while malaria exposure is concentrated in Papua New Guinea and among employees travelling to endemic regions. Typhoid and cholera risks are associated with local water quality and sanitation conditions. In Australia, communicable disease risks are generally lower, primarily relating to seasonal respiratory illnesses, workforce mobility and travel-related exposures. Significant outbreaks can affect workforce availability, productivity and operational continuity, particularly where access to healthcare services is constrained. | Potential financial effect on Harmony Communicable diseases create costs through prevention programmes, screening, treatment services, clinical support and workforce health initiatives. Illness-related absenteeism, reduced productivity and workforce turnover can affect operational performance and labour availability. Additional expenditure may be required during disease outbreaks to protect workers and maintain business continuity. Sustained investment in prevention, surveillance and treatment programmes helps reduce disruption, supports workforce resilience and strengthens operational stability across the portfolio. | |||||||||||
Our approach
We tailor prevention, screening, treatment and follow-up programmes to the communicable disease profile of each region. Our programmes support early diagnosis, continuity of care and treatment
adherence, recognising the links between workers, operations, home communities and public health systems. HIV testing, tuberculosis screening and malaria prevention programmes are provided on a
voluntary basis where relevant, consistent with our commitments to confidentiality, informed consent and non-discrimination.
96
HIV | Tuberculosis | Malaria | Typhoid and cholera | |||||||||||
South Africa We provide voluntary counselling and testing, antiretroviral therapy, preventative treatment and ongoing clinical monitoring. Treatment- adherence support and preventive therapy help maintain health, achieve viral suppression and reduce vulnerability to tuberculosis and other infections. Programmes also address stigma and promote awareness of HIV status. Papua New Guinea Trained onsite personnel provide voluntary HIV counselling and testing, supported by awareness campaigns and referral pathways. HIV prevention, testing and treatment are delivered through a combination of workplace programmes and local health services. Australia HIV prevention, testing and treatment are accessed through the national health system, employee health benefits and referral pathways. | South Africa Employees undergo routine screening, supported by digital chest X-ray technology and occupational health assessments. Contact tracing, household screening and community- based follow-up support continuity of care. Confirmed cases are referred for treatment and monitored to support treatment completion. Papua New Guinea Tuberculosis remains a significant public health concern. Employees are assessed through occupational health programmes and clinical presentations, with cases referred to local healthcare systems for diagnosis, treatment and follow-up. Health promotion supports early identification and treatment adherence. Australia Tuberculosis is not considered a key workforce health risk, with cases managed through the national health system. | South Africa Malaria is primarily a travel-related risk. Employees travelling to endemic areas are supported through health advice, risk assessment and access to preventive measures, including prophylaxis where appropriate. Papua New Guinea Malaria prevention focuses on employees living in or travelling through endemic areas. Controls include insecticide-treated bed nets, education, prophylaxis where appropriate, rapid testing and prompt treatment. Response measures are reviewed regularly to maintain preparedness. Australia Malaria is not endemic. Risk primarily arises from travel to endemic regions and is managed through travel health advice, risk assessment and preventive measures where required. | South Africa Risks are generally low and are managed through water quality monitoring, food safety controls, hygiene standards and access to appropriate medical care and referral services. Papua New Guinea Management focuses on water quality, sanitation, food safety controls, health awareness and early diagnosis. Site inspections and response processes are designed to maintain readiness and minimise workforce impacts. Australia Typhoid and cholera risks are generally low and are managed through routine water quality, hygiene and food safety controls, supported by public health requirements and site health monitoring programmes. | |||||||||||
FY26 progress and achievements
Strengthening HIV prevention through partnership
Hidden Valley mine, Papua New Guinea
Papua New Guinea has the highest HIV prevalence in the Pacific,
with Morobe Province among the most affected areas. Our locally
based workforce regularly moves between site and Lae, linking
workforce health to the region’s broader health profile.
In February 2026, Hidden Valley mine began offering HIV pre-
exposure prophylaxis (PrEP) as a voluntary component of its
workforce health programme, positioning the operation among
the first mining companies in Papua New Guinea to provide PrEP.
When taken as prescribed, PrEP is highly effective in reducing
the risk of HIV acquisition and strengthens primary prevention.
The programme was developed with the Morobe Provincial
Health and Sexually Transmitted Infections Office and ANGAU
Memorial Hospital HIV clinic. Hidden Valley mine provides
workforce access and on-site facilities, while health authorities
provide clinical governance, prescribing oversight and continuity
of care. Clinicians delivered workforce awareness sessions and
trained site medical personnel in clinical assessment, prescribing,
adherence support and confidentiality. Participation is voluntary
and confidential.
Progress towards the WHO/UNAIDS 95-95-95 targets
South Africa
The WHO/UNAIDS 95-95-95 targets provide a global framework
for ending the HIV epidemic and an important benchmark for
measuring our progress in South Africa. Our programme supports
employees through HIV education, counselling and annual
testing. HIV prevalence within our workforce remains higher than
the national average, reflecting workforce demographics and the
visibility provided through extensive voluntary testing, treatment
and clinical management programmes.
South Africa | Target | FY26 | FY25 |
Percentage of employees living with HIV will know their status | 95 | 94 | 93 |
Percentage of employees with diagnosed HIV infection to receive sustained antiretroviral treatment (ART) | 95 | 89 | 89 |
Percentage of employees receiving ART to have viral suppression | 95 | 87 | 85 |
97
Taking tuberculosis prevention further: underground and beyond the mine gate in South Africa | ||||||||||||||||
Advancing early detection through innovation In March 2026, Harmony partnered with South Africa’s Department of Health, the Minerals Council South Africa and the Stop TB Partnership to deploy ultra-portable, AI-assisted chest X-ray screening nearly four kilometres underground at Mponeng. The initiative brought advanced TB screening directly to employees in a deep-level operating environment, supporting earlier identification and clinical decision-making where conventional diagnostic infrastructure is difficult to access. It formed part of Harmony’s mandatory annual medical surveillance and broader efforts to prevent and manage tuberculosis, particularly among employees vulnerable to silica-related lung disease. The deployment also supported an attempt to establish a Guinness World Records entry for operating X-ray screening technology at the greatest depth below the Earth’s surface. The attempt presented an inverse counterpart to an earlier Guinness World Records achievement involving X-ray equipment operated at high altitude near Mount Everest, demonstrating the potential to extend advanced diagnostic capability into some of the world’s most challenging working environments. | ||||||||||||||||
Reaching communities beyond the mine gate Understanding our challenge Tuberculosis has long shadowed the mining industry. Although Harmony has made significant progress, mining remains a high-risk environment: employees work in confined spaces, spend long periods in close contact and may be exposed to dust that increases lung vulnerability. Because TB is airborne, a single infectious person can unknowingly infect many others. Critically, transmission does not stop at the workplace – employees return home each day to families, neighbours and communities, which can create an ongoing cycle of infection between our mines and the areas around them. A new way of thinking Our own data (FY23 – FY26) confirmed that our strong workplace programmes alone – routine screening, early diagnosis, access to treatment, contact tracing and occupational health surveillance – would not be sufficient to eliminate TB. Doornkop, in particular, recorded incidence rates that exceeded the industry, requiring both internal and external interventions. This prompted a shift in mindset: instead of asking “How do we manage TB in our mines?” we began asking “How do we reduce TB transmission across the entire mining community?”. Our response – community outreach In partnership with our Corporate Social Investment team and the National Department of Health, Harmony ran a TB Community Outreach Programme from October 2025 to June 2026. Taking screening and diagnostic services directly into high-risk, peri-mining communities, the programme set out to identify and screen at-risk residents, test TB suspects and close contacts, link every diagnosed person to treatment, expand access to TB Preventive Therapy (TPT), and reduce the community TB infection pool. | Community members who screened negative were offered TPT to prevent future disease. These outcomes complement a marked improvement in workforce incidence, with the Harmony group TB incidence rate falling from 604 per 100 000 in FY23 to 287 per 100 000 in FY26 – driven by a strong internal programme and targeted interventions in Gauteng, including this outreach. | |||||||||||||||
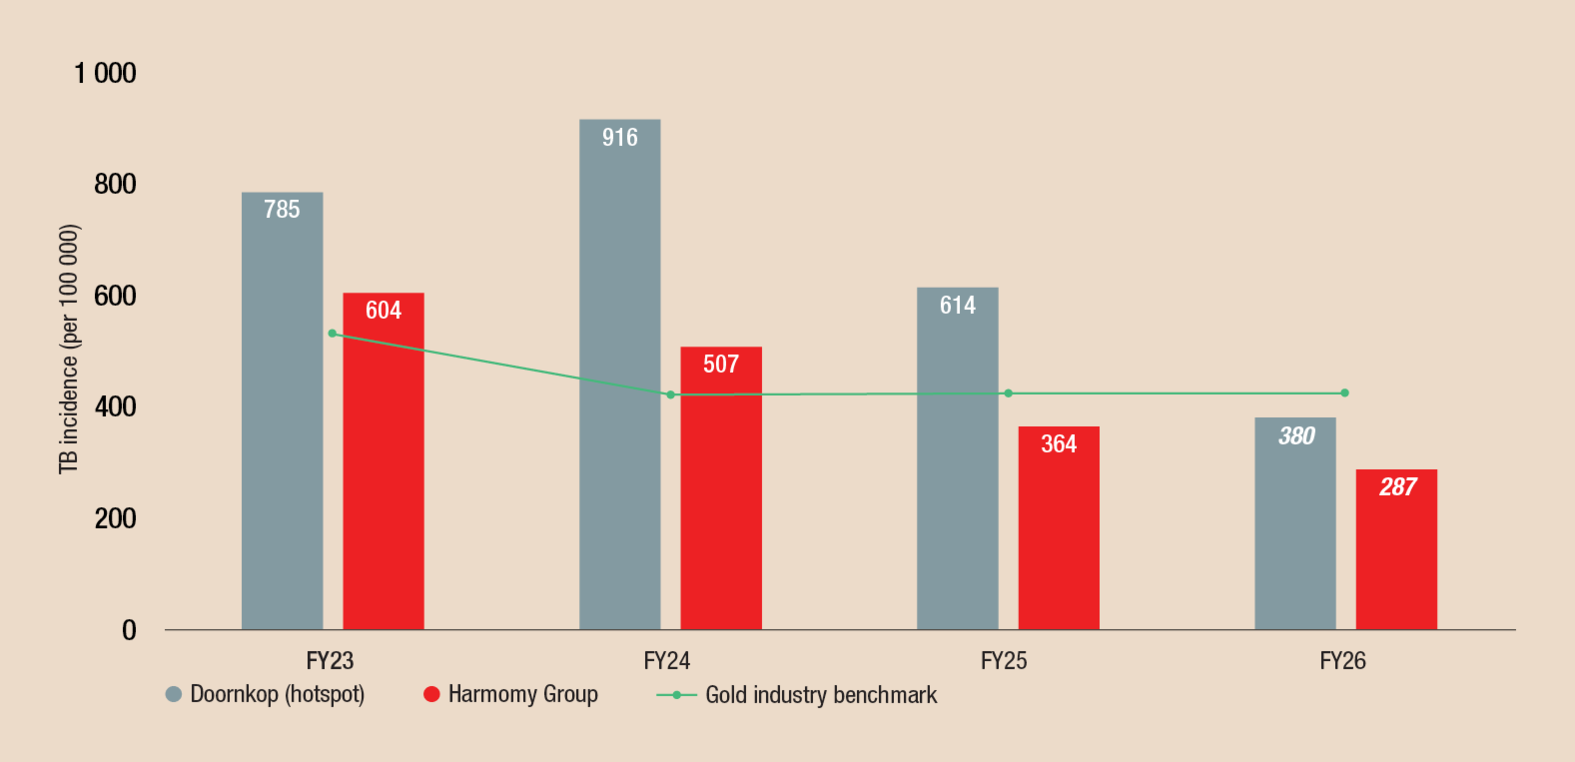 | ||||||||||||||||
TB is both an occupational and a community disease – and TB does not stop at the mine gate. Neither should our response. | ||||||||||||||||
4 756 Community members reached | 2 811 Chest X-rays conducted | 1 113 Sputum samples collected | 38 Cases suggestive of TB detected | |||||||||||||
By strengthening partnerships with the Department of Health and the communities we serve, Harmony is helping to reduce transmission, improve early diagnosis and treatment, and contribute to South Africa’s goal of eliminating TB by 2030. | ||||||||||||||||
98
Performance and effectiveness
Goal | Key controls | South Africa | Papua New Guinea | Australia | Trend | ||||||||||||
HIV/Aids | |||||||||||||||||
South Africa: •WHO/UN AIDS 95/95/95 targets. Papua New Guinea •Support prevention, testing, access and treatment continuity without discrimination. | Voluntary counselling and testing; ART; preventive treatment; clinical monitoring; treatment-adherence support; awareness and stigma reduction; referral pathways; voluntary PrEP in Papua New Guinea. | •Performance improved to 94/89/87 from 93/89/85 •85 372 voluntary counselling session attendances (FY25: 75 640) •70 835 voluntary tests conducted (FY25: 64 128) •9 120 HIV-positive employees (FY25: 9 508) •8 194 employees receiving ART through our HIV/AIDS programme (FY25: 8 709). | •Workplace policy in place •Zero reported instances of HIV-related discrimination •Voluntary testing uptake •PrEP introduced at Hidden Valley in February 2026. | •Workplace policy in place •HIV prevention, testing and treatment are accessed through the national health system, supported by employee benefits and referral pathways. | Improving (South Africa) Baseline developing (Papua New Guinea) | ||||||||||||
Tuberculosis | |||||||||||||||||
South Africa •TB incidence rate should be at or below the national TB incident rate 287/100 000 (national incidence reporting is usually lagging). Papua New Guinea •Eliminate work-related TB and ensure every diagnosed worker completes treatment. | Routine screening; digital chest X‑rays; occupational-health assessments; contact tracing; household and community screening; treatment referrals; treatment monitoring; preventive therapy; integration with silica respiratory surveillance. | •131 cases diagnosed (FY25: 159), contributing to an incidence rate of 287/100 000 (FY25: 364/100 000), a 21% year-on-year reduction •TB Day campaigns screened 10 785 employees (FY25: 8 551) •Community outreach reached 4 756 people, conducted 2 811 chest X-rays and collected 1 113 sputum samples; 38 cases suggestive of TB were identified. | •Zero work-related TB cases. | •TB is not considered a key workforce health risk •Cases are managed through state public-health notification, treatment and specialist-referral pathways •No FY26 case metric is reported. | Improving | ||||||||||||
Malaria | |||||||||||||||||
Papua New Guinea •Eliminate cases arising from work at, or travel to, operations. | Education; vector management; insecticide-treated nets; chemoprophylaxis; rapid diagnostic testing and treatment; pre-travel risk assessment; travel-health advice. | •Primarily a travel-related risk. | •249 cases (FY25: 251). | •Not endemic; risk primarily relates to travel and is managed through travel- health advice, assessment and preventive measures. | Maintaining | ||||||||||||
Waterborne and foodborne disease | |||||||||||||||||
Papua New Guinea •Eliminate illness arising from water, sanitation and food services under operational control. | Potable-water monitoring; sanitation; food-safety controls; hygiene standards; site inspections; health awareness; early diagnosis; food- handler screening and training; typhoid vaccination where warranted. | •Risk is reported as generally low and managed through water quality, food safety, hygiene and access to medical care. | •Zero confirmed typhoid cases (FY25: Zero) •626 gastrointestinal illness episodes (FY25: 667). | Risk is reported as generally low and managed through routine water-quality, hygiene and food-safety controls. | Maintaining | ||||||||||||
Future focus
•Strengthening community-based TB and HIV screening in labour-sending areas remains a priority •Expanding the piloting of enhanced pharmacy access, decentralised dispensing and digital adherence support for HIV-positive employees to other operations •Expanding climate-related malaria risk monitoring in Papua New Guinea. | |||
99
4 | Non-communicable disease and wellbeing | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Non-communicable disease and wellbeing risks are influenced by a combination of lifestyle, social, health system and workplace factors. Health outcomes may be affected by diet, physical inactivity, obesity, tobacco, alcohol and betel nut use, which contribute to conditions such as cardiovascular disease, diabetes, cancer and respiratory disease. Mental wellbeing can be influenced by financial pressures, separation from family, social isolation and access to support services, while sleep disorders and substance use may affect both long-term health outcomes and fitness for work. Limited access to preventative healthcare and early intervention services can also increase the prevalence of undiagnosed or unmanaged health conditions. | Potential impacts on society (our workforce) Non-communicable diseases and related health conditions may reduce quality of life, physical capacity, cognitive function and overall wellbeing. Undetected or poorly managed conditions can progress to prolonged illness, disability, medical emergencies or premature death, while remote operating locations may delay access to definitive care. Mental health conditions, sleep disorders and substance use may further affect concentration, decision-making and fitness for work. The impacts often extend beyond affected workers to families and dependants, particularly where workers are primary income earners. | Potential operational effect on Harmony Exposure profiles vary across regions and workforce populations. In South Africa, chronic disease, mental wellbeing and sleep-related conditions represent significant health challenges, influenced by workforce demographics and healthcare access. In Papua New Guinea, cardiovascular disease and diabetes are growing concerns, while tobacco and betel nut use contribute to long- term health risks. In Australia, chronic disease, mental health conditions and sleep disorders reflect broader population trends, with remote and fly-in fly- out work arrangements influencing health and wellbeing outcomes. | Potential financial effect on Harmony Poor workforce health creates direct and indirect costs through absenteeism, medical incapacity and premature workforce attrition, reducing labour availability and increasing recruitment and training expenditure. Occupational health services, health benefits and medical evacuation from remote sites represent ongoing operating costs. Impaired fitness for work may increase the likelihood of safety incidents, affecting productivity and operational continuity. The loss of experienced employees can further impact operational capability, particularly in specialised and difficult-to- replace roles. Preventative health and wellbeing initiatives can support workforce availability, capability and longer-term operational resilience. | |||||||||||
Our approach
We address non-communicable disease and wellbeing risks
through health screening, clinical management, employee
support and health promotion programmes. Our approach
supports fitness for work while promoting long-term health
and wellbeing through early identification, treatment and
management of chronic disease, mental health conditions,
sleep disorders and lifestyle-related risk factors.
Health service delivery is tailored to the healthcare context of
each region. In South Africa, Harmony directly operates
occupational and primary healthcare services, providing
prevention, screening, treatment and ongoing disease
management. In Papua New Guinea, onsite services are
complemented by specialist and public healthcare providers.
In Australia, occupational health support and emergency
response services operate alongside the national healthcare
system.
Our health services are delivered by qualified clinical personnel
under independent clinical governance arrangements. Medical
information is managed confidentially and is not accessible to
line management.
The programmes described in this pathway are available to
Harmony employees across all operations. Contractors also
have access, except where specified, or are required to
provide equivalent services to their workforce, verified through
contract and mobilisation assurance processes.
100
Non-communicable disease | Lifestyle related health factors | Mental health and wellbeing | Sleep and substance use | Extended illness and incapacity | ||||||||||||||
We screen for, monitor and manage non- communicable diseases that include chronic conditions such as hypertension, diabetes, obesity and cardiovascular disease. Clinical pathways support diagnosis, treatment, monitoring and specialist referral where required. Workers with diagnosed chronic conditions are supported through individual health management plans at all operations. Where Harmony provides primary healthcare services, disease management is delivered onsite. Treatment is accessed through the broader healthcare system, with workplace support focused on monitoring, fitness for work and referral coordination. | Our "fitness for life" approach supports long-term health and wellbeing through health promotion, nutrition literacy, physical activity programmes, tobacco cessation support and healthy lifestyle initiatives. At residential operations, catering arrangements and living environments are recognised as important influences on diet, physical activity and sleep. Programmes are designed to support informed health choices and reduce modifiable risk factors associated with chronic disease. | We provide confidential counselling and employee assistance programmes and integrate mental health screening into routine health surveillance where appropriate. Targeted and remote support is available for workers exposed to distressing events, including healthcare personnel and emergency responders. Mental health programmes promote awareness, early intervention and access to support. Workplace psychosocial hazards are identified and managed under Pathway 1. | We use education, screening, assessment and referral pathways to identify and manage sleep disorders, alcohol use and the use of other substances that may affect health, fitness for work or safe performance. Where appropriate, workers are supported through treatment, rehabilitation and workplace accommodation processes. Fatigue arising from work design is addressed under Pathway 1. | Case management, rehabilitation, reasonable workplace adjustments and return-to-work programmes support workers whose health affects their ability to perform normal duties, regardless of whether the condition is work- related. The objective is to maintain workforce participation where appropriate, support recovery and ensure workers continue to receive suitable health and workplace support throughout their rehabilitation and return-to-work journey. | ||||||||||||||
FY26 progress and achievements
Strengthening integrated chronic disease care
South African operations
During FY26, Harmony continued to coordinate care for employees living with multiple chronic
conditions through an integrated clinical pathway. Rather than treating each condition separately,
the model brings monitoring, treatment and referral together, recognising that conditions such as
hypertension, diabetes and other health concerns frequently coexist and require coordinated
ongoing care.
Making mental health part of routine healthcare
South African operations
Harmony maintained mental health screening as part of routine annual health surveillance in South
Africa, embedding mental wellbeing within the broader healthcare model rather than treating it as a
separate programme. Employee assistance programmes continued to provide confidential
counselling and referral, while Carer for Carers supported the wellbeing of employees delivering
healthcare services.
Expanding access to mental wellbeing support
Papua New Guinea operations
During FY26, we extended employee assistance programme (EAP) services through Converge
International across Papua New Guinea, achieving full EAP coverage across Harmony’s
Australasian operations. The programme provides confidential, professional counselling and
support to workers and their immediate families at no cost, accessible by telephone, video and in
person. Support is available for personal, family, financial and work-related concerns, recognising
that many factors affecting mental wellbeing originate outside the workplace. Access is fully
confidential, with no individual information provided to the business.
Making the service available in Papua New Guinea required more than simply extending access.
Effective counselling depends on trust, cultural understanding and the ability to communicate
comfortably in one’s preferred language. A service offered only in English would have limited
practical reach. Converge provides counsellors fluent in Tok Pisin, with interpreter support
available for other languages. This is what makes the expanded access meaningful rather than
nominal. Our contractors are also required to provide equivalent support to their own personnel.
101
Performance and effectiveness
Goal | Key controls | South Africa | Papua New Guinea | Australia | Trend | ||||||||||||
Chronic diseases | |||||||||||||||||
Group-wide •Reduce the burden of chronic disease through early detection, effective management and improved health environments. Australasia •Reduce the burden of chronic disease across our workforce through early detection, effective management and improved health environments. | Periodic health screening; diagnosis and clinical monitoring; individual health-management plans; treatment and specialist referral; health promotion; nutrition standards; coordination with external care. | •Please refer to the Lifestyle disease management section on the following page •Health assessment coverage 100% of the workforce •71% of workers assessed identified with one or more diagnosed chronic conditions. | •14% of workers assessed identified with one or more diagnosed chronic conditions •14% workers on active health management plans. | •Occupational-health support focuses on monitoring, fitness for work and coordination with external providers. | Improving (programme enrolment) | ||||||||||||
Mental health and wellbeing | |||||||||||||||||
South Africa •Create psychologically safe workplaces and reduce mental health related stigma – 100% screening of employees for mental health conditions •Support workforce mental wellbeing and ensure every worker has access to confidential mental health support. Australasia •Support workforce mental wellbeing and ensure every worker has access to confidential mental health support. | Routine mental-health screening; confidential counselling; employee assistance programmes; referral services; targeted support for workers exposed to distressing events; awareness and early intervention. | •99% (FY25: 97%) of our employees have been screened. | •100% employee coverage. | •100% employee coverage. | Improving | ||||||||||||
Substance use | |||||||||||||||||
Group •Reduce harm from alcohol and substance use and support workers to seek support without fear of adverse consequence •Reduce hazards and absenteeism from impaired judgement by communicating clear expectations that are in line with the country’s laws and regulations. | Case management; rehabilitation; reasonable workplace adjustments; return- to-work programmes; treatment monitoring; management of medical certificates; early intervention and referral. | •Regular testing and screening for substance abuse at the shafts •A substance abuse policy has been drafted. | •Alcohol and other drugs policies in place •Fitness-for-work testing conducted in accordance with site standards and applicable regulation. | •Alcohol and other drugs policies in place •Fitness-for-work testing conducted in accordance with site standards and applicable regulation. | Maintaining | ||||||||||||
102
Lifestyle disease management
Below is a graphic displaying our burden of disease (prevalence) among our South Africa
employees. HIV accounted for 39% of the managed caseload, hypertension 34% and diabetes
19%. In FY26, 23 279 South African employees were enrolled in chronic disease management
(FY25: 22 893), representing approximately 71% of our employees. Lifestyle programme
participation grew to 4 404 employees, expanding by including underweight employees through
tailored nutritious meal plans to support healthy weight gain.
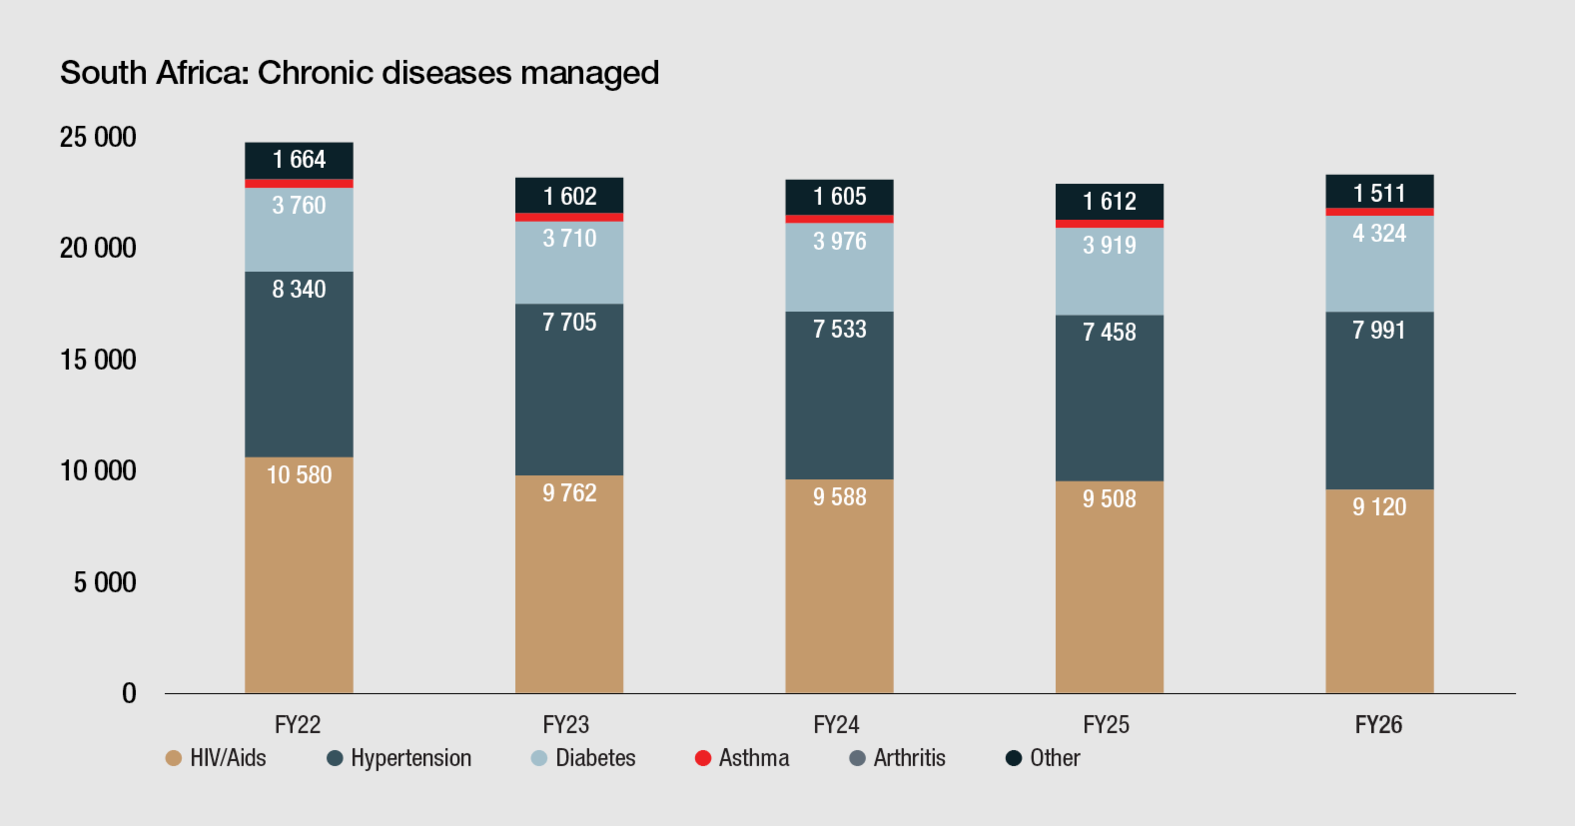
Improving labour availability
Health-related absenteeism at our South African operations was 7.2% in FY26, compared with
7.3% in FY25. We continued to focus on earlier identification of chronic or incapacitating
conditions, consistent management of medical certificates and coordinated support for workers on
prolonged sick leave.
Our at-work management programme monitors treatment and recovery, maintains contact with
affected workers and supports a safe, healthy and productive return to work. Injuries, mental
health and musculoskeletal and respiratory conditions, remained the main contributors to
extended absence.
Across our Australasian operations, health-related absence remained predominantly associated
with respiratory illness, musculoskeletal conditions and other non-occupational health factors. At
Hidden Valley, upper respiratory infections continued to be a common contributor to absence.
Absence management focuses on early intervention, access to appropriate healthcare, case
management and return-to-work support. At CSA mine, workforce health is monitored through
established health and wellbeing programmes and site-based occupational health support. During
construction at Eva Copper, workforce health management is delivered primarily through our
construction alliance partner, whose systems and processes apply to the majority of site
personnel.
Implementing a cost-effective healthcare model
Our healthcare expenditure and impact across the group was as follows:
FY26 | FY25 | ||
Investment in healthcare | R1.1 billion US$68 million | R1.0 billion US$59 million | |
Medical examinations conducted | 102 302 | 93 375 | |
South Africa | |||
Health examinations conducted | 83 494 | 72 039 | |
Total healthcare expenditure (Rb) | R1.1 billion | R1.0 billion | |
Free healthcare benefits: | |||
– Health benefits cost (Rm) | R691 million | R652 million | |
– Employees impacted | 24 545 | 24 610 | |
Medical aid schemes: | |||
– Medical aid scheme cost (Rm) | R416 million | R387 million | |
– Employees impacted | 9 716 | 9 535 | |
Australasia | |||
Health examinations conducted | 18 808 | 21 336 | |
Total health expenditure (Rm) | R37 million | R33 million |
Future focus
•Harmony will continue to advance AI-assisted diagnostics and predictive analytics, optimise pharmaceutical procurement to contain per-capita costs, and expand digital health platforms, including mobile health interfaces •The group aims to expand lifestyle intervention and chronic disease management participation, maintain mental health screening coverage above 95%, and broaden psychosocial services. | |||
103
Engaged workforce
Key matters: Sound labour relations; supporting our people Potential impacts on society, the environment and the economy: Employment can provide secure livelihoods, skills and opportunities for people to participate in the economy. How we manage our workforce can also affect fair labour practices, human rights, inclusion and access to employment and development opportunities. Matters that could impact Harmony: Our ability to attract, develop and retain the skills we need affects workforce capability, productivity and our ability to deliver our strategy. Labour instability, skills shortages and poor workforce engagement can increase costs, disrupt operations and affect Harmony’s reputation as an employer. | ||
Sustainability framework | Supporting our people: Attract and retain a diverse and engaged workforce and focus efforts on: diversity, equity and inclusion; maintaining sound labour relations; and workforce training and education. | ||
Strategic risk and opportunity | Risk: Retaining key skills and experience Critical skills and workforce capability underpin operational performance, safety and delivery of Harmony’s strategy. Opportunity: Workforce development and capability Workforce development, succession planning and strong talent pipelines can strengthen capability and long-term competitiveness. | ||
An engaged, capable workforce is fundamental to sustaining safe, productive
operations and creating lasting value.
Our people are central to delivering Harmony’s strategy and long-term sustainability objectives. Workforce-related risks, including skills
shortages, labour instability, challenges in attracting and retaining talent and a weak organisational culture may affect safety outcomes,
productivity and long-term business performance. In response, we invest in our workforce capability, foster an inclusive and values-
driven culture, maintain constructive labour relations and support the development, wellbeing and engagement of our people.
Workforce impacts, risks and opportunities (IROs)
Maintaining sound labour relations and practices | Local employment and workforce opportunities | Workforce attraction, retention and capability | Fostering a strong organisational culture | Diversity, equity and inclusion (DEI) | |||||||||||||||||||
Constructive engagement with unions and employee representative structures supports fair pay, employee rights and workforce stability, contributing to productive operations and the wellbeing of our workforce. | Our employment practices support local workforce participation, skills development and career opportunities. Through transformation, local content and workforce- related commitments, Harmony contributes to socio-economic development while strengthening stakeholder trust and our social licence to operate. | By being recognised as an employer that offers meaningful careers, development opportunities, competitive rewards and a positive employee experience, Harmony can strengthen workforce capability, improve retention and position itself to deliver long-term growth. | A healthy organisational culture promotes employee wellbeing, accountability and collaboration, supporting workforce engagement, retention and organisational performance. Through leadership development, employee engagement and culture initiatives, we seek to foster a values-driven workplace that supports and enables the delivery of our strategic objectives. | Diversity, equity and inclusion initiatives support equitable access to employment, development and leadership opportunities, helping to build a more representative and inclusive workplace. A diverse workforce strengthens innovation, broadens perspectives and supports Harmony’s ability to attract, retain and develop talent. | |||||||||||||||||||
5
1
2
3
4
Regional context
South Africa Workforce representation, inclusion, skills development and economic empowerment requirements, alongside organised labour dynamics, scarce critical skills and evolving workforce expectations, shape Harmony’s people strategy and workforce priorities. | Papua New Guinea National priorities for local employment, skills development and workforce representation, together with efforts to strengthen gender inclusion and build local capability, influence workforce planning and talent development initiatives. | Australia A competitive labour market, evolving workforce expectations, and gender equality and pay transparency requirements shape workforce attraction and retention strategies. Creating regional employment opportunities and supporting community liveability are also important to attracting and retaining talent. | ||||||||
Performance snapshot
Wage and benefit spend R22.5 billion (FY25: R20.1 billion) | Total employee complement 50 525 (FY25: 47 111) | Training spend R913 million (FY25: R859 million) | People trained 48 628 (FY25: 43 731) | % of workforce who are women 22 (FY25: 21) | ||||||||||||||
104
How we manage workforce IROs
1 | Maintaining sound labour relations and practices | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Union dynamics, collective bargaining cycles, wage expectations and the broader socio- economic environment shape our workforce exposure. These factors may influence labour relations, workforce stability and operational continuity. | Potential impact on society and the economy Sound labour relations and processes support stable employment, fair remuneration and protection of employee rights, including freedom of association. However, prolonged industrial action may disrupt employee income, adversely affect local economies and weaken trust between Harmony, employees, unions and host communities. | Potential operational effect on Harmony Industrial action, workplace disputes and labour instability may disrupt production, affect workforce availability and productivity, and reduce Harmony’s ability to consistently deliver operational plans and strategic objectives. Constructive labour relations and engagement can support workforce stability, operational continuity and productivity. | Potential financial effect on Harmony Poor labour relations may result in production losses, increased labour and security costs, reputational impacts and reduced investor confidence, affecting Harmony’s financial performance and long-term value creation. | |||||||||||
Our approach
Harmony’s approach to maintaining sound labour relations and
effective consultation processes is founded on mutual respect
and transparent, honest engagement with employees and their
representatives. By fostering constructive dialogue, we seek to
build trust, support fair labour practices and maintain workforce
stability across our operations.
Our approach is guided by region-specific remuneration and
employment legislation and supported by internal governance
frameworks, including human resource policies, employee
relations frameworks, the Harmony code of conduct and code of
ethics. These are implemented through workforce planning,
development and engagement processes that support
responsible employment practices and positive workforce
outcomes.
Collective bargaining and union engagement, South Africa
We support labour relations through structured engagement
with five recognised unions and the implementation of a five-year
wage covering 94% of employees. Regional employee relations
structures, the Harmony Tripartite forum, site-level consultation
processes and ongoing engagement support open dialogue,
workforce stability and constructive labour relations.
Employee representation and workforce consultation,
Papua New Guinea
Ongoing engagement through a long-standing employee
representative committee and workforce consultation processes
support constructive labour relations. Regular dialogue enables
employees and management to discuss workplace matters,
address concerns and maintain positive workplace relationships.
Workforce agreements and employee voice, Australia
Employee arrangements in Australia comprise a combination of
workplace agreements and individual employment arrangements.
CSA mine operates under an enterprise agreement, while
Harmony’s broader Australian workforce is employed under
individual contracts aligned with relevant workplace legislation
and standards. In FY27, preparations will commence for
enterprise bargaining at Eva Copper, supporting the development
of an enterprise agreement and employee representation
framework for the mine’s operational workforce.
Labour rights and workforce consultation
Harmony respects employees’ rights to freedom of association,
collective bargaining and workplace consultation. We foster
effective communication and consultation between management
and employees through a range of channels, including workforce
briefings, employee forums, intranet communications,
newsletters, emails, internal broadcasts and social media.
We provide employees and their representatives a minimum of
one month’s notice before significant operational changes, with
consultation and negotiation governed by applicable legislation
and collective agreements.
We prohibit all forms of forced or compulsory labour and child
labour and do not employ individuals below the minimum working
age applicable in the jurisdictions in which we operate. We
support lawful apprenticeship, traineeship or vocational training
opportunities for young workers in accordance with applicable
legislation and internationally recognised child labour standards,
including relevant International Labour Organization conventions.
105
Governance and oversight
Accountability for workforce management and employee-related outcomes is embedded throughout
Harmony’s management structures. Regional executives and operational leaders are accountable for
workforce outcomes within their areas of responsibility, with support from human resources
personnel in recruitment, employee relations, workforce development, succession planning, labour
compliance and employee engagement.
The social and ethics committee provides oversight of human rights, employment-related matters
and broader workforce sustainability considerations, including labour relations, transformation,
employment equity, workforce participation. Progress is monitored through regular reporting and
governance processes.
The governance approach described above applies across all employee-related IROs presented in
this chapter.
FY26 progress
Supporting labour stability
Five-year wage agreement, South Africa
Harmony implements the wage review obligations emanating from the 2024 – 2029 wage agreement
and regularly convenes a wage review implementation plenary with stakeholders. We have
implemented 16 out of the 19 wage review obligations and have processes to address the remaining
three within the stipulated timeframe ending June 2029.
Managing workforce relations through ownership transition
CSA mine, Australia
Our focus has been on understanding the operation, building relationships with employees and
supporting a smooth transition to new ownership. CSA mine operates under a workforce agreement
that was in place at the time of Harmony’s acquisition. The agreement provides a framework for
wages, benefits, training and career development for CSA employees through to 2028, supporting
workforce stability and providing certainty for both employees and the business.
Alongside this framework, Harmony has worked to understand and address legacy workforce issues
while strengthening employee engagement through ongoing dialogue and consultation. Several
matters before Safework NSW originated prior to Harmony’s ownership and continue to be managed
through established processes. These efforts are complemented by our organisational culture
initiatives, which support employee engagement and the integration of Harmony’s values and ways
of working across the operation.
Establishing workforce arrangements for construction and operations
Eva Copper, Australia
The industrial relations approach for Eva Copper during the construction phase differs from that
required for an operating mine. Construction activities are being delivered by major contracting
partners, which are responsible for managing their own workforce and industrial relations matters,
while Harmony provides oversight and governance to support alignment with project objectives,
compliance requirements and risk management expectations.
As part of its project delivery strategy, Harmony has established an Alliance with Thiess to deliver the
civil construction and mining scope of works. The Alliance comprises an integrated Harmony and
Thiess team that supports project delivery and continuity as Eva Copper transitions to operations.
Thiess’ employees within the Alliance will be covered by Thiess’ enterprise agreement, currently
under negotiation and intended to apply to mining and associated maintenance activities undertaken
by Thiess. Responsibility for the employment arrangements and industrial relations matters of Thiess’
employees remains with Thiess.
As Eva Copper progresses towards operations, Harmony will commence preparations for enterprise
bargaining in FY27 to establish workforce arrangements for employees directly employed by
Harmony during the operational phase of the mine.
106
Performance and effectiveness
No strikes, lockouts or labour-related interruptions occurred across Harmony’s operations in FY26. In South Africa, collective bargaining coverage remained stable at 31 897 employees, representing 94% of
the workforce. Union membership is voluntarily and 6% of employees do not belong to trade unions. The table below provides a breakdown of workforce representation across Harmony’s recognised trade
unions in South Africa. All of our employees in category 4 – 8 are union members.
Metric | Definition/calculation | Target type and year | FY26 | FY25 | FY24 | FY23 | FY22 | |
Number of strikes/lockouts >1 week | Number of strikes or lockouts exceeding one week in duration across the group | Zero (ongoing) | – | – | – | – | – | |
Employees covered by collective bargaining (South Africa) | Employees in category 4 – 8, miners and artisans as well as officials (excluding management) | 100% | 31 897 | 31 608 | 31 324 | 32 674 | 34 336 |
Recognised union membership: South African workforce | FY26 % | FY25 % | FY24 % | FY23 % | FY22 % | |
National Union of Mineworkers (NUM) | 51 | 52 | 52 | 53 | 52 | |
Association of Mineworkers and Construction Union (AMCU) | 30 | 29 | 29 | 28 | 28 | |
United Association of South Africa (UASA) | 5 | 5 | 5 | 5 | 5 | |
Solidarity | 2 | 2 | 2 | 2 | 3 | |
National Union of Metalworkers of South Africa (NUMSA) | 6 | 7 | 7 | 6 | 6 | |
No union | 6 | 5 | 5 | 6 | 6 | |
Coalition (NUM, UASA and Solidarity) | 58 | 59 | 59 | 60 | 60 |
Harmony held more than 30 meetings with all unions individually and collectively during FY26, demonstrating the ongoing consultation and dialogue that supports constructive labour relations.
Future focus
•Work with key stakeholders to develop the Australasia regional industrial relations framework for our operational workforces •Improve the use of workforce analytics to support retention and talent management. | |||
107
How we manage workforce IROs
2 | Local employment and workforce opportunities | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Harmony operates in jurisdictions with evolving socio-economic priorities and regulatory requirements relating to employment, workforce participation, transformation and local workforce development. Access to employment opportunities is a key expectation of government, host communities and other stakeholders. These factors shape the regulatory and operating conditions applicable to our mines, including workforce participation, transformation and local employment initiatives and commitments. | Potential impact on society and the economy Harmony contributes to employment, workforce development and career opportunities across our regions of operation. Through these opportunities, we can strengthen workforce participation, contribute to local economic development and support transformation objectives. Conversely, where opportunities are not accessible or equitably distributed, communities and particular groups may be excluded from socio-economic benefits that could support their long-term development and wellbeing. | Potential operational effect on Harmony An inability to meet stakeholder expectations or regulatory requirements relating to employment, workforce participation, transformation and local workforce development may erode trust, increase regulatory scrutiny and contribute to strained relationships with employees, communities and other stakeholders. This could affect Harmony’s social licence to operate and undermine the stability of our operations and growth activities. Inclusive employment and workforce development can strengthen stakeholder relationships, workforce capability and operational stability. | Potential financial effect on Harmony Failure to comply with applicable employment, transformation or localisation requirements may result in regulatory action, fines or penalties. Weakened stakeholder relationships or unmet expectations regarding employment opportunities may also contribute to project delays, operational disruption or additional costs associated with workforce development, recruitment and compliance activities. | |||||||||||
Our approach
We seek to maximise local employment and workforce development opportunities while meeting jurisdiction-specific workforce
participation, transformation and employment requirements.
South Africa Our approach is guided by Mining Charter III, the MPRDA, the Employment Equity Act, the Skills Development Act and the B-BBEE codes, which set out transformation, local employment and skills development requirements. These frameworks seek to increase opportunities for historically disadvantaged persons (HDPs), including women, through measures that promote equitable participation in the workforce and broader economy. We track our compliance with Mining Charter III requirements using the compliance scorecard, and annually submit B-BBEE verification and reporting. | Papua New Guinea At Hidden Valley, employment and training commitments are established through the memorandum of agreement (MoA), including obligations relating to national, landowner and local district employment and workforce development. Our approach is supported by a three-year training and employment plan that sets out workforce development priorities and employment pathways, with preference given to landowners, local communities, Morobe Province residents and other Papua New Guineans. Harmony monitors progress using operational governance processes and regular regulatory reporting. | Australia At CSA mine and Eva Copper, we are seeking to maximise local and regional employment opportunities through workforce planning, recruitment and community engagement. As we develop our workforce approach across both sites, we consider local labour market conditions, residential and fly-in fly-out workforce models, residential employment incentives and longer-term workforce requirements. Commitments to support First Nations employment are formalised through Eva Copper’s native title agreement. Encouragement of First Nations participation at CSA mine will form part of the ongoing development of our workforce approach. | ||||||||
FY26 progress and achievements
Connecting local talent to opportunities
Eva Copper, Australia
As North West Queensland’s largest investment, we expect Eva
Copper to create more than 1 000 jobs during construction. During
FY26, we partnered with Regional Development Australia to establish a
jobs hub to view all project-related vacancies in one place, regardless
of the hiring company. The platform makes it easier for local residents
to identify and apply for opportunities across Harmony and its project
delivery partners.
Recruitment for Harmony-employed positions continues to be guided
by the project’s five-tier employment priority framework, which places
emphasis on candidates from Mount Isa and Cloncurry before
progressively expanding recruitment across North West Queensland,
Queensland, Australia and, if required, international labour markets.
We also continued to advance our approach to Indigenous employment
and participation. This encompassed engagement with Traditional
Owners, Indigenous organisations and our project delivery partners;
consideration of culturally appropriate recruitment and workplace
support measures; and the integration of Indigenous employment
objectives into broader workforce planning activities.
108
Performance and effectiveness
Building local employment and leadership capacity remains a key focus across Harmony’s operations. We monitor workforce participation indicators relevant to each region, such as the representation of
historically disadvantaged persons (HDPs), national employment, local community representation, Indigenous employment, and the progression of local employees into management roles. These measures
help us assess the extent to which employment opportunities and leadership pathways are being created for people from our host countries and communities.
Group | South Africa1 | PNG | AUS | |||||||||||||||||||||
Total employee complement | 50 525 | (FY25: 47 111) | 46 685 | (FY25: 44 480) | 2 459 | (FY25: 2 461) | 1 381 | (FY25: 170) | ||||||||||||||||
Permanent employees | 35 198 | (FY25: 34 350) | 32 977 | (FY25: 32 688) | 1 510 | (FY25: 1 496) | 711 | (FY25: 166) | ||||||||||||||||
Employees from local communities | 86% | (FY25: 85%) | Host communities3 41% | (FY25: 38%) | First Nations Australians4 1% | (FY25: 1%) | ||||||||||||||||||
Foreign nationals2 15% | (FY25: 15%) | PNG citizens: 87% | (FY25: 92%) | |||||||||||||||||||||
Employees from local communities in management | HDP5 74% | (FY25: 72%) | Host communities3 5% | (FY25: 3%) | ||||||||||||||||||||
PNG citizens 53% | (FY25: 60%) | |||||||||||||||||||||||
Contractors | 15 327 | (FY25: 12 761) | 13 708 | (FY25: 11 792) | 949 | (FY25: 965) | 670 | (FY25: 4) | ||||||||||||||||
1Includes South African underground and surface operations.
2Employees from neighbouring countries (primarily Lesotho and Mozambique).
3Host community employees include employees from landowner villages and host districts.
4Persons of Aboriginal or Torres Strait Islander descent as voluntarily disclosed.
5HDPs include women and exclude white males and foreign nationals.
Future focus
•Undertake a workforce and employment equity analysis for our South Africa region to support the development of a revised employment equity plan for 2028 to 2032 •Continue to implement employment equity plans to meet SLP and Mining Charter III compliance •Advance First Nations employment and participation at Eva Copper through partnerships, recruitment and workforce development initiatives •Enhance talent management and career development processes through regular talent review and succession planning. | |||
109
How we manage workforce IROs
3 | Workforce attraction, retention and capability | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Harmony operates in an increasingly competitive employment market characterised by scarce critical skills, changing workforce expectations and evolving workforce demographics and capability requirements. Technological advancement, digitalisation and changing ways of working are reshaping the skills and capabilities required across the mining industry. These factors may affect the group’s ability to attract, develop and retain the capabilities needed to support safe, resilient and stable operations. | Potential impact on society and the economy By providing meaningful employment, skills development and career pathways, Harmony contributes to workforce participation, employability and economic development in the regions where it operates. Conversely, skills shortages may limit employment opportunities, skills transfer and career progression, affecting workforce participation and economic development. | Potential operational effect on Harmony An inability to attract, develop or retain the required workforce capability may result in critical skills shortages, increased reliance on contractors, reduced organisational knowledge and succession depth, and challenges maintaining workforce productivity, safety and operational resilience. Capability constraints may also affect Harmony’s ability to support growth projects and future workforce requirements. Investing in workforce development and talent pipelines can strengthen capability, succession depth and long-term operational resilience. | Potential financial effect on Harmony Competition for scarce critical skills may increase attraction and retention pressures, resulting in higher recruitment and training costs. Workforce shortages, increased turnover and reliance on external labour may also contribute to higher operating costs, reduced productivity and delays in building the workforce required to support operational and project objectives. | |||||||||||
Our approach
We seek to attract, develop and retain the workforce capabilities needed to support safe operations, operational resilience and long-term
performance. Our approach focuses on creating an environment where people can develop, build meaningful careers and choose to remain
with Harmony. This is supported by the ongoing development of our employee value proposition.
Workforce capability requirements continue to evolve in response to changing labour market conditions, workforce demographics, employee
expectations and changing skill needs across the mining industry. To respond to these challenges, we focus on:
Attracting and recruiting talent | Building workforce capability | Supporting career growth and succession | Retaining key skills and experience | Addressing regional workforce priorities | ||||||||||||||
Workforce planning, recruitment and talent pipeline initiatives that support business needs, local employment, workforce participation, diversity and transformation objectives. Our employee value proposition strengthens our ability to attract talent in competitive labour markets. | Technical, professional and leadership development programmes that support workforce capability, organisational resilience and career progression. This includes region-specific education and training initiatives, such as internships, learnerships, graduate programmes and study assistance. | Performance and development processes, talent identification and succession planning that build leadership capability, support internal progression and strengthen organisational continuity. | Competitive remuneration and benefits, career development opportunities and diverse work assignments, underpinned by a positive employee experience and healthy organisational culture that contribute to employee engagement and retention. | Tailoring workforce attraction, development and retention initiatives to regional workforce needs, labour market conditions and operating contexts. We operate in highly competitive mining labour markets characterised by scarce critical skills and strong demand for experienced talent. | ||||||||||||||
Our employee value proposition | ||
Our employee value proposition seeks to define the experience employees can expect throughout their career journey while supporting Harmony’s strategic objective of mining with purpose. Our EVP is underpinned by seven interconnected themes: •Putting safety first •Leading with vision •Providing opportunities for growth •Recognising and rewarding contribution •Valuing health and wellbeing •Championing corporate responsibility •Living values that drive our culture. Together, these themes support a safe, inclusive, high-performing and purpose-driven workplace where employees are empowered to contribute to sustainable business success and shared value creation for stakeholders. Their application is informed by the workforce priorities and operating contexts of our regions. | ||
110
Regional workforce context shaping our employee value proposition
South Africa •Advancing transformation, employment equity and workforce participation objectives in line with Mining Charter III and broader regulatory requirements •Supporting skills development, education and career progression to strengthen workforce capability and future leadership pipelines •Retaining in-demand technical, professional and leadership skills within a unionised and competitive workforce environment. | Papua New Guinea •Meeting national, provincial and key stakeholder expectations for local employment, workforce development and representation •Addressing the scarcity of specialised skills within the market •Building long-term technical and leadership capability to support operational requirements. | Australia •Attracting and retaining employees in competitive regional labour markets, where shortages of experienced talent are compounded by declining graduate numbers in mining-related fields •Supporting workforce stability and capability development through career development, succession planning and employee retention initiatives •Attracting talent in a market where the Harmony brand is not yet well established. | ||||||||
FY26 progress and achievements
Advancing digital learning
Group
During the year, we continued to enhance our digital learning
environment through the introduction of new learning
management systems across the group. These platforms expand
access to learning and development opportunities, support
workforce capability development, and provide greater visibility of
training completion, learning performance and training
requirements.
Integrated with Udemy, the Achieve learning management system
provides employees in South Africa with access to online
learning content and curated learning pathways aligned to
individual, occupational and business development needs.
Multiple learning and development dashboards were also
introduced during the year, providing near-real-time visibility of
workforce development and training data to support reporting,
compliance monitoring and decision-making.
The Australasian learning management system brings together
corporate, operational and site-based training in a single platform.
The platform hosts more than 500 learning modules, including
over 100 corporate programmes, key internal initiatives such
as Building Blue, and site-specific training packages. It also
supports professional development and strengthens attendance
tracking, training oversight and reporting.
Investing in learning and development
South Africa operations
We strengthened capability in core operational disciplines through
targeted interventions across mining, engineering, metallurgy and
ore reserve management. Key programmes included:
•Our engineering artisan development programme, which we
received industry recognition as a leading contributor to artisan
development
•Graduate and internship programmes designed to accelerate
the transition of young professionals into technical and
professional roles
•Learnership programmes that create entry points into the
mining sector for unemployed youth from host communities
•A broad range of study assistance programmes to empower
high-potential leaders with strategic, financial and organisational
leadership capabilities. These sponsored programmes include a
broad range of post graduate qualifications, including MBAs
and PhDs.
Employee value proposition
Australasia operations
As part of our efforts to strengthen workforce attraction and
engagement in a competitive labour market, we launched a
programme of work to develop the regional EVP for Australasia.
Designed to establish the Harmony employer brand locally, the
regional EVP aligns with the group’s broader EVP while reflecting
the operating context and workforce priorities of the Australasia
region.
The regional EVP was finalised in late FY26 and will be launched
in FY27 through recruitment and careers initiatives, industry
partnerships and social media channels to help build awareness
and bring the Harmony story to the Australian market.
Learning from and building on local success
CSA mine, Australia
Following the acquisition of CSA mine in FY26, Harmony has
continued to build on the well-established workforce development
initiatives already in place at the mine. These include
the Pathways to Mining programme, established in 2019, which
provides local students with practical exposure to mining careers,
workplace safety and site operations. More than 100 students
have participated in the programme since its inception, including
24 students across two cohorts in 2026.
By helping students understand the breadth of opportunities
available across the mining industry and gain first-hand
experience of a working mine, the programme helps bridge the
gap between education and employment. It has also contributed
to apprenticeship recruitment, with 10 former participants
commencing apprenticeships over the past three years.
111
Performance and effectiveness
Attracting and recruiting talent
We assess the effectiveness of our attraction and recruitment efforts through workforce movement indicators, including new engagements, promotions and terminations, as well as insights from exit
interviews. Additional measures include decreasing time to fill vacancies, advancing learner and graduate progression, and maximising internal absorption into sustainable roles. Together, these indicators
provide insight into the strength of our talent pipeline and our ability to build the capabilities needed for long-term business performance.
The age composition of our new workforce reflects local labour dynamics and demographic profiles in South Africa, Australia and Papua New Guinea, resulting in jurisdiction specific hiring patterns across
respective age categories. This broadly reflects the importance of recruiting employees with the appropriate technical and operational experience needed to support current workforce requirements and
capability development.
% of new hires | Group % | South Africa % | Papua New Guinea % | Australia % |
Under 30 years old | 29 | 30 | 11 | 21 |
30 – 50 years old | 65 | 65 | 70 | 48 |
Over 50 years old | 6 | 5 | 19 | 31 |
Note: New metric, therefore only FY26 data presented. |
Building workforce capability and career opportunities through education and training
Total group training hours increased by 7.3% in FY26, while training expenditure increased by 6%.
Metric | Definition/calculation | Target type and year | FY26 | FY25 | FY24 | FY23 | FY22 | |
Training hours | Total training hours delivered group-wide | Maintained/increased year-on-year | 2 266 302 | 2 111 513 | 2 166 319 | 2 154 910 | 2 071 384 | |
Training spend (R million) | Spend on training group-wide | R913 million | R859 million | R840 million | R817 million | R665 million | ||
Critical skills programmes (South Africa) | Number of employees on critical skills developmental programmes | 199 | 146 | 182 | 163 | 96 |
The following examples highlight how our FY26 initiatives supported leadership development, technical and trade-based training, educational opportunities and pathways into employment across our regions.
South Africa •3 296 employees participated in our leadership development programme, 31% of whom are women •We invested R9 million in study assistance, supporting 232 employees pursuing formal qualifications •421 employees enrolled in our adult education and training programme to improve literacy and foundational work skills (FY25: 476). | Papua New Guinea •127 greenhire programme participants commenced training, primarily as operators, among other entry-level roles •Eight employees were enrolled in trade testing programmes to develop nationally recognised technical qualifications and support progression into skilled trades roles •Awarded 10 scholarships to tertiary students in mining-related fields •Five graduates are progressing through a structured programme to strengthen technical skills and build capability. | Australia •17 apprentices undertook trade-based training opportunities at CSA mine, including electrical, boiler making, mechanical fitting and machining, heavy diesel fitting, and automotive electrical trades •24 local students participated in CSA mine’s Pathways to Mining programme, building awareness of mining careers and pathways into apprenticeships and entry-level roles. | ||||||||
112
Retaining experienced skills
Employee turnover provides insight into workforce stability, employee experience and organisational effectiveness, while informing workforce planning and future capability requirements. Group voluntary
turnover remained low at 2.1% (FY25: 1.9%), reflecting a stable workforce despite competition for critical mining and technical skills. Involuntary turnover fell to 3.9% (FY25: 4.4%), supporting improved
workforce stability.
South Africa recorded voluntary turnover of 1.7% (FY25: 1.5%), the lowest in the group. We continued to focus on employee development, internal mobility, career progression and employee value
proposition. Maintaining critical technical and leadership skills will remain a focus area in FY27, and we will continue strengthening organisational culture, employee experience, career development, and critical
skills retention initiatives to support workforce sustainability across all regions.
FY26 | FY25 | |||||||||||||||||
Group | Female | Male | >30 | 30 – 50 | 50< | Total | Employees | % | Female | Male | Total | Employees | % | |||||
Voluntary turnover1 | 94 | 651 | 34 | 343 | 368 | 745 | 35 078 | 2.1 | 98 | 543 | 641 | 34 225 | 1.9 | |||||
South Africa | 68 | 483 | 9 | 226 | 316 | 551 | 32 857 | 1.7 | 70 | 433 | 503 | 32 563 | 1.5 | |||||
Papua New Guinea | 11 | 133 | 18 | 91 | 35 | 144 | 1 510 | 9.5 | 20 | 101 | 121 | 1 496 | 8.1 | |||||
Australia | 15 | 35 | 7 | 26 | 17 | 50 | 711 | 7.0 | 8 | 9 | 17 | 166 | 10.2 | |||||
Involuntary turnover2 | 173 | 1 210 | 117 | 532 | 734 | 1 383 | 35 078 | 3.9 | 216 | 1 301 | 1 517 | 34 225 | 4.4 | |||||
South Africa | 158 | 1 129 | 95 | 486 | 706 | 1 287 | 32 857 | 3.9 | 206 | 1 214 | 1 420 | 32 563 | 4.4 | |||||
Papua New Guinea | 14 | 76 | 20 | 44 | 26 | 90 | 1 510 | 6.0 | 8 | 84 | 92 | 1 496 | 6.1 | |||||
Australia | 1 | 5 | 2 | 2 | 2 | 6 | 711 | 0.8 | 2 | 3 | 5 | 166 | 3.0 | |||||
1Resignations, retirements, voluntary severance packages.
2All turnovers not included in the definition of voluntary, such as dismissals, downscaling, retrenchments.
Future focus
•Revise the graduate development programme to be more outcome-based •Develop a critical skills retention plan for the energy transition (including renewable energy and electrification) •Launch of the regional Australasia employee value proposition •Advance pre-employment skills mapping for Eva Copper ramp-up •Deepen our collaboration with the Papua New Guinea University of Technology. | |||
113
How we manage workforce IROs
4 | Fostering a strong organisational culture | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Organisational culture is shaped by leadership, workplace behaviours, labour relations, organisational change, employee engagement and the systems and processes that influence employees’ day-to-day experience of work. Factors including poor communication, workforce conduct issues, safety incidents, limited development opportunities, perceived inequities and job security or workplace uncertainty can weaken trust, connectedness and accountability across the organisation. | Potential impact on society and the economy A strong organisational culture can support employee wellbeing, engagement, inclusion and professional growth, helping employees build rewarding and sustainable careers. Conversely, workplace environments characterised by poor communication, ineffective leadership, workplace conflict, workplace misconduct or limited development opportunities may reduce employees’ sense of belonging, trust and engagement, affecting their wellbeing and workplace experience. | Potential operational effect on Harmony A weakened organisational culture may affect employee engagement, collaboration, productivity and organisational effectiveness. potentially reducing workforce productivity, increasing employee turnover and undermining Harmony’s ability to attract, retain and develop the workforce capability required to support operational performance. A strong organisational culture can strengthen engagement, collaboration and workforce stability, supporting organisational effectiveness and operational performance. | Potential financial effect on Harmony A weakened organisational culture may affect financial performance and long-term value through increased employee turnover, reduced productivity, higher recruitment and onboarding costs, and the loss of critical skills and organisational knowledge. These impacts may increase operating costs, reduce workforce stability and require additional investment to attract, develop and retain the workforce capability needed to support business objectives. | |||||||||||
Our approach
Our approach to fostering a healthy organisational culture focuses
on:
•Embedding our values through leadership, accountability and
workplace behaviours
•Strengthening workplace relationships and employee
experience by fostering trust, collaboration, open
communication and constructive working relationships that
support employee engagement and organisational
effectiveness
•Supporting employee wellbeing and inclusion by creating
environments where employees feel safe, supported and able
to contribute through initiatives that promote physical, mental
and financial wellbeing and inclusive workplace practices
•Driving continuous culture improvement using employee
feedback and culture diagnostics to identify improvement
opportunities, implement targeted actions and monitor
progress over time.
FY26 progress and achievements
Embedding culture improvement plans across
our operations
South Africa
We continued implementing culture improvement plans,
embedding culture discussions, action planning and targeted
interventions into routine operational reviews. These initiatives are
designed to reinforce the positive cultural attributes identified
through our culture assessments while addressing the limiting
values that hinder a cohesive and high-performing culture.
This work was informed by Harmony’s fourth Barrett Culture
Survey conducted in FY24, which achieved a 54% participation
rate, with 23 517 employees participating. The survey identified
positive cultural themes that support a healthy organisational
culture, including job security, pride in the organisation and
perceptions of company growth. Validation workshops further
reinforced these findings, with employees expressing confidence
in Harmony’s long-term sustainability, supported by acquisitions
and life-of-mine extensions.
Harmony achieved a culture score of 76%, significantly above the
global average of 55% and industry average of 53%, indicating a
strong and healthy organisational culture. Our entropy score was
12%, below the 13% threshold, reflecting low levels of limiting
values that can restrict personal and organisational growth.
Although our overall results were positive, entropy scores varied
between 5% and 35% across departments and employee
groups, highlighting opportunities for targeted improvement.
These were identified as skills development, commitment, trust
and quality leadership.
To address these findings, we are developing a culture
improvement plan for all operations and service departments to
reinforce strong cultural elements while addressing limiting values
that hinder a cohesive and high-performing culture. This work is
embedded in routine operational reviews, enabling teams to
continuously assess, refocus and act on cultural priorities aligned
with our strategic goals.
114
Performance and effectiveness
We monitor organisational culture through a range of diagnostic and employee feedback mechanisms, including culture values assessments, pulse surveys, systemic and humanistic perception surveys, and
gender inclusion diagnostics. These insights help us understand employee experiences, identify areas for improvement, and guide targeted interventions and culture improvement actions across our
operations.
Building Blue culture programme
FY26 is the first year we have reported Building Blue metrics. These indicators provide insight into the reach of our culture development programme across the Australasia region and help us track progress as
Building Blue is rolled out across our operations. Since its launch in November 2025, 378 employees have participants in the programme across 1 623 training instances, completing more than 4 038 of
Building Blue learning and development activities. The table below summarises participation and completion rates for the programme’s core learning modules.
Building Blue rollout FY26 | Target number of participants | Total % completed | Brisbane regional office % completed | Hidden Valley mine % completed | CSA mine % completed | Eva Copper % completed |
Induction workshop | 2 301 | 11 | 99 | — | 17 | 51 |
STEP workshop 1.0 | 846 | 14 | 30 | 14 | — | 20 |
Future focus
•In 2027, the South Africa region will continue its focus on strengthening a proactive safety culture through the fifth region-wide Barrett culture survey. Targeted leadership initiatives will develop psychological safety and encourage employees to raise concerns, challenge decisions, and intervene in unsafe conditions, in support of our unwavering commitment to zero harm •Continue the rollout of the Building Blue programme across Australasia. | |||
115
5 | Diversity, equity and inclusion (DEI) | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Failure to identify structural barriers, harassment, or exclusionary practices, may undermine efforts to foster an inclusive and equitable workplace where all employees feel respected, supported and able to contribute and progress. It may also weaken employee trust, organisational culture and the ability to attract and retain a diverse workforce. | Potential impact on society and the economy A diverse and inclusive workforce can expand employment, development and leadership opportunities for women, HDPs, Papua New Guinea Nationals and First Nations Australians. By supporting broader workforce participation and reducing barriers to opportunities, Harmony contributes to more equitable social and economic outcomes in the communities and regions where it operates. | Potential operational effect on Harmony Failure to foster a diverse, equitable and inclusive workplace may limit access to diverse talent and weaken collaboration and innovation. Over time, this may affect workforce capability, employee retention and operational performance. A diverse and inclusive workforce can broaden access to talent, strengthen collaboration and support innovation and operational performance. | Potential financial effect on Harmony Failure to identify and address barriers to diversity, equity and inclusion may result in increased workforce attraction, development and retention costs, while limiting the benefits associated with diverse perspectives, innovation and effective decision-making. Non-compliance with workforce participation, transformation and employment equity requirements may result in regulatory, legal and reputational consequences that could affect business performance and long-term value creation. | |||||||||||
Our approach
Harmony is committed to equal opportunity, diversity, equity and
inclusion and maintains a zero-tolerance approach to
discrimination, harassment and exclusionary behaviour. We seek
to create workplaces where employees are treated with dignity
and respect, have equitable access to opportunities, and feel
valued, supported and able to contribute and develop.
Employment, development and promotion decisions are based on
merit, with explicit prohibitions against discrimination on grounds
such as race, gender, religion, age, disability, sexual orientation, or
political beliefs.
Our approach is shaped by the workforce demographics,
operating contexts and regulatory requirements of the regions in
which we operate. The feedback of our workforce is also critical.
For example, our gender survey, which was last conducted in
2022, has been critical in highlighting areas of focus.
While some barriers to participation, development and career
progression are common across the group, others vary according
to local workforce needs and operating contexts. We seek to
identify and address both organisation-wide and region-specific
barriers with an approach that focuses on:
•Creating equitable access to opportunities through workforce
planning, recruitment, development and leadership initiatives
•Improving workforce diversity and representation through
targeted talent pipelines, development programmes and
leadership accountability
•Promoting respectful workplaces through awareness
programmes, training and initiatives that reinforce our zero-
tolerance approach to discrimination, harassment and bullying
•Strengthening inclusion and belonging through forums,
partnerships and initiatives that support employee engagement,
networking, professional development and employee voice.
Our focus in South Africa includes advancing transformation,
employment equity and gender inclusion objectives. These efforts
are supported by employment equity plans which aim to achieve
our long-term goal to create a workforce that equitably represents
the diversity of our country. This is further driven by our Women
in Mining committees and creating awareness and enforcing safe
work practices, including our zero-tolerance approach.
In Australia and Papua New Guinea, our initiatives focus on
strengthening workforce diversity and inclusion through
leadership accountability, inclusive work practices, reducing the
gender pay gap and addressing unconscious bias in our hiring
processes.
As with culture, we monitor our progress through workforce
diversity metrics, employee surveys, gender inclusion diagnostics
and employee feedback processes. These insights help us
identify opportunities for improvement and inform targeted
initiatives across our operations.
116
FY26 progress and achievements
Advancing transformation and equitable access to
opportunities
South Africa operations
Advancing Mining Charter III commitments remained a strategic
priority, with focused efforts to strengthen the representation
of HDPs and women across all occupational levels. Targeted
interventions (including accelerated development programmes,
succession initiatives, bursaries, internships and learnerships)
supported the advancement of high-potential HDP and female
talent into operational, technical and management roles,
alongside efforts to foster an inclusive workplace culture. In FY26,
we also prioritised filling vacancies with suitably qualified
designated group candidates.
Strengthening gender support and inclusion through
awareness, forums and employee advocates
South Africa operations
We continue to advance gender equity and the safety of women
in the workplace through targeted awareness campaigns,
strengthened governance structures and stakeholder
engagement. Our site-based Women in Mining Forums led
initiatives including cancer awareness drives, securing safety for
women underground campaigns, and workplace audits to assess
the availability and suitability of gender-responsive facilities, such
as sanitary disposal bins and separate ablution facilities
underground.
In alignment with the Department of Mineral and Petroleum
Resources (DMPR) guidance note for the management of gender-
based violence and femicide (GBVF), safety and security challenges
for women in the South African mining industry, we reviewed and
strengthened governance structures, enhanced forum effectiveness
through updated terms of reference, and supported the active
functioning of forums focused on addressing GBVF. We are also a
participatory party on the Mineral Council Women in Mining strategy
and report quarterly on progress against the set milestones.
Promoting respectful and inclusive workplaces
South Africa
We continued the rollout of our workplace training and awareness
programmes specifically focused on preventing sexual
harassment, addressing unconscious bias, and promoting a
workplace free from bullying and harassment. The training is a
direct response to findings from our gender-based biases, sexual
harassment and bullying survey conducted in 2022 and focus on
strengthening workplace behaviours, increasing awareness and
reinforcing our zero-tolerance approach to discrimination,
harassment and bullying. At the end of the training, each
employee signs the pledge to indicate their continuous
commitment.
The programme also includes a module on anti-workplace, sexual
harassment and unconscious bias in our generic induction,
thereby reaching all employees.
Each operation has appointed male and female anti-sexual
harassment officers and provided training to these employee
advocates.
Since 2024 to 30 June 2026, 1 163 employees have attended
this programme (including 194 employees who attended the
unconscious bias awareness reset training). Of the 1 163
employees, 64% are from core disciplines and 40% are women.
For broader awareness reach, an additional 1 125 (of which 20%
are women) employees completed awareness training through
induction programmes, significantly extending awareness across
the workforce. A follow-up survey is planned in FY26/27 to
assess the impact of these interventions.
Addressing gender-based violence through
partnerships and advocacy
South Africa operations
We maintained our three-year commitment of R1 million per
annum to the national partnership between the Minerals Council
South Africa, the GBVF Response Fund and the National
Prosecuting Authority, supporting efforts to strengthen Thuthuzela
Care Centre services in mining communities.
Building on the successful completion of a national Thuthuzela
Care Centre visibility campaign and following an assessment of
infrastructure needs at the Welkom centre, we have allocated the
remaining R2 million from our original R3 million commitment
towards the relocation and upgrading of the Welkom centre. This
investment will strengthen access to essential support services for
survivors of gender-based violence and femicide in one of our key
host communities while contributing to safer and more resilient
communities.
Employee-led initiatives continue to play an important role in this
work. In addition to women in mining forums, operations have
established men’s forums that encourage open dialogue,
challenge harmful behaviours and promote shared responsibility
for addressing gender-based violence within and beyond the
workplace.
Gender equality performance and action plan
Australia operations
As part of evolving legislative requirements in Australia, CSA mine
became subject to new gender equality target-setting obligations
in FY26. In response, we undertook a comprehensive review of
workforce composition, representation and remuneration
outcomes across all our Australian sites, supported by industry
benchmarking and workforce analysis, to establish baseline
measures and gender equality targets.
The review confirmed that female workforce representation
compares favourably with many industry peers. It also found
that the overall gender pay gap is largely driven by workforce
composition, including the under-representation of women in
management and technical roles where remuneration is typically
higher, rather than differences in remuneration for comparable
work.
The resulting three-year action plan includes enhancements to
workplace policies, training and support mechanisms relating to
family and domestic violence, formalised annual review and
reporting of gender pay outcomes, and a target to increase
female representation in management by a minimum of 1% per
annum over the next three years.
117
Performance and effectiveness
South Africa
Representation of women in management within South African operations remained strong at 25% in FY26 (FY25: 24%), reflecting continued progress towards Harmony’s FY27 target of 30%. Board
representation remained at 33% in FY26, exceeding the FY27 target and demonstrating Harmony’s ongoing commitment to diversity, equity and inclusion across leadership levels. Across the broader South
African workforce, representation increased to 22% (FY25: 21%), reflecting continued progress towards a more diverse and inclusive workforce.
Metric | Definition/calculation | Target type and year | FY26 % | FY25 % | FY24 % | FY23 % | FY22 % | |
Women in workforce South Africa | 22 | 21 | 20 | 20 | 19 | |||
Women in leadership, South Africa | Percentage of women in management positions in South African operations (excluding executives and board) | 30% by FY27 | 32 | 24 | 23 | 22 | 21 | |
Female board representation | Percentage of women on the Harmony board (including three executive directors) | 30% by FY27 | 33 | 33 | 25 | 25 | 21 |
We have exceeded our total HDP commitments and Mining Charter III targets on all occupational levels from board to junior management. We accelerated HDP representation in managerial positions, which
has increased to 74% (FY25: 72%).
Although there were notable improvements in achieving our HDP targets, we did not achieve our female representation at junior management level, with 23% (22% in FY25 representation against a target of
30% by 2027). Focus remains on addressing this area.
Performance against Mining Charter III targets | HDPs1 | Female HDPs2 | |||||||||||||||||
Employee1 diversity (%) | Target % | Actual FY26 | Actual FY25 | Actual FY24 | Target % | Actual FY26 | Actual FY25 | Actual FY24 | |||||||||||
By employee category | |||||||||||||||||||
Board3 | 50 | 73 | 73 | 67 | 20 | 33 | 33 | 25 | |||||||||||
Executive management | 50 | 63 | 62 | 57 | 20 | 32 | 29 | 24 | |||||||||||
Senior management | 60 | 62 | 62 | 62 | 25 | 25 | 26 | 27 | |||||||||||
Middle management | 60 | 70 | 67 | 63 | 25 | 32 | 31 | 29 | |||||||||||
Junior management | 70 | 75 | 73 | 72 | 30 | 23 | 22 | 21 | |||||||||||
Core and critical skills | 60 | 76 | 75 | 74 | n/a | N/A | N/A | N/A | |||||||||||
People living with disabilities | 1.5 | 0.3 | 0.3 | 0.3 | n/a | N/A | N/A | N/A | |||||||||||
1Excludes contractors.
2HDPs include women and exclude white males and foreign nationals.
3Harmony’s three executive directors are included as board members.
Harmony response to discrimination labour court matter
There was one incident in this reporting year, where the South African Labour Appeal Court held Harmony liable for discriminatory remarks uttered by one employee to another employee. The concerned guilty
employee was dismissed in this regard. There were no other incidents of discrimination against race, colour, sex, religion, political opinion, national extraction as defined by the International Labour
Organization, or provided for by any applicable legislation pertaining forms of discrimination, involving internal and/or external stakeholders by Harmony or management.
118
Papua New Guinea
Female employees occupy 15% of our workforce (FY25: 15%) and 14% (FY25: 9%) of management
roles.
FY26 | FY25 | FY24 | FY23 | ||
Women in workforce (%) | 15 | 15 | 14 | 15 | |
Women in management (%)1 | 14 | 9 | 10 | 13 |
1FY26 women in management figure is not directly comparable to prior years, as it includes women in junior
management positions. Prior years reflected women in middle management and above only.
Australia
The average number of female employees in our workforce is 27% (FY25: 29%). We aim to exceed
the Australian mining industry average for female representation (22% according to the Australian
Workplace Gender Equality Agency) and continued to do so in FY26. The acquisition of CSA mine
significantly increased the size of our Australian workforce, with the number of women employed
increasing from 47 to 192 in FY26. Of these, 120 women were employed at CSA mine.
Target | FY26 | FY25 | FY24 | FY23 | |||
Women in workforce (%) | 22% | 27 | 29 | 31 | 33 | ||
Women in management (%)1 | 20% | 19 | 15 | 16 | 21 |
1FY26 women in management figure is not directly comparable to prior years, as it includes women in junior
management positions. Prior years reflected women in middle management and above only. Our total number of
Australian employees also grew to 711 (FY25: 166).
Our gender pay gap review confirmed that men and women performing comparable work receive
comparable remuneration, with overall gender pay outcomes primarily influenced by
underrepresentation of women across typically higher remuneration, management and technical roles.
Future focus
•Increase female representation at junior management level towards the Mining Charter III target of 30% by 2027, addressing the current 7% shortfall through targeted talent and career development initiatives. While progress continues, the current representation level of 23% indicates that achieving the 2027 target remains challenging and closing the gap will require accelerated interventions •Conduct a follow-up survey in FY27 to evaluate workplace perceptions and the impact of awareness initiatives addressing harassment, bullying and bias implemented following the 2022 survey •Progress our three-year Australian action plan through ongoing gender pay gap monitoring, enhanced support mechanisms and increased representation of women in leadership. | |||
119
Empowering communities
Key matters: Sustainable communities; post-closure sustainability; social licence to operate Potential impacts on society, the environment and the economy: Mining can bring jobs, economic opportunities and investment, but can also affect livelihoods, community wellbeing, culture and heritage. Building trusted relationships, respecting the rights of our stakeholders, and meeting our commitments are important to creating lasting benefits for our host communities. Matters that could impact Harmony: Our ability to operate and grow depends in part on maintaining the trust and support of our host communities and rights-holders. Community concerns, unresolved grievances or unmet commitments can delay projects and approvals, disrupt operations and increase legal and regulatory costs, with potential consequences for Harmony’s reputation and access to capital. | ||
Sustainability framework | Partnering with communities and associated stakeholders: Create lasting value through partnerships with stakeholders; social investment and enhance positive social impact; informed by proactive, structured, and transparent engagement. | ||
Strategic risk and opportunity | Risks: Political tensions and geopolitical developments; Regulatory and policy uncertainty; Illegal mining and security. Community-related matters may influence stakeholder relationships, social stability, operational continuity and reputation. Exposure may be heightened where community expectations are influenced by broader socio-economic challenges, such as unemployment. Opportunity: Engagement and licence stability Proactive stakeholder and regulatory engagement can strengthen stability, licence security and stakeholder confidence. | ||
Community relationships influence responsible operations, project delivery,
commitment credibility and long-term trust.
Harmony operates in and near communities with distinct social, cultural, economic and rights-holder contexts across South Africa,
Papua New Guinea and Australia. Community expectations relate to employment and procurement opportunities, delivery of formal
commitments, responsible management of operational impacts, access to clear information, responsiveness to concerns and
investment in locally-relevant development priorities.
Community impacts, risks and opportunities (IROs)
Community trust and operational acceptance | Social and Labour Plan commitments | Agreement-based community commitments | Indigenous and Traditional Peoples’ rights | Voluntary corporate social investment | |||||||||||||||||||
Constructive stakeholder relationships help support reputation, operational stability, project development, and long- term value creation. | Delivering Social and Labour Plan commitments supports community development outcomes, regulatory trust and social licence to operate in South Africa. | Meeting agreement-based commitments helps deliver shared benefits, strengthen relationships and support long-term operational certainty. | Land, culture, heritage and customary or Indigenous rights require respectful engagement to build partnerships based on trust, mutual respect and recognition of rights-holder interests. | Targeted community investment can strengthen wellbeing, resilience and local development while supporting positive stakeholder relationships. | |||||||||||||||||||
1
2
3
4
5
Regional context
South Africa Mining operations are located within established mining regions where community expectations are closely linked to employment, skills development, enterprise creation, procurement opportunities and the delivery of Social and Labour Plan (SLP) commitments. Host communities and labour-sending areas from which many employees are drawn face differing socio-economic needs, while varying levels of municipal capacity and service delivery increase the importance of collaboration and long-term development initiatives. Building trust, delivering on commitments and creating shared social and economic value remain central to maintaining strong stakeholder relationships. | Papua New Guinea Community relationships are shaped by strong connections between people, land and customary ownership. Expectations are reflected through benefit-sharing arrangements, agreement-based commitments, landowner relationships and programmes that support local livelihoods, infrastructure, education, health and economic participation. Maintaining transparent engagement and delivering on commitments are important to sustaining trust, supporting community development priorities and fostering long-term operational stability. | Australia The community context is influenced by project development, operational activities and engagement with local communities, landholders, councils and First Nations rights-holders. Community priorities include local employment and business procurement, cultural heritage protection, responsible project development, transparent communication and the delivery of agreed commitments. As the company grows its presence in Queensland and New South Wales, building trusted relationships that support positive regional outcomes and contribute to long-term project certainty and community acceptance are key considerations. | ||||||||
Performance snapshot
Total investment in communities R190 million (FY25: R178 million) | SLP investment (South Africa) R54 million (FY25: R52 million) | Community benefit commitments (Papua New Guinea) R21 million (FY25: R24 million) | Group voluntary CSI spend R62 million (FY25: R52 million) | Concerns, complaints and grievances received 79 (FY25: 120) | Concerns, complaints and grievances closed 57 (FY25: 113) | ||||||||||||||||
120
How we manage community IROs
1 | Community trust and operational acceptance | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Community trust and operational acceptance can be influenced by the effectiveness of stakeholder engagement, grievance resolution, communication, delivery of commitments and management of operational impacts. Expectations relating to employment, procurement, local development, public safety, environmental performance and transparency may increase vulnerability to grievances, stakeholder opposition or reduced operational acceptance where concerns are not addressed timely and effectively. | Potential impacts on society and the economy Community trust and operational acceptance can influence how people and communities experience mining activities. Positive outcomes may include credible engagements, stronger relationships, collaboration and partnerships, greater transparency, reduced conflict and more responsive management of community concerns. Negative outcomes may include mistrust, perceived exclusion from opportunities, reduced confidence in the engagement processes where expectations or concerns are not effectively addressed. | Potential operational effect on Harmony Changes in community trust and operational acceptance may influence Harmony’s ability to maintain stable operations, progress project development activities and deliver commitments effectively. Declining stakeholder confidence may contribute to grievances, reputational impacts, regulatory scrutiny, project delays, increased security requirements or operational disruption, while constructive relationships can support operational continuity, project certainty and long-term value creation. | Potential financial effect on Harmony Community trust and operational acceptance may affect financial performance and prospects through impacts on productivity, operational continuity, approvals and permitting, project timelines, stakeholder engagement activities, grievance management, legal and regulatory costs, security expenditures and reputation. Positive outcomes may reduce disruption risk and support project delivery, while deteriorating stakeholder relationships may result in additional engagement, mitigation or remediation costs and potential delays to operations or development activities. | |||||||||||
Our approach
Community trust and operational acceptance are influenced by
how effectively we identify, understand and respond to
community interests, concerns and expectations throughout the
mining lifecycle. Our approach focuses on regularly engaging host
communities, governments, regulators, landholders, Indigenous-
rights holders, community organisations, local businesses and
other stakeholders affected by, or interested in, our activities.
We seek to understand stakeholder perspectives through
engagement, community relations activities, regulatory and
commitment-management processes, accessible grievance
channels and broader operational reviews. Insights from these
activities help inform operational decision-making, prioritisation
and issue management. Key issues are escalated through formal
risk management processes where appropriate.
Key elements of our approach include:
•Ongoing engagement with affected communities and other
relevant stakeholders
•Site-level processes that support early identification of
emerging issues
•Monitoring of community-related commitments, including
agreement-based, regulatory and voluntary initiatives
•Formal mechanisms to record, investigate and respond
to concerns, complaints and grievances
•Ongoing review of social performance data, programmes and
approaches to strengthen outcomes, inform learnings and drive
continuous improvement.
Through these activities, we seek to maintain constructive
relationships and support effective management of matters that
may influence community wellbeing, stakeholder relationships
and operational acceptance.
Governance and oversight
Group and regional engagement teams oversee stakeholder
and community relations frameworks, social investment and
engagement strategies, and support the continuous improvement
of social performance systems and practices. Site teams
implement stakeholder engagement and community relations
processes, including delivery of engagement plans, management
of local risks and obligations, and maintenance of key stakeholder
relationships.
FY26 progress and achievements
Youth engagement informing new employment
pathways
South Africa operations
We continued to deepen our community engagement approach
through dedicated forums for specific demographic groups and
sectors, creating new opportunities to identify priority issues and
work with communities to develop appropriate responses.
Dedicated youth engagement platforms established in FY25,
and now held quarterly, highlighted employment and business
opportunities as key priorities requiring collective action. Insights
gained through these engagements informed the expansion of
existing youth-focused programmes and the launch of a new
FY26 initiative in South Africa’s growing digital delivery industry,
providing young people with comprehensive training and
pathways to employment.
121
Supporting transparent project development
Eva Copper, Australia
During FY26, Harmony continued to engage stakeholders
connected with Eva Copper, including activities supporting an
environmental permitting process. After acquiring Eva Copper,
Harmony proposed a number of enhancements to the previous
project design. These changes required approval through a
Queensland Government Environmental Authority amendment
process.
Prior to the formal public notification period, we engaged with local
communities, landholders, councils, traditional rights-holders and
other stakeholders to explain the proposed changes, why they
were being considered, and the outcomes of environmental
and social assessment. Equally, these engagements were an
opportunity for Harmony to understand stakeholders’ perspectives
and, where possible, incorporate feedback into the final
submission.
The public notification process subsequently received one formal
submission, which was supportive of the proposed amendment,
reflecting the value of ongoing stakeholder engagement
throughout the project planning phase and our commitment to
listening to and responding to stakeholder feedback. We received
the approved, amended environmental authority from the
Queensland Government in May 2026.
Establishing local relations in Cobar
CSA mine, Australia
Harmony became a new entrant to the Cobar region upon
acquiring the CSA mine in October 2025. Recognising the
importance of establishing accessible channels for engagement,
Harmony introduced the community and communications adviser
role to support ongoing dialogue with local stakeholders and
provide a dedicated point of contact for community enquiries and
concerns. The role supports relationship-building, information
sharing and identification of community issues and opportunities,
helping Harmony better understand local priorities while providing
community members with opportunities to engage directly with
the company as it establishes its presence within the region.
During FY26, we engaged with a broad range of stakeholders,
including community members, landholders, local, state and
federal government, schools, sporting groups, not-for-profit
organisations, neighbouring mining operations and other regional
organisations, as we began building relationships across the
region.
Community engagement activities included participation in local
events, with CSA mine recognised as the most successful
exhibitor at the Cobar Show, marking the first time a mining
company has received the award. We also progressed
preparations for a CSA mine open day and explored opportunities
to establish a dedicated community hub to support ongoing
engagement and accessibility.
Looking ahead, we will continue strengthening stakeholder
relationships through ongoing community engagement activities,
dedicated community engagement forums and participation
in regional initiatives such as the inter-mine committee, which
has been established to identify opportunities for long-term
collaborative projects across the region.
Maintaining visible and accessible community
engagement
Hidden Valley mine, Papua New Guinea
Throughout FY26, we maintained a highly visible and active
presence in Hidden Valley host communities through a broad
programme of engagement, awareness and community support
activities. Community affairs personnel were regularly present in
villages and settlements, providing accessible channels for
stakeholders to obtain information, raise concerns and discuss
community priorities. Activities included quarterly mine updates
with landowner representatives, local communities and
government stakeholders, alongside ongoing consultation on
landownership matters, benefit streams and local development
priorities.
The programme also included a regular schedule of awareness
activities covering topics such as law and order, road safety,
illegal mining, gender-based violence awareness, tailings storage
facility management, cyanide management and disaster
preparedness. Often delivered in collaboration with government
agencies, regulators, police and other stakeholders, these
activities supported community awareness of issues relevant to
both local communities and the safe, responsible operation of the
mine.
In addition to ongoing operational engagement, FY26 included
consultation activities with customary landowner representatives
and community leaders in relation to Hidden Valley mine life
extension opportunities. This included the potential development
of the Kerimenge deposit, a satellite ore body located
approximately 8km from Hidden Valley. Community perspectives
and feedback gathered through these consultations informed
Harmony’s feasibility studies and will help shape the formal
environmental impact assessment process and broader
stakeholder consultation activities planned for FY27.
122
Performance and effectiveness
Community trust and operational acceptance are influenced by a range of factors, and cannot be assessed through activity metrics alone.
While we monitor stakeholder engagements and grievances, we recognise that we have the opportunity to improve the measurement of
engagement effectiveness, stakeholder perceptions and longer-term community outcomes.
Engagements
During FY26, our community affairs and stakeholder engagement teams continued community engagement across a range of key areas,
including:
•Community development, social investment and local economic participation initiatives
•Environmental permitting, compliance, monitoring and cultural heritage management
•Land access, infrastructure projects and landholder engagement
•Employment, skills development and workforce participation opportunities
•Community safety, health and environmental awareness programmes.
Insights from concerns, complaints and grievances received
Issues raised by stakeholders are assessed and classified as concerns, complaints or grievances (CCGs) according to their nature. For
reporting purposes, CCGs are collectively referred to as grievances below, with the breakdown by CCG classification also shown.
Open grievances at the start of FY26 22 (FY25: 30) | Grievances received during FY26 79 (FY25: 120) | Grievances closed during FY26 57 (FY25: 113) | Grievances still open at end of FY26 441 (FY25: 22) | |||||||||||
1 Nine CCGs were received in the second half of June 2026, resulting in a higher number remaining open at year end. An additional four CCGs were pending resolution by third parties (government authorities) and therefore remained open for ongoing monitoring. | ||||||||||||||
Our operations maintain formal processes for recording,
investigating and responding to these matters, with
escalation pathways applied where appropriate. Insights
from this information help identify recurring themes, support
issue resolution and inform ongoing engagement activities.
The number of CCGs recorded across Harmony’s
operations decreased during FY26, with reductions
observed in South Africa, Papua New Guinea and Australia.
Stakeholders most frequently raised matters relating to
procurement and business opportunities, our community
development projects or social and labour plan delivery,
employment and recruitment, and insufficient engagement
or communication. These themes highlight the importance
community stakeholders place on participation in the
economic and social benefits associated with mining, as well
as ongoing access to information and dialogue.
Across most regions, stakeholders raised concerns more
frequently than formal complaints or grievances, suggesting
that existing engagement channels are helping to identify
and address issues at an early stage, before they escalate.
Future focus
•Conduct community consultations to align investments with actual community needs and priorities ahead of the new Social and Labour Plan cycle and implement environmental outreach campaigns in neighbouring schools to raise learners’ awareness of environmental considerations associated to operations in South Africa •Advance environmental impact assessment and stakeholder engagement activities to better understand potential community, social and environmental considerations associated with the Kerimenge deposit •Continue delivering a robust programme of stakeholder engagement as Eva Copper advances through construction, helping keep stakeholders informed, concerns understood and feedback incorporated into project delivery •Continue building relationships with stakeholders across the Cobar region to deepen our understanding of local priorities, concerns and opportunities, and inform future engagement and collaboration activities. | |||
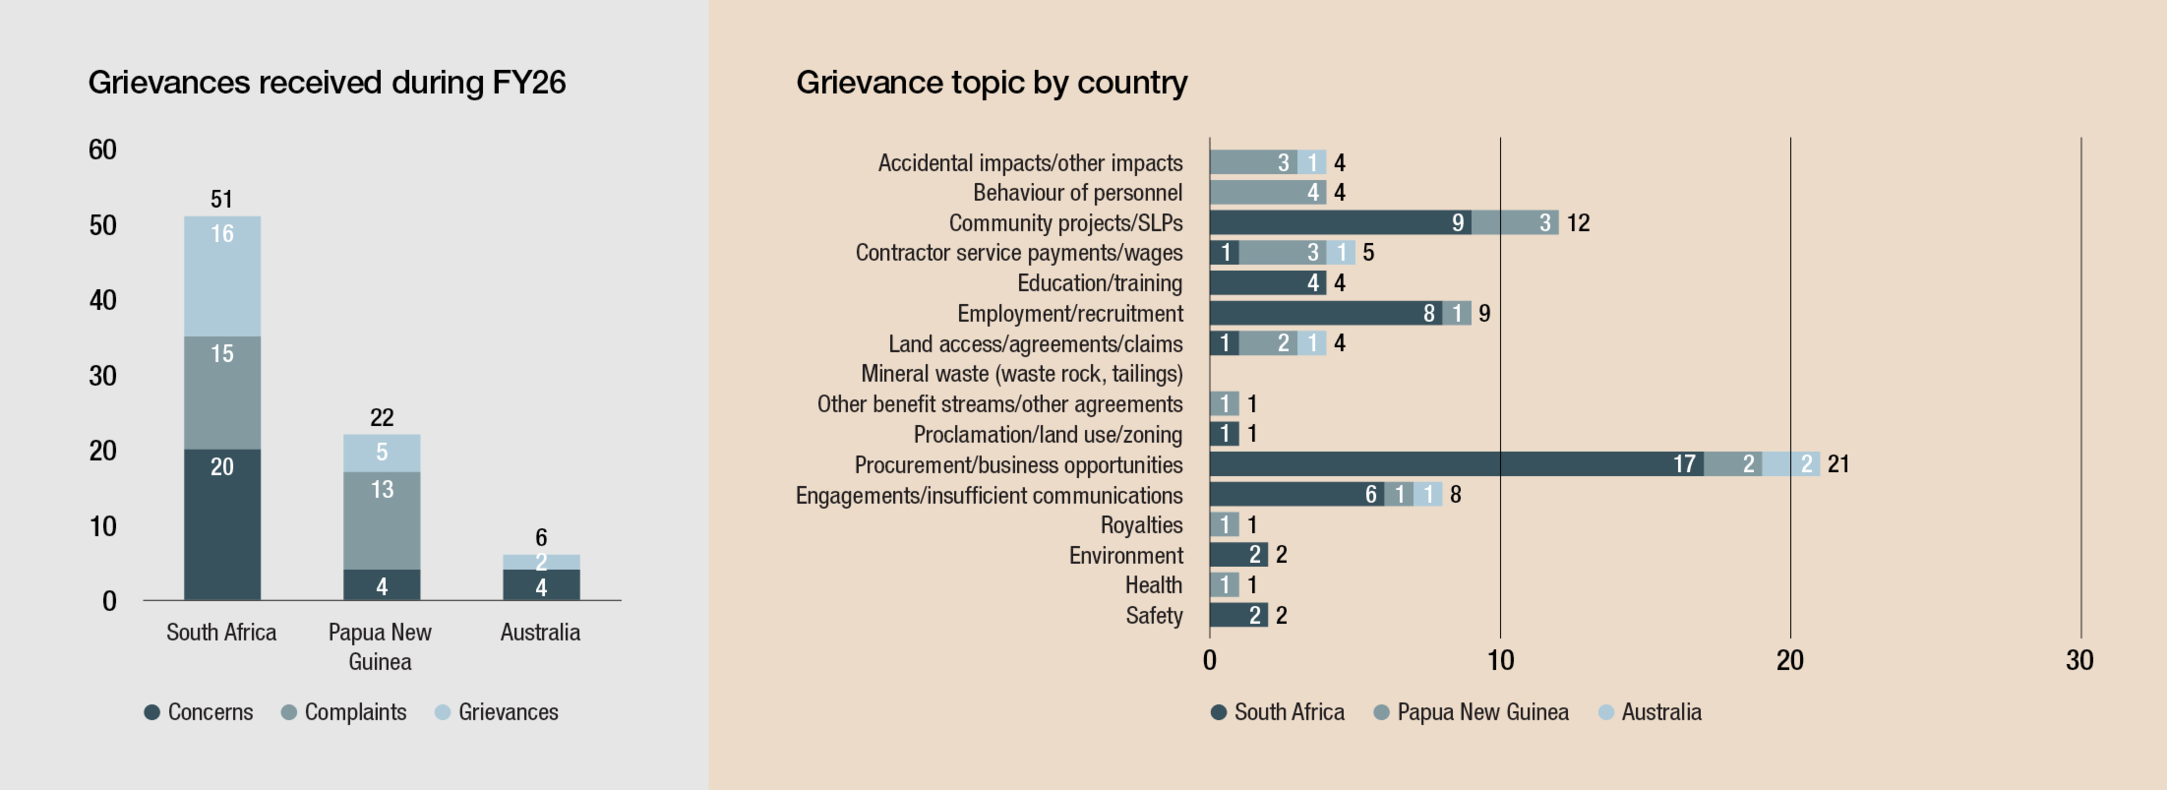
123
How we manage community IROs
2 | Social and Labour Plan (SLP) commitments | I | R | O | SA | |||||||||||||
Impact, risk and opportunity drivers Delivery of regulatory SLP commitments are influenced by local development needs, stakeholder expectations, municipal capacity, skills availability and the effectiveness of implementation partners. Delivery may also be affected by regulatory requirements, procurement and funding processes, project sustainability considerations, political dynamics and the ability to manage grievances relating to employment, procurement, infrastructure and community development outcomes. | Potential impacts on society and the environment Effective delivery of SLP commitments can improve access to infrastructure, education, skills development, enterprise opportunities and essential services, which aids community wellbeing and socio-economic participation. Conversely, delayed, incomplete or poorly targeted initiatives may reduce expected benefits, contribute to unmet expectations and limit positive outcomes for mine-host communities and other key communities from which our employees are drawn. | Potential operational effect on Harmony Failure to effectively deliver approved SLP commitments may contribute to stakeholder dissatisfaction, grievances, regulatory scrutiny and reduced confidence in Harmony’s ability to meet its obligations. This can create challenges for maintaining social licence and regulatory trust, while increasing the potential for community tensions, project implementation difficulties and operational disruption. Conversely, delivery can strengthen stakeholder trust, regulatory confidence and operational stability. | Potential financial effect on Harmony SLP performance may influence Harmony’s financial position through community development expenditure, compliance and reporting costs, regulatory consequences, stakeholder engagement activities and the management of grievances. Where delivery challenges arise, additional investment, remedial actions, capacity-building initiatives or disruption- related costs may be required to support commitment fulfilment and maintain operational acceptance. | |||||||||||
Our approach
Social and labour plans (SLPs) are a regulatory requirement
in South Africa associated with mining rights. They provide
a framework for companies to contribute to local development
and economic participation.
Effective delivery of SLP commitments creates opportunities to
develop local workforce and supplier capability, support
community resilience and contribute to more sustainable socio-
economic outcomes in mine-host communities. Our focus is on
delivering approved commitments in a manner that supports
meaningful community outcomes and regulatory compliance.
Key elements of our approach include:
•Fourth-generation SLPs covering the period from 2023 to
2027, defined and supported planning, implementation and
reporting processes
•Regular monitoring and delivery tracking through monthly,
quarterly and annual governance and reporting mechanisms
•An internal SLP community of practice that supports
implementation, monitors delivery risks and promotes sharing
within Harmony of lessons learned and good practices
•Ongoing engagement with communities, municipalities,
regulators and development partners to support effective
project delivery and address emerging concerns
•Investment in initiatives that support local economic
participation, skills development, infrastructure and long-term
community resilience.
Governance and oversight
The board social and ethics committee provides oversight of SLP
performance through quarterly reporting. Project delivery
oversight is provided through the mine community development
steering committee, which operates under an approved terms of
reference, and was established following the restructuring of the
former social and labour plan steering committee.
Management governance is supported by an SLP community
of practice, chaired by the human resources executive and
comprising SLP element champions and information owners from
across the business. The community of practice maintains view of
regulatory and governance matters and monitors the performance
and compliance of the operations.
FY26 progress and achievements
Delivering community development commitments
South Africa operations
During FY26, our fourth-generation SLP investment continued to
focus on agriculture support, small, medium and micro
enterprises (SMMEs), youth development and infrastructure
initiatives. We continued working with municipalities, government
departments, development organisations and community
representatives to support project delivery and alignment with
local priorities. Multi-stakeholder engagement processes helped
identify implementation challenges, monitor progress and
strengthen accountability for approved commitments.
Through ongoing monitoring, stakeholder engagement and the
findings of DMPR compliance audits, we identified opportunities
to strengthen SLP implementation and governance. The DMPR
audits highlighted challenges in the implementation of human
resource development programmes, delays in completing local
economic development projects, and variances against SLP
commitments for several of our mines, especially the backlog in
third generation SLPs. In response, we implemented coordinated
corrective actions and strengthened governance and reporting
controls, resulting in significant progress in addressing identified
gaps and advancing outstanding commitments.
124
Performance and effectiveness
Harmony continued implementing community development through its fourth generation SLPs across the Free State, Gauteng and North West regions. SLP commitments progressed largely as planned and
are expected to be completed within the current SLP period. Harmony also continued progressing backlog mine community development projects carried forward from the third-generation SLP period. These
projects were delayed due to factors including extended timeframes to secure required agreements, community protest action that affected implementation, and contractor performance matters.
FY26 investments | Agriculture | SMMEs and youth | Infrastructure | |||||||||||
We spent a total of R54 million (US$3.2 million) across three spend categories. The regional split is as follows: •Free State: R22 million •Gauteng: R23 million (including labour- sending areas) •North West: R9 million. | We fund agricultural initiatives for income generation ventures that can later mature into commercial ventures led by local small scale farmers. | The initiatives by Enterprise and Supplier Development are intended to empower youth and female entrepreneurs through giving them access to loan funding, incubation hubs, workshops and providing them with commercial spaces from which to operate their businesses. | We support water and sanitation improvement projects to uplift living conditions for host communities. | |||||||||||
Total investment R5 million | Total investment R34 million | Total investment R15 million | ||||||||||||
•The Wedela, Doornkop and Rietvallei agricultural projects support emerging farmers through vegetable production infrastructure and training programmes. Locally recruited and trained aspirant farmers are expected to graduate in early FY27 •In the Free State, we erected vegetable tunnels in Nyakallong, Kutlwanong, Thabong and Meloding and trained 26 beneficiaries in vegetable production. The tunnels will be fully operational in the new financial year. The installation of the nets for crop farming in Masilonyana was recently completed and planting started in September 2026. | •We are the sole sponsor of the Virginia Sports Academy, which hosts 25 rugby and 25 soccer players of school-going age. We provide full sports scholarships to the learners. The Academy employs 18 people including the manager, the coaches, the catering and the maintenance staff. | •We collaborated with local municipalities in Witpan, Carletonville and Stillpan to refurbish, maintain and operate wastewater treatment plans to avoid raw sewage discharge into river systems •We operate and maintain pumping systems conveying 37Ml/day (on average) of water from Witpan to Mostert Canal for consumption by the residents of the Matjhabeng municipality in Welkom. | ||||||||||||
When reading the Mining Charter III compliance scorecard, there will be a difference in the
expenditure compliance amount due to the charter report’s year end being December 2025.
In July 2026, we concluded a new syndicated multi-tranche, multi-currency loan facilities aligned
with the company’s sustainability and sustainable development targets. As part of the transaction,
Harmony and the lending group have agreed on progressive sustainability key performance
indicators (KPIs) over the next three financial years (FY27, FY28 and FY29). Reflecting the
importance of social performance in value creation, KPI 3 introduces a socio-economic
development measure linked to expenditure on committed Mine Community Development
initiatives in South Africa beyond regulatory compliance requirements.
Future focus
•Development of 5th generation SLPs, which are to cover the period 2028 – 2032 •Completing third-generation SLP backlog projects •Handing over completed projects, mainly from the 3rd generation and those from the 4th generation •Identifying new partnership opportunities and strengthening existing relationships to enhance SLP delivery •Advancing performance against the socio-economic development KPI included in Harmony’s sustainability-linked loan facility. | |||
125
How we manage community IROs
3 | Agreement-based community commitments | I | R | O | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Risks associated with agreement-based commitments are influenced by the effectiveness of agreement delivery, benefit-sharing arrangements, governance processes and stakeholder engagement. Risks may arise where commitments are delayed, responsibilities are unclear, benefits are contested or inequitably distributed, grievances remain unresolved, or agreement parties lack confidence in delivery progress, transparency and accountability. | Potential impacts on society and the environment Agreement-based commitments can create positive impacts through local participation, employment, training, procurement opportunities and support for community priorities. Negative impacts may arise where commitments are not delivered or benefits are contested, resulting in reduced trust, community tensions, disputes, and concerns relating to livelihoods, land, rights and cultural expectations. | Potential operational effect on Harmony Failure to effectively deliver agreement commitments may result in disputes, grievances, legal or advisory costs, remedial expenditure, project delays and reduced operational acceptance. Long-term relationships with host communities, landowners, Traditional Owners and other agreement parties may be affected, potentially influencing operational certainty, reputation and future approvals. | Potential financial effect on Harmony Agreement-based commitments require ongoing expenditure to deliver agreed programmes, projects and benefits. They may also give rise to delivery, administration and stakeholder engagement costs, while changes to agreements can influence future obligations and investment requirements. Effective delivery can strengthen operational acceptance and support project development and ongoing operations. | |||||||||||
Our approach
Many of our agreement-based community commitments arise
from regulatory permitting, land access, native title, benefit-
sharing or other formal requirements associated with
developing and operating mining projects in Australia and
Papua New Guinea. While these agreements often originate
from regulatory permitting, land access, native title or benefit-
sharing requirements, we seek to implement them in a manner
that demonstrates accountability, strengthens long-term
relationships and delivers meaningful outcomes for all
stakeholders.
Our approach focuses on delivering commitments in
accordance with agreed obligations, maintaining transparent
engagement and regularly assessing progress against
commitments. Effective implementation requires coordination
between community affairs, operations, procurement, human
resources, finance, contractors, governments and agreement
parties. This helps support accountability, build trust and
respond to emerging issues before they escalate into disputes
or grievances. Key elements of our approach include:
•Tracking agreement obligations, delivery milestones and
associated commitments
•Maintaining ongoing engagement with landholders,
Indigenous and host communities, and other agreement
parties
•Supporting delivery of negotiated benefits, which may
encompass local participation, training, procurement,
infrastructure and community development initiatives
•Managing concerns and grievances through established
engagement and resolution processes
•Participating in agreement reviews and governance
processes so that commitments remain relevant, effective
and responsive to stakeholder needs.
Governance and oversight
The board, social and ethics committee, chief sustainability
officer and regional executive teams oversee the delivery of
agreement-based commitments through quarterly
performance reporting. Accountability for implementation sits
with the general managers of our mines, supported by
regional and site-based teams responsible for delivering
commitments at an operational level. Separate governance
arrangements apply to the Hidden Valley Mine Trust, with
oversight provided through its established trustee and
management structures.
Our present commitments | |||
Hidden Valley mine memorandum of agreement (MoA) Multi-stakeholder agreement that provides a framework for community development, infrastructure investment, local participation and benefit sharing. | |||
Hidden Valley mine benefit sharing agreement Established the Hidden Valley Mine Trust to fund community- endorsed projects and programmes in customary landowner host communities. | |||
Kalkadoon native title ancillary agreement Supports the management of Kalkadoon native title interests, cultural heritage protection, consultation, compensation and opportunities related to employment, training and business participation in Eva Copper. | |||
Mount Isa mining acceleration agreement A Queensland Government funding agreement that supported the delivery of Eva Copper-related activities and includes commitments relating to local employment, supplier participation and reporting. | |||
126
FY26 progress and achievements
Progressing a new Community Development Agreement
Hidden Valley mine, Papua New Guinea
Following a multi-party review process held between April and June 2025, we worked with
government and landowner representatives throughout FY26 to support the State of Papua New
Guinea’s review and approval of a new community development agreement (CDA), intended to
replace the Hidden Valley MoA that had been in place since 2005. Efforts during the year focused on
securing government endorsement and finalising the revised terms. The agreement was signed by
the majority of parties on 11 August 2026, marking a significant milestone in the process, with
ongoing engagement supporting its full implementation.
In parallel, we continued to implement our existing community development commitments, delivering
programmes and projects that support community wellbeing, local participation and long-term
development outcomes.
Native title agreement
Eva Copper, Australia
Consistent with the construction stage of Eva Copper, our efforts during the year focused on ongoing
engagement to implement the agreement. Key progress included cultural heritage management and
preservation initiatives, establishing the Kalkadoon Rangers programme and continuing to advance
employment, training, procurement and business participation pathways. These activities help
position the project to deliver long-term participation opportunities for the Kalkadoon People.
Mount Isa Mining Acceleration Agreement
Eva Copper, Australia
The Queensland Government awarded Harmony A$20.7 million (R237 million) funding under the Mount
Isa mining acceleration (MIMA) programme to support the Eva Copper early works activities onsite. The
funding initiative is designed to accelerate resource projects in North West Queensland to benefit
Mount Isa, the region’s major city, which is facing economic challenges following a major mine closure.
We successfully met our agreement commitments to receive the funding, completing the early works
programme on time and announcing a final investment decision in November 2025 to construct the
mine.
Part of our agreement with the Queensland Government is to demonstrate and report on clear
community benefits for the city in employment and business supply. We provided quarterly project
reports on our early works progress, as well as measures to prioritise Mount Isa workers and
businesses, and the outcomes of these measures. With early works completed, we will move to
annual reporting to the government over the next three years to demonstrate how Eva Copper is
delivering ongoing economic outcomes for Mount Isa.
127
Performance and effectiveness
Hidden Valley MoA – Community projects and programme delivery
During FY26, we completed 14 projects and programmes across agriculture, community roads and infrastructure, education, skills development and health. We also continued delivery of 10 ongoing
programmes and progressed a further five projects, supporting community wellbeing, local participation and long-term development outcomes.
FY26 Investments | Agriculture programmes | Community roads and infrastructure | Education and skills development | Community health outreach | ||||||||||||||
FY26 investments R9 million (US$0.5 million) | We support farmers to improve food security, strengthen agricultural capability and create sustainable livelihood opportunities. | We invest in infrastructure that improves access to services and contributes to community wellbeing. | We support education, training and enterprise development initiatives that strengthen employment prospects and local participation. | We work with healthcare providers and community to improve access to services and support awareness of key health and social issues. | ||||||||||||||
Hidden Valley MoA community investment | •Continued our multi-year Portion 8 agricultural development project at Wau •Supported coffee sector development through the Portion 8 nursery, ongoing technical support to approximately 250 farmers, assistance with coffee marketing and logistics, and continued capacity building support to the Tia Hanama Weta Cooperative Society, which represents more than 500 members •Continued livelihood and food security programmes, including the tilapia farming programme involving 40 farmers, honey production initiatives involving three beekeepers, and potato farming activities involving 18 farmers. | •Maintained 11 police houses in Bulolo, bringing the FY24 – FY26 programme total to 41 houses •Completed bridge improvement works at Kuembu, Kaisenik and Marbung, while Nauti Bridge reached practical completion and was launched •Maintained 9.5km of community roads •Continued the weekly community bus service across the Hidden Valley mining lease, reducing travel times between host communities, Wau and Bulolo •Commenced works to construct a community hall in Biawen and a double classroom at Samuna primary school. | •Delivered downstream food processing training for 58 host community participants in partnership with the Lae University of Technology •Provided sewing training for 57 community participants to support additional income generation opportunities •Sponsored Year 8 high achiever awards for four host community primary schools. | •Reached approximately 2 350 community members through health outreach programmes delivered with Bulolo District Health and Watut Health Centre •Delivered “Pinktober” breast cancer awareness and screening activities, reaching 1 067 participants and supporting 258 health screenings •Conducted gender-based violence and HIV/AIDS awareness activities reaching approximately 1 474 community members •Delivered school health initiatives reaching approximately 1 000 students across eight schools •Commenced works on a new health clinic at Kaisenik to replace ageing facilities. | ||||||||||||||
Hidden Valley Mine Trust
We contributed R12 million to the Hidden Valley Mine Trust, which continued supporting community-endorsed programmes and projects. Initiatives delivered during the year included school fee assistance for
158 students through the landowner education programme, the provision of 20 sewing machines to the Akikanda community to help participants apply skills gained through sewing training, and the
construction of the Samuna primary school teacher’s house, supporting education delivery to 300 students and families.
Future focus
•Continue engagement to support completion of the remaining CDA approval and signing processes, and prepare for implementation under the updated framework •Continue supporting communities to identify, develop and deliver community-endorsed initiatives through the Hidden Valley Mine Trust. | |||
128
How we manage community IROs
4 | Indigenous and Traditional Peoples’ rights | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Respect for Indigenous and Traditional Peoples’ rights is demonstrated through transparent and culturally appropriate engagement, recognition of rights-holder interests, protection of cultural heritage, and accessible grievance processes. Risks may arise where rights-holder expectations are not adequately understood; where regulatory requirements, agreements or recognised good-practice engagement approaches are not effectively implemented; where cultural heritage is not adequately protected; or where concerns are not addressed through trusted processes. The conduct of contractors, partners and other third parties can also influence rights-holder relationships and trust. | Potential impacts to people and society Mining activities, project development and land access arrangements can affect Indigenous peoples, traditional authorities and customary communities through impacts on cultural heritage, land, livelihoods and cultural identity. Positive outcomes may arise through recognition of rights, protection of cultural heritage, transparent benefit-sharing and stronger relationships. Negative outcomes may occur where consultation is inadequate, cultural heritage is affected, representation is contested, or grievances relating to rights, benefits or land access remain unresolved. | Potential operational effect on Harmony Failure to recognise or respect Indigenous and Traditional Peoples’ rights can affect project development, approvals, permitting, land access and operational continuity. Disputes relating to cultural heritage, benefit-sharing, representation, consultation or rights-holder expectations may reduce trust, create opposition, delay projects, disrupt operations and weaken relationships with affected communities and rights-holders. Respect for Indigenous and Traditional Peoples’ rights can strengthen relationships, operational stability and project certainty. | Potential financial effect on Harmony Financial impacts may arise from the effectiveness of Harmony’s approach to recognising and respecting Indigenous and Traditional Peoples’ rights, including cultural heritage management, engagement and land access processes, agreement implementation, legal and complaint processes, and dispute resolution activities. Where issues are not effectively addressed, financial consequences may arise through project delays, approval risks, operational disruption, remediation costs, reputational impacts and reduced investor confidence. Strong rights management can improve project certainty and constructive agreement implementation. | |||||||||||
Our approach
Respecting Indigenous and Traditional Peoples’ rights is an
important component of Harmony’s commitment to responsible
mining and social stewardship. Our activities may intersect with
the rights, interests, cultural heritage, land use and governance
structures of Indigenous peoples, traditional authorities,
landholders and customary communities across Australia, Papua
New Guinea and South Africa. We seek to understand and
consider these interests through culturally appropriate
engagement, protection of cultural heritage, recognition of rights-
holder perspectives and implementation of processes that
support meaningful participation in decisions that may affect
them. Our approach focuses on building respectful relationships,
managing potential impacts, addressing concerns and supporting
constructive outcomes throughout the mining lifecycle.
Key elements of our approach include:
•Engaging with Indigenous and traditional peoples in a manner
that considers local cultural, legal and governance contexts
•Identifying, assessing and managing potential impacts on
cultural heritage through project planning, operational controls
and heritage management processes
•Implementing and monitoring the delivery of agreed
commitments, where applicable
•Considering rights-holder, cultural heritage and human rights in
community, legal, project and operational decisions
•Working across community, operational, legal and project
teams to support consistent implementation of commitments
and respectful engagement practices
•Providing accessible mechanisms for rights-holders and
communities to raise concerns, seek resolution and support
continuous improvement.
Governance and oversight
Indigenous and Traditional Peoples’ rights are considered through
Harmony’s project development, sustainability governance and
enterprise risk management and project development processes.
Group and regional engagement and sustainability teams provide
oversight of rights-holder engagement approaches, land access
and agreement-related processes, and support the continuous
improvement of social performance systems and practices.
Site teams are responsible for implementing engagement and
community relations activities, managing local risks and
obligations, maintaining relationships with Indigenous rights-
holders and stakeholders, and responding to concerns through
established grievance and engagement processes. Community,
legal, project and operational teams work together to support
culturally appropriate engagement, cultural heritage protection
and effective implementation of commitments where applicable.
129
FY26 progress and achievements
Obtaining support for our prospecting rights
application
Kalgold mine, South Africa
We undertook public consultation to support the Kalgold
prospecting rights application, recognising the sensitivity of an
ongoing land restitution matter involving the Traditional Authority,
the recognised customary leadership structure representing
affected communities in the area. Through transparent and
meaningful engagement, we worked with the Traditional
Authority, host community, municipality and other interested and
affected parties to build an understanding of our proposed
activities. The engagement process resulted in broad stakeholder
support for the application.
Recognising Kalkadoon rights, interests and
aspirations
Eva Copper, Australia
The Kalkadoon People are the Traditional Owners of the land on
which the Eva Copper Project is located and the recognised
native title rights and interest holders under Australian law. Their
connection to Country, cultural heritage and traditional lands
underpins an enduring interest in how project activities are
planned, developed and managed.
We see the Kalkadoon Traditional Owners as key stakeholders in
the development of Eva Copper. As the project advanced
towards construction in FY26, we worked with the Kalkadoon
People to better understand their aspirations, priorities and the
outcomes they wished to see from their involvement in the
project.
These discussions informed a range of initiatives, including:
•Cultural heritage management and preservation activities
•Advancement of employment and business participation
pathways, which also included the Kalkadoon Rangers
Programme, highlighted alongside
•Seeking to reflect Kalkadoon identity, knowledge and culture
throughout the project environment.
These discussions continue through quarterly engagement
forums with Kalkadoon leadership, creating opportunities to
review progress, address emerging issues and work together on
project initiatives.
Supporting customary landowner participation in
future project development discussions
Wafi-Golpu Project, Papua New Guinea
As our discussions with the Government of Papua New Guinea on
the proposed Wafi-Golpu Special Mining Lease continued, the
Wafi-Golpu Joint Venture (WGJV), owned 50:50 by Harmony and
Newmont Corporation, supported leadership development for the
customary landowner representatives who are likely to participate
in future Development Forum discussions required under Papua
New Guinea’s Mining Act. The outcome of a development forum
will be the project’s CDA.
More than 50 executives and selected village leaders from the six
recognised Landowner Associations participated in workshops
facilitated by an independent leadership consultant. The
programme was designed to strengthen leadership capability,
encourage collaboration between representative groups and
support informed participation in discussions relating to the future
development of the project and matters affecting their
communities. Further sessions are planned to build on this initial
programme and support informed, effective participation in future
project-related discussions and decision-making processes.
Advancing continuous improvement in social
performance
Wafi-Golpu Project, Papua New Guinea
In August 2025, the Australian National Contact Point (Aus NCP)
published its report on an OECD Specific Instance complaint
relating to the Wafi-Golpu project. The complaint, lodged by a
number of Huon Gulf coastal villagers represented by the Centre
for Environmental Law and Community Rights Inc. (CELCOR),
raised concerns regarding the proposed deep sea tailings
placement (DSTP) system and alleged breaches of various human
rights and environmental provisions of the OECD Guidelines for
Multinational Enterprises. The report identified areas where
alignment with the Guidelines could be further strengthened and
made a number of recommendations.
These recommendations were broadly consistent with areas of
consultation, engagement and social performance that the Wafi-
Golpu Joint Venture (WGJV) has been progressing through many
years of engagement with host communities. During FY26, the
WGJV used the report as an opportunity to further enhance social
performance, stakeholder engagement and due diligence
processes.
Key activities included completion of a third-party assessment of
risks relating to the prevention of sexual exploitation, abuse and
harassment (PSEAH), together with development of a PSEAH
Action Plan and Gender Equality Plan to support ongoing risk
management and continuous improvement.
Stakeholder engagement processes were also reviewed and
enhanced in response to matters raised regarding environmental
impacts, the proposed DSTP system and community participation
in project-related decision-making. Throughout the year, the WGJV
continued engagement through community awareness forums,
including its ongoing Huon Gulf coastal community campaigns, the
project’s Public Information Centre and discussions with
community, church and other stakeholders. These forums provide
opportunities to share information on project development,
strengthen understanding of community perspectives and enhance
engagement on environmental and social matters associated with
project planning.
Engagement to support project studies and
assessments
Hidden Valley, Papua New Guinea
During FY26, we engaged with customary landowner
representatives and community leaders regarding the potential
development of the Kerimenge deposit. Feedback from these
discussions informed feasibility studies and will help shape future
project investigations, environmental and social impact
assessment and project engagement.
Performance and effectiveness
Harmony does not currently report standalone metrics for this
IRO. Progress is monitored through ongoing engagement with
Indigenous and traditional peoples and other rights-holders,
consideration of stakeholder feedback and concerns, and
progress against initiatives designed to support participation,
cultural heritage protection and connection to Country. Relevant
quantitative indicators are reported elsewhere in this report,
including grievance management chapter, employment and
training outcomes, supplier participation and cultural heritage
management activities).
Future focus
•Continue engagement with Indigenous and traditional peoples and other rights-holders to understand and reflect community priorities, aspirations and concerns in Harmony’s project planning and development activities. | |||
130
How we manage community IROs
5 | Voluntary corporate social investment (CSI) | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers The value created through voluntary community investment is influenced by the extent to which programmes respond to community priorities, support sustainable development outcomes and are delivered through effective partnerships. Risks may arise where investments are poorly targeted, create dependency, deliver uneven benefits, lack clear objectives or governance, or fail to demonstrate meaningful outcomes for communities. | Potential impacts to people and society Voluntary community investment can create positive impacts by supporting wellbeing, education, enterprise development, livelihoods, access to services, community participation and socio-economic resilience beyond formal mining-rights obligations. Negative impacts may arise where projects create dependency, contribute to community tensions, or fail to deliver anticipated outcomes. | Potential operational effect on Harmony Voluntary community investment can influence stakeholder trust, community relationships and operational acceptance. Programmes that are valued by communities may strengthen relationships and support more stable operating environments, while perceptions of poor targeting, inequitable outcomes or unmet expectations may contribute to grievances, reputational challenges and increased stakeholder engagement requirements. | Potential financial effect on Harmony Harmony’s approach to voluntary community investment may affect financial performance and prospects through programme expenditure, partnership investments, stakeholder relationships and social acceptance. Well-targeted investments can support operational stability, local workforce and supplier development, and long-term value creation. They may also support access to sustainability-linked financing where community-related performance measures apply. Where programmes underperform, additional evaluation, redesign or remedial expenditure may be required. | |||||||||||
Our approach
Harmony’s voluntary CSI programmes respond to local socio-
economic challenges and community needs beyond our
regulatory and agreement-based commitments. Guided by our
responsible stewardship approach, we seek to create lasting
positive impacts by supporting initiatives that address poverty,
unemployment and inequality, while strengthening community
wellbeing, resilience and long-term development outcomes.
Our investments are intended to contribute to shared value by
helping build the skills, opportunities, social capital and economic
capacity needed for communities to thrive during mining
operations and beyond.
Our approach includes:
•Supporting education, youth development, training and skills
programmes that strengthen participation in the economy and
improve future opportunities
•Investing in health, wellbeing and community welfare initiatives
that contribute to improved quality of life
•Supporting livelihoods, enterprise development and other
initiatives that help alleviate poverty, unemployment and
economic vulnerability
•Promoting social cohesion, inclusion and community
participation through support for art, sport, culture and local
community initiatives
•Supporting environmental awareness, community safety and
initiatives that contribute to sustainable community outcomes
•Working with governments, community organisations,
educational institutions, suppliers and other partners to
enhance programme reach and effectiveness
•Supporting livelihood diversification and community resilience
to help communities prepare for a future beyond mining
operations.
We review and evolve our programmes over time to reflect
changing community priorities and emerging opportunities,
including those arising from changing industries and economic
conditions.
Governance and oversight
Voluntary CSI is guided by group and regional policy frameworks
and implemented through regional and site-based stakeholder
and community relations teams. Oversight of CSI is provided
through relevant management structures, while dedicated trust
governance arrangements support the stewardship of community
trust funds and trust-supported initiatives. Programme delivery
and outcomes are monitored through established governance,
reporting and review processes.
131
FY26 progress and achievements
Evolving our community investment approach
South Africa operations
During FY26, we continued refining our CSI programme to better
align investment with the evolving needs and opportunities of
mine-host and labour-sending communities. To maximise impact,
we strengthened the alignment between discretionary CSI and
obligation-based community development initiatives, helping
direct investment towards shared community priorities and create
more coordinated development outcomes. Programme delivery
continued through collaboration with the Harmony Community
Trust and a range of government, educational and community
partners.
Building on insights gained through stakeholder engagement and
ongoing assessment of socio-economic conditions, we increased
our focus on youth employment pathways and economic
participation opportunities. This included strengthening
partnerships that help broaden access to skills development,
entrepreneurship and employment opportunities, while creating
stronger connections between training and livelihoods.
As the programme continues to evolve, we are exploring
opportunities to better respond to changing economic conditions
and emerging community needs, while maintaining a strong focus
on education and youth development. This includes encouraging
innovation, entrepreneurship and skills development for youth and
women in industries beyond mining, identifying opportunities to
incorporate technology and emerging digital capabilities into
community development initiatives, and expanding collaborative
partnerships that can increase programme reach, sustainability
and long-term impact.
Designing a community investment programme for
community needs
Eva Copper, Australia
Harmony designed the Eva Copper community investment
programme (CIP) through a community‑driven process that put
local voices at the centre. From the outset, we committed to
building a programme that genuinely reflected the needs and
aspirations of people in Cloncurry, Mount Isa and the wider North
West Region. To ensure the process was independent and
credible, we engaged specialist social planners to provide
oversight, offer expert advice and deliver a CIP grounded in
evidence. The engagement effort combined structured
consultation with open community input. Harmony invited 26
organisations to one‑on‑one discussions and held 15 in‑depth
interviews across the region. This included local government
representatives, First Nations organisations, health and
community services, education providers and business groups.
We also opened the conversation to the public, gathering 250
community votes on the top investment priorities.
The feedback directly shaped the six pillars that now anchor Eva
Copper’s CIP: education and skills, community livability, health
and wellbeing, environment, economic development and First
Nations opportunities. These pillars reflect what the community
said mattered most, with education, livability and wellbeing
ranking highest in public polling. While tailored to the priorities
identified by communities in the North West Region, the six CIP
pillars align with Harmony’s broader community investment
framework, supporting youth, education and skills development;
health and welfare; sports, arts, culture and tradition;
environmental stewardship and community safety; and initiatives
that contribute to economic participation and help address
poverty and disadvantage.
Using the community’s input, the social planners and the Eva
Copper community team translated the insights into a clear
programme structure with three funding streams: expanded
community grants and community assistance initiatives once
mine operations start, and a long‑term legacy fund. Together,
these will create a balanced, transparent framework that supports
community needs and is expected to deliver lasting infrastructure
benefits for the region beyond mining.
Building the foundations for long-term community
investment
CSA mine, Australia
Following the acquisition of CSA mine in October 2025, Harmony
maintained existing community investment and sponsorship
programmes, providing continuity of support for local
organisations and initiatives. During FY26, we re-established the
community engagement function to strengthen stakeholder
relationships and improve understanding of community priorities,
needs and opportunities. These efforts will help refine our CSA
community investment approach during FY27 in a manner that
reflects both local aspirations and Harmony’s approach, focusing
on the delivery of beneficial, long-term outcomes.
132
Performance and effectiveness
South Africa Investment: R30 million | Estimated beneficiaries: 43 400 | ||||||
South Africa focus and highlights Youth unemployment, poverty and inequality remain significant challenges in South Africa’s mine-host and labour-sending communities. Our programme focused primarily on education, youth development and creating pathways to employment, supported through partnerships with government, non-profit organisations, educational institutions and community stakeholders. | ||||||
Creating employment pathways for young people We partnered with the Department of Labour and the Lulalab Foundation to support 220 unemployed youth through accredited training, licensing, equipment provision and employment opportunities in South Africa’s growing “last-mile” delivery sector. Participants received practical support including training, driver licences, scooters, smartphones and workplace placements to help establish income-generating opportunities. Expanding access to tertiary education Recognising barriers faced by students classified as the "missing middle", we expanded our bursary programme to provide first-year tertiary education funding for 30 students whose family circumstances limited access to both government and private sources of financial support. Since 2021, our bursaries have supported 150 students to pursue higher education. Creating better learning environments We invested in education facilities benefitting vulnerable learners and school communities, including construction of ablution facilities for Tshwaraganang School for children living with disability, and new water and sanitation infrastructure at Ntshingeni Primary School in the Eastern Cape. Supporting youth achievement and opportunity Through partnerships with educational institutions, government agencies and community organisations, we supported initiatives that help young people develop skills, pursue education and realise their potential. This included entrepreneurship programmes through ENACTUS South Africa, support for high-achieving matriculants and community sporting programmes reaching more than 6 000 young people. Science Technology Engineering and Mathematics (STEM) school support programmes Over 1 150 grade 10 to 12 learners from our host communities benefited from our Science Technology Engineering and Mathematics (STEM) school support programmes (FY25: 801). Through this strategic investment, we aim to help build the high-level skills needed for STEM careers. Grade 12 learners participating in the Free State school project achieved a 100% matric pass rate and an 87.5% bachelor’s pass rate, including 24 mathematics and 30 physical science distinctions. | ||||||
Papua New Guinea Investment: R12 million | Estimated beneficiaries: 18 080 | ||||||
Papua New Guinea focus and highlights Limited access to services and the need for sustainable economic opportunities remain key challenges in many of our host communities. Our investment focuses on supporting economic participation and improving access to essential services. Programmes seek to support community capability and resilience through agriculture, skills development, education, and water, sanitation and hygiene initiatives. | ||||||
Supporting agricultural livelihoods and economic participation The Wafi-Golpu Joint Venture (WGJV) continued our partnership with the Cocoa Board of Papua New Guinea for a sixth year, supporting more than 10 900 farmers across cocoa regions of Mumeng, Wampar, Salamaua and Labuta. These regions host the participating cocoa cooperatives including Lower Watut, Babuaf, Apele G-Tava, Linge-Hengambu, Nasuapum, Wediruc, Wabubu and, most recently, Bumayong Lutheran Secondary School. The programme provides training designed to strengthen agricultural productivity and market participation. Farmers across several participating communities are now harvesting and marketing cocoa on a regular basis, creating ongoing opportunities for income generation, economic participation and community resilience. The WGJV is also initiating advanced planning for future agribusiness opportunities along the Watut River Valley that will become accessible when the project develops its new 32km Northern Access road. Improving community wellbeing The Madzim/Wori Water, Sanitation and Hygiene (WaSH) project, the eleventh WaSH initiative delivered since 2019, improved access to essential water and sanitation services for participating villages. Community training accompanied the infrastructure investment to support long-term operation, maintenance and local ownership. Supporting women’s participation in the economy In collaboration with the Mineral Resources Authority and MiBank, we helped facilitate women’s economic participation through financial literacy, micro-credit and small business development initiatives, helping build confidence, skills and readiness for access to Small Medium Enterprise finance. Supporting education and community capability We continued investing in literacy initiatives, student recognition programmes and access to educational resources, including support for schools across Watut, Mumeng and Bulolo areas. | ||||||
133
Australia Investment: R3 million | Estimated beneficiaries: 8 220 | ||||||
Australia focus and highlights Supporting resilient, connected and liveable regional communities is important in the regional areas where Harmony is establishing and growing its presence. Our investment focused on education, wellbeing, participation and local organisations that help strengthen local resilience and social connection. Funding supported a broad range of initiatives across North West Queensland and the Cobar region. | ||||||
Inspiring future pathways and supporting learning We supported initiatives that help young people develop skills, explore future opportunities and participate in learning beyond the classroom. This included school excursions and facility improvements, the Outback Science and Engineering Challenge, the Pathways2Mining programme and community-led youth development initiatives in Cobar and Cloncurry. Aiding regional community access to specialist healthcare Investment supported organisations that help regional patients and families access specialist medical treatment through transport and accommodation assistance. This included support for Wings4Kidz and Tour de OROC, which help reduce barriers to healthcare for people living in regional communities. Bringing communities together We supported sporting clubs, community events and cultural initiatives that contribute to regional identity and community life. This included upgrades to the Cobar Camels change rooms and T20 cricket lighting, sponsorship of events such as the Cobar Show, Cobar Races and Festival of the Miners Ghost, support for community events in the Cloncurry region including the Curry Merry Muster Festival and Rodeo, Rockhana Gem and Mineral Festival, Cloncurry and District Show, Quamby All Sports Event and NAIDOC Week celebrations, and support for the Sundowners Kalkutungu Dancers to participate in DanceRites 2026. | ||||||
Future focus
•Elevate our corporate investment approach to long lasting impact initiatives, thereby placing community priorities, needs and opportunities at the centre of investment decision-making •Expand the existing public private partnerships on skills development to meaningfully contribute to the fight against youth unemployment •Review and formalisation of the CSA mine community investment framework. | |||
134
Illegal mining and unauthorised access
Key matters: Management of illegal mining and unauthorised access, safety, post-closure sustainability. Potential impacts on society, the environment and the economy: Illegal mining and unauthorised access can expose employees, illegal miners and communities to serious safety and health risks, while contributing to crime, environmental degradation and social disruption. Unregulated mining activity can also affect community wellbeing and legitimate economic activity. Matters that could impact Harmony: Illegal mining and unauthorised access can threaten operational continuity, assets and revenue, while requiring significant expenditure on security, prevention and rehabilitation. Incidents can also increase regulatory and reputational exposure and contribute to longer-term closure and rehabilitation liabilities. | ||
Sustainability framework | Managing business resilience: Monitoring external influences and key risks and developing appropriate responses to improve business performance and longevity. | ||
Strategic risk and opportunity | Risk: Illegal mining and security Illegal mining and security breaches can affect safety, infrastructure, environmental liabilities, operational continuity and asset value. Opportunity: Security and operational stability Strong security systems, technology and community engagement can protect assets, strengthen resilience and support licence to operate. | ||
Illegal mining and unauthorised access by third parties can threaten employee safety,
operational continuity and community wellbeing.
Influenced by low national employment rates and other socio-economic factors, illegal mining is a persistent challenge in South Africa
and an ongoing concern in Papua New Guinea, where motives for unauthorised access are more varied. Illegal mining and
unauthorised access threaten the safety of our people, the integrity of our operations and the wellbeing of the communities in which we
operate. Failure to invest in and maintain effective security measures exposes Harmony to significant, persistent and often violent risks.
The way we prevent, detect and respond to illegal mining shapes both our financial performance and our impact on employees, host
communities and the environment.
Illegal mining impacts, risks and opportunities (IROs)
Invest in and maintain effective security measures | |||
Failure to invest in and maintain effective security measures exposes Harmony’s people, assets and operations to the significant and persistent risks arising from illegal mining and unauthorised access. Inadequate security directly threatens operational continuity, employee safety and community wellbeing across our South African and Papua New Guinea operations. | |||
1
Regional context
South Africa Illegal mining is a significant and persistent risk, often involving highly organised networks linked to financial and violent crime. Active and legacy underground workings, shafts and associated surface infrastructure create ongoing exposure to unauthorised access, illegal extraction and security-related incidents. | Papua New Guinea Unauthorised access is driven by a range of socio-economic factors, including informal alluvial mining, theft, gold smuggling and opportunistic trespassing. Exposure is concentrated around operating sites and surrounding communities, with security measures focused on prevention, deterrence, lawful intervention and community engagement. | Australia Illegal mining does not pose significant operational, security or safety challenges to Harmony’s Australian operations, including CSA mine. Accordingly, no significant illegal mining or related security disclosures are presented for the region in FY26. | ||||||||
Performance snapshot
Total investment R780 million (FY25: R748 million) | South Africa illegal mining arrests 255% increase at operating shafts with a 93% reduction of incidents at non- operating shafts | Papua New Guinea illegal entries 83% decline (455 in FY26 compared to 2 672 in FY25) | South Africa shafts sealed 50 cumulative since 2008 | Security personnel trained in human rights policy 657 (FY25: 1 000) including personnel, contractors and police | ||||||||||||||
135
How we manage illegal mining IROs
1 | Invest in and maintain effective security measures | I | R | O | SA | PNG | |||||||||||||
Impact, risk and opportunity drivers Illegal mining risks are shaped by socio- economic conditions and criminal networks. In South Africa, structural unemployment and inequality drive incursions. Organised syndicates have professionalised illegal mining, increasingly targeting active shafts as gold prices rise. In Papua New Guinea, unauthorised access at Hidden Valley reflects broader socio-economic motives, including unregulated alluvial mining and theft. Exposure is further shaped by the strength of our controls, the profile of legacy infrastructure, law-enforcement collaboration and the potential legalisation of artisanal mining in South Africa without adequate safeguards. | Potential impacts on society and the economy Illegal mining endangers illegal miners, our employees and security personnel through unstable underground conditions and violent, often armed confrontations. Nearby communities may face elevated crime, human-rights abuses and social harms linked to organised criminal networks. Environmental damage can also follow: contamination of water, air and soil, sedimentation from alluvial mining, and physical hazards such as sinkholes, underground fires and explosions at reopened shafts. Security investment can create local employment, while community awareness, law-enforcement collaboration and responsible closure can help address illegal mining risks and remove access pathways to legacy infrastructure. | Potential operational effect on Harmony Incursions cause production stoppages, damage to underground and surface infrastructure, and theft of gold-bearing material, explosives, diesel and copper cables. Employee safety is compromised by the risk of underground encounters with armed illegal miners and the psychological weight of a high- threat operating environment. At non- operational sites, illegal mining constrains responsible closure and rehabilitation, extending post-closure liabilities. Our response, including site security plans, investigations, law-enforcement coordination and stakeholder engagement, demands significant management focus, and must be rapidly reconfigured when partnerships shift, as with the discontinuation of Operation Vala Umgodi in December 2025. | Potential financial effect on Harmony Illegal mining creates significant cash costs. Expenditure reflects the scale of the threat and is unlikely to reduce in the short term. Additional financial exposure arises from revenue losses through theft of gold-bearing material, asset damage to production and processing systems, higher insurance premiums, regulatory penalties and production delays. Reputational and regulatory risks are equally important. Failure to manage illegal mining could erode our social licence and trigger adverse findings from the DMPR (South Africa) and MRA (Papua New Guinea). Inadequate closure of legacy shafts and other facilities may expose Harmony to long-term security, environmental and financial liabilities. | |||||||||||
Our approach
Our approach to illegal mining and unauthorised access is guided
by our first value: safety. This means prioritising the protection of
our people, assets and the communities in which we operate.
Because the threat is dynamic, well-resourced and increasingly
professionalised, we combine layered engineering and technical
controls with intelligence-led operational responses, sustained
investment in security personnel and technology, and active
collaboration with law enforcement, host communities and
industry peers.
Our conduct in this space is anchored in the Voluntary Principles
on Security and Human Rights (VPSHR), which govern the
behaviour of both directly employed and third-party security
personnel across all operations, and is aligned with the
International Council on Mining and Metals (ICMM) Mining
Principles, the UN Global Compact and the World Gold Council’s
Responsible Gold Mining Principles.
Key elements of our approach include:
•Engineering and technical controls, including demolition,
sealing and rehabilitation of decommissioned infrastructure,
and the installation of fencing, lighting and advanced
surveillance systems at vulnerable sites
•Site-specific security plans, reviewed and monitored regularly
by heads of security and mine management teams
•Behavioural and cultural programmes, including formal VPSHR
training, Force Decision-Making briefings and continuous
reinforcement of use-of-force and human-rights principles
•Real-time monitoring, drone surveillance, artificial-intelligence
supported detection and intelligence-led coordination with
third-party control rooms and tactical response teams
•External partnerships and collaboration with the Department of
Mineral and Petroleum Resources (DMPR), South African
Police Service (SAPS), National Prosecuting Authority (NPA),
Mineral Resources Authority (MRA) and Royal Papua New
Guinea Constabulary to uphold compliance, investigate criminal
activity and support prosecutions
136
•Engagement with host communities and other local
stakeholders to strengthen awareness of risks associated with
illegal mining and unauthorised access, and to facilitate
information sharing that supports risk identification and
mitigation
•Monitoring and reporting of illegal mining incidents and security
performance, including the regular review of site security plans,
tracking of illegal mining arrests, intrusion detections and asset
recoveries, and reporting to site and group security
management teams. Incidents are also reported to the
Department of Mineral and Petroleum Resources (South Africa)
and the Mineral Resources Authority (Papua New Guinea), as
applicable.
Governance and oversight
Accountability for the anti-illegal mining framework rests with the
CEO, who engages with government and industry bodies on the
strategic dimensions of the risk. The Deputy CEO and regional
and site security managers are responsible for implementing
security strategies and for coordinating with industry partners and
regulators, while heads of security deploy the human and
technological resources required at each site.
The audit and risk committee reviews the adequacy of internal
controls, monitors key risks and reviews the effectiveness of
mitigation plans on a quarterly basis as part of the enterprise risk
management process. The social and ethics committee receives
regular updates on key exposures and mitigation progress as part
of broader sustainability risk oversight. Roles and responsibilities
align with local legislation. This includes the Mineral and
Petroleum Resources Development Act (MPRDA) and the Mine
Health and Safety Act in South Africa, and the Mining Act and
relevant security and criminal legislation in Papua New Guinea.
FY26 progress and achievements
Targeting illegal mining through prevention, detection
and enforcement
Security operations, South Africa
During FY26, driven by the global surge in the gold price,
criminal syndicates increasingly targeted operating shafts. At the
same time, illegal mining at non-operating sites declined
significantly as a result of ongoing shaft sealing and rehabilitation
interventions.
In this context, the results achieved during FY26 highlighted the
value of early detection, targeted interventions and long-term
prevention measures.
Through intensified security measures at operating shafts and
strategic collaboration with state law enforcement, we
successfully intercepted the majority of illegal miners before they
gained underground access. Most incidents, that translated into
arrests, were detected through a combination of CCTV
surveillance, third-party control-room monitoring, intelligence and
collaboration with tactical response teams, helping to reduce both
underground safety hazards and operational risks.
The 93% reduction in security incidents at non-operating shafts
confirms the enduring value of responsible mine closure and shaft
sealing as structural responses to illegal mining.
Drone surveillance technology, used at both operating and non-
operating sites, has also proved highly effective and will continue
to be evaluated for further roll-out.
Our participation in Operation Vala Umgodi, a police-led initiative
focused on combatting illegal mining, contributed to 551 arrests
during FY26. The operation, which concluded in December 2025
due to insufficient State funding, highlighted the value of
coordinated action between industry, law enforcement and
government agencies.
The success of Operation Vala Umgodi, and its subsequent
discontinuation, also underscores the value of, and vulnerability
associated with, industry-law-enforcement collaboration as a
foundation of the response. In response to the discontinuation,
Harmony has reviewed its security strategy to mitigate potential
enforcement gaps through enhanced intelligence-led interventions
and technology-enabled monitoring.
Strengthening our Security Governance framework
Security operations, South Africa
A focus of the year was strengthening our alignment with VPSHR
and we made substantial progress on our policies and
procedures.
The Metallurgical, Underground, Open Pit and Services security
codes were revised and signed off, and the VPSHR procedure
and its accompanying training module were successfully
developed, approved and rolled out. This provided a consistent
foundation for the application of human rights principles across
security-related activities. This was also supported with a broader
review of security procedures, with 19 procedures updated, to
align with the abovementioned security codes. A formal VPSHR
risk assessment also commenced during the year.
Capability building remained a key focus through VPSHR training
and force decision-making briefings. These reinforced the
appropriate use of force and support consistent application
of VPSHR requirements in operational settings.
Strengthening deterrence and early intervention
Hidden Valley, Papua New Guinea
Building on strengthened security arrangements established in
FY25, further enhancements to Hidden Valley’s security measures
during FY26 included the implementation of a sector control
strategy, expanded intelligence networks and stronger community
participation.
Security operations were reorganised into four dedicated
operational areas, strengthening supervisory oversight and
maintaining a consistent deterrent presence across the mining
lease. This has supported earlier identification of security risks
and enabled the interception of intruders before they reach
operational areas.
Court proceedings relating to apprehended intruders also
progressed effectively, resulting in conviction certificates being
obtained for all intruders apprehended on site during the year.
The Corporate Reserve Police Initiative was successfully
implemented, integrating eligible Harmony employees into Papua
New Guinea’s Corporate Reserve Constabulary and
strengthening collaboration between site security personnel and
the Royal Papua New Guinea Constabulary.
137
Performance and effectiveness
Security expenditure
Expenditure | FY26 | FY25 | |
Group | R780 million (US$43.1 million) | R748 million (US$41.2 million) | |
South Africa | R751 million (US$41.4 million) | R713 million (US$39.3 million) | |
Papua New Guinea | R29 million (US$1.7 million) | R35 million (US$1.9 million) |
Our spend on security in FY26, which reflects the persistent scale
of the threat, is unlikely to reduce significantly in the short term.
We do not set forward-looking targets on security expenditure,
as the quantum of investment is determined by the threat
environment. Instead, performance is measured through the
reduction in illegal mining incidents and qualitative assessment
of the effectiveness of site-specific security strategies.
Illegal mining arrests at operating shafts increased by 255% in
FY26, led by criminal syndicates motivated by the high gold price.
Our reinforced security detection systems proved effective in
shifting the theatre of enforcement from below to above ground.
Of the 110 arrests linked to operating shafts, 57 (51.8%) were
made before illegal miners could enter underground workings, 48
(43.6%) underground and 5 (4.6%) as they attempted to exit.
Incidents at operating shafts were concentrated at Doornkop (57),
Joel (32), Masimong (19) and Kusasalethu (2).
At the same time, we experienced a 93% decline in illegal mining
incidents at non-operating sites. This reflects the impact of
continued rehabilitation, structural sealing of 50 historic shafts to
date, and stronger collaboration with tactical response teams.
The 105 non-operating incidents recorded in FY26 were
concentrated at Covalent Water Company (95) and Margaret
Water Company (10). These water pumping shafts are linked to
disused or old mines that do not belong to Harmony. It is from
these disused mines that illegal miners enter and then exit later,
through one of our water pumping shafts.
Participation in Operation Vala Umgodi contributed to 551 arrests
before the operation was discontinued in December 2025. Most
of these arrests were on the surface, both onsite and offsite.
With respect to training, 38% of directly employed South African
security personnel and 18% third-party security personnel
completed our formal VPSHR training. We plan to have all training
completed in FY27.
South Africa operations
Metric | FY26 | FY25 | |
Illegal mining arrests1 – operating shafts | 110 | 31 | |
Illegal mining arrests1 – non-operating shafts | 105 | 1 420 | |
Cumulative2 shafts demolished | 50 | 48 | |
Human rights training – employed (% of total employed) | 225 (38%) | 248 (41%) | |
Human rights training – third-party (% of total contractors) | 259 (18%) | 553 (43%) | |
Operation Vala Umgodi arrests | 551 | 2 603 |
1An arrest is an enforcement outcome, converting an incident into a
formal legal proceeding against specific individuals and includes
apprehending trespassers/illegal miners underground or at surface
access points, multi-agency task force operations resulting in the
detention of buyers, syndicate bosses, or operational miners and
handing over of detained suspects to the police for formal charging
under national precious metals or mining acts.
2Cumulative since 2008.
Hidden Valley, Papua New Guinea
Metric | FY26 | FY25 | |
Trespassing/intrusion incidents1 | 455 | 2 672 | |
Human rights training – employees2 | 127 | 71 | |
Human rights training – police and contractors2 | 46 | 128 |
1Defined as unauthorised entry within the Mining Lease (ML) 151
boundary.
2Representing 100% of new employees and/or new police and
contractors engaged at the site.
Incidents of illegal entry to the Hidden Valley mining lease
declined by 83% between FY25 and FY26. This outcome reflects
the combined effect of investment in physical security measures,
the shift to the sector control strategy, and earlier intervention
enabled through strengthened intelligence networks.
VPSHR training was undertaken by 127 employees and 46 police
officers as part of Hidden Valley’s deployment. In parallel, eight
current employees elected to serve in Papua New Guinea’s
Corporate Reserve Constabulary. Participation in this reserve
force optimises site security presence and reinforces Harmony’s
commitment to collaborative security management.
Future focus
•Continued collaboration and partnerships with host communities, government and law enforcement to promote site security •Monitoring developments related to the potential legalisation of artisanal mining in South Africa and advocating for robust safeguards against illicit gold trading and criminal infiltration •Complete VPSHR training (South Africa) and continued retraining of all personnel following the update of security policies •Drone surveillance technology opportunities will continue to be considered while expanding special operations in high risk areas (South Africa). | |||
138
Supply chain
Key matters: Sustainable communities; post-closure sustainability; social licence to operate; geopolitical uncertainty Potential impacts on society, the environment and the economy: Our procurement decisions can influence where economic value is created and who has opportunities to participate in our supply chain. Local and diverse procurement and supplier development can strengthen businesses, build capability and support more resilient local economies, while responsible sourcing helps promote ethical practices across our supply chain. Matters that could impact Harmony: Reliable access to the goods, services and logistics we need is critical to operational continuity and cost stability. Supply disruption, limited supplier capacity or poor supplier practices can increase costs and affect delivery, while a broader and more capable supplier base can strengthen longer-term supply resilience. | ||
Sustainability framework | Responsible procurement: Broaden local economic participation and strengthen supply chain resilience through targeted supplier development and responsible procurement practices. | ||
Strategic risk and opportunity | Risk: Supply chain disruption Disruptions to critical equipment, consumables and services can affect production, project delivery and costs. Opportunity: Supply resilience and cost predictability Supplier diversification, strategic partnerships and inventory optimisation can strengthen resilience and cost predictability. | ||
Reliable, responsible and inclusive supply chains support operational continuity, shared
value outcomes and long-term business resilience.
Our operations depend on a diverse network of suppliers across South Africa, Papua New Guinea, Australia and globally. Procurement
decisions influence supplier participation, supply chain integrity and the distribution of economic opportunities across the regions
where we operate. Managing these considerations effectively helps strengthen supplier relationships, support responsible sourcing and
contribute to resilient local economies.
Supply chain impacts, risks and opportunities (IROs)
Supply resilience and continuity | Responsible sourcing and supplier practices | Local and diverse supplier participation | Enterprise and supplier development and capability building | |||||||||||||||
Reliable access to critical goods, services and logistics supports operational continuity, cost stability and the ability to adapt to and recover from disruption. | Strong supplier governance and ethical sourcing practices help manage risk, strengthen trust and support sustainable value creation. | Expanding participation by local and diverse suppliers helps distribute economic value, strengthen regional economies and create shared benefits. | Supporting supplier development helps build capability, strengthen supply chain resilience and support long-term economic development. | |||||||||||||||
1
2
3
4
Regional context
South Africa South Africa has a mature mining supply market supported by a regulatory framework that prioritises transformation, broad-based economic inclusion and sustainable socio-economic development. Procurement practices are influenced by Social and Labour Plan commitments, Mining Charter III requirements, Broad-Based Black Economic Empowerment (B‑BBEE) objectives, and expectations to promote participation by black-owned, black- women-owned, black-youth-owned, Qualifying Small Enterprises (QSEs) and Exempted Micro Enterprises (EMEs). Responsible procurement is a key enabler of local economic development, enterprise development and long-term supplier sustainability. It contributes to the growth of inclusive supply chains while ensuring security of supply, ethical sourcing, regulatory compliance and sound governance practices. | Papua New Guinea Papua New Guinea’s procurement environment is characterised by a limited domestic manufacturing base and reliance on overseas sourcing for many specialised goods, consumables and services. At the same time, procurement plays a significant role in the national economy. As a result, responsible procurement seeks to balance supply resilience with local content objectives, supplier capability development and sourcing practices that strengthen local enterprises, promote inclusive economic participation and contribute to long- term regional development. | Australia Australia’s procurement environment is characterised by mature supplier markets and a strong focus on maximising local and Australian business participation. This is influenced by both stakeholder expectations for local economic participation and regulatory requirements, including the Australian Industry Participation Plan for Eva Copper. Procurement also plays an important role in supporting First Nations participation and economic opportunities through commitments established under native title agreements. As a result, responsible procurement focuses on strengthening local supplier capability, supporting regional economic participation and maintaining resilient, responsible supply chains. | ||||||||
Performance snapshot
Total investment R56.0 billion (FY25: R45.2 billion) | Spent in South Africa R44.2 billion (FY25: R39.1 billion) | Spent in Papua New Guinea R2.5 billion (FY25: R2.5 billion) | Spent in Australia R9.3 billion (FY25: R3.6 billion) | Preferential procurement – South Africa R18.4 billion (FY25: R16.3 billion) | Preferential procurement – Australasia R5.2 billion (FY25: R2.8 billion) | |||||||||||||||||
139
How we manage supply chain IROs
1 | Supply resilience and continuity | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Supply resilience is influenced by supplier concentration, logistics and infrastructure disruptions, local supplier capability constraints, and market, geopolitical or regulatory changes. These factors can affect the availability, reliability and affordability of critical inputs, equipment, consumables, logistics services and specialist expertise required to support operations and project delivery. | Potential impacts on society and the economy Supply resilience influences the stability of economic activity linked to Harmony’s operations. Disruptions may adversely affect suppliers, contractors and host communities through operational interruptions and project delays, while resilient supply chains can support stable business opportunities, local economic participation and stronger regional supplier markets. | Potential operational effect on Harmony Disruptions to suppliers, logistics networks or critical infrastructure may interrupt production, delay projects, and reduce operational flexibility. Constraints in supplier availability, transport corridors or local market capability can affect the timely delivery of goods and services, creating challenges for maintaining reliable and efficient operations. Greater supply resilience can improve continuity and operational flexibility. | Potential financial effect on Harmony Supply disruption may affect financial performance through production downtime, reduced throughput, higher input costs, expedited freight, emergency sourcing, increased inventory holdings and project delays. Additional impacts may arise through contract variation claims, working capital pressures and management time, while stronger resilience can support revenue continuity and cost stability. | |||||||||||
Our approach
We seek to maintain reliable access to critical goods, services,
equipment, consumables, logistics and specialist capability
required to support safe and efficient operations.
Supply resilience considerations are integrated into procurement
planning, category management, supplier qualification and risk
management processes to help identify and respond to
vulnerabilities arising from supplier concentration, logistics
constraints, infrastructure reliability, market conditions and local
supplier capability. This approach is applied across South Africa,
Papua New Guinea and Australia, while recognising the different
supplier market, regulatory and infrastructure contexts of each
region.
Key elements of our approach include:
•Procurement planning and category management to identify
critical supply requirements and potential vulnerabilities
•Supplier qualification, vetting and engagement processes to
support supplier reliability and continuity
•Diversification of suppliers and sourcing strategies to reduce
dependence on individual suppliers or supply routes
•Inventory and critical spare management where required to
support business continuity
•Supplier development and local capability-building initiatives
that strengthen both supply resilience and inclusive economic
participation
•Contingency planning for critical supplier failure and ongoing
monitoring of supplier concentration risk
•Ongoing supply risk surveillance, including monitoring of
emerging geopolitical, market, logistics and supplier-related
risks that could affect business continuity.
Harmony also engages suppliers, logistics providers,
communities, government bodies and development partners to
strengthen supplier markets, improve visibility of emerging risks
and support resilient supply chains over the long term.
Governance and oversight
Governance of supply resilience and continuity is embedded
within Harmony’s broader procurement, risk management and
operational oversight processes. In conjunction with the relevant
board committees, oversight is provided by the transformational
and supply chain executive for South African operations and the
chief operating officer for Australasian operations, supporting
clear accountability for the management of supply-related risks
and opportunities.
Key supply risks are monitored through regional procurement
oversight arrangements and escalated through management and
risk forums where appropriate. This approach helps define and
embed responsibilities across all levels of the business.
140
FY26 progress and achievements
Improving security of supply for critical reagents
South Africa
During the financial year, we strengthened critical supply
resilience by securing alternative local suppliers for solid cyanide
briquettes and commissioning on‑site dissolution plants, which
enable solid cyanide to be safely dissolved and prepared for use
at our operations. This initiative was implemented in response to a
major disruption affecting our primary cyanide supply chain,
which impacted production. By diversifying suppliers, localising
sourcing and establishing on-site dissolution capability, we
improved security of supply, reduced reliance on single‑route
logistics and strengthened continuity of gold processing activities.
Together, these measures have enhanced operational resilience
and reduced exposure to future supply chain disruptions.
A new procurement operating model for our growing
Australasia region
Australasia operations, Australia and Papua New Guinea
During FY26, we reviewed our procurement and supply chain
operating model in response to the changing scale and
complexity of our Australasia regional operations, including the
addition of CSA mine and future operational requirements
associated with Eva Copper.
Following review and benchmarking against leading industry
practices, we selected a new strategic procurement operating
model and undertook preparatory activities to support its
implementation. The model shifts procurement from a largely site-
based approach focused on Hidden Valley, to one that brings
together specialist expertise across multiple operations, enabling
more coordinated purchasing, stronger supplier engagement,
improved market insights and more consistent contract
management.
The new model is intended to strengthen our ability to secure the
goods and services needed to support safe and reliable
operations, while improving visibility across the supply chain. By
combining dedicated site support with specialist procurement
teams operating across multiple assets, we expect to improve
regional planning, strengthen supplier relationships, enhance
commercial outcomes and reduce exposure to supply constraints
and supplier concentration risks.
Our FY26 activities focused on defining the operating model,
defining roles and responsibilities, and preparing for
implementation across the region. Implementation commenced in
July 2026 and is being progressively rolled out across Harmony’s
Australasia operations, excluding Eva Copper, which will continue
under existing arrangements until it progresses closer to
production.
The shift to this operating model builds prior procurement
and supply chain enhancements initiated in FY25 and further
embedded during FY26. These included the transition to a fourth-
party logistics (4PL) service provider to strengthen coordination
and oversight of regional freight and logistics activities, and
enhancements to logistics and customs clearance processes to
support the reliable movement of critical goods and equipment.
Together, these initiatives have strengthened supply chain visibility
and coordination and supported greater supply resilience across
our growing Australasian operations.
Strengthening freight resilience
CSA mine, Australia
During FY26, we progressed development of a rail terminal at
CSA mine to increase freight capacity and provide greater
flexibility in the movement of copper concentrate and key
consumables. The terminal will support a greater shift to rail,
reducing reliance on road transport and supporting the
management of transport-related safety and operational risks.
Both road and rail infrastructure can be affected by climate-
related events such as flooding and bushfires, disrupting
Australian regional transport routes. Maintaining flexibility across
transport modes, together with alternative logistics pathways and
close coordination with transport providers, strengthens
preparedness and supports continuity should disruption occur.
Performance and effectiveness
Further to our regular departmental and management oversight
activities, we are also examining our supply resilience and
continuity through the company’s broader business continuity
management project.
During FY26, we reviewed Harmony’s existing continuity
arrangements for our strategic supply chain disruption risk. The
assessment identified the opportunity to more formally integrate
supplier continuity, critical consumables, critical spares, fuel,
logistics and third-party dependencies into business continuity
planning.
As the project progresses, supply chain considerations will be
progressively incorporated, helping to strengthen oversight of
critical processes and dependencies and improve readiness
for disruption events.
Metrics reported under other responsible procurement IROs,
such as local procurement and supplier development, provide
supporting insight into supplier market strength and capability.
Future focus
•Implementation and embedding of our new Australasia procurement model •Further strengthen supply chain resilience through increased local sourcing, supplier diversification and reduced dependency on single-source critical commodities. | |||
141
How we manage supply chain IROs
2 | Responsible sourcing and supplier practices | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Responsible sourcing risks arise where supplier environmental, social, labour, human rights or governance practices do not meet expectations. Key drivers include limited supply chain traceability, corruption or unethical conduct, and challenges for local or emerging suppliers in meeting sustainability, safety, insurance and compliance requirements. These factors can affect supplier integrity, accountability and responsible value chain performance. | Potential impacts on society and the environment Responsible sourcing practices can positively influence supplier behaviour by improving environmental, labour, human rights and governance outcomes while strengthening accountability across the value chain. Conversely, inadequate oversight or weak supplier practices may contribute to environmental harm, labour and human rights concerns, corruption, unethical conduct or broader non-compliance, affecting communities, workers and market confidence. | Potential operational effect on Harmony Weak supplier practices may disrupt operations through supplier replacement, contract delays, remediation activities and compliance interventions. Limited visibility over supplier ownership, subcontractors or sourcing arrangements can reduce confidence in responsible sourcing claims, while unethical conduct or non-compliance may require investigations and corrective actions. Strong supplier practices support more reliable partnerships and procurement outcomes. | Potential financial effect on Harmony Responsible sourcing failures may result in regulatory penalties, remediation expenditure, supplier replacement costs, contract delays, investigations, litigation and reputational impacts. They may also increase investor and lender scrutiny, affect confidence in Harmony’s governance and sustainability performance, and contribute to potential cost- of-capital implications. Conversely, strong sourcing integrity can support market access, assurance readiness, stakeholder confidence and access to capital. | |||||||||||
Our approach
Our approach aims to strengthen supply chain integrity,
accountability and transparency while supporting ethical,
compliant and sustainable procurement outcomes. Responsible
sourcing risks and opportunities are identified through
procurement planning, supplier vetting and due diligence, supplier
engagement, compliance reviews, audits and ongoing
procurement oversight. The approach is applied across all
regions but reflects jurisdiction-specific regulatory requirements
and socio-economic priorities.
Key elements of our approach include:
•Supplier due diligence and responsible sourcing controls. This
includes supplier onboarding, screening and vetting processes,
B-BBEE verification and ownership checks in South Africa, and
assessments of legal and ethical business conduct across
Australia and Papua New Guinea. These processes help
identify and manage risks relating to environmental, social,
labour, human rights and governance performance
•Supplier compliance requirements. These include insurance,
anti-bribery and corruption, anti-money laundering and
sanctions compliance obligations, together with adherence to
applicable procurement and regulatory requirements
•Supplier engagement and responsible value chain partnerships.
This includes collaboration with suppliers, contractors and
downstream refining partners to strengthen transparency,
traceability and accountability, and support alignment with
responsible sourcing expectations across the value chain
•Responsible downstream relationships, including engagement
with Rand Refinery, ABC Refinery, Glencore and OR Royalties.
This supports traceability, responsible sourcing expectations
and alignment with recognised precious metals supply chain
standards
•Supplier capability and compliance support. Targeted initiatives
help suppliers understand and meet procurement, regulatory
and sustainability requirements, strengthening compliance,
procurement readiness and long-term supplier performance.
Supplier monitoring, internal audits and compliance reviews to
support procurement integrity, transparency, accountability and
continuous improvement are also routinely undertaken in relation
to our South African supply chain.
Governance and oversight
Governance of responsible sourcing and supplier practices is
embedded within Harmony’s procurement, compliance and risk
management frameworks. In conjunction with the relevant board
committees, oversight is provided by the transformational and
supply chain executive for South African operations and the
chief operating officer for Australasian operations, supporting
accountability for supplier integrity, ethical conduct and
responsible sourcing outcomes.
Regional procurement teams are responsible for implementing
responsible sourcing requirements. This includes supplier due
diligence, screening, compliance monitoring and ongoing supplier
engagement. Key issues relating to supplier conduct are
monitored through established procurement and compliance
processes and escalated through management and risk
governance forums where appropriate.
142
Supporting transparency across the precious metals
value chain
Rand Refinery, South Africa
Harmony has a 10.4% stake in Rand Refinery, which shares
our commitment to stringent environmental performance and
compliance and internationally accepted responsible sourcing,
as guided by the London Bullion Market Association and the
Organisation for Economic Cooperation and Development Due
Diligence Guidance for Responsible Supply Chains of Minerals
from Conflict-Affected and High-Risk Areas.
One of our executive directors is a non-executive director and sits
on the refinery’s social and ethics committee where the refinery’s
sustainability strategies are discussed and influenced. The
certified gold chain of custody is independently audited as
required by independent bodies and legislation.
ABC Refinery, Australia
Harmony sells all produced gold and silver from Hidden Valley
mine to ABC Refinery, the refining division of Pallion. ABC
Refinery’s operations fully comply with:
•Australian regulatory requirements
•OECD Due Diligence Guidance for Responsible Supply Chains
of Minerals from Conflict-Affected and High-Risk Areas,
including the Gold Supplement
•London Bullion Market Association Responsible Gold and Silver
Guidance.
ABC Refinery conducts risk-based supply chain due diligence
supported by reasonable assurance against the LBMA Gold and
Silver Guidance. Supporting its Chain-of-Custody protocols, ABC
Refinery has adopted ProvCheck to authenticate finished
products and provide customers with the origin of their metal,
and employed Source Certain to conduct elemental analyses to
verify all incoming gold. These innovative approaches facilitate
robust traceability and provide customers confidence when
purchasing their precious metals.
Our contract with ABC Refinery reflects Harmony’s role as a
responsible supplier, aligned with sustainable and transparent
sourcing practices and global expectations for environmental
and social responsibility in the precious metals supply chain.
Glencore International AG
All material produced from the CSA mine is sold under an offtake
arrangement with Glencore. Glencore applies a Responsible
Sourcing Policy that incorporates risk-based due diligence
processes to identify and manage environmental, social, human
rights and governance risks within its supply chains and aligns
with recognised international responsible sourcing frameworks.
OR Royalties International
OR Royalties International holds rights to receive all payable silver
production and a portion of payable copper production from
CSA mine. As a royalty and streaming company, OR Royalties
incorporates environmental, social and governance considerations
into its investment processes, and also undertakes ongoing
monitoring of mining partners through reporting obligations, site
visits and sustainability-related provisions in its streaming
agreements.
FY26 progress and achievements
Strengthening controls over B-BBEE supplier
verification
South Africa operations
We strengthened responsible procurement practices during FY26
by formalising a systemic B‑BBEE verification and validation
process to identify fronting, misrepresentation and non‑compliant
ownership claims. The enhanced due‑diligence framework
improves supplier traceability and strengthens controls over
supplier qualification and onboarding, helping align procurement
decisions with legitimate transformation objectives. The initiative
has enhanced procurement integrity, reduced exposure to ethical
and compliance risks, and reinforced accountability across our
supplier base. The verification process is now embedded within
ongoing supplier monitoring and compliance review activities,
supporting transparent, ethical and responsible sourcing across
South African operations.
Expanding oversight of modern slavery and human
rights risks
Australasia operations, Australia and Papua New Guinea
During FY26, we continued to strengthen our approach to
modern slavery risk management and supply chain due diligence
in response to our growing Australasia regional footprint. This
work also supports compliance with Australia’s Modern Slavery
Act, which applies to our Australian and Papua New Guinean
operations and requires ongoing identification, assessment and
reporting of modern slavery risks and response actions.
As a first step in strengthening organisational awareness and
regional oversight of modern slavery risks, we reviewed existing
risk exposures and management responses. The assessment
informed actions to enhance governance oversight and risk
monitoring, including incorporating a broader human rights risk
into the Australasia strategic risk register.
Inherent modern slavery risk of Top 5 countries of direct goods and service suppliers1 | Prevalence per 1 000 people | Vulnerability (out of 100) | Total active suppliers | Percentage of active suppliers (%) | ||
1 | Australia | 1.6 | 7 | 1 050 | 69 | |
2 | Papua New Guinea | 10.3 | 79 | 396 | 26 | |
3 | South Africa | 2.7 | 52 | 11 | 1 | |
4 | Canada | 1.8 | 11 | 11 | 1 | |
5 | United States | 3.3 | 25 | 8 | 1 | |
1 Australasia region sourcing country analysis. Prevalence and vulnerability as reported by Walk Free 2023 Global Slavery Index. | ||||||
Our highest potential for exposure to modern slavery risks exists
in our supply chain. As the preceding table indicates, the
prevalence and vulnerability of individuals to modern slavery risks
varies across key countries from which we source goods and
services. We recognise that as one moves further upstream in the
supply chain, the level of risk can increase. Early stage activities
may occur in regions with less regulatory oversight, limited
infrastructure and higher exposure to social and environmental
vulnerabilities.
To further our understanding of upstream supply chain risks,
we reviewed the available Modern Slavery Statements for key
contractors across Hidden Valley, CSA mine and the Eva Copper
Project. The review provided greater insight into the risks
identified by suppliers, the actions they are taking to manage
those risks, and the relative maturity of their modern slavery
governance and due diligence processes. These insights will
inform ongoing engagement and continuous improvement
activities.
Several initiatives remain in progress. While no instances of
modern slavery have been identified, we note the higher inherent
vulnerability of individuals to modern slavery in Papua New
Guinea, per the Global Slavery Index. We intend to review
engagement mechanisms for labour hire workers in Papua New
Guinea and conduct awareness and engagement activities with
key local suppliers to strengthen their understanding of modern
slavery risks, laws and the standards expected of suppliers
operating within Harmony’s supply chain.
143
Performance and effectiveness
Quantitative performance measures relating to responsible
sourcing continue to evolve. At present, oversight is primarily
supported through supplier onboarding, due diligence, screening
and compliance processes. Procurement targets relating to
preferential, local and diverse supplier participation are reported
under Local and diverse supplier participation (IRO3).
Environmental screening
We do not yet operate a formalised environmental screening
system across our supply chain. However, in South Africa,
environmental considerations are incorporated into supplier
onboarding through questions relating to carbon emissions,
environmental management practices and compliance with South
African environmental regulations. These disclosures support
initial sustainability risk identification and help assess suppliers’
readiness to meet Harmony’s environmental expectations. We are
currently assessing options to strengthen environmental and
social screening processes in our South African supply chain,
including integrating sustainability risk indicators into supplier
onboarding and developing a more formalised screening
framework.
In Australasia, environmental considerations are currently
incorporated into procurement and contractor management
processes rather than through a formal supplier environmental
screening framework. Suppliers and contractors are expected to
comply with project site environmental management plans, with
environmental considerations reviewed, where relevant, during
pre‑contract award processes and site induction and onboarding
requirements. This approach provides a practical mechanism for
identifying and managing environment-related procurement risks
and supporting compliance with our site environmental
expectations.
Social screening
We incorporate ethical conduct and supplier integrity considerations into procurement oversight processes. Allegations or findings
relating to supplier misconduct and other legal or ethical breaches, may be considered as part of supplier qualification, monitoring and
review activities.
For our South Africa region, instances of supplier misconduct that are substantiated through relevant investigations and legal processes
are monitored by Harmony’s internal white collar crime committee. Where misconduct is confirmed, suppliers are deactivated and
removed from Harmony’s vendor database. This process strengthens procurement governance, supports the management of social and
human rights-related risks, and reinforces alignment between Harmony’s ethical, legal standards, legal obligations and transformation
expectations.
In Australasia, we screen 100% of new Australasia region suppliers using the London Stock Exchange Group (LSEG) World-Check
platform. This supports the identification of potential risks relating to financial crime, bribery and corruption, sanctions, money laundering,
human trafficking, forced labour and other labour exploitation concerns. It also assists in identifying suppliers that may be associated
with adverse legal, regulatory or ethical conduct. We deactivate the listings of suppliers that we have not used for two years, and
conduct a new screening process if they are reactivated.
Australia | Papua New Guinea | Other | |
Number of new suppliers screened1 | 162 (FY25: 194) | 9 (FY25: 29) | 4 (FY25: 14) |
Percentage of new suppliers screened | 100% (FY25: 100%) | 100% (FY25: 100%) | 100% (FY25: 100%) |
1 LSEG Well-Check screening. | |||
Future focus
•Continue assessing options to enhance environmental screening within our South African supply chain, including the use of sustainability risk indicators, during supplier onboarding and the development of a more structured screening approach •Review the effectiveness of engagement processes for workers employed through labour hire companies in Papua New Guinea •Expand supplier compliance awareness and engagement activities with Papua New Guinea companies to include awareness of what constitutes modern slavery, Australia’s Modern Slavery Act requirements, and the standards expected of suppliers operating within Harmony’s supply chain. | |||
144
How we manage supply chain IROs
3 | Local and diverse supplier participation | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Mining operations create expectations among host communities, local businesses and under-represented suppliers to participate in, and benefit from, procurement opportunities associated with the operation. These expectations may not always align with supplier capability, scale, financing capacity, technical requirements or procurement processes. Where barriers to participation persist, Harmony may face challenges in meeting local participation objectives and stakeholder expectations, potentially affecting social licence, community relationships, procurement commitments and access to a diverse and resilient supplier base. | Potential impacts on society and the environment Greater participation by local, diverse, host community and under-represented suppliers can support economic inclusion, stronger local enterprise ecosystems, income generation, skills transfer, employment opportunities and more resilient regional economies. Conversely, negative impacts may arise where suppliers face barriers to participation, benefits are unevenly distributed, or procurement commitments create expectations that are not matched by viable and accessible pathways to participation. | Potential operational effect on Harmony The effectiveness of local and diverse supplier participation can influence contract performance, supplier availability, procurement flexibility and relationships with host communities. Where supplier capability, scale or compliance readiness does not align with operational requirements, delivery risks may increase and local and diverse supplier participation objectives may be more difficult to achieve. Effective inclusion can strengthen local supply capacity, broaden the supplier base and support more resilient procurement outcomes. | Potential financial effect on Harmony Local and diverse supplier participation may affect financial performance through supplier competition, pricing outcomes, contract performance, compliance with procurement commitments and broader stakeholder confidence. In some cases, achieving local participation objectives may require investment in supplier development, capability building or procurement support, resulting in higher short-term costs. Effective inclusion can, however, strengthen local supply markets, diversify the supplier base and support longer-term procurement resilience. | |||||||||||
Our approach
We seek to create shared value through procurement by
supporting participation by local, host community, diverse and
under-represented suppliers where this aligns with operational
requirements, supplier capability and market capacity. Our
approach recognises that procurement is an important
mechanism through which economic benefits can be distributed
to host regions, while also supporting supplier diversity, local
market development and long-term business resilience.
Participation initiatives are tailored to regional contexts and reflect
regulatory requirements, agreement-based commitments and
local stakeholder expectations.
Key elements of our approach include:
•Integration of local, diverse and host community participation
objectives into procurement planning, sourcing strategies
and contract packaging approaches to create accessible
participation opportunities while maintaining appropriate
technical, safety, commercial and operational standards
•Supplier engagement, collaboration and partnerships with
contractors, governments, community representatives and
business development organisations to improve procurement
readiness, communicate procurement opportunities, support
supplier participation and strengthen local supplier ecosystems
•Technology-enabled initiatives, including supplier capability
portals and digital reporting tools, to improve visibility of local
suppliers, support subcontracting opportunities and enhance
participation tracking
•Monitoring and reporting of local, diverse and community-
based supplier participation through procurement spend
tracking, regional performance metrics and compliance
processes.
This approach aims to balance community and stakeholder
expectations for local economic participation with the operational,
technical and compliance requirements necessary to support
safe, reliable and efficient business performance.
Our regional supply chain obligations | ||
South Africa •Mining Charter III procurement requirements. | ||
Papua New Guinea •Hidden Valley memorandum of agreement (MoA) – established through consultation and benefit-sharing processes provided under the Mining Act and associated legislation. | ||
Australia The following commitments apply to Eva Copper: •Australian industry participation plan – required under the Australian Jobs Act •Kalkadoon native title ancillary agreement – established through the right to negotiate process under the Native Title Act •Mount Isa mining acceleration programme agreement – includes commitments linked to government funding support. | ||
145
Governance and oversight
Governance of local and diverse supplier participation is
embedded within Harmony’s procurement, compliance and risk
management frameworks. In conjunction with the relevant board
committees, oversight is provided by the transformational and
supply chain executive for South African operations and the chief
operating officer for Australasian operations, supporting
accountability for local procurement outcomes, inclusive
economic participation and compliance with regulatory,
agreement-based and project-specific procurement
commitments.
Regional procurement teams play a central role in identifying and
implementing local and diverse supplier participation
opportunities, as well as tracking and reporting performance
against relevant commitments and objectives. Delivery is
inherently cross-functional, requiring collaboration between
procurement, operations, project teams, community relations and
other business functions to align local participation objectives with
operational requirements, stakeholder expectations and local
market capability. Progress and emerging challenges are
reviewed through management and governance forums to
support accountability and continuous improvement.
FY26 progress and achievements
Progressing our Enterprise and Supplier Development
five-year roadmap
South Africa operations
Mining Charter III is a South African regulatory framework that sets
transformation requirements for the mining industry, including
targets for procurement from black-owned enterprises and
businesses owned by designated groups such as women and
youth.
During FY26, our Enterprise and Supplier Development (ESD)
programme continued to support Mining Charter III commitments
by providing business development, skills enhancement,
mentorship and market-access initiatives for local SMMEs. The
programme focused on supporting participation by black-owned,
black-women owned and Youth-owned businesses within our
supply chain and broader enterprise development ecosystem,
while promoting supplier diversification and local economic
participation.
Digitising our enterprise and supplier development centres
remains a key strategic priority within our five-year roadmap.
During FY26, we continued to assess opportunities to expand the
range of support services available to SMMEs through digital
channels. Planned enhancements include the introduction of
SARS self-service kiosks to facilitate convenient access to tax
compliance certificates, supporting regulatory compliance and
business sustainability. Opportunities under consideration include
the installation of digital information screens to communicate
relevant business and supplier opportunities and improve access
to market information for prospective SMMEs.
Connecting local businesses to project opportunities
Eva Copper, Australia
As Eva Copper progressed towards Harmony’s investment
decision in November 2025 and construction readiness activities
accelerated, we worked to help North West Queensland
businesses understand, prepare for and connect with project-
related opportunities.
These activities supported commitments under the Australian
Industry Participation Plan and the Queensland Government’s
Mount Isa mining acceleration (MIMA) programme, through which
the project received A$20.7 million (R237 million) in grant funding
during February 2026, following the on-time completion of
specified infrastructure works. During the year, we focused on
increasing visibility of upcoming opportunities, strengthening
supplier engagement and encouraging participation from regional
businesses.
Tender opportunities were promoted through the Industry
Capability Network (ICN) Gateway, while Harmony and its delivery
partners participated in local procurement and engagement
forums, including “Meet the Buyer” events, community information
sessions and Northwest Connect. A local business register and
supplier portal were rolled out across key contractors to improve
supplier visibility and help align local capabilities with project
demand. Direct engagement activities, including the Cloncurry
business “Street Walk” and one-on-one meetings, helped build
relationships and improve understanding of regional business
capability.
With the project moving into construction, our focus has shifted
from building awareness and supplier readiness to facilitating
participation in project delivery. Working closely with contractors
and local service providers, we are increasingly focused on
connecting regional suppliers with specific procurement
requirements across categories such as transport, equipment
and operator hire, accommodation, waste management and site
services. This approach seeks to translate local supplier readiness
into practical contracting opportunities and participation in the
construction phase of the project.
Supporting First Nations business participation
Eva Copper, Australia
During FY26, we progressed the implementation of our
Kalkadoon and Indigenous Procurement Plan as project planning
advanced.
Working closely with the Kalkadoon People and project delivery
partners, the focus was on building relationships, improving
understanding of Indigenous business capabilities and creating
stronger connections between First Nations suppliers and future
project opportunities.
Key activities included:
•Mapping Kalkadoon and broader First Nations businesses
against project requirements
•Engaging directly with Indigenous businesses in the Mount Isa
region to better understand their services, workforce capacity
and equipment availability
•Gathering supplier information to support more effective
matching of suitable opportunities.
These efforts were complemented by ongoing collaboration
between Harmony, key contractors and business partners to
align employment, training, supplier and community development
initiatives to help create pathways for First Nations participation
in project delivery.
A highlight of FY26 was the establishment of the Kalkadoon
Ranger programme, supporting the Kalkadoon People’s
aspiration to build a sustainable regional business capable of
delivering land management and mine rehabilitation services
across their traditional country. The initiative emerged through our
engagement with the Kalkadoon People to understand the
business opportunities they wished to develop.
Modernising our Business Development and Supply
and Procurement plan
Hidden Valley, Papua New Guinea
As part of the transition from the Hidden Valley MoA to a new
community development agreement (CDA), we updated the
Business Development and Supply and Procurement Plan which
forms part of the revised CDA. The update provides a clearer and
more contemporary framework for local procurement, supplier
participation and business development commitments.
Approved by the Department of Commerce in January 2026 as
part of the government review process, the updated plan reflects
procurement and supplier development practices that have been
embedded at Hidden Valley for many years and updates an
earlier, construction-focused framework that no longer reflected
the operational realities of the mine.
The approved plan provides greater clarity for stakeholders on
how these obligations are implemented in practice and reinforces
Harmony’s commitment to maximising local participation and
economic benefits for host communities and Papua New Guinea.
146
Performance and effectiveness
Performance Against Mining Charter III Procurement Requirements
In South Africa, Mining Charter III establishes requirements aimed at advancing economic transformation and broadening participation in the mining sector. Our FY26 performance against these selected
procurement requirements is summarised below.
Mining Charter III requirement | Requirement objective | FY26 performance and commentary | ||||||||
Investment in black- owned enterprises | Promotes procurement from black- owned enterprises to support economic transformation, enterprise development and increased participation in the mining value chain. | FY26 recorded a 5% increase in spending with enterprises that are more than 50% black-owned compared to the prior financial year. This growth reflects our continued commitment to preferential procurement and strengthening the participation of black-owned enterprises within our supply chain, with a deliberate focus on creating sustainable economic opportunities within our host communities. | ||||||||
Designated groups | Promotes participation by designated groups, including black women- and youth-owned enterprises, to advance inclusive economic transformation and broaden access to procurement opportunities. | Designated supplier performance continued to strengthen in FY26, with black women-owned (BWO) procurement achieving 20% against a target of 15%, while youth-owned procurement reached 6% against a target of 5%. This performance reflects continued progress in broadening the participation of designated groups and advancing inclusive procurement across our supply chain. During the year, 16 suppliers improved their black-ownership status from below 25% to above 25%, while 71 suppliers exceeded the greater than 50% black ownership threshold. These improvements demonstrate continued progress in supplier transformation and reflect our ongoing focus on strengthening black ownership and participation within our supplier base. Going forward, we will continue to identify opportunities for SMMEs and designated suppliers within high-value procurement categories through supplier gap analysis and pre-technical assessments and vendor on-boarding. These insights will support targeted procurement and supplier development interventions by advancing transformation through transparent and effective governance processes. | ||||||||
Goods and services category | Establishes minimum procurement requirements for qualifying South African goods and services to support local economic development, industrial growth and supplier participation. | Harmony continued to achieve and exceed its Mining Charter procurement targets during FY26 across both goods and services. This sustained performance reflects our continued commitment to transformation and the integration of preferential procurement objectives into our sourcing activities. Our focus remains on maintaining compliance while creating sustainable opportunities for black-owned, black women-owned and youth-owned enterprises across our supply chain. | ||||||||
Procurement spend | FY26 | FY25 | FY24 | |
Total discretionary spend | R21.3 billion (US$1 261 million) | R19.9 billion (US$1 096 million) | R17.6 billion (US$941 million) | |
Percentage of discretionary spend on preferential procurement | 87% | 82% | 84% | |
Percentage of discretionary spend on >50% black-ownership suppliers | 62% | 55% | 60% | |
Percentage of discretionary spend on local host communities | 58% | 58% | 57% | |
Percentage of discretionary spend on black-women-owned enterprises | 16% | 14% | 15% | |
Total preferential procurement spend | R18.4 billion (US$1 089 million) | R16.3 billion (US$898 million) | R14.7 billion (US$736 million) | |
Spent on black-owned businesses | R13.2 billion (US$782 million) | R11.0 billion (US$606 million) | R10.6 billion (US$567 million) | |
Spent on black-women-owned businesses | R3.5 billion (US$207 million) | R2.8 billion (US$154 million) | R2.7 billion (US$92 million) | |
Compliance spend | ||||
Spent on new >51% black-owned and controlled enterprises | R45 million (US$2.7 million) | R19 million (US$1.0 million) | R35 million (US$1.9 million) | |
Spent on 44 new 100% black-owned SMMEs | R47 million (US$2.8 million) | R15 million (US$0.8 million) | R25 million (US$1.3 million) |
147
Procurement Performance within Papua New Guinea
Despite supply chain challenges related to Papua New Guinea’s low manufacturing base, our local procurement for ongoing sourcing in FY26 was 52.5% (excluding once-off purchases and fuel). Typically,
overseas sourcing relates to key supplies, consumables and services not available in Papua New Guinea. The supplier spend represents totals across operations at Hidden Valley mine, our exploration
activities, and our 50% interest in the Wafi-Golpu Project.
Procurement spend | FY26 | FY25 | FY24 | |
Spent in Papua New Guinea | R2.5 billion˜ (US$146 million/PGK210 million) | R2.5 billion (US$140 million/PGK559 million) | R2.7 billion) (US$144 million/PGK541 million) | |
Spent with landowner companies | R575 million (US$34 million/PGK145 million) | R654 million (US$36 million/PGK144 million) | R610 million (US$32 million/PGK122 million) | |
Spent in Morobe Province (excluding landowner companies) | R1.0 billion˜ (US$60 million/PGK252 million) | R1.1 billion (US$61 million/PGK240 million) | R1 242 million (US$66 million/PGK247 million) | |
Spend elsewhere in Papua New Guinea | R867 million (US$51 million/210 million) | R792 million (US$43 million/PGK174 million) | R862 million (US$46 million/PGK172 million) | |
Percentage spent in Papua New Guinea (excluding once-off purchases and fuel) | 53% | 52% | 51% | |
Percentage spent with landowner companies | 24% | 26% | 49% | |
Percentage spent on suppliers based in Morobe Province (including landowner companies) | 65% | 69% | 68% | |
Percentage spent on suppliers based elsewhere in Papua New Guinea | 35% | 31% | 32% | |
Percentage spent on overseas suppliers (excluding once-off purchases and fuel) | 47% | 48% | 49% |
148
Australian, local and First Nations business participation in Eva Copper
Under the Australian Jobs Act 2013, we have obligations to establish an industry participation plan and provide full, fair and reasonable opportunities for businesses to bid for the supply of goods and services
for Eva Copper. All tender package opportunities over A$1 million (R12 million) are notified on Eva Copper’s industry capability network (ICN) gateway website. We are prioritising local procurement by
assessing capability across cascading geographic zones and working with major contractors to apply this approach in their subcontracting.
During FY26, spend for Eva Copper reflected support with project studies, site preparatory works, and the commencement of construction activities following the Harmony board financial investment decision
in November 2025. Our FY26 internal objective was for 20% of project expenditure to be directed to businesses located within North West Queensland and Townsville, including expenditure through major
contractors. Performance against this target is monitored monthly. During FY26, local participation exceeded the target, averaging 28% of total project spend.
FY26 | FY251 | |||
Total procurement spend (direct spend) | R4.4 billion (US$261 million/A$385 million) | R1.3 billion (US$72 million/A$111 million) | ||
Spent on First Nations Kalkadoon-owned businesses | R6.0 million (US$0.4 million/A$0.6 million) | R2.4 million (US$0.1 million/A$0.2 million) | ||
Spent on First Nations-owned businesses (excluding Kalkadoon-owned) | R– million (US$– thousand/A$9.1 thousand) | R– million (US$– thousand/A$9.7 thousand) | ||
Zone 1: Spent in Mount Isa and Cloncurry | R254 million (US$15 million/A$22 million) | R183.7 million (US$10 million/A$16 million) | ||
Zone 2: Spent in North West Queensland | R45 million (US$2.7 million/A$4 million) | R52 million (US$3 million/A$4 million) | ||
Zone 3: Spent in Queensland | R2.9 billion (US$171 million/A$252 million) | R543 million (US$30 million/A$46 million) | ||
Zone 4: Spent in rest of Australia | R1.7 billion (US$103 million/A$151 million) | R349 million (US$19 million/A$30 million) | ||
Spent on overseas suppliers | R– million (US$– million/A$– million | R– million (US$– million/A$– million) | ||
1 FY25 spend at Eva Copper reflected activities associated with project studies and site preparatory works. Comparative figures have been restated to align with the project reporting zones introduced in FY26. | ||||
Extending local economic value through contractor supply chains | ||||||
The economic benefits associated with the Eva Copper project extend beyond Harmony’s direct procurement activities. Through our contractor engagement approach, major contractors engaged for construction are encouraged to source goods and services from businesses across North West Queensland and to report on their local expenditure. This helps extend economic opportunities through contractor supply chains and provides a more complete view of the project’s regional economic contribution. In FY26, major contractors supporting Eva Copper reported: | ||||||
R32 million (US$2 million/A$3 million) spent with businesses in Mount Isa and Cloncurry | R276 million (US$16 million/A$24 million) spent with businesses located in broader North West Queensland | R71 million (US$4 million/A$6 million) spent with Kalkadoon and First Nations-owned businesses | ||||
149
CSA mine
FY26 was the first year in which Harmony reported local procurement performance for CSA mine
following its acquisition on 24 October 2025. The reporting framework introduced during the year
provides improved visibility of procurement expenditure across defined geographic zones and
strengthens our ability to monitor and report on local and regional economic participation over time.
FY261 | % of spend | |
Total procurement spend | R2.5 billion (US$146 million/A$215 million) | 100% |
Zone 1: Spent in Cobar and immediate surrounds | R549 million (US$33 million/A$48 million) | 22.3% |
Zone 2: Regional suppliers (between 50km and 300km) | R282 million (US$17 million/A$25 million) | 11.5% |
Zone 3: Spent in New South Wales | R563 million (US$33 million/A$49 million) | 22.9% |
Zone 4: Spent in Australia | R1 062 million (US$63 million/A$93 million) | 43.2% |
Zone 5: Spent on overseas suppliers | R3 million (A$0.3 million/US$0.2 million) | 0.1% |
1 CSA mine was acquired on 24 October 2025. Spend data by zone is reported for the seven-month period from 1 December 2025 to 30 June 2026 only. | ||
Future focus
•Having established a strong foundation of Mining Charter compliance, our future focus will be on moving beyond compliance towards sustainable and measurable transformation. This will include deepening supplier diversity, increasing meaningful opportunities for black-owned, women-owned and youth-owned enterprises, strengthening SMME development and graduation •Enhance supply resilience by diversifying sourcing for critical materials, enhancing real-time supply chain visibility, and improving supplier performance monitoring •Collaborate with suppliers to improve sustainability performance and strengthen responsible sourcing verification processes across the value chain •Increase procurement from local South African businesses, expand opportunities for diverse suppliers, and support small and emerging enterprises through supplier development, mentorship, and improved access to business opportunities and financing •Ongoing identification of opportunities to increase the proportion of Papua New Guinea procurement spend •Progress implementation of the Eva Copper Kalkadoon and indigenous procurement plan through ongoing engagement with the Kalkadoon People and other First Nations-owned businesses, strengthening pathways to participate in procurement and contracting opportunities •Ongoing delivery of our Eva Copper Australian industry participation plan (AIPP) and MIMA programme commitments. | |||
150
How we manage supply chain IROs
4 | Enterprise and supplier development and capability building | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Mining operations create expectations among host communities, local businesses and under-represented suppliers to participate in, and benefit from, procurement opportunities associated with the operation. These expectations may not always align with supplier capability, scale, financing capacity, technical requirements or procurement processes. Enterprise and supplier development initiatives provide an opportunity to address these barriers by strengthening supplier capability and ability to participate. | Potential impacts to people and society Supplier development can create positive social and economic impacts through business growth, improved capability, employment, business resilience and local economic diversification. These benefits are strongest where suppliers build transferable capabilities that extend beyond a single contract or mine. Negative impacts may arise where support is poorly targeted, inequitable, dependency-creating or misaligned with market needs. | Potential operational effect on Harmony Supplier development outcomes can influence both procurement performance and stakeholder perceptions of whether procurement-related commitments are being met. Successful capability building may strengthen supplier performance, procurement reliability and stakeholder confidence. Where barriers to participation remain unresolved, Harmony may experience challenges relating to community expectations, social licence, procurement objectives and supplier market resilience. | Potential financial effect on Harmony Supplier development may affect financial performance through programme costs, supplier performance, contract reliability, procurement cost stability and the resilience of local supply markets. Effective supplier development can strengthen competition, expand the pool of capable suppliers and support a more resilient supplier market. Poorly targeted investment may result in inefficient spending, contract underperformance, supplier failure or ongoing dependency. | |||||||||||
Our approach
Our approach to supplier development and capability building
seeks to strengthen the capability, resilience and long-term
sustainability of suppliers while supporting inclusive economic
participation and local economic development outcomes.
Activities are tailored to regional procurement needs, supplier
market maturity and community expectations, with a focus on
helping suppliers develop the capabilities required to participate
safely, responsibly and competitively in mining-related value
chains.
Key elements of our approach include:
•South Africa: Enterprise development programmes that
provide loans, mentorship, skills development and capacity-
building support, including initiatives that help black-owned,
women-owned and youth-owned enterprises participate in
mining and manufacturing supply chains
•Papua New Guinea: Supporting customary landowner
businesses to participate in mine-related service and
infrastructure contracts, including freight transport services,
drilling services and local road maintenance works,
complemented by statutory compliance awareness, corporate
compliance workshops, operator and safety training, joint-
venture support and selected equipment leaseback assistance
where appropriate
•Australia: Supporting local and First Nations business
participation through supplier engagement and the promotion
of procurement and subcontracting opportunities. This
currently includes initiatives associated with Eva Copper, such
as development of the Kalkadoon and Indigenous participation
framework, identification of suitable contract packages and
engagement with major contractors to create pathways into
project-related supply chains. Similar approaches may be
considered for CSA mine as our understanding of First Nations
and local business participation evolves.
Governance and oversight
Governance of supplier development and capability building
forms part of Harmony’s broader procurement, compliance and
risk management framework. In conjunction with the relevant
board committees, oversight is provided by the transformational
and supply chain executive for South African operations and the
chief operating officer for Australasian operations.
Delivery requires close collaboration between procurement,
operations, project teams and community relations functions to
identify capability gaps, promote participation opportunities and
support suppliers in meeting operational and commercial
requirements. This approach helps align supplier development
activities with business needs while responding to stakeholder
expectations for local participation and economic benefit sharing.
Progress and emerging challenges are reviewed through
management and governance forums to support accountability
and continuous improvement.
151
FY26 progress and achievements
Building supplier capability and readiness
South Africa operations
Throughout FY26, we continued investing in supplier capability
and enterprise development through a range of targeted support
initiatives, including training, gap analyses, mentorship, funding
support, and supplier readiness assessments. Training remained
the primary intervention, with 274 suppliers participating in various
capability-building programmes aimed at enhancing business
management, technical skills, compliance, and operational
effectiveness. In addition, 485 gap analyses were conducted to
identify areas for improvement and support suppliers in meeting
industry and procurement requirements.
To further support enterprise growth and business readiness,
19 suppliers received funding support, 101 suppliers participated
in business development programmes focused on business
leadership, governance and operational performance.
Collectively, these initiatives help suppliers strengthen their
competitiveness and increase their ability to participate
meaningfully in the mining value chain.
Engaging to understand supplier capability and needs
Eva Copper, Australia
As detailed under IRO3, the local and First Nations supplier
engagement activities undertaken during FY26 provided valuable
insights into regional supplier capability, capacity and market
readiness. This included a dedicated forum in May 2026, which
brought together five First Nations businesses to understand, in
detail, their services, capability, equipment availability and future
aspirations, and to map these capabilities against current and
anticipated project opportunities.
As we progress implementation of our Kalkadoon and Indigenous
Procurement Plan, our next steps will focus on:
•Expanding targeted engagement sessions with Kalkadoon and
other First Nations people across Mount Isa, Cloncurry and
Townsville
•Rolling out training and cultural awareness initiatives for
Harmony procurement teams to support implementation
of our First Nations procurement commitments
•Rolling out awareness training for our employees to strengthen
understanding of First Nations business participation
opportunities, and to share this with our major contractors
•Connecting businesses with established First Nations business
networks and industry organisations to improve access to
existing capability-building programmes, networking
opportunities and broader business development support.
Strengthening local supplier capability and
participation
Hidden Valley, Papua New Guinea
During FY26, Hidden Valley supported local and customary
landowner businesses through a combination of compliance
assistance, training, vendor onboarding and contract
opportunities.
Capacity-building activities included statutory compliance
workshops for labour hire companies, alongside facilitated
engagement with government agencies, including the Internal
Revenue Commission and Nasfund, to strengthen suppliers’
understanding of taxation, superannuation and other regulatory
requirements. We also worked with prospective suppliers to
navigate vendor onboarding processes, while local and
landowner-owned enterprises were awarded contracts for road
maintenance, bridge works, fencing, community infrastructure
and site preparation projects. These initiatives help strengthen
local business capability and expand participation in mine-related
economic opportunities in surrounding communities.
152
Performance and effectiveness
We currently assess supplier development activities through a combination of participation in enterprise and supplier development programmes, supplier engagement activities and the delivery of targeted
support interventions. These activities provide insights into supplier capability, business readiness and participation in procurement opportunities, while helping identify opportunities for further support and
development.
Across all regions, the indicators currently reported provide insights into the reach and delivery of supplier development activities. We recognise opportunities to further enhance our reporting of programme
effectiveness and supplier development outcomes.
South Africa | Papua New Guinea | Australia | ||||||||||||||||||||
During FY26 •274 suppliers (FY25: 152) participated in our ESD programme •101 suppliers (FY25: 62) were assisted with business development •19 suppliers (FY25: 21) were supported with financial assistance. A total of 1 210 supplier development interventions were delivered during the year, including training and capability- building programmes involving 725 suppliers and 485 gap analyses and supplier readiness assessments. These interventions focused on strengthening business capability, compliance, operational effectiveness and preparedness for procurement opportunities. For FY26, 46 100% black-owned vendors were allocated contracts to support various operational requirements. This demonstrates continued commitment to enterprise and supplier development, inclusive procurement and sustainable participation of black-owned businesses across the supply chain. | During FY26 •Seven suppliers were supported through compliance and capability-building activities •Two suppliers were onboarded •Three prospective suppliers were supported with procurement readiness activities •One supplier was awarded new contract opportunities for airstrip fencing and maintenance and community infrastructure works •Two suppliers delivered work under ongoing contracts for community infrastructure, and bridge and road maintenance works. | During FY26, Eva Copper •Worked to advance local and First Nations business participation through business opportunities identification and supplier engagement activities •Embedded reporting requirements with 11 major contractors and delivery partners to track local and First Nations supplier participation •Promoted local and First Nations business participation across both Harmony-managed procurement activities and contractor-led supply chains •Improved visibility of supplier participation outcomes to inform future enterprise and supplier development efforts •Established a baseline for assessing the effectiveness of local procurement and First Nations participation initiatives over time. At CSA mine, given its long operating history, our initial focus will be on developing a clearer understanding of existing local supplier participation, business capability and development needs before determining if supplier development initiatives are required and how they should be structured. | ||||||||||||||||||||
Future focus areas
•Strengthen supplier capability and business sustainability and Improve market access and alignment with procurement opportunities •Advance digitalisation and data-driven monitoring of ESD programmes •Increase participation of local, host community and designated-group suppliers and Strengthen access to funding, mentorship and technical support •Translate our understanding of local and First Nations business capability into targeted engagement, supplier development and networking initiatives that support participation in Eva Copper opportunities and long-term business sustainability •Develop a clearer understanding of local supplier participation and business capability at CSA mine as a foundation for determining future supplier development priorities and initiatives •Continue building the compliance and business capability of local and customary landowner suppliers through training, regulatory awareness and supplier development initiatives at Hidden Valley. | |||
153
Climate and energy
Key matters: Climate and energy; energy and electricity management Potential impacts on society, the environment and the economy: Our energy use and greenhouse gas emissions contribute to climate change, affecting people, ecosystems and economies. Climate change can pressure shared resources and infrastructure, while lower-emissions energy can support decarbonisation and resilience. Matters that could impact Harmony: Climate change and the lower-emissions transition can affect our operations, costs and investment decisions. Physical hazards, energy and carbon costs, regulation and market conditions can influence production, capital requirements and access to finance, while creating opportunities through renewables, changing commodity demand and portfolio positioning. | ||
Sustainability framework | Climate action and resilience: Leverage climate‑related opportunities; strengthen the resilience and adaptive capacity of our operations and supply chain; advance Harmony’s decarbonisation initiatives and use of renewable energy. | ||
Strategic risk and opportunity | Risks: The impact of climate change; Security of electricity and energy supply; Commodity price and foreign exchange volatility Climate-related matters may influence water security, regulatory and policy uncertainty, project execution and funding ability. Opportunity: Decarbonisation and resilience Renewables, efficiency and diversification can strengthen resilience, improve cost predictability and emissions performance, and support copper demand. | ||
Climate and energy are critical to the resilience, performance and future of Harmony’s
operations.
Energy is a critical input to Harmony’s operations and a significant driver of operational costs, performance and reliability. The use of
electricity and fuel across mining activities contributes to GHG emissions potentially changing climate conditions. Evolving regulations
and transitioning to a lower emissions economy continue to reshape the operating environment. Physical climate hazards may affect
infrastructure, water availability, site access and operational continuity and production. Transition-related risks and opportunities
influence energy markets, capital allocation, stakeholder expectations and regulatory obligations. We consider these factors in our
decision-making to strengthen resilience, reduce emissions and support long term value creation.
Climate and energy impacts, risks and opportunities (IROs)
Physical climate resilience and operational continuity | Energy supply and emissions in a transitioning economy | Climate-related policy, regulation and compliance | Climate-related business resilience and growth | |||||||||||||||
Physical climate hazards, including extreme rainfall, flooding, drought, water stress and heat, can affect infrastructure, production, workforce wellbeing, water availability and site access, influencing operational resilience and continuity. | Energy is a critical input to Harmony’s operations and a significant source of GHG emissions. Energy availability, affordability and decarbonisation influence operational performance, costs, emissions and long-term resilience. | Evolving climate-related regulations, and emission disclosure requirements can influence governance, capital allocation, project planning and compliance costs while shaping the transition to a lower emissions economy. | Climate change and the energy transition are reshaping markets, investment priorities and stakeholder expectations. These developments can affect business resilience, growth opportunities, project economics and long-term value creation across Harmony’s portfolio. | |||||||||||||||
1
2
3
4
Regional context
South Africa Energy security, electricity affordability and decarbonisation are key features of South Africa’s operating environment. Reliance on a predominantly coal-based electricity grid, ongoing supply constraints and rising energy costs continue to shape energy management across the mining sector. Climate and energy management is further shaped by the carbon tax, evolving climate- related disclosure expectations and increasing deployment of renewable energy. Water stress, drought and extreme weather may also affect operating conditions in several regions. | Papua New Guinea Geography and climate play an important role in Papua New Guinea’s climate and energy operating context. Remote and mountainous terrain, high rainfall and exposure to flooding and landslide events can affect infrastructure, transportation routes and access corridors. Energy supply is supported by hydropower with backup from on- site generation from diesel. Climate and energy management occurs within a developing policy and regulatory environment. Physical climate hazards remain an important consideration for operational resilience and long-term planning. | Australia Australia’s climate and energy transition is shaped by an established regulatory framework, increasing renewable energy, investment in electrification and other low-emissions technologies. Operations are exposed to drought, heat, extreme weather and changing water availability. Energy supply arrangements differ across jurisdictions and locations, with more remote areas relying on on‑site generation, while emissions reporting obligations, carbon policy mechanisms and mandatory climate-related disclosures continue to influence the operating environment. | ||||||||
Performance snapshot
Scope 1 emissions* (tCO2e) 184 731 (FY25: 172 250) | Scope 2 emissions (tCO2e) 4 636 181 (FY25: 4 316 859) | Scope 3 emissions** (tCO2e) 1 046 690 (FY25: 993 368) | Total energy consumption (TJ) 18 412 (FY25: 17 542) | Renewable solar generation (GWh) 64 (FY25: 64) | |||||||||||||
*Scope 1 emissions exclude 15 354tCO2e biogenic emissions from land clearing in Australia and Papua New Guinea.
**Includes selected scope 3 emissions from category 1, 3 and 6 and excludes Australia.
154
Climate governance and oversight
Climate-related risks and opportunities are governed through our
broader governance framework. The board retains overall
accountability for climate-related risks and opportunities and
climate-related disclosures, supported by its standing committees
and management structures within their respective mandates. In
Australasia, directors of Harmony Gold (Australia) Pty Limited
retain accountability for oversight of key risks under Australian
legislation.
Harmony’s Climate and Energy Policy establishes the principles
and commitments guiding the management of climate-related
risks and opportunities across the group. The Climate community
of practice supports capability development, knowledge sharing
and technical consistency across regions and functions.
Additional climate-focused arrangements support mandatory
Australian climate-related financial reporting requirements,
including AASB S2 Climate-related Disclosures, in respect of our
Australian operations. The Australasia climate steering committee
oversees climate-related assessments, reporting, data
governance, disclosures and assurance activities, while
supporting alignment with group governance and reporting
requirements.
Climate-related risk management
We manage climate-related risks and opportunities through our
enterprise risk management (ERM) framework, supported by
climate-specific approaches where appropriate. Scenario analysis
and regional assessments strengthen understanding of physical
and transition climate-related risks and opportunities.
Strategic risk
“Impact of Climate Change” is recognised as one of Harmony’s
top strategic risks, reflecting the potential for physical and
transition climate-related factors to affect operations,
infrastructure, costs and long-term resilience. Key drivers include
extreme weather events, water scarcity, physical asset
vulnerability, carbon pricing and emissions regulation. The risk is
monitored through our established ERM processes, with strategic
risks and associated management responses subject to board
oversight.
Group scenario analysis
We have undertaken group-level climate scenario analysis over a
number of years, including an update in 2023. Three plausible
climate futures were used to identify and better understand
potential physical and transition climate-related risks across our
global assets. These futures draw on climate scenarios developed
by the Intergovernmental Panel on Climate Change (IPCC), which
explore how different emissions and socio-economic pathways
could influence future global warming (see figure below).
Australasia climate risk and opportunity
assessment
During FY26, we undertook a more detailed climate risk and
opportunity assessment across Australasia to support AASB S2
climate-related disclosures. Building on the earlier group work,
the scenarios were refined for the Australian reporting context
(see table), retaining the group-aligned higher-warming scenario
while exploring lower-warming and disorderly transition pathways.
Harmony Australasia developed the ERM Standard Addendum –
Climate Risk in consultation with group ERM stakeholders.
Informed by ISO 14091:2021, the methodology supplements our
ERM approach with climate-specific considerations including
scenario analysis, time horizons, exposure, sensitivity, vulnerability
and adaptive capacity. Climate-related risks were evaluated using
Harmony’s established risk matrix and escalation criteria,
maintaining alignment with the broader ERM framework.
The assessment considered 2030, 2050 and 2100 climate
horizons, providing a longer-term perspective beyond our shorter
business strategy and planning cycles.
Climate and energy IROs
The climate and energy IROs presented in this report consolidate
significant climate-related themes relevant across Harmony’s
business and value chain. They are informed by strategic risk
management, climate scenario analysis, regional assessments
and broader sustainability processes, recognising that
assessment scope and maturity currently differ across the group.
The IROs should therefore not be interpreted as the output of a
single, uniform group-wide climate risk and opportunity
assessment.
Financial quantification of climate-related risks and opportunities
continues to develop. Further maturity will require expanded
group-wide assessment and stronger links to operational,
financial and life-of-mine information. Potential financial effects
include operating costs, production continuity, capital
expenditure, compliance and insurance, financing, supplier costs,
revenue and asset values.
155
How we manage climate and energy IROs
1 | Physical climate resilience and operational continuity | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Increasing rainfall intensity, flooding, drought and water stress, higher temperatures, heatwaves and other extreme weather shape our exposure. These hazards can vary significantly across our operating regions and are predicted to intensify over time, particularly under higher warming scenarios, influencing infrastructure resilience, water availability and operational continuity. Under lower warming scenarios, physical climate impacts generally increase more gradually but may still affect operations over the medium to long term. | Potential impact on society and the economy Physical climate hazards can affect the communities around our operations, placing pressure on shared water resources, local infrastructure, access routes and livelihoods. severe events may disrupt local economies and strain community relationships. Effective adaptation and resilient site management help protect our workers’ and host communities’ health and safety. | Potential operational effect on Harmony Extreme weather and changing climate conditions may disrupt production, damage infrastructure and affect tailings storage facilities, water and stormwater systems and site access. These disruptions can reduce workforce availability and productivity and limit Harmony’s ability to consistently deliver operational plans and strategic objectives. Adaptation and resilient infrastructure can reduce disruption and strengthen operational resilience. | Potential financial effect on Harmony Physical climate impacts may result in production losses, higher capital and maintenance costs, increased insurance costs or reduced coverage, and remediation expenditure, affecting Harmony’s financial performance and long-term value creation. | |||||||||||
Our approach
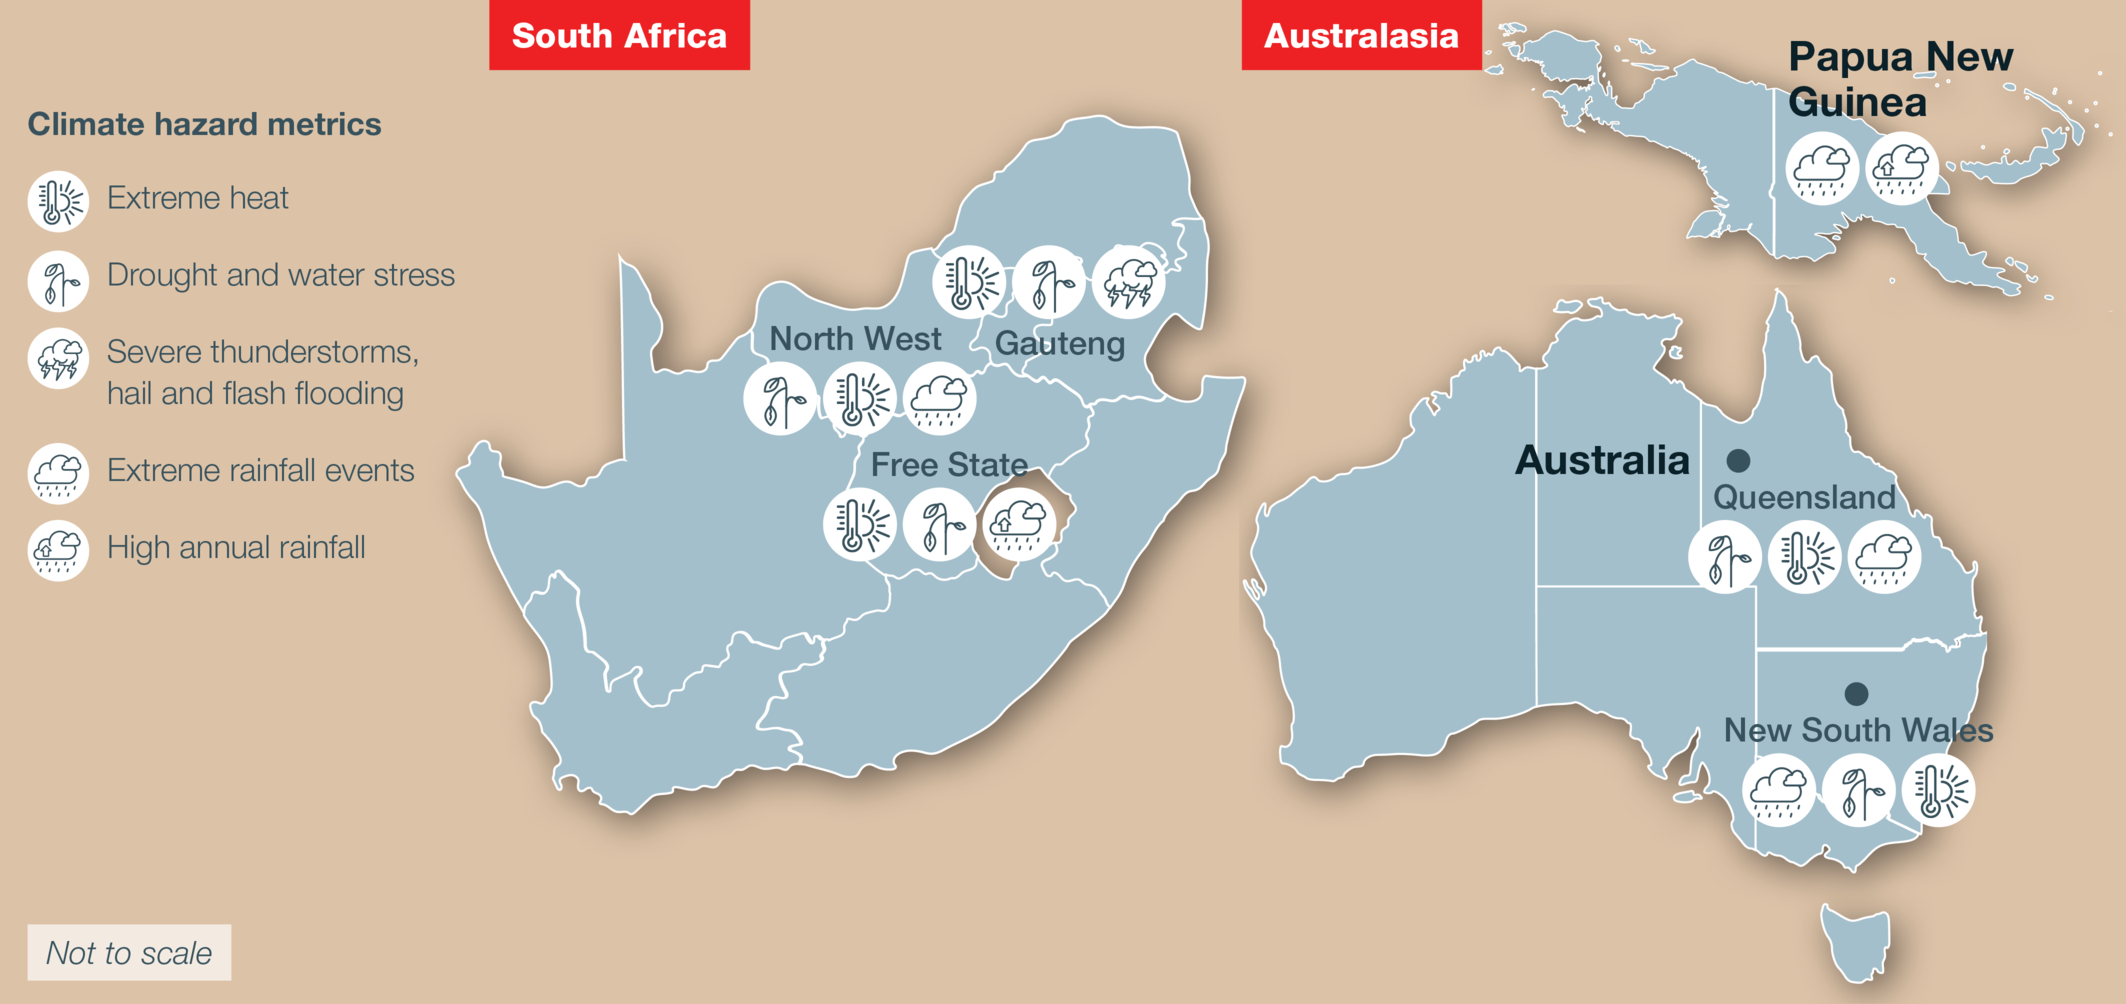
Physical climate hazards can affect operations differently across
Harmony’s regions, depending on local climate conditions, asset
characteristics, operational requirements and adaptive capacity.
Our approach to physical climate resilience focuses on
understanding these vulnerabilities and integrating climate
considerations into planning, infrastructure design, operational
controls and long-term decision-making.
Climate scenario analysis, resilience assessments and established
ERM framework are used to identify key physical climate hazards,
assess potential impacts and support adaptation planning. This
helps inform measures to protect people, maintain operational
continuity and strengthen the resilience of assets and host
communities under a range of future climate conditions. Particular
focus is placed on water availability, extreme rainfall, flooding and
heat related impacts, reflecting their potential influence on
operational continuity, performance and long-term resilience.
The table on the following page outlines key physical climate
hazards identified across our operations and examples of resilience
measures currently in place or under development. These inputs
are used to support resilience assessments and adaptation
planning across the portfolio.
156
Region | Key physical climate hazards | Potential climate-related effects | Current and planned resilience measures | |||||||||||
Gauteng, South Africa | •Extreme heat •Drought and water stress •Severe thunderstorms, hail and flash flooding. | •Increased cooling and ventilation demand at underground operations •Reduced water availability and increased water costs •Disruption to infrastructure, electricity supply and access routes during severe weather events. | •Water stewardship and recycling initiatives •Energy efficiency programmes and ventilation optimisation •Stormwater management and emergency response planning. | |||||||||||
Free State, South Africa | •Extreme heat •Drought and water stress •Extreme rainfall events (and flooding). | •Increased cooling requirements and workforce heat exposure •Water supply constraints for mining and processing activities •Localised flooding, infrastructure disruption and impacts to surface facilities. | •Site water balance management •Water reuse and efficiency initiatives •Flood management controls and operational response procedures. | |||||||||||
North West, South Africa | •Drought and water stress •Extreme heat •Extreme rainfall events. | •Reduced water availability and water quality •Increased cooling demand and productivity impacts during extreme heat •Disruption to operations and supporting infrastructure during intense rainfall events. | •Water security planning and monitoring •Operational controls for extreme weather events •Ongoing assessment of climate-related operational impacts. | |||||||||||
Hidden Valley mine, Morobe Province, Papua New Guinea | •High annual rainfall •Extreme rainfall events. | •Reduced TSF freeboard or storage capacity during extreme rainfall events •Potential disruption to processing and production •Disruption to site access and movement of people and materials •Localised flooding, landslips and slope instability. | •TSF capacity planning and approved construction activities •Emergency spillways and operational trigger action response plans •Real-time slope monitoring and operational response procedures •Surface-water management and geotechnical review following significant rainfall events. | |||||||||||
CSA mine, New South Wales, Australia | •Drought and water stress •Extreme heat •Extreme rainfall events. | •Reduced water availability for underground cooling and processing •Increased cooling requirements and workforce heat exposure •Potential productivity effects during extreme heat •Potential disruption to processing, TSF operations and site access during extreme rainfall. | •TSF design and operational controls •On-site water metering and recycling •Water-access planning •Site-wide water balance assessment. | |||||||||||
Eva Copper Project, Queensland, Australia | •Extreme rainfall events •Drought and water stress •Extreme heat. | •Water-supply constraints during drought conditions •Workforce heat exposure during construction and future operations •Potential disruption to site access during extreme rainfall and seasonal flooding •Implications for water management and project design under more extreme rainfall conditions. | •Water supply and climate-informed project design •Workforce heat management arrangements •Inventory planning for short-duration access disruptions. | |||||||||||
Climate hazard exposure drives management and response
Physical climate hazard exposure varies across Harmony’s operations depending on local climate
conditions, operating context and asset characteristics. As a result, the most significant physical
climate risks, vulnerabilities and resilience priorities differ between regions. The sections below outline
the principal areas of physical climate exposure across South Africa, Papua New Guinea and
Australia, together with the measures used to strengthen resilience and support operational
continuity.
South Africa – Water security and operational continuity
Physical resilience is supported through water stewardship, conservation, recycling and treatment
initiatives alongside established tailings, stormwater and infrastructure controls. Water security is
embedded in long-term planning and investment decisions, recognising its importance to both
mining operations and host communities.
Papua New Guinea – Managing high rainfall and access
At Hidden Valley, resilience is supported through established tailings storage facility controls,
including trigger action response plans, emergency spillways and approved additional structures.
Regular geotechnical and slope monitoring across our landforms assesses rainfall impacts, while
critical inventories are stockpiled and on-site power generation helps reduce reliance on external
infrastructure.
Australia – Water balance, heat and flood-resilient access
At CSA mine, resilience is supported through water management plans, expanded metering, water
sharing arrangements and flood-resilient access planning. Underground operations are supported by
established cooling and ventilation systems. At the Eva Copper Project, future climate hazards have
been considered in project design, including tailings infrastructure, water management and workforce
heat exposure controls.
157
FY26 Progress and Achievements
Completed physical climate resilience assessment
Australia and Papua New Guinea
During FY26, we expanded our understanding of physical climate
resilience through climate scenario analysis and resilience
assessments undertaken across operations in Australia and
Papua New Guinea. The assessments identified key physical
climate hazards, existing resilience measures and opportunities to
further strengthen resilience over time.
Integrating climate considerations into planning and
design
Australia and Papua New Guinea
Climate-related considerations are progressively being integrated
into planning and decision-making processes across the portfolio.
During FY26, forward-looking climate projections were used to
inform future tailings design at Hidden Valley mine, water balance
planning at CSA mine and Eva Copper Project design.
Business continuity planning
Group
During FY26, we continued to strengthen business continuity
planning across the group. This work enhances preparedness for
possible disruptions associated with extreme weather, access
constraints, infrastructure impacts and other operational
interruptions, thereby enhancing organisational resilience.
Understanding water-related physical climate
exposure
Group
During FY26, we continued to assess water-related physical
climate risks across the portfolio, recognising that water
availability, drought and competing water demand are key
resilience considerations across its operating regions. Conversely,
high and extreme rainfall can increase exposure to flooding,
infrastructure disruption and access constraints, particularly in
Papua New Guinea. These assessments support understanding
of climate exposure and inform water stewardship, resilience
planning and longer-term operational decision-making.
Metrics for performance and effectiveness
Assessment outcomes and resilience insights
Australia and Papua New Guinea
During FY26, physical climate resilience assessments in Australasia
provided further insight into climate hazard exposure, vulnerability
and adaptive capacity. As summarised below, the assessments
highlighted differences in resilience across assets and regions,
reflecting variations in operating context, climate exposure,
adaptive capacity and existing controls.
Asset | Resilience | Key resilience strengths | ||||||||
Hidden Valley mine, Papua New Guinea | Moderate to High | •Established TSF controls and trigger action response plans •Geotech monitoring •Inventory management •Onsite power generation. | ||||||||
CSA mine, Australia | Moderate | •Water management and recycling •Cooling systems and ventilation systems •Flood-resilient site access. | ||||||||
Eva Copper Project, Australia | Moderate | •Climate-informed design •Water modelling and planning •Opportunity to incorporate resilience measures in planning. | ||||||||
Water stress is one indicator of physical climate exposure and
should be considered alongside site-specific water balances,
storage capacity, water licences, water reuse and recycling,
operational controls, and projected rainfall and drought
conditions.
Future focus
•Expand climate resilience assessments in South Africa to identify key risks and adaptation priorities •Increase the use of forward-looking climate projections in planning, design and resilience measures •Progress adaptation and resilience initiatives for priority climate exposures •Develop climate resilience metrics covering vulnerability and adaptive capacity. | |||
158
How we manage climate and energy IROs
2 | Energy supply and emissions in a transitioning economy | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Harmony relies on reliable and affordable energy for mining, processing and project development. Energy costs, emissions obligations, technology and climate policy influence operating costs and investment decisions. Transition pressures are generally greater under lower warming scenarios, while higher warming scenarios increase physical risks to energy systems, infrastructure and operational reliability. | Potential impact on society and the economy The consumption of electricity and fuel contributes to GHG emissions, which drive climate change and its impacts on communities, ecosystems and economies. Improving energy efficiency, renewable energy uptake and reducing emissions support decarbonisation efforts and contribute to a more resilient transition to a lower carbon economy. | Potential operational effect on Harmony Harmony’s operations depend on reliable and affordable energy supplies. Electricity supply disruptions, rising energy costs, market volatility and evolving technologies may affect operational continuity, production costs, emissions performance and long-term business resilience. | Potential financial effect on Harmony Changes in energy prices, emissions obligations, carbon-related costs and future energy infrastructure requirements may affect operating costs, capital allocation and long- term project economics. Investments in energy efficiency, renewable energy and emissions reduction initiatives may also create opportunities to lower costs and strengthen long-term resilience. | |||||||||||
Our approach
Energy is a critical input to our operations and a significant source of GHG emissions. We focus on reliable and affordable energy, energy
efficiency, managing emissions and transitioning to lower-emissions energy sources. Energy-related risks and opportunities are
assessed through scenario analysis, emissions forecasting and decarbonisation planning, informing operational planning, investment and
emissions reduction initiatives. Energy transition pathways vary across our regions, reflecting differences in energy systems,
infrastructure and regulatory settings.
South Africa South African operations rely heavily on electricity supplied through the national grid, where infrastructure constraints, electricity reliability and affordability remain important considerations. The electricity mix remains heavily dependent on coal- fired generation, contributing to a comparatively emissions-intensive operating environment and increasing exposure to energy transition risks. Energy security, affordability and emissions reduction are supported through our renewable energy programme, alongside ongoing energy efficiency initiatives and evaluation of future energy supply options. These activities aim to reduce reliance on grid electricity, improve resilience to energy market volatility and support our long-term decarbonisation objectives. | Papua New Guinea Hidden Valley benefits from access to hydropower, resulting in a comparatively lower- emissions electricity profile. However, electricity supply can be inconsistent and diesel generation remains important for maintaining operational continuity and supporting grid stability. Future energy options are influenced by local infrastructure constraints, energy market conditions and mine life considerations. We work closely with power providers to support reliable energy supply while balancing operational requirements, emissions outcomes and long-term investment decisions. Energy planning considers opportunities to improve reliability and efficiency while recognising the practical limitations of alternative energy solutions in the region. | Australia Australia’s electricity grid is progressively decarbonising, although our regional and remote operations face infrastructure constraints. CSA mine has limited access to infrastructure supporting large-scale renewable energy integration, while future energy solutions for Eva Copper depend on project development timelines, infrastructure availability and future power supply arrangements. Harmony is integrating future energy requirements into operational and project planning. At Eva Copper, renewable energy opportunities, including solar and wind, continue to be evaluated alongside initiatives such as the Caterpillar Early Learner programme. Across Australia, decarbonisation planning considers grid transition pathways, emerging technologies and regional infrastructure constraints. | ||||||||
FY26 progress and achievements
South Africa renewable energy programme
South Africa
During FY26, we progressed our renewable energy programme,
supporting the development and implementation of projects
across the portfolio. The programme supports energy security
and resilience while reducing scope 2 GHG emissions through
increased renewable electricity generation.
159
South Africa Renewable Energy Programme1 | Sungazer 1 | Sungazer 2 | Sungazer 3A | Sungazer 3B | Sungazer 4 | Wheeled wind | Short-term PPA |
Commission year | FY24 | FY27 | FY29 | FY30 | FY30 | FY29 | FY27 |
Project status | Operational | Under construction. Phased commissioning from FY27 | Under development | Under development | Under development | Under development (47MW contracted) | Contracted |
Installed/planned capacity (MW) | 30 | 100 | 75 | 33 | 100 | 260 | 255 |
Expected annual generation (GWh/a) | 70 | 230 | 177 | 76 | 230 | 820 | 565 |
Estimated annual scope 2 reduction2 (ktCO2e/a) | 76 | 248 | 191 | 82 | 248 | 886 | 610 |
1For the South Africa renewable energy programme, expected generation and estimated emissions reductions for future projects are based on planning assumptions and may change as projects progress. Sungazer capacities are
stated in MWp (DC), while wheeled wind and short term PPA capacities are stated in MWac. Sungazer 3A, 3B and 4 subject to securing permits and grid access. Short-Term PPA 255MW (FY27 to FY32), with a further 150MW
potential.
2Estimated annual scope 2 emissions reduction based on emissions factor of 1.08tCO2e/MWh.
Improving energy efficiency and operational resilience
South Africa
We continued to implement energy efficiency initiatives across our South African operations to
support reduced energy demand, improved operational efficiency and long-term decarbonisation
objectives. Engagement with power providers, contractors and energy market participants also
continued to support understanding of future energy supply arrangements, infrastructure
requirements and opportunities to improve energy reliability and resilience.
Since the inception of the energy efficiency programme in 2016, cumulative savings of R3.6 billion
have been realised, reducing emissions by approximately 2.95MtCO₂e emissions. This
demonstrates that energy efficiency initiatives can deliver both significant financial value and
measurable emissions reductions, supporting operational competitiveness and decarbonisation
objectives simultaneously.
Assessing future energy requirements across the portfolio
Group
Energy planning activities continued across operating assets and development projects to improve
understanding of future energy requirements, infrastructure constraints and potential
decarbonisation pathways. Assessments considered local energy market conditions, infrastructure
availability, mine life, operational requirements and future project demands to identify opportunities
for lower-emissions energy solutions across the group.
Advancing energy planning for future growth projects
Australia and Papua New Guinea
Energy planning continued across our Australian and Papua New Guinean sites to support reliable,
resilient and lower-emissions electricity supply.
At CSA mine, connection to the New South Wales electricity grid provides an opportunity to
benefit from the progressive decarbonisation of grid electricity. At the Eva Copper Project, we
further investigated opportunities for wind generation as part of future energy planning and the
development of lower-emissions power supply options.
At Hidden Valley, we continue to work with PNG Power to improve electricity supply arrangements
and access to hydro-generated grid electricity.
Strengthening emissions forecasting and transition planning
Group
During FY26, we continued to develop emissions forecasting and energy planning capability
across the portfolio. This work improved the understanding of the relationship between operational
growth, future energy demand and GHG emissions and supports longer-term transition planning,
climate-related disclosures and the review of the group’s emissions reduction pathway.
Metrics for performance and effectiveness
Energy use and GHG emissions are key indicators used to monitor and assess our exposure
to energy-related risks and opportunities and assess progress towards decarbonisation objectives.
During FY26, emissions and energy use from our Australian operations were incorporated into the
group inventory following the acquisition of CSA mine and from the Eva Copper Project (Australia
scope 1 and 2 FY26: 0.07MtCO2e excluding biogenic emissions from land clearing).
In South Africa, scope 2 emissions increased by 6.5% (FY26: 4.53MtCO2e compared with
FY25: 4.26MtCO2e), driven by a higher Eskom emission factor and a 105GWh increase in
electricity use. In Papua New Guinea, scope 1 and 2 emissions decreased by 7% (approximately
0.02MtCO2e), supported by a 4.4% reduction in power consumption, despite an 8.8% increase in
diesel self-generation.
We are also progressing scope 3 inventories across both our South African and Australasian
regions. This work will improve understanding of value chain emissions and support future
emissions management and disclosure.
We continue to strengthen our understanding of future energy demand, emissions pathways
and decarbonisation opportunities through emissions forecasting, energy planning and climate-
related assessments. These activities support long-term decision-making, emissions management
and progress towards climate-related ambitions.
160
GHG emissions by scope (MtCO2e) | FY26 | FY25 | FY24 | FY23 | FY22 | |
Scope 11 | 0.18 | 0.17 | 0.18 | 0.20 | 0.18 | |
South Africa | 0.05 | 0.05 | 0.05 | 0.05 | 0.05 | |
Papua New Guinea2 | 0.12 | 0.12 | 0.13 | 0.15 | 0.13 | |
Australia3 | 0.01 | 0.00 | 0.00 | 0.00 | 0.00 | |
Scope 2 (location-based) | 4.64 | 4.32 | 4.09 | 4.25 | 4.57 | |
South Africa | 4.53 | 4.26 | 4.03 | 4.21 | 4.53 | |
Papua New Guinea2 | 0.04 | 0.06 | 0.05 | 0.04 | 0.04 | |
Australia3 | 0.06 | 0.00 | 0.00 | 0.00 | 0.00 | |
Scope 3 (category 1, 3 and 6)4 | 1.05 | 0.99 | 0.99 | 1.00 | 1.07 | |
South Africa | 1.00 | 0.95 | 0.95 | 0.96 | 1.03 | |
Papua New Guinea | 0.05 | 0.05 | 0.04 | 0.04 | 0.03 |
1Scope 1 emissions exclude 15 354tCO2e biogenic emissions from land clearing for FY26 in Papua New
Guinea and Australia.
2In FY26, Papua New Guinea includes emissions from Hidden Valley mine and exploration activities. Prior
years include Hidden Valley mine only.
3Australia scope 1 and 2 emissions included from FY26 as previous years were below key levels (~1%).
4Selected scope 3 categories (partial inventories) included, based on available data and excludes Australia.
Group energy consumption (GWh) | FY26 | FY25 | FY24 | FY23 | FY22 | |
Electricity (incl. South Africa solar) | 4 437 | 4 250 | 4 176 | 4 111 | 4 254 | |
Diesel | 621 | 562 | 601 | 686 | 605 | |
Other sources (petrol, LPG and heating oil)* | 57 | 62 | 63 | 64 | 66 | |
Total | 5 114 | 4 874 | 4 840 | 4 861 | 4 925 |
*Other sources includes LPG from FY26.
Group electricity consumption – grid and self-generated (stationary sources) (GWh) | FY26 | FY25 | FY24 | FY23 | FY22 | |
South Africa | 4 198 | 4 093 | 4 035 | 4 053 | 4 191 | |
South Africa (self-generation)1 | 64 | 64 | 65 | 3 | – | |
Papua New Guinea | 78 | 93 | 76 | 55 | 63 | |
Papua New Guinea (self-generation)1 | 55 | 46 | 53 | 83 | 58 | |
Australia | 97 | – | – | – | – | |
Australia (self-generation)1 | 4 | – | – | – | – | |
Total | 4 496 | 4 296 | 4 229 | 4 194 | 4 312 |
1Self-generation includes renewable energy-generated electricity in South Africa and diesel-generated
stationary emissions in Australia and Papua New Guinea.
The South Africa renewable energy programme provided relatively consistent renewable
generation in its third year providing approximately 1.5% of the total electricity consumption.
South Africa renewable energy programme metrics | FY26 | FY25 | FY24 | FY23 | FY22 | |
Actual renewable generation (GWh) | 64 | 64 | 65 | 3 | – | |
Estimated scope 2 reductions (MtCO₂e) | 0.069 | 0.066 | 0.065 | 0.006 | – | |
Renewable share of South African electricity consumption (%) | 1.50 | 1.54 | 1.59 | 0.07 | 0.00 | |
Financial benefit/savings (R million) | 34.7 | 30.0 | 23.3 | 0.6 | 0.0 |
161
Emissions reduction ambition and pathway
Harmony’s science-based emissions reduction target was established in FY23 against an FY21
baseline, reflecting the operational footprint and emissions profile at the time. Since then, our portfolio
has evolved through the acquisition of CSA mine, advancement of the Eva Copper Project and
development activity in all regions.
In FY26, we strengthened our understanding of scope 1, scope 2 and scope 3 emissions and future
energy requirements, including refinements to inventory boundaries, forecasting and reporting
methodologies. This included applying operational control principles to projects and development
assets such as Wafi-Golpu, affecting both reported and forecast emissions.
Harmony’s net zero 2045 ambition was established in line with prevailing expectations and focused
on scope 1 and scope 2 GHG emissions. At the time, scope 3 target setting was not required under
SBTi criteria where scope 3 emissions represented less than 40% of total emissions. Our
understanding of the group’s scope 3 and value chain emissions has since continued to mature.
We remain committed to our 2045 net zero ambition. We currently have a Science Based Target
approved by the SBTi covering scope 1 and scope 2 emissions, together with an ambition to achieve
net zero by 2045. In line with the evolving SBTi net zero standard, Harmony recognises that scope 3
emissions may represent a significant portion of our total emissions footprint and may need to be
incorporated into future target setting. As part of our net zero action plan, Harmony is progressing a
comprehensive scope 3 emissions assessment across global operations, strengthening scope 1 and
2 inventory completeness, including Australasian operations. Harmony intends to update and
resubmit targets to the SBTi once the evidence base and governance processes are complete.
Accordingly, we are reviewing our net zero pathway to reflect the group’s evolving operational
footprint, emissions profile and growth objectives. This includes the existing FY36 SBTi target and
supporting trajectories. Interim targets will be also reviewed and milestones aligned with the revised
pathway.
During FY27, we will strengthen emissions data and forecasts, assess decarbonisation pathways and
advance transition planning to support future target setting. We are also engaging with the SBTi
regarding our existing scope 1 and scope 2 target, with revised targets and pathways to be
developed following the review.
Future focus
•Review our SBTi targets and transition pathway •Further develop scope 3 inventories to support disclosure, target setting and transition planning •Strengthen emissions forecasting and data quality across scopes 1, 2 and 3 •Advance decarbonisation pathways across operations and projects, including future energy and emissions reduction opportunities •Expand renewable and low-emission energy solutions, reflecting regional requirements and constraints. | |||
162
How we manage climate and energy IROs
3 | Climate-related policy, regulation and compliance | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Climate-related regulations, disclosure requirements and emissions management obligations continue to evolve across Harmony’s operating jurisdictions. Requirements relating to GHG emissions reporting, climate-related financial disclosures, carbon pricing mechanisms, environmental approvals and assurance are increasing in complexity and stakeholder scrutiny. These developments may influence governance processes, reporting obligations, project planning, investment decisions and compliance activities. Regulatory and policy change is generally more significant under lower warming scenarios, which assume faster decarbonisation and more ambitious climate policies. | Potential impact on society and the economy Climate-related regulation and disclosure requirements are intended to improve transparency, accountability and decision- usefulness for investors, regulators and other stakeholders. Consistent and reliable climate- related reporting supports understanding of how organisations contribute to and are affected by climate change, helping inform capital allocation, risk management and broader transition planning across the economy. | Potential operational effect on Harmony Evolving climate-related obligations may require enhancements to governance arrangements, emissions inventories, reporting systems, internal controls, assurance processes and climate-related risk management activities. Changes in regulatory requirements may also influence project development, approvals, business planning and the management of climate-related risks and opportunities across the portfolio. | Potential financial effect on Harmony Compliance with climate-related regulations and disclosure requirements may increase costs associated with reporting, assurance, emissions management, systems development and specialist capability. Changes to carbon pricing mechanisms, emissions obligations or regulatory requirements may also influence operating costs, project economics, capital allocation decisions and future investment priorities. | |||||||||||
Our approach
Climate-related regulations, disclosure requirements and emissions obligations continue to evolve
across Harmony’s operating jurisdictions. Our approach focuses on understanding and responding
to these developments through effective governance, regulatory monitoring, climate-related
reporting, emissions management and compliance processes.
Requirements differ significantly between regions, reflecting local regulatory frameworks, policy
priorities and market expectations. As a result, compliance priorities and approaches are tailored to
regional operating conditions while supporting our broader climate-related governance and reporting
objectives.
South Africa
South Africa’s climate-related regulatory environment continues to evolve, including developments
relating to Climate Change Act, 2024, the Carbon Tax Act, 2019 and its phased implementation, JSE
guidance on GHG reporting, air emissions management and emerging climate-related disclosure
requirements. As the group’s largest operating region, South Africa’s regulatory landscape plays an
important role in shaping our overall climate-related obligations.
We monitor developments in climate-related legislation and policy while maintaining emissions
reporting, carbon tax compliance and climate-related governance processes. Activities undertaken
through the Renewable Energy Programme and broader emissions management initiatives also
support our response to evolving regulatory requirements and emissions reduction expectations.
Papua New Guinea
Climate-related regulation in Papua New Guinea is less mature than in some other jurisdictions, but
environmental permitting requirements, stakeholder expectations and evolving sustainability
disclosure practices continue to influence operations and project development activities.
We maintain environmental and climate-related compliance processes and monitors regulatory
developments affecting operations, projects and reporting obligations.
Climate considerations are incorporated into planning and risk management where relevant.
Australia
Australia has experienced significant growth in climate-related regulation and disclosure requirements
in recent years, including introduction of mandatory climate-related disclosures, Safeguard
Mechanism reforms and increasing expectations around climate-related governance, assurance
and emissions reporting.
Harmony Australasia has expanded climate-related governance, emissions management and
reporting capabilities to support compliance with emerging regulatory requirements. Activities include
climate-related risk assessment, emissions inventory development, climate-related disclosure
processes, assurance readiness and strengthening of internal governance and reporting controls.
163
FY26 Progress and Achievement
Climate Change Act 2024, Carbon Tax Act, 2019 and emissions compliance
South Africa
We continued to monitor developments in climate-related policy, emissions obligations and
disclosure requirements. During FY26, We progressed climate-related governance and preparedness
activities, including board and management awareness initiatives, monitoring of carbon
budget developments and assessment of emerging regulatory developments. This work supports
future planning and helps governance, reporting and compliance processes to remain aligned with
the evolving regulatory landscape.
We continued to meet our climate-related reporting and compliance obligations, including GHG
emissions reporting and carbon tax requirements. Activities undertaken during FY26 also improved
the group’s understanding of future emissions pathways and the potential implications of regulatory
developments for operations and transition planning.
Building capability for climate-related disclosures
Papua New Guinea and Australia
The introduction of Australian climate-related financial reporting requirements significantly increased
climate-related reporting requirements during FY26. We strengthened scope 1 and scope 2
emissions inventories, emissions forecasting, scope 3 assessment processes, supporting
documentation and internal controls across the Australasian region, while preparing for future
assurance requirements. FY26 also marked our first year of reporting under Australia’s National
Greenhouse and Energy Reporting (NGER) framework, further developing our emissions reporting
processes.
Strengthening climate-related governance and risk management
Papua New Guinea and Australia
FY26 activities included development of the ERM Standard Addendum – Climate Risk, climate-
related risk and opportunity assessments, climate scenario analysis and resilience assessments.
Climate governance was also strengthened through the Australasia Climate Steering Committee,
closer integration with ERM processes and greater cross-operational and functional involvement in
climate-related matters. Together, these activities enhanced oversight and supported more
consistent consideration of climate-related risks and opportunities in governance, risk management
and business planning.
Metrics for performance and effectiveness
Our approach to climate-related policy, regulation and compliance is intended to support regulatory
readiness, transparent reporting and informed decision-making in a rapidly evolving regulatory
environment. During FY26, significant effort was directed towards strengthening climate-related
governance, GHG inventories, climate-related risk assessment processes, forecasting methodologies
and disclosure capability in response to emerging reporting and assurance requirements.
Future focus
•Deliver our first AASB S2 Climate-related Disclosures, in respect of our Australian operations •Review emissions reduction targets and transition pathways in consultation with SBTi •Further develop scope 3 emissions inventories and reporting capability •Enhance assurance readiness, reporting controls and supporting evidence trails •Maintain readiness for evolving regulatory and disclosure requirements across South Africa, Papua New Guinea and Australia. | |||
164
How we manage climate and energy IROs
4 | Climate-related business resilience and growth | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Climate change and the transition to a lower- emissions economy are influencing commodity demand, financing, insurance and stakeholder expectations, creating both risks and opportunities for Harmony. Lower warming scenarios may increase demand for transition- related commodities, while higher warming scenarios may increase physical impacts, market disruption and economic uncertainty, affecting business resilience and project economics. | Potential impact on society and the economy The energy transition is driving investment in infrastructure, technologies and commodities supporting decarbonisation, economic development and energy security. Increased demand for transition-related commodities, including copper, may support the deployment of lower-carbon technologies, while changing investment, supply chains and markets may influence economic activity, employment and social outcomes in the regions where Harmony operates. | Potential operational effect on Harmony Changes in commodity demand, stakeholder expectations and market conditions may influence project development, business planning, portfolio optimisation and long-term growth decisions. Climate-related considerations may also affect insurance availability, access to capital, financing conditions and the assessment of future investment opportunities across the portfolio. | Potential financial effect on Harmony Climate-related market developments may influence commodity prices, project economics, insurance premiums, financing costs, access to capital and long-term asset valuations. Increasing demand for transition- related commodities, renewable energy development and operational efficiencies may create opportunities to strengthen financial performance and long-term value. | |||||||||||
Our approach
We consider how climate change and the energy transition may influence our strategy, portfolio and
long-term business resilience. Business planning, project evaluation and investment decision-making
incorporate climate-related market and economic factors, including commodity demand, energy
requirements, regulatory developments and financing conditions.
Commodity demand and portfolio positioning
The global energy transition is expected to influence demand for commodities supporting
electrification and decarbonisation. During FY26, the acquisition of CSA mine, together with the
continued progression of the Eva Copper Project, expanded our copper production base and growth
pipeline, increasing our participation in energy transition markets.
Gold remained central to Harmony’s portfolio, with continued investment in South African operations
supporting production, cash generation and financial resilience. Together, these investments support
a diversified portfolio positioned for evolving commodity markets.
Financing, insurance and stakeholder expectations
Climate change and the energy transition continue to influence financing, insurance and stakeholder
expectations. Strong governance and transparent climate disclosures support stakeholder
confidence and Harmony’s response to evolving expectations.
We have secured sustainability-linked facilities comprising a US$500 million revolving credit facility, a
R4 billion revolving credit facility, a A$250 million revolving credit facility and a A$250 million term
loan. Aligned with the Loan Market Association Sustainability-Linked Loan Principles, the facilities link
financing outcomes to three sustainability KPIs: renewable electricity capacity, potable water
consumption and socio-economic development beyond compliance.
We have also secured a R3 billion green use of proceeds term loan to fund eligible renewable energy
projects and infrastructure, including solar, battery energy storage and infrastructure supporting
embedded and wheeled power purchase agreements.
165
FY26 Progress and Achievements
Supporting portfolio growth and resilience
Australia and South Africa
During FY26, we completed the acquisition of CSA mine and
continued progressing the Eva Copper Project, expanding our
operating and future growth position in copper. In South Africa,
continued investment, including the Mponeng life-extension
project, supports ongoing production and longer-term value
creation.
Improving understanding of climate-related risks and
opportunities
Papua New Guinea and Australia
Climate scenario analysis and climate-related risk and opportunity
assessments undertaken during FY26 considered potential
market, regulatory, technology and financial impacts across
multiple time horizons. This work informed understanding of
factors that may affect business performance, investment
decisions and future growth.
Building value chain resilience
Group
Work to strengthen emissions inventories, improve understanding
of scope 3 emissions and engage suppliers supported greater
understanding of value chain dependencies and potential
transition-related risks and opportunities.
Future focus
•Progress development of Eva Copper Project •Strengthen consideration of climate-related risks and opportunities in strategic planning and capital allocation •Continue strengthening value chain resilience and supplier engagement •Monitor evolving financing, insurance and stakeholder expectations related to the energy transition. | |||
Performance and Effectiveness
We monitor indicators relevant to climate-related business resilience and growth, including portfolio composition, commodity exposure,
project progression, capital allocation and market conditions. Together, these provide insight into how our portfolio is positioned as
commodity markets and the energy transition evolve.
METRIC | FY26 INSIGHT | |||||
Climate-aligned finance and financing arrangements | Sustainability-linked facilities and climate-related financing mechanisms continue to provide insight into the relationship between climate performance, financing conditions and cost of capital. | |||||
Investor, lender and insurer engagement | Engagement with investors, lenders, insurers and brokers supports understanding of climate-related expectations, financing conditions, insurance market responses and the role of credible climate disclosure in maintaining stakeholder confidence. | |||||
Climate resilience assessment outcomes | Resilience assessments completed across Australia and Papua New Guinea provided improved understanding of resilience strengths, vulnerabilities and opportunities across operations and development projects. | |||||
Climate scenario analysis and risk assessment | Scenario analysis improved understanding of potential market, regulatory, technology and financial impacts across multiple time horizons. | |||||
Exposure to transition-enabling commodities | Acquisition of CSA mine and continued development of the Eva Copper Project increased our participation in copper across operating and growth assets. | |||||
Progression of growth projects | Progression of Eva Copper Project and the Wafi-Golpu permitting process support future growth opportunities. | |||||
Value chain resilience and scope 3 maturity | Scope 3 assessment activities improved understanding of value chain dependencies and transition-related risks and opportunities. | |||||
Renewable energy programme delivery | Progression of Sungazer solar facilities, behind-the-meter solar projects and renewable energy procurement initiatives supports energy security, decarbonisation and reduced exposure to electricity cost increases. | |||||
Energy security and decarbonisation | Advancement of South African renewable energy projects strengthens resilience to electricity supply constraints while supporting scope 2 emissions reductions. | |||||
South African gold portfolio resilience | Continued investment in and expansion of South African gold operations supported production, cash generation and financial resilience, providing capital to fund growth projects, renewable energy investments and decarbonisation initiatives. | |||||
Exposure to favourable commodity markets | Strong gold prices and increased exposure to copper strengthened Harmony’s position in commodities that may support financial resilience and benefit from long-term energy transition trends. | |||||
166
Water stewardship
Key matters: Water management; social license to operate Potential impacts on society, the environment and the economy: Water is a shared resource, and the way we source, use and manage it can affect its availability and quality for communities, ecosystems and other users. Poor water management can place additional pressure on water resources, particularly in areas already experiencing water stress. Matters that could impact Harmony: Our operations depend on reliable access to water and the infrastructure needed to manage it. Constraints on water supply, changing water quality or excess water can increase operating and capital costs, affect production and project development, and require additional treatment, storage or recycling measures. | ||
Sustainability framework | Water: Responsible use, management and recycling of water resources. | ||
Strategic risk and opportunity | Risk: Water security – infrastructure, management and licensing Water availability, infrastructure reliability and licensing can affect operational continuity, compliance and future growth, and are also closely linked to climate, regulatory and policy uncertainty. Opportunity: Water resilience and stewardship Investment in water recycling, treatment, storage and hydrogeological capability can strengthen operational resilience, reduce infrastructure dependency and support responsible water stewardship. | ||
Water stewardship increasingly provides a competitive advantage by reducing
operating costs, enhancing climate resilience and securing long-term access to water
in water-stressed regions.
Our mining, processing and supporting activities depend on access to a reliable, safe and affordable water supply to maintain
operational continuity, while groundwater inflows can affect access to ore bodies, mine planning and long-term water management
requirements. At the same time, mining activities can affect surface water, groundwater and receiving environments through changes
to water-quality, groundwater systems and surface water flows. Climate change can amplify these challenges by increasing flood
intensity, rainfall variability, drought stress and pressure on water management, treatment and containment infrastructure.
Water stewardship impacts, risks and opportunities (IROs)
Water security and adaptive management | Water-related environmental risks | Groundwater management in interconnected basins | |||||||||||
Maintaining a reliable and affordable water supply to support operational continuity amid changing environmental, infrastructure and regulatory contexts. | Managing mining-affected water-quality, hydrogeological and hydrological risks to surface water, groundwater and receiving environments. | Addressing groundwater inflows and basin interdependencies that influence mine flooding risk, operational resilience and long-term water management requirements. | |||||||||||
1
2
3
Regional context
South Africa Operations are located in naturally water-stressed regions. In addition, constrained public infrastructure and rising water costs can affect operational water supply. Deep-level underground mining also requires ongoing management of groundwater inflows, where hydraulically connected mine pumping and closure decisions can influence flooding risk and long-term water management requirements. | Papua New Guinea Papua New Guinea experiences a high-rainfall environment characterised by positive water balances. While water availability is generally not constrained, extreme rainfall events can affect tailings storage capacity, site access, erosion, sedimentation and water-quality management. | Australia Australian sites are exposed to water scarcity, drought, climate variability and periodic extreme rainfall. Water management focuses on securing reliable water supplies while managing flooding risks and the operational impacts of extreme weather. | ||||||||
Performance snapshot
Water recycling 78% (FY25: 73%) | Cumulative reduction in potable water consumption (from the FY22 baseline) 26% (FY25: 13%) | Reduction in potable water dependence1 58% (FY25: 50%) | Potable water dependence2 11% (FY25: 13%) | Potable water consumption from external sources (000m3) 15 776 (FY25: 18 381) | ||||||||||||||
1Potable water withdrawn from external sources as a percentage of total water used, in relation to our FY16 baseline.
2Potable water withdrawn from external sources as a percentage of total water used.
167
How we manage water stewardship IROs
1 | Water security and adaptive management | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Where operations depend on public infrastructure and water resources, water security is influenced by the performance of municipal and third-party water suppliers. Regulatory and pricing changes, including tariffs, licence conditions, water allocations and compliance requirements may affect operating costs or project approvals. Water shortages may result from infrastructure limitations, water allocation constraints and climate-related variability. | Potential impact on the environment and society Where operations draw on shared water resources, water use may increase pressure on shared systems and other users who depend on them. Reducing reliance on potable water, increasing recycling and reuse, and developing alternative water supply and treatment solutions can help preserve water availability and support more resilient water outcomes for operations and host communities. | Potential operational effect on Harmony Constraints on water availability, reliability or affordability can affect mining, processing and supporting activities, disrupting operational continuity, productivity and future growth. Maintaining water security requires ongoing operational planning and adaptation, including water sourcing, treatment, storage, recycling and alternative supply initiatives that support resilient operations. | Potential financial effect on Harmony Water insecurity can affect financial performance and prospects through both the costs of managing water-related risks and the consequences of supply constraints. This includes ongoing expenditure on water treatment, storage, pumping, recycling and infrastructure, as well as potential impacts from lost production, reduced throughput, tariff increases and project delays. Together, these factors can affect revenue continuity, operating and capital expenditure, cash flow and the long-term economics of existing operations and future projects. | |||||||||||
Our approach
Water availability can be influenced by environmental
conditions, infrastructure performance and competing
demands from users who rely on the same water resources. By
reducing our reliance on potable water from external sources,
improving recycling and reuse, and investing in water security
initiatives, we can help preserve water availability and support
more resilient water outcomes for our operations and the
communities we operate alongside.
To manage water security and support operational continuity,
we implement:
•Our water ambition roadmap, which aims to reduce
dependence on external potable resources through
improved efficiency, increasing water recycling and reuse
and implementing water treatment projects
•Reverse osmosis and water treatment optimisation,
including investigating opportunities for new treatment
infrastructure and implementing improvement actions for
existing facilities
•Additional flow meters installations to improve our water
usage data, operational decision-making and assurance
readiness
•Emergency storage, pumping and alternative source
assessments to strengthen resilience to supply interruptions
•Climate-integrated water planning and life-of-mine water
source reviews
•Local government, regulator and utility engagement to
address water supply risks collaboratively
•Operational controls including water balances, site
monitoring, licence compliance processes, performance
reviews, deviation investigation and action tracking.
Governance and oversight
Regional executives, operational and sustainability teams
oversee water management initiatives, while site management
teams are responsible for day-to-day management of water
supply, use and water-related risks. The Water Community of
Practice supports our water ambition roadmap delivery,
compliance, cross-site learning and innovation. Water-related
risks are managed through strategic and site-level risk
registers and reviewed through management, technical, audit
and risk governance processes. This governance approach
applies to all three water IROs.
FY26 progress and achievements
Supporting the long-term sustainability of municipal
wastewater treatment facilities
South Africa operations
Since 2024, Harmony has worked with municipalities in
Matjhabeng, Matlosana and Merafong to rehabilitate, operate
and progressively transition municipal wastewater treatment
facilities that had become dysfunctional and were contributing
to declining water quality in local catchments. Collectively,
these initiatives restored more than 30 million litres per day of
wastewater treatment capacity. The programme supports
improved catchment health, more resilient local water systems
and strengthened water security for both communities and
operations.
168
Assessing beneficial water reuse and treatment
opportunities
Kalgold and Moab Khotsong operations, South Africa
During FY26, feasibility studies were undertaken to assess
treatment options for mine-impacted water at Harmony’s
Moab Khotsong and Kalgold operations.
At Kalgold, the assessment evaluated the potential treatment
of mine-impacted water as part of the site’s broader water
management strategy. Water treatment could provide
additional flexibility in managing excess water accumulating in
the open pits, while also supporting the extension of available
storage capacity in the inactive D-Zone pit, which is currently
utilised for tailings deposition.
At Moab Khotsong, the feasibility assessment revisited a
previously evaluated reverse osmosis water treatment plant
opportunity that had not been considered economically viable
based on potable water offsetting alone. During FY26, the
assessment was expanded to consider broader environmental
compliance and operational requirements associated with
anticipated increases in fissure water volumes arising from
changing groundwater conditions within the basin (refer IRO3).
Water treatment could provide an alternative potable water
source while supporting the management of excess fissure
water and future compliance obligations. These studies will
continue into FY27.
Testing a digital twin for underground water
network optimisation
Phakisa mine, South Africa
During the year, we collaborated with ETA Operations to utilise
a dynamic digital twin of our underground service water
networks to optimise water consumption. Unlike conventional
static models, the digital twin integrates real-time operational
data with predictive modelling that adapts to changing mine
conditions, providing greater visibility of water demand,
system performance and network behaviour.
As part of Harmony’s ongoing focus on operational excellence
and responsible water stewardship, the digital twin supports
continuous monitoring, analysis and optimisation of the
service water network. The technology is used to identify
water losses, improve decision-making related to water use,
thermal load management and enhance infrastructure
performance. Ongoing development and refinement of the
system continue to unlock opportunities for improved
resource efficiency, operational resilience and sustainable
mining practices.
Enhancing water security planning
CSA mine, Australia
During the year, we commenced a comprehensive site-wide
water balance assessment at CSA mine to support the
development of a water management plan. The assessment
will enhance the visibility of water sources, consumption,
recycling opportunities and future supply requirements,
helping to inform operational planning and long-term water
security. In a semi-arid operating environment that depends
on regional water infrastructure, approved groundwater
access and water recycling, the work provides an important
foundation for future water resilience planning. Alongside this,
we are enhancing our real-time water monitoring capabilities
through the installation of SCADA meter readers.
169
Performance and effectiveness
Harmony has five-year (FY23 to FY27) water KPIs, which include a water recycling target of 50% by FY27 and a reduction in potable water consumption of 10% by FY27 (using FY22 as a baseline). During
FY26, Harmony achieved both of these water KPIs.
Metric | Definition/calculation | Target | FY26 | FY25 | FY24 | FY23 | FY22 | |||||
Target % | Actual % | Target % | Actual % | Target % | Actual % | Target % | Actual % | Actual % | ||||
Water recycling | Water reused or recycled as a percentage of total water used; measured through site-level water balance data and metering. | 50% by FY27 | 50 | 78 | 50 | 73 | 50 | 74 | 50 | 77 | 73 | |
Reduction in potable water consumption | Annual potable water consumption from municipal and other external sources, expressed as cumulative reduction against FY22 baseline. | 10% reduction by FY27 | 8 | 26 | 6 | 13 | 4 | 9 | 2 | 6 | N/A | |
Potable water dependence | Potable water withdrawn from external sources as a percentage of total water used. | 5.1% by FY34 | 13 | 11 | 15 | 13 | N/A | 15 | N/A | 15 | 17 | |
Reduction in potable water dependence | Potable water withdrawn from external sources as a percentage of total water used, in relation to the FY16 baseline | 80% reduction by FY34 against FY16 baseline | 51 | 58 | 44 | 50 | N/A | 43 | N/A | 40 | 32 | |
The potable water dependency roadmap was developed in FY25, therefore annual targets relating to this metric are from FY25 onwards. | ||||||||||||
We have decreased our potable water consumption from external sources. We recorded an increase in water recycled in process and a decrease in water used for primary activities. This has resulted in an
increase in the calculated recycling.
FY26 | FY25 | FY24 | FY23 | FY22 | ||
Water used for primary activities (000m³) | 32 341 | 38 930 | 34 813 | 29 350 | 33 417 | |
Water used (000m³) | 27 788 | 33 083 | 28 852 | 24 302 | 28 119 | |
Potable water from external sources (000m³) | 15 776 | 18 381 | 19 305 | 20 029 | 21 190 | |
Non-potable water from external sources (000m³) | 16 565 | 20 549 | 15 509 | 9 320 | 12 227 | |
Surface water used (000m³) | 6 228 | 9 725 | 3 830 | 2 477 | 2 756 | |
Groundwater used (000m³) | 10 338 | 10 824 | 11 679 | 6 843 | 9 470 | |
Water recycled in process (000m³) | 114 572 | 103 535 | 98 051 | 99 932 | 88 599 | |
Water consumption intensity (000m³/t treated) | 0.63 | 0.76 | 0.68 | 0.56 | 0.62 |
We also have site-specific monitoring programmes and targets that help address regulatory needs and site-specific risks, including legacy issues, latent and residual risks. These targets are supported by
appropriate management actions following a hierarchy of controls (avoid, minimise, reuse and recycle), including implementing integrated water and waste management plans and water balances. In July
2026, we concluded a new syndicated multi-tranche, multi-currency loan facilities aligned with the company’s sustainability and sustainable development targets. As part of the transaction, Harmony and the
lending group have agreed on progressive sustainability key performance indicators (KPIs), over the next three financial years (FY27, FY28, FY29). KPI 2, which is a water related target, focuses on a reduction
in potable water consumption from external sources.
Future focus
•Determine the feasibility of expanding Doornkop’s reverse osmosis water treatment plant to increase our water recycling and reuse and reduce our potable water consumption from external sources •Complete our site-wide water balance assessment at CSA mine to inform a site-specific water management plan. | |||
170
How we manage water stewardship IROs
2 | Water-related environmental risks | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Mining activities can alter hydrogeological and hydrological systems and affect surface water, groundwater and receiving environments through watercourse diversions, seepage, discharges, overtopping, process water or slurry releases, and legacy or geochemical impacts. Climate change can amplify these risks by increasing flood intensity, rainfall variability, drought stress and pressure on water management, containment and treatment infrastructure. | Potential impact on the environment and communities Mining activities can affect surface water or groundwater quality where unplanned discharges, water quality criteria exceedances, seepage from waste rock or tailings facilities, or process water incidents occur, potentially affecting downstream users and ecosystems that rely on those water resources. Treatment, remediation and rehabilitation can improve water quality and catchment condition where legacy impacts are reduced or previously impacted water resources are restored. | Potential operational effect on Harmony Mining-related water quality impacts, containment failures or environmental non- compliances can disrupt operations, require changes to mining or processing activities, and result in regulatory intervention. Managing these risks also requires ongoing monitoring, water treatment, infrastructure maintenance, environmental management programmes and operational controls, with significant management attention required to investigate incidents, implement corrective actions and prevent recurrence. | Potential financial effect on Harmony Water-related environmental risks can affect our financial performance through both the costs of prevention and the consequences of non-compliance. This includes ongoing expenditure on monitoring, treatment, containment infrastructure, maintenance and environmental management programmes, as well as potential remediation costs, infrastructure upgrades, operational constraints, incident response activities, regulatory actions and penalties. These factors can increase operating and capital expenditure, affect cash flow and, over time, influence closure liabilities, financing, insurance and reputation. | |||||||||||
Our approach
Managing mining-related water quality, hydrogeological and
hydrological risks requires robust monitoring, treatment and
containment controls, supported by climate-informed planning
and ongoing performance review. These measures help
reduce the likelihood and severity of impacts to surface water,
groundwater and receiving environments.
We implement:
•Risk-based water management, including upstream and
downstream monitoring, trigger action response plans and
deviation review processes
•Drainage controls and waste rock management responses,
informed by monitoring and geochemical risk assessments
•Treatment infrastructure upgrades and process
improvements to address identified performance gaps and
emerging risks
•TSF freeboard management, containment controls, flood
preparedness and storage capacity assessments
•Watercourse diversion and flood protection design controls,
including certified design processes to maintain
hydrological, hydraulic, sediment transport and water-quality
functions where watercourse realignment is required to
facilitate mining
•Baseline and ongoing surface and groundwater monitoring
to improve predictive capability and support regulatory
obligations
•External audits, technical assurance and action tracking to
strengthen accountability and performance oversight.
We operate in compliance with host country regulation,
including obtaining permits and licences and meeting
associated conditions. These permits and licences outline water
quantity limits for extraction and water quality and quantity limits
for discharges. As set out by our regulatory obligations and
internal standards, we aim to have zero unauthorised water
discharges from our operations.
FY26 progress and achievements
Supporting groundwater quality through ecological
controls
South Africa operations
Harmony has partnered with Agreenco to assess
phytoremediation to support soil and water remediation at the
Kareerand tailings storage facility (TSF). During FY26, the final
10 hectares of tree planting was completed, bringing the total
seepage management area to 60 hectares. The programme is
intended to assist in managing shallow seepage, enhancing
biodiversity and increasing carbon sequestration, while
contributing to improved groundwater quality over time.
Ongoing monitoring will be used to assess the effectiveness of
these rehabilitation measures. Additionally, Harmony
partnered with iWater to investigate the use of biochar
to improve tree growth. Biochar was added to the soil, with
plant growth promoting bacteria to improve seeding
development before planting, which resulted in these
seedlings being healthier and developing stronger leaves and
roots.
171
Groundwater resilience through project design
Eva Copper, Australia
Planning progressed for the project’s groundwater supply and management
framework. Groundwater investigations and predictive modelling were
undertaken to support development of the Graben borefield, assess
potential impacts associated with groundwater extraction and mine
development. Study outcomes have informed the groundwater monitoring
and management requirements incorporated into the project approval.
Converting mine-impacted water into strategic value
South Africa operations
During the year, we commissioned the 10 ML/day TauTona reverse
osmosis water treatment plant, enabling the treatment of fissure water
abstracted from the Covalent shafts and its reuse in Mponeng Operations.
By treating and reusing mine-impacted water, the plant reduces the volume
of water requiring storage and management, increasing operational flexibility
and providing additional capacity within the broader water management
system.
This in turn supports the management of water volumes during periods
of rainfall variability and helps reduce the risk of storage constraints and
associated containment challenges. The project also reduces reliance on
externally sourced potable water by providing an alternative operational
water source while supporting the beneficial use of fissure water. Together
these outcomes contribute to improved water security (IRO 1), more
effective management of water-related environmental risks (IRO 2) and
groundwater management (IRO 3).
Achieving improved water quality performance
Hidden Valley, Papua New Guinea
During FY26, monitoring confirmed improved performance following
sewage treatment system upgrade commissioned the prior year.
Optimisation of the upgraded system improved treatment stability, hydraulic
capacity and process efficiency, resulting in transition from frequent low-
level environmental permit exceedances to near full compliance across key
parameters.
Implementing the revised acid and metalliferous drainage management plan
and updated waste rock management strategy the prior year contributed to
positive water quality trends, including a reduction in dissolved manganese
levels downstream of the waste rock dumps. Water quality remained within
the criteria specified in the site’s environmental permit.
Performance and effectiveness
During FY26, authorised water discharge volumes decreased within our South African region and Papua New Guinea
operation.
Authorised water discharge to surface sources (000m3) | FY26 | FY25 | FY24 | |
South Africa | 2 933 | 3 566 | 3 273 | |
Papua New Guinea | 1 620 | 2 281 | 2 688 |
Future focus
•For South African operations: –Complete site-by-site containment vulnerability, dam capacity, flood and climate resilience assessments where identified as key –Conduct phase one of the dam capacity assessment, which consists of determining the design and current storage capacities of our storage infrastructure •Develop the Hidden Valley water quality model to strengthen predictive monitoring capabilities, reducing the risk of downstream riverine impacts and exceedances of permit conditions •Complete the Eva Copper water management plan and site-wide water balance model required under the amended environmental authority to support implementation of the project’s controlled water release framework. | |||
172
How we manage water stewardship IROs
3 | Groundwater management in interconnected basins | I | R | O | SA | |||||||||||||
Impact, risk and opportunity drivers Where operations are located within connected groundwater systems, groundwater inflows, dewatering requirements and changes in regional groundwater conditions, including those influenced by hydraulically connected mine activities, can influence pumping requirements, flooding risk and long-term water management needs. | Potential impact on the environment and society Dewatering and groundwater management support safe access to underground workings. However, dewatering can alter groundwater levels and flow patterns, potentially affecting groundwater availability for other users and groundwater dependent ecosystems. | Potential operational effect on Harmony Managing groundwater inflows requires ongoing pumping, monitoring, modelling, maintenance and long-term planning. Where groundwater levels or inflows increase, whether due to hydrogeological conditions or hydraulically connected mine activities, operations can face increased flooding risk, higher pumping requirements, constraints on mine access and production downtime. In connected basins, maintaining safe water levels may also depend on the continued operation of regional pumping systems. | Potential financial effect on Harmony Groundwater inflows require ongoing expenditure on pumping, monitoring, hydrogeological investigations, compliance activities and long-term management planning. Changes in conditions can increase energy use, flood mitigation, remediation and compensation costs and constrain production. Maintaining safe operating conditions may also require ongoing regional pumping obligations and associated financial commitments. Beneficial reuse of excess groundwater can reduce potable water demand from external sources, although additional treatment infrastructure may be required. | |||||||||||
Our approach
Groundwater systems can extend beyond mine boundaries,
requiring consideration of both site-specific and regional
hydrogeological conditions. This risk is currently most relevant
to our South African operations, where connected mining
basins are influenced not only by Harmony’s dewatering
activities, but also the pumping regimes and closure decisions
of hydraulically connected operations.
We address this through:
•Regional geohydrological and flood modelling to understand
basin connectivity, flooding scenarios and hydraulically
connected mine dependencies
•Engagement with hydraulically connected mines, regulators
and regional water management forums
•Pumping optimisation, underground water level monitoring,
and participation in regional dewatering systems (Margaret
Water Company and Covalent Water Company)
•Conservation and water management plans to assess
drawdown risk for surrounding users
•Water quality characterisation and treatment or reuse
feasibility studies where excess groundwater may support
operational or reclamation activities
•Integration of dewatering assumptions into closure and life-
of-mine planning.
For context, Covalent Water Company and Margaret Water
Company form part of the regional groundwater management
system within connected mining basins. Covalent helps
maintain groundwater levels that keep the Mponeng
operations dry, while Margaret supports groundwater
management associated with Moab Khotsong.
FY26 progress and achievements
Improving geohydrological insights for future
planning
South African operations
We completed a regional geohydrological assessment to
determine the impact of our operations on geohydrology, and
to have an updated understanding of our flood risk in the
regions that we operate. The assessment provides us with a
better understanding of the potential volumes and timing of
inflows into our underground workings. This improved
understanding allows Harmony to proactively assess flooding
risks and identify potential opportunities under various different
scenarios and hydraulically connected mine closing
sequences.
Performance and effectiveness
Performance is assessed through maintenance of target
groundwater levels, pumping system performance and
management of flooding risks within connected basins.
Effective dewatering is a prerequisite for safe underground
mining in our deep-level operations. Given the added
complexity of operating within interconnected basins,
Harmony’s dewatering activities maintained safe access to
their underground workings.
Future focus
•Ongoing engagement with hydraulically connected operations, regulators and interested institutes (DMPR and Council of Geoscience in South Africa). | |||
173
Tailings management
Key matters: TSF and waste management; safety; social licence to operate; post-closure sustainability; biodiversity, land use and environmental degradation Potential impacts on society, the environment and the economy: Matters that could impact society, the environment and the economy: Poor tailings management can affect community and employee safety, land, water, biodiversity and ecosystems, with longer-term impacts from seepage, dust, erosion and inactive facilities. Matters that could impact Harmony: Maintaining the integrity of tailings facilities requires expenditure throughout their lifecycle, from design and construction to monitoring, closure and rehabilitation. A tailings event could disrupt operations and result in substantial remediation, legal and compensation costs, regulatory action and loss of stakeholder confidence, while retreatment can create opportunities to recover value and reduce legacy liabilities. | ||
Sustainability framework | Tailings management: Prioritise the safety of tailings facilities, through all phases of a facility’s lifecycle; apply resilient design principles, redundant controls, and rigorous monitoring and governance. | ||
Strategic risk and opportunity | Risks: Not achieving operational plans at critical operations; Regulatory and policy uncertainty Tailings-related matters may influence processing continuity, environmental compliance, approvals and long-term operational performance. Opportunity: Licence security and approval certainty Proactive regulatory engagement and strong compliance capability can support approvals and strengthen long-term licence security. | ||
Our disciplined lifecycle approach to tailings management underpins safety,
environmental stewardship and long-term value.
Tailings storage facilities (TSFs) pose safety, environmental, community, regulatory and business continuity risks if not managed
throughout its lifecycle. We seek to maintain TSF integrity and manage tailings responsibly through disciplined design, operation,
monitoring, rehabilitation, closure planning and technical oversight. Additionally, reclamation and retreatment can unlock value
from historical deposits, while rehabilitation and closure activities support the long-term stewardship of our TSFs.
Tailings management impacts, risks and opportunities (IROs)
TSF integrity and responsible tailings management | |||
Our approach combines robust governance, technical oversight and risk-based management across the design, construction, operational, environmental, social and financial dimensions of our tailings facilities. Harmony supports safe and responsible tailings management through independent reviews, audits and external assurance. | |||
1
Regional context
South Africa Tailings management is shaped by a large and diverse portfolio of operational, reprocessed and inactive TSFs, including legacy facilities more than 40 years old. Management focuses on long-term stewardship, structural stability, water and seepage management, dust control, reclamation, rehabilitation and closure activities. | Papua New Guinea Tailings management is influenced by high rainfall, complex terrain, seismicity and the need to maintain sufficient storage capacity to support future mining. Management focuses on water management and treatment, seepage monitoring and future storage infrastructure. | Australia Tailings management centres on the operation of the CSA mine South TSF and the development of future facilities for CSA mine and Eva Copper. Management focuses on facility integrity, environmental performance, regulatory compliance and optimising storage capacity through underground paste fill and staged facility development. | ||||||||
Performance snapshot
Total TSFs 871 (FY25: 872) | TSFs being reprocessed/reclaimed 14 (FY25: 11) | Trees planted 30 5003 (FY25: 25 000) | Dust netting installation (km) 10 (FY25: 30) | Vegetating (ha) 5.54 (FY25: 10) | ||||||||||||||
1Acquisition of CSA mine added one TSF to Harmony’s portfolio.
2The Kareerand extension, previously reported as a separate TSF, is now reported as part of the operational Kareerand TSF, reducing the reported
number of facilities by one.
318 500 trees in Free State on dormant TSFs and 12 000 at Doornkop.
44.5 hectares of side slopes at the Doornkop TSF and 1ha on top of Freddies 9 TSF.
174
How we manage tailings IROs
1 | TSF integrity and responsible tailings management | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers TSFs must be designed, operated, monitored, closed and rehabilitated in a manner that maintains structural integrity and supports environmental and social performance throughout their lifecycle. Exposure to tailings- related impacts and risks is influenced by physical and environmental conditions, including high rainfall, flooding, erosion, changing water balances, drought, seismic activity and ground movement. It is also shaped by tailings storage and operational requirements, such as water management, freeboard maintenance and storage capacity constraints, as well as long- term stewardship obligations associated with legacy facilities, closure and post-closure activities, infrastructure security and community safety. | Potential impact on the environment and society Poor TSF management can lead to overtopping, slope failure, liquefaction, seepage, releases of slurry or mine-affected water, dust emissions and erosion. These events can affect land, surface and groundwater, biodiversity, ecosystems and air quality, and severe incidents can result in significant and long-term environmental harm. For communities, significant incidents may create health and safety risks, particularly where people downstream are affected. Unauthorised access to active, inactive or closed facilities may also create safety hazards. Reclaiming and retreating inactive TSFs can reduce the need for new extraction and enable rehabilitation of legacy TSF footprints. | Potential operational effect on Harmony TSFs require ongoing management, monitoring and governance to maintain structural integrity and environmental performance. Facility operating parameters, storage capacity, water management requirements and deposition strategies influence mining and processing activities. Where performance concerns or actions for improvement are identified, or should a tailings-related event occur, additional investigations, engineering controls, monitoring or operational restrictions may be required. These circumstances may affect tailings deposition, processing rates, life-of- mine planning and operational continuity. | Potential financial effect on Harmony Managing TSFs requires ongoing expenditure on design, construction, monitoring, instrumentation, independent review, emergency preparedness, dust and seepage controls, closure activities and capacity expansions. Financial impacts may also arise from additional investigations, engineering works, operational constraints and changes to life-of-mine plans. If a severe incident were to occur, financial impacts may include environmental remediation costs, legal and regulatory exposure, penalties, compensation obligations and adverse impacts on insurance, financing and stakeholder confidence. Reclaiming TSFs can support value recovery and contribute to reducing long-term closure and rehabilitation obligations. | |||||||||||
Our approach
Harmony manages 87 TSFs across South Africa, Papua New
Guinea and Australia. While 19 facilities are operational, the
portfolio also includes facilities being reprocessed or reclaimed,
facilities under construction and a significant number of inactive or
legacy TSFs, including facilities acquired as part of historical
acquisitions. This broad lifecycle exposure requires ongoing
management of TSF integrity, environmental performance, closure
and post-closure stewardship across the portfolio.
Our tailings management approach is informed by group risk and
sustainability frameworks, together with site-specific management
systems and regulatory requirements of the regions in which we
operate. Consequence assessments and classifications establish
the design criteria and performance requirements for TSFs. These
requirements inform design, construction, operation and closure
investigations, assessment and plans throughout the facility
lifecycle.
Number and status of TSFs | ||||||||
Region | Group | South Africa | Papua New Guinea | Australia | ||||
Existing TSFs | 87 | 84 | 2 | 1 | ||||
Operational | 17 | 15 | 1 | 1 | ||||
Being reprocessed/reclaimed | 14 | 14 | 0 | 0 | ||||
Under construction | 1 | 0 | 1 | 0 | ||||
Inactive | 55 | 55 | 0 | 0 | ||||
Under studies/proposed | 5 | 2 | 1 | 2 | ||||
In addition to the TSFs, deep-sea tailings placement has been approved as the tailings management solution for the proposed Wafi-
Golpu Project in Papua New Guinea.
175
Operating context and management profile of our regions
South Africa | Papua New Guinea | Australia | ||||||||||||||
We manage a large portfolio of operational, reprocessed and inactive TSFs, including legacy facilities more than 40 years old. Management focuses on structural stability, water and seepage management, dust control, infrastructure security, reclamation and rehabilitation, and closure-related activities. New and proposed TSFs are designed, constructed and managed in accordance with applicable regulatory requirements and the South African National Standards (SANS) 10286. Every two years, we update our code of practice on mine residue deposits to remain aligned with regulatory guidelines and other industry good practices. We submit updates to the DMPR for approval. | Tailings management in Papua New Guinea is influenced by high rainfall, complex terrain, seismicity and the need to maintain sufficient storage capacity to support future mining. Management focuses on structural stability, water management and capacity planning, seepage monitoring, and life-of-mine planning. Hidden Valley operates one TSF, with a second facility under construction and a third in planning to support future mine life. Our TSF design and construction follows the Australian National Committee of Large Dams (ANCOLD) guidelines with accepted risk-based deviations and conservative factors of safety. We adopt layered assurance elements of the Global Industry Standard on Tailings Management (GISTM). | Tailings management is guided by ANCOLD guidelines and focuses on maintaining facility integrity, environmental performance and regulatory compliance. CSA mine operates an active TSF and utilises underground paste fill as part of its tailings management approach, reducing the volume of tailings requiring surface storage. Future TSF capacity is in the planning phase and would be required to extend mine life. At Eva Copper, TSF design has been completed as part of the updated feasibility study, with construction scheduled to commence in FY27. | ||||||||||||||
How we maintain TSF integrity and performance
Our approach to TSF management is adapted to reflect facility-specific risks, lifecycle stage and local requirements. The activities below illustrate how requirements are established, controls are implemented,
performance is monitored, and findings are used to strengthen tailings management across the facility lifecycle.
 | Define and design | | Implement controls | | Monitor performance | | Evaluate and strengthen | ||||||||||
We establish the requirements, plans and controls for managing TSFs throughout their lifecycle, including: | Implement and operate TSFs in accordance with regulation and approval conditions, approved plans and other requirements, including: | Monitor TSF performance and conformance through operational, environmental and technical verification activities, including: | Evaluate performance, governance effectiveness and opportunities for improvement, including: | ||||||||||||||
•Consequence assessments and classifications •Design criteria and technical standards •Design, construction, operation and closure investigations •Stability assessments and engineering studies •Emergency preparedness and response planning •Reclamation and closure planning •Critical operational controls. | •Operation and maintenance activities •Dust control measures •Environmental monitoring programmes •Monitoring and management of critical controls •Implementation of engineering improvements and remediation activities. | •Facility inspections and surveillance •Instrument and monitoring systems •Drone and physical surveys •Freeboard, bathymetry and water level monitoring •Environmental monitoring programmes •Internal and external audits •Engineer of Record (Australasia) monitoring, inspections and reports •Quarterly consulting engineer reports. | •Board and management reporting •Engineer of Record reviews (Australasia) •Independent technical reviews •Regulatory engagement and inspections •Review of audit findings and monitoring results •Review and application of lessons learned from external tailings incidents, technical studies and industry guidance •Updates to operational procedures, controls, plans and technical standards arising from review outcomes. | ||||||||||||||
176
Community engagement and awareness
Tailings management extends beyond facility design, operation and monitoring. We engage with communities to support awareness of TSF-related risks, emergency preparedness and the safe management
of areas surrounding our facilities. Community engagement varies by region and reflect local operating conditions, community needs and facility profiles.
South Africa | Papua New Guinea | Australia | ||||||||||||||
We work with surrounding communities and local authorities to support emergency preparedness. Our community education initiatives inform people about the dangers of unauthorised access to TSFs, process water containment facilities. Security patrols actively deter unauthorised access, theft, and vandalism. We have also worked with a local supplier to teach mine rehabilitation skills to local communities through the Doornkop TSF dust mitigation project. | At Hidden Valley mine, we maintain a four-siren early warning system to alert downstream communities in the event of a TSF failure. Regular siren testing, community awareness activities and quarterly updates on TSF performance and management support emergency preparedness and provide opportunities for local villages to raise concerns and provide feedback on tailings management. | Engagement on tailings facilities is tailored to each asset’s context and potential impacts. At CSA mine, there is no population at risk of TSF failure. We engage the downstream landowner on TSF management and emergency preparedness, supported by established notification processes. At Eva Copper, consultation has focused on TSF planning, cultural heritage and post-mining land use, including engagement with Traditional Owners, local landholders and regulators to inform planning and decision-making. | ||||||||||||||
Governance and oversight
Regional executives implement group and regional standards,
supported by regional engineering and environmental teams.
Site-specific responsible tailings facility engineers, onsite
tailings operating contractor management teams, Harmony
management teams and Engineers of Record manage daily
TSF operations, review performance and provide technical
recommendations. In Australasia, independent tailings review
boards also provide expert review, opinion and guidance.
FY26 progress and achievements
Engineering improvements to strengthen TSF
performance
South Africa operations
We enhanced infrastructure at selected TSFs to support long-
term stability and lower environmental impact. These
enhancements include:
•Additional collector cut-off drainage systems at St Helena
123 TSF “inverted corner” first end second benches with
planned long-term stabilisation by infilling of affected area
with waste rock and hydraulic placement of cyclone
underflow material
•Reshaping and restoring outer slope to original profile
followed by additional collector cut-off drainage and
placement of filter sand and rock cladding in the affected
area
•Maintaining freeboard stability at TSFs, despite high rainfall.
Managing dust, seepage and environmental
impacts
South Africa operations
Dust controls form part of our broader management of
tailings-related environmental and community impacts. Over
the course of the year:
•Vegetated 4.5ha of side slopes at the Doornkop TSF
and 1ha on top of Freddies 9 TSF as part of our dust
mitigation initiatives
•Installed 10 000 metres of dust netting across dormant
TSFs in the Free State
•Planted 18 500 trees on dormant TSFs in Free State to
support dust management
•At selected TSFs, we use tree-based phytoremediation
(phytoremediation plantation) interventions to management
seepage, stabilise soil, reduce erosion, and support
ecological restoration. We expanded the phytoremediation
plantation at Kareerand TSF by an additional 10ha, planting
approximately 12 000 trees, and bringing the total
phytoremediation plantation area to 60ha. This represents
the final phase of the planned phytoremediation programme
at the Kareerand TSF to mitigate and manage groundwater
seepage.
Advancing tailings storage capacity, water recovery
and monitoring initiatives
Hidden Valley mine, Papua New Guinea
We continued work on TSF capacity to support the feasibility
of an extended life of mine. This included commencing a
further TSF1 embankment raise, progressing construction of
TSF2, and undertaking prefeasibility studies for TSF3. We also
progressed the implementation of cyclone technology,
expected to be operational in early 2027, to improve tailings
density, water recovery and storage efficiency.
In parallel, we are working to increase water recycling through
the processing plant, thereby reducing the use of CAROS
water treatment and the cyanide destruction circuit to treat the
dam’s supernatant prior to release.
We also implemented telemetry for TSF piezometers,
supporting online monitoring and trend analysis of pore
pressure data, while reducing reliance on manual data
collection. This improves visibility of facility performance and
will be expanded to additional instrumentation over time.
177
Performance and effectiveness
Noting that TSFs differ significantly in design, age, lifecycle stage and operating context,
performance is presently assessed using a range of facility-specific measures rather than a single
group-wide indicator.
TSF management effectiveness is assessed through the extent to which facilities maintain
structural integrity and environmental performance, operate within approved parameters and
support ongoing operational requirements. Performance is evaluated using a combination of
monitoring data, inspections, technical assessments, independent reviews, audit outcomes,
compliance performance and progress in implementing improvement actions.
During FY26, we recorded a 90% alignment of active TSFs to operational protocols (externally
assured).
Future focus
•Continue embankment raise of TSF1 and construction of TSF 2 at Hidden Valley mine •Progress on the feasibility study, early works and design pathway for TSF 3 at Hidden Valley mine, subject to required approvals and board consideration •Complete installation of cyclone technology at Hidden Valley mine to improve tailings density, water recovery, storage efficiency, and assist closure activities •Investigate TSF capacity expansion and tailings reuse opportunities for CSA mine •Continue assessments as part of the West Wits reclamation and Free State reclamation opportunities •Progress dust mitigation through vegetation and tree planting at selected dormant TSFs in South Africa •Undertake a gap analysis and update of the South African TSF Rehabilitation and Closure Strategy to align with evolving regulatory requirements, ICMM and GISTM principles and recognised international good practice. | |||
178
Biodiversity
Key matters: Biodiversity, land use and environmental degradation; Post-closure sustainability; Social licence to operate Potential impacts on society, the environment and the economy: Mining has a significant physical footprint, with land disturbance that can affect habitats, species, waterways and broader ecosystem function. The landscapes in which we operate can also hold social and cultural value for communities, making the way we avoid, minimise and rehabilitate disturbance important far beyond the mine site. Matters that could impact Harmony: Biodiversity and land- use considerations can influence where and how we develop and operate our mines. Sensitive areas may require changes to project design, additional management measures or rehabilitation commitments, affecting approvals, costs, closure obligations and access to land. | ||
Sustainability framework | Biodiversity, land use and closure: Champion responsible land, biodiversity and mine closure stewardship by applying the mitigation hierarchy and delivering rehabilitation outcomes that support resilient ecosystems and communities. | ||
Strategic risk and opportunity | Risk: Regulatory and policy uncertainty Evolving environmental requirements and scrutiny can affect approvals, compliance, project timelines and investment decisions. Opportunity: Licence security and approval certainty Proactive regulatory engagement and strong compliance capability can support approvals and strengthen long-term licence security. | ||
Effective biodiversity management helps maintain ecosystem condition, support
ecological resilience, and contribute to improved nature-related outcomes over time.
Protecting biodiversity values requires careful management of how mining and associated infrastructure are planned, developed and
operated. Our operations are located within diverse natural landscapes that support habitats, species, aquatic ecosystems and
culturally significant landscapes. We apply the mitigation hierarchy, prioritising the avoidance and minimisation of impacts, followed by
restoration and other management measures. This approach is intended to protect biodiversity values and maintain ecosystem
condition and resilience in and around Harmony’s operations.
Biodiversity impacts, risks and opportunities (IROs)
Biodiversity and ecosystem condition | |||
Protection of biodiversity values, maintenance of ecosystem condition and support for ecosystem recovery. | |||
1
Regional context
South Africa Harmony’s operations are located across areas of varied biodiversity value. These include the endangered Vaal-Vet sandy conservation area and western Free State clay grassland ecosystem in the Free State, as well as areas containing endangered, vulnerable ecosystems in the North West province. According to the International Union for Conservation of Nature Red List of Threatened Species, the white-backed vulture (Gyps africanus) is the only critically endangered animal recorded on Harmony’s properties. | Papua New Guinea Recognised as one of the world’s most biodiverse countries, Papua New Guinea features extensive tropical forests and high levels of species endemism. Harmony’s interests in Morobe Province are located within steep, forested landscapes that support a range of montane and lowland rainforest habitats. These areas contain conservation-significant flora and fauna, including protected and threatened species, and are influenced by high rainfall, complex terrain, altitude and diverse aquatic systems. | Australia Harmony’s Australian operations and projects occur within semi-arid woodland and shrubland ecosystems across Queensland and New South Wales. These areas support diverse native vegetation communities, waterways and fauna habitats, including habitat for protected and conservation-significant species. Biodiversity values are influenced by habitat connectivity, seasonal rainfall patterns, climatic variability and the condition of terrestrial and aquatic environments. | ||||||||
179
How we manage biodiversity IROs
1 | Biodiversity and ecosystem condition | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Biodiversity-related risks arise where mining activities interact with sensitive habitats, species, waterways and ecosystem functions. Risk exposure is influenced by site-specific environmental sensitivity, biodiversity-related approval requirements, compliance obligations and management commitments, invasive species, erosion, climate-related pressures and the effectiveness of measures implemented to protect biodiversity values and ecosystem condition. | Potential impacts on society and the environment Mining activities can contribute to habitat degradation, fragmentation, species disturbance, erosion, sedimentation and reduced ecosystem resilience. Impacts may extend beyond operational areas to affect waterways, culturally significant landscapes and ecosystem services relied upon by communities. Avoidance, restoration and rehabilitation can protect biodiversity values and improve ecosystem condition over time. | Potential operational effect on Harmony Biodiversity values and ecosystem condition may influence how and where mining activities are undertaken. Sensitive habitats, species, waterways and other ecological values may require avoidance measures, operational controls, monitoring programmes or modifications to mine plans and project designs. Biodiversity-related constraints can also influence the location, timing or extent of new developments, expansions and other land disturbance activities. Early consideration of biodiversity can improve project planning and approval outcomes. | Potential financial effect on Harmony Financial impacts may arise through environmental assessments, biodiversity offsets, monitoring, maintenance, remediation, revegetation and rehabilitation, and closure obligations. Additional costs may result from project redesign, erosion control, invasive species management, legal or regulatory requirements, stakeholder engagement and delayed approvals. Biodiversity performance may also influence closure readiness, rehabilitation liabilities and financing confidence. | |||||||||||
Our approach
Biodiversity is fundamental to healthy ecosystems and resilient
post-mining landscapes. Our approach focuses on the
management hierarchy including avoiding and minimising
impacts, protecting biodiversity values and supporting
ecosystem recovery throughout the mine lifecycle. We
manage biodiversity impacts, risks and opportunities by:
•Seeking to avoid disturbing areas of high biodiversity or
environmental sensitivity during project planning,
development, operation and closure activities
•Undertaking comprehensive baseline surveys and
assessments to identify existing biodiversity conditions and
values
•Implementing biodiversity management actions through
environmental management plans, mine closure plans or
other site-specific measures
•Applying ground and waterway disturbance control
processes, no-go and buffer controls, environmental impact
assessments and monitoring for new and existing projects
that may affect ecological systems and precleaning surveys
to minimise impact on fauna
•Using invasive species management, species protection and
fauna management measures, and environmental
monitoring programmes, including air quality, water and
noise monitoring where relevant to operational impacts
•Implementing progressive rehabilitation and revegetation,
using locally appropriate species and closure approaches
that support ecosystem recovery and post-mining land
•Managing external and climate-related stressors (such as
invasive species, erosion, flooding, illegal mining and
unauthorised land use activities) through invasive species
programmes, erosion and sediment controls, revegetation,
security patrols, mine sealing and closure activities, surface
water management measures and ongoing monitoring of
rehabilitated areas.
We track compliance with regulatory requirements,
environmental management plans and closure commitments,
and assess biodiversity-related risks through site-level
environmental management, monitoring and review
processes.
Governance and oversight
At operational level, regional executives and operational
management are accountable for implementing environmental
management plans that embed biodiversity commitments
across Harmony’s operations. At group level, the sustainability
function provide the governance, standards and monitoring
that guide and assure this implementation.
180
FY26 progress and achievements
Establishing a biodiversity baseline for the
Kerimenge deposit
Hidden Valley, Papua New Guinea
We completed an initial suite of terrestrial and aquatic ecology
baseline studies as part of the pre-feasibility studies for the
Kerimenge deposit, a satellite ore body located approximately
seven kilometres east of Hidden Valley. The work addressed a
significant biodiversity information gap in the Kuembu Creek
Valley and recorded 27 conservation-listed species, including
nine IUCN threatened plant species, vulnerable fauna such as
the Eastern Long-beaked Echidna and New Guinea
Pademelon, and several protected birds-of-paradise. The
studies also included recommendations for additional surveys
in higher- and lower-elevation habitats, which will inform the
next phase of fieldwork and studies design.
Protecting ecosystem condition through planning
and operational controls
South Africa operations
At the South African operations, comprehensive assessments
were conducted for new project areas to identify existing
biodiversity conditions and define management actions
through environmental management plans to minimise
impacts on ecosystems. In operational areas, teams
eradicated invasive plant species and established firebreaks to
reduce impacts on ecosystems. At the Free State operations,
a threatened species was observed during specialist
investigations. Subsequent to the investigation, a biodiversity
action plan was compiled which will be implemented in FY27
to mitigate the impact on the species.
Using ecological evidence to inform project
decisions
Eva Copper, Australia
Through the year, detailed ecological survey and assessment
work continued to inform approvals, project planning and the
development of management measures.
In March 2026, during early stages of ground clearing at our
solar farm, our environmental controls identified a critically
endangered northern blue-tongued skink, a species which
had not been recorded during previous ecological fieldwork.
Further environmental studies, assessments and regulatory
approvals have been advanced in response, and construction
sequencing modified.
Performance and effectiveness
We assess performance through implementation of
biodiversity controls, compliance with environmental
management plans and approval conditions, environmental
monitoring programmes, fauna management outcomes and
rehabilitation performance. Monitoring results, inspections,
incidents and corrective actions are reviewed through site
environmental management systems to understand
biodiversity risks and guide adaptive management responses
where required.
Future focus
•Review and update the biodiversity baseline assessment and compile site specific biodiversity action plans (BAPs) for the South African operations. The BAPs will include rehabilitation strategies, defining high biodiversity areas (no-go areas) and define a biodiversity roadmap to improve ecosystems •Strengthen evidence of ecological condition, rehabilitation success and closure readiness by linking approved disturbance, sensitive habitat mapping, species monitoring, erosion and water quality indicators, rehabilitation success criteria and post-mining land use objectives for the South African region •Develop biodiversity roadmaps that explicitly link growth, disturbance planning, rehabilitation, closure obligations and potential nature-related opportunities for the South African region •Establishment of a Nature and Biodiversity CoP (Community of Practice) to drive biodiversity strategies and initiatives across the group •Undertake additional terrestrial and aquatic ecology studies to inform future environmental impact assessment and feasibility studies for the Kerimenge deposit •Work with regulators to progress regulatory requirements relevant to the Eva Copper Project while embedding enhanced controls for species protection in project planning and execution. | |||
181
Land and rehabilitation management
Key matters: Social licence to operate; Biodiversity, land use and environmental degradation; Post-closure sustainability Potential impacts on society, the environment and the economy: Mining changes land, sometimes for generations beyond active operations. Disturbance can alter landforms, soils, vegetation, water flows and future land uses, while access to land can intersect with landholder rights, cultural heritage and community interests. Effective rehabilitation and closure can help create safe, stable landforms and support post-mining uses. Matters that could impact Harmony: Access to land and our ability to progressively rehabilitate and ultimately close disturbed areas are fundamental across the mine lifecycle. Land access constraints, unstable or poorly rehabilitated areas and changing closure requirements can affect project timing and approvals and increase rehabilitation, monitoring and long-term closure costs. | ||
Sustainability framework | Biodiversity, land use and closure: Champion responsible land, biodiversity and mine closure stewardship by applying the mitigation hierarchy and delivering rehabilitation outcomes that support resilient ecosystems and communities. | ||
Strategic risk and opportunity | Risk: Regulatory and policy uncertainty Evolving environmental and rehabilitation requirements can affect compliance, approvals, closure obligations, project timelines and investment decisions. Opportunity: Licence security and approval certainty Proactive regulatory engagement and strong compliance capability can support approvals and strengthen long-term licence security. | ||
The decisions we make today shape land use outcomes long after mining ends.
Throughout the mining lifecycle, our activities interact with land, water and communities, whether the land is owned by Harmony
or others. How we manage disturbance, maintain access, protect cultural heritage values and plan for closure supports positive
environmental outcomes, constructive stakeholder relationships, regulatory compliance and safe and sustainable post-mining
outcomes.
Land and rehabilitation impacts, risks and opportunities (IROs)
Land use, rehabilitation and closure | Land access and cultural heritage | Land stability and safety | |||||||||||
Responsible management of land to minimise disturbance, progressively rehabilitate disturbed areas and plan for sustainable post-mining land uses. | Maintaining access through negotiated agreements, stakeholder engagement, protection of cultural heritage values and delivery of commitments. | Geotechnical and landform stability, erosion and landslip prevention, access restrictions and management of legacy disturbed areas. | |||||||||||
1
2
3
Regional context
South Africa Many of Harmony’s South African operations are located on land owned by the company and associated with established mining rights. Through business growth and acquisitions, Harmony has also gained an interest in a range of legacy mining assets that require ongoing rehabilitation, closure planning, stakeholder engagement and management of post-mining obligations. | Papua New Guinea The country has a high proportion of customary land ownership, making land access, agreement commitments and stakeholder relationships fundamental to our operations. Our activities are predominately undertaken on land where access and use are governed by negotiated agreements with customary landowners and communities. Cultural heritage and culturally significant places identified on the land may also influence how activities are planned and undertaken. | Australia Australia has extensive legal and regulatory frameworks governing access to third-party land for exploration and mining activities. Activities may be subject to land access agreements with private landowners, or Native Title Act requirements and agreements addressing native title rights and interests. Cultural heritage legislation and jurisdiction-specific rehabilitation and closure requirements also influence how activities are planned and undertaken. | ||||||||
Performance snapshot
Group-level land impacted (ha) 15 057 (FY25: 14 888) | Group mine closure liabilities R10.1 billion (FY25: R9.1 billion) | Rehabilitation and closure planning expenditure R125 million (FY25: 91 million) | ||||||||
182
How we manage the Land and Rehabilitation IROs
1 | Land use, rehabilitation and closure | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Mining and associated infrastructure disturb land, alter landforms and create rehabilitation and closure obligations that can extend well beyond active operations. Historical and inherited mining impacts may present complex legacy challenges requiring long-term remediation, monitoring and land management. Regulatory requirements and stakeholder expectations also influence rehabilitation priorities and future land use outcomes. | Potential impact on the environment, society and economy Mining activities can alter landforms, soils, vegetation, surface water flow and land capability during construction, operations and closure. These changes can affect ecosystems and constrain current or future land uses if disturbed areas are not effectively managed. Legacy infrastructure may also create safety, security and environmental degradation risks, including in relation to illegal mining. Progressive rehabilitation and closure can create positive environmental, social and economic outcomes through agreed post- mining land uses. | Potential operational effect on Harmony Land disturbance, rehabilitation and closure require ongoing planning, approvals and stakeholder engagement throughout the project lifecycle. Activities include securing land access and permits, progressive rehabilitation, facilities decommissioning and monitoring and surveillance. Delays in any of these areas, whether from permitting, approvals, stakeholder engagement or rehabilitation progress, can push out project timing and relinquishment. Progressive rehabilitation can improve closure readiness and support timely relinquishment. | Potential financial effect on Harmony Progressive rehabilitation, closure planning, monitoring, maintenance and regulatory compliance require ongoing expenditure. Financial impacts also include rehabilitation and closure provisions and, where required, financial assurance arrangements lodged with governments or regulators. Additional costs may arise where rehabilitation performance, closure assumptions, regulatory requirements or project schedules change, affecting closure provisions, financial assurance obligations, closure works and long-term monitoring and maintenance obligations that may extend beyond mine closure. | |||||||||||
Our approach
Our approach to land use, rehabilitation and closure spans the
full asset lifecycle, from early project planning through to post-
closure management. Guided by the mitigation hierarchy, we
seek to avoid and minimise land disturbance where possible,
rehabilitate disturbed areas progressively and plan for post-
mining land uses that are safe, stable and support resilient
ecosystems and communities.
Avoiding and minimising land disturbance
Before disturbing land, we consider environmental, social and
operational factors, including land tenure, biodiversity values,
cultural heritage requirements, future closure obligations and
local stakeholder interests. Through project planning,
environmental approvals and site-specific management plans,
we seek to avoid disturbance where possible and minimise
impacts where disturbance cannot be avoided. As regulatory
requirements, land access arrangements and community
contexts differ across jurisdictions, site-specific planning
allows us to apply consistent principles while responding to
local conditions.
During exploration, construction and operations, we manage
land-related impacts through landform design, erosion and
sediment controls, monitoring programmes and operational
management measures designed to reduce the extent and
duration of disturbance.
Progressive rehabilitation
The extent and timing of rehabilitation are influenced by mine
sequencing and the availability of areas suitable for
rehabilitation. Where areas are no longer required for
operations, we seek to rehabilitate them progressively rather
than waiting until closure. This helps reduce the area of
disturbed land awaiting closure, supports the earlier
establishment of stable landforms and can reduce long-term
environmental and closure liabilities.
Depending on site conditions and future land use objectives,
activities may include revegetating available areas, stabilising
slopes, demolishing redundant infrastructure, backfilling and/
or sealing redundant mine shafts and implementing controls to
prevent unauthorised access.
Closure planning and post-mining land use
Closure planning is integrated into operational decision-
making throughout the life of mine. In planning for post-mining
land use, we consider regulatory requirements and
expectations, community aspirations, landowner aspirations
where we operate on third-party owned land, long-term safety
and stability, achievable ecological outcomes and the long-
term viability of alternative land uses.
Our objective is to leave land that is appropriate for its agreed
post-mining use, recognising that closure outcomes may be
ecological, social, economic or a combination of these,
depending on site conditions and stakeholder expectations.
Governance and oversight
Harmony’s regional executives and management oversee land
access, progressive rehabilitation and closure-related
compliance with regulatory and internal standards, including
annual closure cost estimates, financial liability assessments
and rehabilitation and closure plans. Our site teams manage
land issues on a day-to-day basis and execute our
rehabilitation and closure programmes.
183
FY26 progress and achievements
Advancing rehabilitation and closure activities
South Africa operations
During FY26, we continued to expand and maintain tree-
planting and phytoremediation initiatives across our South
African operations, including at Varkenslaagte, Magnum Farm,
Kareerand and selected tailings storage facility (TSF) areas.
These initiatives form part of our long-term rehabilitation
strategy and contribute to the management of groundwater
seepage and pollution plumes associated with sources such
as TSFs, waste rock dumps (WRDs) and pollution control
dams (PCDs).
At Kareerand TSF, we expanded the phytoremediation
plantation area by approximately 10 hectares through the
planting of 12 000 trees, increasing the total woodland area to
approximately 60 hectares. Across various TSFs in the Free
State, a further 18 500 trees were established. We also
established 4.5 hectares of vegetation on the side slopes of
Doringkop TSF and 1 hectare on the top surface of Freddie’s
9 TSF. These initiatives support progressive rehabilitation while
helping to reduce wind borne dust and erosion.
We also continued implementing measures to improve the
long-term safety and stability of redundant mining
infrastructure. During FY26, redundant Freddies 8 Shaft and
ARM 6 Shaft were backfilled, reducing the risk of unauthorised
access and illegal mining while supporting safer and more
sustainable long-term land‑use outcomes.
Ongoing revegetation trials at altitude
Hidden Valley, Papua New Guinea
Rehabilitation and closure planning at Hidden Valley presents
unique challenges due to the site’s elevation and climatic
conditions, requiring rehabilitation methods and plant species
suited to high-altitude environments. Our waste rock dump
revegetation trials continued through the year, providing
important information to further refine the site’s rehabilitation
methods and species selection. Several trial plots have shown
growth and survival rates exceeding expectations. In addition,
the ongoing rehabilitation of erosion prone areas has
continued.
Site access works rehabilitation and closure plan
submission
Eva Copper, Australia
We revised the Progressive Rehabilitation and Closure Plan
(PRCP) to align with the site’s amended environmental
authority and submitted the updated plan to the Queensland
regulator for approval. The plan defines activities, outcomes
and scheduling to rehabilitate land post-mining to a stable
condition. Beyond detailing the methodologies and techniques
to be employed in rehabilitation, the plan is also informed by
studies that assess future condition and water quality of final
mining voids, flood behaviour and the long-term stability of key
built landforms. These studies support the design of safe and
structurally stable landforms (relevant to IRO3) and informed
the rehabilitation milestones and outcomes defined in the
PRCP, which provide the basis for measuring rehabilitation
progress and closure performance.
Consistent with our progressive rehabilitation approach and
environmental approvals, we also rehabilitated areas made
available following site access improvement works, including
areas disturbed during road construction, and a number of
exploration drill site disturbances.
184
Performance and effectiveness
During the year, the undiscounted value of our mine closure liabilities increased by R1.0 billion, from R9.1 billion to R10.1 billion. The increase primarily reflects the acquisition of CSA mine, together with
updates to closure cost estimates, changes in disturbance areas and ongoing operational activities. Our impacted land and tenement footprint also expanded following the acquisition of CSA mine and
exploration tenements in the Cobar region of Australia, while construction commenced at Eva Copper.
Metric | Definition/calculation | Region | FY26 | FY25 | |||
Total land managed/tenement area (ha) | Total land owned, managed or held under relevant tenements and land interests by region. | Group | 442 640 | 367 040 | |||
South Africa | 88 157 | 88 157 | |||||
Papua New Guinea | 44 264 | 44 264 | |||||
Australia | 310 219 | 234 619 | |||||
Land impacted by mining-related infrastructure, services and activities (ha)1 | Area impacted by operational and project activities. | Group | 15 057 | 14 737 | |||
South Africa | 13 732 | 13 732 | |||||
Papua New Guinea | 1 015 | 982 | |||||
Australia | 310 | 174 | |||||
Disturbed land being rehabilitated and re-vegetated (ha) | Group | 106.0 | 58.0 | ||||
Annual area being rehabilitated and re-vegetated. | South Africa | 27 | 38 | ||||
Papua New Guinea | 1 | 1 | |||||
Australia2 | 78 | 19 | |||||
Mine closure liabilities | Undiscounted value of mine closure liabilities. | Group | R10.1 billion | R9.1 billion | |||
South Africa | R7.5 billion | R7.2 billion | |||||
Papua New Guinea | R1.8 billion | R1.8 billion | |||||
Australia | R779 million | R119 million | |||||
Rehabilitation and closure expenditure | Spend on rehabilitation projects or closure planning by region. | Group | R125 million | R91 million | |||
South Africa3 | R107 million | R78 million | |||||
Papua New Guinea4 | R4 million | R10 million | |||||
Australia4 | R14 million | R3 million | |||||
Rehabilitation target – 0.2% | Reduction of impacted land available for rehabilitation. | South Africa | 0.2% | 0.3% |
1Impacted land covers mining-related infrastructure, services and activities.
2Primarily reflects rehabilitation of exploration activities disturbance.
3Spend on rehabilitation projects.
4Spend on closure planning.
Future focus
•Continue demolition and rehabilitation of defunct shafts and derelict infrastructure across South African operations •Undertake a gap analysis and update of the South African TSF Rehabilitation and Closure Strategy to align with evolving regulatory requirements, ICMM principles and recognised international good practice •Expand Hidden Valley revegetation trials to cover additional elevations and ground conditions •Finalise and submit Hidden Valley’s updated mine rehabilitation and closure plan to regulators in Papua New Guinea •Work with Queensland regulator to progress approval of the Eva Copper PRCP •Enhanced annual closure cost assessments and financial provisioning methodologies across the South African operations to support reliable long-term closure liability estimates, adequate financial provision and continued alignment with regulatory requirements. | |||
185
How we manage land and rehabilitation IROs
2 | Land access and cultural heritage | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Access to land depends on maintaining regulatory approvals, agreements and respectful and constructive relationships with landholders, Traditional Owners, customary landowners, communities and regulators. Obligations relating to land access, cultural heritage, environmental performance and agreement commitments influence how activities are planned and undertaken. Failure to identify, implement or fulfil these obligations may result in disputes, access restrictions, delays and loss of trust. | Potential impact on the environment and society Failure to respect landholder rights or fulfil land access, cultural heritage, environmental or agreement-based commitments may result in disputes, loss of trust and reduced stakeholder confidence. Our activities could harm cultural heritage values if places or sites are not identified, understood and appropriately protected before activities commence. Constructive engagement and delivery of commitments can strengthen relationships and contribute to shared outcomes. | Potential operational effect on Harmony Land access constraints, unresolved stakeholder concerns and unmet commitments may delay activities. Inadequate cultural heritage assessments, engagement or project planning may require redesign or remediation. Failure to meet agreement or approval obligations may affect access arrangements, project timing, approvals, relationships and our standing with key stakeholders and regulators. Conversely, effective engagement can support access arrangements, project planning and regulatory processes. | Potential financial effect on Harmony Ongoing costs arise from stakeholder engagement, cultural heritage management, surveys, agreement implementation and compliance activities. Additional costs may result from delays, disputes, legal action, compensation, redesign, remediation or regulatory intervention where obligations are not met. Reputational impacts may also affect financing confidence, project approvals and future development opportunities. | |||||||||||
Our approach
Access to land is fundamental to our ability to explore,
develop, operate and close our assets. This topic is
particularly relevant in Australia and Papua New Guinea,
where exploration, project development and operational
activities occur on land subject to native title, customary
ownership, or privately-owned or leased land. How we access
land and conduct our activities is governed by a range of
legal, regulatory and agreement-based obligations.
Maintaining access to land depends not only on securing
approvals and agreements, but also on conducting activities in
a manner that respects landholder rights, cultural heritage
values and the commitments associated with operating on
third-party land. These requirements vary depending on
activities being undertaken, project stage and stakeholders
involved.
We manage these obligations through:
•Dedicated community affairs and land access personnel
who identify requirements, manage commitments and
engage with our stakeholders
•Integration of land access, cultural heritage and agreement-
based requirements into project planning, contractor
management and operational decision-making
•Employees and contractors implementing access
requirements and agreement commitments associated with
their activities
•Internal procedures, site-level processes, training and
awareness programmes that support compliance with legal,
regulatory and agreement-based obligations.
Governance and oversight
Community affairs and land access personnel track
commitments, manage emerging issues and support ongoing
stakeholder engagement throughout the mine lifecycle.
Delivery of commitments and emerging issues are reviewed
through site and regional oversight processes to support
ongoing compliance with our obligations.
186
FY26 progress and achievements
Working with the Kalkadoon People to protect the
cultural heritage values of Cabbage Tree Creek
Harmony partnered with the Kalkadoon People to protect
cultural heritage ahead of major works at Eva Copper. To
enable a culturally-led salvage programme, we listened to
Kalkadoon priorities and adjusted the construction schedule
for the Cabbage Tree Creek diversion. Working together, we
implemented measures to document, protect and preserve
areas and artefacts of cultural significance.
The challenge
The mine’s construction includes diverting part of Cabbage
Tree Creek near the project’s largest pit to maintain the
creek’s flow around the planned mining area. We know the
area around the creek is important to the Kalkadoon People,
and consultation with Kalkadoon leaders about the diversion
has been ongoing for over two years. Construction risked
disturbing cultural artefacts unless we took careful, culturally
appropriate action.
Our response
Ahead of construction, we invited the Kalkadoon leaders to
project site for a detailed consultation on the diversion works,
to further understand their perspectives and inform the
construction programme design.
The site visit and consultations resulted in the Kalkadoon
leaders providing a list of the actions they wanted Harmony to
undertake before and during the construction programme to
protect and preserve cultural heritage. This included:
•Considering rights-holder, cultural heritage and human
rights matters within community, legal, project and
operational decision-making processes
•Undertaking an extensive cultural heritage salvage
programme in the construction zone
•Providing a secure Keeping Place to house and protect
cultural artefacts
•Cordoning areas of significance to prevent disturbances
during construction
•Including Traditional Owners monitors during land clearance
for construction.
We listened and revised the start of construction in this area
to act on the feedback. We designed the salvage programme
with Kalkadoon leaders and their technical advisers. Harmony
engaged 14 Traditional Owners to lead the salvage
programme and manual excavations. We provided tailored
site inductions and on-the-job training in using digital
recording tools.
Over 35 field days, the salvage assessed approximately 200ha
of land and identified 1 423 artefacts, including chert flakes,
grinding stones and axe blades. Kalkadoon field officers led
hand excavations of key culturally significant artefacts. We
also built a secure 2 500m2 Keeping Place, which now
safeguards the artefact collection and forms a lasting cultural
legacy onsite.
Before the salvage programme commenced, all project team
members onsite completed a cultural heritage refresher
induction to reinforce the importance of respecting our site’s
cultural heritage.
Performance and effectiveness
We assess the effectiveness of our approach through
compliance with land access, cultural heritage and
agreement-based commitments, including commitments
made to landholders, Traditional Owners, customary
landowners and regulators.
We monitor delivery of agreed commitments, completion of
cultural heritage surveys and clearances, land access
incidents, complaints and corrective actions, and any issues
that may affect ongoing access to land. These processes help
us identify areas for improvement, maintain access to land
and fulfil our obligations.
Future focus
•Maintain ongoing compliance with our land access, native title, cultural heritage and agreement obligations. | |||
187
How we manage land and rehabilitation IROs
3 | Land stability and safety | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Mining activities create and modify landforms, slopes, mine openings and other ground conditions that require ongoing design, monitoring and maintenance to remain safe and stable. Stability risks are influenced by topography, climate, ground conditions, excavation, legacy workings and the long-term performance of built landforms and mining- related infrastructure. | Potential impacts on society and the environment Land instability can create safety hazards for employees, contractors, communities and future land users. It may result in erosion, sediment movement, landslips, subsidence, infrastructure damage, restricted access and reduced confidence in rehabilitated landforms, while legacy mining features can continue to present safety risks beyond active operations. Conversely, stable landforms are critical to supporting sustainable future land uses. | Potential operational effect on Harmony Land stability is managed throughout the mine lifecycle through design, monitoring, inspections, remediation and stakeholder engagement. Where actual or potential instability is identified, additional engineering controls, remediation works and emergency response measures may be required. Safety concerns may result in temporary restrictions or suspension of activities while conditions are assessed and stabilised, affecting production, schedules and closure activities. | Potential financial effect on Harmony Costs arise from monitoring, remediation, slope stabilisation, drainage management and other land stability controls. Significant instability events may result in infrastructure damage, production disruption, remediation and rehabilitation rework, regulatory intervention, insurance implications and increased closure costs. Additional monitoring, maintenance and adaptive management may also be required beyond mine closure. | |||||||||||
Our approach
Land stability and safety relates to the physical stability and
safety of land disturbed by mining activities, including built
landforms, rehabilitated areas, mine openings, legacy mining
features and other areas that may affect employees,
contractors, communities or future land users. While the
principles are consistent, the stability risks we manage vary by
geography, climate, mining method and legacy conditions,
ranging from historical mine workings, engineered landforms
and erosion management challenges in South Africa and
Australia, to steep terrain, high rainfall and geotechnical slope
stability challenges in Papua New Guinea.
We seek to design, monitor and maintain disturbed land and
mining-related features to be safe, stable and durable
throughout operations, closure and post-closure. This
includes managing risks associated with erosion, landslips,
subsidence, geotechnical instability, unsafe access and the
long-term performance of built landforms and legacy mining
features. To support these outcomes, we apply site specific
controls, including:
•Landform design incorporating appropriate engineering and
seismic design criteria
•Ongoing geotechnical monitoring, specialist advice and
targeted independent review of stability assessments and
practices
•Monitor and manage erosion, sediment and drainage risks,
including rehabilitation where impacts or potential impacts
are identified
•Demolition, sealing or rehabilitation of decommissioned
infrastructure and mine openings, and the construction of
exclusion bunds where required to reduce unsafe access
•Emergency preparedness, inspections, incident reporting
and corrective actions linked to site management systems.
FY26 progress and achievements
Managing stability in a challenging environment
Hidden Valley, Papua New Guinea
Hidden Valley’s steep terrain and high rainfall require ongoing
management of geotechnical and land stability risks. During
the year, we continued to manage pore water pressures
within pit walls, a key control for maintaining slope stability,
and consequently safety, in the open pit. This included trialling
a 24-hour slope stability radar monitoring service, enabling
wall movement to be identified and escalated in near real time,
improving safety and supporting timely operational responses.
We also progressed construction of the second TSF and
completed geotechnical studies to support the assessment of
possible third TSF, as part of a mine life extension feasibility
study. The work included investigations of ground conditions
and subsurface characteristics to inform future facility design
and stability assessments.
Managing the safe expansion of tailings storage
capacity
CSA mine, Australia
During the year, CSA mine completed the Stage 10 lift of the
Southern TSF, increasing storage capacity while maintaining
the stability and safety of this key operational landform. The lift
incorporated engineered embankment construction, quality
assurance processes and associated controls designed to
support the long-term performance of the facility.
Performance and effectiveness
We assess performance through site-specific geotechnical
monitoring, inspections and stability assessments of pit walls,
landforms, mine openings and other mining-related
infrastructure. This includes the use of monitoring
technologies, such as slope stability radars, which provide
real-time information on ground movement and support the
early identification and management of potential stability risks.
Future focus
•Continue geotechnical monitoring and investigations for existing and proposed infrastructure in Papua New Guinea. | |||
188
Waste management
Key matters: Tailings and waste management; water management; biodiversity, land use and environmental degradation Potential impacts on society, the environment and the economy: The waste generated through mining and processing can create lasting impacts if it is not appropriately managed. Hazardous and other waste can contaminate land and water, affect air quality and expose people to harmful materials, while reducing, reusing and recovering waste can lower disposal requirements and create opportunities for resource recovery. Matters that could impact Harmony: Managing diverse mineral and non-mineral waste streams requires appropriate storage, transport, treatment and disposal throughout the mine lifecycle. Waste incidents or inappropriate disposal can disrupt operations and result in remediation and additional management costs, while greater reuse and resource recovery can reduce waste volumes and recover value. | ||
Sustainability framework | Waste: Responsibly manage waste through reduction initiatives, responsible disposal and unlocking value through circularity. | ||
Strategic risk and opportunity | Risk: Regulatory and policy uncertainty Evolving waste management requirements can affect compliance, environmental liabilities and operating costs. Opportunity: Licence security and stakeholder confidence Proactive engagement and strong compliance capability can strengthen licence security and stakeholder confidence. | ||
Effective waste management is essential to minimising environmental and social
impacts and supporting resource efficiency.
Mining and processing activities generate a range of waste streams, from large-volume mineral wastes such as waste rock and
tailings, to non-mineral waste streams including hazardous waste, hydrocarbons, industrial waste, general waste and recyclable
materials. Without appropriate controls, these materials may affect land, water and air quality, create health and safety risks, and
contribute to long-term environmental liabilities. To minimise potential for impact, we apply the waste hierarchy, prioritising avoidance,
reduction, reuse, recycling and recovery before disposal. This approach supports responsible waste management while identifying
opportunities to improve resource efficiency, reduce waste volumes requiring disposal, and recover value from suitable waste
materials.
Waste management impacts, risks and opportunities (IROs)
Waste management and resource recovery | |||
We manage waste throughout its lifecycle while identifying opportunities to reduce, reuse, recycle and recover value from waste materials. | |||
1
Regional context
South Africa Waste management activities are influenced by large mineral waste volumes, established operating and legacy mining footprints, and rehabilitation requirements. Circular economy opportunities support the reduction of waste footprints while extending the productive use of materials, including the use of waste rock as plant grinding media, backfill material for shaft rehabilitation and, where feasible, crushing material at gold processing plants. Established waste infrastructure supports a broader range of disposal, recycling and recovery pathways. | Papua New Guinea Waste management opportunities are influenced by the remote location, high-rainfall conditions and limited access to external recycling, treatment and disposal services and infrastructure. Management focuses on appropriate waste handling, water quality protection and waste rock geochemical characterisation and strict management. Opportunities for resource recovery and reuse focus on suitable non-acid-forming waste rock used in tailings storage facility construction, drainage improvements, rehabilitation activities and the responsible encapsulation of other wastes. | Australia Waste management activities reflect a combination of operating and development-stage assets, including CSA mine and Eva Copper. Site remoteness limits access to suitably licensed recycling, treatment and disposal facilities, constraining recovery opportunities. At CSA mine, waste rock is preferentially placed underground where possible, or used for while suitable non-acid-forming material is retained for future construction activities. Opportunities focus on practical resource recovery and scrap steel and other recycling opportunities where services and infrastructure are available. | ||||||||
Performance snapshot
General waste from operational salvage yards (t) 34 958 (FY25: 29 900) | Total recycled waste (000t) 7 944 (FY25: 4 739) | Waste rock recycled (000t) 7 922 (FY25: 4 720) | Mineral waste intensity (t/t treated) 1.50 (FY25: 1.53) | |||||||||||
189
How we manage waste management IROs
1 | Waste management and resource recovery | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Waste-related risks and opportunities are shaped by the quantity and types of waste generated, and the effectiveness of controls applied throughout the waste lifecycle. Management outcomes are influenced by waste classification, storage, transport and disposal requirements, contractor capability, regulatory obligations and access to appropriate disposal, recycling and recovery services and infrastructure, particularly in remote operating environments. Resource recovery opportunities depend on waste characteristics, operational demand, available use or markets and recovery pathways, supported by reliable waste data and performance information. | Potential impact on the environment, society and the economy Poorly managed waste may affect land, surface water, groundwater and air quality through contamination, uncontrolled releases or inappropriate disposal practices. Employees, contractors and communities may also be exposed to hazardous materials, odour, dust, disease vectors and other nuisance impacts may affect their wellbeing and confidence. Inappropriately managed waste rock may contribute to land and water quality impacts. Waste reduction, reuse and recycling can reduce landfill requirements and support rehabilitation and local economic opportunities. | Potential operational effect on Harmony Waste-related incidents, fires, containment failures or inappropriate disposal practices may disrupt operations, damage infrastructure, delay activities and require emergency response or remediation. Remote locations and limited access to licensed disposal and recycling services and facilities can increase transport, storage and contractor-management requirements. Historical waste areas and long-term waste disposal footprints may also influence future land use and closure outcomes. Effective waste classification, segregation and resource recovery can improve material efficiency and reduce waste volumes requiring disposal. | Potential financial effect on Harmony Managing waste requires ongoing expenditure on storage, handling, transport, treatment, monitoring, contractor management and licensed disposal. Waste-related incidents or regulatory non-compliances may result in remediation costs, penalties, legal liabilities, project delays, insurance implications and increased closure obligations. Waste reduction, recycling and resource recovery initiatives may reduce disposal and procurement costs, recover value from materials and lower rehabilitation and closure requirements where technically, environmentally and economically feasible. | |||||||||||
Our approach
Harmony manages waste throughout its lifecycle, from
generation and characterisation through to storage, transport,
reuse, recovery and disposal. Our approach is guided by the
waste hierarchy, which prioritises avoidance, reduction, reuse,
recycling and recovery before disposal. By applying this
hierarchy, we seek to minimise potential impacts on people
and the environment, improve resource efficiency and identify
opportunities to recover value from waste materials where
technically, environmentally and economically appropriate.
Waste management can also create local economic
opportunities through waste handling, recycling and recovery
activities that support contractors, suppliers and community
enterprises.
Waste management considerations are integrated into
environmental management systems, operational planning,
risk management processes and closure planning activities.
Key elements of our approach include:
•Characterising waste streams to determine appropriate
handling, storage, disposal, reuse and recovery pathways
•Classifying, segregating, storing, transporting and disposing
of waste in accordance with operational requirements and
regulatory obligations
•Monitoring waste streams, incidents, compliance
obligations and waste-related risks through site-based
management systems and inspections
•Implementing controls for hazardous materials, including
appropriate containment, storage, handling and licensed
disposal pathways
•Promoting waste reduction, reuse, recycling and recovery
opportunities through improved segregation practices,
contractor partnerships and material recovery initiatives
•Assessing opportunities for the safe reuse or recovery of
waste rock and other materials in support of rehabilitation,
closure objectives and long-term land stewardship.
190
Waste-related risks and opportunities are identified through
operational risk processes, monitoring, inspections,
stakeholder engagement and closure planning. Opportunities
for reuse, recycling and recovery vary between operations and
waste streams and depend on technical feasibility, material
characteristics, available infrastructure, market demand and
regulatory requirements. In some locations, access to
appropriately licensed third-party recycling, treatment or
disposal facilities is limited, reducing the range of viable
recovery pathways. Where recovery options are not available
or appropriate, waste is managed through controlled storage
and disposal arrangements.
Governance and oversight
Regional executives and operational, and sustainability teams
oversee waste management initiatives, while site management
teams are responsible for day-to-day waste management
activities. Waste management forms part of Harmony’s
environmental management systems and construction and
operational risk management processes.
FY26 progress and achievements
Building our waste inventory
Australian operations
We established processes to capture and track waste
streams associated with Eva Copper’s construction activities,
improving visibility of waste generation across a large
contractor workforce. Given the number of contractors
operating on site and the use of different reporting systems,
this has required the development of data collection and
estimation approaches to support a more complete waste
inventory. We also incorporated CSA mine waste data into
Harmony’s waste inventory and reporting processes.
Demonstrating improved waste rock management
performance
Hidden Valley, Papua New Guinea
Harmony continued implementing our revised waste rock
management plan which provides procedures for
characterising waste rock types to enable the appropriate
management and placement in the WRD or reuse for
construction activities. The management plan was prepared
and commenced implementation in FY24 – FY25 to address
low-level dissolved manganese exceedances as a result of
placement and certain rainfall conditions. Monitoring has
identified a significant reduction in dissolved manganese levels
downstream of the waste rock dumps, supporting ongoing
compliance with environment permit water quality criteria.
Our key management measures continue to include a bottom
up engineered design comprising construction of engineered
underdrains, optimised and careful paddock dumping of
potentially acid forming waste and non-acid forming caps,
compaction of waste rock layers, separation of oxidised,
partially oxidised and potentially acid forming waste rock and
encapsulation of potentially acid forming waste in fresh non-
acid forming granodiorite where required. Our closure
planning also includes geotechnical and geochemical
modelling to confirm stability and engineered covers to reduce
water and oxygen infiltration all aiming to reduce impacts to
the environment and people.
191
Performance and effectiveness
During FY26, Harmony increased total recycled waste from 4.7Mt to 7.9Mt, driven primarily by
the increased reuse of waste rock across the group. Waste rock deposited decreased from 27Mt
to 24Mt, improving mineral waste intensity from 1.53 to 1.50 tonnes per tonne treated. General
waste generated increased from 29 900 tonnes to 34 958 tonnes, while waste disposed to landfill
increased from 10 470 tonnes to 12 876 tonnes, partly reflecting enhanced waste reporting and
data coverage across operations. Despite a marginal decline in the recycling rate from 65.0% to
60.4%, the significant increase in recycled volumes demonstrates continued progress in
supporting Harmony’s circular economy objectives.
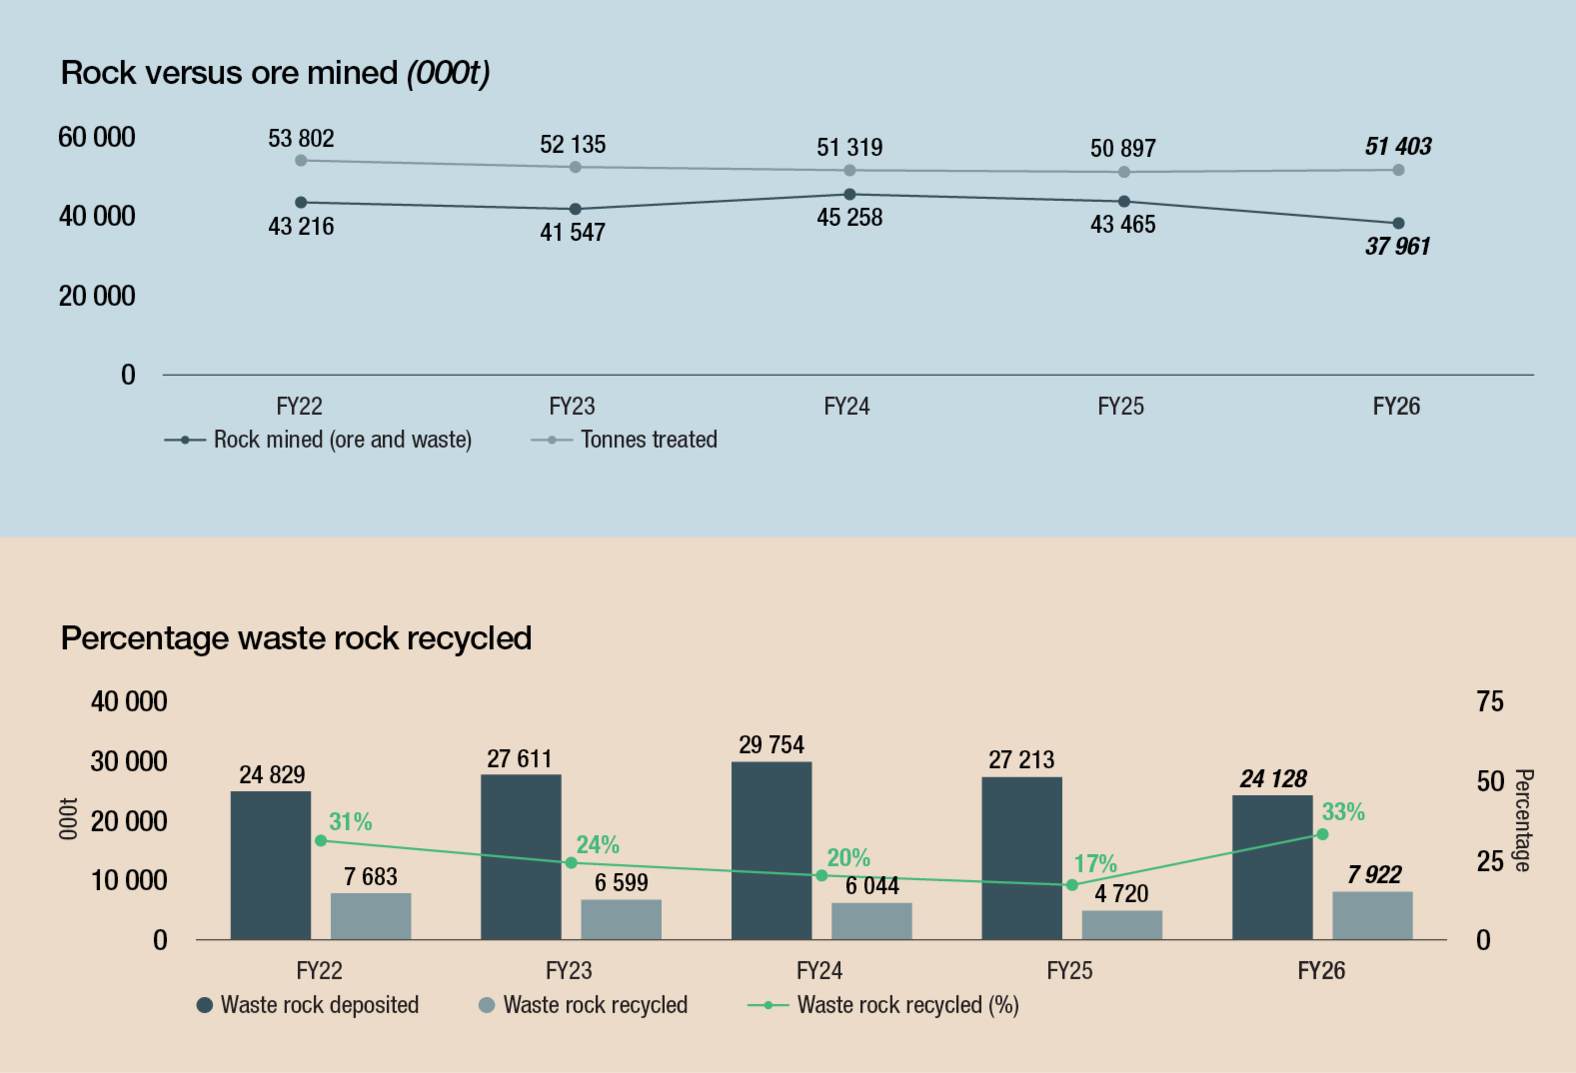
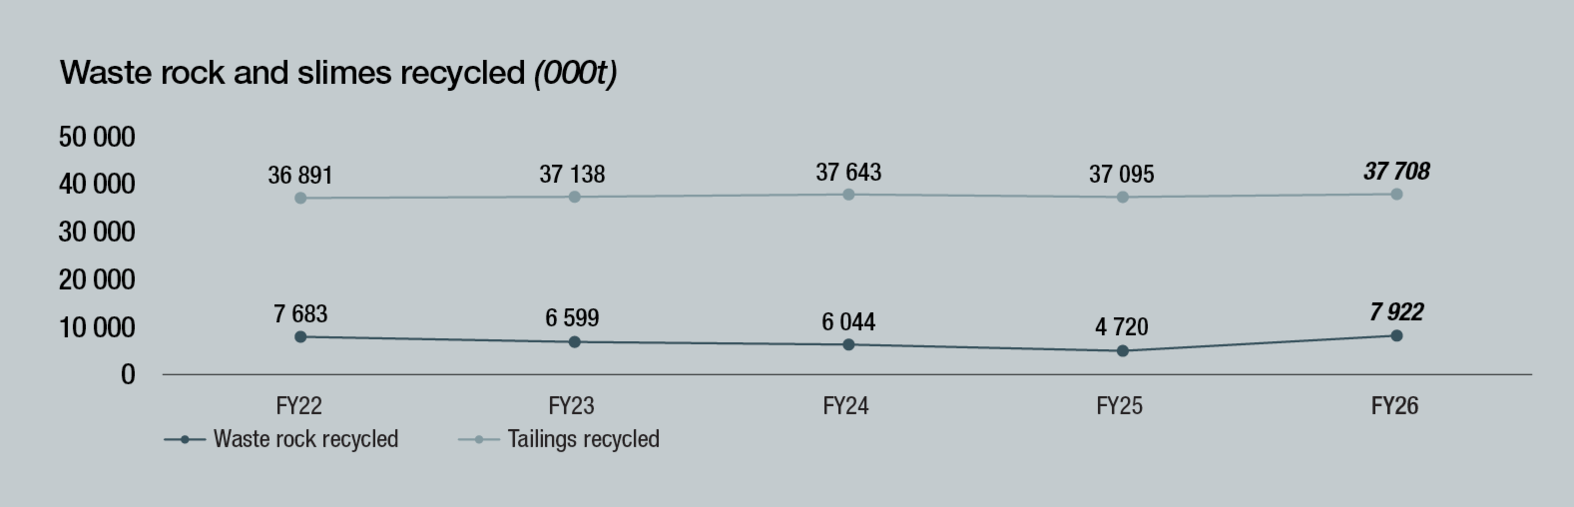
Group waste generated | FY26 | FY25 | FY24 |
Oils and grease | |||
Grease used (t) | 454 | 430 | 480 |
Lubricating and hydraulic oil used (Ml) | 3.3 | 3.1 | 3.0 |
Recycling oil – repurposing hydrocarbons to landfill (000l) | 709 | 646 | 703 |
Hazardous waste | |||
Tailings (Mt) | 53 | 51 | 52 |
Waste rock deposited (Mt) | 24 | 27 | 30 |
Hazardous waste to landfill (t) | 805 | 558 | 1 261 |
Recycled waste | |||
Waste rock recycled (000t) | 7 922 | 4 720 | 6 044 |
Timber (t) | 5 515 | 4 238 | 6 097 |
Steel (t) | 14 779 | 14 686 | 14 939 |
Plastic (t) | 809 | 507 | 697 |
Paper and cardboard | 979 | – | – |
Total recycled waste (000t) | 7 944 | 4 739 | 6 066 |
Total general waste generated from operational salvage yards | 34 958 | 29 900 | 29 290 |
Mineral waste intensity (tonne/tonne treated) | 1.50 | 1.53 | 1.60 |
General waste intensity (tonne/000 tonne treated) | 0.68 | 0.59 | 0.57 |
Future focus
Development of a site-wide waste segregation and resource recovery programme at CSA mine, to move waste management away from mixed disposal and toward source segregation, recycling and reuse. | |||
192
Air quality
Key matters: Sustainable communities Potential impacts on society, the environment and the economy: Dust and air emissions from mining, processing and project activities can affect local air quality and amenity. Where people or sensitive environments are exposed, these emissions can affect respiratory health, quality of life, flora and fauna and community confidence in our operations. Matters that could impact Harmony: Maintaining air quality requires ongoing monitoring, emissions reporting, maintenance and control measures. Exceedances, non-compliance or unresolved community concerns can increase costs and regulatory oversight, restrict activities and contribute to operational or project delays. | ||
Strategic risk and opportunity | Risk: Regulatory and policy uncertainty Air quality requirements can affect compliance, licences, operating costs and operational continuity. Opportunity: Licence security and stakeholder confidence Proactive engagement and strong compliance capability can strengthen licence security and stakeholder confidence. | ||
Effective air quality management is integral to responsible mining practices by
minimising the impacts of dust and air emissions on communities and the environment.
Harmony operates across diverse geographic, environmental and community settings, spanning underground mining, surface mining
and project development activities. Our approach focuses on understanding the specific characteristics, risks and requirements of
each operation and implementing monitoring and control measures that support environmental stewardship and regulatory
compliance.
Air quality impacts, risks and opportunities (IROs)
Air quality performance | |||
Effective air quality management supports compliance with permits and licences, helps maintain positive stakeholder relationships, protects community health and wellbeing, reduces the potential for environmental impacts, project or operational delays and additional operating costs. | |||
1
Regional context
South Africa Dry and windy conditions can increase dust generation, while the proximity of operations to established communities can influence potential community exposure. Air quality management is guided by atmospheric emission licences, environmental authorisations, dust management plans and associated reporting obligations, including submissions to the National Atmospheric Emissions Inventory System. Monitoring and reporting programmes support regulatory compliance and management of site- specific air quality impacts. | Papua New Guinea High rainfall can reduce dust generation, while the location of operations and the surrounding terrain and vegetation can influence the dispersion of air pollutants and potential community exposure. Air quality management is guided by environmental permit conditions, environmental management plans and monitoring requirements established under project approvals. Monitoring programmes support regulatory compliance and the management of air quality impacts across our sites and project development activities. | Australia Variable climatic conditions, the nature of activities and the proximity of operations to local communities can influence air quality and potential community exposure. Air quality management is guided by environmental authorities, licences and approval conditions, including applicable monitoring and reporting requirements. Applicable facilities are also subject to National Pollutant Inventory reporting obligations, with monitoring programmes supporting regulatory compliance and the management of air quality impacts. | ||||||||
193
How we manage air quality IROs
1 | Air quality performance | I | R | O | SA | AUS | PNG | |||||||||||||
Impact, risk and opportunity drivers Dust generation and air emissions are influenced by mining, processing and project development activities, as well as climatic conditions and the proximity of operations to local communities. Sources include TSFs, stockpiles, haul roads, construction activities and processing plants. These factors can affect local air quality and contribute to environmental impacts, community concerns and regulatory compliance obligations. | Potential impacts on society and the environment Dust fallout, particulate matter and other air emissions may result in nuisance impacts, such as concerns around deterioration of local amenity and air quality. Potential impacts on communities may include respiratory health impacts, reduced quality of life, as well as potential impacts to native flora and fauna. These impacts can contribute to community concerns regarding mining, processing and project development activities. | Potential operational effect on Harmony Non-compliance with regulatory, licence or approval air emissions requirements, or concerns raised by communities and other stakeholders, may result in operational disruptions, increased oversight requirements, restrictions on activities or project delays. Managing air quality risks requires ongoing investment in monitoring, maintenance and control measures to support regulatory and operational requirements. | Potential financial effect on Harmony Air quality management requires ongoing expenditure on monitoring, emissions reporting, compliance activities and control measures. Additional financial impacts may arise from regulatory penalties, legal action, corrective and remediation costs, operational disruptions, project delays, and additional capital or operating expenditure required to address air quality-related risks and compliance obligations. | |||||||||||
Our approach
Harmony seeks to minimise the impacts of dust and air
emissions on communities and the environment while
supporting compliance with regulatory, licence and approval
requirements.
Air quality considerations are integrated into environmental
management planning, operational risk management and
compliance processes. Our approach includes monitoring
programmes, engineering and operational controls,
rehabilitation activities and stakeholder response processes
designed to address air quality risks associated with mining,
processing and project development activities. This approach
is applied across South Africa, Papua New Guinea and
Australia, recognising the different climatic, operational and
community contexts for each of our operations.
Key elements of our approach include:
•Monitoring dust and air emissions across our operations
and projects using site-specific programmes. Monitoring,
emissions reporting and compliance activities help assess
performance, identify potential exceedances or nuisance
impacts, and support compliance with applicable regulatory
requirements, licences and approval conditions
•Engineering and operational controls to reduce dust
generation and air emissions from mining, processing and
project development activities. For example, installing
netting and utilising suppressants and abatement
equipment
•Maintenance and emissions control equipment and
infrastructure to support effective performance
•Rehabilitation and revegetation activities that help stabilise
disturbed areas and reduce dust generation
•Complaints management, investigation and corrective
action processes to respond to community concerns,
should these arise, and support continual improvement.
The effectiveness of our air quality management approach is
assessed through ongoing monitoring, compliance verification
and review processes.
Our gold tailings reclamation programme in South Africa
reprocesses inactive tailings facilities utilising technologies and
recovery methods that were not available when the facilities
were originally developed. Material from multiple legacy tailings
facilities, many of which were developed prior to Harmony’s
ownership and under historical mining practices, is reclaimed
and consolidated into a centralised, actively managed facility,
reducing the number and footprint of potential dust emission
sources across the region. This supports improved regional air
quality by enabling more effective dust management and
allowing for the progressive closure and rehabilitation of
legacy tailings facilities. Over time, this reduces the number of
inactive tailings facilities with the potential to contribute to dust
generation and other air quality impacts.
Governance and oversight
Regional executives, supported by regional environment and
sustainability teams, are accountable for establishing and
overseeing air emissions management frameworks, including
relevant policies, procedures, plans and monitoring
requirements. Site management teams are responsible for
daily emissions monitoring and operational implementation.
194
FY26 progress and achievements
Supporting air quality performance through
monitoring and dust management
South Africa operations
Our FY26 activities focused on maintaining air quality
monitoring and compliance programmes across operations,
updating dust management plans and meeting regulatory
reporting obligations, including the submission of annual
National Atmospheric Emission Inventory System reports.
Where monitoring identified exceedances, remedial measures
were implemented to address underlying causes and
strengthen controls. Key dust mitigation actions undertaken
during the year included:
•Installation of 10 000 metres of dust netting and planting of
18 500 trees on dormant TSFs across our Free State
operations
•Establishment of 1ha of dryland vegetation on Freddies 9
TSF
•Rehabilitation of 4.5ha of the Doornkop TSF side slopes to
reduce dust fallout
•Installation of a dust suppression system on Savuka 7 TSF
•Ongoing maintenance of existing dust mitigation measures
in accordance with approved dust management plans.
Establishing Australian air emissions reporting
and strengthening monitoring capability
CSA mine and Eva Copper, Australia
This year marked Harmony’s first year of National Pollutant
Inventory reporting, establishing a baseline for the
measurement and disclosure of air emissions from our
Australian sites.
National pollutant inventory reporting is required where
facilities meet prescribed national reporting thresholds for
activities such as fuel combustion and the handling and
extraction of listed substances. At CSA mine, reporting
reflects the nature and scale of operations, including copper
ore extraction, diesel fuel combustion, mineral processing
activities.
Air quality monitoring programmes at CSA mine are well
established and support ongoing management of air quality
risks and regulatory obligations. In line with industry good
practice, CSA mine undertakes depositional dust monitoring
through a network of seven monitoring locations and applies
the New South Wales Environment Protection Agency dust
deposition guideline of 4g/m2/month (at the site boundary).
During FY26, we commenced work to expand the site’s real-
time dust monitoring capability. An independent review of the
monitoring network was carried out and a real-time dust
monitor installed between the site and nearest sensitive
receivers to the east. Three additional real-time dust monitors
are scheduled to be installed in the first half of FY27 to
supplement the existing static air quality monitoring network.
At Eva Copper, baseline air quality monitoring remained
ongoing via the site’s network of dust deposition gauges,
supporting our understanding of existing conditions and
operational readiness. We also implemented and continued
our active monitoring of dust management controls for our site
construction activities.
Performance and effectiveness
We estimate emissions of key atmospheric pollutants
including nitrogen oxides (NOx) and sulphur oxides (SOx)
using recognised emission estimation methodologies. These
estimates support regulatory reporting and provide an
indication of atmospheric emissions associated with
operational activities.
In FY26, there were no reportable dustfall exceedances,
environmental fines and directives across our regions relevant
to air quality.
Future Focus
•Expand real-time dust monitoring capability at CSA mine with the addition of a further three monitoring stations •Maintain dust monitoring, regulatory reporting and compliance activities across operations and projects •Continue rehabilitation, dust mitigation and corrective action processes to support air quality performance. | |||
195
Ethical leadership and sound corporate governance
Guided by the principles of the King Report and a commitment to Mining with Purpose, the board provides ethical and effective
leadership that creates and sustains value for all stakeholders.
Governance approach and philosophy
Harmony’s approach to corporate governance goes beyond
regulatory compliance. It is rooted in the conviction that sound
governance is a strategic enabler – one that allows the group
to deliver on its business imperatives, sustainability ambitions
and responsibility to all stakeholders. The board, through its
collective leadership, sets the tone at the top by fostering an
ethical culture, exercising sound judgement, and ensuring that
Harmony operates as a responsible corporate citizen across
all jurisdictions in which it operates.
Harmony’s approach to corporate governance is guided by
the four governance outcomes articulated in King V:
•Ethical culture – the board leads by example, embodying
integrity, fairness, accountability, transparency,
responsibility and competence (the ICRAFT framework)
•Performance and value creation – the board drives strategy,
capital allocation and performance oversight to deliver long-
term shared value
•Conformance and prudent control – robust governance
structures, delegation frameworks, risk governance and
assurance processes protect the group from key risks
•Legitimacy – inclusive stakeholder engagement and
comprehensive, transparent reporting build trust and
maintain Harmony’s social licence to operate.
Ethical leadership
The board recognises that ethical conduct is fundamental to
sustainable business performance and long-term value
creation. Directors exercise sound judgement and fulfil their
responsibilities with integrity, accountability and due care.
These principles underpin the board's conduct, deliberations
and decisions, and form part of the regular assessment of
both the board and individual directors. The board charter
articulates the standards of conduct expected of directors,
while established governance practices support the timely
identification, disclosure and management of actual, potential
and perceived conflicts of interest.
Organisational ethics
The board sets the group’s approach to ethics. Oversight and
monitoring of organisational ethics is the mandated
responsibility of the social and ethics committee on behalf of
the board.
Ethics department and ethics management
committee
Harmony continues to collaborate with the Ethics Institute of
South Africa and has procured the expertise of SNG Grant
Thornton, not only to further embed good ethical conduct, but
also to increase the skills required to manage fraud detection,
fraud prevention and reporting. Complementing these external
partnerships, Harmony’s dedicated ethics department
comprises permanent certified ethics officers responsible for
implementing and communicating the ethics management
plan and programme throughout the organisation.
The board is satisfied that arrangements for the prevention
and detection of fraud, corruption and money laundering are
effective and that significant incidents have been appropriately
responded to, to manage consequences and prevent future
occurrences.
The ethics management committee, supported by the ethics
officers and the white-collar crime committee, oversees and
monitors Harmony’s ethical culture and integrity. Harmony
continues to strengthen employee ethics awareness through
expanded training and engagement initiatives across all
operations. The ethics management committee also assesses
whistleblower items/reports and declarations of interest in
terms of the code of conduct and provides feedback to the
executive committee, which then reports to the board’s social
and ethics committee. As a result, ethics are discussed and
examined at every level of management in the company.
The board is satisfied with the effectiveness of Harmony's
ethics management in creating an ethical culture.
196
The board at a glance
Our duty to be a responsible corporate citizen is supported by our board of directors and their commitment to ethical leadership.
Board independence, broader diversity and experience
(as at 30 June 2026)
Transformation | |||
73% | Eleven members are historically disadvantaged persons | ||
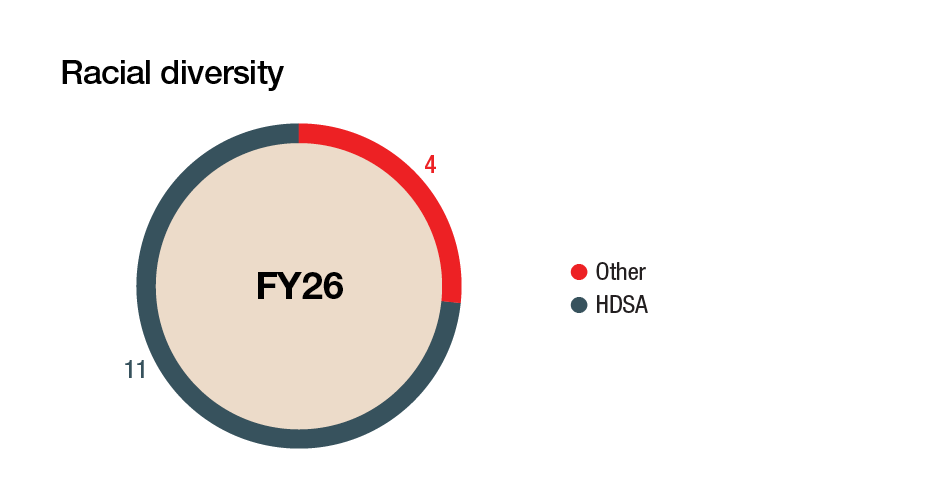 | |||
Representation | |||
33% | Five members are women | ||
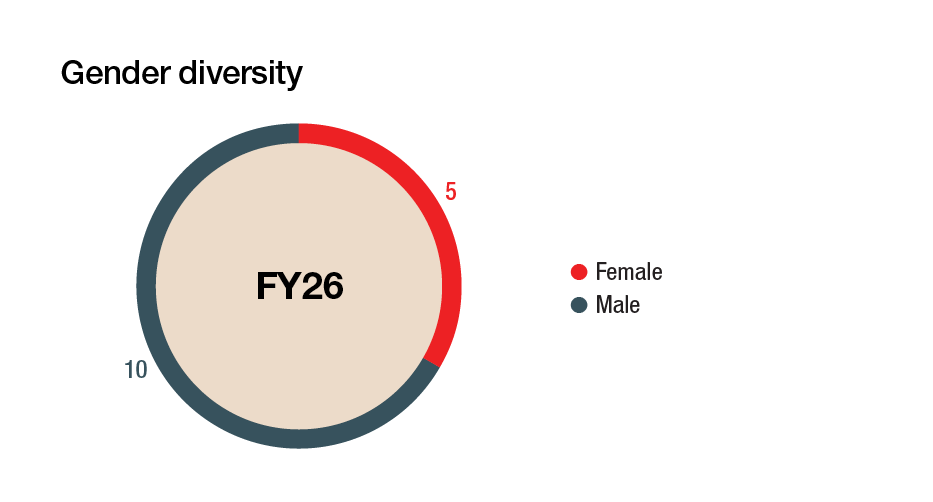 | |||
Tenure, independence and skill areas | |||
73% | Eleven members of the board are independent non-executive directors | ||
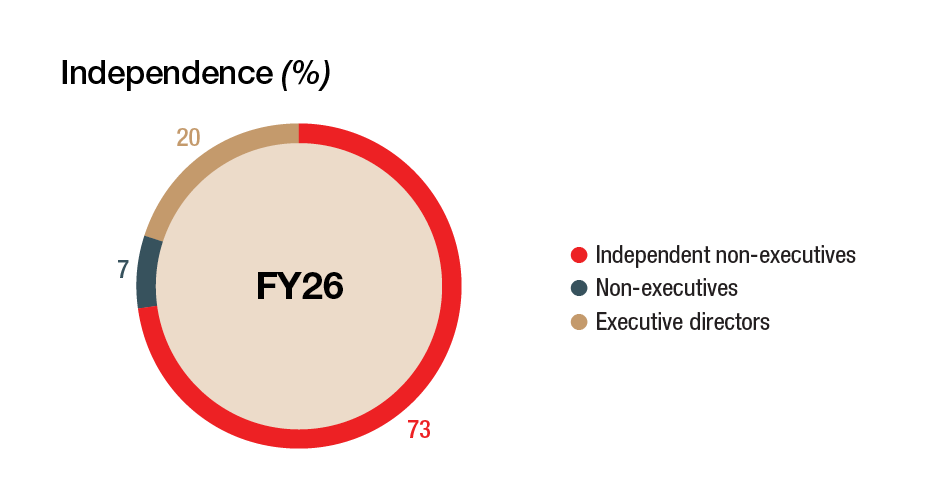 | |||
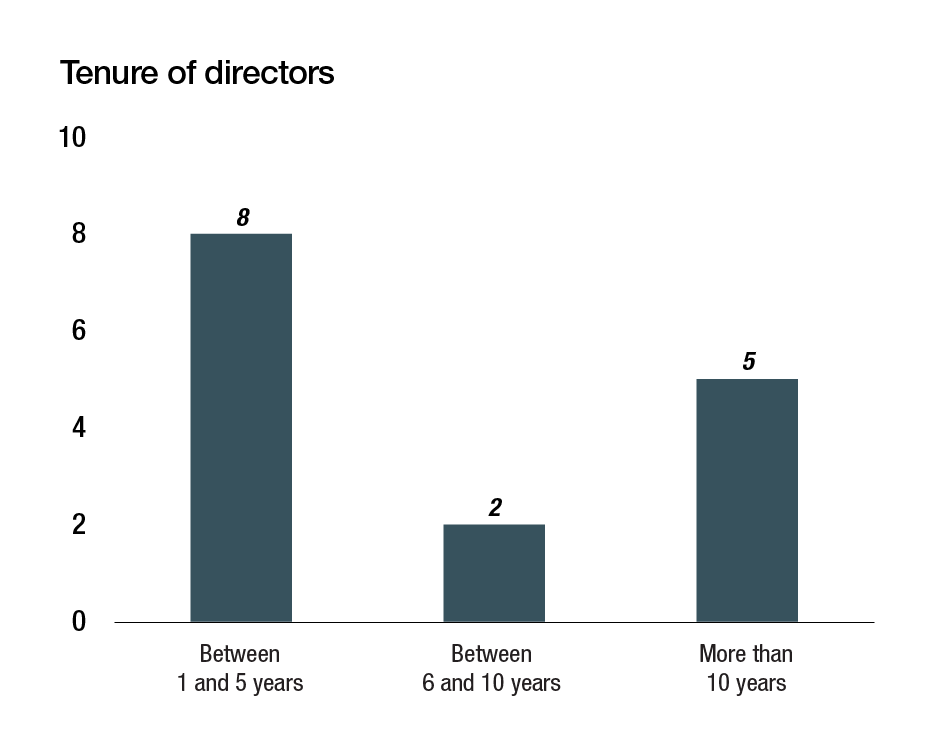 | |||
Governance and compliance policies | ||||
•Terms of reference for the board •Terms of reference for board committees •Board delegation of authority •Code of conduct •Behavioural code •Corporate governance policy and framework •Legal compliance policy and framework •Internal audit charter •Disclosure required by section 303A.11 of the NYSE-listed company manual •Public Access to Information Act manual (PAIA) •Whistleblower policy •Human rights policy •Anti-bribery and anti-corruption policy •Anti-money-laundering policy •Trading in company shares and insider trading policy. | ||||
Foundation of corporate governance compliance | ||||
•Companies Act, JSE Listings Requirements (primary), New York Stock Exchange requirements, memorandum of incorporation, King V •Voluntary compliance with the principles of the United Nations Global Compact, International Council on Mining and Metals, GRI Standards and the International Cyanide Management Code for the Manufacture, Transport and Use of Cyanide in the Production of Gold (Cyanide Code). | ||||
197
Compliance policy and framework
Harmony subscribes to the ICRAFT process in respect of ethical leadership as recommended under King V | |||||||||||||||||||||
Integrity | Of board and governing body (management) | Competence | Knowledge, due care and diligence | Responsibility | For steering the delivery of strategy | ||||||||||||||||
Transparency | Transparent in exercising governance roles and responsibilities | Fairness | Adopting a stakeholder- inclusive approach | Accountability | Board accountability executing their responsibilities | ||||||||||||||||
With its long-standing commitment to good corporate
governance, the Harmony board is satisfied that appropriate
practices are in place to promote the company’s reputation as
an ethical, reputable and legitimate organisation and a
responsible corporate citizen.
Acknowledging the significance of corporate governance and
compliance, the board, through the audit and risk committee,
has a formal corporate governance policy and framework as
well as a legal compliance policy and framework that set out
the principles of good corporate governance for the board as
well as employees at all operational levels.
In terms of the JSE Listings Requirements, Harmony is
required to disclose its application of the principles of King V.
The board, to the best of its knowledge, believes Harmony
has satisfactorily applied the principles of King V.
Responsible corporate citizenship
The mining industry introduces a unique duty and opportunity
to the group to be a responsible corporate citizen. While the
board sets the tone and direction for how corporate
citizenship is approached and managed, the ongoing
oversight and monitoring of the group’s performance against
its social, ethical and environmental targets fall within the
mandate of the social and ethics committee. In addition, the
social and ethics, remuneration, and audit and risk
committees each assume specific oversight responsibilities to
ensure that Harmony’s strategy remains aligned with its
broader commitments to sustainability, ethical conduct and
responsible business practices.
Good performance and value creation
Strategy
The board is responsible for approving the group’s short-,
medium- and long-term strategy as developed by
management. In doing so, it focuses on critical aspects of the
strategy, including the legitimate and reasonable needs,
interests and expectations of key stakeholders as well as the
impact of the group’s activities and output on the various
capitals employed in the business process. Risks and
opportunities connected to the triple context (economy,
society and the environment) in which the group operates are
integral to the board’s strategic reviews of the business.
Policies and operational plans supporting the approved
strategy are submitted regularly by management for review
and formal board approval. The board attends an annual
strategy session to confirm and review the company’s
strategy.
Strategy is part of the ongoing conversation in the boardroom.
Regular oversight of the implementation of Harmony’s
strategies and operational plans takes place against agreed
performance measures and targets.
Given that the company’s reputation as a responsible
corporate citizen is an invaluable attribute and asset, the
consequences of activities and outputs, in terms of the
capitals employed, are continuously assessed by the board
through its committees. This will ensure we are able to
respond responsibly and limit any negative consequences of
our activities, to the extent reasonably possible. In addition,
the board continuously monitors the reliance of the group on
these capital inputs – our natural capital (including Mineral
Resources and Reserves), employees, financial capital,
communities and society at large, our mining infrastructure
and our intellectual and technological know-how – as well as
the solvency, liquidity and going-concern status of Harmony.
Reporting
In protecting and enhancing the legitimacy and reputation of
the group, the board ensures comprehensive reporting takes
place on different platforms.
The board’s intention is to meet and exceed legal
requirements, as well as the legitimate and reasonable
information needs of key stakeholders. The board is satisfied
with management’s basis for determining the relevance or
significance of information to be included in our external
reports. The audit and risk committee, assisted by the social
and ethics committee, is tasked with reviewing all external
reports to verify the integrity of information.
Political donations
Harmony supports the democratic processes in South Africa,
Papua New Guinea and Australia. A policy relating to political
donations has been adopted by the company. During FY26,
there were no political donations made by Harmony.
198
Legislative compliance function
The legal compliance function is responsible for the regulatory environment in which Harmony
operates. Continuous monitoring, assessments and development, regular updates to policies and
procedures, and ongoing staff training and awareness ensure that Harmony stays abreast of
constantly evolving regulatory compliance trends. Compliance information and reports on the status
of legislative compliance are presented at audit and risk committee meetings.
Compliance framework: primary and voluntary
The foundation of Harmony's corporate governance complies with the following primary
frameworks:
a.Companies Act
b.JSE Listings Requirements (primary listing)
c.NYSE listing requirements (secondary listing)
d.The King Report.
Harmony also voluntarily applies the principles of:
a.United Nations Global Compact
b.International Council on Mining and Metals (ICMM) – 10 principles
c.International Cyanide Management Code
d.Voluntary Principles on Security and Human Rights.
Governance, risk culture and value creation across time horizons
Harmony’s governance structures are designed to support value creation, preservation and protection
across all three time horizons. A core board responsibility is establishing and monitoring the
organisation’s attitude to risk and the mechanisms for maintaining integrity and ethical conduct
throughout the group.
Short term (within 12 months) | Medium term (more than one year to four years) | Long term (more than four years) | ||||||
Board oversight of financial results, safety performance, quarterly risk reviews, regulatory compliance across South Africa, Papua New Guinea, Australia and the United States, and monitoring executive performance against approved KPIs | Oversight of strategic initiative delivery (copper expansion, decarbonisation pathway, technology transformation), board succession and transformation milestones, ESG-linked executive performance tracking, and stakeholder relationship management | Governance of Harmony’s evolution toward a diversified, gold and copper company, long-term Mineral Resource stewardship and Mineral Reserves confidence, SBTi- aligned decarbonisation commitments, community legacy and social licence to operate, and long-term capital structure resilience | ||||||
The board’s risk culture is defined by its board-approved risk appetite statement, which sets the
boundaries within which management operates. The anti-corruption, anti-fraud and whistleblowing
framework, overseen by the social and ethics committee, ensures that the board can maintain an
ethical culture across all operations. The board is satisfied that mechanisms for addressing integrity
and ethical issues are functioning effectively.
Effective control – governing structures and processes
Role of the board
The board exercises its leadership role by:
•Steering the group and setting its strategic direction
•Approving policy and planning that gives effect to the direction provided
•Overseeing and monitoring implementation and execution by management
•Ensuring accountability for the group’s performance by means of reporting and disclosures.
The role and function of the board, including guidelines on its composition and procedures, are
detailed in the board charter. This is reviewed annually (and when necessary) to ensure it remains
relevant.
There is a protocol in place should any of the board members or committees need to obtain
independent, external professional advice at the cost of the company on matters within the scope of
their duties. Non-executive directors are also aware of the protocol for requisitioning documentation
from, and setting meetings with, management. Board members have direct and unfettered access
to the chief audit executive, group company secretary and members of executive management.
Based on its annual work plan, the board is satisfied that it fulfilled its responsibilities in the review
period in line with its charter.
Refer to Board and committee attendance in this report.
Board committees
The board has delegated particular roles and responsibilities to standing committees, based on
legal requirements, what is appropriate for the group and to achieve the objectives of delegation.
The board recognises that duties and responsibilities can be delegated, but accountability cannot
be abdicated. The board therefore remains ultimately accountable.
Each committee operates in accordance with formal terms of reference, which are reviewed
annually, and more frequently where necessary, to ensure that they remain appropriate and aligned
with the applicable requirements of the JSE Listings Requirements and the Companies Act, as well
as the relevant recommending practices in King V.
199
Risk governance
The board appreciates that risk is integral to the way it makes
decisions and executes its duties. Risk governance
encompasses both risks and opportunities as well as a
consideration of the potential positive and negative effects of
any risks on achieving Harmony’s objectives. The group’s risk
appetite and tolerance levels, which support its strategic
objectives, are considered annually. The board is supported in
this area by the audit and risk committee.
Responsibility for implementing and executing effective risk
management is delegated by the board to management. The
board acknowledges the need to integrate and embed risk
management in the business activities and culture of the
group. The audit and risk committee is tasked with ensuring
independent assurance on the effectiveness of risk
management in the group, when deemed necessary and
appropriate.
Technology and information governance
Data, information and technology governance (King V Principle
10) is overseen by the audit and risk committee. The board
recognises the growing strategic importance of technology –
including operational technology, cybersecurity, data
management and digital innovation – to Harmony’s business
model and long-term value creation. The board monitors
significant information technology (IT) risks and ensures that
management maintains appropriate controls and capabilities
in this domain.
Cybersecurity
Harmony continued to strengthen its cybersecurity maturity during
the year, evolving from a foundation of preventative security
controls towards a more integrated, resilience-focused and zero
trust security operating model. Core controls such as security
monitoring, endpoint protection, email security, security
awareness, Sarbanes-Oxley (SOX) oversight and National Institute
of Standards and Technology (NIST) aligned practices remain in
place and continue to be enhanced.
The most significant developments have been the advancement of
zero trust capabilities, improving secure access, identity
protection, privileged access management and attack-path
reduction across the group. Cybersecurity visibility has also been
extended into operational technology (OT) environments,
strengthening protection of mining operational systems.
Harmony has further enhanced its cyber resilience by updating its
incident response plan, introducing detailed cyber response
playbooks, appointing specialist incident response support
providers, and conducting executive cyber crisis simulations.
Cyber recovery planning is increasingly aligned to business
continuity and operational resilience objectives to support rapid
recovery from potential cyber incidents.
Governance arrangements have matured through the approval of
a formal cybersecurity policy and establishment of a
comprehensive cybersecurity framework covering IT, OT, cloud,
data protection, third-party security, resilience, monitoring and
emerging technology risks. Oversight continues through board,
executive, risk, audit and specialist governance forums.
Harmony also introduced formal artificial intelligence (AI)
governance through an approved AI policy that addresses
acceptable use, security requirements, accountability, incident
management and mandatory human oversight. AI governance has
been incorporated into the broader cybersecurity governance
framework, ensuring emerging technology risks are proactively
managed.
Together, these developments strengthen Harmony's ability to
prevent, detect, respond to and recover from cyber threats across
its IT and OT environments.
Building AI capability through a disciplined, value-led
approach
Harmony is adopting AI selectively, focusing on practical
applications that can enhance safety, operational performance
and employee productivity. During FY26, Harmony introduced
secure and governed large language model access for knowledge
workers, implemented AI-enabled ESG action management and
began preparing to use AI capabilities embedded in core mining
applications. Additional point-of-value initiatives are being
assessed against defined business cases.
These activities are supported by continued investment in secure
infrastructure, resilient connectivity, cloud-enabled platforms,
service management and employee digital enablement. Together
with Harmony’s approved AI policy and cybersecurity governance
framework, these capabilities support the responsible adoption
and use of AI across the group.
Compliance governance
Code of conduct
Our behavioural code and code of conduct commits
Harmony, our employees and our contractors to the highest
moral standards, free from conflicts of interest. The board
reviews the code at least every second year, while its
application in Harmony is continually monitored by
management. The code of conduct was reviewed and
updated in FY25. Our ethics programme is also subject to
independent assurance as part of the internal audit coverage
plan. The code of conduct addresses critical issues, including
respect for human rights, anti-corruption, gifts and
entertainment and declarations of interests. It encourages
employees and other stakeholders to report any suspected
irregularities. This can be done anonymously through a 24-
hour hotline (managed independently) and other channels. All
incidents reported are investigated and monitored by the
white-collar crime committee, which comprises managers
representing various disciplines in the company and reporting
to the management ethics committee.
Whistleblowing policy
Our whistleblowing policy encourages shareholders,
employees, service providers, contractors and members of
the public to report practices at any of our workplaces that are
in conflict with any law, regulation, legal obligation, ethical
codes or governance policies. It also provides a mechanism
for our stakeholders to report these practices internally, in
confidence, independent of line management, and
anonymously if they wish. The whistleblowing policy informs
whistleblowers of their rights.
Harmony is committed to protecting whistleblowers from any
reprisals or victimisation. The identity of any employee or
stakeholder who reports non-compliance with the code of
conduct and other irregularities is protected. Our anonymous
ethics hotline numbers are widely advertised throughout the
organisation:
•South Africa: +27 (0) 800 204 256
•Papua New Guinea: +675 (0) 00 478 5280
•Australia: +61 (1) 800 940 949.
Human rights
At Harmony, we conduct our activities in a way that respects
human rights as set out in the laws and constitutions of the
countries in which we operate in line with the human rights
policy which was reviewed and updated in FY25. Our
approach to respecting human rights includes adhering to
corporate policies, complying with applicable laws and
regulations, regular dialogue and engagement with our
stakeholders and contributing, directly or indirectly, to the
general wellbeing of communities within which we operate.
Broad-based Black Economic Empowerment Act
The annual compliance report in line with section 13G(2) of
this act.
200
Dealing in Harmony shares
During price-sensitive periods, our employees and directors
are prohibited from dealing in Harmony shares. Written notice
of these restricted periods is communicated to them by the
group company secretary. In terms of regulatory and
governance standards, directors, prescribed officers and the
group company secretary are required to disclose any
dealings in Harmony shares in line with the JSE Listings
Requirements. The clearance procedure for directors,
prescribed officers and the group company secretary to deal
in Harmony shares is regulated by the company’s policy on
trading in shares and insider trading.
Significant fines
Harmony paid no significant fines in any of its areas of
operation. No actions were brought against it for anti-
competitive behaviour, anti-trust or monopoly practices in
FY26.
Foreign private issuers
New York Stock Exchange foreign private issuers, such as
Harmony, must highlight any significant ways in which their
corporate governance practices differ from those followed by
United States domestic companies subject to the listing
standards of the New York Stock Exchange.
Tax governance
Approach to tax
We play an integral role in the economic life of individuals,
communities and businesses where we operate. Our
approach to tax is informed by our intent to build a lasting
legacy both from an environmental and social perspective. We
remain committed to contributing tax revenues to the
economies of the countries in which we operate, while
maintaining transparent and responsible tax management
practices. Our approach is grounded in sustainable
governance, ethical conduct and open engagement with
stakeholders, reflecting our commitment to accountability and
transparency in all fiscal matters.
Tax governance, control and risk management
Harmony’s tax governance framework is founded on strong
corporate governance principles. Aligned with broader
business risk management and legal compliance, oversight is
provided by both the board and our audit and risk committee.
We follow robust internal controls, monitoring compliance with
tax laws and regulations and regularly assess the
effectiveness of our controls as part of our annual reporting
process and related external audit activities.
For specifics on our tax position and how it is managed as
part of our risk management and compliance requirements,
see note 11 “Taxation” of our consolidated financial
statements, set forth beginning on page F-1.
Stakeholder engagement and management of concerns
We maintain a structured, proactive approach to stakeholder
engagement, particularly with respect to tax matters. We have
a formal stakeholder engagement policy to guide and manage
external stakeholder concerns, complaints and grievances.
Any tax-related grievance by any external stakeholder would
be managed according to this policy by our stakeholder
relations officers to ensure the grievance is managed in a
timely and responsible manner.
Remuneration governance
Attracting and retaining the required skills depends largely on
the remuneration levels and practices in any business. It is
therefore vital to ensure the group remunerates fairly,
responsibly and transparently to support the achievement of
strategic objectives and positive outcomes in the short,
medium and long term. The board is supported in this area by
the remuneration committee.
The remuneration policy and remuneration implementation
report are presented to shareholders for consideration at the
2026 annual general meeting in accordance with the
applicable regulatory requirements.
Following the 2026 annual general meeting, Harmony will
disclose the voting results, and where the applicable threshold
for shareholder dissent is met, provide for engagement with
dissenting shareholders in accordance with the applicable
requirements. The subsequent annual report will disclose the
shareholders engaged, the manner and form of engagement,
and the nature of the objections and steps taken to address
them, as applicable.
Internal audit
The audit and risk committee oversees arrangements for
assurance services and functions on behalf of the board to
ensure these are effective in achieving the objectives of an
enabling control environment and supporting the integrity of
information for internal decisions and external reporting.
A combined assurance framework effectively covers the
group’s significant risks and material matters through a
combination of internal functions and external service
providers.
Despite the output of the combined assurance framework,
board members are expected to apply an inquiring mind, form
their own opinion on the integrity of information and reports
and the degree to which an effective control environment has
been achieved.
Internal audit plays an important part in the overall assurance
approach and effectiveness of the assurance framework. The
audit and risk committee oversees the internal audit function
on behalf of the board.
External independent quality assessment
In FY25, the internal audit function underwent an independent
quality review conducted by the Institute of Internal Auditors
South Africa. Consistent with the findings of the FY20 review,
this assessment concluded that the function generally
conforms to the International Standards for the Professional
Practice of Internal Auditing Professional Practice of Internal
Auditing, reflecting a high level of compliance and
effectiveness. No material findings were identified, and
alignment with the newly issued internal audit standards is well
advanced and nearing completion. In line with best practice,
an external independent quality assessment is conducted
every five years, with the next review scheduled for FY30.
201
Sarbanes-Oxley Act (SOX) compliance
We have controls related to financial reporting risks, which are
subject to continuous SOX control performance monitoring
and self-assessment, forming the basis for SOX certification.
These certifications are independently verified by external
auditors.
As at 30 June 2026, management evaluated the effectiveness
of our internal control over financial reporting and concluded
that it was not effective due to the four material weaknesses
described below. One material weakness was newly identified
during the year. The remaining three were first reported as at
30 June 2025 and had not been fully remediated by year end.
In reaching this conclusion, management considered the
matters that resulted in the restatement of comparative
financial information for the years ended 30 June 2024 and
2025, as disclosed in the Financial report, together with the
material weaknesses described below.
Notwithstanding these material weaknesses, management,
including our chief executive officer and financial director,
concluded that our consolidated financial statements as set
forth beginning on page F-1, present fairly, in all material
respects, our financial position, results of our operations and
our cash flows for the periods presented, in conformity with
IFRS Accounting Standards as issued by the International
Accounting Standards Board (IASB).
Newly identified material weakness:
•Ineffective design and operation of controls over the
identification, evaluation and application of complex IFRS
Accounting Standards requirements, affecting, among other
matters, payroll provisions and accruals, and depreciation.
Previously identified material weaknesses not yet fully
remediated:
•Control activities were not defined with sufficient specificity,
including the procedures to be performed, the information
to be used and the criteria for investigating exceptions, to
operate at the required level of precision
•Insufficient evidence of review (including the precision of the
review) of Management Review Controls (MRCs) and
controls that contain an element of review, and of the
procedures performed to verify the completeness and
accuracy of Information Produced by the Entity (IPE) used in
the execution of controls
•Ineffective information technology general controls (ITGCs)
in the areas of user access and change management over
the enterprise resource planning (ERP) system used by our
Australasian operations, and the automated and manual
controls dependent on it.
These deficiencies impact controls across multiple significant
accounts and business processes. As a result, there is a
reasonable possibility that a material misstatement in our
consolidated financial statements would not have been
prevented or detected on a timely basis. As disclosed in the
Financial report, comparative financial information for the years
ended 30 June 2024 and 2025 has been restated to correct
identified errors.
Legitimacy
Inclusive stakeholder engagement model
The board sets the direction for the group’s approach to
stakeholder relationships. An inclusive stakeholder
engagement approach considers whether the legitimate
needs, interests and expectations of all key stakeholders have
been adopted. Information on material stakeholders and the
manner in which relationships with stakeholders are managed,
governed and monitored appears in Stakeholder needs and
expectations.
202
Group organisational structure
The group is led and directed by a unitary board of directors that is guided by ethical leadership practices, supported by board and committee charters that are reviewed regularly. The group executive
management team, headed by the chief executive officer, is responsible for leading implementation and execution of the board-approved strategy, policy and operational planning and governed appropriately
in line with a formal delegation of authority framework.
Board of directors | ||||||||||||||||
The board exercises its leadership role over the group by: | ||||||||||||||||
Steering its strategic direction | Approving policy and planning that gives effect to the strategy | Overseeing and monitoring implementation and execution by management | Ensuring accountability for performance through reporting and disclosure | |||||||||||||
Board committees | |||||||||||||||||||
The board has delegated particular roles and responsibilities to standing committees, but remains ultimately accountable. The board committees’ primary functions include the consideration, oversight and monitoring of strategies, policies, practices, performance and recommendations to the board for final approval related to: | |||||||||||||||||||
Audit and risk | Social and ethics | Remuneration | Nomination | Investment | Technical | ||||||||||||||
•Operating an adequate system of internal control and control processes •Accurate and appropriate reporting of financial statements •Governance of information and technology •Risk management and overall risk governance. | •Occupational health and employee wellbeing, environmental management, corporate social responsibility, human resources, public safety and ethics management •Compliance with relevant regulations •Sustainability-related key performance indicators and levels of assurance. | •Fair reward of directors and executive management for their contribution to Harmony’s performance •Harmony’s compensation policies and practices; administration of its share incentive schemes •Group remuneration policy. | •Formal and transparent procedures on board appointments •Succession planning for directors and members of executive management •Board self-assessment process. | •Potential projects, acquisitions and disposals in line with Harmony’s strategy; ensures due- diligence procedures are followed. | •Safety, strategy and operational performance •Review of strategic plans •Technical guidance and support to management. | ||||||||||||||
Group executive committee | ||
Led by the chief executive officer, in charge of executing board-approved strategy as well as the day-to-day management of all operations. | ||
203
Annual general meeting (AGM)
The AGM of the company will be held on Tuesday, 24 November 2026 at 11:00 (SA time), to
transact the business as stated in the Notice to shareholders.
The issued share capital of Harmony comprises of ordinary and preference shares that entitles the
holder to vote on any matter to be decided by the shareholders
Board leadership
The board provides ethical and effective leadership that balances strategic ambition with
disciplined oversight. Through a combination of independent judgement, diverse expertise and a
stakeholder-inclusive approach, the board steers Harmony’s long-term direction, monitors
performance and risk, and oversees the responsible use of the capitals on which our business
depends. The board remains focused on preserving and creating sustainable value, while ensuring
that governance practices support operational excellence, resilience and accountability across all
jurisdictions in which Harmony operates.
Board focus areas in FY26
The board’s agenda in FY26 was shaped by Harmony’s evolving strategic landscape, the broader
macro-economic environment and the group’s long-term ambitions. Key focus areas and the
board’s associated actions are summarised below:
Focus area | Key actions in FY26 | ||||
Strategic leadership | Approved multi-year strategy, including copper expansion, decarbonisation pathway and portfolio resilience initiatives. Monitored the 10th consecutive year of production guidance delivery. | ||||
CEO transition and succession/ New director onboarding | Oversaw the smooth transition and integration of newly appointed directors through a structured induction and engagement programme, supporting continuity of governance and effective contribution to board deliberations. The Board also reviewed emergency and long-term succession plans to strengthen leadership continuity and organisational resilience. | ||||
Safety and operational oversight | Monitored the implementation of the safety transformation journey, with ongoing oversight by the technical committee and the social and ethics committee. Through continued engagement on risk-based safety practices across South Africa and Australasia, the board remained focused on advancing its zero-harm ambition. | ||||
ESG and sustainability governance | Approved the updated sustainability framework and related policies. Endorsed Harmony’s decarbonisation targets and reviewed progress against SBTi-aligned climate commitments. Considered relevant international sustainability reporting guidance where appropriate. | ||||
Risk management and compliance | Reviewed the group’s top risks via the audit and risk committee. Monitored regulatory compliance across multiple jurisdictions, including South Africa, Papua New Guinea, Australia and the United States. |
Focus area | Key actions in FY26 | ||||
Board composition and transformation | The board recognises that a balanced mix of skills, experience, independence, diversity and institutional knowledge enhances its effectiveness. Through the nomination committee, it has pursued a structured renewal and succession process over the past few years to strengthen board composition and support a broad range of perspectives and expertise. Board composition is reviewed at least once a year to ensure alignment with the Company's strategy and evolving needs. Succession planning remains an ongoing priority, supporting orderly renewal while preserving continuity, institutional knowledge and governance effectiveness. | ||||
Governance effectiveness | Conducted an independent formal board self-evaluation. Reviewed and updated the board and board committee terms of reference and related policies. |
Director training during the year
•IFRS S1, IFRS S2 and South Africa’s Climate Change Act
•Legal and regulatory developments relating to remuneration and reward governance
•Anti-bribery, anti-corruption and anti-money laundering
•King V, including comparison with the Companies Act and JSE Listings Requirements
•Deep dive into the Eva Copper Project and its final investment decision (FID).
204
Board composition, chairman, independence and
meeting attendance
Board transformation and broader diversity
Transformation and diversity remain enduring priorities for the
board. Harmony has adopted a promotion of broader diversity
policy at board level, specifically focused on promoting the
diversity attributes of gender, race, culture, age, field of
knowledge, skills and experience. Through the nomination
committee, the board has implemented a multi-year renewal
and succession programme aligned with Harmony's
transformation objectives and the principles of King V.
During FY26, Frans ("Faan") Lombard was appointed as an
independent non-executive director, succeeding John Wetton,
who retired at the conclusion of the 2025 AGM after 13 years
of service on the board.
Board members collectively hold experience in the following
skill areas:
•Mining operations, safety and technical management
•Finance, capital markets and investment
•Governance, legal and regulatory compliance
•Sustainability, environment and climate change
•Human resources, remuneration and organisational
development
•Community and stakeholder relations, public policy and
government affairs
•Emerging markets and international business.
The board is satisfied that its composition reflects the
appropriate mix of knowledge, skills, gender, race, culture,
age, experience and independence. Through its annual
composition and succession planning reviews, the board
continues to identify opportunities to further strengthen its
collective capabilities, with a number of focus areas being
addressed as part of its ongoing renewal and succession
process in FY27. In addition, the composition of the board
and its leadership structure ensures there is a balance
of power in the boardroom, supported by the board charter,
delegation of authority, committee mandates and actual
decision-making arrangements, and that no one director has
unfettered authority of decision making.
Board composition
As of the publication of this report, the board has 17 highly
experienced and reputable members: 14 are non-executive
directors of whom 13 are independent; three are executive
directors; five are female and 11 are historically disadvantaged
persons.
Refer to assessing independence of directors with tenure of
over nine years below for further information.
The role and function of the board, including guidelines on its
composition and procedures, are detailed in the board
charter. This is reviewed regularly to ensure it remains
relevant. Brief profiles of board members appear in Our
leadership section, with detailed résumés online.
Role of chairman
The chairman of the board, Dr Patrice Motsepe is a non-
executive director but is not classified as independent. The
board is satisfied that, following an assessment that was
undertaken during the year under review (FY26), that the lead
independent director, Dr Mavuso Msimang, met the
requirements for an independent director under the
Companies Act, JSE Listings Requirements, King V, and any
other criteria evidencing objectivity and independence
established by the board.
Mr Faan Lombard was appointed as the company's lead
independent director (and chairman of the nomination
committee) with effect from 14 August 2026 (FY27),
succeeding Dr Msimang, who remains a member of the board
(and nomination committee).
The duties of the chairman and lead independent director
have been included in the board charter and are based on the
recommendations of King V. The roles of the chief executive
officer and chairman are separate. In addition to the chairman
and lead independent director, the board also has an
independent non-executive deputy chairman, Ms Karabo
Nondumo.
These appointments are reviewed annually and form part of
the board’s succession plan for the position of chairman,
deputy chairman and lead independent director.
The board has applied King V guidance, and other relevant
requirements, on board composition and committee
membership. While King V recommends that the board
chairman also chair the nomination committee, the board has
determined that, given the board chairman’s non-independent
status, it is appropriate for the lead independent director to
serve as chairman of the committee. This arrangement
enhances the independence of oversight relating to board
composition, succession and director nominations. The board
chairman therefore serves solely as a member of the
nomination committee.
Assessing independence of directors with tenure of
over nine years
The majority of non-executive directors are classified as
independent and their independence has been reviewed by
the nomination committee. The board appreciates that
independence is primarily a state of mind and all board
members, despite their categorisation, are expected to act
independently and with unfettered discretion at all times. This
expectation is confirmed in the board charter.
Following an assessment undertaken by the nomination
committee of Dr Mavuso Msimang, who has served on the
board for 15 years, Ms Karabo Nondumo (13 years) and Mr
Vishnu Pillay (13 years), during the year under review, the
committee is satisfied that these individuals do not have any
relationships that may impair, or appear to impair, their ability
to apply independent judgement. In addition, there are no
interests, positions, associations or relationships which, from
the perspective of a reasonable and informed third party, are
likely to influence the members unduly or cause bias in their
decision making.
205
The board has carefully considered the tenure of the relevant
members and remains satisfied that they continue to
demonstrate independence of mind and judgement and to
fulfil their roles objectively as independent non-executive
directors. Their extensive experience, institutional knowledge
and standing as individuals of integrity and character remain
valuable to the board and the group, particularly as the board
balances renewal with continuity of critical skills. Their
continued service is aligned with the board’s transitional and
succession plans, supporting the orderly transfer of
knowledge and responsibilities while maintaining effective
oversight and continuity for shareholders.
In line with the board composition transitional plan, the board
(with the assistance of the nomination committee) continued
to review its composition, structure, size, and independence
to ensure alignment with best practice and to advance its
commitment to broader diversity. Mr Vishnu Pillay, one of the
board’s longest-serving members, will retire by rotation this
year. Although eligible for re-election, he will not be seeking
re-election to the board, effective as of the conclusion of the
2026 annual general meeting.
On 15 October 2026, two independent non-executive
directors (Mr Alwyn Pretorius and Mr James Boardman) were
appointed to the board and will stand for election by
shareholders at the forthcoming annual general meeting. The
board is satisfied that the outcomes of the fit-and-proper
assessments, conducted in accordance with the JSE Listings
Requirements, confirm that these two directors meet the
requisite standards of competence, integrity and suitability for
their respective roles.
While these appointments do not add to the demographic
diversity of the board, they broaden its diversity of skills,
experience and perspectives, in line with the company’s
broader board diversity policy. As demonstrated over the past
few years and communicated to stakeholders, the board’s
transition plan remains focused on balancing all aspects of
diversity while ensuring continuity and effective board
oversight.
Nomination, election and appointment
The nomination committee is tasked with identifying potential
candidates for appointment to the board, while actual
appointment is a matter for the board as a whole. The
collective knowledge, skills and experience required by the
board, as well as broader diversity, are all aspects considered
by the board before appropriate candidates are identified for
nomination. The nomination committee conducts the
necessary independence checks and investigations on
potential candidates, as recommended by King V.
All new board members receive formal letters of appointment.
In addition, they participate in an extensive induction
programme to enable them to make the maximum
contribution in the shortest possible time, and further receive,
from Harmony’s appointed JSE sponsor, a formal explanation
on the nature of their responsibilities and obligations arising
from the JSE Listings Requirements. Ongoing mentorship is
provided to members with no or limited governance
experience and they are encouraged to undergo appropriate
training. Provision has also been made in the board’s annual
work plan for regular briefings on legal and corporate
governance developments, as well as risks and changes in the
external environment of the group.
As required by the provisions of Harmony’s Memorandum of
Incorporation, a third of the non-executive directors are
expected to retire by rotation at each annual general meeting
of the company. The board is comfortable in recommending
their reappointment to shareholders and confirms that the
outcomes of the fit-and-proper assessments for these
directors, conducted in accordance with the JSE Listings
Requirements, meet the requisite standards of competence,
integrity and suitability for their respective roles.
The role and function of the board, including guidelines on its
composition and procedures, are detailed in the board
charter, which is reviewed regularly to ensure it remains
relevant and applicable.
Board performance evaluations
The board fully supports the thinking that an appropriate
evaluation of the board and its structures is a strategic value-
adding exercise that facilitates continual improvement of its
performance and effectiveness. An independent formal self-
evaluation process was undertaken in FY26. This included an
assessment of the performance of the board, its chairman and
individual members as well as committees, chief executive
officer and group company secretary. Overall, the self-
evaluation reconfirmed that the board and its committees
were considered:
•Highly effective
•Appropriately positioned to discharge their governance
responsibilities
•Well supported by its committees
•Working as a cohesive unit and that the highest ethical
standards are applied in deliberations and decision making,
enabling the board to provide effective leadership from an
ethical foundation.
The consensus among board members is that the chief
executive officer:
•Communicates consistently and effectively with all
Harmony’s stakeholders
•Created and implemented an effective strategy, supported
by management
•Demonstrates ethical and transparent leadership by living
the company’s culture and reinforcing its values.
Considering the outcome of the evaluation process, the board
is satisfied that the process is improving its performance and
effectiveness.
Conflicts of interest
Each member of the board is required to submit a general
declaration of financial, economic and other relevant interests
and to update these declarations as necessary. In addition,
the declaration of interests in any matter on the agenda of a
board or committee meeting is a standard item at the start of
every meeting. In the event of a potential conflict being
declared, the board proactively manages this conflict within
the boundaries of the law.
206
Appointment and delegation to management
The board is responsible for appointing the chief executive
officer on recommendation by the nomination committee.
Harmony’s chief executive officer, Mr Beyers Nel is
responsible for leading implementation and execution of the
board-approved strategy, policy and operational planning, and
serves as a link between the board and management. He is
accountable and reports to the board. He is not a member of
the remuneration, audit or nomination committees. He does
attend meetings of these committees as required to contribute
insights and information.
Succession planning for this position forms part of the
executive succession plan that is monitored on behalf of the
board by the nomination committee. An emergency
succession plan is also in place and reviewed annually, and
the committee is satisfied that appropriate succession
arrangement are in place.
A formal delegation of authority framework is in place and
reviewed regularly by the board, which is satisfied that it
remains appropriate to the business. The framework
addresses the authority to appoint executives, including those
who may serve as ex officio executive members of the board
and other executive appointments.
Group company secretary
The group company secretary, Ms Shela Mohatla, is a full-
time employee of Harmony who was appointed by the board
on 14 August 2020. She is a chartered secretary by
profession and is a certified director by the Institute of
Directors South Africa.
The board has direct access to the group company secretary
who provides professional and independent guidance to the
board as a whole and to members individually on corporate
governance and legal duties. She also supports the board in
coordinating the effective and efficient functioning of the board
and its committees.
The group company secretary has unrestricted access to the
board and, at all times, retains an arm’s length relationship to
enhance the independence of the position. She is not a
member of the board but, being accountable to the board,
reports to the board via the chairman on all statutory duties
and related functions.
To facilitate and enhance the independence and effectiveness
of the group company secretary, the board ensures the office
of the group company secretary is empowered and the
position carries the necessary authority. The remuneration
committee considers and approves the remuneration of the
group company secretary on behalf of the board.
Following the assessment of the group company secretary by
the board in August 2026, the board is satisfied that the group
company secretary has the necessary competence,
qualifications, experience, gravitas and objectivity to provide
independent guidance and support at the highest level of
decision making in the group.
The board is therefore satisfied that arrangements in place for
accessing professional corporate governance services are
effective.
Discharge of responsibilities
The board is satisfied that the committees properly discharged
their responsibilities over the past year. Furthermore, the
board complies, to the best of its knowledge, with the
Companies Act and its memorandum of incorporation,
monitors such compliance on an ongoing basis and operates
in conformity with its memorandum of incorporation.
Access to independent professional advice
Directors may obtain independent external professional
advice, at the Company's expense, on matters within the
scope of their duties in accordance with an established board-
approved protocol. Non-executive directors also have access
to formal processes for requesting information from, and
engaging directly with, management. In addition, directors
have direct and unrestricted access to the chief audit
executive, group company secretary and members of
executive management.
The board is satisfied with its arrangements for access to
professional and independent guidance on its legal and
corporate governance duties, as well as support for its
effective functioning.
Board oversight and compliance
The board is satisfied that it has discharged its responsibilities
and fulfilled its statutory, regulatory and governance
obligations throughout the 2026 financial year. In reaching this
conclusion, the board has considered the Company's
compliance framework, the effectiveness of its governance
structures and the assurances received during the year.
In particular, the board confirms that:
•Regulatory and listing obligations: The Company has
established and maintained appropriate governance
processes, policies and internal controls designed to
provide reasonable assurance of compliance with the
applicable requirements of the Johannesburg Stock
Exchange (JSE), New York Stock Exchange (NYSE),
together with other relevant regulatory obligations
•Corporate governance standards: The Company remains
committed to the principles of sound corporate governance
and the responsible stewardship of its affairs. The board is
satisfied that the Company's governance practices are
aligned with the applicable principles of the King V Report
on Corporate Governance™ for South Africa 2025 (King
V™), reflecting its commitment to ethical leadership,
accountability, transparency and effective oversight.
•Statutory compliance: The Company has complied with the
relevant provisions of the Companies Act 71 of 2008, as
amended, particularly those relating to its incorporation, and
has conducted its affairs in accordance with its
Memorandum of Incorporation (MoI)
•Compliance with laws and regulations: During the year
under review, no significant instances of non-compliance
with applicable laws or regulations were identified, nor were
any significant fines or penalties imposed on the Company
or its directors arising from regulatory contraventions.
207
Board and committee attendance
Attendance at committee meetings | ||||||||||||||||||
Name | Age | Appointed director | Independent | Audit and risk* | Social and ethics* | Technical* | Investment* | Remuneration* | Nomination* | Attendance at board meetings* | ||||||||
Non-executive directors | ||||||||||||||||||
Dr Patrice Motsepe (chairman) | 64 | 2003** | 3/4 | 4/4 | 100% | |||||||||||||
Ms Karabo Nondumo (deputy chairman) | 48 | 2013 | ü | 3/31 | 5/6 | 6/6 | 4/4 | 4/4 | 100% | |||||||||
Dr Mavuso Msimang (lead independent) | 85 | 2011 | ü | 6/6 | 4/4 | 4/4 | 100% | |||||||||||
Mr John Wetton2 | 77 | 2011 | ü | 3/32 | 2/22 | 3/32 | 2/22 | 100% | ||||||||||
Mr Vishnu Pillay | 69 | 2013 | ü | 5/6 | 5/6 | 5/5 | 4/4 | 4/4 | 100% | |||||||||
Ms Given Sibiya | 58 | 2019 | ü | 5/5 | 6/6 | 5/5 | 4/4 | 100% | ||||||||||
Mr Peter Turner | 69 | 2021 | ü | 6/6 | 6/6 | 4/4 | 100% | |||||||||||
Mr Bongani Nqwababa | 60 | 2022 | ü | 4/5 | 5/6 | 5/5 | 4/4 | 100% | ||||||||||
Mr Martin Prinsloo | 57 | 2022 | ü | 5/5 | 6/6 | 6/6 | 4/4 | 100% | ||||||||||
Mr Mangisi Gule | 74 | 2025 | ü | 5/5 | 4/4 | 100% | ||||||||||||
Ms Zanele Matlala | 63 | 2025 | ü | 5/5 | 3/33 | 4/4 | 100% | |||||||||||
Ms Mametja Moshe | 46 | 2025 | ü | 4/5 | 3/34 | 4/4 | 100% | |||||||||||
Mr Faan Lombard5 | 69 | 2025 | ü | 2/25 | 3/35 | 100% | ||||||||||||
Executive directors | ||||||||||||||||||
Mr Beyers Nel | 49 | 2025 | 4/4 | 100% | ||||||||||||||
Ms Boipelo Lekubo | 43 | 2020 | 4/4 | 100% | ||||||||||||||
Mr Harry Mashego | 62 | 2010 | 4/4 | 100% | ||||||||||||||
As at 30 June 2026 | ||||||||||||||||||
*Includes ad hoc meetings for the year.
**Appointed chairman in 2004.
1Resigned as member on 26 November 2025.
2Retired on 26 November 2025.
3Elected as chairperson and member on 26 November 2025.
4Elected as member on 26 November 2025.
5Appointed to the board on 14 August 2025 and a member of the audit and risk committee on 26 November 2025.
Mr Faan Lombard was appointed as lead independent director and chairperson of the nomination committee, succeeding Dr Mavuso Msimang who remains a member of the nomination committee, with
effect from 14 August 2026.
Mr Alwyn Pretorius and Mr James Boardman were appointed on 15 October 2026.
208
Board committees
The board has constituted six standing board committees to assist it in discharging its
responsibilities. Each committee operates under formal written terms of reference reviewed
annually by the board. While the board delegates certain functions to these committees, it retains
ultimate accountability. All board committees are chaired by an independent non-executive
director.
The board is satisfied that its delegation to committees and individuals within its own structures
promotes the objective and effective discharge of its governance obligations.
The following committees have been established:
•Audit and risk
•Social and ethics
•Remuneration
•Nomination
•Investment
•Technical.
A brief description of each committee, its functions and key activities and actions in FY26 appears
on the following pages.
Terms of reference
Formal terms of reference have been adopted for each board committee and are reviewed
annually (and when necessary) to ensure the content remains relevant and appropriate. The terms
of reference address, as a minimum, the requirements of the JSE Listings Requirements, the
Companies Act and the recommendations of the King Report.
While King V requires that the Terms of Reference must be reviewed periodically or when
circumstances or requirements change, Harmony has elected to comply more rigorously by
retaining an annual review.
The respective terms of reference for each committee are published on Harmony's website at
www.harmony.co.za/about/corporate-governance/board-committees/.
Committee membership
In considering committee membership, the board, assisted by the nomination committee, is
mindful of the need for effective collaboration through cross-membership between committees
where required. The timing of committee meetings is coordinated to facilitate the effective
functioning and contribution of each committee. Duties and responsibilities are documented to
clearly define the specific role and positioning of each committee on topics that may be within the
mandate of more than one committee. Committee membership has also been addressed to
ensure a balanced distribution of power across committees so that no person has the ability to
dominate decision making and no undue reliance is placed on any one person.
The board is satisfied that each committee, as a whole, has the necessary knowledge, skills,
experience and capacity to execute its duties effectively and with reasonable care and diligence.
Each committee has a minimum of three members. Members of executive and senior
management are invited to attend committee meetings as deemed appropriate and necessary for
the effective functioning of the committee. In the reporting year, the majority of members of all
board committees comprised independent non-executive directors. All board committees were
chaired by an independent non-executive director.
Committee meetings
Any director who is not a member of a specific committee is entitled to attend meetings as an
observer, but not entitled to participate without the consent of the committee chairperson. Such
directors have no vote in meetings and will not be entitled to fees for attendance, unless
specifically agreed by the board and provided for in the board fee structure as approved by
shareholders.
The board considers recommendations from its committees in matters requiring its approval, but
remains responsible for applying its collective mind to the information, opinions, recommendations,
reports and statements presented by the committees.
The meeting attendance of each committee member is included under board and committee
attendance on the previous pages.
209
Audit and risk committee
Member | Committee tenure | |
Martin Prinsloo (chairperson)1 | 4 years | |
Given Sibiya | 7 years | |
Bongani Nqwababa | 4 years | |
Zanele Matlala | 1.5 years | |
Mametja Moshe | 1.5 years | |
Faan Lombard2 | 1 year | |
Karabo Nondumo3 | 13 years |
1Appointed as chairperson on 17 January 2025.
2Appointed on 26 November 2025.
3Resigned on 26 November 2025.
Primary functions
•Monitors operation of an adequate system of internal control and control processes
•Monitors preparation of accurate financial reporting and statements in compliance with
all applicable legal and corporate governance requirements and accounting standards
•Monitors risk management, ensures significant risks identified are appropriately addressed
and supports the board in overall governance of risk.
Key activities and actions in FY26
For detail on actions in FY26, refer to the Audit and risk committee: chairperson’s report.
Social and ethics committee
Member | Committee tenure | |
Zanele Matlala (chairperson)1 | 1 year | |
Dr Mavuso Msimang | 15 years | |
Given Sibiya | 4.5 years | |
Mametja Moshe2 | 1 year | |
John Wetton3 | 14 years | |
Karabo Nondumo4 | 4.5 years |
1Appointed as chairperson and member on 26 November 2025.
2Appointed on 26 November 2025.
3 Retired on 26 November 2025.
4Resigned as chairperson on 26 November 2025, however remained a member.
Primary functions
•Oversees policy and strategies on occupational health and employee wellbeing, environmental
management, corporate social responsibility, human resources, public safety and ethics
management
•Monitors implementation of policies and strategies by executives and their management teams
for each discipline noted above
•Assesses Harmony’s compliance against relevant regulations
•Reviews significant issues in each of the above disciplines to evaluate their relevance in the
reporting period, and to identify additional significant issues that warrant reporting, including
sustainability-related key performance indicators and levels of assurance.
Key activities and actions in FY26
•Considered the governance of ethics and ethical leadership
•Reviewed and recommended the social and ethics committee report to be included in the
Integrated report
•Reviewed and considered the ethical, social, economic, human capital, environmental, health
and safety issues affecting the company’s business and stakeholders
•Reviewed and considered the effect of the company’s operations on the economic, social and
environmental wellbeing of communities, as well as significant risks within the ambit of its
responsibilities
•Considered Harmony’s overall decarbonisation strategy
•Considered and approved Harmony’s sustainability framework and related policy
•Approved key elements of sustainability reporting and key performance indicators that were
externally assured
•Considered and monitored the company’s internal and external stakeholder relations
•Considered and approved Harmony’s ethics management strategy
•Considered and approved Harmony’s health and safety policy
•Considered and approved Harmony’s behavioural code and code of conduct
•Considered and approved Harmony’s employment equity policy
•Considered and approved Harmony’s environmental policy
•Considered and monitored the company’s inclusive procurement and enterprise development
•Monitored fraud risk assessment and considered interventions to be in place to prevent fraud and
report
•Reviewed the committee’s terms of reference, aligned with King V, and recommended them to
the board for approval
•Undertook a renewable energy site visit to Moab Khotsong.
See Social and ethics committee: chairperson’s report.
210
Remuneration committee
Member | Committee tenure | |
Given Sibiya (chairperson)1 | 1.5 years | |
Vishnu Pillay | 9 years | |
Bongani Nqwababa | 4 years | |
Mangisi Gule | 1.5 years | |
John Wetton2 | 14 years |
1Appointed as chairperson on 17 January 2025.
2Retired on 26 November 2025.
Primary functions
•Ensures directors and executive management are fairly rewarded for their contribution to
Harmony’s performance
•Assists the board in monitoring, reviewing and approving Harmony’s compensation policies
and practices and administration of its share incentive schemes
•Operates as an independent overseer of the group remuneration policy and makes
recommendations to the board for final approval.
Key activities and actions in FY26
For detail on actions in FY26, refer to the Remuneration committee: chairperson’s report.
•Reviewed benefits and remuneration principles for Harmony executive management
•Reviewed a summary of the suite of Harmony executive management incentive schemes to
obtain a holistic view
•Reviewed and recommended the committee’s terms of reference to the board for approval
•Reviewed and recommended the company’s incentive plan policy to the board for approval
•Reviewed the company’s overall retention strategy and policy based on global trends on staff
retention
•Considered and recommended the remuneration policy and implementation report to the board
for inclusion in the notice of annual general meeting for consideration by shareholders as non-
binding advisory resolutions
•Reviewed executive directors and executive management’s remuneration benchmarks and
recommended their annual salary increases to the board for approval
•Reviewed and recommended the non-executive director travel, accommodation and
entertainment policy to the board for approval
•Reviewed the annual salary increases of the group company secretary and chief audit executive
•Reviewed non-executive director fees with the assistance of an independent service provider
•Considered and recommended the company’s total incentive plan Balanced Scorecard for FY27
for board approval
•Reviewed the committee’s terms of reference, aligned with King V, and recommended them to
the board for approval.
Nomination committee
Member | Committee tenure | |
Dr Mavuso Msimang (chairperson)1 | 14 years | |
Dr Patrice Motsepe | 23 years | |
Vishnu Pillay | 7 years | |
Karabo Nondumo | 4.5 years |
1Appointed as chairperson on 10 May 2018. On 14 August 2026, Mr Faan Lombard was appointed as
chairperson of the committee. Dr Mavuso Msimang remains a member of the committee.
Primary functions
•Ensures procedures governing board appointments are formal and transparent
•Makes recommendations to the board on all new board appointments
•Reviews succession planning for directors and other members of the executive team and
oversees the board’s self-assessment process.
Key activities and actions in FY26
•Reviewed succession planning for directors and other members of the executive team and
oversaw the board’s self-assessment process
•Reviewed succession planning for the chief executive officer
•Reviewed the committee’s terms of reference, aligned with King V, and recommended them to
the board for approval
•Reviewed and recommended for re-election directors who retire by rotation in terms of the
company’s memorandum of incorporation
•Reviewed and made recommendations on the composition, structure and size of the board and
its committees, in line with the board’s policy on the promotion of broader diversity
•Considered the positions of the chairman and deputy chairperson of the board and lead
independent director and made recommendations to the board
•Reviewed and recommended the independence of non-executive directors (especially
independent non-executives serving on the board for longer than nine years)
•Reviewed and recommended immediate and long-term succession plans for the board,
chairman of the board, chief executive officer, executive management and the group company
secretary
•Considered the programme in place for the professional development of directors and regular
briefings on legal and corporate governance developments, risks and changes in the external
operating environment of the organisation
•Considered the policy on the promotion of broader diversity at board level, specifically focusing
on the promotion attributes of gender, race, culture, age, field of knowledge, skills and
experience.
211
Investment committee
Member | Committee tenure | |
Bongani Nqwababa (chairperson)1 | 4 years | |
Karabo Nondumo | 13 years | |
Vishnu Pillay | 13 years | |
Peter Turner | 6 years | |
Martin Prinsloo | 4 years | |
John Wetton2 | 15 years |
1Appointed as chairperson on 17 August 2022.
2Retired on 26 November 2025.
Primary functions
•Considers projects, acquisitions and disposals in line with Harmony’s strategy and ensures due
diligence procedures are followed
•Conducts other investment-related functions designated by the board.
Key activities and actions in FY26
•Considered investments, proposals, projects and proposed acquisitions in line with the board’s
approved strategy and delegation of authority as well as the committee’s terms of reference
•Considered the company’s exploration expenditure
•Reviewed and recommended the budget and business plans for FY27 to the board for approval
•Monitored the progress and delivery of key projects across the Group
•Reviewed the final investment decision for Eva Copper and recommended it to the board for
approval
•Reviewed the committee’s terms of reference, aligned with King V, and recommended them to
the board for approval
•Undertook a site visit to Australia, including Eva Copper and the recently acquired CSA mine
•Provided oversight of the successful integration of CSA into the Group.
Technical committee
Member | Committee tenure | |
Peter Turner (chairperson)1 | 6 years | |
Vishnu Pillay | 13 years | |
Martin Prinsloo | 4 years |
1Appointed as chairperson on 23 February 2023.
Primary functions
•Provides a platform to discuss strategy, performance against targets, operational results,
projects and safety
•Informs the board of key developments, progress against objectives and challenges facing
operations
•Reviews strategic plans before recommending to the board for approval
•Provides technical guidance and support to management.
Key activities and actions in FY26
•Monitored safety across all operations
•Monitored exploration and Ore Reserves in South Africa, Papua New Guinea and Australia
•Monitored all South African, Papua New Guinean and Australian operations
•Evaluated and considered Harmony’s risks and measures taken to mitigate those risks
•Reviewed and recommended to the board the company’s annual budget and business plans for
FY27 to the board for approval
•Considered investments, proposals, projects and proposed acquisitions from a technical
viewpoint
•Considered and recommended the company’s health and safety policy to the social and ethics
committee for approval
•Monitored the progress and delivery of key projects across the Group
•Reviewed the final investment decision for Eva Copper and recommended it to the board for
approval
•Reviewed the committee’s terms of reference, aligned with King V, and recommended them to
the board for approval
•Undertook a site visit to Australia, including Eva Copper and the recently acquired CSA mine
•Provided oversight of the successful integration of CSA into the Group.
212
Remuneration committee: chairperson’s report
Dear shareholder
It is my privilege to present the 2026 remuneration report
on behalf of the remuneration committee (the committee).
During the year under review, the committee continued to
oversee the evolution of Harmony's remuneration framework
to ensure it remains aligned with the Company's strategic
priorities and long-term objectives. In doing so, we sought to
balance the need to attract, retain and motivate talent with our
commitment to responsible remuneration governance and
sustainable value creation.
Our remuneration philosophy is founded on the principles of
fairness, consistency and transparency. We believe that
recognising the contributions of our employees and
supporting their wellbeing are essential to maintaining a
resilient and high-performing organisation. The Committee
therefore remains focused on remuneration practices that are
responsive to changing workforce needs, while remaining
competitive and aligned with stakeholder expectations.
Governance and compliance
Section 30A and 30B of the Companies Act, 71 of 2008 (the
Companies Act), came into force on 22 May 2026, with
immediate effect. These sections replace the erstwhile non-
binding advisory vote mechanism previously provided for
under the JSE Listings Requirements with a binding ordinary
resolution regime, in terms of which shareholders are now
required formally to approve both Harmony’s remuneration
policy and its remuneration report. In particular:
•Section 30A provides that the remuneration policy,
contained in Part 2 below, must be presented to and
approved by shareholders at the annual general meeting by
ordinary resolution and thereafter re-approved at least once
every three years. If a material amendment to the policy is
proposed within that three-year period, the amendment
may only be implemented after it has been approved by
shareholders by ordinary resolution at an annual general
meeting or at a shareholders’ meeting convened for that
purpose. If the remuneration policy is not approved, it must
be presented again for approval at the next annual general
meeting or at a shareholders’ meeting called for that
purpose
•Section 30B provides that the remuneration report –
comprising this background statement, a copy of the
remuneration policy contemplated in section 30A, and an
implementation report – must be presented to and
approved by shareholders at the annual general meeting by
ordinary resolution each year. The implementation report
contains the statutory remuneration and pay-gap
disclosures required by section 30B(3)(c). If the
remuneration report is not approved, the committee must at
the next annual general meeting explain how shareholders’
concerns have been taken into account and the non-
executive directors who are not involved in the day-to-day
management of Harmony and who serve on the committee
must stand for re-election as committee members. If the
report is not approved again, those affected non-executive
directors may continue as directors if re-elected but will not
be eligible to serve on the committee for two years
thereafter. These consequences do not apply to committee
members who have served for less than 12 months in the
year under review.
Consistent with section 30B(3)(c) of the Companies Act,
Harmony has prepared the statutory remuneration and pay-
gap disclosures required for the full employee population
covered by the definition of “employee” in the Labour
Relations Act, 66 of 1995 (LRA). These disclosures, including
the highest-paid and lowest-paid employee, average and
median total remuneration, and the remuneration gap
between the top 5% highest-paid and bottom 5% lowest-paid
employees, are set out in the implementation report in Part 3.
To provide supplementary context aligned with Harmony’s
remuneration policy, the implementation report also includes a
separate policy-based disclosure for permanent full-time
employees. This dual-disclosure approach preserves the
statutory disclosure for all LRA-defined employees while
providing a more comparable view of remuneration outcomes
for the permanent full-time employee population.
The latest draft of the Employment Equity Amendment Bill,
2026 – commonly referred to as the “Fair Pay Bill” – was
introduced into the National Assembly on 30 April 2026 with
an invitation for public commentary by 30 May 2026. The Fair
Pay Bill seeks to amend the Employment Equity Act by
prohibiting the use of historical pay data during recruitment
and mandating the disclosure of salary ranges in job
advertisements. The committee continues to monitor
developments in this regard.
On 25 May 2026, the JSE confirmed that, for South African
primary-listed issuers subject to the Companies Act,
compliance with sections 30A and 30B amounts to
compliance with the JSE Listings Requirements. There is
therefore no need, nor would it be appropriate, to obtain
separate non-binding advisory votes under the JSE Listings
Requirements.
Harmony has adopted the King V Code on Corporate
Governance for South Africa 2025 (King V) for the FY26
financial year, and the principles and recommended practices
in King V, including Principle 11, have been applied in
preparing this report.
In compliance with sections 30A and 30B of the Companies
Act, Harmony will present its remuneration policy for FY27 to
FY29, set out in Part 2 below, and this remuneration report,
comprising this background statement, the remuneration
policy in Part 2 and the implementation report in Part 3, to
shareholders for approval by ordinary resolution at the annual
general meeting.
Safety – committed to zero harm
We are deeply saddened by the loss of six colleagues at our
South African operations during FY26. We extend our deepest
condolences to their families, friends, colleagues and the
communities affected by these tragic events.
The events of FY26 serve as a sobering reminder that, despite
the progress we have made, our work is not yet complete.
Protecting the lives and wellbeing of our people is our
foremost responsibility and underpins the sustainability of our
business. Achieving a workplace free from harm requires
ongoing commitment, disciplined execution and a culture in
which safety is embedded in every activity and decision. We
remain steadfast in our pursuit of this objective and in our
determination to ensure that every person who enters
our operations returns home safely.
213
Our safety performance, as reflected in the Balanced
Scorecard outcomes for FY26, underscores the need for
continued vigilance and improvement. The committee,
together with the board and management, is committed to
strengthening our safety culture, enhancing risk management
practices and reinforcing safe mining as a non-negotiable
value across all our operations.
Safety remains more than a priority; it is a core value that
informs every decision we make. In recognition of its
importance, the weighting of safety in the FY26 Balanced
Scorecard increased to 20% from 15% in FY25, with 5%
specifically linked to leading safety indicators across all
operations. This reflects the Board's and Committee's belief
that sustained safety performance depends not only on
outcomes, but also on the proactive behaviours and practices
that prevent incidents from occurring.
Financial and operational performance
FY26 demonstrated the strength of Harmony’s business, with
record operating free cash flow supported by a favourable
gold price environment and disciplined operational delivery
across the group. Central to this result was the contribution of
our employees, whose focus and commitment continue to
underpin Harmony’s performance. Our strengthened financial
position also enabled us to advance our growth and
diversification ambitions, most notably through the acquisition
of MAC Copper Limited, effective 24 October 2025. This
acquisition is a defining step in building Harmony’s copper
portfolio and broadening the foundations of the business for
the future. These achievements leave Harmony well positioned
to deliver sustainable value for our shareholders and
stakeholders.
Competitive positioning
Harmony's commitment to creating shared value for
employees extends beyond remuneration. The successful
implementation of the Harmony ESOP, ongoing financial
wellness and employee support initiatives, and the continued
benefits arising from the five-year wage agreement with all five
recognised labour unions have strengthened employee
participation, financial wellbeing and workplace stability.
Together, these initiatives support a more inclusive, resilient
and sustainable organisation.
Following the comprehensive review of Harmony’s executive
remuneration policy in the 2025 financial year the committee
continued to assess whether practices remain appropriate for
a company of Harmony’s evolving scale and complexity.
Following the adjustments that were implemented last year,
the executives’ remuneration, apart from the group chief
executive officer (GCEO), is now well aligned with the market.
The GCEO’s variable pay still lags the market, particularly
when the increasing global scope of his role is considered,
and an increase to his total on-target incentive from 180% to
220% is proposed over the three-year period covered by the
remuneration policy. The increase to this percentage, with
60% of this delivered in shares, will further align the GCEO’s
remuneration with company performance, Harmony’s peer
group and shareholder returns.
In August 2025, the remuneration committee reviewed non-
executive directors’ fees against Harmony’s comparator group
to ensure directors fees remain appropriate for Harmony’s
size, global footprint, and increasing operational complexity.
The review confirmed that the fees lagged the market
significantly in certain roles and increases above inflation were
proposed over a two-year period for these roles, with the
intention of bringing overall non-executive director fees in line
with the market median. The first such increase was well
supported by shareholders, with an approval of 97.7% and
the second increase will be proposed this year for approval by
shareholders. The board remains of the view that market-
competitive fees are essential to attract and retain directors
with the requisite skills and experience.
2026 focus areas
•Continued to monitor Harmony’s executive and non-
executive director remuneration positioning against the
comparator group to reflect the company’s increased scale,
global footprint and complexity
•Continued to monitor and address pay fairness and the pay
gap
•Ensure effective application of the retention and attraction
policy by extending financial awards to a few identified,
critical and high value employees
•Noted Harmony’s review of its employee value proposition
(EVP), informed by global executive benchmarks, South
African competitor practices, and worker recognition and
benefits. In FY27, the committee will oversee the
implementation of the revised EVP
•Monitored and implemented the remuneration governance
and reporting requirements arising from sections 30A and
30B of the Companies Act and the adoption of King V
•Implemented the updates to the Balanced Scorecard for
FY26, including greater weighting for safety, leading safety
indicators and project execution.
Changes to the remuneration policy for
FY27 to FY29
Several structural changes were made to the remuneration
policy in order to comply with section 30A of the Companies
Act amendments for the new three-year period from FY27 to
FY29. No substantive changes are proposed to the current
policy apart from the proposed change to the GCEO total
incentive on-target percentage as discussed above
(competitive positioning).
Focus areas for FY27
The market alignment of executive remuneration in the context
of the continuing globalisation and growth of the company.
•Ensuring that the incentive plan design and outcomes align
with business objectives, shareholder returns and King V
Principle 11
•Review effectiveness of Retention and attraction measures
of critically-skilled employees
•A key focus area for FY27 will be the continued embedding
of Harmony's Employee Value Proposition and leadership
philosophy. The planned culture survey will provide valuable
insights for an enabling environment in which employees
can thrive and perform at their best
•Continued focus on employee financial wellness and fair pay
initiatives
•Continue to engage with shareholders and respond to AGM
voting and feedback
•Monitor regulatory developments and ongoing compliance.
Shareholder voting outcomes and
regulatory compliance
The committee continues to monitor local and global
remuneration trends to ensure Harmony’s remuneration
strategy remains appropriately benchmarked. At the 2025
annual general meeting, held under the previous non-binding
advisory voting regime, 93.09% of votes cast supported the
remuneration policy, while 79.47% supported the
implementation report.
214
The committee noted the level of support for the
implementation report and considered the feedback received
from shareholders. This included concerns relating to safety,
which continue to receive attention.
Under section 30B of the Companies Act, this remuneration
report is subject to approval by ordinary resolution. If the
remuneration report is not approved, the committee must
present an explanation at the next annual general meeting
addressing how shareholders’ concerns have been taken into
account, and the non-executive directors who serve on the
committee must stand for re-election as committee members.
Use of consultants and their independence
During the year, the committee engaged the services of
RemChannel (Old Mutual) and Bowmans to provide advice on
remuneration matters. We are satisfied that the guidance
received was both independent and objective.
Statement on effectiveness of policy
The committee is satisfied that the remuneration policy
continues to support its key objectives. While the group
delivered strong operational and financial results, we
acknowledge that further progress is required to improve our
safe production performance. We remain confident that the
Total Incentive Plan promotes alignment between
performance and reward, supports the attraction and
retention of critical talent, encourages sustainable value
creation, and reinforces Harmony's long-term strategic
objectives.
The committee is satisfied that it fulfilled its regulatory, legal
and board-mandated responsibilities.
Closing remarks
I would like to extend my appreciation to my fellow Committee
members, the board, the executive management team and all
employees throughout the group for their continued
dedication and contribution during the year under review.
Their collective efforts and commitment have played an
important role in supporting Harmony's performance and
progress.
The committee remains focused on ensuring that
remuneration practices evolve in line with the company's
strategic priorities, support sustainable value creation and
appropriately recognise individual and collective performance.
In carrying out its duties, the committee seeks to balance the
interests of shareholders, employees and other stakeholders
while maintaining sound governance and responsible
remuneration outcomes.
During the period under review, no committee member had a
personal interest in matters considered by the committee,
other than in relation to the review of non-executive directors'
fees. The committee comprises four independent non-
executive directors, and the chair of the board is not a
member of the committee, ensuring the continued
independence of the committee's deliberations and decision-
making.
Given Sibiya
Chairperson: remuneration committee
23 October 2026
215
Remuneration policy
This remuneration policy is presented for approval by
shareholders by ordinary resolution in terms of section 30A of
the Companies Act at the annual general meeting. Subject to
shareholder approval, this policy will apply on a prospective
basis from FY27 to FY29, subject to ongoing review by the
committee. Should the committee conclude that a material
change to the policy is necessary before the end of that three-
year cycle, shareholders will be asked to approve the amended
remuneration policy afresh before it is implemented. The
committee is responsible for assessing whether any proposed
change is material, having regard to its probable impact on
remuneration outcomes and on shareholder expectations.
Harmony’s reward strategy underpins our business strategy of
safely producing profitable ounces, increasing our margins and
expanding our Reserves and Resources through organic
growth and acquisitions.
To sustain this growth, we rely on experienced, skilled teams
who live our values and maintain stakeholder relationships to
grow profits safely and support a sustainable company.
Our remuneration policy has been designed with our business
strategy in mind – to attract and retain these experienced,
skilled teams, and to motivate them to achieve our key
business goals. To ensure this happens, we need to be certain
that all elements of our remuneration and wider reward offerings
are aligned, fair and competitive. In determining remuneration,
the remuneration committee considers shareholders’ interests
as well as the financial health and future of the company.
Gender and race equality
Harmony’s remuneration policy is to remunerate based on an
individual’s ability, skills, knowledge and experience. Men and
women, irrespective of their race or any other listed or arbitrary
factor, are paid equally for work of equal value
Harmony remains committed to fostering an inclusive and
equitable workplace through remuneration practices that
support gender pay equity. The organisation utilises a common
job grading structure, standardised salary ranges, and objective
remuneration principles across all employee groups, regardless
of gender. Starting salaries are determined by objective factors
applied consistently across the workforce, while performance-
based rewards, including short-term incentives (STI) and long-
term incentives (LTI), are governed by standardised scorecards
and participation criteria.
Performance-linked rewards are allocated through consistently
applied governance frameworks, ensuring that both fixed and
variable remuneration are determined based on role
requirements, performance outcomes, and approved
remuneration policies. These measures form part of Harmony's
broader commitment to diversity, equity and inclusion, helping
to create a workplace where employment and reward
opportunities are based on fairness, capability and contribution.
Fair and responsible pay
The Company’s policy is that remuneration at all levels in the
Group must be fair, responsible and transparent. Guaranteed
remuneration for the broader workforce is aligned with a
Paterson level grading system and independent
benchmarking, with annual adjustments generally linked to
CPI. Employees at all levels participate in the Group’s benefit
offerings, including retirement fund membership, medical aid,
risk cover and the employee assistance programme and study
assistance. The committee ensures that executive
remuneration is fair and responsible in the context of overall
employee remuneration through:
•Levels per job category – eg a female employee in a specific
occupation will be on the exact same Paterson level than a
male employee on the same occupation.
•Pay ranges for different levels in the organisation are the
same whether for a female or a male.
•Starting rates also do not create any form of discrimination
– factors taking into consideration to determine a starting
rate are the same.
•The scorecard measurements and participation factors are
constantly applied to male and female employees with
regards to short term incentives (STI) and long-term
incentives (LTI).
Harmony is committed to the concept of a living wage, which
is based on the philosophy of fair and responsible pay. It
embodies our initiatives to enhance the lives and wellbeing of
our employees by enabling them to improve their living
conditions, and to have better access to social services,
healthcare, education and training.
Guaranteed pay
Guaranteed pay excludes short- and long-term incentives. To
compete effectively for skills in a challenging employment
market, we identify the target market to use in benchmarking
guaranteed pay. This target market includes organisations or
companies that employ similar skill sets to those we require.
Comparisons are made predominantly within the South African
mining sector to ensure that Harmony remains competitive. The
median of the target market is used as the basis of our pay
ranges. This same philosophy is applied to our Australasia
operations.
Adjustments to guaranteed pay are based on market
positioning, consideration of the general increases in the
applicable market, and current and expected inflation in the
applicable jurisdiction.
Total Incentive Performance Measures
The performance for the financial year is measured using a
balanced scorecard that includes measures of shareholder
value created, financial and operational performance, growth,
project execution and sustainability.
The general structure of the scorecard is summarised below.
The details of the applicable scorecards for the current and
forthcoming financial years are included in the implementation
report for the year, including the performance measures,
weightings and targets.
Scorecard components | ||||||
Shareholder value | Measures of absolute and relative total shareholder return | |||||
Financial and operational | Measures such as production, total production cost and free cash flow | |||||
Growth | Measures such as development, and additions to mineral reserves | |||||
Project execution | Project execution schedule Project execution costs | |||||
Sustainability | Safety measures such as LTIFR and leading indicators, and environmental, social and governance indicators | |||||
216
Employees at certain projects and operations within the Group,
below the level of the executive directors and prescribed
officers, may have balanced scorecards that are customised to
reflect performance measures and weightings appropriate for
their roles.
The performance measures and targets for the year are set to
reflect the applicable strategic objectives for the year and are
intended to be similarly stretching each year in the context of
the prevailing business environment.
Minimum shareholding requirement
We require executive directors and prescribed officers to
retain performance shares when they vest and a minimum
shareholding requirement (MSR). The requirement provides
that:
•50% of the shares that will vest to an executive director or
prescribed officer will, immediately prior to the applicable
vesting date, be automatically locked up on the terms and
in accordance with the MSR
•The lock-up will apply for as long as the relevant target MSR
applicable to the executive director or prescribed officer has
not been met
•Once the relevant target MSR has been met, any deferred
shares that subsequently vest in and are settled to an
executive director or prescribed officer will vest and be
settled in accordance with the terms of the deferred share
plan.
An executive director or prescribed officer may elect to
voluntarily lock-up shares that vest in terms of the deferred
share plan even if it results in locked-up shares exceeding the
target MSR – if the locked-up shares exceed the target MSR,
the excess shares will remain in lock-up until the next vesting
date (in terms of any relevant Harmony share incentive plans
applicable at the time) at which point the excess shares will be
released from lock-up and settled in accordance with the
terms of the deferred share plan.
The MSR will continue to apply to an executive director or
prescribed officer as long as they remain an executive director
or prescribed officer.
If an executive director or prescribed officer ceases to be
employed by the group for any reason, their locked-up shares
will be released from the lock-up on the date of terminating
employment.
Target MSR
The target MSR is the relevant target minimum shareholding
value (expressed in South African rand) that is required to be
held by an executive director or prescribed officer from time to
time pursuant to this MSR being a minimum of 100% of their
respective cost to company.
Measurement of target MSR
Each tranche of locked-up shares will be deemed to have a
value for the purposes of determining whether the target MSR
has been met, equal to the one-day volume-weighted average
price (VWAP) of a share in South African rand (ZAR) at the
date of such lock-up, multiplied by the number of shares to be
locked up in such tranche. This value will be increased yearly
by the applicable consumer price index (CPI) rate for the year.
Trading restriction
Appropriate entries in the relevant registers will be made to
record that all the executive director or prescribed officer’s
shares, which are subject to the lock-up, will be noted by the
relevant central securities depository participant in terms of
section 39 of the Financial Markets Act and the appropriate
flag placed on the relevant securities account.
Voting and dividends
An executive director or prescribed officer will, in respect of
vested shares that are subject to the lock-up:
•Exercise all voting rights in respect of such shares
•Receive all distributions payable in respect of such shares.
Application to foreign prescribed officer
The target MSR of the foreign prescribed officer will be
determined on the date on which this MSR is adopted or first
applies to the foreign prescribed officer (whichever occurs
first). In calculating the target MSR of the foreign prescribed
officer, the company will use the cost to company (in ZAR) of
the deputy group chief executive officer.
The ZAR value of any shares that are to be locked up (in terms
of this MSR) will be determined on the applicable vesting date
with reference to the share price on that date.
To determine whether the target MSR has been satisfied, the
pre-tax value of the locked-up shares will be taken into
account.
Deferred share plan limit
The overall limit for deferred shares, issued under the 2018
deferred share plan, is 5% of the shares in issue at the time
the plan was approved, amounting to 25 000 000 shares.
The individual limit is 0.6%, amounting to 3 000 000 shares.
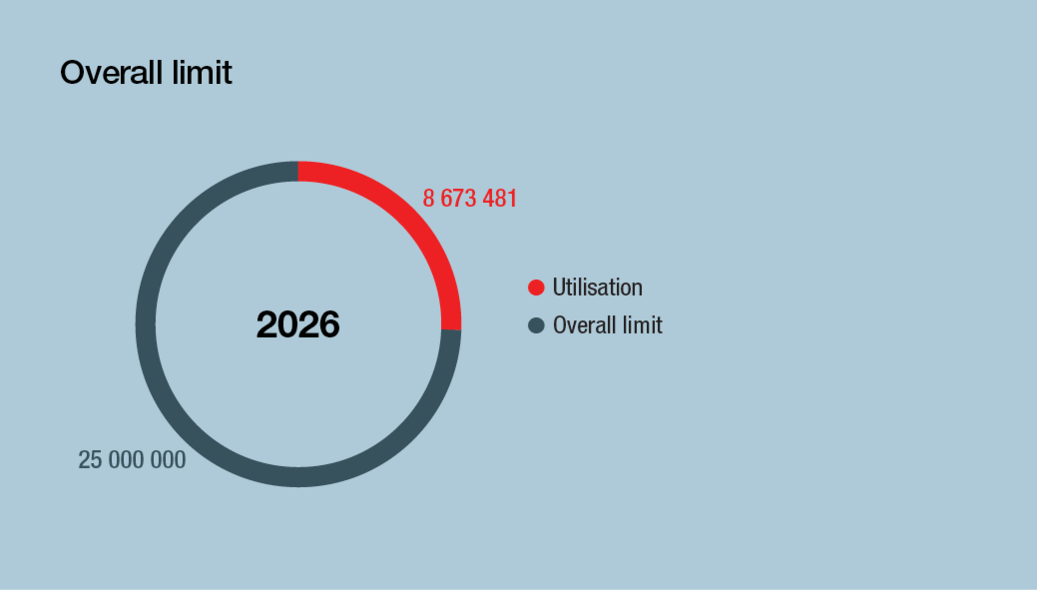
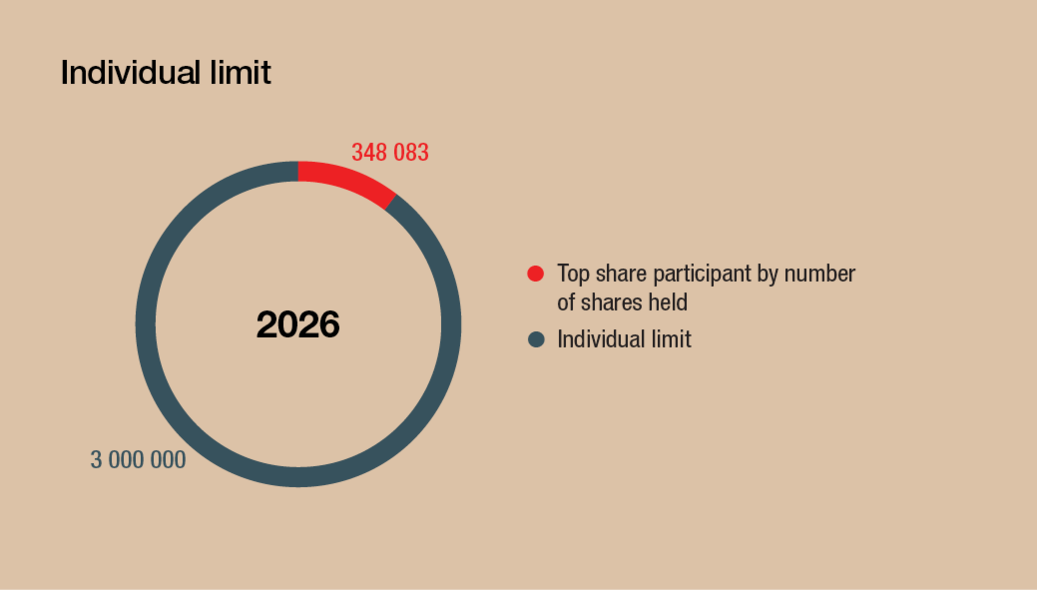
Non-executive director fees
In accordance with King V, the board has adopted a
standalone Non-Executive Director Fee Policy, which sets out
the criteria and principles governing the determination and
payment of non-executive director fees. The Non-Executive
Director Fee Policy addresses, amongst other matters, the
basis on which fees are set and reviewed, the applicable fee
structure, the methodology used for market alignment and
benchmarking, the frequency and nature of fee payments, ad
hoc fee payments, and related matters. A copy of the Non-
Executive Director Fee Policy is made available to
shareholders for their consideration when voting on the
quantum of non-executive director fees in terms of sections
217
66(8) and 66(9) of the Companies Act. The fees actually paid
in respect of the year under review, are disclosed in the
implementation report in Part 3. Non-executive directors do
not participate in any short-term or long-term incentive
schemes. No compensation is payable to a non-executive
director upon termination of their appointment, other than
accrued fees and reimbursement of expenses.
In accordance with King V, market comparisons, the fiduciary
risks carried by non-executive directors, their workload, time
commitments, expertise and preparation expected of each
non-executive director role are considered when reviewing our
non-executive director fees.
In the prior year, shareholders supported and approved a two-
year catch-up process aimed at bringing NED fees into closer
alignment with the market median. For FY26, the Board,
through the remuneration committee, is presenting the
second and final phase of this process to shareholders for
approval. Maintaining appropriately competitive fees supports
the attraction and retention of directors with the skills and
experience required to oversee Harmony’s growing and
globally diversified business.
Performance of management
The individual performance of employees will not be taken into
account in determining the total incentive plan outcome.
Harmony follows a team-based balanced scorecard approach
in determining incentive awards. All management employees
are assessed every year against set key performance
indicators which are used to guide the development,
promotion and salary increase of such employees.
Contracts, severance and termination
Executive directors and prescribed officers have employment
contracts with Harmony that include notice periods of up to
90 days. There are no balloon payments on termination,
automatic entitlement to bonuses or automatic entitlement to
share-based payments other than in terms of the company’s
approved share incentive plans.
Remuneration on appointment, sign-on and
buy-out arrangements
The remuneration on appointment of employees is based on
the market positioning of remuneration for the role, and the
specific skills and experience of the new employee. The
remuneration on appointment of executive directors or
prescribed officers during the year under review are disclosed
in the implementation report. The company may enter into
sign-on or buy-out arrangements with employees to
compensate them for remuneration forfeited from a previous
employer on appointment. Any such arrangement will
generally be limited to the value of awards forfeited and will be
subject to committee approval. Sign-on or buy-out awards
made to executive directors or prescribed officers during the
year under review are disclosed in the implementation report.
Retention arrangements
The committee may approve targeted retention arrangements
for employees in critical roles where there is a demonstrable
risk of loss. Retention awards for executive directors and
prescribed officers are subject to committee approval.
Termination of employment, change of
control, and change of capital structure
The provisions for termination of employment, change of
control and change of capital structure remain consistent with
the rules of the Harmony Gold Mining Company Limited
Deferred Share Plan 2018, approved in December 2018, and
further amended by shareholder approval in December 2021.
Malus and clawback
Malus is the forfeiture of a variable pay award before it vests or
is settled, and clawback refers to a requirement to repay
some or all of an award after it has vested or is settled.
The committee has to determine that a prescribed officer or
executive manager’s total share plan award is subjected to
reduction, forfeiture or clawback (in whole or in part) if:
•There is reasonable evidence of misbehaviour or material
error by a prescribed officer or executive manager
•The financial performance of the group, company, employer
company or relevant business unit for any financial year,
used to determine an award, have subsequently appeared
to be materially inaccurate
•The group, company, employer company or relevant
business unit suffers a material downturn in its financial
performance for which the prescribed officer or executive
manager can be seen to have some liability
•The group, company, employer company or relevant
business unit suffers a material failure of risk management
for which the prescribed officer or executive manager can
be seen to have some liability or in any other circumstances
if the committee determines that it is reasonable to subject
the awards of one or more prescribed officers or executive
managers to reduction or forfeiture.
•Procedures to impose any malus or clawback provisions
must be initiated within three years of the award. To
eliminate doubt, the provisions of this malus and clawback
policy do not detract from any other legal rights or
measures the company has as recourse for acts of fraud,
wrongdoing and/or negligence by its prescribed officers or
executive management.
In addition, the company maintains a separate Incentive-
based Compensation Recovery Policy, compliant with section
10D of the US Securities Exchange Act of 1934 and NYSE
requirements, providing for the recovery of excess incentive-
based compensation in the event of a financial restatement.
The application of malus or clawback, is disclosed in the
Remuneration policy implementation section.
Shareholder feedback
We maintain open communication channels with our
shareholders, listen to feedback and take action where this is
deemed to be in the best interests of the company.
Pay mix for executive directors and
prescribed officers
The tables below illustrate the pay mix for executive directors
and prescribed officers, based on achieving minimum, on-
target and stretch performance. The composition of total
remuneration outcomes for FY26 is illustrated below.
218
Group chief executive officer*
FY26 pay mix
Minimum | On-target | Stretch | |
(%) | (%) | (%) | |
Salary benefits | 84 | 85 | 85 |
Retirement savings and contributions | 16 | 15 | 15 |
Guaranteed pay | 100 | 100 | 100 |
Short-term incentive | – | 72 | 120 |
Long-term incentive | – | 108 | 180 |
Total remuneration | 100 | 280 | 400 |
FY27/28/29 maximum pay mix | |||
Group chief executive officer | |||
Minimum (%) | On-target (%) | Stretch (%) | |
Salary Benefits | 84 | 85 | 85 |
Retirement Savings and Contributions | 16 | 15 | 15 |
Guaranteed pay | 100 | 100 | 100 |
Short-term incentive | – | 88 | 147 |
Long-term incentive | – | 132 | 220 |
Total remuneration | 100 | 320 | 467 |
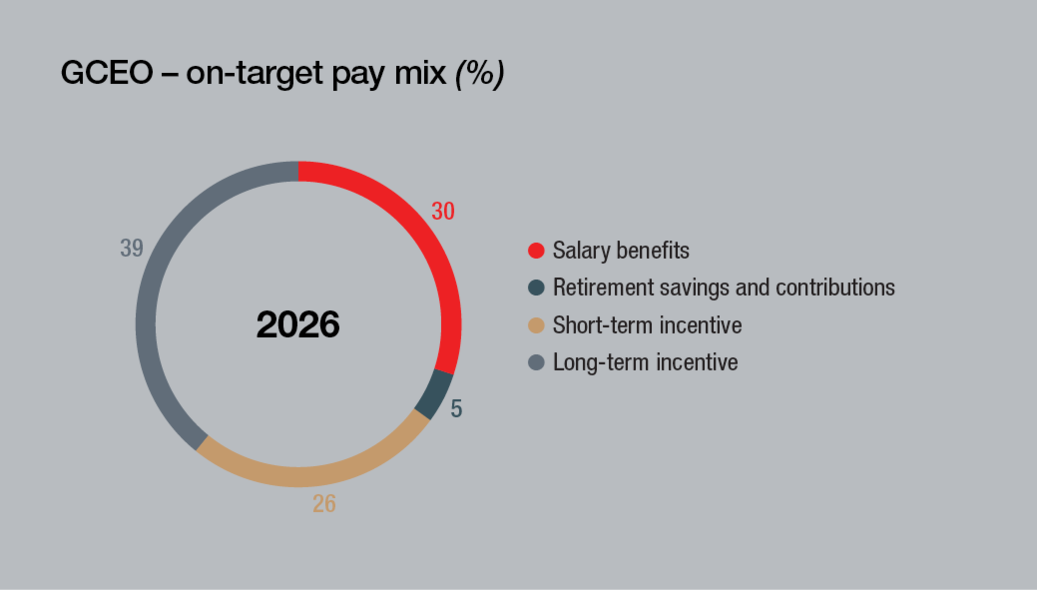
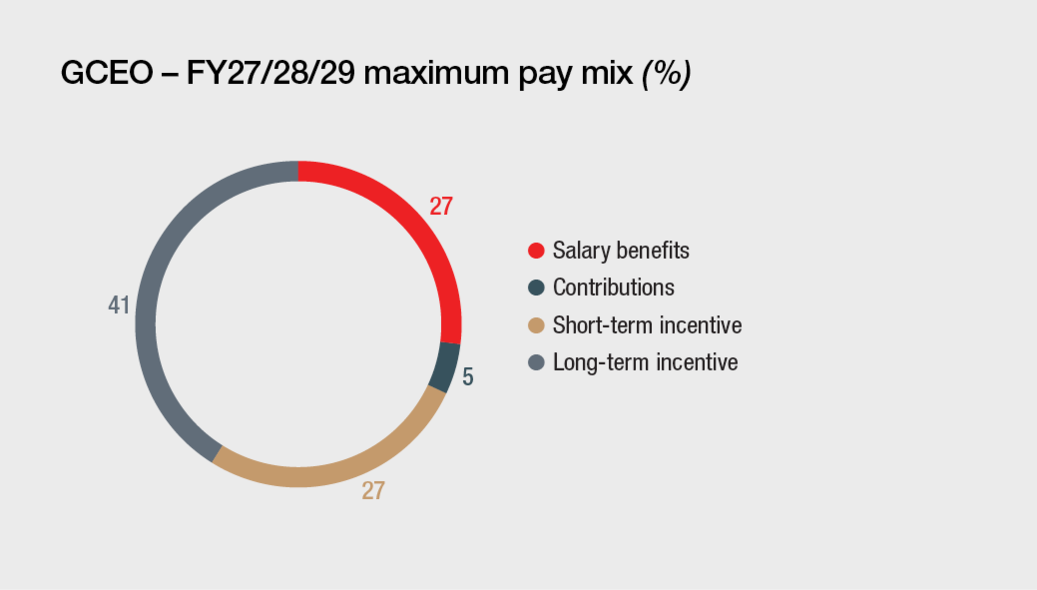
Other executives (financial director, other
executive directors and prescribed
officers)
FY26 pay mix
Minimum | On-target | Stretch | |
(%) | (%) | (%) | |
Salary benefits | 90 | 90 | 90 |
Retirement savings and contributions | 10 | 10 | 10 |
Guaranteed pay | 100 | 100 | 100 |
Short-term incentive | — | 60 | 100 |
Long-term incentive | — | 90 | 150 |
Total remuneration | 100 | 250 | 350 |
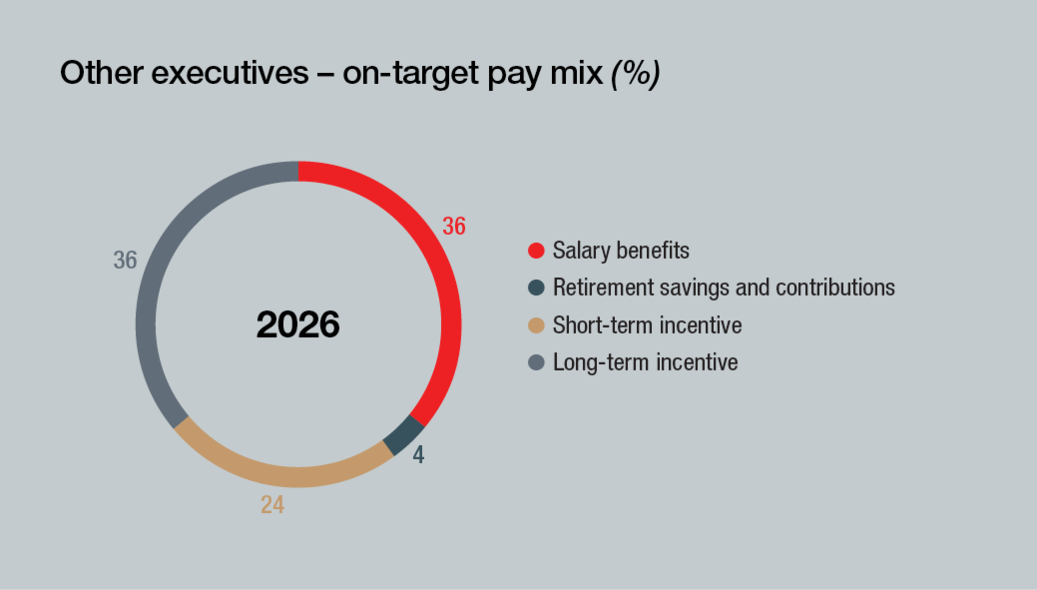
Average monthly wages and benefits
underground
FY26 policy
Total remuneration | Category 4 (%) | Category 8 (%) |
Fixed earnings | 64 | 62 |
Company benefits | 14 | 13 |
Guaranteed pay | 78 | 75 |
Variable pay | 22 | 25 |
Total remuneration | 100 | 100 |
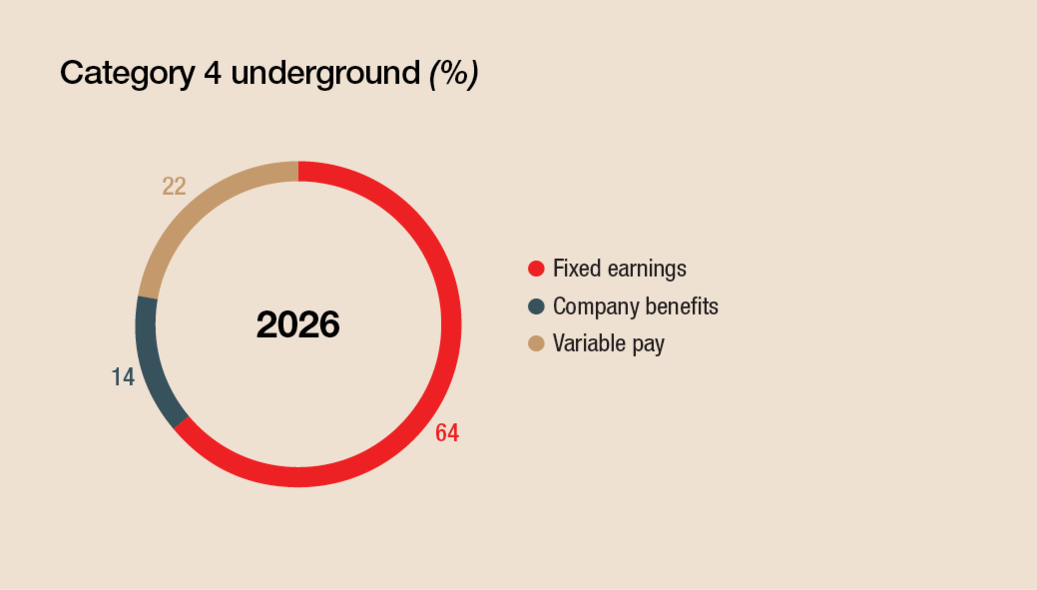
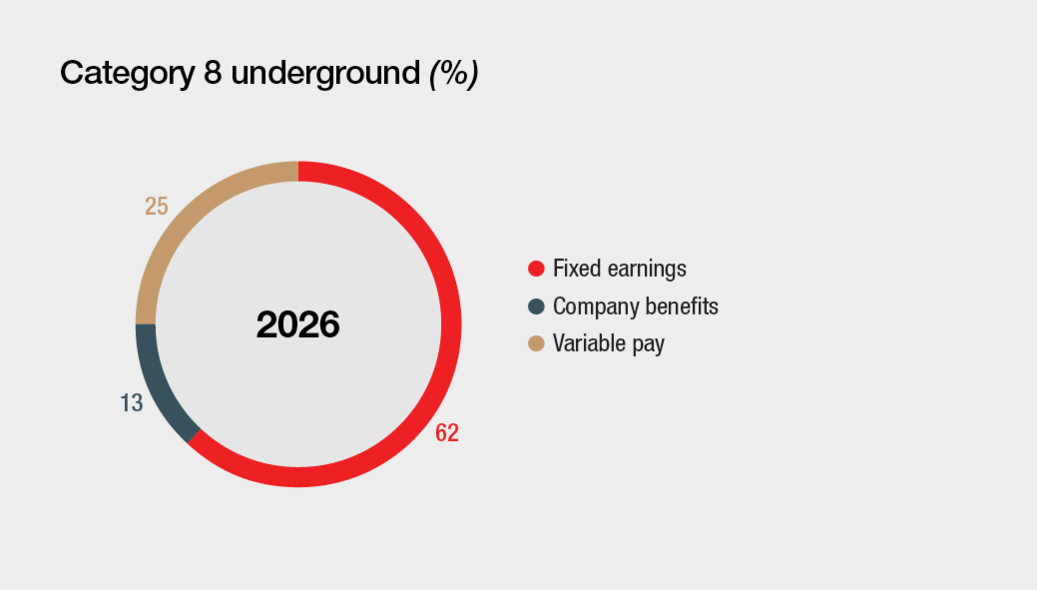
Each component includes:
•Fixed earning: Basic pay, service increment, 13th cheque,
living-out or housing allowance
•Variable income: Average overtime, shift allowance,
average bonus, meal allowance, unemployment insurance
fund/skills development levy, insurance benefit
•Company benefits: Employer provident/pension fund and
medical aid.
219
Total incentive plan
The total incentive is determined every year on the following
basis:
Total incentive (R) | ||||
= | ||||
Guaranteed pay (R) | ||||
x | ||||
On-target factor (%) | ||||
x | ||||
Balanced Scorecard result (%) | ||||
The Balanced Scorecard result includes a number of key short
and long term company performance measures (to be
measured over trailing three- and one-year periods). The
measures are reviewed and defined annually with appropriate
weightings. Details of the Balanced Scorecard for the relevant
financial year, including the applicable measures, weightings
and targets, are disclosed in the implementation report in Part
3. The Balanced Scorecard comprises a combination of
financial, operational, growth, project execution and
sustainability performance measures, reviewed and calibrated
annually by the committee. The specific measures, weightings
and targets for each financial year are disclosed in the
implementation report in Part 3.
The committee retains the discretion to adjust the composition and weightings of the Balanced Scorecard on a forward-looking basis
to reflect Harmony’s evolving strategic priorities.
A portion of the total incentive is paid immediately in cash and the balance is settled by means of deferred shares, which vest at a rate
of 20% per annum over the next five years for executive directors and prescribed officers, and 33.33% per annum over the next three
years for management.
Each element of the total incentive plan is described below:
Guaranteed pay excludes short- and long-term incentives. To compete effectively for skills in a challenging employment market, we identify the target market to use in benchmarking guaranteed pay. This target market includes organisations or companies that employ similar skill sets to those we require. Comparisons are made predominantly within the South African mining sector to ensure that Harmony remains competitive. The median of the target market is used as the basis of our pay ranges. This same philosophy is applied to our Australasia operations. | Description | ||||||||||||||||
è | è | ||||||||||||||||
Element | Total on-target factor (as explained more fully above) | Employee | % guaranteed pay | ||||||||||||||
Group chief executive officer | 180% to 220%* | ||||||||||||||||
Financial director, other executive directors and prescribed officers | 150% | ||||||||||||||||
Balanced Scorecard result | è | Cash portion of total incentive (40%) | è | A portion of the total incentive is settled in cash immediately when the Balanced Scorecard results for the financial year have been determined and approved by the board. | è | ||||||||||||
Cash portion (balance settled in deferred shares) | % of incentive | ||||||||||||||||
Group chief executive officer | 40% | ||||||||||||||||
Financial director, other executive directors and prescribed officers | 40% | ||||||||||||||||
è | Deferred share portion of total incentive (60%) | è | The balance of the total incentive is settled in deferred shares, vesting at a rate of 20% per annum over the next five years for executive directors and prescribed officers, and 33.33% per annum over the next three years for management. | ||||||||||||||
* To ensure competitive remuneration for the GCEO and enhanced alignment with GCEO returns, the range for his total incentive on-target percentage
in the remuneration policy for FY27 to FY29 has been set from 180% to 220%, with 210% to be applied for the FY27 year.
220
Remuneration policy implementation
This implementation report sets out how the remuneration policy was implemented during the financial year ended 30 June 2026. The
committee confirms that remuneration outcomes for FY26 were determined in compliance with the remuneration policy approved by
shareholders at the annual general meeting on 26 November 2025, and there were no substantial deviations from the policy during the
period under review.
We have also included disclosure of Total Earned Remuneration, the schedule of unvested awards and cash flows for executive
directors and prescribed officers, in line with the applicable best practice guidelines. The remuneration of non-executive directors is
disclosed as required by the Companies Act.
Increases to guaranteed packages during the year
An assessment of executive remuneration was undertaken during the year. Taking into consideration prevailing market conditions,
affordability and shareholders’ expectations, an average increase of 4.5% to guaranteed remuneration packages of management was
made in FY26. The average percentage increases awarded to executives, management and bargaining-unit employees staff in FY24,
FY25 and FY26 are illustrated below.
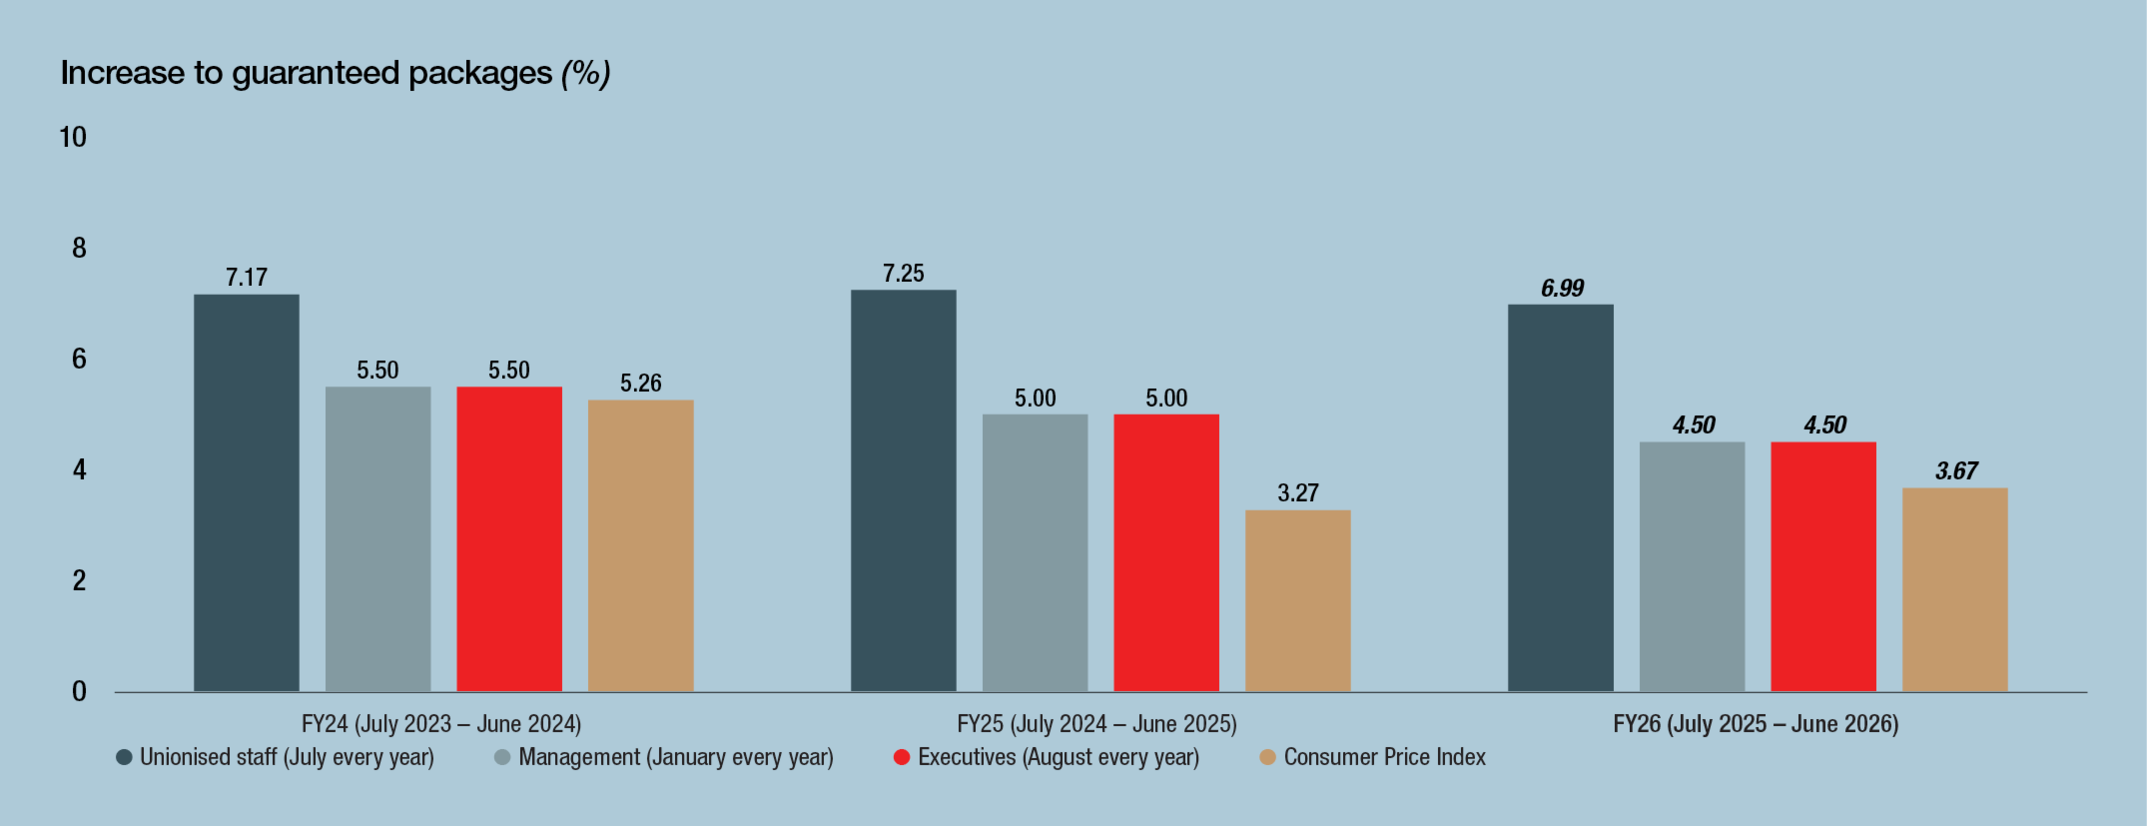
Executive remuneration review
An independent benchmark study (the study) was conducted
by Bowmans to benchmark the executive directors,
prescribed officers and functional executives (collectively,
executive management) against a comparator group (being
African Rainbow Minerals Limited, Valterra Platinum Limited,
Gold Fields Limited, Impala Platinum Holdings Limited,
Northam Platinum Limited and Sibanye‑Stillwater Limited).
The comparator group for the FY26 executive and NED fee
benchmarking is the same as that used for the 2025
benchmarking exercise.
The results of the study indicated that the positioning of the
executive remuneration is now well aligned with the
comparators, except for that of the GCEO, whose variable
pay lags the market. An increase to his variable pay is
contingent on performance and 60% of the total incentive is
delivered in shares. To ensure competitive remuneration for
the GCEO and enhanced alignment with GCEO returns, the
range for his total incentive on-target percentage in the
remuneration policy for FY27 to FY29 has been set from
180% to 220%, with 210% to be applied for the FY27 year.
Pay fairness and equality
In FY26, an average increase of 4.5% in guaranteed
remuneration packages was awarded for management and
executives. The bargaining-unit employees received a 6.99%
increase as approved in the June 2024 wage agreement.
Bargaining-unit employees have received above-inflation
increases for the past six years. The average total monthly
remuneration of our category 4 – 8 employees is set out
below. The Harmony minimum remuneration is substantially
above the statutory minimum wage of less than R4 000 per
month, and the living wage, which is generally viewed as
around R20 000 per month. We continue to focus on fairly
remunerating our employees at this level to address the
challenges of inequality and poverty.
221
Grade
Fixed earnings | Variable income | Company benefits | Total per month | |
(R) | (R) | (R) | (R) | |
Category 4 underground employee (general worker) | 22 090 | 7 569 | 4 958 | 34 617 |
Category 8 underground employee (team leader) | 26 197 | 10 606 | 5 525 | 42 328 |
Section 30B remuneration disclosures:
In accordance with section 30B(3)(c) of the Companies Act, the following remuneration disclosures are made with reference to “employees” as defined in section 213 of the LRA. For this purpose, “total
remuneration” means all salary and benefits received, including employer contributions to benefit funds and any short-term or long-term incentives, as contemplated in section 30B(1)(a) of the Companies Act.
Harmony makes two disclosures: (i) a statutory disclosure covering all categories of employees as defined in section 213 of the LRA (encompassing permanent, part-time, fixed-term and casual employees, as
well as learners, interns and apprentices); and (ii) a supplementary policy-based disclosure for permanent full-time employees only, which provides a more meaningful year-on-year comparison aligned with the
Company’s remuneration philosophy.
These details have been disclosed using the total remuneration on a payroll basis for full-time, permanent employees of Harmony Gold Mining Company Limited South African Operations which provides an
appropriate reflection of the implementation of the Group remuneration policy.
The remuneration details, when all classes of employees, including temporary workers and learners are included, are shown in the footnotes.
FY26 Pay fairness equality (top 5% and lowest 5%)
Total remuneration for all South African permanent, full-time employees | R |
The employee with the highest total remuneration | 28 825 183 |
The employee with the lowest total remuneration | 61 515 |
Average total remuneration1 | 581 848 |
Median total remuneration2 | 428 855 |
Average total remuneration of the top 5%3 | 2 088 406 |
Average total remuneration of the lowest 5%4 | 257 453 |
The ratio of the highest 5% to the lowest 5%5 | 8.11 |
The results below reflect all South African permanent full-time employees, together with fixed-term employees, learners, interns, and apprentices:
1The average total remuneration is R580 154.
2The median total remuneration is R428 414.
3Average total remuneration of the top 5% is R2 085 147.
4Average total remuneration of the lowest 5% is R247 411.
5The ratio of the highest 5% to the lowest 5% is 8.43.
Total Incentive Plan Scorecards
The balanced scorecard for the FY26 financial year is detailed below. The same balanced scorecard will be used for the FY27 financial year.
222
FY27 Balanced Scorecard
Group | South Africa operations | Australasian operations | ||
Scorecard component | (%) | (%) | (%) | |
Shareholder value | Total shareholder return (absolute) | 8.34 | 6.67 | 6.67 |
Total shareholder return (relative to JSE-listed Gold Comparators) | 8.33 | 6.67 | 6.67 | |
Total shareholder return (relative to FTSE Gold Mines Index) | 8.33 | 6.66 | 6.66 | |
Financial and operational | Production | 20.00 | 30.00 | 30.00 |
Total production cost | 10.00 | 15.00 | 15.00 | |
Free cash flow | 5.00 | — | — | |
Growth | Development | — | 10.00 | 10.00 |
Additions to mineral reserves | 10.00 | — | — | |
Project execution | Project execution schedule | 3.00 | 3.00 | 3.00 |
Project execution costs | 2.00 | 2.00 | 2.00 | |
Sustainability | Safety performance: Leading indicators | 5.00 | 5.00 | 5.00 |
Safety performance: Lagging indicators LTIFR | 15.00 | 15.00 | 15.00 | |
Environmental, social and governance (ESG) | 5.00 | — | — | |
Total | 100.00 | 100.00 | 100.00 |
The LTIFR award percentage will be adjusted as follows:
•The actual number of fatalities compared to the average fatalities over the previous three years:
–Equal to or better than the average – full LTIFR award
–Up to 20% above the average – 60% of LTIFR award
–Between 20% and 40% above the average – 40% of LTIFR award
–More than 40% above the average – 0% of LTIFR award.
Applicable Balanced Scorecard for eligible operations/divisions | Functions | % participation | ||||||||
Group | Group CEO office, prescribed officers, new business development and growth managers and corporate services managers exclusively allocated to a group and corporate function. | 100% group | ||||||||
SA operations | Deputy group CEO, executive managers and all on-shaft SA ops managers and off-shaft services managers exclusively allocated to SA ops services (Free State services, Moab Khotsong services, Mponeng services and Randfontein office services). | 100% SA ops | ||||||||
AA* operations | Chief operating officer, executive managers, all on-mine and off-mine AA ops managers and AA managers exclusively allocated to AA ops. | 100% AA ops | ||||||||
AA* – shared-service resources | Specific sub-functions of finance and commercial services, HR and other. | % split to be determined by time spent on each function, respectively, between AA and group divisions | ||||||||
* Australasia.
Details of the FY26 Balanced Scorecard showing the total incentive and actual performance outcomes are disclosed in the remuneration implementation section (part 3).
223
Scorecard components
Total shareholder return
Shareholder value is measured as total shareholder return (TSR) over a three-year period ending in June of each year. It comprises two components:
•Absolute performance over the measurement period, compared to the company’s cost of equity (COE), taking into account the growth in the company’s share price and the value of dividends paid
•Relative performance of the company versus JSE-listed Gold Comparators and FTSE Gold Mines Index over the measurement period.
The threshold, target and stretch performance criteria for TSR (with the recalibrated scorecard outcomes as explained above) are set out below:
Scorecard component | Principle | Threshold 67% | Target 100% | Stretch 167% | ||||||||||||||||||
Shareholder value | TSR (absolute) | To be measured over a three-year period ending in June of each year | COE + 0% per year | COE + 3% per year | COE + 6% per year | |||||||||||||||||
TSR (relative) | To be measured over a three-year period relative to JSE-listed Gold Comparators | On index | Index + 10% | Index + 20% | ||||||||||||||||||
TSR (relative) | To be measured over a three-year period relative to the FTSE Gold Mines Index | On index | Index + 10% | Index + 20% | ||||||||||||||||||
Financial and operational performance
Financial and operational performance comprises gold production and cost management for the financial year measured against the board-approved business plan.
•Production
–Total gold production against board-approved business plan for the year
•Total production cost (SA) and (AA)
–Total cash operating cost and total capital expenditure for the year
•Free cash flow
–Cash flow generated by operations adjusted for exploration capital, dividends and the effect of commodity price and exchange rate changes in excess of 10% (higher or lower).
The threshold, target and stretch performance criteria are set out below:
Scorecard component | Principle | Threshold 67% | Target 100% | Stretch 167% | ||||||||||||||||||
Financial and operational | Production | To be measured against board-approved plan | (5)% | Plan | 5% | |||||||||||||||||
Total production cost (SA) and (AA) | To be measured against board-approved plan | (5)% | Plan | 5% | ||||||||||||||||||
Free cash flow | To be measured against board-approved plan | (30)% | Plan | 30% | ||||||||||||||||||
224
Growth
Growth comprises two areas:
•Development
–Development is measured against the board-approved business plan of ongoing capital development – the development of reef and waste metres (South Africa) and waste tonnes (Australasia) for the
financial year
•Addition to Mineral Reserves
–Addition to Mineral Reserves through acquisitions and major capital projects which will be calculated on a three-year period rolling average.
The threshold, target and stretch performance criteria are set out below:
Scorecard component | Principle | Threshold 67% | Target 100% | Stretch 167% | ||||||||||||||||||
Growth | Development | To be measured against board-approved plan as a leading indicator of medium to long-term sustainability | (5)% | Plan | 5% | |||||||||||||||||
Addition to Mineral Reserves | Will measure Ore Reserve addition on a three-year period rolling average on pre-depletion basis, excluding asset sales | + 1.5Moz | + 2Moz | + 2.5Moz | ||||||||||||||||||
Project execution
Project execution measurement is based on the consolidated weighted average scores of all material projects based on:
•Project execution schedule
–Project key dates and critical path (50%)
–Project percentage completion vs planned completion (50%)
•Project execution costs
–Ratio of actual to planned costs/ratio of actual to planned completion.
The threshold, target and stretch performance criteria are set out below:
Scorecard component | Principle | Threshold 67% | Target 100% | Stretch 167% | ||||||||||||||||||
Project execution | Key dates | Date of completion of key task on critical path | Latest acceptable date | Planned date | Earliest possible date | |||||||||||||||||
Completion percentage ratio | Actual increase in completion percentage/planned increase in completion percentage | 0.8 | 1.0 | 1.2 | ||||||||||||||||||
Costs | Ratio of actual costs compared to planned costs/completion percentage ratio | 1.2 | 1.0 | 0.8 | ||||||||||||||||||
225
Sustainability
Sustainability comprises two components:
•Safety performance:
–Lagging indicators: LTIFR will be measured against the board-approved plan
–Leading indicators: Workplace Hazard Rating (group and SA) and Fatality Critical Control Check Quality (FCCC) measure (Australasia)
•ESG
–ESG will be measured on the basis of continued inclusion in the FTSE4Good Index as verified by FTSE Russell.
The threshold, target and stretch performance criteria are set out below:
Scorecard component | Principle | Threshold 67% | Target 100% | Stretch 167% | ||||||||||||||||||
Sustainability | Lagging Indicators | To be measured against board-approved plan | (5)% | Plan | 5% | |||||||||||||||||
Leading indicators | Group and SA operations – Workplace Hazard Rating | 80% | 87.5% | 95% | ||||||||||||||||||
Australasia operations – Fatal Critical Control Check Quality (stretch vesting for 95% achievement, 0% vesting for <95%) | <95% gives 0% vesting | >=95% | ||||||||||||||||||||
ESG | To be measured on the basis of continued inclusion in the FTSE4Good Index as verified by FTSE Russell | Yes | No | |||||||||||||||||||
5% | N/A | |||||||||||||||||||||
226
Incentive payments attributable to FY26
Total incentive plan
Actual performance outcomes based on the FY26 Balanced Scorecard for the period 1 July 2025 to 30 June 2026 scores on the basis of achievement out of the maximum score is as follows:
FY26 scorecard result for the group
Performance drivers | Description | Threshold (40%) | Target (60%) Strategic Plan | Stretch (100%) | Actual | % Achieved | Qlfy | Weighting | Scorecard line result | Final outcome |
Shareholder value | Total shareholder return (TSR) | |||||||||
– TSR absolute | 44% | 56% | 69.0% | 77% | 77.5% | YES | 8.34 | 100.0% | 8.34% | |
– TSR versus JSE-listed Gold Comparators | 160% | 170% | 180.0% | 215% | 54.2% | YES | 8.33 | 100.0% | 8.33% | |
– TSR versus FTSE Gold Mines | 175% | 185% | 195.0% | 265% | 89.9% | YES | 8.33 | 100.0% | 8.33% | |
Operational and financial | Kilograms total Harmony | 42 728 | 44 977 | 47 226 | 44 464 | 98.9% | YES | 20.00 | 55.4% | 11.09% |
Total production cost (SA) (Rm) | 51 006 | 48 577 | 46 148 | 48 868 | 99.4% | YES | 8.00 | 57.6% | 4.61% | |
Total production cost (AA) (US$/m) | 333 | 317 | 301 | 199 | 137.3% | YES | 2.00 | 100.0% | 2.00% | |
Net free cash flow | 26 754 | 38 221 | 49 687 | 29 874 | 78.2% | YES | 5.00 | 45.4% | 2.27% | |
Growth | Reserve addition (Moz) | 1.500 | 2.000 | 2.500 | 6.476 | YES | 10.00 | 100.0% | 10.00% | |
Project Execution | Project Schedule | Parameters applied to individually identified projects and aggregated to the totals applied in the scorecard | 53.5 | 53.5% | YES | 3.00 | 53.5% | 1.61% | ||
Project Cost | 40.0 | 40.0% | YES | 2.00 | 40.0% | 0.80% | ||||
Sustainability | Safety: Leading Indicators | 80% | 80 – 95% | 95% | 100.1 | 100.1% | YES | 5.00 | 100.0% | 5.00% |
Safety: Lagging Indicators LTIFR total SA ops | 5.86 | 5.58 | 5.30 | 5.06 | 109.4% | YES | 15.00 | 100.0% | 15.00% | |
ESG | YES | 5.00 | 100.0% | 5.00% | ||||||
100.00 | 82.38% | |||||||||
FY23 | FY24 | FY25 | Three-year average | FY26 | % variation | % of LTIFR awarded | |
Loss-of-life incidents versus actual* | 6 | 7 | 11 | 8 | 6 | (25)% | 100% |
Final LTIFR % | 15% | ||||||
Final scorecard result** | 82.38% | ||||||
Final scorecard result as % of target | 137.30% | ||||||
*Final LTIFR percentage after any adjustment for loss-of-life incidents as more fully described below.
**Note that the scorecard outcome is expressed as a percentage of target, so the equivalent score is 82.38/60 = 137.30%.
The LTIFR award percentage was adjusted as follows:
•The actual number of fatalities compared to the average fatalities over the previous three years
–Equal to or better than the average – full LTIFR award
–Up to 20% above the average – 60% of LTIFR award
–Between 20% and 40% above the average – 40% of LTIFR award
–More than 40% above the average – 0% of LTIFR award.
227
FY26 total incentive award calculation
Total incentive (R) | = | Guaranteed pay (R) | x | On-target factor (%) | x | Balanced Scorecard result (%) | ||||||||||
Total incentive plan (TIP) FY26 award | |||||||||||
Executive directors and prescribed officers | Cost to company | Participation factor | BSC results | TIP value | % settled in cash | TIP cash value* | % settled in shares | DSP awarded | Vesting years | ||
BB Nel | 13 794 000 | 300% | 82.38% | 34 090 492 | 40% | 13 636 | 60% | 63 271 | 5 | ||
BP Lekubo | 10 160 553 | 250% | 82.38% | 20 925 659 | 40% | 8 370 | 60% | 38 837 | 5 | ||
HE Mashego | 7 553 226 | 250% | 82.38% | 15 555 869 | 40% | 6 222 | 60% | 28 871 | 5 | ||
AJ Boshoff1 | 7 699 440 | 250% | 71.67% | 13 896 715 | 40% | 5 534 | 60% | 25 869 | 5 | ||
AZ Buthelezi | 7 108 919 | 250% | 82.38% | 14 640 818 | 40% | 5 856 | 60% | 27 173 | 5 | ||
U Govender | 7 108 919 | 250% | 82.38% | 14 640 818 | 40% | 5 856 | 60% | 27 173 | 5 | ||
FS Masemula | 9 104 514 | 250% | 74.24% | 16 897 978 | 40% | 6 759 | 60% | 31 362 | 5 | ||
MP van der Walt | 7 108 919 | 250% | 82.38% | 14 640 818 | 40% | 5 856 | 60% | 27 173 | 5 | ||
JJ van Heerden1 | 9 960 045 | 250% | 82.38% | 20 663 254 | 40% | 8 228 | 60% | 38 465 | 5 | ||
*Figures in R000.
1Salary is paid in A$ and the rand equivalent is influenced by the weakening or strengthening of the ZAR/A$ exchange rate.
228
Remuneration of executive directors and prescribed officers
Total Earned remuneration
Executive director and prescribed officer remuneration, in terms of Total Earned Remuneration, as required by King V and in line with the guidance notes issued by the South African Reward Association, is
detailed below.
Remuneration paid for the year ended 30 June 2026
Salary and benefits | Retirement savings and contributions | Total incentive cash portion accrued | Deferred awards accrued | Total single figure of remuneration | Less: amount accrued not settled in FY26 | Plus: amount of previous accruals settled in FY25* | Total cash remuneration | ||
Executive directors | |||||||||
BB Nel | 11 544 108 | 2 218 907 | 13 636 197 | 20 454 295 | 47 853 507 | (34 090 492) | 15 062 168 | 28 825 183 | |
BP Lekubo | 9 354 338 | 770 401 | 8 370 264 | 12 555 395 | 31 050 398 | (20 925 659) | 7 051 132 | 17 175 871 | |
HE Mashego | 6 646 371 | 1 090 048 | 6 222 348 | 9 333 521 | 23 292 288 | (15 555 869) | 5 241 722 | 12 978 141 | |
Prescribed officers | |||||||||
AJ Boshoff1 | 7 612 849 | 473 608 | 5 533 693 | 8 363 022 | 21 983 172 | (13 896 715) | 7 257 481 | 15 343 938 | |
AZ Buthelezi | 6 141 914 | 969 948 | 5 856 327 | 8 784 491 | 21 752 680 | (14 640 818) | 4 933 385 | 12 045 247 | |
U Govender | 6 331 008 | 776 655 | 5 856 327 | 8 784 491 | 21 748 481 | (14 640 818) | 3 581 773 | 10 689 436 | |
FS Masemula | 8 092 631 | 991 897 | 6 759 191 | 10 138 787 | 25 982 506 | (16 897 978) | 4 804 918 | 13 889 446 | |
MP van der Walt | 6 035 396 | 1 048 661 | 5 856 327 | 8 784 491 | 21 724 875 | (14 640 818) | 4 933 385 | 12 017 442 | |
JJ van Heerden1 | 9 849 118 | 343 861 | 8 228 139 | 12 435 115 | 30 856 233 | (20 663 254) | 6 960 585 | 17 153 564 | |
*Includes cash settlement of Phase 2 of Special Award of R3 575 000 for Mr BB Nel.
1Salary is paid in A$ and the rand equivalent is influenced by the weakening or strengthening of the ZAR/A$ exchange rate.
229
Schedule of unvested awards and cash flows
A schedule of the unvested awards and cash flows from long-term incentive awards of executive directors and prescribed officers, as required by King V and in line with the guideline note, is provided below.
Unvested awards and cash flows for FY26
Executive directors | Share award | Opening | Awarded | Pledged* | Settled | Closing | Cash on settlement | Year-end fair value | |
(R) | (R) | ||||||||
Beyers Nel | Deferred shares | ||||||||
Subtotal | 205 444 | 65 406 | 34 633 | 34 636 | 201 581 | 9 382 192 | 53 031 928 | ||
Vested awards pledged to MSR | |||||||||
Subtotal | 111 869 | – | – | – | 146 502 | – | 38 541 747 | ||
Total | 317 313 | 65 406 | 34 633 | 34 636 | 348 083 | 9 382 192 | 91 573 675 | ||
*Pledged shares should not be taken into account when recalculating the closing balance as they have already been taken into consideration for the closing balance.
Executive directors | Share award | Opening | Awarded | Pledged* | Settled | Closing | Cash on settlement | Year-end fair value | |
(R) | (R) | ||||||||
Boipelo Lekubo | Deferred shares | ||||||||
Subtotal | 227 700 | 40 148 | 40 167 | 40 168 | 187 513 | 10 916 523 | 49 330 919 | ||
Vested awards pledged to MSR | |||||||||
Subtotal | 86 985 | – | – | – | 127 152 | – | 33 451 147 | ||
Total | 314 685 | 40 148 | 40 167 | 40 168 | 314 665 | 10 916 523 | 82 782 066 | ||
*Pledged shares should not be taken into account when recalculating the closing balance as they have already been taken into consideration for the closing balance.
Executive directors | Share award | Opening | Awarded | Pledged* | Settled | Closing | Cash on settlement | Year-end fair value | |
(R) | (R) | ||||||||
Harry Mashego | Deferred shares | ||||||||
Subtotal | 183 827 | 29 845 | 36 227 | 27 814 | 149 631 | 7 591 350 | 39 364 926 | ||
Vested awards pledged to MSR | |||||||||
Subtotal | 84 788 | – | – | 25 272 | 95 743 | 7 614 752 | 25 188 069 | ||
Total | 268 615 | 29 845 | 36 227 | 53 086 | 245 374 | 15 206 102 | 64 552 995 | ||
*Pledged shares should not be taken into account when recalculating the closing balance as they have already been taken into consideration for the closing balance.
230
Prescribed officer | Share award | Opening | Awarded | Pledged | Settled | Closing | Cash on settlement | Year-end fair value |
(R) | (R) | |||||||
Jaco Boshoff | Deferred shares | |||||||
Subtotal | 80 852 | 33 646 | – | 38 322 | 76 176 | 10 498 375 | 20 040 380 | |
Total | 80 852 | 33 646 | – | 38 322 | 76 176 | 10 498 375 | 20 040 380 |
Prescribed officer | Share award | Opening | Awarded | Pledged* | Settled | Closing | Cash on settlement | Year-end fair value | |
(R) | (R) | ||||||||
Anton Buthelezi | Deferred shares | ||||||||
Subtotal | 122 167 | 28 090 | 15 705 | 15 707 | 118 845 | 4 370 679 | 31 265 741 | ||
Vested awards pledged to MSR | |||||||||
Subtotal | 17 447 | – | – | – | 33 152 | – | 8 721 628 | ||
Total | 139 614 | 28 090 | 15 705 | 15 707 | 151 997 | 4 370 679 | 39 987 369 | ||
*Pledged shares should not be taken into account when recalculating the closing balance as they have already been taken into consideration for the closing balance.
Prescribed officer | Share award | Opening | Awarded | Pledged | Settled | Closing | Cash on settlement (R) | Year-end fair value (R) |
Dr Urishanie Govender | Deferred shares | |||||||
Subtotal | – | 20 394 | – | – | 20 394 | – | 5 365 253 | |
Total | 20 394 | – | – | 20 394 | – | 5 365 253 | ||
Prescribed officer | Share award | Opening | Awarded | Pledged | Settled | Closing | Cash on settlement | Year-end fair value |
(R) | (R) | |||||||
Floyd Masemula | Deferred shares | |||||||
Subtotal | 29 863 | 27 358 | – | 9 954 | 47 267 | 2 618 328 | 12 435 003 | |
Total | 29 863 | 27 358 | – | 9 954 | 47 267 | 2 618 328 | 12 435 003 | |
231
Prescribed officer | Share award | Opening | Awarded | Pledged* | Settled | Closing | Cash on settlement | Year-end fair value | |
(R) | (R) | ||||||||
Marian van der Walt | Deferred shares | ||||||||
Subtotal | 161 316 | 28 090 | 25 519 | 25 521 | 138 366 | 6 950 038 | 36 401 326 | ||
Vested awards pledged to MSR | |||||||||
Subtotal | 46 945 | – | – | – | 72 464 | – | 19 063 829 | ||
Total | 208 261 | 28 090 | 25 519 | 25 521 | 210 830 | 6 950 038 | 55 465 155 | ||
*Pledged shares should not be taken into account when recalculating the closing balance as they have already been taken into consideration for the closing balance.
Prescribed officer | Share award | Opening | Awarded | Pledged* | Settled | Closing | Cash on settlement | Year-end fair value | |
(R) | (R) | ||||||||
Johannes van Heerden | Deferred shares | ||||||||
Subtotal | 230 836 | 39 337 | 39 414 | 39 417 | 191 342 | 10 670 300 | 50 338 251 | ||
Vested awards pledged to MSR | |||||||||
Subtotal | 112 436 | – | – | 37 833 | 114 017 | 11 399 526 | 29 995 592 | ||
Total | 343 272 | 39 337 | 39 414 | 77 250 | 305 359 | 22 069 826 | 80 333 843 | ||
*Pledged shares should not be taken into account when recalculating the closing balance as they have already been taken into consideration for the closing balance.
232
Minimum shareholding requirements
Progress towards minimum shareholding requirement targets for each executive director and prescribed officer, as at 30 June 2026.
Minimum shareholding requirements | |||
Executive directors and prescribed officers | Cost to company | MSR Value | MSR Compliance % |
BB Nel* | 13 794 000 | 21 147 029 | 153% |
BP Lekubo* | 10 160 553 | 22 044 746 | 217% |
HE Mashego* | 7 553 226 | 18 197 145 | 241% |
AJ Boshoff¹*** | 9 104 514 | — | — |
AZ Buthelezi* | 7 108 919 | 7 204 133 | 101% |
U Govender*** | 7 108 919 | — | — |
FS Masemula*** | 9 104 514 | — | — |
MP van der Walt* | 7 108 919 | 13 490 629 | 190% |
JJ van Heerden¹* | 9 104 514 | 20 693 502 | 227% |
1In calculating the target MSR of the foreign prescribed officer, the company used the cost to company (in ZAR) of the deputy group chief executive officer.
*Target exceeded – Exceeding 100%.
**Target partially met – Between 50% – 99%.
***Minimum threshold – Below 50%.
Exercise of discretion
The committee did not exercise any discretion in its decision-making on variable remuneration for executive directors or prescribed officers during FY26 that resulted in a departure from the application of the
remuneration policy.
During FY26, no malus and clawback trigger events occurred that required the application of malus or clawback. Following the post-year-end determination on 11 August 2026 that comparative financial
information required restatement, the remuneration committee performed the recovery analysis described in Item 6.F of the Form 20-F.
Termination, sign-on and restraint payments
During FY26, no termination payments, sign-on or buy-out awards, or restraint of trade payments were made to executive directors or prescribed officers, other than statutory entitlements on termination of
employment.
233
Non-executive directors’ fees for FY25 and FY26
In accordance with the binding shareholder approval regime, and following approval of the fees for FY25 and FY26 are set out below:
Director (R000) | FY261 | FY251 | ||||
Dr Patrice Motsepe | 2 407 | 2 383 | ||||
Karabo Nondumo | 1 832 | 2 079 | ||||
Dr Mavuso Msimang | 1 446 | 1 382 | ||||
Mangisi Gule | 878 | 470 | ||||
Frans Lombard2 | 890 | — | ||||
Zanele Matlala | 1 169 | 482 | ||||
Mametja Moshe | 1 112 | 516 | ||||
Bongani Nqwababa | 1 484 | 1 692 | ||||
Vishnu Pillay | 1 376 | 1 482 | ||||
Martin Prinsloo | 1 549 | 1 627 | ||||
Given Sibiya | 1 550 | 1 426 | ||||
Peter Turner | 1 197 | 1 375 | ||||
John Wetton3 | 641 | 1 711 | ||||
Total | 17 531 | 16 625 | ||||
1Directors' remuneration excludes value added tax.
2Appointed as non-executive director on 14 August 2025.
3Retired as non-executive director effective 26 November 2025.
The fees proposed for FY27 are included in the Notice to shareholders.
234
Directors’ emoluments (R 000) | ||||||||
Name | Salaries and benefits 2026 | Retirement savings & contributions during the year 2026 | Bonuses paid1,2 2026 | Total 2026 | Total 2025 | |||
Executive | ||||||||
Beyers Nel2,4 | 11 544 | 2 219 | 15 062 | 28 825 | 6 283 | |||
Boipelo Lekubo | 9 354 | 770 | 7 051 | 17 175 | 16 149 | |||
Dr Harry Mashego | 6 646 | 1 090 | 5 242 | 12 978 | 12 544 | |||
Peter Steenkamp5 | — | — | — | — | 32 905 | |||
Prescribed officers | ||||||||
Beyers Nel4 | — | — | — | — | 10 915 | |||
Floyd Masemula | 8 093 | 992 | 4 805 | 13 890 | 4 154 | |||
Jaco Boshoff3 | 7 613 | 474 | 7 257 | 15 344 | 3 986 | |||
Anton Buthelezi | 6 142 | 970 | 4 933 | 12 045 | 11 919 | |||
Urishanie Govender | 6 331 | 777 | 3 582 | 10 690 | 4 924 | |||
Marian van der Walt | 6 035 | 1 049 | 4 933 | 12 017 | 11 641 | |||
Johannes van Heerden3 | 9 849 | 344 | 6 961 | 17 154 | 18 362 | |||
Total | 71 607 | 8 685 | 59 826 | 140 118 | 133 782 | |||
1.Reflects amounts actually paid during the year.
2.Includes cash settlement of Phase 2 of Special Award of R3 575 000.
3.Salary paid in A$ and the Rand equivalent is influenced by the weakening or strengthening of the Rand/A$ exchange rate.
4.Previously classified as prescribed officer until appointment as executive director effective 1 January 2025.
5.Retired as an employee and consequently resigned as executive director, effective 31 December 2024.
235
Executive directors and management share incentives | ||||||||||||||||||
As at 30 June 2026 | ||||||||||||||||||
Executive directors | Prescribed officers | |||||||||||||||||
Beyers Nel | Boipelo Lekubo | Harry Mashego | Anton Buthelezi | Marian van der Walt | Johannes Van Heerden | Floyd Masemula | Urishanie Govender1 | Jaco Boshoff | ||||||||||
Movements on share incentives | Number of awards | Average price (Rand) | Number of awards | Average price (Rand) | Number of awards | Average price (Rand) | Number of awards | Average price (Rand) | Number of awards | Average price (Rand) | Number of awards | Average price (Rand) | Number of awards | Average price (Rand) | Number of awards | Average price (Rand) | Number of awards | Average price (Rand) |
Deferred management shares | ||||||||||||||||||
Opening balance at 1 July 2025 | 292 380 | n/a | 314 685 | n/a | 268 615 | n/a | 139 614 | n/a | 208 261 | n/a | 343 272 | n/a | 29 863 | n/a | — | n/a | 80 852 | n/a |
Awards granted | 65 406 | n/a | 40 148 | n/a | 29 845 | n/a | 28 090 | n/a | 28 090 | n/a | 39 337 | n/a | 27 358 | n/a | 20 394 | n/a | 33 646 | n/a |
Awards exercised/vested | (34 636) | (40 168) | (53 086) | (15 707) | (25 521) | (77 250) | (9 954) | — | (38 322) | |||||||||
– Average sales price | — | 276.20 | — | 276.20 | — | 276.20 | — | 276.20 | — | 276.20 | — | 276.20 | — | 276.20 | — | 276.20 | — | 276.20 |
– Gain realised on awards exercised and settled (SA Rand) | 9 382 192 | 10 916 523 | 15 206 102 | 4 370 679 | 6 950 038 | 22 069 826 | 2 618 328 | — | 10 498 375 | |||||||||
Awards forfeited and lapsed | — | n/a | — | n/a | — | n/a | — | n/a | — | n/a | — | n/a | — | n/a | — | n/a | — | n/a |
Closing balance at 30 June 2026 | 323 150 | n/a | 314 665 | n/a | 245 374 | n/a | 151 997 | n/a | 210 830 | n/a | 305 359 | n/a | 47 267 | n/a | 20 394 | n/a | 76 176 | n/a |
Gain realised on awards exercised (SA Rand) | 9 382 192 | 10 916 523 | 15 206 102 | 4 370 679 | 6 950 038 | 22 069 826 | 2 618 328 | — | 10 498 375 | |||||||||
Outstanding awards (listed by allocation date) | ||||||||||||||||||
Deferred management shares | 323 150 | 314 665 | 245 374 | 151 997 | 210 830 | 305 359 | 47 267 | 20 394 | 76 176 | |||||||||
18 September 2019 | 16 486 | n/a | — | n/a | — | n/a | — | n/a | — | n/a | — | n/a | — | n/a | — | n/a | — | n/a |
18 September 2020 | 21 245 | n/a | 28 746 | n/a | 16 572 | n/a | — | n/a | — | n/a | 23 609 | n/a | — | n/a | — | n/a | — | n/a |
20 September 2021 | 65 242 | n/a | 79 530 | n/a | 63 443 | n/a | — | n/a | 59 221 | n/a | 69 471 | n/a | — | n/a | — | n/a | — | n/a |
19 September 2022 | 49 646 | n/a | 64 131 | n/a | 50 320 | n/a | 43 724 | n/a | 43 336 | n/a | 55 225 | n/a | — | n/a | — | n/a | — | n/a |
18 September 2023 | 53 210 | n/a | 47 218 | n/a | 42 125 | n/a | 39 647 | n/a | 39 647 | n/a | 52 921 | n/a | — | n/a | — | n/a | 12 272 | n/a |
18 September 2024 | 51 915 | n/a | 54 892 | n/a | 43 069 | n/a | 40 536 | n/a | 40 536 | n/a | 64 796 | n/a | 19 909 | n/a | — | n/a | 30 258 | n/a |
18 September 2025 | 65 406 | n/a | 40 148 | n/a | 29 845 | n/a | 28 090 | n/a | 28 090 | n/a | 39 337 | n/a | 27 358 | n/a | 20 394 | n/a | 33 646 | n/a |
Closing balance at 30 June 2026 | 323 150 | 314 665 | 245 374 | 151 997 | 210 830 | 305 359 | 47 267 | 20 394 | 76 176 | |||||||||
1 Classified as prescribed officer effective 1 October 2024 and qualified for first award in September 2025.
236
Audit and risk committee: chairperson’s report
Dear shareholder
I am pleased to present the audit and risk committee (the
committee) report for the financial year ended 30 June 2026.
This report reflects the key material matters deliberated by the
committee throughout the year.
The committee maintained a clear focus on sound governance
and effective oversight throughout the year. Our work continues
to support informed decision-making and the responsible
stewardship of Harmony’s business.
Introduction
This committee is an independent statutory committee, elected
annually by Harmony’s shareholders in accordance with section
94 of the South African Companies Act of 2008, as amended
(the Act), and the principles of good governance. It operates
within the applicable regulatory and governance framework,
including relevant listings requirements, and in terms of its
approved terms of reference*. Its responsibilities encompass its
statutory duties as well as specific area of oversight delegated by
the board.
During the year, the committee fulfilled its statutory duties in
terms of section 94(7) of the Act and discharged its
responsibilities under the applicable JSE Listings Requirements.
Terms of reference and discharge of
responsibilities
The formal board approved committee terms of reference
(available on our corporate website, www.harmony.co.za), are
reviewed and updated annually (or more frequently if required) by
both the committee and the board. During the year, the terms of
reference were aligned with King V Report on Corporate
Governance™ for South Africa 2025 (King V™). While King V
requires that the terms of reference must be reviewed
periodically or when circumstances or requirements change,
Harmony has elected to comply more rigorously by retaining an
annual review.
The committee is satisfied that, during FY26, it has conducted
its affairs and discharged its legal and other responsibilities in
accordance with its terms of reference.
Composition and function
Members: M Prinsloo (Chairperson); G Sibiya;
B Nqwababa; Z Matlala; M Moshe and F Lombard.
Mr M Prinsloo has served as chairperson of the committee since
17 January 2025. At the AGM held on 26 November 2025,
Mr Prinsloo, Ms G Sibiya and Mr B Nqwababa were re-elected
to the committee, while Ms Z Matlala, Ms M Moshe and
Mr F Lombard were elected as members. All committee
members possess the requisite academic qualifications, financial
literacy, and strong business and financial acumen.
Refer to Notice of the annual general meeting in our Notice to
shareholders for details on the 2026 election of committee
members. The board has reviewed the proposed composition
of the committee against the requirements of the Act and the
regulations that apply to the company, and has confirmed that
the proposed committee will comply with the relevant
requirements, and has the necessary knowledge, skills and
experience to enable the committee to perform its duties.
As at the date of this report, the committee has six members, all
of whom (in the opinion of the board) are independent non-
executive directors.
For further detail on their qualifications, expertise and
experience, refer to our website at www.harmony.co.za/who-
we-are/board.
The chairman of the board is not a member of the committee
but may attend meetings by invitation. Board members are
entitled to attend committee meetings as observers. However,
non-committee members are not entitled to participate without
the consent of the chair and do not have a vote.
The group chief executive officer (CEO) and financial director (FD)
– together with members of the executive team and senior
managers representing areas relevant to the discussions at the
committee, as well as the external auditors, the chief audit
executive and assurance providers attend meetings either by
standing invitation or as and when required.
The internal and external auditors have unlimited access to the
chairperson of the committee. The chief audit executive reports
directly to the committee.
Responsibilities
The responsibilities of the committee are set out in the
committee terms of reference and include, among others:
•To ensure the integrity of financial statements and related
reporting, that they comply with IFRS Accounting Standards,
the SAICA Financial Reporting Guides and other relevant
regulatory bodies stated above and fairly represent the
financial position of the group, the company and our
operations
•To monitor internal controls, the internal audit function,
combined assurance and matters pertaining to the external
auditors
•To oversee corporate governance, particularly in relation to
legislative and regulatory compliance
•To oversee the management of risk, as well as information
technology (IT) governance and cyber security.
The committee believes that it complied with its legal, regulatory
and other responsibilities during the past financial year.
Reporting
The committee reviewed the appropriateness of the following
FY26 reports and their related processes:
•Integrated report and its related suite of reports
•Mineral Resource and Mineral Reserve statement (with the
assistance of the technical committee)
•Annual financial statements and accounting practices
•Annual report filed on Form 20-F with the United States
Securities and Exchange Commission.
The committee submits that these reports represent a fair view
of the group’s performance for FY26 and recommended them to
the board for approval.
Duties discharged in FY26
•Reviewed the company’s quarterly, half year and annual
financial results
•Ensured it has access to all the financial information of
Harmony to allow the company to effectively prepare and
report on its financial statements
•Discussed the appropriateness of accounting principles,
critical accounting policies, management’s judgements and
estimates, all of which were found to be appropriate. These
included impairments, reversal of previously recorded
237
impairments, as well as the fair value exercise for the MAC
Copper acquisition
•Executed its responsibility by ensuring that Harmony has
established the appropriate financial reporting procedures and
these procedures are operating. These procedures, include
consideration of all entities included in the consolidated group
IFRS financial statements
•Considered the JSE‘s latest report on the proactive monitoring
of financial statements
•Considered the appointment of the external auditor,
Ernst & Young Incorporated (EY), as the registered
independent auditor for the ensuing year
•Considered the suitability, and satisfied itself, of the external
audit partner and firm following assessment of the information
provided by that firm, in terms of paragraph 5.7(h)(iii) of the
JSE Listings Requirements, to determine the suitability of its
appointment as the external audit firm and of the designated
individual partner
•Ensured that the appointment of the external audit firm is
presented and included as a resolution at the annual general
meeting
•Satisfied itself that the external audit firm, EY, was suitable and
independent from the company
•Reviewed and approved external audit plans, terms of
engagement and fees, as well as the nature and extent of
non-audit services rendered by the external auditors
•Evaluated the independence and effectiveness of the internal
audit function
•Reviewed and approved internal audit budget, the internal
audit charter and risk-based plans
•Evaluated and coordinated the internal audit, external audit
and sustainability assurance processes
•Received and considered reports from the external and
internal auditors, as well as other assurance providers
•Considered the appropriateness, expertise and experience of
the FD and the finance function – both were found to be
adequate and appropriate
•Evaluated and considered Harmony’s risks, and measures
taken to mitigate those risks
•Considered whether IT risks are adequately addressed and
whether appropriate controls are in place to address these
risks. The committee oversees and monitors the governance
of IT on behalf of the board, a task it views as a critical aspect
of risk management
•Considered and confirmed the company as a going concern
•Considered and approved the company’s non-audit services
policy
•Reviewed and recommended changes to the committee’s
terms of reference to the board for approval
•Reviewed the adequacy of the group’s insurance coverage
•Considered commodity prices and exchange rate parameters
for budget and business planning
•Considered the company’s fraud risk assessment programme
•Reviewed legal matters that could have a significant impact on
the company’s business
•Reviewed treasury-related transactions for board approval
•Oversaw the United States Sarbanes-Oxley Act of 2002 (SOX)
compliance efforts of management, receiving quarterly
updates on controls associated with financial reporting and
monitored the remediation steps agreed with the committee to
remediate the unremediated material weaknesses reported at
the end of 2025.
•Assessed the final conclusion reached by the CEO and FD on
the effectiveness of the internal controls over financial
reporting and their assessment of material weaknesses as well
as the detailed planned remediation steps developed to be
implemented by management.
Key focus areas in FY26
Interim and annual financial statements
The annual financial statements have been prepared in
accordance with IFRS Accounting Standards, SAICA Financial
Reporting Guides, the requirements of the South African
Companies Act 71 of 2008, the Listings Requirements of the
JSE Limited and all applicable regulations.
During the year, the committee considered management’s
identification and correction of prior-period errors relating to
mine-planning assumptions and payroll-related obligations,
which resulted in the retrospective restatement of comparative
information in accordance with IAS 8, Accounting Policies,
Changes in Accounting Estimates and Errors. The committee
considered management’s assessment of the nature and extent
of the errors, the resulting disclosures, the impact on the group’s
financial statements and the related control environment. The
Committee also considered the views of the external auditor and
was satisfied that the corrective accounting treatment and
related disclosures in Note 38 to the annual financial statements
are appropriate.
In terms of paragraph 5.9 of the JSE Listings Requirements,
the committee reviewed and assessed the process implemented
by management to enable the CEO and the FD to pronounce on
the annual financial statements and the system of internal control
over financial reporting. The results from the process were
communicated to the committee. The committee considered any
deficiencies, particularly identified material weaknesses, as well
as the appropriateness of management’s response thereto.
The committee is satisfied with the remediation steps proposed
by management in this regard. The committee, on behalf of the
board, has noted the final confirmation of the CEO and FD.
External auditor – appointment, independence
and tenure
Having considered the external auditor’s previous appointments
and the extent of other work undertaken for the group, the
committee is satisfied that EY are independent of the group,
as per section 94(8) of the Act. The committee also satisfied
itself as to the suitability of EY and the designated audit partner.
A formal procedure has been adopted to govern the process
whereby the external auditor may be considered for non-audit
services and the extent of these services is closely monitored by
the committee. Total fees approved for the external auditor, EY,
for the year were R85.2 million, of which R85.1 million was for
audit-related services, R0.1 million for non-audit services.
This is the third year that EY has been Harmony’s external
auditor. At the 2025 annual general meeting, EY was
reappointed as the independent external auditor.
As part of Harmony’s commitment to transformation, EY
partnered with Motlanalo Chartered Accountants and Auditors, a
level 1 broad-based black economic empowerment company
being a 100% black-women-owned firm.
Refer to Notice of the annual general meeting in our Notice to
shareholders for external auditor reappointment.
Internal audit
In terms of internal audit, the committee is responsible for:
•Ensuring that the group’s internal audit function is
independent and has the necessary resources, standing and
authority within the group to enable it to perform its duties
•Overseeing cooperation between internal audit and the
external auditors, and serving as a link between the board of
directors and these functions.
The internal audit function’s most recent independent quality
review, conducted in FY25 by the Institute of Internal Auditors
South Africa, concluded that the function generally conforms to
the International Standards for the Professional Practice of
Internal Auditing, with no material findings identified. External
238
independent quality assessments are conducted every five
years, with the next review scheduled for FY30.
The committee has confirmed the effectiveness of the group
chief audit executive, Ms B Maluleka-Ngunjiri, and is satisfied
that she has the appropriate expertise and experience to meet
the responsibilities of this position. The chief audit executive
reports quarterly, or as necessary, to the committee on internal
audit and has direct access to the committee, primarily through
its chairperson.
The committee is satisfied that internal audit follows an approved
risk-based internal audit plan and regularly reviews the group’s
risk profile. Internal audit submits an overall statement on the
effectiveness of the group’s governance, risk management and
control processes.
Legislative compliance
Compliance information and reports on the status of legislative
compliance are presented to this committee. The risk of non-
compliance is thus managed through:
•Bi-annual review and updates on the Harmony regulatory
universe
•Compliance risk management plans for high-risk legislation
•The continuous monitoring of the regulatory environment.
Combined assurance
The committee is satisfied that the group has optimised the
assurance coverage obtained from management, and internal
and external assurance providers. The committee is also
satisfied that the various external assurances that are obtained
and related systems and procedures are effective in achieving
the following objectives:
•Supporting the integrity of information used for internal
decision-making by management, the board and its
committees
•Supporting the integrity of external reports
•Minimising assurance fatigue.
Governance of risk
The committee fulfils a dual function – as an audit committee
and as a risk committee. Internal audit conducts regular and full
assessments of the risk management function and framework,
on which it reports to the committee. The committee is satisfied
with the effectiveness of its oversight of risk governance in the
group. A report on risk is also shared with the board on a
quarterly basis.
In the past year, the committee continued to monitor the
enterprise risk management and resilience policy, risk
management guidelines and risk management framework to
ensure continued focus on the company’s material risks. The
board further approves the group’s risk appetite and tolerance
framework.
Appropriateness and experience of FD and
effectiveness of the finance function
The committee confirms that it is satisfied that Ms B Lekubo, the
current FD, possesses the appropriate expertise and experience
to meet the responsibilities of this position.
Treasury and capital structure
During the year, the committee maintained oversight of a
comprehensive review of the group’s treasury universe, including
its funding arrangements, liquidity and capital structure. This
review supported the successful refinancing of the group’s debt
facilities and subsequent issuance of the convertible bond,
further diversifying Harmony’s sources of capital and optimising
its funding profile. These initiatives reflect a disciplined approach
to balance sheet management and have strengthened the
group’s financial flexibility as it advances its strategic and capital
priorities.
Oversight of derivative programme
The committee also monitors and reviews the group’s derivative
and hedging strategy. The derivative programmes currently in
place were introduced in FY16. During FY24, the hedging policy
was expanded and a new gold hedging limit was set as 30%,
20% and 10% of production in a 12-, 24- and 36-month period
(previously 20% over a 24-month period). The limits for silver
remained at 50% over a 24-month period and 50% for uranium
over a 60-month period. Harmony may execute on the hedging
strategy when we achieve a minimum margin of 25% above all-
in sustaining cost (AISC) and inflation. The minimum margin was
increased to 30% above AISC and inflation was introduced for
the last third of the volume hedged. Following the acquisition of
CSA mine, a limit for copper equal to 20% of production over a
24-month period was introduced, subject to securing a minimum
margin of 25% above operating cash costs and inflation. The
foreign exchange exposure of 25% remained during the year.
For more on how these derivative programmes have performed,
see note 17 “Derivative financial instruments” of our consolidated
financial statements, set forth beginning on page F-1.
Technology and information governance
The committee continued its focus on overseeing the strategic
information technology direction of the group, the technology
risks, as well as compliance regarding information and
technology. The framework on which the oversight is conducted
has been extended through the approval of an IT strategy that
guides the deployment and operation of technology and
information in the group.
The roadmap of the information technology strategy provides
clear investment guidance over the medium term on an annual
rolling-forward basis. This ensures that the needs for critical
rejuvenations, cyber security, business solutions and IT
operations are visible and controllable over time.
The alignment of operational technology, engineering
technology, information technology, and other technology
domains has commenced under this strategy. Group
Technology is responsible for establishing information
technology standards, developing the associated taxonomy, and
overseeing integration as well as data and AI platforms.
The governance structures for information and technology are
maturing in their ability to effectively oversee and guide the
sourcing and deployment of IT solutions. Efforts are ongoing to
enhance the efficiency and effectiveness of these forums.
Additionally, work continues to align IT processes, controls, and
the IT risk framework with the broader group enterprise risk
management framework.
Dividend policy and dividends declaration
The board declared a 530 SA cents interim ordinary dividend for
the year ended 30 June 2026, paid on 28 April 2026 and
declared a final ordinary dividend of 750 SA cents for the year
ended 30 June 2026, paid on 12 October 2026 (2025: interim
ordinary dividend of 227 SA cents, paid on 14 April 2025
and final ordinary dividend of 155 SA cents, paid on
13 October 2025). In addition, dividend payments were made in
2025 and 2026 to the non-controlling interest holders in
Tswelopele Beneficiation Operation of R62 million and
R99 million, respectively.
Harmony declared a preference share dividend of R47 million to
the Harmony Gold Community Trust (the Trust) for the year
(2025: R22 million).
In considering the payment of dividends, the board, with the
assistance of the audit and risk committee, took into account
the current financial status of the company and the payment of
239
a proposed dividend subject to the successful application of the
solvency and liquidity test as set out in section 4 of the
Companies Act of 2008.
Harmony has amended its dividend policy to allow for up to 50%
of operating free cash flow after capital, interest, tax and
corporate and other expenditure (net free cash) to be returned to
shareholders, subject to the discretion of the board and leverage
levels measured by the ratio of net debt to earnings before
interest, taxes, depreciation and amortisation (EBITDA). The
revised policy now includes an improved base dividend, which
has been increased from 20% to 30% of net free cash. In
addition, an upside dividend may be paid, based on leverage
levels. When leverage is equal to or above 0.5x and below 1x,
only a base dividend of 30% of net free cash is payable. As
leverage improves, the board may at its sole discretion consider
an upside dividend of up to 20% of net free cash.
Going concern
The committee has reviewed a documented assessment,
including key assumptions prepared by management, of the
going concern status of the group.
The board’s statement on the going concern status of the
group, as supported by the committee, appears in the Directors’
report.
Integrated report
The committee has overseen the integrated reporting process,
reviewed the report and has recommended the 2026 Integrated
report and consolidated financial statements for approval by
the board.
Events post year end
•On 2 July 2026, a drawdown was made related to the
US$500 million RCF and A$250 million term loan of
US$400 million and A$250 million respectively. These funds
were utilised to settle the US$ RCF of US$200 million, US$
term loan of US$100 million and the US$ bridge facility of
US$275 million owing under the group’s existing facilities.
Following the receipt and application of the funds, the
refinancing was implemented, resulting in the new facilities
becoming effective. On 18 September 2026, a drawdown of
A$125 million was made on the A$250 million RCF. On
28 September 2026, a principal payment of US$150 million
(R2.4 billion), was made on the US$500 million RCF.
On 2 October 2026, a payment of US$256 million (R4.2 billion),
comprising US$250 million of capital and US$6 million of
interest, was made on the US$500 million RCF.
•On 14 August 2026, Mr Frans Lombard was appointed as
Lead Independent Director and chair of the nominations
committee of Harmony, in addition to his membership of the
audit and risk committee
•On 26 August 2026, a final dividend of 750 SA cents per
ordinary share was declared, which was paid on 12 October
2026.
•On 29 September 2026, Harmony issued guaranteed senior
unsecured convertible bonds valued at US$500 million
(US$200 000 principal amount per bond), maturing on
29 September 2031 and bearing interest of 1.5% per annum,
payable semi-annually. The bonds are convertible into ordinary
shares at an initial conversion price of R418.60 per share,
subject to customary adjustments. The transaction is a non-
adjusting event after the reporting date.
•On 15 October 2026, Mr Alwyn Pretorius and Mr James
Boardman were appointed to the board of directors of
Harmony as independent non-executive directors.
Refer to note 39 “Subsequent events” of our consolidated
financial statements, set forth beginning on page F-1 for further
details.
In closing
I extend my appreciation to my fellow committee members for
their professionalism, commitment and considered contribution
to the committee’s work throughout the year. I also thank
management for their continued support, constructive
engagement and valuable input.
I look forward to continuing our work together in upholding
sound governance and effective oversight in support of the
committee’s mandate.
Martin Prinsloo
Chairperson: audit and risk committee
23 October 2026
240
Social and ethics committee: chairperson’s report
Dear stakeholder
I am pleased to present Harmony’s social and ethics
committee report for FY26.
Our philosophy of mining with purpose reflects our belief that
building a lasting positive legacy in the countries where we
operate depends not only on what we produce, but also on
how we produce it. Responsible stewardship, operational
excellence, strong governance and disciplined decision-
making are therefore integral to our approach to sustainability.
Responsible mining and sustainable
growth
Mining plays an essential role in supporting economic
development, modern society, and the technologies that
underpin everyday life. For more than seven decades,
Harmony has created
value through our gold mining business, developing distinctive
capabilities in operating mature, deep-level, and historically
marginal mines and creating long-term value from complex
assets.
As the industry evolves, responsible mining requires careful
consideration of the environmental and social impacts
associated with developing and producing the resources
needed for the future.
The energy transition is also a mining transition, with many
future mineral resources becoming deeper, lower grade or
located in increasingly complex operating environments.
Meeting future resource demands will require the responsible
and efficient use of water, energy and other resources, effective
management of waste and biodiversity impacts, and meaningful
stakeholder engagement to maintain trust and create lasting
value.
Harmony’s growth strategy, including our investment in
copper, reflects the opportunities presented in this changing
landscape. As resource demand evolves in response to
electrification, renewable energy systems and broader
economic transformation, our investment in copper
strengthens Harmony’s exposure to these long-term resource
demand trends. As we diversify our portfolio and enter new
operating environments, our commitment to mining with
purpose remains fundamental to how we approach growth,
investment and long-term value creation.
The inclusion of CSA mine this year and the decision to
advance Eva Copper construction mark important steps in
Harmony’s strategic evolution, reflecting our disciplined
approach to portfolio diversification and reinforcing our
commitment to responsible mining, sustainable value creation
and business resilience.
Our social and ethics committee mandate
This context reinforces the importance of strong oversight of
the environmental, social and ethical dimensions of our
business.
The social and ethics committee, a statutory committee
established under the Companies Act, oversees sustainability-
related matters including ethics, stakeholder engagement,
employee relations (including empowerment, transformation,
health and wellness), environmental stewardship, socio-
economic development, and public health and safety.
In fulfilling its role, the committee considers trade-offs across
these areas to support Harmony’s continued delivery of long-
term value.
The committee has discharged all regulatory, legal, and board
mandated responsibilities during the reporting period. In doing
so, it has applied the principles of King V with a strong focus
on ethical governance, responsible conduct, and corporate
citizenship, which are essential to sustaining the company’s
long-term growth.
Safety and health: the cornerstone of our
business
Our people are central to everything we do at Harmony, and
the loss of six colleagues in FY26 represents a significant and
deeply felt tragedy. It also underscores the importance of
continuing our drive to strengthen our controls and deepen
our understanding of risk, while embedding safe behaviours
and decision-making across the group. We remain committed
to achieving our objective of zero harm.
Safety oversight is a shared responsibility within Harmony’s
governance framework. The technical committee is
responsible for employee safety, while the social and ethics
committee oversees employee health and public safety.
Together, we provide oversight to support the fundamental
right to a safe and healthy working environment.
Harmony achieved its lowest lost-time injury frequency rate on
record during FY26. Although encouraged by this progress,
we recognise that continuous improvement remains critical.
Through our strategy to embed safety practices in everything
we do, we foster a proactive safety culture.
We also met our health targets for FY26, with no new cases of
silicosis or noise-induced hearing loss attributable to our
operations. Our health services contribute to operational
stability, workforce productivity, and the long-term
sustainability of our operations. Health and safety risks remain
inherent in mining, and we prioritise comprehensive,
responsive and holistic healthcare as our duty of care.
Sustainability in action: our updated
sustainability framework
As expectations, risks and resource constraints are evolving,
we updated our sustainability framework to reinforce
governance, risk management and business resilience, refine
our sustainability priorities, and strengthen our approach to
identifying and managing Harmony’s material sustainability
and climate-related impacts, risks and opportunities.
Harmony is implementing the applicable mandatory Australian
climate-related financial reporting requirements, including
AASB S2 Climate-related Disclosures, in respect of its
Australian operations. During FY26, we continued to develop
the governance, processes, controls and reporting capabilities
required to support these disclosures and the applicable
assurance requirements. In developing these capabilities,
Harmony may have regard to relevant international
sustainability reporting guidance where appropriate.
241
Ethics management
The committee reviews and approves Harmony’s ethics
strategy and related policies, supporting high standards of
ethical conduct and leadership across the Company. Ongoing
employee training and awareness initiatives, together with our
collaboration with SNG Grant Thornton and other external
experts, help embed a strong ethical culture and strengthen
our ability to detect, prevent and report fraud.
Illegal mining remains an ongoing challenge at our South
African operations and a concern in Papua New Guinea. In
addition to strengthened security and detection measures, we
continue to focus on proactive training and collaboration with
host communities, government and law enforcement agencies
to address this challenge.
Social responsibility
Harmony invests in building resilient communities. Fourth-
generation social and labour plan commitments progressed as
planned, and we advanced existing community development
commitments that support community wellbeing. Harmony also
partnered with the Trust Blu Foundation to build sustainable
digital hubs and support local economic participation, thereby
expanding the reach and impact of our community
development programmes.
Gender inclusion remains a priority, with ongoing efforts to
advance the progression of women in mining through targeted
initiatives, strengthened governance structures and
stakeholder engagement. Harmony is also a participatory
party on the Minerals Council South Africa’s Women in Mining
Strategy 2025 – 2027 and reports quarterly on our progress.
At Eva Copper, we were proud to work closely with the
Kalkadoon People during the year to support a culturally led
heritage salvage programme ahead of construction activities,
preserving 1 423 artefacts and establishing a permanent
Keeping Place that will safeguard this cultural heritage for
future generations.
Stakeholder engagement provides insight into the matters
most important to our stakeholders and business, helping
inform strategy, risk management, sustainability priorities and
our response to emerging impacts, risks and opportunities.
Decarbonisation and environmental
stewardship
We remain committed to achieving our Science Based
Targets initiative (SBTi)-approved target of 63% reduction in
scope 1 and 2 emissions by FY36, while progressing our
ambition of net zero scope 1 and 2 emissions by 2045.
In parallel, we continue to mature our scope 3 emissions
inventory to support future target-settings.
We fell short of our renewable energy substitution target in
FY26 due to delays in the Sungazer 2 project, reflecting
geotechnical challenges, associated design modifications and
additional grid connection requirements.
We exceeded our water recycling target across our
operations, resulting in a corresponding reduction in potable
water consumption.
Key progress during FY23 to FY26 includes:
•Sungazer 1 (30MW) is operating successfully and Sungazer
2 (100MW) is in its final delivery phase, with commercial
operations expected to begin in late 2026
•Securing approval for a 120MW solar facility and a 75MW
battery at Eva Copper
•Operating the world’s largest gold tailings retreatment
business, reducing environmental impact while creating jobs
and unlocking value
•The installation of three reverse osmosis water treatment
plants at Target (FY23), Harmony One (FY24) and TauTona
(FY26) advances our water ambition to reduce our potable
water dependency by 80% by FY34 (against the FY16
baseline).
Looking ahead
The future will depend on mined resources, making
responsible stewardship increasingly important to sustainable
value delivery.
As Harmony grows and the operating environment evolves,
the social and ethics committee will remain focused on
overseeing the group’s:
•Ethical leadership and governance
•Decarbonisation and environmental stewardship
•Employee safety, health and inclusivity
•Community empowerment and socio-economic
development
•Transparent and globally aligned sustainability reporting.
As I reflect on my first year as chair of the committee, I am
grateful for the support and commitment of my fellow
committee members, Harmony’s leadership team, our
employees and partners. I look forward to building on the
progress we have made as we continue to mine with purpose
and uphold the values that underpin our business.
Zanele Matlala
Chairperson: social and ethics committee
23 October 2026
242
Mining Charter III – compliance scorecard
We discuss our performance against the Mining Charter throughout this report. The charter is focused on transformation of the
South African mining industry as a whole by promoting equal access to and ownership, expanding business opportunities for
historically disadvantaged persons (HDPs), redressing the imbalances of historical injustices and enhancing the social and economic
welfare of employees and mine communities.
The Mining Charter is not a static document – it has revised a number of times and is now in its third iteration (effective 2018 and known as Mining Charter III). We will continue to work towards transformation
because we believe this supports our social licence to operate. As a mining company, Harmony hold to the spirit of the Mining Charter and measure our performance against the charter as an entry point to
our transformation journey.
The table summarises our performance against targets for each pillar for the calendar year to 31 December 2025 (the regulatory reporting period). Harmony considers itself to be subject to the Mining Charter.
Harmony’s status under the applicable Mining Charter is determinative of the applications lodged by Harmony for mining rights. The Broad-Based Black Economic Empowerment Act requires the Department
of Trade, Industry and Competition to issue the Code of Good Practice on Broad-Based Black Economic Empowerment or sector codes to measure an entities black economic empowerment initiatives. The
B‑BBEE Act and code do not require the DMPR to apply the B-BBEE code when determining the qualification criteria for the granting of mining rights or the renewal of existing rights. The codes will only apply
to mining companies if they wish to be scored for purposes of contract with organs of state. We have conducted the B-BBEE verification audit for FY26 and have attached our certificate in the following
section of this report.
Mining Charter III scorecard for 2025 (January – December)
Measure | Target | Progress | Score | |||||||||||
1 Reporting | ||||||||||||||
Has the company reported its level of compliance with the Mining Charter for the calendar year? | Report annually | Yes | Yes | ü | ||||||||||
2 Ownership | ||||||||||||||
Minimum target for effective ownership by historically disadvantaged South Africans | Meaningful economic participation; full shareholder rights | 26% | 58% | ü | ||||||||||
3 Employment equity | ||||||||||||||
Diversification of workplace to reflect the country’s demographics and attain competitiveness | Representation of historically disadvantaged persons | Board: 50% | 73% | ü | ||||||||||
Executive committee: 50% | 62% | ü | ||||||||||||
Senior management: 60% | 63% | ü | ||||||||||||
Middle management: 60% | 68% | ü | ||||||||||||
Junior management: 70% | 74% | ü | ||||||||||||
Core and critical skills: 60% | 75% | ü | ||||||||||||
Representation of women | Board: 20% | 33% | ü | |||||||||||
Executive committee: 20% | 29% | ü | ||||||||||||
Senior management: 25% | 25% | ü | ||||||||||||
Middle management: 25% | 31% | ü | ||||||||||||
Junior management: 30% | 23% | û | ||||||||||||
Employees with disabilities | 1.5% | 0.3% | û | |||||||||||
243
Mining Charter III scorecard for 2025 (January – December) continued | ||||||||||||||
Measure | Target | Progress | Score | |||||||||||
4 Human resource development | ||||||||||||||
Development of the requisite skills, particularly in exploration, mining, processing, technology efficiency, beneficiation and environmental conservation | Human resource development expenditure as percentage of total annual leviable amount (excluding mandatory skills development levy) | Invest 5% of leviable amount as defined in human resource development element in proportion to applicable demographics (employees and non-employees) | 5% | ü | ||||||||||
5 Mine community development* | ||||||||||||||
* Meaningful contribution towards mine community development in keeping with the principles of the social licence to operate | Implementation of approved commitments in the SLP | 100% | 100% | ü | ||||||||||
* Mine community development is reported according to Harmony’s financial year, as agreed with DMRE. This report covers mine community development for the period July 2025 to June 2026. | ||||||||||||||
6 Procurement and enterprise development | ||||||||||||||
Total procurement budget spend on goods and services | Mining goods A minimum of 70% of total mining goods procurement spend must be spent on South Africa-manufactured goods sourced from BEE-compliant manufacturing companies. Excludes spend on utilities (electricity and water), fuels, lubricants and land rates | 21% of total mining goods budget must be spent on South African-manufactured goods produced by 50% + 1 vote HDP- owned and controlled companies | 58% | ü | ||||||||||
5% of total mining goods budget must be spent on South Africa-manufactured goods produced by 50% + 1 women- and/youth-owned and controlled companies | 18% | ü | ||||||||||||
44% of total mining goods budget must be spent on South Africa-manufactured goods produced by at least level 4 BEE 25% + 1 compliant companies | 77% | ü | ||||||||||||
Services A minimum of 80% of total spend on services must be sourced from South Africa-based companies | 65% of total services budget must be spent on South African companies that are 50% + 1 vote HDP-owned and controlled companies | 63% | û | |||||||||||
15% of total services budget must be spent on South African companies that are 50% + 1 vote women-owned and controlled companies | 16% | ü | ||||||||||||
5% of total services budget must be spent on South African companies that are 50% + 1 vote youth-owned and controlled | 6% | ü | ||||||||||||
10% of total services budget must be spent on South African companies that are at least at level 4 BEE + 25% + 1 compliant companies | 79% | ü | ||||||||||||
Research and development | A minimum of 70% of total research and development budget to be spent on South Africa-based entities | 100% | ü | |||||||||||
Sample analysis | Use South Africa-based facilities or companies for analysis of 100% of all mineral samples across mining value chain | 100% | ü | |||||||||||
7 Housing and living conditions | ||||||||||||||
Improve standard of housing and living conditions of mine employees | Implement all commitments in the housing and living conditions standard | 100% | ü | |||||||||||