Q1 Q2 Q3 Q4 Q3 Letter to Shareholders October 29, 2026
Q3 2026 Shareholder Letter 2 Financial Highlights $3.6B Network volume of $3.6 billion compared to our outlook of $3.425 - $3.625 billion and grew 29% year-over-year, driven by growth in our Auto vertical, while maintaining our focus on prudent underwriting. $390M Total revenue & other income of $390 million compared to our outlook of $370 - $390 million and grew 12% year-over-year, driven by growth in fee revenue and interest income. $146M Revenue from fees less production costs (“FRLPC”) of $146 million increased 5% year-over-year. FRLPC as a percentage of network volume (“FRLPC %”) contracted 91bps year-over-year to 4.1%. $130M Adjusted EBITDA of $130 million compared to our outlook of $120 - $130 million and grew 22% year-over-year, well ahead of revenue and FRLPC growth, demonstrating continued strong operating leverage. Adjusted EBITDA margin rose 3 percentage points to 33%. GAAP operating income was $113 million. $50M GAAP net income attributable to Pagaya shareholders of $50 million, a 13% margin, compared to our outlook of $42 - $52 million, up $27 million year-over-year driven by total revenue growth and operating leverage. “ Our momentum is building on itself: more partners, more products, and more applications feeding a network that is becoming the essential infrastructure for banks Gal Krubiner Co-Founder & CEO
Growing bank adoption signals the network's strategic value to lenders We onboarded Citizens Financial Group and FNBO, in Personal Loans and Point-of-Sale, respectively, signaling our product-led strategy is resonating with bank partners. That brings the total number of new partners to 6 year-to-date. Disciplined growth and strong operating leverage is delivering record profits We reported a record $50 million in GAAP net income, achieving a net income margin of 34% of FRLPC while application-to-conversion remained at ~1%. Long-Term, committed capital structures provide durable funding visibility This quarter we closed three structures adding over $2 billion of committed capital: a $700 million auto forward flow with Neuberger Berman, our second such partnership; our inaugural $700 million Personal Loan Variable Funding Note; and a second revolving Personal Loan securitization supporting $850 million of production. These funding sources provide further diversification and the capacity to support originations at scale through cycles. Product enhancement and expansion drives higher-quality application flow and record lending partner pipeline We are entering the fourth quarter with a 50% larger partner pipeline year-over-year, supporting future growth. We onboarded two Personal Loan partners onto leading consumer credit marketplaces in the quarter, and continued ramping our Counter Offer and Dual Look product across our Auto partners, tapping into higher-quality new applicant pools. Application volume grew $111 billion year-over-year to $377 billion while our average borrower income improved approximately 15% and 40% in Personal Loan and Auto, respectively, since 4Q’22. Q3 2026 Shareholder Letter 3 Operating Highlights
Q3 2026 Shareholder Letter 4 Gal Krubiner Co-Founder & CEO Dear Fellow Shareholders, This was another outstanding quarter for Pagaya. We delivered record GAAP net income of $50 million, up 121% year-over-year and at the high-end of our guidance range. Network volume grew to $3.6 billion, generating $390 million of revenue and adjusted EBITDA of $130 million, with margins expanding to a record 33%. In short, volume grew, costs stayed flat, and the difference went straight to the bottom line. These figures tell a clear story of rapidly accelerating network adoption. The addition of Citizens and FNBO in the third quarter as new partners demonstrates how our network is becoming more relevant to banks who want to keep and grow their customer relationships. We said we aim to onboard roughly two to four partners a year, and we have delivered that consistently and expect to do more. As our capabilities expand, we are also engaging with a broader set of lenders — including OEMs, banks, and others. Pagaya is entering the fourth quarter with the largest pipeline in our history, up more than 50% year-over-year. This growth reflects the convergence of Pagaya’s unique technology advantages with traditional banks’ increasing imperative to find new ways to serve customers. As The Wall Street Journal recently highlighted, JPMorgan Chase is exploring private credit buyers to boost credit card approvals. To effectively compete with fintechs, major financial institutions must provide the products that their customers need. The reason for this is simple: our average Personal Loan borrower earns $120K, and when a borrower like that goes elsewhere for a personal loan, the bank risks losing a broader high value relationship, including customer deposits. What JPMorgan is currently evaluating through private capital, we have already built with U.S. Bank, Ally and Citizens. The combination of our embedded proprietary AI capabilities and capital markets infrastructure enables these lenders to instantly approve more customers within a seamless, native experience. That allows our partners to deepen customer relationships with more products, while maintaining their own credit and balance sheet priorities without significant investment. Backstopping our proprietary technology and data is a funding infrastructure we have been building deliberately and thoughtfully for years. We raised $3 billion in ABS securitizations this quarter, with an increasing share committed for a year or more. That capacity can be drawn and reused through cycles and is part of our long-term strategy to support the growth of the network. Our partners build on this network with a multi-year horizon, and the capital behind it is structured to match. Pagaya is becoming the critical infrastructure that enables financial institutions to serve more of their customers’ credit needs. The opportunity ahead is significantly larger than what we have built to date, and our performance this quarter demonstrates that we are positioned to capture it. I want to close by thanking our team. These results are theirs.
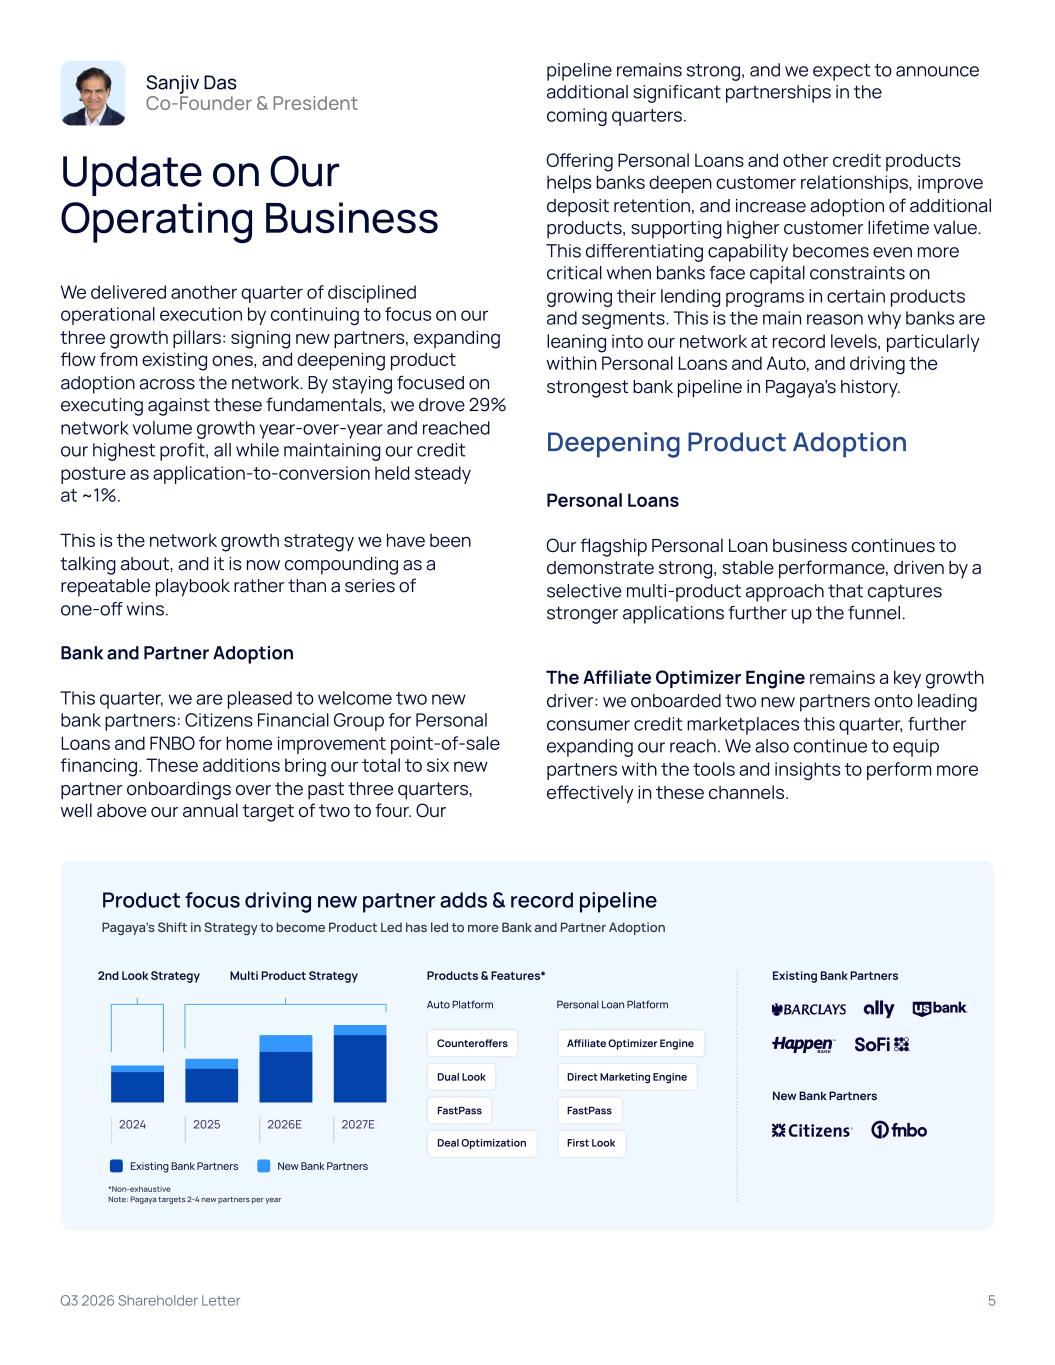
Q3 2026 Shareholder Letter 5 Sanjiv Das Co-Founder & President Update on Our Operating Business We delivered another quarter of disciplined operational execution by continuing to focus on our three growth pillars: signing new partners, expanding flow from existing ones, and deepening product adoption across the network. By staying focused on executing against these fundamentals, we drove 29% network volume growth year-over-year and reached our highest profit, all while maintaining our credit posture as application-to-conversion held steady at ~1%. This is the network growth strategy we have been talking about, and it is now compounding as a repeatable playbook rather than a series of one-off wins. Bank and Partner Adoption This quarter, we are pleased to welcome two new bank partners: Citizens Financial Group for Personal Loans and FNBO for home improvement point-of-sale financing. These additions bring our total to six new partner onboardings over the past three quarters, well above our annual target of two to four. Our pipeline remains strong, and we expect to announce additional significant partnerships in the coming quarters. Offering Personal Loans and other credit products helps banks deepen customer relationships, improve deposit retention, and increase adoption of additional products, supporting higher customer lifetime value. This differentiating capability becomes even more critical when banks face capital constraints on growing their lending programs in certain products and segments. This is the main reason why banks are leaning into our network at record levels, particularly within Personal Loans and Auto, and driving the strongest bank pipeline in Pagaya’s history. Deepening Product Adoption Personal Loans Our flagship Personal Loan business continues to demonstrate strong, stable performance, driven by a selective multi-product approach that captures stronger applications further up the funnel. The Affiliate Optimizer Engine remains a key growth driver: we onboarded two new partners onto leading consumer credit marketplaces this quarter, further expanding our reach. We also continue to equip partners with the tools and insights to perform more effectively in these channels. Product focus driving new partner adds & record pipeline Pagaya’s Shift in Strategy to become Product Led has led to more Bank and Partner Adoption 2nd Look Strategy Multi Product Strategy Products & Features* Auto Platform Counteroffers Dual Look FastPass Deal Optimization Personal Loan Platform Affiliate Optimizer Engine Direct Marketing Engine FastPass First Look Existing Bank Partners New Bank Partners 2024 2025 2026E 2027E *Non-exhaustive Note: Pagaya targets 2-4 new partners per year Existing Bank Partners New Bank Partners
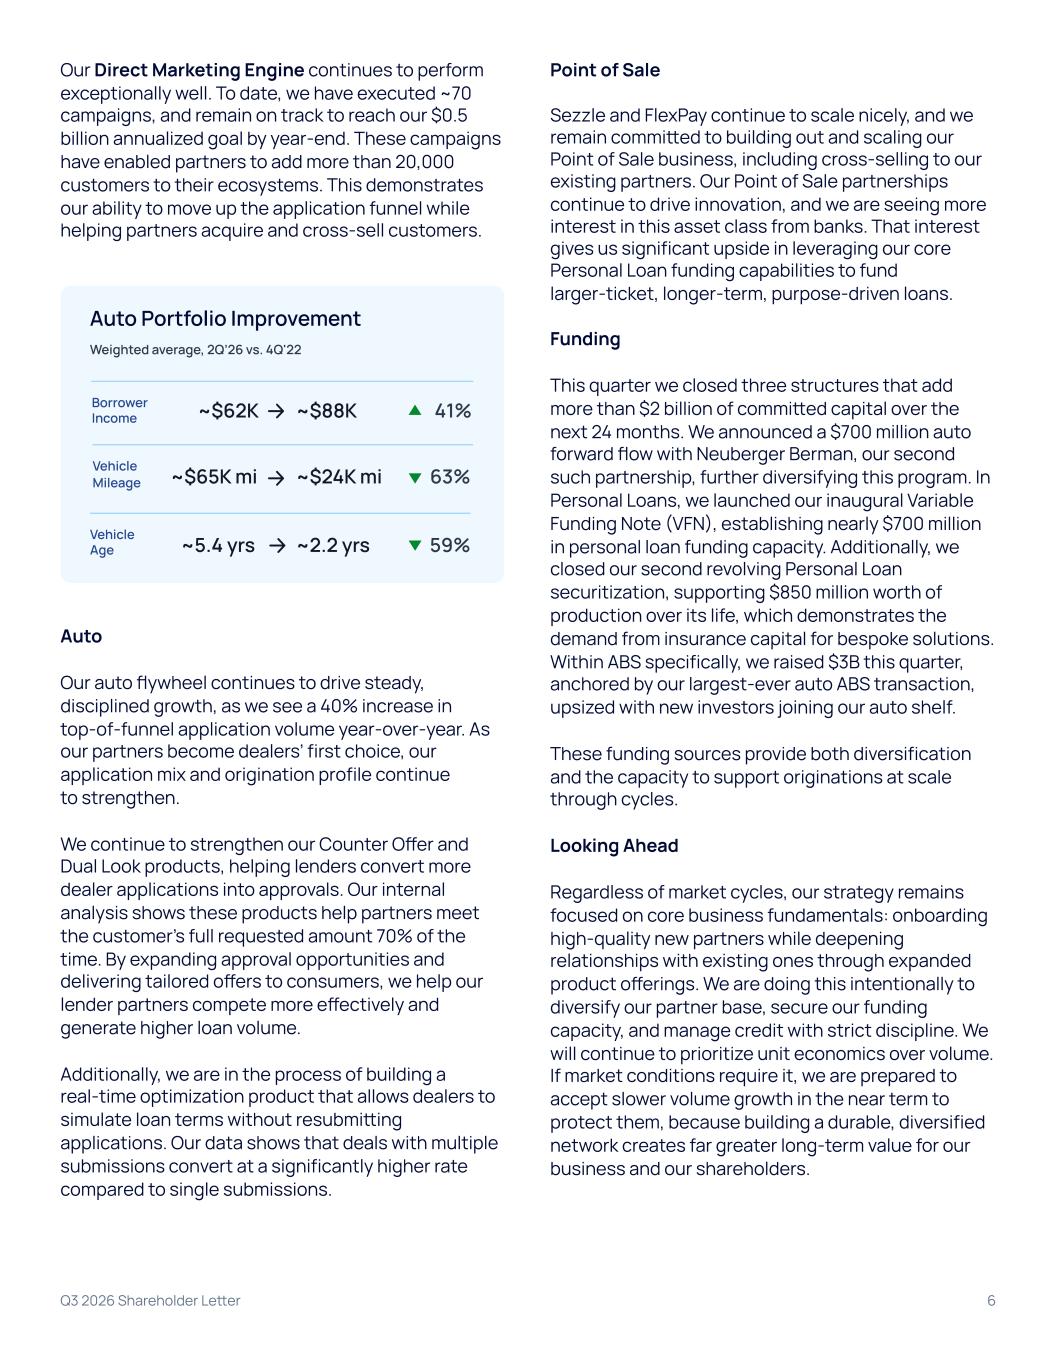
Our Direct Marketing Engine continues to perform exceptionally well. To date, we have executed ~70 campaigns, and remain on track to reach our $0.5 billion annualized goal by year-end. These campaigns have enabled partners to add more than 20,000 customers to their ecosystems. This demonstrates our ability to move up the application funnel while helping partners acquire and cross-sell customers. Auto Portfolio Improvement Weighted average, 2Q’26 vs. 4Q'22 Borrower Income 41%~$62K ~$88K Vehicle Mileage 63%~$65K mi ~$24K mi Vehicle Age 59%~5.4 yrs ~2.2 yrs Auto Our auto flywheel continues to drive steady, disciplined growth, as we see a 40% increase in top-of-funnel application volume year-over-year. As our partners become dealers’ first choice, our application mix and origination profile continue to strengthen. We continue to strengthen our Counter Offer and Dual Look products, helping lenders convert more dealer applications into approvals. Our internal analysis shows these products help partners meet the customer's full requested amount 70% of the time. By expanding approval opportunities and delivering tailored offers to consumers, we help our lender partners compete more effectively and generate higher loan volume. Additionally, we are in the process of building a real-time optimization product that allows dealers to simulate loan terms without resubmitting applications. Our data shows that deals with multiple submissions convert at a significantly higher rate compared to single submissions. Point of Sale Sezzle and FlexPay continue to scale nicely, and we remain committed to building out and scaling our Point of Sale business, including cross-selling to our existing partners. Our Point of Sale partnerships continue to drive innovation, and we are seeing more interest in this asset class from banks. That interest gives us significant upside in leveraging our core Personal Loan funding capabilities to fund larger-ticket, longer-term, purpose-driven loans. Funding This quarter we closed three structures that add more than $2 billion of committed capital over the next 24 months. We announced a $700 million auto forward flow with Neuberger Berman, our second such partnership, further diversifying this program. In Personal Loans, we launched our inaugural Variable Funding Note (VFN), establishing nearly $700 million in personal loan funding capacity. Additionally, we closed our second revolving Personal Loan securitization, supporting $850 million worth of production over its life, which demonstrates the demand from insurance capital for bespoke solutions. Within ABS specifically, we raised $3B this quarter, anchored by our largest-ever auto ABS transaction, upsized with new investors joining our auto shelf. These funding sources provide both diversification and the capacity to support originations at scale through cycles. Looking Ahead Regardless of market cycles, our strategy remains focused on core business fundamentals: onboarding high-quality new partners while deepening relationships with existing ones through expanded product offerings. We are doing this intentionally to diversify our partner base, secure our funding capacity, and manage credit with strict discipline. We will continue to prioritize unit economics over volume. If market conditions require it, we are prepared to accept slower volume growth in the near term to protect them, because building a durable, diversified network creates far greater long-term value for our business and our shareholders. Q3 2026 Shareholder Letter 6
Q3 2026 Shareholder Letter 7 Jon Dobres Chief Financial Officer Third Quarter Results This quarter's record net income of $50 million reflects our execution on a financial strategy centered on sustainable, profitable growth. I want to point out a few examples of execution on our strategy that we mentioned last quarter and now have proven out. Strength of Funding Network Investor demand this quarter was very strong. We executed $1.8 billion of personal loan securitizations and $1.2 billion of auto securitizations in Q3 and increased our investor network to over 180 unique investors Importantly, on our most recent PAID deal spreads tightened more than 30 basis points for investment grade and more than 20 overall. To us, this level of investor interest combined with the proof of tighter spreads is our main signal of investor interest and the strength of our markets. Outside of our core ABS franchise - our long-term, diversified committed capital strategy is delivering. Forward flow, long-term revolving structures and warehouses discussed last quarter have all come to fruition, and the pipeline for non-prefunded ABS partnerships remains strong going into the fourth quarter. Rates Since the beginning of the year benchmark rates increased ~130bps, with ~half occurring since September. Higher benchmark rates in the short-term reduce overall margins. In response to this increase, we implemented an increase in consumer APRs beginning in September: 100 bps in Personal Loans and 140 bps in Auto. We expect higher loan pricing to offset this impact by the start of next year, leading to a higher level of FRLPC as a percentage of network volume in 2027. Even with these changes, we are raising our full year net income guidance and expect to stay within our 4-5% FRLPC percentage of network volume. Operating Leverage We have now had constant Core Opex for 7 straight quarters. We have continued to grow profitability with a model that allows for incremental FRLPC and other income to reach the bottom line at a 90%+ margin. Operating leverage is a feature of our business model, and we expect it to continue in the future. Results For the third quarter of 2026, we reported revenue of $390 million, FRLPC of $146 million, and adjusted EBITDA of $130 million. Network Volume & Revenue Network volume grew 29% year-over-year to $3.6 billion driven by strength in Personal Loans and Auto. Application volume rose 42% year-over-year to $377 billion, driven by new products with existing partners and new partner ramps. Importantly, application-to-volume conversion remained steady at ~1% as we maintain our prudent underwriting standards. Application growth is our leading indicator for future volume from new partners and products, so $377 billion tells us our bank-led lending partner strategy is working. Revenue and other income grew 12% year-over-year to $390 million. Collectively, FRLPC and Other Income, which is predominately interest income, grew 17% year-over-year to $175 million, or 4.8% of network volume. The vast majority of this is received as cash when earned in the quarter. Revenue from fees grew 7% to $362 million, supported by higher volume and partially offset by lower FRLPC as a percentage of network volume (“FRLPC %”). Interest and investment income more than doubled in the period, as a result of our continued growth in our investments. FRLPC grew 5% year-over-year in the third quarter to $146 million. FRLPC % contracted by 91 bps year-over-year to 4.1% driven by an elevated 2-year benchmark rate. As previously communicated, this temporarily reduces day-one FRLPC until we are able to pass the incremental cost onto the end consumer through higher APRs.
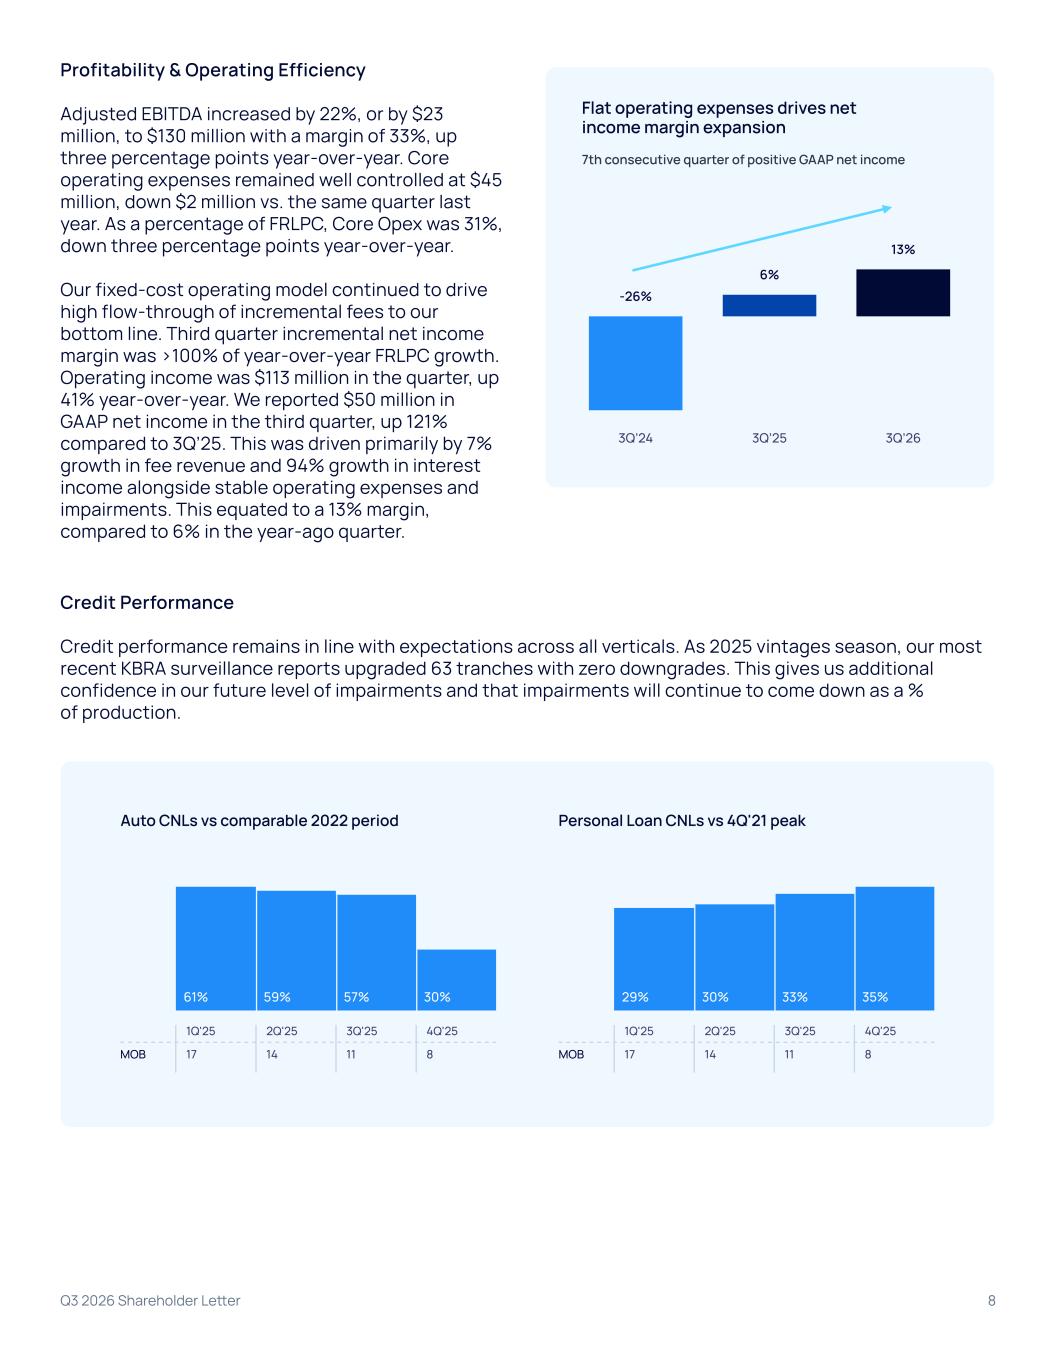
Q3 2026 Shareholder Letter 8 Profitability & Operating Efficiency Adjusted EBITDA increased by 22%, or by $23 million, to $130 million with a margin of 33%, up three percentage points year-over-year. Core operating expenses remained well controlled at $45 million, down $2 million vs. the same quarter last year. As a percentage of FRLPC, Core Opex was 31%, down three percentage points year-over-year. Our fixed-cost operating model continued to drive high flow-through of incremental fees to our bottom line. Third quarter incremental net income margin was >100% of year-over-year FRLPC growth. Operating income was $113 million in the quarter, up 41% year-over-year. We reported $50 million in GAAP net income in the third quarter, up 121% compared to 3Q’25. This was driven primarily by 7% growth in fee revenue and 94% growth in interest income alongside stable operating expenses and impairments. This equated to a 13% margin, compared to 6% in the year-ago quarter. Flat operating expenses drives net income margin expansion 7th consecutive quarter of positive GAAP net income -26% 6% 13% 3Q’24 3Q’25 3Q’26 Credit Performance Credit performance remains in line with expectations across all verticals. As 2025 vintages season, our most recent KBRA surveillance reports upgraded 63 tranches with zero downgrades. This gives us additional confidence in our future level of impairments and that impairments will continue to come down as a % of production. Auto CNLs vs comparable 2022 period 61% 59% 57% 30% 1Q'25 2Q'25 3Q'25 4Q'25 MOB 17 14 11 8 Personal Loan CNLs vs 4Q'21 peak 29% 30% 33% 35% 1Q'25 2Q'25 3Q'25 4Q'25 MOB 17 14 11 8
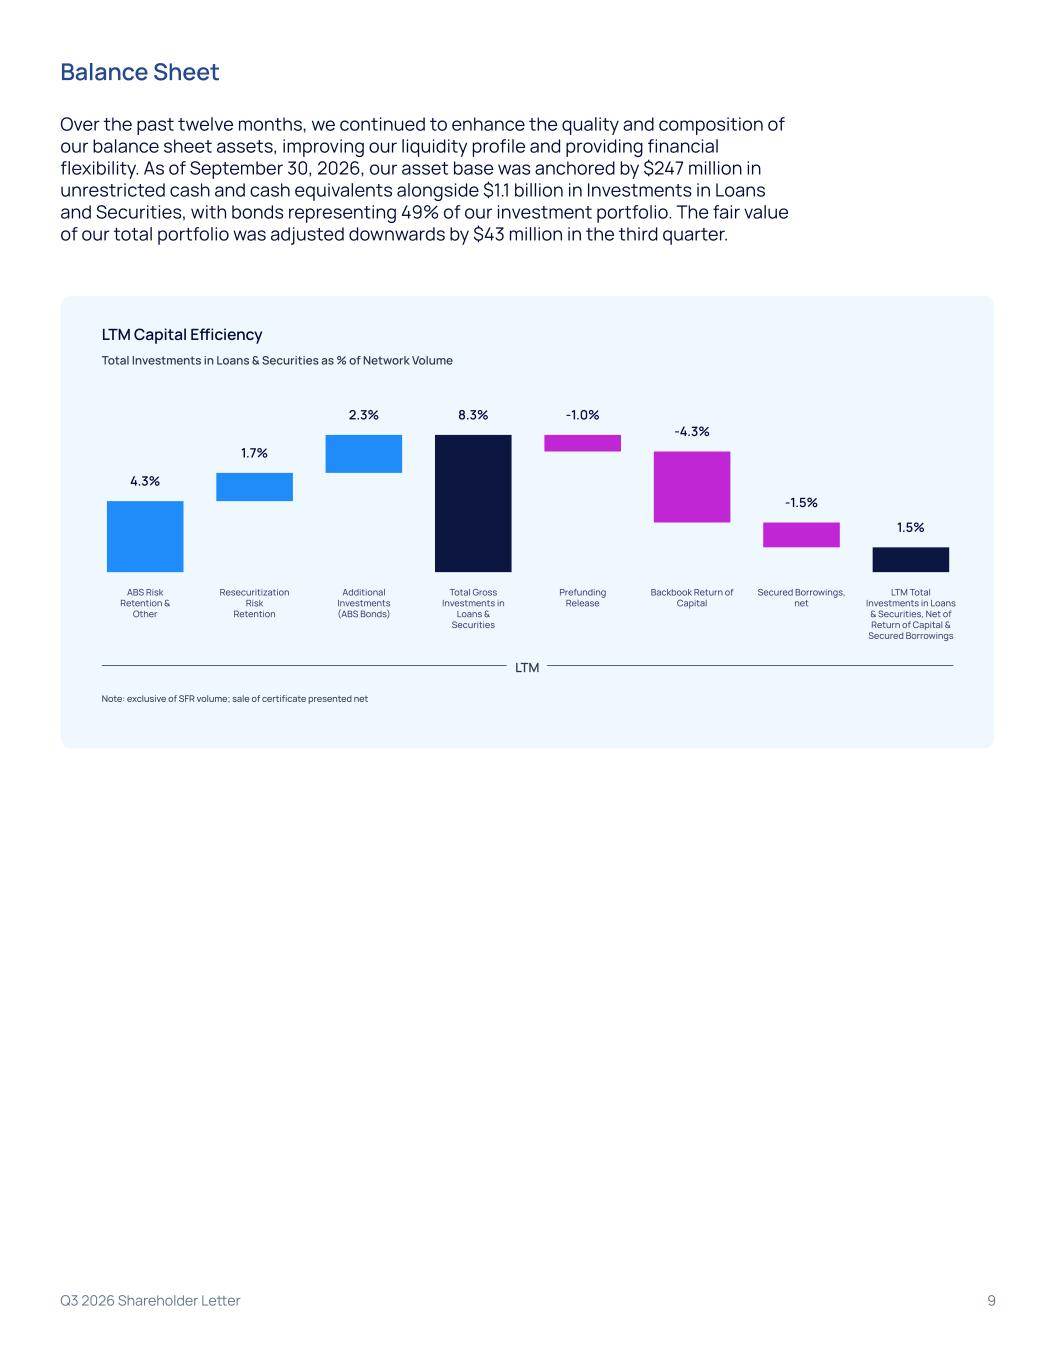
Balance Sheet Over the past twelve months, we continued to enhance the quality and composition of our balance sheet assets, improving our liquidity profile and providing financial flexibility. As of September 30, 2026, our asset base was anchored by $247 million in unrestricted cash and cash equivalents alongside $1.1 billion in Investments in Loans and Securities, with bonds representing 49% of our investment portfolio. The fair value of our total portfolio was adjusted downwards by $43 million in the third quarter. LTM Capital Efficiency Total Investments in Loans & Securities as % of Network Volume Note: exclusive of SFR volume; sale of certificate presented net 4.3% 1.7% 2.3% 8.3% -1.0% -4.3% -1.5% 1.5% ABS Risk Retention & Other Resecuritization Risk Retention Additional Investments (ABS Bonds) Total Gross Investments in Loans & Securities Prefunding Release Backbook Return of Capital Secured Borrowings, net LTM Total Investments in Loans & Securities, Net of Return of Capital & Secured Borrowings LTM Q3 2026 Shareholder Letter 9
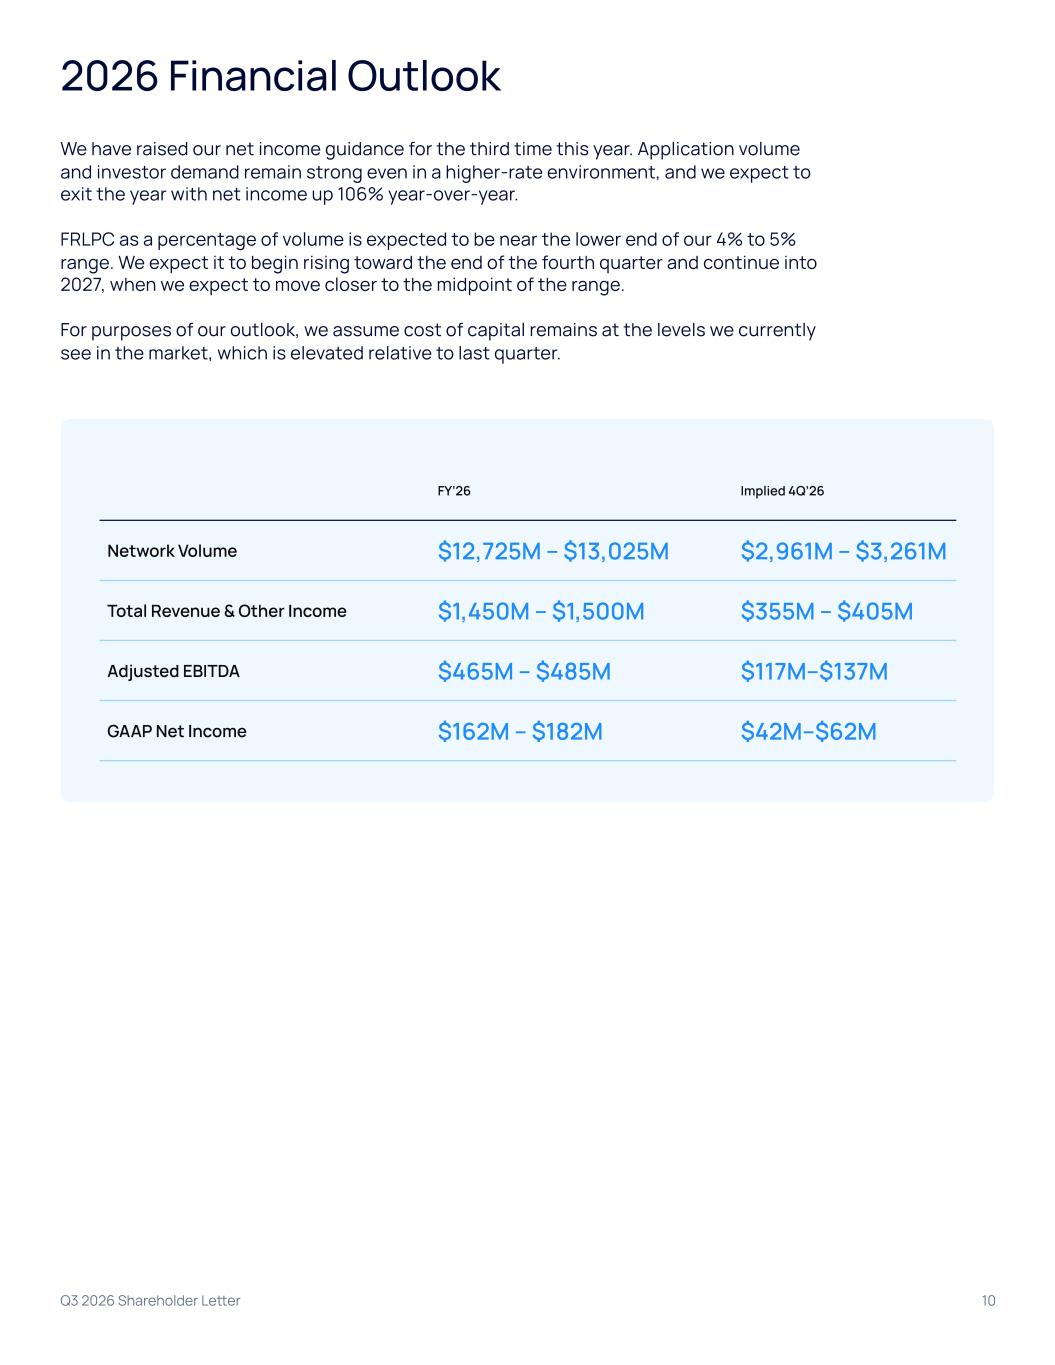
Q3 2026 Shareholder Letter 10 2026 Financial Outlook We have raised our net income guidance for the third time this year. Application volume and investor demand remain strong even in a higher-rate environment, and we expect to exit the year with net income up 106% year-over-year. FRLPC as a percentage of volume is expected to be near the lower end of our 4% to 5% range. We expect it to begin rising toward the end of the fourth quarter and continue into 2027, when we expect to move closer to the midpoint of the range. For purposes of our outlook, we assume cost of capital remains at the levels we currently see in the market, which is elevated relative to last quarter. FY’26 Implied 4Q’26 Network Volume $12,725M – $13,025M $2,961M – $3,261M Total Revenue & Other Income $1,450M – $1,500M $355M – $405M Adjusted EBITDA $465M – $485M $117M–$137M GAAP Net Income $162M – $182M $42M–$62M
Q3 2026 Shareholder Letter 11 Conference Call and Webcast Information The Company will hold a webcast and conference call today, October 29, 2026 at 8:30 a.m. Eastern Time. A live webcast of the call will be available via the Investor Relations section of the Company’s website at investor.pagaya.com. To listen to the live webcast, please go to the site at least five minutes prior to the scheduled start time in order to register, download and install any necessary audio software. Shortly before the call, the accompanying materials will be made available on the Company’s website. Shortly after the call, a replay of the webcast will be available for 90 days on the Company’s website. The conference call can also be accessed by dialing 1-877-407-9208 or 1-201-493-6784. The telephone replay can be accessed by dialing 1- 844-512-2921 or 1-412-317-6671 and providing the conference ID# 13762910. The telephone replay will be available starting shortly after the call until Thursday, November 12, 2026. A replay will also be available on the Investor Relations website following the call. About Pagaya Technologies Pagaya (NASDAQ: PGY) is a global technology company making life-changing financial products and services available to more people nationwide, as it reshapes the financial services ecosystem. By using machine learning, a vast data network and an AI-driven approach, Pagaya provides comprehensive consumer credit and residential real estate solutions for its partners, their customers, and investors. Its proprietary API and capital solutions integrate into its network of partners to deliver seamless user experiences and greater access to the mainstream economy. Pagaya has offices in New York and Tel Aviv. For more information, visit pagaya.com. Investors & Analysts Craig Smyth Investor Relations ir@pagaya.com Media Emily Scheer Public Relations press@pagaya.com
Q3 2026 Shareholder Letter 12 Cautionary Note About Forward-Looking Statements This document contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, that involve risks and uncertainties. These forward-looking statements generally are identified by the words “anticipate,” “believe,” “continue,” “can,” “could,” “estimate,” “expect,” “intend,” “may,” “opportunity,” “future,” “strategy,” “might,” “outlook,” “plan,” “possible,” “potential,” “predict,” “project,” “should,” “strive,” “will,” “would,” “will be,” “will continue,” “will likely result,” and similar expressions. All statements other than statements of historical fact are forward-looking statements, including statements regarding: our strategy, business model, value proposition, unique advantage, proprietary technology, and future products and operations; our funding strategy, diversification and capacity; our partner pipeline and expectations for onboarding new partners; the opportunity for our business; our auto growth flywheel; building out and scaling our POS business; investor interest in our funding products; the impacts of higher benchmark rates and offsetting those impacts with higher APRs; our ability to withstand more difficult interest rate environments; our expectations for cost of capital and the impact on FRLPC; monitoring credit performance; expected expense discipline and interest income growth; and the Company’s financial outlook for Network Volume, Total Revenue and Other Income, Adjusted EBITDA, and GAAP Net Income in the fourth quarter and for the full year 2026, and for FRLPC as a % of Network Volume for the full year 2026. These forward-looking statements involve known and unknown risks, uncertainties and other important factors that may cause the Company’s actual results, performance or achievements to be materially different from any future results, performance or achievements expressed or implied by the forward-looking statements. Risks, uncertainties and assumptions include factors relating to: our rapid growth and our ability to effectively manage our growth and maintain profitability; adverse global economic conditions and other catastrophic events; adverse developments impacting the banking and financial services industries, consumer credit activity, and the availability of equity and debt financing; our reliance on services provided by third-party vendors; our dependence on our AI technology; our reliance on a limited number of partners which presents concentration risk for Network Volume and Revenue; retaining and attracting new partners by improving our platform and offering new and relevant products; our ability to raise capital from investors; developing and maintaining robust and diverse funding sources; the competitive nature of our industry; changes to our accounting policies or financial reporting standards; maintaining our brand image and reputation; managing risks related to fraudulent activity; our reliance on key employees including our founders; effectively managing conflicts of interest related to our financing vehicles; legal proceedings, investigations, or claims; maintaining adequate insurance coverage; the effectiveness of our risk management processes; realizing the intended benefits of any strategic transactions; the regulation of AI technologies by the FTC, CFPB, and other governmental agencies; enforcing our intellectual property rights; our use of open-source software components; our ability to continue receiving accurate data from our partners; cyberattacks and other security breaches; risks related to our single-family rental operations including volatility in the single-family rental market, lease renewal and default rates, HOA regulations, the accuracy of resident-supplied information, leasing fraud, renovation and maintenance costs, and regulations impacting the single-family rental business; our compliance with laws related to consumer protection, consumer finance, lending, fair lending, data protection and privacy, cybersecurity, and investment advisory services, and maintaining required licenses to operate; heightened regulation of the financial services industry; the risks that we are deemed to be an investment company or that we cannot rely on exemptions under various laws to conduct the funding component of our business; our ability to continue accessing the securitization
market; our compliance with anti-corruption, anti-bribery, anti-money laundering, economic and trade sanctions and similar laws; the risk that we would be deemed the true lender for loans originated by our partners; the enforceability of assets we acquire from our partners; risks related to ongoing conflicts including between Russia and Ukraine and Israel, the United States, and Iran; risks related to our operations in Israel including regional hostilities and our employees’ required military service; risks related to being a public company including limited management experience and increased costs; covenants in our indebtedness arrangements that could limit our ability to operate our business; changes in tax laws and the outcome of potential tax audits; and other risks that are described in the Company’s Annual Report on Form 10-K filed on March 2, 2026, as amended on April 30, 2026 and June 1, 2026, and our subsequent filings with the U.S. Securities and Exchange Commission. These forward-looking statements reflect the Company’s views with respect to future events as of the date hereof and are based on assumptions and subject to risks and uncertainties. Given these uncertainties, investors should not place undue reliance on these forward-looking statements. The forward-looking statements are made as of the date hereof, reflect the Company’s current beliefs and are based on information currently available as of the date they are made, and the Company assumes no obligation and does not intend to update these forward-looking statements. Financial Information; Non-GAAP Financial Measures Some of the unaudited financial information and data contained in this shareholder letter, our earnings press release and Form 8-K, such as Fee Revenue Less Production Costs (“FRLPC”), FRLPC as a % of Network Volume, Adjusted EBITDA, Adjusted EBITDA Margin, Adjusted Net Income, Core Operating Expenses and Core Operating Expenses as a % of FRLPC, have not been prepared in accordance with United States Generally Accepted Accounting Principles (“U.S. GAAP”). To supplement the unaudited consolidated financial statements prepared and presented in accordance with U.S. GAAP, management uses the non-GAAP financial measures FRLPC, FRLPC as a % of Network Volume, Adjusted EBITDA, Adjusted EBITDA Margin, Adjusted Net Income, Core Operating Expenses and Core Operating Expenses as a % of FRLPC to provide investors with additional information about our financial performance and to enhance the overall understanding of the results of operations by highlighting the results from ongoing operations and the underlying profitability of our business. Management believes these non-GAAP measures provide an additional tool for investors to use in comparing our core financial performance over multiple periods. However, non-GAAP financial measures have limitations in their usefulness to investors because they have no standardized meaning prescribed by U.S. GAAP and are not prepared under any comprehensive set of accounting rules or principles. In addition, non-GAAP financial measures may be calculated differently from, and therefore may not be directly comparable to, similarly titled measures used by other companies. As a result, non-GAAP financial measures should be viewed as supplementing, and not as an alternative or substitute for, our unaudited consolidated financial statements prepared and presented in accordance with U.S. GAAP. To address these limitations, management provides a reconciliation of Adjusted Net Income and Adjusted EBITDA to net income attributable to Pagaya Technologies Ltd., a reconciliation of FRLPC to operating income, and a reconciliation of Core Operating Expenses to operating expenses, and calculations of Adjusted EBITDA Margin, FRLPC as a % of Network Volume and Core Operating Expenses as a % of FRLPC. Management encourages investors and others to review our financial information in its entirety, not to rely on any single financial measure and to view the non-GAAP financial measures in conjunction with the respective related GAAP financial measures. Non-GAAP financial measures include the following items: Fee Revenue Less Production Costs (“FRLPC”) is defined as operating income plus technology, data and product development, sales and marketing, and general and administrative costs, and less interest income and net investment income (loss). FRLPC as a % of Network Volume is defined as FRLPC divided by network volume. Q3 2026 Shareholder Letter 13
Adjusted Net Income is defined as net income attributable to Pagaya Technologies Ltd. excluding share-based compensation expense, change in fair value of contingent liability, change in fair value of warrant liability, impairment, including credit-related charges, restructuring expenses, transaction-related expenses, and non-recurring expenses associated with mergers and acquisitions and other one-time expenses. Adjusted EBITDA is defined as net income attributable to Pagaya Technologies Ltd. excluding share-based compensation expense, change in fair value of contingent liability, change in fair value of warrant liability, impairment, including credit-related charges, restructuring expenses, transaction-related expenses, non-recurring expenses associated with mergers and acquisitions and other one-time expenses, interest expense, income tax expense (benefit), and depreciation and amortization. Adjusted EBITDA Margin is defined as Adjusted EBITDA divided by Total Revenue and Other Income. Core Operating Expenses is defined as operating expenses less share-based compensation, depreciation and amortization, whole loan losses, transaction-related expenses, restructuring expenses and non-recurring expenses associated with mergers and acquisitions and other one-time expenses. Core Operating Expenses as a % of FRLPC is defined as Core Operating Expenses divided by FRLPC. The foregoing items are excluded from our FRLPC, FRLPC as a % of Network Volume, Adjusted Net Income, Adjusted EBITDA, Adjusted EBITDA Margin, Core Operating Expenses, and Core Operating Expenses as a % of FRLPC measures because they are noncash in nature, or because the amount and timing of these items is unpredictable, is not driven by core results of operations and renders comparisons with prior periods and competitors less meaningful. We believe these non-GAAP measures provide useful information to investors and others in understanding and evaluating our results of operations, as well as providing useful measures for period-to-period comparisons of our business performance. Moreover, we have included these non-GAAP measures because these are key measurements used by our management internally to make operating decisions, including those related to operating expenses, evaluate performance, and perform strategic planning and annual budgeting. However, these non-GAAP measures are presented for supplemental informational purposes only, should not be considered a substitute for or superior to financial information presented in accordance with U.S. GAAP and may be different from similarly titled non-GAAP financial measures used by other companies. The tables below provide reconciliations of these non-GAAP measures to the most directly comparable U.S. GAAP measures. In addition, Pagaya provides an outlook for the fourth quarter and full year 2026 on a non-GAAP basis. The Company cannot reconcile its expected Adjusted EBITDA to expected net income attributable to Pagaya Technologies Ltd. or its expected FRLPC as a % of Network Volume to expected operating income without unreasonable effort because certain items that impact net income attributable to Pagaya Technologies Ltd., operating income, and other reconciling items are out of the Company’s control and/or cannot be reasonably predicted at this time, which unavailable information could have a significant impact on the Company’s U.S. GAAP financial results. Q3 2026 Shareholder Letter 14
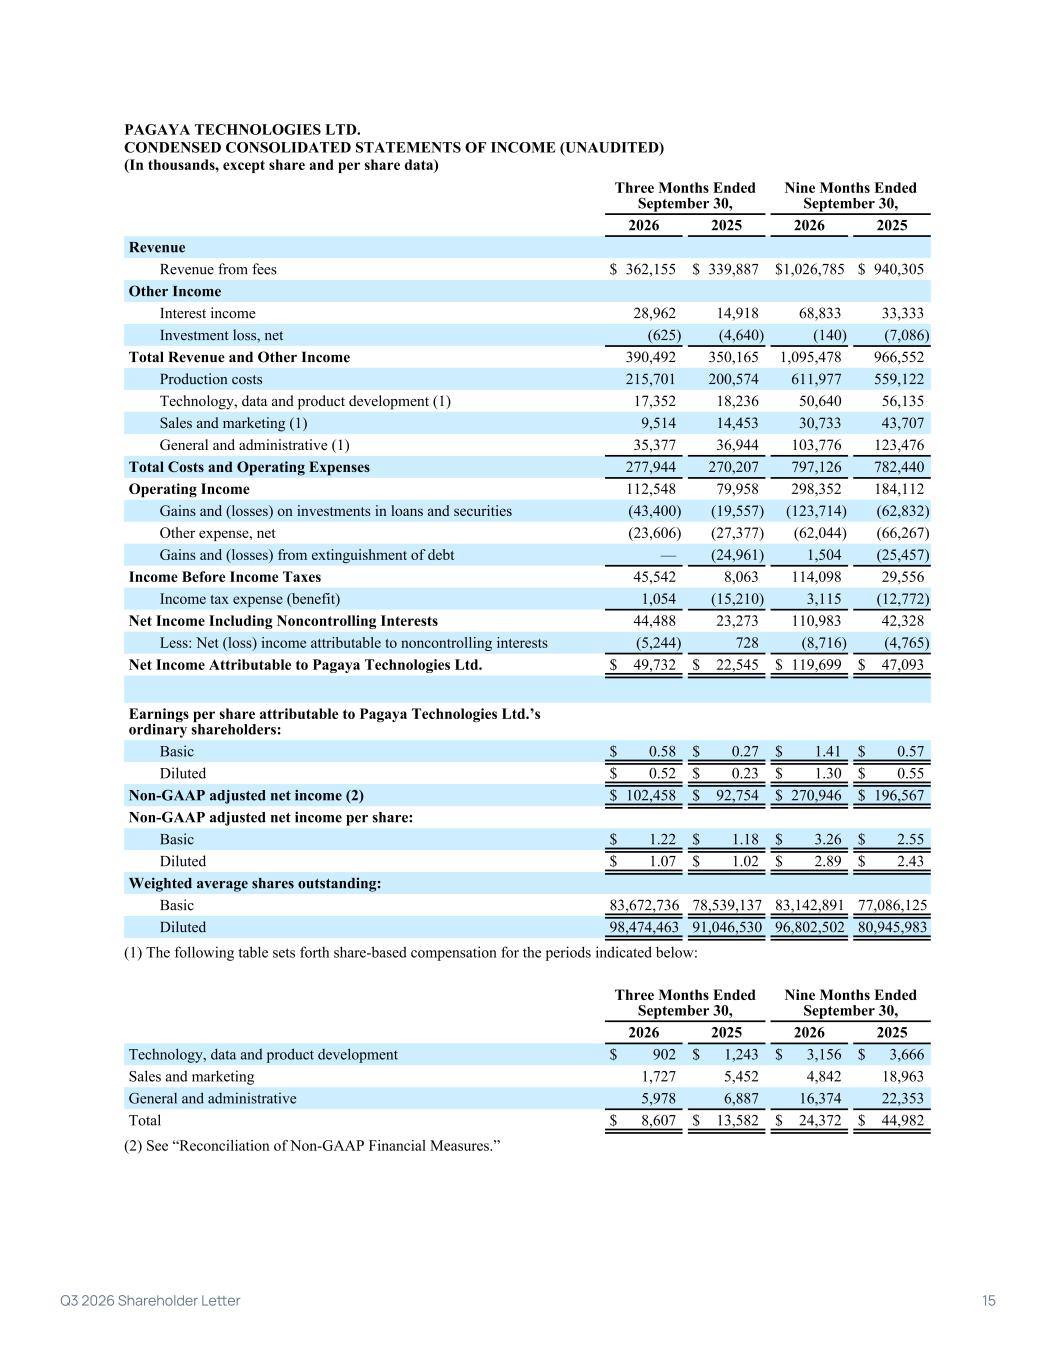
PAGAYA TECHNOLOGIES LTD. CONDENSED CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED) (In thousands, except share and per share data) Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 Revenue Revenue from fees $ 362,155 $ 339,887 $ 1,026,785 $ 940,305 Other Income Interest income 28,962 14,918 68,833 33,333 Investment loss, net (625) (4,640) (140) (7,086) Total Revenue and Other Income 390,492 350,165 1,095,478 966,552 Production costs 215,701 200,574 611,977 559,122 Technology, data and product development (1) 17,352 18,236 50,640 56,135 Sales and marketing (1) 9,514 14,453 30,733 43,707 General and administrative (1) 35,377 36,944 103,776 123,476 Total Costs and Operating Expenses 277,944 270,207 797,126 782,440 Operating Income 112,548 79,958 298,352 184,112 Gains and (losses) on investments in loans and securities (43,400) (19,557) (123,714) (62,832) Other expense, net (23,606) (27,377) (62,044) (66,267) Gains and (losses) from extinguishment of debt — (24,961) 1,504 (25,457) Income Before Income Taxes 45,542 8,063 114,098 29,556 Income tax expense (benefit) 1,054 (15,210) 3,115 (12,772) Net Income Including Noncontrolling Interests 44,488 23,273 110,983 42,328 Less: Net (loss) income attributable to noncontrolling interests (5,244) 728 (8,716) (4,765) Net Income Attributable to Pagaya Technologies Ltd. $ 49,732 $ 22,545 $ 119,699 $ 47,093 Earnings per share attributable to Pagaya Technologies Ltd.’s ordinary shareholders: Basic $ 0.58 $ 0.27 $ 1.41 $ 0.57 Diluted $ 0.52 $ 0.23 $ 1.30 $ 0.55 Non-GAAP adjusted net income (2) $ 102,458 $ 92,754 $ 270,946 $ 196,567 Non-GAAP adjusted net income per share: Basic $ 1.22 $ 1.18 $ 3.26 $ 2.55 Diluted $ 1.07 $ 1.02 $ 2.89 $ 2.43 Weighted average shares outstanding: Basic 83,672,736 78,539,137 83,142,891 77,086,125 Diluted 98,474,463 91,046,530 96,802,502 80,945,983 (1) The following table sets forth share-based compensation for the periods indicated below: Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 Technology, data and product development $ 902 $ 1,243 $ 3,156 $ 3,666 Sales and marketing 1,727 5,452 4,842 18,963 General and administrative 5,978 6,887 16,374 22,353 Total $ 8,607 $ 13,582 $ 24,372 $ 44,982 (2) See “Reconciliation of Non-GAAP Financial Measures.” 1 Q3 2026 Shareholder Letter 15
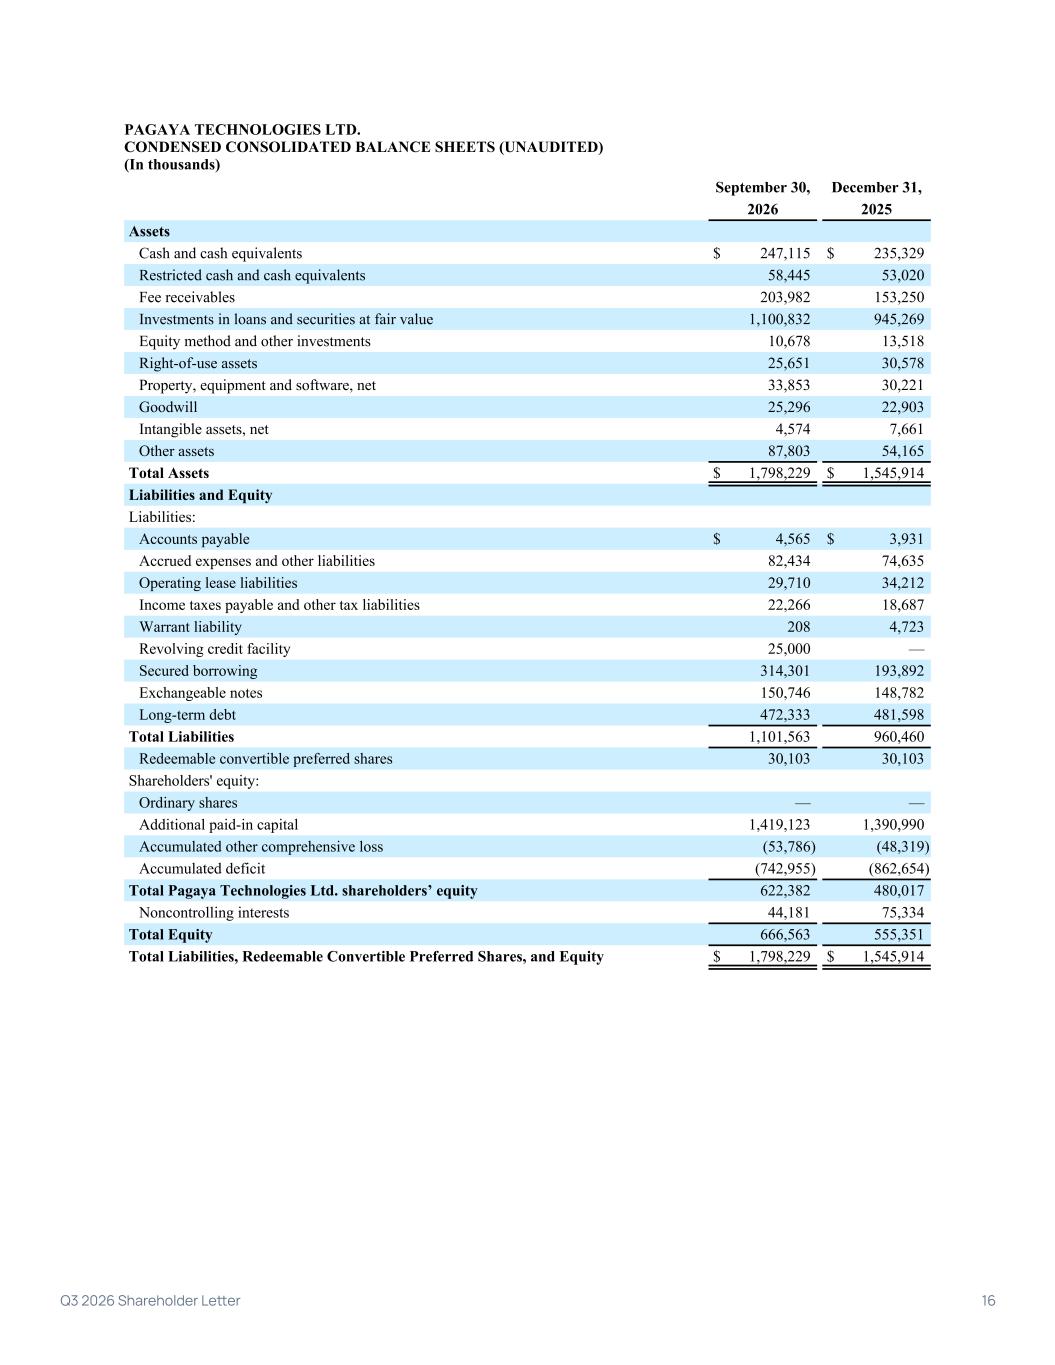
PAGAYA TECHNOLOGIES LTD. CONDENSED CONSOLIDATED BALANCE SHEETS (UNAUDITED) (In thousands) September 30, December 31, 2026 2025 Assets Cash and cash equivalents $ 247,115 $ 235,329 Restricted cash and cash equivalents 58,445 53,020 Fee receivables 203,982 153,250 Investments in loans and securities at fair value 1,100,832 945,269 Equity method and other investments 10,678 13,518 Right-of-use assets 25,651 30,578 Property, equipment and software, net 33,853 30,221 Goodwill 25,296 22,903 Intangible assets, net 4,574 7,661 Other assets 87,803 54,165 Total Assets $ 1,798,229 $ 1,545,914 Liabilities and Equity Liabilities: Accounts payable $ 4,565 $ 3,931 Accrued expenses and other liabilities 82,434 74,635 Operating lease liabilities 29,710 34,212 Income taxes payable and other tax liabilities 22,266 18,687 Warrant liability 208 4,723 Revolving credit facility 25,000 — Secured borrowing 314,301 193,892 Exchangeable notes 150,746 148,782 Long-term debt 472,333 481,598 Total Liabilities 1,101,563 960,460 Redeemable convertible preferred shares 30,103 30,103 Shareholders' equity: Ordinary shares — — Additional paid-in capital 1,419,123 1,390,990 Accumulated other comprehensive loss (53,786) (48,319) Accumulated deficit (742,955) (862,654) Total Pagaya Technologies Ltd. shareholders’ equity 622,382 480,017 Noncontrolling interests 44,181 75,334 Total Equity 666,563 555,351 Total Liabilities, Redeemable Convertible Preferred Shares, and Equity $ 1,798,229 $ 1,545,914 2 Q3 2026 Shareholder Letter 16
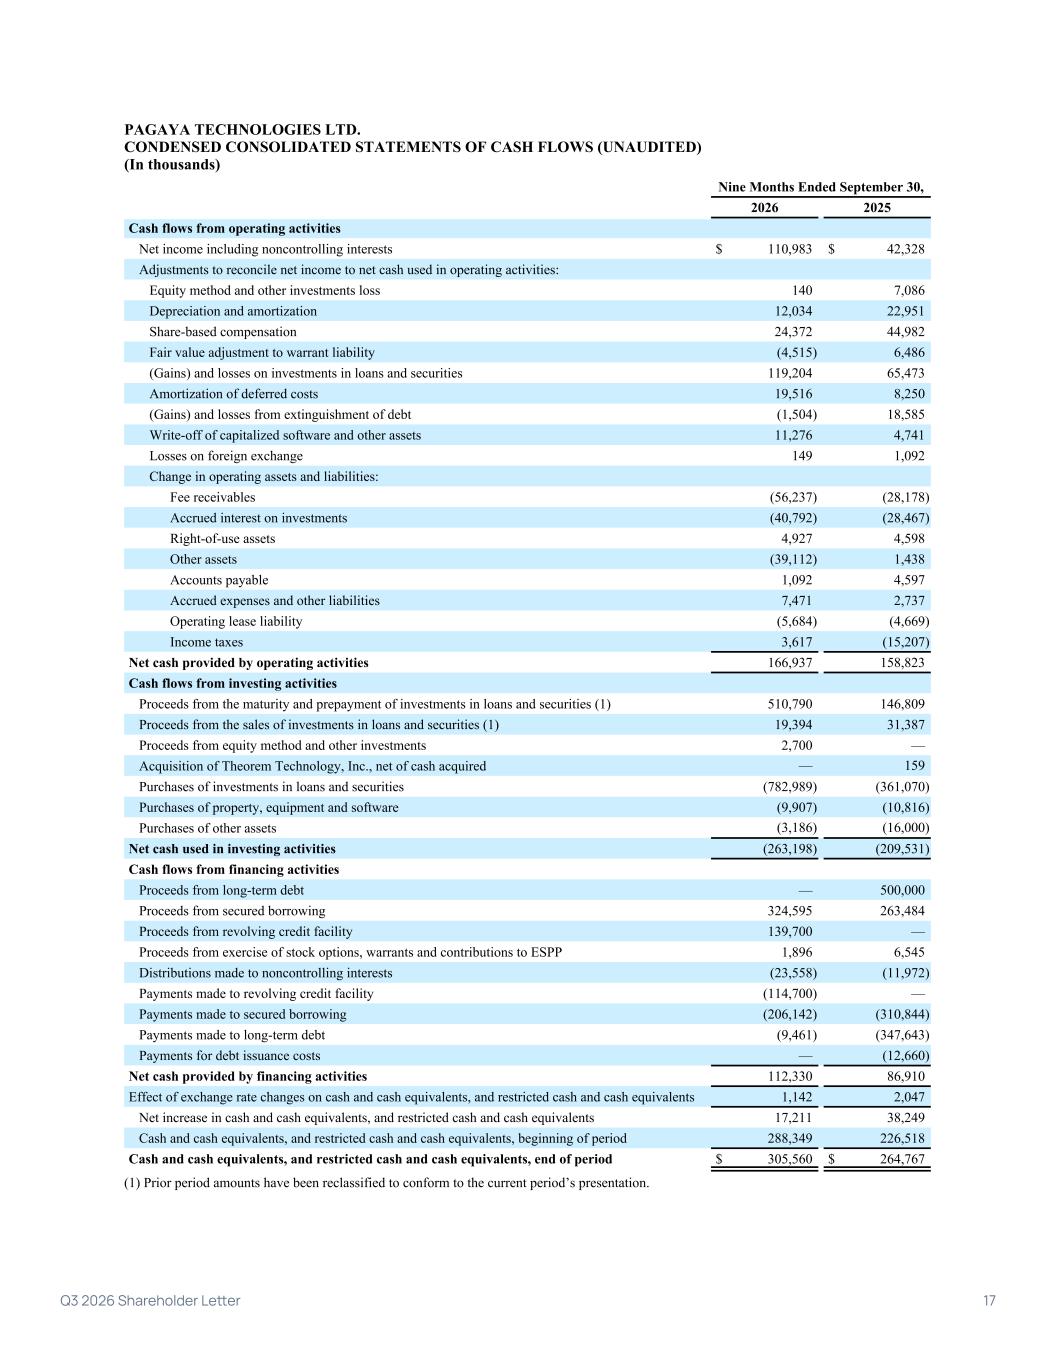
PAGAYA TECHNOLOGIES LTD. CONDENSED CONSOLIDATED STATEMENTS OF CASH FLOWS (UNAUDITED) (In thousands) Nine Months Ended September 30, 2026 2025 Cash flows from operating activities Net income including noncontrolling interests $ 110,983 $ 42,328 Adjustments to reconcile net income to net cash used in operating activities: Equity method and other investments loss 140 7,086 Depreciation and amortization 12,034 22,951 Share-based compensation 24,372 44,982 Fair value adjustment to warrant liability (4,515) 6,486 (Gains) and losses on investments in loans and securities 119,204 65,473 Amortization of deferred costs 19,516 8,250 (Gains) and losses from extinguishment of debt (1,504) 18,585 Write-off of capitalized software and other assets 11,276 4,741 Losses on foreign exchange 149 1,092 Change in operating assets and liabilities: Fee receivables (56,237) (28,178) Accrued interest on investments (40,792) (28,467) Right-of-use assets 4,927 4,598 Other assets (39,112) 1,438 Accounts payable 1,092 4,597 Accrued expenses and other liabilities 7,471 2,737 Operating lease liability (5,684) (4,669) Income taxes 3,617 (15,207) Net cash provided by operating activities 166,937 158,823 Cash flows from investing activities Proceeds from the maturity and prepayment of investments in loans and securities (1) 510,790 146,809 Proceeds from the sales of investments in loans and securities (1) 19,394 31,387 Proceeds from equity method and other investments 2,700 — Acquisition of Theorem Technology, Inc., net of cash acquired — 159 Purchases of investments in loans and securities (782,989) (361,070) Purchases of property, equipment and software (9,907) (10,816) Purchases of other assets (3,186) (16,000) Net cash used in investing activities (263,198) (209,531) Cash flows from financing activities Proceeds from long-term debt — 500,000 Proceeds from secured borrowing 324,595 263,484 Proceeds from revolving credit facility 139,700 — Proceeds from exercise of stock options, warrants and contributions to ESPP 1,896 6,545 Distributions made to noncontrolling interests (23,558) (11,972) Payments made to revolving credit facility (114,700) — Payments made to secured borrowing (206,142) (310,844) Payments made to long-term debt (9,461) (347,643) Payments for debt issuance costs — (12,660) Net cash provided by financing activities 112,330 86,910 Effect of exchange rate changes on cash and cash equivalents, and restricted cash and cash equivalents 1,142 2,047 Net increase in cash and cash equivalents, and restricted cash and cash equivalents 17,211 38,249 Cash and cash equivalents, and restricted cash and cash equivalents, beginning of period 288,349 226,518 Cash and cash equivalents, and restricted cash and cash equivalents, end of period $ 305,560 $ 264,767 (1) Prior period amounts have been reclassified to conform to the current period’s presentation. 3 Q3 2026 Shareholder Letter 17
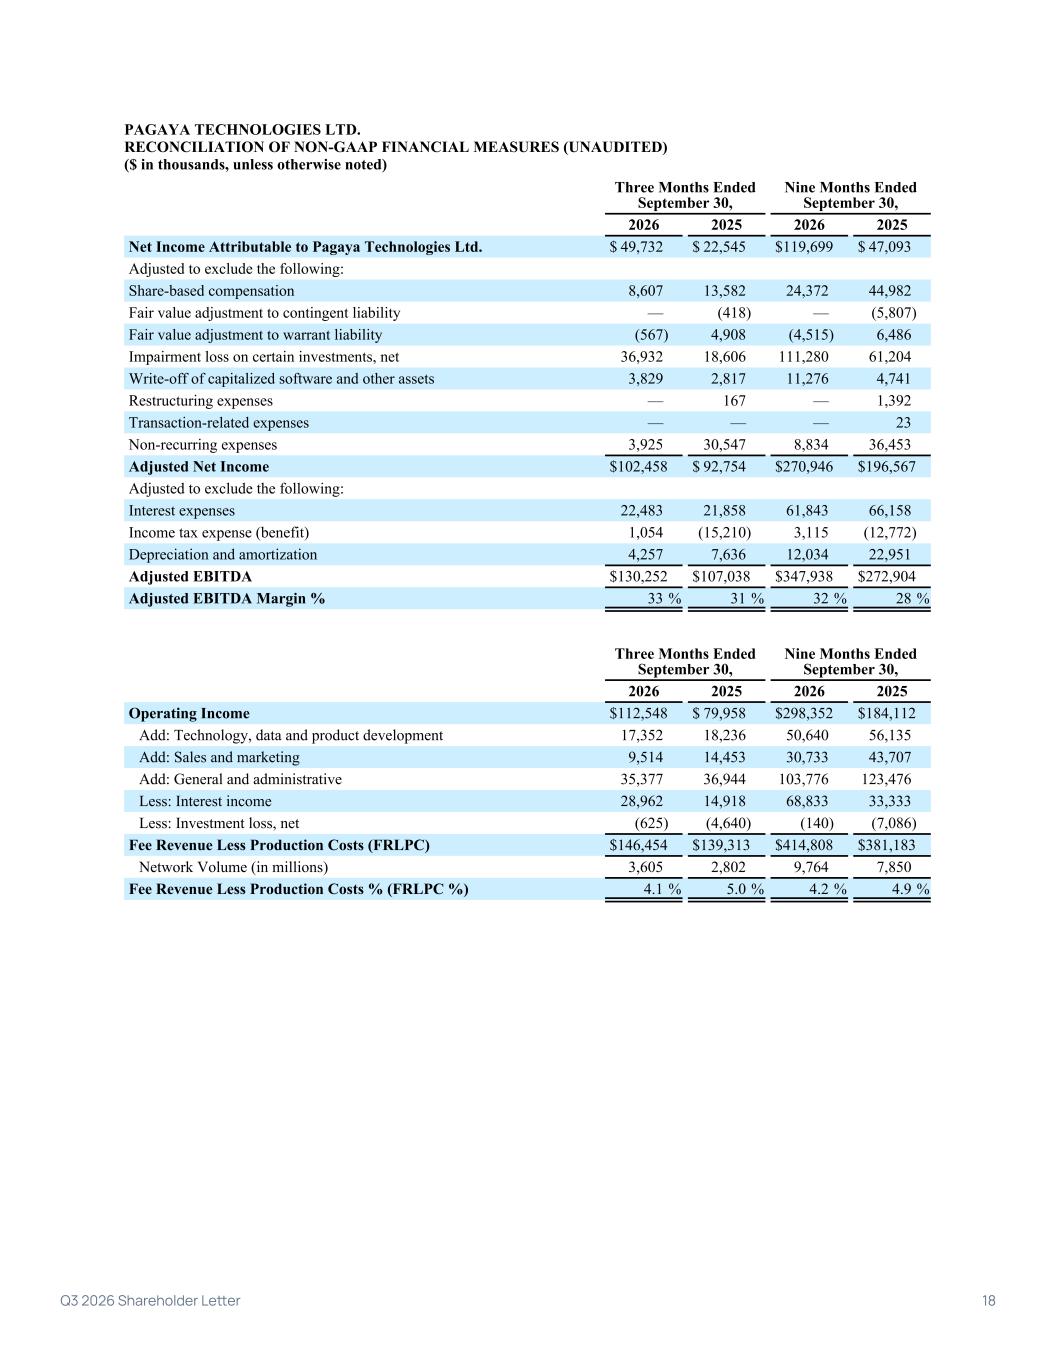
PAGAYA TECHNOLOGIES LTD. RECONCILIATION OF NON-GAAP FINANCIAL MEASURES (UNAUDITED) ($ in thousands, unless otherwise noted) Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 Net Income Attributable to Pagaya Technologies Ltd. $ 49,732 $ 22,545 $ 119,699 $ 47,093 Adjusted to exclude the following: Share-based compensation 8,607 13,582 24,372 44,982 Fair value adjustment to contingent liability — (418) — (5,807) Fair value adjustment to warrant liability (567) 4,908 (4,515) 6,486 Impairment loss on certain investments, net 36,932 18,606 111,280 61,204 Write-off of capitalized software and other assets 3,829 2,817 11,276 4,741 Restructuring expenses — 167 — 1,392 Transaction-related expenses — — — 23 Non-recurring expenses 3,925 30,547 8,834 36,453 Adjusted Net Income $ 102,458 $ 92,754 $ 270,946 $ 196,567 Adjusted to exclude the following: Interest expenses 22,483 21,858 61,843 66,158 Income tax expense (benefit) 1,054 (15,210) 3,115 (12,772) Depreciation and amortization 4,257 7,636 12,034 22,951 Adjusted EBITDA $ 130,252 $ 107,038 $ 347,938 $ 272,904 Adjusted EBITDA Margin % 33 % 31 % 32 % 28 % Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 Operating Income $ 112,548 $ 79,958 $ 298,352 $ 184,112 Add: Technology, data and product development 17,352 18,236 50,640 56,135 Add: Sales and marketing 9,514 14,453 30,733 43,707 Add: General and administrative 35,377 36,944 103,776 123,476 Less: Interest income 28,962 14,918 68,833 33,333 Less: Investment loss, net (625) (4,640) (140) (7,086) Fee Revenue Less Production Costs (FRLPC) $ 146,454 $ 139,313 $ 414,808 $ 381,183 Network Volume (in millions) 3,605 2,802 9,764 7,850 Fee Revenue Less Production Costs % (FRLPC %) 4.1 % 5.0 % 4.2 % 4.9 % 2 Q3 2026 Shareholder Letter 18
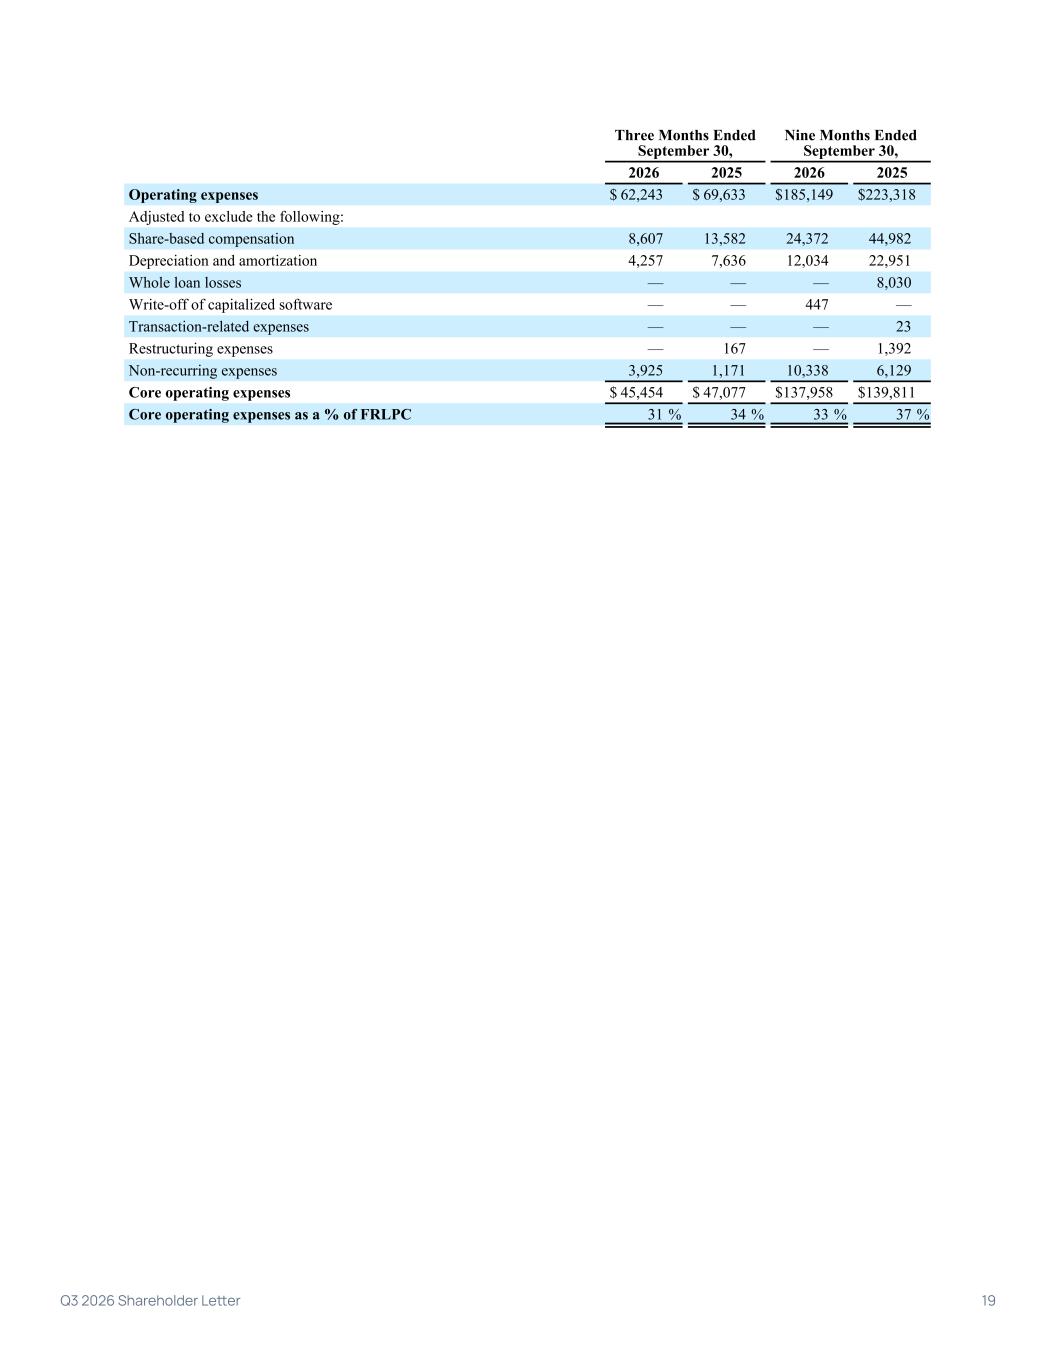
Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 Operating expenses $ 62,243 $ 69,633 $ 185,149 $ 223,318 Adjusted to exclude the following: Share-based compensation 8,607 13,582 24,372 44,982 Depreciation and amortization 4,257 7,636 12,034 22,951 Whole loan losses — — — 8,030 Write-off of capitalized software — — 447 — Transaction-related expenses — — — 23 Restructuring expenses — 167 — 1,392 Non-recurring expenses 3,925 1,171 10,338 6,129 Core operating expenses $ 45,454 $ 47,077 $ 137,958 $ 139,811 Core operating expenses as a % of FRLPC 31 % 34 % 33 % 37 % 3 Q3 2026 Shareholder Letter 19