img109187306_0.jpg

October 28, 2026

Management’s Discussion and Analysis

Management's Discussion and Analysis ("MD&A") for Enerflex Ltd. ("Enerflex" or the “Company") should be read in conjunction with the unaudited interim condensed consolidated financial statements (the "Financial Statements") for the three and nine months ended September 30, 2026 and 2025, the Company’s 2025 Annual Report, the Annual Information Form (“AIF”) for the year ended December 31, 2025, and the cautionary statements regarding forward-looking information and statements in the “Forward-Looking Statements” section of this MD&A.

The MD&A focuses on information and material results from the Financial Statements and considers known risks and uncertainties relating to the energy sector. This discussion should not be considered exhaustive, as it excludes possible future changes that may occur in general economic, political, technological, and environmental conditions. Additionally, other factors and events may or may not occur, which could affect industry conditions and/or Enerflex in the future. Additional information relating to the Company can be found in the Management Information Circular dated March 20, 2026, and the AIF, both of which are available on the Company’s website at www.enerflex.com and under the Company’s SEDAR+ and EDGAR profiles at www.sedarplus.ca and www.sec.gov/edgar, respectively. Additional information is also available in the Annual Report on Form 40-F, which may be found on the Company’s EDGAR profile at www.sec.gov/edgar.

The financial information reported herein has been prepared in accordance with International Financial Reporting Standards (“IFRS Accounting Standards”) as issued by the International Accounting Standards Board (“IASB”) applicable to the preparation of interim financial statements, in particular IAS 34 “Interim Financial Reporting”, and is presented in United States dollars ("USD") unless otherwise stated.

Outlook

Enerflex's strategic priorities include:

(1)
driving productivity improvements across the Company’s global operations through operational excellence;
(2)
focusing on the highest-value growth opportunities and markets where the Company can win, including advancing opportunities in distributed power generation alongside its core natural gas infrastructure markets; and
(3)
allocating capital to drive long-term value creation through disciplined growth, maximizing free cash flow, and providing direct shareholder returns.

We continue to see favorable multi-year fundamentals across our core markets, supported by increasing natural gas production and growing demand for reliable power and energy infrastructure. Operating results are expected to remain underpinned by the highly contracted Energy Infrastructure ("EI") product line and recurring nature of After Market Service ("AMS"), which generated 67% of consolidated gross margin before depreciation and amortization during the first three quarters of 2026.
 

img109187306_1.gif

M-1 img109187306_2.jpg


Performance for Enerflex's Engineered Systems ("ES") product line continues to benefit from healthy demand across compression, processing, and power generation applications. ES backlog increased to a record level during the third quarter, providing strong visibility into future revenue generation and business activity levels into 2028. Enerflex continues to experience growing demand for behind-the-meter ("BTM") power generation solutions, particularly related to data center development, and is leveraging its integrated design, engineering, manufacturing, project execution, commissioning, AMS operations, maintenance, and digital capabilities to capitalize on these opportunities. Including awards secured in early Q4, our backlog of BTM natural gas-fired power generation now exceeds 1.75 gigawatts.

In addition to the initial equipment scope, these projects provide opportunities for future commissioning, installation, operations, maintenance, and digital service offerings through Enerflex’s ReliaCoreTMAsset Performance Management ecosystem, aligning with Enerflex’s commercial initiatives to support the full lifecycle requirements of BTM power generation development.

Capital Allocation

Enerflex is refining its organic capital expenditure guidance for 2026. The Company continues to target spending of $185 million to $195 million during 2026, which includes: (1) organic growth capital expenditures of approximately $100 million (unchanged from prior guidance); (2) maintenance capital expenditures of approximately $55 million (prior guidance of $70 million to $80 million); and (3) property, plant and equipment ("PP&E") and infrastructure investments of $30 million to $40 million to support the Company's ES business line and activity in adjacent markets, including electric power generation (prior guidance of approximately $15 million).

Organic growth capital spending will continue to focus on customer-supported opportunities and is primarily allocated to expand the Company's contract compression fleet in the USA. We continue to target customer-supported fleet growth of 10% to 15% during 2026 and are also securing long-lead time components to support fleet growth into 2030.

The reduction in forecasted maintenance capital reflects efficiencies as well as a shift of some spending into 2027.

As previously announced, Enerflex has authorized investments in its ES facilities and capabilities, including $30 million to $40 million included in Enerflex’s 2026 capital expenditure guidance and approximately $85 million expected to be incurred during 2027. These investments, combined with on-going initiatives to enhance collaboration, leverage scale, improve operational efficiency, and solidify capabilities, are expected to significantly increase revenue capacity of Enerflex’s ES business line.

Enerflex continues to evaluate selective, disciplined tuck-in acquisition opportunities. Inorganic growth will remain focused on enhancing capabilities and accelerating scale in the Company's core North American markets. All opportunities will be balanced with Enerflex's focus on maintaining a strong financial position and providing direct shareholder returns.


img109187306_3.jpg M-2  Q3 2026 Report


Summary Results


Three months ended September 30,


Nine months ended September 30,


($ millions, except per share amounts, percentages and ratios)


2026


2025


2026


2025


Revenue


$

623


$

777


$

1,789


$

1,944


Gross margin ("GM")


142


172


426


439


GM as a percentage of revenue ("GM %")


22.8

%


22.1

%


23.8

%


22.6

%

Selling, general and administrative expenses (“SG&A”)


64


71


224


189


Operating income


77


102


203


249


EBITDA1


117


122


321


361


EBIT1


79


82


209


240


Net earnings


55


37


128


121


Earnings per share - basic


0.45


0.30


1.05


0.98


Long-term debt


539


648


539


648


Net debt2


312


584


312


584


Cash provided by operating activities


147


74


268


166


Key Financial Performance Indicators (“KPIs”)


ES backlog3


$

2,136


$

1,071


$

2,136


$

1,071


ES bookings3


1,024


339


1,995


909


EI contract backlog4


1,182


1,370


1,182


1,370


GM before depreciation and amortization (“GM before D&A”)5


176


206


528


542


GM before D&A as a percentage of revenue ("GM before D&A %")5


28.3

%


26.5

%


29.5

%


27.9

%

Adjusted EBITDA6


129


145


394


388


Free cash flow7


102


43


149


89


Bank-adjusted net debt to EBITDA ratio7,8


0.6

x


1.2x


0.6

x


1.2x


Return on capital employed (“ROCE”)7,8


15.8

%


16.9

%


15.8

%


16.9

%

1 EBITDA is defined as earnings before net finance costs, income taxes, depreciation and amortization. EBIT is defined as earnings before net finance costs and income taxes.

2 Net debt is defined as total long-term debt less cash and cash equivalents, as presented in the Financial Statements.

3 Refer to the “ES Backlog and Bookings” section of this MD&A for further details.

4 Refer to the “EI Contract Backlog” section of this MD&A for further details.

5 Refer to the “Gross Margin before D&A by Product Line and Recurring Gross Margin before D&A” section of this MD&A for further details.

6 Refer to the “Adjusted EBITDA” section of this MD&A for further details.

7 Refer to the “Non-IFRS Measures” section of this MD&A for further details.

8Determined by using the trailing 12-month period.


img109187306_4.jpg

M-3 img109187306_5.jpg


Results Overview

Revenue for the three and nine months ended September 30, 2026 decreased by $154 million and $155 million from the same periods in 2025. The decline was primarily driven by lower ES revenue in the Eastern Hemisphere ("EH") and North America ("NAM") segments, reflecting the commencement of operations at the Bisat-C Expansion Facility in EH in the third quarter of 2025 and certain projects nearing completion during the third quarter of 2026. Lower EI asset sales in Latin America ("LATAM") also contributed to the decrease. These impacts were partially offset by increased AMS parts sales and improved service utilization across all regions.

Gross Margin for the three and nine months ended September 30, 2026 was $142 million (22.8%) and $426 million (23.8%) compared to $172 million (22.1%) and $439 million (22.6%) for the same periods in 2025. The decrease in margin was primarily due to lower revenue in EH and NAM. The increased gross margin percentage for the three and nine months ended September 30, 2026 was the result of improved EI margins from operational efficiencies in LATAM and the operational contributions from Bisat-C project in EH impacting the nine months ended September 30, 2026.

SG&A for the three months ended September 30, 2026 of $64 million decreased by $7 million from the same period in 2025 primarily due to lower share-based compensation expense resulting from a decline in the share price during the third quarter of 2026, compared to share price appreciation in the same period in 2025, partially offset by costs to support growth and operational optimization. SG&A for the nine months ended September 30, 2026 increased by $35 million primarily due to higher share-based compensation expense resulting from a stronger increase in share price in 2026 compared to the same period in 2025, costs to support growth and operational optimization across the business in 2026, and costs incurred for strategic restructuring activities including the disposition of AMS operations in the Asia Pacific (the "APAC") region, partially offset by lower depreciation and amortization.

Net Earnings for the three and nine months ended September 30, 2026 increased by $18 million and $7 million from the same periods in 2025 primarily due to lower unrealized losses on redemption options, lower net finance costs, lower income taxes, and gain on APAC disposition, partially offset by lower gross margin. The increase in net earnings for the nine months ended September 30, 2026 was also partially offset by higher SG&A.

Adjusted EBITDA for the three months ended September 30, 2026 decreased by $16 million from the same period in 2025 primarily due to operational performance. Adjusted EBITDA of $394 million for the nine months ended September 30, 2026 increased from $388 million in the same period of 2025, primarily due to operational contribution from the Bisat-C Expansion in EH.

Cash Provided by Operating Activities for the three and nine months ended September 30, 2026 increased by $73 million and $102 million compared to the same periods in 2025, primarily due to net working capital recovery driven by customer collections, increased advance billings and customer deposits.

Free Cash Flow ("FCF") of $102 million and $149 million for the three and nine months ended September 30, 2026 increased by $59 million and $60 million compared to the same periods in 2025, attributable to higher net working capital recovery, partially offset by higher capital expenditures and lower proceeds from sale of EI assets in LATAM.

ROCE was 15.8% at September 30, 2026. While continuing to reflect strong capital efficiency, ROCE decreased by 1.1% compared to the same period in 2025, primarily reflecting lower trailing twelve-month earnings associated with project timing and activity in EH and NAM, as well as lower EI asset sales in LATAM.

Leverage Ratio: During the third quarter Enerflex continued to manage its leverage ratio through strong performance and disciplined capital allocation, with a net funded debt to EBITDA (“bank-adjusted net debt to EBITDA”) ratio of approximately 0.6x at the end of the third quarter of 2026. At September 30, 2026, the Company was in compliance with its covenants.


img109187306_3.jpg M-4  Q3 2026 Report


Capital Expenditures ("CAPEX"): The Company invested $42 million in CAPEX during the three months ended September 30, 2026, comprising $16 million of maintenance expenditures across its global EI assets and PP&E and $26 million of growth expenditures, primarily to expand the Company's contract compression fleet in the USA.

ES Backlog of $2.1 billion at September 30, 2026 increased from $1.1 billion at December 31, 2025 primarily due to a newly awarded BTM natural gas-fired power generation project of approximately 450 megawatts for a NAM data center developer, partially offset by advancement of ES projects in NAM during the nine months ended September 30, 2026. Enerflex's backlog continues to provide strong visibility into future revenue generation and business activity levels for the ES product line.

ES Bookings of $1.0 billion and $2.0 billion for the three and nine months ended September 30, 2026 increased by $685 million and $1.1 billion compared to the same periods in 2025, primarily due to continued steady client demand for compression and processing products and the newly awarded 450 megawatt power generation project in NAM. The ES product line has realized a stronger book-to-bill ratio (calculated as bookings divided by revenue) of 3.0x during the three months ended September 30, 2026, primarily due to significantly higher bookings. Stronger ES book-to-bill ratio indicates that new bookings continue to well outpace revenue recognition.

EI Contract Backlog of $1.2 billion at September 30, 2026 decreased from $1.3 billion at December 31, 2025 primarily due to revenue recognized during the nine months ended September 30, 2026, partially offset by new EI bookings across all segments.

APAC Disposition: On September 30, 2026, Enerflex completed the previously announced disposition of its AMS operations in the APAC region to INNIO Group for proceeds of $62 million, subject to closing adjustments. The transaction supports Enerflex's disciplined portfolio management strategy and further focuses the Company on its core operating regions. The Company recognized a gain of $5 million in the consolidated statements of earnings. Refer to Note 2 of the Financial Statements.

Additional Power Generation Award: Subsequent to September 30, 2026, Enerflex secured an award to supply over 1.0 gigawatts of low emission BTM natural gas-fired power generation for a North American data center development. Combined with additional project awards, including the approximately 450 megawatts recorded in the third quarter, Enerflex’s backlog of BTM natural gas-fired power generation now exceeds 1.75 gigawatts, with deliveries extending through 2028. This additional 1.0 gigawatt award will be reflected in ES backlog during the fourth quarter of 2026.

Dividend Declaration: Subsequent to September 30, 2026, Enerflex’s Board of Directors elected to declare the Company’s quarterly dividend in U.S. Dollars. The Company approved an increase of approximately 17% to US$0.035 per common share, payable on November 25, 2026, to shareholders of record on November 12, 2026. The Board will continue to evaluate dividend payments on a quarterly basis based on availability of cash flow, anticipated market conditions, and the general needs of the business.


img109187306_4.jpg

M-5 img109187306_5.jpg


Adjusted EBITDA

Enerflex’s financial results include items that are unique and items that Management and users of the Financial Statements adjust for when evaluating results. The Company removes the impact of these items when calculating Adjusted EBITDA. The presentation of Adjusted EBITDA should not be considered in isolation from EBIT or EBITDA and should not be considered a replacement for measures prepared in accordance with IFRS. Adjusted EBITDA may not be comparable to similar non-IFRS measures disclosed by other issuers.

Enerflex believes adjustment of items that are unique or not in the normal course of continuing operations increases the comparability across items within the Financial Statements or between periods of the Financial Statements. Items the Company has adjusted for in the past include, but are not limited to, restructuring, transaction, and integration costs; share-based compensation, which fluctuates based on share price that may be influenced by factors not directly related to the Company's operations; impact of finance leases to account for the lease principal payments received over the term of the related lease and remove the non-cash upfront selling profit; gains or losses on redemption options associated with the senior notes; gains or losses on disposal of a subsidiary; and impairment of goodwill. These items are considered either unique, non-recurring, or non-cash transactions, and are not indicative of the ongoing normal operations of the Company.

Adjusted EBITDA is presented by reporting segment as follows:

Three months ended September 30, 2026


($ millions)


NAM


LATAM


EH


Total


Net earnings1


$

55


Income taxes1


16


Net finance costs1,2


8


EBIT3


$

61


$

15


$

6


$

79


Depreciation and amortization


17


10


11


38


EBITDA


$

78


$

25


$

17


$

117


Restructuring and transaction costs


-


-


2


2


Gain on APAC disposition


-


-


(5

)


(5

)

Share-based compensation


(1

)


1


2


2


Impact of finance leases


Principal payments received


-


-


10


10


Unrealized loss on redemption options3


3


Adjusted EBITDA


$

77


$

26


$

26


$

129


1The Company included net earnings, income taxes, and net finance costs on a consolidated basis to reconcile to EBIT.

2Net finance costs are considered corporate expenditure and have therefore not been allocated to reporting segments.

3EBIT includes $3 million unrealized loss on redemption options associated with the USD denominated senior unsecured notes (the "2031 Notes"). Debt is managed within Corporate and is not allocated to reporting segments.

Three months ended September 30, 2025


($ millions)


NAM


LATAM


EH


Total


Net earnings 1


$

37


Income taxes1


25


Net finance costs1,2


20


EBIT3


$

57


$

11


$

30


$

82


Depreciation and amortization


17


10


13


40


EBITDA


$

74


$

21


$

43


$

122


Share-based compensation


7


2


2


11


Impact of finance leases


Upfront gain


-


-


(14

)


(14

)

Principal payments received


-


-


10


10


Unrealized loss on redemption options3


16


Adjusted EBITDA


$

81


$

23


$

41


$

145


1The Company included net earnings, income taxes, and net finance costs on a consolidated basis to reconcile to EBIT.

2Net finance costs are considered corporate expenditure and have therefore not been allocated to reporting segments.

3EBIT includes $16 million unrealized loss on redemption options associated with the 9.0% senior secured notes (the "2027 Notes"). Debt is managed within Corporate and is not allocated to reporting segments.


img109187306_3.jpg M-6  Q3 2026 Report


Nine months ended September 30, 2026


($ millions)


NAM


LATAM


EH


Total


Net earnings1


$

128


Income taxes1


51


Net finance costs1,2


30


EBIT3


$

132


$

46


$

28


$

209


Depreciation and amortization


48


29


35


112


EBITDA


$

180


$

75


$

63


$

321


Restructuring and transaction costs


3


-


4


7


Gain on APAC disposition


-


-


(5

)


(5

)

Share-based compensation


27


7


9


43


Impact of finance leases


Principal payments received


-


-


31


31


Unrealized gain on redemption options3


(3

)

Adjusted EBITDA


$

210


$

82


$

102


$

394


1The Company included net earnings, income taxes, and net finance costs on a consolidated basis to reconcile to EBIT.

2Net finance costs are considered corporate expenditure and have therefore not been allocated to reporting segments.

3EBIT includes $3 million unrealized gain on redemption options associated with the 2031 Notes. Debt is managed within Corporate and is not allocated to reporting segments.

Nine months ended September 30, 2025


($ millions)


NAM


LATAM


EH


Total


Net earnings1


$

121


Income taxes1


58


Net finance costs1,2


61


EBIT3


$

146


$

50


$

48


$

240


Depreciation and amortization


48


31


42


121


EBITDA


$

194


$

81


$

90


$

361


Share-based compensation


7


2


2


11


Impact of finance leases


Upfront gain


-


-


(14

)


(14

)

Principal payments received


-


-


26


26


Unrealized loss on redemption options3


4


Adjusted EBITDA


$

201


$

83


$

104


$

388


1The Company included net earnings, income taxes, and net finance costs on a consolidated basis to reconcile to EBIT.

2Net finance costs are considered corporate expenditure and have therefore not been allocated to reporting segments.

3EBIT includes $4 million unrealized loss on redemption options associated with the 2027 Notes. Debt is managed within Corporate and is not allocated to reporting segments.


Refer to the section “Segmented Results” of this MD&A for information about results by reporting segment.


img109187306_4.jpg

M-7 img109187306_5.jpg


ES Backlog and Bookings

Enerflex monitors its ES backlog and bookings as indicators of future revenue generation and business activity levels for the ES product line. ES bookings are recorded in the period when a firm commitment or order is received from clients. Bookings increase backlog in the period they are received, while revenue recognized on ES projects decrease backlog in the period the revenue is recognized. Accordingly, ES backlog is an indication of revenue to be recognized in future periods. In the event a project is cancelled, the remaining contract price associated with the unsatisfied performance obligation is derecognized from the backlog. ES backlog represents unsatisfied performance obligations related to the ES product line, and further information on recognition of revenue from the ES backlog is included in Note 9 of the Financial Statements.

Revenue from contracts that have been classified as finance leases for newly built equipment is recorded as ES bookings. The full amount of revenue is removed from backlog at commencement of the lease.

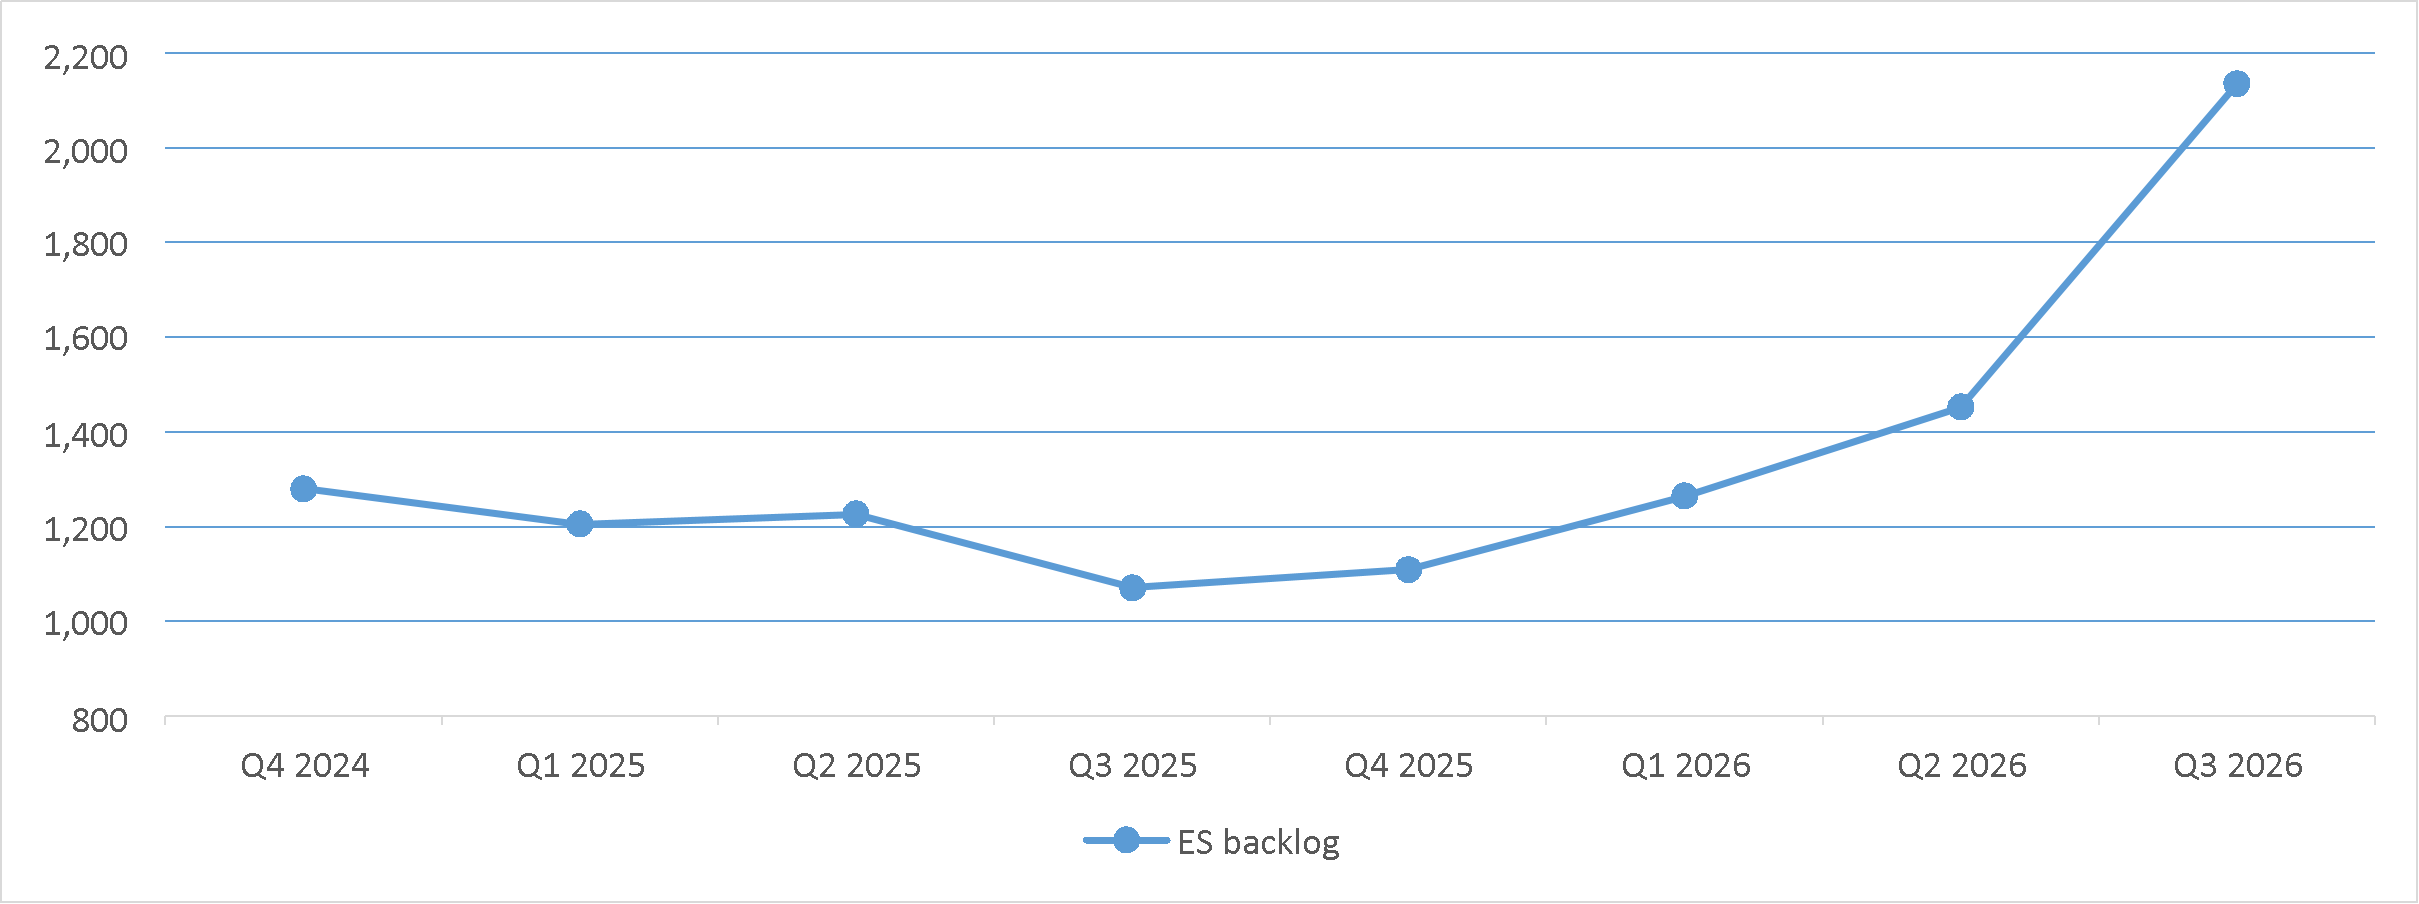
ES backlog of $2.1 billion at September 30, 2026, increased from $1.1 billion at December 31, 2025. The increase was primarily due to new bookings secured in NAM segment, partially offset by advancement of ES projects in NAM during the nine months ended September 30, 2026. Enerflex's ES backlog continues to provide strong visibility into future revenue generation and business activity levels.

The increased level of backlog over a two-year period reflects healthy demand across compression, processing, and power generation applications. The 8-quarter average also serves as a key indicator of operational consistency and revenue visibility, smoothing out short-term fluctuations in ES bookings and project timings. This trend demonstrates that the ES product line continues to benefit from a diversified portfolio of gas compression, processing and power generation projects, reinforcing management's confidence in the ES product line's ability to generate predictable revenue in the near-term.

ES backlog for the past 8 quarters are illustrated below in millions:

img109187306_6.gif

Enerflex recorded ES bookings of $1.0 billion and $2.0 billion during the three and nine months ended September 30, 2026, an increase from $339 million and $909 million during the same periods in 2025, driven by continued demand for the Company's compression and processing products and a newly awarded BTM natural gas-fired power generation project of approximately 450 megawatts for a NAM data center developer.

The ES product line realized a stronger book-to-bill ratio of 3.0x during the three months ended September 30, 2026, indicating that new bookings continue to well outpace revenue recognition. The current ratio supports near-term revenue visibility and reflects a stable demand environment. The 8-quarter average book-to-bill ratio of 1.3x is an indication that the Company is consistently replenishing its backlog in line with project execution.

ES backlog and bookings by reporting segment are disclosed in the “Segmented Results” section of this MD&A.


img109187306_3.jpg M-8  Q3 2026 Report


EI Contract Backlog

The Company’s EI contract backlog is recognized from lease agreements executed with clients for leasing and operations and maintenance of the Company’s EI assets. Lease agreements executed during the period increase EI contract backlog while revenue recognized on EI assets decreases the EI contract backlog in the period the revenue is recognized. EI contract backlog represents unsatisfied performance obligations related to the EI product line. Further information on the recognition of revenue from the EI contract backlog is included in Note 9 of the Financial Statements.

Enerflex has lease agreements with clients for EI assets with initial terms ranging from one to 10 years.

The following table sets forth EI contract backlog by reporting segment:


($ millions)


September 30, 2026


December 31, 2025


NAM


$

149


$

160


LATAM


364


361


EH


669


800


Total EI contract backlog


$

1,182


$

1,321


Enerflex's EI contract backlog at September 30, 2026 decreased by $139 million from December 31, 2025 primarily due to revenue recognized during the nine months ended September 30, 2026, partially offset by new EI bookings across all segments.

Segmented Results

Enerflex has three reporting segments: NAM, LATAM, and EH, each of which is supported by Enerflex’s corporate functions. Corporate overhead is allocated to operating segments based on revenue. In assessing its reporting segments, the Company considers geographic locations, economic characteristics, the nature of products and services provided, the nature of production processes, the types of clients for its products and services, and distribution methods used.


img109187306_4.jpg

M-9 img109187306_5.jpg


NAM


Three months ended September 30,


Nine months ended September 30,


($ millions, except percentages)


2026


2025


2026


2025


ES backlog


$

2,104


$

1,031


$

2,104


$

1,031


ES bookings


1,023


337


1,955


863


EI contract backlog


149


156


149


156


Segment revenue


$

450


$

480


$

1,275


$

1,283


Intersegment revenue


(4

)


(14

)


(12

)


(22

)

Revenue


$

446


$

466


$

1,263


$

1,261


EI


$

42


$

43


$

124


$

117


AMS


75


69


200


193


ES


329


354


939


951


Revenue


446


466


1,263


1,261


EI


21


21


60


56


AMS


11


11


31


31


ES


53


68


162


170


GM


85


100


253


257


GM %


19.1

%


21.5

%


20.0

%


20.4

%


EI


32


31


93


85


AMS


13


12


36


35


ES


55


70


168


175


GM before D&A


100


113


297


295


GM before D&A %


22.4

%


24.2

%


23.5

%


23.4

%


SG&A


24


40


122


107


Foreign exchange loss


-


(1

)


-


1


Operating income


61


61


131


149


EBIT


61


57


132


146


EBITDA


78


74


180


194


Adjusted EBITDA


77


81


210


201


ES Backlog of $2.1 billion at September 30, 2026 increased from $1.1 billion at December 31, 2025 primarily due to the newly awarded BTM power generation project for a data center developer and continued steady demand for the compression, processing, and power generation products in the region.

EI Contract Backlog of $149 million at September 30, 2026 decreased from $160 million at December 31, 2025 primarily due to revenue recognized during the nine months ended September 30, 2026 partially offset by management's continued investment in assets deployed under longer term rental contracts.

Revenue for the three months ended September 30, 2026 decreased by $20 million primarily due to lower ES revenue from the completion of certain projects during the third quarter of 2026, partially offset by higher AMS revenue due to higher parts sales. Revenue for the nine months ended September 30, 2026 remained relatively consistent at $1.3 billion compared to $1.3 billion in the same period in 2025.

Gross Margin decreased by $15 million and $4 million during the three and nine months ended September 30, 2026 primarily due to lower contribution from the ES product line. Gross margin for the nine months ended September 30, 2026 was favorably impacted by increased EI revenue.


img109187306_3.jpg M-10  Q3 2026 Report


SG&A decreased by $16 million for the three months ended September 30, 2026 primarily due to lower share-based compensation expense resulting from the decline in the share price, partially offset by costs to support growth and operational optimization. SG&A increased by $15 million for the nine months ended September 30, 2026 primarily due to increased share-based compensation resulting from higher share price appreciation compared to the same period in 2025 and costs to support growth and operational optimization.

At September 30, 2026, the USA contract compression fleet totaled 521,000 horsepower. The average utilization for the three and nine months ended September 30, 2026 remained consistent at 94% compared to the same periods in 2025 at 94%.


img109187306_4.jpg

M-11 img109187306_5.jpg


LATAM


Three months ended September 30,


Nine months ended September 30,


($ millions, except percentages)


2026


2025


2026


2025


ES backlog


$

16


$

5


$

16


$

5


ES bookings


2


-


37


6


EI contract backlog


364


365


364


365


Segment revenue


$

94


$

88


$

264


$

279


Intersegment revenue


-


-


-


-


Revenue


$

94


$

88


$

264


$

279


EI


$

64


$

68


$

189


$

211


AMS


19


16


51


51


ES


11


4


24


17


Revenue


94


88


264


279


EI


23


20


68


67


AMS


4


5


13


15


ES


1


-


2


2


GM


28


25


83


84


GM %


29.8

%


28.4

%


31.4

%


30.1

%


EI


33


30


97


97


AMS


4


5


13


15


ES


1


-


2


2


GM before D&A


38


35


112


114


GM before D&A %


40.4

%


39.8

%


42.4

%


40.9

%


SG&A


12


14


35


33


Foreign exchange (gain)


1


-


(1

)


(1

)

Operating income


15


11


49


52


EBIT


15


11


46


50


EBITDA


25


21


75


81


Adjusted EBITDA


26


23


82


83


ES Backlog of $16 million at September 30, 2026 increased from $3 million at December 31, 2025 primarily due to new bookings in 2026, partially offset by projects nearing completion.

EI Contract Backlog of $364 million at September 30, 2026 increased from $361 million at December 31, 2025 primarily due to new bookings, partially offset by revenue recognition on existing contracts.

Revenue for the three months ended September 30, 2026 increased by $6 million primarily due to execution of ES projects and increased service utilization and parts sales in the AMS business, partially offset by lower EI revenue resulting from asset sales in 2025. Revenue for the nine months ended September 30, 2026 decreased by $15 million primarily due to higher EI asset sales in 2025, partially offset by higher ES revenue from new projects and AMS activity.

Gross Margin for the three months ended September 30, 2026 increased by $3 million primarily due to increased contribution from the ES project execution and operational efficiencies in the EI business. Gross margin for the nine months ended September 30, 2026 remained relatively consistent at $83 million compared to $84 million in the same period of 2025.

SG&A for the three months ended September 30, 2026 remained relatively consistent at $12 million compared to $14 million in the same period in 2025. SG&A for the nine months ended September 30, 2026 increased by $2 million compared to the same period in 2025, primarily due to increased share-based compensation expense resulting from higher share price appreciation compared to the same period in 2025 and costs to support growth and operational optimization.


img109187306_3.jpg M-12  Q3 2026 Report


EH


Three months ended September 30,


Nine months ended September 30,


($ millions, except percentages)


2026


2025


2026


2025


ES backlog


$

16


$

35


$

16


$

35


ES bookings


(1

)


2


3


40


EI contract backlog


669


849


669


849


Segment revenue


$

84


$

225


$

264


$

407


Intersegment revenue


(1

)


(2

)


(2

)


(3

)

Revenue


$

83


$

223


$

262


$

404


EI


$

45


$

53


$

135


$

136


AMS


37


33


121


118


ES


1


137


6


150


Revenue


83


223


262


404


EI


19


24


59


52


AMS


9


7


28


27


ES


1


16


3


19


GM


29


47


90


98


GM %


34.9

%


21.1

%


34.4

%


24.3

%


EI


28


34


87


85


AMS


9


8


29


29


ES


1


16


3


19


GM before D&A


38


58


119


133


GM before D&A %


45.8

%


26.0

%


45.4

%


32.9

%


SG&A


28


17


67


49


Foreign exchange loss


-


-


-


1


Operating income


1


30


23


48


EBIT


6


30


28


48


EBITDA


17


43


63


90


Adjusted EBITDA


26


41


102


104


ES Backlog of $16 million at September 30, 2026 decreased from $19 million at December 31, 2025 primarily due to ongoing projects nearing completion.

EI Contract Backlog of $669 million at September 30, 2026 decreased from $800 million at December 31, 2025 primarily due to revenue recognition from existing contracts.

Revenue for the three and nine months ended September 30, 2026 decreased by $140 million and $142 million primarily due to commencement of the Bisat-C Expansion project in the third quarter of 2025, partially offset by ongoing contribution from the Bisat-C Expansion and higher AMS parts sales and service utilization.

Gross Margin for the three and nine months ended September 30, 2026 decreased by $18 million and $8 million primarily due to lower revenue discussed above. Gross margin percentage improved primarily due to higher margin contribution from the EI business from the Bisat-C Expansion and AMS service margins.

SG&A for the three and nine months ended September 30, 2026 increased by $11 million and $18 million primarily due to costs to support growth and operational optimization including the disposition of AMS operations in the APAC region and higher share-based compensation expense for the nine months ended September 30, 2026. SG&A for the nine months ended September 30, 2025 also benefited from a non-recurring input tax refund.


img109187306_4.jpg

M-13 img109187306_5.jpg


Non-IFRS Measures

Enerflex measures its financial performance using several key financial performance indicators, some of which do not have standardized meanings as prescribed by IFRS and therefore may not be comparable to similar measures presented by other issuers. These non-IFRS measures include Adjusted EBITDA, ES bookings, ES book-to-bill ratio, GM before D&A, recurring GM before D&A, free cash flow, dividend payout ratio, bank-adjusted net debt to EBITDA ratio, and ROCE. These measures should not be considered as alternatives to net earnings or any other measure of performance under IFRS. Reconciliation of these non-IFRS measures to the most directly comparable IFRS measure is provided below and in the relevant sections where appropriate. ES bookings and ES book-to-bill ratio do not have a directly comparable IFRS measure.

Gross Margin before D&A by Product Line and Recurring Gross Margin before D&A

Enerflex’s three reporting segments oversee execution of three main product lines:

▪
EI: Infrastructure solutions under contract for natural gas processing, compression, treated water, and electric power.
▪
AMS: Provision of after-market services such as mechanical maintenance, parts distribution, operations and maintenance solutions, equipment optimization and maintenance programs, manufacturer warranties, exchange components, and long-term service agreements.
▪
ES: Engineer, design, and manufacture processing, compression, cryogenic, electric power, and treated water solutions.

EI and AMS product lines are considered recurring, as they are typically contracted and extend into future periods, generating ongoing revenue for the Company. While the EI and AMS contracts may vary in duration and are subject to cancellation, the Company believes they exhibit characteristics consistent with recurring business activities. In contrast, the ES product line is non-recurring, as individual sales do not typically generate repeat revenue after delivery of products. The Company does however, benefit from repeat business with many ES customers over time.

The Company uses GM before D&A to evaluate operational performance of each product line. GM before D&A is defined as gross margin excluding depreciation and amortization, which can vary based on the nature and origin of assets. The Company also presents recurring GM before D&A to evaluate its recurring business, and it is defined as GM before D&A from the EI and AMS product lines.

Presentation of GM before D&A and recurring GM before D&A improves transparency into the profitability and capital intensity across the Company's product lines and should not be considered in isolation from gross margin or as a replacement for measures prepared as determined under IFRS.

Reconciliation of GM before D&A and recurring GM before D&A to the most comparable IFRS measure is presented in the tables below.

Three months ended September 30, 2026


($ millions, except percentages)


EI


AMS


Recurring
Product Lines


ES


Total


Revenue


$

151


$

131


$

282


$

341


$

623


Cost of goods sold:


Operating expenses


58


105


163


284


447


Depreciation and amortization


30


2


32


2


34


Gross margin


$

63


$

24


$

87


$

55


$

142


Gross margin %


41.7

%


18.3

%


30.9

%


16.1

%


22.8

%

Gross margin before D&A


$

93


$

26


$

119


$

57


$

176


Gross margin before D&A %


61.6

%


19.8

%


42.2

%


16.7

%


28.3

%

% of total Gross margin before D&A


52.8

%


14.8

%


67.6

%


32.4

%


img109187306_3.jpg M-14  Q3 2026 Report


Three months ended September 30, 2025


($ millions, except percentages)


EI


AMS


Recurring
Product Lines


ES


Total


Revenue


$

164


$

118


$

282


$

495


$

777


Cost of goods sold:


Operating expenses


69


93


162


409


571


Depreciation and amortization


30


2


32


2


34


Gross margin


$

65


$

23


$

88


$

84


$

172


Gross margin %


39.6

%


19.5

%


31.2

%


17.0

%


22.1

%

Gross margin before D&A


$

95


$

25


$

120


$

86


$

206


Gross margin before D&A %


57.9

%


21.2

%


42.6

%


17.4

%


26.5

%

% of total Gross margin before D&A


46.1

%


12.1

%


58.3

%


41.7

%


Nine months ended September 30, 2026


($ millions, except percentages)


EI


AMS


Recurring
Product Lines


ES


Total


Revenue


$

448


$

372


$

820


$

969


$

1,789


Cost of goods sold:


Operating expenses


171


294


465


796


1,261


Depreciation and amortization


90


6


96


6


102


Gross margin


$

187


$

72


$

259


$

167


$

426


Gross margin %


41.7

%


19.4

%


31.6

%


17.2

%


23.8

%

Gross margin before D&A


$

277


$

78


$

355


$

173


$

528


Gross margin before D&A %


61.8

%


21.0

%


43.3

%


17.9

%


29.5

%

% of total Gross margin before D&A


52.5

%


14.8

%


67.2

%


32.8

%


Nine months ended September 30, 2025


($ millions, except percentages)


EI


AMS


Recurring
Product Lines


ES


Total


Revenue


$

464


$

362


$

826


$

1,118


$

1,944


Cost of goods sold:


Operating expenses


197


283


480


922


1,402


Depreciation and amortization


92


6


98


5


103


Gross margin


$

175


$

73


$

248


$

191


$

439


Gross margin %


37.7

%


20.2

%


30.0

%


17.1

%


22.6

%

Gross margin before D&A


$

267


$

79


$

346


$

196


$

542


Gross margin before D&A %


57.5

%


21.8

%


41.9

%


17.5

%


27.9

%

% of total Gross margin before D&A


49.3

%


14.6

%


63.8

%


36.2

%


Free Cash Flow and Dividend Payout Ratio

The Company defines free cash flow ("FCF") as cash provided by (used in) operating activities, less total capital expenditures (growth and maintenance) for EI assets - operating leases and PP&E, mandatory debt repayments, and lease principal repayment, while proceeds on disposals of EI assets - operating leases and PP&E are added back. Management uses this non-IFRS measure to assess the level of free cash generated to fund other non-operating activities. These activities could include dividend payments, share repurchases, and non-mandatory debt repayments. FCF is also used in calculating the dividend payout ratio.


img109187306_4.jpg

M-15 img109187306_5.jpg


Reconciliation of FCF to the most directly comparable IFRS measure, cash provided by (used in) operating activities is presented in the table below.


Three months ended September 30,


Nine months ended September 30,


($ millions)


2026


2025


2026


2025


Funds from operations ("FFO")1


$

96


$

115


$

278


$

266


Net change in working capital and other


51


(41

)


(10

)


(100

)

Cash provided by operating activities ("CFO")2


$

147


$

74


$

268


$

166


Less:


CAPEX - Maintenance and PP&E


(16

)


(18

)


(43

)


(37

)

CAPEX - Growth


(26

)


(15

)


(68

)


(44

)

Lease payments


(5

)


(5

)


(17

)


(16

)

Add:


Proceeds on disposals of PP&E and EI assets - operating leases


2


7


9


20


Free cash flow


$

102


$

43


$

149


$

89


1Enerflex also refers to cash provided by operating activities before net change in working capital and other as FFO.

2Enerflex also refers to cash provided by (used in) operating activities as “Cash flow from Operations” or “CFO”.


The Company defines dividend payout ratio as dividends paid divided by free cash flow. Dividend payout ratio is used to assess the proportion of free cash flow returned to shareholders.

Dividend payout ratio for the trailing 12-months was as follows:


September 30,


($ millions, except percentages)


2026


2025


Trailing 12-months dividends paid


$

15


$

15


Trailing 12-months free cash flow


290


165


Dividend payout ratio


5.2

%


9.1

%


Bank-Adjusted Net Debt to EBITDA Ratio

Enerflex defines bank-adjusted net debt to EBITDA as borrowings under the revolving credit facility ("RCF") and senior notes less cash and cash equivalents, divided by EBITDA for the trailing 12-months, as defined by the Company’s lenders. In assessing the Company's compliance with financial covenants related to its debt, certain adjustments are made to EBITDA to determine Enerflex's bank-adjusted net debt to EBITDA ratio. These adjustments and Enerflex's bank-adjusted net debt to EBITDA ratio are calculated in accordance with and derived from the Company's financing agreements.

ROCE

ROCE is a measure used to analyze operating performance and efficiency of the Company’s capital allocation process. The ratio is calculated by taking trailing twelve months ("TTM") EBIT divided by capital employed. Capital employed is average debt and shareholders’ equity less average cash for the trailing four quarters.


September 30,


($ millions, except percentages)


2026


2025


Trailing 12-months EBIT


$

252


$

287


Average capital employed


Average net debt1


$

443


$

593


Average shareholders’ equity1


1,156


1,102


Average capital employed


$

1,599


$

1,695


ROCE


15.8

%


16.9

%


1Based on a trailing four-quarter average.


img109187306_3.jpg M-16  Q3 2026 Report


Liquidity

The Company expects that cash flows from operations in 2026, together with cash and cash equivalents on hand and currently available credit facilities, will be more than sufficient to fund its requirements for investments in working capital and capital assets.

($ millions)


September 30, 2026


Cash and cash equivalents


 $


227


RCF


800


Less: Drawings on the RCF


(149

)


Less: Letters of Credit1


(74

)


577


Available liquidity


 $


804


1Represents letters of credit that the Company has funded with the RCF. Additional letters of credit of $23 million are funded from the $70 million LC Facility. Refer to Note 8 “Long-Term Debt” of the Financial Statements for further details.

Covenant Compliance

As at September 30, 2026, the Company met the covenant requirements of its funded debt, comprised of the secured RCF and the 2031 Notes, reflecting strong performance and cash flow generation, and Enerflex’s focus on repaying debt and lowering finance costs.

The following table sets forth a summary of the covenant requirements and the Company’s performance:


Nine months ended September 30,


2026


2025


Requirement


Performance


Performance


Senior secured net funded debt to EBITDA ratio1 – Maximum


2.5x


(0.2

x)


0.1

x

Bank-adjusted net debt to EBITDA ratio2 – Maximum


4.0x


0.6

x


1.2

x

Interest coverage ratio3 – Minimum


2.5x


5.8

x


6.1

x

1Senior secured net funded debt to EBITDA is defined as borrowings under the RCF less cash and cash equivalents divided by TTM EBITDA, as defined by the Company’s lenders.

2Refer to the "Bank-Adjusted Net Debt to EBITDA Ratio" section of this MD&A.

3Interest coverage ratio is calculated by dividing the TTM EBITDA by interest expense over the same timeframe, as defined by the Company’s lenders.

Credit Rating

Enerflex’s credit ratings affect the cost and ability to access the capital markets, and it is the Company’s objective to maintain high quality credit ratings. As at October 28, 2026, S&P Global Ratings ("S&P"), Moody’s Investors Service, Inc. ("Moody’s"), and Fitch Ratings, Inc. ("Fitch") assigned the following credit ratings to Enerflex and the 2031 Notes:

S&P

Moody’s

Fitch

Corporate Credit Rating

BB (stable outlook)

Ba2 (stable outlook)

BB (stable outlook)

2031 Notes

BB (stable outlook)

Ba3 (stable outlook)

BB (stable outlook)


img109187306_4.jpg

M-17 img109187306_5.jpg


Summarized Statements of Cash Flow


Three months ended September 30,


Nine months ended September 30,


($ millions)


2026


2025


2026


2025


Cash and cash equivalents, beginning of period (including APAC)


$

90


$

71


$

81


$

92


Cash provided by (used in):


Operating activities


147


74


268


166


Investing activities


(11

)


(30

)


(55

)


(66

)

Financing activities


1


(50

)


(67

)


(126

)

Effect of exchange rate changes on cash and cash
  equivalents denominated in foreign currencies


-


(1

)


-


(2

)


Cash and cash equivalents, end of period


$

227


$

64


$

227


$

64


Cash Provided by Operating Activities for the three and nine months ended September 30, 2026 increased by $73 million and $102 million primarily due to net working capital recovery. Cash provided by operating activities for the nine months ended September 30, 2026 also benefited from higher funds generated from operations.

Cash Used in Investing Activities for the three and nine months ended September 30, 2026 decreased by $19 million and $11 million primarily due to proceeds from the APAC disposition, partially offset by higher capital expenditures and lower proceeds from the sale of EI assets.

Cash Provided by Financing Activities for the three months ended September 30, 2026 increased by $51 million primarily due to net borrowings on the RCF in the current quarter compared to net repayments in the same period in 2025 and the absence of shares repurchased through the normal course issuer bid in 2026. Cash used in financing activities for the nine months ended September 30, 2026 decreased by $59 million primarily due to lower repayments of the RCF in the current quarter and the absence of shares repurchased through the normal course issuer bid in 2026.

Capital Expenditures and Expenditures for Finance Leases

Enerflex distinguishes CAPEX invested in EI assets - operating leases as either maintenance or growth. Maintenance expenditures are necessary costs to continue utilizing existing EI assets - operating leases, while growth expenditures are intended to expand the Company’s EI assets - operating leases. The Company may also incur costs related to the construction of EI assets determined to be finance leases. These costs are accounted for as work-in-progress related to finance leases, and once the project is completed and enters service, they are reclassified to cost of goods sold.

CAPEX and expenditures for finance leases are shown in the table below:


Three months ended September 30,


Nine months ended September 30,


($ millions)


2026


2025


2026


2025


Maintenance and PP&E


$

16


$

18


$

43


$

37


Growth


26


15


68


44


Total CAPEX


42


33


111


81


Expenditures for finance leases


-


14


-


70


Total CAPEX and expenditures for finance leases


$

42


$

47


$

111


$

151


img109187306_3.jpg M-18  Q3 2026 Report


Selling, General & Administrative Expenses

SG&A are comprised of costs incurred by the Company to support business operations that are not directly attributable to the production of goods or services.


Three months ended September 30,


Nine months ended September 30,


($ millions)


2026


2025


2026


2025


Core SG&A1


$

58


$

53


$

171


$

159


Share-based compensation


2


11


43


11


Depreciation and amortization


4


6


10


18


Bad debt expense


-


1


-


1


Total SG&A


$

64


$

71


$

224


$

189


1 Core SG&A is primarily comprised of compensation, third-party services, and information technology expenses.

SG&A for the three months ended September 30, 2026 decreased by $7 million primarily due to lower share-based compensation expense resulting from a decline in the share price during the third quarter of 2026, compared to share price appreciation in the same period in 2025, partially offset by costs to support growth and operational optimization. SG&A for the nine months ended September 30, 2026 increased by $35 million primarily due to increased share-based compensation expense resulting from a higher share price appreciation in 2026 compared to the same period in 2025, costs to support growth and operational optimization across the business in 2026, and costs incurred for strategic restructuring activities including the disposition of AMS operations in the APAC region, partially offset by lower depreciation and amortization.

Income Taxes

The Company reported income tax expense of $16 million and $51 million for the three and nine months ended September 30, 2026 compared to $25 million and $58 million in the same periods in 2025. The decrease was primarily due to the changes in the recognition of deferred tax assets, partially offset by higher earnings in 2026.


img109187306_4.jpg

M-19 img109187306_5.jpg


Financial Position

The following table outlines significant changes in the consolidated statements of financial position as at September 30, 2026, compared to December 31, 2025:

($ millions)


Increase
(Decrease)


Explanation

Current assets


277


Current assets increased primarily due to higher cash balances resulting from stronger cash generation and proceeds from the APAC disposition, as well as higher accounts receivables due to timing of customer billings and collections. The increase also reflected strategic inventory investment in the NAM ES business and a build of inventory for scheduled EI maintenance in LATAM, as well as higher prepayments in NAM and LATAM due to advance payments associated with project execution and equipment procurement. These increases were partially offset by lower unbilled revenue in LATAM and EH due to advanced billings.

EI assets - operating leases


14


EI assets - operating lease increased primarily due to capital expenditures in NAM, partially offset by depreciation and sale of EI assets in LATAM.

EI assets - finance leases receivable


(30)


EI assets - finance leases receivable decreased due to principal payments received.

Goodwill


(16)


Goodwill decreased due to the derecognition of goodwill associated with the APAC business upon its disposition.

Current liabilities


152


Current liabilities increased primarily due to higher deferred revenue from advance customer payments and milestone billings.

Long-term debt


(43)


Long-term debt decreased due to net repayment of the RCF.

Total shareholders' equity


126


Total shareholders' equity increased primarily due to net earnings for the nine months ended September 30, 2026, partially offset by dividend payments in 2026.


Quarterly Summary

($ millions, except per share amounts and ratios)

Q3 2026


Q2 2026


Q1 2026


Q4 2025


Q3 2025


Q2 2025


Q1 2025


Q4 2024


ES backlog

$

2,136


$

1,453


$

1,265


$

1,110


$

1,071


$

1,227


$

1,206


$

1,280


ES bookings


1,024


488


483


377


339


365


205


301


ES book-to-bill ratio


3.0


1.6


1.5


1.1


0.7


1.1


0.7


1.1


EI contract backlog


1,182


1,193


1,283


1,321


1,370


1,462


1,497


1,545


Revenue


623


582


584


627


777


615


552


561


GM


142


139


145


143


172


139


128


140


GM before D&A


176


173


179


177


206


175


161


174


SG&A


64


81


79


83


71


61


57


92


EBIT


79


57


73


43


82


92


66


47


EBITDA


117


94


110


83


122


134


105


92


Adjusted EBITDA


129


128


137


123


145


130


113


121


Net earnings (loss)


55


30


43


(57

)


37


60


24


15


Earnings (loss) per share – basic


0.45


0.25


0.35


(0.47

)


0.30


0.49


0.19


0.12


Earnings (loss) per share – diluted


0.45


0.25


0.35


(0.47

)


0.30


0.49


0.19


0.12


FFO1


96


87


95


60


115


89


62


74


CFO2


147


89


32


179


74


(4

)


96


113


Free cash flow


102


32


15


141


43


(39

)


85


76


Cash dividends declared per share (CAD $)3


0.0425


0.0425


0.0425


0.0425


0.0375


0.0375


0.0375


0.0375


CAPEX – Maintenance & PP&E


16


18


9


20


18


11


8


21


CAPEX – Growth


26


35


7


14


15


23


6


11


1 FFO or “Funds from Operations” is also referred to by Enerflex as “Cash provided by operating activities before net change in working capital and other”.

2 CFO or “Cash flow from Operations” is also referred to by Enerflex as “Cash provided by (used in) operating activities”.

3 Cash dividend declared represents the declaration in the quarter. Starting October 2026, the dividend is declared in U.S. Dollars.


img109187306_3.jpg M-20  Q3 2026 Report


Capital Resources

On September 30, 2026, Enerflex had 122,102,883 common shares outstanding. Enerflex has not established a formal dividend policy. Subsequent to September 30, 2026, Enerflex declared a quarterly dividend of US$0.035 per common share, payable on November 25, 2026 to shareholders of record on November 12, 2026. The Board will continue to evaluate dividend payments on a quarterly basis based on availability of cash flow, anticipated market conditions, and the general needs of the business.

At September 30, 2026, the Company had drawings of $149 million against the RCF (December 31, 2025 – $193 million). The weighted average interest rate on the RCF for the nine months ended September 30, 2026 was 4.8% (Twelve months ended December 31, 2025 – 5.6%).

The composition of the borrowings on the 2031 Notes and RCF were as follows:


Maturity Date


September 30, 2026


December 31, 2025


2031 Notes


January 15, 2031


$

400


$

400


Drawings on the RCF


June 30, 2029


149


193


549


593


Deferred transaction costs


(10

)


(11

)

Long-term debt


$

539


$

582


Non-current portion of long-term debt


$

539


$

582


Long-term debt


$

539


$

582


At September 30, 2026, without considering renewal at similar terms, the USD equivalent principal payments due over the next five years are $549 million.

Legal Proceedings

In the normal course of business, the Company and certain of its subsidiaries are involved in or subject to lawsuits, claims, and other legal proceedings that seek, among other things, compensation for alleged personal injury, breach of contract, property damage or other losses, punitive damages, civil penalties, or injunctive or declaratory relief. Some lawsuits, claims, and legal proceedings involve acquired or disposed assets with respect to which a third party, the Company, or its subsidiary retains liability or indemnifies the other party for conditions that existed prior to the transaction. In accordance with applicable accounting guidance, Enerflex and its subsidiaries accrue reserves for outstanding lawsuits, claims, and proceedings when it is probable that a liability has been incurred and that such liability can be reasonably estimated. The Company does not currently expect that any of the outstanding lawsuits, claims, or legal proceedings will have a material adverse effect on Enerflex, including its consolidated financial position, results of operations, or cash flows. Enerflex’s expectations and estimates are based on information known about the legal matters and its experience in contesting, litigating, and settling similar matters, however the eventual results of outstanding lawsuits, claims, and other legal proceedings are inherently uncertain, and there can be no assurance that monetary damages, fines, penalties, or injunctive relief resulting from adverse judgments or settlements in some or all of the Company’s or its subsidiaries’ outstanding lawsuits, claims, or legal proceedings will not have a material adverse effect on Enerflex, including its consolidated financial position, results of operations, or cash flows. The Company will reassess the probability and estimability of contingent losses as new information becomes available.


img109187306_4.jpg

M-21 img109187306_5.jpg


As previously disclosed, in response to a fatal attack at an adjacent site in Q2 2024, Enerflex declared Force Majeure on an international ES project, suspended activity at the project site, and demobilized its personnel. Enerflex subsequently received notice from its customer purporting to terminate the project contract and commencing arbitration proceedings against Enerflex alleging breach of contract. In Q4 2024, Enerflex delivered notice to the customer terminating the project contract. As part of the arbitration proceedings, Enerflex has brought a counterclaim against the customer to recover amounts owing to Enerflex following Enerflex’s termination of the project contract. Pursuant to the rules for arbitration agreed between Enerflex and its customer, the content of the proceedings is confidential and not otherwise publicly available. In Q2 2025, the customer filed its Statement of Case in the arbitration asserting various claims against, and seeking material monetary damages from, Enerflex. In Q3 2025, the Company filed its Statement of Defence and Counterclaim against the customer. In accordance with the arbitration timeline, the customer filed its Statement of Reply and Defence to Counterclaim in Q4 2025 to which the Company responded in Q1 2026 by filing its Statement of Rejoinder and Reply to Defence to Counterclaim. Enerflex disputes the customer’s claims and asserts that it acted in accordance with the project contract and that its declaration of Force Majeure and its subsequent termination of the project were proper. Given the current stage of the arbitration and the inherent uncertainty of arbitration, the final outcome of the arbitration is unknown. While the Company is pursuing recovery of amounts it believes are owed, it is possible that the Company may not prevail on its counterclaims or in defending against the customer’s claims. In those circumstances, there can be no assurance that the outcome will not have a material adverse effect on Enerflex, including on its consolidated financial position, results of operations, or cash flows. Through the ongoing arbitration proceedings, Enerflex intends to continue vigorously defending itself against the customer’s claims while pursuing its own counterclaims.

As at September 30, 2026, the carrying value of the remaining assets associated with the project on the Company’s consolidated statement of financial position was $161 million. Notwithstanding its termination of the project contract, Enerflex maintains a $31 million Letter of Credit in support of its obligation under the project contract. Enerflex would view any drawing of the financial security in the prevailing circumstances as improper and would be considered as an additional amount owed by the customer.


img109187306_3.jpg M-22  Q3 2026 Report


Disclosure Controls and Procedures

Management is responsible for establishing and maintaining adequate disclosure controls and procedures (“DC&P”). DC&P are designed to ensure that information required to be disclosed in Enerflex’s financial reports is recorded, processed, summarized, and reported to the Company’s Management, including its Chief Executive Officer and Chief Financial Officer, as appropriate, to allow timely decisions regarding required disclosure. Management recognizes that any system of controls and procedures, no matter how well designed and operated, can provide only reasonable assurance of achieving the desired control objectives. Due to the inherent limitations of control systems, not all misstatements may be detected. For example, there may be faulty judgments in decision-making or breakdowns can occur because of a simple error or mistake. Additionally, controls can be circumvented by the acts of individuals, by collusion of two or more people, or by Management override of the control. Controls and procedures can only provide reasonable, not absolute, assurance that the desired control objectives have been met.

Based on the Company’s evaluation, Management concluded that its DC&P were effective as of September 30, 2026.

Internal Control Over Financial Reporting

Management is also responsible for establishing and maintaining adequate internal control over financial reporting (“ICFR”). ICFR is a framework designed to provide reasonable assurance regarding the preparation and reliability of the unaudited interim condensed consolidated financial statements for external reporting in accordance with IFRS Accounting Standards.

Under the supervision, and with the participation of Enerflex’s Management, including the Chief Executive Officer and Chief Financial Officer, the Company conducted an evaluation of the effectiveness of its ICFR and DC&P as of September 30, 2026, the end of the period covered by this MD&A. In conducting this evaluation, Management used the criteria described in Internal Control—Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (the “COSO 2013 Framework”).

Based on the Company’s evaluation, Management concluded that its ICFR were effective as of September 30, 2026.

Changes in Internal Control Over Financial Reporting:

Management regularly reviews its system of ICFR and makes changes to the Company’s processes and systems to improve controls and increase efficiency. There have been no changes in the design of the Company’s ICFR during the three and nine months ended September 30, 2026, that would materially affect, or is reasonably likely to materially affect, the Company’s ICFR.

Subsequent Events

Subsequent to September 30, 2026, Enerflex’s Board of Directors elected to declare the Company’s quarterly dividend in U.S. Dollars. The Company approved an increase of approximately 17% to US$0.035 per common share, payable on November 25, 2026 to shareholders of record on November 12, 2026. The Board will continue to evaluate dividend payments on a quarterly basis based on availability of cash flow, anticipated market conditions, and the general needs of the business.

Subsequent to quarter-end, Enerflex secured an award to supply over 1.0 gigawatts of low emission BTM natural gas-fired power generation for a North American data center development. Combined with additional project awards, including approximately 450 megawatts announced on October 1, 2026, Enerflex’s backlog of BTM natural gas-fired power generation now exceeds 1.75 gigawatts, with deliveries extending through 2028.


img109187306_4.jpg

M-23 img109187306_5.jpg


Forward-Looking Statements

This MD&A contains “forward-looking information” within the meaning of applicable Canadian securities laws and “forward-looking statements” (and together with “forward-looking information”, “FLI”) within the meaning of the safe harbor provisions of the US Private Securities Litigation Reform Act of 1995. FLI relates Management’s expectations about future events, results of operations, and the future performance (both financial and operational) and business prospects of Enerflex. All statements other than statements of historical fact are FLI. FLI may contain, but is not limited to, words such as "anticipate", "future", “create”, “continue”, “expect”, “intend”, “propose”, “might”, “may”, “will”, “generate”, "should", "could", "would", "believe", "predict", "forecast", “future”, “opportunity”, "pursue", "potential", "objective", “focus”, “endeavor”, “commit”, “target”, “growth”, or “ensure”, or the inverse of such terms or similar expressions suggesting future conditions, events, or expectations. In particular, this MD&A includes (without limitation) FLI pertaining to:

•
disclosures under the heading “Outlook” including:
o
favorable multi-year fundamentals across Enerflex’s core markets, supported by increasing natural gas production and growing demand for reliable power and energy infrastructure;
o
operating results will continue to be underpinned by the highly contracted EI product line and recurring nature of AMS;
o
the Company’s ES backlog providing strong visibility into future revenue generation and business activity levels extending into 2028;
o
Enerflex’s ability to capitalize on growing demand for BTM power generation solutions, both in the initial equipment scope and in future commissioning, installation, operations, maintenance, and digital service offerings through Enerflex’s ReliaCore™ Asset Performance Management ecosystem, and the timing associated therewith, if at all;
o
expectations in respect of organic capital expenditure during 2026 of $185 million to $195 million, including (1) organic growth capital expenditures of approximately $100 million; (2) maintenance capital expenditures of approximately $55 million; and (3) PP&E and infrastructure investments of $30 million to $40 million;
o
targeted customer-supported fleet growth of 10% to 15% during 2026;
o
Enerflex’s ability to secure long-lead time components to support fleet growth into 2030, and the timing associated therewith, if at all;
o
the shift of some forecasted maintenance capital expenditures from 2026 into 2027;
o
expectations that approximately $85 million will be invested in Enerflex’s ES facilities and capabilities during 2027 and that those investments, combined with ongoing initiatives to enhance collaboration, leverage scale, improve operational efficiency, and solidify capabilities, will significantly increase the revenue capacity of Enerflex’s ES business line, and the timing associated therewith, if at all; and
o
the ability for Enerflex to identify and successfully execute selective, disciplined tuck-in acquisitions and the timing associated therewith, if at all;
•
the Company’s backlog and the project awards that make up the backlog;
•
the ES backlog and expectations as to future revenue generation and business activity levels;
•
the Company’s backlog of BTM natural gas-fired power generation and the ability for the Company to execute on the projects and complete deliveries extending through 2028;
•
that the Board will set the Company’s quarterly dividends based on the availability of cash flow, anticipated market conditions, and the general needs of the business and that this will support expectations regarding the ability of the Company to continue to pay a sustainable quarterly dividend;


img109187306_3.jpg M-24  Q3 2026 Report


•
the ES product line’s ability to generate predictable revenue in the near-term;
•
the book-to-bill ratio of 3.0x during the three months ended September 30, 2026 supports near-term revenue visibility and reflects a stable demand environment;
•
the availability of free cash generated and that such cash may be used to fund non-operating activities including dividend payments, share repurchases, and other non-mandatory debt repayments, if any;
•
expectations that cash flows from operations in 2026, together with cash and cash equivalents on hand and currently available credit facilities, will be more than sufficient to fund Enerflex’s requirements for investments in working capital and capital assets;
•
the ability of the Company to continue to meet its covenant requirements of its funded debt, including the secured RCF and 2031 Notes;
•
the potential for the Company to incur costs related to the construction of EI assets determined to be finance leases; and
•
expectations that potential liabilities that may arise in connection with outstanding lawsuits, arbitrations or other legal proceedings will not have a material adverse effect on Enerflex, including its consolidated financial position, results of operations or cash flows.


FLI is based on assumptions, estimates, and analysis made in light of the Company’s experience and its perception of trends, current conditions, and expected developments, including assumptions and estimates as to associated timing and costs, as well as other factors that are believed by the Company to be reasonable and relevant in the circumstances. FLI involves known and unknown risks and uncertainties and other factors which are difficult to predict, including, without limitation:

•
expectations that acquisition opportunities will be available to the Company, the Company can evaluate and execute on such opportunities, and that adequate financial capacity and liquidity will remain available, all required regulatory, contractual and third-party approvals will be received, received in a timely manner, and on conditions acceptable to the Company, if any, and any acquisitions can be successfully integrated;
•
the ability of the Company to proactively manage the ES business line in response to near-term risks and uncertainties, including tariffs and commodity price volatility;
•
natural gas and associated liquids and produced water volumes across Enerflex’s global footprint will increase in line with expectations;
•
market conditions, customer activity, and industry fundamentals will support stable demand across Enerflex’s product lines and geographic regions throughout 2026;
•
the high level of contractual commitments within the EI product line and the predictable, recurring revenue from AMS will continue;
•
existing and strong commercial relationships with customers will continue;
•
existing customer contracts within the EI product line will remain in effect and with no material cancellations or renegotiations over their remaining terms;
•
risks related to lawsuits, arbitrations or other legal proceedings;
•
the execution of projects within the ES product line will proceed as scheduled, supported by the timely availability of required equipment, long-lead components, manufacturing capacity, and third-party supply chain support, and the conversion to revenue will proceed without significant delays or cancellations;
•
the Company’s backlog providing strong visibility into future revenue generation and business activity levels;


img109187306_4.jpg

M-25 img109187306_5.jpg


•
no significant unforeseen cost overruns or project delays;
•
the fulfillment by our customers of the terms of their contracts;
•
the Company will successfully execute operational excellence initiatives and realize anticipated productivity improvements across its global operations;
•
Enerflex will maintain sufficient cash flow, profitability, and financial flexibility to support the ongoing payment of a sustainable quarterly cash dividend, subject to market conditions, operational performance, and board approval;
•
Enerflex will maintain sufficient financial flexibility to execute on its capital allocation priorities; and
•
other factors, many of which are beyond the control of Enerflex.

Readers are cautioned that the foregoing list of assumptions and risk factors should not be construed as exhaustive. While the Company believes that there is a reasonable basis for the FLI included in this MD&A, as a result of known and unknown risks, uncertainties, and other factors, Enerflex’s actual results, performance, or achievements could differ and such differences could be material from those expressed in, or implied by, these statements. The FLI included in this MD&A should not be unduly relied upon as a number of factors could cause actual results to differ materially from the results discussed in these forward-looking statements, including but not limited to: the ability to maintain desirable financial ratios; the ability to access various sources of debt and equity capital, generally, and on acceptable terms, if at all; the ability to utilize tax losses in the future; the ability to maintain relationships with partners and to successfully manage and operate the business; risks associated with technology and equipment, including potential cyber attacks; the occurrence of unexpected events such as pandemics, war, terrorist threats, and the instability resulting therefrom; risks associated with existing and potential future lawsuits, arbitrations or other legal proceedings, shareholder proposals, and regulatory actions; and those factors referred to under the heading "Risk Factors" in (i) Enerflex's AIF for the year ended December 31, 2025 and Enerflex’s 2025 Annual Report; and (ii) in other filings with Canadian securities regulators and the SEC, copies of which are available under the electronic profile of the Company on SEDAR+ and EDGAR at www.sedarplus.ca and www.sec.gov/edgar, respectively.

This MD&A contains information that may constitute future-oriented financial information or financial outlook information ("FOFI") about Enerflex and its prospective financial performance, financial position, or cash flows, all of which is subject to the same assumptions, risk factors, limitations, and qualifications as set forth above. Except as otherwise stated herein, the FOFI included in this MD&A was made and approved by Management and the Board as of the date hereof. Readers are cautioned that the assumptions used in the preparation of such information, although considered reasonable at the time of preparation, may prove to be imprecise or inaccurate and, as such, undue reliance should not be placed on FOFI. The Company’s actual results, performance and achievements could differ materially from those expressed in, or implied by, FOFI. The inclusion of FOFI in this MD&A is to provide readers with a more complete perspective on the Company’s future operations and Management's current expectations regarding the Company’s future performance. Readers are cautioned that such information may not be appropriate for other purposes.

The FLI and FOFI contained herein is expressly qualified in its entirety by the above cautionary statement and are given as of the date of this MD&A. Other than as required by law, Enerflex disclaims any intention or obligation to update or revise any FLI or FOFI, whether as a result of new information, future events, or otherwise.


img109187306_3.jpg M-26  Q3 2026 Report