Classification: Avery Dennison - Public 1High-Value Category Investor Showcase 2026 Third Quarter 2026 Financial Review and Analysis (preliminary, unaudited) October 29, 2026 Supplemental Presentation Materials Unless otherwise indicated, comparisons are to the same period in the prior year.
2October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public Certain statements contained in this document are "forward-looking statements" intended to qualify for the safe harbor from liability established by the Private Securities Litigation Reform Act of 1995. These forward-looking statements, and financial or other business targets, are subject to certain risks and uncertainties. We believe that the most significant risk factors that could affect our financial performance in the near term include: (i) the impact on underlying demand for our products from global economic conditions, tariffs, geopolitical uncertainty, and changes in environmental standards, regulations and preferences; (ii) competitors’ actions, including pricing, expansion in key markets, and product offerings; (iii) the cost and availability of raw materials; (iv) the degree to which higher costs can be offset with productivity measures and/or passed on to customers through price increases, without a significant loss of volume; (v) foreign currency fluctuations; and (vi) the execution and integration of acquisitions. Actual results and trends may differ materially from historical or anticipated results depending on a variety of factors, including but not limited to, risks and uncertainties related to the following: ● International Operations – worldwide economic, social, geopolitical and market conditions; changes in geopolitical conditions, including those related to trade relations and tariffs, China, recent conflicts involving the U.S., Israel and Iran and related hostilities in the Middle East, the Russia-Ukraine war, and the Israel-Hamas war; fluctuations in foreign currency exchange rates; and other risks associated with international operations, including in emerging markets ● Our Business – fluctuations in demand affecting sales to customers; fluctuations in the cost and availability of raw materials and energy; changes in our markets due to competitive conditions, technological developments, laws and regulations, and customer preferences; environmental regulations and sustainability trends; the impact of competitive products and pricing; the execution and integration of acquisitions; selling prices; customer and supplier concentrations or consolidations; the financial condition of distributors; outsourced manufacturers; product and service quality claims; restructuring and other cost reduction actions; our ability to generate sustained productivity improvement and our ability to achieve and sustain targeted cost reductions; the timely development and market acceptance of new products, including sustainable or sustainably-sourced products; our investment in development activities and new production facilities; the collection of receivables from customers; and our sustainability and governance practices ● Information Technology – disruptions in information technology systems; cybersecurity events or other security breaches; and successful installation of new or upgraded information technology systems ● Income Taxes – fluctuations in tax rates; changes in tax laws and regulations, and uncertainties associated with interpretations of such laws and regulations; outcome of tax audits; and the realization of deferred tax assets ● Human Capital – recruitment and retention of employees and collective labor arrangements ● Our Indebtedness – our ability to obtain adequate financing arrangements and maintain access to capital; credit rating risks; fluctuations in interest rates; and compliance with our debt covenants ● Ownership of Our Stock – potential significant variability of our stock price and amounts of future dividends and share repurchases ● Legal and Regulatory Matters – protection and infringement of our intellectual property and the impact of legal and regulatory proceedings, including with respect to anti-corruption, environmental, health and safety, and trade compliance ● Other Financial Matters – fluctuations in pension costs and goodwill impairment For a more detailed discussion of these factors, see “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in our 2025 Form 10-K, filed with the Securities and Exchange Commission on February 25, 2026, and subsequent quarterly reports on Form 10-Q. The forward-looking statements included in this document are made only as of the date of this document, and we undertake no obligation to update these statements to reflect subsequent events or circumstances, other than as may be required by law. Safe Harbor Statement
3October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public Use of Non-GAAP Financial Measures This presentation contains certain non-GAAP financial measures as defined by SEC rules. We report our financial results in conformity with accounting principles generally accepted in the United States of America, or GAAP, and also communicate with investors using certain non-GAAP financial measures. These non-GAAP financial measures are not in accordance with, nor are they a substitute for or superior to, the comparable GAAP financial measures. These non-GAAP financial measures are intended to supplement the presentation of our financial results prepared in accordance with GAAP. We use these non-GAAP financial measures internally to evaluate trends in our underlying performance, as well as to facilitate comparisons with the results of competitors for quarters and year-to-date periods, as applicable. Based on feedback from investors and financial analysts, we believe that the supplemental non-GAAP financial measures we provide are also useful to their assessments of our performance and operating trends, as well as liquidity. In accordance with Regulations G and S-K, reconciliations of non-GAAP financial measures from the most directly comparable GAAP financial measures, including limitations associated with these non-GAAP financial measures, are provided in the appendix to this document and/or the financial schedules accompanying the earnings news release for the quarter (see Attachments A-4 through A-8 to news release dated October 29, 2026). Our non-GAAP financial measures exclude the impact of certain events, activities or strategic decisions. The accounting effects of these events, activities or decisions, which are included in the GAAP financial measures, may make it more difficult to assess our underlying performance in a single period. By excluding the accounting effects, positive or negative, of certain items (e.g., restructuring charges, outcomes of certain legal matters and settlements, certain effects of strategic transactions and related costs, losses from debt extinguishments, gains or losses from curtailment or settlement of pension obligations, gains or losses on sales of certain assets, gains or losses on venture and other investments, currency adjustments due to highly inflationary economies, and other items), we believe that we are providing meaningful supplemental information that facilitates an understanding of our core operating results and liquidity measures. While some of the items we exclude from GAAP financial measures recur, they tend to be disparate in amount, frequency or timing. We use the non-GAAP financial measures described below in this presentation. • Sales change ex. currency refers to the increase or decrease in net sales, excluding the estimated impact of foreign currency translation, and, where applicable, currency adjustments for transitional reporting of highly inflationary economies and the reclassification of sales between segments. Additionally, where applicable, sales change ex. currency is also adjusted for the estimated impact of extra days in our fiscal year and the calendar shift resulting from extra days in the prior fiscal year. The estimated impact of foreign currency translation is calculated on a constant currency basis, with prior-period results translated at current-period average exchange rates to exclude the effect of foreign currency fluctuations. Our 2025 fiscal year began on December 29, 2024 and ended on December 31, 2025; fiscal years 2026 and beyond are coincident with the calendar year, beginning on January 1 and ending on December 31. • Organic sales change refers to sales change ex. currency, excluding the estimated impact of acquisitions and product line divestitures. We believe that sales change ex. currency and organic sales change assist investors in evaluating the sales change from the ongoing activities of our businesses and enhance their ability to evaluate our results from period to period. We believe that the following measures assist investors in understanding our core operating trends and comparing our results with those of our competitors. • Adjusted operating income refers to net income adjusted for taxes; other expense (income), net; interest expense; and other non-operating expense (income), net. • Adjusted EBITDA refers to adjusted operating income before depreciation and amortization. • Adjusted operating margin refers to adjusted operating income as a percentage of net sales. • Adjusted EBITDA margin refers to adjusted EBITDA as a percentage of net sales. • Adjusted tax rate refers to the projected full-year GAAP tax rate, adjusted to exclude certain unusual or infrequent events that are expected to significantly impact that rate, such as effects of certain discrete tax planning actions, impacts related to enactments of tax law changes, and other items. • Adjusted net income refers to income before taxes, tax-effected at the adjusted tax rate, and adjusted for tax-effected restructuring charges and other items. • Adjusted net income per common share, assuming dilution (adjusted EPS) refers to adjusted net income divided by the weighted average number of common shares outstanding, assuming dilution. • Net debt to adjusted EBITDA ratio refers to total debt (including finance leases) less cash and cash equivalents, divided by adjusted EBITDA for the last twelve months. We believe that the net debt to adjusted EBITDA ratio assists investors in assessing our leverage position. • Adjusted free cash flow (FCF) refers to cash flow provided by (used in) operating activities, less payments for property, plant and equipment, less payments for software and other deferred charges, plus proceeds from sales of property, plant and equipment, plus (minus) net proceeds from insurance and sales (purchases) of investments. Where applicable, adjusted free cash flow is also adjusted for certain acquisition-related transaction costs, proceeds from company-owned life insurance policies and net cash used for Argentine Blue Chip Swap securities. We believe that adjusted free cash flow assists investors by showing the amount of cash we have available for debt reductions, dividends, share repurchases and acquisitions. • Adjusted free cash flow conversion refers to adjusted free cash flow divided by net income. We believe this measure assists investors in evaluating how efficiently we convert our net income into adjusted free cash flow. This presentation has been furnished (not filed) on Form 8-K with the SEC and may be found on our website at www.investors.averydennison.com.
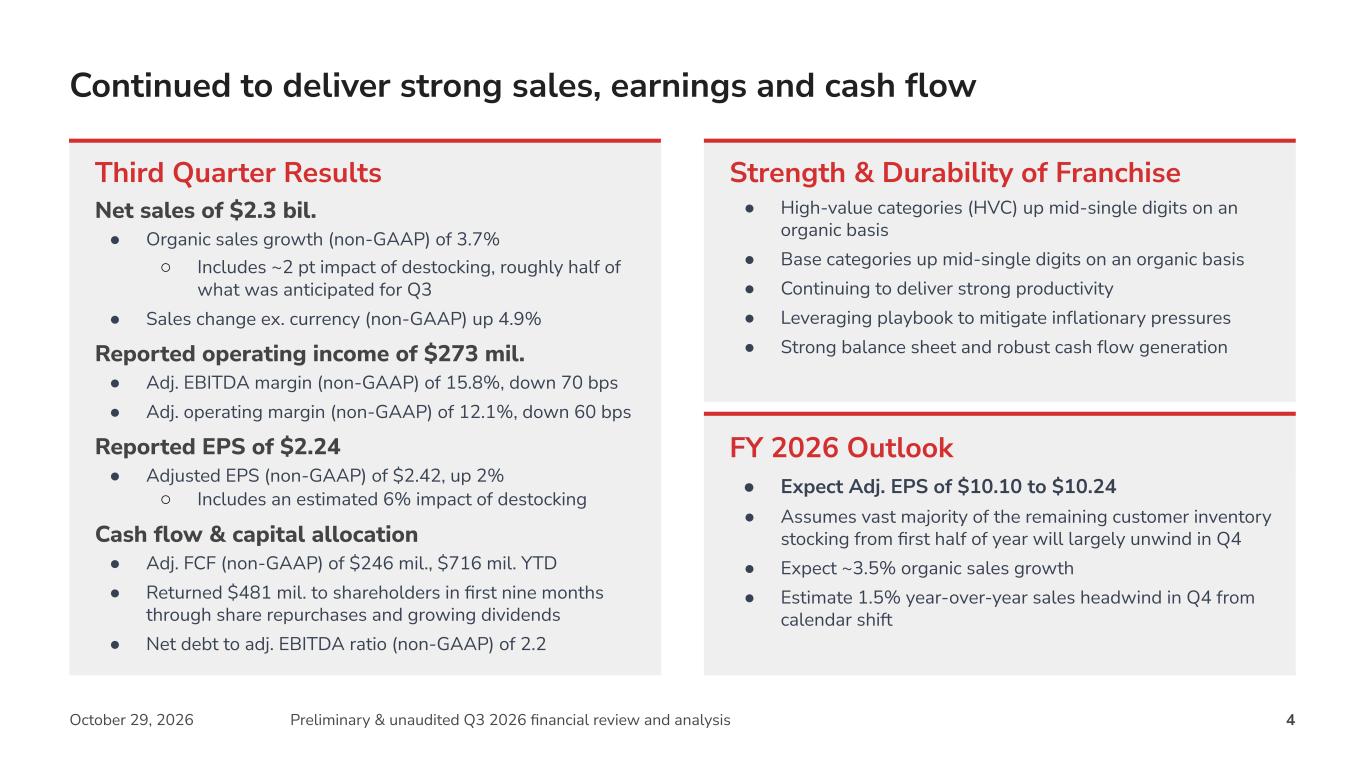
4October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public Continued to deliver strong sales, earnings and cash flow Third Quarter Results Net sales of $2.3 bil. ● Organic sales growth (non-GAAP) of 3.7% ○ Includes ~2 pt impact of destocking, roughly half of what was anticipated for Q3 ● Sales change ex. currency (non-GAAP) up 4.9% Reported operating income of $273 mil. ● Adj. EBITDA margin (non-GAAP) of 15.8%, down 70 bps ● Adj. operating margin (non-GAAP) of 12.1%, down 60 bps Reported EPS of $2.24 ● Adjusted EPS (non-GAAP) of $2.42, up 2% ○ Includes an estimated 6% impact of destocking Cash flow & capital allocation ● Adj. FCF (non-GAAP) of $246 mil., $716 mil. YTD ● Returned $481 mil. to shareholders in first nine months through share repurchases and growing dividends ● Net debt to adj. EBITDA ratio (non-GAAP) of 2.2 Strength & Durability of Franchise ● High-value categories (HVC) up mid-single digits on an organic basis ● Base categories up mid-single digits on an organic basis ● Continuing to deliver strong productivity ● Leveraging playbook to mitigate inflationary pressures ● Strong balance sheet and robust cash flow generation FY 2026 Outlook ● Expect Adj. EPS of $10.10 to $10.24 ● Assumes vast majority of the remaining customer inventory stocking from first half of year will largely unwind in Q4 ● Expect ~3.5% organic sales growth ● Estimate 1.5% year-over-year sales headwind in Q4 from calendar shift
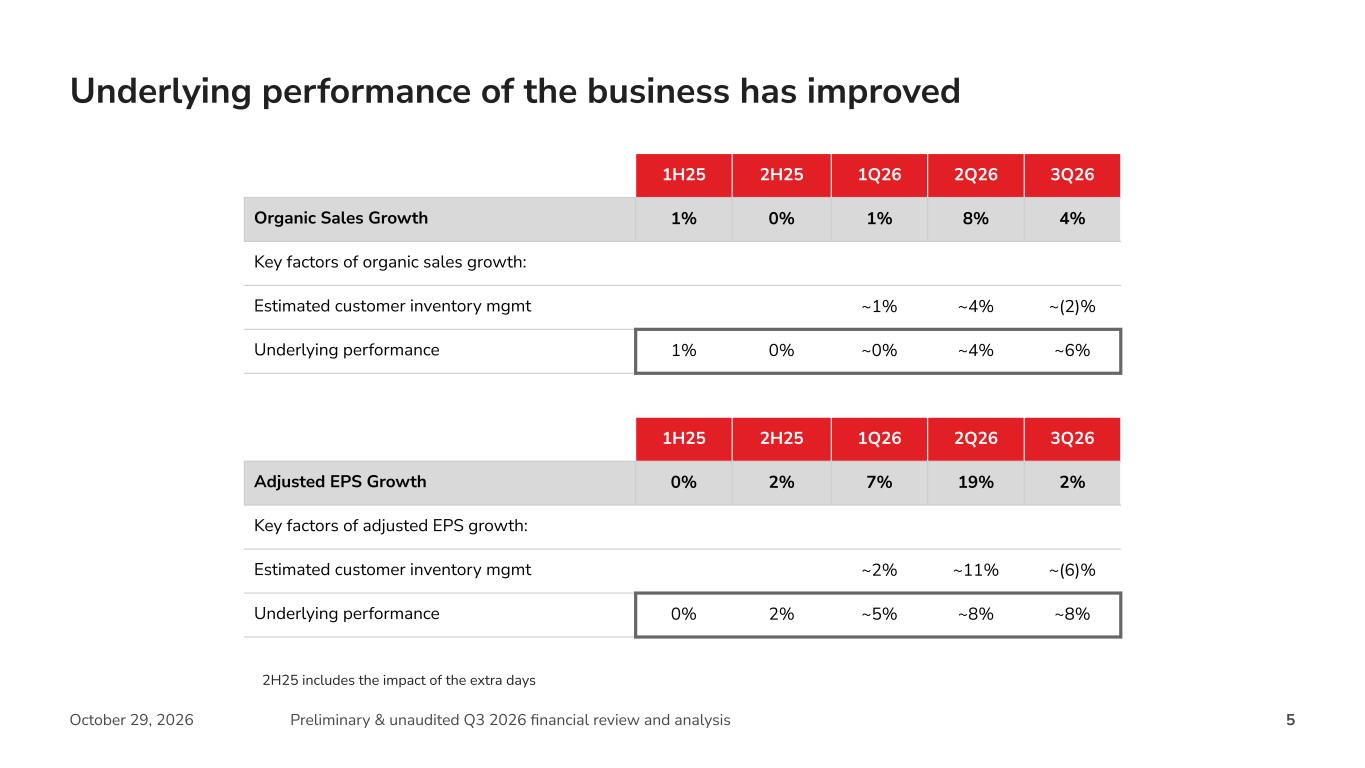
5October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public Underlying performance of the business has improved 2H25 includes the impact of the extra days 1H25 2H25 1Q26 2Q26 3Q26 Organic Sales Growth 1% 0% 1% 8% 4% Key factors of organic sales growth: Estimated customer inventory mgmt ~1% ~4% ~(2)% Underlying performance 1% 0% ~0% ~4% ~6% 1H25 2H25 1Q26 2Q26 3Q26 Adjusted EPS Growth 0% 2% 7% 19% 2% Key factors of adjusted EPS growth: Estimated customer inventory mgmt ~2% ~11% ~(6)% Underlying performance 0% 2% ~5% ~8% ~8%
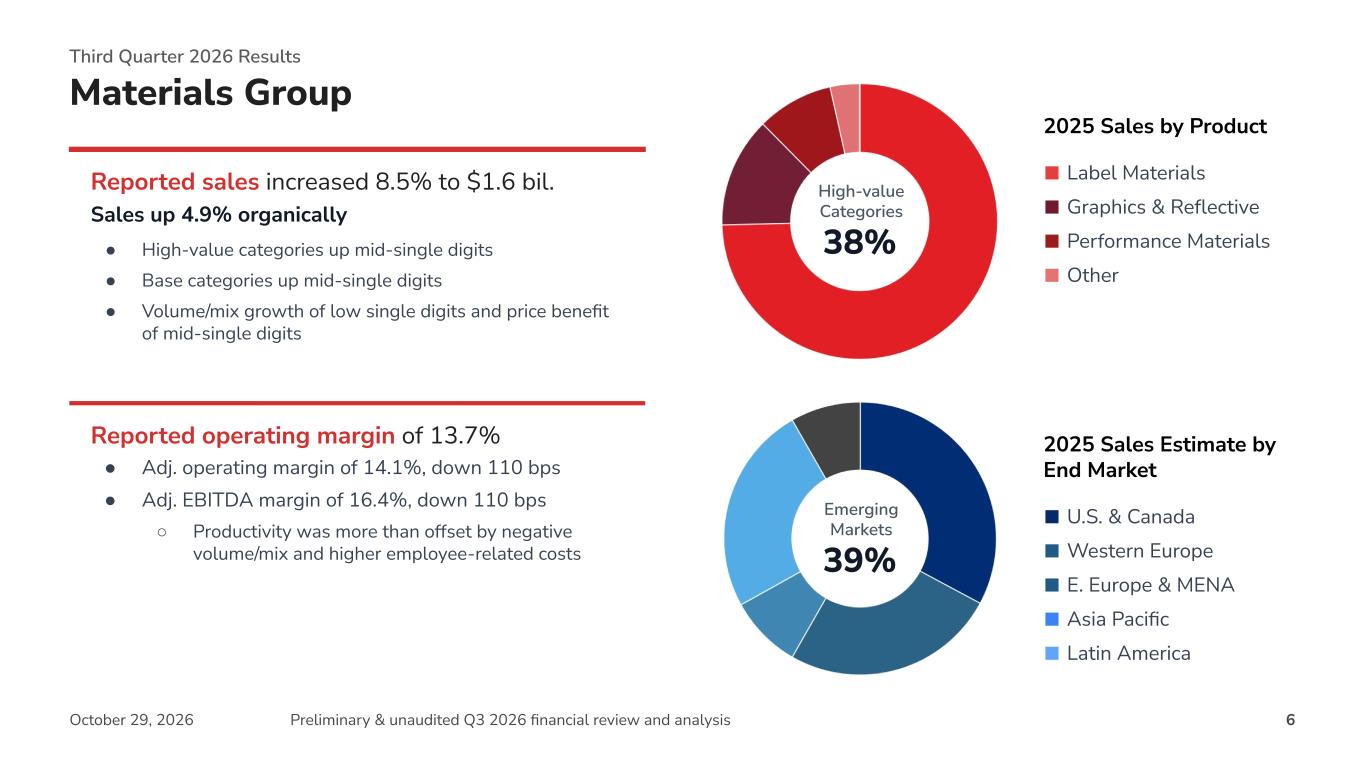
6October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public 2025 Sales by Product ■ Label Materials ■ Graphics & Reflective ■ Performance Materials ■ Other 2025 Sales Estimate by End Market ■ U.S. & Canada ■ Western Europe ■ E. Europe & MENA ■ Asia Pacific ■ Latin America High-value Categories 38% Third Quarter 2026 Results Materials Group Reported sales increased 8.5% to $1.6 bil. Sales up 4.9% organically ● High-value categories up mid-single digits ● Base categories up mid-single digits ● Volume/mix growth of low single digits and price benefit of mid-single digits Reported operating margin of 13.7% ● Adj. operating margin of 14.1%, down 110 bps ● Adj. EBITDA margin of 16.4%, down 110 bps ○ Productivity was more than offset by negative volume/mix and higher employee-related costs Emerging Markets 39%
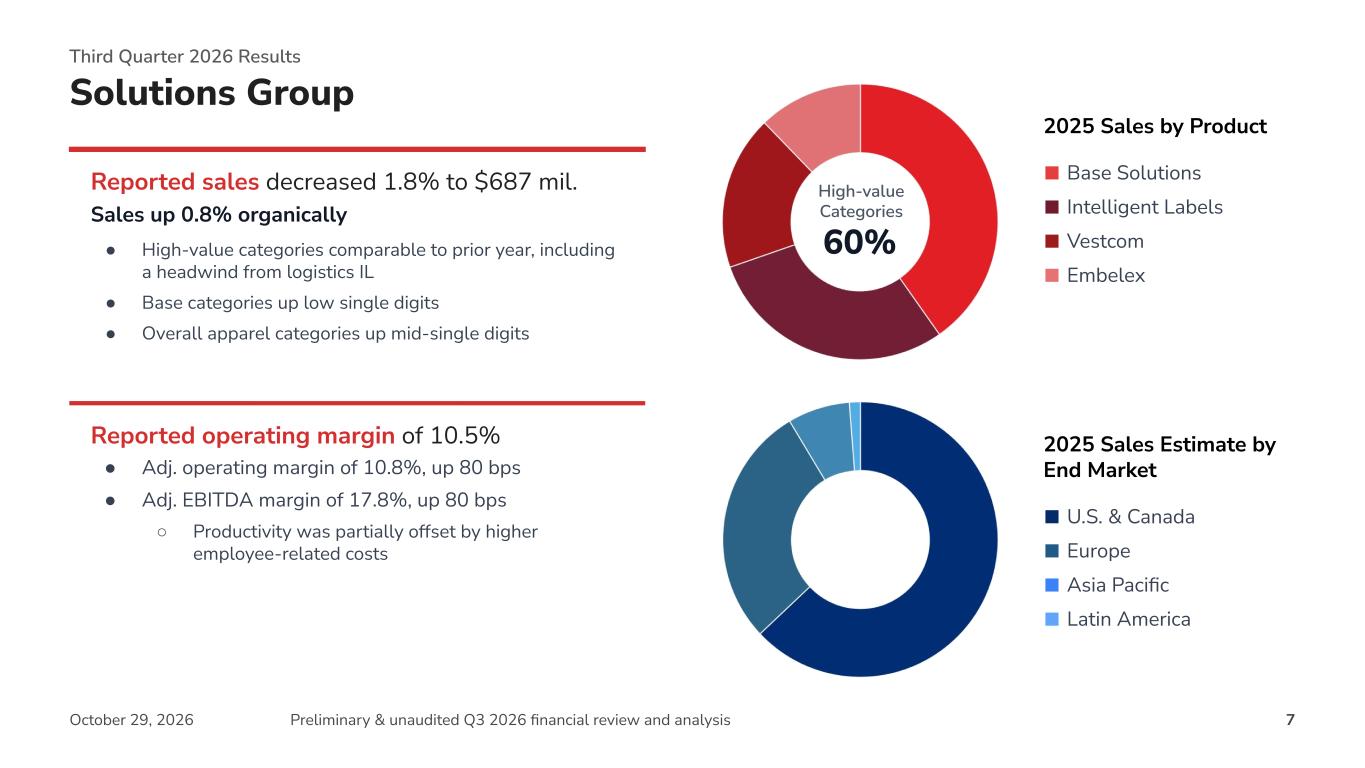
7October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public 2025 Sales by Product ■ Base Solutions ■ Intelligent Labels ■ Vestcom ■ Embelex 2025 Sales Estimate by End Market ■ U.S. & Canada ■ Europe ■ Asia Pacific ■ Latin America High-value Categories 60% Third Quarter 2026 Results Solutions Group Reported sales decreased 1.8% to $687 mil. Sales up 0.8% organically ● High-value categories comparable to prior year, including a headwind from logistics IL ● Base categories up low single digits ● Overall apparel categories up mid-single digits Reported operating margin of 10.5% ● Adj. operating margin of 10.8%, up 80 bps ● Adj. EBITDA margin of 17.8%, up 80 bps ○ Productivity was partially offset by higher employee-related costs
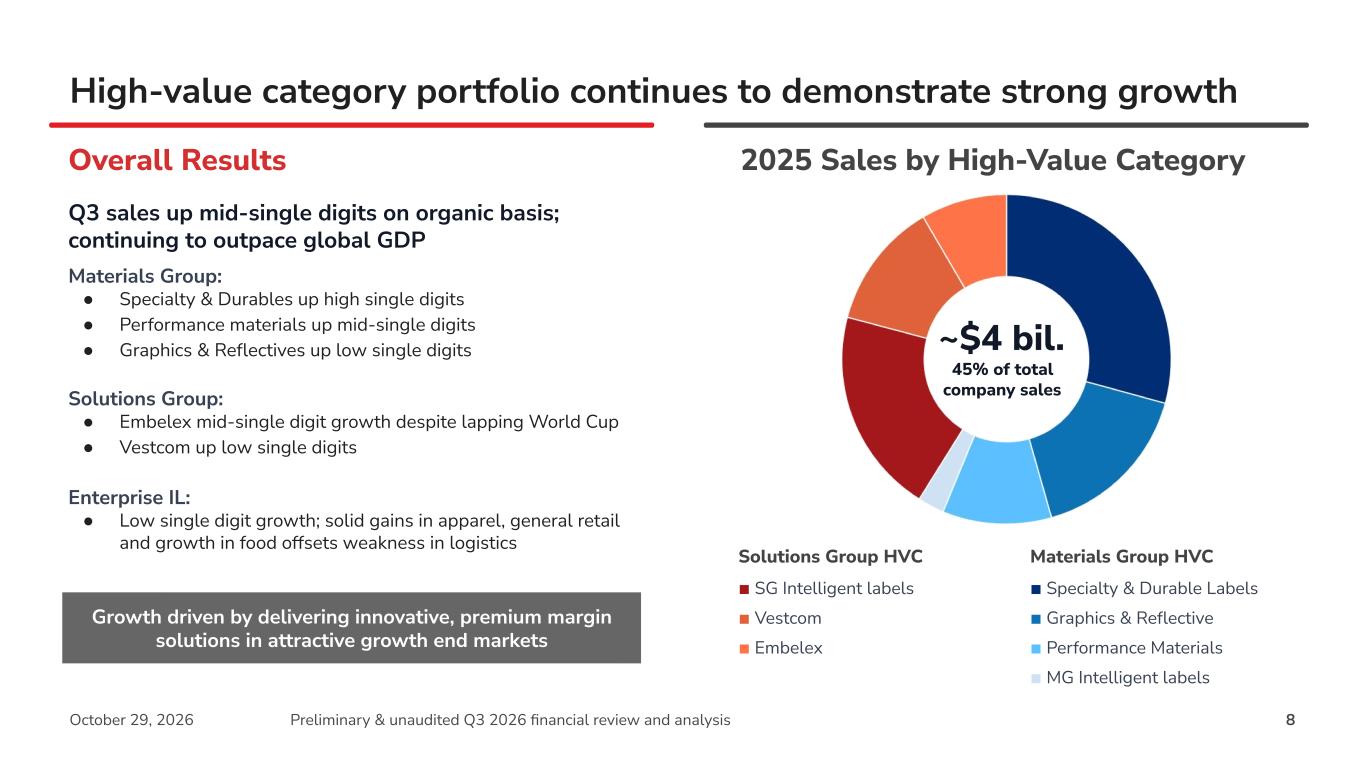
8October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public Solutions Group HVC ■ SG Intelligent labels ■ Vestcom ■ Embelex Materials Group HVC ■ Specialty & Durable Labels ■ Graphics & Reflective ■ Performance Materials ■ MG Intelligent labels Overall Results Q3 sales up mid-single digits on organic basis; continuing to outpace global GDP Materials Group: ● Specialty & Durables up high single digits ● Performance materials up mid-single digits ● Graphics & Reflectives up low single digits Solutions Group: ● Embelex mid-single digit growth despite lapping World Cup ● Vestcom up low single digits Enterprise IL: ● Low single digit growth; solid gains in apparel, general retail and growth in food offsets weakness in logistics Growth driven by delivering innovative, premium margin solutions in attractive growth end markets ~$4 bil. 45% of total company sales 2025 Sales by High-Value Category High-value category portfolio continues to demonstrate strong growth
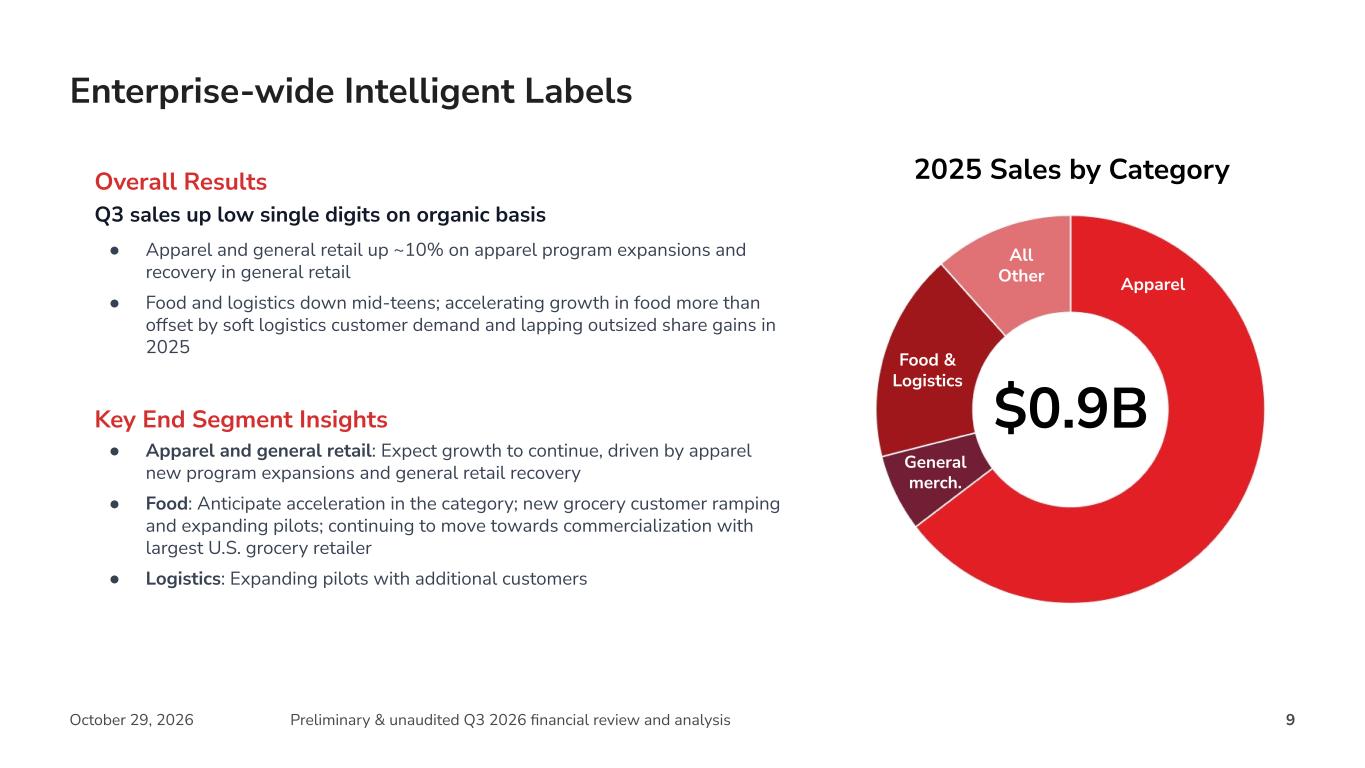
9October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public Enterprise-wide Intelligent Labels 2025 Sales by CategoryOverall Results Q3 sales up low single digits on organic basis ● Apparel and general retail up ~10% on apparel program expansions and recovery in general retail ● Food and logistics down mid-teens; accelerating growth in food more than offset by soft logistics customer demand and lapping outsized share gains in 2025 Key End Segment Insights ● Apparel and general retail: Expect growth to continue, driven by apparel new program expansions and general retail recovery ● Food: Anticipate acceleration in the category; new grocery customer ramping and expanding pilots; continuing to move towards commercialization with largest U.S. grocery retailer ● Logistics: Expanding pilots with additional customers Apparel Food & Logistics All Other General merch. $0.9B
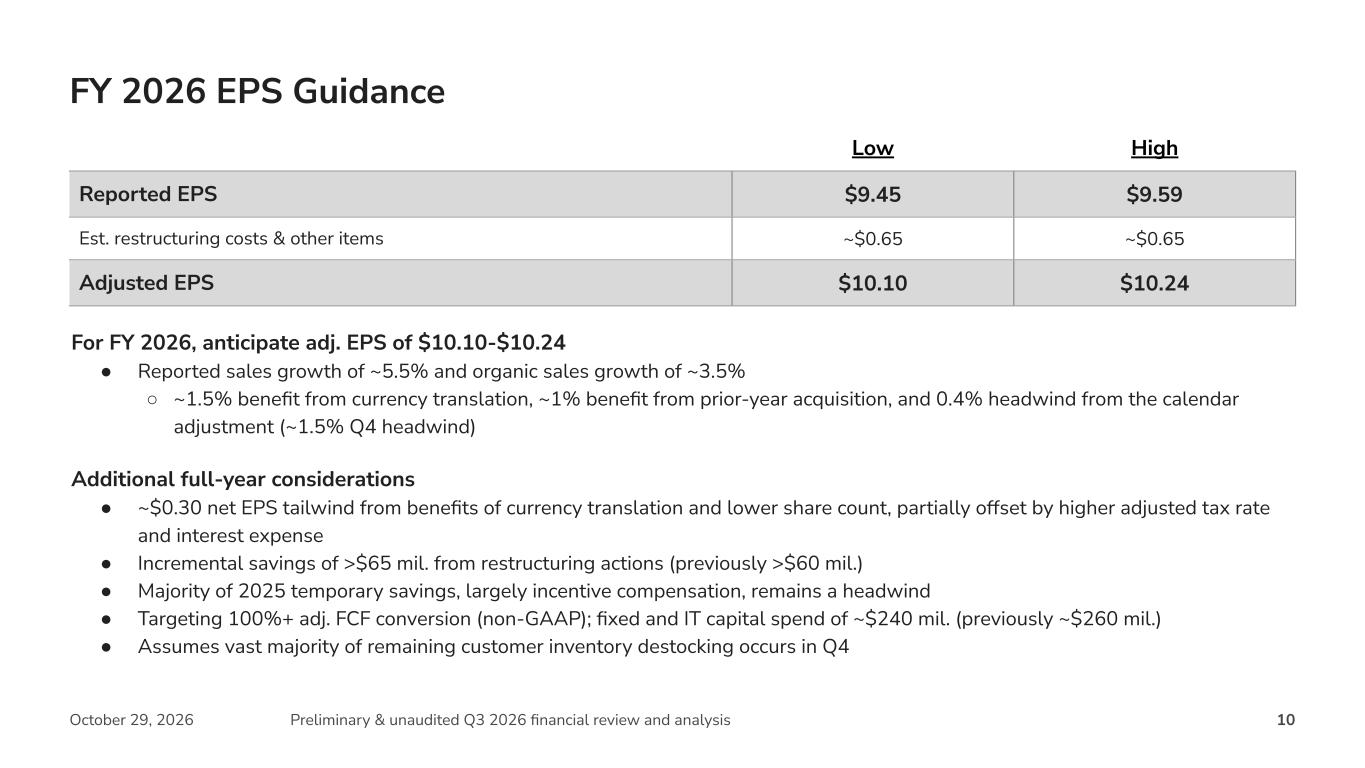
10October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public Low High Reported EPS $9.45 $9.59 Est. restructuring costs & other items ~$0.65 ~$0.65 Adjusted EPS $10.10 $10.24 FY 2026 EPS Guidance For FY 2026, anticipate adj. EPS of $10.10-$10.24 ● Reported sales growth of ~5.5% and organic sales growth of ~3.5% ○ ~1.5% benefit from currency translation, ~1% benefit from prior-year acquisition, and 0.4% headwind from the calendar adjustment (~1.5% Q4 headwind) Additional full-year considerations ● ~$0.30 net EPS tailwind from benefits of currency translation and lower share count, partially offset by higher adjusted tax rate and interest expense ● Incremental savings of >$65 mil. from restructuring actions (previously >$60 mil.) ● Majority of 2025 temporary savings, largely incentive compensation, remains a headwind ● Targeting 100%+ adj. FCF conversion (non-GAAP); fixed and IT capital spend of ~$240 mil. (previously ~$260 mil.) ● Assumes vast majority of remaining customer inventory destocking occurs in Q4
Classification: Avery Dennison - Public 11September 18, 2024 Avery Dennison 2024 Investor Day Appendix Summary Information & Reconciliation of Non-GAAP Financial Measures from GAAP
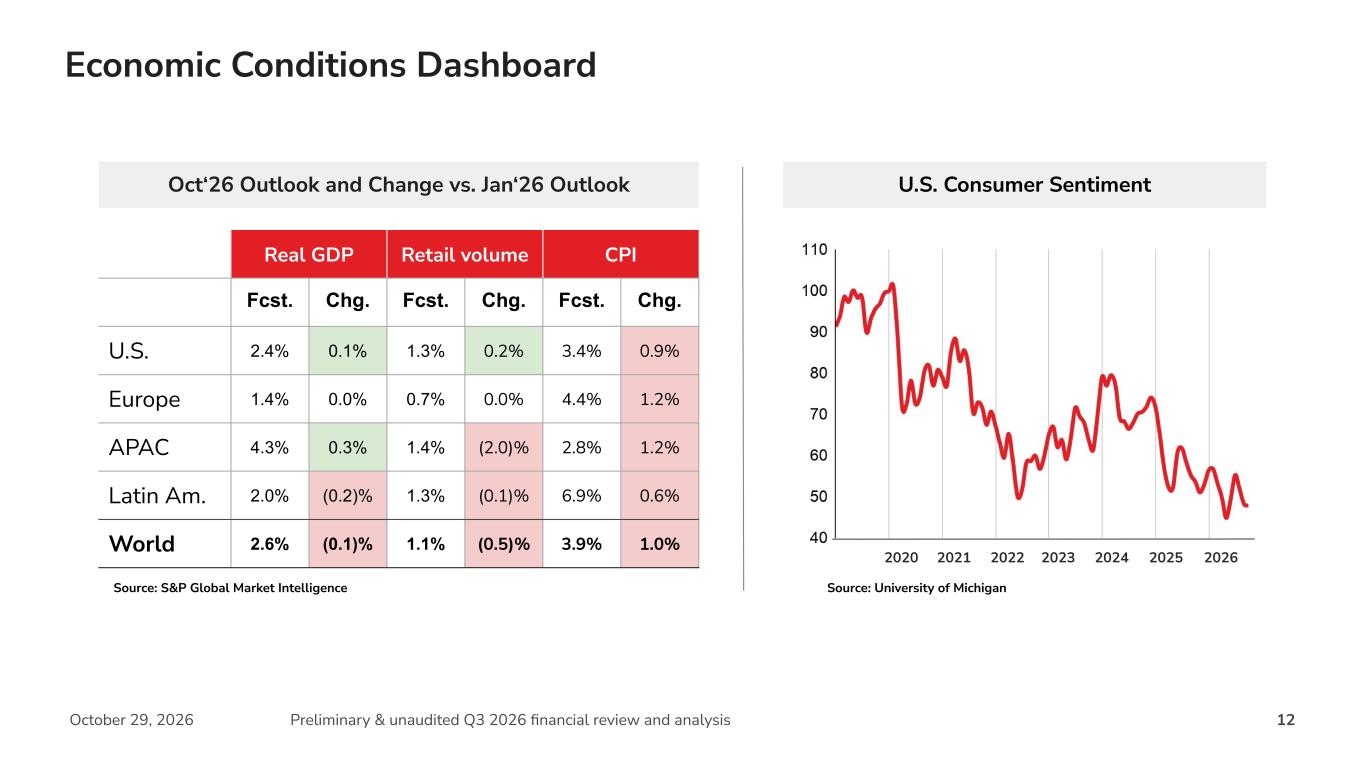
12October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public Source: S&P Global Market Intelligence U.S. Consumer Sentiment Economic Conditions Dashboard 2020 2021 2022 2023 2024 2025 2026 Oct‘26 Outlook and Change vs. Jan‘26 Outlook Source: University of Michigan Real GDP Retail volume CPI Fcst. Chg. Fcst. Chg. Fcst. Chg. U.S. 2.4% 0.1% 1.3% 0.2% 3.4% 0.9% Europe 1.4% 0.0% 0.7% 0.0% 4.4% 1.2% APAC 4.3% 0.3% 1.4% (2.0)% 2.8% 1.2% Latin Am. 2.0% (0.2)% 1.3% (0.1)% 6.9% 0.6% World 2.6% (0.1)% 1.1% (0.5)% 3.9% 1.0%
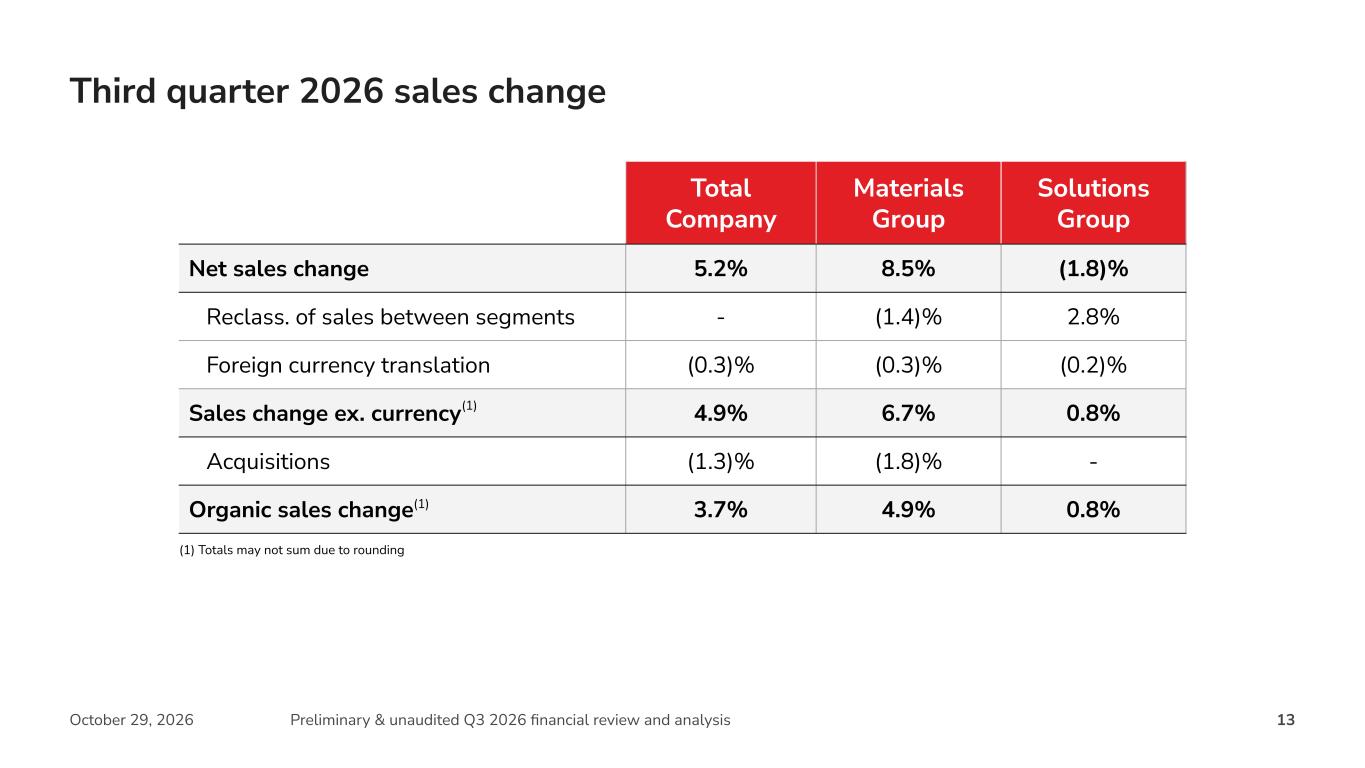
13October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public Third quarter 2026 sales change Total Company Materials Group Solutions Group Net sales change 5.2% 8.5% (1.8)% Reclass. of sales between segments - (1.4)% 2.8% Foreign currency translation (0.3)% (0.3)% (0.2)% Sales change ex. currency 4.9% 6.7% 0.8% Acquisitions (1.3)% (1.8)% - Organic sales change 3.7% 4.9% 0.8% (1) Totals may not sum due to rounding (1) (1)
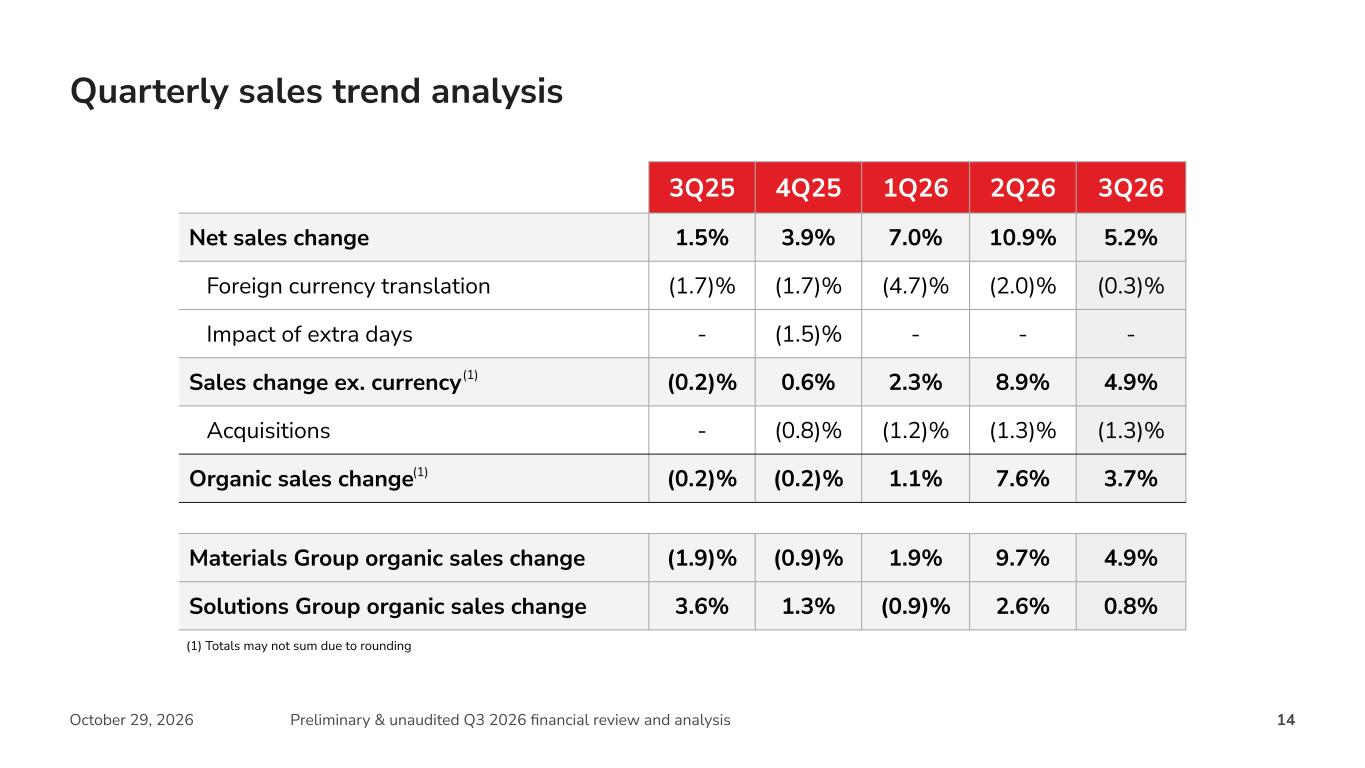
14October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public Quarterly sales trend analysis 3Q25 4Q25 1Q26 2Q26 3Q26 Net sales change 1.5% 3.9% 7.0% 10.9% 5.2% Foreign currency translation (1.7)% (1.7)% (4.7)% (2.0)% (0.3)% Impact of extra days - (1.5)% - - - Sales change ex. currency (0.2)% 0.6% 2.3% 8.9% 4.9% Acquisitions - (0.8)% (1.2)% (1.3)% (1.3)% Organic sales change (0.2)% (0.2)% 1.1% 7.6% 3.7% Materials Group organic sales change (1.9)% (0.9)% 1.9% 9.7% 4.9% Solutions Group organic sales change 3.6% 1.3% (0.9)% 2.6% 0.8% (1) Totals may not sum due to rounding (1) (1)
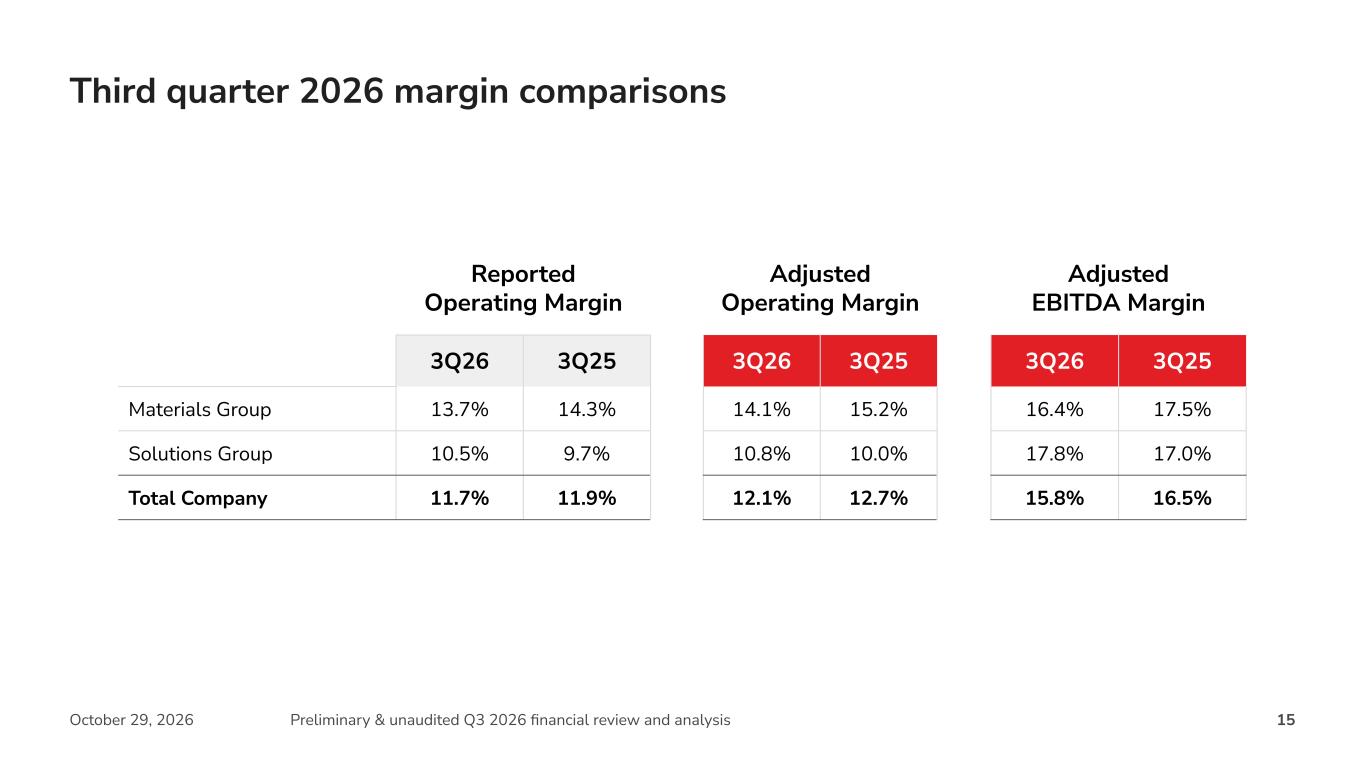
15October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public Third quarter 2026 margin comparisons Reported Operating Margin Adjusted Operating Margin Adjusted EBITDA Margin 3Q26 3Q25 3Q26 3Q25 3Q26 3Q25 Materials Group 13.7% 14.3% 14.1% 15.2% 16.4% 17.5% Solutions Group 10.5% 9.7% 10.8% 10.0% 17.8% 17.0% Total Company 11.7% 11.9% 12.1% 12.7% 15.8% 16.5%
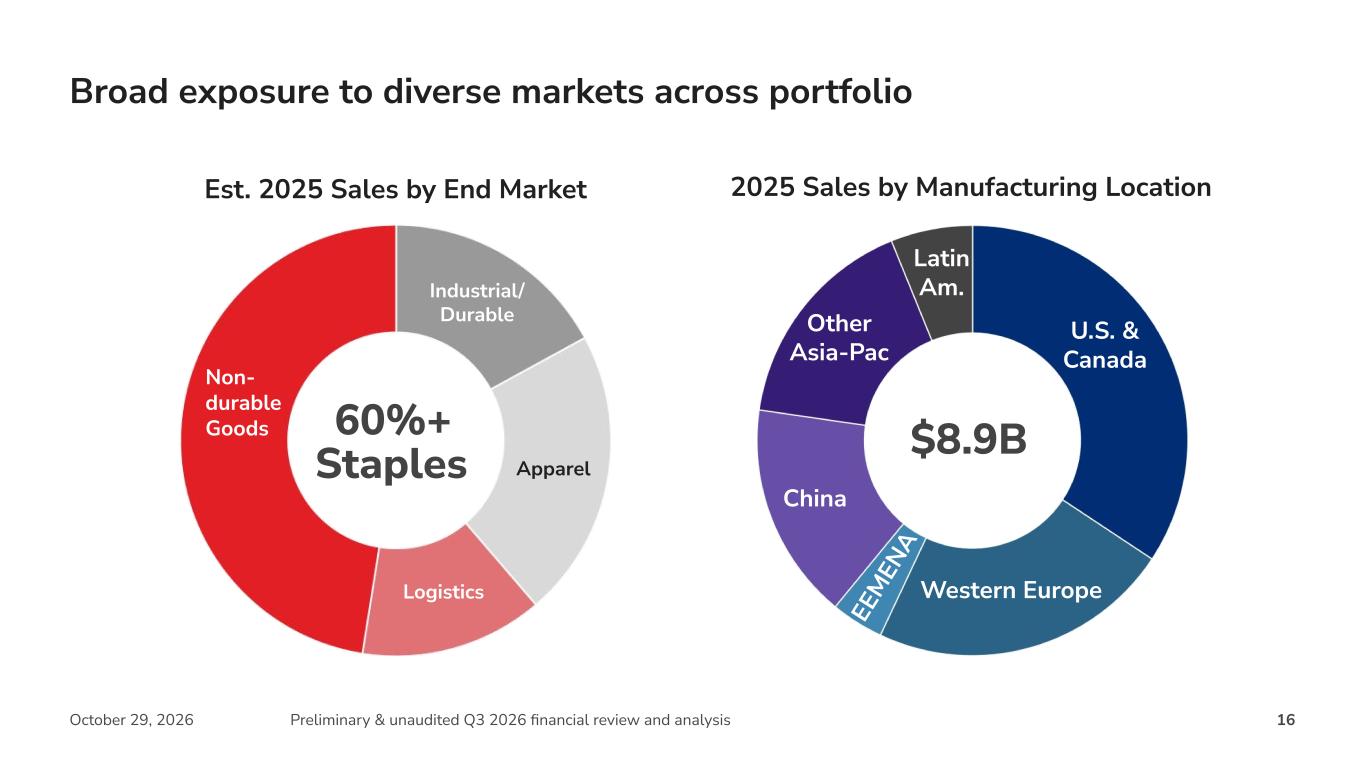
16October 29, 2026 Preliminary & unaudited Q3 2026 financial review and analysis Classification: Avery Dennison - Public Est. 2025 Sales by End Market Industrial/ Durable Apparel Broad exposure to diverse markets across portfolio 60%+ Staples Non- durable Goods Logistics $8.9B 2025 Sales by Manufacturing Location U.S. & Canada Western Europe China Other Asia-Pac Latin Am. EE M EN A
Classification: Avery Dennison - Public 17High-Value Category Investor Showcase 2026 © 2026 Avery Dennison Corporation. All rights reserved. The “Making Possible” tagline, Avery Dennison and all other Avery Dennison brands, product names and codes are trademarks of Avery Dennison Corporation. All other brands or product names are trademarks of their respective owners. Fortune 500® is a trademark of Time, Inc. Branding and other information on any samples depicted are fictitious. Any resemblance to actual names is purely coincidental. #MakingPossible averydennison.com