Exhibit 99.2 3Q26 EARNINGS REPORT PennyMac Mortgage Investment Trust October 2026
FORWARD LOOKING STATEMENTS This presentation contains forward-looking statements within the meaning of Section 21E of the Securities Exchange Act of 1934, as amended, regarding management’s beliefs, estimates, projections and assumptions with respect to, among other things, the Company’s financial results, future operations, business plans and investment strategies, as well as industry and market conditions, all of which are subject to change. Words like “believe,” “expect,” “anticipate,” “promise,” “plan,” and other expressions or words of similar meanings, as well as future or conditional verbs such as “will,” “would,” “should,” “could,” or “may” are generally intended to identify forward-looking statements. Actual results and operations for any future period may vary materially from those projected herein and from past results discussed herein. These forward-looking statements include, but are not limited to, statements regarding future changes in interest rates, housing, and prepayment rates; future loan originations and production; future loan delinquencies, defaults and forbearances; future investment and hedge expenses; future investment strategies, future mortgage servicing rights sales; future private label securitization activity; run-rate return potential and targeted returns on equity; future dividends; future earnings and return on equity as well as other business and financial expectations. Factors which could cause actual results to differ materially from historical results or those anticipated include, but are not limited to: interest rate changes; changes in mortgage and credit spreads; changes in macroeconomic, consumer and real estate market conditions; changes in housing prices, housing sales and real estate values; rising homeownership costs negatively impacting housing affordability; compliance with changing federal, state and local laws and regulations that govern its business; the general economy or the real estate finance and real estate markets; events or circumstances which undermine confidence in the financial and housing markets or otherwise have a broad impact on financial and housing markets; the degree and nature of the Company’s competition; the availability of, and level of competition for, attractive risk adjusted investment opportunities in mortgage loans and mortgage related assets that satisfy the Company’s investment objectives; the concentration of credit risks to which the Company is exposed; the Company’s dependence on and potential conflicts with its manager, servicer and their affiliates; the Company’s ability to mitigate cybersecurity risks, cyber incidents and technology disruptions; the development of artificial intelligence; the availability, terms and deployment of short term and long term capital; the adequacy of the Company’s cash reserves and working capital; the Company’s ability to maintain the desired relationship between its financing and the interest rates and maturities of its assets; the timing and amount of cash flows, if any, from the Company’s investments; the Company’s engagement in private loan securitizations; the Company’s ability to complete private label securitizations on anticipated terms and timelines, including securitizations of non-qualified mortgage loans and other new loan products; the performance of the investments the Company retains from its private label securitizations; the Company’s substantial amount of indebtedness; the performance, financial condition and liquidity of borrowers; the Company’s exposure to risks of loss and disruptions in operations from severe weather events, man-made or other natural conditions, including climate change and pandemics; the ability of the Company’s servicer, which also provides the Company with fulfillment services, to approve and monitor correspondent sellers and underwrite loans to investor standards; incomplete or inaccurate information or documentation provided by customers or counterparties, or adverse changes in the financial condition of the Company’s customers and counterparties; the Company’s indemnification and repurchase obligations in connection with mortgage loans it purchases and later sells or securitizes; the quality and enforceability of the collateral documentation evidencing the Company’s ownership and rights in the assets in which it invests; increased rates of delinquency, defaults and forbearances and/or decreased recovery rates on the Company’s investments; the performance of mortgage loans underlying mortgage backed securities or other investments in which the Company retains credit risk; the Company’s ability to foreclose on its investments in a timely manner or at all; increased prepayments of the mortgages and other loans underlying the Company’s mortgage backed securities or relating to the Company’s mortgage servicing rights and other investments; the Company’s ability to complete pending and potential sales of mortgage servicing rights on anticipated terms and timelines, and to redeploy the resulting proceeds into investments that achieve the anticipated returns; risks associated with the discontinuation of LIBOR; the degree to which the Company’s hedging strategies may or may not protect it from interest rate volatility; the accuracy or changes in the estimates the Company makes about uncertainties, contingencies and asset and liability valuations, and the assumptions underlying its run-rate return potential and targeted returns on equity; the Company’s ability to maintain appropriate internal control over financial reporting; the Company’s ability to detect misconduct and fraud; developments in the secondary markets for the Company’s mortgage loan products; legislative and regulatory changes that impact the mortgage loan industry or housing market; regulatory or other changes that impact government agencies or government sponsored entities, or such changes that increase the cost of doing business with such agencies or entities; federal and state mortgage regulations and enforcement; changes in government support of homeownership and affordability programs; changes in the Company’s investment objectives or investment or operational strategies; limitations imposed on the Company’s business and its ability to satisfy complex rules for it to qualify as a REIT for U.S. federal income tax purposes and qualify for an exclusion from the Investment Company Act of 1940 and the ability of certain of the Company’s subsidiaries to qualify as REITs or as taxable REIT subsidiaries for U.S. federal income tax purposes; changes in governmental regulations, accounting treatment, tax rates and similar matters; the Company’s ability to make distributions to its shareholders in the future; changes in the Company’s dividend policy, including any reduction in the amount of its common share dividend; the Company’s failure to deal appropriately with issues that may give rise to reputational risk; and the Company’s organizational structure and certain requirements in its charter documents. You should not place undue reliance on any forward-looking statement and should consider all of the uncertainties and risks described above, as well as those more fully discussed in reports and other documents filed by the Company with the Securities and Exchange Commission from time to time. The Company undertakes no obligation to publicly update or revise any forward-looking statements or any other information contained herein, and the statements made in this presentation are current as of the date of this presentation only. This presentation contains financial information calculated other than in accordance with U.S. generally accepted accounting principles (“GAAP”), such as adjusted net income, adjusted net income attributable to common shareholders, adjusted earnings per share, annualized adjusted return on equity, income excluding market driven value changes and leverage ratios excluding non-recourse debt that provide a meaningful perspective on the Company’s business results since the Company utilizes this information to evaluate and manage the business. Non-GAAP disclosures have limitations as an analytical tool and should not be viewed as a substitute for financial information determined in accordance with GAAP. 2
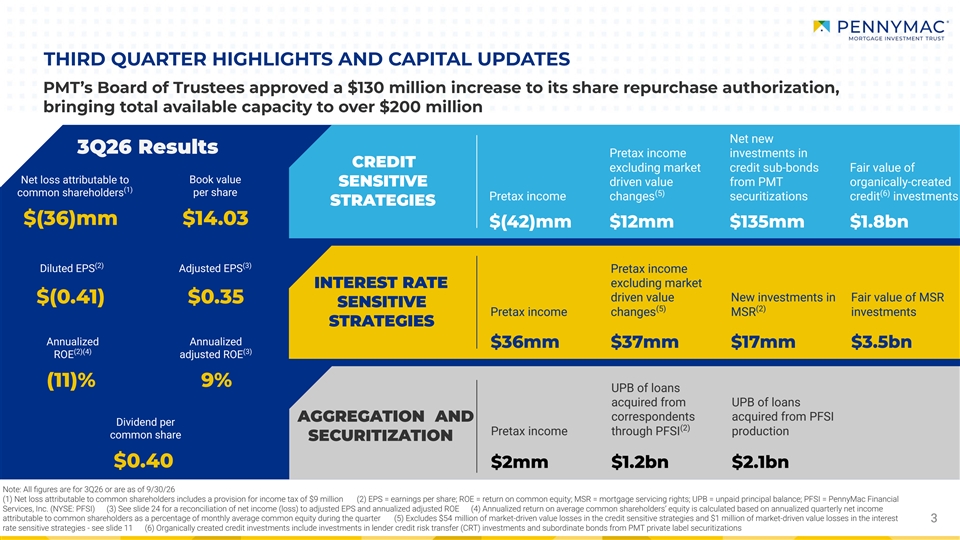
THIRD QUARTER HIGHLIGHTS AND CAPITAL UPDATES PMT’s Board of Trustees approved a $130 million increase to its share repurchase authorization, bringing total available capacity to over $200 million Net new 3Q26 Results Pretax income investments in CREDIT excluding market credit sub-bonds Fair value of Net loss attributable to Book value SENSITIVE driven value from PMT organically-created (1) common shareholders per share (5) (6) Pretax income changes securitizations credit investments STRATEGIES $(36)mm $14.03 $(42)mm $12mm $135mm $1.8bn (2) (3) Diluted EPS Adjusted EPS Pretax income INTEREST RATE excluding market driven value New investments in Fair value of MSR $(0.41) $0.35 SENSITIVE (5) (2) Pretax income changes MSR investments STRATEGIES Annualized Annualized $36mm $37mm $17mm $3.5bn (2)(4) (3) ROE adjusted ROE (11)% 9% UPB of loans acquired from UPB of loans correspondents acquired from PFSI AGGREGATION AND Dividend per (2) Pretax income through PFSI production common share SECURITIZATION $0.40 $2mm $1.2bn $2.1bn Note: All figures are for 3Q26 or are as of 9/30/26 (1) Net loss attributable to common shareholders includes a provision for income tax of $9 million (2) EPS = earnings per share; ROE = return on common equity; MSR = mortgage servicing rights; UPB = unpaid principal balance; PFSI = PennyMac Financial Services, Inc. (NYSE: PFSI) (3) See slide 24 for a reconciliation of net income (loss) to adjusted EPS and annualized adjusted ROE (4) Annualized return on average common shareholders’ equity is calculated based on annualized quarterly net income attributable to common shareholders as a percentage of monthly average common equity during the quarter (5) Excludes $54 million of market-driven value losses in the credit sensitive strategies and $1 million of market-driven value losses in the interest 3 3 3 rate sensitive strategies - see slide 11 (6) Organically created credit investments include investments in lender credit risk transfer (CRT) investments and subordinate bonds from PMT private label securitizations
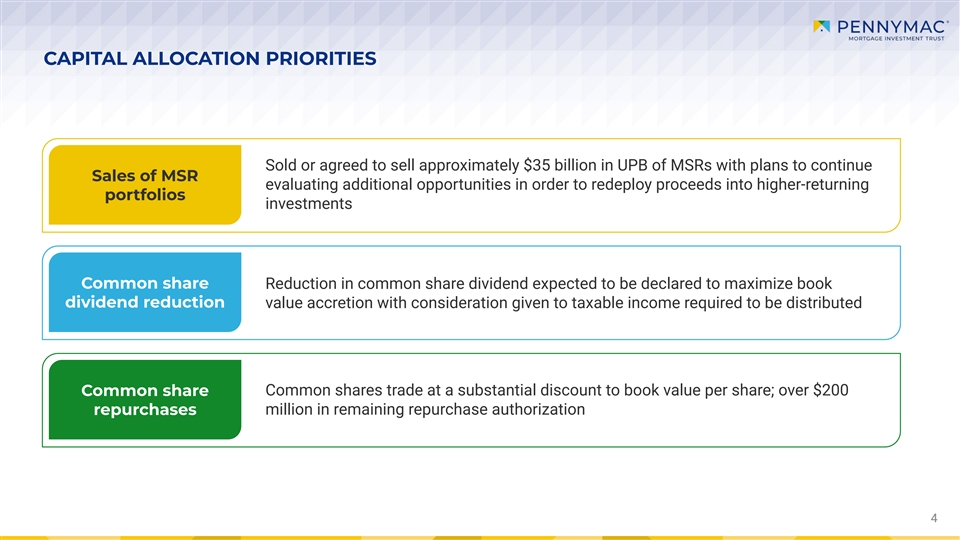
CAPITAL ALLOCATION PRIORITIES Sold or agreed to sell approximately $35 billion in UPB of MSRs with plans to continue Sales of MSR evaluating additional opportunities in order to redeploy proceeds into higher-returning portfolios investments Common share Reduction in common share dividend expected to be declared to maximize book dividend reduction value accretion with consideration given to taxable income required to be distributed Common share Common shares trade at a substantial discount to book value per share; over $200 repurchases million in remaining repurchase authorization 4 4
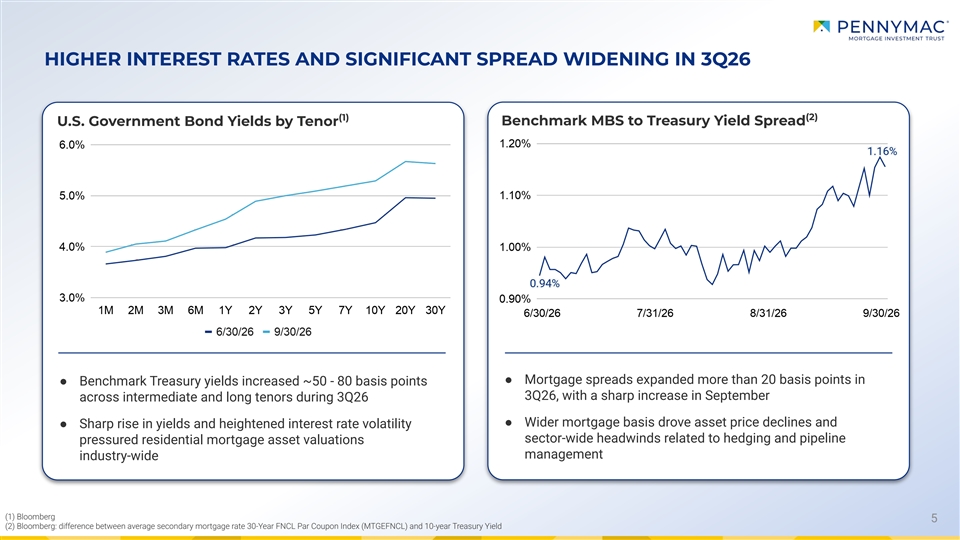
HIGHER INTEREST RATES AND SIGNIFICANT SPREAD WIDENING IN 3Q26 (2) (1) Benchmark MBS to Treasury Yield Spread U.S. Government Bond Yields by Tenor ● Mortgage spreads expanded more than 20 basis points in ● Benchmark Treasury yields increased ~50 - 80 basis points 3Q26, with a sharp increase in September across intermediate and long tenors during 3Q26 ● Wider mortgage basis drove asset price declines and ● Sharp rise in yields and heightened interest rate volatility sector-wide headwinds related to hedging and pipeline pressured residential mortgage asset valuations management industry-wide (1) Bloomberg 5 (2) Bloomberg: difference between average secondary mortgage rate 30-Year FNCL Par Coupon Index (MTGEFNCL) and 10-year Treasury Yield
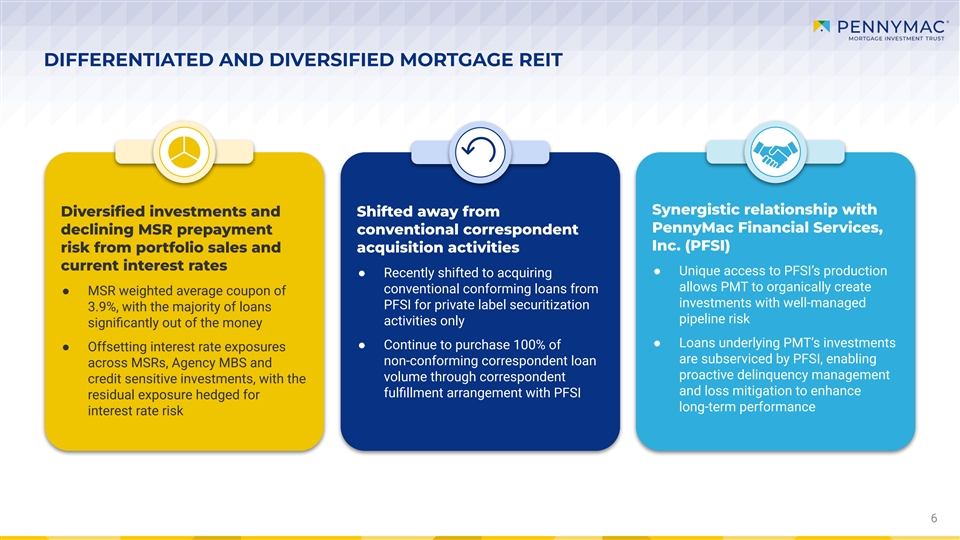
DIFFERENTIATED AND DIVERSIFIED MORTGAGE REIT Synergistic relationship with Diversified investments and Shifted away from PennyMac Financial Services, declining MSR prepayment conventional correspondent Inc. (PFSI) risk from portfolio sales and acquisition activities current interest rates ● Unique access to PFSI’s production ● Recently shifted to acquiring allows PMT to organically create conventional conforming loans from ● MSR weighted average coupon of investments with well-managed PFSI for private label securitization 3.9%, with the majority of loans pipeline risk activities only significantly out of the money ● Loans underlying PMT’s investments ● Continue to purchase 100% of ● Offsetting interest rate exposures are subserviced by PFSI, enabling non-conforming correspondent loan across MSRs, Agency MBS and proactive delinquency management volume through correspondent credit sensitive investments, with the and loss mitigation to enhance fulfillment arrangement with PFSI residual exposure hedged for long-term performance interest rate risk 6
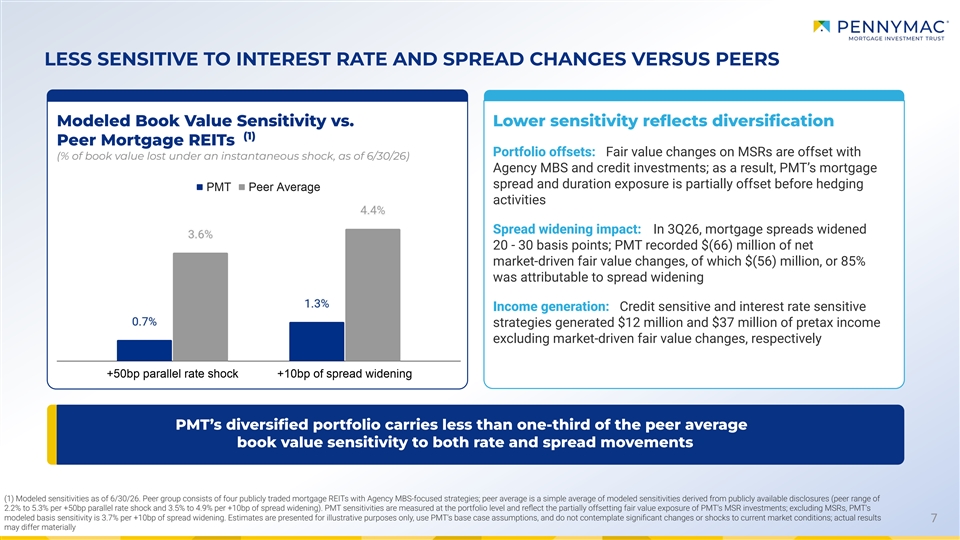
LESS SENSITIVE TO INTEREST RATE AND SPREAD CHANGES VERSUS PEERS Modeled Book Value Sensitivity vs. Lower sensitivity reflects diversification (1) Peer Mortgage REITs Portfolio offsets: Fair value changes on MSRs are offset with (% of book value lost under an instantaneous shock, as of 6/30/26) Agency MBS and credit investments; as a result, PMT’s mortgage spread and duration exposure is partially offset before hedging activities Spread widening impact: In 3Q26, mortgage spreads widened 20 - 30 basis points; PMT recorded $(66) million of net market-driven fair value changes, of which $(56) million, or 85% was attributable to spread widening Income generation: Credit sensitive and interest rate sensitive strategies generated $12 million and $37 million of pretax income excluding market-driven fair value changes, respectively PMT’s diversified portfolio carries less than one-third of the peer average book value sensitivity to both rate and spread movements (1) Modeled sensitivities as of 6/30/26. Peer group consists of four publicly traded mortgage REITs with Agency MBS-focused strategies; peer average is a simple average of modeled sensitivities derived from publicly available disclosures (peer range of 2.2% to 5.3% per +50bp parallel rate shock and 3.5% to 4.9% per +10bp of spread widening). PMT sensitivities are measured at the portfolio level and reflect the partially offsetting fair value exposure of PMT's MSR investments; excluding MSRs, PMT's modeled basis sensitivity is 3.7% per +10bp of spread widening. Estimates are presented for illustrative purposes only, use PMT's base case assumptions, and do not contemplate significant changes or shocks to current market conditions; actual results 7 may differ materially
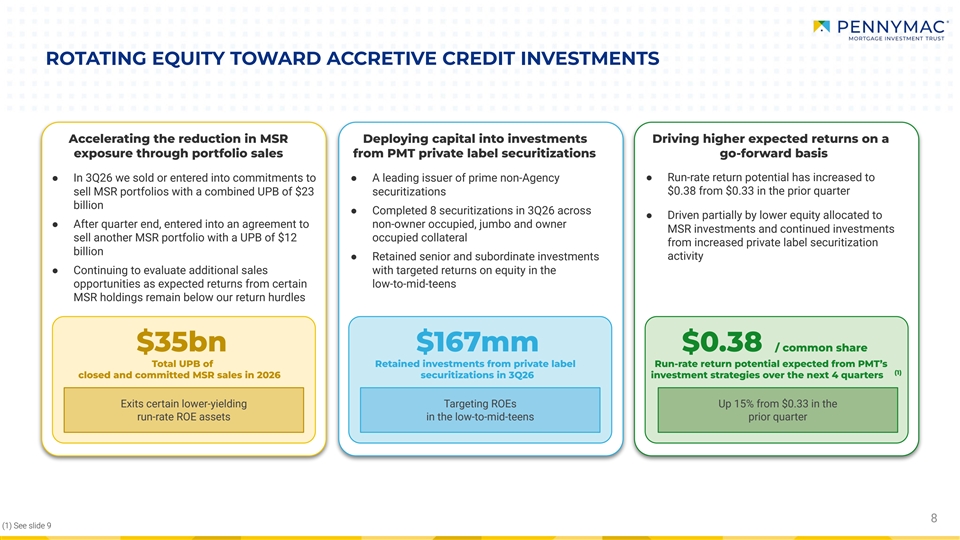
ROTATING EQUITY TOWARD ACCRETIVE CREDIT INVESTMENTS Accelerating the reduction in MSR Deploying capital into investments Driving higher expected returns on a exposure through portfolio sales from PMT private label securitizations go-forward basis ● Run-rate return potential has increased to ● In 3Q26 we sold or entered into commitments to ● A leading issuer of prime non-Agency $0.38 from $0.33 in the prior quarter sell MSR portfolios with a combined UPB of $23 securitizations billion ● Completed 8 securitizations in 3Q26 across ● Driven partially by lower equity allocated to ● After quarter end, entered into an agreement to non-owner occupied, jumbo and owner MSR investments and continued investments sell another MSR portfolio with a UPB of $12 occupied collateral from increased private label securitization billion activity ● Retained senior and subordinate investments ● Continuing to evaluate additional sales with targeted returns on equity in the opportunities as expected returns from certain low-to-mid-teens MSR holdings remain below our return hurdles $35bn $167mm $0.38 / common share Total UPB of Retained investments from private label Run-rate return potential expected from PMT’s (1) closed and committed MSR sales in 2026 securitizations in 3Q26 investment strategies over the next 4 quarters Exits certain lower-yielding Targeting ROEs Up 15% from $0.33 in the run-rate ROE assets in the low-to-mid-teens prior quarter 8 (1) See slide 9
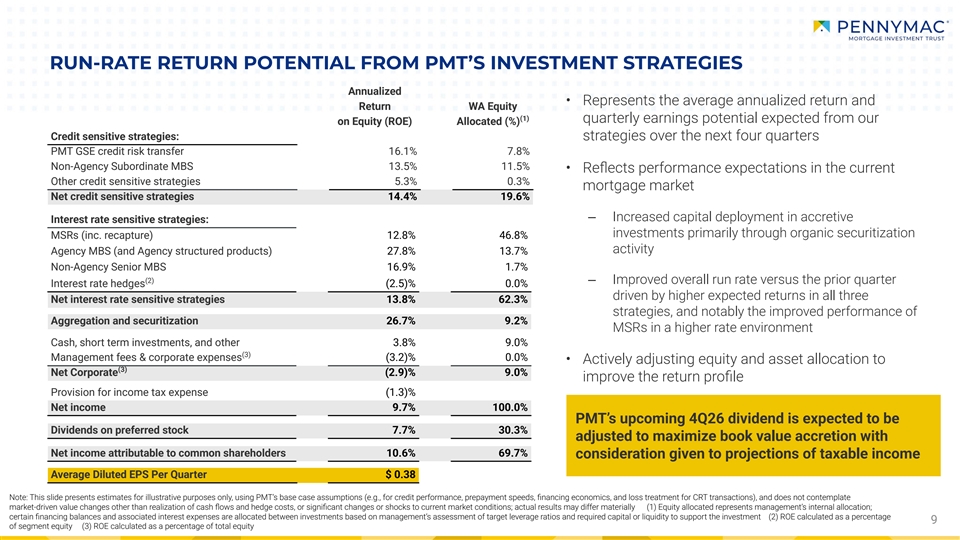
RUN-RATE RETURN POTENTIAL FROM PMT’S INVESTMENT STRATEGIES Annualized • Represents the average annualized return and Return WA Equity (1) quarterly earnings potential expected from our on Equity (ROE) Allocated (%) Credit sensitive strategies: strategies over the next four quarters PMT GSE credit risk transfer 16.1% 7.8% Non-Agency Subordinate MBS 13.5% 11.5% • Reflects performance expectations in the current Other credit sensitive strategies 5.3% 0.3% mortgage market Net credit sensitive strategies 14.4% 19.6% ‒ Increased capital deployment in accretive Interest rate sensitive strategies: investments primarily through organic securitization MSRs (inc. recapture) 12.8% 46.8% activity Agency MBS (and Agency structured products) 27.8% 13.7% Non-Agency Senior MBS 16.9% 1.7% (2)‒ Improved overall run rate versus the prior quarter Interest rate hedges (2.5)% 0.0% driven by higher expected returns in all three Net interest rate sensitive strategies 13.8% 62.3% strategies, and notably the improved performance of Aggregation and securitization 26.7% 9.2% MSRs in a higher rate environment Cash, short term investments, and other 3.8% 9.0% (3) Management fees & corporate expenses (3.2)% 0.0% • Actively adjusting equity and asset allocation to (3) Net Corporate (2.9)% 9.0% improve the return profile Provision for income tax expense (1.3)% Net income 9.7% 100.0% PMT’s upcoming 4Q26 dividend is expected to be Dividends on preferred stock 7.7% 30.3% adjusted to maximize book value accretion with Net income attributable to common shareholders 10.6% 69.7% consideration given to projections of taxable income Average Diluted EPS Per Quarter $ 0.38 Note: This slide presents estimates for illustrative purposes only, using PMT’s base case assumptions (e.g., for credit performance, prepayment speeds, financing economics, and loss treatment for CRT transactions), and does not contemplate market-driven value changes other than realization of cash flows and hedge costs, or significant changes or shocks to current market conditions; actual results may differ materially (1) Equity allocated represents management’s internal allocation; certain financing balances and associated interest expenses are allocated between investments based on management’s assessment of target leverage ratios and required capital or liquidity to support the investment (2) ROE calculated as a percentage 9 of segment equity (3) ROE calculated as a percentage of total equity
KEY OPERATING METRICS & OTHER FINANCIAL SCHEDULES
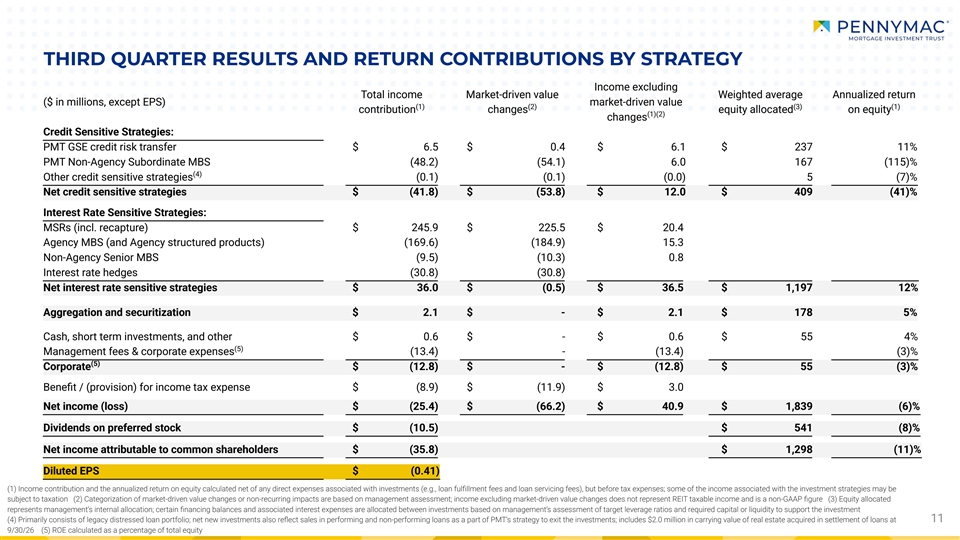
THIRD QUARTER RESULTS AND RETURN CONTRIBUTIONS BY STRATEGY Income excluding Total income Market-driven value Weighted average Annualized return ($ in millions, except EPS) market-driven value (1) (2) (3) (1) contribution changes equity allocated on equity (1)(2) changes Credit Sensitive Strategies: PMT GSE credit risk transfer $ 6.5 $ 0.4 $ 6.1 $ 237 11% PMT Non-Agency Subordinate MBS (48.2) (54.1) 6.0 167 (115)% (4) Other credit sensitive strategies (0.1) (0.1) (0.0) 5 (7)% Net credit sensitive strategies $ (41.8) $ (53.8) $ 12.0 $ 409 (41)% Interest Rate Sensitive Strategies: MSRs (incl. recapture) $ 245.9 $ 225.5 $ 20.4 Agency MBS (and Agency structured products) (169.6) (184.9) 15.3 Non-Agency Senior MBS (9.5) (10.3) 0.8 Interest rate hedges (30.8) (30.8) Net interest rate sensitive strategies $ 36.0 $ (0.5) $ 36.5 $ 1,197 12% Aggregation and securitization $ 2.1 $ - $ 2.1 $ 178 5% Cash, short term investments, and other $ 0.6 $ - $ 0.6 $ 55 4% (5) Management fees & corporate expenses (13.4) - (13.4) (3)% (5) Corporate $ (12.8) $ - $ (12.8) $ 55 (3)% Benefit / (provision) for income tax expense $ (8.9) $ (11.9) $ 3.0 Net income (loss) $ (25.4) $ (66.2) $ 40.9 $ 1,839 (6)% Dividends on preferred stock $ (10.5) $ 541 (8)% Net income attributable to common shareholders $ (35.8) $ 1,298 (11)% Diluted EPS $ (0.41) (1) Income contribution and the annualized return on equity calculated net of any direct expenses associated with investments (e.g., loan fulfillment fees and loan servicing fees), but before tax expenses; some of the income associated with the investment strategies may be subject to taxation (2) Categorization of market-driven value changes or non-recurring impacts are based on management assessment; income excluding market-driven value changes does not represent REIT taxable income and is a non-GAAP figure (3) Equity allocated represents management’s internal allocation; certain financing balances and associated interest expenses are allocated between investments based on management’s assessment of target leverage ratios and required capital or liquidity to support the investment (4) Primarily consists of legacy distressed loan portfolio; net new investments also reflect sales in performing and non-performing loans as a part of PMT’s strategy to exit the investments; includes $2.0 million in carrying value of real estate acquired in settlement of loans at 11 9/30/26 (5) ROE calculated as a percentage of total equity
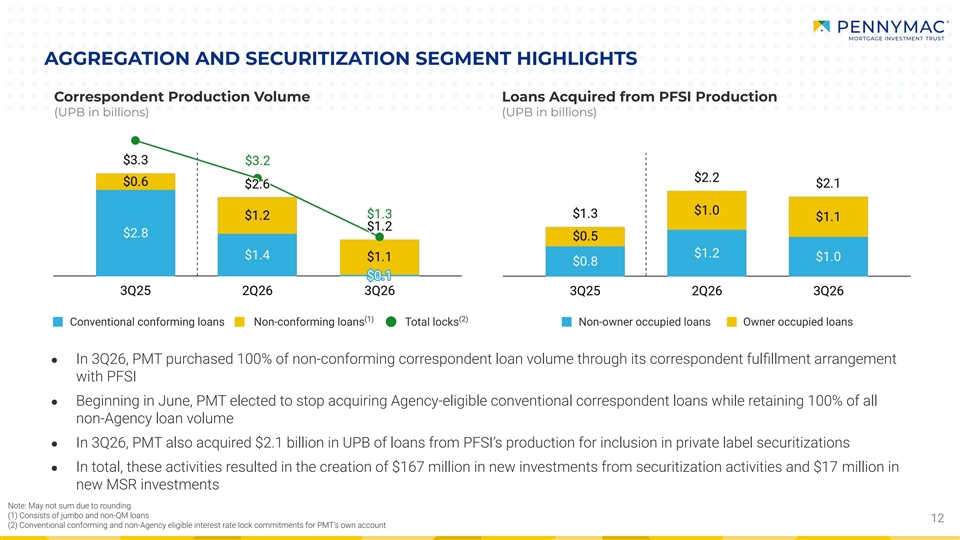
AGGREGATION AND SECURITIZATION SEGMENT HIGHLIGHTS Correspondent Production Volume Loans Acquired from PFSI Production (UPB in billions) (UPB in billions) (1) (2) Conventional conforming loans Non-conforming loans Total locks Non-owner occupied loans Owner occupied loans ● In 3Q26, PMT purchased 100% of non-conforming correspondent loan volume through its correspondent fulfillment arrangement with PFSI ● Beginning in June, PMT elected to stop acquiring Agency-eligible conventional correspondent loans while retaining 100% of all non-Agency loan volume ● In 3Q26, PMT also acquired $2.1 billion in UPB of loans from PFSI’s production for inclusion in private label securitizations ● In total, these activities resulted in the creation of $167 million in new investments from securitization activities and $17 million in new MSR investments Note: May not sum due to rounding (1) Consists of jumbo and non-QM loans 12 (2) Conventional conforming and non-Agency eligible interest rate lock commitments for PMT’s own account
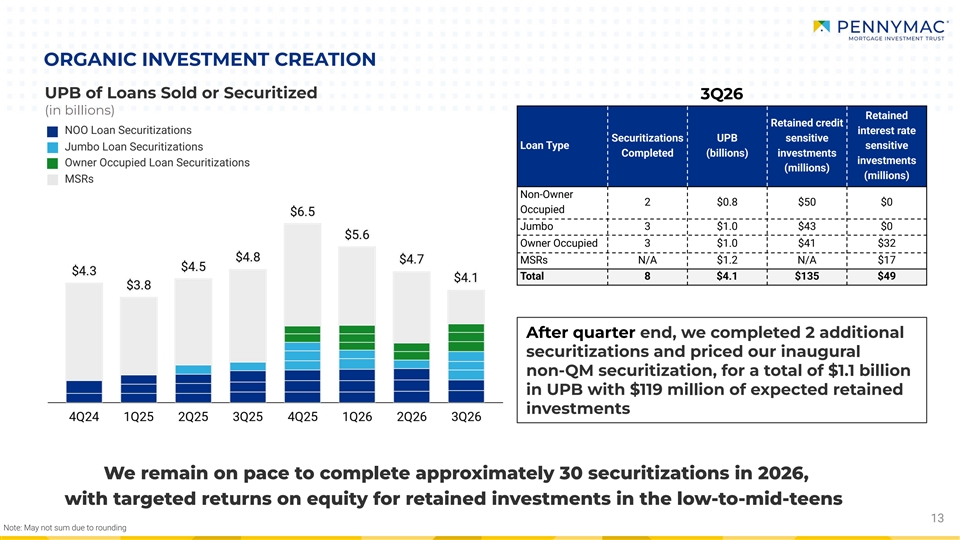
ORGANIC INVESTMENT CREATION UPB of Loans Sold or Securitized 3Q26 (in billions) Retained Retained credit NOO Loan Securitizations interest rate Securitizations UPB sensitive Loan Type sensitive Jumbo Loan Securitizations Completed (billions) investments investments Owner Occupied Loan Securitizations (millions) (millions) MSRs Non-Owner 2 $0.8 $50 $0 Occupied Jumbo 3 $1.0 $43 $0 Owner Occupied 3 $1.0 $41 $32 MSRs N/A $1.2 N/A $17 Total 8 $4.1 $135 $49 After quarter end, we completed 2 additional securitizations and priced our inaugural non-QM securitization, for a total of $1.1 billion in UPB with $119 million of expected retained investments We remain on pace to complete approximately 30 securitizations in 2026, with targeted returns on equity for retained investments in the low-to-mid-teens 13 Note: May not sum due to rounding
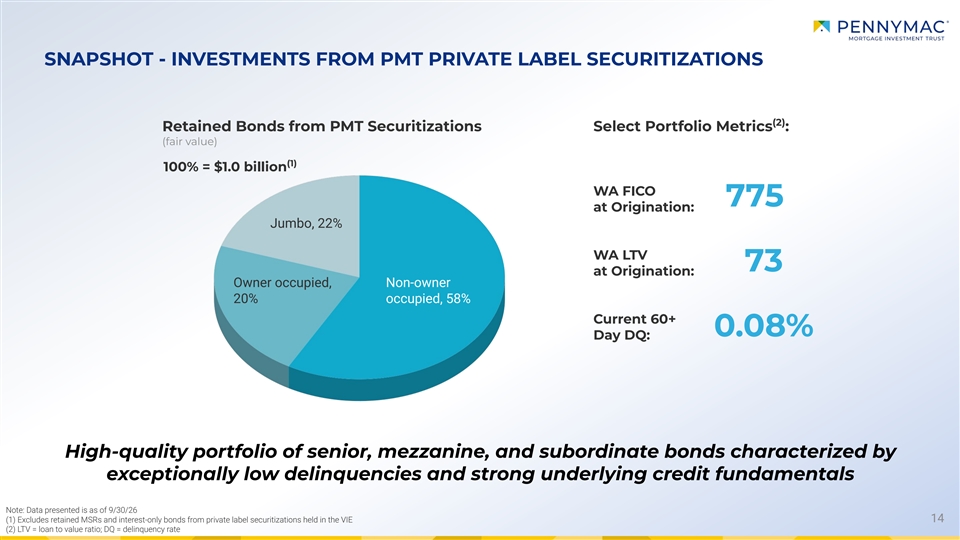
SNAPSHOT - INVESTMENTS FROM PMT PRIVATE LABEL SECURITIZATIONS (2) Retained Bonds from PMT Securitizations Select Portfolio Metrics : (fair value) (1) 100% = $1.0 billion WA FICO 775 at Origination: Jumbo, 22% WA LTV 73 at Origination: Owner occupied, Non-owner 20% occupied, 58% Current 60+ 0.08% Day DQ: High-quality portfolio of senior, mezzanine, and subordinate bonds characterized by exceptionally low delinquencies and strong underlying credit fundamentals Note: Data presented is as of 9/30/26 (1) Excludes retained MSRs and interest-only bonds from private label securitizations held in the VIE 14 (2) LTV = loan to value ratio; DQ = delinquency rate
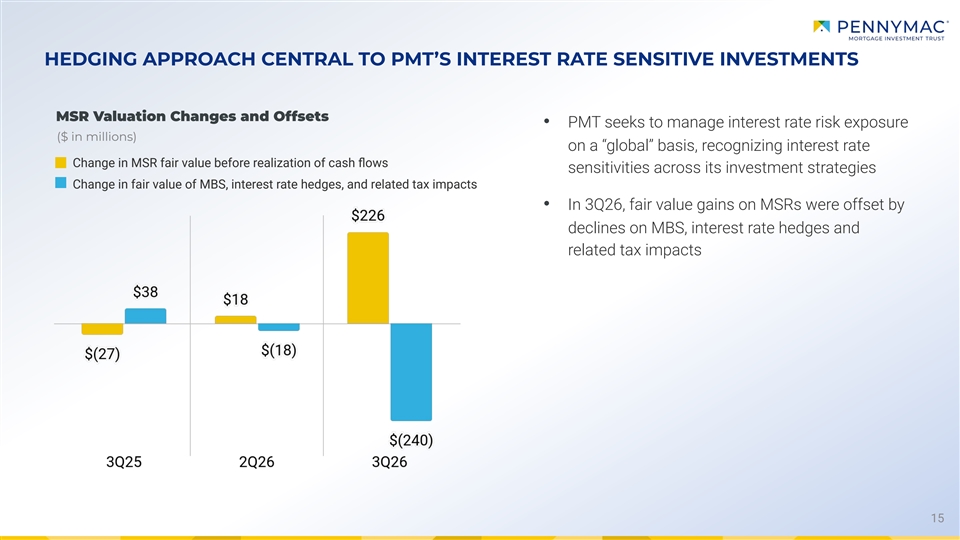
HEDGING APPROACH CENTRAL TO PMT’S INTEREST RATE SENSITIVE INVESTMENTS MSR Valuation Changes and Offsets • PMT seeks to manage interest rate risk exposure ($ in millions) on a “global” basis, recognizing interest rate Change in MSR fair value before realization of cash flows sensitivities across its investment strategies Change in fair value of MBS, interest rate hedges, and related tax impacts • In 3Q26, fair value gains on MSRs were offset by declines on MBS, interest rate hedges and related tax impacts 15
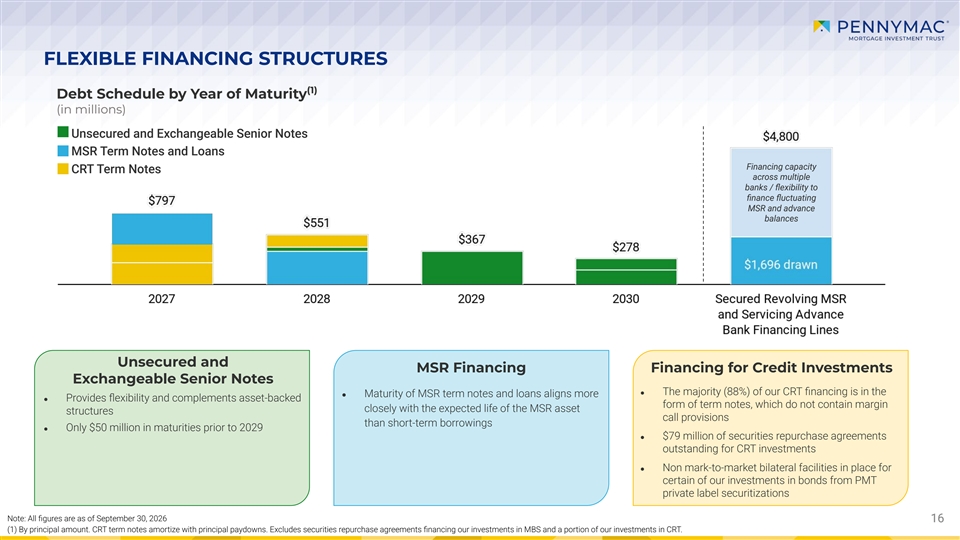
FLEXIBLE FINANCING STRUCTURES (1) Debt Schedule by Year of Maturity (in millions) Unsecured and Exchangeable Senior Notes MSR Term Notes and Loans Financing capacity CRT Term Notes across multiple banks / flexibility to finance fluctuating MSR and advance balances Unsecured and MSR Financing Financing for Credit Investments Exchangeable Senior Notes ● The majority (88%) of our CRT financing is in the ● Maturity of MSR term notes and loans aligns more ● Provides flexibility and complements asset-backed form of term notes, which do not contain margin closely with the expected life of the MSR asset structures call provisions than short-term borrowings ● Only $50 million in maturities prior to 2029 ● $79 million of securities repurchase agreements outstanding for CRT investments ● Non mark-to-market bilateral facilities in place for certain of our investments in bonds from PMT private label securitizations Note: All figures are as of September 30, 2026 16 16 (1) By principal amount. CRT term notes amortize with principal paydowns. Excludes securities repurchase agreements financing our investments in MBS and a portion of our investments in CRT.
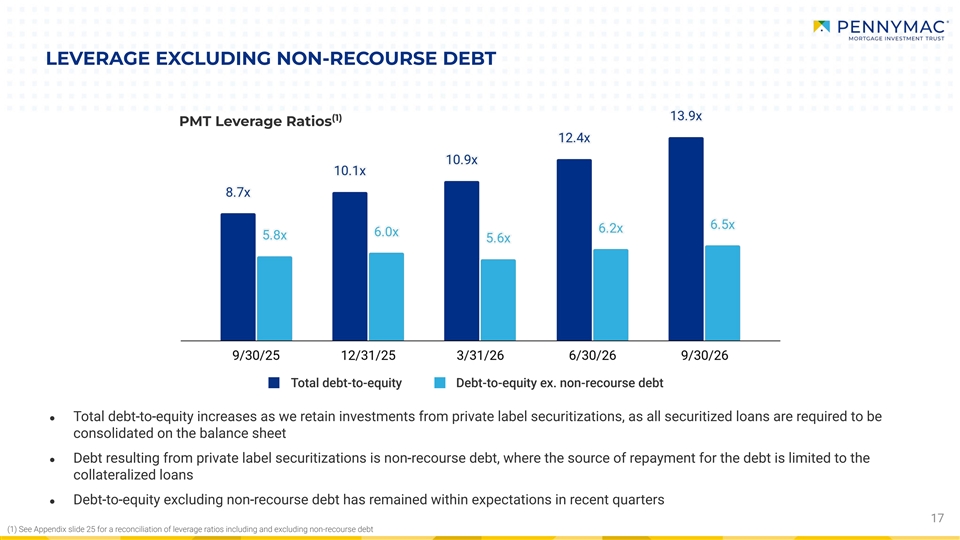
(1) See Appendix slide 25 for a reconciliation of leverage ratios including and excluding non-recourse debt LEVERAGE EXCLUDING NON-RECOURSE DEBT (1) PMT Leverage Ratios Total debt-to-equity Debt-to-equity ex. non-recourse debt ● Total debt-to-equity increases as we retain investments from private label securitizations, as all securitized loans are required to be consolidated on the balance sheet ● Debt resulting from private label securitizations is non-recourse debt, where the source of repayment for the debt is limited to the collateralized loans ● Debt-to-equity excluding non-recourse debt has remained within expectations in recent quarters 17
APPENDIX
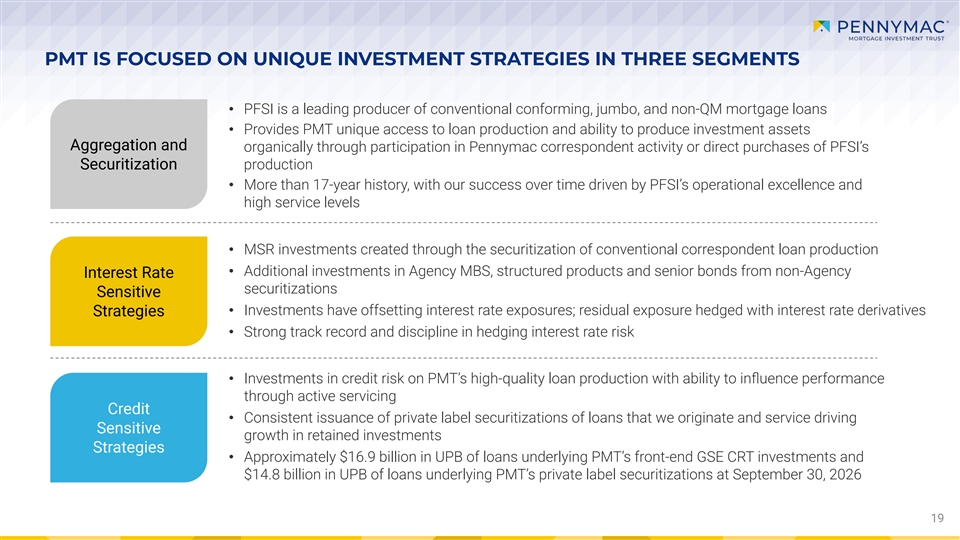
PMT IS FOCUSED ON UNIQUE INVESTMENT STRATEGIES IN THREE SEGMENTS • PFSI is a leading producer of conventional conforming, jumbo, and non-QM mortgage loans • Provides PMT unique access to loan production and ability to produce investment assets Aggregation and organically through participation in Pennymac correspondent activity or direct purchases of PFSI’s Securitization production • More than 17-year history, with our success over time driven by PFSI’s operational excellence and high service levels • MSR investments created through the securitization of conventional correspondent loan production • Additional investments in Agency MBS, structured products and senior bonds from non-Agency Interest Rate securitizations Sensitive Strategies• Investments have offsetting interest rate exposures; residual exposure hedged with interest rate derivatives • Strong track record and discipline in hedging interest rate risk • Investments in credit risk on PMT’s high-quality loan production with ability to influence performance through active servicing Credit • Consistent issuance of private label securitizations of loans that we originate and service driving Sensitive growth in retained investments Strategies • Approximately $16.9 billion in UPB of loans underlying PMT’s front-end GSE CRT investments and $14.8 billion in UPB of loans underlying PMT’s private label securitizations at September 30, 2026 19
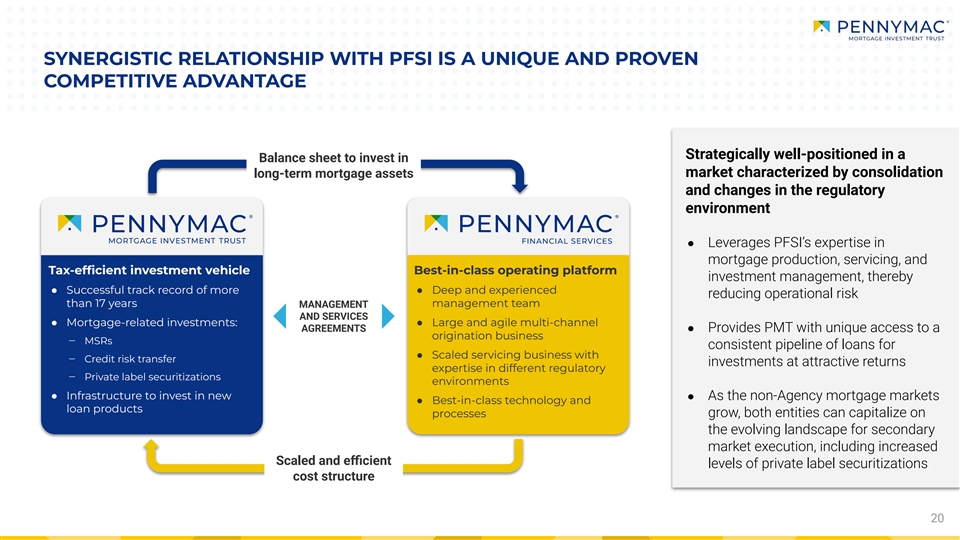
SYNERGISTIC RELATIONSHIP WITH PFSI IS A UNIQUE AND PROVEN COMPETITIVE ADVANTAGE Strategically well-positioned in a Balance sheet to invest in market characterized by consolidation long-term mortgage assets and changes in the regulatory environment ● Leverages PFSI’s expertise in mortgage production, servicing, and Tax-efficient investment vehicle Best-in-class operating platform investment management, thereby ● Successful track record of more ● Deep and experienced reducing operational risk than 17 years management team MANAGEMENT AND SERVICES ● Mortgage-related investments:● Large and agile multi-channel AGREEMENTS● Provides PMT with unique access to a origination business ‒ MSRs consistent pipeline of loans for ● Scaled servicing business with ‒ Credit risk transfer investments at attractive returns expertise in different regulatory ‒ Private label securitizations environments ● Infrastructure to invest in new ● As the non-Agency mortgage markets ● Best-in-class technology and loan products processes grow, both entities can capitalize on the evolving landscape for secondary market execution, including increased Scaled and efficient levels of private label securitizations cost structure 20
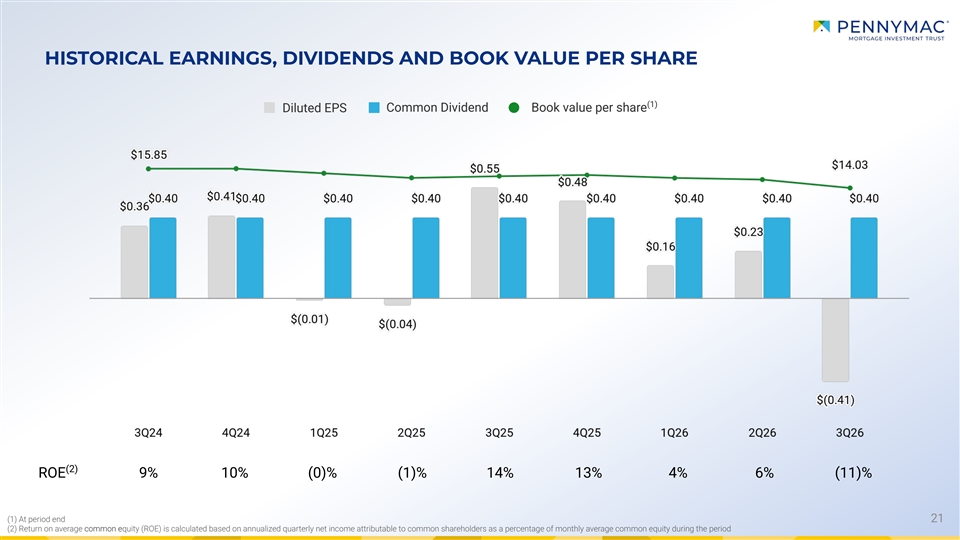
(1) At period end (2) Return on average common equity (ROE) is calculated based on annualized quarterly net income attributable to common shareholders as a percentage of monthly average common equity during the period HISTORICAL EARNINGS, DIVIDENDS AND BOOK VALUE PER SHARE (1) Diluted EPS Common Dividend Book value per share (2) ROE 9% 10% (0)% (1)% 14% 13% 4% 6% (11)% 21
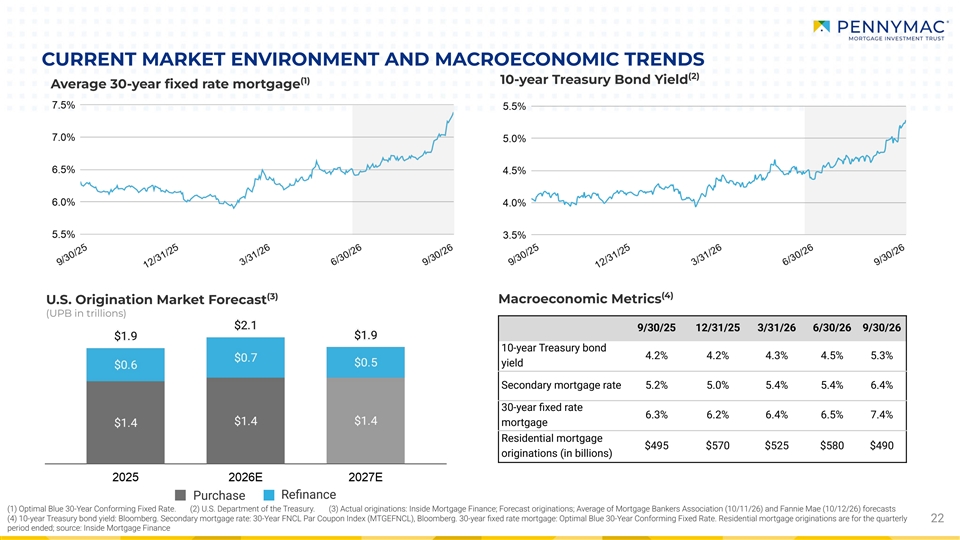
CURRENT MARKET ENVIRONMENT AND MACROECONOMIC TRENDS (2) (1) 10-year Treasury Bond Yield Average 30-year fixed rate mortgage (4) (3) U.S. Origination Market Forecast Macroeconomic Metrics (UPB in trillions) 9/30/25 12/31/25 3/31/26 6/30/26 9/30/26 10-year Treasury bond 4.2% 4.2% 4.3% 4.5% 5.3% yield Secondary mortgage rate 5.2% 5.0% 5.4% 5.4% 6.4% 30-year fixed rate 6.3% 6.2% 6.4% 6.5% 7.4% mortgage Residential mortgage $495 $570 $525 $580 $490 originations (in billions) Refinance Purchase (1) Optimal Blue 30-Year Conforming Fixed Rate. (2) U.S. Department of the Treasury. (3) Actual originations: Inside Mortgage Finance; Forecast originations; Average of Mortgage Bankers Association (10/11/26) and Fannie Mae (10/12/26) forecasts (4) 10-year Treasury bond yield: Bloomberg. Secondary mortgage rate: 30-Year FNCL Par Coupon Index (MTGEFNCL), Bloomberg. 30-year fixed rate mortgage: Optimal Blue 30-Year Conforming Fixed Rate. Residential mortgage originations are for the quarterly 22 period ended; source: Inside Mortgage Finance
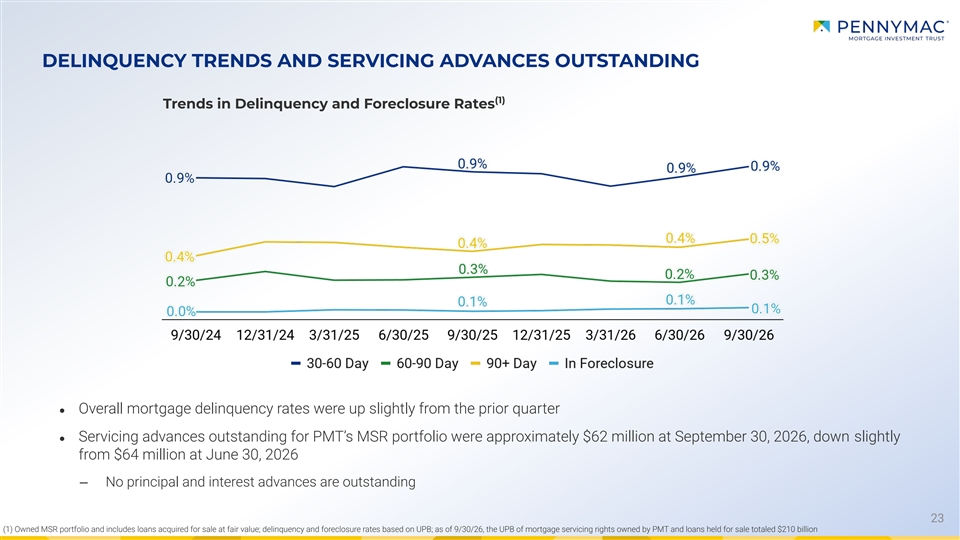
DELINQUENCY TRENDS AND SERVICING ADVANCES OUTSTANDING (1) Trends in Delinquency and Foreclosure Rates ● Overall mortgage delinquency rates were up slightly from the prior quarter ● Servicing advances outstanding for PMT’s MSR portfolio were approximately $62 million at September 30, 2026, down slightly from $64 million at June 30, 2026 ‒ No principal and interest advances are outstanding 23 (1) Owned MSR portfolio and includes loans acquired for sale at fair value; delinquency and foreclosure rates based on UPB; as of 9/30/26, the UPB of mortgage servicing rights owned by PMT and loans held for sale totaled $210 billion
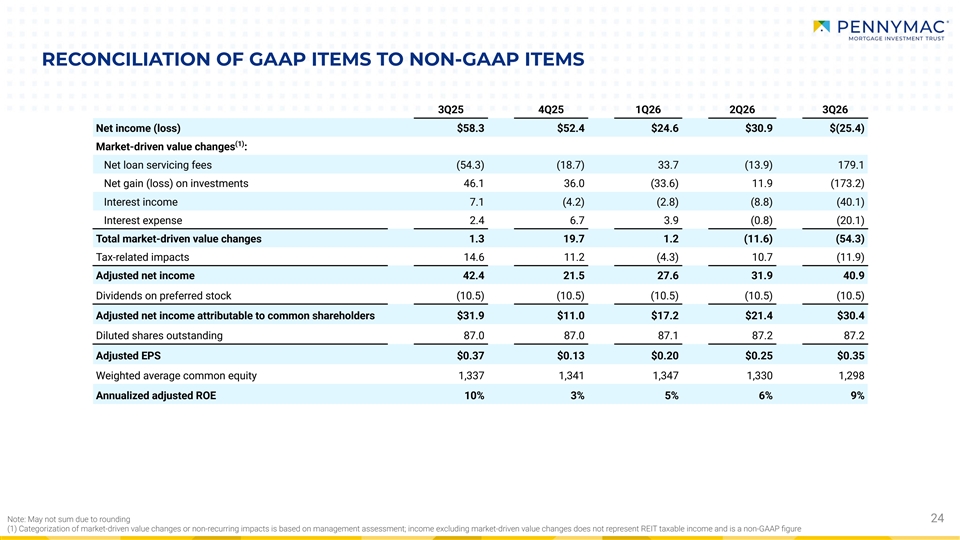
Note: May not sum due to rounding (1) Categorization of market-driven value changes or non-recurring impacts is based on management assessment; income excluding market-driven value changes does not represent REIT taxable income and is a non-GAAP figure RECONCILIATION OF GAAP ITEMS TO NON-GAAP ITEMS 3Q25 4Q25 1Q26 2Q26 3Q26 Net income (loss) $58.3 $52.4 $24.6 $30.9 $(25.4) (1) Market-driven value changes : Net loan servicing fees (54.3) (18.7) 33.7 (13.9) 179.1 Net gain (loss) on investments 46.1 36.0 (33.6) 11.9 (173.2) Interest income 7.1 (4.2) (2.8) (8.8) (40.1) Interest expense 2.4 6.7 3.9 (0.8) (20.1) Total market-driven value changes 1.3 19.7 1.2 (11.6) (54.3) Tax-related impacts 14.6 11.2 (4.3) 10.7 (11.9) Adjusted net income 42.4 21.5 27.6 31.9 40.9 Dividends on preferred stock (10.5) (10.5) (10.5) (10.5) (10.5) Adjusted net income attributable to common shareholders $31.9 $11.0 $17.2 $21.4 $30.4 Diluted shares outstanding 87.0 87.0 87.1 87.2 87.2 Adjusted EPS $0.37 $0.13 $0.20 $0.25 $0.35 Weighted average common equity 1,337 1,341 1,347 1,330 1,298 Annualized adjusted ROE 10% 3% 5% 6% 9% 24
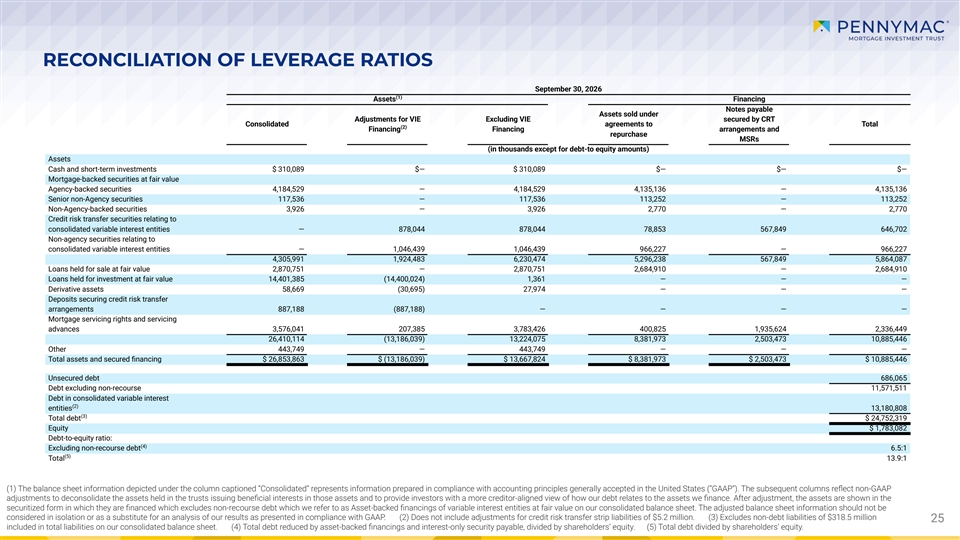
RECONCILIATION OF LEVERAGE RATIOS September 30, 2026 (1) Assets Financing Notes payable Assets sold under Adjustments for VIE Excluding VIE secured by CRT Consolidated agreements to Total (2) Financing Financing arrangements and repurchase MSRs (in thousands except for debt-to equity amounts) Assets Cash and short-term investments $ 310,089 $— $ 310,089 $— $— $— Mortgage-backed securities at fair value Agency-backed securities 4,184,529 — 4,184,529 4,135,136 — 4,135,136 Senior non-Agency securities 117,536 — 117,536 113,252 — 113,252 Non-Agency-backed securities 3,926 — 3,926 2,770 — 2,770 Credit risk transfer securities relating to consolidated variable interest entities — 878,044 878,044 78,853 567,849 646,702 Non-agency securities relating to consolidated variable interest entities — 1,046,439 1,046,439 966,227 — 966,227 4,305,991 1,924,483 6,230,474 5,296,238 567,849 5,864,087 Loans held for sale at fair value 2,870,751 — 2,870,751 2,684,910 — 2,684,910 Loans held for investment at fair value 14,401,385 (14,400,024) 1,361 — — — Derivative assets 58,669 (30,695) 27,974 — — — Deposits securing credit risk transfer arrangements 887,188 (887,188) — — — — Mortgage servicing rights and servicing advances 3,576,041 207,385 3,783,426 400,825 1,935,624 2,336,449 26,410,114 (13,186,039) 13,224,075 8,381,973 2,503,473 10,885,446 Other 443,749 — 443,749 — — — Total assets and secured financing $ 26,853,863 $ (13,186,039) $ 13,667,824 $ 8,381,973 $ 2,503,473 $ 10,885,446 Unsecured debt 686,065 Debt excluding non-recourse 11,571,511 Debt in consolidated variable interest (2) entities 13,180,808 (3) Total debt $ 24,752,319 Equity $ 1,783,082 Debt-to-equity ratio: (4) Excluding non-recourse debt 6.5:1 (5) Total 13.9:1 (1) The balance sheet information depicted under the column captioned “Consolidated” represents information prepared in compliance with accounting principles generally accepted in the United States (“GAAP”). The subsequent columns reflect non-GAAP adjustments to deconsolidate the assets held in the trusts issuing beneficial interests in those assets and to provide investors with a more creditor-aligned view of how our debt relates to the assets we finance. After adjustment, the assets are shown in the securitized form in which they are financed which excludes non-recourse debt which we refer to as Asset-backed financings of variable interest entities at fair value on our consolidated balance sheet. The adjusted balance sheet information should not be considered in isolation or as a substitute for an analysis of our results as presented in compliance with GAAP. (2) Does not include adjustments for credit risk transfer strip liabilities of $5.2 million. (3) Excludes non-debt liabilities of $318.5 million 25 25 included in total liabilities on our consolidated balance sheet. (4) Total debt reduced by asset-backed financings and interest-only security payable, divided by shareholders’ equity. (5) Total debt divided by shareholders’ equity.
26