Exhibit 99.2
First Mid + Evergreen Bancshares October 29, 2026 Investor Contacts: Austin Frank Director of Investor Relations 217 - 258 - 5522 afrank@firstmid.com Jordan Read Chief Financial Officer & Chief Risk Officer 217 - 258 - 3528 jread@firstmid.com NASDAQ: FMBH firstmid.com
Forward Looking Statements This document may contain forward - looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 regarding First Mid Bancshares, Inc. (“First Mid”), Evergreen Bancshares, Inc. (“Evergreen”) and the proposed transactions, including s tat ements regarding anticipated benefits, integration, timing, approvals, customer relationships, operating results, expenses, market c ond itions, credit quality, liquidity, loan and deposit activity, and other expectations regarding the combined business. First Mid intends for the se forward - looking statements to be covered by the safe harbor provisions for forward - looking statements contained in the Private Securitie s Litigation Reform Act of 1995. Forward - looking statements, which are based on certain assumptions and describe future plans, strategies and expectations, are identified by use of the words “believe,” “expect,” “intend,” “anticipate,” “estimate,” “project,” “will,” “ma y,” “should,” or similar expressions. Actual results could differ materially from the results indicated by these statements because the realiz ati on of those results is subject to many risks and uncertainties, including, among other things, the possibility that the anticipated benef its of the proposed transactions will not be realized within the expected time period; the risk that integration of Evergreen with First Mid will be materially delayed or will be more costly or difficult than expected; the inability to complete the proposed transactions due to the fai lur e to satisfy conditions to completion of the proposed transactions, including failure to obtain required regulatory, shareholder and other ap provals; the failure of the proposed transactions to close for any other reason; the effect of the announcement of the proposed transactio ns on customer relationships and operating results; the possibility that the proposed transactions may be more expensive to complete than an tic ipated; changes in interest rates; general economic conditions and market - area conditions; legislative and/or regulatory changes; risks relating to Evergreen as a privately held company whose business and financial information has not been subject to public company reporti ng requirements; monetary and fiscal policies of the U.S. Government, including policies of the U.S. Treasury and the Federal Re ser ve Board; the quality, composition and valuation of loan and investment portfolios; demand for loan products; deposit flows; competition; d ema nd for financial services; accounting principles, policies and guidelines; and the ability to complete the proposed transactions or any of the foregoing risks. Additional information concerning First Mid, including additional factors and risks that could materially affect First Mi d’s financial results, is included in First Mid’s filings with the SEC, including its Annual Reports on Form 10 - K and Quarterly Reports on For m 10 - Q. Forward - looking statements speak only as of the date they are made. Except as required under the federal securities laws or the rules and regulations of the SEC, First Mid does not undertake any obligation to update, revise or review any forward - looking information, whether as a result of new information, future events or otherwise. Disclosures 2
Important Information about the Merger and Additional Information First Mid will file a registration statement on Form S - 4 with the SEC in connection with the proposed transaction. The registrat ion statement will include a proxy statement of Evergreen that also constitutes a prospectus of First Mid, which will be sent to the shareh old ers of Evergreen. Evergreen shareholders are urged to read the proxy statement/prospectus when it becomes available, which will contain important information about First Mid, Evergreen and the proposed transactions, including detailed risk factors. The proxy statement/prospectus and other documents which will be filed by First Mid with the SEC will be available free of ch ar ge at the SEC’s website, www.sec.gov. These documents also can be obtained free of charge by accessing First Mid’s website at ww w.f irstmid.com under the tab “Investor Relations” and then under “SEC Filings.” Alternatively, when available, these documents can be obtai ned free of charge from First Mid upon written request to First Mid Bancshares, PO Box 499, Mattoon, IL 61938, Attention: Investor Relat ion s; or from Evergreen upon written request to Evergreen Bancshares, Inc., 1701 Macklind Avenue, St. Louis, MO 63110, Attention: Chief Fi nan cial Officer. A final proxy statement/prospectus will be mailed to the shareholders of Evergreen. Participants in the Solicitation First Mid and Evergreen, and certain of their respective directors, executive officers, and other members of management and e mpl oyees, are participants in the solicitation of proxies in connection with the proposed transactions. Information about the directors and executive officers of First Mid is set forth in the proxy statement for its 2026 annual meeting of stockholders, which was filed with the SEC on March 17, 2026. This document can be obtained free of charge from the sources provided above. Information about Evergreen’s directors and executive officers, and a description of their direct and indirect interests in the proposed transa cti ons, by security holdings or otherwise, will be included in the proxy statement/prospectus when it becomes available. Investors may obtain add iti onal information regarding the interests of such participants in the proposed transactions by reading the proxy statement/prospect us for such proposed transactions when it becomes available. No Offer or Solicitation This communication shall not constitute an offer to sell or the solicitation of an offer to buy securities, nor shall there b e a ny sale of securities in any jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of such jurisdiction. Disclosures 3
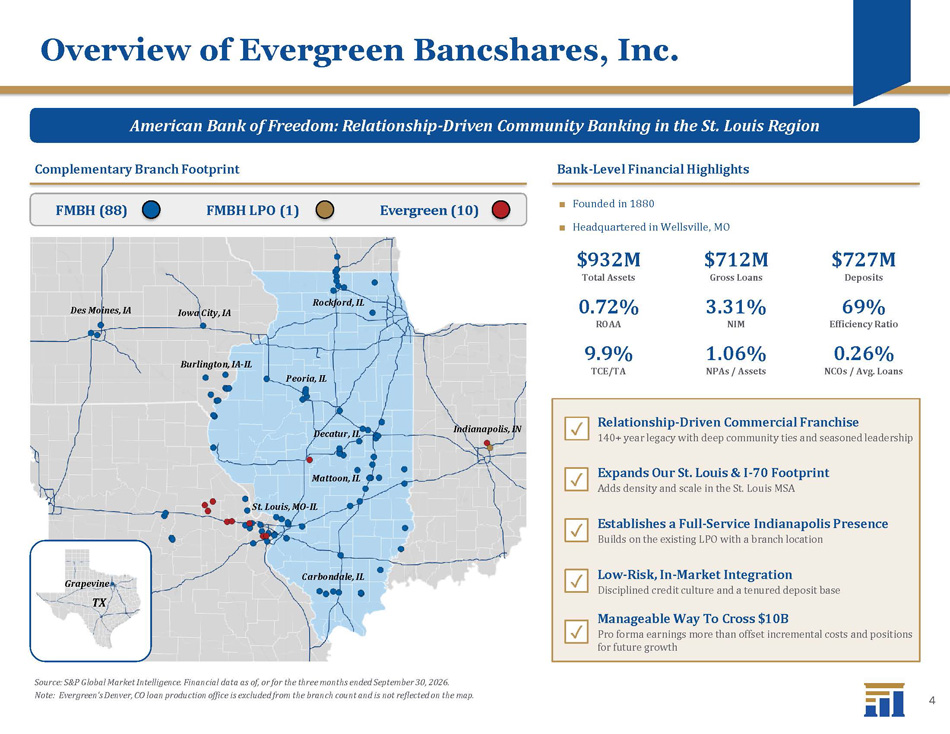
Overview of Evergreen Bancshares, Inc. American Bank of Freedom: Relationship - Driven Community Banking in the St. Louis Region Complementary Branch Footprint Bank - Level Financial Highlights Source: S&P Global Market Intelligence. Financial data as of, or for the three months ended September 30, 2026. Note: Evergreen's Denver, CO loan production office is excluded from the branch count and is not reflected on the map. St. Louis, MO - IL Indianapolis, IN Rockford, IL Des Moines, IA Peoria, IL Burlington, IA - IL Mattoon, IL Decatur, IL Carbondale, IL Iowa City, IA TX Grapevine ■ Founded in 1880 ■ Headquartered in Wellsville, MO $9 32M Total Assets $7 27M Deposits $ 712M Gross Loans 0.72% ROAA 69% Efficiency Ratio 3.31% NIM 9.9% TCE/TA 0.26% NCOs / Avg. Loans 1.06% NPAs / Assets 4 FMBH (88) FMBH LPO (1) Evergreen (10) ✓ Relationship - Driven Commercial Franchise 140+ year legacy with deep community ties and seasoned leadership ✓ Expands Our St. Louis & I - 70 Footprint Adds density and scale in the St. Louis MSA ✓ Establishes a Full - Service Indianapolis Presence Builds on the existing LPO with a branch location ✓ Manageable Way To Cross $10B Pro forma earnings more than offset incremental costs and positions for future growth ✓ Low - Risk, In - Market Integration Disciplined credit culture and a tenured deposit base
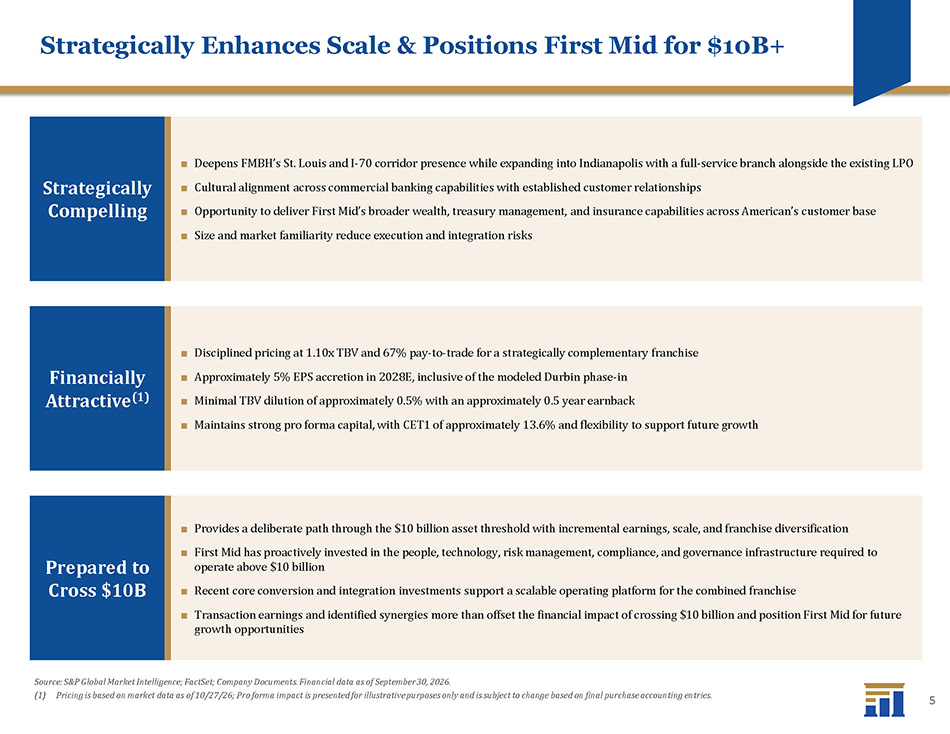
Strategically Enhances Scale & Positions First Mid for $10B+ Strategically Compelling ■ Deepens FMBH’s St. Louis and I - 70 corridor presence while expanding into Indianapolis with a full - service branch alongside the e xisting LPO ■ Cultural alignment across commercial banking capabilities with established customer relationships ■ Opportunity to deliver First Mid’s broader wealth, treasury management, and insurance capabilities across American’s customer ba se ■ Size and market familiarity reduce execution and integration risks Prepared to Cross $10B ■ Provides a deliberate path through the $10 billion asset threshold with incremental earnings, scale, and franchise diversific ati on ■ First Mid has proactively invested in the people, technology, risk management, compliance, and governance infrastructure requ ire d to operate above $10 billion ■ Recent core conversion and integration investments support a scalable operating platform for the combined franchise ■ Transaction earnings and identified synergies more than offset the financial impact of crossing $10 billion and position Firs t M id for future growth opportunities Financially Attractive (1) ■ Disciplined pricing at 1.10x TBV and 67% pay - to - trade for a strategically complementary franchise ■ Approximately 5% EPS accretion in 2028E, inclusive of the modeled Durbin phase - in ■ Minimal TBV dilution of approximately 0.5% with an approximately 0.5 year earnback ■ Maintains strong pro forma capital, with CET1 of approximately 13.6% and flexibility to support future growth Source: S&P Global Market Intelligence; FactSet ; C ompany D ocuments. Financial data as of September 30, 2026. (1) Pricing is based on market data as of 10/27/26; Pro forma impact is presented for illustrative purposes only and is subject t o c hange based on final purchase accounting entries. 5
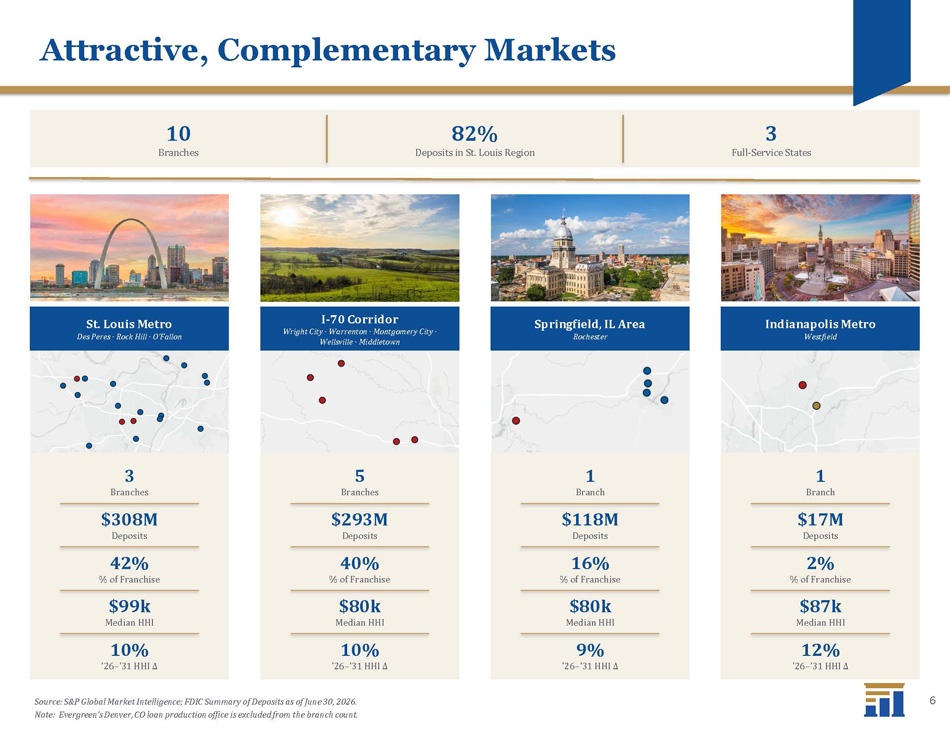
Attractive, Complementary Markets 1 0 Branches 8 2 % Deposits in St. Louis Region 3 Full - Service States St. Louis Metro Des Peres · Rock Hill · O'Fallon I - 70 Corridor Wright City · Warrenton · Montgomery City · Wellsville · Middletown Springfield, IL Area Rochester 3 Branches $30 8 M Deposits 42% % of Franchise 10 % '26 – '31 HHI Δ $ 99 k Median HHI 5 Branches $ 293 M Deposits 40 % % of Franchise 10 % '26 – '31 HHI Δ $ 80 k Median HHI 1 Branch $1 1 8M Deposits 16 % % of Franchise 9 % '26 – '31 HHI Δ $ 80 k Median HHI 1 Branch $17M Deposits 2% % of Franchise 12 % '26 – '31 HHI Δ $ 87 k Median HHI Source: S&P Global Market Intelligence ; FDIC Summary of Deposits as of June 30, 2026 . Note: Evergreen's Denver, CO loan production office is excluded from the branch count. Indianapolis Metro Westfield 6
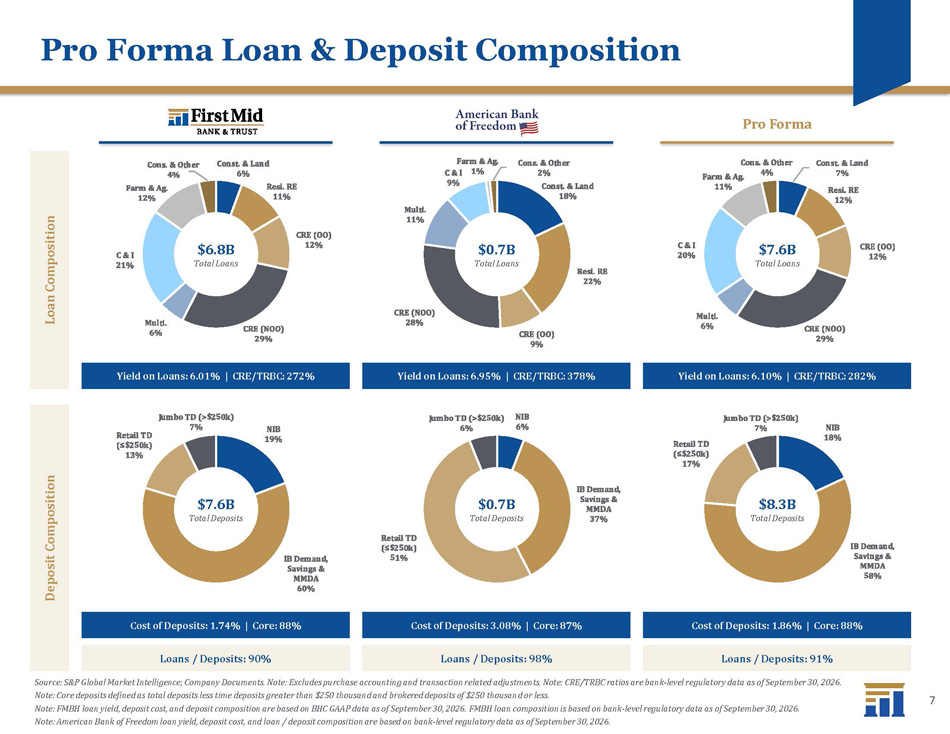
NIB 18% IB Demand, Savings & MMDA 58% Retail TD (≤$250k) 17% Jumbo TD (>$250k) 7% NIB 6% IB Demand, Savings & MMDA 37% Retail TD (≤$250k) 51% Jumbo TD (>$250k) 6% NIB 19% IB Demand, Savings & MMDA 60% Retail TD (≤$250k) 13% Jumbo TD (>$250k) 7% Const. & Land 7% Resi. RE 12% CRE (OO) 12% CRE (NOO) 29% Multi. 6% C & I 20% Farm & Ag. 11% Cons. & Other 4% Const. & Land 18% Resi. RE 22% CRE (OO) 9% CRE (NOO) 28% Multi. 11% C & I 9% Farm & Ag. 1% Cons. & Other 2% Const. & Land 6% Resi. RE 11% CRE (OO) 12% CRE (NOO) 29% Multi. 6% C & I 21% Farm & Ag. 12% Cons. & Other 4% Pro Forma Loan & Deposit Composition Loan Composition Deposit Composition $6. 8B Total Loans Yield on Loans: 6 .01 % | CRE/TRBC: 272% $7.6 B Total Deposits Cost of Deposits: 1.74% | Core: 88% Loans / Deposits: 9 0% $0.7 B Total Loans Yield on Loans: 6.95% | CRE/TRBC: 378% $0.7 B Total Deposits Cost of Deposits: 3.08% | Core: 87% Loans / Deposits: 9 8 % Pro Forma $7.6 B Total Loans Yield on Loans: 6.10% | CRE/TRBC: 282% $8.3 B Total Deposits Cost of Deposits: 1.86% | Core: 88% Loans / Deposits: 9 1% Source: S&P Global Market Intelligence ; C ompany D ocuments. Note: Excludes purchase accounting and transaction related adjustments . Note: CRE/TRBC ratios are bank - level regulatory data as of September 30, 2026. Note : Core deposits defined as total deposits less time deposits greater than $250 thousand and brokered deposits of $250 thousan d o r less. Note : FMBH loan yield, deposit cost, and deposit composition are based on BHC GAAP data as of September 30, 2026. FMBH loan compo sit ion is based on bank - level regulatory data as of September 30, 2026. Note : American Bank of Freedom loan yield, deposit cost, and loan / deposit composition are based on bank - level regulatory data as o f September 30, 2026. 7
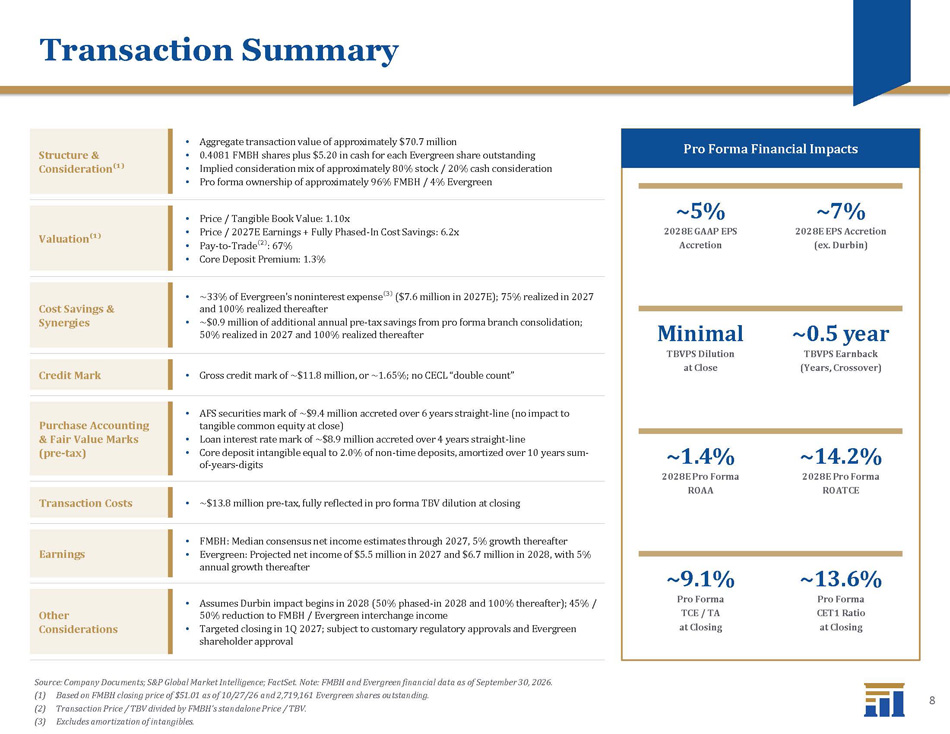
Transaction Summary Structure & Consideration⁽¹⁾ • Aggregate transaction value of approximately $ 70.7 million • 0.4081 FMBH shares plus $5.20 in cash for each Evergreen share outstanding • Implied consideration mix of approximately 80% stock / 20% cash consideration • Pro forma ownership of approximately 96% FMBH / 4% Evergreen Valuation⁽¹⁾ • Price / Tangible Book Value: 1. 10 x • Price / 2027E Earnings + Fully Phased - In Cost Savings: 6. 2 x • Pay - to - Trade⁽²⁾: 6 7 % • Core Deposit Premium: 1.3 % Cost Savings & Synergies • ~33% of Evergreen's noninterest expense ⁽³⁾ ($7.6 million in 2027E); 75% realized in 2027 and 100% realized thereafter • ~$0.9 million of additional annual pre - tax savings from pro forma branch consolidation; 50% realized in 2027 and 100% realized thereafter Credit Mark • Gross credit mark of ~$11.8 million, or ~1.6 5 % ; no CECL “double count” Purchase Accounting & Fair Value Marks (pre - tax) • AFS securities mark of ~$9.4 million accreted over 6 years straight - line (no impact to tangible common equity at close) • Loan interest rate mark of ~$ 8.9 million accreted over 4 years straight - line • Core deposit intangible equal to 2.0% of non - time deposits, amortized over 10 years sum - of - years - digits Transaction Costs • ~$13.8 million pre - tax , fully reflected in pro forma TBV dilution at closing Other Considerations • Assumes Durbin impact begins in 2028 (50% phased - in 2028 and 100% thereafter); 45% / 50% reduction to FMBH / Evergreen interchange income • Targeted closing in 1Q 2027; subject to customary regulatory approvals and Evergreen shareholder approval Pro Forma Financial Impacts ~ 5 % 2028E GAAP EPS Accretion ~ 7 % 2028E EPS Accretion (ex. Durbin) Minimal TBVPS Dilution at Close ~0.5 year TBVPS Earnback (Years, Crossover) ~ 1.4 % 2028E Pro Forma ROAA ~1 4.2 % 2028E Pro Forma ROA TCE ~9. 1 % Pro Forma TCE / TA at Closing ~13. 6 % Pro Forma CET1 Ratio at Closing Earnings • FMBH: Median consensus net income estimates through 2027, 5% growth thereafter • Evergreen: Projected net income of $5.5 million in 2027 and $6.7 million in 2028, with 5% annual growth thereafter 8 Source: Company Documents; S&P Global Market Intelligence; FactSet. Note: FMBH and Evergreen financial data as of September 3 0, 2026. (1) Based on FMBH closing price of $51.01 as of 10/27/26 and 2,719,161 Evergreen shares outstanding. (2) Transaction Price / TBV divided by FMBH's standalone Price / TBV. (3) Excludes amortization of intangibles.
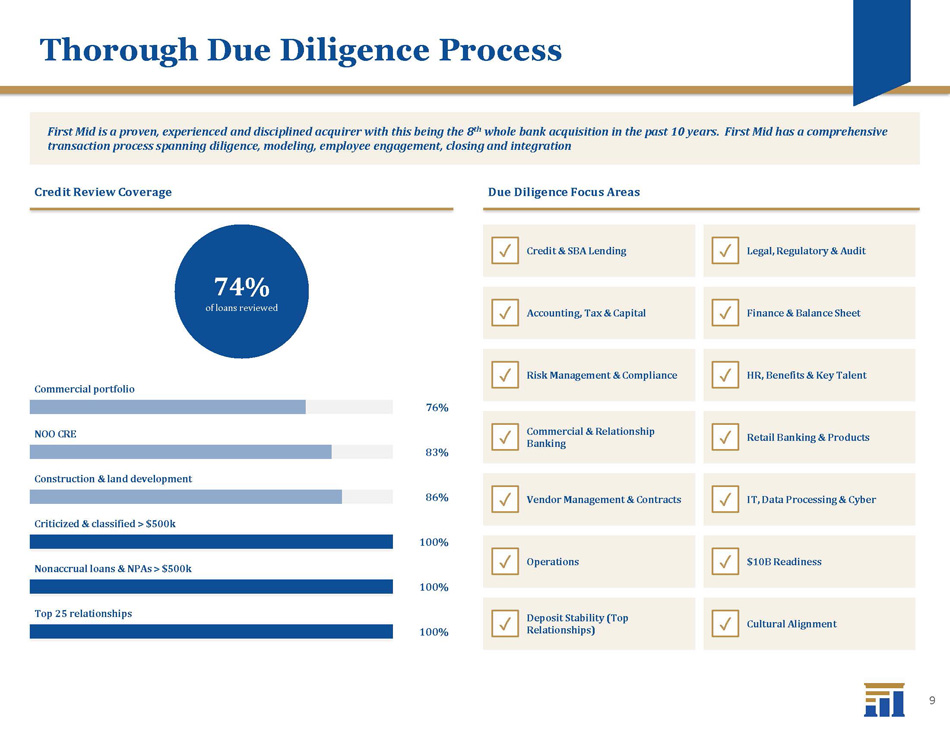
Thorough Due Diligence Process First Mid is a proven, experienced and disciplined acquirer with this being the 8 th whole bank acquisition in the past 10 years. First Mid has a comprehensive transaction process spanning diligence, modeling, employee engagement, closing and integration Credit Review Coverage 7 4 % of loans reviewed Commercial portfolio 76 % NOO CRE 83 % Construction & land development 86 % Criticized & classified > $ 500 k 100 % Nonaccrual loans & NPAs > $500k 100% Top 25 relationships 100% Due Diligence Focus Areas ✓ Credit & SBA Lending ✓ Legal, Regulatory & Audit ✓ Accounting, Tax & Capital ✓ Finance & Balance Sheet ✓ Risk Management & Compliance ✓ HR, Benefits & Key Talent ✓ Commercial & Relationship Banking ✓ Retail Banking & Products ✓ Vendor Management & Contracts ✓ IT, Data Processing & Cyber ✓ Operations ✓ $10B Readiness ✓ Deposit Stability (Top Relationships) ✓ Cultural Alignment 9
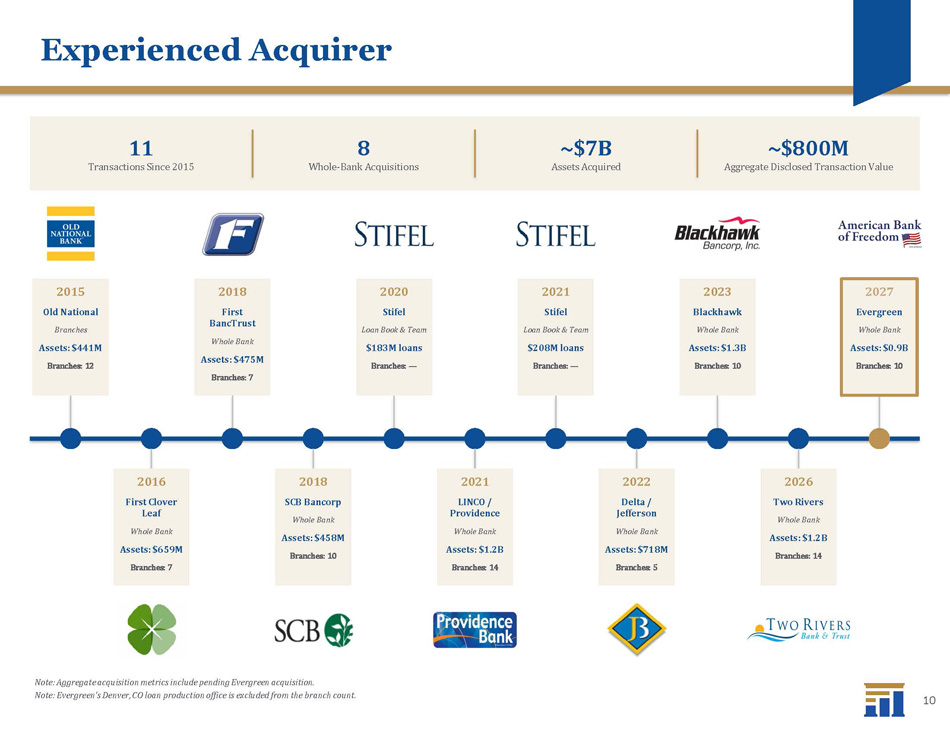
Experienced Acquirer 11 Transactions Since 2015 8 Whole - Bank Acquisitions ~ $7 B Assets Acquired ~$ 8 00 M Aggregate Disclosed Transaction Value 2015 Old National Branches Assets: $441M Branches: 12 2016 First Clover Leaf Whole Bank Assets: $659M Branches: 7 2018 First BancTrust Whole Bank Assets: $475M Branches: 7 2018 SCB Bancorp Whole Bank Assets: $458M Branches: 10 2020 Stifel Loan Book & Team $183M loans Branches: — 2021 LINCO / Providence Whole Bank Assets: $1.2B Branches: 14 2021 Stifel Loan Book & Team $208M loans Branches: — 2022 Delta / Jefferson Whole Bank Assets: $718M Branches: 5 2023 Blackhawk Whole Bank Assets: $1.3B Branches: 10 2026 Two Rivers Whole Bank Assets: $1. 2 B Branches: 14 2027 Evergreen Whole Bank Assets: $0.9 B Branches: 10 Note: Aggregate acquisition metrics include pending Evergreen acquisition. Note: Evergreen's Denver, CO loan production office is excluded from the branch count. 10
Appendix Appendix 11
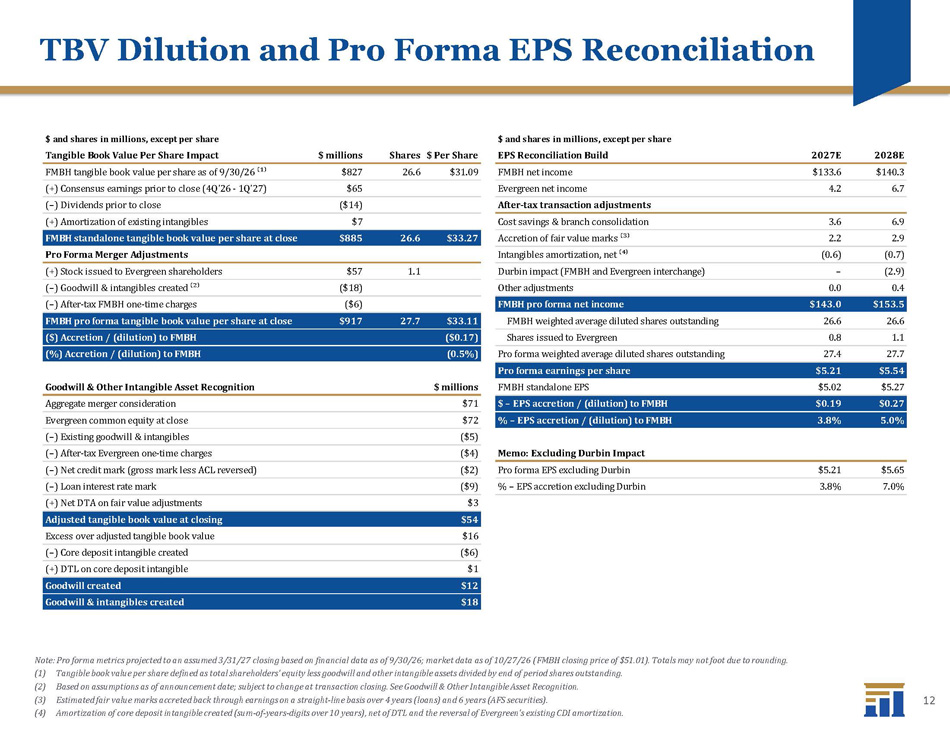
TBV Dilution and Pro Forma EPS Reconciliation Note : Pro forma metrics projected to an assumed 3/31/27 closing based on financial data as of 9/30/26; market data as of 10/27/26 ( FMB H closing price of $51.01). Totals may not foot due to rounding. (1) Tangible book value per share defined as total shareholders' equity less goodwill and other intangible assets divided by end of period shares outstanding. (2) Based on assumptions as of announcement date; subject to change at transaction closing. See Goodwill & Other Intangible Asset Re cognition. (3) Estimated fair value marks accreted back through earnings on a straight - line basis over 4 years (loans) and 6 years (AFS securit ies). (4) Amortization of core deposit intangible created (sum - of - years - digits over 10 years), net of DTL and the reversal of Evergreen's existing CDI amortization. $ and shares in millions, except per share $ and shares in millions, except per share Tangible Book Value Per Share Impact $ millions Shares$ Per Share EPS Reconciliation Build 2027E 2028E FMBH tangible book value per share as of 9/30/26 ⁽¹⁾ $827 26.6 $31.09 FMBH net income $133.6 $140.3 (+) Consensus earnings prior to close (4Q'26 - 1Q'27) $65 Evergreen net income 4.2 6.7 (–) Dividends prior to close ($14) After-tax transaction adjustments (+) Amortization of existing intangibles $7 Cost savings & branch consolidation 3.6 6.9 FMBH standalone tangible book value per share at close $885 26.6 $33.27 Accretion of fair value marks ⁽³⁾ 2.2 2.9 Pro Forma Merger Adjustments Intangibles amortization, net ⁽⁴⁾ (0.6) (0.7) (+) Stock issued to Evergreen shareholders $57 1.1 Durbin impact (FMBH and Evergreen interchange) – (2.9) (–) Goodwill & intangibles created ⁽²⁾ ($18) Other adjustments 0.0 0.4 (–) After-tax FMBH one-time charges ($6) FMBH pro forma net income $143.0 $153.5 FMBH pro forma tangible book value per share at close $917 27.7 $33.11 FMBH weighted average diluted shares outstanding 26.6 26.6 ($) Accretion / (dilution) to FMBH ($0.17) Shares issued to Evergreen 0.8 1.1 (%) Accretion / (dilution) to FMBH (0.5%) Pro forma weighted average diluted shares outstanding 27.4 27.7 Pro forma earnings per share $5.21 $5.54 Goodwill & Other Intangible Asset Recognition $ millions FMBH standalone EPS $5.02 $5.27 Aggregate merger consideration $71 $ – EPS accretion / (dilution) to FMBH $0.19 $0.27 Evergreen common equity at close $72 % – EPS accretion / (dilution) to FMBH 3.8% 5.0% (–) Existing goodwill & intangibles ($5) (–) After-tax Evergreen one-time charges ($4) Memo: Excluding Durbin Impact (–) Net credit mark (gross mark less ACL reversed) ($2) Pro forma EPS excluding Durbin $5.21 $5.65 (–) Loan interest rate mark ($9) % – EPS accretion excluding Durbin 3.8% 7.0% (+) Net DTA on fair value adjustments $3 Adjusted tangible book value at closing $54 Excess over adjusted tangible book value $16 (–) Core deposit intangible created ($6) (+) DTL on core deposit intangible $1 Goodwill created $12 Goodwill & intangibles created $18 12