Exhibit 99.1
3Q 2026
Results
October 28, 2026
Investor Contact
(52) 81-8328-6167
investor@femsa.com
femsa.gcs-web.com
Media Contact
(52) 55-5249-6843
comunicacion@femsa.com
www.femsa.com
HIGHLIGHTS
Monterrey, Mexico, October 28, 2026 — Fomento Económico Mexicano, S.A.B. de C.V. (“FEMSA”) (NYSE: FMX; BMV: FEMSAUBD, FEMSAUB) announced today its operational and financial results for the third quarter of 2026.
Reporting Segments Update: In our continuous effort to improve our disclosure, we have updated FEMSA’s reporting segment structure to better reflect the scale, stage of development, and strategic differentiation of our various operations. This updated structure should provide investors with greater visibility into the drivers of performance across our operations. Our updated reporting segments are as follows: i) OXXO Mexico; ii) Americas & Mobility which now includes all OXXO convenience store operations outside of Mexico (Brazil, Colombia, Chile, Peru and the U.S.), as well as the fuel operations in Mexico and the U.S; iii) Europe; iv) Health; and v) Coca-Cola FEMSA. Only segments i) and ii) changed relative to our previous reporting structure.
October 28, 2026 | Page 1
| · | FEMSA: Total consolidated revenues grew 9.8% and Income from operations increased 9.9% compared to 3Q25. |
| · | OXXO Mexico: Total revenues grew 10.3% and Income from operations increased 5.8% versus 3Q25. |
| · | SPIN: Spin by OXXO had 11.7 million active users1 representing 17.3% growth compared to 3Q25 while Spin Premia had 30.0 million active loyalty users1 representing 8.3% growth compared to 3Q25, and an average tender2 at OXXO Mexico of 52.1% which increased from 48.2% in 3Q25. |
| · | COCA-COLA FEMSA: Total revenues grew 10.9% and Income from Operations increased 15.4% against 3Q25. |
Financial Summary for the Third Quarter and First Nine Months of 2026
Change vs. comparable period
| Total Revenues | Gross Profit | Income
from Operations | Same-Store Sales | |||||||||||||||||||||||||||||
| As Reported | 3Q26 | YTD26 | 3Q26 | YTD26 | 3Q26 | YTD26 | 3Q26 | YTD26 | ||||||||||||||||||||||||
| FEMSA Consolidated | 9.8 | % | 8.7 | % | 9.7 | % | 8.3 | % | 9.9 | % | 7.9 | % | ||||||||||||||||||||
| OXXO Mexico | 10.3 | % | 10.2 | % | 7.4 | % | 9.6 | % | 5.8 | % | 12.0 | % | 9.2 | % | 8.3 | % | ||||||||||||||||
| Americas & Mobility | 18.1 | % | 16.2 | % | 18.6 | % | 20.1 | % | (75.9 | )% | (66.5 | )% | 13.8 | %3 | 10.1 | %3 | ||||||||||||||||
| Europe | (5.2 | )% | (3.1 | )% | (10.8 | )% | (6.5 | )% | (24.8 | )% | (11.6 | )% | (7.7 | )% | (5.5 | )% | ||||||||||||||||
| Health | 7.0 | % | 3.3 | % | (7.4 | )% | (8.7 | )% | (63.2 | )% | (46.1 | )% | 4.6 | % | 1.8 | % | ||||||||||||||||
| Coca-Cola FEMSA | 10.9 | % | 6.2 | % | 14.5 | % | 9.8 | % | 15.4 | % | 8.0 | % | ||||||||||||||||||||
| Comparable(A) | ||||||||||||||||||||||||||||||||
| FEMSA Consolidated | 9.4 | % | 9.4 | % | 9.8 | % | 9.3 | % | 13.4 | % | 12.4 | % | ||||||||||||||||||||
| OXXO Mexico | 10.3 | % | 10.2 | % | 7.4 | % | 9.6 | % | 5.8 | % | 12.0 | % | 9.2 | % | 8.3 | % | ||||||||||||||||
| Americas & Mobility | 10.9 | % | 11.1 | % | 4.5 | % | 9.8 | % | (29.9 | )% | (8.7 | )% | 15.8 | %4 | 16.3 | %4 | ||||||||||||||||
| Europe | 4.0 | % | 2.9 | % | (2.2 | )% | (0.6 | )% | (17.5 | )% | (5.4 | )% | 1.3 | % | 1.0 | % | ||||||||||||||||
| Health | 3.4 | % | 4.9 | % | (8.2 | )% | (5.9 | )% | (63.8 | )% | (44.2 | )% | 6.5 | % | 6.6 | % | ||||||||||||||||
| Coca-Cola FEMSA | 11.3 | % | 10.4 | % | 14.8 | % | 14.1 | % | 16.4 | % | 11.9 | % | ||||||||||||||||||||
Jose Antonio Fernández Garza-Lagüera, FEMSA’s Chief Executive Officer, commented:
“During the third quarter we delivered a strong set of results, led by OXXO Mexico and Coca-Cola FEMSA, our two largest businesses. OXXO Mexico continued to build on the positive momentum seen in recent quarters, while Coca-Cola FEMSA delivered strong growth across the income statement, mainly supported by solid performances in most of its territories.
We are particularly encouraged by the continued recovery at OXXO Mexico, where same-store sales accelerated and customer traffic delivered its strongest performance in more than two years. This result was driven largely by stronger execution in most regions, commercial initiatives focused on key traffic-driving categories, and the consumer-centric strategy we began implementing last year. These initiatives are gaining traction and allowing us to generate additional traffic while maintaining a disciplined approach to profitability. Beyond OXXO Mexico, Coca-Cola FEMSA delivered a very strong quarter, with solid volume trends and double-digit growth in revenues and operating income, reflecting broad-based contributions across its operations.
We also continued to see encouraging progress in some of our growth platforms, with Bara gaining momentum as it accelerates expansion and strengthens the performance of its growing store base, while our OXXO operations in South America maintained a solid commercial trajectory, especially in Colombia. However, certain other business units faced operating headwinds, particularly our Europe and Health divisions, which delivered mixed results. We continue to work hard to bring those business units to their potential.
As we enter the final quarter of the year, we remain mindful that the consumer environment in Mexico continues to be soft, Brazil has faced some volatility recently and that we will face a more demanding comparison base in the coming quarters. Nevertheless, we are encouraged by the momentum we are seeing across most of our businesses. While we recognize that the final stretch of the year will present its share of challenges, we believe the strength of our geographically diversified platform positions us well to continue executing against our long-term strategy in pursuit of sustainable, profitable growth.”
(A) Please refer to page 12 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance.
1 Active User for Spin by OXXO: Any user with a balance
or that has transacted within the last 56 days.
Active User for Spin Premia: User that has transacted at least once with OXXO Premia within the last 90 days.
2 Tender: OXXO MXN sales with Spin Premia redemption or accrual / Total OXXO MXN Sales, during the period.
3 Only includes merchandise.
4 Currency-neutral. Only includes merchandise. Same-store sales includes a weighted average of OXXO Colombia, Chile, Peru and the U.S.A.
October 28, 2026 | Page 2
QUARTERLY RESULTS
Results are compared to the same period of previous year
FEMSA CONSOLIDATED
3Q26 Financial Summary
Amounts expressed in millions of Mexican Pesos (Ps.)
| 3Q26 | 3Q25 | Var. | Comp.(A) | |||||||||||||
| Total Revenues | 235,609 | 214,638 | 9.8 | % | 9.4 | % | ||||||||||
| Gross Profit | 94,050 | 85,709 | 9.7 | % | 9.8 | % | ||||||||||
| Gross Profit Margin (%) | 39.9 | 39.9 | - | |||||||||||||
| Income from Operations | 19,918 | 18,126 | 9.9 | % | 13.4 | % | ||||||||||
| Operating Margin (%) | 8.5 | 8.4 | 10 bps | |||||||||||||
| Adjusted EBITDA1 | 34,833 | 30,843 | 12.9 | % | 14.5 | % | ||||||||||
| EBITDA Margin (%) | 14.8 | 14.4 | 40 bps | |||||||||||||
| Consolidated Net Income | 10,569 | 5,838 | 81.0 | % | ||||||||||||
Net Debt2 ex-KOF3
Amounts expressed in millions of Mexican Pesos (Ps.)
| As of September 30, 2026 | Ps. | US$4 | ||||||
| Cash and Investments | 70,403 | 3,898 | ||||||
| Financial Debt | 54,762 | 3,032 | ||||||
| Lease Liabilities | 110,844 | 6,137 | ||||||
| Net debt (ND) | 95,203 | 5,271 | ||||||
| ND / Adjusted LTM EBITDA | 1.19 | x | - | |||||
Total revenues increased 9.8% in 3Q26 compared to 3Q25, driven by growth in Coca-Cola FEMSA, OXXO Mexico, Americas & Mobility and Health, partially offset by a decrease in Europe. Excluding the consolidation of OXXO Brazil and currency effects, revenues grew 9.4% on a comparable basis and all the reported segments grew.
Gross profit increased 9.7%, while gross margin remained stable at 39.9%. This reflected margin expansion in Coca-Cola FEMSA and Americas & Mobility, offset by contractions in OXXO Mexico, Europe and Health. The decline in margin in OXXO Mexico resulted in part from a demanding comparison base as the third quarter of 2025 included a particularly high concentration of commercial income. On a comparable basis, gross profit increased 9.8%.
Income from operations increased 9.9%, driven by growth in Coca-Cola FEMSA and OXXO Mexico, partially offset by declines in Americas & Mobility, Europe and Health. The consolidated operating margin reached 8.5%, representing a 10 basis-point expansion year-over-year, reflecting margin expansion at Coca-Cola FEMSA, partially offset by margin contractions at OXXO Mexico, Americas & Mobility, Europe and Health. On a comparable basis, income from operations increased 13.4%.
The effective income tax rate was 32.5% in 3Q26. Our income tax provision for 3Q26 was Ps. 5,080 million, an increase of 34.2% relative to 3Q25.
Net consolidated income amounted to Ps. 10,569 million, compared to Ps. 5,838 million in 3Q25, representing an increase of 81.0%. This increase was supported by: i) the absence of the Ps. 3,146 million loss from discontinued operations recorded in 3Q25, which reflected the divestiture of Solistica5; ii) growth in income from operations; and iii) a non-cash foreign exchange gain of Ps. 1,121 million, compared to a loss of Ps. 1,261 million in 3Q25, reflecting a favorable swing of Ps. 2,382 million, mainly due to the depreciation of the Mexican peso against the U.S. dollar, that impacted our investment in ImperialBrady as well as our U.S. dollar-denominated cash and investment position. These effects were partially offset by: i) higher net interest expense of Ps. 4,541 million, compared to Ps. 3,563 million in 3Q25, mainly reflecting lower interest income of Ps. 1,371 million compared to Ps. 1,907 million in 3Q25, driven by lower interest rates and lower cash balances; ii) other financial expenses of Ps. 312 million, compared to income of Ps. 55 million in 3Q25, mainly reflecting a loss on financial instruments at Coca-Cola FEMSA Brazil; and iii) a higher income tax provision of Ps. 5,080 million, compared to Ps. 3,785 million in 3Q25.
Net majority income was Ps. 2.00 per FEMSA BD Unit6, representing 185.7% growth, and US$1.10 per FEMSA ADS4.
Net Debt / Adjusted EBITDA. On an ex-KOF basis, as of September 30, 2026, cash and investments were Ps. 70,403 million and total debt was Ps. 165,605 million, resulting in net debt of Ps. 95,203 million. Our Net Debt / Adjusted LTM EBITDA ratio ex-KOF was 1.19x up from 0.91x in 3Q25. This year-on-year increase mainly reflects the cash outflow related to our capital allocation strategy.
Capital expenditures amounted to Ps. 9,408 million, representing 4.0% of total revenues and a decrease of 28.3% compared to 3Q25, mainly reflecting lower CAPEX at Coca-Cola FEMSA, coupled with lower investments at OXXO Mexico, Europe and Health. This was partially offset by higher CAPEX in Americas & Mobility, related to store expansion investments across the region.
| OXXO MEXICO |  |
3Q26 Financial Summary
– OXXO Mexico
Amounts expressed in millions of Mexican Pesos (Ps.)
| 3Q26 | 3Q25 | Var. | ||||||||||
| Same-store sales (thousands of Ps.)1 | 1,088.6 | 997.1 | 9.2 | % | ||||||||
| Total Revenues | 86,652 | 78,539 | 10.3 | % | ||||||||
| Gross Profit | 38,810 | 36,123 | 7.4 | % | ||||||||
| Gross Profit Margin (%) | 44.8 | 46.0 | (120 bps | ) | ||||||||
| Income from Operations | 8,041 | 7,603 | 5.8 | % | ||||||||
| Income from Operations Margin (%) | 9.3 | 9.7 | (40 bps | ) | ||||||||
| Adjusted EBITDA | 12,655 | 11,631 | 8.8 | % | ||||||||
| Adjusted EBITDA Margin (%) | 14.6 | 14.8 | (20 bps | ) | ||||||||
(A) Please refer to page 12 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance.
1 Adjusted EBITDA: Operating Income + Depreciation + Amortizations + other non-cash charges.
Adjusted EBITDA ex-KOF: FEMSA Consolidated Adjusted EBITDA as described above – Coca-Cola FEMSA’s Consolidated Adjusted EBITDA + Dividends received by FEMSA from Coca-Cola FEMSA and other investments.
2 All Net Debt calculations are shown on an Ex-KOF basis. For a detailed reconciliation of this metric please see table on page 15 of this document.
3 ex-KOF: FEMSA Consolidated reported information – Coca-Cola FEMSA Consolidated reported information. Adjusted EBITDA ex-KOF includes dividends received from Coca-Cola FEMSA
4 The exchange rate published by the Federal Reserve Bank of New York for September 30, 2026 was 18.0609 MXN per USD.
5 Following the third-quarter 2025 divestitures, the initial de-recognition of Solistica at face value resulted in a temporary loss of Ps. 3,146 million (Ps. 99 million loss on a comparable basis). In the fourth quarter, this effect was reversed and the disposal gain recalculated using the investment’s carrying amount. As a result, the Company recognized a full-year gain of Ps. 1,574 million in discontinued operations, reflecting the combined impact of the Solistica and PTM divestitures.
6 “FEMSA Units” consist of FEMSA BD Units and FEMSA B Units. Each FEMSA BD Unit is comprised of one Series B Share, two Series D-B Shares and two Series D-L Shares. Each FEMSA B Unit is comprised of five Series B Shares. Each FEMSA American Depositary Share (“ADS”) represents 10 FEMSA BD Units. The total number of FEMSA Units outstanding as of September 30, 2026 was 3,385,664,115.
1 Same-store Sales OXXO Mexico.
October 28, 2026 | Page 3
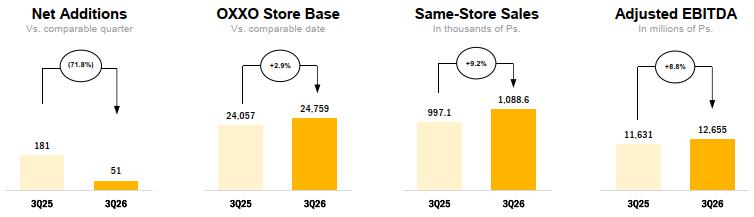
Total revenues increased 10.3% in 3Q26 compared to 3Q25, reflecting a 9.2% increase in same-store sales, coupled with 2.9% store expansion. The growth in same-store sales was driven by a 5.5% increase in the average ticket and a 3.5% increase in store traffic. During the quarter, results were supported by: i) the continued execution of commercial initiatives, including assortment and affordability actions across key categories, which contributed to market share gains in core categories; ii) more favorable weather conditions compared to the prior year; and iii) continued growth in services. These effects were partially offset by above-trend store closures. The increase in average ticket mainly reflected the effect of excise taxes on beverages and cigarettes. During the quarter, the OXXO store base in Mexico expanded by 51 net stores. This included the addition of 191 stores, offset by the closure of 140 older, underperforming locations, as part of a portfolio optimization initiative. OXXO Mexico added 702 net new stores during the last twelve months and had a total of 24,759 stores as of September 30, 2026.
Gross profit increased 7.4% and reached 44.8% of total revenues, representing a 120-basis point contraction compared to 3Q25. This contraction mainly reflects a demanding comparison base as the third quarter of 2025 included a particularly high concentration of commercial income. Normalizing for this effect, OXXO Mexico’s gross margin would have declined in line with the 70-basis point contraction of the second quarter of 2026, reflecting the solid performance of key impulse categories, and the continued growth in higher margin services. This was partially offset by continued commercial initiatives in key categories, aimed at strengthening traffic and market share, including adjustments to price package architecture and price rationalization in relevant traffic-driving categories.
Income from operations increased 5.8% compared to 3Q25 and reached 9.3% of total revenues, representing a 40-basis point margin contraction year over year. This performance was mainly explained by the gross margin contraction described above, the costs associated with the closing of underperforming stores, and higher labor and variable compensation expenses. Operating expenses increased 7.9%, below revenue growth, reflecting the cost containment and operational efficiencies implemented during last year, particularly in administrative expenses, partially offset by higher labor costs.
| AMERICAS1 & MOBILITY2 | |
3Q26 Financial Summary – Americas &
Mobility
Amounts expressed in millions of Mexican Pesos (Ps.)
| 3Q26 | 3Q25 | Var. | Comp.(A) | |||||||||||||
| Same-store sales (thousands of Ps.) | 1,176.6 | 1,033.9 | 13.8 | % | 15.8 | %3 | ||||||||||
| Merchandise1 Sales | 6,936 | 4,177 | 66.0 | % | 19.0 | % | ||||||||||
| Fuel2 and Other Sales | 22,530 | 20,783 | 8.4 | % | 9.3 | % | ||||||||||
| Total Revenues | 29,466 | 24,960 | 18.1 | % | 10.9 | % | ||||||||||
| Merchandise1 Gross Profit | 2,321 | 1,657 | 40.0 | % | 3.2 | % | ||||||||||
| Fuel2 and Other Gross Profit | 2,616 | 2,506 | 4.4 | % | 6.6 | % | ||||||||||
| Gross Profit | 4,937 | 4,163 | 18.6 | % | 4.5 | % | ||||||||||
| Gross Profit Margin (%) | 16.8 | 16.7 | 10 bps | |||||||||||||
| Income from Operations | 170 | 706 | (75.9 | )% | (29.9 | )% | ||||||||||
| Income from Operations Margin (%) | 0.6 | 2.8 | (220 bps | ) | ||||||||||||
| Adjusted EBITDA | 1,418 | 1,404 | 1.0 | % | (0.4 | )% | ||||||||||
| Adjusted EBITDA Margin (%) | 4.8 | 5.6 | (80 bps | ) | ||||||||||||
(A) Please refer to page 12 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance.
1 Americas: OXXO Brazil, Chile, Colombia, Peru and USA.
2 Mobility: Fuel operations in Mexico and the USA, and Mecanica Tek.
3 Same-store Sales is a weighted average of OXXO Colombia, Chile, Peru and the U.S.A
October 28, 2026 | Page 4
AMERICAS1
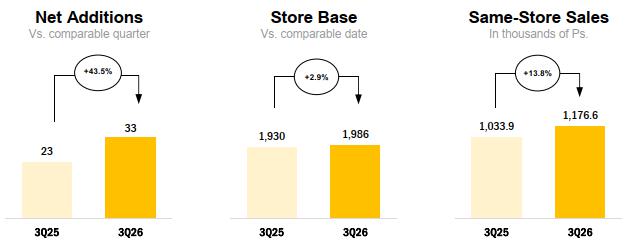
Total revenues increased 18.1% in 3Q26 compared to 3Q25, reflecting an 8.4% increase in our Fuel sales, coupled with a 66.0% increase in our Merchandise sales. The growth in our Fuel sales mainly reflects an increase in volume and traffic in our service stations in Mexico, and flat results in our U.S. fuel business with higher prices being offset by lower volumes. The solid performance in our Merchandise sales mainly reflects the continued growth of our OXXO operations in South America. We also benefited from the integration of OXXO Brazil which we began consolidating on February 1st, 2026. Same-store sales increased 13.8% in Mexican pesos and 15.8% on a comparable basis during the quarter, supported by currency-neutral growth of 5.1% in Brazil, 21.2% in Latam and 1.5% in the U.S. On a comparable basis, which excludes the addition of OXXO Brazil as well as currency effects, total revenues increased 10.9%. During the quarter, the store base expanded by 33 net stores. Americas & Mobility had 56 net store additions during the last twelve months and had a total of 1,986 stores as of September 30, 2026.
Gross profit reached 16.8% of total revenues, representing a 10-basis point margin expansion compared to 3Q25. This includes a reclassification of certain expenses, from cost of goods sold to selling expenses at OXXO operations in Colombia, Chile and Peru, reflected in 3Q25. Gross profit increased 18.6% compared to 3Q25. Excluding the effects of this reclassification, gross profit would have increased 25.4% and gross profit margin would have expanded 110 basis points from an adjusted base of 15.7% in 3Q25, mainly reflecting strong growth in Merchandise gross profit driven by the performance of our OXXO stores in South America, and the consolidation of OXXO Brazil. Fuel gross profit increased 4.4%, reflecting better gross margin at our Fuel operations in the U.S., partially offset by higher fuel costs coupled with maximum price commitments that continued to weigh on unit margins in our fuel business in Mexico.
Income from operations decreased by 75.9% compared to 3Q25 and represented 0.6% of total revenues, representing a 220-basis point margin contraction year over year. This performance was mainly explained by the incorporation of OXXO Brazil losses into the consolidated results, coupled with the continued pressure on Fuel margins in Mexico described above. This was partially offset by improved operating performance in OXXO Chile, Peru and Colombia. Operating expenses increased above total revenue growth, reflecting the incorporation of OXXO Brazil and increased expenses as we continue to build capabilities to support future growth. On a comparable basis, income from operations decreased 29.9%.
| Bara1 |  |
Bara
Total revenues increased by 44.1% in 3Q26 compared to 3Q25, reflecting an average same-store sales increase of 10.3%, with an ongoing strong performance in the grocery, homecare and convenience categories and the addition of 325 net new Bara stores during the last twelve months, a 56.7% year over year increase in the store base. During the quarter, the Bara store base expanded by 112 units reaching a total of 898 Bara stores as of September 30, 2026.
1 Bara store count and results are not consolidated within the Americas & Mobility reported figures.
October 28, 2026 | Page 5
EUROPE
3Q26 Financial Summary
– Europe
Amounts expressed in millions of Mexican Pesos (Ps.)
| 3Q26 | 3Q25 | Var. | Comp.(A) | |||||||||||||
| Same-store sales (thousands of Ps.)1 | 1,852.5 | 2,006.9 | (7.7 | )% | 1.3 | % | ||||||||||
| Total Revenues | 14,063 | 14,837 | (5.2 | )% | 4.0 | % | ||||||||||
| Gross Profit | 5,531 | 6,203 | (10.8 | )% | (2.2 | )% | ||||||||||
| Gross Profit Margin (%) | 39.3 | 41.8 | (250 bps | ) | ||||||||||||
| Income from Operations | 531 | 706 | (24.8 | )% | (17.5 | )% | ||||||||||
| Income from Operations Margin (%) | 3.8 | 4.8 | (100 bps | ) | ||||||||||||
| Adjusted EBITDA | 1,990 | 2,288 | (13.0 | )% | (4.5 | )% | ||||||||||
| Adjusted EBITDA Margin (%) | 14.2 | 15.4 | (120 bps | ) | ||||||||||||
Total revenues decreased 5.2% in 3Q26 compared to 3Q25, reflecting currency headwinds. On a currency-neutral basis, total revenues grew 4.0%, reflecting continued growth in our Swiss retail operations, supported by a favorable sales mix, partially offset by lower B2B sales and softer performance across formats in Germany, impacted by adverse weather, transport-related disruptions and a challenging consumer environment.
Gross profit represented 39.3% of total revenues, a 250-basis point margin contraction, reflecting a reclassification of distribution expenses from selling expenses to cost of goods sold, which is not reflected in 3Q25. Gross profit decreased 10.8% compared to 3Q25 and decreased 2.2% on a currency-neutral basis. Excluding the effects of this reclassification, gross profit would have decreased 7.4% in 3Q26, and the gross profit margin would have contracted 90 basis points from an adjusted base of 40.2% in 3Q25, mainly reflecting lower food and tobacco margins, partially offset by higher promotional income.
Income from operations decreased 24.8% versus 3Q25 and represented 3.8% of total revenues, a 100 basis-point contraction year-on-year, mainly impacted by a lower B2B contribution. This was partially offset by the solid performance of our Swiss retail operations, supported by higher promotional income and effective expense control. On a comparable basis, income from operations decreased 17.5%.
(A) Please refer to page 12 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance.
1 Same-store Sales reflects a weighted average from our foodservice and retail operations.
October 28, 2026 | Page 6
| HEALTH |  |
3Q26
Financial Summary - Health
Amounts expressed in millions of Mexican Pesos (Ps.) except same-store sales
| 3Q26 | 3Q25 | Var. | Comp.(A) | |||||||||||||
| Same-store sales (thousands of Ps.)1 | 1,055.9 | 1,009.1 | 4.6 | % | 6.5 | % | ||||||||||
| Total Revenues | 22,985 | 21,483 | 7.0 | % | 3.4 | % | ||||||||||
| Gross Profit | 5,977 | 6,458 | (7.4 | )% | (8.2 | )% | ||||||||||
| Gross Profit Margin (%) | 26.0 | 30.1 | (410 bps | ) | ||||||||||||
| Income from Operations | 319 | 869 | (63.2 | )% | (63.8 | )% | ||||||||||
| Income from Operations Margin (%) | 1.4 | 4.0 | (260 bps | ) | ||||||||||||
| Adjusted EBITDA | 2,049 | 2,415 | (15.2 | )% | (15.3 | )% | ||||||||||
| Adjusted EBITDA Margin (%) | 8.9 | 11.2 | (230 bps | ) | ||||||||||||
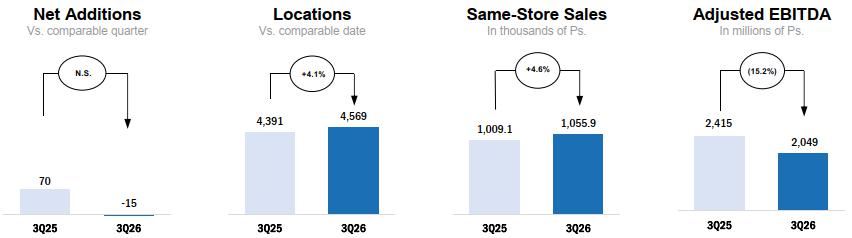
Total revenues increased 7.0% in 3Q26 compared to 3Q25, reflecting a positive performance in Colombia retail and Ecuador, partially offset by lower revenues from Colombia’s institutional business and softer performance in Chile. On a currency-neutral basis total revenues grew 3.4%. During the quarter, the net store base decreased by 15 units, reaching a total of 4,569 locations across our territories as of September 30, 2026, and it added 178 total net locations during the last twelve months. Same-store sales increased 4.6% in Mexican pesos and 6.5% on a currency-neutral basis.
Gross profit represented 26.0% of total revenues, a 410 basis-point margin contraction compared to 3Q25, mainly reflecting the reclassification of distribution expenses from selling expenses to cost of goods sold; this effect is not reflected in 3Q25. The decline in gross profit margin was also driven by an unfavorable sales mix in Chile and Ecuador, and margin pressure in Mexico. Gross profit decreased 7.4% compared to 3Q25, reflecting the effects mentioned above as well as the lower contribution from Colombia’s institutional business, as we de-escalate this segment of the business. Excluding the effects of this reclassification, and on a currency neutral basis, gross profit would have increased 1.4% while the gross profit margin would have contracted 80 basis points from a base of 26.8%.
(A) Please refer to page 12 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance.
1 Same-store Sales reflects a weighted average from our operations.
October 28, 2026 | Page 7
Income from operations decreased 63.2% and represented 1.4% of total revenues, a reduction of 260 basis points from 4.0%, mainly reflecting a non-cash credit-risk provision of Ps. 430 million in connection with the unwinding process of Colombia’s institutional business and lower income from operations in Chile, mainly driven by the gross margin contraction described above. This was partially offset by the solid performance of Colombia retail, and a lower operating loss in Mexico, supported by continued cost and expense control. On a comparable basis, income from operations contracted by 63.8%.
October 28, 2026 | Page 8
| SPIN1 |  |
Spin by OXXO
Spin by OXXO acquired 0.8 million users during the quarter to reach 18.4 million total acquired users in 3Q26, compared to 15.3 million users in 3Q25. This represents an increase of 20.4% YoY and a 1.6% compound monthly growth rate. Active users2 were 63.2% of the total acquired user base representing 17.3% growth YoY and reaching 11.7 million. Total transactions per month increased 56.0%3 YoY to reach an average of 131.2 million per month in 3Q26, reflecting an increase in user engagement.
Spin Premia
Spin Premia acquired 2.1 million users during the quarter to reach 69.2 million total acquired users in 3Q26, compared to 60.9 million users in 3Q25. This represents an increase of 13.6% YoY and a 1.1% compound monthly growth rate. Active users4 were 43.3% of the total acquired user base representing 8.3% growth YoY and reaching 30.0 million. The average tender during the quarter was 52.1%.
| COCA-COLA FEMSA |  |
Coca-Cola FEMSA’s financial results and discussion thereof are incorporated by reference from Coca-Cola FEMSA’s press release, which is attached to this press release or may be accessed by visiting coca-colafemsa.com.
1 Spin results are not included in any FEMSA reporting segments.
2 Active User for Spin by OXXO: Any user with a balance or that has transacted within the last 56 days.
3 Represents the growth of average monthly transactions in 3Q26 compared to average monthly transactions in 3Q25.
4 Active User for Spin Premia: User that has transacted at least once with OXXO Premia within the last 90 days.
October 28, 2026 | Page 9
RESULTS FOR THE FIRST NINE MONTHS OF 2026
Results are compared to the same period of previous year
FEMSA CONSOLIDATED
Financial Summary for the First Nine Months of 2026
Amounts expressed in millions of Mexican Pesos (Ps.)
| 2026 | 2025 | Var. | Comp. (A) | |||||||||||||
| Total Revenues | 674,623 | 620,850 | 8.7 | % | 9.4 | % | ||||||||||
| Gross Profit | 270,849 | 250,148 | 8.3 | % | 9.3 | % | ||||||||||
| Gross Profit Margin (%) | 40.1 | 40.3 | (20 bps | ) | ||||||||||||
| Income from Operations | 53,365 | 49,442 | 7.9 | % | 12.4 | % | ||||||||||
| Operating Margin (%) | 7.9 | 8.0 | (10 bps | ) | ||||||||||||
| Adjusted EBITDA1 | 96,342 | 85,573 | 12.6 | % | 15.4 | % | ||||||||||
| Adjusted EBITDA Margin (%) | 14.3 | 13.8 | 50 bps | |||||||||||||
| Consolidated Net Income | 37,456 | 20,359 | 84.0 | % | ||||||||||||
Total revenues increased 8.7% in the first nine months of 2026 compared to the same period of 2025, driven by growth in Coca-Cola FEMSA, OXXO Mexico, Americas & Mobility and Health, partially offset by a decrease in Europe. Revenues reflected a net negative foreign exchange effect as the Mexican peso appreciated relative to other currencies; as a result, revenues grew 9.4% on a comparable basis.
Gross profit increased 8.3%, reflecting increases at OXXO Mexico, Coca-Cola FEMSA and Americas & Mobility, offset by Europe and Health. Gross margin contracted 20 basis points, reaching 40.1%. This reflects margin expansion in Coca-Cola FEMSA and Americas & Mobility, offset by contractions in OXXO Mexico, Europe and Health. It is important to highlight that the contractions in Europe and Health include the reclassification of distribution expenses from selling expenses to cost of goods sold, which does not impact income from operations. Excluding the effects of this reclassification, the gross margin for the first nine months of 2025 would have been 39.9%, an expansion of 20 basis points. On a comparable basis, which accounts for currency effects and M&A, gross profit increased 9.3%.
Income from operations increased 7.9%, driven by growth in Coca-Cola FEMSA and OXXO Mexico, partially offset by declines in Americas & Mobility, Europe and Health. The consolidated operating margin stood at 7.9%, contracting 10 basis points year over year, reflecting margin expansion in OXXO Mexico and Coca-Cola FEMSA, offset by margin contractions in Americas & Mobility, Europe and Health. On a comparable basis, income from operations increased 12.4%.
The effective income tax rate was 26.7% for the first nine months of 2026. This is largely explained by a one-time gain related to the BradyPLUS and Imperial Dade merger recorded in the first quarter of 2026, reflecting a non-cash accounting gain which increased profitability with no current tax effect. Excluding this impact, the effective income tax rate would be 34.8%. The gap between our effective tax rate and the statutory rate of 30% is mainly explained by non-deductible expenses, primarily at OXXO Mexico, and non-creditable tax loss effects, mainly from Spin. Our income tax provision for the first nine months of 2026 was Ps. 13,656 million, an increase of 6.2% relative to the same period of 2025, mainly reflecting the increase in income from operations.
Net consolidated income amounted to Ps. 37,456 million, representing an increase of 84.0% compared to the first nine months of 2025. This increase primarily reflected a one-time gain related to ImperialBrady, the result of the merger of BradyPLUS and Imperial Dade, recorded in the first quarter of 2026. Excluding this one-time gain, our net consolidated income amounted to Ps. 25,504 million, representing an increase of 12.1% compared to the first nine months of 2025. This increase primarily reflected growth in income from operations, as well as: i) a non-cash foreign exchange gain of Ps. 21 million, compared to a loss of Ps. 4,917 million in 2025, reflecting a favorable swing of Ps. 4,938 million, mainly due to a lower appreciation of the Mexican peso against the U.S. dollar and a lower U.S. dollar cash and investment balance; ii) a lower loss from participation in associates’ results of Ps. 55 million, compared to a loss of Ps. 995 million in 2025, which reflected the results of our participation in the joint venture in Brazil and our participation in ImperialBrady; and iii) the absence of the Ps. 813 million loss from discontinued operations2 recorded in the first nine months of 2025. These effects were partially offset by: i) higher net interest expense of Ps. 12,865 million, compared to Ps. 9,822 million, mainly reflecting lower interest income of Ps. 4,053 million compared to Ps. 6,086 million, driven by lower interest rates and a lower cash and investment balance; ii) other financial expenses of Ps. 226 million, compared to income of Ps. 1,856 million in 2025, which reflected the valuation effect recorded in 2025 related to HKN shares; and iii) a higher income tax provision of Ps. 13,656 million, compared to Ps. 12,855 million.
Net majority income per FEMSA BD Unit3 was Ps. 7.97 (US$4.41 per ADS4).
Capital expenditures amounted to Ps. 24,476 million, representing 3.6% of total revenues and a decrease of 21.3% compared to the first nine months of 2025, mainly reflecting lower CAPEX at Coca-Cola FEMSA, driven by a more selective approach to capital deployment, and at OXXO Mexico, reflecting a more measured pace of store openings compared to the prior year, coupled with lower investments in Health and Europe. This was partially offset by higher CAPEX in Americas & Mobility, mainly reflecting the addition of OXXO Brazil to the comparison base and continued expansion investments across the region.
(A) Please refer to page 12 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance
1 Adjusted EBITDA: Operating Income + Depreciation + Amortizations.
2 Following the third-quarter 2025 divestitures, the initial derecognition of Solistica at face value resulted in a temporary loss of Ps. 3,146 million (Ps. 99 million loss on a comparable basis). In the fourth quarter, this effect was reversed and the disposal gain recalculated using the investment’s carrying amount. As a result, the Company recognized a full-year gain of Ps. 1,574 million in discontinued operations, reflecting the combined impact of the Solistica and PTM divestitures.
3 FEMSA Units” consist of FEMSA BD Units and FEMSA B Units. Each FEMSA BD Unit is comprised of one Series B Share, two Series D-B Shares and two Series D-L Shares. Each FEMSA B Unit is comprised of five Series B Shares. Each FEMSA American Depositary Share (“ADS”) represents 10 FEMSA BD Units. The total number of FEMSA Units outstanding as of September 30, 2026 was 3,385,664,115.
4 The exchange rate published by the Federal Reserve Bank of New York for September 30, 2026 was 18.0609 MXN per USD.
October 28, 2026 | Page 10
RECENT DEVELOPMENTS
| · | On September 23, 2026, FEMSA announced the placement of a Swiss franc-denominated offering of senior unsecured bonds in the Swiss bond market, to be listed on the SIX Swiss Exchange. FEMSA successfully issued CHF $300 million in five-year senior unsecured bonds. The bonds will bear interest at an annual rate of 107 basis points over the relevant benchmark rate, for a yield of 1.73%. |
The issuance received credit ratings of BBB+ from S&P Global Ratings and A from Fitch Ratings. The proceeds from the issuance will be used for general corporate purposes, improving FEMSA’s cost of debt and increasing its financial flexibility under extremely favorable conditions.
This transaction was settled on October 14, 2026.
| · | On September 14, 2026, FEMSA announced that, as part of its ongoing efforts and consistent with its capital allocation framework and commitment to enhance capital returns to shareholders, it entered into a new derivative instrument known as an accelerated share repurchase (“ASR”) agreement with a financial institution in the United States of America to repurchase the Company’s shares through the acquisition of American Depositary Shares (“ADSs”). Under the terms of the ASR agreement, FEMSA agreed to repurchase from such financial institution an aggregate amount of up to US$280 million of its ADSs, subject to agreed-upon market conditions and delivery at maturity. |
The final number of ADSs repurchased and delivered under the ASR agreement will be based on the daily volume-weighted average ADS price during the term of the agreement, less a discount, and subject to the agreement’s terms and conditions which may result in a lower total amount being repurchased. Final settlement is expected to occur before year-end 2026.
CONFERENCE CALL INFORMATION
Our third quarter 2026 Conference Call will be held on: Wednesday, October 28, 2026, 11:00 AM Eastern Time (9:00 AM Mexico City Time). The conference call will be live through our Zoom link. For registration, please visit:
Registration: https://bit.ly/FEMSA_3Q26
If you are unable to participate live, the conference call audio will be available on https://femsa.gcs-web.com/financial-reports/quarterly-results
ABOUT FEMSA
FEMSA is a company that creates economic and social value through companies and institutions and strives to be the best employer and neighbor to the communities in which it operates. It participates in two core sectors, retail and beverages. In retail, FEMSA is present through four divisions: i) OXXO Mexico, operating the largest small-format store chain in Mexico; ii) Americas & Mobility, which includes its OXXO convenience store operations across Latin America and the United States, as well as its gas station business in Mexico and the United States; iii) Europe, operating convenience and foodvenience formats in five European countries; and iv) FEMSA Health, which includes drugstores and related activities in four Latin American countries. In Mexico, OXXO’s operations are enhanced by, and comprise a customer-focused ecosystem with Spin, a digital platform that leverages the OXXO store network to provide Mexican consumers with access to digital financial services, including Spin by OXXO and Spin Premia, among other initiatives. In the beverage sector, FEMSA participates through Coca-Cola FEMSA, the largest franchise bottler of Coca-Cola products in the world by volume. Across its business units, FEMSA has more than 369,000 employees in 18 countries. FEMSA is a member of the Dow Jones Best-in-Class World Index & Dow Jones Best-in-Class MILA Pacific Alliance Index, both from S&P Global; FTSE4Good Emerging Index; MSCI EM Latin America ESG Leaders Index; S&P/BMV Total México ESG, among other indexes.
The translations of Mexican pesos into US dollars are included solely for the convenience of the reader, using the noon buying rate for Mexican pesos as published by the Federal Reserve Bank of New York on September 30, 2026, which was 18.0609 Mexican pesos per US dollar.
October 28, 2026 | Page 11
FORWARD-LOOKING STATEMENTS
This report may contain certain forward-looking statements concerning our future performance that should be considered as good faith estimates made by us. These forward-looking statements reflect management’s expectations and are based upon currently available data. Actual results are subject to future events and uncertainties, which could materially impact our actual performance.
Our consolidated financial statements as of and for the year ended December 31, 2026, are not yet available, and the independent audit of those financial statements is ongoing and has not yet been completed. The unaudited preliminary financial information as of and for the year ended December 31, 2026, presented herein, is preliminary and subject to change as we complete our financial closing procedures and prepare our consolidated financial statements, and as our independent registered public accounting firm completes its audit of such consolidated financial statements. As of the date of this release, our independent registered public accounting firm has not expressed an opinion or any other form of assurance on any financial information as of or for the year ended December 31, 2026, or on our internal control over financial reporting as of December 31, 2026. Our audited consolidated financial statements may differ materially from this preliminary information and will also include notes providing additional disclosures.
COMPARABILITY
Our “comparable” term means, with respect to a year-over-year comparison, the change of a given measure excluding the effects of: (i) mergers, acquisitions, and divestitures; and (ii) translation effects resulting from exchange rate movements. In preparing this measure, management has used its best judgment, estimates, and assumptions to maintain comparability.
Ten pages of tables to follow
October 28, 2026 | Page 12
FEMSA – Consolidated Income Statement
Amounts expressed in millions of Mexican Pesos (Ps.)
| For the third quarter of: | For the nine months of: | |||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | % of rev. | 2025 | % of rev. | % Var. | % Comp.(A) | 2026 | % of rev. | 2025 | % of rev. | % Var. | % Comp.(A) | |||||||||||||||||||||||||||||||||||||
| Total revenues | 235,609 | 100.0 | 214,638 | 100.0 | 9.8 | 9.4 | 674,623 | 100.0 | 620,850 | 100.0 | 8.7 | 9.4 | ||||||||||||||||||||||||||||||||||||
| Cost of sales | 141,558 | 60.1 | 128,929 | 60.1 | 9.8 | 403,774 | 59.9 | 370,702 | 59.7 | 8.9 | ||||||||||||||||||||||||||||||||||||||
| Gross profit | 94,050 | 39.9 | 85,709 | 39.9 | 9.7 | 9.8 | 270,849 | 40.1 | 250,148 | 40.3 | 8.3 | 9.3 | ||||||||||||||||||||||||||||||||||||
| Administrative expenses | 10,091 | 4.3 | 9,794 | 4.6 | 3.0 | 30,163 | 4.5 | 29,523 | 4.8 | 2.2 | ||||||||||||||||||||||||||||||||||||||
| Selling expenses | 64,514 | 27.4 | 58,023 | 27.0 | 11.2 | 188,065 | 27.9 | 171,772 | 27.7 | 9.5 | ||||||||||||||||||||||||||||||||||||||
| Other operating expenses (income), net (1) | (473 | ) | (0.2 | ) | (233 | ) | (0.1 | ) | N.S. | (745 | ) | (0.1 | ) | (590 | ) | (0.1 | ) | 26.3 | ||||||||||||||||||||||||||||||
| Income from operations (2) | 19,918 | 8.5 | 18,126 | 8.4 | 9.9 | 13.4 | 53,365 | 7.9 | 49,442 | 8.0 | 7.9 | 12.4 | ||||||||||||||||||||||||||||||||||||
| Other non-operating expenses (income) | 544 | 436 | 24.8 | (10,871 | ) | 1,536 | N.S. | |||||||||||||||||||||||||||||||||||||||||
| Interest expense | 5,911 | 5,470 | 8.1 | 16,918 | 15,908 | 6.3 | ||||||||||||||||||||||||||||||||||||||||||
| Interest income | 1,371 | 1,907 | (28.1 | ) | 4,053 | 6,086 | (33.4 | ) | ||||||||||||||||||||||||||||||||||||||||
| Interest expense, net | 4,541 | 3,563 | 27.4 | 12,865 | 9,822 | 31.0 | ||||||||||||||||||||||||||||||||||||||||||
| Foreign exchange loss (gain) | (1,121 | ) | 1,261 | N.S. | (21 | ) | 4,917 | N.S. | ||||||||||||||||||||||||||||||||||||||||
| Other financial expenses (income), net | 312 | (55 | ) | N.S. | 226 | (1,856 | ) | N.S. | ||||||||||||||||||||||||||||||||||||||||
| Financing expenses, net | 3,732 | 4,769 | (21.7 | ) | 13,070 | 12,883 | 1.5 | |||||||||||||||||||||||||||||||||||||||||
| Income before income tax and
participation in associates results | 15,643 | 12,920 | 21.1 | 51,167 | 35,023 | 46.1 | ||||||||||||||||||||||||||||||||||||||||||
| Income tax | 5,080 | 3,785 | 34.2 | 13,656 | 12,855 | 6.2 | ||||||||||||||||||||||||||||||||||||||||||
| Participation in associates results | 7 | (151 | ) | N.S. | (55 | ) | (995 | ) | (94.5 | ) | ||||||||||||||||||||||||||||||||||||||
| Continued Operations net income (Loss) | 10,569 | 8,984 | 17.6 | 37,456 | 21,172 | 76.9 | ||||||||||||||||||||||||||||||||||||||||||
| Discontinued Operations net income (Loss) | - | (3,146 | ) | N.S. | - | (813 | ) | N.S. | ||||||||||||||||||||||||||||||||||||||||
| Consolidated net income (Loss) | 10,569 | 5,838 | 81.0 | 37,456 | 20,359 | 84.0 | ||||||||||||||||||||||||||||||||||||||||||
| Net majority income | 6,810 | 2,415 | N.S. | 27,199 | 10,920 | N.S. | ||||||||||||||||||||||||||||||||||||||||||
| Net minority income | 3,759 | 3,423 | 9.8 | 10,257 | 9,439 | 8.7 | ||||||||||||||||||||||||||||||||||||||||||
| Operative Cash Flow & CAPEX | 2026 | % of rev. | 2025 | % of rev. | % Var. | %
Comp.(A) | 2026 | % of rev. | 2025 | % of rev. | % Var. | %
Comp.(A) | ||||||||||||||||||||||||||||||||||||
| Income from operations | 19,918 | 8.5 | 18,126 | 8.4 | 9.9 | 13.4 | 53,365 | 7.9 | 49,442 | 8.0 | 7.9 | 12.4 | ||||||||||||||||||||||||||||||||||||
| Depreciation | 10,811 | 4.6 | 10,316 | 4.8 | 4.8 | 31,979 | 4.7 | 29,897 | 4.8 | 7.0 | ||||||||||||||||||||||||||||||||||||||
| Amortization & other non-cash charges | 4,104 | 1.7 | 2,401 | 1.1 | 70.9 | 10,998 | 1.6 | 6,234 | 1.0 | 76.4 | ||||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA | 34,833 | 14.8 | 30,843 | 14.4 | 12.9 | 14.5 | 96,342 | 14.3 | 85,573 | 13.8 | 12.6 | 15.4 | ||||||||||||||||||||||||||||||||||||
| CAPEX | 9,408 | 13,128 | (28.3 | ) | 24,476 | 31,115 | (21.3 | ) | ||||||||||||||||||||||||||||||||||||||||
(A) Please refer to page 12 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance.
(1) Other operating expenses (income), net = other operating expenses (income) +(-) equity method from operated associates.
(2) Income from operations = gross profit – administrative and selling expenses – other operating expenses (income), net.
October 28, 2026 | Page 13
FEMSA – Consolidated Balance Sheet
Amounts expressed in millions of Mexican Pesos (Ps.)
| ASSETS | Sep-26 | Dec-25 | % Inc. | |||||||||
| Cash and cash equivalents | 111,063 | 107,980 | 2.9 | |||||||||
| Investments | 6,112 | 20,042 | (69.5 | ) | ||||||||
| Accounts receivable | 43,551 | 48,319 | (9.9 | ) | ||||||||
| Inventories | 66,285 | 69,452 | (4.6 | ) | ||||||||
| Other current assets | 41,421 | 37,323 | 11.0 | |||||||||
| Current Assets Available for sale | - | - | - | |||||||||
| Total current assets | 268,432 | 283,116 | (5.2 | ) | ||||||||
| Investments in shares | 11,004 | 25,726 | (57.2 | ) | ||||||||
| Property, plant and equipment, net | 199,936 | 189,672 | 5.4 | |||||||||
| Right of use | 102,205 | 99,543 | 2.7 | |||||||||
| Intangible assets (1) | 147,026 | 145,506 | 1.0 | |||||||||
| Other assets | 80,892 | 52,314 | 54.6 | |||||||||
| TOTAL ASSETS | 809,495 | 795,877 | 1.7 | |||||||||
| LIABILITIES & STOCKHOLDERS’ EQUITY | Sep-26 | Dec-25 | % Inc. | |||||||||
| Bank loans | 2,979 | 5,862 | (49.2 | ) | ||||||||
| Current maturities of long-term debt | 9,687 | 14,812 | (34.6 | ) | ||||||||
| Interest payable | 1,919 | 1,790 | 7.2 | |||||||||
| Current maturities of long-term leases | 17,193 | 15,188 | 13.2 | |||||||||
| Operating liabilities | 201,399 | 172,362 | 16.8 | |||||||||
| Short term liabilities available for sale | - | - | - | |||||||||
| Total current liabilities | 233,177 | 210,014 | 11.0 | |||||||||
| Long-term debt (2) | 126,466 | 126,992 | (0.4 | ) | ||||||||
| Long-term leases | 97,625 | 94,703 | 3.1 | |||||||||
| Labor obligations | 11,265 | 10,719 | 5.1 | |||||||||
| Other liabilities | 29,982 | 24,097 | 24.4 | |||||||||
| Total liabilities | 498,515 | 466,525 | 6.9 | |||||||||
| Total stockholders’ equity | 310,980 | 329,352 | (5.6 | ) | ||||||||
| TOTAL LIABILITIES AND STOCKHOLDERS’ EQUITY | 809,495 | 795,877 | 1.7 | |||||||||
| September 30, 2026 | ||||||||
| DEBT MIX (2) | % of Total | Average Rate | ||||||
| Denominated in: | ||||||||
| Mexican pesos | 58.3 | % | 8.9 | % | ||||
| U.S. Dollars | 26.3 | % | 3.3 | % | ||||
| Euros | 0.0 | % | 0.0 | % | ||||
| Swiss Francs | 0.0 | % | 0.0 | % | ||||
| Colombian pesos | 1.1 | % | 13.1 | % | ||||
| Argentine pesos | 0.7 | % | 28.3 | % | ||||
| Brazilian reais | 12.8 | % | 8.4 | % | ||||
| Chilean pesos | 0.8 | % | 6.0 | % | ||||
| Total debt | 100.0 | % | 7.5 | % | ||||
| Fixed rate (2) | 82.7 | % | ||||||
| Variable rate (2) | 17.3 | % | ||||||
| DEBT MATURITY PROFILE | 2026 | 2027 | 2028 | 2029 | 2030 | 2031+ | ||||||||||||||||||
| % of Total Debt | 1.8 | % | 9.8 | % | 11.2 | % | 6.1 | % | 13.1 | % | 58.1 | % | ||||||||||||
(1) Includes mainly the intangible assets generated by acquisitions.
(2) Includes the effect of derivative financial instruments on long-term debt.
October 28, 2026 | Page 14
Net Debt & Adjusted EBITDA ex-KOF
Amounts expressed in millions of US Dollars (US.)
| Twelve months ended September 30, 2026 | ||||||||||||
| Reported Adj. EBITDA | Adjustments | Adj. EBITDA Ex-KOF | ||||||||||
| OXXO Mexico, Americas & Mobility | 3,170 | - | 3,170 | |||||||||
| Europe | 452 | - | 452 | |||||||||
| Health Division | 475 | - | 475 | |||||||||
| Envoy Solutions | - | - | - | |||||||||
| Coca-Cola FEMSA1 | 3,499 | (3,499 | ) | - | ||||||||
| Other2 | (74 | ) | - | (74 | ) | |||||||
| FEMSA Consolidated | 7,521 | (3,499 | ) | 4,022 | ||||||||
| Dividends Received3 | - | 420 | 420 | |||||||||
| FEMSA Consolidated ex-KOF | 7,521 | (3,079 | ) | 4,442 | ||||||||
| As of September 30, 2026 | ||||||||||||
| Reported | Adjustments | Ex-KOF | ||||||||||
| Cash & Equivalents | 3,898 | - | 3,898 | |||||||||
| Coca-Cola FEMSA Cash & Equivalents | 2,590 | (2,590 | ) | - | ||||||||
| Cash & Equivalents | 6,488 | (2,590 | ) | 3,898 | ||||||||
| Financial Debt | 3,032 | - | 3,032 | |||||||||
| Coca-Cola FEMSA Financial Debt | 4,671 | (4,671 | ) | - | ||||||||
| Lease Liabilities | 6,137 | - | 6,137 | |||||||||
| Coca-Cola FEMSA Lease Liabilities | 220 | (220 | ) | - | ||||||||
| Debt | 14,061 | (4,892 | ) | 9,169 | ||||||||
| FEMSA Net Debt | 7,573 | (2,302 | ) | 5,271 | ||||||||
Translated to USD for readers’ convenience using the exchange rate published by the Federal Reserve Bank of New York for September 30, 2026 which was 18.0609 MXN per USD.
1 Coca-Cola FEMSA adjustment represents 100% of its LTM EBITDA.
2 Includes FEMSA Other Businesses (including Bara and Spin), FEMSA corporate expenses, and the effects of consolidation adjustments
3 Reflects cash dividends received from Coca-Cola FEMSA for approximately US$420 mm during the last twelve months.
October 28, 2026 | Page 15
EPS with Repurchased Shares
Amounts expressed in millions of Mexican Pesos (Ps.)
As Reported
| Total Units Issued(1)(2) | ||||
| FEMSA Units Issued(1) | 3,412,732,415 | |||
| YTD | 3Q26 | |||||
| Net majority income | 27,199 | 6,810 | ||||
| # FEMSA Units Issued(1) | 3,412,732,415 | |||||
| EPS (Mxn Ps. / Unit) | 7.97 | 2.00 | ||||
Proforma
| Total Units Outstanding (3) | ||||
| FEMSA Units Outstanding(1) | 3,385,664,115 | |||
| Units in Treasury | ||||
| FEMSA Units(1) | 27,068,300 | |||
| YTD | 3Q26 | |||||
| Net majority income | 27,199 | 6,810 | ||||
| # FEMSA Units Outstanding | 3,385,664,115 | |||||
| EPS (Mxn Ps. / Unit) | 8.03 | 2.01 | ||||
(1) “FEMSA Units Issued” consist of all FEMSA BD Units and FEMSA B Units issued, including any FEMSA Units held in treasury.
(2) At our Shareholders meeting held on March 27
of 2026, the cancellation of the shares acquired from the stock repurchase program during the period from April 2025 to March 2026
was approved. The total FEMSA Units Cancelled are for the amount of 56,737,112 units.
(3) “FEMSA Units Outstanding" consist of FEMSA BD Units and FEMSA B Units issued and outstanding, excluding any
FEMSA Units held in treasury.
October 28, 2026 | Page 16
OXXO Mexico – Results of Operations
Amounts expressed in millions of Mexican Pesos (Ps.)
| For the third quarter of: | For the nine months of: | |||||||||||||||||||||||||||||||||||||||
| 2026 | % of rev. | 2025 | % of rev. | % Var. | 2026 | % of rev. | 2025 | % of rev. | % Var. | |||||||||||||||||||||||||||||||
| Total revenues | 86,652 | 100.0 | 78,539 | 100.0 | 10.3 | 247,767 | 100.0 | 224,822 | 100.0 | 10.2 | ||||||||||||||||||||||||||||||
| Cost of sales | 47,842 | 55.2 | 42,416 | 54.0 | 12.8 | 135,735 | 54.8 | 122,608 | 54.5 | 10.7 | ||||||||||||||||||||||||||||||
| Gross profit | 38,810 | 44.8 | 36,123 | 46.0 | 7.4 | 112,032 | 45.2 | 102,214 | 45.5 | 9.6 | ||||||||||||||||||||||||||||||
| Administrative expenses | 2,189 | 2.5 | 2,224 | 2.8 | (1.6 | ) | 6,453 | 2.6 | 6,278 | 2.8 | 2.8 | |||||||||||||||||||||||||||||
| Selling expenses | 28,319 | 32.7 | 26,230 | 33.4 | 8.0 | 82,787 | 33.4 | 75,735 | 33.7 | 9.3 | ||||||||||||||||||||||||||||||
| Other operating expenses (income), net | 261 | 0.3 | 66 | 0.1 | N.S. | 428 | 0.2 | 232 | 0.1 | 84.5 | ||||||||||||||||||||||||||||||
| Income from operations | 8,041 | 9.3 | 7,603 | 9.7 | 5.8 | 22,364 | 9.0 | 19,968 | 8.9 | 12.0 | ||||||||||||||||||||||||||||||
| Depreciation | 3,852 | 4.4 | 3,651 | 4.6 | 5.5 | 11,427 | 4.6 | 10,713 | 4.8 | 6.7 | ||||||||||||||||||||||||||||||
| Amortization & other non-cash charges | 762 | 0.9 | 377 | 0.5 | N.S. | 2,685 | 1.1 | 1,105 | 0.5 | N.S. | ||||||||||||||||||||||||||||||
| Adjusted EBITDA | 12,655 | 14.6 | 11,631 | 14.8 | 8.8 | 36,476 | 14.7 | 31,786 | 14.1 | 14.8 | ||||||||||||||||||||||||||||||
| CAPEX | 3,373 | 3,843 | (12.2 | ) | 8,638 | 10,166 | (15.0 | ) | ||||||||||||||||||||||||||||||||
| Information of OXXO Stores | ||||||||||||||||||||||||||||||||||||||||
| Total stores | ||||||||||||||||||||||||||||||||||||||||
| 24,759 | 24,057 | 2.9 | ||||||||||||||||||||||||||||||||||||||
| Net new convenience stores: | ||||||||||||||||||||||||||||||||||||||||
| vs. Last quarter | 51 | 181 | (71.8 | ) | ||||||||||||||||||||||||||||||||||||
| Year-to-date | 462 | 851 | (45.7 | ) | ||||||||||||||||||||||||||||||||||||
| Last-twelve-months | 702 | 1,126 | (37.7 | ) | ||||||||||||||||||||||||||||||||||||
| Same-store data: (1) | ||||||||||||||||||||||||||||||||||||||||
| Sales (thousands of pesos) | 1,088.6 | 997.1 | 9.2 | 1,048.2 | 967.7 | 8.3 | ||||||||||||||||||||||||||||||||||
| Traffic (thousands of transactions) | 17.3 | 16.7 | 3.5 | 16.7 | 16.4 | 1.7 | ||||||||||||||||||||||||||||||||||
| Ticket (pesos) | 62.8 | 59.6 | 5.5 | 62.7 | 58.9 | 6.5 | ||||||||||||||||||||||||||||||||||
(A) Please refer to page 12 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance.
(1) Monthly average information per store, considering same stores with more than twelve months of operations, income from services are included.
October 28, 2026 | Page 17
Americas & Mobility – Results of Operations
Amounts expressed in millions of Mexican Pesos (Ps.)
| For the third quarter of: | For the nine months of: | |||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | % of rev. | 2025 | % of rev. | % Var. | % Comp.(A) | 2026 | % of rev. | 2025 | % of rev. | % Var. | % Comp.(A) | |||||||||||||||||||||||||||||||||||||
| Total revenues | 29,466 | 100.0 | 24,960 | 100.0 | 18.1 | 10.9 | 83,021 | 100.0 | 71,426 | 100.0 | 16.2 | 11.1 | ||||||||||||||||||||||||||||||||||||
| Cost of sales | 24,530 | 83.2 | 20,797 | 83.3 | 17.9 | 69,191 | 83.3 | 59,906 | 83.9 | 15.5 | ||||||||||||||||||||||||||||||||||||||
| Gross profit | 4,937 | 16.8 | 4,163 | 16.7 | 18.6 | 4.5 | 13,830 | 16.7 | 11,520 | 16.1 | 20.1 | 9.8 | ||||||||||||||||||||||||||||||||||||
| Administrative expenses | 1,015 | 3.4 | 491 | 2.0 | N.S. | 2,359 | 2.8 | 1,496 | 2.1 | 57.7 | ||||||||||||||||||||||||||||||||||||||
| Selling expenses | 3,649 | 12.4 | 2,935 | 11.8 | 24.3 | 10,724 | 12.9 | 8,349 | 11.7 | 28.4 | ||||||||||||||||||||||||||||||||||||||
| Other operating expenses (income), net | 103 | 0.3 | 31 | 0.1 | 232.3 | 218 | 0.3 | 96 | 0.1 | N.S. | ||||||||||||||||||||||||||||||||||||||
| Income from operations | 170 | 0.6 | 706 | 2.8 | (75.9 | ) | (29.9 | ) | 530 | 0.6 | 1,580 | 2.2 | (66.5 | ) | (8.7 | ) | ||||||||||||||||||||||||||||||||
| Depreciation | 814 | 2.8 | 711 | 2.8 | 14.5 | 2,330 | 2.8 | 1,885 | 2.6 | 23.6 | ||||||||||||||||||||||||||||||||||||||
| Amortization & other non-cash charges | 434 | 1.5 | (13 | ) | (0.1 | ) | N.S. | 940 | 1.1 | 235 | 0.3 | N.S. | ||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA | 1,418 | 4.8 | 1,404 | 5.6 | 1.0 | (0.4 | ) | 3,801 | 4.6 | 3,700 | 5.2 | 2.7 | 10.2 | |||||||||||||||||||||||||||||||||||
| CAPEX | 365 | 286 | 27.6 | 981 | 705 | 39.1 | ||||||||||||||||||||||||||||||||||||||||||
| Information of Stores | ||||||||||||||||||||||||||||||||||||||||||||||||
| Total stores | 1,986 | 1,930 | 2.9 | |||||||||||||||||||||||||||||||||||||||||||||
| Stores Brazil | 641 | 609 | 5.3 | |||||||||||||||||||||||||||||||||||||||||||||
| Stores Colombia | 648 | 640 | 1.3 | |||||||||||||||||||||||||||||||||||||||||||||
| Stores Chile | 244 | 232 | 5.2 | |||||||||||||||||||||||||||||||||||||||||||||
| Stores Peru | 222 | 207 | 7.2 | |||||||||||||||||||||||||||||||||||||||||||||
| Stores USA | 231 | 242 | (4.5 | ) | ||||||||||||||||||||||||||||||||||||||||||||
| Net new stores: | ||||||||||||||||||||||||||||||||||||||||||||||||
| vs. Last quarter | 33 | 23 | 43.5 | |||||||||||||||||||||||||||||||||||||||||||||
| Year-to-date | 89 | 80 | 11.3 | |||||||||||||||||||||||||||||||||||||||||||||
| Last-twelve-months | 56 | 289 | (80.6 | ) | ||||||||||||||||||||||||||||||||||||||||||||
| Same-store data: (1) | ||||||||||||||||||||||||||||||||||||||||||||||||
| Sales (thousands of pesos) | 1,176.6 | 1,033.9 | 13.8 | 15.8 | 1,122.1 | 1,019.1 | 10.1 | 16.3 | ||||||||||||||||||||||||||||||||||||||||
October 28, 2026 | Page 18
Currency Neutral
| Total Revenue Growth | Total Unit Growth | Same-Store Sales Growth(2) | ||||||||||
| OXXO Americas | 10.9 | 2.9 | 15.8 | |||||||||
| Brazil(3) | NA | 5.3 | 5.1 | |||||||||
| Latam(4) | 24.4 | 3.2 | 21.2 | |||||||||
| USA(5) | (0.2 | ) | (4.5 | ) | 1.5 | |||||||
| Information of Gas Stations | 2026 | 2025 | % Var. | |||||||||
| Total stations | 772 | 798 | (3.3 | ) | ||||||||
| Mexico | 544 | 558 | (2.5 | ) | ||||||||
| USA | 228 | 240 | (5.0 | ) | ||||||||
| Net new service stations: | ||||||||||||
| vs. Last quarter | (9 | ) | (6 | ) | 50.0 | |||||||
| Year-to-date | (18 | ) | (18 | ) | 0.0 | |||||||
| Last-twelve-months | (26 | ) | 229 | N.S. | ||||||||
| Volume (millions of liters) total stations(6) | 986.3 | 953.9 | 3.4 | |||||||||
| Unit margin (pesos per liter)(6) (7) | 2.28 | 2.52 | (9.6 | ) | ||||||||
(A) Please refer to page 12 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance.
(1) Monthly average information per store, considering same stores with more than twelve months of operations, income from services are included.
(2) Same-store Sales OXXO Americas (Colombia, Chile, Peru and the U.S.A.).
(3) Local currency (BRL).
(4) Includes a weighted average of OXXO Colombia, Chile and Peru.
(5) Local currency (USD).
(6) Includes fuel operations in Mexico and in the US, with U.S. volumes converted to Liters.
(7) For readers’ convenience in calculating the equivalent price in U.S. cents per gallon, please refer to the exchange rate of 18.0609 MXN per USD, as published by the Federal Reserve Bank of New York for September 30, 2026, and a conversion factor of 3.785 liters per US gallon.
October 28, 2026 | Page 19
Europe – Results of Operations
Amounts expressed in millions of Mexican Pesos (Ps.)
| For the third quarter of: | For the nine months of: | |||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | %
of rev. | 2025 | %
of rev. | % Var. | % Comp.(A) | 2026 | %
of rev. | 2025 | %
of rev. | % Var. | % Comp.(A) | |||||||||||||||||||||||||||||||||||||
| Total revenues | 14,063 | 100.0 | 14,837 | 100.0 | (5.2 | ) | 4.0 | 41,474 | 100.0 | 42,811 | 100.0 | (3.1 | ) | 2.9 | ||||||||||||||||||||||||||||||||||
| Cost of sales | 8,532 | 60.7 | 8,634 | 58.2 | (1.2 | ) | 24,759 | 59.7 | 24,944 | 58.3 | (0.7 | ) | ||||||||||||||||||||||||||||||||||||
| Gross profit | 5,531 | 39.3 | 6,203 | 41.8 | (10.8 | ) | (2.2 | ) | 16,714 | 40.3 | 17,867 | 41.7 | (6.5 | ) | (0.6 | ) | ||||||||||||||||||||||||||||||||
| Administrative expenses | 950 | 6.8 | 927 | 6.2 | 2.5 | 2,795 | 6.7 | 2,790 | 6.5 | 0.2 | ||||||||||||||||||||||||||||||||||||||
| Selling expenses | 4,090 | 29.1 | 4,582 | 30.9 | (10.7 | ) | 12,461 | 30.0 | 13,414 | 31.3 | (7.1 | ) | ||||||||||||||||||||||||||||||||||||
| Other operating expenses (income), net | (39 | ) | (0.3 | ) | (12 | ) | (0.1 | ) | N.S. | (65 | ) | (0.2 | ) | (62 | ) | (0.1 | ) | 4.8 | ||||||||||||||||||||||||||||||
| Income from operations | 531 | 3.8 | 706 | 4.8 | (24.8 | ) | (17.5 | ) | 1,523 | 3.7 | 1,725 | 4.0 | (11.6 | ) | (5.4 | ) | ||||||||||||||||||||||||||||||||
| Depreciation | 1,280 | 9.1 | 1,374 | 9.3 | (6.8 | ) | 3,923 | 9.5 | 4,078 | 9.5 | (3.8 | ) | ||||||||||||||||||||||||||||||||||||
| Amortization & other non-cash charges | 179 | 1.3 | 208 | 1.4 | (13.9 | ) | 497 | 1.2 | 415 | 1.0 | 19.8 | |||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA | 1,990 | 14.2 | 2,288 | 15.4 | (13.0 | ) | (4.5 | ) | 5,943 | 14.3 | 6,217 | 14.5 | (4.4 | ) | 1.7 | |||||||||||||||||||||||||||||||||
| CAPEX | 320 | 471 | (32.1 | ) | 990 | 1,082 | (8.5 | ) | ||||||||||||||||||||||||||||||||||||||||
| Information of Stores | 2026 | 2025 | % Var. | % Comp.(A) | ||||||||||||||||||||||||||||
| Total stores | 2,762 | 2,772 | (0.4 | ) | ||||||||||||||||||||||||||||
| Same-store data: (1) | ||||||||||||||||||||||||||||||||
| Sales (thousands of pesos) | 1,852.5 | 2,006.9 | (7.7 | ) | 1.3 | 1,834.9 | 1,941.4 | (5.5 | ) | 1.0 | ||||||||||||||||||||||
(A) Refer to page 12 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance.
(1) Monthly average information per store. Same-store Sales reflect a weighted average from our foodservice and retail operations.
October 28, 2026 | Page 20
Health – Results of Operations
Amounts expressed in millions of Mexican Pesos (Ps.)
| For the third quarter of: | For the nine months of: | |||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | % of rev. | 2025 | % of rev. | % Var. | % Comp.(A) | 2026 | % of rev. | 2025 | % of rev. | % Var. | % | |||||||||||||||||||||||||||||||||||||
| Total revenues | 22,985 | 100.0 | 21,483 | 100.0 | 7.0 | 3.4 | 67,488 | 100.0 | 65,305 | 100.0 | 3.3 | 4.9 | ||||||||||||||||||||||||||||||||||||
| Cost of sales | 17,008 | 74.0 | 15,024 | 69.9 | 13.2 | 49,771 | 73.7 | 45,898 | 70.3 | 8.4 | ||||||||||||||||||||||||||||||||||||||
| Gross profit | 5,977 | 26.0 | 6,458 | 30.1 | (7.4 | ) | (8.2 | ) | 17,717 | 26.3 | 19,407 | 29.7 | (8.7 | ) | (5.9 | ) | ||||||||||||||||||||||||||||||||
| Administrative expenses | 680 | 3.0 | 672 | 3.1 | 1.2 | 2,153 | 3.2 | 2,298 | 3.5 | (6.3 | ) | |||||||||||||||||||||||||||||||||||||
| Selling expenses | 4,925 | 21.4 | 4,865 | 22.6 | 1.2 | 14,165 | 21.0 | 14,614 | 22.4 | (3.1 | ) | |||||||||||||||||||||||||||||||||||||
| Other operating expenses (income), net | 52 | 0.2 | 53 | 0.2 | (1.9 | ) | 75 | 0.1 | 41 | 0.1 | 82.9 | |||||||||||||||||||||||||||||||||||||
| Income from operations | 319 | 1.4 | 869 | 4.0 | (63.2 | ) | (63.8 | ) | 1,323 | 2.0 | 2,454 | 3.8 | (46.1 | ) | (44.2 | ) | ||||||||||||||||||||||||||||||||
| Depreciation | 927 | 4.0 | 897 | 4.2 | 3.3 | 2,807 | 4.2 | 2,731 | 4.2 | 2.8 | ||||||||||||||||||||||||||||||||||||||
| Amortization & other non-cash charges | 803 | 3.5 | 648 | 3.0 | 23.9 | 1,963 | 2.9 | 1,190 | 1.8 | 65.0 | ||||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA | 2,049 | 8.9 | 2,415 | 11.2 | (15.2 | ) | (15.3 | ) | 6,093 | 9.0 | 6,376 | 9.8 | (4.4 | ) | (1.1 | ) | ||||||||||||||||||||||||||||||||
| CAPEX | 226 | 325 | (30.5 | ) | 665 | 938 | (29.1 | ) | ||||||||||||||||||||||||||||||||||||||||
| Information of Stores | ||||||||||||||||||||||||||||||||||||||||||||||||
| Total stores | 4,569 | 4,391 | 4.1 | |||||||||||||||||||||||||||||||||||||||||||||
| Stores Mexico | 1,259 | 1,315 | (4.3 | ) | ||||||||||||||||||||||||||||||||||||||||||||
| Stores South America | 3,310 | 3,076 | 7.6 | |||||||||||||||||||||||||||||||||||||||||||||
| Net new stores: | ||||||||||||||||||||||||||||||||||||||||||||||||
| vs. Last quarter | (15 | ) | 70 | N.S | ||||||||||||||||||||||||||||||||||||||||||||
| Year-to-date | 66 | (270 | ) | N.S | ||||||||||||||||||||||||||||||||||||||||||||
| Last-twelve-months | 178 | (141 | ) | N.S | ||||||||||||||||||||||||||||||||||||||||||||
| Same-store data: (1) | ||||||||||||||||||||||||||||||||||||||||||||||||
| Sales (thousands of pesos) | 1,055.9 | 1,009.1 | 4.6 | 6.5 | 1,042.5 | 1,024.5 | 1.8 | 6.6 | ||||||||||||||||||||||||||||||||||||||||
Currency Neutral
| Total Revenue Growth | Total Unit Growth | Same-Store Sales Growth(6) | ||||||||||
| Health(2) | 3.4 | 4.1 | 6.5 | |||||||||
| Mexico | 21.2 | (4.3 | ) | 2.7 | ||||||||
| Chile(3) | 8.4 | 5.2 | (0.8 | ) | ||||||||
| Colombia(4) | (2.2 | ) | 5.0 | 21.9 | ||||||||
| Ecuador(5) | 14.8 | 12.6 | 8.4 | |||||||||
(A) Please refer to page 12 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance.
(1) Monthly average information per location, considering same locations with more than twelve months of all the operations of the Health Division.
(2) Local currency weighted average.
(3) Local currency (CLP).
(4) Local currency (COP).
(5) Local currency (USD).
(6) Only includes retail sales. In Ecuador, includes franchised stores
October 28, 2026 | Page 21
Coca-Cola FEMSA – Results of Operations
Amounts expressed in millions of Mexican Pesos (Ps.)
| For the third quarter of: | For the nine months of: | |||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | % of rev. | 2025 | % of rev. | % Var. | %
Comp.(A) | 2026 | % of rev. | 2025 | % of rev. | % Var. | % Comp.(A) | |||||||||||||||||||||||||||||||||||||
| Total revenues | 79,718 | 100.0 | 71,884 | 100.0 | 10.9 | 11.3 | 227,190 | 100.0 | 213,984 | 100.0 | 6.2 | 10.4 | ||||||||||||||||||||||||||||||||||||
| Cost of sales | 42,636 | 53.5 | 39,493 | 54.9 | 8.0 | 120,815 | 53.2 | 117,134 | 54.7 | 3.1 | ||||||||||||||||||||||||||||||||||||||
| Gross profit | 37,082 | 46.5 | 32,391 | 45.1 | 14.5 | 14.8 | 106,374 | 46.8 | 96,850 | 45.3 | 9.8 | 14.1 | ||||||||||||||||||||||||||||||||||||
| Administrative expenses | 4,015 | 5.0 | 3,722 | 5.2 | 7.9 | 11,942 | 5.3 | 11,256 | 5.3 | 6.1 | ||||||||||||||||||||||||||||||||||||||
| Selling expenses | 21,998 | 27.6 | 18,634 | 25.9 | 18.1 | 64,161 | 28.2 | 56,916 | 26.6 | 12.7 | ||||||||||||||||||||||||||||||||||||||
| Other operating expenses (income), net | (805 | ) | (1.0 | ) | (256 | ) | (0.4 | ) | N.S. | (1,303 | ) | (0.6 | ) | (555 | ) | (0.3 | ) | N.S. | ||||||||||||||||||||||||||||||
| Income from operations | 11,874 | 14.9 | 10,291 | 14.3 | 15.4 | 16.4 | 31,574 | 13.9 | 29,234 | 13.7 | 8.0 | 11.9 | ||||||||||||||||||||||||||||||||||||
| Depreciation | 3,553 | 4.5 | 3,215 | 4.5 | 10.5 | 10,403 | 4.6 | 9,445 | 4.4 | 10.1 | ||||||||||||||||||||||||||||||||||||||
| Amortization & other non-cash charges | 1,367 | 1.7 | 943 | 1.3 | 45.0 | 3,235 | 1.4 | 2,260 | 1.1 | 43.1 | ||||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA | 16,794 | 21.1 | 14,449 | 20.1 | 16.2 | 17.0 | 45,213 | 19.9 | 40,939 | 19.1 | 10.4 | 15.0 | ||||||||||||||||||||||||||||||||||||
| CAPEX | 4,362 | 7,821 | (44.2 | ) | 11,580 | 17,461 | (33.7 | ) | ||||||||||||||||||||||||||||||||||||||||
| Sales Volumes | ||||||||||||||||||||||||||||||||||||||||||||||||
| (Millions of unit cases) | ||||||||||||||||||||||||||||||||||||||||||||||||
| Mexico and Central America | 641.5 | 58.9 | 612.1 | 59.1 | 4.8 | 1,831.9 | 58.0 | 1,802.2 | 59.0 | 1.6 | ||||||||||||||||||||||||||||||||||||||
| South America | 158.2 | 14.5 | 143.8 | 13.9 | 10.1 | 452.8 | 14.3 | 414.7 | 13.6 | 9.2 | ||||||||||||||||||||||||||||||||||||||
| Brazil | 290.0 | 26.6 | 279.2 | 27.0 | 3.9 | 875.3 | 27.7 | 839.9 | 27.5 | 4.2 | ||||||||||||||||||||||||||||||||||||||
| Total | 1,089.8 | 100.0 | 1,035.0 | 100.0 | 5.3 | 3,160.0 | 100.0 | 3,056.8 | 100.0 | 3.4 | ||||||||||||||||||||||||||||||||||||||
(A) Please refer to page 12 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance.
October 28, 2026 | Page 22
FEMSA Macroeconomic Information
| Inflation | ||||||||
| 3Q 2026 | LTM (1) Sep-26 | |||||||
| Mexico | 0.60 | % | 3.42 | % | ||||
| Colombia | 0.62 | % | 6.46 | % | ||||
| Brazil | -0.05 | % | 4.60 | % | ||||
| Argentina | 3.98 | % | 33.70 | % | ||||
| Chile | 0.79 | % | 3.91 | % | ||||
| Euro Zone | 1.20 | % | 3.52 | % | ||||
| Switzerland | -0.46 | % | 0.51 | % | ||||
| Average Exchange Rates for each Period | ||||||||||||||||
| Sep-26 | Sep-25 | |||||||||||||||
| Per USD | Per MXN | Per USD | Per MXN | |||||||||||||
| Mexico | 17.17 | 1.0000 | 18.53 | 1.0000 | ||||||||||||
| Colombia | 3,181.68 | 0.0054 | 3,924.24 | 0.0047 | ||||||||||||
| Brazil | 5.14 | 3.3374 | 5.37 | 3.4514 | ||||||||||||
| Argentina | 1,513.77 | 0.0113 | 1,401.07 | 0.0132 | ||||||||||||
| Chile | 947.27 | 0.0181 | 960.37 | 0.0193 | ||||||||||||
| Euro Zone | 0.87 | 19.8311 | 0.85 | 21.7083 | ||||||||||||
| Switzerland | 0.82 | 20.9583 | 0.80 | 23.2548 | ||||||||||||
| End-of-Period Exchange Rates | ||||||||||||||||
| Sep-26 | Sep-25 | |||||||||||||||
| Per USD | Per MXN | Per USD | Per MXN | |||||||||||||
| Mexico | 17.84 | 1.0000 | 18.38 | 1.0000 | ||||||||||||
| Colombia | 3,341.23 | 0.0053 | 3,901.29 | 0.0047 | ||||||||||||
| Brazil | 5.18 | 3.4437 | 5.32 | 3.4563 | ||||||||||||
| Argentina | 1,517.00 | 0.0118 | 1,380.00 | 0.0133 | ||||||||||||
| Chile | 972.60 | 0.0183 | 962.39 | 0.0191 | ||||||||||||
| Euro Zone | 0.87 | 20.5070 | 0.85 | 21.5061 | ||||||||||||
| Switzerland | 0.83 | 21.4233 | 0.80 | 23.0907 | ||||||||||||
(1) LTM = Last twelve months.
October 28, 2026 | Page 23
| INVESTOR RELATIONS Pamela Ortiz | pamela.ortiz@kof.com Natalia Sariñana | natalia.sarinana@kof.com Bryan Silva | bryan.silva@kof.com Emilio Díaz | emilio.diaz@kof.com kofmxinves@kof.com |
 |
Mexico City, October 26, 2026, Coca-Cola FEMSA, S.A.B. de C.V. (BMV: KOFUBL, NYSE: KOF) (“Coca-Cola FEMSA”, “KOF” or the “Company”), the largest Coca-Cola franchise bottler in the world by sales volume, announces results for the third quarter of 2026.
THIRD QUARTER HIGHLIGHTS
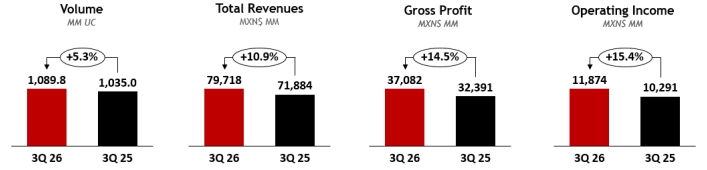
| · | Volume increased 5.3%. |
| · | Revenue increased 10.9%; on a currency neutral basis, revenue grew 11.3%. |
| · | Operating income increased 15.4%; on a currency neutral basis, operating income increased 16.4%. |
| · | Majority net income increased 5.5%, driven mainly by an increase in our operating income, partially offset by a higher comprehensive financial result. |
| · | Earnings per share1 were Ps. 0.37 (Earnings per unit were Ps. 2.96 and per ADS were Ps. 29.62.). |
FIRST NINE MONTHS HIGHLIGHTS
| · | Volume increased 3.4%. |
| · | Revenue increased 6.2%; on a currency neutral basis, revenue grew 10.4%. |
| · | Operating income increased 8.0%; on a currency neutral basis, operating income grew 11.9%. |
| · | Majority net income increased 2.7%. |
| · | Earnings per share1 were Ps. 1.00 (Earnings per unit were Ps. 7.99 and per ADS were Ps. 79.89.). |
FINANCIAL SUMMARY FOR THE THIRD QUARTER RESULTS
Change vs. same period of last year
| Total Revenues | Gross Profit | Operating Income | Majority Net Income | |||||||||||||||||||||||||||||||
| 3Q26 | YTD 2026 | 3Q26 | YTD 2026 | 3Q26 | YTD 2026 | 3Q26 | YTD 2026 | |||||||||||||||||||||||||||
| Consolidated | 10.9 | % | 6.2 | % | 14.5 | % | 9.8 | % | 15.4 | % | 8.0 | % | 5.5 | % | 2.7 | % | ||||||||||||||||||
| As Reported | Mexico & Central America | 8.3 | % | 2.4 | % | 11.6 | % | 5.5 | % | (3.1 | )% | (8.6 | )% | |||||||||||||||||||||
| South America | 14.7 | % | 11.7 | % | 19.2 | % | 17.1 | % | 51.2 | % | 38.9 | % | ||||||||||||||||||||||
| Consolidated | 11.3 | % | 10.4 | % | 14.8 | % | 14.1 | % | 16.4 | % | 11.9 | % | ||||||||||||||||||||||
| Comparable (2) | Mexico & Central America | 9.3 | % | 4.2 | % | 12.6 | % | 7.4 | % | (2.2 | )% | (6.7 | )% | |||||||||||||||||||||
| South America | 14.1 | % | 20.0 | % | 18.4 | % | 25.8 | % | 52.3 | % | 48.1 | % | ||||||||||||||||||||||
Ian Craig, Coca-Cola FEMSA’s CEO, commented:
“I would like to express our solidarity with the communities affected by the earthquake that struck Colombia in August. We joined forces with FEMSA and The Coca-Cola Company to provide beverages, meals, and essential supplies, and remain committed to support affected traditional trade stores.
During the third quarter, we delivered volume growth across all our operations, achieved a record third-quarter consolidated volume, and continued to gain market share. In Mexico, our revenue growth management strategy enabled us to sustain a strong competitive position and drive sequential improvement in our results, despite consumer conditions that remained challenging throughout the quarter.
South America delivered strong performance, with double-digit operating income growth in Brazil and Colombia driving the results. Our leadership position was further strengthened by the acceleration of our digital transformation and the momentum across our broad portfolio.
Our geographic diversification continues to deliver value, with the strength and balance of our operations supporting our consolidated results and reinforcing the resilience of our business”.
| (1) | Quarterly earnings / outstanding shares. Earnings per share (EPS) were calculated using 16,806.7 million shares outstanding. For the convenience of the reader, as a KOFUBL Unit is comprised of 8 shares (3 Series B shares and 5 Series L shares), earnings per unit are equal to EPS multiplied by 8. Each ADS represents 10 KOFUBL Units. | |
| (2) | Please refer to page 10 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance. |
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 2 of 17 |  |
RECENT DEVELOPMENTS
| · | On October 13, 2026, Coca-Cola FEMSA paid the third installment of the ordinary dividend approved for Ps. 0.241875 per share, for a total cash distribution of Ps. 4,065.1 million. |
| · | Coca-Cola FEMSA achieved a score of 82/100 in S&P Global’s 2026 Corporate Sustainability Assessment (CSA), an increase of 12 points over the last two years. This progress reflects the continued strength of our sustainability strategy and sustainability-related disclosures, including our first reporting aligned with the TNFD framework. This achievement underscores our focus on continuous improvement and long-term value creation across the communities we serve. |
CONFERENCE CALL INFORMATION
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 3 of 17 | |
CONSOLIDATED THIRD QUARTER RESULTS
CONSOLIDATED THIRD QUARTER RESULTS
| As Reported | Comparable (1) | |||||||||||||||
| Expressed in millions of Mexican pesos | 3Q 2026 | 3Q 2025 | Δ% | Δ% | ||||||||||||
| Total revenues | 79,718 | 71,884 | 10.9 | % | 11.3 | % | ||||||||||
| Gross profit | 37,082 | 32,391 | 14.5 | % | 14.8 | % | ||||||||||
| Operating income | 11,874 | 10,291 | 15.4 | % | 16.4 | % | ||||||||||
| Adj. EBITDA (2) | 16,794 | 14,449 | 16.2 | % | 17.0 | % | ||||||||||
Volume increased 5.3% to 1,089.8 million-unit cases, driven by volume growth in all our operations.
Total revenues increased 10.9% to Ps. 79,718 million. This increase was driven mainly by volume growth, coupled with revenue management initiatives, which were partially offset by unfavorable mix and negative translation effects from most our operating currencies into Mexican pesos. Excluding currency translation effects, total revenues increased 11.3%.
Gross profit increased 14.5% to Ps. 37,082 million, and gross margin expanded 140 basis points to 46.5%. This expansion was driven mainly by lower sweetener and PET costs supported by our raw material hedging initiatives, coupled with the appreciation of most of our operating currencies as applied to our U.S. dollar-denominated raw material costs. These effects were partially offset by unfavorable mix effects, coupled with higher aluminum costs. Excluding currency translation effects, gross profit increased 14.8%.
Operating income increased 15.4% to Ps. 11,874 million, and operating margin expanded 60 basis points to 14.9%. This margin expansion was driven mainly by the recognition of Ps. 1,055 million, net of expenses, related to insurance claims in Brazil. Additionally, operating leverage and expense efficiencies in IT expenses and rent contributed to profitability. These effects were partially offset by an increase in freight, marketing, labor, and maintenance expenses. Moreover, we registered an operative foreign exchange loss in the quarter as compared to a gain in the same period of the previous year. Excluding currency translation effects, operating income increased 16.4%.
| (1) | Please refer to page 10 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance. |
| (2) | Adjusted EBITDA = operating income + depreciation + amortization & other operating non-cash charges. |
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 4 of 17 | |
Comprehensive financing result recorded an expense of Ps. 2,019 million, compared to an expense of Ps. 1,290 million in the previous year. This increase was driven mainly by higher interest expense, net, reflecting the issuance of new debt during the first quarter of 2026 in Mexican pesos, partially offset by higher interest income from a stronger cash position.
In addition, we recorded a loss on financial instruments of Ps. 377 million, as compared to a loss of Ps. 39 million in the same period of the previous year, reflecting higher interest rates in Brazil.
Additionally, we recognized a lower gain in monetary positions in inflationary subsidiaries related to Argentina for Ps. 64 million as compared to a gain of Ps. 136 million recorded in the same period of the previous year.
These effects were partially offset by a lower foreign exchange loss of Ps. 23 million in the third quarter of 2026 as compared to a loss of Ps. 65 million in the same period of the previous year. The loss this year was driven mainly by the quarterly appreciation of the Colombian peso as applied to our U.S. dollar-denominated cash position.
Income tax as a percentage of income before taxes was 33.4% as compared to 30.9% during the same period of 2025. This increase was driven mainly by inflationary effects in Mexico.
Net income attributable to equity holders of the company increased 5.5% to reach Ps. 6,223 million. This increase was driven mainly by an increase in our operating income, partially offset by a higher income tax and increase in our comprehensive financing result. Earnings per share1 were Ps. 0.37 (Earnings per unit were Ps. 2.96 and per ADS were Ps. 29.62.).
| (1) | Quarterly earnings / outstanding shares. Earnings per share (EPS) were calculated using 16,806.7 million shares outstanding. For the convenience of the reader, as a KOFUBL Unit is comprised of 8 shares (3 Series B shares and 5 Series L shares), earnings per unit are equal to EPS multiplied by 8. Each ADS represents 10 KOFUBL Units. |
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 5 of 17 | |
CONSOLIDATED FIRST NINE MONTHS RESULTS
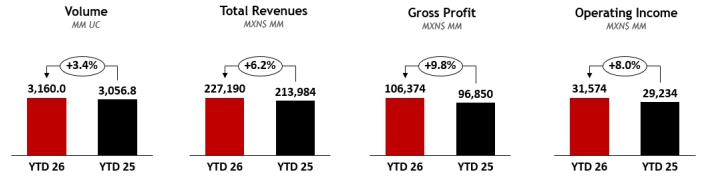
CONSOLIDATED FIRST NINE MONTHS RESULTS
| As Reported | Comparable (1) | |||||||||||||||
| Expressed in millions of Mexican pesos | YTD 2026 | YTD 2025 | Δ% | Δ% | ||||||||||||
| Total revenues | 227,190 | 213,984 | 6.2 | % | 10.4 | % | ||||||||||
| Gross profit | 106,374 | 96,850 | 9.8 | % | 14.1 | % | ||||||||||
| Operating income | 31,574 | 29,234 | 8.0 | % | 11.9 | % | ||||||||||
| Adj. EBITDA (2) | 45,213 | 40,939 | 10.4 | % | 15.0 | % | ||||||||||
Volume increased 3.4% to 3,160.0 million-unit cases, driven by volume increases in all our operations.
Total revenues increased 6.2% to Ps. 227,190 million. This increase was driven mainly by volume growth, coupled with revenue management initiatives, partially offset by unfavorable currency translation effects from most of our operating currencies into Mexican pesos and mix effects. Excluding currency translation effects, total revenues increased 10.4%.
Gross profit increased 9.8% to Ps. 106,374 million, and gross margin expanded 150 basis points to 46.8%. This performance was driven mainly by lower sweetener costs, top-line growth, raw material hedging initiatives, and the appreciation of most of our operating currencies as applied to our U.S. dollar-denominated raw material costs. Excluding currency translation effects, gross profit increased 14.1%.
Operating income increased 8.0% to Ps. 31,574 million, while operating margin expanded 20 basis points to 13.9%. This margin expansion was driven mainly by the recognition of an income of Ps. 1,313 million related to insurance claims in Brazil and Mexico, and higher operating leverage and expense efficiencies such IT expenses and rent. These effects were offset by higher marketing, depreciation, freight, and maintenance expenses. Moreover, we registered a lower operative foreign exchange gain in the period as compared to the same period of the previous year. Excluding currency translation effects, operating income increased 11.9%.
| (1) | Please refer to page 10 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance. |
| (2) | Adjusted EBITDA = operating income + depreciation + amortization & other operating non-cash charges. |
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 6 of 17 | |
Comprehensive financing result recorded an expense of Ps. 5,103 million, compared to an expense of Ps. 3,588 million in the same period of the previous year. This increase was driven mainly by a higher interest expense, net, of Ps. 4,853 million as compared to Ps. 4,049 million in the same period of the previous year resulting from higher interest expense, driven mainly by new debt issued during the second quarter of 2025 and the first quarter of 2026.
Additionally, we recorded a loss in financial instruments of Ps. 456 million as compared to a gain of Ps. 249 million in the same period of the previous year, resulting from the market value of financial instruments.
These effects were partially offset by a gain in monetary positions in inflationary subsidiaries related to Argentina for Ps. 250 million as compared to a gain of Ps. 275 million in the same period of the previous year.
Income tax as a percentage of income before taxes was 33.2% as compared to 33.4% during the same period of 2025.
Net income attributable to equity holders of the company was Ps. 16,784 million as compared to Ps 16,343 million during the same period of the previous year. This increase was driven mainly by an increase in our operating income, partially offset by a higher comprehensive financing result. Earnings per share1 were Ps. 1.00 (Earnings per unit were Ps. 7.99 and per ADS were Ps. 79.89.).
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 7 of 17 | |
MEXICO & CENTRAL AMERICA DIVISION THIRD QUARTER RESULTS
| (Mexico, Guatemala, Costa Rica, Panama, and Nicaragua) |  |
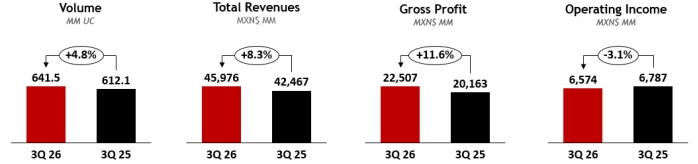
MEXICO & CENTRAL AMERICA DIVISION RESULTS
| As Reported | Comparable (1) | |||||||||||||||
| Expressed in millions of Mexican pesos | 3Q 2026 | 3Q 2025 | Δ% | Δ% | ||||||||||||
| Total revenues | 45,976 | 42,467 | 8.3 | % | 9.3 | % | ||||||||||
| Gross profit | 22,507 | 20,163 | 11.6 | % | 12.6 | % | ||||||||||
| Operating income | 6,574 | 6,787 | (3.1 | )% | (2.2 | )% | ||||||||||
| Adj. EBITDA (2) | 9,571 | 9,280 | 3.1 | % | 4.2 | % | ||||||||||
Volume increased 4.8% to 641.5 million-unit cases, driven by volume growth in all our territories in the division.
Total revenues increased 8.3% to Ps. 45,976 million. This performance was driven mainly by volume increases, coupled with revenue management initiatives, partially offset by unfavorable mix and currency translation effects from most of our operating currencies in the division into Mexican pesos. Excluding currency translation effects, total revenues increased 9.3%.
Gross profit increased 11.6% to Ps. 22,507 million, and gross margin expanded 150 basis points to 49.0%. This margin expansion was driven mainly by lower sweetener and PET costs as compared to the previous year, coupled with the appreciation of all the currencies in the division as applied to our U.S. dollar-denominated raw material costs. These effects were partially offset by unfavorable mix effects. Excluding currency translation, gross profit increased 12.6%
Operating income decreased 3.1% to Ps. 6,574 million, and operating margin contracted 170 basis points to 14.3%. This operating margin contraction was driven mainly by higher operating expenses, particularly in marketing, depreciation, maintenance, and freight. In addition, this year we reported a loss in operating foreign exchange as compared to a gain in the same period of the previous year. These effects were partially offset by expense efficiencies in rent and IT. Excluding currency translation effects, operating income decreased 2.2%
| (1) | Please refer to page 10 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance. |
| (2) | Adjusted EBITDA = operating income + depreciation + amortization & other operating non-cash charges. |
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 8 of 17 | |
SOUTH AMERICA DIVISION THIRD QUARTER RESULTS
| (Brazil, Argentina, Colombia, and Uruguay) |  |
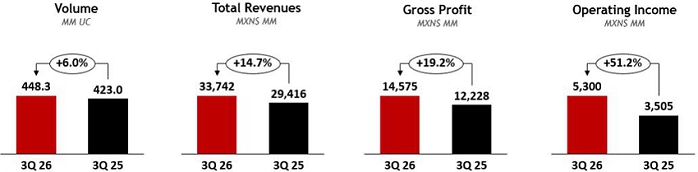
SOUTH AMERICA DIVISION RESULTS
| As Reported | Comparable (1) | |||||||||||||||
| Expressed in millions of Mexican pesos | 3Q 2026 | 3Q 2025 | Δ% | Δ% | ||||||||||||
| Total revenues | 33,742 | 29,416 | 14.7 | % | 14.1 | % | ||||||||||
| Gross profit | 14,575 | 12,228 | 19.2 | % | 18.4 | % | ||||||||||
| Operating income | 5,300 | 3,505 | 51.2 | % | 52.3 | % | ||||||||||
| Adj. EBITDA (2) | 7,223 | 5,169 | 39.7 | % | 39.9 | % | ||||||||||
Volume increased 6.0% to 448.3 million-unit cases, driven by volume growth in all our operations, mainly 15.9% in Colombia and 3.9% in Brazil.
Total revenues increased 14.7% to Ps. 33,742 million. This increase was driven mainly by volume growth, revenue management initiatives, and a favorable currency translation effect from Colombia into Mexican pesos, partially offset by an unfavorable currency translation effect from the rest of our operating currencies in the division into Mexican pesos. Excluding currency translation effects, total revenues increased 14.1%.
Gross profit increased 19.2% to Ps. 14,575 million, and gross margin expanded 160 basis points to 43.2% This expansion was driven mainly by our top-line performance, coupled with our hedging initiatives, together with the appreciation of most of our operating currencies as applied to our U.S. dollar-denominated raw material costs. These effects were partially offset by higher aluminum cost. Excluding currency translation effects, gross profit increased 18.4%.
Operating income increased 51.2% to Ps. 5,300 million, resulting in an operating margin expansion of 380 basis points to 15.7%. This performance includes the recognition of Ps. 1,055 million in income related to insurance claims in Brazil, net of expenses. Additionally, operating leverage and expense efficiencies contributed to the positive performance. These effects were partially offset by higher marketing, freight, depreciation, and labor expenses. Excluding currency translation effects, operating income increased 52.3%.
| (1) | Please refer to page 10 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance. |
| (2) | Adjusted EBITDA = operating income + depreciation + amortization & other operating non-cash charges. |
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 9 of 17 | |
DEFINITIONS
Volume is expressed in unit cases. Unit case refers to 192 ounces of finished beverage product (24 eight-ounce servings) and, when applied to soda fountains, refers to the volume of syrup, powders, and concentrate that is required to produce 192 ounces of finished beverage product.
Transactions refer to the number of single units (e.g., a can or a bottle) sold, regardless of their size or volume or whether they are sold individually or in multipacks, except for soda fountains, which represent multiple transactions based on a standard 12 oz. serving.
Operating income is a non-GAAP financial measure computed as “gross profit – operating expenses – other operating expenses, net + operative equity method (gain) loss in associates.”
Adjusted EBITDA is a non-GAAP financial measure computed as “operating income + depreciation + amortization & other operating non-cash charges.”
Earnings per share are equal to “quarterly earnings / shares outstanding.” Earnings per share (EPS) are calculated using 16,806,658,096 shares outstanding. For the convenience of the reader, as a KOFUBL Unit is comprised of 8 shares (3 Series B shares and 5 Series L shares), earnings per unit are equal to EPS multiplied by 8. Each ADS represents 10 KOFUBL Units.
COMPARABILITY
Our “comparable” term means, with respect to a year-over-year comparison, the change of a given measure excluding translation effects resulting from exchange rate movements. In preparing this measure, management has used its best judgment, estimates, and assumptions to maintain comparability.
Due to the average depreciation of the Argentine peso and most of the operating currencies relative to the Mexican peso in the third quarter of 2026, as compared to the same period of 2025, we had an unfavorable currency translation effect into Mexican pesos. Please see page 17 for exchange rate fluctuations.
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 10 of 17 | |
ABOUT THE COMPANY
Stock listing information: Mexican Stock Exchange, Ticker: KOFUBL | NYSE (ADS), Ticker: KOF | Ratio of KOFUBL to KOF = 10:1
Coca-Cola FEMSA files reports, including annual reports and other information, with the U.S. Securities and Exchange Commission, or the “SEC”, and the Mexican Stock Exchange (Bolsa Mexicana de Valores, or the “BMV”) pursuant to the rules and regulations of the SEC (that apply to foreign private issuers) and of the BMV. Filings we make electronically with the SEC and the BMV are available to the public on the Internet at the SEC’s website at www.sec.gov, the BMV’s website at www.bmv.com.mx, and our website at www.coca-colafemsa.com.
Coca-Cola FEMSA, S.A.B. de C.V. is the largest Coca-Cola franchise bottler in the world by sales volume. The Company produces and distributes trademark beverages of The Coca-Cola Company, offering a wide portfolio to more than 268 million consumers. With over 90,000 employees, the Company markets and sells approximately 4.2 billion-unit cases through more than 2.1 million points of sale a year. Operating 55 manufacturing plants and 256 distribution centers, Coca-Cola FEMSA is committed to generating economic, social, and environmental value for all its stakeholders across the value chain. The Company is a member of the Dow Jones Best-In-Class World Index, Dow Jones Best-In-Class MILA Pacific Alliance Index, FTSE4Good Emerging Index, S&P/BMV Total Mexico ESG Index, and the MSCI ACWI Index. Its operations encompass certain territories in Mexico, Brazil, Guatemala, Colombia, and Argentina and, nationwide, in Costa Rica, Nicaragua, Panama, Uruguay and, in Venezuela, through an investment in Coca-Cola FEMSA de Venezuela, S.A. For further information, please visit www.coca-colafemsa.com

ADDITIONAL INFORMATION
All the financial information presented in this report was prepared under International Financial Reporting Standards (IFRS).
This news release may contain forward-looking statements concerning Coca-Cola FEMSA’s future performance, which should be considered as good faith estimates by Coca-Cola FEMSA. These forward-looking statements reflect management’s expectations and are based upon currently available data. Actual results are subject to future events and uncertainties, many of which are outside Coca-Cola FEMSA’s control, which could materially impact the Company’s actual performance. References herein to “US$” are to United States dollars. This news release contains translations of certain Mexican peso amounts into U.S. dollars for the convenience of the reader. These translations should not be construed as representations that Mexican peso amounts represent such U.S. dollar amounts or could be converted into U.S. dollars at the rate indicated.
(6 pages of tables to follow)
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 11 of 17 | |
COCA-COLA FEMSA
CONSOLIDATED INCOME STATEMENT
Millions of Pesos (1)
| For the Third Quarter of: | For the first Nine Months of: | |||||||||||||||||||||||||||||||||||
| 2026 | %
of Rev. | 2025 | %
of Rev. | Δ%
Reported | Δ%
Comparable (7) | 2026 | %
of Rev. | 2025 | %
of Rev. | Δ%
Reported | Δ%
Comparable (7) | |||||||||||||||||||||||||
| Transactions (million transactions) | 6,528.4 | 6,192.8 | 5.4 | % | 5.4 | % | 18,902.4 | 18,246.4 | 3.6 | % | 3.6 | % | ||||||||||||||||||||||||
| Volume (million unit cases) | 1,089.8 | 1,035.0 | 5.3 | % | 5.3 | % | 3,160.0 | 3,056.8 | 3.4 | % | 3.4 | % | ||||||||||||||||||||||||
| Average price per unit case | 70.84 | 67.31 | 5.2 | % | 69.67 | 67.99 | 2.5 | % | ||||||||||||||||||||||||||||
| Net revenues | 79,360 | 71,685 | 10.7 | % | 226,508 | 213,642 | 6.0 | % | ||||||||||||||||||||||||||||
| Other operating revenues | 358 | 199 | 79.8 | % | 682 | 342 | 99.5 | % | ||||||||||||||||||||||||||||
| Total revenues (2) | 79,718 | 100.0 | % | 71,884 | 100.0 | % | 10.9 | % | 11.3 | % | 227,190 | 100.0 | % | 213,984 | 100.0 | % | 6.2 | % | 10.4 | % | ||||||||||||||||
| Cost of goods sold | 42,636 | 53.5 | % | 39,493 | 54.9 | % | 8.0 | % | 120,815 | 53.2 | % | 117,134 | 54.7 | % | 3.1 | % | ||||||||||||||||||||
| Gross profit | 37,082 | 46.5 | % | 32,391 | 45.1 | % | 14.5 | % | 14.8 | % | 106,374 | 46.8 | % | 96,850 | 45.3 | % | 9.8 | % | 14.1 | % | ||||||||||||||||
| Operating expenses | 26,013 | 32.6 | % | 22,356 | 31.1 | % | 16.4 | % | 76,103 | 33.5 | % | 68,172 | 31.9 | % | 11.6 | % | ||||||||||||||||||||
| Other operative expenses, net | (687 | ) | 0.9 | % | (159 | ) | 0.2 | % | 332.2 | % | (961 | ) | 0.4 | % | (269 | ) | 0.1 | % | 257.6 | % | ||||||||||||||||
| Operative equity method (gain) loss in associates(3) | (118 | ) | 0.1 | % | (97 | ) | 0.1 | % | 22.1 | % | (342 | ) | 0.2 | % | (287 | ) | 0.1 | % | 19.3 | % | ||||||||||||||||
| Operating income (5) | 11,874 | 14.9 | % | 10,291 | 14.3 | % | 15.4 | % | 31,574 | 13.9 | % | 29,234 | 13.7 | % | 8.0 | % | 11.9 | % | ||||||||||||||||||
| Other non operative expenses, net | 16 | 0.0 | % | 180 | 0.3 | % | -91.1 | % | (13 | ) | 0.0 | % | 305 | 0.1 | % | NA | ||||||||||||||||||||
| Non Operative equity method (gain) loss in associates (4) | 9 | 0.0 | % | (13 | ) | 0.0 | % | NA | (28 | ) | 0.0 | % | (144 | ) | 0.1 | % | -80.6 | % | ||||||||||||||||||
| Interest expense | 2,466 | 1,942 | 27.0 | % | 6,835 | 5,879 | 16.3 | % | ||||||||||||||||||||||||||||
| Interest income | 783 | 620 | 26.3 | % | 1,982 | 1,830 | 8.3 | % | ||||||||||||||||||||||||||||
| Interest expense, net | 1,684 | 1,322 | 27.4 | % | 4,853 | 4,049 | 19.8 | % | ||||||||||||||||||||||||||||
| Foreign exchange loss (gain) | 23 | 65 | -64.6 | % | 44 | 62 | -29.4 | % | ||||||||||||||||||||||||||||
| Loss (gain) on monetary position in inflationary subsidiaries | (64 | ) | (136 | ) | -52.8 | % | (250 | ) | (275 | ) | -9.0 | % | ||||||||||||||||||||||||
| Market value (gain) loss on financial instruments | 377 | 39 | 866.6 | % | 456 | (249 | ) | NA | ||||||||||||||||||||||||||||
| Comprehensive financing result | 2,019 | 1,290 | 56.6 | % | 5,103 | 3,588 | 42.2 | % | ||||||||||||||||||||||||||||
| Income before taxes | 9,830 | 8,835 | 11.3 | % | 26,512 | 25,484 | 4.0 | % | ||||||||||||||||||||||||||||
| Income taxes | 3,250 | 33.1 | % | 2,698 | 30.5 | % | 20.5 | % | 8,686 | 8,359 | 3.9 | % | ||||||||||||||||||||||||
| Result of discontinued operations | - | - | NA | - | - | - | NA | |||||||||||||||||||||||||||||
| Consolidated net income | 6,580 | 6,137 | 7.2 | % | 17,826 | 17,126 | 4.1 | % | ||||||||||||||||||||||||||||
| Net income attributable to equity holders of the company | 6,223 | 7.8 | % | 5,898 | 8.2 | % | 5.5 | % | 7.1 | % | 16,784 | 7.4 | % | 16,343 | 7.6 | % | 2.7 | % | 6.5 | % | ||||||||||||||||
| Non-controlling interest | 357 | 0.4 | % | 239 | 0.3 | % | 49.0 | % | 1,043 | 0.5 | % | 782 | 0.4 | % | 33.2 | % | ||||||||||||||||||||
| Adj. EBITDA & CAPEX | 2026 | % of Rev. | 2025 | % of Rev. | Δ% Reported | Δ%
Comparable (7) | 2026 | % of Rev. | 2025 | % of Rev. | Δ% Reported | Δ%
Comparable (7) | ||||||||||||||||||||||||
| Operating income (5) | 11,874 | 14.9 | % | 10,291 | 14.3 | % | 15.4 | % | 16.4 | % | 31,574 | 13.9 | % | 29,234 | 13.7 | % | 8.0 | % | 11.9 | % | ||||||||||||||||
| Depreciation | 3,553 | 3,215 | 10.5 | % | 10,403 | 9,445 | 10.1 | % | ||||||||||||||||||||||||||||
| Amortization and other operative non-cash charges | 1,367 | 943 | 45.0 | % | 3,235 | 2,260 | 43.2 | % | ||||||||||||||||||||||||||||
| Adj. EBITDA (5)(6) | 16,794 | 21.1 | % | 14,449 | 20.1 | % | 16.2 | % | 17.0 | % | 45,213 | 19.9 | % | 40,939 | 19.1 | % | 10.4 | % | 15.0 | % | ||||||||||||||||
| CAPEX(8) | 4,210 | 7,669 | -45.1 | % | 11,384 | 17,301 | -34.2 | % |
| (1) | Except volume and average price per unit case figures. |
| (2) | Please refer to pages 15 and 16 for revenue breakdown. |
| (3) | Includes equity method in Jugos del Valle and Leão Alimentos, among others. |
| (4) | Includes equity method in PIASA, IEQSA, Beta San Miguel, IMER, and KSP Participacoes, among others. |
| (5) | The operating income and adjusted EBITDA lines are presented as non-GAAP measures for the convenience of the reader. |
| (6) | Adjusted EBITDA = operating income + depreciation, amortization & other operating non-cash charges. |
| (7) | Please refer to page 10 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance. |
| (8) | As of September 30, 2026, the investment in fixed assets effectively paid is equivalent to Ps. 9,902 million. |
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 12 of 17 | |
MEXICO & CENTRAL AMERICA DIVISION
RESULTS OF OPERATIONS
Millions of Pesos (1)
| For the Third Quarter of: | For the first Nine Months of: | |||||||||||||||||||||||||||||||||||
| 2026 | %
of Rev. | 2025 | %
of Rev. | Δ% Reported | Δ% Comparable (6) | 2026 | %
of Rev. | 2025 | %
of Rev. | Δ% Reported | Δ% Comparable (6) | |||||||||||||||||||||||||
| Transactions (million transactions) | 3,285.2 | 3,162.9 | 3.9 | % | 3.9 | % | 9,412.4 | 9,345.7 | 0.7 | % | 0.7 | % | ||||||||||||||||||||||||
| Volume (million unit cases) | 641.5 | 612.1 | 4.8 | % | 4.8 | % | 1,831.9 | 1,802.2 | 1.6 | % | 1.6 | % | ||||||||||||||||||||||||
| Average price per unit case | 70.51 | 68.63 | 2.7 | % | 70.18 | 70.02 | 0.2 | % | ||||||||||||||||||||||||||||
| Net revenues | 45,969 | 42,450 | 130,511 | 127,409 | ||||||||||||||||||||||||||||||||
| Other operating revenues | 7 | 18 | 33 | 33 | ||||||||||||||||||||||||||||||||
| Total Revenues (2) | 45,976 | 100.0 | % | 42,467 | 100.0 | % | 8.3 | % | 9.3 | % | 130,543 | 100.0 | % | 127,442 | 100.0 | % | 2.4 | % | 4.2 | % | ||||||||||||||||
| Cost of goods sold | 23,469 | 51.0 | % | 22,304 | 52.5 | % | 66,775 | 51.2 | % | 66,990 | 52.6 | % | ||||||||||||||||||||||||
| Gross profit | 22,507 | 49.0 | % | 20,163 | 47.5 | % | 11.6 | % | 12.6 | % | 63,768 | 48.8 | % | 60,452 | 47.4 | % | 5.5 | % | 7.4 | % | ||||||||||||||||
| Operating expenses | 15,537 | 33.8 | % | 13,378 | 31.5 | % | 45,976 | 35.2 | % | 41,711 | 32.7 | % | ||||||||||||||||||||||||
| Other operative expenses, net | 474 | 1.0 | % | 50 | 0.1 | % | 633 | 0.5 | % | (113 | ) | 0.1 | % | |||||||||||||||||||||||
| Operative equity method (gain) loss in associates (3) | (78 | ) | 0.2 | % | (52 | ) | 0.1 | % | (226 | ) | 0.2 | % | (162 | ) | 0.1 | % | ||||||||||||||||||||
| Operating income (4) | 6,574 | 14.3 | % | 6,787 | 16.0 | % | -3.1 | % | -2.2 | % | 17,386 | 13.3 | % | 19,016 | 14.9 | % | -8.6 | % | -6.7 | % | ||||||||||||||||
| Depreciation, amortization & other operating non-cash charges | 2,997 | 6.5 | % | 2,493 | 5.9 | % | 8,268 | 6.3 | % | 7,098 | 5.6 | % | ||||||||||||||||||||||||
| Adj. EBITDA (4)(5) | 9,571 | 20.8 | % | 9,280 | 21.9 | % | 3.1 | % | 4.2 | % | 25,654 | 19.7 | % | 26,114 | 20.5 | % | -1.8 | % | 0.3 | % | ||||||||||||||||
| (1) | Except volume and average price per unit case figures. |
| (2) | Please refer to pages 15 and 16 for revenue breakdown. |
| (3) | Includes equity method in Jugos del Valle, among others. |
| (4) | The operating income and adjusted EBITDA lines are presented as non-GAAP measures for the convenience of the reader. |
| (5) | Adjusted EBITDA = operating income + depreciation, amortization & other operating non-cash charges. |
| (6) | Please refer to page 10 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance. |
SOUTH AMERICA DIVISION
RESULTS OF OPERATIONS
Millions of Pesos (1)
| For the Third Quarter of: | For the first Nine Months of: | |||||||||||||||||||||||||||||||||||
| 2026 | %
of Rev. | 2025 | %
of Rev. | Δ% Reported | Δ% Comparable (6) | 2026 | %
of Rev. | 2025 | %
of Rev. | Δ% Reported | Δ% Comparable (6) | |||||||||||||||||||||||||
| Transactions (million transactions) | 3,243.2 | 3,029.9 | 7.0 | % | 7.0 | % | 9,490.0 | 8,900.7 | 6.6 | % | 6.6 | % | ||||||||||||||||||||||||
| Volume (million unit cases) | 448.3 | 423.0 | 6.0 | % | 6.0 | % | 1,328.1 | 1,254.6 | 5.9 | % | 5.9 | % | ||||||||||||||||||||||||
| Average price per unit case | 71.30 | 65.39 | 9.0 | % | 68.97 | 65.08 | 6.0 | % | ||||||||||||||||||||||||||||
| Net revenues | 33,391 | 29,235 | 95,997 | 86,233 | ||||||||||||||||||||||||||||||||
| Other operating revenues | 351 | 182 | 650 | 309 | ||||||||||||||||||||||||||||||||
| Total Revenues (2) | 33,742 | 100.0 | % | 29,416 | 100.0 | % | 14.7 | % | 14.1 | % | 96,647 | 100.0 | % | 86,542 | 100.0 | % | 11.7 | % | 20.0 | % | ||||||||||||||||
| Cost of goods sold | 19,167 | 56.8 | % | 17,188 | 58.4 | % | 54,041 | 55.9 | % | 50,144 | 57.9 | % | ||||||||||||||||||||||||
| Gross profit | 14,575 | 43.2 | % | 12,228 | 41.6 | % | 19.2 | % | 18.4 | % | 42,606 | 44.1 | % | 36,398 | 42.1 | % | 17.1 | % | 25.8 | % | ||||||||||||||||
| Operating expenses | 10,476 | 31.0 | % | 8,978 | 30.5 | % | 30,127 | 31.2 | % | 26,460 | 30.6 | % | ||||||||||||||||||||||||
| Other operative expenses, net | (1,161 | ) | 3.4 | % | (209 | ) | 0.7 | % | (1,593 | ) | 1.6 | % | (156 | ) | 0.2 | % | ||||||||||||||||||||
| Operative equity method (gain) loss in associates (3) | (40 | ) | 0.1 | % | (45 | ) | 0.2 | % | (116 | ) | 0.1 | % | (125 | ) | 0.1 | % | ||||||||||||||||||||
| Operating income (4) | 5,300 | 15.7 | % | 3,505 | 11.9 | % | 51.2 | % | 52.3 | % | 14,188 | 14.7 | % | 10,218 | 11.8 | % | 38.9 | % | 48.1 | % | ||||||||||||||||
| Depreciation, amortization & other operating non-cash charges | 1,923 | 5.7 | % | 1,664 | 5.7 | % | 5,371 | 5.6 | % | 4,607 | 5.3 | % | ||||||||||||||||||||||||
| Adj. EBITDA (4)(5) | 7,223 | 21.4 | % | 5,169 | 17.6 | % | 39.7 | % | 39.9 | % | 19,559 | 20.2 | % | 14,825 | 17.1 | % | 31.9 | % | 42.3 | % | ||||||||||||||||
| (1) | Except volume and average price per unit case figures. |
| (2) | Please refer to pages 15 and 16 for revenue breakdown. |
| (3) | Includes equity method in Leão Alimentos, among others. |
| (4) | The operating income and adjusted EBITDA lines are presented as non-GAAP measures for the convenience of the reader. |
| (5) | Adjusted EBITDA = operating income + depreciation, amortization & other operating non-cash charges. |
| (6) | Please refer to page 10 for our definition of “comparable” and a description of the factors affecting the comparability of our financial and operating performance. |
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 13 of 17 | |
COCA-COLA FEMSA
CONSOLIDATED BALANCE SHEET
Millions of Pesos
| Assets | Sep-26 | Dec-25 | % Var. | |||||||||
| Current Assets | ||||||||||||
| Cash, cash equivalents and marketable securities | 46,772 | 28,067 | 67 | % | ||||||||
| Total accounts receivable | 18,570 | 22,146 | -16 | % | ||||||||
| Inventories | 14,781 | 14,014 | 5 | % | ||||||||
| Other current assets | 14,223 | 10,343 | 38 | % | ||||||||
| Total current assets | 94,347 | 74,570 | 27 | % | ||||||||
| Non-Current Assets | - | - | ||||||||||
| Property, plant and equipment | 186,087 | 174,289 | 7 | % | ||||||||
| Accumulated depreciation | (72,663 | ) | (65,159 | ) | 12 | % | ||||||
| Total property, plant and equipment, net | 113,425 | 109,130 | 4 | % | ||||||||
| Right of use assets | 3,678 | 2,617 | 41 | % | ||||||||
| Investment in shares | 10,829 | 10,588 | 2 | % | ||||||||
| Intangible assets and other assets | 104,715 | 102,356 | 2 | % | ||||||||
| Other non-current assets | 17,229 | 15,278 | 13 | % | ||||||||
| Total Assets | 344,224 | 314,539 | 9 | % | ||||||||
| Liabilities & Equity | Sep-26 | Dec-25 | % Var. | |||||||||
| Current Liabilities | ||||||||||||
| Short-term bank loans and notes payable | 11,518 | 7,944 | 45 | % | ||||||||
| Suppliers | 29,293 | 31,898 | -8 | % | ||||||||
| Short-term leasing Liabilities | 938 | 631 | 49 | % | ||||||||
| Other current liabilities | 41,366 | 26,284 | 57 | % | ||||||||
| Total current liabilities | 83,114 | 66,757 | 25 | % | ||||||||
| Non-Current Liabilities | - | - | ||||||||||
| Long-term bank loans and notes payable | 72,852 | 71,834 | 1 | % | ||||||||
| Long Term Leasing Liabilities | 3,040 | 2,273 | 34 | % | ||||||||
| Other long-term liabilities | 24,883 | 19,647 | 27 | % | ||||||||
| Total liabilities | 183,888 | 160,511 | 15 | % | ||||||||
| Equity | - | - | ||||||||||
| Non-controlling interest | 9,255 | 7,827 | 18 | % | ||||||||
| Total controlling interest | 151,080 | 146,201 | 3 | % | ||||||||
| Total equity | 160,335 | 154,029 | 4 | % | ||||||||
| Total Liabilities and Equity | 344,224 | 314,539 | 9 | % | ||||||||
| September 30, 2026 | ||||||||||||
| Debt Mix | % Total Debt (1) | %
Interest Rate Floating (1) (2) | Average Rate | |||||||||
| Currency | ||||||||||||
| Mexican Pesos | 62.0 | % | 3.0 | % | 8.9 | % | ||||||
| U.S. Dollars | 14.4 | % | 34.3 | % | 4.0 | % | ||||||
| Colombian Pesos | 1.8 | % | 81.3 | % | 13.1 | % | ||||||
| Brazilian Reals | 20.8 | % | 42.3 | % | 8.4 | % | ||||||
| Argentine Pesos | 1.1 | % | 0.0 | % | 28.3 | % | ||||||
| Total Debt | 100 | % | 17.0 | % | 8.4 | % | ||||||
(1) After giving effect to swaps.
(2) Calculated based on the weighting of the outstanding debt mix for each year.
Debt Maturity Profile
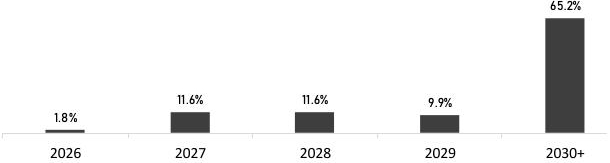
| Financial Ratios | Sep 30, 2026 | Dec 31, 2025 | Δ% | |||||||||
| Net debt including effect of hedges (1)(3) | 39,892 | 52,846 | -24.5 | % | ||||||||
| Net debt including effect of hedges / Adj. EBITDA (1)(3) | 0.63 | 0.89 | ||||||||||
| Adj. EBITDA/ Interest expense, net (1) | 9.32 | 10.26 | ||||||||||
| Capitalization (2) | 36.2 | % | 35.4 | % | ||||||||
(1) Net debt = total debt - cash
(2) Total debt / (total debt + shareholders' equity)
(3) After giving effect to swaps.
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 14 of 17 | |
COCA-COLA FEMSA
QUARTERLY- VOLUME, TRANSACTIONS & REVENUES
Volume
| 3Q 2026 | 3Q 2025 | YoY | ||||||||||||||||||||||||||||||||||||||||||
| Sparkling | Water (1) | Bulk (2) | Stills | Total | Sparkling | Water (1) | Bulk (2) | Stills | Total | Δ % | ||||||||||||||||||||||||||||||||||
| Mexico | 366.0 | 38.1 | 93.3 | 41.6 | 538.9 | 352.3 | 31.7 | 92.8 | 40.4 | 517.2 | 4.2 | % | ||||||||||||||||||||||||||||||||
| Guatemala | 48.9 | 2.8 | 0.5 | 2.6 | 54.9 | 45.5 | 2.3 | 0.8 | 2.2 | 50.8 | 8.1 | % | ||||||||||||||||||||||||||||||||
| CAM South | 39.0 | 2.3 | 0.1 | 6.3 | 47.8 | 36.1 | 2.2 | 0.2 | 5.7 | 44.1 | 8.3 | % | ||||||||||||||||||||||||||||||||
| Mexico and Central America | 453.9 | 43.2 | 93.9 | 50.5 | 641.5 | 434.0 | 36.2 | 93.7 | 48.2 | 612.1 | 4.8 | % | ||||||||||||||||||||||||||||||||
| Colombia | 79.2 | 13.4 | 3.9 | 7.9 | 104.3 | 68.6 | 10.6 | 3.8 | 7.0 | 90.0 | 15.9 | % | ||||||||||||||||||||||||||||||||
| Brazil (3) | 240.5 | 18.1 | 1.7 | 29.7 | 290.0 | 232.2 | 19.8 | 2.3 | 24.9 | 279.2 | 3.9 | % | ||||||||||||||||||||||||||||||||
| Argentina | 31.8 | 5.3 | 1.6 | 3.4 | 42.1 | 30.7 | 5.7 | 1.6 | 4.2 | 42.1 | 0.1 | % | ||||||||||||||||||||||||||||||||
| Uruguay | 9.4 | 1.6 | - | 0.8 | 11.8 | 9.3 | 1.6 | - | 0.8 | 11.7 | 1.2 | % | ||||||||||||||||||||||||||||||||
| South America | 361.0 | 38.4 | 7.1 | 41.8 | 448.3 | 340.8 | 37.7 | 7.7 | 36.8 | 423.0 | 6.0 | % | ||||||||||||||||||||||||||||||||
| TOTAL | 814.9 | 81.6 | 101.0 | 92.3 | 1,089.8 | 774.7 | 73.9 | 101.4 | 85.0 | 1,035.0 | 5.3 | % | ||||||||||||||||||||||||||||||||
(1) Excludes water presentations larger than 5.0 Lt ; includes flavored water.
(2) Bulk Water = Still bottled water in 5.0, 19.0 and 20.0 - liter packaging presentations; includes flavored water
Transactions
| 3Q 2026 | 3Q 2025 | YoY | ||||||||||||||||||||||||||||||||||
| Sparkling | Water | Stills | Total | Sparkling | Water | Stills | Total | Δ % | ||||||||||||||||||||||||||||
| Mexico | 1,938.0 | 278.6 | 297.6 | 2,514.3 | 1,926.0 | 229.6 | 278.5 | 2,434.1 | 3.3 | % | ||||||||||||||||||||||||||
| Guatemala | 357.7 | 26.4 | 28.7 | 412.8 | 345.6 | 22.1 | 23.0 | 390.6 | 5.7 | % | ||||||||||||||||||||||||||
| CAM South | 284.0 | 15.2 | 59.0 | 358.2 | 267.9 | 14.0 | 56.2 | 338.1 | 5.9 | % | ||||||||||||||||||||||||||
| Mexico and Central America | 2,579.8 | 320.1 | 385.3 | 3,285.2 | 2,539.5 | 265.6 | 357.7 | 3,162.9 | 3.9 | % | ||||||||||||||||||||||||||
| Colombia | 578.2 | 131.4 | 58.8 | 768.5 | 510.2 | 106.7 | 53.6 | 670.5 | 14.6 | % | ||||||||||||||||||||||||||
| Brazil (3) | 1,696.9 | 158.1 | 341.1 | 2,196.1 | 1,615.8 | 172.5 | 286.6 | 2,074.9 | 5.8 | % | ||||||||||||||||||||||||||
| Argentina | 158.9 | 30.1 | 30.1 | 219.1 | 159.5 | 32.9 | 34.1 | 226.5 | -3.3 | % | ||||||||||||||||||||||||||
| Uruguay | 46.7 | 6.0 | 6.8 | 59.6 | 45.8 | 6.0 | 6.2 | 58.0 | 2.7 | % | ||||||||||||||||||||||||||
| South America | 2,480.7 | 325.6 | 436.9 | 3,243.2 | 2,331.3 | 318.2 | 380.4 | 3,029.9 | 7.0 | % | ||||||||||||||||||||||||||
| TOTAL | 5,060.5 | 645.7 | 822.2 | 6,528.4 | 4,870.9 | 583.8 | 738.2 | 6,192.8 | 5.4 | % | ||||||||||||||||||||||||||
Revenues
| Expressed in million Mexican Pesos | 3Q 2026 | 3Q 2025 | Δ % | |||||||||
| Mexico | 37,099 | 34,429 | 7.8 | % | ||||||||
| Guatemala | 4,385 | 4,115 | 6.6 | % | ||||||||
| CAM South | 4,492 | 3,923 | 14.5 | % | ||||||||
| Mexico and Central America | 45,976 | 42,467 | 8.3 | % | ||||||||
| Colombia | 8,145 | 5,798 | 40.5 | % | ||||||||
| Brazil (4) | 21,431 | 19,792 | 8.3 | % | ||||||||
| Argentina | 2,946 | 2,542 | 15.9 | % | ||||||||
| Uruguay | 1,220 | 1,283 | -4.9 | % | ||||||||
| South America | 33,742 | 29,416 | 14.7 | % | ||||||||
| TOTAL | 79,718 | 71,884 | 10.9 | % | ||||||||
(3) Volume and transactions in Brazil do not include beer
(4) Brazil includes beer revenues of Ps. 1,155.5 million for the third quarter of 2026 and Ps. 1,246.1 million for the same period of the previous year.
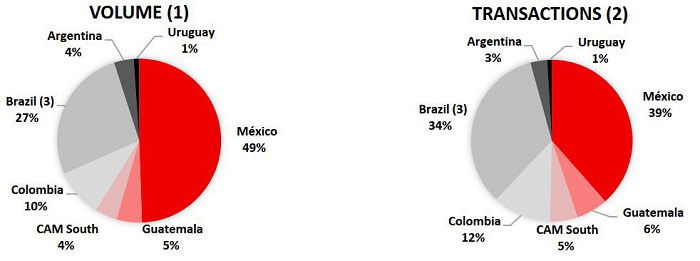
| (1) | Volume is expressed in unit cases. Unit case refers to 192 ounces of finished beverage product (24 eight-ounce servings) and, when applied to soda fountains, refers to the volume of syrup, powders, and concentrate that is required to produce 192 ounces of finished beverage product. |
| (2) | Transactions refer to the number of single units (e.g., a can or a bottle) sold, regardless of their size or volume or whether they are sold individually or in multipacks, except for soda fountains, which represent multiple transactions based on a standard 12 oz. serving. |
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 15 of 17 | |
COCA-COLA FEMSA
YTD- VOLUME, TRANSACTIONS & REVENUES
Volume
| YTD 2026 | YTD 2025 | YoY | ||||||||||||||||||||||||||||||||||||||||||
| Sparkling | Water (1) | Bulk (2) | Stills | Total | Sparkling | Water (1) | Bulk (2) | Stills | Total | Δ % | ||||||||||||||||||||||||||||||||||
| Mexico | 1,033.1 | 106.5 | 273.4 | 122.2 | 1,535.2 | 1,019.9 | 99.9 | 278.3 | 122.4 | 1,520.5 | 1.0 | % | ||||||||||||||||||||||||||||||||
| Guatemala | 139.8 | 7.7 | 1.4 | 7.1 | 156.0 | 133.6 | 6.4 | 2.3 | 6.5 | 148.8 | 4.8 | % | ||||||||||||||||||||||||||||||||
| CAM South | 114.7 | 7.3 | 0.5 | 18.2 | 140.7 | 108.8 | 6.6 | 0.5 | 17.0 | 132.9 | 5.8 | % | ||||||||||||||||||||||||||||||||
| Mexico and Central America | 1,287.6 | 121.5 | 275.4 | 147.5 | 1,831.9 | 1,262.3 | 112.9 | 281.1 | 145.8 | 1,802.2 | 1.6 | % | ||||||||||||||||||||||||||||||||
| Colombia | 221.3 | 35.6 | 11.1 | 21.9 | 289.9 | 193.7 | 30.0 | 10.8 | 19.1 | 253.7 | 14.3 | % | ||||||||||||||||||||||||||||||||
| Brazil (3) | 720.0 | 60.7 | 6.4 | 88.1 | 875.3 | 697.8 | 61.6 | 6.9 | 73.5 | 839.9 | 4.2 | % | ||||||||||||||||||||||||||||||||
| Argentina | 91.1 | 16.9 | 5.2 | 12.8 | 126.0 | 91.2 | 16.9 | 4.3 | 12.3 | 124.7 | 1.0 | % | ||||||||||||||||||||||||||||||||
| Uruguay | 28.8 | 5.6 | - | 2.5 | 36.9 | 28.4 | 5.4 | - | 2.4 | 36.3 | 1.8 | % | ||||||||||||||||||||||||||||||||
| South America | 1,061.1 | 118.8 | 22.8 | 125.4 | 1,328.1 | 1,011.1 | 113.9 | 22.1 | 107.4 | 1,254.6 | 5.9 | % | ||||||||||||||||||||||||||||||||
| TOTAL | 2,348.7 | 240.3 | 298.1 | 272.9 | 3,160.0 | 2,273.4 | 226.9 | 303.3 | 253.3 | 3,056.8 | 3.4 | % | ||||||||||||||||||||||||||||||||
(1) Excludes water presentations larger than 5.0 Lt ; includes flavored water.
(2) Bulk Water = Still bottled water in 5.0, 19.0 and 20.0 - liter packaging presentations; includes flavored water
Transactions
| YTD 2026 | YTD 2025 | YoY | ||||||||||||||||||||||||||||||||||
| Sparkling | Water | Stills | Total | Sparkling | Water | Stills | Total | Δ % | ||||||||||||||||||||||||||||
| Mexico | 5,548.5 | 774.7 | 865.6 | 7,188.8 | 5,639.7 | 712.0 | 849.9 | 7,201.5 | -0.2 | % | ||||||||||||||||||||||||||
| Guatemala | 1,021.2 | 72.2 | 77.6 | 1,171.0 | 1,004.3 | 61.3 | 70.7 | 1,136.4 | 3.0 | % | ||||||||||||||||||||||||||
| CAM South | 830.7 | 46.7 | 175.1 | 1,052.5 | 796.5 | 43.1 | 168.3 | 1,007.8 | 4.4 | % | ||||||||||||||||||||||||||
| Mexico and Central America | 7,400.5 | 893.6 | 1,118.3 | 9,412.4 | 7,440.5 | 816.4 | 1,088.9 | 9,345.7 | 0.7 | % | ||||||||||||||||||||||||||
| Colombia | 1,612.4 | 351.3 | 162.4 | 2,126.1 | 1,426.9 | 301.6 | 147.2 | 1,875.8 | 13.3 | % | ||||||||||||||||||||||||||
| Brazil (3) | 4,985.0 | 527.0 | 998.0 | 6,510.0 | 4,792.5 | 533.4 | 845.5 | 6,171.4 | 5.5 | % | ||||||||||||||||||||||||||
| Argentina | 471.4 | 93.4 | 105.2 | 670.1 | 471.6 | 98.7 | 102.4 | 672.6 | -0.4 | % | ||||||||||||||||||||||||||
| Uruguay | 141.6 | 21.2 | 21.0 | 183.8 | 140.5 | 20.7 | 19.8 | 180.9 | 1.6 | % | ||||||||||||||||||||||||||
| South America | 7,210.4 | 993.0 | 1,286.6 | 9,490.0 | 6,831.5 | 954.3 | 1,114.8 | 8,900.7 | 6.6 | % | ||||||||||||||||||||||||||
| TOTAL | 14,610.9 | 1,886.5 | 2,404.9 | 18,902.4 | 14,272.0 | 1,770.7 | 2,203.7 | 18,246.4 | 3.6 | % | ||||||||||||||||||||||||||
Revenues
| Expressed in million Mexican Pesos | YTD 2026 | YTD 2025 | Δ % | |||||||||
| Mexico | 104,939 | 102,320 | 2.6 | % | ||||||||
| Guatemala | 12,563 | 12,746 | -1.4 | % | ||||||||
| CAM South | 13,041 | 12,376 | 5.4 | % | ||||||||
| Mexico and Central America | 130,543 | 127,442 | 2.4 | % | ||||||||
| Colombia | 20,628 | 16,547 | 24.7 | % | ||||||||
| Brazil (4) | 63,332 | 58,461 | 8.3 | % | ||||||||
| Argentina | 8,867 | 7,656 | 15.8 | % | ||||||||
| Uruguay | 3,820 | 3,878 | -1.5 | % | ||||||||
| South America | 96,647 | 86,542 | 11.7 | % | ||||||||
| TOTAL | 227,190 | 213,984 | 6.2 | % | ||||||||
(3) Volume and transactions in Brazil do not include beer
(4) Brazil includes beer revenues of Ps. 3,608.6 million for the first nine months of 2026 and Ps. 3,614.5 million for the same period of the previous year.
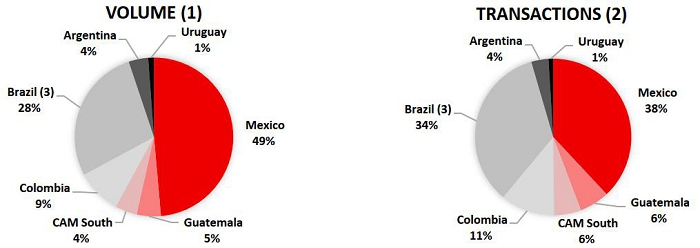
| (1) | Volume is expressed in unit cases. Unit case refers to 192 ounces of finished beverage product (24 eight-ounce servings) and, when applied to soda fountains, refers to the volume of syrup, powders, and concentrate that is required to produce 192 ounces of finished beverage product. |
| (2) | Transactions refer to the number of single units (e.g., a can or a bottle) sold, regardless of their size or volume or whether they are sold individually or in multipacks, except for soda fountains, which represent multiple transactions based on a standard 12 oz. serving. |
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 16 of 17 | |
COCA-COLA FEMSA
MACROECONOMIC INFORMATION
Inflation (1)
| LTM | 3Q26 | YTD | ||||||||||
| Mexico | 3.42 | % | 0.58 | % | 2.12 | % | ||||||
| Colombia | 6.46 | % | 1.23 | % | 5.78 | % | ||||||
| Brazil | 4.60 | % | 0.23 | % | 3.61 | % | ||||||
| Argentina | 33.70 | % | 5.94 | % | 23.75 | % | ||||||
| Costa Rica | -0.19 | % | -0.04 | % | -0.45 | % | ||||||
| Panama | 2.22 | % | -0.68 | % | 2.25 | % | ||||||
| Guatemala | 3.80 | % | 0.51 | % | 3.14 | % | ||||||
| Nicaragua | 3.27 | % | -0.17 | % | 2.02 | % | ||||||
| Uruguay | 4.76 | % | 0.58 | % | 3.86 | % |
(1) Source: inflation estimated by the company based on historic publications from the Central Bank of each country.
Average Exchange Rates for each period (2)
| Quarterly
Exchange Rate (Local Currency per USD) | Year to
Date Exchange Rate (Local Currency per USD) | |||||||||||||||||||||||
| 3Q26 | 3Q25 | Δ % | YTD 26 | YTD 25 | Δ % | |||||||||||||||||||
| Mexico | 17.25 | 18.65 | -7.5 | % | 17.40 | 19.23 | -9.5 | % | ||||||||||||||||
| Colombia | 3,193.49 | 4,007.71 | -20.3 | % | 3,497.48 | 4,053.13 | -13.7 | % | ||||||||||||||||
| Brazil | 5.14 | 5.45 | -5.7 | % | 5.15 | 5.59 | -7.9 | % | ||||||||||||||||
| Argentina | 1,499.89 | 1,333.04 | 12.5 | % | 1,442.64 | 1,244.54 | 15.9 | % | ||||||||||||||||
| Costa Rica | 453.20 | 507.49 | -10.7 | % | 466.08 | 506.50 | -8.0 | % | ||||||||||||||||
| Panama | 1.00 | 1.00 | 0.0 | % | 1.00 | 1.00 | 0.0 | % | ||||||||||||||||
| Guatemala | 7.63 | 7.66 | -0.5 | % | 7.64 | 7.68 | -0.5 | % | ||||||||||||||||
| Nicaragua | 36.62 | 36.62 | 0.0 | % | 36.62 | 36.62 | 0.0 | % | ||||||||||||||||
| Uruguay | 40.22 | 40.09 | 0.3 | % | 39.80 | 41.08 | -3.1 | % | ||||||||||||||||
End-of-period Exchange Rates
| Closing Exchange Rate (Local Currency per USD) | Closing Exchange Rate (Local Currency per USD) | |||||||||||||||||||||||
| Sep-26 | Sep-25 | Δ % | Jun-26 | Jun-25 | Δ % | |||||||||||||||||||
| Mexico | 17.84 | 18.38 | -2.9 | % | 17.47 | 18.89 | -7.5 | % | ||||||||||||||||
| Colombia | 3,341.23 | 3,901.29 | -14.4 | % | 3,443.59 | 4,069.67 | -15.4 | % | ||||||||||||||||
| Brazil | 5.18 | 5.32 | -2.6 | % | 5.18 | 5.46 | -5.1 | % | ||||||||||||||||
| Argentina | 1,517.00 | 1,380.00 | 9.9 | % | 1,482.00 | 1,205.00 | 23.0 | % | ||||||||||||||||
| Costa Rica | 458.43 | 506.00 | -9.4 | % | 457.17 | 508.28 | -10.1 | % | ||||||||||||||||
| Panama | 1.00 | 1.00 | 0.0 | % | 1.00 | 1.00 | 0.0 | % | ||||||||||||||||
| Guatemala | 7.64 | 7.66 | -0.2 | % | 7.62 | 7.68 | -0.9 | % | ||||||||||||||||
| Nicaragua | 36.62 | 36.62 | 0.0 | % | 36.62 | 36.62 | 0.0 | % | ||||||||||||||||
| Uruguay | 40.29 | 39.85 | 1.1 | % | 40.12 | 39.55 | 1.4 | % | ||||||||||||||||
(2) Average exchange rate for each period computed with the average exchange rate of each month.
Coca-Cola FEMSA Reports 3Q26 Results
October 26th, 2026 | Page 17 of 17 | |