2026 Third Quarter Earnings Call October 29, 2026 Supplemental information
Encompass Health 2 The information contained in this presentation includes certain assumptions, estimates, projections and other forward- looking statements that reflect Encompass Health’s current outlook, views and plans with respect to future events, including the business outlook, guidance and growth targets, future reimbursement rates, labor availability and costs, the effect of tariffs on costs, legislative and regulatory developments, such as the effects of Medicaid and Medicare payment system changes, including RCD, TEAM, and state supplemental payment programs, strategy, capital expenditures, acquisition and other development activities, such as the de novo pipeline and bed additions, operational and quality of care initiatives, dividend strategies, leverage, repurchases of securities, outstanding shares of common stock, effective tax rates, financial performance, financial assumptions and considerations, balance sheet and cash flow plans, market barriers to entry, and addressable market size. These assumptions, estimates, projections and other forward-looking statements are based on what the Company believes, as of the date hereof, to be reasonable. Inevitably, there will be differences between such forward- looking statements and actual events or results, and those differences may be material. There can be no assurance any estimates, projections or forward-looking statements will be realized. All such assumptions, estimates, projections and forward-looking statements speak only as of the date hereof. Encompass Health undertakes no duty to publicly update or revise the information contained herein. You are cautioned not to place undue reliance on the assumptions, estimates, projections and other forward-looking statements in this presentation as they are based on current expectations and general assumptions and are subject to various risks, uncertainties and other factors, including those set forth in the earnings release attached as Exhibit 99.1 to the Company’s Form 8-K dated October 28, 2026 (the “Q3 Earnings Release Form 8-K”), the Form 10-K for the year ended December 31, 2025, the Forms 10-Q for the quarters ended March 31, 2026, June 30, 2026 and when filed, September 30, 2026, and in other documents Encompass Health previously filed with the SEC, many of which are beyond Encompass Health’s control, that may cause actual events or results to differ materially from the views, beliefs and estimates expressed herein. Note regarding presentation of non-GAAP financial measures The following presentation includes certain “non-GAAP financial measures” as defined in Regulation G under the Securities Exchange Act of 1934, including Adjusted EBITDA, leverage ratios, adjusted earnings per share, and adjusted free cash flow. Schedules are attached that reconcile the non-GAAP financial measures included in the following presentation to the most directly comparable financial measures calculated and presented in accordance with Generally Accepted Accounting Principles in the United States. The Q3 Earnings Release Form 8-K provides further explanation and disclosure regarding Encompass Health’s use of non-GAAP financial measures and should be read in conjunction with this supplemental information. Forward-looking statements
Encompass Health 3 Summary ................................................................................................................................................................................ 4 Revenue ................................................................................................................................................................................. 5 Adjusted EBITDA .................................................................................................................................................................. 6 Earnings per share ............................................................................................................................................................... 7-8 Adjusted free cash flow ..................................................................................................................................................... 9 2026 Guidance and guidance considerations ............................................................................................................... 10-11 Adjusted free cash flow assumptions ............................................................................................................................. 12 Uses of free cash flow ........................................................................................................................................................ 13 Appendix Map of locations ................................................................................................................................................................... 15 Growth targets, fundamentals and value drivers ........................................................................................................ 16 Multiple modalities for capacity expansion .................................................................................................................. 17 Development activity ......................................................................................................................................................... 18 RCD and TEAM ...................................................................................................................................................................... 19 Debt maturity profile and schedule ................................................................................................................................ 20-21 New-store/same-store growth .......................................................................................................................................... 22 Payment sources .................................................................................................................................................................. 23 Operational metrics ............................................................................................................................................................ 24 Share information ................................................................................................................................................................ 25 Reconciliations to GAAP ..................................................................................................................................................... 26-33 End notes ............................................................................................................................................................................... 34-35 Table of contents
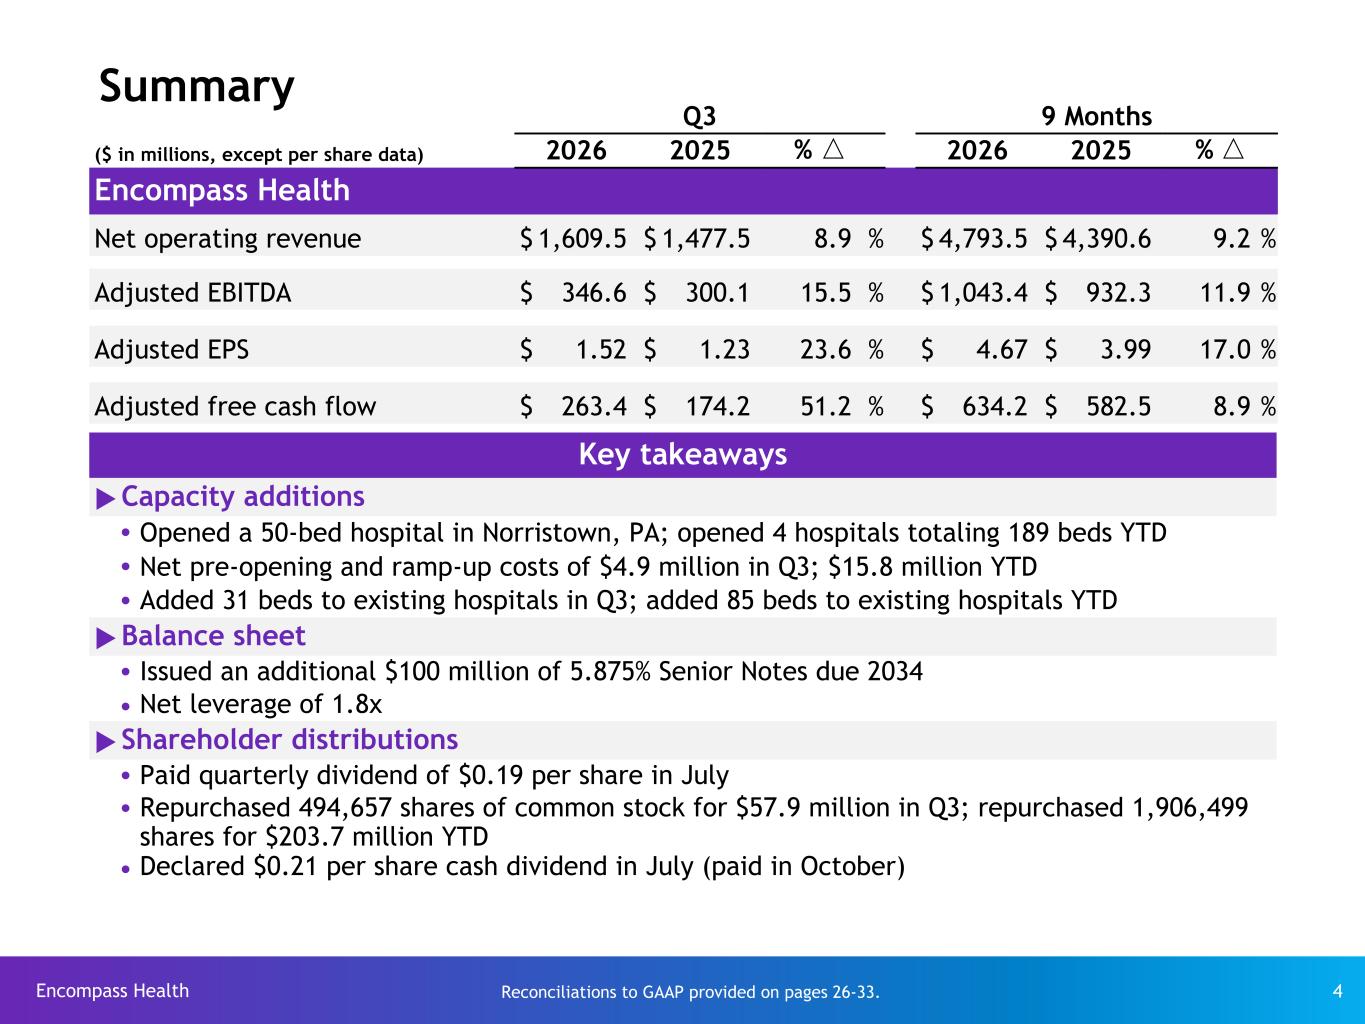
Encompass Health 4 Summary Q3 9 Months ($ in millions, except per share data) 2026 2025 % △ 2026 2025 % △ Encompass Health Net operating revenue $ 1,609.5 $ 1,477.5 8.9 % $ 4,793.5 $ 4,390.6 9.2 % Adjusted EBITDA $ 346.6 $ 300.1 15.5 % $ 1,043.4 $ 932.3 11.9 % Adjusted EPS $ 1.52 $ 1.23 23.6 % $ 4.67 $ 3.99 17.0 % Adjusted free cash flow $ 263.4 $ 174.2 51.2 % $ 634.2 $ 582.5 8.9 % Reconciliations to GAAP provided on pages 26-33. Key takeaways uCapacity additions Ÿ Opened a 50-bed hospital in Norristown, PA; opened 4 hospitals totaling 189 beds YTD Ÿ Net pre-opening and ramp-up costs of $4.9 million in Q3; $15.8 million YTD Ÿ Added 31 beds to existing hospitals in Q3; added 85 beds to existing hospitals YTD uBalance sheet Ÿ Issued an additional $100 million of 5.875% Senior Notes due 2034 Ÿ Net leverage of 1.8x uShareholder distributions Ÿ Paid quarterly dividend of $0.19 per share in July Ÿ Repurchased 494,657 shares of common stock for $57.9 million in Q3; repurchased 1,906,499 shares for $203.7 million YTD Ÿ Declared $0.21 per share cash dividend in July (paid in October)
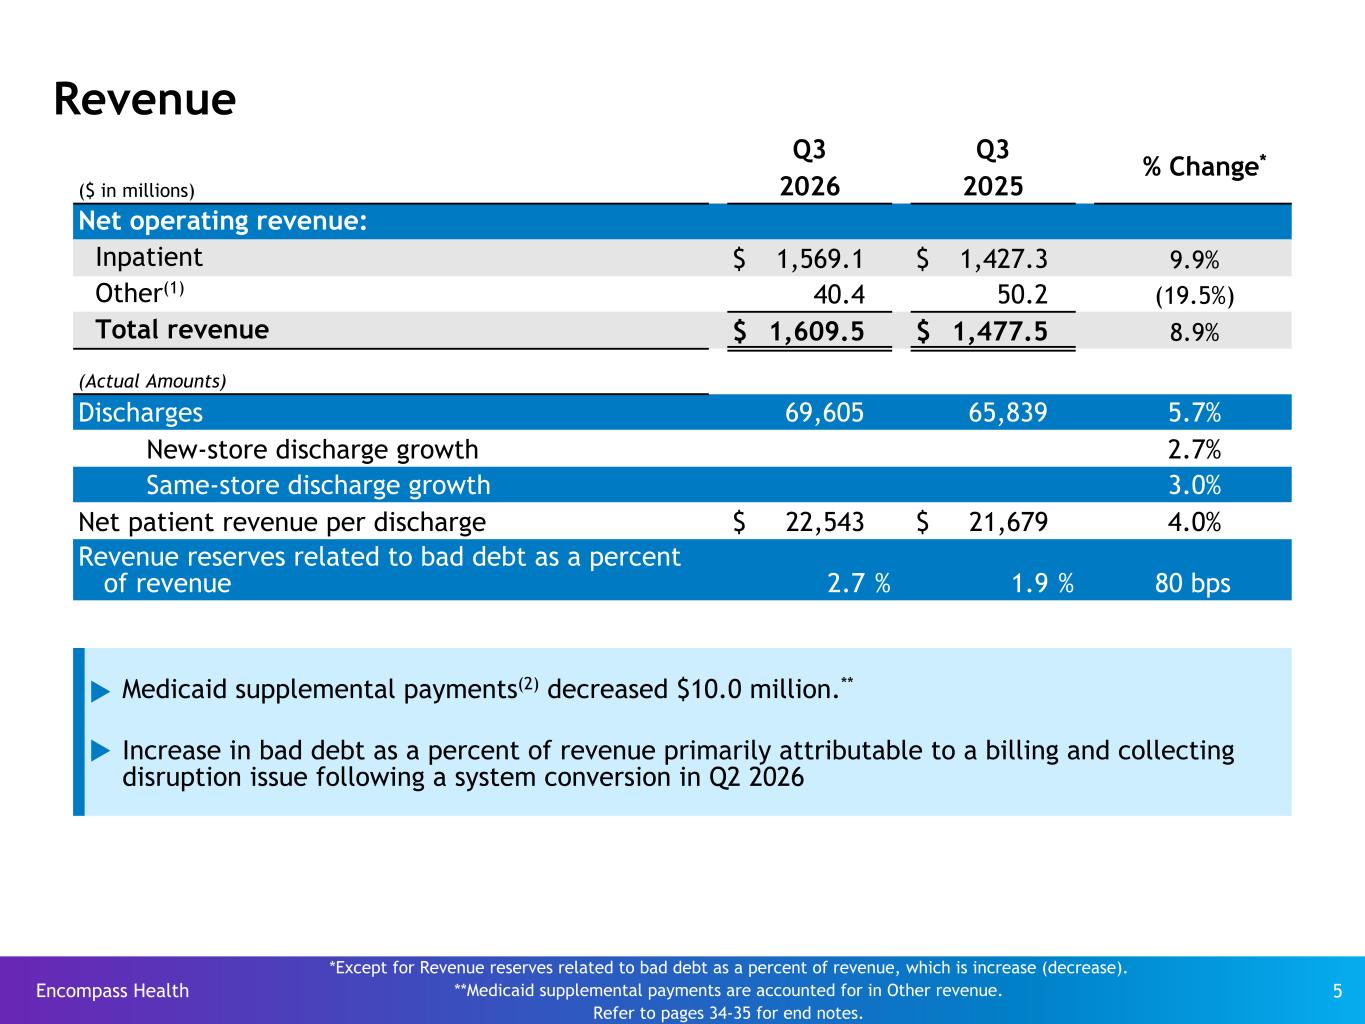
Encompass Health 5 Revenue Q3 Q3 % Change* ($ in millions) 2026 2025 Net operating revenue: Inpatient $ 1,569.1 $ 1,427.3 9.9% Other(1) 40.4 50.2 (19.5%) Total revenue $ 1,609.5 $ 1,477.5 8.9% (Actual Amounts) Discharges 69,605 65,839 5.7% New-store discharge growth 2.7% Same-store discharge growth 3.0% Net patient revenue per discharge $ 22,543 $ 21,679 4.0% Revenue reserves related to bad debt as a percent of revenue 2.7 % 1.9 % 80 bps *Except for Revenue reserves related to bad debt as a percent of revenue, which is increase (decrease). **Medicaid supplemental payments are accounted for in Other revenue. Refer to pages 34-35 for end notes. u Medicaid supplemental payments(2) decreased $10.0 million.** u Increase in bad debt as a percent of revenue primarily attributable to a billing and collecting disruption issue following a system conversion in Q2 2026
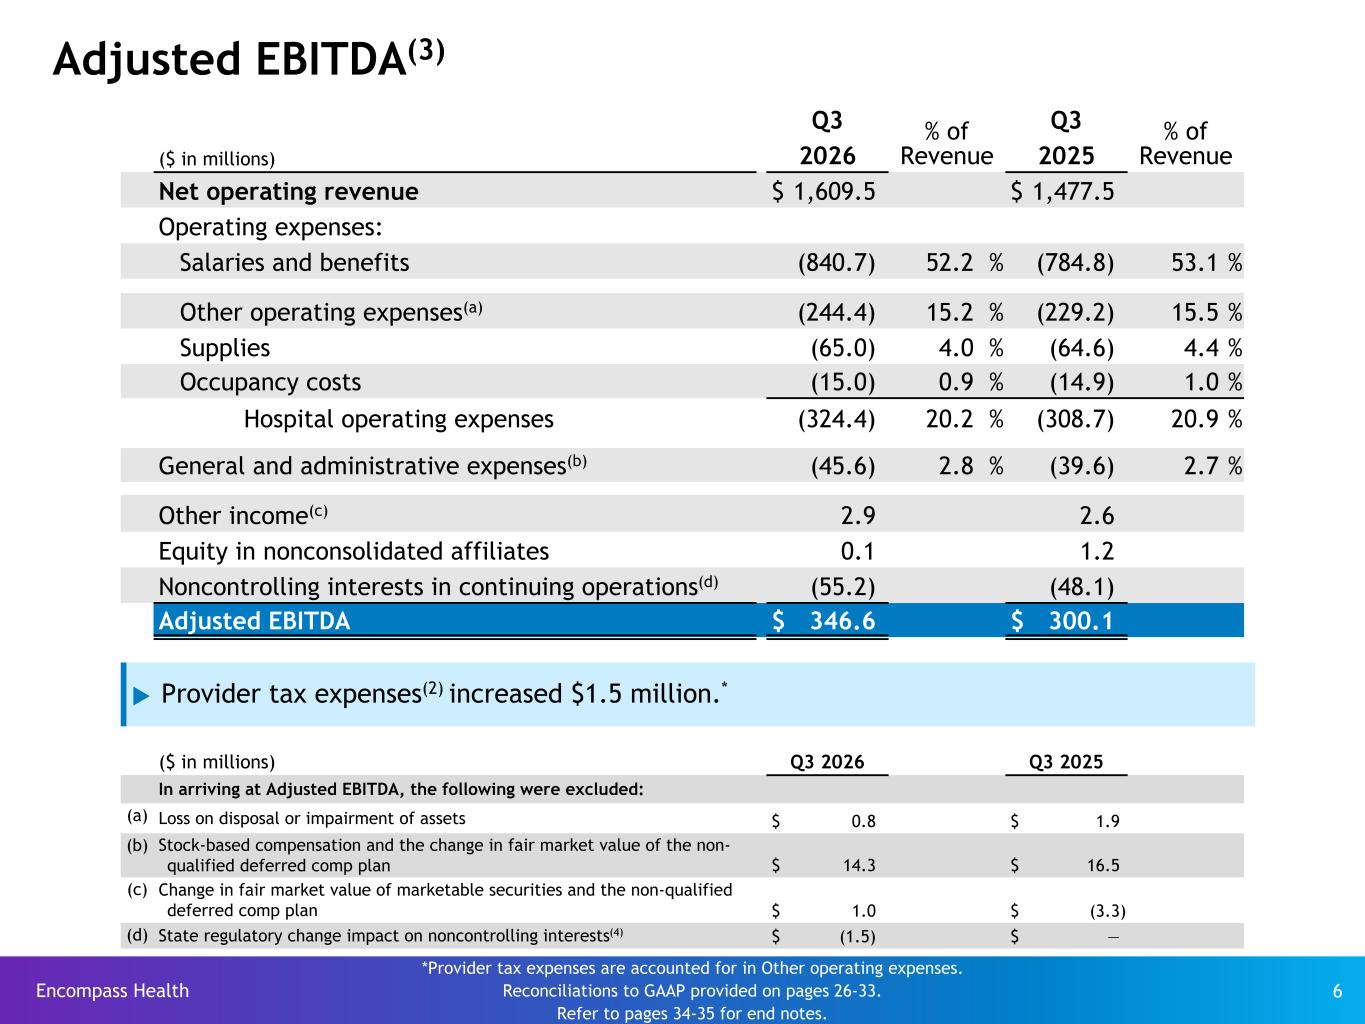
Encompass Health 6 Adjusted EBITDA(3) Q3 % of Revenue Q3 % of Revenue($ in millions) 2026 2025 Net operating revenue $ 1,609.5 $ 1,477.5 Operating expenses: Salaries and benefits (840.7) 52.2 % (784.8) 53.1 % Other operating expenses(a) (244.4) 15.2 % (229.2) 15.5 % Supplies (65.0) 4.0 % (64.6) 4.4 % Occupancy costs (15.0) 0.9 % (14.9) 1.0 % Hospital operating expenses (324.4) 20.2 % (308.7) 20.9 % General and administrative expenses(b) (45.6) 2.8 % (39.6) 2.7 % Other income(c) 2.9 2.6 Equity in nonconsolidated affiliates 0.1 1.2 Noncontrolling interests in continuing operations(d) (55.2) (48.1) Adjusted EBITDA $ 346.6 $ 300.1 ($ in millions) Q3 2026 Q3 2025 In arriving at Adjusted EBITDA, the following were excluded: (a) Loss on disposal or impairment of assets $ 0.8 $ 1.9 (b) Stock-based compensation and the change in fair market value of the non- qualified deferred comp plan $ 14.3 $ 16.5 (c) Change in fair market value of marketable securities and the non-qualified deferred comp plan $ 1.0 $ (3.3) (d) State regulatory change impact on noncontrolling interests(4) $ (1.5) $ — *Provider tax expenses are accounted for in Other operating expenses. Reconciliations to GAAP provided on pages 26-33. Refer to pages 34-35 for end notes. u Provider tax expenses(2) increased $1.5 million.*
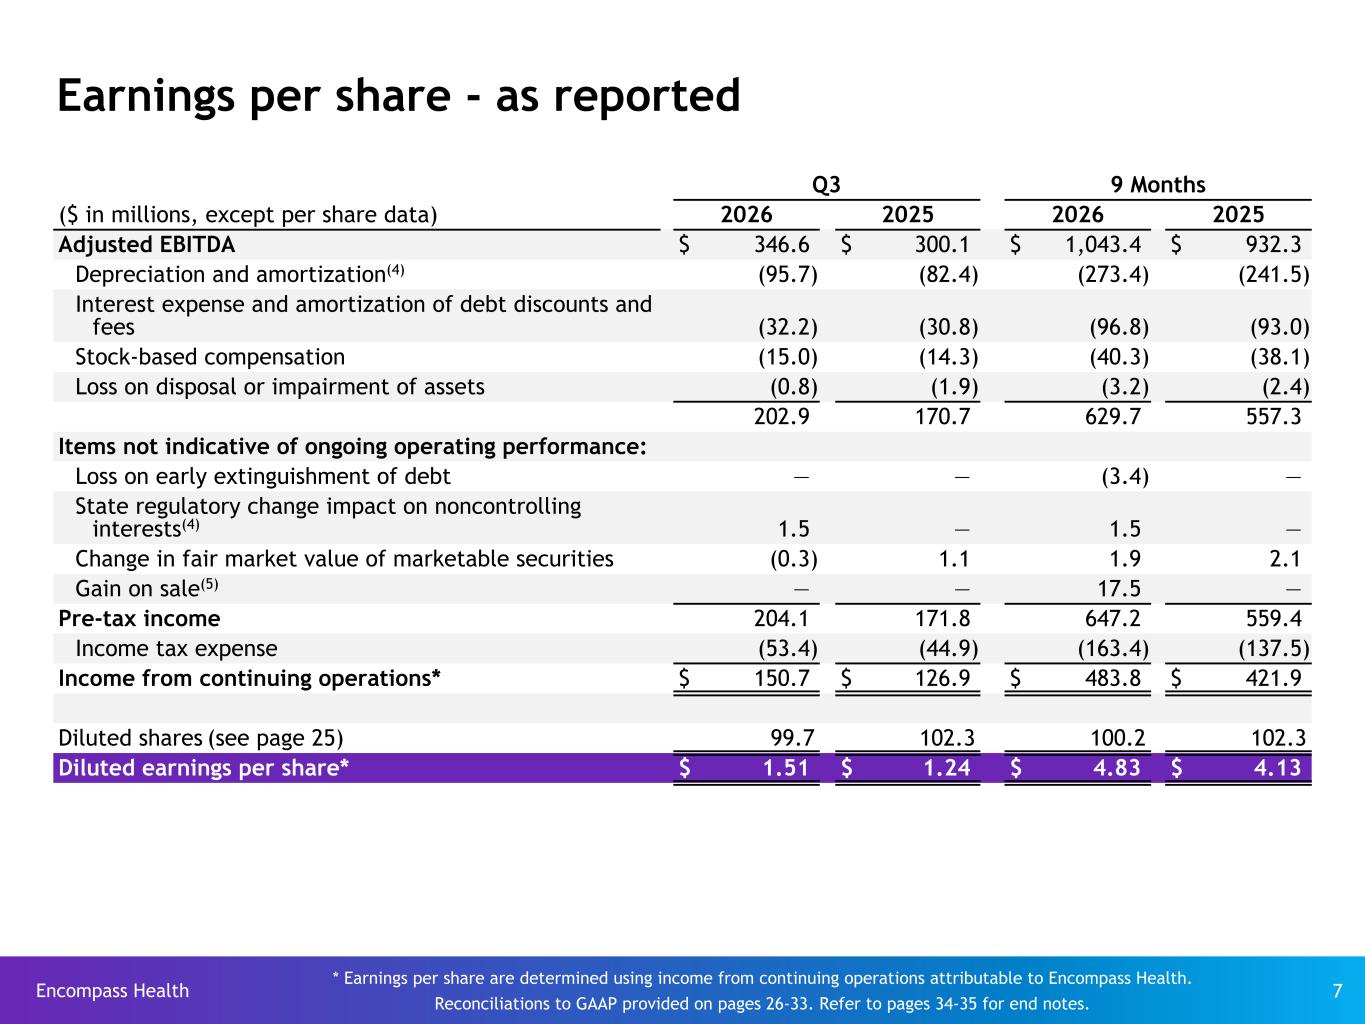
Encompass Health 7 Earnings per share - as reported Q3 9 Months ($ in millions, except per share data) 2026 2025 2026 2025 Adjusted EBITDA $ 346.6 $ 300.1 $ 1,043.4 $ 932.3 Depreciation and amortization(4) (95.7) (82.4) (273.4) (241.5) Interest expense and amortization of debt discounts and fees (32.2) (30.8) (96.8) (93.0) Stock-based compensation (15.0) (14.3) (40.3) (38.1) Loss on disposal or impairment of assets (0.8) (1.9) (3.2) (2.4) 202.9 170.7 629.7 557.3 Items not indicative of ongoing operating performance: Loss on early extinguishment of debt — — (3.4) — State regulatory change impact on noncontrolling interests(4) 1.5 — 1.5 — Change in fair market value of marketable securities (0.3) 1.1 1.9 2.1 Gain on sale(5) — — 17.5 — Pre-tax income 204.1 171.8 647.2 559.4 Income tax expense (53.4) (44.9) (163.4) (137.5) Income from continuing operations* $ 150.7 $ 126.9 $ 483.8 $ 421.9 Diluted shares (see page 25) 99.7 102.3 100.2 102.3 Diluted earnings per share* $ 1.51 $ 1.24 $ 4.83 $ 4.13 * Earnings per share are determined using income from continuing operations attributable to Encompass Health. Reconciliations to GAAP provided on pages 26-33. Refer to pages 34-35 for end notes.
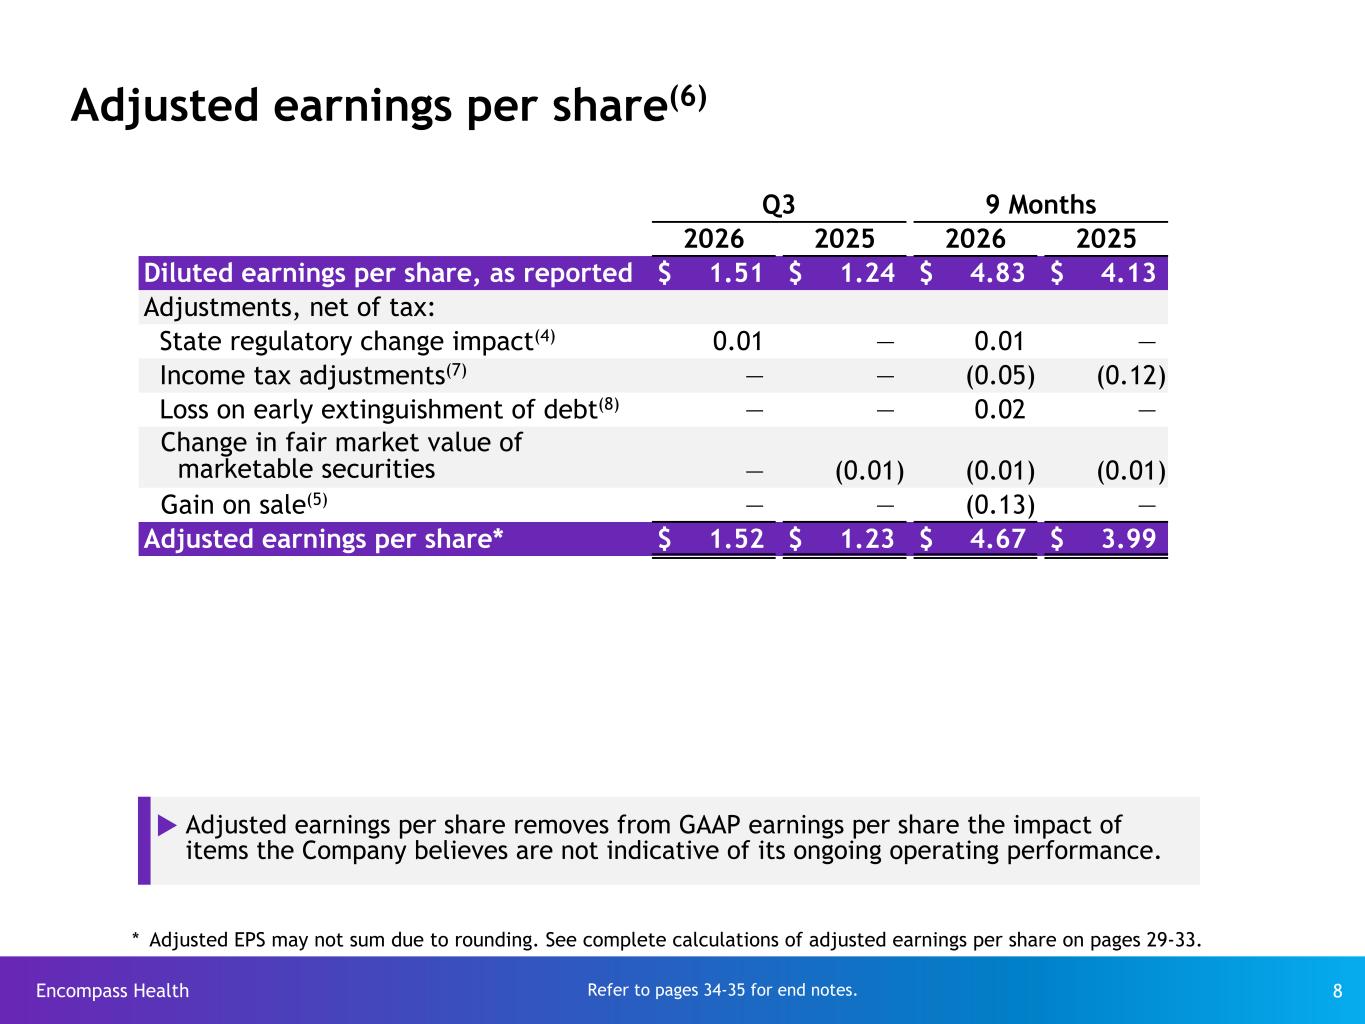
Encompass Health 8 Adjusted earnings per share(6) Refer to pages 34-35 for end notes. Q3 9 Months 2026 2025 2026 2025 Diluted earnings per share, as reported $ 1.51 $ 1.24 $ 4.83 $ 4.13 Adjustments, net of tax: State regulatory change impact(4) 0.01 — 0.01 — Income tax adjustments(7) — — (0.05) (0.12) Loss on early extinguishment of debt(8) — — 0.02 — Change in fair market value of marketable securities — (0.01) (0.01) (0.01) Gain on sale(5) — — (0.13) — Adjusted earnings per share* $ 1.52 $ 1.23 $ 4.67 $ 3.99 u Adjusted earnings per share removes from GAAP earnings per share the impact of items the Company believes are not indicative of its ongoing operating performance. * Adjusted EPS may not sum due to rounding. See complete calculations of adjusted earnings per share on pages 29-33.
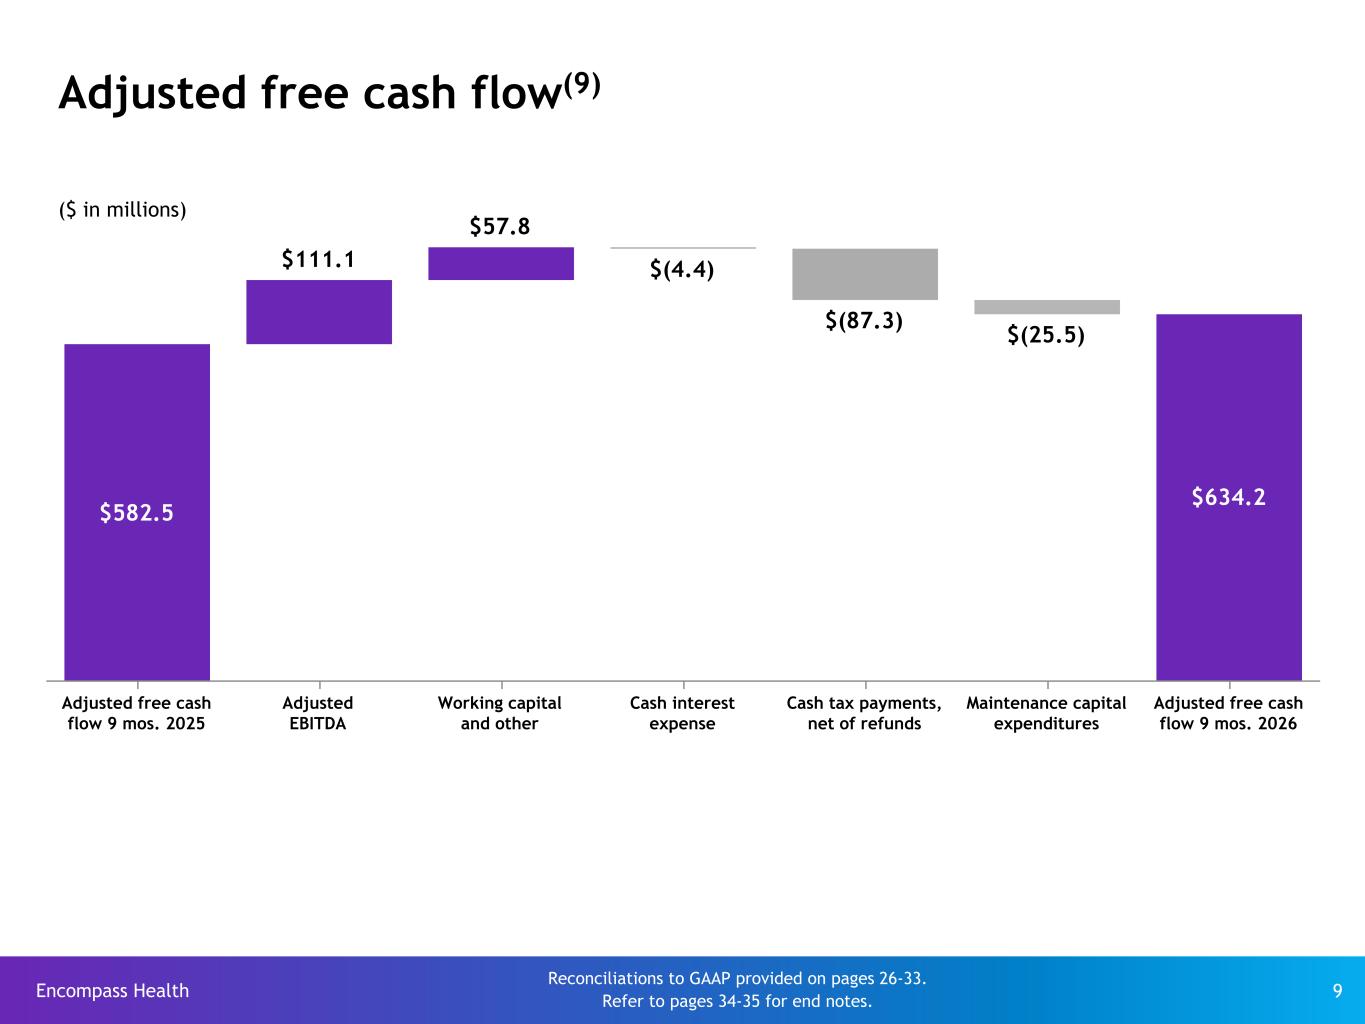
Encompass Health 9 $582.5 $111.1 $57.8 $(4.4) $(87.3) $(25.5) $634.2 Adjusted free cash flow 9 mos. 2025 Adjusted EBITDA Working capital and other Cash interest expense Cash tax payments, net of refunds Maintenance capital expenditures Adjusted free cash flow 9 mos. 2026 Adjusted free cash flow(9) Reconciliations to GAAP provided on pages 26-33. Refer to pages 34-35 for end notes. ($ in millions)
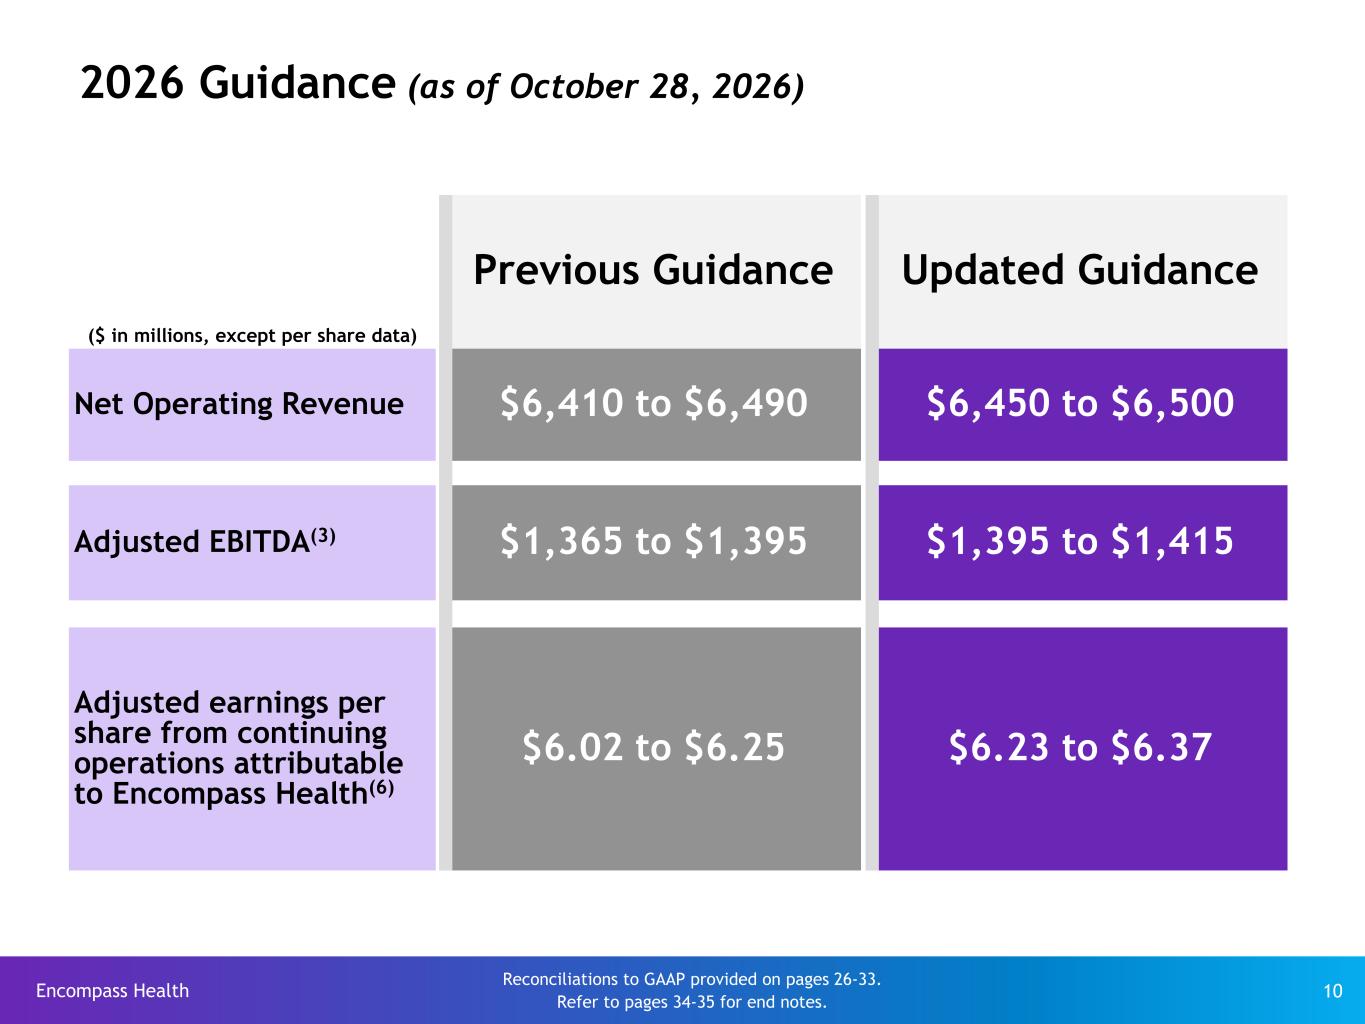
Encompass Health 10 2026 Guidance (as of October 28, 2026) Previous Guidance Updated Guidance ($ in millions, except per share data) Net Operating Revenue $6,410 to $6,490 $6,450 to $6,500 Adjusted EBITDA(3) $1,365 to $1,395 $1,395 to $1,415 Adjusted earnings per share from continuing operations attributable to Encompass Health(6) $6.02 to $6.25 $6.23 to $6.37 Reconciliations to GAAP provided on pages 26-33. Refer to pages 34-35 for end notes.
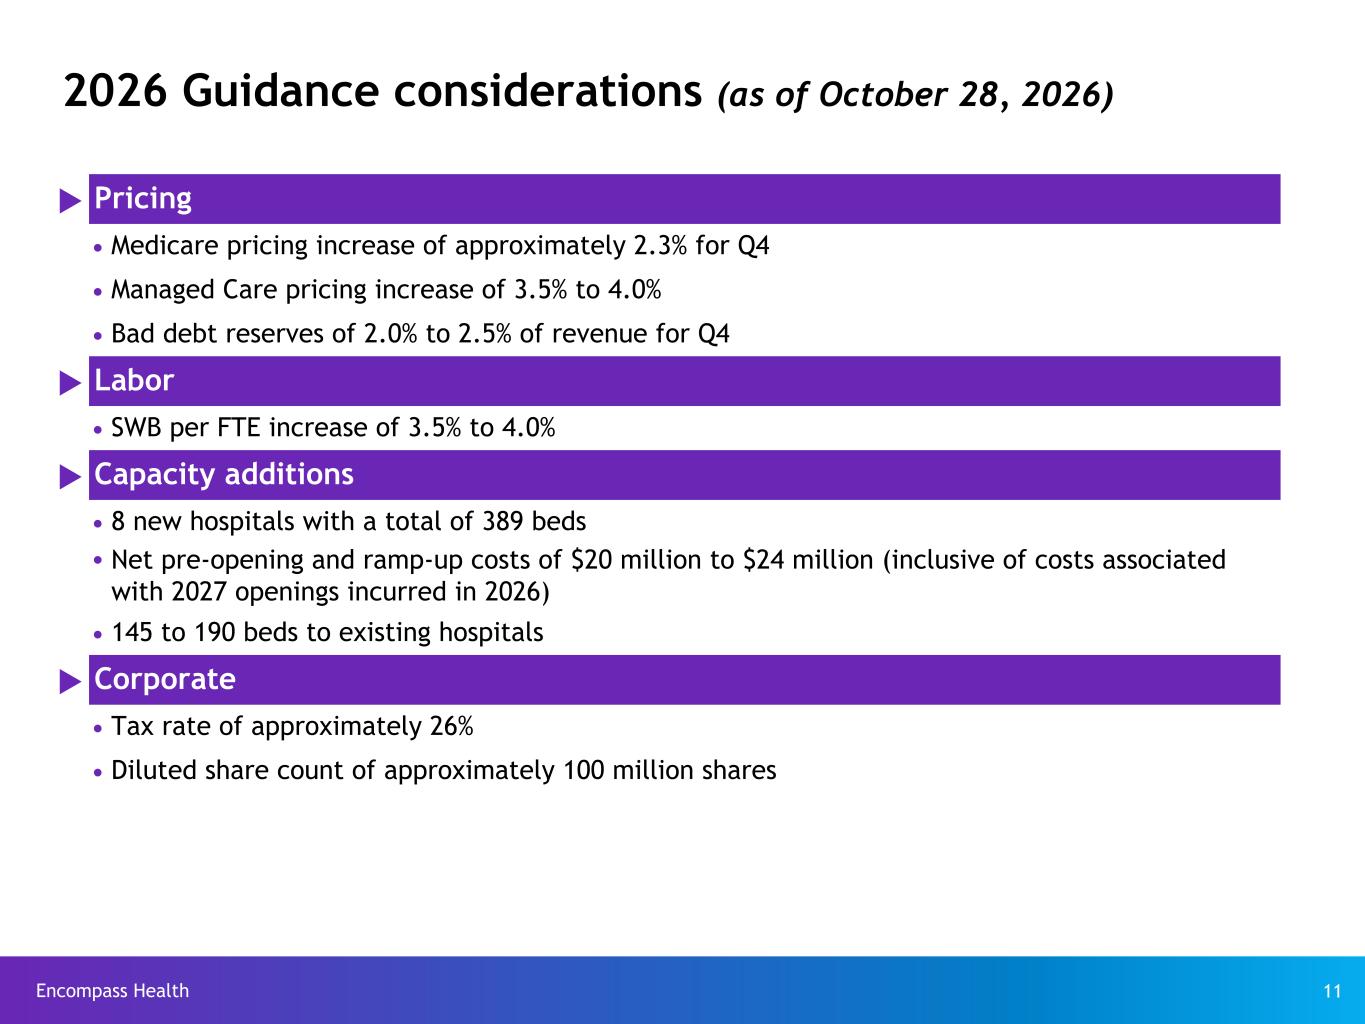
Encompass Health 11 2026 Guidance considerations (as of October 28, 2026) u Pricing Ÿ Medicare pricing increase of approximately 2.3% for Q4 Ÿ Managed Care pricing increase of 3.5% to 4.0% Ÿ Bad debt reserves of 2.0% to 2.5% of revenue for Q4 u Labor Ÿ SWB per FTE increase of 3.5% to 4.0% u Capacity additions Ÿ 8 new hospitals with a total of 389 beds Ÿ Net pre-opening and ramp-up costs of $20 million to $24 million (inclusive of costs associated with 2027 openings incurred in 2026) Ÿ 145 to 190 beds to existing hospitals u Corporate Ÿ Tax rate of approximately 26% Ÿ Diluted share count of approximately 100 million shares
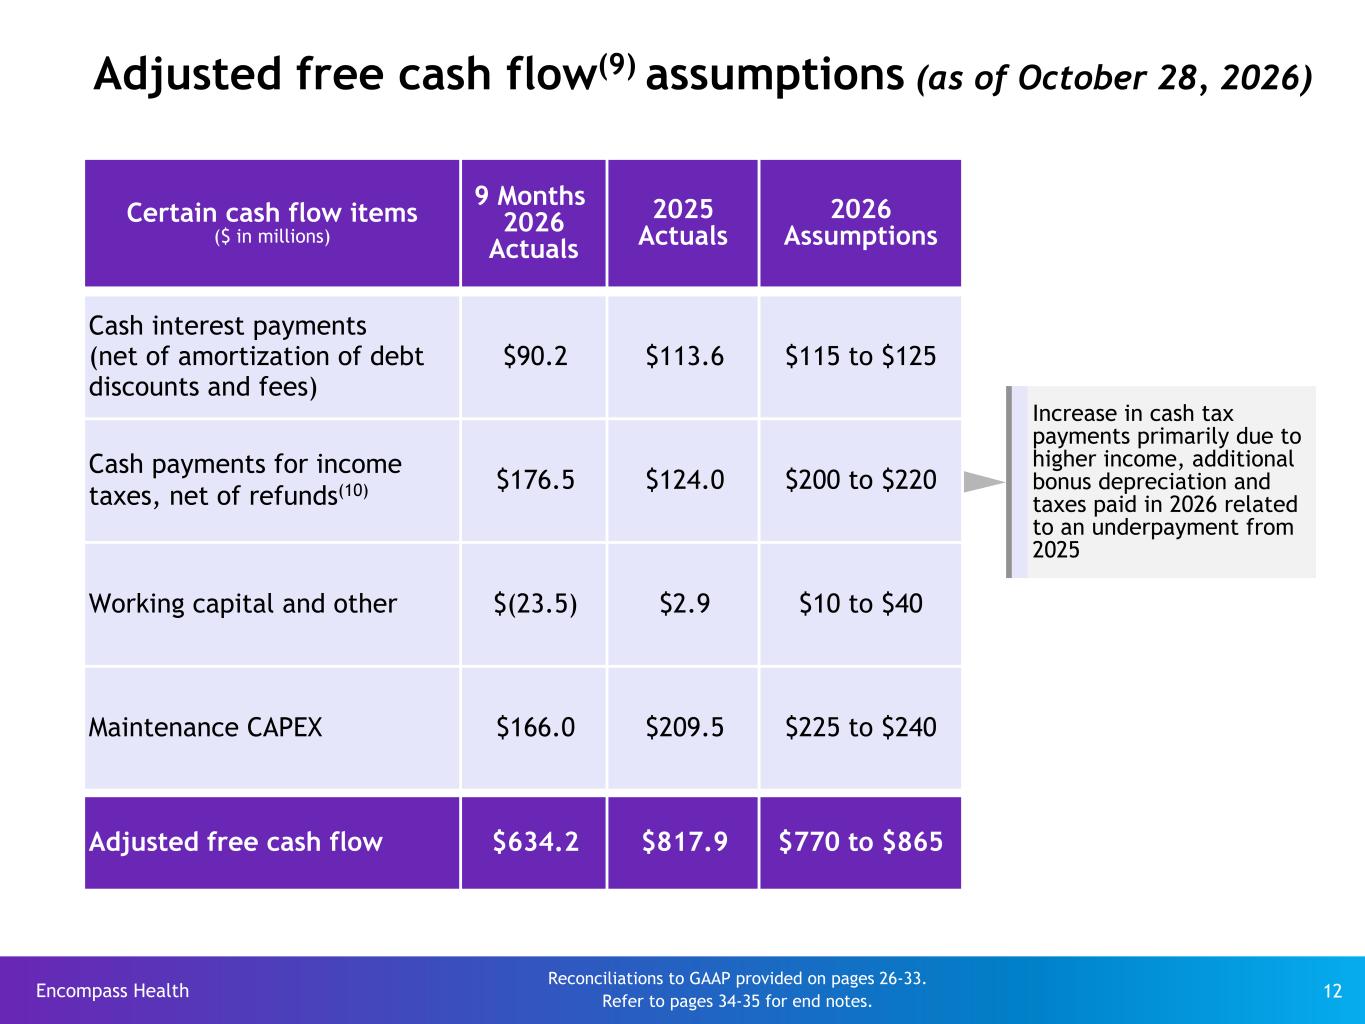
Encompass Health 12 Adjusted free cash flow(9) assumptions (as of October 28, 2026) Certain cash flow items ($ in millions) 9 Months 2026 Actuals 2025 Actuals 2026 Assumptions Cash interest payments (net of amortization of debt discounts and fees) $90.2 $113.6 $115 to $125 Cash payments for income taxes, net of refunds(10) $176.5 $124.0 $200 to $220 Working capital and other $(23.5) $2.9 $10 to $40 Maintenance CAPEX $166.0 $209.5 $225 to $240 Adjusted free cash flow $634.2 $817.9 $770 to $865 Reconciliations to GAAP provided on pages 26-33. Refer to pages 34-35 for end notes. Increase in cash tax payments primarily due to higher income, additional bonus depreciation and taxes paid in 2026 related to an underpayment from 2025
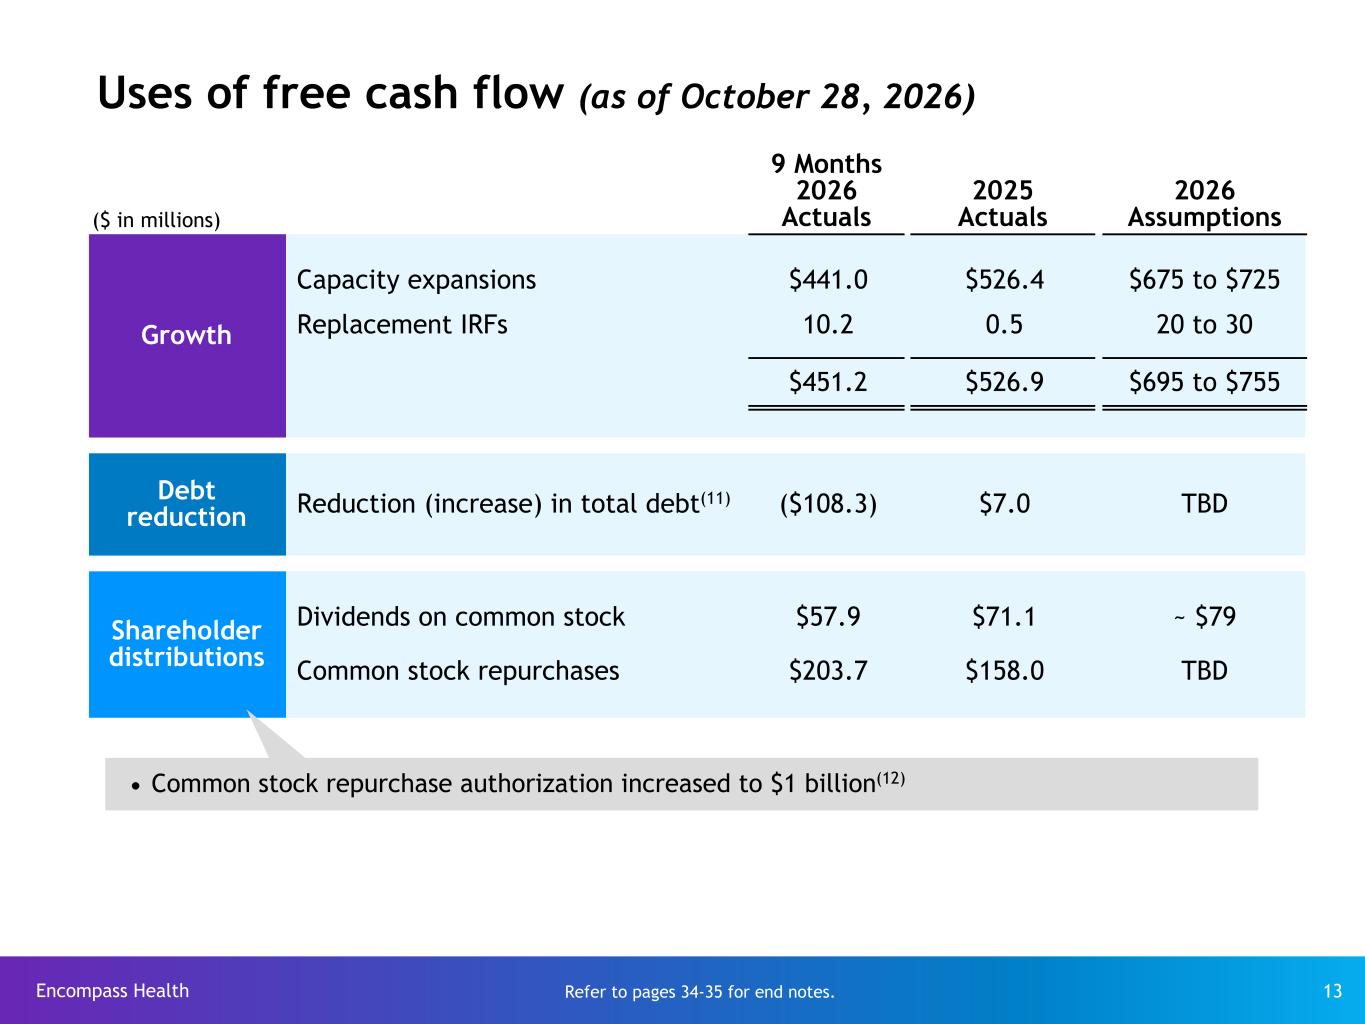
Encompass Health 13 Uses of free cash flow (as of October 28, 2026) ($ in millions) 9 Months 2026 Actuals 2025 Actuals 2026 Assumptions Growth Capacity expansions $441.0 $526.4 $675 to $725 Replacement IRFs 10.2 0.5 20 to 30 $451.2 $526.9 $695 to $755 Debt reduction Reduction (increase) in total debt(11) ($108.3) $7.0 TBD Shareholder distributions Dividends on common stock $57.9 $71.1 ~ $79 Common stock repurchases $203.7 $158.0 TBD Refer to pages 34-35 for end notes. Ÿ Common stock repurchase authorization increased to $1 billion(12)
Appendix
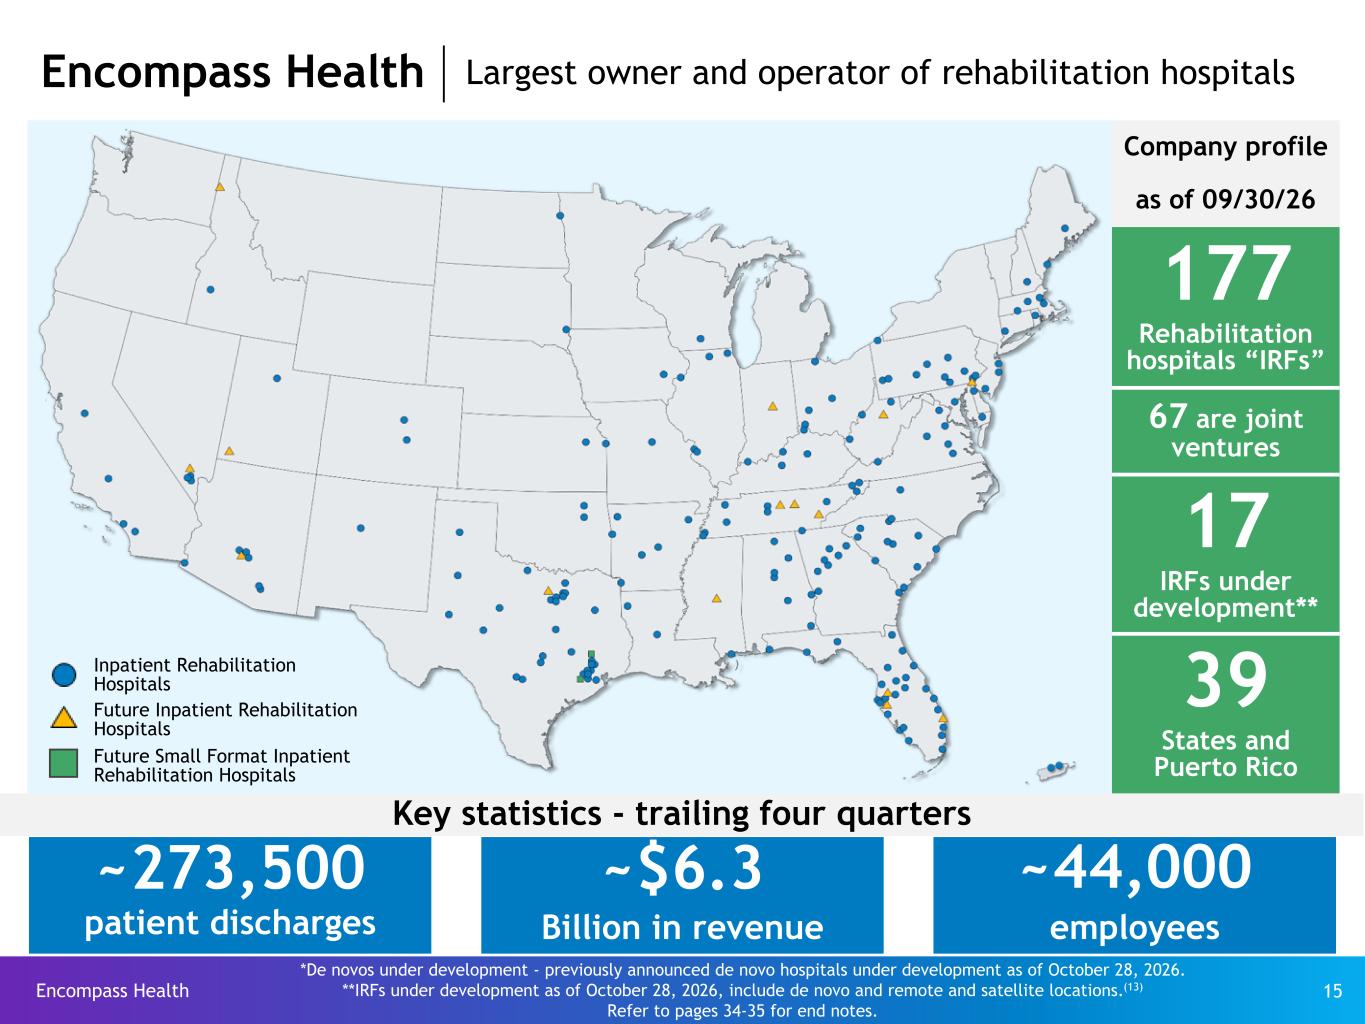
Encompass Health 15 *De novos under development - previously announced de novo hospitals under development as of October 28, 2026. **IRFs under development as of October 28, 2026, include de novo and remote and satellite locations.(13) Refer to pages 34-35 for end notes. Encompass Health Largest owner and operator of rehabilitation hospitals Company profile as of 09/30/26 177 Rehabilitation hospitals “IRFs” 67 are joint ventures 17 IRFs under development** 39 States and Puerto Rico Inpatient Rehabilitation Hospitals Future Inpatient Rehabilitation Hospitals Future Small Format Inpatient Rehabilitation Hospitals Key statistics - trailing four quarters ~273,500 patient discharges ~$6.3 Billion in revenue ~44,000 employees
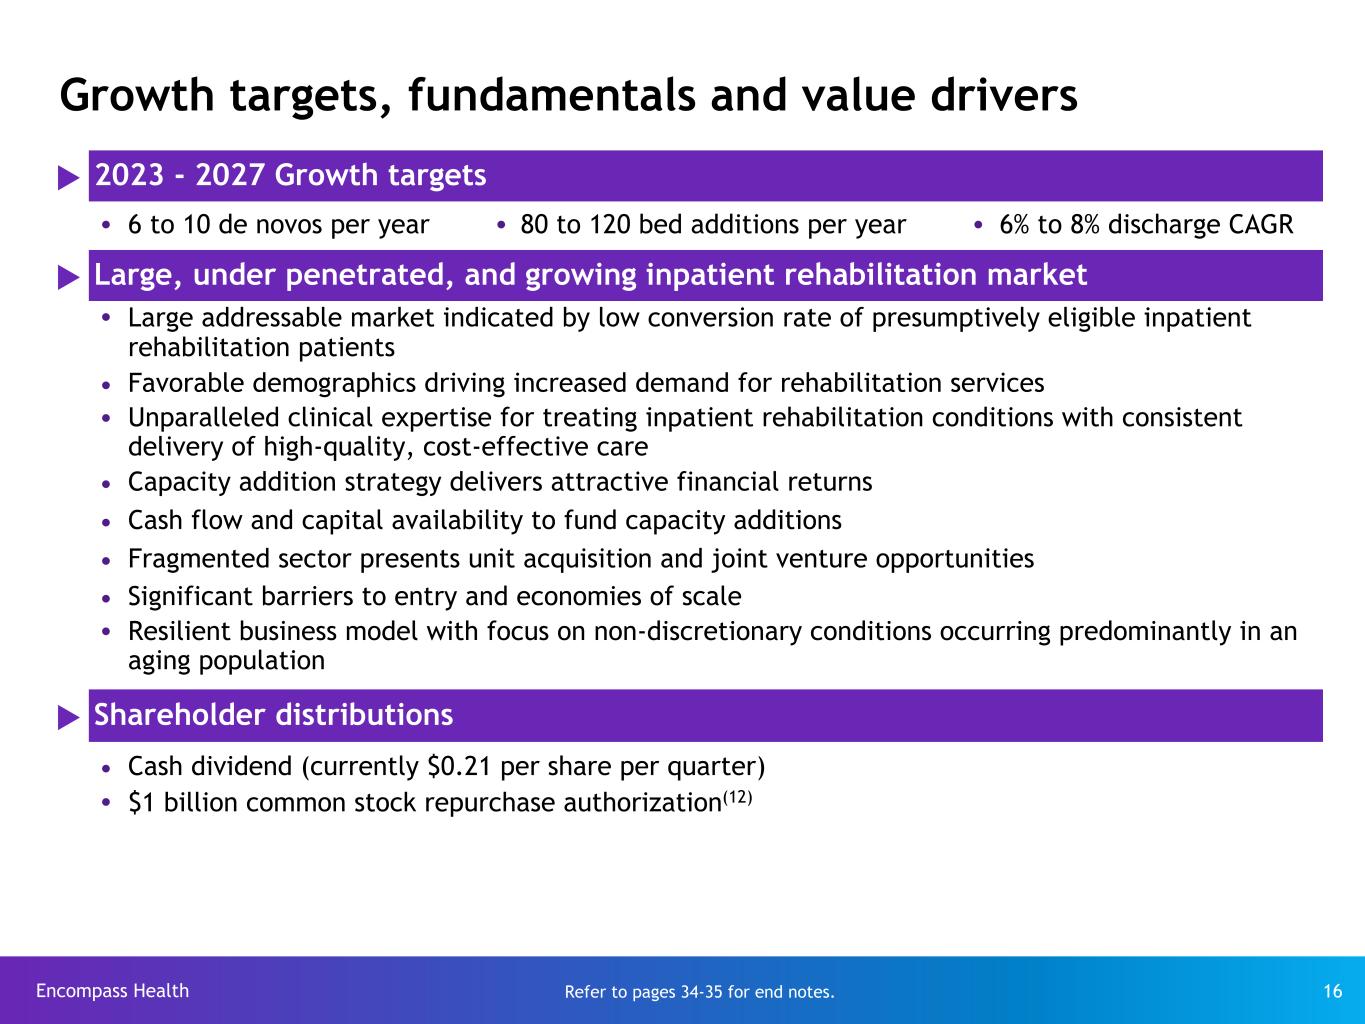
Encompass Health 16 u 2023 - 2027 Growth targets Ÿ 6 to 10 de novos per year Ÿ 80 to 120 bed additions per year Ÿ 6% to 8% discharge CAGR u Large, under penetrated, and growing inpatient rehabilitation market Ÿ Large addressable market indicated by low conversion rate of presumptively eligible inpatient rehabilitation patients Ÿ Favorable demographics driving increased demand for rehabilitation services Ÿ Unparalleled clinical expertise for treating inpatient rehabilitation conditions with consistent delivery of high-quality, cost-effective care Ÿ Capacity addition strategy delivers attractive financial returns Ÿ Cash flow and capital availability to fund capacity additions Ÿ Fragmented sector presents unit acquisition and joint venture opportunities Ÿ Significant barriers to entry and economies of scale Ÿ Resilient business model with focus on non-discretionary conditions occurring predominantly in an aging population u Shareholder distributions Ÿ Cash dividend (currently $0.21 per share per quarter) Ÿ $1 billion common stock repurchase authorization(12) Refer to pages 34-35 for end notes. Growth targets, fundamentals and value drivers
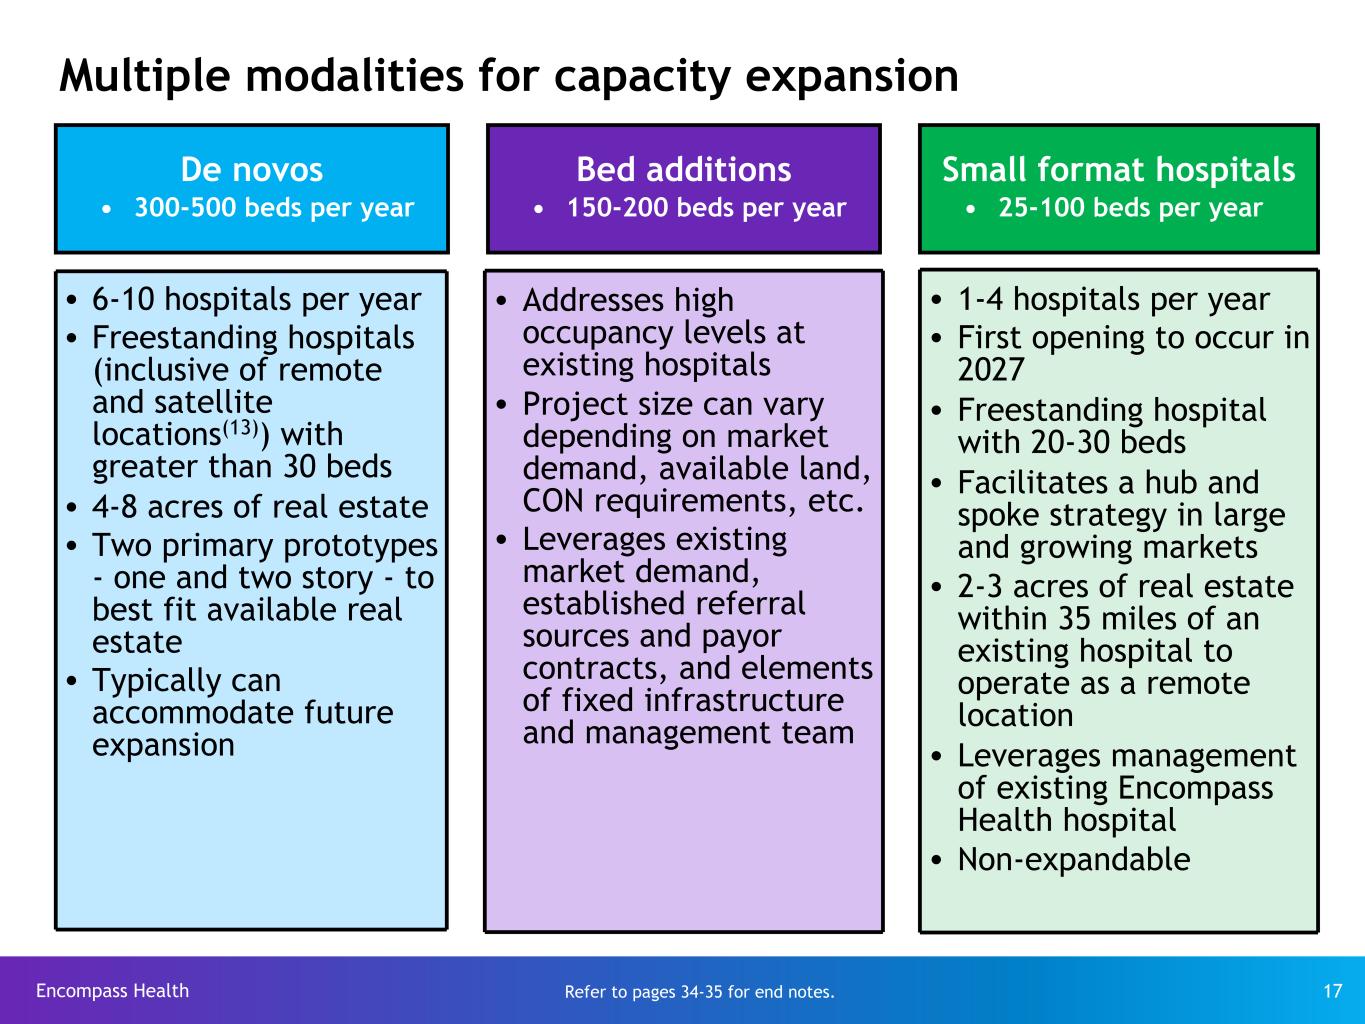
Encompass Health 17 Multiple modalities for capacity expansion De novos • 300-500 beds per year Small format hospitals • 25-100 beds per year Ÿ 6-10 hospitals per year Ÿ Freestanding hospitals (inclusive of remote and satellite locations(13)) with greater than 30 beds Ÿ 4-8 acres of real estate Ÿ Two primary prototypes - one and two story - to best fit available real estate Ÿ Typically can accommodate future expansion Ÿ Addresses high occupancy levels at existing hospitals Ÿ Project size can vary depending on market demand, available land, CON requirements, etc. Ÿ Leverages existing market demand, established referral sources and payor contracts, and elements of fixed infrastructure and management team Ÿ 1-4 hospitals per year Ÿ First opening to occur in 2027 Ÿ Freestanding hospital with 20-30 beds Ÿ Facilitates a hub and spoke strategy in large and growing markets Ÿ 2-3 acres of real estate within 35 miles of an existing hospital to operate as a remote location Ÿ Leverages management of existing Encompass Health hospital Ÿ Non-expandable Refer to pages 34-35 for end notes. Bed additions • 150-200 beds per year
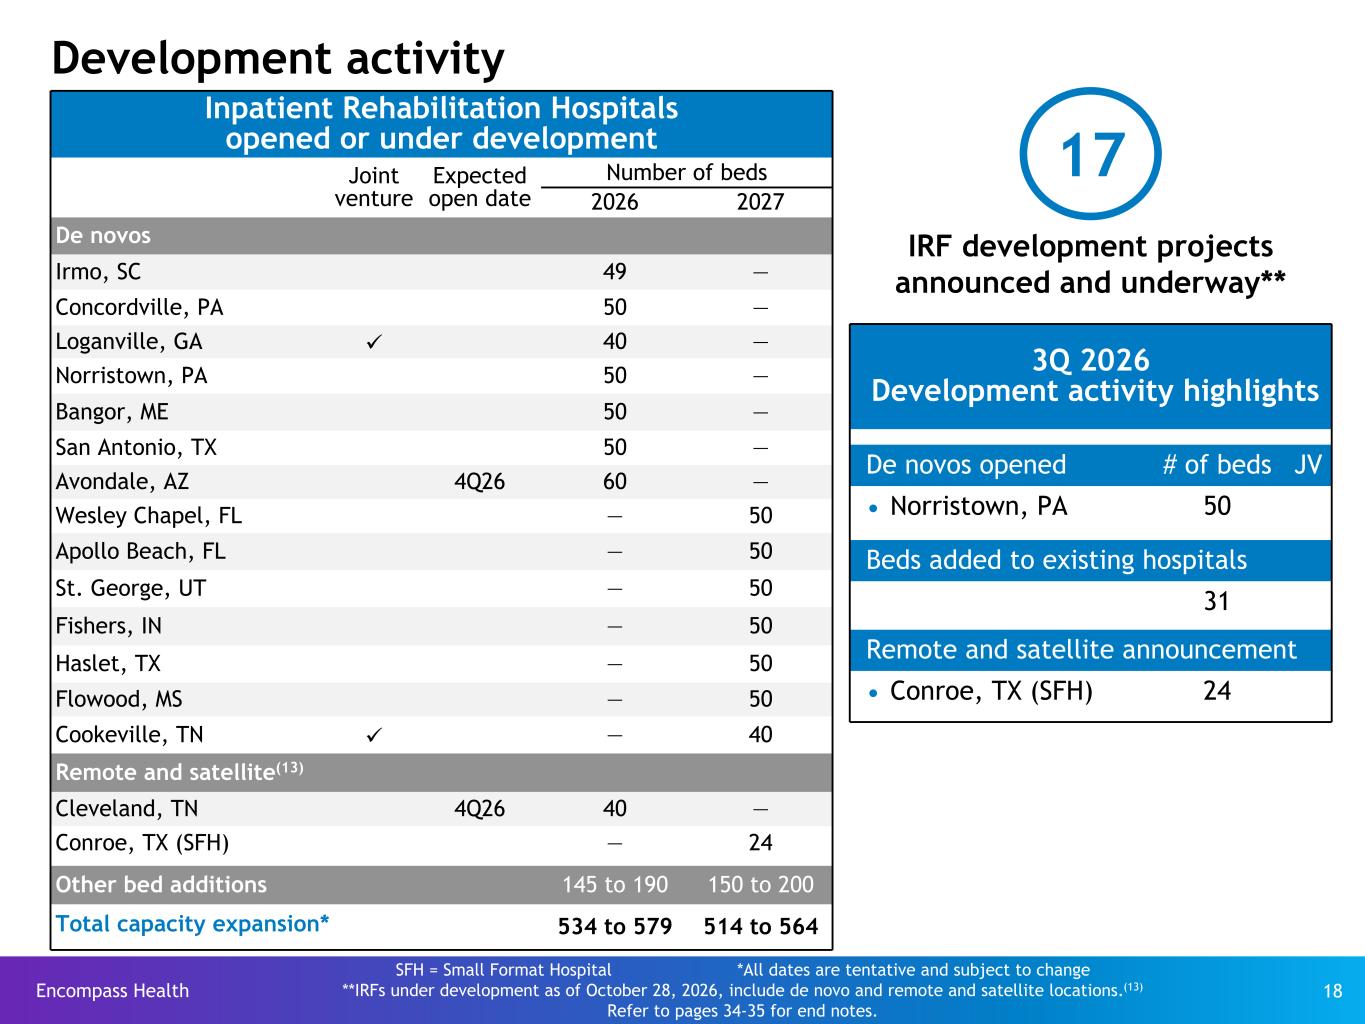
Encompass Health 18 Inpatient Rehabilitation Hospitals opened or under development Joint venture Expected open date Number of beds 2026 2027 De novos Irmo, SC 49 — Concordville, PA 50 — Loganville, GA ü 40 — Norristown, PA 50 — Bangor, ME 50 — San Antonio, TX 50 — Avondale, AZ 4Q26 60 — Wesley Chapel, FL — 50 Apollo Beach, FL — 50 St. George, UT — 50 Fishers, IN — 50 Haslet, TX — 50 Flowood, MS — 50 Cookeville, TN ü — 40 Remote and satellite(13) Cleveland, TN 4Q26 40 — Conroe, TX (SFH) — 24 Other bed additions 145 to 190 150 to 200 Total capacity expansion* 534 to 579 514 to 564 Development activity 3Q 2026 Development activity highlights uDe novos opened # of beds JV Ÿ Norristown, PA 50 Beds added to existing hospitals 31 Remote and satellite announcement Ÿ Conroe, TX (SFH) 24 IRF development projects announced and underway** 17 SFH = Small Format Hospital *All dates are tentative and subject to change **IRFs under development as of October 28, 2026, include de novo and remote and satellite locations.(13) Refer to pages 34-35 for end notes.
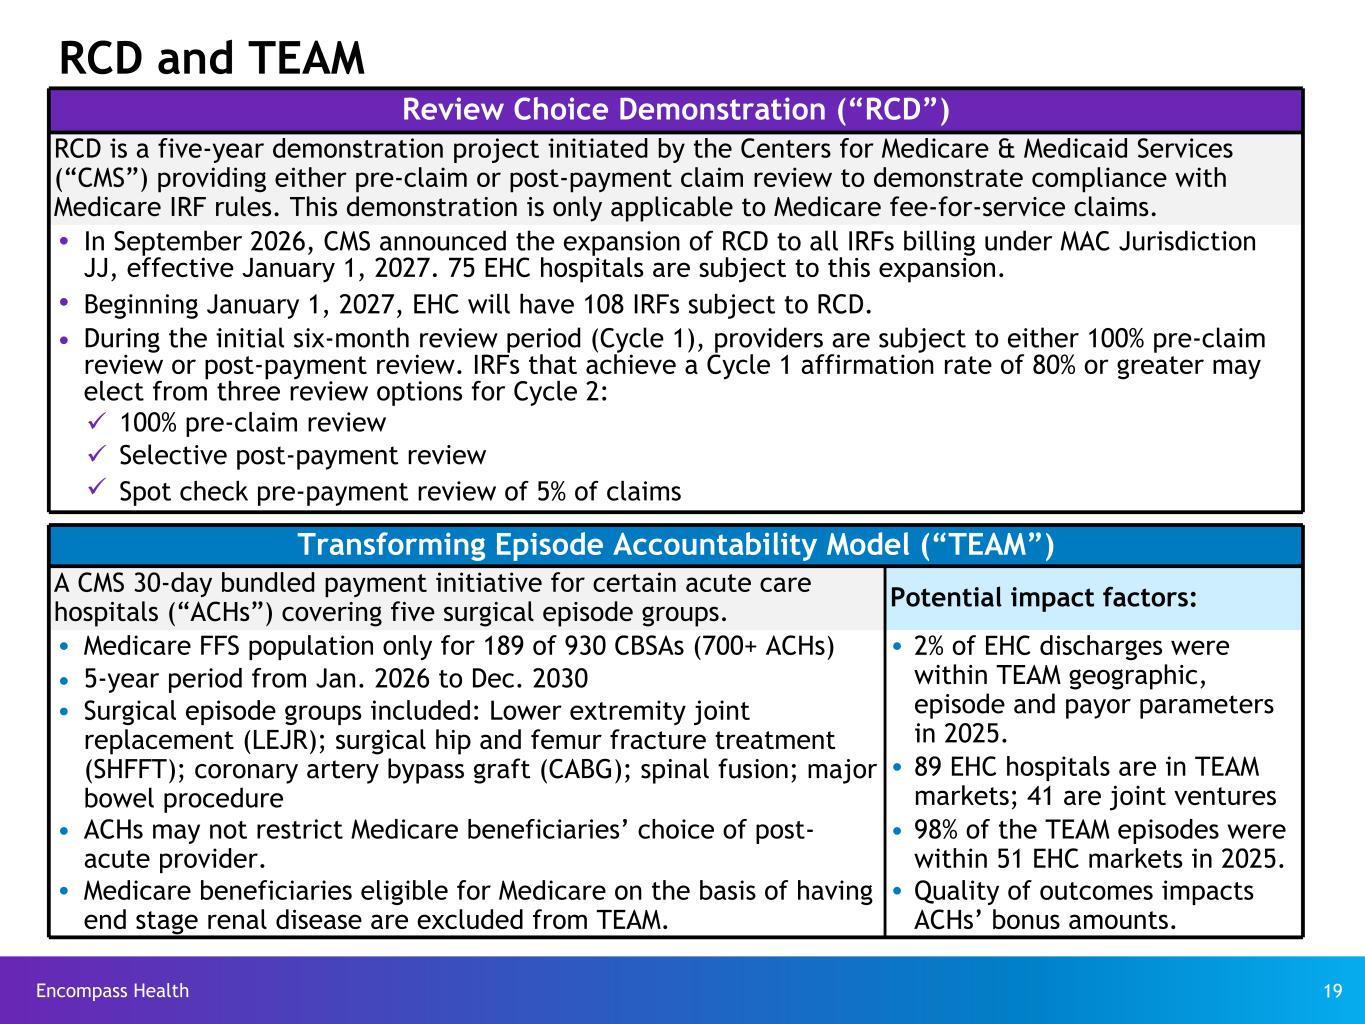
Encompass Health 19 RCD and TEAM Review Choice Demonstration (“RCD”) RCD is a five-year demonstration project initiated by the Centers for Medicare & Medicaid Services (“CMS”) providing either pre-claim or post-payment claim review to demonstrate compliance with Medicare IRF rules. This demonstration is only applicable to Medicare fee-for-service claims. Ÿ In September 2026, CMS announced the expansion of RCD to all IRFs billing under MAC Jurisdiction JJ, effective January 1, 2027. 75 EHC hospitals are subject to this expansion. Ÿ Beginning January 1, 2027, EHC will have 108 IRFs subject to RCD. Ÿ During the initial six-month review period (Cycle 1), providers are subject to either 100% pre-claim review or post-payment review. IRFs that achieve a Cycle 1 affirmation rate of 80% or greater may elect from three review options for Cycle 2: ü 100% pre-claim review ü Selective post-payment review ü Spot check pre-payment review of 5% of claims Transforming Episode Accountability Model (“TEAM”) A CMS 30-day bundled payment initiative for certain acute care hospitals (“ACHs”) covering five surgical episode groups. Potential impact factors: Ÿ Medicare FFS population only for 189 of 930 CBSAs (700+ ACHs) Ÿ 2% of EHC discharges were within TEAM geographic, episode and payor parameters in 2025. Ÿ 5-year period from Jan. 2026 to Dec. 2030 Ÿ Surgical episode groups included: Lower extremity joint replacement (LEJR); surgical hip and femur fracture treatment (SHFFT); coronary artery bypass graft (CABG); spinal fusion; major bowel procedure Ÿ 89 EHC hospitals are in TEAM markets; 41 are joint ventures Ÿ ACHs may not restrict Medicare beneficiaries’ choice of post- acute provider. Ÿ 98% of the TEAM episodes were within 51 EHC markets in 2025. Ÿ Medicare beneficiaries eligible for Medicare on the basis of having end stage renal disease are excluded from TEAM. Ÿ Quality of outcomes impacts ACHs’ bonus amounts.
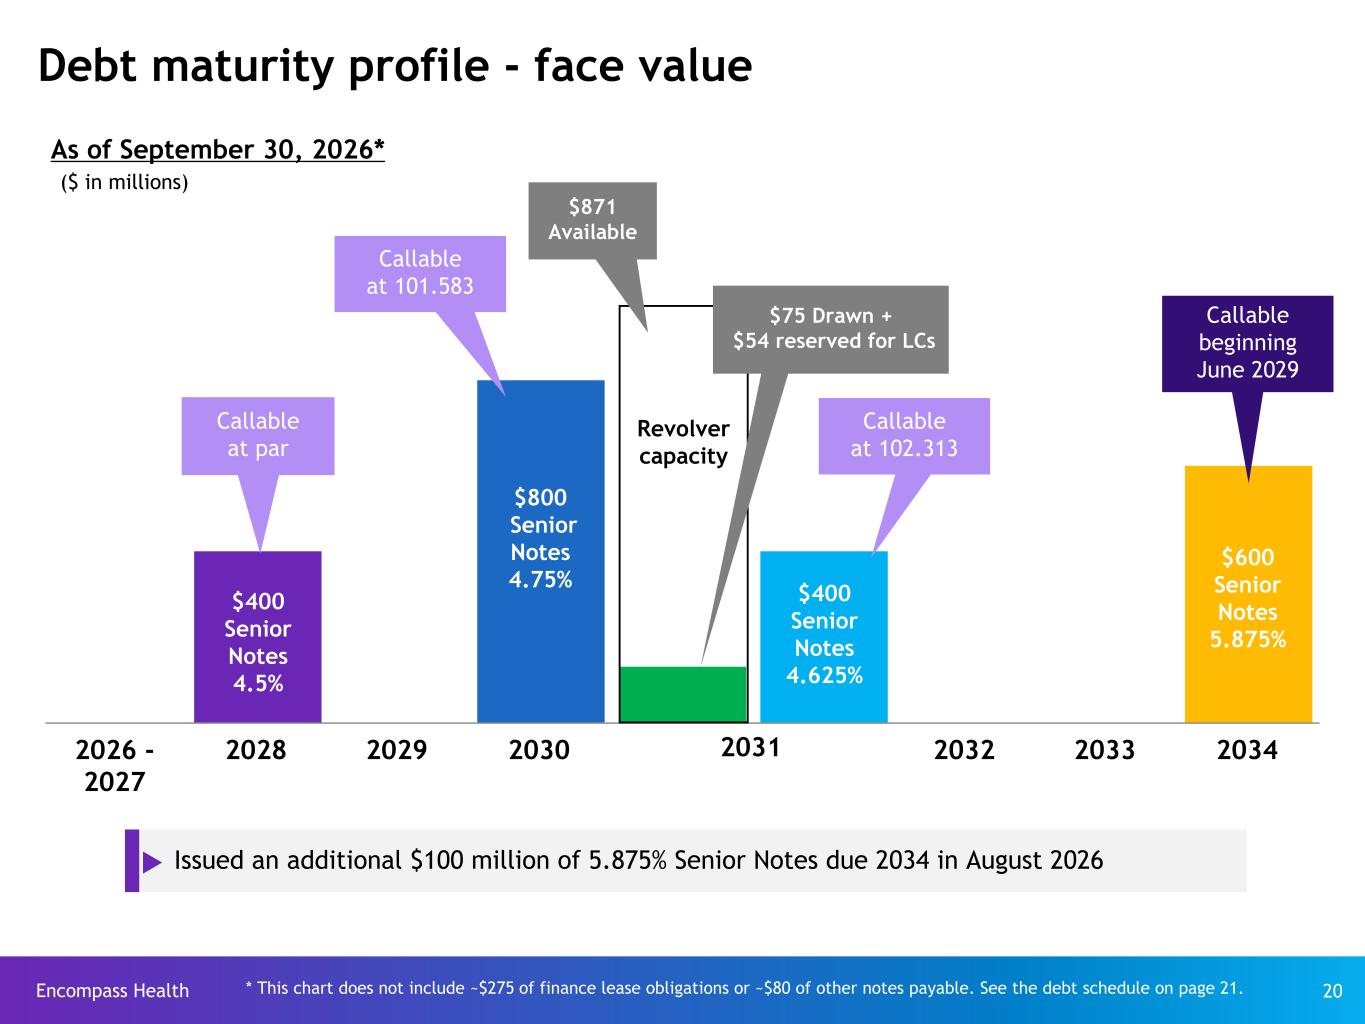
Encompass Health 20 2026 - 2027 2028 2029 2030 2031 2031 2032 2033 2034 * This chart does not include ~$275 of finance lease obligations or ~$80 of other notes payable. See the debt schedule on page 21. Debt maturity profile - face value ($ in millions) Revolver capacity $800 Senior Notes 4.75% $400 Senior Notes 4.5% As of September 30, 2026* $871 Available $75 Drawn + $54 reserved for LCs Callable at par $400 Senior Notes 4.625% Callable at 101.583 2031 Callable at 102.313 Callable beginning June 2029 $600 Senior Notes 5.875% u Issued an additional $100 million of 5.875% Senior Notes due 2034 in August 2026
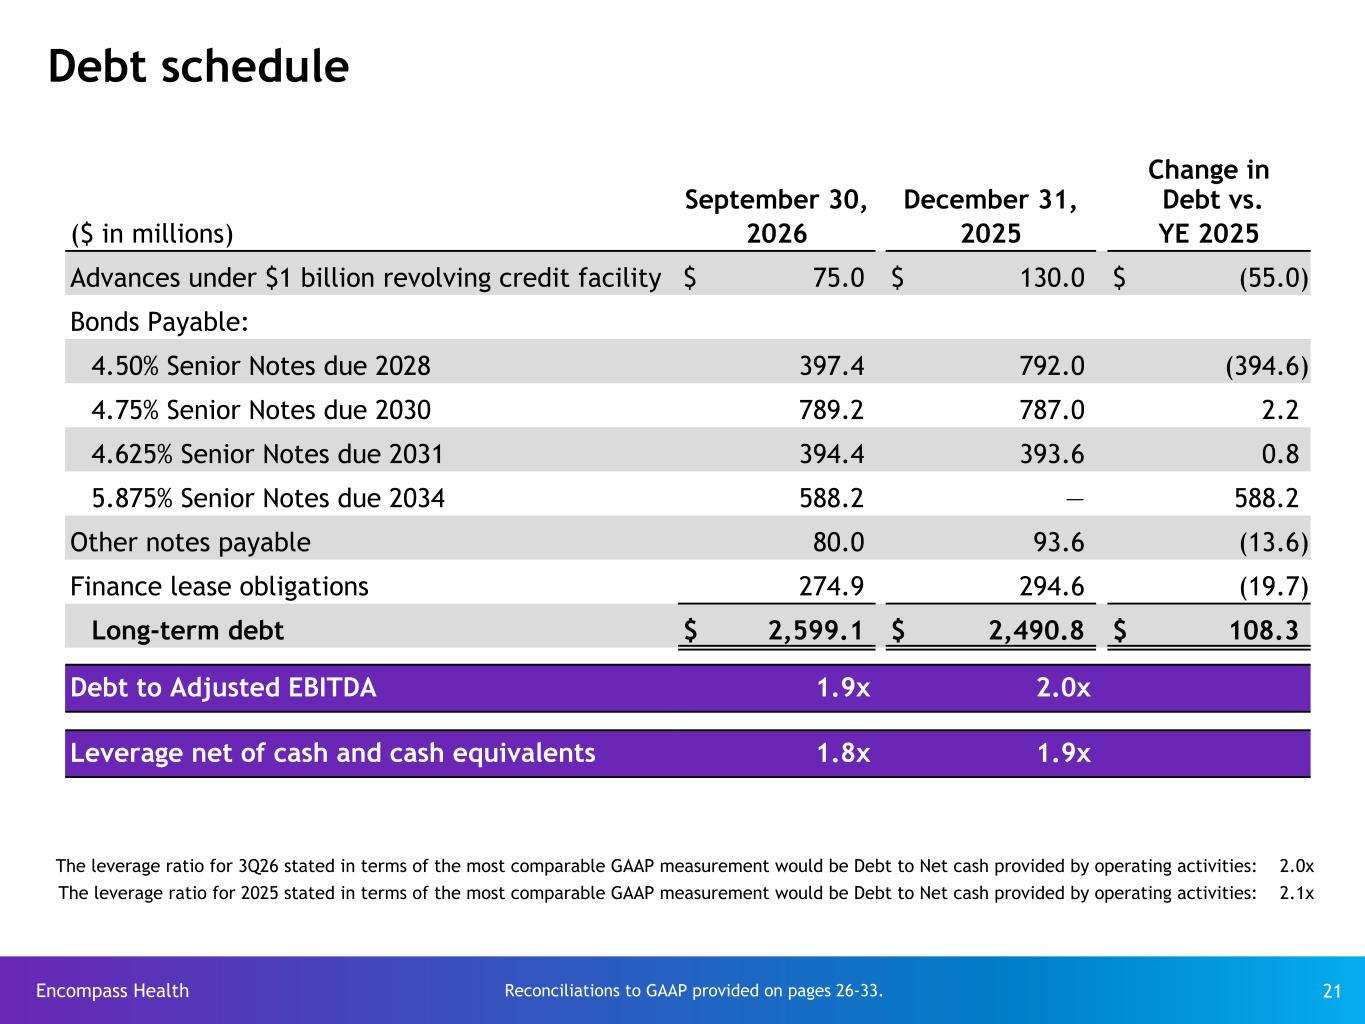
Encompass Health 21 Debt schedule Change in September 30, December 31, Debt vs. ($ in millions) 2026 2025 YE 2025 Advances under $1 billion revolving credit facility $ 75.0 $ 130.0 $ (55.0) Bonds Payable: 4.50% Senior Notes due 2028 397.4 792.0 (394.6) 4.75% Senior Notes due 2030 789.2 787.0 2.2 4.625% Senior Notes due 2031 394.4 393.6 0.8 5.875% Senior Notes due 2034 588.2 — 588.2 Other notes payable 80.0 93.6 (13.6) Finance lease obligations 274.9 294.6 (19.7) Long-term debt $ 2,599.1 $ 2,490.8 $ 108.3 Debt to Adjusted EBITDA 1.9x 2.0x Leverage net of cash and cash equivalents 1.8x 1.9x Reconciliations to GAAP provided on pages 26-33. The leverage ratio for 3Q26 stated in terms of the most comparable GAAP measurement would be Debt to Net cash provided by operating activities: 2.0x The leverage ratio for 2025 stated in terms of the most comparable GAAP measurement would be Debt to Net cash provided by operating activities: 2.1x
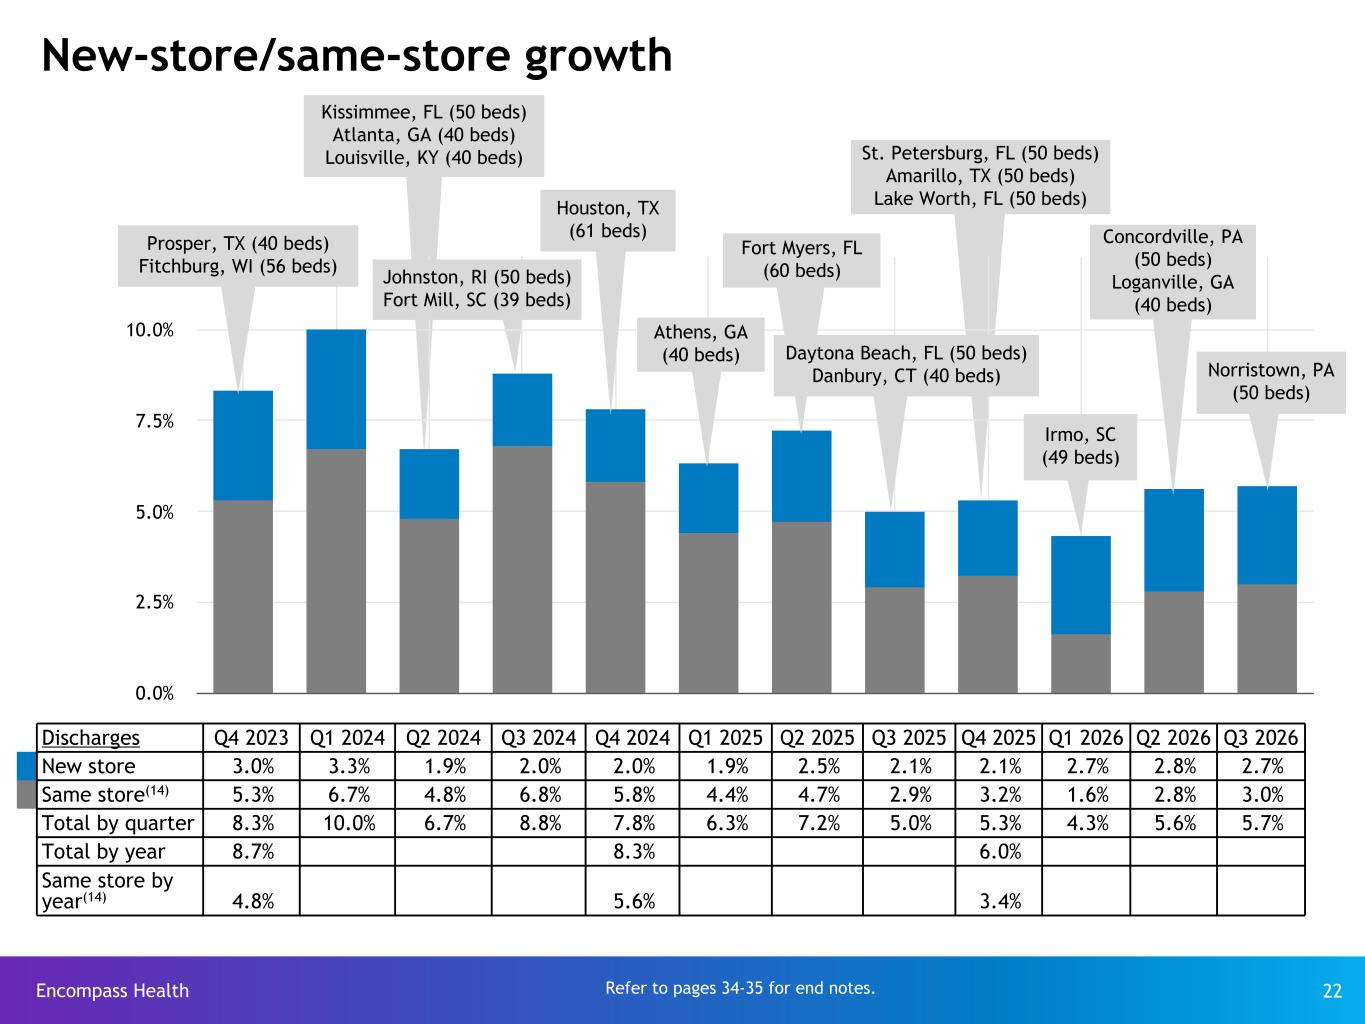
Encompass Health 22 0.0% 2.5% 5.0% 7.5% 10.0% New-store/same-store growth Discharges Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 New store 3.0% 3.3% 1.9% 2.0% 2.0% 1.9% 2.5% 2.1% 2.1% 2.7% 2.8% 2.7% Same store(14) 5.3% 6.7% 4.8% 6.8% 5.8% 4.4% 4.7% 2.9% 3.2% 1.6% 2.8% 3.0% Total by quarter 8.3% 10.0% 6.7% 8.8% 7.8% 6.3% 7.2% 5.0% 5.3% 4.3% 5.6% 5.7% Total by year 8.7% 8.3% 6.0% Same store by year(14) 4.8% 5.6% 3.4% Johnston, RI (50 beds) Fort Mill, SC (39 beds) Athens, GA (40 beds) Irmo, SC (49 beds) Prosper, TX (40 beds) Fitchburg, WI (56 beds) Kissimmee, FL (50 beds) Atlanta, GA (40 beds) Louisville, KY (40 beds) Refer to pages 34-35 for end notes. Houston, TX (61 beds) Fort Myers, FL (60 beds) Daytona Beach, FL (50 beds) Danbury, CT (40 beds) St. Petersburg, FL (50 beds) Amarillo, TX (50 beds) Lake Worth, FL (50 beds) Concordville, PA (50 beds) Loganville, GA (40 beds) Norristown, PA (50 beds)
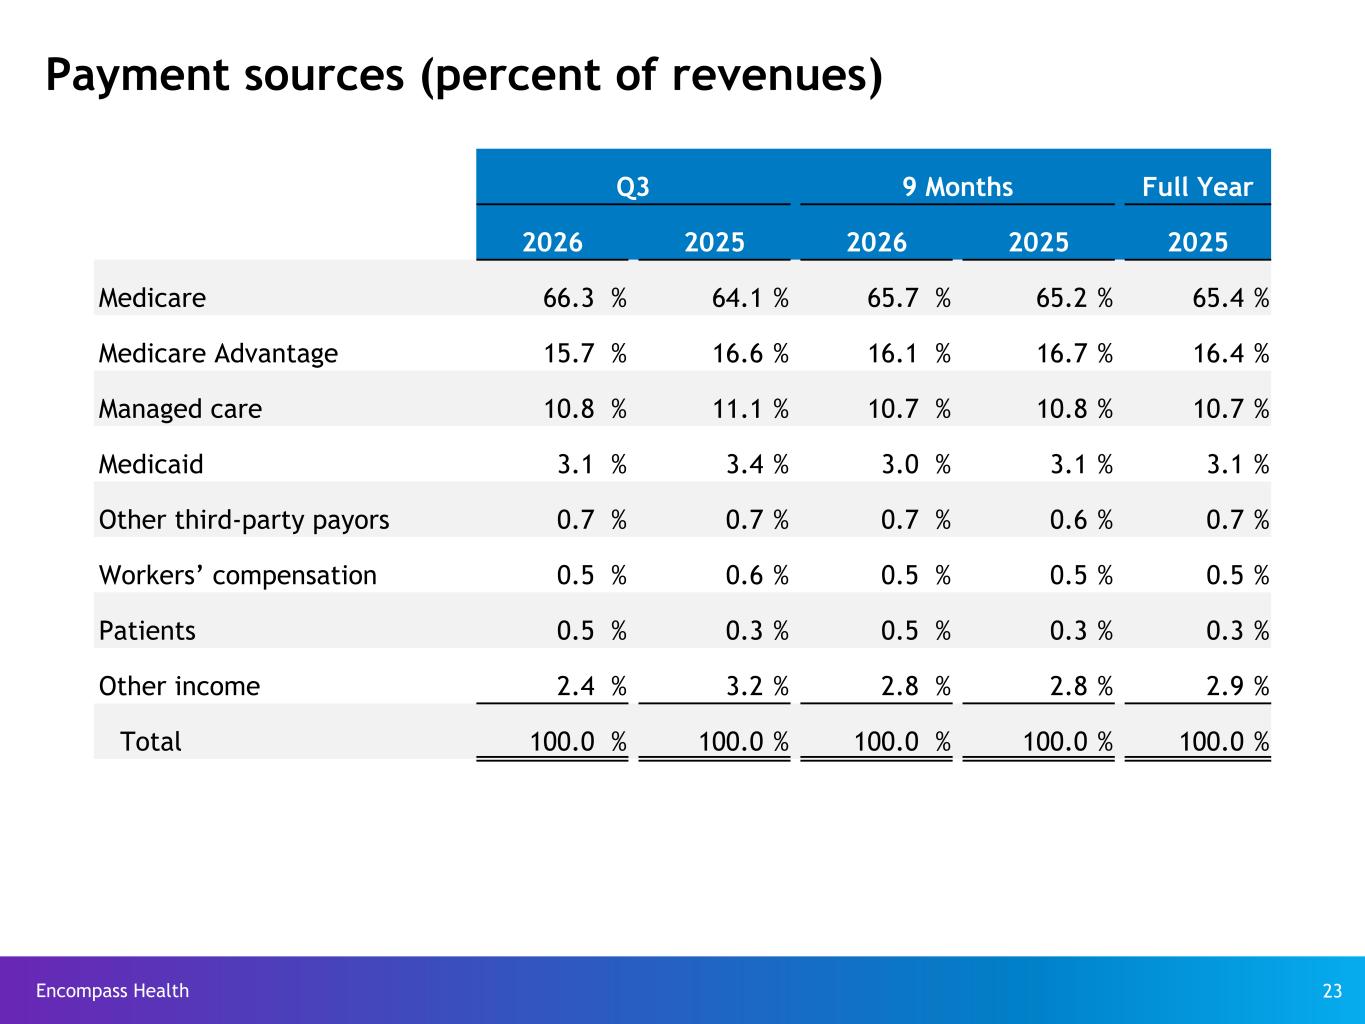
Encompass Health 23 Payment sources (percent of revenues) Q3 9 Months Full Year 2026 2025 2026 2025 2025 Medicare 66.3 % 64.1 % 65.7 % 65.2 % 65.4 % Medicare Advantage 15.7 % 16.6 % 16.1 % 16.7 % 16.4 % Managed care 10.8 % 11.1 % 10.7 % 10.8 % 10.7 % Medicaid 3.1 % 3.4 % 3.0 % 3.1 % 3.1 % Other third-party payors 0.7 % 0.7 % 0.7 % 0.6 % 0.7 % Workers’ compensation 0.5 % 0.6 % 0.5 % 0.5 % 0.5 % Patients 0.5 % 0.3 % 0.5 % 0.3 % 0.3 % Other income 2.4 % 3.2 % 2.8 % 2.8 % 2.9 % Total 100.0 % 100.0 % 100.0 % 100.0 % 100.0 %
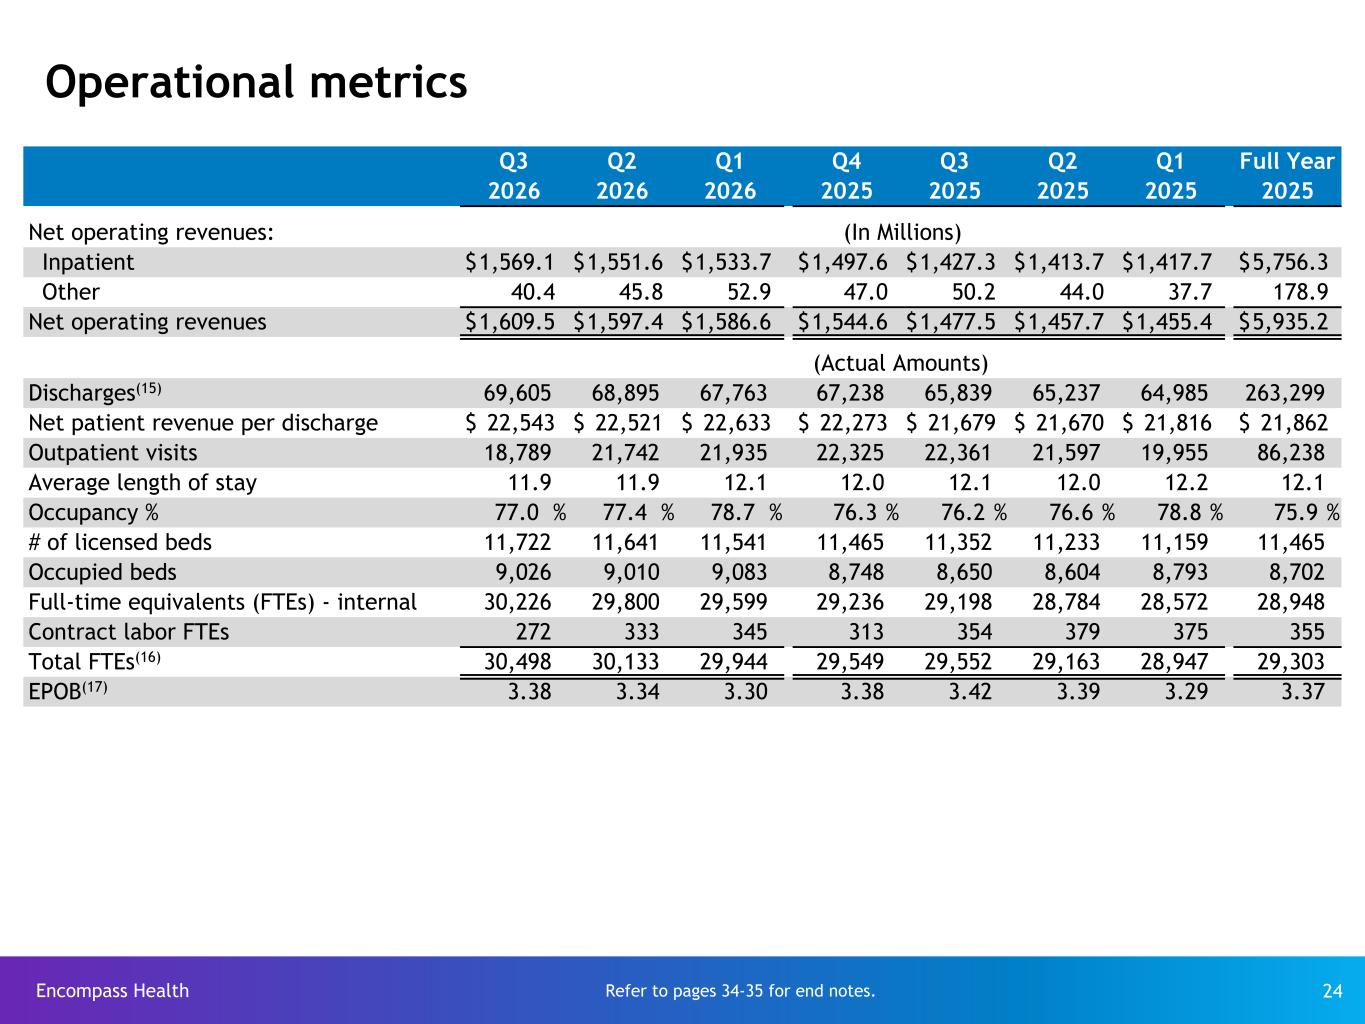
Encompass Health 24 Operational metrics Q3 Q2 Q1 Q4 Q3 Q2 Q1 Full Year 2026 2026 2026 2025 2025 2025 2025 2025 Net operating revenues: (In Millions) Inpatient $ 1,569.1 $ 1,551.6 $ 1,533.7 $ 1,497.6 $ 1,427.3 $ 1,413.7 $ 1,417.7 $ 5,756.3 Other 40.4 45.8 52.9 47.0 50.2 44.0 37.7 178.9 Net operating revenues $ 1,609.5 $ 1,597.4 $ 1,586.6 $ 1,544.6 $ 1,477.5 $ 1,457.7 $ 1,455.4 $ 5,935.2 (Actual Amounts) Discharges(15) 69,605 68,895 67,763 67,238 65,839 65,237 64,985 263,299 Net patient revenue per discharge $ 22,543 $ 22,521 $ 22,633 $ 22,273 $ 21,679 $ 21,670 $ 21,816 $ 21,862 Outpatient visits 18,789 21,742 21,935 22,325 22,361 21,597 19,955 86,238 Average length of stay 11.9 11.9 12.1 12.0 12.1 12.0 12.2 12.1 Occupancy % 77.0 % 77.4 % 78.7 % 76.3 % 76.2 % 76.6 % 78.8 % 75.9 % # of licensed beds 11,722 11,641 11,541 11,465 11,352 11,233 11,159 11,465 Occupied beds 9,026 9,010 9,083 8,748 8,650 8,604 8,793 8,702 Full-time equivalents (FTEs) - internal 30,226 29,800 29,599 29,236 29,198 28,784 28,572 28,948 Contract labor FTEs 272 333 345 313 354 379 375 355 Total FTEs(16) 30,498 30,133 29,944 29,549 29,552 29,163 28,947 29,303 EPOB(17) 3.38 3.34 3.30 3.38 3.42 3.39 3.29 3.37 Refer to pages 34-35 for end notes.
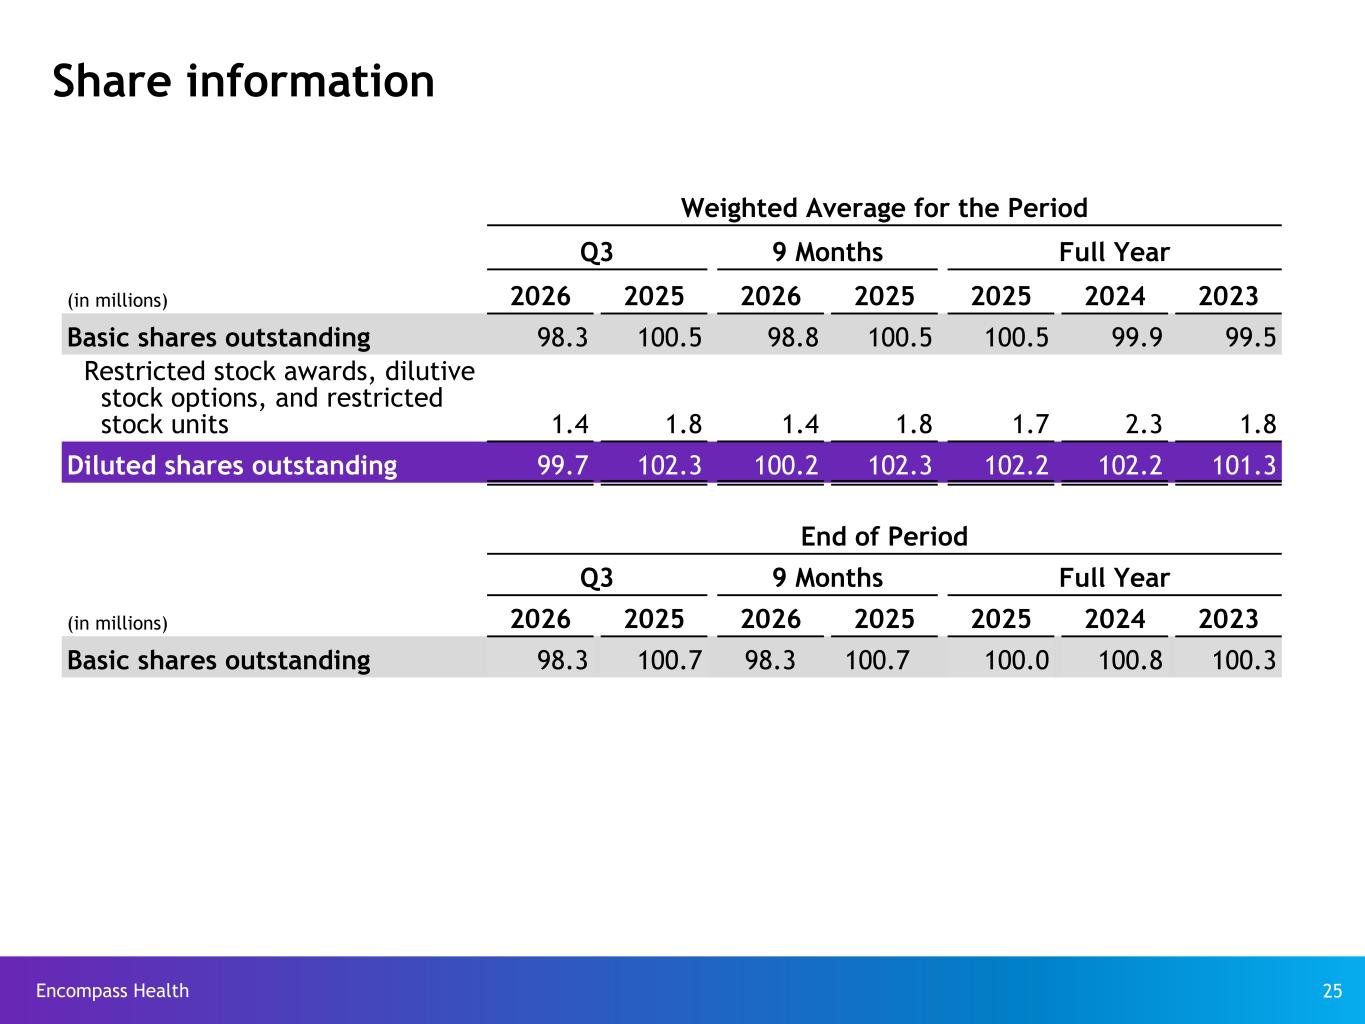
Encompass Health 25 Share information Weighted Average for the Period Q3 9 Months Full Year (in millions) 2026 2025 2026 2025 2025 2024 2023 Basic shares outstanding 98.3 100.5 98.8 100.5 100.5 99.9 99.5 Restricted stock awards, dilutive stock options, and restricted stock units 1.4 1.8 1.4 1.8 1.7 2.3 1.8 Diluted shares outstanding 99.7 102.3 100.2 102.3 102.2 102.2 101.3 End of Period Q3 9 Months Full Year (in millions) 2026 2025 2026 2025 2025 2024 2023 Basic shares outstanding 98.3 100.7 98.3 100.7 100.0 100.8 100.3
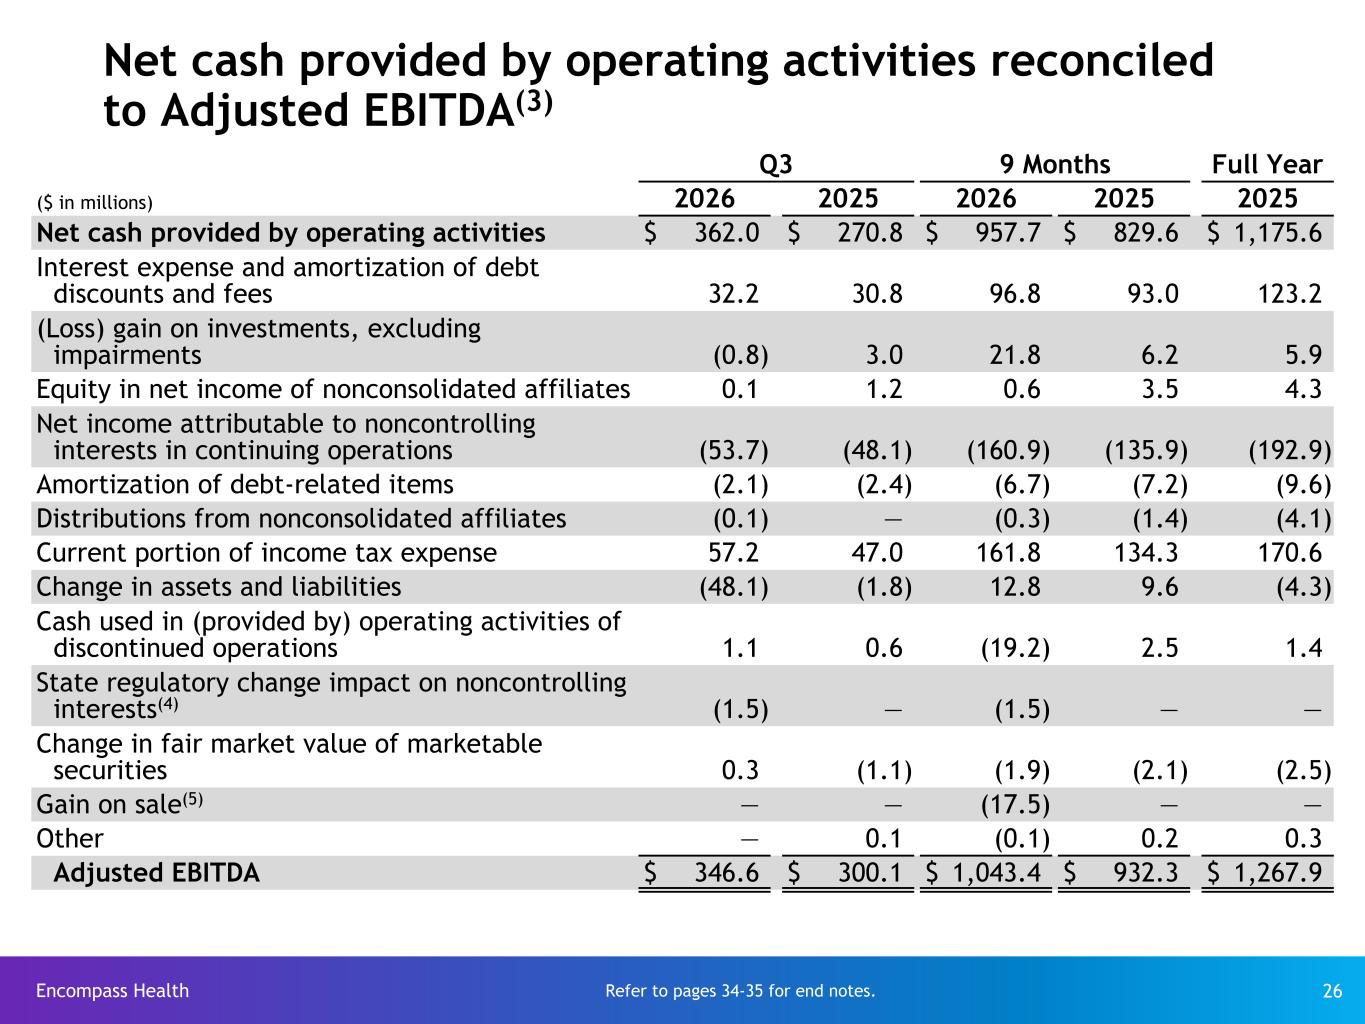
Encompass Health 26 Net cash provided by operating activities reconciled to Adjusted EBITDA(3) Q3 9 Months Full Year ($ in millions) 2026 2025 2026 2025 2025 Net cash provided by operating activities $ 362.0 $ 270.8 $ 957.7 $ 829.6 $ 1,175.6 Interest expense and amortization of debt discounts and fees 32.2 30.8 96.8 93.0 123.2 (Loss) gain on investments, excluding impairments (0.8) 3.0 21.8 6.2 5.9 Equity in net income of nonconsolidated affiliates 0.1 1.2 0.6 3.5 4.3 Net income attributable to noncontrolling interests in continuing operations (53.7) (48.1) (160.9) (135.9) (192.9) Amortization of debt-related items (2.1) (2.4) (6.7) (7.2) (9.6) Distributions from nonconsolidated affiliates (0.1) — (0.3) (1.4) (4.1) Current portion of income tax expense 57.2 47.0 161.8 134.3 170.6 Change in assets and liabilities (48.1) (1.8) 12.8 9.6 (4.3) Cash used in (provided by) operating activities of discontinued operations 1.1 0.6 (19.2) 2.5 1.4 State regulatory change impact on noncontrolling interests(4) (1.5) — (1.5) — — Change in fair market value of marketable securities 0.3 (1.1) (1.9) (2.1) (2.5) Gain on sale(5) — — (17.5) — — Other — 0.1 (0.1) 0.2 0.3 Adjusted EBITDA $ 346.6 $ 300.1 $ 1,043.4 $ 932.3 $ 1,267.9 Refer to pages 34-35 for end notes.
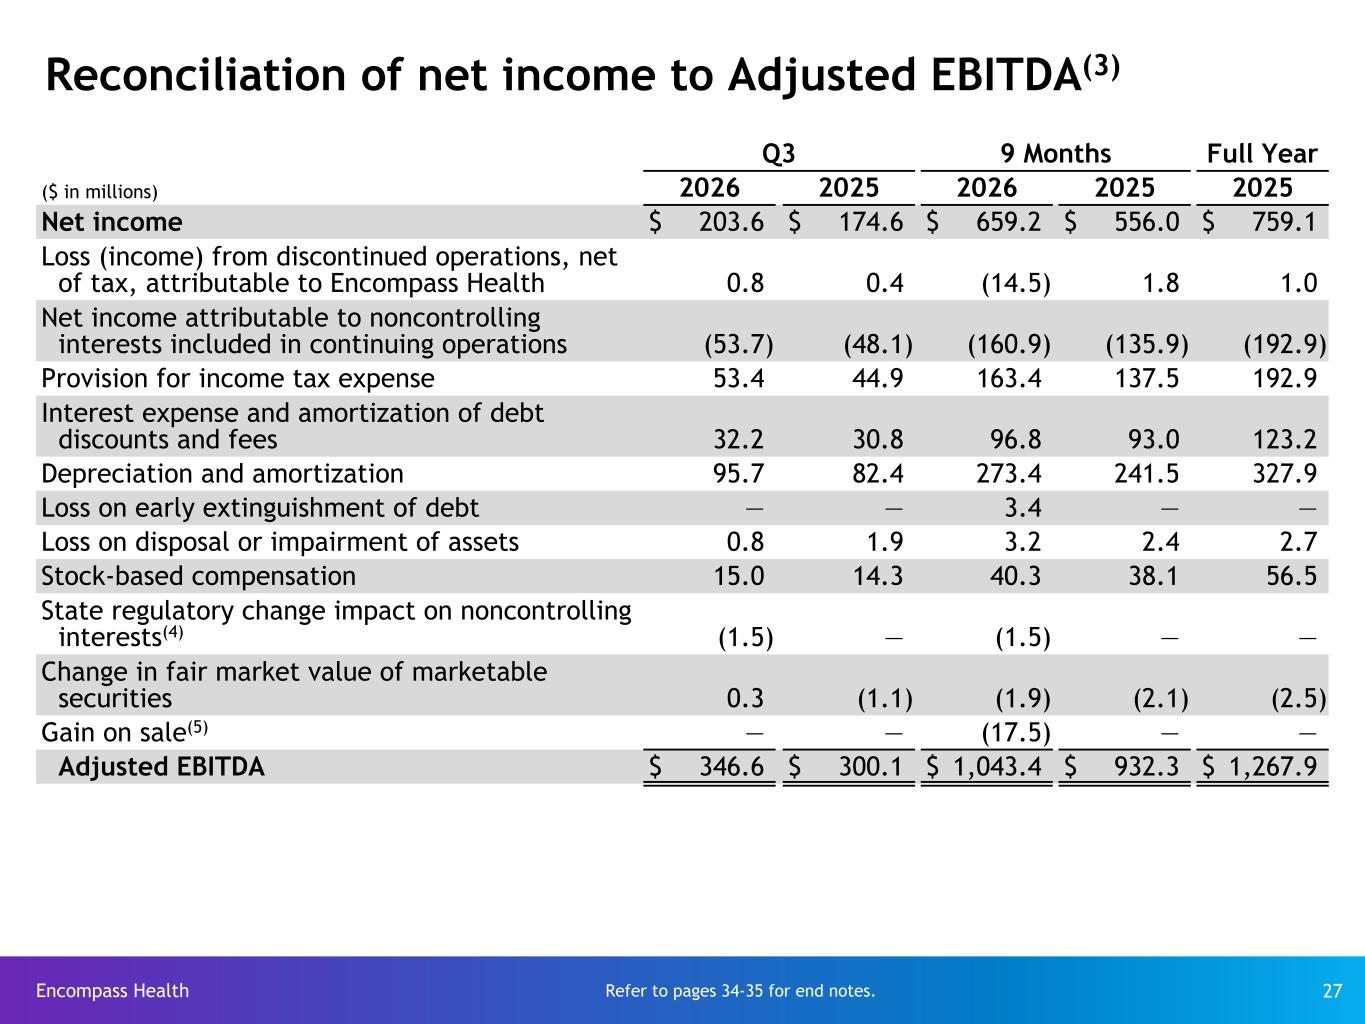
Encompass Health 27 Reconciliation of net income to Adjusted EBITDA(3) Q3 9 Months Full Year ($ in millions) 2026 2025 2026 2025 2025 Net income $ 203.6 $ 174.6 $ 659.2 $ 556.0 $ 759.1 Loss (income) from discontinued operations, net of tax, attributable to Encompass Health 0.8 0.4 (14.5) 1.8 1.0 Net income attributable to noncontrolling interests included in continuing operations (53.7) (48.1) (160.9) (135.9) (192.9) Provision for income tax expense 53.4 44.9 163.4 137.5 192.9 Interest expense and amortization of debt discounts and fees 32.2 30.8 96.8 93.0 123.2 Depreciation and amortization 95.7 82.4 273.4 241.5 327.9 Loss on early extinguishment of debt — — 3.4 — — Loss on disposal or impairment of assets 0.8 1.9 3.2 2.4 2.7 Stock-based compensation 15.0 14.3 40.3 38.1 56.5 State regulatory change impact on noncontrolling interests(4) (1.5) — (1.5) — — Change in fair market value of marketable securities 0.3 (1.1) (1.9) (2.1) (2.5) Gain on sale(5) — — (17.5) — — Adjusted EBITDA $ 346.6 $ 300.1 $ 1,043.4 $ 932.3 $ 1,267.9 Refer to pages 34-35 for end notes.
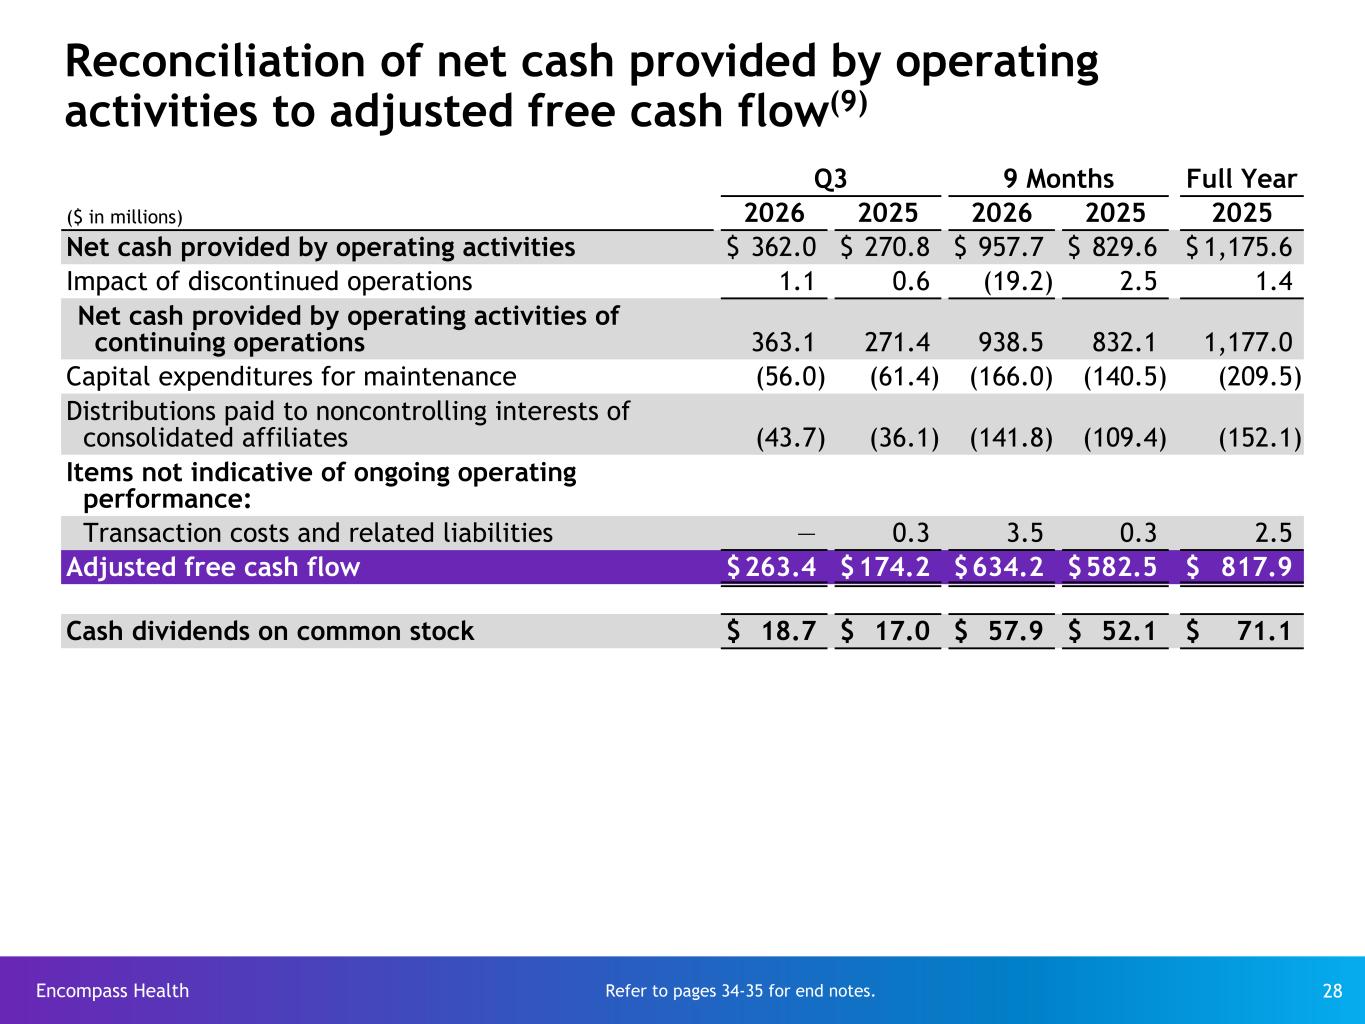
Encompass Health 28 Reconciliation of net cash provided by operating activities to adjusted free cash flow(9) Q3 9 Months Full Year ($ in millions) 2026 2025 2026 2025 2025 Net cash provided by operating activities $ 362.0 $ 270.8 $ 957.7 $ 829.6 $ 1,175.6 Impact of discontinued operations 1.1 0.6 (19.2) 2.5 1.4 Net cash provided by operating activities of continuing operations 363.1 271.4 938.5 832.1 1,177.0 Capital expenditures for maintenance (56.0) (61.4) (166.0) (140.5) (209.5) Distributions paid to noncontrolling interests of consolidated affiliates (43.7) (36.1) (141.8) (109.4) (152.1) Items not indicative of ongoing operating performance: Transaction costs and related liabilities — 0.3 3.5 0.3 2.5 Adjusted free cash flow $ 263.4 $ 174.2 $ 634.2 $ 582.5 $ 817.9 Cash dividends on common stock $ 18.7 $ 17.0 $ 57.9 $ 52.1 $ 71.1 Refer to pages 34-35 for end notes.
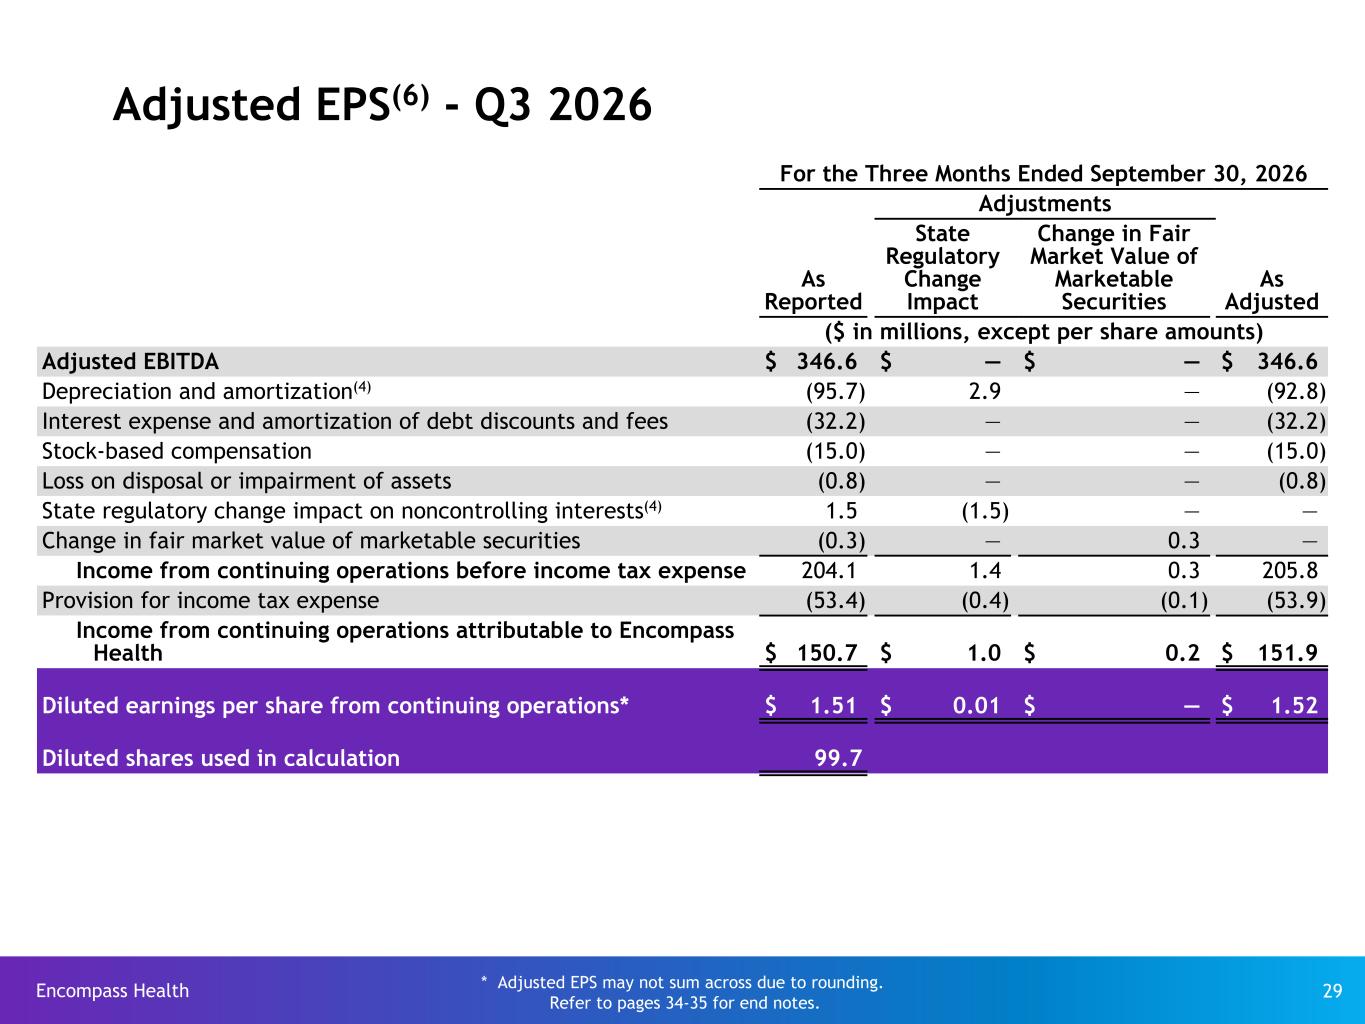
Encompass Health 29 For the Three Months Ended September 30, 2026 Adjustments As Reported State Regulatory Change Impact Change in Fair Market Value of Marketable Securities As Adjusted ($ in millions, except per share amounts) Adjusted EBITDA $ 346.6 $ — $ — $ 346.6 Depreciation and amortization(4) (95.7) 2.9 — (92.8) Interest expense and amortization of debt discounts and fees (32.2) — — (32.2) Stock-based compensation (15.0) — — (15.0) Loss on disposal or impairment of assets (0.8) — — (0.8) State regulatory change impact on noncontrolling interests(4) 1.5 (1.5) — — Change in fair market value of marketable securities (0.3) — 0.3 — Income from continuing operations before income tax expense 204.1 1.4 0.3 205.8 Provision for income tax expense (53.4) (0.4) (0.1) (53.9) Income from continuing operations attributable to Encompass Health $ 150.7 $ 1.0 $ 0.2 $ 151.9 Diluted earnings per share from continuing operations* $ 1.51 $ 0.01 $ — $ 1.52 Diluted shares used in calculation 99.7 * Adjusted EPS may not sum across due to rounding. Refer to pages 34-35 for end notes. Adjusted EPS(6) - Q3 2026
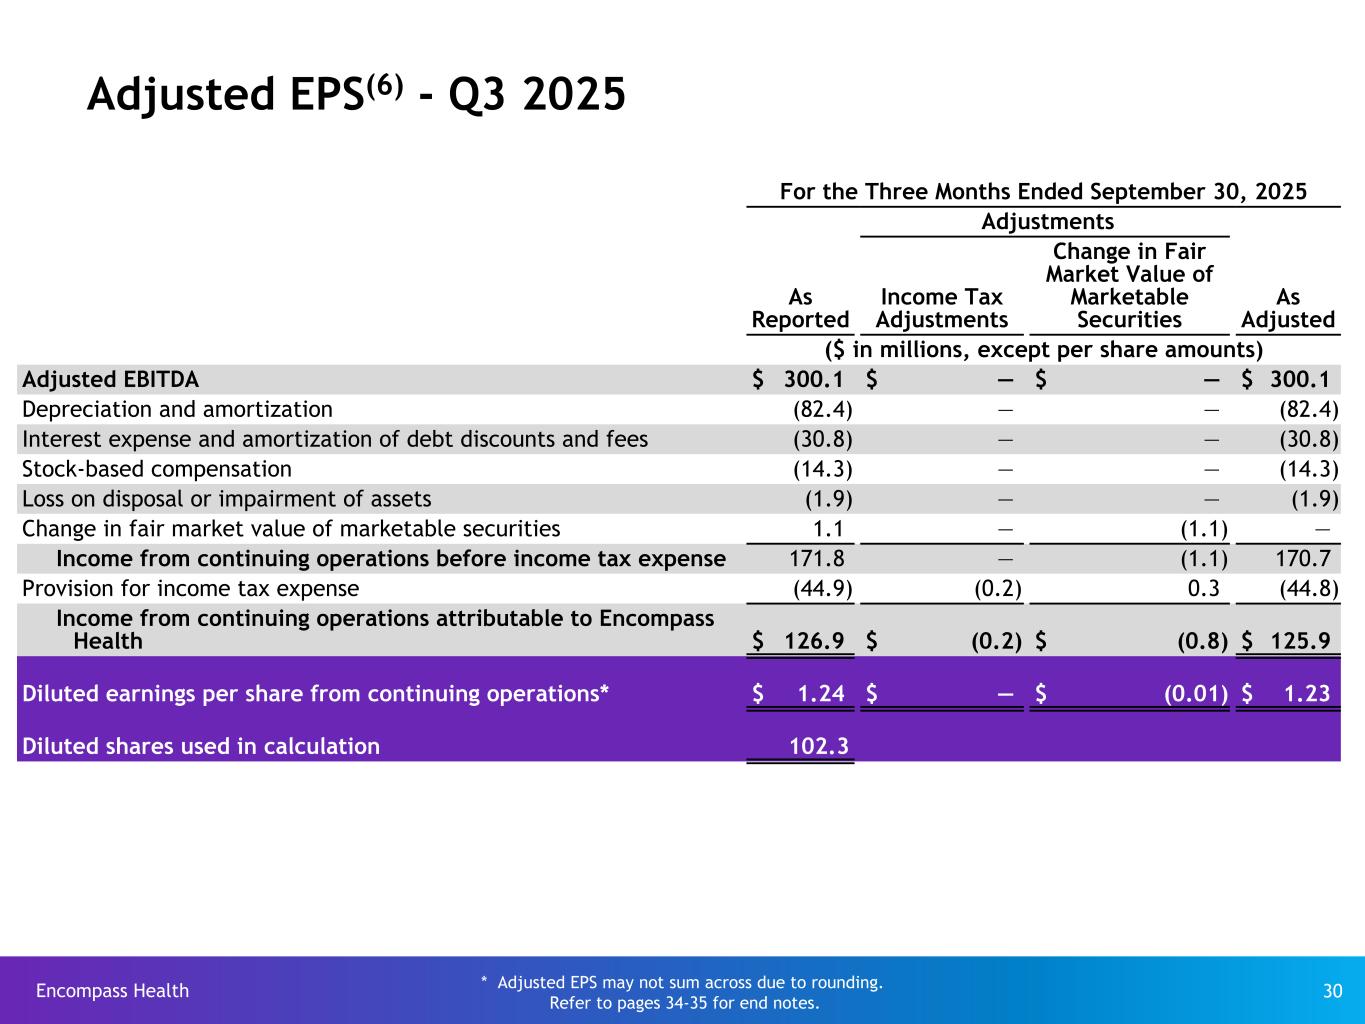
Encompass Health 30 For the Three Months Ended September 30, 2025 Adjustments As Reported Income Tax Adjustments Change in Fair Market Value of Marketable Securities As Adjusted ($ in millions, except per share amounts) Adjusted EBITDA $ 300.1 $ — $ — $ 300.1 Depreciation and amortization (82.4) — — (82.4) Interest expense and amortization of debt discounts and fees (30.8) — — (30.8) Stock-based compensation (14.3) — — (14.3) Loss on disposal or impairment of assets (1.9) — — (1.9) Change in fair market value of marketable securities 1.1 — (1.1) — Income from continuing operations before income tax expense 171.8 — (1.1) 170.7 Provision for income tax expense (44.9) (0.2) 0.3 (44.8) Income from continuing operations attributable to Encompass Health $ 126.9 $ (0.2) $ (0.8) $ 125.9 Diluted earnings per share from continuing operations* $ 1.24 $ — $ (0.01) $ 1.23 Diluted shares used in calculation 102.3 Adjusted EPS(6) - Q3 2025 * Adjusted EPS may not sum across due to rounding. Refer to pages 34-35 for end notes.
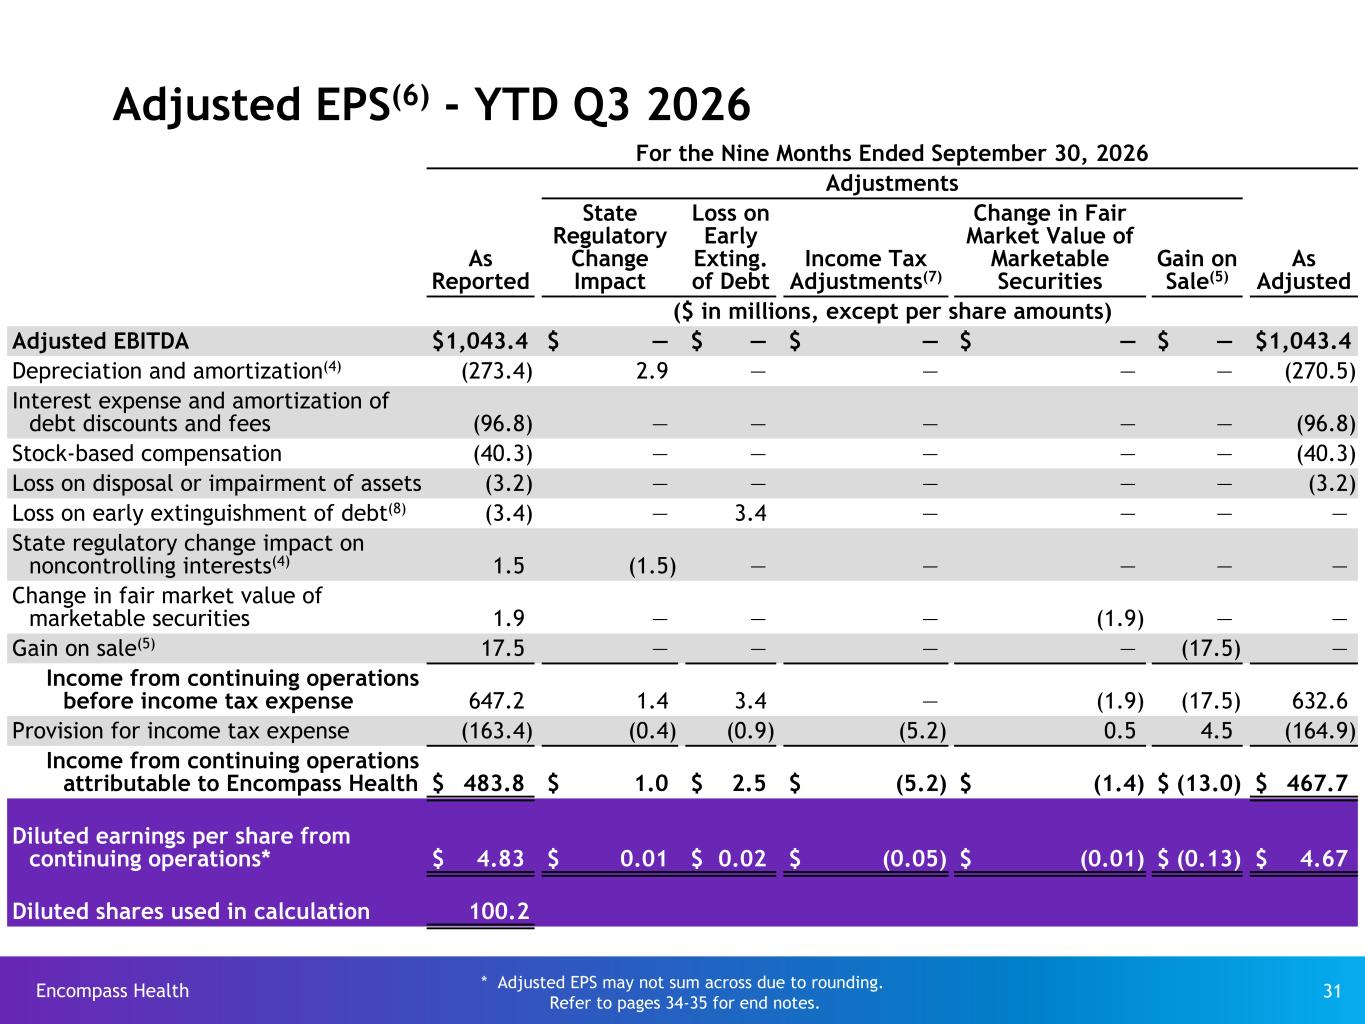
Encompass Health 31 For the Nine Months Ended September 30, 2026 Adjustments As Reported State Regulatory Change Impact Loss on Early Exting. of Debt Income Tax Adjustments(7) Change in Fair Market Value of Marketable Securities Gain on Sale(5) As Adjusted ($ in millions, except per share amounts) Adjusted EBITDA $ 1,043.4 $ — $ — $ — $ — $ — $ 1,043.4 Depreciation and amortization(4) (273.4) 2.9 — — — — (270.5) Interest expense and amortization of debt discounts and fees (96.8) — — — — — (96.8) Stock-based compensation (40.3) — — — — — (40.3) Loss on disposal or impairment of assets (3.2) — — — — — (3.2) Loss on early extinguishment of debt(8) (3.4) — 3.4 — — — — State regulatory change impact on noncontrolling interests(4) 1.5 (1.5) — — — — — Change in fair market value of marketable securities 1.9 — — — (1.9) — — Gain on sale(5) 17.5 — — — — (17.5) — Income from continuing operations before income tax expense 647.2 1.4 3.4 — (1.9) (17.5) 632.6 Provision for income tax expense (163.4) (0.4) (0.9) (5.2) 0.5 4.5 (164.9) Income from continuing operations attributable to Encompass Health $ 483.8 $ 1.0 $ 2.5 $ (5.2) $ (1.4) $ (13.0) $ 467.7 Diluted earnings per share from continuing operations* $ 4.83 $ 0.01 $ 0.02 $ (0.05) $ (0.01) $ (0.13) $ 4.67 Diluted shares used in calculation 100.2 * Adjusted EPS may not sum across due to rounding. Refer to pages 34-35 for end notes. Adjusted EPS(6) - YTD Q3 2026
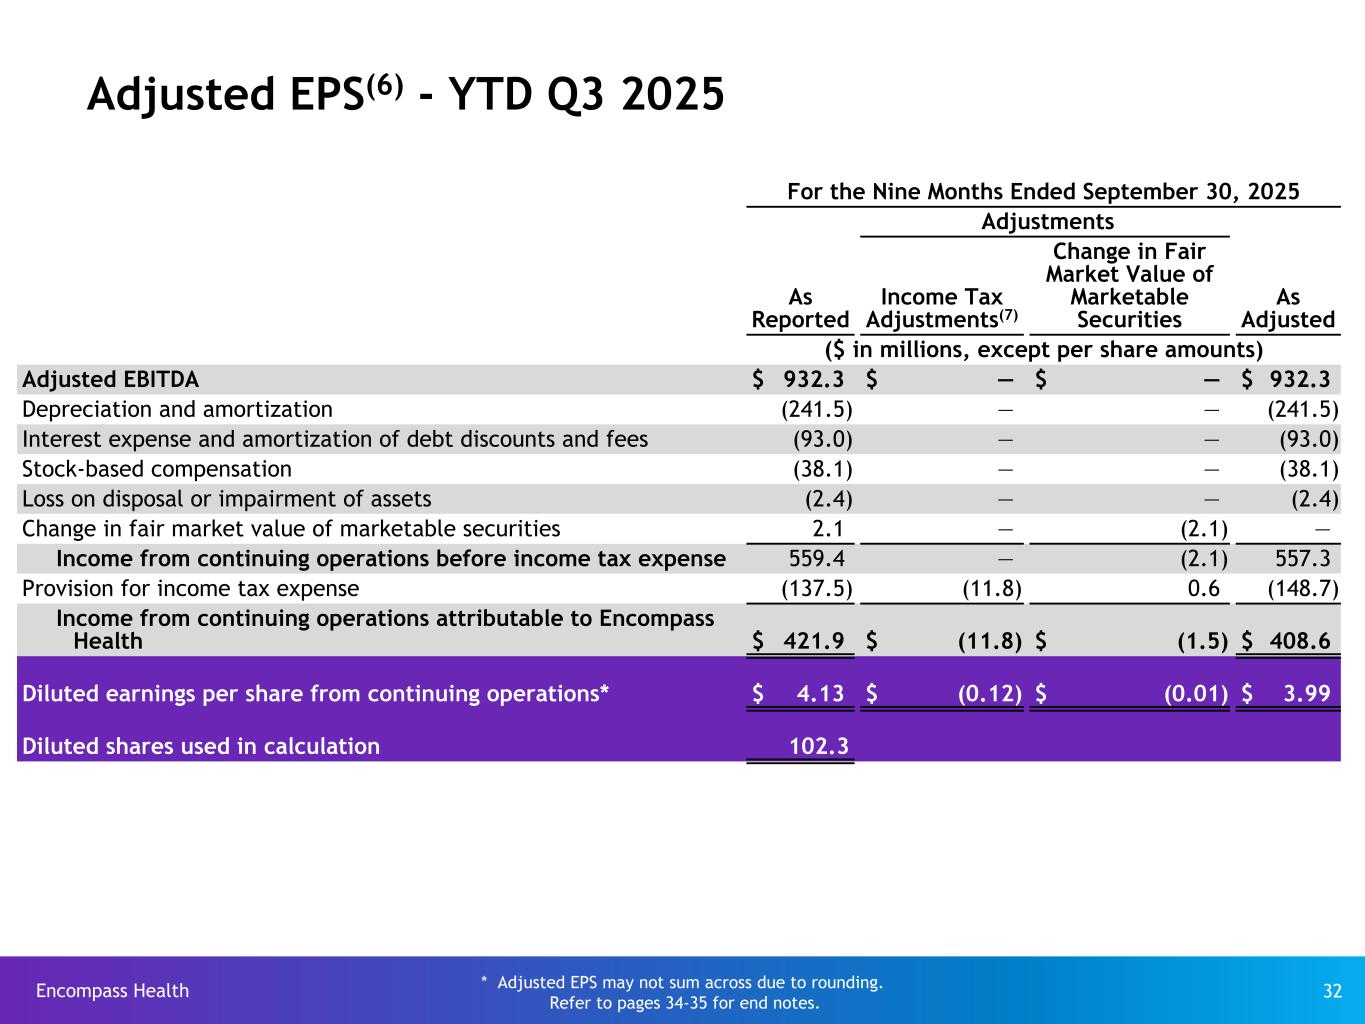
Encompass Health 32 For the Nine Months Ended September 30, 2025 Adjustments As Reported Income Tax Adjustments(7) Change in Fair Market Value of Marketable Securities As Adjusted ($ in millions, except per share amounts) Adjusted EBITDA $ 932.3 $ — $ — $ 932.3 Depreciation and amortization (241.5) — — (241.5) Interest expense and amortization of debt discounts and fees (93.0) — — (93.0) Stock-based compensation (38.1) — — (38.1) Loss on disposal or impairment of assets (2.4) — — (2.4) Change in fair market value of marketable securities 2.1 — (2.1) — Income from continuing operations before income tax expense 559.4 — (2.1) 557.3 Provision for income tax expense (137.5) (11.8) 0.6 (148.7) Income from continuing operations attributable to Encompass Health $ 421.9 $ (11.8) $ (1.5) $ 408.6 Diluted earnings per share from continuing operations* $ 4.13 $ (0.12) $ (0.01) $ 3.99 Diluted shares used in calculation 102.3 Adjusted EPS(6) - YTD Q3 2025 * Adjusted EPS may not sum across due to rounding. Refer to pages 34-35 for end notes.
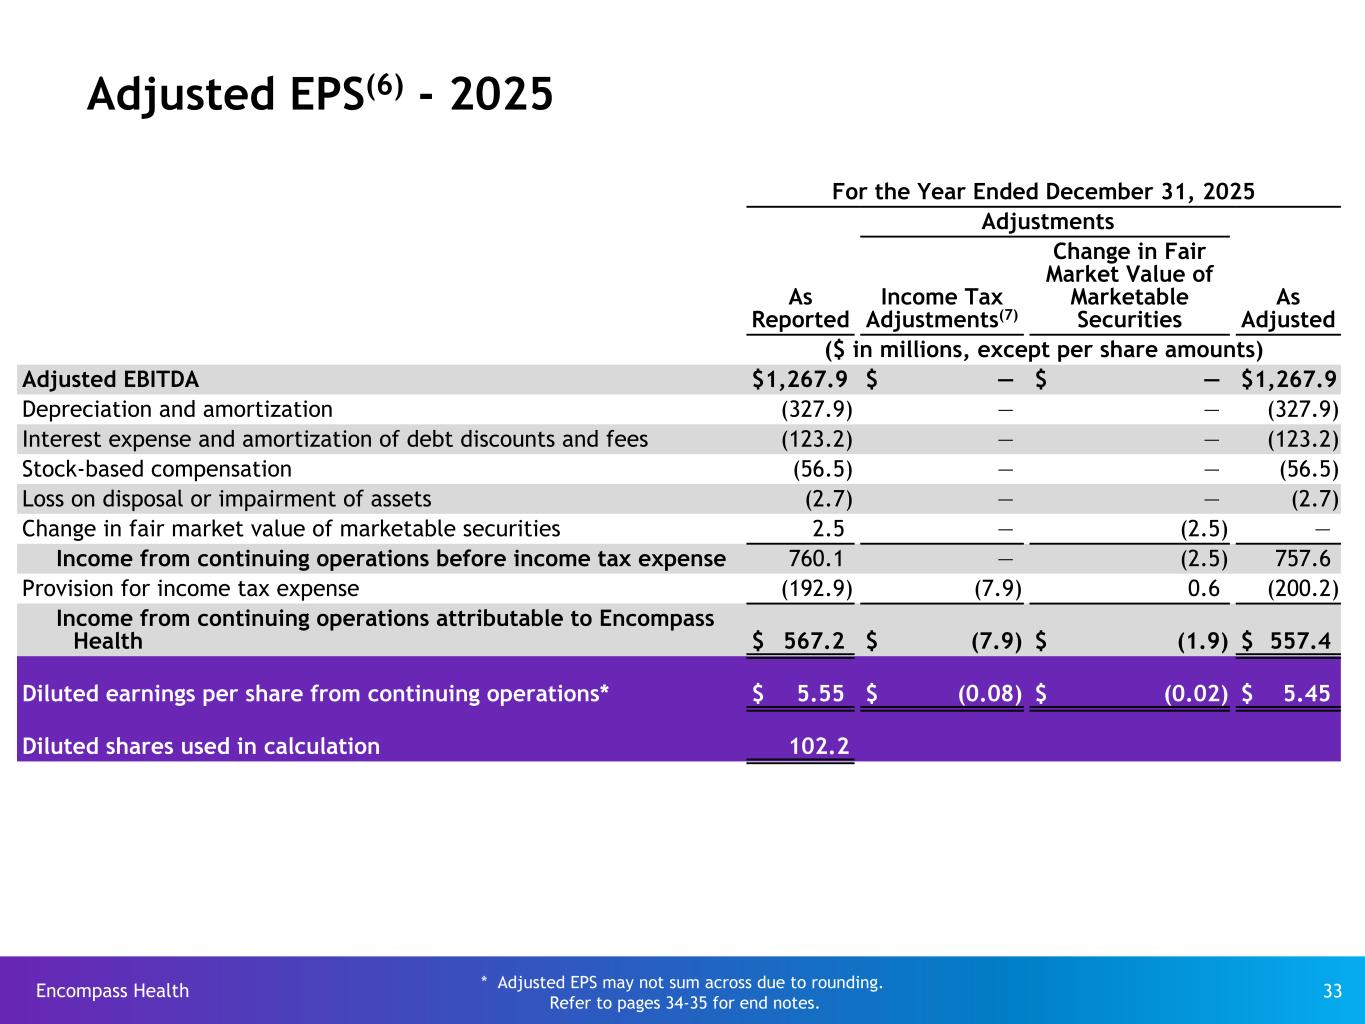
Encompass Health 33 For the Year Ended December 31, 2025 Adjustments As Reported Income Tax Adjustments(7) Change in Fair Market Value of Marketable Securities As Adjusted ($ in millions, except per share amounts) Adjusted EBITDA $ 1,267.9 $ — $ — $ 1,267.9 Depreciation and amortization (327.9) — — (327.9) Interest expense and amortization of debt discounts and fees (123.2) — — (123.2) Stock-based compensation (56.5) — — (56.5) Loss on disposal or impairment of assets (2.7) — — (2.7) Change in fair market value of marketable securities 2.5 — (2.5) — Income from continuing operations before income tax expense 760.1 — (2.5) 757.6 Provision for income tax expense (192.9) (7.9) 0.6 (200.2) Income from continuing operations attributable to Encompass Health $ 567.2 $ (7.9) $ (1.9) $ 557.4 Diluted earnings per share from continuing operations* $ 5.55 $ (0.08) $ (0.02) $ 5.45 Diluted shares used in calculation 102.2 Adjusted EPS(6) - 2025 * Adjusted EPS may not sum across due to rounding. Refer to pages 34-35 for end notes.
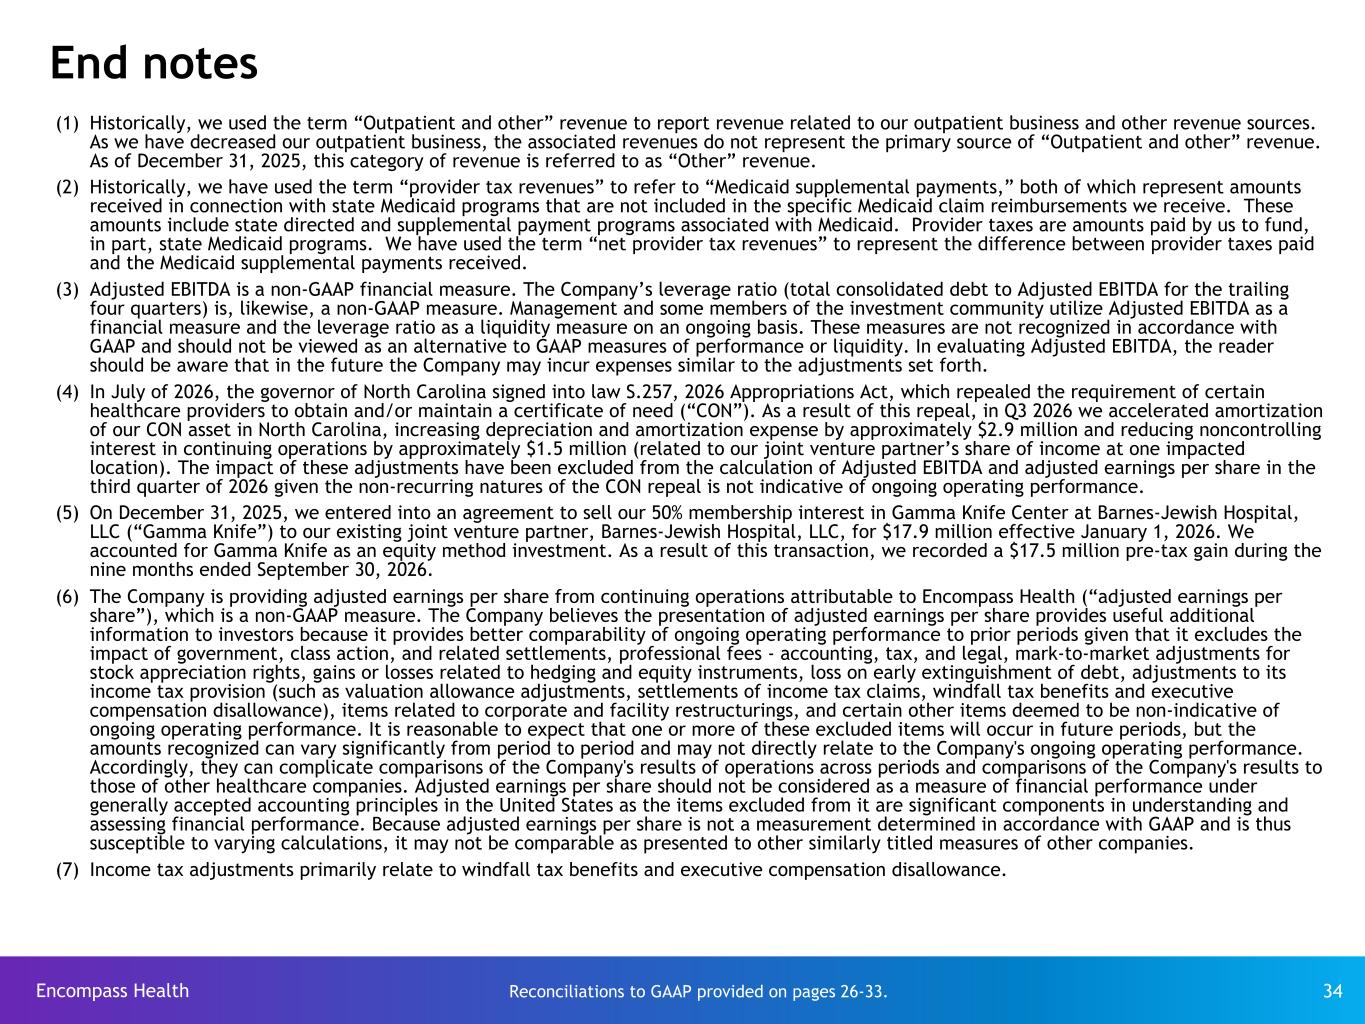
Encompass Health 34 End notes Reconciliations to GAAP provided on pages 26-33. (1) Historically, we used the term “Outpatient and other” revenue to report revenue related to our outpatient business and other revenue sources. As we have decreased our outpatient business, the associated revenues do not represent the primary source of “Outpatient and other” revenue. As of December 31, 2025, this category of revenue is referred to as “Other” revenue. (2) Historically, we have used the term “provider tax revenues” to refer to “Medicaid supplemental payments,” both of which represent amounts received in connection with state Medicaid programs that are not included in the specific Medicaid claim reimbursements we receive. These amounts include state directed and supplemental payment programs associated with Medicaid. Provider taxes are amounts paid by us to fund, in part, state Medicaid programs. We have used the term “net provider tax revenues” to represent the difference between provider taxes paid and the Medicaid supplemental payments received. (3) Adjusted EBITDA is a non-GAAP financial measure. The Company’s leverage ratio (total consolidated debt to Adjusted EBITDA for the trailing four quarters) is, likewise, a non-GAAP measure. Management and some members of the investment community utilize Adjusted EBITDA as a financial measure and the leverage ratio as a liquidity measure on an ongoing basis. These measures are not recognized in accordance with GAAP and should not be viewed as an alternative to GAAP measures of performance or liquidity. In evaluating Adjusted EBITDA, the reader should be aware that in the future the Company may incur expenses similar to the adjustments set forth. (4) In July of 2026, the governor of North Carolina signed into law S.257, 2026 Appropriations Act, which repealed the requirement of certain healthcare providers to obtain and/or maintain a certificate of need (“CON”). As a result of this repeal, in Q3 2026 we accelerated amortization of our CON asset in North Carolina, increasing depreciation and amortization expense by approximately $2.9 million and reducing noncontrolling interest in continuing operations by approximately $1.5 million (related to our joint venture partner’s share of income at one impacted location). The impact of these adjustments have been excluded from the calculation of Adjusted EBITDA and adjusted earnings per share in the third quarter of 2026 given the non-recurring natures of the CON repeal is not indicative of ongoing operating performance. (5) On December 31, 2025, we entered into an agreement to sell our 50% membership interest in Gamma Knife Center at Barnes-Jewish Hospital, LLC (“Gamma Knife”) to our existing joint venture partner, Barnes-Jewish Hospital, LLC, for $17.9 million effective January 1, 2026. We accounted for Gamma Knife as an equity method investment. As a result of this transaction, we recorded a $17.5 million pre-tax gain during the nine months ended September 30, 2026. (6) The Company is providing adjusted earnings per share from continuing operations attributable to Encompass Health (“adjusted earnings per share”), which is a non-GAAP measure. The Company believes the presentation of adjusted earnings per share provides useful additional information to investors because it provides better comparability of ongoing operating performance to prior periods given that it excludes the impact of government, class action, and related settlements, professional fees - accounting, tax, and legal, mark-to-market adjustments for stock appreciation rights, gains or losses related to hedging and equity instruments, loss on early extinguishment of debt, adjustments to its income tax provision (such as valuation allowance adjustments, settlements of income tax claims, windfall tax benefits and executive compensation disallowance), items related to corporate and facility restructurings, and certain other items deemed to be non-indicative of ongoing operating performance. It is reasonable to expect that one or more of these excluded items will occur in future periods, but the amounts recognized can vary significantly from period to period and may not directly relate to the Company's ongoing operating performance. Accordingly, they can complicate comparisons of the Company's results of operations across periods and comparisons of the Company's results to those of other healthcare companies. Adjusted earnings per share should not be considered as a measure of financial performance under generally accepted accounting principles in the United States as the items excluded from it are significant components in understanding and assessing financial performance. Because adjusted earnings per share is not a measurement determined in accordance with GAAP and is thus susceptible to varying calculations, it may not be comparable as presented to other similarly titled measures of other companies. (7) Income tax adjustments primarily relate to windfall tax benefits and executive compensation disallowance.
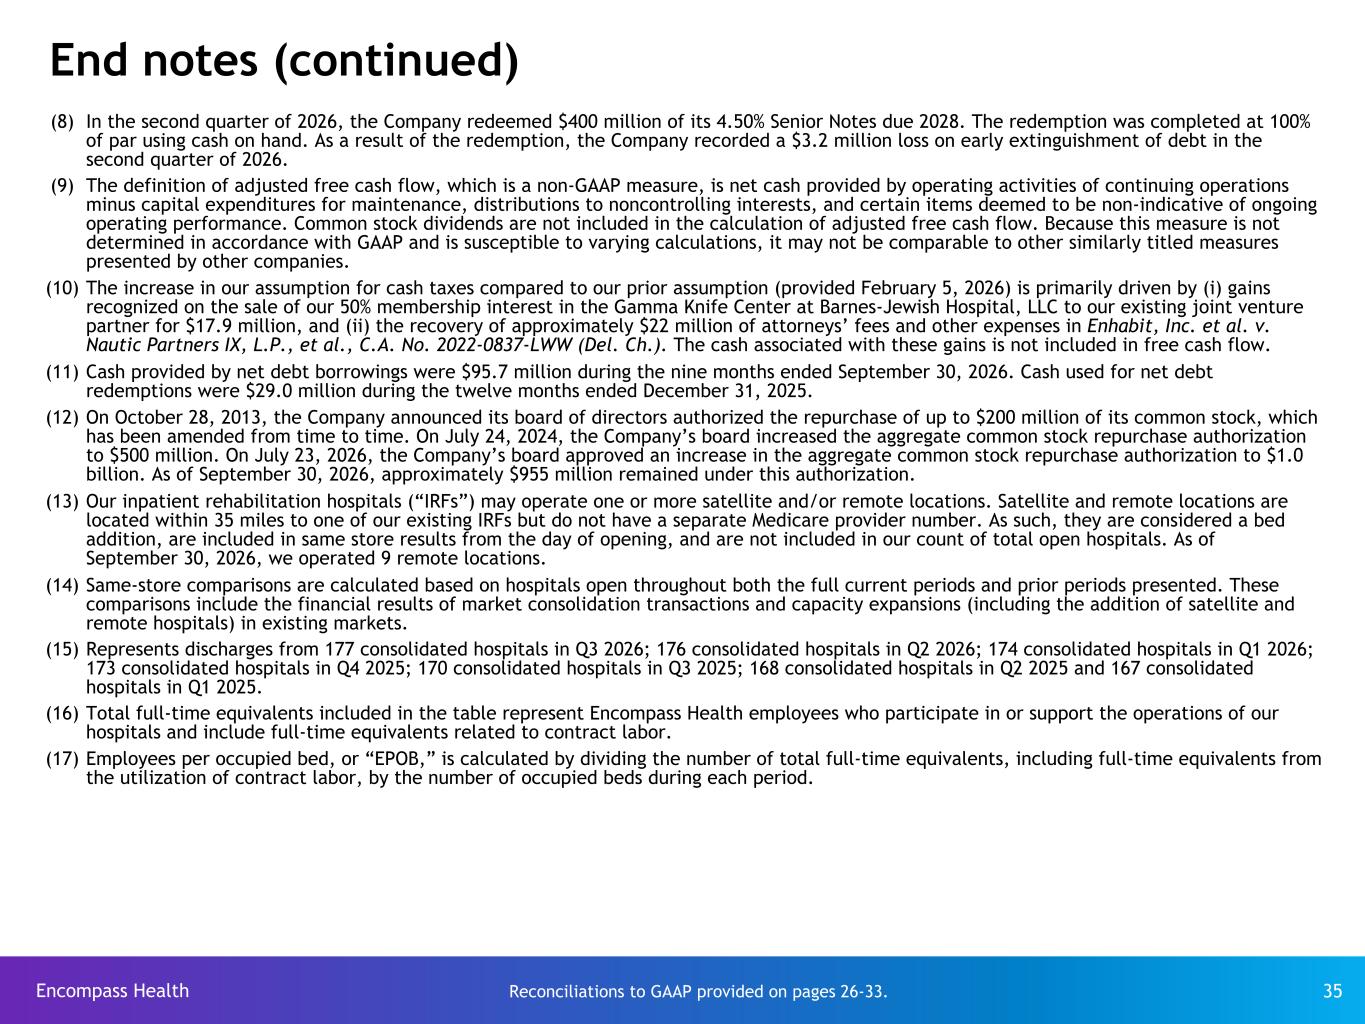
Encompass Health 35 End notes (continued) (8) In the second quarter of 2026, the Company redeemed $400 million of its 4.50% Senior Notes due 2028. The redemption was completed at 100% of par using cash on hand. As a result of the redemption, the Company recorded a $3.2 million loss on early extinguishment of debt in the second quarter of 2026. (9) The definition of adjusted free cash flow, which is a non-GAAP measure, is net cash provided by operating activities of continuing operations minus capital expenditures for maintenance, distributions to noncontrolling interests, and certain items deemed to be non-indicative of ongoing operating performance. Common stock dividends are not included in the calculation of adjusted free cash flow. Because this measure is not determined in accordance with GAAP and is susceptible to varying calculations, it may not be comparable to other similarly titled measures presented by other companies. (10) The increase in our assumption for cash taxes compared to our prior assumption (provided February 5, 2026) is primarily driven by (i) gains recognized on the sale of our 50% membership interest in the Gamma Knife Center at Barnes-Jewish Hospital, LLC to our existing joint venture partner for $17.9 million, and (ii) the recovery of approximately $22 million of attorneys’ fees and other expenses in Enhabit, Inc. et al. v. Nautic Partners IX, L.P., et al., C.A. No. 2022-0837-LWW (Del. Ch.). The cash associated with these gains is not included in free cash flow. (11) Cash provided by net debt borrowings were $95.7 million during the nine months ended September 30, 2026. Cash used for net debt redemptions were $29.0 million during the twelve months ended December 31, 2025. (12) On October 28, 2013, the Company announced its board of directors authorized the repurchase of up to $200 million of its common stock, which has been amended from time to time. On July 24, 2024, the Company’s board increased the aggregate common stock repurchase authorization to $500 million. On July 23, 2026, the Company’s board approved an increase in the aggregate common stock repurchase authorization to $1.0 billion. As of September 30, 2026, approximately $955 million remained under this authorization. (13) Our inpatient rehabilitation hospitals (“IRFs”) may operate one or more satellite and/or remote locations. Satellite and remote locations are located within 35 miles to one of our existing IRFs but do not have a separate Medicare provider number. As such, they are considered a bed addition, are included in same store results from the day of opening, and are not included in our count of total open hospitals. As of September 30, 2026, we operated 9 remote locations. (14) Same-store comparisons are calculated based on hospitals open throughout both the full current periods and prior periods presented. These comparisons include the financial results of market consolidation transactions and capacity expansions (including the addition of satellite and remote hospitals) in existing markets. (15) Represents discharges from 177 consolidated hospitals in Q3 2026; 176 consolidated hospitals in Q2 2026; 174 consolidated hospitals in Q1 2026; 173 consolidated hospitals in Q4 2025; 170 consolidated hospitals in Q3 2025; 168 consolidated hospitals in Q2 2025 and 167 consolidated hospitals in Q1 2025. (16) Total full-time equivalents included in the table represent Encompass Health employees who participate in or support the operations of our hospitals and include full-time equivalents related to contract labor. (17) Employees per occupied bed, or “EPOB,” is calculated by dividing the number of total full-time equivalents, including full-time equivalents from the utilization of contract labor, by the number of occupied beds during each period. Reconciliations to GAAP provided on pages 26-33.