After careful consideration, the SPAC Board has unanimously determined that the Business Combination is fair, advisable and in the best interests of the SPAC and all of its shareholders, unanimously approved the Business Combination and unanimously recommends that shareholders vote “FOR” the adoption of the Business Combination Agreement, and approval of the Transactions, including the Domestication and Mergers, and “FOR” all other proposals presented to the SPAC Shareholders in this proxy statement/prospectus. The Business Combination was not structured to require the approval of at least a majority of SPAC’s unaffiliated shareholders because such a vote is not required under Cayman Islands law. When you consider the recommendation of the proposals herein by the SPAC Board, you should keep in mind that the Sponsor and SPAC’s directors and officers and their affiliates have interests in the Business Combination that may conflict with your interests as a shareholder. See the section entitled “The Business Combination - Interests of the Sponsor and SPAC’s Directors and Officers in the Business Combination” for a further discussion of these considerations.
On June 12, 2026, the board of directors (the “SPAC Board”) of Graf Global Corp., a Cayman Islands exempted company (“SPAC”), unanimously approved the Business Combination Agreement, dated June 12, 2026 (the “Business Combination Agreement”), by and among SPAC, Halfcourt Holdco, Inc., a Delaware corporation (“Pubco”), Halfcourt Merger Sub Inc., a Delaware corporation and a wholly-owned subsidiary of Pubco (“SPAC Merger Sub”), Halfcourt Merger Sub LLC, a Delaware limited liability company and a wholly-owned subsidiary of Pubco (“Company Merger Sub” and together with SPAC Merger Sub, the “Merger Subs”), and BIG3 HoldCo LLC, a Delaware limited liability company (together with its successors, the “Company”), pursuant to which the following will occur: (i) SPAC will, as an intermediate and transitory step in the business combination transaction, transfer by way of continuation out of the Cayman Islands and into the State of Delaware so as to re-domicile as and become a Delaware corporation pursuant to Part 12 of the Companies Act (As Revised) of the Cayman Islands (the “Companies Act”) and the applicable provisions of the Delaware General Corporation Law (the “DGCL”) (the “Domestication”, and SPAC after the Domestication, “Post-Domestication SPAC”), (ii) following the Domestication, SPAC Merger Sub will merge with and into Post-Domestication SPAC, with Post-Domestication SPAC continuing as the surviving entity (the “SPAC Merger”), (iii) following the SPAC Merger, Company Merger Sub will merge with and into the Company, with the Company continuing as the surviving entity (the “Company Merger”, and together with the SPAC Merger, the “Mergers”), (iv) as a result of the Mergers, Post-Domestication SPAC and the Company will become wholly-owned subsidiaries of Pubco, and Pubco will be renamed “Big3 Basketball Holdings, Inc.” and become a publicly traded company, and (v) the other transactions contemplated by the Business Combination Agreement and documents related thereto (such transactions, together with the Domestication and the Mergers, the “Business Combination”). A copy of the Business Combination Agreement is attached to this proxy statement/prospectus as Annex A.
Prior to the SPAC’s IPO, on November 24, 2021, the Sponsor paid an aggregate of $25,000 for 7,187,500 SPAC Class B Ordinary Shares (including the SPAC Class A Ordinary Shares issuable upon conversion of the SPAC Class B Ordinary Shares, the “Founder Shares”), or approximately $0.003 per share. On February 8, 2024, the Sponsor surrendered 1,437,500 Founder Shares for no consideration, resulting in the Sponsor holding 5,750,000 Founder Shares. The number of Founder Shares outstanding was originally determined based on the expectation that the total size of the SPAC IPO would be a maximum of 23,000,000 SPAC Ordinary Shares, assuming the over-allotment option was exercised in full, and therefore that such Founder Shares would represent approximately 20% of the issued and outstanding SPAC Ordinary Shares after the IPO. Simultaneously with the consummation of the IPO, the Sponsor and the IPO Underwriter, respectively, purchased 4,000,000 and 2,000,000 private placement warrants (the “SPAC Private Warrants”) at a price of $1.00 per SPAC Private Warrant in a private placement, generating gross proceeds to the SPAC of $6,000,000. Of the 5,750,000 Founder Shares held by the Sponsor following the February 8, 2024 surrender, (i) 90,000 Founder Shares were transferred to three Independent Directors (30,000 Founder Shares each) on June 7, 2024, (ii) 2,750,000 Founder Shares will be forfeited and surrendered immediately before the Domestication, (iii) 500,000 Founder Shares may be transferred by the Sponsor, in its discretion, to third parties to incentivize non-redemptions or investments into the SPAC or Pubco and if not so transferred or used will be forfeited, and (iv) 500,000 of the Founder Shares will be subject to an earnout provision.
On June 10, 2026, SPAC, Harraden Circle Investments LLC (“Harraden”), and James A. Graf entered into a convertible promissory note (the “Convertible Promissory Note”), replacing a prior promissory note dated June 4, 2026, and consolidating $200,000 in working capital advances previously made by Harraden into a fully drawn, non-interest bearing, unsecured loan (the “Loan”) that was fully outstanding as of June 30, 2026 and is due upon the earlier of the initial business combination or SPAC’s liquidation. At Harraden’s discretion, the Loan may convert into SPAC Class A Ordinary Shares at $10.00 per share, with Harraden also entitled to one warrant per dollar funded, issuable immediately prior to Closing on terms identical to the SPAC Private Warrants issued to the Sponsor.
Subsequently, on August 10, 2026, SPAC, Harraden, and James A. Graf entered into a second, separate convertible promissory note (the “August Convertible Promissory Note”), under which SPAC may borrow up to an additional $300,000 for working capital and general corporate purposes (the “August Loan”) on similar non-interest bearing, unsecured terms due upon the earlier of the initial business combination or liquidation. The August Loan has been fully drawn as of the date of this proxy statement/prospectus. At Harraden’s discretion, the August Loan may convert into SPAC Class A Ordinary Shares at $10.00 per share (the “Conversion Shares”), and for each dollar funded Harraden is entitled to one warrant to purchase one SPAC Class A Ordinary Share on terms identical to the SPAC Private Warrants (the “Issuance Warrants”), plus one unrestricted SPAC Ordinary Share transferred by the Sponsor (the “Transferred Shares”), each issuable immediately prior to Closing. Under both the Convertible Promissory Note and the August Convertible Promissory Note, in lieu of issuing the Conversion Shares, Issuance Warrants, and/or Transferred Shares, the Sponsor may re-allocate securities among members of the Sponsor and Graf Global Management LLC to satisfy SPAC’s related obligations.
Additionally, pursuant to the Sponsor Support Agreement, Sponsor agreed to provide financing support in connection with the Business Combination. If the Closing SPAC Cash is less than $100,000,000, the Sponsor will be required invest, or cause its affiliate
or designee to invest, an aggregate of at least $5,000,000 of gross proceeds in a Transaction Financing (the “Sponsor Investment”). If Closing SPAC Cash is greater than $100,000,000, then Sponsor has the option to make the Sponsor Investment. The purchase price of the Sponsor Investment will be equal to the lowest purchase price paid by any other investor in the Transaction Financing and will be made upon such other terms that are no less favorable to the Sponsor (or such affiliate or designee) than the terms offered to any other investor in any Transaction Financing.
Further, if necessary in order to finance transaction costs in connection with the Business Combination, the Sponsor or certain of the SPAC’s officers and directors may, but are not obligated to, loan the SPAC funds as may be required (“Working Capital Loans”). If SPAC completes the Business Combination, SPAC would repay any such Working Capital Loans out of the proceeds of the Trust Account released to SPAC, without interest, or, at the lender’s discretion, up to $1,500,000 of such Working Capital Loans may be convertible into SPAC Private Warrants at a price of $1.00 per warrant; provided that, for purposes of such $1,500,000 limit, the Convertible Promissory Note and August Convertible Promissory Note, each with Harraden, will be treated as Working Capital Loans and will count toward such limit. Such warrants would be identical to the SPAC Private Warrants sold in the private placement consummated simultaneously with the IPO. In the event that SPAC does not consummate an initial Business Combination, no proceeds held in the Trust Account would be used to repay the Working Capital Loans. Except for the foregoing, the terms of such Working Capital Loans, if any, have not been determined and no written agreements exist with respect to such loans. As of the date of this proxy statement/prospectus, there was a total of $500,000 of outstanding Working Capital Loans, consisting of the Convertible Promissory Note and August Convertible Promissory Note with Harraden.
SUMMARY
This summary provides an overview of selected information contained in this proxy statement/prospectus and does not contain all of the information that may be important to you. We encourage you to read carefully this entire proxy statement/prospectus, including the annexes and accompanying financial statements of SPAC, the Company and Pubco, to fully understand the proposed Business Combination before voting on the proposals to be considered at the extraordinary general meeting. Please see the section entitled “Where You Can Find More Information.”
Parties to the Business Combination
SPAC
SPAC is a blank check company incorporated to effect a merger, share exchange, asset acquisition, share purchase, reorganization or similar business combination with one or more businesses. SPAC was incorporated on November 17, 2021 as a Cayman Islands exempted company. The SPAC Public Units, SPAC Public Shares, and SPAC Public Warrants are currently listed on NYSE American under the ticker symbols “TONT U”, “TONT”, and “TONT WS”, respectively.
On June 26, 2026, the SPAC held an extraordinary general meeting at which shareholders approved an amendment to the SPAC Organizational Documents to extend the date by which SPAC has to consummate an initial business combination from June 27, 2026 to September 27, 2026, and provided that SPAC has executed a definitive agreement for an initial business combination by September 27, 2026 but has not consummated an initial business combination by such date, to permit the SPAC Board, in its sole discretion, to further extend such date up to three times in one month increments, to up to December 27, 2026. In connection with such extension, shareholders holding an aggregate of 14,590,367 SPAC Class A Ordinary Shares exercised their right to redeem their shares for approximately $10.86 per share from the funds held in the Trust Account, leaving approximately $91.4 million in cash in the Trust Account after satisfaction of such redemptions. Following such redemptions, SPAC had an aggregate of 14,159,633 SPAC Ordinary Shares outstanding, of which 14,159,632 were SPAC Class A Ordinary Shares and 1 was a SPAC Class B Ordinary Share.
The mailing address of SPAC’s principal executive offices is 1790 Hughes Landing Blvd., Suite 400, The Woodlands, Texas 77380, and its telephone number is (310) 745-8669.
The Company
The Company is a Delaware limited liability company formed on September 18, 2024 to act as the holding company for the Big3 Basketball league, which was formed in 2017. The Company is the leading professional 3-on-3 basketball league and sits at the intersection of basketball, hip-hop and entertainment. For more information about the Company, see the sections entitled “Information About the Company” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations of the Company.”
The Company’s principal executive offices are located at 429 Lenox Ave, Suite 421, Miami Beach, Florida 33139 and its telephone number is (800) 528-6276.
Company Merger Sub
Company Merger Sub is a Delaware limited liability company formed on June 8, 2026 and a wholly-owned subsidiary of Pubco. Company Merger Sub was formed for the purpose of effectuating the Company Merger described herein and it has not conducted any activities other than those incidental to its formation and the transactions contemplated by the Business Combination Agreement. Company Merger Sub will not be the surviving entity in the Company Merger, as contemplated by the Business Combination Agreement and described herein.
Company Merger Sub’s principal executive offices are located at 429 Lenox Ave, Suite 421, Miami Beach, Florida 33139 and its telephone number is (800) 528-6276.
SPAC Merger Sub
SPAC Merger Sub is a Delaware corporation incorporated on June 8, 2026 and a wholly-owned subsidiary of Pubco. SPAC Merger Sub was formed for the purpose of effectuating the SPAC Merger described herein and it has not conducted any activities other than those incidental to its formation and the transactions contemplated by the Business Combination Agreement. SPAC Merger Sub will not be the surviving entity in the SPAC Merger, as contemplated by the Business Combination Agreement and described herein.
SPAC Merger Sub’s principal executive offices are located at 429 Lenox Ave, Suite 421, Miami Beach, Florida 33139 and its telephone number is (800) 528-6276.
Pubco
Pubco was incorporated in Delaware on June 5, 2026, for the purpose of effectuating the Business Combination described herein. Pubco currently has no material assets and does not currently operate any businesses. The Merger Subs are wholly-owned subsidiaries of Pubco. As a result of the Business Combination, SPAC and the Company will become wholly-owned subsidiaries of Pubco and Pubco will become a publicly traded company.
In connection with the Mergers, Pubco intends to apply for the listing of its Class A Common Stock and Warrants on the NYSE under the proposed symbols “TONT” and “TONT WS,” respectively, to be effective at the Closing. Pubco will not have units traded following the consummation of the Business Combination.
Pubco’s principal executive offices are located at 429 Lenox Ave, Suite 421, Miami Beach, Florida 33139 and its telephone number is (800) 528-6276.
The Business Combination
Background of the Business Combination
SPAC is a blank check company incorporated on November 17, 2021 as a Cayman Islands exempted company, formed for the purpose of effecting a merger, share exchange, asset acquisition, stock purchase, reorganization or similar business combination with one or more businesses. Graf Global Corp. is the eighth special purpose acquisition company that James A. Graf has been directly involved with as a member of the sponsor, management and/or board, including seven special purpose acquisition companies that closed business combinations over the past 15 years, among them Target Hospitality Corp., WillScot Holdings Corp. and Velodyne Lidar, Inc. The Sponsor, Graf Global Sponsor LLC, is a Delaware limited liability company formed prior to the IPO to organize, direct and manage the business and affairs of SPAC, with Mr. Graf serving as its sole managing member. See “Questions and Answers About the Business Combination — Who is the Sponsor?” for more information. On June 27, 2024, SPAC completed its initial public offering of 23,000,000 units, including the full exercise of the underwriters’ overallotment option, generating gross proceeds of $230,000,000 before transaction costs, with $230,000,000 placed into the trust account. Simultaneously with the closing of the IPO, SPAC consummated a private placement of warrants generating total proceeds of $6,000,000.
Following the closing of the IPO, SPAC’s officers and directors commenced an active search for prospective businesses or assets to acquire, considering more than 100 potential business combination ideas and engaging in discussions with approximately 30 targets under executed non-disclosure agreements, none of which imposed standstill or similar restrictions. The majority of the potential business combination target companies that SPAC considered were companies in the businesses of technology, industrial services, energyand energy transition, space, autonomous mobility, crypto currencies and sports teams among others. Other than the Company, SPAC was not aware of and did not consider other companies operating professional sports leagues. SPAC ultimately ceased pursuit of these prospective targets for reasons that included an inability to prevail in competitive auctions on acceptable terms, an inability to agree on valuation, targets lacking SEC-compliant financial statements on a workable timetable, targets lacking sufficient access to capital, targets not being ready to pursue a business combination or having preferable all-cash alternatives, and extensive structuring or regulatory considerations that would have added execution uncertainty.
In April 2026, SPAC began discussions with the Company and its advisors regarding a potential business combination, facilitated by Fehmi Zeko, managing partner of MC Strategic Advisors, financial advisor to the Company, and a board director of the Company. Mr. Zeko had mentioned the Company to Mr. Graf informally several times over the years and originally introduced Jeffrey
Kwatinetz, Co-founder and Chairman of the Company, to Mr. Graf and Graf I in early 2020, when a possible transaction with a special purpose acquisition company was first broached. None of those conversations were substantive, however, given the relative early stage of the business, and in early 2020 in particular, the uncertain impact of emerging COVID-19 on the Company’s upcoming season, no due diligence was performed, no prospective investors were contacted and no draft term sheets were delivered. On April 2, 2026, SPAC and the Company signed a non-disclosure agreement, and on April 12, 2026, Mr. Graf delivered a draft letter of intent and term sheet proposing an initial valuation of $185 million, which was subsequently increased to $195 million. Following due diligence, data room access, and negotiations between the parties and their respective advisors, including discussion of the per-share price used for the Company’s share consideration and the mechanism for obtaining Company equityholder approval, the Big3 LOI was signed by SPAC and the Company on April 28, 2026, with the SPAC Board unanimously supporting the transaction. During negotiation of the Business Combination Agreement, following discussions with one of the Company’s large institutional investors, the Company informed SPAC that it would not proceed at a transaction value of less than $290 million, which SPAC accepted as the only material change in valuation from the signed letter of intent. SPAC did not retain a financial advisor to assist with establishing a valuation for the Company. Instead, SPAC relied in part on the over 100 years of collective investment banking, capital markets and deal-making experience of its management team and SPAC Board to value the Company and assess market receptivity to such a story. In accepting the Company’s proposed $290 million valuation, the SPAC team did not review revenue or profit projections for the Company, given the emerging nature of the Company’s business, expected transformation of the business model with the expected capital and public currency provided by the transaction, and the absence of directly comparable public companies. SPAC believed that there were no other publicly-traded professional sports leagues in the United States, and SPAC determined that valuation metrics for standalone publicly-traded major sports teams or other athletic promotions are not necessarily relevant to the business of an emerging league.
On June 11, 2026, the SPAC Board unanimously (i) determined that it was in SPAC’s best interest and the interest of SPAC Shareholders for SPAC to enter into the Business Combination Agreement and each ancillary agreement thereto, (ii) approved the transactions contemplated by the Business Combination Agreement and the ancillary agreements, and (iii) adopted resolutions recommending the adoption of the Business Combination Agreement and the approval of each ancillary agreement thereto by SPAC Shareholders. The Business Combination Agreement and related ancillary transaction documents were finalized and executed by SPAC, the Company and other parties thereto on June 12, 2026, and the parties issued a joint press release announcing the transaction on that same date.
For more information, see “Proposal No. 1 — The Business Combination Proposal — Background of the Business Combination.”
Business Combination Agreement
Pre-Domestication
Prior to the Domestication, pursuant to the Business Combination Agreement: (1) the Redemption will occur; (2) the Unit Separation will occur, whereby each SPAC Public Unit will separate into one SPAC Class A Ordinary Share and one-half of one SPAC Public Warrant, after which all SPAC Public Units will be cancelled; (3) the Sponsor will surrender the Sponsor Forfeited Shares and Discretionary Founder Shares (to the extent such shares are not transferred or used pursuant to the Sponsor Support Agreement); and (4) the SPAC Class B Share Conversion will occur, whereby the Sponsor will convert the sole remaining outstanding SPAC Class B Ordinary Share into one SPAC Class A Ordinary Share on a one-for-one basis.
Domestication
One day before the SPAC Merger Effective Time, subject to SPAC Class B Ordinary Shareholder approval and the required Cayman and Delaware filings, SPAC will transfer by continuation from the Cayman Islands to Delaware, deregistering as a Cayman exempted company and converting into a Delaware corporation. Upon the Domestication: (1) each outstanding SPAC Class A Ordinary Share will convert into one share of Post-Domestication SPAC Common Stock; and (2) each outstanding whole SPAC Warrant will become one Post-Domestication SPAC Warrant exercisable for one share of Post-Domestication SPAC Common Stock instead of one SPAC Class A Ordinary Share. No fractional shares or warrants will be issued; fractional entitlements will be rounded down and carry no stockholder or warrant holder rights.
The SPAC Merger
At the SPAC Merger Effective Time, SPAC Merger Sub will merge with and into Post-Domestication SPAC, with Post-Domestication SPAC surviving. Pursuant to the SPAC Merger: (1) each outstanding share of Post-Domestication SPAC Common
Stock will automatically convert into the right to receive one share of Pubco Class A Common Stock, and will thereupon be cancelled and cease to exist, and (2) each Post-Domestication SPAC Warrant will convert into one Pubco Warrant.
Pre-Company Merger
Immediately before the Company Merger Effective Time, each outstanding Company Convertible Security (other than Company Warrants), including accrued interest, will convert in full into Company Interests. The SPAC Merger and Company Merger will be effected by filing certificates of merger with the Delaware Secretary of State under the DGCL and DLLCA, respectively, with the SPAC Merger occurring first, on the Closing Date (or such other date/time as the Company and SPAC agree).
The Company Merger
At the Company Merger Effective Time, Company Merger Sub will merge with and into the Company, with the Company surviving. Pursuant to the Company Merger: (1) each Company Interest issued and outstanding will be cancelled and cease to exist in exchange for the right to receive its portion of the Merger Consideration, (2) each Company Warrant that is outstanding will be converted into and become a warrant exercisable for Pubco Class A Common Stock (as of the date of this proxy statement/prospectus, there are no Company Warrants outstanding), (3) any outstanding Company Convertible (excluding Company Warrants that are converted into warrants exercisable for Pubco Class A Common Stock, of which none are outstanding as of the date of this proxy statement/prospectus) and Preferred Units (other than Preferred Units that are converted into Merger Consideration), if not exercised or converted prior to the Company Merger Effective Time, will be cancelled, retired and terminated.
Structure Diagrams
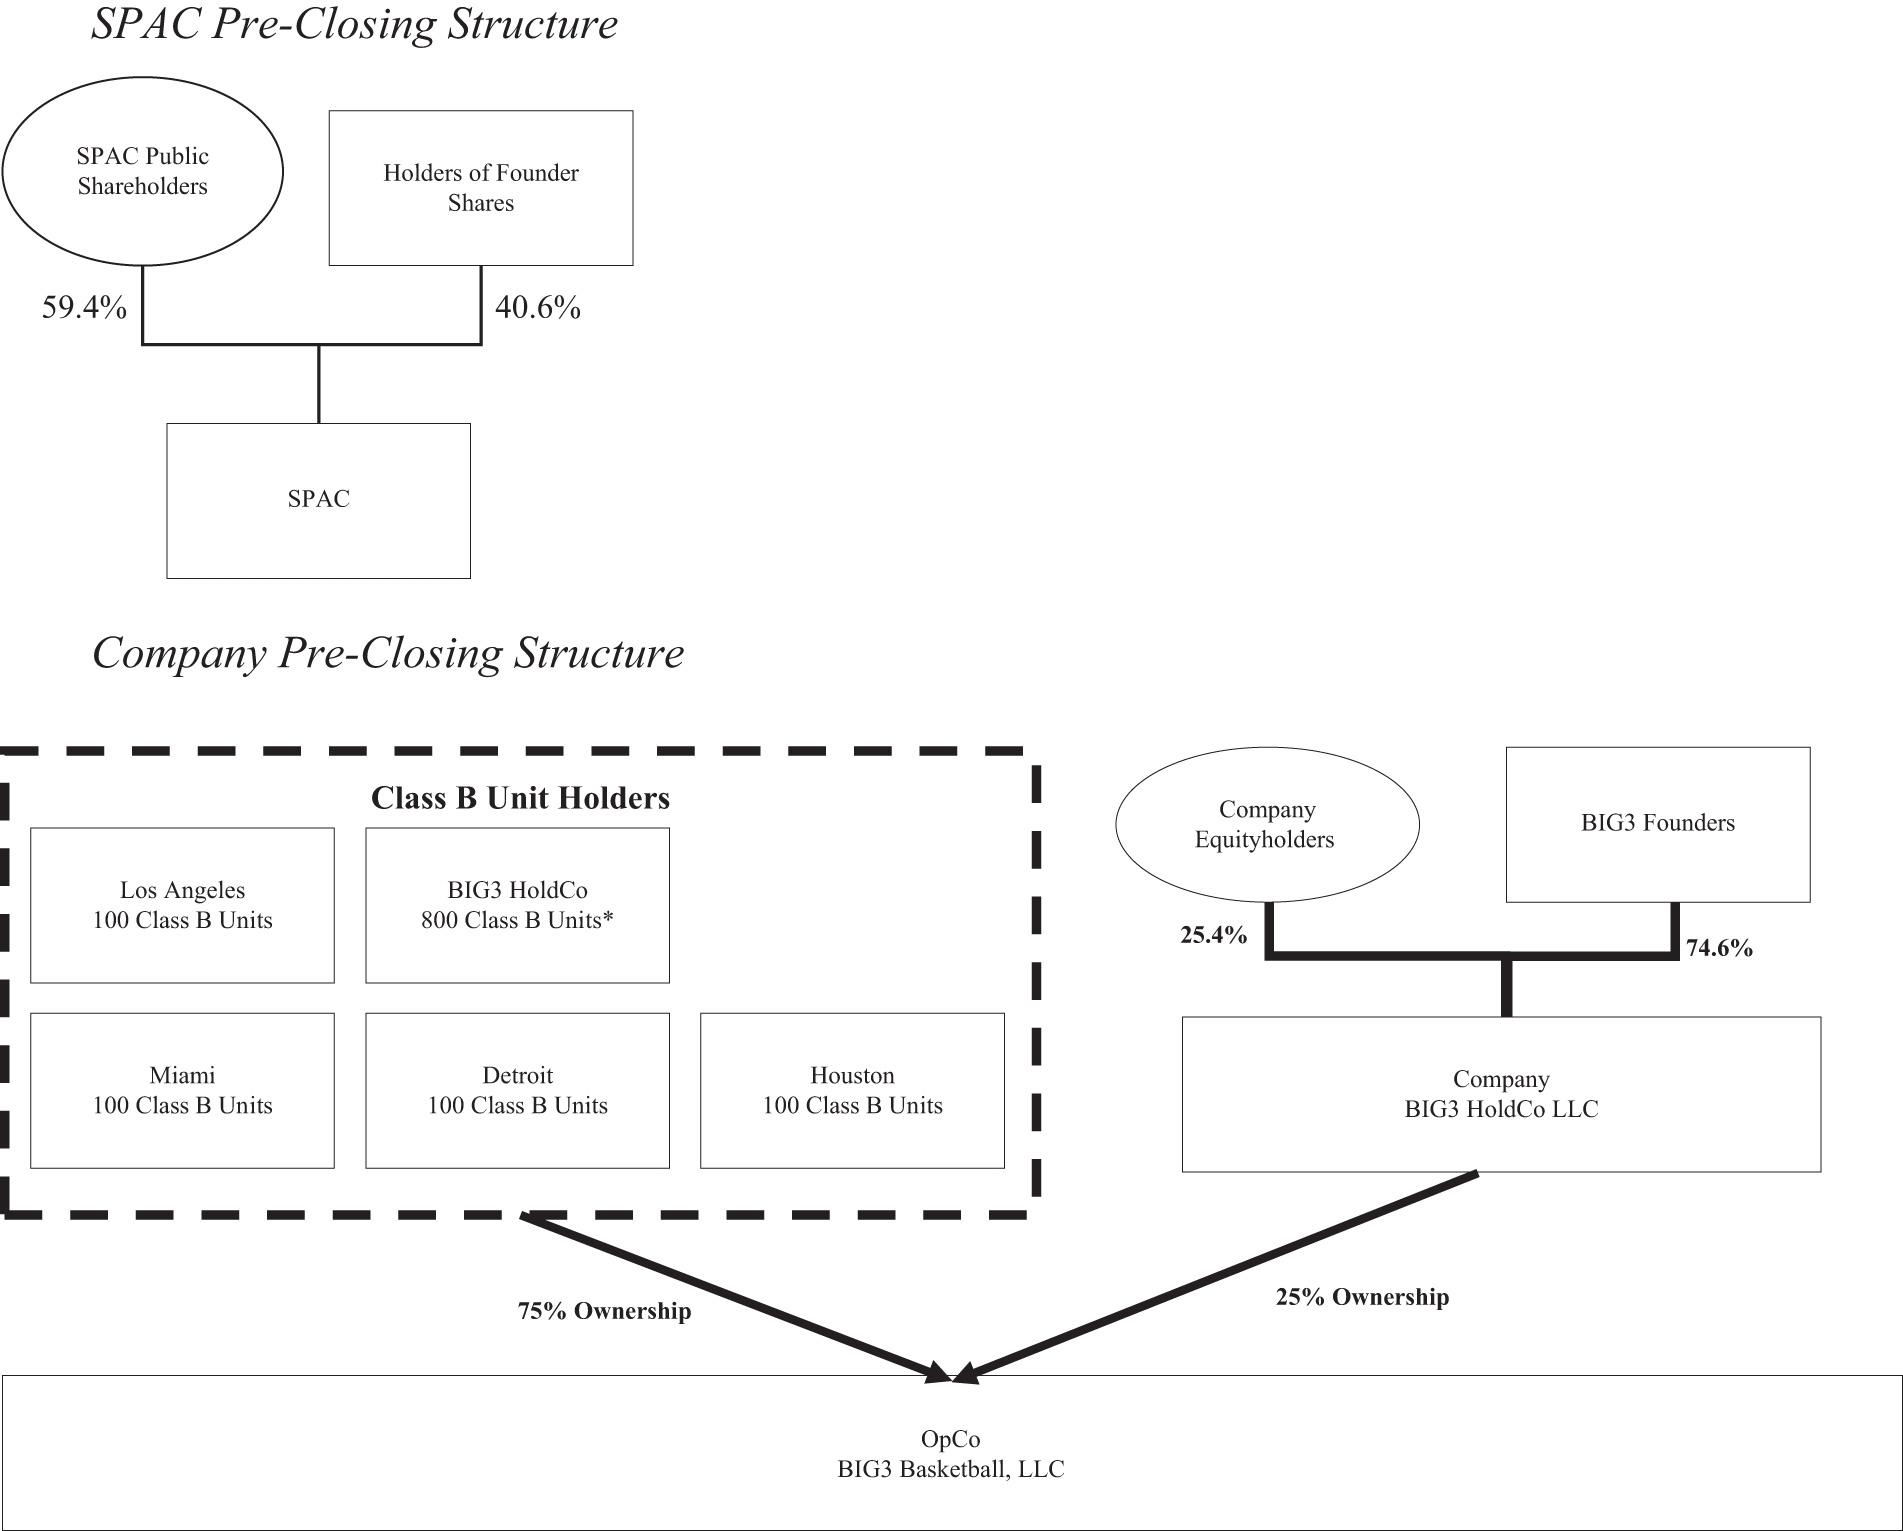
*Includes 4 league-owned teams plus 4 expansion teams
See “Our Business Model” in the Business section for a more complete description of the ownership of OpCo
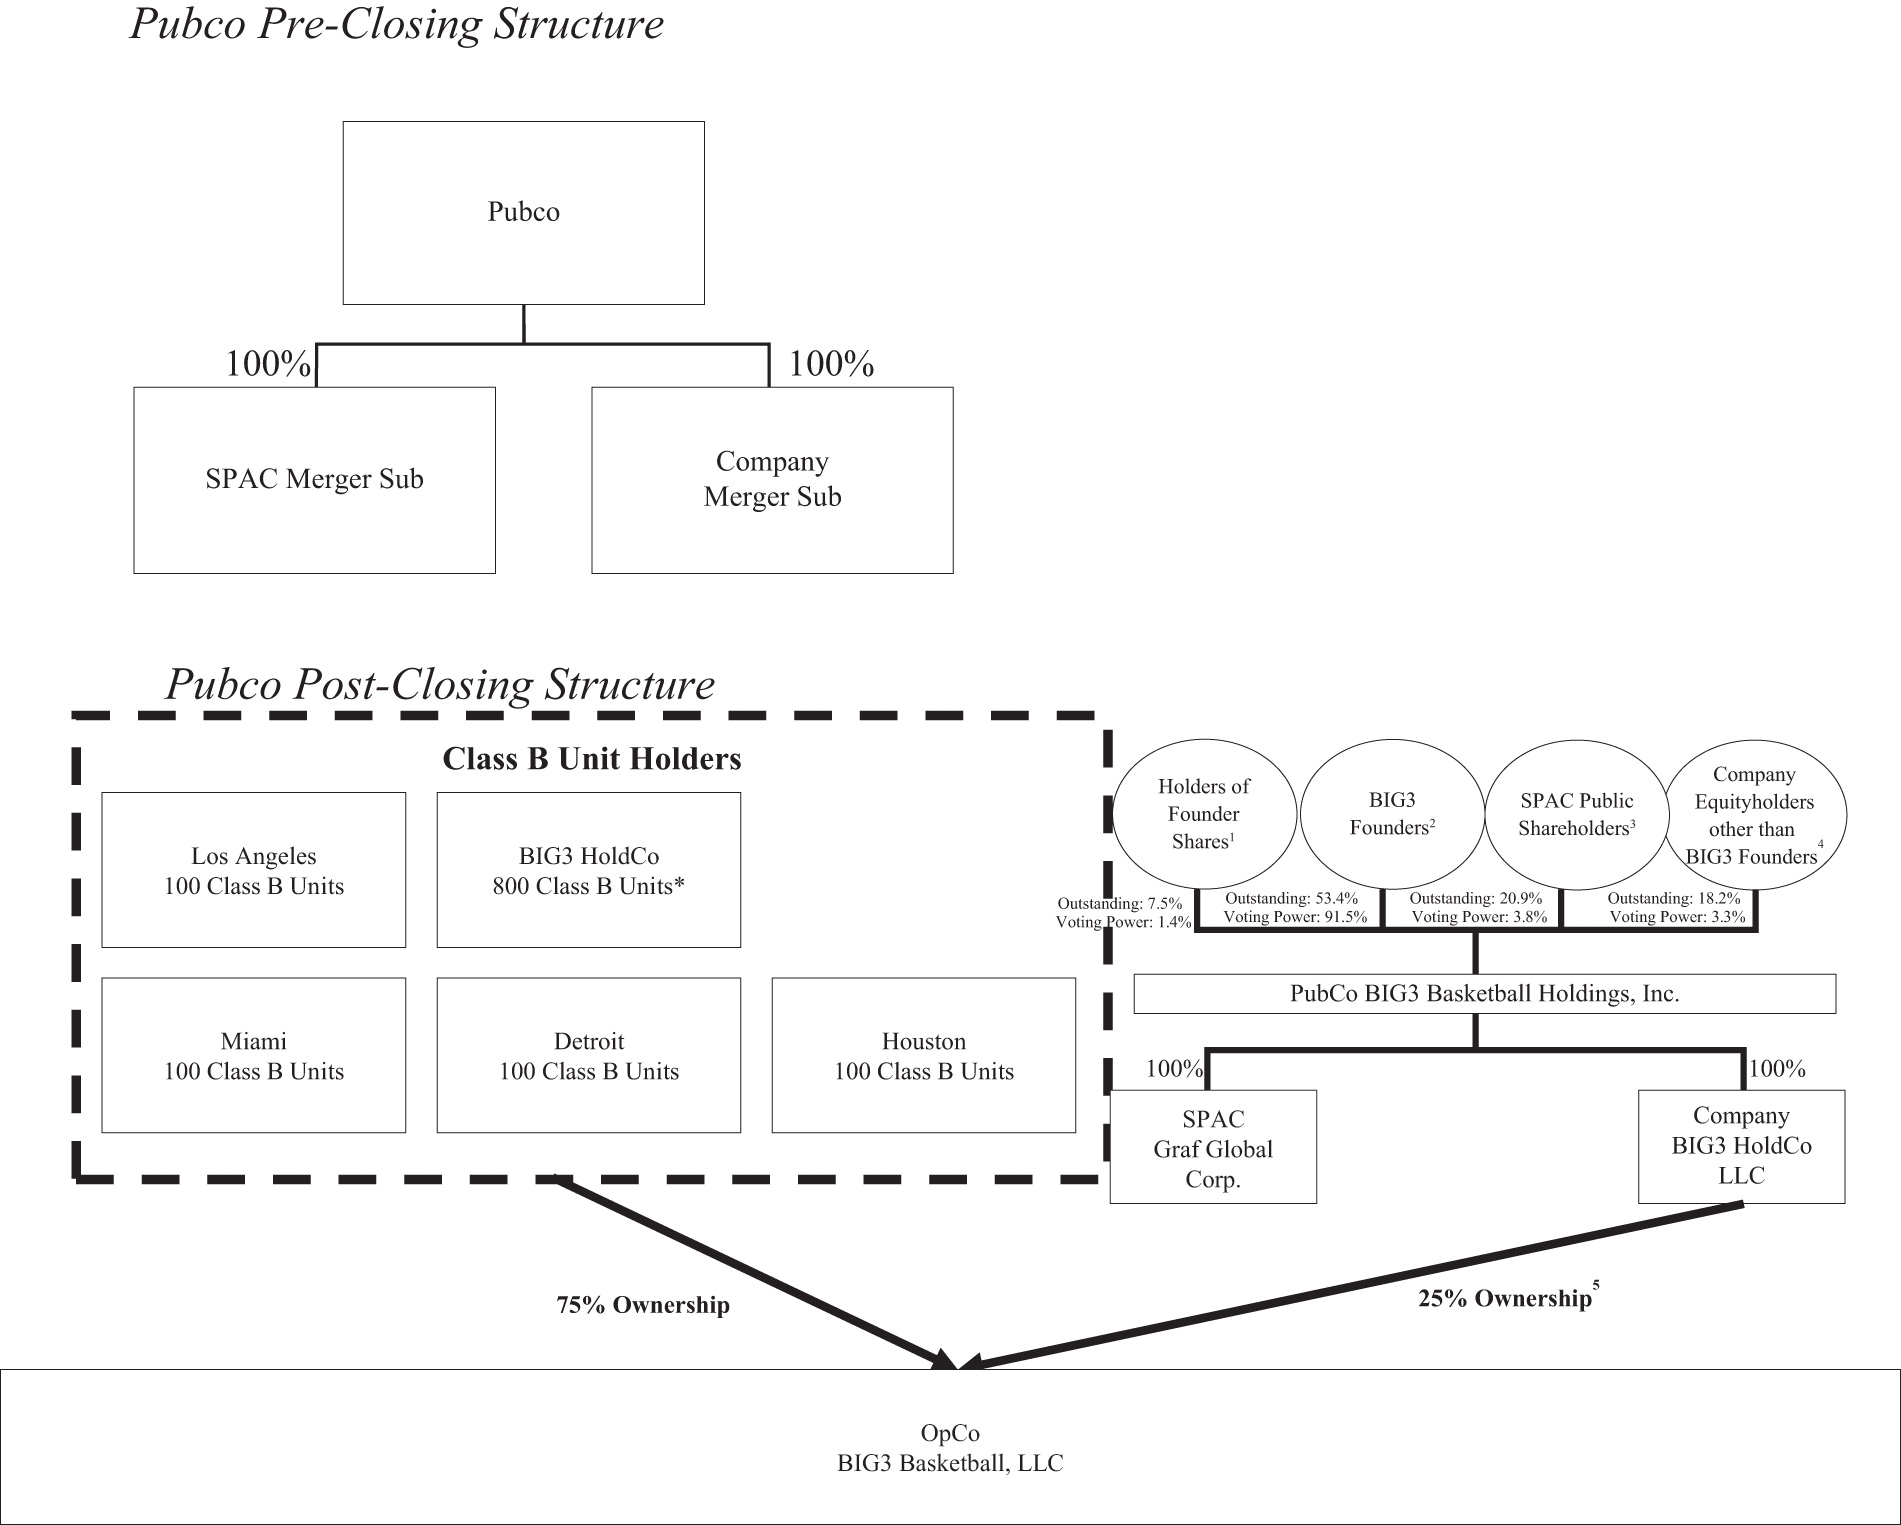
| (1) | Reflects the forfeiture of 2,750,000 Sponsor Forfeited Shares, assumes all 500,000 Discretionary Founder Shares are used to incentivize non-redemptions of SPAC Public Shares, and includes 500,000 Sponsor Earnout Shares that will be outstanding but subject to vesting. Assumes no Sponsor Investment. |
| (2) | Includes 1,492,036 Earnout Shares. |
| (3) | Assumes the No Additional Redemptions Scenario. |
| (4) | Includes 507,964 Earnout Shares. |
| (5) | See “Our Business Model” in the Business section for a more complete description of the ownership of OpCo |
Merger Consideration to the Company’s Shareholders
Pursuant to the Business Combination Agreement, at the Company Merger Effective Time, all outstanding Company Interests (including those issued upon conversions and exercises) will be cancelled and converted into the right to receive the Merger Consideration, consisting of newly issued shares of Pubco Common Stock equal to (x) $290,000,000 plus the Company’s Cash Position at the Company Merger Effective Time, divided by (y) $10.83. Each Seller’s Percentage Merger Consideration will be paid in Pubco Class A Common Stock, except that Big3 Founders holding Class A Units, Class B Units, or Preferred Units will receive their Percentage Merger Consideration in the form of Pubco Class B Common Stock.
Dual-Class Structure of Pubco Common Stock
Pubco’s Proposed Pubco Charter will authorize two classes of Pubco Common Stock: Pubco Class A Common Stock and Pubco Class B Common Stock. Pubco Class A Common Stock will entitle the holders thereof to one vote per share on all matters on which the shares of Pubco Class A Common Stock will be entitled to vote, and Pubco Class B Common Stock will entitle the holders thereof to ten (10) votes per share on all matters on which the shares of Pubco Class B Common Stock are entitled to vote. Based on the 20,210,627 shares of Pubco Class A Common Stock and 19,976,476 shares of Pubco Class B Common Stock expected to be outstanding at the Closing (assuming the No Additional Redemptions Scenario, no Transaction Financing, the forfeiture of 2,750,000 Sponsor Forfeited Shares, but including the 2,000,000 Earnout Shares, which will be issued and outstanding at the Closing and subject to vesting, and assuming the Company’s Cash Position is $0.00 (as of June 30, 2026)), the holders of Pubco Class A Common Stock are expected to have 20,210,627 votes in the aggregate and the holders of Pubco Class B Common Stock are expected to have 199,764,760 votes in the aggregate on all matters submitted to the holders of shares of Pubco Common Stock for a vote. The Pubco Class B Common Stock will be exclusively held by the Big3 Founders. Accordingly, the Dual Class Structure will increase the voting power of the Big3 Founders. If additional shares of Pubco Class B Common Stock are issued after the Closing (which will be permitted pursuant to the Proposed Pubco Charter in connection with a dividend or stock adjustment), the effect of the Dual Class Structure on the concentration of voting control may increase. The Pubco Class A Common Stock and the Pubco Class B Common Stock have identical economic rights on a per share basis, including dividend and liquidation rights.
Additionally, each share of Pubco Class B Common Stock will automatically convert into one fully paid and nonassessable share of Pubco Class A Common Stock on (a) the date specified by the holders of two-thirds of the then outstanding shares of Pubco Class B Common Stock, voting as a separate class, or in the affirmative written election executed by the holders of two-thirds of the then outstanding shares of Pubco Class B Common Stock, (b) the date fixed by the Pubco Board that is no less than 10 days and no more than 30 days following the date that the number of outstanding shares of Pubco Class B Common Stock held by the Big3 Founders and their Permitted Transferees (as defined in the Proposed Pubco Charter) represents less than one-third of the aggregate number of shares of Pubco Class B Common Stock outstanding immediately following the Business Combination, or (c) the date that is ten (10) years from the closing of the Business Combination.
In addition, each share of Pubco Class B Common Stock held by a Big3 Founder will automatically convert into one fully paid and non-assessable share of Pubco Class A Common Stock upon the earliest of: (a) 5:00 p.m., New York City time, on the day immediately following the date on which that Big3 Founder ceases to hold at least 50% of the Pubco Class B Common Stock it held immediately following consummation of the Business Combination (as equitably adjusted for any reclassification, stock dividend, subdivision, combination or recapitalization of Pubco Class B Common Stock); (b) any transfer, assignment, sale, conveyance, hypothecation or other disposition, whether voluntary, involuntary, for value or by operation of law, other than to a Permitted Transferee; and (c) the death, incapacity, or adjudicated incompetency or placement under guardianship or conservatorship of a Big3 Founder. Each such conversion occurs automatically, without further action by the holder and regardless of whether any certificate representing the converted shares is surrendered; immediately upon conversion, the holder is treated for all purposes as a holder of Pubco Class A Common Stock into which the Pubco Class B Common Stock converted. Separately, each share of Pubco Class B Common Stock is convertible at any time at the holder’s option into one fully paid and non-assessable share of Pubco Class A Common Stock upon written notice to Pubco.
For more information, see “Description of Pubco’s Securities — Authorized Share Capital” and “Risk Factors — Pubco will have a dual-class common stock structure under which each share of Pubco Class B Common Stock carries ten votes and each share of Pubco Class A Common Stock carries one vote, concentrating voting control with the Big3 Founders.”
Earnout
At the Closing, Pubco will cause the Earnout Participants to be issued an aggregate of an additional 2,000,000 Earnout Shares (subject to adjustment for stock dividends, stock splits, and the like), which will be unvested and subject to forfeiture. The Earnout Shares will vest upon the satisfaction of stock price conditions during the five years following the Closing. While any Earnout Shares remain subject to the vesting conditions specified in the Business Combination Agreement, the holder thereof will not be entitled to exercise the voting rights carried by such Earnout Shares and will not be entitled to receive any dividends or other distributions in respect of such Earnout Shares. For more information, see “Proposal No. 1 – The Business Combination Proposal – The Business Combination Agreement – Earnout.”
Sponsor Forfeitures and Sponsor Earnout
Pursuant to the Sponsor Support Agreement, immediately prior to the Domestication, subject to satisfaction or waiver of the closing conditions, the Sponsor will forfeit 2,750,000 Founder Shares and may, at its discretion, transfer up to an additional 500,000 Founder Shares to third parties to incentivize non-redemptions, investments, or other support for the Transactions; any unused portion of the Discretionary Founder Shares will also be forfeited. The Sponsor will retain no further rights in the forfeited or transferred shares, and SPAC is authorized to take all actions necessary to effect the forfeiture.
Additionally, pursuant to the Sponsor Support Agreement 500,000 shares of Pubco Class A Common Stock to be held by the Sponsor as of the Closing will be subject to vesting, as described in more detail below under “Sponsor Support Agreement”.
For more information, see “Proposal No. 1 – The Business Combination Proposal – Ancillary Agreements – Sponsor Support Agreement.”
Transfer Restrictions
Sponsor Support Agreement
The Sponsor Support Agreement prohibits each Insider from, among other things, selling, assigning or transferring any SPAC Ordinary Shares or SPAC Warrants held by such Insider except to certain permitted transferees, until the earliest of (a) the Closing Date, (b) such date and time as the Business Combination Agreement is terminated in accordance with its terms; (c) the liquidation of SPAC; (d) the written agreement of each of the terminating Insider(s), SPAC, Pubco and the Company with respect to terminating the rights and obligations under the Sponsor Support Agreement of a specific Insider or a subset of Insiders; and (e) the written agreement of all Insiders, SPAC, Pubco and the Company to terminate the Sponsor Support Agreement in its entirety. Pursuant to the Sponsor Support Agreement, each Insider unconditionally and irrevocably agreed not to submit any SPAC Class A Ordinary Shares owned by it for redemption in connection with the Transactions or an Extension.
Lock-up Agreements
Concurrently with the Closing, the BIG3 Founders and other Sellers holding greater than 3% of the outstanding Company Interests, the Sponsor, IPO Underwriter, and each director of SPAC will enter into a Lock-Up Agreement, pursuant to which such person will agree not to (i) lend, offer, pledge, hypothecate, encumber, donate, assign, sell, contract to sell, sell any option or contract to purchase, purchase any option or contract to sell, grant any option, right or warrant to purchase, or otherwise transfer or dispose of, directly or indirectly, any shares of Pubco Common Stock to be received by such person in the Business Combination, (ii) enter into any swap or other arrangement that transfers to another, in whole or in part, any of the economic consequences of ownership of such shares of Pubco Common Stock, or (iii) publicly disclose the intention to do any of the foregoing, for a period commencing from the Closing and ending (x) on the date that is six (6) months after the Closing for the Pubco Common Stock, or (y) on the date that is thirty (30) days after the Closing for the Pubco Warrants (including the Pubco Common Stock underlying the Pubco Warrants), subject to certain customary transfer exceptions.
SPAC estimates that approximately 30.8 million shares of Pubco Class A Common Stock and 6.0 million Pubco Private Warrants will be subject to lockup pursuant to the Lock-Up Agreement immediately following the Closing, representing approximately 76.7% of the total issued and outstanding shares of Pubco Common Stock in the No Additional Redemptions Scenario and 34.3% of the total issued and outstanding Pubco Warrants following the Business Combination.
Set forth below is a tabular presentation of the post-closing lock-ups:
Lock-Up Party | | Number and Type of Securities | | Lock-Up Term | | Permitted Transferees |
|---|---|---|---|---|---|---|
Sponsor | 4,000,000 Pubco Warrants (including underlying shares) | The earlier of (x) 30 days after the Closing Date and (y) the date Pubco completes a liquidation, merger, capital stock exchange, reorganization or other similar transaction that results in all of Pubco’s stockholders having the right to exchange their shares of Pubco Common Stock for cash, securities or other property. | Permitted transferees and transfers include: (i) transfers to Pubco directors and officers (including affiliates and family members, (ii) transfer by laws of descent, (iii) transfers by operations of law, (iv) transfers to a partnership, limited liability company, or entity of which the securityholder is the legal and beneficial owner, (v) affiliates, (vi) transfers to a trustor or trust, and (vii) transfers upon dissolution. | |||
2,410,000 Pubco Class A Common Stock | The earlier of (x) six (6) months after the Closing Date and (y) the date Pubco completes a liquidation, merger, capital stock exchange, reorganization or other similar transaction that results in all of Pubco’s stockholders having the right to exchange their shares of Pubco Common Stock for cash, securities or other property. | Permitted transferees and transfers include: (i) transfers to Pubco directors and officers (including affiliates and family members, (ii) transfer by laws of descent, (iii) transfers by operations of law, (iv) transfers to a partnership, limited liability company, or entity of which the securityholder is the legal and beneficial owner, (v) affiliates, (vi) transfers to a trustor or trust, and (vii) transfers upon dissolution. | ||||
IPO Underwriter | 2,000,000 Pubco Warrants (including underlying shares) | The earlier of (x) 30 days after the Closing Date and (y) the date Pubco completes a liquidation, merger, capital stock exchange, reorganization or other similar transaction that results in all of Pubco’s stockholders having the right to exchange their shares of Pubco Common Stock for cash, securities or other property. | Permitted transferees and transfers include: (i) transfers to Pubco directors and officers (including affiliates and family members, (ii) transfer by laws of descent, (iii) transfers by operations of law, (iv) transfers to a partnership, limited liability company, or entity of which the securityholder is the legal and beneficial owner, (v) affiliates, (vi) transfers to a trustor or trust, and (vii) transfers upon dissolution. | |||
SPAC Independent Directors | 90,000 Pubco Class A Common Stock, in the aggregate (30,000 shares each) | The earlier of (x) six (6) months after the Closing Date and (y) the date Pubco completes a liquidation, merger, capital stock exchange, reorganization or other similar transaction that results in all of Pubco’s stockholders having the right to exchange their shares of Pubco Common Stock for cash, securities or other property. | Permitted transferees and transfers include: (i) transfers to Pubco directors and officers (including affiliates and family members, (ii) transfer by laws of descent, (iii) transfers by operations of law, (iv) transfers to a partnership, limited liability company, or entity of which the securityholder is the legal and beneficial owner, (v) affiliates, (vi) transfers to a trustor or trust, and (vii) transfers upon dissolution. |
Lock-Up Party | | Number and Type of Securities | | Lock-Up Term | | Permitted Transferees |
|---|---|---|---|---|---|---|
The BIG3 Founders and other Sellers holding greater than 3% of the outstanding Company Interests | Merger Consideration and Earnout Shares | The earlier of (x) six (6) months after the Closing Date and (y) the date Pubco completes a liquidation, merger, capital stock exchange, reorganization or other similar transaction that results in all of Pubco’s stockholders having the right to exchange their shares of Pubco Common Stock for cash, securities or other property. | Permitted transferees and transfers include: (i) transfers to Pubco directors and officers (including affiliates and family members, (ii) transfer by laws of descent, (iii) transfers by operations of law, (iv) transfers to a partnership, limited liability company, or entity of which the securityholder is the legal and beneficial owner, (v) affiliates, (vi) transfers to a trustor or trust, and (vii) transfers upon dissolution. |
Sources and Uses of Proceeds
The following tables summarize the anticipated sources and uses of funds in the Business Combination, in various redemptions scenarios. Such tables are for illustrative purposes only. Where actual amounts are not known or knowable, the figures below represent good faith estimates of such amounts.
Assuming No Additional Redemptions | ||||||||
Sources (in millions) | | | Uses (in millions) | | ||||
Trust Account funds as of June 30, 2026 | $ | 91.4 |
| Redemptions | $ | — | ||
Additional related party notes payable | 0.3 |
| Transaction expenses |
| 12.4 | |||
| Deferred underwriting fee |
| 9.8 | |||||
| Related party notes payable |
| 0.5 | |||||
| Cash |
| 69.0 | |||||
Total Sources | $ | 91.7 |
| Total Uses | $ | 91.7 | ||
Assuming 25% Redemptions(1) | ||||||||
Sources (in millions) | | | Uses (in millions) | | ||||
Trust Account funds as of June 30, 2026 | $ | 91.4 |
| Redemptions | $ | 22.8 | ||
Additional related party notes payable | 0.3 |
| Transaction expenses |
| 12.4 | |||
| Deferred underwriting fee |
| 9.8 | |||||
| Related party notes payable |
| 0.5 | |||||
| Cash |
| 46.2 | |||||
Total Sources | $ | 91.7 |
| Total Uses | $ | 91.7 | ||
Assuming 50% Redemptions(1) | ||||||||
Sources (in millions) | | | Uses (in millions) | | ||||
Trust Account funds as of June 30, 2026 | $ | 91.4 |
| Redemptions | $ | 45.7 | ||
Additional related party notes payable | 0.3 |
| Transaction expenses |
| 12.4 | |||
| Deferred underwriting fee |
| 9.8 | |||||
| Related party notes payable |
| 0.5 | |||||
| Cash |
| 23.3 | |||||
Total Sources | $ | 91.7 |
| Total Uses | $ | 91.7 | ||
Assuming 75% Redemptions(1) | ||||||||
Sources (in millions) | | | Uses (in millions) | | ||||
Trust Account funds as of June 30, 2026 | $ | 91.4 |
| Redemptions | $ | 68.5 | ||
Additional related party notes payable | 0.3 |
| Transaction expenses |
| 12.4 | |||
| Deferred underwriting fee |
| 9.8 | |||||
| Related party notes payable |
| 0.5 | |||||
| Cash |
| 0.5 | |||||
Total Sources | $ | 91.7 |
| Total Uses | $ | 91.7 | ||
Assuming 100% Redemptions(1) | ||||||||
Sources (in millions) | | | | Uses (in millions) | | | ||
Trust Account funds as of June 30, 2026 | $ | 91.4 |
| Redemptions | $ | 91.4 | ||
Additional related party notes payable | 0.3 |
| Transaction expenses(2) |
| — | |||
| Deferred underwriting fee(2) |
| — | |||||
| Related party note payable(2) |
| 0.3 | |||||
| Cash |
| — | |||||
Total Sources | $ | 91.7 |
| Total Uses | $ | 91.7 | ||
| (1) | Each of the 25% Redemptions Scenario, 50% Redemptions Scenario, 75% Redemptions Scenario, and 100% Redemptions Scenario results in an amount of net cash, after the redemptions and the payment of transaction expenses, that is not sufficient to meet the Minimum Cash Condition, without additional financing. As of the date of this proxy statement/prospectus, SPAC has not entered into any Financing Agreement for Transaction Financing, no Sponsor Investment has been made, and the Minimum Cash Condition has not been satisfied. In the event that the Minimum Cash Condition is not satisfied as a result of redemptions of SPAC Public Shares which reduce the amount available to be released to the parties from the Trust Account and/or the failure to obtain third-party financing, the Company may elect not to consummate the Business Combination. Alternately, in the event that the Minimum Cash Condition is not satisfied as a result of redemptions of SPAC Public Shares which reduce the amount available to be released to the parties from the Trust Account and/or the failure to obtain third-party financing, the Company may, in its sole discretion, waive the Minimum Cash Condition. If the Company waives the Minimum Cash Condition, SPAC intends to file a Current Report on Form 8-K within four business days of such event, however such condition may be waived at any time prior to the Closing, including after the deadline for submitting redemption requests or the Extraordinary General Meeting, and, given such timing, you may not be notified before the deadline for submitting redemption requests or the Extraordinary General Meeting. |
| (2) | Under the 100% redemptions scenario, no cash would be released from the Trust Account to fund the payment of transaction expenses, the deferred underwriting fee, or the related party notes payable. Accordingly, these amounts would remain outstanding obligations of the combined company and would need to be funded from other sources, deferred or renegotiated. |
Financing Cooperation
During the period from the date of the Business Combination Agreement and continuing until the earlier of the termination of the Business Combination Agreement or the Closing, SPAC agreed to use its reasonable best efforts to enter into Financing Agreements with accredited investors for one or more Transaction Financings by Pubco, on terms and using a structure and approach reasonably agreed by SPAC and the Company. Pubco, SPAC, and the Company will each use reasonable best efforts to consummate the Financing Agreements by Closing, satisfy their respective conditions and covenants thereunder, and enforce their rights to cause the accredited investors to pay the applicable purchase price to (or as directed by) Pubco. Each party must promptly notify the others in writing of any breach, default, or related notice under a Financing Agreement, or if it does not expect to receive all or part of the Transaction Financing as contemplated.
Additionally, pursuant to the Sponsor Support Agreement, Sponsor agreed to provide financing support in connection with the Business Combination in the form of the Sponsor Investment. If the Closing SPAC Cash is less than $100,000,000, the Sponsor will be required invest, or cause its affiliate or designee to invest, an aggregate of at least $5,000,000 of gross proceeds in a Transaction Financing. If Closing SPAC Cash is greater than $100,000,000, then Sponsor has the option to make such Sponsor Investment. The purchase price of the Sponsor Investment will be equal to the lowest purchase price paid by any other investor in the Transaction
Financing and will be made upon such other terms that are no less favorable to the Sponsor (or such affiliate or designee) than the terms offered to any other investor in any Transaction Financing.
Closing Conditions
Mutual Closing Conditions
Pursuant to the Business Combination Agreement, closing of the Transactions is subject to mutual conditions, including: approval of the Required SPAC Shareholder Approval; expiration or termination of any applicable antitrust waiting periods; receipt of required governmental and other consents; the absence of any law or order prohibiting the Transactions; effectiveness of the Registration Statement through Closing; consummation of the Domestication; and approval of Pubco Class A Common Stock for listing on the Stock Exchange.
Conditions to the Obligations of the Company
Pursuant to the Business Combination Agreement, the Company’s obligation to close is further conditioned on: the accuracy of SPAC’s representations and warranties and SPAC’s material compliance with its covenants; the Sponsor Support Agreement remaining in full force and effect; delivery by SPAC of customary closing certificates (officer’s certificate, secretary’s certificate with organizational documents and board/shareholder approvals, good standing certificates, and other closing deliverables); and a minimum cash condition of at least $50,000,000, calculated as Trust Account proceeds available at Closing (after redemptions) plus Transaction Financing proceeds, less unpaid SPAC and Company expenses.
Conditions to the Obligations of SPAC
Pursuant to the Business Combination Agreement, SPAC’s obligation to close is further conditioned on: the accuracy of the Company’s representations and warranties and material compliance by the Company, SPAC Merger Sub, Company Merger Sub, and Pubco with their respective covenants; no Material Adverse Effect on the Company since signing; the Target Companies’ and Sellers’ material compliance with the Seller Written Consent; noteholder consent to convert all Notes into Company Interests prior to Closing; delivery by the Company of customary closing certificates and deliverables (including officer and secretary certificates, good standing certificates, director/manager resignations, executive employment agreements, the Sponsor Indemnification Agreement, FIRPTA and Section 1446(f) certifications, and lien releases); procurement of D&O tail insurance; election or appointment of Pubco’s post-Closing board; adoption of the Proposed Pubco Charter and Proposed Pubco Bylaws; adoption of the 2026 Equity Incentive Plan; and evidence that specified Company indebtedness has been discharged in full.
Termination
Pursuant to the Business Combination Agreement, the Business Combination Agreement may be terminated and the Transactions abandoned at any time before the Closing Date: (i) by mutual written consent of SPAC and the Company; (ii) by either party if the Closing conditions are not satisfied or waived by the earlier of December 27, 2026 or the Business Combination Deadline, unless the terminating party’s own breach caused the delay; (iii) by either party if a governmental order permanently prohibiting the Transactions becomes final and non-appealable, unless that party’s breach substantially caused the order; (iv) by the Company, if SPAC materially breaches its representations, warranties, covenants, or agreements such that a closing condition would fail, and the breach is incurable or uncured within 20 days’ notice or by the Business Combination Deadline (whichever is earlier), provided the Company is not itself in material uncured breach; (v) by SPAC, on the same terms, if the Company materially breaches its representations, warranties, covenants, or agreements; (vi) by SPAC, if a Material Adverse Effect on the Target Companies occurs after signing and remains uncured; (vii) by either party, if the Required SPAC Shareholder Approval is not obtained at the Extraordinary General Meeting; or (viii) by SPAC, if the Company fails to deliver the Audited Financials by the required date.
Ancillary Agreements
Sponsor Support Agreement
In connection with the execution of the Business Combination Agreement, on June 12, 2026, SPAC entered into a sponsor support agreement with the Sponsor, each of SPAC’s independent directors (together with Sponsor, the “Insiders”), Pubco and the Company, pursuant to which the Insiders agreed to, among other things, vote in favor of the SPAC Shareholder Approval Matters (as
defined in the proxy statement/prospectus) and otherwise support the Business Combination. In addition, the Sponsor Support Agreement prohibits each Insider from, among other things, selling, assigning or transferring any SPAC Ordinary Shares or SPAC Warrants held by such Insider except to certain permitted transferees, until the earliest of (a) the date of the Closing, (b) such date and time as the Business Combination Agreement is terminated in accordance with its terms; (c) the liquidation of SPAC; (d) the written agreement of each of the terminating Insider(s), SPAC, Pubco and the Company with respect to terminating the rights and obligations under the Sponsor Support Agreement of a specific Insider or a subset of Insiders; and (e) the written agreement of all Insiders, SPAC, Pubco and the Company to terminate the Sponsor Support Agreement in its entirety.
Pursuant to the Sponsor Support Agreement (i) each Insider unconditionally and irrevocably agreed not to redeem any SPAC Class A Ordinary Shares owned by it in connection with the Business Combination, and (ii) the Sponsor also agreed, effective as of immediately prior to the Domestication and conditioned upon the Closing, to forfeit and surrender to SPAC an aggregate of 2,750,000 Founder Shares held by the Sponsor.
Additionally, pursuant to the Sponsor Support Agreement (i) the Sponsor may, in its discretion, transfer to third parties up to an additional 500,000 Founder Shares held by it to incentivize non-redemptions or investments into SPAC or Pubco, provided that any portion of the Discretionary Founder Shares that are not so transferred will be forfeited, and (ii) 500,000 shares of Pubco Class A Common Stock to be held by the Sponsor as of the Closing will be subject to vesting and will vest upon the following conditions: (a) if the funds in the trust account of the SPAC plus any financing, minus cash used for redemptions of the SPAC Public Shares equals or exceeds $200 million, (b) if during the Earnout Period, the closing price of Pubco Class A Common Stock equals or exceeds $15.00 for at least 20 days out of 30 consecutive trading days, and (c) if there is a sale of Pubco during the Earnout Period, and the holders of Pubco Common Stock receive a Sale Price that is greater or equal to the Earnout Price.
Additionally, pursuant to the Sponsor Support Agreement, Sponsor agreed to provide financing support in connection with the Business Combination. If the Closing SPAC Cash is less than $100,000,000, the Sponsor will be required invest, or cause its affiliate or designee to invest, an aggregate of at least $5,000,000 of gross proceeds in a Transaction Financing. If Closing SPAC Cash is greater than $100,000,000, then Sponsor has the option to make the Sponsor Investment. The purchase price of the Sponsor Investment will be equal to the lowest purchase price paid by any other investor in the Transaction Financing and will be made upon such other terms that are no less favorable to the Sponsor (or such affiliate or designee) than the terms offered to any other investor in any Transaction Financing.
For more information, see “Proposal No. 1 – The Business Combination Proposal – Ancillary Agreements — Sponsor Support Agreement.”
Lock-Up Agreements
For a summary of the terms of the Lock-Up Agreements, see above under “--Transfer Restrictions - Lock-Up Agreements.”
For more information, see “Proposal No. 1 – The Business Combination Proposal – Ancillary Agreements — Lock-Up Agreement.”
Registration Rights Agreement
Concurrently with the Closing, Pubco, the Sponsor, the IPO Underwriter, SPAC’s officers and directors, and certain Sellers, and the Non-Redeeming Shareholders with respect to the Assigned Shares, will enter into the Registration Rights Agreement, pursuant to which, among other things, Pubco will agree that, within 30 days after the Closing Date, Pubco will file with the SEC (at Pubco’s sole cost and expense) a registration statement registering the resale of certain securities held by or issuable to the parties thereto, and Pubco will use its reasonable best efforts to have the Resale Registration Statement declared effective as soon as reasonably practicable after the filing thereof. Such holders will also be entitled to customary piggyback registration rights and demand registration rights pursuant to the terms of the Registration Rights Agreement. SPAC estimates that approximately 27.2 million shares of Pubco Class A Common Stock and 6.0 million Pubco Private Warrants will be subject to registration rights pursuant to the Registration Rights Agreement immediately following the Closing, representing approximately 67.7% of the total issued and outstanding shares of Pubco Common Stock in the No Additional Redemptions Scenario and 34.3% of the total issued and outstanding Pubco Warrants following the Business Combination.
For more information, see “Proposal No. 1 – The Business Combination Proposal – Ancillary Agreements — Registration Rights Agreement.”
Warrant Assumption Agreement
Concurrently with the Closing, SPAC, Pubco, and Continental Stock Transfer & Trust Company, as Warrant Agent, will enter into a the Warrant Assumption Agreement, pursuant to which, among other things, SPAC will assign to Pubco all of SPAC’s right, title and interest in and to, and Pubco will assume all of SPAC’s liabilities and obligations under the Existing Warrant Agreement. As a result, at the Closing, each SPAC Warrant will automatically cease to represent a right to acquire SPAC Class A Ordinary Shares and instead will represent a right to acquire Pubco Class A Common Stock pursuant to the terms and conditions of the Existing Warrant Agreement (as amended by the Warrant Assumption Agreement).
For more information, see “Proposal No. 1 – The Business Combination Proposal – Ancillary Agreements — Warrant Assumption Agreement.”
Sponsor Indemnification Agreement
Concurrently with the Closing, Pubco, the Company, and the Sponsor will enter into the Sponsor Indemnification Agreement, pursuant to which, among other things, Pubco and the Company will indemnify, defend and hold harmless the Sponsor and its shareholders, members, directors, managers, and officers (each, a “Sponsor Indemnified Person”) from and against any and all Sponsor Indemnified Liabilities (as defined in the Sponsor Indemnification Agreement) arising out of or relating to any pending or threatened action, cause of action, suit, litigation, investigation, proceeding, inquiry, arbitration or claim against any of them or in which any of them may be a participant or may otherwise be involved (including as a witness) that arise out of or relate to SPAC’s operations or conduct of its business, the Business Combination, and/or any claim against the Sponsor and/or a Sponsor Indemnified Person alleging any expressed or implied management, control or endorsement of any activities of SPAC, or any express or implied association with Pubco, the Company, or SPAC, or any of their respective affiliates. The Sponsor Indemnification Agreement will not however apply to claims arising primarily out of (a) any breach by such Sponsor Indemnified Person of any other agreement between such Sponsor Indemnified Person, on the one hand, and Pubco, the Company, SPAC, or any of their respective subsidiaries, on the other hand, or (b) the willful misconduct, gross negligence or bad faith of such Sponsor Indemnified Person.
For more information, see “Proposal No. 1 – The Business Combination Proposal – Ancillary Agreements — Sponsor Indemnification Agreement.”
Ownership of Pubco After the Closing
The following tables illustrate estimated ownership levels in Pubco, immediately following the consummation of the Business Combination, based on varying levels of redemptions by SPAC Public Shareholders. Each redemptions scenario assumes no Transaction Financing, no Sponsor Investment, the forfeiture of 2,750,000 Sponsor Forfeited Shares, includes the 2,000,000 Earnout Shares, which will be issued and outstanding at the Closing and subject to vesting, and assumes the Company’s Cash Position is $0.00 (as of June 30, 2026).
The following table excludes the dilutive effect of Pubco Warrants, Company Converted Warrants, and Pubco Class A Common Stock that will initially be available for issuance under the 2026 Equity Incentive Plan.
| No Additional Redemptions | |
| ||||||||||||||||||||||||||||||||||||||
| Scenario | | 25% Redemptions Scenario | | 50% Redemptions Scenario | | 75% Redemptions Scenario | | 100% Redemptions Scenario |
| |||||||||||||||||||||||||||||||
Percent | Percent | Percent | Percent | Percent |
| ||||||||||||||||||||||||||||||||||||
of | of | of | of | of |
| ||||||||||||||||||||||||||||||||||||
Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent |
| |||||||||||||||||||||
Class A | Class B | Pubco | of | Class A | Class B | Pubco | of | Class A | Class B | Pubco | of | Class A | Class B | Pubco | of | Class A | Class B | Pubco | of |
| |||||||||||||||||||||
Common | Common | Common | Voting | Common | Common | Common | Voting | Common | Common | Common | Voting | Common | Common | Common | Voting | Common | Common | Common | Voting |
| |||||||||||||||||||||
Pro Forma Ownership | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) |
|
Public Shares(2) | 8,409,633 |
| — |
| 20.9 | % | 3.8 | % | 6,307,225 |
| — |
| 16.6 | % | 2.9 | % | 4,204,817 |
| — |
| 11.7 | % | 1.9 | % | 2,102,409 |
| — |
| 6.2 | % | 1.0 | % | — |
| — |
| 0.0 | % | 0.0 | % | |
Founder Shares(3)(4)(5)(6)(7)(8)(9) | 3,000,000 |
| — |
| 7.5 | % | 1.4 | % | 3,000,000 |
| — |
| 7.9 | % | 1.4 | % | 3,000,000 |
| — |
| 8.3 | % | 1.4 | % | 3,000,000 |
| — |
| 8.9 | % | 1.4 | % | 3,000,000 |
| — |
| 9.4 | % | 1.4 | % | |
Company shareholders (other than Big3 Founders) | 7,308,958 |
| — |
| 18.2 | % | 3.3 | % | 7,308,958 |
| — |
| 19.2 | % | 3.4 | % | 7,308,958 |
| — |
| 20.3 | % | 3.4 | % | 7,308,958 |
| — |
| 21.6 | % | 3.4 | % | 7,308,958 |
| — |
| 23.0 | % | 3.5 | % | |
Big3 Founders | 1,492,036 |
| 19,976,476 |
| 53.4 | % | 91.5 | % | 1,492,036 |
| 19,976,476 |
| 56.4 | % | 92.4 | % | 1,492,036 |
| 19,976,476 |
| 59.7 | % | 93.3 | % | 1,492,036 |
| 19,976,476 |
| 63.4 | % | 94.2 | % | 1,492,036 |
| 19,976,476 |
| 67.6 | % | 95.1 | % | |
Total | 20,210,627 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 18,108,219 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 16,005,811 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 13,903,403 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 11,800,994 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | |
*Less than 1%.
| (1) | Each share of Pubco Class A Common Stock will entitle the holder thereof to one (1) vote per share on all matters on which the Pubco Class A Common Stock are entitled to vote, and each share of Pubco Class B Common Stock will entitle the holder thereof to ten (10) votes per share on all matters on which the Pubco Class B Common Stock are entitled to vote. |
| (2) | Amount comprises the unredeemed Public Shares in a variety of redemptions scenarios. This amount reflects the assumed redemption of (i) 0 shares under the No Additional Redemptions Scenario, (ii) 2,102,408 shares under the 25% Redemptions Scenario, (iii) 4,204,816 shares under the 50% Redemptions Scenario, (iv) 6,307,224 shares under the 75% Redemptions Scenario, and (v) 8,409,633 shares under the 100% Redemptions Scenario. |
| (3) | In each redemptions scenario, includes 500,000 Discretionary Founder Shares, assuming that all such shares will be used to incentivize non-redemptions or investments into the SPAC or Pubco or otherwise to support the Transactions. Such amount includes 425,602 Assigned Shares. On June 26, 2026, in connection with the Extension Meeting, SPAC and the Sponsor entered into non-redemption agreements with Non-Redeeming Shareholders covering 4,256,015 SPAC Class A Ordinary Shares, under which those shareholders agreed not to redeem (or to rescind any redemption of) such shares in connection with a vote to approve the Extension Amendment Proposal presented at the Extension Meeting. The Non-Redeeming Shareholders were not affiliates of SPAC, the Sponsor, or SPAC’s officers or directors. In exchange, the Sponsor agreed to transfer 425,602 Founder Shares to the Non-Redeeming Shareholders promptly after closing of the Business Combination, conditioned on (i) the shares not being redeemed, (ii) approval of the Extension Amendment Proposal, and (iii) consummation of the Business Combination. The Non-Redeeming Shareholders also received registration rights for the Assigned Shares under the same registration rights agreement used by the Sponsor. The Assigned Shares come from the Sponsor’s pool of up to 500,000 Discretionary Founder Shares earmarked to incentivize non-redemptions/investment in support of the Business Combination. Any unused portion of the Discretionary Founder Shares will be forfeited at the Closing. |
| (4) | Amount includes 30,000 Founder Shares held by each of SPAC’s Independent Directors. |
| (5) | Amount includes 300,000 Transferred Shares, assuming the repayment of the following loans in cash at the Closing. On June 10, 2026, SPAC, Harraden, and James A. Graf entered into the Convertible Promissory Note, replacing a prior promissory note dated June 4, 2026, and consolidating $200,000 in working capital advances previously made by Harraden into a fully drawn, non-interest bearing, unsecured Loan that was fully outstanding as of June 30, 2026 and is due upon the earlier of the initial business combination or SPAC’s liquidation. At Harraden’s discretion, the Loan may convert into SPAC Class A Ordinary Shares at $10.00 per share, with Harraden also entitled to one warrant per dollar funded, issuable immediately prior to Closing on terms identical to SPAC Private Warrants issued to the Sponsor. Subsequently, on August 10, 2026, SPAC, Harraden, and James A. Graf entered into the August Convertible Promissory Note, under which SPAC may borrow up to an additional $300,000 for working capital |
| and general corporate purposes on similar non-interest bearing, unsecured terms due upon the earlier of the initial business combination or liquidation. At Harraden’s discretion, the August Loan may convert into SPAC Class A Ordinary Shares at $10.00 per share, and for each dollar funded Harraden is entitled to one warrant to purchase one SPAC Class A Ordinary Share on terms identical to SPAC Private Warrants, plus one unrestricted SPAC Ordinary Share transferred by the Sponsor, each issuable or to be transferred, as applicable, immediately prior to Closing. |
| (6) | Amount includes 500,000 Founder Shares that will be subject to vesting and will vest: (a) if the funds in the Trust Account plus any financing, minus cash used for redemptions of SPAC Public Shares equals or exceeds $200 million, (b) if during the Earnout Period, the closing price of Pubco Class A Common Stock equals or exceeds $15.00 for at least 20 days out of 30 consecutive trading days, or (c) if there is a Sale of Pubco during the Earnout Period, and the holders of Pubco Common Stock receive a Sale Price that is greater or equal to the Earnout Price. |
| (7) | Amount excludes 2,750,000 Sponsor Forfeited Shares, which will be forfeited by the Sponsor upon the consummation of the Business Combination. |
| (8) | Includes 507,964 Earnout Shares, which will be issued and outstanding as of the Closing. |
| (9) | Includes 1,492,036 Earnout Shares, which will be issued and outstanding as of the Closing. |
Dilutive Instruments
The following table shows possible sources of dilution and the extent of such dilution that non-redeeming SPAC Public Shareholders could experience in connection with the closing of the Business Combination. In an effort to illustrate the extent of such dilution, the table below assumes the exercise of all Pubco Warrants for a cash exercise price of $11.50. The table excludes Pubco Common Stock that will initially be available for issuance under the 2026 Equity Incentive Plan, as such shares will not be outstanding on the Closing Date.
| No Additional Redemptions |
| |||||||||||||||||||||||||||||||||||||||
| Scenario | | 25% Redemptions Scenario | | 50% Redemptions Scenario | | 75% Redemptions Scenario | | 100% Redemptions Scenario |
| |||||||||||||||||||||||||||||||
Percent | Percent | Percent | Percent | Percent |
| ||||||||||||||||||||||||||||||||||||
of | of | of | of | of |
| ||||||||||||||||||||||||||||||||||||
Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent |
| |||||||||||||||||||||
Class A | Class B | Pubco | of | Class A | Class B | Pubco | of | Class A | Class B | Pubco | of | Class A | Class B | Pubco | of | Class A | Class B | Pubco | of |
| |||||||||||||||||||||
Common | Common | Common | Voting | Common | Common | Common | Voting | Common | Common | Common | Voting | Common | Common | Common | Voting | Common | Common | Common | Voting |
| |||||||||||||||||||||
Pro Forma Ownership | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) |
|
Public Shares(2) | 8,409,633 |
| — |
| 14.6 | % | 3.5 | % | 6,307,225 |
| — |
| 11.3 | % | 2.7 | % | 4,204,817 |
| — |
| 7.9 | % | 1.8 | % | 2,102,409 |
| — |
| 4.1 | % | * |
| — |
| — |
| 0.0 | % | 0.0 | % | |
Founder Shares(3)(4)(5)(6)(7)(8)(9) | 3,000,000 |
| — |
| 5.2 | % | 1.3 | % | 3,000,000 |
| — |
| 5.4 | % | 1.3 | % | 3,000,000 |
| — |
| 5.6 | % | 1.3 | % | 3,000,000 |
| — |
| 5.8 | % | 1.3 | % | 3,000,000 |
| — |
| 6.1 | % | 1.3 | % | |
Public Warrants | 11,500,000 |
| — |
| 19.9 | % | 4.8 | % | 11,500,000 |
| — |
| 20.7 | % | 4.9 | % | 11,500,000 |
| — |
| 21.5 | % | 4.9 | % | 11,500,000 |
| — |
| 22.4 | % | 5.0 | % | 11,500,000 |
| — |
| 23.3 | % | 5.0 | % | |
Private Placement Warrants(10) | 6,000,000 |
| — |
| 10.4 | % | 2.5 | % | 6,000,000 |
| — |
| 10.8 | % | 2.5 | % | 6,000,000 |
| — |
| 11.2 | % | 2.6 | % | 6,000,000 |
| — |
| 11.7 | % | 2.6 | % | 6,000,000 |
| — |
| 12.2 | % | 2.6 | % | |
Company shareholders (other than Big3 Founders) | 7,308,958 |
| — |
| 12.7 | % | 3.1 | % | 7,308,958 |
| — |
| 13.1 | % | 3.1 | % | 7,308,958 |
| — |
| 13.7 | % | 3.1 | % | 7,308,958 |
| — |
| 14.2 | % | 3.2 | % | 7,308,958 |
| — |
| 14.8 | % | 3.2 | % | |
Big3 Founders | 1,492,036 |
| 19,976,476 |
| 37.2 | % | 84.7 | % | 1,492,036 |
| 19,976,476 |
| 38.6 | % | 85.5 | % | 1,492,036 |
| 19,976,476 |
| 40.1 | % | 86.3 | % | 1,492,036 |
| 19,976,476 |
| 41.8 | % | 87.1 | % | 1,492,036 |
| 19,976,476 |
| 43.6 | % | 87.9 | % | |
Total | 37,710,627 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 35,608,219 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 33,505,811 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 31,403,403 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 29,003,994 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | |
*Less than 1%.
| (1) | Each share of Pubco Class A Common Stock will entitle the holder thereof to one (1) vote per share on all matters on which the Pubco Class A Common Stock are entitled to vote, and each share of Pubco Class B Common Stock will entitle the holder thereof to ten (10) votes per share on all matters on which the Pubco Class B Common Stock are entitled to vote. |
| (2) | Amount comprises the unredeemed Public Shares in a variety of redemptions scenarios. This amount reflects the assumed redemption of (i) 0 shares under the No Additional Redemptions Scenario, (ii) 2,102,408 shares under the 25% Redemptions Scenario, (iii) 4,204,816 shares under the 50% Redemptions Scenario, (iv) 6,307,224 shares under the 75% Redemptions Scenario, and (v) 8,409,633 shares under the 100% Redemptions Scenario. |
| (3) | In each redemptions scenario, includes 500,000 Discretionary Founder Shares, assuming that all such shares will be used to incentivize non-redemptions or investments into the SPAC or Pubco or otherwise to support the Transactions. Such amount includes 425,602 Assigned Shares. On June 26, 2026, in connection with the Extension Meeting, SPAC and the Sponsor entered into non-redemption agreements with Non-Redeeming Shareholders covering 4,256,015 SPAC Class A Ordinary Shares, under which those shareholders agreed not to redeem (or to rescind any redemption of) such shares in connection with a vote to approve the Extension Amendment Proposal presented at the Extension Meeting. The Non-Redeeming Shareholders were not affiliates of SPAC, the Sponsor, or SPAC’s officers or directors. In exchange, the Sponsor agreed to transfer 425,602 Founder Shares to the Non-Redeeming Shareholders promptly after closing of the Business Combination, conditioned on (i) the shares not being redeemed, (ii) approval of the Extension Amendment Proposal, and (iii) consummation of the Business Combination. The Non-Redeeming Shareholders also received registration rights for the Assigned Shares under the same registration rights agreement used by the Sponsor. The Assigned Shares come from the Sponsor’s pool of up to 500,000 Discretionary Founder Shares earmarked to incentivize non-redemptions/investment in support of the Business Combination. Any unused portion of the Discretionary Founder Shares will be forfeited at the Closing. |
| (4) | Amount includes 30,000 Founder Shares held by each of SPAC’s Independent Directors. |
| (5) | Amount includes 300,000 Transferred Shares, assuming the repayment of the following loans in cash at the Closing. On June 10, 2026, SPAC, Harraden, and James A. Graf entered into the Convertible Promissory Note, replacing a prior promissory note dated June 4, 2026, and consolidating $200,000 in working capital advances previously made by Harraden into a fully drawn, non-interest bearing, unsecured Loan that was fully outstanding as of June 30, 2026 and is due upon the earlier of the initial business combination or SPAC’s liquidation. At Harraden’s discretion, the Loan may convert into SPAC Class A Ordinary Shares at $10.00 per share, with Harraden also entitled to one warrant per dollar funded, issuable immediately prior to Closing on terms identical to SPAC Private Warrants issued to the Sponsor. Subsequently, on August 10, 2026, SPAC, Harraden, and James A. Graf entered into the August Convertible Promissory Note, under which SPAC may borrow up to an additional $300,000 for working capital and general corporate purposes on similar non-interest bearing, unsecured terms due upon the earlier of the initial business combination or liquidation. At Harraden’s discretion, the August Loan may convert into SPAC Class A Ordinary Shares at $10.00 per share, and for each dollar funded Harraden is entitled to one warrant to purchase one SPAC Class A Ordinary Share on terms identical to SPAC Private Warrants, plus one unrestricted SPAC Ordinary Share transferred by the Sponsor, each issuable or to be transferred, as applicable, immediately prior to Closing. |
| (6) | Amount includes 500,000 Founder Shares that will be subject to vesting and will vest: (a) if the funds in the Trust Account plus any financing, minus cash used for redemptions of SPAC Public Shares equals or exceeds $200 million, (b) if during the Earnout Period, the closing price of Pubco Class A Common Stock equals or exceeds $15.00 for at least 20 days out of 30 consecutive trading days, or (c) if there is a Sale of Pubco during the Earnout Period, and the holders of Pubco Common Stock receive a Sale Price that is greater or equal to the Earnout Price. |
| (7) | Amount excludes 2,750,000 Sponsor Forfeited Shares, which will be forfeited by the Sponsor upon the consummation of the Business Combination. |
| (8) | Includes 507,964 Earnout Shares, which will be issued and outstanding as of the Closing. |
| (9) | Includes 1,492,036 Earnout Shares, which will be issued and outstanding as of the Closing. |
| (10) | Amount assumes that the SPAC Private Warrants required to be issued or transferred to Harraden pursuant to the Loan and the August Loan are transferred to Harraden by the Sponsor, resulting in no additional dilution. |
Share ownership presented in the two tables above is only presented for illustrative purposes and does not necessarily reflect what Pubco’s share ownership will be after the Closing. SPAC and Company cannot predict how many of the SPAC Public Shareholders will exercise their right to have their SPAC Public Shares redeemed for cash. As a result, the redemption amount and the number of SPAC Public Shares redeemed in connection with the Business Combination may differ from the amounts presented above, and therefore the ownership percentages of SPAC Public Shareholders may also differ if the actual redemptions are different from these assumptions. The SPAC Public Shareholders that do not elect to redeem their SPAC Public Shares will experience immediate dilution as a result of the Business Combination. The SPAC Public Shareholders currently own approximately 59.4% of the issued and outstanding SPAC Ordinary Shares. As noted in the above table, even if no SPAC Public Shareholders redeem their SPAC Public Shares in the Business Combination, the SPAC Public Shareholders’ ownership will decrease from approximately 59.4% of the SPAC Ordinary Shares prior to the Business Combination to owning approximately 20.9% of Pubco Common Stock issued and outstanding at that time and 3.8% of the voting power of the outstanding Pubco Common Stock. As redemptions increase, the overall percentage ownership and voting percentage held by Sponsor, other holders of Founder Shares, and Company equityholders will increase as compared to the overall percentage ownership and voting percentage held by SPAC Public Shareholders, thereby increasing dilution to SPAC Public Shareholders. If the amount of any Transaction Financing is greater than the assumptions above, such financing would further increase dilution to SPAC Public Shareholders. Additionally, to the extent that the Sponsor Investment is made in the form of equity or equity-linked securities, the Sponsor will receive such additional equity pursuant to such investment, which will increase the Sponsor’s percentage ownership and decrease the percentage ownership of the SPAC Public Shareholders and others. The number of such potential equity interests will not be calculable until definitive agreements for any Sponsor Investment are entered into, if any. For more information about the consideration to be received in the Business Combination, these scenarios, and the underlying assumptions, see “Unaudited Pro Forma Combined Financial Information.” See also “Risk Factors — The SPAC Public Shareholders will experience immediate dilution as a consequence of the issuance of Pubco Common Stock as consideration in the Business Combination, potential issuances in connection with financing, and due to future issuances of equity awards to Company employees, directors, or consultants. Having a minority share position may reduce the influence that our current shareholders have on the management of Pubco.”
Each of the 25% Redemptions Scenario, 50% Redemptions Scenario, 75% Redemptions Scenario, and 100% Redemptions Scenario results in an amount of net cash, after the redemptions and the payment of transaction expenses, that is not sufficient to meet the Minimum Cash Condition, without additional financing. As of the date of this proxy statement/prospectus, SPAC has not entered into any Financing Agreement for Transaction Financing, no Sponsor Investment has been made, and the Minimum Cash Condition has not been satisfied. In the event that the Minimum Cash Condition is not satisfied as a result of redemptions of SPAC Public Shares which reduce the amount available to be released to the parties from the Trust Account and/or the failure to obtain third-party financing, the Company may elect not to consummate the Business Combination. Alternately, in the event that the Minimum Cash Condition is not satisfied as a result of redemptions of SPAC Public Shares which reduce the amount available to be released to the parties from the Trust Account and/or the failure to obtain third-party financing, the Company may, in its sole discretion, waive the Minimum Cash Condition. If the Company waives the Minimum Cash Condition, SPAC intends to file a Current Report on Form 8-K within four business days of such event, however such condition may be waived at any time prior to the Closing, including after the deadline for submitting redemption requests or the Extraordinary General Meeting, and, given such timing, you may not be notified before the deadline for submitting redemption requests or the Extraordinary General Meeting.
Interests of Sponsor and SPAC’s Officers and Directors
The Sponsor and SPAC’s officers and directors have interests in the Business Combination that differ from, or are in addition to, and may conflict with, the interests of unaffiliated SPAC Shareholders. SPAC’s officers and directors also have fiduciary or contractual obligations to other entities requiring them to present business combination opportunities to those entities first, though SPAC believes no such opportunities were withheld from it as a result. The SPAC Board considered these interests in evaluating, negotiating, and recommending approval of the Business Combination, and shareholders should likewise consider them in voting on the Business Combination Proposal. These interests include, among others:
| ● | the fact that the Sponsor originally acquired an aggregate of 7,187,500 Founder Shares which were purchased for an aggregate of $25,000, or approximately $0.003 per share, prior to the SPAC IPO. On February 8, 2024, the Sponsor surrendered 1,437,500 Founder Shares for no consideration, resulting in the Sponsor holding 5,750,000 Founder Shares. Of these 5,750,000 Founder Shares held by the Sponsor following the February 8, 2024 surrender, (i) 90,000 Founder Shares were transferred to the Independent Directors (30,000 Founder Shares each) on June 7, 2024, (ii) 2,750,000 Founder Shares will be forfeited and surrendered immediately before the Domestication, (iii) 500,000 Founder Shares may be transferred by the Sponsor, in its discretion, to third parties to incentivize non-redemptions or investments into the SPAC or Pubco and if |
| not so transferred or used will be forfeited, and (iv) 500,000 of the Founder Shares will be subject to an earnout. The remaining Founder Shares are expected to have a significantly higher value at the time of the Business Combination than their original purchase price. At the Closing, the Sponsor and Independent Directors will hold an aggregate of 2,500,000 Pubco Class A Common Stock issued upon the conversion of 2,500,000 Founder Shares, which if unrestricted and freely tradeable, would be valued at approximately $27.3 million, based on the $10.93 closing price of the SPAC Class A Ordinary Shares on NYSE American on October 20, 2026. However, such shares of Pubco Class A Common Stock will be subject to a lock-up described elsewhere in this proxy statement/prospectus. Additionally, pursuant to the Convertible Promissory Note and the August Convertible Promissory Note, Harraden has the option to receive Conversion Shares and is entitled to receive Issuance Warrants and Transferred Shares. The Issuance Warrants are identical to the SPAC Private Warrants held by the Sponsor. The Transferred Shares are to be transferred from the Sponsor to Harraden for each dollar funded by Harraden pursuant to the August Convertible Promissory Note. The Transferred Shares are subject to no transfer restrictions or any other lock-up provisions, earn outs, or other contingencies. Under both the Convertible Promissory Note and the August Convertible Promissory Note, in lieu of issuing the Conversion Shares, Issuance Warrants, and/or Transferred Shares, the Sponsor may re-allocate securities among members of the Sponsor and Graf Global Management LLC to satisfy SPAC’s related obligations. The issuance and/or transfer of these securities is expected to reduce the post-Closing ownership percentage of the Sponsor. |
| ● | the fact that, as a result of the low purchase price paid for the Founder Shares, if the Business Combination is completed, the Sponsor and Independent Directors are likely to be able to make a substantial profit on its investment even at a time when the Pubco Class A Common Stock have lost significant value. Accordingly, the economic interests of the Sponsor and Independent Directors diverge from the economic interests of SPAC Public Shareholders because the Sponsor and Independent Directors will realize a gain on their investment from the completion of any business combination while SPAC Public Shareholders will realize a gain only if the post-closing trading price exceeds $10.00 per share; |
| ● | the fact that the Sponsor holds 4,000,000 SPAC Private Warrants, initially purchased for $1.00 per SPAC Private Warrant, or $4,000,000 in the aggregate, in a private placement that occurred simultaneously with the closing of the SPAC IPO; such warrants will automatically be assumed by Pubco at the effective time of the SPAC Merger and will become Pubco Private Warrants exercisable for 4,000,000 Pubco Class A Common Stock at an initial exercise price of $11.50 per share. SPAC estimates that, at the Closing, if unrestricted and freely tradeable, such Pubco Warrants would be valued at approximately $1.0 million, based on the $0.25 closing price of the SPAC Public Warrants on NYSE American on October 20, 2026. However, such Pubco Warrants will be subject to a lock-up described elsewhere in this proxy statement/prospectus; |
| ● | the fact that Sponsor and the Independent Directors and have waived their rights to redeem any SPAC Ordinary Shares held by them in connection with the shareholder vote to approve the Business Combination; |
| ● | the fact that, if SPAC were to liquidate rather than complete an initial business combination, the Sponsor will lose its entire investment in SPAC, which totals approximately $4,348,000 as of the date of this proxy statement/prospectus, comprising the $25,000 purchase price for the Founder Shares, the $4,000,000 purchase price for the SPAC Private Warrants purchased by Sponsor in a private placement concurrently with the SPAC IPO, and approximately $3,000 of other loans, advances, and out-of-pocket expenses, and $320,000 of accrued administrative services fees. However, if SPAC fails to consummate a business combination by the Business Combination Deadline and liquidates, such loans will not be converted into warrants and any loans, advances, and out-of-pocket expenses will only be repaid to the extent of any cash outside of the Trust Account. The potential loss of this investment may have incentivized Sponsor and its affiliates to pursue a business combination transaction on unfavorable terms in order to avoid a liquidation; |
| ● | the fact that, if the Trust Account is liquidated, including in the event SPAC is unable to complete an initial business combination by the Business Combination Deadline, the Sponsor has agreed that it will be liable to SPAC if and to the extent any claims by a third party for services rendered or products sold to SPAC, or a prospective target business with which SPAC has entered into a written letter of intent, confidentiality or other similar agreement or business combination agreement, reduce the amount of funds in the Trust Account to below the lesser of (i) $10.00 per SPAC Public Share and (ii) the actual amount per SPAC Public Share held in the Trust Account as of the date of the liquidation of the Trust Account, if less than $10.00 per SPAC Public Share due to reductions in the value of the trust assets, less taxes payable and up to $100,000 of interest to pay dissolution expenses; provided that such obligation will not apply to any claims by a third party who executed a waiver of any and all rights to seek access to the Trust Account (whether or not such waiver is enforceable), any claims by |
| SPAC’s independent registered public accounting firm, or any claims under the indemnity of the underwriters of the SPAC IPO against certain liabilities, including liabilities under the Securities Act; |
| ● | the fact that [●], a [director/officer] of SPAC, is expected to be a [director/officer] of Pubco after the Closing. As such, in the future, [●] may receive fees for his service to Pubco, which may consist of cash or stock-based awards, and any other remuneration that the Pubco Board determines to pay; |
| ● | the fact that, pursuant to the Registration Rights Agreement, the Sponsor and Independent Directors will have customary registration rights, including demand and piggy-back rights, subject to cooperation and cut-back provisions with respect to the Pubco Class A Common Stock and Pubco Warrants held by them following the consummation of the Business Combination. SPAC estimates that the Sponsor and Independent Directors will hold an aggregate of 2,500,000 Pubco Class A Common Stock, 4,000,000 Pubco Warrants, and 4,000,000 Pubco Class A Common Stock underlying Pubco Warrants subject to registration rights; |
| ● | the fact that at or immediately prior to the Closing, if the Closing SPAC Cash is less than $100,000,000, the Sponsor must invest, or cause its affiliate or designee to invest, an aggregate of at least $5,000,000 of gross proceeds in a Transaction Financing. To the extent that the Sponsor Investment is made in the form of equity or equity-linked securities, the Sponsor will receive such additional equity pursuant to such investment. The number of such potential equity interests will not be calculable until definitive agreements for any Sponsor Investment are entered into, if any; |
| ● | the fact that, pursuant to the Administrative Services Agreement, commencing on June 25, 2024, through the earlier of consummation of the SPAC’s initial business combination and its liquidation, SPAC agreed to pay an affiliate of the Sponsor $20,000 per month for office space, utilities and secretarial and administrative support services provided to members of the management team. As of the date of this proxy statement/prospectus, the Company had outstanding accrued administrative support services fees of $320,000. Such amounts may not be recoverable if SPAC liquidates without completing an initial business combination; |
| ● | the fact that Pubco and the Company agreed to enter into the Sponsor Indemnification Agreement with Sponsor at the Closing, pursuant to which Pubco and the Company will indemnify, exonerate and hold harmless the Sponsor and the Sponsor Indemnified Persons from and against any and all Sponsor Indemnified Liabilities arising out of or relating to any pending or threatened action, cause of action, suit, litigation, investigation, proceeding, inquiry, arbitration or claim against any of them or in which any of them may be a participant or may otherwise be involved (including as a witness) that arise out of or relates to SPAC’s operations or conduct of its business, the Business Combination, and/or any claim against the Sponsor and/or a Sponsor Indemnified Person alleging any expressed or implied management, control or endorsement of any activities of SPAC, or any express or implied association with Pubco, Company, or SPAC, or any of their respective affiliates. The Sponsor Indemnification Agreement will not however apply to claims arising primarily out of (a) any breach by such Sponsor Indemnified Person of any other agreement between such Sponsor Indemnified Person, on the one hand, and Company, Pubco or SPAC or any of their respective subsidiaries, on the other hand, or (b) the willful misconduct, gross negligence or bad faith of such Sponsor Indemnified Person; and |
| ● | the continued indemnification of former and current directors and officers of SPAC and the continuation of directors’ and officer’s liability insurance after the Business Combination. |
Compensation to be Received by Sponsor and SPAC’s Officers and Directors
Set forth below is a summary of the amount of compensation and securities received or to be received by the Sponsor and SPAC’s officers and directors in connection with the Business Combination.
| Securities to be Received | | Other Compensation | |
|---|---|---|---|---|
The Sponsor |
| 2,410,000 Pubco Class A Common Stock issued upon the exchange of 2,410,000 Founder Shares in the SPAC Merger. On November 24, 2021, the Sponsor paid an aggregate of $25,000 for 7,187,500 Founder Shares, or approximately $0.003 per share. On February 8, 2024, the Sponsor surrendered 1,437,500 Founder Shares for no consideration, resulting in the Sponsor holding 5,750,000 Founder Shares. Of these 5,750,000 Founder Shares held by the Sponsor following the February 8, 2024 surrender, (i) 90,000 Founder Shares were transferred to three independent directors (30,000 Founder Shares each) on June 7, 2024, (ii) 2,750,000 Founder Shares will be forfeited and surrendered immediately before the Domestication, (iii) 500,000 Founder Shares may be transferred by the Sponsor, in its discretion, to third parties to incentivize non-redemptions or investments into the SPAC or Pubco, and (iv) 500,000 of the Founder Shares will be subject to an earnout provision. 4,000,000 Pubco Private Warrants upon the assumption of 4,000,000 SPAC Private Warrants. |
| $20,000 per month through the Closing for office space, utilities, secretarial and administrative support services provided by the Sponsor to members of the SPAC management team. As of the date of this proxy statement/prospectus, $320,000 of accrued administrative services fees was outstanding. Indemnification by Pubco and Company pursuant to the Sponsor Indemnification Agreement, and coverage under Pubco’s directors’ and officer’s insurance policy pursuant to the terms of the Business Combination Agreement. |
James A. Graf |
| See “Sponsor” above. Mr. Graf may be deemed to control the Sponsor. |
| Reimbursement for loans, advances, and out-of-pocket expenses. As of the date of this proxy statement/prospectus, $3,000 was outstanding. Continued indemnification and the continuation of directors’ and officers’ liability insurance after the Business Combination. |
Louis Bélanger-Martin | 30,000 Pubco Class A Common Stock issued upon the exchange of 30,000 Founder Shares. | Reimbursement for loans and advances to SPAC and for out-of-pocket expenses incurred related to identifying, negotiating, investigating and completing the Business Combination. As of the date of this proxy statement/prospectus, no such amounts were outstanding. Continued indemnification and the continuation of directors’ and officer’s liability insurance after the Business Combination. | ||
Kenneth Weinstein | 30,000 Pubco Class A Common Stock issued upon the exchange of 30,000 Founder Shares. | Reimbursement for loans and advances to SPAC and for out-of-pocket expenses incurred related to identifying, negotiating, investigating and completing the Business Combination. As of the date of this proxy statement/prospectus, no such amounts were outstanding. Continued indemnification and the continuation of directors’ and officer’s liability insurance after the Business Combination. |
| Securities to be Received | | Other Compensation | |
|---|---|---|---|---|
Fred S. Zeidman | 30,000 Pubco Class A Common Stock issued upon the exchange of 30,000 Founder Shares. | Reimbursement for loans and advances to SPAC and for out-of-pocket expenses incurred related to identifying, negotiating, investigating and completing the Business Combination. As of the date of this proxy statement/prospectus, no such amounts were outstanding. Continued indemnification and the continuation of directors’ and officer’s liability insurance after the Business Combination. |
Potential Purchases of SPAC Class A Ordinary Shares and SPAC Public Warrants
The Sponsor and SPAC’s officers and directors do not have any plans at this time to purchase SPAC Public Shares or SPAC Public Warrants from SPAC Public Shareholders. Other than (i) the Discretionary Founder Shares, which the Sponsor may, in its discretion, transfer to third parties to incentivize non-redemptions or investments in SPAC or Pubco, and (ii) the 425,602 Assigned Shares (which shall be drawn from the Discretionary Founder Shares allocation noted above) to be issued to the Non-Redeeming Shareholders pursuant to the Extension Non-Redemption Agreements in exchange for the Non-Redeeming Shareholders agreeing to not redeem, or to rescind any prior redemption request, in connection with the shareholder vote at the Extension Meeting, the Sponsor does not plan to take any other actions to incentivize non-redemption. However, at any time prior to the Extraordinary General Meeting, during a period when they are not then aware of any material nonpublic information regarding SPAC or its securities, the Sponsor and SPAC’s officers and directors or their affiliates may purchase SPAC Public Shares or SPAC Public Warrants in privately negotiated transactions or in the open market, although they are under no obligation to do so. There is no limit on the number of SPAC Public Shares or SPAC Public Warrants that such persons may purchase in such transactions, subject to compliance with applicable law and Stock Exchange rules. However, other than as expressly stated herein, they have no current commitments, plans or intentions to engage in such transactions and have not formulated any terms or conditions for any such transactions. None of the funds in the Trust Account will be used to purchase SPAC Public Shares or SPAC Public Warrants in such transactions. Such purchases of SPAC Public Shares may include a contractual acknowledgment that such shareholder, although still the record holder of SPAC’s shares, is no longer the beneficial owner thereof and therefore agrees not to exercise its redemption rights.
In the event that the Sponsor and SPAC’s officers and directors or their affiliates purchase SPAC Public Shares in privately negotiated transactions from SPAC Public Shareholders who have already elected to exercise their redemption rights, such selling shareholders would be required to revoke their prior elections to redeem their shares. The purpose of such transaction could be to increase the likelihood of obtaining shareholder approval of the Business Combination, reduce the number of outstanding SPAC Public Warrants, or satisfy the Minimum Cash Condition, where it appears that such requirement would otherwise not be met. SPAC expects any such purchases will be reported pursuant to Section 13 and Section 16 of the Exchange Act to the extent such purchasers are subject to such reporting requirements.
In addition, if such purchases are made, the public “float” of SPAC Class A Ordinary Shares and SPAC Public Warrants and the number of beneficial holders of SPAC Class A Ordinary Shares and SPAC Public Warrants may be reduced, possibly making it difficult to obtain or maintain the quotation, listing or trading of the SPAC Public Units, SPAC Public Shares, and SPAC Public Warrants on the NYSE American.
In the event that the Sponsor and SPAC’s officers and directors or their affiliates were to purchase SPAC Public Shares or SPAC Public Warrants from SPAC Public Shareholders, such purchases would be structured in compliance with the requirements of Rule 14e-5 under the Exchange Act. To the extent that the Sponsor and SPAC’s officers and directors or their affiliates purchase SPAC Public Shares in compliance with the requirements of Rule 14e-5 under the Exchange Act, such shares would not be voted in favor of approving the Business Combination. See “Business Combination — Potential Purchases of SPAC Public Shares or SPAC Public Warrants” for more information.
SPAC Board’s Reasons for Approval
Before reaching its decision on June 11, 2026, the SPAC Board consulted with its management team, legal counsel and other advisors and considered a variety of factors in connection with its evaluation of the Business Combination. In light of the complexity of those factors, the SPAC Board, as a whole, did not consider it practicable to, nor did it attempt to, quantify or otherwise assign relative weights to the specific factors it took into account in reaching its decision, and different individual members of the SPAC Board may have given different weight to different factors in their evaluation of the Business Combination.
Further, the prospectus for the IPO identified the general criteria and guidelines that SPAC believed would be important in evaluating prospective target businesses, although SPAC also indicated it may enter into a business combination with a target business that does not meet these criteria or guidelines. The SPAC Board considered these criteria in its evaluation of the Company and determined that the Business Combination presents an attractive business opportunity in light of a variety of factors, including the Company’s leading industry position, stable free cash flow profile, committed and capable management team, and growth potential. The SPAC Board did not obtain a fairness opinion from an independent investment banking firm and did not otherwise use traditional valuation metrics, but relied in part on the SPAC management team’s collective experience in evaluating the transaction. The SPAC Board also considered the potential detriments of the Business Combination, including the Company’s early stage of growth, industry and competitive risks, the absence of possible structural protections for minority shareholders, macroeconomic risks, the uncertainty of the potential benefits of the Business Combination being achieved, and the risks and costs to SPAC if the Business Combination is not achieved, including the risk that it may result in SPAC being unable to complete a business combination and force SPAC to liquidate.
For a description of the SPAC Board’s reasons for the approval of the Business Combination and the unanimous recommendation of the SPAC Board, see the subsection entitled “Proposal No. 1 — The Business Combination Proposal — The SPAC Board’s Reasons for the Approval of the Business Combination”.
The Extraordinary General Meeting
The following is a summary of the process and procedures for registering for and attending the Extraordinary General Meeting and voting and redeeming your SPAC Public Shares in connection with the Extraordinary General Meeting. For more information, see section titled “Extraordinary General Meeting.”
Date, Time, and Place
The Extraordinary General Meeting will be held at [●] a.m., Eastern Time, on [●]. The Extraordinary General Meeting will be held virtually, conducted via live webcast at [●]. For purposes of Cayman Islands law and SPAC Organizational Documents, the physical location of the Extraordinary General Meeting will be at the offices of White & Case LLP at 1221 Avenue of the Americas, New York, NY 10020.
Proposals to be Submitted at the Extraordinary General Meeting
At the Extraordinary General Meeting, SPAC is asking holders of SPAC Ordinary Shares to consider and vote upon:
| ● | the Business Combination Proposal; |
| ● | the Domestication Proposal; |
| ● | the SPAC Merger Proposal; |
| ● | the Post-Domestication Organizational Documents Proposal; |
| ● | the Advisory Organizational Documents Proposals; |
| ● | the Equity Incentive Plan Proposal; and |
| ● | the Adjournment Proposal (if presented). |
Registering for the Extraordinary General Meeting
Shareholders wishing to attend the Extraordinary General Meeting virtually should register by [●], Eastern Time, on [●]. Shareholders registered directly with Continental may pre-register (recommended but not required) at https://www.cstproxy.com/[●] using the 12-digit control number on their proxy card or meeting notice, and must log back in with that number just before the meeting starts.
Beneficial shareholders (holding through a bank, broker, or other nominee) must instead obtain a legal proxy from their account holder, email a copy to proxy@continentalstock.com to receive a 12-digit control number and meeting access instructions. Beneficial shareholders should contact Continental at least five Business Days prior to the Extraordinary General Meeting date in order to ensure access.
Record Date
SPAC has fixed [●], 2026 as the Record Date for the Extraordinary General Meeting. SPAC Shareholders at the close of business on the Record Date are entitled to vote on matters that come before the Extraordinary General Meeting. Each SPAC Ordinary Share is entitled to one vote. The shareholder may only vote his, hers, or its shares if he, she, or it is present in person or is represented by proxy at the Extraordinary General Meeting.
As of the Record Date, the Sponsor and other holders of Founder Shares held of record and were entitled to vote an aggregate of 5,750,000 SPAC Ordinary Shares. The SPAC Ordinary Shares held by such persons currently constitutes approximately 40.6% of the outstanding SPAC Ordinary Shares. Pursuant to the Sponsor Support Agreement, the Sponsor and the other holders of Founder Shares have agreed to vote any SPAC Ordinary Shares held by them as of the Record Date in favor of the Business Combination, including voting in favor of each proposal. No consideration has been or will be paid by SPAC, the Company, or Pubco to the Sponsor and other holders of Founder Shares in connection with such agreements. To the extent that the Sponsor and SPAC’s officers and directors or their affiliates purchase SPAC Public Shares in compliance with the requirements of Rule 14e-5 under the Exchange Act, such shares would not be voted in favor of approving the Business Combination.
Voting Power; Abstentions and Broker Non-Votes
With respect to each proposal in this proxy statement/prospectus, you may vote “FOR,” “AGAINST” or “ABSTAIN.”
If a shareholder fails to return a proxy card and does not attend the Extraordinary General Meeting in person, then the shareholder’s shares will not be counted for purposes of determining whether a quorum is present at the Extraordinary General Meeting.
Abstentions will be counted in connection with the determination of whether a valid quorum is established but will not constitute votes cast at the Extraordinary General Meeting and therefore will have no effect on the Business Combination Proposal, Domestication Proposal, Post-Domestication Organizational Documents Proposal, Advisory Organizational Documents Proposals, Equity Incentive Plan Proposal, or Adjournment Proposal as a matter of Cayman law. Abstentions will have the same effect as a vote against the SPAC Merger Proposal.
If your shares are held in a stock brokerage account or by a bank or other nominee, you are considered the “beneficial holder” of the shares held for you in what is known as “street name.” If this is the case, this proxy statement/prospectus may have been forwarded to you by your brokerage firm, bank or other nominee, or its agent, and you may need to obtain a proxy form from the institution that holds your shares and follow the instructions included on that form regarding how to instruct your broker, bank or nominee as to how to vote your shares. Under the rules of various national and regional securities exchanges, your broker, bank, or nominee cannot vote your shares with respect to non-discretionary matters unless you provide instructions on how to vote in accordance with the information and procedures provided to you by your broker, bank, or nominee. We believe all the proposals presented to the shareholders will be considered non-discretionary and therefore your broker, bank, or nominee cannot vote your shares without your instruction. Your bank, broker, or other nominee can vote your shares only if you provide instructions on how to vote. As the beneficial holder, you have the right to direct your broker, bank or other nominee as to how to vote your shares and you should instruct your broker to vote your shares in accordance with directions you provide. If you do not provide voting instructions to your broker on a particular proposal on which your broker does not have discretionary authority to vote, your shares will not be voted on that proposal. This is called a “broker non-vote.” Broker non-votes are not considered present for the purposes of establishing a
quorum, will not count as votes cast at the Extraordinary General Meeting, and otherwise will have no effect on a particular proposal, assuming a valid quorum is established, except for the SPAC Merger Proposal. Broker non-votes will not be considered present for the purposes of establishing a quorum, will not count as a vote cast at the Extraordinary General Meeting and will therefore have the same effect as a vote against the SPAC Merger Proposal.
Redemption Rights
SPAC Public Shareholders (other than the Sponsor and other holders of Founder Shares) may request redemption of all or a portion of their SPAC Public Shares for cash if the Business Combination is consummated. To exercise this right, a holder must, prior to the deadline (two business days before the Extraordinary General Meeting): separate any SPAC Public Units into SPAC Public Shares and SPAC Public Warrants (if applicable); submit a written redemption request to Continental identifying the beneficial owner; and tender or deliver the SPAC Public Shares to Continental, physically or through DTC. Redeeming holders will receive a pro rata portion of the Trust Account (net of taxes payable), estimated at approximately $[●] per Public Share as of the Record Date. Because market prices may exceed the Redemption Price, SPAC Public Shareholders should compare the two before electing redemption, though SPAC cannot guarantee sufficient market liquidity to sell shares at any given price.
A redemption request may be withdrawn before the redemption deadline, and thereafter only with SPAC’s consent until Closing. Shares delivered for redemption can be returned by Continental if withdrawn in time. No redemption will be honored unless shares are actually delivered to Continental by the deadline. Redemptions are capped at 15% of outstanding SPAC Public Shares per holder (together with affiliates or persons acting in concert), with any excess shares not redeemed.
The SPAC Public Shareholders currently own approximately 59.4% of the issued and outstanding SPAC Ordinary Shares. Even if no SPAC Public Shareholders redeem their SPAC Public Shares in the Business Combination, the SPAC Public Shareholders’ ownership will decrease from approximately 59.4% of the SPAC Ordinary Shares prior to the Business Combination to owning approximately 20.9% of Pubco Common Stock issued and outstanding at that time and 3.8% of the voting power of the outstanding Pubco Common Stock. As redemptions increase, the overall percentage ownership and voting percentage held by Sponsor, other holders of Founder Shares, and Company equityholders will increase as compared to the overall percentage ownership and voting percentage held by SPAC Public Shareholders, thereby increasing dilution to SPAC Public Shareholders.
Appraisal and Dissenters’ Rights
Neither SPAC’s shareholders nor SPAC’s warrant holders have appraisal or dissenters’ rights in connection with the Business Combination or the Domestication under Cayman Islands law or the DGCL. SPAC’s shareholders do not have dissenters’ rights in connection with the Business Combination or the Domestication under Cayman Islands law. See the section entitled “Appraisal Rights” for more information.
Regulatory Approvals
Each of SPAC and Company has agreed to use their respective reasonable best efforts to take all actions to consummate and make effective the transactions contemplated by the Business Combination Agreement in the most expeditious manner practicable and to obtain in the most expeditious manner practicable all actions, waivers, consents, approvals, orders and authorizations necessary to be obtained from any third party or any governmental entity in order to complete the transactions contemplated by the Business Combination Agreement. Please see the subsection entitled “The Business Combination – Regulatory Approvals” for additional information.
Stock Exchange Listing
It is a condition to the consummation of the Business Combination that the Pubco Class A Common Stock be listed on the Stock Exchange, subject only to official notice of issuance. Pubco intends to apply for listing, to be effective at Closing, of the Pubco Class A Common Stock and Pubco Warrants on the NYSE American under the symbols “TONT” and “TONT WS”, respectively. However, it is important for you to consider that, at the time of the deadline for submitting redemption requests or the Extraordinary General Meeting, the Pubco may not have received from NYSE American either confirmation of the listing of the Pubco Class A Common Stock and Pubco Public Warrants or confirmation that approval will be obtained prior to the consummation of the Business Combination, and you will not be notified prior to the deadline for submitting redemption requests or the Extraordinary General Meeting if Pubco has not yet received such approval or confirmation. As a result, you may be asked to vote to approve the Business
Combination and the other proposals included in this proxy statement/prospectus without knowing whether Pubco’s securities will be listed on NYSE American or another securities exchange and, further, it is possible that such listing may never be achieved and the Business Combination could still be consummated if such condition is waived. Please see the subsection entitled “The Business Combination — Stock Exchange Listing” for additional information.
Comparison of Shareholders’ Rights
The rights of SPAC Shareholders are currently governed by the Companies Act and the SPAC Organizational Documents. Upon completion of the Business Combination and the Domestication, the rights of SPAC Shareholders who become stockholders of Pubco will be governed by the DGCL and the Pubco Organizational Documents. The Companies Act and Cayman Islands law generally differ in some material respects from laws generally applicable to United States corporations and their stockholders. In addition, the SPAC Organizational Documents differ in certain material respects from the Pubco Organizational Documents. For a detailed comparison, see “Comparison of Corporate Governance and Shareholder Rights.”
Recommendation to SPAC Shareholders
The SPAC Board believes that the Business Combination Proposal and the other proposals to be presented at the Extraordinary General Meeting are fair, advisable and in the best interests of the SPAC and all of its shareholders and recommends that SPAC Shareholders vote “FOR” the approval of the Business Combination Proposal, “FOR” the approval of the Domestication Proposal, “FOR” the approval of the SPAC Merger Proposal, “FOR” the approval of the Post-Domestication Organizational Documents Proposal, “FOR” the approval of each of the Advisory Organizational Documents Proposals, “FOR” the approval of the Equity Incentive Plan Proposal, and “FOR” the approval of the Adjournment Proposal, if presented.
Material U.S. Federal Income Tax Consequences of the Business Combination
For a discussion summarizing material U.S. federal income tax considerations of the Domestication, an exercise of Redemption Rights, the Mergers and other transactions comprising the Business Combination (including the consequences of the Company Merger to Sellers), and the ownership and disposition of Pubco Securities, please see “Material U.S. Federal Income Tax Considerations”.
Anticipated Accounting Treatment
The Business Combination will be accounted for as a reverse recapitalization in accordance with GAAP. Under this method of accounting, although SPAC will acquire all of the outstanding equity interests of the Company in the Business Combination, SPAC will be treated as the “acquired” company and the Company will be treated as the accounting acquirer for financial statement reporting purposes. Accordingly, the Business Combination will be treated as the equivalent of the Company issuing stock for the net assets of SPAC, accompanied by a recapitalization. The net assets of SPAC will be stated at historical cost, with no goodwill or other intangible assets recorded. Operations prior to the Business Combination will be those of the Company.
The Company has been determined to be the accounting acquirer based on evaluation of the following facts and circumstances under both the No Additional Redemptions Scenario and the 100% Redemptions Scenario:
| ● | The Company’s equityholders will have the greatest voting interest in the Pubco; |
| ● | The Company’s equityholders will have the ability to control decisions regarding election and removal of directors and officers of the Pubco; |
| ● | The Company will comprise the ongoing operations of the Pubco; and |
| ● | The Company’s existing senior management will be the senior management of the Pubco. |
See “Unaudited Pro Forma Condensed Combined Financial Information” for more information.
Emerging Growth Company
SPAC is and Pubco will be an “emerging growth company” as defined in Section 2(a) of the Securities Act, as modified by the JOBS Act, and may take advantage of certain exemptions from various reporting requirements that are applicable to other public companies that are not emerging growth companies including, but not limited to, not being required to comply with the auditor attestation requirements of Section 404 of the Sarbanes-Oxley Act, reduced disclosure obligations regarding executive compensation in its periodic reports and proxy statements, and exemptions from the requirements of holding a non-binding advisory vote on executive compensation and shareholder approval of any golden parachute payments not previously approved.
Further, Section 102(b)(1) of the JOBS Act exempts emerging growth companies from being required to comply with new or revised financial accounting standards until private companies (that is, those that have not had a registration statement under the Securities Act declared effective or do not have a class of securities registered under the Exchange Act) are required to comply with the new or revised financial accounting standards. The JOBS Act provides that a company can elect to opt out of the extended transition period and comply with the requirements that apply to non-emerging growth companies but any such election to opt out is irrevocable. SPAC has not elected, and Pubco is not expected to elect, to opt out of such extended transition period, which means that when a standard is issued or revised and it has different application dates for public or private companies, we, as an emerging growth company, can adopt the new or revised standard at the time private companies adopt the new or revised standard. This may make comparison of our financial statements with another public company which is neither an emerging growth company nor an emerging growth company which has opted out of using the extended transition period difficult or impossible because of the potential differences in accounting standards used.
Pubco will remain an emerging growth company until the earlier of: (1) the last day of the fiscal year (a) following the fifth anniversary of the effective date of the registration statement of which this proxy statement/prospectus is a part, (b) in which Pubco has total annual revenue of at least $1.235 billion, or (c) in which Pubco is deemed to be a large accelerated filer, which means the market value of its common equity that is held by non-affiliates exceeds $700 million as of the end of the prior fiscal year’s second fiscal quarter; and (2) the date on which Pubco has issued more than $1.00 billion in non-convertible debt securities during the prior three-year period.
Smaller Reporting Company
SPAC is a “smaller reporting company” as defined in Item 10(f)(1) of Regulation S-K. Smaller reporting companies may take advantage of certain reduced disclosure obligations, including, among other things, providing only two years of audited financial statements.
Following the Closing, Pubco will be required to re-determine its status as a smaller reporting company prior to the time it makes its first filing with the SEC (other than the Current Report on Form 8-K filed with Form 10 Information (as defined in Rule 144(i)(3) of the Securities Act)). Pubco will be able to continue to take advantage of the smaller reporting company scaled disclosures if its voting and non-voting common stock held by non-affiliates is less than $250.0 million measured as of a date within four business days after the consummation of the Business Combination, or the Company’s annual revenue is less than $100.0 million as of the most recently completed fiscal year reported in the Current Report on Form 8-K filed with Form 10 Information (as defined in Rule 144(i)(3) of the Securities Act). If Pubco is no longer a smaller reporting company after this initial determination, it would need to reflect its re-determined status in any filing that is due after the 45-day period following the Closing. We expect that Pubco will remain a smaller reporting company after the Closing. To the extent that Pubco takes advantage of the reduced disclosure obligations available for smaller reporting companies, it may also make comparison of our financial statements with other public companies difficult or impossible.
Risk Factor Summary
In evaluating the Business Combination and the proposals set forth in this proxy statement/prospectus, you should carefully read this proxy statement/prospectus, including the annexes, and especially review and consider the matters addressed under the heading “Cautionary Statements Regarding Forward-Looking Statements” and the risk factors set forth in the section entitled “Risk Factors.” These risks include, but are not limited to, the summary included below.
| ● | The Company has a history of losses and may not achieve or maintain profitability in the future. |
| ● | The Company may have future capital needs and may not be able to obtain additional financing to fund its capital needs on acceptable terms, or at all. |
| ● | The Company’s business is concentrated in a single sports property, Big3 Basketball, and it does not have a diversified portfolio of properties, franchises, or content verticals to offset a decline in the popularity or financial performance of Big3 Basketball. |
| ● | The Company does not currently have a long-term paid media rights agreement in place for the distribution of its games, and its inability to obtain a favorable media rights agreement could prevent it from achieving profitability. |
| ● | The markets in which the Company operates are highly competitive, and the growing global popularity of 3-on-3 basketball may intensify competition for players, media rights, and sponsorships. |
| ● | The Company depends on the continued services of executive management and other key employees, including its founders and league commissioner, and the loss of these individuals could adversely affect its business. |
| ● | The Company could face a variety of risks if it expands into other new and complementary businesses and/or makes certain investments or acquisitions. |
| ● | Failure to protect the Company’s IT systems and confidential information against breakdowns, security breaches, and other cybersecurity risks, including risks arising from the use of artificial intelligence, could adversely affect its business. |
| ● | The Company is subject to extensive governmental regulations, including the FCPA and trade sanctions laws, and its failure to comply with these regulations could adversely affect its business. |
| ● | Pubco will have a dual-class common stock structure under which each share of Pubco Class B Common Stock carries ten votes and each share of Pubco Class A Common Stock carries one vote, concentrating voting control with the Big3 Founders. |
| ● | Pubco will be a holding company with no operations of its own and will depend on its indirect interest in OpCo for its cash flows, and Pubco’s organizational structure may limit the cash available to Pubco and may complicate its financial reporting. |
| ● | If Pubco were deemed to be an “investment company” under the Investment Company Act, its business, financial condition, and results of operations could be materially and adversely affected. |
| ● | There is no public market for the shares of Pubco Class A Common Stock or the Pubco Warrants, and SPAC cannot be sure that an active trading market will develop or that Pubco will obtain or maintain listing on the NYSE or another national securities exchange. |
| ● | SPAC’s independent registered public accounting firm’s report contains an explanatory paragraph that expresses substantial doubt about SPAC’s ability to continue as a “going concern.” |
| ● | Neither the SPAC Board nor any committee thereof obtained a third-party valuation or fairness opinion in determining whether to pursue the Business Combination, so there is no assurance from an independent source that the price SPAC is paying for the Company is fair from a financial point of view. |
| ● | The Sponsor, SPAC’s directors and officers and their affiliates have interests in the Business Combination that are different from, or in addition to and/or in conflict with, those of SPAC Shareholders generally. |
| ● | SPAC Public Shareholders will experience immediate dilution as a consequence of the issuance of Pubco Common Stock as consideration in the Business Combination and due to future issuances of equity awards and other securities. |
| ● | SPAC may not be able to complete the Business Combination within the Combination Period, in which case SPAC would cease all operations except for the purpose of winding up and SPAC would redeem its SPAC Public Shares and liquidate. |
| ● | SPAC may be targeted by securities class action and derivative lawsuits that could result in substantial costs and may delay or prevent the Business Combination from being completed. |
| ● | The Mergers may not qualify as a Section 351 Transaction and the SPAC Merger may not qualify as a Section 368(a) Reorganization, which could result in adverse tax consequences to the parties, to holders of SPAC securities and to the Sellers. |
| ● | The Domestication may result in adverse tax consequences for holders of SPAC Class A Ordinary Shares and SPAC Warrants. |
SPAC is a blank check company incorporated on November 17, 2021 as a Cayman Islands exempted company, formed for the purpose of effecting a merger, share exchange, asset acquisition, stock purchase, reorganization or similar business combination with one or more businesses. Graf Global Corp. is the eighth special purpose acquisition company that James A. Graf has been directly involved with as a member of the sponsor, management and/or board, including seven special purpose acquisition companies that closed business combinations over the past 15 years, among them Target Hospitality Corp., WillScot Holdings Corp. and Velodyne Lidar, Inc. The Sponsor, Graf Global Sponsor LLC, is a Delaware limited liability company formed prior to the IPO to organize, direct and manage the business and affairs of SPAC, with Mr. Graf serving as its sole managing member. See “Questions and Answers About the Business Combination — Who is the Sponsor?” for more information. On June 27, 2024, SPAC completed its initial public offering of 23,000,000 units, including the full exercise of the underwriters’ overallotment option, generating gross proceeds of $230,000,000 before transaction costs, with $230,000,000 placed into the trust account. Simultaneously with the closing of the IPO, SPAC consummated a private placement of warrants generating total proceeds of $6,000,000.
Following the closing of the IPO, SPAC’s officers and directors commenced an active search for prospective businesses or assets to acquire, considering more than 100 potential business combination ideas and engaging in discussions with approximately 30 targets under executed non-disclosure agreements, none of which imposed standstill or similar restrictions. The majority of the potential business combination target companies that SPAC considered were companies in the businesses of technology, industrial services, energyand energy transition, space, autonomous mobility, crypto currencies and sports teams among others. Other than the Company, SPAC was not aware of and did not consider other companies operating professional sports leagues. SPAC ultimately ceased pursuit of these prospective targets for reasons that included an inability to prevail in competitive auctions on acceptable terms, an inability to agree on valuation, targets lacking SEC-compliant financial statements on a workable timetable, targets lacking sufficient access to capital, targets not being ready to pursue a business combination or having preferable all-cash alternatives, and extensive structuring or regulatory considerations that would have added execution uncertainty.
In April 2026, SPAC began discussions with the Company and its advisors regarding a potential business combination, facilitated by Fehmi Zeko, managing partner of MC Strategic Advisors, financial advisor to the Company, and a board director of the Company. Mr. Zeko had mentioned the Company to Mr. Graf informally several times over the years and originally introduced Jeffrey
Kwatinetz, Co-founder and Chairman of the Company, to Mr. Graf and Graf I in early 2020, when a possible transaction with a special purpose acquisition company was first broached. None of those conversations were substantive, however, given the relative early stage of the business, and in early 2020 in particular, the uncertain impact of emerging COVID-19 on the Company’s upcoming season, no due diligence was performed, no prospective investors were contacted and no draft term sheets were delivered. On April 2, 2026, SPAC and the Company signed a non-disclosure agreement, and on April 12, 2026, Mr. Graf delivered a draft letter of intent and term sheet proposing an initial valuation of $185 million, which was subsequently increased to $195 million. Following due diligence, data room access, and negotiations between the parties and their respective advisors, including discussion of the per-share price used for the Company’s share consideration and the mechanism for obtaining Company equityholder approval, the Big3 LOI was signed by SPAC and the Company on April 28, 2026, with the SPAC Board unanimously supporting the transaction. During negotiation of the Business Combination Agreement, following discussions with one of the Company’s large institutional investors, the Company informed SPAC that it would not proceed at a transaction value of less than $290 million, which SPAC accepted as the only material change in valuation from the signed letter of intent. SPAC did not retain a financial advisor to assist with establishing a valuation for the Company. Instead, SPAC relied in part on the over 100 years of collective investment banking, capital markets and deal-making experience of its management team and SPAC Board to value the Company and assess market receptivity to such a story. In accepting the Company’s proposed $290 million valuation, the SPAC team did not review revenue or profit projections for the Company, given the emerging nature of the Company’s business, expected transformation of the business model with the expected capital and public currency provided by the transaction, and the absence of directly comparable public companies. SPAC believed that there were no other publicly-traded professional sports leagues in the United States, and SPAC determined that valuation metrics for standalone publicly-traded major sports teams or other athletic promotions are not necessarily relevant to the business of an emerging league.
On June 11, 2026, the SPAC Board unanimously (i) determined that it was in SPAC’s best interest and the interest of SPAC Shareholders for SPAC to enter into the Business Combination Agreement and each ancillary agreement thereto, (ii) approved the transactions contemplated by the Business Combination Agreement and the ancillary agreements, and (iii) adopted resolutions recommending the adoption of the Business Combination Agreement and the approval of each ancillary agreement thereto by SPAC Shareholders. The Business Combination Agreement and related ancillary transaction documents were finalized and executed by SPAC, the Company and other parties thereto on June 12, 2026, and the parties issued a joint press release announcing the transaction on that same date.
Pre-Domestication
Prior to the Domestication, pursuant to the Business Combination Agreement: (1) the Redemption will occur; (2) the Unit Separation will occur, whereby each SPAC Public Unit will separate into one SPAC Class A Ordinary Share and one-half of one SPAC Public Warrant, after which all SPAC Public Units will be cancelled; (3) the Sponsor will surrender the Sponsor Forfeited Shares and Discretionary Founder Shares (to the extent such shares are not transferred or used pursuant to the Sponsor Support Agreement); and (4) the SPAC Class B Share Conversion will occur, whereby the Sponsor will convert the sole remaining outstanding SPAC Class B Ordinary Share into one SPAC Class A Ordinary Share on a one-for-one basis.
Domestication
One day before the SPAC Merger Effective Time, subject to SPAC Class B Ordinary Shareholder approval and the required Cayman and Delaware filings, SPAC will transfer by continuation from the Cayman Islands to Delaware, deregistering as a Cayman exempted company and converting into a Delaware corporation. Upon the Domestication: (1) each outstanding SPAC Class A Ordinary Share will convert into one share of Post-Domestication SPAC Common Stock; and (2) each outstanding whole SPAC Warrant will become one Post-Domestication SPAC Warrant exercisable for one share of Post-Domestication SPAC Common Stock instead of one SPAC Class A Ordinary Share. No fractional shares or warrants will be issued; fractional entitlements will be rounded down and carry no stockholder or warrant holder rights.
The SPAC Merger
At the SPAC Merger Effective Time, SPAC Merger Sub will merge with and into Post-Domestication SPAC, with Post-Domestication SPAC surviving. Pursuant to the SPAC Merger: (1) each outstanding share of Post-Domestication SPAC Common
Stock will automatically convert into the right to receive one share of Pubco Class A Common Stock, and will thereupon be cancelled and cease to exist, and (2) each Post-Domestication SPAC Warrant will convert into one Pubco Warrant.
Pre-Company Merger
Immediately before the Company Merger Effective Time, each outstanding Company Convertible Security (other than Company Warrants), including accrued interest, will convert in full into Company Interests. The SPAC Merger and Company Merger will be effected by filing certificates of merger with the Delaware Secretary of State under the DGCL and DLLCA, respectively, with the SPAC Merger occurring first, on the Closing Date (or such other date/time as the Company and SPAC agree).
The Company Merger
At the Company Merger Effective Time, Company Merger Sub will merge with and into the Company, with the Company surviving. Pursuant to the Company Merger: (1) each Company Interest issued and outstanding will be cancelled and cease to exist in exchange for the right to receive its portion of the Merger Consideration, (2) each Company Warrant that is outstanding will be converted into and become a warrant exercisable for Pubco Class A Common Stock (as of the date of this proxy statement/prospectus, there are no Company Warrants outstanding), (3) any outstanding Company Convertible (excluding Company Warrants that are converted into warrants exercisable for Pubco Class A Common Stock, of which none are outstanding as of the date of this proxy statement/prospectus) and Preferred Units (other than Preferred Units that are converted into Merger Consideration), if not exercised or converted prior to the Company Merger Effective Time, will be cancelled, retired and terminated.
Recommendation to SPAC Shareholders
The SPAC Board believes that the Business Combination Proposal and the other proposals to be presented at the Extraordinary General Meeting are fair, advisable and in the best interests of the SPAC and all of its shareholders and recommends that SPAC Shareholders vote “FOR” the approval of the Business Combination Proposal, “FOR” the approval of the Domestication Proposal, “FOR” the approval of the SPAC Merger Proposal, “FOR” the approval of the Post-Domestication Organizational Documents Proposal, “FOR” the approval of each of the Advisory Organizational Documents Proposals, “FOR” the approval of the Equity Incentive Plan Proposal, and “FOR” the approval of the Adjournment Proposal, if presented.
The following tables illustrate estimated ownership levels in Pubco, immediately following the consummation of the Business Combination, based on varying levels of redemptions by SPAC Public Shareholders. Each redemptions scenario assumes no Transaction Financing, no Sponsor Investment, the forfeiture of 2,750,000 Sponsor Forfeited Shares, includes the 2,000,000 Earnout Shares, which will be issued and outstanding at the Closing and subject to vesting, and assumes the Company’s Cash Position is $0.00 (as of June 30, 2026).
The following table excludes the dilutive effect of Pubco Warrants, Company Converted Warrants, and Pubco Class A Common Stock that will initially be available for issuance under the 2026 Equity Incentive Plan.
| No Additional Redemptions | |
| ||||||||||||||||||||||||||||||||||||||
| Scenario | | 25% Redemptions Scenario | | 50% Redemptions Scenario | | 75% Redemptions Scenario | | 100% Redemptions Scenario |
| |||||||||||||||||||||||||||||||
Percent | Percent | Percent | Percent | Percent |
| ||||||||||||||||||||||||||||||||||||
of | of | of | of | of |
| ||||||||||||||||||||||||||||||||||||
Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent |
| |||||||||||||||||||||
Class A | Class B | Pubco | of | Class A | Class B | Pubco | of | Class A | Class B | Pubco | of | Class A | Class B | Pubco | of | Class A | Class B | Pubco | of |
| |||||||||||||||||||||
Common | Common | Common | Voting | Common | Common | Common | Voting | Common | Common | Common | Voting | Common | Common | Common | Voting | Common | Common | Common | Voting |
| |||||||||||||||||||||
Pro Forma Ownership | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) |
|
Public Shares(2) | 8,409,633 |
| — |
| 20.9 | % | 3.8 | % | 6,307,225 |
| — |
| 16.6 | % | 2.9 | % | 4,204,817 |
| — |
| 11.7 | % | 1.9 | % | 2,102,409 |
| — |
| 6.2 | % | 1.0 | % | — |
| — |
| 0.0 | % | 0.0 | % | |
Founder Shares(3)(4)(5)(6)(7)(8)(9) | 3,000,000 |
| — |
| 7.5 | % | 1.4 | % | 3,000,000 |
| — |
| 7.9 | % | 1.4 | % | 3,000,000 |
| — |
| 8.3 | % | 1.4 | % | 3,000,000 |
| — |
| 8.9 | % | 1.4 | % | 3,000,000 |
| — |
| 9.4 | % | 1.4 | % | |
Company shareholders (other than Big3 Founders) | 7,308,958 |
| — |
| 18.2 | % | 3.3 | % | 7,308,958 |
| — |
| 19.2 | % | 3.4 | % | 7,308,958 |
| — |
| 20.3 | % | 3.4 | % | 7,308,958 |
| — |
| 21.6 | % | 3.4 | % | 7,308,958 |
| — |
| 23.0 | % | 3.5 | % | |
Big3 Founders | 1,492,036 |
| 19,976,476 |
| 53.4 | % | 91.5 | % | 1,492,036 |
| 19,976,476 |
| 56.4 | % | 92.4 | % | 1,492,036 |
| 19,976,476 |
| 59.7 | % | 93.3 | % | 1,492,036 |
| 19,976,476 |
| 63.4 | % | 94.2 | % | 1,492,036 |
| 19,976,476 |
| 67.6 | % | 95.1 | % | |
Total | 20,210,627 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 18,108,219 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 16,005,811 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 13,903,403 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 11,800,994 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | |
*Less than 1%.
| (1) | Each share of Pubco Class A Common Stock will entitle the holder thereof to one (1) vote per share on all matters on which the Pubco Class A Common Stock are entitled to vote, and each share of Pubco Class B Common Stock will entitle the holder thereof to ten (10) votes per share on all matters on which the Pubco Class B Common Stock are entitled to vote. |
| (2) | Amount comprises the unredeemed Public Shares in a variety of redemptions scenarios. This amount reflects the assumed redemption of (i) 0 shares under the No Additional Redemptions Scenario, (ii) 2,102,408 shares under the 25% Redemptions Scenario, (iii) 4,204,816 shares under the 50% Redemptions Scenario, (iv) 6,307,224 shares under the 75% Redemptions Scenario, and (v) 8,409,633 shares under the 100% Redemptions Scenario. |
| (3) | In each redemptions scenario, includes 500,000 Discretionary Founder Shares, assuming that all such shares will be used to incentivize non-redemptions or investments into the SPAC or Pubco or otherwise to support the Transactions. Such amount includes 425,602 Assigned Shares. On June 26, 2026, in connection with the Extension Meeting, SPAC and the Sponsor entered into non-redemption agreements with Non-Redeeming Shareholders covering 4,256,015 SPAC Class A Ordinary Shares, under which those shareholders agreed not to redeem (or to rescind any redemption of) such shares in connection with a vote to approve the Extension Amendment Proposal presented at the Extension Meeting. The Non-Redeeming Shareholders were not affiliates of SPAC, the Sponsor, or SPAC’s officers or directors. In exchange, the Sponsor agreed to transfer 425,602 Founder Shares to the Non-Redeeming Shareholders promptly after closing of the Business Combination, conditioned on (i) the shares not being redeemed, (ii) approval of the Extension Amendment Proposal, and (iii) consummation of the Business Combination. The Non-Redeeming Shareholders also received registration rights for the Assigned Shares under the same registration rights agreement used by the Sponsor. The Assigned Shares come from the Sponsor’s pool of up to 500,000 Discretionary Founder Shares earmarked to incentivize non-redemptions/investment in support of the Business Combination. Any unused portion of the Discretionary Founder Shares will be forfeited at the Closing. |
| (4) | Amount includes 30,000 Founder Shares held by each of SPAC’s Independent Directors. |
| (5) | Amount includes 300,000 Transferred Shares, assuming the repayment of the following loans in cash at the Closing. On June 10, 2026, SPAC, Harraden, and James A. Graf entered into the Convertible Promissory Note, replacing a prior promissory note dated June 4, 2026, and consolidating $200,000 in working capital advances previously made by Harraden into a fully drawn, non-interest bearing, unsecured Loan that was fully outstanding as of June 30, 2026 and is due upon the earlier of the initial business combination or SPAC’s liquidation. At Harraden’s discretion, the Loan may convert into SPAC Class A Ordinary Shares at $10.00 per share, with Harraden also entitled to one warrant per dollar funded, issuable immediately prior to Closing on terms identical to SPAC Private Warrants issued to the Sponsor. Subsequently, on August 10, 2026, SPAC, Harraden, and James A. Graf entered into the August Convertible Promissory Note, under which SPAC may borrow up to an additional $300,000 for working capital |
| and general corporate purposes on similar non-interest bearing, unsecured terms due upon the earlier of the initial business combination or liquidation. At Harraden’s discretion, the August Loan may convert into SPAC Class A Ordinary Shares at $10.00 per share, and for each dollar funded Harraden is entitled to one warrant to purchase one SPAC Class A Ordinary Share on terms identical to SPAC Private Warrants, plus one unrestricted SPAC Ordinary Share transferred by the Sponsor, each issuable or to be transferred, as applicable, immediately prior to Closing. |
| (6) | Amount includes 500,000 Founder Shares that will be subject to vesting and will vest: (a) if the funds in the Trust Account plus any financing, minus cash used for redemptions of SPAC Public Shares equals or exceeds $200 million, (b) if during the Earnout Period, the closing price of Pubco Class A Common Stock equals or exceeds $15.00 for at least 20 days out of 30 consecutive trading days, or (c) if there is a Sale of Pubco during the Earnout Period, and the holders of Pubco Common Stock receive a Sale Price that is greater or equal to the Earnout Price. |
| (7) | Amount excludes 2,750,000 Sponsor Forfeited Shares, which will be forfeited by the Sponsor upon the consummation of the Business Combination. |
| (8) | Includes 507,964 Earnout Shares, which will be issued and outstanding as of the Closing. |
| (9) | Includes 1,492,036 Earnout Shares, which will be issued and outstanding as of the Closing. |
Dilutive Instruments
The following table shows possible sources of dilution and the extent of such dilution that non-redeeming SPAC Public Shareholders could experience in connection with the closing of the Business Combination. In an effort to illustrate the extent of such dilution, the table below assumes the exercise of all Pubco Warrants for a cash exercise price of $11.50. The table excludes Pubco Common Stock that will initially be available for issuance under the 2026 Equity Incentive Plan, as such shares will not be outstanding on the Closing Date.
| No Additional Redemptions |
| |||||||||||||||||||||||||||||||||||||||
| Scenario | | 25% Redemptions Scenario | | 50% Redemptions Scenario | | 75% Redemptions Scenario | | 100% Redemptions Scenario |
| |||||||||||||||||||||||||||||||
Percent | Percent | Percent | Percent | Percent |
| ||||||||||||||||||||||||||||||||||||
of | of | of | of | of |
| ||||||||||||||||||||||||||||||||||||
Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent | Pubco | Pubco | Outstanding | Percent |
| |||||||||||||||||||||
Class A | Class B | Pubco | of | Class A | Class B | Pubco | of | Class A | Class B | Pubco | of | Class A | Class B | Pubco | of | Class A | Class B | Pubco | of |
| |||||||||||||||||||||
Common | Common | Common | Voting | Common | Common | Common | Voting | Common | Common | Common | Voting | Common | Common | Common | Voting | Common | Common | Common | Voting |
| |||||||||||||||||||||
Pro Forma Ownership | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) | | Stock | | Stock | | Stock | | Power(1) |
|
Public Shares(2) | 8,409,633 |
| — |
| 14.6 | % | 3.5 | % | 6,307,225 |
| — |
| 11.3 | % | 2.7 | % | 4,204,817 |
| — |
| 7.9 | % | 1.8 | % | 2,102,409 |
| — |
| 4.1 | % | * |
| — |
| — |
| 0.0 | % | 0.0 | % | |
Founder Shares(3)(4)(5)(6)(7)(8)(9) | 3,000,000 |
| — |
| 5.2 | % | 1.3 | % | 3,000,000 |
| — |
| 5.4 | % | 1.3 | % | 3,000,000 |
| — |
| 5.6 | % | 1.3 | % | 3,000,000 |
| — |
| 5.8 | % | 1.3 | % | 3,000,000 |
| — |
| 6.1 | % | 1.3 | % | |
Public Warrants | 11,500,000 |
| — |
| 19.9 | % | 4.8 | % | 11,500,000 |
| — |
| 20.7 | % | 4.9 | % | 11,500,000 |
| — |
| 21.5 | % | 4.9 | % | 11,500,000 |
| — |
| 22.4 | % | 5.0 | % | 11,500,000 |
| — |
| 23.3 | % | 5.0 | % | |
Private Placement Warrants(10) | 6,000,000 |
| — |
| 10.4 | % | 2.5 | % | 6,000,000 |
| — |
| 10.8 | % | 2.5 | % | 6,000,000 |
| — |
| 11.2 | % | 2.6 | % | 6,000,000 |
| — |
| 11.7 | % | 2.6 | % | 6,000,000 |
| — |
| 12.2 | % | 2.6 | % | |
Company shareholders (other than Big3 Founders) | 7,308,958 |
| — |
| 12.7 | % | 3.1 | % | 7,308,958 |
| — |
| 13.1 | % | 3.1 | % | 7,308,958 |
| — |
| 13.7 | % | 3.1 | % | 7,308,958 |
| — |
| 14.2 | % | 3.2 | % | 7,308,958 |
| — |
| 14.8 | % | 3.2 | % | |
Big3 Founders | 1,492,036 |
| 19,976,476 |
| 37.2 | % | 84.7 | % | 1,492,036 |
| 19,976,476 |
| 38.6 | % | 85.5 | % | 1,492,036 |
| 19,976,476 |
| 40.1 | % | 86.3 | % | 1,492,036 |
| 19,976,476 |
| 41.8 | % | 87.1 | % | 1,492,036 |
| 19,976,476 |
| 43.6 | % | 87.9 | % | |
Total | 37,710,627 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 35,608,219 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 33,505,811 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 31,403,403 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | 29,003,994 |
| 19,976,476 |
| 100.0 | % | 100.0 | % | |
*Less than 1%.
| (1) | Each share of Pubco Class A Common Stock will entitle the holder thereof to one (1) vote per share on all matters on which the Pubco Class A Common Stock are entitled to vote, and each share of Pubco Class B Common Stock will entitle the holder thereof to ten (10) votes per share on all matters on which the Pubco Class B Common Stock are entitled to vote. |
| (2) | Amount comprises the unredeemed Public Shares in a variety of redemptions scenarios. This amount reflects the assumed redemption of (i) 0 shares under the No Additional Redemptions Scenario, (ii) 2,102,408 shares under the 25% Redemptions Scenario, (iii) 4,204,816 shares under the 50% Redemptions Scenario, (iv) 6,307,224 shares under the 75% Redemptions Scenario, and (v) 8,409,633 shares under the 100% Redemptions Scenario. |
| (3) | In each redemptions scenario, includes 500,000 Discretionary Founder Shares, assuming that all such shares will be used to incentivize non-redemptions or investments into the SPAC or Pubco or otherwise to support the Transactions. Such amount includes 425,602 Assigned Shares. On June 26, 2026, in connection with the Extension Meeting, SPAC and the Sponsor entered into non-redemption agreements with Non-Redeeming Shareholders covering 4,256,015 SPAC Class A Ordinary Shares, under which those shareholders agreed not to redeem (or to rescind any redemption of) such shares in connection with a vote to approve the Extension Amendment Proposal presented at the Extension Meeting. The Non-Redeeming Shareholders were not affiliates of SPAC, the Sponsor, or SPAC’s officers or directors. In exchange, the Sponsor agreed to transfer 425,602 Founder Shares to the Non-Redeeming Shareholders promptly after closing of the Business Combination, conditioned on (i) the shares not being redeemed, (ii) approval of the Extension Amendment Proposal, and (iii) consummation of the Business Combination. The Non-Redeeming Shareholders also received registration rights for the Assigned Shares under the same registration rights agreement used by the Sponsor. The Assigned Shares come from the Sponsor’s pool of up to 500,000 Discretionary Founder Shares earmarked to incentivize non-redemptions/investment in support of the Business Combination. Any unused portion of the Discretionary Founder Shares will be forfeited at the Closing. |
| (4) | Amount includes 30,000 Founder Shares held by each of SPAC’s Independent Directors. |
| (5) | Amount includes 300,000 Transferred Shares, assuming the repayment of the following loans in cash at the Closing. On June 10, 2026, SPAC, Harraden, and James A. Graf entered into the Convertible Promissory Note, replacing a prior promissory note dated June 4, 2026, and consolidating $200,000 in working capital advances previously made by Harraden into a fully drawn, non-interest bearing, unsecured Loan that was fully outstanding as of June 30, 2026 and is due upon the earlier of the initial business combination or SPAC’s liquidation. At Harraden’s discretion, the Loan may convert into SPAC Class A Ordinary Shares at $10.00 per share, with Harraden also entitled to one warrant per dollar funded, issuable immediately prior to Closing on terms identical to SPAC Private Warrants issued to the Sponsor. Subsequently, on August 10, 2026, SPAC, Harraden, and James A. Graf entered into the August Convertible Promissory Note, under which SPAC may borrow up to an additional $300,000 for working capital and general corporate purposes on similar non-interest bearing, unsecured terms due upon the earlier of the initial business combination or liquidation. At Harraden’s discretion, the August Loan may convert into SPAC Class A Ordinary Shares at $10.00 per share, and for each dollar funded Harraden is entitled to one warrant to purchase one SPAC Class A Ordinary Share on terms identical to SPAC Private Warrants, plus one unrestricted SPAC Ordinary Share transferred by the Sponsor, each issuable or to be transferred, as applicable, immediately prior to Closing. |
| (6) | Amount includes 500,000 Founder Shares that will be subject to vesting and will vest: (a) if the funds in the Trust Account plus any financing, minus cash used for redemptions of SPAC Public Shares equals or exceeds $200 million, (b) if during the Earnout Period, the closing price of Pubco Class A Common Stock equals or exceeds $15.00 for at least 20 days out of 30 consecutive trading days, or (c) if there is a Sale of Pubco during the Earnout Period, and the holders of Pubco Common Stock receive a Sale Price that is greater or equal to the Earnout Price. |
| (7) | Amount excludes 2,750,000 Sponsor Forfeited Shares, which will be forfeited by the Sponsor upon the consummation of the Business Combination. |
| (8) | Includes 507,964 Earnout Shares, which will be issued and outstanding as of the Closing. |
| (9) | Includes 1,492,036 Earnout Shares, which will be issued and outstanding as of the Closing. |
| (10) | Amount assumes that the SPAC Private Warrants required to be issued or transferred to Harraden pursuant to the Loan and the August Loan are transferred to Harraden by the Sponsor, resulting in no additional dilution. |
The Sponsor and SPAC’s officers and directors have interests in the Business Combination that differ from, or are in addition to, and may conflict with, the interests of unaffiliated SPAC Shareholders. SPAC’s officers and directors also have fiduciary or contractual obligations to other entities requiring them to present business combination opportunities to those entities first, though SPAC believes no such opportunities were withheld from it as a result. The SPAC Board considered these interests in evaluating, negotiating, and recommending approval of the Business Combination, and shareholders should likewise consider them in voting on the Business Combination Proposal. These interests include, among others:
| ● | the fact that the Sponsor originally acquired an aggregate of 7,187,500 Founder Shares which were purchased for an aggregate of $25,000, or approximately $0.003 per share, prior to the SPAC IPO. On February 8, 2024, the Sponsor surrendered 1,437,500 Founder Shares for no consideration, resulting in the Sponsor holding 5,750,000 Founder Shares. Of these 5,750,000 Founder Shares held by the Sponsor following the February 8, 2024 surrender, (i) 90,000 Founder Shares were transferred to the Independent Directors (30,000 Founder Shares each) on June 7, 2024, (ii) 2,750,000 Founder Shares will be forfeited and surrendered immediately before the Domestication, (iii) 500,000 Founder Shares may be transferred by the Sponsor, in its discretion, to third parties to incentivize non-redemptions or investments into the SPAC or Pubco and if |
| not so transferred or used will be forfeited, and (iv) 500,000 of the Founder Shares will be subject to an earnout. The remaining Founder Shares are expected to have a significantly higher value at the time of the Business Combination than their original purchase price. At the Closing, the Sponsor and Independent Directors will hold an aggregate of 2,500,000 Pubco Class A Common Stock issued upon the conversion of 2,500,000 Founder Shares, which if unrestricted and freely tradeable, would be valued at approximately $27.3 million, based on the $10.93 closing price of the SPAC Class A Ordinary Shares on NYSE American on October 20, 2026. However, such shares of Pubco Class A Common Stock will be subject to a lock-up described elsewhere in this proxy statement/prospectus. Additionally, pursuant to the Convertible Promissory Note and the August Convertible Promissory Note, Harraden has the option to receive Conversion Shares and is entitled to receive Issuance Warrants and Transferred Shares. The Issuance Warrants are identical to the SPAC Private Warrants held by the Sponsor. The Transferred Shares are to be transferred from the Sponsor to Harraden for each dollar funded by Harraden pursuant to the August Convertible Promissory Note. The Transferred Shares are subject to no transfer restrictions or any other lock-up provisions, earn outs, or other contingencies. Under both the Convertible Promissory Note and the August Convertible Promissory Note, in lieu of issuing the Conversion Shares, Issuance Warrants, and/or Transferred Shares, the Sponsor may re-allocate securities among members of the Sponsor and Graf Global Management LLC to satisfy SPAC’s related obligations. The issuance and/or transfer of these securities is expected to reduce the post-Closing ownership percentage of the Sponsor. |
| ● | the fact that, as a result of the low purchase price paid for the Founder Shares, if the Business Combination is completed, the Sponsor and Independent Directors are likely to be able to make a substantial profit on its investment even at a time when the Pubco Class A Common Stock have lost significant value. Accordingly, the economic interests of the Sponsor and Independent Directors diverge from the economic interests of SPAC Public Shareholders because the Sponsor and Independent Directors will realize a gain on their investment from the completion of any business combination while SPAC Public Shareholders will realize a gain only if the post-closing trading price exceeds $10.00 per share; |
| ● | the fact that the Sponsor holds 4,000,000 SPAC Private Warrants, initially purchased for $1.00 per SPAC Private Warrant, or $4,000,000 in the aggregate, in a private placement that occurred simultaneously with the closing of the SPAC IPO; such warrants will automatically be assumed by Pubco at the effective time of the SPAC Merger and will become Pubco Private Warrants exercisable for 4,000,000 Pubco Class A Common Stock at an initial exercise price of $11.50 per share. SPAC estimates that, at the Closing, if unrestricted and freely tradeable, such Pubco Warrants would be valued at approximately $1.0 million, based on the $0.25 closing price of the SPAC Public Warrants on NYSE American on October 20, 2026. However, such Pubco Warrants will be subject to a lock-up described elsewhere in this proxy statement/prospectus; |
| ● | the fact that Sponsor and the Independent Directors and have waived their rights to redeem any SPAC Ordinary Shares held by them in connection with the shareholder vote to approve the Business Combination; |
| ● | the fact that, if SPAC were to liquidate rather than complete an initial business combination, the Sponsor will lose its entire investment in SPAC, which totals approximately $4,348,000 as of the date of this proxy statement/prospectus, comprising the $25,000 purchase price for the Founder Shares, the $4,000,000 purchase price for the SPAC Private Warrants purchased by Sponsor in a private placement concurrently with the SPAC IPO, and approximately $3,000 of other loans, advances, and out-of-pocket expenses, and $320,000 of accrued administrative services fees. However, if SPAC fails to consummate a business combination by the Business Combination Deadline and liquidates, such loans will not be converted into warrants and any loans, advances, and out-of-pocket expenses will only be repaid to the extent of any cash outside of the Trust Account. The potential loss of this investment may have incentivized Sponsor and its affiliates to pursue a business combination transaction on unfavorable terms in order to avoid a liquidation; |
| ● | the fact that, if the Trust Account is liquidated, including in the event SPAC is unable to complete an initial business combination by the Business Combination Deadline, the Sponsor has agreed that it will be liable to SPAC if and to the extent any claims by a third party for services rendered or products sold to SPAC, or a prospective target business with which SPAC has entered into a written letter of intent, confidentiality or other similar agreement or business combination agreement, reduce the amount of funds in the Trust Account to below the lesser of (i) $10.00 per SPAC Public Share and (ii) the actual amount per SPAC Public Share held in the Trust Account as of the date of the liquidation of the Trust Account, if less than $10.00 per SPAC Public Share due to reductions in the value of the trust assets, less taxes payable and up to $100,000 of interest to pay dissolution expenses; provided that such obligation will not apply to any claims by a third party who executed a waiver of any and all rights to seek access to the Trust Account (whether or not such waiver is enforceable), any claims by |
| SPAC’s independent registered public accounting firm, or any claims under the indemnity of the underwriters of the SPAC IPO against certain liabilities, including liabilities under the Securities Act; |
| ● | the fact that [●], a [director/officer] of SPAC, is expected to be a [director/officer] of Pubco after the Closing. As such, in the future, [●] may receive fees for his service to Pubco, which may consist of cash or stock-based awards, and any other remuneration that the Pubco Board determines to pay; |
| ● | the fact that, pursuant to the Registration Rights Agreement, the Sponsor and Independent Directors will have customary registration rights, including demand and piggy-back rights, subject to cooperation and cut-back provisions with respect to the Pubco Class A Common Stock and Pubco Warrants held by them following the consummation of the Business Combination. SPAC estimates that the Sponsor and Independent Directors will hold an aggregate of 2,500,000 Pubco Class A Common Stock, 4,000,000 Pubco Warrants, and 4,000,000 Pubco Class A Common Stock underlying Pubco Warrants subject to registration rights; |
| ● | the fact that at or immediately prior to the Closing, if the Closing SPAC Cash is less than $100,000,000, the Sponsor must invest, or cause its affiliate or designee to invest, an aggregate of at least $5,000,000 of gross proceeds in a Transaction Financing. To the extent that the Sponsor Investment is made in the form of equity or equity-linked securities, the Sponsor will receive such additional equity pursuant to such investment. The number of such potential equity interests will not be calculable until definitive agreements for any Sponsor Investment are entered into, if any; |
| ● | the fact that, pursuant to the Administrative Services Agreement, commencing on June 25, 2024, through the earlier of consummation of the SPAC’s initial business combination and its liquidation, SPAC agreed to pay an affiliate of the Sponsor $20,000 per month for office space, utilities and secretarial and administrative support services provided to members of the management team. As of the date of this proxy statement/prospectus, the Company had outstanding accrued administrative support services fees of $320,000. Such amounts may not be recoverable if SPAC liquidates without completing an initial business combination; |
| ● | the fact that Pubco and the Company agreed to enter into the Sponsor Indemnification Agreement with Sponsor at the Closing, pursuant to which Pubco and the Company will indemnify, exonerate and hold harmless the Sponsor and the Sponsor Indemnified Persons from and against any and all Sponsor Indemnified Liabilities arising out of or relating to any pending or threatened action, cause of action, suit, litigation, investigation, proceeding, inquiry, arbitration or claim against any of them or in which any of them may be a participant or may otherwise be involved (including as a witness) that arise out of or relates to SPAC’s operations or conduct of its business, the Business Combination, and/or any claim against the Sponsor and/or a Sponsor Indemnified Person alleging any expressed or implied management, control or endorsement of any activities of SPAC, or any express or implied association with Pubco, Company, or SPAC, or any of their respective affiliates. The Sponsor Indemnification Agreement will not however apply to claims arising primarily out of (a) any breach by such Sponsor Indemnified Person of any other agreement between such Sponsor Indemnified Person, on the one hand, and Company, Pubco or SPAC or any of their respective subsidiaries, on the other hand, or (b) the willful misconduct, gross negligence or bad faith of such Sponsor Indemnified Person; and |
| ● | the continued indemnification of former and current directors and officers of SPAC and the continuation of directors’ and officer’s liability insurance after the Business Combination. |
Set forth below is a summary of the amount of compensation and securities received or to be received by the Sponsor and SPAC’s officers and directors in connection with the Business Combination.
| Securities to be Received | | Other Compensation | |
|---|---|---|---|---|
The Sponsor |
| 2,410,000 Pubco Class A Common Stock issued upon the exchange of 2,410,000 Founder Shares in the SPAC Merger. On November 24, 2021, the Sponsor paid an aggregate of $25,000 for 7,187,500 Founder Shares, or approximately $0.003 per share. On February 8, 2024, the Sponsor surrendered 1,437,500 Founder Shares for no consideration, resulting in the Sponsor holding 5,750,000 Founder Shares. Of these 5,750,000 Founder Shares held by the Sponsor following the February 8, 2024 surrender, (i) 90,000 Founder Shares were transferred to three independent directors (30,000 Founder Shares each) on June 7, 2024, (ii) 2,750,000 Founder Shares will be forfeited and surrendered immediately before the Domestication, (iii) 500,000 Founder Shares may be transferred by the Sponsor, in its discretion, to third parties to incentivize non-redemptions or investments into the SPAC or Pubco, and (iv) 500,000 of the Founder Shares will be subject to an earnout provision. 4,000,000 Pubco Private Warrants upon the assumption of 4,000,000 SPAC Private Warrants. |
| $20,000 per month through the Closing for office space, utilities, secretarial and administrative support services provided by the Sponsor to members of the SPAC management team. As of the date of this proxy statement/prospectus, $320,000 of accrued administrative services fees was outstanding. Indemnification by Pubco and Company pursuant to the Sponsor Indemnification Agreement, and coverage under Pubco’s directors’ and officer’s insurance policy pursuant to the terms of the Business Combination Agreement. |
James A. Graf |
| See “Sponsor” above. Mr. Graf may be deemed to control the Sponsor. |
| Reimbursement for loans, advances, and out-of-pocket expenses. As of the date of this proxy statement/prospectus, $3,000 was outstanding. Continued indemnification and the continuation of directors’ and officers’ liability insurance after the Business Combination. |
Louis Bélanger-Martin | 30,000 Pubco Class A Common Stock issued upon the exchange of 30,000 Founder Shares. | Reimbursement for loans and advances to SPAC and for out-of-pocket expenses incurred related to identifying, negotiating, investigating and completing the Business Combination. As of the date of this proxy statement/prospectus, no such amounts were outstanding. Continued indemnification and the continuation of directors’ and officer’s liability insurance after the Business Combination. | ||
Kenneth Weinstein | 30,000 Pubco Class A Common Stock issued upon the exchange of 30,000 Founder Shares. | Reimbursement for loans and advances to SPAC and for out-of-pocket expenses incurred related to identifying, negotiating, investigating and completing the Business Combination. As of the date of this proxy statement/prospectus, no such amounts were outstanding. Continued indemnification and the continuation of directors’ and officer’s liability insurance after the Business Combination. |
| Securities to be Received | | Other Compensation | |
|---|---|---|---|---|
Fred S. Zeidman | 30,000 Pubco Class A Common Stock issued upon the exchange of 30,000 Founder Shares. | Reimbursement for loans and advances to SPAC and for out-of-pocket expenses incurred related to identifying, negotiating, investigating and completing the Business Combination. As of the date of this proxy statement/prospectus, no such amounts were outstanding. Continued indemnification and the continuation of directors’ and officer’s liability insurance after the Business Combination. |
The following tables summarize the anticipated sources and uses of funds in the Business Combination, in various redemptions scenarios. Such tables are for illustrative purposes only. Where actual amounts are not known or knowable, the figures below represent good faith estimates of such amounts.
Assuming No Additional Redemptions | ||||||||
Sources (in millions) | | | Uses (in millions) | | ||||
Trust Account funds as of June 30, 2026 | $ | 91.4 |
| Redemptions | $ | — | ||
Additional related party notes payable | 0.3 |
| Transaction expenses |
| 12.4 | |||
| Deferred underwriting fee |
| 9.8 | |||||
| Related party notes payable |
| 0.5 | |||||
| Cash |
| 69.0 | |||||
Total Sources | $ | 91.7 |
| Total Uses | $ | 91.7 | ||
Assuming 25% Redemptions(1) | ||||||||
Sources (in millions) | | | Uses (in millions) | | ||||
Trust Account funds as of June 30, 2026 | $ | 91.4 |
| Redemptions | $ | 22.8 | ||
Additional related party notes payable | 0.3 |
| Transaction expenses |
| 12.4 | |||
| Deferred underwriting fee |
| 9.8 | |||||
| Related party notes payable |
| 0.5 | |||||
| Cash |
| 46.2 | |||||
Total Sources | $ | 91.7 |
| Total Uses | $ | 91.7 | ||
Assuming 50% Redemptions(1) | ||||||||
Sources (in millions) | | | Uses (in millions) | | ||||
Trust Account funds as of June 30, 2026 | $ | 91.4 |
| Redemptions | $ | 45.7 | ||
Additional related party notes payable | 0.3 |
| Transaction expenses |
| 12.4 | |||
| Deferred underwriting fee |
| 9.8 | |||||
| Related party notes payable |
| 0.5 | |||||
| Cash |
| 23.3 | |||||
Total Sources | $ | 91.7 |
| Total Uses | $ | 91.7 | ||
Assuming 75% Redemptions(1) | ||||||||
Sources (in millions) | | | Uses (in millions) | | ||||
Trust Account funds as of June 30, 2026 | $ | 91.4 |
| Redemptions | $ | 68.5 | ||
Additional related party notes payable | 0.3 |
| Transaction expenses |
| 12.4 | |||
| Deferred underwriting fee |
| 9.8 | |||||
| Related party notes payable |
| 0.5 | |||||
| Cash |
| 0.5 | |||||
Total Sources | $ | 91.7 |
| Total Uses | $ | 91.7 | ||
Assuming 100% Redemptions(1) | ||||||||
Sources (in millions) | | | | Uses (in millions) | | | ||
Trust Account funds as of June 30, 2026 | $ | 91.4 |
| Redemptions | $ | 91.4 | ||
Additional related party notes payable | 0.3 |
| Transaction expenses(2) |
| — | |||
| Deferred underwriting fee(2) |
| — | |||||
| Related party note payable(2) |
| 0.3 | |||||
| Cash |
| — | |||||
Total Sources | $ | 91.7 |
| Total Uses | $ | 91.7 | ||
| (1) | Each of the 25% Redemptions Scenario, 50% Redemptions Scenario, 75% Redemptions Scenario, and 100% Redemptions Scenario results in an amount of net cash, after the redemptions and the payment of transaction expenses, that is not sufficient to meet the Minimum Cash Condition, without additional financing. As of the date of this proxy statement/prospectus, SPAC has not entered into any Financing Agreement for Transaction Financing, no Sponsor Investment has been made, and the Minimum Cash Condition has not been satisfied. In the event that the Minimum Cash Condition is not satisfied as a result of redemptions of SPAC Public Shares which reduce the amount available to be released to the parties from the Trust Account and/or the failure to obtain third-party financing, the Company may elect not to consummate the Business Combination. Alternately, in the event that the Minimum Cash Condition is not satisfied as a result of redemptions of SPAC Public Shares which reduce the amount available to be released to the parties from the Trust Account and/or the failure to obtain third-party financing, the Company may, in its sole discretion, waive the Minimum Cash Condition. If the Company waives the Minimum Cash Condition, SPAC intends to file a Current Report on Form 8-K within four business days of such event, however such condition may be waived at any time prior to the Closing, including after the deadline for submitting redemption requests or the Extraordinary General Meeting, and, given such timing, you may not be notified before the deadline for submitting redemption requests or the Extraordinary General Meeting. |
| (2) | Under the 100% redemptions scenario, no cash would be released from the Trust Account to fund the payment of transaction expenses, the deferred underwriting fee, or the related party notes payable. Accordingly, these amounts would remain outstanding obligations of the combined company and would need to be funded from other sources, deferred or renegotiated. |
SPAC Public Shareholders (other than the Sponsor and other holders of Founder Shares) may request redemption of all or a portion of their SPAC Public Shares for cash if the Business Combination is consummated. To exercise this right, a holder must, prior to the deadline (two business days before the Extraordinary General Meeting): separate any SPAC Public Units into SPAC Public Shares and SPAC Public Warrants (if applicable); submit a written redemption request to Continental identifying the beneficial owner; and tender or deliver the SPAC Public Shares to Continental, physically or through DTC. Redeeming holders will receive a pro rata portion of the Trust Account (net of taxes payable), estimated at approximately $[●] per Public Share as of the Record Date. Because market prices may exceed the Redemption Price, SPAC Public Shareholders should compare the two before electing redemption, though SPAC cannot guarantee sufficient market liquidity to sell shares at any given price.
A redemption request may be withdrawn before the redemption deadline, and thereafter only with SPAC’s consent until Closing. Shares delivered for redemption can be returned by Continental if withdrawn in time. No redemption will be honored unless shares are actually delivered to Continental by the deadline. Redemptions are capped at 15% of outstanding SPAC Public Shares per holder (together with affiliates or persons acting in concert), with any excess shares not redeemed.
The SPAC Public Shareholders currently own approximately 59.4% of the issued and outstanding SPAC Ordinary Shares. Even if no SPAC Public Shareholders redeem their SPAC Public Shares in the Business Combination, the SPAC Public Shareholders’ ownership will decrease from approximately 59.4% of the SPAC Ordinary Shares prior to the Business Combination to owning approximately 20.9% of Pubco Common Stock issued and outstanding at that time and 3.8% of the voting power of the outstanding Pubco Common Stock. As redemptions increase, the overall percentage ownership and voting percentage held by Sponsor, other holders of Founder Shares, and Company equityholders will increase as compared to the overall percentage ownership and voting percentage held by SPAC Public Shareholders, thereby increasing dilution to SPAC Public Shareholders.
The following table presents the net tangible book value per share at various redemption levels that may occur in connection with the consummation of the Business Combination assuming various sources of material probable dilution, but excluding the effects of the Business Combination transaction itself. This presentation takes into account the reclassification of unredeemed Public Shares to permanent equity, and the payment of SPAC’s estimated transaction costs in connection with the Business Combination. In addition to excluding the Business Combination itself, this presentation excludes shares of PubCo Class A Common Stock that will initially be available for issuance under the Equity Incentive Plan.
No Additional | 25% | 50% | 75% | 100% | |||||||||||
| Redemptions | | Redemptions | | Redemptions | | Redemptions | | Redemptions | ||||||
Offering Price of the Securities in SPAC IPO per share | $ | 10.00 | $ | 10.00 | $ | 10.00 | $ | 10.00 | $ | 10.00 | |||||
SPAC’s net tangible book value as of June 30, 2026, as adjusted | $ | 73,208,373 | $ | 50,362,552 | $ | 27,516,731 | $ | 4,670,911 | $ | (18,174,921) | |||||
SPAC’s shares outstanding, as adjusted for redemptions |
| 11,409,633 |
| 9,307,225 |
| 7,204,817 |
| 5,102,409 |
| 3,000,000 | |||||
SPAC’s net tangible book value per share as of June 30, 2026, as adjusted | $ | 6.42 | $ | 5.41 | $ | 3.82 | $ | 0.92 | $ | (6.06) | |||||
Dilution per share to the existing SPAC’s Shareholders | $ | 3.58 | $ | 4.59 | $ | 6.18 | $ | 9.08 | $ | 16.06 | |||||
The following table illustrates the as adjusted net tangible book value per share to SPAC’s Shareholders.
No Additional | 25% | 50% | 75% | 100% | |||||||||||
| Redemptions | | Redemptions | | Redemptions | | Redemptions | | Redemptions | ||||||
As adjusted net tangible book value per share | $ | 6.42 | $ | 5.41 | $ | 3.82 | $ | 0.92 | $ | (6.06) | |||||
Numerator adjustments: |
| |
| |
| |
| |
| | |||||
SPAC’s net tangible book value as of June 30, 2026 | $ | (12,940,421) | $ | (12,940,421) | $ | (12,940,421) | $ | (12,940,421) | $ | (12,940,421) | |||||
Transaction costs attributed to SPAC |
| (5,234,500) |
| (5,234,500) |
| (5,234,500) |
| (5,234,500) |
| (5,234,500) | |||||
Funds released from Trust |
| 91,383,294 |
| 68,537,473 |
| 45,691,652 |
| 22,845,832 |
| — | |||||
As adjusted net tangible book value | $ | 73,208,373 | $ | 50,362,552 | $ | 27,516,731 | $ | 4,670,911 | $ | (18,174,921) | |||||
Denominator adjustments: |
| |
| |
| |
| |
| | |||||
SPAC Public Shares outstanding |
| 8,409,633 |
| 6,307,225 |
| 4,204,817 |
| 2,102,409 |
| — | |||||
SPAC Founder Shares outstanding |
| 3,000,000 |
| 3,000,000 |
| 3,000,000 |
| 3,000,000 |
| 3,000,000 | |||||
As adjusted total shares outstanding |
| 11,409,633 |
| 9,307,225 |
| 7,204,817 |
| 5,102,409 |
| 3,000,000 | |||||
To the extent that additional shares are issued pursuant to the foregoing, SPAC’s Shareholders will experience further dilution. In addition, SPAC may enter into other transactions. To the extent it issues such securities, investors and SPAC’s Shareholders may experience further dilution.