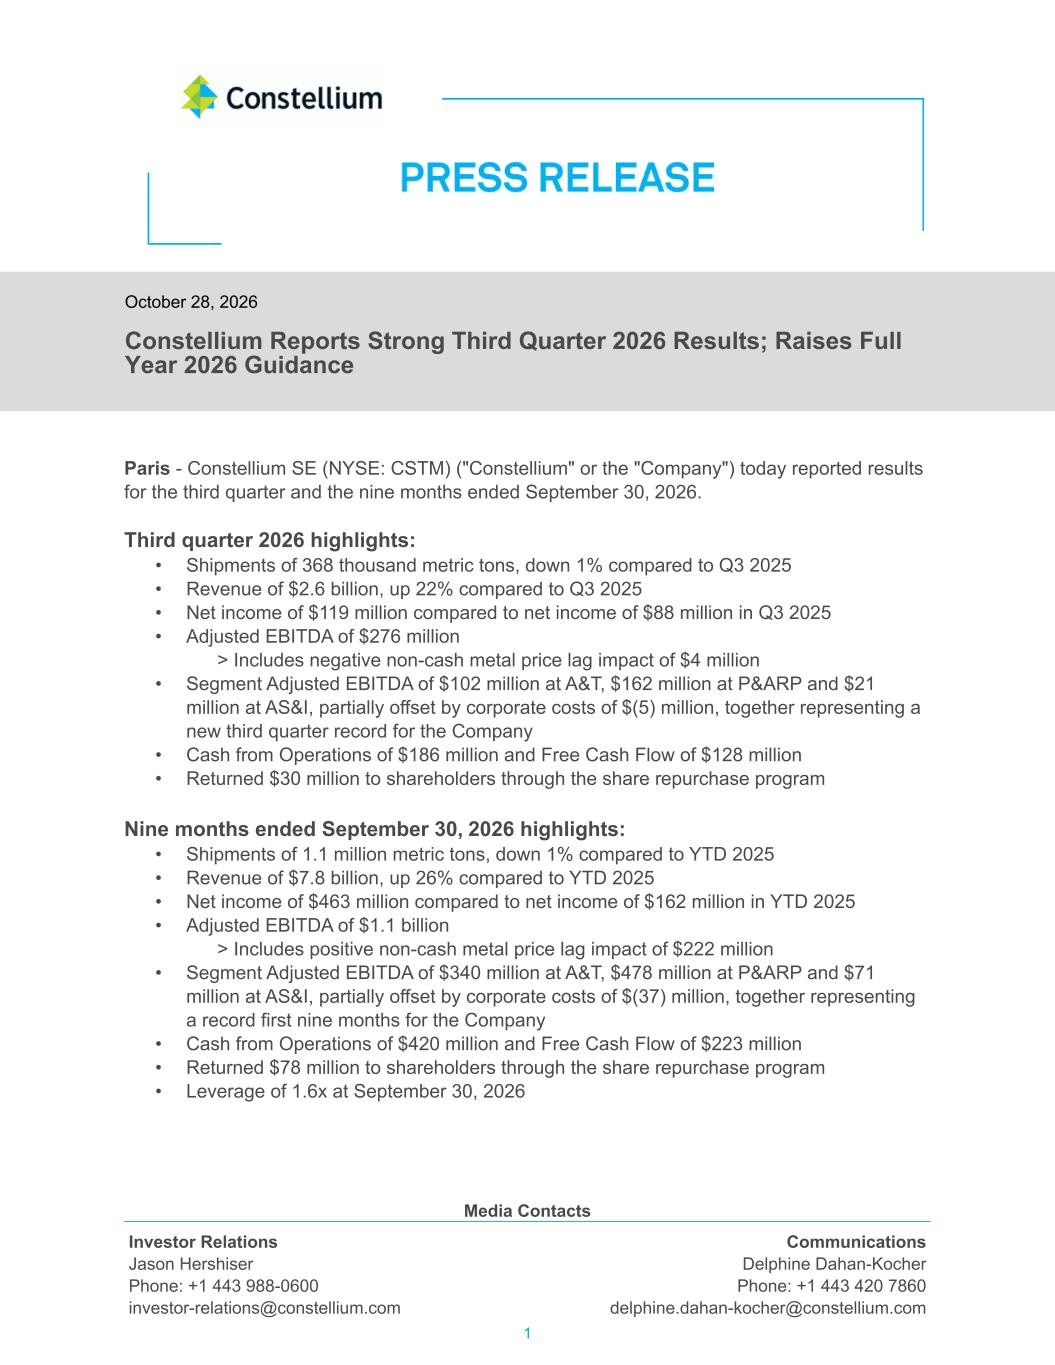
October 28, 2026 Constellium Reports Strong Third Quarter 2026 Results; Raises Full Year 2026 Guidance Paris - Constellium SE (NYSE: CSTM) ("Constellium" or the "Company") today reported results for the third quarter and the nine months ended September 30, 2026. Third quarter 2026 highlights: • Shipments of 368 thousand metric tons, down 1% compared to Q3 2025 • Revenue of $2.6 billion, up 22% compared to Q3 2025 • Net income of $119 million compared to net income of $88 million in Q3 2025 • Adjusted EBITDA of $276 million > Includes negative non-cash metal price lag impact of $4 million • Segment Adjusted EBITDA of $102 million at A&T, $162 million at P&ARP and $21 million at AS&I, partially offset by corporate costs of $(5) million, together representing a new third quarter record for the Company • Cash from Operations of $186 million and Free Cash Flow of $128 million • Returned $30 million to shareholders through the share repurchase program Nine months ended September 30, 2026 highlights: • Shipments of 1.1 million metric tons, down 1% compared to YTD 2025 • Revenue of $7.8 billion, up 26% compared to YTD 2025 • Net income of $463 million compared to net income of $162 million in YTD 2025 • Adjusted EBITDA of $1.1 billion > Includes positive non-cash metal price lag impact of $222 million • Segment Adjusted EBITDA of $340 million at A&T, $478 million at P&ARP and $71 million at AS&I, partially offset by corporate costs of $(37) million, together representing a record first nine months for the Company • Cash from Operations of $420 million and Free Cash Flow of $223 million • Returned $78 million to shareholders through the share repurchase program • Leverage of 1.6x at September 30, 2026 Media Contacts Investor Relations Communications Jason Hershiser Delphine Dahan-Kocher Phone: +1 443 988-0600 Phone: +1 443 420 7860 investor-relations@constellium.com delphine.dahan-kocher@constellium.com 1
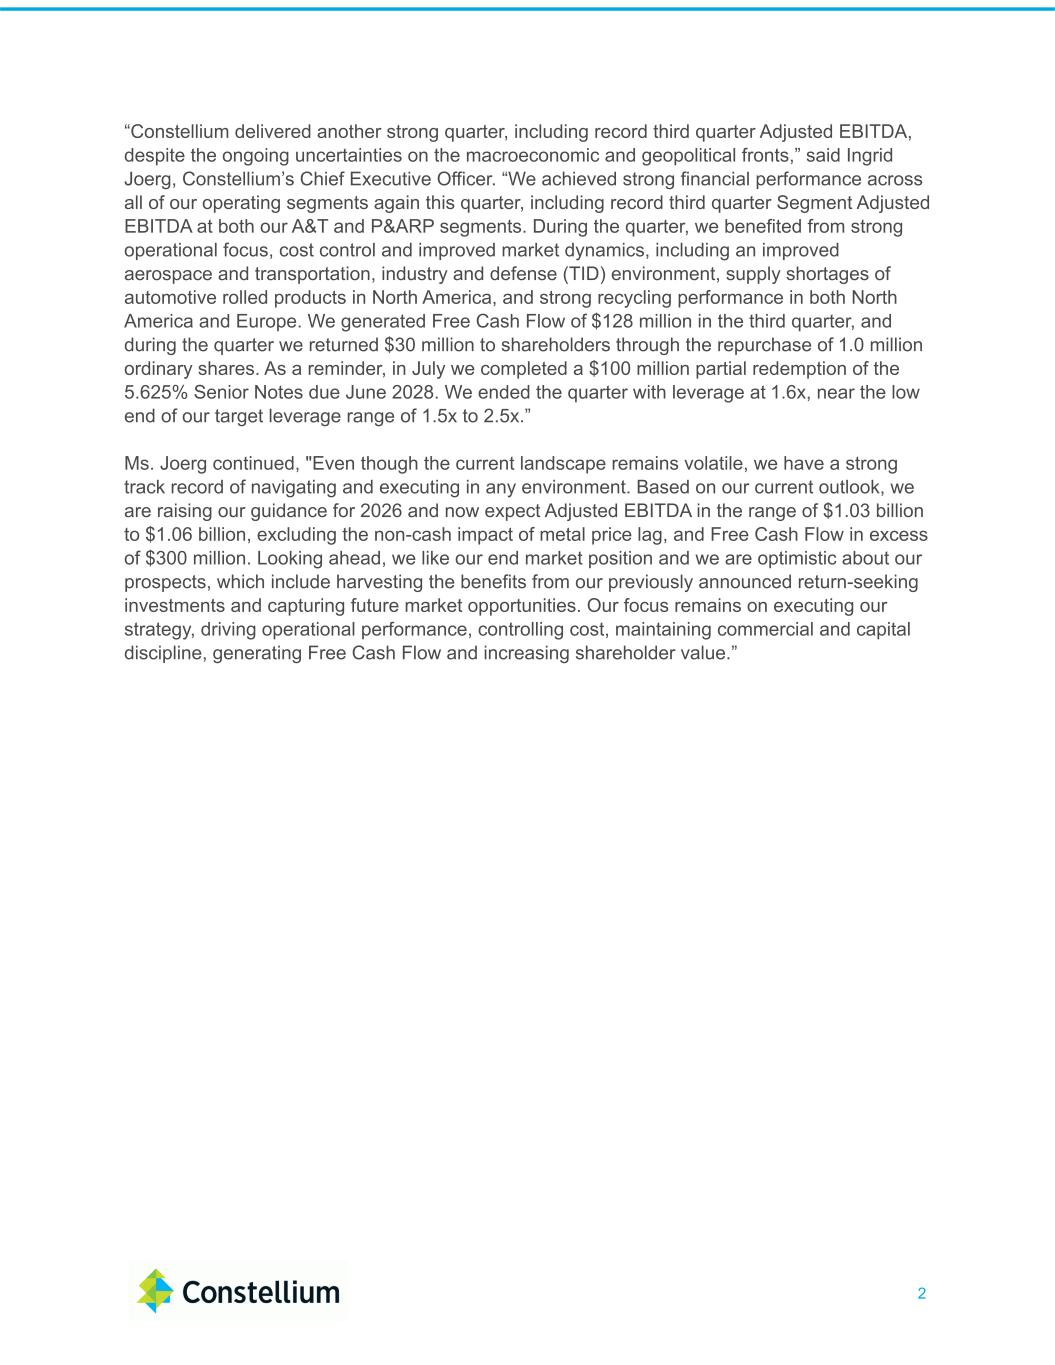
“Constellium delivered another strong quarter, including record third quarter Adjusted EBITDA, despite the ongoing uncertainties on the macroeconomic and geopolitical fronts,” said Ingrid Joerg, Constellium’s Chief Executive Officer. “We achieved strong financial performance across all of our operating segments again this quarter, including record third quarter Segment Adjusted EBITDA at both our A&T and P&ARP segments. During the quarter, we benefited from strong operational focus, cost control and improved market dynamics, including an improved aerospace and transportation, industry and defense (TID) environment, supply shortages of automotive rolled products in North America, and strong recycling performance in both North America and Europe. We generated Free Cash Flow of $128 million in the third quarter, and during the quarter we returned $30 million to shareholders through the repurchase of 1.0 million ordinary shares. As a reminder, in July we completed a $100 million partial redemption of the 5.625% Senior Notes due June 2028. We ended the quarter with leverage at 1.6x, near the low end of our target leverage range of 1.5x to 2.5x.” Ms. Joerg continued, "Even though the current landscape remains volatile, we have a strong track record of navigating and executing in any environment. Based on our current outlook, we are raising our guidance for 2026 and now expect Adjusted EBITDA in the range of $1.03 billion to $1.06 billion, excluding the non-cash impact of metal price lag, and Free Cash Flow in excess of $300 million. Looking ahead, we like our end market position and we are optimistic about our prospects, which include harvesting the benefits from our previously announced return-seeking investments and capturing future market opportunities. Our focus remains on executing our strategy, driving operational performance, controlling cost, maintaining commercial and capital discipline, generating Free Cash Flow and increasing shareholder value.” 2
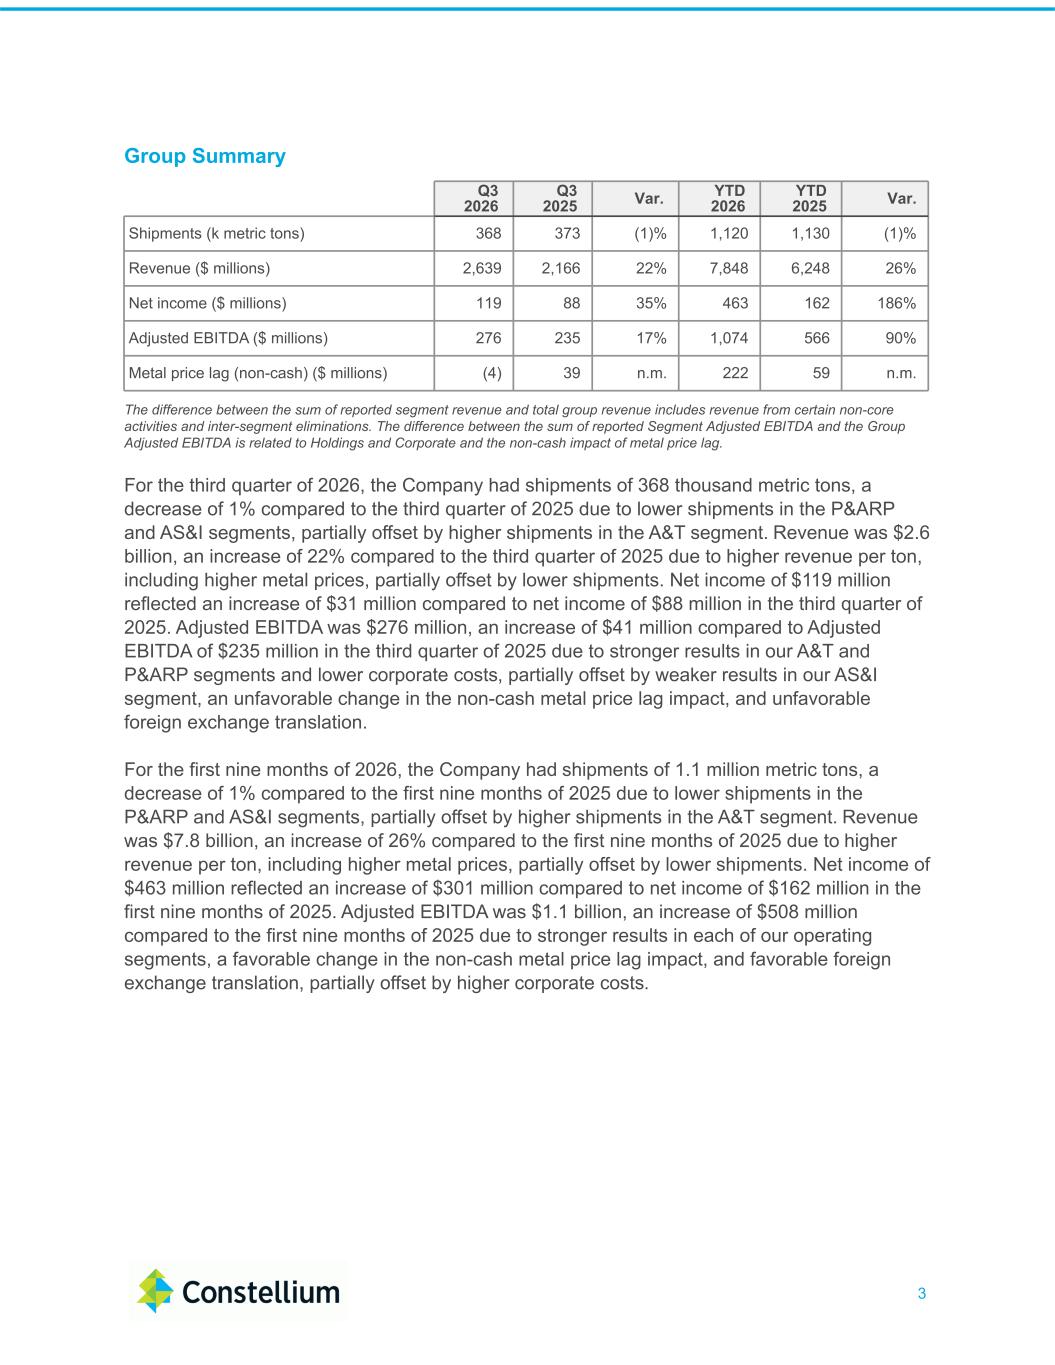
Group Summary Q3 2026 Q3 2025 Var. YTD 2026 YTD 2025 Var. Shipments (k metric tons) 368 373 (1) % 1,120 1,130 (1) % Revenue ($ millions) 2,639 2,166 22 % 7,848 6,248 26 % Net income ($ millions) 119 88 35 % 463 162 186 % Adjusted EBITDA ($ millions) 276 235 17 % 1,074 566 90 % Metal price lag (non-cash) ($ millions) (4) 39 n.m. 222 59 n.m. The difference between the sum of reported segment revenue and total group revenue includes revenue from certain non-core activities and inter-segment eliminations. The difference between the sum of reported Segment Adjusted EBITDA and the Group Adjusted EBITDA is related to Holdings and Corporate and the non-cash impact of metal price lag. For the third quarter of 2026, the Company had shipments of 368 thousand metric tons, a decrease of 1% compared to the third quarter of 2025 due to lower shipments in the P&ARP and AS&I segments, partially offset by higher shipments in the A&T segment. Revenue was $2.6 billion, an increase of 22% compared to the third quarter of 2025 due to higher revenue per ton, including higher metal prices, partially offset by lower shipments. Net income of $119 million reflected an increase of $31 million compared to net income of $88 million in the third quarter of 2025. Adjusted EBITDA was $276 million, an increase of $41 million compared to Adjusted EBITDA of $235 million in the third quarter of 2025 due to stronger results in our A&T and P&ARP segments and lower corporate costs, partially offset by weaker results in our AS&I segment, an unfavorable change in the non-cash metal price lag impact, and unfavorable foreign exchange translation. For the first nine months of 2026, the Company had shipments of 1.1 million metric tons, a decrease of 1% compared to the first nine months of 2025 due to lower shipments in the P&ARP and AS&I segments, partially offset by higher shipments in the A&T segment. Revenue was $7.8 billion, an increase of 26% compared to the first nine months of 2025 due to higher revenue per ton, including higher metal prices, partially offset by lower shipments. Net income of $463 million reflected an increase of $301 million compared to net income of $162 million in the first nine months of 2025. Adjusted EBITDA was $1.1 billion, an increase of $508 million compared to the first nine months of 2025 due to stronger results in each of our operating segments, a favorable change in the non-cash metal price lag impact, and favorable foreign exchange translation, partially offset by higher corporate costs. 3
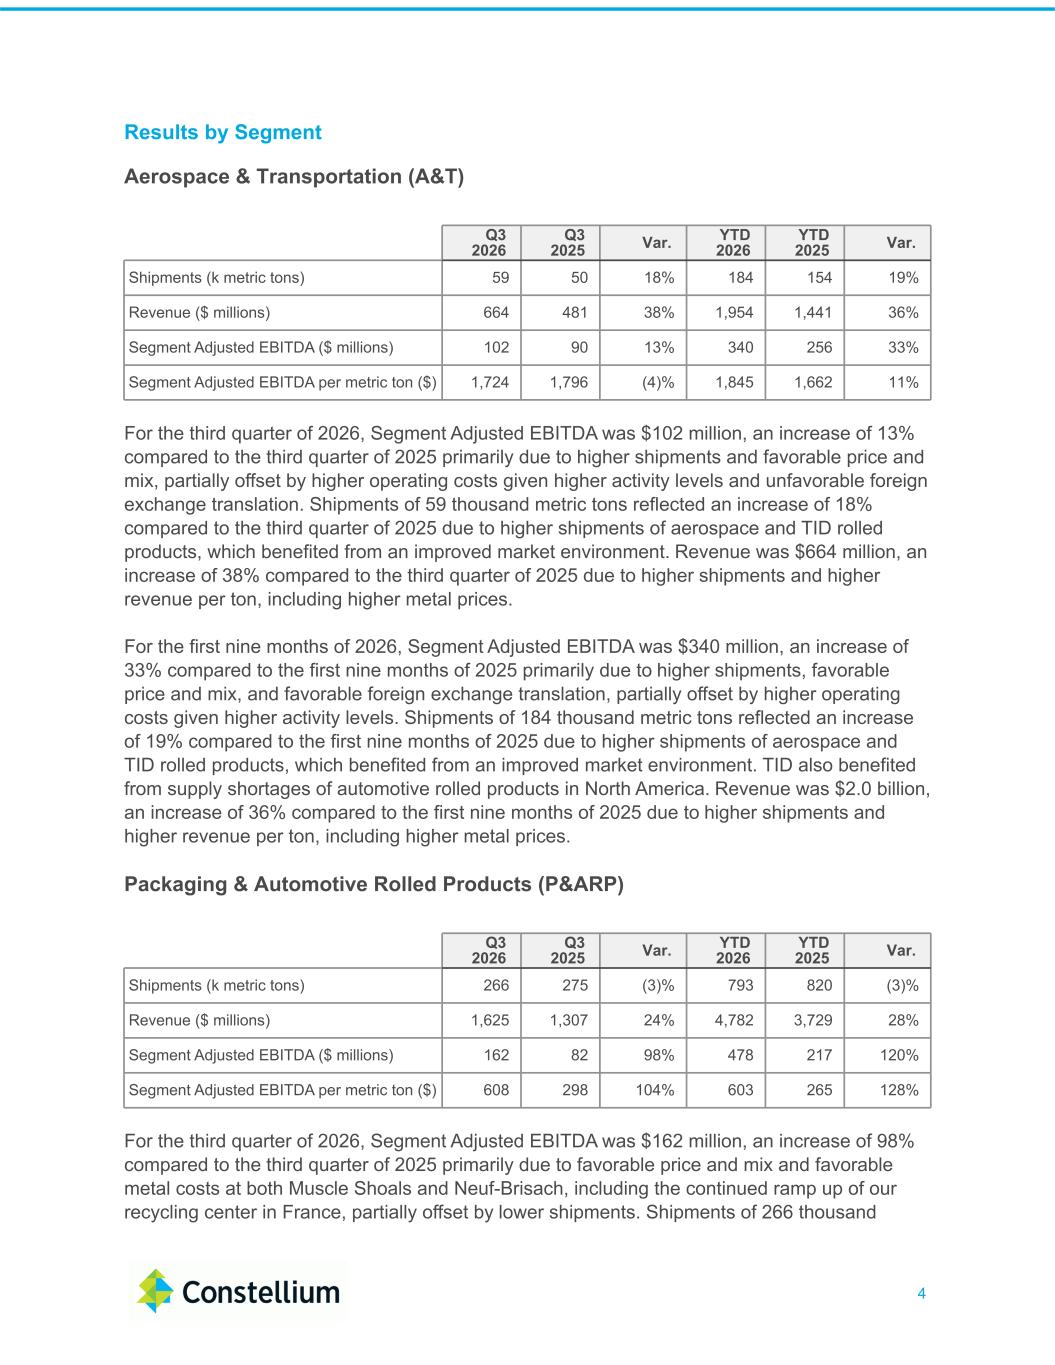
Results by Segment Aerospace & Transportation (A&T) Q3 2026 Q3 2025 Var. YTD 2026 YTD 2025 Var. Shipments (k metric tons) 59 50 18 % 184 154 19 % Revenue ($ millions) 664 481 38 % 1,954 1,441 36 % Segment Adjusted EBITDA ($ millions) 102 90 13 % 340 256 33 % Segment Adjusted EBITDA per metric ton ($) 1,724 1,796 (4) % 1,845 1,662 11 % For the third quarter of 2026, Segment Adjusted EBITDA was $102 million, an increase of 13% compared to the third quarter of 2025 primarily due to higher shipments and favorable price and mix, partially offset by higher operating costs given higher activity levels and unfavorable foreign exchange translation. Shipments of 59 thousand metric tons reflected an increase of 18% compared to the third quarter of 2025 due to higher shipments of aerospace and TID rolled products, which benefited from an improved market environment. Revenue was $664 million, an increase of 38% compared to the third quarter of 2025 due to higher shipments and higher revenue per ton, including higher metal prices. For the first nine months of 2026, Segment Adjusted EBITDA was $340 million, an increase of 33% compared to the first nine months of 2025 primarily due to higher shipments, favorable price and mix, and favorable foreign exchange translation, partially offset by higher operating costs given higher activity levels. Shipments of 184 thousand metric tons reflected an increase of 19% compared to the first nine months of 2025 due to higher shipments of aerospace and TID rolled products, which benefited from an improved market environment. TID also benefited from supply shortages of automotive rolled products in North America. Revenue was $2.0 billion, an increase of 36% compared to the first nine months of 2025 due to higher shipments and higher revenue per ton, including higher metal prices. Packaging & Automotive Rolled Products (P&ARP) Q3 2026 Q3 2025 Var. YTD 2026 YTD 2025 Var. Shipments (k metric tons) 266 275 (3) % 793 820 (3) % Revenue ($ millions) 1,625 1,307 24 % 4,782 3,729 28 % Segment Adjusted EBITDA ($ millions) 162 82 98 % 478 217 120 % Segment Adjusted EBITDA per metric ton ($) 608 298 104 % 603 265 128 % For the third quarter of 2026, Segment Adjusted EBITDA was $162 million, an increase of 98% compared to the third quarter of 2025 primarily due to favorable price and mix and favorable metal costs at both Muscle Shoals and Neuf-Brisach, including the continued ramp up of our recycling center in France, partially offset by lower shipments. Shipments of 266 thousand 4
metric tons reflected a decrease of 3% compared to the third quarter of 2025 due to lower shipments of packaging rolled products, partially offset by higher shipments of automotive rolled products, which benefited from supply shortages in North America. Revenue was $1.6 billion, an increase of 24% compared to the third quarter of 2025 due to higher revenue per ton, including higher metal prices, partially offset by lower shipments. For the first nine months of 2026, Segment Adjusted EBITDA was $478 million, an increase of 120% compared to the first nine months of 2025 primarily due to favorable price and mix, favorable metal costs at both Muscle Shoals and Neuf-Brisach, including the continued ramp up of our recycling center in France, and favorable foreign exchange translation, partially offset by lower shipments. Shipments of 793 thousand metric tons reflected a decrease of 3% compared to the first nine months of 2025 mainly due to lower shipments of packaging rolled products, partially offset by higher shipments of automotive rolled products, which benefited from supply shortages in North America. Revenue was $4.8 billion, an increase of 28% compared to the first nine months of 2025 due to higher revenue per ton, including higher metal prices, partially offset by lower shipments. Automotive Structures & Industry (AS&I) Q3 2026 Q3 2025 Var. YTD 2026 YTD 2025 Var. Shipments (k metric tons) 46 48 (4) % 151 155 (3) % Revenue ($ millions) 402 409 (2) % 1,275 1,211 5 % Segment Adjusted EBITDA ($ millions) 21 33 (36) % 71 67 6 % Segment Adjusted EBITDA per metric ton ($) 454 683 (34) % 470 431 9 % For the third quarter of 2026, Segment Adjusted EBITDA was $21 million, a decrease of 36% compared to the third quarter of 2025 primarily due to lower shipments and unfavorable price and mix primarily driven by net customer compensation for underperformance of an automotive program received in the third quarter of 2025, partially offset by lower operating costs. Shipments of 46 thousand metric tons reflected a decrease of 4% compared to the third quarter of 2025 due to lower shipments of both automotive and other extruded products. Revenue was $402 million, a decrease of 2% compared to the third quarter of 2025 due to lower shipments, partially offset by higher revenue per ton, including higher metal prices. For the first nine months of 2026, Segment Adjusted EBITDA was $71 million, an increase of 6% compared to the first nine months of 2025 primarily due to lower operating costs and favorable foreign exchange translation, partially offset by lower shipments and unfavorable price and mix primarily driven by net customer compensation for underperformance of an automotive program received in the third quarter of 2025. Shipments of 151 thousand metric tons reflected a decrease of 3% compared to the first nine months of 2025 due to lower shipments of both automotive and other extruded products. Revenue was $1.3 billion, an increase of 5% compared to the first nine months of 2025 primarily due to higher revenue per ton, including higher metal prices, partially offset by lower shipments. 5
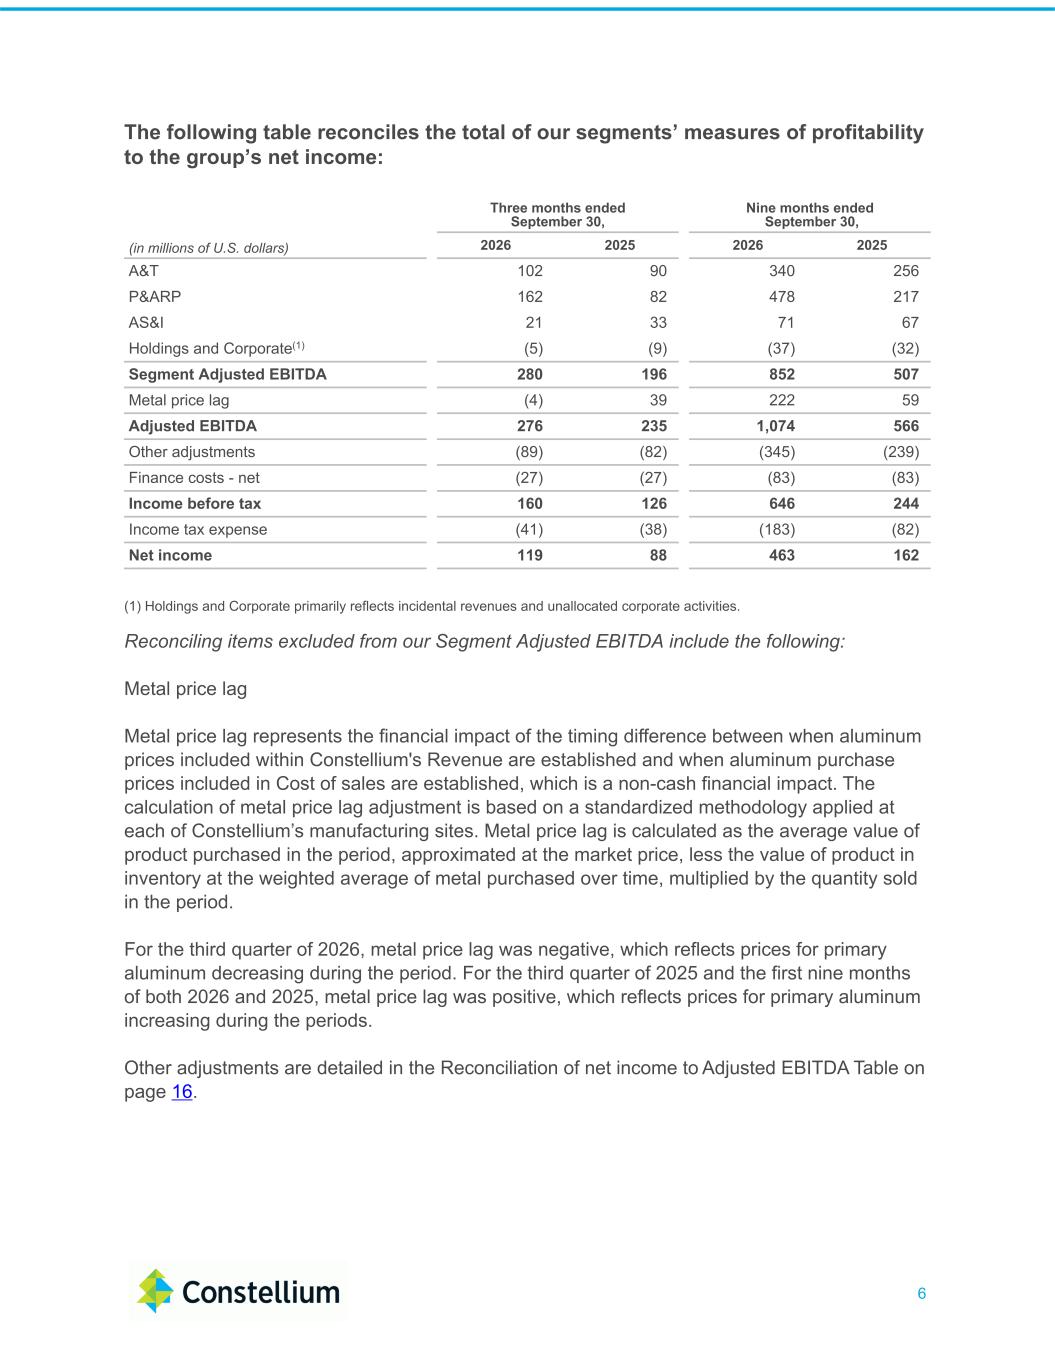
The following table reconciles the total of our segments’ measures of profitability to the group’s net income: Three months ended September 30, Nine months ended September 30, (in millions of U.S. dollars) 2026 2025 2026 2025 A&T 102 90 340 256 P&ARP 162 82 478 217 AS&I 21 33 71 67 Holdings and Corporate(1) (5) (9) (37) (32) Segment Adjusted EBITDA 280 196 852 507 Metal price lag (4) 39 222 59 Adjusted EBITDA 276 235 1,074 566 Other adjustments (89) (82) (345) (239) Finance costs - net (27) (27) (83) (83) Income before tax 160 126 646 244 Income tax expense (41) (38) (183) (82) Net income 119 88 463 162 (1) Holdings and Corporate primarily reflects incidental revenues and unallocated corporate activities. Reconciling items excluded from our Segment Adjusted EBITDA include the following: Metal price lag Metal price lag represents the financial impact of the timing difference between when aluminum prices included within Constellium's Revenue are established and when aluminum purchase prices included in Cost of sales are established, which is a non-cash financial impact. The calculation of metal price lag adjustment is based on a standardized methodology applied at each of Constellium’s manufacturing sites. Metal price lag is calculated as the average value of product purchased in the period, approximated at the market price, less the value of product in inventory at the weighted average of metal purchased over time, multiplied by the quantity sold in the period. For the third quarter of 2026, metal price lag was negative, which reflects prices for primary aluminum decreasing during the period. For the third quarter of 2025 and the first nine months of both 2026 and 2025, metal price lag was positive, which reflects prices for primary aluminum increasing during the periods. Other adjustments are detailed in the Reconciliation of net income to Adjusted EBITDA Table on page 16. 6
Net Income For the third quarter of 2026, net income of $119 million compares to net income of $88 million in the third quarter of the prior year. The increase in net income is primarily related to higher gross profit (revenue less cost of sales, excluding depreciation and amortization), partially offset by unfavorable changes in other gains and losses. For the first nine months of 2026, net income of $463 million compares to net income of $162 million in the first nine months of the prior year. The increase in net income is primarily related to higher gross profit (revenue less cost of sales, excluding depreciation and amortization) and favorable changes in other gains and losses, partially offset by higher selling and administrative expenses and higher income tax expense. Cash Flow Cash flows from operating activities were $420 million for the first nine months of 2026 compared to cash flows from operating activities of $271 million in the first nine months of the prior year. Free Cash Flow was $223 million in the first nine months of 2026 compared to $68 million in the first nine months of the prior year. The increase in Free Cash Flow was primarily due to higher Segment Adjusted EBITDA, partially offset by an unfavorable change in working capital. Cash flows used in investing activities were $195 million for the first nine months of 2026 compared to cash flows used in investing activities of $200 million in the first nine months of the prior year. Cash flows used in financing activities were $184 million for the first nine months of 2026 compared to cash flows used in financing activities of $103 million in the first nine months of the prior year. During the first nine months of 2026, the Company repurchased 2.8 million ordinary shares of the Company for $78 million and redeemed $100 million out of the $325 million outstanding aggregate principal amount of its 5.625% Senior Notes due June 2028. During the first nine months of 2025, the Company repurchased 6.5 million ordinary shares of the Company for $75 million. Liquidity and Net Debt Liquidity at September 30, 2026 was $992 million, comprised of $158 million of cash and cash equivalents and $834 million available under our committed lending facilities and factoring arrangements. Total debt was $1,817 million at September 30, 2026, compared to $1,944 million at December 31, 2025. Net debt was $1,658 million at September 30, 2026, compared to $1,824 million at December 31, 2025. As a reminder, in July the Company completed a $100 million partial redemption of the 5.625% Senior Notes due June 2028, leaving $225 million aggregate principal amount outstanding. 7
Outlook Based on our current outlook, we are raising our guidance for 2026 and now expect Adjusted EBITDA in the range of $1.03 billion to $1.06 billion, excluding the non-cash impact of metal price lag, and Free Cash Flow in excess of $300 million. We are not able to provide a reconciliation of this Adjusted EBITDA guidance to net income, the comparable GAAP measure, because certain items that are excluded from Adjusted EBITDA cannot be reasonably predicted or are not in our control. In particular, we are unable to forecast the timing or magnitude of realized and unrealized gains and losses on derivative instruments, metal price lag, impairment or restructuring charges, or taxes without unreasonable efforts, and these items could significantly impact, either individually or in the aggregate, net income in the future. Recent Developments On October 22, 2026, the Pan-U.S. ABL was amended to, among other things, increase the available commitments from $550 million to $700 million and extend the maturity to October 22, 2031. 8
Forward-looking statements Certain statements contained in this press release constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. This press release contains “forward-looking statements” with respect to our business, results of operations and financial condition, including, among others, statements regarding anticipated macroeconomic, end- market and industry environments, our areas of execution focus, and earnings guidance. You can identify forward-looking statements because they contain words such as, but not limited to, “anticipates,” “approximately,” “believes,” “continue,” “could,” “estimates,” “expects,” “intends,” “likely,” “may,” “plans,” “should,” “targets,” “will,” “would,” and similar expressions (or the negative of these terminologies or expressions). All forward-looking statements involve risks and uncertainties and are based on underlying assumptions that may prove incorrect. Many risks and uncertainties are inherent in our industry and markets, while others are more specific to our business and operations. These risks and uncertainties include, but are not limited to: market competition; global or regional economic downturns or industry specific conditions, including the impacts of tax and tariff programs, inflation, foreign currency exchange, and industry consolidation; disruption to business operations; natural disasters including severe flooding and other weather-related events; geopolitical tensions and conflicts, including the ongoing conflict between Russia and Ukraine and the ongoing conflict involving the United States, Israel and Iran; the inability to meet customer demand and quality requirements; the loss of key customers, suppliers or other business relationships; supply disruptions; excessive inflation; the capacity and effectiveness of our hedging policy activities; the loss of key employees; levels of indebtedness which could limit our operating flexibility and opportunities; and other risk factors set forth under the heading “Risk Factors” in our Annual Report on Form 10-K, and as described from time to time in subsequent reports filed with the U.S. Securities and Exchange Commission. The occurrence of the events described and the achievement of the expected results depend on many events, some or all of which are not predictable or within our control. Consequently, actual results may differ materially from the forward-looking statements contained in this press release. We undertake no obligation to update or revise any forward-looking statement as a result of new information, future events or otherwise, except as required by law. About Constellium Constellium (NYSE: CSTM) is a global sector leader that develops innovative, value-added aluminum products for a broad scope of markets and applications, including aerospace, packaging and automotive. Constellium generated $8.4 billion of revenue in 2025. Constellium’s earnings materials for the third quarter and the nine months ended September 30, 2026 are also available on the company’s website (www.constellium.com). 9
Non-GAAP measures In addition to the results reported in accordance with United States Generally Accepted Accounting Principles (“U.S. GAAP”), this press release includes information regarding certain financial measures which are not prepared in accordance with U.S. GAAP (“non-GAAP measures”). The non-GAAP measures used in this press release are: Adjusted EBITDA, Free Cash Flow and Net debt. Reconciliations to the most directly comparable U.S. GAAP financial measures are presented in the schedules to this press release. We believe these non-GAAP measures are important supplemental measures of our operating and financial performance. By providing these measures, together with the reconciliations, we believe we are enhancing investors’ understanding of our business, our results of operations and our financial position, as well as assisting investors in evaluating the extent to which we are executing our strategic initiatives. However, these non-GAAP financial measures supplement our U.S. GAAP disclosures and should not be considered an alternative to the U.S. GAAP measures and may not be comparable to similarly titled measures of other companies. Adjusted EBITDA is not a presentation made in accordance with U.S. GAAP, is not a measure of financial condition, liquidity or profitability and should not be considered as an alternative to profit or loss for the period, revenues or operating cash flows determined in accordance with U.S. GAAP. The most directly comparable U.S. GAAP measure to Adjusted EBITDA is our net income or loss for the relevant period. Adjusted EBITDA is defined as income / (loss) from continuing operations before income taxes, results from joint ventures, net finance costs, other expenses and depreciation and amortization as adjusted to exclude restructuring costs, impairment charges, unrealized gains or losses on derivatives and on foreign exchange differences on transactions which do not qualify for hedge accounting, share based compensation expense, non-operating gains / (losses) on pension and other post-employment benefits, factoring expenses, effects of certain purchase accounting adjustments, start-up and development costs or acquisition, integration and separation costs, certain incremental costs and other exceptional, unusual or generally non-recurring items. We believe Adjusted EBITDA is useful to investors as it illustrates the underlying performance of continuing operations by excluding certain non-recurring and non-operating items. We believe that Adjusted EBITDA is frequently used by securities analysts, investors and other stakeholders in their evaluation of the Company’s performance. Free Cash Flow is defined as net cash flow from operating activities, less capital expenditures, net of property, plant and equipment inflows. Management believes that Free Cash Flow is a useful measure of the net cash flow generated or used by the business as it takes into account both the cash generated or consumed by operating activities, including working capital, and the capital expenditure requirements of the business. However, Free Cash Flow is not a presentation made in accordance with U.S. GAAP and should not be considered as an alternative to operating cash flows determined in accordance with U.S. GAAP. Free Cash Flow has certain inherent limitations, including the fact that it does not represent residual cash flows available for discretionary spending, notably because it does not reflect principal repayments required in connection with our debt or capital lease obligations. 10
Net debt is defined as debt plus or minus the fair value of cross currency basis swaps net of margin calls less cash and cash equivalents and cash pledged for the issuance of guarantees. Management believes that Net debt is a useful measure of indebtedness because it takes into account the cash and cash equivalent balances held by the Company as well as the total external debt of the Company. Net debt is not a presentation made in accordance with U.S. GAAP and should not be considered as an alternative to debt determined in accordance with U.S. GAAP. Leverage is defined as Net debt divided by last twelve months Segment Adjusted EBITDA, which excludes the non-cash impact of metal price lag. 11
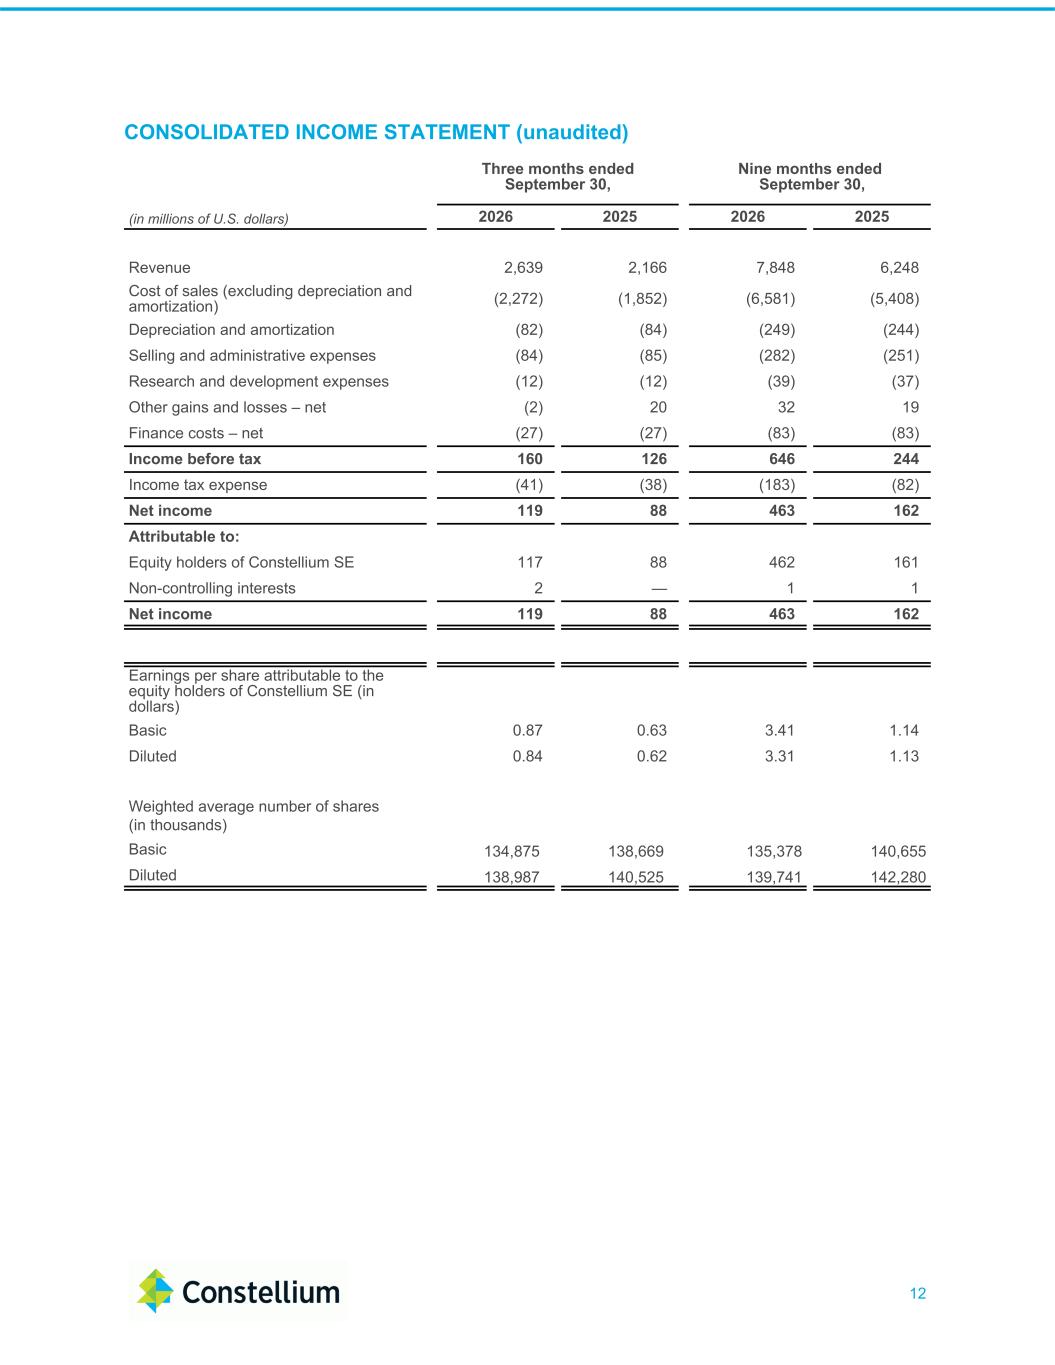
CONSOLIDATED INCOME STATEMENT (unaudited) Three months ended September 30, Nine months ended September 30, (in millions of U.S. dollars) 2026 2025 2026 2025 Revenue 2,639 2,166 7,848 6,248 Cost of sales (excluding depreciation and amortization) (2,272) (1,852) (6,581) (5,408) Depreciation and amortization (82) (84) (249) (244) Selling and administrative expenses (84) (85) (282) (251) Research and development expenses (12) (12) (39) (37) Other gains and losses – net (2) 20 32 19 Finance costs – net (27) (27) (83) (83) Income before tax 160 126 646 244 Income tax expense (41) (38) (183) (82) Net income 119 88 463 162 Attributable to: Equity holders of Constellium SE 117 88 462 161 Non-controlling interests 2 — 1 1 Net income 119 88 463 162 Earnings per share attributable to the equity holders of Constellium SE (in dollars) Basic 0.87 0.63 3.41 1.14 Diluted 0.84 0.62 3.31 1.13 Weighted average number of shares (in thousands) Basic 134,875 138,669 135,378 140,655 Diluted 138,987 140,525 139,741 142,280 12
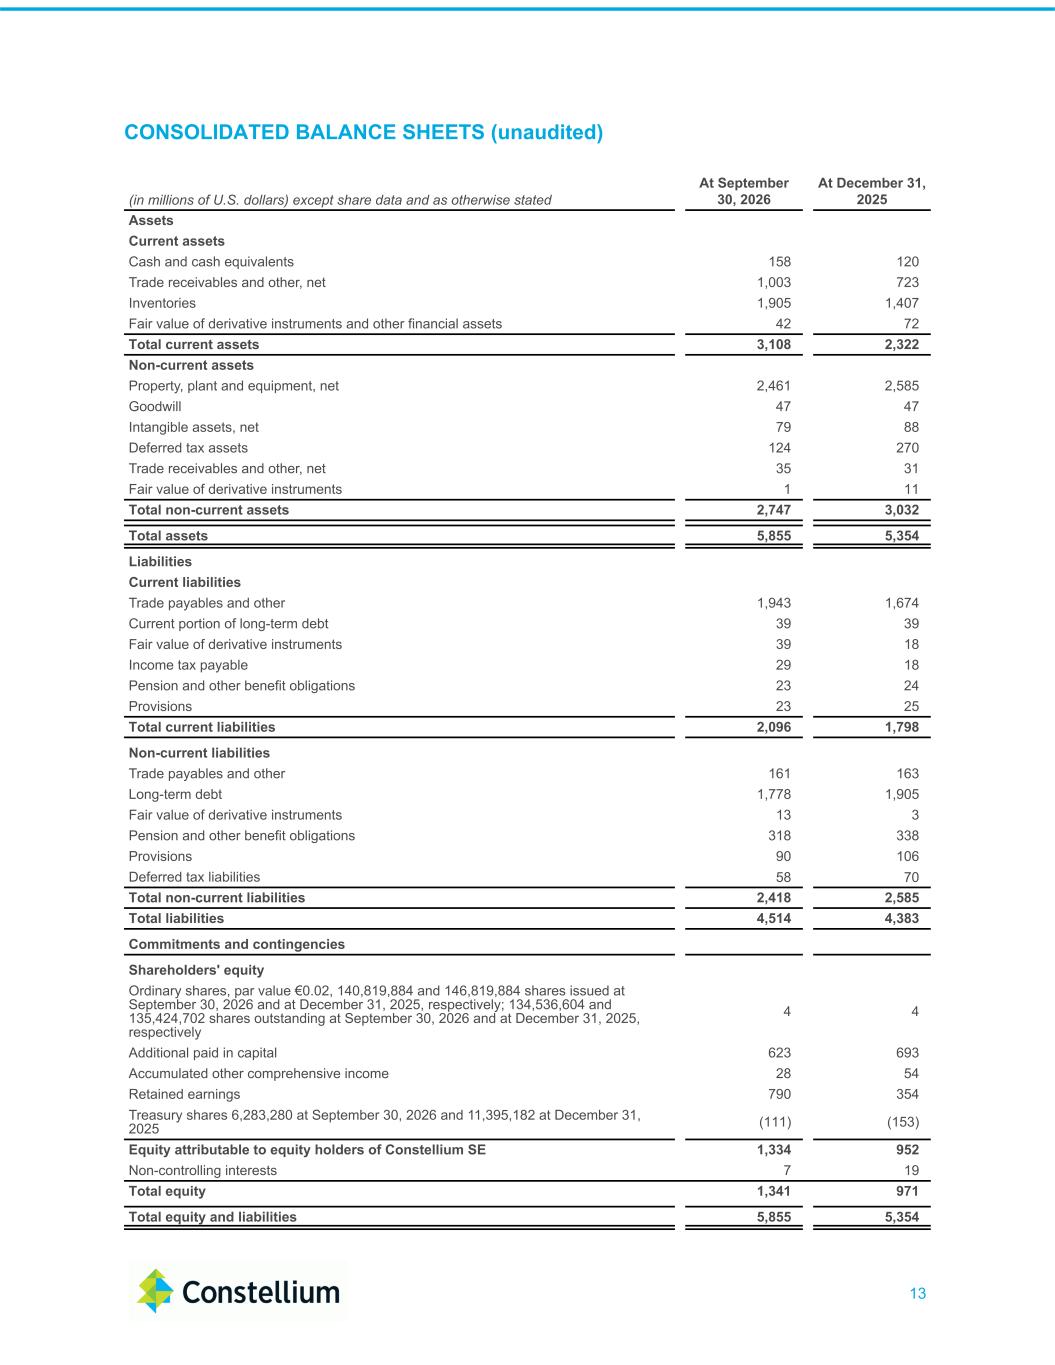
CONSOLIDATED BALANCE SHEETS (unaudited) (in millions of U.S. dollars) except share data and as otherwise stated At September 30, 2026 At December 31, 2025 Assets Current assets Cash and cash equivalents 158 120 Trade receivables and other, net 1,003 723 Inventories 1,905 1,407 Fair value of derivative instruments and other financial assets 42 72 Total current assets 3,108 2,322 Non-current assets Property, plant and equipment, net 2,461 2,585 Goodwill 47 47 Intangible assets, net 79 88 Deferred tax assets 124 270 Trade receivables and other, net 35 31 Fair value of derivative instruments 1 11 Total non-current assets 2,747 3,032 Total assets 5,855 5,354 Liabilities Current liabilities Trade payables and other 1,943 1,674 Current portion of long-term debt 39 39 Fair value of derivative instruments 39 18 Income tax payable 29 18 Pension and other benefit obligations 23 24 Provisions 23 25 Total current liabilities 2,096 1,798 Non-current liabilities Trade payables and other 161 163 Long-term debt 1,778 1,905 Fair value of derivative instruments 13 3 Pension and other benefit obligations 318 338 Provisions 90 106 Deferred tax liabilities 58 70 Total non-current liabilities 2,418 2,585 Total liabilities 4,514 4,383 Commitments and contingencies Shareholders' equity Ordinary shares, par value €0.02, 140,819,884 and 146,819,884 shares issued at September 30, 2026 and at December 31, 2025, respectively; 134,536,604 and 135,424,702 shares outstanding at September 30, 2026 and at December 31, 2025, respectively 4 4 Additional paid in capital 623 693 Accumulated other comprehensive income 28 54 Retained earnings 790 354 Treasury shares 6,283,280 at September 30, 2026 and 11,395,182 at December 31, 2025 (111) (153) Equity attributable to equity holders of Constellium SE 1,334 952 Non-controlling interests 7 19 Total equity 1,341 971 Total equity and liabilities 5,855 5,354 13
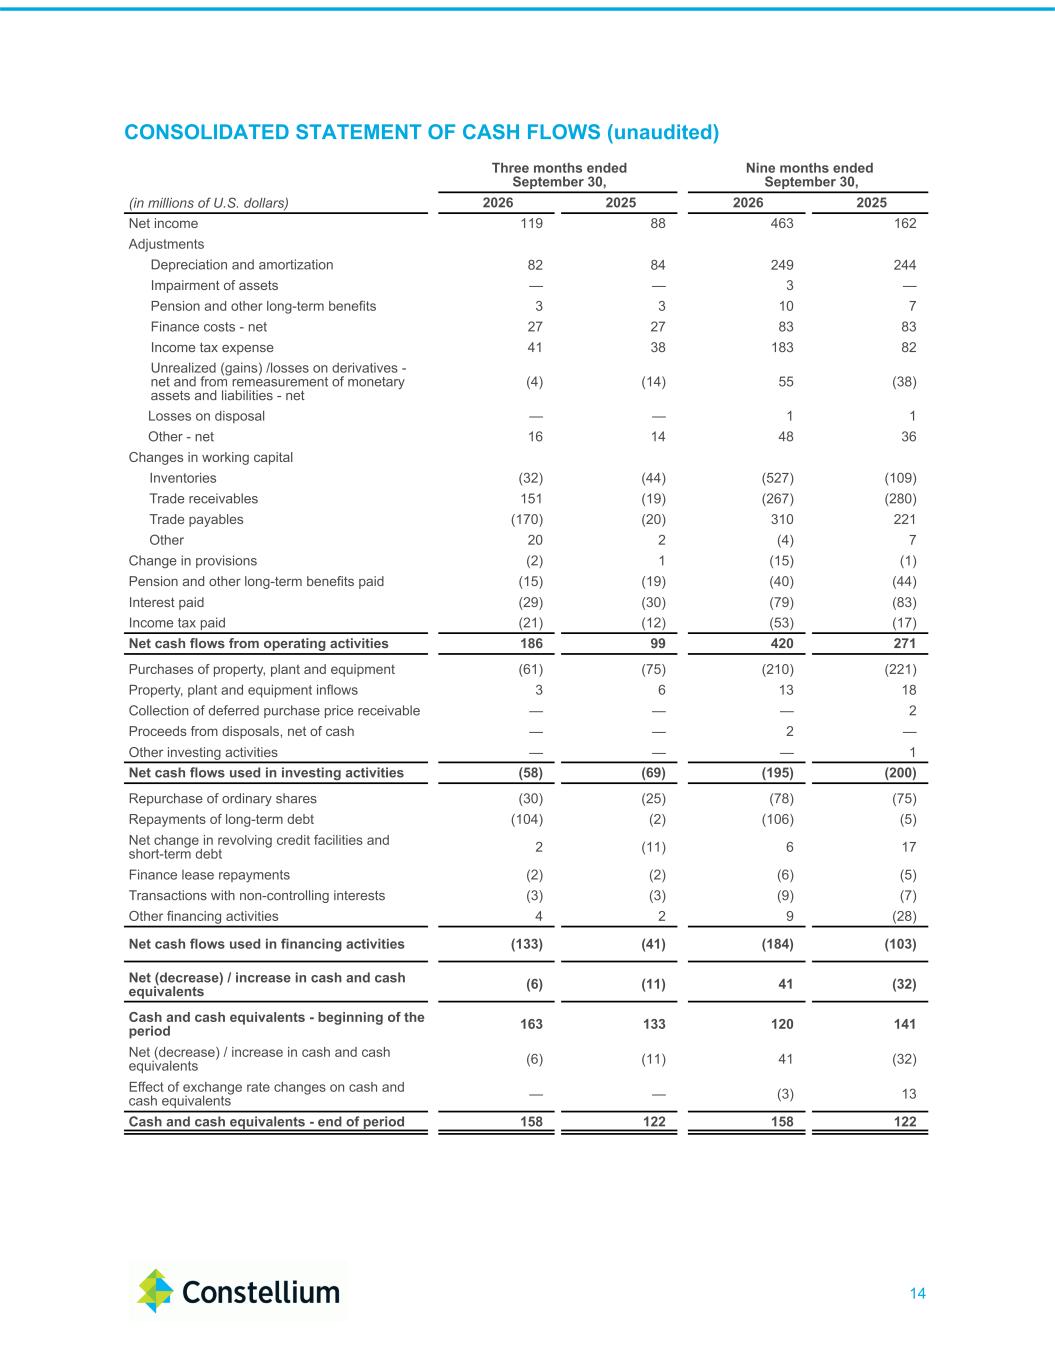
CONSOLIDATED STATEMENT OF CASH FLOWS (unaudited) Three months ended September 30, Nine months ended September 30, (in millions of U.S. dollars) 2026 2025 2026 2025 Net income 119 88 463 162 Adjustments Depreciation and amortization 82 84 249 244 Impairment of assets — — 3 — Pension and other long-term benefits 3 3 10 7 Finance costs - net 27 27 83 83 Income tax expense 41 38 183 82 Unrealized (gains) /losses on derivatives - net and from remeasurement of monetary assets and liabilities - net (4) (14) 55 (38) Losses on disposal — — 1 1 Other - net 16 14 48 36 Changes in working capital Inventories (32) (44) (527) (109) Trade receivables 151 (19) (267) (280) Trade payables (170) (20) 310 221 Other 20 2 (4) 7 Change in provisions (2) 1 (15) (1) Pension and other long-term benefits paid (15) (19) (40) (44) Interest paid (29) (30) (79) (83) Income tax paid (21) (12) (53) (17) Net cash flows from operating activities 186 99 420 271 Purchases of property, plant and equipment (61) (75) (210) (221) Property, plant and equipment inflows 3 6 13 18 Collection of deferred purchase price receivable — — — 2 Proceeds from disposals, net of cash — — 2 — Other investing activities — — — 1 Net cash flows used in investing activities (58) (69) (195) (200) Repurchase of ordinary shares (30) (25) (78) (75) Repayments of long-term debt (104) (2) (106) (5) Net change in revolving credit facilities and short-term debt 2 (11) 6 17 Finance lease repayments (2) (2) (6) (5) Transactions with non-controlling interests (3) (3) (9) (7) Other financing activities 4 2 9 (28) Net cash flows used in financing activities (133) (41) (184) (103) Net (decrease) / increase in cash and cash equivalents (6) (11) 41 (32) Cash and cash equivalents - beginning of the period 163 133 120 141 Net (decrease) / increase in cash and cash equivalents (6) (11) 41 (32) Effect of exchange rate changes on cash and cash equivalents — — (3) 13 Cash and cash equivalents - end of period 158 122 158 122 14
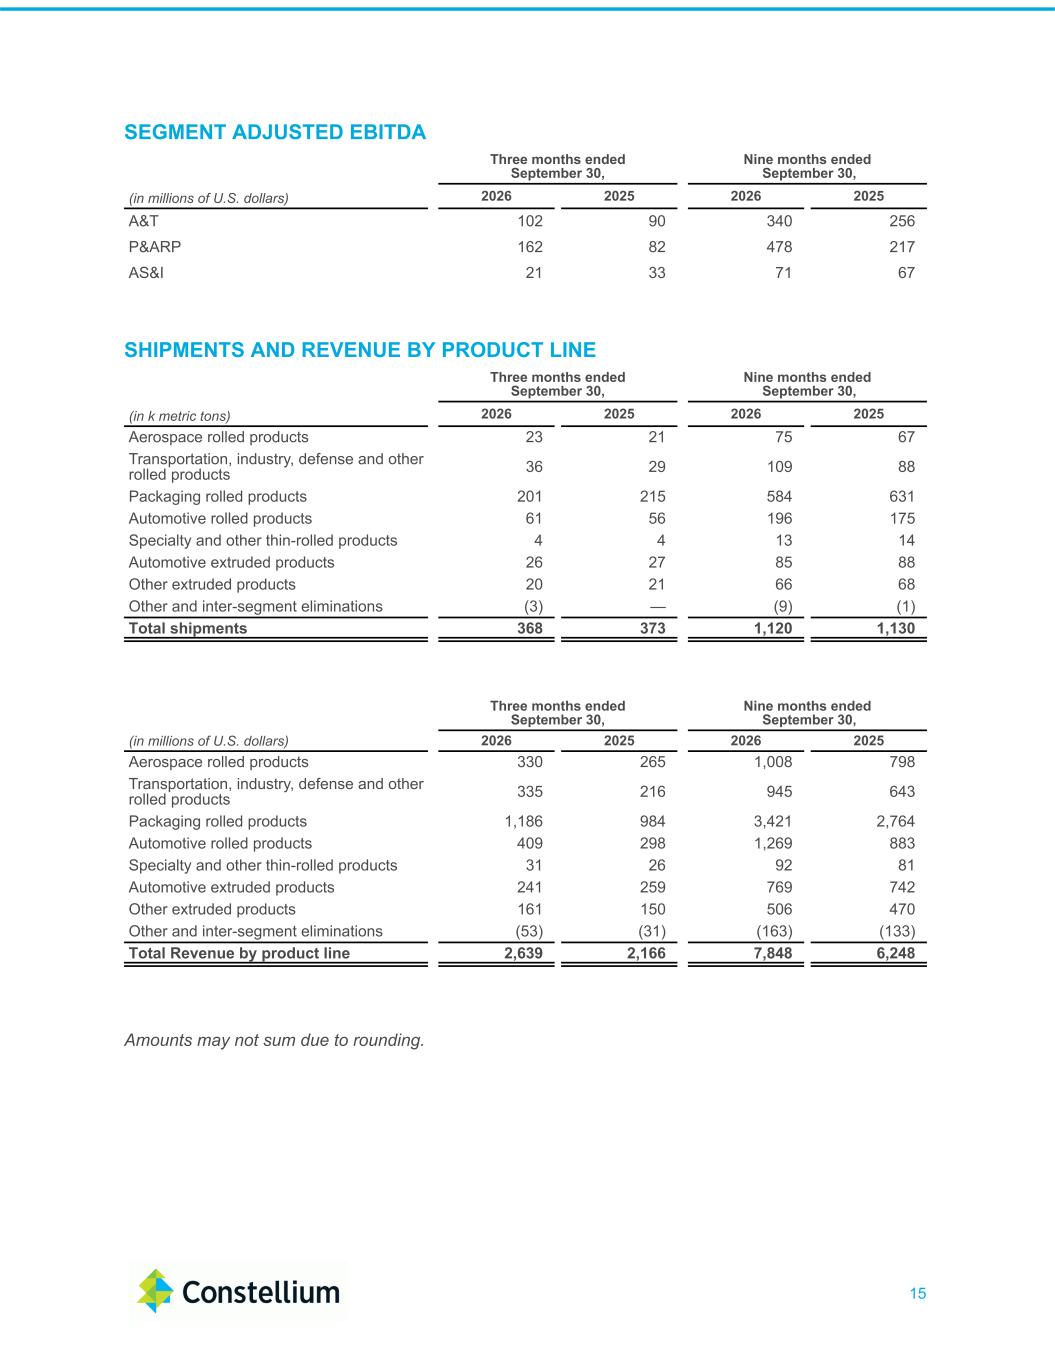
SEGMENT ADJUSTED EBITDA Three months ended September 30, Nine months ended September 30, (in millions of U.S. dollars) 2026 2025 2026 2025 A&T 102 90 340 256 P&ARP 162 82 478 217 AS&I 21 33 71 67 SHIPMENTS AND REVENUE BY PRODUCT LINE Three months ended September 30, Nine months ended September 30, (in k metric tons) 2026 2025 2026 2025 Aerospace rolled products 23 21 75 67 Transportation, industry, defense and other rolled products 36 29 109 88 Packaging rolled products 201 215 584 631 Automotive rolled products 61 56 196 175 Specialty and other thin-rolled products 4 4 13 14 Automotive extruded products 26 27 85 88 Other extruded products 20 21 66 68 Other and inter-segment eliminations (3) — (9) (1) Total shipments 368 373 1,120 1,130 Three months ended September 30, Nine months ended September 30, (in millions of U.S. dollars) 2026 2025 2026 2025 Aerospace rolled products 330 265 1,008 798 Transportation, industry, defense and other rolled products 335 216 945 643 Packaging rolled products 1,186 984 3,421 2,764 Automotive rolled products 409 298 1,269 883 Specialty and other thin-rolled products 31 26 92 81 Automotive extruded products 241 259 769 742 Other extruded products 161 150 506 470 Other and inter-segment eliminations (53) (31) (163) (133) Total Revenue by product line 2,639 2,166 7,848 6,248 Amounts may not sum due to rounding. 15
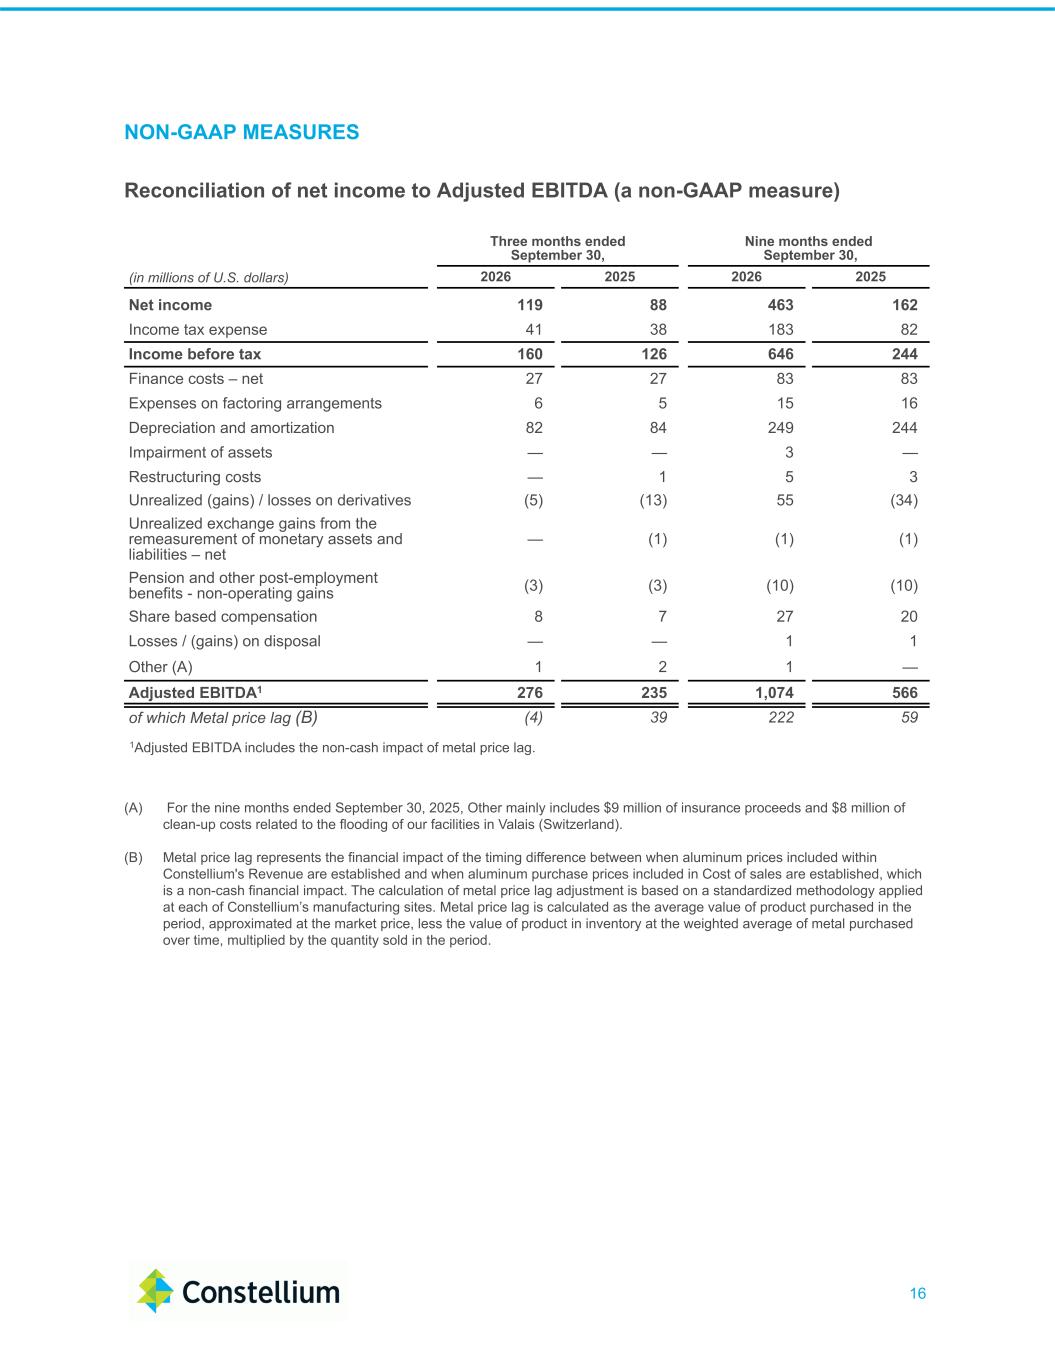
NON-GAAP MEASURES Reconciliation of net income to Adjusted EBITDA (a non-GAAP measure) Three months ended September 30, Nine months ended September 30, (in millions of U.S. dollars) 2026 2025 2026 2025 Net income 119 88 463 162 Income tax expense 41 38 183 82 Income before tax 160 126 646 244 Finance costs – net 27 27 83 83 Expenses on factoring arrangements 6 5 15 16 Depreciation and amortization 82 84 249 244 Impairment of assets — — 3 — Restructuring costs — 1 5 3 Unrealized (gains) / losses on derivatives (5) (13) 55 (34) Unrealized exchange gains from the remeasurement of monetary assets and liabilities – net — (1) (1) (1) Pension and other post-employment benefits - non-operating gains (3) (3) (10) (10) Share based compensation 8 7 27 20 Losses / (gains) on disposal — — 1 1 Other (A) 1 2 1 — Adjusted EBITDA1 276 235 1,074 566 of which Metal price lag (B) (4) 39 222 59 1Adjusted EBITDA includes the non-cash impact of metal price lag. (A) For the nine months ended September 30, 2025, Other mainly includes $9 million of insurance proceeds and $8 million of clean-up costs related to the flooding of our facilities in Valais (Switzerland). (B) Metal price lag represents the financial impact of the timing difference between when aluminum prices included within Constellium's Revenue are established and when aluminum purchase prices included in Cost of sales are established, which is a non-cash financial impact. The calculation of metal price lag adjustment is based on a standardized methodology applied at each of Constellium’s manufacturing sites. Metal price lag is calculated as the average value of product purchased in the period, approximated at the market price, less the value of product in inventory at the weighted average of metal purchased over time, multiplied by the quantity sold in the period. 16
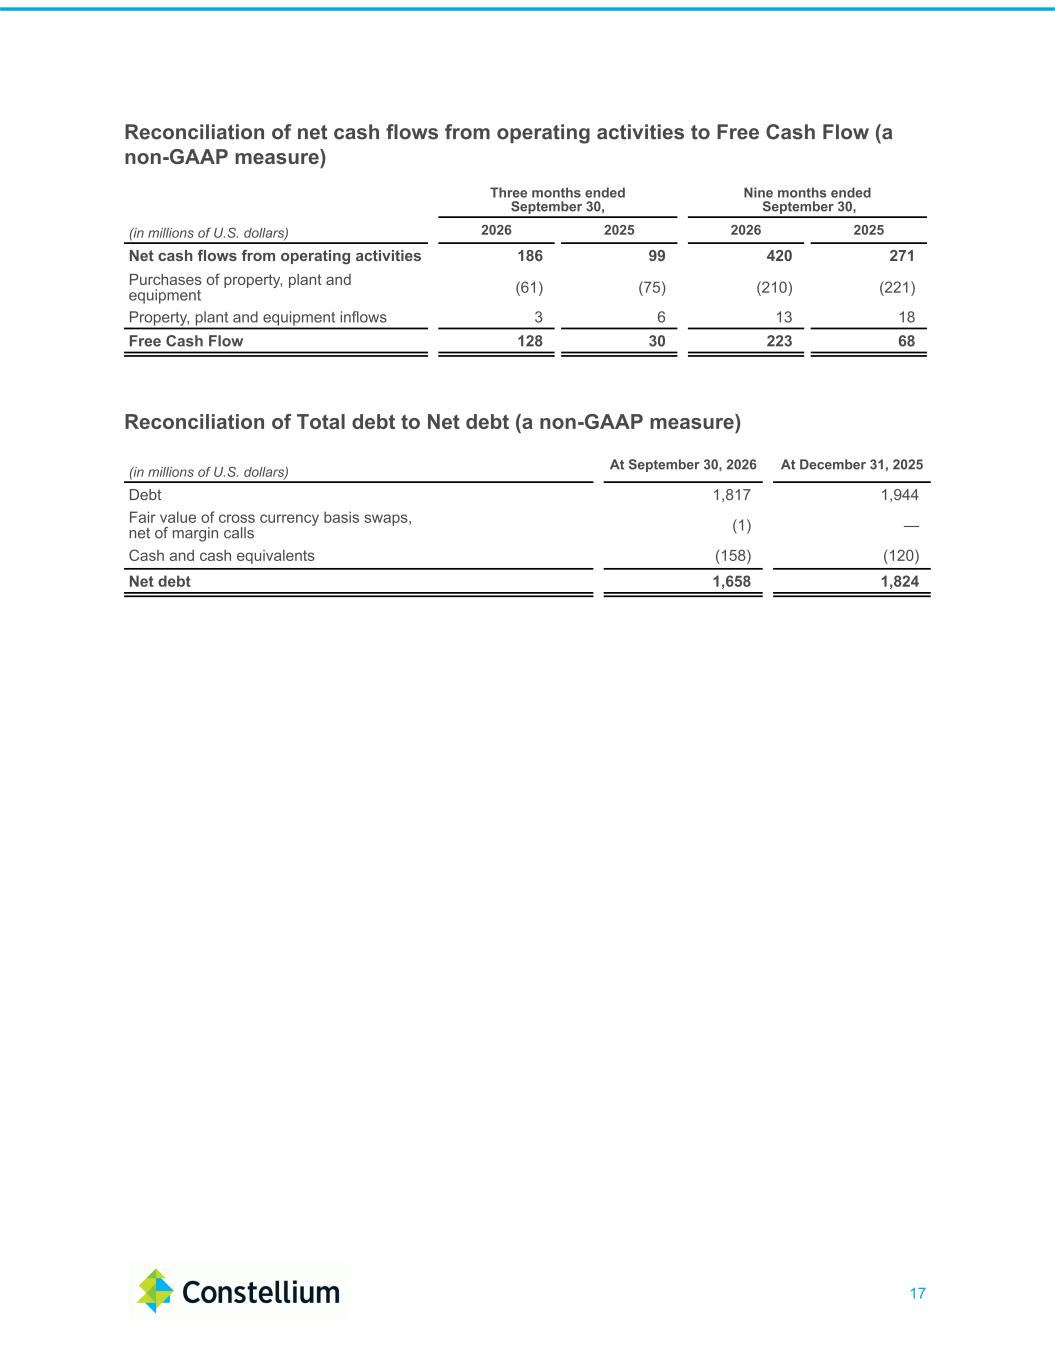
Reconciliation of net cash flows from operating activities to Free Cash Flow (a non-GAAP measure) Three months ended September 30, Nine months ended September 30, (in millions of U.S. dollars) 2026 2025 2026 2025 Net cash flows from operating activities 186 99 420 271 Purchases of property, plant and equipment (61) (75) (210) (221) Property, plant and equipment inflows 3 6 13 18 Free Cash Flow 128 30 223 68 Reconciliation of Total debt to Net debt (a non-GAAP measure) (in millions of U.S. dollars) At September 30, 2026 At December 31, 2025 Debt 1,817 1,944 Fair value of cross currency basis swaps, net of margin calls (1) — Cash and cash equivalents (158) (120) Net debt 1,658 1,824 17