Shareholder Report
Aug. 31, 2026
USD ($)
Holding
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R6 | $38 | 0.37% |
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 452,589,287 | Total Management Fee ($)#: | $1,816,061 | |
| Total Number of Holdings: | 23 |
# Includes the effect of any management fee waivers, if applicable.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| U.S. Treasury and U.S. Government Agency Securities and Equivalents | 63.5% |
| Repurchase Agreements, collateralized by U.S. Treasury and/or U.S. Government Agency Securities | 36.5% |
Composition including fixed income credit quality
| A-1+ | 51.4% |
| A-1 | 48.6% |
Maturity breakdown
| 0 - 7 days | 44.4% |
| 8 - 29 days | 7.0% |
| 30 - 59 days | 30.1% |
| 60 - 89 days | 9.3% |
| 90 - 365 days | 9.2% |
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R4 | $43 | 0.42% |
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 452,589,287 | Total Management Fee ($)#: | $1,816,061 | |
| Total Number of Holdings: | 23 |
# Includes the effect of any management fee waivers, if applicable.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| U.S. Treasury and U.S. Government Agency Securities and Equivalents | 63.5% |
| Repurchase Agreements, collateralized by U.S. Treasury and/or U.S. Government Agency Securities | 36.5% |
Composition including fixed income credit quality
| A-1+ | 51.4% |
| A-1 | 48.6% |
Maturity breakdown
| 0 - 7 days | 44.4% |
| 8 - 29 days | 7.0% |
| 30 - 59 days | 30.1% |
| 60 - 89 days | 9.3% |
| 90 - 365 days | 9.2% |
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R3 | $43 | 0.42% |
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 452,589,287 | Total Management Fee ($)#: | $1,816,061 | |
| Total Number of Holdings: | 23 |
# Includes the effect of any management fee waivers, if applicable.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| U.S. Treasury and U.S. Government Agency Securities and Equivalents | 63.5% |
| Repurchase Agreements, collateralized by U.S. Treasury and/or U.S. Government Agency Securities | 36.5% |
Composition including fixed income credit quality
| A-1+ | 51.4% |
| A-1 | 48.6% |
Maturity breakdown
| 0 - 7 days | 44.4% |
| 8 - 29 days | 7.0% |
| 30 - 59 days | 30.1% |
| 60 - 89 days | 9.3% |
| 90 - 365 days | 9.2% |
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R2 | $43 | 0.42% |
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 452,589,287 | Total Management Fee ($)#: | $1,816,061 | |
| Total Number of Holdings: | 23 |
# Includes the effect of any management fee waivers, if applicable.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| U.S. Treasury and U.S. Government Agency Securities and Equivalents | 63.5% |
| Repurchase Agreements, collateralized by U.S. Treasury and/or U.S. Government Agency Securities | 36.5% |
Composition including fixed income credit quality
| A-1+ | 51.4% |
| A-1 | 48.6% |
Maturity breakdown
| 0 - 7 days | 44.4% |
| 8 - 29 days | 7.0% |
| 30 - 59 days | 30.1% |
| 60 - 89 days | 9.3% |
| 90 - 365 days | 9.2% |
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R1 | $43 | 0.42% |
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 452,589,287 | Total Management Fee ($)#: | $1,816,061 | |
| Total Number of Holdings: | 23 |
# Includes the effect of any management fee waivers, if applicable.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| U.S. Treasury and U.S. Government Agency Securities and Equivalents | 63.5% |
| Repurchase Agreements, collateralized by U.S. Treasury and/or U.S. Government Agency Securities | 36.5% |
Composition including fixed income credit quality
| A-1+ | 51.4% |
| A-1 | 48.6% |
Maturity breakdown
| 0 - 7 days | 44.4% |
| 8 - 29 days | 7.0% |
| 30 - 59 days | 30.1% |
| 60 - 89 days | 9.3% |
| 90 - 365 days | 9.2% |
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| I | $43 | 0.42% |
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 452,589,287 | Total Management Fee ($)#: | $1,816,061 | |
| Total Number of Holdings: | 23 |
# Includes the effect of any management fee waivers, if applicable.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| U.S. Treasury and U.S. Government Agency Securities and Equivalents | 63.5% |
| Repurchase Agreements, collateralized by U.S. Treasury and/or U.S. Government Agency Securities | 36.5% |
Composition including fixed income credit quality
| A-1+ | 51.4% |
| A-1 | 48.6% |
Maturity breakdown
| 0 - 7 days | 44.4% |
| 8 - 29 days | 7.0% |
| 30 - 59 days | 30.1% |
| 60 - 89 days | 9.3% |
| 90 - 365 days | 9.2% |
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| C | $43 | 0.42% |
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 452,589,287 | Total Management Fee ($)#: | $1,816,061 | |
| Total Number of Holdings: | 23 |
# Includes the effect of any management fee waivers, if applicable.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| U.S. Treasury and U.S. Government Agency Securities and Equivalents | 63.5% |
| Repurchase Agreements, collateralized by U.S. Treasury and/or U.S. Government Agency Securities | 36.5% |
Composition including fixed income credit quality
| A-1+ | 51.4% |
| A-1 | 48.6% |
Maturity breakdown
| 0 - 7 days | 44.4% |
| 8 - 29 days | 7.0% |
| 30 - 59 days | 30.1% |
| 60 - 89 days | 9.3% |
| 90 - 365 days | 9.2% |
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| B | $43 | 0.42% |
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 452,589,287 | Total Management Fee ($)#: | $1,816,061 | |
| Total Number of Holdings: | 23 |
# Includes the effect of any management fee waivers, if applicable.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| U.S. Treasury and U.S. Government Agency Securities and Equivalents | 63.5% |
| Repurchase Agreements, collateralized by U.S. Treasury and/or U.S. Government Agency Securities | 36.5% |
Composition including fixed income credit quality
| A-1+ | 51.4% |
| A-1 | 48.6% |
Maturity breakdown
| 0 - 7 days | 44.4% |
| 8 - 29 days | 7.0% |
| 30 - 59 days | 30.1% |
| 60 - 89 days | 9.3% |
| 90 - 365 days | 9.2% |
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| A | $43 | 0.42% |
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 452,589,287 | Total Management Fee ($)#: | $1,816,061 | |
| Total Number of Holdings: | 23 |
# Includes the effect of any management fee waivers, if applicable.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| U.S. Treasury and U.S. Government Agency Securities and Equivalents | 63.5% |
| Repurchase Agreements, collateralized by U.S. Treasury and/or U.S. Government Agency Securities | 36.5% |
Composition including fixed income credit quality
| A-1+ | 51.4% |
| A-1 | 48.6% |
Maturity breakdown
| 0 - 7 days | 44.4% |
| 8 - 29 days | 7.0% |
| 30 - 59 days | 30.1% |
| 60 - 89 days | 9.3% |
| 90 - 365 days | 9.2% |
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
Ratings are assigned to portfolio securities utilizing ratings from Moody’s, Fitch, and Standard & Poor’s rating agencies and applying the following hierarchy: If all three agencies provide a rating, the middle rating (after dropping the highest and lowest ratings) is assigned; if two of the three agencies rate a security, the lower of the two is assigned. Ratings are shown in the S&P scale. All ratings are subject to change. The fund did not hold unrated securities. The fund is not rated by these agencies.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| A | $93 | 0.87% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class A shares of the MFS Core Equity Fund (fund) provided a total return of 14.93%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 3000® Index:
-
Stock selection within both the consumer cyclicals and health care sectors benefited the fund's relative performance.
-
Stock selection within the financial services sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 3000® Index:
-
Stock selection within the technology sector weighed on the fund's relative performance.
-
Stock selection within the capital goods, communication services, and consumer staples sectors also held back relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
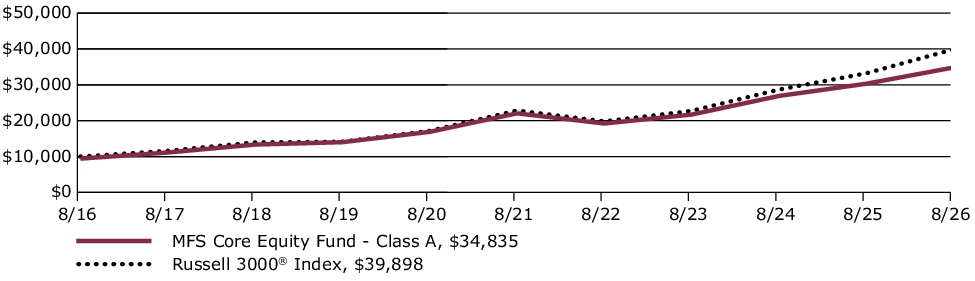
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class A over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance. This graph includes the deduction of the maximum applicable sales charge.
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| A without sales charge | 14.93% | 9.57% | 13.97% |
| A with initial sales charge (5.75%) | 8.32% | 8.28% | 13.29% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/a for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 6,509,449,817 | Total Management Fee ($)#: | 32,783,354 | |
| Total Number of Holdings: | 173 | Portfolio Turnover Rate (%): | 57 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.5% |
| Money Market Funds | 0.5% |
Global equity sectors
| Technology | 35.0% |
| Financial Services | 13.2% |
| Capital Goods | 12.7% |
| Health Care | 10.9% |
| Consumer Cyclicals | 9.5% |
| Communication Services | 9.2% |
| Energy | 6.3% |
| Consumer Staples | 2.7% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| B | $173 | 1.62% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class B shares of the MFS Core Equity Fund (fund) provided a total return of 14.10%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 3000® Index:
-
Stock selection within both the consumer cyclicals and health care sectors benefited the fund's relative performance.
-
Stock selection within the financial services sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 3000® Index:
-
Stock selection within the technology sector weighed on the fund's relative performance.
-
Stock selection within the capital goods, communication services, and consumer staples sectors also held back relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
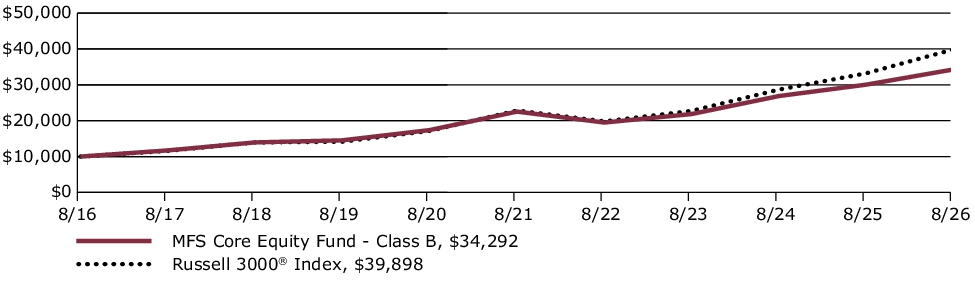
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class B over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| B without sales charge | 14.10% | 8.76% | 13.11% |
| B with CDSC (declining over six years from 4% to 0%)× | 10.19% | 8.47% | 13.11% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/b for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 6,509,449,817 | Total Management Fee ($)#: | 32,783,354 | |
| Total Number of Holdings: | 173 | Portfolio Turnover Rate (%): | 57 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.5% |
| Money Market Funds | 0.5% |
Global equity sectors
| Technology | 35.0% |
| Financial Services | 13.2% |
| Capital Goods | 12.7% |
| Health Care | 10.9% |
| Consumer Cyclicals | 9.5% |
| Communication Services | 9.2% |
| Energy | 6.3% |
| Consumer Staples | 2.7% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| C | $173 | 1.62% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class C shares of the MFS Core Equity Fund (fund) provided a total return of 14.06%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 3000® Index:
-
Stock selection within both the consumer cyclicals and health care sectors benefited the fund's relative performance.
-
Stock selection within the financial services sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 3000® Index:
-
Stock selection within the technology sector weighed on the fund's relative performance.
-
Stock selection within the capital goods, communication services, and consumer staples sectors also held back relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
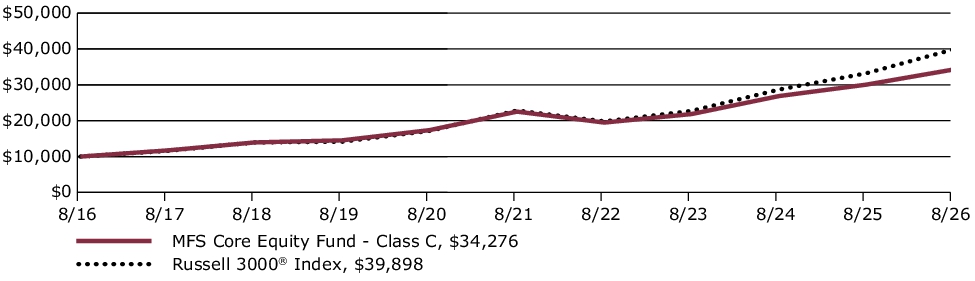
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class C over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| C without sales charge | 14.06% | 8.75% | 13.11% |
| C with CDSC (1% for 12 months)× | 13.09% | 8.75% | 13.11% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/c for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 6,509,449,817 | Total Management Fee ($)#: | 32,783,354 | |
| Total Number of Holdings: | 173 | Portfolio Turnover Rate (%): | 57 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.5% |
| Money Market Funds | 0.5% |
Global equity sectors
| Technology | 35.0% |
| Financial Services | 13.2% |
| Capital Goods | 12.7% |
| Health Care | 10.9% |
| Consumer Cyclicals | 9.5% |
| Communication Services | 9.2% |
| Energy | 6.3% |
| Consumer Staples | 2.7% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| I | $67 | 0.62% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class I shares of the MFS Core Equity Fund (fund) provided a total return of 15.21%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 3000® Index:
-
Stock selection within both the consumer cyclicals and health care sectors benefited the fund's relative performance.
-
Stock selection within the financial services sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 3000® Index:
-
Stock selection within the technology sector weighed on the fund's relative performance.
-
Stock selection within the capital goods, communication services, and consumer staples sectors also held back relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
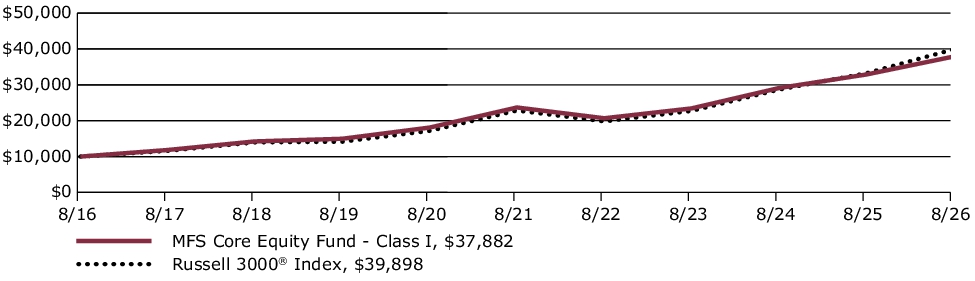
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class I over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| I without sales charge | 15.21% | 9.85% | 14.25% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/i for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 6,509,449,817 | Total Management Fee ($)#: | 32,783,354 | |
| Total Number of Holdings: | 173 | Portfolio Turnover Rate (%): | 57 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.5% |
| Money Market Funds | 0.5% |
Global equity sectors
| Technology | 35.0% |
| Financial Services | 13.2% |
| Capital Goods | 12.7% |
| Health Care | 10.9% |
| Consumer Cyclicals | 9.5% |
| Communication Services | 9.2% |
| Energy | 6.3% |
| Consumer Staples | 2.7% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R1 | $173 | 1.62% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
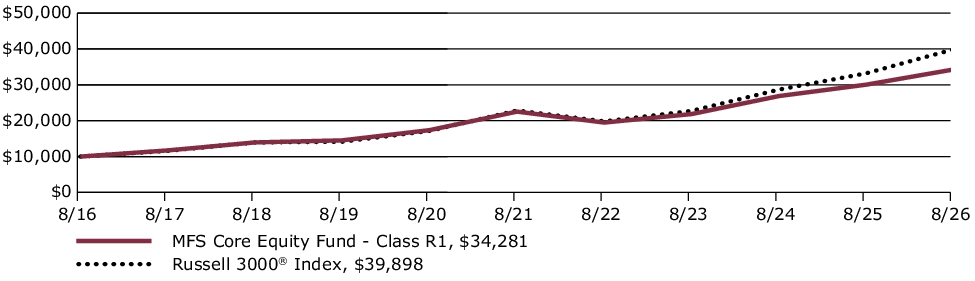
For the twelve months ended August 31, 2026, Class R1 shares of the MFS Core Equity Fund (fund) provided a total return of 14.09%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 3000® Index:
-
Stock selection within both the consumer cyclicals and health care sectors benefited the fund's relative performance.
-
Stock selection within the financial services sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 3000® Index:
-
Stock selection within the technology sector weighed on the fund's relative performance.
-
Stock selection within the capital goods, communication services, and consumer staples sectors also held back relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R1 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R1 without sales charge | 14.09% | 8.76% | 13.11% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r1 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 6,509,449,817 | Total Management Fee ($)#: | 32,783,354 | |
| Total Number of Holdings: | 173 | Portfolio Turnover Rate (%): | 57 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.5% |
| Money Market Funds | 0.5% |
Global equity sectors
| Technology | 35.0% |
| Financial Services | 13.2% |
| Capital Goods | 12.7% |
| Health Care | 10.9% |
| Consumer Cyclicals | 9.5% |
| Communication Services | 9.2% |
| Energy | 6.3% |
| Consumer Staples | 2.7% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R2 | $120 | 1.12% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
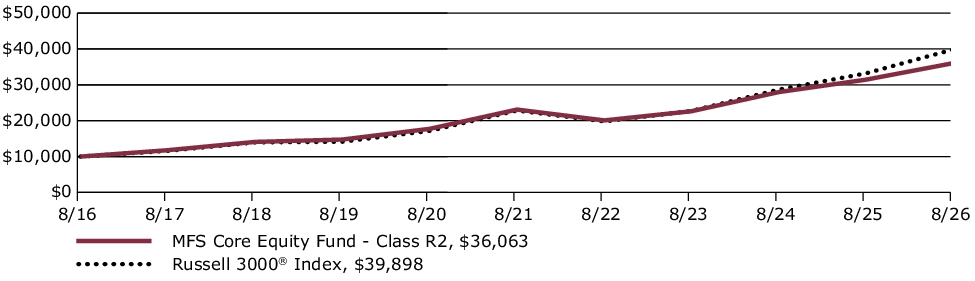
For the twelve months ended August 31, 2026, Class R2 shares of the MFS Core Equity Fund (fund) provided a total return of 14.64%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 3000® Index:
-
Stock selection within both the consumer cyclicals and health care sectors benefited the fund's relative performance.
-
Stock selection within the financial services sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 3000® Index:
-
Stock selection within the technology sector weighed on the fund's relative performance.
-
Stock selection within the capital goods, communication services, and consumer staples sectors also held back relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R2 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R2 without sales charge | 14.64% | 9.31% | 13.69% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r2 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 6,509,449,817 | Total Management Fee ($)#: | 32,783,354 | |
| Total Number of Holdings: | 173 | Portfolio Turnover Rate (%): | 57 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.5% |
| Money Market Funds | 0.5% |
Global equity sectors
| Technology | 35.0% |
| Financial Services | 13.2% |
| Capital Goods | 12.7% |
| Health Care | 10.9% |
| Consumer Cyclicals | 9.5% |
| Communication Services | 9.2% |
| Energy | 6.3% |
| Consumer Staples | 2.7% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R3 | $93 | 0.87% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
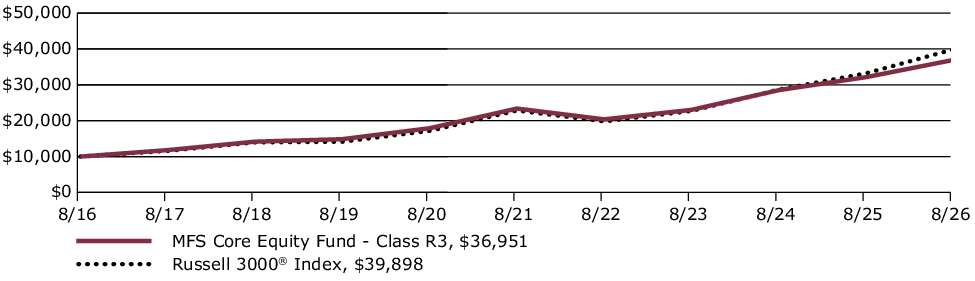
For the twelve months ended August 31, 2026, Class R3 shares of the MFS Core Equity Fund (fund) provided a total return of 14.93%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 3000® Index:
-
Stock selection within both the consumer cyclicals and health care sectors benefited the fund's relative performance.
-
Stock selection within the financial services sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 3000® Index:
-
Stock selection within the technology sector weighed on the fund's relative performance.
-
Stock selection within the capital goods, communication services, and consumer staples sectors also held back relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R3 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R3 without sales charge | 14.93% | 9.58% | 13.96% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r3 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 6,509,449,817 | Total Management Fee ($)#: | 32,783,354 | |
| Total Number of Holdings: | 173 | Portfolio Turnover Rate (%): | 57 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.5% |
| Money Market Funds | 0.5% |
Global equity sectors
| Technology | 35.0% |
| Financial Services | 13.2% |
| Capital Goods | 12.7% |
| Health Care | 10.9% |
| Consumer Cyclicals | 9.5% |
| Communication Services | 9.2% |
| Energy | 6.3% |
| Consumer Staples | 2.7% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R4 | $67 | 0.62% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
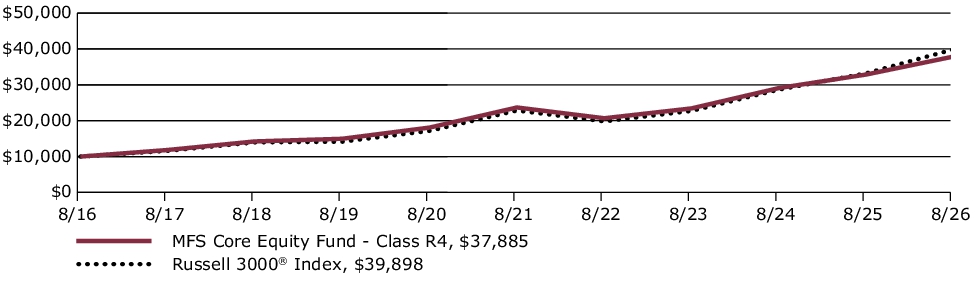
For the twelve months ended August 31, 2026, Class R4 shares of the MFS Core Equity Fund (fund) provided a total return of 15.22%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 3000® Index:
-
Stock selection within both the consumer cyclicals and health care sectors benefited the fund's relative performance.
-
Stock selection within the financial services sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 3000® Index:
-
Stock selection within the technology sector weighed on the fund's relative performance.
-
Stock selection within the capital goods, communication services, and consumer staples sectors also held back relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R4 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R4 without sales charge | 15.22% | 9.85% | 14.25% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r4 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 6,509,449,817 | Total Management Fee ($)#: | 32,783,354 | |
| Total Number of Holdings: | 173 | Portfolio Turnover Rate (%): | 57 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.5% |
| Money Market Funds | 0.5% |
Global equity sectors
| Technology | 35.0% |
| Financial Services | 13.2% |
| Capital Goods | 12.7% |
| Health Care | 10.9% |
| Consumer Cyclicals | 9.5% |
| Communication Services | 9.2% |
| Energy | 6.3% |
| Consumer Staples | 2.7% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R6 | $58 | 0.54% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R6 shares of the MFS Core Equity Fund (fund) provided a total return of 15.33%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 3000® Index:
-
Stock selection within both the consumer cyclicals and health care sectors benefited the fund's relative performance.
-
Stock selection within the financial services sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 3000® Index:
-
Stock selection within the technology sector weighed on the fund's relative performance.
-
Stock selection within the capital goods, communication services, and consumer staples sectors also held back relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R6 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
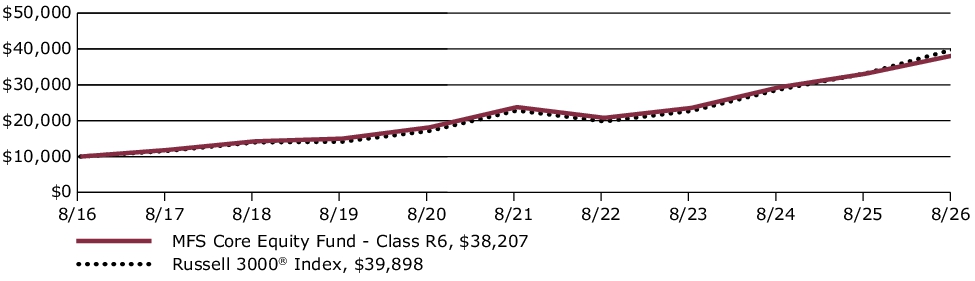
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R6 without sales charge | 15.33% | 9.94% | 14.34% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r6 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 6,509,449,817 | Total Management Fee ($)#: | 32,783,354 | |
| Total Number of Holdings: | 173 | Portfolio Turnover Rate (%): | 57 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.5% |
| Money Market Funds | 0.5% |
Global equity sectors
| Technology | 35.0% |
| Financial Services | 13.2% |
| Capital Goods | 12.7% |
| Health Care | 10.9% |
| Consumer Cyclicals | 9.5% |
| Communication Services | 9.2% |
| Energy | 6.3% |
| Consumer Staples | 2.7% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
Top ten holdings
| NVIDIA Corp. | 7.4% |
| Microsoft Corp. | 5.6% |
| Apple, Inc. | 5.5% |
| Amazon.com, Inc. | 4.7% |
| Alphabet, Inc., "A" | 4.7% |
| Broadcom, Inc. | 3.5% |
| Meta Platforms, Inc., "A" | 2.1% |
| JPMorgan Chase & Co. | 1.9% |
| Pfizer, Inc. | 1.8% |
| Gilead Sciences, Inc. | 1.8% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R6 | $94 | 0.85% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R6 shares of the MFS New Discovery Fund (fund) provided a total return of 22.28%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 2000® Growth Index, generated a return of 23.25%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 2000® Growth Index:
-
Stock selection within the information technology sector supported the fund's relative performance.
-
-
Top detractors from performance relative to the Russell 2000® Growth Index:
-
Stock selection within both the consumer discretionary and industrials sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R6 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
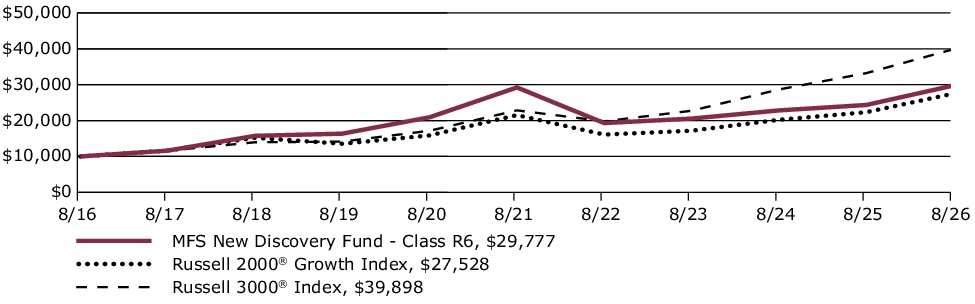
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R6 without sales charge | 22.28% | 0.37% | 11.53% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 2000® Growth Index ∆ | 23.25% | 5.04% | 10.66% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r6 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,140,841,934 | Total Management Fee ($)#: | 17,475,466 | |
| Total Number of Holdings: | 118 | Portfolio Turnover Rate (%): | 95 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 93.9% |
| Money Market Funds | 6.1% |
Equity sectors
| Health Care | 31.4% |
| Industrials | 20.3% |
| Information Technology | 16.2% |
| Materials | 5.9% |
| Consumer Discretionary | 5.4% |
| Financials | 4.8% |
| Energy | 4.3% |
| Consumer Staples | 2.7% |
| Real Estate | 2.6% |
| Communication Services | 0.3% |
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R4 | $107 | 0.96% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R4 shares of the MFS New Discovery Fund (fund) provided a total return of 22.15%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 2000® Growth Index, generated a return of 23.25%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 2000® Growth Index:
-
Stock selection within the information technology sector supported the fund's relative performance.
-
-
Top detractors from performance relative to the Russell 2000® Growth Index:
-
Stock selection within both the consumer discretionary and industrials sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R4 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
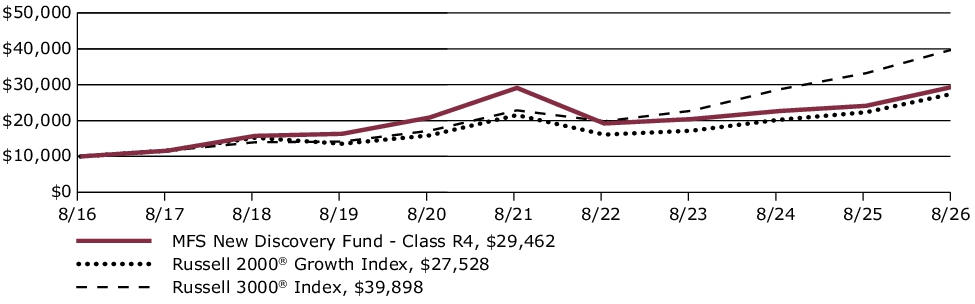
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R4 without sales charge | 22.15% | 0.24% | 11.41% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 2000® Growth Index ∆ | 23.25% | 5.04% | 10.66% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r4 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,140,841,934 | Total Management Fee ($)#: | 17,475,466 | |
| Total Number of Holdings: | 118 | Portfolio Turnover Rate (%): | 95 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 93.9% |
| Money Market Funds | 6.1% |
Equity sectors
| Health Care | 31.4% |
| Industrials | 20.3% |
| Information Technology | 16.2% |
| Materials | 5.9% |
| Consumer Discretionary | 5.4% |
| Financials | 4.8% |
| Energy | 4.3% |
| Consumer Staples | 2.7% |
| Real Estate | 2.6% |
| Communication Services | 0.3% |
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R3 | $134 | 1.21% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R3 shares of the MFS New Discovery Fund (fund) provided a total return of 21.85%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 2000® Growth Index, generated a return of 23.25%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 2000® Growth Index:
-
Stock selection within the information technology sector supported the fund's relative performance.
-
-
Top detractors from performance relative to the Russell 2000® Growth Index:
-
Stock selection within both the consumer discretionary and industrials sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R3 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
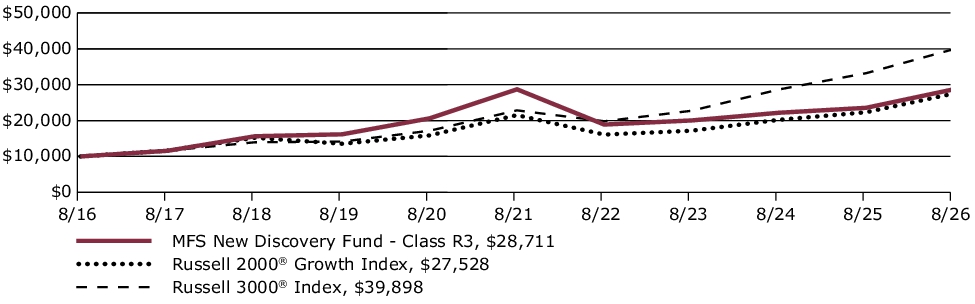
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R3 without sales charge | 21.85% | (0.00)% | 11.12% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 2000® Growth Index ∆ | 23.25% | 5.04% | 10.66% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r3 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,140,841,934 | Total Management Fee ($)#: | 17,475,466 | |
| Total Number of Holdings: | 118 | Portfolio Turnover Rate (%): | 95 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 93.9% |
| Money Market Funds | 6.1% |
Equity sectors
| Health Care | 31.4% |
| Industrials | 20.3% |
| Information Technology | 16.2% |
| Materials | 5.9% |
| Consumer Discretionary | 5.4% |
| Financials | 4.8% |
| Energy | 4.3% |
| Consumer Staples | 2.7% |
| Real Estate | 2.6% |
| Communication Services | 0.3% |
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R2 | $162 | 1.46% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R2 shares of the MFS New Discovery Fund (fund) provided a total return of 21.51%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 2000® Growth Index, generated a return of 23.25%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 2000® Growth Index:
-
Stock selection within the information technology sector supported the fund's relative performance.
-
-
Top detractors from performance relative to the Russell 2000® Growth Index:
-
Stock selection within both the consumer discretionary and industrials sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R2 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
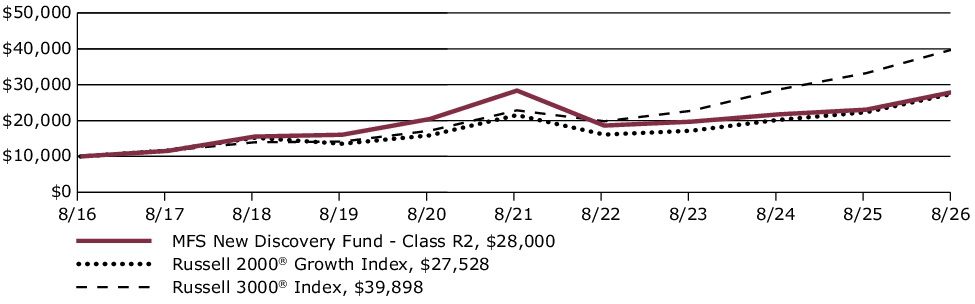
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R2 without sales charge | 21.51% | (0.25)% | 10.84% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 2000® Growth Index ∆ | 23.25% | 5.04% | 10.66% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r2 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,140,841,934 | Total Management Fee ($)#: | 17,475,466 | |
| Total Number of Holdings: | 118 | Portfolio Turnover Rate (%): | 95 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 93.9% |
| Money Market Funds | 6.1% |
Equity sectors
| Health Care | 31.4% |
| Industrials | 20.3% |
| Information Technology | 16.2% |
| Materials | 5.9% |
| Consumer Discretionary | 5.4% |
| Financials | 4.8% |
| Energy | 4.3% |
| Consumer Staples | 2.7% |
| Real Estate | 2.6% |
| Communication Services | 0.3% |
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R1 | $217 | 1.96% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R1 shares of the MFS New Discovery Fund (fund) provided a total return of 20.94%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 2000® Growth Index, generated a return of 23.25%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 2000® Growth Index:
-
Stock selection within the information technology sector supported the fund's relative performance.
-
-
Top detractors from performance relative to the Russell 2000® Growth Index:
-
Stock selection within both the consumer discretionary and industrials sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R1 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
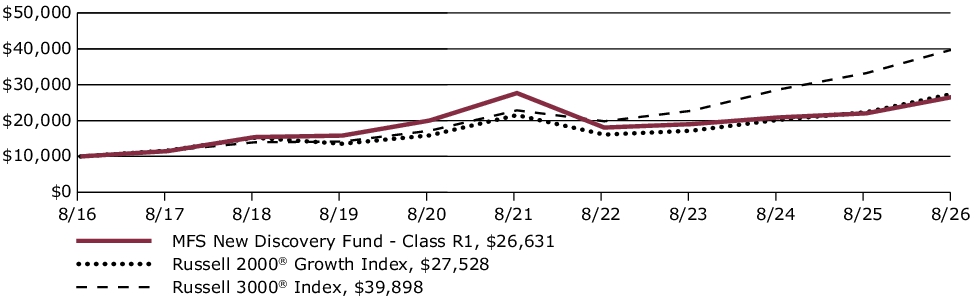
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R1 without sales charge | 20.94% | (0.76)% | 10.29% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 2000® Growth Index ∆ | 23.25% | 5.04% | 10.66% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r1 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,140,841,934 | Total Management Fee ($)#: | 17,475,466 | |
| Total Number of Holdings: | 118 | Portfolio Turnover Rate (%): | 95 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 93.9% |
| Money Market Funds | 6.1% |
Equity sectors
| Health Care | 31.4% |
| Industrials | 20.3% |
| Information Technology | 16.2% |
| Materials | 5.9% |
| Consumer Discretionary | 5.4% |
| Financials | 4.8% |
| Energy | 4.3% |
| Consumer Staples | 2.7% |
| Real Estate | 2.6% |
| Communication Services | 0.3% |
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| I | $107 | 0.96% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class I shares of the MFS New Discovery Fund (fund) provided a total return of 22.13%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 2000® Growth Index, generated a return of 23.25%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 2000® Growth Index:
-
Stock selection within the information technology sector supported the fund's relative performance.
-
-
Top detractors from performance relative to the Russell 2000® Growth Index:
-
Stock selection within both the consumer discretionary and industrials sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class I over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
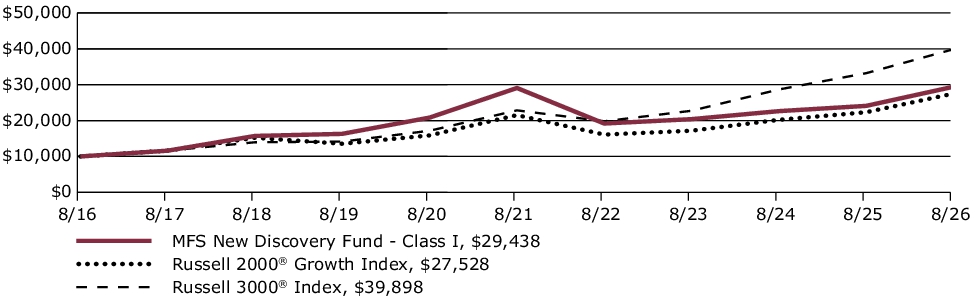
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| I without sales charge | 22.13% | 0.24% | 11.40% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 2000® Growth Index ∆ | 23.25% | 5.04% | 10.66% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/i for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,140,841,934 | Total Management Fee ($)#: | 17,475,466 | |
| Total Number of Holdings: | 118 | Portfolio Turnover Rate (%): | 95 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 93.9% |
| Money Market Funds | 6.1% |
Equity sectors
| Health Care | 31.4% |
| Industrials | 20.3% |
| Information Technology | 16.2% |
| Materials | 5.9% |
| Consumer Discretionary | 5.4% |
| Financials | 4.8% |
| Energy | 4.3% |
| Consumer Staples | 2.7% |
| Real Estate | 2.6% |
| Communication Services | 0.3% |
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| C | $217 | 1.96% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class C shares of the MFS New Discovery Fund (fund) provided a total return of 20.96%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 2000® Growth Index, generated a return of 23.25%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 2000® Growth Index:
-
Stock selection within the information technology sector supported the fund's relative performance.
-
-
Top detractors from performance relative to the Russell 2000® Growth Index:
-
Stock selection within both the consumer discretionary and industrials sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class C over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
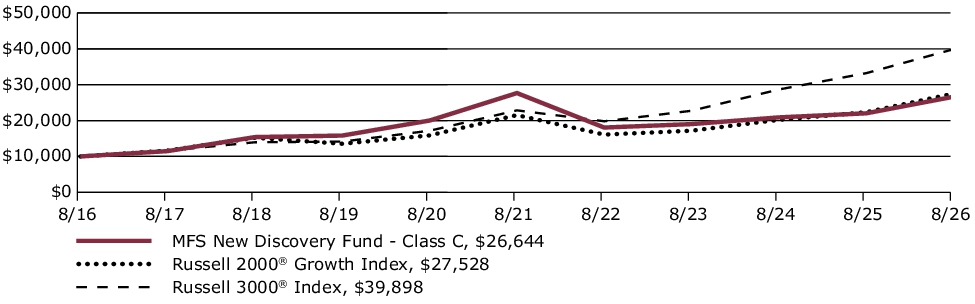
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| C without sales charge | 20.96% | (0.75)% | 10.30% |
| C with CDSC (1% for 12 months)× | 19.96% | (0.75)% | 10.30% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 2000® Growth Index ∆ | 23.25% | 5.04% | 10.66% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/c for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,140,841,934 | Total Management Fee ($)#: | 17,475,466 | |
| Total Number of Holdings: | 118 | Portfolio Turnover Rate (%): | 95 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 93.9% |
| Money Market Funds | 6.1% |
Equity sectors
| Health Care | 31.4% |
| Industrials | 20.3% |
| Information Technology | 16.2% |
| Materials | 5.9% |
| Consumer Discretionary | 5.4% |
| Financials | 4.8% |
| Energy | 4.3% |
| Consumer Staples | 2.7% |
| Real Estate | 2.6% |
| Communication Services | 0.3% |
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| B | $217 | 1.96% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class B shares of the MFS New Discovery Fund (fund) provided a total return of 20.94%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 2000® Growth Index, generated a return of 23.25%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 2000® Growth Index:
-
Stock selection within the information technology sector supported the fund's relative performance.
-
-
Top detractors from performance relative to the Russell 2000® Growth Index:
-
Stock selection within both the consumer discretionary and industrials sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class B over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
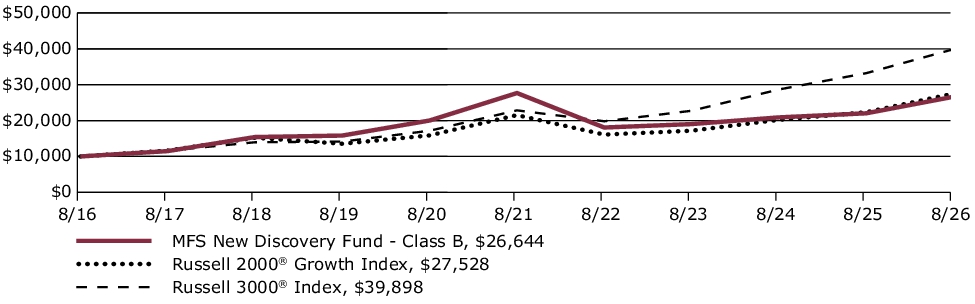
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| B without sales charge | 20.94% | (0.76)% | 10.30% |
| B with CDSC (declining over six years from 4% to 0%)× | 16.94% | (1.04)% | 10.30% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 2000® Growth Index ∆ | 23.25% | 5.04% | 10.66% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/b for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,140,841,934 | Total Management Fee ($)#: | 17,475,466 | |
| Total Number of Holdings: | 118 | Portfolio Turnover Rate (%): | 95 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 93.9% |
| Money Market Funds | 6.1% |
Equity sectors
| Health Care | 31.4% |
| Industrials | 20.3% |
| Information Technology | 16.2% |
| Materials | 5.9% |
| Consumer Discretionary | 5.4% |
| Financials | 4.8% |
| Energy | 4.3% |
| Consumer Staples | 2.7% |
| Real Estate | 2.6% |
| Communication Services | 0.3% |
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| A | $134 | 1.21% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class A shares of the MFS New Discovery Fund (fund) provided a total return of 21.88%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 2000® Growth Index, generated a return of 23.25%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 2000® Growth Index:
-
Stock selection within the information technology sector supported the fund's relative performance.
-
-
Top detractors from performance relative to the Russell 2000® Growth Index:
-
Stock selection within both the consumer discretionary and industrials sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class A over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests. This graph includes the deduction of the maximum applicable sales charge.
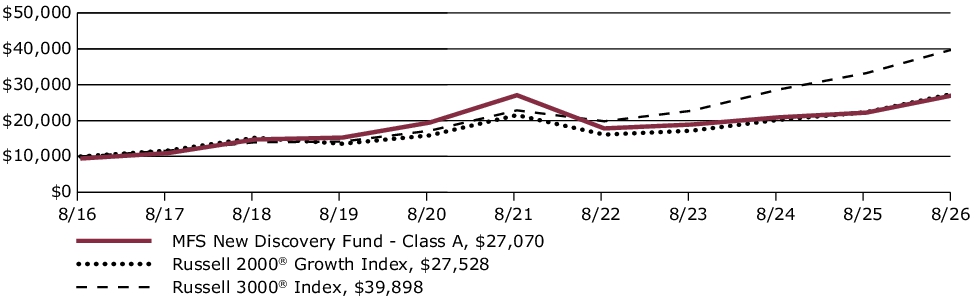
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| A without sales charge | 21.88% | (0.00)% | 11.13% |
| A with initial sales charge (5.75%) | 14.87% | (1.18)% | 10.47% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 2000® Growth Index ∆ | 23.25% | 5.04% | 10.66% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/a for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,140,841,934 | Total Management Fee ($)#: | 17,475,466 | |
| Total Number of Holdings: | 118 | Portfolio Turnover Rate (%): | 95 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 93.9% |
| Money Market Funds | 6.1% |
Equity sectors
| Health Care | 31.4% |
| Industrials | 20.3% |
| Information Technology | 16.2% |
| Materials | 5.9% |
| Consumer Discretionary | 5.4% |
| Financials | 4.8% |
| Energy | 4.3% |
| Consumer Staples | 2.7% |
| Real Estate | 2.6% |
| Communication Services | 0.3% |
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| CACI International, Inc., "A" | 2.5% |
| Ligand Pharmaceuticals, Inc. | 2.3% |
| Merit Medical Systems, Inc. | 2.1% |
| Charles River Laboratories International, Inc. | 2.0% |
| Chefs' Warehouse, Inc. | 1.9% |
| Waystar Holding Corp. | 1.7% |
| Moog, Inc., "A" | 1.6% |
| Advanced Energy Industries, Inc. | 1.6% |
| SSR Mining, Inc. | 1.6% |
| Element Solutions, Inc. | 1.6% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| A | $108 | 0.98% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class A shares of the MFS Research International Fund (fund) provided a total return of 20.81%, at net asset value. This compares with a return of 21.62% for the fund’s benchmark, the MSCI EAFE (Europe, Australasia, Far East) Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI EAFE Index:
-
Stock selection within the financial services and technology sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI EAFE Index:
-
Stock selection within the health care and consumer staples sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class A over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance. This graph includes the deduction of the maximum applicable sales charge.
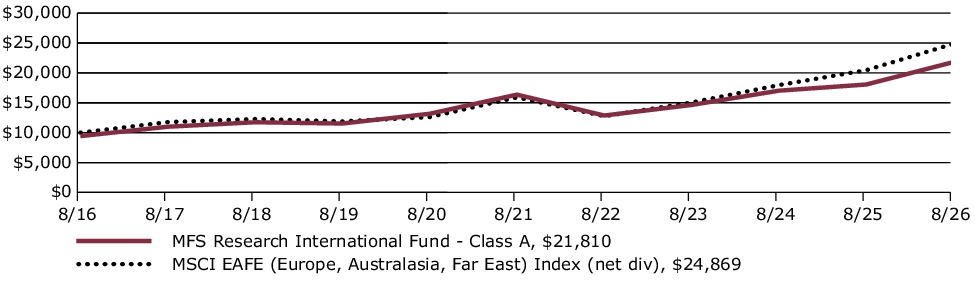
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| A without sales charge | 20.81% | 5.92% | 8.75% |
| A with initial sales charge (5.75%) | 13.86% | 4.67% | 8.11% |
| Comparative Benchmark(s) | |||
| MSCI EAFE (Europe, Australasia, Far East) Index (net div) ∆ | 21.62% | 9.35% | 9.54% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/a for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 17,611,863,872 | Total Management Fee ($)#: | 107,956,758 | |
| Total Number of Holdings: | 117 | Portfolio Turnover Rate (%): | 35 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.3% |
| Money Market Funds | 1.7% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
Issuer country weightings
| Japan | 22.5% |
| United Kingdom | 16.7% |
| France | 11.2% |
| Switzerland | 7.2% |
| Netherlands | 6.2% |
| Germany | 6.0% |
| United States | 5.7% |
| Italy | 3.3% |
| Hong Kong | 2.4% |
| Other Countries | 18.8% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| B | $189 | 1.72% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class B shares of the MFS Research International Fund (fund) provided a total return of 19.96%, at net asset value. This compares with a return of 21.62% for the fund’s benchmark, the MSCI EAFE (Europe, Australasia, Far East) Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI EAFE Index:
-
Stock selection within the financial services and technology sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI EAFE Index:
-
Stock selection within the health care and consumer staples sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class B over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
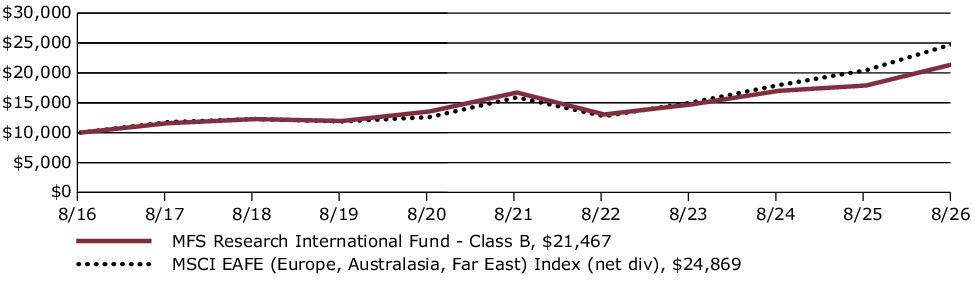
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| B without sales charge | 19.96% | 5.13% | 7.94% |
| B with CDSC (declining over six years from 4% to 0%)× | 15.96% | 4.80% | 7.94% |
| Comparative Benchmark(s) | |||
| MSCI EAFE (Europe, Australasia, Far East) Index (net div) ∆ | 21.62% | 9.35% | 9.54% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/b for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 17,611,863,872 | Total Management Fee ($)#: | 107,956,758 | |
| Total Number of Holdings: | 117 | Portfolio Turnover Rate (%): | 35 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.3% |
| Money Market Funds | 1.7% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
Issuer country weightings
| Japan | 22.5% |
| United Kingdom | 16.7% |
| France | 11.2% |
| Switzerland | 7.2% |
| Netherlands | 6.2% |
| Germany | 6.0% |
| United States | 5.7% |
| Italy | 3.3% |
| Hong Kong | 2.4% |
| Other Countries | 18.8% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| C | $190 | 1.73% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class C shares of the MFS Research International Fund (fund) provided a total return of 19.94%, at net asset value. This compares with a return of 21.62% for the fund’s benchmark, the MSCI EAFE (Europe, Australasia, Far East) Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI EAFE Index:
-
Stock selection within the financial services and technology sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI EAFE Index:
-
Stock selection within the health care and consumer staples sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class C over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
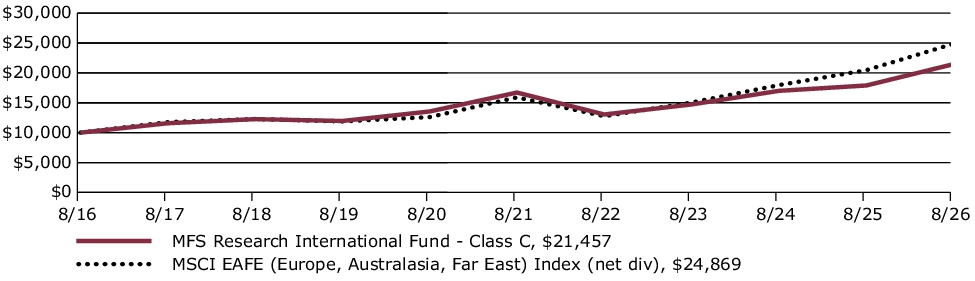
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| C without sales charge | 19.94% | 5.13% | 7.93% |
| C with CDSC (1% for 12 months)× | 18.94% | 5.13% | 7.93% |
| Comparative Benchmark(s) | |||
| MSCI EAFE (Europe, Australasia, Far East) Index (net div) ∆ | 21.62% | 9.35% | 9.54% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/c for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 17,611,863,872 | Total Management Fee ($)#: | 107,956,758 | |
| Total Number of Holdings: | 117 | Portfolio Turnover Rate (%): | 35 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.3% |
| Money Market Funds | 1.7% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
Issuer country weightings
| Japan | 22.5% |
| United Kingdom | 16.7% |
| France | 11.2% |
| Switzerland | 7.2% |
| Netherlands | 6.2% |
| Germany | 6.0% |
| United States | 5.7% |
| Italy | 3.3% |
| Hong Kong | 2.4% |
| Other Countries | 18.8% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| I | $81 | 0.73% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class I shares of the MFS Research International Fund (fund) provided a total return of 21.10%, at net asset value. This compares with a return of 21.62% for the fund’s benchmark, the MSCI EAFE (Europe, Australasia, Far East) Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI EAFE Index:
-
Stock selection within the financial services and technology sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI EAFE Index:
-
Stock selection within the health care and consumer staples sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class I over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
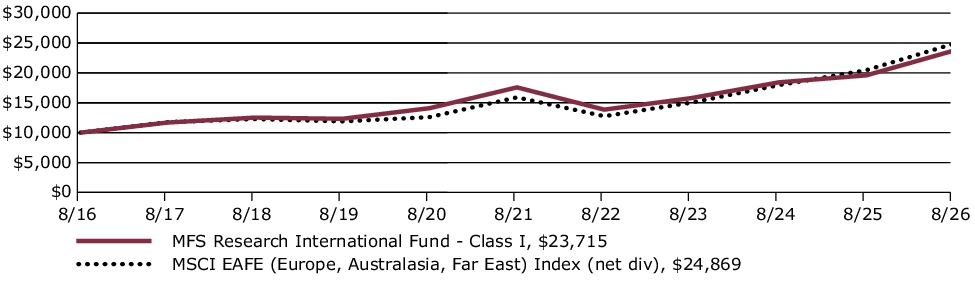
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| I without sales charge | 21.10% | 6.18% | 9.02% |
| Comparative Benchmark(s) | |||
| MSCI EAFE (Europe, Australasia, Far East) Index (net div) ∆ | 21.62% | 9.35% | 9.54% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/i for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 17,611,863,872 | Total Management Fee ($)#: | 107,956,758 | |
| Total Number of Holdings: | 117 | Portfolio Turnover Rate (%): | 35 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.3% |
| Money Market Funds | 1.7% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
Issuer country weightings
| Japan | 22.5% |
| United Kingdom | 16.7% |
| France | 11.2% |
| Switzerland | 7.2% |
| Netherlands | 6.2% |
| Germany | 6.0% |
| United States | 5.7% |
| Italy | 3.3% |
| Hong Kong | 2.4% |
| Other Countries | 18.8% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R1 | $190 | 1.73% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R1 shares of the MFS Research International Fund (fund) provided a total return of 19.92%, at net asset value. This compares with a return of 21.62% for the fund’s benchmark, the MSCI EAFE (Europe, Australasia, Far East) Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI EAFE Index:
-
Stock selection within the financial services and technology sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI EAFE Index:
-
Stock selection within the health care and consumer staples sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R1 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
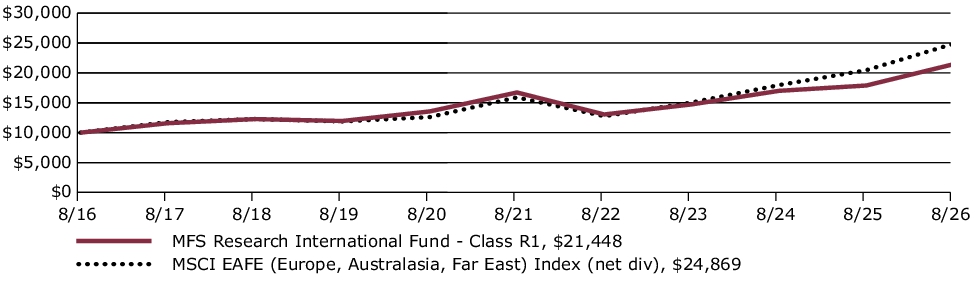
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R1 without sales charge | 19.92% | 5.11% | 7.93% |
| Comparative Benchmark(s) | |||
| MSCI EAFE (Europe, Australasia, Far East) Index (net div) ∆ | 21.62% | 9.35% | 9.54% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r1 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 17,611,863,872 | Total Management Fee ($)#: | 107,956,758 | |
| Total Number of Holdings: | 117 | Portfolio Turnover Rate (%): | 35 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.3% |
| Money Market Funds | 1.7% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
Issuer country weightings
| Japan | 22.5% |
| United Kingdom | 16.7% |
| France | 11.2% |
| Switzerland | 7.2% |
| Netherlands | 6.2% |
| Germany | 6.0% |
| United States | 5.7% |
| Italy | 3.3% |
| Hong Kong | 2.4% |
| Other Countries | 18.8% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R2 | $136 | 1.23% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R2 shares of the MFS Research International Fund (fund) provided a total return of 20.54%, at net asset value. This compares with a return of 21.62% for the fund’s benchmark, the MSCI EAFE (Europe, Australasia, Far East) Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI EAFE Index:
-
Stock selection within the financial services and technology sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI EAFE Index:
-
Stock selection within the health care and consumer staples sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R2 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
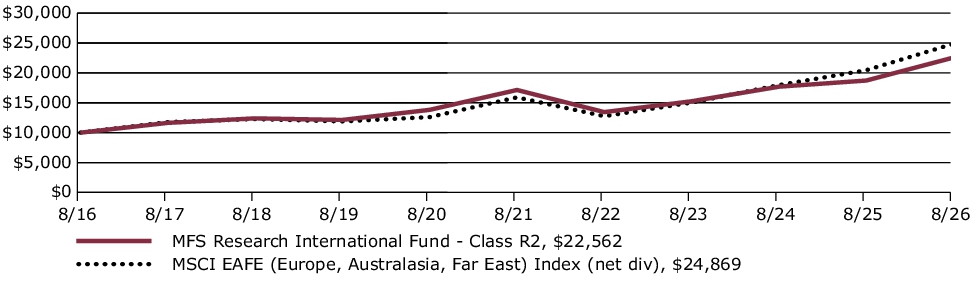
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R2 without sales charge | 20.54% | 5.65% | 8.48% |
| Comparative Benchmark(s) | |||
| MSCI EAFE (Europe, Australasia, Far East) Index (net div) ∆ | 21.62% | 9.35% | 9.54% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r2 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 17,611,863,872 | Total Management Fee ($)#: | 107,956,758 | |
| Total Number of Holdings: | 117 | Portfolio Turnover Rate (%): | 35 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.3% |
| Money Market Funds | 1.7% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
Issuer country weightings
| Japan | 22.5% |
| United Kingdom | 16.7% |
| France | 11.2% |
| Switzerland | 7.2% |
| Netherlands | 6.2% |
| Germany | 6.0% |
| United States | 5.7% |
| Italy | 3.3% |
| Hong Kong | 2.4% |
| Other Countries | 18.8% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R3 | $108 | 0.98% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R3 shares of the MFS Research International Fund (fund) provided a total return of 20.82%, at net asset value. This compares with a return of 21.62% for the fund’s benchmark, the MSCI EAFE (Europe, Australasia, Far East) Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI EAFE Index:
-
Stock selection within the financial services and technology sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI EAFE Index:
-
Stock selection within the health care and consumer staples sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R3 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
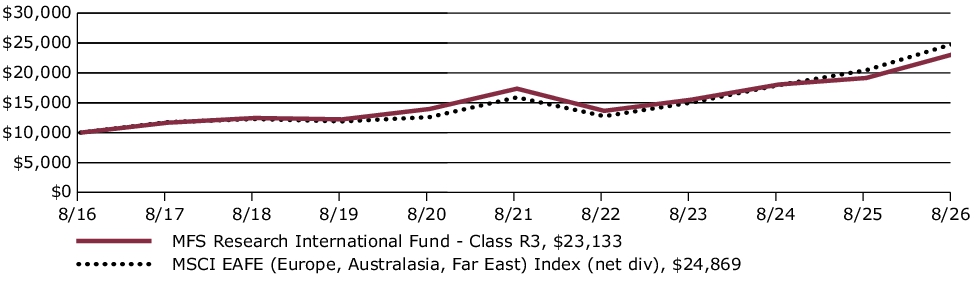
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R3 without sales charge | 20.82% | 5.91% | 8.75% |
| Comparative Benchmark(s) | |||
| MSCI EAFE (Europe, Australasia, Far East) Index (net div) ∆ | 21.62% | 9.35% | 9.54% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r3 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 17,611,863,872 | Total Management Fee ($)#: | 107,956,758 | |
| Total Number of Holdings: | 117 | Portfolio Turnover Rate (%): | 35 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.3% |
| Money Market Funds | 1.7% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
Issuer country weightings
| Japan | 22.5% |
| United Kingdom | 16.7% |
| France | 11.2% |
| Switzerland | 7.2% |
| Netherlands | 6.2% |
| Germany | 6.0% |
| United States | 5.7% |
| Italy | 3.3% |
| Hong Kong | 2.4% |
| Other Countries | 18.8% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R4 | $81 | 0.73% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R4 shares of the MFS Research International Fund (fund) provided a total return of 21.11%, at net asset value. This compares with a return of 21.62% for the fund’s benchmark, the MSCI EAFE (Europe, Australasia, Far East) Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI EAFE Index:
-
Stock selection within the financial services and technology sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI EAFE Index:
-
Stock selection within the health care and consumer staples sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R4 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
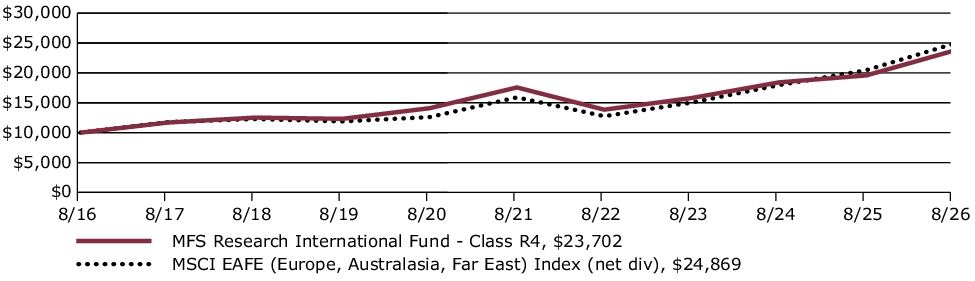
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R4 without sales charge | 21.11% | 6.18% | 9.01% |
| Comparative Benchmark(s) | |||
| MSCI EAFE (Europe, Australasia, Far East) Index (net div) ∆ | 21.62% | 9.35% | 9.54% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r4 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 17,611,863,872 | Total Management Fee ($)#: | 107,956,758 | |
| Total Number of Holdings: | 117 | Portfolio Turnover Rate (%): | 35 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.3% |
| Money Market Funds | 1.7% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
Issuer country weightings
| Japan | 22.5% |
| United Kingdom | 16.7% |
| France | 11.2% |
| Switzerland | 7.2% |
| Netherlands | 6.2% |
| Germany | 6.0% |
| United States | 5.7% |
| Italy | 3.3% |
| Hong Kong | 2.4% |
| Other Countries | 18.8% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R6 | $70 | 0.63% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R6 shares of the MFS Research International Fund (fund) provided a total return of 21.24%, at net asset value. This compares with a return of 21.62% for the fund’s benchmark, the MSCI EAFE (Europe, Australasia, Far East) Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI EAFE Index:
-
Stock selection within the financial services and technology sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI EAFE Index:
-
Stock selection within the health care and consumer staples sectors weighed on relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R6 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
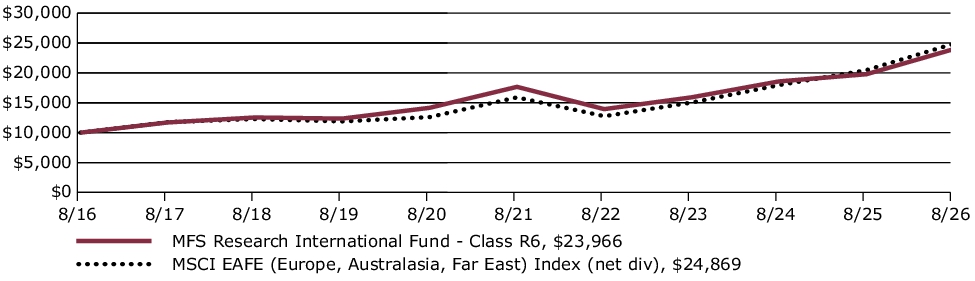
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R6 without sales charge | 21.24% | 6.29% | 9.13% |
| Comparative Benchmark(s) | |||
| MSCI EAFE (Europe, Australasia, Far East) Index (net div) ∆ | 21.62% | 9.35% | 9.54% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r6 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 17,611,863,872 | Total Management Fee ($)#: | 107,956,758 | |
| Total Number of Holdings: | 117 | Portfolio Turnover Rate (%): | 35 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.3% |
| Money Market Funds | 1.7% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
Issuer country weightings
| Japan | 22.5% |
| United Kingdom | 16.7% |
| France | 11.2% |
| Switzerland | 7.2% |
| Netherlands | 6.2% |
| Germany | 6.0% |
| United States | 5.7% |
| Italy | 3.3% |
| Hong Kong | 2.4% |
| Other Countries | 18.8% |
Top ten holdings
| Schneider Electric SE | 2.9% |
| Mizuho Financial Group, Inc. | 2.6% |
| Hitachi Ltd. | 2.5% |
| ASML Holding N.V. | 2.2% |
| Taiwan Semiconductor Manufacturing Co. Ltd. | 2.1% |
| Novartis AG | 2.1% |
| TotalEnergies SE | 2.0% |
| Tokyo Electron Ltd. | 2.0% |
| Banco Bilbao Vizcaya Argentaria S.A. | 1.7% |
| BNP Paribas S.A. | 1.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R6 | $88 | 0.77% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R6 shares of the MFS Technology Fund (fund) provided a total return of 29.41%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index. The fund's other benchmark, the Standard & Poor's North American Technology Sector Index, generated a return of 41.03%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s North American Technology Sector Index:
-
The combination of stock selection and an overweight position in the semi & electronic components industry benefited the fund's relative performance.
-
The fund's underweight position in the entertainment & leisure industry also helped relative returns.
-
-
Top detractors from performance relative to the Standard & Poor’s North American Technology Sector Index:
-
Stock selection within the hardware, peripherals & assembly industry held back relative performance.
-
The combination of stock selection and overweight positions in both the software and business services industries further weakened the fund's relative results.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R6 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
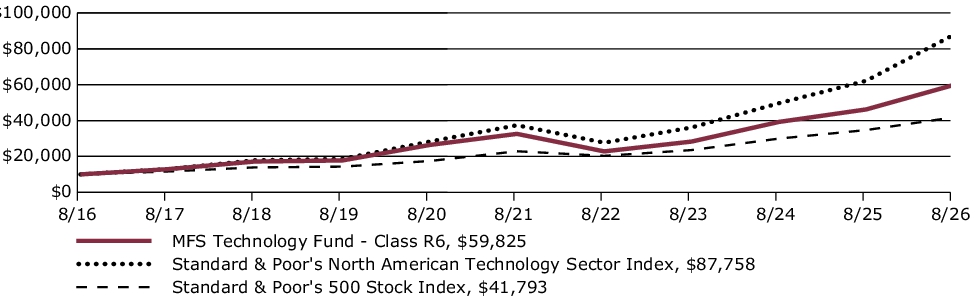
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R6 without sales charge | 29.41% | 12.92% | 19.59% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
| Standard & Poor's North American Technology Sector Index ∆ | 41.03% | 18.59% | 24.26% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r6 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,372,124,346 | Total Management Fee ($)#: | 15,777,828 | |
| Total Number of Holdings: | 54 | Portfolio Turnover Rate (%): | 59 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 97.3% |
| Money Market Funds | 2.7% |
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
Top five industries
| Software | 33.6% |
| Semiconductor & Electronic Components | 31.9% |
| Hardware, Peripherals, & Assembly | 19.8% |
| Interactive Media Services | 11.2% |
| Electrical Equipment | 2.0% |
For purposes of these classifications, MFS uses its own internal sector/industry classification methodology, which may deviate from classification methodologies used by other industry participants (e.g., the Global Industry Classification Standard).
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R4 | $99 | 0.86% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R4 shares of the MFS Technology Fund (fund) provided a total return of 29.28%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index. The fund's other benchmark, the Standard & Poor's North American Technology Sector Index, generated a return of 41.03%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s North American Technology Sector Index:
-
The combination of stock selection and an overweight position in the semi & electronic components industry benefited the fund's relative performance.
-
The fund's underweight position in the entertainment & leisure industry also helped relative returns.
-
-
Top detractors from performance relative to the Standard & Poor’s North American Technology Sector Index:
-
Stock selection within the hardware, peripherals & assembly industry held back relative performance.
-
The combination of stock selection and overweight positions in both the software and business services industries further weakened the fund's relative results.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R4 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
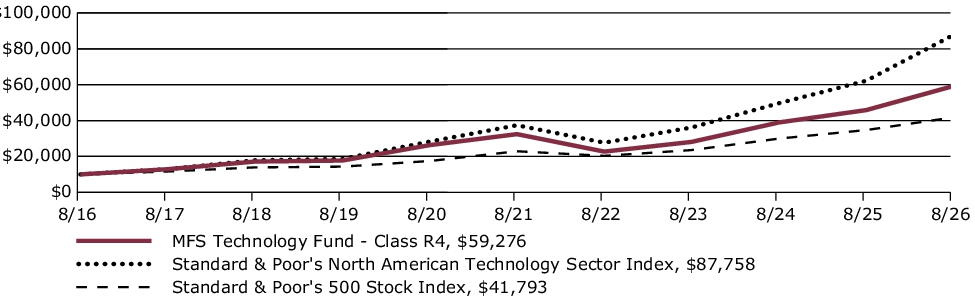
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R4 without sales charge | 29.28% | 12.81% | 19.48% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
| Standard & Poor's North American Technology Sector Index ∆ | 41.03% | 18.59% | 24.26% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r4 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,372,124,346 | Total Management Fee ($)#: | 15,777,828 | |
| Total Number of Holdings: | 54 | Portfolio Turnover Rate (%): | 59 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 97.3% |
| Money Market Funds | 2.7% |
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
Top five industries
| Software | 33.6% |
| Semiconductor & Electronic Components | 31.9% |
| Hardware, Peripherals, & Assembly | 19.8% |
| Interactive Media Services | 11.2% |
| Electrical Equipment | 2.0% |
For purposes of these classifications, MFS uses its own internal sector/industry classification methodology, which may deviate from classification methodologies used by other industry participants (e.g., the Global Industry Classification Standard).
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R3 | $127 | 1.11% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R3 shares of the MFS Technology Fund (fund) provided a total return of 28.97%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index. The fund's other benchmark, the Standard & Poor's North American Technology Sector Index, generated a return of 41.03%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s North American Technology Sector Index:
-
The combination of stock selection and an overweight position in the semi & electronic components industry benefited the fund's relative performance.
-
The fund's underweight position in the entertainment & leisure industry also helped relative returns.
-
-
Top detractors from performance relative to the Standard & Poor’s North American Technology Sector Index:
-
Stock selection within the hardware, peripherals & assembly industry held back relative performance.
-
The combination of stock selection and overweight positions in both the software and business services industries further weakened the fund's relative results.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R3 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
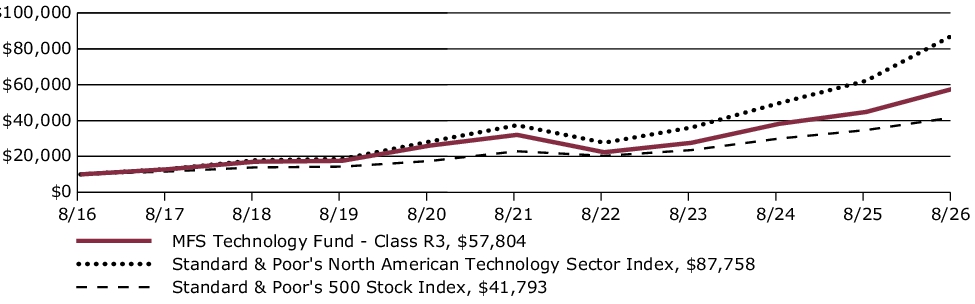
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R3 without sales charge | 28.97% | 12.53% | 19.18% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
| Standard & Poor's North American Technology Sector Index ∆ | 41.03% | 18.59% | 24.26% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r3 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,372,124,346 | Total Management Fee ($)#: | 15,777,828 | |
| Total Number of Holdings: | 54 | Portfolio Turnover Rate (%): | 59 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 97.3% |
| Money Market Funds | 2.7% |
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
Top five industries
| Software | 33.6% |
| Semiconductor & Electronic Components | 31.9% |
| Hardware, Peripherals, & Assembly | 19.8% |
| Interactive Media Services | 11.2% |
| Electrical Equipment | 2.0% |
For purposes of these classifications, MFS uses its own internal sector/industry classification methodology, which may deviate from classification methodologies used by other industry participants (e.g., the Global Industry Classification Standard).
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R2 | $155 | 1.36% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R2 shares of the MFS Technology Fund (fund) provided a total return of 28.66%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index. The fund's other benchmark, the Standard & Poor's North American Technology Sector Index, generated a return of 41.03%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s North American Technology Sector Index:
-
The combination of stock selection and an overweight position in the semi & electronic components industry benefited the fund's relative performance.
-
The fund's underweight position in the entertainment & leisure industry also helped relative returns.
-
-
Top detractors from performance relative to the Standard & Poor’s North American Technology Sector Index:
-
Stock selection within the hardware, peripherals & assembly industry held back relative performance.
-
The combination of stock selection and overweight positions in both the software and business services industries further weakened the fund's relative results.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R2 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
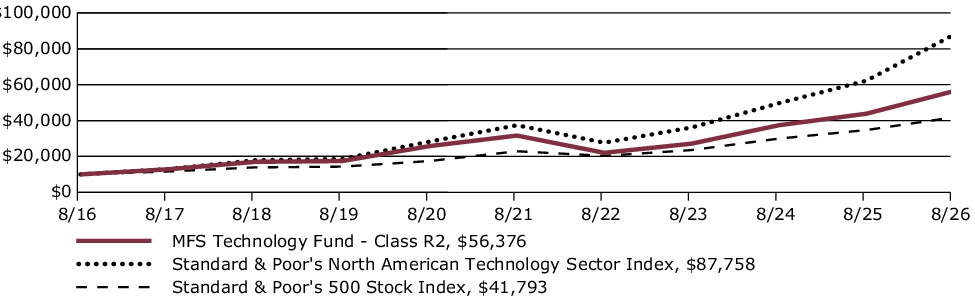
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R2 without sales charge | 28.66% | 12.25% | 18.88% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
| Standard & Poor's North American Technology Sector Index ∆ | 41.03% | 18.59% | 24.26% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r2 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,372,124,346 | Total Management Fee ($)#: | 15,777,828 | |
| Total Number of Holdings: | 54 | Portfolio Turnover Rate (%): | 59 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 97.3% |
| Money Market Funds | 2.7% |
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
Top five industries
| Software | 33.6% |
| Semiconductor & Electronic Components | 31.9% |
| Hardware, Peripherals, & Assembly | 19.8% |
| Interactive Media Services | 11.2% |
| Electrical Equipment | 2.0% |
For purposes of these classifications, MFS uses its own internal sector/industry classification methodology, which may deviate from classification methodologies used by other industry participants (e.g., the Global Industry Classification Standard).
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R1 | $212 | 1.86% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R1 shares of the MFS Technology Fund (fund) provided a total return of 28.00%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index. The fund's other benchmark, the Standard & Poor's North American Technology Sector Index, generated a return of 41.03%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s North American Technology Sector Index:
-
The combination of stock selection and an overweight position in the semi & electronic components industry benefited the fund's relative performance.
-
The fund's underweight position in the entertainment & leisure industry also helped relative returns.
-
-
Top detractors from performance relative to the Standard & Poor’s North American Technology Sector Index:
-
Stock selection within the hardware, peripherals & assembly industry held back relative performance.
-
The combination of stock selection and overweight positions in both the software and business services industries further weakened the fund's relative results.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R1 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
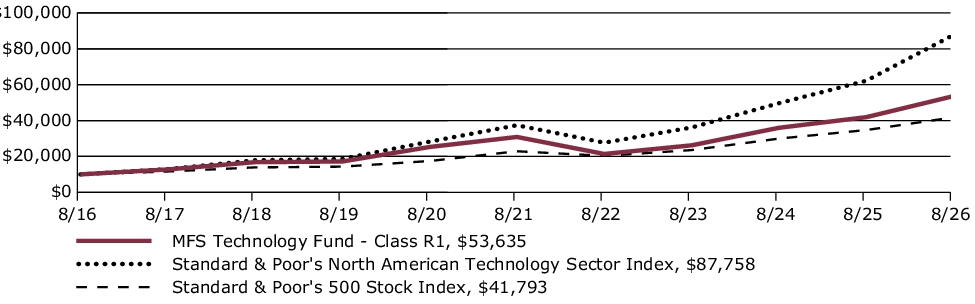
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R1 without sales charge | 28.00% | 11.69% | 18.29% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
| Standard & Poor's North American Technology Sector Index ∆ | 41.03% | 18.59% | 24.26% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r1 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,372,124,346 | Total Management Fee ($)#: | 15,777,828 | |
| Total Number of Holdings: | 54 | Portfolio Turnover Rate (%): | 59 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 97.3% |
| Money Market Funds | 2.7% |
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
Top five industries
| Software | 33.6% |
| Semiconductor & Electronic Components | 31.9% |
| Hardware, Peripherals, & Assembly | 19.8% |
| Interactive Media Services | 11.2% |
| Electrical Equipment | 2.0% |
For purposes of these classifications, MFS uses its own internal sector/industry classification methodology, which may deviate from classification methodologies used by other industry participants (e.g., the Global Industry Classification Standard).
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| I | $99 | 0.86% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class I shares of the MFS Technology Fund (fund) provided a total return of 29.30%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index. The fund's other benchmark, the Standard & Poor's North American Technology Sector Index, generated a return of 41.03%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s North American Technology Sector Index:
-
The combination of stock selection and an overweight position in the semi & electronic components industry benefited the fund's relative performance.
-
The fund's underweight position in the entertainment & leisure industry also helped relative returns.
-
-
Top detractors from performance relative to the Standard & Poor’s North American Technology Sector Index:
-
Stock selection within the hardware, peripherals & assembly industry held back relative performance.
-
The combination of stock selection and overweight positions in both the software and business services industries further weakened the fund's relative results.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class I over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
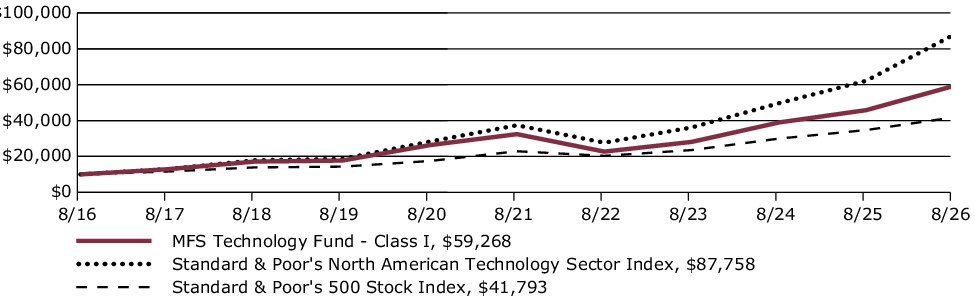
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| I without sales charge | 29.30% | 12.81% | 19.48% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
| Standard & Poor's North American Technology Sector Index ∆ | 41.03% | 18.59% | 24.26% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/i for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,372,124,346 | Total Management Fee ($)#: | 15,777,828 | |
| Total Number of Holdings: | 54 | Portfolio Turnover Rate (%): | 59 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 97.3% |
| Money Market Funds | 2.7% |
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
Top five industries
| Software | 33.6% |
| Semiconductor & Electronic Components | 31.9% |
| Hardware, Peripherals, & Assembly | 19.8% |
| Interactive Media Services | 11.2% |
| Electrical Equipment | 2.0% |
For purposes of these classifications, MFS uses its own internal sector/industry classification methodology, which may deviate from classification methodologies used by other industry participants (e.g., the Global Industry Classification Standard).
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| C | $212 | 1.86% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class C shares of the MFS Technology Fund (fund) provided a total return of 27.98%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index. The fund's other benchmark, the Standard & Poor's North American Technology Sector Index, generated a return of 41.03%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s North American Technology Sector Index:
-
The combination of stock selection and an overweight position in the semi & electronic components industry benefited the fund's relative performance.
-
The fund's underweight position in the entertainment & leisure industry also helped relative returns.
-
-
Top detractors from performance relative to the Standard & Poor’s North American Technology Sector Index:
-
Stock selection within the hardware, peripherals & assembly industry held back relative performance.
-
The combination of stock selection and overweight positions in both the software and business services industries further weakened the fund's relative results.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class C over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
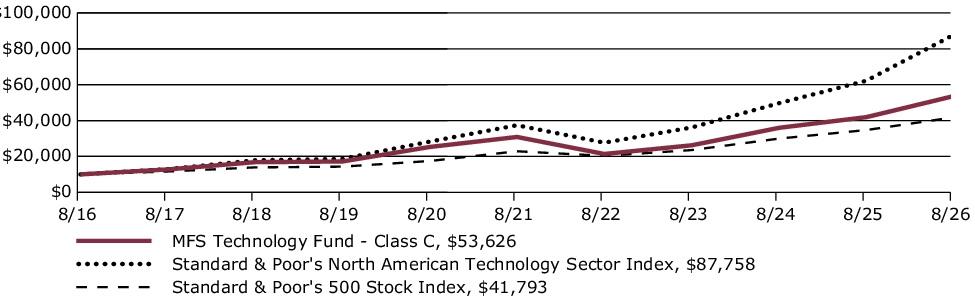
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| C without sales charge | 27.98% | 11.68% | 18.29% |
| C with CDSC (1% for 12 months)× | 26.98% | 11.68% | 18.29% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
| Standard & Poor's North American Technology Sector Index ∆ | 41.03% | 18.59% | 24.26% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/c for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,372,124,346 | Total Management Fee ($)#: | 15,777,828 | |
| Total Number of Holdings: | 54 | Portfolio Turnover Rate (%): | 59 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 97.3% |
| Money Market Funds | 2.7% |
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
Top five industries
| Software | 33.6% |
| Semiconductor & Electronic Components | 31.9% |
| Hardware, Peripherals, & Assembly | 19.8% |
| Interactive Media Services | 11.2% |
| Electrical Equipment | 2.0% |
For purposes of these classifications, MFS uses its own internal sector/industry classification methodology, which may deviate from classification methodologies used by other industry participants (e.g., the Global Industry Classification Standard).
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| B | $212 | 1.86% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class B shares of the MFS Technology Fund (fund) provided a total return of 27.99%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index. The fund's other benchmark, the Standard & Poor's North American Technology Sector Index, generated a return of 41.03%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s North American Technology Sector Index:
-
The combination of stock selection and an overweight position in the semi & electronic components industry benefited the fund's relative performance.
-
The fund's underweight position in the entertainment & leisure industry also helped relative returns.
-
-
Top detractors from performance relative to the Standard & Poor’s North American Technology Sector Index:
-
Stock selection within the hardware, peripherals & assembly industry held back relative performance.
-
The combination of stock selection and overweight positions in both the software and business services industries further weakened the fund's relative results.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class B over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
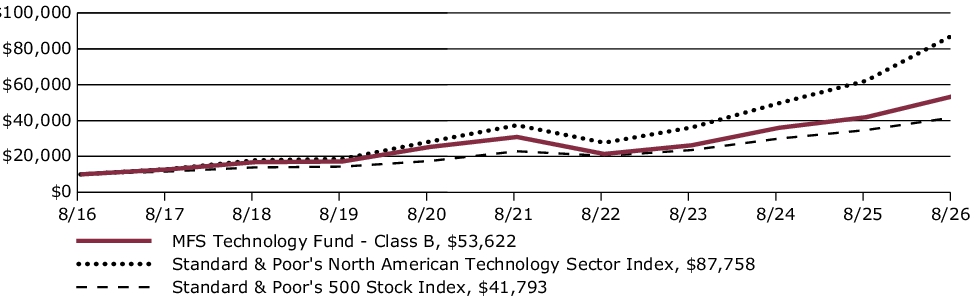
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| B without sales charge | 27.99% | 11.68% | 18.29% |
| B with CDSC (declining over six years from 4% to 0%)× | 23.99% | 11.49% | 18.29% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
| Standard & Poor's North American Technology Sector Index ∆ | 41.03% | 18.59% | 24.26% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/b for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,372,124,346 | Total Management Fee ($)#: | 15,777,828 | |
| Total Number of Holdings: | 54 | Portfolio Turnover Rate (%): | 59 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 97.3% |
| Money Market Funds | 2.7% |
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
Top five industries
| Software | 33.6% |
| Semiconductor & Electronic Components | 31.9% |
| Hardware, Peripherals, & Assembly | 19.8% |
| Interactive Media Services | 11.2% |
| Electrical Equipment | 2.0% |
For purposes of these classifications, MFS uses its own internal sector/industry classification methodology, which may deviate from classification methodologies used by other industry participants (e.g., the Global Industry Classification Standard).
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| A | $127 | 1.11% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class A shares of the MFS Technology Fund (fund) provided a total return of 28.97%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index. The fund's other benchmark, the Standard & Poor's North American Technology Sector Index, generated a return of 41.03%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s North American Technology Sector Index:
-
The combination of stock selection and an overweight position in the semi & electronic components industry benefited the fund's relative performance.
-
The fund's underweight position in the entertainment & leisure industry also helped relative returns.
-
-
Top detractors from performance relative to the Standard & Poor’s North American Technology Sector Index:
-
Stock selection within the hardware, peripherals & assembly industry held back relative performance.
-
The combination of stock selection and overweight positions in both the software and business services industries further weakened the fund's relative results.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class A over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests. This graph includes the deduction of the maximum applicable sales charge.
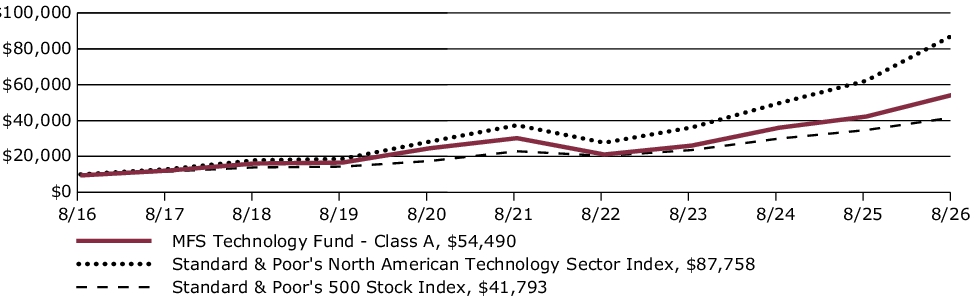
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| A without sales charge | 28.97% | 12.53% | 19.18% |
| A with initial sales charge (5.75%) | 21.55% | 11.20% | 18.48% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
| Standard & Poor's North American Technology Sector Index ∆ | 41.03% | 18.59% | 24.26% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/a for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 2,372,124,346 | Total Management Fee ($)#: | 15,777,828 | |
| Total Number of Holdings: | 54 | Portfolio Turnover Rate (%): | 59 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 97.3% |
| Money Market Funds | 2.7% |
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
Top five industries
| Software | 33.6% |
| Semiconductor & Electronic Components | 31.9% |
| Hardware, Peripherals, & Assembly | 19.8% |
| Interactive Media Services | 11.2% |
| Electrical Equipment | 2.0% |
For purposes of these classifications, MFS uses its own internal sector/industry classification methodology, which may deviate from classification methodologies used by other industry participants (e.g., the Global Industry Classification Standard).
Top ten holdings
| Microsoft Corp. | 9.1% |
| Alphabet, Inc., "A" | 8.3% |
| Apple, Inc. | 8.2% |
| NVIDIA Corp. | 7.3% |
| Broadcom, Inc. | 7.2% |
| Cisco Systems, Inc. | 3.1% |
| Advanced Micro Devices | 3.0% |
| Arista Networks, Inc. | 2.9% |
| Shopify, Inc. | 2.7% |
| JFrog Ltd. | 2.7% |
This report describes certain changes to the Fund that occurred during the reporting period.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| A | $85 | 0.80% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class A shares of the MFS Value Fund (fund) provided a total return of 13.53%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 1000® Value Index, generated a return of 29.72%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 1000® Value Index:
-
The fund's underweight position in the consumer discretionary sector benefited relative performance.
-
An underweight position and stock selection in the real estate sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 1000® Value Index:
-
Stock selection and an underweight position in the information technology sector weighed on relative performance.
-
The fund's overweight position and stock selection in the industrials sector detracted from relative returns. An overweight position in the financials sector further weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class A over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests. This graph includes the deduction of the maximum applicable sales charge.
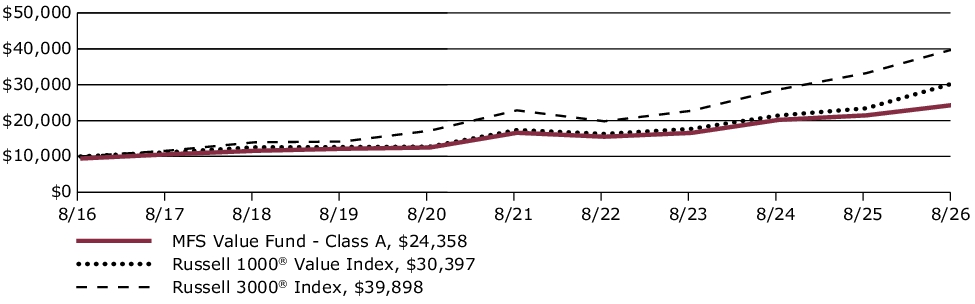
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| A without sales charge | 13.53% | 7.97% | 9.96% |
| A with initial sales charge (5.75%) | 7.00% | 6.70% | 9.31% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 1000® Value Index ∆ | 29.72% | 11.84% | 11.76% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/a for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 46,014,206,763 | Total Management Fee ($)#: | 230,847,371 | |
| Total Number of Holdings: | 70 | Portfolio Turnover Rate (%): | 29 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.6% |
| Money Market Funds | 0.4% |
Equity sectors
| Financials | 26.1% |
| Industrials | 14.8% |
| Information Technology | 14.3% |
| Health Care | 14.0% |
| Consumer Discretionary | 9.1% |
| Utilities | 7.2% |
| Energy | 6.6% |
| Consumer Staples | 4.2% |
| Real Estate | 1.5% |
| Materials | 1.0% |
| Communication Services | 0.8% |
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MATERIAL FUND CHANGES
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
This report describes certain changes to the Fund that occurred during the reporting period.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| B | $165 | 1.55% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class B shares of the MFS Value Fund (fund) provided a total return of 12.68%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 1000® Value Index, generated a return of 29.72%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 1000® Value Index:
-
The fund's underweight position in the consumer discretionary sector benefited relative performance.
-
An underweight position and stock selection in the real estate sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 1000® Value Index:
-
Stock selection and an underweight position in the information technology sector weighed on relative performance.
-
The fund's overweight position and stock selection in the industrials sector detracted from relative returns. An overweight position in the financials sector further weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class B over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
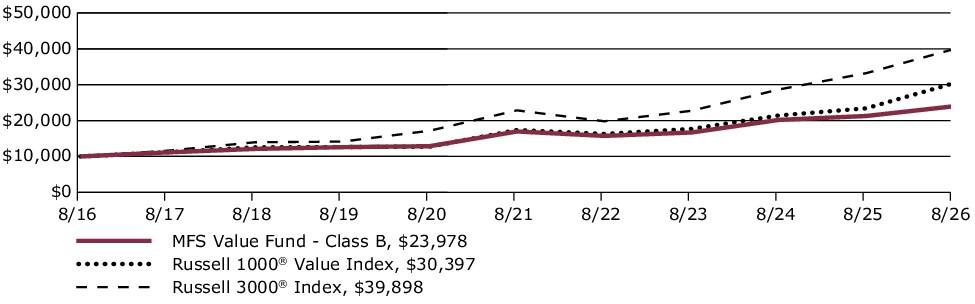
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| B without sales charge | 12.68% | 7.16% | 9.14% |
| B with CDSC (declining over six years from 4% to 0%)× | 8.68% | 6.86% | 9.14% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 1000® Value Index ∆ | 29.72% | 11.84% | 11.76% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/b for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 46,014,206,763 | Total Management Fee ($)#: | 230,847,371 | |
| Total Number of Holdings: | 70 | Portfolio Turnover Rate (%): | 29 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.6% |
| Money Market Funds | 0.4% |
Equity sectors
| Financials | 26.1% |
| Industrials | 14.8% |
| Information Technology | 14.3% |
| Health Care | 14.0% |
| Consumer Discretionary | 9.1% |
| Utilities | 7.2% |
| Energy | 6.6% |
| Consumer Staples | 4.2% |
| Real Estate | 1.5% |
| Materials | 1.0% |
| Communication Services | 0.8% |
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MATERIAL FUND CHANGES
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
This report describes certain changes to the Fund that occurred during the reporting period.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| C | $165 | 1.55% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class C shares of the MFS Value Fund (fund) provided a total return of 12.70%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 1000® Value Index, generated a return of 29.72%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 1000® Value Index:
-
The fund's underweight position in the consumer discretionary sector benefited relative performance.
-
An underweight position and stock selection in the real estate sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 1000® Value Index:
-
Stock selection and an underweight position in the information technology sector weighed on relative performance.
-
The fund's overweight position and stock selection in the industrials sector detracted from relative returns. An overweight position in the financials sector further weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class C over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
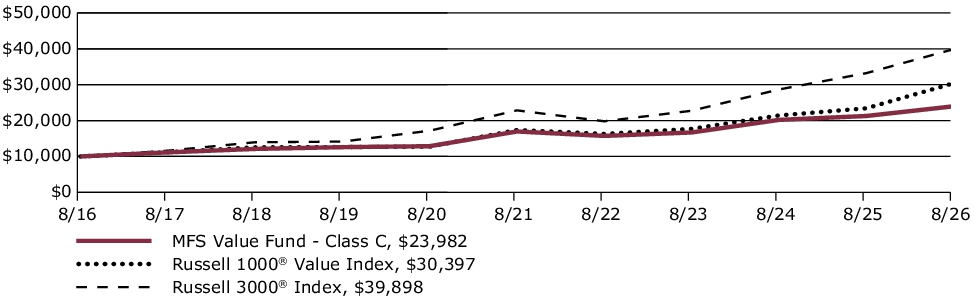
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| C without sales charge | 12.70% | 7.17% | 9.14% |
| C with CDSC (1% for 12 months)× | 11.70% | 7.17% | 9.14% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 1000® Value Index ∆ | 29.72% | 11.84% | 11.76% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/c for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 46,014,206,763 | Total Management Fee ($)#: | 230,847,371 | |
| Total Number of Holdings: | 70 | Portfolio Turnover Rate (%): | 29 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.6% |
| Money Market Funds | 0.4% |
Equity sectors
| Financials | 26.1% |
| Industrials | 14.8% |
| Information Technology | 14.3% |
| Health Care | 14.0% |
| Consumer Discretionary | 9.1% |
| Utilities | 7.2% |
| Energy | 6.6% |
| Consumer Staples | 4.2% |
| Real Estate | 1.5% |
| Materials | 1.0% |
| Communication Services | 0.8% |
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MATERIAL FUND CHANGES
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
This report describes certain changes to the Fund that occurred during the reporting period.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| I | $59 | 0.55% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class I shares of the MFS Value Fund (fund) provided a total return of 13.80%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 1000® Value Index, generated a return of 29.72%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 1000® Value Index:
-
The fund's underweight position in the consumer discretionary sector benefited relative performance.
-
An underweight position and stock selection in the real estate sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 1000® Value Index:
-
Stock selection and an underweight position in the information technology sector weighed on relative performance.
-
The fund's overweight position and stock selection in the industrials sector detracted from relative returns. An overweight position in the financials sector further weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class I over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
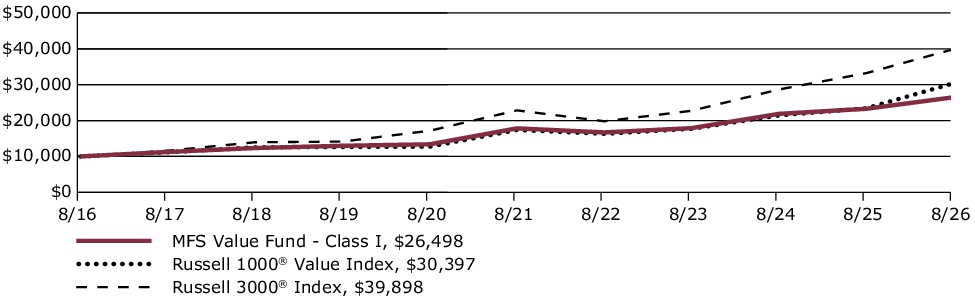
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| I without sales charge | 13.80% | 8.24% | 10.24% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 1000® Value Index ∆ | 29.72% | 11.84% | 11.76% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/i for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 46,014,206,763 | Total Management Fee ($)#: | 230,847,371 | |
| Total Number of Holdings: | 70 | Portfolio Turnover Rate (%): | 29 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.6% |
| Money Market Funds | 0.4% |
Equity sectors
| Financials | 26.1% |
| Industrials | 14.8% |
| Information Technology | 14.3% |
| Health Care | 14.0% |
| Consumer Discretionary | 9.1% |
| Utilities | 7.2% |
| Energy | 6.6% |
| Consumer Staples | 4.2% |
| Real Estate | 1.5% |
| Materials | 1.0% |
| Communication Services | 0.8% |
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MATERIAL FUND CHANGES
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
This report describes certain changes to the Fund that occurred during the reporting period.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R1 | $165 | 1.55% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R1 shares of the MFS Value Fund (fund) provided a total return of 12.68%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 1000® Value Index, generated a return of 29.72%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 1000® Value Index:
-
The fund's underweight position in the consumer discretionary sector benefited relative performance.
-
An underweight position and stock selection in the real estate sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 1000® Value Index:
-
Stock selection and an underweight position in the information technology sector weighed on relative performance.
-
The fund's overweight position and stock selection in the industrials sector detracted from relative returns. An overweight position in the financials sector further weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R1 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
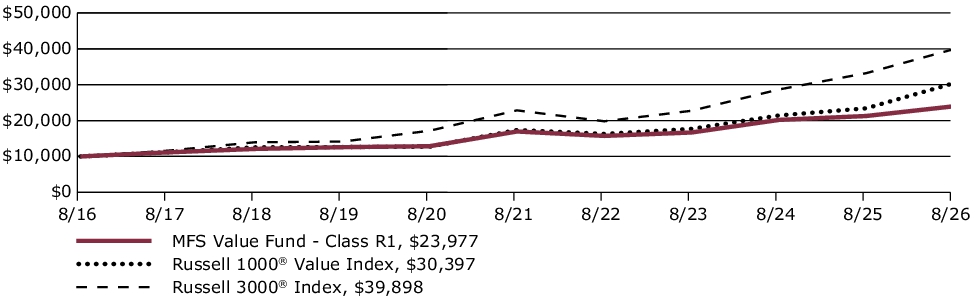
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R1 without sales charge | 12.68% | 7.17% | 9.14% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 1000® Value Index ∆ | 29.72% | 11.84% | 11.76% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r1 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 46,014,206,763 | Total Management Fee ($)#: | 230,847,371 | |
| Total Number of Holdings: | 70 | Portfolio Turnover Rate (%): | 29 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.6% |
| Money Market Funds | 0.4% |
Equity sectors
| Financials | 26.1% |
| Industrials | 14.8% |
| Information Technology | 14.3% |
| Health Care | 14.0% |
| Consumer Discretionary | 9.1% |
| Utilities | 7.2% |
| Energy | 6.6% |
| Consumer Staples | 4.2% |
| Real Estate | 1.5% |
| Materials | 1.0% |
| Communication Services | 0.8% |
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MATERIAL FUND CHANGES
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
This report describes certain changes to the Fund that occurred during the reporting period.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R2 | $112 | 1.05% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R2 shares of the MFS Value Fund (fund) provided a total return of 13.24%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 1000® Value Index, generated a return of 29.72%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 1000® Value Index:
-
The fund's underweight position in the consumer discretionary sector benefited relative performance.
-
An underweight position and stock selection in the real estate sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 1000® Value Index:
-
Stock selection and an underweight position in the information technology sector weighed on relative performance.
-
The fund's overweight position and stock selection in the industrials sector detracted from relative returns. An overweight position in the financials sector further weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R2 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
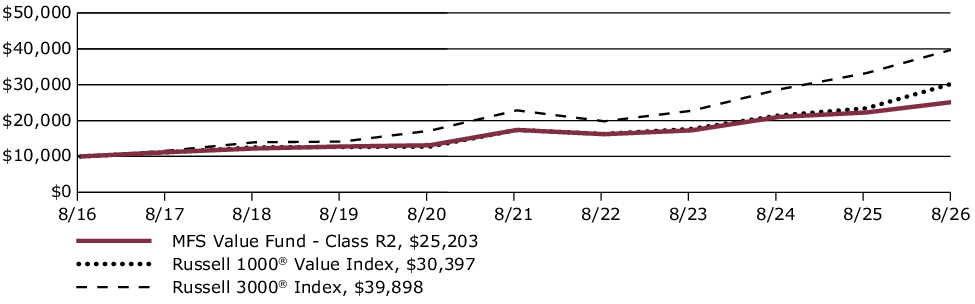
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R2 without sales charge | 13.24% | 7.70% | 9.68% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 1000® Value Index ∆ | 29.72% | 11.84% | 11.76% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r2 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 46,014,206,763 | Total Management Fee ($)#: | 230,847,371 | |
| Total Number of Holdings: | 70 | Portfolio Turnover Rate (%): | 29 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.6% |
| Money Market Funds | 0.4% |
Equity sectors
| Financials | 26.1% |
| Industrials | 14.8% |
| Information Technology | 14.3% |
| Health Care | 14.0% |
| Consumer Discretionary | 9.1% |
| Utilities | 7.2% |
| Energy | 6.6% |
| Consumer Staples | 4.2% |
| Real Estate | 1.5% |
| Materials | 1.0% |
| Communication Services | 0.8% |
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MATERIAL FUND CHANGES
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
This report describes certain changes to the Fund that occurred during the reporting period.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R3 | $85 | 0.80% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R3 shares of the MFS Value Fund (fund) provided a total return of 13.54%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 1000® Value Index, generated a return of 29.72%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 1000® Value Index:
-
The fund's underweight position in the consumer discretionary sector benefited relative performance.
-
An underweight position and stock selection in the real estate sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 1000® Value Index:
-
Stock selection and an underweight position in the information technology sector weighed on relative performance.
-
The fund's overweight position and stock selection in the industrials sector detracted from relative returns. An overweight position in the financials sector further weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R3 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
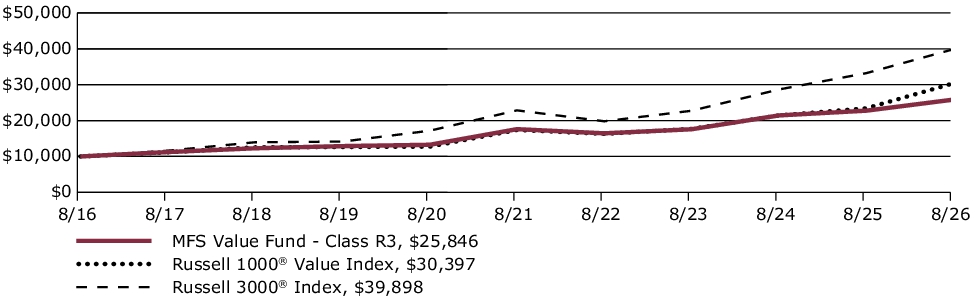
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R3 without sales charge | 13.54% | 7.98% | 9.96% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 1000® Value Index ∆ | 29.72% | 11.84% | 11.76% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r3 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 46,014,206,763 | Total Management Fee ($)#: | 230,847,371 | |
| Total Number of Holdings: | 70 | Portfolio Turnover Rate (%): | 29 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.6% |
| Money Market Funds | 0.4% |
Equity sectors
| Financials | 26.1% |
| Industrials | 14.8% |
| Information Technology | 14.3% |
| Health Care | 14.0% |
| Consumer Discretionary | 9.1% |
| Utilities | 7.2% |
| Energy | 6.6% |
| Consumer Staples | 4.2% |
| Real Estate | 1.5% |
| Materials | 1.0% |
| Communication Services | 0.8% |
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MATERIAL FUND CHANGES
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
This report describes certain changes to the Fund that occurred during the reporting period.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R4 | $59 | 0.55% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R4 shares of the MFS Value Fund (fund) provided a total return of 13.82%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 1000® Value Index, generated a return of 29.72%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 1000® Value Index:
-
The fund's underweight position in the consumer discretionary sector benefited relative performance.
-
An underweight position and stock selection in the real estate sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 1000® Value Index:
-
Stock selection and an underweight position in the information technology sector weighed on relative performance.
-
The fund's overweight position and stock selection in the industrials sector detracted from relative returns. An overweight position in the financials sector further weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R4 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
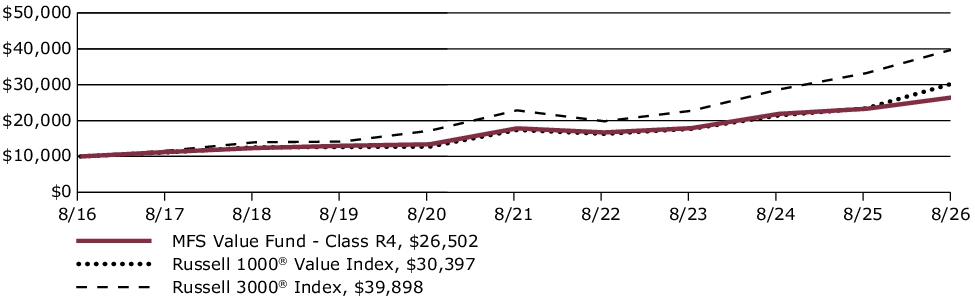
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R4 without sales charge | 13.82% | 8.24% | 10.24% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 1000® Value Index ∆ | 29.72% | 11.84% | 11.76% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r4 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 46,014,206,763 | Total Management Fee ($)#: | 230,847,371 | |
| Total Number of Holdings: | 70 | Portfolio Turnover Rate (%): | 29 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.6% |
| Money Market Funds | 0.4% |
Equity sectors
| Financials | 26.1% |
| Industrials | 14.8% |
| Information Technology | 14.3% |
| Health Care | 14.0% |
| Consumer Discretionary | 9.1% |
| Utilities | 7.2% |
| Energy | 6.6% |
| Consumer Staples | 4.2% |
| Real Estate | 1.5% |
| Materials | 1.0% |
| Communication Services | 0.8% |
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MATERIAL FUND CHANGES
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
This report describes certain changes to the Fund that occurred during the reporting period.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R6 | $47 | 0.44% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R6 shares of the MFS Value Fund (fund) provided a total return of 13.93%, at net asset value. This compares with a return of 20.10% for the fund’s benchmark, the Russell 3000® Index. The fund's other benchmark, the Russell 1000® Value Index, generated a return of 29.72%.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Russell 1000® Value Index:
-
The fund's underweight position in the consumer discretionary sector benefited relative performance.
-
An underweight position and stock selection in the real estate sector further supported relative returns.
-
-
Top detractors from performance relative to the Russell 1000® Value Index:
-
Stock selection and an underweight position in the information technology sector weighed on relative performance.
-
The fund's overweight position and stock selection in the industrials sector detracted from relative returns. An overweight position in the financials sector further weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R6 over a ten year period or since inception, if shorter, in comparison to (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests.
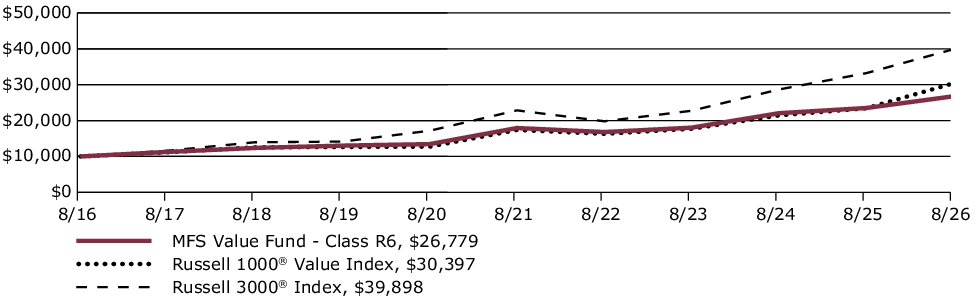
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of (i) a broad measure of market performance and (ii) an additional index that MFS believes more closely reflects the market segments in which the fund invests, over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R6 without sales charge | 13.93% | 8.36% | 10.35% |
| Comparative Benchmark(s) | |||
| Russell 3000® Index ∆ | 20.10% | 11.80% | 14.84% |
| Russell 1000® Value Index ∆ | 29.72% | 11.84% | 11.76% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r6 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 46,014,206,763 | Total Management Fee ($)#: | 230,847,371 | |
| Total Number of Holdings: | 70 | Portfolio Turnover Rate (%): | 29 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.6% |
| Money Market Funds | 0.4% |
Equity sectors
| Financials | 26.1% |
| Industrials | 14.8% |
| Information Technology | 14.3% |
| Health Care | 14.0% |
| Consumer Discretionary | 9.1% |
| Utilities | 7.2% |
| Energy | 6.6% |
| Consumer Staples | 4.2% |
| Real Estate | 1.5% |
| Materials | 1.0% |
| Communication Services | 0.8% |
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| Amazon.com, Inc. | 5.5% |
| Microsoft Corp. | 5.5% |
| JPMorgan Chase & Co. | 4.1% |
| Apple, Inc. | 3.0% |
| Cigna Group | 2.5% |
| Johnson & Johnson | 2.4% |
| ExxonMobil Holdings Corp. | 2.3% |
| RTX Corp. | 2.2% |
| Morgan Stanley | 2.1% |
| ConocoPhillips | 2.0% |
MATERIAL FUND CHANGES
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
Effective June 10, 2026, the MFS Value Fund adopted a policy to invest at least 80% of its net assets in value companies and expanded on the factors used to define value companies.
This is a summary of certain changes to the fund since September 1, 2025. For more complete information, you may review the fund's prospectus as amended, which is available at funds.mfs.com or upon request at 1‑800‑225‑2606.
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R6 | $59 | 0.56% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R6 shares of the MFS Low Volatility Equity Fund (fund) provided a total return of 11.44%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the communication services sector benefited the fund's relative performance.
-
Stock selection in the financial sector, along with an overweight position and favorable stock selection in the health care sector, also supported relative results.
-
-
Top detractors from performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the information technology sector held back relative performance.
-
Stock selection and overweight positions in the consumer staples and industrials sectors also weighed on the fund's relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R6 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
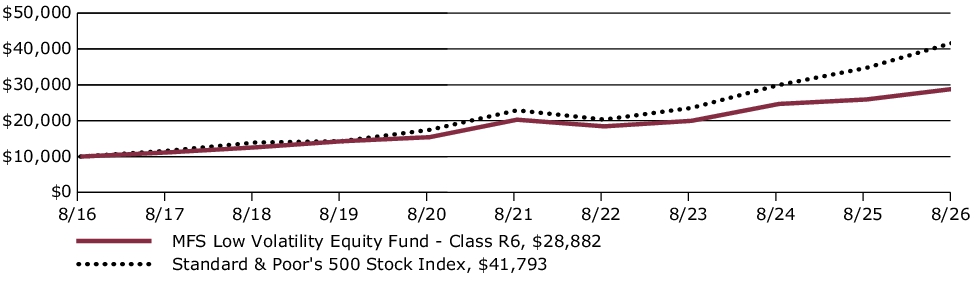
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R6 without sales charge | 11.44% | 7.33% | 11.19% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r6 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 317,343,526 | Total Management Fee ($)#: | 1,656,252 | |
| Total Number of Holdings: | 97 | Portfolio Turnover Rate (%): | 49 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.7% |
| Money Market Funds | 0.3% |
Equity sectors
| Information Technology | 27.7% |
| Health Care | 14.4% |
| Financials | 12.8% |
| Consumer Staples | 10.4% |
| Industrials | 7.4% |
| Utilities | 6.9% |
| Consumer Discretionary | 5.7% |
| Energy | 5.3% |
| Communication Services | 5.1% |
| Real Estate | 3.5% |
| Materials | 0.5% |
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R4 | $68 | 0.64% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R4 shares of the MFS Low Volatility Equity Fund (fund) provided a total return of 11.37%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the communication services sector benefited the fund's relative performance.
-
Stock selection in the financial sector, along with an overweight position and favorable stock selection in the health care sector, also supported relative results.
-
-
Top detractors from performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the information technology sector held back relative performance.
-
Stock selection and overweight positions in the consumer staples and industrials sectors also weighed on the fund's relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R4 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
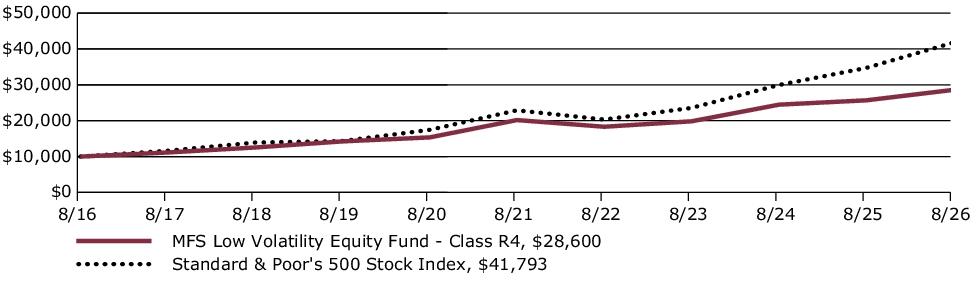
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R4 without sales charge | 11.37% | 7.23% | 11.08% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r4 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 317,343,526 | Total Management Fee ($)#: | 1,656,252 | |
| Total Number of Holdings: | 97 | Portfolio Turnover Rate (%): | 49 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.7% |
| Money Market Funds | 0.3% |
Equity sectors
| Information Technology | 27.7% |
| Health Care | 14.4% |
| Financials | 12.8% |
| Consumer Staples | 10.4% |
| Industrials | 7.4% |
| Utilities | 6.9% |
| Consumer Discretionary | 5.7% |
| Energy | 5.3% |
| Communication Services | 5.1% |
| Real Estate | 3.5% |
| Materials | 0.5% |
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R3 | $94 | 0.89% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R3 shares of the MFS Low Volatility Equity Fund (fund) provided a total return of 11.05%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the communication services sector benefited the fund's relative performance.
-
Stock selection in the financial sector, along with an overweight position and favorable stock selection in the health care sector, also supported relative results.
-
-
Top detractors from performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the information technology sector held back relative performance.
-
Stock selection and overweight positions in the consumer staples and industrials sectors also weighed on the fund's relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R3 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
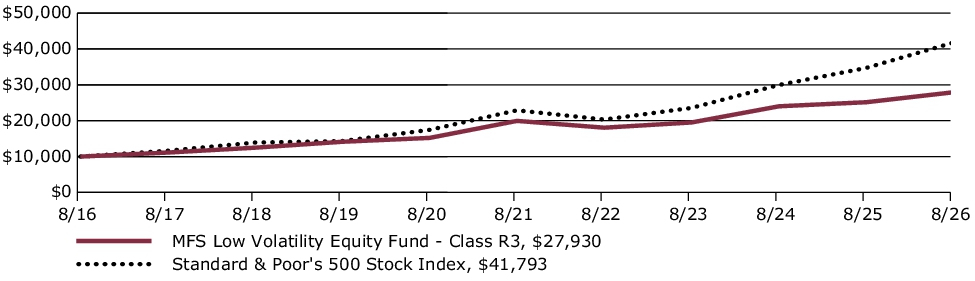
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R3 without sales charge | 11.05% | 6.96% | 10.82% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r3 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 317,343,526 | Total Management Fee ($)#: | 1,656,252 | |
| Total Number of Holdings: | 97 | Portfolio Turnover Rate (%): | 49 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.7% |
| Money Market Funds | 0.3% |
Equity sectors
| Information Technology | 27.7% |
| Health Care | 14.4% |
| Financials | 12.8% |
| Consumer Staples | 10.4% |
| Industrials | 7.4% |
| Utilities | 6.9% |
| Consumer Discretionary | 5.7% |
| Energy | 5.3% |
| Communication Services | 5.1% |
| Real Estate | 3.5% |
| Materials | 0.5% |
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R2 | $120 | 1.14% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R2 shares of the MFS Low Volatility Equity Fund (fund) provided a total return of 10.81%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the communication services sector benefited the fund's relative performance.
-
Stock selection in the financial sector, along with an overweight position and favorable stock selection in the health care sector, also supported relative results.
-
-
Top detractors from performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the information technology sector held back relative performance.
-
Stock selection and overweight positions in the consumer staples and industrials sectors also weighed on the fund's relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R2 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
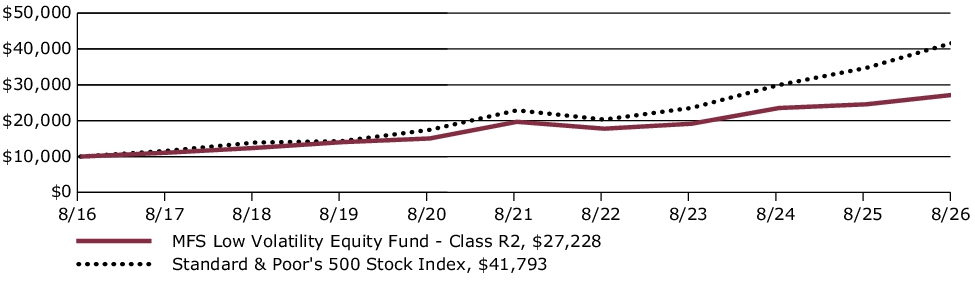
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R2 without sales charge | 10.81% | 6.70% | 10.54% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r2 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 317,343,526 | Total Management Fee ($)#: | 1,656,252 | |
| Total Number of Holdings: | 97 | Portfolio Turnover Rate (%): | 49 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.7% |
| Money Market Funds | 0.3% |
Equity sectors
| Information Technology | 27.7% |
| Health Care | 14.4% |
| Financials | 12.8% |
| Consumer Staples | 10.4% |
| Industrials | 7.4% |
| Utilities | 6.9% |
| Consumer Discretionary | 5.7% |
| Energy | 5.3% |
| Communication Services | 5.1% |
| Real Estate | 3.5% |
| Materials | 0.5% |
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R1 | $172 | 1.64% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R1 shares of the MFS Low Volatility Equity Fund (fund) provided a total return of 10.29%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the communication services sector benefited the fund's relative performance.
-
Stock selection in the financial sector, along with an overweight position and favorable stock selection in the health care sector, also supported relative results.
-
-
Top detractors from performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the information technology sector held back relative performance.
-
Stock selection and overweight positions in the consumer staples and industrials sectors also weighed on the fund's relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R1 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
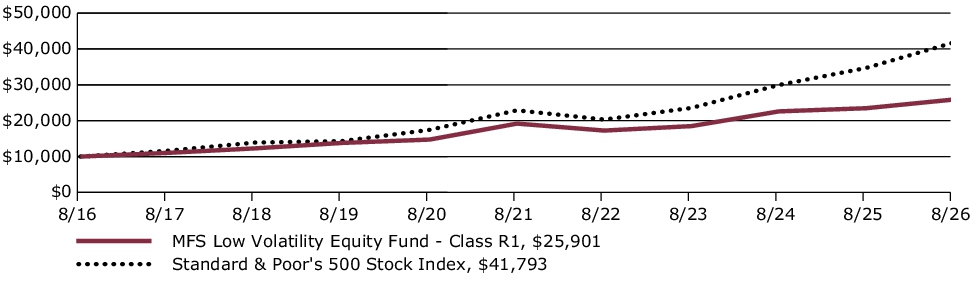
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R1 without sales charge | 10.29% | 6.18% | 9.98% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r1 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 317,343,526 | Total Management Fee ($)#: | 1,656,252 | |
| Total Number of Holdings: | 97 | Portfolio Turnover Rate (%): | 49 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.7% |
| Money Market Funds | 0.3% |
Equity sectors
| Information Technology | 27.7% |
| Health Care | 14.4% |
| Financials | 12.8% |
| Consumer Staples | 10.4% |
| Industrials | 7.4% |
| Utilities | 6.9% |
| Consumer Discretionary | 5.7% |
| Energy | 5.3% |
| Communication Services | 5.1% |
| Real Estate | 3.5% |
| Materials | 0.5% |
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| I | $68 | 0.64% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class I shares of the MFS Low Volatility Equity Fund (fund) provided a total return of 11.38%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the communication services sector benefited the fund's relative performance.
-
Stock selection in the financial sector, along with an overweight position and favorable stock selection in the health care sector, also supported relative results.
-
-
Top detractors from performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the information technology sector held back relative performance.
-
Stock selection and overweight positions in the consumer staples and industrials sectors also weighed on the fund's relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class I over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
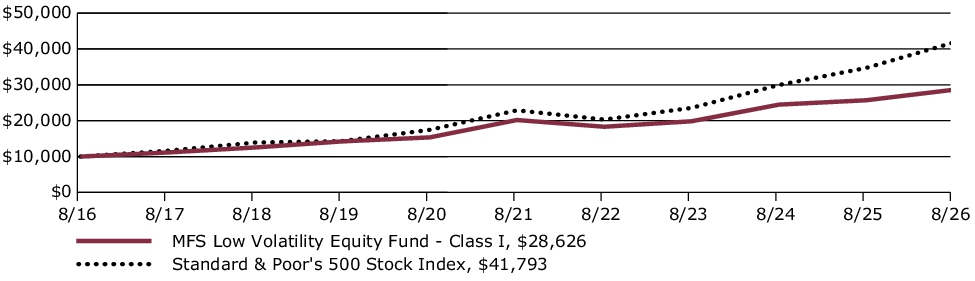
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| I without sales charge | 11.38% | 7.23% | 11.09% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/i for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 317,343,526 | Total Management Fee ($)#: | 1,656,252 | |
| Total Number of Holdings: | 97 | Portfolio Turnover Rate (%): | 49 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.7% |
| Money Market Funds | 0.3% |
Equity sectors
| Information Technology | 27.7% |
| Health Care | 14.4% |
| Financials | 12.8% |
| Consumer Staples | 10.4% |
| Industrials | 7.4% |
| Utilities | 6.9% |
| Consumer Discretionary | 5.7% |
| Energy | 5.3% |
| Communication Services | 5.1% |
| Real Estate | 3.5% |
| Materials | 0.5% |
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| C | $172 | 1.64% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class C shares of the MFS Low Volatility Equity Fund (fund) provided a total return of 10.27%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the communication services sector benefited the fund's relative performance.
-
Stock selection in the financial sector, along with an overweight position and favorable stock selection in the health care sector, also supported relative results.
-
-
Top detractors from performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the information technology sector held back relative performance.
-
Stock selection and overweight positions in the consumer staples and industrials sectors also weighed on the fund's relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class C over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
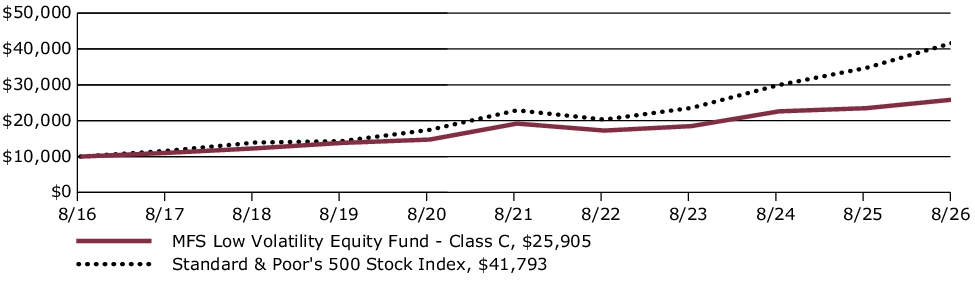
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| C without sales charge | 10.27% | 6.18% | 9.99% |
| C with CDSC (1% for 12 months)× | 9.31% | 6.18% | 9.99% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/c for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 317,343,526 | Total Management Fee ($)#: | 1,656,252 | |
| Total Number of Holdings: | 97 | Portfolio Turnover Rate (%): | 49 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.7% |
| Money Market Funds | 0.3% |
Equity sectors
| Information Technology | 27.7% |
| Health Care | 14.4% |
| Financials | 12.8% |
| Consumer Staples | 10.4% |
| Industrials | 7.4% |
| Utilities | 6.9% |
| Consumer Discretionary | 5.7% |
| Energy | 5.3% |
| Communication Services | 5.1% |
| Real Estate | 3.5% |
| Materials | 0.5% |
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| B | $172 | 1.64% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class B shares of the MFS Low Volatility Equity Fund (fund) provided a total return of 10.27%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the communication services sector benefited the fund's relative performance.
-
Stock selection in the financial sector, along with an overweight position and favorable stock selection in the health care sector, also supported relative results.
-
-
Top detractors from performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the information technology sector held back relative performance.
-
Stock selection and overweight positions in the consumer staples and industrials sectors also weighed on the fund's relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class B over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
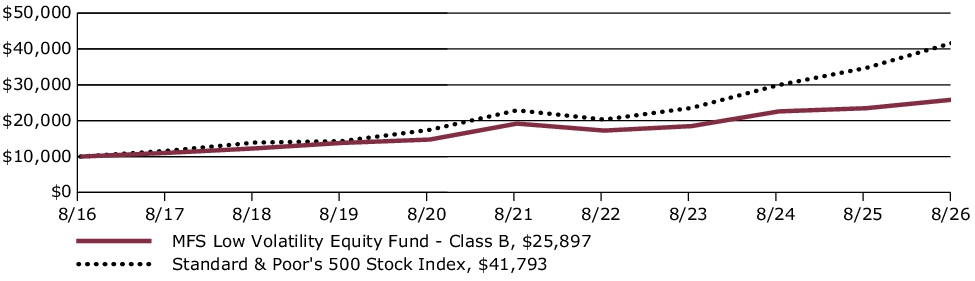
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| B without sales charge | 10.27% | 6.17% | 9.98% |
| B with CDSC (declining over six years from 4% to 0%)× | 6.42% | 5.90% | 9.98% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/b for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 317,343,526 | Total Management Fee ($)#: | 1,656,252 | |
| Total Number of Holdings: | 97 | Portfolio Turnover Rate (%): | 49 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.7% |
| Money Market Funds | 0.3% |
Equity sectors
| Information Technology | 27.7% |
| Health Care | 14.4% |
| Financials | 12.8% |
| Consumer Staples | 10.4% |
| Industrials | 7.4% |
| Utilities | 6.9% |
| Consumer Discretionary | 5.7% |
| Energy | 5.3% |
| Communication Services | 5.1% |
| Real Estate | 3.5% |
| Materials | 0.5% |
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| A | $94 | 0.89% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class A shares of the MFS Low Volatility Equity Fund (fund) provided a total return of 11.05%, at net asset value. This compares with a return of 20.38% for the fund’s benchmark, the Standard & Poor's 500 Stock Index.
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the communication services sector benefited the fund's relative performance.
-
Stock selection in the financial sector, along with an overweight position and favorable stock selection in the health care sector, also supported relative results.
-
-
Top detractors from performance relative to the Standard & Poor’s 500 Stock Index:
-
Stock selection and an underweight position in the information technology sector held back relative performance.
-
Stock selection and overweight positions in the consumer staples and industrials sectors also weighed on the fund's relative returns.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class A over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance. This graph includes the deduction of the maximum applicable sales charge.
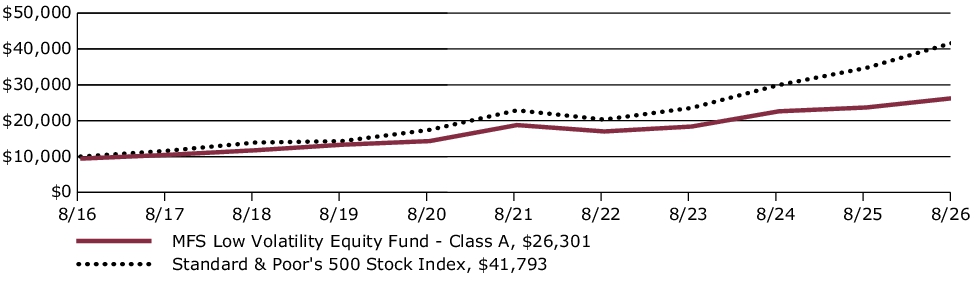
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| A without sales charge | 11.05% | 6.96% | 10.81% |
| A with initial sales charge (5.75%) | 4.66% | 5.71% | 10.15% |
| Comparative Benchmark(s) | |||
| Standard & Poor's 500 Stock Index ∆ | 20.38% | 12.79% | 15.37% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/a for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 317,343,526 | Total Management Fee ($)#: | 1,656,252 | |
| Total Number of Holdings: | 97 | Portfolio Turnover Rate (%): | 49 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 99.7% |
| Money Market Funds | 0.3% |
Equity sectors
| Information Technology | 27.7% |
| Health Care | 14.4% |
| Financials | 12.8% |
| Consumer Staples | 10.4% |
| Industrials | 7.4% |
| Utilities | 6.9% |
| Consumer Discretionary | 5.7% |
| Energy | 5.3% |
| Communication Services | 5.1% |
| Real Estate | 3.5% |
| Materials | 0.5% |
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
MFS uses the Global Industry Classification Standard (GICS®) for sector/industry reporting. MFS has applied its own internal sector/industry classification methodology for equity securities and non-equity securities that are unclassified by GICS.
Top ten holdings
| NVIDIA Corp. | 3.8% |
| Valero Energy Corp. | 3.3% |
| Johnson & Johnson | 3.1% |
| Alphabet, Inc., "A" | 3.0% |
| McKesson Corp. | 2.9% |
| Monster Worldwide, Inc. | 2.8% |
| Teledyne Technologies, Inc. | 2.8% |
| Apple, Inc. | 2.8% |
| Merck & Co., Inc. | 2.7% |
| Microsoft Corp. | 2.7% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| A | $105 | 0.99% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class A shares of the MFS Low Volatility Global Equity Fund (fund) provided a total return of 11.98%, at net asset value. This compares with a return of 22.35% for the fund’s benchmark, the MSCI All Country World Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI All Country World Index:
-
Stock selection within both the health care and communication services sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI All Country World Index:
-
Stock selection and an underweight position in the information technology sector held back relative returns.
-
The fund's overweight position and stock selection in the consumer staples sector also weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class A over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance. This graph includes the deduction of the maximum applicable sales charge.
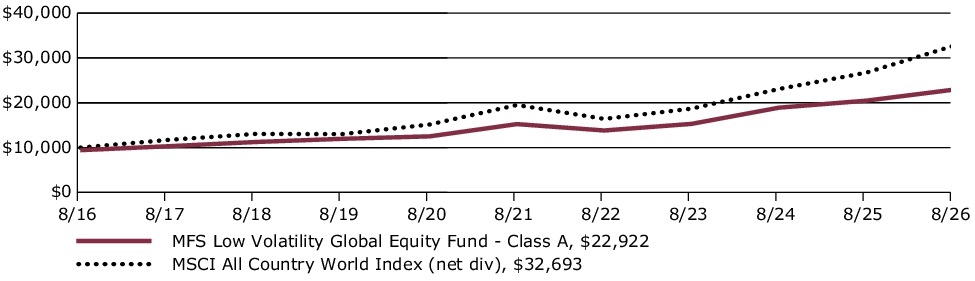
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| A without sales charge | 11.98% | 8.50% | 9.29% |
| A with initial sales charge (5.75%) | 5.54% | 7.22% | 8.65% |
| Comparative Benchmark(s) | |||
| MSCI All Country World Index (net div) ∆ | 22.35% | 10.88% | 12.58% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/a for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 300,940,594 | Total Management Fee ($)#: | 1,590,456 | |
| Total Number of Holdings: | 108 | Portfolio Turnover Rate (%): | 41 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.5% |
| Money Market Funds | 1.5% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
Issuer country weightings
| United States | 52.4% |
| Japan | 7.9% |
| Canada | 6.2% |
| United Kingdom | 4.7% |
| Singapore | 4.2% |
| Netherlands | 3.0% |
| Taiwan | 2.7% |
| Switzerland | 2.7% |
| Italy | 2.6% |
| Other Countries | 13.6% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| B | $184 | 1.74% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class B shares of the MFS Low Volatility Global Equity Fund (fund) provided a total return of 11.21%, at net asset value. This compares with a return of 22.35% for the fund’s benchmark, the MSCI All Country World Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI All Country World Index:
-
Stock selection within both the health care and communication services sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI All Country World Index:
-
Stock selection and an underweight position in the information technology sector held back relative returns.
-
The fund's overweight position and stock selection in the consumer staples sector also weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class B over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
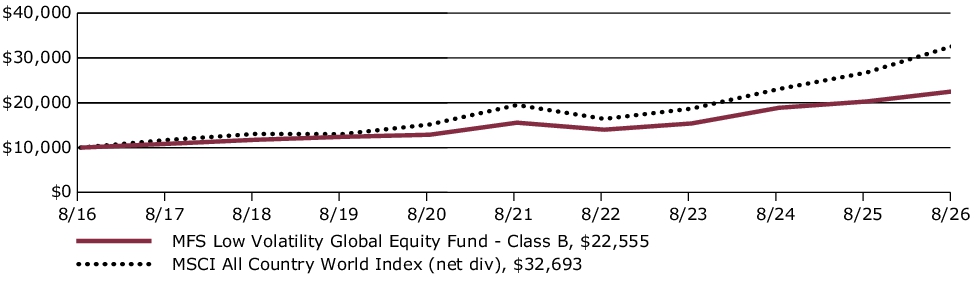
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| B without sales charge | 11.21% | 7.71% | 8.47% |
| B with CDSC (declining over six years from 4% to 0%)× | 7.21% | 7.41% | 8.47% |
| Comparative Benchmark(s) | |||
| MSCI All Country World Index (net div) ∆ | 22.35% | 10.88% | 12.58% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
CDSC – Contingent Deferred Sales Charge.
Visit mfs.com/perf/b for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 300,940,594 | Total Management Fee ($)#: | 1,590,456 | |
| Total Number of Holdings: | 108 | Portfolio Turnover Rate (%): | 41 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.5% |
| Money Market Funds | 1.5% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
Issuer country weightings
| United States | 52.4% |
| Japan | 7.9% |
| Canada | 6.2% |
| United Kingdom | 4.7% |
| Singapore | 4.2% |
| Netherlands | 3.0% |
| Taiwan | 2.7% |
| Switzerland | 2.7% |
| Italy | 2.6% |
| Other Countries | 13.6% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| C | $184 | 1.74% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class C shares of the MFS Low Volatility Global Equity Fund (fund) provided a total return of 11.14%, at net asset value. This compares with a return of 22.35% for the fund’s benchmark, the MSCI All Country World Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI All Country World Index:
-
Stock selection within both the health care and communication services sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI All Country World Index:
-
Stock selection and an underweight position in the information technology sector held back relative returns.
-
The fund's overweight position and stock selection in the consumer staples sector also weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class C over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
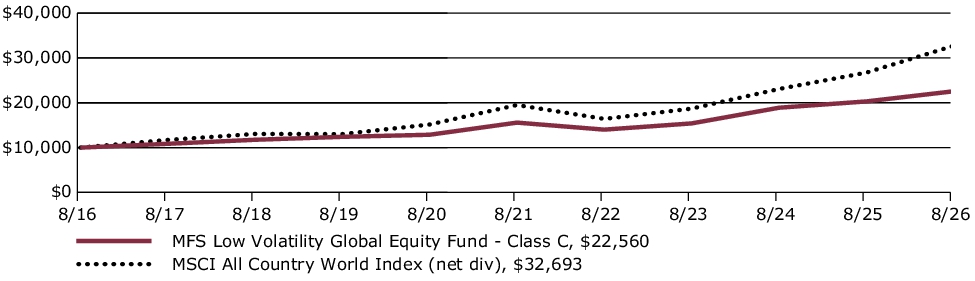
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| C without sales charge | 11.14% | 7.69% | 8.48% |
| C with CDSC (1% for 12 months)× | 10.14% | 7.69% | 8.48% |
| Comparative Benchmark(s) | |||
| MSCI All Country World Index (net div) ∆ | 22.35% | 10.88% | 12.58% |
|
∆
|
Source: FactSet Research Systems Inc.
|
|
×
|
Assuming redemption at the end of the applicable period.
|
Visit mfs.com/perf/c for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 300,940,594 | Total Management Fee ($)#: | 1,590,456 | |
| Total Number of Holdings: | 108 | Portfolio Turnover Rate (%): | 41 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.5% |
| Money Market Funds | 1.5% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
Issuer country weightings
| United States | 52.4% |
| Japan | 7.9% |
| Canada | 6.2% |
| United Kingdom | 4.7% |
| Singapore | 4.2% |
| Netherlands | 3.0% |
| Taiwan | 2.7% |
| Switzerland | 2.7% |
| Italy | 2.6% |
| Other Countries | 13.6% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| I | $79 | 0.74% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class I shares of the MFS Low Volatility Global Equity Fund (fund) provided a total return of 12.26%, at net asset value. This compares with a return of 22.35% for the fund’s benchmark, the MSCI All Country World Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI All Country World Index:
-
Stock selection within both the health care and communication services sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI All Country World Index:
-
Stock selection and an underweight position in the information technology sector held back relative returns.
-
The fund's overweight position and stock selection in the consumer staples sector also weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class I over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
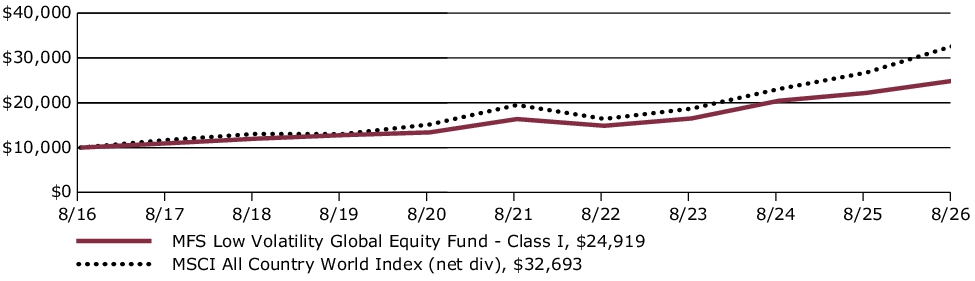
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| I without sales charge | 12.26% | 8.77% | 9.56% |
| Comparative Benchmark(s) | |||
| MSCI All Country World Index (net div) ∆ | 22.35% | 10.88% | 12.58% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/i for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 300,940,594 | Total Management Fee ($)#: | 1,590,456 | |
| Total Number of Holdings: | 108 | Portfolio Turnover Rate (%): | 41 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.5% |
| Money Market Funds | 1.5% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
Issuer country weightings
| United States | 52.4% |
| Japan | 7.9% |
| Canada | 6.2% |
| United Kingdom | 4.7% |
| Singapore | 4.2% |
| Netherlands | 3.0% |
| Taiwan | 2.7% |
| Switzerland | 2.7% |
| Italy | 2.6% |
| Other Countries | 13.6% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R1 | $184 | 1.74% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R1 shares of the MFS Low Volatility Global Equity Fund (fund) provided a total return of 11.21%, at net asset value. This compares with a return of 22.35% for the fund’s benchmark, the MSCI All Country World Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI All Country World Index:
-
Stock selection within both the health care and communication services sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI All Country World Index:
-
Stock selection and an underweight position in the information technology sector held back relative returns.
-
The fund's overweight position and stock selection in the consumer staples sector also weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R1 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
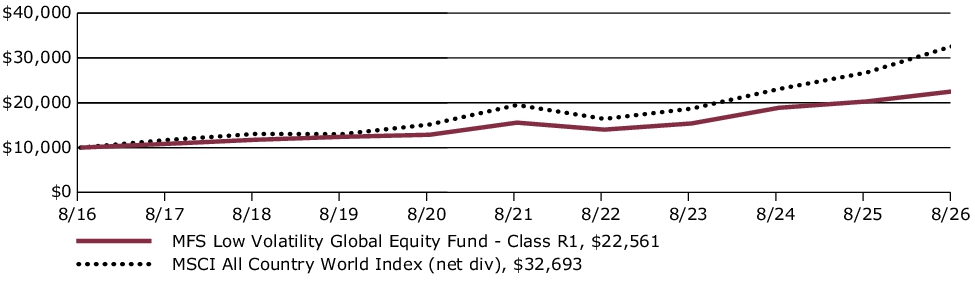
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R1 without sales charge | 11.21% | 7.70% | 8.48% |
| Comparative Benchmark(s) | |||
| MSCI All Country World Index (net div) ∆ | 22.35% | 10.88% | 12.58% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r1 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 300,940,594 | Total Management Fee ($)#: | 1,590,456 | |
| Total Number of Holdings: | 108 | Portfolio Turnover Rate (%): | 41 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.5% |
| Money Market Funds | 1.5% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
Issuer country weightings
| United States | 52.4% |
| Japan | 7.9% |
| Canada | 6.2% |
| United Kingdom | 4.7% |
| Singapore | 4.2% |
| Netherlands | 3.0% |
| Taiwan | 2.7% |
| Switzerland | 2.7% |
| Italy | 2.6% |
| Other Countries | 13.6% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R2 | $131 | 1.24% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R2 shares of the MFS Low Volatility Global Equity Fund (fund) provided a total return of 11.74%, at net asset value. This compares with a return of 22.35% for the fund’s benchmark, the MSCI All Country World Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI All Country World Index:
-
Stock selection within both the health care and communication services sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI All Country World Index:
-
Stock selection and an underweight position in the information technology sector held back relative returns.
-
The fund's overweight position and stock selection in the consumer staples sector also weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R2 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
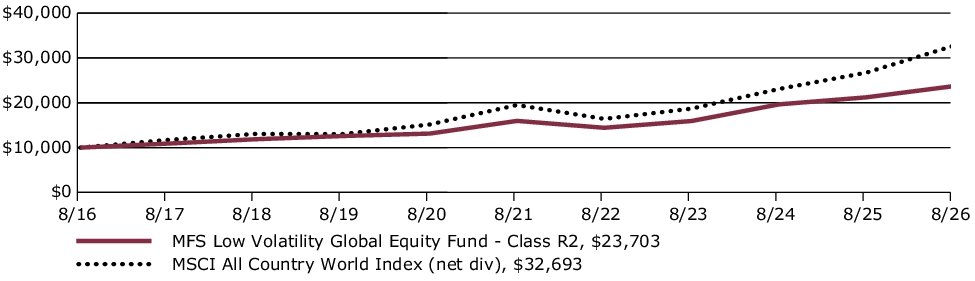
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R2 without sales charge | 11.74% | 8.24% | 9.01% |
| Comparative Benchmark(s) | |||
| MSCI All Country World Index (net div) ∆ | 22.35% | 10.88% | 12.58% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r2 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 300,940,594 | Total Management Fee ($)#: | 1,590,456 | |
| Total Number of Holdings: | 108 | Portfolio Turnover Rate (%): | 41 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.5% |
| Money Market Funds | 1.5% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
Issuer country weightings
| United States | 52.4% |
| Japan | 7.9% |
| Canada | 6.2% |
| United Kingdom | 4.7% |
| Singapore | 4.2% |
| Netherlands | 3.0% |
| Taiwan | 2.7% |
| Switzerland | 2.7% |
| Italy | 2.6% |
| Other Countries | 13.6% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R3 | $105 | 0.99% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R3 shares of the MFS Low Volatility Global Equity Fund (fund) provided a total return of 12.02%, at net asset value. This compares with a return of 22.35% for the fund’s benchmark, the MSCI All Country World Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI All Country World Index:
-
Stock selection within both the health care and communication services sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI All Country World Index:
-
Stock selection and an underweight position in the information technology sector held back relative returns.
-
The fund's overweight position and stock selection in the consumer staples sector also weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R3 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
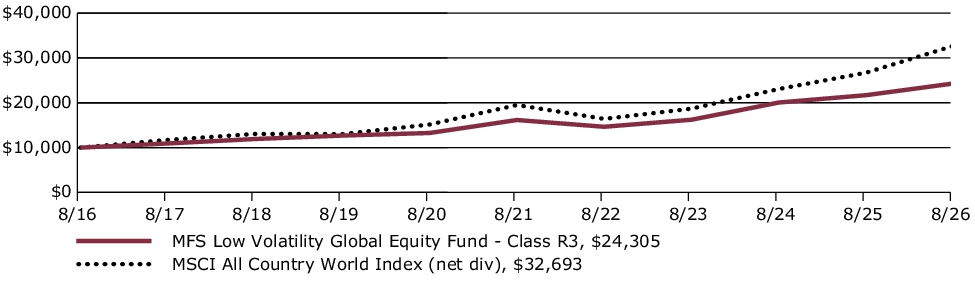
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R3 without sales charge | 12.02% | 8.51% | 9.29% |
| Comparative Benchmark(s) | |||
| MSCI All Country World Index (net div) ∆ | 22.35% | 10.88% | 12.58% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r3 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 300,940,594 | Total Management Fee ($)#: | 1,590,456 | |
| Total Number of Holdings: | 108 | Portfolio Turnover Rate (%): | 41 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.5% |
| Money Market Funds | 1.5% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
Issuer country weightings
| United States | 52.4% |
| Japan | 7.9% |
| Canada | 6.2% |
| United Kingdom | 4.7% |
| Singapore | 4.2% |
| Netherlands | 3.0% |
| Taiwan | 2.7% |
| Switzerland | 2.7% |
| Italy | 2.6% |
| Other Countries | 13.6% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R4 | $79 | 0.74% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R4 shares of the MFS Low Volatility Global Equity Fund (fund) provided a total return of 12.32%, at net asset value. This compares with a return of 22.35% for the fund’s benchmark, the MSCI All Country World Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI All Country World Index:
-
Stock selection within both the health care and communication services sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI All Country World Index:
-
Stock selection and an underweight position in the information technology sector held back relative returns.
-
The fund's overweight position and stock selection in the consumer staples sector also weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R4 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
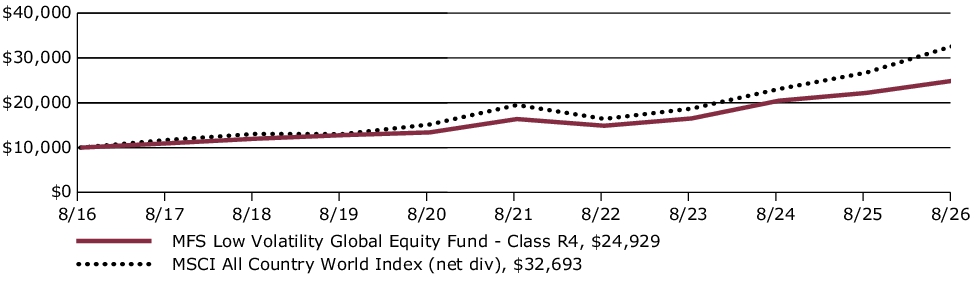
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R4 without sales charge | 12.32% | 8.78% | 9.56% |
| Comparative Benchmark(s) | |||
| MSCI All Country World Index (net div) ∆ | 22.35% | 10.88% | 12.58% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r4 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 300,940,594 | Total Management Fee ($)#: | 1,590,456 | |
| Total Number of Holdings: | 108 | Portfolio Turnover Rate (%): | 41 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.5% |
| Money Market Funds | 1.5% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
Issuer country weightings
| United States | 52.4% |
| Japan | 7.9% |
| Canada | 6.2% |
| United Kingdom | 4.7% |
| Singapore | 4.2% |
| Netherlands | 3.0% |
| Taiwan | 2.7% |
| Switzerland | 2.7% |
| Italy | 2.6% |
| Other Countries | 13.6% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
FUND EXPENSES
What were the fund costs for the last year?
| (based on a hypothetical $10,000 investment) | ||
| Class Name | Costs of a $10,000 investment | Costs paid as a percentage of a $10,000 investment |
| R6 | $70 | 0.66% |
MANAGEMENT'S DISCUSSION OF FUND PERFORMANCE
-
For the twelve months ended August 31, 2026, Class R6 shares of the MFS Low Volatility Global Equity Fund (fund) provided a total return of 12.37%, at net asset value. This compares with a return of 22.35% for the fund’s benchmark, the MSCI All Country World Index (net div).
-
Global equity markets reached record levels during the period, withstanding considerable volatility amid tariffs, geopolitical conflict and high levels of uncertainty. A new geopolitical event distressed markets as US and Israeli forces launched strikes against Iran, disrupting Mideast oil and natural gas exports. During the period, renewed focus on defense and infrastructure spending brightened the economic outlook in Europe while in Japan, the election of a pro-growth prime minister sent stocks to new highs. Optimism over artificial intelligence remained high globally.
-
While the US Supreme Court struck down part of the Trump administration’s tariff strategy, the administration began deploying other authorities to largely replace the ones that were ruled unconstitutional.
-
Higher energy prices and the lingering impact from tariffs kept inflation elevated in the US, prompting the Federal Reserve to end its easing cycle. Both the European Central Bank and the Bank of Japan raised rates toward the end of the period.
-
In fixed income markets, previously range-bound global bond yields climbed following the February 2026 onset of the conflict in the Middle East and as investors appeared to price in greater fiscal and monetary uncertainty. During the Iran war, global credit spreads widened modestly before stabilizing near pre-conflict levels, supported by strong demand and resilient underlying fundamentals. Similarly, US rate volatility (as measured by the Merrill Lynch Option Volatility Estimate (MOVE) Index) rose from intra-period lows before retracting back near prior levels.
-
Top contributors to performance relative to the MSCI All Country World Index:
-
Stock selection within both the health care and communication services sectors benefited the fund's relative performance.
-
-
Top detractors from performance relative to the MSCI All Country World Index:
-
Stock selection and an underweight position in the information technology sector held back relative returns.
-
The fund's overweight position and stock selection in the consumer staples sector also weakened relative performance.
-
FUND PERFORMANCE
The fund’s past performance is not a good predictor of the fund’s future performance. The graph and table below do not reflect the deduction of taxes that a shareholder would pay on fund distributions or the redemption of fund shares. The graph and table below assume reinvestment of dividends and capital gain distributions.
Growth of a Hypothetical $10,000 Investment
This graph shows the performance of a hypothetical $10,000 investment in Class R6 over a ten year period or since inception, if shorter, in comparison to a broad measure of market performance.
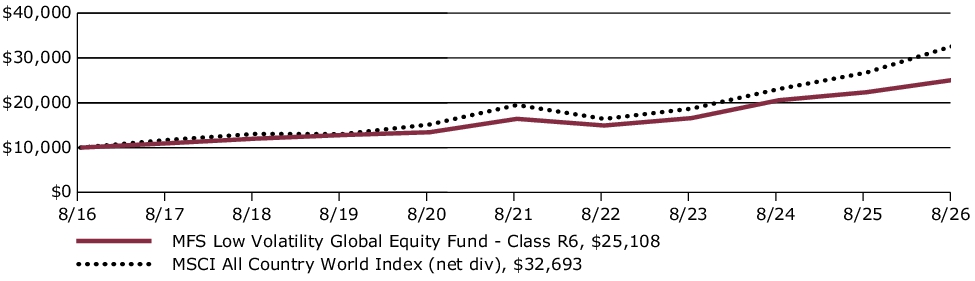
Average Annual Total Returns through 8/31/26
This table shows the average annual total returns of the class of shares noted for the periods shown, both with (if any) and without sales charges. It also shows the average annual total returns of a broad measure of market performance over the same periods.
| Share Class | 1-yr | 5-yr | 10-yr |
| R6 without sales charge | 12.37% | 8.87% | 9.64% |
| Comparative Benchmark(s) | |||
| MSCI All Country World Index (net div) ∆ | 22.35% | 10.88% | 12.58% |
|
∆
|
Source: FactSet Research Systems Inc.
|
Visit mfs.com/perf/r6 for more recent performance information.
FUND STATISTICS AS OF 8/31/26
| Net Assets ($): | 300,940,594 | Total Management Fee ($)#: | 1,590,456 | |
| Total Number of Holdings: | 108 | Portfolio Turnover Rate (%): | 41 |
# Includes the effect of any management fee waivers, if applicable.
Where the fund holds derivatives, they are not included in the total number of portfolio holdings.
PORTFOLIO COMPOSITION (BASED ON TOTAL INVESTMENTS AS OF 8/31/26)
Portfolio structure
| Equities | 98.5% |
| Money Market Funds | 1.5% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
Issuer country weightings
| United States | 52.4% |
| Japan | 7.9% |
| Canada | 6.2% |
| United Kingdom | 4.7% |
| Singapore | 4.2% |
| Netherlands | 3.0% |
| Taiwan | 2.7% |
| Switzerland | 2.7% |
| Italy | 2.6% |
| Other Countries | 13.6% |
Top ten holdings
| Johnson & Johnson | 3.2% |
| McKesson Corp. | 2.9% |
| Colgate-Palmolive Co. | 2.9% |
| Taiwan Semiconductor Manufacturing Co. Ltd., ADR | 2.7% |
| Roche Holding AG | 2.7% |
| DBS Group Holdings Ltd. | 2.4% |
| Microsoft Corp. | 2.3% |
| IG Group Holdings PLC | 2.2% |
| Koninklijke KPN N.V. | 2.2% |
| CLP Holdings Ltd. | 2.1% |
| [1] | Includes the effect of any management fee waivers, if applicable. |
| [2] | Includes the effect of any management fee waivers, if applicable. |
| [3] | Includes the effect of any management fee waivers, if applicable. |
| [4] | Includes the effect of any management fee waivers, if applicable. |
| [5] | Includes the effect of any management fee waivers, if applicable. |
| [6] | Includes the effect of any management fee waivers, if applicable. |
| [7] | Includes the effect of any management fee waivers, if applicable. |
| [8] | Includes the effect of any management fee waivers, if applicable. |
| [9] | Includes the effect of any management fee waivers, if applicable. |
| [10] | Includes the effect of any management fee waivers, if applicable. |
| [11] | Includes the effect of any management fee waivers, if applicable. |
| [12] | Includes the effect of any management fee waivers, if applicable. |
| [13] | Includes the effect of any management fee waivers, if applicable. |
| [14] | Includes the effect of any management fee waivers, if applicable. |
| [15] | Includes the effect of any management fee waivers, if applicable. |
| [16] | Includes the effect of any management fee waivers, if applicable. |
| [17] | Includes the effect of any management fee waivers, if applicable. |
| [18] | Includes the effect of any management fee waivers, if applicable. |
| [19] | Includes the effect of any management fee waivers, if applicable. |
| [20] | Includes the effect of any management fee waivers, if applicable. |
| [21] | Includes the effect of any management fee waivers, if applicable. |
| [22] | Includes the effect of any management fee waivers, if applicable. |
| [23] | Includes the effect of any management fee waivers, if applicable. |
| [24] | Includes the effect of any management fee waivers, if applicable. |
| [25] | Includes the effect of any management fee waivers, if applicable. |
| [26] | Includes the effect of any management fee waivers, if applicable. |
| [27] | Includes the effect of any management fee waivers, if applicable. |
| [28] | Includes the effect of any management fee waivers, if applicable. |
| [29] | Includes the effect of any management fee waivers, if applicable. |
| [30] | Includes the effect of any management fee waivers, if applicable. |
| [31] | Includes the effect of any management fee waivers, if applicable. |
| [32] | Includes the effect of any management fee waivers, if applicable. |
| [33] | Includes the effect of any management fee waivers, if applicable. |
| [34] | Includes the effect of any management fee waivers, if applicable. |
| [35] | Includes the effect of any management fee waivers, if applicable. |
| [36] | Includes the effect of any management fee waivers, if applicable. |
| [37] | Includes the effect of any management fee waivers, if applicable. |
| [38] | Includes the effect of any management fee waivers, if applicable. |
| [39] | Includes the effect of any management fee waivers, if applicable. |
| [40] | Includes the effect of any management fee waivers, if applicable. |
| [41] | Includes the effect of any management fee waivers, if applicable. |
| [42] | Includes the effect of any management fee waivers, if applicable. |
| [43] | Includes the effect of any management fee waivers, if applicable. |
| [44] | Includes the effect of any management fee waivers, if applicable. |
| [45] | Includes the effect of any management fee waivers, if applicable. |
| [46] | Includes the effect of any management fee waivers, if applicable. |
| [47] | Includes the effect of any management fee waivers, if applicable. |
| [48] | Includes the effect of any management fee waivers, if applicable. |
| [49] | Includes the effect of any management fee waivers, if applicable. |
| [50] | Includes the effect of any management fee waivers, if applicable. |
| [51] | Includes the effect of any management fee waivers, if applicable. |
| [52] | Includes the effect of any management fee waivers, if applicable. |
| [53] | Includes the effect of any management fee waivers, if applicable. |
| [54] | Includes the effect of any management fee waivers, if applicable. |
| [55] | Includes the effect of any management fee waivers, if applicable. |
| [56] | Includes the effect of any management fee waivers, if applicable. |
| [57] | Includes the effect of any management fee waivers, if applicable. |
| [58] | Includes the effect of any management fee waivers, if applicable. |
| [59] | Includes the effect of any management fee waivers, if applicable. |
| [60] | Includes the effect of any management fee waivers, if applicable. |
| [61] | Includes the effect of any management fee waivers, if applicable. |
| [62] | Includes the effect of any management fee waivers, if applicable. |
| [63] | Includes the effect of any management fee waivers, if applicable. |
| [64] | Includes the effect of any management fee waivers, if applicable. |
| [65] | Includes the effect of any management fee waivers, if applicable. |
| [66] | Includes the effect of any management fee waivers, if applicable. |
| [67] | Includes the effect of any management fee waivers, if applicable. |
| [68] | Includes the effect of any management fee waivers, if applicable. |
| [69] | Includes the effect of any management fee waivers, if applicable. |
| [70] | Includes the effect of any management fee waivers, if applicable. |
| [71] | Includes the effect of any management fee waivers, if applicable. |
| [72] | Includes the effect of any management fee waivers, if applicable. |