| 3Q26 Earnings Release October 27th, 2026 |
| DISCLAIMER This document may contain forward-looking statements. These statements are based on estimates, information or methods that may be incorrect or inaccurate and that may not occur. These estimates are also subject to risks, uncertainties, and assumptions that include, among other factors, general economic, political, and commercial conditions in Brazil and in the markets where we operate, as well as existing and future government regulations. Potential investors are cautioned that these forward-looking statements do not constitute guarantees of future performance, given that they involve risks and uncertainties. Gerdau does not undertake, and expressly waives, any obligation to update any of these forward-looking statements, which speak only as of the date they were made. |
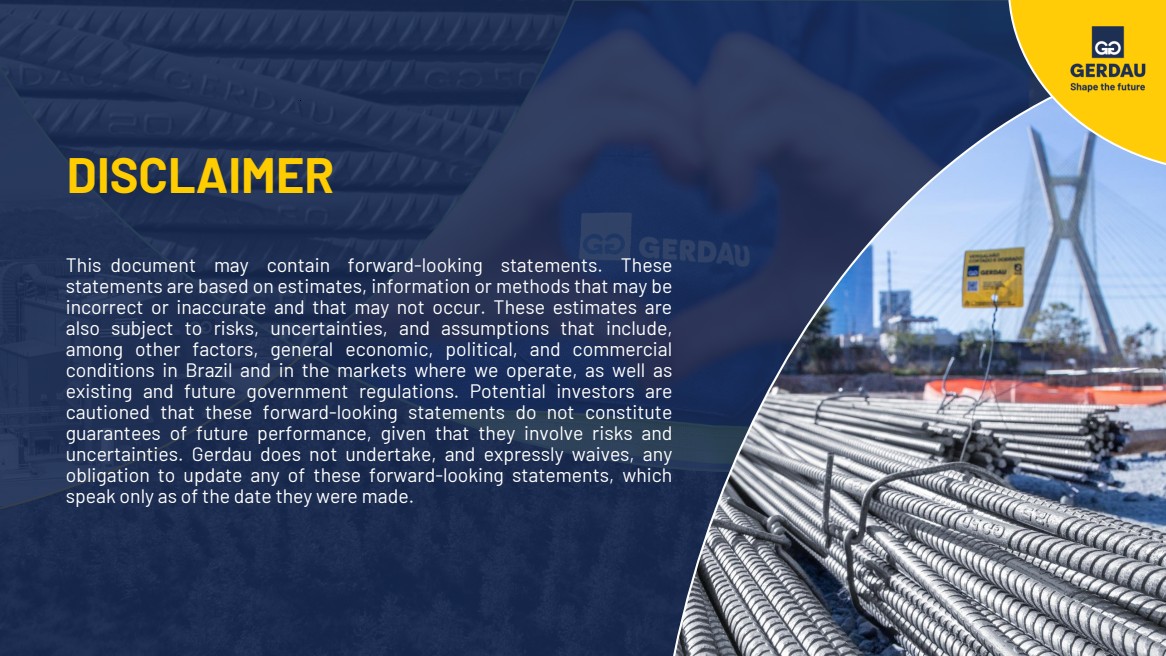
| 3 Highlights STRONG RESULTS IN NORTH AMERICA PROJECTS PROGRESS Recycling center operations started in Pindamonhangaba Miguel Burnieris in final integrated testing, with start-up expected for 4Q26 Stable vs. 2Q26 Performance supported by resilient demand in our main markets Slight recovery in results, despite continued pressure from imports and high steel supply SHIPMENTS 2.9 Mt OF STEEL GRADUAL IMPROVEMENT IN BRAZIL EBITDA accounted for 76% of consolidated EBITDA, with a 27.7% margin, the highest level in four years |
| 4 Financial performance 1 Calculated based on corporate net income. GERDAU S.A.: 3Q26 DIVIDENDS: METALÚRGICA GERDAU S.A.: Payment as of December 15, 2026 R$ 0.34/share ~R$ 212 m R$ 0.16/share ~R$ 667 m 3Q26 FREE CASH FLOW: R$ 1.4 billion Positive Free Cash Flow, supported by lower working capital consumption vs. 2Q26 9M26 CAPEX INVESTMENTS: R$ 3.1 billion 66% of total Capex planned for the year invested ADJUSTED EBITDA 3Q26: R$ 3.8 billion +10% vs. 2Q26, driven by improved results in North America and Brazil LEVERAGE: 0.58x ND/EBITDA Solid balance sheet with low leverage RENEWAL AND EXPANSION OF THE RCF: US$ 1.125 billion +29% in availability, maturing in 2031 EARNINGS PER SHARE1 : R$ 0.79 3Q26 ADJUSTED NET INCOME: R$ 1.5 billion +4% vs. 2Q26 Vs. R$ 0.74 in 2Q26 RATING AGENCIES: Positive Outlook Fitch (Jul/26) and S&P (Out/26) revised the outlook from Stable to Positive |
| 5 Outlook* NORTH AMERICA 4Q26: Stable margin Continued discipline in capital allocation and operational efficiency ▪ Lower volumes and higher scrap costs, reflecting typical seasonality for the period; ▪ Solid orders backlog, mainly driven by demand from renewable energy and data center markets; ▪ Higher prices, supporting operational profitability; ▪ Scheduled maintenance shutdown at Midlothian, with temporary cost impacts; ▪ USMCA negotiations ongoing, with no concrete indications of changes in steel tariffs; ▪ Developments from the U.S. elections remain potential sources of volatility for the sector. * Does not constitute guidance. BRAZIL 4Q26: Margin compression ▪ Seasonal slowdown in domestic demand and higher exports, negatively impacting the sales mix; ▪ Price pressure, with input costs still elevated (mainly coal); ▪ Start-up of the Miguel Burnier Mining Project; ▪ Progress on trade defense measures (antidumping duties on hot-rolled coils and wire rod); ▪ Monitoring of apparent steel consumption, pressured by high inflation and interest rates. |
| Q&A To ask questions, please indicate your name and institution via Raise Hand icon, wait to be announced. Once announced, accept the prompt to activate your microphone and camera. |
| ANEXOS 7 Appendices |
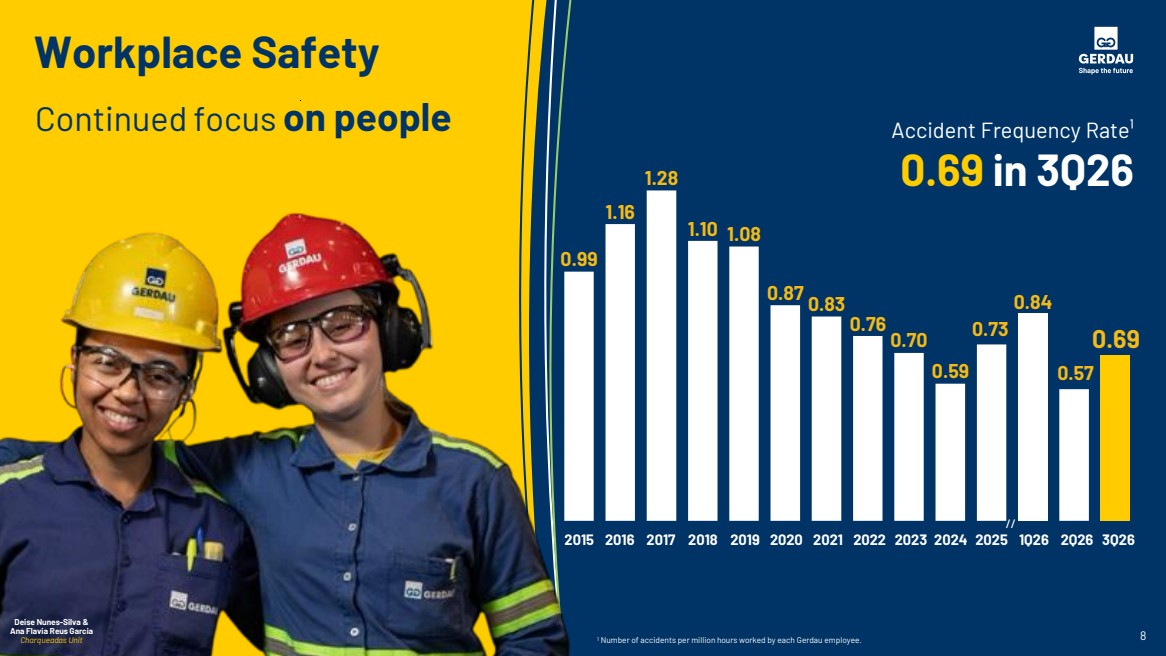
| Workplace Safety Continued focus on people Accident Frequency Rate¹ 0.69 in 3Q26 0.99 1.16 1.28 1.10 1.08 0.87 0.83 0.76 0.70 0.59 0.73 0.84 0.57 0.69 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2Q26 // 1 Number of accidents per million hours worked by each Gerdau employee. 2025 Deise Nunes-Silva & Ana Flavia Reus Garcia Charqueadas Unit 8 1Q26 3Q26 |
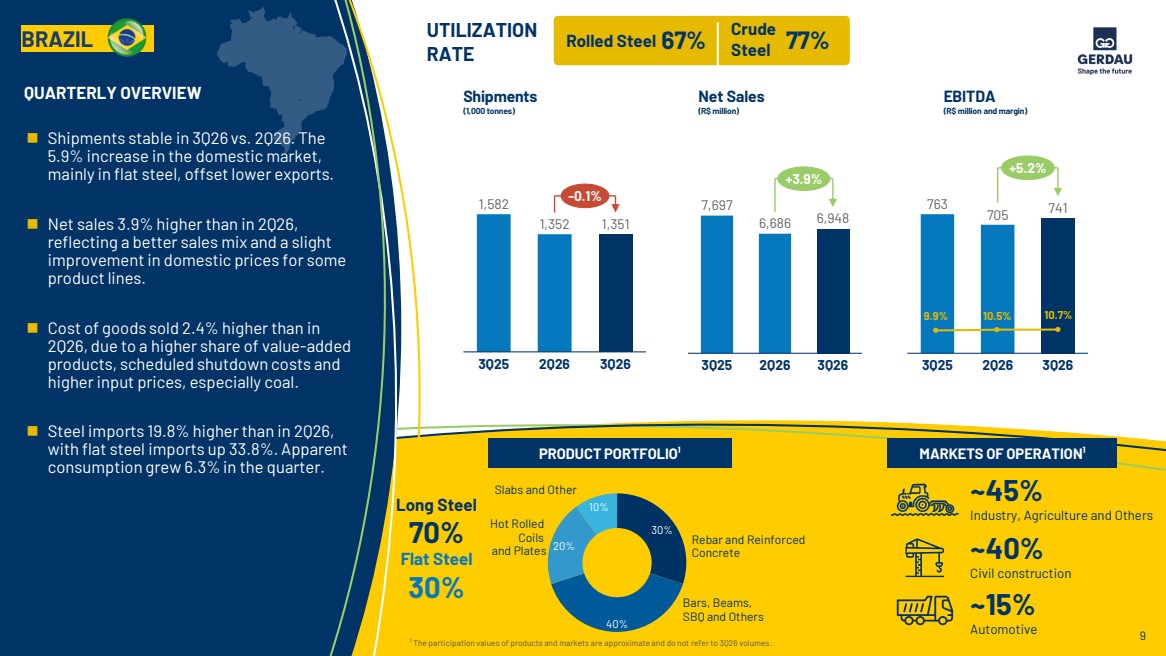
| 9 QUARTERLY OVERVIEW ◼ Shipments stable in 3Q26 vs. 2Q26. The 5.9% increase in the domestic market, mainly in flat steel, offset lower exports. ◼ Net sales 3.9% higher than in 2Q26, reflecting a better sales mix and a slight improvement in domestic prices for some product lines. ◼ Cost of goods sold 2.4% higher than in 2Q26, due to a higher share of value-added products, scheduled shutdown costs and higher input prices, especially coal. ◼ Steel imports 19.8% higher than in 2Q26, with flat steel imports up 33.8%. Apparent consumption grew 6.3% in the quarter. UTILIZATION RATE ~45% Industry, Agriculture and Others ~40% Civil construction ~15% Automotive PRODUCT PORTFOLIO¹ MARKETS OF OPERATION¹ 30% 40% 20% 10% Rebar and Reinforced Concrete Bars, Beams, SBQ and Others Hot Rolled Coils and Plates Slabs and Other ¹ The participation values of products and markets are approximate and do not refer to 3Q26 volumes. Long Steel 70% Flat Steel 30% BRAZIL Shipments (1,000 tonnes) Net Sales (R$ million) EBITDA (R$ million and margin) Rolled Steel 67% Crude Steel 77% 3Q25 2Q26 3Q26 1,582 1,352 1,351 -0.1% 3Q25 2Q26 3Q26 7,697 6,686 6,948 +3.9% 763 705 741 3Q25 2Q26 3Q26 +5.2% 9.9% 10.5% 10.7% |
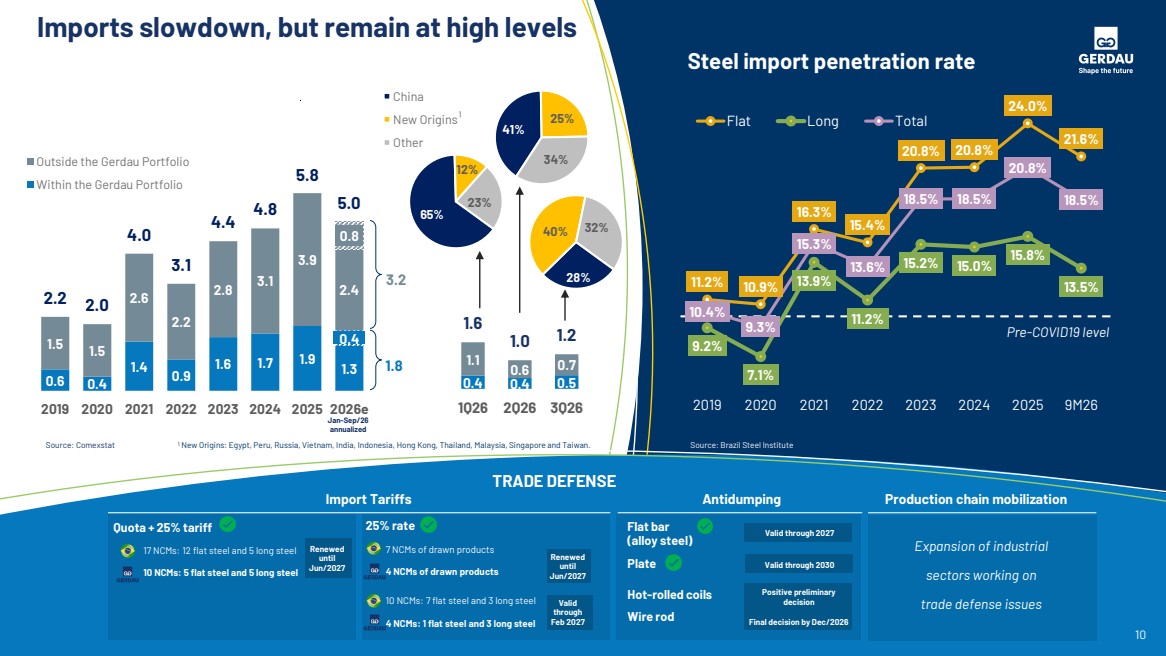
| Imports slowdown, but remain at high levels Source: Comexstat Steel import penetration rate Source: Brazil Steel Institute 1 New Origins: Egypt, Peru, Russia, Vietnam, India, Indonesia, Hong Kong, Thailand, Malaysia, Singapore and Taiwan. 10 TRADE DEFENSE Import Tariffs Antidumping 25% rate 7 NCMs of drawn products 4 NCMs of drawn products 10 NCMs: 7 flat steel and 3 long steel 4 NCMs: 1 flat steel and 3 long steel Quota + 25% tariff 17 NCMs: 12 flat steel and 5 long steel 10 NCMs: 5 flat steel and 5 long steel Flat bar (alloy steel) Plate Hot-rolled coils Wire rod Production chain mobilization Expansion of industrial sectors working on trade defense issues Renewed until Jun/2027 Renewed until Jun/2027 Valid through Feb 2027 Valid through 2027 Positive preliminary decision Final decision by Dec/2026 Valid through 2030 0.6 0.4 1.4 0.9 1.6 1.7 1.9 1.3 0.4 1.5 1.5 2.6 2.2 2.8 3.1 3.9 2.4 0.8 2.2 2.0 4.0 3.1 4.4 4.8 5.8 5.0 0.0 1.0 2.0 3.0 4.0 5.0 6.0 7.0 2019 2020 2021 2022 2023 2024 2025 2026e Outside the Gerdau Portfolio Within the Gerdau Portfolio 1.8 3.2 0.4 0.4 0.5 1.1 0.6 0.7 1.6 1.0 1.2 1Q26 2Q26 3Q26 65% 12% 23% 41% 25% 34% China New Origins Other ¹ Pre-COVID19 level 28% 40% 32% Jan-Sep/26 annualized 11.2% 10.9% 16.3% 15.4% 20.8% 20.8% 24.0% 21.6% 9.2% 7.1% 13.9% 11.2% 15.2% 15.0% 15.8% 13.5% 10.4% 9.3% 15.3% 13.6% 18.5% 18.5% 20.8% 18.5% 2019 2020 2021 2022 2023 2024 2025 9M26 Flat Long Total |
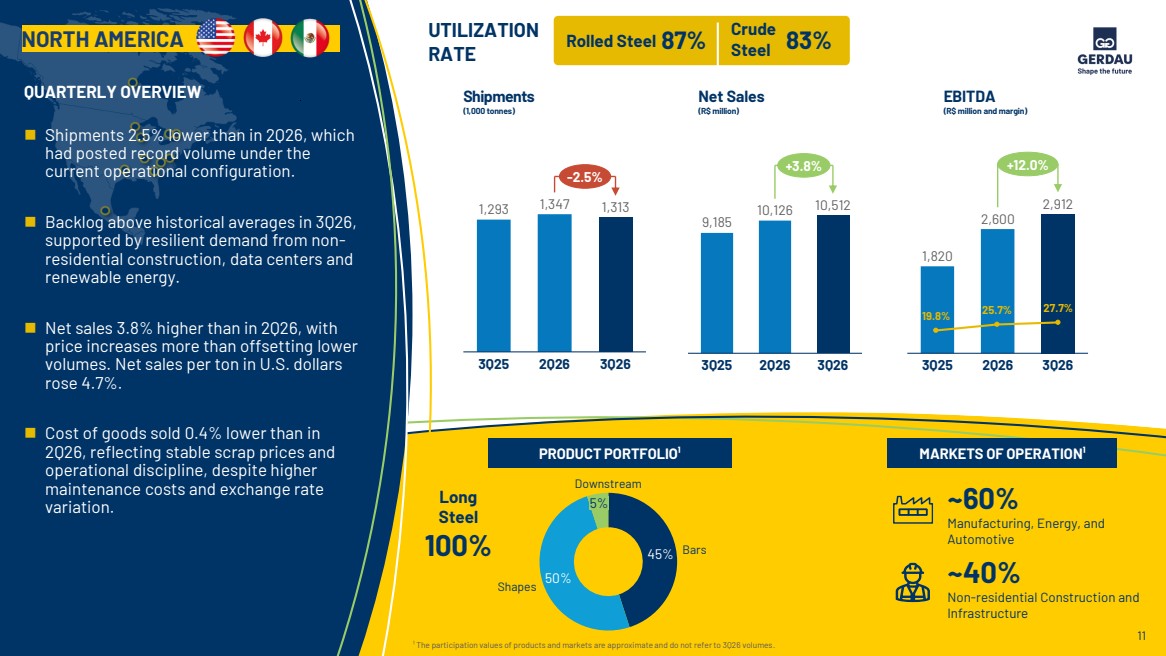
| 11 Shipments (1,000 tonnes) Net Sales (R$ million) EBITDA (R$ million and margin) QUARTERLY OVERVIEW ◼ Shipments 2.5% lower than in 2Q26, which had posted record volume under the current operational configuration. ◼ Backlog above historical averages in 3Q26, supported by resilient demand from non-residential construction, data centers and renewable energy. ◼ Net sales 3.8% higher than in 2Q26, with price increases more than offsetting lower volumes. Net sales per ton in U.S. dollars rose 4.7%. ◼ Cost of goods sold 0.4% lower than in 2Q26, reflecting stable scrap prices and operational discipline, despite higher maintenance costs and exchange rate variation. 45% 50% Bars Shapes 5% Downstream ~40% Non-residential Construction and Infrastructure ~60% Manufacturing, Energy, and Automotive Long Steel 100% ¹ The participation values of products and markets are approximate and do not refer to 3Q26 volumes. NORTH AMERICA UTILIZATION RATE PRODUCT PORTFOLIO¹ MARKETS OF OPERATION¹ Rolled Steel 87% Crude Steel 83% 3Q25 2Q26 3Q26 1,293 1,347 1,313 -2.5% 3Q25 2Q26 3Q26 9,185 10,126 10,512 +3.8% 3Q25 2Q26 3Q26 1,820 2,600 2,912 +12.0% 19.8% 25.7% 27.7% |
| Shipments (1,000 tonnes) Net Sales (R$ million) EBITDA (R$ million and margin) 12 78% UTILIZATION RATE Rolled Steel Crude Steel 54% QUARTERLY OVERVIEW 80% 20% Bars & Beams Downstream & Others ~70% Distribution (semi-finished) ~20% Civil construction ~10% Industry SOUTH AMERICA 289 282 309 3Q25 2Q26 3Q26 +9.7% 3Q25 2Q26 3Q26 1,376 1,279 1,440 +12.6% 234 205 160 3Q25 2Q26 3Q26 -22.0% 17.0% 16.0% 11.1% PRODUCT PORTFOLIO¹ MARKETS OF OPERATION¹ Long Steel 100% ◼ Shipments 9.7% higher than in 2Q26, driven by the civil construction market in Peru, which posted record sales in August. ◼ Net sales 12.6% higher than in 2Q26, reflecting higher volumes sold in Peru and the appreciation of the U.S. dollar against the Brazilian real (+1.7%). ◼ Adjusted EBITDA of R$ 160 million, 22.0% lower than in 2Q26, with an 11.1% margin, due to scheduled shutdowns and lower fixed cost dilution. ◼ Cost of goods sold 17.7% higher than in 2Q26, impacted by scheduled maintenance shutdowns, mainly in Argentina. ¹ The participation values of products and markets are approximate and do not refer to 3Q26 volumes. |
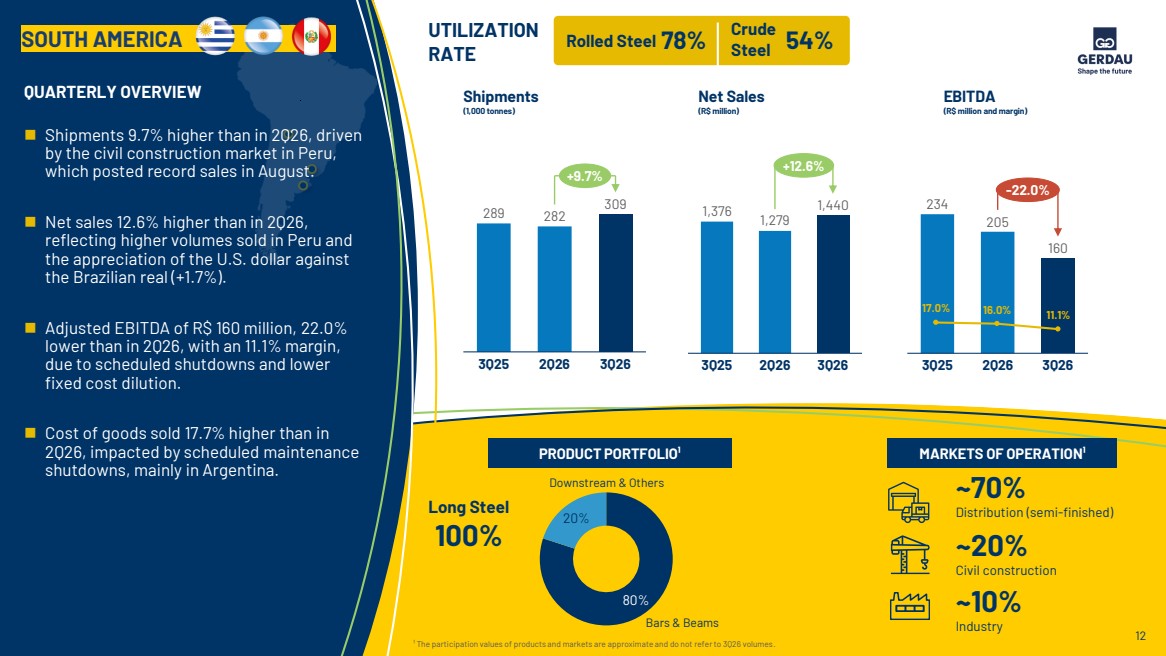
| Operational performance 1 Non-accounting measurement prepared by the Company. The Company states the Adjusted EBITDA to provide additional information on cash generated in the period. | 2 I Includes iron ore and co-products sales. Importance of geographic diversification for resilient results ADJUSTED EBITDA (R$ million) and ADJUSTED EBITDA MARGIN ¹ NET SALES² (R$ million) North Am. Brazil South Am. Eliminations (220) 11 Eliminations 10,512 10,126 1,440 (210) 6,686 Net Sales 3Q26 1,279 Net Sales 2Q26 386 North Am. 262 Brazil 161 South Am. 17,871 18,691 6,948 +5% -171 741 (80) 2,912 160 2,600 205 EBITDA 2Q26 312 North Am. 36 Brazil (45) South Am. 3,430 19.2% 3,771 20.2% 705 (42) 38 Eliminations EBITDA 3Q26 +10% 2Q26 vs. 3Q26 763 741 (80) 1,820 234 EBITDA 3Q25 North Am. (21) Brazil (75) South Am. 38 Eliminations 2,912 160 (42) EBITDA 3Q26 2,737 15.2% 3,771 20.2% 1,092 +38% (274) Eliminations 10,512 6,948 9,185 7,697 (210) 1,376 Net Sales 3Q26 Net Sales 3Q25 1,328 North Am. (748) Brazil 63 South Am. 65 17,983 18,691 1,440 +4% 3Q25 vs. 3Q26 13 |
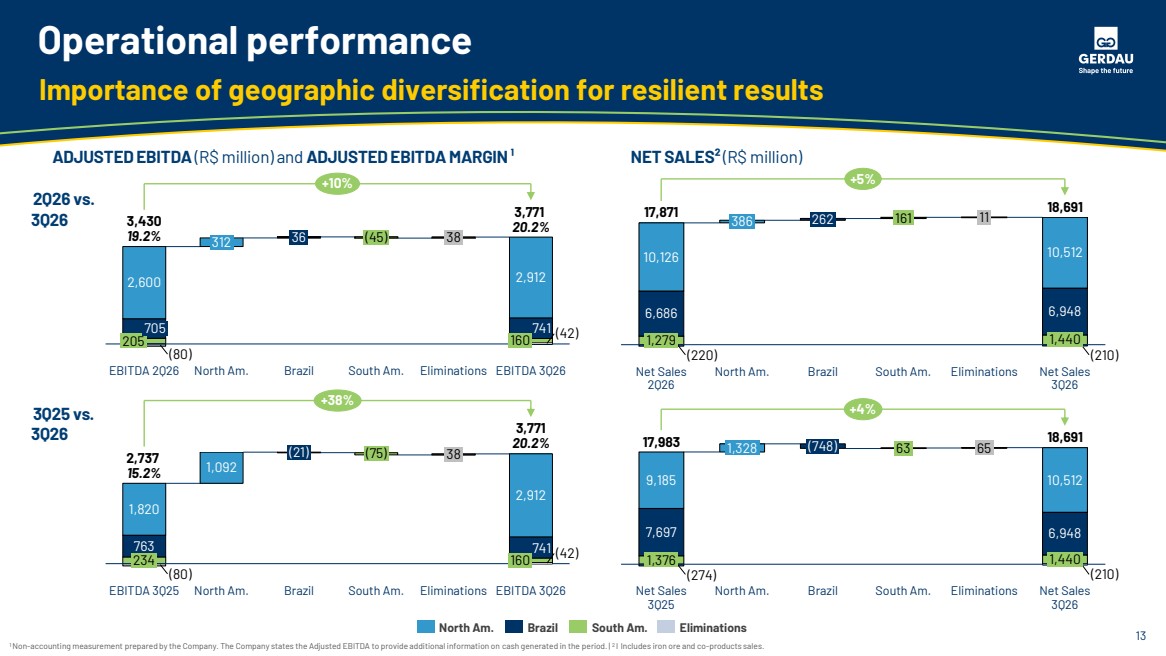
| 14 Cash flow & net cash variation 1 Includes thecash effect of customers, inventories,andsuppliersaccounts. | 2 Includes the addition of R$1.1billionin CAPEXinvestments in 3Q26, adjusted for the cash effect ofthechange in accounts payable to Property,plant, and equipment suppliersin theamount of R$146million, relatedto acquisitions from previousperiodspaid in the currentperiod. | 4 Includes thepayment ofinterest on loans andfinancing and interest on lease. | 5 ProportionalEBITDA of the joint venturesnet of dividendsreceivedfrom these JVs. | 6 Disbursements for otherintangibleassets and lease payments. | 7 Other changes includeOther Assetsand Liabilities accounts. CASH FLOW (R$ million) NET CASH VARIATION (R$ million) 5,440 2Q26 Cash 1,439 3Q26 Free Cash Flow (127) Financing Variation (426) Dividends (32) Share buyback (292) M&A 40 Exchange variation & other 6,043 3Q26 Cash 3,771 3Q26 Adjusted EBITDA (272) Working Capital 1 (548) Income Tax 2 (1,101) CAPEX3 (69) Interest4 (189) JVs Proportional EBITDA 5 (179) Intangibles and Leasing 6 27 Other 7 1,439 3Q26 Free Cash Flow |
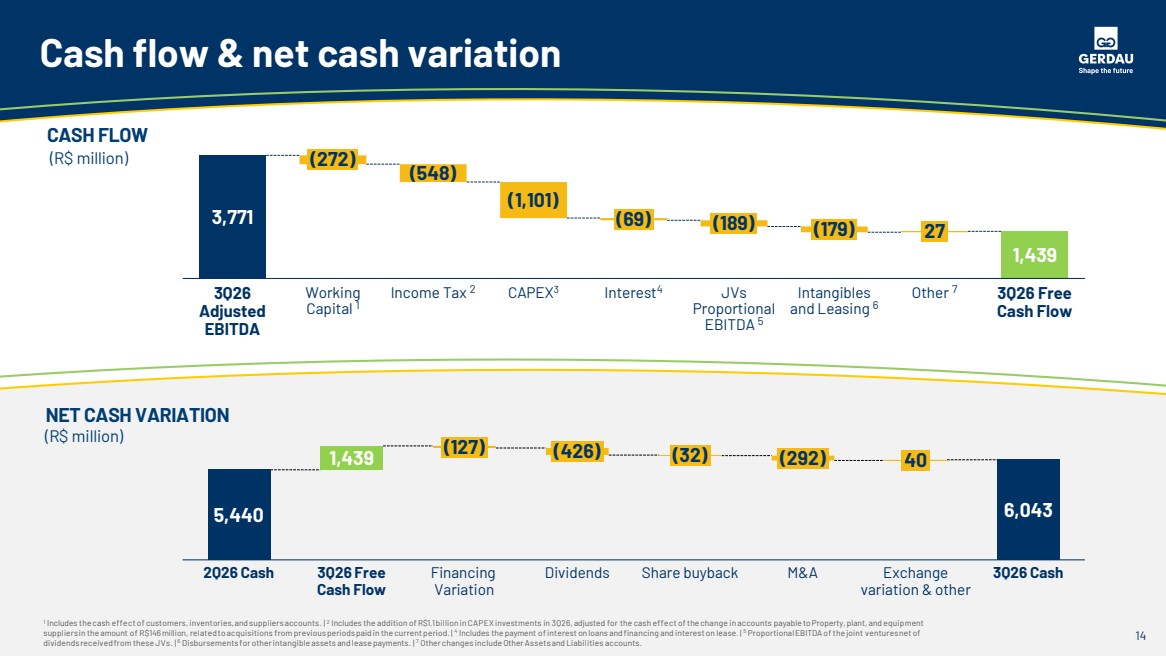
| 6.0 0.9 1.5 1.5 1.4 3.4 2.8 4.5 0.9 1.3 CASH, DEBT, AND LEVERAGE (R$ billion) LIQUIDITY POSITION AND DEBT AMORTIZATION1 (R$ billion) RATINGS: ¹ Global Revolving Credit Facility POLÍTICA FINANCEIRA GERDAU: 15 GROSS DEBT < R$12 BILLION AVERAGE TERM > 6 YEARS NET DEBT /EBITDA ≤1.5X BBB POSITIVE BBB POSITIVE Baa2 STABLE GERDAU FINANCIAL POLICY : 8.8 9.9 3Q25 7.8 6.4 4Q25 8.2 5.6 1Q26 8.1 5.4 2Q26 7.7 6.0 3Q26 18.6 14.2 13.8 13.6 13.7 Net Debt Cash 0.81x 0.76x 0.74x 0.69x 0.58x Gross Debt Net debt/Adjusted EBITDA Liquidity & indebtedness AVERAGE COST 7.5 years AVERAGE TERM BRL: CDI – 0.21% Y/Y USD: 6.13% Y/Y Liquidity 2027 0.1 2028 0.1 2029 0.3 2032 0.3 2035 0.3 2036 onwards 11.8 6.0 4.5 1.3 0.9 0.9 1.5 1.5 1.4 3.4 2.8 Cash and Equiv. RCF ¹ Bonds Debentures Bank loans RCF renewal (+29%) 15 |
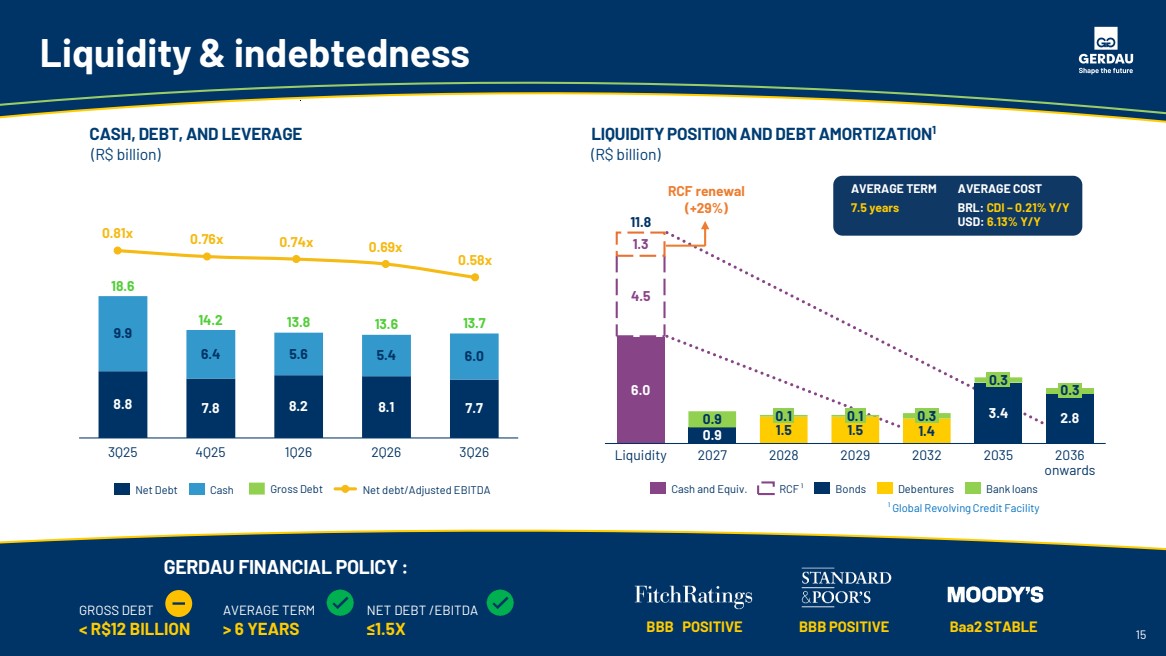
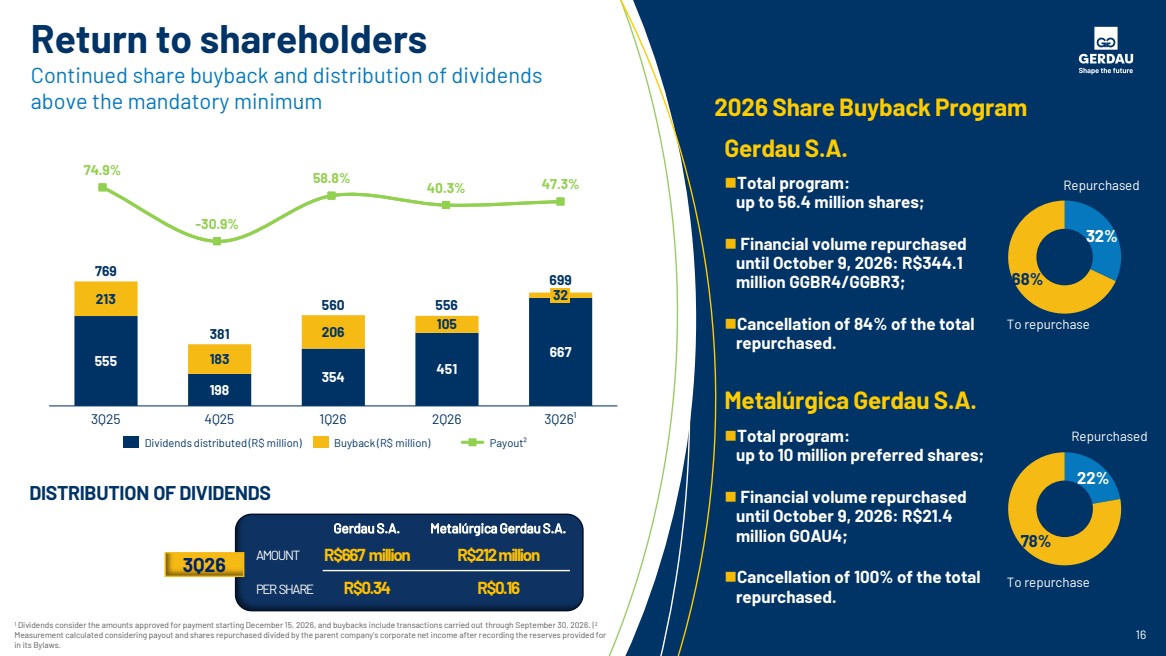
| 555 198 354 451 667 213 183 206 105 Return to shareholders Continued share buyback and distribution of dividends above the mandatory minimum 2026 Share Buyback Program ◼Total program: up to 56.4 million shares; ◼ Financial volume repurchased until October 9, 2026: R$344.1 million GGBR4/GGBR3; ◼Cancellation of 84% of the total repurchased. Repurchased 32% 68% 555 198 354 451 667 213 183 206 105 3Q25 4Q25 1Q26 2Q26 769 381 560 556 3Q26¹ 699 32 74.9% -30.9% 58.8% 40.3% 47.3% Dividends distributed (R$ million) Buyback (R$ million) Payout² DISTRIBUTION OF DIVIDENDS AMOUNT PER SHARE R$667 million R$0.34 3Q26 Gerdau S.A. R$212million R$0.16 Metalúrgica Gerdau S.A. 1 Dividends consider the amounts approved for payment starting December 15, 2026, and buybacks include transactions carried out through September 30, 2026. | 2 Measurement calculated considering payout and shares repurchased divided by the parent company’s corporate net income after recording the reserves provided for in its Bylaws. 16 Metalúrgica Gerdau S.A. ◼Total program: up to 10 million preferred shares; ◼ Financial volume repurchased until October 9, 2026: R$21.4 million GOAU4; ◼Cancellation of 100% of the total repurchased. Repurchased 22% 78% Gerdau S.A. To repurchase To repurchase |
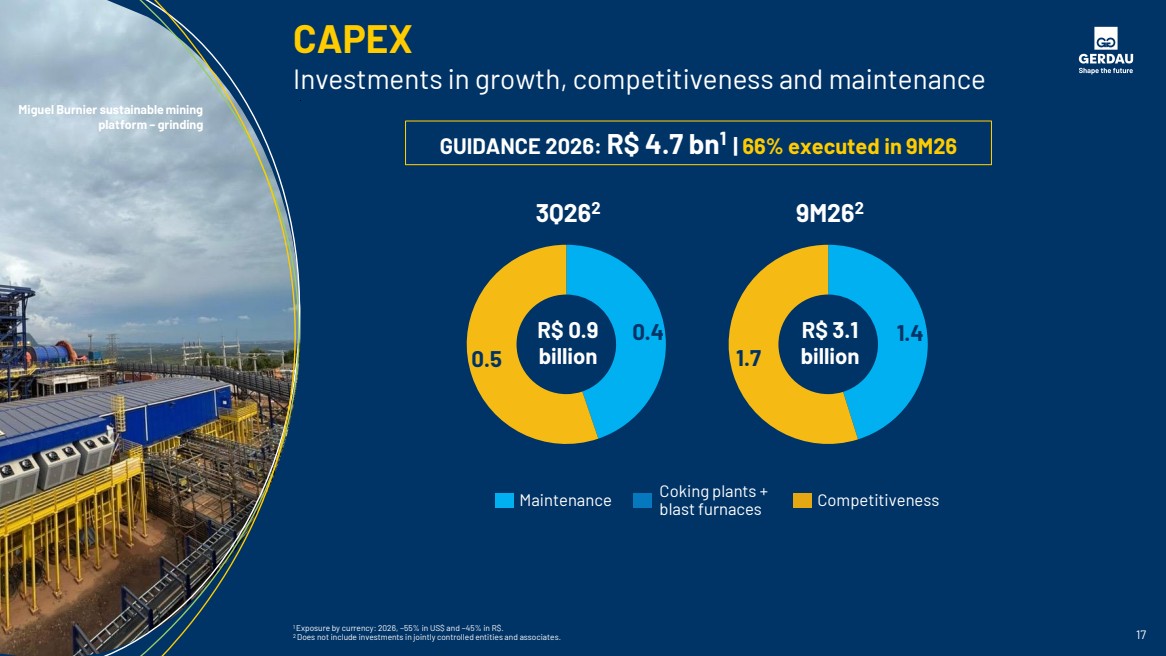
| CAPEX Investments in growth, competitiveness and maintenance Maintenance Coking plants + blast furnaces Competitiveness 3Q262 0.4 0.5 R$ 0.9 billion 17 9M262 1.4 1.7 R$ 3.1 billion GUIDANCE 2026: R$ 4.7 bn1 | 66% executed in 9M26 Miguel Burnier sustainable mining platform – grinding 1 Exposure by currency: 2026, ~55% in US$ and ~45% in R$. 2 Does not include investments in jointly controlled entities and associates. |
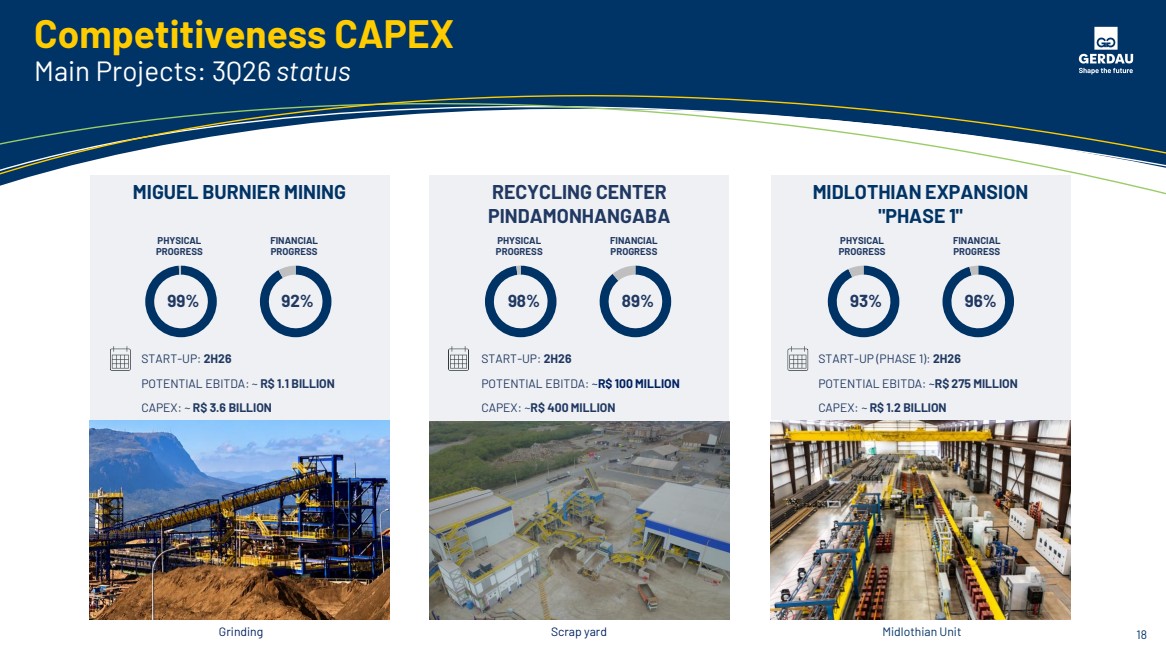
| Competitiveness CAPEX Main Projects: 3Q26 status MIGUEL BURNIER MINING 99% 92% Grinding RECYCLING CENTER PINDAMONHANGABA 98% 89% MIDLOTHIAN EXPANSION "PHASE 1" 93% 96% 18 PHYSICAL PROGRESS FINANCIAL PROGRESS START-UP: 2H26 POTENTIAL EBITDA: ~ R$ 1.1 BILLION CAPEX: ~ R$ 3.6 BILLION PHYSICAL PROGRESS FINANCIAL PROGRESS START-UP: 2H26 POTENTIAL EBITDA: ~R$ 100 MILLION CAPEX: ~R$ 400 MILLION PHYSICAL PROGRESS FINANCIAL PROGRESS START-UP (PHASE 1): 2H26 POTENTIAL EBITDA: ~R$ 275 MILLION CAPEX: ~ R$ 1.2 BILLION Scrap yard Midlothian Unit |
|
| Follow Gerdau on social media. Earnings Release 4Q26 February 16, 2027 Videoconference February 17, 2027 inform@gerdau.com | ri.gerdau.com |