Confidential Third Quarter 2026 Earnings October 27, 2026 Chris Cartwright, President and CEO Todd Cello, CFO Exhibit 99.2
2© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. Non-GAAP Financial InformationForward-Looking Statements This investor presentation contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements are based on the current beliefs and expectations of TransUnion’s management and are subject to significant risks and uncertainties. Actual results may differ materially from those described in the forward-looking statements. Factors that could cause TransUnion’s actual results to differ materially from those described in the forward-looking statements include: macroeconomic effects and changes in market conditions, including the impact of tariffs, inflation, risk of recession, trade policy, and industry trends and adverse developments in the debt, consumer credit and financial services markets, including the impact on the carrying value of our assets in all of the markets where we operate; ongoing conflict in the Middle East; our ability to provide competitive services and prices; our ability to retain or renew existing agreements with large or long-term customers; our ability to maintain the security and integrity of our data; our ability to deliver services timely without interruption; uncertainty related to FICO’s new Mortgage Direct License Program; our ability to maintain our access to data sources; government regulation and changes in the regulatory environment; uncertainty related to potential governmental actions or public statements regarding mortgage credit reporting requirements, the pricing of our services, the consumer reporting industry or our business, and the potential impact to our business and stock price as a result of such actions or public statements; litigation or regulatory proceedings; our approach to the use of artificial intelligence; our ability to effectively manage our costs; our ability to maintain effective internal control over financial reporting or disclosure controls and procedures; economic and political stability in the United States and risks associated with the international markets where we operate; our ability to effectively develop and maintain strategic alliances and joint ventures; our ability to timely develop new services and the market’s willingness to adopt our new services; our ability to manage and expand our operations and keep up with rapidly changing technologies; our ability to acquire businesses, successfully secure financing for our acquisitions, timely consummate our acquisitions, successfully integrate the operations of our acquisitions, control the costs of integrating our acquisitions and realize the intended benefits of such acquisitions; our ability to protect and enforce our intellectual property, trade secrets and other forms of unpatented intellectual property; our ability to defend our intellectual property from infringement claims by third parties; the ability of our outside service providers and key vendors to fulfill their obligations to us; further consolidation in our end-customer markets; the increased availability of free or inexpensive consumer information; losses against which we do not insure; our ability to make timely payments of principal and interest on our indebtedness; our ability to satisfy covenants in the agreements governing our indebtedness; our ability to maintain our liquidity; stock price volatility; share repurchase plans; dividend rate; our reliance on key management personnel; and changes in tax laws or adverse outcomes resulting from examination of our tax returns; and other one- time events and other factors that can be found in our Annual Report on Form 10-K for the year ended December 31, 2025, and any subsequent Quarterly Report on Form 10-Q or Current Report on Form 8-K, which are filed with the SEC and are available on TransUnion’s website (www.transunion.com/tru) and on the SEC’s website (www.sec.gov). TransUnion undertakes no obligation to publicly release the result of any revisions to these forward-looking statements to reflect the impact of events or circumstances that may arise after the date of this investor presentation. This investor presentation includes certain non-GAAP measures that are more fully described in the appendices to Exhibit 99.1, “Press release of TransUnion dated October 27, 2026, announcing results for the quarter ended September 30, 2026,” under the heading ‘Non- GAAP Financial Measures,’” furnished to the Securities and Exchange Commission on October 27, 2026. These financial measures should be reviewed in conjunction with the relevant GAAP financial measures and are not presented as alternative measures of GAAP. Other companies in our industry may define or calculate these measures differently than we do, limiting their usefulness as comparative measures. Because of these limitations, these non-GAAP financial measures should not be considered in isolation or as substitutes for performance measures calculated in accordance with GAAP. Reconciliations of these non-GAAP financial measures to their most directly comparable GAAP financial measures for each of the periods included in this presentation are included in the Appendices at the back of this investor presentation. Confidential
3© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. Third quarter 2026 highlights1 Innovation-led growth in action: Insurance vertical2 3@ Copyright 2026 Tran Union, its ubsidiaries and/or affiliates. All Rights Reserved. Third quarter 2026 financial results3 Fourth quarter and full-year 2026 guidance4 Confidential
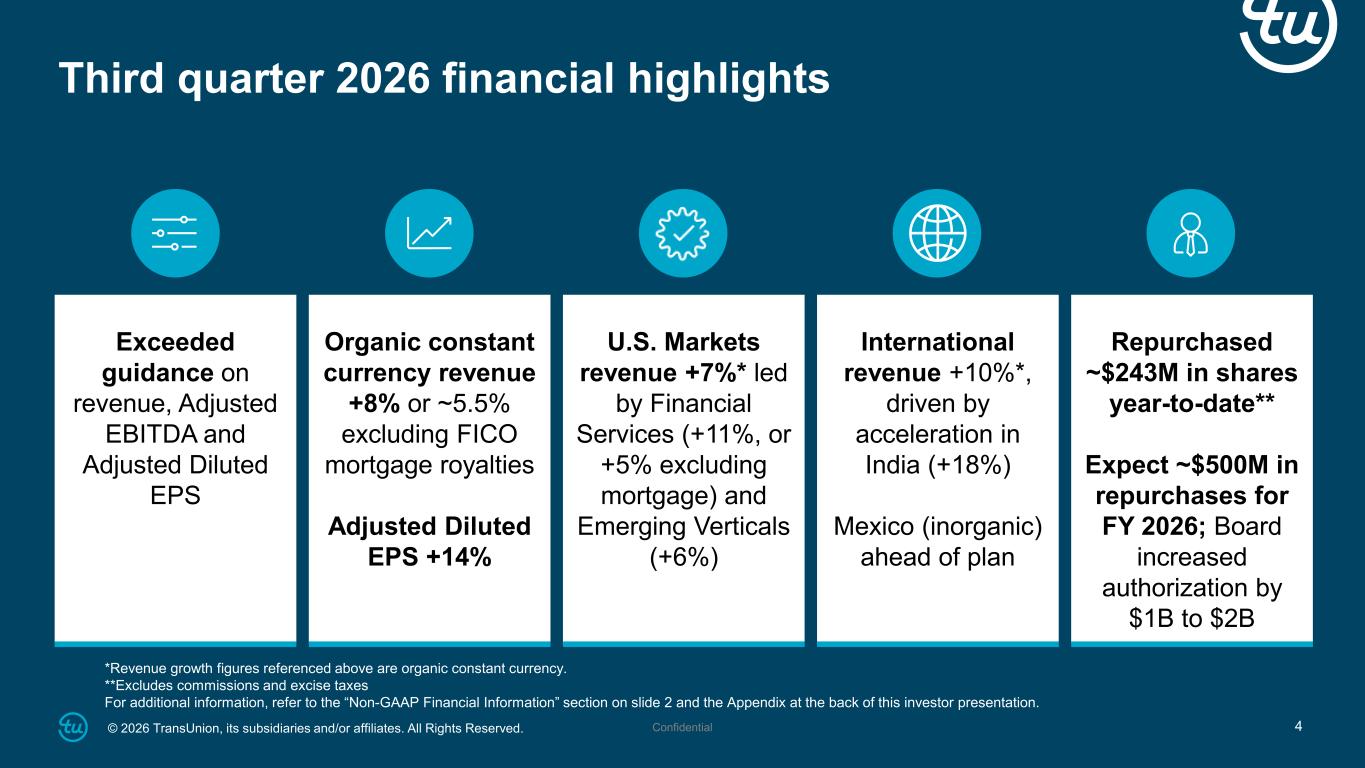
4© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. *Revenue growth figures referenced above are organic constant currency. **Excludes commissions and excise taxes For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation. International revenue +10%*, driven by acceleration in India (+18%) Mexico (inorganic) ahead of plan U.S. Markets revenue +7%* led by Financial Services (+11%, or +5% excluding mortgage) and Emerging Verticals (+6%) Organic constant currency revenue +8% or ~5.5% excluding FICO mortgage royalties Adjusted Diluted EPS +14% Exceeded guidance on revenue, Adjusted EBITDA and Adjusted Diluted EPS Repurchased ~$243M in shares year-to-date** Expect ~$500M in repurchases for FY 2026; Board increased authorization by $1B to $2B Third quarter 2026 financial highlights Confidential
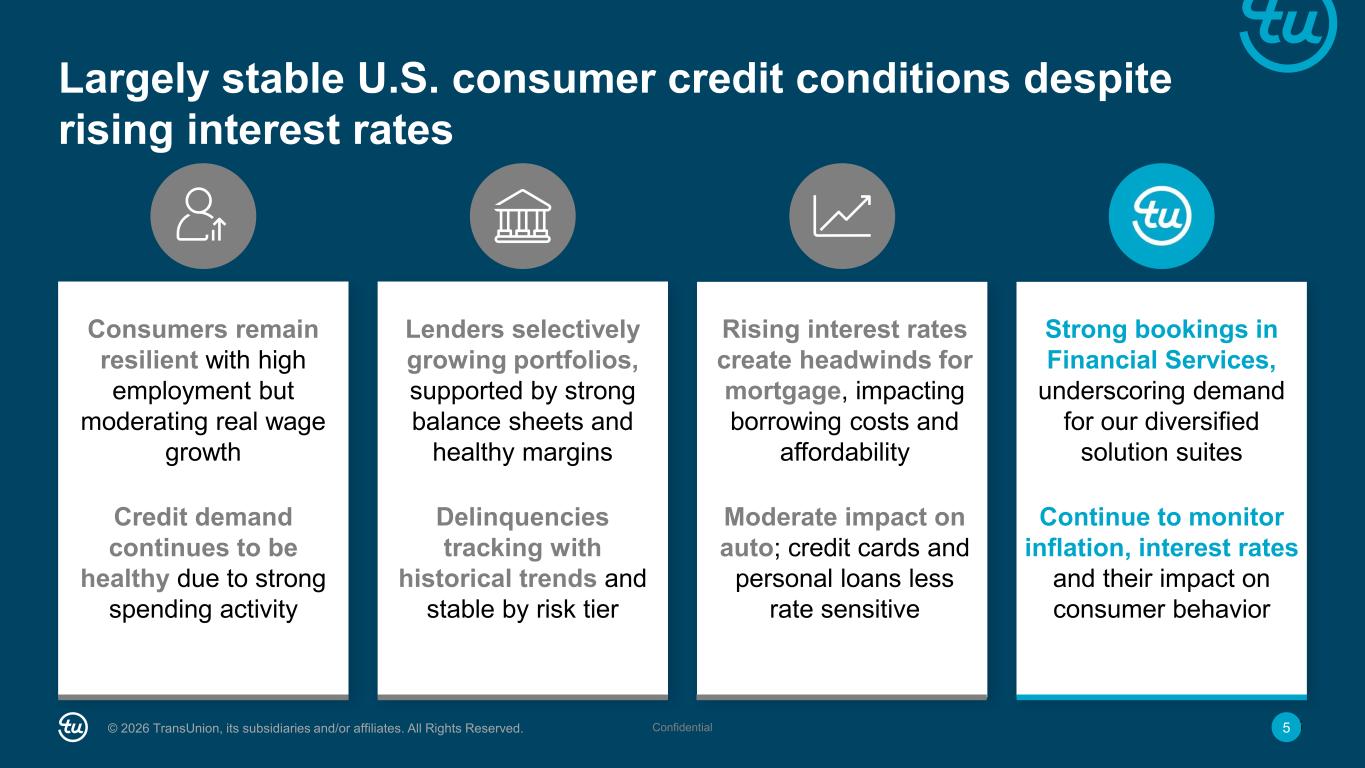
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 5Confidential 5 Consumers remain resilient with high employment but moderating real wage growth Credit demand continues to be healthy due to strong spending activity Strong bookings in Financial Services, underscoring demand for our diversified solution suites Continue to monitor inflation, interest rates and their impact on consumer behavior Rising interest rates create headwinds for mortgage, impacting borrowing costs and affordability Moderate impact on auto; credit cards and personal loans less rate sensitive Lenders selectively growing portfolios, supported by strong balance sheets and healthy margins Delinquencies tracking with historical trends and stable by risk tier Largely stable U.S. consumer credit conditions despite rising interest rates
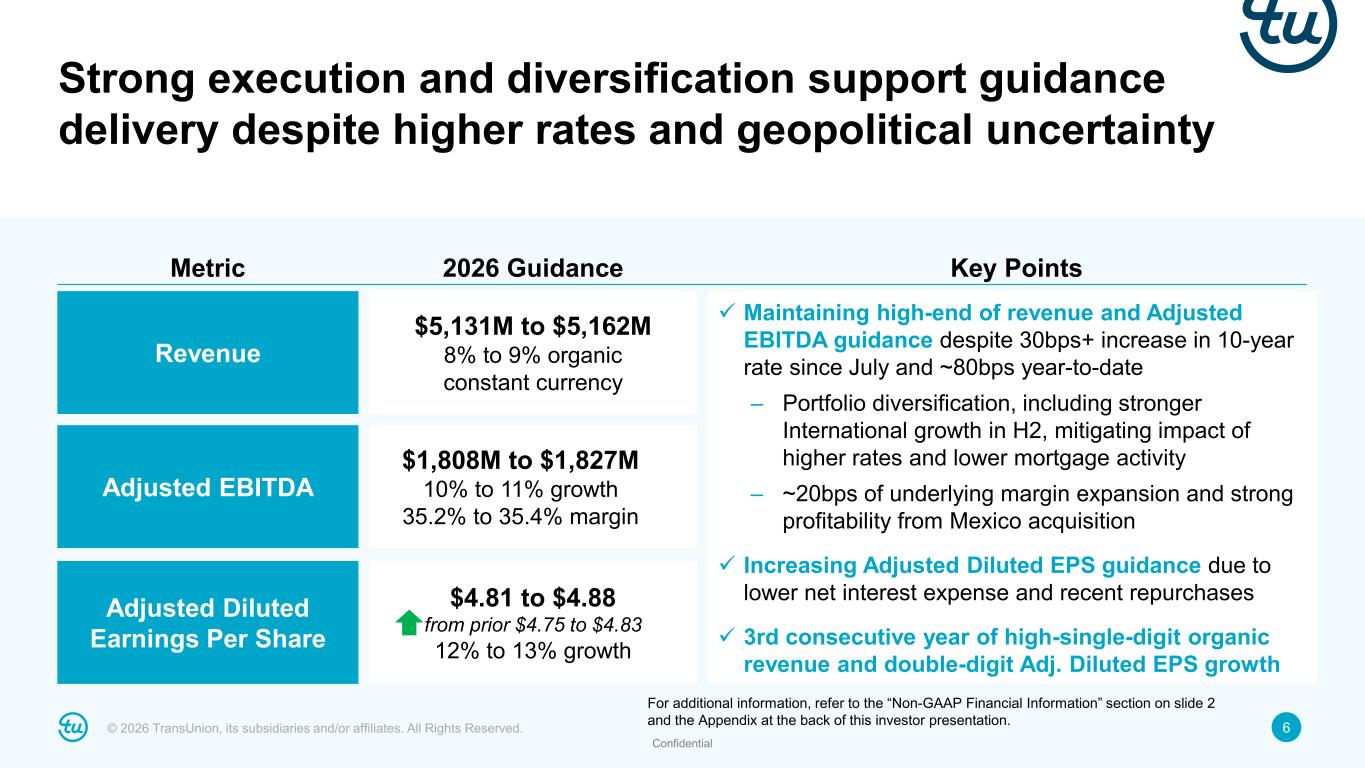
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 6Confidential 6 Maintaining high-end of revenue and Adjusted EBITDA guidance despite 30bps+ increase in 10-year rate since July and ~80bps year-to-date – Portfolio diversification, including stronger International growth in H2, mitigating impact of higher rates and lower mortgage activity – ~20bps of underlying margin expansion and strong profitability from Mexico acquisition Increasing Adjusted Diluted EPS guidance due to lower net interest expense and recent repurchases 3rd consecutive year of high-single-digit organic revenue and double-digit Adj. Diluted EPS growth Revenue Adjusted EBITDA Adjusted Diluted Earnings Per Share Metric 2026 Guidance Key Points $5,131M to $5,162M 8% to 9% organic constant currency $1,808M to $1,827M 10% to 11% growth 35.2% to 35.4% margin $4.81 to $4.88 from prior $4.75 to $4.83 12% to 13% growth Strong execution and diversification support guidance delivery despite higher rates and geopolitical uncertainty For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation. Confidential
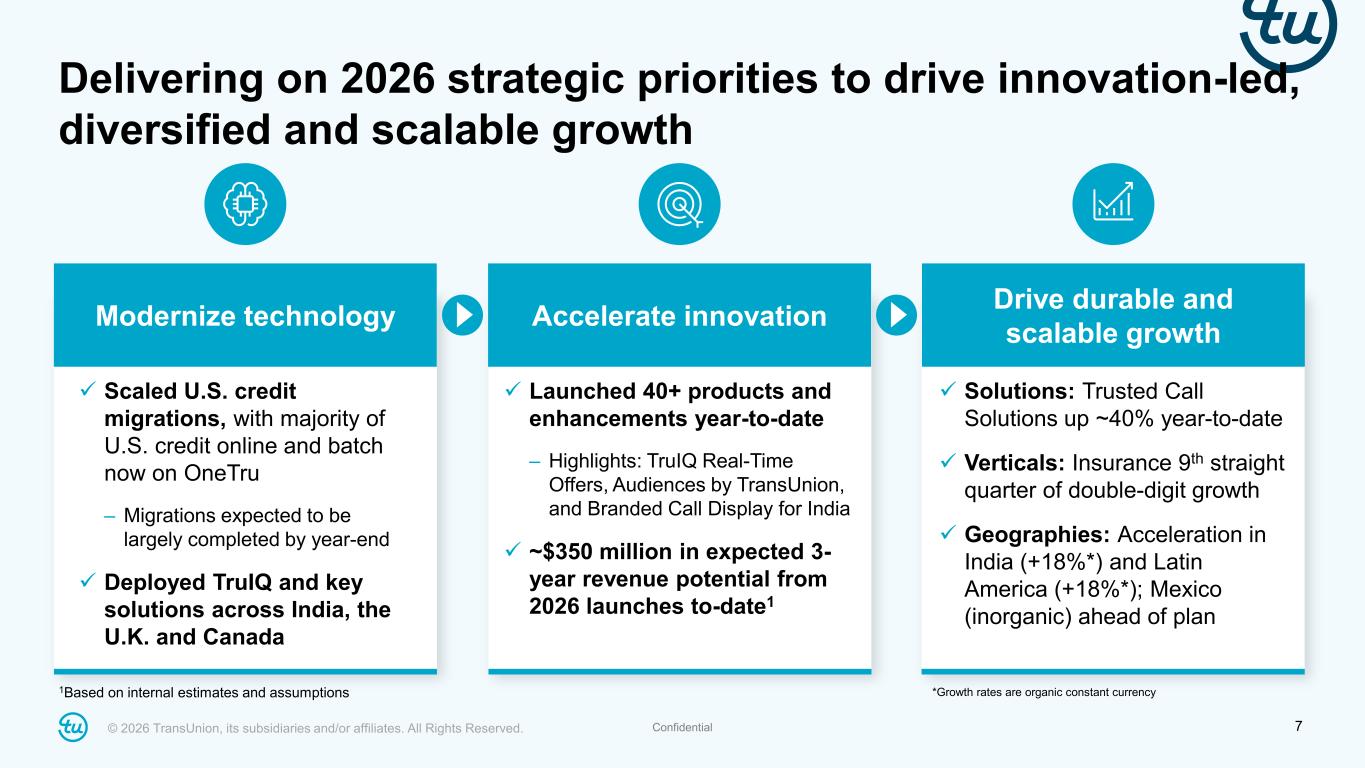
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 7Confidential Scaled U.S. credit migrations, with majority of U.S. credit online and batch now on OneTru – Migrations expected to be largely completed by year-end Deployed TruIQ and key solutions across India, the U.K. and Canada Modernize technology Delivering on 2026 strategic priorities to drive innovation-led, diversified and scalable growth Accelerate innovation Drive durable and scalable growth Launched 40+ products and enhancements year-to-date – Highlights: TruIQ Real-Time Offers, Audiences by TransUnion, and Branded Call Display for India ~$350 million in expected 3- year revenue potential from 2026 launches to-date1 Solutions: Trusted Call Solutions up ~40% year-to-date Verticals: Insurance 9th straight quarter of double-digit growth Geographies: Acceleration in India (+18%*) and Latin America (+18%*); Mexico (inorganic) ahead of plan *Growth rates are organic constant currency1Based on internal estimates and assumptions
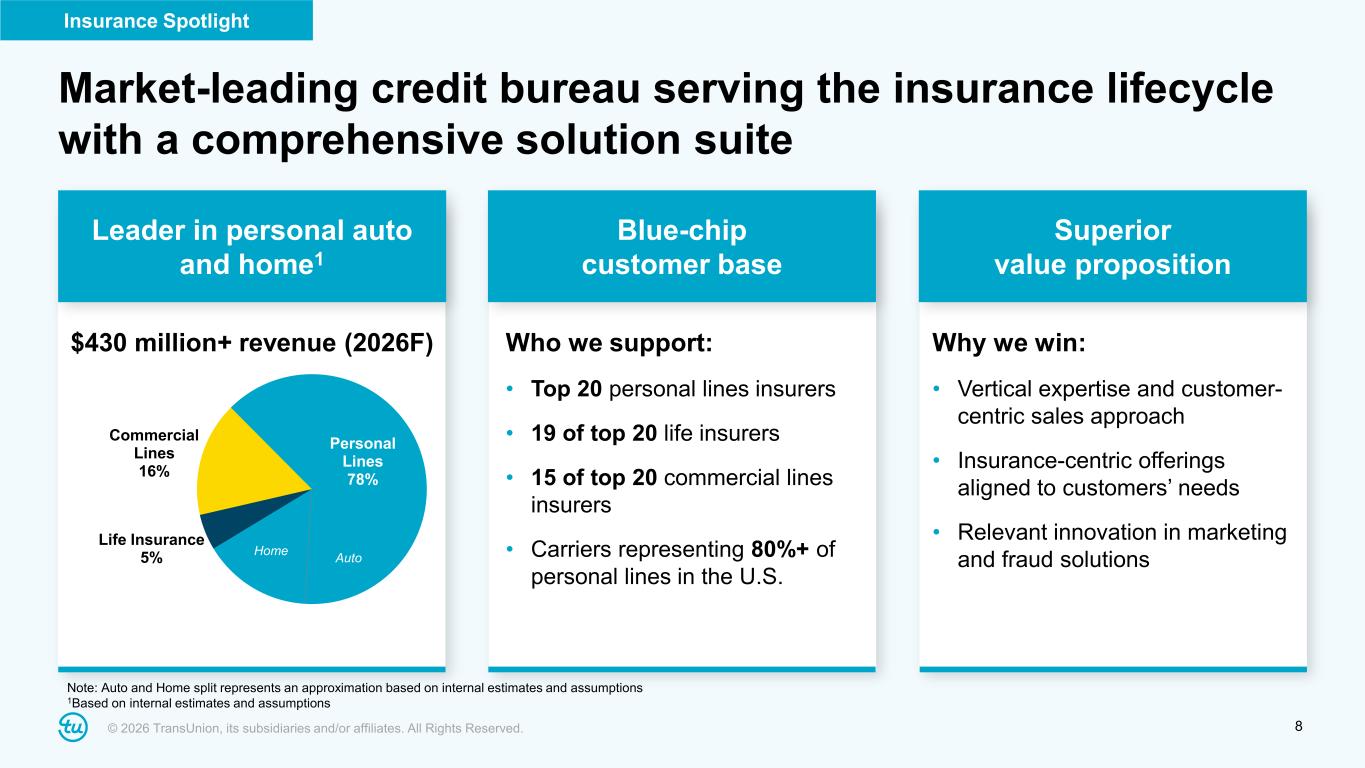
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 8 Who we support: • Top 20 personal lines insurers • 19 of top 20 life insurers • 15 of top 20 commercial lines insurers • Carriers representing 80%+ of personal lines in the U.S. Market-leading credit bureau serving the insurance lifecycle with a comprehensive solution suite Commercial Lines 16% Personal Lines 78% Life Insurance 5% AutoHome Why we win: • Vertical expertise and customer- centric sales approach • Insurance-centric offerings aligned to customers’ needs • Relevant innovation in marketing and fraud solutions Insurance Spotlight Leader in personal auto and home1 Blue-chip customer base Superior value proposition $430 million+ revenue (2026F) Note: Auto and Home split represents an approximation based on internal estimates and assumptions 1Based on internal estimates and assumptions
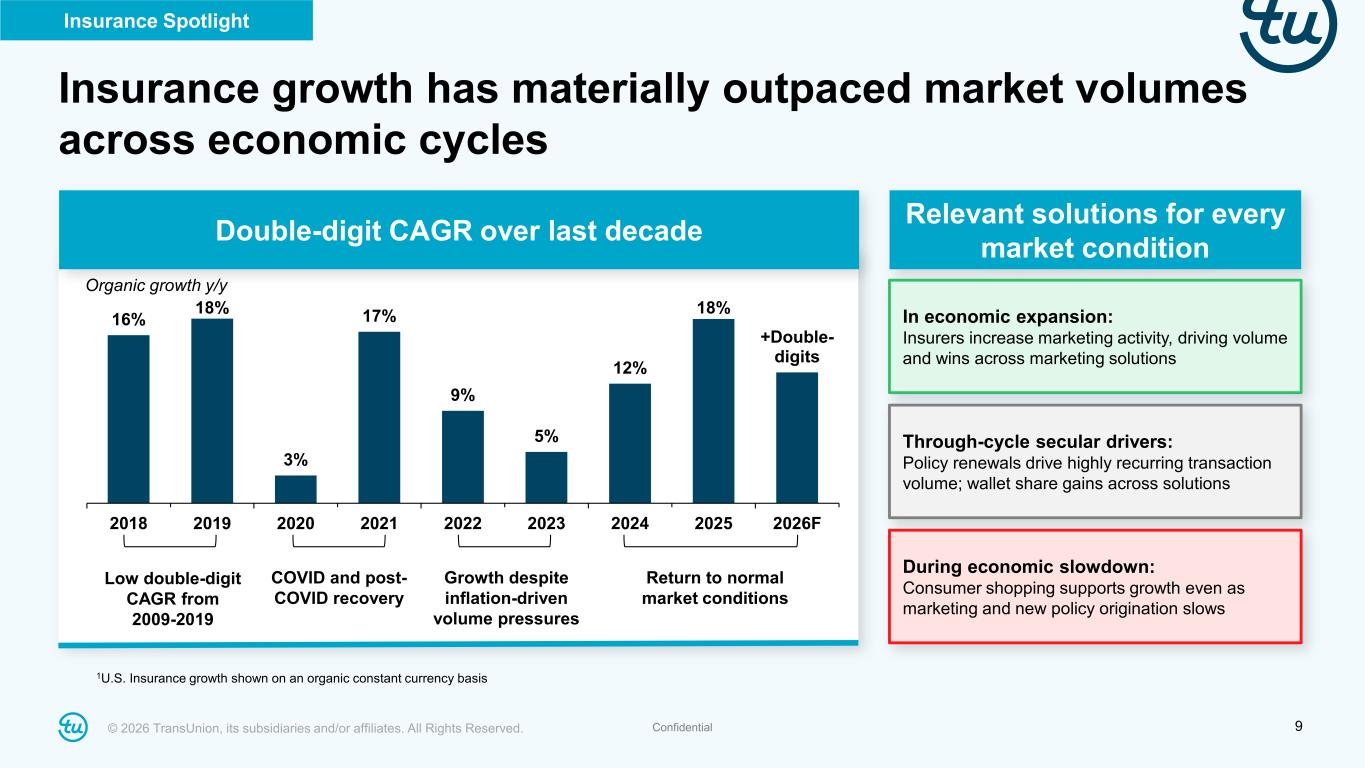
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 9Confidential Insurance growth has materially outpaced market volumes across economic cycles 16% 18% 3% 17% 9% 5% 12% 18% +Double- digits 2018 2019 2020 2021 2022 2023 2024 2025 2026F 1U.S. Insurance growth shown on an organic constant currency basis Double-digit CAGR over last decade Relevant solutions for every market condition Organic growth y/y In economic expansion: Insurers increase marketing activity, driving volume and wins across marketing solutions Through-cycle secular drivers: Policy renewals drive highly recurring transaction volume; wallet share gains across solutions During economic slowdown: Consumer shopping supports growth even as marketing and new policy origination slows Insurance Spotlight Low double-digit CAGR from 2009-2019 COVID and post- COVID recovery Growth despite inflation-driven volume pressures Return to normal market conditions
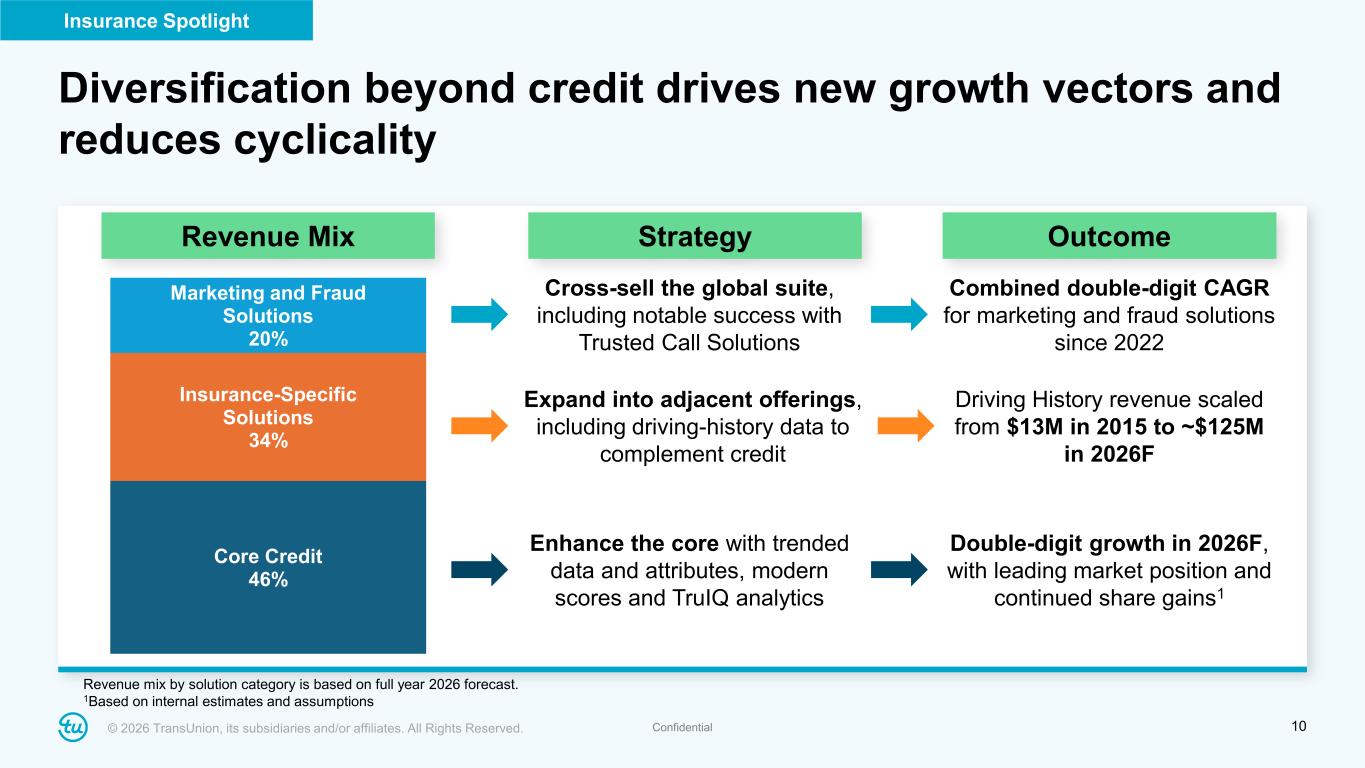
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 10Confidential Diversification beyond credit drives new growth vectors and reduces cyclicality Core Credit 46% Insurance-Specific Solutions 34% Marketing and Fraud Solutions 20% Insurance Spotlight Strategy Cross-sell the global suite, including notable success with Trusted Call Solutions Combined double-digit CAGR for marketing and fraud solutions since 2022 Outcome Expand into adjacent offerings, including driving-history data to complement credit Driving History revenue scaled from $13M in 2015 to ~$125M in 2026F Enhance the core with trended data and attributes, modern scores and TruIQ analytics Double-digit growth in 2026F, with leading market position and continued share gains1 Revenue Mix Revenue mix by solution category is based on full year 2026 forecast. 1Based on internal estimates and assumptions
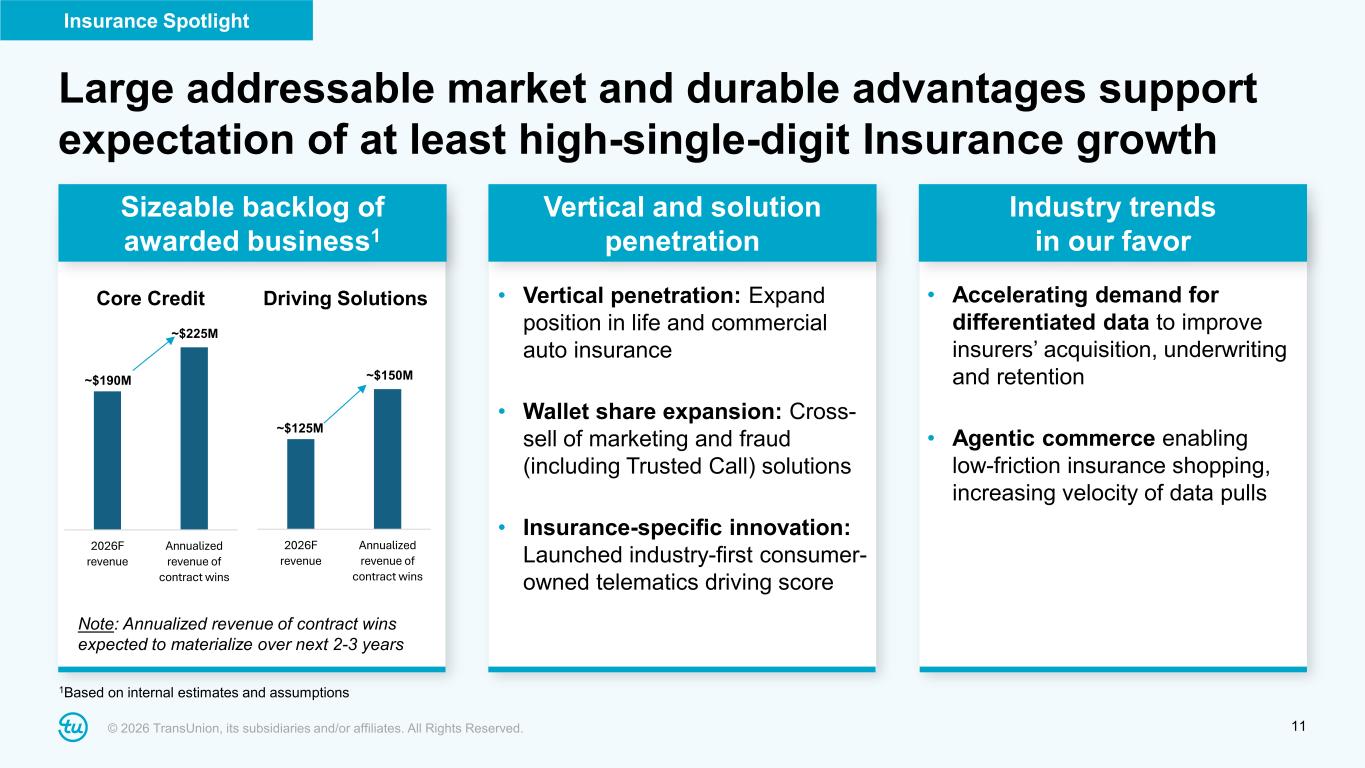
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 11 • Accelerating demand for differentiated data to improve insurers’ acquisition, underwriting and retention • Agentic commerce enabling low-friction insurance shopping, increasing velocity of data pulls Large addressable market and durable advantages support expectation of at least high-single-digit Insurance growth ~$190M ~$225M 2026F revenue Annualized revenue of contract wins ~$125M ~$150M 2026F revenue Annualized revenue of contract wins Insurance Spotlight • Vertical penetration: Expand position in life and commercial auto insurance • Wallet share expansion: Cross- sell of marketing and fraud (including Trusted Call) solutions • Insurance-specific innovation: Launched industry-first consumer- owned telematics driving score Sizeable backlog of awarded business1 Vertical and solution penetration Industry trends in our favor Core Credit Driving Solutions Note: Annualized revenue of contract wins expected to materialize over next 2-3 years 1Based on internal estimates and assumptions
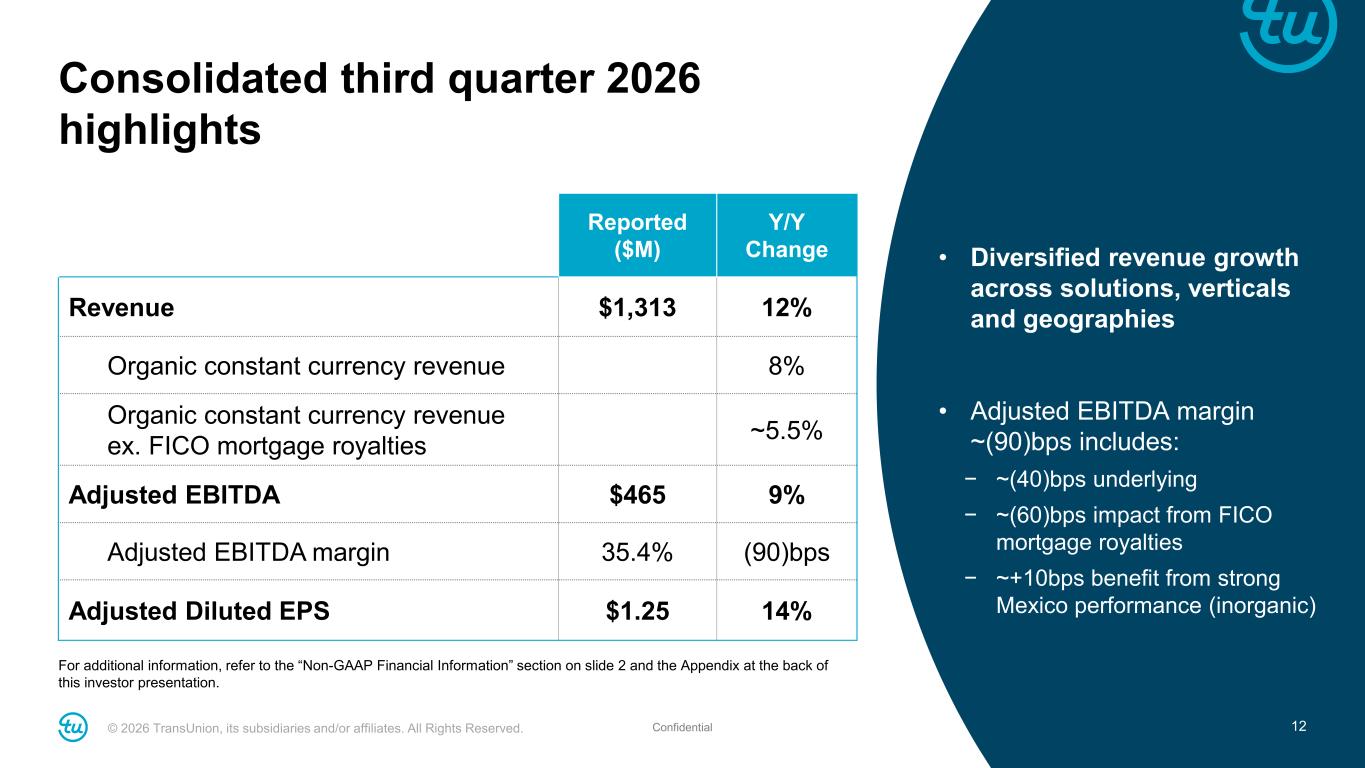
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 12Confidential Consolidated third quarter 2026 highlights Reported ($M) Y/Y Change Revenue $1,313 12% Organic constant currency revenue 8% Organic constant currency revenue ex. FICO mortgage royalties ~5.5% Adjusted EBITDA $465 9% Adjusted EBITDA margin 35.4% (90)bps Adjusted Diluted EPS $1.25 14% • Diversified revenue growth across solutions, verticals and geographies • Adjusted EBITDA margin ~(90)bps includes: − ~(40)bps underlying − ~(60)bps impact from FICO mortgage royalties − ~+10bps benefit from strong Mexico performance (inorganic) For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation.
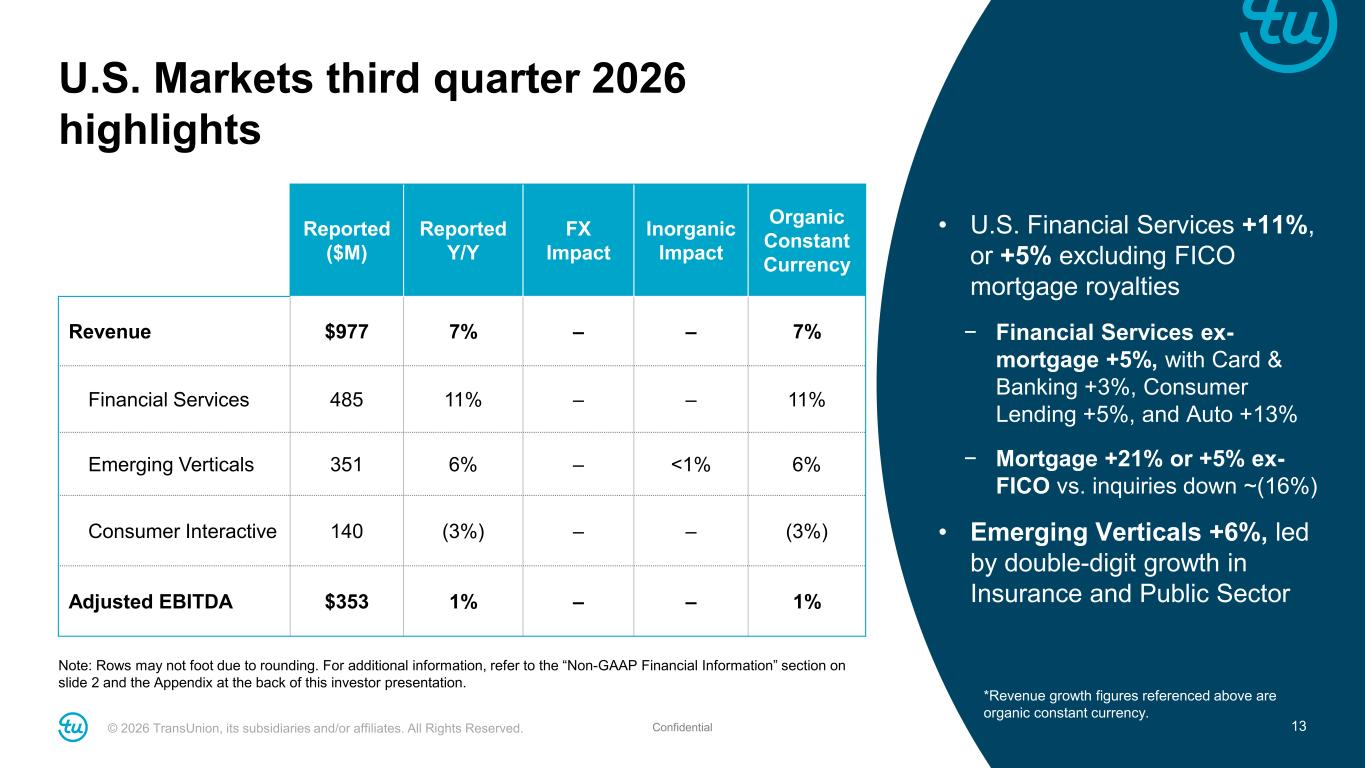
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 13Confidential U.S. Markets third quarter 2026 highlights Note: Rows may not foot due to rounding. For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation. • U.S. Financial Services +11%, or +5% excluding FICO mortgage royalties − Financial Services ex- mortgage +5%, with Card & Banking +3%, Consumer Lending +5%, and Auto +13% − Mortgage +21% or +5% ex- FICO vs. inquiries down ~(16%) • Emerging Verticals +6%, led by double-digit growth in Insurance and Public Sector Reported ($M) Reported Y/Y FX Impact Inorganic Impact Organic Constant Currency Revenue $977 7% – – 7% Financial Services 485 11% – – 11% Emerging Verticals 351 6% – <1% 6% Consumer Interactive 140 (3%) – – (3%) Adjusted EBITDA $353 1% – – 1% *Revenue growth figures referenced above are organic constant currency.
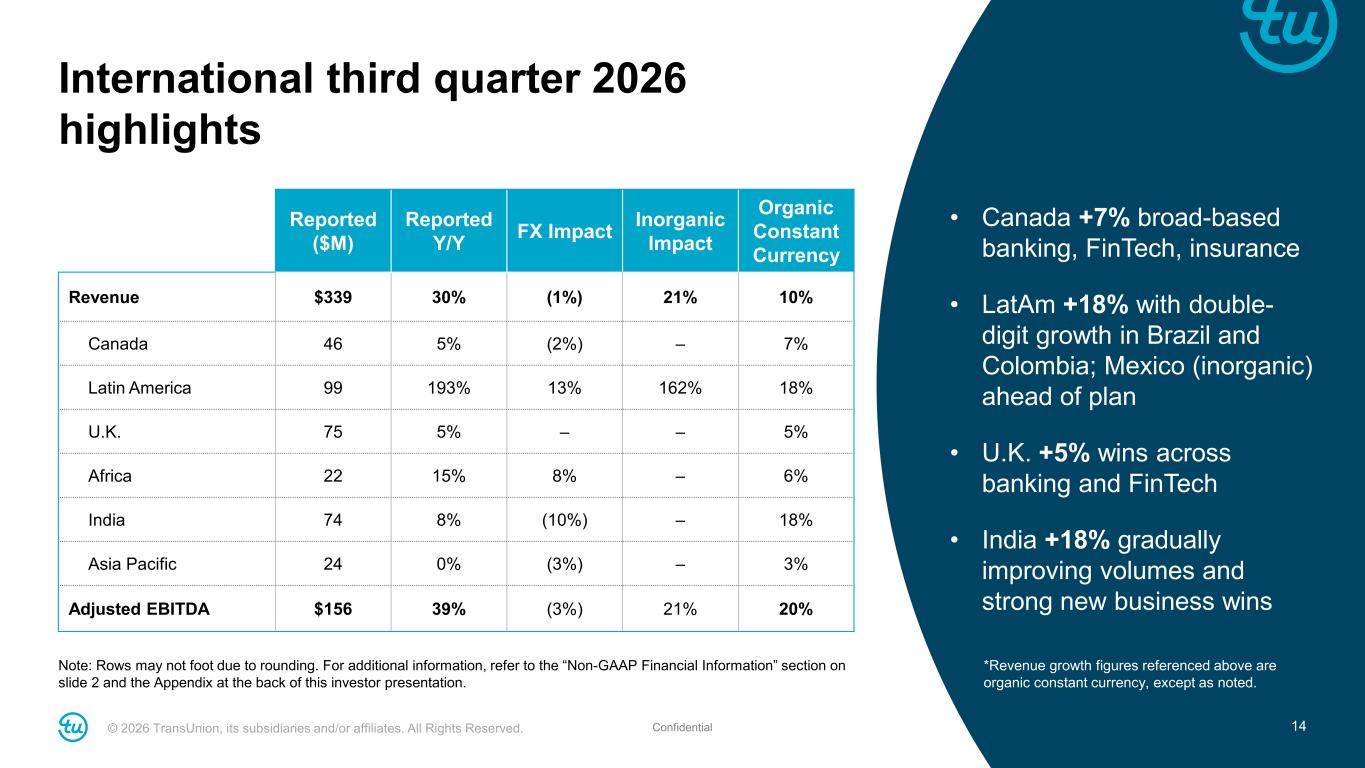
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 14Confidential International third quarter 2026 highlights Note: Rows may not foot due to rounding. For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation. Reported ($M) Reported Y/Y FX Impact Inorganic Impact Organic Constant Currency Revenue $339 30% (1%) 21% 10% Canada 46 5% (2%) – 7% Latin America 99 193% 13% 162% 18% U.K. 75 5% – – 5% Africa 22 15% 8% – 6% India 74 8% (10%) – 18% Asia Pacific 24 0% (3%) – 3% Adjusted EBITDA $156 39% (3%) 21% 20% *Revenue growth figures referenced above are organic constant currency, except as noted. • Canada +7% broad-based banking, FinTech, insurance • LatAm +18% with double- digit growth in Brazil and Colombia; Mexico (inorganic) ahead of plan • U.K. +5% wins across banking and FinTech • India +18% gradually improving volumes and strong new business wins
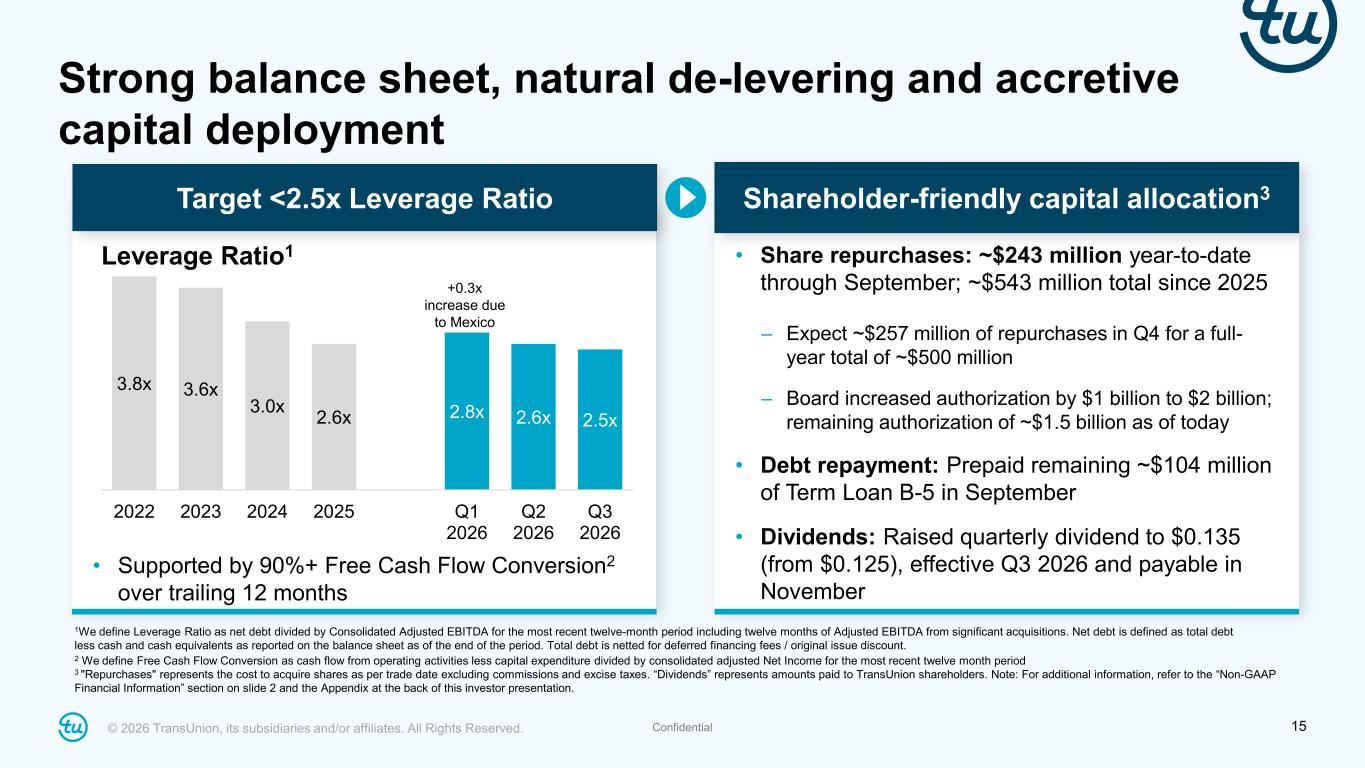
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 15Confidential Strong balance sheet, natural de-levering and accretive capital deployment Shareholder-friendly capital allocation3 Target <2.5x Leverage Ratio 1We define Leverage Ratio as net debt divided by Consolidated Adjusted EBITDA for the most recent twelve-month period including twelve months of Adjusted EBITDA from significant acquisitions. Net debt is defined as total debt less cash and cash equivalents as reported on the balance sheet as of the end of the period. Total debt is netted for deferred financing fees / original issue discount. 2 We define Free Cash Flow Conversion as cash flow from operating activities less capital expenditure divided by consolidated adjusted Net Income for the most recent twelve month period 3 "Repurchases" represents the cost to acquire shares as per trade date excluding commissions and excise taxes. “Dividends” represents amounts paid to TransUnion shareholders. Note: For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation. 3.8x 3.6x 3.0x 2.6x 2.8x 2.6x 2.5x 2022 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 • Share repurchases: ~$243 million year-to-date through September; ~$543 million total since 2025 – Expect ~$257 million of repurchases in Q4 for a full- year total of ~$500 million – Board increased authorization by $1 billion to $2 billion; remaining authorization of ~$1.5 billion as of today • Debt repayment: Prepaid remaining ~$104 million of Term Loan B-5 in September • Dividends: Raised quarterly dividend to $0.135 (from $0.125), effective Q3 2026 and payable in November Leverage Ratio1 +0.3x increase due to Mexico • Supported by 90%+ Free Cash Flow Conversion2 over trailing 12 months
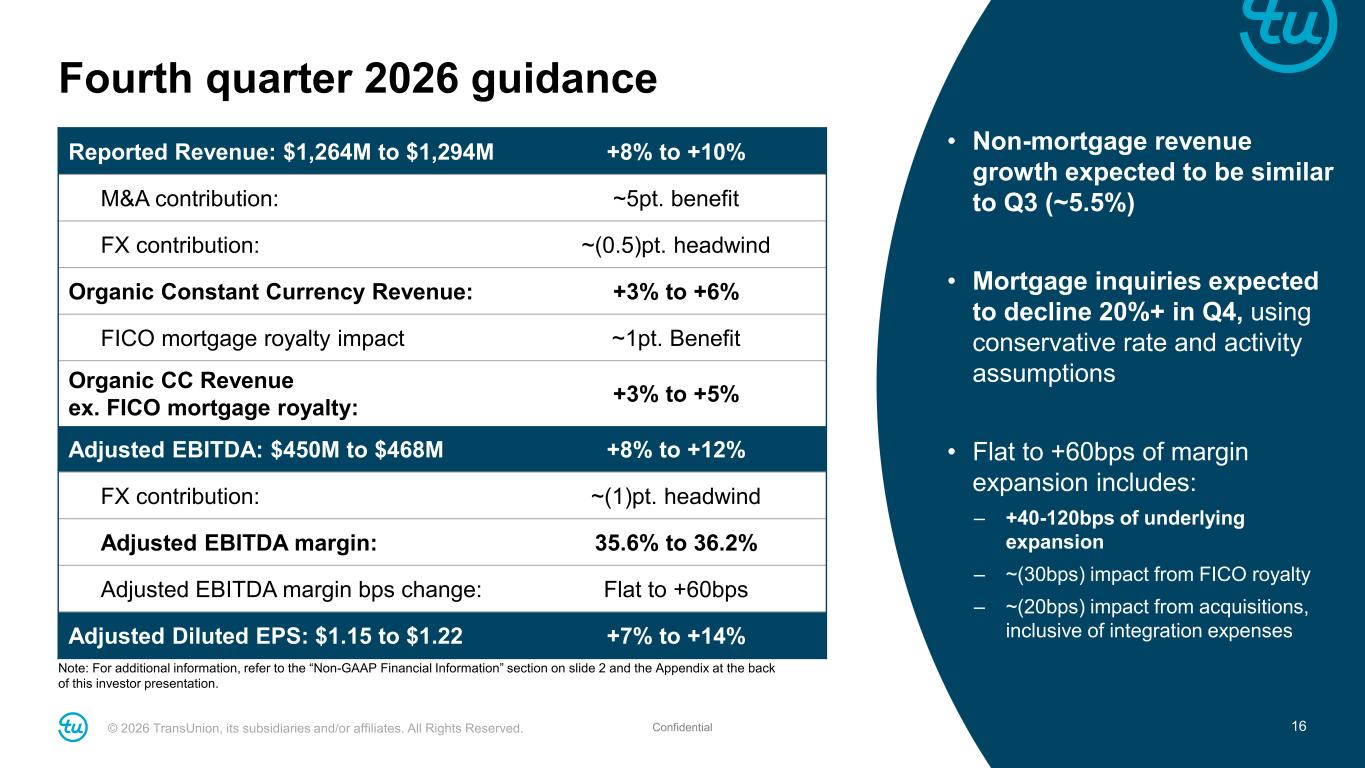
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 16Confidential Reported Revenue: $1,264M to $1,294M +8% to +10% M&A contribution: ~5pt. benefit FX contribution: ~(0.5)pt. headwind Organic Constant Currency Revenue: +3% to +6% FICO mortgage royalty impact ~1pt. Benefit Organic CC Revenue ex. FICO mortgage royalty: +3% to +5% Adjusted EBITDA: $450M to $468M +8% to +12% FX contribution: ~(1)pt. headwind Adjusted EBITDA margin: 35.6% to 36.2% Adjusted EBITDA margin bps change: Flat to +60bps Adjusted Diluted EPS: $1.15 to $1.22 +7% to +14% Fourth quarter 2026 guidance Note: For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation. • Non-mortgage revenue growth expected to be similar to Q3 (~5.5%) • Mortgage inquiries expected to decline 20%+ in Q4, using conservative rate and activity assumptions • Flat to +60bps of margin expansion includes: – +40-120bps of underlying expansion – ~(30bps) impact from FICO royalty – ~(20bps) impact from acquisitions, inclusive of integration expenses
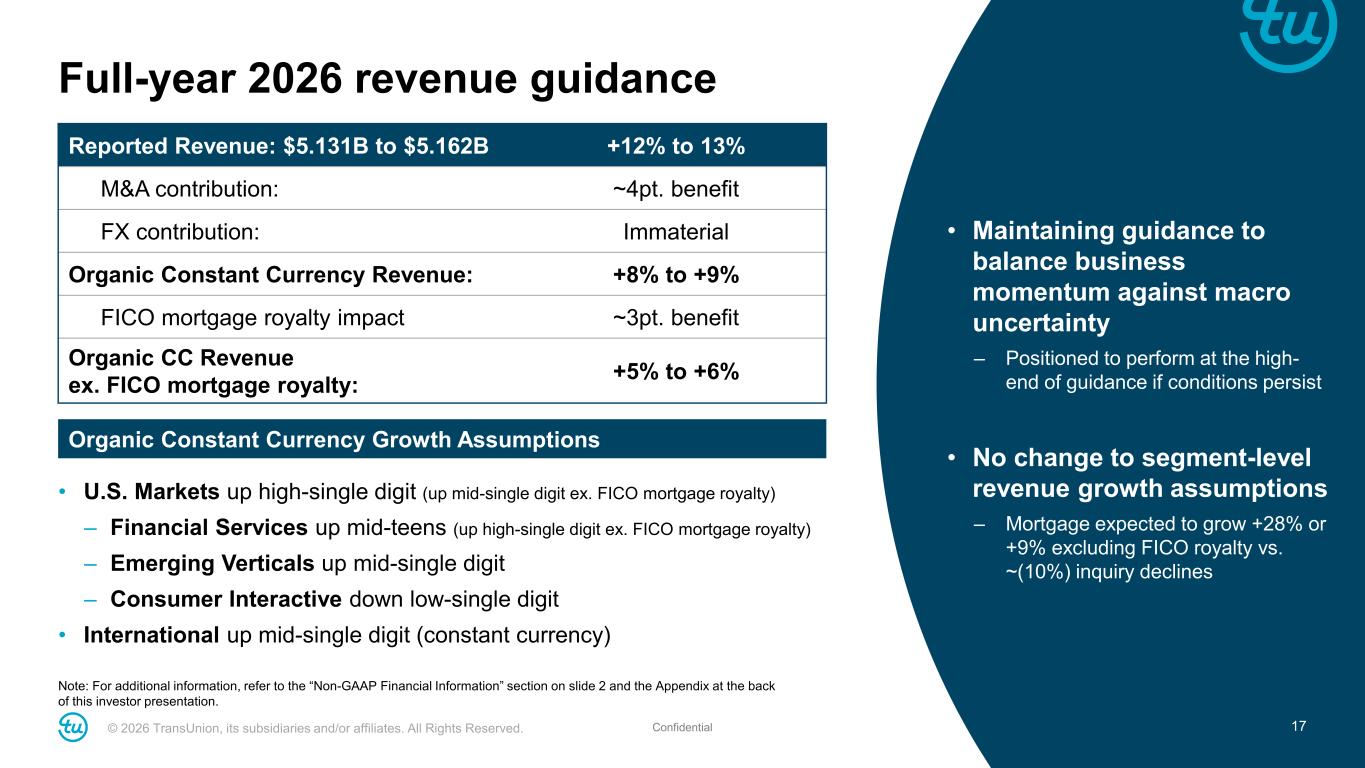
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 17Confidential Full-year 2026 revenue guidance Reported Revenue: $5.131B to $5.162B +12% to 13% M&A contribution: ~4pt. benefit FX contribution: Immaterial Organic Constant Currency Revenue: +8% to +9% FICO mortgage royalty impact ~3pt. benefit Organic CC Revenue ex. FICO mortgage royalty: +5% to +6% Organic Constant Currency Growth Assumptions • U.S. Markets up high-single digit (up mid-single digit ex. FICO mortgage royalty) – Financial Services up mid-teens (up high-single digit ex. FICO mortgage royalty) – Emerging Verticals up mid-single digit – Consumer Interactive down low-single digit • International up mid-single digit (constant currency) Note: For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation. • Maintaining guidance to balance business momentum against macro uncertainty – Positioned to perform at the high- end of guidance if conditions persist • No change to segment-level revenue growth assumptions – Mortgage expected to grow +28% or +9% excluding FICO royalty vs. ~(10%) inquiry declines
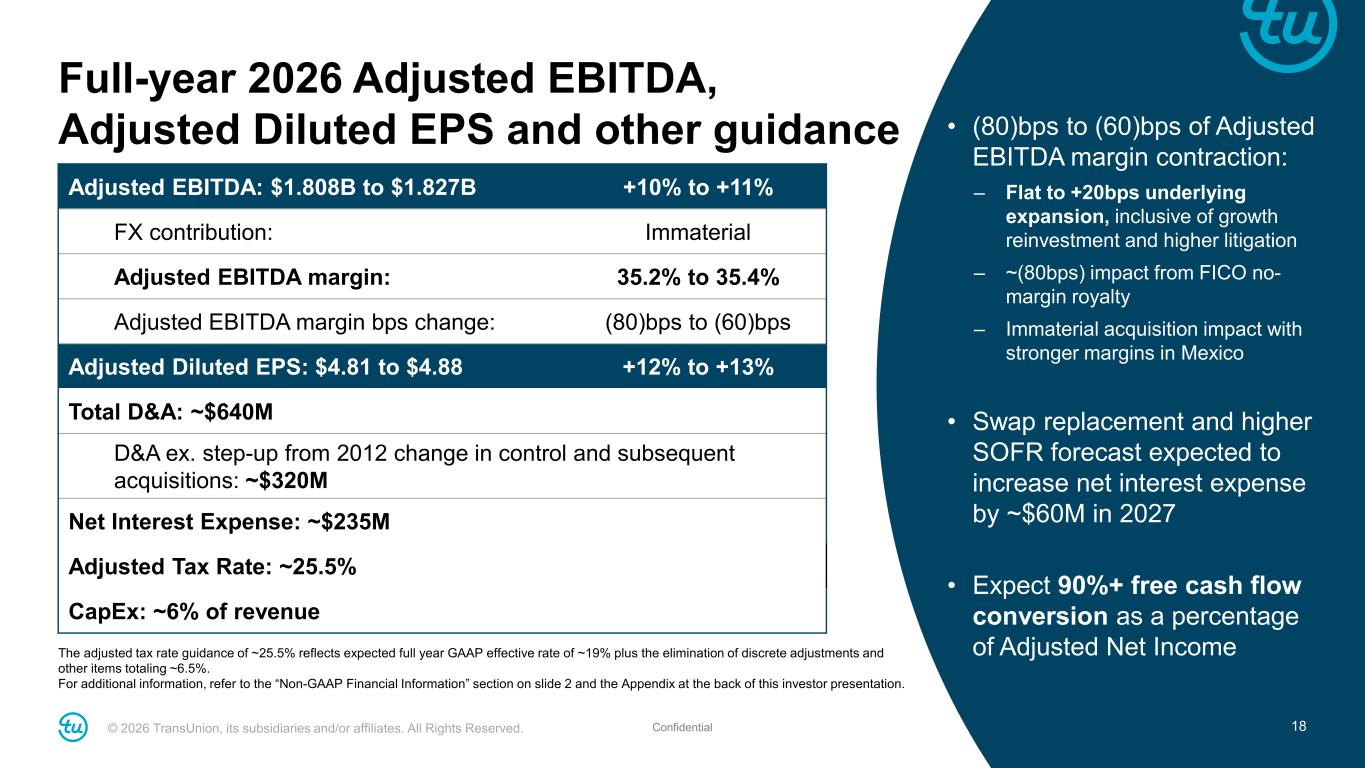
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 18Confidential The adjusted tax rate guidance of ~25.5% reflects expected full year GAAP effective rate of ~19% plus the elimination of discrete adjustments and other items totaling ~6.5%. For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation. Full-year 2026 Adjusted EBITDA, Adjusted Diluted EPS and other guidance Adjusted EBITDA: $1.808B to $1.827B +10% to +11% FX contribution: Immaterial Adjusted EBITDA margin: 35.2% to 35.4% Adjusted EBITDA margin bps change: (80)bps to (60)bps Adjusted Diluted EPS: $4.81 to $4.88 +12% to +13% Total D&A: ~$640M D&A ex. step-up from 2012 change in control and subsequent acquisitions: ~$320M Net Interest Expense: ~$235M Adjusted Tax Rate: ~25.5% CapEx: ~6% of revenue • (80)bps to (60)bps of Adjusted EBITDA margin contraction: – Flat to +20bps underlying expansion, inclusive of growth reinvestment and higher litigation – ~(80bps) impact from FICO no- margin royalty – Immaterial acquisition impact with stronger margins in Mexico • Swap replacement and higher SOFR forecast expected to increase net interest expense by ~$60M in 2027 • Expect 90%+ free cash flow conversion as a percentage of Adjusted Net Income
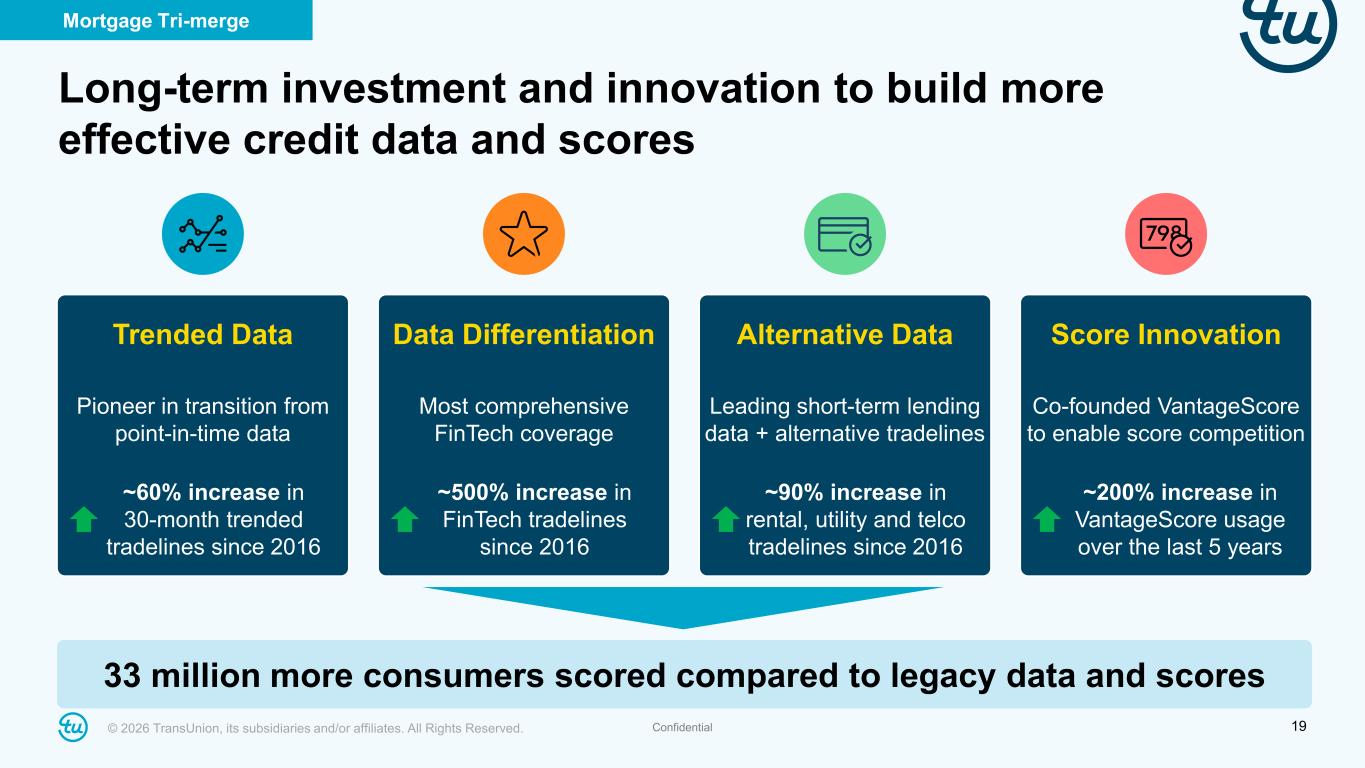
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 19Confidential Long-term investment and innovation to build more effective credit data and scores Trended Data Pioneer in transition from point-in-time data Mortgage Tri-merge 33 million more consumers scored compared to legacy data and scores Data Differentiation Most comprehensive FinTech coverage Alternative Data Leading short-term lending data + alternative tradelines Score Innovation Co-founded VantageScore to enable score competition ~60% increase in 30-month trended tradelines since 2016 ~500% increase in FinTech tradelines since 2016 ~90% increase in rental, utility and telco tradelines since 2016 ~200% increase in VantageScore usage over the last 5 years
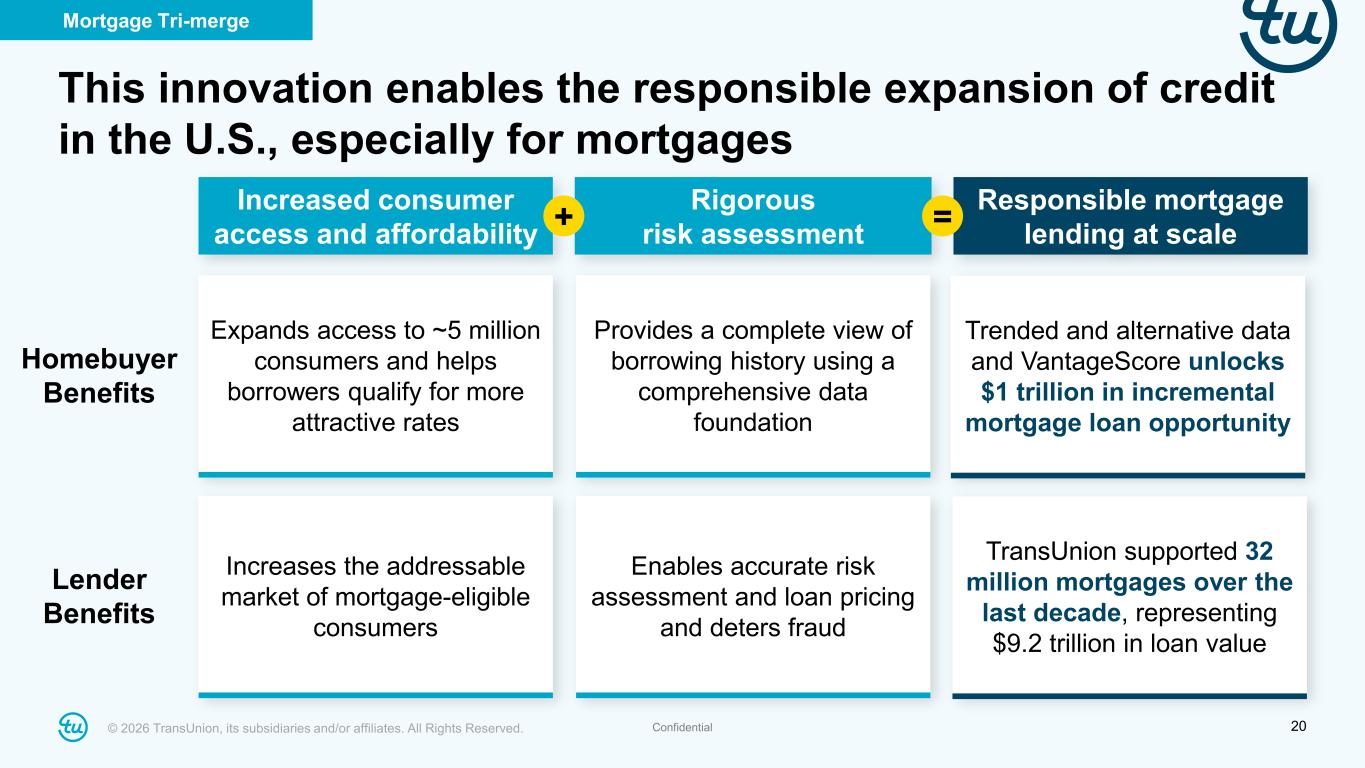
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 20Confidential Expands access to ~5 million consumers and helps borrowers qualify for more attractive rates Provides a complete view of borrowing history using a comprehensive data foundation Trended and alternative data and VantageScore unlocks $1 trillion in incremental mortgage loan opportunity Increases the addressable market of mortgage-eligible consumers Enables accurate risk assessment and loan pricing and deters fraud This innovation enables the responsible expansion of credit in the U.S., especially for mortgages Mortgage Tri-merge Increased consumer access and affordability Rigorous risk assessment Responsible mortgage lending at scale+ = Homebuyer Benefits Lender Benefits TransUnion supported 32 million mortgages over the last decade, representing $9.2 trillion in loan value
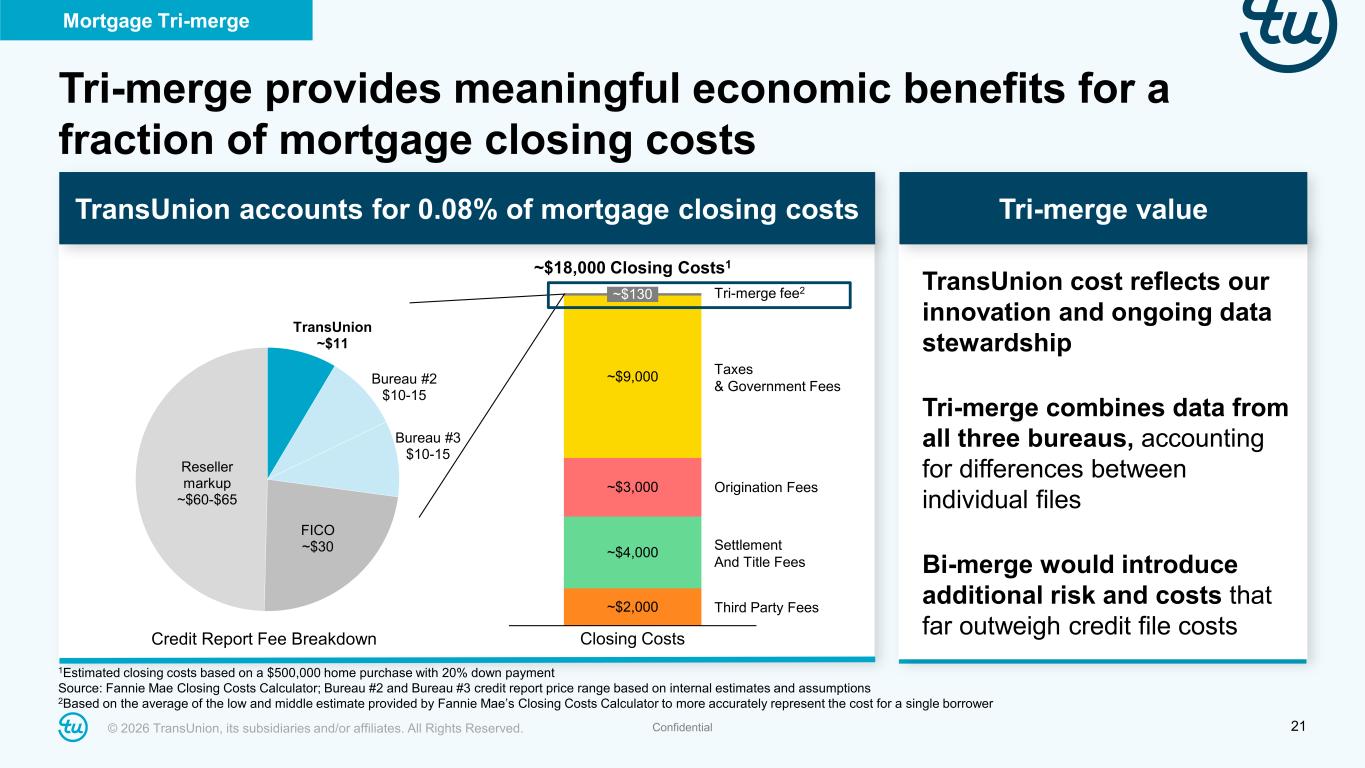
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 21Confidential TransUnion accounts for 0.08% of mortgage closing costs Tri-merge value TransUnion cost reflects our innovation and ongoing data stewardship Tri-merge combines data from all three bureaus, accounting for differences between individual files Bi-merge would introduce additional risk and costs that far outweigh credit file costs ~$2,000 ~$4,000 ~$3,000 ~$9,000 ~$130 Closing Costs Tri-merge fee2 Taxes & Government Fees Origination Fees Settlement And Title Fees Third Party Fees Credit Report Fee Breakdown TransUnion ~$11 Bureau #2 $10-15 Bureau #3 $10-15 FICO ~$30 Reseller markup ~$60-$65 Tri-merge provides meaningful economic benefits for a fraction of mortgage closing costs Mortgage Tri-merge ~$18,000 Closing Costs1 1Estimated closing costs based on a $500,000 home purchase with 20% down payment Source: Fannie Mae Closing Costs Calculator; Bureau #2 and Bureau #3 credit report price range based on internal estimates and assumptions 2Based on the average of the low and middle estimate provided by Fannie Mae’s Closing Costs Calculator to more accurately represent the cost for a single borrower
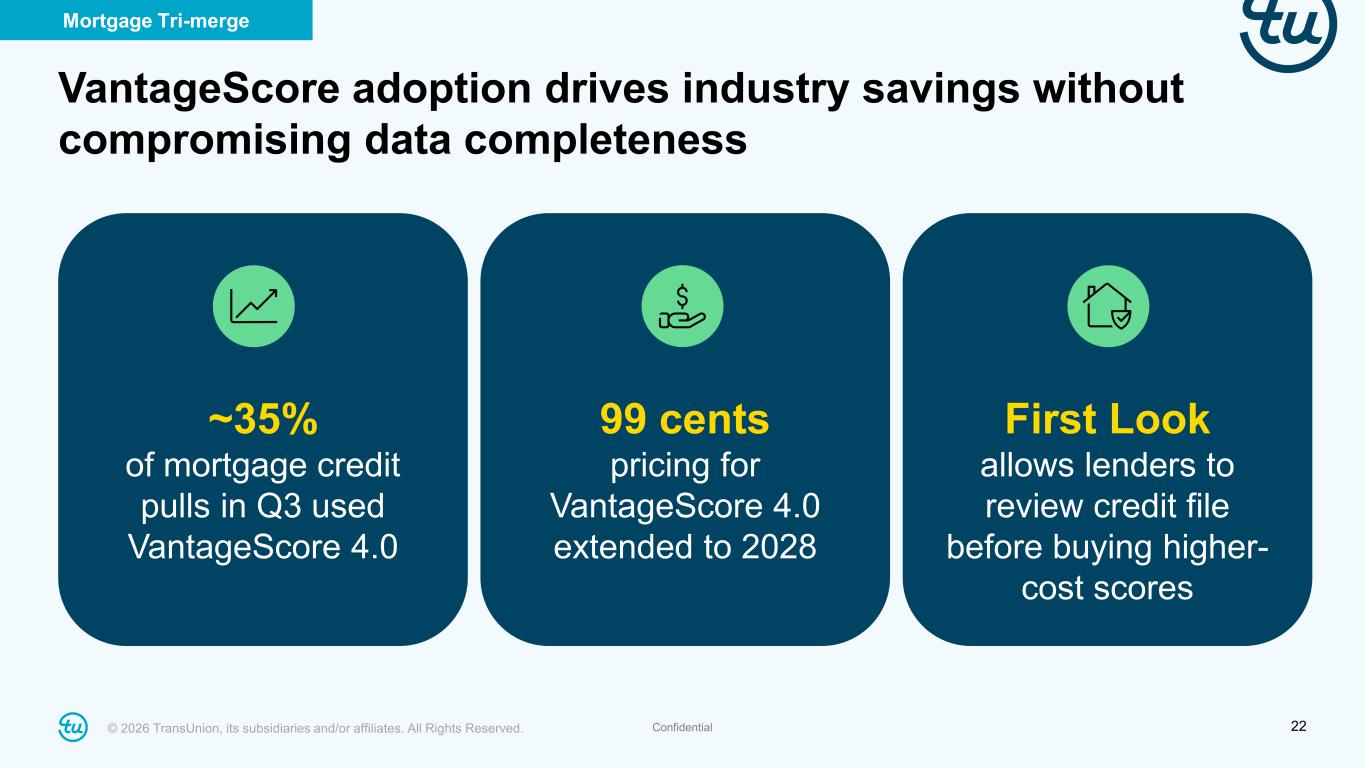
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 22Confidential VantageScore adoption drives industry savings without compromising data completeness Mortgage Tri-merge ~35% of mortgage credit pulls in Q3 used VantageScore 4.0 99 cents pricing for VantageScore 4.0 extended to 2028 First Look allows lenders to review credit file before buying higher- cost scores
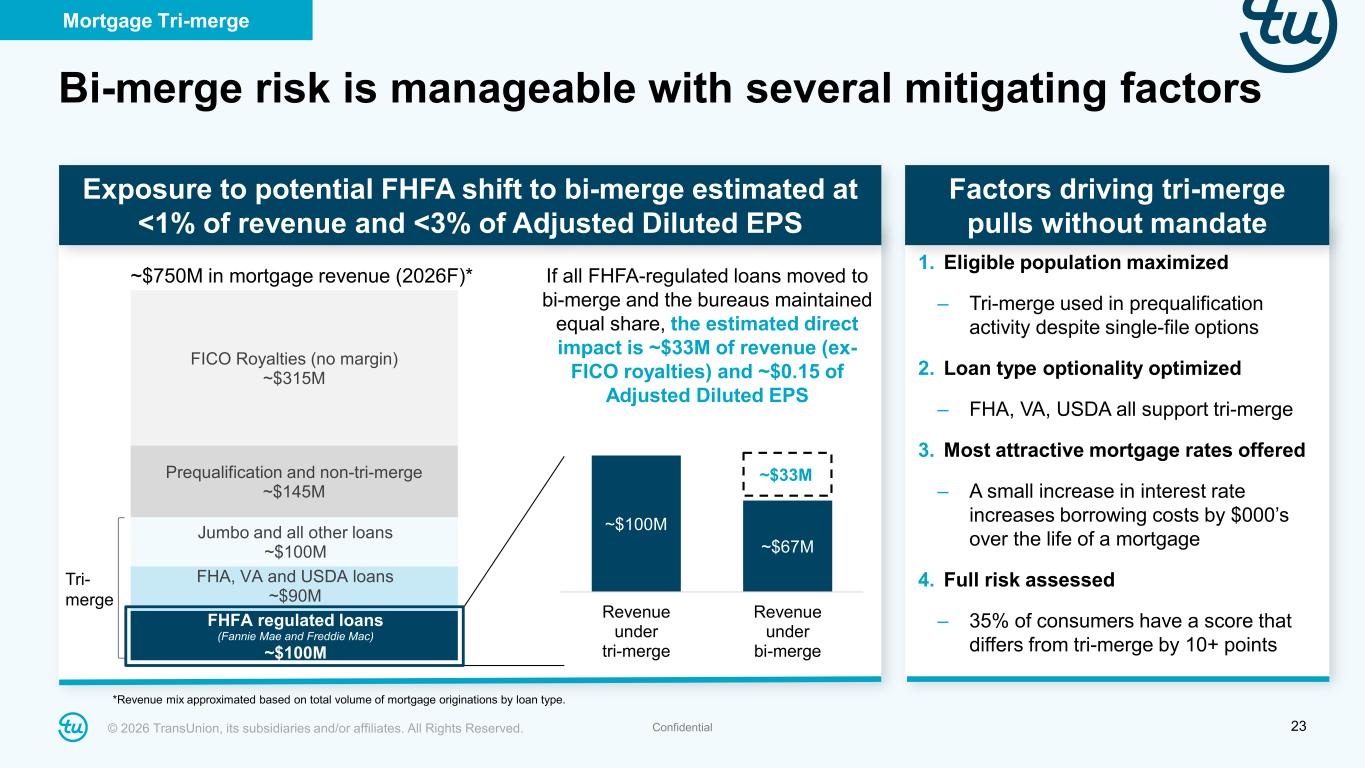
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 23Confidential Exposure to potential FHFA shift to bi-merge estimated at <1% of revenue and <3% of Adjusted Diluted EPS Factors driving tri-merge pulls without mandate 1. Eligible population maximized – Tri-merge used in prequalification activity despite single-file options 2. Loan type optionality optimized – FHA, VA, USDA all support tri-merge 3. Most attractive mortgage rates offered – A small increase in interest rate increases borrowing costs by $000’s over the life of a mortgage 4. Full risk assessed – 35% of consumers have a score that differs from tri-merge by 10+ points ~$750M in mortgage revenue (2026F)* *Revenue mix approximated based on total volume of mortgage originations by loan type. Mortgage Tri-merge Bi-merge risk is manageable with several mitigating factors FHFA regulated loans (Fannie Mae and Freddie Mac) ~$100M FHA, VA and USDA loans ~$90M Jumbo and all other loans ~$100M Prequalification and non-tri-merge ~$145M FICO Royalties (no margin) ~$315M ~$100M ~$67M Revenue under tri-merge Revenue under bi-merge If all FHFA-regulated loans moved to bi-merge and the bureaus maintained equal share, the estimated direct impact is ~$33M of revenue (ex- FICO royalties) and ~$0.15 of Adjusted Diluted EPS Tri- merge ~$33M
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 24Confidential Expect +8% to +9% organic constant currency revenue growth and +12% to +13% Adjusted Diluted EPS growth in 2026 Delivered strong Q3 with +8% organic constant currency revenue growth and +14% Adjusted Diluted EPS growth Executing against strategic priorities to deliver innovation-led, diversified and scalable growth Note: For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation.
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 25Confidential Q&A
Greg Bardi Investor Relations gregory.bardi@transunion.com Jason Stuhldreher Investor Relations jason.stuhldreher@transunion.com
Appendices and Non-GAAP Reconciliations
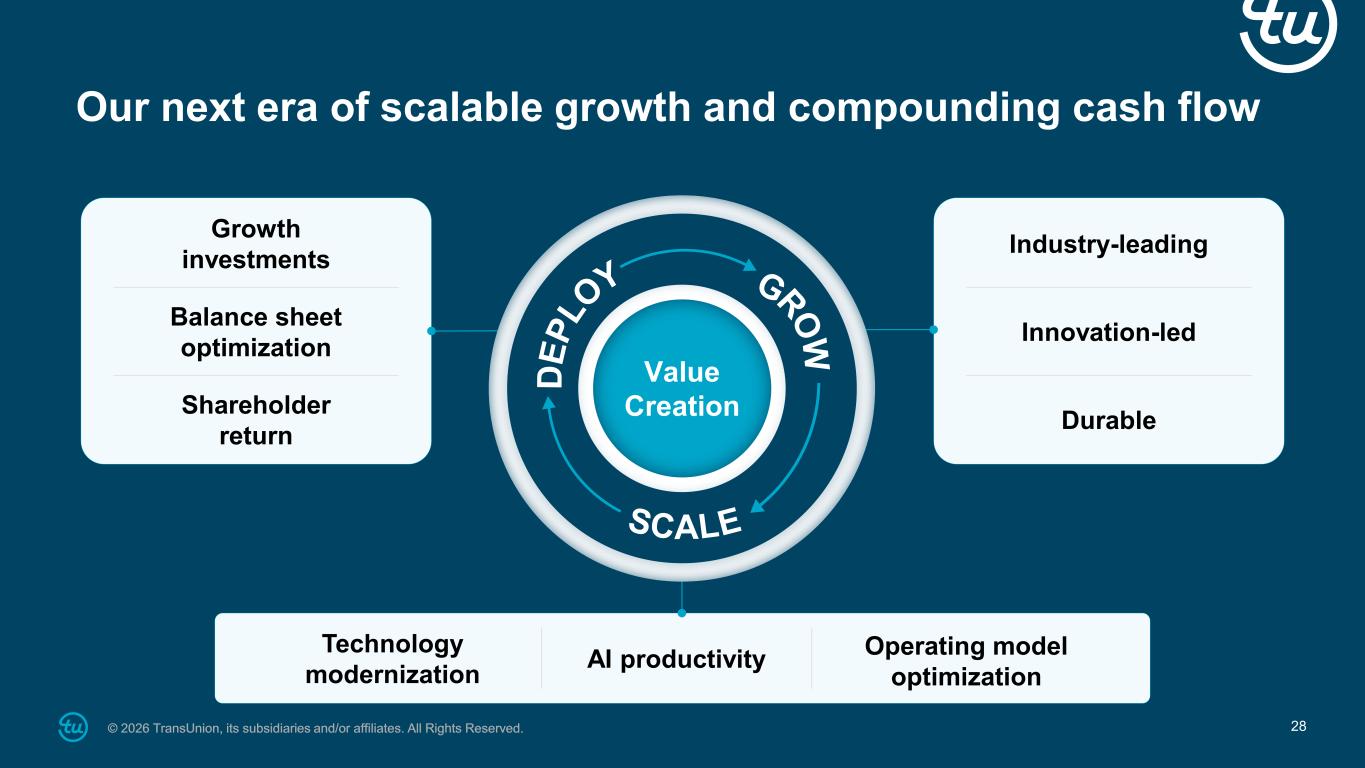
28© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. Our next era of scalable growth and compounding cash flow Industry-leading Durable Innovation-led Growth investments Shareholder return Balance sheet optimization Value Creation Technology modernization AI productivity Operating model optimization
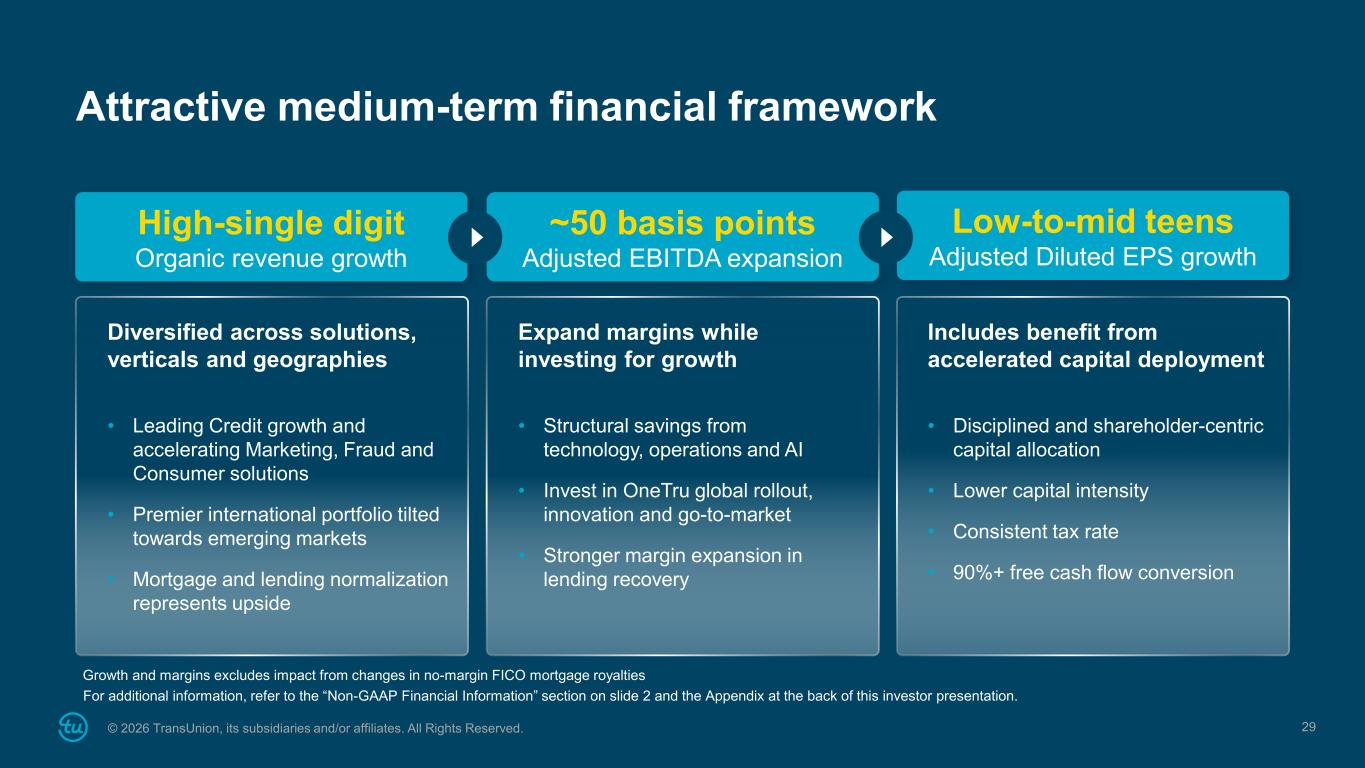
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 29 High-single digit Organic revenue growth Diversified across solutions, verticals and geographies • Leading Credit growth and accelerating Marketing, Fraud and Consumer solutions • Premier international portfolio tilted towards emerging markets • Mortgage and lending normalization represents upside For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation. ~50 basis points Adjusted EBITDA expansion Expand margins while investing for growth • Structural savings from technology, operations and AI • Invest in OneTru global rollout, innovation and go-to-market • Stronger margin expansion in lending recovery Low-to-mid teens Adjusted Diluted EPS growth Includes benefit from accelerated capital deployment • Disciplined and shareholder-centric capital allocation • Lower capital intensity • Consistent tax rate • 90%+ free cash flow conversion Growth and margins excludes impact from changes in no-margin FICO mortgage royalties Attractive medium-term financial framework
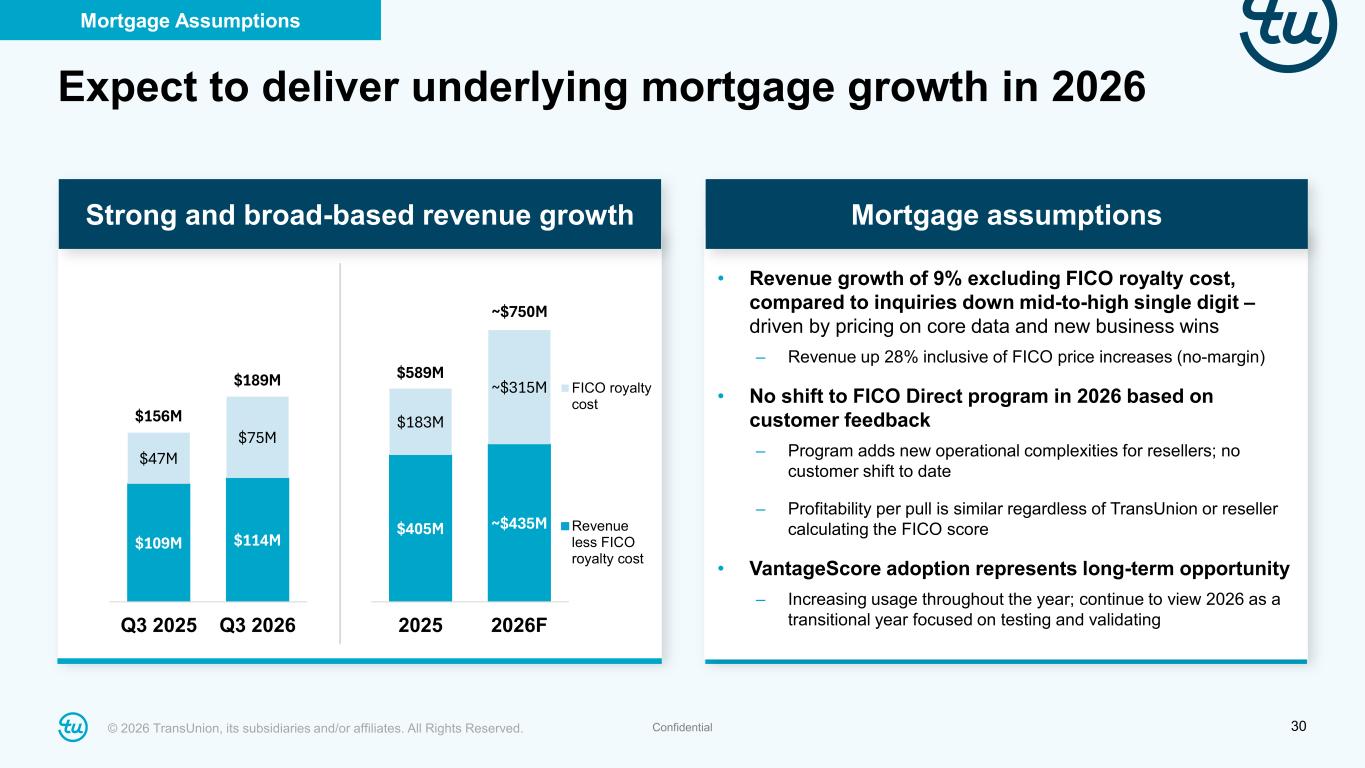
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 30Confidential Strong and broad-based revenue growth Expect to deliver underlying mortgage growth in 2026 ~70bps of underlying margin expansion Mortgage Assumptions Mortgage assumptions • Revenue growth of 9% excluding FICO royalty cost, compared to inquiries down mid-to-high single digit – driven by pricing on core data and new business wins – Revenue up 28% inclusive of FICO price increases (no-margin) • No shift to FICO Direct program in 2026 based on customer feedback – Program adds new operational complexities for resellers; no customer shift to date – Profitability per pull is similar regardless of TransUnion or reseller calculating the FICO score • VantageScore adoption represents long-term opportunity – Increasing usage throughout the year; continue to view 2026 as a transitional year focused on testing and validating $405M ~$435M $183M ~$315M $589M ~$750M 2025 2026F FICO royalty cost Revenue less FICO royalty cost $109M $114M $47M $75M $156M $189M Q3 2025 Q3 2026
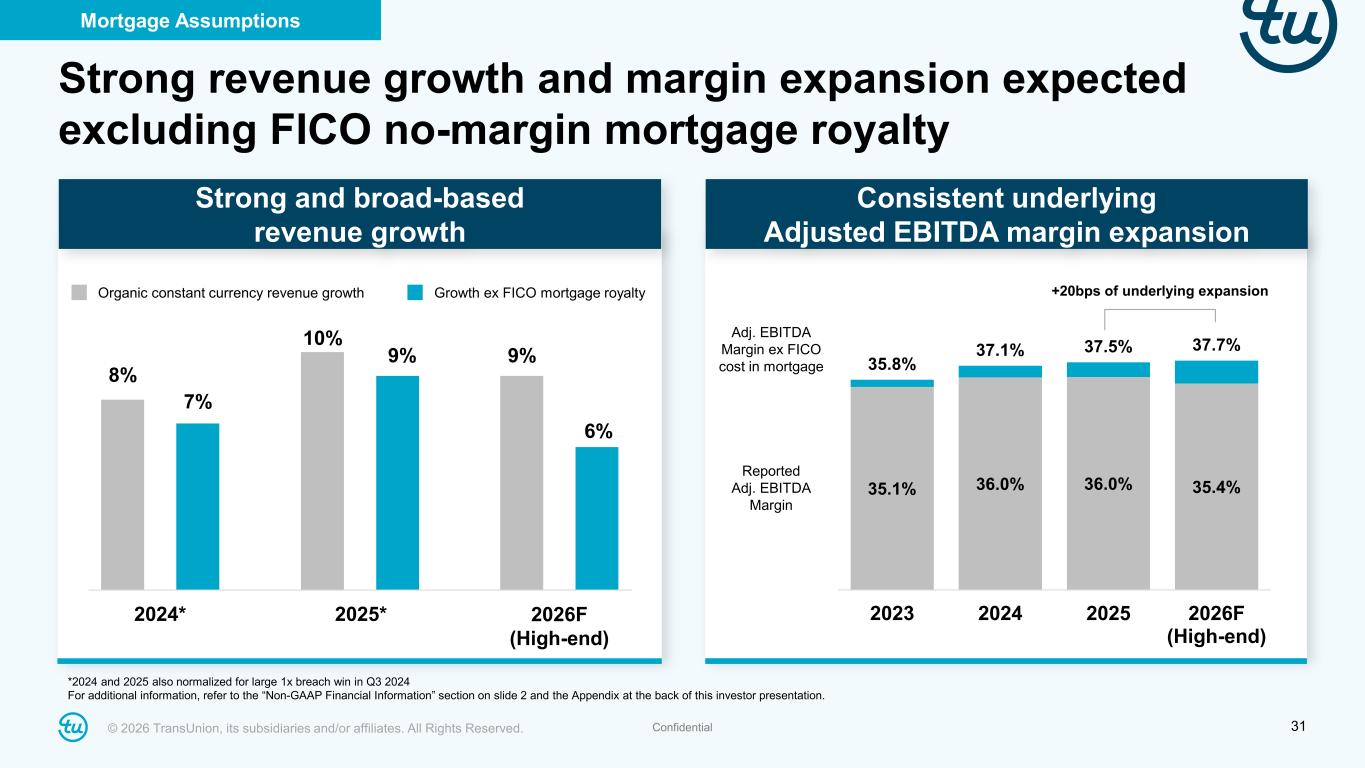
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 31Confidential Strong and broad-based revenue growth Consistent underlying Adjusted EBITDA margin expansion 2025* 2026F (High-end) 10% 9% 9% 6% 35.1% 36.0% 36.0% 35.4% 35.8% 37.1% 37.5% 37.7% 2023 2024 2025 2026F (High-end) Reported Adj. EBITDA Margin Adj. EBITDA Margin ex FICO cost in mortgage8% 7% 2024* Organic constant currency revenue growth Growth ex FICO mortgage royalty +20bps of underlying expansion *2024 and 2025 also normalized for large 1x breach win in Q3 2024 For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation. Mortgage Assumptions Strong revenue growth and margin expansion expected excluding FICO no-margin mortgage royalty
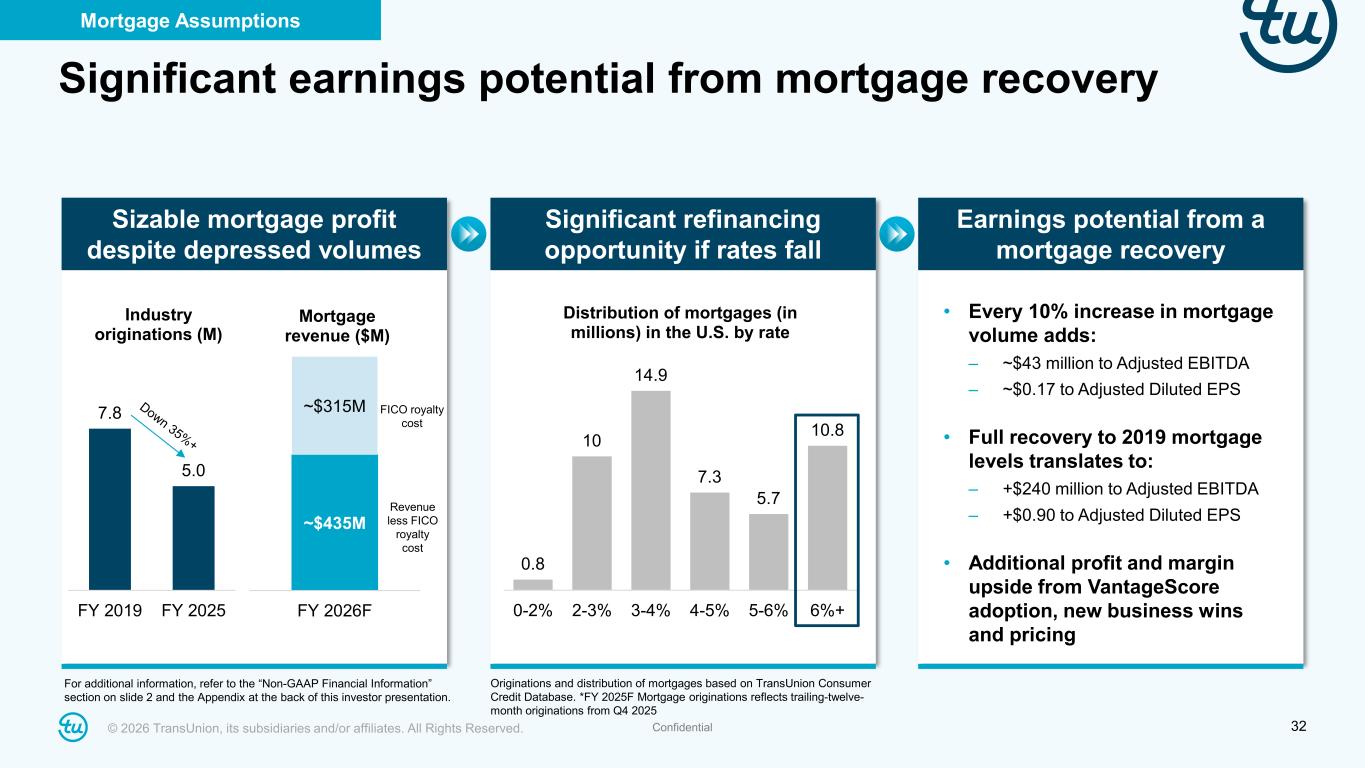
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 32Confidential Significant earnings potential from mortgage recovery Sizable mortgage profit despite depressed volumes Originations and distribution of mortgages based on TransUnion Consumer Credit Database. *FY 2025F Mortgage originations reflects trailing-twelve- month originations from Q4 2025 7.8 5.0 FY 2019 FY 2025 Industry originations (M) ~$435M ~$315M FY 2026F Mortgage revenue ($M) Significant refinancing opportunity if rates fall 0.8 10 14.9 7.3 5.7 10.8 0-2% 2-3% 3-4% 4-5% 5-6% 6%+ Distribution of mortgages (in millions) in the U.S. by rate Earnings potential from a mortgage recovery • Every 10% increase in mortgage volume adds: – ~$43 million to Adjusted EBITDA – ~$0.17 to Adjusted Diluted EPS • Full recovery to 2019 mortgage levels translates to: – +$240 million to Adjusted EBITDA – +$0.90 to Adjusted Diluted EPS • Additional profit and margin upside from VantageScore adoption, new business wins and pricing FICO royalty cost Revenue less FICO royalty cost For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation. Mortgage Assumptions
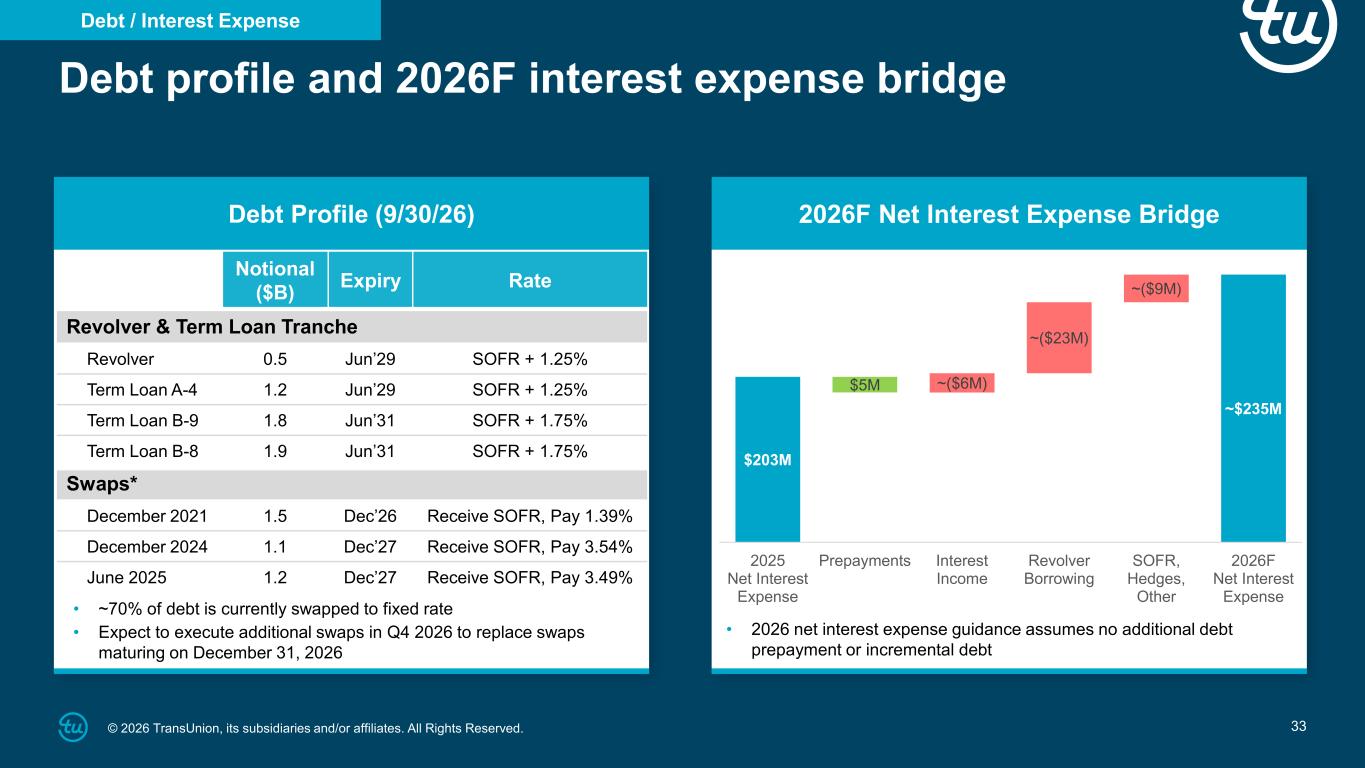
33© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. Debt profile and 2026F interest expense bridge Debt Profile (9/30/26) 2026F Net Interest Expense Bridge Notional ($B) Expiry Rate Revolver & Term Loan Tranche Revolver 0.5 Jun’29 SOFR + 1.25% Term Loan A-4 1.2 Jun’29 SOFR + 1.25% Term Loan B-9 1.8 Jun’31 SOFR + 1.75% Term Loan B-8 1.9 Jun’31 SOFR + 1.75% Swaps* December 2021 1.5 Dec’26 Receive SOFR, Pay 1.39% December 2024 1.1 Dec’27 Receive SOFR, Pay 3.54% June 2025 1.2 Dec’27 Receive SOFR, Pay 3.49% • ~70% of debt is currently swapped to fixed rate • Expect to execute additional swaps in Q4 2026 to replace swaps maturing on December 31, 2026 • 2026 net interest expense guidance assumes no additional debt prepayment or incremental debt Debt / Interest Expense $203M ~$235M $5M ~($6M) ~($23M) ~($9M) 2025 Net Interest Expense Prepayments Interest Income Revolver Borrowing SOFR, Hedges, Other 2026F Net Interest Expense
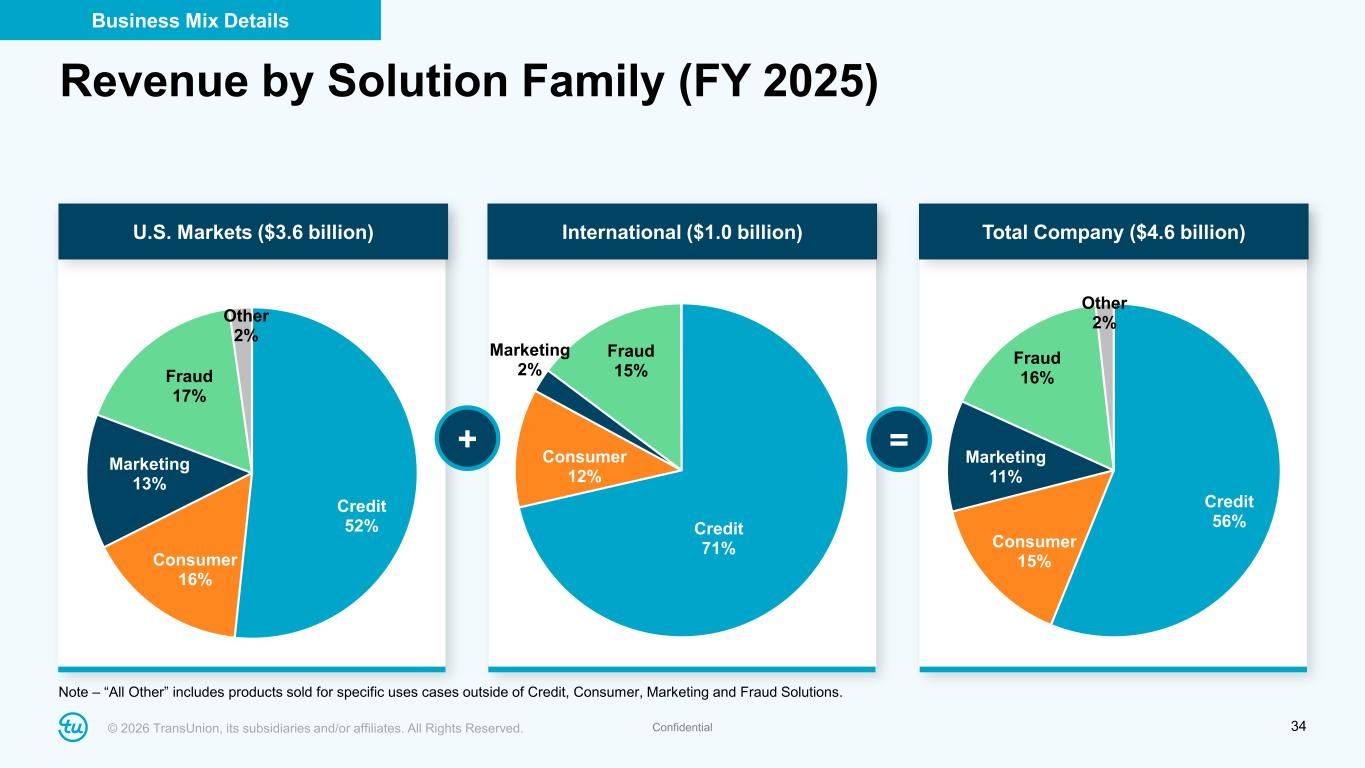
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 34Confidential Credit 56% Consumer 15% Marketing 11% Fraud 16% Other 2% Credit 52% Consumer 16% Marketing 13% Fraud 17% Other 2% Credit 71% Consumer 12% Marketing 2% Fraud 15% + = Revenue by Solution Family (FY 2025) U.S. Markets ($3.6 billion) International ($1.0 billion) Total Company ($4.6 billion) Note – “All Other” includes products sold for specific uses cases outside of Credit, Consumer, Marketing and Fraud Solutions. Business Mix Details
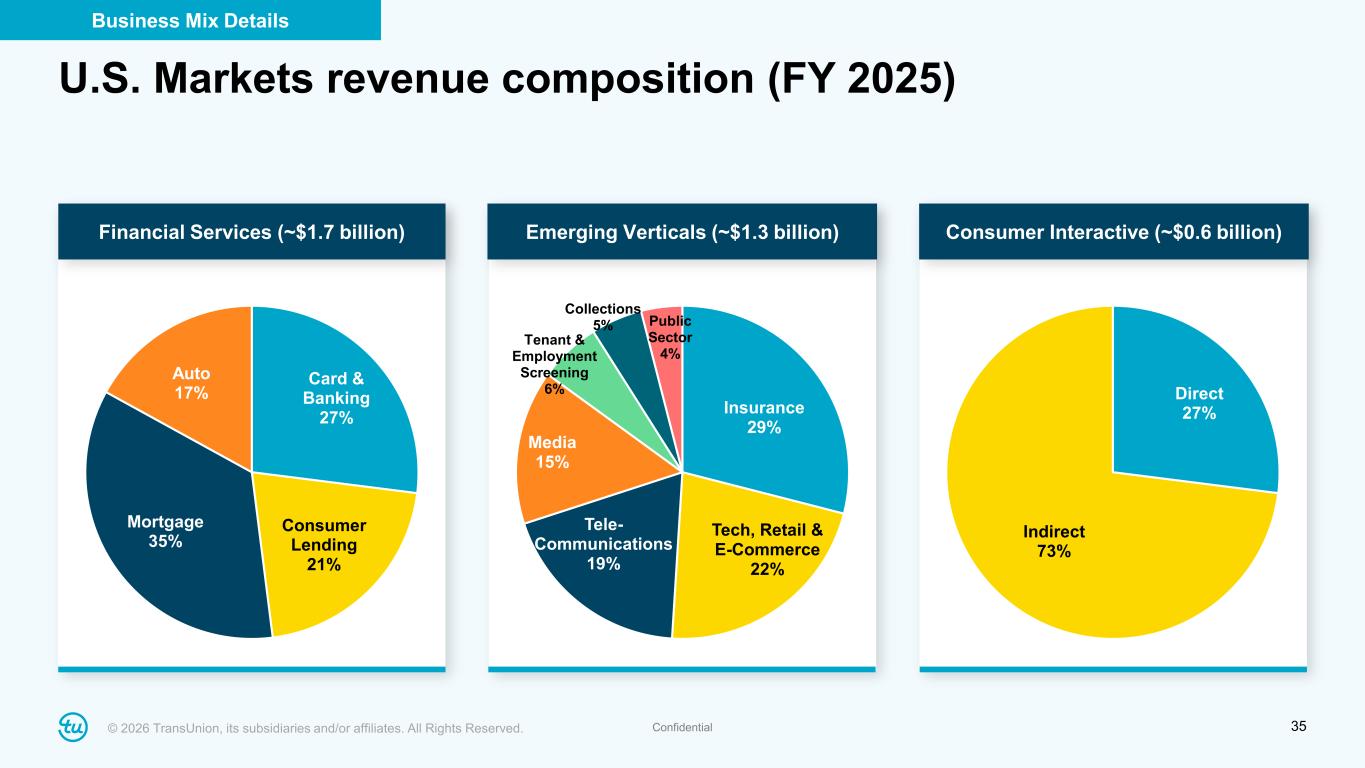
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 35Confidential U.S. Markets revenue composition (FY 2025) Card & Banking 27% Consumer Lending 21% Mortgage 35% Auto 17% Insurance 29% Tech, Retail & E-Commerce 22% Tele- Communications 19% Media 15% Tenant & Employment Screening 6% Collections 5% Public Sector 4% Direct 27% Indirect 73% Financial Services (~$1.7 billion) Emerging Verticals (~$1.3 billion) Consumer Interactive (~$0.6 billion) Business Mix Details
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 36 Foundational differentiation – proprietary data, OneTru and domain expertise – creates a clear right to win 1 Interrelated Credit, Marketing, Fraud and Consumer Solutions solve customers’ most pressing needs 2 Accelerated innovation and scalable growth enabled by our transformation 3 4 AI is an accelerant, enhancing customer impact, innovation and productivity 5 Compelling and compounding earnings power and shareholder- centric capital return Positioned to deliver innovation-led and scalable growth 36 TransUnion – Investment Highlights
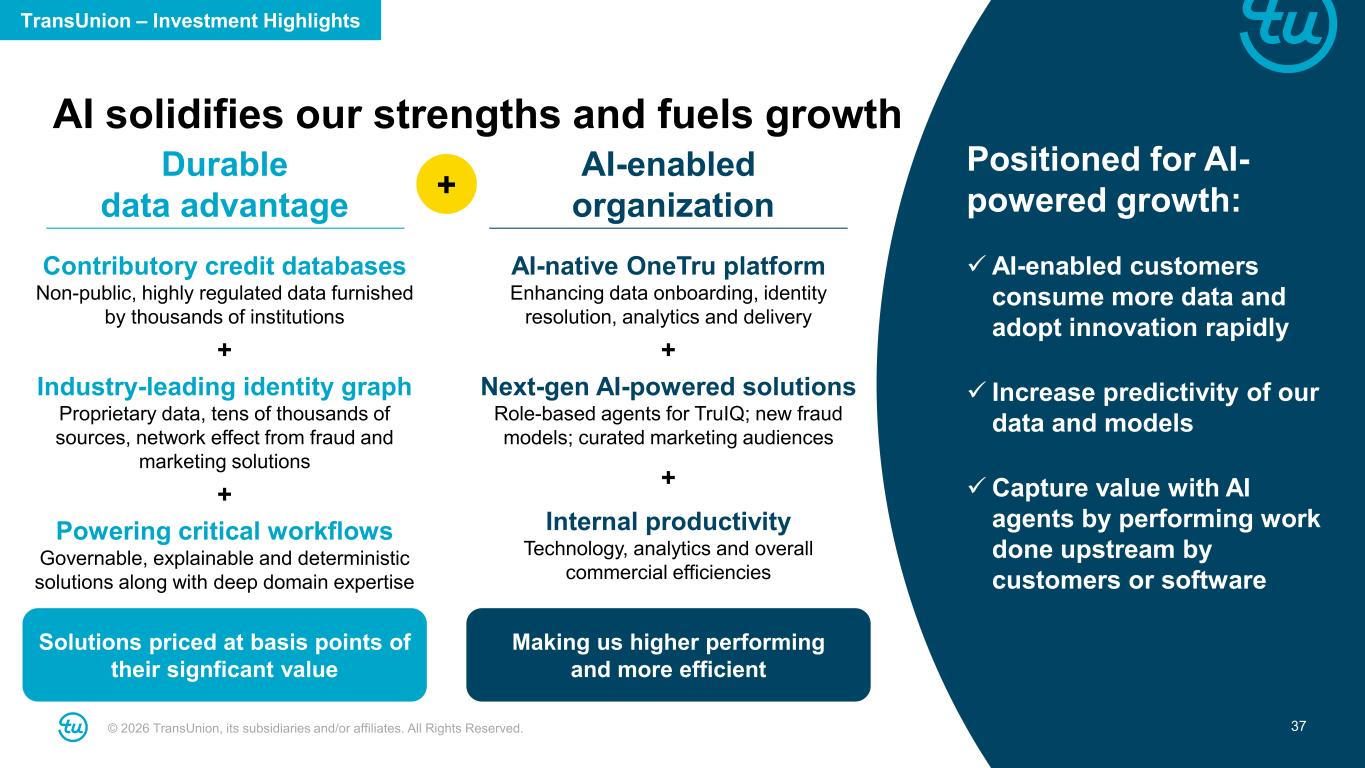
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 3737 AI solidifies our strengths and fuels growth AI-enabled customers consume more data and adopt innovation rapidly Increase predictivity of our data and models Capture value with AI agents by performing work done upstream by customers or software Contributory credit databases Non-public, highly regulated data furnished by thousands of institutions + Industry-leading identity graph Proprietary data, tens of thousands of sources, network effect from fraud and marketing solutions + Powering critical workflows Governable, explainable and deterministic solutions along with deep domain expertise Durable data advantage AI-enabled organization AI-native OneTru platform Enhancing data onboarding, identity resolution, analytics and delivery + Next-gen AI-powered solutions Role-based agents for TruIQ; new fraud models; curated marketing audiences + Internal productivity Technology, analytics and overall commercial efficiencies + Solutions priced at basis points of their signficant value Making us higher performing and more efficient Positioned for AI- powered growth: TransUnion – Investment Highlights
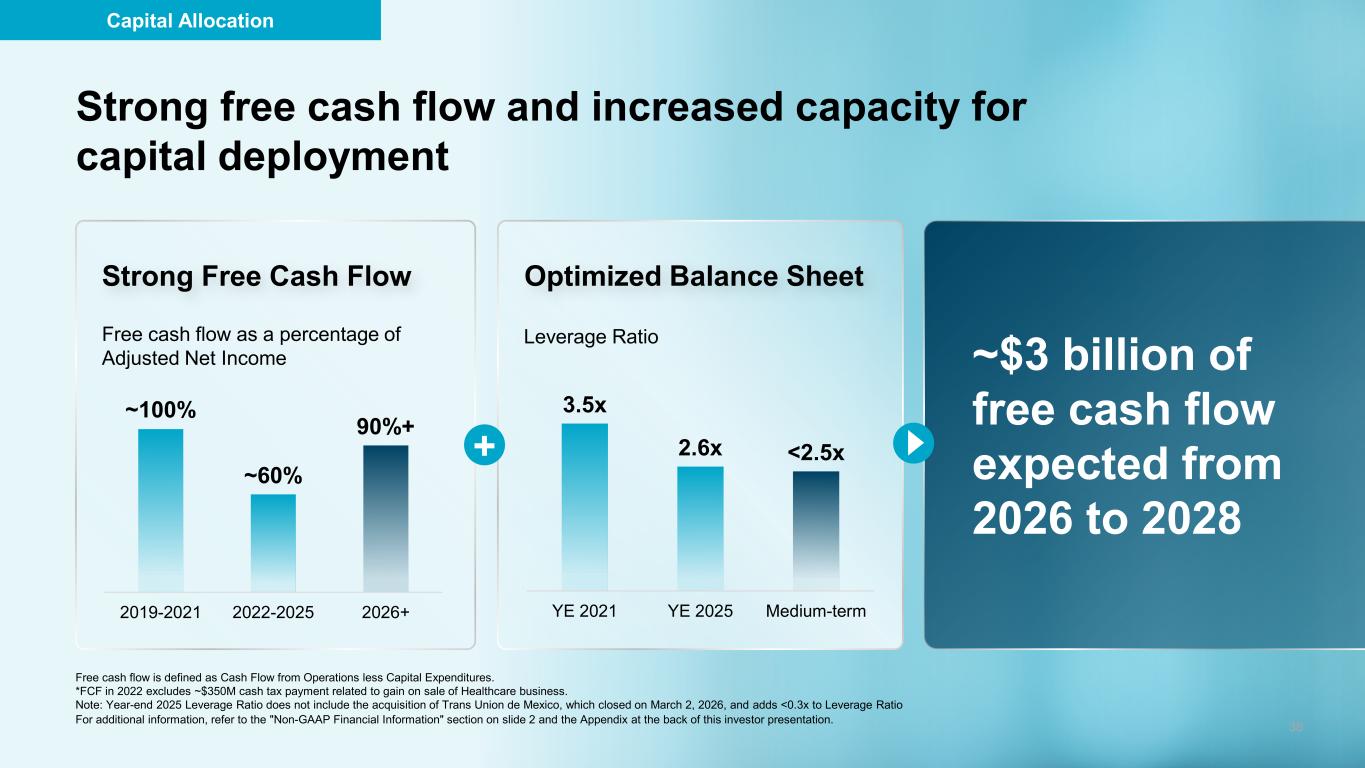
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 38 Free cash flow is defined as Cash Flow from Operations less Capital Expenditures. *FCF in 2022 excludes ~$350M cash tax payment related to gain on sale of Healthcare business. Note: Year-end 2025 Leverage Ratio does not include the acquisition of Trans Union de Mexico, which closed on March 2, 2026, and adds <0.3x to Leverage Ratio ~100% ~60% 90%+ 2019-2021 2022-2025 2026+ 3.5x 2.6x <2.5x YE 2021 YE 2025 Medium-term Strong Free Cash Flow Optimized Balance Sheet + Free cash flow as a percentage of Adjusted Net Income Leverage Ratio ~$3 billion of free cash flow expected from 2026 to 2028 Strong free cash flow and increased capacity for capital deployment For additional information, refer to the "Non-GAAP Financial Information" section on slide 2 and the Appendix at the back of this investor presentation. 38 Capital Allocation
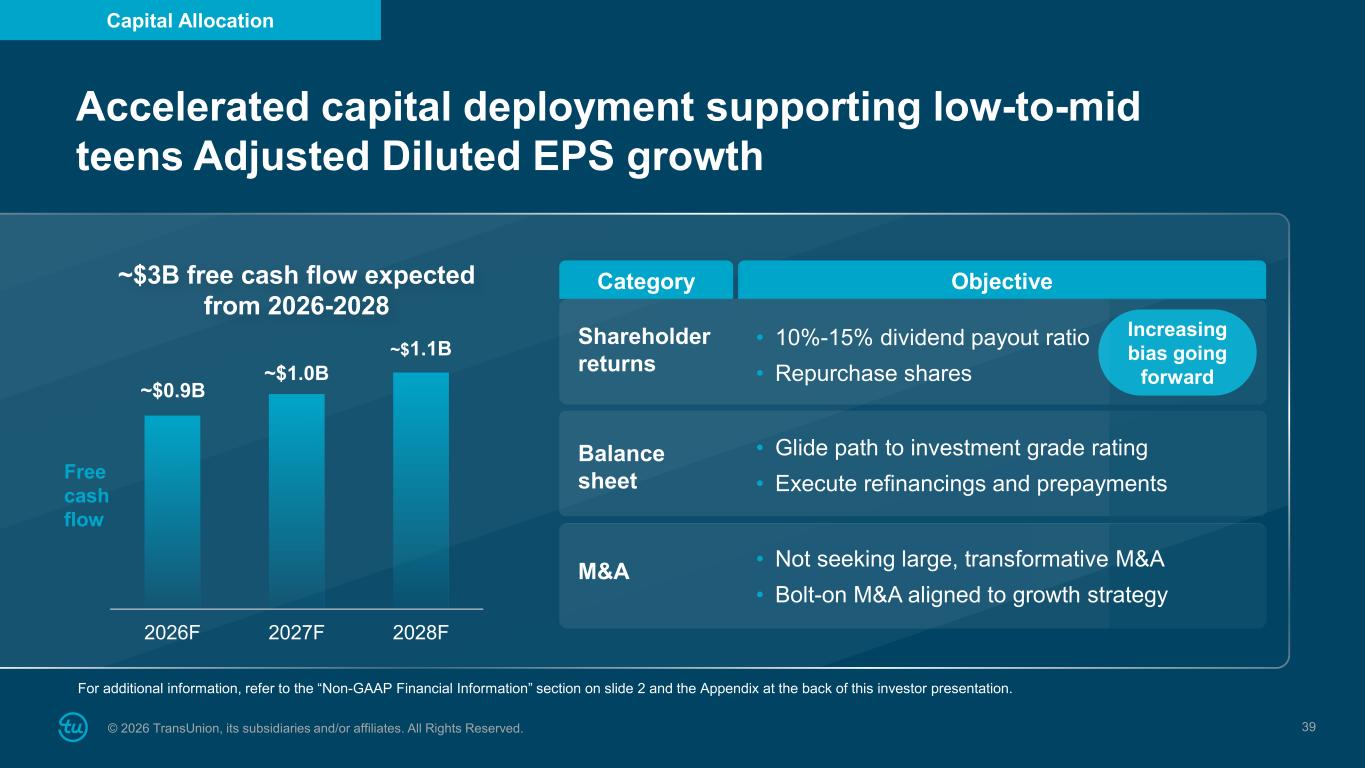
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 39 For additional information, refer to the “Non-GAAP Financial Information” section on slide 2 and the Appendix at the back of this investor presentation. Increasing bias going forward ~$3B free cash flow expected from 2026-2028 2026F 2027F 2028F ~$0.9B ~$1.0B ~$1.1B Free cash flow ObjectiveCategory Shareholder returns Balance sheet M&A • Not seeking large, transformative M&A • Bolt-on M&A aligned to growth strategy • Glide path to investment grade rating • Execute refinancings and prepayments • 10%-15% dividend payout ratio • Repurchase shares Accelerated capital deployment supporting low-to-mid teens Adjusted Diluted EPS growth Capital Allocation
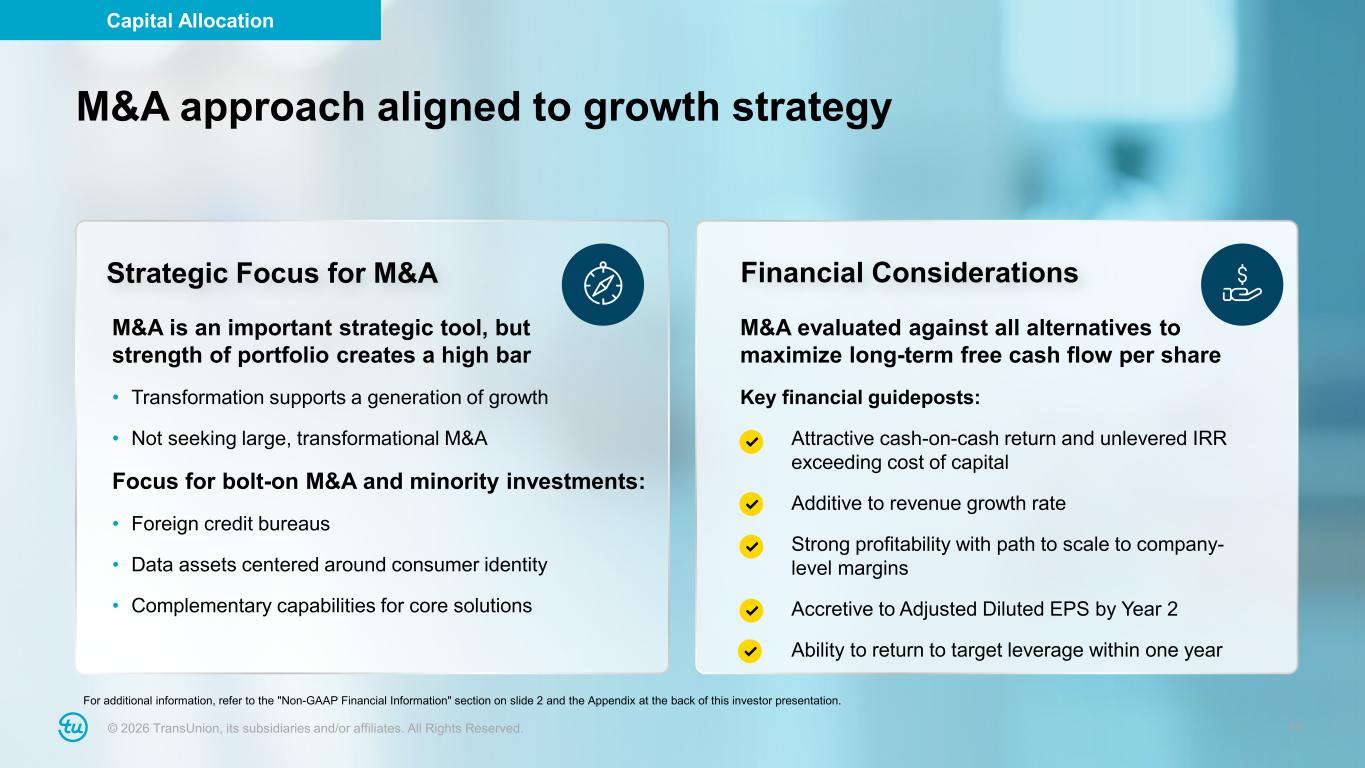
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 40 Strategic Focus for M&A Financial Considerations M&A is an important strategic tool, but strength of portfolio creates a high bar • Transformation supports a generation of growth • Not seeking large, transformational M&A Focus for bolt-on M&A and minority investments: • Foreign credit bureaus • Data assets centered around consumer identity • Complementary capabilities for core solutions M&A evaluated against all alternatives to maximize long-term free cash flow per share Key financial guideposts: Attractive cash-on-cash return and unlevered IRR exceeding cost of capital Additive to revenue growth rate Strong profitability with path to scale to company- level margins Accretive to Adjusted Diluted EPS by Year 2 Ability to return to target leverage within one year M&A approach aligned to growth strategy For additional information, refer to the "Non-GAAP Financial Information" section on slide 2 and the Appendix at the back of this investor presentation. 40 Capital Allocation
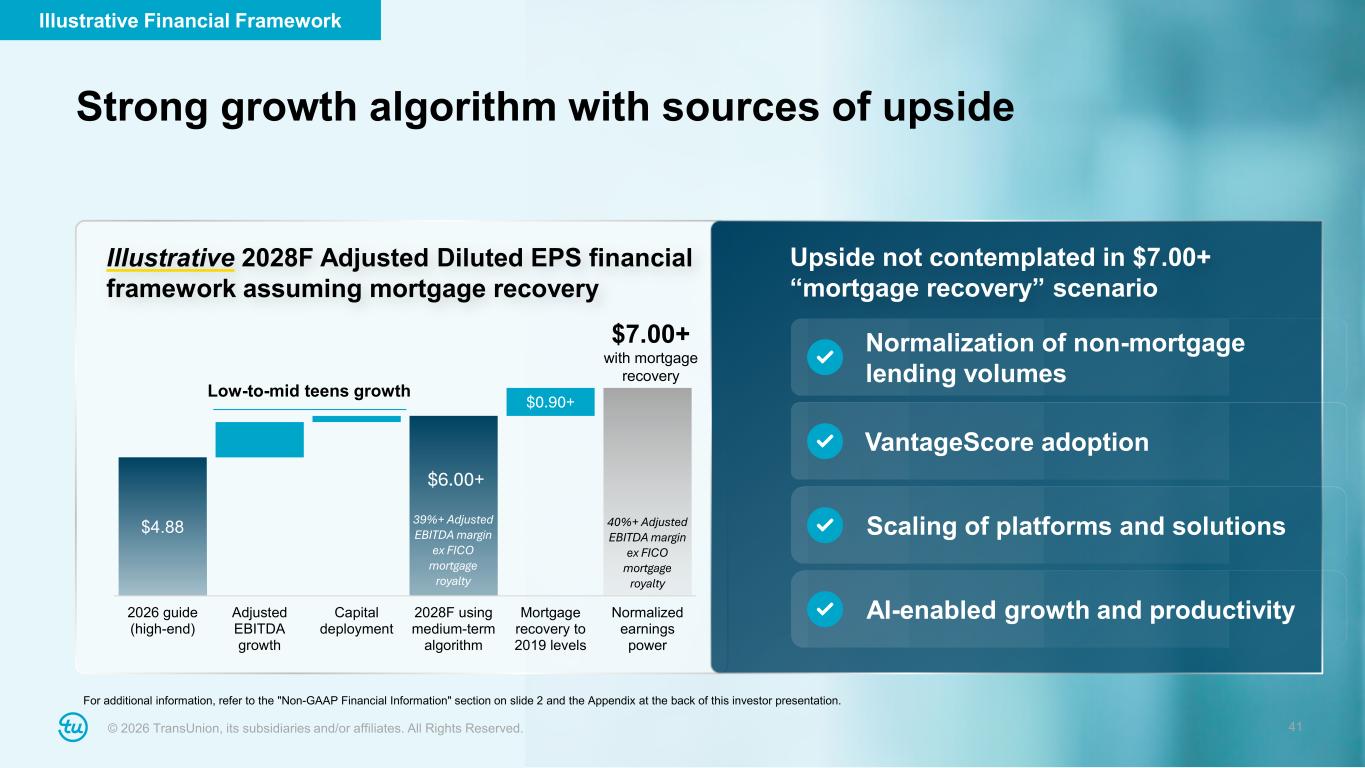
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 41 Low-to-mid teens growth $4.88 $0.90+ 2026 guide (high-end) Adjusted EBITDA growth Capital deployment 2028F using medium-term algorithm Mortgage recovery to 2019 levels Normalized earnings power $6.00+ 39%+ Adjusted EBITDA margin ex FICO mortgage royalty 40%+ Adjusted EBITDA margin ex FICO mortgage royalty $7.00+ with mortgage recovery Illustrative 2028F Adjusted Diluted EPS financial framework assuming mortgage recovery Upside not contemplated in $7.00+ “mortgage recovery” scenario Normalization of non-mortgage lending volumes VantageScore adoption Scaling of platforms and solutions Strong growth algorithm with sources of upside For additional information, refer to the "Non-GAAP Financial Information" section on slide 2 and the Appendix at the back of this investor presentation. 41 AI-enabled growth and productivity Illustrative Financial Framework
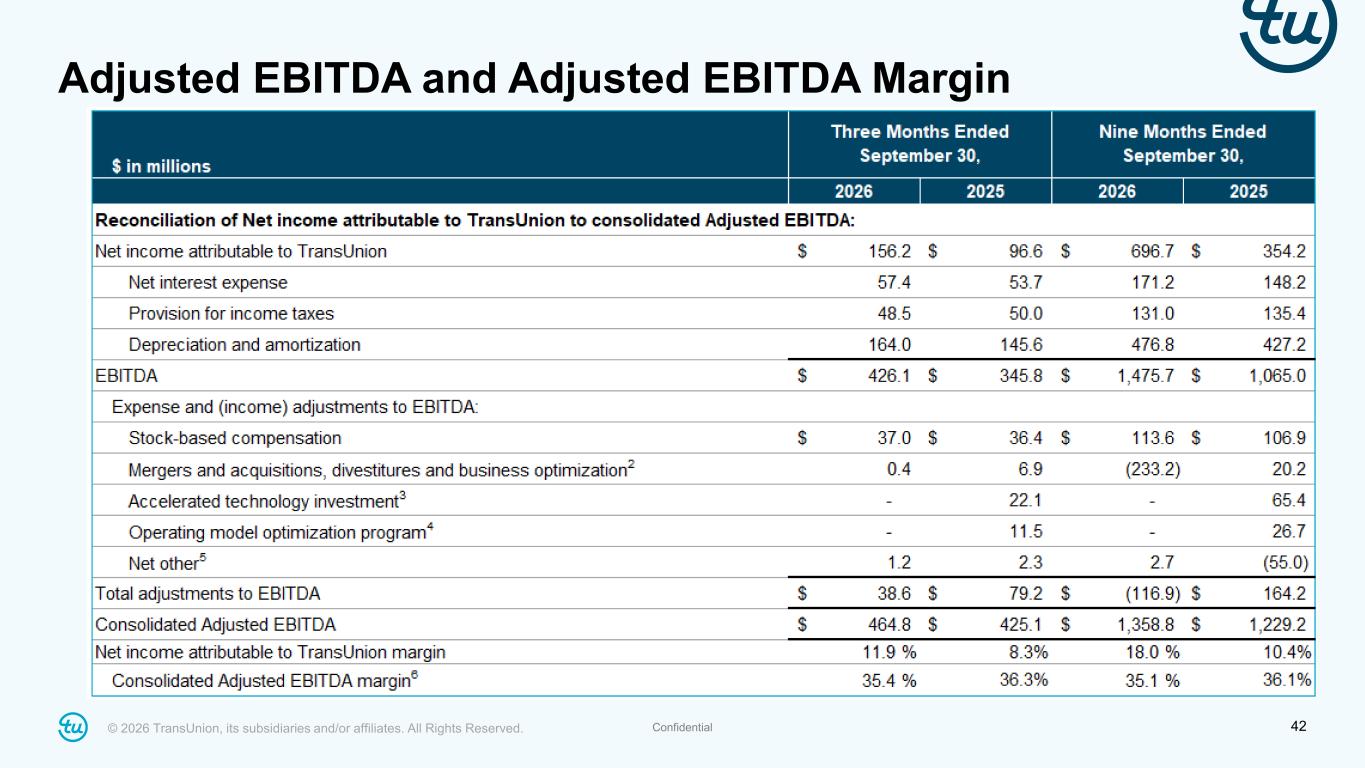
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 42Confidential Adjusted EBITDA and Adjusted EBITDA Margin
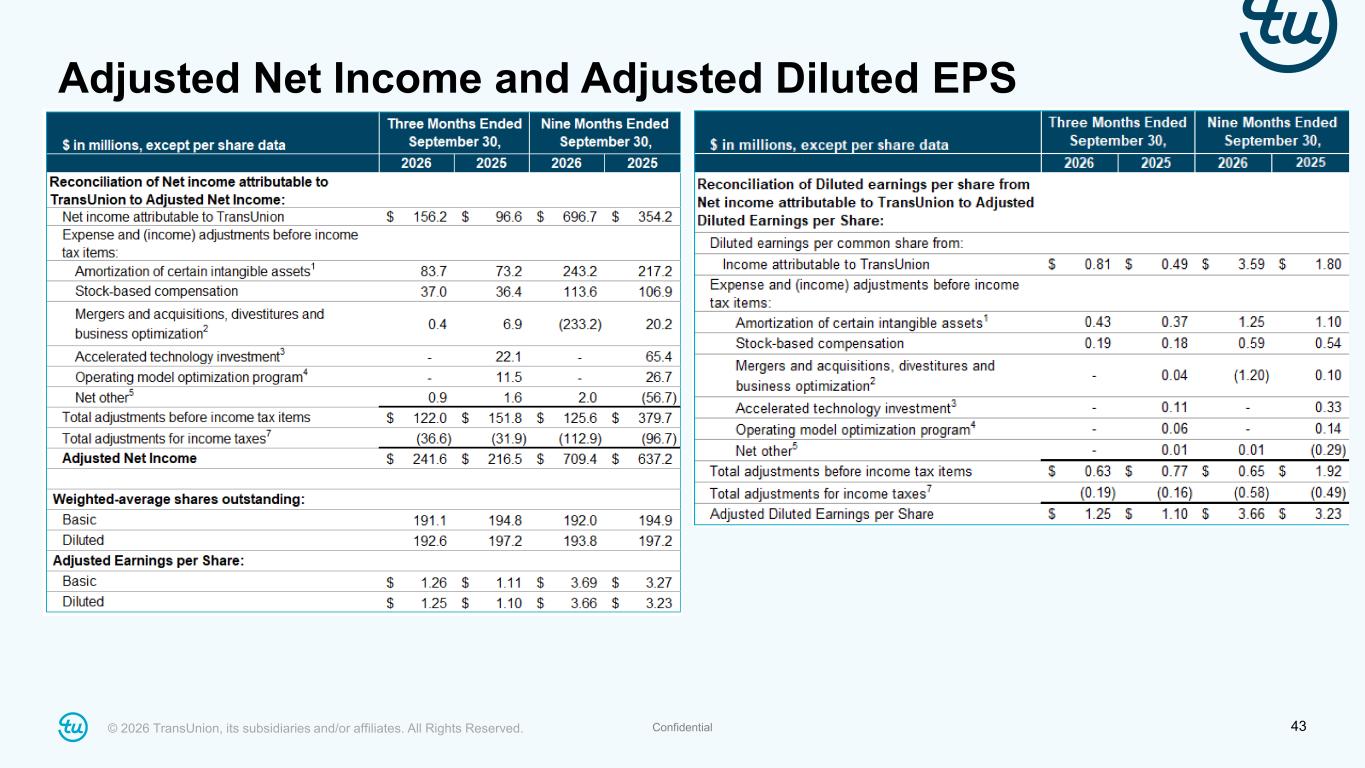
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 43Confidential Adjusted Net Income and Adjusted Diluted EPS
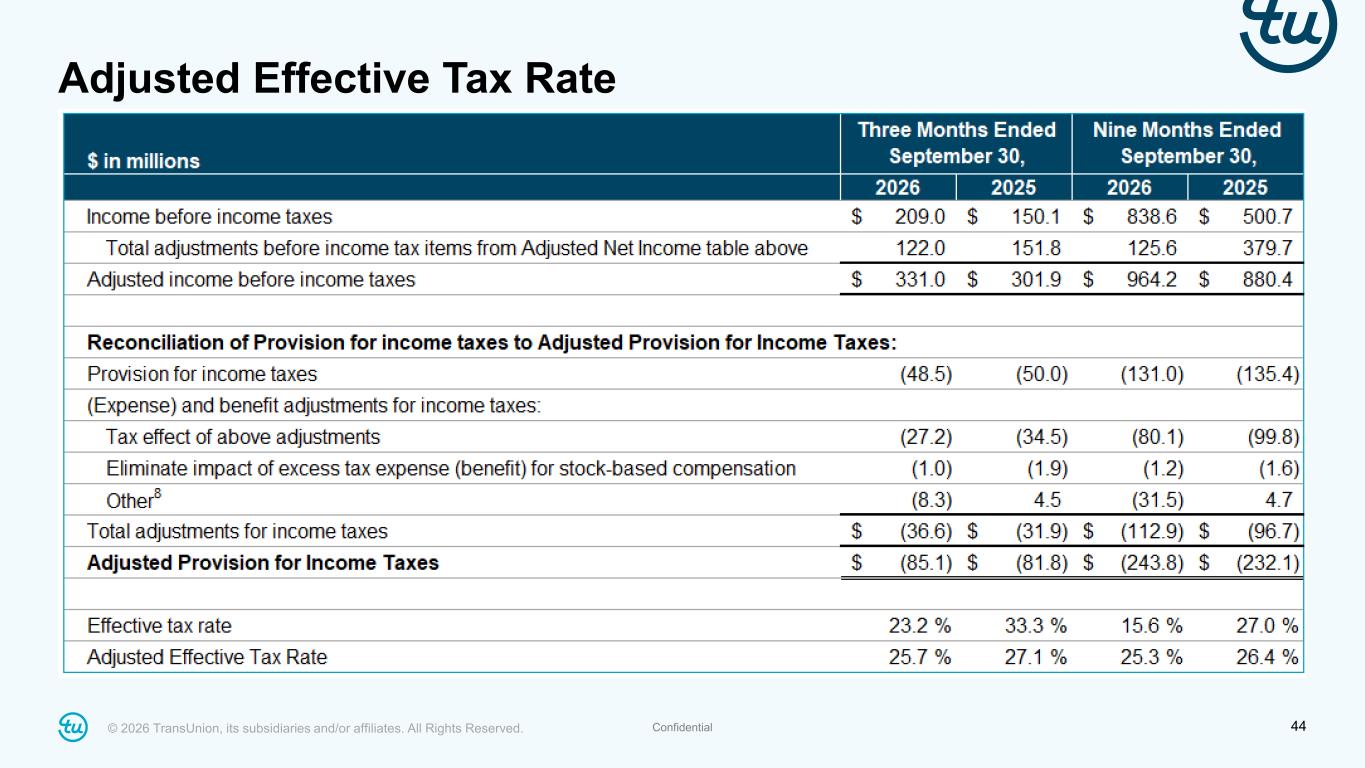
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 44Confidential Adjusted Effective Tax Rate
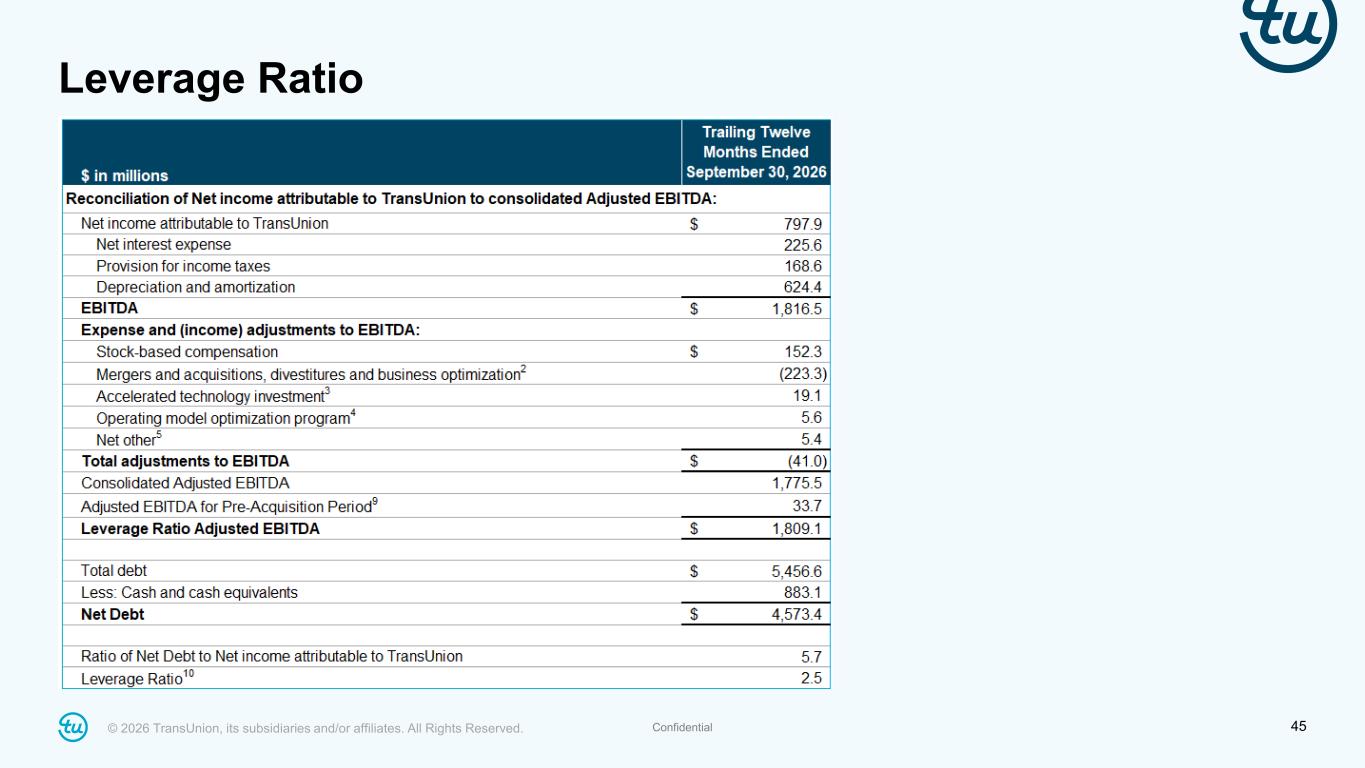
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 45Confidential Leverage Ratio
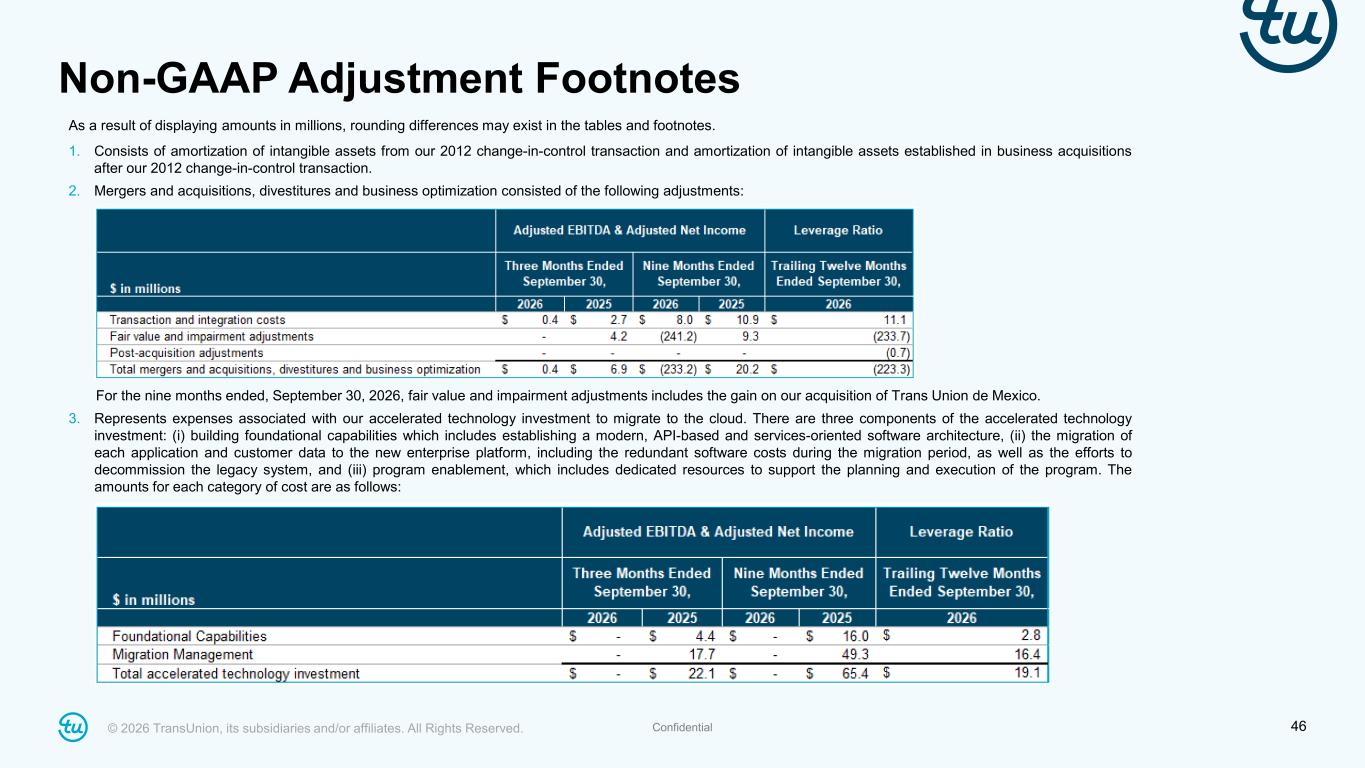
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 46Confidential Non-GAAP Adjustment Footnotes As a result of displaying amounts in millions, rounding differences may exist in the tables and footnotes. 1. Consists of amortization of intangible assets from our 2012 change-in-control transaction and amortization of intangible assets established in business acquisitions after our 2012 change-in-control transaction. 2. Mergers and acquisitions, divestitures and business optimization consisted of the following adjustments: For the nine months ended, September 30, 2026, fair value and impairment adjustments includes the gain on our acquisition of Trans Union de Mexico. 3. Represents expenses associated with our accelerated technology investment to migrate to the cloud. There are three components of the accelerated technology investment: (i) building foundational capabilities which includes establishing a modern, API-based and services-oriented software architecture, (ii) the migration of each application and customer data to the new enterprise platform, including the redundant software costs during the migration period, as well as the efforts to decommission the legacy system, and (iii) program enablement, which includes dedicated resources to support the planning and execution of the program. The amounts for each category of cost are as follows:
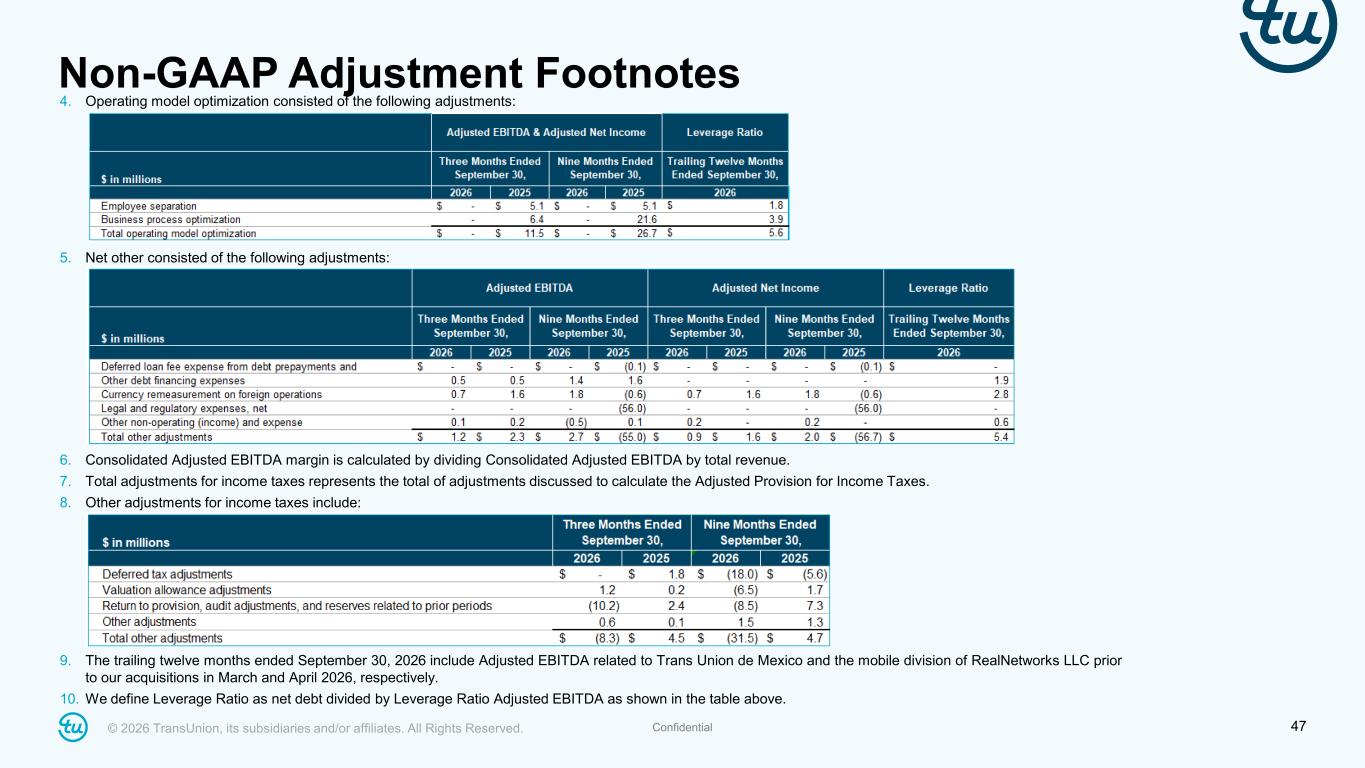
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 47Confidential Non-GAAP Adjustment Footnotes 4. Operating model optimization consisted of the following adjustments: 5. Net other consisted of the following adjustments: 6. Consolidated Adjusted EBITDA margin is calculated by dividing Consolidated Adjusted EBITDA by total revenue. 7. Total adjustments for income taxes represents the total of adjustments discussed to calculate the Adjusted Provision for Income Taxes. 8. Other adjustments for income taxes include: 9. The trailing twelve months ended September 30, 2026 include Adjusted EBITDA related to Trans Union de Mexico and the mobile division of RealNetworks LLC prior to our acquisitions in March and April 2026, respectively. 10. We define Leverage Ratio as net debt divided by Leverage Ratio Adjusted EBITDA as shown in the table above.
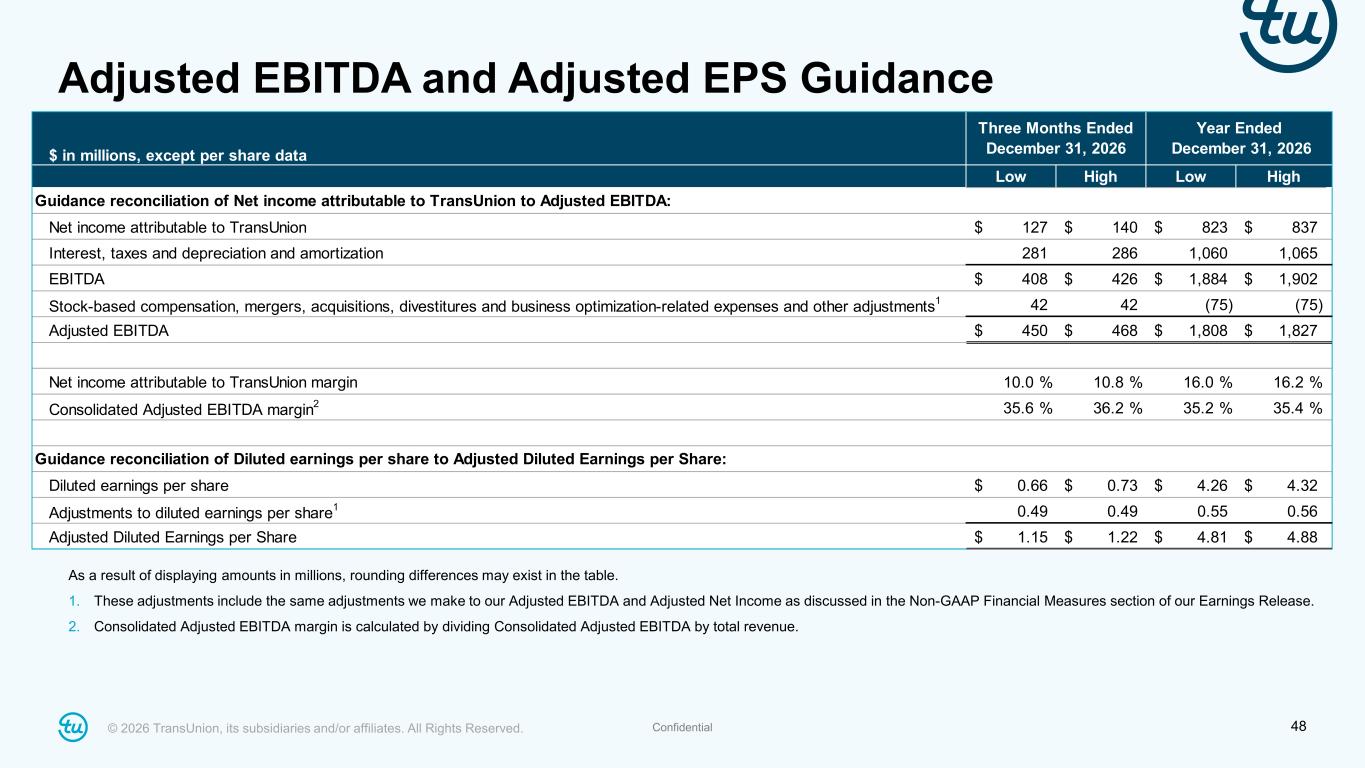
© 2026 TransUnion, its subsidiaries and/or affiliates. All Rights Reserved. 48Confidential Adjusted EBITDA and Adjusted EPS Guidance As a result of displaying amounts in millions, rounding differences may exist in the table. 1. These adjustments include the same adjustments we make to our Adjusted EBITDA and Adjusted Net Income as discussed in the Non-GAAP Financial Measures section of our Earnings Release. 2. Consolidated Adjusted EBITDA margin is calculated by dividing Consolidated Adjusted EBITDA by total revenue. $ in millions, except per share data Low High Low Guidance reconciliation of Net income attributable to TransUnion to Adjusted EBITDA: Net income attributable to TransUnion 127$ 140$ 823$ 837$ Interest, taxes and depreciation and amortization 281 286 1,060 1,065 EBITDA 408$ 426$ 1,884$ 1,902$ Stock-based compensation, mergers, acquisitions, divestitures and business optimization-related expenses and other adjustments1 42 42 (75) (75) Adjusted EBITDA 450$ 468$ 1,808$ 1,827$ Net income attributable to TransUnion margin 10.0 % 10.8 % 16.0 % 16.2 % Consolidated Adjusted EBITDA margin2 35.6 % 36.2 % 35.2 % 35.4 % Guidance reconciliation of Diluted earnings per share to Adjusted Diluted Earnings per Share: Diluted earnings per share 0.66$ 0.73$ 4.26$ 4.32$ Adjustments to diluted earnings per share1 0.49 0.49 0.55 0.56 Adjusted Diluted Earnings per Share 1.15$ 1.22$ 4.81$ 4.88$ Three Months Ended December 31, 2026 Year Ended December 31, 2026 High