T H I R D Q U A R T E R 2 0 2 6 I N V E S T OR PR E S E N T AT I O N
Safe Harbor Statement and Disclaimer Forward-Looking Statements In this presentation, “we,” “our,” “us,” “Five Star,” or “the Company” refers to Five Star Bancorp, a California corporation, and our consolidated subsidiaries, including Five Star Bank, a California state-chartered bank, unless the context indicates that we refer only to the parent company, Five Star Bancorp. This presentation contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements represent plans, estimates, objectives, goals, guidelines, expectations, intentions, projections, and statements of the Company’s beliefs concerning future events, business plans, objectives, expected operating results, and the assumptions upon which those statements are based. Forward-looking statements include without limitation, any statement that may predict, forecast, indicate, or imply future results, performance, or achievements, and are typically identified with words such as “may,” “could,” “should,” “will,” “would,” “believe,” “anticipate,” “estimate,” “expect,” “aim,” “intend,” “plan,” or words or phrases of similar meaning. The Company cautions that the forward-looking statements are based largely on the Company’s expectations and are subject to a number of known and unknown risks and uncertainties that are subject to change based on factors which are, in many instances, beyond the Company’s control. Such forward-looking statements are based on various assumptions (some of which may be beyond the Company’s control) and are subject to risks and uncertainties, which change over time, and other factors which could cause actual results to differ materially from those currently anticipated. New risks and uncertainties may emerge from time to time, and it is not possible for the Company to predict their occurrence or how they will affect the Company. If one or more of the factors affecting the Company’s forward-looking information and statements proves incorrect, then the Company’s actual results, performance, or achievements could differ materially from those expressed in, or implied by, forward-looking information and statements contained in this presentation. Therefore, the Company cautions you not to place undue reliance on the Company’s forward-looking information and statements. Important factors that could cause actual results to differ materially from those in the forward-looking statements are set forth in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025 and Quarterly Reports on Form 10-Q for the three months ended March 31, 2026 and June 30, 2026 under the section entitled “Risk Factors,” and other documents filed by the Company with the Securities and Exchange Commission from time to time. The Company disclaims any duty to revise or update the forward-looking statements, whether written or oral, to reflect actual results or changes in the factors affecting the forward-looking statements, except as specifically required by law. Industry Information This presentation includes statistical and other industry and market data that we obtained from government reports and other third-party sources. Our internal data, estimates, and forecasts are based on information obtained from government reports, trade, and business organizations and other contacts in the markets in which we operate and our management’s understanding of industry conditions. Although we believe that this information (including the industry publications and third-party research, surveys, and studies) is accurate and reliable, we have not independently verified such information. In addition, estimates, forecasts, and assumptions are necessarily subject to a high degree of uncertainty and risk due to a variety of factors. Finally, forward-looking information obtained from these sources is subject to the same qualifications and the additional uncertainties regarding the other forward-looking statements in this presentation. Unaudited Financial Data Numbers contained in this presentation for the quarter ended September 30, 2026 and for other quarterly periods are unaudited. Additionally, all figures presented as year-to-date and for periods that represent a full fiscal year ended December 31, represent unaudited results. As a result, subsequent information may cause a change in certain accounting estimates and other financial information, including the Company’s allowance for credit losses, fair values, and income taxes. Non-GAAP Financial Measures The Company uses financial information in its analysis of the Company’s performance that is not in conformity with accounting principles generally accepted in the United States of America (“GAAP”). The Company believes that these non-GAAP financial measures provide useful information to management and investors that is supplementary to the Company’s financial condition, results of operations, and cash flows computed in accordance with GAAP. However, the Company acknowledges that its non-GAAP financial measures have a number of limitations. See the appendix to this presentation for a reconciliation of these non-GAAP measures to the most directly comparable GAAP financial measures. 2
COM PA N Y OV ERV I EW
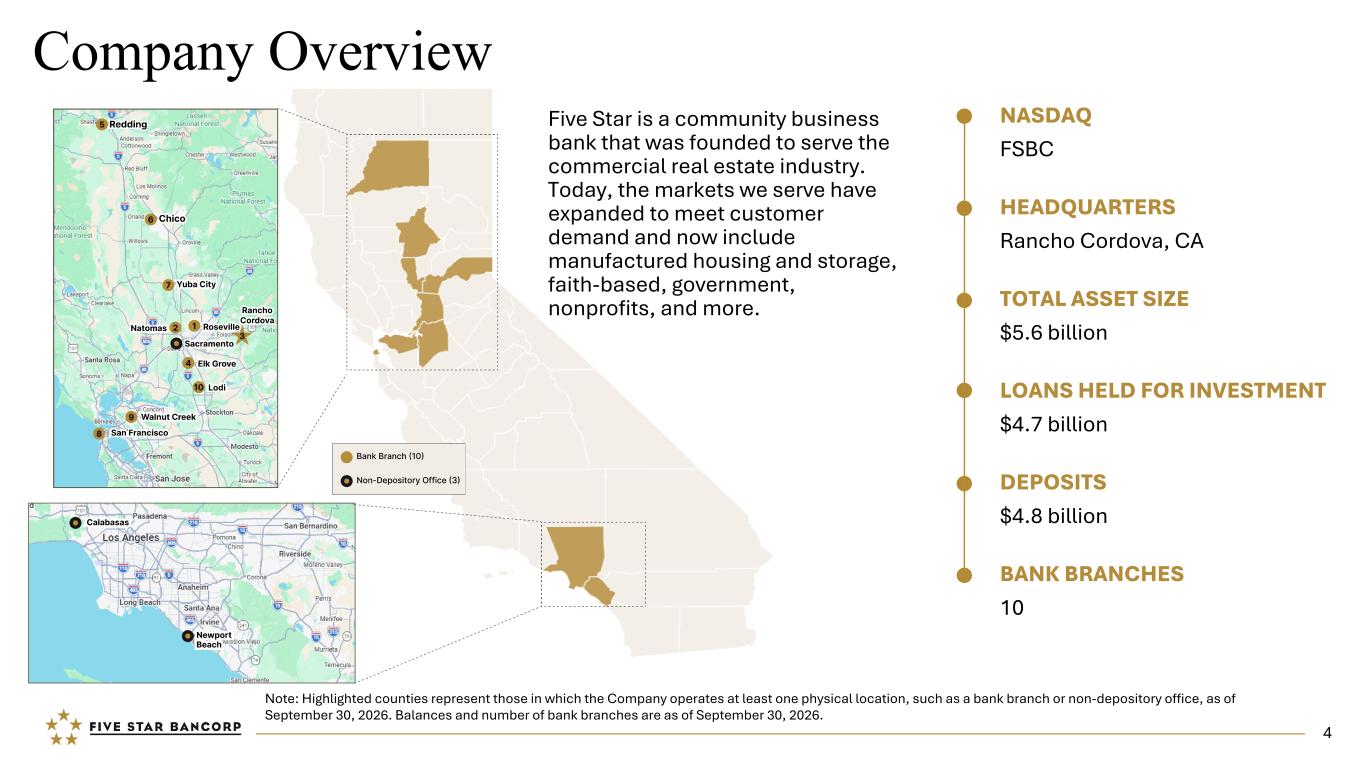
Company Overview NASDAQ FSBC HEADQUARTERS Rancho Cordova, CA TOTAL ASSET SIZE $5.6 billion LOANS HELD FOR INVESTMENT $4.7 billion DEPOSITS $4.8 billion BANK BRANCHES 10 Note: Highlighted counties represent those in which the Company operates at least one physical location, such as a bank branch or non-depository office, as of September 30, 2026. Balances and number of bank branches are as of September 30, 2026. Five Star is a community business bank that was founded to serve the commercial real estate industry. Today, the markets we serve have expanded to meet customer demand and now include manufactured housing and storage, faith-based, government, nonprofits, and more. 4
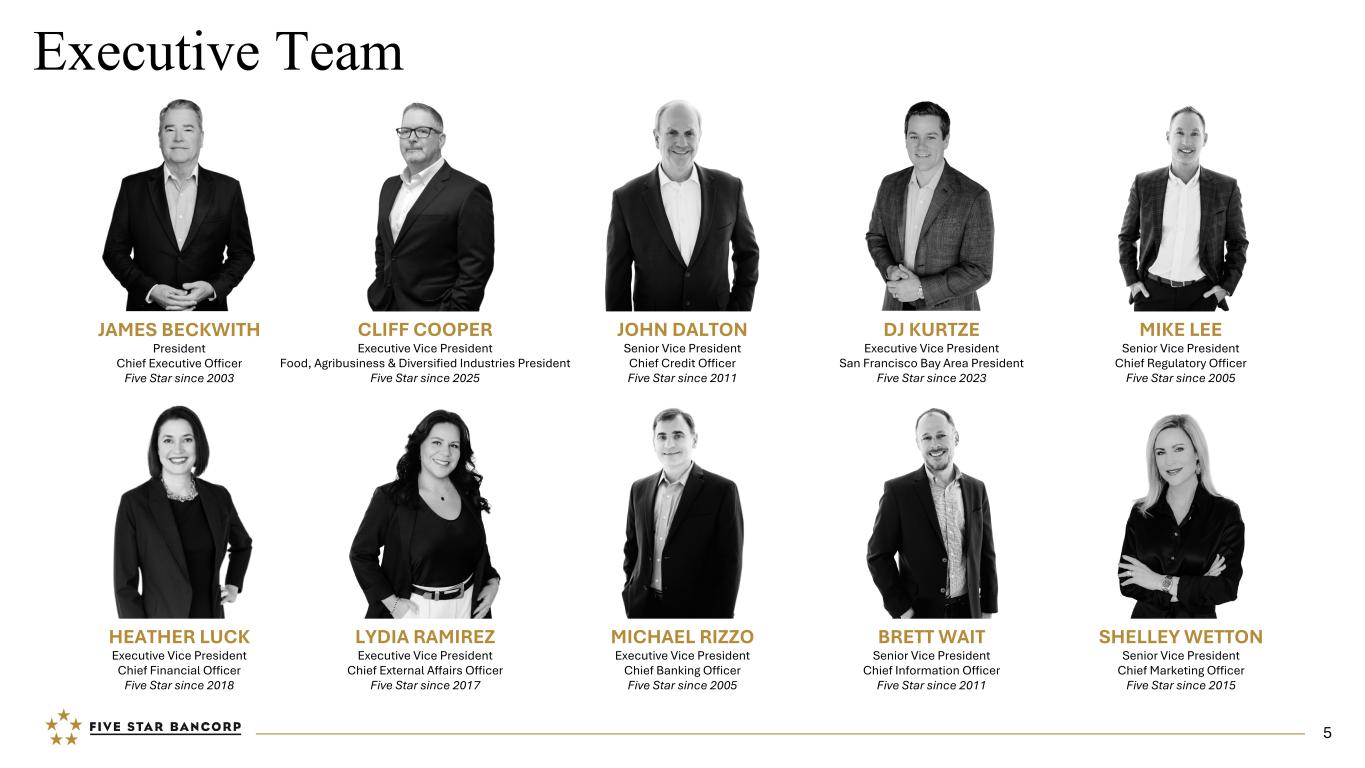
Executive Team JAMES BECKWITH President Chief Executive Officer Five Star since 2003 JOHN DALTON Senior Vice President Chief Credit Officer Five Star since 2011 MIKE LEE Senior Vice President Chief Regulatory Officer Five Star since 2005 MICHAEL RIZZO Executive Vice President Chief Banking Officer Five Star since 2005 BRETT WAIT Senior Vice President Chief Information Officer Five Star since 2011 LYDIA RAMIREZ Executive Vice President Chief External Affairs Officer Five Star since 2017 HEATHER LUCK Executive Vice President Chief Financial Officer Five Star since 2018 SHELLEY WETTON Senior Vice President Chief Marketing Officer Five Star since 2015 DJ KURTZE Executive Vice President San Francisco Bay Area President Five Star since 2023 CLIFF COOPER Executive Vice President Food, Agribusiness & Diversified Industries President Five Star since 2025 5
Recent Awards and Rankings Five Star Bank Awards and Rankings S&P Global Market Intelligence 2025 | TOP 3 BEST-PERFORMING COMMUNITY BANKS IN THE NATION (Banks with $3B - $10B in Assets) 2025 | RAYMOND JAMES COMMUNITY BANKERS CUP (Ranked in Top 10% of Community Banks in the Nation) Bank Director Magazine (Ranking Banking) 2025 | RANKED 4TH ON THE LIST OF THE BEST U.S. BANKS (Banks with Assets Less Than $5B) Bank Director Magazine (Ranking Banking) 2025 | RANKED 13TH ON THE LIST OF TOP 25 U.S. BANKS Piper Sandler’s 2026 | SM-ALL STARS Bank Executive and Employee Awards SACRAMENTO BUSINESS JOURNAL 40 Under 40 Power 100 List C-Suite Award Champions for DE&I Women Who Mean Business Fastest Growing Banks by Deposits SAN FRANCISCO BUSINESS TIMES 40 Under 40 Newsmaker 100 List Best Places to Work #1 Ranking SACRAMENTO METRO CHAMBER OF COMMERCE Sacramentan of the Year Award HISPANIC CHAMBER OF COMMERCE Champion Latina Estrella Award COMMERCIAL REAL ESTATE WOMEN SACRAMENTO Women of Impact Award SACRAMENTO STATE ALUMNI ASSOCIATION Distinguished Alumni Award 6
FI NA NCI A L H IGH LIGH T S
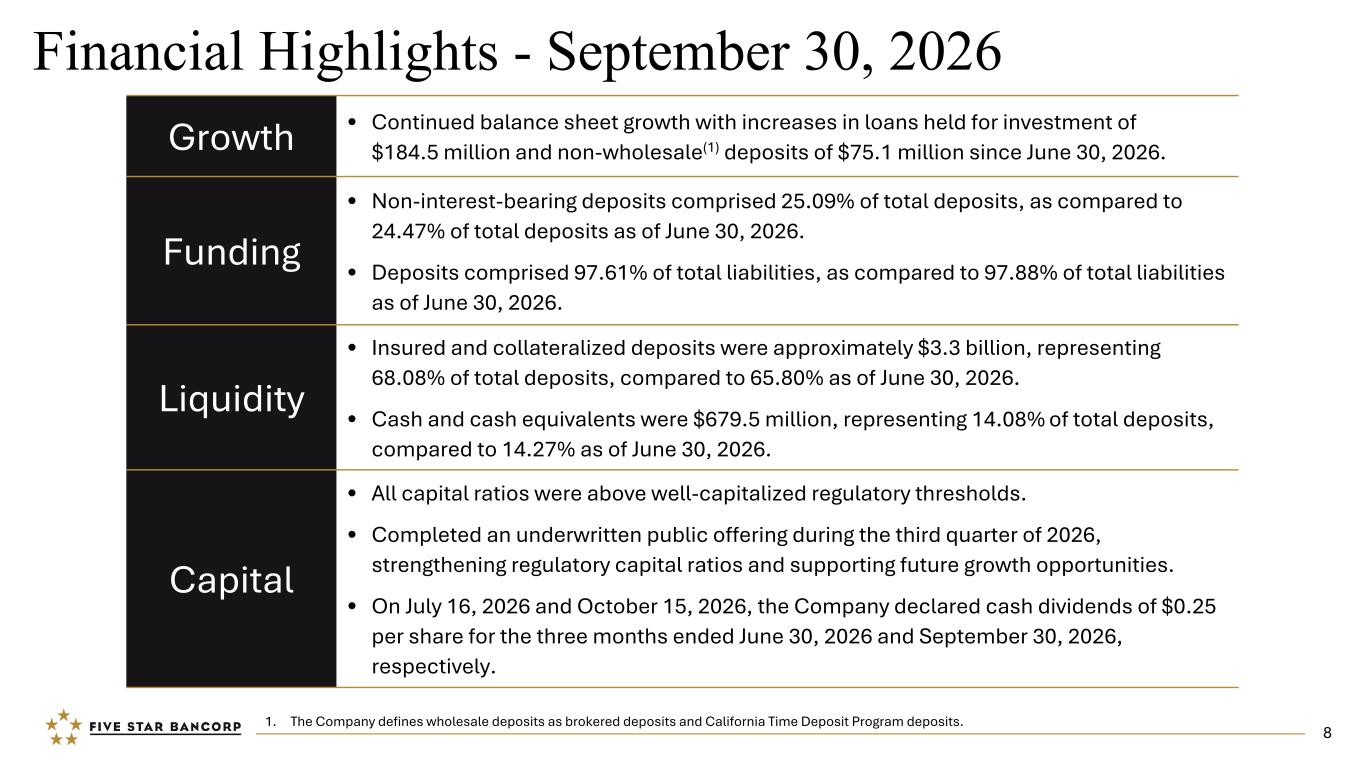
Growth • Continued balance sheet growth with increases in loans held for investment of $184.5 million and non-wholesale(1) deposits of $75.1 million since June 30, 2026. Funding • Non-interest-bearing deposits comprised 25.09% of total deposits, as compared to 24.47% of total deposits as of June 30, 2026. • Deposits comprised 97.61% of total liabilities, as compared to 97.88% of total liabilities as of June 30, 2026. Liquidity • Insured and collateralized deposits were approximately $3.3 billion, representing 68.08% of total deposits, compared to 65.80% as of June 30, 2026. • Cash and cash equivalents were $679.5 million, representing 14.08% of total deposits, compared to 14.27% as of June 30, 2026. Capital • All capital ratios were above well-capitalized regulatory thresholds. • Completed an underwritten public offering during the third quarter of 2026, strengthening regulatory capital ratios and supporting future growth opportunities. • On July 16, 2026 and October 15, 2026, the Company declared cash dividends of $0.25 per share for the three months ended June 30, 2026 and September 30, 2026, respectively. Financial Highlights - September 30, 2026 1. The Company defines wholesale deposits as brokered deposits and California Time Deposit Program deposits. 8
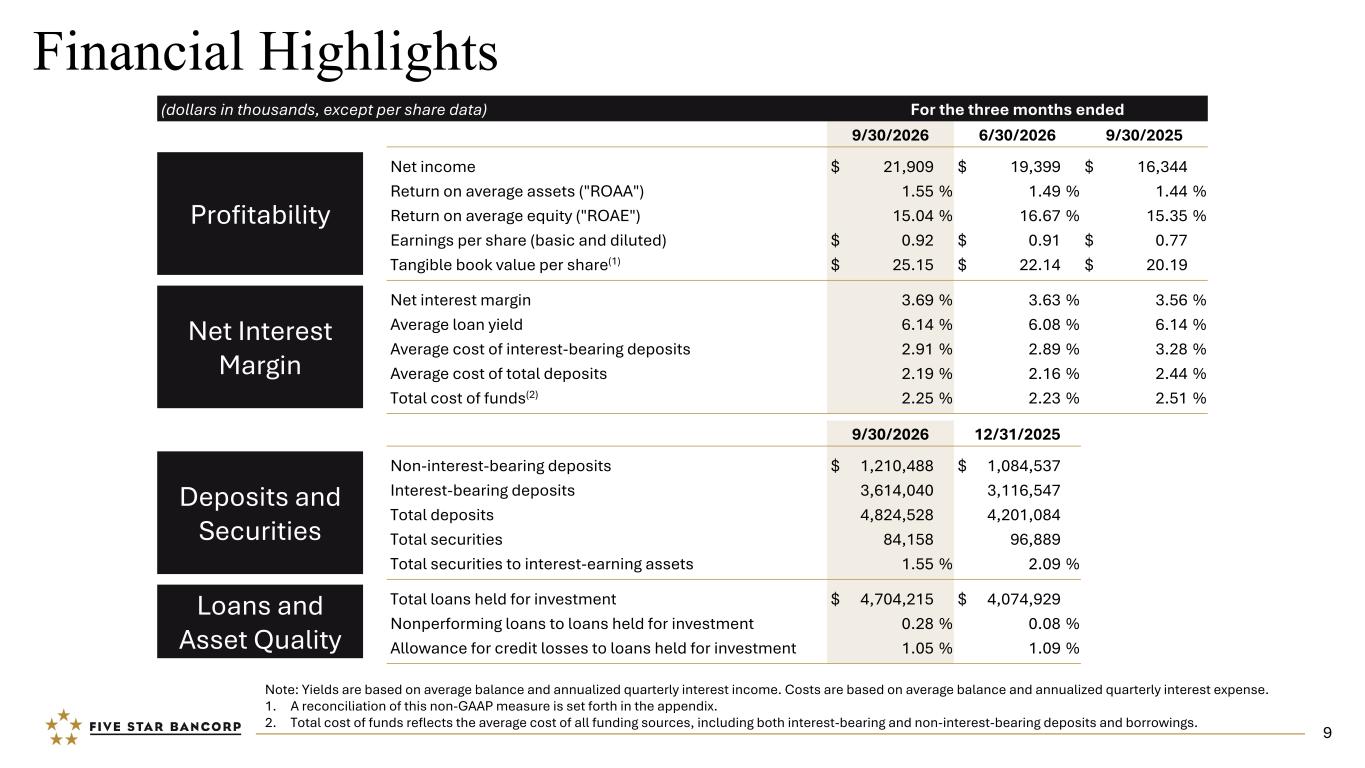
Financial Highlights (dollars in thousands, except per share data) For the three months ended 9/30/2026 6/30/2026 9/30/2025 Profitability Net income $ 21,909 $ 19,399 $ 16,344 Return on average assets ("ROAA") 1.55 % 1.49 % 1.44 % Return on average equity ("ROAE") 15.04 % 16.67 % 15.35 % Earnings per share (basic and diluted) $ 0.92 $ 0.91 $ 0.77 Tangible book value per share(1) $ 25.15 $ 22.14 $ 20.19 Net Interest Margin Net interest margin 3.69 % 3.63 % 3.56 % Average loan yield 6.14 % 6.08 % 6.14 % Average cost of interest-bearing deposits 2.91 % 2.89 % 3.28 % Average cost of total deposits 2.19 % 2.16 % 2.44 % Total cost of funds(2) 2.25 % 2.23 % 2.51 % 9/30/2026 12/31/2025 Deposits and Securities Non-interest-bearing deposits $ 1,210,488 $ 1,084,537 Interest-bearing deposits 3,614,040 3,116,547 Total deposits 4,824,528 4,201,084 Total securities 84,158 96,889 Total securities to interest-earning assets 1.55 % 2.09 % Loans and Asset Quality Total loans held for investment $ 4,704,215 $ 4,074,929 Nonperforming loans to loans held for investment 0.28 % 0.08 % Allowance for credit losses to loans held for investment 1.05 % 1.09 % Note: Yields are based on average balance and annualized quarterly interest income. Costs are based on average balance and annualized quarterly interest expense. 1. A reconciliation of this non-GAAP measure is set forth in the appendix. 2. Total cost of funds reflects the average cost of all funding sources, including both interest-bearing and non-interest-bearing deposits and borrowings. 9
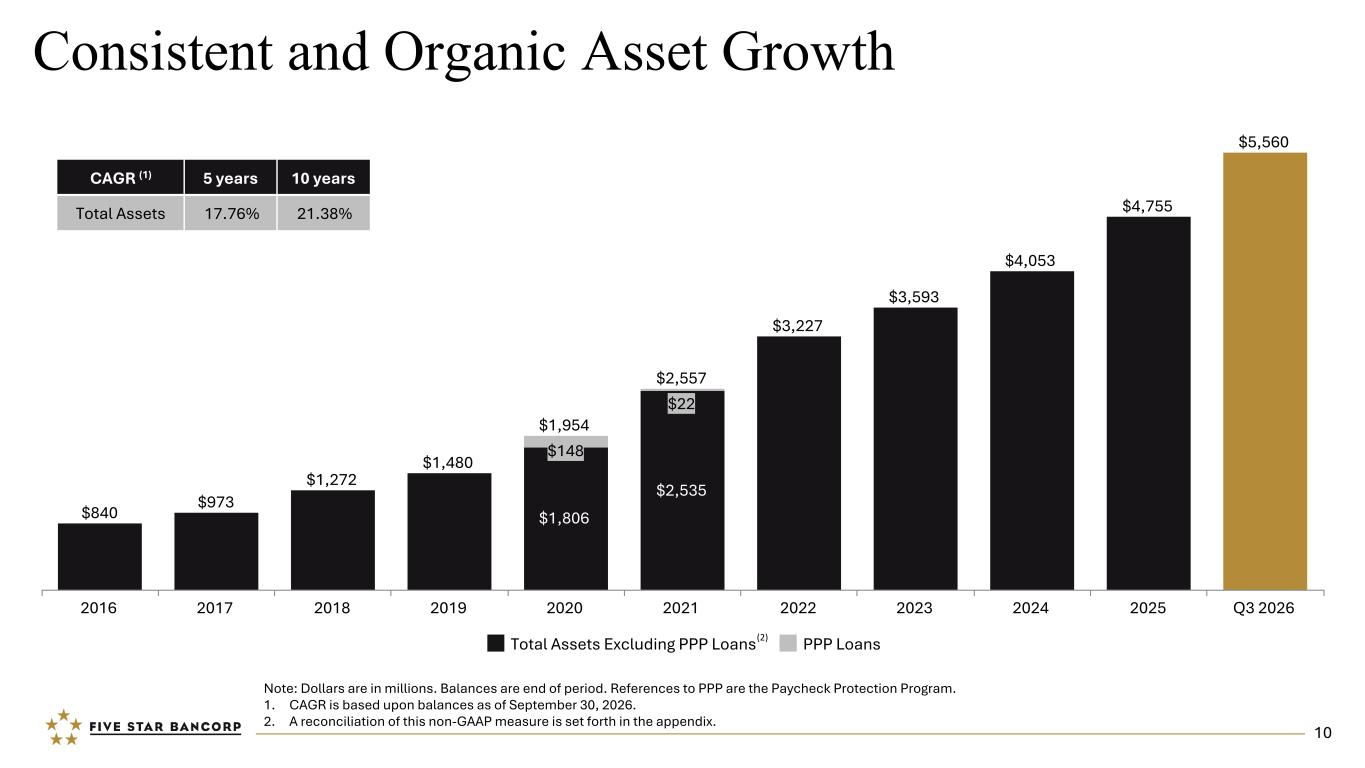
$840 $973 $1,272 $1,480 $1,954 $2,557 $3,227 $3,593 $4,053 $4,755 $5,560 $1,806 $2,535 $148 $22 Total Assets Excluding PPP Loans PPP Loans 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 Q3 2026 Consistent and Organic Asset Growth Note: Dollars are in millions. Balances are end of period. References to PPP are the Paycheck Protection Program. 1. CAGR is based upon balances as of September 30, 2026. 2. A reconciliation of this non-GAAP measure is set forth in the appendix. (2) CAGR (1) 5 years 10 years Total Assets 17.76% 21.38% 10
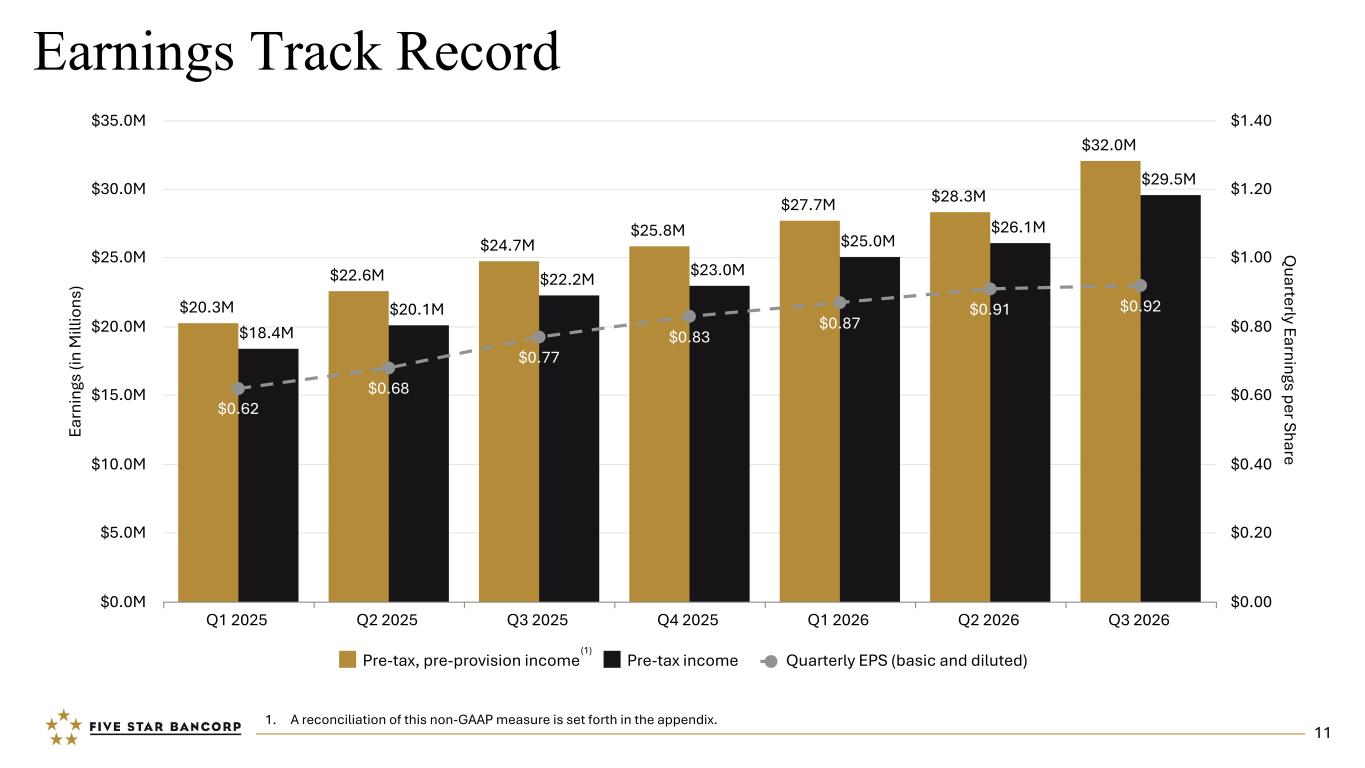
Earnings Track Record Ea rn in gs (i n M ill io ns ) Q uarterly Earnings per Share $20.3M $22.6M $24.7M $25.8M $27.7M $28.3M $32.0M $18.4M $20.1M $22.2M $23.0M $25.0M $26.1M $29.5M $0.62 $0.68 $0.77 $0.83 $0.87 $0.91 $0.92 Pre-tax, pre-provision income Pre-tax income Quarterly EPS (basic and diluted) Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 $0.0M $5.0M $10.0M $15.0M $20.0M $25.0M $30.0M $35.0M $0.00 $0.20 $0.40 $0.60 $0.80 $1.00 $1.20 $1.40 1. A reconciliation of this non-GAAP measure is set forth in the appendix. (1) 11
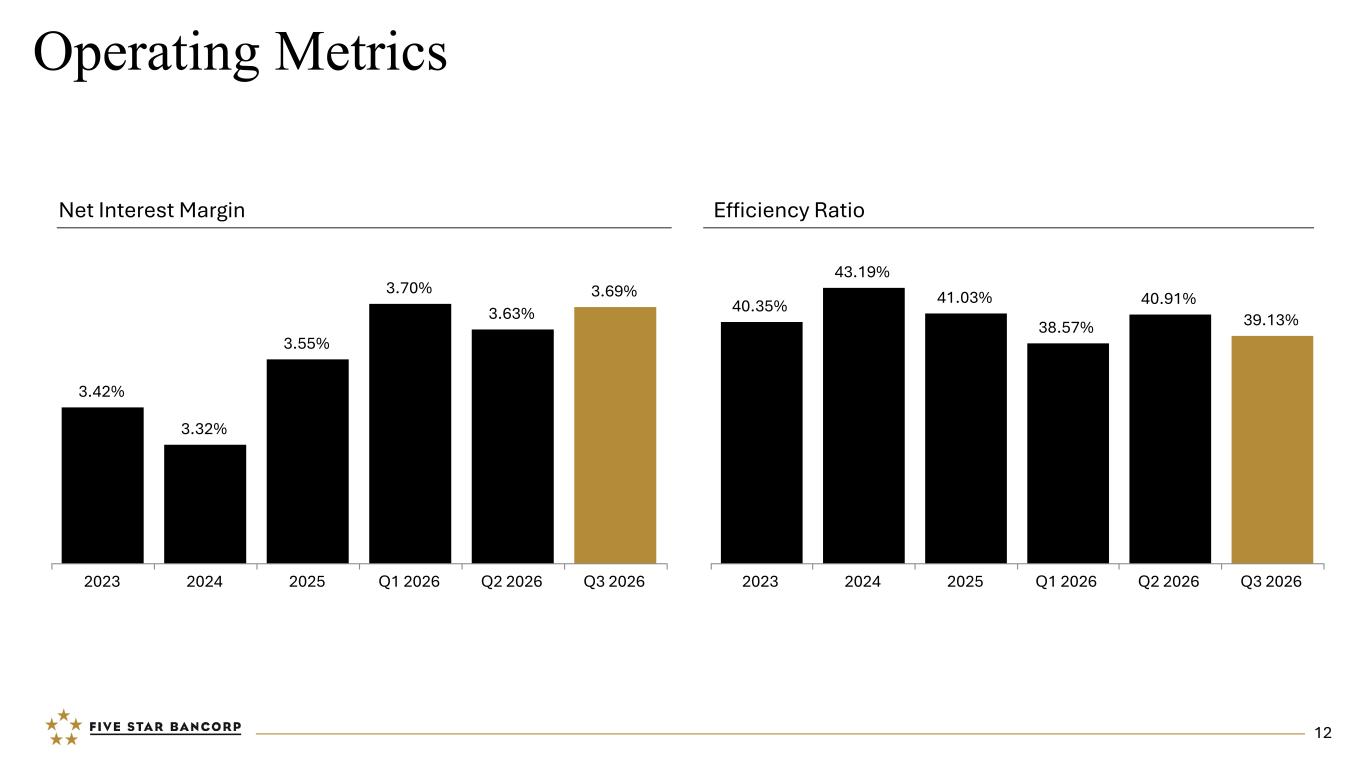
Operating Metrics Efficiency RatioNet Interest Margin 3.42% 3.32% 3.55% 3.70% 3.63% 3.69% 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 40.35% 43.19% 41.03% 38.57% 40.91% 39.13% 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 12
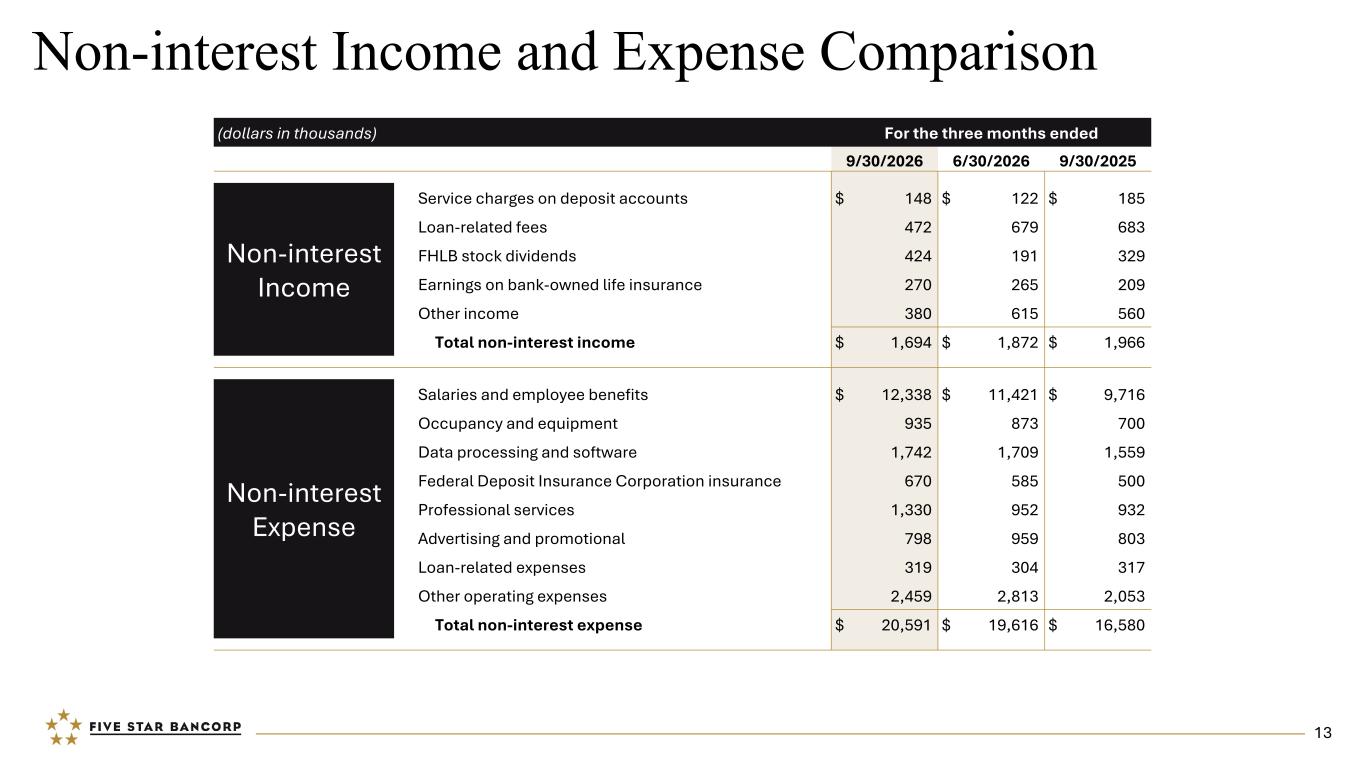
Non-interest Income and Expense Comparison (dollars in thousands) For the three months ended 9/30/2026 6/30/2026 9/30/2025 Non-interest Income Service charges on deposit accounts $ 148 $ 122 $ 185 Loan-related fees 472 679 683 FHLB stock dividends 424 191 329 Earnings on bank-owned life insurance 270 265 209 Other income 380 615 560 Total non-interest income $ 1,694 $ 1,872 $ 1,966 Non-interest Expense Salaries and employee benefits $ 12,338 $ 11,421 $ 9,716 Occupancy and equipment 935 873 700 Data processing and software 1,742 1,709 1,559 Federal Deposit Insurance Corporation insurance 670 585 500 Professional services 1,330 952 932 Advertising and promotional 798 959 803 Loan-related expenses 319 304 317 Other operating expenses 2,459 2,813 2,053 Total non-interest expense $ 20,591 $ 19,616 $ 16,580 13
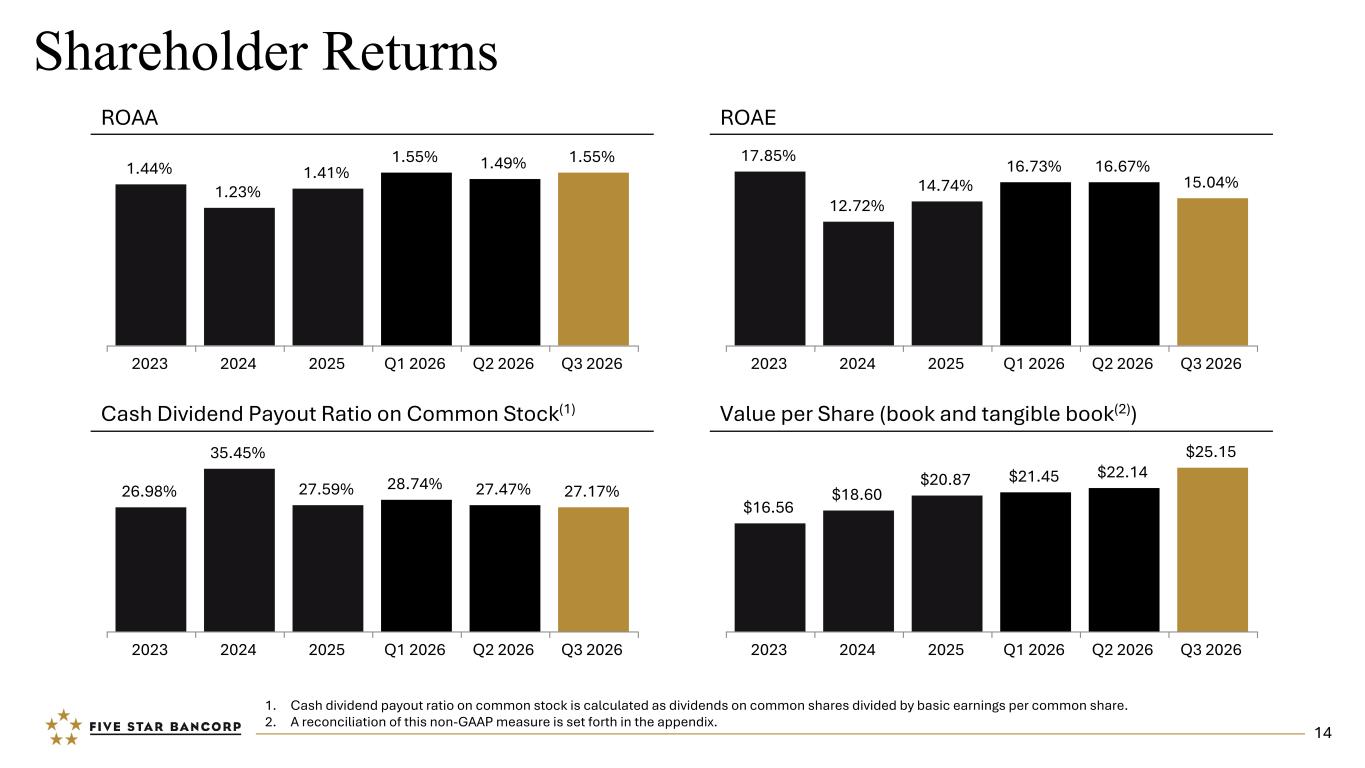
Shareholder Returns ROAA ROAE Value per Share (book and tangible book(2)) 1. Cash dividend payout ratio on common stock is calculated as dividends on common shares divided by basic earnings per common share. 2. A reconciliation of this non-GAAP measure is set forth in the appendix. 1.44% 1.23% 1.41% 1.55% 1.49% 1.55% 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 17.85% 12.72% 14.74% 16.73% 16.67% 15.04% 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 $16.56 $18.60 $20.87 $21.45 $22.14 $25.15 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 26.98% 35.45% 27.59% 28.74% 27.47% 27.17% 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 14 Cash Dividend Payout Ratio on Common Stock(1)
Loans and Credit Quality 15 LOA N S A N D CRE DI T QUA L I T Y
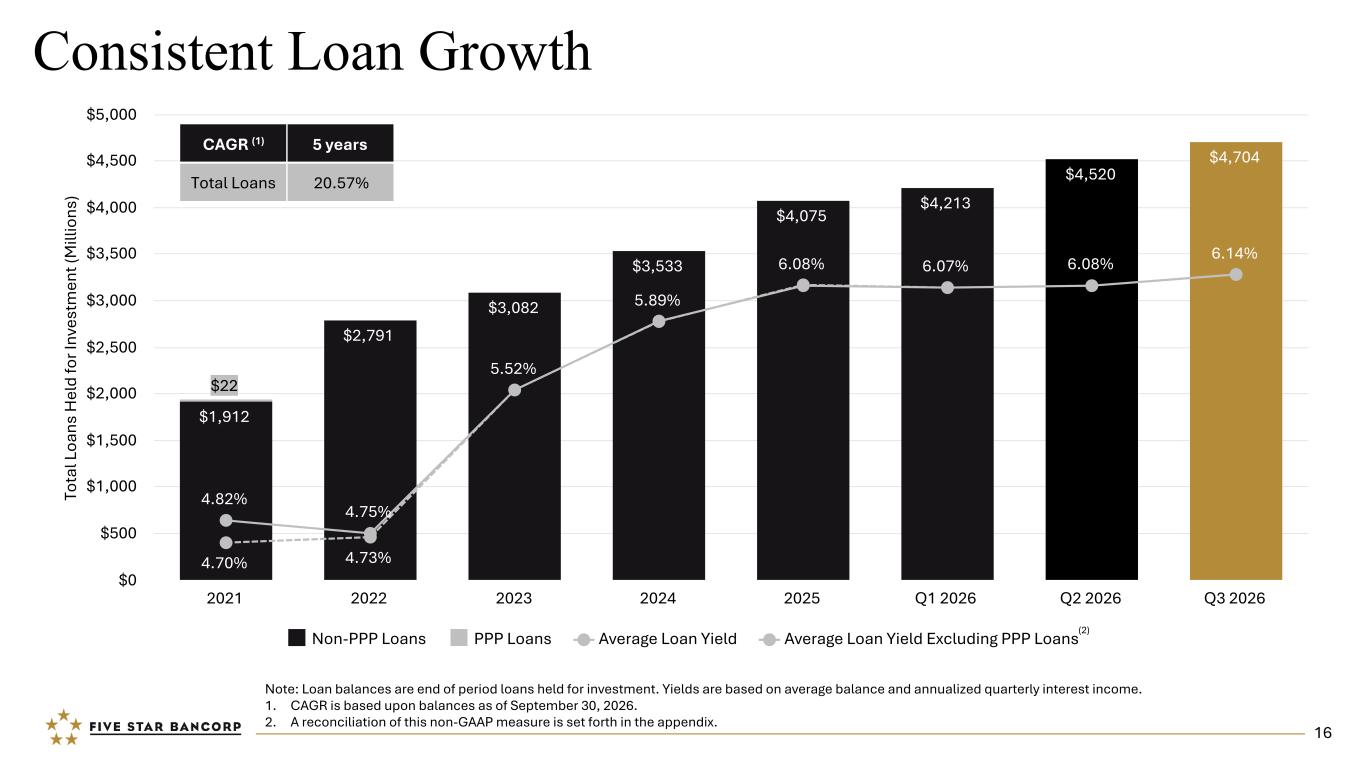
To ta l L oa ns H el d fo r I nv es tm en t ( M ill io ns ) $1,912 $2,791 $3,082 $3,533 $4,075 $4,213 $4,520 $4,704 $22 4.82% 4.75% 5.52% 5.89% 6.08% 6.07% 6.08% 6.14% 4.70% 4.73% Non-PPP Loans PPP Loans Average Loan Yield Average Loan Yield Excluding PPP Loans 2021 2022 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 $0 $500 $1,000 $1,500 $2,000 $2,500 $3,000 $3,500 $4,000 $4,500 $5,000 Consistent Loan Growth Note: Loan balances are end of period loans held for investment. Yields are based on average balance and annualized quarterly interest income. 1. CAGR is based upon balances as of September 30, 2026. 2. A reconciliation of this non-GAAP measure is set forth in the appendix. (2) CAGR (1) 5 years Total Loans 20.57% 16
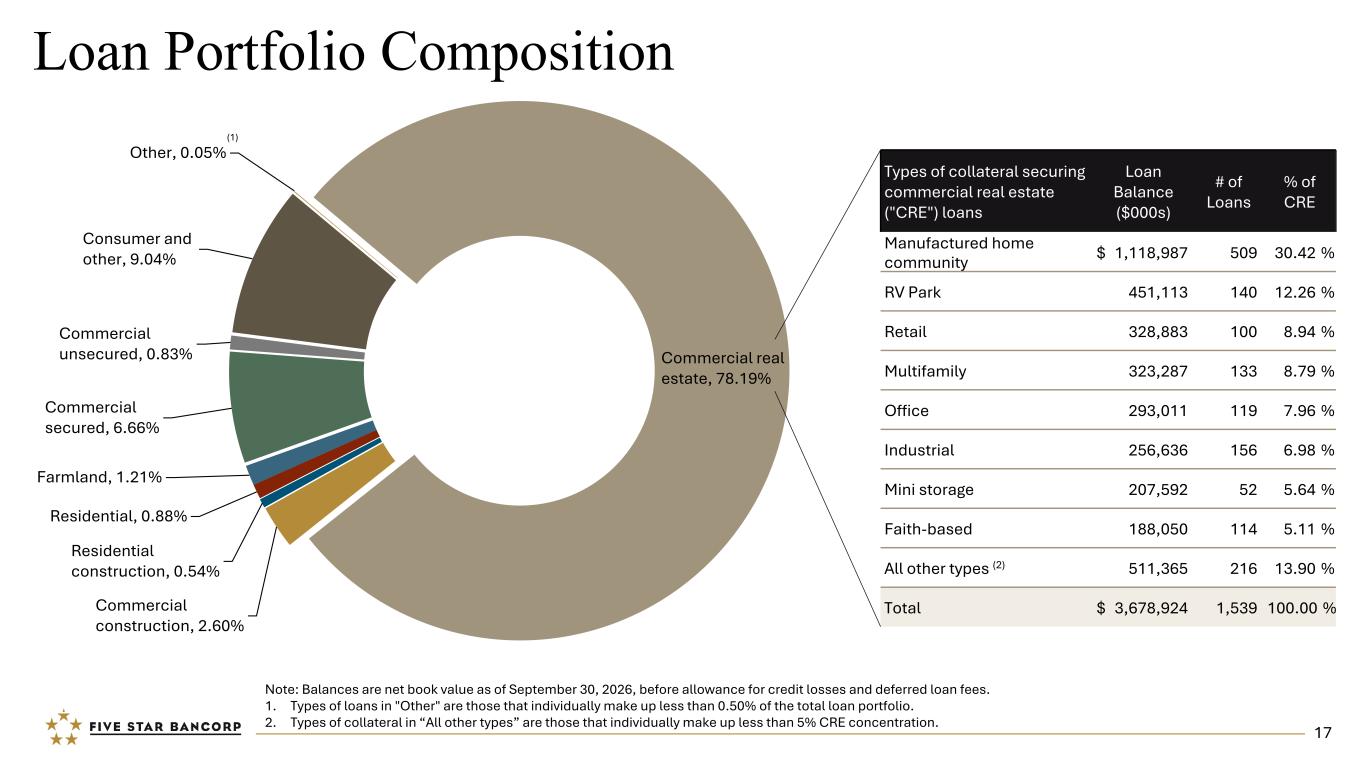
Commercial real estate, 78.19% Commercial construction, 2.60% Residential construction, 0.54% Residential, 0.88% Farmland, 1.21% Commercial secured, 6.66% Commercial unsecured, 0.83% Consumer and other, 9.04% Other, 0.05% Loan Portfolio Composition Types of collateral securing commercial real estate ("CRE") loans Loan Balance ($000s) # of Loans % of CRE Manufactured home community $ 1,118,987 509 30.42 % RV Park 451,113 140 12.26 % Retail 328,883 100 8.94 % Multifamily 323,287 133 8.79 % Office 293,011 119 7.96 % Industrial 256,636 156 6.98 % Mini storage 207,592 52 5.64 % Faith-based 188,050 114 5.11 % All other types (2) 511,365 216 13.90 % Total $ 3,678,924 1,539 100.00 % Note: Balances are net book value as of September 30, 2026, before allowance for credit losses and deferred loan fees. 1. Types of loans in "Other" are those that individually make up less than 0.50% of the total loan portfolio. 2. Types of collateral in “All other types” are those that individually make up less than 5% CRE concentration. (1) 17
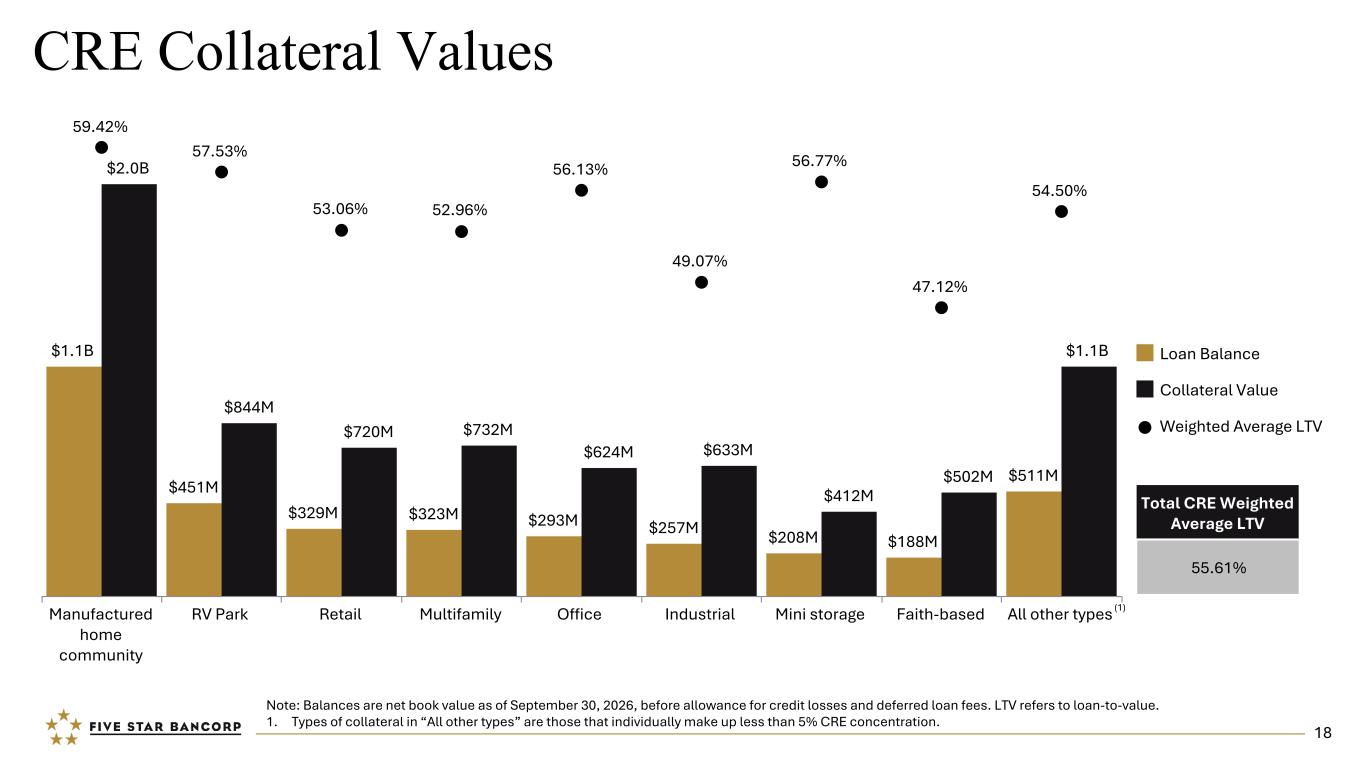
$1.1B $451M $329M $323M $293M $257M $208M $188M $511M $2.0B $844M $720M $732M $624M $633M $412M $502M $1.1B 59.42% 57.53% 53.06% 52.96% 56.13% 49.07% 56.77% 47.12% 54.50% Loan Balance Collateral Value Weighted Average LTV Manufactured home community RV Park Retail Multifamily Office Industrial Mini storage Faith-based All other types CRE Collateral Values (1) Note: Balances are net book value as of September 30, 2026, before allowance for credit losses and deferred loan fees. LTV refers to loan-to-value. 1. Types of collateral in “All other types” are those that individually make up less than 5% CRE concentration. Total CRE Weighted Average LTV 55.61% 18
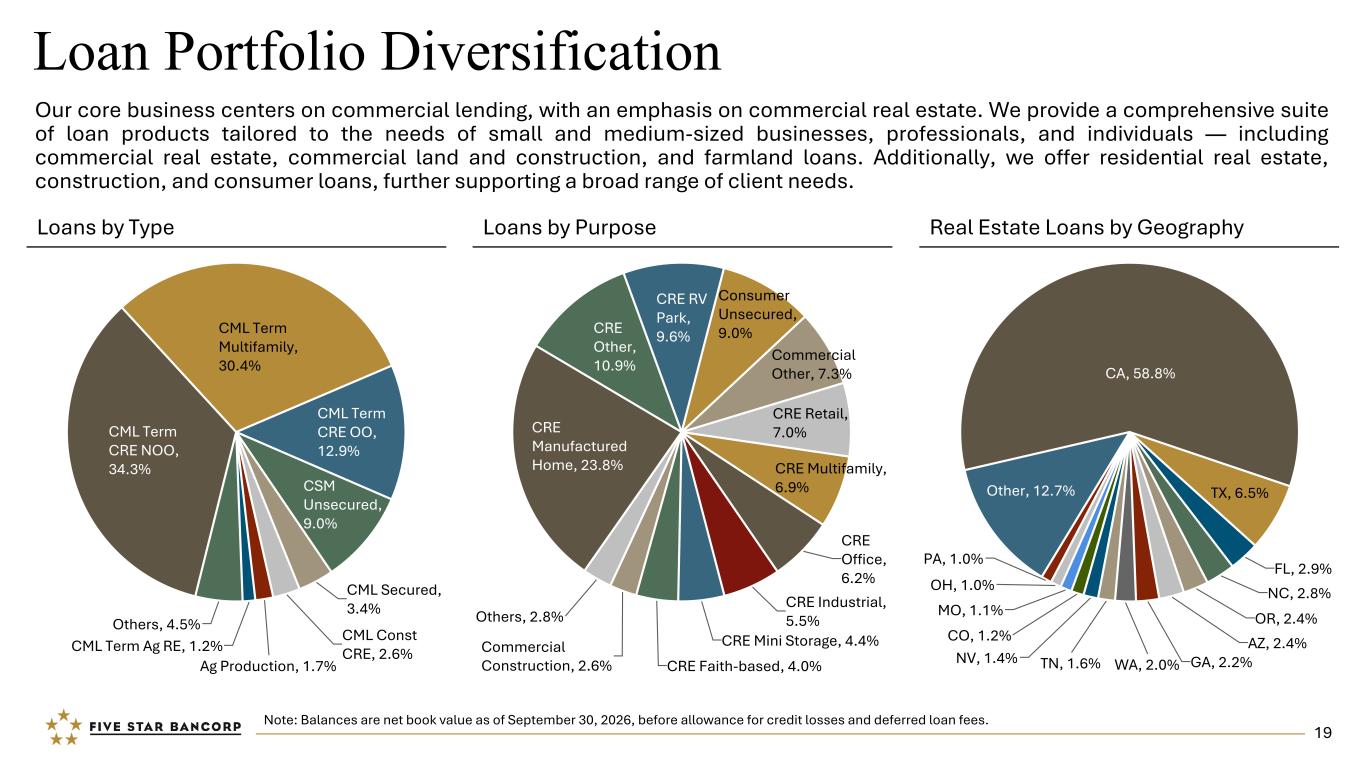
CA, 58.8% TX, 6.5% FL, 2.9% NC, 2.8% OR, 2.4% AZ, 2.4% GA, 2.2%WA, 2.0%TN, 1.6%NV, 1.4% CO, 1.2% MO, 1.1% OH, 1.0% PA, 1.0% Other, 12.7% CML Term CRE NOO, 34.3% CML Term Multifamily, 30.4% CML Term CRE OO, 12.9% CSM Unsecured, 9.0% CML Secured, 3.4% CML Const CRE, 2.6% Ag Production, 1.7% CML Term Ag RE, 1.2% Others, 4.5% CRE Manufactured Home, 23.8% CRE Other, 10.9% CRE RV Park, 9.6% Consumer Unsecured, 9.0% Commercial Other, 7.3% CRE Retail, 7.0% CRE Multifamily, 6.9% CRE Office, 6.2% CRE Industrial, 5.5% CRE Mini Storage, 4.4% CRE Faith-based, 4.0% Commercial Construction, 2.6% Others, 2.8% Loan Portfolio Diversification Our core business centers on commercial lending, with an emphasis on commercial real estate. We provide a comprehensive suite of loan products tailored to the needs of small and medium-sized businesses, professionals, and individuals — including commercial real estate, commercial land and construction, and farmland loans. Additionally, we offer residential real estate, construction, and consumer loans, further supporting a broad range of client needs. Note: Balances are net book value as of September 30, 2026, before allowance for credit losses and deferred loan fees. Loans by Type Loans by Purpose Real Estate Loans by Geography 19
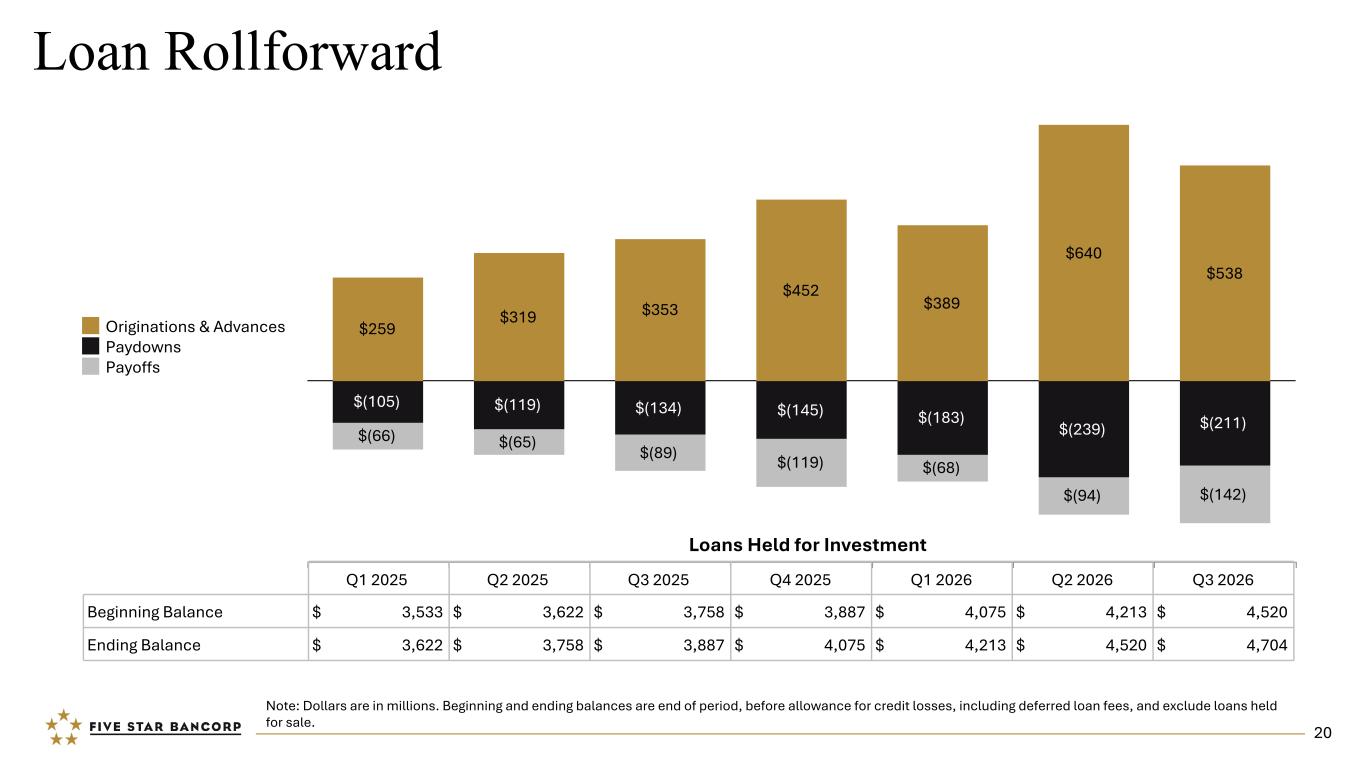
Loan Rollforward Note: Dollars are in millions. Beginning and ending balances are end of period, before allowance for credit losses, including deferred loan fees, and exclude loans held for sale. $259 $319 $353 $452 $389 $640 $538 $(105) $(119) $(134) $(145) $(183) $(239) $(211) $(66) $(65) $(89) $(119) $(68) $(94) $(142) Originations & Advances Paydowns Payoffs Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Beginning Balance $ 3,533 $ 3,622 $ 3,758 $ 3,887 $ 4,075 $ 4,213 $ 4,520 Ending Balance $ 3,622 $ 3,758 $ 3,887 $ 4,075 $ 4,213 $ 4,520 $ 4,704 Loans Held for Investment 20
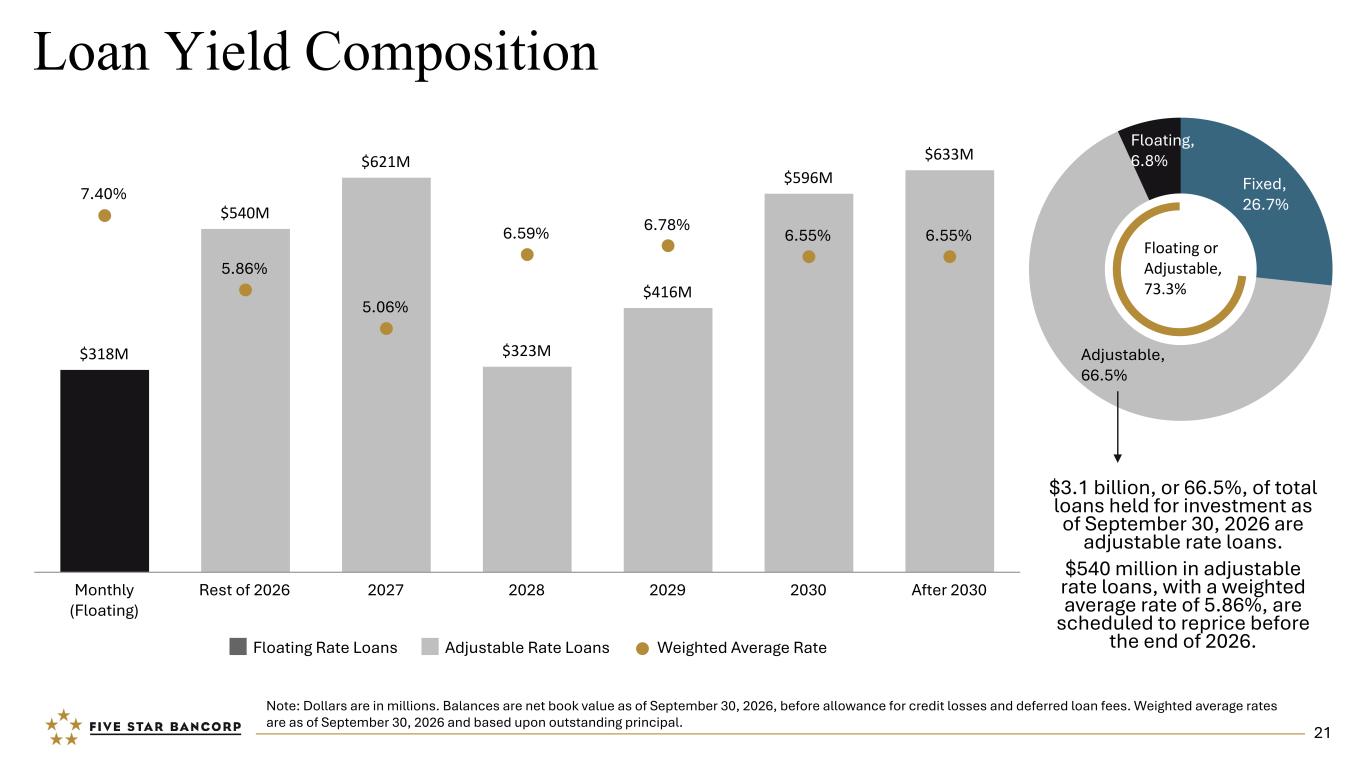
Loan Yield Composition Note: Dollars are in millions. Balances are net book value as of September 30, 2026, before allowance for credit losses and deferred loan fees. Weighted average rates are as of September 30, 2026 and based upon outstanding principal. Fixed, 26.7% Adjustable, 66.5% Floating, 6.8% Floating or Adjustable, 73.3% $318M $540M $621M $323M $416M $596M $633M 7.40% 5.86% 5.06% 6.59% 6.78% 6.55% 6.55% Floating Rate Loans Adjustable Rate Loans Weighted Average Rate Monthly (Floating) Rest of 2026 2027 2028 2029 2030 After 2030 $3.1 billion, or 66.5%, of total loans held for investment as of September 30, 2026 are adjustable rate loans. $540 million in adjustable rate loans, with a weighted average rate of 5.86%, are scheduled to reprice before the end of 2026. 21
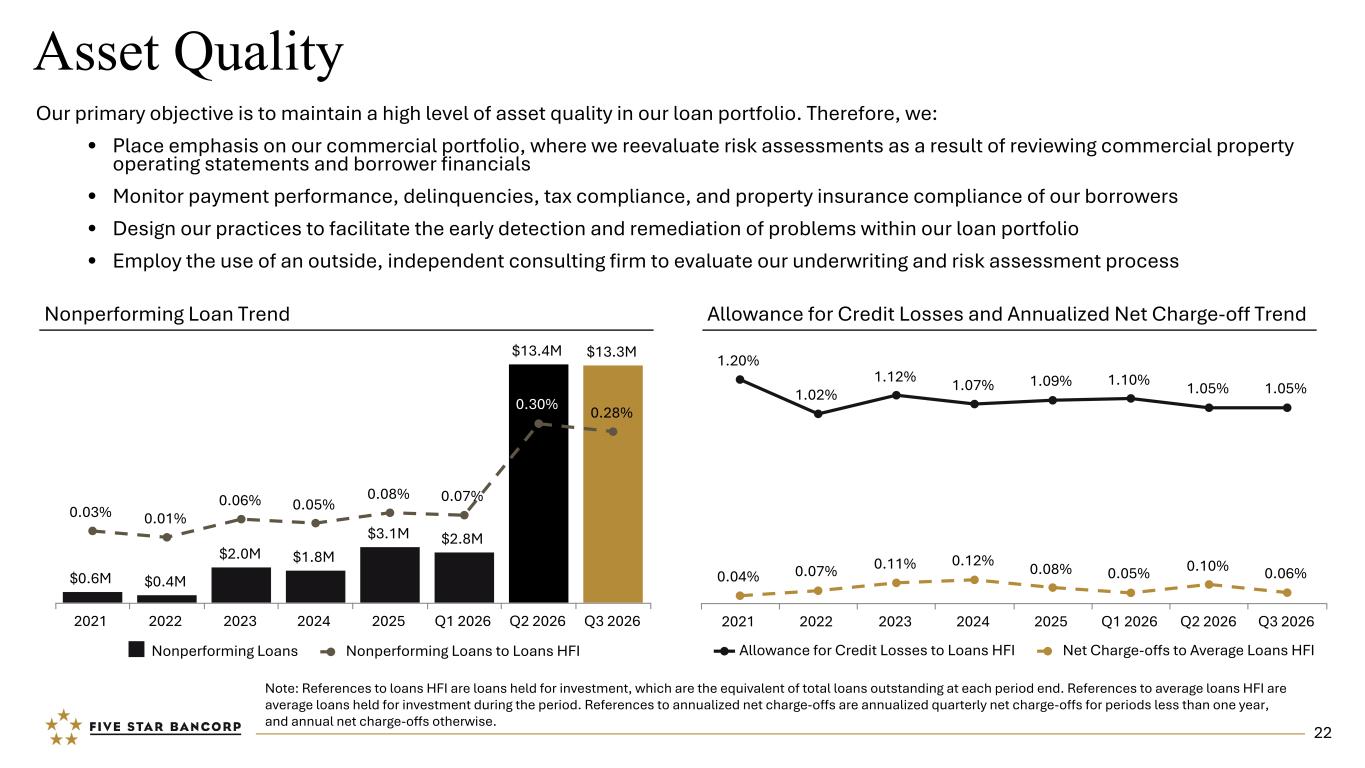
1.20% 1.02% 1.12% 1.07% 1.09% 1.10% 1.05% 1.05% 0.04% 0.07% 0.11% 0.12% 0.08% 0.05% 0.10% 0.06% Allowance for Credit Losses to Loans HFI Net Charge-offs to Average Loans HFI 2021 2022 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 Asset Quality Nonperforming Loan Trend Allowance for Credit Losses and Annualized Net Charge-off Trend Note: References to loans HFI are loans held for investment, which are the equivalent of total loans outstanding at each period end. References to average loans HFI are average loans held for investment during the period. References to annualized net charge-offs are annualized quarterly net charge-offs for periods less than one year, and annual net charge-offs otherwise. $0.6M $0.4M $2.0M $1.8M $3.1M $2.8M $13.4M $13.3M 0.03% 0.01% 0.06% 0.05% 0.08% 0.07% 0.30% 0.28% Nonperforming Loans Nonperforming Loans to Loans HFI 2021 2022 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 Our primary objective is to maintain a high level of asset quality in our loan portfolio. Therefore, we: • Place emphasis on our commercial portfolio, where we reevaluate risk assessments as a result of reviewing commercial property operating statements and borrower financials • Monitor payment performance, delinquencies, tax compliance, and property insurance compliance of our borrowers • Design our practices to facilitate the early detection and remediation of problems within our loan portfolio • Employ the use of an outside, independent consulting firm to evaluate our underwriting and risk assessment process 22
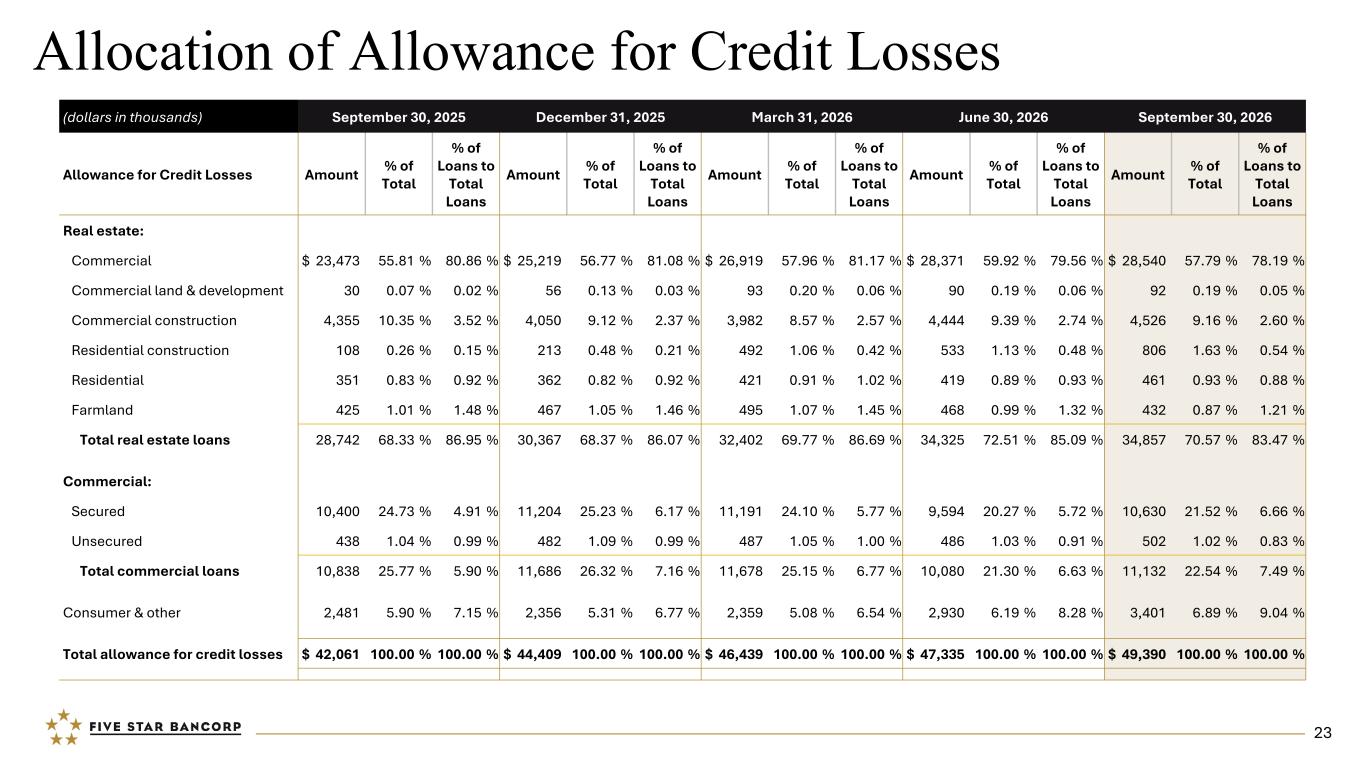
Allocation of Allowance for Credit Losses (dollars in thousands) September 30, 2025 December 31, 2025 March 31, 2026 June 30, 2026 September 30, 2026 Allowance for Credit Losses Amount % of Total % of Loans to Total Loans Amount % of Total % of Loans to Total Loans Amount % of Total % of Loans to Total Loans Amount % of Total % of Loans to Total Loans Amount % of Total % of Loans to Total Loans Real estate: Commercial $ 23,473 55.81 % 80.86 % $ 25,219 56.77 % 81.08 % $ 26,919 57.96 % 81.17 % $ 28,371 59.92 % 79.56 % $ 28,540 57.79 % 78.19 % Commercial land & development 30 0.07 % 0.02 % 56 0.13 % 0.03 % 93 0.20 % 0.06 % 90 0.19 % 0.06 % 92 0.19 % 0.05 % Commercial construction 4,355 10.35 % 3.52 % 4,050 9.12 % 2.37 % 3,982 8.57 % 2.57 % 4,444 9.39 % 2.74 % 4,526 9.16 % 2.60 % Residential construction 108 0.26 % 0.15 % 213 0.48 % 0.21 % 492 1.06 % 0.42 % 533 1.13 % 0.48 % 806 1.63 % 0.54 % Residential 351 0.83 % 0.92 % 362 0.82 % 0.92 % 421 0.91 % 1.02 % 419 0.89 % 0.93 % 461 0.93 % 0.88 % Farmland 425 1.01 % 1.48 % 467 1.05 % 1.46 % 495 1.07 % 1.45 % 468 0.99 % 1.32 % 432 0.87 % 1.21 % Total real estate loans 28,742 68.33 % 86.95 % 30,367 68.37 % 86.07 % 32,402 69.77 % 86.69 % 34,325 72.51 % 85.09 % 34,857 70.57 % 83.47 % Commercial: Secured 10,400 24.73 % 4.91 % 11,204 25.23 % 6.17 % 11,191 24.10 % 5.77 % 9,594 20.27 % 5.72 % 10,630 21.52 % 6.66 % Unsecured 438 1.04 % 0.99 % 482 1.09 % 0.99 % 487 1.05 % 1.00 % 486 1.03 % 0.91 % 502 1.02 % 0.83 % Total commercial loans 10,838 25.77 % 5.90 % 11,686 26.32 % 7.16 % 11,678 25.15 % 6.77 % 10,080 21.30 % 6.63 % 11,132 22.54 % 7.49 % Consumer & other 2,481 5.90 % 7.15 % 2,356 5.31 % 6.77 % 2,359 5.08 % 6.54 % 2,930 6.19 % 8.28 % 3,401 6.89 % 9.04 % Total allowance for credit losses $ 42,061 100.00 % 100.00 % $ 44,409 100.00 % 100.00 % $ 46,439 100.00 % 100.00 % $ 47,335 100.00 % 100.00 % $ 49,390 100.00 % 100.00 % 23
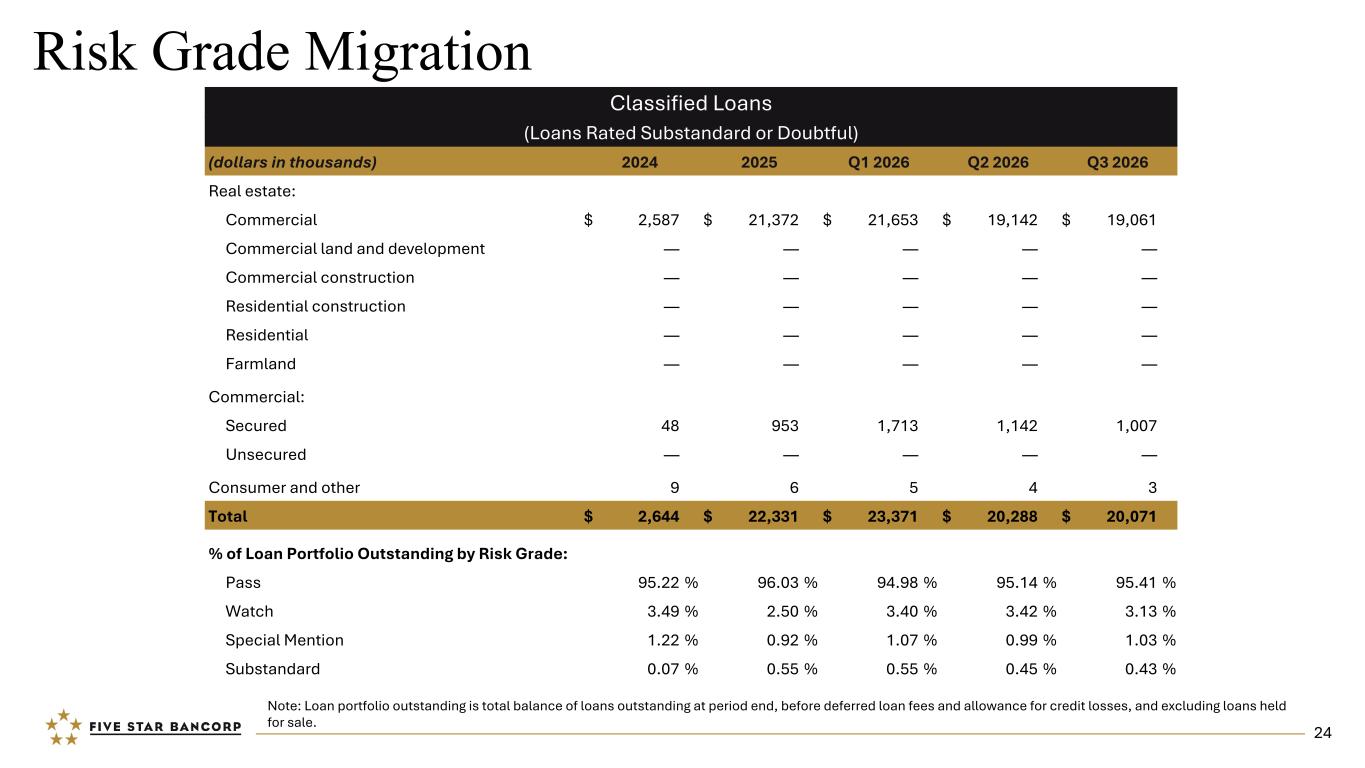
Risk Grade Migration Classified Loans (Loans Rated Substandard or Doubtful) (dollars in thousands) 2024 2025 Q1 2026 Q2 2026 Q3 2026 Real estate: Commercial $ 2,587 $ 21,372 $ 21,653 $ 19,142 $ 19,061 Commercial land and development — — — — — Commercial construction — — — — — Residential construction — — — — — Residential — — — — — Farmland — — — — — Commercial: Secured 48 953 1,713 1,142 1,007 Unsecured — — — — — Consumer and other 9 6 5 4 3 Total $ 2,644 $ 22,331 $ 23,371 $ 20,288 $ 20,071 % of Loan Portfolio Outstanding by Risk Grade: Pass 95.22 % 96.03 % 94.98 % 95.14 % 95.41 % Watch 3.49 % 2.50 % 3.40 % 3.42 % 3.13 % Special Mention 1.22 % 0.92 % 1.07 % 0.99 % 1.03 % Substandard 0.07 % 0.55 % 0.55 % 0.45 % 0.43 % Note: Loan portfolio outstanding is total balance of loans outstanding at period end, before deferred loan fees and allowance for credit losses, and excluding loans held for sale. 24
DEPOSI T A ND C A PI TA L OV ERV I EW
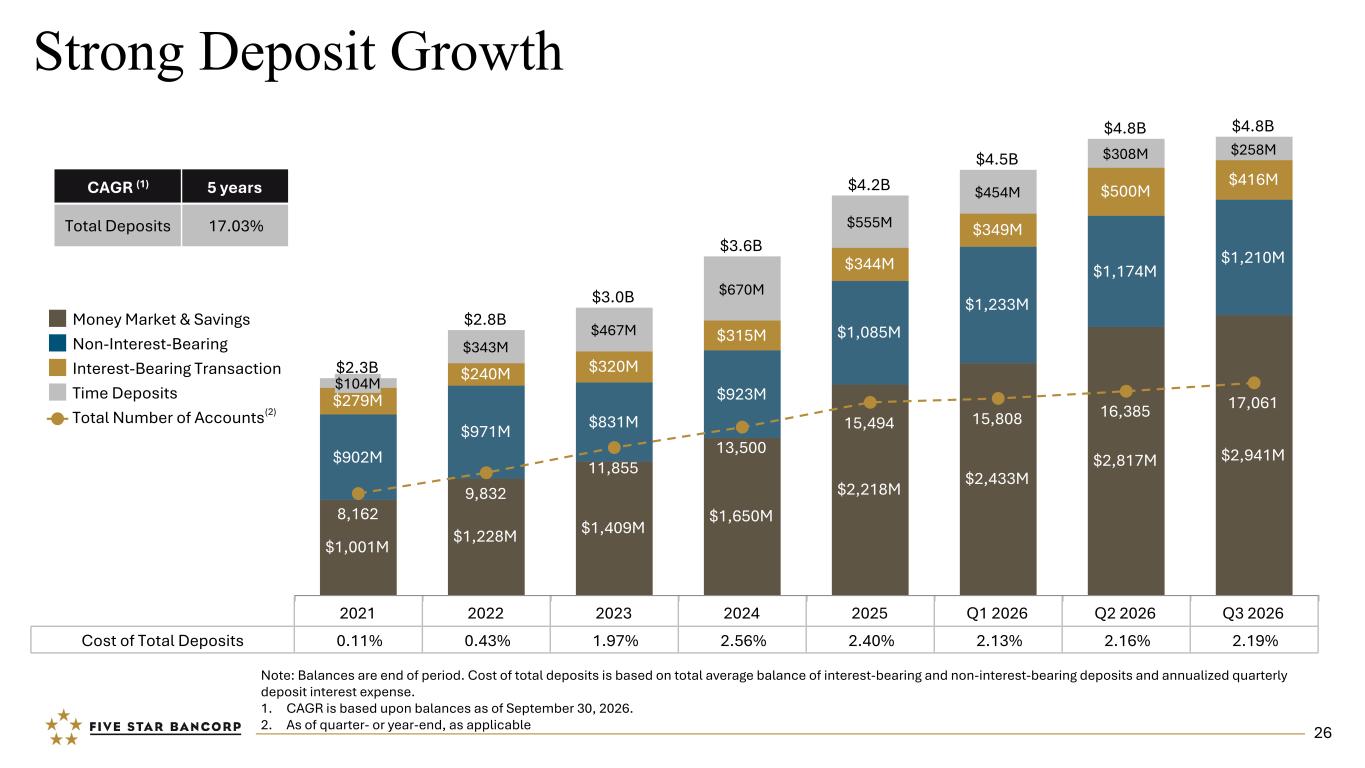
$2.3B $2.8B $3.0B $3.6B $4.2B $4.5B $4.8B $4.8B $1,001M $1,228M $1,409M $1,650M $2,218M $2,433M $2,817M $2,941M$902M $971M $831M $923M $1,085M $1,233M $1,174M $1,210M $279M $240M $320M $315M $344M $349M $500M $416M $104M $343M $467M $670M $555M $454M $308M $258M 8,162 9,832 11,855 13,500 15,494 15,808 16,385 17,061 Money Market & Savings Non-Interest-Bearing Interest-Bearing Transaction Time Deposits Total Number of Accounts 2021 2022 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 Strong Deposit Growth Note: Balances are end of period. Cost of total deposits is based on total average balance of interest-bearing and non-interest-bearing deposits and annualized quarterly deposit interest expense. 1. CAGR is based upon balances as of September 30, 2026. 2. As of quarter- or year-end, as applicable Cost of Total Deposits 0.11% 0.43% 1.97% 2.56% 2.40% 2.13% 2.16% 2.19% CAGR (1) 5 years Total Deposits 17.03% (2) 26
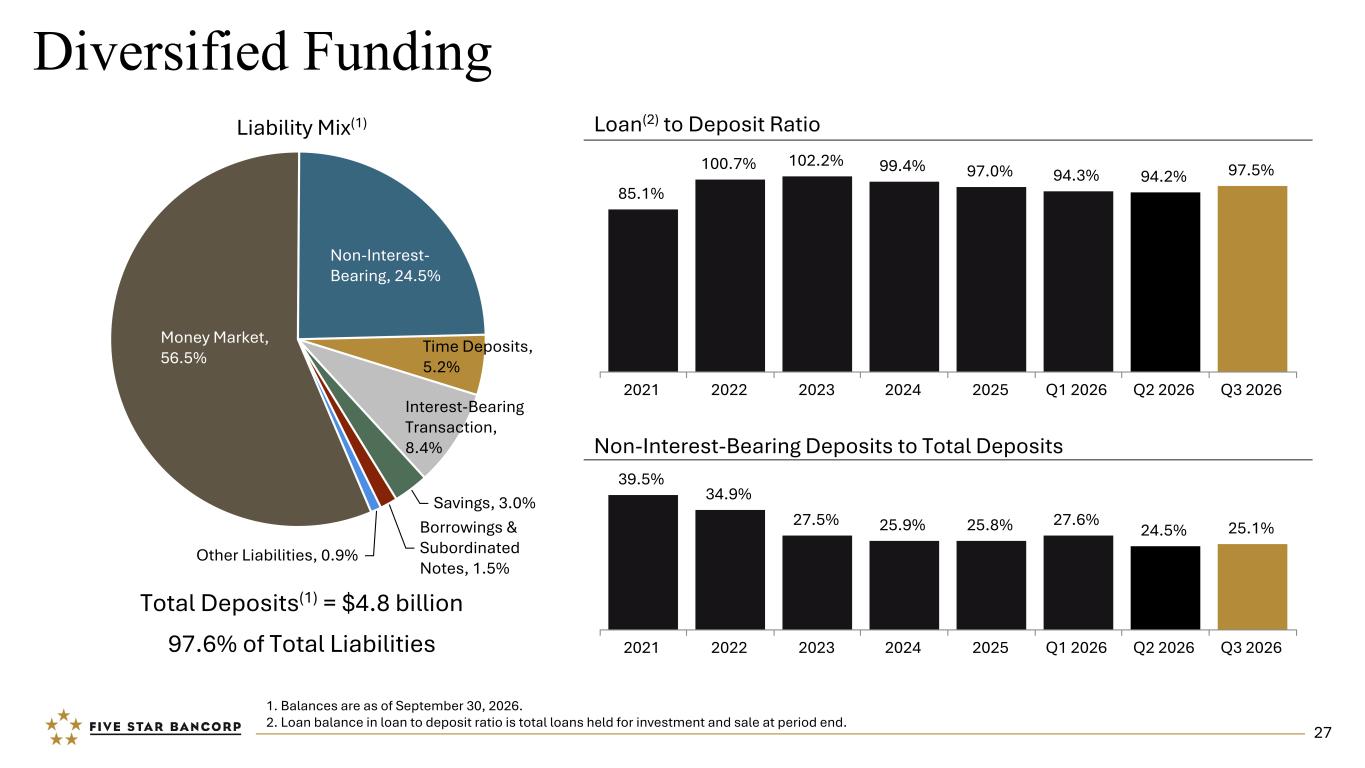
Diversified Funding Total Deposits(1) = $4.8 billion 97.6% of Total Liabilities Liability Mix(1) 1. Balances are as of September 30, 2026. 2. Loan balance in loan to deposit ratio is total loans held for investment and sale at period end. Loan(2) to Deposit Ratio Non-Interest-Bearing Deposits to Total Deposits 85.1% 100.7% 102.2% 99.4% 97.0% 94.3% 94.2% 97.5% 2021 2022 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 39.5% 34.9% 27.5% 25.9% 25.8% 27.6% 24.5% 25.1% 2021 2022 2023 2024 2025 Q1 2026 Q2 2026 Q3 2026 Money Market, 56.5% Non-Interest- Bearing, 24.5% Time Deposits, 5.2% Interest-Bearing Transaction, 8.4% Savings, 3.0% Borrowings & Subordinated Notes, 1.5% Other Liabilities, 0.9% 27
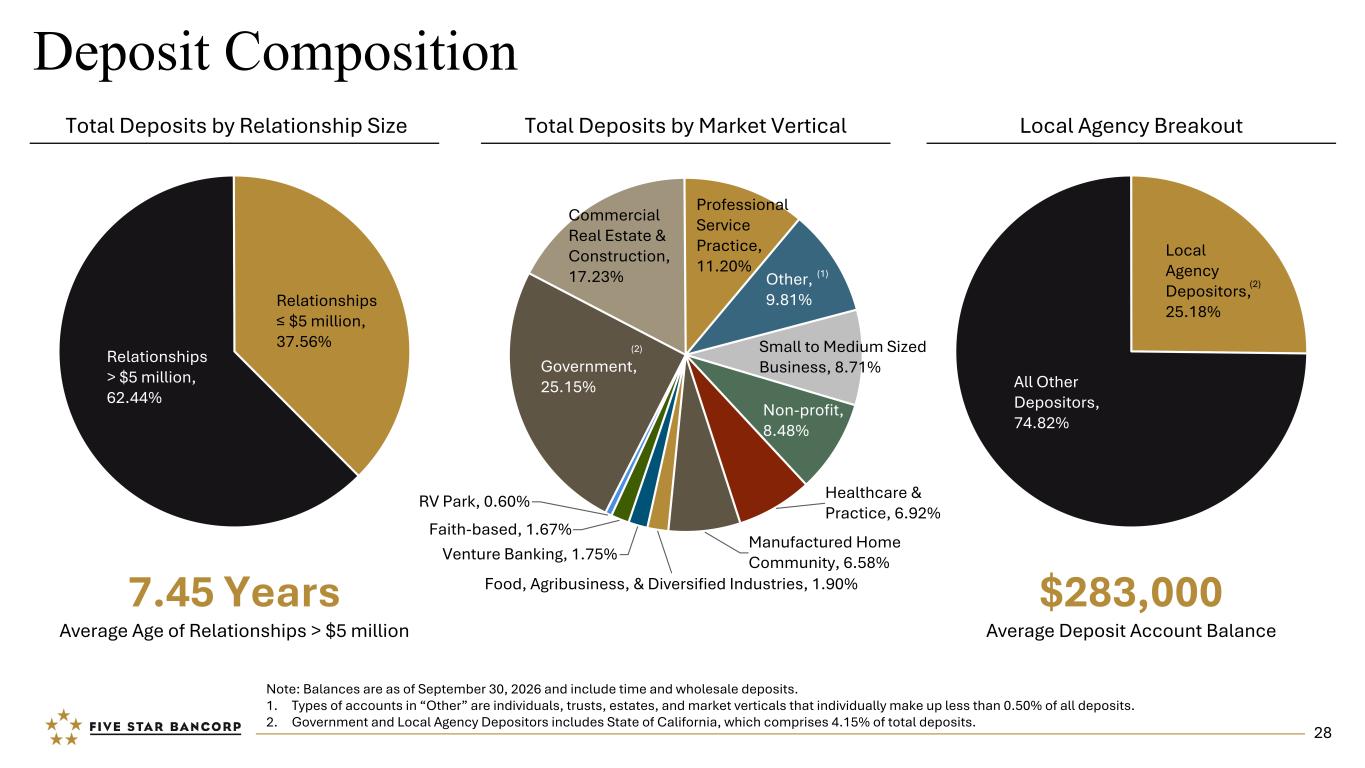
Government, 25.15% Commercial Real Estate & Construction, 17.23% Professional Service Practice, 11.20% Other, 9.81% Small to Medium Sized Business, 8.71% Non-profit, 8.48% Healthcare & Practice, 6.92% Manufactured Home Community, 6.58% Food, Agribusiness, & Diversified Industries, 1.90% Venture Banking, 1.75% Faith-based, 1.67% RV Park, 0.60% Deposit Composition 7.45 Years Average Age of Relationships > $5 million Note: Balances are as of September 30, 2026 and include time and wholesale deposits. 1. Types of accounts in “Other” are individuals, trusts, estates, and market verticals that individually make up less than 0.50% of all deposits. 2. Government and Local Agency Depositors includes State of California, which comprises 4.15% of total deposits. $283,000 Average Deposit Account Balance Relationships > $5 million, 62.44% Relationships ≤ $5 million, 37.56% Total Deposits by Relationship Size Local Agency BreakoutTotal Deposits by Market Vertical Local Agency Depositors, 25.18% All Other Depositors, 74.82% (2) (1) (2) 28
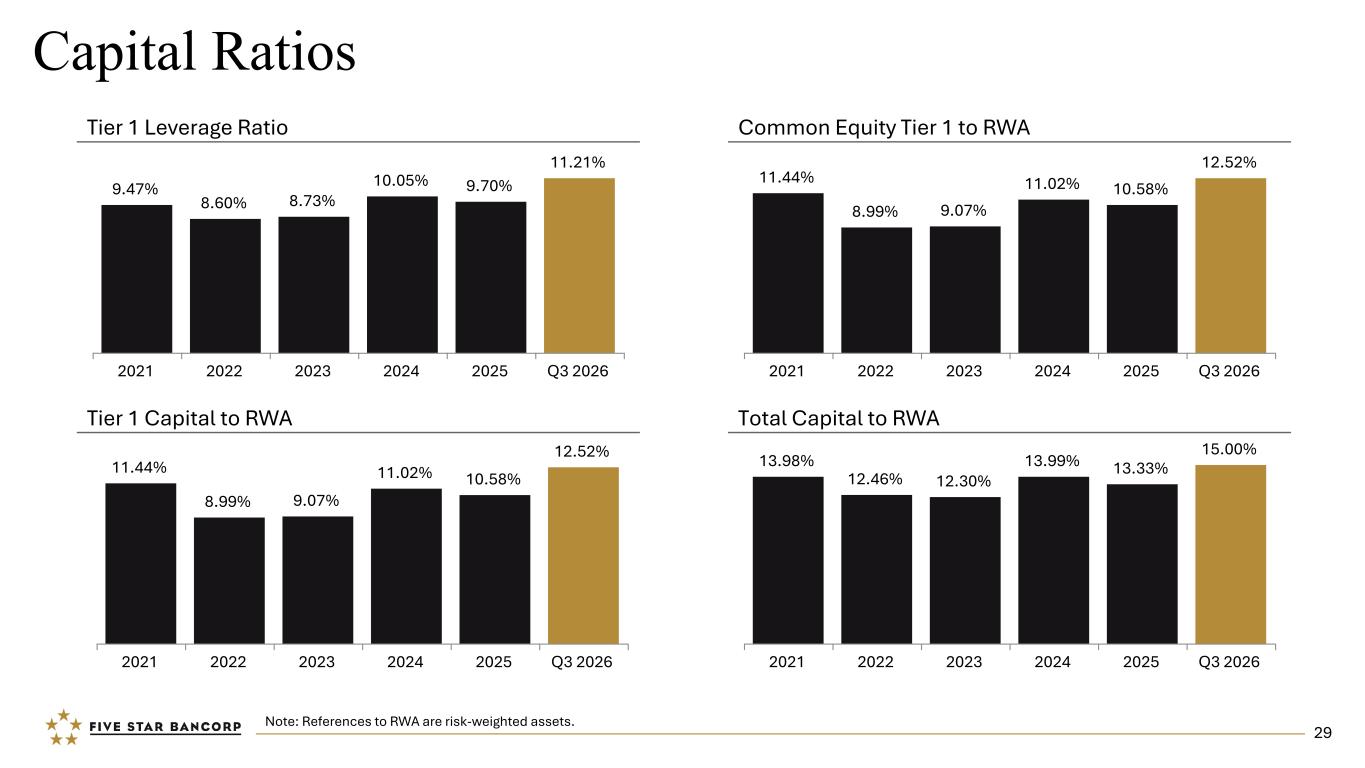
Capital Ratios Tier 1 Leverage Ratio Tier 1 Capital to RWA Total Capital to RWA Common Equity Tier 1 to RWA Note: References to RWA are risk-weighted assets. 9.47% 8.60% 8.73% 10.05% 9.70% 11.21% 2021 2022 2023 2024 2025 Q3 2026 11.44% 8.99% 9.07% 11.02% 10.58% 12.52% 2021 2022 2023 2024 2025 Q3 2026 11.44% 8.99% 9.07% 11.02% 10.58% 12.52% 2021 2022 2023 2024 2025 Q3 2026 13.98% 12.46% 12.30% 13.99% 13.33% 15.00% 2021 2022 2023 2024 2025 Q3 2026 29
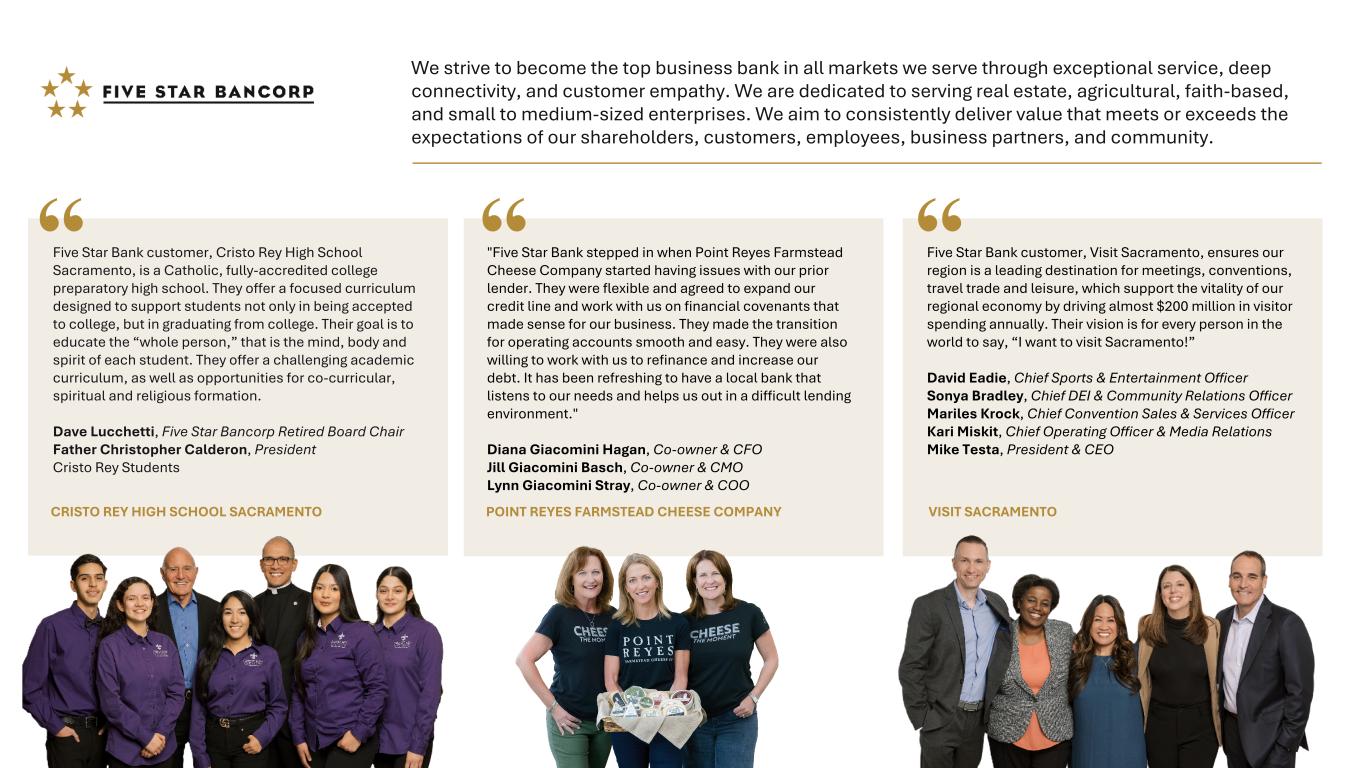
“Five Star Bank customer, Visit Sacramento, ensures our region is a leading destination for meetings, conventions, travel trade and leisure, which support the vitality of our regional economy by driving almost $200 million in visitor spending annually. Their vision is for every person in the world to say, “I want to visit Sacramento!” David Eadie, Chief Sports & Entertainment Officer Sonya Bradley, Chief DEI & Community Relations Officer Mariles Krock, Chief Convention Sales & Services Officer Kari Miskit, Chief Operating Officer & Media Relations Mike Testa, President & CEO VISIT SACRAMENTO Five Star Bank customer, Cristo Rey High School Sacramento, is a Catholic, fully-accredited college preparatory high school. They offer a focused curriculum designed to support students not only in being accepted to college, but in graduating from college. Their goal is to educate the “whole person,” that is the mind, body and spirit of each student. They offer a challenging academic curriculum, as well as opportunities for co-curricular, spiritual and religious formation. Dave Lucchetti, Five Star Bancorp Retired Board Chair Father Christopher Calderon, President Cristo Rey Students CRISTO REY HIGH SCHOOL SACRAMENTO “ "Five Star Bank stepped in when Point Reyes Farmstead Cheese Company started having issues with our prior lender. They were flexible and agreed to expand our credit line and work with us on financial covenants that made sense for our business. They made the transition for operating accounts smooth and easy. They were also willing to work with us to refinance and increase our debt. It has been refreshing to have a local bank that listens to our needs and helps us out in a difficult lending environment." Diana Giacomini Hagan, Co-owner & CFO Jill Giacomini Basch, Co-owner & CMO Lynn Giacomini Stray, Co-owner & COO POINT REYES FARMSTEAD CHEESE COMPANY “ We strive to become the top business bank in all markets we serve through exceptional service, deep connectivity, and customer empathy. We are dedicated to serving real estate, agricultural, faith-based, and small to medium-sized enterprises. We aim to consistently deliver value that meets or exceeds the expectations of our shareholders, customers, employees, business partners, and community.
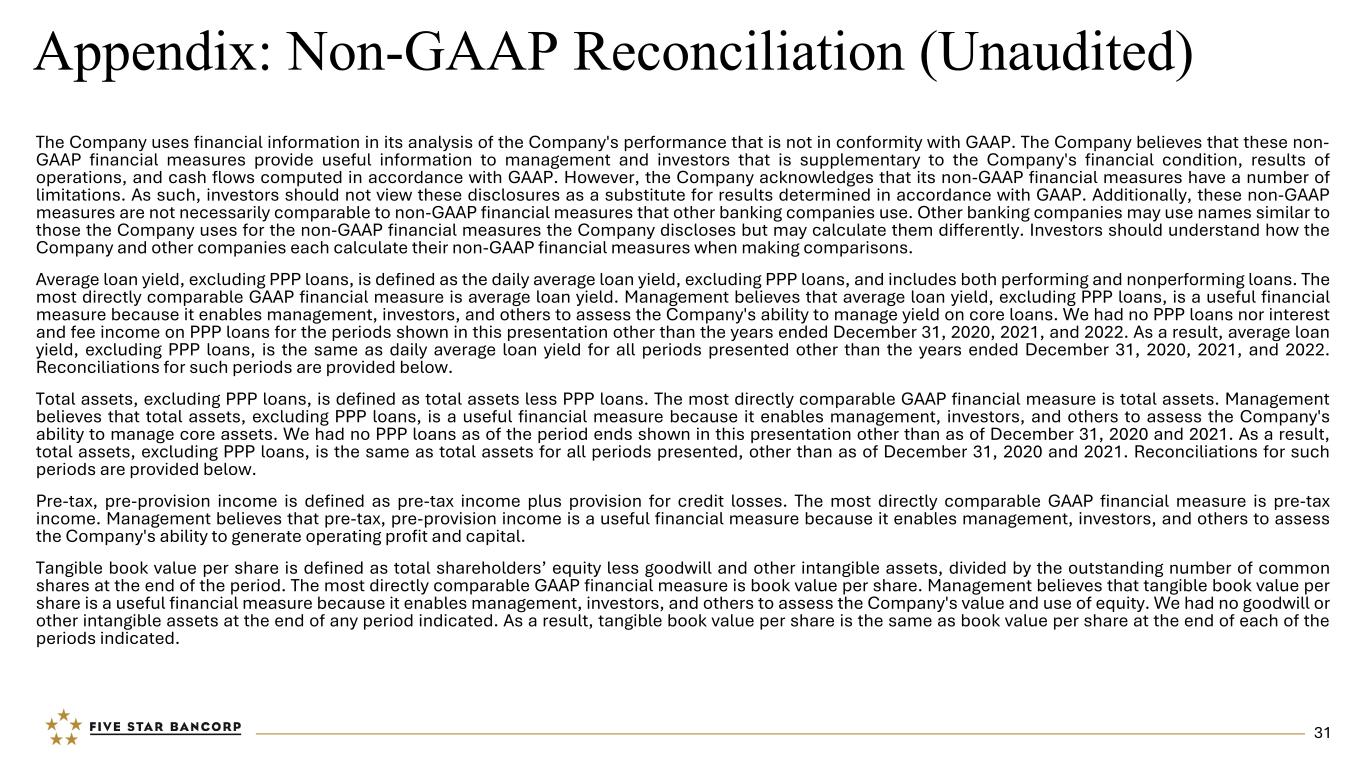
Appendix: Non-GAAP Reconciliation (Unaudited) The Company uses financial information in its analysis of the Company's performance that is not in conformity with GAAP. The Company believes that these non- GAAP financial measures provide useful information to management and investors that is supplementary to the Company's financial condition, results of operations, and cash flows computed in accordance with GAAP. However, the Company acknowledges that its non-GAAP financial measures have a number of limitations. As such, investors should not view these disclosures as a substitute for results determined in accordance with GAAP. Additionally, these non-GAAP measures are not necessarily comparable to non-GAAP financial measures that other banking companies use. Other banking companies may use names similar to those the Company uses for the non-GAAP financial measures the Company discloses but may calculate them differently. Investors should understand how the Company and other companies each calculate their non-GAAP financial measures when making comparisons. Average loan yield, excluding PPP loans, is defined as the daily average loan yield, excluding PPP loans, and includes both performing and nonperforming loans. The most directly comparable GAAP financial measure is average loan yield. Management believes that average loan yield, excluding PPP loans, is a useful financial measure because it enables management, investors, and others to assess the Company's ability to manage yield on core loans. We had no PPP loans nor interest and fee income on PPP loans for the periods shown in this presentation other than the years ended December 31, 2020, 2021, and 2022. As a result, average loan yield, excluding PPP loans, is the same as daily average loan yield for all periods presented other than the years ended December 31, 2020, 2021, and 2022. Reconciliations for such periods are provided below. Total assets, excluding PPP loans, is defined as total assets less PPP loans. The most directly comparable GAAP financial measure is total assets. Management believes that total assets, excluding PPP loans, is a useful financial measure because it enables management, investors, and others to assess the Company's ability to manage core assets. We had no PPP loans as of the period ends shown in this presentation other than as of December 31, 2020 and 2021. As a result, total assets, excluding PPP loans, is the same as total assets for all periods presented, other than as of December 31, 2020 and 2021. Reconciliations for such periods are provided below. Pre-tax, pre-provision income is defined as pre-tax income plus provision for credit losses. The most directly comparable GAAP financial measure is pre-tax income. Management believes that pre-tax, pre-provision income is a useful financial measure because it enables management, investors, and others to assess the Company's ability to generate operating profit and capital. Tangible book value per share is defined as total shareholders’ equity less goodwill and other intangible assets, divided by the outstanding number of common shares at the end of the period. The most directly comparable GAAP financial measure is book value per share. Management believes that tangible book value per share is a useful financial measure because it enables management, investors, and others to assess the Company's value and use of equity. We had no goodwill or other intangible assets at the end of any period indicated. As a result, tangible book value per share is the same as book value per share at the end of each of the periods indicated. 31
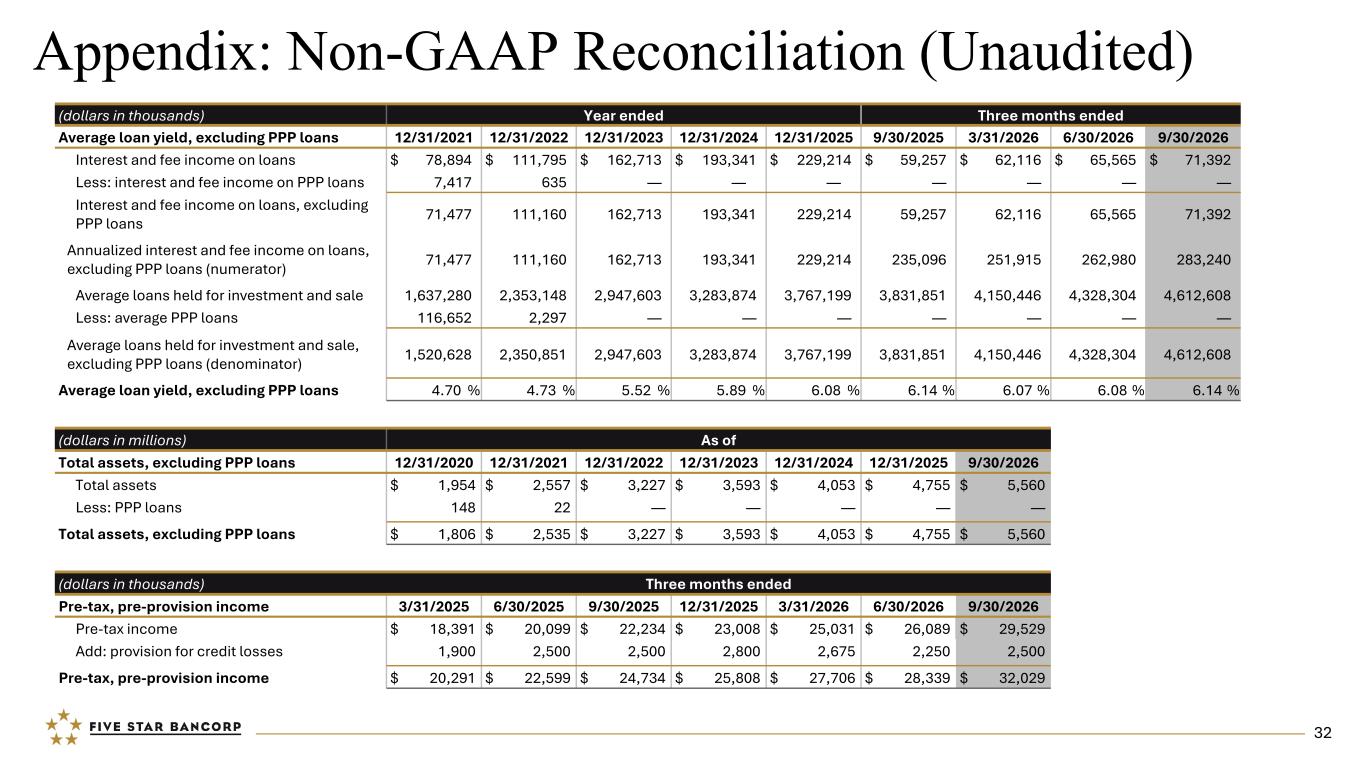
Appendix: Non-GAAP Reconciliation (Unaudited) (dollars in millions) As of Total assets, excluding PPP loans 12/31/2020 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2026 Total assets $ 1,954 $ 2,557 $ 3,227 $ 3,593 $ 4,053 $ 4,755 $ 5,560 Less: PPP loans 148 22 — — — — — Total assets, excluding PPP loans $ 1,806 $ 2,535 $ 3,227 $ 3,593 $ 4,053 $ 4,755 $ 5,560 (dollars in thousands) Three months ended Pre-tax, pre-provision income 3/31/2025 6/30/2025 9/30/2025 12/31/2025 3/31/2026 6/30/2026 9/30/2026 Pre-tax income $ 18,391 $ 20,099 $ 22,234 $ 23,008 $ 25,031 $ 26,089 $ 29,529 Add: provision for credit losses 1,900 2,500 2,500 2,800 2,675 2,250 2,500 Pre-tax, pre-provision income $ 20,291 $ 22,599 $ 24,734 $ 25,808 $ 27,706 $ 28,339 $ 32,029 (dollars in thousands) Year ended Three months ended Average loan yield, excluding PPP loans 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 9/30/2025 3/31/2026 6/30/2026 9/30/2026 Interest and fee income on loans $ 78,894 $ 111,795 $ 162,713 $ 193,341 $ 229,214 $ 59,257 $ 62,116 $ 65,565 $ 71,392 Less: interest and fee income on PPP loans 7,417 635 — — — — — — — Interest and fee income on loans, excluding PPP loans 71,477 111,160 162,713 193,341 229,214 59,257 62,116 65,565 71,392 Annualized interest and fee income on loans, excluding PPP loans (numerator) 71,477 111,160 162,713 193,341 229,214 235,096 251,915 262,980 283,240 Average loans held for investment and sale 1,637,280 2,353,148 2,947,603 3,283,874 3,767,199 3,831,851 4,150,446 4,328,304 4,612,608 Less: average PPP loans 116,652 2,297 — — — — — — — Average loans held for investment and sale, excluding PPP loans (denominator) 1,520,628 2,350,851 2,947,603 3,283,874 3,767,199 3,831,851 4,150,446 4,328,304 4,612,608 Average loan yield, excluding PPP loans 4.70 % 4.73 % 5.52 % 5.89 % 6.08 % 6.14 % 6.07 % 6.08 % 6.14 % 32