Exhibit 99.1
| © 2026 AAR CORP. All rights reserved worldwide Investor Education Presentation October 2026 |
| Disclaimer This presentation and its contents are confidential and proprietary to AAR CORP. (the “Company,” “AAR,” “we” and “our”), and no part of it or its subject matter may be reproduced, redistributed, or otherwise divulged, directly or indirectly, to any other person or published in whole or in part for any purpose without the prior written consent of the Company. This presentation is provided for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any securities. This presentation does not contain all the information that is or may be material to investors or potential investors, is not intended to provide the basis for any third-party evaluation of any securities or other financial instruments and should not be considered as advice or a recommendation to investors or potential investors in respect of the holding, purchasing or selling of securities or other financial instruments. This presentation contains certain forward-looking statements as that term is defined in the Private Securities Litigation Reform Act of 1995. Forward-looking statements often address our expected future operating and financial performance and financial condition, or targets, goals, commitments, and other business plans, and often may also be identified because they contain words such as “anticipate,” “continue,” “estimate,” “expect,” “project,” “plan,” “potential,” “predict,” “intend,” “believe,” “may,” “might,” “will,” “would,” “should,” “seek,” “could,” “positions,” “likely,” “target,” “goal,” “strategy” or similar expressions and the negatives of those terms. These forward-looking statements are subject to certain risks and uncertainties that may cause actual results to differ materially from historical results or those anticipated, depending on a variety of factors, including: factors that adversely affect the commercial aviation industry; adverse events and negative publicity in the aviation industry; a reduction in sales to the U.S. government and its contractors; cost overruns and losses on fixed-price contracts; nonperformance by subcontractors or suppliers; our ability to manage our operational footprint; a reduction in outsourcing of maintenance and repair activity by airlines; a shortage of skilled personnel or work stoppages; competition from other companies; financial, operational and legal risks arising as a result of operating internationally; the failure to complete, integrate and realize the anticipated benefits of acquisitions, including execution of related operational and financial plans; circumstances associated with divestitures; the inability to recover costs due to fluctuations in market values for aviation products and equipment; cyber or other security threats or disruptions; the need to make significant capital expenditures to keep pace with technological developments in our industry; restrictions on the use of intellectual property and tooling important to our business; the inability to protect the value of our intellectual property; our ability to manage our debt and fund our other liquidity needs; limitations on our ability to access the debt and equity capital markets or to draw down funds under loan agreements; non-compliance with restrictive and financial covenants contained in our debt and loan agreements; changes in or non-compliance with laws and regulations related to federal contractors, the aviation industry, international operations, safety and environmental matters, and the costs of complying with such laws and regulations; exposure to product liability and property claims that may be in excess of our liability insurance coverage; the risk that the pending acquisition (the “MRO Holdings Acquisition”) of MRO Holdings, Inc., a sociedad anónima organized under the laws of Panama (“MRO Holdings”), may not be completed in a timely manner or at all; the failure to satisfy the closing conditions to the MRO Holdings Acquisition, including the receipt of required regulatory approvals; the occurrence of any event, change or other circumstance or condition that could give rise to the termination of the Share Purchase Agreement entered in connection with the MRO Holdings Acquisition, including in certain circumstances requiring the Company to pay a termination fee; the ability of the Company to obtain the necessary financing arrangements; the effect of the announcement or pendency of the MRO Holdings Acquisition on the Company’s business relationships, operating results and business generally; risks that the MRO Holdings Acquisition may disrupt the Company’s current business plans and operations; the Company’s ability to retain and hire key personnel in light of the MRO Holdings Acquisition; risks related to diverting management’s attention from the Company’s ongoing business operations; unexpected costs, charges or expenses resulting from the MRO Holdings Acquisition; potential litigation relating to the MRO Holdings Acquisition; the ability of the Company to successfully integrate MRO Holdings and its subsidiaries following the Closing and to achieve the anticipated benefits of the MRO Holdings Acquisition, including estimated cost and operational synergies, and the timeline to realize such benefits; the effects of the MRO Holdings Acquisition on the Company’s earnings, financial condition, net leverage ratio and credit ratings; the impact of the MRO Holdings Acquisition on the Company’s business and future financial condition and operating results, including the ability of the Company or MRO Holdings to repay or prepay indebtedness incurred in connection with the MRO Holdings Acquisition or otherwise; and other factors disclosed in the section entitled “Risk Factors” of the Company’s Annual Report on Form 10-K for the fiscal year ended May 31, 2026 and the Company’s Quarterly Report on Form 10-Q for the fiscal quarter ended August 31, 2026, in each case as may be updated or supplemented by any subsequent filings with the Securities and Exchange Commission (the “SEC”). Should one or more of these risks or uncertainties materialize adversely, or should underlying assumptions or estimates prove incorrect, actual results may vary materially from those described. The Company derives many of its forward-looking statements from its operating budgets and forecasts, which are based on many detailed assumptions. While the Company believes that its assumptions are reasonable, it cautions that it is very difficult to predict the impact of known factors, and it is impossible to anticipate all factors that could affect actual results. These events and uncertainties are difficult or impossible to predict accurately and many are beyond the Company’s control. The risks described in these reports are not the only risks the Company faces, as additional risks and uncertainties not currently known or foreseeable or deemed immaterial may materially adversely affect the Company’s business, financial condition or results of operations in future periods. All forward-looking statements attributable to the Company, or persons acting on its behalf, are expressly qualified in their entirety by the foregoing cautionary statements. The forward-looking statements included in this presentation are made only as of the date hereof. The Company assumes no obligation to update or revise any forward-looking statement, whether as a result of new information, future events or otherwise, except as required by law. This presentation includes certain forward-looking statements regarding the expected benefits of the MRO Holdings Acquisition, including the expected achievement of run-rate cost synergies, estimates reflecting such run-rate cost synergies, expected tax benefits and expected growth in financial performance as a result of the MRO Holdings Acquisition. There can be no assurance that any of these outcomes will occur or will be achieved within the expected timeframes or at the levels anticipated. These estimates and assumptions are inherently subject to significant uncertainties and risks, including those relating to the successful integration of MRO Holdings and the Company’s ability to achieve the anticipated benefits of the MRO Holdings Acquisition. These expected benefits are based on management’s current estimates and assumptions, have not been realized as of the date of this presentation, do not reflect the costs required to achieve them, and should not be viewed as a projection that such benefits will be realized within the anticipated timeframe, or at all. Additionally, certain estimates, targets and the pro forma data presented in this presentation have been included for illustrative purposes and are based on AAR’s internal models and financial and accounting practices. AAR’s independent auditors have not audited, reviewed, compiled or performed any procedures with respect to such information for the purpose of their inclusion in this presentation, and accordingly, they have not expressed an opinion or provided any other form of assurance with respect thereto for the purpose of this presentation. Although such information is based upon assumptions that AAR believes to be reasonable, there can be no assurance that actual results will not differ, perhaps materially, from such information. Such information should not be relied upon as being necessarily indicative of future results. Unless otherwise indicated, the historical financial information of AAR included in this presentation has been prepared in accordance with accounting principles generally accepted in the United States (“GAAP”), and the historical financial information of MRO Holdings included in this presentation has been prepared in accordance with International Financial Reporting Standards (“IFRS”), which differs in certain significant respects from GAAP. As a result, MRO Holdings’ historical financial information may not be comparable in all respects to AAR’s historical financial information or to financial information prepared in accordance with GAAP. AAR has a fiscal year ending on May 31 of each year and MRO Holdings has a fiscal year ending on December 31 of each year. In this presentation, unless indicated otherwise or the context otherwise requires, any reference to a year in the context of AAR’s financial statements, information or data preceded by the word “fiscal” or the letters “FY” refers to AAR’s fiscal year ended May 31 of that year and any reference to a year in the context of MRO’s financial statements, information or data preceded by the word “fiscal” or the letters “FY” refers to MRO’s fiscal year ended December 31 of that year. In light of the different fiscal year ends for AAR and MRO Holdings, certain financial information of MRO Holdings in this presentation has been derived from information for different periods in order to conform to our fiscal periods. Any reference to a year preceded by the letters “CY” refers to a calendar year ending on December 31. Unless otherwise indicated, pro forma financial information in this presentation gives effect to the MRO Holdings Acquisition and the related financing transactions as if they had occurred on June 1, 2025, the first day of AAR’s fiscal year 2026. Because AAR’s and MRO Holdings’ fiscal years end on different dates, pro forma information for FY2026 combines AAR’s financial information for the fiscal year ended May 31, 2026 with MRO Holdings’ financial information for the twelve months ended March 31, 2026, which was derived by adding MRO Holdings’ financial information for the year ended December 31, 2025 to its financial information for the three months ended March 31, 2026 and subtracting its financial information for the three months ended March 31, 2025. The pro forma financial information includes preliminary adjustments to conform MRO Holdings’ financial information from IFRS to GAAP and to align MRO Holdings’ accounting policies with those of AAR. AAR has not completed its assessment of all such adjustments, and such adjustments are preliminary and subject to change, which could be material, as additional information becomes available and additional analysis is performed. The pro forma financial information is unaudited, is presented for illustrative purposes only, has not been prepared in accordance with Article 11 of Regulation S-X, and may differ materially from pro forma financial information prepared in accordance with Article 11 of Regulation S-X. It does not purport to represent what AAR’s results would have been had the MRO Holdings Acquisition been completed on the dates indicated or to project AAR’s results for any future period. Information relating to MRO Holdings has been provided by MRO Holdings and has not been independently verified by AAR. This presentation also includes certain preliminary estimated unaudited financial information of MRO Holdings as of and for the three and nine months ended September 30, 2026, and pro forma preliminary estimated financial information for the twelve months ended August 31, 2026, which combines AAR’s financial information for the twelve months ended August 31, 2026 with MRO Holdings’ preliminary estimated financial information for the twelve months ended September 30, 2026. MRO Holdings’ preliminary estimated financial information for the twelve months ended September 30, 2026 was derived by adding MRO Holdings’ financial information for the year ended December 31, 2025 to its preliminary estimated financial information for the nine months ended September 30, 2026 and subtracting its preliminary estimated financial information for the nine months ended September 30, 2025. Such preliminary estimated information has been prepared by, and is the responsibility of, management, reflects estimates based on currently available information, and remains subject to the completion of financial closing procedures. No independent auditor has audited, reviewed, compiled or performed any procedures with respect to such information. Actual results may differ materially, and you should not place undue reliance on such information. This presentation includes certain financial information of the Company that has not been prepared in accordance with accounting principles generally accepted in the United States (“non-GAAP”), including but not limited to Adjusted Sales, Adjusted EBITDA, Adjusted EBITDA Margin, Adjusted Operating Income, Adjusted Operating Margin, Adjusted Operating Cash Flow, Net Debt and net leverage, pro forma and as adjusted pro forma versions of such measures, and certain financial information of MRO Holdings that has not been prepared in accordance with IFRS (“non-IFRS”), including but not limited to Adjusted Operating Revenues, Adjusted EBITDA, Adjusted EBITDA Margin and Adjusted Operating Cash Flow, and, in each case, certain ratios and other metrics derived therefrom. Please see the Appendix of this presentation for more information about these non-GAAP measures of the Company and non-IFRS measures of MRO Holdings. The Company is not providing a reconciliation of forward-looking non-GAAP financial measures of the Company or forward-looking non-IFRS financial measures of MRO Holdings to the most directly comparable forward-looking GAAP or IFRS financial measures, as applicable, because the information is not available without unreasonable effort. This is due to the inherent difficulty of forecasting the timing and amount of certain items, such as, but not limited to, unusual gains and losses, the ultimate outcome of pending litigation, the impact and timing of potential acquisitions and divestitures, and other structural changes or their probable significance. Each of the adjustments has not occurred, are out of the Company’s control or cannot be reasonably predicted. For this reason, the Company is unable to address the probable significance of the unavailable information. Non- GAAP and non-IFRS financial measures should not be used as a substitute for the corresponding GAAP or IFRS measures. Non-GAAP and Non-IFRS measures in this presentation may be calculated in a way that is not comparable to similarly-titled measures reported by other companies. These non-GAAP and non-IFRS financial measures are not measures of financial performance in accordance with GAAP or IFRS and may exclude items that are significant in understanding and assessing the Company’s and MRO Holdings’ financial results. Therefore, these measures should not be considered in isolation or as an alternative to other measures of the Company’s or MRO Holdings’ profitability, liquidity or performance under GAAP or IFRS. Schedules that reconcile certain non-GAAP or non-IFRS financial measures to a financial measure included in financial statements calculated and presented in accordance with GAAP or IFRS are included in the appendix to this presentation. This presentation contains information concerning the Company’s industry, including market position, market size, and growth rates of the markets in which the Company participates that are based on industry publications and reports. This information involves a number of assumptions and limitations, and you are cautioned not to give undue weight to these estimates. The Company has not independently verified the accuracy or completeness of the data contained in these industry publications and reports. The industry in which the Company operates is subject to a high degree of uncertainty and risk due to a variety of factors. These and other factors could cause results to differ materially from those expressed in these publications and reports. This presentation may contain trademarks, service marks, trade names and copyrights of other companies, which are the property of their respective owners, and the use herein does not imply an affiliation with or endorsement by the owners of these trademarks, service marks, tradenames and copyrights. Solely for convenience, some of the trademarks, service marks, trade names and copyrights referred to in this presentation may be listed without the TM, SM, ©, or ® symbols, but the Company will assert, to the fullest extent under applicable law, the rights of the applicable owners, if any, to these trademarks, service marks, trade names, and copyrights. Third-party logos included herein may represent past customers, present customers, competitors, or may be provided simply for illustrative purposes only. Inclusion of such logos does not necessarily imply affiliation with or endorsement by such firms or businesses. There is no guarantee the Company will work, or continue to work, with any of the firms or businesses whose logos are included herein. Certain amounts, percentages and other figures in this presentation have been subject to rounding adjustments and may not sum due to rounding. © 2026 AAR CORP. All rights reserved worldwide 2 |
| Today’s Agenda © 2026 AAR CORP. All rights reserved worldwide 3 I Acquisition Overview Appendix II AAR Overview III MRO Holdings Overview IV Key Credit Highlights V Financial Overview |
| Today’s Presenters © 2026 AAR CORP. All rights reserved worldwide 4 Dylan Wolin Senior Vice President & CFO John M. Holmes Chairman, President & CEO Ben Esbaum VP, Strategy & Corporate Development Christopher Tillett VP, Investor Relations |
| I. Acquisition Overview © 2026 AAR CORP. All rights reserved worldwide 5 |
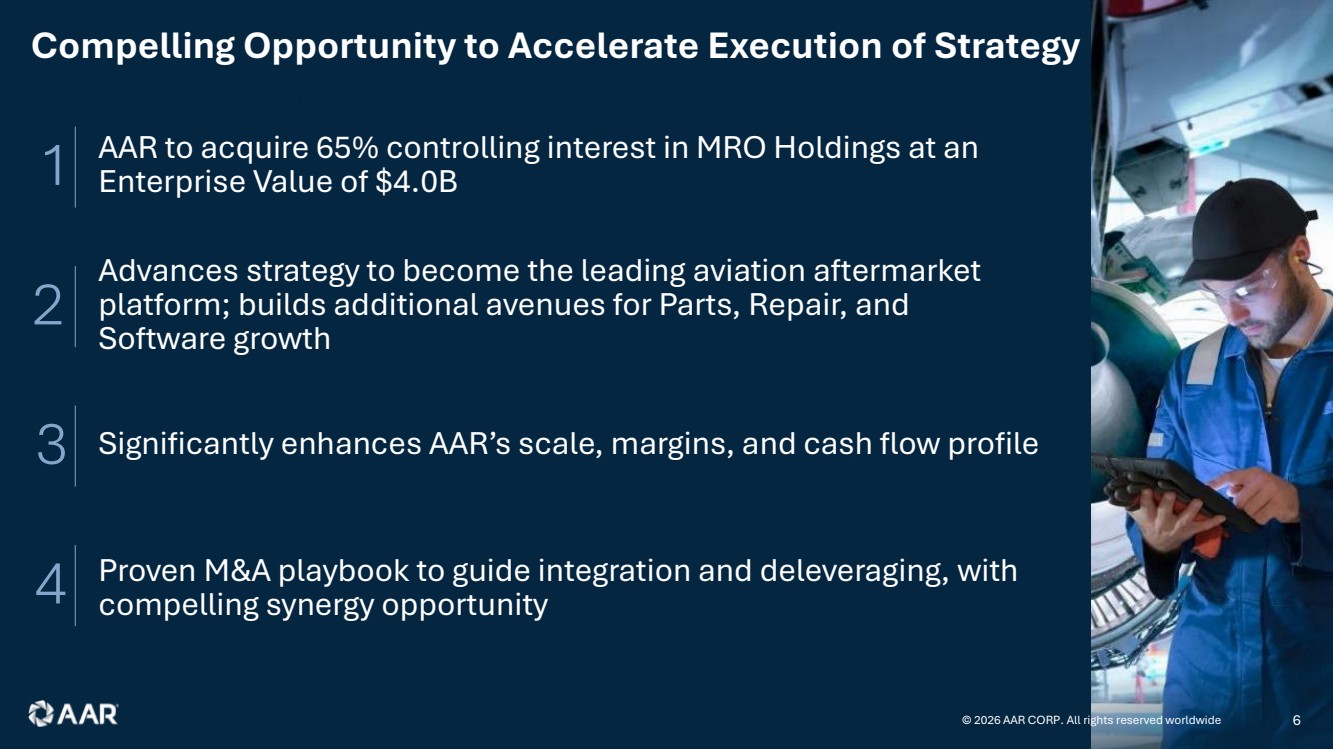
| Compelling Opportunity to Accelerate Execution of Strategy 1 AAR to acquire 65% controlling interest in MRO Holdings at an Enterprise Value of $4.0B Proven M&A playbook to guide integration and deleveraging, with 4 compelling synergy opportunity © 2026 AAR CORP. All rights reserved worldwide 6 2 Advances strategy to become the leading aviation aftermarket platform; builds additional avenues for Parts, Repair, and Software growth 3 Significantly enhances AAR’s scale, margins, and cash flow profile |
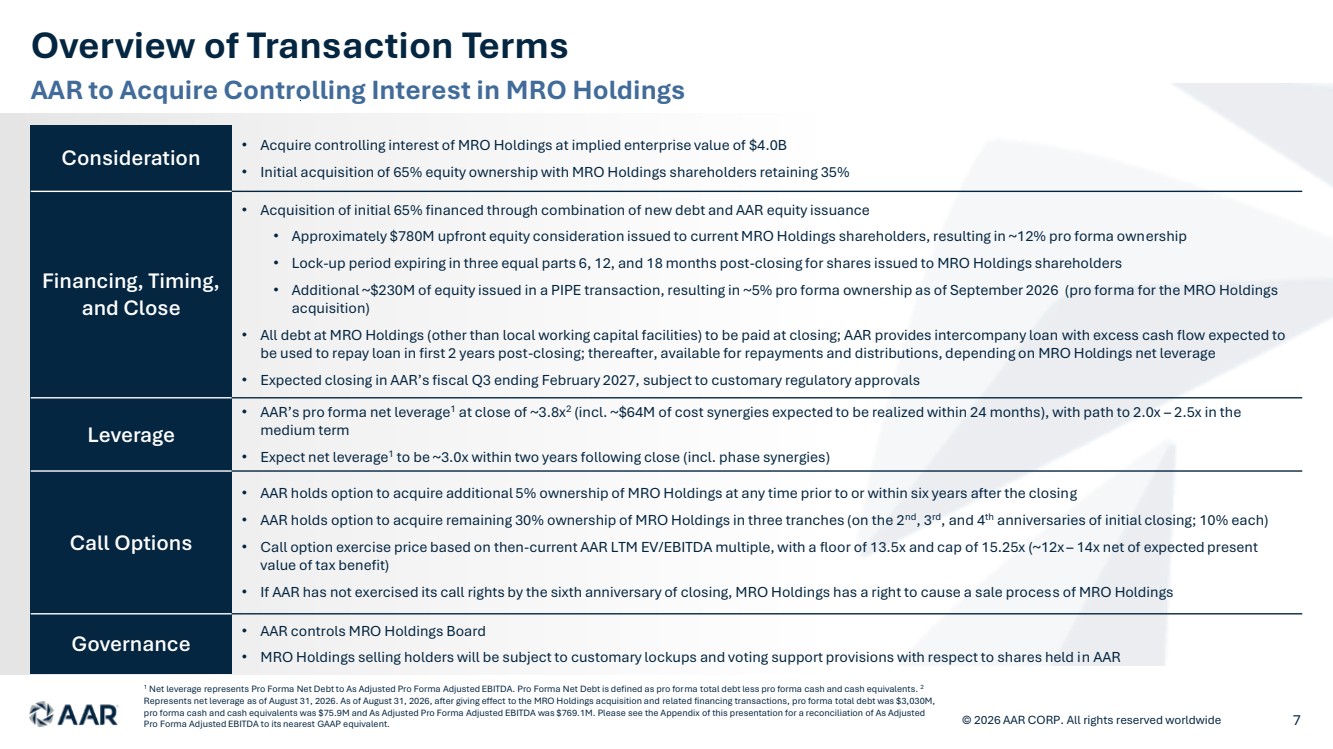
| AAR to Acquire Controlling Interest in MRO Holdings Overview of Transaction Terms © 2026 AAR CORP. All rights reserved worldwide 7 Consideration • Acquire controlling interest of MRO Holdings at implied enterprise value of $4.0B • Initial acquisition of 65% equity ownership with MRO Holdings shareholders retaining 35% Financing, Timing, and Close • Acquisition of initial 65% financed through combination of new debt and AAR equity issuance • Approximately $780M upfront equity consideration issued to current MRO Holdings shareholders, resulting in ~12% pro forma ownership • Lock-up period expiring in three equal parts 6, 12, and 18 months post-closing for shares issued to MRO Holdings shareholders • Additional ~$230M of equity issued in a PIPE transaction, resulting in ~5% pro forma ownership as of September 2026 (pro forma for the MRO Holdings acquisition) • All debt at MRO Holdings (other than local working capital facilities) to be paid at closing; AAR provides intercompany loan with excess cash flow expected to be used to repay loan in first 2 years post-closing; thereafter, available for repayments and distributions, depending on MRO Holdings net leverage • Expected closing in AAR’s fiscal Q3 ending February 2027, subject to customary regulatory approvals Leverage • AAR’s pro forma net leverage1 at close of ~3.8x2 (incl. ~$64M of cost synergies expected to be realized within 24 months), with path to 2.0x – 2.5x in the medium term • Expect net leverage1 to be ~3.0x within two years following close (incl. phase synergies) Call Options • AAR holds option to acquire additional 5% ownership of MRO Holdings at any time prior to or within six years after the closing • AAR holds option to acquire remaining 30% ownership of MRO Holdings in three tranches (on the 2nd, 3rd, and 4th anniversaries of initial closing; 10% each) • Call option exercise price based on then-current AAR LTM EV/EBITDA multiple, with a floor of 13.5x and cap of 15.25x (~12x – 14x net of expected present value of tax benefit) • If AAR has not exercised its call rights by the sixth anniversary of closing, MRO Holdings has a right to cause a sale process of MRO Holdings Governance • AAR controls MRO Holdings Board • MRO Holdings selling holders will be subject to customary lockups and voting support provisions with respect to shares held in AAR 1 Net leverage represents Pro Forma Net Debt to As Adjusted Pro Forma Adjusted EBITDA. Pro Forma Net Debt is defined as pro forma total debt less pro forma cash and cash equivalents. 2 Represents net leverage as of August 31, 2026. As of August 31, 2026, after giving effect to the MRO Holdings acquisition and related financing transactions, pro forma total debt was $3,030M, pro forma cash and cash equivalents was $75.9M and As Adjusted Pro Forma Adjusted EBITDA was $769.1M. Please see the Appendix of this presentation for a reconciliation of As Adjusted Pro Forma Adjusted EBITDA to its nearest GAAP equivalent. |
| AAR to acquire a controlling interest of 65% in MRO Holdings Acquisition Significantly Enhances AAR’s Profile © 2026 AAR CORP. All rights reserved worldwide 8 1 Based on Pro Forma AAR FY2026 revenue as compared to AAR's standalone FY2026 sales. 2 Adjusted EBITDA Margin is a non-GAAP financial measure. See Appendix for reconciliation of non-GAAP financial measures. • Highly strategic acquisition in core Airframe MRO business • Achieves scale that accelerates growth of Parts, Repair, and Software aftermarket platform • Scale helps drive additional volume to high-margin Component MRO activity • Builds channels for existing OEM distribution partners and new OEM agreements • Creates additional avenues for data collection for Software solutions • Transaction structure enables long-term partnership with proven operators that have regional expertise Enhances Financial Profile • Increases AAR’s FY26 sales by ~30+%1 on a pro forma basis • Expands AAR's Adjusted EBITDA Margin by ~400 bps from ~12% to ~16% on a pro forma basis (before synergies)2 • Meaningfully enhances cash conversion profile • ~$75M run-rate cost synergies expected across site optimization, procurement savings, Indirect SG&A, and the application of AAR processes to MRO Holdings' operations • Significant cross-selling opportunities not captured in plan • Run-rate synergies expected to be achieved by FYE May 2030 Strategic Transaction Transformative Benefits • Nearshoring of Widebody maintenance work currently being done in Asia • Increased European and Middle Eastern fleet capture for service in the Americas • Cross-selling opportunities across services Growth Vectors Synergies |
| II. AAR Overview © 2026 AAR CORP. All rights reserved worldwide 9 |
| © 2026 AAR CORP. All rights reserved worldwide 10 Company Overview |
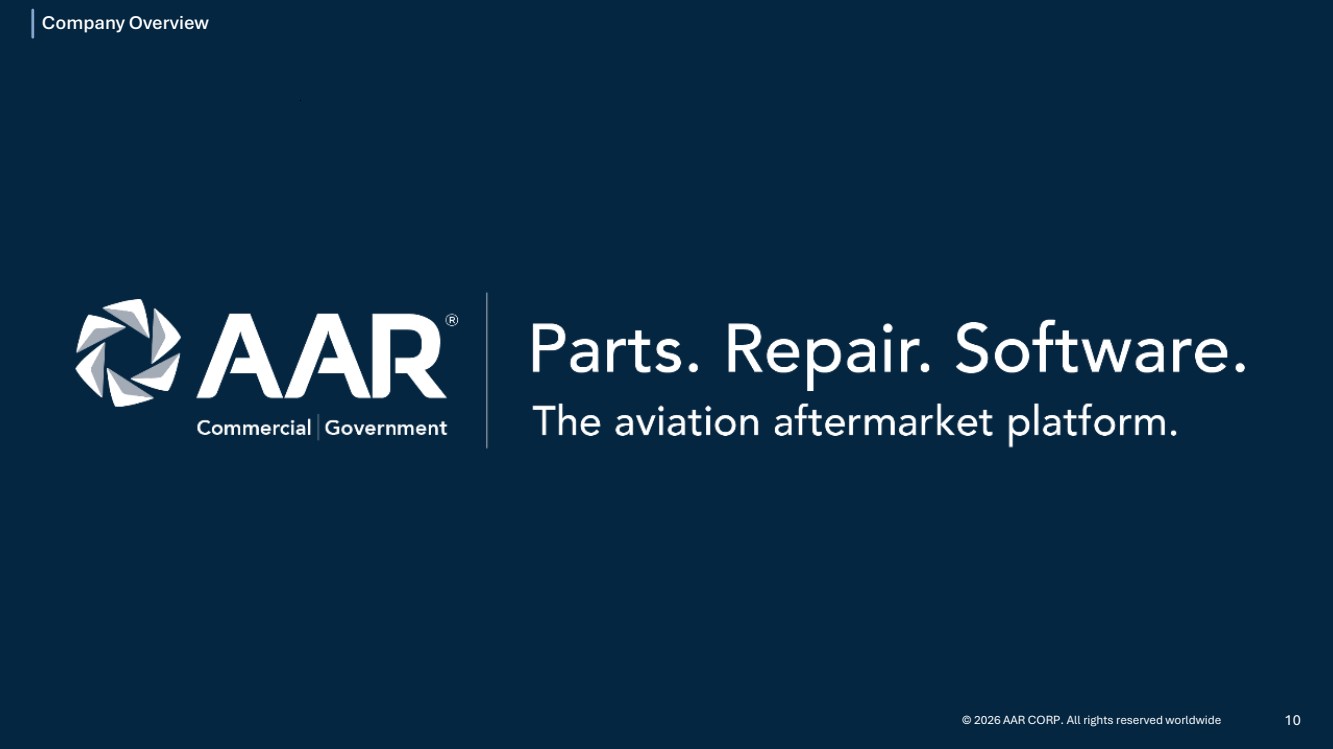
| © 2026 AAR CORP. All rights reserved worldwide 11 PARTS REPAIR SOFTWARE • Large independent provider with scale, global presence, & two-way exclusive agreements • Structured as true extension of Original Equipment Manufacturers (“OEMs”) into global after market • Value-added model, high fill rate enabling market share gains New Parts Distribution • Differentiated ability to source material • Deep technical and engineering expertise • Provider of choice for customers Used Serviceable Material • High value, complex repairs on current & next-gen platforms • Focus on narrowbody and regional aircraft, supported by multi-year agreements • Industry-leading turnaround times • Paperless hangar technology, deep expertise, and proprietary operating model Airframe MRO (Heavy Maintenance) • Differentiated repair skillset across a range of current and next-gen engines and accessories • Global component repair footprint Component MRO • Comprehensive, cloud-based ERP system used by major airlines and MROs to digitize aircraft maintenance • Solutions support entire spectrum of maintenance activities and create required system of record • High-margin software with SaaS-based recurring revenue model • Recent additions of Aerostrat and Airvoyant to extend the reach of Trax’s capabilities AAR Software Company Overview AAR’s Key Focus Areas Nearly 100% New Parts Distribution Renewal Rate Over Last 8 Years ~90% Exclusive Distribution Agreements 35 OEMs Under Distribution contracts 30+ Global Locations ~1,200 Aircraft Serviced Per Year 15,000+ Components Repaired Per Year 7M+ Labor Hours Per Year 14 Sites 130+ Customers 6,000+ Aircraft Drives Volume to Parts & Repair |
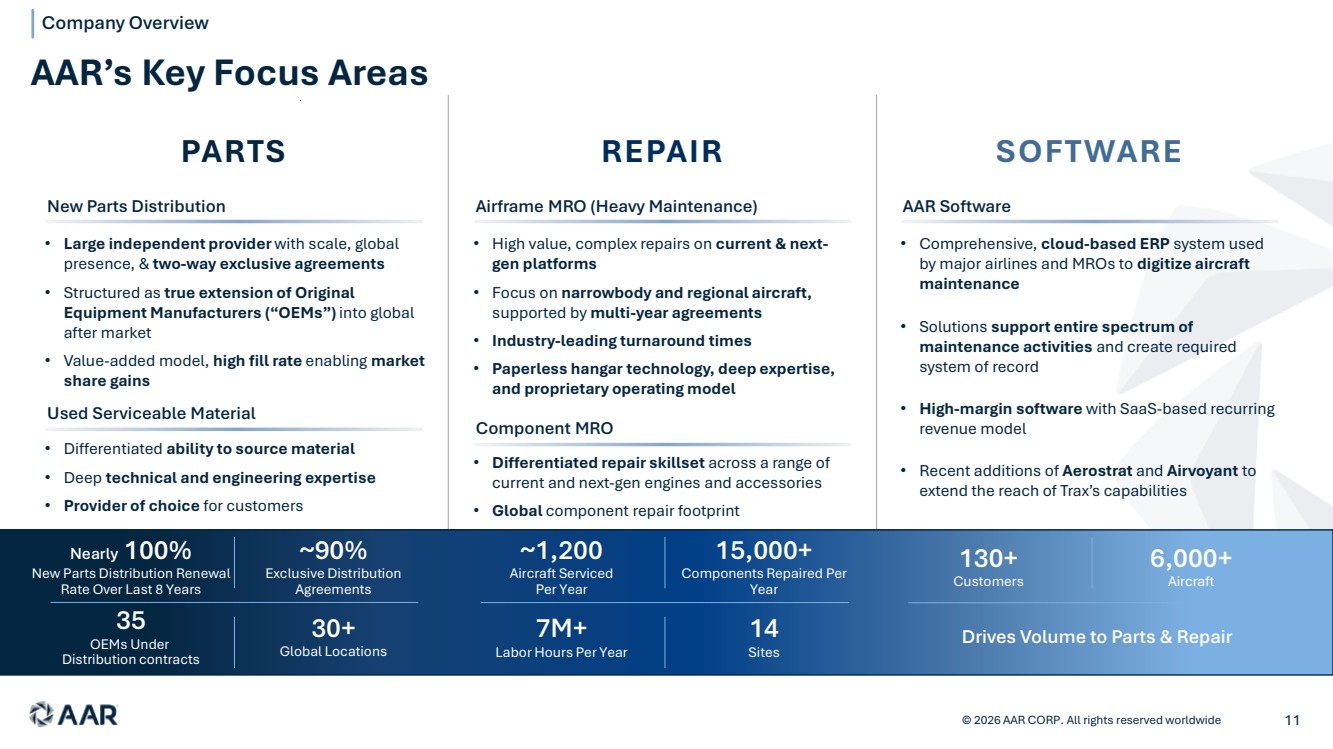
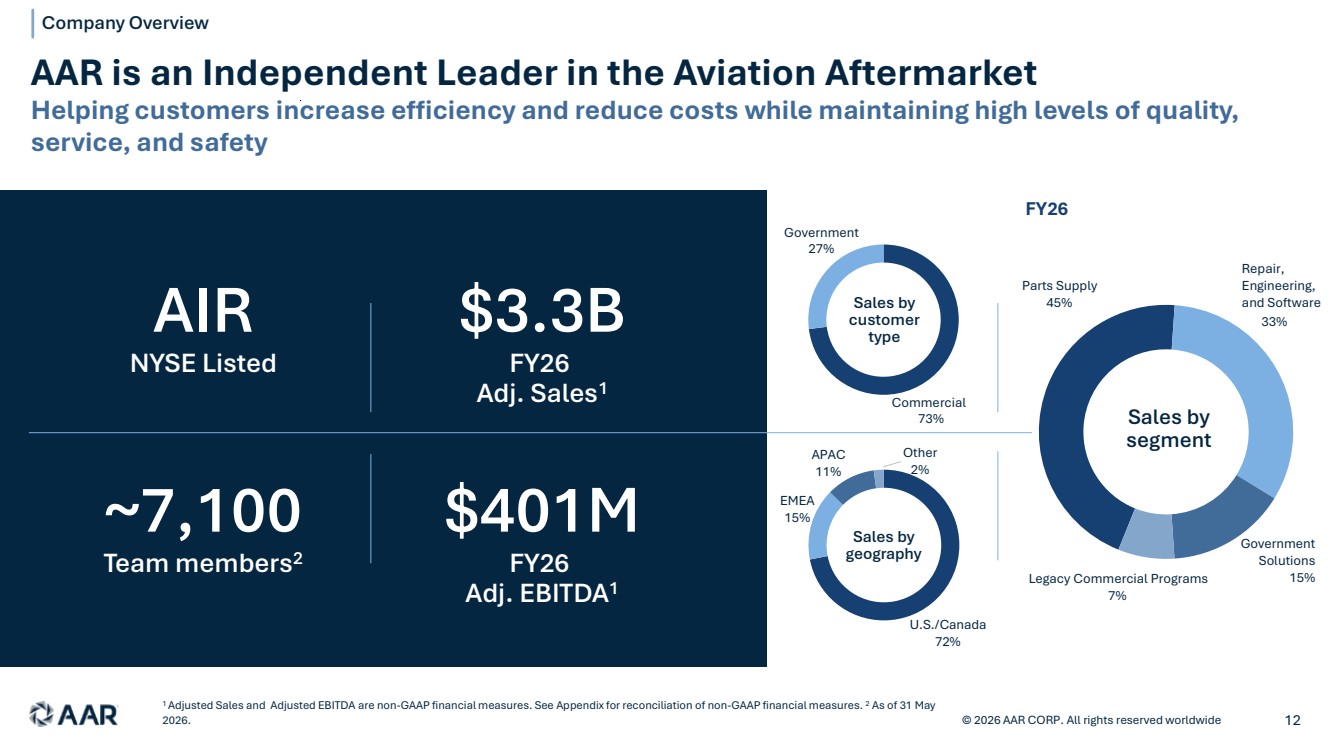
| $3.3B FY26 Adj. Sales1 $401M FY26 Adj. EBITDA1 AIR NYSE Listed ~7,100 Team members2 Commercial Government U.S./Canada 72% EMEA 15% APAC 11% Other 2% Parts Supply 45% Repair, Engineering, and Software Government Solutions Legacy Commercial Programs 15% Sales by customer type Sales by geography Sales by segment © 2026 AAR CORP. All rights reserved worldwide 12 FY26 AAR is an Independent Leader in the Aviation Aftermarket Company Overview Helping customers increase efficiency and reduce costs while maintaining high levels of quality, service, and safety 1 Adjusted Sales and Adjusted EBITDA are non-GAAP financial measures. See Appendix for reconciliation of non-GAAP financial measures. 2 As of 31 May 2026. 7% 33% 73% 27% |
| © 2026 AAR CORP. All rights reserved worldwide 13 Highly Diversified Base of Commercial, Government and Military Customers across OEMs Company Overview OEMs Government & military customers US: Air Force; Navy; Army; Department of State Colombia: Colombian Aerospace Force Japan: Ministry of Defense Netherlands: Royal Netherlands Air Force Norway: Royal Norwegian Air Force United Kingdom: Ministry of Defence Commercial customers |
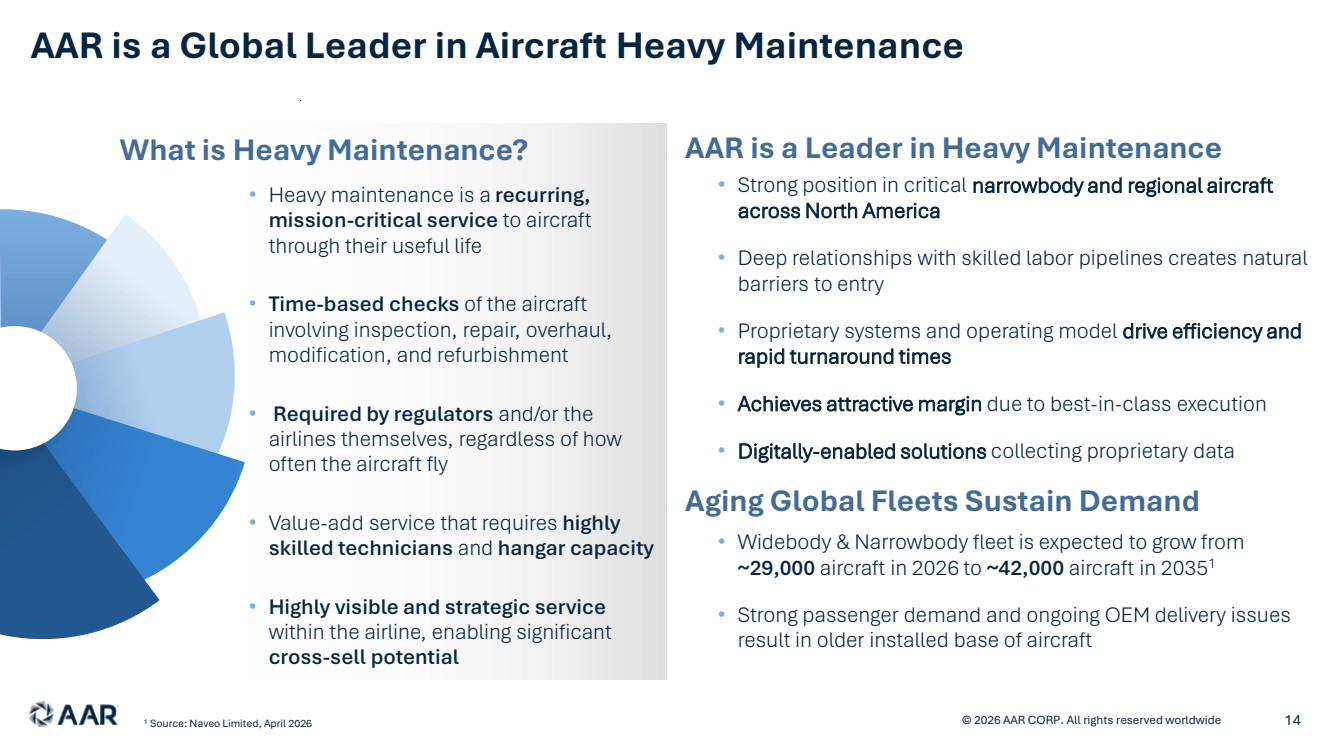
| AAR is a Global Leader in Aircraft Heavy Maintenance © 2026 AAR CORP. All rights reserved worldwide 14 AAR is a Leader in Heavy Maintenance • Widebody & Narrowbody fleet is expected to grow from ~29,000 aircraft in 2026 to ~42,000 aircraft in 20351 • Strong passenger demand and ongoing OEM delivery issues result in older installed base of aircraft • Strong position in critical narrowbody and regional aircraft across North America • Deep relationships with skilled labor pipelines creates natural barriers to entry • Proprietary systems and operating model drive efficiency and rapid turnaround times • Achieves attractive margin due to best-in-class execution • Digitally-enabled solutions collecting proprietary data Aging Global Fleets Sustain Demand 1 Source: Naveo Limited, April 2026 What is Heavy Maintenance? • Heavy maintenance is a recurring, mission-critical service to aircraft through their useful life • Time-based checks of the aircraft involving inspection, repair, overhaul, modification, and refurbishment • Required by regulators and/or the airlines themselves, regardless of how often the aircraft fly • Value-add service that requires highly skilled technicians and hangar capacity • Highly visible and strategic service within the airline, enabling significant cross-sell potential |
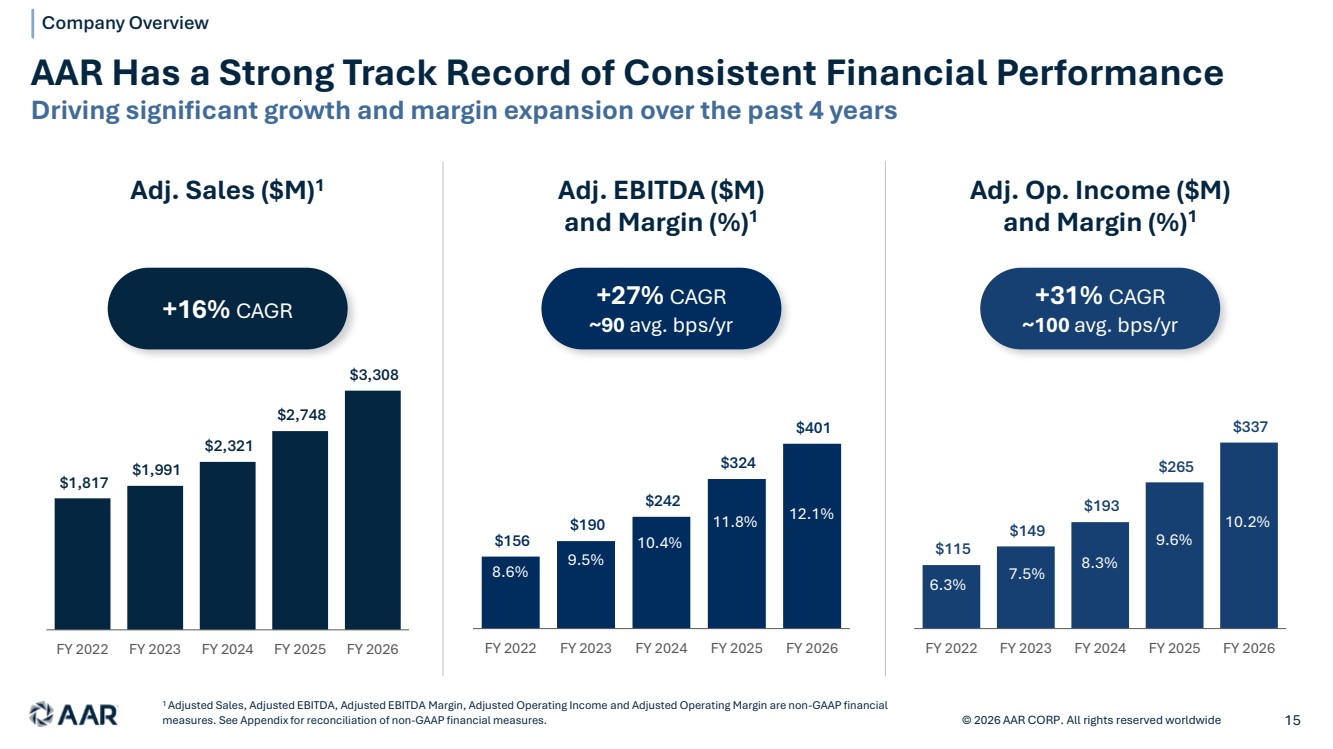
| © 2026 AAR CORP. All rights reserved worldwide 15 AAR Has a Strong Track Record of Consistent Financial Performance Driving significant growth and margin expansion over the past 4 years $1,817 $1,991 $2,321 $2,748 $3,308 FY 2022 FY 2023 FY 2024 FY 2025 FY 2026 Adj. Sales ($M)1 Adj. EBITDA ($M) and Margin (%)1 $156 $190 $242 $324 $401 8.6% 9.5% 10.4% 11.8% 12.1% FY 2022 FY 2023 FY 2024 FY 2025 FY 2026 Adj. Op. Income ($M) and Margin (%)1 $115 $149 $193 $265 $337 6.3% 7.5% 8.3% 9.6% 10.2% FY 2022 FY 2023 FY 2024 FY 2025 FY 2026 +16% CAGR +27% CAGR ~90 avg. bps/yr +31% CAGR ~100 avg. bps/yr Company Overview 1 Adjusted Sales, Adjusted EBITDA, Adjusted EBITDA Margin, Adjusted Operating Income and Adjusted Operating Margin are non-GAAP financial measures. See Appendix for reconciliation of non-GAAP financial measures. |
| Large, global traffic base supports continued fleet growth and long-term aftermarket demand Recent capacity reductions are a function of route profitability, not demand Aviation has historically demonstrated strong recovery following exogenous shocks Expect airlines to remain risk-averse and not overly reliant on aircraft retirements Global Commercial Air Travel Growth Remains Resilient © 2026 AAR CORP. All rights reserved worldwide 16 ~4% CAGR ~5% CAGR High scenario Base scenario 2026E 2027E 2028E 2029E 2030E 0% 10% 20% Narrow range of outcomes contributes to resilient demand ~3% CAGR Low scenario Global Available Seat Kilometer (ASK) growth1 5% 15% 25% (5%) ASK Growth Company Overview Source: Company Estimates, Naveo Limited, IATA, Jefferies, RBC. 1 As of April 2026 |
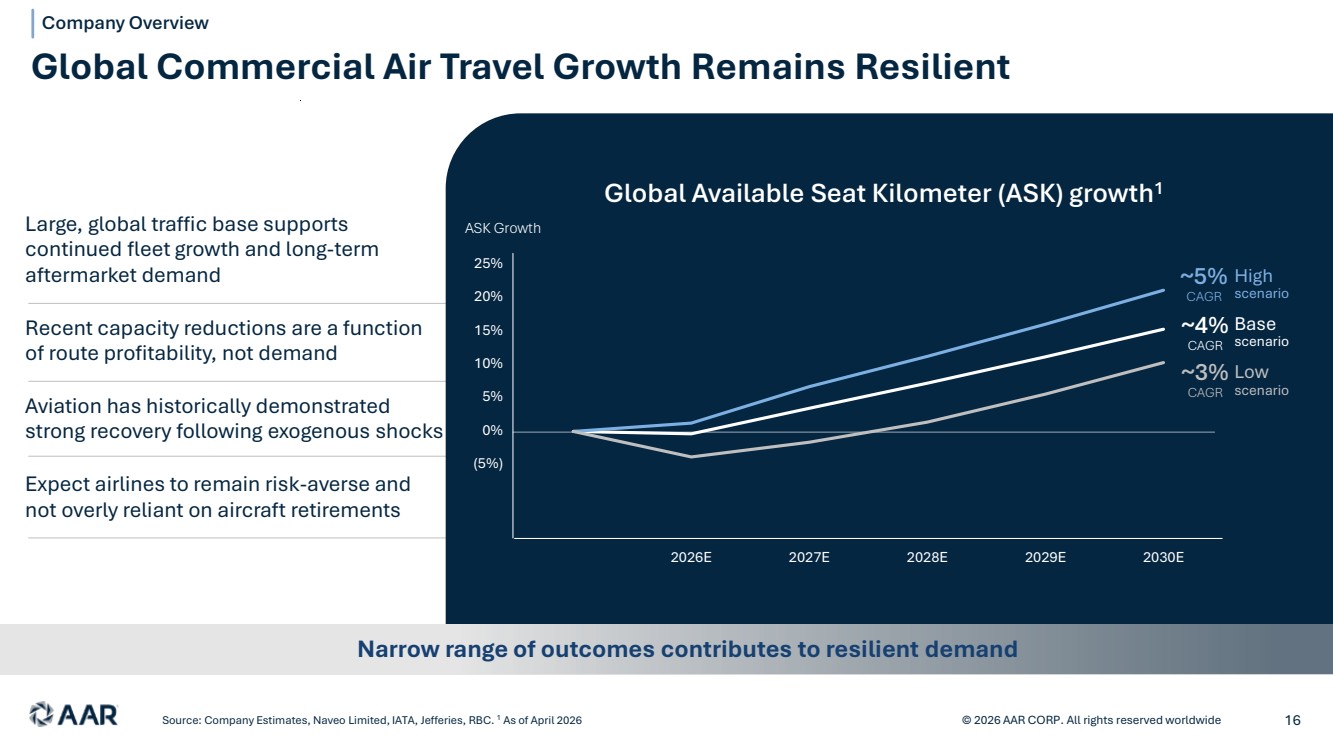
| 28,680 29,964 31,390 32,961 34,685 36,176 37,539 38,947 40,406 41,910 13.4 13.7 14.0 14.2 14.4 14.4 14.3 14.2 14.1 14.0 12.0 12.5 13.0 13.5 14.0 14.5 15.0 15.5 16.0 0 5,000 10,000 15,000 20,000 25,000 30,000 35,000 40,000 45,000 2026 2027 2028 2029 2030 2031 2032 2033 2034 2035 Growing & Aging Global Aircraft Fleet © 2026 AAR CORP. All rights reserved worldwide 17 Average fleet age will continue to rise through the end of the decade, remain elevated thereafter • Widebody & narrowbody fleet is expected to grow from ~29,000 aircraft in 2026 to ~42,000 aircraft in 2035 • Average fleet age is expected to peak by 2031, but remain elevated vs. historic levels • Low retirement levels and delivery constraints result in larger, older installed base Sustained demand for Parts, Repair, and Software Greater use of independent aftermarket support as supply availability tightens & OEM lead times extend Global fleets will continue to age, net of deliveries and retirements Total fleet (narrowbody + widebody) Avg. aircraft age (years) Company Overview Source: Naveo Limited, April 2026 |
| III. MRO Holdings Overview © 2026 AAR CORP. All rights reserved worldwide 18 |
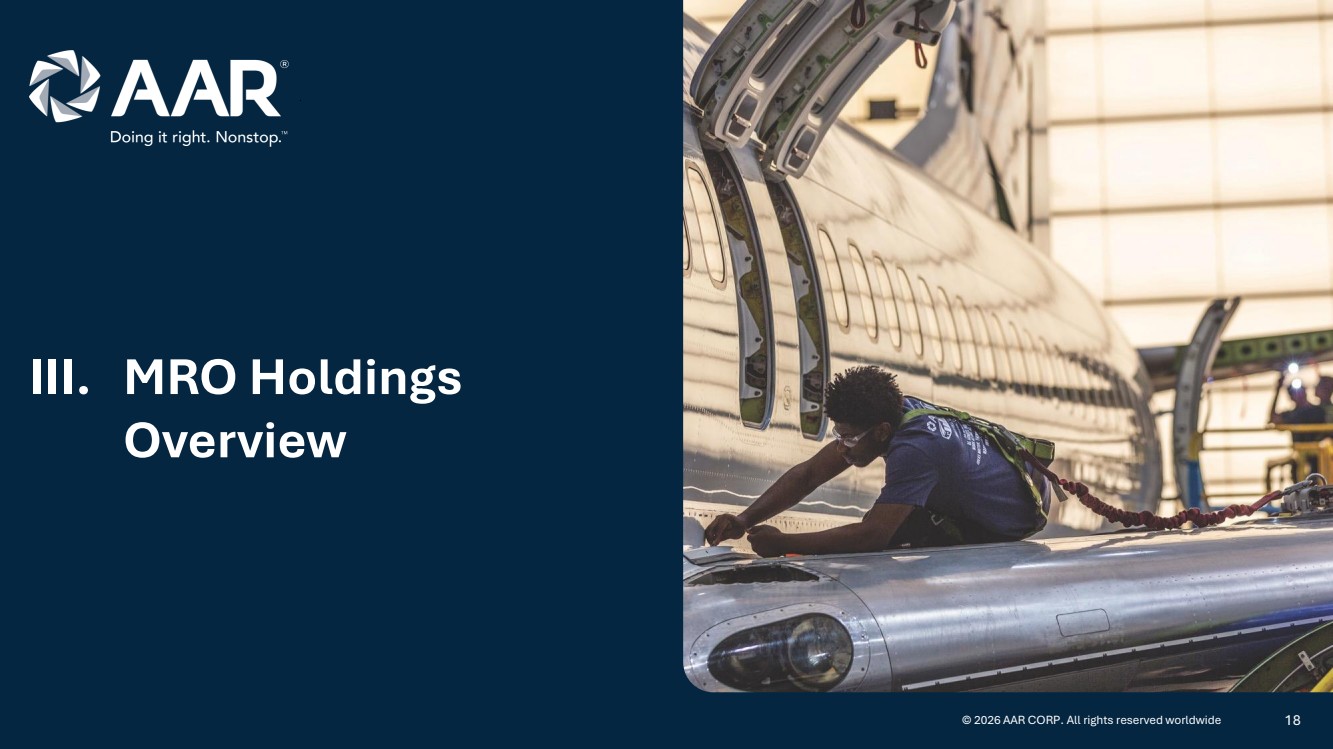
| A leader in airframe maintenance, repair, and overhaul services across the Americas MRO Holdings at a Glance © 2026 AAR CORP. All rights reserved worldwide Note: Financial information for MRO Holdings is prepared in accordance with IFRS. 1 As of August 2026. 2 As of April 2026. 3 Adjusted Operating Revenues, Adjusted EBITDA, Adjusted EBITDA Margin are non-IFRS financial measures. See Appendix for reconciliation of non-IFRS financial measures. 19 Key Statistics $1,024M Adj. Operating Revenues3 (LTM Jun 2026) $291M Adj. EBITDA3 (LTM Jun 2026) 29% Adj. EBITDA margin3 (LTM Jun 2026) 5 Airframe MRO Facilities1 12M Annual service hours (CY 2026E) 10,000+ Team members2 100% Aftermarket Airframe MRO Business • Specializes in airframe heavy maintenance checks • Comprehensive capabilities across narrowbody and select widebody platforms • Blue-chip customers comprising some of the largest airlines in the Americas; ~90% sales to U.S. customers • Strategic nearshore footprint across Colombia, Mexico, and El Salvador Ancillary Businesses • Integrated in-house support platform spanning engineering and logistical solutions • End-to-end lifecycle support for heavy maintenance • Embedded backshop and repair capabilities across facilities Double-Digit Sales CAGR Sales ($M) Adj. EBITDA ($M) Double-Digit Adj. EBITDA CAGR 2015A 2016A 2017A 2018A 2019A 2020A 2021A 2022A 2023A 2024A 2025A 2015A 2016A 2017A 2018A 2019A 2020A 2021A 2022A 2023A 2024A 2025A |
| IV. Key Credit Highlights © 2026 AAR CORP. All rights reserved worldwide 20 |
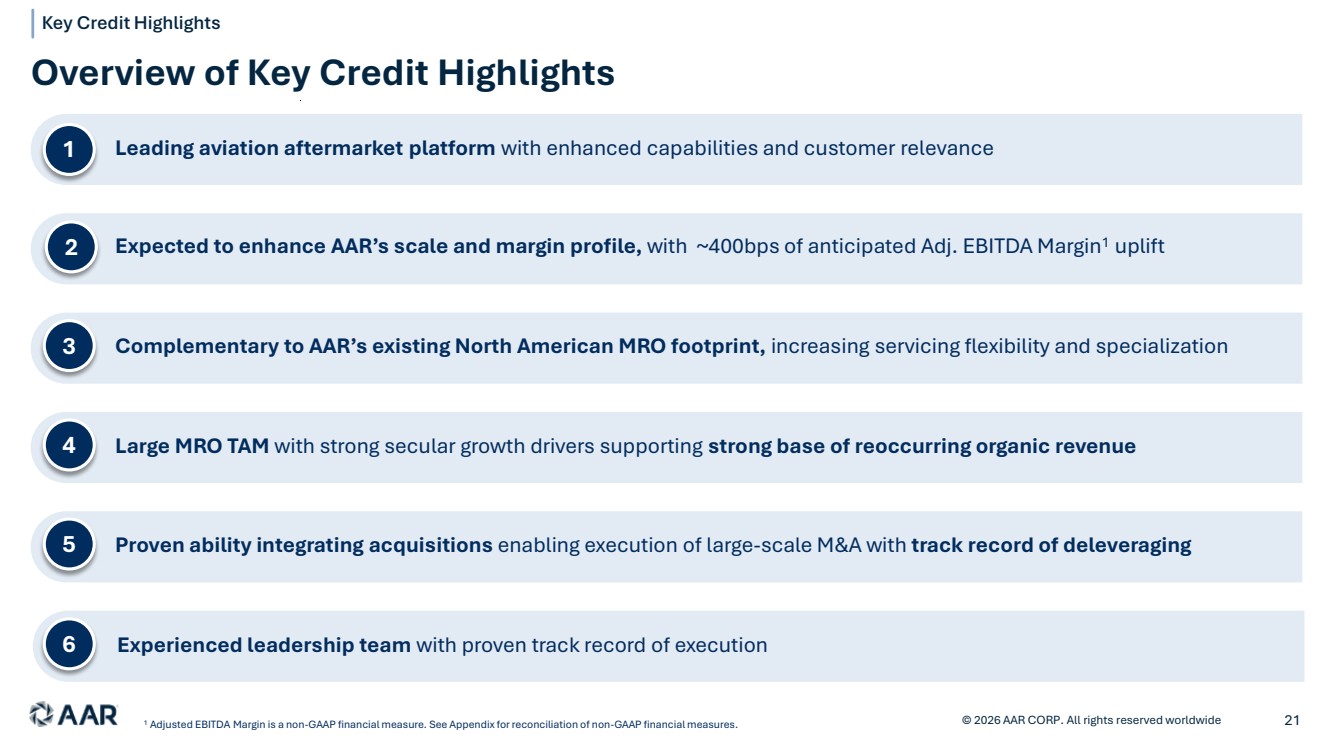
| © 2026 AAR CORP. All rights reserved worldwide 21 Overview of Key Credit Highlights Key Credit Highlights 1 Leading aviation aftermarket platform with enhanced capabilities and customer relevance 3 Complementary to AAR’s existing North American MRO footprint, increasing servicing flexibility and specialization 4 Large MRO TAM with strong secular growth drivers supporting strong base of reoccurring organic revenue 5 Proven ability integrating acquisitions enabling execution of large-scale M&A with track record of deleveraging 66 Experienced leadership team with proven track record of execution Expected to enhance AAR’s scale and margin profile, with ~400bps of anticipated Adj. EBITDA Margin1 2 uplift 1 Adjusted EBITDA Margin is a non-GAAP financial measure. See Appendix for reconciliation of non-GAAP financial measures. |
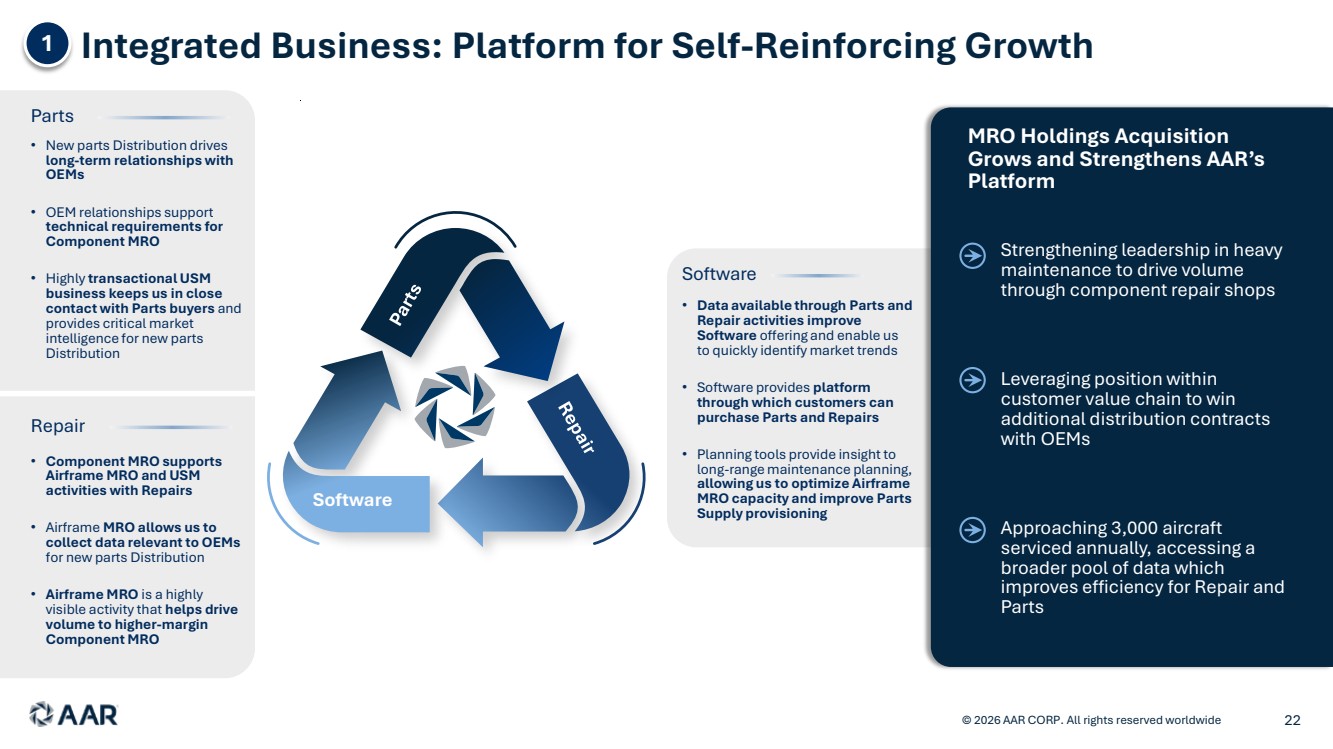
| Integrated Business: Platform for Self-Reinforcing Growth © 2026 AAR CORP. All rights reserved worldwide 22 • New parts Distribution drives long-term relationships with OEMs • OEM relationships support technical requirements for Component MRO • Highly transactional USM business keeps us in close contact with Parts buyers and provides critical market intelligence for new parts Distribution • Component MRO supports Airframe MRO and USM activities with Repairs • Airframe MRO allows us to collect data relevant to OEMs for new parts Distribution • Airframe MRO is a highly visible activity that helps drive volume to higher-margin Component MRO Parts Repair • Data available through Parts and Repair activities improve Software offering and enable us to quickly identify market trends • Software provides platform through which customers can purchase Parts and Repairs • Planning tools provide insight to long-range maintenance planning, allowing us to optimize Airframe MRO capacity and improve Parts Supply provisioning Software PARTS Software Strengthening leadership in heavy maintenance to drive volume through component repair shops Leveraging position within customer value chain to win additional distribution contracts with OEMs Approaching 3,000 aircraft serviced annually, accessing a broader pool of data which improves efficiency for Repair and Parts MRO Holdings Acquisition Grows and Strengthens AAR’s Platform 1 |
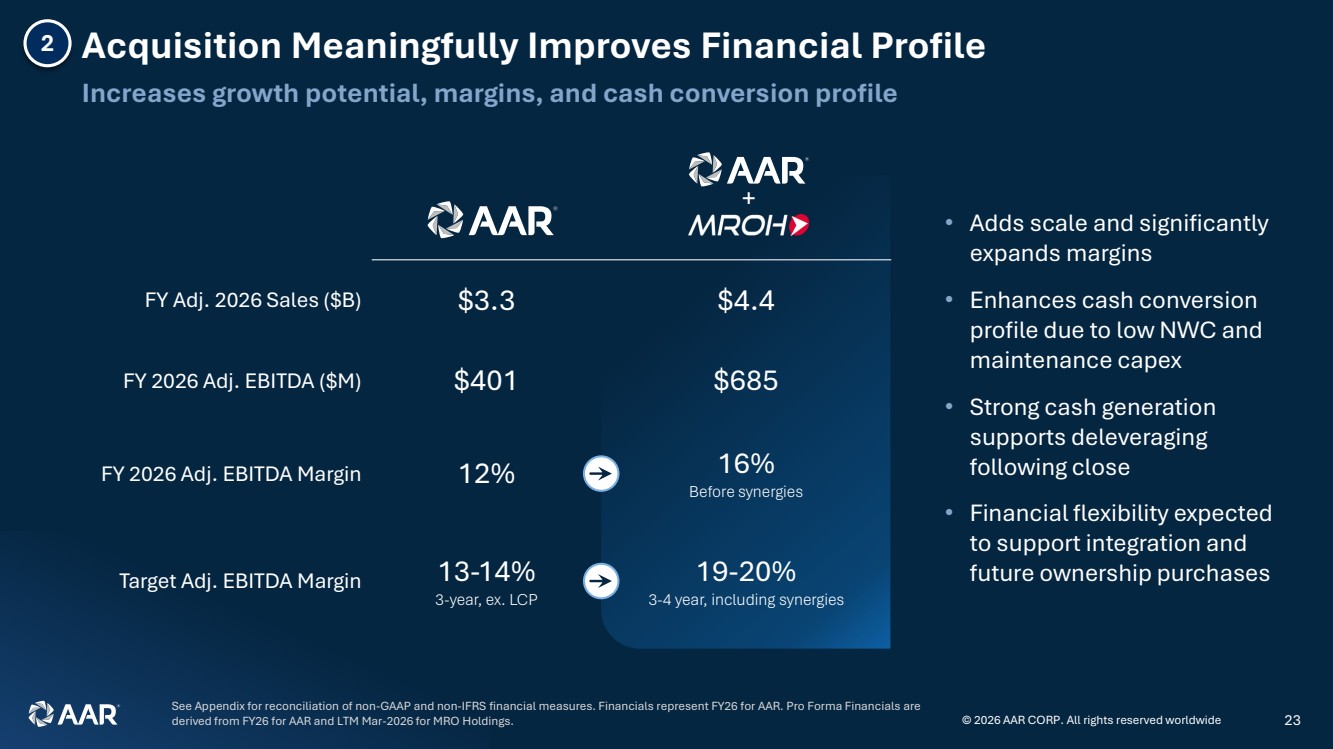
| Acquisition Meaningfully Improves Financial Profile Increases growth potential, margins, and cash conversion profile © 2026 AAR CORP. All rights reserved worldwide 23 See Appendix for reconciliation of non-GAAP and non-IFRS financial measures. Financials represent FY26 for AAR. Pro Forma Financials are derived from FY26 for AAR and LTM Mar-2026 for MRO Holdings. FY Adj. 2026 Sales ($B) $3.3 $4.4 FY 2026 Adj. EBITDA ($M) $401 $685 FY 2026 Adj. EBITDA Margin 12% 16% Before synergies Target Adj. EBITDA Margin 13-14% 3-year, ex. LCP 19-20% 3-4 year, including synergies + • Adds scale and significantly expands margins • Enhances cash conversion profile due to low NWC and maintenance capex • Strong cash generation supports deleveraging following close • Financial flexibility expected to support integration and future ownership purchases 2 |
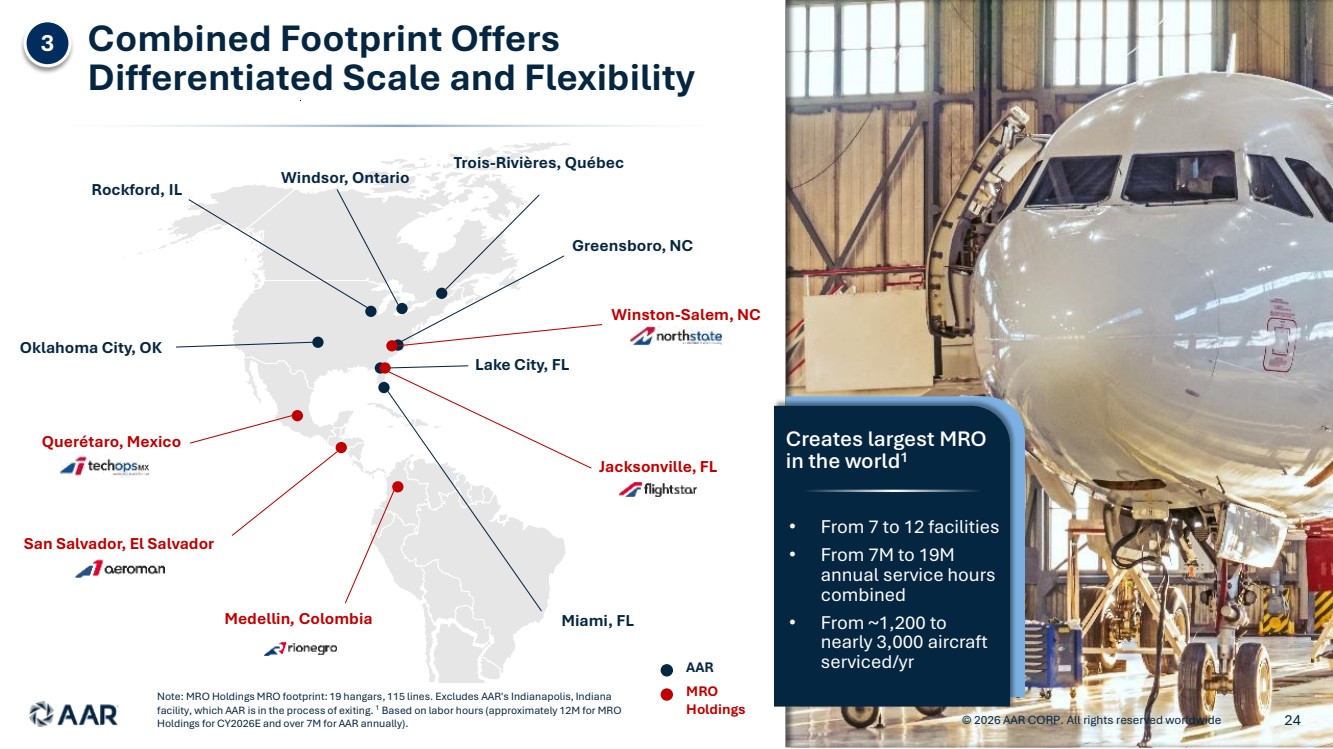
| AAR MRO Holdings Combined Footprint Offers Differentiated Scale and Flexibility © 2026 AAR CORP. All rights reserved worldwide 24 Note: MRO Holdings MRO footprint: 19 hangars, 115 lines. Excludes AAR's Indianapolis, Indiana facility, which AAR is in the process of exiting. 1 Based on labor hours (approximately 12M for MRO Holdings for CY2026E and over 7M for AAR annually). Greensboro, NC Lake City, FL Windsor, Ontario Trois-Rivières, Québec Rockford, IL Miami, FL Oklahoma City, OK Medellin, Colombia Winston-Salem, NC Jacksonville, FL Querétaro, Mexico San Salvador, El Salvador • From 7 to 12 facilities • From 7M to 19M annual service hours combined • From ~1,200 to nearly 3,000 aircraft serviced/yr Creates largest MRO in the world1 3 |
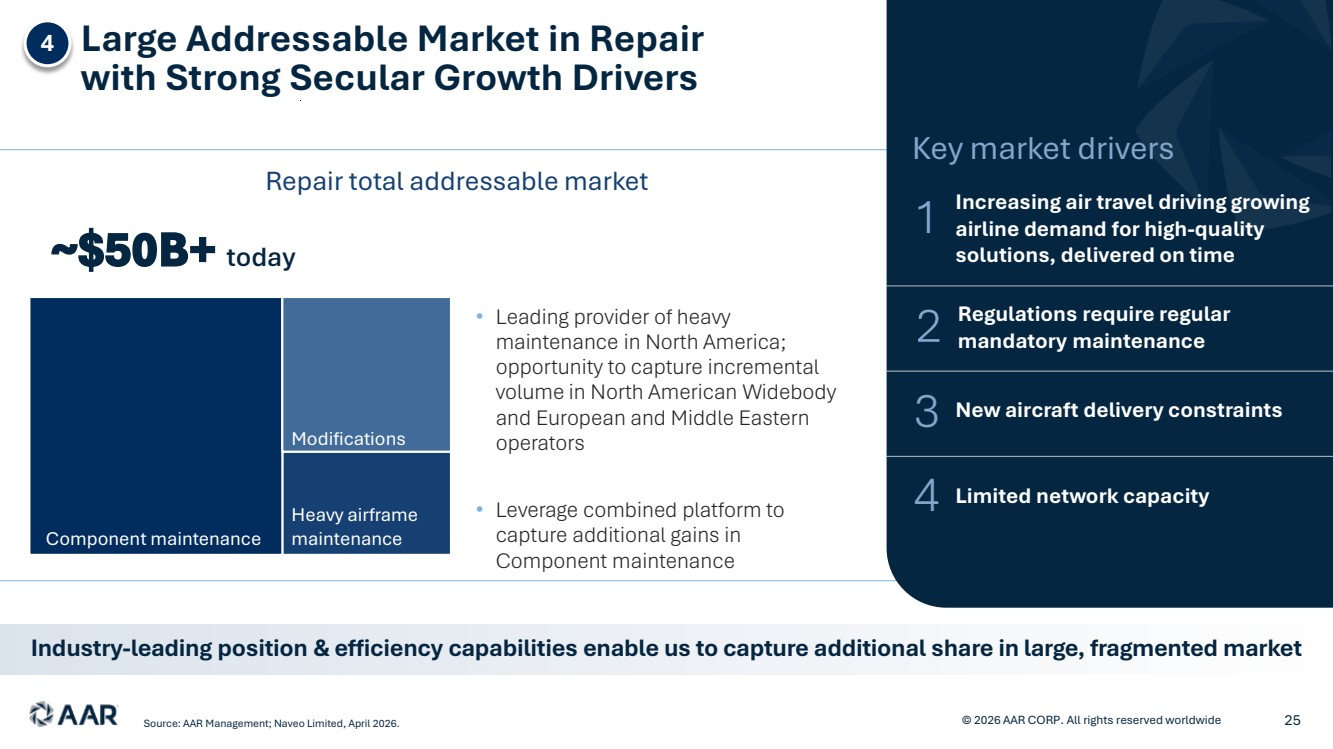
| Large Addressable Market in Repair with Strong Secular Growth Drivers Industry-leading position & efficiency capabilities enable us to capture additional share in large, fragmented market © 2026 AAR CORP. All rights reserved worldwide 25 Key market drivers 1 Increasing air travel driving growing airline demand for high-quality solutions, delivered on time 2 Regulations require regular mandatory maintenance 3 New aircraft delivery constraints 4 Limited network capacity Component maintenance Heavy airframe maintenance ~$50B+ today Repair total addressable market Modifications • Leading provider of heavy maintenance in North America; opportunity to capture incremental volume in North American Widebody and European and Middle Eastern operators • Leverage combined platform to capture additional gains in Component maintenance Source: AAR Management; Naveo Limited, April 2026. 4 |
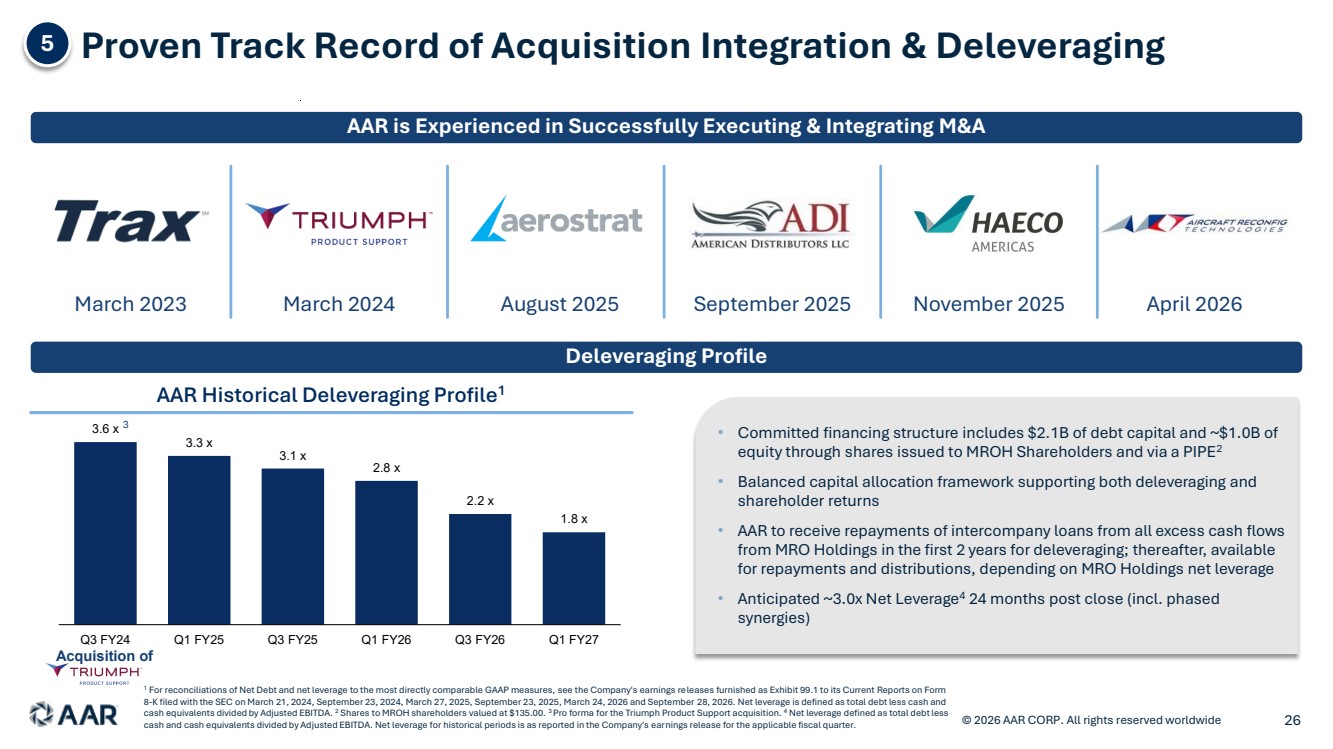
| 3.6 x 3.3 x 3.1 x 2.8 x 2.2 x 1.8 x Q3 FY24 Q1 FY25 Q3 FY25 Q1 FY26 Q3 FY26 Q1 FY27 Proven Track Record of Acquisition Integration & Deleveraging © 2026 AAR CORP. All rights reserved worldwide 26 Deleveraging Profile • Committed financing structure includes $2.1B of debt capital and ~$1.0B of equity through shares issued to MROH Shareholders and via a PIPE2 • Balanced capital allocation framework supporting both deleveraging and shareholder returns • AAR to receive repayments of intercompany loans from all excess cash flows from MRO Holdings in the first 2 years for deleveraging; thereafter, available for repayments and distributions, depending on MRO Holdings net leverage • Anticipated ~3.0x Net Leverage4 24 months post close (incl. phased synergies) 1 For reconciliations of Net Debt and net leverage to the most directly comparable GAAP measures, see the Company's earnings releases furnished as Exhibit 99.1 to its Current Reports on Form 8-K filed with the SEC on March 21, 2024, September 23, 2024, March 27, 2025, September 23, 2025, March 24, 2026 and September 28, 2026. Net leverage is defined as total debt less cash and cash equivalents divided by Adjusted EBITDA. 2 Shares to MROH shareholders valued at $135.00. 3 Pro forma for the Triumph Product Support acquisition. 4 Net leverage defined as total debt less cash and cash equivalents divided by Adjusted EBITDA. Net leverage for historical periods is as reported in the Company's earnings release for the applicable fiscal quarter. AAR is Experienced in Successfully Executing & Integrating M&A March 2023 March 2024 August 2025 September 2025 November 2025 April 2026 5 AAR Historical Deleveraging Profile1 Acquisition of 3 |
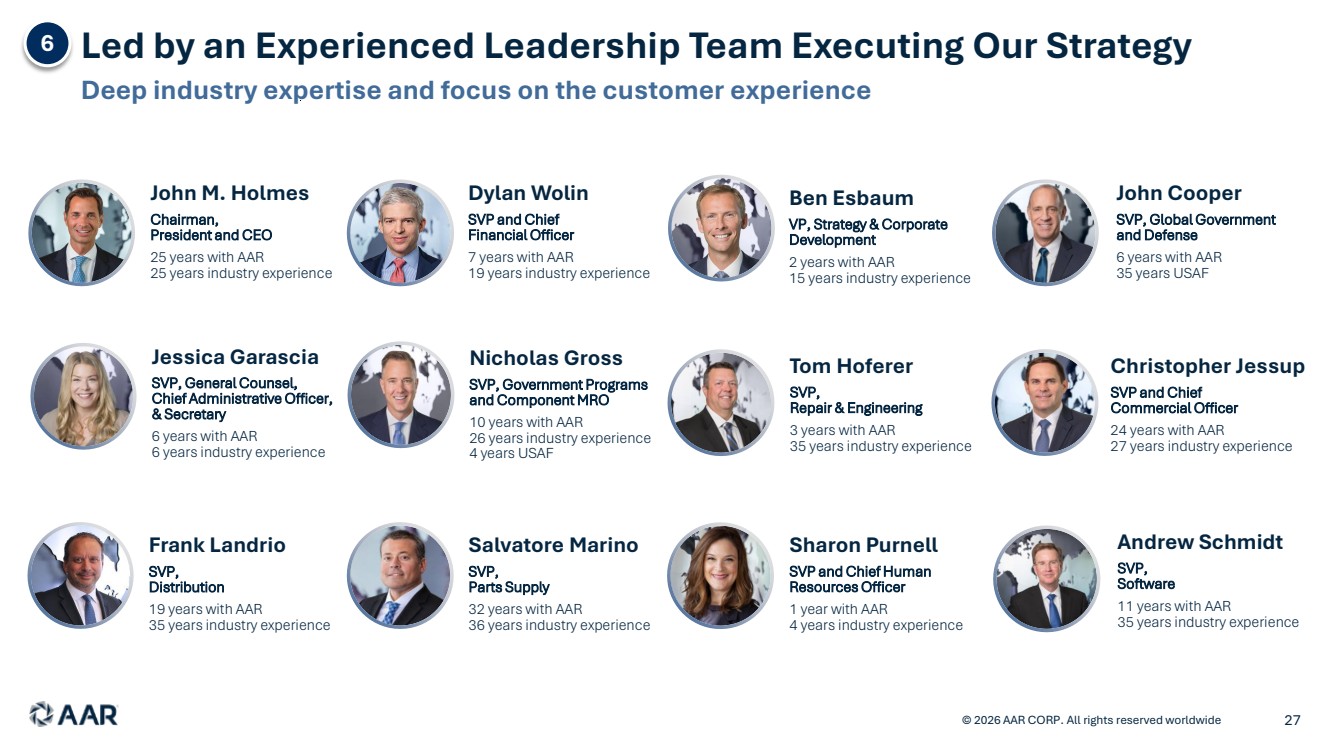
| Deep industry expertise and focus on the customer experience Led by an Experienced Leadership Team Executing Our Strategy © 2026 AAR CORP. All rights reserved worldwide 27 6 Christopher Jessup SVP and Chief Commercial Officer 24 years with AAR 27 years industry experience Nicholas Gross SVP, Government Programs and Component MRO 10 years with AAR 26 years industry experience 4 years USAF Dylan Wolin SVP and Chief Financial Officer 7 years with AAR 19 years industry experience John M. Holmes Chairman, President and CEO 25 years with AAR 25 years industry experience Jessica Garascia SVP, General Counsel, Chief Administrative Officer, & Secretary 6 years with AAR 6 years industry experience John Cooper SVP, Global Government and Defense 6 years with AAR 35 years USAF Ben Esbaum VP, Strategy & Corporate Development 2 years with AAR 15 years industry experience Frank Landrio SVP, Distribution 19 years with AAR 35 years industry experience Andrew Schmidt SVP, Software 11 years with AAR 35 years industry experience Sharon Purnell SVP and Chief Human Resources Officer 1 year with AAR 4 years industry experience Tom Hoferer SVP, Repair & Engineering 3 years with AAR 35 years industry experience Salvatore Marino SVP, Parts Supply 32 years with AAR 36 years industry experience |
| V. Financial Overview © 2026 AAR CORP. All rights reserved worldwide 28 |
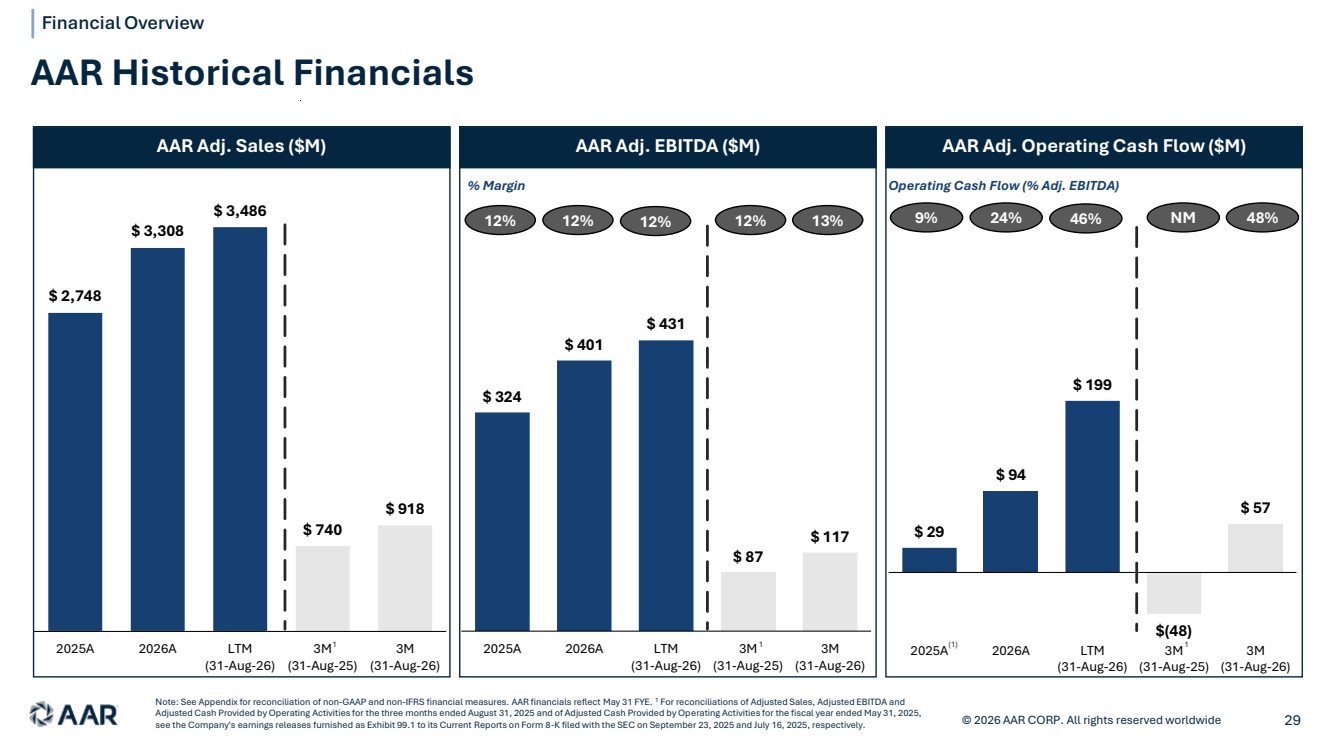
| $ 29 $ 94 $ 199 $(48) $ 57 2025A 2026A LTM (31-Aug-26) 3M (31-Aug-25) 3M (31-Aug-26) 9% 24% 46% NM 48% $ 2,748 $ 3,308 $ 3,486 $ 740 $ 918 2025A 2026A LTM (31-Aug-26) 3M (31-Aug-25) 3M (31-Aug-26) $ 324 $ 401 $ 431 $ 87 $ 117 2025A 2026A LTM (31-Aug-26) 3M (31-Aug-25) 3M (31-Aug-26) 12% 12% 12% 12% 13% © 2026 AAR CORP. All rights reserved worldwide 29 AAR Historical Financials Financial Overview Note: See Appendix for reconciliation of non-GAAP and non-IFRS financial measures. AAR financials reflect May 31 FYE. 1 For reconciliations of Adjusted Sales, Adjusted EBITDA and Adjusted Cash Provided by Operating Activities for the three months ended August 31, 2025 and of Adjusted Cash Provided by Operating Activities for the fiscal year ended May 31, 2025, see the Company's earnings releases furnished as Exhibit 99.1 to its Current Reports on Form 8-K filed with the SEC on September 23, 2025 and July 16, 2025, respectively. AAR Adj. Sales ($M) AAR Adj. EBITDA ($M) AAR Adj. Operating Cash Flow ($M) Operating Cash Flow (% Adj. EBITDA) 1 1 (1) 1 % Margin |
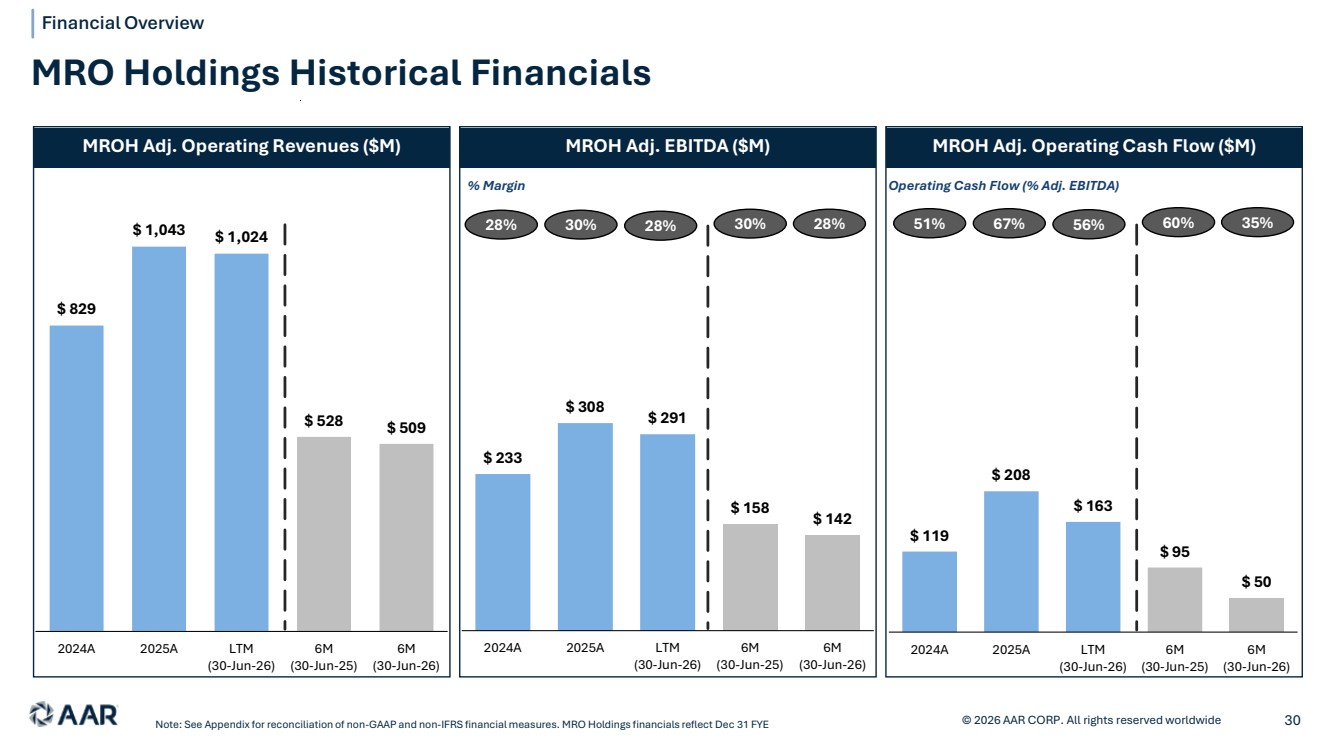
| © 2026 AAR CORP. All rights reserved worldwide 30 MRO Holdings Historical Financials MROH Adj. Operating Revenues ($M) MROH Adj. EBITDA ($M) MROH Adj. Operating Cash Flow ($M) Financial Overview Note: See Appendix for reconciliation of non-GAAP and non-IFRS financial measures. MRO Holdings financials reflect Dec 31 FYE $ 829 $ 1,043 $ 1,024 $ 528 $ 509 2024A 2025A LTM (30-Jun-26) 6M (30-Jun-25) 6M (30-Jun-26) Operating Cash Flow (% Adj. EBITDA) $ 119 $ 208 $ 163 $ 95 $ 50 2024A 2025A LTM (30-Jun-26) 6M (30-Jun-25) 6M (30-Jun-26) 51% 67% 56% 60% 35% % Margin $ 233 $ 308 $ 291 $ 158 $ 142 2024A 2025A LTM (30-Jun-26) 6M (30-Jun-25) 6M (30-Jun-26) 28% 30% 28% 30% 28% |
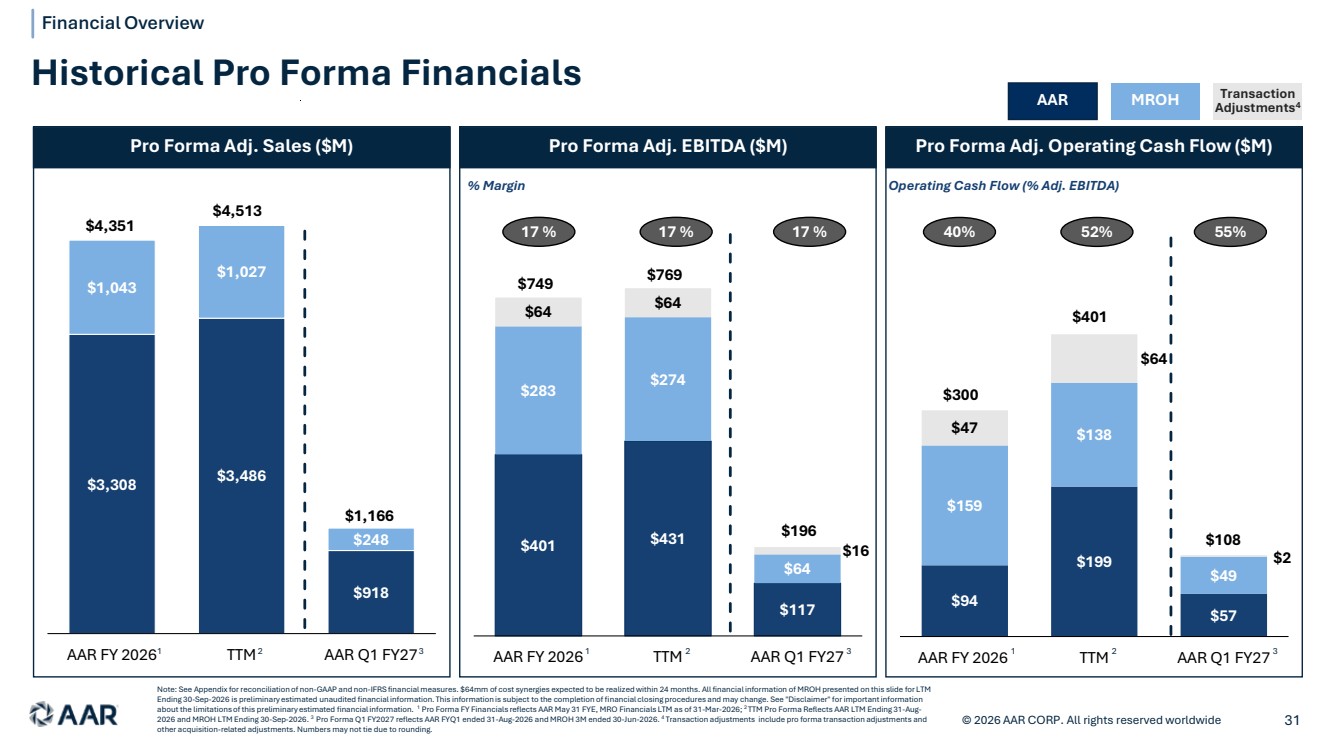
| $401 $431 $117 $283 $274 $64 $64 $64 $16 AAR FY 2026 TTM AAR Q1 FY27 17 % 17 % 17 % $749 $769 $196 $94 $199 $57 $159 $138 $49 $47 $64 $2 AAR FY 2026 TTM AAR Q1 FY27 40% 52% 55% $300 $401 $108 $3,308 $3,486 $918 $1,043 $1,027 $248 AAR FY 2026 TTM AAR Q1 FY27 $4,351 $4,513 $1,166 © 2026 AAR CORP. All rights reserved worldwide 31 Historical Pro Forma Financials Financial Overview Pro Forma Adj. Sales ($M) Pro Forma Adj. EBITDA ($M) Pro Forma Adj. Operating Cash Flow ($M) Note: See Appendix for reconciliation of non-GAAP and non-IFRS financial measures. $64mm of cost synergies expected to be realized within 24 months. All financial information of MROH presented on this slide for LTM Ending 30-Sep-2026 is preliminary estimated unaudited financial information. This information is subject to the completion of financial closing procedures and may change. See "Disclaimer" for important information about the limitations of this preliminary estimated financial information. 1 Pro Forma FY Financials reflects AAR May 31 FYE, MRO Financials LTM as of 31-Mar-2026; 2 TTM Pro Forma Reflects AAR LTM Ending 31-Aug-2026 and MROH LTM Ending 30-Sep-2026. 3 Pro Forma Q1 FY2027 reflects AAR FYQ1 ended 31-Aug-2026 and MROH 3M ended 30-Jun-2026. 4 Transaction adjustments include pro forma transaction adjustments and other acquisition-related adjustments. Numbers may not tie due to rounding. AAR MROH 1 2 3 1 2 3 1 2 3 Operating Cash Flow (% Adj. EBITDA) Transaction Adjustments4 % Margin |
| Appendix © 2026 AAR CORP. All rights reserved worldwide 32 |
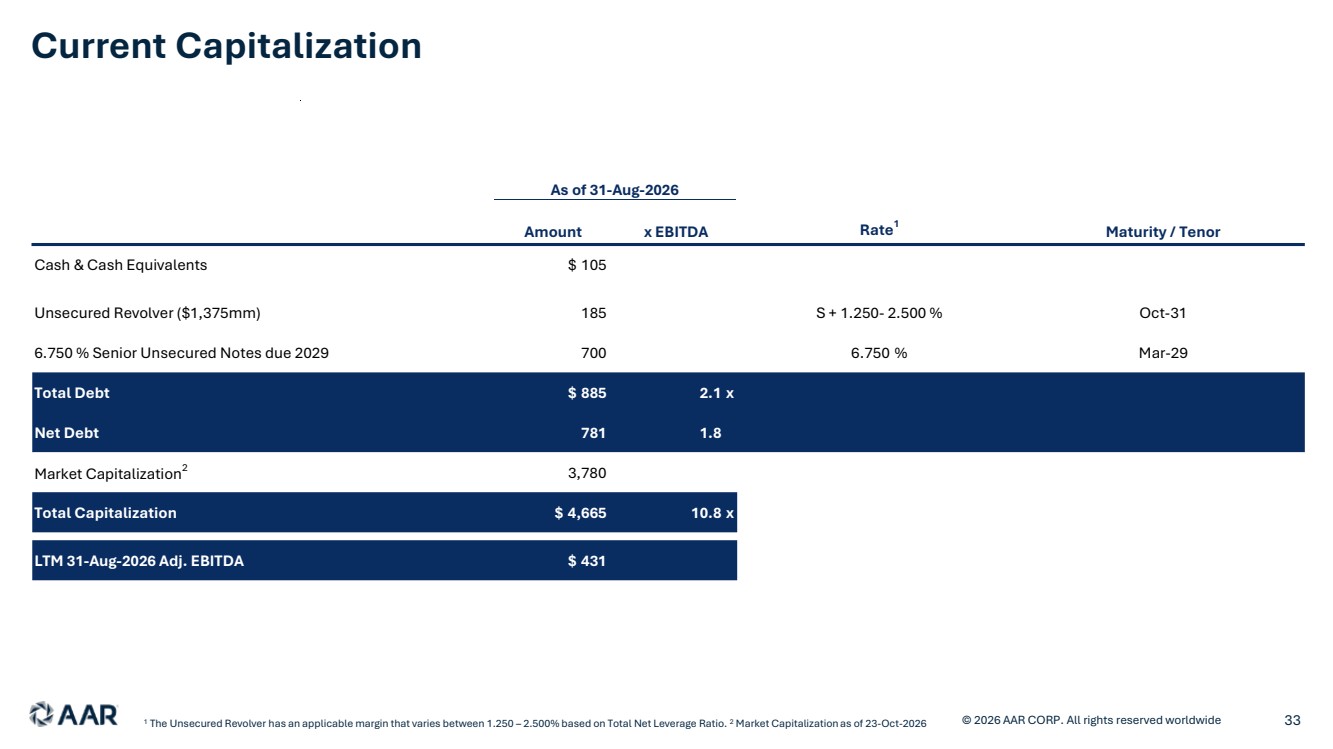
| Current Capitalization 1 The Unsecured Revolver has an applicable margin that varies between 1.250 – 2.500% based on Total Net Leverage Ratio. 2 Market Capitalization as of 23-Oct-2026 © 2026 AAR CORP. All rights reserved worldwide 33 As of 31-Aug-2026 Amount x EBITDA Rate1 Maturity / Tenor Cash & Cash Equivalents $ 105 Unsecured Revolver ($1,375mm) 185 S + 1.250- 2.500 % Oct-31 6.750 % Senior Unsecured Notes due 2029 700 6.750 % Mar-29 Total Debt $ 885 2.1 x Net Debt 781 1.8 Market Capitalization2 3,780 Total Capitalization $ 4,665 10.8 x LTM 31-Aug-2026 Adj. EBITDA $ 431 |
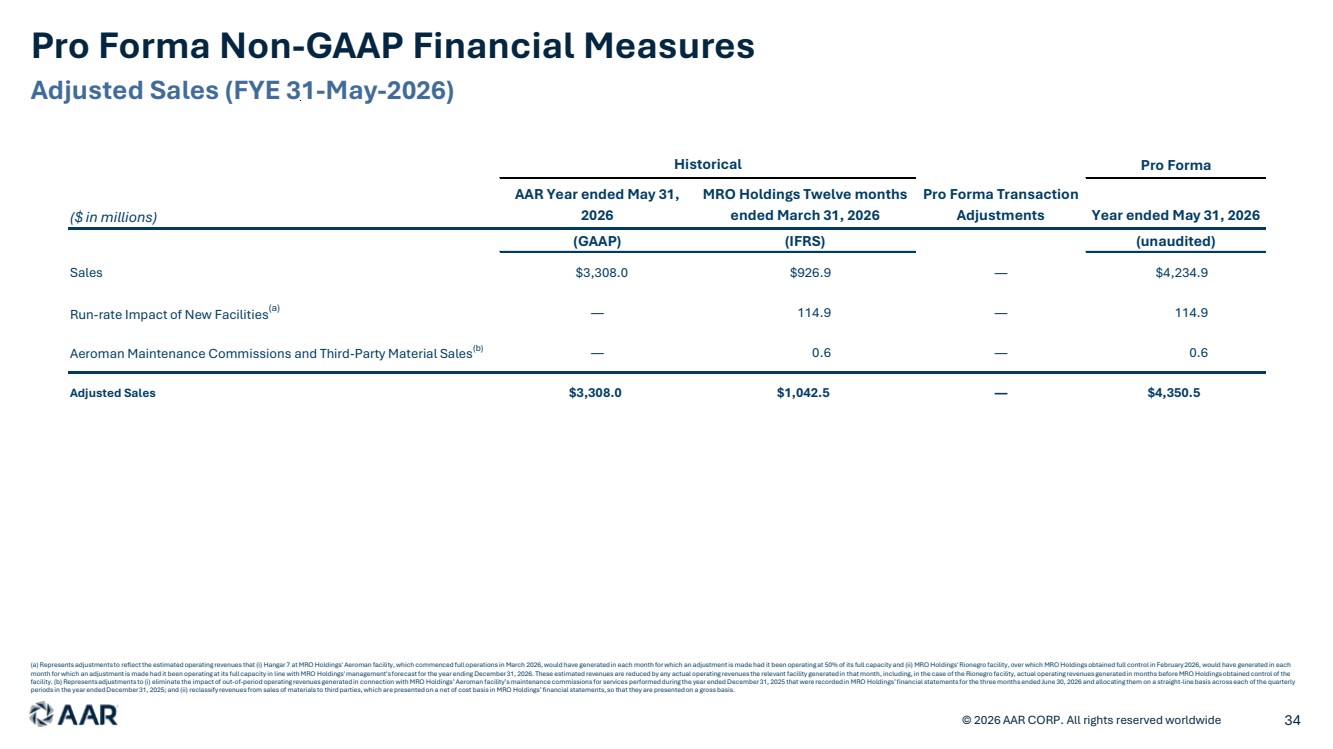
| Pro Forma Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 34 Adjusted Sales (FYE 31-May-2026) (a) Represents adjustments to reflect the estimated operating revenues that (i) Hangar 7 at MRO Holdings' Aeroman facility, which commenced full operations in March 2026, would have generated in each month for which an adjustment is made had it been operating at 50% of its full capacity and (ii) MRO Holdings' Rionegro facility, over which MRO Holdings obtained full control in February 2026, would have generated in each month for which an adjustment is made had it been operating at its full capacity in line with MRO Holdings' management's forecast for the year ending December 31, 2026. These estimated revenues are reduced by any actual operating revenues the relevant facility generated in that month, including, in the case of the Rionegro facility, actual operating revenues generated in months before MRO Holdings obtained control of the facility. (b) Represents adjustments to (i) eliminate the impact of out-of-period operating revenues generated in connection with MRO Holdings’ Aeroman facility’s maintenance commissions for services performed during the year ended December 31, 2025 that were recorded in MRO Holdings’ financial statements for the three months ended June 30, 2026 and allocating them on a straight-line basis across each of the quarterly periods in the year ended December 31, 2025; and (ii) reclassify revenues from sales of materials to third parties, which are presented on a net of cost basis in MRO Holdings’ financial statements, so that they are presented on a gross basis. Pro Forma ($ in millions) AAR Year ended May 31, 2026 MRO Holdings Twelve months ended March 31, 2026 Pro Forma Transaction Adjustments Year ended May 31, 2026 (GAAP) (IFRS) (unaudited) Sales $3,308.0 $926.9 — $4,234.9 Run-rate Impact of New Facilities(a) — 114.9 — 114.9 Aeroman Maintenance Commissions and Third-Party Material Sales(b) — 0.6 — 0.6 Adjusted Sales $3,308.0 $1,042.5 — $4,350.5 Historical |
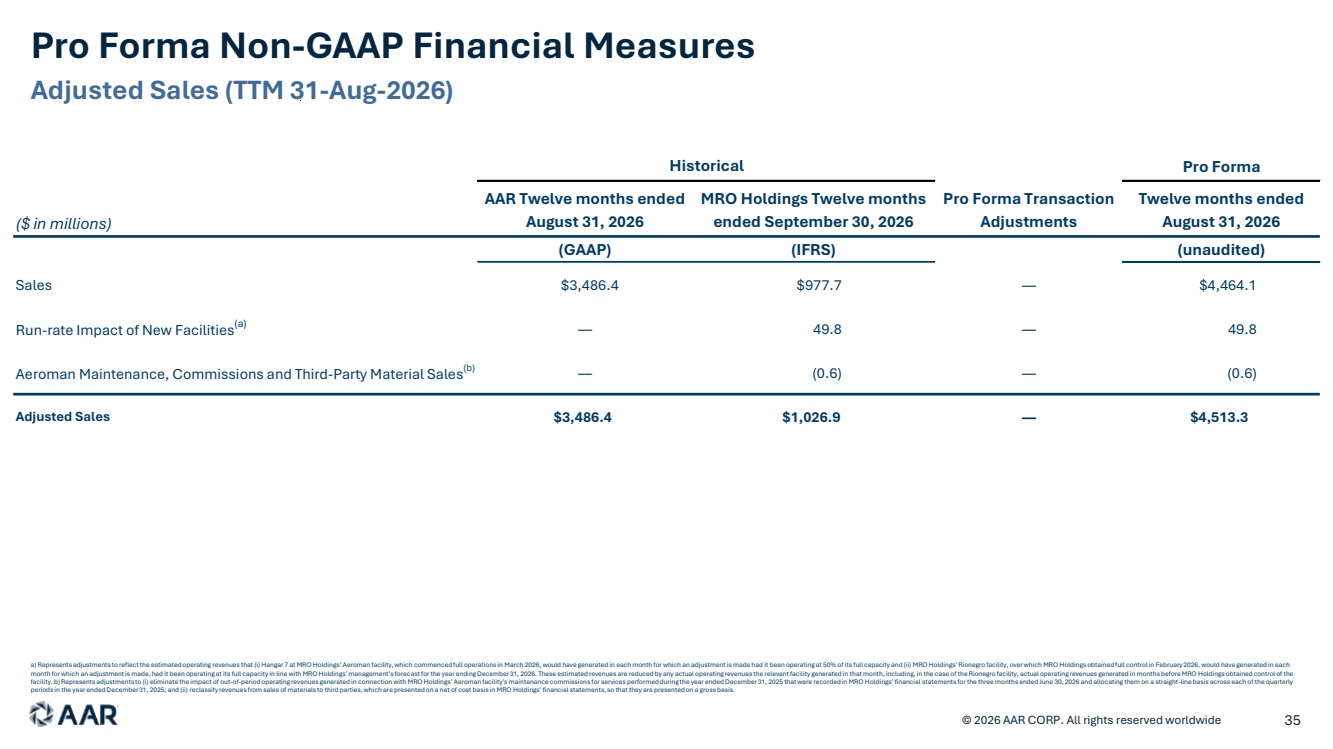
| Pro Forma Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 35 Adjusted Sales (TTM 31-Aug-2026) a) Represents adjustments to reflect the estimated operating revenues that (i) Hangar 7 at MRO Holdings’ Aeroman facility, which commenced full operations in March 2026, would have generated in each month for which an adjustment is made had it been operating at 50% of its full capacity and (ii) MRO Holdings’ Rionegro facility, over which MRO Holdings obtained full control in February 2026, would have generated in each month for which an adjustment is made, had it been operating at its full capacity in line with MRO Holdings’ management’s forecast for the year ending December 31, 2026. These estimated revenues are reduced by any actual operating revenues the relevant facility generated in that month, including, in the case of the Rionegro facility, actual operating revenues generated in months before MRO Holdings obtained control of the facility. b) Represents adjustments to (i) eliminate the impact of out-of-period operating revenues generated in connection with MRO Holdings’ Aeroman facility’s maintenance commissions for services performed during the year ended December 31, 2025 that were recorded in MRO Holdings’ financial statements for the three months ended June 30, 2026 and allocating them on a straight-line basis across each of the quarterly periods in the year ended December 31, 2025; and (ii) reclassify revenues from sales of materials to third parties, which are presented on a net of cost basis in MRO Holdings’ financial statements, so that they are presented on a gross basis. Pro Forma ($ in millions) AAR Twelve months ended August 31, 2026 MRO Holdings Twelve months ended September 30, 2026 Pro Forma Transaction Adjustments Twelve months ended August 31, 2026 (GAAP) (IFRS) (unaudited) Sales $3,486.4 $977.7 — $4,464.1 Run-rate Impact of New Facilities(a) — 49.8 — 49.8 Aeroman Maintenance, Commissions and Third-Party Material Sales(b) — (0.6) — (0.6) Adjusted Sales $3,486.4 $1,026.9 — $4,513.3 Historical |
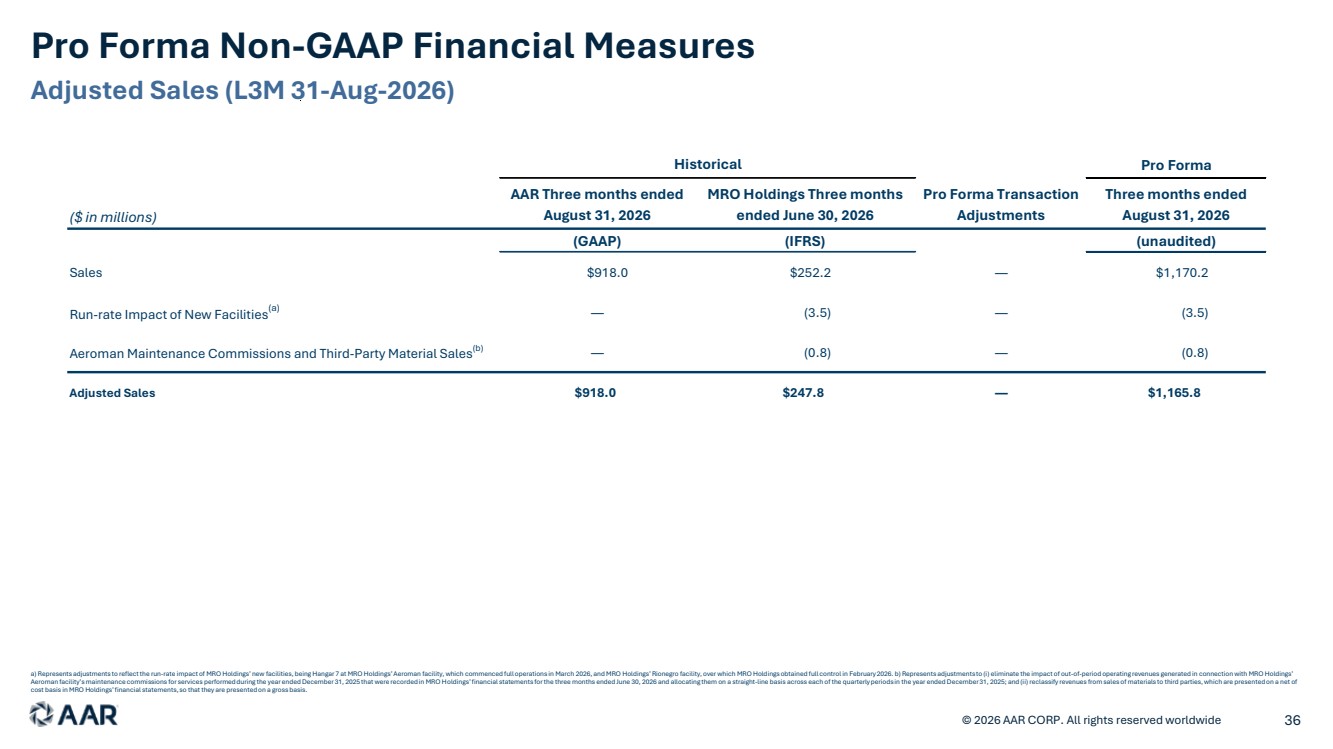
| Pro Forma Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 36 Adjusted Sales (L3M 31-Aug-2026) a) Represents adjustments to reflect the run-rate impact of MRO Holdings’ new facilities, being Hangar 7 at MRO Holdings’ Aeroman facility, which commenced full operations in March 2026, and MRO Holdings’ Rionegro facility, over which MRO Holdings obtained full control in February 2026. b) Represents adjustments to (i) eliminate the impact of out-of-period operating revenues generated in connection with MRO Holdings’ Aeroman facility’s maintenance commissions for services performed during the year ended December 31, 2025 that were recorded in MRO Holdings’ financial statements for the three months ended June 30, 2026 and allocating them on a straight-line basis across each of the quarterly periods in the year ended December 31, 2025; and (ii) reclassify revenues from sales of materials to third parties, which are presented on a net of cost basis in MRO Holdings’ financial statements, so that they are presented on a gross basis. Pro Forma ($ in millions) AAR Three months ended August 31, 2026 MRO Holdings Three months ended June 30, 2026 Pro Forma Transaction Adjustments Three months ended August 31, 2026 (GAAP) (IFRS) (unaudited) Sales $918.0 $252.2 — $1,170.2 Run-rate Impact of New Facilities(a) — (3.5) — (3.5) Aeroman Maintenance Commissions and Third-Party Material Sales(b) — (0.8) — (0.8) Adjusted Sales $918.0 $247.8 — $1,165.8 Historical |
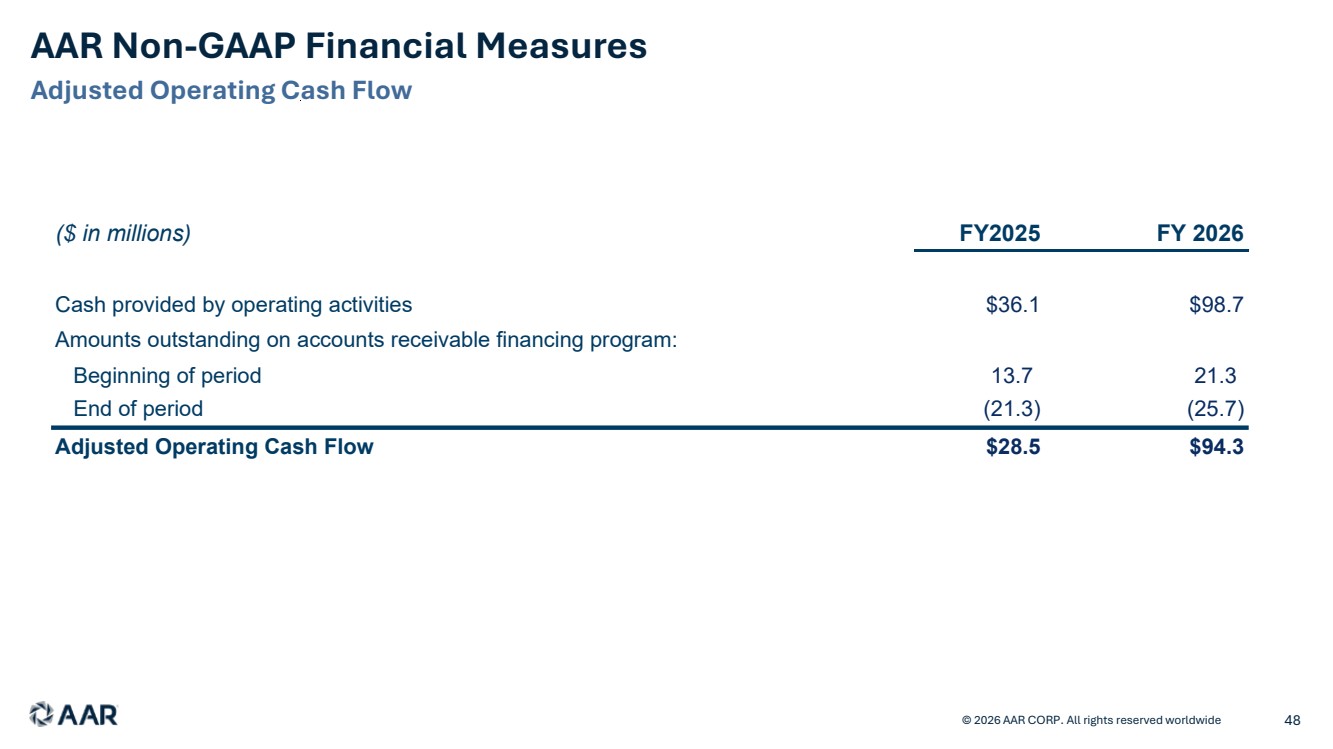
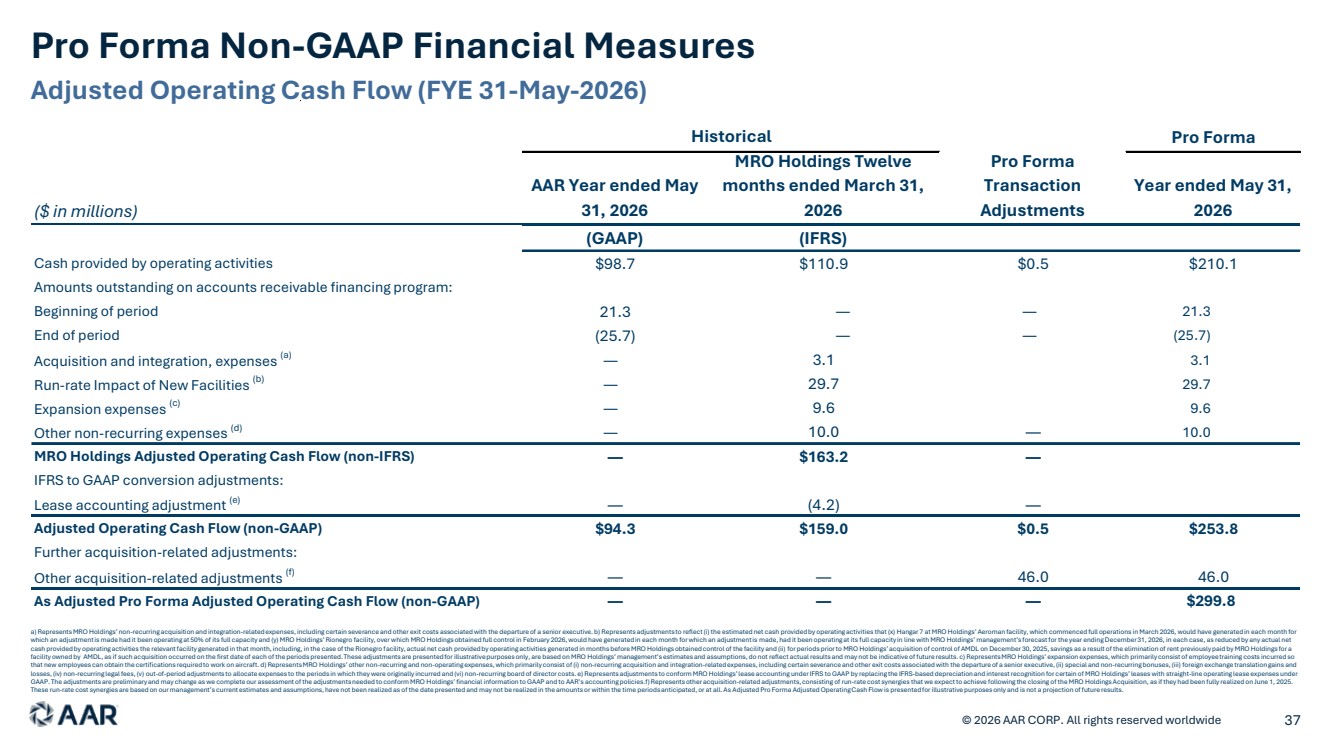
| Pro Forma Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 37 Adjusted Operating Cash Flow (FYE 31-May-2026) a) Represents MRO Holdings’ non-recurring acquisition and integration-related expenses, including certain severance and other exit costs associated with the departure of a senior executive. b) Represents adjustments to reflect (i) the estimated net cash provided by operating activities that (x) Hangar 7 at MRO Holdings’ Aeroman facility, which commenced full operations in March 2026, would have generated in each month for which an adjustment is made had it been operating at 50% of its full capacity and (y) MRO Holdings’ Rionegro facility, over which MRO Holdings obtained full control in February 2026, would have generated in each month for which an adjustment is made, had it been operating at its full capacity in line with MRO Holdings’ management’s forecast for the year ending December 31, 2026, in each case, as reduced by any actual net cash provided by operating activities the relevant facility generated in that month, including, in the case of the Rionegro facility, actual net cash provided by operating activities generated in months before MRO Holdings obtained control of the facility and (ii) for periods prior to MRO Holdings’ acquisition of control of AMDL on December 30, 2025, savings as a result of the elimination of rent previously paid by MRO Holdings for a facility owned by AMDL, as if such acquisition occurred on the first date of each of the periods presented. These adjustments are presented for illustrative purposes only, are based on MRO Holdings’ management’s estimates and assumptions, do not reflect actual results and may not be indicative of future results. c) Represents MRO Holdings’ expansion expenses, which primarily consist of employee training costs incurred so that new employees can obtain the certifications required to work on aircraft. d) Represents MRO Holdings’ other non-recurring and non-operating expenses, which primarily consist of (i) non-recurring acquisition and integration-related expenses, including certain severance and other exit costs associated with the departure of a senior executive, (ii) special and non-recurring bonuses, (iii) foreign exchange translation gains and losses, (iv) non-recurring legal fees, (v) out-of-period adjustments to allocate expenses to the periods in which they were originally incurred and (vi) non-recurring board of director costs. e) Represents adjustments to conform MRO Holdings’ lease accounting under IFRS to GAAP by replacing the IFRS-based depreciation and interest recognition for certain of MRO Holdings’ leases with straight-line operating lease expenses under GAAP. The adjustments are preliminary and may change as we complete our assessment of the adjustments needed to conform MRO Holdings’ financial information to GAAP and to AAR’s accounting policies.f) Represents other acquisition-related adjustments, consisting of run-rate cost synergies that we expect to achieve following the closing of the MRO Holdings Acquisition, as if they had been fully realized on June 1, 2025. These run-rate cost synergies are based on our management’s current estimates and assumptions, have not been realized as of the date presented and may not be realized in the amounts or within the time periods anticipated, or at all. As Adjusted Pro Forma Adjusted Operating Cash Flow is presented for illustrative purposes only and is not a projection of future results. Pro Forma ($ in millions) AAR Year ended May 31, 2026 MRO Holdings Twelve months ended March 31, 2026 Pro Forma Transaction Adjustments Year ended May 31, 2026 (GAAP) (IFRS) Cash provided by operating activities $98.7 $110.9 $0.5 $210.1 Amounts outstanding on accounts receivable financing program: Beginning of period 21.3 — — 21.3 End of period (25.7) — — (25.7) Acquisition and integration, expenses (a) — 3.1 3.1 Run-rate Impact of New Facilities (b) — 29.7 29.7 Expansion expenses (c) — 9.6 9.6 Other non-recurring expenses (d) — 10.0 — 10.0 MRO Holdings Adjusted Operating Cash Flow (non-IFRS) — $163.2 — IFRS to GAAP conversion adjustments: Lease accounting adjustment (e) — (4.2) — Adjusted Operating Cash Flow (non-GAAP) $94.3 $159.0 $0.5 $253.8 Further acquisition-related adjustments: Other acquisition-related adjustments (f) — — 46.0 46.0 As Adjusted Pro Forma Adjusted Operating Cash Flow (non-GAAP) — — — $299.8 Historical |
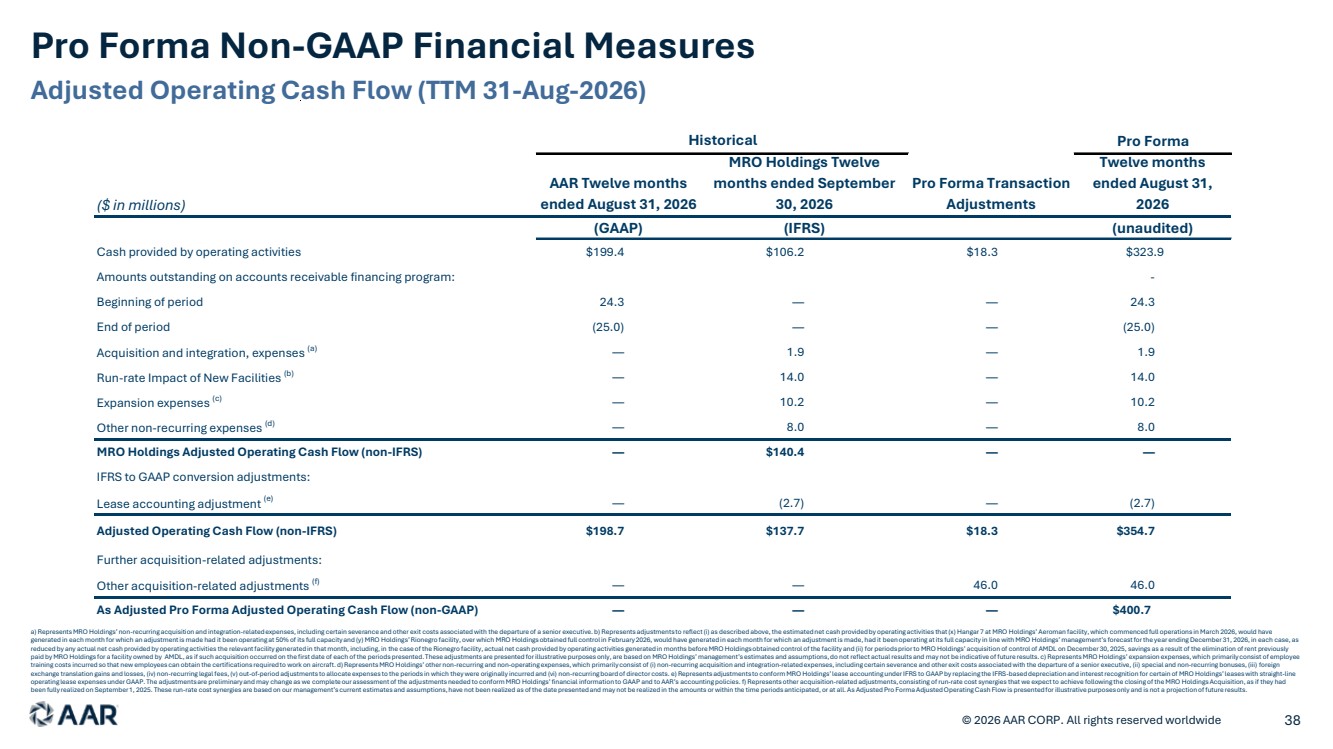
| Pro Forma Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 38 Adjusted Operating Cash Flow (TTM 31-Aug-2026) a) Represents MRO Holdings’ non-recurring acquisition and integration-related expenses, including certain severance and other exit costs associated with the departure of a senior executive. b) Represents adjustments to reflect (i) as described above, the estimated net cash provided by operating activities that (x) Hangar 7 at MRO Holdings’ Aeroman facility, which commenced full operations in March 2026, would have generated in each month for which an adjustment is made had it been operating at 50% of its full capacity and (y) MRO Holdings’ Rionegro facility, over which MRO Holdings obtained full control in February 2026, would have generated in each month for which an adjustment is made, had it been operating at its full capacity in line with MRO Holdings’ management’s forecast for the year ending December 31, 2026, in each case, as reduced by any actual net cash provided by operating activities the relevant facility generated in that month, including, in the case of the Rionegro facility, actual net cash provided by operating activities generated in months before MRO Holdings obtained control of the facility and (ii) for periods prior to MRO Holdings’ acquisition of control of AMDL on December 30, 2025, savings as a result of the elimination of rent previously paid by MRO Holdings for a facility owned by AMDL, as if such acquisition occurred on the first date of each of the periods presented. These adjustments are presented for illustrative purposes only, are based on MRO Holdings’ management’s estimates and assumptions, do not reflect actual results and may not be indicative of future results. c) Represents MRO Holdings’ expansion expenses, which primarily consist of employee training costs incurred so that new employees can obtain the certifications required to work on aircraft. d) Represents MRO Holdings’ other non-recurring and non-operating expenses, which primarily consist of (i) non-recurring acquisition and integration-related expenses, including certain severance and other exit costs associated with the departure of a senior executive, (ii) special and non-recurring bonuses, (iii) foreign exchange translation gains and losses, (iv) non-recurring legal fees, (v) out-of-period adjustments to allocate expenses to the periods in which they were originally incurred and (vi) non-recurring board of director costs. e) Represents adjustments to conform MRO Holdings’ lease accounting under IFRS to GAAP by replacing the IFRS-based depreciation and interest recognition for certain of MRO Holdings’ leases with straight-line operating lease expenses under GAAP. The adjustments are preliminary and may change as we complete our assessment of the adjustments needed to conform MRO Holdings’ financial information to GAAP and to AAR’s accounting policies. f) Represents other acquisition-related adjustments, consisting of run-rate cost synergies that we expect to achieve following the closing of the MRO Holdings Acquisition, as if they had been fully realized on September 1, 2025. These run-rate cost synergies are based on our management’s current estimates and assumptions, have not been realized as of the date presented and may not be realized in the amounts or within the time periods anticipated, or at all. As Adjusted Pro Forma Adjusted Operating Cash Flow is presented for illustrative purposes only and is not a projection of future results. Pro Forma ($ in millions) AAR Twelve months ended August 31, 2026 MRO Holdings Twelve months ended September 30, 2026 Pro Forma Transaction Adjustments Twelve months ended August 31, 2026 (GAAP) (IFRS) (unaudited) Cash provided by operating activities $199.4 $106.2 $18.3 $323.9 Amounts outstanding on accounts receivable financing program: - Beginning of period 24.3 — — 24.3 End of period (25.0) — — (25.0) Acquisition and integration, expenses (a) — 1.9 — 1.9 Run-rate Impact of New Facilities (b) — 14.0 — 14.0 Expansion expenses (c) — 10.2 — 10.2 Other non-recurring expenses (d) — 8.0 — 8.0 MRO Holdings Adjusted Operating Cash Flow (non-IFRS) — $140.4 — — IFRS to GAAP conversion adjustments: Lease accounting adjustment (e) — (2.7) — (2.7) Adjusted Operating Cash Flow (non-IFRS) $198.7 $137.7 $18.3 $354.7 Further acquisition-related adjustments: Other acquisition-related adjustments (f) — — 46.0 46.0 As Adjusted Pro Forma Adjusted Operating Cash Flow (non-GAAP) — — — $400.7 Historical |
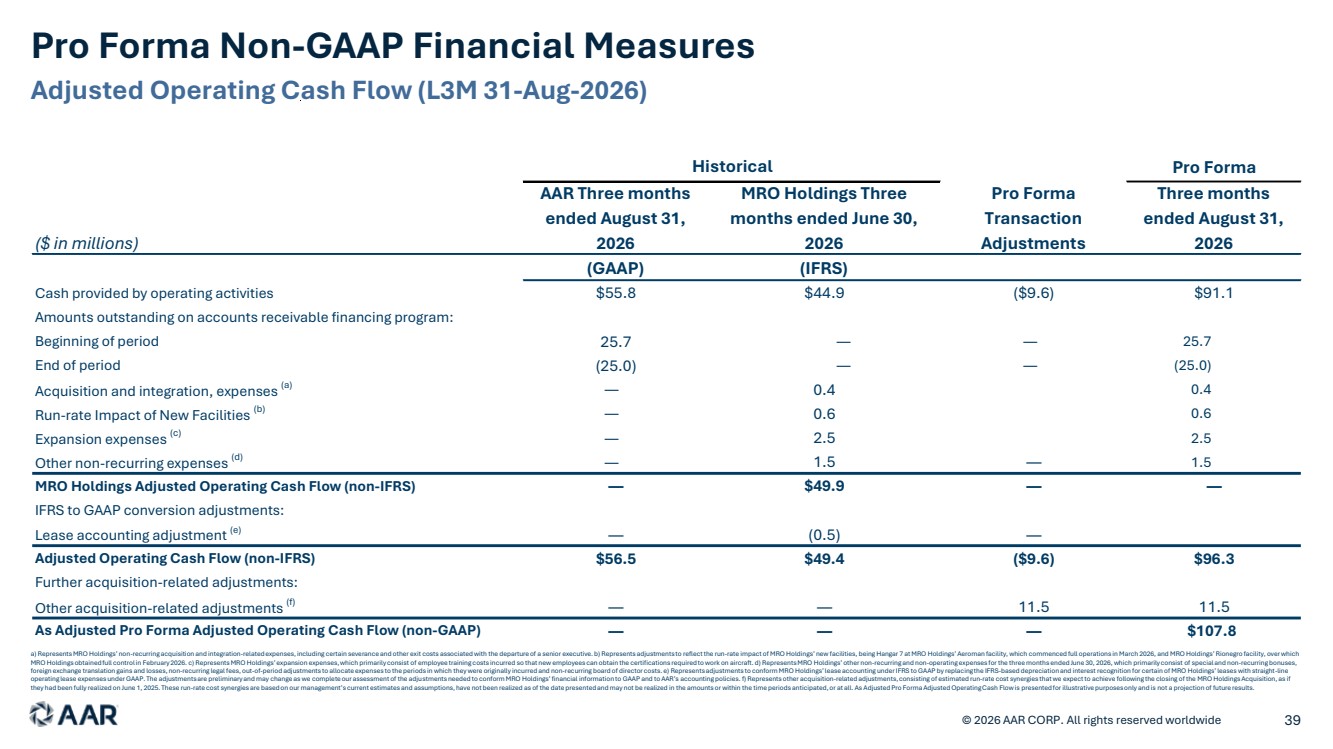
| Pro Forma Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 39 Adjusted Operating Cash Flow (L3M 31-Aug-2026) a) Represents MRO Holdings’ non-recurring acquisition and integration-related expenses, including certain severance and other exit costs associated with the departure of a senior executive. b) Represents adjustments to reflect the run-rate impact of MRO Holdings’ new facilities, being Hangar 7 at MRO Holdings’ Aeroman facility, which commenced full operations in March 2026, and MRO Holdings’ Rionegro facility, over which MRO Holdings obtained full control in February 2026. c) Represents MRO Holdings’ expansion expenses, which primarily consist of employee training costs incurred so that new employees can obtain the certifications required to work on aircraft. d) RepresentsMRO Holdings’ other non-recurring and non-operating expenses for the three months ended June 30, 2026, which primarily consist of special and non-recurring bonuses, foreign exchange translation gains and losses, non-recurring legal fees, out-of-period adjustments to allocate expenses to the periods in which they were originally incurred and non-recurring board of director costs. e) Represents adjustments to conform MRO Holdings’ lease accounting under IFRS to GAAP by replacing the IFRS-based depreciation and interest recognition for certain of MRO Holdings’ leases with straight-line operating lease expenses under GAAP. The adjustments are preliminary and may change as we complete our assessment of the adjustments needed to conform MRO Holdings’ financial information to GAAP and to AAR’s accounting policies. f) Represents other acquisition-related adjustments, consisting of estimated run-rate cost synergies that we expect to achieve following the closing of the MRO Holdings Acquisition, as if they had been fully realized on June 1, 2025. These run-rate cost synergies are based on our management’s current estimates and assumptions, have not been realized as of the date presented and may not be realized in the amounts or within the time periods anticipated, or at all. As Adjusted Pro Forma Adjusted Operating Cash Flow is presented for illustrative purposes only and is not a projection of future results. Pro Forma ($ in millions) AAR Three months ended August 31, 2026 MRO Holdings Three months ended June 30, 2026 Pro Forma Transaction Adjustments Three months ended August 31, 2026 (GAAP) (IFRS) Cash provided by operating activities $55.8 $44.9 ($9.6) $91.1 Amounts outstanding on accounts receivable financing program: Beginning of period 25.7 — — 25.7 End of period (25.0) — — (25.0) Acquisition and integration, expenses (a) — 0.4 0.4 Run-rate Impact of New Facilities (b) — 0.6 0.6 Expansion expenses (c) — 2.5 2.5 Other non-recurring expenses (d) — 1.5 — 1.5 MRO Holdings Adjusted Operating Cash Flow (non-IFRS) — $49.9 — — IFRS to GAAP conversion adjustments: Lease accounting adjustment (e) — (0.5) — Adjusted Operating Cash Flow (non-IFRS) $56.5 $49.4 ($9.6) $96.3 Further acquisition-related adjustments: Other acquisition-related adjustments (f) — — 11.5 11.5 As Adjusted Pro Forma Adjusted Operating Cash Flow (non-GAAP) — — — $107.8 Historical |
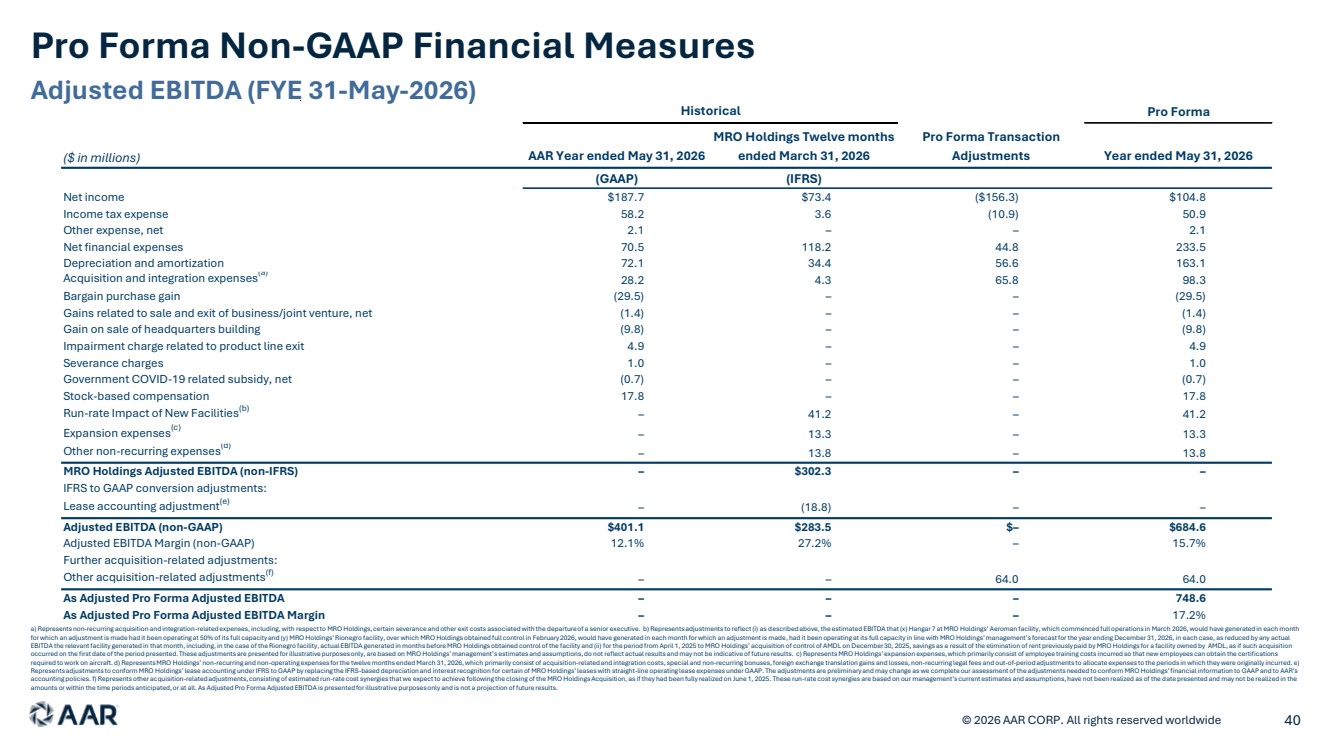
| Pro Forma Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 40 Adjusted EBITDA (FYE 31-May-2026) a) Represents non-recurring acquisition and integration-related expenses, including, with respect to MRO Holdings, certain severance and other exit costs associated with the departure of a senior executive. b) Represents adjustments to reflect (i) as described above, the estimated EBITDA that (x) Hangar 7 at MRO Holdings’ Aeroman facility, which commenced full operations in March 2026, would have generated in each month for which an adjustment is made had it been operating at 50% of its full capacity and (y) MRO Holdings’ Rionegro facility, over which MRO Holdings obtained full control in February 2026, would have generated in each month for which an adjustment is made, had it been operating at its full capacity in line with MRO Holdings’ management’s forecast for the year ending December 31, 2026, in each case, as reduced by any actual EBITDA the relevant facility generated in that month, including, in the case of the Rionegro facility, actual EBITDA generated in months before MRO Holdings obtained control of the facility and (ii) for the period from April 1, 2025 to MRO Holdings’ acquisition of control of AMDL on December 30, 2025, savings as a result of the elimination of rent previously paid by MRO Holdings for a facility owned by AMDL, as if such acquisition occurred on the first date of the period presented. These adjustments are presented for illustrative purposes only, are based on MRO Holdings’ management’s estimates and assumptions, do not reflect actual results and may not be indicative of future results. c) Represents MRO Holdings’ expansion expenses, which primarily consist of employee training costs incurred so that new employees can obtain the certifications required to work on aircraft. d) Represents MRO Holdings’ non-recurring and non-operating expenses for the twelve months ended March 31, 2026, which primarily consist of acquisition-related and integration costs, special and non-recurring bonuses, foreign exchange translation gains and losses, non-recurring legal fees and out-of-period adjustments to allocate expenses to the periods in which they were originally incurred. e) Represents adjustments to conform MRO Holdings’ lease accounting under IFRS to GAAP by replacing the IFRS-based depreciation and interest recognition for certain of MRO Holdings’ leases with straight-line operating lease expenses under GAAP. The adjustments are preliminary and may change as we complete our assessment of the adjustments needed to conform MRO Holdings’ financial information to GAAP and to AAR’s accounting policies. f) Represents other acquisition-related adjustments, consisting of estimated run-rate cost synergies that we expect to achieve following the closing of the MRO Holdings Acquisition, as if they had been fully realized on June 1, 2025. These run-rate cost synergies are based on our management’s current estimates and assumptions, have not been realized as of the date presented and may not be realized in the amounts or within the time periods anticipated, or at all. As Adjusted Pro Forma Adjusted EBITDA is presented for illustrative purposes only and is not a projection of future results. Pro Forma ($ in millions) AAR Year ended May 31, 2026 MRO Holdings Twelve months ended March 31, 2026 Pro Forma Transaction Adjustments Year ended May 31, 2026 (GAAP) (IFRS) Net income $187.7 $73.4 ($156.3) $104.8 Income tax expense 58.2 3.6 (10.9) 50.9 Other expense, net 2.1 – – 2.1 Net financial expenses 70.5 118.2 44.8 233.5 Depreciation and amortization 72.1 34.4 56.6 163.1 Acquisition and integration expenses(a) 28.2 4.3 65.8 98.3 Bargain purchase gain (29.5) – – (29.5) Gains related to sale and exit of business/joint venture, net (1.4) – – (1.4) Gain on sale of headquarters building (9.8) – – (9.8) Impairment charge related to product line exit 4.9 – – 4.9 Severance charges 1.0 – – 1.0 Government COVID-19 related subsidy, net (0.7) – – (0.7) Stock-based compensation 17.8 – – 17.8 Run-rate Impact of New Facilities(b) – 41.2 – 41.2 Expansion expenses(c) – 13.3 – 13.3 Other non-recurring expenses(d) – 13.8 – 13.8 MRO Holdings Adjusted EBITDA (non-IFRS) – $302.3 – – IFRS to GAAP conversion adjustments: Lease accounting adjustment(e) – (18.8) – – Adjusted EBITDA (non-GAAP) $401.1 $283.5 $– $684.6 Adjusted EBITDA Margin (non-GAAP) 12.1% 27.2% – 15.7% Further acquisition-related adjustments: Other acquisition-related adjustments(f) – – 64.0 64.0 As Adjusted Pro Forma Adjusted EBITDA – – – 748.6 As Adjusted Pro Forma Adjusted EBITDA Margin – – – 17.2% Historical |
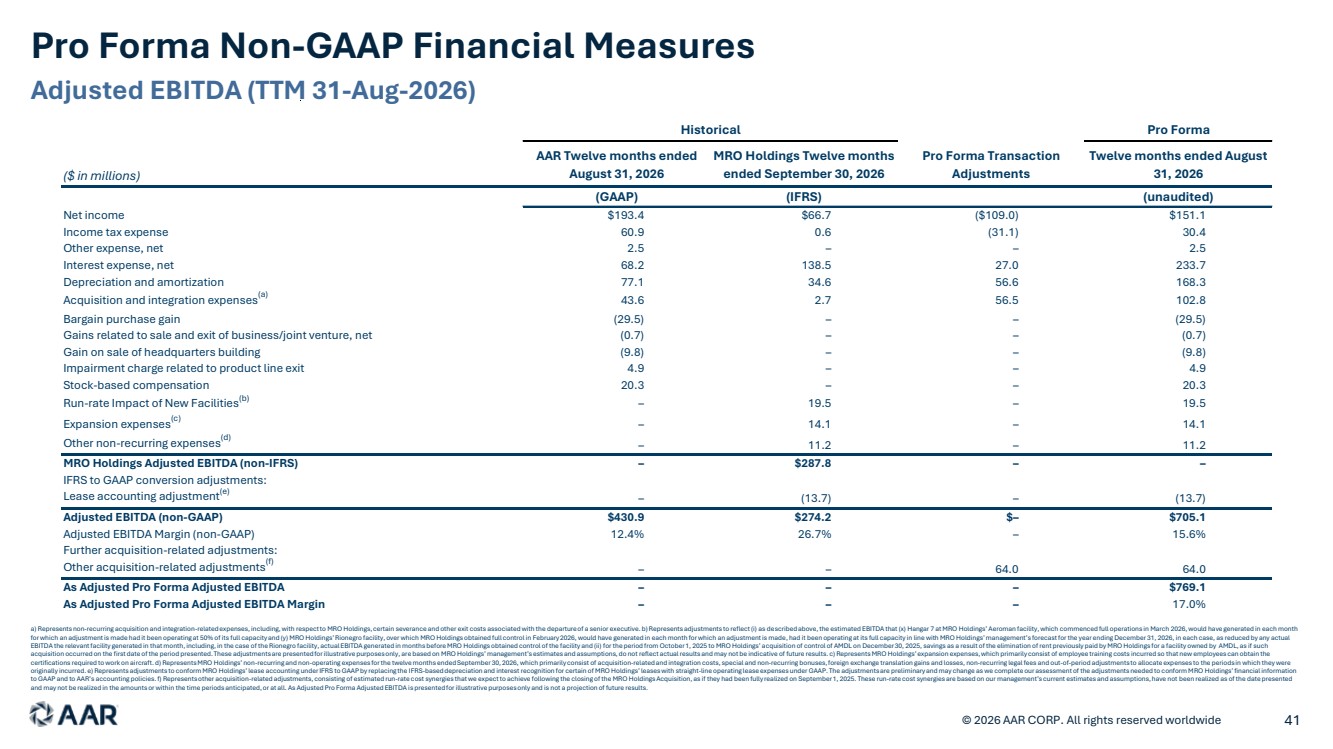
| Pro Forma Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 41 Adjusted EBITDA (TTM 31-Aug-2026) a) Represents non-recurring acquisition and integration-related expenses, including, with respect to MRO Holdings, certain severance and other exit costs associated with the departure of a senior executive. b) Represents adjustments to reflect (i) as described above, the estimated EBITDA that (x) Hangar 7 at MRO Holdings’ Aeroman facility, which commenced full operations in March 2026, would have generated in each month for which an adjustment is made had it been operating at 50% of its full capacity and (y) MRO Holdings’ Rionegro facility, over which MRO Holdings obtained full control in February 2026, would have generated in each month for which an adjustment is made, had it been operating at its full capacity in line with MRO Holdings’ management’s forecast for the year ending December 31, 2026, in each case, as reduced by any actual EBITDA the relevant facility generated in that month, including, in the case of the Rionegro facility, actual EBITDA generated in months before MRO Holdings obtained control of the facility and (ii) for the period from October 1, 2025 to MRO Holdings’ acquisition of control of AMDL on December 30, 2025, savings as a result of the elimination of rent previously paid by MRO Holdings for a facility owned by AMDL, as if such acquisition occurred on the first date of the period presented. These adjustments are presented for illustrative purposes only, are based on MRO Holdings’ management’s estimates and assumptions, do not reflect actual results and may not be indicative of future results. c) Represents MRO Holdings’ expansion expenses, which primarily consist of employee training costs incurred so that new employees can obtain the certifications required to work on aircraft. d) Represents MRO Holdings’ non-recurring and non-operating expenses for the twelve months ended September 30, 2026, which primarily consist of acquisition-related and integration costs, special and non-recurring bonuses, foreign exchange translation gains and losses, non-recurring legal fees and out-of-period adjustments to allocate expenses to the periods in which they were originally incurred. e) Represents adjustments to conform MRO Holdings’ lease accounting under IFRS to GAAP by replacing the IFRS-based depreciation and interest recognition for certain of MRO Holdings’ leases with straight-line operating lease expenses under GAAP. The adjustments are preliminary and may change as we complete our assessment of the adjustments needed to conform MRO Holdings’ financial information to GAAP and to AAR’s accounting policies. f) Represents other acquisition-related adjustments, consisting of estimated run-rate cost synergies that we expect to achieve following the closing of the MRO Holdings Acquisition, as if they had been fully realized on September 1, 2025. These run-rate cost synergies are based on our management’s current estimates and assumptions, have not been realized as of the date presented and may not be realized in the amounts or within the time periods anticipated, or at all. As Adjusted Pro Forma Adjusted EBITDA is presented for illustrative purposes only and is not a projection of future results. Pro Forma ($ in millions) AAR Twelve months ended August 31, 2026 MRO Holdings Twelve months ended September 30, 2026 Pro Forma Transaction Adjustments Twelve months ended August 31, 2026 (GAAP) (IFRS) (unaudited) Net income $193.4 $66.7 ($109.0) $151.1 Income tax expense 60.9 0.6 (31.1) 30.4 Other expense, net 2.5 – – 2.5 Interest expense, net 68.2 138.5 27.0 233.7 Depreciation and amortization 77.1 34.6 56.6 168.3 Acquisition and integration expenses(a) 43.6 2.7 56.5 102.8 Bargain purchase gain (29.5) – – (29.5) Gains related to sale and exit of business/joint venture, net (0.7) – – (0.7) Gain on sale of headquarters building (9.8) – – (9.8) Impairment charge related to product line exit 4.9 – – 4.9 Stock-based compensation 20.3 – – 20.3 Run-rate Impact of New Facilities(b) – 19.5 – 19.5 Expansion expenses(c) – 14.1 – 14.1 Other non-recurring expenses(d) – 11.2 – 11.2 MRO Holdings Adjusted EBITDA (non-IFRS) – $287.8 – – IFRS to GAAP conversion adjustments: Lease accounting adjustment(e) – (13.7) – (13.7) Adjusted EBITDA (non-GAAP) $430.9 $274.2 $– $705.1 Adjusted EBITDA Margin (non-GAAP) 12.4% 26.7% – 15.6% Further acquisition-related adjustments: Other acquisition-related adjustments(f) – – 64.0 64.0 As Adjusted Pro Forma Adjusted EBITDA – – – $769.1 As Adjusted Pro Forma Adjusted EBITDA Margin – – – 17.0% Historical |
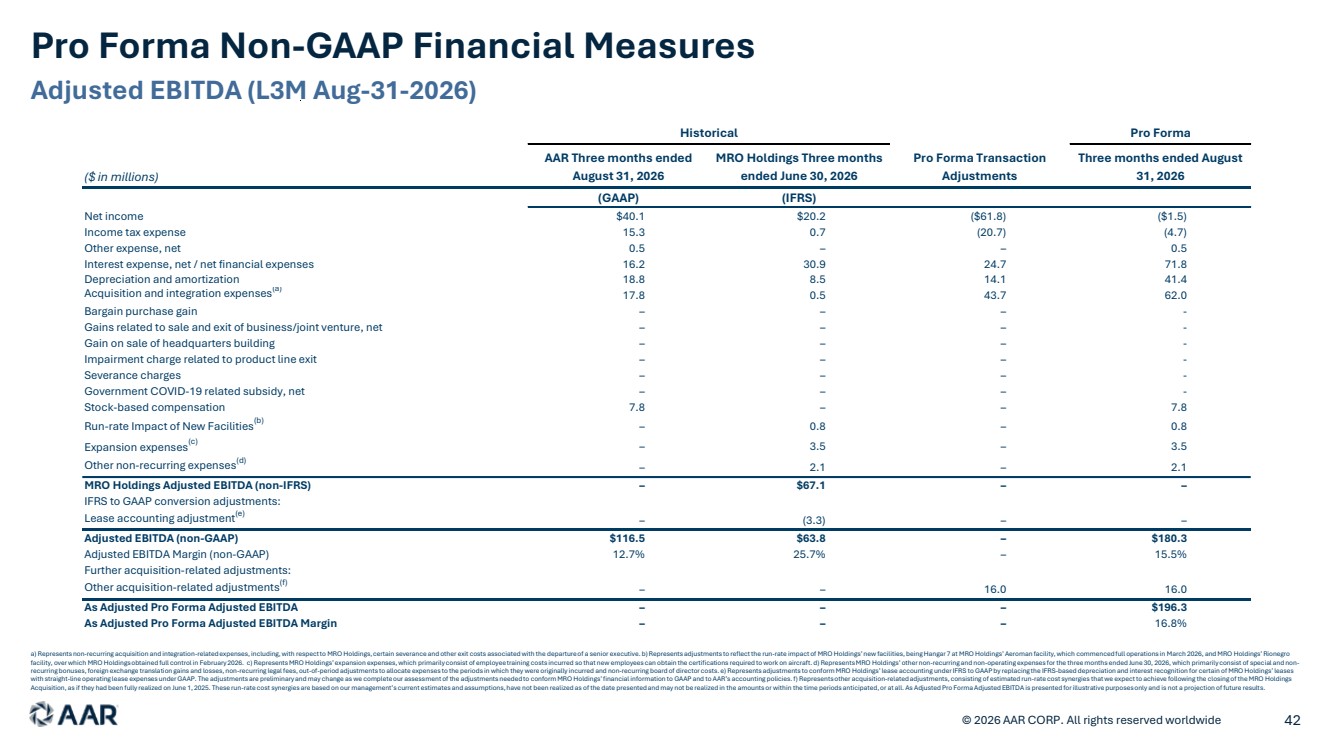
| Pro Forma Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 42 Adjusted EBITDA (L3M Aug-31-2026) a) Represents non-recurring acquisition and integration-related expenses, including, with respect to MRO Holdings, certain severance and other exit costs associated with the departure of a senior executive. b) Represents adjustments to reflect the run-rate impact of MRO Holdings’ new facilities, being Hangar 7 at MRO Holdings’ Aeroman facility, which commenced full operations in March 2026, and MRO Holdings’ Rionegro facility, over which MRO Holdings obtained full control in February 2026. c) Represents MRO Holdings’ expansion expenses, which primarily consist of employee training costs incurred so that new employees can obtain the certifications required to work on aircraft. d) Represents MRO Holdings’ other non-recurring and non-operating expenses for the three months ended June 30, 2026, which primarily consist of special and non-recurring bonuses, foreign exchange translation gains and losses, non-recurring legal fees, out-of-period adjustments to allocate expenses to the periods in which they were originally incurred and non-recurring board of director costs. e) Represents adjustments to conform MRO Holdings’ lease accounting under IFRS to GAAP by replacing the IFRS-based depreciation and interest recognition for certain of MRO Holdings’ leases with straight-line operating lease expenses under GAAP. The adjustments are preliminary and may change as we complete our assessment of the adjustments needed to conform MRO Holdings’ financial information to GAAP and to AAR’s accounting policies. f) Represents other acquisition-related adjustments, consisting of estimated run-rate cost synergies that we expect to achieve following the closing of the MRO Holdings Acquisition, as if they had been fully realized on June 1, 2025. These run-rate cost synergies are based on our management’s current estimates and assumptions, have not been realized as of the date presented and may not be realized in the amounts or within the time periods anticipated, or at all. As Adjusted Pro Forma Adjusted EBITDA is presented for illustrative purposes only and is not a projection of future results. Pro Forma ($ in millions) AAR Three months ended August 31, 2026 MRO Holdings Three months ended June 30, 2026 Pro Forma Transaction Adjustments Three months ended August 31, 2026 (GAAP) (IFRS) Net income $40.1 $20.2 ($61.8) ($1.5) Income tax expense 15.3 0.7 (20.7) (4.7) Other expense, net 0.5 – – 0.5 Interest expense, net / net financial expenses 16.2 30.9 24.7 71.8 Depreciation and amortization 18.8 8.5 14.1 41.4 Acquisition and integration expenses(a) 17.8 0.5 43.7 62.0 Bargain purchase gain – – – - Gains related to sale and exit of business/joint venture, net – – – - Gain on sale of headquarters building – – – - Impairment charge related to product line exit – – – - Severance charges – – – - Government COVID-19 related subsidy, net – – – - Stock-based compensation 7.8 – – 7.8 Run-rate Impact of New Facilities(b) – 0.8 – 0.8 Expansion expenses(c) – 3.5 – 3.5 Other non-recurring expenses(d) – 2.1 – 2.1 MRO Holdings Adjusted EBITDA (non-IFRS) – $67.1 – – IFRS to GAAP conversion adjustments: Lease accounting adjustment(e) – (3.3) – – Adjusted EBITDA (non-GAAP) $116.5 $63.8 – $180.3 Adjusted EBITDA Margin (non-GAAP) 12.7% 25.7% – 15.5% Further acquisition-related adjustments: Other acquisition-related adjustments(f) – – 16.0 16.0 As Adjusted Pro Forma Adjusted EBITDA – – – $196.3 As Adjusted Pro Forma Adjusted EBITDA Margin – – – 16.8% Historical |
| MRO Holdings Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 43 Adjusted Operating Revenues a) Represents adjustments to (i) eliminate the impact of out-of-period operating revenues generated in connection with MRO Holdings’ Aeroman facility’s maintenance commissions for services performed during the year ended December 31, 2025 that were recorded in MRO Holdings’ financial statements for the three months ended June 30, 2026 and allocating them on a straight-line basis across each of the quarterly periods in the year ended December 31, 2025; and (ii) reclassify revenues from sales of materials to third parties, which are presented on a net of cost basis in MRO Holdings’ financial statements, so that they are presented on a gross basis. b) Represents adjustments to reflect, as described below, the estimated operating revenues that (i) Hangar 7 at MRO Holdings’ Aeroman facility, which commenced full operations in March 2026, would have generated in each month for which an adjustment is made had it been operating at 50% of its full capacity and (ii) MRO Holdings’ Rionegro facility, over which MRO Holdings obtained full control in February 2026, would have generated in each month for which an adjustment is made, had it been operating at its full capacity in line with MRO Holdings’ management’s forecast for the year ending December 31, 2026. These estimated revenues are reduced by any actual operating revenues the relevant facility generated in that month, including, in the case of the Rionegro facility, actual operating revenues generated in months before MRO Holdings obtained control of the facility. The adjustments for Hangar 7 add back, for each month before Hangar 7 commenced full operations in March 2026, an amount equal to the Hangar 7 Estimated Monthly Revenue, less the actual operating revenues generated by Hangar 7 in that month. Hangar 7 generated actual operating revenues in February 2026 and March 2026. No adjustments for Hangar 7 are reflected for periods before January 2025 or after March 2026. The Hangar 7 Estimated Monthly Revenue is calculated by multiplying the number of labor hours that MRO Holdings expects Hangar 7 to complete per year at full capacity by MRO Holdings’ budgeted average revenue per labor hour, divided by twelve months and applying a 50% factor to reflect the expected ramp-up of the facility. The adjustments for the Rionegro facility add back, for each month in the periods presented, an amount equal to the Rionegro Estimated Monthly Revenue, less the actual operating revenues generated by the Rionegro facility in that month. For months before MRO Holdings obtained control of the facility in February 2026, the adjustment gives effect to the facility’s estimated operating revenues as if MRO Holdings had controlled and operated it during those months. For months after MRO Holdings obtained control, the adjustment normalizes the facility’s actual monthly operating revenues to the amounts in MRO Holdings’ forecast for the year ending December 31, 2026. The Rionegro Estimated Monthly Revenue is based on MRO Holdings' forecast of the facility’s operating revenues for the year ending December 31, 2026, divided by twelve months. The adjustments for the Hangar 7 Estimated Monthly Revenue and Rionegro Estimated Monthly Revenue are presented for illustrative purposes only, are based on MRO Holdings’ management’s estimates and assumptions, do not reflect actual results and may not be indicative of future results. ($ in millions) Year ended December 31, 2024 Year ended December 31, 2025 Six months ended June 30, 2025 Six months ended June 30, 2026 Twelve months ended June 30, 2026 Three months ended September 30, 2026 Operating Revenues $829.2 $920.4 $465.8 $489.1 $943.7 $261.6 Aeroman Maintenance Commissions and Third-Party Material Sales(a) – 0.8 0.4 (0.8) (0.4) - Run-rate Impact of New Facilities(b) – 121.6 61.6 20.6 80.6 - Adjusted Operating Revenues $829.2 $1,042.8 $527.8 $508.9 $1,023.9 $261.6 Historical |
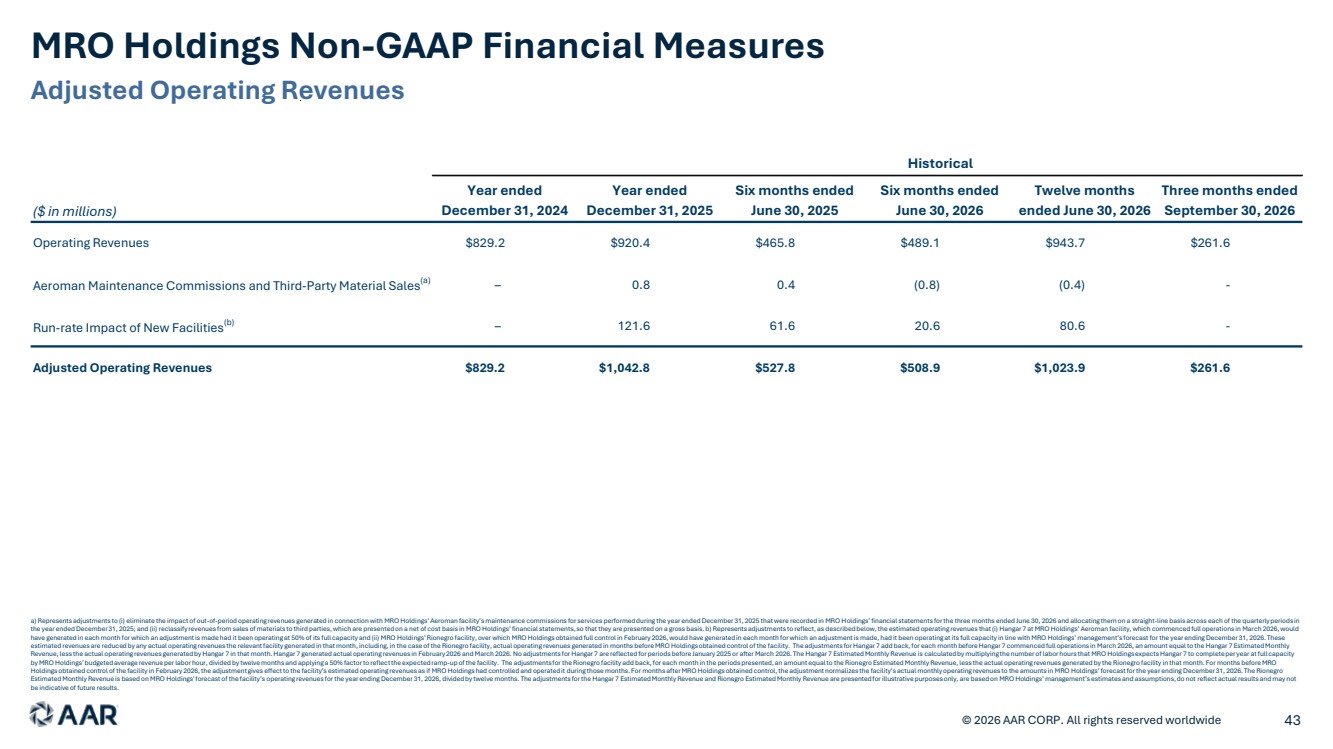
| MRO Holdings Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 44 Adjusted EBITDA a) Represents adjustments to reflect (i) as described below, the estimated EBITDA that (x) Hangar 7 at MRO Holdings’ Aeroman facility, which commenced full operations in March 2026, would have generated in each month for which an adjustment is made had it been operating at 50% of its full capacity and (y) MRO Holdings’ Rionegro facility, over which MRO Holdings obtained full control in February 2026, would have generated in each month for which an adjustment is made, had it been operating at its full capacity in line with MRO Holdings’ management’s forecast for the year ending December 31, 2026, in each case, as reduced by any actual EBITDA the relevant facility generated in that month, including, in the case of the Rionegro facility, actual EBITDA generated in months before MRO Holdings obtained control of the facility and (ii) for periods prior to MRO Holdings’ acquisition of control of AMDL on December 30, 2025, savings as a result of the elimination of rent previously paid by MRO Holdings for a facility owned by AMDL, as if such acquisition occurred on the first date of each of the periods presented. The adjustments for Hangar 7 add back, for each month before Hangar 7 commenced full operations in March 2026, an amount equal to the Hangar 7 Estimated Monthly EBITDA, less the actual EBITDA generated by Hangar 7 in that month. Hangar 7 generated actual EBITDA in February 2026 and March 2026. No adjustments for Hangar 7 are reflected for periods before January 2025 or after March 2026. The Hangar 7 Estimated Monthly EBITDA is calculated by multiplying the number of labor hours that MRO Holdings expects Hangar 7 to complete per year at full capacity by MRO Holdings' budgeted average EBITDA per labor hour, divided by twelve months and applying a 50% factor to reflect the expected ramp-up of the facility. The adjustments for the Rionegro facility add back, for each month in the periods presented, an amount equal to the Rionegro Estimated Monthly EBITDA, less the actual EBITDA generated by the Rionegro facility in that month. For months before MRO Holdings obtained control of the facility in February 2026, the adjustment gives effect to the facility's estimated EBITDA as if MRO Holdings had controlled and operated it during those months. For months after MRO Holdings obtained control, the adjustment normalizes the facility's actual monthly EBITDA to the amounts in MRO Holdings' forecast for the year ending December 31, 2026. The Rionegro Estimated Monthly EBITDA is based on MRO Holdings' forecast of the facility's EBITDA for the year ending December 31, 2026, divided by twelve months. The adjustments for the Hangar 7 Estimated Monthly EBITDA, Rionegro Estimated Monthly EBITDA and savings from the acquisition of AMDL are presented for illustrative purposesonly, are based on MRO Holdings’ management’s estimates and assumptions, do not reflect actual results and may not be indicative of future results. b) Primarily consists of employee training costs which are incurred in order for new employees to achieve certifications to work on aircraft. c) Primarily consists of special and non-recurring bonuses, foreign exchange translation gains and losses, non-recurring legalfees, out-of-period adjustments to allocate expenses to the periods in which they were originally incurred and non-recurring, non-operational board of director costs. ($ in millions) Year ended December 31, 2024 Year ended December 31, 2025 Six months ended June 30, 2025 Six months ended June 30, 2026 Twelve months ended June 30, 2026 Three months ended September 30, 2026 Net Income $59.1 $90.2 $63.8 $38.1 $64.6 $24.5 Income tax expense (1.1) 3.3 2.8 1.3 1.8 0.9 Interest expense, net 113.4 109.5 42.8 60.5 127.2 31.4 Depreciation and amortization 35.1 35.6 17.7 16.0 33.9 9.6 Run-rate and Savings Impact of New Facilities(a) 12.4 45.3 22.8 8.1 30.6 0.2 Expansion expenses(b) 9.6 11.6 5.0 7.6 14.2 3.2 Other non-recurring expenses(c) 4.1 12.4 3.5 10.3 19.2 2.5 Adjusted EBITDA $232.5 $308.0 $158.4 $141.8 $291.4 $72.4 Net income margin 7.1% 9.8% 13.7% 7.8% 6.8% 9.4% Adjusted EBITDA margin 28.0% 29.5% 30.0% 27.9% 28.5% 27.7% Historical |
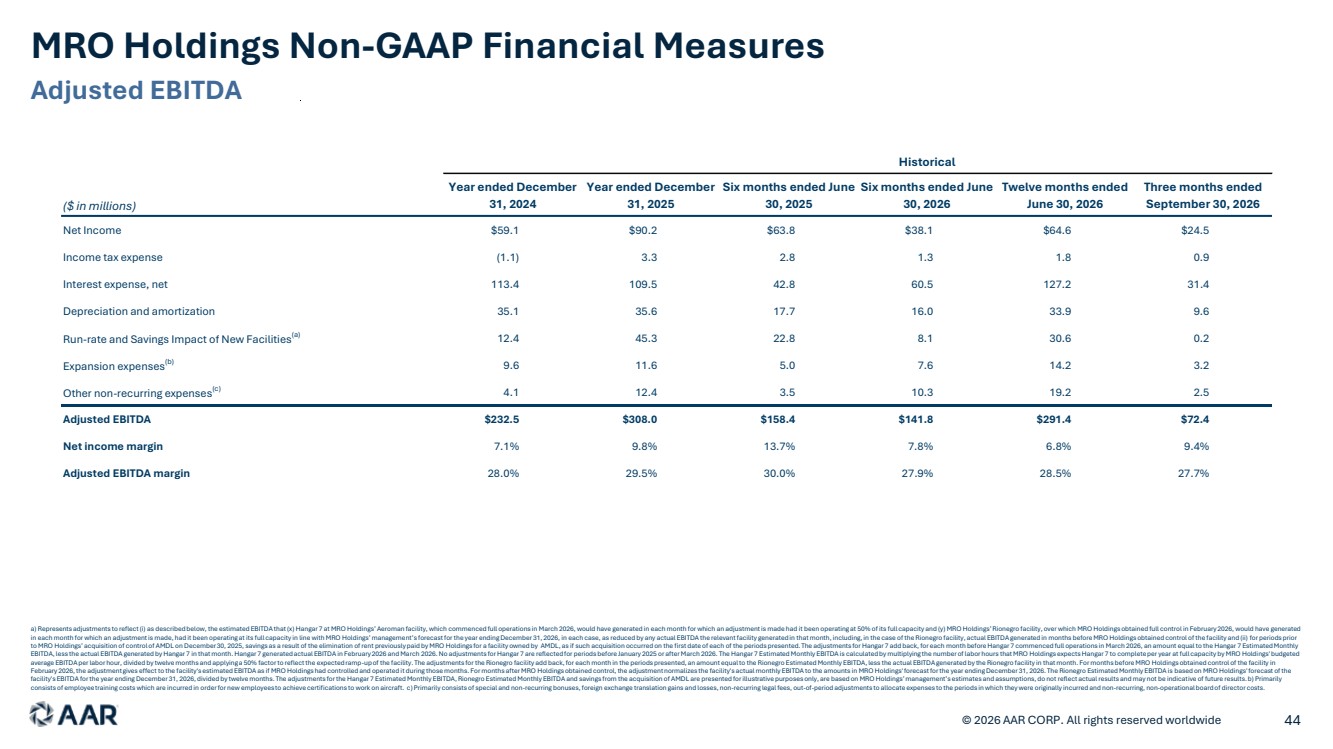
| MRO Holdings Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 45 Adjusted Operating Cash Flow a) Represents adjustments to reflect (i) as described below, the estimated net cash provided by operating activities that (x) Hangar 7 at MRO Holdings’ Aeroman facility, which commenced full operations in March 2026, would have generated in each month for which an adjustment is made had it been operating at 50% of its full capacity and (y) MRO Holdings’ Rionegro facility, over which MRO Holdings obtained full control in February 2026, would have generated in each month for which an adjustment is made, had it been operating at its full capacity in line with MRO Holdings’ management’s forecast for the year ending December 31, 2026, in each case, as reduced by any actual net cash provided by operating activities the relevant facility generated in that month, including, in the case of the Rionegro facility, actual net cash provided by operating activities generated in months before MRO Holdings obtained control of the facility and (ii) for periods prior to MRO Holdings’ acquisition of control of AMDL on December 30, 2025, savings as a result of the elimination of rent previously paid by MRO Holdings for a facility owned by AMDL, as if such acquisition occurred on the first date of each of the periods presented. The adjustments for Hangar 7 add back, for each month before Hangar 7 commenced full operations in March 2026, an amount equal to the Hangar 7 Estimated Monthly Operating Cash, less the actual net cash provided by operating activities generated by Hangar 7 in that month. Hangar 7 generated actual net cash provided by operating activities in February 2026 and March 2026. No adjustments for Hangar 7 are reflected for periods before January 2025 or after March 2026. The Hangar 7 Estimated Monthly Operating Cash is calculated by multiplying the number of labor hours that MRO Holdings expects Hangar 7 to complete per year at full capacity by MRO Holdings’ budgeted average net cash provided by operating activities per labor hour, divided by twelve months and applying a 50% factor to reflect the expected ramp-up of the facility. The adjustments for the Rionegro facility add back, for each month in the periods presented, an amount equal to the Rionegro Estimated Monthly Operating Cash, less the actual net cash provided by operating activities generated by the Rionegro facility in that month. For months before MRO Holdings obtained control of the facility in February 2026, the adjustment gives effect to the facility's estimated net cash provided by operating activities as if MRO Holdings had controlled and operated it during those months. For months after MRO Holdings obtained control, the adjustment normalizes the facility's actual monthly net cash provided by operating activities to the amounts in MRO Holdings' forecast for the year ending December 31, 2026. The Rionegro Estimated Monthly Operating Cash is based on MRO Holdings' forecast of the facility's net cash provided by operating activities for the year ending December 31, 2026, divided by twelve months. The adjustments for the Hangar 7 Estimated Monthly Operating Cash, Rionegro Estimated Monthly Operating Cash and savings from the acquisition of AMDL are presented for illustrative purposes only, are based on MRO Holdings’ management’s estimates and assumptions, do not reflect actual results and may not be indicative of future results. b) Primarily consists of employee training costs which are incurred in order for new employees to achieve certifications to work on aircraft. c) Primarily consists of (i) non-recurring acquisition and integration-related expenses, including certain severance and other exit costs associated with the departure of a senior executive, (ii) special and non-recurring bonuses, (iii) foreign exchange translation gains and losses, (iv) non-recurring legal fees, (v) out-of-period adjustments to allocate expenses to the periods in which they were originally incurred and (vi) non-recurring board of director costs. ($ in millions) Year ended December 31, 2024 Year ended December 31, 2025 Six months ended June 30, 2025 Six months ended June 30, 2026 Twelve months ended June 30, 2026 Three months ended September 30, 2026 Net cash provided by operating activities $100.1 $157.9 $72.8 $31.5 $116.5 $16.8 Run-rate and Savings Impact of New Facilities(a) 8.9 32.6 16.4 5.8 22.0 0.2 Expansion expenses(b) 6.9 8.3 3.6 5.4 10.2 2.3 Other non-recurring expenses(c) 2.9 8.9 2.5 7.4 13.8 1.8 Adjusted Operating Cash Flow $118.8 $207.8 $95.4 $50.2 $162.6 $21.1 Adjusted Operating Cash Flow as a Percentage of Adjusted EBITDA 51.1% 67.5% 60.2% 35.4% 55.8% 29.1% Historical |
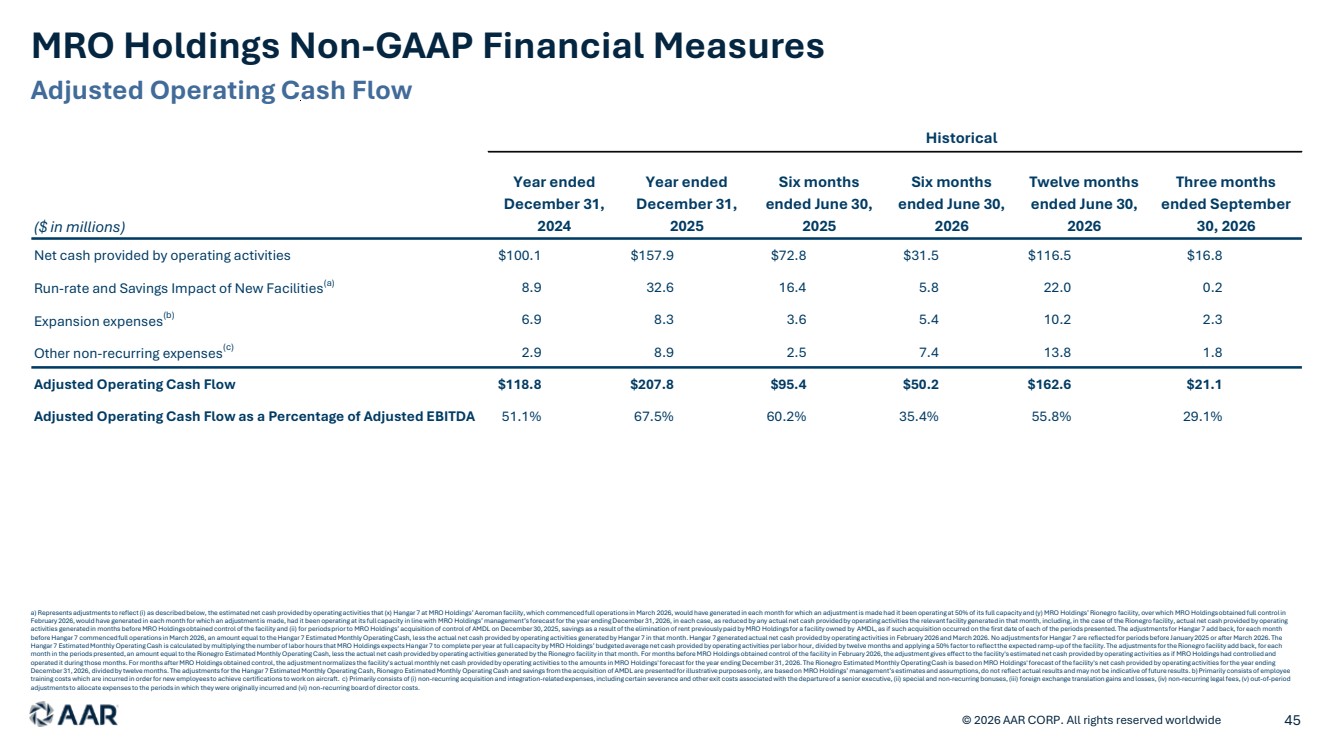
| AAR Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 46 Adjusted Sales, Adjusted EBITDA, Adjusted EBITDA Margin ($ in millions) FY 2022 FY 2023 FY 2024 FY 2025 FY 2026 LTM Q1 2027 Sales $1,820.0 $1,990.5 $2,318.9 $2,780.5 $3,308.0 $3,486.4 Contract termination/restructuring & loss provision, net and bankruptcy charge (2.9) 0.1 2.3 (32.2) - - Adjusted sales $1,817.1 $1,990.6 $2,321.2 $2,748.3 $3,308.0 $3,486.4 Net income (loss) $78.7 $90.2 $46.3 $12.5 $187.7 $193.4 Loss from discontinued operations (0.2) (0.4) - - - - Income tax expense (benefit) 26.6 31.4 12.0 26.4 58.2 60.9 Other (income) expense, net (2.2) 0.8 0.4 0.3 2.1 2.5 Interest expense, net 2.3 11.2 41.0 73.6 70.5 68.2 Loss on extinguishment of debt - - - - - - Depreciation and amortization 33.1 27.9 41.2 55.2 72.1 77.1 Acquisition and integration expenses - 6.2 29.7 10.8 28.2 43.6 Bargain purchase gain - - - - (29.5) (29.5) Gain on sale of headquarters building - - - - (9.8) (9.8) Impairment charge related to product line exit - - - - 4.9 4.9 FCPA settlement, investigation, and remediation costs 3.7 4.7 10.5 65.3 - - Loss (Gain) related to sale and exit of business/joint venture, net 1.7 0.7 2.8 70.3 (1.4) (0.7) Russian bankruptcy court judgment (reversal) - 1.8 11.2 (11.1) - - Contract termination/restructuring & loss provision, net 0.9 2.0 4.8 0.2 - - Government COVID-related subsidies, net (4.9) (1.6) - 0.8 (0.7) - Pension settlement charge - - 26.7 - - - Severance costs 2.0 0.1 0.5 - 1.0 - Asset impairment and exit charges 3.5 - - - - - Facility consolidation and repositioning costs 0.2 - - - - - Customer bankruptcy and credit charges 1.0 1.5 - - - - Strategic financing evaluation costs - - - - - - Costs related to strategic projects (reversals) 1.8 (0.2) - - - - Stock-based compensation 8.2 13.5 15.3 19.9 17.8 20.3 Adjusted EBITDA $156.4 $189.8 $242.4 $324.2 $401.1 $430.9 Adjusted EBITDA Margin 8.6% 9.5% 10.4% 11.8% 12.1% 12.4% |
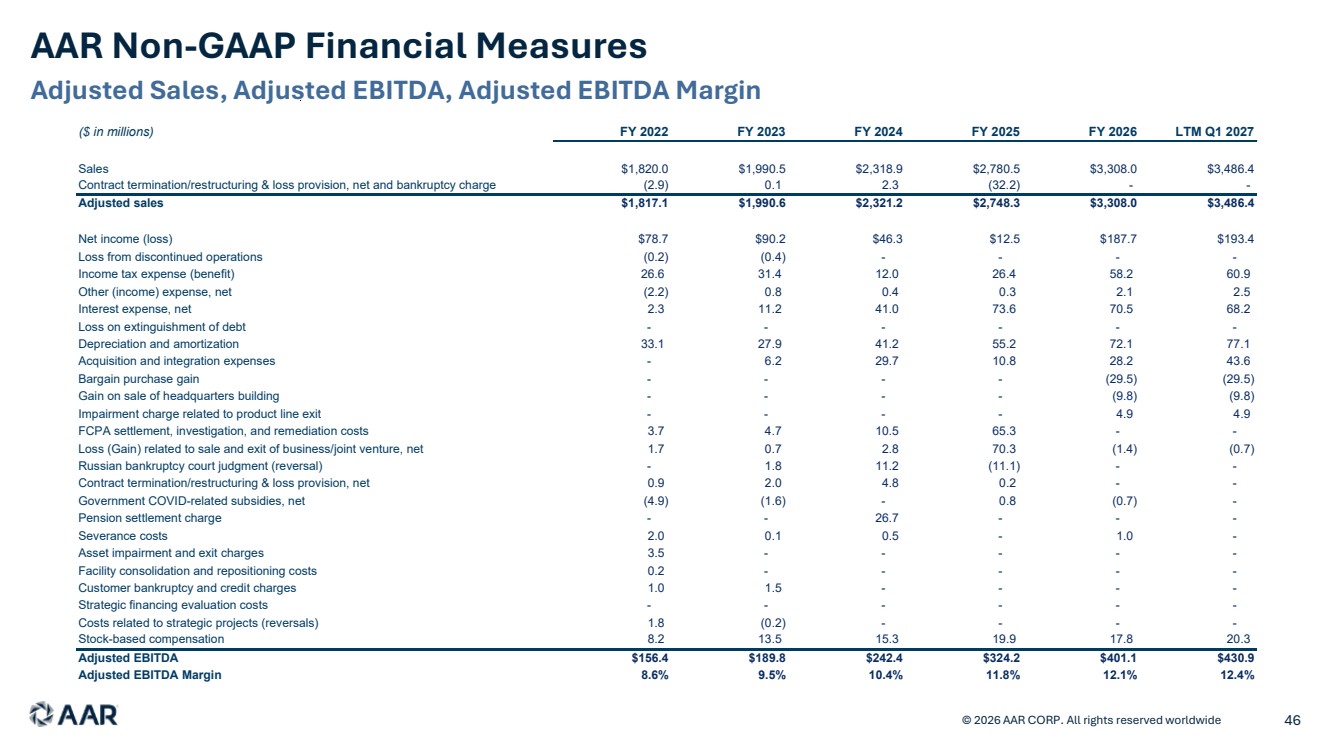
| AAR Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 47 Adjusted Operating Income ($ in millions) FY 2022 FY 2023 FY 2024 FY 2025 FY 2026 Sales $1,820.0 $1,990.5 $2,318.9 $2,780.5 $3,308.0 Contract termination/restructuring & loss provision, net and bankruptcy charge (2.9) 0.1 2.3 (32.2) - Adjusted sales $1,817.1 $1,990.6 $2,321.2 $2,748.3 $3,308.0 Operating Income (loss) $106.9 $133.9 $129.2 $185.2 $277.8 Acquisition, integration, and amortization expenses - 7.0 36.7 26.8 54.0 Impairment charge related to product line exit - - - - 4.9 Customer bankruptcy & Credit Charges 1.0 1.5 - - - Government COVID-related subsidy liability (reversal) (4.9) (1.6) - 0.8 (0.7) Severance & Furlough Costs 2.0 0.1 0.5 - 1.0 FCPA settlement and investigation costs 3.7 4.7 10.5 65.3 - Contract termination cost (benefit) 0.9 2.0 4.8 0.2 - Asset Impairment and Exit Charges 3.5 Facility Consolidation and Repositioning Costs 0.2 Gain related to the sale of joint venture - - - (2.1) - Costs related to Strategic Projects 1.8 (0.2) - - - Russian bankruptcy court judgment (reversal) - 1.8 11.2 (11.1) - Adjusted Operating Income $115.1 $149.2 $192.9 $265.1 $337.0 Adjusted Operating Margin 6.3% 7.5% 8.3% 9.6% 10.2% |
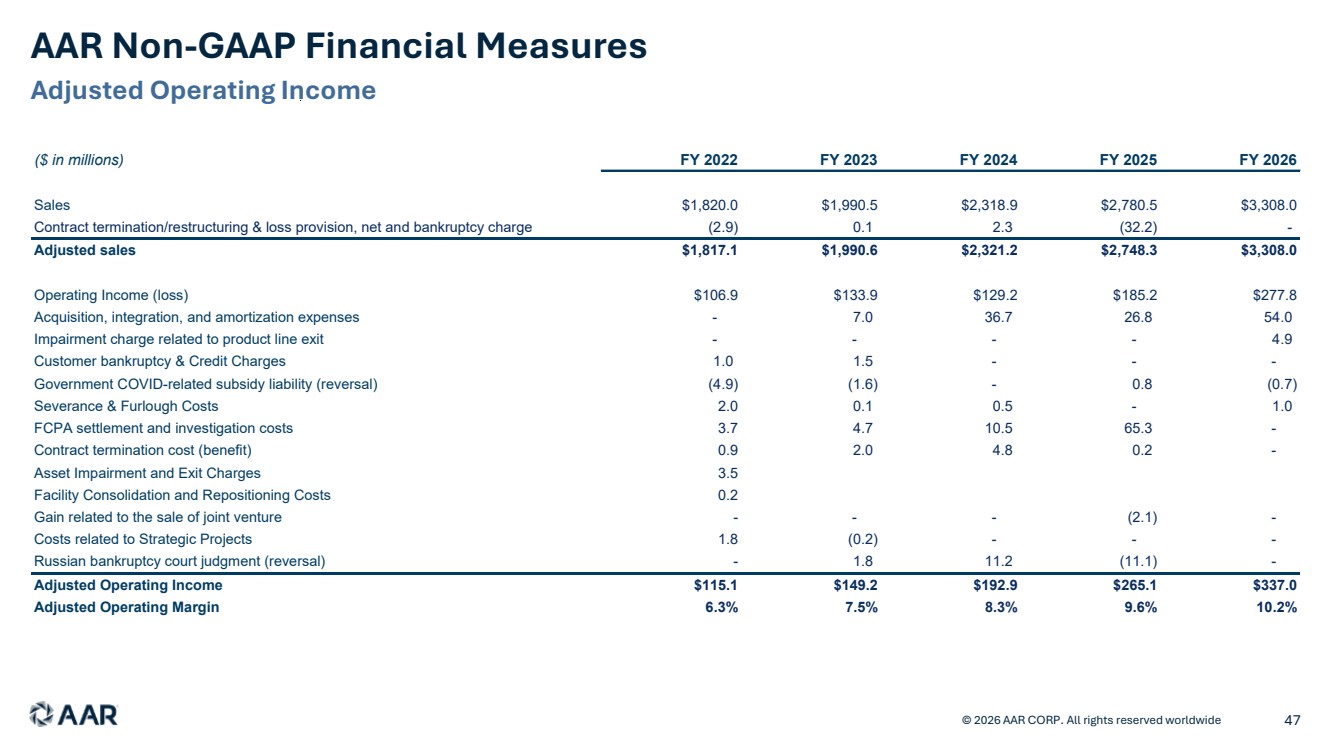
| AAR Non-GAAP Financial Measures © 2026 AAR CORP. All rights reserved worldwide 48 Adjusted Operating Cash Flow ($ in millions) FY2025 FY 2026 Cash provided by operating activities $36.1 $98.7 Amounts outstanding on accounts receivable financing program: Beginning of period 13.7 21.3 End of period (21.3) (25.7) Adjusted Operating Cash Flow $28.5 $94.3 |