3Q 2026 Investor Overview
Forward Looking Statements This presentation contains forward-looking statements. These forward-looking statements reflect our current views with respect to, among other things, future events and our financial performance. Any statements about our management’s expectations, beliefs, plans, predictions, forecasts, objectives, assumptions or future events or performance are not historical facts and may be forward- looking. These statements are often, but not always, made through the use of words or phrases such as “anticipate,” “believes,” “can,” “could,” “may,” “predicts,” “potential,” “should,” “will,” “estimate,” “plans,” “projects,” “continuing,” “ongoing,” “expects,” "optimistic," “intends” and similar words or phrases. Any or all of the forward-looking statements in this presentation may turn out to be inaccurate. The inclusion of forward-looking information in this presentation should not be regarded as a representation by us or any other person that the future plans, estimates or expectations contemplated by us will be achieved. We have based these forward-looking statements largely on our current expectations and projections about future events and financial trends that we believe may affect our financial condition, results of operations, business strategy and financial needs. Our actual results could differ materially from those anticipated in such forward-looking statements. Accordingly, we caution you that any such forward-looking statements are not a guarantee of future performance and that actual results may prove to be materially different from the results expressed or implied by the forward-looking statements due to a number of factors. For details on some of the factors that could affect these expectations, see risk factors and other cautionary language included in the Company's Annual Report on Form 10-K and other periodic and current reports filed with the Securities and Exchange Commission. While there is no assurance that any list of risks and uncertainties or risk factors is complete, below are certain factors which could cause actual results to differ materially from those contained or implied in the forward-looking statements: the strength of the United States (“U.S.”) economy in general and the strength of the local economies in which we conduct operations; geopolitical concerns, including acts or threats of terrorism and the ongoing wars in Iran and Ukraine; uncertainty in U.S. fiscal and monetary policy, including the interest rate policies of the Board of Governors of the Federal Reserve System; inflation, interest rate, market, and monetary fluctuations; volatility and disruptions in global capital and credit markets; changes in U.S. trade policies, including the implementation of tariffs and other protectionist trade policies; the effects of federal government shutdowns, debt ceiling standoff, or other fiscal policy uncertainty; competitive pressures on product pricing and services; success, impact, and timing of our business strategies, including market acceptance of any new products or services; the impact of changes in financial services policies, laws, and regulations, including those concerning taxes, banking, securities, and insurance, and the application thereof by regulatory bodies; cybersecurity threats and the cost of defending against them; climate change, and other catastrophic disasters; the effectiveness of the Company's internal control over financial reporting and disclosure controls and procedures; the Company’s ability to remediate the material weakness in the Company’s internal control over financial reporting; the effect of the IFH acquisition or any other acquisitions we have made or may make, including, without limitation, the failure to achieve the expected revenue growth and/or expense savings from such acquisitions, and/or the failure to effectively integrate an acquisition target into our operations, including the planned growth of Windsor AdvantageTM; the possibility that the Company’s pending merger with Peoples does not close when expected or at all because required regulatory or other approvals and other conditions to closing are not received or satisfied on a timely basis or at all; the possibility that the anticipated benefits and cost savings from the merger with Peoples may not be fully realized or may take longer to realize than expected; disruptions to the Company’s business as a result of the announcement and pendency of the merger with Peoples; the possibility that the merger with Peoples may be more expensive to complete than anticipated, including as a result of unexpected factors or events; and our ability to manage the risks involved in the foregoing. Except as otherwise indicated, this presentation speaks as of the date hereof. The delivery of this presentation shall not, under any circumstances, create any implication that there has been no change in the affairs of the Company after the date hereof. Certain of the information contained herein may be derived from information provided by industry sources. The Company believes that such information is accurate and that the sources from which it has been obtained are reliable. The Company cannot guarantee the accuracy of such information, however, and has not independently verified such information. While the Company is not aware of any misstatements regarding the industry data presented in this presentation, the Company’s estimates involve risks and uncertainties and are subject to change based on various factors. Similarly, the Company believes that its internal research is reliable, even though such research has not been verified by independent sources. Non-U.S. GAAP Financial Measures This presentation may include certain non–U.S. generally accepted accounting principles ("GAAP") financial measures intended to supplement, not substitute for, comparable GAAP measures. These non-GAAP financial measures should not be considered in isolation, and should be considered as additions to, and not substitutes for or superior to, measures of financial performance prepared in accordance with GAAP. There are a number of limitations related to the use of these non-GAAP financial measures versus their nearest GAAP equivalents. For example, other companies may calculate non-GAAP financial measures differently or may use other measures to evaluate their performance, all of which could reduce the usefulness of the Company's non-GAAP financial measures as tools for comparison. If included in this presentation, see the Appendix to this presentation for a reconciliation of the non-GAAP financial measures used in (or conveyed orally during) this presentation to their most directly comparable GAAP financial measures. Core Financial Measures As used in this presentation, Core net income, Core fee revenue, Core ROA, Core ROE, ROTCE, Core ROTCE, Core NIM, Core Loan Yield, Core efficiency ratio, Commercial Bank ACL Coverage Ratio, and Tangible Book Value are non-GAAP financial measures. These non-GAAP financial metrics exclude the impact of income from the call of brokered time deposits, merger-related expenses and certain other pre-tax adjustments which are not indicative of operating performance and tax impacts of such adjustments. Reconciliations of these and other non-GAAP measures to their comparable GAAP measures are set forth in the Appendix to this presentation. 2
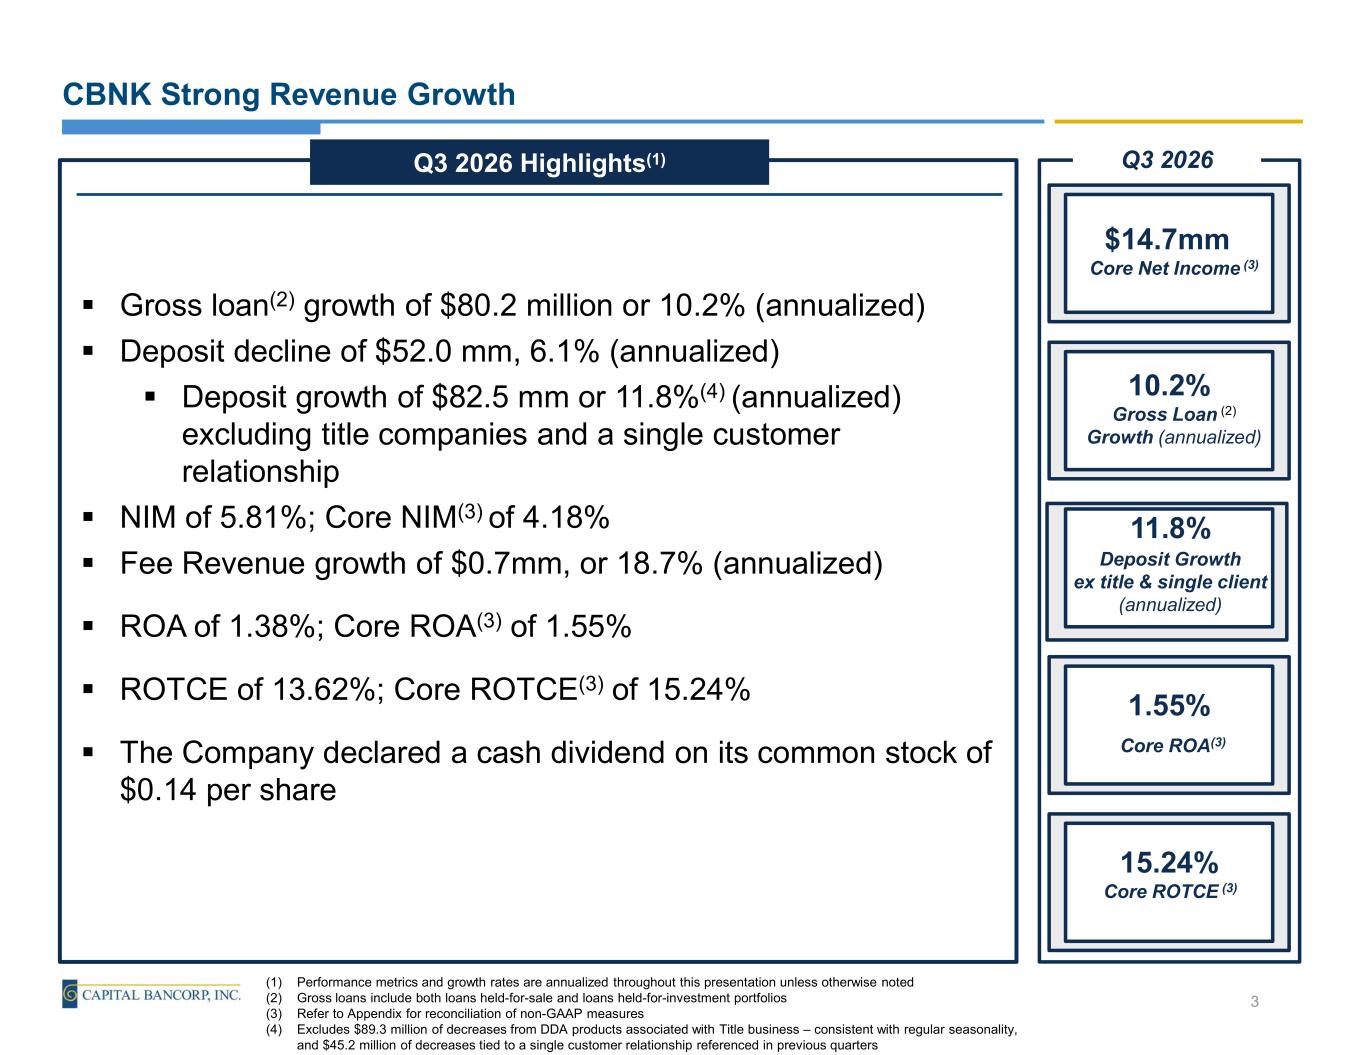
CBNK Strong Revenue Growth (1) Performance metrics and growth rates are annualized throughout this presentation unless otherwise noted (2) Gross loans include both loans held-for-sale and loans held-for-investment portfolios (3) Refer to Appendix for reconciliation of non-GAAP measures (4) Excludes $89.3 million of decreases from DDA products associated with Title business – consistent with regular seasonality, and $45.2 million of decreases tied to a single customer relationship referenced in previous quarters Gross loan(2) growth of $80.2 million or 10.2% (annualized) Deposit decline of $52.0 mm, 6.1% (annualized) Deposit growth of $82.5 mm or 11.8%(4) (annualized) excluding title companies and a single customer relationship NIM of 5.81%; Core NIM(3) of 4.18% Fee Revenue growth of $0.7mm, or 18.7% (annualized) ROA of 1.38%; Core ROA(3) of 1.55% ROTCE of 13.62%; Core ROTCE(3) of 15.24% The Company declared a cash dividend on its common stock of $0.14 per share Q3 2026 Highlights(1) Core Net Income (3) $14.7mm Gross Loan (2) Growth (annualized) 10.2% Deposit Growth ex title & single client (annualized) 11.8% Core ROA(3) 1.55% Core ROTCE (3) 15.24% Q3 2026 3
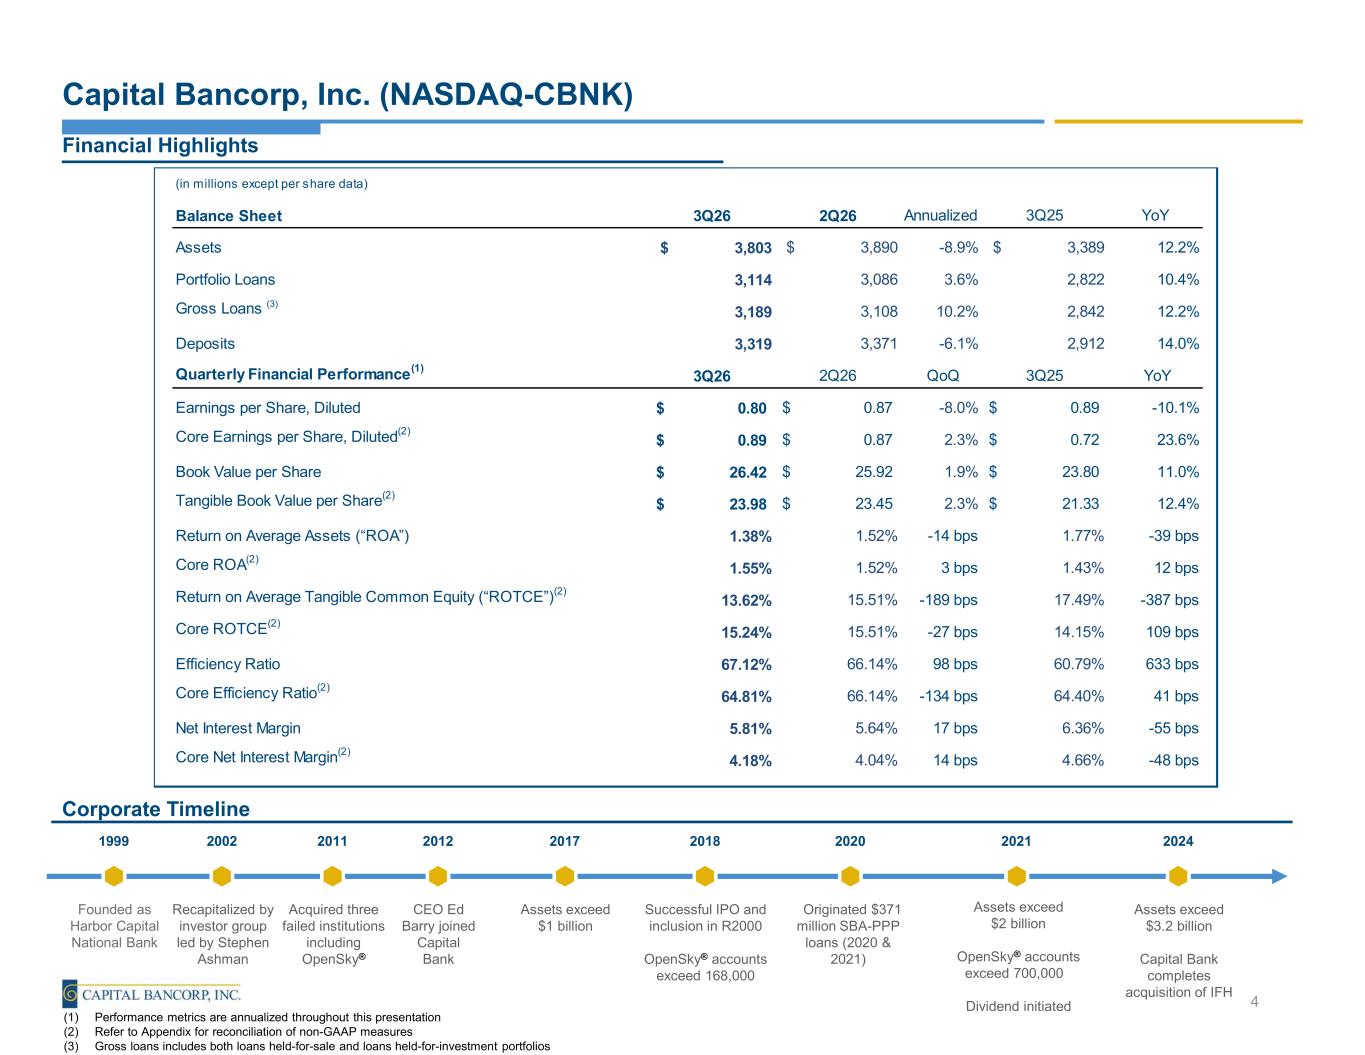
Capital Bancorp, Inc. (NASDAQ-CBNK) Financial Highlights Corporate Timeline Founded as Harbor Capital National Bank Recapitalized by investor group led by Stephen Ashman Acquired three failed institutions including OpenSky® CEO Ed Barry joined Capital Bank Assets exceed $1 billion Successful IPO and inclusion in R2000 OpenSky® accounts exceed 168,000 1999 2002 2011 2012 2017 2018 Originated $371 million SBA-PPP loans (2020 & 2021) 2020 Assets exceed $2 billion OpenSky® accounts exceed 700,000 Dividend initiated 2021 (1) Performance metrics are annualized throughout this presentation (2) Refer to Appendix for reconciliation of non-GAAP measures (3) Gross loans includes both loans held-for-sale and loans held-for-investment portfolios Assets exceed $3.2 billion Capital Bank completes acquisition of IFH 2024 4 (in millions except per share data) Balance Sheet 3Q26 2Q26 Annualized 3Q25 YoY Assets $ 3,803 $ 3,890 -8.9% $ 3,389 12.2% Portfolio Loans 3,114 3,086 3.6% 2,822 10.4% Gross Loans (3) 3,189 3,108 10.2% 2,842 12.2% Deposits 3,319 3,371 -6.1% 2,912 14.0% Quarterly Financial Performance(1) 3Q26 2Q26 QoQ 3Q25 YoY Earnings per Share, Diluted 0.80$ 0.87$ -8.0% 0.89$ -10.1% Core Earnings per Share, Diluted(2) 0.89$ 0.87$ 2.3% 0.72$ 23.6% Book Value per Share 26.42$ 25.92$ 1.9% 23.80$ 11.0% Tangible Book Value per Share(2) 23.98$ 23.45$ 2.3% 21.33$ 12.4% Return on Average Assets (“ROA”) 1.38% 1.52% -14 bps 1.77% -39 bps Core ROA(2) 1.55% 1.52% 3 bps 1.43% 12 bps Return on Average Tangible Common Equity (“ROTCE”)(2) 13.62% 15.51% -189 bps 17.49% -387 bps Core ROTCE(2) 15.24% 15.51% -27 bps 14.15% 109 bps Efficiency Ratio 67.12% 66.14% 98 bps 60.79% 633 bps Core Efficiency Ratio(2) 64.81% 66.14% -134 bps 64.40% 41 bps Net Interest Margin 5.81% 5.64% 17 bps 6.36% -55 bps Core Net Interest Margin(2) 4.18% 4.04% 14 bps 4.66% -48 bps
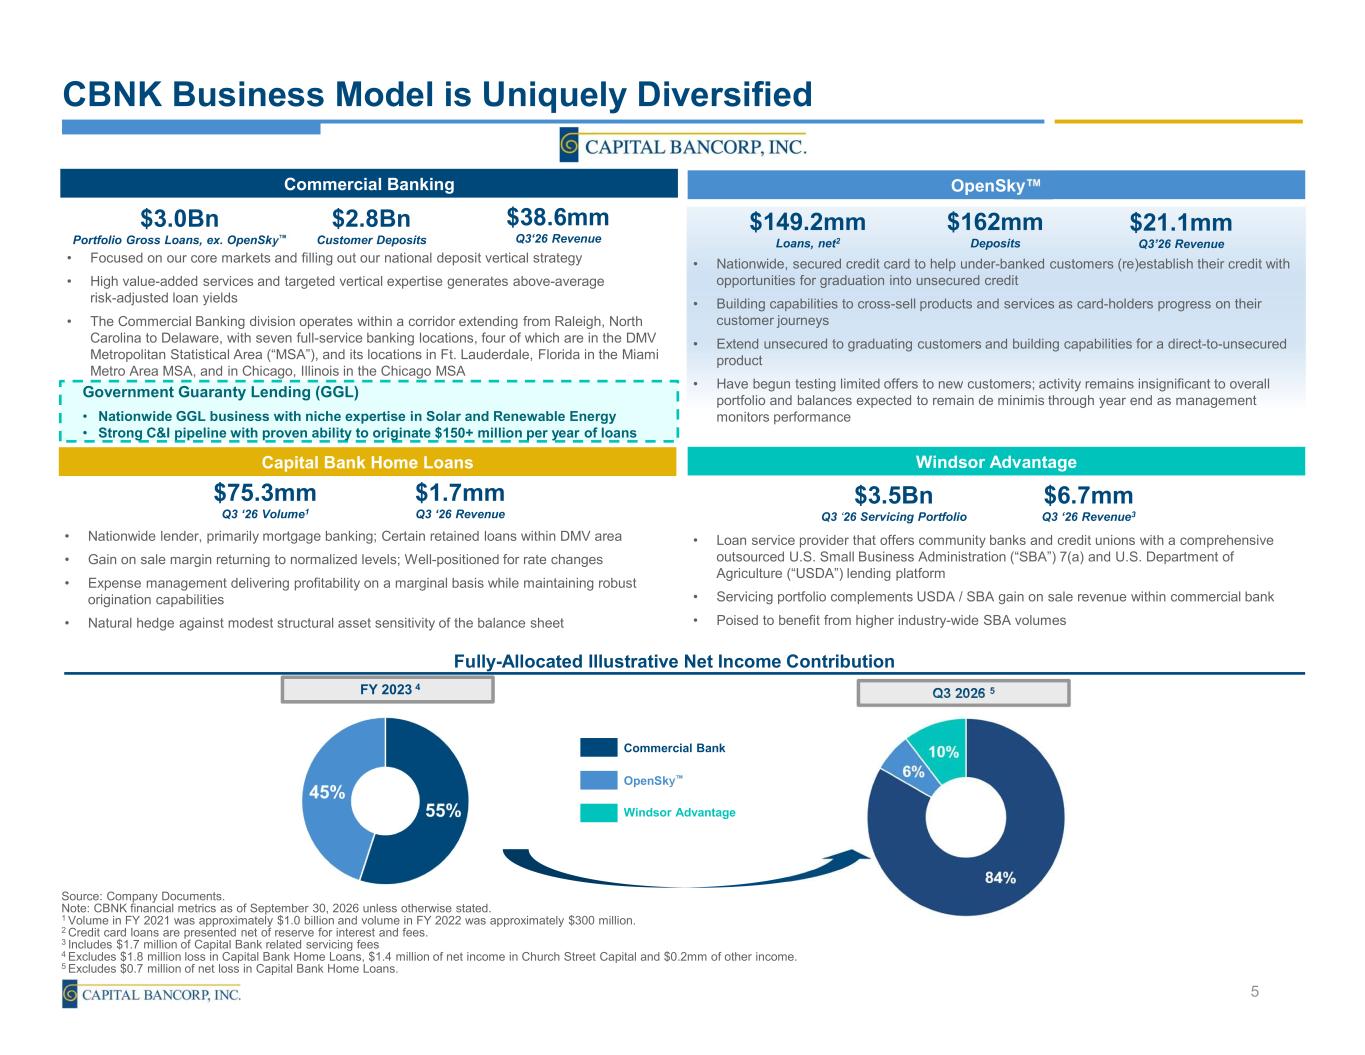
$3.5Bn Q3 ‘26 Servicing Portfolio $6.7mm Q3 ‘26 Revenue3 • Loan service provider that offers community banks and credit unions with a comprehensive outsourced U.S. Small Business Administration (“SBA”) 7(a) and U.S. Department of Agriculture (“USDA”) lending platform • Servicing portfolio complements USDA / SBA gain on sale revenue within commercial bank • Poised to benefit from higher industry-wide SBA volumes CBNK Business Model is Uniquely Diversified Source: Company Documents. Note: CBNK financial metrics as of September 30, 2026 unless otherwise stated. 1 Volume in FY 2021 was approximately $1.0 billion and volume in FY 2022 was approximately $300 million. 2 Credit card loans are presented net of reserve for interest and fees. 3 Includes $1.7 million of Capital Bank related servicing fees 4 Excludes $1.8 million loss in Capital Bank Home Loans, $1.4 million of net income in Church Street Capital and $0.2mm of other income. 5 Excludes $0.7 million of net loss in Capital Bank Home Loans. Commercial Bank OpenSky Windsor Advantage Commercial Banking Government Guaranty Lending (GGL) • Nationwide GGL business with niche expertise in Solar and Renewable Energy • Strong C&I pipeline with proven ability to originate $150+ million per year of loans $3.0Bn Portfolio Gross Loans, ex. OpenSky $2.8Bn Customer Deposits • Focused on our core markets and filling out our national deposit vertical strategy • High value-added services and targeted vertical expertise generates above-average risk-adjusted loan yields • The Commercial Banking division operates within a corridor extending from Raleigh, North Carolina to Delaware, with seven full-service banking locations, four of which are in the DMV Metropolitan Statistical Area (“MSA”), and its locations in Ft. Lauderdale, Florida in the Miami Metro Area MSA, and in Chicago, Illinois in the Chicago MSA $38.6mm Q3‘26 Revenue Fully-Allocated Illustrative Net Income Contribution 5 $75.3mm Q3 ‘26 Volume1 $1.7mm Q3 ‘26 Revenue • Nationwide lender, primarily mortgage banking; Certain retained loans within DMV area • Gain on sale margin returning to normalized levels; Well-positioned for rate changes • Expense management delivering profitability on a marginal basis while maintaining robust origination capabilities • Natural hedge against modest structural asset sensitivity of the balance sheet $162mm Deposits $149.2mm Loans, net2 • Nationwide, secured credit card to help under-banked customers (re)establish their credit with opportunities for graduation into unsecured credit • Building capabilities to cross-sell products and services as card-holders progress on their customer journeys • Extend unsecured to graduating customers and building capabilities for a direct-to-unsecured product • Have begun testing limited offers to new customers; activity remains insignificant to overall portfolio and balances expected to remain de minimis through year end as management monitors performance $21.1mm Q3’26 Revenue Capital Bank Home Loans OpenSky Windsor Advantage FY 2023 4 Q3 2026 5
Financial Information
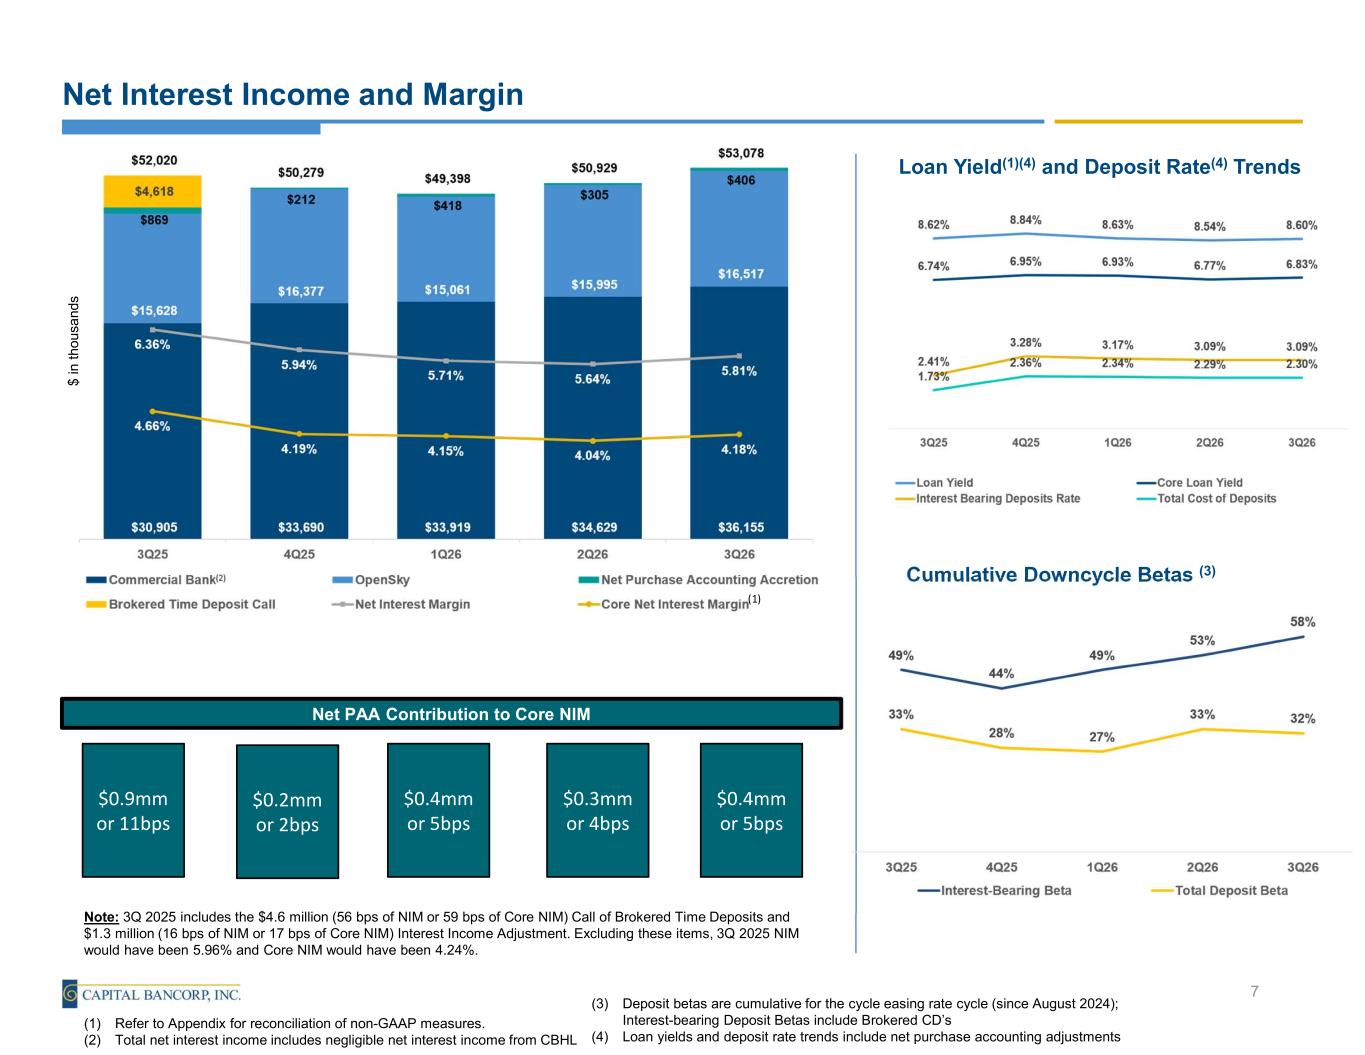
Net Interest Income and Margin $ in t ho u sa nd s 7 (1) Refer to Appendix for reconciliation of non-GAAP measures. (2) Total net interest income includes negligible net interest income from CBHL Loan Yield(1)(4) and Deposit Rate(4) Trends Cumulative Downcycle Betas (3) (3) Deposit betas are cumulative for the cycle easing rate cycle (since August 2024); Interest-bearing Deposit Betas include Brokered CD’s (4) Loan yields and deposit rate trends include net purchase accounting adjustments Note: 3Q 2025 includes the $4.6 million (56 bps of NIM or 59 bps of Core NIM) Call of Brokered Time Deposits and $1.3 million (16 bps of NIM or 17 bps of Core NIM) Interest Income Adjustment. Excluding these items, 3Q 2025 NIM would have been 5.96% and Core NIM would have been 4.24%. Net PAA Contribution to Core NIM $0.9mm or 11bps $0.2mm or 2bps $0.4mm or 5bps $0.3mm or 4bps $0.4mm or 5bps (1)
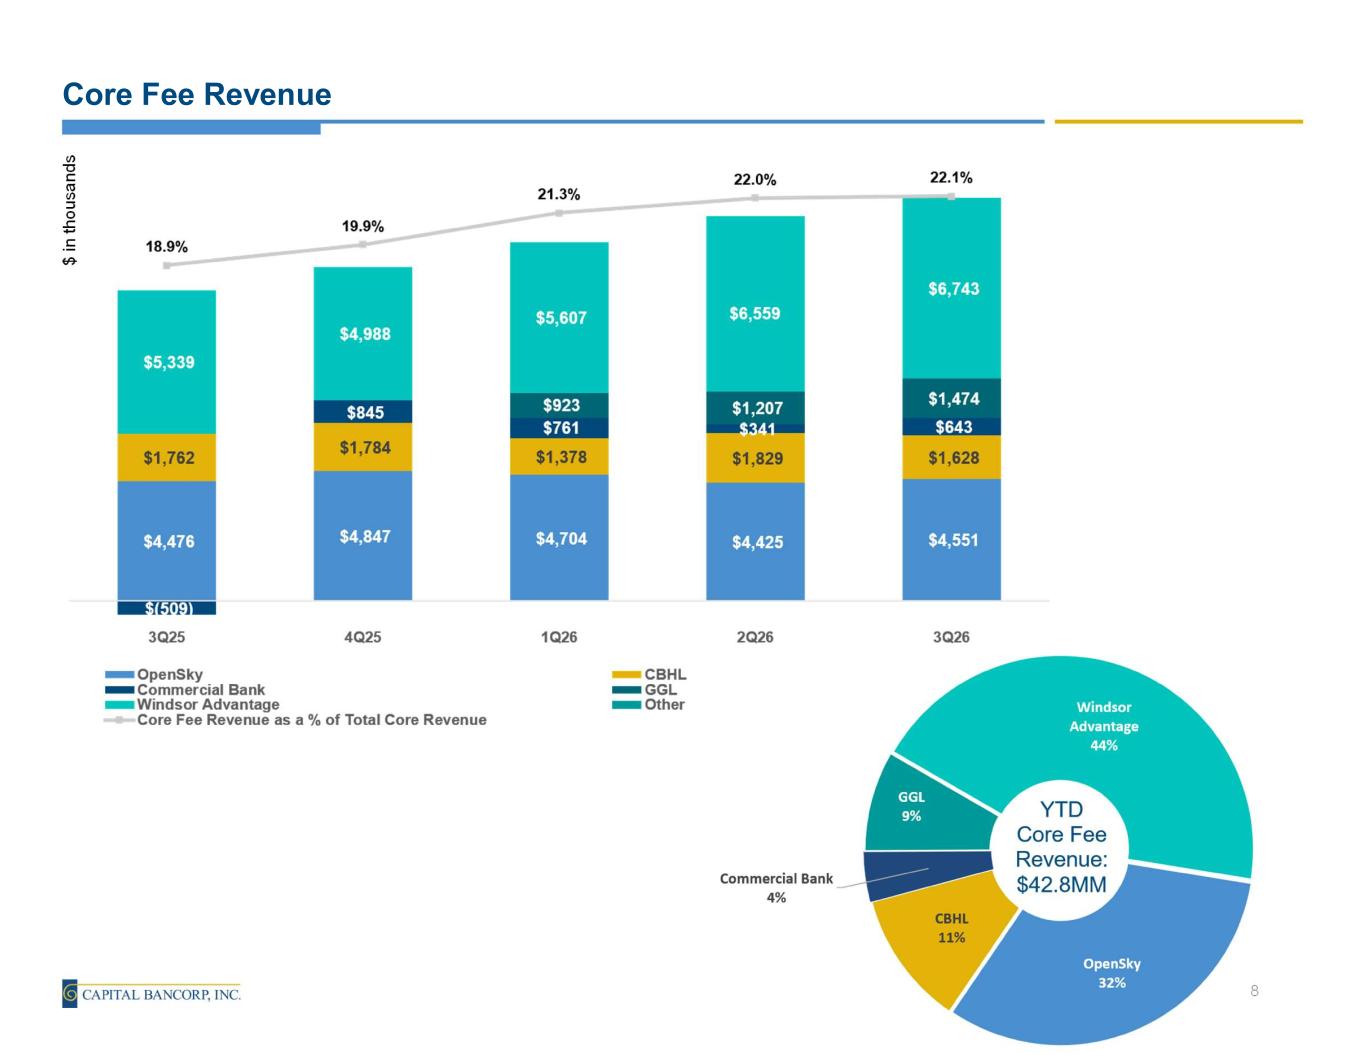
Core Fee Revenue $ in t ho us an d s 8
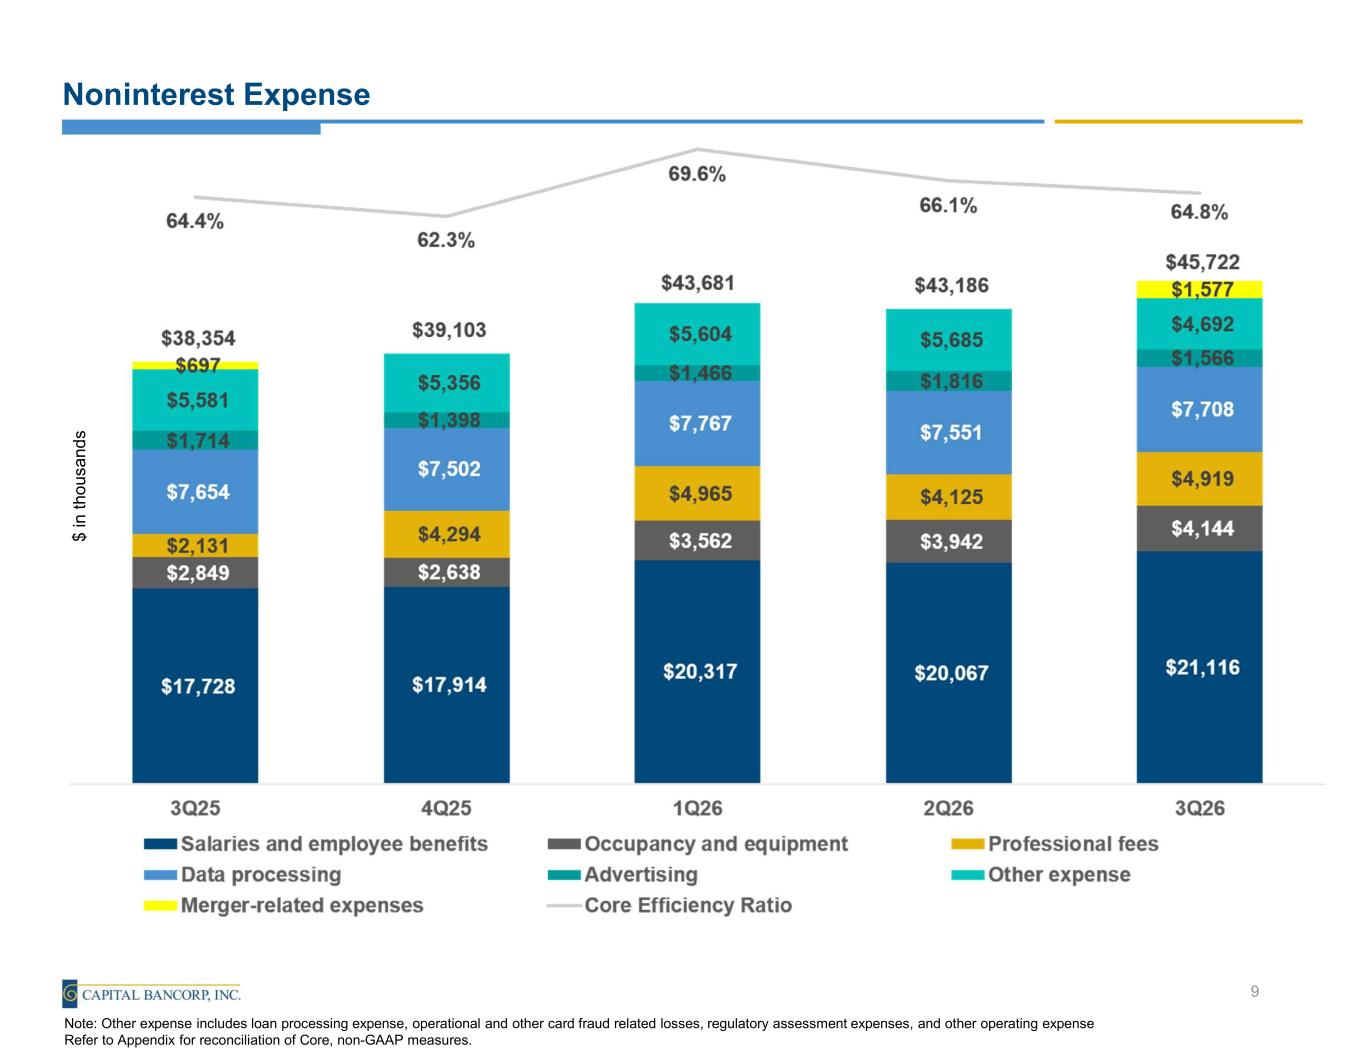
Noninterest Expense $ in t ho us an d s 9 Note: Other expense includes loan processing expense, operational and other card fraud related losses, regulatory assessment expenses, and other operating expense Refer to Appendix for reconciliation of Core, non-GAAP measures.
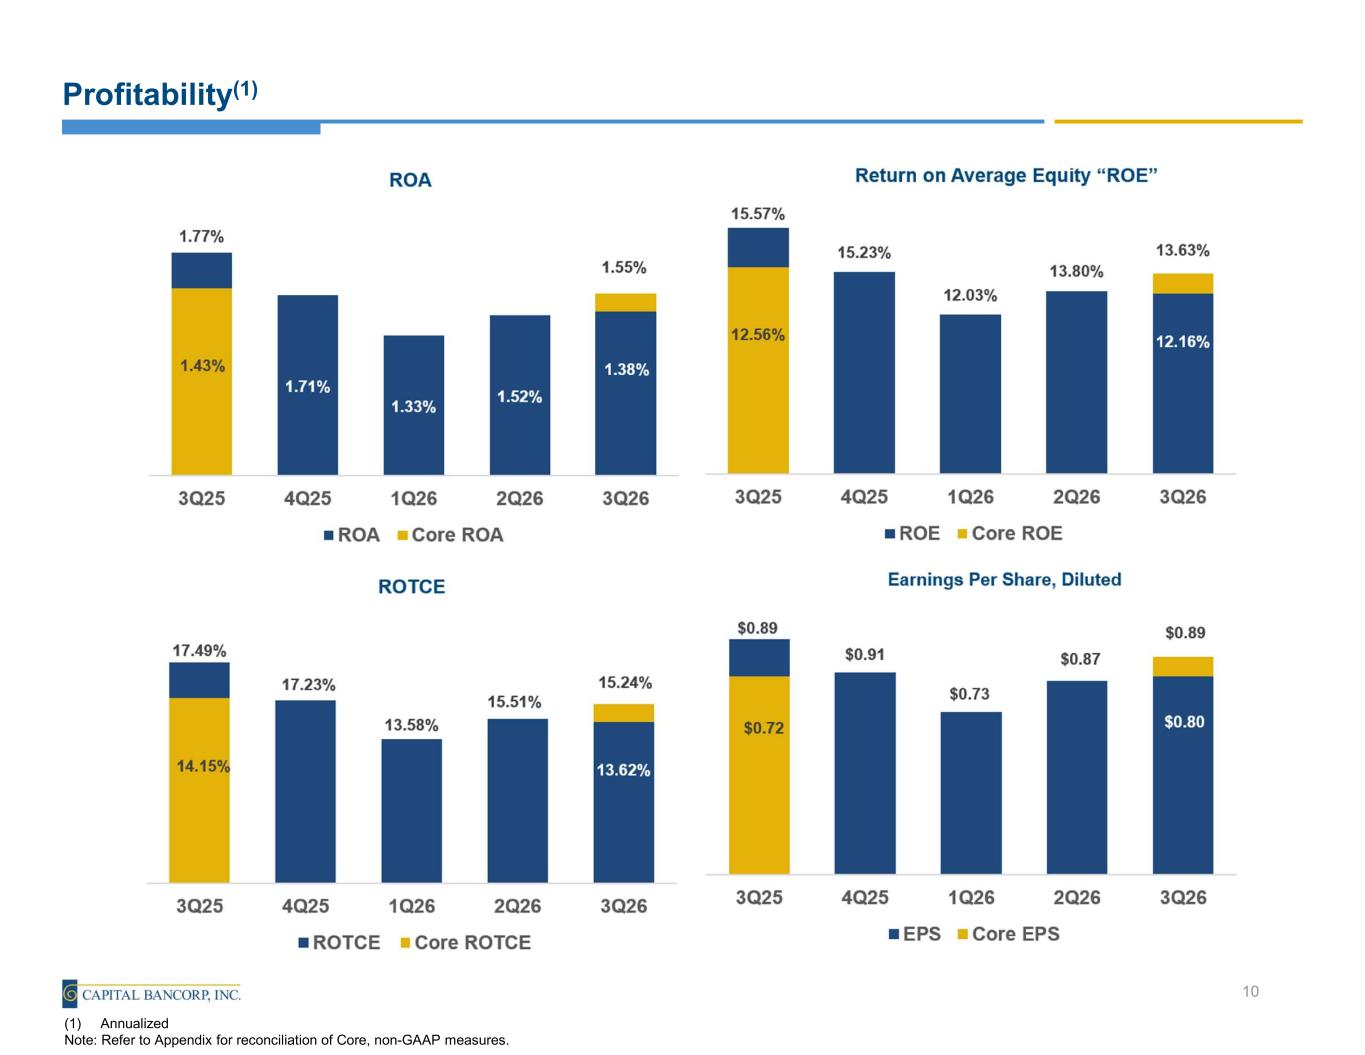
Profitability(1) 10 (1) Annualized Note: Refer to Appendix for reconciliation of Core, non-GAAP measures.
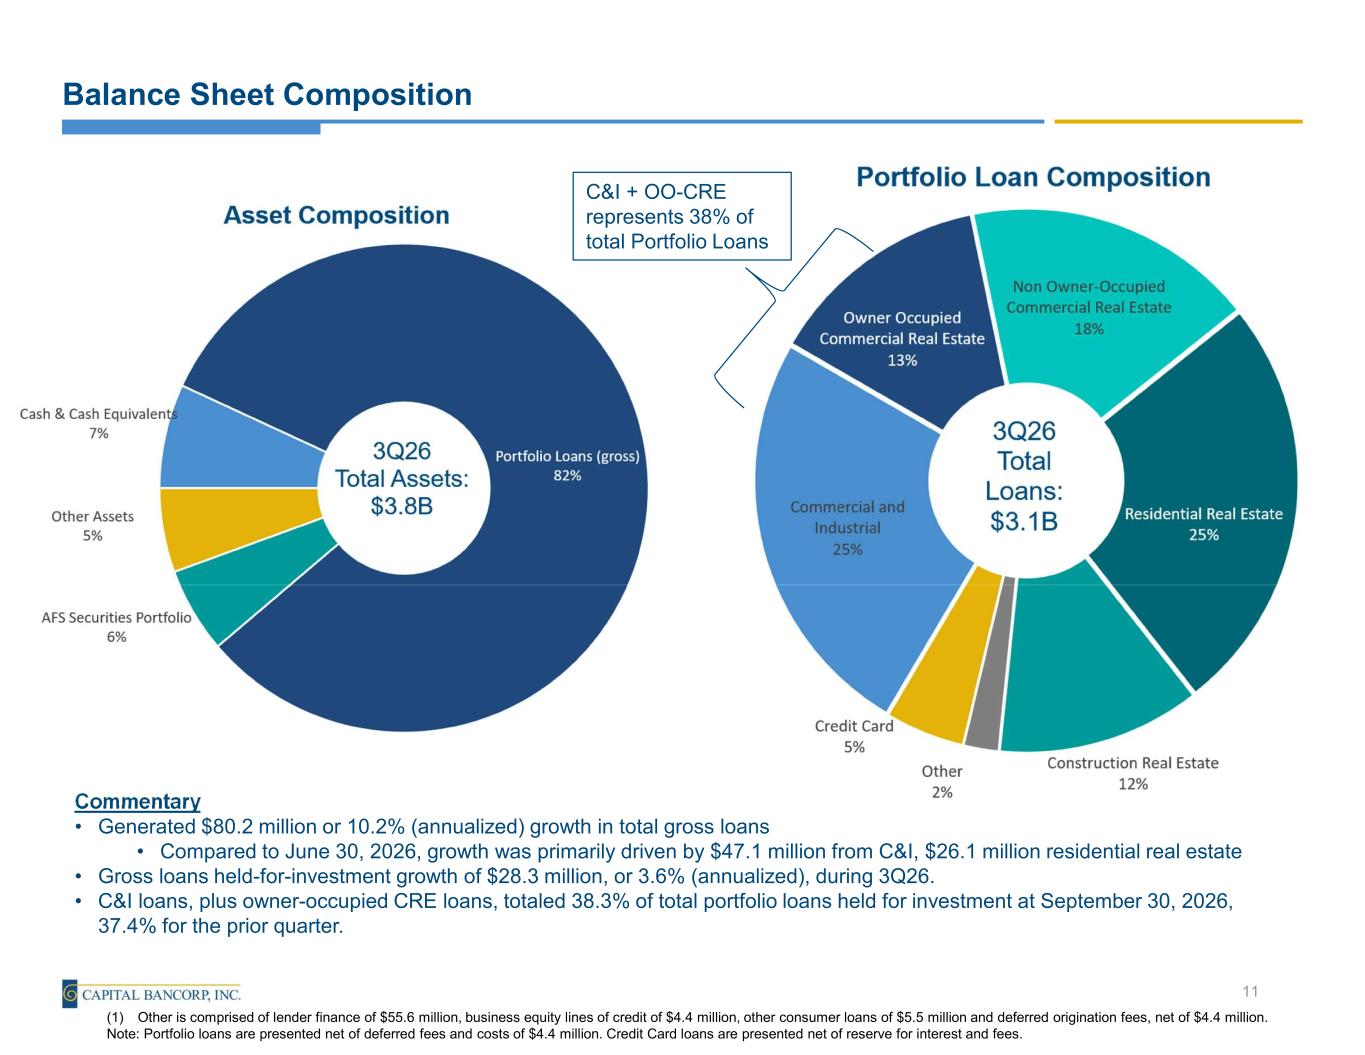
Balance Sheet Composition Commentary • Generated $80.2 million or 10.2% (annualized) growth in total gross loans • Compared to June 30, 2026, growth was primarily driven by $47.1 million from C&I, $26.1 million residential real estate • Gross loans held-for-investment growth of $28.3 million, or 3.6% (annualized), during 3Q26. • C&I loans, plus owner-occupied CRE loans, totaled 38.3% of total portfolio loans held for investment at September 30, 2026, 37.4% for the prior quarter. 11 (1) Other is comprised of lender finance of $55.6 million, business equity lines of credit of $4.4 million, other consumer loans of $5.5 million and deferred origination fees, net of $4.4 million. Note: Portfolio loans are presented net of deferred fees and costs of $4.4 million. Credit Card loans are presented net of reserve for interest and fees. C&I + OO-CRE represents 38% of total Portfolio Loans
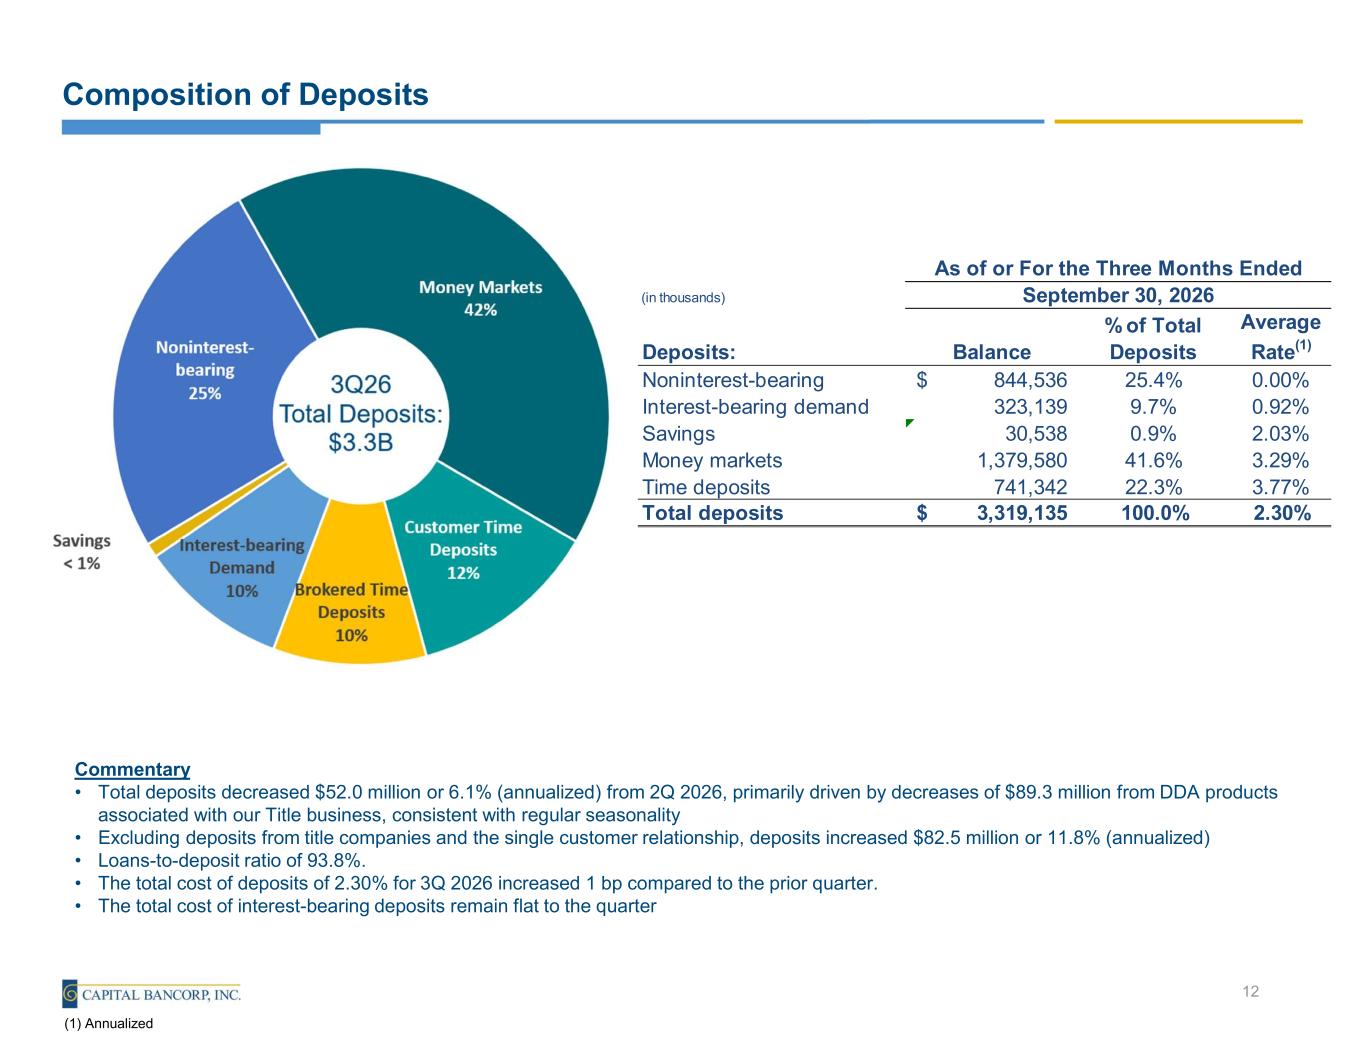
Composition of Deposits Commentary • Total deposits decreased $52.0 million or 6.1% (annualized) from 2Q 2026, primarily driven by decreases of $89.3 million from DDA products associated with our Title business, consistent with regular seasonality • Excluding deposits from title companies and the single customer relationship, deposits increased $82.5 million or 11.8% (annualized) • Loans-to-deposit ratio of 93.8%. • The total cost of deposits of 2.30% for 3Q 2026 increased 1 bp compared to the prior quarter. • The total cost of interest-bearing deposits remain flat to the quarter 12 (1) Annualized (in thousands) Deposits: Balance % of Total Deposits Average Rate(1) Noninterest-bearing 844,536$ 25.4% 0.00% Interest-bearing demand 323,139 9.7% 0.92% Savings 30,538 0.9% 2.03% Money markets 1,379,580 41.6% 3.29% Time deposits 741,342 22.3% 3.77% Total deposits 3,319,135$ 100.0% 2.30% As of or For the Three Months Ended September 30, 2026
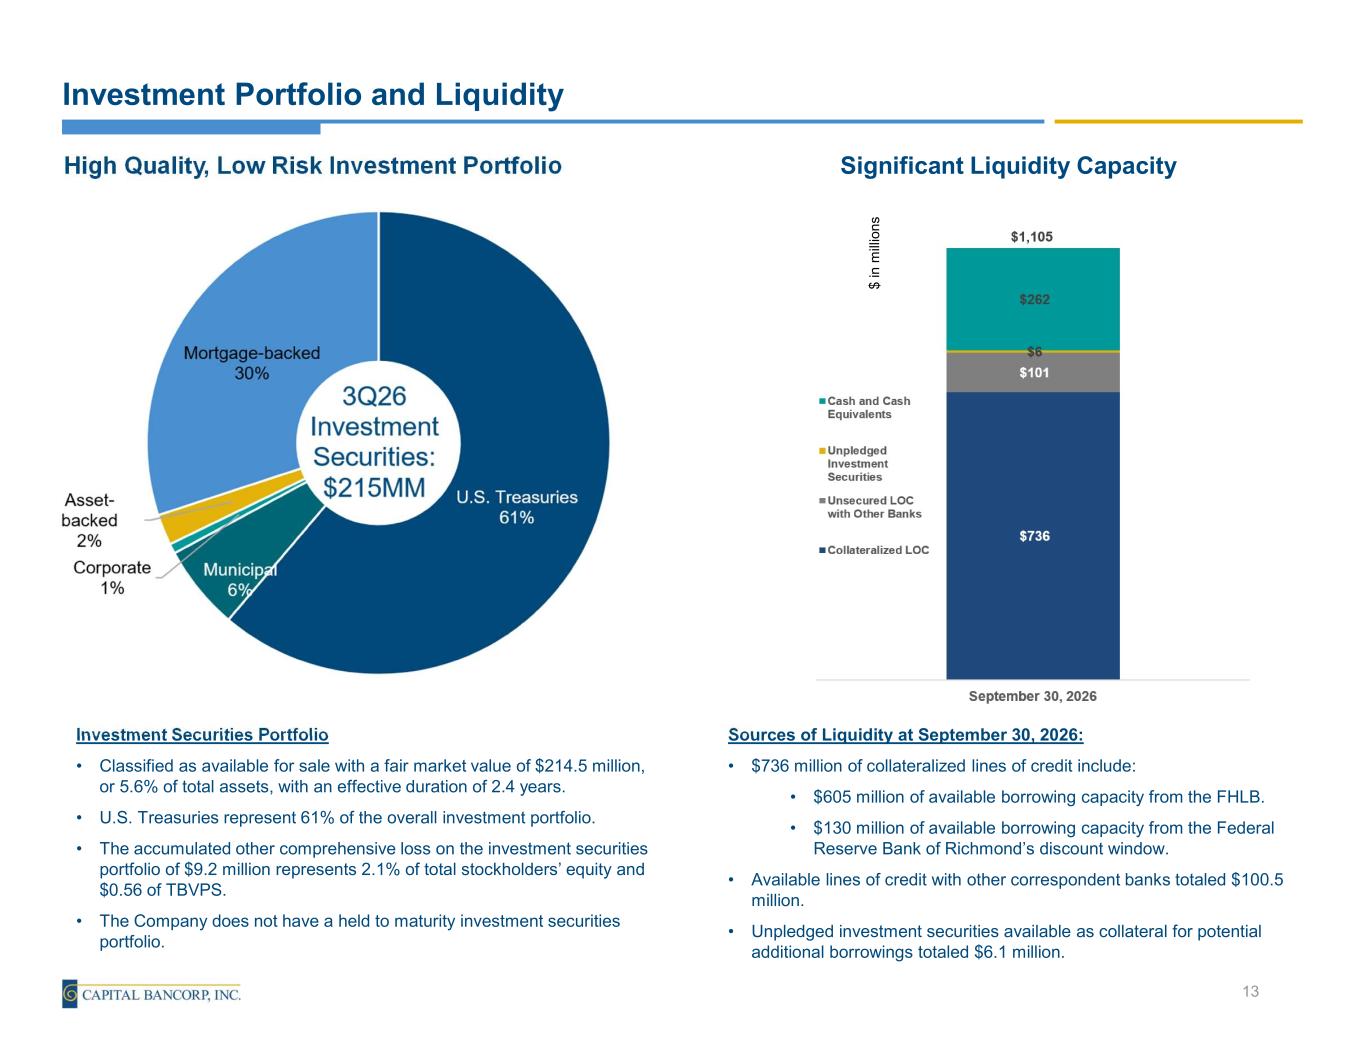
Investment Portfolio and Liquidity Investment Securities Portfolio • Classified as available for sale with a fair market value of $214.5 million, or 5.6% of total assets, with an effective duration of 2.4 years. • U.S. Treasuries represent 61% of the overall investment portfolio. • The accumulated other comprehensive loss on the investment securities portfolio of $9.2 million represents 2.1% of total stockholders’ equity and $0.56 of TBVPS. • The Company does not have a held to maturity investment securities portfolio. 13 High Quality, Low Risk Investment Portfolio Sources of Liquidity at September 30, 2026: • $736 million of collateralized lines of credit include: • $605 million of available borrowing capacity from the FHLB. • $130 million of available borrowing capacity from the Federal Reserve Bank of Richmond’s discount window. • Available lines of credit with other correspondent banks totaled $100.5 million. • Unpledged investment securities available as collateral for potential additional borrowings totaled $6.1 million. Significant Liquidity Capacity $ in m ill io n s
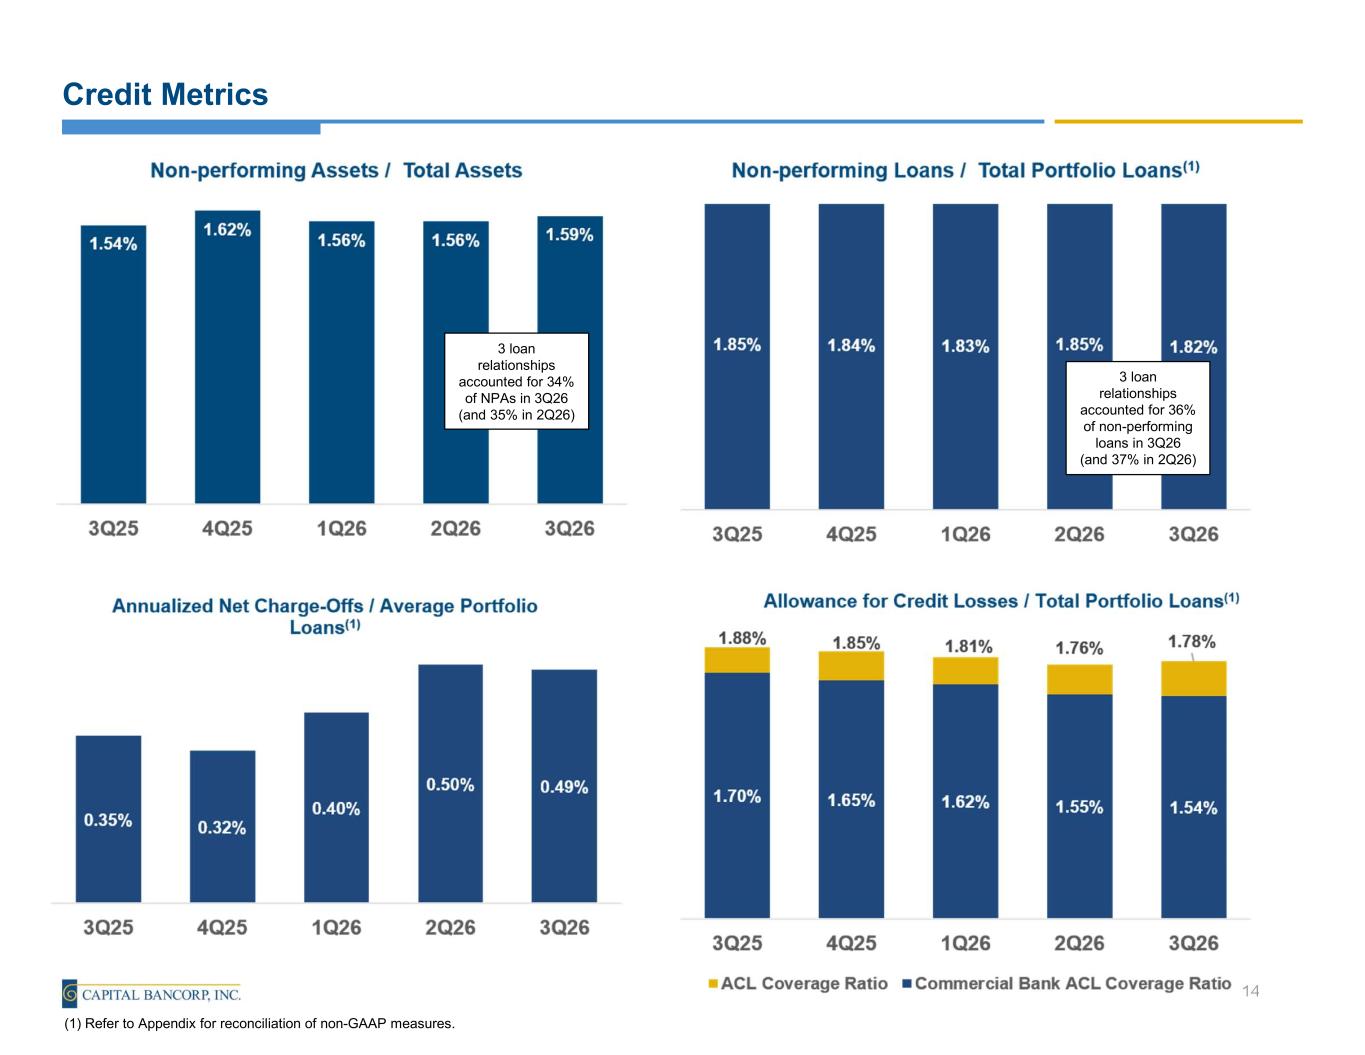
Credit Metrics 14 (1) Refer to Appendix for reconciliation of non-GAAP measures. 3 loan relationships accounted for 36% of non-performing loans in 3Q26 (and 37% in 2Q26) 3 loan relationships accounted for 34% of NPAs in 3Q26 (and 35% in 2Q26)
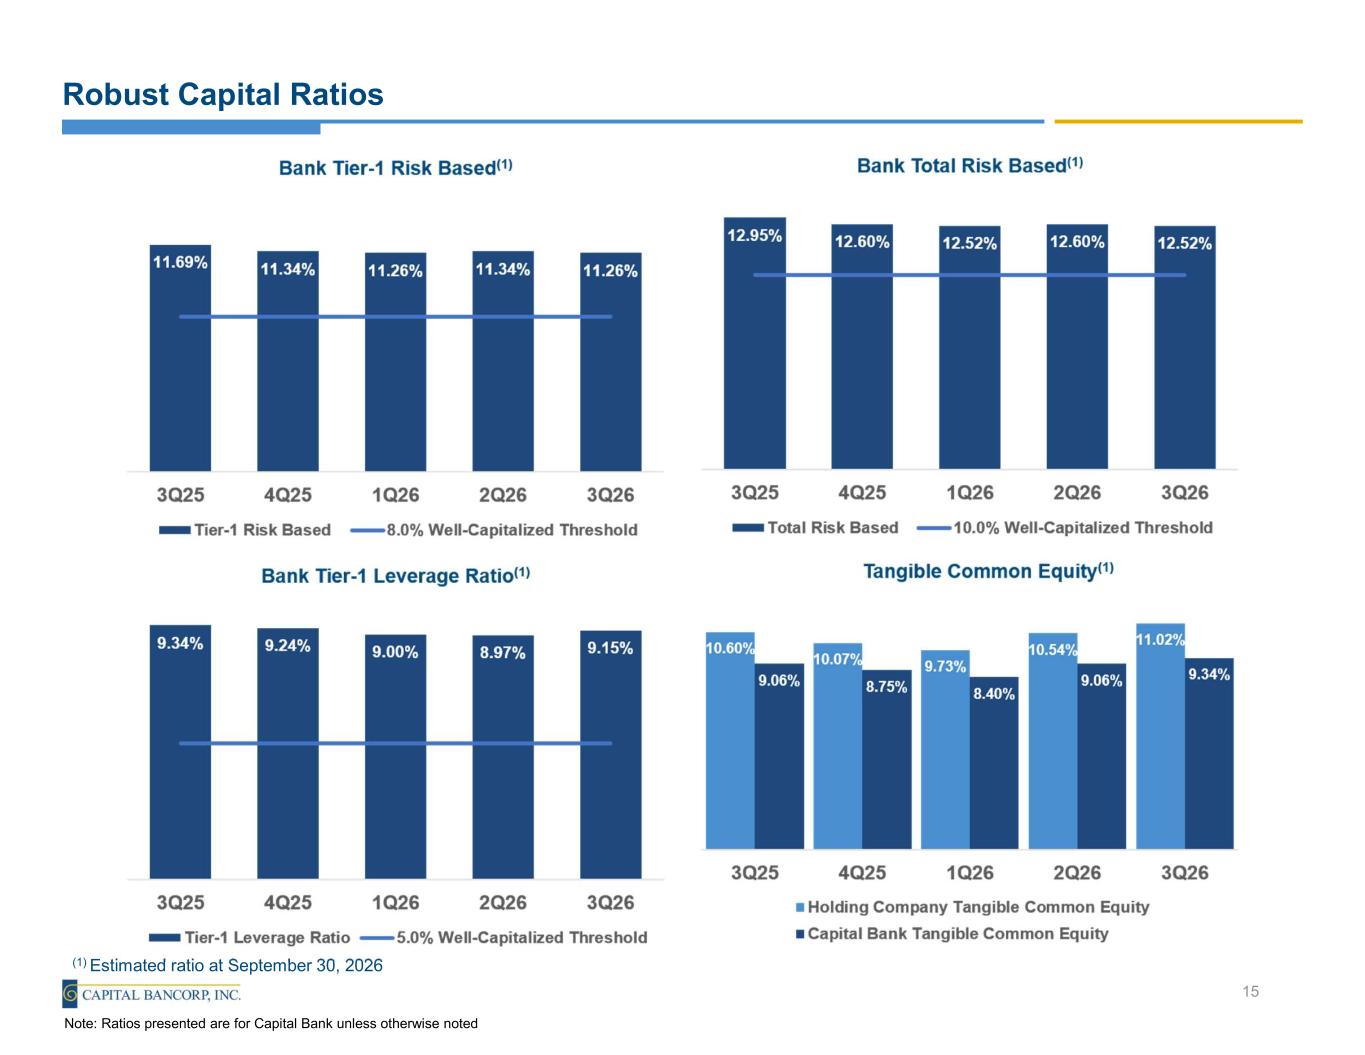
Robust Capital Ratios 15 Note: Ratios presented are for Capital Bank unless otherwise noted (1) Estimated ratio at September 30, 2026
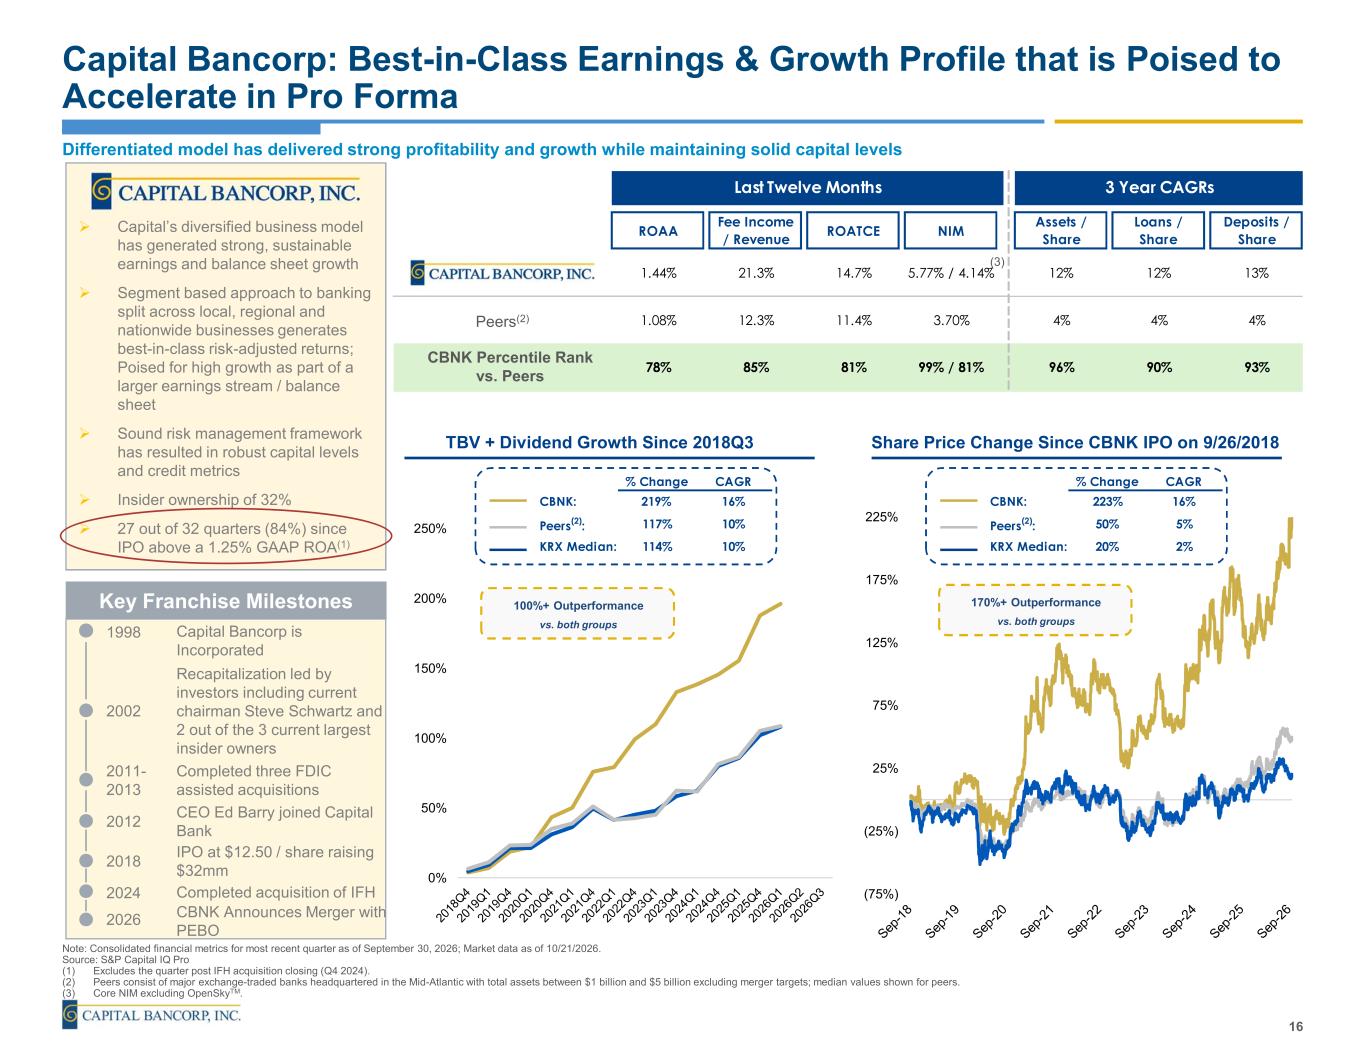
Last Twelve Months 3 Year CAGRs ROAA Fee Income / Revenue ROATCE NIM Assets / Share Loans / Share Deposits / Share 1.44% 21.3% 14.7% 5.77% / 4.14% 12% 12% 13% 1.08% 12.3% 11.4% 3.70% 4% 4% 4% 78% 85% 81% 99% / 81% 96% 90% 93% Capital Bancorp: Best-in-Class Earnings & Growth Profile that is Poised to Accelerate in Pro Forma Note: Consolidated financial metrics for most recent quarter as of September 30, 2026; Market data as of 10/21/2026. Source: S&P Capital IQ Pro (1) Excludes the quarter post IFH acquisition closing (Q4 2024). (2) Peers consist of major exchange-traded banks headquartered in the Mid-Atlantic with total assets between $1 billion and $5 billion excluding merger targets; median values shown for peers. (3) Core NIM excluding OpenSkyTM. 16 Differentiated model has delivered strong profitability and growth while maintaining solid capital levels Capital’s diversified business model has generated strong, sustainable earnings and balance sheet growth Segment based approach to banking split across local, regional and nationwide businesses generates best-in-class risk-adjusted returns; Poised for high growth as part of a larger earnings stream / balance sheet Sound risk management framework has resulted in robust capital levels and credit metrics Insider ownership of 32% 27 out of 32 quarters (84%) since IPO above a 1.25% GAAP ROA(1) Key Franchise Milestones 2024 2018 2002 1998 Capital Bancorp is Incorporated IPO at $12.50 / share raising $32mm Recapitalization led by investors including current chairman Steve Schwartz and 2 out of the 3 current largest insider owners Completed acquisition of IFH CEO Ed Barry joined Capital Bank 2012 Peers(2) CBNK Percentile Rank vs. Peers (3) TBV + Dividend Growth Since 2018Q3 Share Price Change Since CBNK IPO on 9/26/2018 2011- 2013 Completed three FDIC assisted acquisitions (3) % Change CAGR CBNK: 219% 16% Peers(2): 117% 10% KRX Median: 114% 10% % Change CAGR CBNK: 223% 16% Peers(2): 50% 5% KRX Median: 20% 2% 2026 CBNK Announces Merger with PEBO 0% 50% 100% 150% 200% 250% (75%) (25%) 25% 75% 125% 175% 225% 170%+ Outperformance vs. both groups 100%+ Outperformance vs. both groups
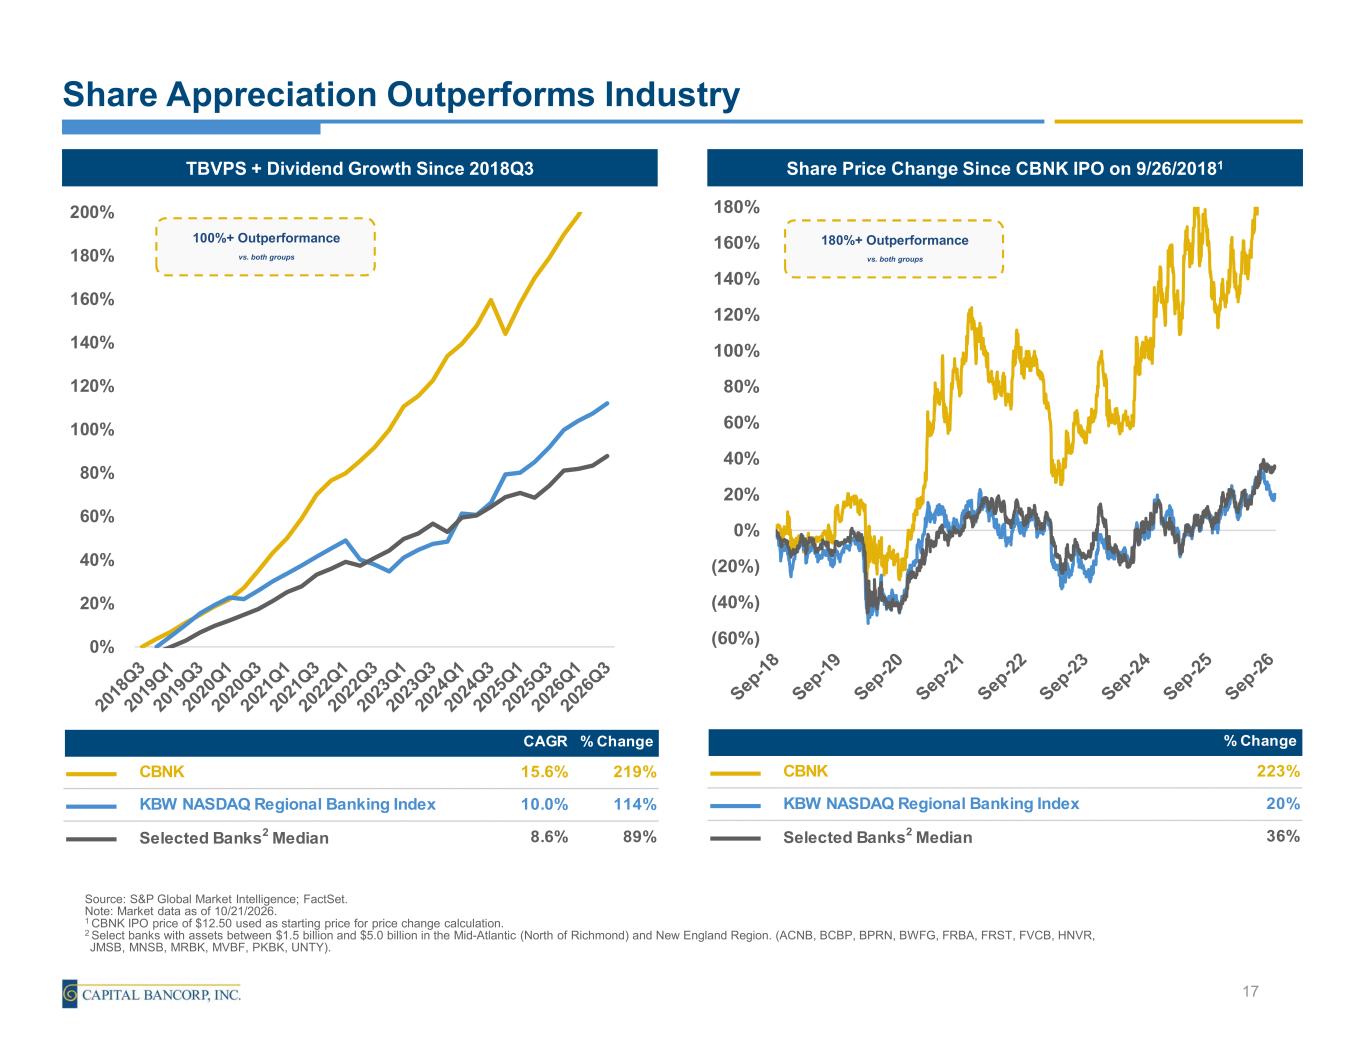
Share Appreciation Outperforms Industry 17 Share Price Change Since CBNK IPO on 9/26/20181TBVPS + Dividend Growth Since 2018Q3 100%+ Outperformance vs. both groups 180%+ Outperformance vs. both groups Source: S&P Global Market Intelligence; FactSet. Note: Market data as of 10/21/2026. 1 CBNK IPO price of $12.50 used as starting price for price change calculation. 2 Select banks with assets between $1.5 billion and $5.0 billion in the Mid-Atlantic (North of Richmond) and New England Region. (ACNB, BCBP, BPRN, BWFG, FRBA, FRST, FVCB, HNVR, JMSB, MNSB, MRBK, MVBF, PKBK, UNTY). CAGR % Change CBNK 15.6% 219% KBW NASDAQ Regional Banking Index 10.0% 114% Selected Banks2 Median 8.6% 89% 0% 20% 40% 60% 80% 100% 120% 140% 160% 180% 200% 58.48% (60%) (40%) (20%) 0% 20% 40% 60% 80% 100% 120% 140% 160% 180% % Change CBNK 223% KBW NASDAQ Regional Banking Index 20% Selected Banks2 Median 36%
Jake Dalaya Chief Financial Officer (301)-637-5118 NASDAQ: CBNK
Non-U.S. GAAP Financial Measures
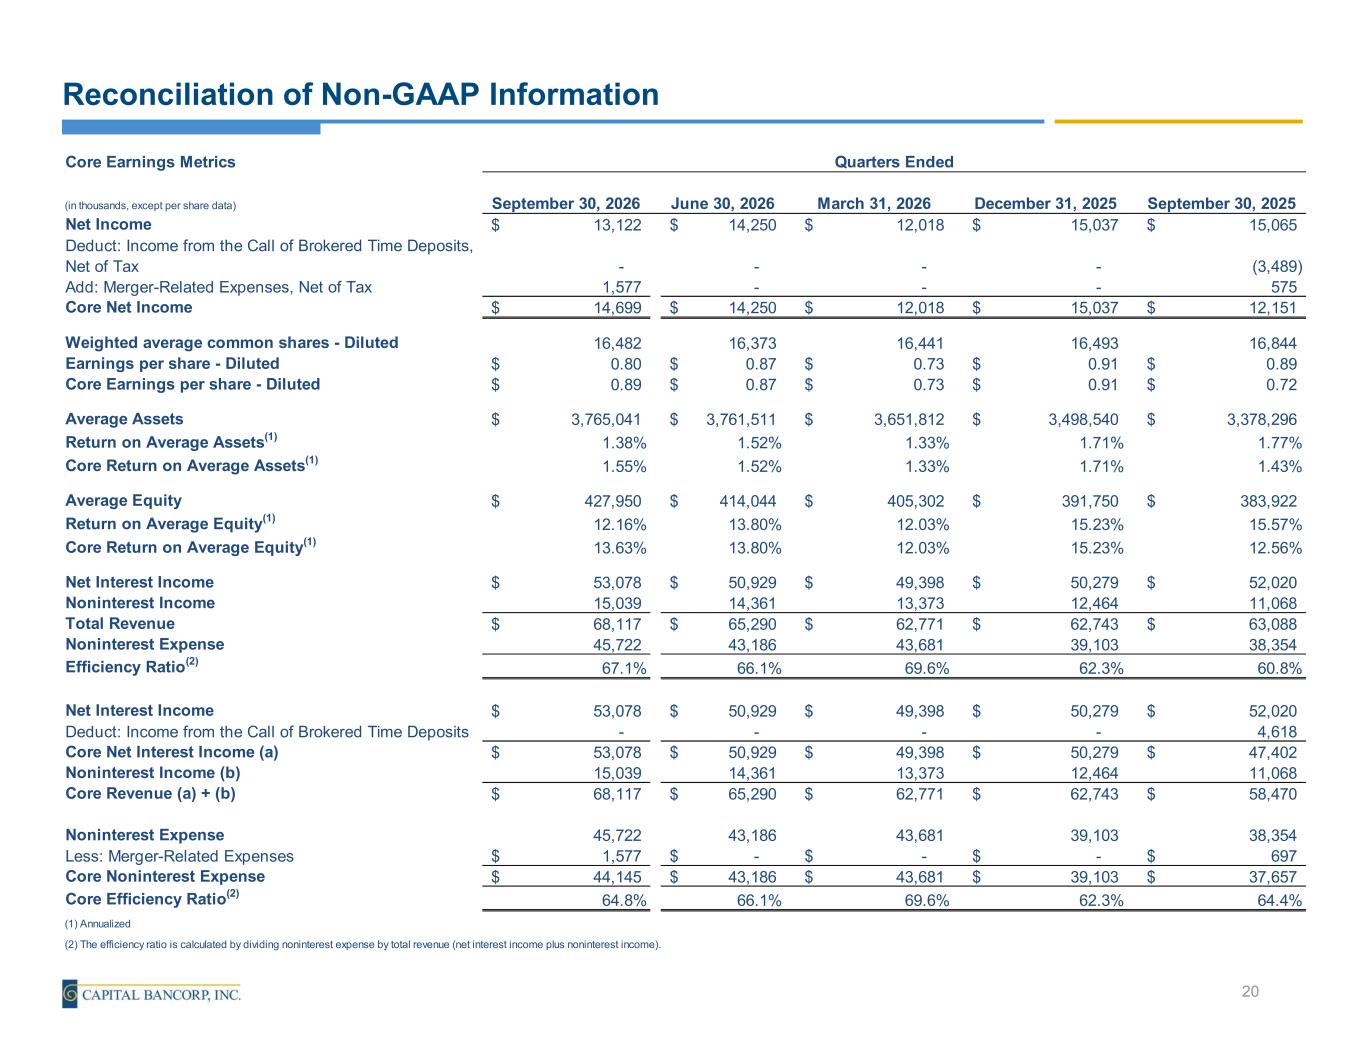
Reconciliation of Non-GAAP Information 20 Core Earnings Metrics (in thousands, except per share data) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Net Income 13,122$ 14,250$ 12,018$ 15,037$ 15,065$ Deduct: Income from the Call of Brokered Time Deposits, Net of Tax - - - - (3,489) Add: Merger-Related Expenses, Net of Tax 1,577 - - - 575 Core Net Income 14,699$ 14,250$ 12,018$ 15,037$ 12,151$ Weighted average common shares - Diluted 16,482 16,373 16,441 16,493 16,844 Earnings per share - Diluted 0.80$ 0.87$ 0.73$ 0.91$ 0.89$ Core Earnings per share - Diluted 0.89$ 0.87$ 0.73$ 0.91$ 0.72$ Average Assets 3,765,041$ 3,761,511$ 3,651,812$ 3,498,540$ 3,378,296$ Return on Average Assets(1) 1.38% 1.52% 1.33% 1.71% 1.77% Core Return on Average Assets(1) 1.55% 1.52% 1.33% 1.71% 1.43% Average Equity 427,950$ 414,044$ 405,302$ 391,750$ 383,922$ Return on Average Equity(1) 12.16% 13.80% 12.03% 15.23% 15.57% Core Return on Average Equity(1) 13.63% 13.80% 12.03% 15.23% 12.56% Net Interest Income 53,078$ 50,929$ 49,398$ 50,279$ 52,020$ Noninterest Income 15,039 14,361 13,373 12,464 11,068 Total Revenue 68,117$ 65,290$ 62,771$ 62,743$ 63,088$ Noninterest Expense 45,722 43,186 43,681 39,103 38,354 Efficiency Ratio(2) 67.1% 66.1% 69.6% 62.3% 60.8% Net Interest Income 53,078$ 50,929$ 49,398$ 50,279$ 52,020$ Deduct: Income from the Call of Brokered Time Deposits - - - - 4,618 Core Net Interest Income (a) 53,078$ 50,929$ 49,398$ 50,279$ 47,402$ Noninterest Income (b) 15,039 14,361 13,373 12,464 11,068 Core Revenue (a) + (b) 68,117$ 65,290$ 62,771$ 62,743$ 58,470$ Noninterest Expense 45,722 43,186 43,681 39,103 38,354 Less: Merger-Related Expenses 1,577$ -$ -$ -$ 697$ Core Noninterest Expense 44,145$ 43,186$ 43,681$ 39,103$ 37,657$ Core Efficiency Ratio(2) 64.8% 66.1% 69.6% 62.3% 64.4% (1) Annualized (2) The efficiency ratio is calculated by dividing noninterest expense by total revenue (net interest income plus noninterest income). Quarters Ended
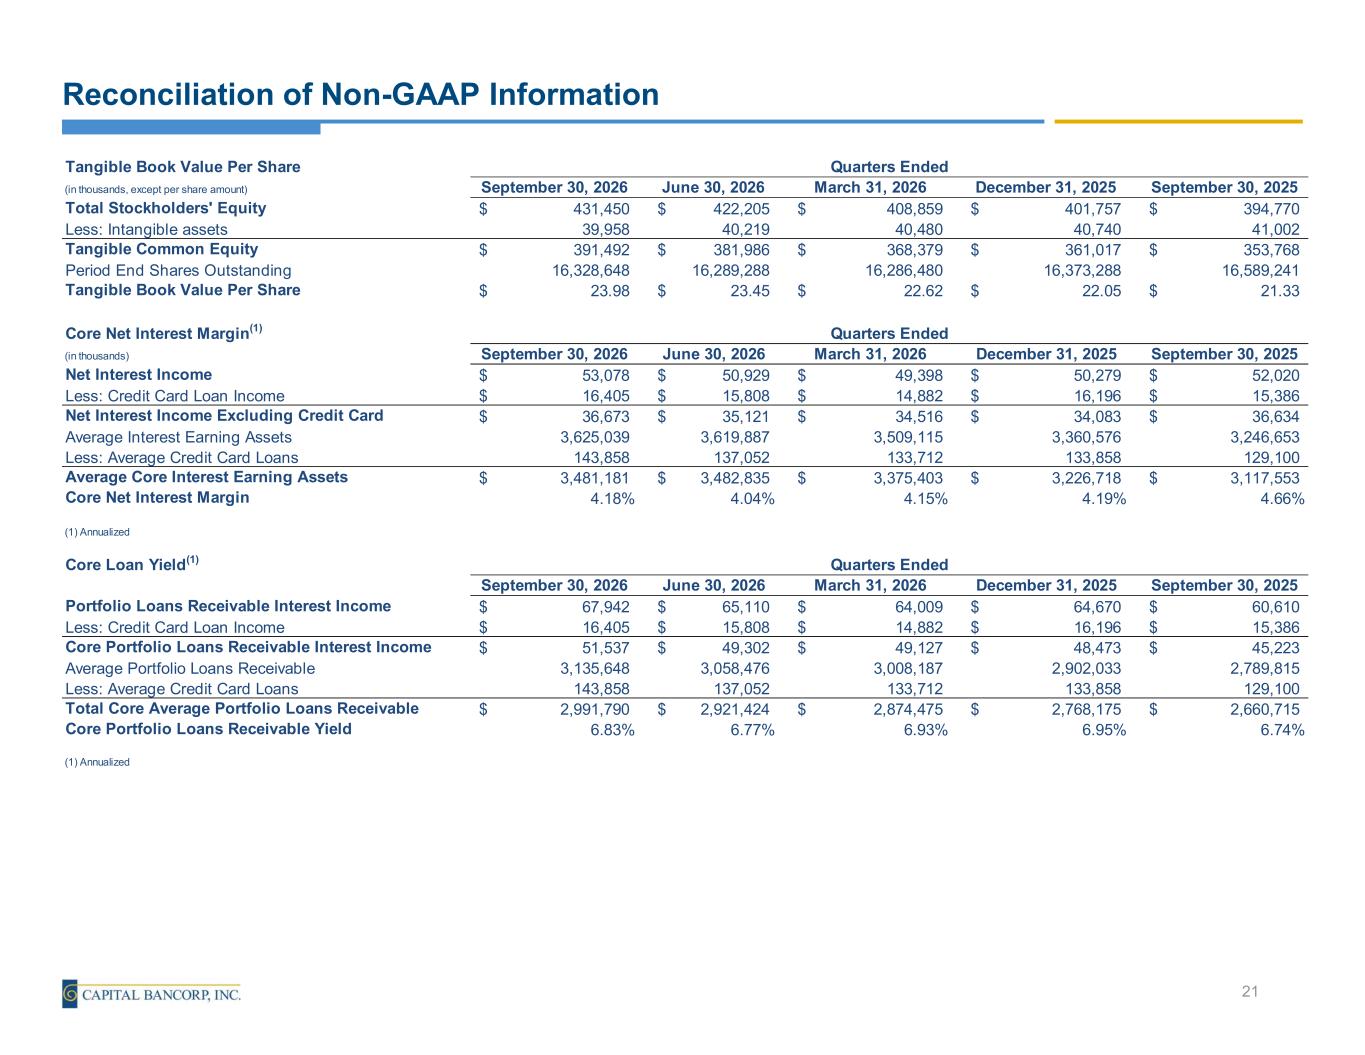
Reconciliation of Non-GAAP Information 21 Tangible Book Value Per Share (in thousands, except per share amount) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Total Stockholders' Equity 431,450$ 422,205$ 408,859$ 401,757$ 394,770$ Less: Intangible assets 39,958 40,219 40,480 40,740 41,002 Tangible Common Equity 391,492$ 381,986$ 368,379$ 361,017$ 353,768$ Period End Shares Outstanding 16,328,648 16,289,288 16,286,480 16,373,288 16,589,241 Tangible Book Value Per Share 23.98$ 23.45$ 22.62$ 22.05$ 21.33$ Core Net Interest Margin(1) (in thousands) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Net Interest Income 53,078$ 50,929$ 49,398$ 50,279$ 52,020$ Less: Credit Card Loan Income 16,405$ 15,808$ 14,882$ 16,196$ 15,386$ Net Interest Income Excluding Credit Card 36,673$ 35,121$ 34,516$ 34,083$ 36,634$ Average Interest Earning Assets 3,625,039 3,619,887 3,509,115 3,360,576 3,246,653 Less: Average Credit Card Loans 143,858 137,052 133,712 133,858 129,100 Average Core Interest Earning Assets 3,481,181$ 3,482,835$ 3,375,403$ 3,226,718$ 3,117,553$ Core Net Interest Margin 4.18% 4.04% 4.15% 4.19% 4.66% (1) Annualized Core Loan Yield(1) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Portfolio Loans Receivable Interest Income 67,942$ 65,110$ 64,009$ 64,670$ 60,610$ Less: Credit Card Loan Income 16,405$ 15,808$ 14,882$ 16,196$ 15,386$ Core Portfolio Loans Receivable Interest Income 51,537$ 49,302$ 49,127$ 48,473$ 45,223$ Average Portfolio Loans Receivable 3,135,648 3,058,476 3,008,187 2,902,033 2,789,815 Less: Average Credit Card Loans 143,858 137,052 133,712 133,858 129,100 Total Core Average Portfolio Loans Receivable 2,991,790$ 2,921,424$ 2,874,475$ 2,768,175$ 2,660,715$ Core Portfolio Loans Receivable Yield 6.83% 6.77% 6.93% 6.95% 6.74% (1) Annualized Quarters Ended Quarters Ended Quarters Ended
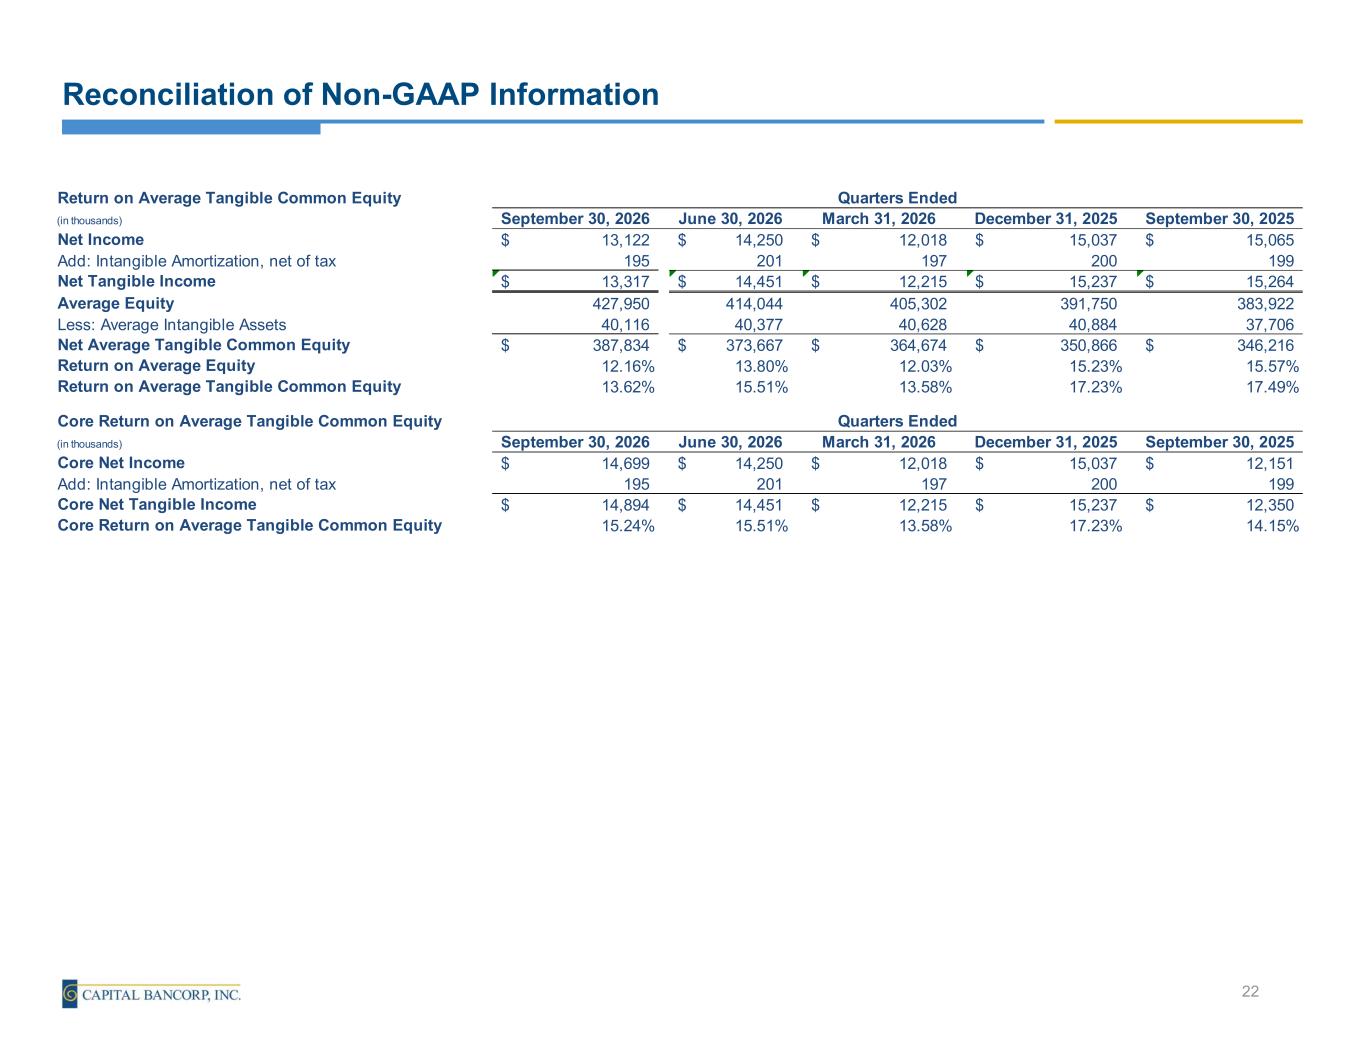
Reconciliation of Non-GAAP Information 22 Return on Average Tangible Common Equity (in thousands) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Net Income 13,122$ 14,250$ 12,018$ 15,037$ 15,065$ Add: Intangible Amortization, net of tax 195 201 197 200 199 Net Tangible Income 13,317$ 14,451$ 12,215$ 15,237$ 15,264$ Average Equity 427,950 414,044 405,302 391,750 383,922 Less: Average Intangible Assets 40,116 40,377 40,628 40,884 37,706 Net Average Tangible Common Equity 387,834$ 373,667$ 364,674$ 350,866$ 346,216$ Return on Average Equity 12.16% 13.80% 12.03% 15.23% 15.57% Return on Average Tangible Common Equity 13.62% 15.51% 13.58% 17.23% 17.49% Core Return on Average Tangible Common Equity (in thousands) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Core Net Income 14,699$ 14,250$ 12,018$ 15,037$ 12,151$ Add: Intangible Amortization, net of tax 195 201 197 200 199 Core Net Tangible Income 14,894$ 14,451$ 12,215$ 15,237$ 12,350$ Core Return on Average Tangible Common Equity 15.24% 15.51% 13.58% 17.23% 14.15% Quarters Ended Quarters Ended
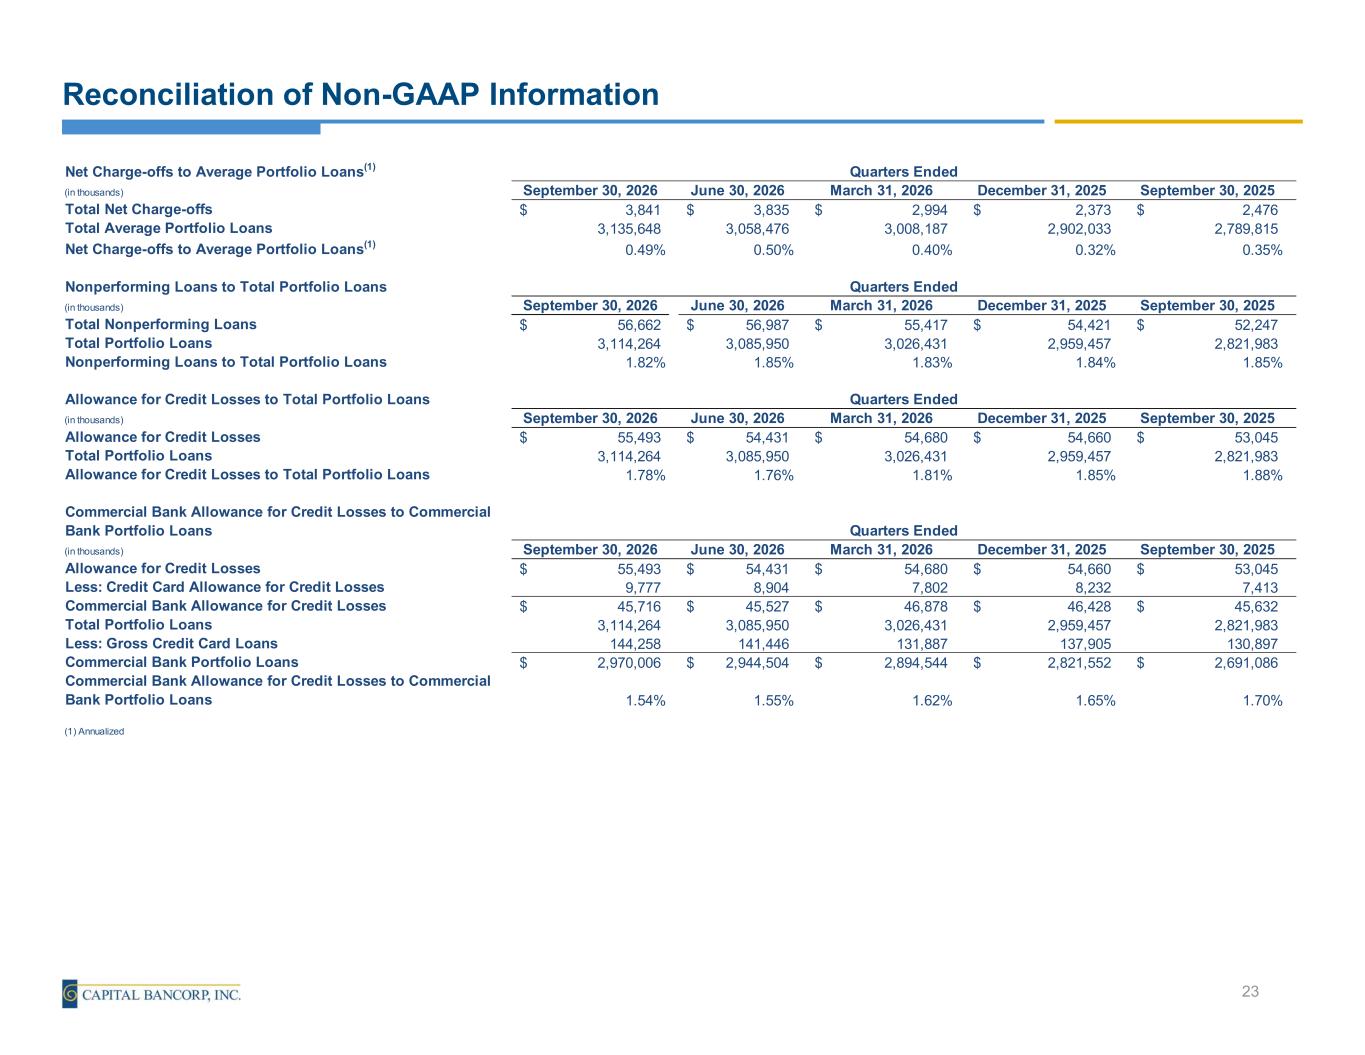
Reconciliation of Non-GAAP Information 23 Net Charge-offs to Average Portfolio Loans(1) (in thousands) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Total Net Charge-offs 3,841$ 3,835$ 2,994$ 2,373$ 2,476$ Total Average Portfolio Loans 3,135,648 3,058,476 3,008,187 2,902,033 2,789,815 Net Charge-offs to Average Portfolio Loans(1) 0.49% 0.50% 0.40% 0.32% 0.35% Nonperforming Loans to Total Portfolio Loans (in thousands) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Total Nonperforming Loans 56,662$ 56,987$ 55,417$ 54,421$ 52,247$ Total Portfolio Loans 3,114,264 3,085,950 3,026,431 2,959,457 2,821,983 Nonperforming Loans to Total Portfolio Loans 1.82% 1.85% 1.83% 1.84% 1.85% Allowance for Credit Losses to Total Portfolio Loans (in thousands) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Allowance for Credit Losses 55,493$ 54,431$ 54,680$ 54,660$ 53,045$ Total Portfolio Loans 3,114,264 3,085,950 3,026,431 2,959,457 2,821,983 Allowance for Credit Losses to Total Portfolio Loans 1.78% 1.76% 1.81% 1.85% 1.88% Commercial Bank Allowance for Credit Losses to Commercial Bank Portfolio Loans (in thousands) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Allowance for Credit Losses 55,493$ 54,431$ 54,680$ 54,660$ 53,045$ Less: Credit Card Allowance for Credit Losses 9,777 8,904 7,802 8,232 7,413 Commercial Bank Allowance for Credit Losses 45,716$ 45,527$ 46,878$ 46,428$ 45,632$ Total Portfolio Loans 3,114,264 3,085,950 3,026,431 2,959,457 2,821,983 Less: Gross Credit Card Loans 144,258 141,446 131,887 137,905 130,897 Commercial Bank Portfolio Loans 2,970,006$ 2,944,504$ 2,894,544$ 2,821,552$ 2,691,086$ Commercial Bank Allowance for Credit Losses to Commercial Bank Portfolio Loans 1.54% 1.55% 1.62% 1.65% 1.70% (1) Annualized Quarters Ended Quarters Ended Quarters Ended Quarters Ended