Exhibit 99.2 Merger Overview North Haven Private Income Fund LLC & North Haven Private Income Fund A LLC Investor Presentation | October 2026
Important Disclosures The information outlined in this presentation (the “Presentation”) is presented for discussion purposes only and may not be relied on in any manner as, legal, tax, investment, accounting or other advice or as an offer to sell or a solicitation of an offer to buy an interest in North Haven Private Income Fund LLC (“PIF”) and North Haven Private Income Fund A LLC (“PIF A” and together with PIF, each a “Company” and together, the “Companies”) or any investment fund sponsored by Morgan Stanley. For the avoidance of doubt, the Companies are not subsidiaries of, or consolidated with, Morgan Stanley. Furthermore, Morgan Stanley has no obligation, contractual or otherwise, to financially support any Company and has no history of financially supporting any business development company (“BDC”) on the MS Private Credit platform, even during periods of financial distress All information in this Presentation is as of June 30, 2026 unless stated otherwise, is subject to change, and will not be updated or otherwise revised to reflect information that subsequently becomes available or circumstances existing or changes occurring after the date hereof. This Presentation contains forward-looking statements that involve substantial risks and uncertainties. Such statements involve known and unknown risks, uncertainties and other factors and you should not place undue reliance on such statements. These forward-looking statements are not historical facts, but rather are based on current expectations, estimates and projections about the Companies, the Companies’ current and prospective portfolio investments, industry, beliefs and opinions and assumptions. Words such as “anticipates,” “expects,” “intends,” “plans,” “will,” “may,” “continue,” “believes,” “seeks,” “estimates,” “would,” “could,” “should,” “targets,” “projects,” “potential,” “predicts,” and variations of these words and similar expressions are intended to identify forward-looking statements. These statements are not guarantees of future performance and are subject to risks, uncertainties and other factors, some of which are beyond our control and difficult to predict and could cause actual results to differ materially from those expressed or forecasted in the forward-looking statements. Certain factors could cause actual results and conditions to differ materially from those contained in any forward-looking statements, including, among other things, risks and uncertainties associated with (i) the timing or likelihood of the transaction described herein (the “Transaction”) closing; (ii) the ability to realize the anticipated benefits of the Transaction; (iii) the possibility that competing offers or acquisition proposals will be made; (iv) the possibility that any or all of the various conditions to the consummation of the Transaction may not be satisfied or waived; (v) risks related to diverting management’s attention from ongoing business operations; (vi) the risk that unitholder litigation in connection with the Transaction may result in significant costs of defense and liability; (vii) general economic, political and industry trends and other external factors, including government shutdowns and uncertainty surrounding the financial and political stability of the United States and other countries; (viii) the impact on each Company’s business of U.S. and international financial reform legislation, rules and regulations; (ix) the risk associated with possible disruptions in the operations of each Company or the economy generally, including disruptions from the impact of global health events and natural disasters; (x) changes in political, economic or industry conditions, the interest rate environment or conditions affecting the financial and capital markets that could result in changes to the value of each Company’s assets; (xi) the effect of an inflationary economic environment, and its impact on each Company on their respective portfolio companies, financial condition and results of operations; (xii) the impact of interruptions in the supply chain on each Company’s portfolio companies; (xiii) disruptions related to tariffs and other trade or sanctions issues; (xiv) PIF’s plans, expectations, objectives and intentions, as a result of the Transaction; (xv) the future operating results and net investment income projections of each Company; (xvi) the ability of the MS Capital Partners Adviser Inc. (the “Adviser”) to locate suitable investments for PIF and to monitor and administer its investments; (xvii) the ability of the Adviser or its affiliates to attract and retain highly talented professionals; (xviii) each Company’s ability to maintain their respective qualification as a BDC and as a regulated investment company under the Internal Revenue Code of 1986, as amended; (xix) the business prospects of each Company and the prospects of their respective portfolio companies; (xx) the impact of the investments that each Company expects to make; (xxi) the expected financings and investments and additional leverage that each Company may seek to incur in the future; and (xxii) other considerations that may be disclosed from time to time in each Company’s publicly disseminated documents and filings. Although we believe that the assumptions on which these forward-looking statements are based are reasonable, any of the assumptions could prove to be inaccurate, and as a result, the forward- looking statements based on those assumptions also could be inaccurate. In light of these and other uncertainties, the inclusion of a projection or forward-looking statements in this Presentation should not be regarded as a representation by us that our plans and objectives will be achieved. You should not place undue reliance on these forward-looking statements, which apply only as of the date of this Presentation. Moreover, we assume no duty and do not undertake to update the forward-looking statements. You are advised to consult any additional disclosures that we make directly to you or through reports that we have filed or in the future file with the Securities and Exchange Commission (the “SEC”), including Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q and Current Reports on Form 8-K. 2 MERGER OVERVIEW PRESENTATION
Important Disclosures (Cont’d) This Presentation contains information about each Company and certain of their respective affiliates and each Company’s historical performance. You should not view information related to the past performance of a Company as indicative of the Company’s future results, the achievement of which is dependent on many factors, many of which are beyond the control of the Company and the Adviser and cannot be assured. Further, an investment in the Company is discrete from, and does not represent an interest in, any other Morgan Stanley entity. Nothing contained herein shall be relied upon as a promise or representation whether as to the past or future performance of the Company or any other Morgan Stanley entity. Each Company is required to file annual, quarterly and current reports and other information with the SEC. The information presented herein should be read in conjunction with each Company’s most recent Current Report on Form 8-K, Quarterly Report on Form 10-Q, and Annual Report on Form 10-K. Each Company’s filings with the SEC are available to the public through the SEC’s website (http://www.sec.gov). There can be no assurance that projections and other forward-looking information will not change based on subsequent developments and without further notice, and no assurance can be given as to the outcome of such projections or forward-looking information. The statements contained herein reflect the views and opinions of the Adviser’s investment team as of the date hereof and not as of any future date and will not be updated or supplemented. There can be no assurance that the Companies will (i) achieve terms for investments that are similar to the terms described in the Presentation, (ii) meet targeted returns or diversification objectives, (iii) be able to implement their investment strategy or achieve their investment objectives or (iv) participate in investments similar to the ones described in the transactions presented herein. Any financial information presented with respect to the Transaction presented herein, including pro forma financial information, is based on the Adviser’s estimates. Information throughout the Presentation provided by sources other than the Companies (including information relating to portfolio companies) has not been independently verified and, accordingly, none of the Companies make any representation or warranty in respect of this information. The following slides contain summaries of certain financial and statistical information about each Company and certain quarterly information about each Company’s portfolio. The information contained in this Presentation is summary information that may be derived from information included in SEC filings and is intended to be considered in the context of each Company’s SEC filings and other public announcements that it may make, by press release or otherwise, from time to time. We undertake no duty or obligation to publicly update or revise the information contained in this Presentation. 3 MERGER OVERVIEW PRESENTATION
SECTION 1 Merger Overview
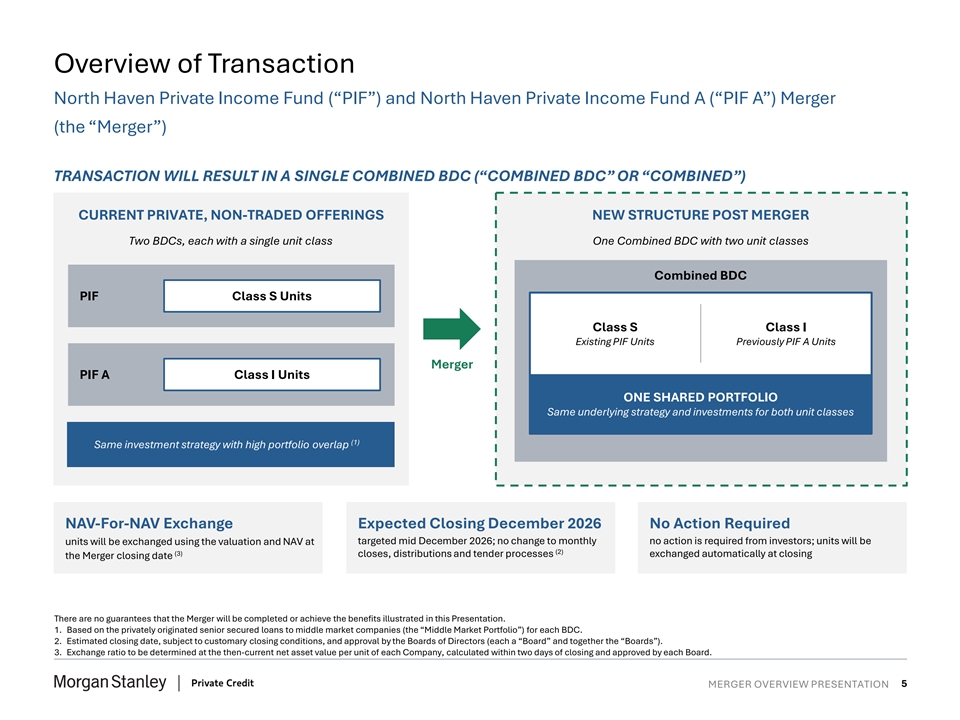
Overview of Transaction North Haven Private Income Fund (“PIF”) and North Haven Private Income Fund A (“PIF A”) Merger (the “Merger”) TRANSACTION WILL RESULT IN A SINGLE COMBINED BDC (“COMBINED BDC” OR “COMBINED”) CURRENT PRIVATE, NON-TRADED OFFERINGS NEW STRUCTURE POST MERGER Two BDCs, each with a single unit class One Combined BDC with two unit classes Combined BDC PIF Class S Units Class S Class I Existing PIF Units Previously PIF A Units Merger PIF A Class I Units ONE SHARED PORTFOLIO Same underlying strategy and investments for both unit classes (1) Same investment strategy with high portfolio overlap NAV-For-NAV Exchange Expected Closing December 2026 No Action Required targeted mid December 2026; no change to monthly no action is required from investors; units will be units will be exchanged using the valuation and NAV at (2) (3) closes, distributions and tender processes exchanged automatically at closing the Merger closing date There are no guarantees that the Merger will be completed or achieve the benefits illustrated in this Presentation. 1. Based on the privately originated senior secured loans to middle market companies (the “Middle Market Portfolio”) for each BDC. 2. Estimated closing date, subject to customary closing conditions, and approval by the Boards of Directors (each a “Board” and together the “Boards”). 3. Exchange ratio to be determined at the then-current net asset value per unit of each Company, calculated within two days of closing and approved by each Board. 5 MERGER OVERVIEW PRESENTATION
Strategic Rationale Execute on long-term structural vision • Since the inception of PIF in 2022, the proposed merger has been an integral part of the platform’s long-term strategic plan, with PIF A launched to synthetically replicate a multi-unit-class structure while awaiting the necessary regulatory approvals which were novel at the time • The multi-class exemptive relief order previously granted to PIF and PIF A permits PIF to issue multiple unit classes and allows for combining vehicles that were originally established separately • The Combined BDC adopts the multi-class, single-entity structure offered by Competitor BDCs and we believe will better align Morgan Stanley (1) Private Credit’s private, non-traded BDC offerings with the market Enhance positioning to capitalize on an attractive deployment environment (2) • We believe the current market for new deals is attractive, with improving terms and public-market volatility creating a favorable backdrop • We believe that greater scale better positions the Combined BDC to participate in new deal deployment, which ultimately has the potential to drive performance Create value for investors through improved: 1) Economics; 2) Scale and diversification; 3) Leverage and funding profile; and 4) Competitive positioning Data as of June 30, 2026, unless otherwise noted. There are no guarantees that the Merger will be completed or achieve the benefits illustrated in this Presentation. 1. BDCs included in competitor landscape include Apollo Debt Solutions, Ares Strategic Income Fund, Blackstone Private Credit Fund, Golub Capital Private Credit Fund, Goldman Sachs Private Credit Corp., HPS Corporate Lending Fund, Blue Owl Credit Income Corp., T Rowe Price OHA Select Private Credit Fund and Oaktree Strategic Credit Fund (the “Competitor BDCs”). 2. The opinions expressed herein are those of the Adviser as of the date of the presentation and are subject to change due to changes in market or economic conditions. 6 MERGER OVERVIEW PRESENTATION
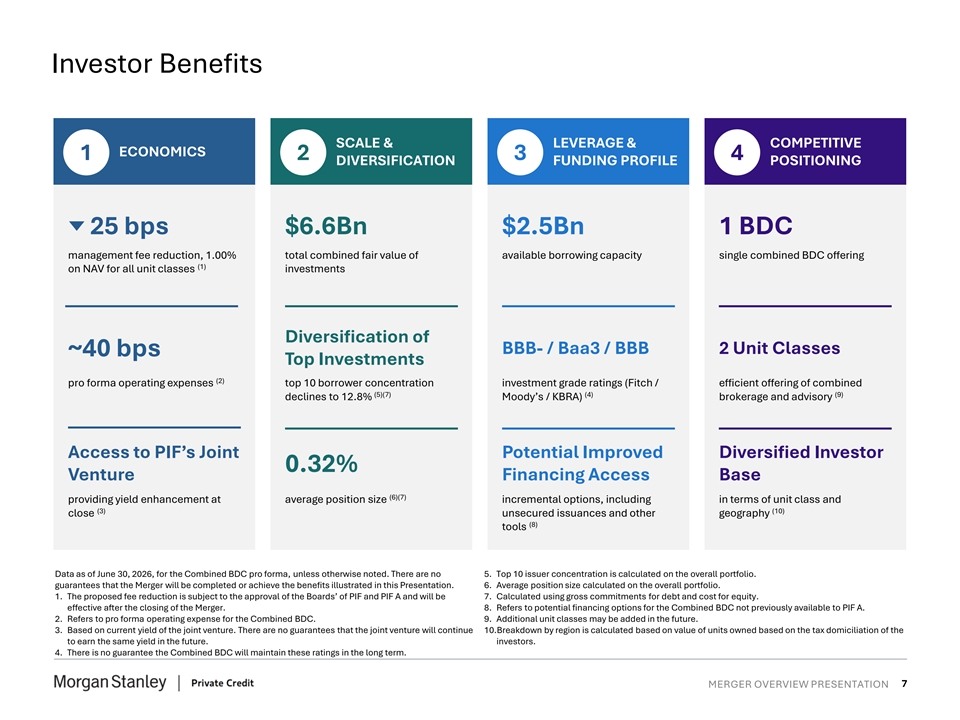
Investor Benefits Place content below this line SCALE & LEVERAGE & COMPETITIVE ECONOMICS 1 2 3 4 DIVERSIFICATION FUNDING PROFILE POSITIONING 25 bps $6.6Bn $2.5Bn 1 BDC management fee reduction, 1.00% total combined fair value of available borrowing capacity single combined BDC offering (1) on NAV for all unit classes investments Diversification of BBB- / Baa3 / BBB 2 Unit Classes ~40 bps Top Investments (2) pro forma operating expenses top 10 borrower concentration investment grade ratings (Fitch / efficient offering of combined (5)(7) (4) (9) declines to 12.8% Moody’s / KBRA) brokerage and advisory Access to PIF’s Joint Potential Improved Diversified Investor 0.32% Venture Financing Access Base (6)(7) providing yield enhancement at average position size incremental options, including in terms of unit class and (3) (10) close unsecured issuances and other geography (8) tools Data as of June 30, 2026, for the Combined BDC pro forma, unless otherwise noted. There are no 5. Top 10 issuer concentration is calculated on the overall portfolio. guarantees that the Merger will be completed or achieve the benefits illustrated in this Presentation. 6. Average position size calculated on the overall portfolio. 1. The proposed fee reduction is subject to the approval of the Boards’ of PIF and PIF A and will be 7. Calculated using gross commitments for debt and cost for equity. effective after the closing of the Merger. 8. Refers to potential financing options for the Combined BDC not previously available to PIF A. 2. Refers to pro forma operating expense for the Combined BDC. 9. Additional unit classes may be added in the future. Source and 3. Based on current yield of the joint venture. There are no guarantees that the joint venture will continue 10.Breakdown by region is calculated based on value of units owned based on the tax domiciliation of the Footnotes Guideline to earn the same yield in the future. investors. 4. There is no guarantee the Combined BDC will maintain these ratings in the long term. 7 MERGER OVERVIEW PRESENTATION
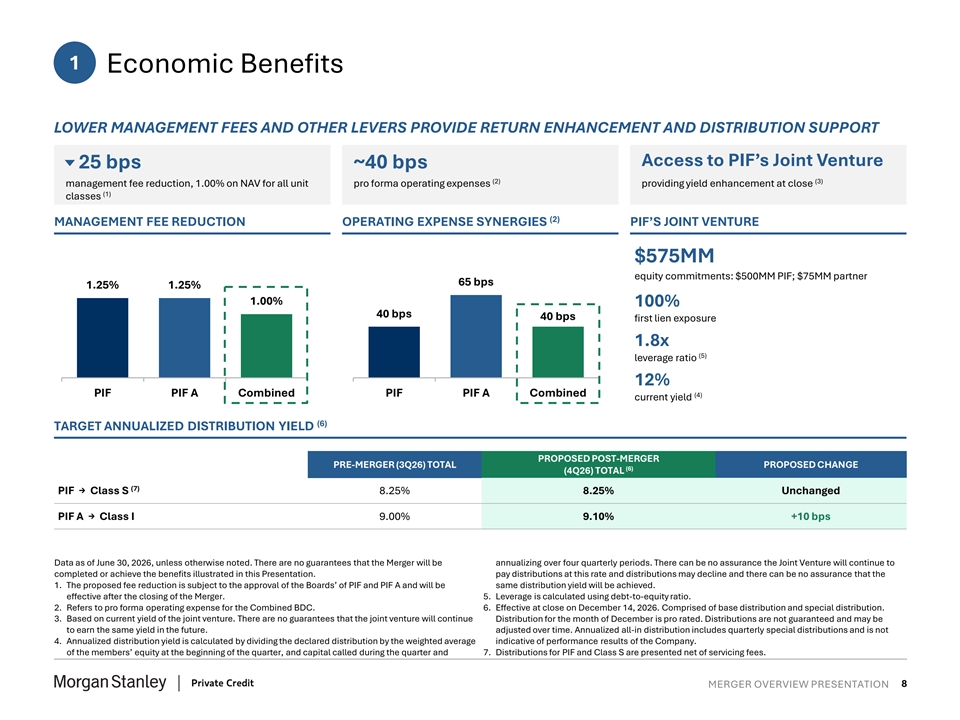
1 Economic Benefits LOWER MANAGEMENT FEES AND OTHER LEVERS PROVIDE RETURN ENHANCEMENT AND DISTRIBUTION SUPPORT Access to PIF’s Joint Venture 25 bps ~40 bps (2) (3) management fee reduction, 1.00% on NAV for all unit pro forma operating expenses providing yield enhancement at close (1) classes (2) MANAGEMENT FEE REDUCTION OPERATING EXPENSE SYNERGIES PIF’S JOINT VENTURE $575MM equity commitments: $500MM PIF; $75MM partner 65 bps 1.25% 1.25% 1.00% 100% 40 bps 40 bps first lien exposure 1.8x (5) leverage ratio 12% PIF PIF A Combined PIF PIF A Combined (4) current yield (6) TARGET ANNUALIZED DISTRIBUTION YIELD PROPOSED POST-MERGER PRE-MERGER (3Q26) TOTAL PROPOSED CHANGE (6) (4Q26) TOTAL (7) PIF → Class S 8.25% 8.25% Unchanged PIF A → Class I 9.00% 9.10% +10 bps Data as of June 30, 2026, unless otherwise noted. There are no guarantees that the Merger will be annualizing over four quarterly periods. There can be no assurance the Joint Venture will continue to completed or achieve the benefits illustrated in this Presentation. pay distributions at this rate and distributions may decline and there can be no assurance that the 1. The proposed fee reduction is subject to the approval of the Boards’ of PIF and PIF A and will be same distribution yield will be achieved. effective after the closing of the Merger. 5. Leverage is calculated using debt-to-equity ratio. 2. Refers to pro forma operating expense for the Combined BDC. 6. Effective at close on December 14, 2026. Comprised of base distribution and special distribution. 3. Based on current yield of the joint venture. There are no guarantees that the joint venture will continue Distribution for the month of December is pro rated. Distributions are not guaranteed and may be to earn the same yield in the future. adjusted over time. Annualized all-in distribution includes quarterly special distributions and is not 4. Annualized distribution yield is calculated by dividing the declared distribution by the weighted average indicative of performance results of the Company. of the members’ equity at the beginning of the quarter, and capital called during the quarter and 7. Distributions for PIF and Class S are presented net of servicing fees. 8 MERGER OVERVIEW PRESENTATION
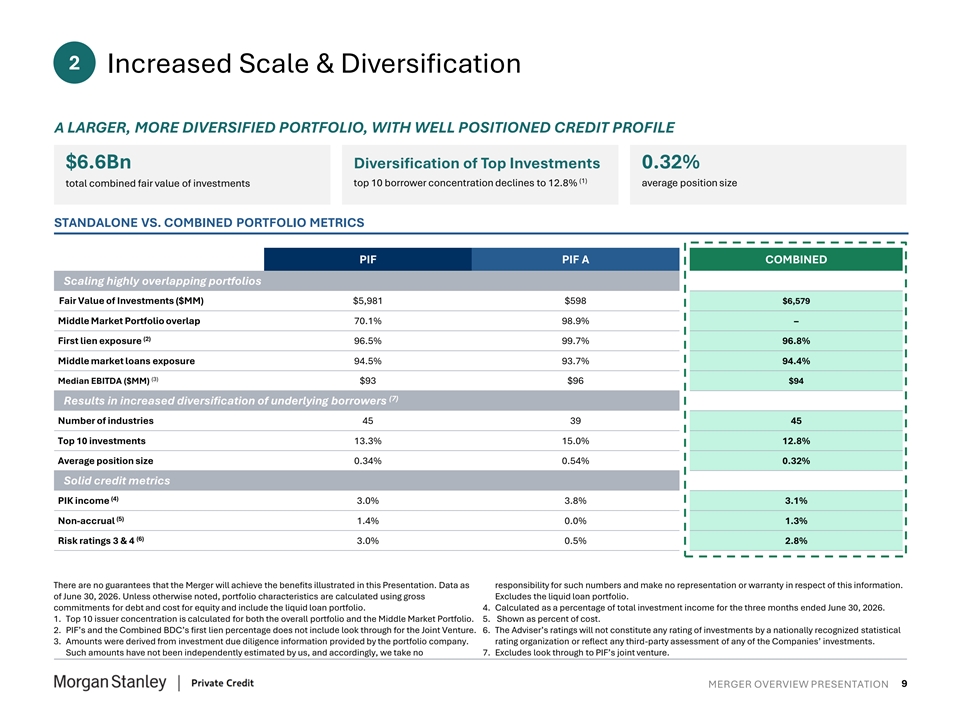
2 Increased Scale & Diversification Place content A LARGER, MORE DIVERSIFIED PORTFOLIO, WITH WELL POSITIONED CREDIT PROFILE below this line Diversification of Top Investments $6.6Bn 0.32% (1) total combined fair value of investments top 10 borrower concentration declines to 12.8% average position size STANDALONE VS. COMBINED PORTFOLIO METRICS PIF PIF A COMBINED Scaling highly overlapping portfolios Fair Value of Investments ($MM) $5,981 $598 $6,579 Middle Market Portfolio overlap 70.1% 98.9% – (2) First lien exposure 96.5% 99.7% 96.8% Middle market loans exposure 94.5% 93.7% 94.4% (3) Median EBITDA ($MM) $93 $96 $94 (7) Results in increased diversification of underlying borrowers Number of industries 45 39 45 Top 10 investments 13.3% 15.0% 12.8% Average position size 0.34% 0.54% 0.32% Solid credit metrics (4) PIK income 3.0% 3.8% 3.1% (5) Non-accrual 1.4% 0.0% 1.3% (6) Risk ratings 3 & 4 3.0% 0.5% 2.8% There are no guarantees that the Merger will achieve the benefits illustrated in this Presentation. Data as responsibility for such numbers and make no representation or warranty in respect of this information. of June 30, 2026. Unless otherwise noted, portfolio characteristics are calculated using gross Excludes the liquid loan portfolio. commitments for debt and cost for equity and include the liquid loan portfolio. 4. Calculated as a percentage of total investment income for the three months ended June 30, 2026. 1. Top 10 issuer concentration is calculated for both the overall portfolio and the Middle Market Portfolio. 5. Shown as percent of cost. Source and 2. PIF’s and the Combined BDC’s first lien percentage does not include look through for the Joint Venture. 6. The Adviser’s ratings will not constitute any rating of investments by a nationally recognized statistical Footnotes Guideline 3. Amounts were derived from investment due diligence information provided by the portfolio company. rating organization or reflect any third-party assessment of any of the Companies’ investments. Such amounts have not been independently estimated by us, and accordingly, we take no 7. Excludes look through to PIF’s joint venture. 9 MERGER OVERVIEW PRESENTATION
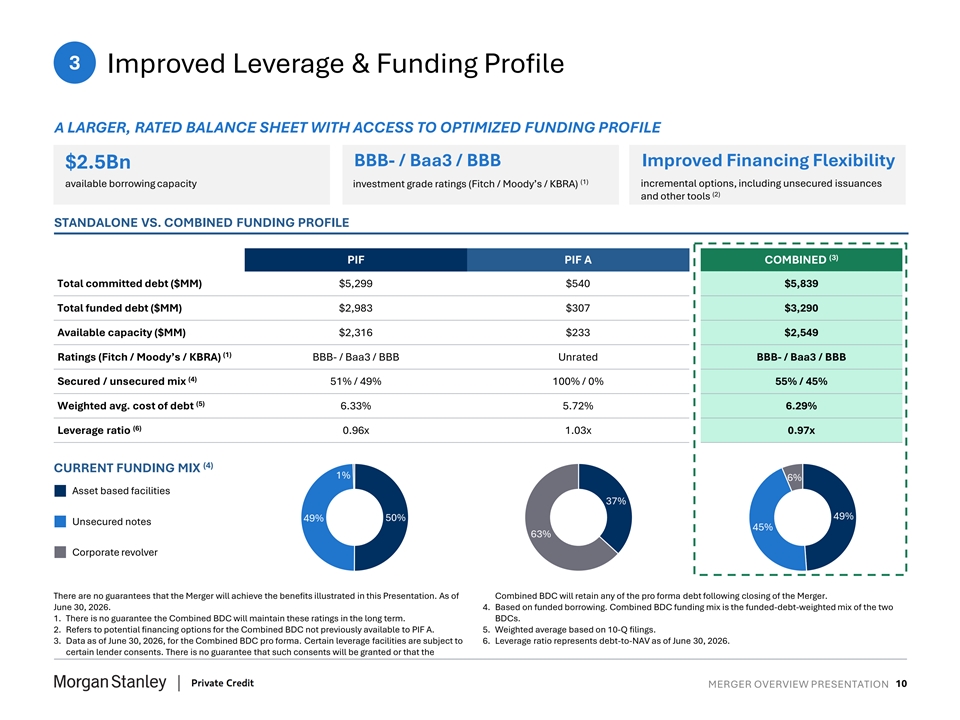
3 Improved Leverage & Funding Profile A LARGER, RATED BALANCE SHEET WITH ACCESS TO OPTIMIZED FUNDING PROFILE BBB- / Baa3 / BBB Improved Financing Flexibility $2.5Bn (1) available borrowing capacity incremental options, including unsecured issuances investment grade ratings (Fitch / Moody’s / KBRA) (2) and other tools STANDALONE VS. COMBINED FUNDING PROFILE (3) PIF PIF A COMBINED Total committed debt ($MM) $5,299 $540 $5,839 Total funded debt ($MM) $2,983 $307 $3,290 Available capacity ($MM) $2,316 $233 $2,549 (1) Ratings (Fitch / Moody’s / KBRA) BBB- / Baa3 / BBB Unrated BBB- / Baa3 / BBB (4) Secured / unsecured mix 51% / 49% 100% / 0% 55% / 45% (5) Weighted avg. cost of debt 6.33% 5.72% 6.29% (6) Leverage ratio 0.96x 1.03x 0.97x (4) CURRENT FUNDING MIX 1% 6% Asset based facilities 37% 49% 49% 50% Unsecured notes 45% 63% Corporate revolver There are no guarantees that the Merger will achieve the benefits illustrated in this Presentation. As of Combined BDC will retain any of the pro forma debt following closing of the Merger. June 30, 2026. 4. Based on funded borrowing. Combined BDC funding mix is the funded-debt-weighted mix of the two 1. There is no guarantee the Combined BDC will maintain these ratings in the long term. BDCs. 2. Refers to potential financing options for the Combined BDC not previously available to PIF A. 5. Weighted average based on 10-Q filings. 3. Data as of June 30, 2026, for the Combined BDC pro forma. Certain leverage facilities are subject to 6. Leverage ratio represents debt-to-NAV as of June 30, 2026. certain lender consents. There is no guarantee that such consents will be granted or that the 10 MERGER OVERVIEW PRESENTATION
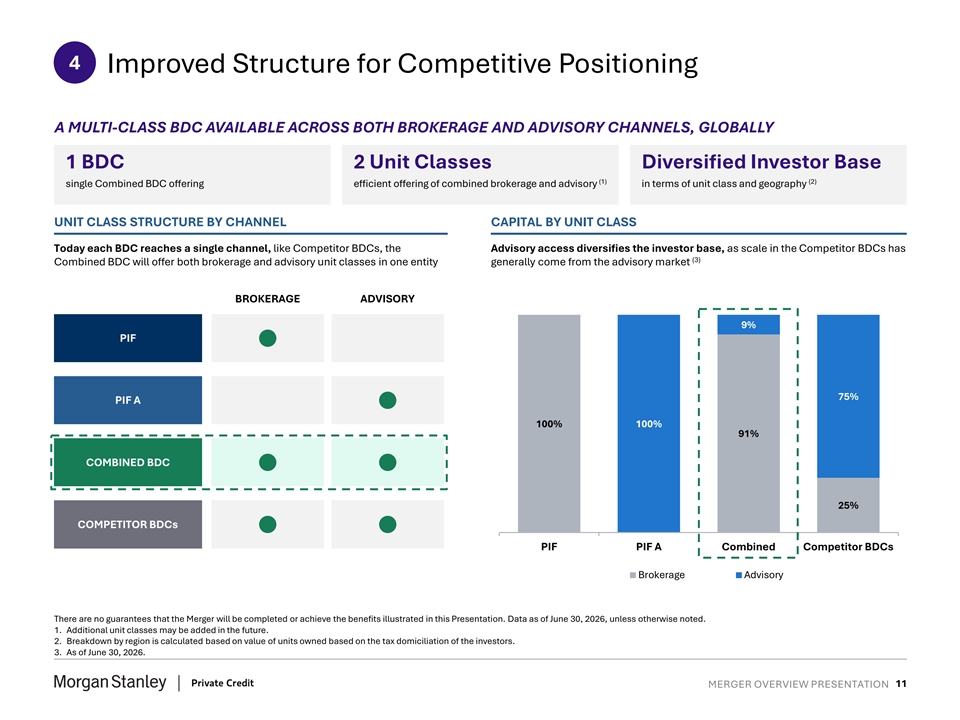
4 Improved Structure for Competitive Positioning A MULTI-CLASS BDC AVAILABLE ACROSS BOTH BROKERAGE AND ADVISORY CHANNELS, GLOBALLY 1 BDC 2 Unit Classes Diversified Investor Base (1) (2) single Combined BDC offering efficient offering of combined brokerage and advisory in terms of unit class and geography UNIT CLASS STRUCTURE BY CHANNEL CAPITAL BY UNIT CLASS Today each BDC reaches a single channel, like Competitor BDCs, the Advisory access diversifies the investor base, as scale in the Competitor BDCs has (3) Combined BDC will offer both brokerage and advisory unit classes in one entity generally come from the advisory market BROKERAGE ADVISORY 9% PIF 75% PIF A 100% 100% 91% COMBINED BDC 25% COMPETITOR BDCs PIF PIF A Combined Competitor BDCs Brokerage Advisory There are no guarantees that the Merger will be completed or achieve the benefits illustrated in this Presentation. Data as of June 30, 2026, unless otherwise noted. 1. Additional unit classes may be added in the future. 2. Breakdown by region is calculated based on value of units owned based on the tax domiciliation of the investors. 3. As of June 30, 2026. 11 MERGER OVERVIEW PRESENTATION
Frequently Asked Questions What was the approval process for the Merger? The Board of Directors for both PIF and PIF A, including, after separate meetings and discussion and the unanimous recommendation of special committees of the Boards comprised solely of Independent Directors, unanimously approved the Merger Agreement, including the Merger and the related matters. The Independent Directors of PIF A received an opinion from a financial advisor and Independent Directors of PIF were advised by a financial advisor. Why were unitholders not requested to vote on this Merger? Each BDC’s limited liability company operating agreement specifically allows the Board of Directors to approve a merger transaction without a vote unless required by the Investment Company Act of 1940, as amended (the “1940 Act”), or state law. As the Merger is a merger of identically structured BDCs (same liquidity, same investment strategy and same fees) votes are not required under state law or 1940 Act. When will the fee reduction go into effect? We expect that the Board of Directors of PIF will approve an amendment to the PIF investment advisory agreement to reduce the management fee from 1.25% to 1.00% prior to the closing of the Merger. As a result, the combined BDC will have a management fee of 1.00% of net asset value following the merger, effective January 1, 2027. Who is responsible for paying any expenses related to completing the Merger? As disclosed in the Merger Agreement, all fees and expenses incurred in connection with the Merger will be borne by each BDC pro rata with exception of any direct expenses borne by each directly. Morgan Stanley will pay up to $1.5mm of the expenses related to the Merger. Does the timing of the Merger have any impact on the subscription closings or tender process? No. Each Company’s upcoming subscription periods scheduled from November 1, 2026, through closing of the Merger and are expected to close as scheduled. Starting with the first subscription period after closing of the Merger, currently anticipated to be the January 1, 2027 closing, subscriptions will be accepted by the surviving PIF entity as the Combined BDC. The Q4 2026 tender offer is expected to be held by each BDC on the normal schedule and conclude before the closing of the Merger. The payment of each tender will occur in January 2027. Is any action required of unitholders of each BDC? No action is required of unitholders of the Companies at this time. Is the Merger expected to be taxable to the unitholders in each BDC? No, the Merger is not be expected to have any tax consequence for either BDC’s unitholders. 12 MERGER OVERVIEW PRESENTATION
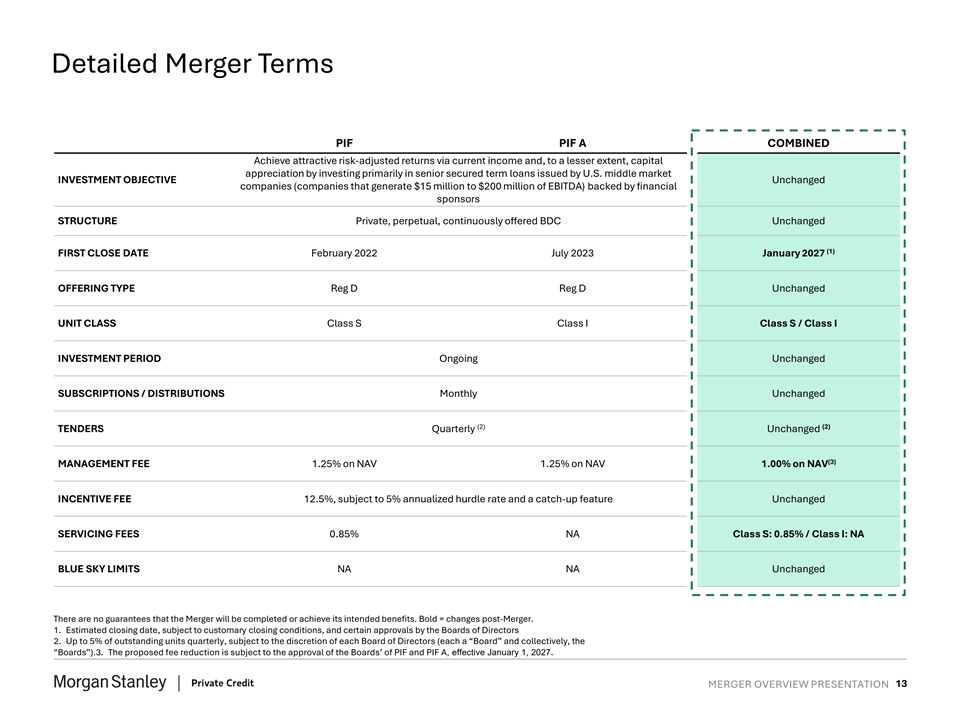
Detailed Merger Terms PIF PIF A COMBINED Achieve attractive risk-adjusted returns via current income and, to a lesser extent, capital appreciation by investing primarily in senior secured term loans issued by U.S. middle market INVESTMENT OBJECTIVE Unchanged companies (companies that generate $15 million to $200 million of EBITDA) backed by financial sponsors STRUCTURE Private, perpetual, continuously offered BDC Unchanged (1) FIRST CLOSE DATE February 2022 July 2023 January 2027 OFFERING TYPE Reg D Reg D Unchanged UNIT CLASS Class S Class I Class S / Class I INVESTMENT PERIOD Ongoing Unchanged SUBSCRIPTIONS / DISTRIBUTIONS Monthly Unchanged (2) (2) TENDERS Quarterly Unchanged (3) MANAGEMENT FEE 1.25% on NAV 1.25% on NAV 1.00% on NAV INCENTIVE FEE 12.5%, subject to 5% annualized hurdle rate and a catch-up feature Unchanged SERVICING FEES 0.85% NA Class S: 0.85% / Class I: NA BLUE SKY LIMITS NA NA Unchanged There are no guarantees that the Merger will be completed or achieve its intended benefits. Bold = changes post-Merger. 1. Estimated closing date, subject to customary closing conditions, and certain approvals by the Boards of Directors 2. Up to 5% of outstanding units quarterly, subject to the discretion of each Board of Directors (each a “Board” and collectively, the “Boards”).3. The proposed fee reduction is subject to the approval of the Boards’ of PIF and PIF A, effective January 1, 2027. 13 MERGER OVERVIEW PRESENTATION