The existence of financial and personal interests of one or more of ALCY’s directors may result in a conflict of interest on the part of such director(s) between what he, she or they may believe is in the best interests of ALCY and its shareholders and what he, she or they may believe is best for himself, herself or themselves in determining to recommend that shareholders vote for the proposals. In addition, ALCY’s officers have interests in the Proposed Transaction that may conflict with your interests as a shareholder. See “The Business Combination Proposal — Certain Interests of ALCY’s Directors and Officers and Others in the Business Combination.”
The Business Combination Agreement was unanimously approved by all of ALCY’s directors on August 19, 2025. Pursuant to the Business Combination Agreement, (a) ALCY will domesticate from the Cayman Islands to Delaware by merging with and into Pubco with Pubco surviving the merger and changing its name to Cartiga Holdings, Inc. (the “Domestication”), (b) after the Domestication, Newco will merge with and into the Company with the Company surviving the merger (hereinafter sometimes referred to as “OpCo”) and continue its existence under the Delaware Limited Liability Company Act (the “LLC Act”), and OpCo becoming a controlled subsidiary of Pubco (the “Merger”); and (c) the existing limited liability company agreement of OpCo will be amended and restated in the form attached to the Business Combination Agreement, to, among other things, make Pubco the sole managing member of OpCo. The Merger and the other transactions contemplated by the Business Combination Agreement are collectively referred to as the “Business Combination,” and as a result of the Business Combination, Pubco will be the publicly traded reporting company in an “Up-C” structure, with two classes of common stock, changing its name to “Cartiga Holdings, Inc.” and sometimes referred to herein as “New Cartiga.”
For information on the percentage of the issued and outstanding shares of Pubco Class A Common Stock immediately following the Closing that are expected to be held by the Company Equity Interest Holders (as defined below), the Sponsor and ALCY’s current public security holders, in various redemption scenarios, based on Cartiga’s balance of equity as of June 30, 2026, see “Questions and Answers for Shareholders of ALCY — What equity stake will current ALCY shareholders and Company Equity Interest Holders hold in Pubco immediately after the consummation of the Proposed Transaction?”
On May 7, 2026, ALCY received a notice (the “Notice”) from The Nasdaq Stock Market LLC (“Nasdaq”), stating that ALCY did not comply with Nasdaq Interpretive Material IM-5101-2, and that its securities were subject to delisting. ALCY’s registration statement, filed in connection with ALCY’s IPO, became effective on May 4, 2023. Pursuant to IM-5101-2, ALCY must complete one or more business combinations within 36 months of the effectiveness of its IPO registration statement. Since the Business Combination was not consummated by May 4, 2026, ALCY did not comply with IM-5101-2, and its securities were suspended from trading on Nasdaq at the opening of business on May 14, 2026.
ALCY Class A ordinary shares, ALCY Units and ALCY Warrants are currently trading on OTC Markets Group, Inc. — Pink Open Market (“OTC”) under the symbols “ALCYF,” “ALCUF” and “ALCWF,” respectively. ALCY has applied to obtain the listing of the Pubco Class A Common Stock and Pubco Warrants on Nasdaq under the symbols “LITF” and “LITFW,” respectively, upon the Closing. Pubco will not have publicly traded units following the Closing. Pursuant to the terms of the Business Combination Agreement, as a closing condition, ALCY is required to cause the Pubco Class A Common Stock to be issued in connection with the Business Combination to be approved for listing on Nasdaq or another national securities exchange, but there can be no assurance that such listing condition will be met. If such listing condition is not met, the Business Combination will not be consummated unless the listing condition is waived by the parties to the Business Combination Agreement. It is important for you to know that, at the time of the extraordinary general meeting, ALCY may not have received from Nasdaq either confirmation of the listing of the Pubco Class A Common Stock or that approval will be obtained prior to the consummation of the Business Combination. As a result, you may be asked to vote to approve the Business Combination and the other proposals included in the accompanying proxy statement/prospectus without such confirmation, and, further, it is possible that such confirmation may never be received, and the Business Combination could still be consummated if such condition is waived and therefore the Pubco Class A Common Stock would not be listed on any nationally recognized securities exchange.
| Interest in Securities | | Other Compensation | |
Sponsor | Alchemy DeepTech Capital LLC, the Sponsor, and its affiliates paid $50,000, or approximately $0.02 per share, for its 2,875,000 founder shares purchased in connection with ALCY’s formation, and 538,000 Class A ordinary shares purchased for $10.00 per share in a private placement that closed at the time of the IPO. At Closing of the Business Combination, the Sponsor shall hold a total of up to 3,413,000 shares of the Pubco Class A Common Stock depending on how much is raised in the PIPE financing. If Available Closing Buyer Cash is less than $5,000,000, then, as a result of Cartiga’s waiver of the Minimum Cash Condition on October 22, 2026, and pursuant to Section 8.17 of the Business Combination Agreement, the Sponsor shall forfeit 1,713,000 of its shares and hold a minimum of 1,700,000 shares of Pubco Class A Common Stock. | At Closing, pursuant to the Business Combination Agreement, Pubco will use cash from the Trust Account to pay any merger transaction expenses and to reimburse or pay the Sponsor or its affiliates for any outstanding Sponsor Promissory Notes or other obligations of ALCY to the Sponsor or its affiliates. Unless the parties obtain additional financing sufficient to repay the Sponsor Promissory Notes in cash at Closing, ALCY and the relevant holders will agree on an alternative form of compensation, which may include shares, on terms and conditions to be determined. ALCY currently estimates that the outstanding principal under the Sponsor promissory notes was $2,186,000 as of June 30, 2026. An affiliate of the Sponsor is receiving $10,000 monthly for administrative services in connection with the business combination. |
The retention of shares by the Sponsor and the reimbursements payable to the Sponsor at Closing will not result in a material dilution of the equity interests of non-redeeming ALCY stockholders. See “The Business Combination Proposal — Ownership of Pubco after the Closing.”
SUMMARY OF THE PROXY STATEMENT/PROSPECTUS
This summary highlights selected information from this proxy statement/prospectus, but does not contain all of the information that may be important to you. To better understand the Proposals to be considered at the extraordinary general meeting, including the Business Combination Proposal, whether or not you plan to attend such meeting, we urge you to read this proxy statement/prospectus (including the Annexes) carefully, including “Risk Factors.” See also “Where You Can Find More Information.”
ALCY was introduced to Cartiga on October 6, 2023, after which the parties began preliminary discussions and information exchange. ALCY delivered a non-binding letter of intent (“LOI”) to Cartiga on November 12, 2023; Cartiga countersigned on February 28, 2024 (the LOI was later restated and exclusivity extended). From March through July 2024, the parties and their advisors conducted detailed due diligence and structured the potential transaction, and on December 17, 2024, agreed on a $540 million equity valuation for Cartiga. In parallel, the parties selected an “Up-C” structure and discussed a minimum cash condition calibrated to about $40 million, to be satisfied through a PIPE and cash remaining in trust, given anticipated business needs and potential redemptions. An advanced draft of the Business Combination Agreement was agreed among counsel on March 27, 2025. ALCY’s board approved the Business Combination on August 19, 2025, and the parties executed the Business Combination Agreement dated August 22, 2025; the transaction was announced publicly on August 25, 2025. For more information, please see “Background to the Business Combination” in this section.
The ALCY Board did not obtain a third-party valuation or fairness opinion in connection with their determination to approve the Business Combination with Cartiga. The directors and officers of ALCY and ALCY’s advisors have substantial experience in evaluating the operating and financial merits of companies from a wide range of industries and concluded that their experience and backgrounds, together with the experience and sector expertise of ALCY’s financial advisors and consultants, enabled them to make the necessary analyses and determinations regarding the Business Combination with Cartiga. In addition, ALCY’s directors and officers and ALCY’s advisors have substantial experience with mergers and acquisitions. Accordingly, investors will be relying solely on the judgment of the ALCY Board and ALCY’s advisors in valuing Cartiga’s business.
Parties to the Business Combination
Alchemy Investments Acquisition Corp 1 (“ALCY”)
ALCY is a blank check company incorporated on October 27, 2021 as a Cayman Islands exempted company formed for the purpose of effecting a merger, share exchange, asset acquisition, share purchase, reorganization or similar business combination with one or more businesses.
ALCY Class A ordinary shares, ALCY Units and ALCY Warrants are currently trading on OTC under the symbols “ALCYF,” “ALCUF” and “ALCWF,” respectively.
The mailing address of ALCY’s principal executive office is 850 Library Avenue, Suite 204-F, Newark, Delaware. Its telephone number is (212) 877-1588. ALCY’s corporate website address is www.alchemyinvest.co. ALCY’s website and the information contained on, or that can be accessed through, the website is not deemed to be incorporated by reference in, and is not considered part of, this proxy statement/prospectus.
Alchemy Acquisition Holdings, Inc. (“Pubco”)
Alchemy Acquisition Holdings, Inc., a Delaware corporation, is a wholly-owned subsidiary of ALCY formed solely for the purpose of effecting the Domestication and the Business Combination. Pursuant to the Domestication, ALCY will merge with and into Alchemy Acquisition Holdings, Inc. with Pubco being the surviving entity. Alchemy Acquisition Holdings, Inc. was incorporated in Delaware on June 11, 2025. Alchemy Acquisition Holdings, Inc. owns no material assets and does not operate any business. The mailing address of Alchemy Acquisition Holdings, Inc.’s principal executive office is located at 850 Library Avenue, Suite 204-F, Newark, Delaware. Its telephone number is (212) 877-1588.
Newco
Alchemy Merger Sub, LLC, is a Delaware limited liability company and wholly-owned subsidiary of Pubco (“Newco”). Pursuant to the Merger, Newco will merge with and into Cartiga with Cartiga being the surviving entity and continuing as a controlled subsidiary of Pubco. Newco was formed in Delaware on June 11, 2025. Newco owns no material assets and does not operate any business.
Cartiga, LLC (“Cartiga”)
Cartiga is a Delaware limited liability company in the business of originating and managing assets linked to (or secured by) consumer and commercial litigation claims and related receivables.
Cartiga’s principal executive office is located at 400 Park Avenue, 12th Floor, New York, NY 10022 and its telephone number is 1-866-733-2416. Cartiga’s corporate website address is www.cartiga.com. Cartiga’s website and the information contained on, or that can be accessed through, the website is not deemed to be incorporated by reference in, and is not considered part of, this proxy statement/prospectus.
ALCY Board of Directors’ Reasons for the Approval of the Business Combination
The officers and directors of ALCY have substantial experience in evaluating the operating and financial merits of companies from a wide range of industries and concluded that their experience and background enabled such officers and directors of ALCY to make the necessary analyses and determinations regarding the Business Combination. After careful consideration of the terms and conditions of the Business Combination Agreement, the ALCY Board has determined that the Business Combination and the transactions contemplated thereby are fair to and in the best interests of ALCY and its shareholders because they believe that Cartiga is a company with strong revenue growth potential. It has been operating for some time and the ALCY Board believes that it has demonstrated a good return on investment capital for its client base. In reaching its decision with respect to the Business Combination and the transactions contemplated thereby, the ALCY Board also reviewed various industry and financial data and the due diligence and evaluation materials provided by Cartiga, demonstrating that Cartiga has a business plan dedicated to both near term cash flow and long term growth. For additional information regarding the positive and negative factors the ALCY Board considered in evaluating the Transactions, see the section entitled “The Business Combination Proposal — ALCY Board of Directors’ Reasons for the Approval of the Business Combination.”
The Proposals to be Submitted at the Extraordinary General Meeting
On August 22, 2025, ALCY (or “Parent”), entered into a business combination agreement (as it may be amended and/or restated from time to time, the “Business Combination Agreement”), by and among Alchemy Acquisition Holdings, Inc., a Delaware corporation and wholly-owned subsidiary of ALCY (“Pubco”), Alchemy Merger Sub, LLC, a Delaware limited liability company and wholly-owned subsidiary of Pubco (“Newco”), Cartiga, LLC, a Delaware limited liability company (the “Company”) and Halle Benett, as the representative (the “Sellers’ Representative”) of holders of the Company’s securities (the “Sellers”).
Proposal No. 1 — The Business Combination Proposal
As discussed in this proxy statement/prospectus, ALCY is asking its shareholders to approve by ordinary resolution and adopt the Business Combination Agreement, a copy of which is attached to this proxy statement/prospectus as Annex A. The Business Combination Agreement provides for, among other things, (a) ALCY will domesticate from the Cayman Islands to Delaware by merging with and into Pubco with Pubco surviving the merger and changing its name to Cartiga Holdings, Inc. (the “Domestication”), (b) after the Domestication, Newco will merge with and into the Company with the Company surviving the merger (hereinafter sometimes referred to as “OpCo”) and continue its existence under the Delaware Limited Liability Company Act (the “LLC Act”), and OpCo becoming a controlled subsidiary of Pubco (the “Merger”); and (c) the existing limited liability company agreement of OpCo will be amended and restated in the form attached to the Business Combination Agreement, to, among other things, make Pubco the sole managing member of OpCo. The Merger and the other transactions contemplated by the Business Combination Agreement are collectively referred to as the “Business Combination,” and as a result of the Business Combination, Pubco will be the publicly traded reporting company in an “Up-C” structure, with two classes of common stock, changing its name to “Cartiga Holdings, Inc.” and sometimes referred to herein as “New Cartiga.” In connection with the Domestication, (i) after giving effect to redemptions occurring in connection with the Business Combination, each ALCY Class A Ordinary Share will convert automatically, on a one-for-one basis, into one share of Class A common stock, par value $0.0001 per share, of Pubco (each a share of “Pubco Class A Common Stock”); (ii) each then issued and outstanding
ALCY Warrant will become exercisable for one share of Pubco Class A Common Stock (each a “Pubco Warrant”), pursuant to the Warrant Agreement, dated as of May 4, 2023, by and between ALCY and Continental Stock Transfer & Trust Company, as warrant agent, and (iii) each then issued and outstanding ALCY Unit shall separate and convert automatically into one share of Pubco Class A Common Stock, and one-half of one Pubco Warrant, the result being that every outstanding ALCY Class A Ordinary Share, ALCY Class B Ordinary Share, ALCY Preference Share, ALCY Unit and ALCY Warrant shall convert to an equal number of shares of Pubco Class A Common Stock, shares of Pubco Class B Common Stock, shares of Pubco Preferred Stock, Pubco Units and Pubco Warrants, respectively. For more information, see “The Domestication Merger Proposal.”
Following the Domestication of ALCY to the State of Delaware, Newco will merge with and into Cartiga, with Cartiga surviving the Merger in accordance with the terms and subject to the conditions of the Business Combination Agreement, as more fully described elsewhere in this proxy statement/prospectus. Following the Merger, the separate limited liability company existence of Newco shall cease, and Cartiga (the Company) shall continue as the OpCo. At the Effective Time, the existing limited liability company agreement of OpCo will be amended and restated in the form attached to the Business Combination Agreement to, among other things, make Pubco the sole managing member of OpCo. After consideration of the factors identified and discussed in “The Business Combination Proposal — ALCY Board of Directors’ Reasons for the Approval of the Business Combination,” the ALCY Board concluded that the Business Combination met the requirements disclosed in the prospectus related to the IPO. For more information about the transactions contemplated by the Business Combination Agreement, see “The Business Combination Proposal.”
Organizational Structure
On August 22, 2025, ALCY entered into the Business Combination Agreement with Cartiga, pursuant to which, among other things, subject to shareholder approval, following the Domestication, (a) Pubco will acquire equity securities and become the managing member of OpCo and (b) Pubco will issue voting equity securities without economic rights to the holders of the Company Equity Interests. Our organizational structure following the completion of the Business Combination, as described herein, is commonly referred to as an umbrella partnership-C corporation (or Up-C) structure. This organizational structure will allow the Cartiga holders of Company Equity Interests to retain their equity ownership in Cartiga, an entity that is classified as a partnership for U.S. federal income tax purposes, in the form of OpCo Units. Those investors who, prior to the Business Combination, held ALCY Class A Ordinary Shares or ALCY Class B Ordinary Shares will, by contrast, hold their equity ownership in Pubco, which is a domestic corporation for U.S. federal income tax purposes. ALCY believes that the holders of the Company Equity Interests will generally find it advantageous to continue to hold their equity interests in an entity that is not taxable as a corporation for U.S. federal income tax purposes. ALCY does not believe that the Up-C organizational structure will give rise to any significant business or strategic detriment to ALCY. Cartiga expects to benefit from the Up-C structure in the form of generally retaining 15% of the cash tax savings derived from certain tax benefits that are the subject of the Tax Receivable Agreement that Pubco may realize in connection with and after the Business Combination. See the section entitled “Risk Factors — Risks Related to the Domestication and the Business Combination” of this proxy statement/prospectus.
Pubco’s structure following the Business Combination, as described under the subsection entitled “The Business Combination Proposal — The Business Combination Agreement — Structure of the Merger” is commonly referred to as an “Up-C” structure, which is often used by partnerships and limited liability companies when they undertake an initial public offering either directly or through a business combination with a special purpose acquisition company, such as ALCY.
In connection with the Closing, the combined company will be organized in an “Up-C” structure and the only direct assets of Pubco will consist of equity interests in OpCo. The Up-C structure allows the Cartiga Members, to retain a portion of their equity ownership in Cartiga, an entity that is classified as a partnership for U.S. federal income tax purposes, in the form of post-merger units of OpCo. Immediately following the Closing, Pubco will be the sole manager of and control OpCo, and Pubco will own between approximately [·]% and [·]% of the outstanding equity of OpCo through OpCo Units, and the Cartiga Members will own between approximately [·]% and [·]% of the outstanding equity of OpCo through OpCo Units.
Each share of Pubco Class B Common Stock has no economic rights but entitles its holder to one vote on all matters to be voted on by stockholders generally. Holders of shares of Pubco Class A Common Stock and shares of Pubco Class B Common Stock will vote together as a single class on all matters presented to our stockholders for their vote or approval, except as otherwise required by applicable law or by the Proposed Charter. We do not intend to list any shares of Pubco Class B Common Stock on any exchange.
Following the Closing, under the OpCo LLCA, any Cartiga Member who receives OpCo Units and Pubco Class B Common Stock in the Business Combination will, subject to certain timing procedures and other conditions set forth therein, have the right (the “OpCo Holder Redemption Right”) to exchange all or a portion of its OpCo Units, together with an equal number of shares of Pubco Class B Common Stock for shares of Pubco Class A Common Stock at an exchange ratio of one share of Pubco Class A Common Stock for each OpCo Unit exchanged, subject to conversion rate adjustments for stock splits, stock dividends and reclassifications and other similar transactions.
In connection with any exchange of OpCo Units pursuant to the OpCo Holder Redemption Right, Pubco shall receive a number of OpCo Units equal to the number of shares of Pubco Class A Common Stock issued to the OpCo unitholder, and a corresponding number of shares of Pubco Class B Common Stock held by the relevant OpCo unitholder will be cancelled. As the OpCo Units are exchanged, holding other assumptions constant, Pubco’s ownership stake in OpCo will be correspondingly increased, the number of shares of Pubco Class A Common Stock outstanding will be increased and the number of shares of Pubco Class B Common Stock will be decreased. See “The Business Combination Proposal — Additional Agreements to be Executed at Closing — Second Amended and Restated Limited Liability Company Agreement.”
In connection with the Business Combination, Pubco, OpCo and the TRA Holders will enter into the Tax Receivable Agreement (“TRA”), pursuant to which, among other things, Pubco will be required to pay to each holder of Company Equity Interests 85% of the amount of cash tax savings, if any, that Pubco actually realizes (or in some circumstances is deemed to realize) as a result of the Basis Adjustments and Imputed Interest (as defined in the TRA). For more information on the Tax Receivable Agreement, please see the section entitled “The Business Combination Proposal — Additional Agreements to be Executed at Closing — Tax Receivable Agreement” of this proxy statement/prospectus. Prior to and as a condition of the Closing, pursuant to the Domestication, ALCY will change its jurisdiction of incorporation to Delaware by merging with and into Pubco, a Delaware corporation, with Pubco surviving, in accordance with Section 252 of the DGCL and Part XVI of the Companies Act. For more information, see the section of this proxy statement/prospectus entitled “The Domestication Merger Proposal.”
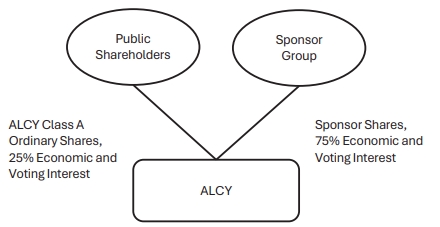
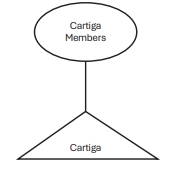
The following diagrams illustrate in simplified terms the current structure of ALCY and Cartiga and the expected structure of Pubco immediately following the Closing (ownership voting and economic percentages are presented assuming full Redemptions and 3,413,000 shares of Pubco Class A Common Stock after the conversion of the outstanding Class B Ordinary Shares held by the Sponsor, and excluding the 5,750,000 shares of Pubco Class A Common Stock issuable upon exercise of 5,750,000 whole Pubco Warrants).
Simplified Pre-Combination Structure
ALCY | | Cartiga LLC |
|
|
Simplified Post-Combination Structure(1)
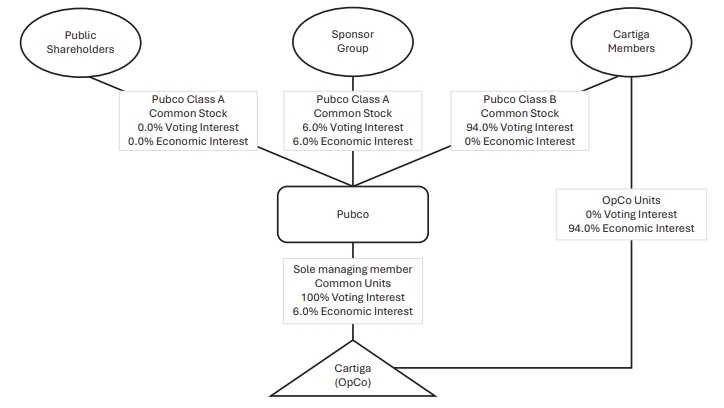
(1) | Assumes maximum redemptions by the public shareholders |
Consideration
Under the Business Combination Agreement, Pubco has agreed to pay the Aggregate Merger Consideration, which is the number of OpCo Units and newly issued shares of Pubco Class B Common Stock equal to (i) the Base Purchase Price of $540,000,000 divided by (ii) $10.00 in exchange for all of the limited liability equity interests (the Company Equity Interests) of the Company.
Each holder of Company Equity Interests, immediately prior to closing, will receive an amount of the Aggregate Merger Consideration equal to the quotient of (a) $540,000,000 divided by (b) the product of $10.00 multiplied by the quotient of (i) the number of Company Equity Interests owned by each Seller as of the Closing, divided by (ii) the total number of issued and outstanding Company Equity Interests as of the Closing.
ALCY shall complete the Domestication prior to the Effective Time. At the Effective Time, by virtue of the Merger and without any further action on the part of any party to the Business Combination Agreement or otherwise, each Company Equity Interest issued and outstanding immediately prior to the Effective Time shall be canceled and automatically converted into each Seller’s right to receive their respective Merger Consideration. As of the Effective Time, all Company Equity Interests shall thereafter cease to have any rights with respect thereto, except the right to receive the foregoing consideration. The units of equity interests of Newco that are issued and outstanding immediately prior to the Effective Time will, by virtue of the Merger and without further action on the part of ALCY, be converted into an aggregate number of OpCo Units equal to the number of shares of Pubco Class A Common Stock and Pubco Class B Common Stock issued and outstanding immediately prior to the Effective Time. Each share of the Pubco Class B Common Stock that is issued and outstanding immediately prior to the Effective Time shall be automatically converted into one (1) share of Pubco Class A Common Stock. At the Effective Time, newly issued Pubco Class B Common Stock will be issued to the Cartiga Members as part of the Merger Consideration described above. No certificates or scrip representing fractional ALCY Ordinary Shares will be issued pursuant to the Business Combination.
Post-Closing Board of Directors and Executive Officers
Immediately following the closing, New Cartiga’s board of directors will consist of no more than seven (7) directors, of which the Company has the right to designate six (6) directors and the Sponsor has the right to designate one (1) director. At the Closing, all of the respective officers of ALCY and Pubco shall resign and the following individuals, which may be the same officers as those of the Company, are expected to be appointed as the officers of New Cartiga: Samuel Wathen, President and Chief Executive Officer; Gregory Bleier, Executive Vice President, Chief Financial Officer; and Ryan Melcher, Executive Vice President, General Counsel & Corporate Secretary.
Under the Shareholders Agreement, Melodeon and ASRS are granted rights to nominate directors to Pubco’s board based on their respective ownership levels. Melodeon may nominate up to three directors, with thresholds at 60%, 40%, and 15% ownership. ASRS may nominate up to two directors, with thresholds at 50% and 25% ownership. If Melodeon and ASRS collectively own at least 75% of Pubco’s outstanding shares, they may jointly nominate one independent director. ASRS is also entitled to representation on board committees, subject to applicable independence and listing standards. For so long as ASRS beneficially owns at least 25% of Pubco’s outstanding shares, certain corporate actions require the approval of ASRS-nominated directors. See “The Business Combination Proposal — Additional Agreements to be Executed at Closing — Shareholders Agreement” for more information.
Registration Statement and Shareholder Approval
ALCY will prepare and file with the SEC a Registration Statement on Form S-4, that will include a preliminary proxy statement/prospectus, and when available, a definitive proxy statement and final prospectus, and call an extraordinary general meeting of the holders of ALCY Ordinary Shares to vote at the meeting (the “Extraordinary Meeting”). The approval of the post-Closing organizational documents and the Domestication require a special resolution under Cayman Islands law, being the affirmative vote of a majority of not less than two-thirds of the votes cast by the ALCY Ordinary Shares, represented in person or by proxy and entitled to vote thereon at the extraordinary general meeting. The affirmative vote of a simple majority of the votes cast by holders of ALCY Ordinary Shares, represented in person or by proxy and entitled to vote thereon at the Extraordinary Meeting is required to approve the Business Combination Agreement, the Business Combination and certain other actions related thereto as provided in the Companies Act, the Current M&A and applicable listing rules of The Nasdaq Stock Market LLC (“Nasdaq”).
Representations and Warranties; Covenants
ALCY, Pubco (or New Cartiga), Newco and the Company have made customary representations, warranties and covenants in the Business Combination Agreement, including, among other things, covenants with respect to the conduct of the business of ALCY and the Company prior to the closing of the Business Combination. The parties have also agreed to customary “no shop” obligations. The representations and warranties of ALCY, Pubco, Newco and the Company will not survive the closing of the Merger.
Closing Conditions
The Closing of the Business Combination is subject to certain customary conditions of the respective parties, including, among other things, that: (a) the applicable ALCY shareholder and the Company’s member approvals shall have been obtained; (b) there shall have been no Company Material Adverse Effect or Buyer Material Adverse Effect (each as defined in the Business Combination Agreement) since the date of the Business Combination Agreement; (c) the waiting period (or any extension thereof) applicable under the Hart-Scott-Rodino Antitrust Improvements Act of 1976 shall have expired or terminated; (d) the Available Closing Buyer Cash (as defined in the Business Combination Agreement) shall not be less than $40,000,000 (which condition was irrevocably waived in full by Cartiga on October 22, 2026 pursuant to the Waiver); (e) Pubco’s initial listing application in connection with the Transactions (as defined in the Business Combination Agreement) shall have been approved by Nasdaq so that immediately following the Merger, New Cartiga satisfies all applicable initial listing requirements of Nasdaq; and (f) each of the parties to the Additional Agreements shall have delivered, or caused to be delivered, duly executed copies of the Ancillary Agreements. “Ancillary Agreements” means the Support and Non-Redemption Agreement, the Support Agreement, the A&R Registration Rights Agreement, the Lock-up Agreements, the OpCo LLCA, the Shareholders Agreement, the Tax Receivable Agreement and the Exchange Agreement (each as defined below).
Because Cartiga waived the Minimum Cash Condition on October 22, 2026, if, at closing, the Available Closing Buyer Cash is less than $40,000,000, the Sponsor will be required to forfeit a portion of its shares in the combined company. The number of shares retained by the Sponsor will be determined according to a tiered schedule based on the actual Available Closing Buyer Cash at closing, with the Sponsor retaining fewer shares as the closing cash decreases. For example, if Available Closing Buyer Cash is at least $35,000,000 but less than $40,000,000, the Sponsor will maintain 3,198,875 shares; if less than $5,000,000, the Sponsor will maintain 1,700,000 shares.
Termination
The Business Combination Agreement may be terminated by Pubco or the Company under certain circumstances, including, among others: (a) by mutual written consent of Pubco and the Company; (b) by either Pubco or the Company if the closing of the Business Combination has not occurred on or before May 1, 2026; (c) by either Pubco or the Company if any Governmental Authority (as defined in the Business Combination Agreement) in the United States shall have enacted, issued, promulgated, enforced or entered any injunction, order, decree or ruling (whether temporary, preliminary or permanent) which has become final and nonappealable and has the effect of making consummation of the Transactions, including the Merger, illegal or otherwise preventing or prohibiting consummation of the Transactions, the Merger; (d) by Pubco if the Company shall have failed to obtain the necessary member approvals; (e) by the Company if ALCY shall have failed to obtain the necessary shareholder approval within forty-five (45) days after the Registration Statement becomes effective; (f) by Pubco upon a breach of any representation, warranty, covenant or agreement on the part of the Company set forth in the Business Combination Agreement, or if any representation or warranty of the Company shall have become untrue; provided that Pubco has not waived a Terminating Company Breach (as defined in the Business Combination Agreement) and ALCY, Pubco and Newco are not then in material breach of their representations, warranties, covenants or agreements in the Business Combination Agreement; provided, further, that if such Terminating Company Breach is curable by the Company, Pubco may not terminate the Business Combination Agreement so long as the Company continues to exercise its reasonable efforts to cure such breach, unless such breach is not cured within thirty (30) days after notice of such breach is provided by Pubco to the Company; (g) by the Company upon a breach of any representation, warranty, covenant or agreement on the part of ALCY, Pubco or Newco set forth in the Business Combination Agreement, or if any representation or warranty of ALCY, Pubco or Newco shall have become untrue; provided that the Company has not waived a Terminating Buyer Breach (as defined in the Business Combination Agreement) and the Company is not then in material breach of its representations, warranties, covenants or agreements; provided, further, that, if such Terminating Buyer Breach is curable by ALCY, Pubco and Newco, the Company may not terminate the Business Combination Agreement for so long as ALCY, Pubco and Newco continue to exercise their reasonable efforts to cure such breach, unless such breach is not cured within thirty (30) days after notice of such breach is provided by the Company to Pubco; (h) by the Company if the Closing has not occurred on or before the 45th day after the date on which Registration Statement is declared effective and the Available Closing Buyer Cash condition has not been met; or (i) by the Company, if prior to the receipt of the Company Member Approval, the Company Board authorizes the Company, to the extent permitted by and subject to compliance with the terms of the Business Combination Agreement, to enter into a definitive agreement in connection with a Superior Offer; provided, that the Company shall have paid any required termination fee; and provided further, that in the event of such termination, the Company substantially concurrently enters into such definitive agreement in connection with such Superior Offer.
The Business Combination Agreement and the foregoing summary thereof has been included in this proxy statement/prospectus to provide investors and shareholders with information regarding its terms. It is not intended to provide any other factual information about ALCY, Pubco, Newco and the Company or any of their respective subsidiaries or affiliates. The representations, warranties and covenants contained in the Business Combination Agreement were made only for purposes of that agreement and as of specific dates, were solely for the benefit of the parties to the Business Combination Agreement, may be subject to limitations agreed upon by the contracting parties, including being qualified by disclosures not reflected in the Business Combination Agreement, were made for the purpose of allocating contractual risk between the parties to the Business Combination Agreement instead of establishing matters as facts, and may be subject to standards of materiality applicable to the contracting parties that differ from those applicable to investors or shareholders and reports and documents filed with the SEC. Investors and shareholders are not third party beneficiaries under the Business Combination Agreement and should not rely on the representations, warranties and covenants or any descriptions thereof as characterizations of the actual state of facts or condition of ALCY, Pubco, Newco, or the Company or any of their respective subsidiaries or affiliates. Moreover, information concerning the subject matter of the representations and warranties may change after the date of the Business Combination Agreement, which subsequent information may or may not be fully reflected in ALCY’s public disclosures.
Additional Agreements Executed at the Signing of the Business Combination Agreement
Support and Non-Redemption Agreement
In connection with the Business Combination Agreement, ALCY, Pubco, certain shareholders of ALCY (“ALCY Securityholders”), the Company and the directors and officers of ALCY entered into a support and non-redemption agreement (the “Support and Non-Redemption Agreement”) providing that, among other things, (a) ALCY Securityholders and the respective directors and officers of each of ALCY and Pubco will vote their equity securities of ALCY in favor of the Parent Proposals (as defined in the Business Combination Agreement), (b) ALCY Securityholders will not exercise their Redemption Rights (as defined in the Business Combination Agreement) and (c) ALCY Securityholders will waive any adjustment to the conversion ratio set forth in the Parent Organizational Documents (as defined in the Business Combination Agreement).
Support Agreement
ALCY, Pubco, the Company, and certain equity holders of the Company (the “Company Securityholders”) entered into a support agreement (the “Support Agreement”) providing that, among other things, such Company Securityholders will vote their equity securities of the Company in favor of the transactions contemplated by the Business Combination Agreement and the Merger.
Lock-up Agreements
ALCY, Pubco, the Company, and the Sellers entered into Lock-up Agreements (the “Lock-up Agreements”) pursuant to which the Pubco Class B Common Stock and OpCo Units included in the Merger Consideration, as well as any Pubco Class A Common Stock exchanged therefor pursuant to the Exchange Agreement (as defined below) they may hold (together referred to as the “Lock-Up Shares”), shall be subject to a lock-up period commencing on the Closing Date and ending on the earlier of (a) the date that is six (6) months after the Closing Date and (b) the date following the Closing Date on which ALCY completes a liquidation, merger, share exchange or other similar transaction that results in all of ALCY’s shareholders having the right to exchange their shares of common stock for cash, securities or other property; provided, however, that the Lock-up Shares will be released from the lock-up if, subsequent to Closing Date, the closing price of Pubco Class A Common Stock equals or exceeds $12.00 per share (as adjusted for share splits, share dividends, reorganizations, recapitalizations and the like) for any 20 trading days within any 30-trading day period commencing at least 150 days after the Closing Date.
Additional Agreements to be Executed at Closing
The Business Combination Agreement provides that, upon consummation of the Business Combination (the “Closing”), New Cartiga will enter into the following additional agreements.
Amended and Restated Registration Rights Agreement
In connection with the Closing, ALCY, Pubco (and subsequent to the Business Combination, New Cartiga), the Company, certain shareholders of ALCY (“ALCY Holders”), and certain members of the Company (together with ALCY Holders, the “Holders”) will enter into that certain Amended and Restated Registration Rights Agreement (the “A&R Registration Rights Agreement”) pursuant to which, Pubco will agree to file, within thirty (30) calendar days after the consummation of the Business Combination, a shelf registration statement registering the resale of New Cartiga equity held by the Holders, and will grant to the Holders certain registration rights, including customary piggyback registration rights and demand registration rights, which are subject to customary terms and conditions, including with respect to cooperation and reduction of underwritten shelf takedown provisions (subject to certain lock-up restrictions referenced therein, including those documented in the Lock-up Agreements (as defined below)).
Tax Receivable Agreement
In connection with the Business Combination, Pubco will enter into a Tax Receivable Agreement (the TRA) with certain Cartiga Members (the “TRA Holders”). OpCo intends to have in effect an election under Section 754 of the Code for each taxable year in which sales and exchanges of OpCo Units in connection with or following the Business Combination (“TRA Exchanges”) occur, which is expected to result in adjustments to the tax basis of the assets of OpCo as a result of such TRA Exchanges. The TRA generally provides for the payment by Pubco to the TRA Holders of 85% of the cash tax benefits, if any, that Pubco realizes (or in certain cases is deemed to realize), calculated using certain simplifying assumptions as a result of (i) tax basis adjustments resulting from TRA Exchanges and (ii) certain other tax benefits related to entering into the TRA, including tax benefits attributable to making payments under the TRA. These current and potential future tax basis adjustments are expected to increase (for tax purposes) the depreciation and amortization deductions available to Pubco and, therefore, may reduce the amount of U.S. federal, state and local tax that Pubco would otherwise be required to pay in the future. The tax basis adjustments upon TRA Exchanges may also decrease gains (or increase losses) on future dispositions of certain assets to the extent tax basis is allocated to those assets. Actual tax benefits realized by Pubco may differ from tax benefits calculated under the TRA as a result of the use of certain assumptions in the TRA, including the use of an assumed state and local income tax rate to calculate tax benefits. The payment obligation under the TRA is an obligation of Pubco and not of OpCo. Pubco will generally retain the benefit of the remaining 15% of these cash tax benefits.
We expect that the payments Pubco will be required to make under the TRA could be substantial. Estimating the amount and timing of Pubco’s realization of tax benefits subject to the TRA is by its nature imprecise. The actual increases in tax basis covered by the TRA, as well as the amount and timing of Pubco’s ability to use any deductions (or decreases in gain or increases in loss) arising from such increases in tax basis, are dependent upon significant future events, including but not limited to the timing of the redemptions of OpCo Units, the price of the Pubco Class A Common Stock at the time of a TRA Exchange, the extent to which such redemptions are taxable transactions, the depreciation and amortization periods that apply to the increase in tax basis, the amount, character, and timing of taxable income Pubco generates in the future, the U.S. federal income tax rate then applicable, and the portion of Pubco’s payments under the TRA that constitute imputed interest or give rise to depreciable or amortizable tax basis. Accordingly, estimating the amount and timing of payments that may become due under the TRA is also by its nature imprecise. For purposes of the TRA, net cash savings in tax generally will be calculated by comparing Pubco’s actual tax liability (determined by using the actual applicable U.S. federal income tax rate and an assumed combined state and local income tax rate) to the amount Pubco would have been required to pay had it not been able to utilize any of the tax benefits subject to the TRA. Thus, the amount and timing of any payments under the TRA are also dependent upon significant future events, including those noted above in respect of estimating the amount and timing of Pubco’s realization of tax benefits.
Payments under the TRA will be based on the tax reporting positions Pubco determines, and the Internal Revenue Service (the “IRS”) or another tax authority may challenge all or a part of the existing tax basis, tax basis increases, or other tax attributes subject to the TRA, and a court could sustain such challenge. The parties to the TRA will not reimburse Pubco for any payments previously made if such tax basis or other tax benefits are subsequently disallowed, except that any excess payments made to a party under the TRA will be netted against future payments otherwise to be made under the TRA, if any, after the determination of such excess.
In addition, the TRA provides that if (1) Pubco breaches any of its material obligations under the TRA (including in the event that Pubco is more than three months late making a payment that is due under the TRA, subject to certain exceptions), (2) Pubco is subject to certain bankruptcy, insolvency or similar proceedings, or (3) at any time, Pubco elects an early termination of the TRA, Pubco’s obligations under the TRA (with respect to all OpCo Units, whether or not such OpCo Units have been the subject of a TRA Exchange before or after such transaction) would accelerate and become payable in a lump sum amount equal to the present value of the anticipated future tax benefits calculated based on certain assumptions, including that Pubco would have sufficient taxable income to fully utilize the deductions arising from the tax deductions, tax basis and other tax attributes subject to the TRA.
The TRA also provides that, upon certain changes of control or other significant transactions, in the discretion of each TRA Party, Pubco’s obligations under the TRA may be accelerated and become payable in a lump sum as described above. Such acceleration would be based on certain assumptions, including that Pubco or its successor would have sufficient taxable income to fully utilize the increased tax deductions and tax basis and other benefits covered by the TRA. As a result, upon any acceleration of Pubco’s obligations under the TRA (including upon a change of control), Pubco could be required to make payments under the TRA that are greater than 85% of its actual cash tax savings, which could negatively impact its liquidity. The change of control provisions in the TRA may also result in situations where the TRA Parties have interests that differ from or are in addition to those of other holders of Pubco Class A Common Stock.
Finally, because Pubco is a holding company with no operations of its own, its ability to make payments under the TRA depends on the ability of OpCo to make distributions to it. To the extent that Pubco is unable to make payments under the TRA for any reason, such payments will be deferred and will accrue interest until paid, which could negatively impact Pubco’s results of operations and could also affect its liquidity in periods in which such payments are made.
The foregoing description of the TRA is not complete and is qualified in its entirety by reference to the TRA, which is attached as Annex I to this proxy statement/prospectus.
Exchange Agreement
In connection with the Business Combination, Pubco, OpCo and certain Cartiga Members will enter into an Exchange Agreement (the “Exchange Agreement”). Pursuant to the Exchange Agreement, such Cartiga Members will have the right from time to time, on the terms and conditions contained in the Exchange Agreement, to exchange their OpCo Units and Pubco Class B Common Stock for, at the option of Pubco, shares of Pubco Class A Common Stock or cash.
For additional information about each of these agreements, see “The Business Combination Proposal — Additional Agreements to be Executed at Closing.”
Second Amended and Restated Limited Liability Company Agreement
In connection with the Business Combination, Cartiga will amend and restate its limited liability company agreement by adopting the Second A&R Operating Agreement (the “OpCo LLCA”) in substantially the form attached as an exhibit hereto. The OpCo LLCA will (i) permit the issuance and ownership of the post-Recapitalization equity of Cartiga as contemplated by the Business Combination Agreement and (ii) admit Pubco as the managing member of Cartiga. Melodeon Arizona LBS Fund LP will control Pubco immediately after the Closing by virtue of its ownership of Pubco Class B Common Stock.
Shareholders Agreement
In connection with the Business Combination, Pubco, the Company, Melodeon LBS GP, LLC (“Melodeon”) and its affiliated funds, and the Arizona State Retirement System (“ASRS”) will enter into a Shareholders Agreement (the “Shareholders Agreement”). The Shareholders Agreement sets forth the governance and consent rights of Melodeon and ASRS, as well as restrictions on share transfers and other shareholder obligations.
Under the Shareholders Agreement, Melodeon and ASRS are granted rights to nominate directors to Pubco’s board based on their respective ownership levels. Melodeon may nominate up to three directors, with thresholds at 60%, 40%, and 15% ownership. ASRS may nominate up to two directors, with thresholds at 50% and 25% ownership. If Melodeon and ASRS collectively own at least 75% of Pubco’s outstanding shares, they may jointly nominate one independent director. ASRS is also entitled to representation on board committees, subject to applicable independence and listing standards.
For so long as ASRS beneficially owns at least 25% of Pubco’s outstanding shares, certain corporate actions require the approval of ASRS-nominated directors. These include acquisitions or joint ventures exceeding 9.9% of Pubco’s net asset value, the first underwritten public offering, a sale of Pubco, material divestitures or asset sales exceeding 9.9% of net asset value, certain securities issuances and revenue-sharing agreements, borrowings resulting in a debt-to-equity ratio exceeding 3.5:1, initiation of bankruptcy proceedings, certain tax elections and audit settlements, non-pro rata shareholder distributions, changes to Pubco’s business lines, and increases to the share limits under Pubco’s incentive plan.
Transfers of Pubco shares to affiliates are permitted only if the transferee agrees to be bound by the Shareholders Agreement and becomes a party thereto. The Shareholders Agreement also provides for indemnification by Pubco of the stockholders party thereto, and their affiliates, for liabilities arising from their control or influence over Pubco or actions of their board designees, subject to customary exceptions. The Shareholders Agreement will terminate when neither Melodeon nor ASRS retains board nomination rights under its terms.
The Closing was conditioned upon ALCY satisfying the Minimum Cash Condition, which was waived on October 22, 2026, in order not to limit the ability to raise capital in a private placement financing (the PIPE). The Business Combination Agreement provided that the parties would use commercially reasonable efforts in connection with facilitating any necessary financing transactions required to meet the Minimum Cash Condition, which is waived in order to raise a lesser amount in accordance with current market conditions. These efforts are expected to include the pursuit of debt arrangements with certain investors (the “PIPE Investors”) for the issuance of debt securities with an aggregate principal amount of up to $40 million (the “Proposed PIPE Investments”). Because the minimum cash condition was waived, the business combination closing is not contingent on a PIPE financing. The No Additional Redemptions Scenario and the Maximum Redemptions Scenario reflect no PIPE Investments. It is anticipated that the Combined Entity will incur this indebtedness after the closing of the transaction when market conditions permit.
PIPE Financing
Cartiga and ALCY may obtain financing in connection with the Business Combination. As of the date of this proxy statement/prospectus, Cartiga and ALCY do not have any commitments for such financing nor have the parties entered into any agreements in connection with any financing. Upon completion of the financing, if any, Cartiga and ALCY intend to use the proceeds of the financing for (i) payment of Cartiga, ALCY and Sponsor’s expenses associated with the completion of the Business Combination and (ii) as working capital purposes for Pubco. In connection with any financing, Cartiga and/or ALCY may issue equity securities which may have a dilutive effect on the non-redeeming shareholders of ALCY.
Our Sponsor — Alchemy DeepTech Capital LLC
Our sponsor is Alchemy DeepTech Capital LLC (the “Sponsor”). Our promoters are the Sponsor and our directors and executive officers, several of whom are members of the Sponsor. Our directors and executive officers are: Steven M. Wasserman (Non-Executive Chairman), Mattia Tomba (Co-CEO & Director), Vittorio Savoia (Co-CEO & Director), Harshana Sidath Jayaweera (CFO), and independent directors Debbie S. Zoldan, Pablo Terpolilli, Carlo Tursi and Jinal Kumar Bipin Shah.
Given the management teams overlap between the Sponsor and ALCY, the Sponsor plays a material role in directing, supporting, and managing ALCY’s activities throughout its lifecycle, including its formation, operation, and the pursuit of a business combination. The Sponsor’s roles and responsibilities include:
| ● | Operational and administrative support: providing office space and secretarial and administrative and support services to ALCY. |
| ● | Capital contributions and financing: the Sponsor is responsible for providing the initial capital to fund ALCY’s formation and operational expenses. The Sponsor may also contribute additional funds via loans to cover ALCY’s on-going expenses associated with the business combination process. |
| ● | Day-to-day management: given the overlap between the Sponsor’s and ALCY’s management team, the Sponsor’s personnel actively support ALCY’s corporate governance, maintaining compliance, business combination transaction identification and execution. |
The Sponsor has no ongoing business and was established solely to provide risk capital to ALCY.
Furthermore, the Sponsor and our management have the following roles and responsibilities in connection with the Business Combination:
| ● | Source, evaluate and negotiate targets. Following the IPO, the management team led the search process (contacting ~35 potential targets and evaluating ~20), conducted diligence, and negotiated transaction terms, including the Business Combination with Cartiga. |
| ● | Control and voting commitments. As of the date of this proxy statement/prospectus, insiders (including the Sponsor) own the majority of ALCY outstanding ordinary shares and have agreed to vote in favor of the Business Combination and to waive redemption with respect to their shares. |
| ● | Post-closing governance. Under the Business Combination Agreement, the Sponsor has the right to designate one independent director to Pubco’s board (reasonably acceptable to Cartiga). |
| ● | Set forth below is a summary of the terms and amount of the compensation received or to be received by the Sponsor and its affiliates in connection with the Business Combination or any related financing transaction, the amount of securities issued or to be issued by ALCY to the Sponsor and its affiliates and the price paid or to be paid for such securities or any related financing transaction. |
| Interest in Securities | | Other Compensation | |
Sponsor | Alchemy DeepTech Capital LLC, the Sponsor, and its affiliates paid $50,000, or approximately $0.02 per share, for its 2,875,000 founder shares purchased in connection with ALCY’s formation, and 538,000 Class A ordinary shares purchased for $10.00 per share in a private placement that closed at the time of the IPO. At Closing of the Business Combination, the Sponsor shall hold a total of up to 3,413,000 shares of the Pubco Class A Common Stock depending on how much is raised in the PIPE financing. If Available Closing Buyer Cash is less than $5,000,000, then, as a result of Cartiga’s waiver of the Minimum Cash Condition on October 22, 2026, and pursuant to Section 8.17 of the Business Combination Agreement, the Sponsor shall forfeit 1,713,000 of its shares and hold a minimum of 1,700,000 shares of Pubco Class A Common Stock. | At Closing, pursuant to the Business Combination Agreement, Pubco will use cash from the Trust Account to pay any merger transaction expenses and to reimburse or pay the Sponsor or its affiliates for any outstanding Sponsor Promissory Notes, Working Capital Loans or other obligations of ALCY to the Sponsor or its affiliates. Unless the parties obtain additional financing sufficient to repay the Sponsor Promissory Notes in cash at Closing, ALCY and the relevant holders will agree on an alternative form of compensation, which may include shares, on terms and conditions to be determined. ALCY currently estimates that the outstanding principal under the Sponsor promissory notes was $2,186,000 as of June 30, 2026, excluding $263,006 of accrued interest and $95,183 of accrued related party expenses. $10,000 per month since the closing of the IPO for administrative services |
| ● | The retention of shares by the Sponsor and the reimbursements payable to the Sponsor at Closing will not result in a material dilution of the equity interests of non-redeeming ALCY stockholders. See “The Business Combination Proposal — Ownership of Pubco after the Closing.” |
Pursuant to a letter agreement dated May 4, 2023, our sponsor, directors and officers agreed to restrictions on their ability to transfer, assign, or sell the founder shares and private placement shares (and the underlying securities), as summarized in the table below.
Subject Securities | | Expiration Date | | Persons Subject to | | Exceptions to Transfer |
Founder Shares | Earlier to occur of (A) one year after the completion of our initial business combination and (B) subsequent to our initial business combination, (x) if the last sale price of our Class A ordinary shares equals or exceeds $12.00 per share (as adjusted for share sub-divisions, share dividends, reorganizations, recapitalizations and the like) for any 20 trading days within any 30-trading day period commencing at least 150 days after our initial business combination, or (y) the date on which we complete a liquidation, merger, share exchange, reorganization or other similar transaction that results in all of our shareholders having the right to exchange their ordinary shares for cash, securities or other property after the completion of our initial business combination | Alchemy DeepTech Capital LLC | Transfers are permitted (a) to the Company’s officers or directors, any affiliate or family member of any of the Company’s officers or directors, any members or partners of the Sponsor or any affiliates of such members and funds and accounts advised by such members, any affiliates of the Sponsor, or any employees of such affiliates; (b) in the case of an individual, by gift to a member of one of the individual’s immediate family, any estate planning vehicle or to a trust, the beneficiary of which is a member of the individual’s immediate family, an affiliate of such person or to a charitable organization; (c) in the case of an individual, by virtue of laws of descent and distribution upon death of the individual; (d) in the case of an individual, pursuant to a qualified domestic relations order; (e) by private sales or transfers made in connection with the consummation of a Business Combination at prices no greater than the price at which the Founder Shares or Private Placement Shares, as applicable, were originally purchased; (f) pro rata distributions from the Sponsor to its members, partners, or stockholders pursuant to the Sponsor’s operating agreement; (g) by virtue of the laws of the Cayman Islands or the Sponsor’s organizational documents upon liquidation or dissolution of the Sponsor; (h) to the Company for no value for cancellation in connection with the consummation of an initial Business Combination, (i) in the event of the Company’s liquidation prior to the completion of a Business Combination; or (j) in the event of completion of a liquidation, merger, share exchange or other similar transaction which results in all of the Company’s Public Shareholders having the right to exchange their Ordinary Shares for cash, securities or other property subsequent to the completion of an initial Business Combination; provided, however, that in the case of clauses (a) through (g) these permitted transferees must enter into a written agreement agreeing to be bound by these transfer restrictions. |
Subject Securities | | Expiration Date | | Persons Subject to | | Exceptions to Transfer |
Private Placement Shares | until 30 days after the completion of an initial Business Combination | Alchemy DeepTech Capital LLC | Same as above | |||
Working Capital Shares | until 30 days after the completion of an initial Business Combination |
Proposal No. 2 — The Domestication Merger Proposal
Immediately prior to the Domestication, pursuant to the Current M&A, each ALCY Class B Ordinary Share then issued and outstanding will automatically convert into one ALCY Class A Ordinary Share. Immediately following such conversion, in connection with the Domestication, (a) each ALCY Class A Ordinary Share issued and outstanding immediately prior to the Domestication will automatically convert into one share of Pubco Class A Common Stock, (b) each ALCY Warrant will be automatically converted into a Pubco Warrant on the same terms as the ALCY Warrants, and (c) each ALCY Unit issued and outstanding as of immediately prior to the Domestication will automatically be canceled and each holder thereof will receive one share of Pubco Class A Common Stock and one-half of one Pubco Warrant, per ALCY Unit. No fractional Pubco Warrants will be issued in the process described in clause (c).
If the Business Combination Proposal is approved, then ALCY will ask the holders of ALCY Ordinary Shares to approve by a special resolution, the Domestication Merger Proposal. As a condition to closing the Business Combination pursuant to the terms of the Business Combination Agreement, the ALCY Board has unanimously approved the Domestication Merger Proposal. The Domestication Merger Proposal, if approved, will authorize a change of ALCY’s jurisdiction of incorporation from the Cayman Islands to the State of Delaware. Accordingly, while ALCY is currently governed by the Companies Act, upon the Domestication, Pubco will be governed by the DGCL. There are differences between Cayman Islands corporate law and Delaware corporate law as well as between the Current M&A and the Proposed Organizational Documents. Accordingly, ALCY encourages shareholders to carefully review the information in “Comparison of Corporate Governance and Shareholder Rights.”
For additional information, see “The Domestication Merger Proposal.”
Proposal No. 3 — The Stock Issuance Proposal
If each of the Business Combination Proposal, and the Domestication Merger Proposal are approved, ALCY’s shareholders are also being asked to approve by ordinary resolution the Stock Issuance Proposal for purposes of complying with the applicable provisions of Nasdaq Listing Rules.
Under Nasdaq Listing Rule 5635(a), shareholder approval is required prior to the issuance of securities in connection with the acquisition of another company if, due to the present or potential issuance of common stock, including shares issued pursuant to an earn-out provision or similar type of provision, or securities convertible into or exercisable for common stock, such securities are not issued in a public offering for cash and (A) have, or will have upon issuance, voting power equal to or in excess of 20% of the voting power outstanding before the issuance of common stock (or securities convertible into or exercisable for common stock); or (B) the number of shares of common stock to be issued is or will be equal to or in excess of 20% of the number of shares of common stock outstanding before the issuance of the stock or securities.
Under Nasdaq Listing Rule 5635(b), shareholder approval is required prior to an issuance of securities when the issuance or potential issuance will result in a change of control of the issuer.
Under Nasdaq Listing Rule 5635(d), shareholder approval is required for a transaction other than a public offering involving the sale, issuance or potential issuance by an issuer of common stock (or securities convertible into or exercisable for common stock) at a price that is less than the lower of (i) the closing price immediately preceding the signing of the binding agreement or (ii) the average closing price of the common stock for the five trading days immediately preceding the signing of the binding agreement, if the number of shares of common stock (or securities convertible into or exercisable for common stock) to be issued equals 20% or more of the shares of common stock, or 20% or more of the voting power, outstanding before the issuance.
The aggregate shares of Pubco Class A Common Stock that Pubco will and potentially will issue in connection with the Proposed Transaction will exceed 20% of both the voting power and the shares of Pubco Class A Common Stock outstanding before such issuance and may result in a change of control under the applicable Nasdaq Listing Rules. Accordingly, ALCY is seeking the approval of ALCY shareholders for the issuance of shares of Pubco Class A Common Stock in connection with the Proposed Transaction. For additional information, see “The Stock Issuance Proposal.”
Proposal No. 4 — The Organizational Documents Proposal
If each of the Business Combination Proposal, the Domestication Merger Proposal, and the Stock Issuance Proposal are approved, ALCY will ask its shareholders to approve by special resolution the Organizational Documents Proposal in connection with the replacement of the Current M&A, under the Companies Act, with the Proposed Organizational Documents, under the DGCL. The ALCY Board has unanimously approved the Organizational Documents Proposal and believes such proposal is necessary to adequately address the needs of Pubco following the Closing. Approval of the Organizational Documents Proposal is a condition to the consummation of the Business Combination.
For additional information, see “The Organizational Documents Proposal.”
Proposal No. 5 — The Advisory Organizational Documents Proposals
ALCY will ask its shareholders to approve by ordinary resolution on a non-binding advisory basis four (4) separate Advisory Organizational Documents Proposals in connection with the replacement of the Current M&A, under the Companies Act, with the Proposed Organizational Documents, under the DGCL. The ALCY Board has unanimously approved the Advisory Organizational Documents Proposals and believes such proposals are necessary to adequately address the needs of Pubco after the Business Combination. Approval of the Advisory Organizational Documents Proposals is not a condition to the consummation of the Business Combination.
A brief summary of each of the Advisory Organizational Documents Proposals is set forth below. These summaries are qualified in their entirety by reference to the complete text of the Proposed Organizational Documents.
(A) Advisory Organizational Documents Proposal 5A (Authorized Shares) — to authorize the amendment and redesignation of the authorized share capital of ALCY from (a) 479,000,000 ALCY Class A Ordinary Shares, 20,000,000 ALCY Class B Ordinary Shares and 1,000,000 preference shares, par value $0.0001 per share, of ALCY to (b) [·] shares of Pubco Class A Common Stock, [·] shares of Pubco Class B Common Stock and [·] shares of Pubco Preferred Stock;
(B) Advisory Organizational Documents Proposal 5B (Exclusive Forum Provision) — to authorize adopting Delaware as the exclusive forum for certain stockholder litigation and adopting the federal district courts of the United States as the exclusive forum for resolving complaints asserting a cause of action under the Securities Act;
(C) Advisory Organizational Documents Proposal 5C (Required Vote to Amend Charter) — to approve provisions providing that the affirmative vote of at least a majority of the voting power of all the then outstanding shares of capital stock of Pubco entitled to vote thereon, voting together as a single class, will be required to amend, alter, repeal or rescind any provision of the Proposed Charter;
(D) Advisory Organizational Documents Proposal 5D (Additional Changes) — to approve and adopt an amendment to the Current M&A to authorize certain additional changes, including, among other things, (a) making Pubco’s corporate existence perpetual, and (b) removing certain provisions related to ALCY’s status as a blank check company that will no longer be applicable upon Closing, all of which the ALCY Board believes is necessary to adequately address the needs of Pubco after the Business Combination.
For additional information, see “The Advisory Organizational Documents Proposals.”
Proposal No. 6 — The Equity Incentive Plan Proposal
If each of the Business Combination Proposal, the Domestication Merger Proposal, the Stock Issuance Proposal and the Organizational Documents Proposal is approved, ALCY is proposing that its shareholders approve by ordinary resolution the Equity Incentive Plan, which will become effective upon the Closing and will be used by Pubco on a going-forward basis following the Closing.
For additional information, see “The Equity Incentive Plan Proposal.”
Proposal No. 7 — The Adjournment Proposal
If, based on the tabulated vote, there are not sufficient votes at the time of the extraordinary general meeting to authorize ALCY to consummate the Business Combination (because any of the Condition Precedent Proposals has not been approved (including as a result of the failure of any other cross-conditioned Condition Precedent Proposals to be approved)), the ALCY Board may submit a proposal to the shareholders to approve by way of an ordinary resolution the adjournment of the extraordinary general meeting to a later date or dates, if necessary, to permit further solicitation and vote of proxies.
For additional information, see “The Adjournment Proposal.”
Date, Time and Place of the Extraordinary General Meeting
The extraordinary general meeting will be held virtually at [·], Eastern Time, on [·] and will be a virtual meeting conducted via live webcast at [·]. For the purposes of Cayman Islands law and the Current M&A, the physical location of the extraordinary general meeting will be at the offices of .
Registering for the Extraordinary General Meeting
Any shareholder wishing to attend the extraordinary general meeting virtually should register for the extraordinary general meeting by [·], at [·]. To register for the extraordinary general meeting, please follow these instructions as applicable to the nature of your ownership of ALCY Ordinary Shares:
| ● | If your shares are registered in your name with the Transfer Agent and you wish to attend the virtual meeting, go to [·], enter the 12-digit control number included on your proxy card or notice of the extraordinary general meeting and click on the “Click here to preregister for the online meeting” link at the top of the page. Just prior to the start of the extraordinary general meeting you will need to log back into the extraordinary general meeting site using your control number. Pre-registration is recommended, but is not required in order to attend. |
| ● | Beneficial shareholders (those holding shares through a stock brokerage account or by a bank or other holder of record) who wish to attend the extraordinary general meeting must obtain a legal proxy by contacting their account representative at the bank, broker, or other nominee that holds their Public Shares and e-mail a copy (a legible photograph is sufficient) of their legal proxy to proxy@continentalstock.com. Beneficial shareholders who e-mail a valid legal proxy will be issued a 12-digit meeting control number that will allow them to register to attend and participate in the virtual extraordinary general meeting. After contacting the Transfer Agent, a beneficial holder will receive an e-mail prior to the extraordinary general meeting with a link and instructions for attending the virtual extraordinary general meeting. Beneficial shareholders should contact the Transfer Agent at least five business days prior to the extraordinary general meeting date in order to ensure access. |
Voting Power; Record Date
ALCY shareholders will be entitled to vote or direct votes to be cast at the extraordinary general meeting if they owned ALCY Ordinary Shares at the close of business on [·], which is the Record Date for the extraordinary general meeting. Shareholders will have one vote for each ALCY Ordinary Share owned at the close of business on the Record Date. If your shares are held in “street name” or are in a margin or similar account, you should contact your broker to ensure that votes related to the shares you beneficially own are properly counted. ALCY Warrants do not have voting rights. As of the close of business on the Record Date, there were 3,659,056 ALCY Ordinary Shares outstanding, of which 188,556 were Public Shares held by persons other than the Insiders.
Quorum and Vote of ALCY Shareholders
A quorum of ALCY shareholders is necessary to hold a valid meeting. A quorum will be present at the ALCY extraordinary general meeting if the holders of at least a majority of the issued and outstanding shares entitled to vote at the extraordinary general meeting are represented in person or by proxy (which would include presence at the extraordinary general meeting). Abstentions and broker non-votes, while considered present for the purposes of establishing a quorum, will not count as a vote cast at the extraordinary general meeting and otherwise will have no effect on a particular proposal under Cayman Islands law.
As of the Record Date for the extraordinary general meeting, 1,829,529 ALCY Ordinary Shares would be required to achieve a quorum. Because the Sponsor has the right to vote 3,413,000 ALCY Ordinary Shares, no additional holders of ALCY Ordinary Shares will need to be present at the extraordinary general meeting to establish a quorum.
The proposals presented at the extraordinary general meeting require the following votes:
| ● | Business Combination Proposal — The approval of the Business Combination Proposal requires an ordinary resolution under Cayman Islands law, being the affirmative vote of a simple majority of the votes cast by the holders of ALCY Ordinary Shares, represented in person or by proxy and entitled to vote thereon at the extraordinary general meeting. |
| ● | Domestication Merger Proposal — The approval of the Domestication Merger Proposal requires a special resolution under Cayman Islands law, being the affirmative vote of a majority of not less than two-thirds of the votes cast by the holders of ALCY Ordinary Shares, represented in person or by proxy and entitled to vote thereon at the extraordinary general meeting. |
| ● | Stock Issuance Proposal — The approval of the Stock Issuance Proposal requires an ordinary resolution, being the affirmative vote of a simple majority of the votes cast by the holders of ALCY Ordinary Shares, represented in person or by proxy and entitled to vote thereon at the extraordinary general meeting. |
| ● | Organizational Documents Proposal — The approval of the Organizational Documents Proposal requires a special resolution under Cayman Islands law, being the affirmative vote of a majority of not less than two-thirds of the votes cast by the holders of ALCY Ordinary Shares, represented in person or by proxy and entitled to vote thereon at the extraordinary general meeting. |
| ● | Advisory Organizational Documents Proposals — The separate approval of each of the Advisory Organizational Documents Proposals, each of which is a non-binding vote, requires an ordinary resolution, being the affirmative vote of a simple majority of the votes cast by the holders of ALCY Ordinary Shares, represented in person or by proxy and entitled to vote thereon at the extraordinary general meeting. |
| ● | Equity Incentive Plan Proposal — The approval of the Equity Incentive Plan Proposal requires an ordinary resolution, being the affirmative vote of a simple majority of the votes cast by the holders of ALCY Ordinary Shares, represented in person or by proxy and entitled to vote thereon at the extraordinary general meeting. |
| ● | Adjournment Proposal — The approval of the Adjournment Proposal requires an ordinary resolution under Cayman Islands law, being the affirmative vote of a simple majority of the votes cast by the holders of ALCY Ordinary Shares, represented in person or by proxy and entitled to vote thereon at the extraordinary general meeting. |
Abstentions and broker non-votes, while considered present for the purposes of establishing a quorum, will not count as a vote cast at the extraordinary general meeting and otherwise will have no effect on a particular proposal under Cayman Islands law.
The Insiders have agreed to vote all of their ALCY Ordinary Shares in favor of the proposals being presented at the extraordinary general meeting. The Sponsor, which includes among its members each of the directors and officers of ALCY, and Cantor together own 3,470,500 ALCY Ordinary Shares, including the sole outstanding ALCY Class B Ordinary Share. As a result, as of the date of this proxy statement/prospectus, the Insiders own approximately 94.8% of the issued and outstanding ALCY Ordinary Shares. Accordingly, no additional votes of holders of Public Shares will be required to approve the Business Combination Proposal, the Domestication Merger Proposal, the Stock Issuance Proposal, the Organizational Documents Proposal, the Advisory Organizational
Documents Proposals, the Equity Incentive Plan Proposal, and, if presented, the Adjournment Proposal even if all other outstanding shares are voted against such proposals.
Redemption Rights
Pursuant to the Current M&A, a Public Shareholder may request that ALCY redeem all or a portion of its Public Shares for cash if the Proposed Transaction is consummated, and in connection with any proposal to extend the time period for completion of the business combination. As a holder of Public Shares, you will be entitled to receive cash for any Public Shares to be redeemed only if you:
| ● | (a) hold Public Shares or (b) hold Public Shares through ALCY Units and elect to separate your ALCY Units into the underlying Public Shares and Public Warrants prior to exercising your Redemption Rights with respect to the Public Shares; |
| ● | submit a written request to the Transfer Agent, including the legal name, phone number and address of the beneficial owner of the Public Shares for which Redemption is requested, that ALCY redeem all or a portion of your Public Shares for cash; and |
| ● | tender or deliver the certificates for your Public Shares (if any) along with the redemption forms to the Transfer Agent physically or electronically through DTC. |
Holders must complete the procedures for electing to redeem their Public Shares in the manner described above prior to [·], Eastern Time, on [·] (up to two business days prior to the initially scheduled vote on the Business Combination Proposal) in order for their Public Shares to be redeemed.
Public Shareholders may elect to redeem all or a portion of the Public Shares held by them regardless of if or how they vote in respect of the Business Combination Proposal and regardless of whether they hold Public Shares on the Record Date. Holders of ALCY Units must elect to separate ALCY Units held by them into the underlying Public Shares and Public Warrants prior to exercising their Redemption Rights with respect to the Public Shares. If the Proposed Transaction is not consummated, the Public Shares will be returned to the respective holder, broker or bank. If the Proposed Transaction is consummated, and if a Public Shareholder properly exercises its right to redeem all or a portion of the Public Shares that it holds and timely tenders or delivers the certificates for its shares (if any) along with the redemption forms to the Transfer Agent, ALCY will redeem such Public Shares for a per-share price, payable in cash, equal to the aggregate amount then on deposit in the Trust Account calculated as of two business days prior to the Business Combination, including interest earned on the Trust Account and not previously released to ALCY to pay income taxes, if any, (less up to $100,000 of interest to pay dissolution expenses), divided by the number of Public Shares then in issue. For illustrative purposes, as of [·], this would have amounted to approximately $[·] per issued and outstanding Public Share. If a Public Shareholder exercises its Redemption Rights in full, then it will be electing to exchange its Public Shares for cash and will no longer own Public Shares. See “Extraordinary General Meeting of ALCY — Redemption Rights” for a detailed description of the procedures to be followed if you wish to redeem your Public Shares for cash.
Notwithstanding the foregoing, a Public Shareholder, together with any affiliate of such Public shareholder or any other person with whom such Public Shareholder is acting in concert or as a “group” (as defined in Section 13(d)(3) of the Exchange Act), will be restricted from redeeming its Public Shares with respect to more than an aggregate of 15% of the Public Shares without ALCY’s prior consent. Accordingly, if a Public Shareholder, alone or acting in concert or as a group, seeks to redeem more than 15% of the Public Shares, then any such shares in excess of that 15% limit would not be redeemed for cash without ALCY’s prior consent.
Holders of the Public Warrants will not have Redemption Rights with respect to the Public Warrants.
Ownership of Pubco after the Closing
The following table summarizes pro forma ownership of Pubco Common Stock on an as-exchanged basis under the redemption scenarios shown, using the 737,543 Public Shares outstanding at June 30, 2026 and assuming no PIPE financing. The table includes illustrative issuance of 717,500 Class A shares for transaction fees and 254,419 Class A shares for existing related party payables at $10.00 per share, consistent with the pro forma financial statements. The fee shares comprise 517,500 shares for Cantor and 200,000 shares for KBW. Loeb’s remaining $1,750,000 fee and $500,000 of other closing expenses are assumed paid in cash. Unless the parties obtain additional financing sufficient to repay the Sponsor Promissory Notes in cash at Closing, ALCY and the relevant holders will agree on an alternative form of compensation, which may include shares, on terms and conditions to be determined.
None | 25% | 50% | 75% | Maximum |
| ||||||||||||||||
Redemptions | Shares | % | Shares | % | Shares | % | Shares | % | Shares | % |
| ||||||||||
ALCY Public Shareholders(1) | | 737,543 | | 1.3 | % | 553,157 | | 1.0 | % | 368,772 | | 0.6 | % | 184,386 | | 0.3 | % | 0 | | 0.0 | % |
Sponsor and Cantor(2) |
| 1,757,500 |
| 3.1 | % | 1,757,500 |
| 3.1 | % | 1,757,500 |
| 3.1 | % | 1,757,500 |
| 3.1 | % | 1,757,500 |
| 3.1 | % |
Cartiga Unit Holders(3) |
| 54,000,000 |
| 94.0 | % | 54,000,000 |
| 94.3 | % | 54,000,000 |
| 94.6 | % | 54,000,000 |
| 94.9 | % | 54,000,000 |
| 95.2 | % |
Fee settlement shares | 717,500 | 1.2 | % | 717,500 | 1.3 | % | 717,500 | 1.3 | % | 717,500 | 1.3 | % | 717,500 | 1.3 | % | ||||||
Related party settlement shares | 254,419 | 0.4 | % | 254,419 | 0.4 | % | 254,419 | 0.4 | % | 254,419 | 0.4 | % | 254,419 | 0.4 | % | ||||||
Total(4) |
| 57,466,962 |
| 100 | % | 57,282,576 |
| 100 | % | 57,098,191 |
| 100 | % | 56,913,805 |
| 100 | % | 56,729,419 |
| 100 | % |
(1) | Includes the Public Shares outstanding at June 30, 2026 that are assumed not to be redeemed under the illustrative scenario shown. Later redemptions of 548,987 Public Shares are not reflected in this June 30 presentation. |
(2) | Includes 1,700,000 Sponsor Shares, after the assumed forfeiture of 1,713,000 shares (3,413,000 less 1,700,000) under Section 8.17 of the Business Combination Agreement, assuming Available Closing Buyer Cash below $5,000,000 and waiver of the minimum cash condition, and 57,500 existing shares held by Cantor Fitzgerald & Co. |
(3) | Represents the number of shares of Pubco Class A Common Stock that would be issued assuming the exchange of the OpCo Units (together with the corresponding Pubco Class B Common Stock) held by the Company Equity Interest Holders for Pubco Class A Common Stock pursuant to the Exchange Agreement. |
(4) | Includes illustrative fee settlement and existing related party payable conversion shares, but excludes the exercise of Public Warrants and any additional, undrawn Working Capital Loans. No PIPE financing is assumed. |
Dilutive Instruments
The table below shows possible sources of dilution and the extent of such dilution that non-redeeming Public Shareholders could experience in connection with the closing of the Business Combination. In an effort to illustrate the extent of such dilution, the table below assumes the exercise of all Public Warrants which are exercisable for one share of common stock at a price of $11.50 per share.
None | 25% | 50% | 75% | Maximum |
| ||||||||||||||||
Redemptions | Shares | % | Shares | % | Shares | % | Shares | % | Shares | % |
| ||||||||||
ALCY Public Shareholders(1) | | 737,543 | | 1.17 | % | 553,157 | | 0.88 | % | 368,772 | | 0.59 | % | 184,386 | | 0.29 | % | 0 | | 0.00 | % |
Sponsor and Cantor(2) |
| 1,757,500 |
| 2.78 | % | 1,757,500 |
| 2.79 | % | 1,757,500 |
| 2.80 | % | 1,757,500 |
| 2.80 | % | 1,757,500 |
| 2.81 | % |
Public Warrants (assumed exercise) |
| 5,750,000 |
| 9.10 | % | 5,750,000 |
| 9.12 | % | 5,750,000 |
| 9.15 | % | 5,750,000 |
| 9.18 | % | 5,750,000 |
| 9.20 | % |
Related party settlement shares |
| 254,419 |
| 0.40 | % | 254,419 |
| 0.40 | % | 254,419 |
| 0.40 | % | 254,419 |
| 0.41 | % | 254,419 |
| 0.41 | % |
Cartiga Unit Holders(3) |
| 54,000,000 |
| 85.42 | % | 54,000,000 |
| 85.67 | % | 54,000,000 |
| 85.92 | % | 54,000,000 |
| 86.17 | % | 54,000,000 |
| 86.43 | % |
Fee settlement shares | 717,500 | 1.13 | % | 717,500 | 1.14 | % | 717,500 | 1.14 | % | 717,500 | 1.14 | % | 717,500 | 1.15 | % | ||||||
Fully Diluted Shares(4) |
| 63,216,962 |
| 100 | % | 63,032,576 |
| 100 | % | 62,848,191 |
| 100 | % | 62,663,805 |
| 100 | % | 62,479,419 |
| 100 | % |
(1) | Includes the Public Shares outstanding at June 30, 2026 that are assumed not to be redeemed under the illustrative scenario shown. Later redemptions of 548,987 Public Shares are not reflected in this June 30 presentation. |
(2) | Includes 1,700,000 Sponsor Shares, after the assumed forfeiture of 1,713,000 shares (3,413,000 less 1,700,000) under Section 8.17 of the Business Combination Agreement, assuming Available Closing Buyer Cash below $5,000,000 and waiver of the minimum cash condition, and 57,500 existing shares held by Cantor Fitzgerald & Co. |
(3) | Represents the number of shares of Pubco Class A Common Stock that would be issued assuming the exchange of the OpCo Units (together with the corresponding Pubco Class B Common Stock) held by the Company Equity Interest Holders for Pubco Class A Common Stock pursuant to the Exchange Agreement. |
(4) | Fully diluted shares equal the sum of the rows above. Existing related party payables of $2,544,189 are assumed settled through 254,419 Class A shares at $10.00 per share, and $7,175,000 of transaction fees through 717,500 shares. These shares are included once. The separate, undrawn Working Capital Loan facility permits conversion of up to $1.5 million at $10.00 per share (150,000 shares); no additional borrowing or conversion under that facility is assumed. No PIPE shares are assumed. The related party share settlement and $10.00 price are illustrative assumptions only; actual settlement may be in cash if additional financing is obtained, or in another form of compensation, including shares, on terms and conditions to be determined by agreement with the holders. |
Supplemental Ownership Information Reflecting the September 2026 Redemptions
Following the redemption of 548,987 Public Shares in September 2026, 188,556 Public Shares remained outstanding, compared with 737,543 Public Shares outstanding at June 30, 2026. The following supplemental tables illustrate ownership of Pubco Common Stock on an as-exchanged basis after giving effect to those completed redemptions.
The “No Further Redemptions” scenario assumes that none of the remaining 188,556 Public Shares are redeemed in connection with the Business Combination. The other scenarios assume further redemptions of 25%, 50%, 75% and 100% of those remaining Public Shares. The assumptions regarding Sponsor share forfeiture and the illustrative issuance of shares to settle transaction fees and related party payables remain consistent with the tables above.
Ownership Excluding the Exercise of Public Warrants
| No Further | 25% Further | 50% Further | 75% Further | | Maximum Further | |||||||||||||||
Redemptions | Redemptions | Redemptions | Redemptions | Redemptions | |||||||||||||||||
Shares | | % | Shares | | % | Shares | | % | Shares | | % | Shares | | % | |||||||
ALCY Public Shareholders(1) | 188,556 | 0.3 | % | 141,417 | 0.2 | % | 94,278 | 0.2 | % | 47,139 | 0.1 | % | 0 | 0.0 | % | ||||||
Sponsor and Cantor(2) | 1,757,500 | 3.1 | % | 1,757,500 | 3.1 | % | 1,757,500 | 3.1 | % | 1,757,500 | 3.1 | % | 1,757,500 | 3.1 | % | ||||||
Cartiga Unit Holders(3) | 54,000,000 | 94.9 | % | 54,000,000 | 95.0 | % | 54,000,000 | 95.0 | % | 54,000,000 | 95.1 | % | 54,000,000 | 95.2 | % | ||||||
Fee settlement shares | 717,500 | 1.3 | % | 717,500 | 1.3 | % | 717,500 | 1.3 | % | 717,500 | 1.3 | % | 717,500 | 1.3 | % | ||||||
Related party settlement shares | 254,419 | 0.4 | % | 254,419 | 0.4 | % | 254,419 | 0.4 | % | 254,419 | 0.4 | % | 254,419 | 0.4 | % | ||||||
Total(4) | 56,917,975 | 100 | % | 56,870,836 | 100 | % | 56,823,697 | 100 | % | 56,776,558 | 100 | % | 56,729,419 | 100 | % | ||||||
Ownership Including the Assumed Exercise of Public Warrants
| No Further | 25% Further | 50% Further | 75% Further | | Maximum Further | |||||||||||||||
Redemptions | Redemptions | Redemptions | Redemptions | Redemptions | |||||||||||||||||
Shares | | % | Shares | | % | Shares | | % | Shares | | % | Shares | | % | |||||||
ALCY Public Shareholders(1) | 188,556 | 0.30 | % | 141,417 | 0.23 | % | 94,278 | 0.15 | % | 47,139 | 0.08 | % | 0 | 0.00 | % | ||||||
Sponsor and Cantor(2) | 1,757,500 | 2.80 | % | 1,757,500 | 2.81 | % | 1,757,500 | 2.81 | % | 1,757,500 | 2.81 | % | 1,757,500 | 2.81 | % | ||||||
Public Warrants (assumed exercise) | 5,750,000 | 9.18 | % | 5,750,000 | 9.18 | % | 5,750,000 | 9.19 | % | 5,750,000 | 9.20 | % | 5,750,000 | 9.20 | % | ||||||
Related party settlement shares | 254,419 | 0.41 | % | 254,419 | 0.41 | % | 254,419 | 0.41 | % | 254,419 | 0.41 | % | 254,419 | 0.41 | % | ||||||
Cartiga Unit Holders(3) | 54,000,000 | 86.17 | % | 54,000,000 | 86.23 | % | 54,000,000 | 86.30 | % | 54,000,000 | 86.36 | % | 54,000,000 | 86.43 | % | ||||||
Fee settlement shares | 717,500 | 1.14 | % | 717,500 | 1.15 | % | 717,500 | 1.15 | % | 717,500 | 1.15 | % | 717,500 | 1.15 | % | ||||||
Fully Diluted Shares(4) | 62,667,975 | 100 | % | 62,620,836 | 100 | % | 62,573,697 | 100 | % | 62,526,558 | 100 | % | 62,479,419 | 100 | % | ||||||
(1) | Represents the 188,556 Public Shares remaining outstanding following the September 2026 redemptions, less any further redemptions assumed under the applicable scenario. The redemption percentages shown apply solely to those remaining Public Shares. |
(2) | Includes 1,700,000 Sponsor Shares after the assumed forfeiture of 1,713,000 Sponsor Shares, and 57,500 existing shares held by Cantor Fitzgerald & Co., consistent with the assumptions described above. |
(3) | Cartiga Unit Holders are presented on an as-exchanged basis, assuming the exchange of their OpCo Units and corresponding shares of Pubco Class B Common Stock for shares of Pubco Class A Common Stock pursuant to the Exchange Agreement. |
(4) | Includes the illustrative issuance of 717,500 Class A shares to settle transaction fees and 254,419 Class A shares to settle existing related party payables, subject to the assumptions and qualifications described in the tables above. No PIPE financing or |
additional borrowing or conversion under the undrawn Working Capital Loan facility is assumed. The second table also includes 5,750,000 shares issuable upon the assumed exercise of the Public Warrants, using the same share-count methodology as the existing warrant dilution table.
Calculation of Pro Forma Net Tangible Book Value
The following table represents the calculation of the adjusted net book value which will be used to calculate the net tangible book value per share as of June 30, 2026. The amounts are drawn from the pro forma combined balance sheet and already reflect the assumed fee and related party payable share settlements and transaction expenses; no duplicate deduction is made.
As of June 30, 2026:
As of June 30, 2026 | | | No redemptions |
Pro forma combined total assets | $ | 627,228,000 | |
Less goodwill | $ | (35,602,000) | |
Less intangible assets | $ | (10,477,000) | |
Less pro forma combined total liabilities | $ | (392,934,000) | |
Pro forma net tangible book value | $ | 188,215,000 |
Net Tangible Book Value Per Share and Dilution
As of June 30, 2026, the net tangible book value per share of ALCY was $(0.59). After giving effect to the business combination with Cartiga and assuming no redemptions, the pro forma net tangible book value per share on the fully diluted, as-exchanged basis described below would be $2.98. This represents an immediate increase in net tangible book value of $3.57 per share for existing ALCY shareholders, and an immediate dilution of $7.02 per share to investors purchasing shares at the transaction price of $10.00 per share.
Pro Forma Net Tangible Book Value and Dilution Table
The following table presents pro forma net tangible book value per share and dilution under various redemption scenarios, using an illustrative redemption price of $12.34 per share ($9,103,236 in trust at June 30, 2026 divided by 737,543 Public Shares). Shares outstanding are presented on a fully diluted, as-exchanged basis and include 5,750,000 shares issuable upon exercise of the Public Warrants and the illustrative fee and related party payable settlement shares. No hypothetical Public Warrant exercise proceeds are added to NTBV.
| No redemptions | | 25% | | 50% | | 75% | | Maximum | ||||||
Trust Remaining | $ | 9,103,236 | $ | 6,827,427 | $ | 4,551,618 | $ | 2,275,809 | $ | 0 | |||||
Pro Forma NTBV | $ | 188,215,000 | $ | 185,938,750 | $ | 183,662,500 | $ | 181,386,250 | $ | 179,110,000 | |||||
Shares Outstanding (fully diluted) | 63,216,962 | 63,032,576 | 62,848,191 | 62,663,805 | 62,479,419 | ||||||||||
NTBV per Share | $ | 2.98 | $ | 2.95 | $ | 2.92 | $ | 2.89 | $ | 2.87 | |||||
Redemption Price | $ | 12.34 | $ | 12.34 | $ | 12.34 | $ | 12.34 | $ | 12.34 | |||||
Dilution per Share | $ | 9.37 | $ | 9.39 | $ | 9.42 | $ | 9.45 | $ | 9.48 | |||||
Based on the revised June 30, 2026 pro forma balance sheet and the redemption scenarios presented. Estimated transaction fee budgets total $11,875,000 before payments, including $9,675,000 for ALCY (including $500,000 of other closing expenses for Toppan, Continental and other vendors) and $2,200,000 for Cartiga. Remaining costs at Closing total $10,222,640.70, comprising $9,425,000 for ALCY and $797,640.70 for Cartiga. The model assumes $7,175,000 is settled in shares and $3,047,640.70 in cash. Related party debt and payable settlement is separate from these transaction costs.
The table above sets forth pro forma net tangible book value per share and resulting dilution measured against the illustrative redemption price of $12.34 per share. Assuming no redemptions, pro forma net tangible book value per share would be $2.98, resulting in dilution of $9.37 per share. Assuming maximum redemptions, pro forma net tangible book value per share would be $2.87, resulting in dilution of $9.48 per share.
The actual dilution experienced will depend on the number of public shares redeemed in connection with the business combination.
None of ALCY’s shareholders, or ALCY’s warrant holders have appraisal rights in connection with the Proposed Transaction or the Domestication under Cayman Islands law or the DGCL. ALCY’s shareholders do not have dissenters’ rights in connection with the Proposed Transaction or the Domestication under Cayman Islands law.
Proxy Solicitation
Proxies may be solicited by mail, telephone or in person. ALCY has engaged Advantage Proxy to assist in the solicitation of proxies.
If a shareholder grants a proxy, it may still vote its shares in person if it revokes its proxy before the extraordinary general meeting. A shareholder also may change its vote by submitting a later-dated proxy as described in “Extraordinary General Meeting of ALCY — Revoking Your Proxy.”
Interests of ALCY Directors, Officers and Others in the Proposed Transaction
When you consider the recommendation of the ALCY Board in favor of approval of the Business Combination Proposal, you should keep in mind that the Sponsor, ALCY’s directors and executive officers and others have interests in such proposal that are different from, or in addition to, those of ALCY shareholders and holders of Public Warrants generally. See “The Business Combination Proposal — Certain Interests of ALCY’s Directors and Officers and Others in the Business Combination.”
Compensation Received by the Sponsor
Within five (5) business days following the consummation of the business combination, the Sponsor of ALCY may convert its working capital notes (our “Working Capital Notes”) into Class A Shares, at a price of $10.00 per Class A Share, which will be exchanged for shares of common stock in the post business combination entity. If ALCY completes a business combination, ALCY will repay the Working Capital Notes out of the proceeds of the Trust Account released to ALCY. Otherwise, the Working Capital Notes would be repaid only out of funds held outside the Trust Account. In the event that a business combination does not close, ALCY may use a portion of proceeds held outside the Trust Account to repay the Working Capital Notes but no proceeds held in the Trust Account would be used to repay the Working Capital Loans.
Set forth below is a summary of the terms and amount of the compensation received or to be received by the Sponsor and its affiliates in connection with the Business Combination or any related financing transaction, the amount of securities issued or to be issued by ALCY to the Sponsor and its affiliates and the price paid or to be paid for such securities or any related financing transaction.
| Interest in Securities | | Other Compensation | |
Sponsor | Alchemy DeepTech Capital LLC, the Sponsor, and its affiliates paid $50,000, or approximately $0.02 per share, for its 2,875,000 founder shares purchased in connection with ALCY’s formation, and 538,000 Class A ordinary shares purchased for $10.00 per share in a private placement that closed at the time of the IPO. At Closing of the Business Combination, the Sponsor shall hold a total of up to 3,413,000 shares of the Pubco Class A Common Stock depending on how much is raised in the PIPE financing. If Available Closing Buyer Cash is less than $5,000,000 , then, as a result of Cartiga’s waiver of the Minimum Cash Condition on October 22, 2026, and pursuant to Section 8.17 of the Business Combination Agreement, the Sponsor shall forfeit 1,713,000 of its shares and hold a minimum of 1,700,000 shares of Pubco Class A Common Stock. | At Closing, pursuant to the Business Combination Agreement, Pubco will use cash from the Trust Account to pay any merger transaction expenses and to reimburse or pay the Sponsor or its affiliates for any outstanding Sponsor Promissory Notes, Working Capital Loans or other obligations of ALCY to the Sponsor or its affiliates. Unless the parties obtain additional financing sufficient to repay the Sponsor Promissory Notes in cash at Closing, ALCY and the relevant holders will agree on an alternative form of compensation, which may include shares, on terms and conditions to be determined. Outstanding principal under the Sponsor Promissory Notes was $2,186,000 as of June 30, 2026, excluding $263,006 of accrued interest and $95,183 of accrued related party expenses. Transaction costs are presented separately above. |
An affiliate of the Sponsor is receiving $10,000 monthly for administrative services in connection with the business combination. |
The retention of shares by the Sponsor and the reimbursements payable to the Sponsor at Closing will not result in a material dilution of the equity interests of non-redeeming ALCY stockholders. See “The Business Combination Proposal — Ownership of Pubco after the Closing.”
Conflicts of Interest
The existence of financial and personal interests of one or more of ALCY’s directors may result in a conflict of interest on the part of such director(s) between what he, she or they may believe is in the best interests of ALCY and its shareholders and what he, she or they may believe is best for himself, herself or themselves in determining to recommend that shareholders vote for the proposals. In addition, ALCY’s officers have interests in the Proposed Transaction that may conflict with your interests as a shareholder.
Since the Sponsor, its affiliates, representatives and certain initial shareholders of ALCY (the “Initial Shareholders”), have interests that are different, or in addition to (and which may conflict with), the interests of the other holders of ALCY Class A Ordinary Shares, a conflict of interest may exist in determining whether the Business Combination with Cartiga is appropriate. Such interests include that the Initial Shareholders will lose their entire investment in ALCY if ALCY does not complete a business combination. When you consider the recommendation of the ALCY Board in favor of approval of the Business Combination, you should keep in mind that the Initial Shareholders have interests in such proposal that are different from, or in addition to (which may conflict with), those of the ALCY shareholders generally.
These interests include, among other things:
| ● | The Sponsor paid $50,000 or approximately $0.0174 per share, for its 2,875,000 Founder Shares, which such Founder Shares, if unrestricted and freely tradeable, would be valued at approximately $[*], based on the $[*] closing price of the ALCY Class A Ordinary Shares on OTC on [*], 2026. We estimate that, at the Closing, the Sponsor will hold an aggregate of up to 3,413,000 shares of Pubco Class A Common Stock or a minimum of 1,700,000 shares, depending on the amount forfeited for not meeting the minimum cash condition in the Merger Agreement, and not including any shares issued upon conversion of the Working Capital Loans, which, if unrestricted and freely tradeable, would be valued at approximately $[*], based on the $[*] closing price of the ALCY Class A Ordinary Shares on OTC on [•], 2026. However, given that such shares of Pubco Class A Common Stock will be subject to certain restrictions, including those described elsewhere in this proxy statement/prospectus, ALCY believes such shares have less value. |
| ● | If ALCY is not able to complete the Proposed Transaction with Cartiga by September 9, 2027 by depositing $5,656.68 in the Trust Account on a monthly basis for each one-month extension until September 9, 2027, and is not able to complete another business combination by such date, unless otherwise extended by a shareholder-approved amendment to the Current M&A, it would cease all operations except for the purpose of winding up, redeeming all of the outstanding Public Shares for cash and, subject to the approval of its remaining shareholders and the ALCY Board, liquidating and dissolving, subject in each case to its obligations under Cayman Islands law to provide for claims of creditors and the requirements of other applicable law. In such event, the Founder Shares owned by the Sponsor would be worthless because following the redemption of the Public Shares, ALCY would likely have few, if any, net assets and because the Insiders have agreed to waive their respective rights to liquidating distributions from the Trust Account in respect of the Founder Shares if ALCY fails to complete a business combination within the required period. |
| ● | As a result of the low purchase price paid for the Founder Shares, even if the trading price of the Pubco Class A Common Stock were as low as $[*] per share, the aggregate market value of the Founder Shares alone (without taking into account the value of the Pubco Class A Common Stock and Pubco Warrants issued or the Public Shares held by the Sponsor) would be approximately equal to the investment in ALCY by the Sponsor. As a result, if the Business Combination is completed, the Sponsor is likely to be able to make a substantial profit on its investment in us even at a time when the Pubco Class A Common Stock has lost significant value. On the other hand, if the Business Combination is not completed and ALCY liquidates without completing another initial business combination before the end of the completion window, the Sponsor would lose its entire investment in us. |
| ● | Upon liquidation, the Sponsor will lose its entire investment in the Founder Shares and Private Placement Shares, which totals $6,005,000 in the aggregate (595,500 ALCY Class A Ordinary Shares purchased by the Initial Shareholders for a total purchase price of $5,955,000 in the private placement at the time of the IPO plus the initial investment of $50,000 for the Founder Shares). The potential loss of this investment could incentivize the Sponsor and its affiliates to pursue a business combination transaction on unfavorable terms in order to avoid a liquidation. |
| ● | Steven M. Wasserman is expected to be a director of Pubco after the Closing. As such, in the future, Mr. Wasserman may receive fees for his service as director, which may consist of cash or stock-based awards, and any other remuneration that Pubco Board determines to pay to its non-employee directors. |
| ● | ALCY’s existing directors and officers will be eligible for continued indemnification and continued coverage under ALCY’s directors’ and officers’ liability insurance policy after the Merger and pursuant to the Business Combination Agreement and indemnification agreements entered into with such directors and officers in connection with the IPO. |
| ● | In order to protect the amounts held in the Trust Account, the Sponsor has agreed that it will be liable to ALCY if and to the extent any claims by a third party (other than ALCY’s independent registered public accounting firm) for services rendered or products sold to ALCY, or a prospective target business with which ALCY has discussed entering into a transaction agreement, reduce the amount of funds in the Trust Account to below the lesser of (a) $10.00 per Public Share and (b) the actual amount per Public Share held in the Trust Account as of the date of the liquidation of the Trust Account, if less than $10.00 per Public Share, due to reductions in value of the trust assets, in each case net of the interest that may be withdrawn to pay taxes. This liability will not apply to any claims by a third party who executed a waiver of any and all rights to seek access to the Trust Account and as to any claims under the indemnity of the underwriters of the IPO against certain liabilities, including liabilities under the Securities Act. |
| ● | The Sponsor and its affiliates have made an aggregate of $2,186,000 of advances to ALCY as of the date of this proxy statement/prospectus, which will be repaid in cash at the closing of the Business Combination for advancing working capital and payment of the monthly extensions, or, if agreed with the holders, settled in shares of Common Stock at $10.00 per share. Additionally, ALCY’s officers and directors and their affiliates are entitled to reimbursement of out-of-pocket expenses incurred by them related to identifying, investigating, negotiating and completing an initial business combination. As of the date of this proxy statement/prospectus the current value of the reimbursement of the out-of-pocket expenses owed to ALCY’s officers and directors and their affiliates is $[*]. However, if ALCY is not able to complete the Proposed Transaction with Cartiga by September 9, 2027 by depositing $5,656.68 in the Trust Account on a monthly basis for each one-month extension until September 9, 2027, and is not able to complete another business combination by such date, unless otherwise extended by a shareholder-approved amendment to the Current M&A, such persons will not have any claim against the Trust Account for reimbursement. Accordingly, ALCY may not be able to reimburse these advances and expenses if the Business Combination or another business combination is not completed by such date. |
| ● | Pursuant to the A&R Registration Rights Agreement, the Insiders will have customary registration rights, including demand and piggy-back rights, subject to cooperation and cut-back provisions with respect to the Pubco Class A Common Stock and Pubco Warrants held by such parties following the consummation of the Proposed Transaction. We estimate that the Insiders will hold an aggregate of up to 3,413,000 shares of Pubco Class A Common Stock subject to registration rights. This amount may be reduced depending on how much is raised in the PIPE financing. If Available Closing Buyer Cash is less than $5,000,000, then, as a result of Cartiga’s waiver of the Minimum Cash Condition on October 22, 2026, and pursuant to Section 8.17 of the Business Combination Agreement, the Sponsor shall forfeit 1,713,000 of its shares and hold a minimum of 1,700,000 shares of Pubco Class A Common Stock. |
| ● | The fact that certain officers and directors of ALCY have an economic interest in the 3,413,000 Founder Shares and Private Placement Shares currently owned by the Sponsor and purchased by the Sponsor in connection with the ALCY IPO, as a result of their direct or indirect membership interests in the Sponsor. This includes 2,875,000 Founder Shares that were purchased by the Sponsor for approximately $0.02 per share ($50,000 in the aggregate), and 538,000 Class A ordinary shares that were purchased in the private placement that closed at the time of the IPO, for $10.00 per share ($5,380,000 in the aggregate). VAM Partners LLC (“VAM Partners”), is the managing member of the Sponsor. The economic interest (or deemed economic interest) of this entity in the Founder Shares retained by the Sponsor is shown below: |
| Number of | |
Founder Shares | ||
Name and Title of Person | (deemed) | |
Alchemy DeepTech Capital LLC, Sponsor(1) |
| 3,413,000(2) |
| (1) | Includes 2,754,378 ALCY ordinary shares in which VAM Partners has an economic interest due to its member ownership interest in the sponsor. VAM Partners is the managing member of the Sponsor. VAM Partners is governed by a four-member board of directors which acts by majority vote. Accordingly, no individual director of VAM Partners exercises voting or dispositive control over any of the securities held by our sponsor, including those in which such director has a pecuniary interest. Therefore, none of the directors are deemed to have or share beneficial ownership of securities held by the Sponsor. The managing member of VAM Partners is Alchemy Investment Management LLC, which has an economic interest in 584,453 Founder Shares, which is owned 66.7% by Mattia Tomba, and 33.3% by Al Noor Gulf Ventures L.L.C.-FZ, an entity controlled by Vittorio Savoia, our co-Chief Executive Officer, who is also the ultimate beneficial owner. |
| (2) | This amount may be reduced depending on how much is raised in the PIPE financing. If Available Closing Buyer Cash is less than $5,000,000, then, as a result of Cartiga’s waiver of the Minimum Cash Condition on October 22, 2026, and pursuant to Section 8.17 of the Business Combination Agreement, the Sponsor shall forfeit 1,713,000 of its shares and hold a minimum of 1,700,000 shares of Pubco Class A Common Stock. |
In light of the foregoing, the Sponsor and its affiliates will receive material benefits from the completion of the Business Combination and may be incentivized to complete the Business Combination with Cartiga rather than liquidate even if (i) Cartiga is a less favorable target company or (ii) the terms of the Business Combination are less favorable to shareholders. As a result, our Sponsor and directors and officers may have interests in the completion of the Business Combination that are materially different than, and may conflict with, the interests of other shareholders. Further, the Sponsor may receive a positive return on the Founder Shares even if ALCY’s public shareholders experience a negative return on their investment after consummation of the Business Combination. See “The Business Combination Proposal — Ownership of Pubco after the Closing.”
The personal and financial interests of the Sponsor as well as ALCY’s directors and officers may have influenced their motivation in identifying and selecting Cartiga as a business combination target, completing an initial business combination with Cartiga and influencing the operation of the business following the Closing. In considering the recommendations of the ALCY Board to vote for the proposals, its shareholders should consider these interests.
Regulatory Matters
Neither ALCY nor Cartiga is aware of any material regulatory approvals or actions that are required for completion of the Business Combination, other than the regulatory notices and approvals discussed in “The Business Combination Proposal — Business Combination Agreement — Closing Conditions — Conditions to the Obligations of Each Party.” It is presently contemplated that if any such additional regulatory approvals or actions are required, those approvals or actions will be sought. There can be no assurance, however, that any additional approvals or actions will be obtained.
Stock Exchange Listing
Pubco has applied to list the Pubco Class A Common Stock and Pubco Warrants on Nasdaq under the proposed symbols “LITF” and “LITFW,” respectively, upon the Closing.
Pursuant to the terms of the Business Combination Agreement, as a closing condition, Pubco is required to cause the Pubco Class A Common Stock to be issued in connection with the Business Combination to be approved for listing on Nasdaq or another national securities exchange, but there can be no assurance that such listing condition will be met. If such listing condition is not met, the Business Combination will not be consummated unless the listing condition is waived by the parties to the Business Combination Agreement. It is important for you to know that, at the time of the extraordinary general meeting, Pubco may not have received from Nasdaq either confirmation of the listing of the Pubco Class A Common Stock or that approval will be obtained prior to the consummation of the Business Combination. As a result, you may be asked to vote to approve the Business Combination and the other proposals included in this proxy statement/prospectus without such confirmation, and, further, it is possible that such confirmation may never be received and the Business Combination could still be consummated if such condition is waived and therefore the Pubco Class A Common Stock would not be listed on any nationally recognized securities exchange.
Recommendation to Shareholders of ALCY
The ALCY Board believes that the Business Combination Proposal and the other proposals to be presented at the extraordinary general meeting are in the best interests of ALCY and ALCY’s shareholders and unanimously recommends that its shareholders vote “FOR” the approval of the Business Combination Proposal, “FOR” the approval of the Domestication Merger Proposal, “FOR” the approval of the Stock Issuance Proposal, “FOR” the approval of the Organizational Documents Proposal, “FOR” the approval, on an advisory basis, of each of the separate Advisory Organizational Documents Proposals, “FOR” the approval of the Equity Incentive Plan Proposal and “FOR” the approval of the Adjournment Proposal, if presented to the extraordinary general meeting.
The existence of financial and personal interests of one or more of ALCY’s directors may result in a conflict of interest on the part of such director(s) between what he, she or they may believe is in the best interests of ALCY and its shareholders and what he, she or they may believe is best for himself, herself or themselves in determining to recommend that shareholders vote for the proposals. In addition, ALCY’s officers have interests in the Proposed Transaction that may conflict with your interests as a shareholder. See “The Business Combination Proposal — Certain Interests of ALCY’s Directors and Officers and Others in the Business Combination.”
U.S. Federal Income Tax Considerations
For a discussion summarizing certain U.S. federal income tax considerations of the Domestication and an exercise of Redemption Rights in connection with the Proposed Transaction, please see “Material U.S. Federal Income Tax Considerations.”
Accounting Considerations
The Business Combination will be accounted for as a reverse recapitalization, in accordance with U.S. Generally Accepted Accounting Principles (“GAAP”). Under this method of accounting, ALCY will be treated as the “acquired” company for financial reporting purposes. Accordingly, the Business Combination will be reflected as if Cartiga had issued shares to acquire the net assets of ALCY, with the transaction being accompanied by a recapitalization. The net assets of ALCY will be recorded at their historical carrying values, and no goodwill or other intangible assets will be recognized in connection with the transaction.
Although ALCY is the legal acquirer, Cartiga is considered the accounting acquirer for purposes of financial reporting.
Immediately prior to the closing of the Business Combination, Melodeon is the sole member and economic owner of Cartiga. ASRS beneficially owns approximately 85% of Melodeon’s outstanding interest in Cartiga. Together, ASRS and Melodeon will control six of the seven seats on the board of directors of the post-combination public company.
Following the closing, Melodeon and ASRS will continue to appoint a majority of Pubco’s board and will retain the same level of voting control that they held in Cartiga prior to the transaction.
Accordingly, because Melodeon (via ASRS) controls Cartiga before the transaction and will continue to control Pubco after the transaction, the Business Combination qualifies as a common-control transaction under applicable accounting guidance.
Summary Risk Factors
ALCY believes it is important to communicate its expectations to its securityholders. However, there may be events in the future that neither ALCY nor Cartiga are able to predict accurately or over which they have control. The section in this proxy statement/prospectus entitled “Risk Factors” and the other cautionary language discussed in this proxy statement/prospectus provide examples of certain risks, uncertainties and events that may cause actual results to differ materially from the expectations described by ALCY or Cartiga in such forward-looking statements. Set forth below is only a summary of certain principal risks associated with an investment in our securities. You should carefully consider the following discussion of risks, as well as the discussion of risks included elsewhere in this proxy statement/prospectus, including those described under “Risk Factors.”
| ● | Cartiga depends on its management team and other key employees, and the loss of one or more of these employees or an inability to attract and retain highly skilled employees could adversely affect its business. |
| ● | Cartiga’s management team has limited experience managing a public company and regulatory compliance may divert their attention from the day-to-day management of Cartiga’s business. |
| ● | Material adverse developments in domestic and global economic conditions, or the occurrence of other world events, could materially adversely affect Cartiga’s revenue and results of operations. |
| ● | Catastrophic events, including those which impact third parties on which we materially rely, could materially adversely affect Cartiga’s business, results of operations and/or financial condition. |
| ● | ALCY has identified a material weakness in its internal control over financial reporting. If ALCY fails to remediate this material weakness, maintain effective internal control over financial reporting or identify additional material weaknesses in its internal control over financial reporting, ALCY’s ability to report its financial condition and results of operations in a timely and accurate manner could be adversely affected, investor confidence in ALCY could diminish, and the value of its stock may decline. |
| ● | Cartiga has identified a material weakness in its internal control over financial reporting. If Cartiga fails to remediate this material weakness, maintain effective internal control over financial reporting or identify additional material weaknesses in its internal control over financial reporting, Cartiga’s ability to report its financial condition and results of operations in a timely and accurate manner could be adversely affected, investor confidence in Cartiga could diminish, and the value of its stock may decline. |
| ● | The ability of Public Shareholders to exercise Redemption Rights with respect to a large number of Public Shares may adversely affect the liquidity and trading of Pubco securities following Closing. |
| ● | The price of Pubco Class A Common Stock may be volatile. |
| ● | Cartiga’s executive officers and directors will continue to exercise significant control over the company after the Business Combination, which will limit your ability to influence corporate matters and could delay or prevent a change in corporate control. |
| ● | The requirements of being a public company may strain Pubco’s resources and distract management and we will incur substantial costs as a result of being a public company. |
| ● | Sales of a substantial amount of Pubco Class A Common Stock in the public market, particularly sales by our executive officers, directors and significant stockholders, or the perception that these sales could occur, could cause the market price of Pubco Class A Common Stock to decline. |
| ● | A decline in the price of Pubco Class A Common Stock could affect the company’s ability to raise working capital and adversely impact the company’s ability to continue operations. |
| ● | Cartiga does not intend to pay any cash dividends in the foreseeable future and, therefore, any return on your investment in the company’s capital stock must come from increases in the fair market value and trading price of the capital stock. |
| ● | If the price of Pubco Class A Common Stock fluctuates after the Business Combination, you could lose a significant part of your investment. |
| ● | The public stockholders will experience immediate dilution as a consequence of the issuance of Pubco Class A Common Stock as consideration in the Business Combination and due to future issuances pursuant to the Cartiga Equity Incentive Plan. Having a minority share position may reduce the influence that ALCY’s current stockholders have on the management of Pubco. |
| ● | Pubco Warrants will become exercisable for Pubco Class A Common Stock, which would increase the number of shares eligible for future resale in the public market and result in dilution to our shareholders. Such dilution will increase if more Public Shares are redeemed. |
| ● | There can be no assurance that the shares of Pubco Class A Common Stock that will be issued in connection with the Business Combination will be approved for listing on Nasdaq following the Closing, or that Pubco will be able to comply with the continued listing rules of Nasdaq. |
| ● | Following the Business Combination, Pubco will be a “controlled company” within the meaning of Nasdaq listing standards and will comply with reduced corporate governance standards as a result. |
| ● | The future exercise of registration rights may adversely affect the market price of the Pubco Class A Common Stock. |
| ● | Even if the Business Combination is consummated, the Public Warrants may never be in the money, and they may expire worthless and the terms of the warrants may be amended in a manner adverse to a holder if holders of at least 50% of the then outstanding Public Warrants approve of such amendment. |
| ● | Pubco may redeem your unexpired Pubco Warrants prior to their exercise at a time that is disadvantageous to you, thereby making your Pubco Warrants worthless. |
| ● | The Pubco Warrants may have an adverse effect on the market price of the Pubco Class A Common Stock. |
| ● | Pubco will be a holding company and its only material asset after completion of the business combination will be its interest in OpCo, and it will therefore be dependent upon distributions made by OpCo to pay taxes, and make payments under the Tax Receivable Agreement and for other expenses. |
| ● | Pubco will be required to pay the Cartiga Members and any other persons that become parties to the Tax Receivable Agreement for certain tax benefits Pubco may receive, and the amounts payable may be substantial. |
| ● | To the extent Pubco receives tax distributions in excess of its actual tax liabilities and retains such excess cash, the Cartiga Members may benefit from such accumulated cash balances if they exercise their exchange rights. |
| ● | If OpCo were to become a publicly traded partnership taxable as a corporation for U.S. federal income tax purposes, Pubco and OpCo might be subject to potentially significant tax inefficiencies, and Pubco would not be able to recover payments previously made by it under the Tax Receivable Agreement even if the corresponding tax benefits were subsequently determined to have been unavailable due to such status. |
| ● | Increases in applicable tax rates, changes in applicable tax laws or disagreements with tax authorities can adversely affect Pubco’s business, financial condition or results of operations. |
| ● | Pubco will be a “smaller reporting company” and “emerging growth company” under the U.S. federal securities laws, and the reduced reporting requirements applicable to smaller reporting companies and emerging growth companies could make our common stock less attractive to investors. |
| ● | We are required by the Nasdaq Listing Rules to consummate a Business Combination within 36 months of the effectiveness of our IPO Registration Statement. In the event we do not consummate a Business Combination within this time period, our securities could be subject to delisting. |
| ● | The Sponsor has agreed to vote in favor of the Business Combination, regardless of how ALCY’s Public Shareholders vote. |
| ● | Since the Sponsor and ALCY’s directors and officers have interests that are different, or in addition to (and which may conflict with), the interests of our shareholders, a conflict of interest may have existed in determining whether the Business Combination with Cartiga is appropriate as our initial business combination. Such interests include that the Sponsor will lose its entire investment in us if our business combination is not completed. |
| ● | The exercise of ALCY’s directors’ and officers’ discretion in agreeing to changes or waivers in the terms of the Business Combination may result in a conflict of interest when determining whether such changes to the terms of the Business Combination or waivers of conditions are appropriate and in ALCY’s shareholders’ best interest. |
| ● | The historical financial results of Cartiga and unaudited condensed combined pro forma financial information included elsewhere in this proxy statement/prospectus may not be indicative of what Pubco’s actual financial position or results of operations would have been. |
| ● | If third parties bring claims against us, the proceeds held in the Trust Account could be reduced and the per share redemption amount received by shareholders may be less than $10.00 per share (which was the offering price per ALCY Unit in ALCY’s IPO). |
| ● | The process of taking a company public by means of a business combination with a SPAC is different from taking a company public through an underwritten public offering and may create risks for unaffiliated investors. |
| ● | Upon consummation of the Business Combination, the rights of holders of Pubco Class A Common Stock arising under the DGCL as well as Proposed Organizational Documents will differ from and may be less favorable to the rights of holders of ALCY Class A Ordinary Shares arising under the Companies Act as well as our Current M&A. |
Alchemy Investments Acquisition Corp 1 (“ALCY”)
ALCY is a blank check company incorporated on October 27, 2021 as a Cayman Islands exempted company formed for the purpose of effecting a merger, share exchange, asset acquisition, share purchase, reorganization or similar business combination with one or more businesses.
ALCY Class A ordinary shares, ALCY Units and ALCY Warrants are currently trading on OTC under the symbols “ALCYF,” “ALCUF” and “ALCWF,” respectively.
The mailing address of ALCY’s principal executive office is 850 Library Avenue, Suite 204-F, Newark, Delaware. Its telephone number is (212) 877-1588. ALCY’s corporate website address is www.alchemyinvest.co. ALCY’s website and the information contained on, or that can be accessed through, the website is not deemed to be incorporated by reference in, and is not considered part of, this proxy statement/prospectus.
Alchemy Acquisition Holdings, Inc. (“Pubco”)
Alchemy Acquisition Holdings, Inc., a Delaware corporation, is a wholly-owned subsidiary of ALCY formed solely for the purpose of effecting the Domestication and the Business Combination. Pursuant to the Domestication, ALCY will merge with and into Alchemy Acquisition Holdings, Inc. with Pubco being the surviving entity. Alchemy Acquisition Holdings, Inc. was incorporated in Delaware on June 11, 2025. Alchemy Acquisition Holdings, Inc. owns no material assets and does not operate any business. The mailing address of Alchemy Acquisition Holdings, Inc.’s principal executive office is located at 850 Library Avenue, Suite 204-F, Newark, Delaware. Its telephone number is (212) 877-1588.
Newco
Alchemy Merger Sub, LLC, is a Delaware limited liability company and wholly-owned subsidiary of Pubco (“Newco”). Pursuant to the Merger, Newco will merge with and into Cartiga with Cartiga being the surviving entity and continuing as a controlled subsidiary of Pubco. Newco was formed in Delaware on June 11, 2025. Newco owns no material assets and does not operate any business.
Cartiga, LLC (“Cartiga”)
Cartiga is a Delaware limited liability company in the business of originating and managing assets linked to (or secured by) consumer and commercial litigation claims and related receivables.
Cartiga’s principal executive office is located at 400 Park Avenue, 12th Floor, New York, NY 10022 and its telephone number is 1-866-733-2416. Cartiga’s corporate website address is www.cartiga.com. Cartiga’s website and the information contained on, or that can be accessed through, the website is not deemed to be incorporated by reference in, and is not considered part of, this proxy statement/prospectus.
The Proposals to be Submitted at the Extraordinary General Meeting
On August 22, 2025, ALCY (or “Parent”), entered into a business combination agreement (as it may be amended and/or restated from time to time, the “Business Combination Agreement”), by and among Alchemy Acquisition Holdings, Inc., a Delaware corporation and wholly-owned subsidiary of ALCY (“Pubco”), Alchemy Merger Sub, LLC, a Delaware limited liability company and wholly-owned subsidiary of Pubco (“Newco”), Cartiga, LLC, a Delaware limited liability company (the “Company”) and Halle Benett, as the representative (the “Sellers’ Representative”) of holders of the Company’s securities (the “Sellers”).
Proposal No. 1 — The Business Combination Proposal
As discussed in this proxy statement/prospectus, ALCY is asking its shareholders to approve by ordinary resolution and adopt the Business Combination Agreement, a copy of which is attached to this proxy statement/prospectus as Annex A. The Business Combination Agreement provides for, among other things, (a) ALCY will domesticate from the Cayman Islands to Delaware by merging with and into Pubco with Pubco surviving the merger and changing its name to Cartiga Holdings, Inc. (the “Domestication”), (b) after the Domestication, Newco will merge with and into the Company with the Company surviving the merger (hereinafter sometimes referred to as “OpCo”) and continue its existence under the Delaware Limited Liability Company Act (the “LLC Act”), and OpCo becoming a controlled subsidiary of Pubco (the “Merger”); and (c) the existing limited liability company agreement of OpCo will be amended and restated in the form attached to the Business Combination Agreement, to, among other things, make Pubco the sole managing member of OpCo. The Merger and the other transactions contemplated by the Business Combination Agreement are collectively referred to as the “Business Combination,” and as a result of the Business Combination, Pubco will be the publicly traded reporting company in an “Up-C” structure, with two classes of common stock, changing its name to “Cartiga Holdings, Inc.” and sometimes referred to herein as “New Cartiga.” In connection with the Domestication, (i) after giving effect to redemptions occurring in connection with the Business Combination, each ALCY Class A Ordinary Share will convert automatically, on a one-for-one basis, into one share of Class A common stock, par value $0.0001 per share, of Pubco (each a share of “Pubco Class A Common Stock”); (ii) each then issued and outstanding
ALCY Warrant will become exercisable for one share of Pubco Class A Common Stock (each a “Pubco Warrant”), pursuant to the Warrant Agreement, dated as of May 4, 2023, by and between ALCY and Continental Stock Transfer & Trust Company, as warrant agent, and (iii) each then issued and outstanding ALCY Unit shall separate and convert automatically into one share of Pubco Class A Common Stock, and one-half of one Pubco Warrant, the result being that every outstanding ALCY Class A Ordinary Share, ALCY Class B Ordinary Share, ALCY Preference Share, ALCY Unit and ALCY Warrant shall convert to an equal number of shares of Pubco Class A Common Stock, shares of Pubco Class B Common Stock, shares of Pubco Preferred Stock, Pubco Units and Pubco Warrants, respectively. For more information, see “The Domestication Merger Proposal.”
Following the Domestication of ALCY to the State of Delaware, Newco will merge with and into Cartiga, with Cartiga surviving the Merger in accordance with the terms and subject to the conditions of the Business Combination Agreement, as more fully described elsewhere in this proxy statement/prospectus. Following the Merger, the separate limited liability company existence of Newco shall cease, and Cartiga (the Company) shall continue as the OpCo. At the Effective Time, the existing limited liability company agreement of OpCo will be amended and restated in the form attached to the Business Combination Agreement to, among other things, make Pubco the sole managing member of OpCo. After consideration of the factors identified and discussed in “The Business Combination Proposal — ALCY Board of Directors’ Reasons for the Approval of the Business Combination,” the ALCY Board concluded that the Business Combination met the requirements disclosed in the prospectus related to the IPO. For more information about the transactions contemplated by the Business Combination Agreement, see “The Business Combination Proposal.”
Recommendation to Shareholders of ALCY
The ALCY Board believes that the Business Combination Proposal and the other proposals to be presented at the extraordinary general meeting are in the best interests of ALCY and ALCY’s shareholders and unanimously recommends that its shareholders vote “FOR” the approval of the Business Combination Proposal, “FOR” the approval of the Domestication Merger Proposal, “FOR” the approval of the Stock Issuance Proposal, “FOR” the approval of the Organizational Documents Proposal, “FOR” the approval, on an advisory basis, of each of the separate Advisory Organizational Documents Proposals, “FOR” the approval of the Equity Incentive Plan Proposal and “FOR” the approval of the Adjournment Proposal, if presented to the extraordinary general meeting.
The existence of financial and personal interests of one or more of ALCY’s directors may result in a conflict of interest on the part of such director(s) between what he, she or they may believe is in the best interests of ALCY and its shareholders and what he, she or they may believe is best for himself, herself or themselves in determining to recommend that shareholders vote for the proposals. In addition, ALCY’s officers have interests in the Proposed Transaction that may conflict with your interests as a shareholder. See “The Business Combination Proposal — Certain Interests of ALCY’s Directors and Officers and Others in the Business Combination.”
The ALCY Board did not obtain a third-party valuation or fairness opinion in connection with their determination to approve the Business Combination with Cartiga. The directors and officers of ALCY and ALCY’s advisors have substantial experience in evaluating the operating and financial merits of companies from a wide range of industries and concluded that their experience and backgrounds, together with the experience and sector expertise of ALCY’s financial advisors and consultants, enabled them to make the necessary analyses and determinations regarding the Business Combination with Cartiga. In addition, ALCY’s directors and officers and ALCY’s advisors have substantial experience with mergers and acquisitions. Accordingly, investors will be relying solely on the judgment of the ALCY Board and ALCY’s advisors in valuing Cartiga’s business.
Dilutive Instruments
The table below shows possible sources of dilution and the extent of such dilution that non-redeeming Public Shareholders could experience in connection with the closing of the Business Combination. In an effort to illustrate the extent of such dilution, the table below assumes the exercise of all Public Warrants which are exercisable for one share of common stock at a price of $11.50 per share.
None | 25% | 50% | 75% | Maximum |
| ||||||||||||||||
Redemptions | Shares | % | Shares | % | Shares | % | Shares | % | Shares | % |
| ||||||||||
ALCY Public Shareholders(1) | | 737,543 | | 1.17 | % | 553,157 | | 0.88 | % | 368,772 | | 0.59 | % | 184,386 | | 0.29 | % | 0 | | 0.00 | % |
Sponsor and Cantor(2) |
| 1,757,500 |
| 2.78 | % | 1,757,500 |
| 2.79 | % | 1,757,500 |
| 2.80 | % | 1,757,500 |
| 2.80 | % | 1,757,500 |
| 2.81 | % |
Public Warrants (assumed exercise) |
| 5,750,000 |
| 9.10 | % | 5,750,000 |
| 9.12 | % | 5,750,000 |
| 9.15 | % | 5,750,000 |
| 9.18 | % | 5,750,000 |
| 9.20 | % |
Related party settlement shares |
| 254,419 |
| 0.40 | % | 254,419 |
| 0.40 | % | 254,419 |
| 0.40 | % | 254,419 |
| 0.41 | % | 254,419 |
| 0.41 | % |
Cartiga Unit Holders(3) |
| 54,000,000 |
| 85.42 | % | 54,000,000 |
| 85.67 | % | 54,000,000 |
| 85.92 | % | 54,000,000 |
| 86.17 | % | 54,000,000 |
| 86.43 | % |
Fee settlement shares | 717,500 | 1.13 | % | 717,500 | 1.14 | % | 717,500 | 1.14 | % | 717,500 | 1.14 | % | 717,500 | 1.15 | % | ||||||
Fully Diluted Shares(4) |
| 63,216,962 |
| 100 | % | 63,032,576 |
| 100 | % | 62,848,191 |
| 100 | % | 62,663,805 |
| 100 | % | 62,479,419 |
| 100 | % |
(1) | Includes the Public Shares outstanding at June 30, 2026 that are assumed not to be redeemed under the illustrative scenario shown. Later redemptions of 548,987 Public Shares are not reflected in this June 30 presentation. |
(2) | Includes 1,700,000 Sponsor Shares, after the assumed forfeiture of 1,713,000 shares (3,413,000 less 1,700,000) under Section 8.17 of the Business Combination Agreement, assuming Available Closing Buyer Cash below $5,000,000 and waiver of the minimum cash condition, and 57,500 existing shares held by Cantor Fitzgerald & Co. |
(3) | Represents the number of shares of Pubco Class A Common Stock that would be issued assuming the exchange of the OpCo Units (together with the corresponding Pubco Class B Common Stock) held by the Company Equity Interest Holders for Pubco Class A Common Stock pursuant to the Exchange Agreement. |
(4) | Fully diluted shares equal the sum of the rows above. Existing related party payables of $2,544,189 are assumed settled through 254,419 Class A shares at $10.00 per share, and $7,175,000 of transaction fees through 717,500 shares. These shares are included once. The separate, undrawn Working Capital Loan facility permits conversion of up to $1.5 million at $10.00 per share (150,000 shares); no additional borrowing or conversion under that facility is assumed. No PIPE shares are assumed. The related party share settlement and $10.00 price are illustrative assumptions only; actual settlement may be in cash if additional financing is obtained, or in another form of compensation, including shares, on terms and conditions to be determined by agreement with the holders. |
Supplemental Ownership Information Reflecting the September 2026 Redemptions
Following the redemption of 548,987 Public Shares in September 2026, 188,556 Public Shares remained outstanding, compared with 737,543 Public Shares outstanding at June 30, 2026. The following supplemental tables illustrate ownership of Pubco Common Stock on an as-exchanged basis after giving effect to those completed redemptions.
The “No Further Redemptions” scenario assumes that none of the remaining 188,556 Public Shares are redeemed in connection with the Business Combination. The other scenarios assume further redemptions of 25%, 50%, 75% and 100% of those remaining Public Shares. The assumptions regarding Sponsor share forfeiture and the illustrative issuance of shares to settle transaction fees and related party payables remain consistent with the tables above.
Ownership Excluding the Exercise of Public Warrants
| No Further | 25% Further | 50% Further | 75% Further | | Maximum Further | |||||||||||||||
Redemptions | Redemptions | Redemptions | Redemptions | Redemptions | |||||||||||||||||
Shares | | % | Shares | | % | Shares | | % | Shares | | % | Shares | | % | |||||||
ALCY Public Shareholders(1) | 188,556 | 0.3 | % | 141,417 | 0.2 | % | 94,278 | 0.2 | % | 47,139 | 0.1 | % | 0 | 0.0 | % | ||||||
Sponsor and Cantor(2) | 1,757,500 | 3.1 | % | 1,757,500 | 3.1 | % | 1,757,500 | 3.1 | % | 1,757,500 | 3.1 | % | 1,757,500 | 3.1 | % | ||||||
Cartiga Unit Holders(3) | 54,000,000 | 94.9 | % | 54,000,000 | 95.0 | % | 54,000,000 | 95.0 | % | 54,000,000 | 95.1 | % | 54,000,000 | 95.2 | % | ||||||
Fee settlement shares | 717,500 | 1.3 | % | 717,500 | 1.3 | % | 717,500 | 1.3 | % | 717,500 | 1.3 | % | 717,500 | 1.3 | % | ||||||
Related party settlement shares | 254,419 | 0.4 | % | 254,419 | 0.4 | % | 254,419 | 0.4 | % | 254,419 | 0.4 | % | 254,419 | 0.4 | % | ||||||
Total(4) | 56,917,975 | 100 | % | 56,870,836 | 100 | % | 56,823,697 | 100 | % | 56,776,558 | 100 | % | 56,729,419 | 100 | % | ||||||
Ownership Including the Assumed Exercise of Public Warrants
| No Further | 25% Further | 50% Further | 75% Further | | Maximum Further | |||||||||||||||
Redemptions | Redemptions | Redemptions | Redemptions | Redemptions | |||||||||||||||||
Shares | | % | Shares | | % | Shares | | % | Shares | | % | Shares | | % | |||||||
ALCY Public Shareholders(1) | 188,556 | 0.30 | % | 141,417 | 0.23 | % | 94,278 | 0.15 | % | 47,139 | 0.08 | % | 0 | 0.00 | % | ||||||
Sponsor and Cantor(2) | 1,757,500 | 2.80 | % | 1,757,500 | 2.81 | % | 1,757,500 | 2.81 | % | 1,757,500 | 2.81 | % | 1,757,500 | 2.81 | % | ||||||
Public Warrants (assumed exercise) | 5,750,000 | 9.18 | % | 5,750,000 | 9.18 | % | 5,750,000 | 9.19 | % | 5,750,000 | 9.20 | % | 5,750,000 | 9.20 | % | ||||||
Related party settlement shares | 254,419 | 0.41 | % | 254,419 | 0.41 | % | 254,419 | 0.41 | % | 254,419 | 0.41 | % | 254,419 | 0.41 | % | ||||||
Cartiga Unit Holders(3) | 54,000,000 | 86.17 | % | 54,000,000 | 86.23 | % | 54,000,000 | 86.30 | % | 54,000,000 | 86.36 | % | 54,000,000 | 86.43 | % | ||||||
Fee settlement shares | 717,500 | 1.14 | % | 717,500 | 1.15 | % | 717,500 | 1.15 | % | 717,500 | 1.15 | % | 717,500 | 1.15 | % | ||||||
Fully Diluted Shares(4) | 62,667,975 | 100 | % | 62,620,836 | 100 | % | 62,573,697 | 100 | % | 62,526,558 | 100 | % | 62,479,419 | 100 | % | ||||||
(1) | Represents the 188,556 Public Shares remaining outstanding following the September 2026 redemptions, less any further redemptions assumed under the applicable scenario. The redemption percentages shown apply solely to those remaining Public Shares. |
(2) | Includes 1,700,000 Sponsor Shares after the assumed forfeiture of 1,713,000 Sponsor Shares, and 57,500 existing shares held by Cantor Fitzgerald & Co., consistent with the assumptions described above. |
(3) | Cartiga Unit Holders are presented on an as-exchanged basis, assuming the exchange of their OpCo Units and corresponding shares of Pubco Class B Common Stock for shares of Pubco Class A Common Stock pursuant to the Exchange Agreement. |
(4) | Includes the illustrative issuance of 717,500 Class A shares to settle transaction fees and 254,419 Class A shares to settle existing related party payables, subject to the assumptions and qualifications described in the tables above. No PIPE financing or |
additional borrowing or conversion under the undrawn Working Capital Loan facility is assumed. The second table also includes 5,750,000 shares issuable upon the assumed exercise of the Public Warrants, using the same share-count methodology as the existing warrant dilution table.
Calculation of Pro Forma Net Tangible Book Value
The following table represents the calculation of the adjusted net book value which will be used to calculate the net tangible book value per share as of June 30, 2026. The amounts are drawn from the pro forma combined balance sheet and already reflect the assumed fee and related party payable share settlements and transaction expenses; no duplicate deduction is made.
As of June 30, 2026:
As of June 30, 2026 | | | No redemptions |
Pro forma combined total assets | $ | 627,228,000 | |
Less goodwill | $ | (35,602,000) | |
Less intangible assets | $ | (10,477,000) | |
Less pro forma combined total liabilities | $ | (392,934,000) | |
Pro forma net tangible book value | $ | 188,215,000 |
Net Tangible Book Value Per Share and Dilution
As of June 30, 2026, the net tangible book value per share of ALCY was $(0.59). After giving effect to the business combination with Cartiga and assuming no redemptions, the pro forma net tangible book value per share on the fully diluted, as-exchanged basis described below would be $2.98. This represents an immediate increase in net tangible book value of $3.57 per share for existing ALCY shareholders, and an immediate dilution of $7.02 per share to investors purchasing shares at the transaction price of $10.00 per share.
Pro Forma Net Tangible Book Value and Dilution Table
The following table presents pro forma net tangible book value per share and dilution under various redemption scenarios, using an illustrative redemption price of $12.34 per share ($9,103,236 in trust at June 30, 2026 divided by 737,543 Public Shares). Shares outstanding are presented on a fully diluted, as-exchanged basis and include 5,750,000 shares issuable upon exercise of the Public Warrants and the illustrative fee and related party payable settlement shares. No hypothetical Public Warrant exercise proceeds are added to NTBV.
| No redemptions | | 25% | | 50% | | 75% | | Maximum | ||||||
Trust Remaining | $ | 9,103,236 | $ | 6,827,427 | $ | 4,551,618 | $ | 2,275,809 | $ | 0 | |||||
Pro Forma NTBV | $ | 188,215,000 | $ | 185,938,750 | $ | 183,662,500 | $ | 181,386,250 | $ | 179,110,000 | |||||
Shares Outstanding (fully diluted) | 63,216,962 | 63,032,576 | 62,848,191 | 62,663,805 | 62,479,419 | ||||||||||
NTBV per Share | $ | 2.98 | $ | 2.95 | $ | 2.92 | $ | 2.89 | $ | 2.87 | |||||
Redemption Price | $ | 12.34 | $ | 12.34 | $ | 12.34 | $ | 12.34 | $ | 12.34 | |||||
Dilution per Share | $ | 9.37 | $ | 9.39 | $ | 9.42 | $ | 9.45 | $ | 9.48 | |||||
Based on the revised June 30, 2026 pro forma balance sheet and the redemption scenarios presented. Estimated transaction fee budgets total $11,875,000 before payments, including $9,675,000 for ALCY (including $500,000 of other closing expenses for Toppan, Continental and other vendors) and $2,200,000 for Cartiga. Remaining costs at Closing total $10,222,640.70, comprising $9,425,000 for ALCY and $797,640.70 for Cartiga. The model assumes $7,175,000 is settled in shares and $3,047,640.70 in cash. Related party debt and payable settlement is separate from these transaction costs.
The table above sets forth pro forma net tangible book value per share and resulting dilution measured against the illustrative redemption price of $12.34 per share. Assuming no redemptions, pro forma net tangible book value per share would be $2.98, resulting in dilution of $9.37 per share. Assuming maximum redemptions, pro forma net tangible book value per share would be $2.87, resulting in dilution of $9.48 per share.
The actual dilution experienced will depend on the number of public shares redeemed in connection with the business combination.
None of ALCY’s shareholders, or ALCY’s warrant holders have appraisal rights in connection with the Proposed Transaction or the Domestication under Cayman Islands law or the DGCL. ALCY’s shareholders do not have dissenters’ rights in connection with the Proposed Transaction or the Domestication under Cayman Islands law.
Interests of ALCY Directors, Officers and Others in the Proposed Transaction
When you consider the recommendation of the ALCY Board in favor of approval of the Business Combination Proposal, you should keep in mind that the Sponsor, ALCY’s directors and executive officers and others have interests in such proposal that are different from, or in addition to, those of ALCY shareholders and holders of Public Warrants generally. See “The Business Combination Proposal — Certain Interests of ALCY’s Directors and Officers and Others in the Business Combination.”
| Interest in Securities | | Other Compensation | |
Sponsor | Alchemy DeepTech Capital LLC, the Sponsor, and its affiliates paid $50,000, or approximately $0.02 per share, for its 2,875,000 founder shares purchased in connection with ALCY’s formation, and 538,000 Class A ordinary shares purchased for $10.00 per share in a private placement that closed at the time of the IPO. At Closing of the Business Combination, the Sponsor shall hold a total of up to 3,413,000 shares of the Pubco Class A Common Stock depending on how much is raised in the PIPE financing. If Available Closing Buyer Cash is less than $5,000,000 , then, as a result of Cartiga’s waiver of the Minimum Cash Condition on October 22, 2026, and pursuant to Section 8.17 of the Business Combination Agreement, the Sponsor shall forfeit 1,713,000 of its shares and hold a minimum of 1,700,000 shares of Pubco Class A Common Stock. | At Closing, pursuant to the Business Combination Agreement, Pubco will use cash from the Trust Account to pay any merger transaction expenses and to reimburse or pay the Sponsor or its affiliates for any outstanding Sponsor Promissory Notes, Working Capital Loans or other obligations of ALCY to the Sponsor or its affiliates. Unless the parties obtain additional financing sufficient to repay the Sponsor Promissory Notes in cash at Closing, ALCY and the relevant holders will agree on an alternative form of compensation, which may include shares, on terms and conditions to be determined. Outstanding principal under the Sponsor Promissory Notes was $2,186,000 as of June 30, 2026, excluding $263,006 of accrued interest and $95,183 of accrued related party expenses. Transaction costs are presented separately above. |
An affiliate of the Sponsor is receiving $10,000 monthly for administrative services in connection with the business combination. |
The retention of shares by the Sponsor and the reimbursements payable to the Sponsor at Closing will not result in a material dilution of the equity interests of non-redeeming ALCY stockholders. See “The Business Combination Proposal — Ownership of Pubco after the Closing.”
Calculation of Pro Forma Net Tangible Book Value
The following table represents the calculation of the adjusted net book value which will be used to calculate the net tangible book value per share as of June 30, 2026. The amounts are drawn from the pro forma combined balance sheet and already reflect the assumed fee and related party payable share settlements and transaction expenses; no duplicate deduction is made.
As of June 30, 2026:
As of June 30, 2026 | | | No redemptions |
Pro forma combined total assets | $ | 627,228,000 | |
Less goodwill | $ | (35,602,000) | |
Less intangible assets | $ | (10,477,000) | |
Less pro forma combined total liabilities | $ | (392,934,000) | |
Pro forma net tangible book value | $ | 188,215,000 |
Net Tangible Book Value Per Share and Dilution
As of June 30, 2026, the net tangible book value per share of ALCY was $(0.59). After giving effect to the business combination with Cartiga and assuming no redemptions, the pro forma net tangible book value per share on the fully diluted, as-exchanged basis described below would be $2.98. This represents an immediate increase in net tangible book value of $3.57 per share for existing ALCY shareholders, and an immediate dilution of $7.02 per share to investors purchasing shares at the transaction price of $10.00 per share.
Pro Forma Net Tangible Book Value and Dilution Table
The following table presents pro forma net tangible book value per share and dilution under various redemption scenarios, using an illustrative redemption price of $12.34 per share ($9,103,236 in trust at June 30, 2026 divided by 737,543 Public Shares). Shares outstanding are presented on a fully diluted, as-exchanged basis and include 5,750,000 shares issuable upon exercise of the Public Warrants and the illustrative fee and related party payable settlement shares. No hypothetical Public Warrant exercise proceeds are added to NTBV.
| No redemptions | | 25% | | 50% | | 75% | | Maximum | ||||||
Trust Remaining | $ | 9,103,236 | $ | 6,827,427 | $ | 4,551,618 | $ | 2,275,809 | $ | 0 | |||||
Pro Forma NTBV | $ | 188,215,000 | $ | 185,938,750 | $ | 183,662,500 | $ | 181,386,250 | $ | 179,110,000 | |||||
Shares Outstanding (fully diluted) | 63,216,962 | 63,032,576 | 62,848,191 | 62,663,805 | 62,479,419 | ||||||||||
NTBV per Share | $ | 2.98 | $ | 2.95 | $ | 2.92 | $ | 2.89 | $ | 2.87 | |||||
Redemption Price | $ | 12.34 | $ | 12.34 | $ | 12.34 | $ | 12.34 | $ | 12.34 | |||||
Dilution per Share | $ | 9.37 | $ | 9.39 | $ | 9.42 | $ | 9.45 | $ | 9.48 | |||||
Based on the revised June 30, 2026 pro forma balance sheet and the redemption scenarios presented. Estimated transaction fee budgets total $11,875,000 before payments, including $9,675,000 for ALCY (including $500,000 of other closing expenses for Toppan, Continental and other vendors) and $2,200,000 for Cartiga. Remaining costs at Closing total $10,222,640.70, comprising $9,425,000 for ALCY and $797,640.70 for Cartiga. The model assumes $7,175,000 is settled in shares and $3,047,640.70 in cash. Related party debt and payable settlement is separate from these transaction costs.
The table above sets forth pro forma net tangible book value per share and resulting dilution measured against the illustrative redemption price of $12.34 per share. Assuming no redemptions, pro forma net tangible book value per share would be $2.98, resulting in dilution of $9.37 per share. Assuming maximum redemptions, pro forma net tangible book value per share would be $2.87, resulting in dilution of $9.48 per share.
The actual dilution experienced will depend on the number of public shares redeemed in connection with the business combination.
None of ALCY’s shareholders, or ALCY’s warrant holders have appraisal rights in connection with the Proposed Transaction or the Domestication under Cayman Islands law or the DGCL. ALCY’s shareholders do not have dissenters’ rights in connection with the Proposed Transaction or the Domestication under Cayman Islands law.
The following table presents pro forma net tangible book value per share and dilution under various redemption scenarios, using an illustrative redemption price of $12.34 per share ($9,103,236 in trust at June 30, 2026 divided by 737,543 Public Shares). Shares outstanding are presented on a fully diluted, as-exchanged basis and include 5,750,000 shares issuable upon exercise of the Public Warrants and the illustrative fee and related party payable settlement shares. No hypothetical Public Warrant exercise proceeds are added to NTBV.
| No redemptions | | 25% | | 50% | | 75% | | Maximum | ||||||
Trust Remaining | $ | 9,103,236 | $ | 6,827,427 | $ | 4,551,618 | $ | 2,275,809 | $ | 0 | |||||
Pro Forma NTBV | $ | 188,215,000 | $ | 185,938,750 | $ | 183,662,500 | $ | 181,386,250 | $ | 179,110,000 | |||||
Shares Outstanding (fully diluted) | 63,216,962 | 63,032,576 | 62,848,191 | 62,663,805 | 62,479,419 | ||||||||||
NTBV per Share | $ | 2.98 | $ | 2.95 | $ | 2.92 | $ | 2.89 | $ | 2.87 | |||||
Redemption Price | $ | 12.34 | $ | 12.34 | $ | 12.34 | $ | 12.34 | $ | 12.34 | |||||
Dilution per Share | $ | 9.37 | $ | 9.39 | $ | 9.42 | $ | 9.45 | $ | 9.48 | |||||
Based on the revised June 30, 2026 pro forma balance sheet and the redemption scenarios presented. Estimated transaction fee budgets total $11,875,000 before payments, including $9,675,000 for ALCY (including $500,000 of other closing expenses for Toppan, Continental and other vendors) and $2,200,000 for Cartiga. Remaining costs at Closing total $10,222,640.70, comprising $9,425,000 for ALCY and $797,640.70 for Cartiga. The model assumes $7,175,000 is settled in shares and $3,047,640.70 in cash. Related party debt and payable settlement is separate from these transaction costs.