Exhibit 99.1
BIDDANCE AI SYSTEMS, INC. AND SUBSIDIARIES
INDEX TO UNAUDITED CONDENSED CONSOLIDATED FINANCIAL STATEMENTS
| F-1 |
BIDDANCE AI SYSTEMS, INC. AND SUBSIDIARIES
UNAUDITED CONDENSED CONSOLIDATED BALANCE SHEETS
(Expressed in U.S. Dollars, except for the number of shares)
| June 30, 2026 | December 31, 2025 | |||||||
| (Unaudited) | ||||||||
| Assets | ||||||||
| Current assets | ||||||||
| Cash and cash equivalents | $ | 17,088,014 | $ | 3,611,999 | ||||
| Short-term investments | 19,970,243 | 18,364,219 | ||||||
| Accounts receivable, net | 5,350,006 | 5,407,989 | ||||||
| Advances to suppliers, net | 4,422 | 290,680 | ||||||
| Inventories, net | 85,568 | 79,411 | ||||||
| Loans receivable | 589,528 | 6,020,220 | ||||||
| Other receivable | 5,846,247 | 6,846,247 | ||||||
| Prepaid expenses and other current assets | 10,507 | 171,661 | ||||||
| Total current assets | 48,944,535 | 40,792,426 | ||||||
| Non-current assets | ||||||||
| Non-current accounts receivable, net | - | 1,027,421 | ||||||
| Non-current loans receivable | - | 285,996 | ||||||
| Property, equipment and software, net | 332,488 | 475,189 | ||||||
| Total non-current assets | 332,488 | 1,788,606 | ||||||
| Total Assets | $ | 49,277,023 | $ | 42,581,032 | ||||
| Liabilities and Shareholders’ Equity | ||||||||
| Current liabilities | ||||||||
| Accounts payable | $ | 255,982 | $ | 292,065 | ||||
| Loan payable – related party | - | 2,645,465 | ||||||
| Deferred revenue | 65,298 | 73,059 | ||||||
| Taxes payable | 1,832,077 | 1,795,736 | ||||||
| Accrued expenses and other current liabilities | 160,776 | 148,342 | ||||||
| Total current liabilities | 2,314,133 | 4,954,667 | ||||||
| Non-current Liabilities | ||||||||
| Deferred income tax liabilities, net | 1,559,142 | 1,616,053 | ||||||
| Total non-current liabilities | 1,559,142 | 1,616,053 | ||||||
| Total Liabilities | 3,873,275 | 6,570,720 | ||||||
| Commitments and Contingencies | - | - | ||||||
| Shareholders’ Equity | ||||||||
| Class A Ordinary Shares, US$0.375 par value; 800,000 shares authorized, 799,861 shares issued and outstanding as of June 30, 2026; 800,000 shares authorized, 5,629 shares issued and outstanding as of December 31, 2025* | 299,948 | 2,111 | ||||||
| Class B Ordinary Shares, US$0.0001 par value; 150,000,000 shares authorized, 8,192,000 shares issued and outstanding | 819 | 819 | ||||||
| Additional paid-in capital | 35,040,217 | 24,920,060 | ||||||
| Statutory reserve | 836,215 | 836,215 | ||||||
| Retained earnings | 9,301,135 | 10,671,200 | ||||||
| Accumulated other comprehensive loss | (74,586 | ) | (420,093 | ) | ||||
| Total Shareholders’ Equity | 45,403,748 | 36,010,312 | ||||||
| Total Liabilities and Shareholders’ Equity | $ | 49,277,023 | $ | 42,581,032 | ||||
| * | The shares data are presented on a retroactive basis to reflect the 1-for-25 reverse share split of the Class A ordinary shares effective on July 6, 2026 (Notes 14 and 19). |
The accompanying notes are an integral part of these condensed consolidated financial statements.
| F-2 |
BIDDANCE AI SYSTEMS, INC. AND SUBSIDIARIES
UNAUDITED CONDENSED CONSOLIDATED STATEMENTS OF OPERATIONS AND COMPREHENSIVE LOSS
(Expressed in U.S. Dollars, except for the number of shares)
| Six Months Ended June 30, | ||||||||
| 2026 | 2025 | |||||||
| (Unaudited) | (Unaudited) | |||||||
| Revenues | $ | 1,226,046 | $ | 741,541 | ||||
| Cost of revenues | (1,024,835 | ) | (567,675 | ) | ||||
| Gross profit | 201,211 | 173,866 | ||||||
| Operating expenses: | ||||||||
| General and administrative | 2,002,067 | 1,519,128 | ||||||
| Selling | 1,411 | 2,325 | ||||||
| Total operating expenses | 2,003,478 | 1,521,453 | ||||||
| Operating loss | (1,802,267 | ) | (1,347,587 | ) | ||||
| Other income (expense) | ||||||||
| Net investment gain | 102,363 | 82,463 | ||||||
| Interest income | 210,639 | 412,683 | ||||||
| Interest expense | - | (153,049 | ) | |||||
| Other income (expense), net | 14,337 | (11,501 | ) | |||||
| Total other income, net | 327,339 | 330,596 | ||||||
| Loss before income taxes | (1,474,928 | ) | (1,016,991 | ) | ||||
| Income tax benefit | (104,863 | ) | (100,882 | ) | ||||
| Net loss | $ | (1,370,065 | ) | $ | (916,109 | ) | ||
| Comprehensive loss | ||||||||
| Net loss | $ | (1,370,065 | ) | $ | (916,109 | ) | ||
| Foreign currency translation gain | 345,507 | 236,419 | ||||||
| Comprehensive loss | $ | (1,024,558 | ) | $ | (679,690 | ) | ||
| Loss per ordinary share | ||||||||
| Basic and diluted | $ | (0.16 | ) | $ | (0.11 | ) | ||
| Weighted average number of ordinary shares outstanding | ||||||||
| Basic and diluted* | 8,313,997 | 8,197,629 | ||||||
| * | The shares data are presented on a retroactive basis to reflect the 1-for-25 reverse share split of the Class A ordinary shares effective on July 6, 2026 (Notes 14 and 19). |
The accompanying notes are an integral part of these unaudited condensed consolidated financial statements.
| F-3 |
BIDDANCE AI SYSTEMS, INC. AND SUBSIDIARIES
UNAUDITED CONDENSED CONSOLIDATED STATEMENTS OF CHANGES IN SHAREHOLDERS’ EQUITY
Six Months Ended June 30, 2026 and 2025
(Expressed in U.S. Dollars, except for the number of shares)
| Class A Ordinary Shares* | Class B Ordinary Shares | Additional | Accumulated other | Total | ||||||||||||||||||||||||||||||||
| Number of shares | Amount | Number of shares | Amount | paid-in capital | Statutory reserve | Retained earnings | comprehensive loss | Shareholders’ Equity | ||||||||||||||||||||||||||||
| Balance as of December 31, 2024 | 5,629 | $ | 2,111 | 8,192,000 | $ | 819 | $ | 24,920,060 | $ | 836,215 | $ | 10,491,058 | $ | (975,343 | ) | $ | 35,274,920 | |||||||||||||||||||
| Foreign currency translation adjustment | - | - | - | - | - | - | - | 236,419 | 236,419 | |||||||||||||||||||||||||||
| Net loss | - | - | - | - | - | - | (916,109 | ) | - | (916,109 | ) | |||||||||||||||||||||||||
| Balance as of June 30, 2025 (unaudited) | 5,629 | $ | 2,111 | 8,192,000 | $ | 819 | $ | 24,920,060 | $ | 836,215 | $ | 9,574,949 | $ | (738,924 | ) | $ | 34,595,230 | |||||||||||||||||||
| Class A Ordinary Shares* | Class B Ordinary Shares | Additional | Accumulated other | Total | ||||||||||||||||||||||||||||||||
| Number of shares | Amount | Number of shares | Amount | paid-in capital | Statutory reserve | Retained earnings | comprehensive loss | Shareholders’ Equity | ||||||||||||||||||||||||||||
| Balance as of December 31, 2025 | 5,629 | $ | 2,111 | 8,192,000 | $ | 819 | $ | 24,920,060 | $ | 836,215 | $ | 10,671,200 | $ | (420,093 | ) | $ | 36,010,312 | |||||||||||||||||||
| Foreign currency translation adjustment | - | - | - | - | - | - | - | 345,507 | 345,507 | |||||||||||||||||||||||||||
| Issuance of ordinary shares | 794,232 | 297,837 | - | - | 10,120,157 | - | - | 10,417,994 | ||||||||||||||||||||||||||||
| Net loss | - | - | - | - | - | - | (1,370,065 | ) | - | (1,370,065 | ) | |||||||||||||||||||||||||
| Balance as of June 30, 2026 (unaudited) | 799,861 | $ | 299,948 | 8,192,000 | $ | 819 | $ | 35,040,217 | $ | 836,215 | $ | 9,301,135 | $ | (74,586 | ) | $ | 45,403,748 | |||||||||||||||||||
| * | The shares data are presented on a retroactive basis to reflect the 1-for-25 reverse share split of the Class A ordinary shares effective on July 6, 2026 (Notes 14 and 19). |
The accompanying notes are an integral part of these unaudited condensed consolidated financial statements.
| F-4 |
BIDDANCE AI SYSTEMS, INC. AND SUBSIDIARIES
UNAUDITED CONDENSED CONSOLIDATED STATEMENTS OF CASH FLOWS
(Expressed in U.S. Dollars)
| Six Months Ended June 30, | ||||||||
| 2026 | 2025 | |||||||
| (Unaudited) | (Unaudited) | |||||||
| Cash flows from operating activities: | ||||||||
| Net loss | $ | (1,370,065 | ) | $ | (916,109 | ) | ||
| Adjustments to reconcile net loss to net cash (used in) provided by operating activities: | ||||||||
| Depreciation and amortization | 154,064 | 145,775 | ||||||
| Loss on disposal of property, plant and equipment | 1,433 | - | ||||||
| Accrued interest income from loans, net | - | (104,790 | ) | |||||
| Net investment gain | (55,640 | ) | (66,820 | ) | ||||
| Provision for expected credit losses of receivables | 506,980 | 482,621 | ||||||
| Provision for obsolete inventories | 2,019 | 3,832 | ||||||
| Deferred income tax | (105,252 | ) | (100,882 | ) | ||||
| Changes in operating assets and liabilities: | ||||||||
| Short-term investments - trading securities | (1,312,113 | ) | 2,427,711 | |||||
| Accounts receivable | 710,590 | 1,044,167 | ||||||
| Advance to suppliers | 291,845 | (2,272,803 | ) | |||||
| Inventories | (5,700 | ) | 12,483 | |||||
| Prepaid expenses and other current assets | 164,540 | 265,122 | ||||||
| Accounts payable | (42,330 | ) | (50,983 | ) | ||||
| Advance from customers | - | 291,466 | ||||||
| Deferred revenue | (9,888 | ) | (16,056 | ) | ||||
| Tax payable | (18,497 | ) | 5,781 | |||||
| Due to related parties | - | 16,546 | ||||||
| Accrued expenses and other current liabilities | 7,798 | (13,461 | ) | |||||
| Net cash (used in) provided by operating activities | (1,080,216 | ) | 1,153,600 | |||||
| Cash flows from investing activities: | ||||||||
| Loans to third parties | (291,443 | ) | (413,645 | ) | ||||
| Loans repayment by third parties | 3,439,030 | 137,882 | ||||||
| Purchases of held-to-maturity investments | (1,000,000 | ) | (1,650,000 | ) | ||||
| Redemption of held-to-maturity investments | 2,000,000 | 700,000 | ||||||
| Refund of deposit for acquisition | - | 1,000,000 | ||||||
| Net cash provided by (used in) investing activities | 4,147,587 | (225,763 | ) | |||||
| Cash flows from financing activities: | ||||||||
| Proceeds from issuance of ordinary shares | 10,417,994 | - | ||||||
| Net cash provided by financing activities | 10,417,994 | - | ||||||
| Effect of exchange rate changes on cash | (9,350 | ) | 33,690 | |||||
| Net increase in cash | 13,476,015 | 961,527 | ||||||
| Cash and cash equivalents at the beginning of period | 3,611,999 | 7,236,798 | ||||||
| Cash and cash equivalents at the end of period | $ | 17,088,014 | $ | 8,198,325 | ||||
| Supplemental disclosures of cash flow information: | ||||||||
| Cash paid for income taxes | $ | - | $ | - | ||||
| Cash paid for interest | $ | - | $ | - | ||||
The accompanying notes are an integral part of these unaudited condensed consolidated financial statements.
| F-5 |
BIDDANCE AI SYSTEMS, INC. AND SUBSIDIARIES
NOTES TO UNAUDITED CONDENSED CONSOLIDATED FINANCIAL STATEMENTS
June 30, 2026 and 2025
NOTE 1 – NATURE OF OPERATIONS
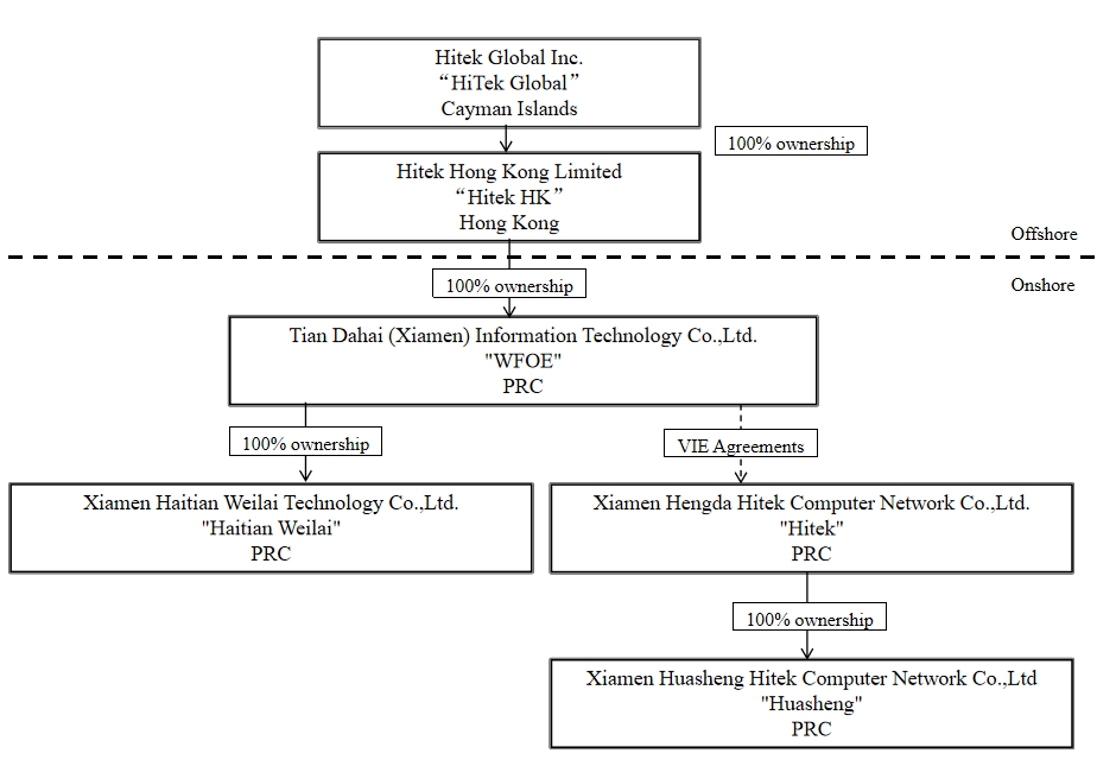
Hitek Global Inc. (“HiTek Global”) was incorporated under the laws of the Cayman Islands on November 3, 2017 in anticipation of an initial public offering (“IPO”) that was completed in 2023. HiTek Global, through its subsidiaries, variable interest entity (“VIE”) and VIE’s subsidiary (collectively, the “Company”) generates revenues from the sale of hardware and equipment, sale of software, and delivery of tax services to customers in the People’s Republic of China (the “PRC”).
The Company’s corporate structure as of June 30, 2026 was as follows:
On August 24, 2026, HiTek Global completed the process of changing its jurisdiction of incorporation from the Cayman Islands to the British Virgin Islands and changed its name to Biddance AI Systems, Inc. (See Note 19).
NOTE 2 – BASIS OF PRESENTATION AND SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES
Basis of Presentation
The condensed consolidated financial statements (“CFS”) as of June 30, 2026 and for the six months ended June 30, 2026 and 2025 are unaudited. The accompanying unaudited condensed CFS were prepared by the Company in accordance with accounting principles generally accepted in the United States of America (“U.S. GAAP”) for interim financial reporting. Operating results as presented are not necessarily indicative of the results expected for a full year. Certain prior year amounts have been reclassified to conform with the current year presentation. The reclassification has no effect on the results of operations.
| F-6 |
Principles of Consolidation
The accompanying unaudited condensed CFS include financial information for the Company and its wholly-owned subsidiaries and those VIEs where the Company is the primary beneficiary. In preparing the unaudited condensed CFS, all significant inter-company accounts and transactions were eliminated.
VIE Agreements with HiTek
Due to PRC legal restrictions of foreign ownership in certain sectors, neither we nor our subsidiaries own any equity interest in HiTek. Instead, WFOE, HiTek and HiTek’s shareholders entered into a series of contractual arrangements (“VIE Agreements”) on March 31, 2018, which have not been tested in a court of law. The VIE Agreements by and among WFOE, HiTek, and HiTek’s shareholders include (i) certain power of attorney agreements and equity interest pledge agreement, which provide WFOE effective control over HiTek; (ii) an exclusive technical consulting and service agreement which allows WFOE to receive substantially all of the economic benefits from HiTek; and (iii) certain exclusive equity interest purchase agreements which provide WFOE with an exclusive option to purchase all or part of the equity interests in and/or assets of HiTek when and to the extent permitted by PRC laws. Accordingly, the Company is considered the primary beneficiary of VIE for accounting purpose and has consolidated the VIE and the VIE’s subsidiaries’ assets, liabilities, results of operations, and cash flows in the accompanying consolidated financial statements.
Each of the VIE Agreements is described in detail below:
Exclusive Technical Consulting and Service Agreement
Pursuant to the Exclusive Technical Consulting and Service Agreement between HiTek and WFOE, WFOE provides HiTek with technical support, consulting services and other management services relating to its day-to-day business operations and management, on an exclusive basis. The Exclusive Technical Consulting and Service Agreement came into effect as of March 31, 2018. For services rendered to HiTek by WFOE under this agreement, WFOE is entitled to collect a service fee that shall be paid per quarter of 100% of HiTek’s quarterly profit. The term of the Exclusive Technical Consulting and Service Agreement is ten years unless it is terminated by WFOE with 30-day prior notice.
Equity Interest Pledge Agreement
WFOE, HiTek and HiTek shareholders entered into an Equity Interest Pledge Agreement, pursuant to which HiTek shareholders pledged all of their equity interests in HiTek to WFOE in order to guarantee the performance of HiTek’s obligations under the Exclusive Technical Consulting and Service Agreement as described above. The Equity Interest Pledge Agreement came into effect as of March 31, 2018. During the term of the pledge, WFOE is entitled to receive any dividends declared on the pledged equity interests of HiTek. The Equity Interest Pledge Agreement ends when all contractual obligations under the Exclusive Technical Consulting and Service Agreement have been fully performed.
Exclusive Equity Interests Purchase Agreement
Under the Exclusive Equity Interests Purchase Agreement, the HiTek Shareholders granted WFOE (or its designee) an exclusive option to purchase, to the extent permitted under PRC law, part or all of their equity interests in HiTek. The option price is equal to the capital paid in by the HiTek Shareholders subject to any appraisal or restrictions required by applicable PRC laws and regulations. The Exclusive Equity Interests Purchase Agreement remains effective for a term of ten years and may be extended for another ten years at WFOE’s election.
| F-7 |
Power of Attorney
Pursuant to the Power of Attorney, each HiTek Shareholder authorizes WFOE to act on their behalf as their exclusive agent and attorney with respect to all rights as shareholders, including but not limited to: (a) the attendance of the shareholder’s meeting and the execution of relative shareholder resolution(s) of HiTek; (b) exercising all the shareholder’s rights, including voting, that shareholders are entitled to under the laws of China and the articles of association, including but not limited to the sale or transfer or pledge or disposition of shares in part or in whole; and (c) designating and appointing on behalf of shareholders the legal representative, the executive director, supervisor, the chief executive officer and other senior management members of HiTek.
Excluding the effect of intercompany balances, the VIEs accounted for 28% and 99% of the Company’s total assets and total liabilities, respectively, as of June 30, 2026, and 46% and 99% of the Company’s total assets and total liabilities, respectively, as of December 31, 2025. As of June 30, 2026 and December 31, 2025, $214,976 and $307,191 of cash was denominated in RMB, respectively.
Risks in relation to the VIE structure
The Company’s operations and businesses through its VIE could be found by PRC authorities to violate PRC law and regulations prohibiting or restricting foreign ownership of companies that engage in such operations and businesses. While the Company’s management considers the possibility of such a finding by PRC regulatory authorities under current law and regulations to be remote, on January 19, 2015, the Ministry of Commerce of the PRC, or (the “MOFCOM”) released on its Website for public comment a proposed PRC law (the “Draft FIE Law”) that appears to include VIEs within the scope of entities that could be considered foreign invested companies (or “FIEs”) that would be subject to restrictions under existing PRC law on foreign investment in certain industries. Specifically, the Draft FIE Law introduces the concept of “actual control” for determining if an entity is considered to be an FIE. In addition to control through direct or indirect ownership or equity, the Draft FIE Law includes control through contractual arrangements within the definition of “actual control.” If the Draft FIE Law is passed by the People’s Congress of the PRC and goes into effect in its current form, these provisions regarding control through contractual arrangements could be construed to reach the Company’s VIE arrangements, and as a result, the Company’s VIE could become subject to the current restrictions on foreign investment in certain categories of industry. If a finding were made by PRC authorities, under existing law and regulations or under the Draft FIE Law if it becomes effective, about the Company’s operation of certain of its operations and businesses through its VIEs, regulatory authorities with jurisdiction over the licensing and operation of such operations and businesses would have broad discretion in dealing with such a violation, including levying fines, confiscating the Company’s income, revoking the business or operating licenses of the affected businesses, requiring the Company to restructure its ownership structure or operations, or requiring the Company to discontinue all or any portion of its operations. Any of these actions could cause significant disruption to the Company’s business operations and have a severe adverse impact on the Company’s cash flows, financial position and operating performance.
In addition, the contracts among WFOE, HiTek and HiTek’s shareholders would not be enforceable in China if PRC government authorities or courts found that such contracts contravene PRC laws and regulations or are otherwise not enforceable for public policy reasons. If the Company was unable to enforce these contractual arrangements, the Company would not be able to exert effective control over the VIEs. Consequently, the VIEs’ results of operations, assets and liabilities would not be included in the Company’s consolidated financial statements. If such were the case, the Company’s cash flows, financial position, and operating performance would be materially adversely affected. The Company’s contractual arrangements WFOE, HiTek and HiTek’s shareholders are approved and in place. Management believes such contracts are enforceable and considers the possibility remote that PRC regulatory authorities with jurisdiction over the Company’s operations and contractual relationships would find the contracts to be unenforceable.
The Company’s operations and businesses are conducted by its VIEs, which hold revenue-producing assets. The VIEs also have an assembled workforce, focused primarily on R&D, whose costs are expensed as incurred. The Company’s operations and businesses may be adversely impacted if the Company loses the ability to use and enjoy assets held by its VIE.
VIEs are generally entities that lack sufficient equity to finance their activities without additional financial support from other parties or whose equity holders lack adequate decision-making ability. All VIEs and their subsidiaries of the Company must be evaluated to determine the primary beneficiary of the risks and rewards of the VIE. The primary beneficiary is required to consolidate the VIE for financial reporting purposes.
| F-8 |
Summary information regarding consolidated VIEs and their subsidiaries is as follows.
| As of June 30, 2026 | As of December 31, 2025 | |||||||
| (Unaudited) | ||||||||
| Total current assets | $ | 17,904,033 | $ | 19,622,217 | ||||
| Total non-current assets | 332,488 | 1,788,606 | ||||||
| Total Assets | $ | 18,236,521 | $ | 21,410,823 | ||||
| Total Liabilities | $ | 3,904,015 | $ | 6,954,572 | ||||
| Six Months Ended June 30, | ||||||||
| 2026 | 2025 | |||||||
| (Unaudited) | (Unaudited) | |||||||
| Revenues | $ | 795,544 | $ | 737,904 | ||||
| Net loss | $ | (560,526 | ) | $ | (469,268 | ) | ||
| Six Months Ended June 30, | ||||||||
| 2026 | 2025 | |||||||
| (Unaudited) | (Unaudited) | |||||||
| Net cash (used in) provided by operating activities | $ | (552,224 | ) | $ | 1,844,037 | |||
| Net cash provided by (used in) investing activities | $ | 451,737 | $ | (275,763 | ) | |||
Use of Estimates and Assumptions
The preparation of the Company’s consolidated financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and disclosure of contingent assets and liabilities at the date of the consolidated financial statements and the reported amounts of revenues and expenses during the reporting period.
Significant accounting estimates reflected in the Company’s consolidated financial statements include allowance for expected credit losses, inventory obsolescence, deferred taxes, and the useful lives of property and equipment. Since the use of estimates is an integral component of the financial reporting process, actual results could differ from those estimates.
Reverse Share Split
On June 4, 2026, the Board approved a reverse split at a ratio of 1-for-25 that became effective on July 6, 2026. Pursuant to the Board approval, every 25 issued and unissued Class A ordinary shares were combined into one Class A ordinary share. No fractional shares were issued in connection with the reverse split. Any fractional share resulting from the reverse split was rounded up to the nearest whole share at the participant level. Following the reverse split, the par value of each Class A ordinary share was changed from $0.015 to $0.375. All shares and per share data presented in the unaudited condensed consolidated financial statements and related notes have been retroactively restated to reflect the reverse split (See Notes 14 and 19).
Fair Values of Financial Instruments
The U.S. GAAP regarding fair value of financial instruments and related fair value measurements define fair value, establish a three-level valuation hierarchy that requires an entity to maximize the use of observable inputs and minimize the use of unobservable inputs when measuring fair value.
The three levels of inputs are defined as follows:
| ● | Level 1 inputs to the valuation methodology are quoted prices (unadjusted) for identical assets or liabilities in active markets. |
| ● | Level 2 inputs to the valuation methodology include quoted prices for similar assets and liabilities in active markets, and inputs that are observable for the asset or liability, either directly or indirectly, for substantially the full term of the financial instrument. |
| ● | Level 3 inputs to the valuation methodology are unobservable. |
| F-9 |
ASC 825-10 “Financial Instruments” allows entities to choose to measure certain financial assets and liabilities at fair value (fair value option). The fair value option may be elected on an instrument-by-instrument basis and is irrevocable, unless a new election date occurs. If the fair value option is elected for an instrument, unrealized gains and losses for that instrument should be reported in earnings at each subsequent reporting date. The Company did not elect to apply the fair value option to any outstanding instruments.
The carrying amounts in the consolidated balance sheets for cash, short-term investment, accounts receivable, advances to suppliers, inventories, loans receivable, prepaid expenses and other current assets, accounts payable, advances from customers, loan payable, deferred revenue, taxes payable, and accrued expenses and other current liabilities approximate their fair value based on the short-term maturity of these instruments.
The Company’s investments measured at fair value on a recurring basis consist of trading securities and bank deposits. The valuation for the Level 1 position is based on quoted prices in active markets. For detailed information, please see “NOTE 3 – INVESTMENTS.”
Loss Per Share (“EPS”)
Basic EPS is computed by dividing net loss by the weighted-average number of ordinary shares outstanding during the period. Diluted EPS is computed by dividing net loss by the weighted-average number of ordinary shares and dilutive potential ordinary shares outstanding during the period.
Cash and Cash Equivalents
Cash consists of cash on hand and in banks. The Company considers all highly liquid investments with an original maturity of three months or less when purchased to be cash equivalents. The Company maintains cash with various financial institutions in the PRC. As of June 30, 2026 and December 31, 2025, cash balances held in PRC banks were uninsured. The Company has not experienced any losses in bank accounts during the six months ended June 30, 2026 and 2025.
Concentrations of Credit Risk
Currently, all of the Company’s operations are in the PRC. Accordingly, the Company’s business, financial condition and results of operations may be influenced by the political, economic, and legal environment in the PRC, and by the general state of the PRC’s economy. The Company’s operations in the PRC are subject to specific considerations and significant risks not typically associated with companies in the United States of America. The Company’s results may be adversely affected by changes in governmental policies with respect to laws and regulations, anti-inflationary measures, currency conversion and remittance abroad, and rates and methods of taxation, among other things.
Financial instruments which potentially subject the Company to concentrations of credit risk consist principally of cash, short-term investments, trade accounts receivable, and accounts receivable from related parties and advances to suppliers. A portion of the Company’s sales are credit sales which are to the customers whose ability to pay is dependent upon the industry economics prevailing in these areas; however, concentrations of credit risk with respect to trade accounts receivables is limited due to generally short payment terms. The Company also performs ongoing credit evaluations of its customers to help further reduce credit risk.
Investments
Short-term investments consist of trading securities and held-to-maturity securities, which include trading stock, mutual funds and wealth management products issued by commercial banks with maturity within one year. Considering some of the Company’s short-term investments are highly liquid in nature, changes in the fair value and related transactions of short-term investments are presented as operating activities in the Company’s consolidated statements of cash flows. Long-term investments include mutual funds and wealth management products with a maturity of over one year. The Company accounts for investments in accordance with FASB ASC Topic 320 “Investments — Debt and Equity Securities.” Dividend and interest income, including amortization of the premium and discount at acquisition, for all categories of investments in securities is included in consolidated statements of operations. Net realized and unrealized holding gains and losses for investments are included in consolidated statements of operations.
| F-10 |
If a security is acquired with the intent of selling it within hours or days, the security is classified as a trading security. The Company classifies investments in trading stock and mutual funds as trading securities. Unrealized holding gains and losses for trading securities are included in earnings.
If the Company has positive intent and ability to hold the security to maturity, the security is classified as a held-to-maturity security. The Company classifies its investment in wealth management products as held-to-maturity securities as the Company intends to hold these investments until maturity. The investment in wealth management products is valued at carrying value, which approximates the amortized cost. For individual securities classified as held-to-maturity securities, the Company evaluates whether a decline in fair value below the amortized cost basis is other-than-temporary, in accordance with ASC 320. Other-than-temporary impairment loss is recognized in earnings equal to the entire excess of the debt security’s amortized cost basis over its fair value at the balance sheet date of the reporting period for which the assessment is made. The Company did not record any impairment charge for the six months ended June 30, 2026 and 2025.
Expected Credit Losses
The Company maintains an allowance for expected credit losses in accordance with ASC 326 and records it as an offset to related asset such as accounts receivable, and the provision for estimated credit losses is expensed. The Company assesses collectability by reviewing receivables on a collective basis where similar characteristics exist, primarily based on the size and nature of specific customers’ receivables. In determining the amount of the allowance for credit losses, the Company considers historical collectability based on past due status, the age of the receivable balances, credit quality of the Company’s customers based on ongoing credit evaluations, current economic conditions, reasonable and supportable forecasts of future economic conditions, and other factors that may affect the Company’s ability to collect from customers. Bad debts are written off as incurred.
Advances to Suppliers
Advances to suppliers are amounts prepaid to suppliers for purchases of inventories and outsourced software services. In evaluating the recoverability of such advances, the Company mainly considers the age of the balance and the ability of the suppliers to perform the related obligations.
Inventories
Inventories include computer, network hardware, and selected safety monitoring equipment for sale to petrochemical companies. Inventories are stated at the lower of cost (weighted average basis) or net realizable value. The methods of determining inventory costs are used consistently from year to year. Allowance for inventory obsolescence is provided when the market value of certain inventory items is lower than the cost.
Other Receivable
Other receivable represents the principal and realized gain from short-term investments that have not yet been remitted to the Company subsequent to the termination of the associated investment agreements.
Property, Equipment and Software
Property, equipment and software are carried at cost and are depreciated on a straight-line basis over the estimated useful lives of the assets. The cost of repairs and maintenance is expensed as incurred; major replacements and improvements are capitalized. When assets are retired or disposed of, the cost and accumulated depreciation and amortization are removed from the accounts, and any resulting gains or losses are included in the statement of operations in the year of disposition. The Company examines the possibility of decreases in the value of property, equipment and software, when events or changes in circumstances reflect the fact that their recorded value may not be recoverable.
| F-11 |
Estimated useful lives are as follows, taking into account the assets’ estimated residual value:
| Classification | Estimated useful lives | |
| Furniture and office equipment | 2-3 years | |
| Computer equipment | 2-3 years | |
| Transportation equipment | 5 years | |
| Buildings | 20 years | |
| Building improvements | 5 years | |
| Software | 3 years |
Impairment of Long-lived Assets
In accordance with ASC Topic 360, the Company reviews long-lived assets for impairment whenever events or changes in circumstances indicate that the carrying amount of the assets may not be fully recoverable. The Company recognizes an impairment loss when the sum of expected undiscounted future cash flows is less than the carrying amount of the asset. The amount of impairment is measured as the difference between the asset’s estimated fair value and its book value. The Company did not record any impairment charge during the six months ended June 30, 2026 and 2025.
Revenue Recognition
The Company follows ASU 2014-09, Topic 606, “Revenue from Contracts with Customers” and its related amendments (collectively referred to as “ASC 606”) for its revenue recognition accounting policy that depicts the transfer of promised goods or services to customers in an amount that reflects the consideration to which the Company expects to be entitled in exchange for those goods or services. In accordance with ASC 606, revenue is recognized when all of the following five steps are met: (i) identify the contract(s) with the customer; (ii) identify the performance obligations in the contract; (iii) determine the transaction price; (iv) allocate the transaction price to the performance obligations; (v) recognize revenue when (or as) each performance obligation is satisfied.
The Company generates revenues primarily from three sources: (1) hardware and equipment sales, (2) software sales, and (3) tax services. The Company recognizes revenue when performance obligations under the terms of a contract with its customers are satisfied, which occurs when controls over the goods or services have been transferred to the customer. The Company’s revenue is reported on a gross basis since the Company is primarily obligated in the transaction, is subject to inventory risk and credit risk and has discretion to establish prices. Revenue is recorded net of value-added tax.
The Company elected a practical expedient that it does not adjust the promised amount of consideration for the effects of a significant financing component if the Company expects that, upon the inception of contracts, the period between when the Company transfers its promised services or goods to its customers and when the customers pay for those services or goods will be one year or less.
Hardware and Equipment Sales
Hardware and equipment sales consist primarily of (a) sale of computer and network equipment to end users across various industries, and (b) sale of selected safety monitoring equipment to petrochemical companies. Based on contracts signed with customers, the Company has a single performance obligation and it recognizes revenue when ownership of such hardware and equipment is transferred to the customers.
Software Sales
The Company focuses on perpetual license sales for a self-developed software Communication Interface System (“CIS”). CIS is based on LINUX, which is a general embedded interface system used by petrochemical companies. The system is used to communicate the RCTX-X module, collect the work diagram, the electricity diagram, the pressure temperature and other measures, and can extract the data and import it to the software of the windows platform to display analysis.
Software contracts with customers include sale of perpetual license software, installation of software, operation training service and warranty. The installation and operation training are essential to the functionality of the software which are provided to the clients prior to the acceptance of the software. The Company provides one year warranty which mainly is for telephone supports. The Company concludes the warranty as assurance-type. The Company recognizes revenue from software sales when the software is accepted by the customer. The Company did not have any revenue from software sales during the six months ended June 30, 2026 and 2025.
| F-12 |
Tax Services
In 2023, Xiamen Taxation Bureau implemented the use of electronic invoices to replace the traditional tax control system. Enterprises can use a free electronic invoice platform provided by the tax bureau, which has had a significant impact on the Company’s tax service business. In 2024, the Company cooperated with a third party to popularize an electronic tax control platform and upgrade its tax services. Such services primarily include the installation of the electronic tax control platform, operation training, such as training on issuing electronic invoice and complete tax declaration automatically, and after-sales telephone supporting services. While installation and operation training are essential to the functionality of the electronic tax control platform, after-sales telephone supporting services is an assurance-type. The entire tax service is accounted for as a single performance obligation.
Since June 2024, the Company charges an annual service fee from customers who use the electronic tax control platform popularized by the Company. Revenue from tax services is recognized as the services are performed and amounts are earned, using the straight-line method over the term of the related service agreement.
Below is a summary of the Company’s revenues by key revenue stream:
| Six Months Ended June 30, | ||||||||
| 2026 | 2025 | |||||||
| (Unaudited) | (Unaudited) | |||||||
| Hardware and equipment sales | $ | 1,132,887 | $ | 616,929 | ||||
| Tax services | 93,159 | 124,612 | ||||||
| Total Revenues | $ | 1,226,046 | $ | 741,541 | ||||
Contract balances
Prepayments from customers prior to the services being performed are recorded as deferred revenue. Deferred revenue consists primarily of annual service fees from customers who use the electronic tax control platform popularized by the Company but the services have not yet been performed. The Company recognizes the tax service amount as revenue on a straight-line basis in accordance with the service period, which typically is less than 12 months. For the six months ended June 30, 2026 and 2025, the Company recognized revenue of $47,205 and $55,720 respectively, that was included in deferred revenue at the beginning of each period.
Practical expedients and exemptions
The Company generally expenses sales commissions as incurred because the amortization period would have been one year or less.
Cost of Revenues
Cost of revenues is comprised of (i) the direct cost of hardware and equipment purchased from third parties; (ii) logistics-related costs, which include product packaging and freight-in charges; and (iii) salaries and benefits for employees who handle the product sales and other costs necessary to provide the services to the customers.
Selling Expenses
Selling expenses consists of advertising and marketing expenses for promotion of our products.
General and Administrative Expenses
General and administrative expenses consist primarily of costs of salary and welfare for general administrative and management staff, facilities costs, depreciation and amortization expenses, professional fees, accounting fees, meals and entertainment, utilities, additional expenses for public offering, and other miscellaneous expenses incurred in connection with general operations. All depreciation and amortization were recorded in general and administrative expenses because fixed assets are mainly for sales and administrative purposes.
| F-13 |
Income Taxes
The Company is governed by the Income Tax Law of the PRC. The Company accounts for income taxes using the asset/liability method prescribed by ASC 740, “Accounting for Income Taxes.” Under this method, deferred tax assets and liabilities are determined based on the difference between the financial reporting and tax bases of assets and liabilities using enacted tax rates that will be in effect in the period in which the differences are expected to reverse. The Company records a valuation allowance to offset deferred tax assets if, based on the weight of available evidence, it is more-likely-than-not that some portion, or all, of the deferred tax assets will not be realized. The effect on deferred taxes of a change in tax rates is recognized as income or loss in the period that includes the enactment date.
The Company applies ASC 740-10-50, “Accounting for Uncertainty in Income Taxes,” which provides clarification related to the process associated with accounting for uncertain tax positions recognized in the Company’s consolidated financial statements. Audit periods remain open for review until the statute of limitations has passed. The completion of review or the expiration of the statute of limitations for a given audit period could result in an adjustment to the Company’s liability for income taxes. Any such adjustment could be material to the Company’s results of operations for any given quarterly or annual period based, in part, upon the results of operations for the given period.
Value Added Taxes (“VAT”)
VAT is reported as a deduction of revenue when incurred. Entities that are VAT general taxpayers are allowed to offset qualified input VAT paid to suppliers against their output VAT liabilities. Net VAT balance between input VAT and output VAT is recorded in taxes payable.
Foreign Currency Translation
The functional currency of the Company’s operations in the PRC is the Chinese Yuan or Renminbi (“RMB”). The consolidated financial statements are translated to U.S. dollars using the period end rates of exchange for assets and liabilities, equity is translated at historical exchange rates, and average rates of exchange (for the period) are used for revenues and expenses and cash flows. As a result, amounts relating to assets and liabilities reported on the statements of cash flows may not necessarily agree with the changes in the corresponding balances on the balance sheets. Translation adjustments resulting from the process of translating the local currency financial statements into U.S. dollars are included in determining comprehensive income / loss. Transactions denominated in foreign currencies are translated into the functional currency at the exchange rates prevailing on the transaction dates. Assets and liabilities denominated in foreign currencies are translated into the functional currency at the exchange rates prevailing at the balance sheet date with any transaction gains and losses that arise from exchange rate fluctuations on transactions denominated in a currency other than the functional currency are included in the results of operations as incurred.
All of the Company’s revenue transactions are transacted in its functional currency. The Company does not enter into any material transaction in foreign currencies. Transaction gains or losses have not had, and are not expected to have, a material effect on the results of operations of the Company.
The exchange rates as of June 30, 2026 (unaudited) and December 31, 2025 and for the six months ended June 30, 2026 and 2025 (unaudited) are as follows:
| June 30, | December 31, | Six months Ended June 30, | ||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||
| Foreign currency | Balance Sheet | Balance Sheet | Profits/Loss | Profits/Loss | ||||||||||||
| RMB:1USD | 6.7851 | 6.9931 | 6.8624 | 7.1875 | ||||||||||||
| F-14 |
Comprehensive Loss
Comprehensive loss is comprised of net loss and all changes to the statements of shareholders’ equity, except those due to investments by shareholders and changes in paid-in capital. For the Company, comprehensive loss for the six months ended June 30, 2026 and 2025 consisted of net loss and unrealized gain from foreign currency translation adjustment.
Related Parties
A party is considered related to the Company if it directly or indirectly or through one or more intermediaries, controls, is controlled by, or is under common control with the Company. Related parties also include principal owners of the Company, its management, members of the immediate families of principal owners of the Company and its management and other parties with which the Company may deal if one party controls or can significantly influence the management or operating policies of the other to an extent that one of the transacting parties might be prevented from fully pursuing its own separate interests. A party which can significantly influence the management or operating policies of the transacting parties or if it has an ownership interest in one of the transacting parties and can significantly influence the other to an extent that one or more of the transacting parties might be prevented from fully pursuing its own separate interests is also a related party.
Segment Reporting
ASC Topic 280, “Segment Reporting,” requires use of the management approach model for segment reporting. The Company identifies operating segments as components of the consolidated operations for which discrete financial information is available and is regularly reviewed by the chief operating decision maker (“CODM”), in making decisions regarding resource allocation and evaluating financial performance. The Company defines the term CODM to be its Chief Executive Officer. The Company determined it operates in one operating and reportable segment. The CODM reviews operating income (loss) presented only on a consolidated basis and uses this information for purposes of allocating resources and evaluating financial performance. There are no reconciling items between segment information and consolidated financial information.
The significant segment expenses and other segment items that are provided to the CODM align with expense information that is included in the Company’s consolidated statements of operations and notes thereto.
The measure of segment assets is reported in the balance sheet as total consolidated assets. The Company’s long-lived assets are located in China.
Leases
The Company follows ASC 842 to account for its operating leases and has elected not to record assets and liabilities on its consolidated balance sheets for new or existing lease arrangements with terms of 12 months or less. The Company recognizes lease expenses for such lease on a straight-line basis over the lease term. The Company will evaluate the carrying value of its right-of use (“ROU”) assets if there are indicators of impairment and review the recoverability of the related asset group. From January 1, 2024, the Company has no lease arrangements that qualify for recognition under ASC 842. As a result, the Company does not have any ROU assets or lease liabilities related to ASC 842.
Warrants classification
When the Company issues freestanding instruments, it first analyzes the provisions of ASC Topic 480, Distinguishing Liabilities from Equity (“ASC 480”) in order to determine whether the instrument should be classified as a liability, with subsequent changes in fair value recognized in the statements of comprehensive loss in each period. If the instrument is not within the scope of ASC 480, the Company further analyzes the provisions of ASC Topic 815, Derivatives and Hedging (“ASC 815-40”) in order to determine whether the instrument is considered indexed to the entity’s own stock, and qualifies for classification within equity. If the provisions of ASC 815-40 for equity classification are not met, the instrument will be classified as a liability, with subsequent changes in fair value recognized in the statements of comprehensive loss in each period.
| F-15 |
Recent Accounting Pronouncements
In November 2024, the FASB issued ASU 2024-03 on Disaggregation of Income Statement Expenses that enhances disclosure of certain costs and expenses to provide enhanced transparency into the expenses presented in the income statement. The updates are effective for annual periods beginning after December 15, 2026. The Company does not expect the adoption of this ASU will have a material impact on its consolidated financial statements.
The Company does not believe other recently issued but not yet effective accounting standards, if currently adopted, would have a material effect on its consolidated financial statements.
NOTE 3 – INVESTMENTS
Investments consist of trading securities and held-to-maturity securities. Trading securities primarily include trading stock, mutual funds and wealth management products issued by commercial banks which are held for the purpose of selling them in the near term. Held-to-maturity securities primarily include wealth management products which the Company has positive intent and ability to hold them to maturity.
Held-to-maturity securities with maturity over one year are recorded in long-term investments. Below is a summary of the Company’s investments as of June 30, 2026 and December 31, 2025.
| Quoted | Significant | Significant | ||||||||||||||
| Prices in | Other | Other | ||||||||||||||
| Active | Observable | Unobservable | ||||||||||||||
| June 30, | Markets | Inputs | Inputs | |||||||||||||
| 2026 | (Level 1) | (Level 2) | (Level 3) | |||||||||||||
| (Unaudited) | ||||||||||||||||
| Short-term investments | ||||||||||||||||
| Trading securities carried at fair value | $ | 8,870,243 | $ | 89,735 | $ | 8,780,508 | $ | - | ||||||||
| Held-to-maturity securities carried at cost | 11,100,000 | - | 11,100,000 | - | ||||||||||||
| Total | $ | 19,970,243 | $ | 89,735 | $ | 19,880,508 | $ | - | ||||||||
| Quoted | Significant | Significant | ||||||||||||||
| Prices in | Other | Other | ||||||||||||||
| Active | Observable | Unobservable | ||||||||||||||
| December 31, | Markets | Inputs | Inputs | |||||||||||||
| 2025 | (Level 1) | (Level 2) | (Level 3) | |||||||||||||
| Short-term investments | ||||||||||||||||
| Trading securities carried at fair value | $ | 7,264,219 | $ | 93,150 | $ | 7,171,069 | $ | - | ||||||||
| Held-to-maturity securities carried at cost | 11,100,000 | - | 11,100,000 | - | ||||||||||||
| Total | $ | 18,364,219 | $ | 93,150 | $ | 18,271,069 | $ | - | ||||||||
Net investment gain for the six months ended June 30, 2026 and 2025 consists of the following:
| 2026 | 2025 | |||||||
| (Unaudited) | (Unaudited) | |||||||
| Gain from sales of short-term investments: | ||||||||
| Trading securities | $ | 9,086 | $ | 24,849 | ||||
| Held-to-maturity debt securities | 37,514 | 15,616 | ||||||
| Unrealized gain of short-term investments: | ||||||||
| Trading securities | 55,763 | 41,998 | ||||||
| Net investment gain | $ | 102,363 | $ | 82,463 | ||||
| F-16 |
NOTE 4 – ACCOUNTS RECEIVABLE, NET
At June 30, 2026 and December 31, 2025, accounts receivable, net consisted of the following.
June 30, 2026 | December 31, 2025 | |||||||
| (Unaudited) | ||||||||
| Accounts receivable | $ | 6,363,085 | $ | 6,920,852 | ||||
| Less: allowance for expected credit losses | (1,013,079 | ) | (485,442 | ) | ||||
| Accounts receivable, net | 5,350,006 | 6,435,410 | ||||||
| Less: current portion | 5,350,006 | 5,407,989 | ||||||
| Non-current accounts receivable, net | $ | - | $ | 1,027,421 | ||||
The following table describes the movements in the allowance for expected credit losses during the six months ended June 30, 2026 and 2025.
| 2026 | 2025 | |||||||
| (Unaudited) | (Unaudited) | |||||||
| Balance at December 31, | $ | 485,442 | $ | 125,643 | ||||
| Provision for expected credit losses | 506,980 | 482,621 | ||||||
| Foreign exchange difference | 20,657 | 8,376 | ||||||
| Balance at June 30 (Unaudited) | $ | 1,013,079 | $ | 616,640 | ||||
NOTE 5 – INVENTORIES, NET
At June 30, 2026 and December 31, 2025, inventories consisted of the following.
June 30, 2026 | December 31, 2025 | |||||||
| (Unaudited) | ||||||||
| Purchased goods | $ | 106,150 | $ | 97,399 | ||||
| Less: reserve for obsolete inventories | (20,582 | ) | (17,988 | ) | ||||
| Total | $ | 85,568 | $ | 79,411 | ||||
The following table describes the movements in the reserve for obsolete inventories during the six months ended June 30, 2026 and 2025.
| 2026 | 2025 | |||||||
| (Unaudited) | (Unaudited) | |||||||
| Balance at December 31, | $ | 17,988 | $ | 16,756 | ||||
| Reserve for obsolete inventories | 2,019 | 3,832 | ||||||
| Foreign exchange difference | 575 | 365 | ||||||
| Balance at June 30 (Unaudited) | $ | 20,582 | $ | 20,953 | ||||
The Company established a reserve for 100% of its GTDs inventory in light of the introduction of the free electronic invoice platform by the tax bureau. Such reserve for GTDs inventory was fully written off in 2025. The allowance as of June 30, 2026 was related mainly to the Company’s network switches and routers.
| F-17 |
NOTE 6 – PREPAID EXPENSES AND OTHER CURRENT ASSETS
At June 30, 2026 and December 31, 2025, prepaid expenses and current assets consisted of the following.
June 30, 2026 | December 31, 2025 | |||||||
| (Unaudited) | ||||||||
| Interest receivable from third-party loans | $ | 2,948 | $ | 168,952 | ||||
| Other receivables (1) | 7,559 | 2,709 | ||||||
| Total | $ | 10,507 | $ | 171,661 | ||||
| (1) | Other receivables primarily consist of reserve funds and social security. |
NOTE 7 – LOANS RECEIVABLE
At June 30, 2026 and December 31, 2025, loans receivable consisted of the following.
June 30, 2026 | December 31, 2025 | |||||||
| (Unaudited) | ||||||||
| Guangxi Beihengda Mining Co., Ltd. (1) | $ | - | $ | 5,290,930 | ||||
| Beijing Liansheng Innovation Technology Co., Ltd (2) | 294,764 | 285,996 | ||||||
| Guangzhou Ruilide Information System Co., Ltd (3) | - | 443,294 | ||||||
| Xinjiang New Thai Hua Construction Engineering Co., Ltd (4) | 294,764 | 285,996 | ||||||
| Total loan receivable | 589,528 | 6,306,216 | ||||||
| Less: current portion | 589,528 | 6,020,220 | ||||||
| Non-current loan receivable | $ | - | $ | 285,996 | ||||
| (1) |
On January 21, 2022, March 28, 2022 and June 14, 2022, the Company made three loans of RMB30,000,000 ($4,421,453), RMB3,000,000 ($442,145) and RMB7,000,000 ($1,031,672) to a third party, which were restricted for its operating activities, carrying interest at 12%. The RMB30,000,000 loan ($4,421,453) was extended to January 21, 2028. The RMB7,000,000 loan ($1,031,672) was extended to June 14, 2028. The RMB3,000,000 loan ($442,145) was repaid in August 2022 with interest of RMB120,000 ($17,686). Pursuant to a mining right pledge agreement dated August 5, 2022 between HiTek, as representative of the Lenders and the Borrower, these three loans are secured by the Borrower’s coal mining permit issued by Bobai County Natural Resources Bureau, which grants the Borrower a 20-year mining right for certain building granite mine in Daguang Village, Shuiming Town, Bobai County, Guangxi Province, for production of 1.306 million cubic meters per year.
In March 2026, the Company, Guangxi Beihengda Mining Co., Ltd. (“Guangxi Beihengda”), and Beijing Baihengda Petroleum Technology Co., Ltd (“Beijing Baihengda”) entered into an agreement that Guangxi Beihengda assumed the Company’s loan payable and the corresponding interest payable owed to Beijing Baihengda. In March 2026, Guangxi Beihengda settled the obligations by remitting to the Company the principal of $2,678,899 (RMB18,500,000) and interest of $241,101 (RMB1,665,000). |
| (2) | On January 17, 2024, the Company provided a loan of RMB2,000,000 ($294,764) with 1.0% per month interest to Beijing Liansheng Innovation Technology Co., Ltd for six months, maturing on July 16, 2024 for its operating activities. The maturity date of the loan was first extended in July 2024 to January 16, 2025, then extended in January 2025 to January 16, 2026, and subsequently extended in January 2026 to January 16, 2027. |
| (3) |
On April 29, 2025, the Company provided a loan of RMB3,000,000 ($442,145) with 1.0% per month interest to Guangzhou Ruilide Information System Co., Ltd (“Ruilide”) for two months, maturing on June 28, 2025. The loan was restricted for its operating activities. Ruilide repaid RMB1,000,000 ($147,382) in June 2025, and RMB500,000 ($73,691) in July 2025. The remaining RMB1,500,000 ($221,073) loan was extended to May 31, 2026.
On August 26, 2025, the Company provided a loan of RMB1,600,000 ($235,811) with 1.0% per month interest to Ruilide, maturing on May 31, 2026. The loan was restricted for its operating activities.
On March 27 and April 2, 2026, the Company received loan repayment that totaled RMB3,100,000 ($456,883). |
| (4) |
On August 5, 2025, the Company provided a loan of RMB2,000,000 ($294,764) with 1.0% per month interest to Xinjiang New Thai Hua Construction Engineering Co., Ltd (“New Thai Hua”) for six months, maturing on February 4, 2026.
Upon receipt of repayment of RMB2,000,000 ($294,764) from New Thai Hua on January 26, 2026, the loan was renewed with 1.0% per month interest for six months, maturing on July 27, 2026.
Upon receipt of repayment of RMB2,000,000 ($294,764) from New Thai Hua on July 28, 2026, the loan was renewed with 1.0% per month interest for six months, maturing on January 28, 2027. |
Interest income for the six months ended June 30, 2026 and 2025 was $123,365 and $313,590, respectively.
| F-18 |
NOTE 8 - OTHER RECEIVABLE
On April 25, 2023, the Company entered into an investment agreement with a third party, pursuant to which the principal amount was $1,000,000 with an original maturity of two years. In March 2025, the Company elected to extend the term of the investment for an additional one-year term, with a new maturity date of April 24, 2026.
On June 3, 2024, the Company entered into an investment agreement with another third party, pursuant to which the principal amount was $5,000,000 with an original maturity of one year. Upon the initial maturity in June 2025, the Company elected to extend the term of the investment for an additional one-year term, with a new maturity date of June 2, 2026.
On December 31, 2025, the Company terminated the above-mentioned investment agreements prior to their maturity dates. As a result, for reporting purposes, $6,000,000 principal and $846,247 realized gain were recorded in other receivable as of December 31, 2025. The Company received a principal repayment of $1,000,000 during March and April 2026 and another repayment of $215,014 representing realized gain in August 2026. In addition, the Company received repayment of $5,650,000 that was paid to a bank account designated by the Company in August 2026.
NOTE 9 – PROPERTY, EQUIPMENT AND SOFTWARE, NET
At June 30, 2026 and December 31, 2025, property, equipment and software consisted of the following.
June 30, 2026 | December 31, 2025 | |||||||
| (Unaudited) | ||||||||
| Office furniture | $ | 51,011 | $ | 49,494 | ||||
| Transportation equipment | 143,407 | 167,274 | ||||||
| Buildings and improvements | 613,337 | 595,094 | ||||||
| Software | 1,742,456 | 1,690,629 | ||||||
| 2,550,211 | 2,502,491 | |||||||
| Less: accumulated depreciation and amortization | (2,217,723 | ) | (2,027,302 | ) | ||||
| $ | 332,488 | $ | 475,189 | |||||
No impairment charge was recorded on property, equipment and software during the six months ended June 30, 2026 and 2025.
NOTE 10 – TAXES PAYABLE
At June 30, 2026 and December 31, 2025, taxes payable consisted of the following.
June 30, 2026 | December 31, 2025 | |||||||
| (Unaudited) | ||||||||
| Value-added taxes | $ | 1,293,920 | $ | 1,271,687 | ||||
| Income taxes | 385,180 | 373,341 | ||||||
| Other | 152,977 | 150,708 | ||||||
| Total | $ | 1,832,077 | $ | 1,795,736 | ||||
NOTE 11 – ACCRUED EXPENSES AND OTHER CURRENT LIABILITIES
At June 30, 2026 and December 31, 2025, accrued expenses and other current liabilities consisted of the following.
June 30, 2026 | December 31, 2025 | |||||||
| (Unaudited) | ||||||||
| Payroll | $ | 117,200 | $ | 120,416 | ||||
| Other | 43,576 | 27,926 | ||||||
| Total | $ | 160,776 | $ | 148,342 | ||||
| F-19 |
NOTE 12 – LOAN PAYABLE
On January 21, March 28 and June 14, 2022, the Company entered into three loans of RMB15,000,000 ($2,210,726), RMB1,500,000 ($221,073) and RMB3,500,000 ($515,836) from Beijing Baihengda, carrying interest at 12%. The RMB15,000,000 ($2,210,726) loan was extended for three years and will mature on January 21, 2028. In May 2025, the RMB3,500,000 ($515,836) loan was extended and will mature on June 14, 2028. The RMB1,500,000 ($221,073) loan was repaid prior to December 31, 2022.
On March 18, 2025, Mr. Yin became a 10% equity owner in Beijing Baihengda. For financial statements presentation purposes, the original loan payable was reclassified to loan payable - related party as of December 31, 2025.
In March 2026, the Company, Guangxi Beihengda and Beijing Baihengda entered into an agreement that Guangxi Beihengda assumed the Company’s loan payable and the corresponding interest payable owed to Beijing Baihengda, effective on January 1, 2026. See NOTE 7 – LOANS RECEIVABLE.
The interest expense for the six months ended June 30, 2026 and 2025 was nil and $153,049, respectively.
NOTE 13 – RELATED PARTY TRANSACTIONS
The table below sets forth the major related parties and their relationships with the Company as of June 30, 2026.
| Name of related parties | Relationship with the Group | |
| Yin Shenping (Mr. Yin) | Chairman of the Board | |
| Beijing Baihengda Petroleum Technology Co., Ltd (Beijing Baihengda) | Mr. Yin holds 10% equity interest in Beijing Baihengda |
The following related party balances are non-interest bearing:
June 30, 2026 | December 31, 2025 | |||||||
| (Unaudited) | ||||||||
| Loan payable – related party: | ||||||||
| Beijing Baihengda (1) | $ | - | $ | 2,645,465 | ||||
| $ | - | $ | 2,645,465 | |||||
| (1) | Mr. Yin became a 10% equity owner in Beijing Baihengda on March 18, 2025. For financial statements presentation purposes, the original loan payable was reclassified to loan payable - related party. See NOTE 12 – LOAN PAYABLE. |
| F-20 |
NOTE 14 – ORDINARY SHARES
On November 24, 2025, the 2025 annual general meeting adopted resolutions that the Company’s authorized share capital be amended from US$50,000 divided into 431,808,000 Class A ordinary shares at a par value of US$0.0001 each, 58,192,000 Class B ordinary shares at a par value of US$0.0001 each and 10,000,000 preference shares at a par value of US$0.0001 each to US$316,000 divided into 3,000,000,000 Class A ordinary shares at a par value of US$0.0001 each, 150,000,000 Class B ordinary shares at a par value of US$0.0001 each and 10,000,000 preference shares at a par value of US$0.0001 each by the creation of an additional 2,568,192,000 Class A Ordinary Shares at a par value US $0.0001 each and 91,808,000 Class B Ordinary Shares at a par value US $0.0001 each.
On March 12, 2026, the Company entered into a sales agreement with Maxim Group LLC (the “Sales Agent”), pursuant to which the Company would offer and sell, from time to time, to or through the Sales Agent, shares of its Class A ordinary shares, par value $0.0001 per share having an aggregate offering price of up to $100,000,000.
| ● | On March 19, 2026, 10,000 shares (3 shares post reverse splits) of Class A ordinary shares were issued thereunder and the Company received gross proceeds of $10,637. |
| ● | On March 24, 2026, 5,852,011 shares (1,561 shares post reverse splits) of Class A ordinary shares were issued thereunder and the Company received gross proceeds of $799,911. |
| ● | On March 26, 2026, the Sales Agent terminated the sales agreement with immediate effect in accordance with its terms. |
On March 27, 2026, the Company entered into a securities purchase agreement with certain investor for the purchase and sale of 1,500,000 Class A ordinary shares of the Company and pre-funded warrants to purchase up to 98,500,000 Class A ordinary shares in a registered direct offering (the “March Offering”). The Class A ordinary shares were sold at a purchase price of $0.03 per share, and the pre-funded warrants were sold at a purchase price of $0.0299 per warrant, for an initial aggregate amount of $3,000,000, before deducting placement agent fees and expenses. In connection with the March Offering, the Company received net proceeds of $2,449,987 and issued an aggregate of 34,196,667 shares (26,667 shares post reverse splits) at par values of $0.0001, $0.005 and $0.015 (all were $0.375 post reverse splits).
On June 2, 2026, the Company entered into a securities purchase agreement with certain investors for the purchase and sale, in a registered direct offering (the “June Offering”), of an aggregate of 4,000,000 Class A ordinary shares, par value $0.015 per share, of the Company or pre-funded warrants in lieu thereof, together with ordinary warrants to purchase Class A ordinary shares. Each Class A ordinary share or pre-funded warrant in lieu thereof was sold at a purchase price of $2.00. Each warrant has an exercise price of $4.5678 per Class A Ordinary Share and is exercisable to purchase approximately 3.8 Class A ordinary shares. The aggregate gross proceeds to the Company from the June Offering were $8,000,000, before deducting placement agent fees and other offering expenses and excluding any proceeds that may be received upon the exercise of the warrants. In connection with the June Offering, the Company received net proceeds of $7,157,489 and issued 19,150,000 shares (766,000 shares post reverse split) of Class A ordinary shares at par value of $0.015 ($0.375 post reverse split).
Reverse Share Split
On November 24, 2025, the shareholders of the Company authorized the board of directors (the “Board”) to implement one or more consolidations of the Class A ordinary shares, with the specific ratio or ratios and timing to be determined by the Board within the parameters approved by the shareholders. On March 25, 2026, the board approved a reverse split at a ratio of 1-for-50 (the “March 2026 Reverse Split”), which became effective on April 6, 2026. Following the March 2026 Reverse Split, the par value of each Class A ordinary share was changed from $0.0001 to $0.005.
On May 4, 2026, the Board approved another reverse split (the “May 2026 Reverse Split”) at a ratio of 1-for-3, which became effective on May 29, 2026. Following the May 2026 Reverse Split, the par value of each Class A ordinary share was changed from $0.005 to $0.015.
On June 4, 2026, the Board approved another reverse split (the “July 2026 Reverse Split”) at a ratio of 1-for-25, which became effective on July 6, 2026. Following the July 2026 Reverse Split, the par value of each Class A ordinary share was changed from $0.015 to $0.375.
| F-21 |
NOTE 15 – WARRANTS
On July 29, 2024, the Company closed a private placement of (a) 14,907,000 Class A ordinary shares, par value $0.0001 per share, and (b) warrants to purchase up to 14,907,000 Class A ordinary shares (the “Private Placement”) pursuant to the Securities Purchase Agreement dated June 11, 2024, between the Company and the purchasers. The warrants are exercisable upon issuance with a term of two years at $0.55 per share. The warrants also contain a cashless exercise provision. In connection with the Private Placement, the Company collected $8,200,000 from the purchasers in June 2024 to purchase Class A ordinary shares and filed a registration statement on August 22, 2024 to register the resale of the Class A ordinary shares issued and Class A ordinary shares to be issued upon exercise of the warrants. Since the warrants are indexed to the Company’s own stock, they are treated as equity for accounting purposes.
The summary of warrant activities for the six months ended June 30, 2026 was as follows:
| Ordinary Shares Number Outstanding | Weighted Average Exercise Price | Contractual Life in Years | ||||||||||
| Outstanding as of December 31, 2025 | 14,907,000 | $ | 0.55 | 1.0 | ||||||||
| Granted | - | - | - | |||||||||
| Exercises | - | - | - | |||||||||
| Expired | - | - | - | |||||||||
| Warrants Outstanding as of June 30, 2026 | 14,907,000 | 0.55 | 0.1 | |||||||||
| Warrants Exercisable as of June 30, 2026 | 14,907,000 | $ | 0.55 | 0.1 | ||||||||
The warrants had an expiration date of July 28, 2026. No warrants were exercised between January 1 to July 28, 2026.
NOTE 16 – INCOME TAXES
The entities within the Company file separate tax returns in the respective tax jurisdictions in which they operate.
Cayman Islands
HiTek Global was a tax-exempt entity incorporated in Cayman Islands.
Hong Kong
Hitek HK was incorporated in Hong Kong and does not conduct any substantial operations. No provision for Hong Kong profits tax has been made in the consolidated financial statements as Hitek HK Limited has no assessable profits for the six months ended June 30, 2026 and 2025.
PRC
The Company’s PRC operating subsidiary and VIEs, being incorporated in the PRC, are governed by the income tax law of the PRC and are subject to PRC enterprise income tax (“EIT”). The EIT rate of PRC is 25%, which applies to both domestic and foreign invested enterprises. From January 1, 2022 to December 31, 2024, if a small profit-making enterprise had annual taxable income less than or equal to RMB 1 million, only 12.5% of its annual taxable income will be subject to income tax at a reduced rate of 20%; for those with annual taxable income more than RMB 1 million but did not exceed RMB 3 million, 25% of their annual taxable income will be subject to income tax at a reduced rate of 20%. In March 2023, on the basis of the previous preferential policy, State Administration of Taxation and Ministry of Finance issued a notice stating that, from January 1, 2023 to December 31, 2024, for those with annual taxable income less than or equal to RMB 1 million, 25% of their annual taxable income will be subject to income tax at the same reduced rate of 20%. In August 2023, State Administration of Taxation and Ministry of Finance issued a notice stating that the above preferential policies were extended to December 31, 2027.
The Company’s loss before income taxes includes the following for the six months ended June 30.
| 2026 | 2025 | |||||||
| (Unaudited) | (Unaudited) | |||||||
| Non-PRC operations | $ | (809,587 | ) | $ | (445,352 | ) | ||
| PRC operations | (665,341 | ) | (571,639 | ) | ||||
| Total loss before income taxes | $ | (1,474,928 | ) | $ | (1,016,991 | ) | ||
| F-22 |
Income tax expense was comprised of the following for the six months ended June 30.
| 2026 | 2025 | |||||||
| (Unaudited) | (Unaudited) | |||||||
| Current tax expense | $ | 389 | $ | - | ||||
| Deferred tax benefit | (105,252 | ) | (100,882 | ) | ||||
| Total income tax benefit | $ | (104,863 | ) | $ | (100,882 | ) | ||
Deferred income taxes reflect the net tax effects of temporary differences between the carrying amounts of assets and liabilities for financial reporting purposes and the amounts used for income tax purposes. The cumulative tax effect at the expected rate of 25% of significant items comprising the net deferred tax amount at June 30, 2026 and December 31, 2025 as follows.
| June 30, 2026 | December 31, 2025 | |||||||
| (Unaudited) | ||||||||
| Deferred tax assets | ||||||||
| Net operating loss | $ | 123,134 | $ | 60,681 | ||||
| Deferred revenue | 15,417 | 17,230 | ||||||
| Unbilled cost | 475,467 | 461,325 | ||||||
| Unbilled interest | 39,462 | 38,288 | ||||||
| Depreciation | 11,486 | 9,373 | ||||||
| Software amortization | 323,096 | 287,015 | ||||||
| Allowance for expected credit losses | 367,413 | 232,109 | ||||||
| Inventories obsolescence | (6,198 | ) | (6,509 | ) | ||||
| Unrealized losses on trading securities | 2,283 | 1,787 | ||||||
| Accrued bonus | 46,992 | 45,595 | ||||||
| Other | 50,231 | 48,569 | ||||||
| Total deferred tax assets | 1,448,783 | 1,195,463 | ||||||
| Valuation allowance | (76,599 | ) | (15,529 | ) | ||||
| Total deferred tax assets, net | 1,372,184 | 1,179,934 | ||||||
| Deferred tax liabilities | ||||||||
| Unbilled revenue | (2,344,731 | ) | (2,264,589 | ) | ||||
| Unbilled interest income | (459,596 | ) | (420,187 | ) | ||||
| Deferred government subsidy | (43,590 | ) | (42,293 | ) | ||||
| Unrealized gain on short-term investment | (79,545 | ) | (60,877 | ) | ||||
| Other | (3,864 | ) | (8,041 | ) | ||||
| Total deferred tax liabilities | (2,931,326 | ) | (2,795,987 | ) | ||||
| Deferred tax liabilities, net | $ | (1,559,142 | ) | $ | (1,616,053 | ) | ||
Following is a reconciliation of income tax expense at the effective rate to income tax at the calculated statutory rates for the six months ended June 30.
| 2026 | 2025 | |||||||||||||||
| (Unaudited) | (Unaudited) | |||||||||||||||
| Loss before income taxes | $ | (1,474,928 | ) | $ | (1,016,991 | ) | ||||||||||
| Statutory tax rate of 25% | (368,732 | ) | 25.0 | % | (254,248 | ) | 25.0 | % | ||||||||
| Reconciling items: | ||||||||||||||||
| Tax effect of non-deductible expense | 618 | - | % | 570 | (0.1 | )% | ||||||||||
| Tax effect of PRC preferential tax rates | 1,176 | (0.1 | )% | 1,293 | (0.1 | )% | ||||||||||
| Effect of non-PRC entities not subject to PRC tax | 202,164 | (13.7 | )% | 111,338 | (10.9 | )% | ||||||||||
| Others | 59,911 | (4.1 | )% | 40,165 | (3.9 | )% | ||||||||||
| Income tax benefit | $ | (104,863 | ) | 7.1 | % | $ | (100,882 | ) | 10.0 | % | ||||||
Uncertain Tax Positions
The Company had no significant unrecognized uncertain tax positions or unrecognized liabilities, interest or penalties associated with unrecognized tax benefit for the six months ended June 30, 2026 and 2025.
| F-23 |
NOTE 17 – CONCENTRATIONS
Major Customers
Details of the Company’s major customers (including those accounting for 10% or more of the Company’s total revenues) are as follows.
| Six Months Ended June 30, | ||||||||||||||||
| 2026 | 2025 | |||||||||||||||
| (Unaudited) | (Unaudited) | |||||||||||||||
| Customer A | 429,827 | 35 | % | - | - | % | ||||||||||
| Total | $ | 429,827 | 35 | % | $ | - | - | % | ||||||||
Details of the Company’s major customers (those accounting for 10% or more of the Company’s accounts receivable) are as follows.
| June 30, 2026 | December 31, 2025 | |||||||||||||||
| (Unaudited) | ||||||||||||||||
| Customer A | $ | 3,355,990 | 53 | % | $ | 3,961,809 | 57 | % | ||||||||
| Customer B | 1,627,500 | 26 | % | 1,697,673 | 25 | % | ||||||||||
| Customer C | 1,012,218 | 16 | % | 982,111 | 14 | % | ||||||||||
| Total | $ | 5,995,708 | 95 | % | $ | 6,641,593 | 96 | % | ||||||||
Major Suppliers
Details of the Company’s major suppliers (those accounting for 10% or more of the Company’s total purchases) are as follows.
| Six Months Ended June 30, | ||||||||||||||||
| 2026 | 2025 | |||||||||||||||
| (Unaudited) | (Unaudited) | |||||||||||||||
| Supplier A | $ | 385,782 | 38 | % | $ | - | - | % | ||||||||
| Supplier B | 77,797 | 8 | % | 59,123 | 11 | % | ||||||||||
| Supplier C | 6,692 | 1 | % | 72,358 | 14 | % | ||||||||||
| Total | $ | 470,271 | 47 | % | $ | 131,481 | 25 | % | ||||||||
Details of the Company’s major suppliers (those accounting for 10% or more of the Company’s accounts payable) are as follows.
| June 30, 2026 | December 31, 2025 | |||||||||||||||
| (unaudited) | ||||||||||||||||
| Supplier A | $ | 50,000 | 20 | % | $ | 85,860 | 29 | % | ||||||||
| Supplier D | - | - | % | 46,660 | 16 | % | ||||||||||
| Supplier E | 27,943 | 11 | % | - | - | % | ||||||||||
| Total | $ | 77,943 | 31 | % | $ | 132,520 | 45 | % | ||||||||
| F-24 |
NOTE 18 – COMMITMENTS AND CONTINGENCIES
Contingencies
The Company may be involved in various legal proceedings, claims and other disputes arising from the commercial operations, projects, employees and other matters which, in general, are subject to uncertainties and in which the outcomes are not predictable. The Company determines whether an estimated loss from a contingency should be accrued by assessing whether a loss is deemed probable and can be reasonably estimated. As of June 30, 2026 and as of the date in which these unaudited condensed consolidated financials are released, the Company was not aware of any litigation or proceedings against it.
NOTE 19 – SUBSEQUENT EVENTS
The Company performed an evaluation of events and transactions for potential recognition or disclosure through the date on which the CFS are released. Except as disclosed below, the Company is not aware of any material subsequent event.
Loan Receivable
On July 28, 2026, New Thai Hua repaid RMB2,000,000 ($294,764) to the Company. Upon receipt of repayment, the loan was renewed with 1.0% per month interest for six months, maturing on January 28, 2027.
Reverse Split
On June 4, 2026, the Board approved another reverse split (the “July 2026 Reverse Split”) at a ratio of 1-for-25, which became effective on July 6, 2026. Following the July 2026 Reverse Split, the par value of each Class A ordinary share was changed from $0.015 to $0.375.
Acquisition
In August 2026, the Company entered into a Share Purchase Agreement (the “SPA”) with MAI THI MY UT (the “Seller”), Ju Fu Limited, Fourth Coco Technology Limited and Beijing Fourth Coco Technology Co., Ltd. pursuant to which the Company agreed to acquire from the Seller all of the issued and outstanding shares of Ju Fu Limited, a business company incorporated in the British Virgin Islands (“Ju Fu”) (such transaction, the “Acquisition”). Ju Fu, through its wholly owned subsidiaries, Fourth Coco Technology Limited and Beijing Fourth Coco Technology Co., Ltd., is engaged in the advertising and digital marketing business conducted under the brand of “Beijing Fourth Coco” (四个椰子).
The acquisition was structured to close in two tranches. The first closing (the “First Closing”) was completed in August 2026. In connection with the First Closing, the Company paid the US$6,000,000 first closing cash payment, of which US$5,650,000 and US$350,000 were paid on August 11 and August 12, 2026, respectively.
The Company plans to complete the second closing (the “Second Closing”) of the Acquisition prior to the end of October 2026. In connection with the Second Closing, the Company made the second closing cash payment of US$5,000,000 on October 16, 2026. The Company will issue 4,000,000 Class A ordinary shares of the Company to the Seller. Upon completion of the Second Closing and the transfer of all issued and outstanding shares of Ju Fu to the Company, Ju Fu will become a wholly owned subsidiary of the Company.
Under the SPA, up to US$3,000,000 of additional deferred cash consideration may become payable following the Second Closing, subject to the achievement of specified performance targets of Ju Fu and its subsidiaries. The consideration shares remain subject to the applicable lock-up, leak-out, sale-proceeds limitation, carry-forward, forfeiture, surrender and cancellation provisions set forth in the SPA.
| F-25 |
Other Matters
At the 2026 Annual General Meeting of Shareholders of Hitek Global Inc. held in July 2026, the Company’s shareholders approved (i) the transfer by way of continuation of the Company from the Cayman Islands to the British Virgin Islands and (ii) the change of the Company’s name from “Hitek Global Inc.” to “Biddance AI Systems, Inc.” On August 24, 2026, pursuant to such approvals, the Company completed its continuation from the Cayman Islands to the British Virgin Islands (the “Migration”) and changed its name from “Hitek Global Inc.” to “Biddance AI Systems, Inc.”. In connection with the continuation, the Company adopted the new memorandum and articles of association under the laws of the British Virgin Islands.
Effective October 9, 2026, the Company’s trading symbol for its Class A ordinary shares on the Nasdaq Stock Market was changed from “HKIT” to “BDAI.”
After the Migration, the Company’s corporate structure is as follows:
NOTE 20 - CONDENSED FINANCIAL INFORMATION OF THE PARENT COMPANY
Pursuant to Rules 12-04(a), 5-04(c), and 4-08(e)(3) of Regulation S-X, the condensed financial information of the parent company shall be filed when the restricted net assets of consolidated subsidiaries exceed 25 percent of consolidated net assets as of the end of the most recently completed fiscal year. The Company performed a test on the restricted net assets of consolidated subsidiaries in accordance with such rules and concluded they were applicable to the Company as the restricted net assets of the Company’s PRC subsidiary and VIEs exceeded 25% of the consolidated net assets of the Company. Therefore, the condensed consolidated financial statements for the parent company are included herein.
| F-26 |
PARENT COMPANY BALANCE SHEETS
| June 30, 2026 | December 31, 2025 | |||||||
| Assets | ||||||||
| Current assets | ||||||||
| Cash and cash equivalents | $ | 16,841,902 | $ | 3,278,253 | ||||
| Short-term investments | 11,100,000 | 11,100,000 | ||||||
| Accounts receivable, net | 1,627,500 | 1,697,673 | ||||||
| Advances to suppliers, net | - | - | ||||||
| Intercompany receivables | 15,000 | 15,000 | ||||||
| Other receivable | 5,846,247 | 6,846,247 | ||||||
| Total current assets | 35,430,649 | 22,937,173 | ||||||
| Non-current assets | ||||||||
| Investments in non-VIE subsidiaries | 14,307,351 | 14,523,251 | ||||||
| Total non-current assets | 14,307,351 | 14,523,251 | ||||||
| Total Assets | $ | 49,738,000 | $ | 37,460,424 | ||||
| Liabilities and Shareholders’ Equity | ||||||||
| Current liabilities | ||||||||
| Accounts payable | $ | 50,000 | $ | 85,860 | ||||
| Intercompany payable | 4,284,252 | 1,364,252 | ||||||
| Total current liabilities | 4,334,252 | 1,450,112 | ||||||
| Total Liabilities | 4,334,252 | 1,450,112 | ||||||
| Commitments and Contingencies | - | - | ||||||
| Shareholders’ Equity | ||||||||
| Class A Ordinary Shares, US$0.375 par value; 800,000 shares authorized, 799,861 shares issued and outstanding as of June 30, 2026; 800,000 shares authorized, 5,629 shares issued and outstanding as of December 31, 2025* | 299,948 | 2,111 | ||||||
| Class B Ordinary Shares, US$0.0001 par value; 150,000,000 shares authorized, 8,192,000 shares issued and outstanding; | 819 | 819 | ||||||
| Additional paid-in capital | 35,040,217 | 24,920,060 | ||||||
| Statutory reserve | 836,215 | 836,215 | ||||||
| Retained earnings | 9,301,135 | 10,671,200 | ||||||
| Accumulated other comprehensive loss | (74,586 | ) | (420,093 | ) | ||||
| Total Shareholders’ Equity | 45,403,748 | 36,010,312 | ||||||
| Total Liabilities and Shareholders’ Equity | $ | 49,738,000 | $ | 37,460,424 | ||||
| * | The shares data are presented on a retroactive basis to reflect the 1-for-25 reverse share split of the Class A ordinary shares effective on July 6, 2026 (Notes 14 and 19). |
| F-27 |
PARENT COMPANY STATEMENTS OF OPERATIONS
| Six Months Ended June 30, | ||||||||
| 2026 | 2025 | |||||||
| (Unaudited) | (Unaudited) | |||||||
| Revenues | 429,827 | - | ||||||
| Cost of revenues | (385,782 | ) | - | |||||
| Gross profit | 44,045 | - | ||||||
| Operating expenses: | ||||||||
| General and administrative | $ | 977,419 | $ | 548,003 | ||||
| Total operating expenses | 977,419 | 548,003 | ||||||
| Operating loss | (933,374 | ) | (548,003 | ) | ||||
| Other income (expense) | ||||||||
| Net investment gain | 37,514 | 15,616 | ||||||
| Interest income | 87,203 | 98,813 | ||||||
| Other expense, net | - | (11,608 | ) | |||||
| Total other income, net | 124,717 | 102,821 | ||||||
| Share of loss from subsidiaries | (561,408 | ) | (470,927 | ) | ||||
| Net loss | $ | (1,370,065 | ) | $ | (916,109 | ) | ||
| Comprehensive income | ||||||||
| Net loss | $ | (1,370,065 | ) | $ | (916,109 | ) | ||
| Comprehensive loss | $ | (1,370,065 | ) | $ | (916,109 | ) | ||
| Loss per ordinary share | ||||||||
| Basic and diluted | $ | (0.16 | ) | $ | (0.11 | ) | ||
| Weighted average number of ordinary shares outstanding | ||||||||
| Basic and diluted* | 8,313,997 | 8,197,629 | ||||||
| * | The shares data are presented on a retroactive basis to reflect the 1-for-25 reverse share split of the Class A ordinary shares effective on July 6, 2026 (Notes 14 and 19). |
| F-28 |
PARENT COMPANY STATEMENTS OF CASH FLOWS
| Six Months Ended June 30, | ||||||||
| 2026 | 2025 | |||||||
| (Unaudited) | (Unaudited) | |||||||
| Cash flows from operating activities: | ||||||||
| Net loss | $ | (1,370,065 | ) | $ | (916,109 | ) | ||
| Adjustments to reconcile net loss to net cash provided by (used in) operating activities: | ||||||||
| Net investment loss | 561,408 | 470,927 | ||||||
| Changes in operating assets and liabilities: | ||||||||
| Accounts receivable | 70,173 | - | ||||||
| Advances to suppliers | - | (791,780 | ) | |||||
| Prepaid expenses and other current assets | - | 239,097 | ||||||
| Accounts payable | (35,861 | ) | - | |||||
| Advances from customers | - | 299,995 | ||||||
| Due to intercompany | 2,920,000 | 2,255 | ||||||
| Net cash provided by (used in) operating activities | 2,145,655 | (695,615 | ) | |||||
| Cash flows from investing activities | ||||||||
| Purchases of held-to maturity investments | (1,000,000 | ) | (1,650,000 | ) | ||||
| Redemption of held-to-maturity investments | 2,000,000 | 700,000 | ||||||
| Refund of deposit for acquisition | - | 1,000,000 | ||||||
| Net cash provided by investing activities | 1,000,000 | 50,000 | ||||||
| Cash flows from financing activities | ||||||||
| Proceeds from issuance of ordinary shares | 10,417,994 | - | ||||||
| Net cash provided by financing activities | 10,417,994 | - | ||||||
| Net increase (decrease) in cash | 13,563,649 | (645,615 | ) | |||||
| Cash and equivalents at beginning of period | 3,278,253 | 6,489,424 | ||||||
| Cash and equivalents at end of period | $ | 16,841,902 | $ | 5,843,809 | ||||
| F-29 |