Exhibit
99.2
Opus Capital Markets Consultants, LLC
|
| 5599
San Felipe Street - Suite 420 | Houston, TX 77056 | www.opuscmc.com | 224.632.1300
|
Executive
Narrative
October
20, 2026
Performed
by
Opus
Capital Markets Consultants, LLC
For
Rithm
Capital Corp.
The report summarizes
the results of a quality control (“QC”) due diligence review performed on a pool of three hundred fifteen (315) credit and
compliance loans by Opus Capital Markets Consultants, LLC (“Consultant”) on behalf of Rithm Capital Corp. (“Client”).
As detailed herein,
the pool contains one hundred seventy-eight (178) Non-QM loans and one hundred thirty-seven (137) ATR/QM: Exempt loans, of which thirty-six
(36) are Business Purpose loans and one hundred one (101) are DSCR loans.
Consultant performed
a QC review of a prior securitization review completed by Recovco Mortgage Management LLC (“Recovco”) on behalf of Rithm
Capital Corp. (“Client”). Consultant validated the one (1) exception identified in the population of one (1) credit and compliance
loan.
Consultant additionally
summarizes the results of a due diligence review performed on a pool of three hundred fourteen (314) credit and compliance loans, provided
by Rithm Capital Corp. (“Client”) who is a client of Opus Capital Markets Consultants, LLC (“Consultant”), from
which 100% of the loan population was chosen and loaded into the LauraMac underwriting software. Consultant performed a detailed compliance
and credit review of all loans.
The scope of review
previously completed by Recovco and QC’d by Opus CMC of one (1) loan is identified as the scope of services under the terms of
Exhibit A below.
The scope of review
completed by Opus CMC of three hundred fourteen (314) loans is identified as the scope of services under the terms of Exhibit B below.
The scope of review
previously completed by Recovco of one (1) loan is identified as the scope of services under the terms of Exhibit C below.
EXHIBIT
A
Scope of
Services
QC Review
The Consultant shall obtain all
necessary Option files, reports, guidelines, data tapes, and narratives that were reviewed or produced by the original due diligence
vendor. Prior to commencing the Quality Control (QC) review, the Consultant shall perform a comprehensive review of the applicable underwriting
guidelines and the original scope of work.
A QC Review shall be conducted
to verify the accuracy of the final report and narrative documents produced by the original due diligence vendor. The QC Review shall
encompass the following components:
| a) | Scope Review:
The Consultant shall review the original scope of review details to confirm that all
applicable requirements were contemplated and performed in the original review. |
| b) | Guidelines:
The Consultant shall review applicable guidelines and perform a data analysis of the
final reports to confirm the completeness and validity of the report content. |
| c) | Findings Review:
The Consultant shall conduct a comprehensive review of all Investment Options identified
with exceptions in the final report. This review shall include verification that all required
trailing documents are present within the respective Investment Option files. Additionally,
the Consultant shall confirm that all documentation used to resolve previously identified
conditions is valid and sufficient to address the original exception. In instances where
trailing documents are unavailable, the Consultant shall analyze the report commentary to
ensure that adequate explanatory notes are included, detailing how the exception was otherwise
resolved. |
| d) | Securitization
Preparation: The Consultant shall create and provide all required securitization documents,
including securitization reporting, reliance letters, narrative summaries, attestations,
and a 15-E disclosure, as applicable. |
EXHIBIT
B
Opus
Capital Markets Consultants, LLC
STATEMENT
OF WORK
Credit
Review
Credit Qualification
A re-underwriting
review will be conducted in order to verify that the requisite underwriting guidelines as specified by Client are met. Confirmation of
the loan terms will be performed through recalculation and review of documentation contained in the loan file provided to the Consultant.
The Credit Qualification review will consist of the following:
| e) | Guidelines: Determine
whether each mortgage loan meets the requisite guideline requirements as specified by the
Client. In lieu of specific requirements, Consultant should consider Regulation Z including
Appendix Q if applicable. If the loan pre-dates the requirements of Regulation Z and Appendix
Q, Consultant will consider Fannie Mae’s Single-Family guidelines. |
| | | |
| f) | Employment:
Review the file documentation for minimum required level of employment, income and asset
verifications pursuant to Client provided underwriting guidelines. |
| | | |
| g) | Income: Recalculate
borrower(s) monthly gross income and verify calculations of income as used by the original
loan underwriter at origination to determine compliance with the Client provided underwriting
guidelines. |
| | | |
| h) | Assets: Confirm
the presence of adequate asset documentation to comply with the Client provided underwriting
guideline requirements for closing funds, reserves and borrower liquidity. |
| | | |
| i) | Debt Ratio:
Recalculate the debt to income ratio and verify the ratio accuracy used by the loan underwriter
at origination to determine compliance with Client provided underwriting guidelines and regulatory
requirements. |
| | | |
| j) | Property Valuation:
Analyze all appraisals and alternative value tools used to qualify the loan for integrity
of comparable sales, completeness of data, eligibility of the appraiser and reasonableness
of estimated value. Review the appraisal to determine the appraisal(s) meet the requirements
of Client provided underwriting guidelines. |
| | | |
| k) | Loan-to-Value Ratio:
Recalculate and verify the loan-to-value ratio and combined loan-to-value ratio were accurate
at origination and meet Client provided underwriting guideline and regulatory requirements. |
| | | |
| l) | Credit History:
Review the credit report to verify that the borrower(s) demonstrate adequate credit depth
to comply with the Client provided underwriting guideline requirements. |
| | | |
| m) | Credit Scores:
Verify that borrower(s) meet minimum credit score requirements of the Client provided underwriting
guidelines. |
| | | |
| n) | Compensating Factors:
Verify exceptions to the Client provided underwriting guidelines are documented and reasonable. |
Document
Review
A review of each
loan file will be performed to confirm the presence of material documentation as applicable to the specifics of the loan transaction.
The Document Review will consist of the following:
a) Collateral
Docs
| · | Title
Commitment / Policy: Verify the presence of the title commitment or final title policy. Confirm
vested parties and the description of the property, liens and tax assessments. |
| | | |
| · | Mortgage
Note / Security Instrument: Verify the presence of the mortgage note or security instrument.
Confirm that the document has been executed by all borrowers and that all riders, addendums
and endorsement are present and duly executed. |
| | | |
| · | Mortgage / Deed of Trust: Verify the presence of a copy Mortgage or Deed of Trust. Confirm
that the documents have been executed by all required parties and that all riders, addendums and exhibits are present and duly executed.
If the loan closed within 12 months of the review, Consultant will confirm the presence of a letter from the title company specifying
the date the Mortgage / Deed Trust was sent for recording. If the closing did not occur within 12 months of the review and a copy of the
recorded Mortgage /Deed of Trust is not contained in the loan file, the Client will submit a report from an independent document custodian
verifying the presence of a recoded mortgage or a stamped / signed copy of the document stating the date the document was sent for recording. |
| | | |
| · | Conveyance
Deed: Verify as applicable that a proper conveyance deed is present in the loan file. Confirm
the proper transfer of ownership interest of the subject parties is detailed on the deed. |
b) Closing
Docs
| · | Final
Hud-1 Settlement Statement: If required, verify the presence of a final HUD-1. Verify the
completeness of required data and signatures or certification depending upon state compliance
requirements. |
| | | |
| · | Final
Truth-in-Lending Disclosure: If required, verify the presence of a final Truth-in-Lending
Disclosure. Verify the completeness of required data and that all required signatures are
present. |
| | | |
| · | Notice
of Right to Cancel: If required based on the specifics of the loan transaction, confirm the
presence and required execution of the Notice of Right to Cancel. |
| | | |
| · | Loan
Estimate: If required verify the presence of the current Loan Estimate (LE) at the time of
origination |
| | | |
| · | Closing
Disclosure: If required verify the presence of the current Closing Disclosure (CD) at the
time of origination. |
c) Credit Docs
| · | Loan
Application: Verify the presence and completeness of both the initial and final loan applications. |
| | | |
| · | Underwriting
Worksheet: Verify the presence of the relative underwriting worksheet i.e. form 1008, FHA
MCAW and VA’s Loan Analysis. |
| | | |
| · | Credit
Report: Verify the presence of a credit report for each borrower. Confirm that the credit
report was pulled within the timing requirements allowable per the Client provided underwriting
guidelines. |
| · | Housing
Payment History: In the absence of housing payment histories on the borrower(s) credit report(s),
verify that that the file contains a verification of rent or a verification of mortgage form. |
| | | |
| · | Letters
of Explanation: When Letters of Explanation are required by the Client provided underwriting
guidelines, verify the presence of any such letters exist in the loan file. |
| | | |
| · | Gift
Letters: When Gift Letters are required by the Client provided underwriting guidelines, verify
the presence of any such letters exist in the loan file. |
| | | |
| · | Income
Documentation: Verify the presence of income and employment related documentation required
by the Client provided underwriting guidelines for all borrowing parties contributing income
to the debt ratio calculation. |
| | | |
| · | Asset
Documentation: Verify the presence of asset documentation required by the Client provided
underwriting guidelines in the loan file. |
| | | |
| · | Property
Valuation Tools: Verify that each loan file contains adequate appraisal and other third party
valuation tools to satisfy the minimum required documentation under the relative Client provided
underwriting guidelines. |
| | | |
| · | Proof
of Insurance: Verify the presence of insurance certificates for mortgage, hazard and flood
insurance on an as needed basis depending upon the specifics of the loan. Confirm that adequate
coverage is present to meet the requirements of the Client provided underwriting guidelines. |
Regulatory
Compliance
Each mortgage loan file will be
subject to a post-closing regulatory compliance review to verify that each mortgage loan closed in compliance with the applicable federal,
state and local anti-predatory lending statutes in effect at the time of origination of the Mortgage Loan and that the loans meet the
applicable disclosure requirements provided under (i) the federal Truth in Lending Act (“TILA”), as implemented by Regulation
Z, 12 C.F.R. Part 1026; (ii) Section 4 of the Real Estate Settlement Procedures Act (“RESPA”), as implemented by Regulation
X, 24 C.F.R. Part 3500; (iii) the National Flood Insurance Act, (iv) the disclosure requirements and prohibitions of Section 50(a)(6),
Article XVI of the Texas Constitution and associated regulations; and (v) the disclosure requirements and prohibitions of the applicable
state, county and municipal laws and ordinances enacted to combat predatory lending. The review is conducted using both Paragon and Compliance
Ease.
If applicable, the regulatory compliance
review will be conducted in line with the most recently dated Structured Finance Association (SFA) TRID Compliance Review Scope.
| a) | Federal
Truth in Lending Act/Regulation Z: |
A review of the material
compliance disclosures set forth in Reg Z, as amended, including the Truth in Lending Disclosure and the Notice of Right-to-Cancel, if
applicable; and a review and comparison of the material disclosures with a report outlining any TILA violations. This includes a re-calculation
of disclosed finance charge [§1026.18(d)], proper execution by all required parties [§1026.17(b)], principal and interest calculations
[§1026.18(s)], payment stream(s), recalculation of disclosed APR [§1026.22], and a review to ensure disclosure differences
are within the allowed tolerances [§1026.18(d) and §1026.23(g)]. A review of the Notice of Right to Cancel (§1026.15 /
§1026.23): Review includes a verification of the transaction date and expiration date, ensures proper execution of the Notice of
Right to Cancel by all required parties verifies the disbursement date and determines if a full 3-day rescission period was adequately
provided to the borrower(s).
| b) | Federal
Truth in Lending Act/ Regulation Z: |
A review of the material
compliance disclosures set forth in Reg Z, as amended, including the Truth in Lending Disclosure and the Notice of Right-to-Cancel, if
applicable; and a review and comparison of the material disclosures with a report outlining any TILA violations. This includes a re-calculation
of disclosed finance charge [§1026.18(d)], proper execution by all required parties [§1026.17(b)], principal and interest calculations
[§1026.18(s)], payment stream(s), recalculation of disclosed APR [§1026.22], and a review to ensure disclosure differences
are within the allowed tolerances [§1026.18(d) and §1026.23(g)]. A review of the Notice of Right to Cancel (§1026.15 /
§1026.23): Review includes a verification of the transaction date and expiration date, ensures proper execution of the Notice
of Right to Cancel by all required parties verifies the disbursement date and determines if a full 3-day rescission period was adequately
provided to the borrower(s). Further, a review of proper rescission model form usage will be conducted in accordance with Circuit Court
ruling methodology related to use of the H8 vs. H9 forms on same lender rescindable transactions. A condition must be placed if the transaction
is a refinance by the original creditor and the borrower was provided the Form H-8 rescission notice. Opus CMC will note in the condition
whether or not there was a new advance that is subject to rescission per TILA/Regulation Z.
| i. | Business Days
as Defined by Regulation Z |
General business day
is defined as the days on which a creditor’s offices are open to the public for carrying on substantially all of its business functions
excluding Sundays and holidays specified by §1026.2(a)(6). Specific business day is defined as all calendar days (Monday through
Saturday) excluding Sundays and holidays specified by 5 U.S.C. 6103(a)
| c) | MDIA
(Mortgage Disclosure Information Act) - Applications Dated After 07/30/2009 and Prior to
10/03/2015): |
| i) | Initial Delivery:
Creditor must deliver the Initial Disclosures within 3 “general” business days
of application |
| ii) | No Pre-disclosure
Fees: Creditor may not charge fees, other than credit report fee, prior to borrower receiving
the Initial Disclosures |
| iii) | 7 Day Waiting
Period: Creditor must deliver the Initial Disclosures more than 7 “specific”
business days prior to closing |
| iv) | 3 Day Waiting
Period: Creditor must issue revised disclosures if APR in initial disclosures becomes inaccurate.
Closing may not occur until the 3rd “specific” business day after the consumer
receives the corrected disclosures. |
| v) | APR on Final
TIL: APR on Final TIL must be within tolerance 1/8 or ¼ of percent difference in APR
based on regular or irregular payment stream. |
| d) | Home
Ownership Equity Protection Act (HOEPA) testing, to include: |
| i) | APR test [HOEPA
(§1026.32(a)(1))] ] |
| ii) | If missing initial
application, missing initial application date or missing rate lock confirmation results in
inability to determine application date or rate set date for purposes of high cost / higher-priced
mortgage loan testing, vendor will test based on: (1) a six-month window prior to closing
date for missing application date; and (2) all dates between application and closing for
missing rate set date. A condition should be set to identify that the application date or
rate lock date is missing and that alternative (look-back) testing was utilized. Other evidence
in the file (e.g. date of initial disclosures, rate lock expiration on GFE) may be relied
upon to estimate application or rate set date but will be determined by the Client on a case
by case basis. |
| iii) | Points and
Fees test [HOEPA (§1026.32(a)(2))] |
| iv) | Review of HOEPA
disclosure (§1026.32(c)) for accuracy (i.e. payment stream, highest payment scenario;
dates disclosed, dates acknowledged) |
| v) | Review and confirm
documentation type (i.e. full, stated, no ratio) |
| vi) | Review for evidence
of prepayment penalty |
| vii) | Verification
of Debt to Income conformity, when necessary. |
HOEPA (Section 32) loan
coverage has been expanded to include purchase-money mortgages and open-end credit plans (i.e., home equity lines of credit or HELOCS),
as well as the amendment of rate and points and fees threshold testing. Consultant system requirements have been updated to address the
expansion of coverage as well as amendments to threshold testing. In addition, there is a homeownership counseling requirement to be
verified for all covered loans.
| e) | Federal
Higher Priced Mortgage Loan Testing, to include: |
HPML(§1026.35(a)(1))]
- A loan will be considered a Higher Priced Mortgage Loan if the APR exceeds the Average Prime Offer Rate by 1.50% or more percentage
points on Conforming First Liens, 2.50% for Jumbo First Liens and 3.50% or more percentage points on Second Liens.
Escrow
Requirement - Loans that fall under the guidelines of a Higher Priced Mortgage Loan (HPML) will require escrow accounts to be in place
for the first five years of the transaction. A loan will be considered a Higher Priced Mortgage Loan based on the guidelines shown above
(HPML Testing – APR)
HPML
Appraisal Rule - An HPML designation also requires additional appraisal requirements. Requirements include:
| |
· |
Three-day disclosure from application of the right to a free copy |
| |
· |
Written appraisal from certified or licensed appraiser |
| |
· |
Delivery of copies no later than three days prior to consummation |
| |
· |
If the property falls under the ‘flipping’ definition, a second appraisal is required and must document: |
| |
· |
The difference in the original sales price and the subsequent sales price |
| |
· |
Changes in market conditions |
There is additional responsibility
for providing copies of ALL documentation used in the valuation of the property, not just the final appraisal, and requirements for full
appraisals, versus other forms of valuations. System enhancements have also been made to require verification of documentation and acknowledgement
by the reviewer of evidence supporting the new requirements.
| f) | RESPA/Regulation
X (Loans with an Application Date prior to 10/03/2015): |
Each mortgage loan will
be reviewed to ensure compliance with the January 1, 2010, or most current amendments to Regulation X. The RESPA/Regulation X review
will consist of the following:
| |
· |
Good Faith Estimate (GFE): |
| |
· |
Consultant will confirm compliance with current RESPA requirements in effect at origination of the Mortgage Loan including the presence of the current GFE form in effect at the time of origination. |
| |
· |
Verify the GFE was provided to the borrower(s) within three days of “Application”. |
| |
· |
Application shall be defined by Regulation X and generally be considered complete when the following seven conditions are met: |
| 1. | Borrower(s)
First and Last Name |
| 2. | Borrower(s)
Social Security Number (to enable the loan originator to obtain a credit report) |
| 3. | Subject
Property Address (including “To Be Determined”) |
| 4. | Mortgage
Loan Amount Sought |
| 5. | Estimation
of Property Value |
| 7. | Any
other requirement as defined in the lender’s policies and procedures |
| |
· |
Consultant will verify that all Broker fees, including Yield Spread Premium (“YSP”) were accurately disclosed and reflected in the appropriate locations. |
| |
· |
Fees will be reviewed to ensure they are reasonable and customary fees for the lender and title and escrow companies and that those fees were accurately disclosed on the GFE and were reflected in the proper location on the document. |
| |
· |
Analysis to determine whether a Changed Circumstance form is required to accompany each revised Good Faith Estimate (GFE) |
| |
· |
Change of Circumstance Definition: |
| 1. | Acts
of God, war, disaster or other emergency; |
| 2. | Information
particular to borrower or transaction that was relied on in providing the GFE and that changes
or is found to be inaccurate after GFE has been provided to borrower; |
| 3. | New
information particular to the borrower or transaction that was not relied on in providing
the GFE; or |
| 4. | Other
circumstances that are particular to borrower or transaction, including boundary disputes,
need for flood insurance or environmental problems |
| 5. | In
the event any of the above occurs, the loan originator is required to provide a new revised
GFE to the borrower within 3 business days of receiving information sufficient to establish
“changed circumstances” and document the reason the revised GFE was provided. |
| 6. | Rate
Locks: If the rate has not been locked by the borrower or a locked rate has expired, the
charge or credit for rate chosen, adjusted origination charges, per diem interest and loan
terms related to the rate may change. If borrower later locks the rate, a new GFE must be
provided showing the revised rate-dependent charges and terms. All other charges and terms
must remain the same as on the original GFE, except as otherwise provided above for “changed
circumstances.” |
| |
· |
Final HUD-1: Consultant will confirm compliance with current RESPA requirements in effect at origination of the Mortgage Loan including: |
| o | Confirm
the presence of the current applicable Final HUD-1 form |
| o | Confirm
the Final HUD-1 accurately lists all broker and YSP fees. |
| |
· |
Good Faith Estimate (GFE ) and Final HUD-1 Analysis: Confirm compliance with current RESPA requirements in effect at origination of the Mortgage Loan including: |
(1) Analysis of Origination
fees disclosed on the Good Faith Estimate (GFE) and those charged to the borrower(s) on the Final HUD-1 (no variance) - No variance for
the following charges:
(a) Origination Charge
(b) Credit or Charge
for Interest Rate Chosen
(c) Adjusted Origination
Charge
(d) Transfer Taxes
(2) Analysis of Third-Party
fees disclosed on the Good Faith Estimate (GFE) and those charged to the borrower(s) on the Final HUD-1 (10% tolerance) - 10% tolerance
between GFE and actual charges at settlement for sum of following services:
(a) Lender-required settlement
services (lender selects third-party provider);
(b) Lender-required services,
title services and required title insurance, and owner’s title insurance, when the borrower uses a settlement service provider
identified by the loan originator; and
(c) Government recording
charges
| |
· |
Analysis to confirm all fees are accurately reflected in the correct tolerance category on the Good Faith Estimate (GFE) and Final HUD-1 |
| |
· |
Analysis to confirm lender accurately provided borrower adequate restitution in the event of tolerance violations and timelines for restitution/document correction were adhered to |
| |
· |
Analysis to confirm loan terms are accurately disclosed between the Good Faith Estimate (GFE) and Final HUD-1 |
| |
· |
Analysis to confirm page 3 of the HUD-1 accurately reflects fees disclosed on the Good Faith Estimate (GFE) and Final HUD-1 |
| g) | QM /
ATR (QUALIFIED MORTGAGE/ABILITY TO REPAY) DODD FRANK REVIEW |
(LOANS WITH APPLICATION DATE
ON OR AFTER 01/10/2014) Covers Legacy QM Rules (applications on or after 01/10/2014); elective compliance date of Revised QM Rules (applications
on or after 3/1/2021); mandatory date of Revised QM Rules for GSE Purchase/Securitization (applications on or after 7/1/2021); and mandatory
date of Revised QM Rules (applications on or after 10/1/2022)
| (1) | QM/ATR
(Qualified Mortgage/Ability to Repay) |
| i. | Consultant
will incorporate checkpoints for the ATR’s eight verification steps for any origination
QC work. Consultant has the option to run ATR checks on any transactions subject to QM that
fall outside the ability to meet QM guidelines, whether due to coverage exceptions or due
to failing QM criteria. Thus, any transaction that is being tested for QM will also have
the ability to be screened for ATR if the QM testing fails or the loan is exempt from QM |
| ii. | Consultant
is required to verify all information within the scope of the eight verification steps before
an ATR loan can pass. These eight tests include verifications of any amounts used in the
loan consideration and a page(s) reference to the third-party records/documentation/images |
| 2. | Current
Employment Status |
| 3. | Monthly
qualifying payments for the proposed loan |
| 4. | Monthly
payment on any simultaneous loans |
| 5. | Monthly
payment for mortgage related obligations for the proposed loans |
| 6. | Debts,
alimony and child support |
| 7. | Qualifying
monthly DTI and/or residual income |
| iii. | If
all of the verifications are made and each of the eight topic areas is confirmed to agree
with the representations made by the lender, and there are no credit exceptions to the lender’s
guidelines, the loan will pass the ATR test. If any of the conditions fail or the loan lacks
the documentation to support the stated values in any of the areas, affected items will not
be considered verified and the loan will be subject to failing the ATR test. |
| iv. | ATR
results will be reported as ATR-Pass. ATR-Fail and ATR-Exempt. This is in addition to existing
credit and compliance related reporting by the Consultant. |
| i. | Consultant’s
scope includes review of all available QM types: |
| 1. | Legacy
QM (for applications taken on or after January 10, 2014 until September 30, 2022); |
| 2. | Revised
QM (for applications taken on or after March 1, 2021); |
| 3. | Agency
QM (for applications taken on or after January 10, 2014 until June 30, 2021); |
| 4. | Agency
QM with APOR (for applications taken on or after July 1, 2021); and |
| 5. | Government
QM (for applications taken on or after January 10, 2014). |
| (2) | Generally
Applicable Factors |
| a. | The following
factors are reviewed for Legacy, Revised, and Agency QM categories: |
| i. | REGULAR PAYMENTS.
Provides for regular periodic payments that are substantially equal, except for the effect
of certain interest rate changes for adjustable or step rates. |
| ii. | TERM. Loan term
does not exceed 30 years. |
| iii. | POINTS AND FEES.
Points and fees do not exceed the applicable threshold for the appropriate loan amount. |
| (3) | QM
Rules Points and Fees Testing |
| a. | Points and fees
include: |
| i. | Finance charges,
unless excluded; |
| ii. | The portion of
upfront private mortgage insurance that exceeds FHA premiums; |
| iii. | Loan originator
compensation – Compensation/YSP known at the time of the consummation will be included
but Consultant does not review lender or broker compensation programs as part of its QM testing; |
| iv. | Real estate-related
fees if the creditor receives direct or indirect compensation in connection with the fee
or charge, the fee or charge is paid to a creditor affiliate or the fee or charge is not
reasonable; |
| v. | Premiums for credit
insurance, credit property insurance, and other insurances where the creditor is the beneficiary,
debt cancellation or suspension coverage payments; |
| vi. | Maximum
prepayment penalty; and |
| vii. | Prepayment penalty
paid in a refinance. |
| b. | Points and fees
exclude: |
| ii. | Bona fide third-party
charges not retained by the creditor; |
| iii. | Government mortgage
insurance premiums; |
| iv. | Private mortgage
insurance premiums up to an amount equal to government insurance premiums; |
| v. | Up to two bona
fide discount points if the interest before the discount does not exceed APOR by 1% based
on a calculation that is consistent with established industry practices for determining the
amount of reduction in the interest rate or time-price differential appropriate for the amount
of discount points paid by the consumer; if no discount points excluded up to one bona fide
discount point if the loan’s interest rate before the discount does not exceed APOR
2%; and |
| c. | A loan is a QM
loan if the points and fees do not exceed (values marked with “*” are indexed
for inflation): |
| i. | 3 percent of the
total loan amount for a loan greater than or equal to $100,000;* |
| ii. | $3,000* for a
loan greater than or equal to $60,000* but less than $100,000;* |
| iii. | 5
percent of the total loan amount for a loan greater than or equal to $20,000* but less than $60,000;* |
| iv. | $1,000*
for a loan greater than or equal to $12,500* but less than $20,000;* |
| v. | 8 percent of the
total loan amount for a loan less than $12,500* |
| a. | In addition to
the Generally Applicable Factors above, all Legacy QM loans must meet the following: |
| i. | Monthly Payment.
The amount of the monthly payment on the loan is calculated using the maximum rate that may
apply during the first five years and considers the monthly payment for simultaneous loans
and mortgage obligations. |
| ii. | Appendix Q. Considers
and verifies income, assets, employment, and debts in accordance with Appendix Q. |
| iii. | DTI. The DTI
ratio of total monthly debt to total monthly income does not exceed 43 percent. |
| iv. | Verified. Only
verified amounts will be included in the QM debt-to-income test - verified income and assets,
loan and simultaneous loan payments, insurance, taxes and HOA, alimony, child support and
open debts. The calculated value will be the verified debts divided by the verified income
represented as a ratio, with amounts less than or equal to 43.00% passing, and anything
above 43.00% failing. Failing this test also results in returning an overall QM status of
Fail. |
| a. | In addition to
the Generally Applicable Factors above, all Revised QM loans must meet the following: |
| i. | Monthly Payment.
The amount of the monthly payment on the loan is calculated using the maximum rate that may
apply during the first five years and considers the monthly payment for simultaneous loans
and mortgage obligations. |
| ii. | Consider and
Verify. The creditor must consider and verify the consumer’s current or reasonably
expected income or assets other than the value of the dwelling (including any real property
attached to the dwelling) that secures the loan, debt obligations, alimony, child support,
and debt-to-income ratio or residual income. |
| 1. | Consider.
As part of the “consider” requirement, Consultant will review the (a) creditor’s
policies and procedures provided by Client, as well as any exceptions thereto, for how the
creditor takes into account the underwriting factors enumerated above, and (b) the documentation
retained by creditor, such as an underwriting worksheet or a final automated underwriting
system certification in combination with the creditor’s
applicable underwriting standards and any applicable exceptions described in its policies
and procedures, showing how the creditor took these factors into account in its ability-to-repay
determination. |
| 2. | Verify.
Creditor is deemed to have complied with the “verify” requirement if it complies
with the verification standards in one or more of these following agency manuals: |
| a. | Chapters B3-3
through B3-6 of the Fannie Mae Single Family Selling Guide, published June 3, 2020; |
| b. | Sections 5102
through 5500 of the Freddie Mac Single-Family Seller/Servicer Guide, published June 10, 2020; |
| c. | Sections II.A.1
and II.A.4-5 of the Federal Housing Administration’s Single-Family Housing Policy Handbook,
issued October 24, 2019; |
| d. | Chapter 4 of
the U.S. Department of Veterans Affairs’ Lenders Handbook, revised February 22, 2019; |
| e. | Chapter 4 of
the U.S. Department of Agriculture’s Field Office Handbook for the Direct Single Family
Housing Program, revised March 15, 2019; and |
| f. | Chapters 9 through
11 of the U.S. Department of Agriculture’s Handbook for the Single-Family Guaranteed
Loan Program, revised March 19, 2020. |
| 3. | For purposes
of compliance with the requirement to verify through reasonably reliable third-party records,
a creditor need only comply with those provisions in the manuals that require creditors to
verify income, assets, debt obligations, alimony and child support using specified documents
or to classify and count particular inflows, property, and obligations as income, assets,
debt obligations, alimony, and child support. |
| 4. | Revised versions
of manuals. A creditor also complies with the verification requirement where it complies
with revised versions of the manuals listed above, provided that the two versions are “substantially
similar.” |
| 5. | The Revised QM
Rule permits the creditor to “mix and match” verification standards from different
agency manuals. Consultant will test the creditor’s “verification” of third-
party records in instances when the creditor either uses (a) its own procedures or alternatively,
(b) the verification standards of one or more of the agency handbooks listed above. |
| 6. | Note: the creditor
(or client, as the case may be,) must provide written policies and procedures and related
documentation such as underwriter worksheets in order for Consultant to review loans under
the Revised QM Rules, and in particular, with regard to the “consider” and “verify”
requirements. Further, if the creditor (or client, as the case may be) intends to use the
verification safe harbor, its written policies and procedures must specify the precise agency
handbook(s) that it is relying on with specific references to the particular provisions addressing
income, assets, debt obligations, alimony and child support using specified documents or
to classify and count particular inflows, property, and obligations as income, assets, debt
obligations, alimony, and child support – as well as the specific dates(s) of the agency
handbook(s) issuance, publication or revision. In addition, Consultant is not responsible
for determining whether revised versions of the manuals listed above are “substantially
similar” for purposes of the verification
safe harbor; such a determination of the sole responsibility of the creditor (or client,
as the case may be). |
| 7. | Note: due to
the inherent subjectivity of the foregoing “consider” and “verify”
requirements, Consultant will review the creditor’s (or client’s, as the case
may be) (i) policies and procedures and worksheets and (ii) methods and criteria for verification
of income and assets (regardless of whether the “safe harbor” is utilized) for
content only, and will not opine whether such policies and procedures, worksheets and verification
methods and criteria themselves comply with applicable law, and cannot guarantee that a court,
governmental regulator, rating agency or another third party diligence provider would reach
the same conclusions using such work product. |
| iii. | APR-APOR
Spread and Loan Thresholds. |
| 1. | The
APR on the loan does not exceed APOR for a comparable transaction as of the date the interest
rate is set the following loan amount thresholds (values marked with “*” are
indexed for inflation): |
| a. | For
a first-lien loan with a loan amount greater than or equal to ‘$110,260,* 2.25 or more
percentage points; |
| b. | For
a first-lien loan with a loan amount greater than or equal to $66,156* but less than $110,260*,
3.5 or more percentage points; |
| c. | For
a first-lien loan with a loan amount less than $66,156,* 6.5 or more percentage points; |
| d. | For
a subordinate-lien loan with a loan amount great than or equal to $66,156*, 3.5 or more percentage
points; and |
| e. | For
a subordinate-lien loan with a loan amount less than $66,156*, 6.5 or more percentage points;
and |
| f. | For
a first-lien loan secured by a manufactured home with loan amount less than $110,260*, 6.5
or more percentage points. |
| 2. | Short
Term ARMs. The APR used on short term ARMs of five years or less uses the maximum rate
in the first five years for the entire term of the loan. |
| iv. | ATR
Presumptions for Revised QM Rules |
| 1. | Safe Harbor.
For first-lien transactions, a loan receives a conclusive presumption that the consumer had
the ability to repay (and hence receives the “safe harbor” presumption of QM
compliance) if the APR does not exceed the APOR for a comparable transaction by 1.5 percentage
points or more as of the date the interest rate is set. |
| 2. | Higher Priced.
A first-lien loan receives a rebuttable presumption that the consumer had the ability to
repay if the APR exceeds the APOR for a comparable transaction by 1.5 percentage points or
more but by less than 2.25 percentage points. There are higher thresholds for loans with
smaller loan amounts, for subordinate-lien transactions, and for certain manufactured housing
loans—all of which will be tested by Consultant. |
| (6) | Agency
QM/ Temporary Qualified Mortgage (TQM) covered by the GSE Patch |
| a. | In addition to
the Generally Applicable Factors above, all Agency QM loans must be eligible for sale to
Fannie Mae or Freddie Mac. The selling guides for the agencies include: |
| ii. | DTI – using
the same calculation guidelines as QM |
| (7) | Agency QM
with APOR/ General Qualified Mortgage (QM) testing. Meets the test for “Agency
QM” and the APOR test applicable for Revised QM. |
| (8) | Government
QM/ General Qualified Mortgage (QM) Testing |
| a. | A Government QM
is defined as a qualified mortgage by the U.S. Department of Housing and Urban Development
under 24 CFR 201.7 and 24 CFR 203.19, the U.S. Department of Veterans Affairs under 38 CFR
36.4300 and 38 CFR 36.4500, or the U.S. Department of Agriculture under 7 CFR 3555.109. The
guidelines include: |
| ii. | DTI – using
the same calculation guidelines as QM |
| (9) | QM/ATR
Reporting (Covers both Legacy and Revised QM Rules as Applicable) |
| a. | For QM/TQM testing,
the results of the debt-to-income test (Legacy QM), APR-APOR spread test (Revised QM), or
guideline review (TQM) and the Points and Fees test will result in the following available
compliance conditions as requested by the rating agencies: |
| |
• |
QM/TQM-ATR Pass / Non-HPML | |
[QM or TQM – Pass / HPML – No] |
| |
• |
QM/TQM-ATR Pass / HPML | |
[QM or TQM – Pass / HPML – Yes] |
| |
• |
ATR Fail / Non-HPML | |
[QM or TQM – Fail / HPML – No] |
| |
• |
ATR Fail / HPML | |
[QM or TQM - Fail / HPML – Yes] |
| |
• |
NonQM / Compliant | |
[NonQM or TQM Loan, Exempt / ATR – Compliant] |
| |
• |
NonQM / Noncompliant | |
[NonQM or TQM Loan, Exempt / ATR –Noncompliant] |
| |
• |
Not Covered – / Exempt | |
[QM or TQM – Exempt / ATR – Exempt] |
| b. | For Revised QM
Rules testing, the following results will be provided to establish Verified Safe Harbor designation: |
| |
• |
VSH Confirmed |
|
[Verified Safe Harbor] |
| |
• |
NVSH Confirmed |
|
[Not Verified Safe Harbor] |
As with ATR testing,
these QM results are in addition to the existing credit and compliance related reporting currently performed by Consultant. Customized
reporting is available based on mutual agreement on individual Customer needs.
| (10) | Legacy
and Revised QM Rules |
| a. | Current testing
for Higher Priced Covered Transactions will be performed using one of two formulas, normal
QM and FHA TQM. For QM, a loan will be considered a Higher Priced Covered Transaction if
the APR exceeds the Average Prime Offer Rate by 1.50% or more percentage points on conforming
First Liens and 3.50% or more percentage points on Second Liens. For FHA TQM, the formula
is modified to be the Average Prime Offer Rate plus 1.15%, plus the monthly MI premium factor. |
| h) | Regulatory
Compliance Disclaimer |
Please be advised that Consultant
will not make a determination as to whether loans complied with federal, state or local laws, constitutional provisions, regulations
or ordinances that are not expressly enumerated herein. There can be no assurance that the review uncovered all issues relating to the
origination of the mortgage loans, their compliance with applicable law and regulation and the original appraisals relating of the mortgaged
properties or uncovered all relevant factors that could affect the future performance of the mortgage loans. Furthermore, the findings
reached by Consultant are dependent upon its receiving complete and accurate data regarding the mortgage loans from loans originators
and other third parties upon which Consultant is relying in reaching such findings.
Please be further advised that
Consultant does not employ personnel who are licensed to practice law in various jurisdictions, and the findings set forth in the reports
prepared by Consultant do not constitute legal advice or opinions. They are recommendations or conclusions based on information provided
to Consultant. All final decisions as to whether to purchase or enter into a transaction related to any individual mortgage loan or the
mortgage loans in the aggregate, any investment strategy and any legal conclusions, including potential liability related to the purchase
or other transaction involving any such loans, shall be made solely by the Client, or other agreed upon party, that has engaged Consultant
to prepare its reports pursuant to its instructions and guidelines. Client, or other agreed upon party, acknowledges and agrees that
the scoring models applied by Consultant are designed to identify potential risk and the Client, or other agreed upon party, assumes
sole responsibility for determining the suitability of the information for its particular use.
| i) | Seasoning
And Certain Compliance Exceptions |
Pursuant to the applicable NRSRO
criteria, Consultant graded certain compliance exceptions as non-material based on seasoning of the mortgage loan. Certain mortgage loans
were seasoned beyond the applicable period under TILA in which affirmative claims could be brought by a consumer. The time period is
not limited for claims, other than recession, which are raised as a defense to foreclosure. Information contained in any Consultant reports
related to the applicable statute of limitations for certain claims may not be accurate or reflect the most recent controlling case law.
Further, a particular court in a particular jurisdiction may extend, not enforce or otherwise allow claims beyond the statute of limitations
identified in the report based on certain factors, including the facts and circumstances of an individual loan.
TRID
TILA RESPA Integrated Disclosure
Statement of Work
Eligibility
The following criteria are used
in determining whether TRID applies:
| |
· |
The Application Date is October 3, 2015, or later (the earlier of the date the broker or lender received the borrower’s application). |
| |
· |
The Loan Purpose and Property Type includes a closed-end mortgage secured by real estate: |
| o | Refinance
(Cash Out or Rate Term) |
| o | Construction
and Construction to Permanent Financing |
| o | SFR,
1-4 Unit, PUD, Condo and Coops (Coop may be excluded based on Client instructions) |
| |
· |
The Loan Purpose and Property Type does not include: |
| o | Dwellings
that are not attached to real property |
| o | Mobile
homes, where the consumer does not own the land, |
| |
· |
For purposes of determination of Occupancy, TRID applies to loans for owner occupied, second home and vacant land. |
| |
· |
Opus CMC will apply the standard exemptions from TILA, i.e., business purposes loans, loans for agricultural purposes and loans secured by five (5) or more units. |
(a) Please be aware that
TILA contains a TRID-specific exemption for certain subordinate lien loans for the purposes of various types of assistance programs such
as down payment or closing cost, property rehabilitation, energy efficiency or foreclosure avoidance or prevention. Opus CMC will not
test such loans for TRID compliance.
Loan Estimate (″LE″)
| |
· |
Verification of compliance with timing requirements as to whether the Initial LE was delivered within three (3) business days from the Application Date. The Initial LE shall use the delivery date to calculate the earliest closing Consummation Date (no less than seven (7) business days from the delivery of the Initial LE). The delivery date is the date the creditor hand delivers the disclosures or places the disclosures in the mail, 1026.19(e)(1)(b) If the LE does not contain a signature line for the consumer’s confirmation of receipt, then Opus CMC will look for the “Loan Acceptance” statement under “Other Considerations” or other client-documented acknowledgement and borrower intent to proceed. |
| |
· |
Verification that the correct form is used and all sections of the Initial LE are completed (no blanks, “NA’s” or incomplete sections) and the Initial LE is accurate as follows: |
| |
· |
Verification of the technical formatting of the LE is NOT included in the standard review. The formatting of the document is the responsibility of the document preparation source. |
| |
· |
General loan information and loan terms sections completed and formatting is accurate. |
| i. | Verify
loan term, purpose, and product descriptions follow the prescribed format. |
| ii. | Verify
all applicants applying for credit, as disclosed on the application, are listed on the LE |
| |
· |
“Can this amount increase after closing?” and “Does the loan have these features” sections are completed and are accurate based on the terms disclosed on the LE. |
| |
· |
If rate is locked, were lock expiration date, time and time zone disclosed. |
| |
· |
Settlement charges good through date, time and time zone disclosed with minimum of 10 days during which borrower is permitted to shop knowing fees are locked during that timeframe. |
| |
· |
Projected Payments and Estimated Taxes, Insurance & Assessments sections are complete and accurate based on the loan terms and information known at the time of disclosure. |
| |
· |
The Closing Costs and Cash-to-Close sections are complete and accurate based on the information provided on page 2 of the LE. |
| |
· |
Fees disclosed properly (alphabetical order within Section with certain exceptions, and all title fees start with ″Title – ″) in Closing Cost Details section. |
| |
· |
It is recommended that an Itemization of Fees is provided for any fees disclosed as “Aggregate”. It is quite difficult to determine if the fees are disclosed properly without this information. |
| |
· |
Any addenda found in file listing ADDITIONAL fees for sections other than Section C |
| |
· |
If Interest Only Payments, Optional Payments, Step Payments, or Seasonal Payments, is Adjustable Payment (″AP″) Table
disclosed and accurate based on early disclosures in the file. |
| |
· |
If ARM or Step Rate, is Adjustable Interest Rate (″AIR″) Table disclosed and accurate based on the early disclosures in the file. |
| |
· |
The Comparison section is complete and accurate as follows: |
| |
· |
In 5 Years calculations for Total of Payments (TOP) and Total Principal Paid are accurate based on the terms and fees disclosed on page 1 and 2 of the LE. |
| |
· |
APR is accurate within tolerance based on the terms disclosed on the LE |
| |
· |
Total interest Percentage (TIP) is accurate based on the loan terms disclosed on the LE. |
| |
· |
Rounding rules verified as per 1026.37(o)(4). |
| |
· |
Other Considerations Section is complete |
If there has been a
revision to the LE, validate that the Revised LE is provided within three (3) days of COC, BRC or interest rate lock. Review as necessary
for sufficient information to establish one of the six (6) valid reasons to reset tolerance fees set forth in TRID:
| o | Changed
Circumstance affecting settlement charges |
| o | Change
Circumstance affecting eligibility |
| o | Revisions
requested by the consumer |
| o | Interest
rate dependent charges |
| o | Expiration
of the LE and |
| o | Delayed
settlement date on a construction loan |
| o | Timing
Requirement for LE 7 days prior to consummation |
| 3. | Determination
of Final Binding LE |
| |
· |
Review and analyze each LE in file to determine final Binding LE. If there is a change in loan terms, change in interest rate or increase in charges subject to variances without valid reason for a Revised LE as set forth above, findings will be cited. If a Revised LE was issued without a valid reason, the previous valid LE would be considered the Binding LE for the purposes of comparison with the Closing Disclosure. [Also see Variance Tests and Closing Disclosure for COC/BRC events disclosed after issuance of Initial CD] |
| |
· |
Verification of compliance with timing requirements that there have been no loan estimates provided to the borrower after a Closing Disclosure has been delivered, and whether the Final LE was provided at least four (4) business days prior to the closing Consummation Date. |
| |
· |
If the LE does not contain a signature line for the consumer’s confirmation of receipt, then Opus CMC will look for the “Loan Acceptance” statement under “Other Considerations” or other client-documented acknowledgement and borrower intent to proceed. |
| |
· |
Verification that the correct form is used and all sections of the Initial LE are completed (no blanks, “NA’s” or incomplete sections) and the Initial LE is accurate as follows: |
| |
· |
Verification of the technical formatting of the LE is NOT included in the standard review. The formatting of the document is the responsibility of the document preparation source. |
| |
· |
General loan information and loan terms sections completed and formatting is accurate. |
| |
· |
Verify loan term, purpose, and product descriptions follow the prescribed format. |
| |
· |
Verify all applicants applying for credit, as disclosed on the application, are listed on the LE |
| |
· |
“Can this amount increase after closing?” and “Does the loan have these features” sections are completed and are accurate based on the terms disclosed on the LE. |
| |
· |
If rate is locked, were lock expiration date, time and time zone disclosed. |
| |
· |
Settlement charges good through date, time and time zone disclosed with minimum of 10 days during which borrower is permitted to shop knowing fees are locked during that timeframe. |
| |
· |
Projected Payments and Estimated Taxes, Insurance & Assessments sections are complete and accurate based on the loan terms and information known at the time of disclosure. |
| |
· |
The Closing Costs and Cash-to-Close sections are complete and accurate based on the information provided on page 2 of the LE. |
| |
· |
Fees disclosed properly (alphabetical order within Section with certain exceptions, and all title fees start with ″Title – ″) in Closing Cost Details section. |
| |
· |
It is recommended that an Itemization of Fees is provided for any fees disclosed as “Aggregate”. It is quite difficult to determine if the fees are disclosed properly without this information |
| |
· |
Any addenda found in file listing ADDITIONAL fees for sections other than Section C |
| |
· |
If Interest Only Payments, Optional Payments, Step Payments, or Seasonal
Payments, is Adjustable Payment (″AP″) Table
disclosed and accurate based on early disclosures in the file. |
| |
· |
If ARM or Step Rate, is Adjustable Interest Rate (″AIR″) Table disclosed and accurate based on the early disclosures in the file. |
| |
· |
The Comparison section is complete. |
| |
· |
Rounding rules verified as per 1026.37(o)(4). |
| |
· |
Other Considerations Section is complete |
| 4. | Written
List of Providers (“WLSP”) |
If the lender places fees in the
Services You Can Shop For category, verify that the file contains a Written List of Providers provided to the borrower within three (3)
business days of application. The WLSP must include at least one available provider for each service and state the consumer may choose
a different provider for that service. If a written list of service providers is not provided, the fees will be treated as a 10% Tolerance
fee but a finding for missing service provider list will be noted. If a written list of service providers is provided outside of three
(3) days of the application date, the fees will be treated as a 10% Tolerance fee but a finding for a service provider list being provided
outside of three (3) days from application will be noted.
Utilize one (1) of the following
Variance Categories in performing variance tests:
Zero Tolerance/Variance*
- A finding will be cited if any charges increase from the Binding LE to the Final CD without COC or BRC. Such increases include:
| |
· |
Fees paid to the lender, broker or an affiliate of either lender or broker [fees paid to an affiliate of the lender for services NOT required by the creditor are not subject to tolerance/variance per CFR 1026.19(e)(3)(iii)(E)]; |
| |
· |
Fees paid to an unaffiliated third party if the lender did not permit the borrower to shop for servicer; and |
Any fees that increase on the CD
and are paid at closing by someone other than the borrower (e.g. seller or other third party) should be treated as borrower-paid for
purposes of the tolerance calculations in 12 CFR § 1026.19(e)(3)(i) – (iii). For example, if a $500 appraisal fee (for which
the borrower could not shop) was disclosed on the LE as paid by the borrower or in part by the seller, and the fee subsequently increases
to $750 on the CD, the $250 increase must be considered, and a tolerance refund of $250 will be due to the borrower unless the increase
had been re-disclosed subject to a valid changed circumstance. However, if a fee is not disclosed on the LE, or only the portion that
is borrower-paid is disclosed on the LE, there is no tolerance violation (a) if there is evidence in the file to show that the fee was
intended to be paid by the seller in full or in part (e.g. fee is addressed in the purchase contract and the amount to be paid by the
seller on the CD corresponds with the contract) or (b) if the fee is known to be a fee that is the responsibility of the seller (i.e.
a transfer tax in which local law/regulation provides that the seller is responsible for the fee). Fees paid by the lender should be
reviewed for compliance with 12 CFR § 1026.19(e)(3)(i) (i.e. fees that increase and are subject to an increased lender credit do
not constitute a violation, but a decreased lender credit that was not re-disclosed subject to a valid changed circumstance is a violation
and will require a refund).
10% Tolerance/Variance*
– A finding will be cited if the aggregate of the charges increase by more than 10% from the Binding LE to the Final CD without
COC or BRC. If a fee/service is listed on the LE but not charged/reflected on the Final CD, the fee will be removed and not considered
in calculating the 10% variance threshold pursuant to Comment 19(e)(3)(ii)-5. Such increases include:
| |
· |
Charges for third party services not paid to creditor or affiliate AND borrower permitted to shop for service but selects a provider on the creditor’s Written List of Service Providers. |
| |
· |
Prepaid mortgage insurance will be treated as a 10% tolerance fee if it can be shopped for (and not identified as an affiliate), otherwise it will be treated as a zero tolerance fee. |
| |
· |
Client considers seller-paid fees or fees paid by third-parties as borrower-paid for the purposes of tolerance calculations in 12 CFR §1026.19(e)(3)(i) – (iii) as detailed in section (5) Variance tests (v) |
No Tolerance/Unlimited –
No finding will be cited if any of the charges change from the Binding LE to the Final CD, provided that the disclosed amount on the
LE is based on information reasonably known to the creditor at the time of disclosure (disclosed in good faith), such as:
| |
· |
Property insurance premiums; |
| |
· |
Charges for services required by the creditor but the borrower is permitted to shop for and borrower selects a third party provider not on the lender’s Written Service Provider List; and |
| |
· |
Charges for third party services NOT required by the creditor (even if paid to an affiliate of the creditor). |
Notes of interest for “No
Tolerance/Unlimited”: No finding will be cited if any of the charges change from the Binding LE to the Final CD, provided that
the disclosed amount on the LE is based on information reasonably known to the creditor at the time of the disclosure (disclosed in good
faith),
| |
· |
Prepaid property taxes charged by local and state governments periodically will have no tolerance under the general ‘best information reasonably available’ standard unless otherwise instructed by the Client. |
| |
· |
As noted above, Opus CMC will review the loan file for evidence the disclosure was not made in “Good Faith”. “Good faith” means the creditor made the estimate based on the information reasonably available to them at the time the LE was provided. Absent such evidence, Opus CMC will consider the disclosures made in “good faith”. Two examples where a disclosure would be considered not made in “good faith” and a finding cited are: |
| 1. | The
creditor requires homeowner’s insurance but fails to include a homeowner’s insurance
premium; a finding will be added that the LE was not issued in good faith. |
| 2. | The
creditor knows the loan must close on the 15th of the month but estimates prepaid interest
to be paid from the 30th of that month, a finding will be added that the LE was not issued
in good faith. |
| |
· |
Review for documentation itemizing fees from the Binding LE to determine unrounded amounts of fees to use for performing tolerance testing only if a tolerance violation occurs. If no fee itemization is found, tolerance testing will be performed based on the information in the disclosures and a tolerance violation will be noted if applicable. Utilize fee information from closing instructions or a vendor compliance report, if the file contains the referenced support documentation. |
| |
· |
Additionally, if a documented valid COC or BRC occurs resulting in a change to loan terms, settlement charges or interest rate within four (4) business days of consummation, the variance test will be performed based on the revised amounts disclosed on the initial CD (or subsequent CD if change occurs after initial CD has been provided) provided that the change is related to the COC or BRC. |
| |
· |
For loans with no Interim LE and no COC or BRC occurring four (4) days prior to consummation, fees and charges on the CD are tested for compliance with permitted variances against fees disclosed on Initial LE. |
| |
· |
For loans with an Interim LE, the following procedures will be applied: |
| o | Review
of each Interim LE and fees and charges on the CD are tested for compliance with variance
thresholds against fees supported by a valid COC or BRC related to the charge that increases |
| |
· |
In cases where an Interim LE is issued with several fee increases, but only some are supported by or related to a valid COC or BRC, those fees which are not supported by or related to a valid COC, BRC or disclosed on an LE that was not provided timely (within three (3) business days of changed circumstance) will be tested for variance using the amounts disclosed in the Initial LE previously valid LE. |
Closing disclosure (″CD″)
| |
· |
Opus CMC will conduct a general CD review and verify the following: |
| |
· |
Recommendation: Closing Disclosure provided at closing be marked “Final.” Although this is not a requirement, marking the Closing Disclosure as Final will ensure a timely review. |
| |
· |
That the correct form is used and all sections of the CD are completed (no blanks or incomplete sections). |
| |
· |
Acknowledgement of receipt by all borrowers with a right to rescind under 1026.23 by verifying that each borrower with a right to rescind was provided with a copy of the CD. This could include the non-borrowing spouse. Acknowledgement is based on lender guidelines |
| |
· |
If the CD does not contain a signature line for the consumer’s signature, Opus CMC will look for the required alternative statement in “Other Disclosures” with the heading of “Loan Acceptance”. While not required, Opus CMC highly recommends that the client require the CD to be signed and dated by the consumer as it will ensure a timely review. |
| |
· |
If a subsequent CD is issued having changes to (a) the loan product which affects disclosed terms and loan information; (b) the addition of a prepayment penalty; or (c) an APR which exceeds the previously disclosed APR by more than 1/8 or ¼ of one percent on regular or irregular transactions, as the case may be for accuracy. Consultant will test that the borrower was given an additional three (3)-business day waiting period from the date of final pre-close CD with (a) the final loan product; (b) the prepayment penalty addition; or (c) the APR, and that the final pre-close CD has been received by borrower by consummation. APR reductions beyond these tolerances require the additional 3 day waiting period unless the overstated APR was based on an overestimated finance charge. |
| |
· |
On the interim and final pre-close CDs the following checks and limitations apply: |
| |
· |
Verification of the technical formatting of the CD is out of scope in the standard review. The formatting of the document is the responsibility of the document preparation source. |
| |
· |
Closing, Transaction and Loan Information sections have been completed with accurate information. |
| |
· |
Loan terms sections are completed. |
| o | Opus
CMC will verify loan term, purpose, and product descriptions follow the prescribed format. |
| o | Opus
CMC will verify all applicants applying for credit, as disclosed on the application are listed
on the LE |
| |
· |
“Can this amount increase after closing?” and “Does the loan have these features” sections are completed accurately. |
| |
· |
Projected Payments and Estimated Taxes, Insurance & Assessments sections are completed accurately. |
| |
· |
Fees have been disclosed properly (alphabetically, correct buckets and all title fees start with ″Title – ″) in Closing Cost Details section. |
| |
· |
Any addenda found in file listing ADDITIONAL fees for sections other than Section C (Services You Can Shop For) is completed properly. |
| |
· |
Calculating Cash to Close table completed accurately. |
| |
· |
Summaries of Transaction section completed accurately |
| |
· |
Loan Disclosures section complete:
|
| o | CD
Assumption, Demand Feature, Negative Amortization, and Partial Payments sections completed
properly (at least and only one box selected). |
| o | Late
Payment completed properly (terms disclosed and accurate per note). |
| o | Escrow
Amount section completed properly (only one box selected and amounts disclosed). |
| § | Escrow
Property Costs over Year 1 to be calculated per the payments scheduled to be made in a 1
year period after consummation (1026.38)(I)(7)(i)(A)(1). |
| § | Non-Escrowed
Property Costs over 1 Year to be calculated using either 11 or 12 months as determined by
client. (1026.38)(I)(7)(i)(B)(1) |
| |
· |
If Interest Only, Optional Payments, Step Payments, or Seasonal Payments, is Adjustable Payment (″AP″) Table disclosed accurately. |
| |
· |
If ARM or Step, is Adjustable Interest Rate (″AIR″) Table disclosed accurately. |
| |
· |
Loan Calculations section complete and accurate. |
| o | Total
of Payments is accurate per 1026.38(o)(1). |
| § | Include
fees in section A, B, and C that are paid by the borrower as well as the seller or other
if those fees are customarily paid by the borrower. |
| o | Capture
amounts disclosed in Loan Calculations section and test for TILA tolerance violations on
disclosed APR and Finance Charge. |
| o | Total
Interest Percentage (TIP) accurate with proper rounding. |
| § | Other
Disclosures section complete with at least one choice selected as applicable. |
| § | Review
for the creditor’s selection of one of the two options in the Liability After Foreclosure
section, but will not make an independent judgment whether or not the selection is correct
for the property state. Only issue a condition if either no selection is made or if both
selections are made. |
| § | Contact
Information section is complete with information from each party of the transaction provided
as applicable. |
| § | Rounding
rules verified as per 1026.38(t)(4). Rounding on all percentages except APR is percentages
should be truncated so that a zero is not disclosed in the last decimal place (7.250 should
be rounded to 7.25). |
TRID Method of Receipt Of LE
And CD
Determine the method of receipt
of the revised LE and CD and perform a compliance test with timing requirements. For purposes of the review and verification, the date
the borrower is deemed to have received the disclosure(s) is based on any of the following methods:
| |
· |
In Person: borrower signature date is used. |
| |
· |
Electronic* - No Receipt Confirmation in File: three (3) business days from later of document issue date or proof of e-delivery date is used. |
| |
· |
Electronic* - With Receipt Confirmation in File, date of receipt confirmation is used. |
| |
· |
Electronic* - Delivery confirmation of an email, assuming the borrower(s) have consented to electronic delivery. |
| |
· |
Mail (USPS or other parcel delivery service) – No Receipt Confirmation in File: three (3) business days from later of document issue date or proof of mailing date is used. Delivery confirmation, i.e., confirmation that documents have been delivered to the borrower(s) door. Signature receipt by anyone other than the borrower(s) to the mortgage transaction constitutes evidence of delivery, not receipt, for the purposes of the receipt requirements. |
| |
· |
Mail (USPS or other parcel delivery service) – With Receipt
Confirmation in File: date of receipt confirmation is used. Delivery confirmation, i.e., confirmation that documents have been
delivered to the borrower(s) door. Signature receipt
by anyone other than the borrower(s) to the mortgage transaction constitutes evidence of delivery, not receipt, for the purposes of the
receipt requirements. Unknown (unable to determine delivery method or unable to verify borrower received disclosures in any other method
than by USPS Mail method): follow the USPS Mail delivery method of three (3) business days from the document issue date. As noted above,
a signature by anyone other than the borrower(s) constitutes evidence of delivery and the method of receipt will be considered unknown,
requiring an additional three (3) days from the date the non-borrower received the documents. |
*NOTE: If disclosures are sent
electronically, a finding will be cited if there is no evidence in the file that the borrower consented to receive disclosures electronically.
Default to the three (3) business day mail rule for delivery without the proper documentation of borrower consent.
Other Recommended TRID Compliance
Tests
Apply the following additional
compliance tests which were included in the recommended review scope resulting from the 2015 CFPB Amendments:
| |
· |
Use of TRID forms prior to TRID effective date: a finding will be cited if the new TRID forms are utilized on a loan with an application received prior to the October 3, 2015 effective date. |
| |
· |
Use of TRID forms on loans not covered by TRID: a finding will be cited if the new TRID forms are utilized on loans not covered by TRID (i.e., HELOC, i.e. reverse mortgages, i.e. Chattel Dwelling loans (loans on mobile homes that are not also secured by the underlying real property or loans on houseboats). |
| |
· |
Your Home Loan Toolkit: a finding will be cited if the new Your Home Loan Toolkit Disclosure or evidence the disclosure was delivered or placed in the mail is not in the file or was not provided to the borrower within three (3) business days of application. |
| |
· |
Consummation Date: Consummation varies by applicable state law and the term is not often clearly defined. Accordingly, generally use the notary date. If there are multiple borrowers and they do not all sign the documents on the same day, then use the latest signature date. |
| |
· |
Post-Consummation Disclosures: TRID review scope will not include testing for compliance with the following post-consummation disclosures under TRID: |
(a) Escrow Closing Notice;
and
(b) Mortgage servicing
transfer and partial payment notices.
Subsequent Changes After Consummation
The following prescribed cures
as set forth in section 1026.19 (f)(2)(iii) through (v) are acceptable for changes and corrections to the Final CD after consummation.
1026.19(f)(2)(iii) – Changes
due to events occurring after consummation.
| |
· |
If within 30 days of consummation, an event in connection with the settlement of the transaction occurs that causes the final CD to become inaccurate and such inaccuracy results in a change to an amount actually paid by the borrower(s) from the amount disclosed, test for evidence that a new, corrected CD is delivered or placed in the mail to the borrower within thirty (30) days of receiving information that an event occurred. |
1026.19(f)(2)(iv) – Changes
due to clerical errors.
| |
· |
Non-numeric clerical errors, for the purpose of this scope document are any error not related to a disclosed dollar amount or percentage. Test for evidence a new, corrected CD is delivered or placed in the mail to the borrower within sixty (60) calendar days of consummation. Examples of non-numeric clerical errors include but are not limited to: |
| o | Corrections
to the closing information section. |
| o | Corrections
to the transaction information section. |
| o | Corrections
to loan id # or MIC #. |
| o | Corrections
to non-numeric identifiers in the Estimated Taxes, Insurance & Assessments section. |
| o | Corrections
to the fee labels and/or order of fees. |
| o | Corrections
to the location of the fee(s). |
| o | Corrections
to missing cure language. |
| o | Corrections
to the “Did This Change” section of Calculating Cash to Close. |
| o | Corrections
to the Loan Disclosures section |
| o | Corrections
to non-numeric items in the Escrow Account section. |
| o | Corrections
to the Other Disclosures section. |
| o | Corrections
to the Contact Information section. |
| |
· |
1026.19(f)(2)(v) – Refunds related to the good faith analysis. |
| o | Test
for evidence such as a copy of the refund check, a new corrected CD, and evidence the creditor
delivered or placed in the mail to the borrower within sixty (60) calendar days of consummation. |
A post-consummation CD is understood
to be a re-issued CD with a Date Issued represented as the date the post-consummation CD was issued. Corrections to the final pre-close
CD should not be accepted as a post-consummation CD noted in the prescribed cures above.
Errors on LE’s and Interim
CD’s and numeric errors on final CD’s do not have prescribed cures as per the regulation and therefore will not be reported
as having been cured. The assessment of risk and decision to accept a finding that does not have a prescribed cure is the responsibility
of the purchaser of the loan.
Additional Disclosures and Requirements:
Consultant will confirm compliance
with current documentation and timing requirements in effect at origination of the Mortgage Loan including:
| |
· |
Servicing Transfer Disclosure (for applications prior to 10/03/2015): |
| o | Confirm
the presence of the Servicing Transfer Disclosure form in file |
| o | Verify
the Servicing Transfer Disclosure was provided to the borrower(s) within three general business
days of “Application” |
| |
· |
Special Information Booklet (for applications prior to 10/03/2015)/ Home Loan Tool Kit (for applications on or after 10/03/2015): |
| o | Confirm
the presence of the Home Loan Tool Kit is in file for covered loans. |
| o | Confirm
the Home Loan Tool Kit is provided within three general business days of application |
| |
· |
Affiliated Business Disclosure |
| o | Confirm
the presence of the Affiliated Business Disclosure in file in the event the lender has affiliated
business arrangements |
| o | Confirm
the Affiliated Business Disclosure provided within three general business days of “Application”
(Consultant reviews for this disclosure to be provided within three general business days,
as the lender will typically know at the time of application if borrower(s) will be referred
to affiliates for provision of third party services) |
| o | Confirm
the Affiliated Business Disclosure is executed. |
| |
· |
Initial Escrow Disclosure Statement |
| o | Confirm
the presence of the Initial Escrow Disclosure Statement in file |
| o | Confirm
the Initial Escrow Disclosure Statement was provided at closing or within 45 days after settlement |
Equal Credit
Opportunity Act (Regulation B)
| |
· |
Confirm the lender has provided the borrower a disclosure of the right to receive a copy of appraisals within three (3) business days of application. This disclosure requirement may be met by disclosure on the Loan Estimate pursuant to 12 CFR § 1026.27(m)(1). |
| |
· |
Confirm that the lender has provided (delivered) copies of appraisals and all other written valuations (as disclosed to the borrower on the HUD-1 and/or contained in the Mortgage Loan File) to the borrower at least three (3) business days prior to consummation Opus CMC uses the following test: Was appraisal/valuation documentation processed at least 6 days prior to account opening/ consummation date (3 day rule plus 3 days mailing time)? |
| |
· |
For a borrower that has waived the 3-business day disclosure requirement, confirm that the borrower has either (1) signed the waiver at least three (3) business days prior to consummation or (2) has signed an acknowledgment that the waiver occurred at least three (3) business days prior to consummation. Additionally, confirm that the lender has provided copies of appraisals and other written valuations at or prior to consummation. |
Fair Credit
Report Act (Regulation V)
| |
· |
Confirm that the lender has provided the borrower the risk-based pricing notice (as required by 12 CFR § 1022.73) or credit score disclosure (as required by 12 CFR § 1022.74(d)), as applicable; (a) If the lender has provided the risk-based pricing notice, confirm the disclosure was provided before consummation, but not earlier than the approval decision was communicated to the consumer; and (b) If the lender has provided the credit score disclosure, confirm the disclosure was provided before consummation. |
| |
· |
Confirm that the lender has provided a copy of the disclosure of credit score and the Notice to Home Loan Applicant (as required by 15 U.S.C. § 1681g) before consummation. |
High-Cost,
State & Local Anti-Predatory Regulations
In addition to federal thresholds,
Consultant will review the anti-predatory lending statutes in the following states and local municipalities, as applicable, as well as
any additional applicable regulations implemented during the Term of this SOW.
| |
· |
Arkansas Home Loan Protection Act, Ark. Stat. Ann. § 23-53-101 et seq. |
| |
· |
California Anti-Predatory Lending Statute, Cal. Fin. Code § 4970 et seq. |
| |
· |
California Higher-Priced Mortgage Loan Statute, Cal. Fin. Code §4995 et seq. |
| |
· |
Colorado Consumer Equity Protection Act, Colo, Rev. Stat. § 5-3.5-101 et seq.. |
| |
· |
Connecticut Abusive Home Loan Lending Practices Act, Conn. Stat. Ann. §36a- 746 et seq., as amended from time to time. |
| |
· |
Connecticut Nonprime Home Loans Statute, Conn. Gen. Stat. §§ 36a-760 et seq. (as originally enacted and as amended by Senate Bill 949). |
| |
· |
District of Columbia Home Loan Protection Act, D.C. Official Code § 26-1151.01 et seq., as implemented by 20 D.C. Municipal Reg § 2000.1 et seq. |
| |
· |
Florida Fair Lending Act, Fla. Stat. Ann. § 494.0078 et seq. (for loans closed before July 1, 2014). |
| |
· |
Georgia Fair Lending Act, Ga. Stat. Ann. § 7-6A-1 et seq. (as originally enacted by House Bill 02-1361 and as modified by Senate Bill 03-53). |
| |
· |
Idaho Residential Mortgage Practices Act, Idaho Code § 26-3101 et seq. |
| |
· |
Illinois High Risk Home Loan Regulations, 38 Ill. Admin. Code §345.10 et seq. |
| |
· |
Illinois High Risk Home Loan Act, Public Act. 93-0561 (2003) codified at 815, ILCS §§ 137/5 et seq., and as amended by SB 1692 (2012), effective January 10, 2014. |
| |
· |
Illinois Predatory Lending Database Program, Public Act 95-0691 (SB 1167). |
| |
· |
City of Chicago, Illinois, Anti-Predatory Lending Ordinance, Chicago Municipal Code, §§ 2-32-440; 2-32-455; 2-92-325; 4-4-155; 8-4-325. |
| |
· |
Cook County, Illinois, Anti-Predatory Lending Ordinance, Cook County Code of Ordinances § 34-341. |
| |
· |
Cook County, Illinois, Anti-Predatory Lending Pilot Program, Illinois House Bill 4050 (2005). |
| |
· |
Indiana Home Loan Practices Act, as amended by HB 1179 (2005), Ind. Code § 24-9-1 et seq. |
| |
· |
Section 16a-3-308a of the Kansas Consumer Credit Code, Kan. Stat. Ann. §16a.101 et seq. |
| |
· |
Kentucky Anti-Predatory Lending Statute, Ky. Rev. Stat. § 360.100 et seq. |
| |
· |
Maine, An Act to Enhance Consumer Protections in Relation to Certain Mortgages (for loans closed prior to September 27, 2011), Me. Rev. Stat. Ann. Tit. 9-A, §§ 8-103(1); 8-206(8);8-206A, as amended by Legislative Documents 1869 (2007), 2125 (2008) and 1439 (2009). |
| |
· |
Maine Consumer Credit Code - Truth-in-Lending, (for loans closed on or after September 27, 2011), Me. Rev. Stat. Ann. tit. 9-A, §§ 8-501 et seq., as amended from time to time. |
| |
· |
Maryland Commercial Law, Md. Code Ann., Com. Law §§ 12-124.1; 12-127; 12- 409.1; 12-1029. |
| |
· |
Maryland Regulations for Higher Priced Mortgage Loans, as promulgated under the Maryland Mortgage Lender Law, Md. Code Ann., Fin. Instit. Code §§ 11-501 et seq.; Md. Code Regs. §§ 09.03.06.01 et seq. |
| |
· |
Massachusetts High-Cost Mortgage Regulations, 209 CMR Parts 32 and 40, as amended from time to time. |
| |
· |
Massachusetts Predatory Home Loan Practices Act, M.G.L. Chapter 183C, §§ 1 et seq. |
| |
· |
Massachusetts “Borrower’s Interest” Standard, M.G.L. Chapter 183, §28C. |
| |
· |
Massachusetts Mortgage Lender and Broker Regulations, 940 CMR §800 (15-17). |
| |
· |
Massachusetts Regulations for Higher Priced Mortgage Loans, 209 CMR §§ 32.00 et.seq., as amended from time to time. |
| |
· |
Massachusetts Subprime ARMs to First Time Homebuyers, M.G.L. Chapter 184, §17B.5. |
| |
· |
Michigan Consumer Mortgage Protection Act, Mich. Stat. Ann. § 445-1631 et seq. |
| |
· |
Minnesota Mortgage Originator and Service Licensing Act, § 58.137 et seq. (S.F. 2988 (2002)), as amended by House File 1004 (2007) and Senate File 988 (2007). |
| |
· |
Nebraska Mortgage Bankers Registration and Licensing Act, Neb. Stat § 45-702 et seq. |
| |
· |
Nevada Anti-Predatory Lending Law, Assembly Bill No. 284 (2003) and Amended by Assembly Bill No. 440 (2007), codified as NRS § 598D.010 et seq. |
| |
· |
New Jersey Home Ownership Security Act of 2002, NJ Stat. Ann. § C:46:10B-22 et seq., as amended from time to time. |
| |
· |
New Mexico Home Loan Protection Act, Senate Bill 449 (Regular Session 2003), codified at NM Rev. Stat. § 58-21A-1 et seq. and as amended from time to time. |
| |
· |
New York High-Cost Home Loan Regulations, 3 NYCCR Part 41 (2001). |
| |
· |
New York High-Cost Home Loan Act, N.Y. Bank. L. Ch. 626., as codified in NY Bank. Law § 6-l, and as implemented by 3 NYCCR Part 41 as amended from time to time. |
| |
· |
New York Subprime Home Loans Statute, NY Bank. Law § 6-m. |
| |
· |
North Carolina Anti-Predatory Lending Law, N.C. Gen. Stat. §§ 24-1.1A to 24- 10.2 and North Carolina Amendments to Anti-Predatory Lending Law, N.C. Gen. Stat. §§ 24-9; 24-1.1(E)(a); 24-10.2(a), as amended from time to time. |
| |
· |
Ohio Anti-Predatory Lending Statute, HB 386 as amended by Senate Bill 185 (2006), and as codified in various sections of the Ohio Code. |
| |
· |
Ohio Consumer Sales Practices Act, Ohio Rev. Code Ann. § 1345.01, as implemented by Ohio Admin. Rules § 109 4-3-01 et seq. |
| |
· |
City of Cleveland Heights, Ohio, Anti-Predatory Lending Ordinance, Ordinance No. 72-2003 (PSH), Mun. Code §§ 757.01 et seq. |
| |
· |
Summit County, Ohio, Anti-Predatory Lending Ordinance, Ordinance No. 2004- 618, Muni. Code §§ 201.01 et seq. |
| |
· |
Oklahoma Anti-Predatory Lending Law, House Bill No. 1574 (2003), as codified in various sections of Title 14A of the Oklahoma Consumer Credit Code. |
| |
· |
Oklahoma Higher-Priced Mortgage Loans Law, Okla. Admin. Code §§ 160:45-9- 1 et seq. |
| |
· |
Pennsylvania Consumer Equity Protection Act, 63 Pa. Cons. Stat. Ann. § 456.501 et seq. |
| |
· |
Rhode Island Home Loan Protection Act, R.I. Gen. L. 34-25.1-2 et seq, as implemented by Emergency Banking Regulation 3 (2006) and Final Banking Regulation 3 (2007) and amended by Senate Bill 371 (2007).
|
| |
· |
City of Providence, Rhode Island, Anti-Predatory Lending Ordinance, Chapter 2006-33, Ordinance No. 245. |
| |
· |
South Carolina High-Cost and Consumer Home Loans Act, S.C. Code § 37-23-10 et seq. |
| |
· |
Tennessee Home Loan Protection Act, Tenn. H.R. 3597 (2006), as codified at Tenn. Code Ann. §§ 45-20-101 et seq. |
| |
· |
Texas High-Cost Home Loan Statute, Tx. Fin. Code Ann.§
343.201 et seq.
|
| |
· |
Section 50(a)(6), Article XVI of the Texas Constitution |
| |
· |
Section 50(f)(2), Article XVI of the Texas Constitution |
| |
· |
Utah Residential Mortgage Practices Amendments, Utah Code Ann. § 61-2c-102 et seq. |
| |
· |
Utah High-Cost Home Loan Act, Utah Code § 61-2d-101 et seq. |
| |
· |
Vermont Interest Act, 9 V.S.A. § 104, implemented by Regulation B-98-2. |
| |
· |
Virginia Mortgage Lender and Broker Act (for loans originated prior to July 1, 2003), Va. Code Ann. §§ 6.1-413; 6.1-422; 6.1-428. |
| |
· |
Virginia Mortgage Lender and Broker Act (for loans originated on or after July 1, 2003 to September 30, 2010, as amended), Va. Code Ann. §§ 6.1-411, 6.1-422.1, 6.1-425.1 and 6.1-425.2. |
| |
· |
Virginia Mortgage Lender and Broker Act (for loans originated on or after October 1, 2010), Va. Code Ann. §§ 6.2-1600 et seq., as amended from time to time. |
| |
· |
Virginia Senate Bill 797 (2008), effective July 1, 2008 (uncodified). |
| |
· |
West Virginia Residential Mortgage Lender, Broker and Servicer Act, W.Va. Code § 31-17 et seq. |
| |
· |
Wisconsin Responsible High-Cost Mortgage Lending Act, Wis. Stat. § 428.202, as implemented by Wis. Admin. Code DFI-Bkg 46.01 et seq. |
Flood
Insurance Testing
National Flood Insurance Program
(NFIP)
Each mortgage loan will be reviewed
to ensure adherence to flood insurance coverage requirements as outlined under the NFIP, including identification of flood zones and
subsequent policy documentation for evidence of adequate coverage amounts.
Homeowner
Flood Insurance Affordability Act (HFIAA)
Each mortgage loan made by an FDIC-supervised
institution or servicer acting on its behalf shall require the escrow of all premiums and fess for flood insurance for any designated
loan secured by residential improved real estate or a mobile home, made, increased, extended or renewed on or after January 1, 2016.
Frequency – Payable with
same frequency as payments designated for the loans
Exceptions
| |
· |
Loan is an extension of credit primarily for business, commercial or agricultural purposes |
| |
· |
Loan is in a subordinate position to a senior lien secured by the same residential improved real estate or mobile for which the borrower has obtained flood insurance |
| |
· |
Flood Insurance coverage for the residential real estate is provided by a policy that |
| b. | Provided
by a condominium association, cooperative or other applicable group and |
| c. | The
premium for which is paid by the condominium association, cooperative, homeowners association,
or other group as a common expense. |
Misrepresentation
and Third-Party Review
Validate that fraud reports and
independent third-party property valuations reports are in the file. The review will consist of the following:
Misrepresentation Review and
Valuation Review
Review on each loan to identify
potential misrepresentations of income, employment, identity, occupancy, transaction and appraisal misrepresentation or other areas of
potential misrepresentation. The Misrepresentation may include the following:
| |
· |
Signatures: Validate signature consistency across documents. To the extent imaged or hard copy files are provided, Consultant will utilize reasonable efforts to validate the consistency of signatures across documents. |
| |
· |
Alerts: Assess credit report alerts for accuracy and potential issues. |
| |
· |
Social Security Numbers: Compare SSN(s) across all file documents. |
| |
· |
Document Integrity: Review for apparent alterations to loan documents. To the extent imaged or hard copy files are provided, Consultant will utilize reasonable review of alterations to the loan documents. |
| |
· |
Data Consistency: Review the documents contained in the loan file for consistency of data. |
| |
· |
Third Party Fraud Tools: To the extent a third party fraud tool is contained in the loan file, the Consultant will ensure high level or critical warnings are reviewed and addressed. |
Independent Third-Party Values
Review each loan to determine whether
a third party valuation product was required and if required, that the third party product value was compared to the original appraised
value to identify a value variance and apply the appropriate rating agency grade after reviewing the required valuation products. i)
Consultant will perform the following steps.
| |
· |
Value is based on as-is condition or provides satisfactory completion of all material conditions including inspections, licenses, and certifications (including certificates of occupancy) to be made or issued with respect to all occupied portions of the mortgaged property and with respect to the use and occupancy of the same, have been made or obtained from the appropriate authorities. |
| |
· |
Property is described in average or better condition |
| |
· |
No apparent appraiser independence violation statements |
| |
· |
Appraisal addresses any adverse comments |
| |
· |
Appraisal is completed on appropriate GSE Forms |
| |
· |
Appraisal contains required attachments. |
| |
· |
Appraiser was appropriately licensed at the time the appraisal was signed |
If the valuation vendor does not
supply the updated valuation product directly to the Consultant, the Client will authorize the valuation vendor to issue an attestation
with sufficient information for the Consultant to determine the correct valuation product was utilized to verify the accuracy of the
origination appraisal.
Value Review Disclaimer
| |
· |
The individuals performing the above procedures are not person providing valuations for the purpose of the Uniform Standards of Professional Appraisal Practice (“USPAP”) or necessarily licensed as appraiser under Federal or State law, and the services being performed do not constitute appraisal reviews for the purposes of USPAP or Federal or State law. |
| |
· |
Opus CMC makes no representation or warranty as to the value of the mortgaged property, notwithstanding that Opus CMC may have reviewed the valuation information for reasonableness. |
| |
· |
Opus CMC is not an Appraisal Management Company (“AMC”) and therefore does not opine on the actual value of the underlying property. |
| |
· |
Opus CMC is not a creditor within the meaning of the Equal Credit Opportunity Act (“ECOA”) or other lending laws and regulations, and therefore Opus CMC will not have and communications with or responsibility to any individual concerning property valuations. |
Properties in FEMA declared
disaster zones.
If a FEMA declared disaster occurs
after the inspection date on the appraisal, Consultant will review the file to determine if an exterior inspection to ensure:
| |
· |
No apparent damage to the property |
| |
· |
Property appears to be occupied |
Data
Compare
Client will provide
a data tape with the following data fields and Consultant will compare the field to the applicable source document and report any variance
| |
· |
Second Mortgage Lien Amount |
Rating
Agency Grading Criteria
Fitch Ratings Grading Criteria
Grading shall be provided for each
exception, each exception category and holistically for each loan. The methodology for the application of the RMBS grading as defined
by Fitch in their current industry publications as updated from time to time.
Moody’s Investor Services
Grading Criteria
Grading shall be provided for each
exception, each exception category and holistically for each loan. The methodology for the application of the RMBS grading as defined
by Moody’s in their current industry publications as updated from time to time.
Kroll Bond Rating Agency LLC Grading Criteria
Grading shall be provided for each
exception, each exception category and holistically for each loan. The methodology for the application of the RMBS grading as defined
by Kroll in their current industry publications as updated from time to time.
S&P Global Ratings Grading
Criteria
Grading shall be provided for each
exception, each exception category and holistically for each loan. The methodology for the application of the RMBS grading as defined
by Standard & Poor’s in their current industry publications and updated from time to time.
DBRS Morningstar Grading Criteria
Grading shall be provided for each
exception, each exception category and holistically for each loan. The methodology for the application of the RMBS grading as defined
by DBRS in their current industry publications and updated from time to time.
Opus
CMC Grading Criteria
Opus CMC Grading Criteria
Grading shall be provided for each
exception, each exception category and holistically for each loan. The following grading is not intended for securitization reviews and
Opus CMC will not issue a Rating Agency Narrative, Reliance or Form ABS Due Diligence 15E if Client elects to utilize the following grading
criteria. The methodology for the application of grading is defined by Opus CMC and updated from time to time shall be determined as
follows:
Opus CMC Credit Grades
| |
· |
Level 1 Credit Grade Definition: Loan was originated in accordance with the mortgage loan originator underwriting guidelines without exception. |
| |
· |
Level 2 Credit Grade Definition: Loan was originated in substantial compliance with the originator's underwriting guidelines and there are sufficient compensating factors for any exceptions. |
| |
· |
Level 3 Credit Grade Definition: Loan was not originated in substantial compliance with the originator's underwriting guidelines and there are insufficient compensating factors for the exceptions or is missing material documentation. |
Opus CMC Property Grades
| |
· |
Level 1 Property Grade Definition: Property value appears to be within 10% of original appraised amount and there are no material deficiencies in the appraisal process. |
| |
· |
Level 2 Property Grade Definition: Property value appears to be within 10% of original appraised amount, but minor issues in the appraisal process were identified. |
| |
· |
Level 3 Property Grade Definition: Property value does not appear to fall within 10% of the original appraised value and/or material deficiencies exist with respect to the appraisal process or the file is missing material documentation. |
Opus CMC Compliance Grades
| |
· |
Level 1 Compliance Grade Definition: Loan complies with all applicable laws and regulations reviewed under the applicable scope of work. |
| |
· |
Level 2 Compliance Grade Definition: There are minor issues regarding legal and/or regulatory compliance but such issues do not represent risks to the enforceability of the borrower's obligation under the loan documents and will not result in assignee liability to the investor. |
| |
· |
Level 3 Compliance Grade Definition: Loan is not in compliance with laws and regulations reviewed under the applicable scope of work or the loan is missing material documentation. |
Redacted
Information
| |
· |
Property Address, City, County, MSA, Zip |
| |
· |
Account Number, including Originator and Servicer Loan Number |
| |
· |
Names of Borrowers or any other Individuals |
| |
· |
Company and Entity Names |
| |
· |
Financial Institution Names |
| |
· |
Any Location Information (other than state), including City, County, MSA and Zip |
| |
· |
Account Numbers of any type |
| |
· |
Insurance Claim Numbers |
| |
· |
Insurance Policy Numbers |
| |
· |
Foreclosure Action dates and Case Numbers |
| |
· |
Bankruptcy Action dates and Case Numbers |
| |
· |
Any reference that would allow the identification of the location of a property (e.g. neighborhood, body of water, schools, major highways) |
| |
· |
Driver’s License Numbers |
DSCR
Loan Review
A re-underwriting review will be
conducted in order to verify that the requisite underwriting guidelines as specified by Client (the “Underwriting Guidelines”)
are met. Confirmation of the loan terms will be performed through recalculation and review of documentation contained in the loan file
provided to the Consultant. The Credit Qualification review guidelines will consist of the following:
Borrower
Underwriting:
| |
· |
Borrower Liquidity: Review and confirm borrower’s liquidity position adheres to Underwriting Guidelines. |
| |
· |
Credit / Background Check: Review and confirm each guarantor and/or owner of the borrowing entity requirements meet Underwriting Guidelines, including OFAC. |
| |
· |
Property management questionnaire: Review the questionnaire to confirm management experience meets Underwriting Guidelines. |
| |
· |
Borrowing Entity: Confirm the entity is in good standing and duly formed (if applicable documents are in the file). |
| | | Verify
the individual signing on behalf of the organization has the authority to bind the entity
(if applicable documents are in the file). |
| |
· |
Loan-to-Value (LTV)/Loan-to-Cost (LTC) Limits: Confirm the LTV/LTC meets Underwriting Guidelines. |
| |
· |
Permitted Loan Terms: Confirm the loan terms are eligible per the Underwriting Guidelines. |
| |
· |
Property Requirements and Market Requirements: Confirm the loan Property and Market Requirements are eligible per the Underwriting Guidelines. |
| |
· |
DSCR—ensure components of Debt Service Coverage Ratio are identified correctly: Recalculation of DSCR |
Title Insurance Requirements
are met per Underwriting Guidelines only as follows
| |
· |
Confirm Loss payee language must be present and required insurance policies and coverage amounts meet the Underwriting Guidelines |
| |
· |
Condominium Eligibility: Confirm Condo Master Policy is present and meets the Underwriting Guidelines |
| |
· |
Property Insurance: Confirm each mortgaged property has a policy in place and proper coverage amount in adherence to the Underwriting Guidelines. |
| |
· |
Preliminary/Commitment Title: Review and confirm first lien holder position, validate no loan file discrepancies, delinquent taxes, and/or additional liens at time of consummation. |
Credit
Document Check
| |
· |
Loan Application: Verify the presence and completeness of both the initial and final loan applications. |
| |
· |
Credit Report: Verify the presence of a credit report for each borrower. Confirm that the credit report was pulled within the timing requirements allowable per the Client provided underwriting guidelines. |
| |
· |
Housing Payment History: In the absence of housing payment histories on the borrower(s) credit report(s), verify that that the file contains a verification of rent or a verification of mortgage form. |
| |
· |
Letters of Explanation: When Letters of Explanation are required by the Client provided underwriting guidelines, verify the presence of any such letters exist in the loan file. |
| |
· |
Gift Letters: When Gift Letters are required by the Client provided underwriting guidelines, verify the presence of any such letters exist in the loan file. |
| |
· |
Income Documentation: Verify the presence of income and employment related documentation required by the Client provided underwriting guidelines for all borrowing parties contributing income to the debt ratio calculation. |
| |
· |
Asset Documentation: Verify the presence of asset documentation required by the Client provided underwriting guidelines in the loan file. |
| |
· |
Property Valuation Tools: Verify that each loan file contains adequate appraisal and other third party valuation tools to satisfy the minimum required documentation under the relative Client provided underwriting guidelines. |
| |
· |
Proof of Insurance: Verify the presence of insurance certificates for mortgage, hazard and flood insurance on an as needed basis depending upon the specifics of the loan. Confirm that adequate coverage is present to meet the requirements of the Client provided underwriting guidelines. |
Compliance
| o | No
compliance testing for the DSCR review |
| o | State
and Local High Cost Mortgage regulations, including: |
| § | Cook
County High Cost Ordinance |
| § | City
of Chicago High Cost Ordinance |
| o | Anti-predatory
lending laws, including: |
| § | Minnesota
§58 on or after 8/1/2008 |
| § | Virginia
Lender and Broker Act after 6/1/2008 |
EXHIBIT C
RECOVCO
MORTGAGE MANAGEMENT, LLC
STATEMENT
OF WORK
DUE DILIGENCE
SERVICES
Scope of
Services
CREDIT UNDERWRITING:
Recovco
performed a review of the loan package to determine whether such package meets the credit and property underwriting criteria of applicable
guidelines, in effect at the time of such loan’s origination and that adequate support for the underwriting decision is contained
in the file. Recovco reported to Client any exceptions utilizing Client accessed Recovco systems or other mutually agreed upon written
report.
To complete
these activities, Recovco completed a review utilizing the following review scope:
Recovco will
review asset origination to determine conformity to the stated underwriting or credit extension guidelines, standards, criteria or other
requirements, including, as applicable, the Ability to Repay and Qualified Mortgage requirements described below, that were provided
to Recovco and/or as directed by Client. When applicable, a review of the mortgage loan file to the Automated Underwriting System output
within the mortgage loan file will also be performed.
Credit Application:
For the Credit Application, Recovco will verify that the application: (i) was signed by all listed borrowers, (ii) was substantially
filled out, (iii) contained all known borrower-owned properties on the Real Estate Owned section 2, and (iv) included the borrower’s
employment history.
Credit Report:
Recovco’s review will include confirming that a credit report, that met guideline requirements, was present for each borrower and
that such borrower’s credit profile adhered to guidelines. In order to make this determination, Recovco: will (i) capture the monthly
consumer debt payments for use in relevant calculations, (ii) note and research the Real Estate Owned and fraud alerts, and (iii) gather
data required for the ASF tape submission including (a) the most recent FICO (scores from Equifax, Experian, and Transunion if available),
(b) the most recent FICO date, (c) the longest trade line, (d) the maximum trade line, (e) the number of trade lines, and (f) the credit
usage ratio.
Employment
and Income: Recovco will determine whether applicable supporting employment and income documentation required by the guidelines, and
as applicable Appendix Q or ATR, was present in the mortgage loan file and where possible, wasn’t fraudulent. This documentation
will be used to verify whether the income used to qualify the mortgage loan was calculated in accordance with guidelines and may have
included items such as: (i) verbal or written verification of employment, (ii) pay stubs, (iii) W-2 forms, (iv) tax returns, (v) financial
statements, (vi) IRS tax transcripts, and for certain programs (vii) bank statements.
Asset Review:
Recovco will assess whether the asset documentation required by the guidelines, and as applicable, Appendix Q or ATR, was present in
the mortgage loan file. Utilizing this documentation, Recovco will complete a review of the reserve calculation and any large deposits.
Documentation verifying assets for down payment, closing costs, prepaid items and reserves may have included: (i) verification-of-deposit,
(ii) depository account statements, (iii) stock or security account statements, (iv) gift funds, (v) escrow or earnest money deposits,
and (vi) settlement statements or other evidence of conveyance and transfer of funds (if a sale of assets was involved).
Hazard/Flood
Insurance/Taxes: Recovco will review the insurance present on the mortgage loan. During this review, Recovco will (i) verify that the
hazard insurance met the minimum required amount of coverage in the guidelines, (ii) confirm that the mortgage clause listed the lender’s
name and “its successors and assigns,”, (iii) confirm that the premium amount on both the hazard and flood insurance matched
what was used in the debt-to-income (“DTI”) calculations, (iv) review the tax certificate to verify and compare monthly escrows
used to calculate DTI matched, (v) confirm that the flood certification was for the correct borrower, property, lender and mortgage loan
number, and (vi) complete other property specific items including (a) for condominium properties, confirming that the blanket policy
met the minimum amount of coverage in the guidelines and (b) for properties in a flood zone per the flood certification, confirming that
flood insurance met guideline requirements and met the minimum required amount of coverage in the guidelines.
DU/LP Review:
When provided and appropriate, Recovco will verify that DU findings included an approved/eligible decision as required per guidelines.
However, all mortgage loans are manually underwritten with documentation requirements determined by Client guidelines and not AUS findings.
Occupancy
Review: Recovco will confirm the property occupancy is consistent with the mortgage loan approval and borrowers’ application disclosure
based solely on information contained in the mortgage loan file and any fraud report obtained in connection with the mortgage loan.
Guideline
Review: Recovco will confirm the mortgage loan was originated in accordance with required guidelines by reviewing conformity of
mortgage loan, transaction type, and borrower characteristics to stated guidelines. Mortgage characteristics to be examined
include (i) DTI of the borrower, (ii) the LTV/CLTV/HTLTV, (iii) the credit score for each borrower, (iv) asset reserves of the
borrower, (v) property type, (vi) property usage, and (vii) other property specific items including (a) for condominium or
cooperative properties, assessing whether the condominium or cooperative project adheres to required guidelines.
Fraud Review:
Recovco will review fraud report results in each mortgage loan file, to the extent present, in conjunction with source documents found
in the mortgage loan file to assess the likelihood of any misrepresentations associated with the origination of the mortgage loan. If
the mortgage loan file did not contain a fraud report and the counterparty did not produce one, Recovco will condition the mortgage loan
for the missing fraud report product.
If a report
was present, Recovco will review the report for (i) any name variations for the borrowers, (ii) any social security number variations
for the borrowers, (iii) any potential occupancy issues based on the borrower’s address history, (iv) any noted employment issues,
and (v) any additional consumers associated with the borrower’s profile. If any findings are noted, Recovco will confirm that such
findings and/or variations were addressed by the originator in the origination of the asset or that such red flag issues were fully addressed
via mortgage loan documentation provided.
Additional
Review of Mortgage Loan File: Recovco will review the closing documents to ensure that the mortgage loan file information is complete,
accurate, and contains consistent documentation. Included in this portion of the review are items such as reviewing for (i) evidence
of primary mortgage insurance, and (ii) the presence of loan modification documents, and (iii) general conformity to Fannie Mae or Freddie
Mac approved formats at the time of origination.
If standard
GSE forms were not used for the mortgage loan, Recovco will seek to confirm the existence of: (i) a “due on sale” clause,
(ii) mortgagors requirement to maintain adequate insurance at the mortgagor’s own expense, and (iii) the holder’s right to
foreclose and to confirm that any homestead exemption has been waived as required by applicable law within the forms utilized.
REGULATORY COMPLIANCE REVIEW:
Please
be advised that Recovco did not make a determination as to whether the mortgage loans complied with federal, state or local laws, constitutional
provisions, regulations or ordinances that are not expressly enumerated below. There can be no assurance that the Review uncovered all
relevant factors relating to the origination of the mortgage loans, their compliance with applicable law and regulations and the original
appraisals relating to the mortgaged properties or uncovered all relevant factors that could affect the future performance of the mortgage
loans. Furthermore, the findings reached by Recovco are dependent upon its receiving complete and accurate data regarding the mortgage
loans from mortgage loan originators and other third parties upon which Recovco is relying in reaching such findings.
Please
be further advised that Recovco does not employ personnel who are licensed to practice law in the various jurisdictions, and the findings
set forth in the reports prepared by Recovco do not constitute legal advice or opinions. They are recommendations or conclusions based
on information provided to Recovco. Information contained in any Recovco report related to the applicable statute of limitations for
certain claims may not be accurate or reflect the most recent controlling case law. Further, a particular court in a particular jurisdiction
may extend, not enforce or otherwise allow claims beyond the statute of limitations identified in the report based on certain factors,
including the facts and circumstances of an individual mortgage loan. Risk levels associated with a loan may have changed an exception
level, given rating agency published guidance, written guidance, or other guidance from the rating agency team on the transaction. All
final decisions as to whether to purchase or enter into a transaction related to any individual mortgage loan or the mortgage loans in
the aggregate, any investment strategy and any legal conclusions, including the potential liability related to the purchase or other
transaction involving any such mortgage loan or mortgage loans, shall be made solely by the Client, or other agreed upon party, that
has engaged Recovco to prepare its reports pursuant to its instructions and guidelines. The Client, or other agreed upon party, acknowledges
and agrees that the scoring models applied by Recovco are designed to identify potential risk and the Client, or other agreed upon party,
assumes sole responsibility for determining the suitability of the information for its particular use. Recovco does not make any representation
or warranty as to the value of any mortgage loan or mortgage loans collateral that has been reviewed by Recovco.
Regulatory
Compliance Analysis: TPR will test each Mortgage Loan to verify that it closed in compliance with the applicable federal, state and
local anti-predatory lending statutes in effect at the time of origination of the Mortgage Loan and that the Mortgage Loan meets (i)
the Truth in Lending Act (“TILA”), as amended by HOEPA, 15 U.S.C. §1601 et seq., as implemented by Regulation Z, 12
C.F.R. Part 1026; (ii) the Real Estate Settlement Procedures Act (“RESPA”), 12 U.S.C. §2603, as implemented by Regulation
X, 12 C.F.R. Part 1024; (iii) the disclosure requirements and prohibitions of Section 50(a)(6), Article XVI of the Texas Constitution
and associated regulations (as applicable); and (iv) the disclosure requirements and prohibitions of the applicable state and local laws
and ordinances that were enacted to combat predatory lending.
| 1. | The
following section is applicable to Mortgage Loans with an application date on or after October
3, 2015: |
| a. | Documentation.
Review of the following documents for regulatory compliance: |
| i. | Initial
and final application (1003) |
| ii. | Note,
including all addendums |
| iii. | Copy
of note for any junior liens (if applicable) |
| iv. | Mortgage
/ Deed of Trust, including all riders |
| v. | Initial
and Re-disclosed Loan Estimates (“LE”) |
| vi. | Initial
CD (i.e., the CD required to be received by the borrower(s) at least 3 business days prior
to consummation) and re-disclosed CDs (as applicable and permitted by TILA/Regulation Z) |
| vii. | Notice
of Right to Cancel (if applicable) |
| viii. | Rate
Lock date information; |
| b. | High
Cost/Higher-Priced Loans |
| i. | Review
of federal, state & local high cost, higher-priced and/or anti-predatory laws and regulations,
including those set forth on Schedule 1. Any loan that is determined to be classified
and/or defined as high cost, higher-priced, subprime, threshold, predatory high risk, covered
or similar classification/definition must be reported. |
| ii. | Missing
initial application / rate lock confirmation – If missing initial application, missing
initial application date or missing rate lock confirmation results in inability to determine
application date or rate set date for purposes of high cost / higher-priced mortgage loan
testing, vendor will test based on: (1) a 6-month window prior to closing date for missing
application date; and (2) all dates between application and closing for missing rate set
date. Other evidence in file (e.g. date of initial disclosures, rate lock expiration on GFE)
may be relied upon to estimate application or rate set date but will be determined on a case
by case basis. |
| c. | TILA/Regulation
Z. Review to determine compliance with the requirements of TILA/Regulation Z including, but
not limited to, the following: |
| i. | A
review and comparison of LEs and CDs with a report outlining any TILA violations, including
a re-calculation of disclosed finance charge, principal and interest calculations, proper
completion of the Projected Payments table, recalculation of disclosed APR and a review to
determine disclosure differences were within the allowed tolerances and disclosures were
provided within the required timeframe; |
| A. | Confirm
the presence of the current LE in effect at the time of origination; |
| B. | Verify
LE was provided to the borrower(s) within three (3) business days of the date the lender
(or broker if applicable) received an “application” and at least 7 business days
prior to consummation; |
| C. | Verify
LE was provided to the borrower(s) within three (3) business days of: (a) the date the rate
was locked; and (b) the date an expired rate lock was re-locked (if applicable). Evidence
of rate lock (e.g., rate lock agreement, screen shot) is necessary to confirm rate lock date.
A revised LE is not required to be disclosed if the rate has been extended with no other
changes to the previously disclosed interest-rate dependent charges or terms provided the
borrower has not entered into a new rate lock agreement with the lender. |
| D. | Verify
the final LE was provided at least 4 business days prior to consummation and that no LE was
provided to the borrower after a CD was provided; |
| E. | Verify
all sections of the LE were accurately completed and that information was reflected in the
appropriate locations; |
| F. | Determine
whether a valid and properly documented reason (changed circumstance affecting settlement
charges, changed circumstance affecting eligibility, revision requested by the consumer,
interest rate has been locked, LE has expired, delayed settlement date on construction loan)
accompanies a revised LE containing any increase in fee(s) (subject to the good faith provisions
in 12 CFR § 1026(e)(3)), and verify if an LE was provided within 3 business days of
the lender’s (or broker’s) receipt of information sufficient to establish that
a reason for a revision applies. |
| 1. | Any
increase in (1) a fee that is subject to zero tolerance or (2) fees that cause the aggregate
amount of charges as defined in 12 CFR § 1026.19(e)(3)(ii) to increase by more than
10% that are disclosed on a LE but not accompanied by one of the six specified reasons should
be disregarded for purposes of tolerance testing, including any reset of tolerances.
For that fee, the amount on the previously properly-disclosed LE should be used for testing
of the zero and 10% tolerance categories. All other fees that have changed and are disclosed
in compliance with TILA should be included in the tolerance testing, including changes to
interest-rate related charges that change while the interest rate is floating and/or change
upon re-disclosure within three (3) business days of rate lock or re-lock. |
| 2. | Increases
in fees as defined in 12 CFR § 1026.(e)(3)(iii) are permissible provided there is no
evidence that the lender (or broker, if applicable) did not disclose the increase based on
the best information reasonably available at the time (e.g. failure to disclose a homeowner’s
insurance premium when homeowner’s insurance is required; prepaid interest amounts
that are not consistent with the date the loan will close or with changes to loan terms). |
| 3. | Documentation
that simply restates the change (e.g. fee increased) with no further explanation is not sufficient. |
| G. | A
difference between the disclosed Total Interest Percentage (TIP) and the calculated TIP (either
under- or over-disclosed) should be conditioned. If the difference in calculation is due
to the rounding of the loan payment to whole cents as permitted by 12 CFR § 1026.17(c)(3),
this should be noted in the condition. |
| iii. | Closing
Disclosure (“CD”): |
| A. | Confirm
the current applicable CD was provided; |
| B. | Verify
all sections of the CD were accurately completed and that information was reflected in the
appropriate locations; |
| C. | Verify
that the borrower, or each consumer with the right to rescind the transaction (if applicable),
was provided with a copy of the CD within 3 business days of consummation; |
| D. | If
the initial CD has been provided in lieu of a revised LE because there were fewer than four
business days between the time the revised LE was required to be delivered and consummation,
the CD may be used to reset fee tolerances provided the loan did in fact close within that
timeframe and valid changed circumstances are documented to support fee increases as discussed
below. |
| 1. | Any
increase in (1) a fee that is subject to zero tolerance or (2) fees that cause the aggregate
amount of charges as defined in 12 CFR § 1026.19(e)(3)(ii) to increase by more than
10% is limited to one of the six reasons specified in the rule (changed circumstance affecting
settlement charges, changed circumstance affecting eligibility, revision requested by the
consumer, interest rate has been locked, LE has expired, delayed settlement date on construction
loan). |
| i. | Any
of these increased fees that are disclosed on the CD but not accompanied by one of the six
specified reasons should be disregarded for purposes of tolerance testing, including any
reset of tolerances. For that fee, the amount on the previously properly-disclosed
LE should be used for testing of the zero and 10% tolerance categories. All other fees that
have changed and are disclosed in compliance with TILA should be included in the tolerance
testing, including changes to interest-rate related charges that change while the interest
rate is floating and/or change upon re-disclosure within three (3) business days of rate
lock or re-lock). |
| 2. | Documentation
that simply restates the change (e.g. fee increased, etc.) with no further explanation is
not sufficient. |
| E. | Increases
in fees as defined in 12 CFR § 1026.(e)(3)(iii) that are disclosed on the initial CD
or any re-disclosed CD are permissible provided there is no evidence that the lender did
not disclose the increase based on the best information reasonably available at the time
(e.g. failure to disclose a homeowner’s insurance premium when homeowner’s insurance
is required; prepaid interest amounts that are not consistent with the date the loan will
close or with changes to loan terms). |
| F. | Any
fees that are paid at closing by someone other than the borrower (e.g.; seller or other third
party) should be treated as borrower-paid for purposes of the tolerance calculations in 12
CFR § 1026.19I(3)(i) – (iii). For example, if a $500 appraisal fee (for which
the borrower could not shop) that was disclosed on the LE as paid in full or in part by the
seller increases to $750 on the CD, the $250 increase must be considered, and a tolerance
refund of $250 will be due to the borrower unless the increase had been re-disclosed subject
to a valid changed circumstance. Fees paid by the lender should be reviewed for compliance
with 12 CFR § 1026.19I(3)(i) (i.e.; an increased lender credit to cover an increased
fee does not constitute a zero tolerance violation, but a decreased lender credit that was
not re-disclosed subject to a valid changed circumstance is a violation and will require
a refund). |
| G. | A
difference between the disclosed Total Interest Percentage (TIP) and the calculated TIP (either
under- or over-disclosed) should be conditioned. If the difference in calculation is due
to the rounding of the loan payment to whole cents as permitted by 12 CFR § 1026.17I(3),
this should be noted in the condition. |
| H. | For
loans originated prior to October 10, 2017, any difference between the disclosed Total of
Payments (TOP) and the calculated TOP (either under- or over-disclosed) should be conditioned.
Effective for loans originated on/after October 10, 2017, the applicable tolerances in 12
CFR § 1026.23(g)(1)(ii) and § 1026.23(h)(2)(ii) (i.e. $35 tolerance for under-disclosure
of TOP for loans subject to rescission) apply. TPR will note if a tolerance has been exceeded
and, if so, the amount necessary to cure the tolerance violation. |
| I. | Review
to confirm if any changes occurred before consummation that required a new 3-business day
waiting period and, if so, if revised disclosures were provided and the required waiting
period was met; |
| 1. | If
the APR decreases by greater than 1/8 of one percentage point, (or ¼ of one percentage
point for an irregular transaction), confirm the disclosed APR resulted from the disclosed
finance charge (i.e. the finance charge also decreased). |
| J. | Review
any CDs provided to the borrower post-consummation to confirm revised disclosures and refunds
were provided as required and within the required timeframes. |
| iv. | Written
Estimate of Terms or Costs – confirm that any term/cost estimate provided to the borrower
meets the content requirements of TILA and is not provided after the borrower has been, or
is required to be, provided the LE. |
| A. | A
Written Estimate of Terms or Costs may be provided within the 3-business day period after
the lender’s receipt of a loan application as long as the Written Estimate is provided
before the borrower receives the LE. |
| v. | Written
List of Settlement Service Providers: |
| A. | If
the borrower was permitted to shop for any settlement services as evidenced by the LE, confirm
the Written List of Settlement Service Providers is in the Mortgage Loan File and meets the
content requirements of TILA, including providing the name of at least one provider for each
service for which the borrower was permitted to shop; and |
| 1. | If
the borrower was permitted to shop for a settlement service as evidenced on the LE and the
List of Settlement Service Providers was not provided or did not list a provider for that
service, the cost of the service must be included in the ten percent tolerance category unless
the settlement service provider was the creditor or an affiliate of the creditor, in which
case the cost of the service is considered an increase subject to the zero tolerance category.
TPR will note if the tolerance has been exceeded and, if so, the amount necessary to cure
the tolerance violation. TPR will also note a violation for failing to provide at least one
settlement service provider for a service for which the borrower was entitled to shop. |
| B. | Verify
the List of Settlement Service Providers was provided to the borrower(s) at the time of the
LE disclosing the applicable service(s). |
| vi. | Special
Information Booklet (“Your Home Loan Toolkit”): |
| A. | Confirm
the presence of the Special Information Booklet (“Your Home Loan Toolkit”) in
the Mortgage Loan File or that the Mortgage Loan File contains sufficient evidence that the
disclosure was provided to the borrower (e.g., cover letter reflecting the Booklet
as an enclosure) on purchase and construction (construction to permanent loans) Mortgage
Loans; and |
| B. | Confirm
the Special Information Booklet (“Your Home Loan Toolkit”) was provided within
three (3) business days of the date the lender (or broker if applicable) received an “application.” |
| vii. | A
review of the Notice of Right to Cancel, including a verification of the transaction date and expiration date, ensuring proper execution
of the Notice of Right to Cancel by all required parties, verifying the disbursement date and determining if a full three (3) day rescission
period was adequately provided to the borrower(s); |
| A. | A
condition must be placed if the transaction is a refinance by the original creditor and the
borrower was provided the Form H-8 rescission notice. TPR will note in the condition whether
or not there was a new advance that is subject to rescission per TILA/Regulation Z. |
| viii. | Where
the loan file contains evidence of a loan modification (other than a modification pursuant to the Home Affordable Modification Program
(HAMP), review file to determine if the loan was a true modification that would not require new TILA disclosures. If not a true
modification, must be treated as a refinancing for purposes of new TILA disclosures. Review notes / mortgages / mod agreements
& determine if existing note / mortgage have been satisfied and replaced. If so, qualifies as refinancing unless: |
| A. | Reduction
in APR with corresponding change in payment schedule (shortening of maturity, reduction in
payment amount or number of payments). However, if maturity is lengthened or if payment
amount or # of payments is increased beyond that remaining on existing transaction, new disclosures
are required; OR |
| B. | Change
in payment schedule or collateral requirements as a result of default/ delinquency. However,
if rate is increased or additional credit is advanced beyond amounts already accrued plus
insurance premiums, or a fixed rate loan is being modified into an adjustable rate loan,
new disclosures required. |
| ix. | A
review to ensure the Mortgage Loan meets the applicable Ability-to-Repay (“ATR”) requirements as set forth in regulations
promulgated by the Consumer Financial Protection Bureau as found at 12 CFR § 1026.43. For purposes of such review, where loans were
originated by a broker, consider the loan application date to be the date the loan file was received by the original creditor. |
| d. | RESPA/Regulation
X: Review to ensure compliance with RESPA/Regulation X documentation and timing requirements
in effect at origination of the Mortgage Loan for RESPA disclosures (Servicing Disclosure
Statement; Affiliated Business Arrangement Disclosure; Initial Escrow Disclosure Statement;
List of Homeownership Counselling Organizations). |
| e. | Equal
Credit Opportunity Act/Regulation B: Confirm compliance with the January 18, 2014 requirements
regarding the disclosure of the right to receive a copy of appraisals within three (3) business
days of application, the right to receive a copy of the appraisals at least three (3) business
days prior to consummation and any applicable waiver. The disclosure of the right to receive
a copy of appraisals may be met by the disclosure on the Loan Estimate pursuant to 12 CFR
§ 1026.27(m)(1). |
| f. | Fair
Credit Reporting Act/Regulation V: Confirm compliance with the current FCRA/Regulation V
requirements regarding risk-based pricing notice, credit score disclosure and Notice to Home
Loan Applicant, as applicable. |
| g. | Mandatory
Arbitration – TPR will report mandatory arbitration provisions present in the loan
file. |
| h. | Single
Premium Credit Insurance – TPR will report single premium credit insurance policies
or debt cancellation agreements present in the loan file. |
| i. | TPR
will test for state prepayment and late charge restrictions. If a prepayment penalty that
exceeds the state permitted penalty has expired, this must be reported. |
| 2. | The
following section is applicable to Mortgage Loans with an application date prior to October
3, 2015: |
| a. | Documentation.
Review of the following documents for regulatory compliance: |
| i. | Initial
and final application (1003) |
| ii. | Note,
including all addendums |
| iii. | Copy
of note for any junior liens (if applicable) |
| iv. | Mortgage
/ Deed of Trust, including all riders |
| v. | Final
HUD-1 Settlement Statement (“HUD-1”). If the final HUD-1 is missing, TPR will
review for compliance using the estimated HUD-1 if available in the file. TPR will report
if the final HUD-1 is missing and note in the condition that (a) testing was performed using
an estimated HUD-1 or (b) there was no estimated or final HUD-1 in the file available for
testing. |
| vi. | Initial,
Final and Re-disclosed Truth in Lending Disclosures (“TIL”) |
| vii. | Notice
of Right to Cancel (if applicable) |
| viii. | Initial
and Re-disclosed Good Faith Estimates (“GFE”) |
| ix. | Rate
Lock date information; |
| b. | High Cost/Higher-Priced
Loans |
| i. | Review
of federal, state & local high cost, higher-priced and/or anti-predatory laws and regulations,
including those set forth on Schedule 1. Any loan that is determined to be classified
and/or defined as high cost, higher-priced, subprime, threshold, predatory high risk, covered
or similar classification/definition must be reported. |
| ii. | Missing
initial application / rate lock confirmation – If missing initial application, missing
initial application date or missing rate lock confirmation results in inability to determine
application date or rate set date for purposes of high cost / higher-priced mortgage loan
testing, vendor will test based on: (1) a 6-month window prior to closing date for missing
application date; and (2) all dates between application and closing for missing rate set
date. Other evidence in file (e.g. date of initial disclosures, rate lock expiration on GFE)
may be relied upon to estimate application or rate set date but will be determined on a case
by case basis. |
| c. | TILA/Regulation
Z. Review to determine compliance with the applicable requirements of TILA/Regulation Z including,
but not limited to, the following: |
| i. | A
review and comparison of the initial and final TIL, and any re-disclosed TIL(s), with a report
outlining any TILA violations, including a re-calculation of disclosed finance charge, proper
execution by all required parties, principal and interest calculations, proper completion
of the interest rate and payment summary, recalculation of disclosed APR, and a review to
determine disclosure differences were within the allowed tolerances and disclosures were
provided within the required timeframes; |
| ii. | A
review of the Notice of Right to Cancel, including a verification of the transaction date
and expiration date, ensuring proper execution of the Notice of Right to Cancel by all required
parties verifying the disbursement date and determining if a full three (3) day rescission
period was adequately provided to the borrower(s); |
| A. | A
condition must be placed if the transaction is a refinance by the original creditor and the
borrower was provided the Form H-8 rescission notice. TPR will note in the condition whether
or not there was a new advance that is subject to rescission per TILA/Regulation Z. |
| iii. | Where
the loan file contains evidence of a loan modification (other than a modification pursuant to the Home Affordable Modification Program
(HAMP), review file to determine if the loan was a true modification that would not require new TILA disclosures. If not a true
modification, must be treated as a refinancing for purposes of new TILA disclosures. Review notes / mortgages / mod agreements
& determine if existing note / mortgage have been satisfied and replaced. If so, qualifies as refinancing unless: |
| A. | Reduction
in APR with corresponding change in payment schedule (shortening of maturity, reduction in
payment amount or number of payments). However, if maturity is lengthened or if payment
amount or # of payments is increased beyond that remaining on existing transaction, new disclosures
are required; OR |
| B. | Change
in payment schedule or collateral requirements as a result of default/ delinquency. However,
if rate is increased or additional credit is advanced beyond amounts already accrued plus
insurance premiums, or a fixed rate loan is being modified into an adjustable rate loan,
new disclosures required. |
| iv. | For
Mortgage Loans with an application date on or after January 10, 2014, a review to ensure the Mortgage Loan meets the applicable Ability-to-Repay
(ATR) and Qualified Mortgage (QM) qualifications as set forth in regulations promulgated by the Consumer Financial Protection Bureau
as found at 12 CFR 1026.43. For purposes of such review, where loans were originated by a broker, consider the loan application date
to be the date the loan file was received by the original creditor. |
| d. | RESPA/Regulation
X: Review to ensure compliance with the applicable requirements of RESPA/Regulation X including,
but not limited to, the following: |
| i. | Good
Faith Estimate (“GFE”): |
| A. | Confirm
the presence of the current GFE form in effect at the time of origination. Verify GFE was
provided to the borrower(s) within three (3) business days of the date the lender (or broker
if applicable) received an “application,” which is to be defined by the lender; |
| B. | RESPA
2010: Determine whether a valid and properly documented change in circumstance accompanies
any re-disclosed GFE containing the following: |
| 1. | any
change(s) to loan terms, including any increase in rate after the rate has been locked and/or
change to loan program; and |
| 2. | Any
increase in fee(s). |
| ii. | Final
HUD-1: Confirm compliance with the RESPA requirements in effect as of origination of the
Mortgage Loan including, but not limited to: |
| A. | Current
applicable HUD-1 form was provided; |
| B. | Escrow
deposit on the HUD-1 matches the initial escrow statement amount; and |
| C. | Verify
all sections of the HUD-1 were accurately completed and that information was reflected in
the appropriate locations. |
| iii. | GFE
and Final HUD-1 Comparison (RESPA 2010): Confirm compliance with the RESPA requirements in effect as of origination of the Mortgage Loan
including, but not limited to: |
| A. | Review
changes disclosed on the latest GFE provided to the borrower to ensure that they were within
the allowed tolerances as set forth in the RESPA requirements. |
| B. | Confirm
Mortgage Loan terms and fees disclosed on the third page of the HUD-1 accurately reflected
how they were disclosed on the GFE and how the Mortgage Loan closed; |
| 1. | A
change in loan amount from the latest GFE to the HUD-1 is acceptable and should not be conditioned.
Any other changes to loan terms must be noted. |
| C. | Review
any attempt to cure a RESPA violation to ensure that the proper reimbursement was made and/or
a new HUD-1 was provided and that it was done within the required thirty (30) day window. |
| e. | Additional
RESPA/Regulation X Disclosures and Requirements: Confirm compliance with RESPA/Regulation
X documentation and timing requirements in effect at origination of the Mortgage Loan for
other RESPA disclosures (Servicing Disclosure Statement; Special Information Booklet; Affiliated
Business Arrangement Disclosure; Initial Escrow Disclosure Statement). |
| f. | Equal
Credit Opportunity Act/Regulation B: Confirm compliance with the January 18, 2014 requirements
regarding the disclosure of the right to receive a copy of appraisals within three (3) business
days of application, the right to receive a copy of the appraisals at least three (3) business
days prior to consummation and any applicable waiver. |
| g. | Fair
Credit Reporting Act/Regulation V: Confirm compliance with the FCRA/Regulation V requirements
regarding risk-based pricing notice, credit score disclosure and Notice to Home Loan Applicant,
as applicable. |
| h. | Mandatory
Arbitration – TPR will test for mandatory arbitration provisions in the loan file. |
| i. | Single
Premium Credit Insurance – TPR will test for purchase loans with single premium credit
insurance policies or debt cancellation agreements present in the loan file. |
| j. | TPR
will test for state prepayment and late charge restrictions. If a prepayment penalty that
exceeds the state permitted penalty has expired, this must be reported. |
| k. | Georgia
and New Jersey – Vendor will report the following loans: |
| i. | Mortgage
loans subject to the Georgia Fair Lending Act and originated between October 1, 2002 and
March 6, 2003. |
| ii. | Cash-out
refinance mortgage loans originated between November 27, 2003 and July 5, 2004 that meet
the definition of a “covered home loan” pursuant to the New Jersey Homeownership
Security Act. |
Business Purpose Loan submitted
pursuant to this Exhibit and designed by Client as a Business Purpose Loan will be automatically deemed and reported as “Exempt”
and Recovco will not perform any ATR/QM Testing or TRID Testing.
Qualified Mortgage
With respect to QM (Safe Harbor
and Higher-priced) designated loans, Recovco reviews the loan to determine whether, based on available information in the loan file:
(i) the loan contains risky loan features and terms (e.g. an interest only feature or negative amortization), (ii) the “points
and fees” exceed the applicable QM threshold, (iii) the monthly payment was calculated appropriately, (iv) the creditor considered
and verified income or assets at or before consummation, (v) the creditor appropriately considered debt obligations, alimony and child
support, and (vi) at the time of consummation, if the debt-to-income ratio exceeds 43% (calculated in accordance with Appendix Q to Regulation
Z). This portion of the Review includes a recalculation of all income and liabilities with attention to the appropriate documentation
of each source.
If a loan
was designated as QM and identified as eligible for guarantee, purchase, or insurance by an applicable agency as permitted under the
QM final rule, Recovco reviews the loan to determine whether, based on available information in the loan file the loan satisfied (i),
(ii) and (iii) in the preceding paragraph and reviews the Automated Underwriting System output within the file to confirm agency eligibility.
For each QM
designated loan that satisfied the applicable requirements enumerated above, Recovco then determines whether the loan is a Safe Harbor
QM or Higher Priced QM by comparing the loan’s actual annual percentage rate, as recalculated, to the applicable average prime
offer rate plus a certain applicable percentage.
The Review
also includes determining, as applicable, whether a loan is a qualified mortgage as defined by the Department of Housing and Urban Development
(24 C.F.R. 201 and 203 et seq.), and the Department of Veterans Affairs (38 C.F.R. Part 36 et seq.).
General Ability to Repay
Recovco reviews
the loan to determine whether, based on available information in the loan file, the creditor considered, as applicable, the following
eight underwriting factors, and verified such information using reasonably reliable third-party records, at or before consummation: (i)
the consumer’s current or reasonably expected income or assets, (ii) if the creditor relied on income from the consumer’s
employment in determining repayment ability, the consumer’s current employment status; (iii) the consumer’s monthly payment;
(iv) the consumer’s monthly payment on any simultaneous loan that the creditor knows or has reason to know will be made; (v) the
consumer’s monthly payment for mortgage-related obligations; (vi) the consumer’s current debt obligations, alimony, and child
support; (vii) the consumer’s monthly debt-to-income ratio or residual income; and (viii) the consumer’s credit history.
This portion of the Review also focuses on full recalculation of income and debts, as well as the documentation provided to support each
item used in originator’s determination of the ability to repay.
Note: for
loans designated as QM – agency eligible, Recovco will not review for compliance with the requirements of Appendix Q or General
Ability to Repay.
Recovco
reviews loans to determine their conformity with the ATR/QM factors above, and is not rendering an independent assessment or opinion,
warranting or representing that a loan will be deemed to conform to Safe Harbor, Rebuttable Presumption, ATR or other status based on
any additional or revised factors that may be considered by legislative, regulatory, administrative or judicial authorities (“Authorities”).
Recovco does not represent or warrant that the factors for which it is reviewing the loans constitute all of the factors and/or criteria
that Authorities may consider in determining the status of a loan. Recovco’s review is based on information contained in the loan
file at the time it is provided to Recovco to review, and only reflects information as of that point in time.
VALUATION
REVIEW:
For
each Mortgage Loan, Recovco performed Property Valuation Review Services in accordance with the following waterfall:
The value
of the underlying property. Recovco’s review will include verifying the appraisal report was (i) on the appropriate form, (ii)
materially complete, (iii) in conformity with the guideline requirements for the property type in question, (iv) completed by an appraiser
that was actively licensed to perform the valuation, (v) completed such that the named client on the appraisal report is the lender or
a related entity that is permitted to engage the lender per Title XI of FIRREA, (vi) made and signed prior to the final approval of the
mortgage loan application, (vii) completed and dated within the guidelines restrictions, (vii) made on an “as is” basis or
provides satisfactory evidence of completion of all material conditions including all inspections, licenses, and certificates (including
certificates of occupancy) to be made or issued with respect to all occupied portions of the mortgaged property and with respect to the
use and occupancy of the same, have been made or obtained from the appropriate authorities.
With regard
to the use of comparable properties, Recovco’s review will (i) review the relative comparable data (gross and net adjustments,
sale dates and distance from subject property) and ensure that such comparable properties are within standard appraisal guidelines; (ii)
confirm the property value and square footage of the subject property was bracketed by comparable properties, (iii) verify that comparable
properties used are similar in size, style, and location to the subject, and (iv) check for the reasonableness of adjustments when reconciling
value between the subject property and comparable properties.
Other aspects
of Recovco’s review include (i) verifying that the address matched the mortgage note, (ii) noting whether the property zip code
was declared a FEMA disaster area classified as IA (Individual Assistance) or IH (Individual and Household Assistance) after the valuation
date and notifying the Client of same, (iii) confirming the appraisal report does not include any apparent environmental problems, (iv)
confirming the appraisal notes the current use of the property is legal or legal non-conforming (grandfathered), (v) reviewing pictures
to ensure (a) that the property is in average or better condition and any repairs are noted where required and (b) that the subject property
is the one for which the valuation was ordered and that there are no negative external factors; and (vi) confirming that the value product
that was used as part of the origination decision conforms with rating agency requirements.
If
more than one valuation was provided, Recovco will confirm consistency among the valuation products and if there are discrepancies that
could not be resolved, Recovco will create an exception and work with the client on the next steps which may include ordering of additional
valuation products such as collateral desktop analyses, broker’s price opinions, and full appraisals. If the property valuation
products included in Recovco’s review result in a variance of more than 10% then the client will be notified of such variance.
If CU Score of 2.5 or less was allowed, then nothing further was
required.
For
each Mortgage Loan, Recovco will perform Property Valuation Review Services as indicated in the terms below:
| 1. | 100%
of the Loans: Recovco will review the origination appraisal for the following items:
(i) the age of the appraisal, (ii) verification of the property address, (iii) completeness
and accuracy of the appraisal form, (iv) verification of the appraiser licensing, (v) the
comparable sales analysis including age, distance, and adjustments, (vi) zoning concerns,
(vii) appraisal was performed using approved forms, and (viii) made on an “as is”
basis. |
| 2. | Additional
valuation: Recovco will review the additional valuation provided from origination or
ordered upon request: (i) the age of the valuation, (ii) verification of the property address,
(iii) completeness and accuracy of the valuation form, (iv) the comparable sales analysis
including age, distance, and adjustments, (v) zoning concerns, and (vi) made on an “as
is” basis. |
NRSRO
GRADING CRITERIA:
Upon completion
of the loan file review, Recovco assigned grading which considered factors based on the review criteria, product, and NRSRO requirements.
The NRSRO
criteria referenced for this report and utilized for grading descriptions is based upon the following:
| CREDIT
EVENT GRADE |
| A |
The
loan meets the published guidelines without exception or waiver. The employment, income, assets and occupancy are supported
and justifiable. The borrower’s willingness and ability to repay the loan is documented and reasonable. QM designation
status has been confirmed. |
| B |
The
loan does not meet every applicable requirement of the underwriting guidelines; however, the majority of requirements are met, and
strong compensating factors have been document in support of guideline exceptions. |
| C |
The
loan does not meet every applicable requirement of the underwriting guidelines due to limited, weak or no compensating factors to
support the exception. Status of occupancy, employment, income and asset were not remedied or were remediated post-closing. Fully
supported. Fraud was identified and/or credit document defects were not remedies or were remediated post-closing. Lender/aggregator
QC designation was not confirmed. The loan file was not provided for review or not sufficiently document in order to complete
the review. |
| D |
The
loan file was not provided for review or not sufficiently document in order to complete the review. |
| REGULATORY
COMPLIANCE EVENT GRADE |
| A |
Loan
is compliant with all applicable laws and regulations. The legal documents accurately reflect the agreed upon loan terms
and are executed by all applicable parties. The loan has met ATR standards as documented by the originator and if applicable
has been verified as a qualified mortgage. |
| B |
Identified
exceptions have been determined to be non-material and will not impact the enforceability of the loan and/or remediation of material
defects has taken place and the remediated exception will not impact the ability to foreclose. All cures are fully and
appropriately documented. |
| C |
The
loan does not meet every ATR standards, is missing required disclosures or contains inaccurate disclosures which have not been/cannot
be remediated and/or a benefit to the borrower cannot be determined. The agreed upon loan terms do not align to legal
documents and/or legal documents were not appropriately executed. |
| D |
The
loan file was not provided for review or not sufficiently document in order to complete the review. |
| VALUATION
EVENT GRADE |
| A |
Value
is supported and within 10.00% of the original appraised value, the property is 100% complete and property and valuation meet the
required underwriting guidelines. |
| B |
The
property is complete but may require minor repairs that do not affect the habituality, marketability or value or allowable incomplete
repairs are supplemented with a builder holdback agreement as required by underwriting guidelines. |
| C |
Value
is not supported within 10.00% of the original appraised value, the subject property constructions is not complete and/or appraisal
was not on an as-is basis and final inspection is not documented. The appraisal was not conducted on an approved form
and/or appraiser was not appropriately licensed. |
| D |
The
file was missing the appraisal or there was insufficient valuation documentation to perform a review. |
| OVERALL
EVENT GRADE |
| A |
Loan
meets Credit, Compliance, and Valuation guidelines and has sufficient accuracy and completeness of data to conduct a thorough review. |
| B |
The
loan substantially meets published Client/Seller guidelines and/or eligibility in the validation of income, assets, or credit; is
in material compliance with all applicable laws and regulations; and the value and valuation methodology are supported and substantially
meet published guidelines. |
| C |
The
loan does not meet the published guidelines; and/or violates one material law or regulation; and/or the value and valuation methodology
is not supported or did not meet published guidelines. |
| D |
Loan
is missing documentation to perform an adequate review. |
Pool
Details
| Purpose |
| Type |
Count |
%
of Pool |
| Cash
out Refi |
80 |
25.40% |
| Purchase |
192 |
60.95% |
| Rate
/ Term Refi |
43 |
13.65% |
| Total |
315 |
100.00% |
| Property
Type |
| Type |
Count |
%
of Pool |
| Single
Family Detached |
155 |
49.21% |
| Co-op |
0 |
0.00% |
| Condo,
Low Rise |
47 |
14.92% |
| Condo,
High Rise |
5 |
1.59% |
| PUD |
64 |
20.32% |
| 1
Family Attached |
8 |
2.54% |
| 2
Family |
18 |
5.71% |
| 3
Family |
10 |
3.17% |
| 4
Family |
8 |
2.54% |
| Total |
315 |
100.00% |
| Occupancy |
| Type |
Count |
%
of Pool |
| Primary
Residence |
152 |
48.25% |
| Second
Home |
21 |
6.67% |
| Investment
Property |
142 |
45.08% |
| Total |
315 |
100.00% |
| Product
Type |
| Type |
Count |
%
of Pool |
| Fixed |
314 |
99.68% |
| ARM |
1 |
0.32% |
| Total |
315 |
100.00% |
Tape
Discrepancies
| Data
Element |
Count |
Accuracy |
| Note
Date |
1 |
99.68% |
| Property
Type |
6 |
98.10% |
| Qualifying
CLTV |
39 |
87.62% |
| Borrower DTI Ratio Percent |
1 |
99.68% |
| Qualifying
LTV |
38 |
87.94% |
| Total
Number of Loans |
315 |
|
Multiple Loans to One Borrower:
TPR firm reviewed common identifiers for all loans in the population and confirmed there were nine (9) obligors with multiple loans in
the pool.
Property Inspection Waivers:
No loans had a Property Inspection Waiver.
Loan
Grading Definitions
Credit
| S&P |
Moody’s |
Fitch |
Kroll |
DBRS |
Definition |
| A |
A |
A |
A |
A |
Loan
conforms to all applicable guidelines, no conditions noted |
| B |
B |
B |
B |
B |
Loan
does not meet every applicable credit guideline. However, most of the loan characteristics are within the guidelines and
there are documented and significant compensating factors |
| C |
C |
C |
C |
C |
The
loan does not meet every applicable credit guideline, and most of the loan characteristics are outside of guidelines; or there are
weak or no compensating factors |
| D |
D |
D |
D |
D |
The
loan file is missing critical documentation required to perform the review |
Compliance
| S&P |
Moody’s |
Kroll |
DBRS |
Definition |
| A |
A |
A |
A |
The
loan was originated in compliance with applicable federal, state, and local predatory and high cost, TILA, and Regulation Z laws
and regulations |
| B |
B |
B |
B |
The
loan was originated in compliance with applicable federal, state, and local predatory and high cost, TILA, and Regulation Z laws
and regulations; however, minor evidentiary issue(s) exist |
| C |
C |
C |
C |
The
loan includes material violation(s) with applicable federal, state, and local predatory and high cost, TILA, and Regulation Z laws
and regulations |
| D |
D |
D |
D |
The
loan file is missing critical documentation required to perform the review |
| Fitch |
Definition |
| A |
The
loan was originated in compliance with applicable federal, state, and local predatory and high cost, TILA, and Regulation Z laws
and regulations |
| B |
The
loan is in compliance with all applicable laws and regulations and a benefit to the borrower is present and documented |
| C |
The
loan includes material violation(s) with applicable federal, state, and local predatory and high cost, TILA, and Regulation Z laws
and regulations |
| D |
The
loan file is missing critical documentation required to perform the review |
Property
Valuation
| Moody’s |
Fitch |
Kroll |
DBRS |
Definition |
| A |
A |
A |
A |
Value
is within a 10% variance of third party product. Appraisal meets lender guidelines. Subject property is 100% complete. Property condition
is average or better. Standard GSE form was utilized. Appraiser is licensed. Appraisal is complete. |
| B |
B |
B |
B |
Meets
all terms for an A, but property requires cosmetic or minor repairs that do not affect value or habitability |
| C |
C |
C |
C |
Any
of the following items: Origination value and third party valuation product value has a variance of 10% or greater, cannot validate
value, property is incomplete, property condition is less than average, GSE form was not utilized, and/or the appraisal and/or does
not meet guidelines |
| D |
D |
D |
D |
The
loan file was missing the appraisal and/or other valuations products needed to complete the review |
| S&P |
Definition |
| A |
First
Level Review Value is within a 10% variance to the original appraisal. Appraisal meets lender guidelines. Subject property is 100%
complete. Property condition is average or better. Standard GSE form was utilized. Appraiser is licensed. Appraisal is complete. |
| B |
First
Level Review Value is greater than a 10% variance to the original appraisal but the second level review value is within 10% variance
of the original appraised value. In addition, property requires cosmetic or minor repairs that do not affect value or habitability |
| C |
Any
of the following items: Second Level Review Value is greater than a 10% variance to the original appraisal, cannot validate value,
property is incomplete, property condition is less than average, GSE form was not utilized, and/or the appraisal and/or does not
meet guidelines |
| D |
The
loan file was missing the appraisal and/or other valuations products needed to complete the review |
Loan
Review Findings
The following
summarizes Consultant’s final loan securitization and event grades assigned to the final reviewed loan pool and reported in the
Agency Grading Report dated September 16, 2022 and October 20, 2026.
| Overall
Grade Summary |
|
|
| Fitch
and Kroll NRSRO Grade |
#
of Loans |
%
of Loans |
| A |
303 |
96.19% |
| B |
12 |
3.81% |
| C |
0 |
0.00% |
| D |
0 |
0.00% |
| |
|
|
| Compliance
Grade Summary |
|
|
| Fitch
and Kroll NRSRO Grade |
#
of Loans |
%
of Loans |
| A |
313 |
99.37% |
| B |
2 |
0.63% |
| C |
0 |
0.00% |
| D |
0 |
0.00% |
| |
|
|
| Credit
Grade Summary |
|
|
| Fitch
and Kroll NRSRO Grade |
#
of Loans |
%
of Loans |
| A |
305 |
96.83% |
| B |
10 |
3.17% |
| C |
0 |
0.00% |
| D |
0 |
0.00% |
| |
|
|
| Property
Grade Summary |
|
|
| Fitch
and Kroll NRSRO Grade |
#
of Loans |
%
of Loans |
| A |
315 |
100.00% |
| B |
0 |
0.00% |
| C |
0 |
0.00% |
| D |
0 |
0.00% |
Total
Loans Reviewed - (315)
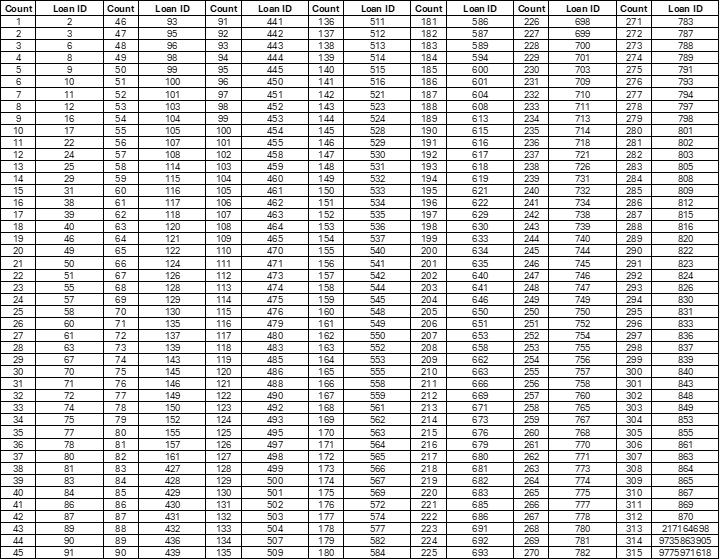
If
you have any questions, please contact Uriah Clavier at Uriah.Clavier@Opuscmc.com