Exhibit 99.8
FAIRNESS OPINION PRESENTED TO UY SCUTI ACQUISITION
Client: UY Scuti Acquisition
Contract No.: SH25/01/28RZP
Report date: 3 September 2026
3 September 2026
Board of Directors
UY Scuti Acquisition
Dear Sirs,
With regard to the Transaction (as defined herein), King Kee Appraisal and Advisory Limited (“KKG”) hereby delivers to UY Scuti Acquisition (“UYSC”) its written opinion (the “Opinion”) dated 3 September 2026, and subject to suppositions, limitations, qualifications and other matters considered with relation to the preparation of the Opinion, to the effect that the compensation (as defined below) to be paid by UYSC to the shareholders of Isdera Group Limited (“Isdera” or “Company”) for the Transaction be fair and reasonable, from the strictly financial standpoint, for the unaffiliated security holders of UYSC.
KKG understands that UYSC has proposed to enter into a Business Combination Agreement dated 18 July 2025 with Isdera and its shareholders (the “Merger Agreement”), whereby UYSC will acquire 100% of the outstanding equity of the Company (the “Transaction”). Additionally, the parties will subsequently enter into an amended BCA with a consideration of $920 million. In accordance with your instructions, we have undertaken an investigation and analysis to express an independent opinion of the market value of 100% equity value of Isdera. The report which follows is dated 3 September 2026 (the “Report Date”).
KKG understands that pursuant to the Merger Agreement, the total consideration proposed to the Company or the Company shareholders at the Closing in the Transaction (the “Transaction Consideration”) is based on a total equity value of the Company of USD 920 million.
KKG presented the Opinion to the UYSC board of directors with regard to and for effects of the evaluation of the Transaction.
We planned and performed our analysis so as to obtain all the information and explanations which we considered necessary in order to provide us with sufficient evidence to express our opinion on the subject asset. We believe that the valuation procedures we employed provide a reasonable basis for our opinion.
Our analysis of the 100% equity value of Isdera was developed through the application of an income approach known as discounted cash flow methodology and market approach. Under these methods, the enterprise value result depends on the present worth of future economic benefits to be derived from the projected sales income. Indication of the result is developed by discounting projected future net cash flows available for payment of shareholders’ interest to their present worth.
As part of our analysis, we have reviewed information prepared by the Company and relevant operational information regarding the subject business from public sources. We have relied to a considerable extent on such information in arriving at our opinion of value.
The conclusion of value is based on accepted valuation procedures and practices that rely substantially on our use of numerous assumptions and our consideration of various factors that are relevant to the operation of the Company. We have also considered various risks and uncertainties that have potential impact on the businesses. Further, while the assumptions and consideration of such matters are considered by us to be reasonable, they are inherently subject to significant business, economic and competitive uncertainties and contingencies, many of which are beyond the control of the Company and KKG.
2
We do not intend to express any opinion on matters which require legal or other specialized expertise or knowledge, beyond what is customarily employed by valuers. Our conclusions assume continuation of prudent management of the Company over whatever period of time that is reasonable and necessary to maintain the character and integrity of the assets valued.
The nature of the amount of compensation to be paid in the Transaction was not determined by KKG. The negotiation of, and the decision to celebrate, the Transaction and any related Merger Agreement was exclusively carried out by the UYSC Board of Directors. Likewise, we were not requested, nor did we participate in, the negotiation of the terms of the Transaction, nor were we requested, nor did we render, any advising or service with relation to the Transaction, other than the rendering of this Opinion.
The Opinion is not a recommendation to UYSC with respect to whether recommend or not proceedings, with the authorization to carry out the Transaction to the form and terms and conditions, as to how to go about it or not.
The Opinion’s complete text dated 3 September 2026, which describes, among others, the assumptions used, procedures followed, factors considered and limitations of the completed revision, is attached to this statement and shall be incorporated in its totality to this document as reference. The Summary is qualified in its entirety for reference to the complete Opinion text.
Based on the investigation and analyses outlined in the report which follows, we are of the opinion that the market value of 100% equity value of Isdera is reasonably stated as below:
|
Market value of 100% equity value (In USD'000) |
| 856,000 ~ 946,000 |
3
We are further of the opinion that, as at the date hereof, the consideration of USD 920 million to be paid by UYSC pursuant to the Transaction is fair, from a financial point of view, to the shareholders of UYSC.
Yours faithfully,
For and on behalf of
King Kee Appraisal and Advisory Limited
| /s/ Richard Zhang | ||
| Richard Zhang | ||
| Managing Director | ||
| ASA, MRICS, CPV |
4
REMARK:
This report and the conclusion of values arrived at herein are for the sole and specific purposes as noted herein. Furthermore, the report and conclusion of values are not intended by the author, and should not be construed by the reader, to be investment advice in any manner whatsoever. The conclusion of values represents the consideration based on information furnished by the Company/engagement parties and other sources.
TABLE OF CONTENTS
| Introduction | 6 |
| Engagement | 6 |
| Purpose of Valuation | 6 |
| Basis of Opinion | 6 |
| The following factors form an integral part of our basis of opinion: | 7 |
| Scope of Review | 7 |
| Sources of Information | 7 |
| Methodology | 8 |
| Selection of Analysis Approach and Methodology | 8 |
| Major Assumptions | 9 |
| Summary of Market Approach | 10 |
| Business Projection under Income Approach | 11 |
| Discount Rate | 12 |
| Terminal Value | 14 |
| Analysis Comments | 14 |
| Risk Factors | 15 |
| Fairness Opinion Conclusion | 15 |
| Exhibit A – Limiting Conditions | 17 |
| Exhibit B – Professional Declaration | 19 |
| Exhibit C – Analysis Result under Market Approach | 20 |
| Exhibit D – Analysis Result under Income Approach (Cross-check) | 21 |
5
Introduction
This report has been prepared in accordance with instructions from UYSC to express an independent opinion of the market value of 100% equity value of Isdera. The report which follows is dated 3 September 2026 (the “Report Date”).
As we understand it, completion of the Transaction is subject to a number of conditions, including, but not limited to, the receipt of all required approvals. KKG has assumed that all of the terms and conditions required to implement the Transaction will be satisfied, and that the Transaction will be completed as described in the Merger Agreement, as amended, without material variation in the terms and conditions.
Engagement
The board of directors of UYSC (board of directors) has engaged KKG to prepare a fairness opinion. The fairness opinion serves as a basis to assess the financial adequacy of Isdera.
The fairness opinion intends to give UYSC board of directors a neutral opinion and assure that the offered price is fair and reasonable from a financial point of view to the public shareholders of UYSC.
The fairness opinion does not constitute a recommendation regarding the acceptance or rejection of the offer. The fairness opinion does not contain any assessment of the possible impact an acceptance or rejection of the offer may have and makes no statement about the future performance of a UYSC share and the price at which the UYSC shares that are not being tendered may trade in the future.
Since our assessment is largely based on information obtained directly or indirectly from Isdera, our responsibility is limited to the careful and professional analysis and assessment of the information provided to us. Furthermore, Isdera confirmed to us that they are not aware of any facts or circumstances, according to which the information provided would be misleading, inaccurate or incomplete.
KKG is an independent valuation company. It has received a fixed fee for its services and is not affected by the results of this possible merger.
Purpose of Valuation
The purpose of this analysis is to express an independent opinion of the market value of the 100% equity value of Isdera.
Basis of Opinion
The Opinion does not concern itself with any other aspect of the Transaction and no opinion or point of view was expressed with regard to relative merits of the Transaction compared to other strategic alternatives that shall be at the disposal of Isdera, or where UYSC could participate, or regarding the underlying business decision of UYSC to proceed or complete the Transaction.
The Opinion is neither, i) a recommendation regarding the convenience of the Transaction, nor of the terms and conditions of this; nor ii) a recommendation to UYSC regarding whether or not to recommend proceeding with the authorization to carry out the Transaction or the form or terms and conditions as to how to do so or not.
Relationships with Interested Parties
None of KKG, its associates or affiliates, is an insider, or holds any securities of UYSC or the Company or any of their associates or affiliates. KKG is not an advisor to any person or company with respect to the Transaction. Other than pursuant to the Engagement Agreement, KKG has not previously provided any financial advisory services to UYSC for which it has received compensation in the past 12 months.
Other than the Engagement Agreement, there are no understandings, agreements, or commitments between KKG and UYSC.
6
The following factors form an integral part of our basis of opinion:
1. Assumptions on the market and the asset that are considered to be fair and reasonable;
2. Financial performance that shows a consistent trend of the operation;
3. Consideration and analysis on the micro and macro economy affecting the subject asset;
4. Analysis on tactical planning, management standard and synergy of the subject asset;
5. Analytical review of the subject asset;
6. Assessment of the leverage and liquidity of the subject asset.
Scope of Review
In connection with this Fairness Opinion, KKG has reviewed and relied upon, among other things, the following:
1. Certain files submitted by Isdera, including technical reports relating to Isdera ’s resource properties, annual reports, material change reports, management information and interim financial statements;
2. The financial terms, to the extent they are publicly available, of certain transactions of a nature comparable to the Transaction, that KKG considered to be relevant;
3. Certain public filings and other publicly available information of companies which are comparable in nature to the Company, that KKG considered to be relevant;
4. Discussions with members of Isdera Management where the Transaction, the financial condition of Isdera, and certain other matters KKG believed necessary or appropriate for the purpose of rendering this Fairness Opinion were discussed;
5. Merger Agreement in respect of the Transaction;
6. Such other information, analyses, investigations and discussions as KKG considered necessary or appropriate in the circumstances.
Sources of Information
Our analysis is based on data and information furnished by Isdera Management, which includes, but not limited to, the following;
1. Annual reports of the Company on 31 March 2023-2026;
2. Company’s Business Projection; and
3. Other operational and market information in relation to the Company’s business.
7
We have also discussed and examined other operational and business information through interviews with relevant senior management. We have relied to a considerable extent on such information in arriving at our opinion of value. We assumed that the data we obtained in the course of the valuation, along with the opinions and representations provided to us by the Company, are true and accurate.
We also conducted research using various sources including government statistics and other publications to verify the reasonableness and fairness of information provided and we believe that the information is reasonable and reliable.
Methodology
In arriving at our assessed value, we have considered three generally accepted approaches, namely, market approach, cost approach and income approach.
Market Approach considers prices recently paid for similar assets, with adjustments made to market prices to reflect condition and utility of the appraised assets relative to the market comparative. Assets for which there is an established secondary market may be valued by this approach.
Benefits of using this approach include its simplicity, clarity, speed and the need for few or no assumptions. It also introduces objectivity in application as publicly available inputs are used. However, one has to be wary of the hidden assumptions in those inputs as there are inherent assumptions on the value of those comparable assets. It is also difficult to find comparable assets. Furthermore, this approach relies exclusively on the efficient market hypothesis.
Cost Approach considers the cost to reproduce or replace in new condition the assets appraised in accordance with current market prices for similar assets, with allowance for accrued depreciation or obsolescence present, whether arising from physical, functional or economic causes. The cost approach generally furnishes the most reliable indication of value for assets without a known secondary market. Despite the simplicity and transparency of this approach, it does not directly incorporate information about the economic benefits contributed by the subject asset.
Income Approach is the conversion of expected periodic benefits of ownership into an indication of value. It is based on the principle that an informed buyer would pay no more for the project than an amount equal to the present worth of anticipated future benefits (income) from the same or a substantially similar project with a similar risk profile.
This approach allows for the prospective valuation of future profits and there are numerous empirical and theoretical justifications for the present value of expected future cash flows. However, this approach relies on numerous assumptions over a long-time horizon and the result may be very sensitive to certain inputs. It also presents a single scenario only.
Selection of Analysis Approach and Methodology
In our opinion, the cost approach is inappropriate for valuing the 100% equity value of Isdera. The cost approach does not directly incorporate information about the economic benefits contributed by equity value of Isdera. In addition, there is uncertainty inherent in the Company’s Business Projection, we have therefore relied on the market approach in determining our opinion of value, and used the income approach as a cross-check for the value conclusion.
The market approach considers prices recently paid for similar assets, with adjustments made to market prices to reflect condition and utility of the appraised assets relative to the market comparative. Assets for which there is an established secondary market may be valued by this approach. Benefits of using this approach include its simplicity, clarity, speed and the need for few or no assumptions. It also introduces objectivity in application as publicly available inputs are used.
8
The application of an income approach technique is known as discounted cash flow method to develop the future value of the business into a present market value. This method eliminates the discrepancy in time value of money by using a discount rate to reflect all business risks including intrinsic and extrinsic uncertainties in relation to the business.
Under this method, the result depends on the present worth of future economic benefits to be derived from the projected service income. Indications of the result have been developed by discounting projected future net cash flows available for payment of shareholders’ interest to their present worth at discount rates which in our opinion are appropriate for the risks of the business. In considering the appropriate discount rate to be applied, we have taken into account a number of factors including the current cost of finance and the considered risk inherent in the business.
Major Assumptions
Assumptions considered to have significant sensitivity effects in this analysis have been evaluated in order to provide a more accurate and reasonable basis for arriving at our assessed value, the following key assumptions have been made:
The facilities and systems proposed are assumed to be sufficient for future expansion in order to realize the growth potential of the business and maintain a competitive edge.
There will be no material change in the existing political, legal, technological, fiscal or economic conditions, which might adversely affect the business of the Company.
The projected business performance can be achieved with the effort of the management of the Company.
The financial and operational information provided to us by Isdera is true and accurate.
There are no hidden or unexpected conditions associated with the assets valued that might adversely affect the reported value. Further, we assume no responsibility for changes in market conditions after the date of the Transaction.
The information and other material (financial and otherwise) provided orally by, or in the presence of, an officer of the Company or in writing by the Company, or its agents to KKG relating to the Company or any of its respective subsidiaries or the Transaction for the purpose of preparing this Opinion was, at the date such Information was provided to KKG, and is, complete, true and correct in all material respects, and did not and does not contain any untrue statement of a material fact in respect of the Company, its subsidiaries or the Transaction and did not and does not omit to state a material fact in respect of the Company, its subsidiaries or the Transaction necessary to make such Information not misleading in light of the circumstances under which it was made or provided.
Since the dates on which information was provided to KKG by the Company, except as subsequently disclosed in writing to KKG or in a public filing with securities regulatory authorities, there has been no material change, financial or otherwise, in the financial condition, assets, liabilities (contingent or otherwise), business, operations or prospects of the Company or any of its subsidiaries and no material change has occurred which would have or which would reasonably be expected to have a material effect on this Fairness Opinion.
There will be no material change in the financial condition of the Company as at the BCA date from that as indicated by the latest historical financial statements provided to KKG.
Further, in preparing this Fairness Opinion, in addition to the facts and conclusions contained in the Information, the completion of the Transaction is subject to a number of conditions outside the control of UYSC and Isdera, and KKG has assumed all conditions precedent to the completion of the Transaction can be satisfied in due course and all consents, permissions, exemptions or orders of relevant regulatory authorities will be obtained, without adverse conditions or qualification.
This Fairness Opinion is limited to the fairness, from a financial point of view, of the Transaction to UYSC’s public shareholders and KKG expresses no opinion as to any alternative transaction. KKG expresses no opinion as to the fairness of the Transaction relative to the consideration offered under any proposed alternative transaction. This Fairness Opinion does not constitute a recommendation to any shareholder of UYSC as to how such shareholder should vote with respect to the Transaction. Furthermore, KKG has not been asked to address, and this Fairness Opinion does not address, the fairness of the Transaction to the holders of any class of securities of UYSC other than the holders of UYSC’s common shares.
9
KKG believes that this Fairness Opinion must be considered and reviewed as a whole and that selecting portions of the stated analyses or factors considered by KKG, without considering all the stated analyses and factors together, could create a misleading view of the process underlying or the scope of this Fairness Opinion. The preparation of a fairness opinion of this nature is a complex process and is not necessarily amenable to partial analysis or summary description. Any attempt to do so could lead to undue emphasis on any particular factor or analysis.
This Fairness Opinion is given as of the date hereof, and KKG disclaims any undertaking or obligation to advise any person of any change in any fact or matter affecting this Fairness Opinion which may come or be brought to KKG ’s attention after the date hereof. Without limiting the foregoing, in the event that there is any material in the Company or UYSC, or any change in any material fact affecting this Fairness Opinion after the date hereof, KKG reserves the right to change, modify or withdraw this Fairness Opinion.
KKG did not, in considering the fairness, from a financial point of view, of the Transaction to the public shareholders of UYSC, assess any tax consequences that any particular shareholder of Isdera may face as a result of the Transaction.
Summary of Market Approach
In determining the market multiple, a list of comparable companies was identified. The selection includes companies that:
| ● | Are primarily engaged in the automobile manufacturing industry with a focus in the field of electronic vehicles; and |
| ● | Are listed on a U.S. stock exchange or other major international stock exchange and searchable in Capital IQ database. |
The details of the comparable companies which are considered as fair and representative samples are listed below (market data is shown as of 31 March 2025).
Comparable Companies
| Company name | Ticker | Market cap (In USD million) | D/E ratio | Unlevered beta | EV/ Sales | |||||||||||||
| Faraday Future Intelligent Electri | NasdaqCM: FFAI | 96 | 76.0 | % | n/a | nmf | ||||||||||||
| Lotus Technology Inc. | NasdaqGS:LOT | 1,085 | 119.8 | % | n/a | 2.7 | x | |||||||||||
| Robo.ai Inc. | NasdaqCM:AIIO | 91 | 15.6 | % | n/a | 8.4 | x | |||||||||||
| VinFast Auto Ltd. | NasdaqGS:VFS | 7,437 | 76.1 | % | n/a | 6.1 | x | |||||||||||
| Rivian Automotive, Inc. | NasdaqGS:RIVN | 14,077 | 31.5 | % | 1.20 | 2.8 | x | |||||||||||
| Polestar Automotive Holding UK | NasdaqGM:PSNY | 2,216 | 224.5 | % | 0.56 | 3.2 | x | |||||||||||
| Lucid Group, Inc. | NasdaqGS:LCID | 7,336 | 24.4 | % | 1.69 | 10.7 | x | |||||||||||
| NIO Inc. | NYSE:NIO | 7,913 | 105.7 | % | 0.83 | 1.1 | x | |||||||||||
| Zhejiang Leapmotor Technology | SEHK:9863 | 8,635 | 3.5 | % | 1.15 | 1.8 | x | |||||||||||
| Stellantis N.V. | BIT:STLAM | 31,949 | 115.7 | % | n/a | nmf | ||||||||||||
Multiple Selection
Given the Company has not generated profits, and also the automobile industry business performance can be reflected by sales level, the sales market multiple (“EV/Sales”) is selected in this method. Specifically, the average of market multiple of 4.6x is applied to Isdera’s forecasted revenue in 2029, discounted back to the present using Isdera’s WACC, to determine Isdera’s value under the comparable public companies method of the market approach.
Value adjustment
Minority shareholders are often in a passive position in investment, and it is difficult to make contributions to the operation of the company or even make no contributions. Therefore, when the minority equity of companies is traded, there is usually a discount to the potential net asset value. This reflects the relationship between the lack of control and minority shareholders' equity. On the contrary, when most shareholders' equity is traded, there is usually a premium to the net asset value. We consider the market multiple based on market daily valuation of the comparable companies implies a valuation on a non-control basis, and as such an adjustment has been made to the market multiple result in order to conclude on a control basis.
10
The 25% control premium comes from two studies: one study shows that the average acquisition premium is between 35% and 42%, while another study on the transaction shows that the average acquisition premium is between 16% and 29%. We selected 25% as the reasonable control premium of the target company. The acquisition premium not only reflects the premium required for control, but also includes the view on the degree of merger benefits.
Business Projection under Income Approach
Revenue
Isdera, a Cayman Islands company, is the parent company of Xinghui Automotive Technology (Hainan) Co., Ltd, a company in the business of designing automobiles in the People's Republic of China ("Xinghui Automotive Technology"). Based on the discussion with the Company management, the revenue forecast is projected as below:
| In USD'000 | FY26 Actual | FY27 Projection | FY28 Projection | FY29 Projection | FY30 Projection | FY31 Projection | ||||||||||||||||||
| Revenue | - | 5,000 | 62,000 | 240,975 | 398,003 | 613,541 | ||||||||||||||||||
| Growth rate | n/a | n/a | 1140.00 | % | 288.67 | % | 65.16 | % | 54.16 | % | ||||||||||||||
Costs of Goods Sold (“COGS”)
Based on the discussion with the Company management, the COGS forecast is projected as below:
| In USD'000 | FY26 Actual | FY27 Projection | FY28 Projection | FY29 Projection | FY30 Projection | FY31 Projection | ||||||||||||||||||
| COGS | - | 4,250 | 29,900 | 110,439 | 181,101 | 278,094 | ||||||||||||||||||
| % of revenue | n/a | 85.00 | % | 48.23 | % | 45.83 | % | 45.50 | % | 45.33 | % | |||||||||||||
Operating Expenses
Based on the discussion with the management, the operating expenses for the explicit forecast horizon are projected as below.
| In USD'000 | FY26 Actual | FY27 Projection | FY28 Projection | FY29 Projection | FY30 Projection | FY31 Projection | ||||||||||||||||||
| Operating expenses | 4,000 | 1,750 | 15,500 | 60,244 | 99,501 | 153,385 | ||||||||||||||||||
| % of revenue | n/a | 35.00 | % | 25.00 | % | 25.00 | % | 25.00 | % | 25.00 | % | |||||||||||||
Income Taxes
Based on the discussion with the Company management, the income taxes are projected as below, applying 25% China statutory corporate income tax rate.
| In USD'000 | FY26 Actual | FY27 Projection | FY28 Projection | FY29 Projection | FY30 Projection | FY31 Projection | ||||||||||||||||||
| Income taxes | - | - | 4,150 | 17,573 | 29,350 | 45,516 | ||||||||||||||||||
Capital expenditure (“Capex”)
Based on the discussion with the Company management, the Capex and depreciation and amortization expenses (“D&A”) are projected as below.
| In USD'000 | FY26 Actual | FY27 Projection | FY28 Projection | FY29 Projection | FY30 Projection | FY31 Projection | ||||||||||||||||||
| Capex | 698 | 345 | 4,278 | 16,627 | 27,462 | 42,334 | ||||||||||||||||||
| D&A | 490 | 2,000 | 2,000 | 2,000 | 2,000 | 2,000 | ||||||||||||||||||
11
Working Capital
Based on the discussion with the management, the working capital for the explicit forecast horizon is projected as below:
| In USD'000 | FY26 Actual | FY27 Projection | FY28 Projection | FY29 Projection | FY30 Projection | FY31 Projection | ||||||||||||||||||
| Net working capital | (6,568 | ) | (1,765 | ) | (21,886 | ) | (85,064 | ) | (140,495 | ) | (216,580 | ) | ||||||||||||
| % of revenue | n/a | -35.30 | % | -35.30 | % | -35.30 | % | -35.30 | % | -35.30 | % | |||||||||||||
Discount Rate
In applying the discounted cash flow method, it is necessary to determine an appropriate discount rate for the assets under review. The discount rate represents an estimate of the rate of return required by a third-party investor for an investment of this type. The rate of return expected from an investment by an investor relates to perceived risk. Risk factors relevant in our selection of an appropriate discount rate include:
1. Interest rate risk, which measures variability of returns, caused by changes in the general level of interest rates.
2. Purchasing power risk, which measures loss of purchasing power over time due to inflation.
3. Liquidity risk, which measures the ease with which an instrument can be sold at the prevailing market price.
4. Market risk, which measures the effects of the general market on the price behavior of securities.
5. Business risk, which measures the uncertainty inherent in projections of operating income.
6. Exchange rate, which measures the possible influence that changes in exchange rates, might have on the value of the investment.
Consideration of risk also involves elements such as quality of management, degree of liquidity, and other factors affecting the rate of return acceptable to a given investor in a specific investment. An adjustment for risk is an increment added to a base rate to compensate for the extent of risk believed to be involved in the investment.
Required Return on Equity Capital
We have used Capital Assets Pricing Model (the “CAPM”) to estimate the required return on equity capital.
The CAPM is a fundamental tenet of modern portfolio theory which has been generally accepted basis for marketplace valuations of equity capital. The CAPM technique is widely accepted in the investment and financial analysis communities for the purpose of estimating a company’s required return on equity capital.
The equation of CAPM is shown as follow:
Expected Required Return on Equity=Risk Free + Nominal Beta (β) × Risk Premium
The return on equity required of a company represents the total rate of return investors expect to earn, through a combination of dividends and capital appreciation, as a reward for risk taking. The Capital Asset Pricing Model (“CAPM”) is used to calculate the required rate of return on equity investment by using publicly-traded companies.
12
Parameters for Cost of Equity
In determining the equity discount rate for the Company, the following parameters have been used:
| Parameters | Source | |||||
| Unlevered Beta | 1.09 | Comparable companies | ||||
| Company D/E ratio | 79.3 | % | Comparable companies | |||
| Tax rate | 25.0 | % | Company's income tax rate | |||
| Levered Beta | 1.73 | |||||
| Risk-free rate | 1.8 | % | 10-yr China government bond yield | |||
| Equity risk premium | 5.3 | % | Source: Aswath Damodaran | |||
| Size premium | 3.0 | % | Source: Kroll's Valuation Handbook | |||
| Specific risk premium | 7.5 | % | Factor to account for forecast risk | |||
| Cost of equity | 21.5 | % | ||||
| Cost of debt | 3.6 | % | ||||
Weighted Average Cost of Capital
WACC is calculated by multiplying the cost of each capital component by its proportional weight and then summing:
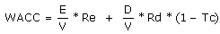
| Re | = | Required return on equity |
| Rd | = | Required return on debt |
| E | = | Market value of the firm’s equity |
| D | = | Market value of the firm’s debt |
| V | = | E + D |
| E/V | = | Percentage of financing that is equity |
| D/V | = | Percentage of financing that is debt |
| Tc | = | Corporate tax rate |
| WACC calculation | ||||
| Cost of equity | 21.5 | % | ||
| Cost of debt | 2.7 | % | ||
| D/E ratio | 79.3 | % | ||
| WACC (Round) | 13.2 | % | ||
13
Terminal Value
We have assumed that the Company will grow at a fixed long-term growth rate beyond the terminal year as reach its optimal operating structure. We have thus applied a terminal multiple on the projected cash flows at terminal year to derive the value of the Company beyond the projection period. The terminal multiple is derived using the Gordon Growth Model, a mathematical simplification to capitalize an earnings stream that is expected to grow at a long-term sustainable rate “g” and discount rate “k” into perpetuity. The formula is as follows:
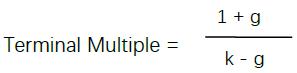
| g | = | Long-term growth rate of 2% (Source: China long-term inflation rate from EIU database) |
| k | = | WACC |
Analysis Comments
The valuation of an interest in a business enterprise requires consideration of all relevant factors affecting the operation of the business and its ability to generate future investment returns. The factors considered in the valuation includes, but not limited to, the following:
1. The nature of the business and the historical performance of the enterprise;
2. The financial condition of the business and the economic outlook in general;
3. The operational contracts and agreements in relation to the business;
4. Past and projected operating results;
5. The financial and business risk of the enterprise including the continuity of income and the projected future results; and
6. The nature of the related agreements.
We confirm that we have carried out an inspection on the assets of the Company and we have made relevant searches, inquiries and have obtained such further information which is considered necessary for the purposes of this valuation.
In arriving at our assessed value, we have mainly considered the core business of the business. We have not made provision for other non-operating cash flow items such as interest income, exchange rate gain/loss, etc. in the valuation model.
The conclusion of value is based on accepted valuation procedures and practices that rely substantially on the use of numerous assumptions and the consideration of many uncertainties, not all of which can be easily quantified or ascertained. Further, while the assumptions and consideration of such matters are considered by us to be reasonable, they are inherently subject to significant business, economic and competitive uncertainties and contingencies, many of which are beyond the control of the Company and KKG.
14
Risk Factors
We caution readers to be aware of the following risks which we believe could influence the assessment. Such risks can range from very subject specific factors to more systematic factors.
Social, Political and Macroeconomic Considerations
Various economic, political and social phenomena surrounding the subject items may change so as to affect our opinion of value. International or nationwide policy and / or legislative changes that alter existing rights and obligations may directly or indirectly influence the subject items. Macroeconomic circumstances including inflation, interest rate fluctuations and existing and forecast levels of growth in the broader economy may also have an effect. Societal factors encompassing the perception and preferences of people in general may swing rendering the subject items more or less desirable and thus more or less valuable. The Company is subject to various laws and regulations governing its operations in China. Future political and legal changes in China might have either favorable or unfavorable impacts on the Company.
Environmental Conditions
Phenomena within the physical environment can severely impact the factors of production and demand factors within an economy for the counterparty. The occurrence of natural disasters, resource depletion and variations in climate conditions may influence resource availability and prices for inputs on the supply side or may influence market access and preferences for products and services associated to the counterparty from end-user demand.
Realization of forecast and projection
This valuation is premised in part on the historical financial information and projections provided by the management of the Company. We have assumed accuracy of the information provided and relied to a considerable extent on such information in arriving at our opinion of value. Although appropriate tests and analyses have been carried out to verify the reasonableness and fairness of the information provided, events and circumstances frequently do not occur as expected. Since projections relate to the future, there will usually be differences between projections and actual results and in some cases, those variances may be material. Accordingly, to the extent any of the abovementioned information requires adjustment; the resulting investment value may differ.
Fairness Opinion Conclusion
Based upon and subject to the foregoing, and such other factors as KKG considered relevant, KKG is of the opinion that, as at the date hereof, the consideration of USD 920 million to be paid by UYSC to the Isdera shareholders pursuant to the Transaction is fair, from a financial point of view, to the shareholders of UYSC.
We are of the opinion that the market value of 100% equity value of Isdera is reasonably stated as below:
| Market value of 100% equity value (In USD'000) |
| 856,000 ~ 946,000 |
15
Limiting Conditions
This report and opinion of value are subject to our Limiting Conditions as included in Exhibit A of this report.
Yours faithfully,
For and on behalf of
King Kee Appraisal and Advisory Limited
| /s/ Richard Zhang | |
| Richard Zhang | |
| Managing Director |
ASA, MRICS, CPV
16
Exhibit A – Limiting Conditions
| 1. | In the preparation of our reports, we relied on the accuracy, completeness and reasonableness of the financial information, forecast, assumptions and other data provided to us by the Company/engagement parties and/or its representatives. We did not carry out any work in the nature of an audit and neither are we required to express an audit or viability opinion. We take no responsibility for the accuracy of such information. The responsibility for determining expected values rests solely with the Company/engagement parties and our reports were only used as part of the Company’s/engagement parties’ analysis in reaching their conclusion of value. |
| 2. | We have explained as part of our service engagement procedure that it is the director’s responsibility to ensure proper books of accounts are maintained, and the financial information and forecast give a true and fair view and have been prepared in accordance with the relevant standards and companies ordinance. |
| 3. | Public information and industry and statistical information have been obtained from sources we deem to be reputable; however, we make no representation as to the accuracy or completeness of such information, and have accepted the information without any verification. |
| 4. | KKG shall not be required to give testimony or attendance in court or to any government agency by reason of this analysis, with reference to the project described herein. Should there be any kind of subsequent services required, the corresponding expenses and time costs will be reimbursed from you. Such kind of additional work may incur without prior notification to you. |
| 5. | No opinion is intended to be expressed for matters which require legal or other specialized expertise or knowledge, beyond what is customarily employed by valuers. |
| 6. | The use of and/or the validity of the report is subject to the terms of engagement letter/proposal and the full settlement of the fees and all the expenses. |
| 7. | Our conclusions assume continuation of prudent management policies over whatever period of time that is considered to be necessary in order to maintain the character and integrity of the assets valued. |
| 8. | We assume that there are no hidden or unexpected conditions associated with the subject matter under review that might adversely affect the reported review result. Further, we assume no responsibility for changes in market conditions, government policy or other conditions after the Valuation/Reference Date. We cannot provide assurance on the achievability of the results forecasted by the Company/engagement parties because events and circumstances frequently do not occur as expected; difference between actual and expected results may be material; and achievement of the forecasted results is dependent on actions, plans and assumptions of management. |
| 9. | This calculation of values expressed herein is valid only for the purpose stated in the engagement letter/or proposal. In accordance with our standard practice, we must state that this report was prepared for the Board of UYSC and no responsibility is accepted with respect to any third party for the whole or any part of its contents. |
17
| 10. | Where a distinct and definite representation has been made to us by party/parties interested in the assets valued, we are entitled to rely on that representation without further investigation into the veracity of the representation if such investigation is beyond the scope of normal scenario analysis work. |
| 11. | You agree to indemnify and hold us and our personnel harmless against and from any and all losses, claims, actions, damages, expenses or liabilities, including reasonable attorney’s fees, to which we may become subjects in connection with this engagement. Our maximum liability relating to services rendered under this engagement (regardless of form of action, whether in contract, negligence or otherwise) shall be limited to the charges paid to us for the portion of its services or work products giving rise to liability. In no event shall we be liable for consequential, special, incidental or punitive loss, damage or expense (including without limitation, lost profits, opportunity costs, etc.), even if it has been advised of their possible existence. |
| 12. | We are not environmental consultants or auditors, and we take no responsibility for any actual or potential environmental liabilities exist, and the effect on the value of the asset is encouraged to obtain a professional environmental assessment. We do not conduct or provide environmental assessments and have not performed one for the subject property. |
| 13. | This analysis is premised in part on the historical financial information and future forecast provided by the management of the Company/engagement parties. We have assumed the accuracy and reasonableness of the information provided and relied to a considerable extent on such information in arriving at our calculation of value. Since projections relate to the future, there will usually be differences between projections and actual results and in some cases, and those variances may be material. Accordingly, to the extent any of the abovementioned information requires adjustments, the resulting value may differ significantly. |
| 14. | Actual transactions involving the subject assets / business might be concluded at a higher or lower value, depending upon the circumstances of the transaction and the business, and the knowledge and motivation of the buyers and sellers at that time. |
| 15. | This report and the conclusion of values arrived at herein are for the sole and specific purposes as noted herein. Furthermore, the report and conclusion of values are not intended by the author, and should not be construed by the reader, to be investment advice in any manner whatsoever. The conclusion of values represents the consideration based on information furnished by the Company/engagement parties and other sources. |
18
Exhibit B – Professional Declaration
The valuers certify, to the best of their knowledge and belief, that:
| 1. | Information has been obtained from sources that are believed to be reliable. All facts which have a bearing on the value concluded have been considered by the valuers and no important facts have been intentionally disregarded. |
| 2. | The reported analyses, opinions, and conclusions are subject to the assumptions as stated in the report and based on the valuers’ personal, unbiased professional analyses, opinions, and conclusions. The valuation analysis is also bounded by the limiting conditions. |
| 3. | The reported analyses, opinions, and conclusions are independent and objective. |
| 4. | The valuers have no present or prospective interest in the asset that is the subject of this report, and have no personal interest or bias with respect to the parties involved. |
| 5. | The valuers’ compensation is not contingent upon the amount of the value estimate, the attainment of a stipulated result, the occurrence of a subsequent event, or the reporting of a predetermined value or direction in value that favors the cause of the client. |
| 6. | The analyses, opinions, and conclusions were developed, and this report has been prepared, in accordance with the International Valuation Standards published by the International Valuation Standards Council. |
19
Exhibit C – Analysis Result under Market Approach
| Market Approach | ||||||||||||
| Comparable company | Capital IQ Ticker | Country | EV/Sales | |||||||||
| Faraday Future Intelligent Electric Inc. | NasdaqCM:FFAI | United States | nmf | |||||||||
| Lotus Technology Inc. | NasdaqGS:LOT | China | 2.7 | x | ||||||||
| Robo.ai Inc. | NasdaqCM:AIO | United Arab Emirates | 8.4 | x | ||||||||
| VinFast Auto Ltd. | NasdaqGS:VFS | Vietnam | 6.1 | x | ||||||||
| Rivian Automotive, Inc. | NasdaqGS:RIVN | United States | 2.8 | x | ||||||||
| Polestar Automotive Holding UK PLC | NasdaqGM:PSNY | Sweden | 3.2 | x | ||||||||
| Lucid Group, Inc. | NasdaqGS:LCID | United States | 10.7 | x | ||||||||
| ZEEKR Intelligent Technology Holding Lim | NYSE:ZK | China | 1.1 | x | ||||||||
| NIO Inc. | NYSE:NIO | China | 1.8 | x | ||||||||
| Zhejiang Leapmotor Technology Co., Ltd. | SEHK:9863 | China | nmf | |||||||||
| Average | 4.6 | x | ||||||||||
| Market approach (USD'000) | ||||||||||||
| Selected multiple | 4.6 | x | ||||||||||
| Target financials | 156,316 | |||||||||||
| Business enterprise value | 719,053 | |||||||||||
| Plus: Non-operating assets/liabilities | 197.0 | |||||||||||
| Minus: Debt | - | |||||||||||
| Plus: Cash | 1,808.2 | |||||||||||
| 100% equity value before control premium | 721,058 | |||||||||||
| Control premium | 25.0 | % | 180,265 | |||||||||
| 100% equity value after control premium | 901,000 | |||||||||||
| High end | 5.0 | % | 946,000 | |||||||||
| Low end | -5.0 | % | 856,000 | |||||||||
Note:
| ● | The target financials is based on revenue forecast in 2029, discounted back to present using the Company’s WACC of 13.2%. |
| ● | Minority shareholders are often in a passive position in investment, and it is difficult to make contributions to the operation of the company or even make no contributions. Therefore, when the minority equity of companies is traded, there is usually a discount to the potential net asset value. This reflects the relationship between the lack of control and minority shareholders' equity. On the contrary, when most shareholders' equity is traded, there is usually a premium to the net asset value. |
| ● | The 25% control premium comes from two studies: one study shows that the average acquisition premium is between 35% and 42%, while another study on the transaction shows that the average acquisition premium is between 16% and 29%. We selected 25% as the reasonable control premium of the target company. The acquisition premium not only reflects the premium required for control, but also includes the view on the degree of merger benefits. |
20
Exhibit D – Analysis Result under Income Approach (Cross-check)
| Discounted cash flow analysis | ||||||||||||||||||||||||||||||||
| USD '000 | 2025a | 2026e | 2027e | 2028e | 2029e | 2030e | 2031e | Terminal Year | ||||||||||||||||||||||||
| Revenue | - | - | 5,000 | 62,000 | 240,975 | 398,003 | 613,541 | 625,812 | ||||||||||||||||||||||||
| growth rate | n/a | n/a | n/a | 1,140.0 | % | 288.7 | % | 65.2 | % | 54.2 | % | 2.0 | % | |||||||||||||||||||
| COGS | - | - | (4,250 | ) | (29,900 | ) | (110,439 | ) | (181,101 | ) | (278,094 | ) | (283,655 | ) | ||||||||||||||||||
| Gross profit | - | - | 750 | 32,100 | 130,536 | 216,901 | 335,448 | 342,157 | ||||||||||||||||||||||||
| as a % of revenue | n/a | n/a | 15.0 | % | 51.8 | % | 54.2 | % | 54.5 | % | 54.7 | % | 54.7 | % | ||||||||||||||||||
| Operating expenses | (3,107 | ) | (4,000 | ) | (1,750 | ) | (15,500 | ) | (60,244 | ) | (99,501 | ) | (153,385 | ) | (156,453 | ) | ||||||||||||||||
| Operating income (EBIT) | (3,107 | ) | (4,000 | ) | (1,000 | ) | 16,600 | 70,293 | 117,401 | 182,062 | 185,704 | |||||||||||||||||||||
| as a % of revenue | n/a | n/a | (20.0 | )% | 26.8 | % | 29.2 | % | 29.5 | % | 29.7 | % | 29.7 | % | ||||||||||||||||||
| Income tax | - | - | - | (4,150 | ) | (17,573 | ) | (29,350 | ) | (45,516 | ) | (46,426 | ) | |||||||||||||||||||
| After-tax operating income | (3,107 | ) | (4,000 | ) | (1,000 | ) | 12,450 | 52,719 | 88,051 | 136,547 | 139,278 | |||||||||||||||||||||
| as a % of revenue | n/a | n/a | (20.0 | )% | 20.1 | % | 21.9 | % | 22.1 | % | 22.3 | % | 22.3 | % | ||||||||||||||||||
| Change in working capital | 972 | (4,803 | ) | 20,121 | 63,178 | 55,431 | 76,085 | - | ||||||||||||||||||||||||
| Capital expenditures | (687 | ) | (345 | ) | (4,278 | ) | (16,627 | ) | (27,462 | ) | (42,334 | ) | (2,040 | ) | ||||||||||||||||||
| Depreciation & amortization | 490 | 2,000 | 2,000 | 2,000 | 2,000 | 2,000 | 2,040 | |||||||||||||||||||||||||
| After-tax cash flow | (3,237 | ) | (4,148 | ) | 30,293 | 101,270 | 118,019 | 172,298 | 139,278 | |||||||||||||||||||||||
| Terminal value | 1,247,646 | |||||||||||||||||||||||||||||||
| Partial period | 1.00 | 1.00 | 1.00 | 1.00 | 1.00 | 1.00 | 1.00 | |||||||||||||||||||||||||
| Discount period | 0.50 | 1.50 | 2.50 | 3.50 | 4.50 | 5.50 | 5.50 | |||||||||||||||||||||||||
| PV factor 13.2% | 0.94 | 0.83 | 0.73 | 0.65 | 0.57 | 0.51 | 0.51 | |||||||||||||||||||||||||
| PV of after-tax cash flows | (3,043 | ) | (3,446 | ) | 22,237 | 65,692 | 67,652 | 87,277 | 631,992 | |||||||||||||||||||||||
| PV of after-tax cash flows | 236,370 | |||||||||||||||||||||||||||||||
| PV of terminal | 631,992 | |||||||||||||||||||||||||||||||
| Total enterprise value (rounded) | 868,000 | |||||||||||||||||||||||||||||||
| Non-operating assets/liabilities | 197 | |||||||||||||||||||||||||||||||
| Total debt | - | |||||||||||||||||||||||||||||||
| Excess cash | 1,808 | |||||||||||||||||||||||||||||||
| Indicated 100% equity value (rounded) | 870,000 | |||||||||||||||||||||||||||||||
| Indicated 100% equity value range (rounded) | 827,000 - 914,000 | |||||||||||||||||||||||||||||||
21