Corporación Inmobiliaria Vesta, S. A. B. de C. V. and Subsidiaries Unaudited Condensed Consolidated Interim Financial Statements for the nine and three-month periods ended September 30, 2026 and 2025
Corporación Inmobiliaria Vesta, S. A. B. de C. V. and Subsidiaries Unaudited Condensed Consolidated Interim Financial Statements for nine and three- month periods ended September 30, 2026 and 2025 Table of contents Page Unaudited Condensed Consolidated Interim Statements of Financial Position 1 Unaudited Condensed Consolidated Interim Statements of Profit and Other Comprehensive Income 3 Unaudited Condensed Consolidated Interim Statements of Changes in Stockholders’ Equity 4 Unaudited Condensed Consolidated Interim Statements of Cash Flows 5 Notes to Unaudited Condensed Consolidated Interim Financial Statements 7
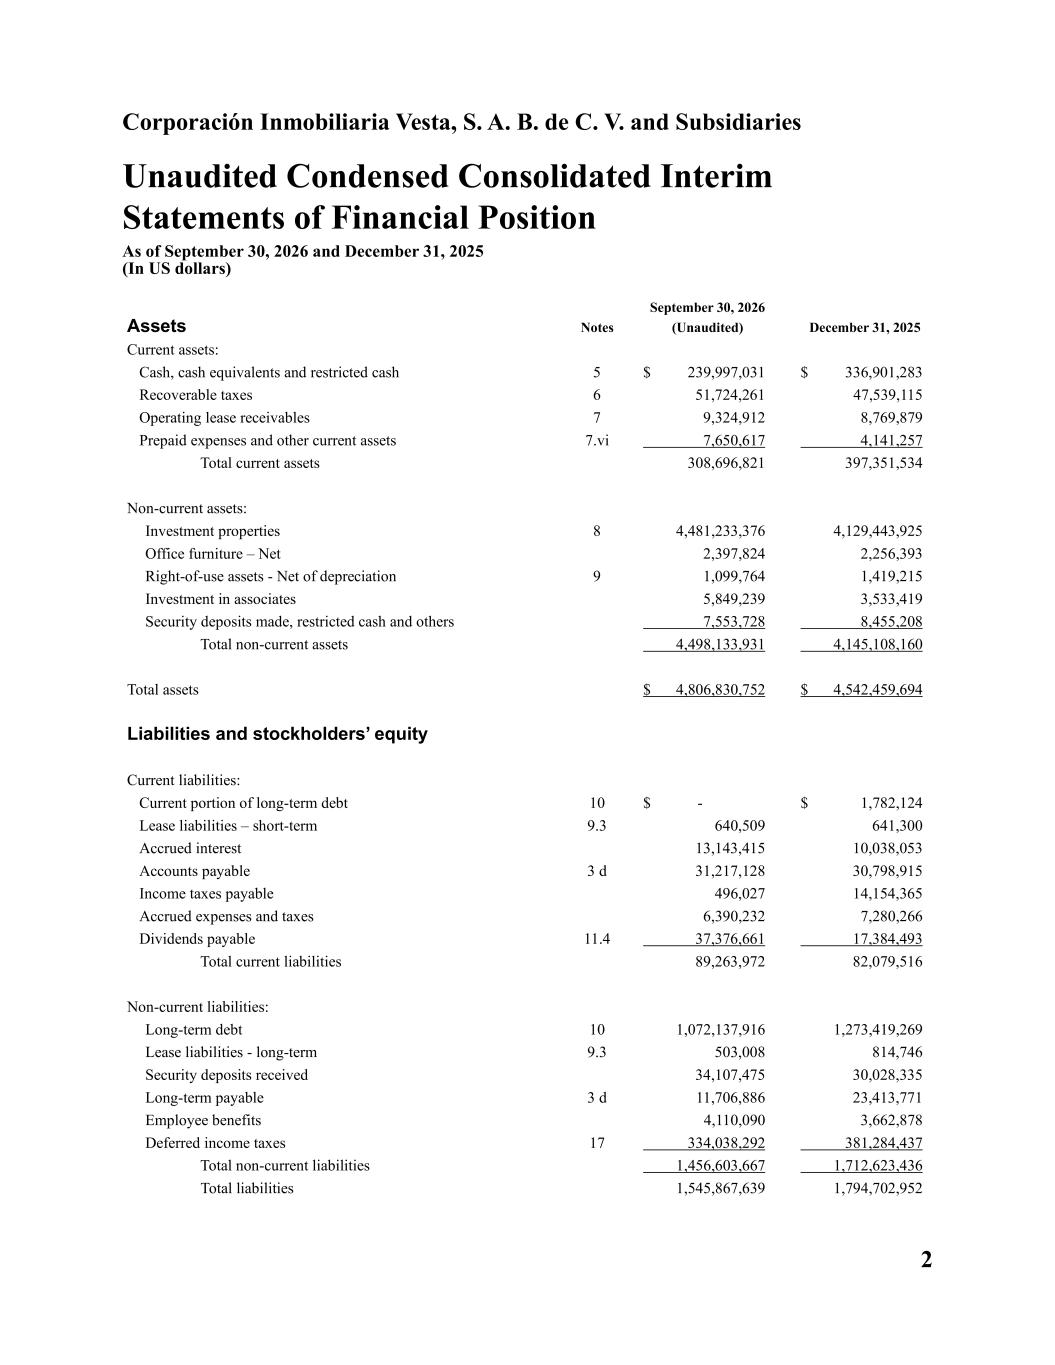
2 Corporación Inmobiliaria Vesta, S. A. B. de C. V. and Subsidiaries Unaudited Condensed Consolidated Interim Statements of Financial Position As of September 30, 2026 and December 31, 2025 (In US dollars) Assets Notes September 30, 2026 (Unaudited) December 31, 2025 Current assets: Cash, cash equivalents and restricted cash 5 $ 239,997,031 $ 336,901,283 Recoverable taxes 6 51,724,261 47,539,115 Operating lease receivables 7 9,324,912 8,769,879 Prepaid expenses and other current assets 7.vi 7,650,617 4,141,257 Total current assets 308,696,821 397,351,534 Non-current assets: Investment properties 8 4,481,233,376 4,129,443,925 Office furniture – Net 2,397,824 2,256,393 Right-of-use assets - Net of depreciation 9 1,099,764 1,419,215 Investment in associates 5,849,239 3,533,419 Security deposits made, restricted cash and others 7,553,728 8,455,208 Total non-current assets 4,498,133,931 4,145,108,160 Total assets $ 4,806,830,752 $ 4,542,459,694 Liabilities and stockholders’ equity Current liabilities: Current portion of long-term debt 10 $ - $ 1,782,124 Lease liabilities – short-term 9.3 640,509 641,300 Accrued interest 13,143,415 10,038,053 Accounts payable 3 d 31,217,128 30,798,915 Income taxes payable 496,027 14,154,365 Accrued expenses and taxes 6,390,232 7,280,266 Dividends payable 11.4 37,376,661 17,384,493 Total current liabilities 89,263,972 82,079,516 Non-current liabilities: Long-term debt 10 1,072,137,916 1,273,419,269 Lease liabilities - long-term 9.3 503,008 814,746 Security deposits received 34,107,475 30,028,335 Long-term payable 3 d 11,706,886 23,413,771 Employee benefits 4,110,090 3,662,878 Deferred income taxes 17 334,038,292 381,284,437 Total non-current liabilities 1,456,603,667 1,712,623,436 Total liabilities 1,545,867,639 1,794,702,952
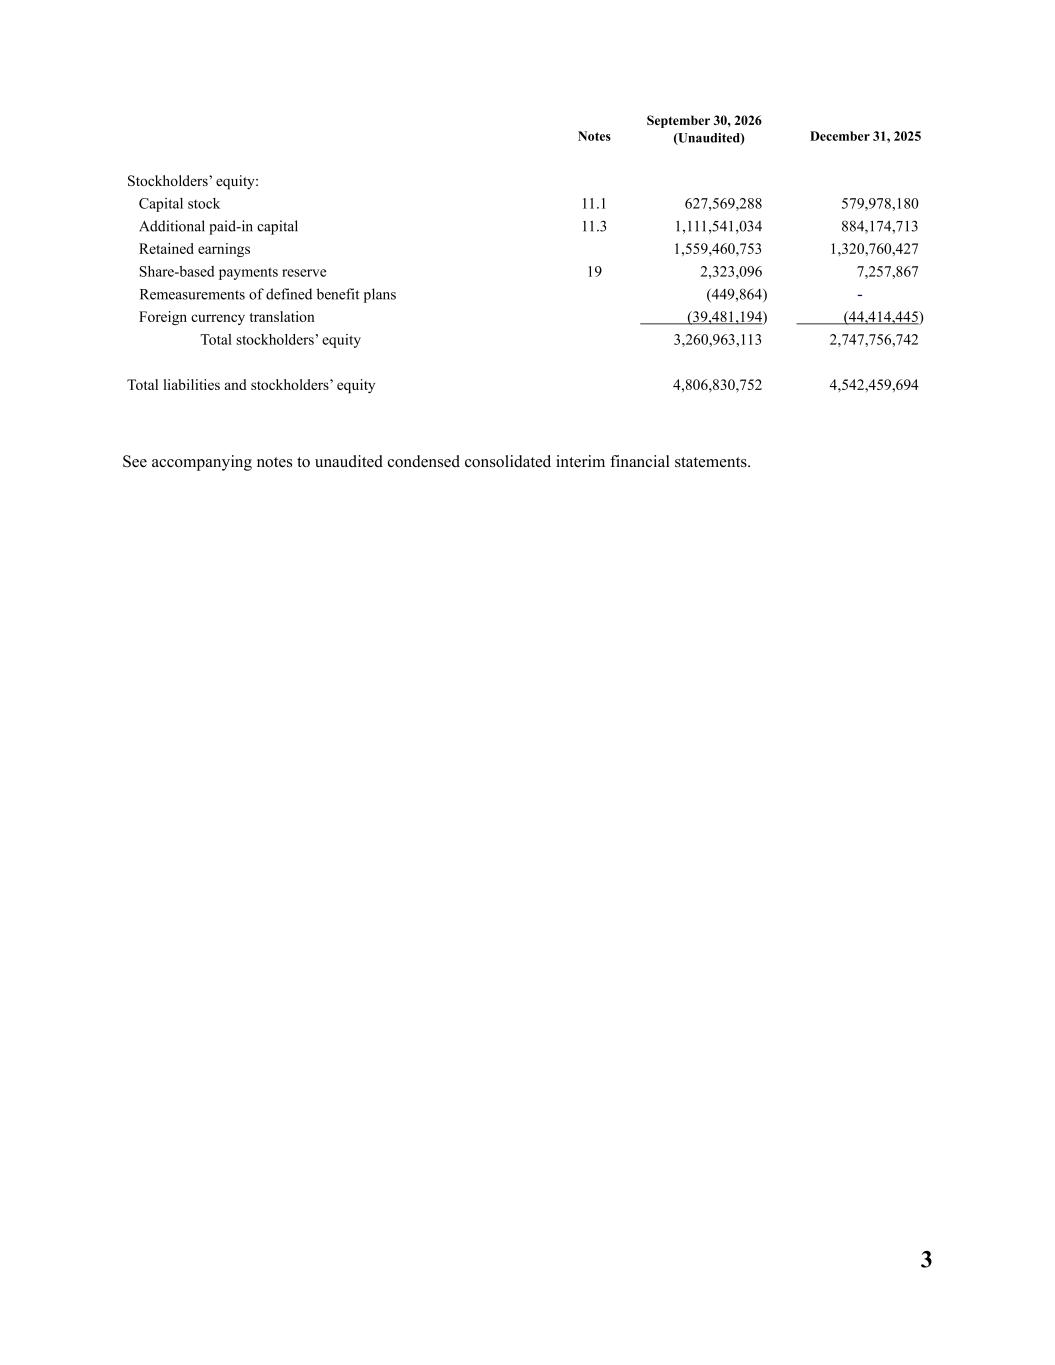
3 Notes September 30, 2026 (Unaudited) December 31, 2025 Stockholders’ equity: Capital stock 11.1 627,569,288 579,978,180 Additional paid-in capital 11.3 1,111,541,034 884,174,713 Retained earnings 1,559,460,753 1,320,760,427 Share-based payments reserve 19 2,323,096 7,257,867 Remeasurements of defined benefit plans (449,864) - Foreign currency translation (39,481,194) (44,414,445) Total stockholders’ equity 3,260,963,113 2,747,756,742 Total liabilities and stockholders’ equity 4,806,830,752 4,542,459,694 See accompanying notes to unaudited condensed consolidated interim financial statements.
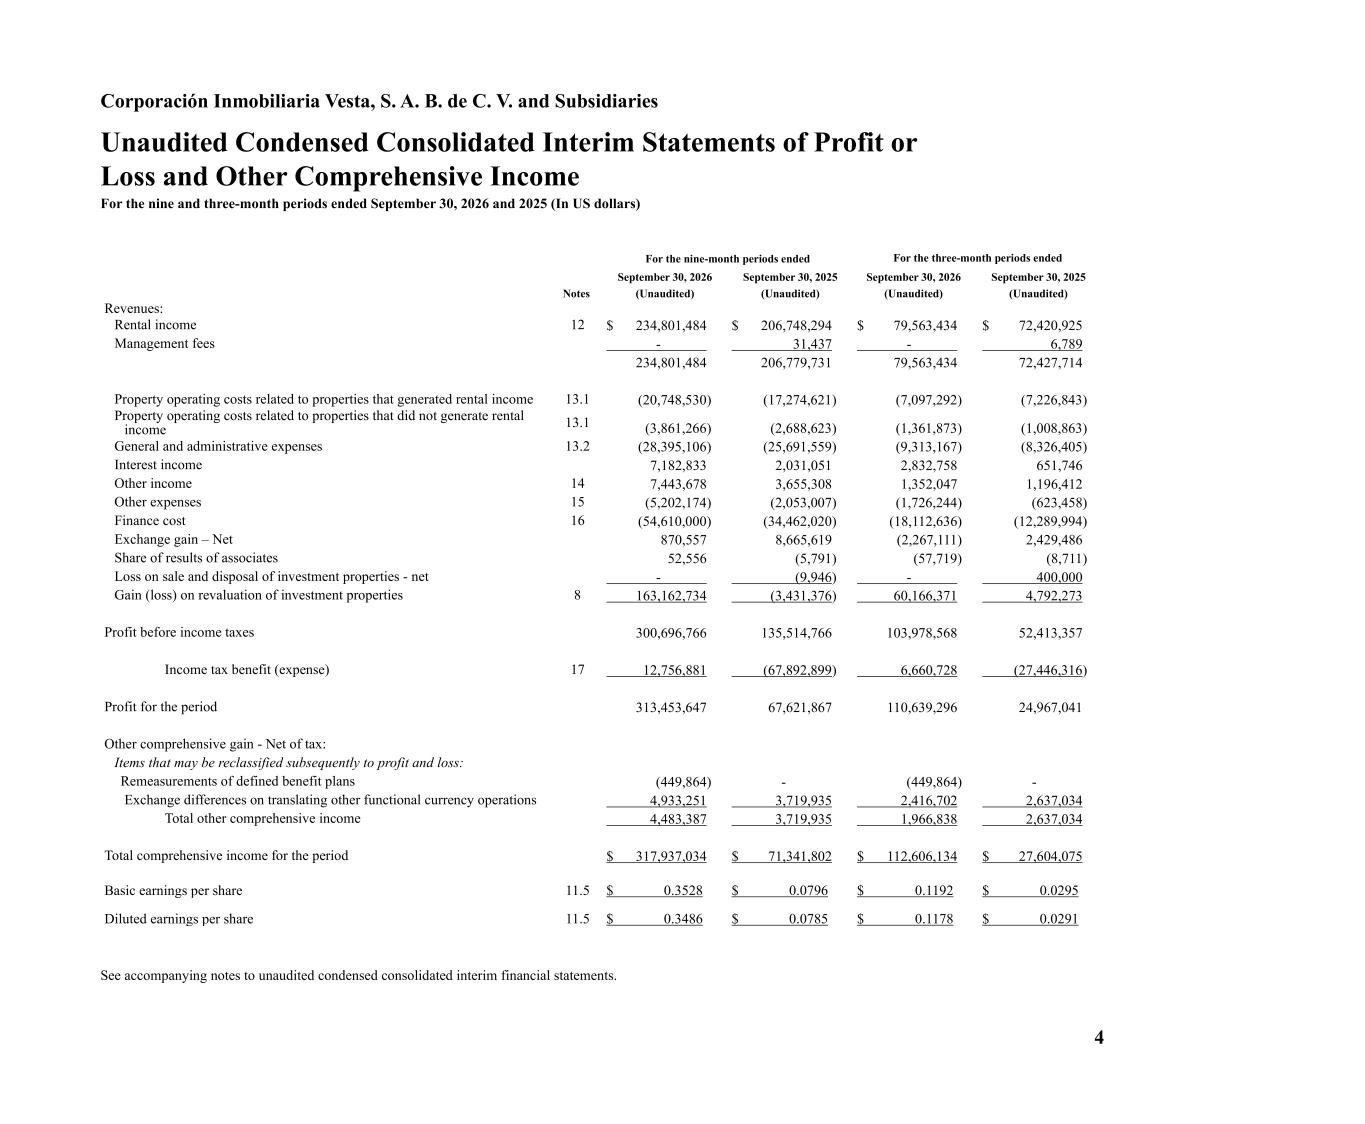
4 Corporación Inmobiliaria Vesta, S. A. B. de C. V. and Subsidiaries Unaudited Condensed Consolidated Interim Statements of Profit or Loss and Other Comprehensive Income For the nine and three-month periods ended September 30, 2026 and 2025 (In US dollars) For the nine-month periods ended For the three-month periods ended Notes September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Revenues: Rental income 12 $ 234,801,484 $ 206,748,294 $ 79,563,434 $ 72,420,925 Management fees - 31,437 - 6,789 234,801,484 206,779,731 79,563,434 72,427,714 Property operating costs related to properties that generated rental income 13.1 (20,748,530) (17,274,621) (7,097,292) (7,226,843) Property operating costs related to properties that did not generate rental income 13.1 (3,861,266) (2,688,623) (1,361,873) (1,008,863) General and administrative expenses 13.2 (28,395,106) (25,691,559) (9,313,167) (8,326,405) Interest income 7,182,833 2,031,051 2,832,758 651,746 Other income 14 7,443,678 3,655,308 1,352,047 1,196,412 Other expenses 15 (5,202,174) (2,053,007) (1,726,244) (623,458) Finance cost 16 (54,610,000) (34,462,020) (18,112,636) (12,289,994) Exchange gain – Net 870,557 8,665,619 (2,267,111) 2,429,486 Share of results of associates 52,556 (5,791) (57,719) (8,711) Loss on sale and disposal of investment properties - net - (9,946) - 400,000 Gain (loss) on revaluation of investment properties 8 163,162,734 (3,431,376) 60,166,371 4,792,273 Profit before income taxes 300,696,766 135,514,766 103,978,568 52,413,357 Income tax benefit (expense) 17 12,756,881 (67,892,899) 6,660,728 (27,446,316) Profit for the period 313,453,647 67,621,867 110,639,296 24,967,041 Other comprehensive gain - Net of tax: Items that may be reclassified subsequently to profit and loss: Remeasurements of defined benefit plans (449,864) - (449,864) - Exchange differences on translating other functional currency operations 4,933,251 3,719,935 2,416,702 2,637,034 Total other comprehensive income 4,483,387 3,719,935 1,966,838 2,637,034 Total comprehensive income for the period $ 317,937,034 $ 71,341,802 $ 112,606,134 $ 27,604,075 Basic earnings per share 11.5 $ 0.3528 $ 0.0796 $ 0.1192 $ 0.0295 Diluted earnings per share 11.5 $ 0.3486 $ 0.0785 $ 0.1178 $ 0.0291 See accompanying notes to unaudited condensed consolidated interim financial statements.
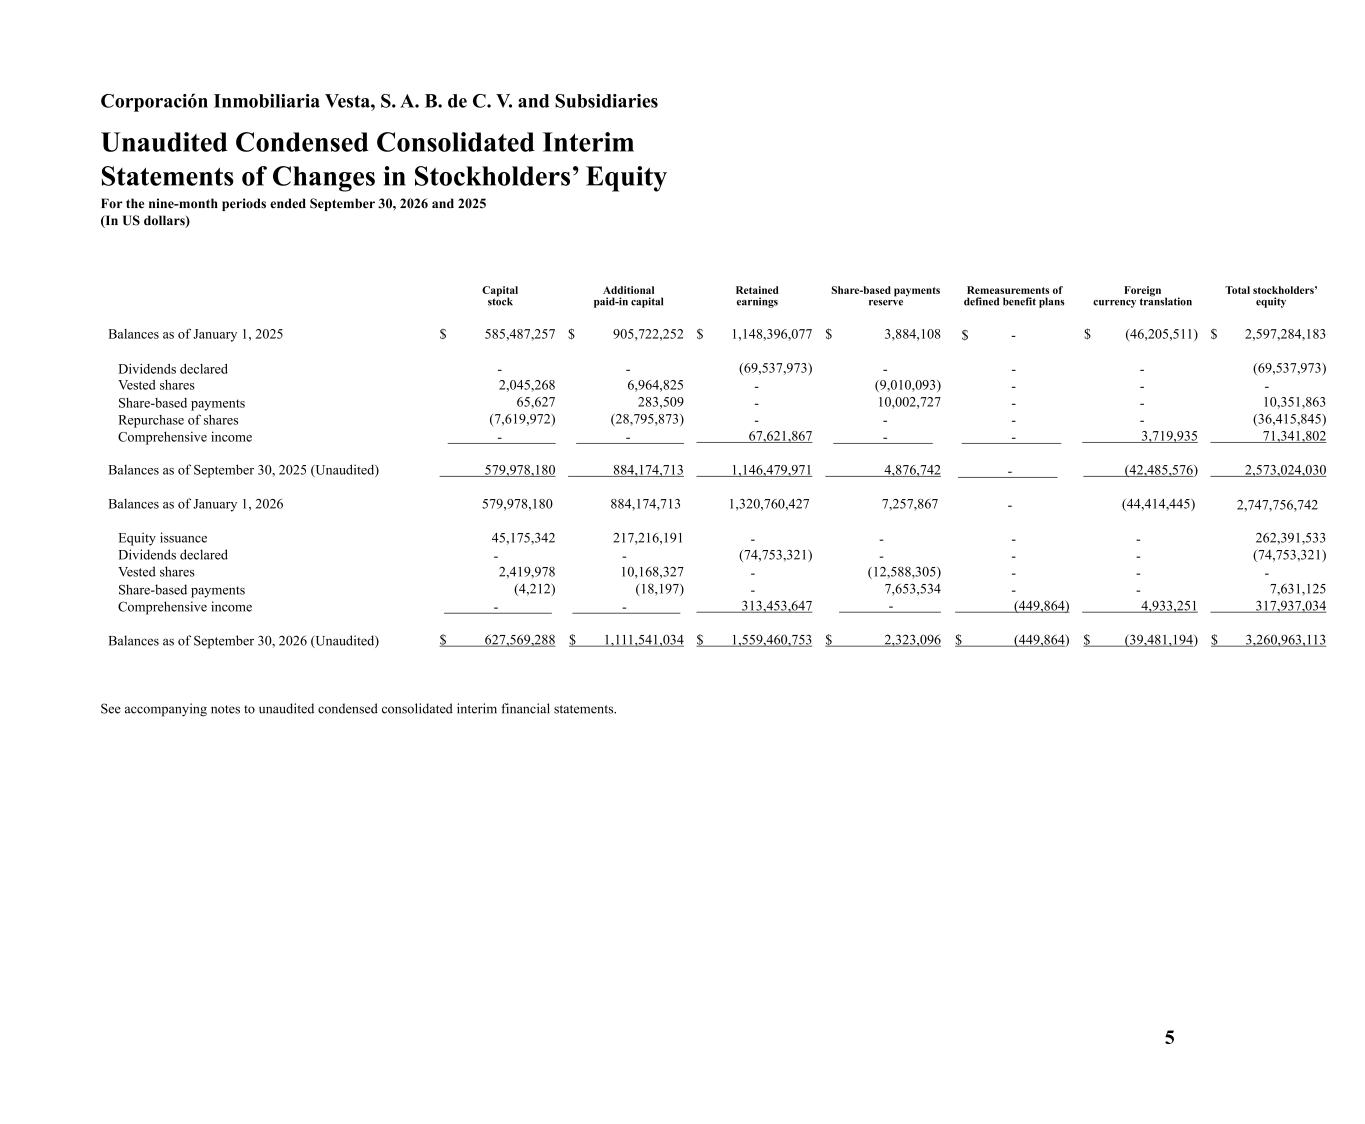
5 Corporación Inmobiliaria Vesta, S. A. B. de C. V. and Subsidiaries Unaudited Condensed Consolidated Interim Statements of Changes in Stockholders’ Equity For the nine-month periods ended September 30, 2026 and 2025 (In US dollars) Capital stock Additional paid-in capital Retained earnings Share-based payments reserve Remeasurements of defined benefit plans Foreign currency translation Total stockholders’ equity Balances as of January 1, 2025 $ 585,487,257 $ 905,722,252 $ 1,148,396,077 $ 3,884,108 $ - $ (46,205,511) $ 2,597,284,183 Dividends declared - - (69,537,973) - - - (69,537,973) Vested shares 2,045,268 6,964,825 - (9,010,093) - - - Share-based payments 65,627 283,509 - 10,002,727 - - 10,351,863 Repurchase of shares (7,619,972) (28,795,873) - - - - (36,415,845) Comprehensive income - - 67,621,867 - - 3,719,935 71,341,802 Balances as of September 30, 2025 (Unaudited) 579,978,180 884,174,713 1,146,479,971 4,876,742 - (42,485,576) 2,573,024,030 Balances as of January 1, 2026 579,978,180 884,174,713 1,320,760,427 7,257,867 - (44,414,445) 2,747,756,742 Equity issuance 45,175,342 217,216,191 - - - - 262,391,533 Dividends declared - - (74,753,321) - - - (74,753,321) Vested shares 2,419,978 10,168,327 - (12,588,305) - - - Share-based payments (4,212) (18,197) - 7,653,534 - - 7,631,125 Comprehensive income - - 313,453,647 - (449,864) 4,933,251 317,937,034 Balances as of September 30, 2026 (Unaudited) $ 627,569,288 $ 1,111,541,034 $ 1,559,460,753 $ 2,323,096 $ (449,864) $ (39,481,194) $ 3,260,963,113 See accompanying notes to unaudited condensed consolidated interim financial statements.
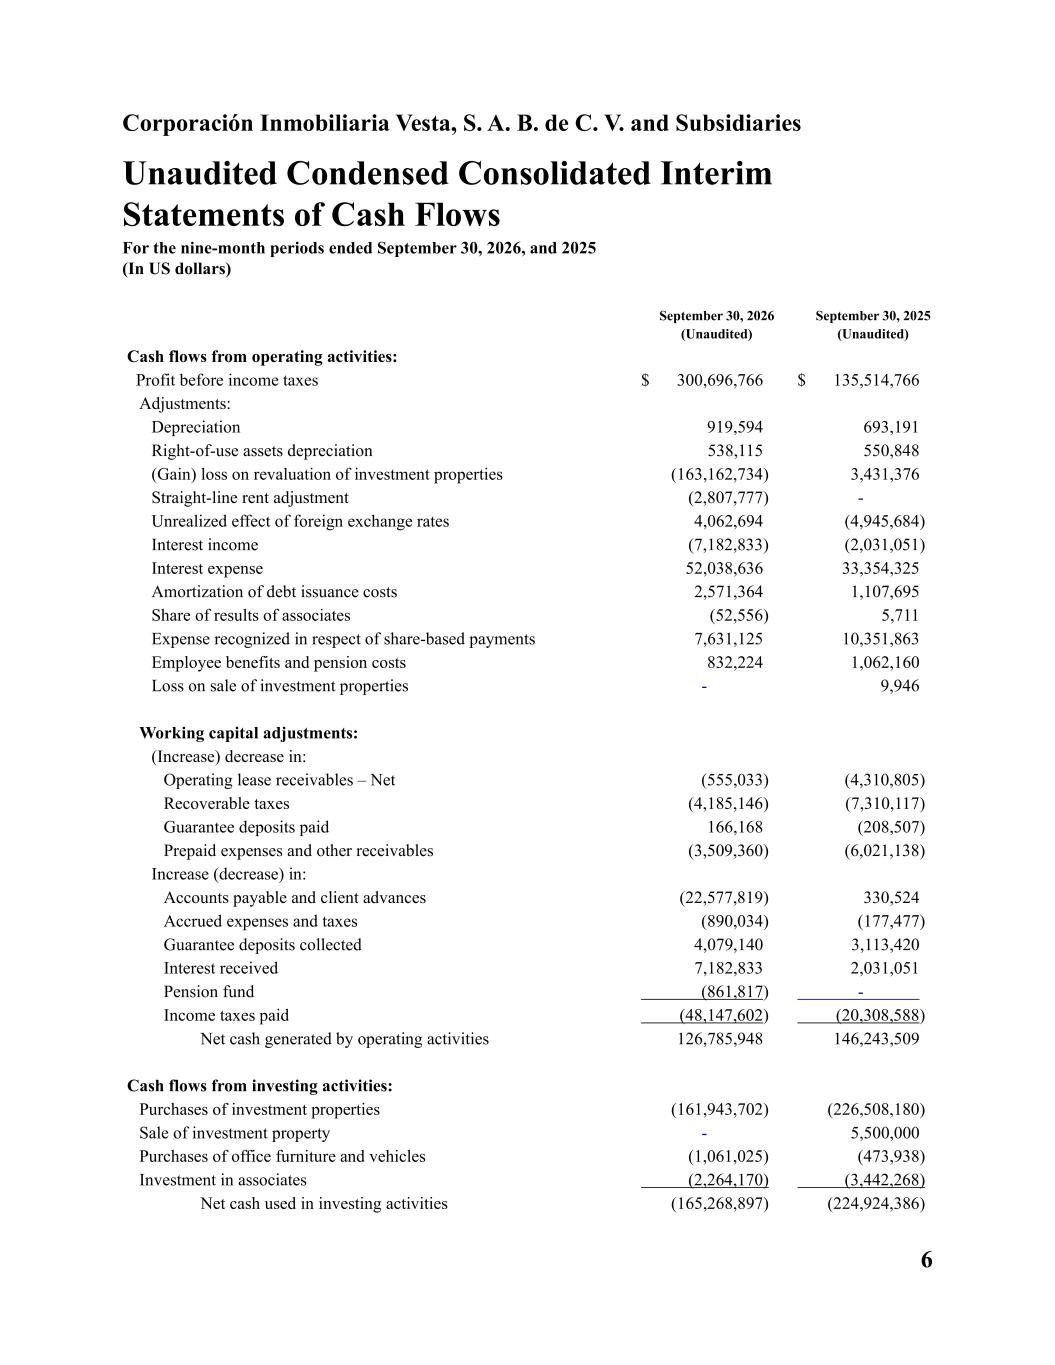
6 Corporación Inmobiliaria Vesta, S. A. B. de C. V. and Subsidiaries Unaudited Condensed Consolidated Interim Statements of Cash Flows For the nine-month periods ended September 30, 2026, and 2025 (In US dollars) September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Cash flows from operating activities: Profit before income taxes $ 300,696,766 $ 135,514,766 Adjustments: Depreciation 919,594 693,191 Right-of-use assets depreciation 538,115 550,848 (Gain) loss on revaluation of investment properties (163,162,734) 3,431,376 Straight-line rent adjustment (2,807,777) - Unrealized effect of foreign exchange rates 4,062,694 (4,945,684) Interest income (7,182,833) (2,031,051) Interest expense 52,038,636 33,354,325 Amortization of debt issuance costs 2,571,364 1,107,695 Share of results of associates (52,556) 5,711 Expense recognized in respect of share-based payments 7,631,125 10,351,863 Employee benefits and pension costs 832,224 1,062,160 Loss on sale of investment properties - 9,946 Working capital adjustments: (Increase) decrease in: Operating lease receivables – Net (555,033) (4,310,805) Recoverable taxes (4,185,146) (7,310,117) Guarantee deposits paid 166,168 (208,507) Prepaid expenses and other receivables (3,509,360) (6,021,138) Increase (decrease) in: Accounts payable and client advances (22,577,819) 330,524 Accrued expenses and taxes (890,034) (177,477) Guarantee deposits collected 4,079,140 3,113,420 Interest received 7,182,833 2,031,051 Pension fund (861,817) - Income taxes paid (48,147,602) (20,308,588) Net cash generated by operating activities 126,785,948 146,243,509 Cash flows from investing activities: Purchases of investment properties (161,943,702) (226,508,180) Sale of investment property - 5,500,000 Purchases of office furniture and vehicles (1,061,025) (473,938) Investment in associates (2,264,170) (3,442,268) Net cash used in investing activities (165,268,897) (224,924,386)
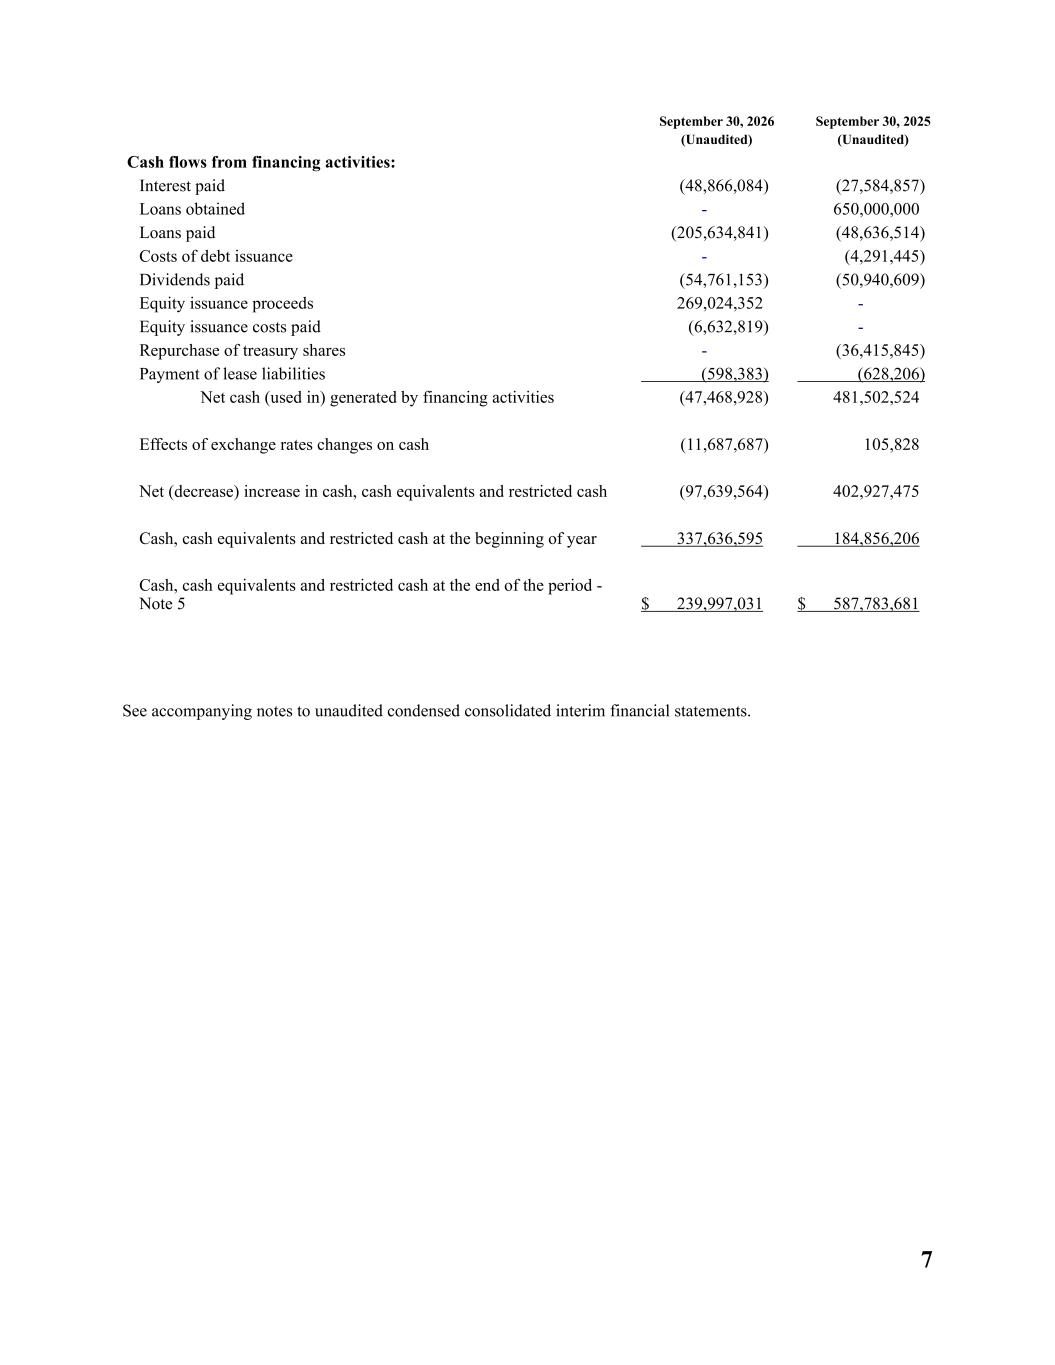
7 September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Cash flows from financing activities: Interest paid (48,866,084) (27,584,857) Loans obtained - 650,000,000 Loans paid (205,634,841) (48,636,514) Costs of debt issuance - (4,291,445) Dividends paid (54,761,153) (50,940,609) Equity issuance proceeds 269,024,352 - Equity issuance costs paid (6,632,819) - Repurchase of treasury shares - (36,415,845) Payment of lease liabilities (598,383) (628,206) Net cash (used in) generated by financing activities (47,468,928) 481,502,524 Effects of exchange rates changes on cash (11,687,687) 105,828 Net (decrease) increase in cash, cash equivalents and restricted cash (97,639,564) 402,927,475 Cash, cash equivalents and restricted cash at the beginning of year 337,636,595 184,856,206 Cash, cash equivalents and restricted cash at the end of the period - Note 5 $ 239,997,031 $ 587,783,681 See accompanying notes to unaudited condensed consolidated interim financial statements.
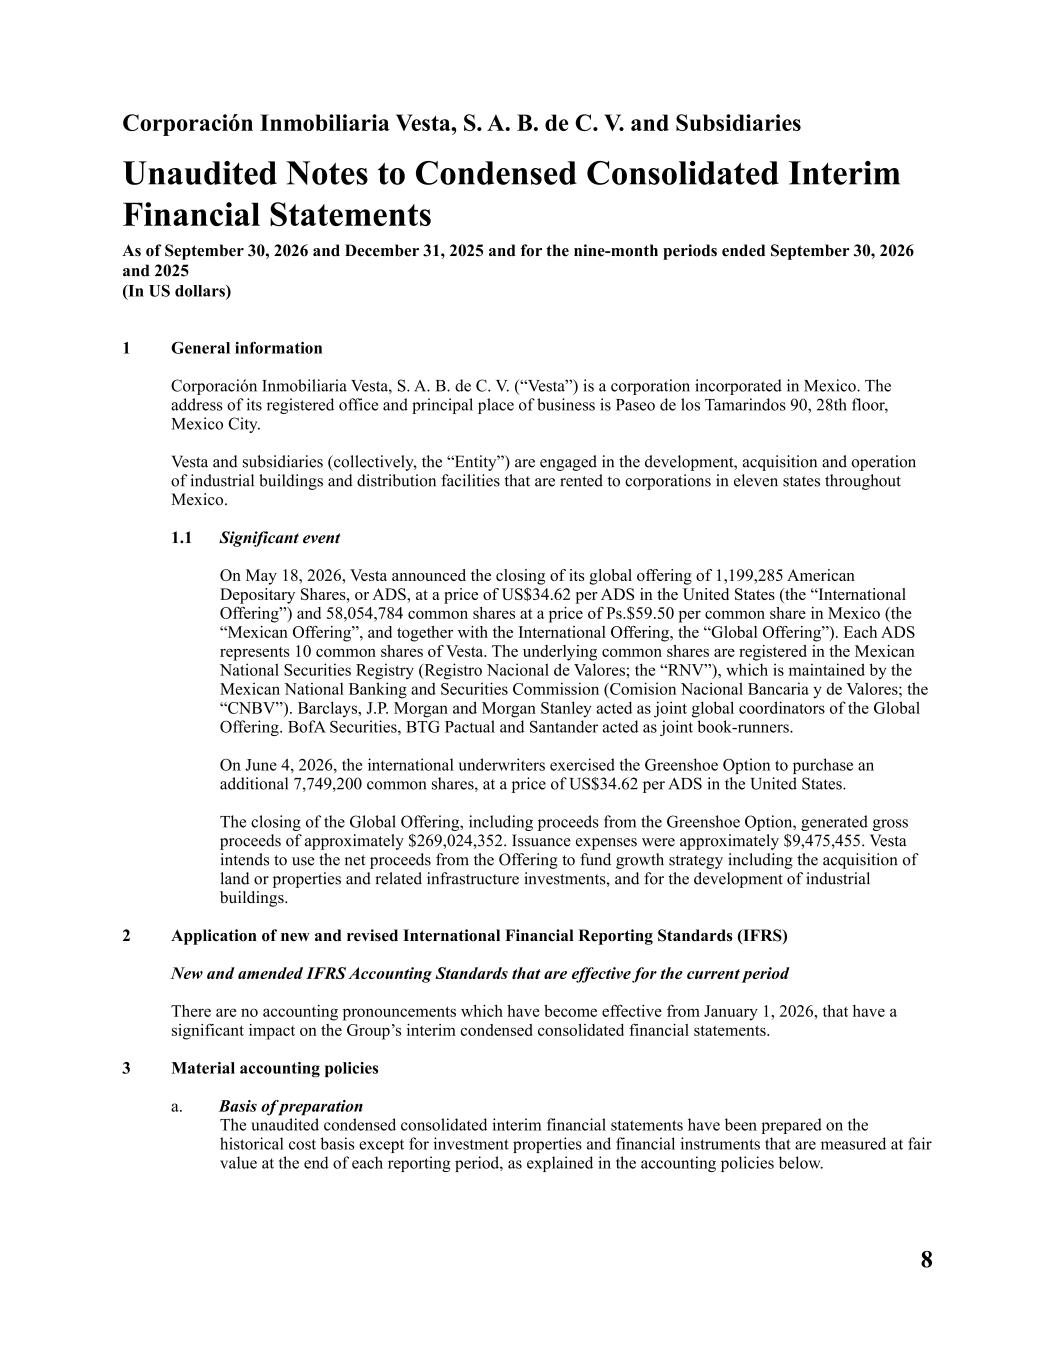
8 Corporación Inmobiliaria Vesta, S. A. B. de C. V. and Subsidiaries Unaudited Notes to Condensed Consolidated Interim Financial Statements As of September 30, 2026 and December 31, 2025 and for the nine-month periods ended September 30, 2026 and 2025 (In US dollars) 1 General information Corporación Inmobiliaria Vesta, S. A. B. de C. V. (“Vesta”) is a corporation incorporated in Mexico. The address of its registered office and principal place of business is Paseo de los Tamarindos 90, 28th floor, Mexico City. Vesta and subsidiaries (collectively, the “Entity”) are engaged in the development, acquisition and operation of industrial buildings and distribution facilities that are rented to corporations in eleven states throughout Mexico. 1.1 Significant event On May 18, 2026, Vesta announced the closing of its global offering of 1,199,285 American Depositary Shares, or ADS, at a price of US$34.62 per ADS in the United States (the “International Offering”) and 58,054,784 common shares at a price of Ps.$59.50 per common share in Mexico (the “Mexican Offering”, and together with the International Offering, the “Global Offering”). Each ADS represents 10 common shares of Vesta. The underlying common shares are registered in the Mexican National Securities Registry (Registro Nacional de Valores; the “RNV”), which is maintained by the Mexican National Banking and Securities Commission (Comision Nacional Bancaria y de Valores; the “CNBV”). Barclays, J.P. Morgan and Morgan Stanley acted as joint global coordinators of the Global Offering. BofA Securities, BTG Pactual and Santander acted as joint book-runners. On June 4, 2026, the international underwriters exercised the Greenshoe Option to purchase an additional 7,749,200 common shares, at a price of US$34.62 per ADS in the United States. The closing of the Global Offering, including proceeds from the Greenshoe Option, generated gross proceeds of approximately $269,024,352. Issuance expenses were approximately $9,475,455. Vesta intends to use the net proceeds from the Offering to fund growth strategy including the acquisition of land or properties and related infrastructure investments, and for the development of industrial buildings. 2 Application of new and revised International Financial Reporting Standards (IFRS) New and amended IFRS Accounting Standards that are effective for the current period There are no accounting pronouncements which have become effective from January 1, 2026, that have a significant impact on the Group’s interim condensed consolidated financial statements. 3 Material accounting policies a. Basis of preparation The unaudited condensed consolidated interim financial statements have been prepared on the historical cost basis except for investment properties and financial instruments that are measured at fair value at the end of each reporting period, as explained in the accounting policies below.
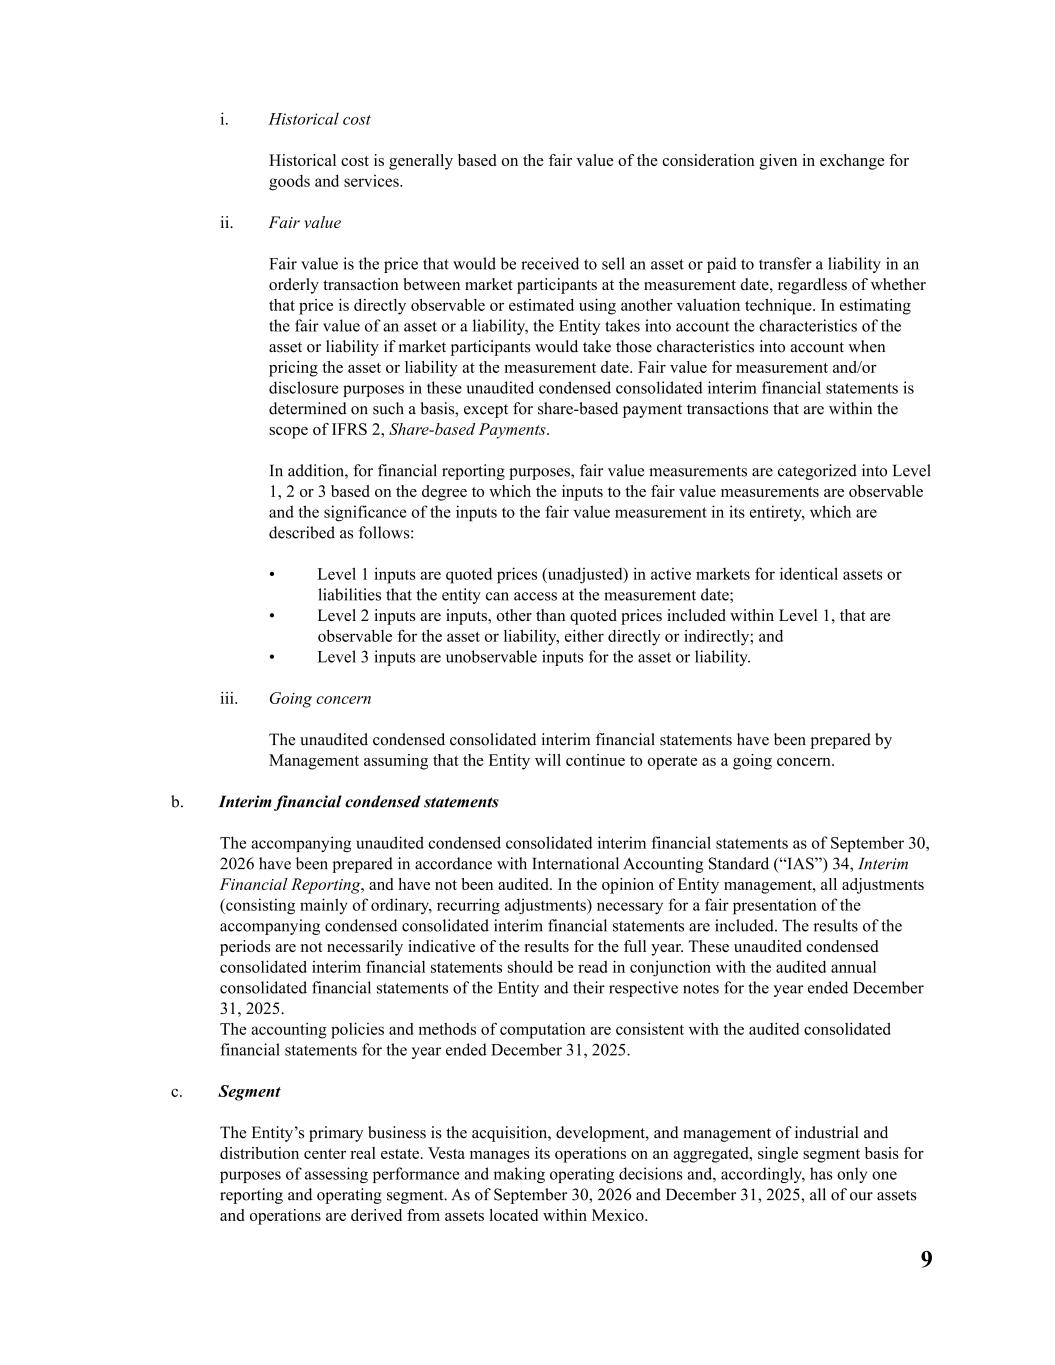
9 i. Historical cost Historical cost is generally based on the fair value of the consideration given in exchange for goods and services. ii. Fair value Fair value is the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date, regardless of whether that price is directly observable or estimated using another valuation technique. In estimating the fair value of an asset or a liability, the Entity takes into account the characteristics of the asset or liability if market participants would take those characteristics into account when pricing the asset or liability at the measurement date. Fair value for measurement and/or disclosure purposes in these unaudited condensed consolidated interim financial statements is determined on such a basis, except for share-based payment transactions that are within the scope of IFRS 2, Share-based Payments. In addition, for financial reporting purposes, fair value measurements are categorized into Level 1, 2 or 3 based on the degree to which the inputs to the fair value measurements are observable and the significance of the inputs to the fair value measurement in its entirety, which are described as follows: • Level 1 inputs are quoted prices (unadjusted) in active markets for identical assets or liabilities that the entity can access at the measurement date; • Level 2 inputs are inputs, other than quoted prices included within Level 1, that are observable for the asset or liability, either directly or indirectly; and • Level 3 inputs are unobservable inputs for the asset or liability. iii. Going concern The unaudited condensed consolidated interim financial statements have been prepared by Management assuming that the Entity will continue to operate as a going concern. b. Interim financial condensed statements The accompanying unaudited condensed consolidated interim financial statements as of September 30, 2026 have been prepared in accordance with International Accounting Standard (“IAS”) 34, Interim Financial Reporting, and have not been audited. In the opinion of Entity management, all adjustments (consisting mainly of ordinary, recurring adjustments) necessary for a fair presentation of the accompanying condensed consolidated interim financial statements are included. The results of the periods are not necessarily indicative of the results for the full year. These unaudited condensed consolidated interim financial statements should be read in conjunction with the audited annual consolidated financial statements of the Entity and their respective notes for the year ended December 31, 2025. The accounting policies and methods of computation are consistent with the audited consolidated financial statements for the year ended December 31, 2025. c. Segment The Entity’s primary business is the acquisition, development, and management of industrial and distribution center real estate. Vesta manages its operations on an aggregated, single segment basis for purposes of assessing performance and making operating decisions and, accordingly, has only one reporting and operating segment. As of September 30, 2026 and December 31, 2025, all of our assets and operations are derived from assets located within Mexico.
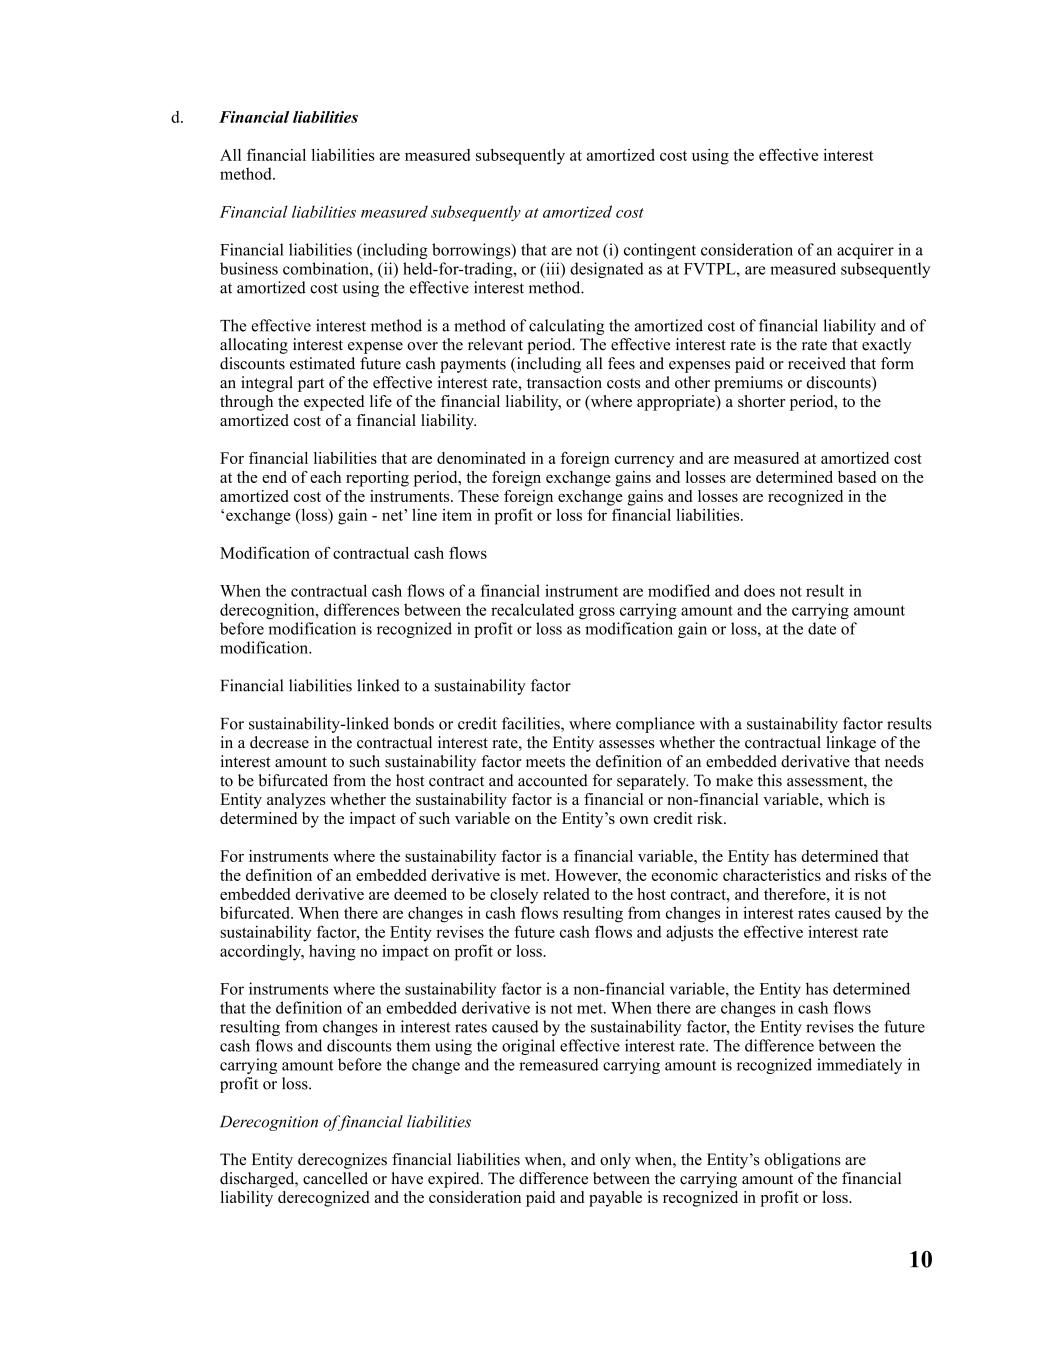
10 d. Financial liabilities All financial liabilities are measured subsequently at amortized cost using the effective interest method. Financial liabilities measured subsequently at amortized cost Financial liabilities (including borrowings) that are not (i) contingent consideration of an acquirer in a business combination, (ii) held-for-trading, or (iii) designated as at FVTPL, are measured subsequently at amortized cost using the effective interest method. The effective interest method is a method of calculating the amortized cost of financial liability and of allocating interest expense over the relevant period. The effective interest rate is the rate that exactly discounts estimated future cash payments (including all fees and expenses paid or received that form an integral part of the effective interest rate, transaction costs and other premiums or discounts) through the expected life of the financial liability, or (where appropriate) a shorter period, to the amortized cost of a financial liability. For financial liabilities that are denominated in a foreign currency and are measured at amortized cost at the end of each reporting period, the foreign exchange gains and losses are determined based on the amortized cost of the instruments. These foreign exchange gains and losses are recognized in the ‘exchange (loss) gain - net’ line item in profit or loss for financial liabilities. Modification of contractual cash flows When the contractual cash flows of a financial instrument are modified and does not result in derecognition, differences between the recalculated gross carrying amount and the carrying amount before modification is recognized in profit or loss as modification gain or loss, at the date of modification. Financial liabilities linked to a sustainability factor For sustainability-linked bonds or credit facilities, where compliance with a sustainability factor results in a decrease in the contractual interest rate, the Entity assesses whether the contractual linkage of the interest amount to such sustainability factor meets the definition of an embedded derivative that needs to be bifurcated from the host contract and accounted for separately. To make this assessment, the Entity analyzes whether the sustainability factor is a financial or non-financial variable, which is determined by the impact of such variable on the Entity’s own credit risk. For instruments where the sustainability factor is a financial variable, the Entity has determined that the definition of an embedded derivative is met. However, the economic characteristics and risks of the embedded derivative are deemed to be closely related to the host contract, and therefore, it is not bifurcated. When there are changes in cash flows resulting from changes in interest rates caused by the sustainability factor, the Entity revises the future cash flows and adjusts the effective interest rate accordingly, having no impact on profit or loss. For instruments where the sustainability factor is a non-financial variable, the Entity has determined that the definition of an embedded derivative is not met. When there are changes in cash flows resulting from changes in interest rates caused by the sustainability factor, the Entity revises the future cash flows and discounts them using the original effective interest rate. The difference between the carrying amount before the change and the remeasured carrying amount is recognized immediately in profit or loss. Derecognition of financial liabilities The Entity derecognizes financial liabilities when, and only when, the Entity’s obligations are discharged, cancelled or have expired. The difference between the carrying amount of the financial liability derecognized and the consideration paid and payable is recognized in profit or loss.
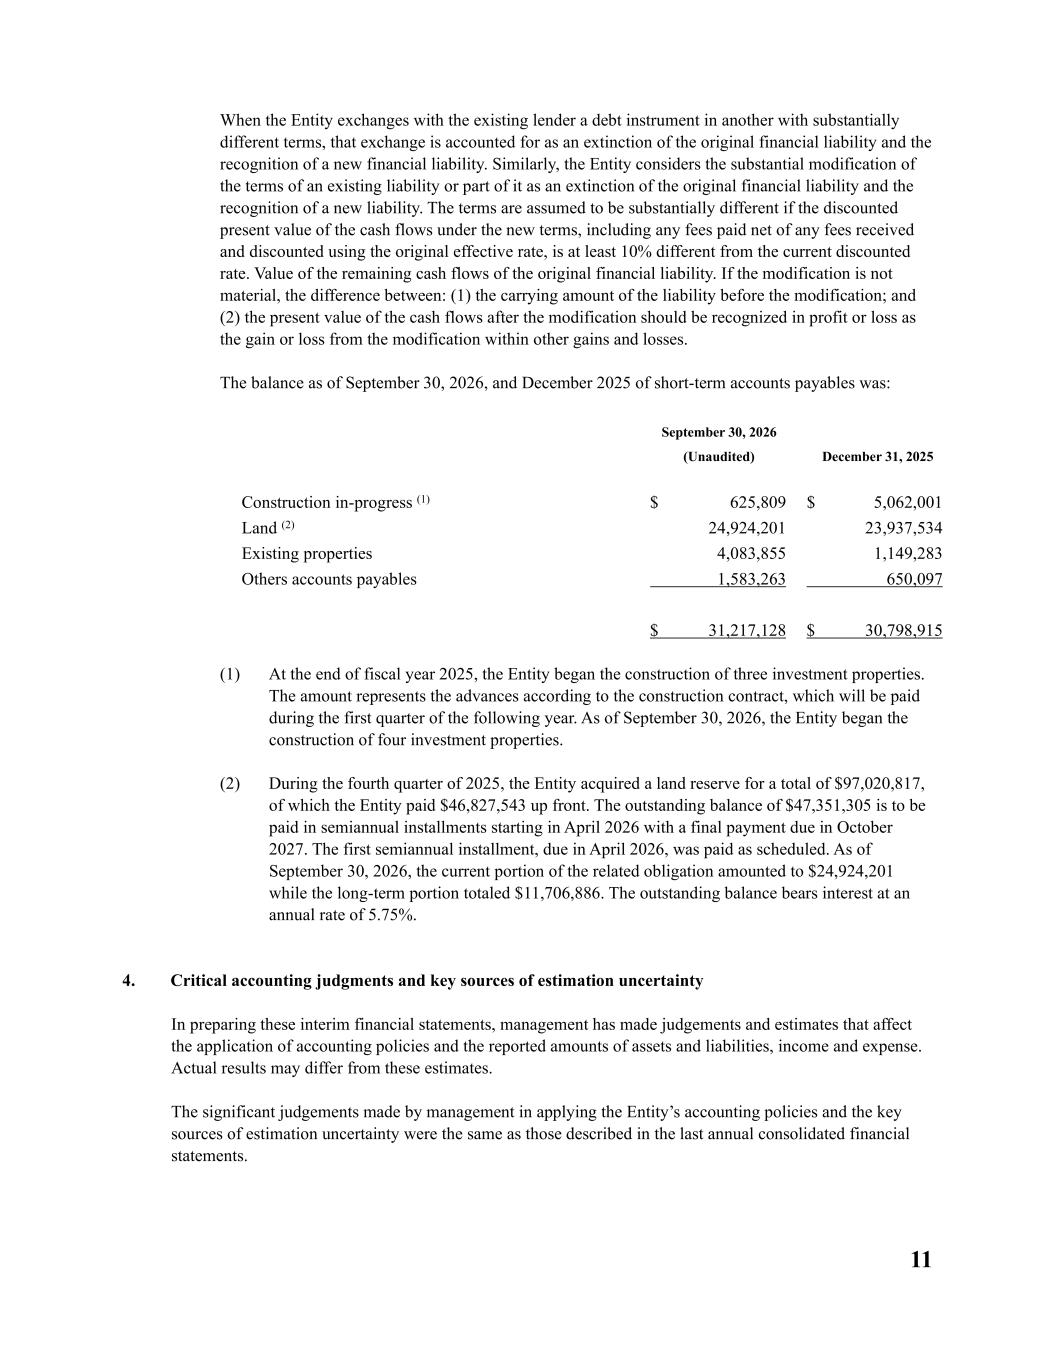
11 When the Entity exchanges with the existing lender a debt instrument in another with substantially different terms, that exchange is accounted for as an extinction of the original financial liability and the recognition of a new financial liability. Similarly, the Entity considers the substantial modification of the terms of an existing liability or part of it as an extinction of the original financial liability and the recognition of a new liability. The terms are assumed to be substantially different if the discounted present value of the cash flows under the new terms, including any fees paid net of any fees received and discounted using the original effective rate, is at least 10% different from the current discounted rate. Value of the remaining cash flows of the original financial liability. If the modification is not material, the difference between: (1) the carrying amount of the liability before the modification; and (2) the present value of the cash flows after the modification should be recognized in profit or loss as the gain or loss from the modification within other gains and losses. The balance as of September 30, 2026, and December 2025 of short-term accounts payables was: September 30, 2026 (Unaudited) December 31, 2025 Construction in-progress (1) $ 625,809 $ 5,062,001 Land (2) 24,924,201 23,937,534 Existing properties 4,083,855 1,149,283 Others accounts payables 1,583,263 650,097 $ 31,217,128 $ 30,798,915 (1) At the end of fiscal year 2025, the Entity began the construction of three investment properties. The amount represents the advances according to the construction contract, which will be paid during the first quarter of the following year. As of September 30, 2026, the Entity began the construction of four investment properties. (2) During the fourth quarter of 2025, the Entity acquired a land reserve for a total of $97,020,817, of which the Entity paid $46,827,543 up front. The outstanding balance of $47,351,305 is to be paid in semiannual installments starting in April 2026 with a final payment due in October 2027. The first semiannual installment, due in April 2026, was paid as scheduled. As of September 30, 2026, the current portion of the related obligation amounted to $24,924,201 while the long-term portion totaled $11,706,886. The outstanding balance bears interest at an annual rate of 5.75%. 4. Critical accounting judgments and key sources of estimation uncertainty In preparing these interim financial statements, management has made judgements and estimates that affect the application of accounting policies and the reported amounts of assets and liabilities, income and expense. Actual results may differ from these estimates. The significant judgements made by management in applying the Entity’s accounting policies and the key sources of estimation uncertainty were the same as those described in the last annual consolidated financial statements.
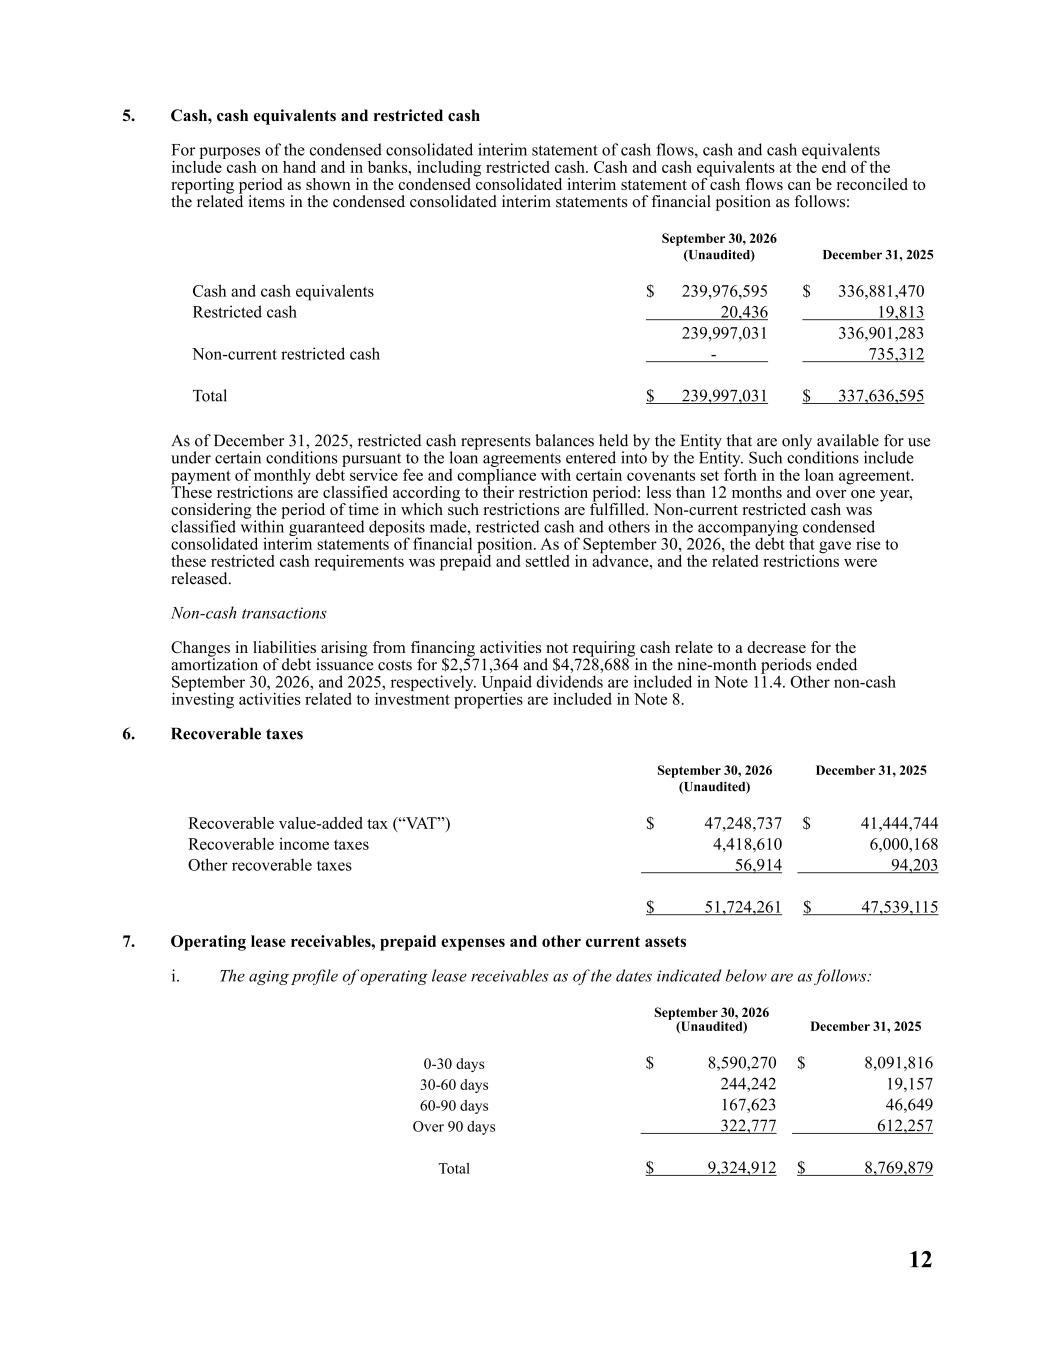
12 5. Cash, cash equivalents and restricted cash For purposes of the condensed consolidated interim statement of cash flows, cash and cash equivalents include cash on hand and in banks, including restricted cash. Cash and cash equivalents at the end of the reporting period as shown in the condensed consolidated interim statement of cash flows can be reconciled to the related items in the condensed consolidated interim statements of financial position as follows: September 30, 2026 (Unaudited) December 31, 2025 Cash and cash equivalents $ 239,976,595 $ 336,881,470 Restricted cash 20,436 19,813 239,997,031 336,901,283 Non-current restricted cash - 735,312 Total $ 239,997,031 $ 337,636,595 As of December 31, 2025, restricted cash represents balances held by the Entity that are only available for use under certain conditions pursuant to the loan agreements entered into by the Entity. Such conditions include payment of monthly debt service fee and compliance with certain covenants set forth in the loan agreement. These restrictions are classified according to their restriction period: less than 12 months and over one year, considering the period of time in which such restrictions are fulfilled. Non-current restricted cash was classified within guaranteed deposits made, restricted cash and others in the accompanying condensed consolidated interim statements of financial position. As of September 30, 2026, the debt that gave rise to these restricted cash requirements was prepaid and settled in advance, and the related restrictions were released. Non‑cash transactions Changes in liabilities arising from financing activities not requiring cash relate to a decrease for the amortization of debt issuance costs for $2,571,364 and $4,728,688 in the nine-month periods ended September 30, 2026, and 2025, respectively. Unpaid dividends are included in Note 11.4. Other non-cash investing activities related to investment properties are included in Note 8. 6. Recoverable taxes September 30, 2026 (Unaudited) December 31, 2025 Recoverable value-added tax (“VAT”) $ 47,248,737 $ 41,444,744 Recoverable income taxes 4,418,610 6,000,168 Other recoverable taxes 56,914 94,203 $ 51,724,261 $ 47,539,115 7. Operating lease receivables, prepaid expenses and other current assets i. The aging profile of operating lease receivables as of the dates indicated below are as follows: September 30, 2026 (Unaudited) December 31, 2025 0-30 days $ 8,590,270 $ 8,091,816 30-60 days 244,242 19,157 60-90 days 167,623 46,649 Over 90 days 322,777 612,257 Total $ 9,324,912 $ 8,769,879
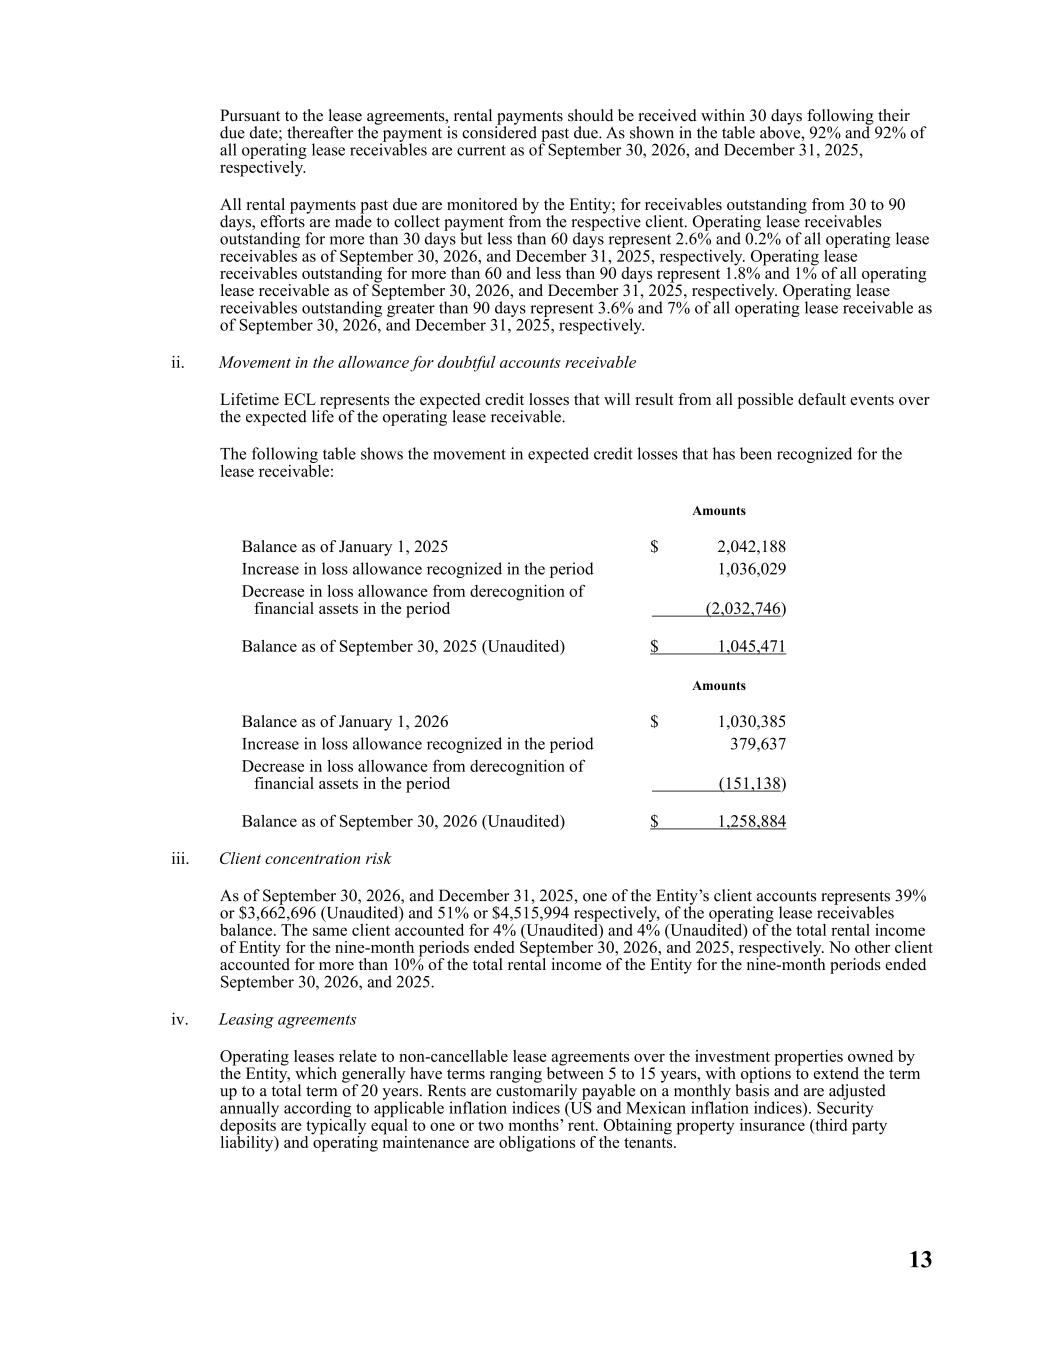
13 Pursuant to the lease agreements, rental payments should be received within 30 days following their due date; thereafter the payment is considered past due. As shown in the table above, 92% and 92% of all operating lease receivables are current as of September 30, 2026, and December 31, 2025, respectively. All rental payments past due are monitored by the Entity; for receivables outstanding from 30 to 90 days, efforts are made to collect payment from the respective client. Operating lease receivables outstanding for more than 30 days but less than 60 days represent 2.6% and 0.2% of all operating lease receivables as of September 30, 2026, and December 31, 2025, respectively. Operating lease receivables outstanding for more than 60 and less than 90 days represent 1.8% and 1% of all operating lease receivable as of September 30, 2026, and December 31, 2025, respectively. Operating lease receivables outstanding greater than 90 days represent 3.6% and 7% of all operating lease receivable as of September 30, 2026, and December 31, 2025, respectively. ii. Movement in the allowance for doubtful accounts receivable Lifetime ECL represents the expected credit losses that will result from all possible default events over the expected life of the operating lease receivable. The following table shows the movement in expected credit losses that has been recognized for the lease receivable: Amounts Balance as of January 1, 2025 $ 2,042,188 Increase in loss allowance recognized in the period 1,036,029 Decrease in loss allowance from derecognition of financial assets in the period (2,032,746) Balance as of September 30, 2025 (Unaudited) $ 1,045,471 Amounts Balance as of January 1, 2026 $ 1,030,385 Increase in loss allowance recognized in the period 379,637 Decrease in loss allowance from derecognition of financial assets in the period (151,138) Balance as of September 30, 2026 (Unaudited) $ 1,258,884 iii. Client concentration risk As of September 30, 2026, and December 31, 2025, one of the Entity’s client accounts represents 39% or $3,662,696 (Unaudited) and 51% or $4,515,994 respectively, of the operating lease receivables balance. The same client accounted for 4% (Unaudited) and 4% (Unaudited) of the total rental income of Entity for the nine-month periods ended September 30, 2026, and 2025, respectively. No other client accounted for more than 10% of the total rental income of the Entity for the nine-month periods ended September 30, 2026, and 2025. iv. Leasing agreements Operating leases relate to non-cancellable lease agreements over the investment properties owned by the Entity, which generally have terms ranging between 5 to 15 years, with options to extend the term up to a total term of 20 years. Rents are customarily payable on a monthly basis and are adjusted annually according to applicable inflation indices (US and Mexican inflation indices). Security deposits are typically equal to one or two months’ rent. Obtaining property insurance (third party liability) and operating maintenance are obligations of the tenants.
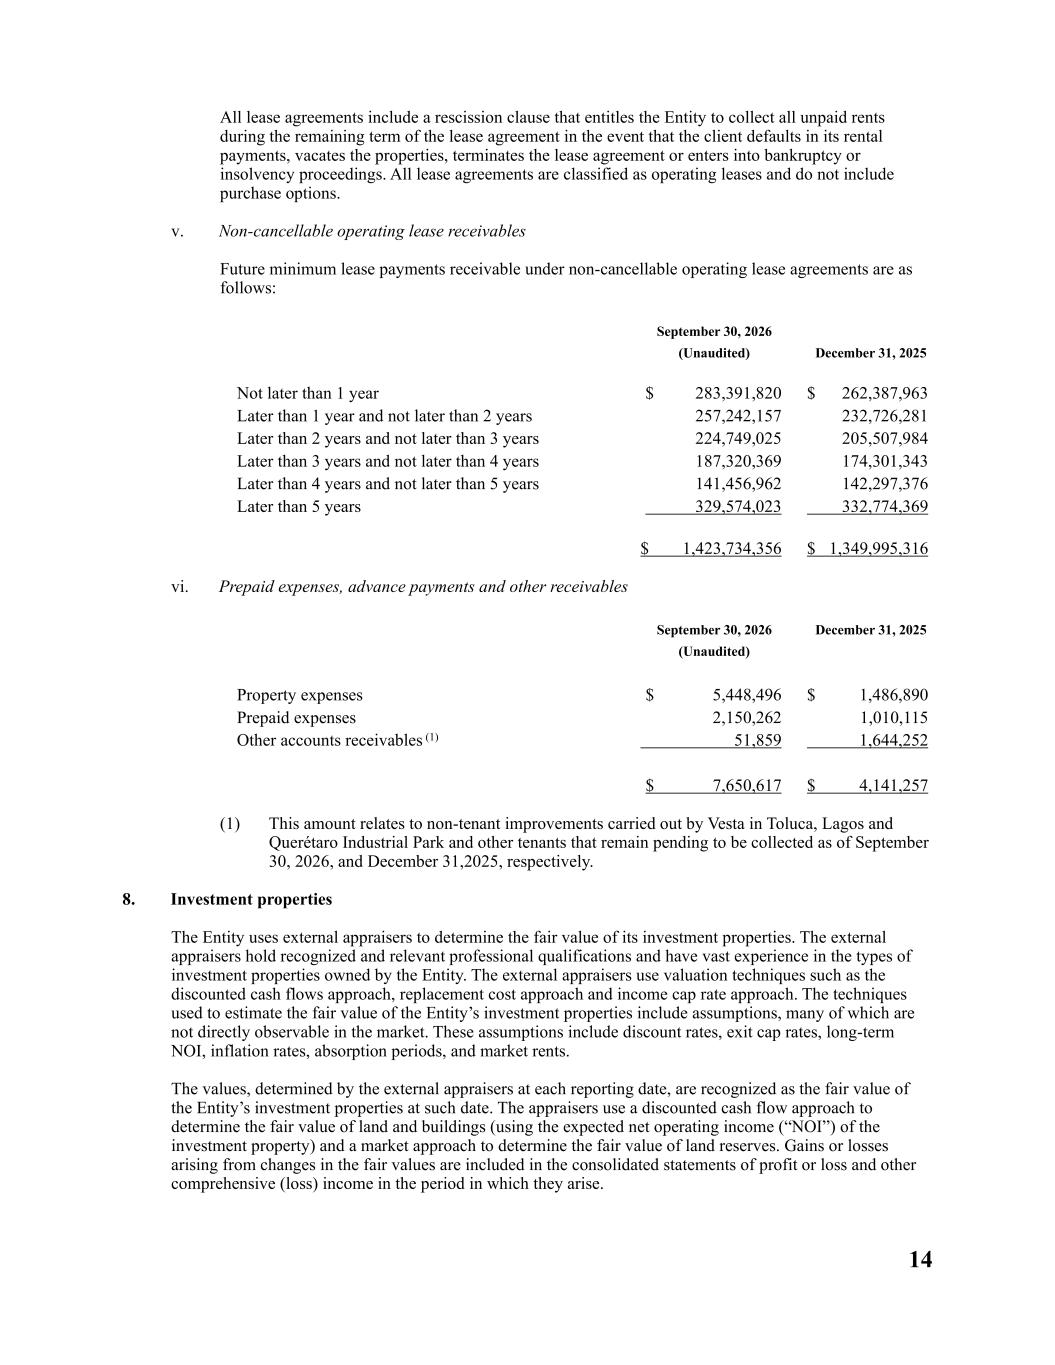
14 All lease agreements include a rescission clause that entitles the Entity to collect all unpaid rents during the remaining term of the lease agreement in the event that the client defaults in its rental payments, vacates the properties, terminates the lease agreement or enters into bankruptcy or insolvency proceedings. All lease agreements are classified as operating leases and do not include purchase options. v. Non-cancellable operating lease receivables Future minimum lease payments receivable under non-cancellable operating lease agreements are as follows: September 30, 2026 (Unaudited) December 31, 2025 Not later than 1 year $ 283,391,820 $ 262,387,963 Later than 1 year and not later than 2 years 257,242,157 232,726,281 Later than 2 years and not later than 3 years 224,749,025 205,507,984 Later than 3 years and not later than 4 years 187,320,369 174,301,343 Later than 4 years and not later than 5 years 141,456,962 142,297,376 Later than 5 years 329,574,023 332,774,369 $ 1,423,734,356 $ 1,349,995,316 vi. Prepaid expenses, advance payments and other receivables September 30, 2026 (Unaudited) December 31, 2025 Property expenses $ 5,448,496 $ 1,486,890 Prepaid expenses 2,150,262 1,010,115 Other accounts receivables (1) 51,859 1,644,252 $ 7,650,617 $ 4,141,257 (1) This amount relates to non-tenant improvements carried out by Vesta in Toluca, Lagos and Querétaro Industrial Park and other tenants that remain pending to be collected as of September 30, 2026, and December 31,2025, respectively. 8. Investment properties The Entity uses external appraisers to determine the fair value of its investment properties. The external appraisers hold recognized and relevant professional qualifications and have vast experience in the types of investment properties owned by the Entity. The external appraisers use valuation techniques such as the discounted cash flows approach, replacement cost approach and income cap rate approach. The techniques used to estimate the fair value of the Entity’s investment properties include assumptions, many of which are not directly observable in the market. These assumptions include discount rates, exit cap rates, long-term NOI, inflation rates, absorption periods, and market rents. The values, determined by the external appraisers at each reporting date, are recognized as the fair value of the Entity’s investment properties at such date. The appraisers use a discounted cash flow approach to determine the fair value of land and buildings (using the expected net operating income (“NOI”) of the investment property) and a market approach to determine the fair value of land reserves. Gains or losses arising from changes in the fair values are included in the consolidated statements of profit or loss and other comprehensive (loss) income in the period in which they arise.
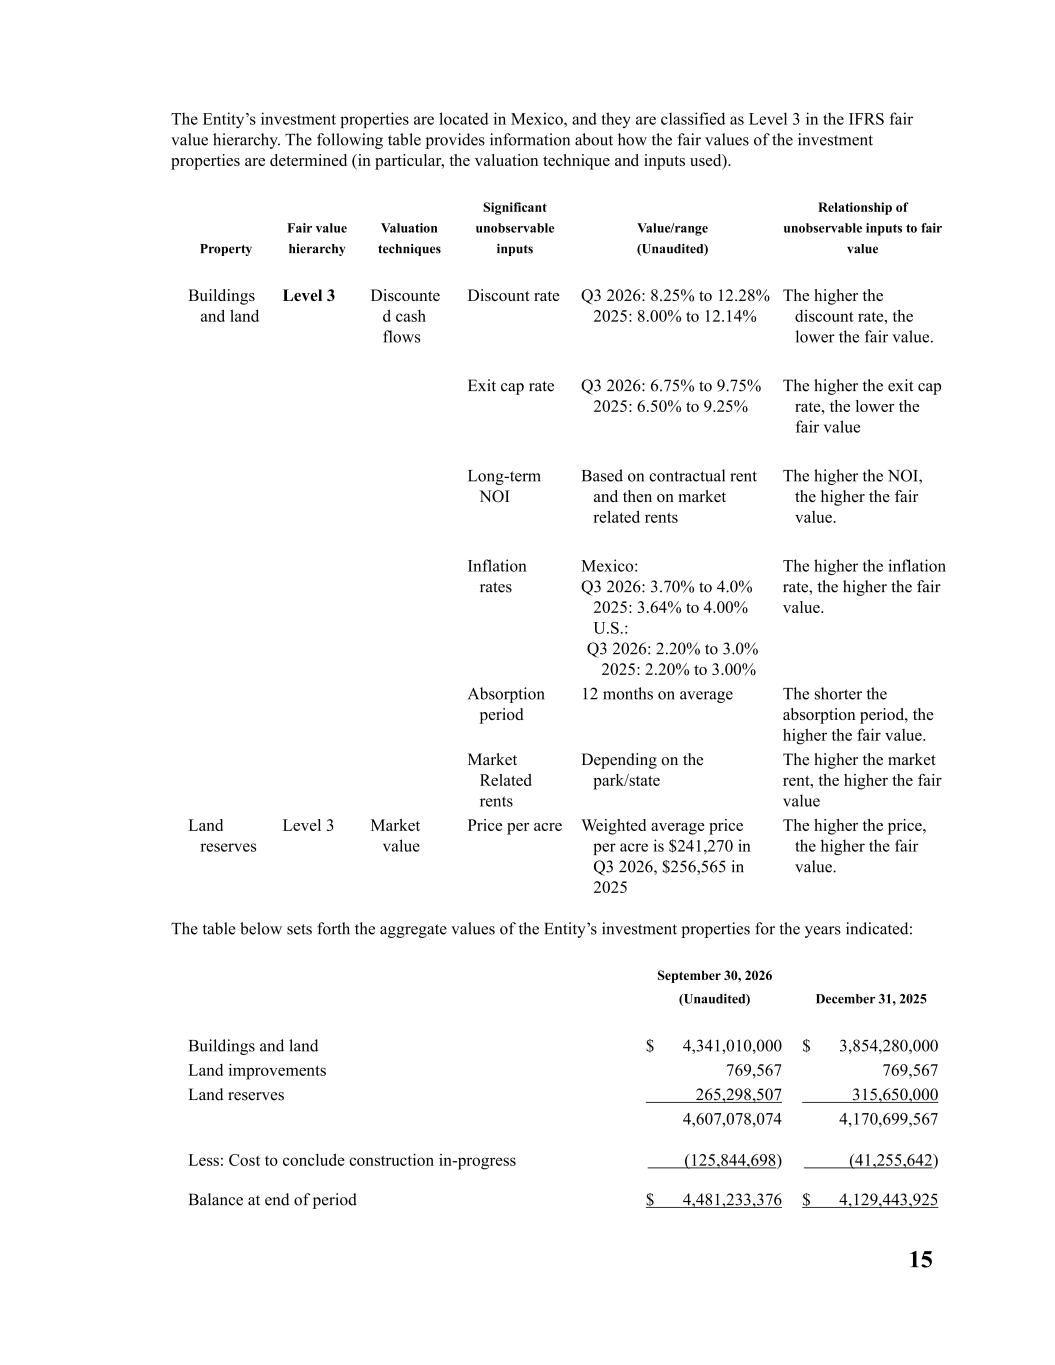
15 The Entity’s investment properties are located in Mexico, and they are classified as Level 3 in the IFRS fair value hierarchy. The following table provides information about how the fair values of the investment properties are determined (in particular, the valuation technique and inputs used). Property Fair value hierarchy Valuation techniques Significant unobservable inputs Value/range (Unaudited) Relationship of unobservable inputs to fair value Buildings and land Level 3 Discounte d cash flows Discount rate Q3 2026: 8.25% to 12.28% 2025: 8.00% to 12.14% The higher the discount rate, the lower the fair value. Exit cap rate Q3 2026: 6.75% to 9.75% 2025: 6.50% to 9.25% The higher the exit cap rate, the lower the fair value Long-term NOI Based on contractual rent and then on market related rents The higher the NOI, the higher the fair value. Inflation rates Mexico: Q3 2026: 3.70% to 4.0% 2025: 3.64% to 4.00% U.S.: Q3 2026: 2.20% to 3.0% 2025: 2.20% to 3.00% The higher the inflation rate, the higher the fair value. Absorption period 12 months on average The shorter the absorption period, the higher the fair value. Market Related rents Depending on the park/state The higher the market rent, the higher the fair value Land reserves Level 3 Market value Price per acre Weighted average price per acre is $241,270 in Q3 2026, $256,565 in 2025 The higher the price, the higher the fair value. The table below sets forth the aggregate values of the Entity’s investment properties for the years indicated: September 30, 2026 (Unaudited) December 31, 2025 Buildings and land $ 4,341,010,000 $ 3,854,280,000 Land improvements 769,567 769,567 Land reserves 265,298,507 315,650,000 4,607,078,074 4,170,699,567 Less: Cost to conclude construction in-progress (125,844,698) (41,255,642) Balance at end of period $ 4,481,233,376 $ 4,129,443,925
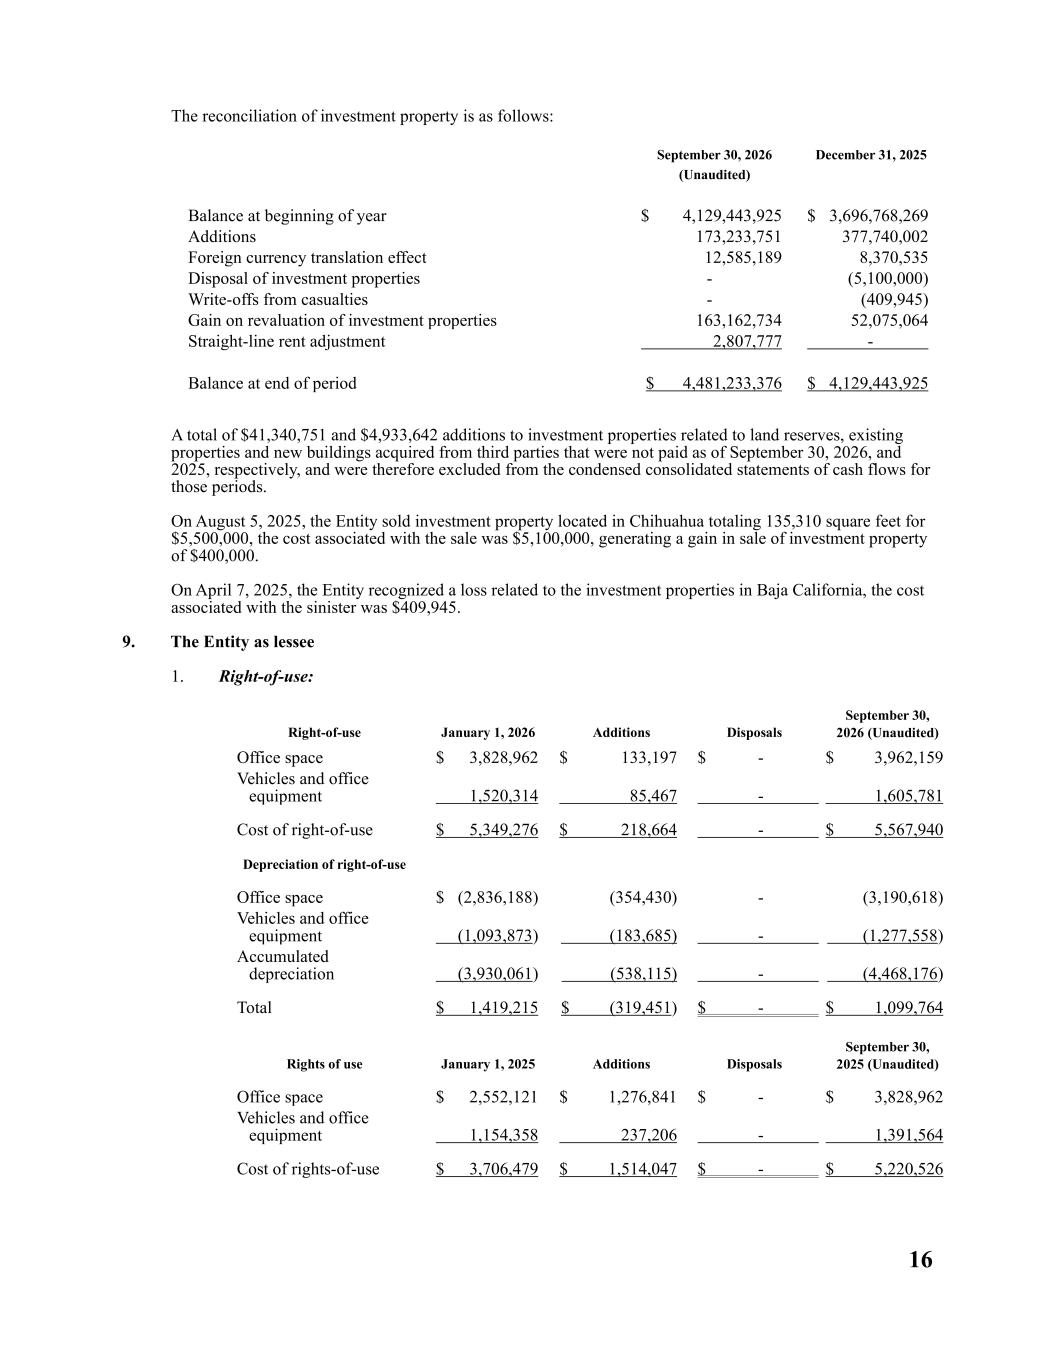
16 The reconciliation of investment property is as follows: September 30, 2026 (Unaudited) December 31, 2025 Balance at beginning of year $ 4,129,443,925 $ 3,696,768,269 Additions 173,233,751 377,740,002 Foreign currency translation effect 12,585,189 8,370,535 Disposal of investment properties - (5,100,000) Write-offs from casualties - (409,945) Gain on revaluation of investment properties 163,162,734 52,075,064 Straight-line rent adjustment 2,807,777 - Balance at end of period $ 4,481,233,376 $ 4,129,443,925 A total of $41,340,751 and $4,933,642 additions to investment properties related to land reserves, existing properties and new buildings acquired from third parties that were not paid as of September 30, 2026, and 2025, respectively, and were therefore excluded from the condensed consolidated statements of cash flows for those periods. On August 5, 2025, the Entity sold investment property located in Chihuahua totaling 135,310 square feet for $5,500,000, the cost associated with the sale was $5,100,000, generating a gain in sale of investment property of $400,000. On April 7, 2025, the Entity recognized a loss related to the investment properties in Baja California, the cost associated with the sinister was $409,945. 9. The Entity as lessee 1. Right-of-use: Right-of-use January 1, 2026 Additions Disposals September 30, 2026 (Unaudited) Office space $ 3,828,962 $ 133,197 $ - $ 3,962,159 Vehicles and office equipment 1,520,314 85,467 - 1,605,781 Cost of right-of-use $ 5,349,276 $ 218,664 - $ 5,567,940 Depreciation of right-of-use Office space $ (2,836,188) (354,430) - (3,190,618) Vehicles and office equipment (1,093,873) (183,685) - (1,277,558) Accumulated depreciation (3,930,061) (538,115) - (4,468,176) Total $ 1,419,215 $ (319,451) $ - $ 1,099,764 Rights of use January 1, 2025 Additions Disposals September 30, 2025 (Unaudited) Office space $ 2,552,121 $ 1,276,841 $ - $ 3,828,962 Vehicles and office equipment 1,154,358 237,206 - 1,391,564 Cost of rights-of-use $ 3,706,479 $ 1,514,047 $ - $ 5,220,526
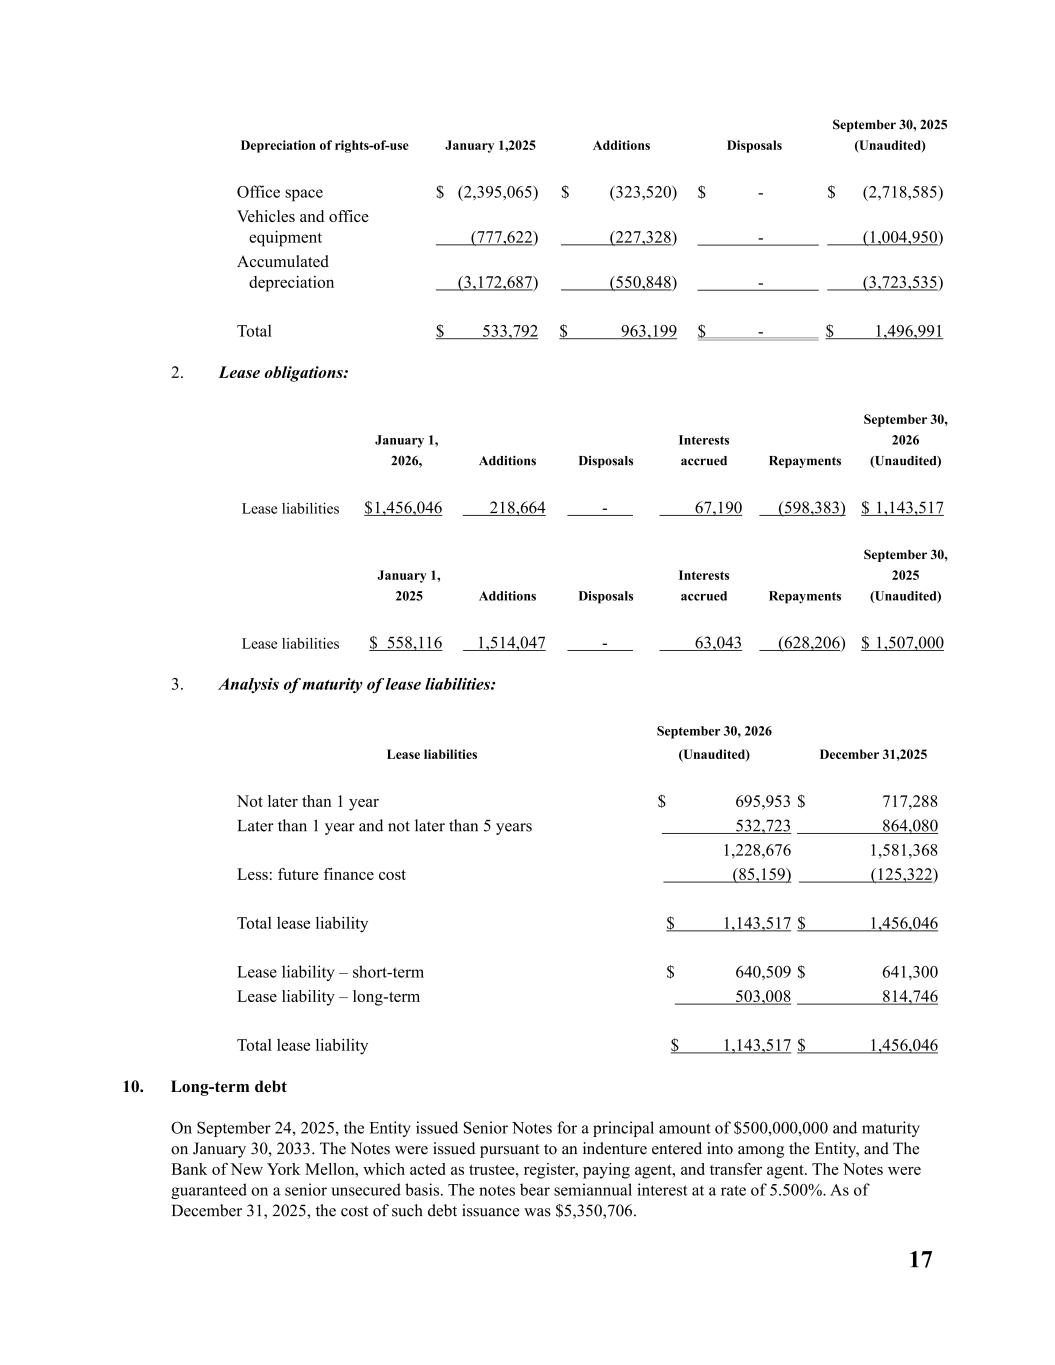
17 Depreciation of rights-of-use January 1,2025 Additions Disposals September 30, 2025 (Unaudited) Office space $ (2,395,065) $ (323,520) $ - $ (2,718,585) Vehicles and office equipment (777,622) (227,328) - (1,004,950) Accumulated depreciation (3,172,687) (550,848) - (3,723,535) Total $ 533,792 $ 963,199 $ - $ 1,496,991 2. Lease obligations: January 1, 2026, Additions Disposals Interests accrued Repayments September 30, 2026 (Unaudited) Lease liabilities $ 1,456,046 218,664 - 67,190 (598,383) $ 1,143,517 January 1, 2025 Additions Disposals Interests accrued Repayments September 30, 2025 (Unaudited) Lease liabilities $ 558,116 1,514,047 - 63,043 (628,206) $ 1,507,000 3. Analysis of maturity of lease liabilities: Lease liabilities September 30, 2026 (Unaudited) December 31,2025 Not later than 1 year $ 695,953 $ 717,288 Later than 1 year and not later than 5 years 532,723 864,080 1,228,676 1,581,368 Less: future finance cost (85,159) (125,322) Total lease liability $ 1,143,517 $ 1,456,046 Lease liability – short-term $ 640,509 $ 641,300 Lease liability – long-term 503,008 814,746 Total lease liability $ 1,143,517 $ 1,456,046 10. Long-term debt On September 24, 2025, the Entity issued Senior Notes for a principal amount of $500,000,000 and maturity on January 30, 2033. The Notes were issued pursuant to an indenture entered into among the Entity, and The Bank of New York Mellon, which acted as trustee, register, paying agent, and transfer agent. The Notes were guaranteed on a senior unsecured basis. The notes bear semiannual interest at a rate of 5.500%. As of December 31, 2025, the cost of such debt issuance was $5,350,706.
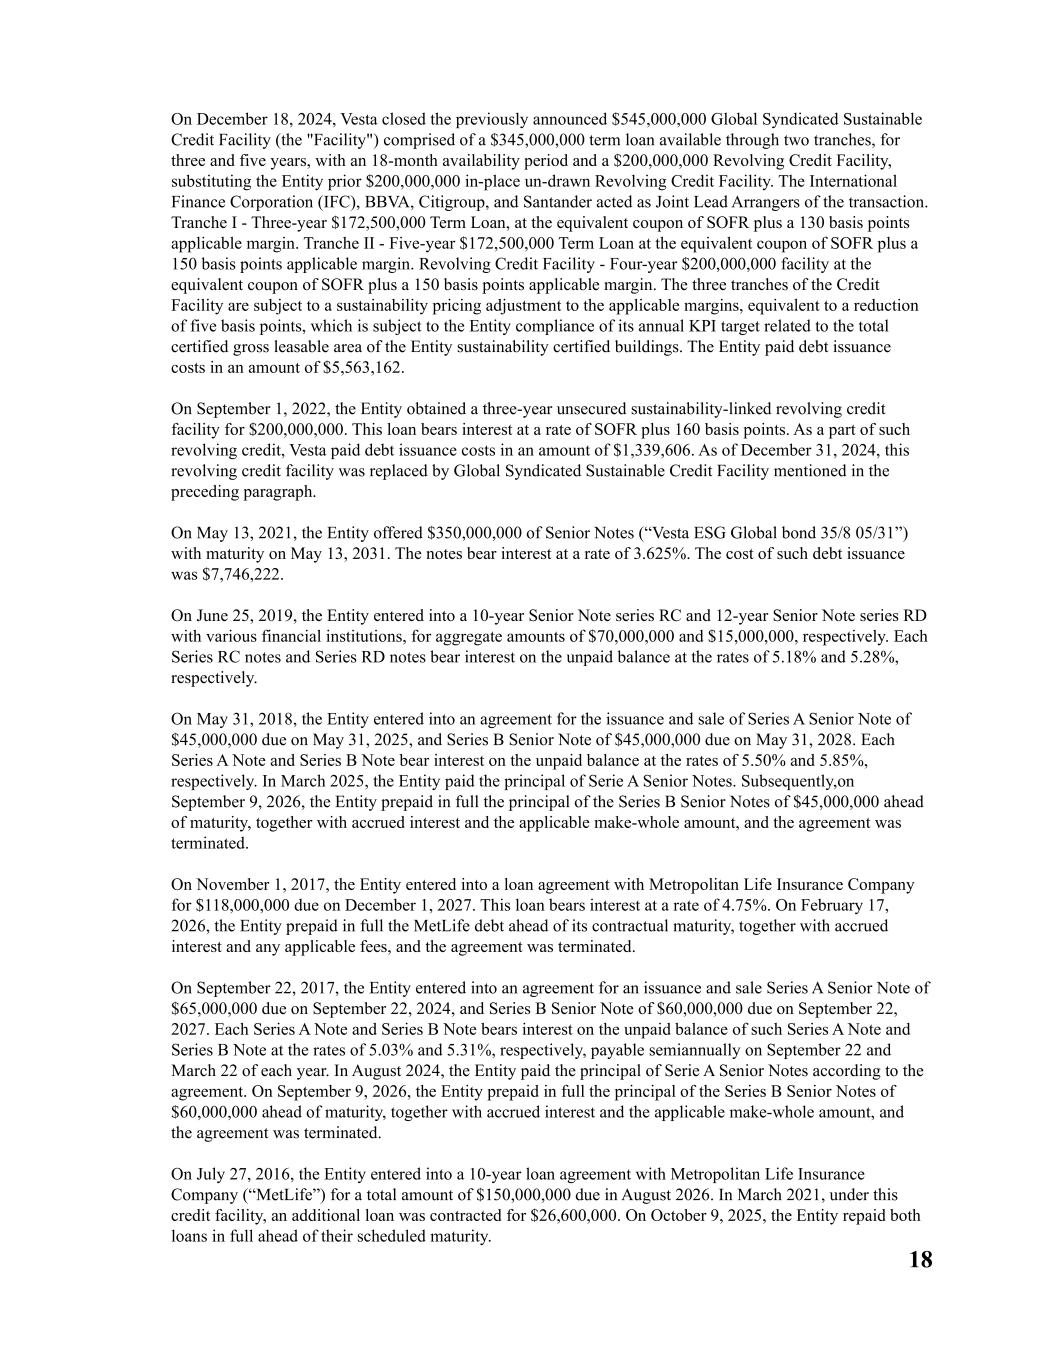
18 On December 18, 2024, Vesta closed the previously announced $545,000,000 Global Syndicated Sustainable Credit Facility (the "Facility") comprised of a $345,000,000 term loan available through two tranches, for three and five years, with an 18-month availability period and a $200,000,000 Revolving Credit Facility, substituting the Entity prior $200,000,000 in-place un-drawn Revolving Credit Facility. The International Finance Corporation (IFC), BBVA, Citigroup, and Santander acted as Joint Lead Arrangers of the transaction. Tranche I - Three-year $172,500,000 Term Loan, at the equivalent coupon of SOFR plus a 130 basis points applicable margin. Tranche II - Five-year $172,500,000 Term Loan at the equivalent coupon of SOFR plus a 150 basis points applicable margin. Revolving Credit Facility - Four-year $200,000,000 facility at the equivalent coupon of SOFR plus a 150 basis points applicable margin. The three tranches of the Credit Facility are subject to a sustainability pricing adjustment to the applicable margins, equivalent to a reduction of five basis points, which is subject to the Entity compliance of its annual KPI target related to the total certified gross leasable area of the Entity sustainability certified buildings. The Entity paid debt issuance costs in an amount of $5,563,162. On September 1, 2022, the Entity obtained a three-year unsecured sustainability-linked revolving credit facility for $200,000,000. This loan bears interest at a rate of SOFR plus 160 basis points. As a part of such revolving credit, Vesta paid debt issuance costs in an amount of $1,339,606. As of December 31, 2024, this revolving credit facility was replaced by Global Syndicated Sustainable Credit Facility mentioned in the preceding paragraph. On May 13, 2021, the Entity offered $350,000,000 of Senior Notes (“Vesta ESG Global bond 35/8 05/31”) with maturity on May 13, 2031. The notes bear interest at a rate of 3.625%. The cost of such debt issuance was $7,746,222. On June 25, 2019, the Entity entered into a 10-year Senior Note series RC and 12-year Senior Note series RD with various financial institutions, for aggregate amounts of $70,000,000 and $15,000,000, respectively. Each Series RC notes and Series RD notes bear interest on the unpaid balance at the rates of 5.18% and 5.28%, respectively. On May 31, 2018, the Entity entered into an agreement for the issuance and sale of Series A Senior Note of $45,000,000 due on May 31, 2025, and Series B Senior Note of $45,000,000 due on May 31, 2028. Each Series A Note and Series B Note bear interest on the unpaid balance at the rates of 5.50% and 5.85%, respectively. In March 2025, the Entity paid the principal of Serie A Senior Notes. Subsequently,on September 9, 2026, the Entity prepaid in full the principal of the Series B Senior Notes of $45,000,000 ahead of maturity, together with accrued interest and the applicable make-whole amount, and the agreement was terminated. On November 1, 2017, the Entity entered into a loan agreement with Metropolitan Life Insurance Company for $118,000,000 due on December 1, 2027. This loan bears interest at a rate of 4.75%. On February 17, 2026, the Entity prepaid in full the MetLife debt ahead of its contractual maturity, together with accrued interest and any applicable fees, and the agreement was terminated. On September 22, 2017, the Entity entered into an agreement for an issuance and sale Series A Senior Note of $65,000,000 due on September 22, 2024, and Series B Senior Note of $60,000,000 due on September 22, 2027. Each Series A Note and Series B Note bears interest on the unpaid balance of such Series A Note and Series B Note at the rates of 5.03% and 5.31%, respectively, payable semiannually on September 22 and March 22 of each year. In August 2024, the Entity paid the principal of Serie A Senior Notes according to the agreement. On September 9, 2026, the Entity prepaid in full the principal of the Series B Senior Notes of $60,000,000 ahead of maturity, together with accrued interest and the applicable make-whole amount, and the agreement was terminated. On July 27, 2016, the Entity entered into a 10-year loan agreement with Metropolitan Life Insurance Company (“MetLife”) for a total amount of $150,000,000 due in August 2026. In March 2021, under this credit facility, an additional loan was contracted for $26,600,000. On October 9, 2025, the Entity repaid both loans in full ahead of their scheduled maturity.
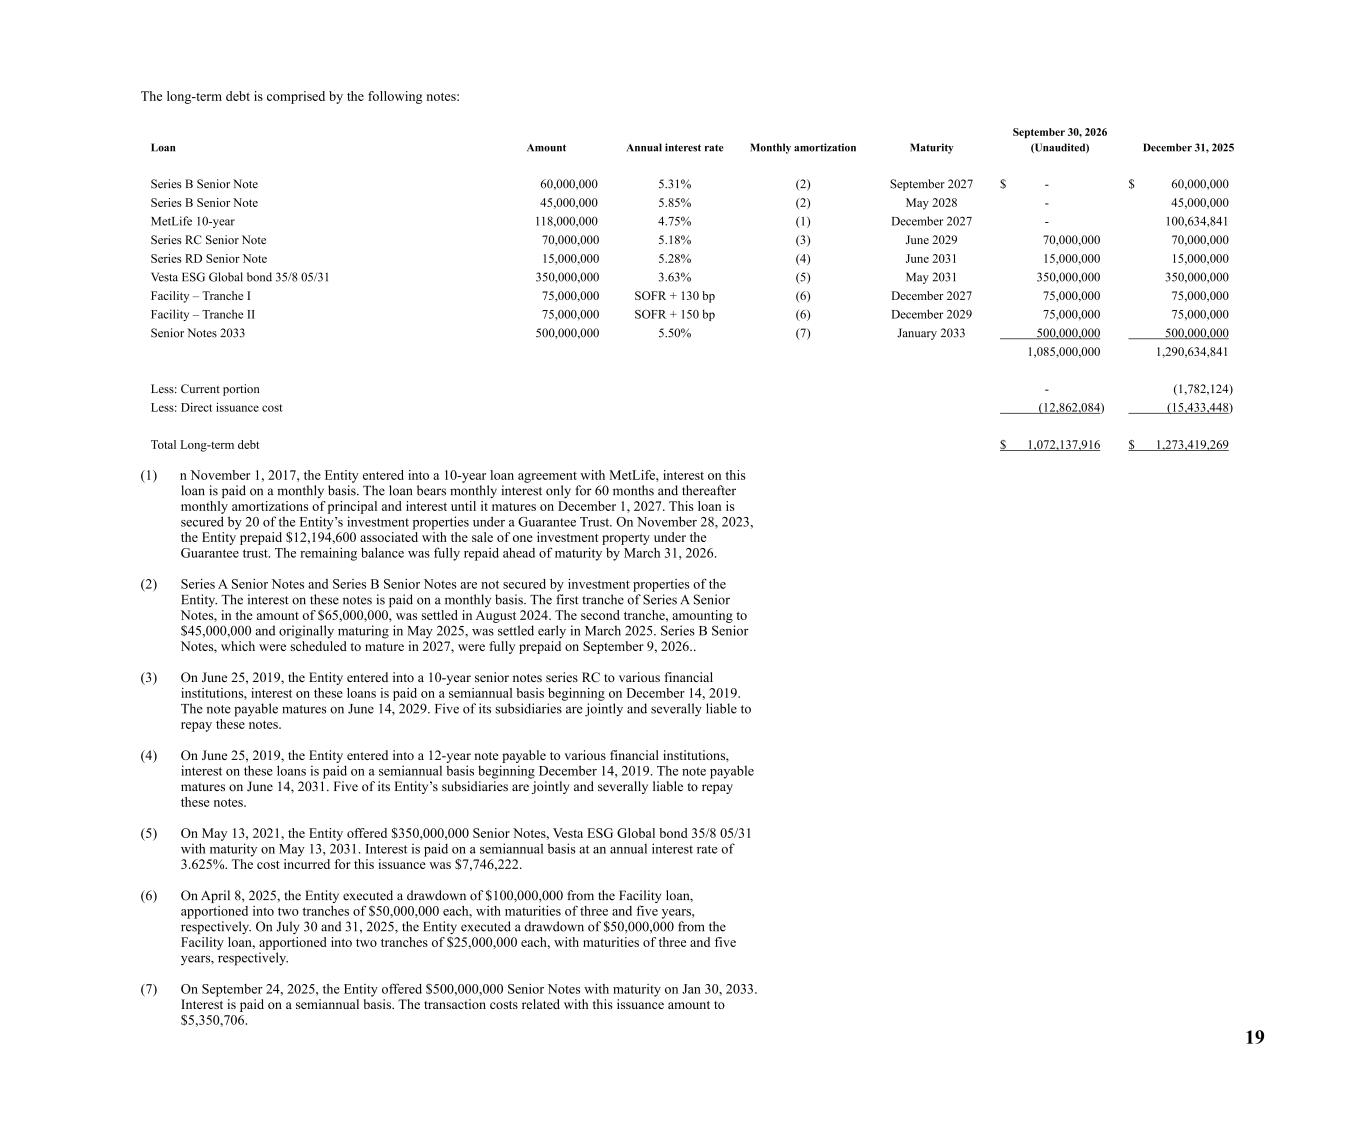
19 The long-term debt is comprised by the following notes: Loan Amount Annual interest rate Monthly amortization Maturity September 30, 2026 (Unaudited) December 31, 2025 Series B Senior Note 60,000,000 5.31% (2) September 2027 $ - $ 60,000,000 Series B Senior Note 45,000,000 5.85% (2) May 2028 - 45,000,000 MetLife 10-year 118,000,000 4.75% (1) December 2027 - 100,634,841 Series RC Senior Note 70,000,000 5.18% (3) June 2029 70,000,000 70,000,000 Series RD Senior Note 15,000,000 5.28% (4) June 2031 15,000,000 15,000,000 Vesta ESG Global bond 35/8 05/31 350,000,000 3.63% (5) May 2031 350,000,000 350,000,000 Facility – Tranche I 75,000,000 SOFR + 130 bp (6) December 2027 75,000,000 75,000,000 Facility – Tranche II 75,000,000 SOFR + 150 bp (6) December 2029 75,000,000 75,000,000 Senior Notes 2033 500,000,000 5.50% (7) January 2033 500,000,000 500,000,000 1,085,000,000 1,290,634,841 Less: Current portion - (1,782,124) Less: Direct issuance cost (12,862,084) (15,433,448) Total Long-term debt $ 1,072,137,916 $ 1,273,419,269 (1) n November 1, 2017, the Entity entered into a 10-year loan agreement with MetLife, interest on this loan is paid on a monthly basis. The loan bears monthly interest only for 60 months and thereafter monthly amortizations of principal and interest until it matures on December 1, 2027. This loan is secured by 20 of the Entity’s investment properties under a Guarantee Trust. On November 28, 2023, the Entity prepaid $12,194,600 associated with the sale of one investment property under the Guarantee trust. The remaining balance was fully repaid ahead of maturity by March 31, 2026. (2) Series A Senior Notes and Series B Senior Notes are not secured by investment properties of the Entity. The interest on these notes is paid on a monthly basis. The first tranche of Series A Senior Notes, in the amount of $65,000,000, was settled in August 2024. The second tranche, amounting to $45,000,000 and originally maturing in May 2025, was settled early in March 2025. Series B Senior Notes, which were scheduled to mature in 2027, were fully prepaid on September 9, 2026.. (3) On June 25, 2019, the Entity entered into a 10-year senior notes series RC to various financial institutions, interest on these loans is paid on a semiannual basis beginning on December 14, 2019. The note payable matures on June 14, 2029. Five of its subsidiaries are jointly and severally liable to repay these notes. (4) On June 25, 2019, the Entity entered into a 12-year note payable to various financial institutions, interest on these loans is paid on a semiannual basis beginning December 14, 2019. The note payable matures on June 14, 2031. Five of its Entity’s subsidiaries are jointly and severally liable to repay these notes. (5) On May 13, 2021, the Entity offered $350,000,000 Senior Notes, Vesta ESG Global bond 35/8 05/31 with maturity on May 13, 2031. Interest is paid on a semiannual basis at an annual interest rate of 3.625%. The cost incurred for this issuance was $7,746,222. (6) On April 8, 2025, the Entity executed a drawdown of $100,000,000 from the Facility loan, apportioned into two tranches of $50,000,000 each, with maturities of three and five years, respectively. On July 30 and 31, 2025, the Entity executed a drawdown of $50,000,000 from the Facility loan, apportioned into two tranches of $25,000,000 each, with maturities of three and five years, respectively. (7) On September 24, 2025, the Entity offered $500,000,000 Senior Notes with maturity on Jan 30, 2033. Interest is paid on a semiannual basis. The transaction costs related with this issuance amount to $5,350,706.
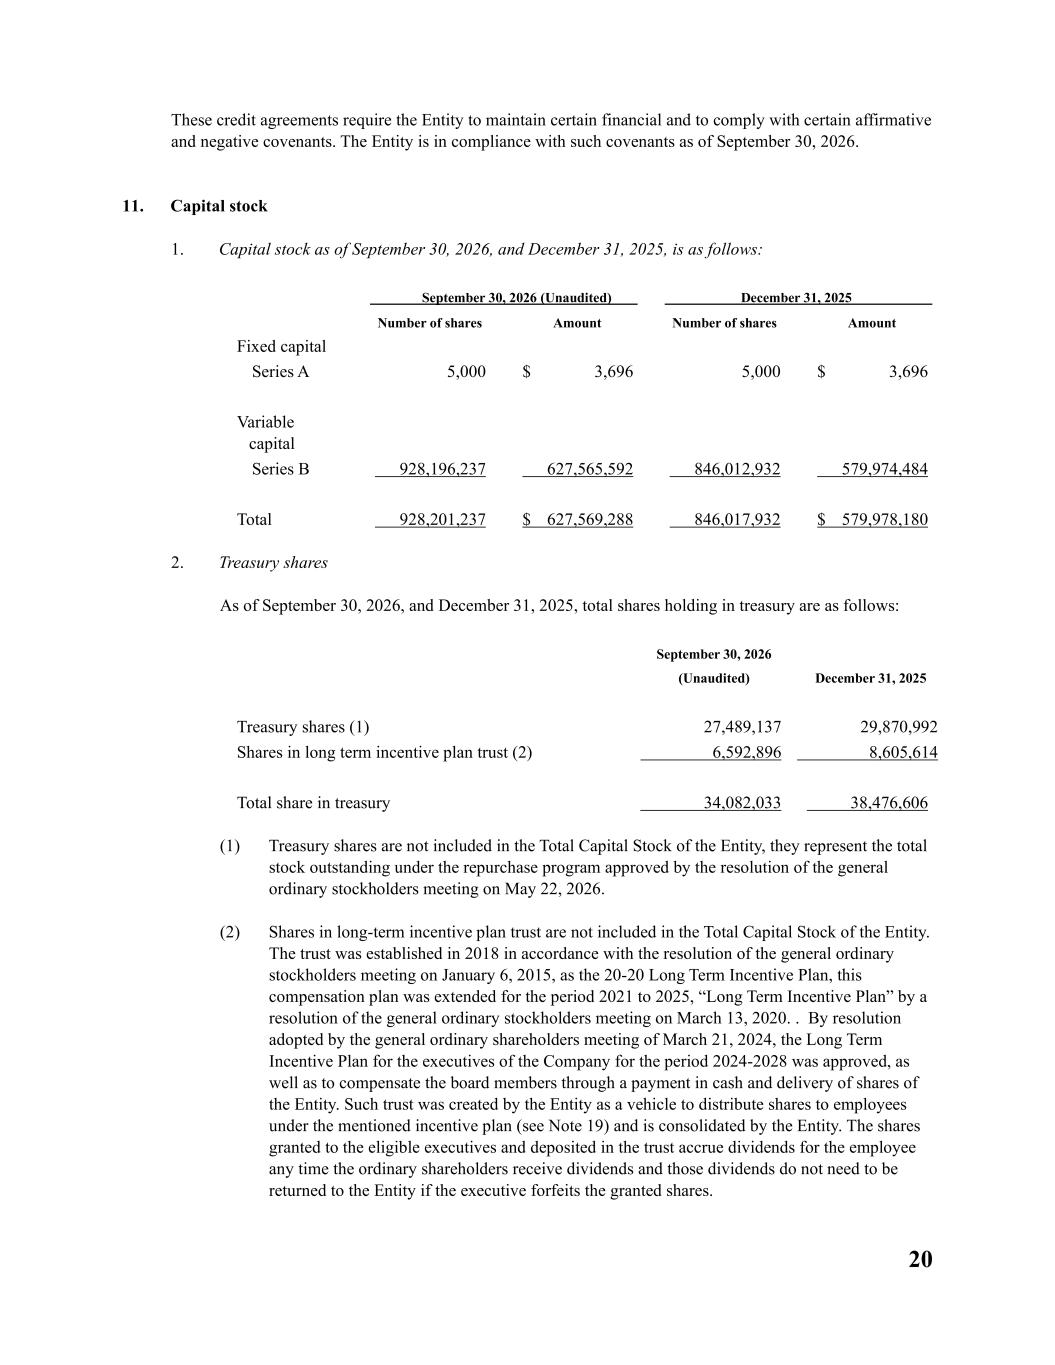
20 These credit agreements require the Entity to maintain certain financial and to comply with certain affirmative and negative covenants. The Entity is in compliance with such covenants as of September 30, 2026. 11. Capital stock 1. Capital stock as of September 30, 2026, and December 31, 2025, is as follows: September 30, 2026 (Unaudited) December 31, 2025 Number of shares Amount Number of shares Amount Fixed capital Series A 5,000 $ 3,696 5,000 $ 3,696 Variable capital Series B 928,196,237 627,565,592 846,012,932 579,974,484 Total 928,201,237 $ 627,569,288 846,017,932 $ 579,978,180 2. Treasury shares As of September 30, 2026, and December 31, 2025, total shares holding in treasury are as follows: September 30, 2026 (Unaudited) December 31, 2025 Treasury shares (1) 27,489,137 29,870,992 Shares in long term incentive plan trust (2) 6,592,896 8,605,614 Total share in treasury 34,082,033 38,476,606 (1) Treasury shares are not included in the Total Capital Stock of the Entity, they represent the total stock outstanding under the repurchase program approved by the resolution of the general ordinary stockholders meeting on May 22, 2026. (2) Shares in long-term incentive plan trust are not included in the Total Capital Stock of the Entity. The trust was established in 2018 in accordance with the resolution of the general ordinary stockholders meeting on January 6, 2015, as the 20-20 Long Term Incentive Plan, this compensation plan was extended for the period 2021 to 2025, “Long Term Incentive Plan” by a resolution of the general ordinary stockholders meeting on March 13, 2020. . By resolution adopted by the general ordinary shareholders meeting of March 21, 2024, the Long Term Incentive Plan for the executives of the Company for the period 2024-2028 was approved, as well as to compensate the board members through a payment in cash and delivery of shares of the Entity. Such trust was created by the Entity as a vehicle to distribute shares to employees under the mentioned incentive plan (see Note 19) and is consolidated by the Entity. The shares granted to the eligible executives and deposited in the trust accrue dividends for the employee any time the ordinary shareholders receive dividends and those dividends do not need to be returned to the Entity if the executive forfeits the granted shares.
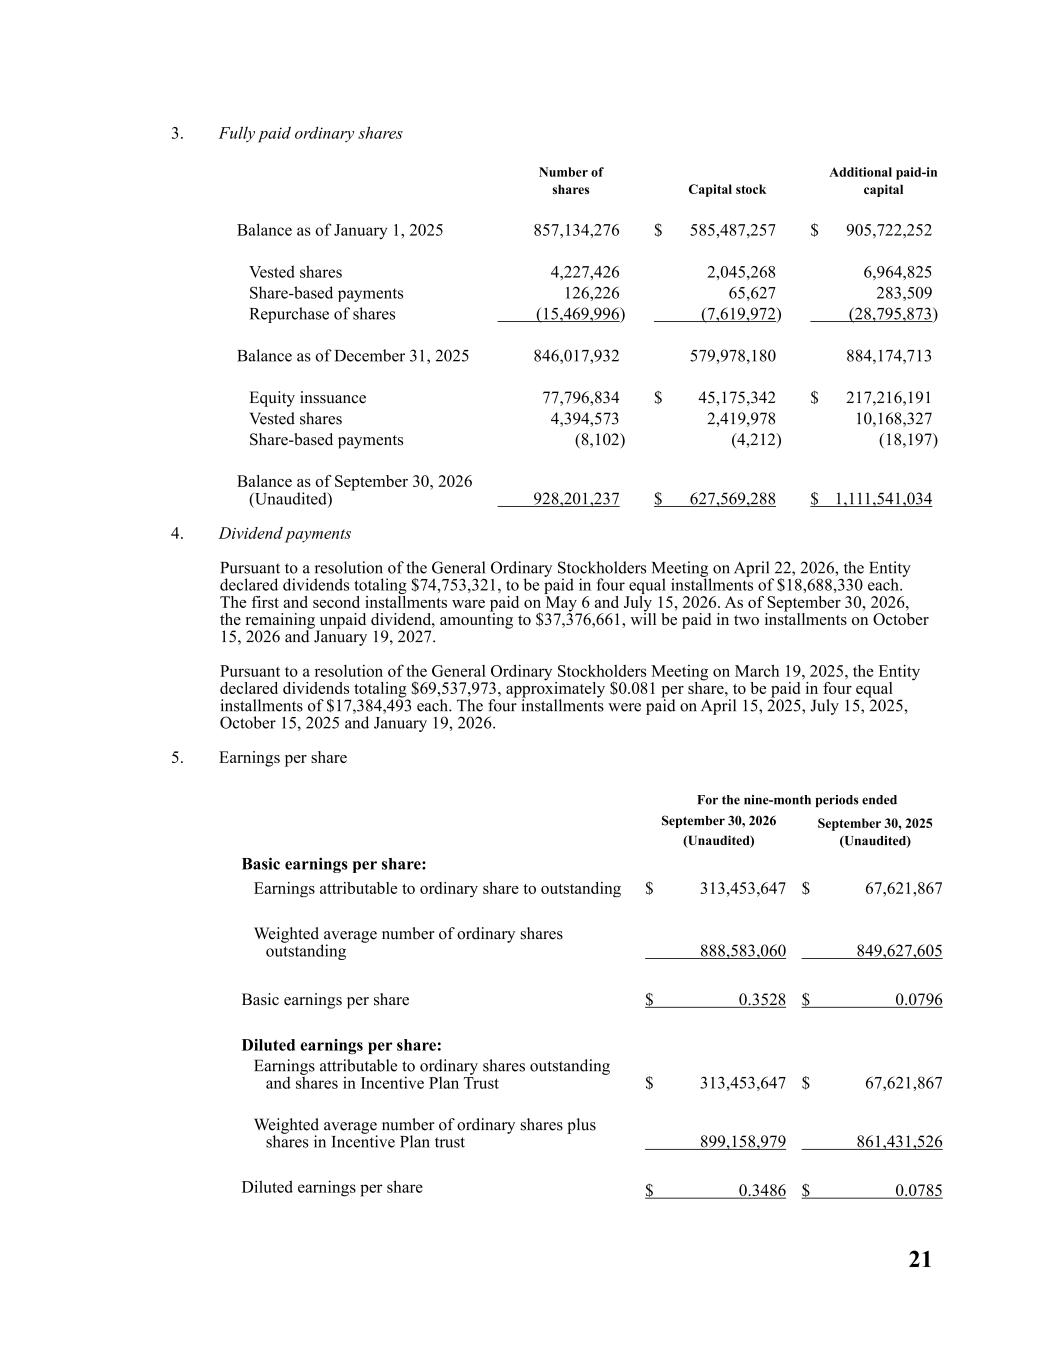
21 3. Fully paid ordinary shares Number of shares Capital stock Additional paid-in capital Balance as of January 1, 2025 857,134,276 $ 585,487,257 $ 905,722,252 Vested shares 4,227,426 2,045,268 6,964,825 Share-based payments 126,226 65,627 283,509 Repurchase of shares (15,469,996) (7,619,972) (28,795,873) Balance as of December 31, 2025 846,017,932 579,978,180 884,174,713 Equity inssuance 77,796,834 $ 45,175,342 $ 217,216,191 Vested shares 4,394,573 2,419,978 10,168,327 Share-based payments (8,102) (4,212) (18,197) Balance as of September 30, 2026 (Unaudited) 928,201,237 $ 627,569,288 $ 1,111,541,034 4. Dividend payments Pursuant to a resolution of the General Ordinary Stockholders Meeting on April 22, 2026, the Entity declared dividends totaling $74,753,321, to be paid in four equal installments of $18,688,330 each. The first and second installments ware paid on May 6 and July 15, 2026. As of September 30, 2026, the remaining unpaid dividend, amounting to $37,376,661, will be paid in two installments on October 15, 2026 and January 19, 2027. Pursuant to a resolution of the General Ordinary Stockholders Meeting on March 19, 2025, the Entity declared dividends totaling $69,537,973, approximately $0.081 per share, to be paid in four equal installments of $17,384,493 each. The four installments were paid on April 15, 2025, July 15, 2025, October 15, 2025 and January 19, 2026. 5. Earnings per share For the nine-month periods ended September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Basic earnings per share: Earnings attributable to ordinary share to outstanding $ 313,453,647 $ 67,621,867 Weighted average number of ordinary shares outstanding 888,583,060 849,627,605 Basic earnings per share $ 0.3528 $ 0.0796 Diluted earnings per share: Earnings attributable to ordinary shares outstanding and shares in Incentive Plan Trust $ 313,453,647 $ 67,621,867 Weighted average number of ordinary shares plus shares in Incentive Plan trust 899,158,979 861,431,526 Diluted earnings per share $ 0.3486 $ 0.0785
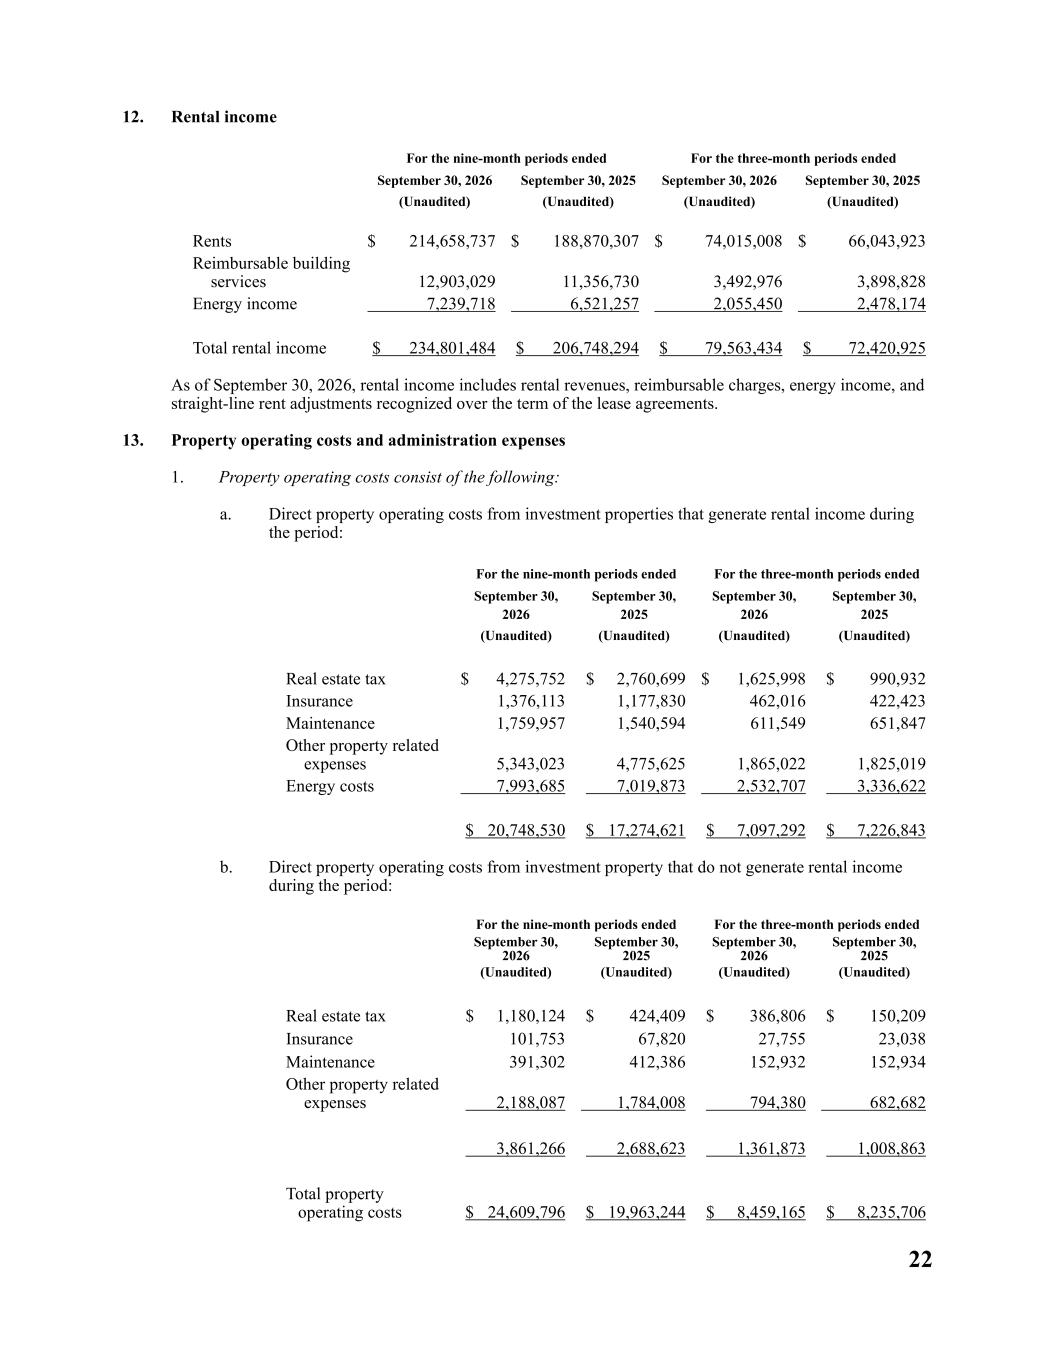
22 12. Rental income For the nine-month periods ended For the three-month periods ended September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Rents $ 214,658,737 $ 188,870,307 $ 74,015,008 $ 66,043,923 Reimbursable building services 12,903,029 11,356,730 3,492,976 3,898,828 Energy income 7,239,718 6,521,257 2,055,450 2,478,174 Total rental income $ 234,801,484 $ 206,748,294 $ 79,563,434 $ 72,420,925 As of September 30, 2026, rental income includes rental revenues, reimbursable charges, energy income, and straight-line rent adjustments recognized over the term of the lease agreements. 13. Property operating costs and administration expenses 1. Property operating costs consist of the following: a. Direct property operating costs from investment properties that generate rental income during the period: For the nine-month periods ended For the three-month periods ended September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Real estate tax $ 4,275,752 $ 2,760,699 $ 1,625,998 $ 990,932 Insurance 1,376,113 1,177,830 462,016 422,423 Maintenance 1,759,957 1,540,594 611,549 651,847 Other property related expenses 5,343,023 4,775,625 1,865,022 1,825,019 Energy costs 7,993,685 7,019,873 2,532,707 3,336,622 $ 20,748,530 $ 17,274,621 $ 7,097,292 $ 7,226,843 b. Direct property operating costs from investment property that do not generate rental income during the period: For the nine-month periods ended For the three-month periods ended September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Real estate tax $ 1,180,124 $ 424,409 $ 386,806 $ 150,209 Insurance 101,753 67,820 27,755 23,038 Maintenance 391,302 412,386 152,932 152,934 Other property related expenses 2,188,087 1,784,008 794,380 682,682 3,861,266 2,688,623 1,361,873 1,008,863 Total property operating costs $ 24,609,796 $ 19,963,244 $ 8,459,165 $ 8,235,706
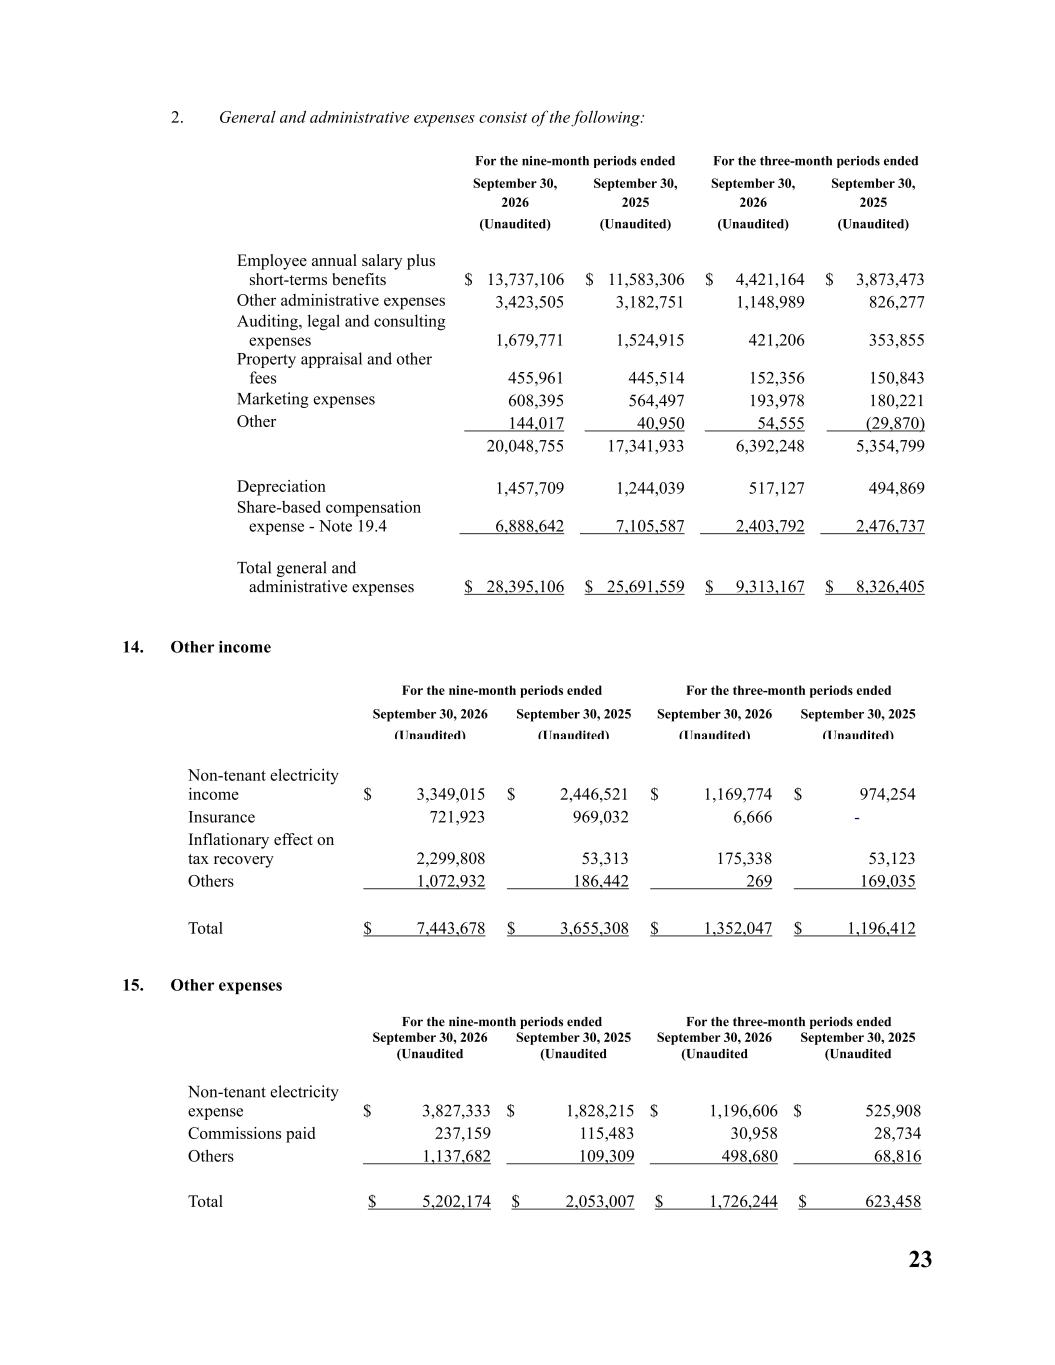
23 2. General and administrative expenses consist of the following: For the nine-month periods ended For the three-month periods ended September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Employee annual salary plus short-terms benefits $ 13,737,106 $ 11,583,306 $ 4,421,164 $ 3,873,473 Other administrative expenses 3,423,505 3,182,751 1,148,989 826,277 Auditing, legal and consulting expenses 1,679,771 1,524,915 421,206 353,855 Property appraisal and other fees 455,961 445,514 152,356 150,843 Marketing expenses 608,395 564,497 193,978 180,221 Other 144,017 40,950 54,555 (29,870) 20,048,755 17,341,933 6,392,248 5,354,799 Depreciation 1,457,709 1,244,039 517,127 494,869 Share-based compensation expense - Note 19.4 6,888,642 7,105,587 2,403,792 2,476,737 Total general and administrative expenses $ 28,395,106 $ 25,691,559 $ 9,313,167 $ 8,326,405 14. Other income For the nine-month periods ended For the three-month periods ended September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Non-tenant electricity income $ 3,349,015 $ 2,446,521 $ 1,169,774 $ 974,254 Insurance 721,923 969,032 6,666 - Inflationary effect on tax recovery 2,299,808 53,313 175,338 53,123 Others 1,072,932 186,442 269 169,035 Total $ 7,443,678 $ 3,655,308 $ 1,352,047 $ 1,196,412 15. Other expenses For the nine-month periods ended For the three-month periods ended September 30, 2026 (Unaudited September 30, 2025 (Unaudited September 30, 2026 (Unaudited September 30, 2025 (Unaudited Non-tenant electricity expense $ 3,827,333 $ 1,828,215 $ 1,196,606 $ 525,908 Commissions paid 237,159 115,483 30,958 28,734 Others 1,137,682 109,309 498,680 68,816 Total $ 5,202,174 $ 2,053,007 $ 1,726,244 $ 623,458
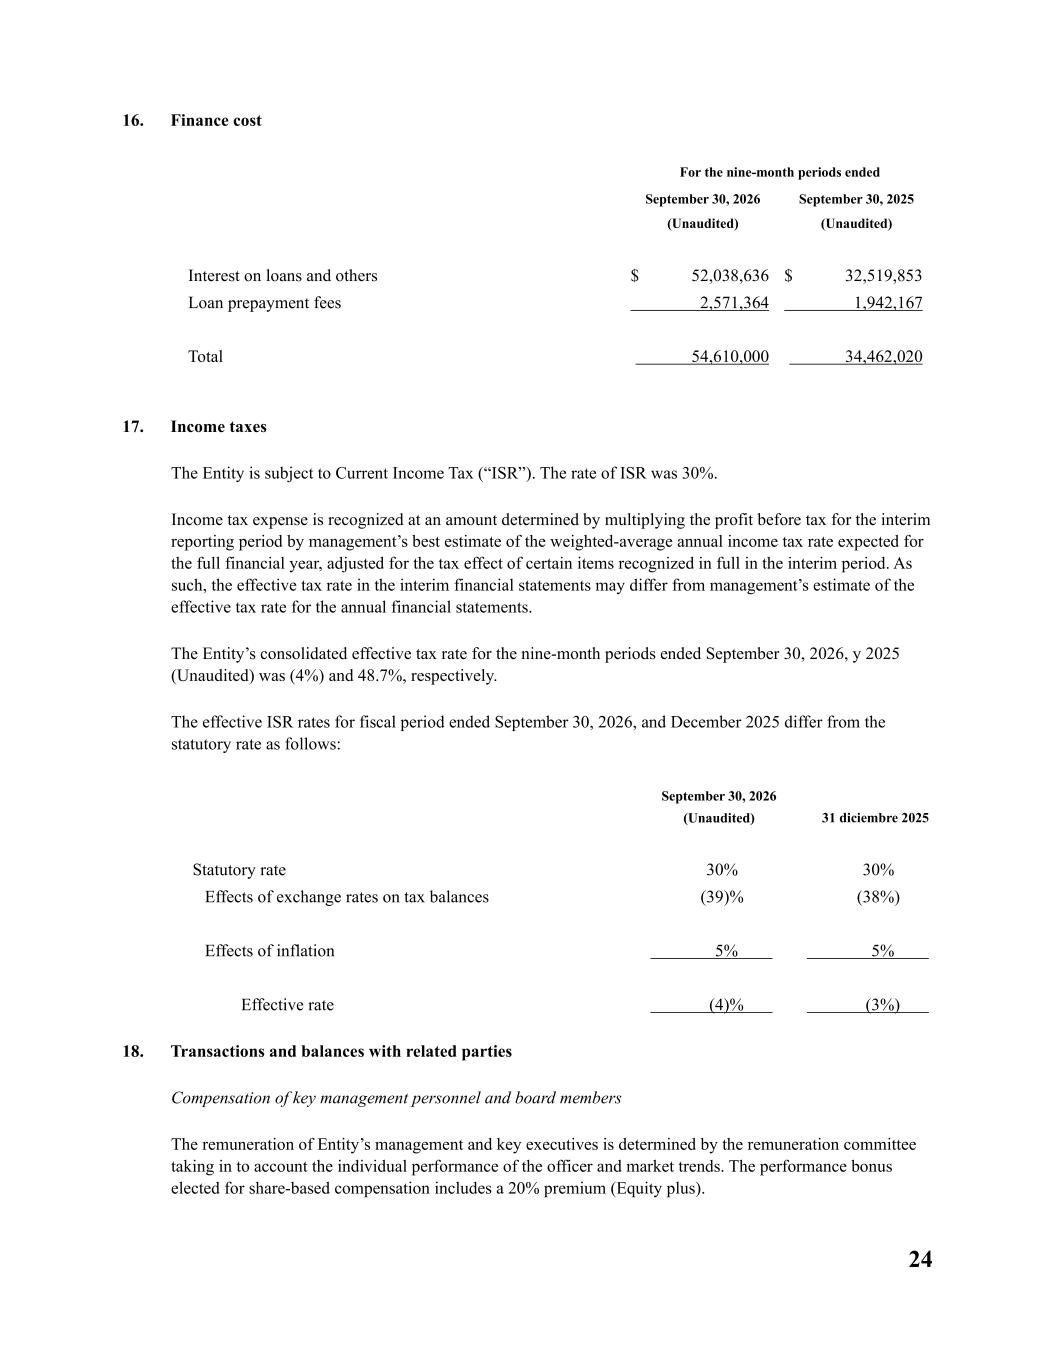
24 16. Finance cost For the nine-month periods ended September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Interest on loans and others $ 52,038,636 $ 32,519,853 Loan prepayment fees 2,571,364 1,942,167 Total 54,610,000 34,462,020 17. Income taxes The Entity is subject to Current Income Tax (“ISR”). The rate of ISR was 30%. Income tax expense is recognized at an amount determined by multiplying the profit before tax for the interim reporting period by management’s best estimate of the weighted-average annual income tax rate expected for the full financial year, adjusted for the tax effect of certain items recognized in full in the interim period. As such, the effective tax rate in the interim financial statements may differ from management’s estimate of the effective tax rate for the annual financial statements. The Entity’s consolidated effective tax rate for the nine-month periods ended September 30, 2026, y 2025 (Unaudited) was (4%) and 48.7%, respectively. The effective ISR rates for fiscal period ended September 30, 2026, and December 2025 differ from the statutory rate as follows: September 30, 2026 (Unaudited) 31 diciembre 2025 Statutory rate 30% 30% Effects of exchange rates on tax balances (39)% (38%) Effects of inflation 5% 5% Effective rate (4)% (3%) 18. Transactions and balances with related parties Compensation of key management personnel and board members The remuneration of Entity’s management and key executives is determined by the remuneration committee taking in to account the individual performance of the officer and market trends. The performance bonus elected for share-based compensation includes a 20% premium (Equity plus).
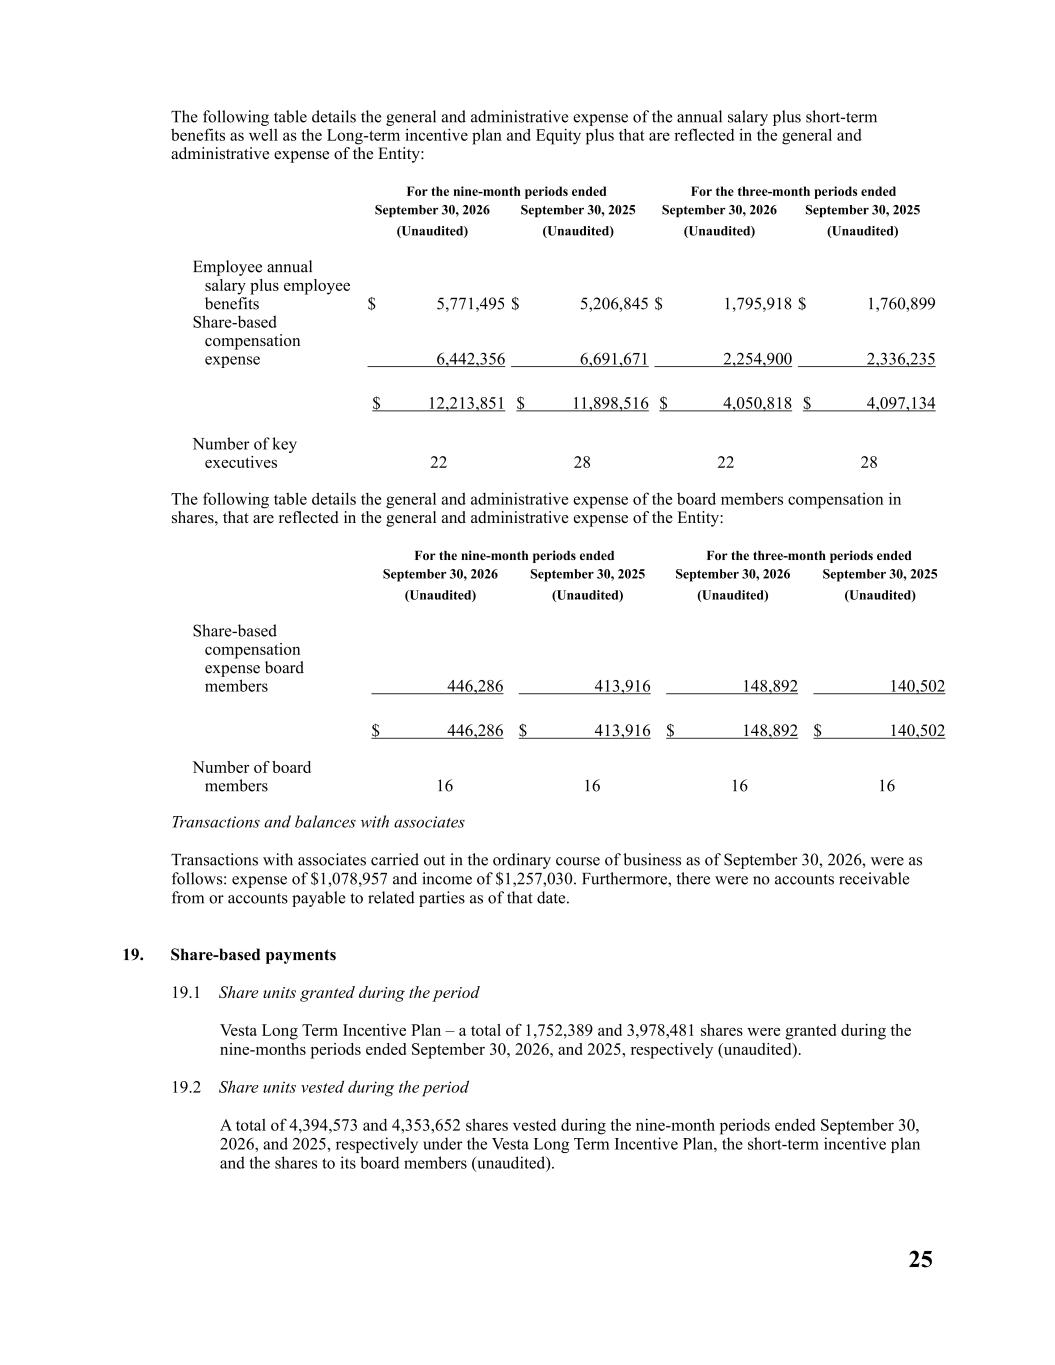
25 The following table details the general and administrative expense of the annual salary plus short-term benefits as well as the Long-term incentive plan and Equity plus that are reflected in the general and administrative expense of the Entity: For the nine-month periods ended For the three-month periods ended September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Employee annual salary plus employee benefits $ 5,771,495 $ 5,206,845 $ 1,795,918 $ 1,760,899 Share-based compensation expense 6,442,356 6,691,671 2,254,900 2,336,235 $ 12,213,851 $ 11,898,516 $ 4,050,818 $ 4,097,134 Number of key executives 22 28 22 28 The following table details the general and administrative expense of the board members compensation in shares, that are reflected in the general and administrative expense of the Entity: For the nine-month periods ended For the three-month periods ended September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Share-based compensation expense board members 446,286 413,916 148,892 140,502 $ 446,286 $ 413,916 $ 148,892 $ 140,502 Number of board members 16 16 16 16 Transactions and balances with associates Transactions with associates carried out in the ordinary course of business as of September 30, 2026, were as follows: expense of $1,078,957 and income of $1,257,030. Furthermore, there were no accounts receivable from or accounts payable to related parties as of that date. 19. Share-based payments 19.1 Share units granted during the period Vesta Long Term Incentive Plan – a total of 1,752,389 and 3,978,481 shares were granted during the nine-months periods ended September 30, 2026, and 2025, respectively (unaudited). 19.2 Share units vested during the period A total of 4,394,573 and 4,353,652 shares vested during the nine-month periods ended September 30, 2026, and 2025, respectively under the Vesta Long Term Incentive Plan, the short-term incentive plan and the shares to its board members (unaudited).
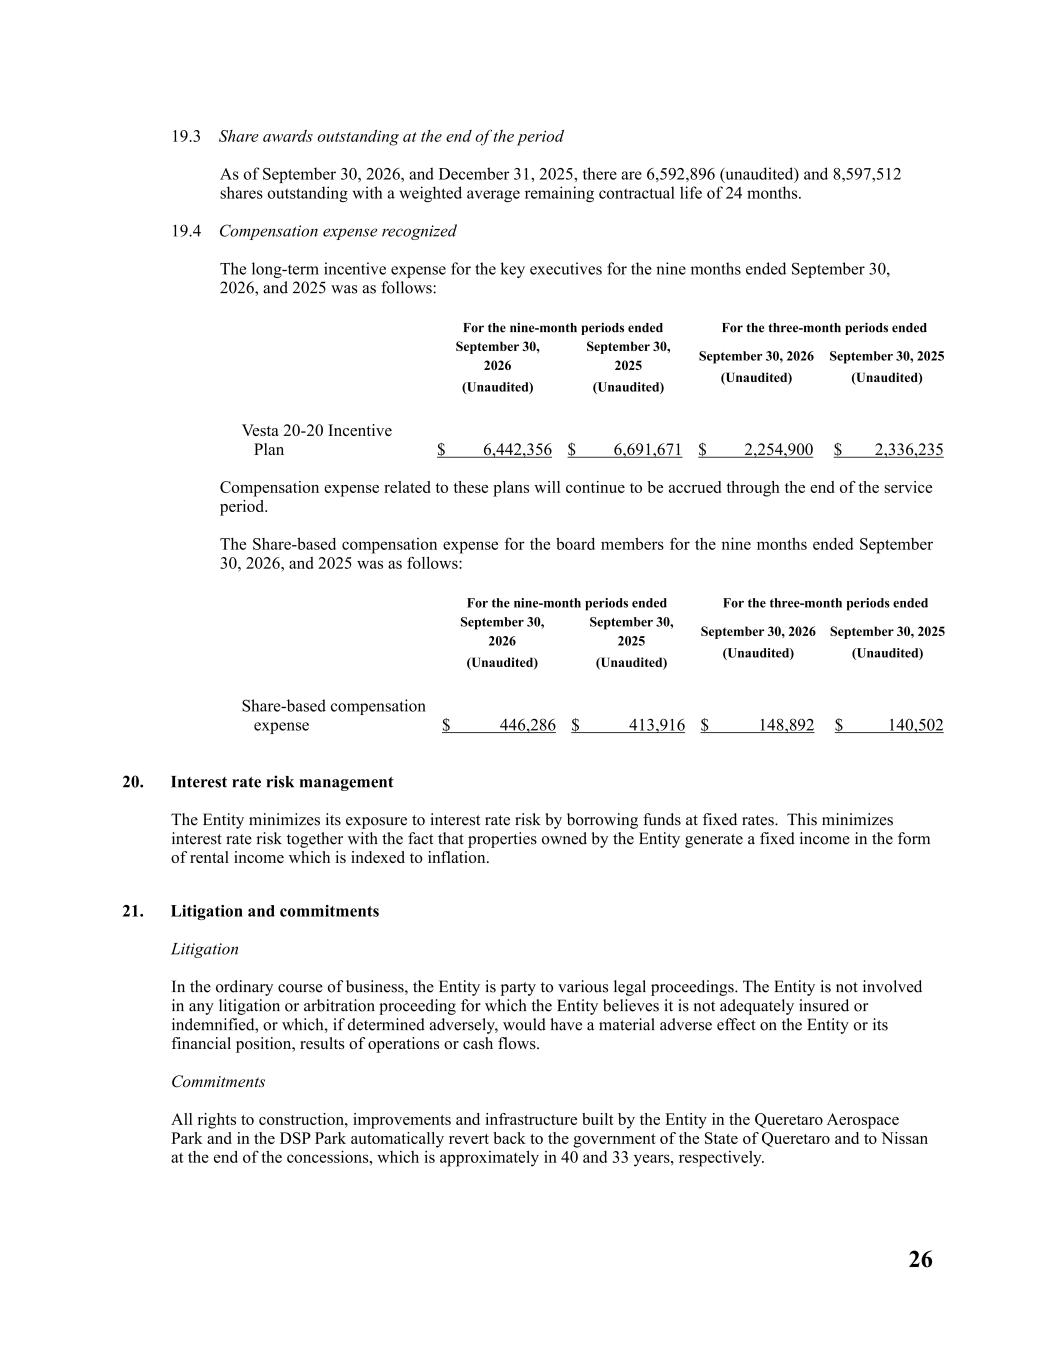
26 19.3 Share awards outstanding at the end of the period As of September 30, 2026, and December 31, 2025, there are 6,592,896 (unaudited) and 8,597,512 shares outstanding with a weighted average remaining contractual life of 24 months. 19.4 Compensation expense recognized The long-term incentive expense for the key executives for the nine months ended September 30, 2026, and 2025 was as follows: For the nine-month periods ended For the three-month periods ended September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Vesta 20-20 Incentive Plan $ 6,442,356 $ 6,691,671 $ 2,254,900 $ 2,336,235 Compensation expense related to these plans will continue to be accrued through the end of the service period. The Share-based compensation expense for the board members for the nine months ended September 30, 2026, and 2025 was as follows: For the nine-month periods ended For the three-month periods ended September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) September 30, 2026 (Unaudited) September 30, 2025 (Unaudited) Share-based compensation expense $ 446,286 $ 413,916 $ 148,892 $ 140,502 20. Interest rate risk management The Entity minimizes its exposure to interest rate risk by borrowing funds at fixed rates. This minimizes interest rate risk together with the fact that properties owned by the Entity generate a fixed income in the form of rental income which is indexed to inflation. 21. Litigation and commitments Litigation In the ordinary course of business, the Entity is party to various legal proceedings. The Entity is not involved in any litigation or arbitration proceeding for which the Entity believes it is not adequately insured or indemnified, or which, if determined adversely, would have a material adverse effect on the Entity or its financial position, results of operations or cash flows. Commitments All rights to construction, improvements and infrastructure built by the Entity in the Queretaro Aerospace Park and in the DSP Park automatically revert back to the government of the State of Queretaro and to Nissan at the end of the concessions, which is approximately in 40 and 33 years, respectively.
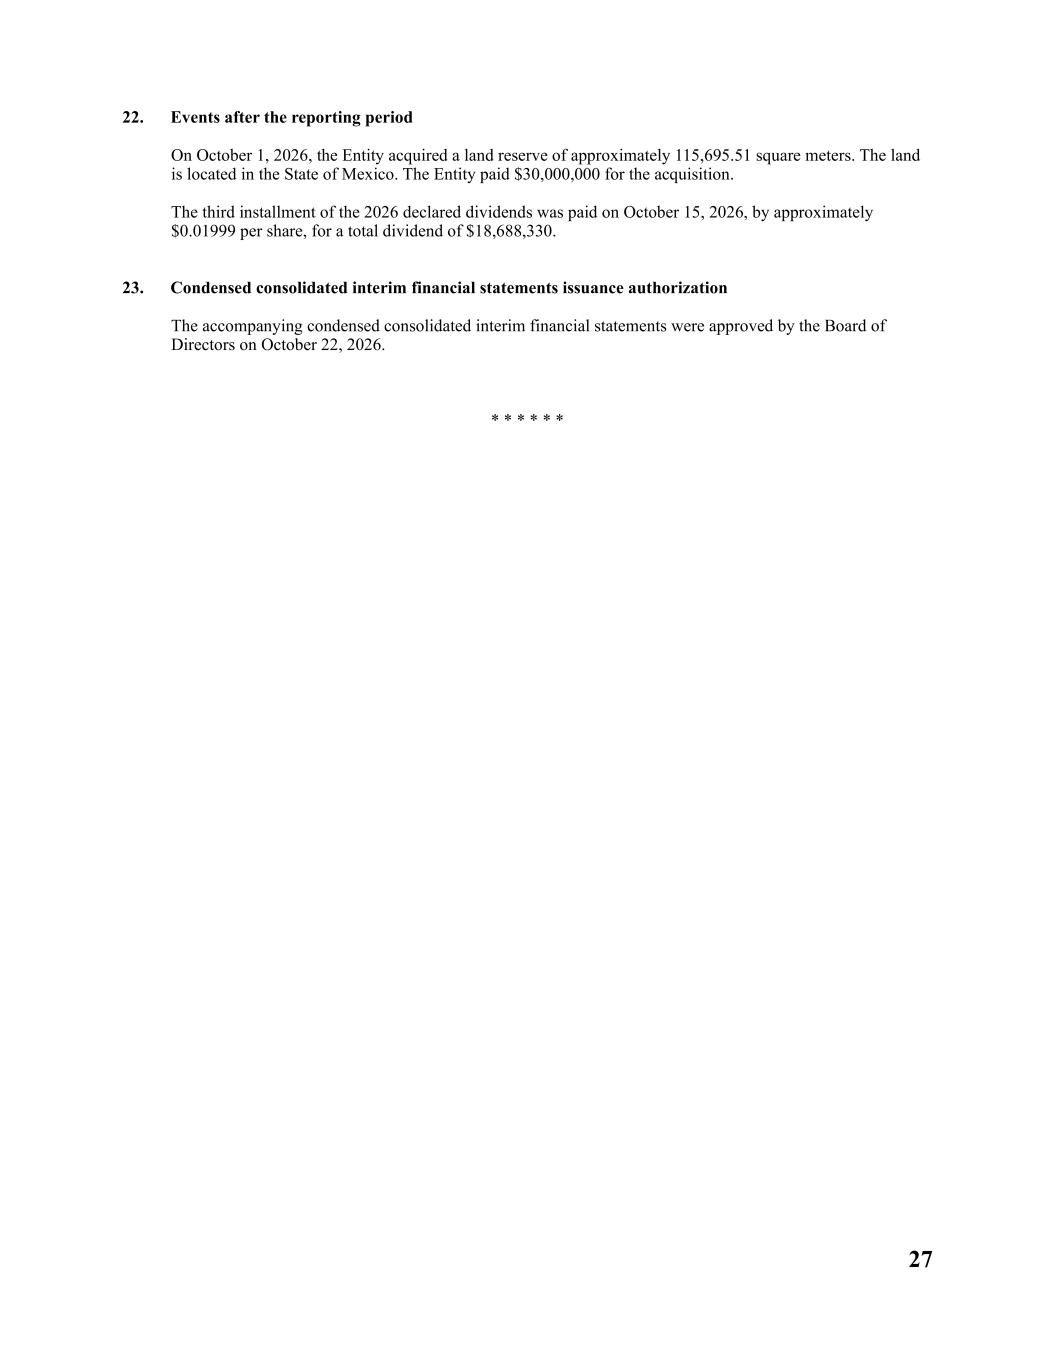
27 22. Events after the reporting period On October 1, 2026, the Entity acquired a land reserve of approximately 115,695.51 square meters. The land is located in the State of Mexico. The Entity paid $30,000,000 for the acquisition. The third installment of the 2026 declared dividends was paid on October 15, 2026, by approximately $0.01999 per share, for a total dividend of $18,688,330. 23. Condensed consolidated interim financial statements issuance authorization The accompanying condensed consolidated interim financial statements were approved by the Board of Directors on October 22, 2026. * * * * * *