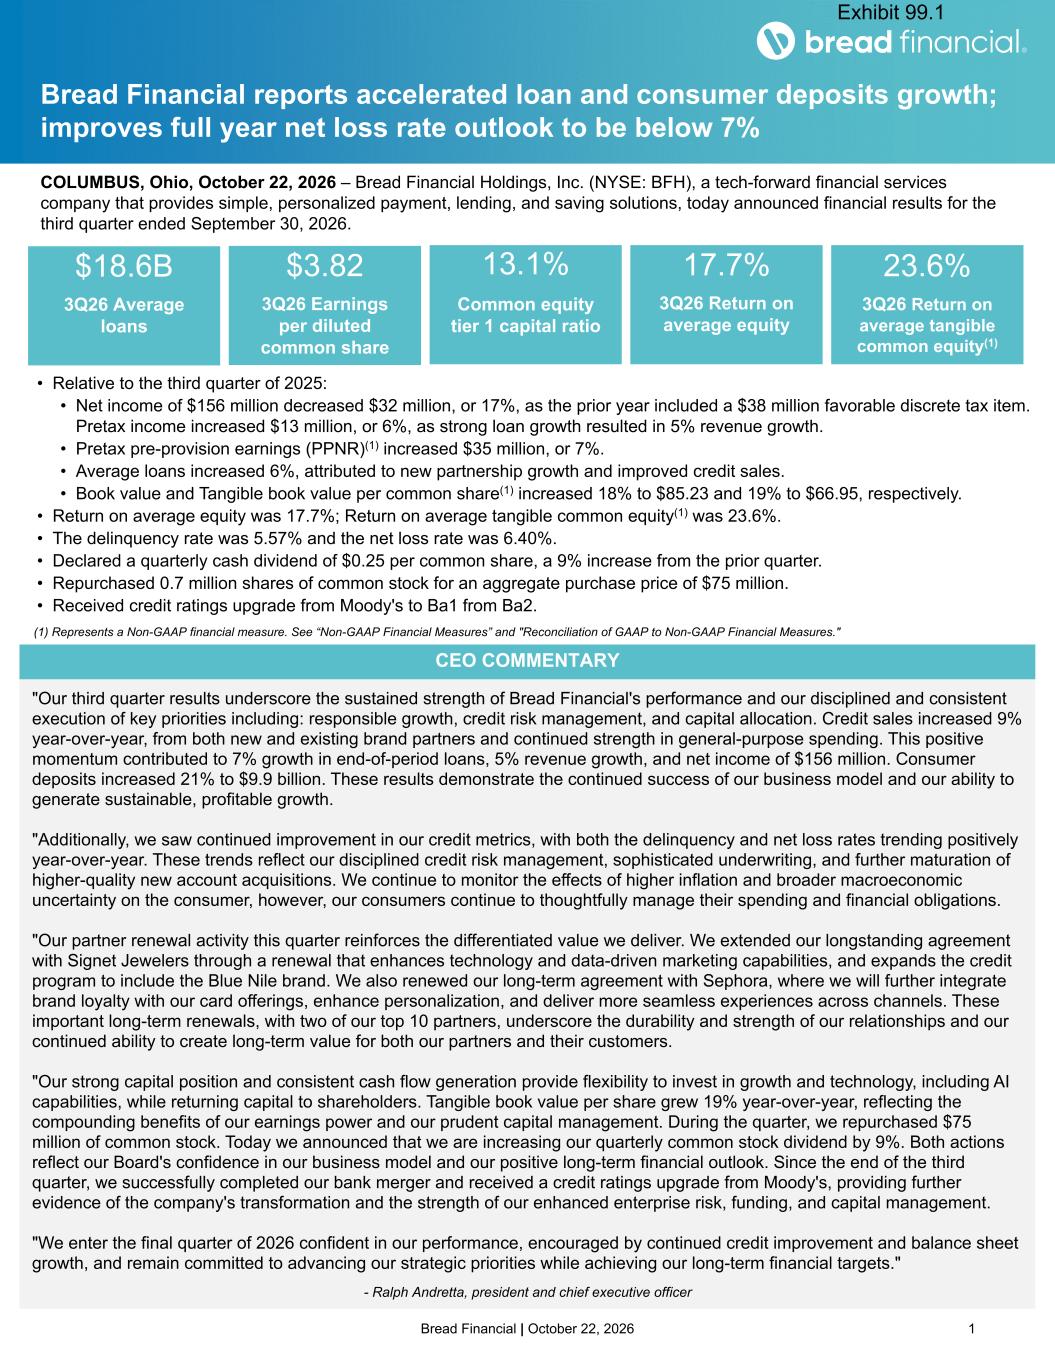
Bread Financial | October 22, 2026 1 "Our third quarter results underscore the sustained strength of Bread Financial's performance and our disciplined and consistent execution of key priorities including: responsible growth, credit risk management, and capital allocation. Credit sales increased 9% year-over-year, from both new and existing brand partners and continued strength in general-purpose spending. This positive momentum contributed to 7% growth in end-of-period loans, 5% revenue growth, and net income of $156 million. Consumer deposits increased 21% to $9.9 billion. These results demonstrate the continued success of our business model and our ability to generate sustainable, profitable growth. "Additionally, we saw continued improvement in our credit metrics, with both the delinquency and net loss rates trending positively year-over-year. These trends reflect our disciplined credit risk management, sophisticated underwriting, and further maturation of higher-quality new account acquisitions. We continue to monitor the effects of higher inflation and broader macroeconomic uncertainty on the consumer, however, our consumers continue to thoughtfully manage their spending and financial obligations. "Our partner renewal activity this quarter reinforces the differentiated value we deliver. We extended our longstanding agreement with Signet Jewelers through a renewal that enhances technology and data-driven marketing capabilities, and expands the credit program to include the Blue Nile brand. We also renewed our long-term agreement with Sephora, where we will further integrate brand loyalty with our card offerings, enhance personalization, and deliver more seamless experiences across channels. These important long-term renewals, with two of our top 10 partners, underscore the durability and strength of our relationships and our continued ability to create long-term value for both our partners and their customers. "Our strong capital position and consistent cash flow generation provide flexibility to invest in growth and technology, including AI capabilities, while returning capital to shareholders. Tangible book value per share grew 19% year-over-year, reflecting the compounding benefits of our earnings power and our prudent capital management. During the quarter, we repurchased $75 million of common stock. Today we announced that we are increasing our quarterly common stock dividend by 9%. Both actions reflect our Board's confidence in our business model and our positive long-term financial outlook. Since the end of the third quarter, we successfully completed our bank merger and received a credit ratings upgrade from Moody's, providing further evidence of the company's transformation and the strength of our enhanced enterprise risk, funding, and capital management. "We enter the final quarter of 2026 confident in our performance, encouraged by continued credit improvement and balance sheet growth, and remain committed to advancing our strategic priorities while achieving our long-term financial targets." - Ralph Andretta, president and chief executive officer Bread Financial reports accelerated loan and consumer deposits growth; improves full year net loss rate outlook to be below 7% (1) Represents a Non-GAAP financial measure. See “Non-GAAP Financial Measures” and "Reconciliation of GAAP to Non-GAAP Financial Measures." $18.6B 3Q26 Average loans $3.82 3Q26 Earnings per diluted common share 13.1% Common equity tier 1 capital ratio 23.6% 3Q26 Return on average tangible common equity(1) • Relative to the third quarter of 2025: • Net income of $156 million decreased $32 million, or 17%, as the prior year included a $38 million favorable discrete tax item. Pretax income increased $13 million, or 6%, as strong loan growth resulted in 5% revenue growth. • Pretax pre-provision earnings (PPNR)(1) increased $35 million, or 7%. • Average loans increased 6%, attributed to new partnership growth and improved credit sales. • Book value and Tangible book value per common share(1) increased 18% to $85.23 and 19% to $66.95, respectively. • Return on average equity was 17.7%; Return on average tangible common equity(1) was 23.6%. • The delinquency rate was 5.57% and the net loss rate was 6.40%. • Declared a quarterly cash dividend of $0.25 per common share, a 9% increase from the prior quarter. • Repurchased 0.7 million shares of common stock for an aggregate purchase price of $75 million. • Received credit ratings upgrade from Moody's to Ba1 from Ba2. CEO COMMENTARY COLUMBUS, Ohio, October 22, 2026 – Bread Financial Holdings, Inc. (NYSE: BFH), a tech-forward financial services company that provides simple, personalized payment, lending, and saving solutions, today announced financial results for the third quarter ended September 30, 2026. 17.7% 3Q26 Return on average equity Exhibit 99.1
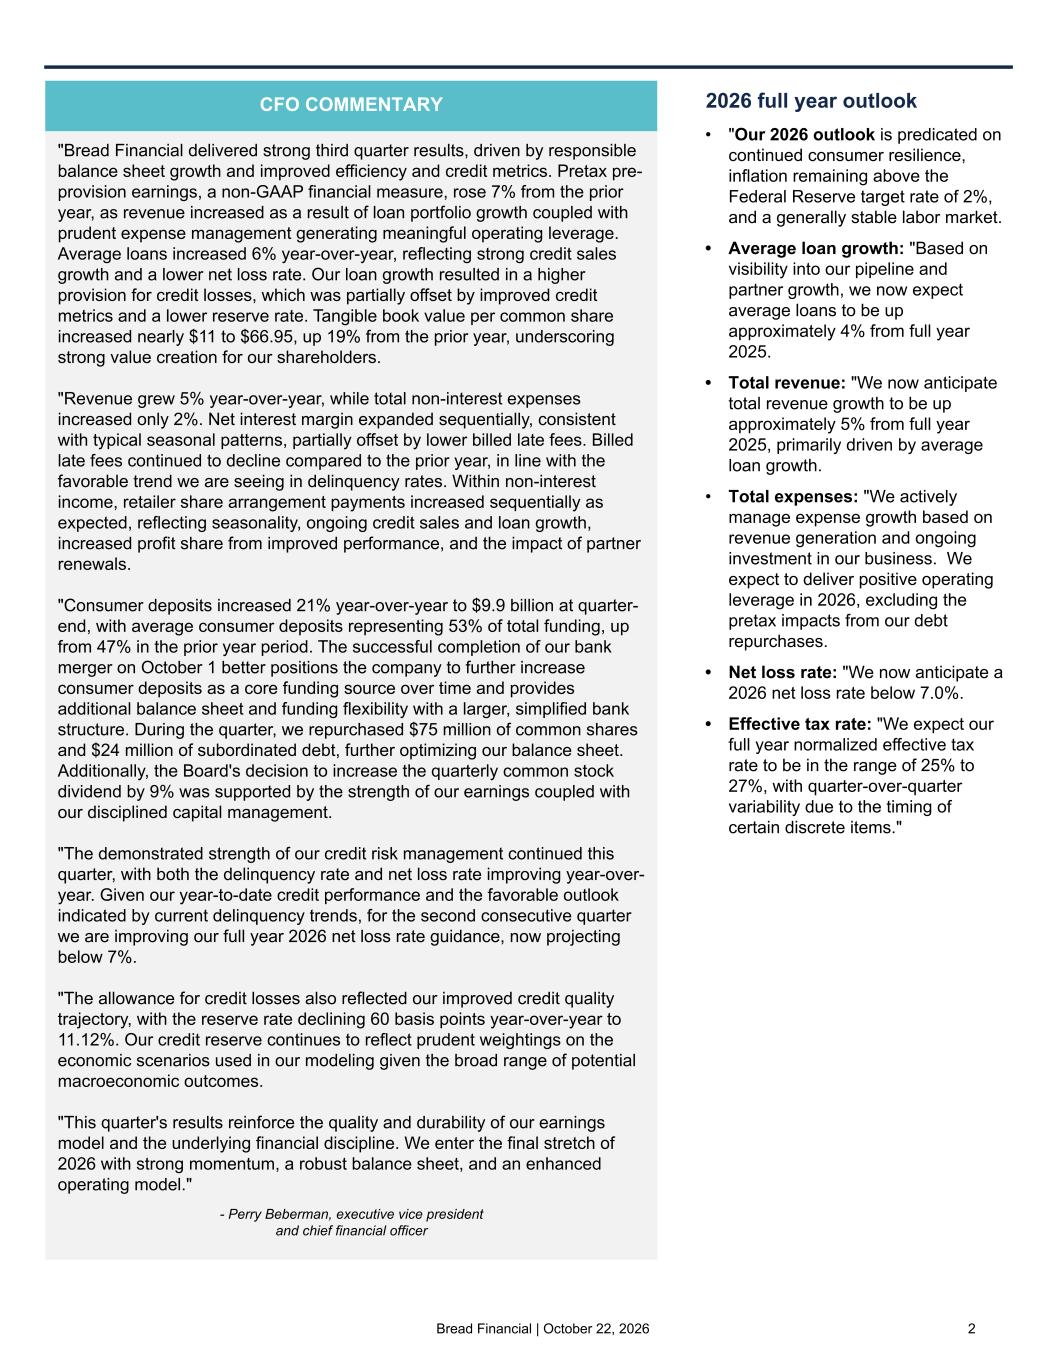
Bread Financial | October 22, 2026 2 "Bread Financial delivered strong third quarter results, driven by responsible balance sheet growth and improved efficiency and credit metrics. Pretax pre- provision earnings, a non-GAAP financial measure, rose 7% from the prior year, as revenue increased as a result of loan portfolio growth coupled with prudent expense management generating meaningful operating leverage. Average loans increased 6% year-over-year, reflecting strong credit sales growth and a lower net loss rate. Our loan growth resulted in a higher provision for credit losses, which was partially offset by improved credit metrics and a lower reserve rate. Tangible book value per common share increased nearly $11 to $66.95, up 19% from the prior year, underscoring strong value creation for our shareholders. "Revenue grew 5% year-over-year, while total non-interest expenses increased only 2%. Net interest margin expanded sequentially, consistent with typical seasonal patterns, partially offset by lower billed late fees. Billed late fees continued to decline compared to the prior year, in line with the favorable trend we are seeing in delinquency rates. Within non-interest income, retailer share arrangement payments increased sequentially as expected, reflecting seasonality, ongoing credit sales and loan growth, increased profit share from improved performance, and the impact of partner renewals. "Consumer deposits increased 21% year-over-year to $9.9 billion at quarter- end, with average consumer deposits representing 53% of total funding, up from 47% in the prior year period. The successful completion of our bank merger on October 1 better positions the company to further increase consumer deposits as a core funding source over time and provides additional balance sheet and funding flexibility with a larger, simplified bank structure. During the quarter, we repurchased $75 million of common shares and $24 million of subordinated debt, further optimizing our balance sheet. Additionally, the Board's decision to increase the quarterly common stock dividend by 9% was supported by the strength of our earnings coupled with our disciplined capital management. "The demonstrated strength of our credit risk management continued this quarter, with both the delinquency rate and net loss rate improving year-over- year. Given our year-to-date credit performance and the favorable outlook indicated by current delinquency trends, for the second consecutive quarter we are improving our full year 2026 net loss rate guidance, now projecting below 7%. "The allowance for credit losses also reflected our improved credit quality trajectory, with the reserve rate declining 60 basis points year-over-year to 11.12%. Our credit reserve continues to reflect prudent weightings on the economic scenarios used in our modeling given the broad range of potential macroeconomic outcomes. "This quarter's results reinforce the quality and durability of our earnings model and the underlying financial discipline. We enter the final stretch of 2026 with strong momentum, a robust balance sheet, and an enhanced operating model." - Perry Beberman, executive vice president and chief financial officer 2026 full year outlook • "Our 2026 outlook is predicated on continued consumer resilience, inflation remaining above the Federal Reserve target rate of 2%, and a generally stable labor market. • Average loan growth: "Based on visibility into our pipeline and partner growth, we now expect average loans to be up approximately 4% from full year 2025. • Total revenue: "We now anticipate total revenue growth to be up approximately 5% from full year 2025, primarily driven by average loan growth. • Total expenses: "We actively manage expense growth based on revenue generation and ongoing investment in our business. We expect to deliver positive operating leverage in 2026, excluding the pretax impacts from our debt repurchases. • Net loss rate: "We now anticipate a 2026 net loss rate below 7.0%. • Effective tax rate: "We expect our full year normalized effective tax rate to be in the range of 25% to 27%, with quarter-over-quarter variability due to the timing of certain discrete items." CFO COMMENTARY
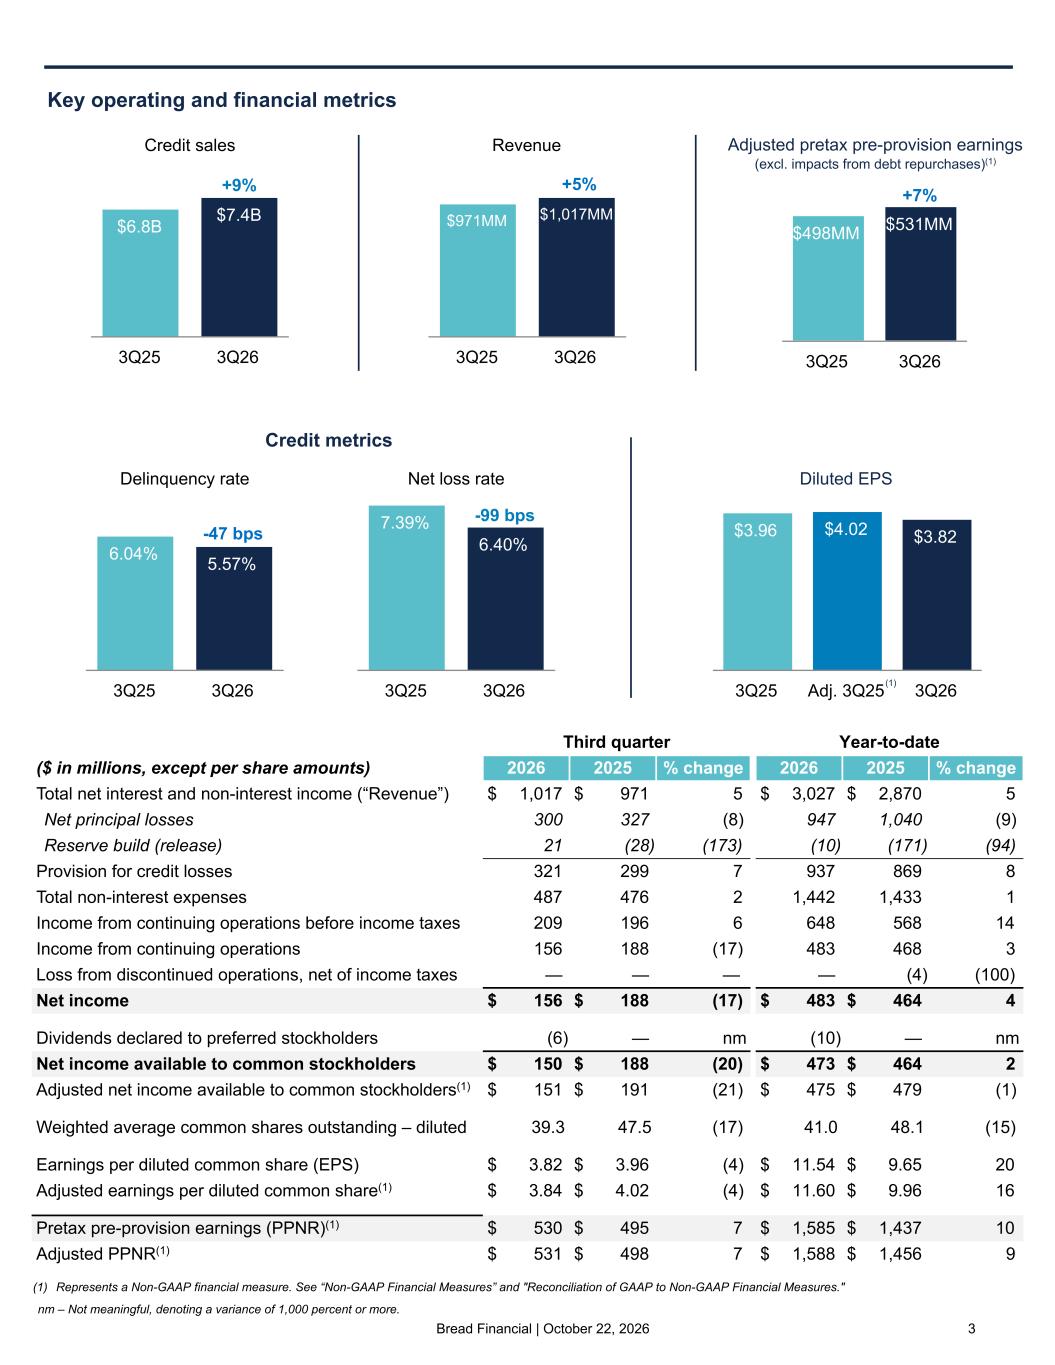
Bread Financial | October 22, 2026 3 PPNR $498MM $531MM 3Q25 3Q26 Third quarter Year-to-date ($ in millions, except per share amounts) 2026 2025 % change 2026 2025 % change Total net interest and non-interest income (“Revenue”) $ 1,017 $ 971 5 $ 3,027 $ 2,870 5 Net principal losses 300 327 (8) 947 1,040 (9) Reserve build (release) 21 (28) (173) (10) (171) (94) Provision for credit losses 321 299 7 937 869 8 Total non-interest expenses 487 476 2 1,442 1,433 1 Income from continuing operations before income taxes 209 196 6 648 568 14 Income from continuing operations 156 188 (17) 483 468 3 Loss from discontinued operations, net of income taxes — — — — (4) (100) Net income $ 156 $ 188 (17) $ 483 $ 464 4 Dividends declared to preferred stockholders (6) — nm (10) — nm Net income available to common stockholders $ 150 $ 188 (20) $ 473 $ 464 2 Adjusted net income available to common stockholders(1) $ 151 $ 191 (21) $ 475 $ 479 (1) Weighted average common shares outstanding – diluted 39.3 47.5 (17) 41.0 48.1 (15) Earnings per diluted common share (EPS) $ 3.82 $ 3.96 (4) $ 11.54 $ 9.65 20 Adjusted earnings per diluted common share(1) $ 3.84 $ 4.02 (4) $ 11.60 $ 9.96 16 Pretax pre-provision earnings (PPNR)(1) $ 530 $ 495 7 $ 1,585 $ 1,437 10 Adjusted PPNR(1) $ 531 $ 498 7 $ 1,588 $ 1,456 9 Revenue $971MM $1,017MM 3Q25 3Q26 +5% Key operating and financial metrics Credit metrics (1) Represents a Non-GAAP financial measure. See “Non-GAAP Financial Measures” and "Reconciliation of GAAP to Non-GAAP Financial Measures." Credit sales $6.8B $7.4B 3Q25 3Q26 +9% Net loss rate 7.39% 6.40% 3Q25 3Q26 Delinquency rate 6.04% 5.57% 3Q25 3Q26 Diluted EPS $3.96 $4.02 $3.82 3Q25 Adj. 3Q25 3Q26 -47 bps -99 bps +7% Adjusted pretax pre-provision earnings (excl. impacts from debt repurchases)(1) nm – Not meaningful, denoting a variance of 1,000 percent or more. (1)
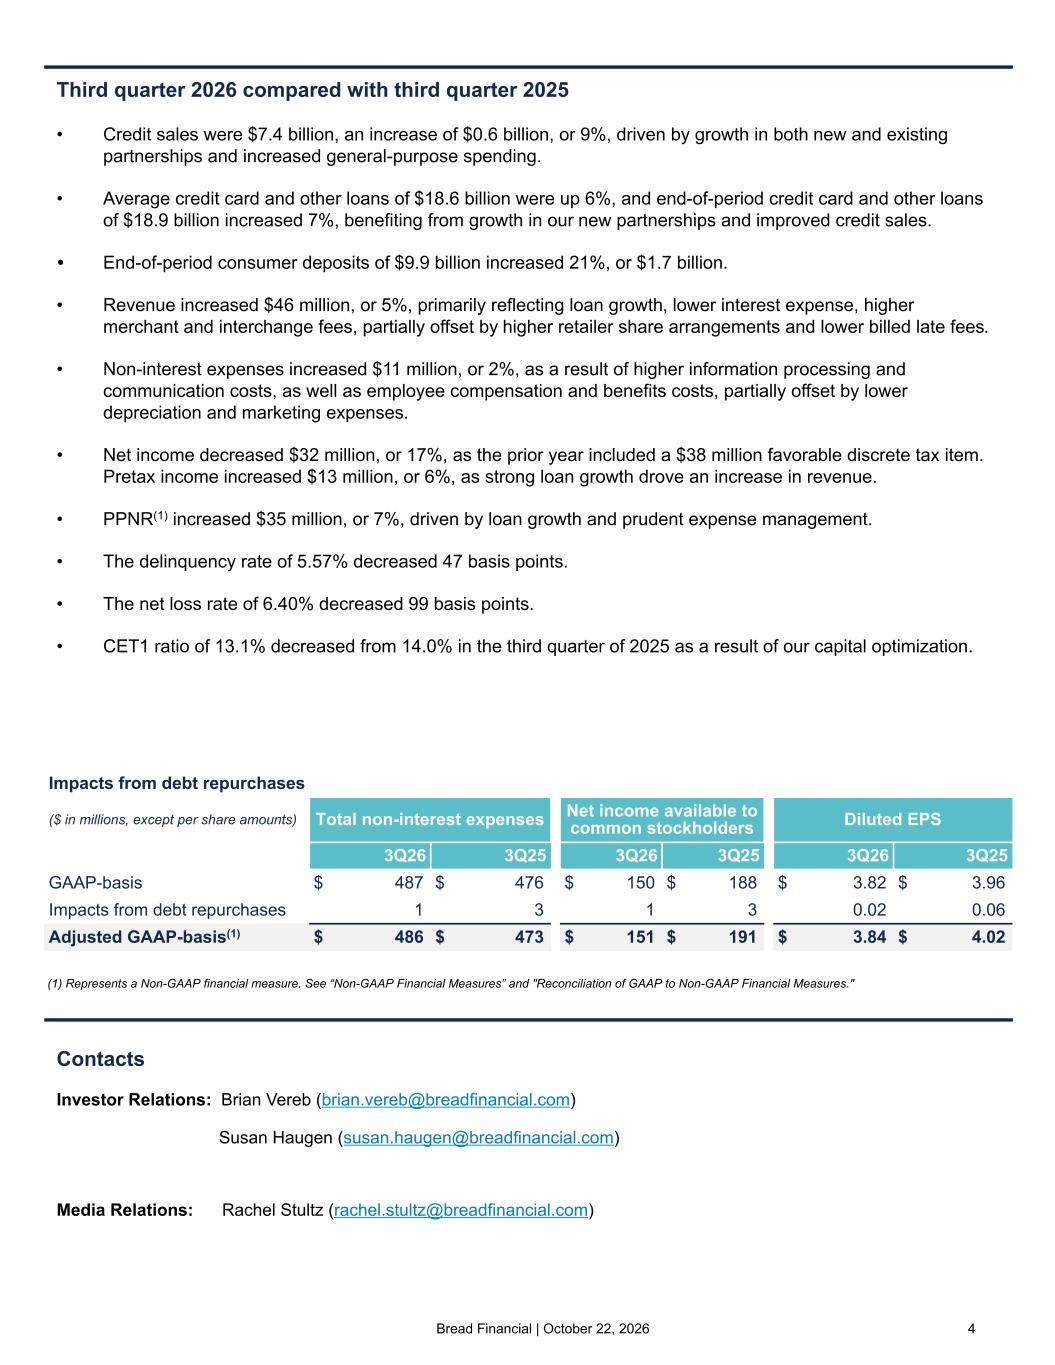
Bread Financial | October 22, 2026 4 Third quarter 2026 compared with third quarter 2025 • Credit sales were $7.4 billion, an increase of $0.6 billion, or 9%, driven by growth in both new and existing partnerships and increased general-purpose spending. • Average credit card and other loans of $18.6 billion were up 6%, and end-of-period credit card and other loans of $18.9 billion increased 7%, benefiting from growth in our new partnerships and improved credit sales. • End-of-period consumer deposits of $9.9 billion increased 21%, or $1.7 billion. • Revenue increased $46 million, or 5%, primarily reflecting loan growth, lower interest expense, higher merchant and interchange fees, partially offset by higher retailer share arrangements and lower billed late fees. • Non-interest expenses increased $11 million, or 2%, as a result of higher information processing and communication costs, as well as employee compensation and benefits costs, partially offset by lower depreciation and marketing expenses. • Net income decreased $32 million, or 17%, as the prior year included a $38 million favorable discrete tax item. Pretax income increased $13 million, or 6%, as strong loan growth drove an increase in revenue. • PPNR(1) increased $35 million, or 7%, driven by loan growth and prudent expense management. • The delinquency rate of 5.57% decreased 47 basis points. • The net loss rate of 6.40% decreased 99 basis points. • CET1 ratio of 13.1% decreased from 14.0% in the third quarter of 2025 as a result of our capital optimization. Contacts Investor Relations: Brian Vereb (brian.vereb@breadfinancial.com) Susan Haugen (susan.haugen@breadfinancial.com) Media Relations: Rachel Stultz (rachel.stultz@breadfinancial.com) (1) Represents a Non-GAAP financial measure. See “Non-GAAP Financial Measures” and "Reconciliation of GAAP to Non-GAAP Financial Measures." Impacts from debt repurchases ($ in millions, except per share amounts) Total non-interest expenses Net income available to common stockholders Diluted EPS 3Q26 3Q25 3Q26 3Q25 3Q26 3Q25 GAAP-basis $ 487 $ 476 $ 150 $ 188 $ 3.82 $ 3.96 Impacts from debt repurchases 1 3 1 3 0.02 0.06 Adjusted GAAP-basis(1) $ 486 $ 473 $ 151 $ 191 $ 3.84 $ 4.02
Bread Financial | October 22, 2026 5 Forward-looking statements This release contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. Forward-looking statements give our expectations or forecasts of future events and can generally be identified by the use of words such as “believe,” “expect,” “anticipate,” “estimate,” “intend,” “project,” “plan,” “likely,” “may,” “should” or other words or phrases of similar import. Similarly, statements that describe our business strategy, outlook, objectives, plans, intentions or goals also are forward-looking statements. Examples of forward-looking statements include, but are not limited to, statements we make regarding, and the guidance we give with respect to, our anticipated operating or financial results, future financial performance and outlook, future dividend declarations, and future economic conditions. We believe that our expectations are based on reasonable assumptions. Forward-looking statements, however, are subject to a number of risks and uncertainties that are difficult to predict and, in many cases, beyond our control. Accordingly, our actual results could differ materially from the projections, anticipated results or other expectations expressed in this release, and no assurances can be given that our expectations will prove to have been correct. Factors that could cause the outcomes to differ materially include, but are not limited to, the following: macroeconomic conditions, including inflation, interest rates, labor market conditions, financial and capital market conditions, recessionary pressures or concerns over a prolonged economic slowdown, and the related impact on consumer spending behavior, payments, debt levels, savings rates and other behaviors; domestic and international political events and conditions, including significant shifts in trade policy, such as changes to, or the imposition of, tariffs and/or trade barriers and consequently any economic impacts, volatility, uncertainty and geopolitical instability resulting therefrom, as well as ongoing wars and military conflicts, and international tensions or hostilities; local or global public health issues, climate-related events, impacts to the power grid, and natural disasters; future credit performance, including the level of future delinquency and charge-off rates; loss of, or reduction in demand for services and/or products from, significant brand partners or customers in the highly competitive markets in which we operate, including competition from new and non-traditional competitors, such as financial technology companies, and with respect to new products, services and technologies, such as the emergence or increase in popularity of agentic commerce, digital payment platforms and currencies and other alternative payment and deposit solutions; the concentration of our business in U.S. consumer credit; inaccuracies in the models and estimates on which we rely, including our credit risk management models and the amount of our Allowance for credit losses; the inability to realize the intended benefits of acquisitions, dispositions and other strategic initiatives; our level of indebtedness and ability to access financial or capital markets; pending and future federal and state legislation, executive action, regulation, supervisory guidance, and regulatory and legal actions, including, but not limited to, those related to financial regulatory reform and consumer financial services practices, as well as any such actions that would place limits on credit card interest rates or late fees, interchange fees or other charges; failures or breaches in our operational or security systems, including as a result of cyberattacks, unanticipated impacts from technology modernization projects or otherwise; and any liability or other adverse impacts arising out of or related to the spinoff of our former LoyaltyOne segment or the bankruptcy filings of Loyalty Ventures Inc. (LVI) and certain of its subsidiaries, including the pending litigation against us in connection with the spinoff. The foregoing factors, along with other risks and uncertainties that could cause actual results to differ materially from those expressed or implied in forward-looking statements, are described in greater detail under the headings “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in our Annual Report on Form 10-K for the most recently ended fiscal year, which may be updated in Item 1A of, or elsewhere in, our Quarterly Reports on Form 10-Q filed for periods subsequent to such Form 10-K. Our forward-looking statements speak only as of the date made, and we undertake no obligation, other than as required by applicable law, to update or revise any forward-looking statements, whether as a result of new information, subsequent events, anticipated or unanticipated circumstances or otherwise.
Bread Financial | October 22, 2026 6 Non-GAAP financial measures We prepare our Consolidated Financial Statements in accordance with accounting principles generally accepted in the United States of America (GAAP). However, certain information included herein constitutes Non-GAAP Financial Measures. Our calculations of Non-GAAP Financial Measures may differ from the calculations of similarly titled measures by other companies. In particular: • We have previously repurchased and may, from time to time, in the future continue to repurchase debt, including any outstanding senior unsecured notes, subordinated notes or convertible notes. In such transactions, we may pay a premium to induce these repurchases, or in certain cases repurchase at a discount, which, from a GAAP perspective, would result in an impact to Total non-interest expenses, with a corresponding impact also reflected in Net income available to common stockholders and consequently our Earnings per diluted common share. For our prior debt repurchases, we show adjustments to these three financial statement line items to exclude the impacts from our debt repurchases. We use Adjusted total non-interest expenses, Adjusted net income available to common stockholders, and Adjusted earnings per diluted common share to evaluate the ongoing operations of the Company excluding the volatility that can occur from the impacts of our debt repurchases. • Pretax pre-provision earnings (PPNR) represents Income from continuing operations before income taxes and the Provision for credit losses. PPNR excluding impacts from debt repurchases then excludes from PPNR the loss or gain on any debt repurchases in the period. We use PPNR and PPNR excluding impacts from debt repurchases as metrics to evaluate our results of operations before income taxes, excluding the movements that can occur within Provision for credit losses and the one-time nature of the impacts from debt repurchases. • Return on average tangible common equity (ROTCE) represents annualized Income from continuing operations less Dividends to preferred stockholders, divided by average Tangible common equity. Tangible common equity (TCE) represents Total stockholders’ equity reduced by Preferred stock and Goodwill and intangible assets, net. We use ROTCE as a metric to evaluate the Company’s performance. • Tangible book value per common share represents TCE divided by common shares outstanding. We use Tangible book value per common share, a metric used across the industry, to assess capital and performance, in conjunction with ROTCE. We believe the use of these Non-GAAP financial measures provide additional clarity in understanding our results of operations and trends. For a reconciliation of these Non-GAAP financial measures to the most directly comparable GAAP measures, please see the “Reconciliation of GAAP to Non-GAAP Financial Measures.”
Bread Financial | October 22, 2026 7 Financial supplement This earnings release should be read in conjunction with the Financial Supplement for the third quarter of 2026, available at investor.breadfinancial.com and in a Form 8-K furnished today with the Securities and Exchange Commission. Conference call/webcast information Bread Financial will host a conference call on Thursday, October 22, 2026, at 8:30 a.m. (Eastern Time) to discuss the company’s third quarter results. The conference call will be available via the internet at investor.breadfinancial.com. There will be several slides accompanying the webcast. Please go to the website at least 15 minutes prior to the call to register, download and install any necessary software. The recorded webcast will also be available on the company’s website. About Bread Financial® Bread Financial® (NYSE: BFH) is a tech-forward financial services company that provides simple, personalized payment, lending and saving solutions to millions of U.S. consumers. Our payment solutions deliver growth for some of the most recognized brands in travel & entertainment, health & beauty, technology, electronics, jewelry, home and specialty apparel through our co-brand and private label credit cards and pay-over-time products providing choice and value to our shared customers. Additionally, we offer Bread Financial general purpose credit cards and saving products that empower our customers and their passions for a better life. Bread Financial proudly marks 30 years of success in 2026. To learn more about our global associates, our performance and our sustainability progress, visit breadfinancial.com or follow us on Instagram and LinkedIn.
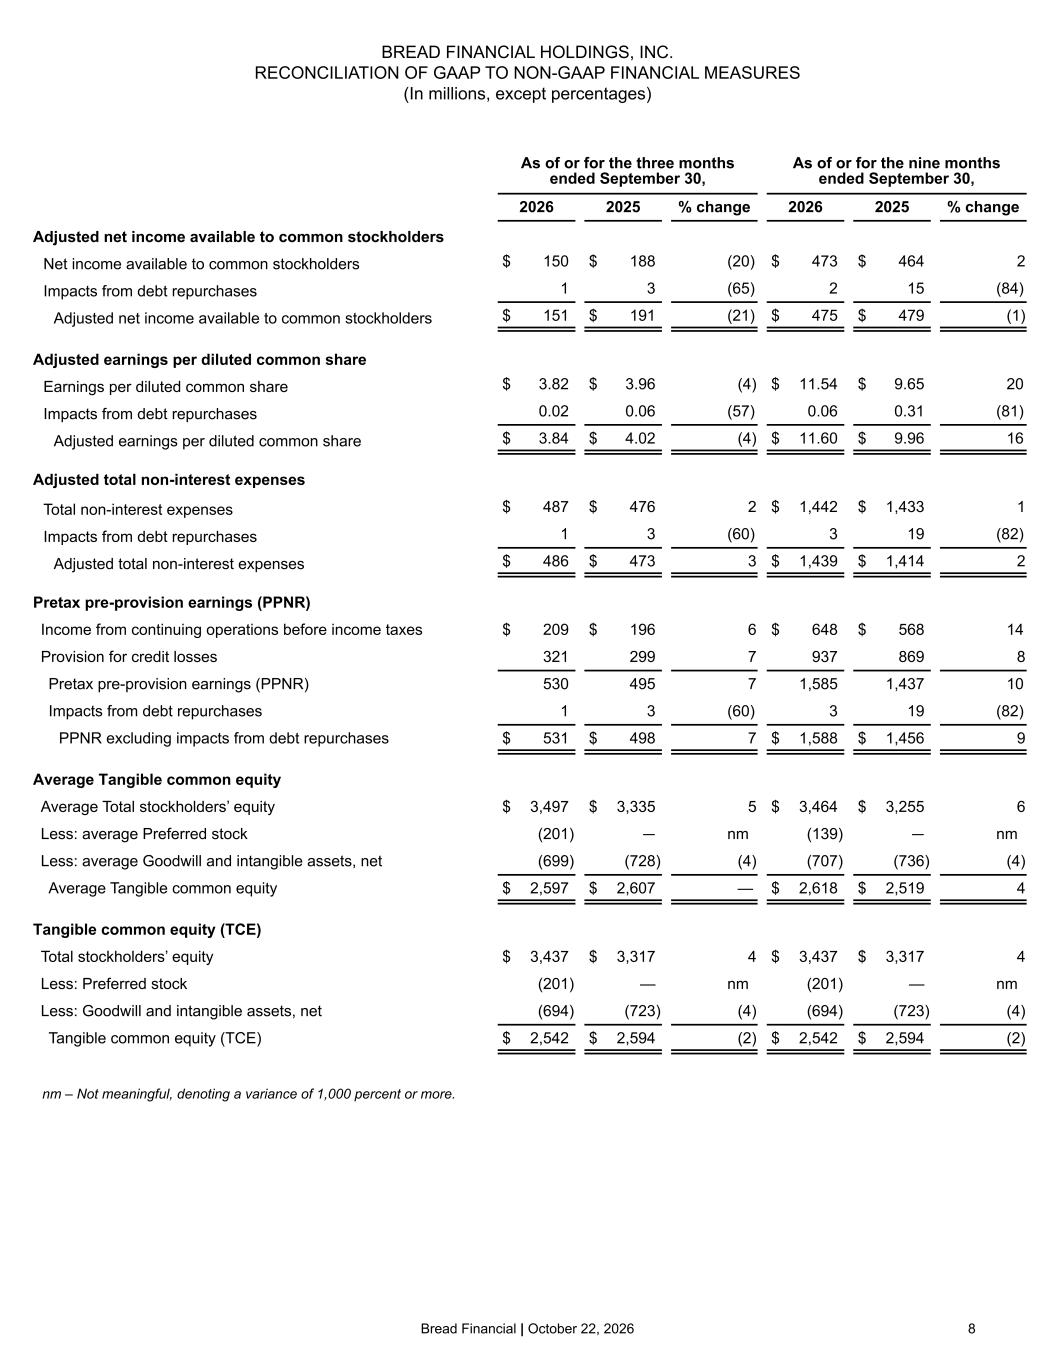
Bread Financial | October 22, 2026 8 BREAD FINANCIAL HOLDINGS, INC. RECONCILIATION OF GAAP TO NON-GAAP FINANCIAL MEASURES (In millions, except percentages) As of or for the three months ended September 30, As of or for the nine months ended September 30, 2026 2025 % change 2026 2025 % change Adjusted net income available to common stockholders Net income available to common stockholders $ 150 $ 188 (20) $ 473 $ 464 2 Impacts from debt repurchases 1 3 (65) 2 15 (84) Adjusted net income available to common stockholders $ 151 $ 191 (21) $ 475 $ 479 (1) Adjusted earnings per diluted common share Earnings per diluted common share $ 3.82 $ 3.96 (4) $ 11.54 $ 9.65 20 Impacts from debt repurchases 0.02 0.06 (57) 0.06 0.31 (81) Adjusted earnings per diluted common share $ 3.84 $ 4.02 (4) $ 11.60 $ 9.96 16 Adjusted total non-interest expenses Total non-interest expenses $ 487 $ 476 2 $ 1,442 $ 1,433 1 Impacts from debt repurchases 1 3 (60) 3 19 (82) Adjusted total non-interest expenses $ 486 $ 473 3 $ 1,439 $ 1,414 2 Pretax pre-provision earnings (PPNR) Income from continuing operations before income taxes $ 209 $ 196 6 $ 648 $ 568 14 Provision for credit losses 321 299 7 937 869 8 Pretax pre-provision earnings (PPNR) 530 495 7 1,585 1,437 10 Impacts from debt repurchases 1 3 (60) 3 19 (82) PPNR excluding impacts from debt repurchases $ 531 $ 498 7 $ 1,588 $ 1,456 9 Average Tangible common equity Average Total stockholders’ equity $ 3,497 $ 3,335 5 $ 3,464 $ 3,255 6 Less: average Preferred stock (201) — nm (139) — nm Less: average Goodwill and intangible assets, net (699) (728) (4) (707) (736) (4) Average Tangible common equity $ 2,597 $ 2,607 — $ 2,618 $ 2,519 4 Tangible common equity (TCE) Total stockholders’ equity $ 3,437 $ 3,317 4 $ 3,437 $ 3,317 4 Less: Preferred stock (201) — nm (201) — nm Less: Goodwill and intangible assets, net (694) (723) (4) (694) (723) (4) Tangible common equity (TCE) $ 2,542 $ 2,594 (2) $ 2,542 $ 2,594 (2) nm – Not meaningful, denoting a variance of 1,000 percent or more.