Exhibit 99.1
Kilroy Realty
Supplemental Financial Report
Q3 2026
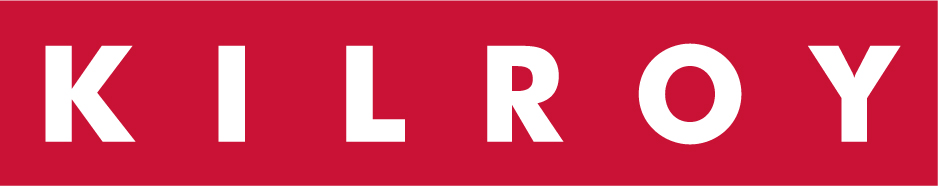
Kilroy Oyster Point, South San Francisco, CA
i
Where Innovation Works |
KILROY REALTY CORPORATION REPORTS
THIRD QUARTER FINANCIAL AND OPERATIONAL RESULTS
---------------
LOS ANGELES, October 22, 2026 - Kilroy Realty Corporation (NYSE: KRC) (“Kilroy” or the “Company”) today reported financial and operational results for
the third quarter ended September 30, 2026.
“Momentum in our West Coast markets continued to accelerate in the third quarter, with over 800,000 square feet of long-term leases signed, representing
one of the Company’s highest quarterly leasing volumes since 2019,” said Angela Aman, Chief Executive Officer. “The breadth of activity was particularly
notable, as we recorded sequential leased occupancy gains across all five of our regions and strong re-leasing spreads, driven by activity from a wide variety
of users and industries. Looking ahead, our high-quality portfolio, solid balance sheet, and nimble approach position us well to capitalize on the real-time
fundamental improvements we are seeing across our regions.”
Financial Results
•Revenues of $271.6 million for the quarter ended September 30, 2026, as compared to $279.7 million for the quarter ended September 30, 2025
•Net income available to common stockholders of $15.5 million, or $0.13 per diluted share, for the quarter ended September 30, 2026, as compared
to $156.2 million, or $1.31 per diluted share, for the quarter ended September 30, 2025
•Funds from operations (“FFO”) of $104.6 million, or $0.88 per diluted share, for the quarter ended September 30, 2026, as compared to $130.6
million, or $1.08 per diluted share, for the quarter ended September 30, 2025
Leasing and Occupancy
•Stabilized Portfolio was 76.9% occupied and 83.0% leased at September 30, 2026, representing 610 basis points of leases signed but not yet
commenced
◦Excluding Kilroy Oyster Point Phase 2 (“KOP 2”), the Stabilized Portfolio was 80.7% occupied and 84.8% leased at September 30, 2026,
representing 410 basis points of leases signed but not yet commenced
•During the quarter, signed approximately 815,000 square feet of leases
◦Leasing activity was comprised of 345,000 square feet of new leasing on previously vacant space, 127,000 square feet of new leasing on
currently occupied space, and 343,000 square feet of renewal leasing
▪Renewal leasing included a 12-year, approximately 243,000 square-foot renewal at Crossing 900 with Box, Inc., a leading content
management company
▪Leasing activity during the quarter included approximately 12,000 square feet of short-term leasing
•GAAP and cash rents on leases signed during the quarter increased 30.6% and 9.7%, respectively, from prior levels on Second Generation leasing,
excluding short-term leasing
◦Excluding leases signed on space vacant for more than 12 months, GAAP and cash rents on leases signed during the quarter increased
37.9% and 13.9%, respectively
Land Site Under Contract
•In August, entered into an agreement, subject to a non-refundable deposit, to sell the land at Kilroy East Village in San Diego for $19.5 million in
gross sales proceeds. The transaction is anticipated to close during the fourth quarter
Balance Sheet / Liquidity
•In July, repaid the outstanding $200.0 million of 4.350% Private Placement Senior Notes Series B due October 2026, at par
ii
Where Innovation Works |
Dividend
•The Board of Directors declared and paid a regular quarterly cash dividend on its common stock of $0.54 per share, equivalent to an annual rate of
$2.16 per share. The dividend was paid on October 14, 2026 to stockholders of record on September 30, 2026 (the ex-dividend date)
iii
Where Innovation Works |
Net Income Available to Common Stockholders / FFO Guidance
The Company is updating Nareit-defined FFO per share guidance for the full year 2026 to $3.55 to $3.59 per diluted share, from the previous range of $3.49
to $3.63. The table below reflects key assumptions for 2026 guidance.
Key Assumptions | July 2026 Assumptions | Current Assumptions | ||
Average full year occupancy | 76.50% to 78.00% | 77.00% to 77.50% | ||
Average full year occupancy excluding KOP 2 | 80.50% to 81.50% | 80.75% to 81.25% | ||
Same Property Cash Net Operating Income (“NOI”) growth (1) | 0.25% to 1.25% | 0.75% to 1.00% | ||
NOI from Development Properties (2) | $(22.5) to $(24.0) million | +/- $(21.0) million | ||
Non-Cash GAAP NOI adjustments (1) (3) | $13.0 to $15.0 million | $13.0 to $14.0 million | ||
GAAP lease termination fee income | $3.0 to $4.5 million | $1.1 to $1.5 million | ||
General and administrative and Leasing costs | $(87.5) to $(89.5) million | $(89.5) to $(90.5) million | ||
Interest income | $2.0 to $3.0 million | +/- $3.0 million | ||
Gross interest expense | $(208.0) to $(209.5) million | $(207.5) to $(208.5) million | ||
Capitalized interest (4) | $48.5 to $49.5 million | $49.0 to $49.5 million | ||
Total development spending (5) | +/- $150.0 million | +/- $150.0 million | ||
Operating property dispositions | $347.5 to $500.0 million | $347.5 to $500.0 million |
Full Year 2026 Range as of July 2026 | Full Year 2026 Range as of October 2026 | ||||||
Low End | High End | Low End | High End | ||||
$ and shares/units in thousands, except per share/unit amounts | |||||||
Net income available to common stockholders per share - diluted | $0.08 | $0.22 | $0.23 | $0.27 | |||
Weighted average common shares outstanding - diluted (6) | 118,100 | 118,100 | 117,500 | 117,500 | |||
Net income available to common stockholders | $9,055 | $25,743 | $26,607 | $31,375 | |||
Adjustments: | |||||||
Net income attributable to noncontrolling common units of the Operating Partnership | 300 | 300 | 300 | 300 | |||
Net income attributable to noncontrolling interests in consolidated property partnerships | 17,000 | 17,000 | 17,000 | 17,000 | |||
Depreciation and amortization of real estate assets | 379,400 | 379,400 | 369,000 | 369,000 | |||
Gain on sale of depreciable operating property | (23,525) | (23,525) | (23,525) | (23,525) | |||
Impairment of real estate assets | 61,778 | 61,778 | 61,778 | 61,778 | |||
Funds From Operations attributable to noncontrolling interests in consolidated property partnerships | (28,000) | (28,000) | (28,000) | (28,000) | |||
Funds From Operations (1) | $416,008 | $432,696 | $423,160 | $427,928 | |||
Weighted average common shares/units outstanding – diluted (7) | 119,200 | 119,200 | 119,200 | 119,200 | |||
Nareit Funds From Operations per common share/unit – diluted (1) | $3.49 | $3.63 | $3.55 | $3.59 | |||
________________________
(1)For additional information, please refer to pages 36-38 “Management Statements on Non-GAAP Supplemental Measures”.
(2)NOI from Development Properties is primarily attributable to the Company’s KOP 2 project. 2026 guidance assumes the continued capitalization of the Company’s Flower Mart project through year end.
(3)Non-Cash GAAP NOI adjustments include the following items: Deferred income and lease incentives, net, Amortization of deferred revenue related to tenant-funded tenant improvements, Straight-line rents, net,
Amortization of net below market rents, Deferred settlement and restoration fee income, and Other.
iv
Where Innovation Works |
(4)2026 capitalized interest guidance assumes the continued capitalization of the Company’s Flower Mart project through year end.
(5)Total development spending includes recently stabilized, in-process, and future development projects.
(6)Calculated based on estimated weighted average shares outstanding, including non-participating share-based awards and the dilutive impact of contingently issuable shares.
(7)Calculated based on the weighted average shares outstanding, including participating and non-participating share-based awards, and the dilutive impact of contingently issuable shares, and assuming the exchange of
all common limited partnership units outstanding. Reported amounts are attributable to common stockholders, common unitholders, and restricted stock unitholders.
The Company’s guidance estimates for the full year 2026, and the reconciliation of Net income available to common stockholders per share - diluted and
FFO per share and unit - diluted included within this press release, reflect management’s views on current and future market conditions, including
assumptions with respect to rental rates, occupancy levels, and the earnings impact of the events referenced in this press release. These guidance
estimates do not include the impact on the Company’s operating results from any events outside of the Company’s control, as the timing and magnitude of
any such events are not known at the time the Company provides guidance. There can be no assurance that the Company’s actual results will not differ
materially from these estimates.
Conference Call and Audio Webcast
The Company’s management will discuss third quarter results and the current business environment during the Company’s October 23, 2026 earnings
conference call. The call will begin at 10:00 a.m. Pacific Time and last approximately one hour. To participate and obtain conference call dial-in details,
register by using the following link, https://events.q4inc.com/analyst/810842787?pwd=5kxxJfrm. Those interested in listening via the Internet can access the
conference call at https://events.q4inc.com/attendee/810842787. It may be necessary to download audio software to hear the conference call.
v
Where Innovation Works |
Table of Contents
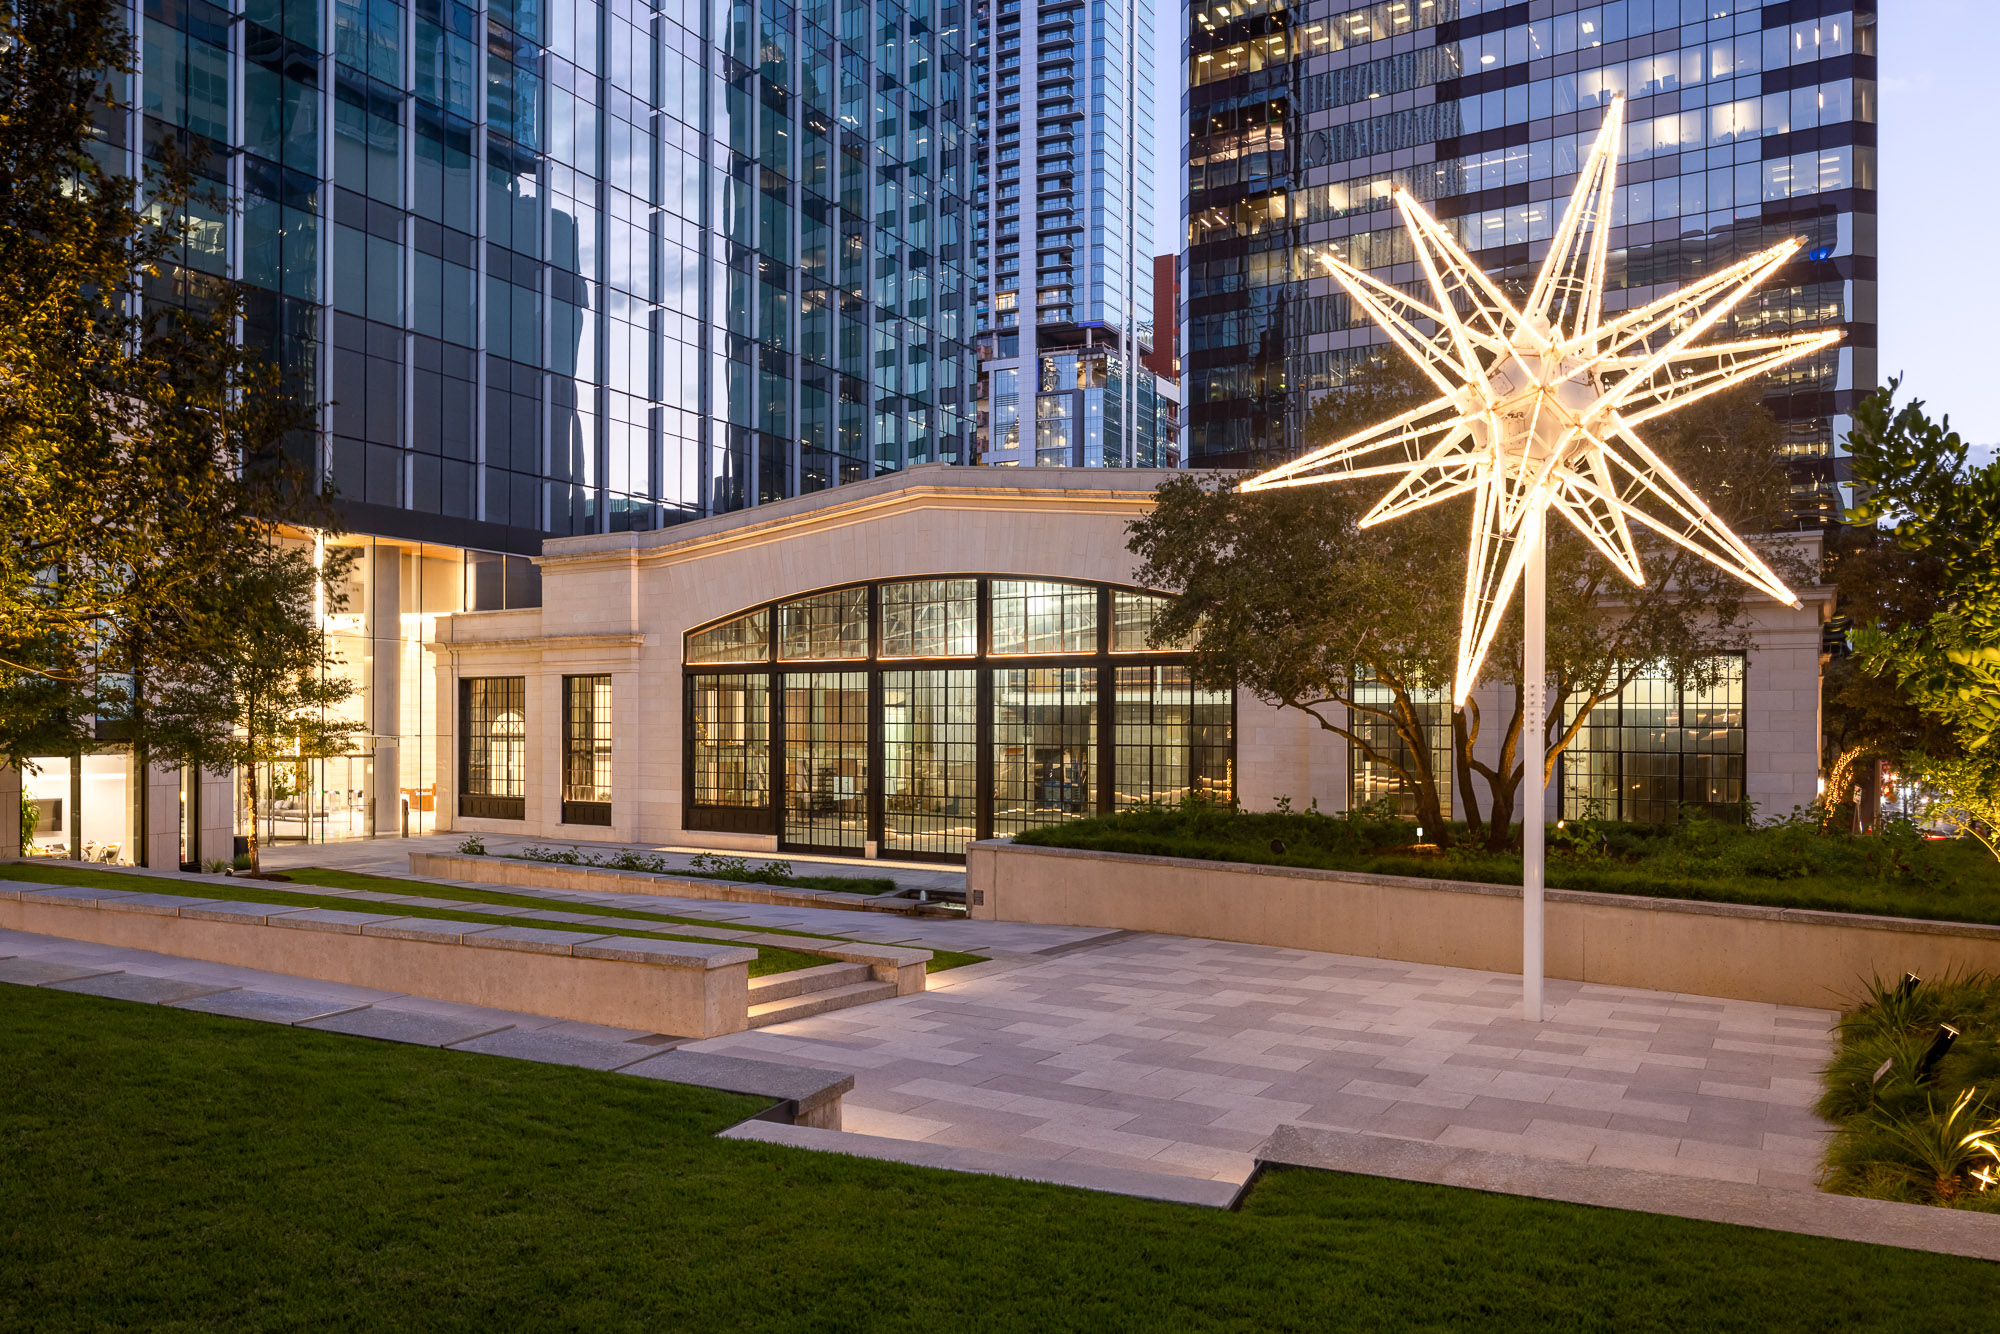
350 Mission, San Francisco, CA
01
Corporate Data &
Financial Highlights
–Company Background
–Financial Highlights
–Consolidated Balance Sheets
–Consolidated Statements of Operations
–Funds From Operations & Funds Available for Distribution
–Supplemental Income Statement Detail
–Net Operating Income
–Same Property Net Operating Income Analysis (Cash Basis)
–EBITDAre and Adjusted EBITDAre
The Post at Indeed Tower, Austin, TX
Kilroy Realty Q3 2026 Supplemental Report | 2
Where Innovation Works |
Company
Background
Kilroy Realty Corporation (NYSE: KRC) is a publicly traded real estate
investment trust and member of the S&P MidCap 400 Index. The Company
owns, manages, develops, and acquires real estate assets consisting
primarily of premier office and life science properties in the San Francisco
Bay Area, Los Angeles, Seattle, San Diego, and Austin.
Stabilized Office & Life Science Portfolio
at September 30, 2026
123
17.1M
buildings
square feet
76.9%
83.0%
occupied
leased
610 bps
815
leased but not
yet occupied
thousand square feet
of leases executed in
3Q 2026
Investor Relations | |
12200 W. Olympic Blvd., Suite 200 | |
Los Angeles, CA 90064 | |
(310) 481-8400 | |
Web: www.kilroyrealty.com | |
E-mail: investorrelations@kilroyrealty.com | |
John N. Perry | SVP, Investor Relations and Capital Markets |
Board of Directors | |
Gary R. Stevenson | Chair |
Angela M. Aman | |
Edward F. Brennan, PhD | |
Daryl J. Carter | |
Jolie A. Hunt | |
David A. Kieske | |
Cia Buckley Marakovits | |
Louisa G. Ritter | |
Executive and Senior Management Team | |
Angela M. Aman | Chief Executive Officer |
Justin W. Smart | President |
A. Robert Paratte | EVP, Chief Leasing Officer |
Sherrie S. Schwartz | EVP, Chief Human Resources Officer |
Lauren N. Stadler | EVP, General Counsel and Secretary |
Eliott L. Trencher | EVP, Chief Investment Officer and Interim Chief Financial Officer and Treasurer |
Chandni Jalan | SVP, Chief Accounting Officer |
Equity Research Coverage | ||
Barclays | Brendan Lynch | (212) 526-9428 |
BofA Securities | Jana Galan | (646) 855-5042 |
BMO Capital Markets Corp. | John P. Kim | (212) 885-4115 |
BTIG | Thomas Catherwood | (212) 738-6140 |
Citigroup Investment Research | Seth Bergey | (212) 816-2066 |
Deutsche Bank Securities, Inc. | Peter Abramowitz | (212) 250-9504 |
Evercore ISI | Steve Sakwa | (212) 446-9462 |
Goldman Sachs & Co. LLC | Caitlin Burrows | (212) 902-4736 |
Green Street Advisors | Dylan Burzinski | (949) 640-8780 |
Jefferies LLC | Joe Dickstein | (212) 778-8771 |
J.P. Morgan | Anthony Paolone | (212) 622-6682 |
Keybanc Capital Markets | Upal Rana | (917) 368-2316 |
Mizuho Securities USA LLC | Vikram Malhotra | (212) 282-3827 |
RBC Capital Markets | Mike Carroll | (440) 715-2649 |
Scotiabank | Nicholas Yulico | (212) 225-6904 |
Wells Fargo | Blaine Heck | (410) 662-2556 |
Wolfe Research | Ally Yaseen | (646) 582-9253 |
Kilroy Realty Corporation is followed by the analysts listed above. Please note that any opinions, estimates, or forecasts regarding Kilroy Realty Corporation’s performance made by these analysts are theirs alone and do not represent opinions, forecasts, or predictions of Kilroy Realty Corporation or its management. Kilroy Realty Corporation does not by its reference above or distribution imply its endorsement of or concurrence with such information, conclusions or recommendations. | ||
Kilroy Realty Q3 2026 Supplemental Report | 3
Where Innovation Works |
Financial Highlights
(unaudited, $ in thousands, except per share amounts)
Three Months Ended | Nine Months Ended | |||||||||||||
9/30/2026 | 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | 9/30/2026 | 9/30/2025 | ||||||||
INCOME STATEMENT ITEMS: | ||||||||||||||
Revenues | $271,604 | $272,371 | $270,053 | $272,187 | $279,744 | $814,028 | $840,480 | |||||||
Lease Termination Fees | 315 | 364 | 398 | 1,541 | 309 | 1,077 | 11,569 | |||||||
Capitalized Interest and Debt Costs | 11,867 | 11,632 | 13,991 | 20,632 | 22,574 | 37,490 | 64,455 | |||||||
Capitalized Internal Overhead Costs (1) | 3,702 | 3,852 | 3,977 | 4,120 | 4,682 | 11,531 | 13,123 | |||||||
Other Capitalized Development Costs (2) | 2,437 | 1,554 | 3,190 | 6,382 | 7,353 | 7,181 | 17,832 | |||||||
Non-Cash Amortization of Share-Based Compensation Awards | 3,229 | 3,079 | 4,869 | 5,145 | 5,436 | 11,177 | 13,945 | |||||||
EARNINGS METRICS: | ||||||||||||||
Net Income (Loss) Available to Common Stockholders | $15,506 | $19,905 | $(19,267) | $12,444 | $156,220 | $16,144 | $263,677 | |||||||
Net Operating Income (3) | 173,180 | 180,293 | 178,403 | 176,426 | 188,775 | 531,876 | 559,793 | |||||||
EBITDAre (4) | 152,963 | 159,986 | 156,406 | 158,139 | 171,561 | 469,355 | 515,060 | |||||||
Company's Share of EBITDAre (4) | 145,590 | 152,478 | 148,583 | 150,555 | 164,126 | 446,651 | 486,759 | |||||||
Company's Share of Adjusted EBITDAre (4) | 144,970 | 151,231 | 147,629 | 148,350 | 161,007 | 443,830 | 481,994 | |||||||
Funds From Operations (5) | 104,633 | 109,338 | 108,846 | 117,158 | 130,561 | 322,817 | 388,762 | |||||||
Funds Available for Distribution (5) | 62,806 | 83,626 | 91,106 | 90,534 | 100,939 | 237,538 | 313,924 | |||||||
PER SHARE INFORMATION (6): | ||||||||||||||
Net income (loss) available to common stockholders per share – diluted | $0.13 | $0.17 | $(0.16) | $0.10 | $1.31 | $0.14 | $2.21 | |||||||
Funds From Operations per common share/unit – diluted (5) | 0.88 | 0.92 | 0.91 | 0.97 | 1.08 | 2.71 | 3.23 | |||||||
Dividends declared per common share | 0.54 | 0.54 | 0.54 | 0.54 | 0.54 | 1.62 | 1.62 | |||||||
RATIOS (7): | ||||||||||||||
Net Operating Income Margin | 63.8% | 66.2% | 66.1% | 64.8% | 67.5% | 65.3% | 66.6% | |||||||
Net Debt to Company's Share of EBITDAre Ratio (4) | 7.2x | 7.0x | 7.0x | 7.0x | 6.4x | N/A | N/A | |||||||
Net Debt to Company's Share of Adjusted EBITDAre Ratio (4) | 7.3x | 7.1x | 7.1x | 7.1x | 6.5x | N/A | N/A | |||||||
Fixed Charge Coverage Ratio - Company’s Share of EBITDAre (4) | 3.0x | 3.1x | 3.0x | 3.0x | 3.2x | 3.0x | 3.2x | |||||||
FFO / FAD Payout Ratio (5) | 60.6% / 101.0% | 58.0% / 75.8% | 58.3% / 69.6% | 55.1% / 71.3% | 49.4% / 63.9% | 58.9% / 80.1% | 49.8% / 61.6% | |||||||
STABILIZED PORTFOLIO INFORMATION: | ||||||||||||||
Period End Occupancy Percentage | 76.9% | 77.0% | 77.6% | 81.6% | 81.0% | 76.9% | 81.0% | |||||||
Period End Leased Percentage | 83.0% | 81.5% | 82.3% | 83.8% | 83.3% | 83.0% | 83.3% | |||||||
Period End Occupancy Percentage excluding KOP 2 | 80.7% | 80.8% | 81.5% | N/A | N/A | 80.7% | N/A | |||||||
Period End Leased Percentage excluding KOP 2 | 84.8% | 83.3% | 84.3% | N/A | N/A | 84.8% | N/A | |||||||
Average Occupancy | 76.8% | 77.6% | 77.4% | 80.9% | 80.7% | 77.3% | 81.0% | |||||||
Average Occupancy excluding KOP 2 | 80.5% | 81.4% | 81.4% | N/A | N/A | 81.1% | N/A | |||||||
Lease Composition (Net / Gross) (8) | 54% / 46% | 53% / 47% | 52% / 48% | 52% / 48% | 50% / 50% | N/A | N/A | |||||||
________________________
Note: Refer to pages 40-43 “Definitions Included in Supplemental” for definitions of commonly used terms included throughout this report. Refer to pages 36-38 “Non-GAAP Supplemental Measures” for management statements on the
Company’s non-GAAP measures presented in this report.
(1)Primarily represents compensation costs capitalized to construction and development projects.
(2)Represents incidental property operating and carry costs capitalized to development projects.
(3)Refer to page 44 for a reconciliation of GAAP Net Income Available to Common Stockholders to Net Operating Income.
(4)Refer to pages 10 and 45 for reconciliations of GAAP Net Income (Loss) Available to Common Stockholders to EBITDAre, Company’s Share of EBITDAre, and Company’s Share of Adjusted EBITDAre.
(5)Refer to page 6 for reconciliations of GAAP Net Income (Loss) Available to Common Stockholders to Funds From Operations and Funds Available for Distribution and page 46 for a reconciliation of GAAP Net Cash Provided by
Operating Activities to Funds Available for Distribution.
(6)Reported amounts are attributable to common stockholders, common unitholders, and restricted stock unitholders.
(7)Ratios are calculated based on current period amounts, except Net Debt to Company’s Share of EBITDAre and Adjusted EBITDAre Ratios, which are calculated on a trailing 12-month basis. Refer to page 34 for additional
information.
(8)Based on Annualized Base Rent, including 100% of consolidated property partnerships, as of the end of the period presented.
Kilroy Realty Q3 2026 Supplemental Report | 4
Where Innovation Works |
Consolidated Balance Sheets
(unaudited, $ in thousands)
9/30/2026 | 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | ||||||
ASSETS: | ||||||||||
Land | $1,730,514 | $1,730,514 | $1,730,514 | $1,641,913 | $1,661,679 | |||||
Buildings and improvements | 9,103,217 | 9,051,287 | 9,011,023 | 8,505,486 | 8,658,236 | |||||
Undeveloped land and construction in progress | 1,627,372 | 1,602,626 | 1,585,042 | 2,387,742 | 2,355,181 | |||||
Total real estate assets held for investment | 12,461,103 | 12,384,427 | 12,326,579 | 12,535,141 | 12,675,096 | |||||
Accumulated depreciation and amortization | (3,014,889) | (2,936,240) | (2,857,265) | (2,843,811) | (2,952,576) | |||||
Total real estate assets held for investment, net | 9,446,214 | 9,448,187 | 9,469,314 | 9,691,330 | 9,722,520 | |||||
Real estate and other assets held for sale, net | — | — | 188,771 | 115,155 | — | |||||
Cash and cash equivalents | 94,301 | 253,805 | 192,904 | 179,316 | 372,416 | |||||
Restricted cash | 250 | — | — | — | — | |||||
Marketable securities | 34,025 | 34,990 | 31,417 | 30,807 | 33,569 | |||||
Current receivables, net | 16,818 | 12,184 | 15,712 | 12,765 | 13,191 | |||||
Deferred rent receivables, net | 420,433 | 423,968 | 425,420 | 424,794 | 436,886 | |||||
Deferred leasing costs and acquisition-related intangible assets, net | 272,405 | 264,033 | 271,213 | 278,232 | 229,175 | |||||
Right of use ground lease assets, net | 127,261 | 127,548 | 127,834 | 128,116 | 128,396 | |||||
Prepaid expenses and other assets, net | 64,065 | 67,233 | 52,273 | 54,561 | 56,046 | |||||
Total Assets | $10,475,772 | $10,631,948 | $10,774,858 | $10,915,076 | $10,992,199 | |||||
LIABILITIES AND EQUITY: | ||||||||||
Liabilities: | ||||||||||
Secured debt, net | $588,777 | $590,095 | $591,398 | $592,685 | $593,956 | |||||
Unsecured debt, net | 3,748,263 | 3,947,034 | 3,997,993 | 3,996,774 | 3,995,555 | |||||
Unsecured line of credit | 40,000 | — | — | — | — | |||||
Accounts payable, accrued expenses, and other liabilities | 309,288 | 260,644 | 303,808 | 288,963 | 321,188 | |||||
Ground lease liabilities | 126,979 | 127,198 | 127,414 | 127,628 | 127,830 | |||||
Accrued dividends and distributions | 63,430 | 63,422 | 63,421 | 65,009 | 64,996 | |||||
Deferred revenue and acquisition-related intangible liabilities, net | 112,854 | 117,845 | 122,272 | 125,628 | 127,931 | |||||
Rents received in advance and tenant security deposits | 82,705 | 77,736 | 79,638 | 75,701 | 74,888 | |||||
Liabilities related to real estate assets held for sale | — | — | — | 4,945 | — | |||||
Total liabilities | 5,072,296 | 5,183,974 | 5,285,944 | 5,277,333 | 5,306,344 | |||||
Equity: | ||||||||||
Stockholders’ Equity | ||||||||||
Common stock | 1,163 | 1,163 | 1,163 | 1,184 | 1,183 | |||||
Additional paid-in capital | 5,171,034 | 5,166,167 | 5,161,140 | 5,230,747 | 5,223,369 | |||||
Retained earnings | 10,558 | 58,881 | 102,859 | 188,876 | 240,810 | |||||
Total stockholders’ equity | 5,182,755 | 5,226,211 | 5,265,162 | 5,420,807 | 5,465,362 | |||||
Noncontrolling Interests | ||||||||||
Common units of the Operating Partnership | 50,512 | 50,935 | 51,328 | 51,911 | 53,154 | |||||
Consolidated property partnerships | 170,209 | 170,828 | 172,424 | 165,025 | 167,339 | |||||
Total noncontrolling interests | 220,721 | 221,763 | 223,752 | 216,936 | 220,493 | |||||
Total equity | 5,403,476 | 5,447,974 | 5,488,914 | 5,637,743 | 5,685,855 | |||||
Total Liabilities And Equity | $10,475,772 | $10,631,948 | $10,774,858 | $10,915,076 | $10,992,199 |
Kilroy Realty Q3 2026 Supplemental Report | 5
Where Innovation Works |
Consolidated Statements of Operations
(unaudited, $ and shares in thousands, except per share amounts)
Three Months Ended | Nine Months Ended | ||||||||||||||
9/30/2026 | 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | 9/30/2026 | 9/30/2025 | |||||||||
Revenues | |||||||||||||||
Rental income | $266,750 | $268,321 | $265,330 | $267,363 | $274,909 | $800,401 | $826,224 | ||||||||
Other property income | 4,854 | 4,050 | 4,723 | 4,824 | 4,835 | 13,627 | 14,256 | ||||||||
Total revenues | 271,604 | 272,371 | 270,053 | 272,187 | 279,744 | 814,028 | 840,480 | ||||||||
Expenses | |||||||||||||||
Property expenses | 64,639 | 60,134 | 59,283 | 64,673 | 61,764 | 184,056 | 179,053 | ||||||||
Real estate taxes | 30,253 | 28,302 | 28,782 | 26,556 | 25,878 | 87,337 | 81,008 | ||||||||
Ground leases | 3,217 | 3,278 | 3,187 | 2,991 | 3,018 | 9,682 | 9,057 | ||||||||
General and administrative expenses | 18,408 | 18,933 | 20,699 | 19,485 | 18,247 | 58,040 | 53,623 | ||||||||
Leasing costs | 2,980 | 2,814 | 3,010 | 2,592 | 2,610 | 8,804 | 7,760 | ||||||||
Depreciation and amortization | 93,165 | 93,560 | 94,344 | 92,623 | 87,487 | 281,069 | 262,231 | ||||||||
Total expenses | 212,662 | 207,021 | 209,305 | 208,920 | 199,004 | 628,988 | 592,732 | ||||||||
Other Income (Expenses) | |||||||||||||||
Interest income | 620 | 1,247 | 954 | 2,205 | 3,119 | 2,821 | 4,765 | ||||||||
Interest expense | (39,376) | (41,634) | (38,511) | (32,148) | (32,152) | (119,521) | (94,144) | ||||||||
Other income (expense) | O t h e r i n c o m e ( e x p e n s e ) | 83 | (248) | 389 | 44 | 91 | 224 | 124 | |||||||
Gains on sales of depreciable operating properties | G a i n s o n s a l e s o f d e p r e c i a b l e o p e r a t i n g p r o p e r t i e s | — | — | 23,525 | — | 110,484 | G a i n s o n s a l e s o f d e p r e c i a b l e o p e r a t i n g p r o p e r t i e s | 23,525 | G a i n s o n s a l e s o f d e p r e c i a b l e o p e r a t i n g p r o p e r t i e s | 127,038 | |||||
Impairment of real estate assets (1) | — | — | (61,778) | (16,259) | — | (61,778) | — | ||||||||
Total other (expenses) income | (38,673) | (40,635) | (75,421) | (46,158) | 81,542 | (154,729) | 37,783 | ||||||||
Net Income (Loss) | 20,269 | 24,715 | (14,673) | 17,109 | 162,282 | 30,311 | 285,531 | ||||||||
Net (income) loss attributable to noncontrolling common units of the Operating Partnership | (151) | (193) | 185 | (120) | (1,524) | (159) | (2,562) | ||||||||
Net income attributable to noncontrolling interests in consolidated property partnerships | (4,612) | (4,617) | (4,779) | (4,545) | (4,538) | (14,008) | (19,292) | ||||||||
Total net income attributable to noncontrolling interests | (4,763) | (4,810) | (4,594) | (4,665) | (6,062) | (14,167) | (21,854) | ||||||||
Net Income (Loss) Available To Common Stockholders | $15,506 | $19,905 | $(19,267) | $12,444 | $156,220 | $16,144 | $263,677 | ||||||||
Weighted average common shares outstanding – basic | 116,309 | 116,292 | 117,637 | 118,338 | 118,296 | 116,741 | 118,259 | ||||||||
Weighted average common shares outstanding – diluted | 117,240 | 117,063 | 117,637 | 119,153 | 118,822 | 117,544 | 118,724 | ||||||||
Net Income (Loss) Available To Common Stockholders Per Share | |||||||||||||||
Net income (loss) available to common stockholders per share – basic | $0.13 | $0.17 | $(0.16) | $0.10 | $1.32 | $0.14 | $2.22 | ||||||||
Net income (loss) available to common stockholders per share – diluted | $0.13 | $0.17 | $(0.16) | $0.10 | $1.31 | $0.14 | $2.21 | ||||||||
________________________
(1)During the three months ended March 31, 2026, we recognized an impairment charge of approximately $61.8 million to reduce the carrying amount of the Columbia Square Living and Jardine residential towers to their
current fair value less closing costs. The sale of these properties closed in April 2026. During the three months ended December 31, 2025, we recognized an impairment charge of approximately $16.3 million to reduce
the carrying amount of Sunset Media Center to its current fair value less closing costs. The sale of this property closed in December 2025.
Kilroy Realty Q3 2026 Supplemental Report | 6
Where Innovation Works |
Funds From Operations & Funds Available for Distribution
(unaudited, $ and shares in thousands, except per share amounts)
Three Months Ended | Nine Months Ended | ||||||||||||||
9/30/2026 | 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | 9/30/2026 | 9/30/2025 | |||||||||
FUNDS FROM OPERATIONS: | |||||||||||||||
Net income (loss) available to common stockholders | $15,506 | $19,905 | $(19,267) | $12,444 | $156,220 | $16,144 | $263,677 | ||||||||
Adjustments: | |||||||||||||||
Net income (loss) attributable to noncontrolling common units of the Operating Partnership | 151 | 193 | (185) | 120 | 1,524 | 159 | 2,562 | ||||||||
Net income attributable to noncontrolling interests in consolidated property partnerships | 4,612 | 4,617 | 4,779 | 4,545 | 4,538 | 14,008 | 19,292 | ||||||||
Depreciation and amortization of real estate assets | 91,737 | 92,131 | 92,885 | 91,213 | 86,080 | 276,753 | 258,058 | ||||||||
Gains on sales of depreciable operating properties | — | — | (23,525) | — | (110,484) | (23,525) | (127,038) | ||||||||
Impairment of real estate assets | — | — | 61,778 | 16,259 | — | 61,778 | — | ||||||||
Funds From Operations attributable to noncontrolling interests in consolidated property partnerships | (7,373) | (7,508) | (7,619) | (7,423) | (7,317) | (22,500) | (27,789) | ||||||||
Funds From Operations | $104,633 | $109,338 | $108,846 | $117,158 | $130,561 | $322,817 | $388,762 | ||||||||
Weighted average common shares/units outstanding – basic (1) | 117,978 | 117,956 | 119,251 | 119,869 | 119,870 | 118,390 | 119,823 | ||||||||
Weighted average common shares/units outstanding – diluted (1) | 118,910 | 118,726 | 119,957 | 120,684 | 120,397 | 119,193 | 120,288 | ||||||||
FFO per common share/unit – basic (2) | $0.89 | $0.93 | $0.91 | $0.98 | $1.09 | $2.73 | $3.24 | ||||||||
FFO per common share/unit – diluted (2) | $0.88 | $0.92 | $0.91 | $0.97 | $1.08 | $2.71 | $3.23 | ||||||||
FUNDS AVAILABLE FOR DISTRIBUTION: | |||||||||||||||
Funds From Operations | $104,633 | $109,338 | $108,846 | $117,158 | $130,561 | $322,817 | $388,762 | ||||||||
Adjustments: | |||||||||||||||
Recurring tenant improvements, leasing commissions, and capital expenditures | (47,038) | (28,111) | (18,743) | (31,724) | (36,959) | (93,892) | (88,377) | ||||||||
Amortization of deferred revenue related to tenant-funded tenant improvements | (3,353) | (3,315) | (3,218) | (3,547) | (3,639) | (9,886) | (11,097) | ||||||||
Straight-line rents, net | 2,832 | 1,502 | (701) | 2,358 | 1,303 | 3,633 | 9,270 | ||||||||
Amortization of net below market rents | (682) | (651) | (641) | (624) | (764) | (1,974) | (2,455) | ||||||||
Amortization of deferred financing costs and net debt discount/premium | 1,867 | 2,637 | 1,662 | 1,162 | 1,218 | 6,166 | 3,615 | ||||||||
Non-cash amortization of share-based compensation awards | 3,229 | 3,079 | 4,869 | 5,145 | 5,436 | 11,177 | 13,945 | ||||||||
Lease related adjustments and other (3) | (818) | (1,261) | (1,380) | (640) | 1,877 | (3,459) | (2,426) | ||||||||
Adjustments attributable to noncontrolling interests in consolidated property partnerships | 2,136 | 408 | 412 | 1,246 | 1,906 | 2,956 | 2,687 | ||||||||
Funds Available for Distribution | $62,806 | $83,626 | $91,106 | $90,534 | $100,939 | $237,538 | $313,924 | ||||||||
________________________
(1)Calculated based on weighted average shares outstanding including participating share-based awards and assuming the exchange of all common limited partnership units outstanding. Diluted amounts also include non-
participating share-based awards and the dilutive impact of contingently issuable shares.
(2)Reported per common share/unit amounts are attributable to common stockholders, common unitholders, and restricted stock unitholders.
(3)Includes deferred income and lease incentives, net, deferred settlement and restoration fee income, and deferred lease termination fee income. Includes non-cash ground rent expense beginning in Q1 2026.
Kilroy Realty Q3 2026 Supplemental Report | 7
Where Innovation Works |
Supplemental Income Statement Detail
(unaudited, $ in thousands)
Three Months Ended | Nine Months Ended | |||||||||||||||
9/30/2026 | 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | 9/30/2026 | 9/30/2025 | ||||||||||
Revenues | Income Statement Category | |||||||||||||||
* | Base rent | Rental income | $195,695 | $195,445 | $193,622 | $197,081 | $201,633 | $584,762 | $606,228 | |||||||
* | Tenant reimbursements | Rental income | 52,936 | 46,994 | 46,527 | 47,779 | 51,867 | 146,457 | 146,215 | |||||||
* | Other revenues (1) | Rental income | 14,878 | 15,951 | 18,417 | 18,442 | 16,656 | 49,246 | 52,253 | |||||||
Deferred income and lease incentives, net (2) | Rental income | 614 | 965 | 1,060 | 257 | 707 | 2,639 | 2,312 | ||||||||
Amortization of deferred revenue related to tenant-funded tenant improvements | Rental income | 3,353 | 3,315 | 3,218 | 3,547 | 3,639 | 9,886 | 11,097 | ||||||||
Straight-line rents, net | Rental income | (2,832) | (1,502) | 701 | (2,358) | (1,303) | (3,633) | (9,270) | ||||||||
Amortization of net below market rents | Rental income | 682 | 651 | 641 | 624 | 764 | 1,974 | 2,455 | ||||||||
* | Settlement and restoration fee income | Rental income | 1,109 | 6,138 | 746 | 450 | 2,663 | 7,993 | 3,365 | |||||||
Deferred settlement and restoration fee income | Rental income | — | — | — | — | (2,026) | — | — | ||||||||
Cash lease termination fee income | Rental income | 42 | — | 9 | 1,158 | 867 | 51 | 11,455 | ||||||||
Deferred lease termination fee income | Rental income | 273 | 364 | 389 | 383 | (558) | 1,026 | 114 | ||||||||
* | Other property income (3) | Other property income | 4,854 | 4,050 | 4,723 | 4,824 | 4,835 | 13,627 | 14,256 | |||||||
Total Revenues | $271,604 | $272,371 | $270,053 | $272,187 | $279,744 | $814,028 | $840,480 | |||||||||
________________________
* Represents a component of Cash Net Operating Income.
(1)Primarily comprised of residential income, contractual parking income, and net of revenues deemed uncollectible.
(2)Includes non-cash adjustments attributable to lease-related matters, including GAAP revenue recognition timing differences.
(3)Primarily comprised of transient parking income.
Kilroy Realty Q3 2026 Supplemental Report | 8
Where Innovation Works |
Net Operating Income
(unaudited, $ in thousands)
Three Months Ended | Nine Months Ended | ||||||||||||||
9/30/2026 | 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | 9/30/2026 | 9/30/2025 | |||||||||
Cash Operating Revenues: | |||||||||||||||
Base rent | $195,695 | $195,445 | $193,622 | $197,081 | $201,633 | $584,762 | $606,228 | ||||||||
Tenant reimbursements | 52,936 | 46,994 | 46,527 | 47,779 | 51,867 | 146,457 | 146,215 | ||||||||
Other revenues (1) | 14,878 | 15,951 | 18,417 | 18,442 | 16,656 | 49,246 | 52,253 | ||||||||
Settlement and restoration fee income | 1,109 | 6,138 | 746 | 450 | 2,663 | 7,993 | 3,365 | ||||||||
Other property income (2) | 4,854 | 4,050 | 4,723 | 4,824 | 4,835 | 13,627 | 14,256 | ||||||||
Total cash operating revenues | 269,472 | 268,578 | 264,035 | 268,576 | 277,654 | 802,085 | 822,317 | ||||||||
Cash Operating Expenses: | |||||||||||||||
Property expenses | 64,639 | 60,134 | 59,283 | 64,673 | 61,764 | 184,056 | 179,053 | ||||||||
Real estate taxes | 30,253 | 28,302 | 28,782 | 26,556 | 25,878 | 87,337 | 81,008 | ||||||||
Ground leases | 3,148 | 3,210 | 3,118 | 2,913 | 2,940 | 9,476 | 8,823 | ||||||||
Total cash operating expenses | 98,040 | 91,646 | 91,183 | 94,142 | 90,582 | 280,869 | 268,884 | ||||||||
Cash Net Operating Income (3) | 171,432 | 176,932 | 172,852 | 174,434 | 187,072 | 521,216 | 553,433 | ||||||||
Deferred income and lease incentives, net (4) | 614 | 965 | 1,060 | 257 | 707 | 2,639 | 2,312 | ||||||||
Amortization of deferred revenue related to tenant-funded tenant improvements | 3,353 | 3,315 | 3,218 | 3,547 | 3,639 | 9,886 | 11,097 | ||||||||
Straight-line rents, net | (2,832) | (1,502) | 701 | (2,358) | (1,303) | (3,633) | (9,270) | ||||||||
Amortization of net below market rents | 682 | 651 | 641 | 624 | 764 | 1,974 | 2,455 | ||||||||
Deferred settlement and restoration fee income | — | — | — | — | (2,026) | — | — | ||||||||
Other (5) | (69) | (68) | (69) | (78) | (78) | (206) | (234) | ||||||||
Net Operating Income (3) | 173,180 | 180,293 | 178,403 | 176,426 | 188,775 | 531,876 | 559,793 | ||||||||
Lease termination fees | 315 | 364 | 398 | 1,541 | 309 | 1,077 | 11,569 | ||||||||
General and administrative expenses | (18,408) | (18,933) | (20,699) | (19,485) | (18,247) | (58,040) | (53,623) | ||||||||
Leasing costs | (2,980) | (2,814) | (3,010) | (2,592) | (2,610) | (8,804) | (7,760) | ||||||||
Other income (expense) | 83 | (248) | 389 | 44 | 91 | 224 | 124 | ||||||||
Interest income | 620 | 1,247 | 954 | 2,205 | 3,119 | 2,821 | 4,765 | ||||||||
Interest expense | (39,376) | (41,634) | (38,511) | (32,148) | (32,152) | (119,521) | (94,144) | ||||||||
Depreciation and amortization | (93,165) | (93,560) | (94,344) | (92,623) | (87,487) | (281,069) | (262,231) | ||||||||
Gains on sales of depreciable operating properties | — | — | 23,525 | — | 110,484 | 23,525 | 127,038 | ||||||||
Impairment of real estate assets | — | — | (61,778) | (16,259) | — | (61,778) | — | ||||||||
Net Income (Loss) | $20,269 | $24,715 | $(14,673) | $17,109 | $162,282 | $30,311 | $285,531 | ||||||||
________________________
(1)Primarily comprised of residential income, contractual parking income, and net of revenues deemed uncollectible.
(2)Primarily comprised of transient parking income.
(3)Refer to page 44 for a reconciliation of GAAP Net Income Available to Common Stockholders to Cash Net Operating Income and Net Operating Income.
(4)Includes non-cash adjustments attributable to lease-related matters, including GAAP revenue recognition timing differences.
(5)Includes other non-cash amounts primarily related to ground rent expense.
Kilroy Realty Q3 2026 Supplemental Report | 9
Where Innovation Works |
Same Property Net Operating Income Analysis (Cash Basis)
(unaudited, $ in thousands)
Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||
2026 | 2025 | % Contribution | 2026 | 2025 | % Contribution | |||||||
Total Same Property Portfolio | ||||||||||||
Number of properties | 113 | 113 | ||||||||||
Square Feet | 15,635,655 | 15,635,655 | ||||||||||
Average Occupancy (1) | 81.2% | 81.6% | 81.7% | 81.5% | ||||||||
Percent of Stabilized Portfolio | 91.2% | 91.2% | ||||||||||
Cash Operating Revenues: | ||||||||||||
Base rent | $187,622 | $185,885 | 1.0% | $560,043 | $558,602 | 0.3% | ||||||
Tenant reimbursements | 50,094 | 49,148 | 0.5% | 139,041 | 137,700 | 0.3% | ||||||
Other revenues (2) | 14,621 | 12,289 | 1.3% | 42,564 | 38,490 | 0.8% | ||||||
Settlement and restoration fee income | 1,108 | 2,663 | (0.9)% | 7,971 | 3,365 | 0.9% | ||||||
Other property income (3) | 4,235 | 4,124 | 0.1% | 11,834 | 12,058 | —% | ||||||
Total cash operating revenues | 257,680 | 254,109 | 2.0% | 761,453 | 750,215 | 2.3% | ||||||
Cash Operating Expenses: | ||||||||||||
Property expenses | 58,619 | 55,019 | (2.1)% | 164,730 | 158,824 | (1.2)% | ||||||
Real estate taxes | 25,296 | 23,011 | (1.3)% | 71,774 | 70,199 | (0.3)% | ||||||
Ground leases | 3,147 | 2,940 | (0.1)% | 9,475 | 8,823 | (0.1)% | ||||||
Total cash operating expenses | 87,062 | 80,970 | (3.5)% | 245,979 | 237,846 | (1.6)% | ||||||
Cash Net Operating Income (4) (5) (6) | $170,618 | $173,139 | (1.5)% | $515,474 | $512,369 | 0.7% | ||||||
________________________
(1)Calculated as the average of the daily ending occupancy percentages.
(2)Primarily comprised of residential income, contractual parking income, and net of revenues deemed uncollectible.
(3)Primarily comprised of transient parking income.
(4)For Same Property Cash Net Operating Income, restoration and settlement fee income is recognized in the period in which it is received, which may not correspond with the timing of GAAP revenue recognition. Tenant
prepayments are recognized in the applicable lease billing period.
(5)Refer to page 44 for a reconciliation of GAAP Net Income Available to Common Stockholders to Same Property Cash Net Operating Income.
(6)For the three months ended September 30, 2026 and 2025, Same Property Cash Net Operating Income from our One Paseo Living residential property represented 2.9% and 3.0% of total Same Property Cash Net
Operating Income, respectively. For the nine months ended September 30, 2026 and 2025, Same Property Cash Net Operating Income from our One Paseo Living residential property represented 2.9% and 2.8% of
total Same Property Cash Net Operating Income, respectively.
Kilroy Realty Q3 2026 Supplemental Report | 10
Where Innovation Works |
EBITDAre and Adjusted EBITDAre
(unaudited, $ in thousands)
Three Months Ended | Nine Months Ended | ||||||||||||||
9/30/2026 | 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | 9/30/2026 | 9/30/2025 | |||||||||
Net Income (Loss) | $20,269 | $24,715 | $(14,673) | $17,109 | $162,282 | $30,311 | $285,531 | ||||||||
Interest expense | 39,376 | 41,634 | 38,511 | 32,148 | 32,152 | 119,521 | 94,144 | ||||||||
Depreciation and amortization | 93,165 | 93,560 | 94,344 | 92,623 | 87,487 | 281,069 | 262,231 | ||||||||
Taxes | 153 | 77 | (29) | — | 124 | 201 | 192 | ||||||||
Gains on sales of depreciable operating properties | — | — | (23,525) | — | (110,484) | (23,525) | (127,038) | ||||||||
Impairment of real estate assets | — | — | 61,778 | 16,259 | — | 61,778 | — | ||||||||
EBITDAre | 152,963 | 159,986 | 156,406 | 158,139 | 171,561 | 469,355 | 515,060 | ||||||||
EBITDAre attributable to noncontrolling interests in consolidated property partnerships | (7,373) | (7,508) | (7,823) | (7,584) | (7,435) | (22,704) | (28,301) | ||||||||
Company's Share of EBITDAre | 145,590 | 152,478 | 148,583 | 150,555 | 164,126 | 446,651 | 486,759 | ||||||||
Interest income | (620) | (1,247) | (954) | (2,205) | (3,119) | (2,821) | (4,765) | ||||||||
Company's Share of Adjusted EBITDAre | $144,970 | $151,231 | $147,629 | $148,350 | $161,007 | $443,830 | $481,994 | ||||||||
02
Portfolio Data
–Stabilized Portfolio Occupancy Overview by Region
–Leases Executed
–Stabilized Portfolio Capital Expenditures
–Stabilized Portfolio Lease Expirations
–Top 20 Tenants
–Tenant Industry Diversification
–2026 Acquisitions
–2026 Dispositions and Assets Under Contract
–Consolidated Ventures (Noncontrolling Property Partnerships)
Maple Plaza, Beverly Hills, CA
Kilroy Realty Q3 2026 Supplemental Report | 12
Where Innovation Works |
Stabilized Portfolio Occupancy Overview by Region (1) (2)
(unaudited)
Total Rentable Square Feet | Occupied at | Leased at | ||||||||||||
YTD NOI % | Rentable Square Feet % | 9/30/2026 | 6/30/2026 | 9/30/2026 | 6/30/2026 | |||||||||
SAN FRANCISCO BAY AREA | ||||||||||||||
San Francisco CBD | 25.6% | 19.9% | 3,410,022 | 81.2% | 81.3% | 81.3% | 82.0% | |||||||
South San Francisco (3) | 7.9% | 9.8% | 1,677,847 | 48.0% | 47.9% | 73.5% | 69.5% | |||||||
Other Peninsula | 5.8% | 4.3% | 745,127 | 89.2% | 89.4% | 95.4% | 89.4% | |||||||
Silicon Valley | 5.0% | 3.6% | 622,640 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
Total San Francisco Bay Area | 44.3% | 37.6% | 6,455,636 | 75.3% | 75.3% | 82.7% | 81.3% | |||||||
LOS ANGELES | ||||||||||||||
El Segundo | 2.8% | 6.4% | 1,103,595 | 66.0% | 65.4% | 66.5% | 65.8% | |||||||
Hollywood / West Hollywood | 7.4% | 6.2% | 1,057,790 | 85.9% | 86.1% | 95.6% | 95.6% | |||||||
Long Beach | 2.6% | 5.6% | 957,063 | 77.2% | 78.5% | 84.0% | 81.6% | |||||||
West Los Angeles | 1.3% | 3.8% | 655,094 | 56.0% | 55.2% | 63.8% | 63.0% | |||||||
Beverly Hills | 1.8% | 1.8% | 306,366 | 74.9% | 80.4% | 86.8% | 84.1% | |||||||
Culver City | 0.2% | 1.0% | 166,207 | 56.2% | 52.2% | 60.3% | 52.2% | |||||||
Total Los Angeles | 16.1% | 24.8% | 4,246,115 | 72.2% | 72.5% | 78.5% | 77.2% | |||||||
SEATTLE | ||||||||||||||
Lake Union / Denny Regrade | 11.4% | 12.1% | 2,078,012 | 81.2% | 80.7% | 86.8% | 85.9% | |||||||
Bellevue | 5.7% | 5.4% | 919,295 | 75.5% | 74.9% | 80.7% | 75.6% | |||||||
Total Seattle | 17.1% | 17.5% | 2,997,307 | 79.5% | 78.9% | 84.9% | 82.7% | |||||||
SAN DIEGO | ||||||||||||||
Del Mar | 13.1% | 10.7% | 1,853,360 | 88.3% | 89.2% | 90.5% | 89.4% | |||||||
Little Italy / Point Loma | 0.8% | 1.9% | 320,371 | 62.9% | 62.9% | 69.8% | 67.3% | |||||||
University Towne Center | 1.8% | 1.7% | 283,134 | 81.6% | 81.6% | 90.3% | 90.3% | |||||||
Torrey Pines | 1.7% | 1.4% | 232,166 | 75.1% | 75.1% | 75.1% | 75.1% | |||||||
Total San Diego | 17.4% | 15.7% | 2,689,031 | 83.4% | 84.1% | 86.7% | 85.6% | |||||||
AUSTIN | ||||||||||||||
Austin CBD | 5.1% | 4.4% | 758,975 | 84.0% | 84.0% | 90.4% | 88.8% | |||||||
Total Austin | 5.1% | 4.4% | 758,975 | 84.0% | 84.0% | 90.4% | 88.8% | |||||||
Total Stabilized Portfolio | 100.0% | 100.0% | 17,147,064 | 76.9% | 77.0% | 83.0% | 81.5% | |||||||
Total Stabilized Portfolio Excluding KOP 2 | 80.7% | 80.8% | 84.8% | 83.3% | ||||||||||
Average Occupancy (4) | ||||||
Quarter to Date | Quarter to Date (Excluding KOP 2) | Year to Date | Year to Date (Excluding KOP 2) | |||
76.8% | 80.5% | 77.3% | 81.1% | |||
________________________
(1)Includes all properties owned and included in the stabilized portfolio as of the end of the period presented. Excludes our residential property.
(2)Occupied and leased percentage calculations presented throughout this report are based on rentable square footage at the end of the period, inclusive of all remeasurements that occurred during the period.
(3)KOP 2 stabilized during the three months ended March 31, 2026.
(4)Calculated as the average of the daily ending occupancy percentages.
Kilroy Realty Q3 2026 Supplemental Report | 13
Where Innovation Works |
Stabilized Portfolio Occupancy Overview by Region, continued (1)
(unaudited)
Rentable Square Feet | Occupied at | Leased at | ||||||||||||
Campus | Submarket | 9/30/2026 | 6/30/2026 | 9/30/2026 | 6/30/2026 | |||||||||
SAN FRANCISCO BAY AREA, CALIFORNIA | ||||||||||||||
100 Hooper Street | 100 Hooper | San Francisco CBD | 417,914 | 94.4% | 94.4% | 94.4% | 94.4% | |||||||
100 First Street | 100 First Street | San Francisco CBD | 480,457 | 88.2% | 92.2% | 88.3% | 92.2% | |||||||
201 Third Street | 201 Third Street | San Francisco CBD | 355,960 | 89.8% | 86.4% | 89.8% | 90.7% | |||||||
303 Second Street | 303 Second Street | San Francisco CBD | 784,658 | 63.7% | 63.1% | 64.0% | 64.0% | |||||||
350 Mission Street | 350 Mission Street | San Francisco CBD | 455,340 | 99.7% | 99.7% | 99.7% | 99.7% | |||||||
360 Third Street | 360 Third Street | San Francisco CBD | 436,357 | 45.7% | 45.7% | 45.7% | 45.7% | |||||||
250 Brannan Street | 250 Brannan | San Francisco CBD | 100,850 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
301 Brannan Street | 301 Brannan | San Francisco CBD | 82,834 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
333 Brannan Street | 333 / 345 Brannan | San Francisco CBD | 185,602 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
345 Brannan Street | 333 / 345 Brannan | San Francisco CBD | 110,050 | 99.7% | 99.7% | 99.7% | 99.7% | |||||||
350 Oyster Point Boulevard | Kilroy Oyster Point - Phase 1 | South San Francisco | 234,892 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
352 Oyster Point Boulevard | Kilroy Oyster Point - Phase 1 | South San Francisco | 232,215 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
354 Oyster Point Boulevard | Kilroy Oyster Point - Phase 1 | South San Francisco | 193,472 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
363 Oyster Point Boulevard * | Kilroy Oyster Point - Phase 2 | South San Francisco | 318,935 | 0.0% | 0.0% | 0.0% | 0.0% | |||||||
365 Oyster Point Boulevard * | Kilroy Oyster Point - Phase 2 | South San Francisco | 272,333 | 23.5% | 22.9% | 53.6% | 53.0% | |||||||
369 Oyster Point Boulevard * | Kilroy Oyster Point - Phase 2 | South San Francisco | 280,470 | 0.0% | 0.0% | 100.0% | 100.0% | |||||||
345 Oyster Point Boulevard | Oyster Point Tech Center | South San Francisco | 40,410 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
347 Oyster Point Boulevard | Oyster Point Tech Center | South San Francisco | 39,780 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
349 Oyster Point Boulevard | Oyster Point Tech Center | South San Francisco | 65,340 | 0.0% | 0.0% | 100.0% | 0.0% | |||||||
900 Jefferson Avenue | Crossing 900 | Other Peninsula | 237,139 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
900 Middlefield Road | Crossing 900 | Other Peninsula | 122,134 | 98.2% | 100.0% | 98.2% | 100.0% | |||||||
4100 Bohannon Drive | Menlo Corporate Center | Other Peninsula | 48,645 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
4200 Bohannon Drive | Menlo Corporate Center | Other Peninsula | 44,081 | 48.6% | 48.9% | 48.6% | 48.9% | |||||||
4300 Bohannon Drive | Menlo Corporate Center | Other Peninsula | 64,905 | 85.2% | 85.3% | 85.2% | 85.3% | |||||||
4400 Bohannon Drive * | Menlo Corporate Center | Other Peninsula | 49,065 | 6.3% | 6.3% | 100.0% | 6.3% | |||||||
4500 Bohannon Drive | Menlo Corporate Center | Other Peninsula | 64,139 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
4600 Bohannon Drive | Menlo Corporate Center | Other Peninsula | 49,863 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
4700 Bohannon Drive | Menlo Corporate Center | Other Peninsula | 65,156 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
680 E. Middlefield Road | 680 & 690 Middlefield | Silicon Valley | 171,676 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
690 E. Middlefield Road | 680 & 690 Middlefield | Silicon Valley | 171,215 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
1701 Page Mill Road | Page Mill / Porter | Silicon Valley | 128,688 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
3150 Porter Drive | Page Mill / Porter | Silicon Valley | 36,886 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
1290-1300 Terra Bella Avenue | Terra Bella | Silicon Valley | 114,175 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
Total San Francisco Bay Area | 6,455,636 | 75.3% | 75.3% | 82.7% | 81.3% | |||||||||
________________________
* Excluded from the Same Property portfolio.
(1)Includes all properties owned and included in the stabilized portfolio as of the end of the period presented.
Kilroy Realty Q3 2026 Supplemental Report | 14
Where Innovation Works |
Stabilized Portfolio Occupancy Overview by Region, continued (1)
(unaudited)
Rentable Square Feet | Occupied at | Leased at | ||||||||||||
Campus | Submarket | 9/30/2026 | 6/30/2026 | 9/30/2026 | 6/30/2026 | |||||||||
LOS ANGELES, CALIFORNIA | ||||||||||||||
2240 E. Imperial Highway | Kilroy Airport Center | El Segundo | 122,870 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
2250 E. Imperial Highway | Kilroy Airport Center | El Segundo | 298,728 | 37.7% | 37.7% | 37.7% | 37.7% | |||||||
2260 E. Imperial Highway | Kilroy Airport Center | El Segundo | 298,728 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
909 N. Pacific Coast Highway | The Nines | El Segundo | 244,880 | 67.3% | 66.4% | 69.4% | 68.3% | |||||||
999 N. Pacific Coast Highway | The Nines | El Segundo | 138,389 | 21.3% | 18.3% | 21.3% | 18.3% | |||||||
1500 N. El Centro Avenue | Columbia Square | Hollywood / West Hollywood | 113,447 | 63.6% | 63.6% | 63.6% | 63.6% | |||||||
1525 N. Gower Street | Columbia Square | Hollywood / West Hollywood | 9,610 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
1575 N. Gower Street | Columbia Square | Hollywood / West Hollywood | 264,430 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
6115 W. Sunset Boulevard | Columbia Square | Hollywood / West Hollywood | 26,237 | 73.4% | 73.4% | 98.2% | 98.2% | |||||||
6121 W. Sunset Boulevard | Columbia Square | Hollywood / West Hollywood | 93,418 | 0.0% | 0.0% | 100.0% | 100.0% | |||||||
1350 Ivar Avenue | On Vine | Hollywood / West Hollywood | 16,448 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
1355 Vine Street | On Vine | Hollywood / West Hollywood | 183,129 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
1375 Vine Street | On Vine | Hollywood / West Hollywood | 159,236 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
1395 Vine Street | On Vine | Hollywood / West Hollywood | 2,575 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
8560 W. Sunset Boulevard | The Sunset | Hollywood / West Hollywood | 76,359 | 97.0% | 98.9% | 100.0% | 100.0% | |||||||
8570 W. Sunset Boulevard | The Sunset | Hollywood / West Hollywood | 49,276 | 99.0% | 99.0% | 99.0% | 99.0% | |||||||
8580 W. Sunset Boulevard | The Sunset | Hollywood / West Hollywood | 6,875 | 41.0% | 41.0% | 41.0% | 41.0% | |||||||
8590 W. Sunset Boulevard | The Sunset | Hollywood / West Hollywood | 56,750 | 99.7% | 99.7% | 99.7% | 99.7% | |||||||
3750 Kilroy Airport Way | Aero | Long Beach | 7,558 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
3760 Kilroy Airport Way | Aero | Long Beach | 167,317 | 84.8% | 83.1% | 100.0% | 84.8% | |||||||
3780 Kilroy Airport Way | Aero | Long Beach | 222,191 | 98.1% | 98.1% | 98.1% | 98.1% | |||||||
3800 Kilroy Airport Way | Aero | Long Beach | 192,476 | 52.0% | 52.0% | 61.5% | 55.0% | |||||||
3840 Kilroy Airport Way | Aero | Long Beach | 138,903 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
3880 Kilroy Airport Way | Aero | Long Beach | 97,246 | 39.0% | 39.0% | 47.7% | 47.7% | |||||||
3900 Kilroy Airport Way | Aero | Long Beach | 131,372 | 72.2% | 83.8% | 81.9% | 93.4% | |||||||
2100/2110 Colorado Avenue | Santa Monica Media Center | West Los Angeles | 109,225 | 53.2% | 53.2% | 100.0% | 100.0% | |||||||
12233 W. Olympic Boulevard | Tribeca West | West Los Angeles | 156,746 | 41.3% | 38.0% | 41.3% | 38.0% | |||||||
12100 W. Olympic Boulevard | Westside Media Center | West Los Angeles | 155,679 | 68.7% | 68.7% | 68.7% | 68.7% | |||||||
12200 W. Olympic Boulevard | Westside Media Center | West Los Angeles | 154,544 | 37.7% | 37.7% | 37.7% | 37.7% | |||||||
12312 W. Olympic Boulevard | Westside Media Center | West Los Angeles | 78,900 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
335-345 N. Maple Drive * | Maple Plaza | Beverly Hills | 306,366 | 74.9% | 80.4% | 86.8% | 84.1% | |||||||
3101-3243 S. La Cienega Boulevard | Blackwelder | Culver City | 166,207 | 56.2% | 52.2% | 60.3% | 52.2% | |||||||
Total Los Angeles | 4,246,115 | 72.2% | 72.5% | 78.5% | 77.2% | |||||||||
________________________
* Excluded from the Same Property portfolio.
(1)Includes all properties owned and included in the stabilized portfolio as of the end of the period presented.
Kilroy Realty Q3 2026 Supplemental Report | 15
Where Innovation Works |
Stabilized Portfolio Occupancy Overview by Region, continued (1)
(unaudited)
Rentable Square Feet | Occupied at | Leased at | ||||||||||||
Campus | Submarket | 9/30/2026 | 6/30/2026 | 9/30/2026 | 6/30/2026 | |||||||||
SEATTLE, WASHINGTON | ||||||||||||||
333 Dexter Avenue North | 333 Dexter | Lake Union / Denny Regrade | 618,766 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
401 Terry Avenue North | 401 Terry | Lake Union / Denny Regrade | 174,530 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
701 N. 34th Street | Fremont Lake Union Center | Lake Union / Denny Regrade | 142,820 | 64.0% | 64.0% | 64.0% | 64.0% | |||||||
801 N. 34th Street | Fremont Lake Union Center | Lake Union / Denny Regrade | 173,615 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
837 N. 34th Street | Fremont Lake Union Center | Lake Union / Denny Regrade | 112,487 | 100.0% | 71.3% | 100.0% | 100.0% | |||||||
2001 8th Avenue | West8 | Lake Union / Denny Regrade | 535,395 | 36.7% | 40.6% | 58.4% | 54.7% | |||||||
320 Westlake Avenue North | Westlake Terry | Lake Union / Denny Regrade | 184,644 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
321 Terry Avenue North | Westlake Terry | Lake Union / Denny Regrade | 135,755 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
601 108th Avenue NE | Key Center | Bellevue | 490,738 | 64.1% | 63.3% | 73.5% | 64.1% | |||||||
10900 NE 4th Street | Skyline Tower | Bellevue | 428,557 | 88.7% | 88.2% | 88.9% | 88.7% | |||||||
Total Seattle | 2,997,307 | 79.5% | 78.9% | 84.9% | 82.7% | |||||||||
________________________
(1)Includes all properties owned and included in the stabilized portfolio as of the end of the period presented.
Kilroy Realty Q3 2026 Supplemental Report | 16
Where Innovation Works |
Stabilized Portfolio Occupancy Overview by Region, continued (1)
(unaudited)
Rentable Square Feet | Occupied at | Leased at | ||||||||||||
Campus | Submarket (2) | 9/30/2026 | 6/30/2026 | 9/30/2026 | 6/30/2026 | |||||||||
SAN DIEGO, CALIFORNIA | ||||||||||||||
12225 El Camino Real | Carmel Valley Corporate Center | Del Mar | 58,401 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
12235 El Camino Real | Carmel Valley Corporate Center | Del Mar | 53,751 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
12400 High Bluff Drive | 12400 High Bluff Drive | Del Mar | 216,518 | 91.5% | 91.5% | 91.5% | 91.5% | |||||||
3579 Valley Centre Drive | Kilroy Centre Del Mar | Del Mar | 54,960 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
3611 Valley Centre Drive | Kilroy Centre Del Mar | Del Mar | 132,425 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
3661 Valley Centre Drive | Kilroy Centre Del Mar | Del Mar | 124,756 | 34.2% | 34.2% | 64.1% | 34.2% | |||||||
3721 Valley Centre Drive | Kilroy Centre Del Mar | Del Mar | 117,777 | 80.4% | 94.8% | 80.4% | 94.8% | |||||||
3811 Valley Centre Drive | Kilroy Centre Del Mar | Del Mar | 118,912 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
12770 El Camino Real | One Paseo | Del Mar | 75,035 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
12780 El Camino Real | One Paseo | Del Mar | 140,591 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
12790 El Camino Real | One Paseo | Del Mar | 87,944 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
12830 El Camino Real | One Paseo | Del Mar | 196,444 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
12860 El Camino Real | One Paseo | Del Mar | 92,042 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
3745 Paseo Place | One Paseo | Del Mar | 95,885 | 94.4% | 94.1% | 95.7% | 96.8% | |||||||
12707 High Bluff Drive | One Paseo Junction | Del Mar | 59,245 | 91.2% | 91.2% | 94.6% | 91.2% | |||||||
12777 High Bluff Drive | One Paseo Junction | Del Mar | 44,486 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
12340 El Camino Real | The Caminos | Del Mar | 110,950 | 25.9% | 25.9% | 25.9% | 25.9% | |||||||
12390 El Camino Real | The Caminos | Del Mar | 73,238 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
2100 Kettner Boulevard | 2100 Kettner | Little Italy / Point Loma | 212,915 | 50.1% | 50.1% | 60.5% | 56.8% | |||||||
2305 Historic Decatur Road | Kilroy Liberty Station | Little Italy / Point Loma | 107,456 | 88.3% | 88.3% | 88.3% | 88.3% | |||||||
4690 Executive Drive * | 4690 Executive | University Towne Center | 52,074 | 0.0% | 0.0% | 47.3% | 47.3% | |||||||
9455 Towne Centre Drive | 9455 Towne Centre Drive | University Towne Center | 160,444 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
9514 Towne Centre Drive | 9514 Towne Centre Drive | University Towne Center | 70,616 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
3530 John Hopkins Court * | Nautilus | Torrey Pines | 45,589 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
3535 General Atomics Court * | Nautilus | Torrey Pines | 80,543 | 28.1% | 28.1% | 28.1% | 28.1% | |||||||
3550 John Hopkins Court * | Nautilus | Torrey Pines | 62,739 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
3565 General Atomics Court * | Nautilus | Torrey Pines | 43,295 | 100.0% | 100.0% | 100.0% | 100.0% | |||||||
Total San Diego | 2,689,031 | 83.4% | 84.1% | 86.7% | 85.6% | |||||||||
________________________
* Excluded from the Same Property portfolio.
(1)Includes all properties owned and included in the stabilized portfolio as of the end of the period presented.
(2)The Company defines the Del Mar submarket as Del Mar, Del Mar Heights, and Carmel Valley.
Kilroy Realty Q3 2026 Supplemental Report | 17
Where Innovation Works |
Stabilized Portfolio Occupancy Overview by Region, continued (1)
(unaudited)
Rentable Square Feet | Occupied at | Leased at | ||||||||||||
Campus | Submarket | 9/30/2026 | 6/30/2026 | 9/30/2026 | 6/30/2026 | |||||||||
AUSTIN, TEXAS | ||||||||||||||
200 W. 6th Street | Indeed Tower | Austin CBD | 758,975 | 84.0% | 84.0% | 90.4% | 88.8% | |||||||
Total Austin | 758,975 | 84.0% | 84.0% | 90.4% | 88.8% | |||||||||
Total Stabilized Portfolio | 17,147,064 | 76.9% | 77.0% | 83.0% | 81.5% | |||||||||
Total Stabilized Portfolio Excluding KOP 2 | 80.7% | 80.8% | 84.8% | 83.3% | ||||||||||
Average Residential Occupancy | ||||||||||||
Quarter to Date | Year to Date | |||||||||||
RESIDENTIAL PROPERTY | Campus | Submarket (2) | Total No. of Units | 9/30/2026 | 6/30/2026 | 9/30/2026 | ||||||
SAN DIEGO, CALIFORNIA | ||||||||||||
3200 Paseo Village Way | One Paseo Living | Del Mar | 608 | 94.8% | 95.6% | 95.1% | ||||||
________________________
(1)Includes all properties owned and included in the stabilized portfolio as of the end of the period presented.
(2)The Company defines the Del Mar submarket as Del Mar, Del Mar Heights, and Carmel Valley.
Kilroy Realty Q3 2026 Supplemental Report | 18
Where Innovation Works |
Leases Executed (1)
# of Leases | Square Feet | Weighted Average Lease Term (Mo.) | TI/LC Per Sq.Ft. (2) | TI/LC Per Sq.Ft. / Year (2) | ||||||||||||
Quarter to Date | New | Renewal | New | Renewal | Total | |||||||||||
2nd Gen Leasing | 19 | 14 | 335,401 | 343,139 | 678,540 | 99 | $94.43 | $11.48 | ||||||||
1st Gen / Major Repositioning / In-Process Development & Redevelopment Leasing | 8 | — | 124,271 | — | 124,271 | 101 | $283.72 | $39.01 | ||||||||
Total | 27 | 14 | 459,672 | 343,139 | 802,811 | |||||||||||
# of Leases | Square Feet | Weighted Average Lease Term (Mo.) | TI/LC Per Sq.Ft. (2) | TI/LC Per Sq.Ft. / Year (2) | ||||||||||||
Year to Date | New | Renewal | New | Renewal | Total | |||||||||||
2nd Gen Leasing | 57 | 38 | 699,845 | 522,145 | 1,221,990 | 81 | $78.32 | $11.08 | ||||||||
1st Gen / Major Repositioning / In-Process Development & Redevelopment Leasing | 16 | — | 414,248 | — | 414,248 | 148 | $300.54 | $29.53 | ||||||||
Total | 73 | 38 | 1,114,093 | 522,145 | 1,636,238 | |||||||||||
Quarter to Date | Year to Date | |||||||
2nd Gen Leasing Change in Rents | Changes in GAAP Rents (3) | Changes in Cash Rents (4) | Changes in GAAP Rents (3) | Changes in Cash Rents (4) | ||||
Leases Signed On Space Vacant Less Than or Equal to 12 Months | 37.9% | 13.9% | 32.8% | 12.6% | ||||
All Leases Signed | 30.6% | 9.7% | 17.5% | 2.1% | ||||
Retention Rate Calculations | Quarter to Date | Year to Date | ||
Retention Rate | 78.3% | 45.0% | ||
Retention Rate, including subtenants | 81.2% | 50.2% |
Leases Signed But Not Yet Commenced (5) | Period of Estimated Lease Commencement (6) | |||||||||
Q4 2026 | H1 2027 | H2 2027 | 2028 and Beyond | Total | ||||||
Square Feet | 250,650 | 315,277 | 327,366 | 509,270 | 1,402,563 | |||||
Annualized Base Rent (“ABR”) | $14,153 | $17,359 | $16,741 | $52,448 | $100,701 | |||||
ABR per Sq. Ft. | $56.47 | $55.06 | $51.14 | $102.99 | $71.80 | |||||
Net Leases | 78% | |||||||||
Gross Leases | 22% | |||||||||
Total ABR | 100% | |||||||||
________________________
(1)Includes 100% of consolidated property partnerships. Excludes leases with a lease term of less than one year (i.e. short-term leases). During the three months ended September 30, 2026, the Company signed 11,880
square feet of new short-term leasing on vacant space. During the nine months ended September 30, 2026, the Company signed 122,169 square feet of short-term leases, comprised of 76,437 square feet of new
leasing on vacant space and 45,732 square feet of renewal leasing.
(2)Includes tenant improvements and third-party leasing commissions, and excludes tenant-funded tenant improvements and indirect leasing costs.
(3)Calculated as the change between the expiring GAAP rent and the new GAAP rent for the same space. When necessary, lease structures are modified (adjusted for net leases) for comparability. Space that was vacant
when the property was acquired is excluded from these calculations.
(4)Calculated as the change between the expiring cash rent and the new cash rent for the same space. When necessary, lease structures are modified (adjusted for net leases) for comparability. Space that was vacant
when the property was acquired is excluded from these calculations.
(5)Includes 1,041,888 square feet of new leasing on previously vacant space, 144,798 square feet of non-stabilized development leasing, and 215,877 square feet that has been backfilled or re-leased to a subtenant as of
September 30, 2026, but has not yet commenced.
(6)Represents estimated achievement of revenue recognition for the associated lease agreements.
Kilroy Realty Q3 2026 Supplemental Report | 19
Where Innovation Works |
Stabilized Portfolio Capital Expenditures
($ in thousands)
Quarter to Date | Year to Date | ||||||||||||||
Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | 2026 | 2025 | |||||||||
Recurring Capital Expenditures: (1) | |||||||||||||||
Capital Improvements | $8,451 | $6,576 | $2,974 | $10,068 | $9,529 | $18,001 | $29,712 | ||||||||
Tenant Improvements & Leasing Commissions | 38,587 | 21,535 | 15,769 | 21,656 | 27,430 | 75,891 | 58,665 | ||||||||
Total | $47,038 | $28,111 | $18,743 | $31,724 | $36,959 | $93,892 | $88,377 | ||||||||
Average Capital Expenditures to Average NOI Ratio - Trailing Five Quarters | 18.1% | ||||||||||||||
Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | 2026 | 2025 | |||||||||
Major Repositioning Capital Expenditures: (2) | |||||||||||||||
Capital Improvements | $— | $— | $— | $60 | $39 | $— | $834 | ||||||||
Total | $— | $— | $— | $60 | $39 | $— | $834 | ||||||||
Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | 2026 | 2025 | |||||||||
First Generation Capital Expenditures: | |||||||||||||||
Tenant Improvements & Leasing Commissions | $21,372 | $14,738 | $8,980 | $5,098 | $4,268 | $45,090 | $14,016 | ||||||||
Total | $21,372 | $14,738 | $8,980 | $5,098 | $4,268 | $45,090 | $14,016 | ||||||||
________________________
(1)Includes 100% of consolidated property partnerships.
(2)Represents significant non-recurring capital expenditures for repositioning space that is expected to result in additional revenue generated when the space is re-leased.
Kilroy Realty Q3 2026 Supplemental Report | 20
Where Innovation Works |
Stabilized Portfolio Lease Expirations (1) (2) (3)
($ in thousands, except for Annualized Base Rent per sq. ft.)
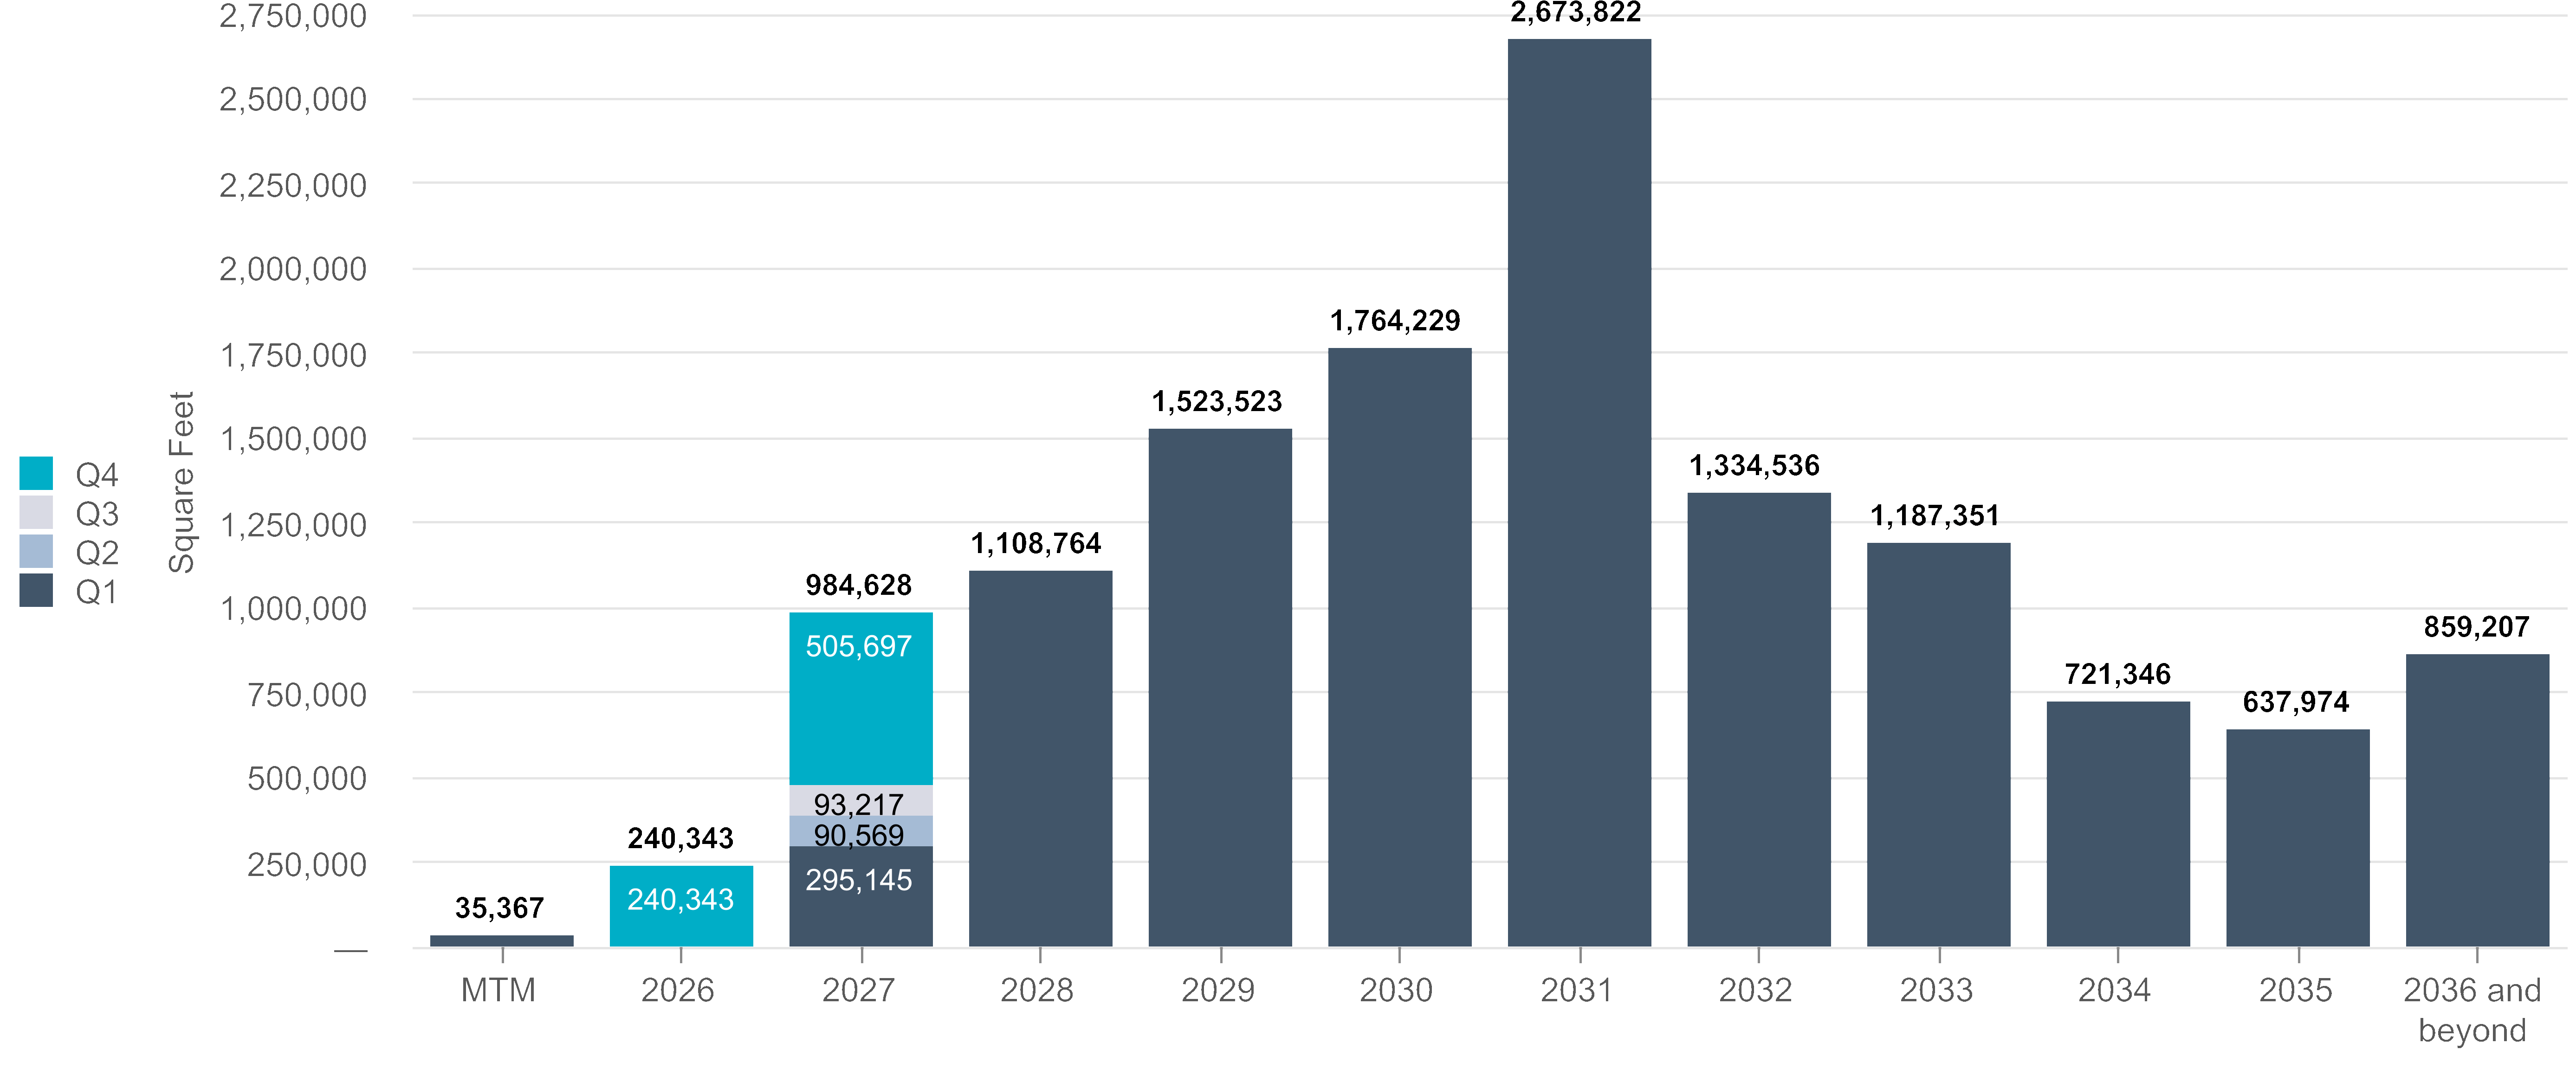
# of Expiring Leases | 22 | 67 | 77 | 70 | 73 | 79 | 28 | 23 | 21 | 17 | 32 |
% of Total Leased Sq. Ft. | 1.8% | 7.6% | 8.5% | 11.7% | 13.5% | 20.5% | 10.2% | 9.2% | 5.5% | 4.9% | 6.6% |
ABR | $10,710 | $36,146 | $68,070 | $80,152 | $106,144 | $164,652 | $87,249 | $69,878 | $47,294 | $36,991 | $60,523 |
% of Total ABR | 1.4% | 4.7% | 8.9% | 10.4% | 13.8% | 21.4% | 11.4% | 9.1% | 6.2% | 4.8% | 7.9% |
ABR per Sq. Ft. | $44.56 | $36.71 | $61.39 | $52.61 | $60.16 | $61.58 | $65.38 | $58.85 | $65.56 | $57.98 | $70.44 |
________________________
(1)Represents all in-place leases as of September 30, 2026, excluding intercompany leases.
(2)Adjusting for leases that have been backfilled or re-leased to a subtenant as of September 30, 2026 but not yet commenced, the 2026, 2027, 2028, and 2031 expirations would be reduced by 86,875, 26,143, 53,394,
and 30,608 square feet, respectively.
(3)Includes 100% of consolidated property partnerships.
Kilroy Realty Q3 2026 Supplemental Report | 21
Where Innovation Works |
Stabilized Portfolio Lease Expirations by Region (1)
($ in thousands, except for Annualized Base Rent per sq. ft.)
Year | Region | # of Expiring Leases | Total Square Feet | % of Total Leased Sq. Ft. | Annualized Base Rent | % of Total Annualized Base Rent | Annualized Base Rent per Sq. Ft. | |||||||
2026 | San Francisco Bay Area | 3 | 19,545 | 0.1% | $1,197 | 0.2% | $61.24 | |||||||
Los Angeles | 13 | 106,052 | 0.9% | 3,729 | 0.5% | 35.16 | ||||||||
Seattle | 4 | 109,332 | 0.8% | 5,464 | 0.7% | 49.98 | ||||||||
San Diego | 2 | 5,414 | —% | 320 | —% | 59.11 | ||||||||
Austin | — | — | —% | — | —% | — | ||||||||
Total | 22 | 240,343 | 1.8% | $10,710 | 1.4% | $44.56 | ||||||||
2027 | San Francisco Bay Area | 5 | 34,600 | 0.3% | $1,347 | 0.2% | $38.93 | |||||||
Los Angeles | 46 | 794,446 | 6.1% | 27,453 | 3.6% | 34.56 | ||||||||
Seattle | 9 | 69,446 | 0.5% | 2,119 | 0.3% | 30.51 | ||||||||
San Diego | 7 | 86,136 | 0.7% | 5,227 | 0.6% | 60.68 | ||||||||
Austin | — | — | —% | — | —% | — | ||||||||
Total | 67 | 984,628 | 7.6% | $36,146 | 4.7% | $36.71 | ||||||||
2028 | San Francisco Bay Area | 14 | 623,426 | 4.8% | $40,773 | 5.4% | $65.40 | |||||||
Los Angeles | 43 | 207,793 | 1.6% | 12,321 | 1.6% | 59.29 | ||||||||
Seattle | 8 | 91,050 | 0.7% | 4,008 | 0.5% | 44.02 | ||||||||
San Diego | 12 | 186,495 | 1.4% | 10,968 | 1.4% | 58.81 | ||||||||
Austin | — | — | —% | — | —% | — | ||||||||
Total | 77 | 1,108,764 | 8.5% | $68,070 | 8.9% | $61.39 | ||||||||
2029 | San Francisco Bay Area | 16 | 583,477 | 4.5% | $31,960 | 4.2% | $54.78 | |||||||
Los Angeles | 24 | 439,892 | 3.4% | 22,818 | 3.0% | 51.87 | ||||||||
Seattle | 12 | 243,270 | 1.9% | 10,897 | 1.3% | 44.79 | ||||||||
San Diego | 17 | 252,673 | 1.9% | 14,242 | 1.9% | 56.37 | ||||||||
Austin | 1 | 4,211 | —% | 235 | —% | 55.81 | ||||||||
Total | 70 | 1,523,523 | 11.7% | $80,152 | 10.4% | $52.61 | ||||||||
2030 | San Francisco Bay Area | 16 | 856,319 | 6.6% | $55,157 | 7.2% | $64.41 | |||||||
Los Angeles | 21 | 232,023 | 1.8% | 13,765 | 1.7% | 59.33 | ||||||||
Seattle | 9 | 459,089 | 3.5% | 21,656 | 2.8% | 47.17 | ||||||||
San Diego | 26 | 211,344 | 1.6% | 15,161 | 2.0% | 71.74 | ||||||||
Austin | 1 | 5,454 | —% | 405 | 0.1% | 74.26 | ||||||||
Total | 73 | 1,764,229 | 13.5% | $106,144 | 13.8% | $60.16 | ||||||||
2031 and Beyond | San Francisco Bay Area | 39 | 2,703,793 | 20.8% | $210,297 | 27.3% | $77.78 | |||||||
Los Angeles | 64 | 1,198,127 | 9.1% | 68,153 | 8.9% | 56.88 | ||||||||
Seattle | 34 | 1,402,508 | 10.7% | 61,627 | 8.0% | 43.94 | ||||||||
San Diego | 45 | 1,488,507 | 11.4% | 97,824 | 13.0% | 65.72 | ||||||||
Austin | 18 | 621,301 | 4.9% | 28,686 | 3.6% | 46.17 | ||||||||
Total | 200 | 7,414,236 | 56.9% | $466,587 | 60.8% | $62.93 |
________________________
(1)Includes 100% of consolidated property partnerships.
Kilroy Realty Q3 2026 Supplemental Report | 22
Where Innovation Works |
Top 20 Tenants (1) (2)
($ in thousands)
# | Tenant Name | Region | Annualized Base Rental Revenue | Rentable Square Feet | Percentage of Total Annualized Base Rental Revenue | Percentage of Total Rentable Square Feet | Year(s) of Significant Lease Expiration(s) (3) | Weighted Average Remaining Lease Term (Years) | ||||||||
1 | Global technology company | Seattle / San Diego | $44,696 | 849,826 | 5.8% | 5.0% | 2032 / 2033 / 2037 | 6.8 | ||||||||
2 | Cruise LLC | San Francisco Bay Area | 35,449 | 374,618 | 4.6% | 2.2% | 2031 | 5.2 | ||||||||
3 | Stripe, Inc. | San Francisco Bay Area | 33,110 | 425,687 | 4.3% | 2.5% | 2034 | 7.8 | ||||||||
4 | Adobe Systems, Inc. | San Francisco Bay Area / Seattle | 27,917 | 537,368 | 3.6% | 3.1% | 2027 (4) / 2031 | 4.6 | ||||||||
5 | Box, Inc. | San Francisco Bay Area | 25,334 | 296,613 | 3.3% | 1.7% | 2028 (5) / 2040 | 11.6 | ||||||||
6 | Salesforce, Inc. | San Francisco Bay Area / Seattle | 24,706 | 472,016 | 3.2% | 2.8% | 2029 / 2030 / 2032 | 3.6 | ||||||||
7 | Okta, Inc. | San Francisco Bay Area | 24,206 | 293,001 | 3.2% | 1.7% | 2028 | 2.1 | ||||||||
8 | DoorDash, Inc. | San Francisco Bay Area | 23,842 | 236,759 | 3.1% | 1.4% | 2032 | 5.3 | ||||||||
9 | Netflix, Inc. | Los Angeles | 21,854 | 361,388 | 2.9% | 2.1% | 2032 | 5.8 | ||||||||
10 | Cytokinetics, Inc. | San Francisco Bay Area | 18,167 | 234,892 | 2.4% | 1.4% | 2033 | 7.1 | ||||||||
11 | DIRECTV, LLC | Los Angeles | 16,085 | 532,956 | 2.1% | 3.1% | 2026 / 2027 (6) | 0.9 | ||||||||
12 | Tandem Diabetes Care, Inc. | San Diego | 15,884 | 181,949 | 2.1% | 1.1% | 2035 | 8.6 | ||||||||
13 | Synopsys, Inc. | San Francisco Bay Area | 15,492 | 342,891 | 2.0% | 2.0% | 2030 | 3.9 | ||||||||
14 | Neurocrine Biosciences, Inc. | San Diego | 14,397 | 273,021 | 1.9% | 1.6% | 2029 / 2031 | 4.5 | ||||||||
15 | Viacom International, Inc. | Los Angeles | 13,718 | 220,330 | 1.8% | 1.3% | 2028 | 2.3 | ||||||||
16 | Indeed, Inc. | Austin CBD | 13,430 | 330,394 | 1.8% | 1.9% | 2034 | 8.3 | ||||||||
17 | Sony Group Corporation | San Francisco Bay Area / Los Angeles | 13,397 | 131,642 | 1.7% | 0.8% | 2030 | 3.5 | ||||||||
18 | Amazon.com | Seattle | 12,921 | 283,979 | 1.7% | 1.7% | 2030 | 3.4 | ||||||||
19 | Nektar Therapeutics, Inc. | San Francisco Bay Area | 12,297 | 135,974 | 1.6% | 0.8% | 2030 | 3.3 | ||||||||
20 | Splunk, Inc. | San Francisco Bay Area | 10,323 | 100,850 | 1.3% | 0.6% | 2031 | 5.2 | ||||||||
Total Top 20 Tenants | $417,225 | 6,616,154 | 54.4% | 38.8% | 5.0 | |||||||||||
________________________
(1)Includes subsidiaries of the tenant listed.
(2)The information presented is based on Annualized Base Rent as of September 30, 2026 and includes 100% of consolidated property partnerships.
(3)Significant lease expirations include those greater than 25,000 rentable square feet.
(4)The 2027 lease expiration represents 31,409 rentable square feet that expires on June 30, 2027.
(5)The 2028 lease expiration represents 53,676 square feet that expires on June 30, 2028, of which 26,859 square feet has been re-leased, commencing on July 1, 2028.
(6)The 2026 lease expiration represents 49,255 rentable square feet that expired on September 30, 2026, and the 2027 lease expiration represents the remaining 483,701 rentable square feet that expires on September
30, 2027.
Kilroy Realty Q3 2026 Supplemental Report | 23
Where Innovation Works |
Tenant Industry Diversification (1) (2)
Annualized Base Rent | Square Feet |
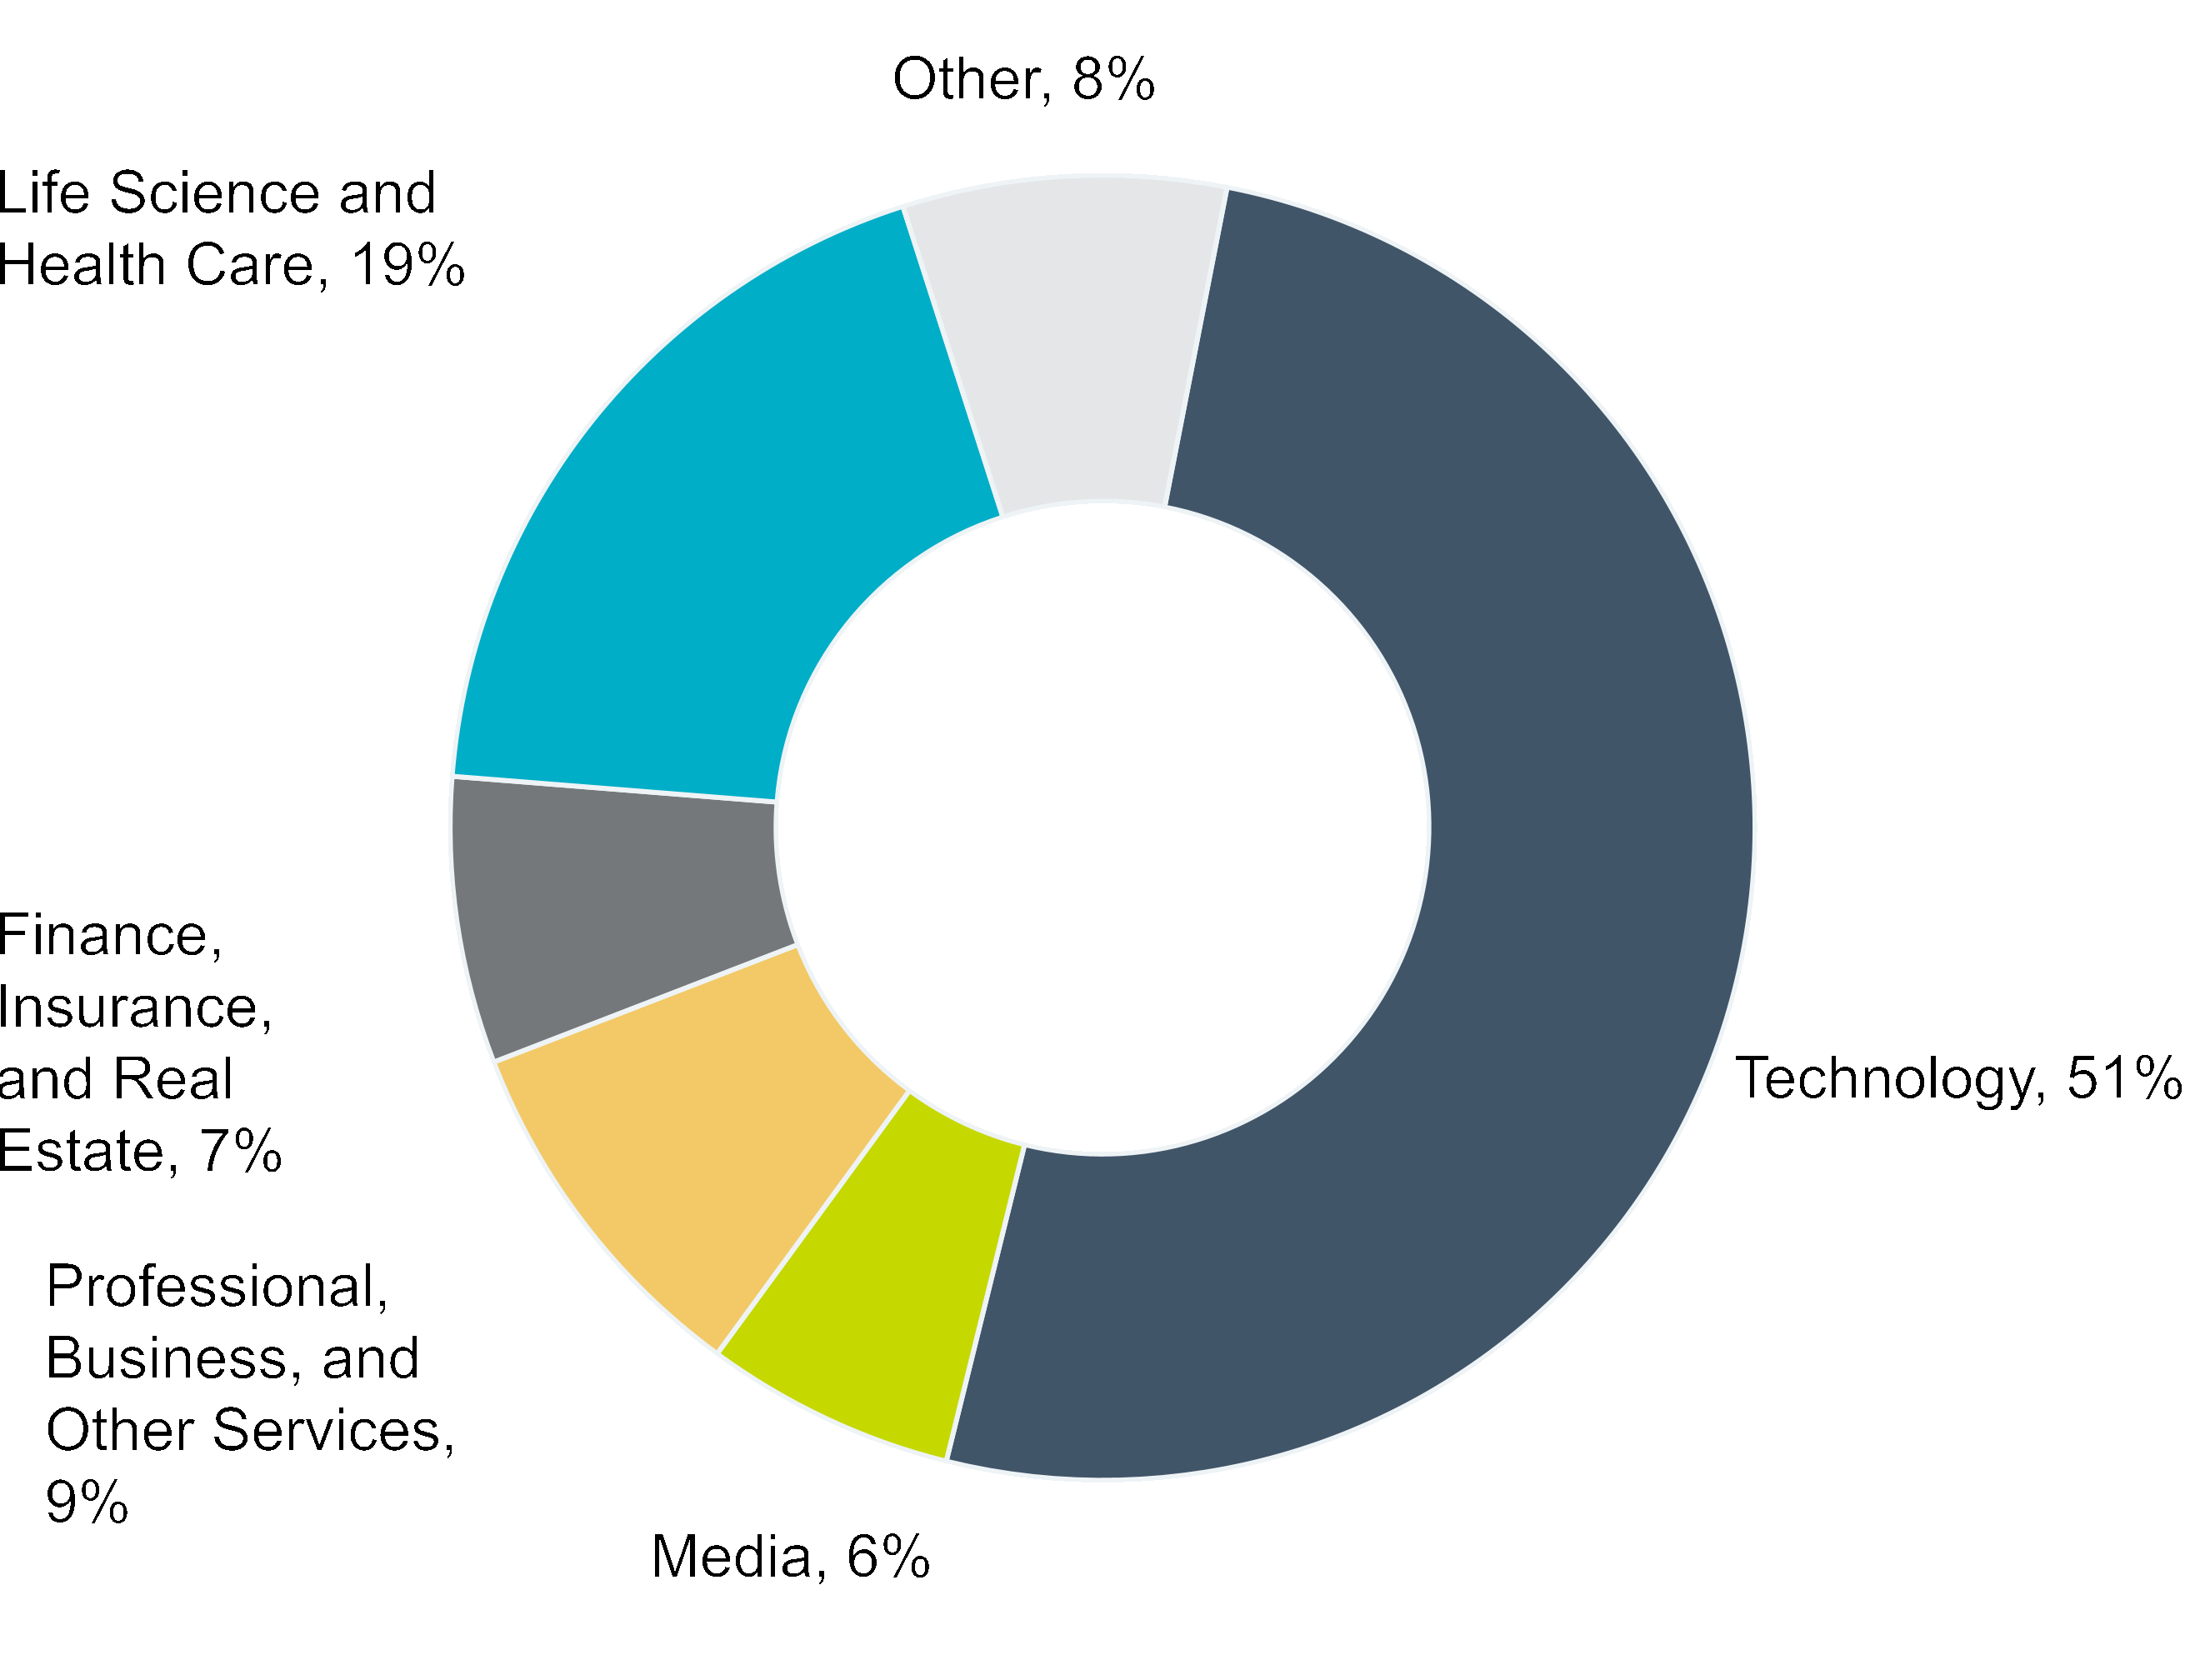
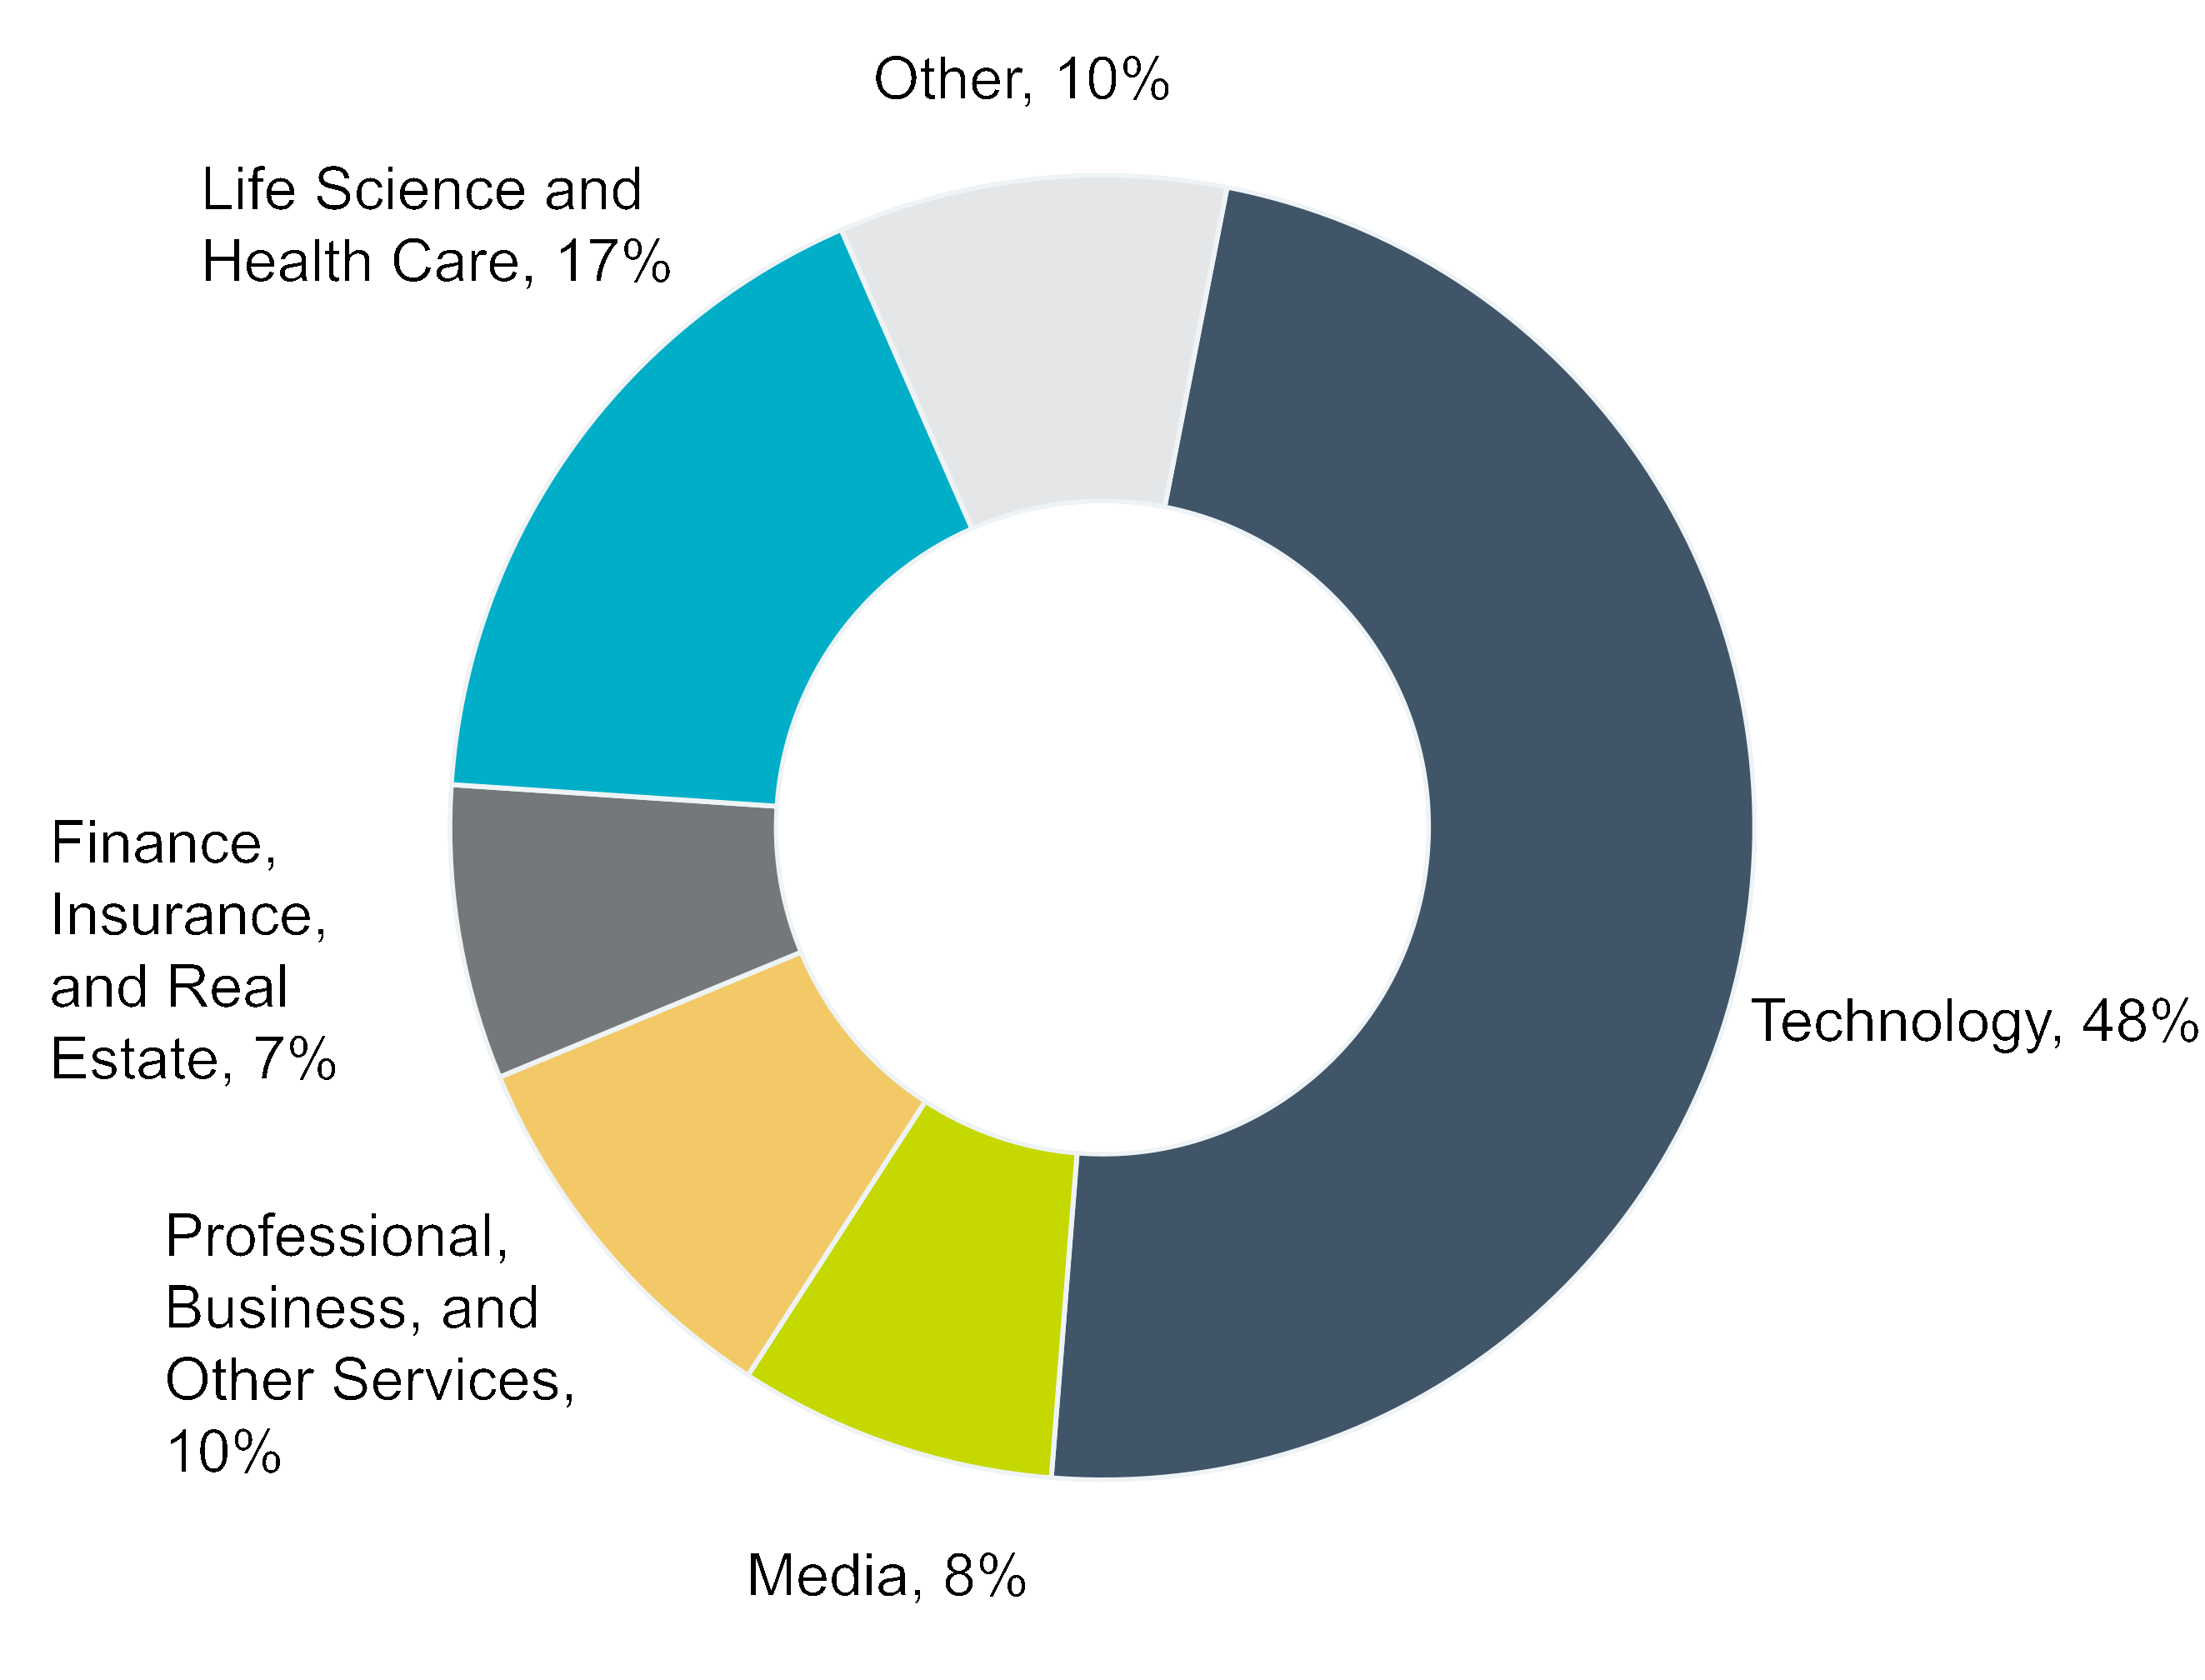
________________________
(1)Based on the North American Industry Classification System as of September 30, 2026.
(2)Includes 100% of consolidated property partnerships. Based on occupied square footage in the Stabilized Portfolio as of September 30, 2026, excluding month-to-month and intercompany leases.
Kilroy Realty Q3 2026 Supplemental Report | 24
Where Innovation Works |
2026 Acquisitions
($ in millions)
Submarket | Month of Acquisition | Acreage | Purchase Price (1) | |||||
1st Quarter | ||||||||
Land | ||||||||
1900 Broadway (2) | Other Peninsula | February | 1.1 | $36.0 | ||||
2nd Quarter | ||||||||
None | — | — | ||||||
3rd Quarter | ||||||||
None | — | — | ||||||
Total | 1.1 | $36.0 |
________________________
(1)Excludes acquisition-related costs and purchase price credits.
(2)During the three months ended March 31, 2026, acquired an interest in a fully-entitled land site that can support a 251,000-square-foot office building. Concurrent with closing, signed a 20-year lease with Cooley LLP for
approximately 145,000 square feet, bringing the project to 58% leased. Our joint venture partner contributed $9.0 million toward the purchase of the land.
Kilroy Realty Q3 2026 Supplemental Report | 25
Where Innovation Works |
2026 Dispositions and Assets Under Contract
($ in millions)
Operating Property Dispositions | Submarket | Month of Disposition | Number of Buildings | Rentable Square Feet / No. of Units | Sales Price (1) | |||||
1st Quarter | ||||||||||
Office | ||||||||||
Kilroy Sabre Springs (2) | I-15 Corridor | January | 3 | 427,764 | $124.5 | |||||
12348 High Bluff Drive (Del Mar Tech Center) | Del Mar | March | 1 | 39,192 | 21.0 | |||||
Total | 4 | 466,956 | $145.5 | |||||||
2nd Quarter | ||||||||||
Residential | ||||||||||
Hollywood Residential Properties (3) | Hollywood | April | 393 units | $202.0 | ||||||
3rd Quarter | ||||||||||
None | — | — | — | |||||||
Total Office and Residential | $347.5 |
Development Pipeline Under Contract (4) | Submarket | Acreage Under Contract | Anticipated Sales Price (1) | |||
1633 26th Street (5) | West Los Angeles | 2 acres | $41.0 | |||
Santa Fe Summit - PA1 (5) | 56 Corridor | 5 acres | 38.0 | |||
Santa Fe Summit - PA2 (5) | 56 Corridor | 17 acres | 86.0 | |||
East Village (6) | East Village | 3 acres | 19.5 | |||
Total Anticipated Proceeds | $184.5 |
________________________
(1)Represents actual or anticipated gross sales price before the impact of commissions, closing costs, and purchase price credits.
(2)Kilroy Sabre Springs includes the following buildings: 13480, 13500, and 13520 Evening Creek Drive North, San Diego, CA.
(3)The Hollywood Residential Properties include the 200-unit Columbia Square Living property located at 1550 N. El Centro Avenue, Los Angeles, CA and the 193-unit Jardine property located at 6390 De Longpre
Avenue, Los Angeles, CA.
(4)Subject to purchase and sale agreements and non-refundable deposits as of the date of this filing.
(5)Anticipated to close upon receipt of residential entitlements and permits, which is expected to occur beginning in phases in early 2027.
(6)Anticipated to close during the fourth quarter. No impairment was recorded as of September 30, 2026 as the property did not meet held-for-sale criteria and was deemed recoverable based on a probability-weighted
undiscounted future cash flow assessment.
Kilroy Realty Q3 2026 Supplemental Report | 26
Where Innovation Works |
Consolidated Ventures (Noncontrolling Property Partnerships)
(unaudited, $ in thousands)
Property | Venture Partner | Submarket | Portfolio | Rentable Square Feet | KRC Ownership % (1) | |||||
100 First Street, San Francisco, CA | Norges Bank Investment Management | San Francisco CBD | Stabilized | 480,457 | 56% | |||||
303 Second Street, San Francisco, CA | Norges Bank Investment Management | San Francisco CBD | Stabilized | 784,658 | 56% | |||||
900 Jefferson Avenue and 900 Middlefield Road, Redwood City, CA (2) | Local developer | Other Peninsula | Stabilized | 359,273 | 93% | |||||
1900 Broadway, Redwood City, CA | Local developer | Other Peninsula | Development | 251,000 | 97% |
Stabilized Portfolio Consolidated Venture Net Operating Income Reconciliation | Three Months Ended September 30, | Nine Months Ended September 30, | |||||
2026 | 2025 | 2026 | 2025 | ||||
Cash Operating Revenues: | |||||||
Base rent | $26,573 | $25,307 | $79,768 | $79,637 | |||
Tenant reimbursements | 4,157 | 4,390 | 11,916 | 11,849 | |||
Other revenues (3) | 149 | 20 | 229 | 2,221 | |||
Settlement and restoration fee income | 525 | — | 525 | 212 | |||
Other property income (4) | 591 | 625 | 1,619 | 1,849 | |||
Total cash operating revenues | 31,995 | 30,342 | 94,057 | 95,768 | |||
Cash Operating Expenses: | |||||||
Property expenses | 7,421 | 6,776 | 20,581 | 20,059 | |||
Real estate taxes | 2,345 | 2,283 | 6,919 | 6,743 | |||
Total cash operating expenses | 9,766 | 9,059 | 27,500 | 26,802 | |||
Cash Net Operating Income | 22,229 | 21,283 | 66,557 | 68,966 | |||
Deferred income and lease incentives, net (5) | 215 | 370 | 957 | 1,112 | |||
Amortization of deferred revenue related to tenant-funded tenant improvements | 412 | 482 | 1,284 | 1,416 | |||
Straight-line rents, net | (421) | 176 | (2,734) | (1,794) | |||
Net Operating Income | 22,435 | 22,311 | 66,064 | 69,700 | |||
Lease termination fees | 134 | 134 | 402 | 10,992 | |||
General and administrative expenses | — | (1) | (18) | (10) | |||
Leasing costs | (79) | (39) | (142) | (91) | |||
Other expense | — | — | (1) | (4) | |||
Interest income | 87 | — | 87 | — | |||
Depreciation and amortization | (7,936) | (8,045) | (23,866) | (24,599) | |||
Net Income | $14,641 | $14,360 | $42,526 | $55,988 | |||
KRC Share of Cash Net Operating Income (6) | $14,606 | $14,312 | $43,189 | $45,743 | |||
________________________
(1)Reflects the KRC ownership percentage at time of agreement. For 900 Jefferson Avenue and 900 Middlefield Road, actual percentage may vary depending on cash flows or promote structure. For 1900 Broadway,
reflects expected KRC ownership percentage upon completion of development activities.
(2)For 900 Jefferson Avenue and 900 Middlefield Road, KRC and our partner receive an 8% preferred return on invested capital. Any cash flows received above that amount are shared with our partner as a 10% promote,
with the remaining proceeds distributed according to our respective ownership percentages.
(3)Primarily comprised of contractual parking income and net of revenues deemed uncollectible.
(4)Primarily comprised of transient parking income.
(5)Includes non-cash adjustments attributable to lease-related matters, including GAAP revenue recognition timing differences.
(6)Reflects KRC share after consolidating elimination entries.
03
Development
–Stabilized Development & Redevelopment Projects
–In-Process Development & Redevelopment Projects
–Future Development Pipeline
Kilroy Oyster Point Phase 2, South San Francisco, CA
Kilroy Realty Q3 2026 Supplemental Report | 28
Where Innovation Works |
Stabilized Development & Redevelopment Projects
($ in millions)
% Leased | ||||||||||||||||
Location | Construction Start Date | Stabilization Date (1) | Rentable Square Feet | Total Estimated Investment | Total Project % Occupied | As of 9/30/2026 | As of Filing | |||||||||
1st Quarter | ||||||||||||||||
363, 365, and 369 Oyster Point Boulevard (Kilroy Oyster Point - Phase 2) | South San Francisco | 2Q 2021 | 1Q 2026 | 871,738 | $1,175 | 7% | 49% | 49% | ||||||||
2nd Quarter | ||||||||||||||||
None | — | — | —% | —% | —% | |||||||||||
3rd Quarter | ||||||||||||||||
None | — | — | —% | —% | —% | |||||||||||
Total | 871,738 | $1,175 | 7% | 49% | 49% | |||||||||||
________________________
(1)Represents the earlier of the date the project achieves 95% occupancy or one year from substantial completion of base building components.
Kilroy Realty Q3 2026 Supplemental Report | 29
Where Innovation Works |
In-Process Development & Redevelopment Projects
($ in millions)
% Leased | ||||||||||||||||
UNDER CONSTRUCTION | Location | Construction Start Date | Estimated Stabilization Date | Estimated Rentable Square Feet | Total Estimated Investment | Total Cash Costs Incurred | As of 9/30/2026 | As of Filing | ||||||||
None | — | $— | $— | —% | —% | |||||||||||
Total | — | $— | $— | —% | —% | |||||||||||
Kilroy Realty Q3 2026 Supplemental Report | 30
Where Innovation Works |
Future Development Pipeline
($ in millions)
Location | Approx. Developable Square Feet / Resi Units (1) | Cost Basis, Net (2) | ||||||
San Francisco Bay Area | ||||||||
Flower Mart | San Francisco CBD | 2,300,000 | $690 | |||||
Kilroy Oyster Point - Phases 3 and 4 | South San Francisco | 875,000 - 1,000,000 | 253 | |||||
1900 Broadway (3) | Other Peninsula | 251,000 | 78 | |||||
Los Angeles | ||||||||
1633 26th Street (4) | West Los Angeles | 190,000 | 17 | |||||
Seattle | ||||||||
SIXO | Lake Union / Denny Regrade | 925,000 and 650 units | 197 | |||||
San Diego | ||||||||
Santa Fe Summit (4) | 56 Corridor | 600,000 - 650,000 | 118 | |||||
2045 Pacific Highway | Little Italy / Point Loma | 275,000 | 52 | |||||
Kilroy East Village (4) | East Village | 1,100 units | 63 | |||||
Austin | ||||||||
Stadium Tower | Stadium District / Domain | 493,000 | 76 | |||||
Total | $1,544 | |||||||
________________________
(1)Project scope, including the estimated developable square feet or number of residential units, could change materially from estimates provided due to one or more of the following: significant changes in the economy,
market conditions, tenant requirements and demands, construction costs, new supply, regulatory and entitlement processes, or project design.
(2)Represents costs incurred as of September 30, 2026, net of environmental liability obligations, asset retirement obligations, and municipal bonds proceeds received related to public infrastructure improvements.
(3)Owned in a consolidated joint venture. Project is 58% pre-leased and is anticipated to commence construction in 2027, with delivery scheduled for 2030, at which time the Company’s ownership interest is expected to
be 97%.
(4)Subject to signed purchase and sale agreements and non-refundable deposits as of the date of this filing. Refer to page 25 “2026 Dispositions and Assets Under Contract” for additional information.
04
Debt &
Capitalization Data
–Capital Structure
–Debt Maturities
–Debt Covenants & Leverage Ratios
Blackwelder, Culver City, CA
Kilroy Realty Q3 2026 Supplemental Report | 32
Where Innovation Works |
Capital Structure
As of September 30, 2026
($ in thousands)
Shares / Units | Aggregate Principal Amount or $ Value Equivalent | % of Total Market Capitalization | Stated Rate (1) | Effective Rate (2) | Maturity Date | |||||||
Unsecured Debt | ||||||||||||
Revolving Credit Facility (3) | $40,000 | 0.5% | 4.90% | 4.90% | 7/31/2030 | |||||||
Term Loan Facility (4) | 200,000 | 2.4% | 5.05% | 5.18% | 7/31/2031 | |||||||
Private Placement Senior Notes Series A due 2027 | 175,000 | 2.1% | 3.35% | 3.42% | 2/17/2027 | |||||||
Private Placement Senior Notes Series B due 2029 | 75,000 | 0.9% | 3.45% | 3.51% | 2/17/2029 | |||||||
Private Placement Senior Notes due 2031 | 350,000 | 4.2% | 4.27% | 4.32% | 1/31/2031 | |||||||
Senior Notes due 2028 (5) | 400,000 | 4.8% | 4.75% | 4.87% | 12/15/2028 | |||||||
Senior Notes due 2029 | 400,000 | 4.8% | 4.25% | 4.38% | 8/15/2029 | |||||||
Senior Notes due 2030 | 500,000 | 6.0% | 3.05% | 3.17% | 2/15/2030 | |||||||
Senior Notes due 2032 (5) | 425,000 | 5.1% | 2.50% | 2.63% | 11/15/2032 | |||||||
Senior Notes due 2033 (5) | 450,000 | 5.4% | 2.65% | 2.73% | 11/15/2033 | |||||||
Senior Notes due 2035 | 400,000 | 4.8% | 5.88% | 6.08% | 10/15/2035 | |||||||
Senior Notes due 2036 | 400,000 | 4.8% | 6.25% | 6.41% | 1/15/2036 | |||||||
$3,815,000 | 45.8% | 4.14% | 4.48% | |||||||||
Secured Debt (6) | ||||||||||||
100 Hooper St., San Francisco Bay Area | $145,834 | 1.8% | 3.57% | 3.81% | 12/1/2026 | |||||||
320 Westlake Ave. N. and 321 Terry Ave. N., Seattle | 74,761 | 0.9% | 4.48% | 4.58% | 7/1/2027 | |||||||
One Paseo Mixed-Use Campus, San Diego | 375,000 | 4.5% | 5.90% | 6.13% | 8/10/2034 | |||||||
$595,595 | 7.2% | 5.15% | 5.37% | |||||||||
Total Debt | $4,410,595 | 53.0% | 4.27% | 4.60% | ||||||||
Equity and Noncontrolling Interest in the Operating Partnership (7) | ||||||||||||
Common limited partnership units outstanding (8) | 1,133,562 | $37,714 | 0.5% | |||||||||
Shares of common stock outstanding | 116,308,988 | 3,869,600 | 46.5% | |||||||||
Total Equity and Noncontrolling Interest in the Operating Partnership | $3,907,314 | 47.0% | ||||||||||
Total Market Capitalization | $8,317,909 | 100.0% | ||||||||||
________________________
(1)The unsecured revolving credit facility and unsecured term loan facility's interest rates were calculated using the Secured Overnight Financing Rate (“SOFR”) and a margin of 1.000% and 1.150%, respectively, based on
the Company’s credit rating, as of September 30, 2026. All other stated rates represent fixed interest rates.
(2)Includes the impact of an unused facility fee, amortization of deferred financing costs, and amortization of premiums/discounts.
(3)The unsecured revolving credit facility has a total borrowing capacity of $1.25 billion and two available six-month extension options.
(4)The unsecured term loan facility has a total borrowing capacity of $250.0 million. The additional $50.0 million of term loan capacity consists of delayed-draw commitments that may be drawn upon through June 11,
2027.
(5)Green bond.
(6)The mortgage notes are secured by the properties listed.
(7)Value based on closing share price of $33.27 as of September 30, 2026.
(8)Includes common units of the Operating Partnership not owned by the Company. Excludes noncontrolling interests in consolidated property partnerships.
Kilroy Realty Q3 2026 Supplemental Report | 33
Where Innovation Works |
Debt Maturities
As of September 30, 2026
($ in thousands)
Total Debt (3) | $146,470 | $249,125 | $400,000 | $475,000 | $540,000 | $550,000 | $425,000 | $450,000 | $375,000 | $400,000 | $400,000 |
Weighted Average Stated Rate | 3.57% | 3.69% | 4.75% | 4.12% | 3.19% | 4.55% | 2.50% | 2.65% | 5.90% | 5.88% | 6.25% |
% of Total | 3% | 6% | 9% | 11% | 12% | 12% | 10% | 10% | 9% | 9% | 9% |
________________________
(1)The unsecured revolving credit facility has a total borrowing capacity of $1.25 billion and two available six-month extension options.
(2)The unsecured term loan facility has a total borrowing capacity of $250.0 million. The additional $50.0 million of term loan capacity consists of delayed-draw commitments that may be drawn upon through June 11,
2027.
(3)Includes scheduled principal payments for amortizing loans.
Kilroy Realty Q3 2026 Supplemental Report | 34
Where Innovation Works |
Debt Covenants & Leverage Ratios
($ in thousands)
KEY DEBT COVENANTS (1) | Covenant | Actual Performance as of September 30, 2026 | ||
Unsecured Credit and Term Loan Facilities and Private Placement Notes: | ||||
Total debt to total asset value | less than 60% | 33% | ||
Fixed charge coverage ratio | greater than 1.5x | 3.1x | ||
Unsecured debt ratio | greater than 1.67x | 2.88x | ||
Unencumbered asset pool debt service coverage | greater than 1.75x | 3.58x | ||
Unsecured Senior Notes due 2028, 2029, 2030, 2032, 2033, 2035, and 2036: | ||||
Total debt to total asset value | less than 60% | 34% | ||
Interest coverage | greater than 1.5x | 4.2x | ||
Secured debt to total asset value | less than 40% | 5% | ||
Unencumbered asset pool value to unsecured debt | greater than 150% | 307% | ||
NET DEBT TO COMPANY'S SHARE OF EBITDAre RATIOS | 9/30/2026 | 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | |||||
Total principal amount of debt | $4,410,595 | $4,572,227 | $4,623,842 | $4,625,442 | $4,627,026 | |||||
Cash and cash equivalents | (94,301) | (253,805) | (192,904) | (179,316) | (372,416) | |||||
Net debt | $4,316,294 | $4,318,422 | $4,430,938 | $4,446,126 | $4,254,610 | |||||
Trailing 12-months Company's Share of EBITDAre (2)(3) | $597,206 | $615,742 | $631,178 | $637,314 | $660,337 | |||||
Trailing 12-months Company's Share of Adjusted EBITDAre (2)(3) | $592,180 | $608,217 | $624,388 | $630,344 | $650,782 | |||||
Net Debt to Company's Share of EBITDAre Ratio | 7.2x | 7.0x | 7.0x | 7.0x | 6.4x | |||||
Net Debt to Company's Share of Adjusted EBITDAre Ratio | 7.3x | 7.1x | 7.1x | 7.1x | 6.5x | |||||
________________________
(1)All covenant ratio titles utilize terms and are calculated as defined in the respective debt and credit agreements.
(2)Calculated as the sum of the Company's Share of EBITDAre and Adjusted EBITDAre for the trailing four quarters.
(3)Refer to page 45 for reconciliations of historical GAAP Net Income Available to Common Stockholders to EBITDAre for the three months ended June 30, 2025, March 31, 2025, and December 31, 2024.
05
Non-GAAP
Supplemental
Measures
West8, Seattle, WA
Kilroy Realty Q3 2026 Supplemental Report | 36
Where Innovation Works |
Management Statements on Non-GAAP Supplemental Measures
This section includes management’s statements regarding certain non-GAAP financial measures provided in this supplemental financial report and, with
respect to Funds From Operations available to common stockholders and common unitholders (“FFO”), in the Company’s earnings release on October 22,
2026 and the reasons why management believes that these measures provide useful information to investors about the Company’s financial condition and
results of operations.
Net Operating Income:
Management believes that Net Operating Income (“NOI”) is a useful supplemental measure of the Company’s operating performance. The Company’s NOI metrics
are defined as follows:
•Net Operating Income - Consolidated operating revenues comprised of rental income and other property income, excluding lease termination fees, less
consolidated property and related expenses (property expenses, real estate taxes, and ground leases).
•Cash Net Operating Income - NOI adjusted for certain non-cash amounts (e.g. straight-line rents, net, amortization of deferred revenue related to tenant-
funded tenant improvements, deferred income and lease incentives, net, deferred settlement and restoration fee income, the amortization of net below
market rents, and related provision for bad debts).
•Same Property Cash Net Operating Income - Cash NOI for all of the properties that were owned and included in the Company’s Stabilized Portfolio for
two comparable reporting periods.
The Company excludes lease termination fees from the calculation of rental revenue for the Company’s NOI metrics as they are non-recurring in nature and their
exclusion provides a measure that the Company believes is more indicative of its operating performance. Other real estate investment trusts (“REITs”) may use
different methodologies for calculating NOI, Cash NOI, and Same Property Cash NOI, and accordingly, the Company’s NOI metrics may not be comparable to other
REITs.
The Company uses these NOI metrics to evaluate its operating performance on a portfolio basis since the NOI metrics allow the Company to evaluate the impact
that factors such as occupancy levels, lease structure, rental rates, and tenant base have on the Company’s results, margins and returns. In addition, management
believes that its NOI metrics provide useful information to the investment community about the Company’s financial and operating performance when compared to
other REITs since NOI, Cash NOI, and Same Property Cash NOI are generally recognized as standard measures of performance in the real estate industry.
Because the Company’s NOI metrics exclude lease termination fees, leasing costs, general and administrative expenses, interest expense, depreciation and
amortization, other income and expenses, impairment of real estate assets, and gains and losses, they provide performance measures that, when compared year
over year, reflect the consolidated revenues and expenses directly associated with owning and operating commercial real estate and the impact to operations from
trends in occupancy rates, rental rates, and operating costs, providing a perspective on operations not immediately apparent from net income. Additionally, because
Same Property Cash NOI excludes the change in Cash NOI from developed, redeveloped, acquired, disposed of, and held-for-sale properties, it highlights operating
trends on a cash basis such as occupancy levels, rental rates, and operating costs on properties.
The Company’s NOI metrics should not be viewed as alternative measures of the Company’s financial performance since they do not reflect general and
administrative expenses, leasing costs, lease termination fees, interest expense, depreciation and amortization costs, other nonproperty income and losses and the
level of capital expenditures necessary to maintain the operating performance of the Company’s properties, or trends in development and construction activities
which are significant economic costs and activities that could materially impact the Company’s results from operations. In addition, Same Property Cash NOI should
not be viewed as an alternative measure of the Company’s financial performance since it does not reflect the operations of the Company's entire portfolio.
Kilroy Realty Q3 2026 Supplemental Report | 37
Where Innovation Works |
Management Statements on Non-GAAP Supplemental Measures, continued
EBITDAre, Company's Share of EBITDAre, and Company's Share of Adjusted EBITDAre:
The Company calculates Earnings Before Interest, Taxes, Depreciation and Amortization for Real Estate (“EBITDAre”) in accordance with the 2017 White Paper on
EBITDAre approved by the Board of Governors of Nareit. Management believes that consolidated earnings before interest expense, tax expense, depreciation and
amortization, gain/loss on early extinguishment of debt, gains and losses on the sale of depreciable real estate and non-real estate assets, net income attributable to
noncontrolling interests, preferred dividends and distributions, original issuance costs of redeemed preferred stock and preferred units, and impairment losses
(EBITDAre) is a useful supplemental measure of the Company’s operating performance. When considered with other GAAP measures and FFO, management
believes EBITDAre gives the investment community a more complete understanding of the Company’s consolidated operating results, including the impact of
general and administrative expenses and acquisition-related expenses, before the impact of investing and financing transactions and facilitates comparisons with
competitors. Management also believes it is appropriate to present EBITDAre as it is used in several of the Company’s financial covenants for both its secured and
unsecured debt. However, EBITDAre should not be viewed as an alternative measure of the Company’s operating performance since it excludes financing costs as
well as depreciation and amortization costs, which are significant economic costs that could materially impact the Company’s results of operations and liquidity. Other
REITs may use different methodologies for calculating EBITDAre and, accordingly, the Company’s EBITDAre calculation may not be comparable to those of other
REITs. The Company’s Share of EBITDAre is EBITDAre less amounts attributable to noncontrolling interests in consolidated property partnerships. The Company’s
Share of Adjusted EBITDAre is the Company’s share of EBITDAre less interest income.
Net Debt to Company's Share of EBITDAre Ratio and Net Debt to Company's Share of Adjusted EBITDAre Ratio:
Management believes that the ratios of the principal balance of debt, less cash and cash equivalents and certificates of deposit, divided by the Company’s share of
EBITDAre as well as the Company's share of Adjusted EBITDAre are useful supplemental measures of the level of borrowed capital being used to increase the
potential return of the Company’s real estate investments and proxies for a measure management believes is used by many lenders and rating agencies to evaluate
the Company’s ability to repay and service its debt obligations. The Company believes the ratios are beneficial disclosure to investors as supplemental means of
evaluating its ability to meet obligations senior to those of the equity holders. Other REITs may use different methodologies for calculating these ratios and,
accordingly, the Company’s Net Debt to Company’s Share of EBITDAre Ratio and Net Debt to Company's Share of Adjusted EBITDAre Ratio may not be
comparable to those of other REITs.
Kilroy Realty Q3 2026 Supplemental Report | 38
Where Innovation Works |
Management Statements on Non-GAAP Supplemental Measures, continued
Funds From Operations:
The Company calculates Funds From Operations available to common stockholders and common unitholders (“FFO”) in accordance with the 2018 Restated White
Paper on FFO approved by the Board of Governors of Nareit. The White Paper defines FFO as net income or loss (calculated in accordance with GAAP), excluding
depreciation and amortization related to real estate, gains and losses from the sale of certain real estate assets, gains and losses from change in control, and
impairment write-downs of certain real estate assets and investments in entities when the impairment is directly attributable to decreases in the value of depreciable
real estate held by the entity. The reconciling items include amounts to adjust earnings from consolidated partially-owned entities and equity in earnings of
unconsolidated affiliates to FFO. The calculation of FFO includes the amortization of deferred revenue related to tenant-funded tenant improvements and excludes
the depreciation of the related tenant improvement assets. The Company also adds back net income attributable to noncontrolling common units of the Operating
Partnership because it reports FFO attributable to common stockholders and common unitholders.
Management believes that FFO is a useful supplemental measure of the Company’s operating performance. The exclusion from FFO of gains and losses from the
sale of operating real estate assets allows investors and analysts to readily identify the operating results of the assets that form the core of the Company’s activity
and assists in comparing those operating results between periods. Also, because FFO is generally recognized as the industry standard for reporting the operations of
REITs, it facilitates comparisons of operating performance to other REITs. However, other REITs may use different methodologies to calculate FFO, and accordingly,
the Company’s FFO may not be comparable to those of other REITs.
Implicit in historical cost accounting for real estate assets in accordance with GAAP is the assumption that the value of real estate assets diminishes predictably over
time. Since real estate values have historically risen or fallen with market conditions, many industry investors and analysts have considered presentations of
operating results for real estate companies using historical cost accounting alone to be insufficient. Because FFO excludes depreciation and amortization of real
estate assets, management believes that FFO along with the required GAAP presentations provides a more complete measurement of the Company’s performance
relative to its competitors and a more appropriate basis on which to make decisions involving operating, financing, and investing activities than the required GAAP
presentations alone would provide.
FFO should not be viewed as an alternative measure of the Company’s operating performance since it does not reflect either depreciation and amortization costs or
the level of capital expenditures and leasing costs necessary to maintain the operating performance of the Company’s properties, which are significant economic
costs and could materially impact the Company’s results from operations.
Funds Available for Distribution:
Management believes that Funds Available for Distribution available to common stockholders and common unitholders (“FAD”) is a useful supplemental measure of
the Company’s liquidity. The Company computes FAD by adjusting FFO for recurring tenant improvements, leasing commissions, and capital expenditures,
amortization of deferred revenue related to tenant-funded tenant improvements, straight-line rents, net, amortization of net above (below) market rents for acquisition
properties, non-cash amortization of deferred financing costs and net debt discounts and premiums, non-cash amortization of share-based compensation awards,
lease related adjustments (including non-cash ground rent expense beginning in Q1 2026), gains and losses on sales of non-real estate assets, and amounts
attributable to noncontrolling interests in consolidated property partnerships. FAD provides an additional perspective on the Company’s ability to fund cash needs
and make distributions to stockholders by adjusting FFO for the impact of certain cash and non-cash items, as well as adjusting FFO for recurring capital
expenditures and leasing costs. Management also believes that FAD provides useful information to the investment community about the Company’s financial position
as compared to other REITs since FAD is a liquidity measure used by other REITs. However, other REITs may use different methodologies for calculating FAD and,
accordingly, the Company’s FAD may not be comparable to those of other REITs.
06
Definitions &
Reconciliations
2100 Kettner, San Diego, CA
Kilroy Realty Q3 2026 Supplemental Report | 40
Where Innovation Works |
Definitions Included in Supplemental
Annualized Base Rent:
Annualized monthly contractual base rents from existing tenants in occupancy, including the impact of the straight-lining of rent escalations and the
amortization of free rent periods and excluding the impact of the following: amortization of deferred revenue related to tenant-funded tenant improvements,
amortization of above/below market rents, amortization for lease incentives due under existing leases, and expense reimbursement revenue. Amounts
represent percentage of total portfolio annualized contractual base rental revenue.
Capital Expenditures:
Expenditures for capital improvements, tenant improvements costs (excluding tenant-funded tenant improvements), and leasing commissions.
Effective Rate:
Represents the Stated Rate, including the impact of the amortization of any premiums/discounts and debt issuance costs.
Estimated Stabilization Date (Development):
Management’s estimation of the earlier of stabilized occupancy (95%) or one year from the date of the cessation of major base building construction
activities for office, life science, and retail properties, and the date of substantial completion for residential properties.
FAD Payout Ratio:
Calculated as current-quarter dividends accrued to common stockholders and common unitholders (excluding dividend equivalents accrued to restricted
stock unitholders) divided by FAD.
First Generation ("1st Gen") Capital Expenditures:
Capital expenditures for space not yet leased at recently completed Development and Redevelopment Properties that have been added to the Stabilized
Portfolio. Does not include expenditures for In-Process development and Redevelopment Projects or acquisition properties. These costs are not subtracted
in the calculation of FAD.
1st Gen Leasing:
New leasing activity on vacant space at recently completed Development, Redevelopment, and properties classified as Major Repositioning that have been
added to the Stabilized Portfolio. Also includes new leasing activity at space that was vacant upon acquisition.
Fixed Charge Coverage Ratio - Company’s Share of EBITDAre:
Calculated as Company’s Share of current period EBITDAre divided by gross interest expense (excluding amortization of deferred debt issuance costs and
debt discounts/premiums) and current year accrued preferred dividends.
FFO Payout Ratio:
Calculated as current-quarter dividends accrued to common stockholders and common unitholders (excluding dividend equivalents accrued to restricted
stock unitholders) divided by FFO attributable to common stockholders and unitholders.
Kilroy Realty Q3 2026 Supplemental Report | 41
Where Innovation Works |
Definitions Included in Supplemental, continued
GAAP Rent:
Rental revenue recognized on a straight-line basis over the lease term, including the impact of contractual rent escalations, free rent periods, and
amortization for lease incentives due under existing leases.
Gross Lease Types:
Represents leases where the landlord is obligated to pay the tenant's proportionate share of certain operating expenses.
Interest Coverage Ratio:
Calculated as EBITDAre divided by gross interest expense (excluding amortization of deferred debt costs and debt premiums/discounts).
Major Repositioning:
Space for which significant non-recurring capital expenditures are incurred to reposition and is expected to result in additional revenue generated when re-
leased. Capital improvements for this space are not subtracted in the calculation of FAD. Tenant improvement and leasing commissions for this space are
included in 2nd Gen Capital Expenditures.
Net Lease Types:
Represents leases where the tenant is obligated to pay a share of certain operating expenses.
Net Operating Income Margin:
Calculated as Net Operating Income divided by total revenues.
Percentage Leased
Represents Percentage Occupied, adjusted for leases executed but have not yet achieved revenue recognition.
Percentage Occupied
Represents economic occupancy for space that has achieved revenue recognition for the associated lease agreements.
Recurring Capital Expenditures:
Recurring capital expenditures related to previously leased space and space at acquired operating properties in the Stabilized Portfolio. Also includes tenant
improvements, leasing commissions, market ready, and spec suite capital expenditures for properties classified as Major Repositioning. These recurring
costs are subtracted in the calculation of FAD.
Redevelopment Properties/Projects:
Properties or projects for which the Company expects to spend significant development and construction costs pursuant to a formal plan to change its use.
Rentable Square Feet:
Reflects the latest Building Owners and Managers Association (“BOMA”) measurement. All occupied and leased percentages presented throughout this
report are calculated based on rentable square feet at the end of the period(s) presented.
Kilroy Realty Q3 2026 Supplemental Report | 42
Where Innovation Works |
Definitions Included in Supplemental, continued
Retention Rate (Leases Executed):
Calculated as the percentage of square footage renewed by existing tenants at lease expiration or termination divided by the square footage of space
renewed by existing tenants and lease expirations during the period. Excludes square footage of short-term leases.
Retention Rate (Leases Executed Including Subtenants):
Retention rate, inclusive of leases with subtenants where the Company does not expect to experience downtime in occupancy between leases.
Same Property Portfolio:
The Same Property Portfolio includes all properties owned and included in the Stabilized Portfolio for two comparable reporting periods, i.e., owned and
included in the Stabilized Portfolio as of January 1, 2025 and still owned and included in the Stabilized Portfolio as of September 30, 2026. It includes the
residential portfolio, which consists of the 608 residential units at the Company’s One Paseo mixed-use property in the Del Mar, California submarket.
Excludes undeveloped land, development and Redevelopment Properties currently committed for construction, under construction, or in the tenant
improvement phase, and properties classified as held for sale.
Same Property Portfolio Rollforward | ||||
Number of Buildings | Square Feet | |||
Same Property Portfolio as of December 31, 2025 | 112 | 15,549,413 | ||
Stabilized Acquisition Properties Added (1) | 2 | 103,731 | ||
Dispositions and Held for Sale (2) | (1) | (39,192) | ||
Remeasurements | — | 21,703 | ||
Same Property Portfolio as of September 30, 2026 | 113 | 15,635,655 | ||
Stabilized Development Property Excluded from Same Property | 5 | 972,877 | ||
Stabilized Acquisition Properties Excluded from Same Property | 5 | 538,532 | ||
Stabilized Portfolio as of September 30, 2026 | 123 | 17,147,064 |
________________________
(1) One Paseo Junction was added to the Same Property Portfolio in 2026.
(2) Excludes the two residential properties classified as held for sale as of March 31, 2026 and disposed of in April 2026, measured in units, as well as Kilroy Sabre Springs,
which was classified as held for sale as of December 31, 2025 and not included in the Same Property Portfolio.
Second Generation ("2nd Gen") Leasing
Leasing at properties in the Stabilized Portfolio related to space that has been previously leased. All renewals are considered 2nd Gen leasing.
Kilroy Realty Q3 2026 Supplemental Report | 43
Where Innovation Works |
Definitions Included in Supplemental, continued
Stabilized Portfolio:
The Stabilized Portfolio includes all properties with the exception of the development and Redevelopment Properties currently committed for construction,
under construction, or in the tenant improvement phase, undeveloped land, and properties classified as held for sale.
Stabilized Portfolio Rollforward (1) | ||||
Number of Buildings | Square Feet | |||
Stabilized Portfolio as of December 31, 2025 | 121 | 16,292,164 | ||
Stabilized Development Properties | 3 | 871,738 | ||
Dispositions (2) | (1) | (39,192) | ||
Remeasurements | — | 22,354 | ||
Stabilized Portfolio as of September 30, 2026 | 123 | 17,147,064 |
________________________
(1) Excludes our residential property measured in units.
(2) Excludes Kilroy Sabre Springs, which was classified as held for sale as of December 31, 2025 and not included in the Stabilized Portfolio, and the two residential properties disposed of in April 2026,
measured in units.
Stated Rate:
The rate at which interest expense is recorded per the respective loan documents.
Straight-Line Rents, Net:
Represents the straight-line rent income recognized during the period offset by cash received during the period that was applied to deferred rents receivable
balances for terminated leases and the provision for bad debts recorded for deferred rent receivable balances.
Tenant Improvement Phase:
Represents projects that have reached cold shell condition and are ready for tenant improvements, which may require additional major base building
modifications before being placed in service.
Total Debt
Represents the gross aggregate principal amount due as of September 30, 2026. Excludes unamortized deferred financing costs for the unsecured revolving
credit and term loan facilities, unsecured senior notes, and secured debt, and unamortized discounts for the unsecured senior notes.
Total Portfolio:
The Total Portfolio includes all properties, with the exception of the Development and Redevelopment Properties currently committed for construction, under
construction, or in the tenant improvement phase, and undeveloped land.
Total Portfolio | ||||
Number of Buildings | Square Feet | |||
Stabilized Portfolio | 123 | 17,147,064 | ||
Total Portfolio as of September 30, 2026 | 123 | 17,147,064 |
Kilroy Realty Q3 2026 Supplemental Report | 44
Where Innovation Works |
Reconciliation of Net Income Available to Common Stockholders to
Same Property Cash Net Operating Income (1)
(unaudited, $ in thousands)
Three Months Ended | Nine Months Ended | ||||||||
9/30/2026 | 9/30/2025 | 9/30/2026 | 9/30/2025 | ||||||
Net Income Available to Common Stockholders | $15,506 | $156,220 | $16,144 | $263,677 | |||||
Net income available to noncontrolling common units of the Operating Partnership | 151 | 1,524 | 159 | 2,562 | |||||
Net income attributable to noncontrolling interests in consolidated property partnerships | 4,612 | 4,538 | 14,008 | 19,292 | |||||
Net Income | 20,269 | 162,282 | 30,311 | 285,531 | |||||
Adjustments: | |||||||||
Impairment of real estate assets | — | — | 61,778 | — | |||||
Gains on sales of depreciable operating properties | — | (110,484) | (23,525) | (127,038) | |||||
Depreciation and amortization | 93,165 | 87,487 | 281,069 | 262,231 | |||||
Interest expense | 39,376 | 32,152 | 119,521 | 94,144 | |||||
Interest income | (620) | (3,119) | (2,821) | (4,765) | |||||
Other (income) expense | (83) | (91) | (224) | (124) | |||||
Leasing costs | 2,980 | 2,610 | 8,804 | 7,760 | |||||
General and administrative expenses | 18,408 | 18,247 | 58,040 | 53,623 | |||||
Lease termination fees | (315) | (309) | (1,077) | (11,569) | |||||
Net Operating Income | 173,180 | 188,775 | 531,876 | 559,793 | |||||
Other (2) | 69 | 78 | 206 | 234 | |||||
Deferred settlement and restoration fee income | — | 2,026 | — | — | |||||
Amortization of net below market rents | (682) | (764) | (1,974) | (2,455) | |||||
Straight-line rents, net | 2,832 | 1,303 | 3,633 | 9,270 | |||||
Amortization of deferred revenue related to tenant-funded tenant improvements | (3,353) | (3,639) | (9,886) | (11,097) | |||||
Deferred income and lease incentives, net (3) | (614) | (707) | (2,639) | (2,312) | |||||
Cash Net Operating Income | 171,432 | 187,072 | 521,216 | 553,433 | |||||
Non-Same Property Cash Net Operating Income | (814) | (13,933) | (5,742) | (41,064) | |||||
Same Property Cash Net Operating Income | $170,618 | $173,139 | $515,474 | $512,369 | |||||
________________________
(1)Based upon the Same Property Portfolio as of September 30, 2026, which was comprised of 113 properties.
(2)Includes other non-cash amounts primarily related to ground rent expense.
(3)Includes non-cash adjustments attributable to lease-related matters, including GAAP revenue recognition timing differences.
Kilroy Realty Q3 2026 Supplemental Report | 45
Where Innovation Works |
Reconciliation of Historical Net Income Available to Common
Stockholders to Company’s Share of Adjusted EBITDAre
(unaudited, $ in thousands)
Three Months Ended | ||||||
6/30/2025 | 3/31/2025 | 12/31/2024 | ||||
Net Income | $79,568 | $43,681 | $65,034 | |||
Interest expense | 30,844 | 31,148 | 33,245 | |||
Depreciation and amortization | 87,625 | 87,119 | 89,121 | |||
Taxes (1) | 17 | 51 | — | |||
Gain on sale of operating properties | (16,554) | — | — | |||
Gain on sales of long-lived assets | — | — | (5,979) | |||
EBITDAre | 181,500 | 161,999 | 181,421 | |||
EBITDAre attributable to noncontrolling interests in consolidated property partnerships | (13,586) | (7,280) | (7,843) | |||
Company's Share of EBITDAre | 167,914 | 154,719 | 173,578 | |||
Interest income | (512) | (1,134) | (4,790) | |||
Company's Share of Adjusted EBITDAre | $167,402 | $153,585 | $168,788 | |||
________________________
(1)Commencing in January 1, 2025, the Company began adjusting for taxes, which are included in Other income (expense) on the Company’s Consolidated Statement of Operations. EBITDAre and Adjusted EBITDAre for
the period ending December 31, 2024 have not been conformed to our new presentation to maintain consistency with previously reported financial ratios.
Kilroy Realty Q3 2026 Supplemental Report | 46
Where Innovation Works |
Reconciliation of GAAP Net Cash Provided by Operating Activities to
Funds Available for Distribution
(unaudited, $ in thousands)
Three Months Ended | Nine Months Ended | ||||||||||||||
9/30/2026 | 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | 9/30/2026 | 9/30/2025 | |||||||||
GAAP Net Cash Provided by Operating Activities | $156,148 | $78,207 | $150,695 | $109,078 | $176,568 | $385,050 | $457,235 | ||||||||
Adjustments: | |||||||||||||||
Recurring tenant improvements, leasing commissions, and capital expenditures | (47,038) | (28,111) | (18,743) | (31,724) | (36,959) | (93,892) | (88,377) | ||||||||
Depreciation of non-real estate furniture, fixtures, and equipment | (1,428) | (1,429) | (1,459) | (1,410) | (1,407) | (4,316) | (4,173) | ||||||||
Net changes in operating assets and liabilities (1) | (39,387) | 42,682 | (30,811) | 22,819 | (31,579) | (27,516) | (24,642) | ||||||||
Noncontrolling interests in consolidated property partnerships’ share of FFO and FAD | (5,238) | (7,100) | (7,207) | (6,177) | (5,411) | (19,545) | (25,102) | ||||||||
Cash adjustments related to investing and financing activities | (251) | (623) | (1,369) | (2,052) | (273) | (2,243) | (1,017) | ||||||||
Funds Available for Distribution | $62,806 | $83,626 | $91,106 | $90,534 | $100,939 | $237,538 | $313,924 | ||||||||
________________________
(1)Primarily includes changes in the following assets and liabilities: marketable securities, current receivables, prepaid expenses and other assets, accounts payable, accrued expenses and other liabilities, rents received
in advance, and tenant security deposits.
This Supplemental Financial Report contains "forward-looking statements"
within the meaning of Section 27A of the Securities Act of 1933, as
amended, and Section 21E of the Securities Exchange Act of 1934, as
amended. These statements include, among other things, information
concerning lease expirations, debt maturities, potential investments,
development and redevelopment activity, projected construction costs,
dispositions, and other forward-looking financial data. In some instances,
forward-looking statements can be identified by the use of forward-looking
terminology such as “expect,” “future,” “will,” “would,” “pursue,” or “project”,
and variations of such words and similar expressions that do not relate to
historical matters. Forward-looking statements are based on Kilroy Realty
Corporation’s current expectations, beliefs, and assumptions, and are not
guarantees of future performance. Forward-looking statements are
inherently subject to uncertainties, risks, changes in circumstances, trends,
and factors that are difficult to predict, many of which are outside of Kilroy
Realty Corporation’s control. Accordingly, actual performance, results, and
events may vary materially from those indicated or implied in the forward-
looking statements, and you should not rely on the forward-looking
statements as predictions of future performance, results, or events.
Numerous factors could cause actual future performance, results, and
events to differ materially from those indicated in the forward-looking
statements, including, among others: global market and general economic
conditions, including actual and potential tariffs and periods of heightened
inflation, and their effect on our liquidity and financial conditions and those
of our tenants; adverse economic or real estate conditions generally, and
specifically, in the States of California, Texas, and Washington; risks
associated with our investment in real estate assets, which are illiquid, and
with trends in the real estate industry; defaults on or non-renewal of leases
by tenants; any significant downturn in tenants’ businesses, including
bankruptcy, lack of liquidity or lack of funding, and the impact labor
disruptions or strikes, such as episodic strikes in the media industry, may
have on our tenants’ businesses; our ability to re-lease property at or
above current market rates; reduced demand for office space, including as
a result of remote working and flexible working arrangements that allow
work from remote locations other than an employer's office premises; costs
to comply with government regulations, including environmental
remediation; the availability of cash for distribution and debt service, and
exposure to risk of default under debt obligations; increases in interest
rates and our ability to manage interest rate exposure; changes in interest
rates and the availability of financing on attractive terms or at all, which
may adversely impact our future interest expense and our ability to pursue
development, redevelopment, and acquisition opportunities and refinance
existing debt; a decline in real estate asset valuations, which may limit our
ability to dispose of assets at attractive prices, or obtain or maintain debt
financing, and which may result in write-offs or impairment charges;
significant competition, which may decrease the occupancy and rental
rates of properties; potential losses that may not be covered by insurance;
the ability to successfully complete acquisitions and dispositions on
announced terms; the ability to successfully operate acquired, developed,
and Redeveloped properties; the ability to successfully complete
development and Redevelopment projects on schedule and within
budgeted amounts; delays or refusals in obtaining all necessary zoning,
land use, and other required entitlements, governmental permits and
authorizations for our development and Redevelopment properties;
increases in anticipated capital expenditures, tenant improvement, and/or
leasing costs; defaults on leases for land on which some of our properties
are located; adverse changes to, or enactment or implementations of, tax
laws or other applicable laws, regulations, or legislation, as well as
business and consumer reactions to such changes; risks associated with
joint venture investments, including our lack of sole decision-making
authority, our reliance on co-venturers' financial condition, and disputes
between us and our co-venturers; environmental uncertainties and risks
related to natural disasters; risks associated with climate change and our
sustainability strategies, and our ability to achieve our sustainability goals;
and our ability to maintain our status as a REIT. These factors are not
exhaustive and additional factors could adversely affect our business and
financial performance. For a discussion of additional factors that could
materially adversely affect Kilroy Realty Corporation’s business and
financial performance, see the factors included under the caption “Risk
Factors” in Kilroy Realty Corporation’s annual report on Form 10-K for the
year ended December 31, 2025, and its other filings with the Securities
and Exchange Commission. All forward-looking statements are based on
currently available information and speak only as of the dates on which
they are made. Kilroy Realty Corporation assumes no obligation to update
any forward-looking statement made in this Supplemental Financial Report
that becomes untrue because of subsequent events, new information, or
otherwise, except to the extent we are required to do so in connection with
our ongoing requirements under federal securities laws.
Where Innovation Works