1 3Q26 Update (Nasdaq: BHRB)
2 Cautionary Statement Regarding Forward-Looking Information This presentation includes “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995, Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, including with respect to (or based on) the beliefs, goals, intentions, and expectations of Burke & Herbert regarding our: merger with LINKBANCORP, Inc. (“LNKB”) effective as of May 1, 2026 (the “merger”) and the expected cost savings, synergies, returns, and other anticipated benefits from the integration of LNKB; revenues, earnings, earnings per share, loan production, asset quality, and capital levels, among other matters; estimates of the future costs and benefits of the actions we may take; assessments of expected losses on loans; assessments of interest rate and other market risks; ability to achieve financial and other strategic goals; and other statements that are not historical facts. Forward–looking statements are typically identified by such words as “believe,” “expect,” “anticipate,” “intend,” “outlook,” “estimate,” “forecast,” “project,” “will,” “should,” and other similar words and expressions, and are subject to numerous assumptions, risks, and uncertainties, which change over time. Additionally, forward–looking statements speak only as of the date they are made; Burke & Herbert does not assume any duty, and does not undertake, to update such forward– looking statements, whether written or oral, that may be made from time to time, whether as a result of new information, future events, or otherwise. Furthermore, because forward–looking statements are subject to assumptions and uncertainties, actual results or future events could differ, possibly materially, from those indicated in or implied by such forward-looking statements as a result of a variety of factors, many of which are beyond the control of Burke & Herbert. Such statements are based upon the current beliefs and expectations of the management of Burke & Herbert and are subject to significant risks and uncertainties outside of its control. Caution should be exercised against placing undue reliance on forward-looking statements. The factors that could cause actual results to differ materially include the following: the possibility that the anticipated benefits of the merger will not be realized when expected or at all, including as a result of the impact of, or problems arising from (if any), the integration of the two companies or as a result of the strength of the economy and competitive factors in the areas where Burke & Herbert and LNKB do business; costs or difficulties associated with newly developed or acquired operations; diversion of management’s attention from ongoing business operations and opportunities; the possibility that the parties may be unable to achieve expected synergies and operating efficiencies in the merger within the expected timeframes or at all and to successfully integrate LNKB’s operations and those of Burke & Herbert;
3 Cautionary Statement Regarding Forward-Looking Information that the integration of LNKB may be more difficult, time-consuming or costly than expected; revenues following the merger may be lower than expected; Burke & Herbert’s success in executing its business plans and strategies and managing the risks involved in the foregoing; and risks related to the potential impact of global macroeconomic conditions and changes in general economic, political and market factors on the merger or our operations generally (either nationally or locally in the areas in which we conduct, or will conduct, business), including inflation, changes in interest rates, market volatility and monetary fluctuations, and changes in federal government policies and practices, including the impact with respect to spending on industries concentrated in our market area, as well as the impact from tariffs on the markets we serve; increased competition; changes in consumer confidence and demand for financial services, including changes in consumer borrowing, repayment, investment, and deposit practices; changes in asset quality and credit risk; our ability to control costs and expenses; adverse developments in borrower industries or declines in real estate values; changes in and compliance with federal and state laws and regulations that pertain to our business and capital levels; our ability to raise capital as needed; the impact, extent and timing of technological changes; emerging external focus among regulators and other officials related to risks in connection with the development and use of artificial intelligence; the effects of any cybersecurity breaches or events; the potential adverse effects of unusual and infrequently occurring events, such as weather-related disasters, terrorist acts, geopolitical conflicts and tensions, or public health events (such as pandemics), and of governmental and societal responses thereto; and the other factors discussed in the “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” sections of Burke & Herbert’s Annual Report on Form 10-K for the year ended December 31, 2025, its Quarterly Reports on Form 10-Q for the quarters ended March 31, 2026, and June 30, 2026, and other reports Burke & Herbert files with the SEC. Non-GAAP Financial Measures This presentation contains certain financial measures determined by methods other than in accordance with accounting principles generally accepted in the United States of America (“GAAP”). Such non-GAAP financial measures may include the following: fully tax-equivalent net interest margin, operating net income, adjusted non-interest expense, adjusted efficiency ratio tangible common equity, tangible assets, tangible common equity excluding AOCI, and tangible book value per common share. Management uses these non-GAAP financial measures to assess the performance of the Company’s core business and the strength of its capital position. Management believes that these non-GAAP financial measures provide meaningful additional information about the Company to assist investors in evaluating operating results, financial strength, and capitalization. The non-GAAP financial measures should be considered as additional views of the way our financial measures are affected by significant charges for credit costs and other factors. These non-GAAP financial measures should not be considered as a substitute for operating results determined in accordance with GAAP and may not be comparable to other similarly titled measures of other companies. The computations of the non-GAAP financial measures used in this presentation are referenced in a footnote or in the appendix to this presentation.
4 Company Overview
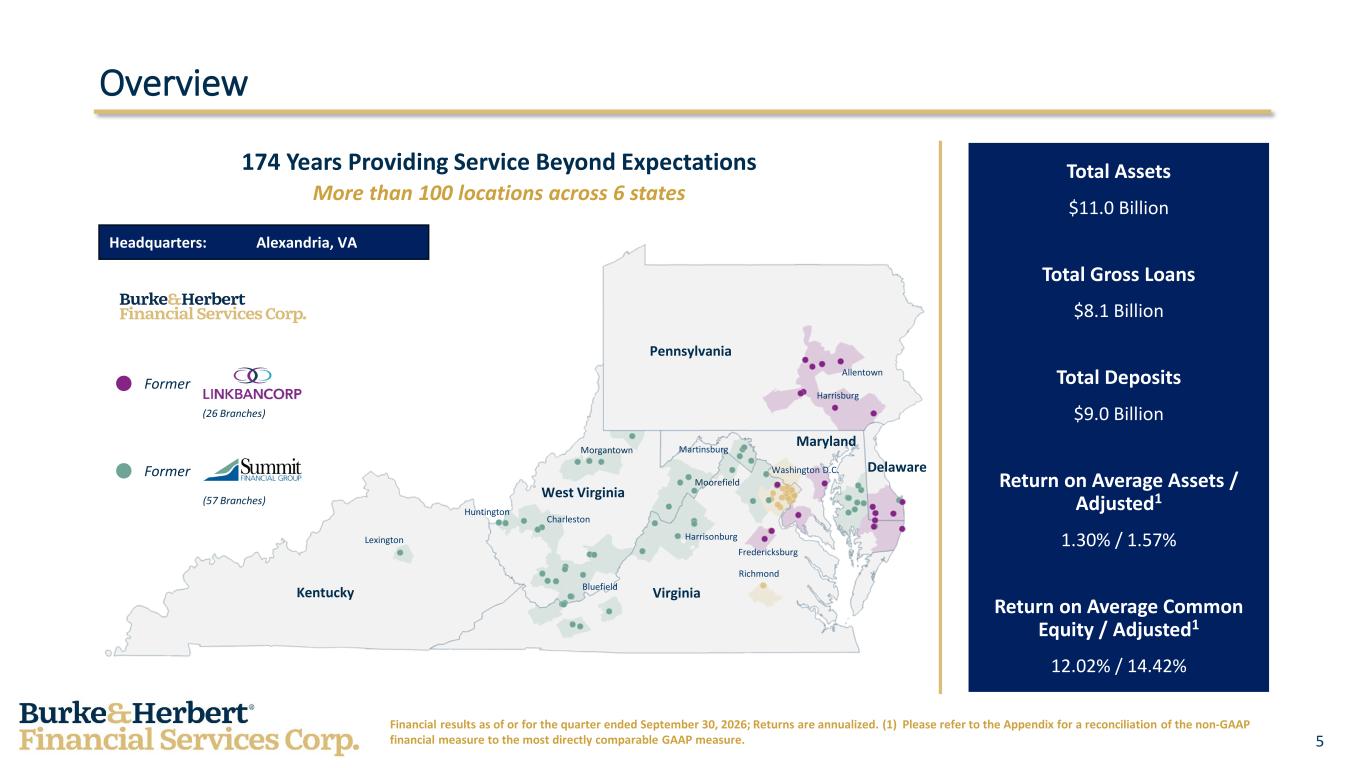
5 Delaware Maryland West Virginia Kentucky Virginia Pennsylvania Lexington Charleston Huntington Bluefield Richmond Harrisonburg Moorefield Morgantown Martinsburg Washington D.C. Harrisburg Allentown Overview Headquarters: Alexandria, VA 174 Years Providing Service Beyond Expectations More than 100 locations across 6 states Total Assets $11.0 Billion Total Gross Loans $8.1 Billion Total Deposits $9.0 Billion Return on Average Assets / Adjusted1 1.30% / 1.57% Return on Average Common Equity / Adjusted1 12.02% / 14.42% Financial results as of or for the quarter ended September 30, 2026; Returns are annualized. (1) Please refer to the Appendix for a reconciliation of the non-GAAP financial measure to the most directly comparable GAAP measure. Former Former (57 Branches) (26 Branches) Fredericksburg
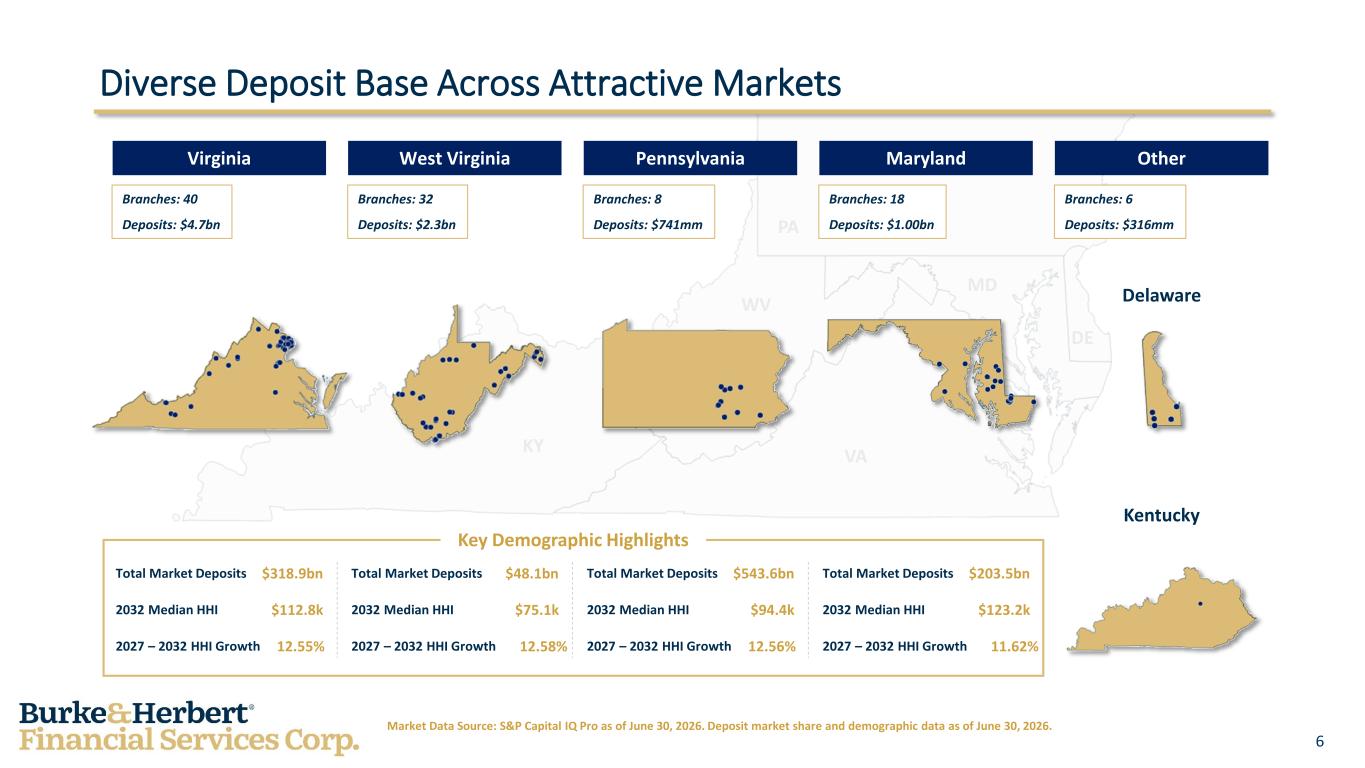
6 4 Market Data Source: S&P Capital IQ Pro as of June 30, 2026. Deposit market share and demographic data as of June 30, 2026. Diverse Deposit Base Across Attractive Markets West Virginia Branches: 32 Deposits: $2.3bn Pennsylvania Branches: 8 Deposits: $741mm Other Branches: 6 Deposits: $316mm Virginia Branches: 40 Deposits: $4.7bn Maryland Branches: 18 Deposits: $1.00bn Delaware Kentucky Key Demographic Highlights Total Market Deposits $318.9bn 2032 Median HHI $112.8k 2027 – 2032 HHI Growth 12.55% Total Market Deposits $48.1bn 2032 Median HHI $75.1k 2027 – 2032 HHI Growth 12.58% Total Market Deposits $543.6bn 2032 Median HHI $94.4k 2027 – 2032 HHI Growth 12.56% Total Market Deposits $203.5bn 2032 Median HHI $123.2k 2027 – 2032 HHI Growth 11.62%
7 Core Values Driven by our values, we endeavor to be your quintessential community bank — delivering service beyond expectations Serve & Lead We are dedicated to serving our customers and our teams, leading with quiet confidence and integrity to inspire the trust of all those we serve. Deliver More We are driven to go above and beyond, continually innovating and improving on how we deliver the best possible experiences and outcomes for all those we serve. Elevate Everyone We embrace our differences and respect everyone's unique contributions. We seek to empower individuals through our actions and words because we believe that when one succeeds, we all succeed. Always Invested We take ownership and responsibility for our work and are invested in the long-term success of our customers, colleagues, and communities.
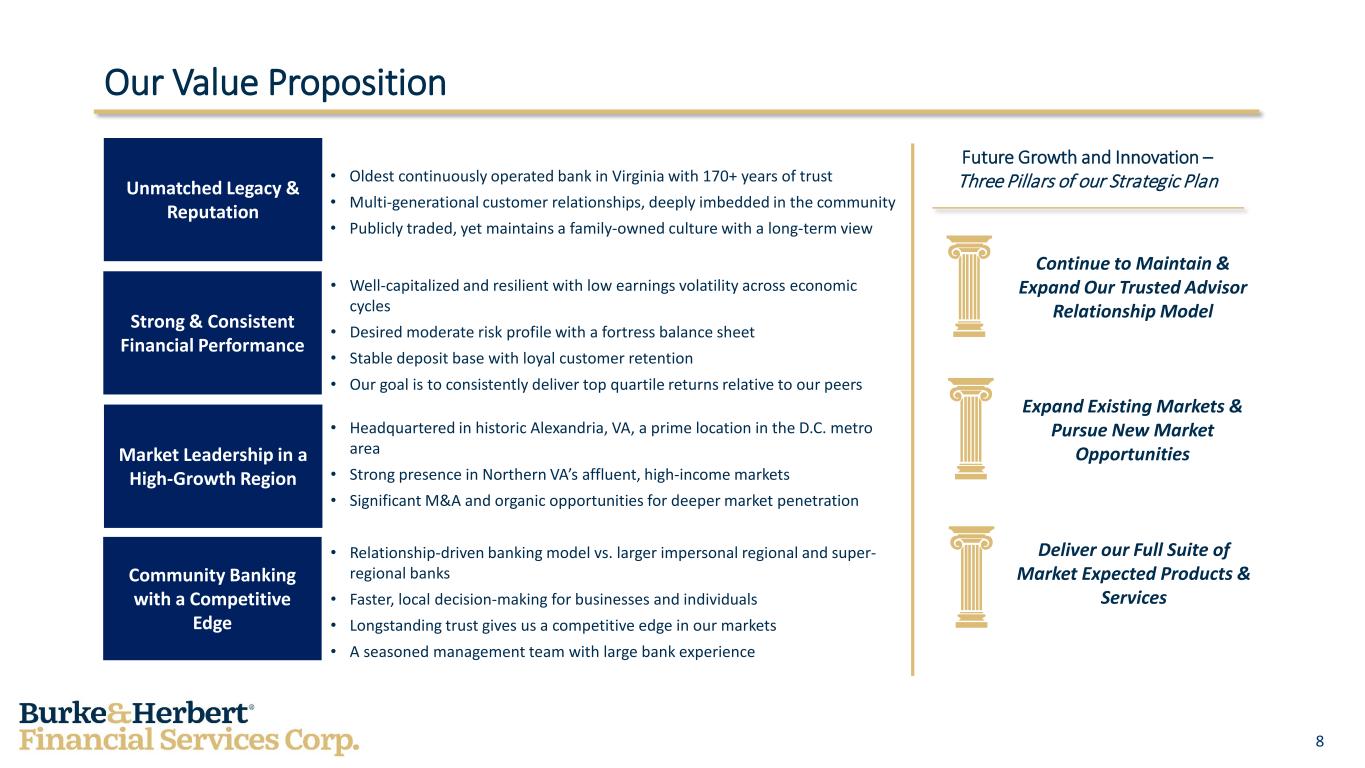
8 Our Value Proposition Unmatched Legacy & Reputation Strong & Consistent Financial Performance Market Leadership in a High-Growth Region Community Banking with a Competitive Edge • Oldest continuously operated bank in Virginia with 170+ years of trust • Multi-generational customer relationships, deeply imbedded in the community • Publicly traded, yet maintains a family-owned culture with a long-term view • Well-capitalized and resilient with low earnings volatility across economic cycles • Desired moderate risk profile with a fortress balance sheet • Stable deposit base with loyal customer retention • Our goal is to consistently deliver top quartile returns relative to our peers • Headquartered in historic Alexandria, VA, a prime location in the D.C. metro area • Strong presence in Northern VA’s affluent, high-income markets • Significant M&A and organic opportunities for deeper market penetration • Relationship-driven banking model vs. larger impersonal regional and super- regional banks • Faster, local decision-making for businesses and individuals • Longstanding trust gives us a competitive edge in our markets • A seasoned management team with large bank experience Future Growth and Innovation – Three Pillars of our Strategic Plan Continue to Maintain & Expand Our Trusted Advisor Relationship Model Expand Existing Markets & Pursue New Market Opportunities Deliver our Full Suite of Market Expected Products & Services
9 Financial Overview
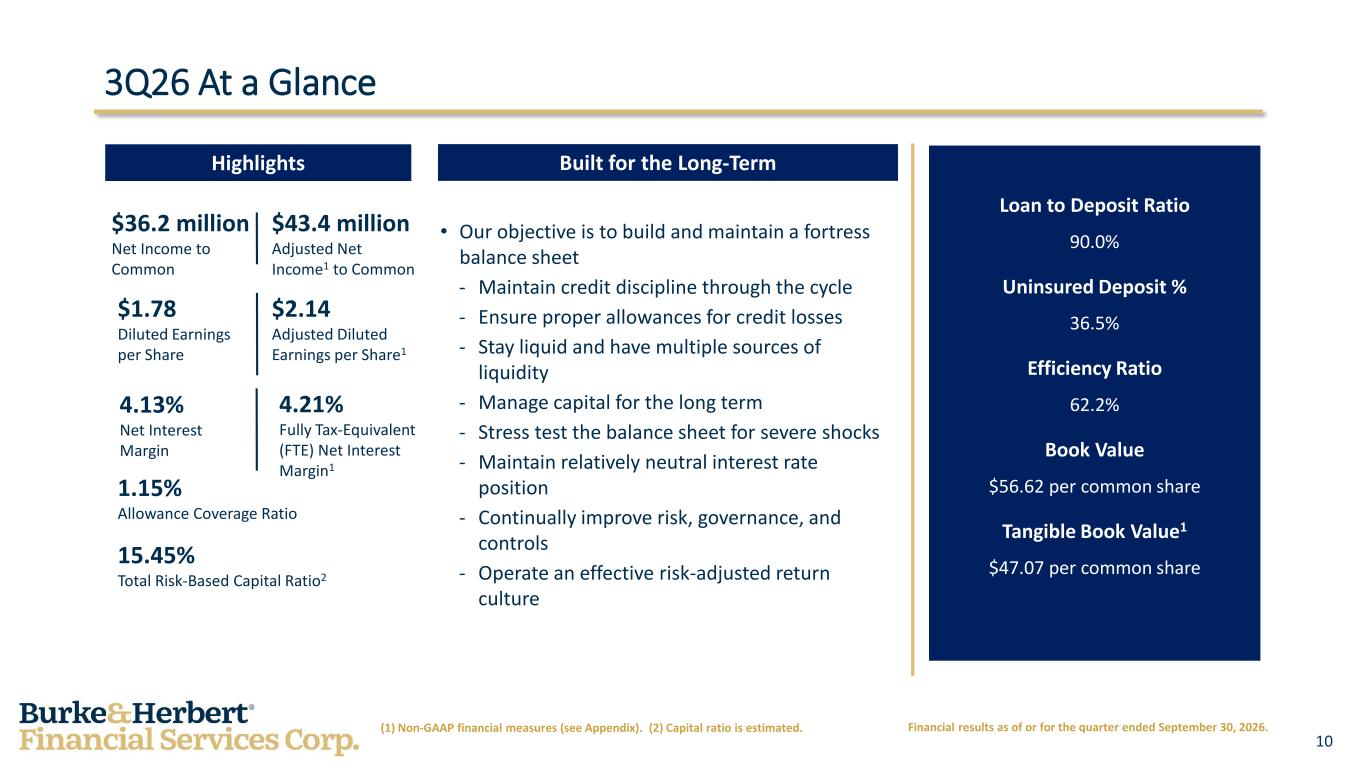
10 3Q26 At a Glance Highlights Built for the Long-Term $36.2 million Net Income to Common $1.78 Diluted Earnings per Share 4.13% Net Interest Margin 1.15% Allowance Coverage Ratio 15.45% Total Risk-Based Capital Ratio2 (1) Non-GAAP financial measures (see Appendix). (2) Capital ratio is estimated. • Our objective is to build and maintain a fortress balance sheet - Maintain credit discipline through the cycle - Ensure proper allowances for credit losses - Stay liquid and have multiple sources of liquidity - Manage capital for the long term - Stress test the balance sheet for severe shocks - Maintain relatively neutral interest rate position - Continually improve risk, governance, and controls - Operate an effective risk-adjusted return culture Loan to Deposit Ratio 90.0% Uninsured Deposit % 36.5% Efficiency Ratio 62.2% Book Value $56.62 per common share Tangible Book Value1 $47.07 per common share Financial results as of or for the quarter ended September 30, 2026. $43.4 million Adjusted Net Income1 to Common $2.14 Adjusted Diluted Earnings per Share1 4.21% Fully Tax-Equivalent (FTE) Net Interest Margin1
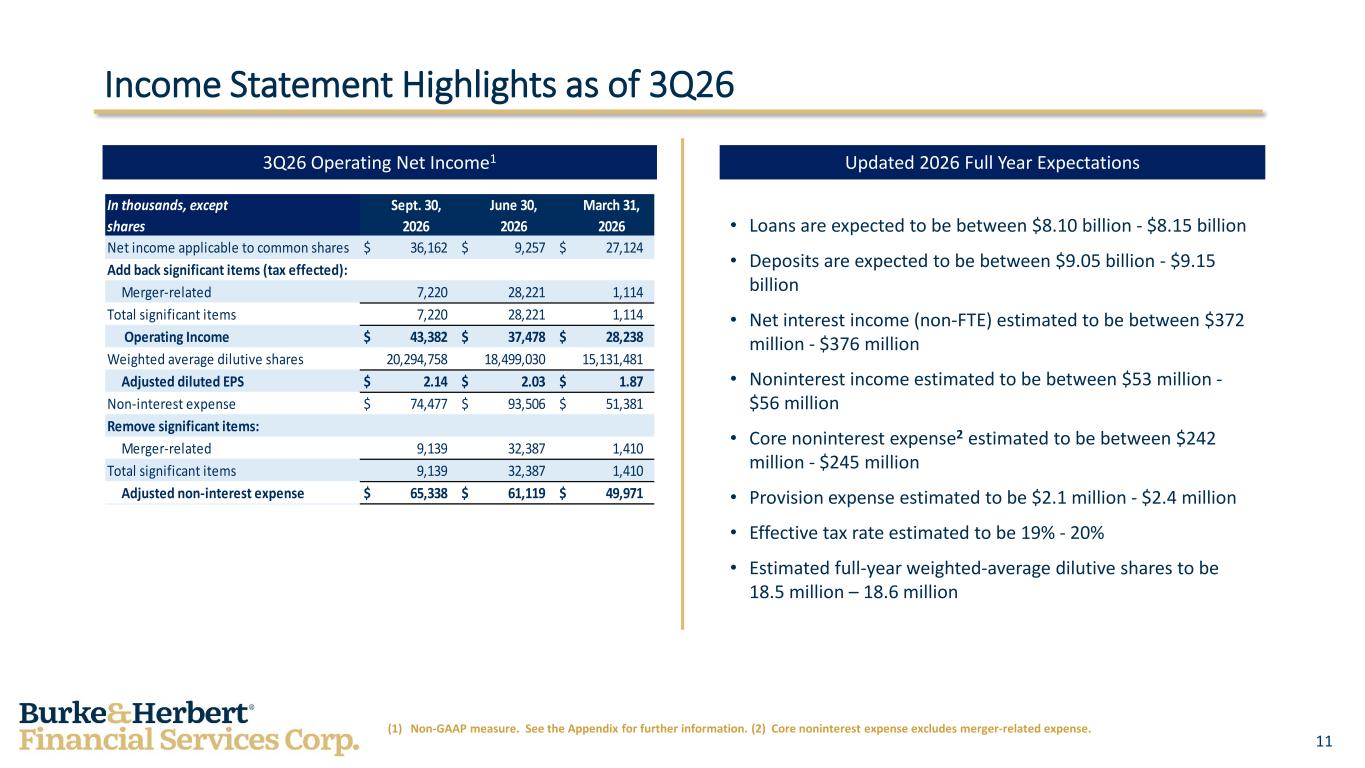
11 Income Statement Highlights as of 3Q26 (1) Non-GAAP measure. See the Appendix for further information. (2) Core noninterest expense excludes merger-related expense. • Loans are expected to be between $8.10 billion - $8.15 billion • Deposits are expected to be between $9.05 billion - $9.15 billion • Net interest income (non-FTE) estimated to be between $372 million - $376 million • Noninterest income estimated to be between $53 million - $56 million • Core noninterest expense2 estimated to be between $242 million - $245 million • Provision expense estimated to be $2.1 million - $2.4 million • Effective tax rate estimated to be 19% - 20% • Estimated full-year weighted-average dilutive shares to be 18.5 million – 18.6 million 3Q26 Operating Net Income1 Updated 2026 Full Year Expectations In thousands, except Sept. 30, June 30, March 31, shares 2026 2026 2026 Net income applicable to common shares $ 36,162 $ 9,257 $ 27,124 Add back significant items (tax effected): Merger-related 7,220 28,221 1,114 Total significant items 7,220 28,221 1,114 Operating Income $ 43,382 $ 37,478 $ 28,238 Weighted average dilutive shares 20,294,758 18,499,030 15,131,481 Adjusted diluted EPS $ 2.14 $ 2.03 $ 1.87 Non-interest expense $ 74,477 $ 93,506 $ 51,381 Remove significant items: Merger-related 9,139 32,387 1,410 Total significant items 9,139 32,387 1,410 Adjusted non-interest expense $ 65,338 $ 61,119 $ 49,971
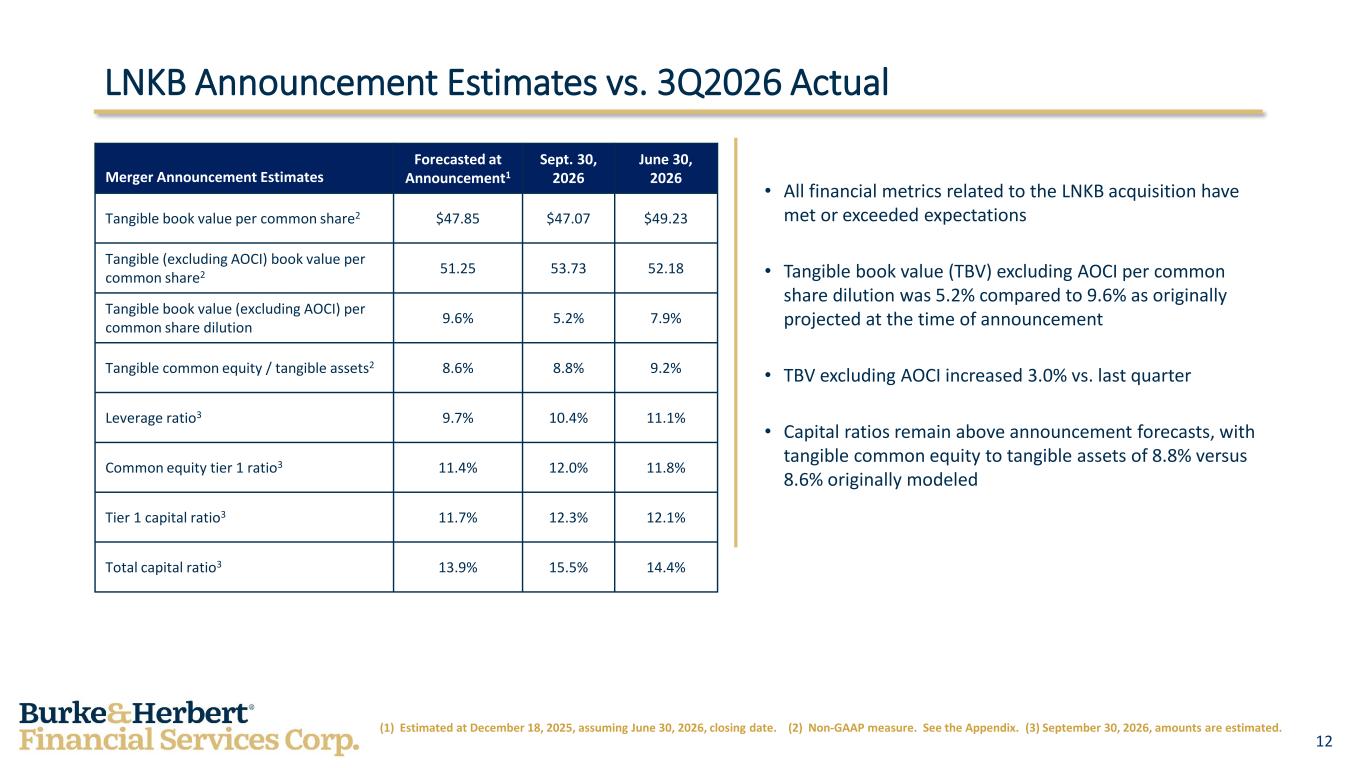
12 LNKB Announcement Estimates vs. 3Q2026 Actual (1) Estimated at December 18, 2025, assuming June 30, 2026, closing date. (2) Non-GAAP measure. See the Appendix. (3) September 30, 2026, amounts are estimated. Merger Announcement Estimates Forecasted at Announcement1 Sept. 30, 2026 June 30, 2026 Tangible book value per common share2 $47.85 $47.07 $49.23 Tangible (excluding AOCI) book value per common share2 51.25 53.73 52.18 Tangible book value (excluding AOCI) per common share dilution 9.6% 5.2% 7.9% Tangible common equity / tangible assets2 8.6% 8.8% 9.2% Leverage ratio3 9.7% 10.4% 11.1% Common equity tier 1 ratio3 11.4% 12.0% 11.8% Tier 1 capital ratio3 11.7% 12.3% 12.1% Total capital ratio3 13.9% 15.5% 14.4% • All financial metrics related to the LNKB acquisition have met or exceeded expectations • Tangible book value (TBV) excluding AOCI per common share dilution was 5.2% compared to 9.6% as originally projected at the time of announcement • TBV excluding AOCI increased 3.0% vs. last quarter • Capital ratios remain above announcement forecasts, with tangible common equity to tangible assets of 8.8% versus 8.6% originally modeled
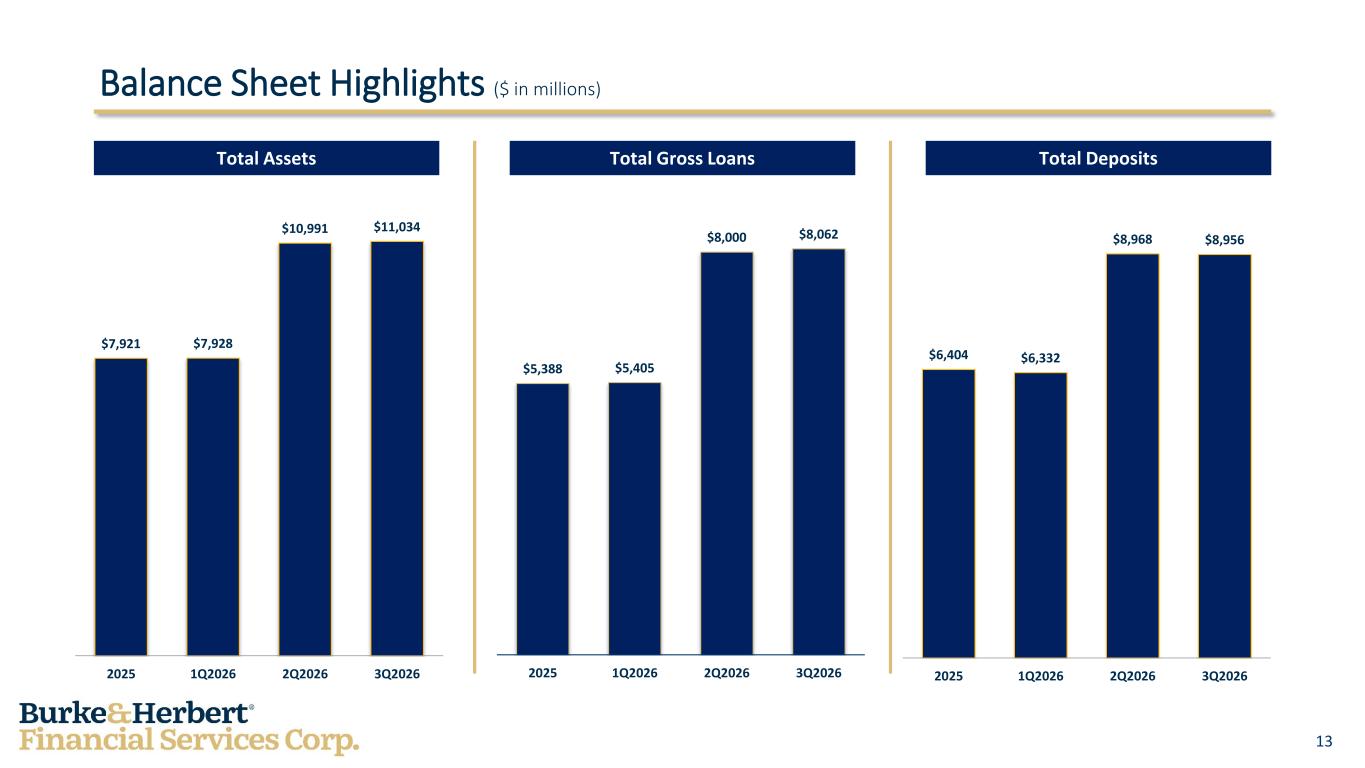
13 Total Assets Balance Sheet Highlights ($ in millions) Total DepositsTotal Gross Loans $7,921 $7,928 $10,991 $11,034 2025 1Q2026 2Q2026 3Q2026 $5,388 $5,405 $8,000 $8,062 2025 1Q2026 2Q2026 3Q2026 $6,404 $6,332 $8,968 $8,956 2025 1Q2026 2Q2026 3Q2026
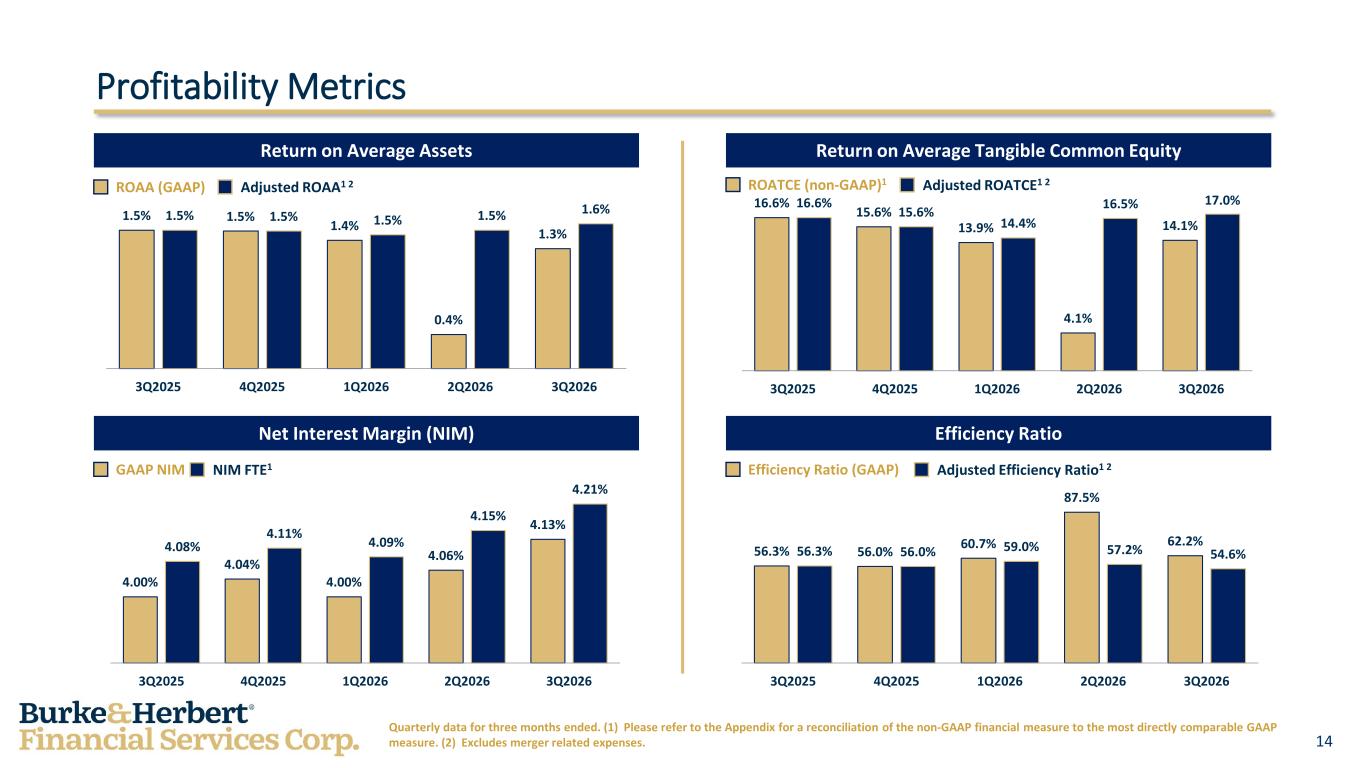
14 Net Interest Margin (NIM) Return on Average Tangible Common Equity ROATCE (non-GAAP)1 Adjusted ROATCE1 2 Profitability Metrics Return on Average Assets Efficiency Ratio Quarterly data for three months ended. (1) Please refer to the Appendix for a reconciliation of the non-GAAP financial measure to the most directly comparable GAAP measure. (2) Excludes merger related expenses. ROAA (GAAP) Adjusted ROAA1 2 GAAP NIM NIM FTE1 Efficiency Ratio (GAAP) Adjusted Efficiency Ratio1 2 1.5% 1.5% 1.4% 0.4% 1.3% 1.5% 1.5% 1.5% 1.5% 1.6% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 16.6% 15.6% 13.9% 4.1% 14.1% 16.6% 15.6% 14.4% 16.5% 17.0% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 4.00% 4.04% 4.00% 4.06% 4.13% 4.08% 4.11% 4.09% 4.15% 4.21% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 56.3% 56.0% 60.7% 87.5% 62.2% 56.3% 56.0% 59.0% 57.2% 54.6% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026
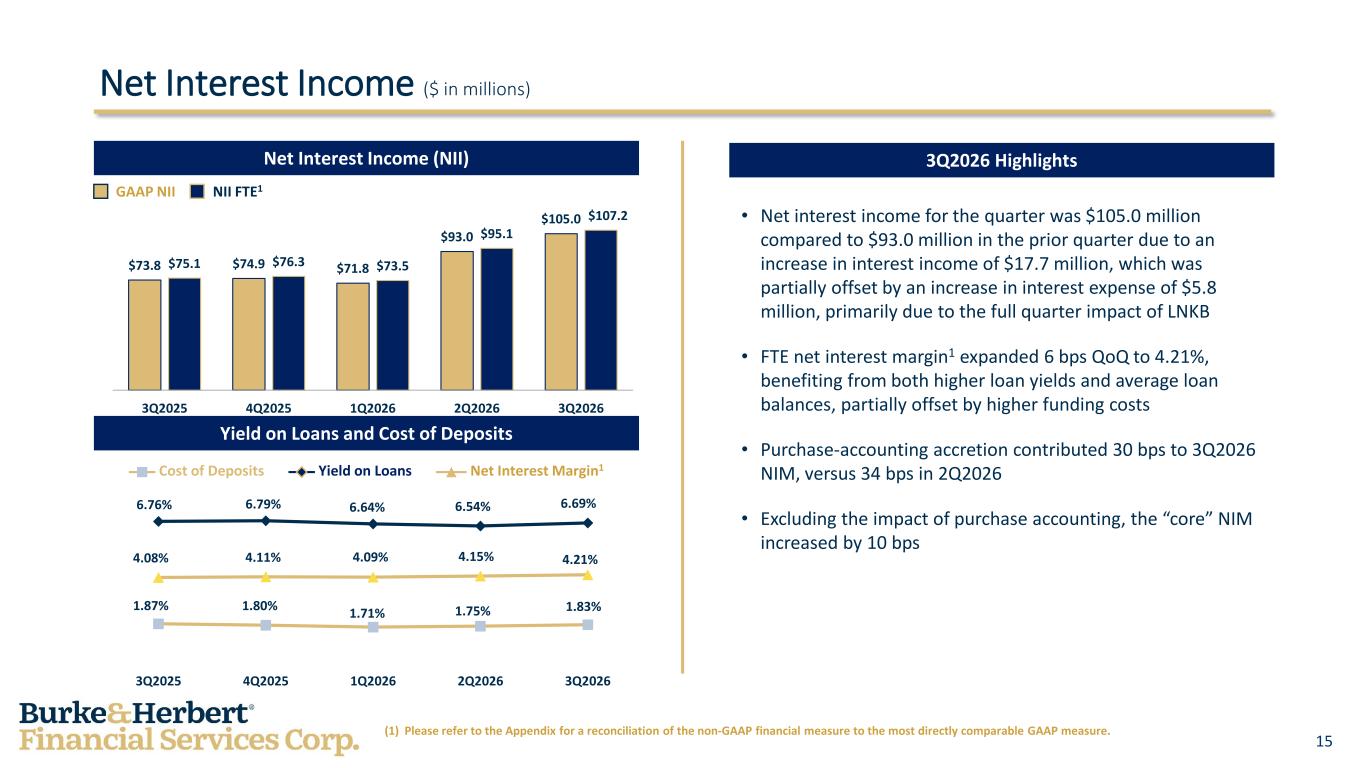
15 • Net interest income for the quarter was $105.0 million compared to $93.0 million in the prior quarter due to an increase in interest income of $17.7 million, which was partially offset by an increase in interest expense of $5.8 million, primarily due to the full quarter impact of LNKB • FTE net interest margin1 expanded 6 bps QoQ to 4.21%, benefiting from both higher loan yields and average loan balances, partially offset by higher funding costs • Purchase-accounting accretion contributed 30 bps to 3Q2026 NIM, versus 34 bps in 2Q2026 • Excluding the impact of purchase accounting, the “core” NIM increased by 10 bps Net Interest Income ($ in millions) GAAP NII NII FTE1 Yield on LoansCost of Deposits Yield on Loans and Cost of Deposits Net Interest Income (NII) 3Q2026 Highlights (1) Please refer to the Appendix for a reconciliation of the non-GAAP financial measure to the most directly comparable GAAP measure. $73.8 $74.9 $71.8 $93.0 $105.0 $75.1 $76.3 $73.5 $95.1 $107.2 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 6.76% 6.79% 6.64% 6.54% 6.69% 1.87% 1.80% 1.71% 1.75% 1.83% 4.08% 4.11% 4.09% 4.15% 4.21% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 Net Interest Margin1
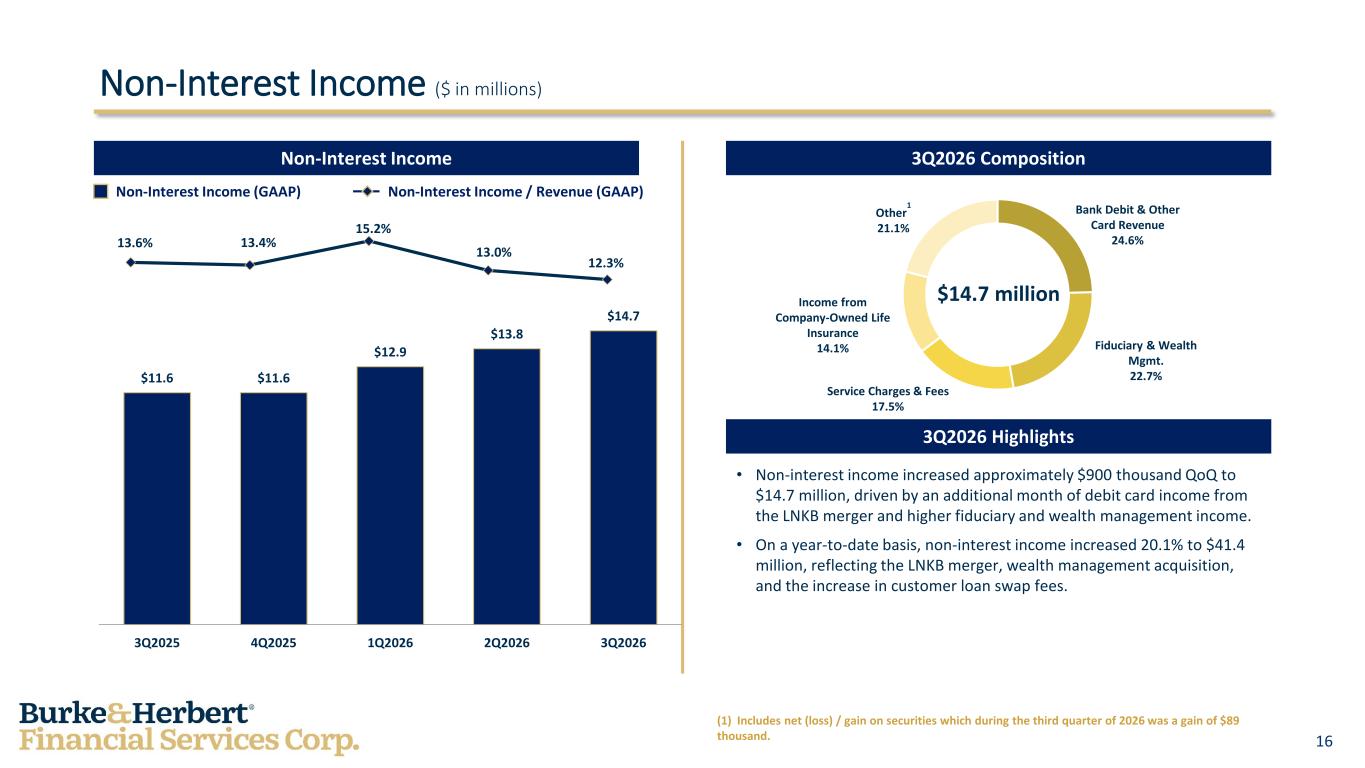
16 Non-Interest Income ($ in millions) Non-Interest Income Non-Interest Income (GAAP) Non-Interest Income / Revenue (GAAP) • Non-interest income increased approximately $900 thousand QoQ to $14.7 million, driven by an additional month of debit card income from the LNKB merger and higher fiduciary and wealth management income. • On a year-to-date basis, non-interest income increased 20.1% to $41.4 million, reflecting the LNKB merger, wealth management acquisition, and the increase in customer loan swap fees. $14.7 million 3Q2026 Composition 3Q2026 Highlights Fiduciary & Wealth Mgmt. 22.7% Other 1 21.1% Income from Company-Owned Life Insurance 14.1% Service Charges & Fees 17.5% $11.6 $11.6 $12.9 $13.8 $14.7 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 13.6% 13.4% 15.2% 13.0% 12.3% Bank Debit & Other Card Revenue 24.6% (1) Includes net (loss) / gain on securities which during the third quarter of 2026 was a gain of $89 thousand.
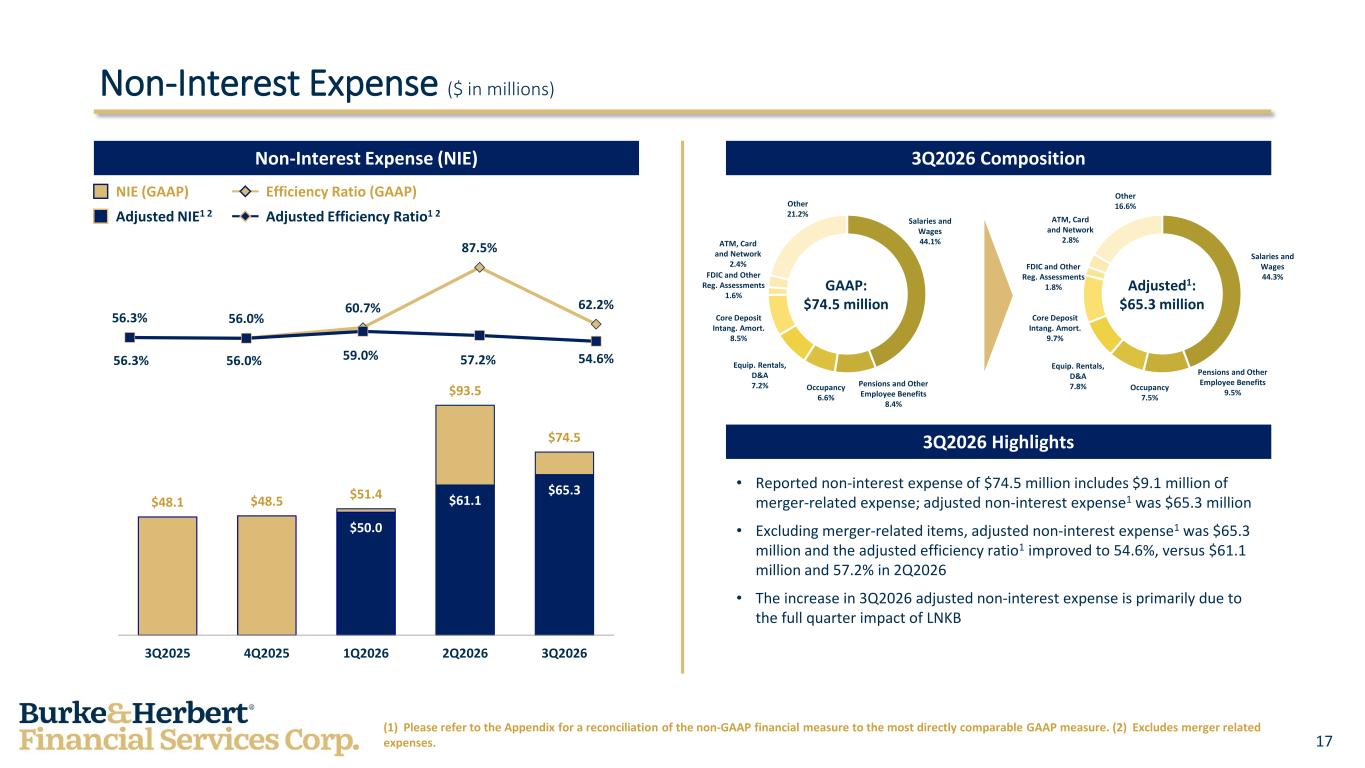
17 Non-Interest Expense ($ in millions) Adjusted NIE1 2 Adjusted Efficiency Ratio1 2 NIE (GAAP) Efficiency Ratio (GAAP) (1) Please refer to the Appendix for a reconciliation of the non-GAAP financial measure to the most directly comparable GAAP measure. (2) Excludes merger related expenses. 3Q2026 CompositionNon-Interest Expense (NIE) 3Q2026 Highlights • Reported non-interest expense of $74.5 million includes $9.1 million of merger-related expense; adjusted non-interest expense1 was $65.3 million • Excluding merger-related items, adjusted non-interest expense1 was $65.3 million and the adjusted efficiency ratio1 improved to 54.6%, versus $61.1 million and 57.2% in 2Q2026 • The increase in 3Q2026 adjusted non-interest expense is primarily due to the full quarter impact of LNKB GAAP: $74.5 million Adjusted1: $65.3 million $48.1 $48.5 $51.4 $93.5 $74.5 $50.0 $61.1 $65.3 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 56.3% 56.0% 60.7% 87.5% 62.2% 56.3% 56.0% 59.0% 57.2% 54.6% Salaries and Wages 44.1% Pensions and Other Employee Benefits 8.4% Occupancy 6.6% Equip. Rentals, D&A 7.2% Core Deposit Intang. Amort. 8.5% FDIC and Other Reg. Assessments 1.6% ATM, Card and Network 2.4% Other 21.2% Salaries and Wages 44.3% Pensions and Other Employee Benefits 9.5%Occupancy 7.5% Equip. Rentals, D&A 7.8% Core Deposit Intang. Amort. 9.7% FDIC and Other Reg. Assessments 1.8% ATM, Card and Network 2.8% Other 16.6%
18 Loan Portfolio and Asset Quality
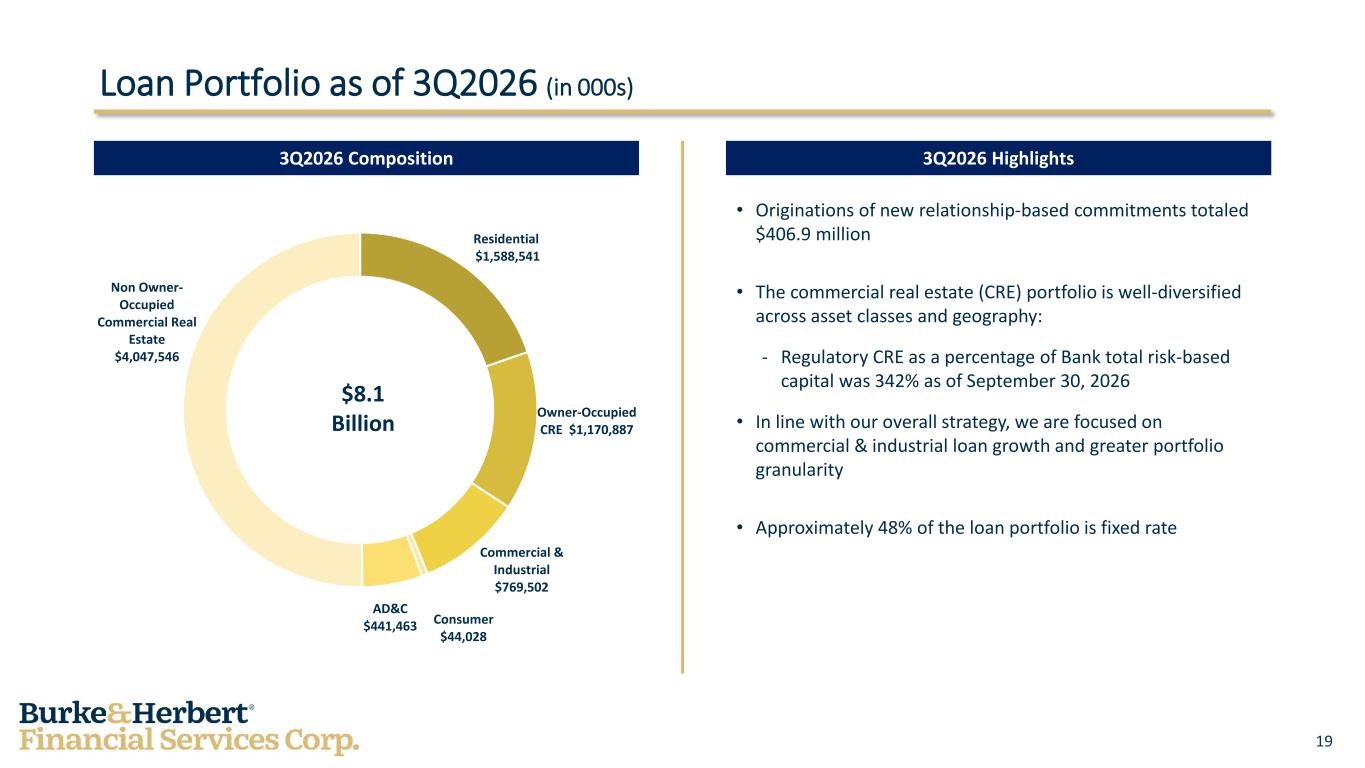
19 • Originations of new relationship-based commitments totaled $406.9 million • The commercial real estate (CRE) portfolio is well-diversified across asset classes and geography: - Regulatory CRE as a percentage of Bank total risk-based capital was 342% as of September 30, 2026 • In line with our overall strategy, we are focused on commercial & industrial loan growth and greater portfolio granularity • Approximately 48% of the loan portfolio is fixed rate Loan Portfolio as of 3Q2026 (in 000s) 3Q2026 Composition 3Q2026 Highlights Residential $1,588,541 Owner-Occupied CRE $1,170,887 Commercial & Industrial $769,502 Consumer $44,028 AD&C $441,463 Non Owner- Occupied Commercial Real Estate $4,047,546 $8.1 Billion
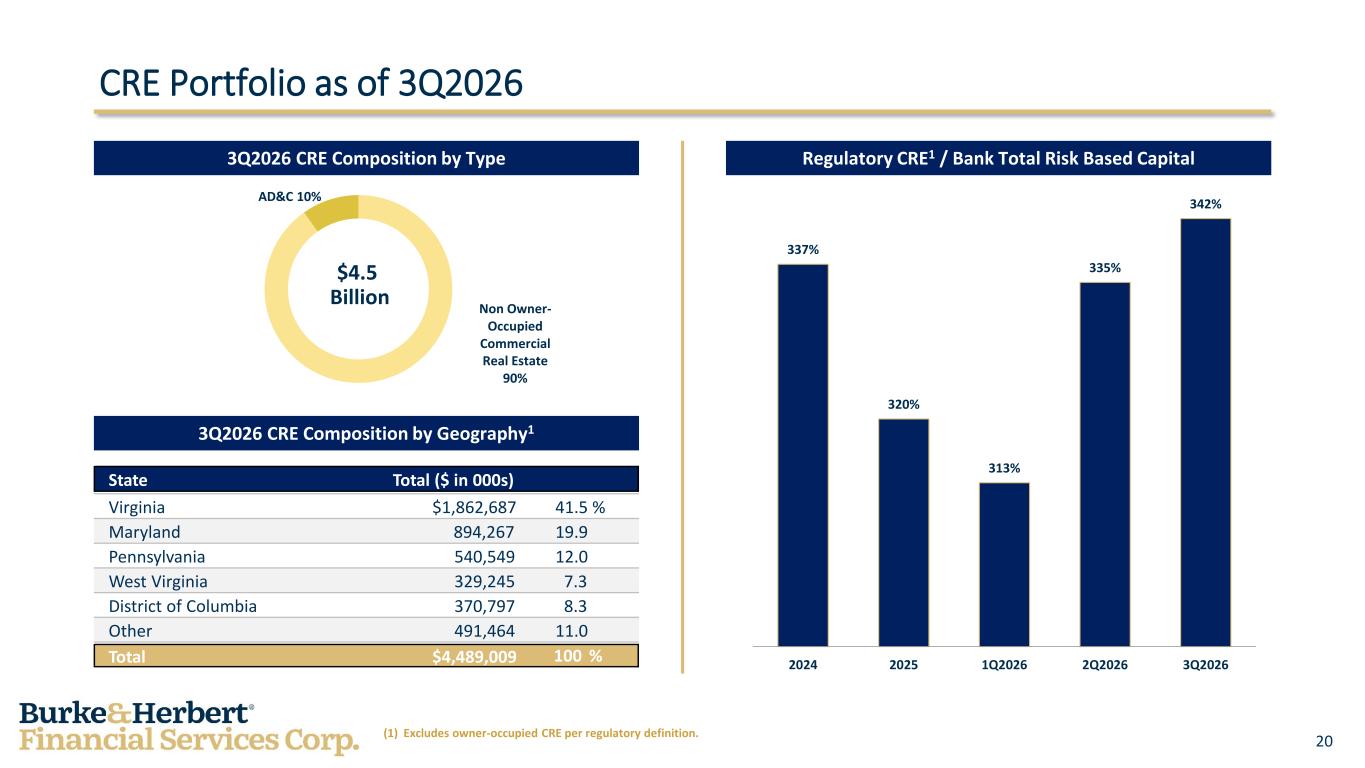
20 Non Owner- Occupied Commercial Real Estate 90% AD&C 10% CRE Portfolio as of 3Q2026 Regulatory CRE1 / Bank Total Risk Based Capital3Q2026 CRE Composition by Type 3Q2026 CRE Composition by Geography1 (1) Excludes owner-occupied CRE per regulatory definition. $4.5 Billion 337% 320% 313% 335% 342% 2024 2025 1Q2026 2Q2026 3Q2026 State Total ($ in 000s) Virginia $1,862,687 41.5 % Maryland 894,267 19.9 Pennsylvania 540,549 12.0 West Virginia 329,245 7.3 District of Columbia 370,797 8.3 Other 491,464 11.0 Total $4,489,009 100 %
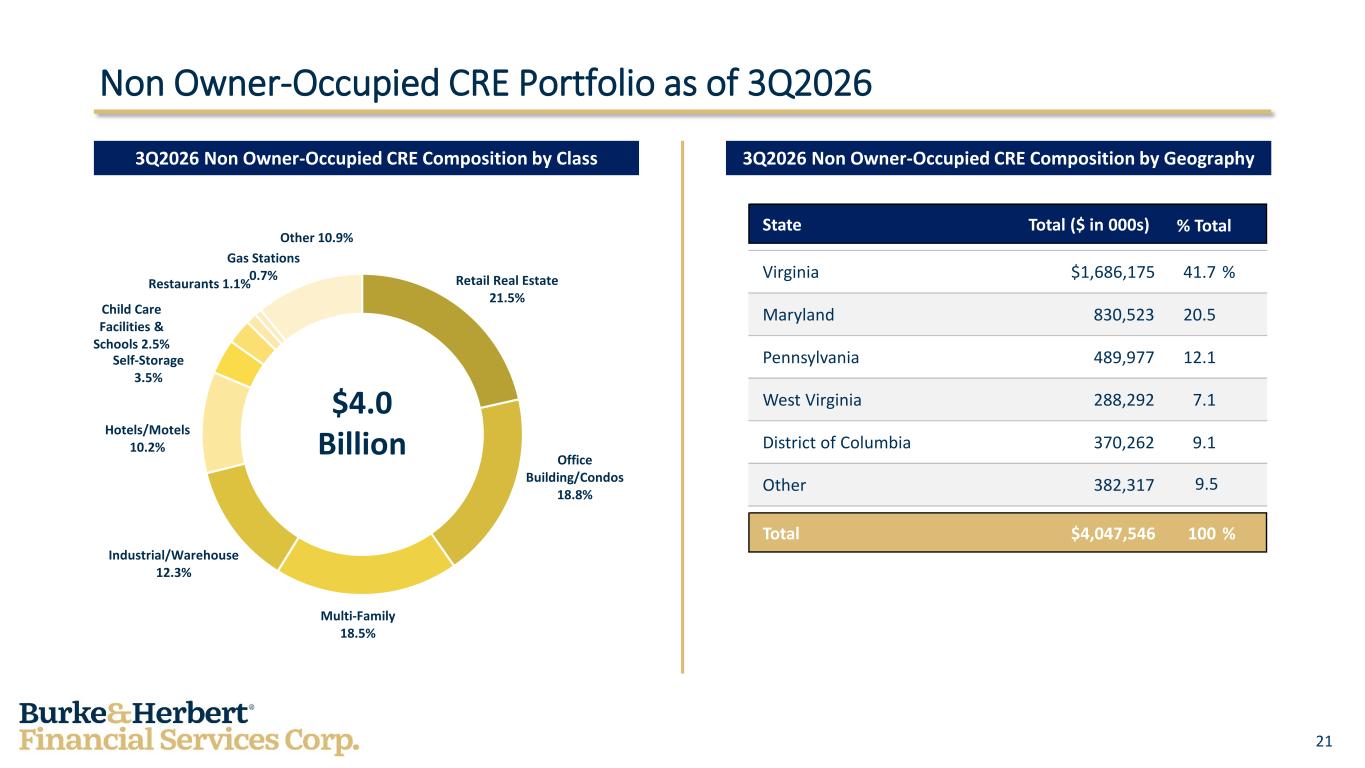
21 Retail Real Estate 21.5% Office Building/Condos 18.8% Multi-Family 18.5% Industrial/Warehouse 12.3% Hotels/Motels 10.2% Self-Storage 3.5% Child Care Facilities & Schools 2.5% Restaurants 1.1% Gas Stations 0.7% Other 10.9% Non Owner-Occupied CRE Portfolio as of 3Q2026 3Q2026 Non Owner-Occupied CRE Composition by Geography3Q2026 Non Owner-Occupied CRE Composition by Class $4.0 Billion State Total ($ in 000s) Virginia $1,686,175 41.7 % Maryland 830,523 20.5 Pennsylvania 489,977 12.1 West Virginia 288,292 7.1 District of Columbia 370,262 9.1 Other 382,317 9.5 Total $4,047,546 100 % % Total
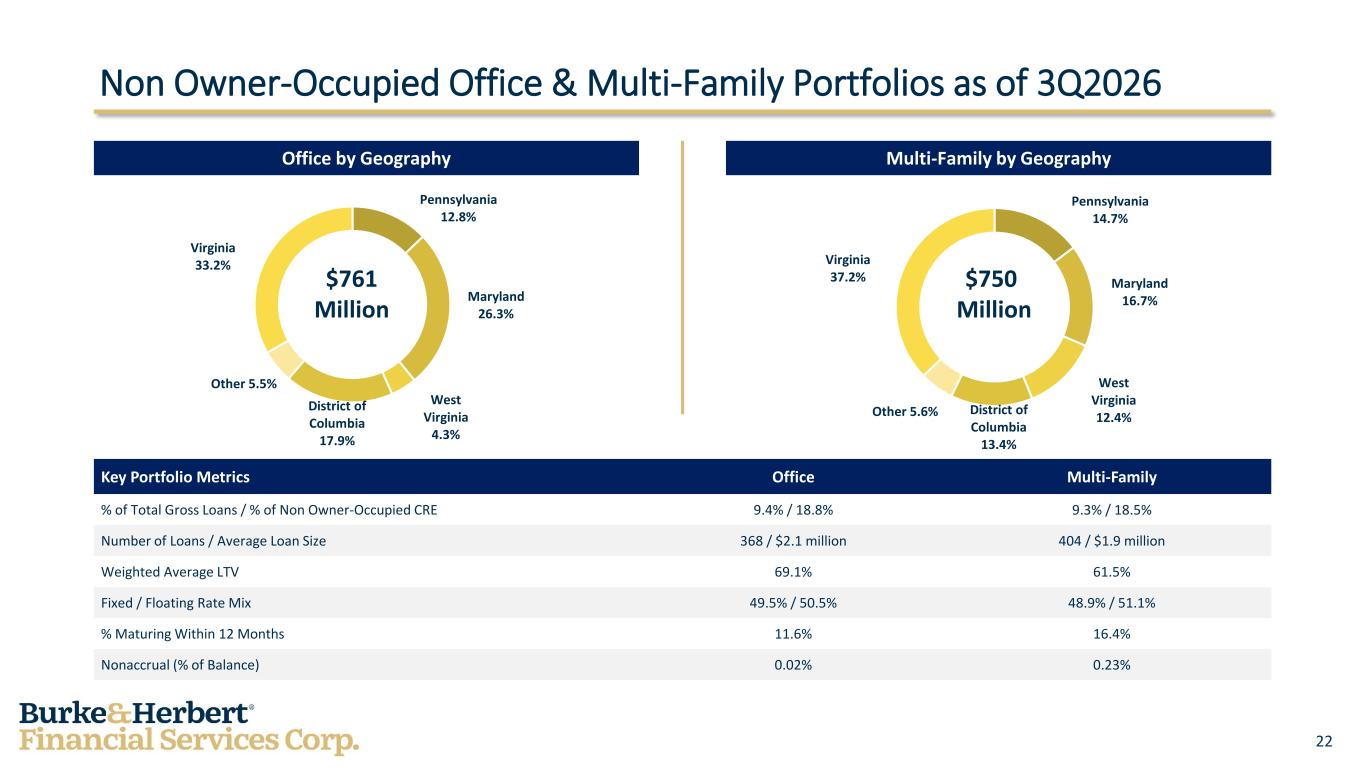
22 Pennsylvania 14.7% Maryland 16.7% West Virginia 12.4%District of Columbia 13.4% Other 5.6% Virginia 37.2% Pennsylvania 12.8% Maryland 26.3% West Virginia 4.3% District of Columbia 17.9% Other 5.5% Virginia 33.2% Non Owner-Occupied Office & Multi-Family Portfolios as of 3Q2026 Key Portfolio Metrics Office Multi-Family % of Total Gross Loans / % of Non Owner-Occupied CRE 9.4% / 18.8% 9.3% / 18.5% Number of Loans / Average Loan Size 368 / $2.1 million 404 / $1.9 million Weighted Average LTV 69.1% 61.5% Fixed / Floating Rate Mix 49.5% / 50.5% 48.9% / 51.1% % Maturing Within 12 Months 11.6% 16.4% Nonaccrual (% of Balance) 0.02% 0.23% Multi-Family by GeographyOffice by Geography $761 Million $750 Million
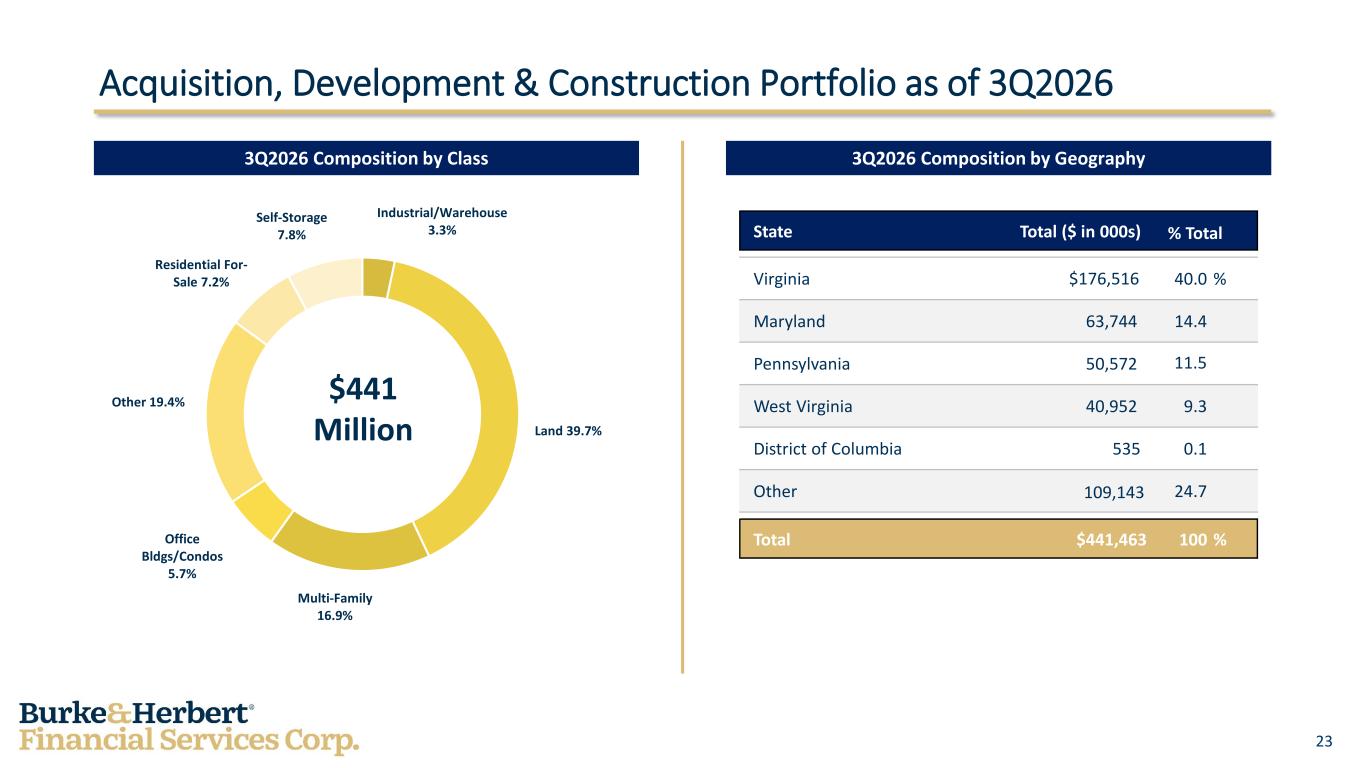
23 Industrial/Warehouse 3.3% Land 39.7% Multi-Family 16.9% Office Bldgs/Condos 5.7% Other 19.4% Residential For- Sale 7.2% Self-Storage 7.8% Acquisition, Development & Construction Portfolio as of 3Q2026 3Q2026 Composition by Geography3Q2026 Composition by Class $441 Million State Total ($ in 000s) Virginia $176,516 40.0 % Maryland 63,744 14.4 Pennsylvania 50,572 11.5 West Virginia 40,952 9.3 District of Columbia 535 0.1 Other 109,143 24.7 Total $441,463 100 % % Total
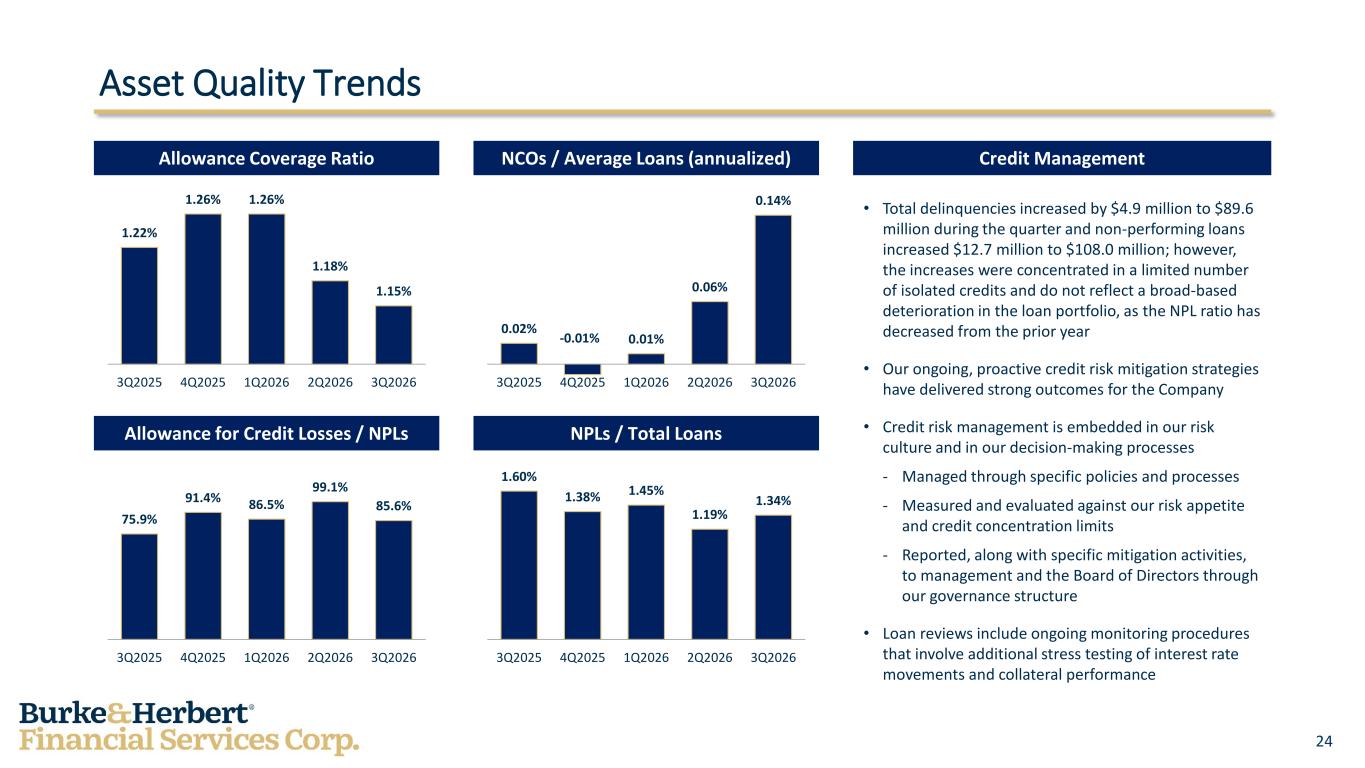
24 Asset Quality Trends • Total delinquencies increased by $4.9 million to $89.6 million during the quarter and non-performing loans increased $12.7 million to $108.0 million; however, the increases were concentrated in a limited number of isolated credits and do not reflect a broad-based deterioration in the loan portfolio, as the NPL ratio has decreased from the prior year • Our ongoing, proactive credit risk mitigation strategies have delivered strong outcomes for the Company • Credit risk management is embedded in our risk culture and in our decision-making processes - Managed through specific policies and processes - Measured and evaluated against our risk appetite and credit concentration limits - Reported, along with specific mitigation activities, to management and the Board of Directors through our governance structure • Loan reviews include ongoing monitoring procedures that involve additional stress testing of interest rate movements and collateral performance Credit ManagementNCOs / Average Loans (annualized)Allowance Coverage Ratio Allowance for Credit Losses / NPLs NPLs / Total Loans 1.22% 1.26% 1.26% 1.18% 1.15% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 0.02% -0.01% 0.01% 0.06% 0.14% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 75.9% 91.4% 86.5% 99.1% 85.6% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 1.60% 1.38% 1.45% 1.19% 1.34% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026
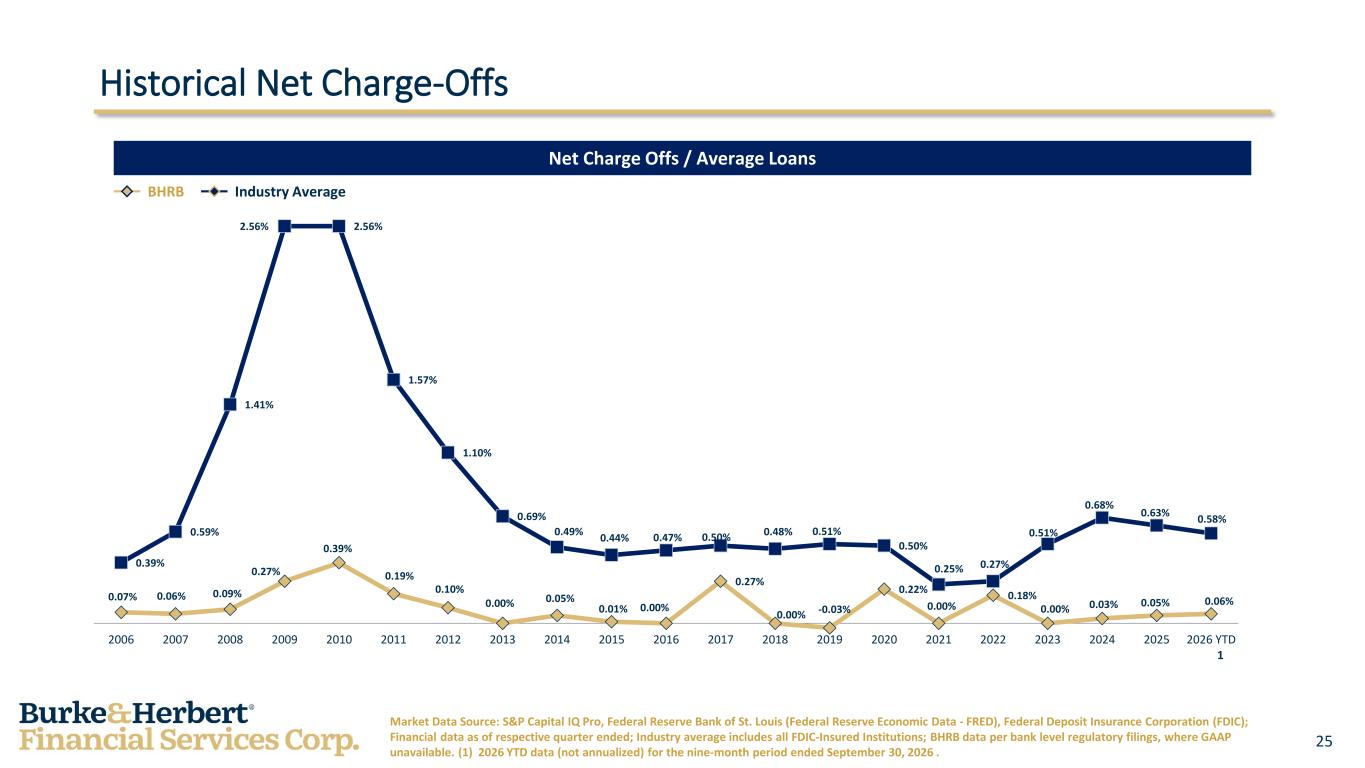
25 BHRB Industry Average Historical Net Charge-Offs Net Charge Offs / Average Loans Market Data Source: S&P Capital IQ Pro, Federal Reserve Bank of St. Louis (Federal Reserve Economic Data - FRED), Federal Deposit Insurance Corporation (FDIC); Financial data as of respective quarter ended; Industry average includes all FDIC-Insured Institutions; BHRB data per bank level regulatory filings, where GAAP unavailable. (1) 2026 YTD data (not annualized) for the nine-month period ended September 30, 2026 . 1 0.07% 0.06% 0.09% 0.27% 0.39% 0.19% 0.10% 0.00% 0.05% 0.01% 0.00% 0.27% 0.00% -0.03% 0.22% 0.00% 0.18% 0.00% 0.03% 0.05% 0.06% 0.39% 0.59% 1.41% 2.56% 2.56% 1.57% 1.10% 0.69% 0.49% 0.44% 0.47% 0.50% 0.48% 0.51% 0.50% 0.25% 0.27% 0.51% 0.68% 0.63% 0.58% 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026 YTD
26 Funding and Liquidity
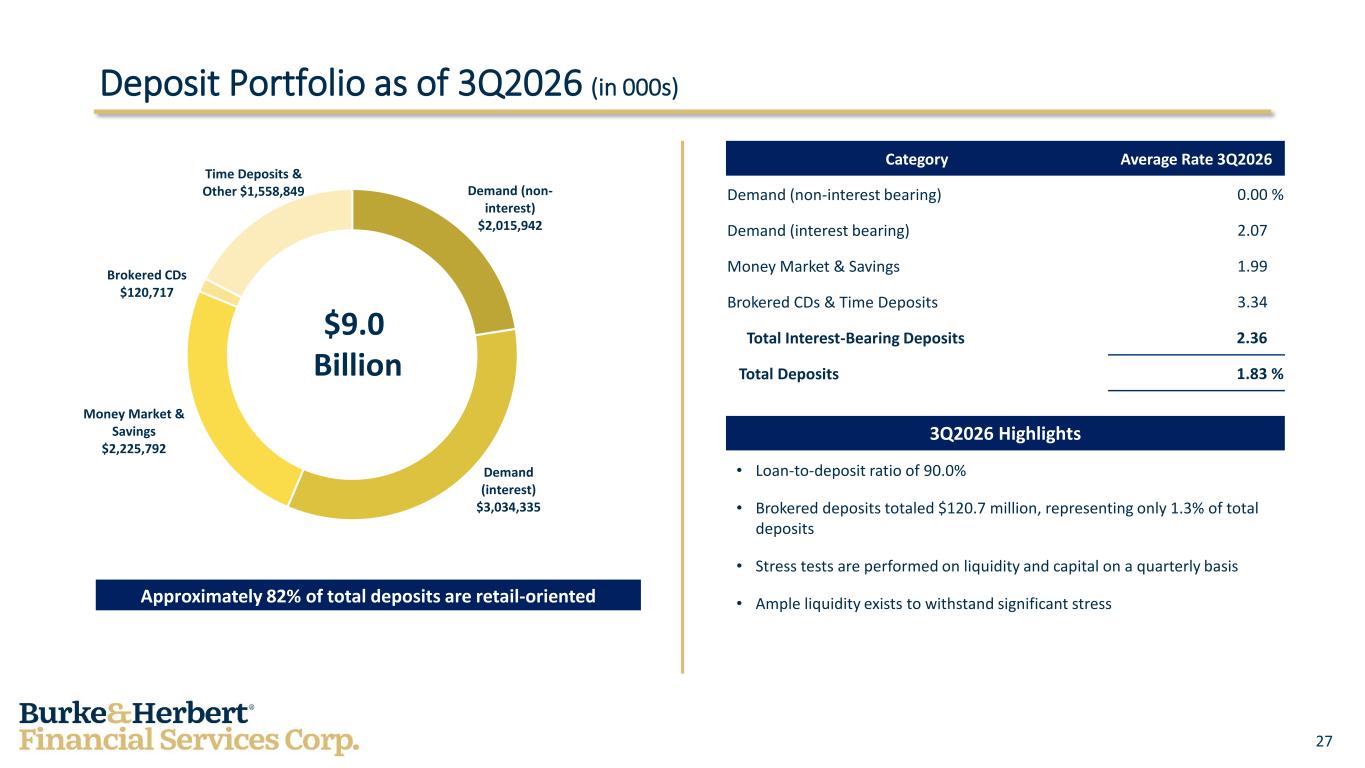
27 Demand (non- interest) $2,015,942 Demand (interest) $3,034,335 Money Market & Savings $2,225,792 Brokered CDs $120,717 Time Deposits & Other $1,558,849 Category Average Rate 3Q2026 Demand (non-interest bearing) 0.00 % Demand (interest bearing) 2.07 % Money Market & Savings 1.99 % Brokered CDs & Time Deposits 3.34 % Total Interest-Bearing Deposits 2.36 % Total Deposits 1.83 % Deposit Portfolio as of 3Q2026 (in 000s) 3Q2026 Highlights • Loan-to-deposit ratio of 90.0% • Brokered deposits totaled $120.7 million, representing only 1.3% of total deposits • Stress tests are performed on liquidity and capital on a quarterly basis • Ample liquidity exists to withstand significant stressApproximately 82% of total deposits are retail-oriented $9.0 Billion
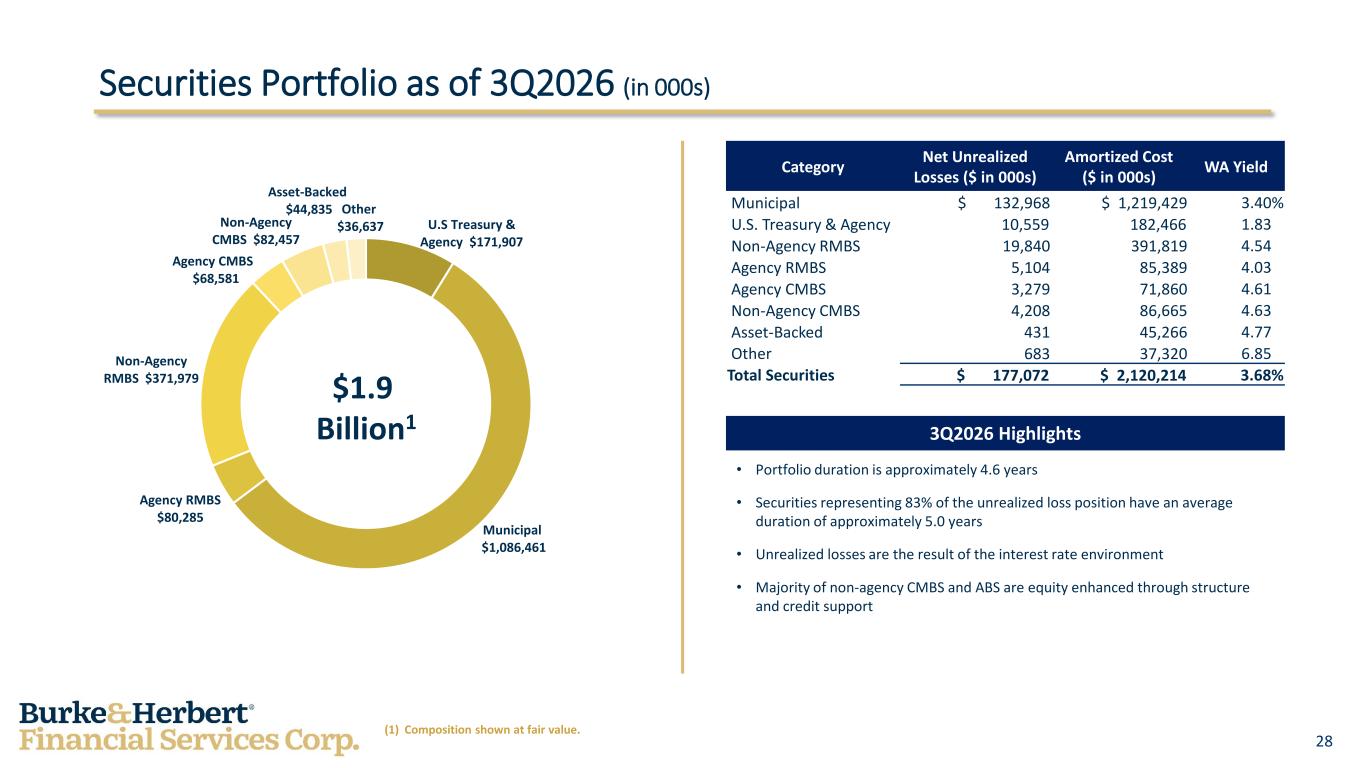
28 U.S Treasury & Agency $171,907 Municipal $1,086,461 Agency RMBS $80,285 Non-Agency RMBS $371,979 Agency CMBS $68,581 Non-Agency CMBS $82,457 Asset-Backed $44,835 Other $36,637 • Portfolio duration is approximately 4.6 years • Securities representing 83% of the unrealized loss position have an average duration of approximately 5.0 years • Unrealized losses are the result of the interest rate environment • Majority of non-agency CMBS and ABS are equity enhanced through structure and credit support Category Net Unrealized Losses ($ in 000s) Amortized Cost ($ in 000s) WA Yield Municipal $ 132,968 $ 1,219,429 3.40% U.S. Treasury & Agency 10,559 182,466 1.83% Non-Agency RMBS 19,840 391,819 4.54% Agency RMBS 5,104 85,389 4.03% Agency CMBS 3,279 71,860 4.61% Non-Agency CMBS 4,208 86,665 4.63% Asset-Backed 431 45,266 4.77% Other 683 37,320 6.85% Total Securities $ 177,072 $ 2,120,214 3.68% Securities Portfolio as of 3Q2026 (in 000s) 3Q2026 Highlights $1.9 Billion1 (1) Composition shown at fair value.
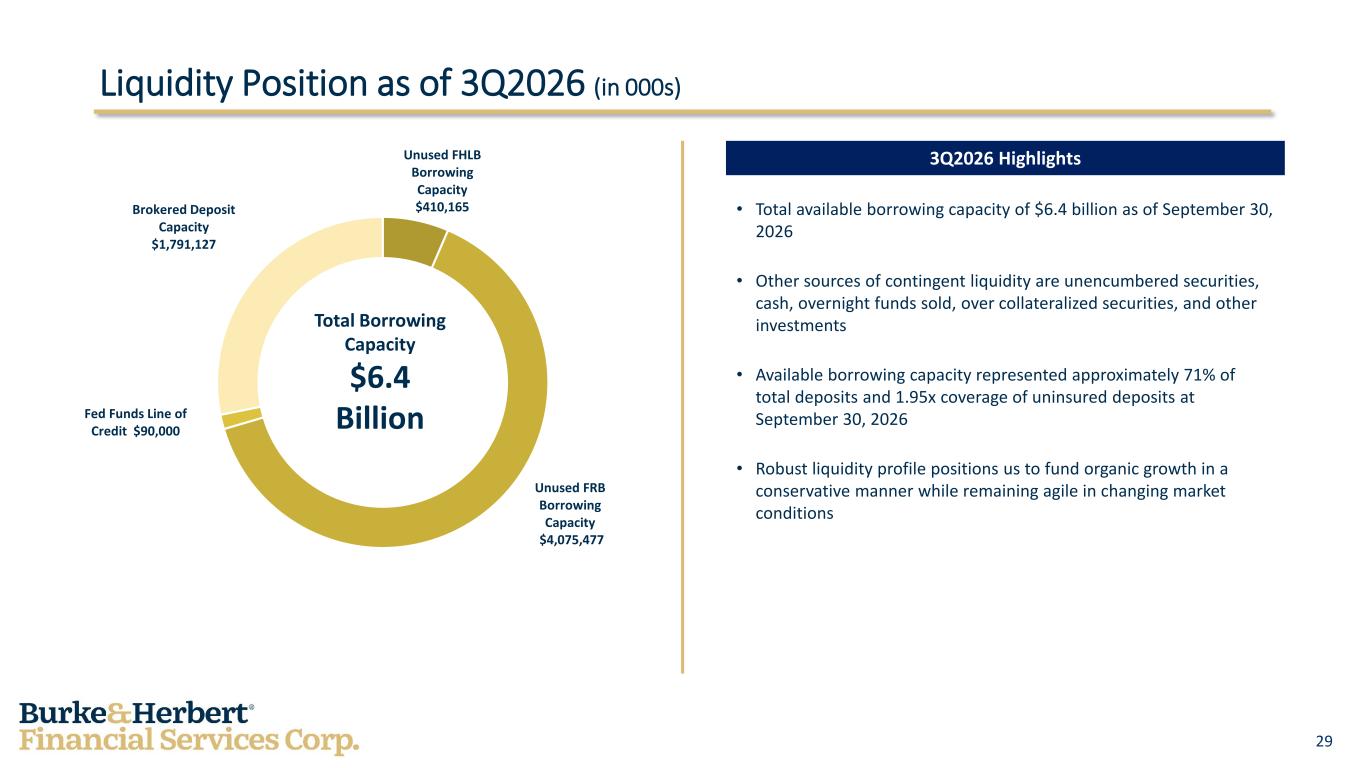
29 Unused FHLB Borrowing Capacity $410,165 Unused FRB Borrowing Capacity $4,075,477 Fed Funds Line of Credit $90,000 Brokered Deposit Capacity $1,791,127 • Total available borrowing capacity of $6.4 billion as of September 30, 2026 • Other sources of contingent liquidity are unencumbered securities, cash, overnight funds sold, over collateralized securities, and other investments • Available borrowing capacity represented approximately 71% of total deposits and 1.95x coverage of uninsured deposits at September 30, 2026 • Robust liquidity profile positions us to fund organic growth in a conservative manner while remaining agile in changing market conditions Liquidity Position as of 3Q2026 (in 000s) 3Q2026 Highlights Total Borrowing Capacity $6.4 Billion
30 Capital Position
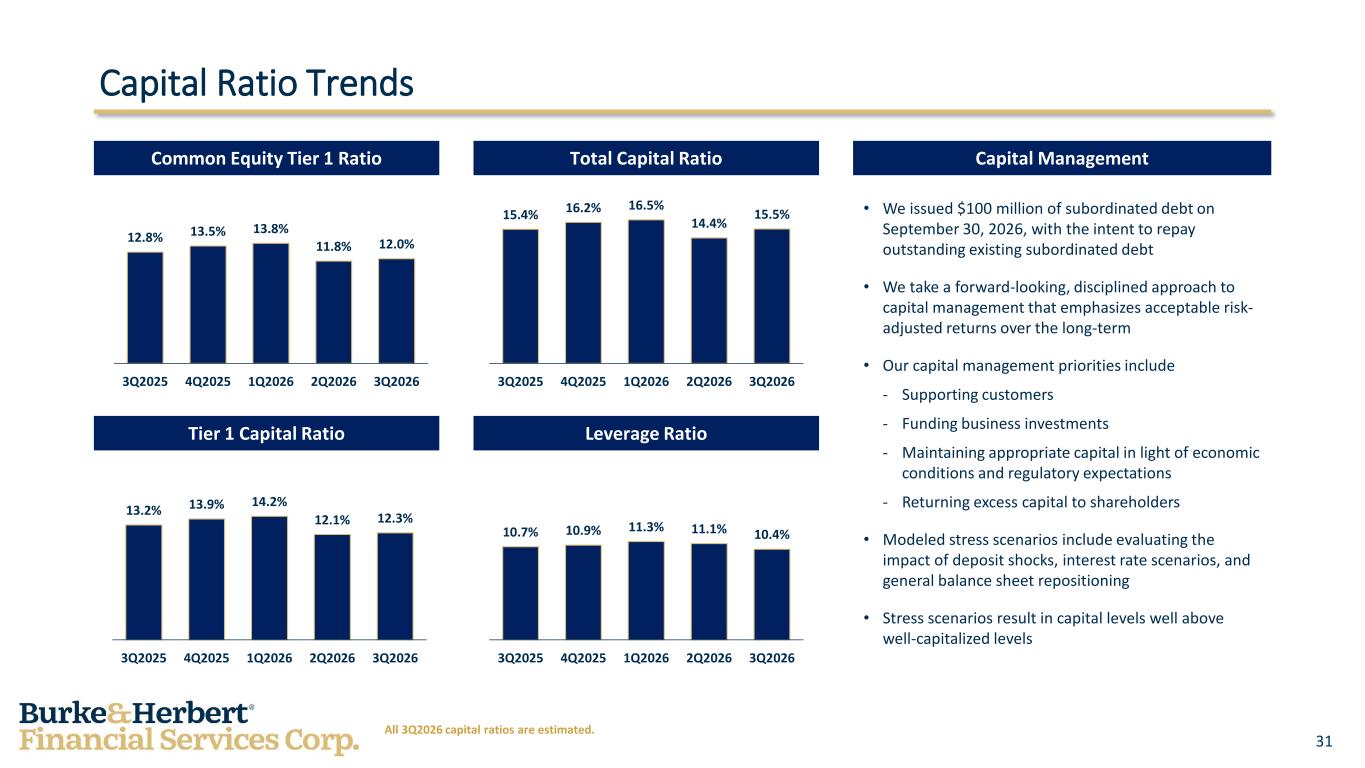
31 Capital Ratio Trends • We issued $100 million of subordinated debt on September 30, 2026, with the intent to repay outstanding existing subordinated debt • We take a forward-looking, disciplined approach to capital management that emphasizes acceptable risk- adjusted returns over the long-term • Our capital management priorities include - Supporting customers - Funding business investments - Maintaining appropriate capital in light of economic conditions and regulatory expectations - Returning excess capital to shareholders • Modeled stress scenarios include evaluating the impact of deposit shocks, interest rate scenarios, and general balance sheet repositioning • Stress scenarios result in capital levels well above well-capitalized levels Capital ManagementTotal Capital RatioCommon Equity Tier 1 Ratio Tier 1 Capital Ratio Leverage Ratio 12.8% 13.5% 13.8% 11.8% 12.0% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 15.4% 16.2% 16.5% 14.4% 15.5% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 13.2% 13.9% 14.2% 12.1% 12.3% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 10.7% 10.9% 11.3% 11.1% 10.4% 3Q2025 4Q2025 1Q2026 2Q2026 3Q2026 All 3Q2026 capital ratios are estimated.
32 Final Thoughts • Our business model is built on customer service and is designed to consistently deliver top quartile returns relative to our peers • Our approach is concentrated on growing and deepening relationships across our businesses that meet our risk/return measures • We are focused on our strategic priorities which are designed to enhance value over the long term - Being a trusted advisor to our customers - Delivering our full suite of products and services - Profitably expanding our geographic footprint • We take the long-view and maintain a moderate risk profile through the economic cycle
33 Appendix
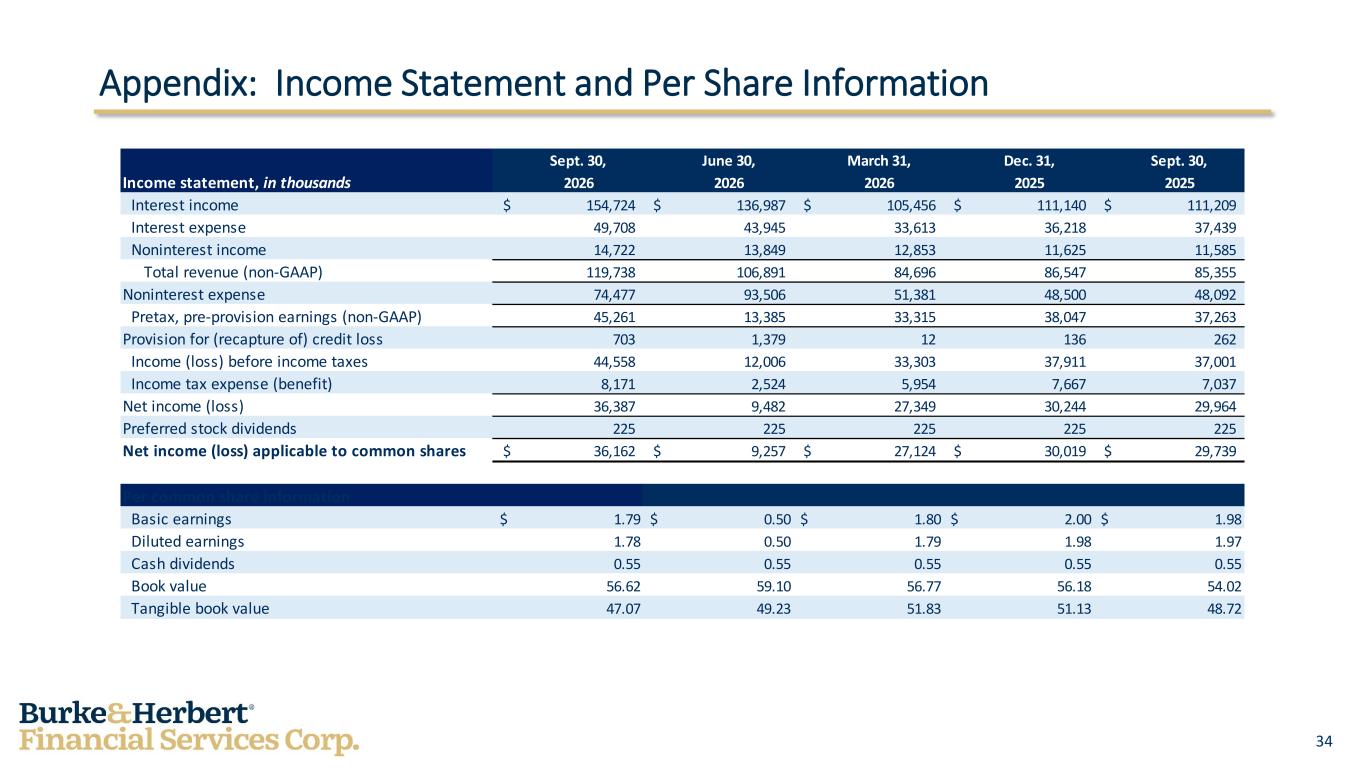
34 Appendix: Income Statement and Per Share Information Sept. 30, June 30, March 31, Dec. 31, Sept. 30, Income statement, in thousands 2026 2026 2026 2025 2025 Interest income $ 154,724 $ 136,987 $ 105,456 $ 111,140 $ 111,209 Interest expense 49,708 43,945 33,613 36,218 37,439 Noninterest income 14,722 13,849 12,853 11,625 11,585 Total revenue (non-GAAP) 119,738 106,891 84,696 86,547 85,355 Noninterest expense 74,477 93,506 51,381 48,500 48,092 Pretax, pre-provision earnings (non-GAAP) 45,261 13,385 33,315 38,047 37,263 Provision for (recapture of) credit loss 703 1,379 12 136 262 Income (loss) before income taxes 44,558 12,006 33,303 37,911 37,001 Income tax expense (benefit) 8,171 2,524 5,954 7,667 7,037 Net income (loss) 36,387 9,482 27,349 30,244 29,964 Preferred stock dividends 225 225 225 225 225 Net income (loss) applicable to common shares $ 36,162 $ 9,257 $ 27,124 $ 30,019 $ 29,739 Per common share information Basic earnings $ 1.79 $ 0.50 $ 1.80 $ 2.00 $ 1.98 Diluted earnings 1.78 0.50 1.79 1.98 1.97 Cash dividends 0.55 0.55 0.55 0.55 0.55 Book value 56.62 59.10 56.77 56.18 54.02 Tangible book value 47.07 49.23 51.83 51.13 48.72
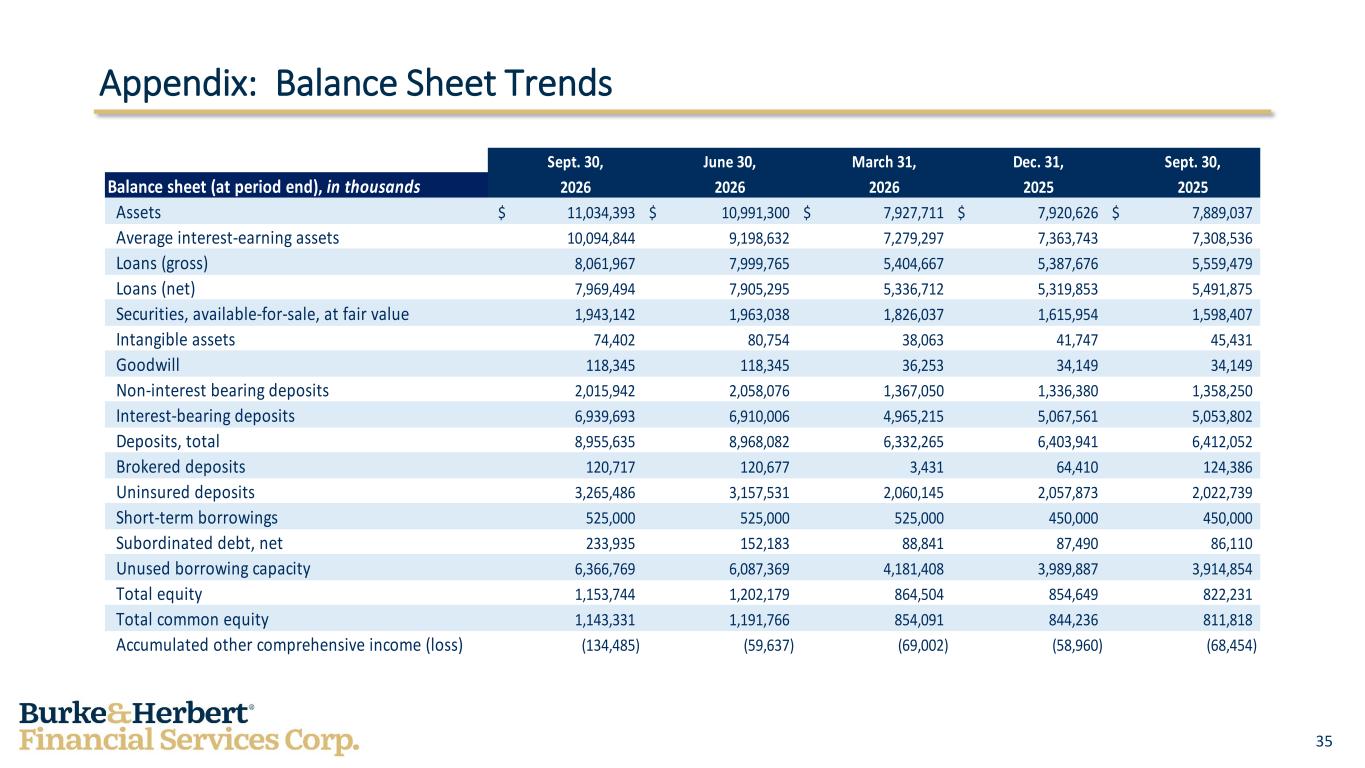
35 Appendix: Balance Sheet Trends Sept. 30, June 30, March 31, Dec. 31, Sept. 30, Balance sheet (at period end), in thousands 2026 2026 2026 2025 2025 Assets $ 11,034,393 $ 10,991,300 $ 7,927,711 $ 7,920,626 $ 7,889,037 Average interest-earning assets 10,094,844 9,198,632 7,279,297 7,363,743 7,308,536 Loans (gross) 8,061,967 7,999,765 5,404,667 5,387,676 5,559,479 Loans (net) 7,969,494 7,905,295 5,336,712 5,319,853 5,491,875 Securities, available-for-sale, at fair value 1,943,142 1,963,038 1,826,037 1,615,954 1,598,407 Intangible assets 74,402 80,754 38,063 41,747 45,431 Goodwill 118,345 118,345 36,253 34,149 34,149 Non-interest bearing deposits 2,015,942 2,058,076 1,367,050 1,336,380 1,358,250 Interest-bearing deposits 6,939,693 6,910,006 4,965,215 5,067,561 5,053,802 Deposits, total 8,955,635 8,968,082 6,332,265 6,403,941 6,412,052 Brokered deposits 120,717 120,677 3,431 64,410 124,386 Uninsured deposits 3,265,486 3,157,531 2,060,145 2,057,873 2,022,739 Short-term borrowings 525,000 525,000 525,000 450,000 450,000 Subordinated debt, net 233,935 152,183 88,841 87,490 86,110 Unused borrowing capacity 6,366,769 6,087,369 4,181,408 3,989,887 3,914,854 Total equity 1,153,744 1,202,179 864,504 854,649 822,231 Total common equity 1,143,331 1,191,766 854,091 844,236 811,818 Accumulated other comprehensive income (loss) (134,485) (59,637) (69,002) (58,960) (68,454)
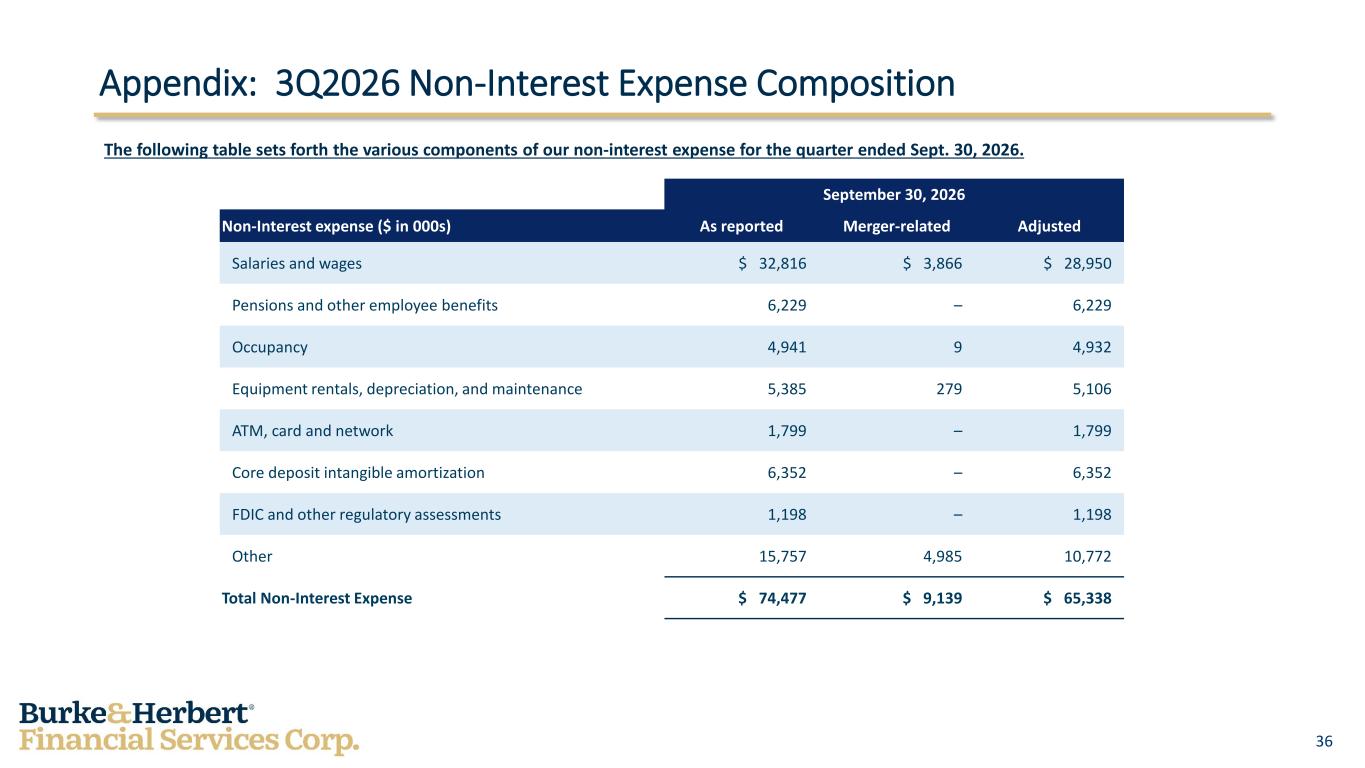
36 September 30, 2026 Non-Interest expense ($ in 000s) As reported Merger-related Adjusted Salaries and wages $ 32,816 $ 3,866 $ 28,950 Pensions and other employee benefits 6,229 – 6,229 Occupancy 4,941 9 4,932 Equipment rentals, depreciation, and maintenance 5,385 279 5,106 ATM, card and network 1,799 – 1,799 Core deposit intangible amortization 6,352 – 6,352 FDIC and other regulatory assessments 1,198 – 1,198 Other 15,757 4,985 10,772 Total Non-Interest Expense $ 74,477 $ 9,139 $ 65,338 The following table sets forth the various components of our non-interest expense for the quarter ended Sept. 30, 2026. Appendix: 3Q2026 Non-Interest Expense Composition
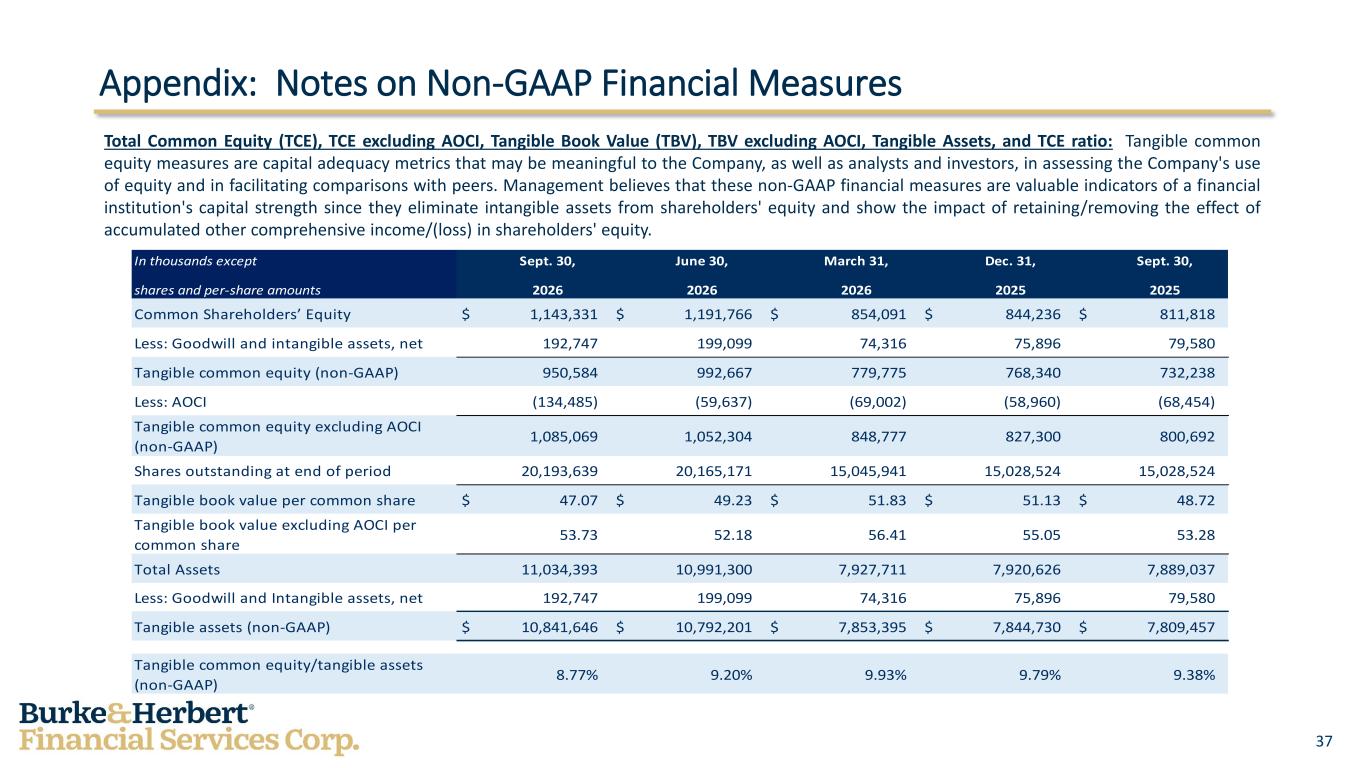
37 Appendix: Notes on Non-GAAP Financial Measures Total Common Equity (TCE), TCE excluding AOCI, Tangible Book Value (TBV), TBV excluding AOCI, Tangible Assets, and TCE ratio: Tangible common equity measures are capital adequacy metrics that may be meaningful to the Company, as well as analysts and investors, in assessing the Company's use of equity and in facilitating comparisons with peers. Management believes that these non-GAAP financial measures are valuable indicators of a financial institution's capital strength since they eliminate intangible assets from shareholders' equity and show the impact of retaining/removing the effect of accumulated other comprehensive income/(loss) in shareholders' equity. In thousands except Sept. 30, June 30, March 31, Dec. 31, Sept. 30, shares and per-share amounts 2026 2026 2026 2025 2025 Common Shareholders’ Equity $ 1,143,331 $ 1,191,766 $ 854,091 $ 844,236 $ 811,818 Less: Goodwill and intangible assets, net 192,747 199,099 74,316 75,896 79,580 Tangible common equity (non-GAAP) 950,584 992,667 779,775 768,340 732,238 Less: AOCI (134,485) (59,637) (69,002) (58,960) (68,454) Tangible common equity excluding AOCI (non-GAAP) 1,085,069 1,052,304 848,777 827,300 800,692 Shares outstanding at end of period 20,193,639 20,165,171 15,045,941 15,028,524 15,028,524 Tangible book value per common share $ 47.07 $ 49.23 $ 51.83 $ 51.13 $ 48.72 Tangible book value excluding AOCI per common share 53.73 52.18 56.41 55.05 53.28 Total Assets 11,034,393 10,991,300 7,927,711 7,920,626 7,889,037 Less: Goodwill and Intangible assets, net 192,747 199,099 74,316 75,896 79,580 Tangible assets (non-GAAP) $ 10,841,646 $ 10,792,201 $ 7,853,395 $ 7,844,730 $ 7,809,457 Tangible common equity/tangible assets (non-GAAP) 8.77% 9.20% 9.93% 9.79% 9.38%
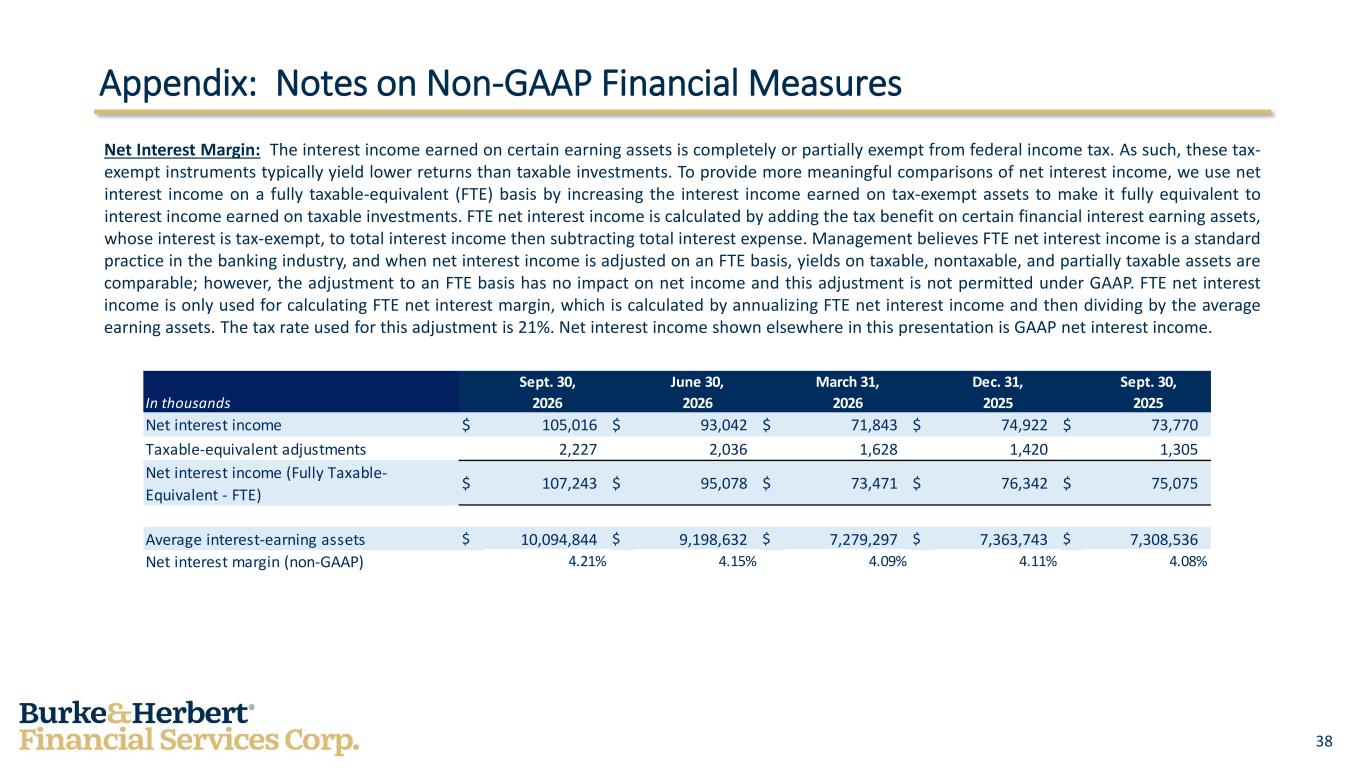
38 Appendix: Notes on Non-GAAP Financial Measures Net Interest Margin: The interest income earned on certain earning assets is completely or partially exempt from federal income tax. As such, these tax- exempt instruments typically yield lower returns than taxable investments. To provide more meaningful comparisons of net interest income, we use net interest income on a fully taxable-equivalent (FTE) basis by increasing the interest income earned on tax-exempt assets to make it fully equivalent to interest income earned on taxable investments. FTE net interest income is calculated by adding the tax benefit on certain financial interest earning assets, whose interest is tax-exempt, to total interest income then subtracting total interest expense. Management believes FTE net interest income is a standard practice in the banking industry, and when net interest income is adjusted on an FTE basis, yields on taxable, nontaxable, and partially taxable assets are comparable; however, the adjustment to an FTE basis has no impact on net income and this adjustment is not permitted under GAAP. FTE net interest income is only used for calculating FTE net interest margin, which is calculated by annualizing FTE net interest income and then dividing by the average earning assets. The tax rate used for this adjustment is 21%. Net interest income shown elsewhere in this presentation is GAAP net interest income. Sept. 30, June 30, March 31, Dec. 31, Sept. 30, In thousands 2026 2026 2026 2025 2025 Net interest income $ 105,016 $ 93,042 $ 71,843 $ 74,922 $ 73,770 Taxable-equivalent adjustments 2,227 2,036 1,628 1,420 1,305 Net interest income (Fully Taxable- Equivalent - FTE) $ 107,243 $ 95,078 $ 73,471 $ 76,342 $ 75,075 Average interest-earning assets $ 10,094,844 $ 9,198,632 $ 7,279,297 $ 7,363,743 $ 7,308,536 Net interest margin (non-GAAP) 4.21% 4.15% 4.09% 4.11% 4.08%
39 Appendix: Notes on Non-GAAP Financial Measures Return and Adjusted Return on Average Tangible Common Equity and Average Assets: In management’s view, adjusted return on average common equity, return on average tangible common equity, adjusted return on average tangible common equity, and adjusted return on average assets are performance metrics that may be meaningful to the Company, as well as analysts and investors, in evaluating the Company’s profitability and efficiency in deploying capital and assets and in facilitating comparisons with peers. These non-GAAP financial measures provide additional insight into the Company’s underlying operating performance by focusing on returns generated from common equity, tangible common equity, and total assets, as applicable. The adjusted measures exclude the after-tax effect of one-time merger-related expenses, which management believes enhances period-to-period comparability and provides a more representative view of the Company’s ongoing earnings performance. Return on average tangible common equity measures further isolate performance attributable to tangible capital by excluding the impact of intangible assets, while return on average assets reflects the Company’s effectiveness in generating earnings from its overall asset base. Management believes these measures, when considered together and alongside GAAP results, provide useful supplemental information for assessing profitability, capital efficiency, and operating trends. (See table on next slide)
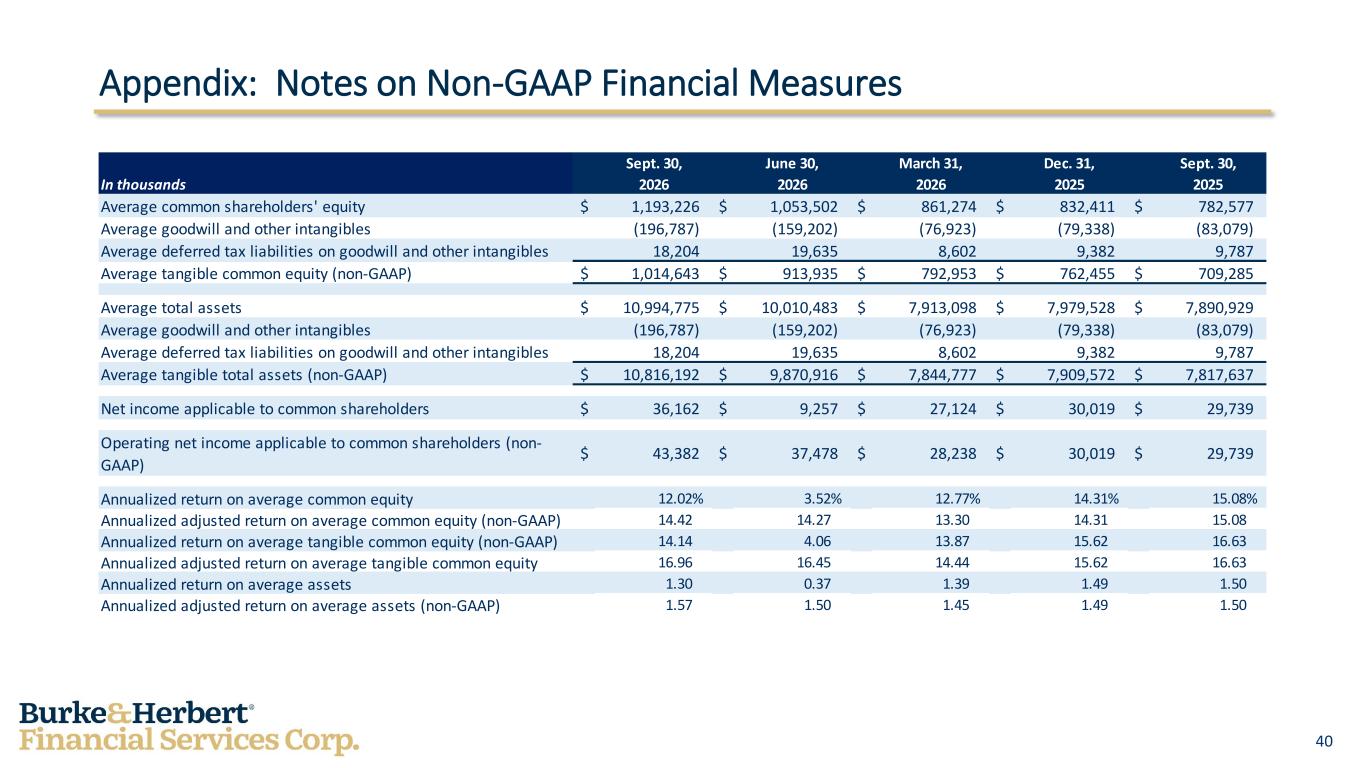
40 Appendix: Notes on Non-GAAP Financial Measures Sept. 30, June 30, March 31, Dec. 31, Sept. 30, In thousands 2026 2026 2026 2025 2025 Average common shareholders' equity $ 1,193,226 $ 1,053,502 $ 861,274 $ 832,411 $ 782,577 Average goodwill and other intangibles (196,787) (159,202) (76,923) (79,338) (83,079) Average deferred tax liabilities on goodwill and other intangibles 18,204 19,635 8,602 9,382 9,787 Average tangible common equity (non-GAAP) $ 1,014,643 $ 913,935 $ 792,953 $ 762,455 $ 709,285 Average total assets $ 10,994,775 $ 10,010,483 $ 7,913,098 $ 7,979,528 $ 7,890,929 Average goodwill and other intangibles (196,787) (159,202) (76,923) (79,338) (83,079) Average deferred tax liabilities on goodwill and other intangibles 18,204 19,635 8,602 9,382 9,787 Average tangible total assets (non-GAAP) $ 10,816,192 $ 9,870,916 $ 7,844,777 $ 7,909,572 $ 7,817,637 Net income applicable to common shareholders $ 36,162 $ 9,257 $ 27,124 $ 30,019 $ 29,739 Operating net income applicable to common shareholders (non- GAAP) $ 43,382 $ 37,478 $ 28,238 $ 30,019 $ 29,739 Annualized return on average common equity 12.02% 3.52% 12.77% 14.31% 15.08% Annualized adjusted return on average common equity (non-GAAP) 14.42 14.27 13.30 14.31 15.08 Annualized return on average tangible common equity (non-GAAP) 14.14 4.06 13.87 15.62 16.63 Annualized adjusted return on average tangible common equity 16.96 16.45 14.44 15.62 16.63 Annualized return on average assets 1.30 0.37 1.39 1.49 1.50 Annualized adjusted return on average assets (non-GAAP) 1.57 1.50 1.45 1.49 1.50
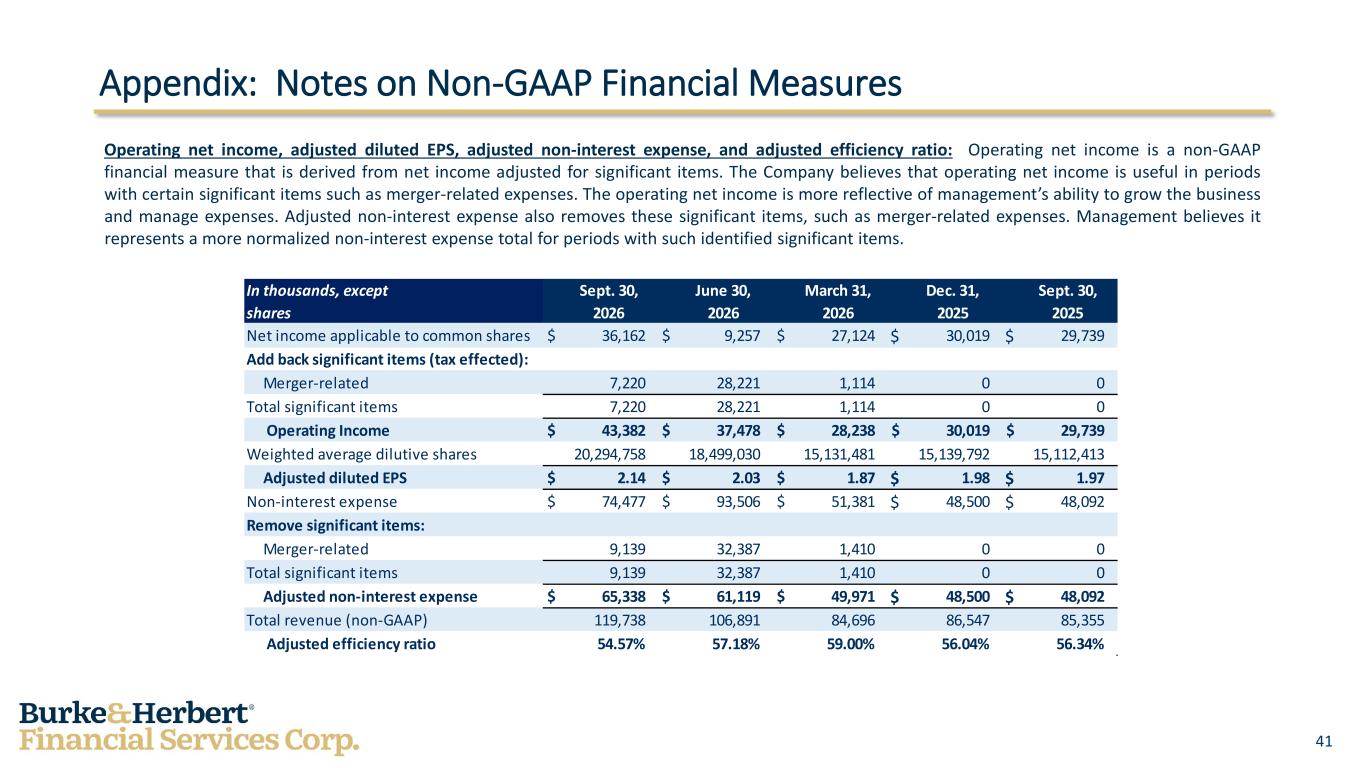
41 Operating net income, adjusted diluted EPS, adjusted non-interest expense, and adjusted efficiency ratio: Operating net income is a non-GAAP financial measure that is derived from net income adjusted for significant items. The Company believes that operating net income is useful in periods with certain significant items such as merger-related expenses. The operating net income is more reflective of management’s ability to grow the business and manage expenses. Adjusted non-interest expense also removes these significant items, such as merger-related expenses. Management believes it represents a more normalized non-interest expense total for periods with such identified significant items. Appendix: Notes on Non-GAAP Financial Measures In thousands, except Sept. 30, June 30, March 31, Dec. 31, Sept. 30, shares 2026 2026 2026 2025 2025 Net income applicable to common shares $ 36,162 $ 9,257 $ 27,124 $ 30,019 $ 29,739 Add back significant items (tax effected): Merger-related 7,220 28,221 1,114 0 0 Total significant items 7,220 28,221 1,114 0 0 Operating Income $ 43,382 $ 37,478 $ 28,238 $ 30,019 $ 29,739 Weighted average dilutive shares 20,294,758 18,499,030 15,131,481 15,139,792 15,112,413 Adjusted diluted EPS $ 2.14 $ 2.03 $ 1.87 $ 1.98 $ 1.97 Non-interest expense $ 74,477 $ 93,506 $ 51,381 $ 48,500 $ 48,092 Remove significant items: Merger-related 9,139 32,387 1,410 0 0 Total significant items 9,139 32,387 1,410 0 0 Adjusted non-interest expense $ 65,338 $ 61,119 $ 49,971 $ 48,500 $ 48,092 Total revenue (non-GAAP) 119,738 106,891 84,696 86,547 85,355 Adjusted efficiency ratio 54.57% 57.18% 59.00% 56.04% 56.34%