Third Quarter 2026 Earnings Presentation October 22, 2026
Disclaimer FORWARD-LOOKING STATEMENTS This communication may contain certain forward-looking statements, including, but not limited to, certain plans, expectations, goals, projections, and statements about the benefits of the acquisition of Pacific Premier Bancorp, Inc. (“Pacific Premier”) by Columbia Banking System, Inc. (“Columbia”) the plans, objectives, expectations and intentions of Columbia and other statements that are not historical facts. Such statements are subject to numerous assumptions, risks, and uncertainties. All statements other than statements of historical fact, including statements about beliefs and expectations, are forward-looking statements. Forward-looking statements may be identified by words such as “expect,” “anticipate,” “believe,” “intend,” “estimate,” “plan,” “target,” “goal,” or similar expressions, or future or conditional verbs such as “will,” “may,” “might,” “should,” “would,” “could,” or similar variations. The forward-looking statements are intended to be subject to the safe harbor provided by Section 27A of the Securities Act of 1933, Section 21E of the Securities Exchange Act of 1934, and the Private Securities Litigation Reform Act of 1995. In this presentation we make forward-looking statements about strategic and growth initiatives and the result of such activity. Risks and uncertainties that could cause results to differ from forward-looking statements we make include, without limitation: current and future economic and market conditions, including the effects of declines in housing and commercial real estate prices, high unemployment rates, renewed or continued high inflation and any recession or slowdown in economic growth particularly in the western United States; economic forecast variables that are either materially worse or better than end of quarter projections and deterioration in the economy that could result in increased loan and lease losses, especially those risks associated with concentrations in real estate related loans; risks related to our acquisition of Pacific Premier (the "Transaction"), including, among others, (i) any revenue synergies from the Transaction may not be fully realized or may take longer than anticipated to be realized, and (ii) deposit attrition as a result of the Transaction; the impact of proposed or imposed tariffs by the U.S. government and retaliatory tariffs proposed or imposed by U.S. trading partners that could have an adverse impact on customers; our ability to effectively manage problem credits; the impact of bank failures or adverse developments at other banks on general investor sentiment regarding the liquidity and stability of banks; changes in interest rates that could significantly reduce net interest income and negatively affect asset yields and valuations and funding sources; changes in the scope and cost of FDIC insurance and other coverage; our ability to successfully implement efficiency and operational excellence initiatives; our ability to successfully develop and market new products and technology; changes in laws or regulations; potential adverse reactions or changes to business or employee relationships; the effect of geopolitical instability, including wars, conflicts and terrorist attacks; and natural disasters and other similar unexpected events outside of our control. We also caution that the amount and timing of any future common stock dividends or repurchases will depend on the earnings, cash requirements and financial condition of Columbia, market conditions, capital requirements, applicable law and regulations (including federal securities laws and federal banking and state regulations), and other factors deemed relevant by Columbia and its Board of Directors. NON-GAAP FINANCIAL MEASURES In addition to results presented in accordance with GAAP, this presentation contains certain non-GAAP financial measures. A reconciliation of GAAP to non-GAAP measures is included in the Appendix. The Company believes presenting certain non-GAAP financial measures provides investors with information useful in understanding our financial performance, our performance trends, and our financial position. We utilize these measures for internal planning and forecasting purposes, and operating pre-provision net revenue and operating return on tangible common equity are also used as part of our incentive compensation program for our executive officers. We, as well as securities analysts, investors, and other interested parties, also use these measures to compare peer company operating performance. We believe that our presentation and discussion, together with the accompanying reconciliations, provides a complete understanding of factors and trends affecting our business and allows investors to view performance in a manner similar to management. These non-GAAP measures should not be considered a substitution for GAAP basis measures and results, and we strongly encourage investors to review our consolidated financial statements in their entirety and not to rely on any single financial measure. Because non-GAAP financial measures are not standardized, it may not be possible to compare these financial measures with other companies’ non-GAAP financial measures having the same or similar names. 2
Table of Contents 3 Page Columbia Corporate Overview 4 Third Quarter 2026 8 Appendix 22 Loan Portfolio Slides 23 Liquidity Overview 27 Securities Portfolio 28 Summary Income Statements 29 Summary Balance Sheets 30 Non-GAAP Reconciliations 31
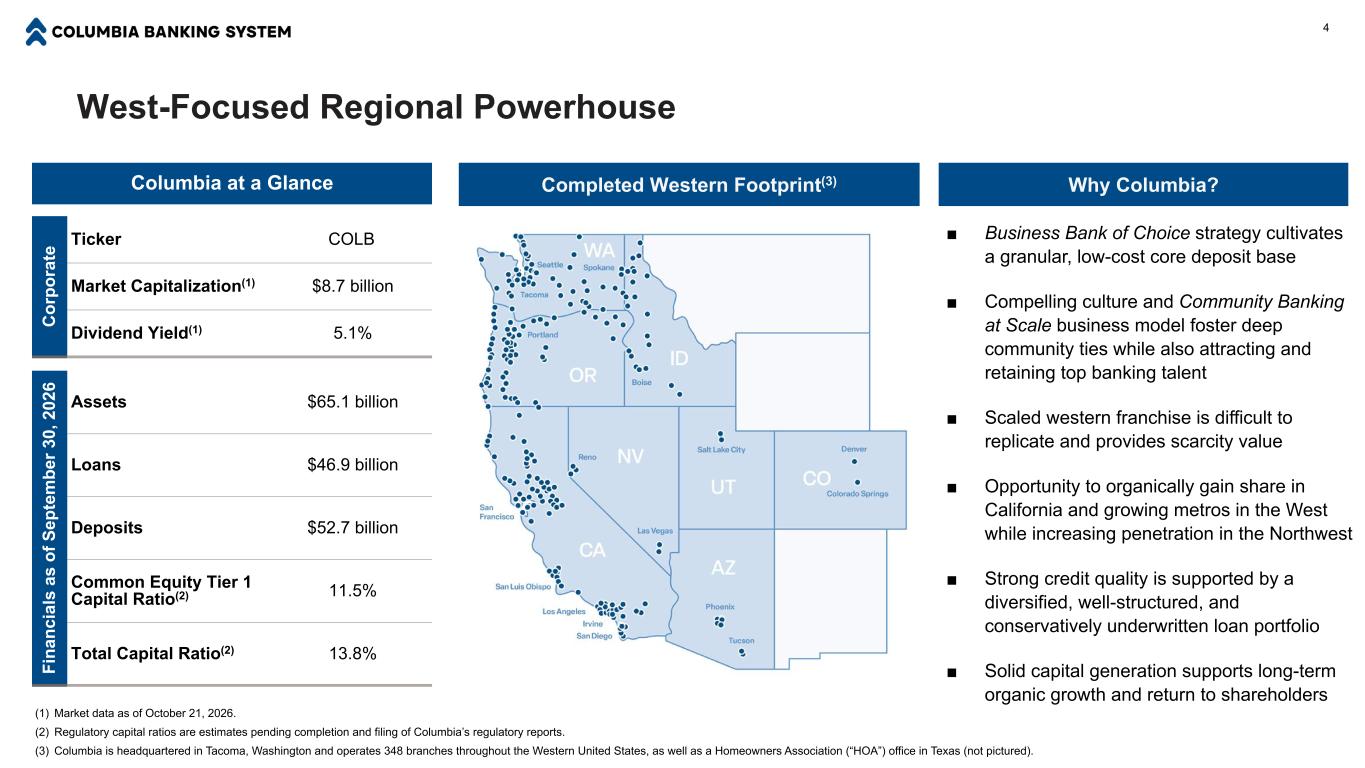
West-Focused Regional Powerhouse 4 Completed Western Footprint(3) Why Columbia? ■ Business Bank of Choice strategy cultivates a granular, low-cost core deposit base ■ Compelling culture and Community Banking at Scale business model foster deep community ties while also attracting and retaining top banking talent ■ Scaled western franchise is difficult to replicate and provides scarcity value ■ Opportunity to organically gain share in California and growing metros in the West while increasing penetration in the Northwest ■ Strong credit quality is supported by a diversified, well-structured, and conservatively underwritten loan portfolio ■ Solid capital generation supports long-term organic growth and return to shareholders Columbia at a Glance C or po ra te Ticker COLB Market Capitalization(1) $8.7 billion Dividend Yield(1) 5.1% Fi na nc ia ls a s of S ep te m be r 3 0, 2 02 6 Assets $65.1 billion Loans $46.9 billion Deposits $52.7 billion Common Equity Tier 1 Capital Ratio(2) 11.5% Total Capital Ratio(2) 13.8% (1) Market data as of October 21, 2026. (2) Regulatory capital ratios are estimates pending completion and filing of Columbia’s regulatory reports. (3) Columbia is headquartered in Tacoma, Washington and operates 348 branches throughout the Western United States, as well as a Homeowners Association (“HOA”) office in Texas (not pictured).
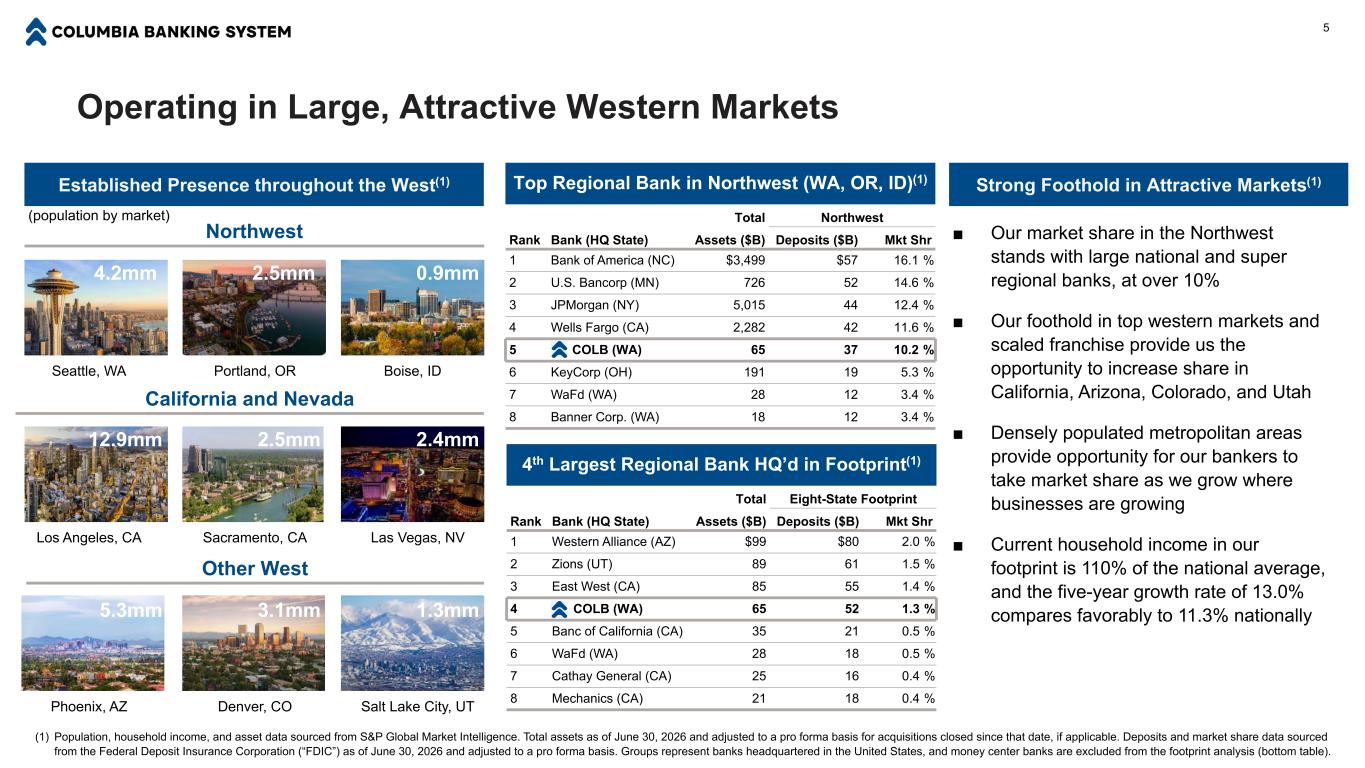
Operating in Large, Attractive Western Markets 5 Established Presence throughout the West(1) Northwest (population by market) Seattle, WA Portland, OR California and Nevada Los Angeles, CA Sacramento, CA Other West Phoenix, AZ Denver, CO 4.2mm 2.5mm 12.9mm 2.5mm 5.3mm 3.1mm Top Regional Bank in Northwest (WA, OR, ID)(1) Total Northwest Rank Bank (HQ State) Assets ($B) Deposits ($B) Mkt Shr 1 Bank of America (NC) $3,499 $57 16.1 % 2 U.S. Bancorp (MN) 726 52 14.6 % 3 JPMorgan (NY) 5,015 44 12.4 % 4 Wells Fargo (CA) 2,282 42 11.6 % 5 COLB (WA) 65 37 10.2 % 6 KeyCorp (OH) 191 19 5.3 % 7 WaFd (WA) 28 12 3.4 % 8 Banner Corp. (WA) 18 12 3.4 % 4th Largest Regional Bank HQ’d in Footprint(1) Total Eight-State Footprint Rank Bank (HQ State) Assets ($B) Deposits ($B) Mkt Shr 1 Western Alliance (AZ) $99 $80 2.0 % 2 Zions (UT) 89 61 1.5 % 3 East West (CA) 85 55 1.4 % 4 COLB (WA) 65 52 1.3 % 5 Banc of California (CA) 35 21 0.5 % 6 WaFd (WA) 28 18 0.5 % 7 Cathay General (CA) 25 16 0.4 % 8 Mechanics (CA) 21 18 0.4 % Strong Foothold in Attractive Markets(1) ■ Our market share in the Northwest stands with large national and super regional banks, at over 10% ■ Our foothold in top western markets and scaled franchise provide us the opportunity to increase share in California, Arizona, Colorado, and Utah ■ Densely populated metropolitan areas provide opportunity for our bankers to take market share as we grow where businesses are growing ■ Current household income in our footprint is 110% of the national average, and the five-year growth rate of 13.0% compares favorably to 11.3% nationally Boise, ID Salt Lake City, UT Las Vegas, NV 0.9mm 2.4mm 1.3mm (1) Population, household income, and asset data sourced from S&P Global Market Intelligence. Total assets as of June 30, 2026 and adjusted to a pro forma basis for acquisitions closed since that date, if applicable. Deposits and market share data sourced from the Federal Deposit Insurance Corporation (“FDIC”) as of June 30, 2026 and adjusted to a pro forma basis. Groups represent banks headquartered in the United States, and money center banks are excluded from the footprint analysis (bottom table).
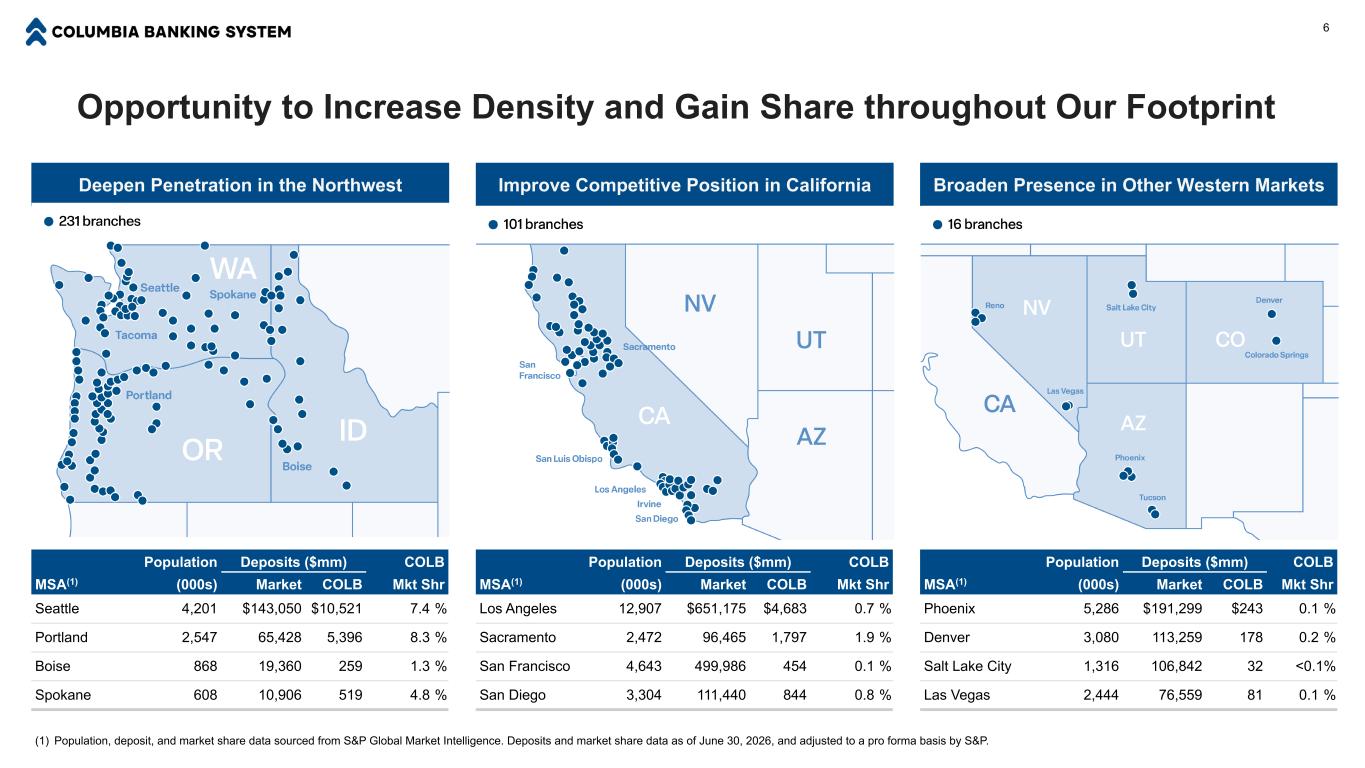
Population Deposits ($mm) COLB MSA(1) (000s) Market COLB Mkt Shr Seattle 4,201 $143,050 $10,521 7.4 % Portland 2,547 65,428 5,396 8.3 % Boise 868 19,360 259 1.3 % Spokane 608 10,906 519 4.8 % Opportunity to Increase Density and Gain Share throughout Our Footprint 6 Improve Competitive Position in California Broaden Presence in Other Western MarketsDeepen Penetration in the Northwest Population Deposits ($mm) COLB MSA(1) (000s) Market COLB Mkt Shr Phoenix 5,286 $191,299 $243 0.1 % Denver 3,080 113,259 178 0.2 % Salt Lake City 1,316 106,842 32 <0.1% Las Vegas 2,444 76,559 81 0.1 % Population Deposits ($mm) COLB MSA(1) (000s) Market COLB Mkt Shr Los Angeles 12,907 $651,175 $4,683 0.7 % Sacramento 2,472 96,465 1,797 1.9 % San Francisco 4,643 499,986 454 0.1 % San Diego 3,304 111,440 844 0.8 % (1) Population, deposit, and market share data sourced from S&P Global Market Intelligence. Deposits and market share data as of June 30, 2026, and adjusted to a pro forma basis by S&P.
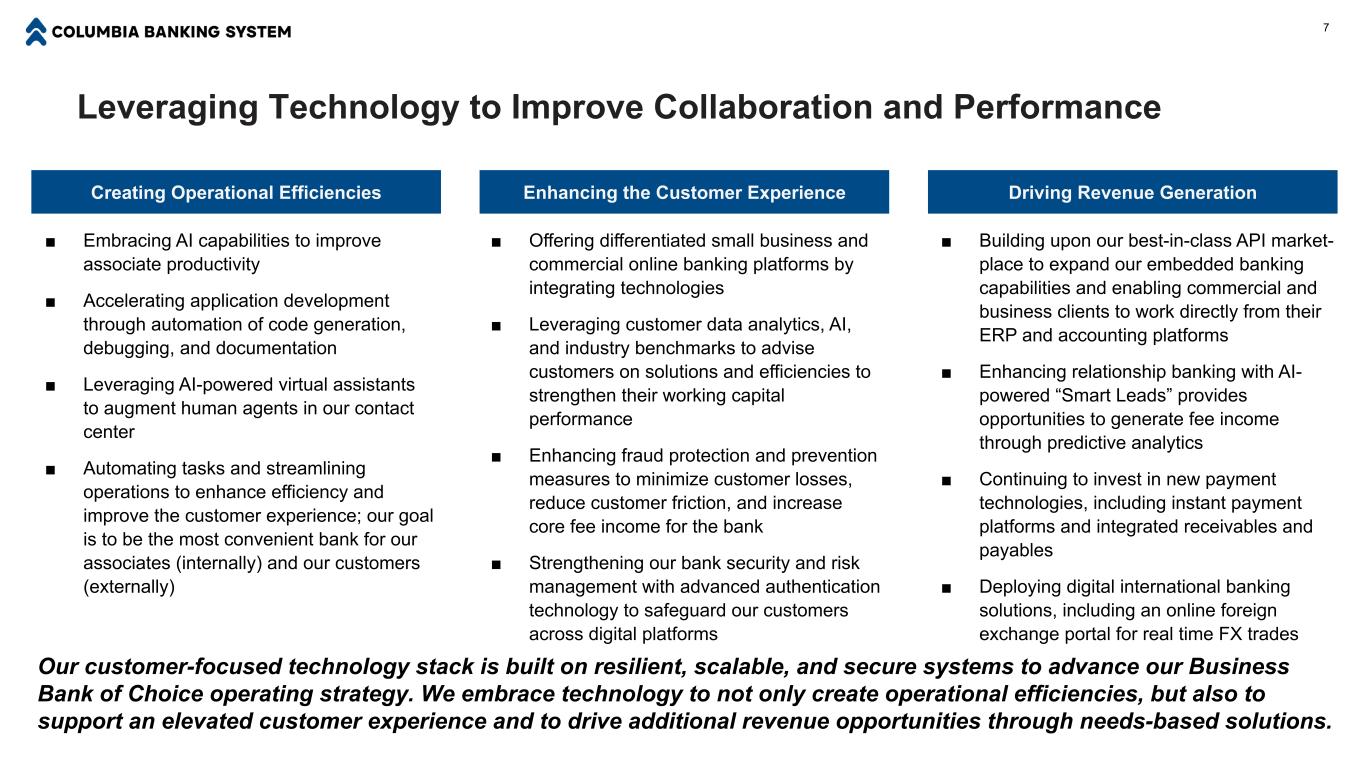
Leveraging Technology to Improve Collaboration and Performance 7 Enhancing the Customer Experience Driving Revenue GenerationCreating Operational Efficiencies ■ Building upon our best-in-class API market- place to expand our embedded banking capabilities and enabling commercial and business clients to work directly from their ERP and accounting platforms ■ Enhancing relationship banking with AI- powered “Smart Leads” provides opportunities to generate fee income through predictive analytics ■ Continuing to invest in new payment technologies, including instant payment platforms and integrated receivables and payables ■ Deploying digital international banking solutions, including an online foreign exchange portal for real time FX trades ■ Offering differentiated small business and commercial online banking platforms by integrating technologies ■ Leveraging customer data analytics, AI, and industry benchmarks to advise customers on solutions and efficiencies to strengthen their working capital performance ■ Enhancing fraud protection and prevention measures to minimize customer losses, reduce customer friction, and increase core fee income for the bank ■ Strengthening our bank security and risk management with advanced authentication technology to safeguard our customers across digital platforms ■ Embracing AI capabilities to improve associate productivity ■ Accelerating application development through automation of code generation, debugging, and documentation ■ Leveraging AI-powered virtual assistants to augment human agents in our contact center ■ Automating tasks and streamlining operations to enhance efficiency and improve the customer experience; our goal is to be the most convenient bank for our associates (internally) and our customers (externally) Our customer-focused technology stack is built on resilient, scalable, and secure systems to advance our Business Bank of Choice operating strategy. We embrace technology to not only create operational efficiencies, but also to support an elevated customer experience and to drive additional revenue opportunities through needs-based solutions.
Third Quarter 2026 8
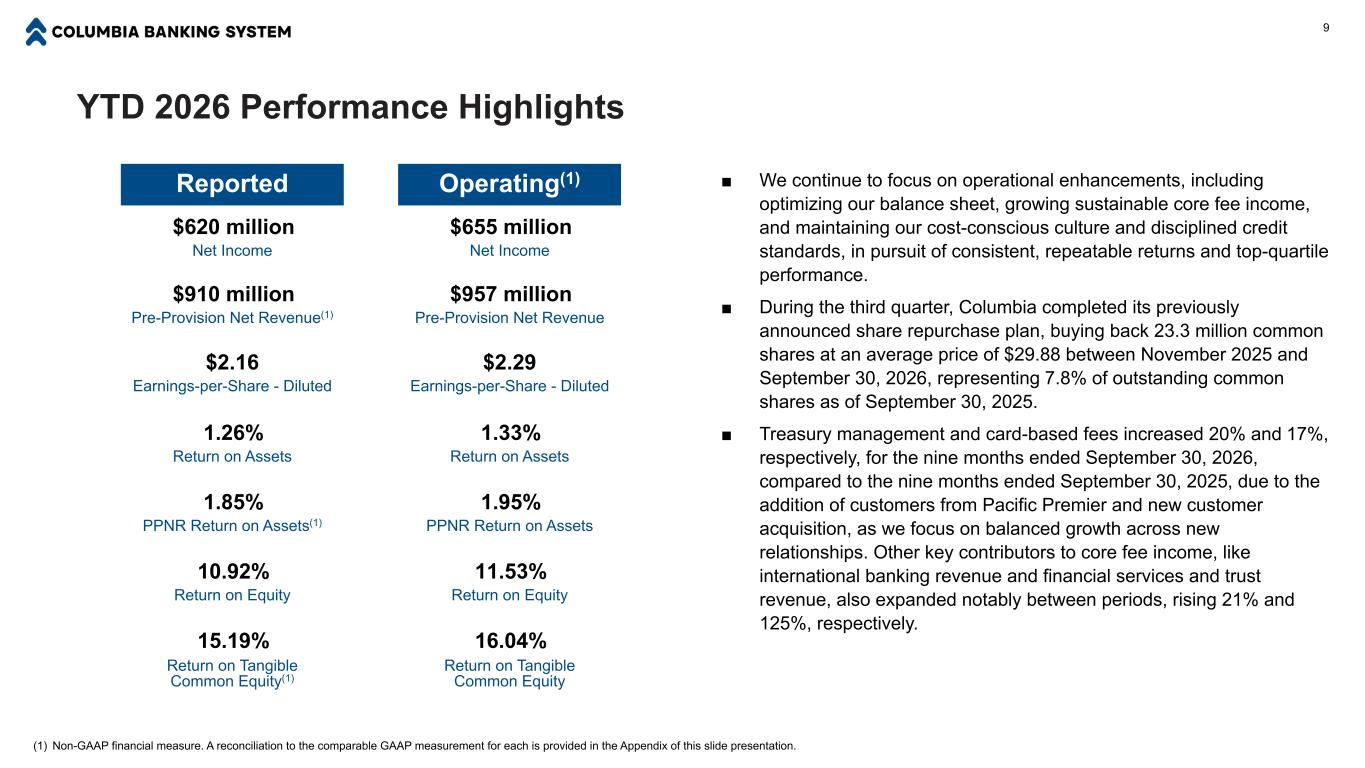
YTD 2026 Performance Highlights 9 ■ We continue to focus on operational enhancements, including optimizing our balance sheet, growing sustainable core fee income, and maintaining our cost-conscious culture and disciplined credit standards, in pursuit of consistent, repeatable returns and top-quartile performance. ■ During the third quarter, Columbia completed its previously announced share repurchase plan, buying back 23.3 million common shares at an average price of $29.88 between November 2025 and September 30, 2026, representing 7.8% of outstanding common shares as of September 30, 2025. ■ Treasury management and card-based fees increased 20% and 17%, respectively, for the nine months ended September 30, 2026, compared to the nine months ended September 30, 2025, due to the addition of customers from Pacific Premier and new customer acquisition, as we focus on balanced growth across new relationships. Other key contributors to core fee income, like international banking revenue and financial services and trust revenue, also expanded notably between periods, rising 21% and 125%, respectively. Reported Operating(1) $620 million $655 million Net Income Net Income $910 million $957 million Pre-Provision Net Revenue(1) Pre-Provision Net Revenue $2.16 $2.29 Earnings-per-Share - Diluted Earnings-per-Share - Diluted 1.26% 1.33% Return on Assets Return on Assets 1.85% 1.95% PPNR Return on Assets(1) PPNR Return on Assets 10.92% 11.53% Return on Equity Return on Equity 15.19% 16.04% Return on Tangible Common Equity(1) Return on Tangible Common Equity (1) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement for each is provided in the Appendix of this slide presentation.
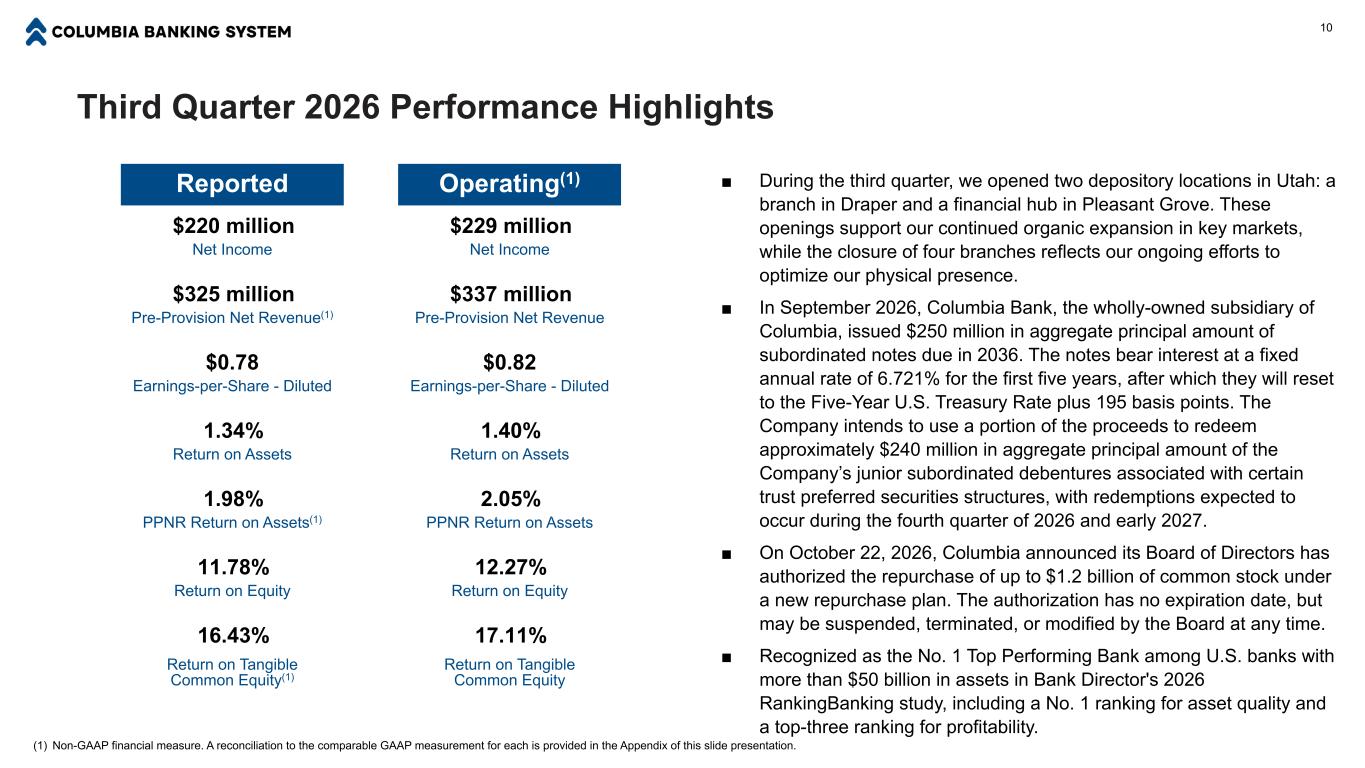
Third Quarter 2026 Performance Highlights 10 ■ During the third quarter, we opened two depository locations in Utah: a branch in Draper and a financial hub in Pleasant Grove. These openings support our continued organic expansion in key markets, while the closure of four branches reflects our ongoing efforts to optimize our physical presence. ■ In September 2026, Columbia Bank, the wholly-owned subsidiary of Columbia, issued $250 million in aggregate principal amount of subordinated notes due in 2036. The notes bear interest at a fixed annual rate of 6.721% for the first five years, after which they will reset to the Five-Year U.S. Treasury Rate plus 195 basis points. The Company intends to use a portion of the proceeds to redeem approximately $240 million in aggregate principal amount of the Company’s junior subordinated debentures associated with certain trust preferred securities structures, with redemptions expected to occur during the fourth quarter of 2026 and early 2027. ■ On October 22, 2026, Columbia announced its Board of Directors has authorized the repurchase of up to $1.2 billion of common stock under a new repurchase plan. The authorization has no expiration date, but may be suspended, terminated, or modified by the Board at any time. ■ Recognized as the No. 1 Top Performing Bank among U.S. banks with more than $50 billion in assets in Bank Director's 2026 RankingBanking study, including a No. 1 ranking for asset quality and a top-three ranking for profitability. Reported Operating(1) $220 million $229 million Net Income Net Income $325 million $337 million Pre-Provision Net Revenue(1) Pre-Provision Net Revenue $0.78 $0.82 Earnings-per-Share - Diluted Earnings-per-Share - Diluted 1.34% 1.40% Return on Assets Return on Assets 1.98% 2.05% PPNR Return on Assets(1) PPNR Return on Assets 11.78% 12.27% Return on Equity Return on Equity 16.43% 17.11% Return on Tangible Common Equity(1) Return on Tangible Common Equity (1) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement for each is provided in the Appendix of this slide presentation.
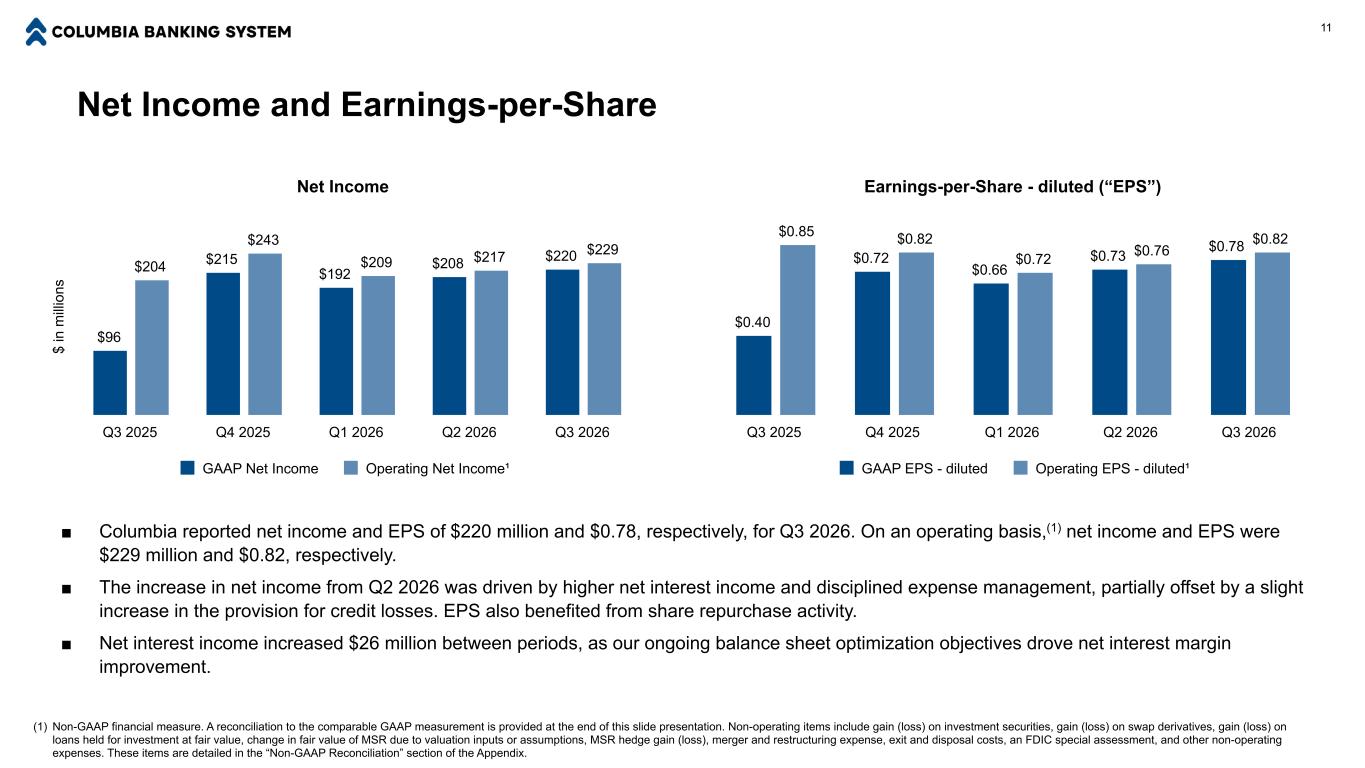
Net Income and Earnings-per-Share 11 $ in m ill io ns Net Income $96 $215 $192 $208 $220 $204 $243 $209 $217 $229 GAAP Net Income Operating Net Income¹ Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 ■ Columbia reported net income and EPS of $220 million and $0.78, respectively, for Q3 2026. On an operating basis,(1) net income and EPS were $229 million and $0.82, respectively. ■ The increase in net income from Q2 2026 was driven by higher net interest income and disciplined expense management, partially offset by a slight increase in the provision for credit losses. EPS also benefited from share repurchase activity. ■ Net interest income increased $26 million between periods, as our ongoing balance sheet optimization objectives drove net interest margin improvement. (1) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement is provided at the end of this slide presentation. Non-operating items include gain (loss) on investment securities, gain (loss) on swap derivatives, gain (loss) on loans held for investment at fair value, change in fair value of MSR due to valuation inputs or assumptions, MSR hedge gain (loss), merger and restructuring expense, exit and disposal costs, an FDIC special assessment, and other non-operating expenses. These items are detailed in the “Non-GAAP Reconciliation” section of the Appendix. Earnings-per-Share - diluted (“EPS”) $0.40 $0.72 $0.66 $0.73 $0.78 $0.85 $0.82 $0.72 $0.76 $0.82 GAAP EPS - diluted Operating EPS - diluted¹ Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026
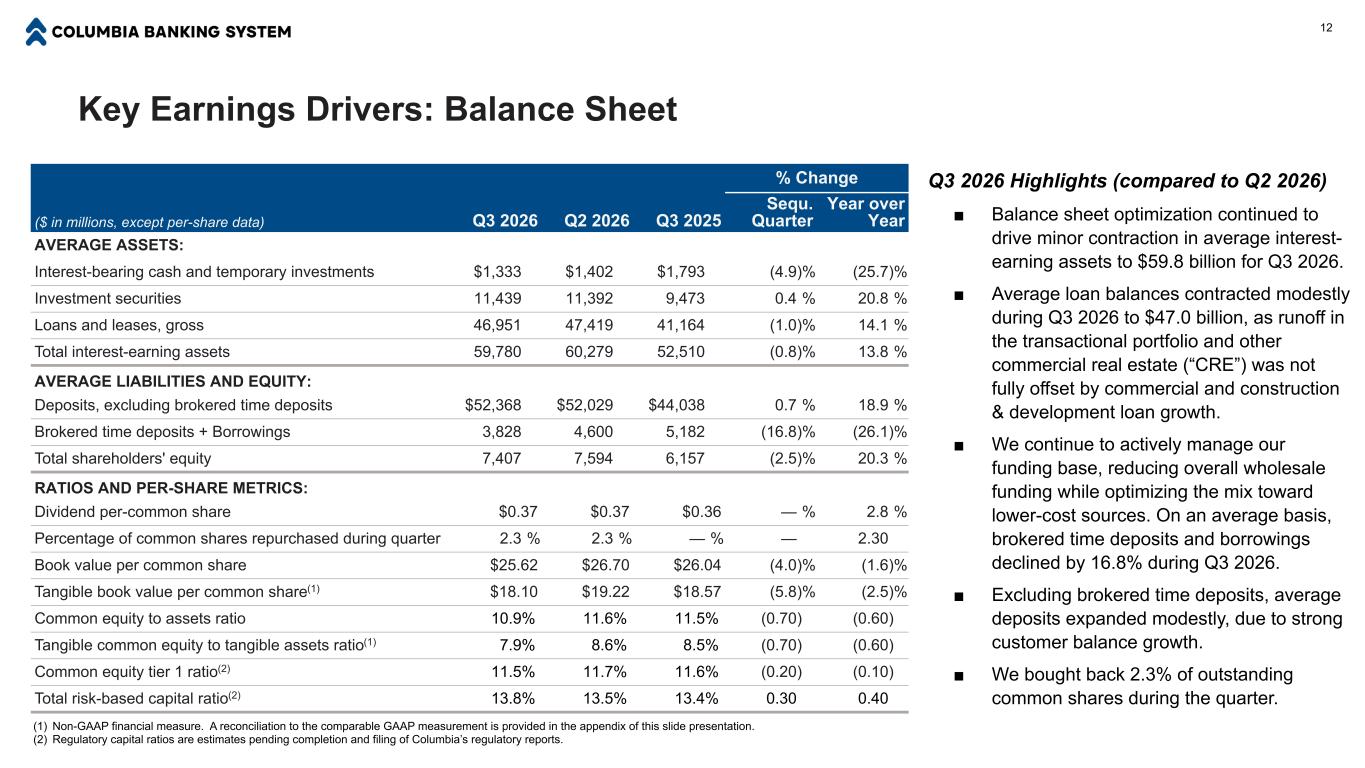
Key Earnings Drivers: Balance Sheet (1) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement is provided in the appendix of this slide presentation. (2) Regulatory capital ratios are estimates pending completion and filing of Columbia’s regulatory reports. % Change ($ in millions, except per-share data) Q3 2026 Q2 2026 Q3 2025 Sequ. Quarter Year over Year AVERAGE ASSETS: Interest-bearing cash and temporary investments $1,333 $1,402 $1,793 (4.9) % (25.7) % Investment securities 11,439 11,392 9,473 0.4 % 20.8 % Loans and leases, gross 46,951 47,419 41,164 (1.0) % 14.1 % Total interest-earning assets 59,780 60,279 52,510 (0.8) % 13.8 % AVERAGE LIABILITIES AND EQUITY: Deposits, excluding brokered time deposits $52,368 $52,029 $44,038 0.7 % 18.9 % Brokered time deposits + Borrowings 3,828 4,600 5,182 (16.8) % (26.1) % Total shareholders' equity 7,407 7,594 6,157 (2.5) % 20.3 % RATIOS AND PER-SHARE METRICS: Dividend per-common share $0.37 $0.37 $0.36 — % 2.8 % Percentage of common shares repurchased during quarter 2.3 % 2.3 % — % — 2.30 Book value per common share $25.62 $26.70 $26.04 (4.0) % (1.6) % Tangible book value per common share(1) $18.10 $19.22 $18.57 (5.8) % (2.5) % Common equity to assets ratio 10.9% 11.6% 11.5% (0.70) (0.60) Tangible common equity to tangible assets ratio(1) 7.9% 8.6% 8.5% (0.70) (0.60) Common equity tier 1 ratio(2) 11.5% 11.7% 11.6% (0.20) (0.10) Total risk-based capital ratio(2) 13.8% 13.5% 13.4% 0.30 0.40 12 Q3 2026 Highlights (compared to Q2 2026) ■ Balance sheet optimization continued to drive minor contraction in average interest- earning assets to $59.8 billion for Q3 2026. ■ Average loan balances contracted modestly during Q3 2026 to $47.0 billion, as runoff in the transactional portfolio and other commercial real estate (“CRE”) was not fully offset by commercial and construction & development loan growth. ■ We continue to actively manage our funding base, reducing overall wholesale funding while optimizing the mix toward lower-cost sources. On an average basis, brokered time deposits and borrowings declined by 16.8% during Q3 2026. ■ Excluding brokered time deposits, average deposits expanded modestly, due to strong customer balance growth. ■ We bought back 2.3% of outstanding common shares during the quarter.
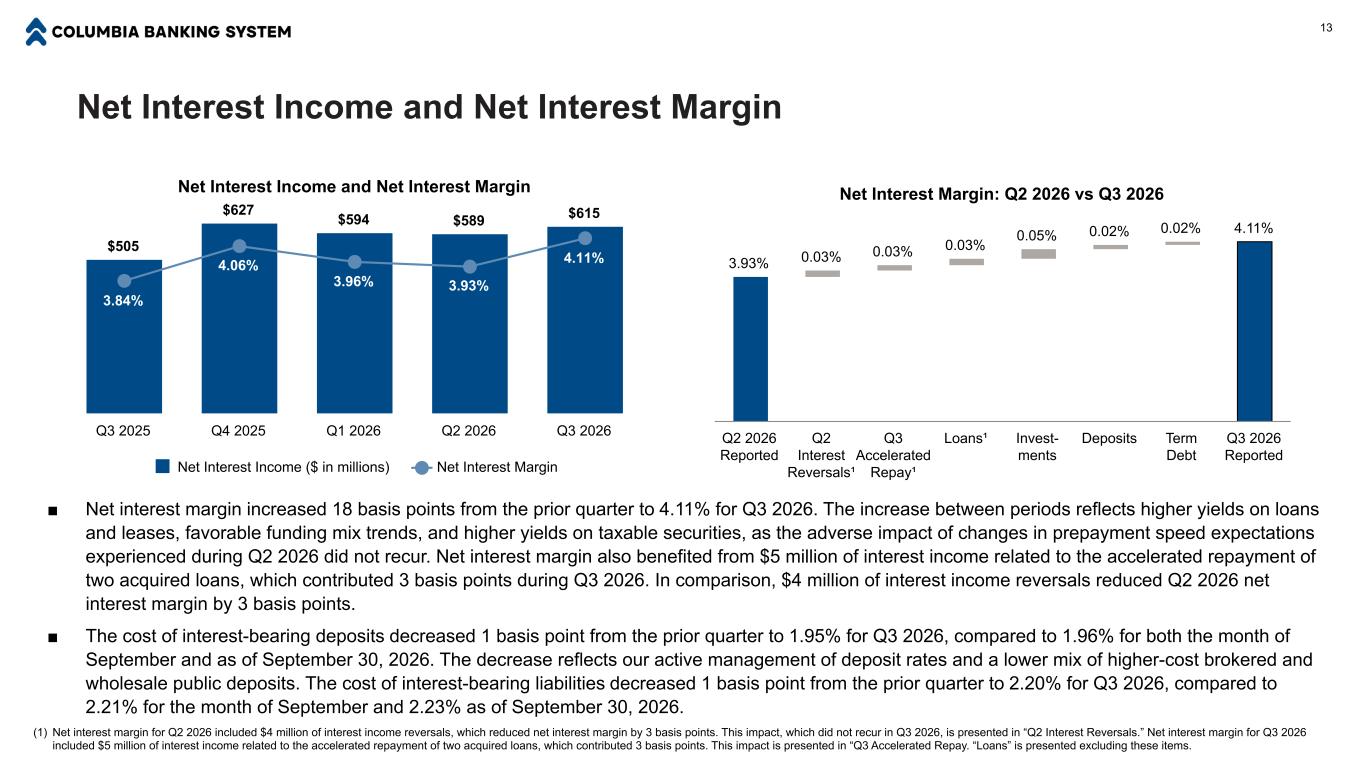
Net Interest Income and Net Interest Margin Net Interest Income and Net Interest Margin $505 $627 $594 $589 $615 3.84% 4.06% 3.96% 3.93% 4.11% Net Interest Income ($ in millions) Net Interest Margin Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Net Interest Margin: Q2 2026 vs Q3 2026 3.93% 0.03% 0.03% 0.03% 0.05% 0.02% 0.02% 4.11% Q2 2026 Reported Q2 Interest Reversals¹ Q3 Accelerated Repay¹ Loans¹ Invest- ments Deposits Term Debt Q3 2026 Reported 13 ■ Net interest margin increased 18 basis points from the prior quarter to 4.11% for Q3 2026. The increase between periods reflects higher yields on loans and leases, favorable funding mix trends, and higher yields on taxable securities, as the adverse impact of changes in prepayment speed expectations experienced during Q2 2026 did not recur. Net interest margin also benefited from $5 million of interest income related to the accelerated repayment of two acquired loans, which contributed 3 basis points during Q3 2026. In comparison, $4 million of interest income reversals reduced Q2 2026 net interest margin by 3 basis points. ■ The cost of interest-bearing deposits decreased 1 basis point from the prior quarter to 1.95% for Q3 2026, compared to 1.96% for both the month of September and as of September 30, 2026. The decrease reflects our active management of deposit rates and a lower mix of higher-cost brokered and wholesale public deposits. The cost of interest-bearing liabilities decreased 1 basis point from the prior quarter to 2.20% for Q3 2026, compared to 2.21% for the month of September and 2.23% as of September 30, 2026. (1) Net interest margin for Q2 2026 included $4 million of interest income reversals, which reduced net interest margin by 3 basis points. This impact, which did not recur in Q3 2026, is presented in “Q2 Interest Reversals.” Net interest margin for Q3 2026 included $5 million of interest income related to the accelerated repayment of two acquired loans, which contributed 3 basis points. This impact is presented in “Q3 Accelerated Repay. “Loans” is presented excluding these items.
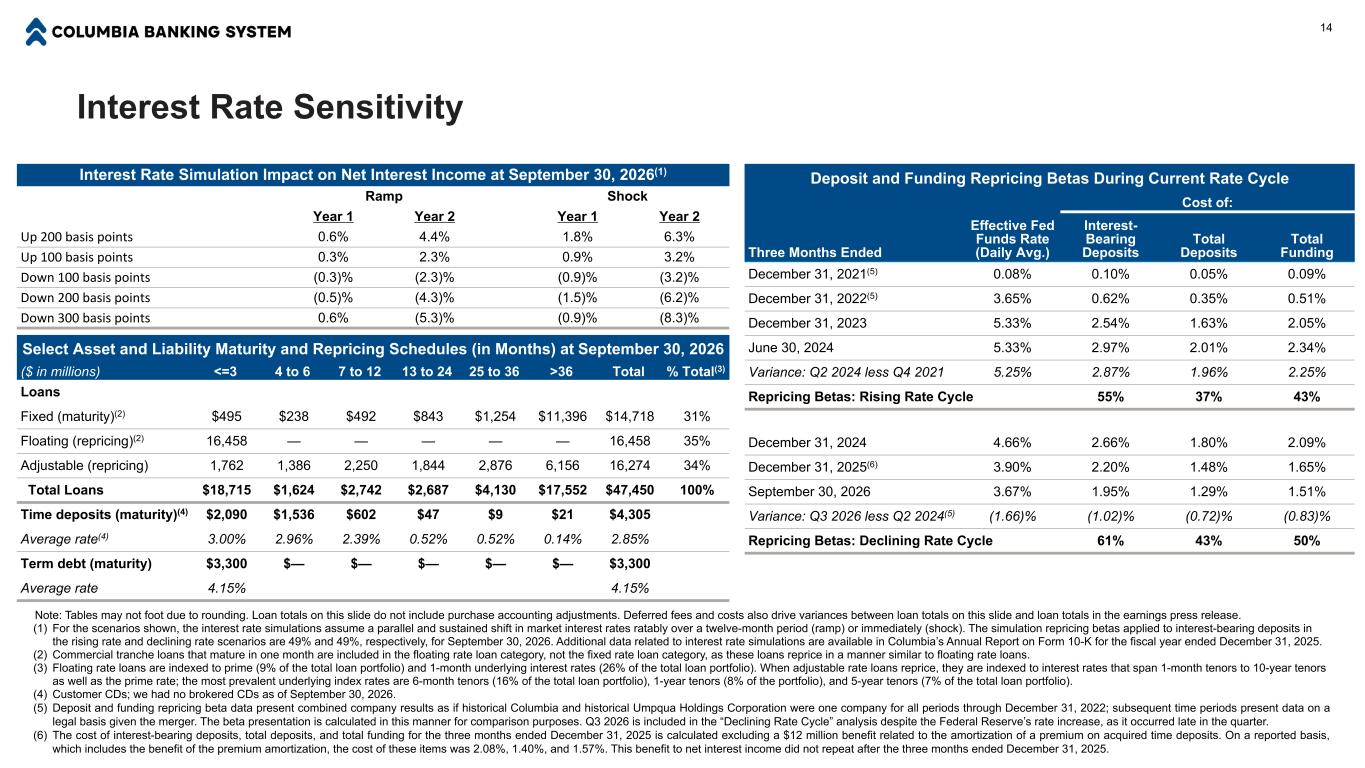
Select Asset and Liability Maturity and Repricing Schedules (in Months) at September 30, 2026 ($ in millions) <=3 4 to 6 7 to 12 13 to 24 25 to 36 >36 Total % Total(3) Loans Fixed (maturity)(2) $495 $238 $492 $843 $1,254 $11,396 $14,718 31% Floating (repricing)(2) 16,458 — — — — — 16,458 35% Adjustable (repricing) 1,762 1,386 2,250 1,844 2,876 6,156 16,274 34% Total Loans $18,715 $1,624 $2,742 $2,687 $4,130 $17,552 $47,450 100% Time deposits (maturity)(4) $2,090 $1,536 $602 $47 $9 $21 $4,305 Average rate(4) 3.00% 2.96% 2.39% 0.52% 0.52% 0.14% 2.85% Term debt (maturity) $3,300 $— $— $— $— $— $3,300 Average rate 4.15% 4.15% Interest Rate Sensitivity 14 Note: Tables may not foot due to rounding. Loan totals on this slide do not include purchase accounting adjustments. Deferred fees and costs also drive variances between loan totals on this slide and loan totals in the earnings press release. (1) For the scenarios shown, the interest rate simulations assume a parallel and sustained shift in market interest rates ratably over a twelve-month period (ramp) or immediately (shock). The simulation repricing betas applied to interest-bearing deposits in the rising rate and declining rate scenarios are 49% and 49%, respectively, for September 30, 2026. Additional data related to interest rate simulations are available in Columbia’s Annual Report on Form 10-K for the fiscal year ended December 31, 2025. (2) Commercial tranche loans that mature in one month are included in the floating rate loan category, not the fixed rate loan category, as these loans reprice in a manner similar to floating rate loans. (3) Floating rate loans are indexed to prime (9% of the total loan portfolio) and 1-month underlying interest rates (26% of the total loan portfolio). When adjustable rate loans reprice, they are indexed to interest rates that span 1-month tenors to 10-year tenors as well as the prime rate; the most prevalent underlying index rates are 6-month tenors (16% of the total loan portfolio), 1-year tenors (8% of the portfolio), and 5-year tenors (7% of the total loan portfolio). (4) Customer CDs; we had no brokered CDs as of September 30, 2026. (5) Deposit and funding repricing beta data present combined company results as if historical Columbia and historical Umpqua Holdings Corporation were one company for all periods through December 31, 2022; subsequent time periods present data on a legal basis given the merger. The beta presentation is calculated in this manner for comparison purposes. Q3 2026 is included in the “Declining Rate Cycle” analysis despite the Federal Reserve’s rate increase, as it occurred late in the quarter. (6) The cost of interest-bearing deposits, total deposits, and total funding for the three months ended December 31, 2025 is calculated excluding a $12 million benefit related to the amortization of a premium on acquired time deposits. On a reported basis, which includes the benefit of the premium amortization, the cost of these items was 2.08%, 1.40%, and 1.57%. This benefit to net interest income did not repeat after the three months ended December 31, 2025. Interest Rate Simulation Impact on Net Interest Income at September 30, 2026(1) Ramp Shock Year 1 Year 2 Year 1 Year 2 Up 200 basis points 0.6% 4.4% 1.8% 6.3% Up 100 basis points 0.3% 2.3% 0.9% 3.2% Down 100 basis points (0.3)% (2.3)% (0.9)% (3.2)% Down 200 basis points (0.5)% (4.3)% (1.5)% (6.2)% Down 300 basis points 0.6% (5.3)% (0.9)% (8.3)% Deposit and Funding Repricing Betas During Current Rate Cycle Effective Fed Funds Rate (Daily Avg.) Cost of: Three Months Ended Interest- Bearing Deposits Total Deposits Total Funding December 31, 2021(5) 0.08% 0.10% 0.05% 0.09% December 31, 2022(5) 3.65% 0.62% 0.35% 0.51% December 31, 2023 5.33% 2.54% 1.63% 2.05% June 30, 2024 5.33% 2.97% 2.01% 2.34% Variance: Q2 2024 less Q4 2021 5.25% 2.87% 1.96% 2.25% Repricing Betas: Rising Rate Cycle 55% 37% 43% December 31, 2024 4.66% 2.66% 1.80% 2.09% December 31, 2025(6) 3.90% 2.20% 1.48% 1.65% September 30, 2026 3.67% 1.95% 1.29% 1.51% Variance: Q3 2026 less Q2 2024(5) (1.66)% (1.02)% (0.72)% (0.83)% Repricing Betas: Declining Rate Cycle 61% 43% 50%
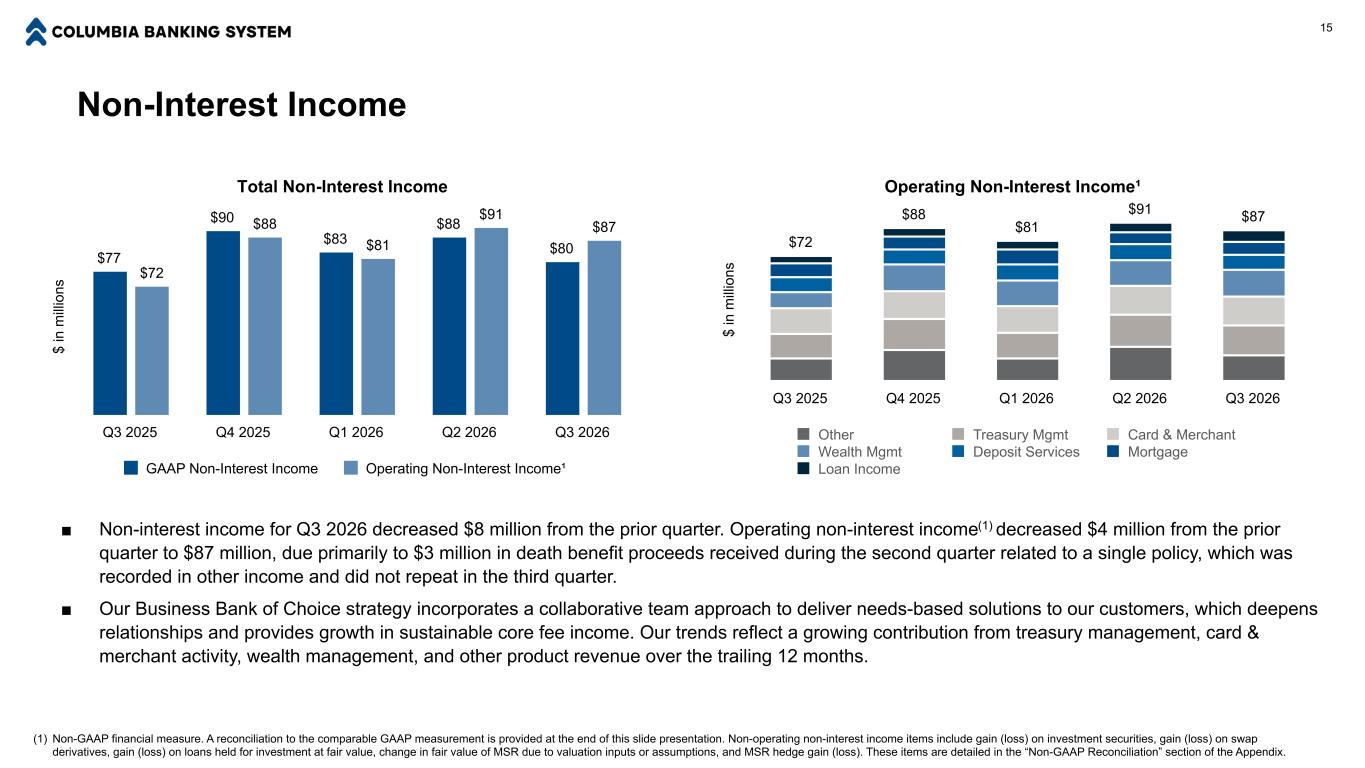
Non-Interest Income 15 $ in m ill io ns Total Non-Interest Income $77 $90 $83 $88 $80 $72 $88 $81 $91 $87 GAAP Non-Interest Income Operating Non-Interest Income¹ Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 ■ Non-interest income for Q3 2026 decreased $8 million from the prior quarter. Operating non-interest income(1) decreased $4 million from the prior quarter to $87 million, due primarily to $3 million in death benefit proceeds received during the second quarter related to a single policy, which was recorded in other income and did not repeat in the third quarter. ■ Our Business Bank of Choice strategy incorporates a collaborative team approach to deliver needs-based solutions to our customers, which deepens relationships and provides growth in sustainable core fee income. Our trends reflect a growing contribution from treasury management, card & merchant activity, wealth management, and other product revenue over the trailing 12 months. $ in m ill io ns Operating Non-Interest Income¹ $72 $88 $81 $91 $87 Other Treasury Mgmt Card & Merchant Wealth Mgmt Deposit Services Mortgage Loan Income Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 (1) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement is provided at the end of this slide presentation. Non-operating non-interest income items include gain (loss) on investment securities, gain (loss) on swap derivatives, gain (loss) on loans held for investment at fair value, change in fair value of MSR due to valuation inputs or assumptions, and MSR hedge gain (loss). These items are detailed in the “Non-GAAP Reconciliation” section of the Appendix.
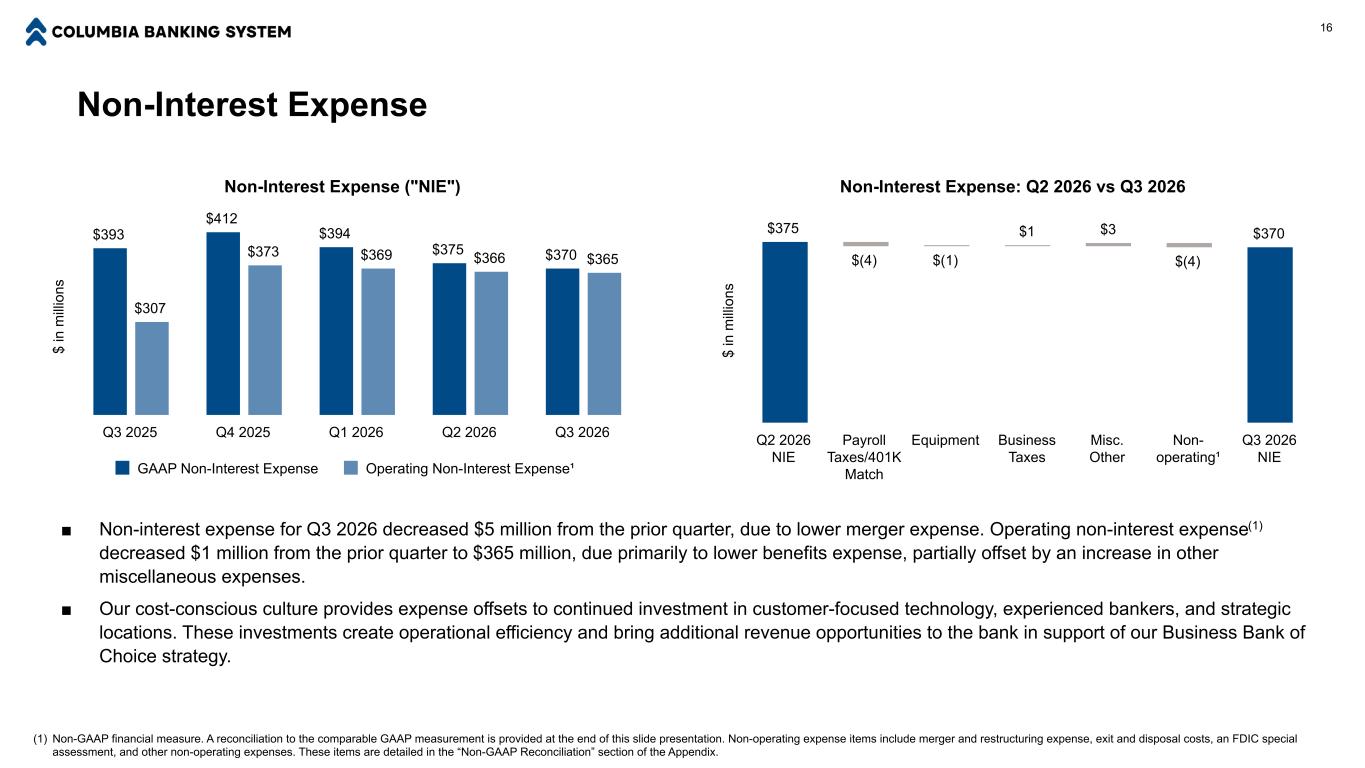
Non-Interest Expense 16 $ in m ill io ns Non-Interest Expense ("NIE") $393 $412 $394 $375 $370 $307 $373 $369 $366 $365 GAAP Non-Interest Expense Operating Non-Interest Expense¹ Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 ■ Non-interest expense for Q3 2026 decreased $5 million from the prior quarter, due to lower merger expense. Operating non-interest expense(1) decreased $1 million from the prior quarter to $365 million, due primarily to lower benefits expense, partially offset by an increase in other miscellaneous expenses. ■ Our cost-conscious culture provides expense offsets to continued investment in customer-focused technology, experienced bankers, and strategic locations. These investments create operational efficiency and bring additional revenue opportunities to the bank in support of our Business Bank of Choice strategy. $ in m ill io ns Non-Interest Expense: Q2 2026 vs Q3 2026 $375 $(4) $(1) $1 $3 $(4) $370 Q2 2026 NIE Payroll Taxes/401K Match Equipment Business Taxes Misc. Other Non- operating¹ Q3 2026 NIE (1) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement is provided at the end of this slide presentation. Non-operating expense items include merger and restructuring expense, exit and disposal costs, an FDIC special assessment, and other non-operating expenses. These items are detailed in the “Non-GAAP Reconciliation” section of the Appendix.
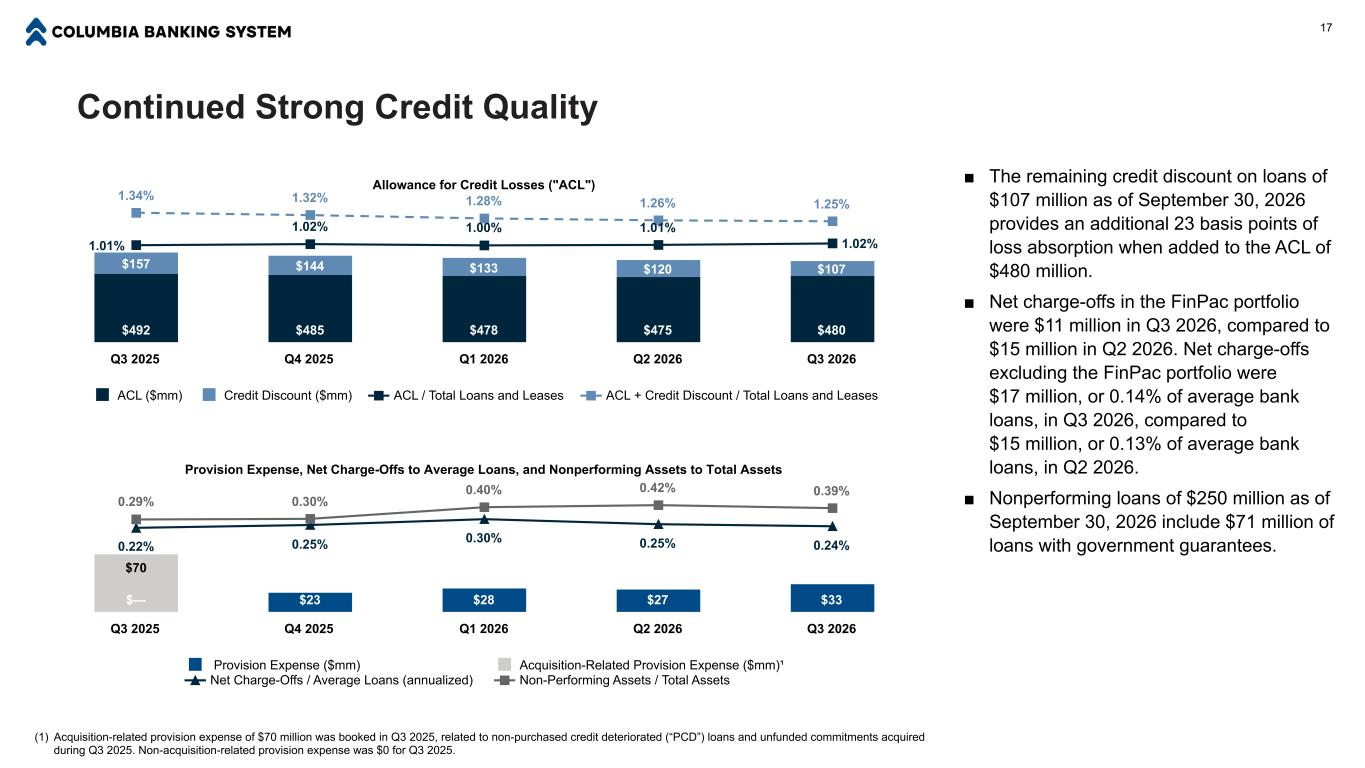
Continued Strong Credit Quality Provision Expense, Net Charge-Offs to Average Loans, and Nonperforming Assets to Total Assets $— $23 $28 $27 $33 $70 0.22% 0.25% 0.30% 0.25% 0.24% 0.29% 0.30% 0.40% 0.42% 0.39% Provision Expense ($mm) Acquisition-Related Provision Expense ($mm)¹ Net Charge-Offs / Average Loans (annualized) Non-Performing Assets / Total Assets Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 17 Allowance for Credit Losses ("ACL") $492 $485 $478 $475 $480 $157 $144 $133 $120 $107 1.01% 1.02% 1.00% 1.01% 1.02% 1.34% 1.32% 1.28% 1.26% 1.25% ACL ($mm) Credit Discount ($mm) ACL / Total Loans and Leases ACL + Credit Discount / Total Loans and Leases Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 ■ The remaining credit discount on loans of $107 million as of September 30, 2026 provides an additional 23 basis points of loss absorption when added to the ACL of $480 million. ■ Net charge-offs in the FinPac portfolio were $11 million in Q3 2026, compared to $15 million in Q2 2026. Net charge-offs excluding the FinPac portfolio were $17 million, or 0.14% of average bank loans, in Q3 2026, compared to $15 million, or 0.13% of average bank loans, in Q2 2026. ■ Nonperforming loans of $250 million as of September 30, 2026 include $71 million of loans with government guarantees. (1) Acquisition-related provision expense of $70 million was booked in Q3 2025, related to non-purchased credit deteriorated (“PCD”) loans and unfunded commitments acquired during Q3 2025. Non-acquisition-related provision expense was $0 for Q3 2025.
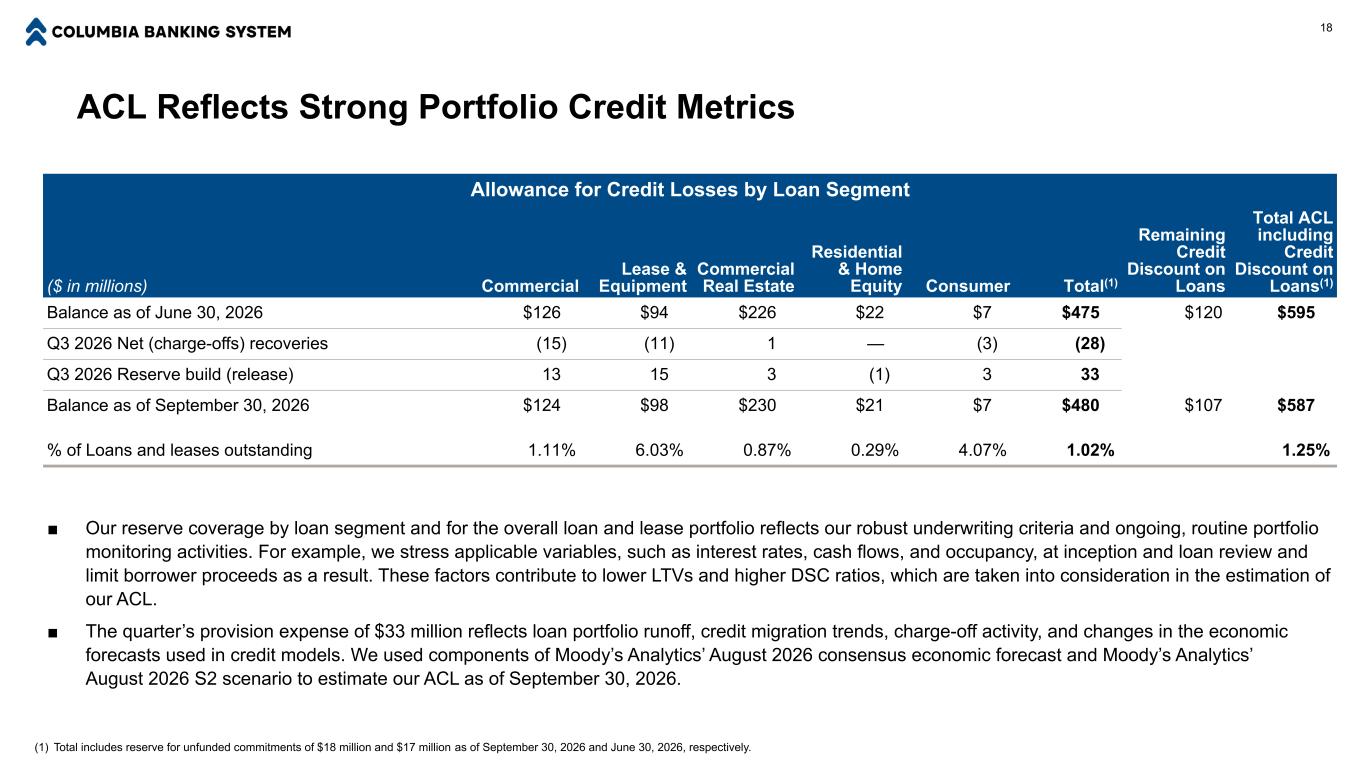
ACL Reflects Strong Portfolio Credit Metrics (1) Total includes reserve for unfunded commitments of $18 million and $17 million as of September 30, 2026 and June 30, 2026, respectively. 18 ■ Our reserve coverage by loan segment and for the overall loan and lease portfolio reflects our robust underwriting criteria and ongoing, routine portfolio monitoring activities. For example, we stress applicable variables, such as interest rates, cash flows, and occupancy, at inception and loan review and limit borrower proceeds as a result. These factors contribute to lower LTVs and higher DSC ratios, which are taken into consideration in the estimation of our ACL. ■ The quarter’s provision expense of $33 million reflects loan portfolio runoff, credit migration trends, charge-off activity, and changes in the economic forecasts used in credit models. We used components of Moody’s Analytics’ August 2026 consensus economic forecast and Moody’s Analytics’ August 2026 S2 scenario to estimate our ACL as of September 30, 2026. Allowance for Credit Losses by Loan Segment ($ in millions) Commercial Lease & Equipment Commercial Real Estate Residential & Home Equity Consumer Total(1) Remaining Credit Discount on Loans Total ACL including Credit Discount on Loans(1) Balance as of June 30, 2026 $126 $94 $226 $22 $7 $475 $120 $595 Q3 2026 Net (charge-offs) recoveries (15) (11) 1 — (3) (28) Q3 2026 Reserve build (release) 13 15 3 (1) 3 33 Balance as of September 30, 2026 $124 $98 $230 $21 $7 $480 $107 $587 % of Loans and leases outstanding 1.11% 6.03% 0.87% 0.29% 4.07% 1.02% 1.25%
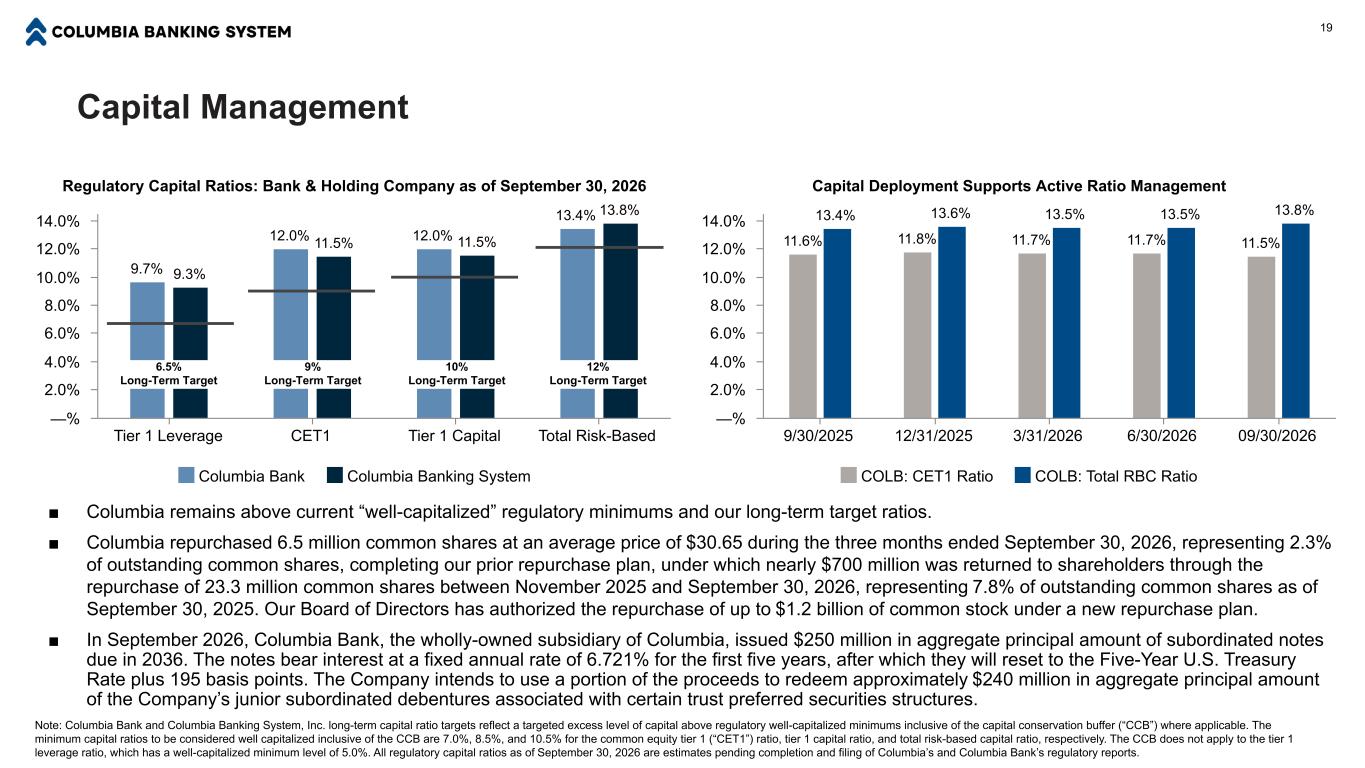
Capital Management 19 Regulatory Capital Ratios: Bank & Holding Company as of September 30, 2026 9.7% 12.0% 12.0% 13.4% 9.3% 11.5% 11.5% 13.8% Columbia Bank Columbia Banking System Tier 1 Leverage CET1 Tier 1 Capital Total Risk-Based —% 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% 14.0% ■ Columbia remains above current “well-capitalized” regulatory minimums and our long-term target ratios. ■ Columbia repurchased 6.5 million common shares at an average price of $30.65 during the three months ended September 30, 2026, representing 2.3% of outstanding common shares, completing our prior repurchase plan, under which nearly $700 million was returned to shareholders through the repurchase of 23.3 million common shares between November 2025 and September 30, 2026, representing 7.8% of outstanding common shares as of September 30, 2025. Our Board of Directors has authorized the repurchase of up to $1.2 billion of common stock under a new repurchase plan. ■ In September 2026, Columbia Bank, the wholly-owned subsidiary of Columbia, issued $250 million in aggregate principal amount of subordinated notes due in 2036. The notes bear interest at a fixed annual rate of 6.721% for the first five years, after which they will reset to the Five-Year U.S. Treasury Rate plus 195 basis points. The Company intends to use a portion of the proceeds to redeem approximately $240 million in aggregate principal amount of the Company’s junior subordinated debentures associated with certain trust preferred securities structures. Note: Columbia Bank and Columbia Banking System, Inc. long-term capital ratio targets reflect a targeted excess level of capital above regulatory well-capitalized minimums inclusive of the capital conservation buffer (“CCB”) where applicable. The minimum capital ratios to be considered well capitalized inclusive of the CCB are 7.0%, 8.5%, and 10.5% for the common equity tier 1 (“CET1”) ratio, tier 1 capital ratio, and total risk-based capital ratio, respectively. The CCB does not apply to the tier 1 leverage ratio, which has a well-capitalized minimum level of 5.0%. All regulatory capital ratios as of September 30, 2026 are estimates pending completion and filing of Columbia’s and Columbia Bank’s regulatory reports. Capital Deployment Supports Active Ratio Management 11.6% 11.8% 11.7% 11.7% 11.5% 13.4% 13.6% 13.5% 13.5% 13.8% COLB: CET1 Ratio COLB: Total RBC Ratio 9/30/2025 12/31/2025 3/31/2026 6/30/2026 09/30/2026 —% 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% 14.0% 12% Long-Term Target 10% Long-Term Target 9% Long-Term Target 6.5% Long-Term Target
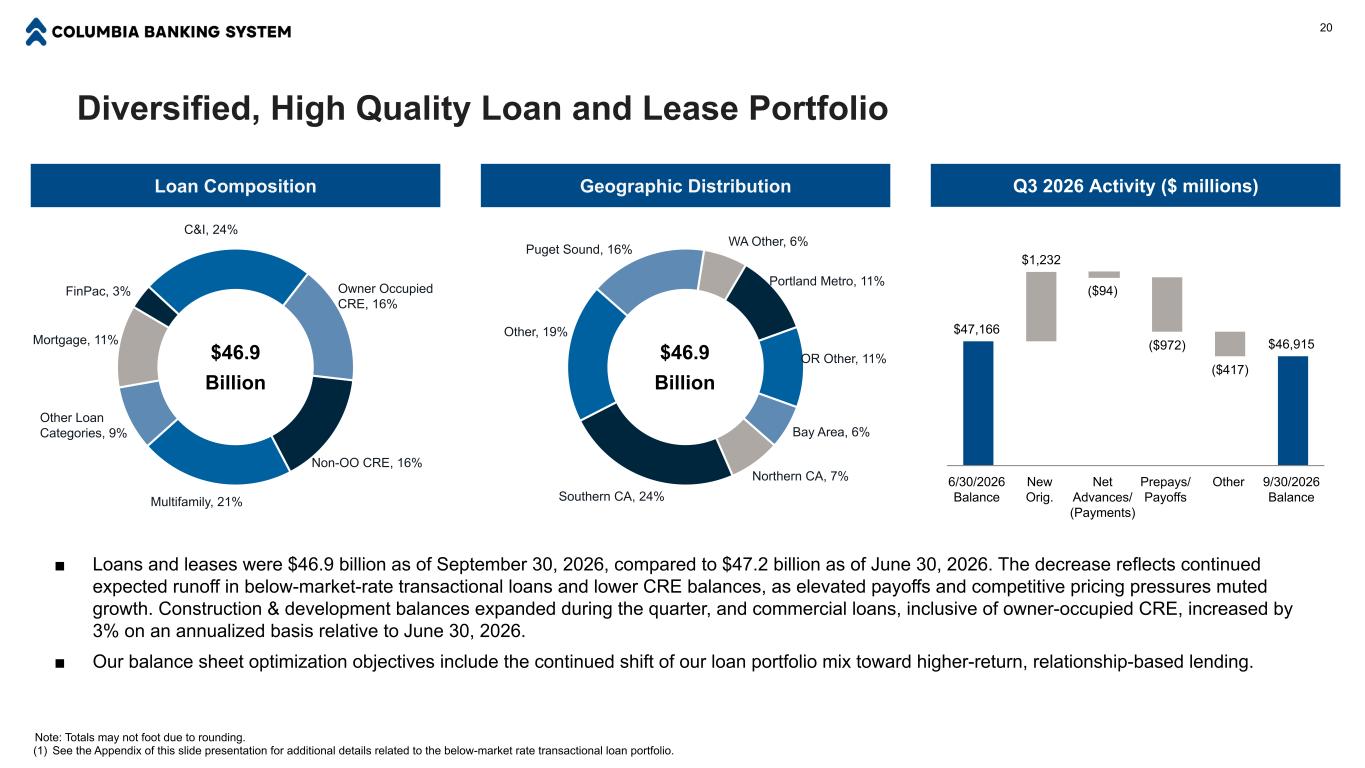
Diversified, High Quality Loan and Lease Portfolio $47,166 $1,232 ($94) ($972) ($417) $46,915 6/30/2026 Balance New Orig. Net Advances/ (Payments) Prepays/ Payoffs Other 9/30/2026 Balance 20 Mortgage, 11% FinPac, 3% C&I, 24% Owner Occupied CRE, 16% Non-OO CRE, 16% Multifamily, 21% Other Loan Categories, 9% Q3 2026 Activity ($ millions) Other, 19% Puget Sound, 16% WA Other, 6% Portland Metro, 11% OR Other, 11% Bay Area, 6% Northern CA, 7% Southern CA, 24% Geographic Distribution ■ Loans and leases were $46.9 billion as of September 30, 2026, compared to $47.2 billion as of June 30, 2026. The decrease reflects continued expected runoff in below-market-rate transactional loans and lower CRE balances, as elevated payoffs and competitive pricing pressures muted growth. Construction & development balances expanded during the quarter, and commercial loans, inclusive of owner-occupied CRE, increased by 3% on an annualized basis relative to June 30, 2026. ■ Our balance sheet optimization objectives include the continued shift of our loan portfolio mix toward higher-return, relationship-based lending. Loan Composition $46.9 Billion $46.9 Billion Note: Totals may not foot due to rounding. (1) See the Appendix of this slide presentation for additional details related to the below-market rate transactional loan portfolio.
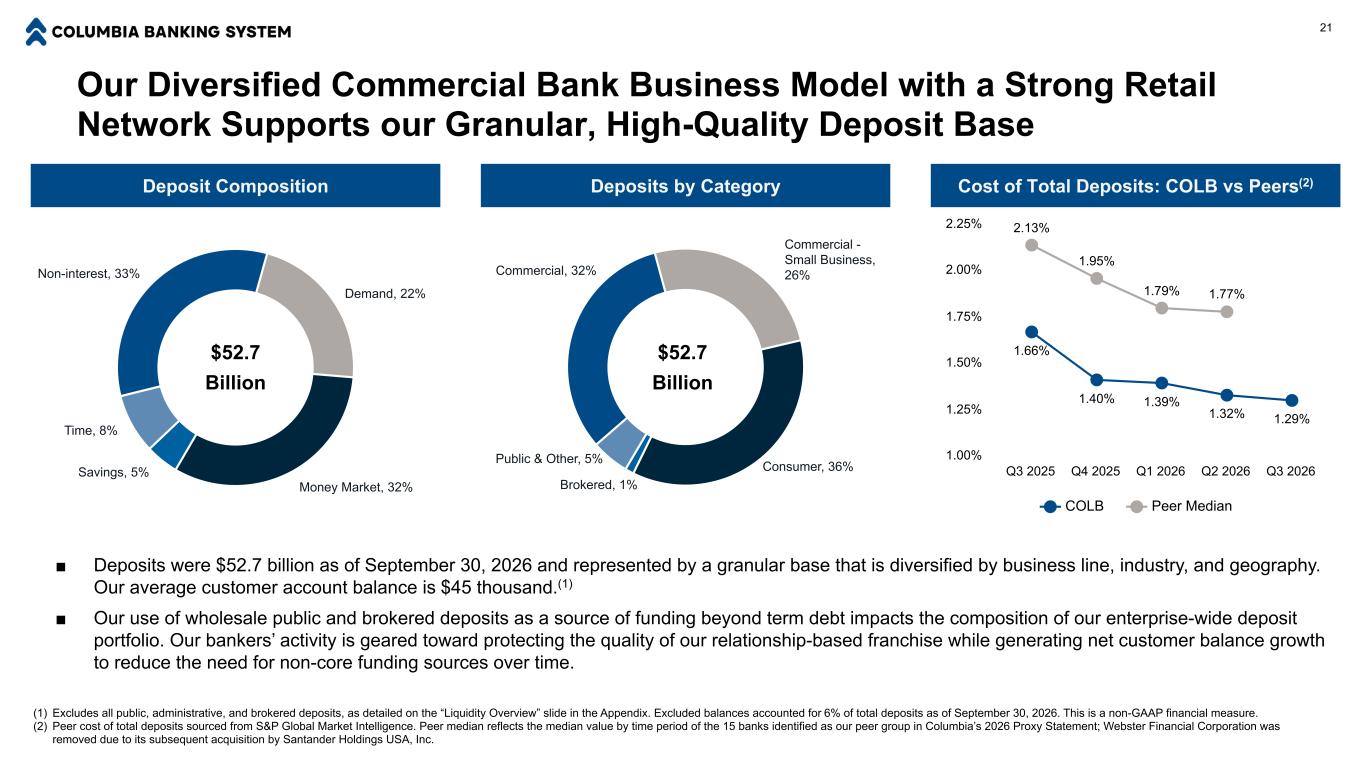
Our Diversified Commercial Bank Business Model with a Strong Retail Network Supports our Granular, High-Quality Deposit Base Non-interest, 33% Demand, 22% Money Market, 32% Savings, 5% Time, 8% Deposit Composition 21 ■ Deposits were $52.7 billion as of September 30, 2026 and represented by a granular base that is diversified by business line, industry, and geography. Our average customer account balance is $45 thousand.(1) ■ Our use of wholesale public and brokered deposits as a source of funding beyond term debt impacts the composition of our enterprise-wide deposit portfolio. Our bankers’ activity is geared toward protecting the quality of our relationship-based franchise while generating net customer balance growth to reduce the need for non-core funding sources over time. Commercial, 32% Commercial - Small Business, 26% Consumer, 36% Brokered, 1% Public & Other, 5% Deposits by Category Cost of Total Deposits: COLB vs Peers(2) (1) Excludes all public, administrative, and brokered deposits, as detailed on the “Liquidity Overview” slide in the Appendix. Excluded balances accounted for 6% of total deposits as of September 30, 2026. This is a non-GAAP financial measure. (2) Peer cost of total deposits sourced from S&P Global Market Intelligence. Peer median reflects the median value by time period of the 15 banks identified as our peer group in Columbia’s 2026 Proxy Statement; Webster Financial Corporation was removed due to its subsequent acquisition by Santander Holdings USA, Inc. $52.7 Billion $52.7 Billion 1.66% 1.40% 1.39% 1.32% 1.29% 2.13% 1.95% 1.79% 1.77% COLB Peer Median Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 1.00% 1.25% 1.50% 1.75% 2.00% 2.25%
Appendix 22 Page Loan Portfolio Slides 23 Liquidity Overview 27 Securities Portfolio 28 Summary Income Statements 29 Summary Balance Sheets 30 Non-GAAP Reconciliations 31
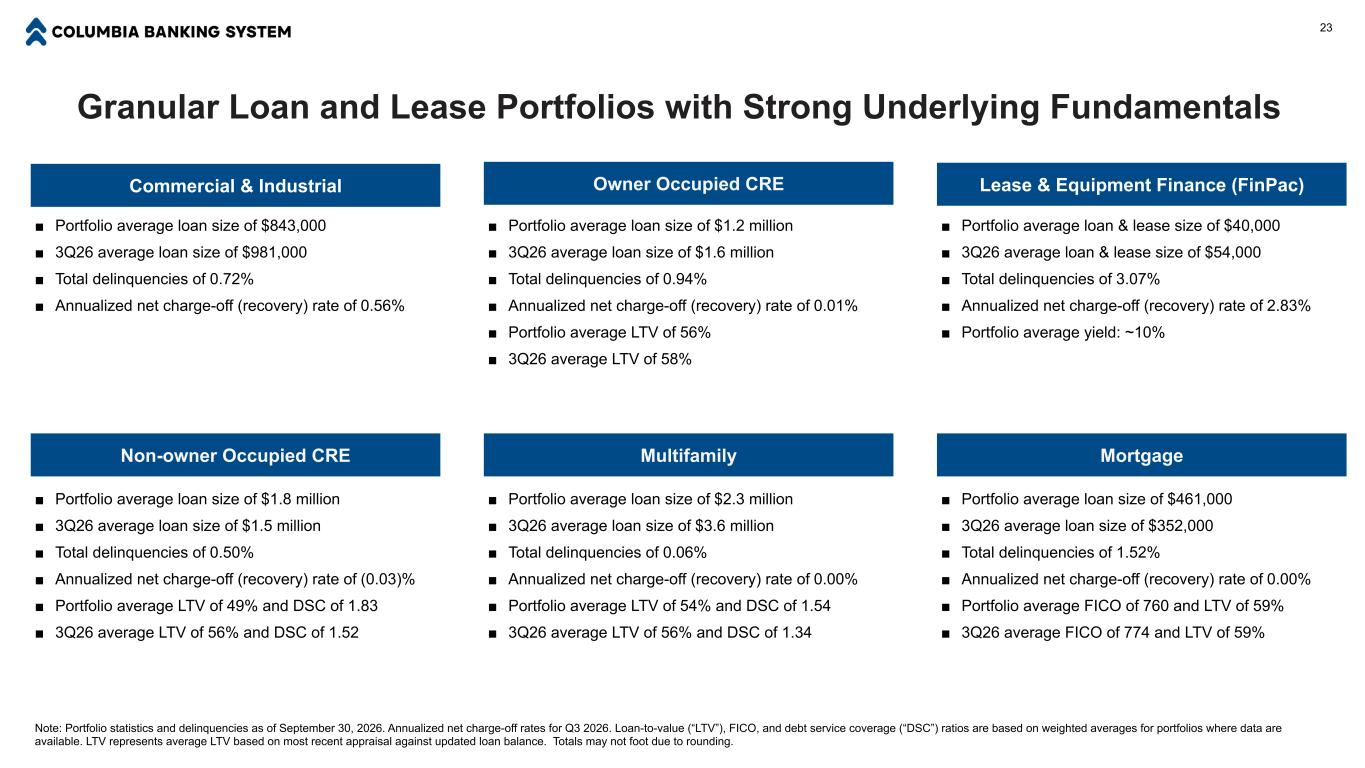
Granular Loan and Lease Portfolios with Strong Underlying Fundamentals Note: Portfolio statistics and delinquencies as of September 30, 2026. Annualized net charge-off rates for Q3 2026. Loan-to-value (“LTV”), FICO, and debt service coverage (“DSC”) ratios are based on weighted averages for portfolios where data are available. LTV represents average LTV based on most recent appraisal against updated loan balance. Totals may not foot due to rounding. ■ Portfolio average loan size of $461,000 ■ 3Q26 average loan size of $352,000 ■ Total delinquencies of 1.52% ■ Annualized net charge-off (recovery) rate of 0.00% ■ Portfolio average FICO of 760 and LTV of 59% ■ 3Q26 average FICO of 774 and LTV of 59% Non-owner Occupied CRE ■ Portfolio average loan size of $1.8 million ■ 3Q26 average loan size of $1.5 million ■ Total delinquencies of 0.50% ■ Annualized net charge-off (recovery) rate of (0.03)% ■ Portfolio average LTV of 49% and DSC of 1.83 ■ 3Q26 average LTV of 56% and DSC of 1.52 Commercial & Industrial ■ Portfolio average loan size of $843,000 ■ 3Q26 average loan size of $981,000 ■ Total delinquencies of 0.72% ■ Annualized net charge-off (recovery) rate of 0.56% Multifamily ■ Portfolio average loan size of $2.3 million ■ 3Q26 average loan size of $3.6 million ■ Total delinquencies of 0.06% ■ Annualized net charge-off (recovery) rate of 0.00% ■ Portfolio average LTV of 54% and DSC of 1.54 ■ 3Q26 average LTV of 56% and DSC of 1.34 Owner Occupied CRE ■ Portfolio average loan size of $1.2 million ■ 3Q26 average loan size of $1.6 million ■ Total delinquencies of 0.94% ■ Annualized net charge-off (recovery) rate of 0.01% ■ Portfolio average LTV of 56% ■ 3Q26 average LTV of 58% Lease & Equipment Finance (FinPac) ■ Portfolio average loan & lease size of $40,000 ■ 3Q26 average loan & lease size of $54,000 ■ Total delinquencies of 3.07% ■ Annualized net charge-off (recovery) rate of 2.83% ■ Portfolio average yield: ~10% Mortgage 23
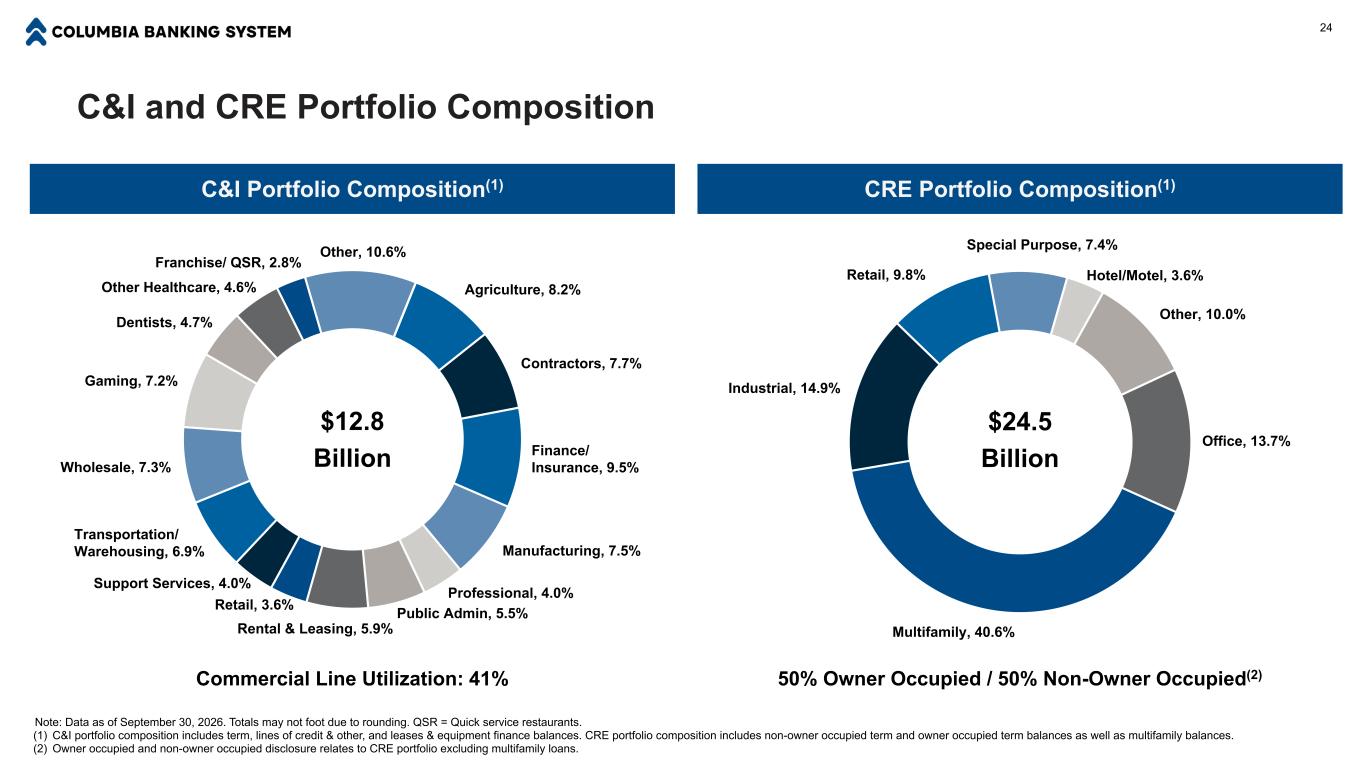
C&I and CRE Portfolio Composition Agriculture, 8.2% Contractors, 7.7% Finance/ Insurance, 9.5% Manufacturing, 7.5% Professional, 4.0% Public Admin, 5.5% Rental & Leasing, 5.9% Retail, 3.6% Support Services, 4.0% Transportation/ Warehousing, 6.9% Wholesale, 7.3% Gaming, 7.2% Dentists, 4.7% Other Healthcare, 4.6% Franchise/ QSR, 2.8% Other, 10.6% Office, 13.7% Multifamily, 40.6% Industrial, 14.9% Retail, 9.8% Special Purpose, 7.4% Hotel/Motel, 3.6% Other, 10.0% CRE Portfolio Composition(1)C&I Portfolio Composition(1) Note: Data as of September 30, 2026. Totals may not foot due to rounding. QSR = Quick service restaurants. (1) C&I portfolio composition includes term, lines of credit & other, and leases & equipment finance balances. CRE portfolio composition includes non-owner occupied term and owner occupied term balances as well as multifamily balances. (2) Owner occupied and non-owner occupied disclosure relates to CRE portfolio excluding multifamily loans. 50% Owner Occupied / 50% Non-Owner Occupied(2)Commercial Line Utilization: 41% 24 $12.8 Billion $24.5 Billion
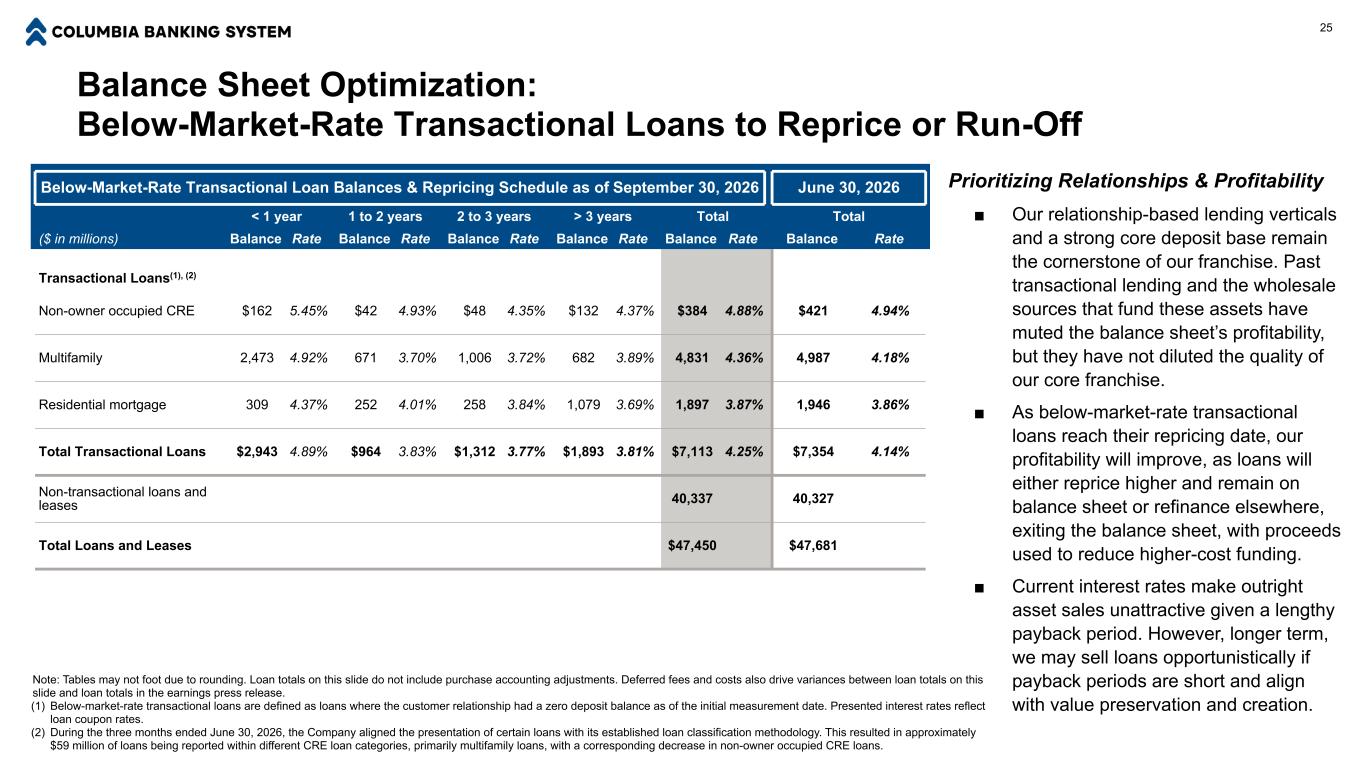
Balance Sheet Optimization: Below-Market-Rate Transactional Loans to Reprice or Run-Off 25 Below-Market-Rate Transactional Loan Balances & Repricing Schedule as of September 30, 2026 June 30, 2026 < 1 year 1 to 2 years 2 to 3 years > 3 years Total Total ($ in millions) Balance Rate Balance Rate Balance Rate Balance Rate Balance Rate Balance Rate Transactional Loans(1), (2) Non-owner occupied CRE $162 5.45% $42 4.93% $48 4.35% $132 4.37% $384 4.88% $421 4.94% Multifamily 2,473 4.92% 671 3.70% 1,006 3.72% 682 3.89% 4,831 4.36% 4,987 4.18% Residential mortgage 309 4.37% 252 4.01% 258 3.84% 1,079 3.69% 1,897 3.87% 1,946 3.86% Total Transactional Loans $2,943 4.89% $964 3.83% $1,312 3.77% $1,893 3.81% $7,113 4.25% $7,354 4.14% Non-transactional loans and leases 40,337 40,327 Total Loans and Leases $47,450 $47,681 Prioritizing Relationships & Profitability ■ Our relationship-based lending verticals and a strong core deposit base remain the cornerstone of our franchise. Past transactional lending and the wholesale sources that fund these assets have muted the balance sheet’s profitability, but they have not diluted the quality of our core franchise. ■ As below-market-rate transactional loans reach their repricing date, our profitability will improve, as loans will either reprice higher and remain on balance sheet or refinance elsewhere, exiting the balance sheet, with proceeds used to reduce higher-cost funding. ■ Current interest rates make outright asset sales unattractive given a lengthy payback period. However, longer term, we may sell loans opportunistically if payback periods are short and align with value preservation and creation. Note: Tables may not foot due to rounding. Loan totals on this slide do not include purchase accounting adjustments. Deferred fees and costs also drive variances between loan totals on this slide and loan totals in the earnings press release. (1) Below-market-rate transactional loans are defined as loans where the customer relationship had a zero deposit balance as of the initial measurement date. Presented interest rates reflect loan coupon rates. (2) During the three months ended June 30, 2026, the Company aligned the presentation of certain loans with its established loan classification methodology. This resulted in approximately $59 million of loans being reported within different CRE loan categories, primarily multifamily loans, with a corresponding decrease in non-owner occupied CRE loans.
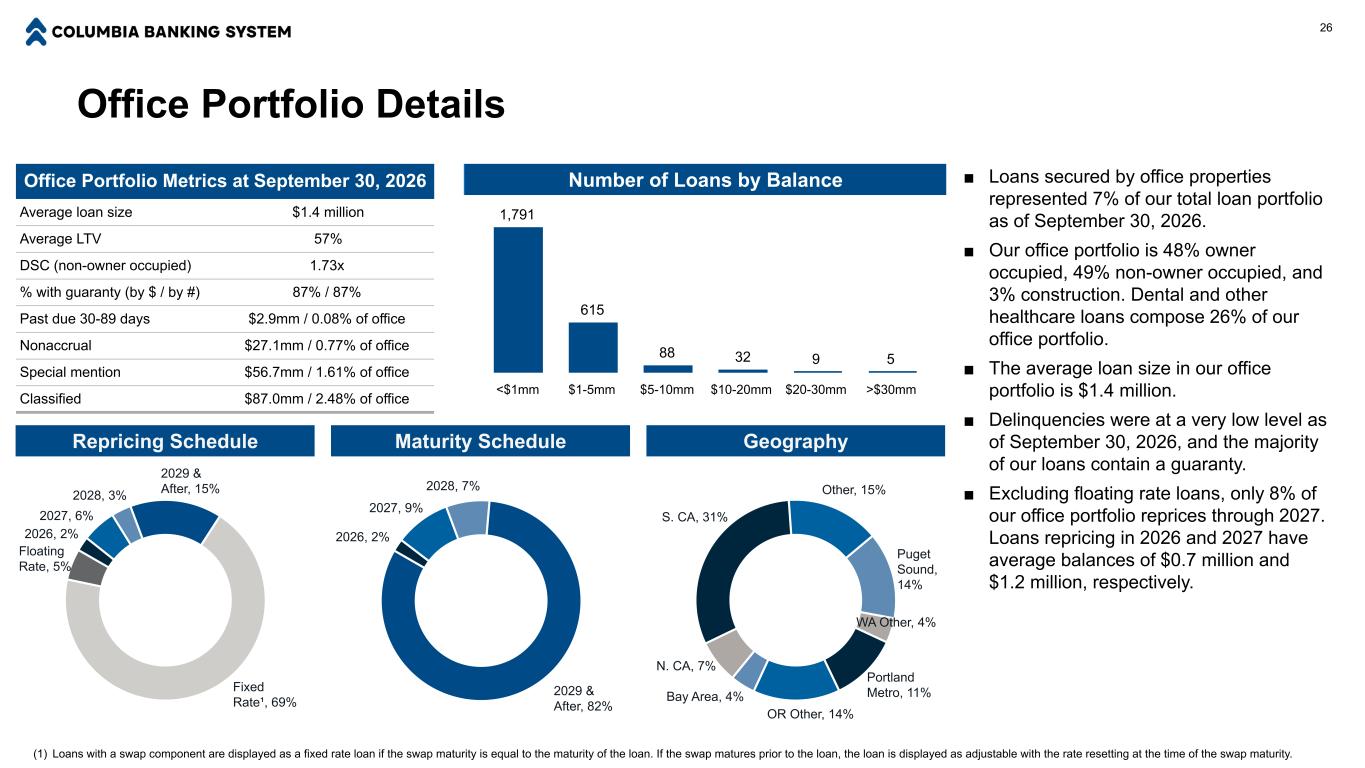
Office Portfolio Details Puget Sound, 14% WA Other, 4% Portland Metro, 11% OR Other, 14% Bay Area, 4% N. CA, 7% S. CA, 31% Other, 15% Office Portfolio Metrics at September 30, 2026 Average loan size $1.4 million Average LTV 57% DSC (non-owner occupied) 1.73x % with guaranty (by $ / by #) 87% / 87% Past due 30-89 days $2.9mm / 0.08% of office Nonaccrual $27.1mm / 0.77% of office Special mention $56.7mm / 1.61% of office Classified $87.0mm / 2.48% of office Number of Loans by Balance Geography 26 ■ Loans secured by office properties represented 7% of our total loan portfolio as of September 30, 2026. ■ Our office portfolio is 48% owner occupied, 49% non-owner occupied, and 3% construction. Dental and other healthcare loans compose 26% of our office portfolio. ■ The average loan size in our office portfolio is $1.4 million. ■ Delinquencies were at a very low level as of September 30, 2026, and the majority of our loans contain a guaranty. ■ Excluding floating rate loans, only 8% of our office portfolio reprices through 2027. Loans repricing in 2026 and 2027 have average balances of $0.7 million and $1.2 million, respectively. 1,746 441 71 38 7 6 <$1mm $1-5mm $5-10mm $10-20mm $20-30mm >$30mm 2026, 2% 2027, 6% 2028, 3% 2029 & After, 15% Fixed Rate¹, 69% Floating Rate, 5% Repricing Schedule (1) Loans with a swap component are displayed as a fixed rate loan if the swap maturity is equal to the maturity of the loan. If the swap matures prior to the loan, the loan is displayed as adjustable with the rate resetting at the time of the swap maturity. 2026, 2% 2027, 9% 2028, 7% 2029 & After, 82% Maturity Schedule , 19 8 9 6 7 1,791 615 88 2 9 5
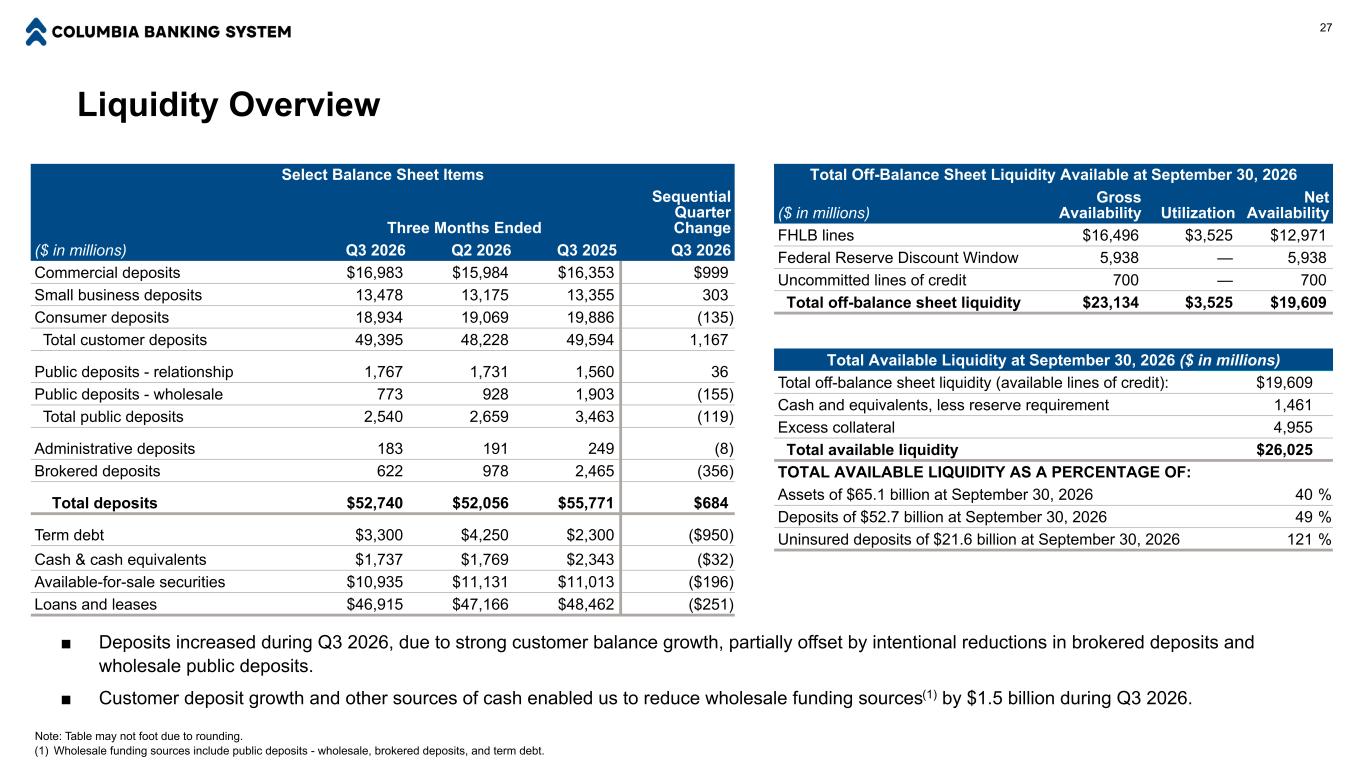
Liquidity Overview Total Available Liquidity at September 30, 2026 ($ in millions) Total off-balance sheet liquidity (available lines of credit): $19,609 Cash and equivalents, less reserve requirement 1,461 Excess collateral 4,955 Total available liquidity $26,025 TOTAL AVAILABLE LIQUIDITY AS A PERCENTAGE OF: Assets of $65.1 billion at September 30, 2026 40 % Deposits of $52.7 billion at September 30, 2026 49 % Uninsured deposits of $21.6 billion at September 30, 2026 121 % Total Off-Balance Sheet Liquidity Available at September 30, 2026 ($ in millions) Gross Availability Utilization Net Availability FHLB lines $16,496 $3,525 $12,971 Federal Reserve Discount Window 5,938 — 5,938 Uncommitted lines of credit 700 — 700 Total off-balance sheet liquidity $23,134 $3,525 $19,609 27 ■ Deposits increased during Q3 2026, due to strong customer balance growth, partially offset by intentional reductions in brokered deposits and wholesale public deposits. ■ Customer deposit growth and other sources of cash enabled us to reduce wholesale funding sources(1) by $1.5 billion during Q3 2026. Select Balance Sheet Items Three Months Ended Sequential Quarter Change ($ in millions) Q3 2026 Q2 2026 Q3 2025 Q3 2026 Commercial deposits $16,983 $15,984 $16,353 $999 Small business deposits 13,478 13,175 13,355 303 Consumer deposits 18,934 19,069 19,886 (135) Total customer deposits 49,395 48,228 49,594 1,167 Public deposits - relationship 1,767 1,731 1,560 36 Public deposits - wholesale 773 928 1,903 (155) Total public deposits 2,540 2,659 3,463 (119) Administrative deposits 183 191 249 (8) Brokered deposits 622 978 2,465 (356) Total deposits $52,740 $52,056 $55,771 $684 Term debt $3,300 $4,250 $2,300 ($950) Cash & cash equivalents $1,737 $1,769 $2,343 ($32) Available-for-sale securities $10,935 $11,131 $11,013 ($196) Loans and leases $46,915 $47,166 $48,462 ($251) Note: Table may not foot due to rounding. (1) Wholesale funding sources include public deposits - wholesale, brokered deposits, and term debt.
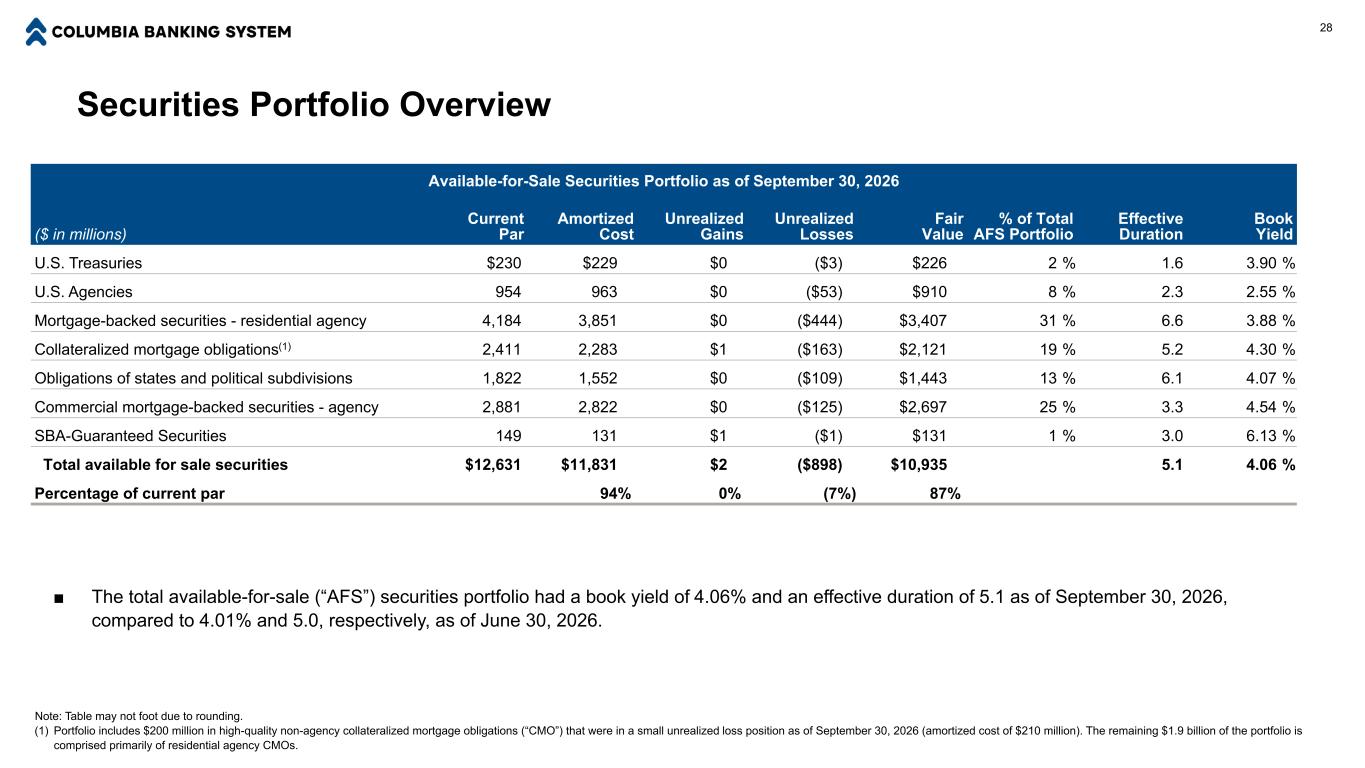
Available-for-Sale Securities Portfolio as of September 30, 2026 ($ in millions) Current Par Amortized Cost Unrealized Gains Unrealized Losses Fair Value % of Total AFS Portfolio Effective Duration Book Yield U.S. Treasuries $230 $229 $0 ($3) $226 2 % 1.6 3.90 % U.S. Agencies 954 963 $0 ($53) $910 8 % 2.3 2.55 % Mortgage-backed securities - residential agency 4,184 3,851 $0 ($444) $3,407 31 % 6.6 3.88 % Collateralized mortgage obligations(1) 2,411 2,283 $1 ($163) $2,121 19 % 5.2 4.30 % Obligations of states and political subdivisions 1,822 1,552 $0 ($109) $1,443 13 % 6.1 4.07 % Commercial mortgage-backed securities - agency 2,881 2,822 $0 ($125) $2,697 25 % 3.3 4.54 % SBA-Guaranteed Securities 149 131 $1 ($1) $131 1 % 3.0 6.13 % Total available for sale securities $12,631 $11,831 $2 ($898) $10,935 5.1 4.06 % Percentage of current par 94% 0% (7%) 87% 28 Securities Portfolio Overview Note: Table may not foot due to rounding. (1) Portfolio includes $200 million in high-quality non-agency collateralized mortgage obligations (“CMO”) that were in a small unrealized loss position as of September 30, 2026 (amortized cost of $210 million). The remaining $1.9 billion of the portfolio is comprised primarily of residential agency CMOs. ■ The total available-for-sale (“AFS”) securities portfolio had a book yield of 4.06% and an effective duration of 5.1 as of September 30, 2026, compared to 4.01% and 5.0, respectively, as of June 30, 2026.
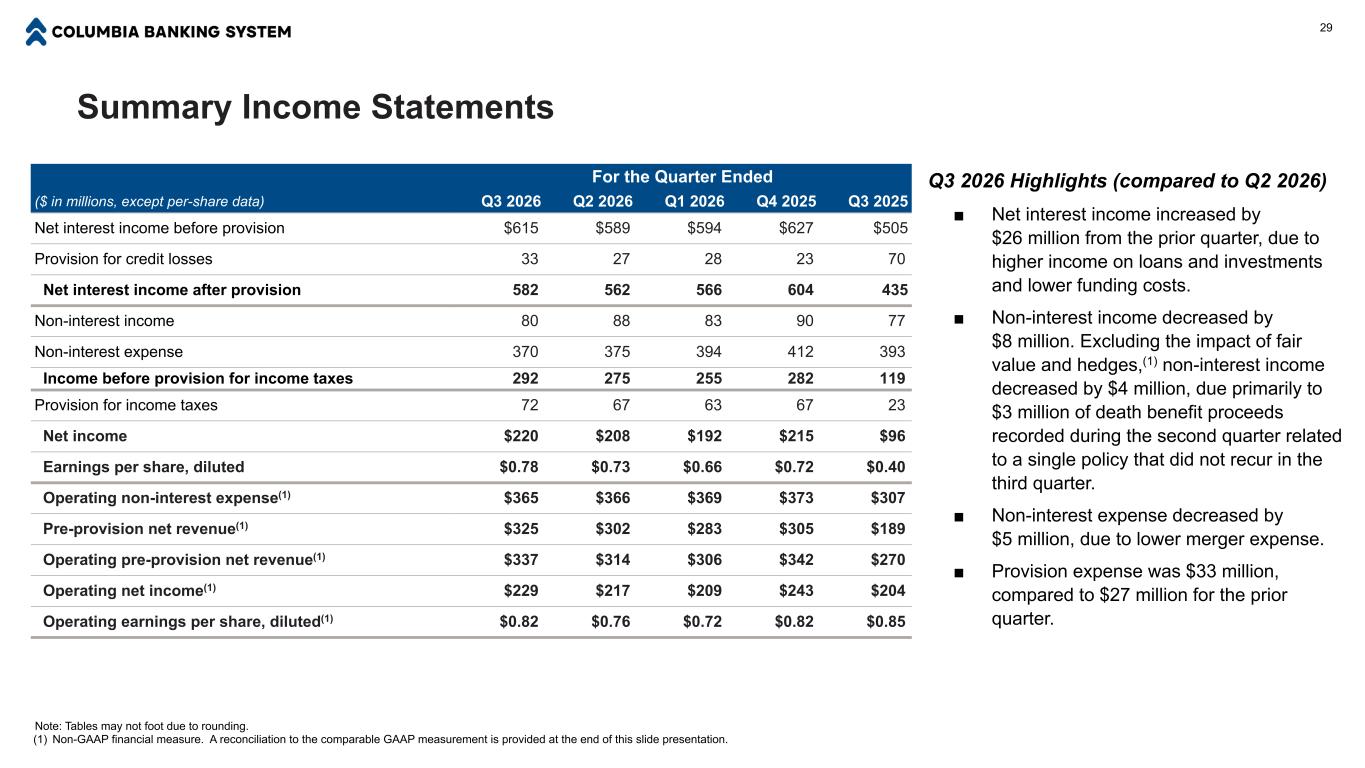
Summary Income Statements Note: Tables may not foot due to rounding. (1) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement is provided at the end of this slide presentation. For the Quarter Ended ($ in millions, except per-share data) Q3 2026 Q2 2026 Q1 2026 Q4 2025 Q3 2025 Net interest income before provision $615 $589 $594 $627 $505 Provision for credit losses 33 27 28 23 70 Net interest income after provision 582 562 566 604 435 Non-interest income 80 88 83 90 77 Non-interest expense 370 375 394 412 393 Income before provision for income taxes 292 275 255 282 119 Provision for income taxes 72 67 63 67 23 Net income $220 $208 $192 $215 $96 Earnings per share, diluted $0.78 $0.73 $0.66 $0.72 $0.40 Operating non-interest expense(1) $365 $366 $369 $373 $307 Pre-provision net revenue(1) $325 $302 $283 $305 $189 Operating pre-provision net revenue(1) $337 $314 $306 $342 $270 Operating net income(1) $229 $217 $209 $243 $204 Operating earnings per share, diluted(1) $0.82 $0.76 $0.72 $0.82 $0.85 29 Q3 2026 Highlights (compared to Q2 2026) ■ Net interest income increased by $26 million from the prior quarter, due to higher income on loans and investments and lower funding costs. ■ Non-interest income decreased by $8 million. Excluding the impact of fair value and hedges,(1) non-interest income decreased by $4 million, due primarily to $3 million of death benefit proceeds recorded during the second quarter related to a single policy that did not recur in the third quarter. ■ Non-interest expense decreased by $5 million, due to lower merger expense. ■ Provision expense was $33 million, compared to $27 million for the prior quarter.
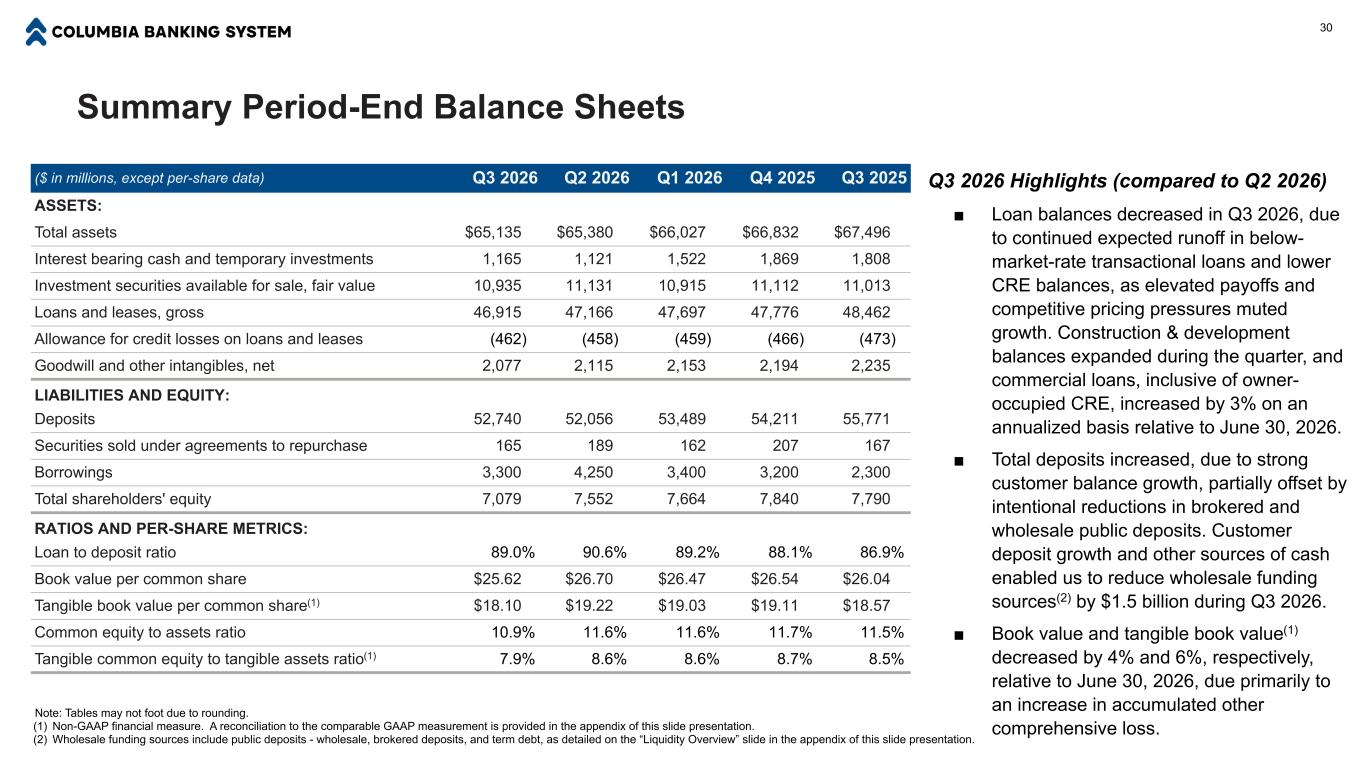
Summary Period-End Balance Sheets Note: Tables may not foot due to rounding. (1) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement is provided in the appendix of this slide presentation. (2) Wholesale funding sources include public deposits - wholesale, brokered deposits, and term debt, as detailed on the “Liquidity Overview” slide in the appendix of this slide presentation. ($ in millions, except per-share data) Q3 2026 Q2 2026 Q1 2026 Q4 2025 Q3 2025 ASSETS: Total assets $65,135 $65,380 $66,027 $66,832 $67,496 Interest bearing cash and temporary investments 1,165 1,121 1,522 1,869 1,808 Investment securities available for sale, fair value 10,935 11,131 10,915 11,112 11,013 Loans and leases, gross 46,915 47,166 47,697 47,776 48,462 Allowance for credit losses on loans and leases (462) (458) (459) (466) (473) Goodwill and other intangibles, net 2,077 2,115 2,153 2,194 2,235 LIABILITIES AND EQUITY: Deposits 52,740 52,056 53,489 54,211 55,771 Securities sold under agreements to repurchase 165 189 162 207 167 Borrowings 3,300 4,250 3,400 3,200 2,300 Total shareholders' equity 7,079 7,552 7,664 7,840 7,790 RATIOS AND PER-SHARE METRICS: Loan to deposit ratio 89.0% 90.6% 89.2% 88.1% 86.9% Book value per common share $25.62 $26.70 $26.47 $26.54 $26.04 Tangible book value per common share(1) $18.10 $19.22 $19.03 $19.11 $18.57 Common equity to assets ratio 10.9% 11.6% 11.6% 11.7% 11.5% Tangible common equity to tangible assets ratio(1) 7.9% 8.6% 8.6% 8.7% 8.5% 30 Q3 2026 Highlights (compared to Q2 2026) ■ Loan balances decreased in Q3 2026, due to continued expected runoff in below- market-rate transactional loans and lower CRE balances, as elevated payoffs and competitive pricing pressures muted growth. Construction & development balances expanded during the quarter, and commercial loans, inclusive of owner- occupied CRE, increased by 3% on an annualized basis relative to June 30, 2026. ■ Total deposits increased, due to strong customer balance growth, partially offset by intentional reductions in brokered and wholesale public deposits. Customer deposit growth and other sources of cash enabled us to reduce wholesale funding sources(2) by $1.5 billion during Q3 2026. ■ Book value and tangible book value(1) decreased by 4% and 6%, respectively, relative to June 30, 2026, due primarily to an increase in accumulated other comprehensive loss.
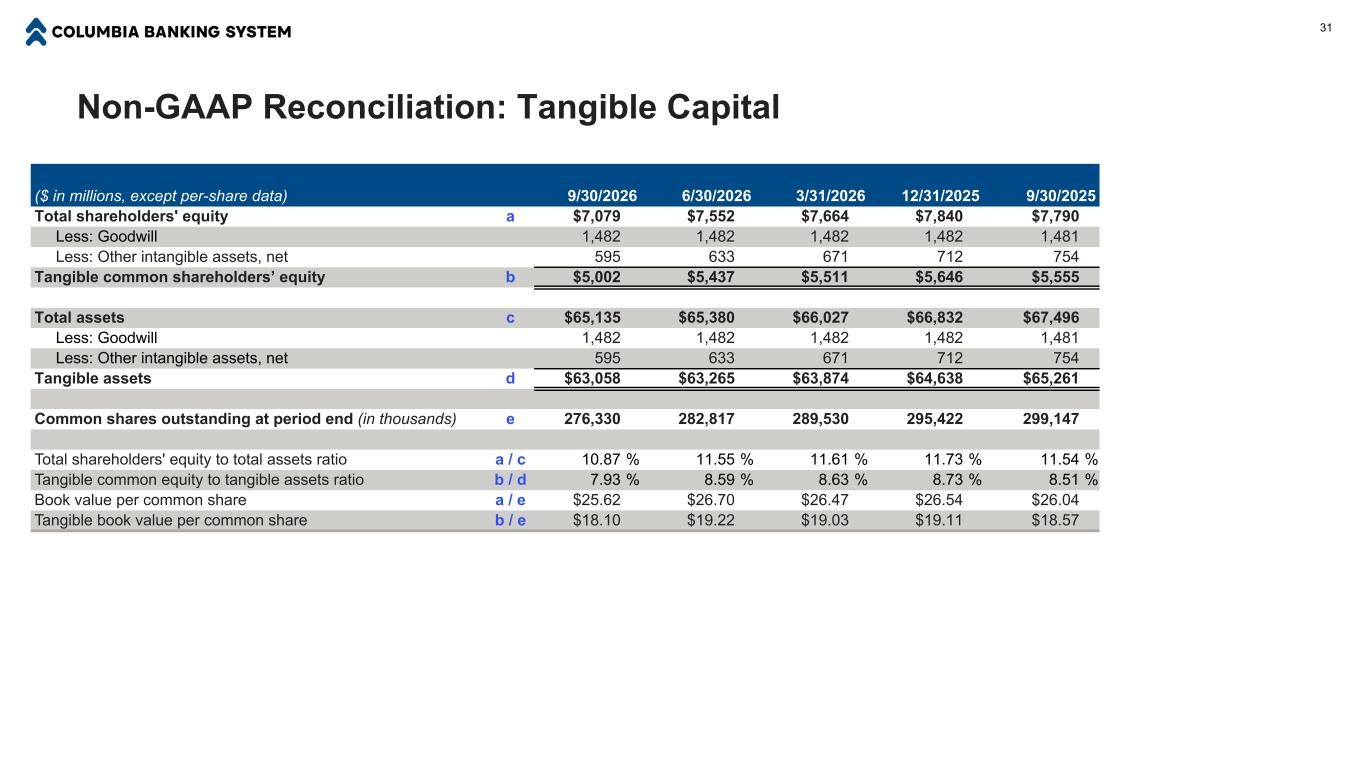
Non-GAAP Reconciliation: Tangible Capital ($ in millions, except per-share data) 9/30/2026 6/30/2026 3/31/2026 12/31/2025 9/30/2025 Total shareholders' equity a $7,079 $7,552 $7,664 $7,840 $7,790 Less: Goodwill 1,482 1,482 1,482 1,482 1,481 Less: Other intangible assets, net 595 633 671 712 754 Tangible common shareholders’ equity b $5,002 $5,437 $5,511 $5,646 $5,555 Total assets c $65,135 $65,380 $66,027 $66,832 $67,496 Less: Goodwill 1,482 1,482 1,482 1,482 1,481 Less: Other intangible assets, net 595 633 671 712 754 Tangible assets d $63,058 $63,265 $63,874 $64,638 $65,261 Common shares outstanding at period end (in thousands) e 276,330 282,817 289,530 295,422 299,147 Total shareholders' equity to total assets ratio a / c 10.87 % 11.55 % 11.61 % 11.73 % 11.54 % Tangible common equity to tangible assets ratio b / d 7.93 % 8.59 % 8.63 % 8.73 % 8.51 % Book value per common share a / e $25.62 $26.70 $26.47 $26.54 $26.04 Tangible book value per common share b / e $18.10 $19.22 $19.03 $19.11 $18.57 31
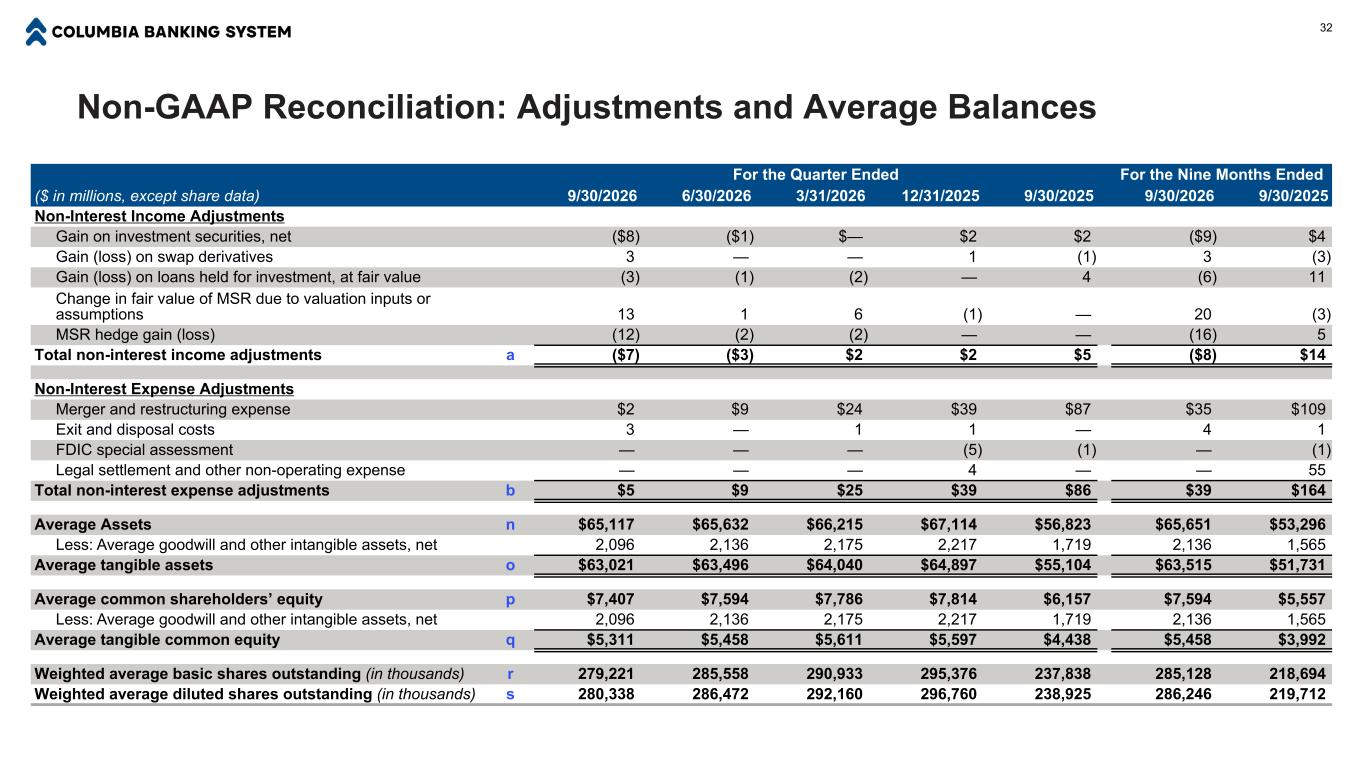
Non-GAAP Reconciliation: Adjustments and Average Balances For the Quarter Ended For the Nine Months Ended ($ in millions, except share data) 9/30/2026 6/30/2026 3/31/2026 12/31/2025 9/30/2025 9/30/2026 9/30/2025 Non-Interest Income Adjustments Gain on investment securities, net ($8) ($1) $— $2 $2 ($9) $4 Gain (loss) on swap derivatives 3 — — 1 (1) 3 (3) Gain (loss) on loans held for investment, at fair value (3) (1) (2) — 4 (6) 11 Change in fair value of MSR due to valuation inputs or assumptions 13 1 6 (1) — 20 (3) MSR hedge gain (loss) (12) (2) (2) — — (16) 5 Total non-interest income adjustments a ($7) ($3) $2 $2 $5 ($8) $14 Non-Interest Expense Adjustments Merger and restructuring expense $2 $9 $24 $39 $87 $35 $109 Exit and disposal costs 3 — 1 1 — 4 1 FDIC special assessment — — — (5) (1) — (1) Legal settlement and other non-operating expense — — — 4 — — 55 Total non-interest expense adjustments b $5 $9 $25 $39 $86 $39 $164 Average Assets n $65,117 $65,632 $66,215 $67,114 $56,823 $65,651 $53,296 Less: Average goodwill and other intangible assets, net 2,096 2,136 2,175 2,217 1,719 2,136 1,565 Average tangible assets o $63,021 $63,496 $64,040 $64,897 $55,104 $63,515 $51,731 Average common shareholders’ equity p $7,407 $7,594 $7,786 $7,814 $6,157 $7,594 $5,557 Less: Average goodwill and other intangible assets, net 2,096 2,136 2,175 2,217 1,719 2,136 1,565 Average tangible common equity q $5,311 $5,458 $5,611 $5,597 $4,438 $5,458 $3,992 Weighted average basic shares outstanding (in thousands) r 279,221 285,558 290,933 295,376 237,838 285,128 218,694 Weighted average diluted shares outstanding (in thousands) s 280,338 286,472 292,160 296,760 238,925 286,246 219,712 32
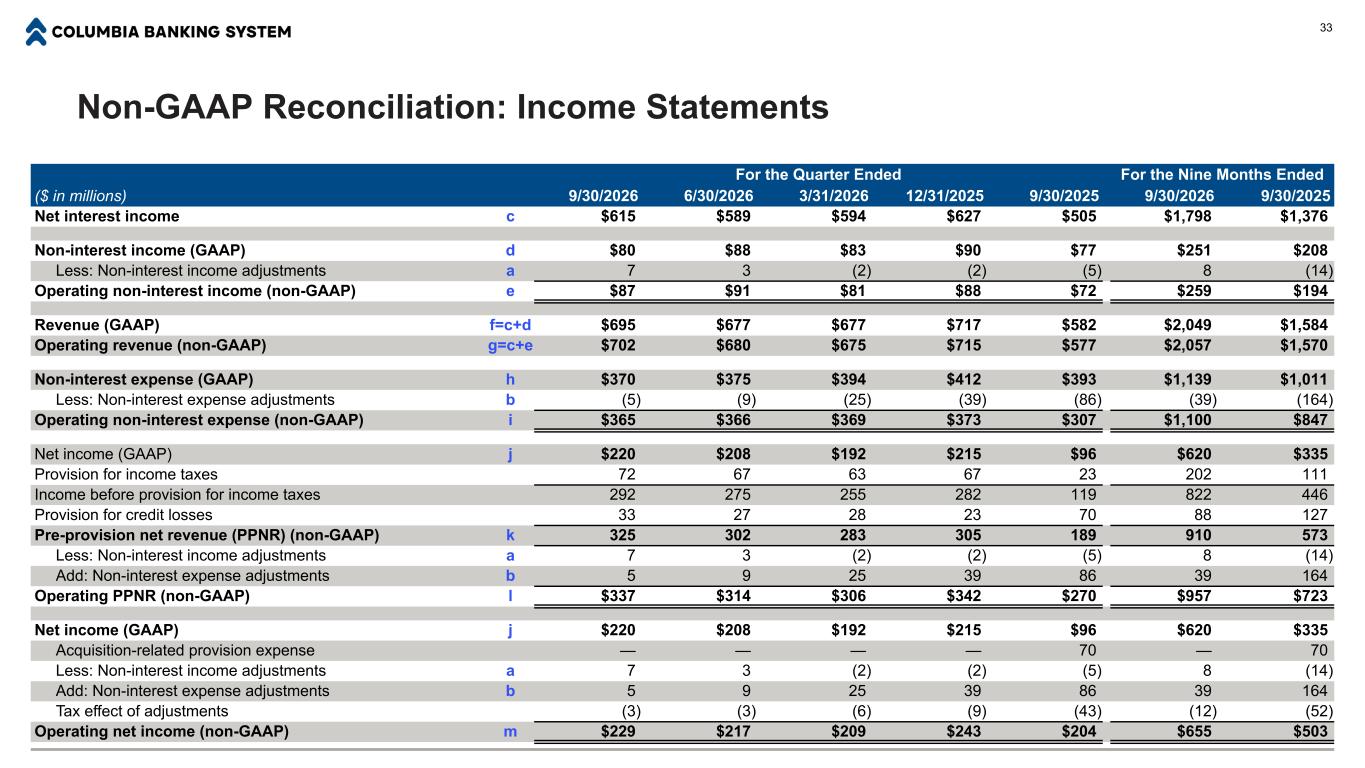
Non-GAAP Reconciliation: Income Statements For the Quarter Ended For the Nine Months Ended ($ in millions) 9/30/2026 6/30/2026 3/31/2026 12/31/2025 9/30/2025 9/30/2026 9/30/2025 Net interest income c $615 $589 $594 $627 $505 $1,798 $1,376 Non-interest income (GAAP) d $80 $88 $83 $90 $77 $251 $208 Less: Non-interest income adjustments a 7 3 (2) (2) (5) 8 (14) Operating non-interest income (non-GAAP) e $87 $91 $81 $88 $72 $259 $194 Revenue (GAAP) f=c+d $695 $677 $677 $717 $582 $2,049 $1,584 Operating revenue (non-GAAP) g=c+e $702 $680 $675 $715 $577 $2,057 $1,570 Non-interest expense (GAAP) h $370 $375 $394 $412 $393 $1,139 $1,011 Less: Non-interest expense adjustments b (5) (9) (25) (39) (86) (39) (164) Operating non-interest expense (non-GAAP) i $365 $366 $369 $373 $307 $1,100 $847 Net income (GAAP) j $220 $208 $192 $215 $96 $620 $335 Provision for income taxes 72 67 63 67 23 202 111 Income before provision for income taxes 292 275 255 282 119 822 446 Provision for credit losses 33 27 28 23 70 88 127 Pre-provision net revenue (PPNR) (non-GAAP) k 325 302 283 305 189 910 573 Less: Non-interest income adjustments a 7 3 (2) (2) (5) 8 (14) Add: Non-interest expense adjustments b 5 9 25 39 86 39 164 Operating PPNR (non-GAAP) l $337 $314 $306 $342 $270 $957 $723 Net income (GAAP) j $220 $208 $192 $215 $96 $620 $335 Acquisition-related provision expense — — — — 70 — 70 Less: Non-interest income adjustments a 7 3 (2) (2) (5) 8 (14) Add: Non-interest expense adjustments b 5 9 25 39 86 39 164 Tax effect of adjustments (3) (3) (6) (9) (43) (12) (52) Operating net income (non-GAAP) m $229 $217 $209 $243 $204 $655 $503 33
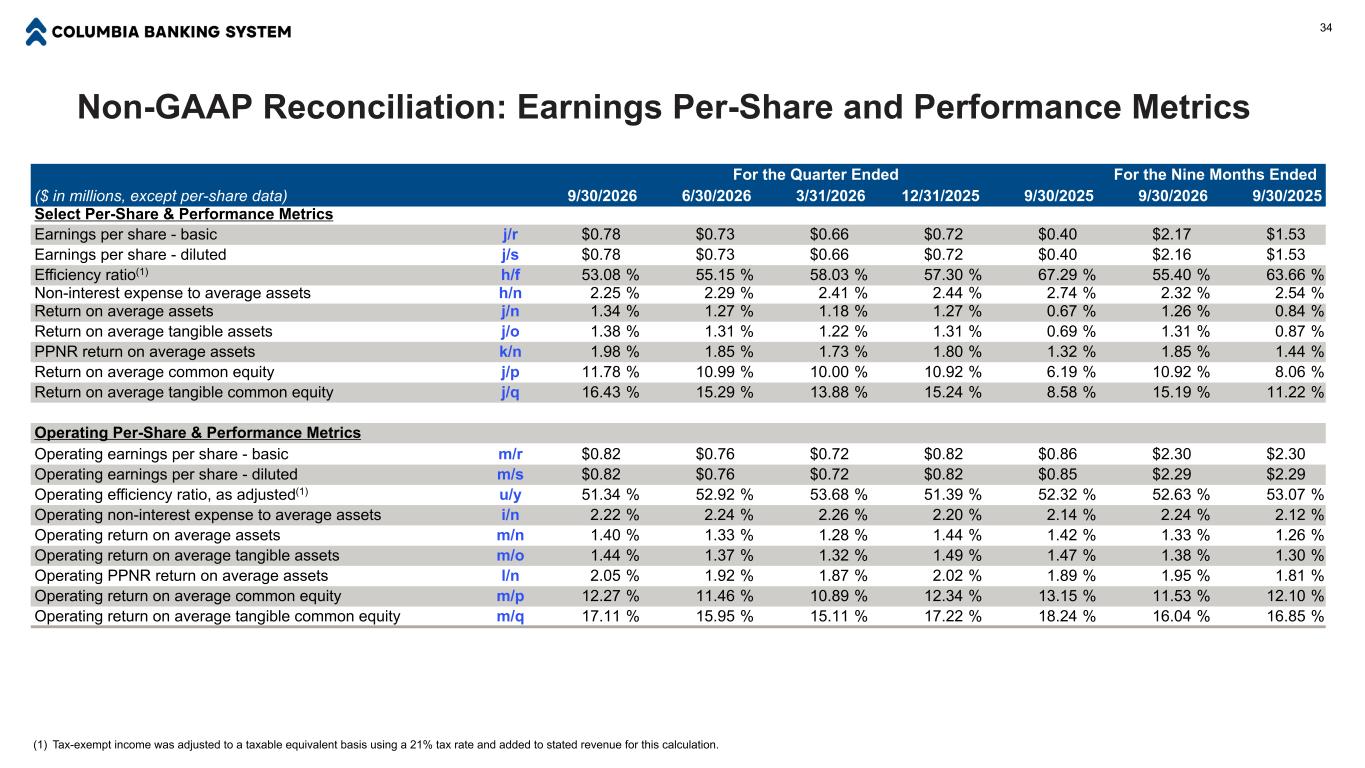
Non-GAAP Reconciliation: Earnings Per-Share and Performance Metrics For the Quarter Ended For the Nine Months Ended ($ in millions, except per-share data) 9/30/2026 6/30/2026 3/31/2026 12/31/2025 9/30/2025 9/30/2026 9/30/2025 Select Per-Share & Performance Metrics Earnings per share - basic j/r $0.78 $0.73 $0.66 $0.72 $0.40 $2.17 $1.53 Earnings per share - diluted j/s $0.78 $0.73 $0.66 $0.72 $0.40 $2.16 $1.53 Efficiency ratio(1) h/f 53.08 % 55.15 % 58.03 % 57.30 % 67.29 % 55.40 % 63.66 % Non-interest expense to average assets h/n 2.25 % 2.29 % 2.41 % 2.44 % 2.74 % 2.32 % 2.54 % Return on average assets j/n 1.34 % 1.27 % 1.18 % 1.27 % 0.67 % 1.26 % 0.84 % Return on average tangible assets j/o 1.38 % 1.31 % 1.22 % 1.31 % 0.69 % 1.31 % 0.87 % PPNR return on average assets k/n 1.98 % 1.85 % 1.73 % 1.80 % 1.32 % 1.85 % 1.44 % Return on average common equity j/p 11.78 % 10.99 % 10.00 % 10.92 % 6.19 % 10.92 % 8.06 % Return on average tangible common equity j/q 16.43 % 15.29 % 13.88 % 15.24 % 8.58 % 15.19 % 11.22 % Operating Per-Share & Performance Metrics Operating earnings per share - basic m/r $0.82 $0.76 $0.72 $0.82 $0.86 $2.30 $2.30 Operating earnings per share - diluted m/s $0.82 $0.76 $0.72 $0.82 $0.85 $2.29 $2.29 Operating efficiency ratio, as adjusted(1) u/y 51.34 % 52.92 % 53.68 % 51.39 % 52.32 % 52.63 % 53.07 % Operating non-interest expense to average assets i/n 2.22 % 2.24 % 2.26 % 2.20 % 2.14 % 2.24 % 2.12 % Operating return on average assets m/n 1.40 % 1.33 % 1.28 % 1.44 % 1.42 % 1.33 % 1.26 % Operating return on average tangible assets m/o 1.44 % 1.37 % 1.32 % 1.49 % 1.47 % 1.38 % 1.30 % Operating PPNR return on average assets l/n 2.05 % 1.92 % 1.87 % 2.02 % 1.89 % 1.95 % 1.81 % Operating return on average common equity m/p 12.27 % 11.46 % 10.89 % 12.34 % 13.15 % 11.53 % 12.10 % Operating return on average tangible common equity m/q 17.11 % 15.95 % 15.11 % 17.22 % 18.24 % 16.04 % 16.85 % (1) Tax-exempt income was adjusted to a taxable equivalent basis using a 21% tax rate and added to stated revenue for this calculation. 34
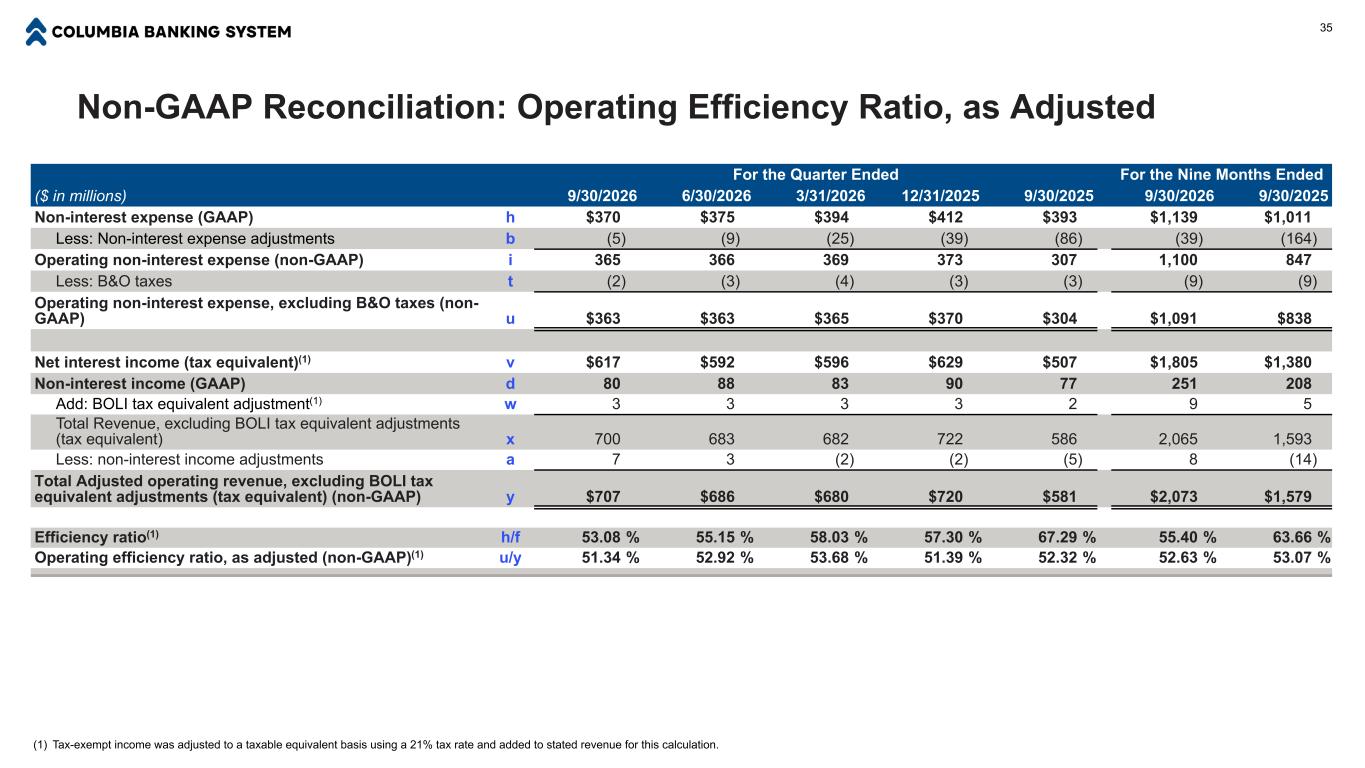
Non-GAAP Reconciliation: Operating Efficiency Ratio, as Adjusted 35 For the Quarter Ended For the Nine Months Ended ($ in millions) 9/30/2026 6/30/2026 3/31/2026 12/31/2025 9/30/2025 9/30/2026 9/30/2025 Non-interest expense (GAAP) h $370 $375 $394 $412 $393 $1,139 $1,011 Less: Non-interest expense adjustments b (5) (9) (25) (39) (86) (39) (164) Operating non-interest expense (non-GAAP) i 365 366 369 373 307 1,100 847 Less: B&O taxes t (2) (3) (4) (3) (3) (9) (9) Operating non-interest expense, excluding B&O taxes (non- GAAP) u $363 $363 $365 $370 $304 $1,091 $838 Net interest income (tax equivalent)(1) v $617 $592 $596 $629 $507 $1,805 $1,380 Non-interest income (GAAP) d 80 88 83 90 77 251 208 Add: BOLI tax equivalent adjustment(1) w 3 3 3 3 2 9 5 Total Revenue, excluding BOLI tax equivalent adjustments (tax equivalent) x 700 683 682 722 586 2,065 1,593 Less: non-interest income adjustments a 7 3 (2) (2) (5) 8 (14) Total Adjusted operating revenue, excluding BOLI tax equivalent adjustments (tax equivalent) (non-GAAP) y $707 $686 $680 $720 $581 $2,073 $1,579 Efficiency ratio(1) h/f 53.08 % 55.15 % 58.03 % 57.30 % 67.29 % 55.40 % 63.66 % Operating efficiency ratio, as adjusted (non-GAAP)(1) u/y 51.34 % 52.92 % 53.68 % 51.39 % 52.32 % 52.63 % 53.07 % (1) Tax-exempt income was adjusted to a taxable equivalent basis using a 21% tax rate and added to stated revenue for this calculation.