South Plains Financial Investor Presentation October 22, 2026
Safe Harbor Statement and Other Disclosures FORWARD-LOOKING STATEMENTS This
presentation contains, and future oral and written statements of South Plains Financial, Inc. (“South Plains”, “SPFI”, or the “Company”) and City Bank (“City Bank” or the “Bank”) may contain, statements about future events that constitute
forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements reflect South Plains’ current views with respect to future events and South Plains’ financial performance.
Any statements about South Plains’ expectations, beliefs, plans, predictions, forecasts, objectives, assumptions or future events or performance are not historical facts and may be forward-looking. These statements are often, but not always,
made through the use of words or phrases such as “anticipate,” “believes,” “can,” “could,” “may,” “predicts,” “potential,” “should,” “will,” “estimate,” “plans,” “projects,” “continuing,” “ongoing,” “expects,” “intends” and similar words or
phrases. Forward-looking statements include, but are not limited to: (i) projections and estimates of revenues, expenses, income or loss, earnings or loss per share, and other financial items, (ii) statements of plans, objectives and
expectations of South Plains or its management, (iii) statements of future economic performance, and (iv) statements of assumptions underlying such statements. Forward-looking statements should not be relied on because they involve known and
unknown risks, uncertainties and other factors, some of which are beyond the control of South Plains and City Bank. These risks, uncertainties and other factors may cause the actual results, performance, and achievements of South Plains and
City Bank to be materially different from the anticipated future results, performance or achievements expressed in, or implied by, the forward-looking statements. Factors that could cause such changes include, but are not limited to, the impact
on us and our customers of a decline in general economic conditions and any regulatory responses thereto; slower economic growth rates or potential recession in the United States and our market areas; uncertainty or perceived instability in the
banking industry as a whole; increased competition for deposits in our market areas among traditional and nontraditional financial services companies, and related changes in deposit customer behavior; the impact of changes in market interest
rates, whether due to a continuation of the elevated interest rate environment, further increases in interest rates, or future reductions in interest rates and a resulting decline in net interest income; the persistent inflationary pressures in
the United States; the uncertain impacts of current and future monetary policies of the Board of Governors of the Federal Reserve System; a deterioration of credit quality; changes in unemployment rates in the United States and our market
areas; adverse changes in customer sentiment, spending, borrowing and savings habits; elevated asset prices; declines in housing and commercial real estate values and prices; a deterioration of the credit rating for U.S. long-term sovereign
debt or the impact of uncertain or changing political conditions, including federal government shutdowns and uncertainty regarding United States fiscal debt, deficit and budget matters; cyber incidents or other failures, disruptions or breaches
of our operational or security systems or infrastructure, or those of our third-party vendors or other service providers, including as a result of cyber-attacks; severe weather, natural disasters, military conflicts (including the conflicts in
the Middle East, the possible expansion of such conflicts and potential geopolitical and economic consequences), acts of terrorism, geopolitical instability, domestic civil unrest or other external events, including as a result of the impact of
the policies of the current U.S. presidential administration or Congress; the impacts of tariffs, sanctions, and other trade policies of the United States and its global trading counterparts and the resulting impact on the Company and its
customers; competition and market expansion opportunities; changes in non-interest expenditures or in the anticipated benefits of such expenditures; our ability to keep pace with changes in, and the risks related to the development,
implementation, use and management of, emerging technologies, including digital assets, artificial intelligence and machine learning; potential costs related to the impacts of climate change; current or future litigation, regulatory
examinations or other legal and/or regulatory actions; our ability to successfully make and integrate acquisitions, which may include regulatory approvals and conditions, and our ability to recognize the expected benefits and synergies of our
completed acquisitions; changes in accounting principles and standards, including those related to loan loss recognition under the current expected credit loss, or CECL, methodology; and changes in applicable laws, regulations, or policies in
the United States. Additional information regarding these risks and uncertainties to which South Plains’ business and future financial performance are subject is contained in South Plains’ most recent Annual Report on Form 10-K and Quarterly
Reports on Form 10-Q on file with the SEC, including the sections entitled “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” of such documents, and other documents South Plains files or
furnishes with the SEC from time to time, which are available on the SEC’s website, www.sec.gov. Actual results, performance or achievements could differ materially from those contemplated, expressed, or implied by the forward-looking
statements due to additional risks and uncertainties of which South Plains is not currently aware or which it does not currently view as, but in the future may become, material to its business or operating results. Due to these and other
possible uncertainties and risks, the Company can give no assurance that the results contemplated in the forward-looking statements will be realized and readers are cautioned not to place undue reliance on the forward-looking statements
contained in this press release. Any forward-looking statements presented herein are made only as of the date of this press release, and South Plains does not undertake any obligation to update or revise any forward-looking statements to
reflect changes in assumptions, new information, the occurrence of unanticipated events, or otherwise, except as required by applicable law. All forward-looking statements, express or implied, included in the press release are qualified in
their entirety by this cautionary statement. NON-GAAP FINANCIAL MEASURES Management believes that certain non-GAAP performance measures used in this presentation provide meaningful information about underlying trends in its business and
operations and provide both management and investors a more complete understanding of the Company’s financial position and performance. Non-GAAP financial measures should be viewed in addition to, and not as an alternative for, SPFI’s reported
results prepared in accordance with GAAP. Non-GAAP financial measures have limitations as analytical tools, and investors should not consider them in isolation or as a substitute for analysis of the results or financial condition of the Company
as reported under GAAP. Numbers in this presentation may not sum due to rounding. 2
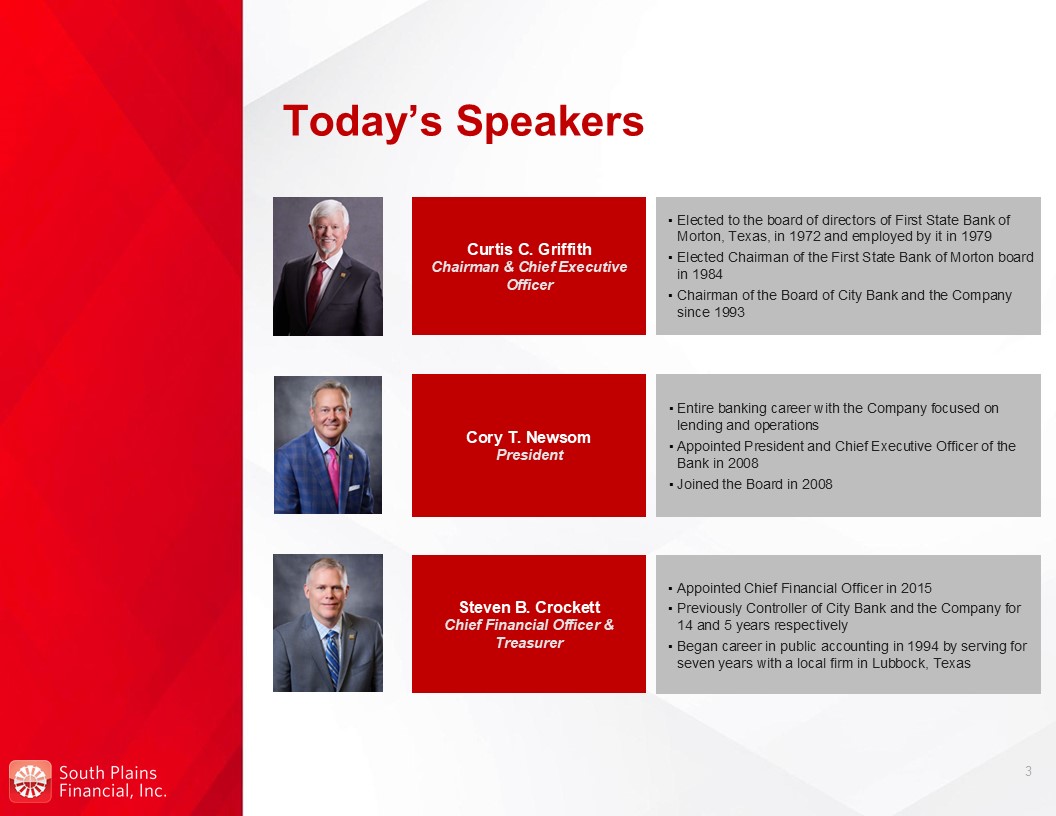
Today’s Speakers Curtis C. Griffith Chairman & Chief Executive
Officer Elected to the board of directors of First State Bank of Morton, Texas, in 1972 and employed by it in 1979 Elected Chairman of the First State Bank of Morton board in 1984 Chairman of the Board of City Bank and the Company since
1993 Steven B. Crockett Chief Financial Officer & Treasurer Appointed Chief Financial Officer in 2015 Previously Controller of City Bank and the Company for 14 and 5 years respectively Began career in public accounting in 1994 by
serving for seven years with a local firm in Lubbock, Texas Cory T. Newsom President Entire banking career with the Company focused on lending and operations Appointed President and Chief Executive Officer of the Bank in 2008 Joined the
Board in 2008 3
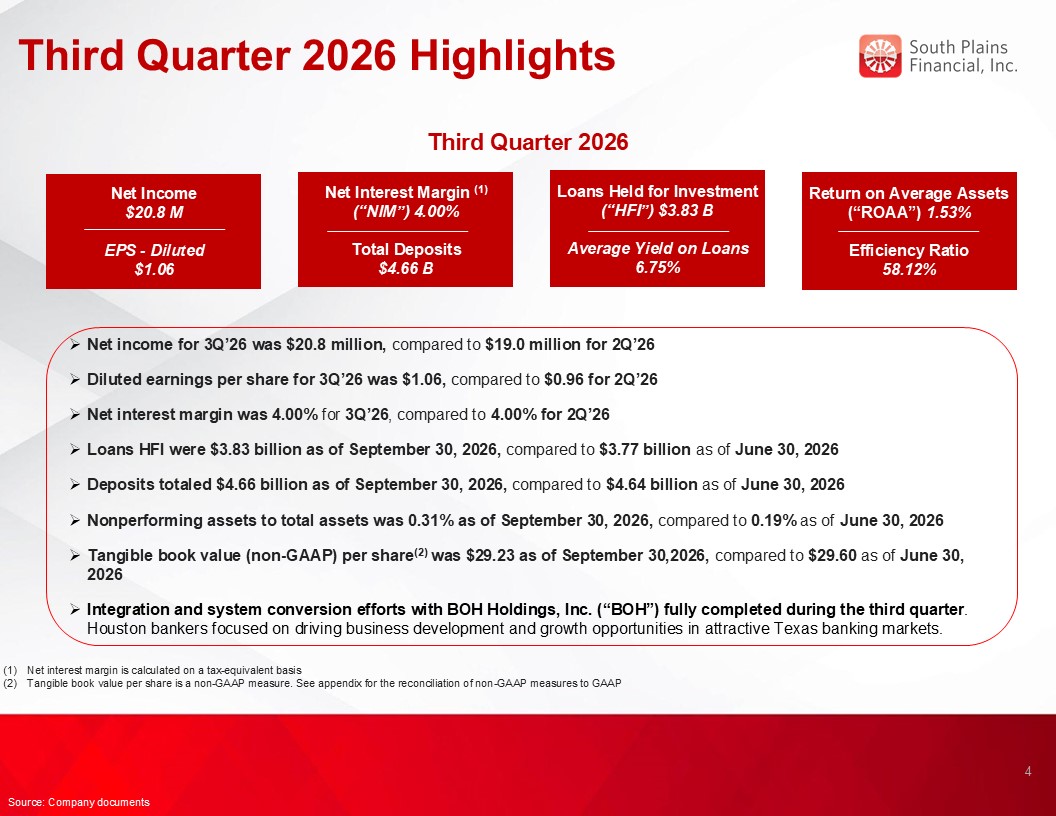
Third Quarter 2026 Highlights Net income for 3Q’26 was $20.8 million, compared to
$19.0 million for 2Q’26 Diluted earnings per share for 3Q’26 was $1.06, compared to $0.96 for 2Q’26 Net interest margin was 4.00% for 3Q’26, compared to 4.00% for 2Q’26 Loans HFI were $3.83 billion as of September 30, 2026, compared to $3.77
billion as of June 30, 2026 Deposits totaled $4.66 billion as of September 30, 2026, compared to $4.64 billion as of June 30, 2026 Nonperforming assets to total assets was 0.31% as of September 30, 2026, compared to 0.19% as of June 30,
2026 Tangible book value (non-GAAP) per share(2) was $29.23 as of September 30,2026, compared to $29.60 as of June 30, 2026 Integration and system conversion efforts with BOH Holdings, Inc. (“BOH”) fully completed during the third quarter.
Houston bankers focused on driving business development and growth opportunities in attractive Texas banking markets. 4 Source: Company documents Net interest margin is calculated on a tax-equivalent basis Tangible book value per share is
a non-GAAP measure. See appendix for the reconciliation of non-GAAP measures to GAAP Loans Held for Investment (“HFI”) $3.83 B Average Yield on Loans 6.75% Net Income $20.8 M EPS - Diluted $1.06 Net Interest Margin (1) (“NIM”)
4.00% Total Deposits $4.66 B Return on Average Assets (“ROAA”) 1.53% Efficiency Ratio 58.12% Third Quarter 2026
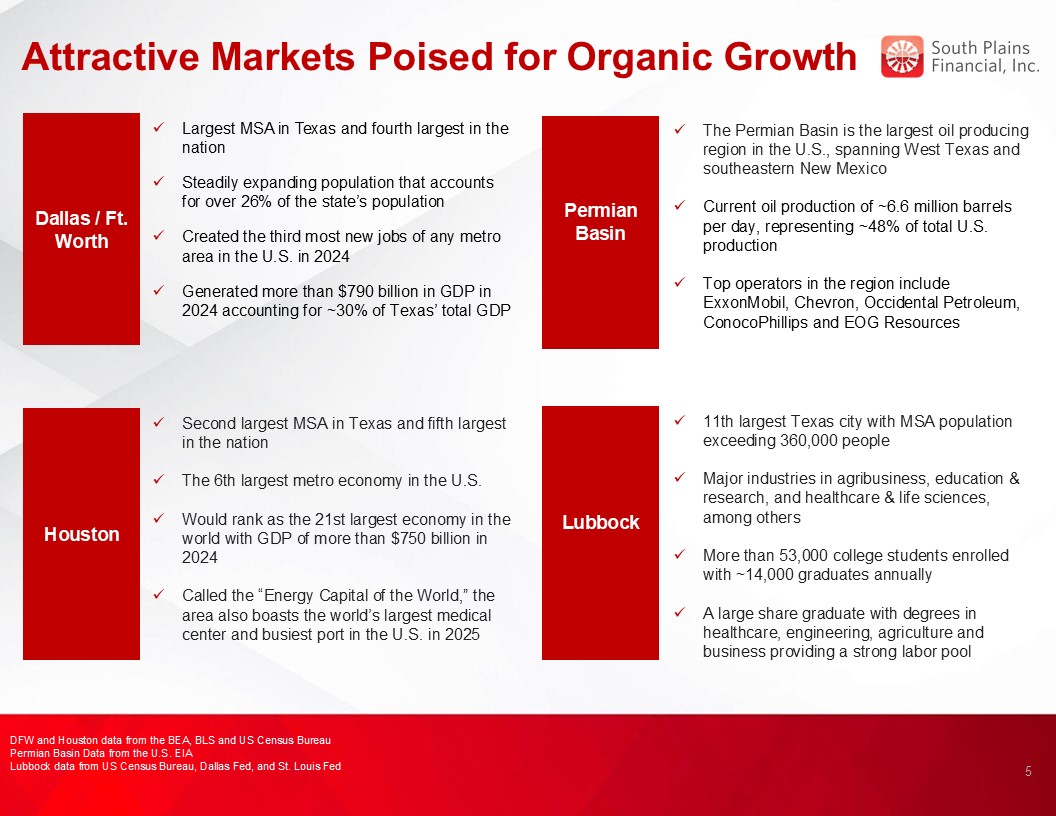
Attractive Markets Poised for Organic Growth Permian Basin Basin Dallas / Ft.
Worth The Permian Basin is the largest oil producing region in the U.S., spanning West Texas and southeastern New Mexico Current oil production of ~6.6 million barrels per day, representing ~48% of total U.S. production Top operators in the
region include ExxonMobil, Chevron, Occidental Petroleum, ConocoPhillips and EOG Resources Largest MSA in Texas and fourth largest in the nation Steadily expanding population that accounts for over 26% of the state’s population Created the
third most new jobs of any metro area in the U.S. in 2024 Generated more than $790 billion in GDP in 2024 accounting for ~30% of Texas’ total GDP Houston Second largest MSA in Texas and fifth largest in the nation The 6th largest metro
economy in the U.S. Would rank as the 21st largest economy in the world with GDP of more than $750 billion in 2024 Called the “Energy Capital of the World,” the area also boasts the world’s largest medical center and busiest port in the U.S.
in 2025 Lubbock Basin 11th largest Texas city with MSA population exceeding 360,000 people Major industries in agribusiness, education & research, and healthcare & life sciences, among others More than 53,000 college students
enrolled with ~14,000 graduates annually A large share graduate with degrees in healthcare, engineering, agriculture and business providing a strong labor pool 5 DFW and Houston data from the BEA, BLS and US Census Bureau Permian Basin
Data from the U.S. EIA Lubbock data from US Census Bureau, Dallas Fed, and St. Louis Fed
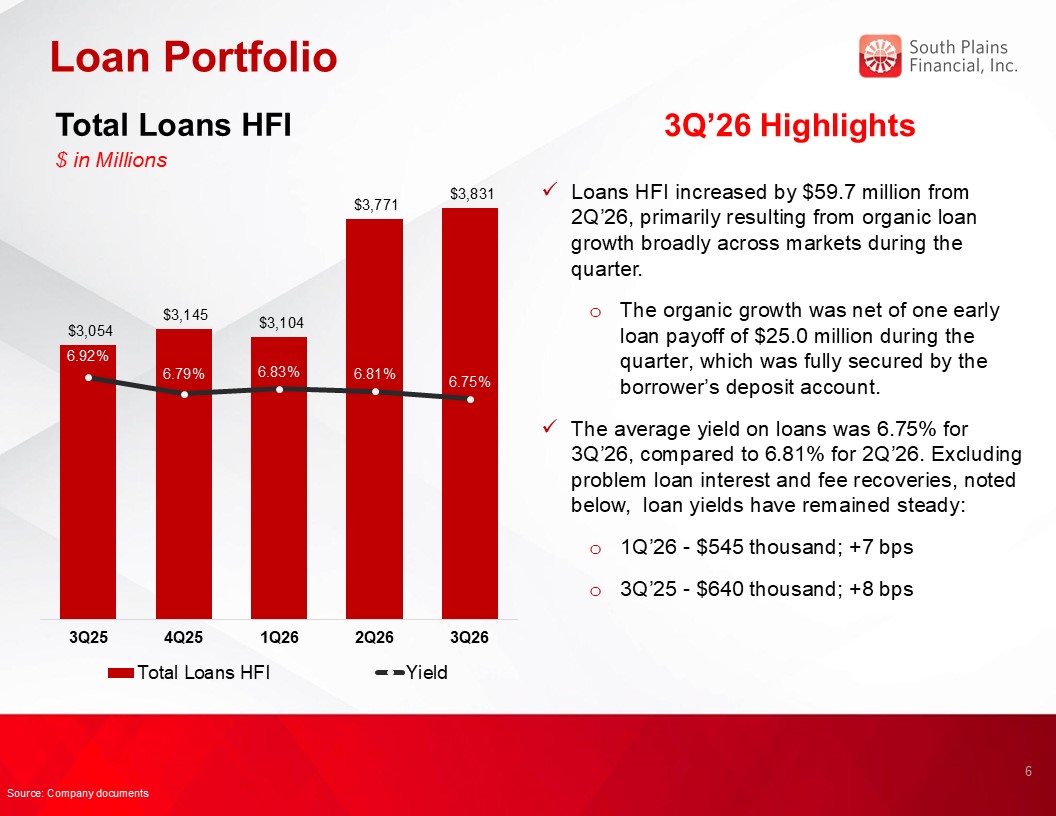
Loan Portfolio 3Q’26 Highlights Loans HFI increased by $59.7 million from 2Q’26,
primarily resulting from organic loan growth broadly across markets during the quarter. The organic growth was net of one early loan payoff of $25.0 million during the quarter, which was fully secured by the borrower’s deposit account. The
average yield on loans was 6.75% for 3Q’26, compared to 6.81% for 2Q’26. Excluding problem loan interest and fee recoveries, noted below, loan yields have remained steady: 1Q’26 - $545 thousand; +7 bps 3Q’25 - $640 thousand; +8 bps Total
Loans HFI $ in Millions 6 Source: Company documents
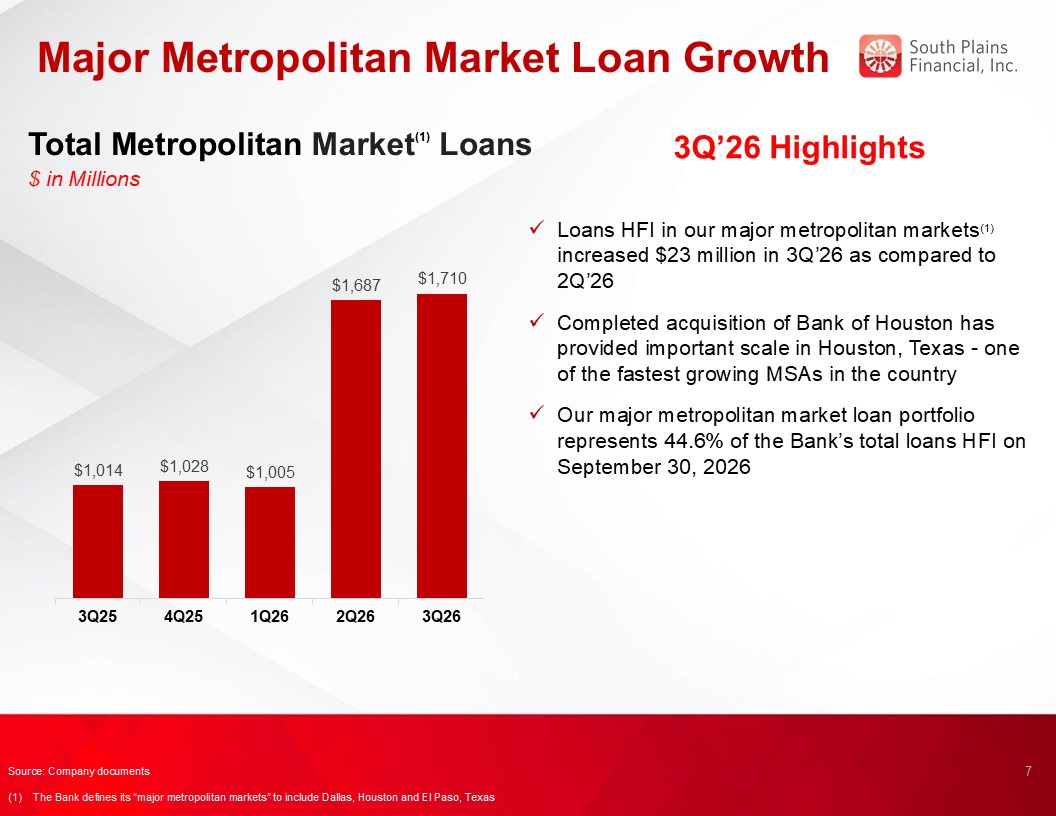
Major Metropolitan Market Loan Growth 3Q’26 Highlights Loans HFI in our major
metropolitan markets(1) increased $23 million in 3Q’26 as compared to 2Q’26 Completed acquisition of Bank of Houston has provided important scale in Houston, Texas - one of the fastest growing MSAs in the country Our major metropolitan market
loan portfolio represents 44.6% of the Bank’s total loans HFI on September 30, 2026 Total Metropolitan Market(1) Loans $ in Millions 7 5.00% Source: Company documents (1) The Bank defines its “major metropolitan markets” to include
Dallas, Houston and El Paso, Texas
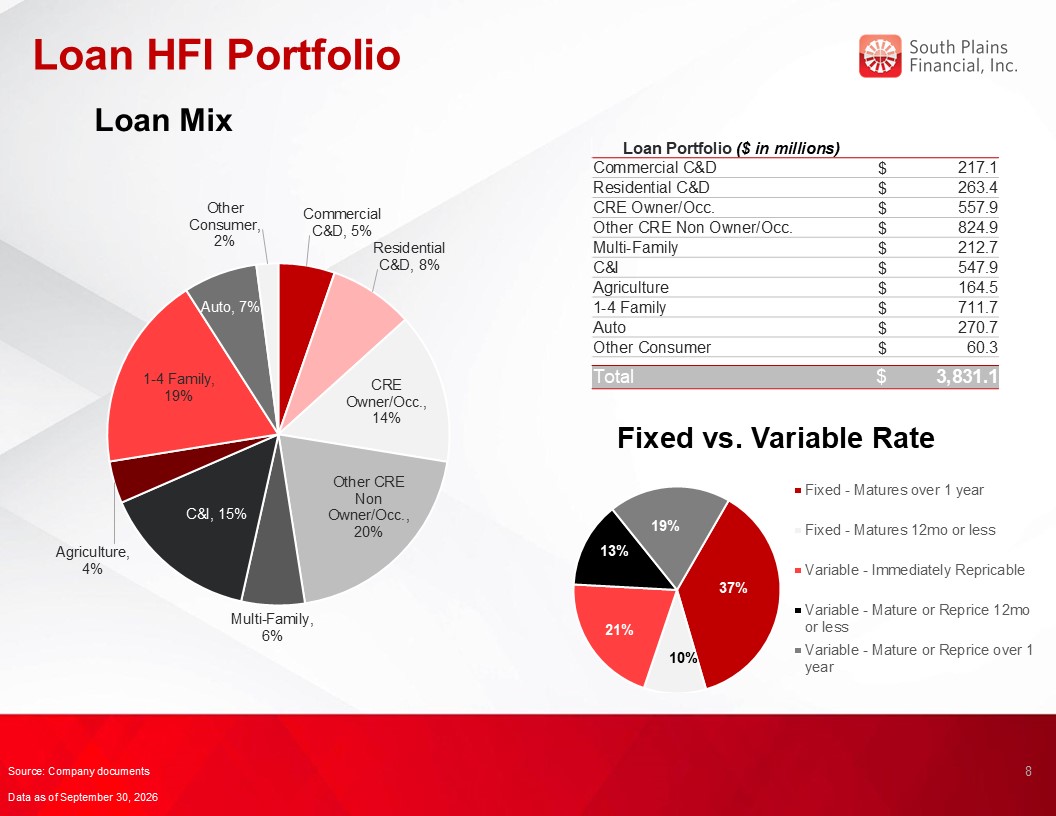
Loan HFI Portfolio Loan Mix Loan Portfolio ($ in millions) Commercial
C&D $ 217.1 Residential C&D $ 263.4 CRE Owner/Occ. $ 557.9 Other CRE Non Owner/Occ. $ 824.9 Multi-Family $ 212.7 C&I $ 547.9 Agriculture $ 164.5 1-4 Family $ 711.7 Auto $ 270.7 Other
Consumer $ 60.3 Total $ 3,831.1 Fixed vs. Variable Rate 8 Source: Company documents Data as of September 30, 2026
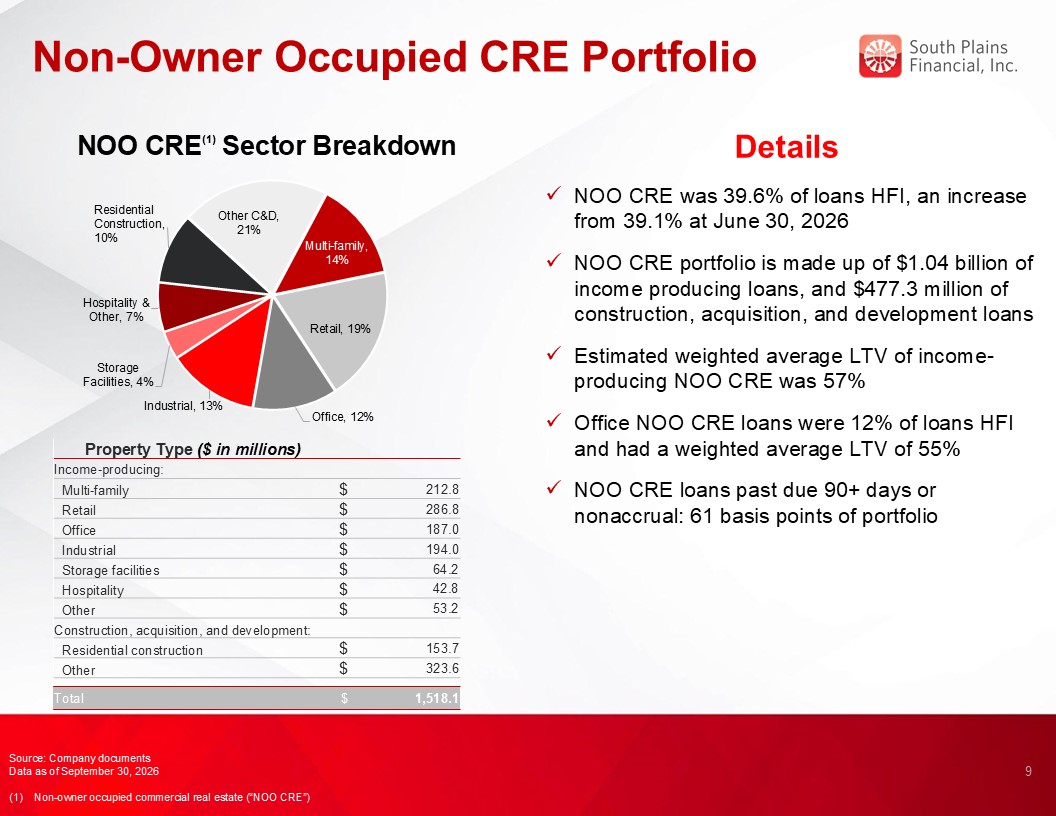
Non-Owner Occupied CRE Portfolio 9 Details NOO CRE was 39.6% of loans HFI, an
increase from 39.1% at June 30, 2026 NOO CRE portfolio is made up of $1.04 billion of income producing loans, and $477.3 million of construction, acquisition, and development loans Estimated weighted average LTV of income-producing NOO CRE
was 57% Office NOO CRE loans were 12% of loans HFI and had a weighted average LTV of 55% NOO CRE loans past due 90+ days or nonaccrual: 61 basis points of portfolio NOO CRE(1) Sector Breakdown Source: Company documents Data as of September
30, 2026 (1) Non-owner occupied commercial real estate (“NOO CRE”) Property Type ($ in millions) Income-producing: Multi-family $ 212.8 Retail $ 286.8 Office $ 187.0 Industrial $ 194.0 Storage facilities $ 64.2
Hospitality $ 42.8 Other $ 53.2 Construction, acquisition, and development: Residential construction $ 153.7 Other $ 323.6 Total $ 1,518.1
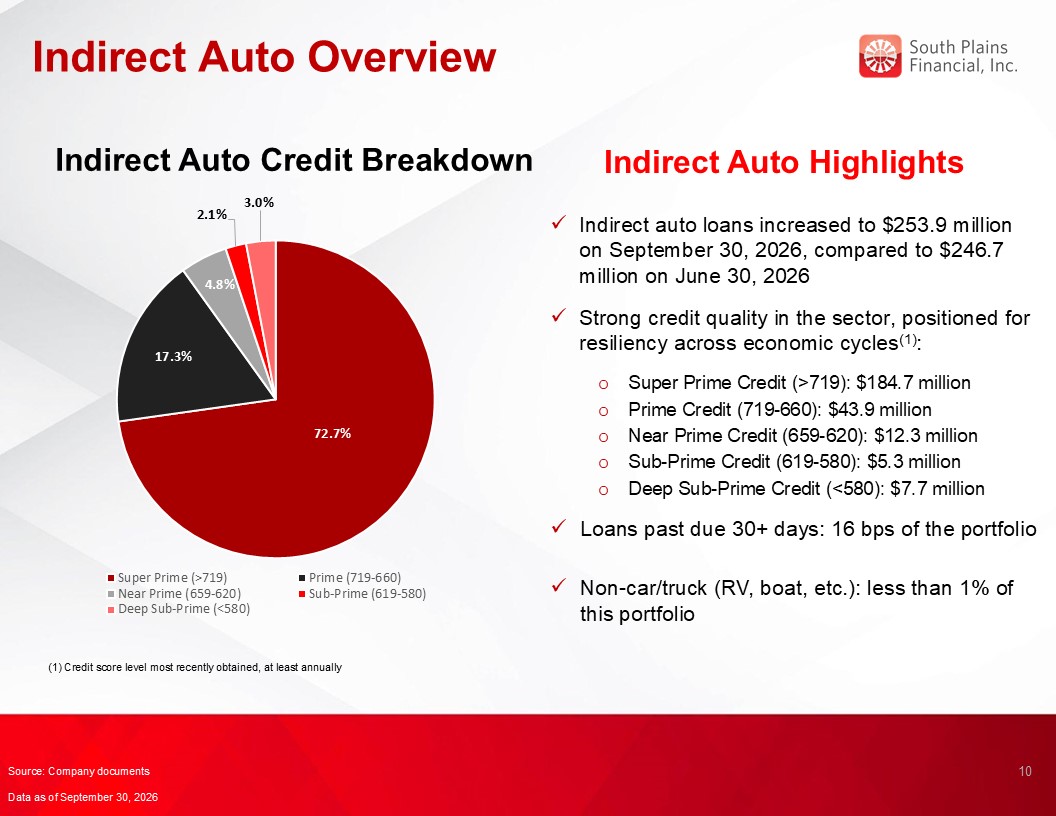
Indirect Auto Overview Indirect Auto Highlights Indirect auto loans increased to
$253.9 million on September 30, 2026, compared to $246.7 million on June 30, 2026 Strong credit quality in the sector, positioned for resiliency across economic cycles(1): Super Prime Credit (>719): $184.7 million Prime Credit (719-660):
$43.9 million Near Prime Credit (659-620): $12.3 million Sub-Prime Credit (619-580): $5.3 million Deep Sub-Prime Credit (<580): $7.7 million Loans past due 30+ days: 16 bps of the portfolio Non-car/truck (RV, boat, etc.): less than 1%
of this portfolio Indirect Auto Credit Breakdown 10 Source: Company documents Data as of September 30, 2026 (1) Credit score level most recently obtained, at least annually
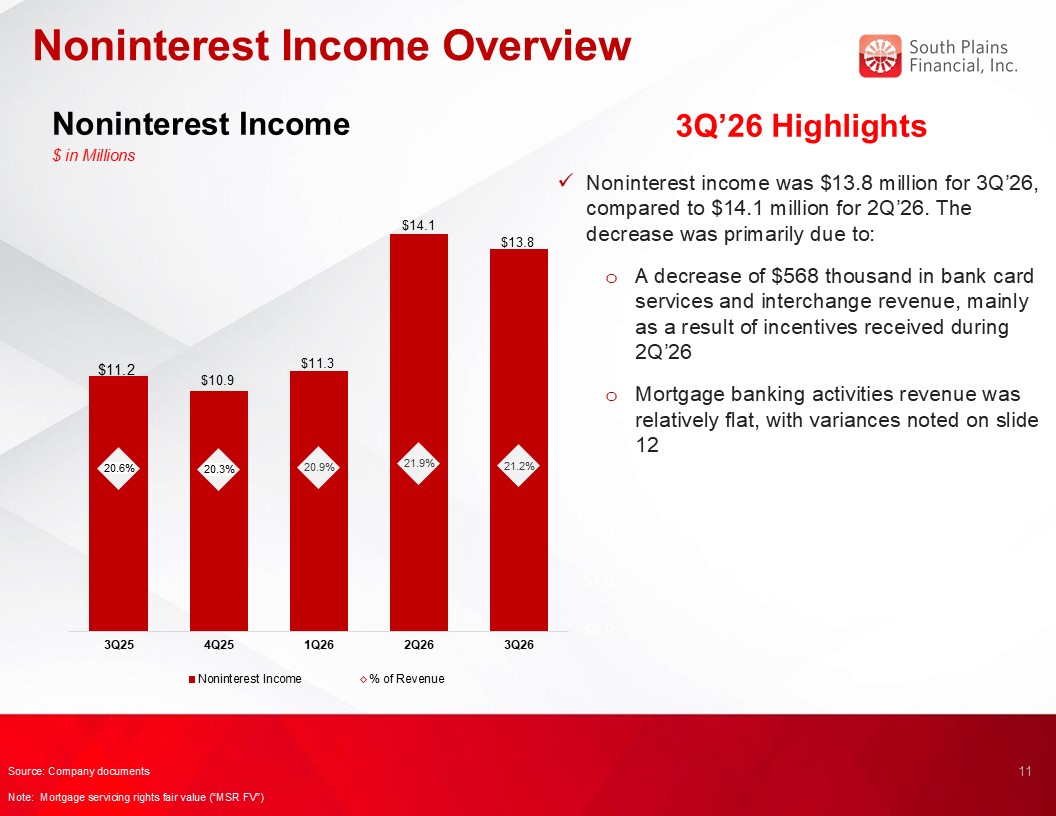
Noninterest Income Overview Noninterest Income $ in Millions 3Q’26
Highlights Noninterest income was $13.8 million for 3Q’26, compared to $14.1 million for 2Q’26. The decrease was primarily due to: A decrease of $568 thousand in bank card services and interchange revenue, mainly as a result of incentives
received during 2Q’26 Mortgage banking activities revenue was relatively flat, with variances noted on slide 12 11 Source: Company documents Note: Mortgage servicing rights fair value (“MSR FV”)
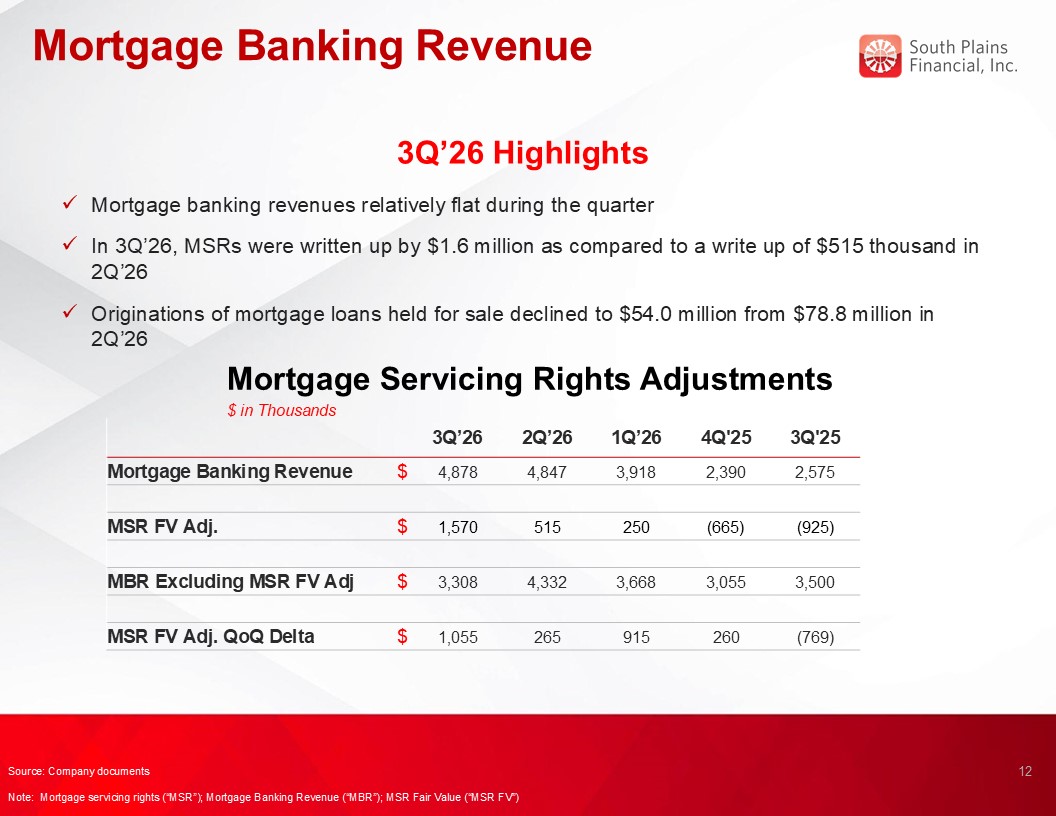
Mortgage Banking Revenue Mortgage Servicing Rights Adjustments $ in
Thousands 3Q’26 Highlights Mortgage banking revenues relatively flat during the quarter In 3Q’26, MSRs were written up by $1.6 million as compared to a write up of $515 thousand in 2Q’26 Originations of mortgage loans held for sale
declined to $54.0 million from $78.8 million in 2Q’26 12 Source: Company documents Note: Mortgage servicing rights (“MSR”); Mortgage Banking Revenue (“MBR”); MSR Fair Value (“MSR FV”) 3Q’26 2Q’26 1Q’26 4Q'25 3Q'25 Mortgage Banking
Revenue $ 4,878 4,847 3,918 2,390 2,575 MSR FV Adj. $ 1,570 515 250 (665) (925) MBR Excluding MSR FV Adj $ 3,308 4,332 3,668 3,055 3,500 MSR FV Adj. QoQ Delta $ 1,055 265 915 260 (769)
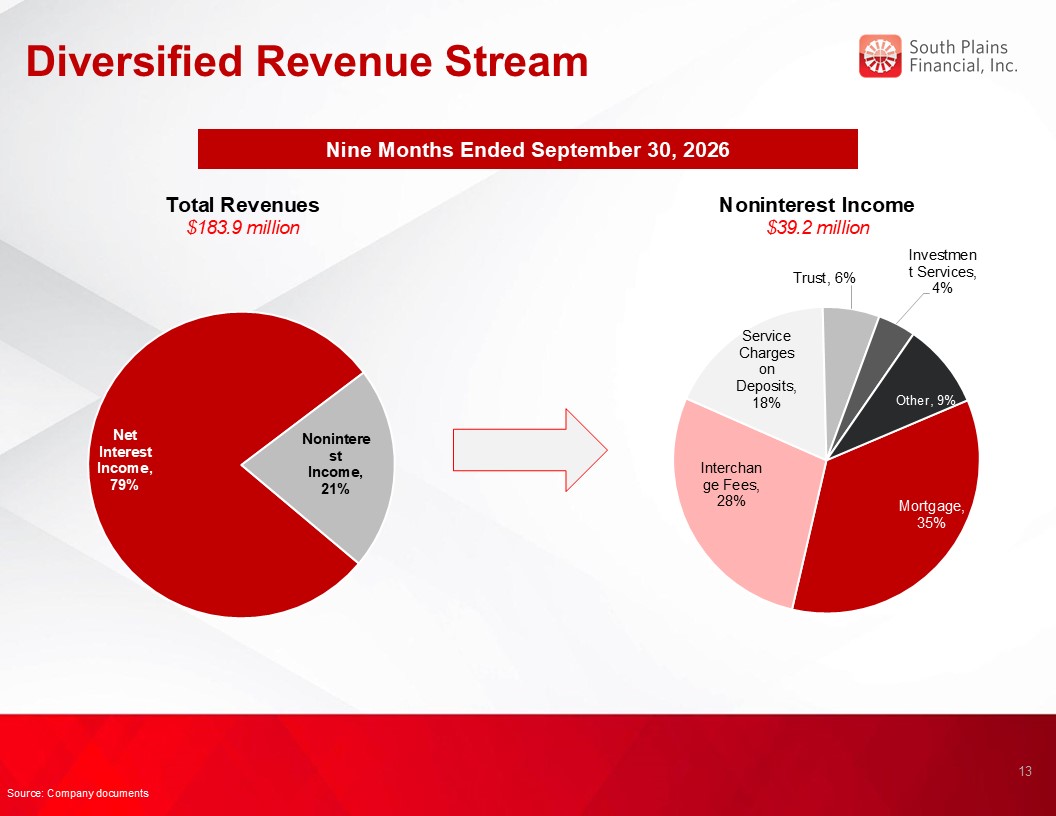
Diversified Revenue Stream Nine Months Ended September 30, 2026 Total
Revenues $183.9 million Noninterest Income $39.2 million 13 Source: Company documents
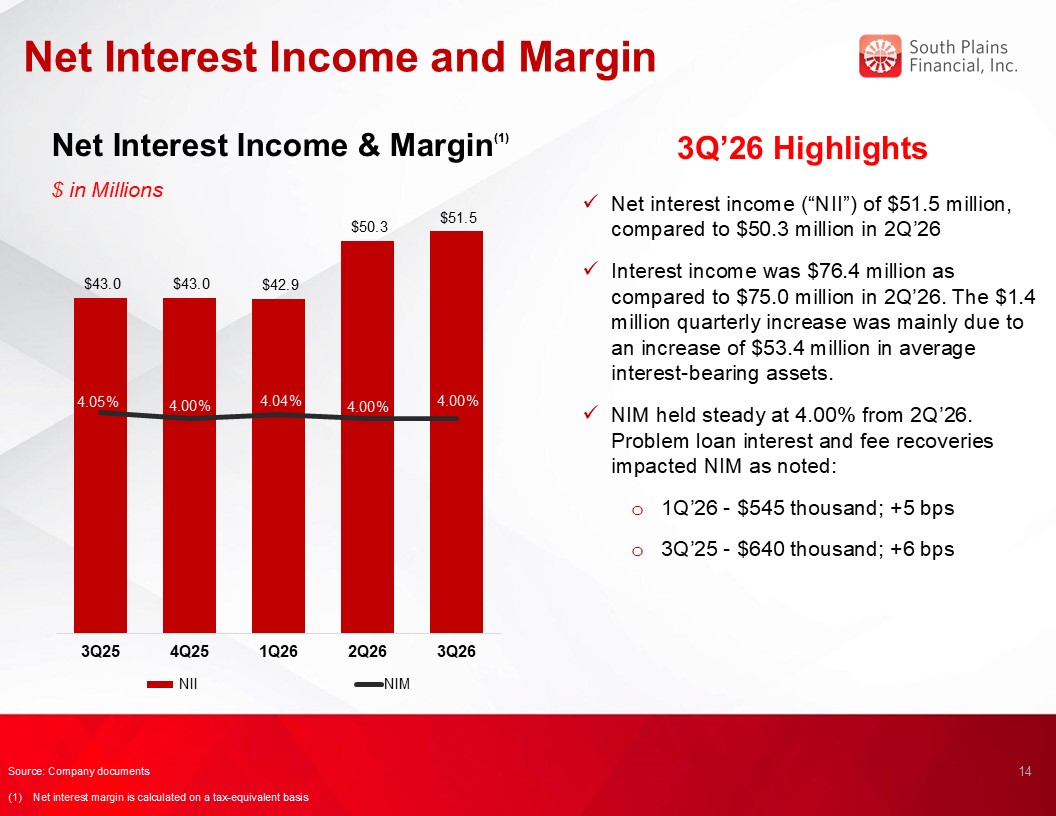
Net Interest Income and Margin Net Interest Income & Margin(1) $ in
Millions 3Q’26 Highlights Net interest income (“NII”) of $51.5 million, compared to $50.3 million in 2Q’26 Interest income was $76.4 million as compared to $75.0 million in 2Q’26. The $1.4 million quarterly increase was mainly due to an
increase of $53.4 million in average interest-bearing assets. NIM held steady at 4.00% from 2Q’26. Problem loan interest and fee recoveries impacted NIM as noted: 1Q’26 - $545 thousand; +5 bps 3Q’25 - $640 thousand; +6
bps 14 3.54% Source: Company documents (1) Net interest margin is calculated on a tax-equivalent basis
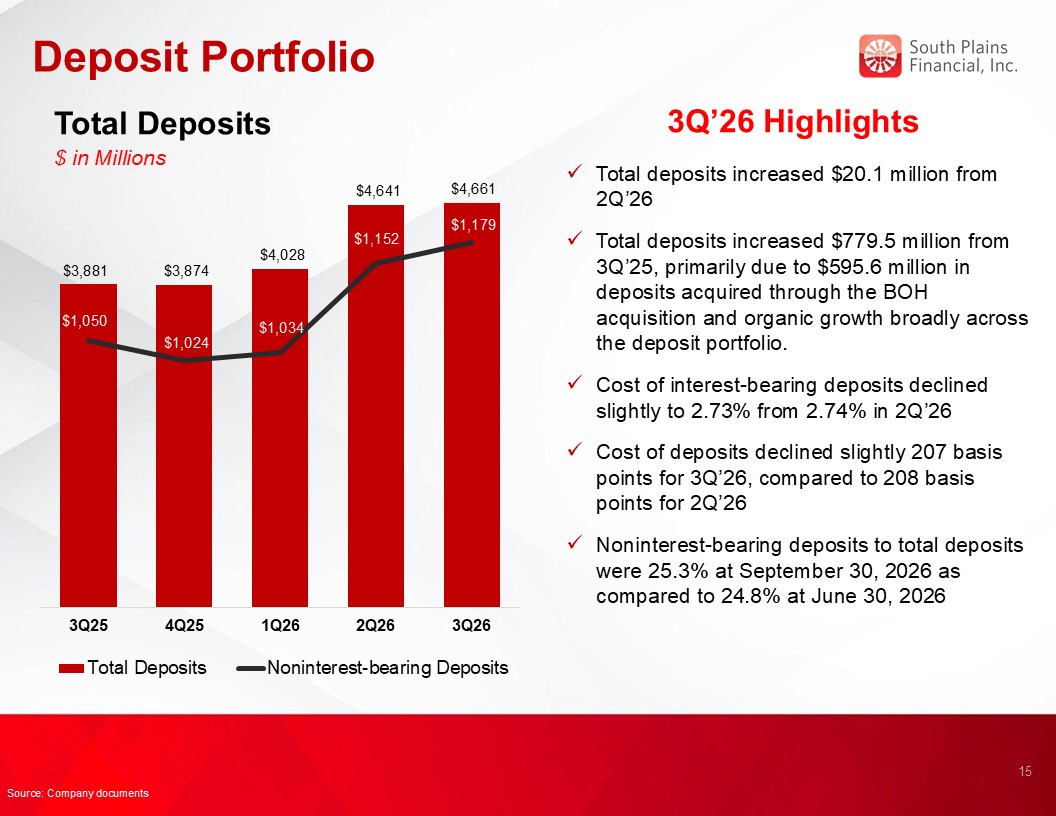
Deposit Portfolio Total Deposits $ in Millions 3Q’26 Highlights Total deposits
increased $20.1 million from 2Q’26 Total deposits increased $779.5 million from 3Q’25, primarily due to $595.6 million in deposits acquired through the BOH acquisition and organic growth broadly across the deposit portfolio. Cost of
interest-bearing deposits declined slightly to 2.73% from 2.74% in 2Q’26 Cost of deposits declined slightly 207 basis points for 3Q’26, compared to 208 basis points for 2Q’26 Noninterest-bearing deposits to total deposits were 25.3% at
September 30, 2026 as compared to 24.8% at June 30, 2026 15 Source: Company documents
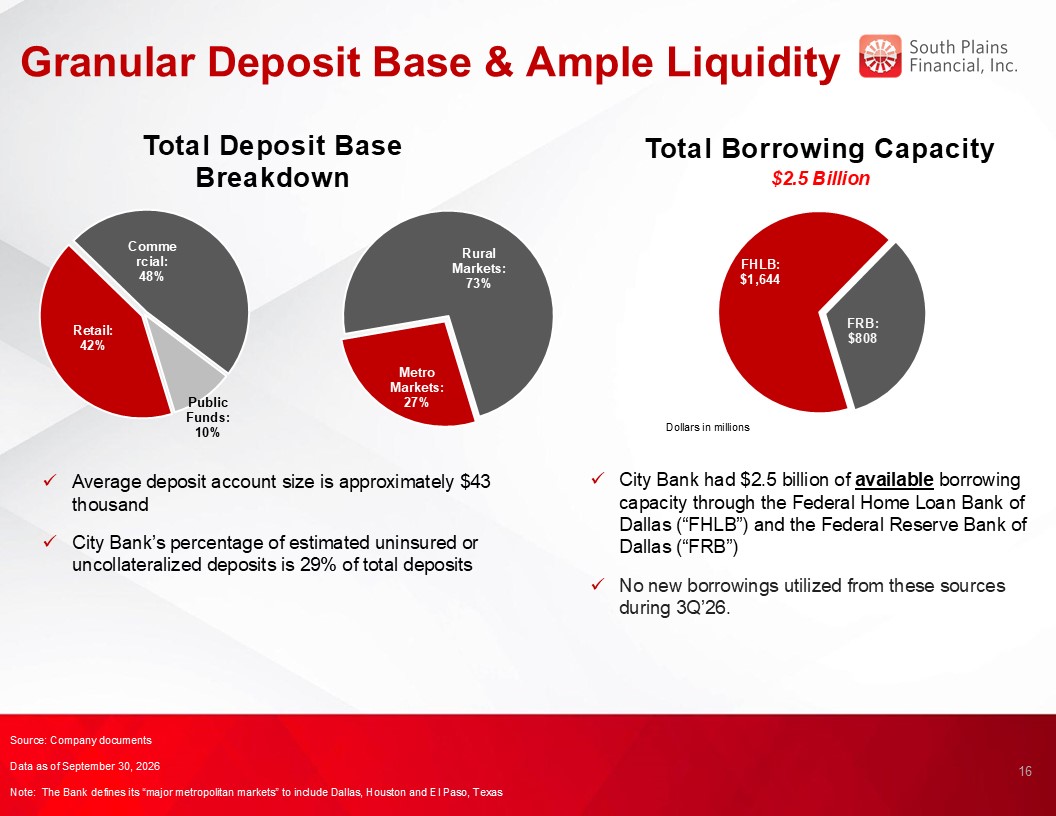
Granular Deposit Base & Ample Liquidity Total Borrowing Capacity $2.5
Billion 16 Total Deposit Base Breakdown Average deposit account size is approximately $43 thousand City Bank’s percentage of estimated uninsured or uncollateralized deposits is 29% of total deposits City Bank had $2.5 billion of available
borrowing capacity through the Federal Home Loan Bank of Dallas (“FHLB”) and the Federal Reserve Bank of Dallas (“FRB”) No new borrowings utilized from these sources during 3Q’26. Source: Company documents Data as of September 30,
2026 Note: The Bank defines its “major metropolitan markets” to include Dallas, Houston and El Paso, Texas
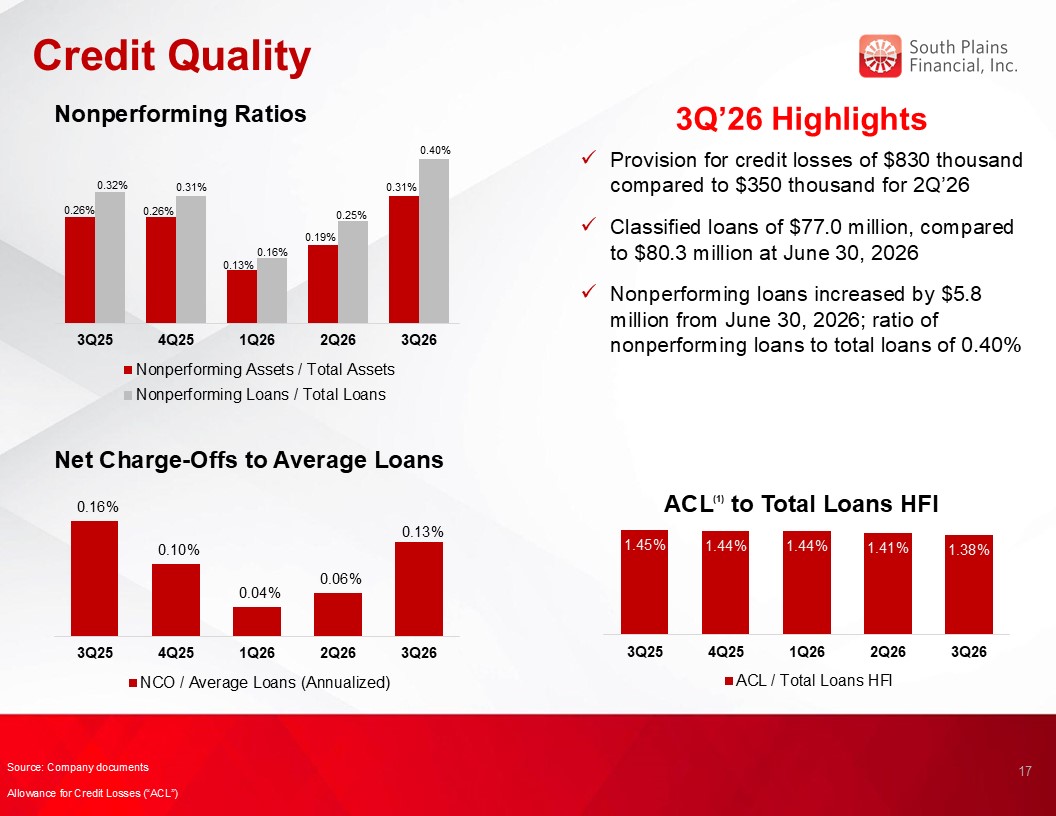
Credit Quality 3Q’26 Highlights Nonperforming Ratios Net Charge-Offs to Average
Loans ACL(1) to Total Loans HFI 17 Provision for credit losses of $830 thousand compared to $350 thousand for 2Q’26 Classified loans of $77.0 million, compared to $80.3 million at June 30, 2026 Nonperforming loans increased by $5.8 million
from June 30, 2026; ratio of nonperforming loans to total loans of 0.40% Source: Company documents Allowance for Credit Losses (“ACL”)
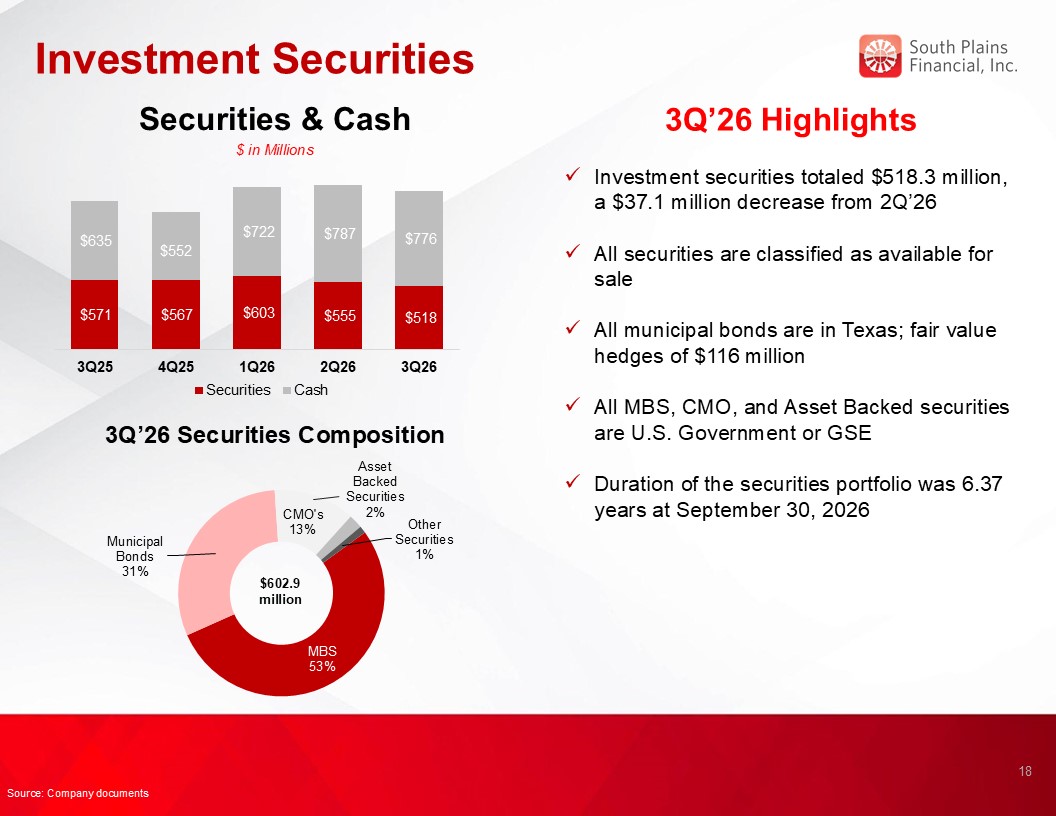
Investment Securities 3Q’26 Highlights Investment securities totaled $518.3
million, a $37.1 million decrease from 2Q’26 All securities are classified as available for sale All municipal bonds are in Texas; fair value hedges of $116 million All MBS, CMO, and Asset Backed securities are U.S. Government or
GSE Duration of the securities portfolio was 6.37 years at September 30, 2026 3Q’26 Securities Composition $602.9 million Securities & Cash $ in Millions 18 Source: Company documents
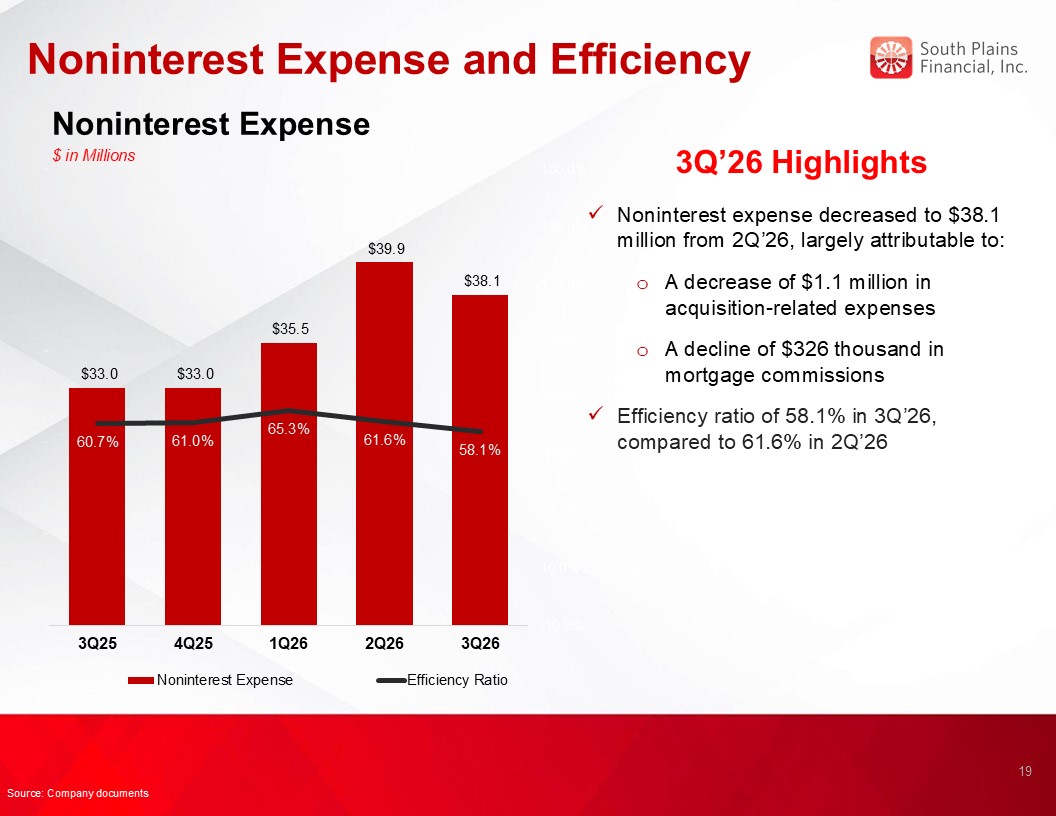
Noninterest Expense and Efficiency 3Q’26 Highlights Noninterest expense
decreased to $38.1 million from 2Q’26, largely attributable to: A decrease of $1.1 million in acquisition-related expenses A decline of $326 thousand in mortgage commissions Efficiency ratio of 58.1% in 3Q’26, compared to 61.6% in
2Q’26 19 Source: Company documents Noninterest Expense $ in Millions
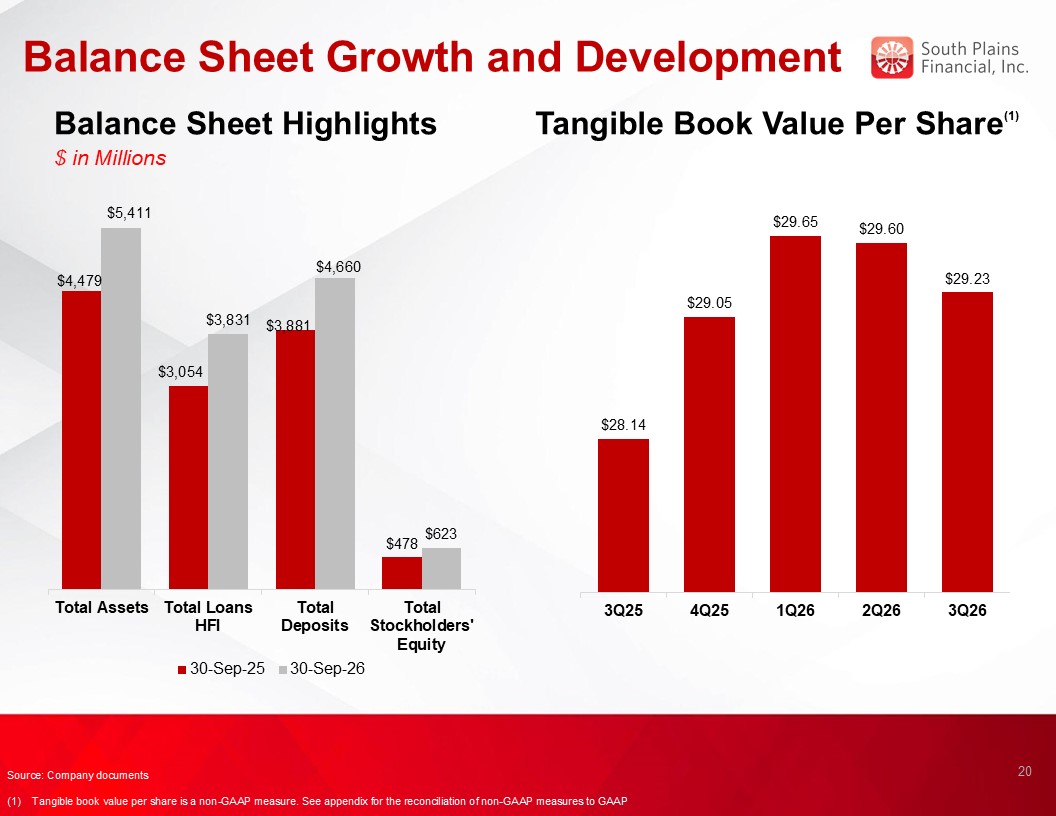
Balance Sheet Growth and Development Balance Sheet Highlights $ in
Millions Tangible Book Value Per Share(1) 20 Source: Company documents (1) Tangible book value per share is a non-GAAP measure. See appendix for the reconciliation of non-GAAP measures to GAAP
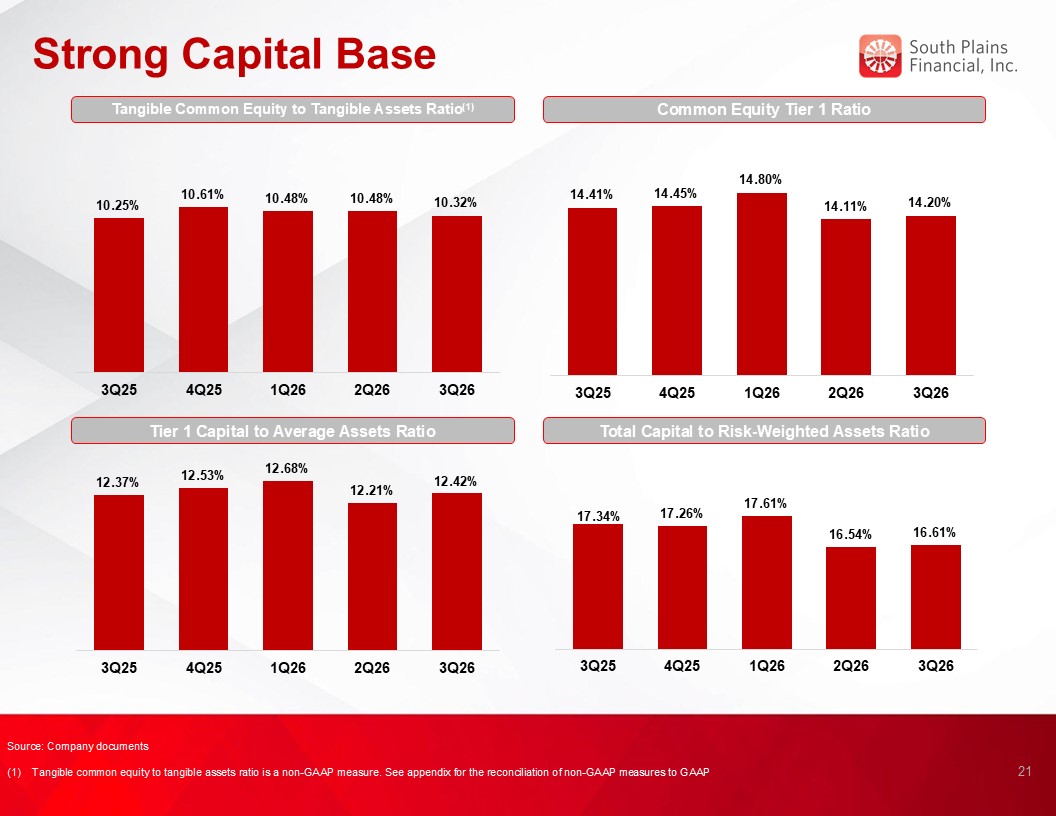
Strong Capital Base Common Equity Tier 1 Ratio Tier 1 Capital to Average Assets
Ratio Total Capital to Risk-Weighted Assets Ratio 21 Source: Company documents (1) Tangible common equity to tangible assets ratio is a non-GAAP measure. See appendix for the reconciliation of non-GAAP measures to GAAP Tangible Common
Equity to Tangible Assets Ratio(1)
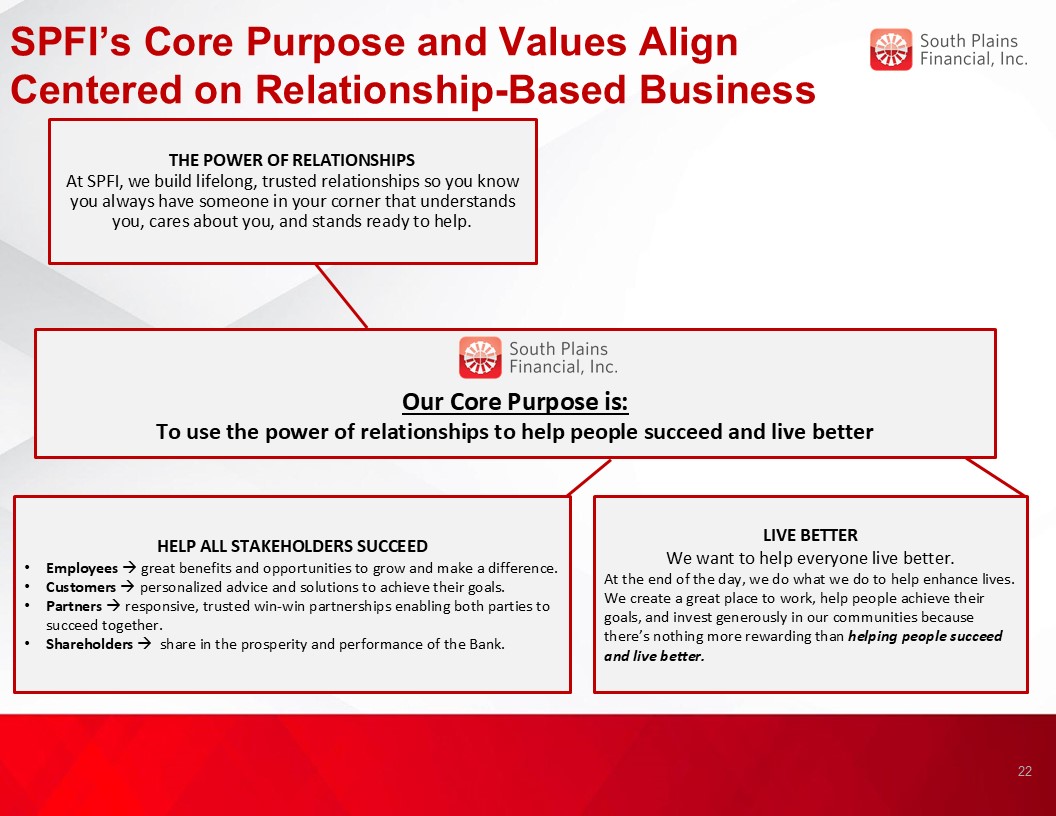
SPFI’s Core Purpose and Values Align Centered on Relationship-Based Business Our
Core Purpose is: To use the power of relationships to help people succeed and live better HELP ALL STAKEHOLDERS SUCCEED Employees great benefits and opportunities to grow and make a difference. Customers personalized advice and
solutions to achieve their goals. Partners responsive, trusted win-win partnerships enabling both parties to succeed together. Shareholders share in the prosperity and performance of the Bank. THE POWER OF RELATIONSHIPS At SPFI, we
build lifelong, trusted relationships so you know you always have someone in your corner that understands you, cares about you, and stands ready to help. LIVE BETTER We want to help everyone live better. At the end of the day, we do what
we do to help enhance lives. We create a great place to work, help people achieve their goals, and invest generously in our communities because there’s nothing more rewarding than helping people succeed and live better. 22
Appendix 23
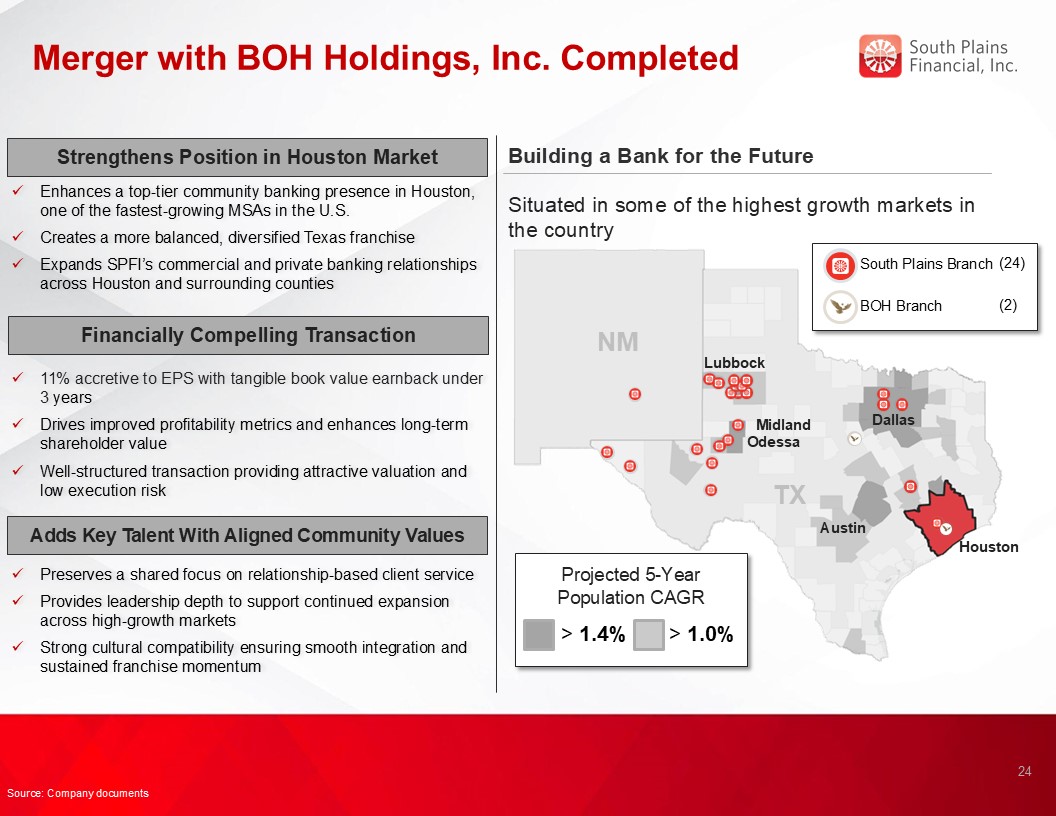
Merger with BOH Holdings, Inc. Completed Building a Bank for the
Future Houston Odessa Austin Midland > 1.4% Situated in some of the highest growth markets in the country Projected 5-Year Population CAGR > 1.0% TX NM Lubbock Dallas South Plains Branch (24) BOH
Branch (2) 24 Strengthens Position in Houston Market Enhances a top-tier community banking presence in Houston, one of the fastest-growing MSAs in the U.S. Creates a more balanced, diversified Texas franchise Expands SPFI’s commercial and
private banking relationships across Houston and surrounding counties 11% accretive to EPS with tangible book value earnback under 3 years Drives improved profitability metrics and enhances long-term shareholder value Well-structured
transaction providing attractive valuation and low execution risk Financially Compelling Transaction Preserves a shared focus on relationship-based client service Provides leadership depth to support continued expansion across high-growth
markets Strong cultural compatibility ensuring smooth integration and sustained franchise momentum Adds Key Talent With Aligned Community Values Source: Company documents
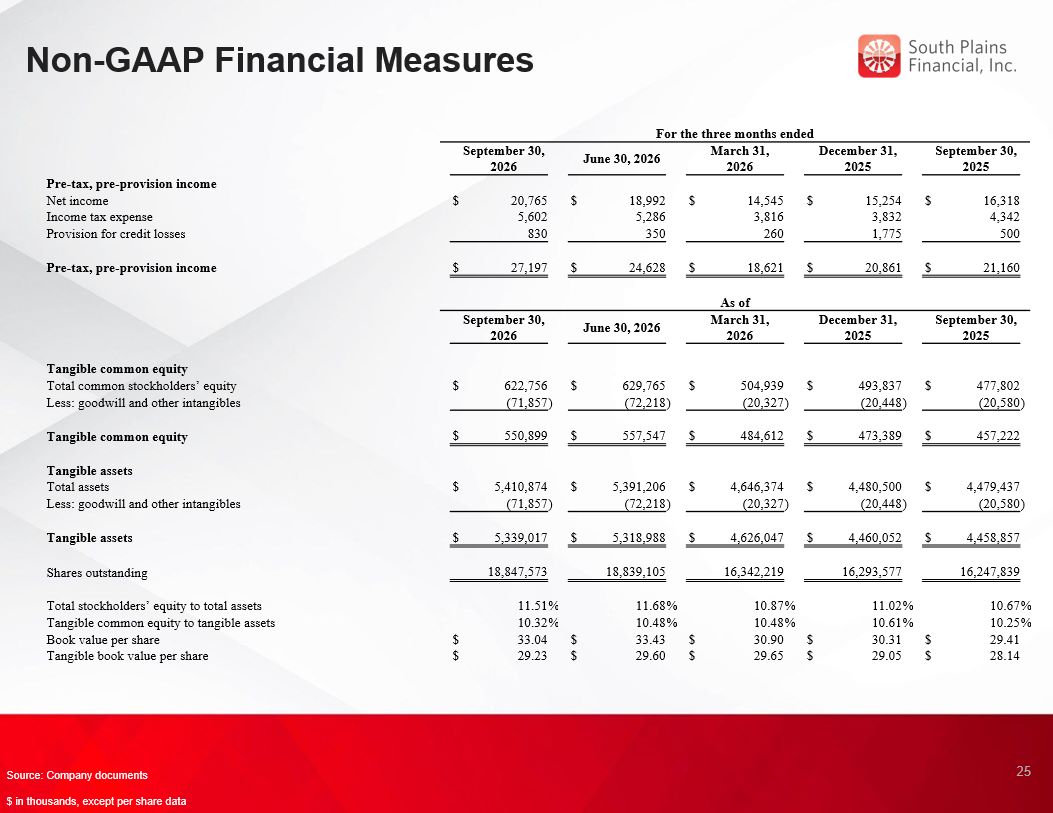
Non-GAAP Financial Measures 25 Source: Company documents $ in thousands, except
per share data For the three months ended September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 Pre-tax, pre-provision
income Net income $ 20,765 $ 18,992 $ 14,545 $ 15,254 $ 16,318 Income tax
expense 5,602 5,286 3,816 3,832 4,342 Provision for credit
losses 830 350 260 1,775 500 Pre-tax, pre-provision
income $ 27,197 $ 24,628 $ 18,621 $ 20,861 $ 21,160 As of September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30,
2025 Tangible common equity Total common stockholders’
equity $ 622,756 $ 629,765 $ 504,939 $ 493,837 $ 477,802 Less: goodwill and other
intangibles (71,857 ) (72,218 ) (20,327 ) (20,448 ) (20,580 ) Tangible common
equity $ 550,899 $ 557,547 $ 484,612 $ 473,389 $ 457,222 Tangible assets Total
assets $ 5,410,874 $ 5,391,206 $ 4,646,374 $ 4,480,500 $ 4,479,437 Less: goodwill and other
intangibles (71,857 ) (72,218 ) (20,327 ) (20,448 ) (20,580 ) Tangible
assets $ 5,339,017 $ 5,318,988 $ 4,626,047 $ 4,460,052 $ 4,458,857 Shares
outstanding 18,847,573 18,839,105 16,342,219 16,293,577 16,247,839 Total stockholders’ equity to total
assets 11.51 % 11.68 % 10.87 % 11.02 % 10.67 % Tangible common equity to tangible assets 10.32 % 10.48 % 10.48 % 10.61 % 10.25 % Book value per
share $ 33.04 $ 33.43 $ 30.90 $ 30.31 $ 29.41 Tangible book value per share $ 29.23 $ 29.60 $ 29.65 $ 29.05 $ 28.14