Exhibit 99.2
USCB FINANCIAL HOLDINGS EARNINGS PRESENTATION THIRD QUARTER 2026 NASDAQ: USCB
FORWARD-LOOKING STATEMENTS This presentation may contain statements that are not historical in nature and are intended to be, and are hereby identified as, forward-looking statements for purposes of the safe harbor provided by Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements are those that are not historical facts. The words “may,” “will,” “anticipate,” “could,” “ should,” “would,” “believe,” “contemplate,” “expect,” “aim,” “plan,” “estimate,” “continue,” “seek,” and “intend,” the negative of these terms, as well as other similar words and expressions of the future, are intended to identify forward-looking statements. These forward-looking statements include, but are not limited to, statements related to our projected growth, anticipated future financial performance, and management’s long-term performance goals, as well as statements relating to the anticipated effects on our results of operations and financial condition from expected or potential developments or events, or business and growth strategies, including anticipated internal growth and potential future additional balance sheet restructuring. All numbers included in this presentation are unaudited unless otherwise noted. These forward-looking statements involve significant risks and uncertainties that could cause our actual results to differ materially from those anticipated in such statements. Potential risks and uncertainties include, but are not limited to: the strength of the United States economy in general and the strength of the local economies in which we conduct operations; our ability to successfully manage interest rate risk, credit risk, liquidity risk, and other risks inherent to our industry; the accuracy of our financial statement estimates and assumptions, including the estimates used for our allowance for credit losses; the efficiency and effectiveness of our internal control procedures and
processes; our ability to comply with the extensive laws and regulations to which we are subject, including the laws for each jurisdiction where we operate; adverse changes or conditions in the capital and financial markets, including actual or potential stresses in the banking industry; deposit attrition and the level of our uninsured deposits; legislative or regulatory changes and changes, including the enactment of the One Big Beautiful Bill, in accounting principles, policies, practices or guidelines; the lack of a significantly diversified loan portfolio and our concentration in the South Florida market, including the risks of geographic, depositor, and industry concentrations, including our concentration in loans secured by real estate, in particular, commercial real estate; the effects of climate change; the concentration of ownership of our common stock; fluctuations in the price of our common stock; our ability to fund or access the capital markets at attractive rates and terms and manage our growth, both organic growth as well as growth through other means, such as potential future acquisitions; inflation, interest rate, unemployment rate, and market and monetary fluctuations; the effects of potential new or increased tariffs, retaliatory tariffs and trade restrictions; the impact of international hostilities and geopolitical events; increased competition and its effect on the pricing of our products and services as well as our net interest rate spread and net interest margin; the loss of key employees; the effectiveness of our risk management strategies, including operational risks, including, but not limited to, client, employee, or fourth-party fraud and security breaches; and other risks described in this presentation and other filings we make with the Securities and Exchange Commission (“SEC”). All forward-looking statements are necessarily only estimates of future results, and there can be no assurance that actual results will
not differ materially from expectations. Therefore, you are cautioned not to place undue reliance on any forward-looking statements. Further, any forward-looking statements included in this presentation are made only as of the date hereof, and we undertake no obligation to update or revise any forward-looking statements to reflect events or circumstances occurring after the date on which the statements are made or to reflect the occurrence of unanticipated events, unless required to do so under the federal securities laws. You should also review the risk factors described in the reports USCB Financial Holdings, Inc. has filed or will file with the SEC. Non-GAAP Financial Measures This presentation includes financial information determined by methods other than in accordance with generally accepted accounting principles (“GAAP”). This financial information includes certain operating performance measures. Management has included these non-GAAP financial measures because it believes these measures may provide useful supplemental information for evaluating the Company’s expectations and underlying performance trends. Further, management uses these measures in managing and evaluating the Company’s business and intends to refer to them in discussions about our operations and performance. Operating performance measures should be viewed in addition to, and not as an alternative to or substitute for, measures determined in accordance with GAAP, and are not necessarily comparable to non-GAAP measures that may be presented by other companies. Reconciliations of these non-GAAP measures to the most directly comparable GAAP measures can be found in the Non-GAAP financial measures reconciliation tables included in this presentation. 2
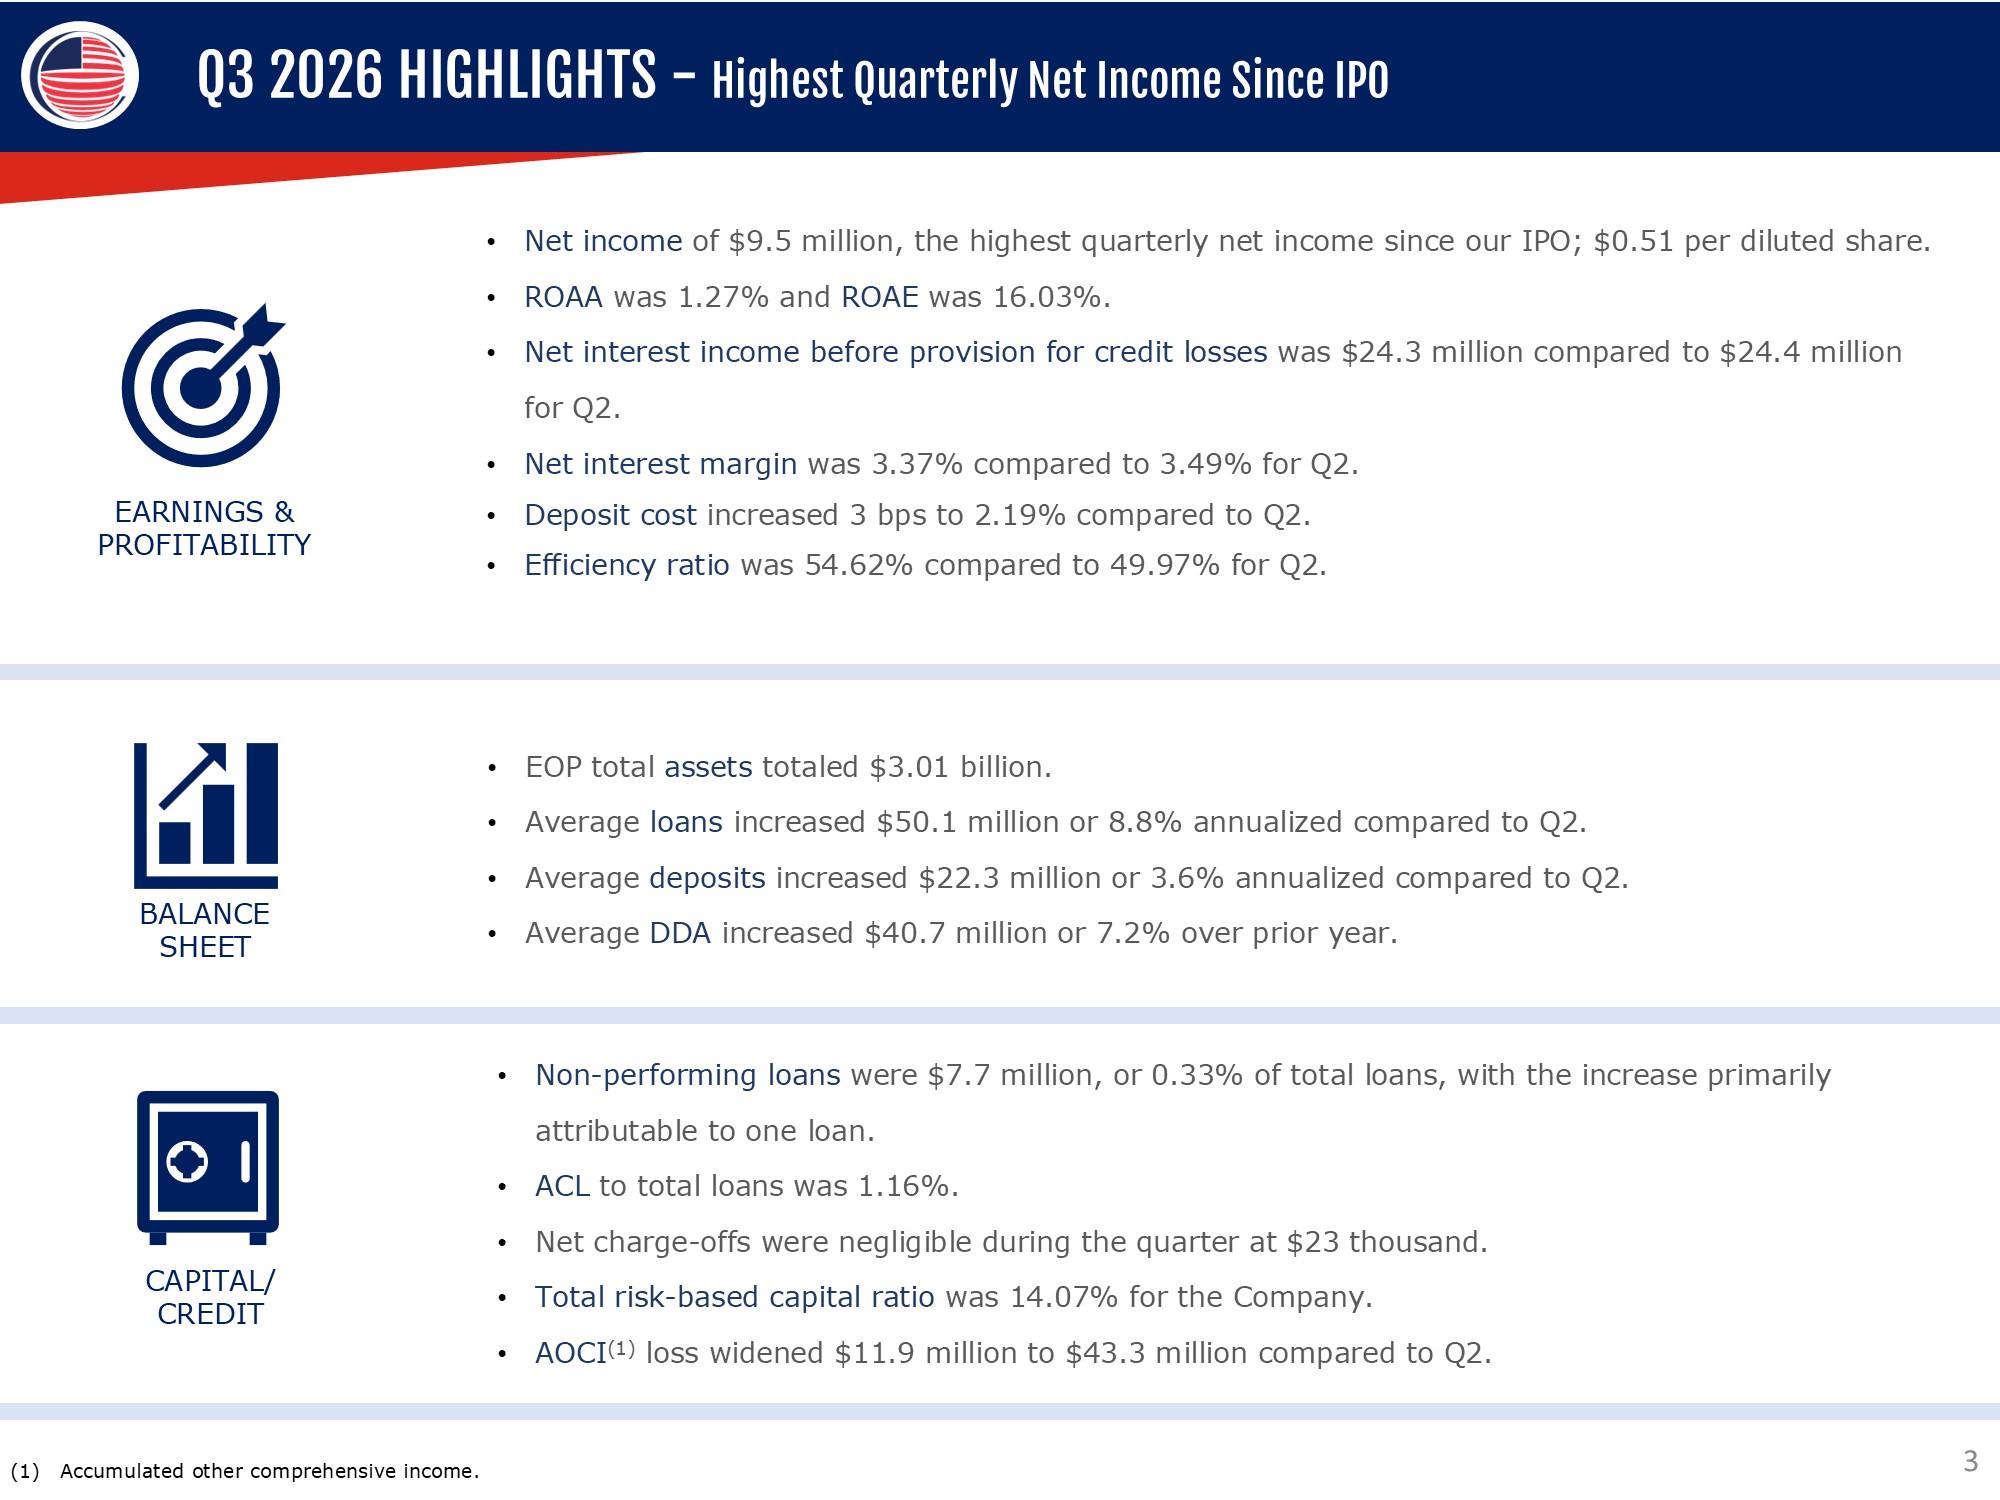
Q3 2026 HIGHLIGHTS - Highest Quarterly Net Income Since IPO EARNINGS & PROFITABILITY Net income of $9.5 million, the highest quarterly net income since our IPO; $0.51 per diluted share. ROAA was 1.27% and ROAE was 16.03%. Net interest income before provision for credit losses was $24.3 million compared to $24.4 million for Q2. Net interest margin was 3.37% compared to 3.49% for Q2. Deposit cost increased 3 bps to 2.19% compared to Q2. Efficiency ratio was 54.62% compared to 49.97% for Q2. BALANCE SHEET EOP total assets totaled $3.01 billion. Average loans increased $50.1 million or 8.8% annualized compared to Q2. Average deposits increased $22.3 million or 3.6% annualized compared to Q2. Average DDA increased $40.7 million or 7.2% over prior year. Accumulated other comprehensive income. CAPITAL/ CREDIT Non-performing loans were $7.7 million, or 0.33% of total loans, with the increase primarily attributable to one loan. ACL to total loans was 1.16%. Net charge-offs were negligible during the quarter at $23 thousand. Total risk-based capital ratio was 14.07% for the Company. AOCI(1) loss widened $11.9 million to $43.3 million compared to Q2. Accumulated other comprehensive income. 3
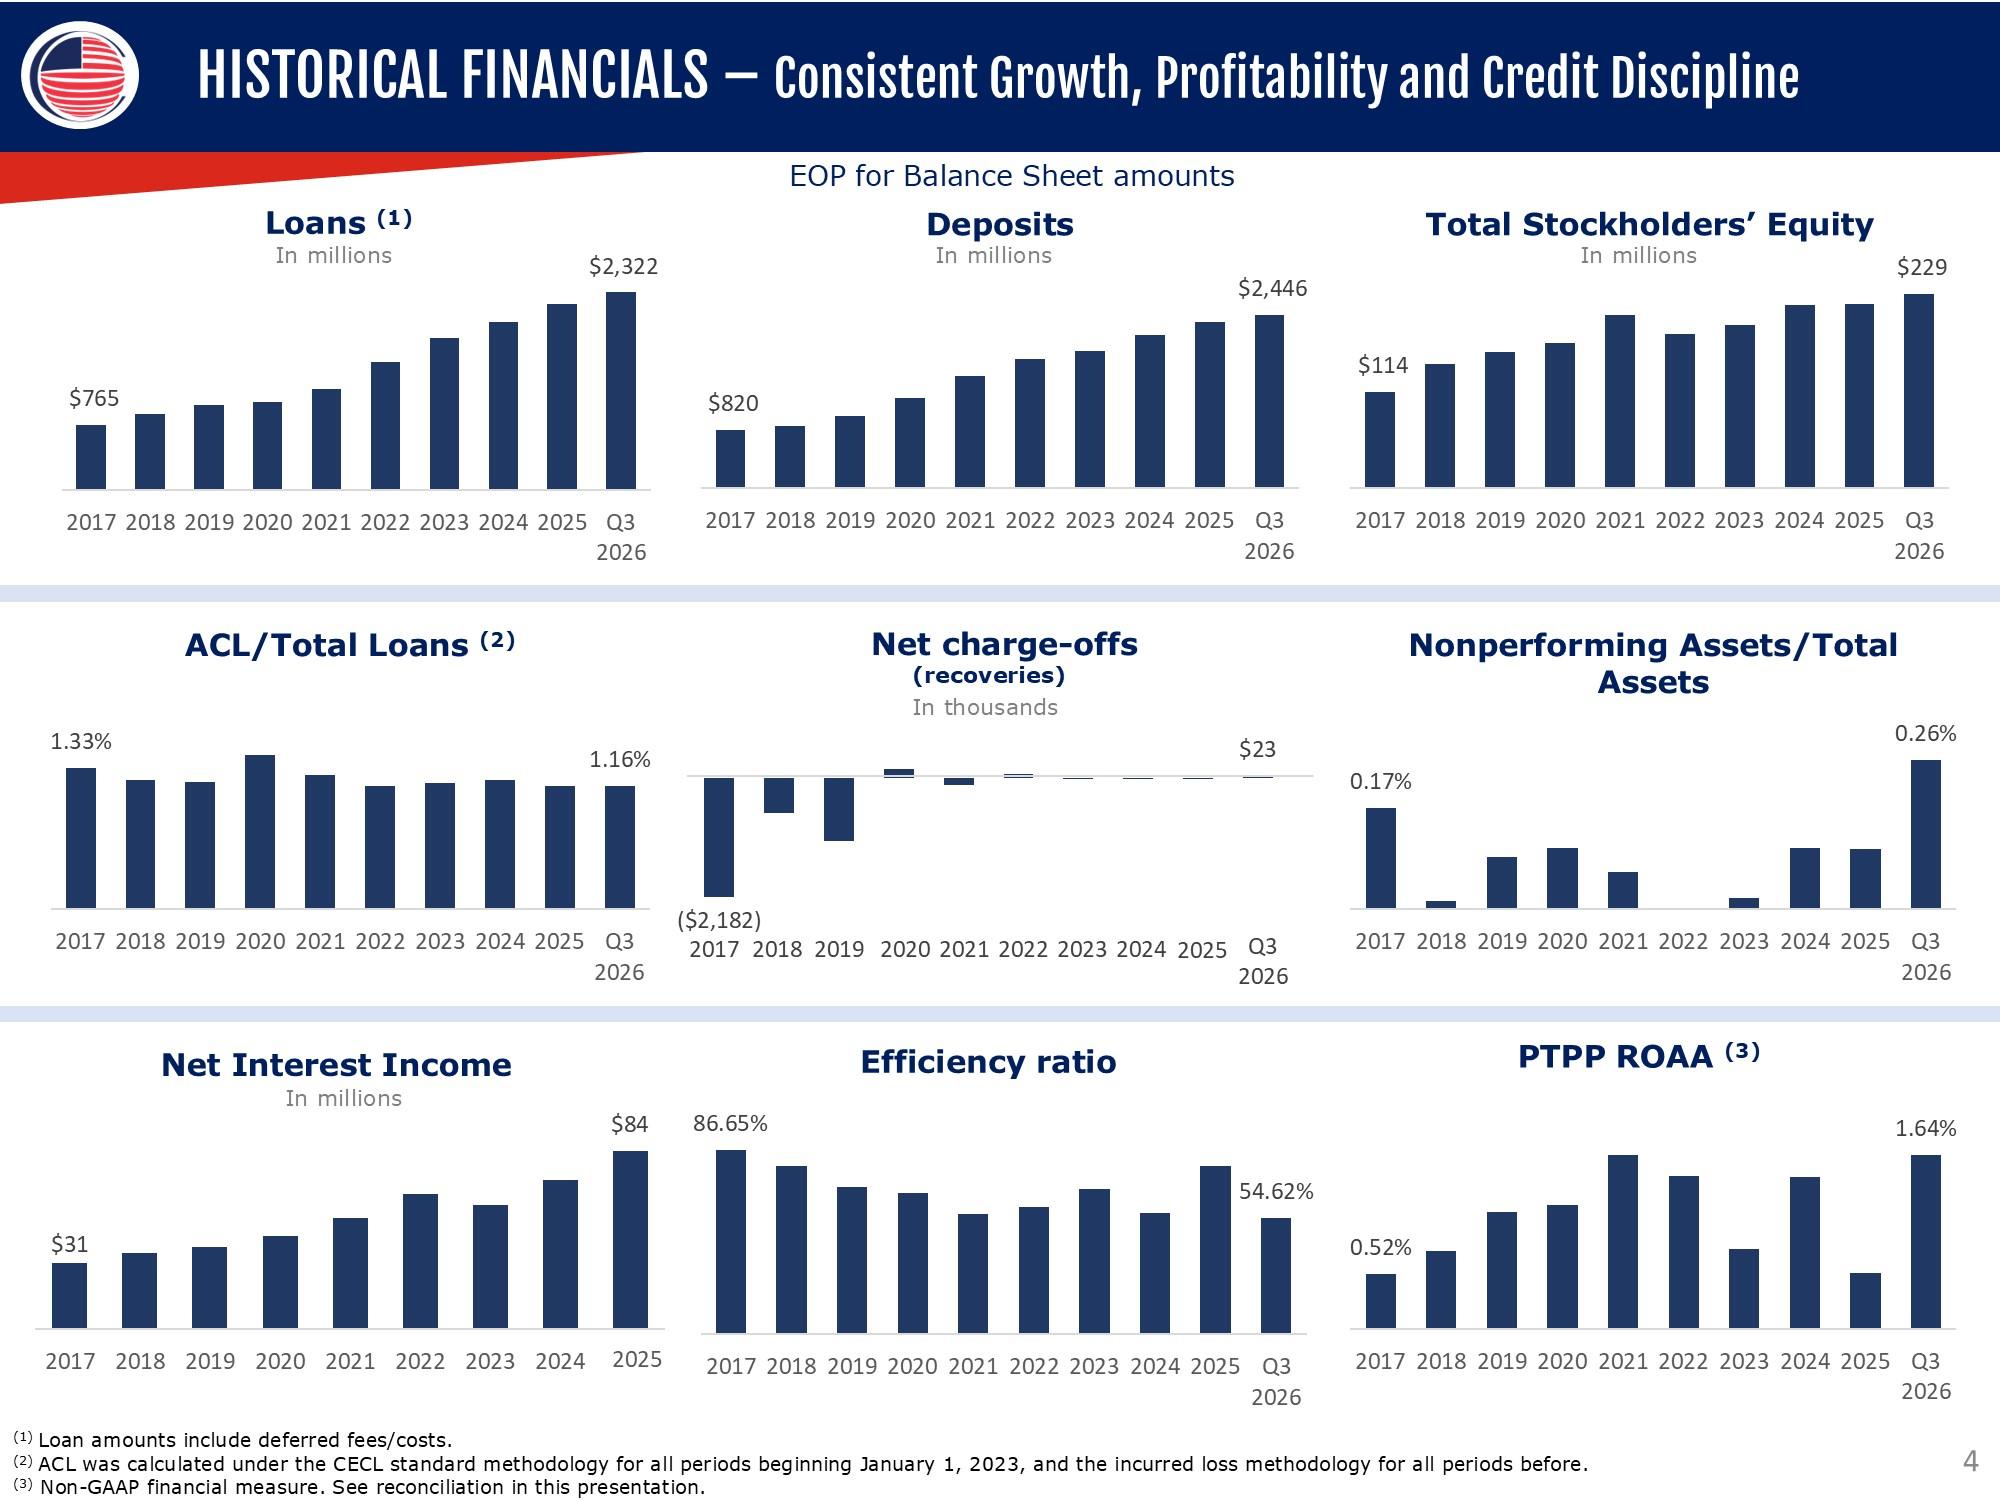
HISTORICAL FINANCIALS – Consistent Growth, Profitability and Credit Discipline EOP for Balance Sheet amounts Loans (1) (In millions) $765 $2,322 2017 2017 2018 2019 2020 2021 2022 2023 2024 2025 Q3 2026 Deposits (In millions) $820 $2,446 2017 2017 2018 2019 2020 2021 2022 2023 2024 2025 Q3 2026 Total Stockholders’ Equity (In millions) $114 $229 2017 2017 2018 2019 2020 2021 2022 2023 2024 2025 Q3 2026 ACL/Total Loans (2) 1.33% 1.16% 2017 2017 2018 2019 2020 2021 2022 2023 2024 2025 Q3 2026 Net charge-offs (recoveries) (In thousands) ($2,182) $23 2017 2017 2018 2019 2020 2021 2022 2023 2024 2025 Q3 2026 Nonperforming Assets/Total Assets 0.17% 0.26% 2017 2017 2018 2019 2020 2021 2022 2023 2024 2025 Q3 2026 Net Interest Income (In millions) $31 $84 2017 2017 2018 2019 2020 2021 2022 2023 2024 2025 Q3 2026 Efficiency ratio 86.65% 54.62% 2017 2017 2018 2019 2020 2021 2022 2023 2024 2025 Q3 2026 PTPP ROAA (3) 0.52% 1.64% 2017 2017 2018 2019 2020 2021 2022 2023 2024 2025 Q3 2026 (1) Loan amounts include deferred fees/costs. (2) ACL was calculated under the CECL standard methodology for all periods beginning January 1, 2023, and the incurred loss methodology for all periods before. (3) Non-GAAP financial measure. See reconciliation in this presentation. 4
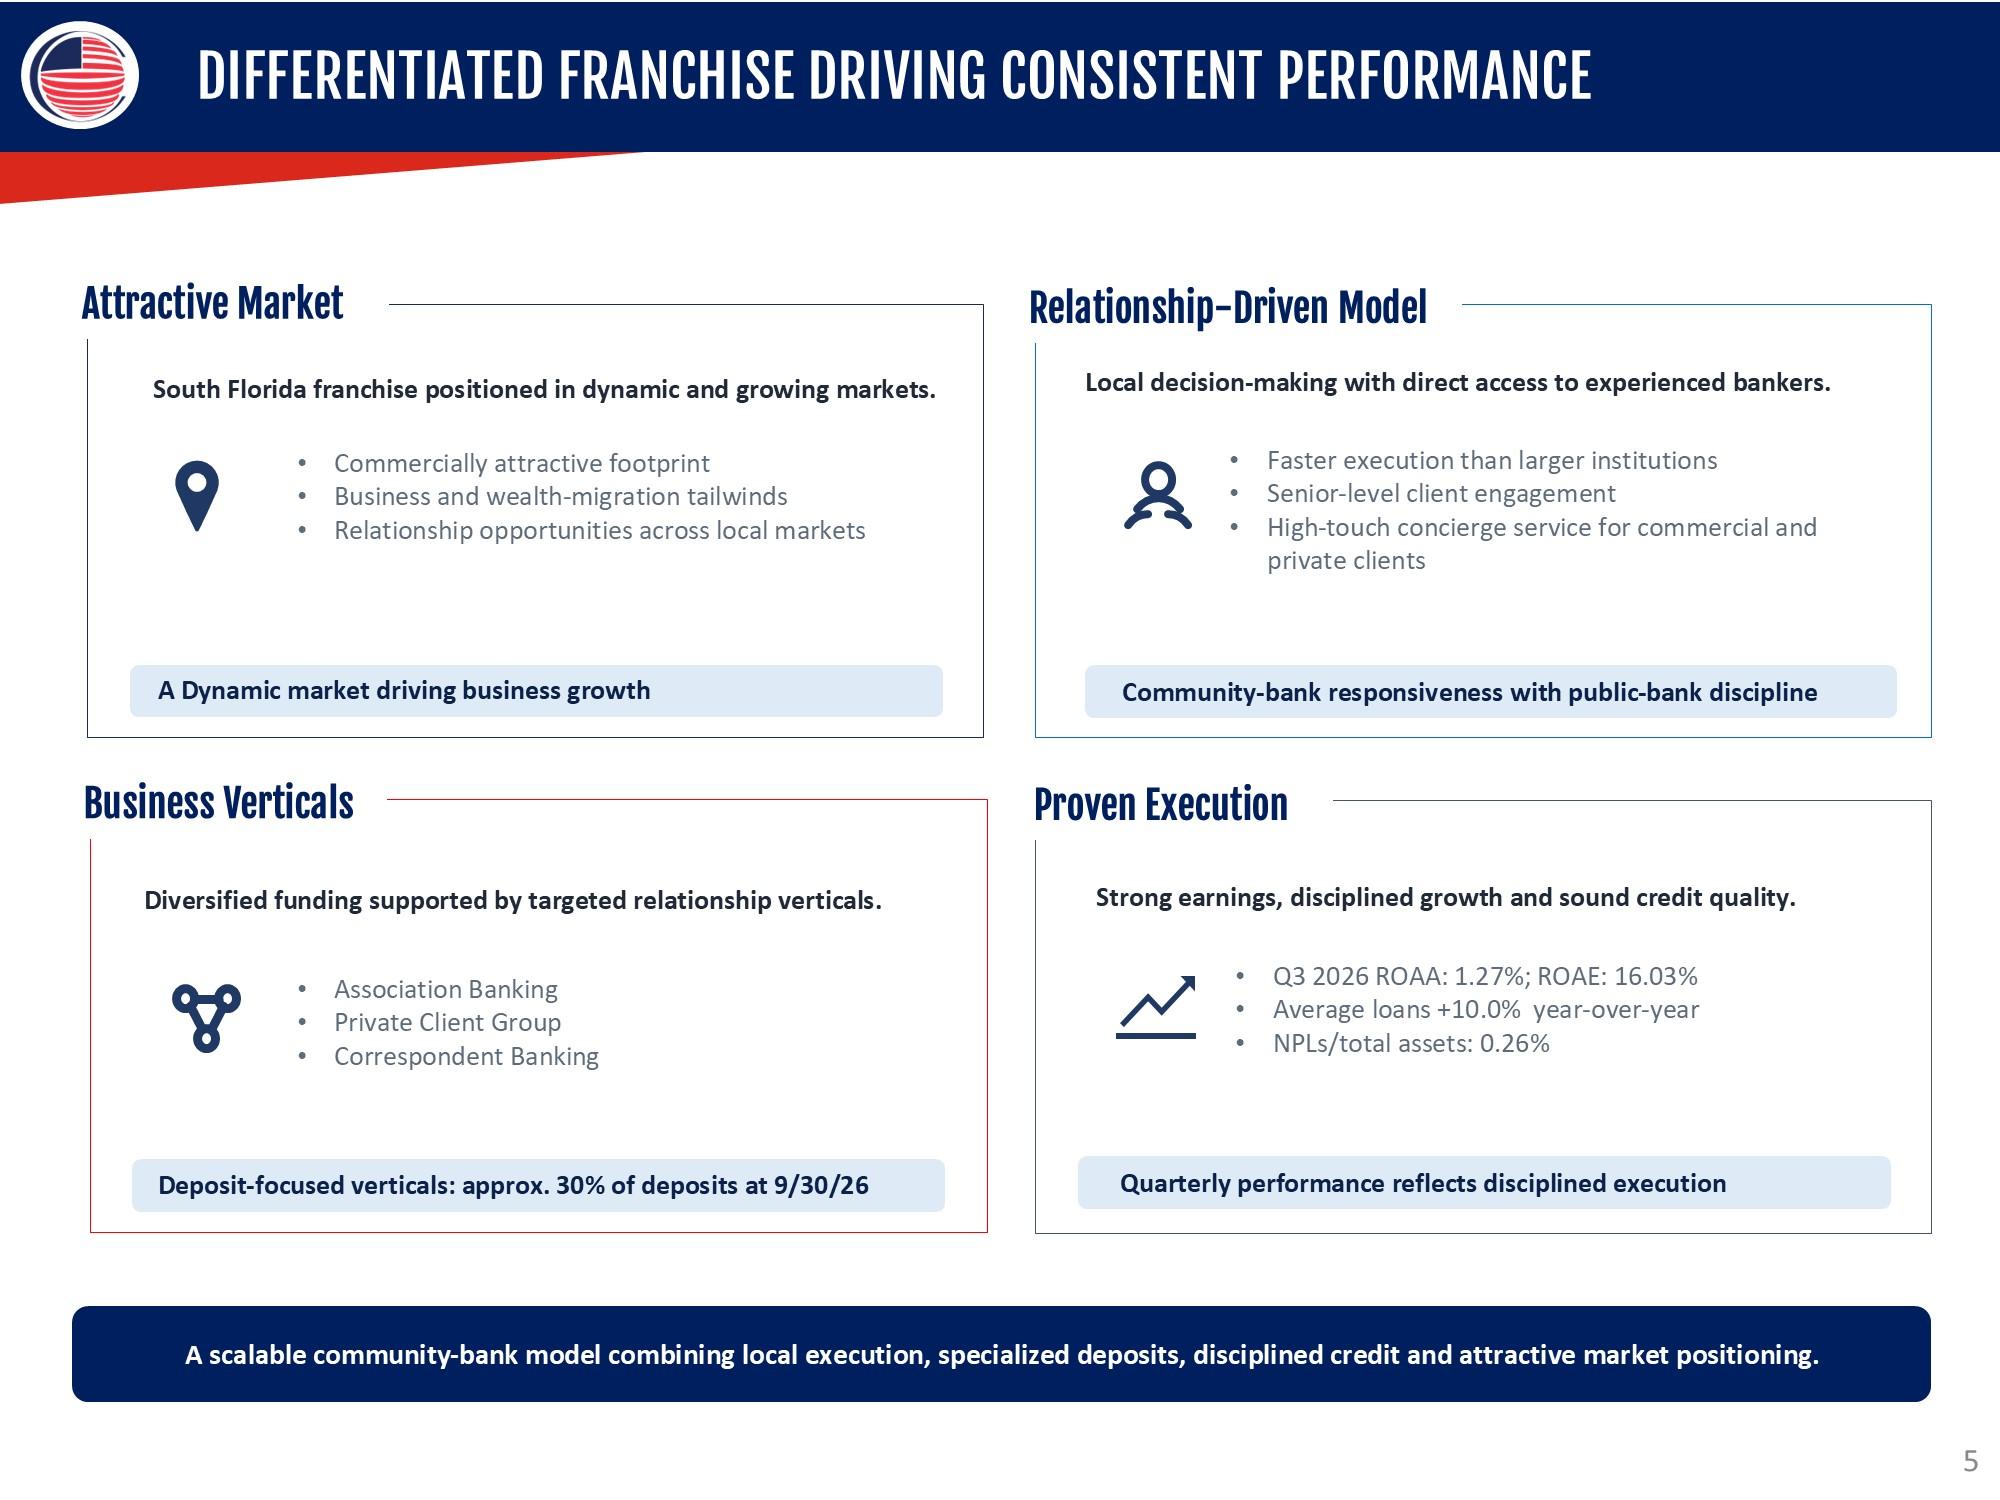
DIFFERENTIATED FRANCHISE DRIVING CONSISTENT PERFORMANCE Attractive Market South Florida franchise positioned in dynamic and growing markets. Commercially attractive footprint Business and wealth-migration tailwinds Relationship opportunities across local markets A Dynamic market driving business growth Relationship-Driven Model Local decision-making with direct access to experienced bankers. Faster execution than larger institutions Senior-level client engagement High-touch concierge service for commercial and private clients Community-bank responsiveness with public-bank discipline Business Verticals Diversified funding supported by targeted relationship verticals. Association Banking Private Client Group Correspondent Banking Deposit-focused verticals: approx. 30% of deposits at 9/30/26 Proven Execution Strong earnings, disciplined growth and sound credit quality. Q3 2026 ROAA: 1.27%; ROAE: 16.03% Average loans +10.0% year-over-year NPLs/total assets: 0.26% Quarterly performance reflects disciplined execution A scalable community-bank model combining local execution, specialized deposits, disciplined credit and attractive market positioning. 5
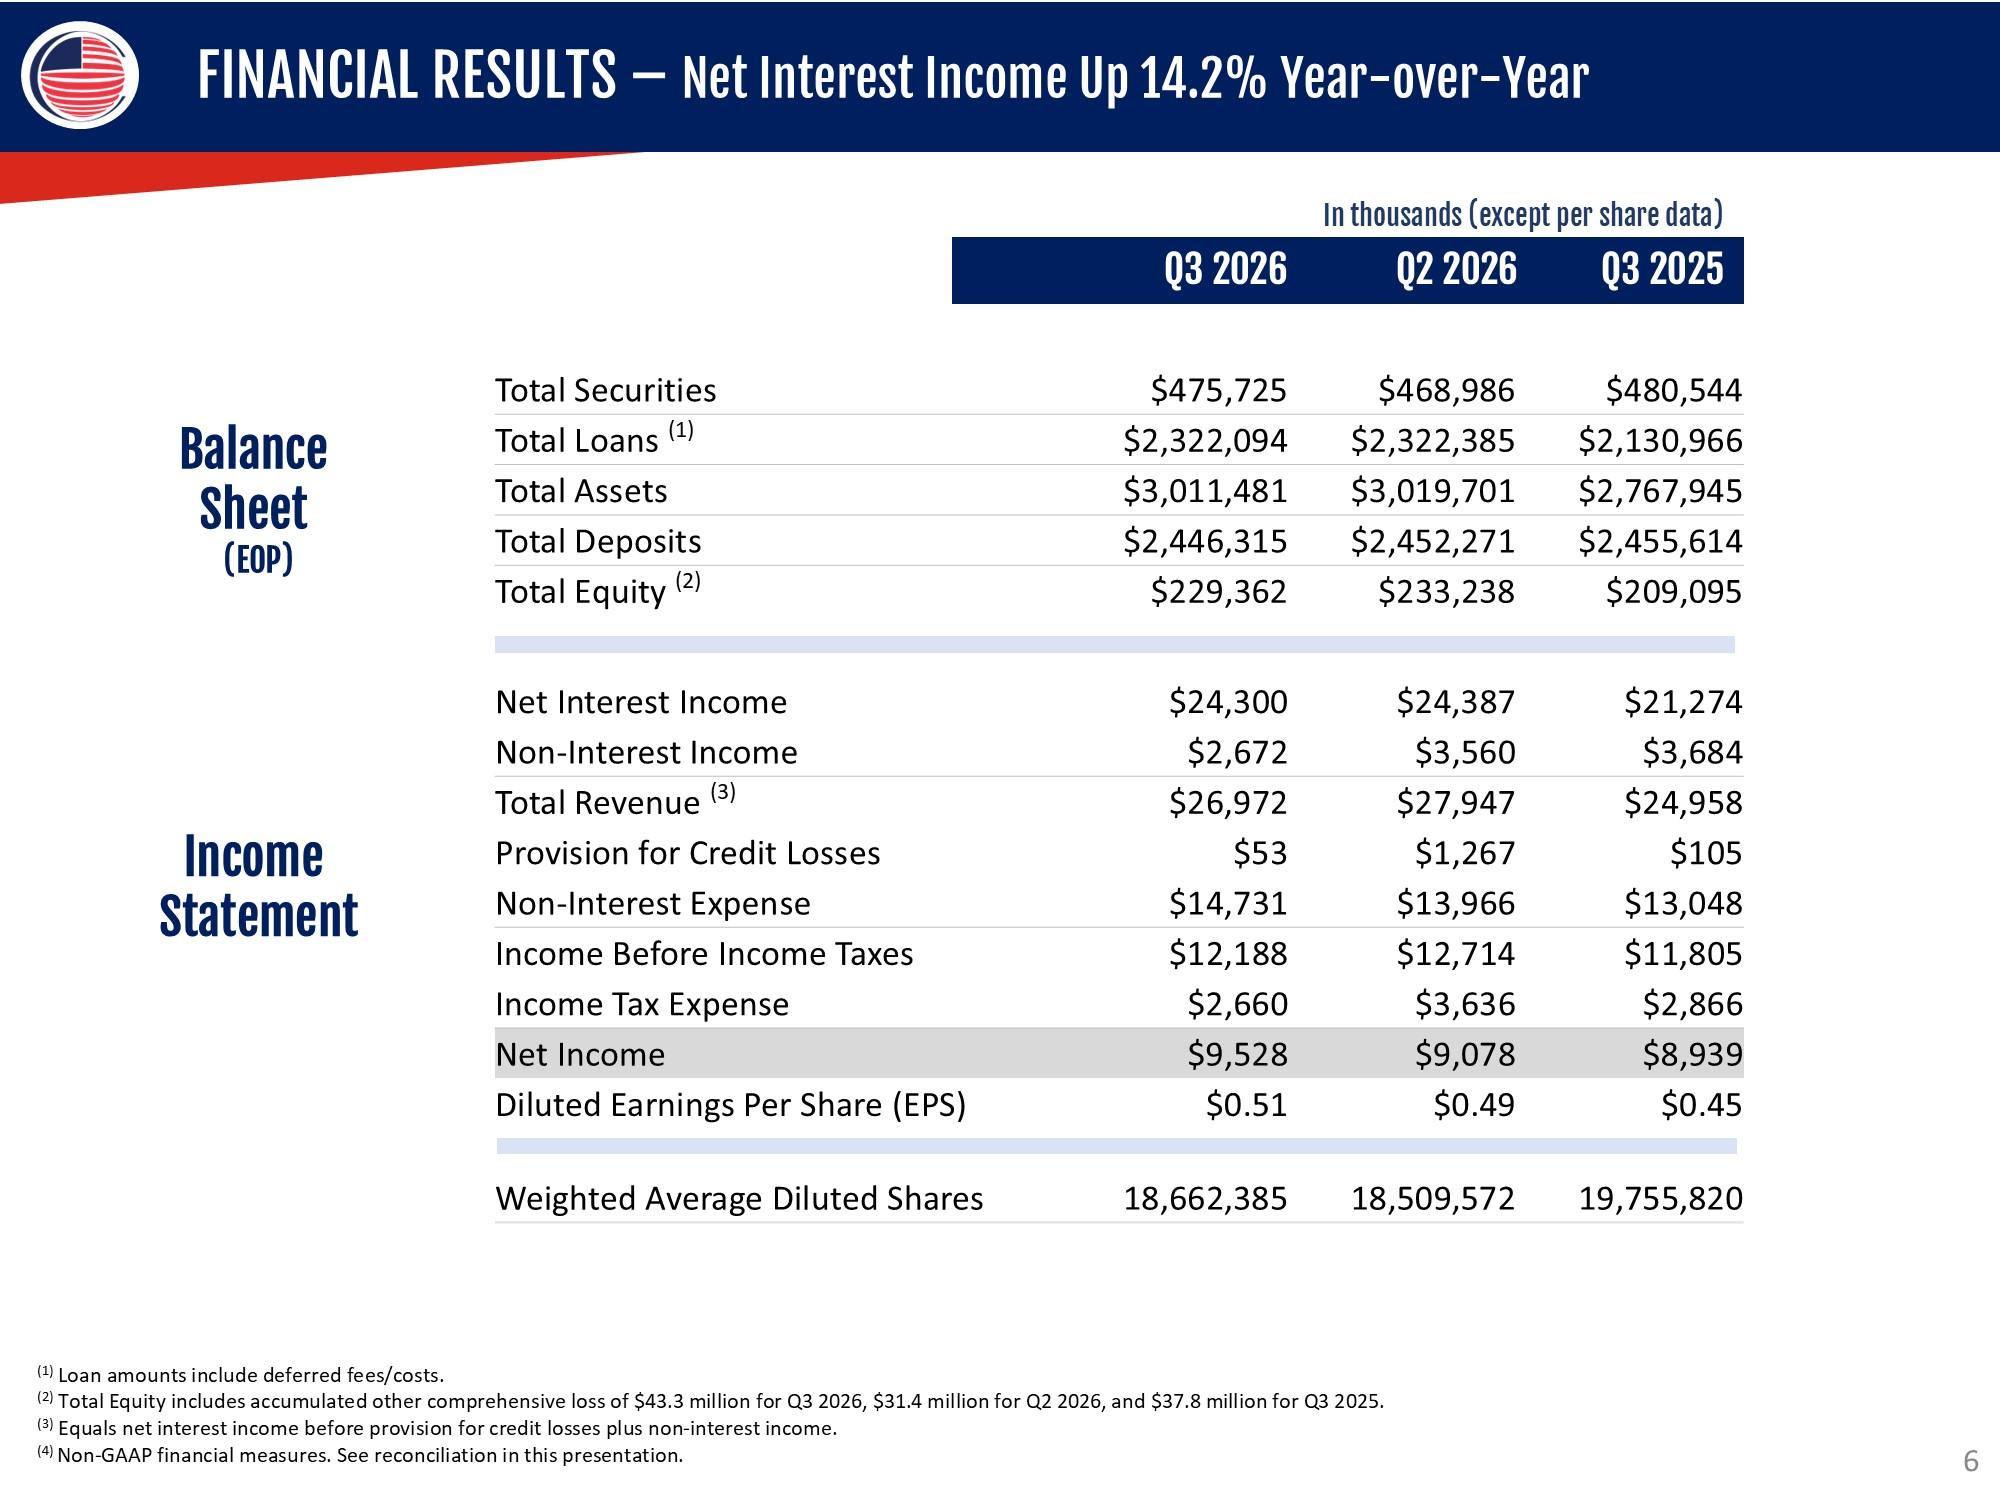
FINANCIAL RESULTS – Net Interest Income Up 14.2% Year-over-Year Balance Sheet (EOP) Income Statement Q3 2026 Q2 2026 Q3 2025 In thousands (except per share data) Total Securities $475,725 $468,986 $480,544 Total Loans (1) $2,322,094 $2,322,385 $2,130,966 Total Assets $3,011,481 $3,019,701 $2,767,945 Total Deposits $2,446,315 $2,452,271 $2,455,614 Total Equity (2) $229,362 $233,238 $209,095 Net Interest Income $24,300 $24,387 $21,274 Non-Interest Income $2,672 $3,560 $3,684 Total Revenue (3) $26,972 $27,947 $24,958 Provision for Credit Losses $53 $1,267 $105 Non-Interest Expense $14,731 $13,966 $13,048 Income Before Income Taxes $12,188 $12,714 $11,805 Income Tax Expense $2,660 $3,636 $2,866 Net Income $9,528 $9,078 $8,939 Diluted Earnings Per Share (EPS) $0.51 $0.49 $0.45 Weighted Average Diluted Shares 18,662,385 18,509,572 19,755,820 (1) Loan amounts include deferred fees/costs. (2) Total Equity includes accumulated other comprehensive loss of $43.3 million for Q3 2026, $31.4 million for Q2 2026, and $37.8 million for Q3 2025. (3) Equals net interest income before provision for credit losses plus non-interest income. (4) Non-GAAP financial measures. See reconciliation in this presentation. 6
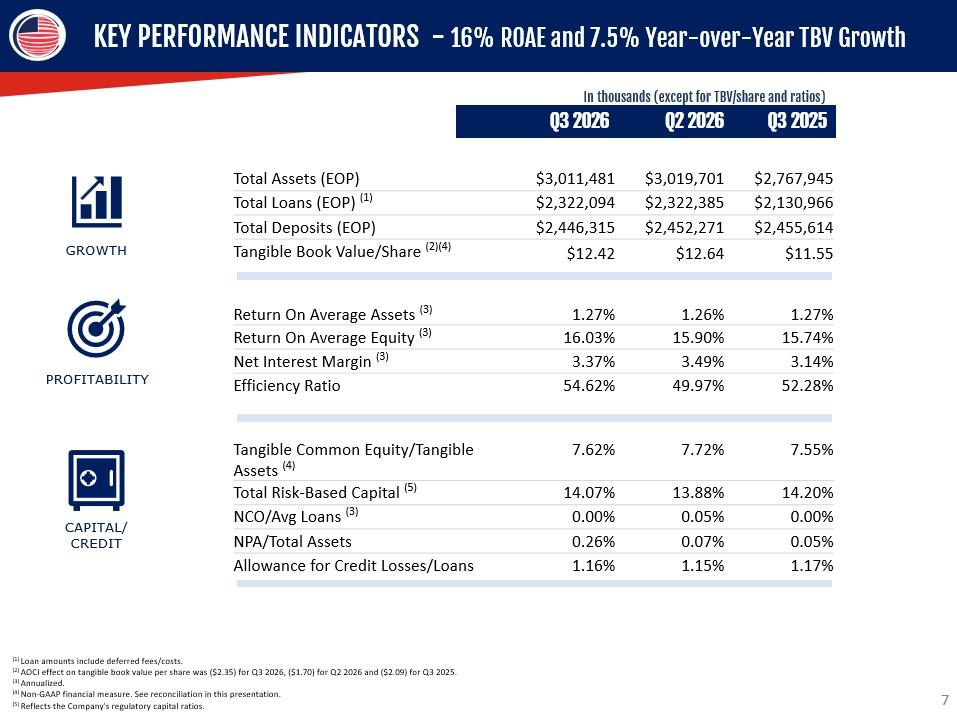
KEY PERFORMANCE INDICATORS - 16% ROAE and 7.5% Year-over-Year TBV Growth In thousands (except for TBV/share and ratios) Q3 2026 Q2 2026 Q3 2025 GROWTH PROFITABILITY CAPITAL/CREDIT Total Assets (EOP) $3,011,481 $3,019,701 $2,767,945 Total Loans (EOP) (1) $2,322,094 $2,322,385 $2,130,966 Total Deposits (EOP) $2,446,315 $2,452,271 $2,455,614 Tangible Book Value/Share (2)(4) $12.42 $12.64 $11.55 Return On Average Assets (3) 1.27% 1.26% 1.27% Return On Average Equity (3) 16.03% 15.90% 15.74% Net Interest Margin (3) 3.37% 3.49% 3.14% Efficiency Ratio 54.62% 49.97% 52.28% Tangible Common Equity/Tangible Assets (4) 7.62% 7.72% 7.55% Total Risk-Based Capital (5) 14.07% 13.88% 14.20% NCO/Avg Loans (3) 0.00% 0.05% 0.00% NPA/Total Assets 0.26% 0.07% 0.05% Allowance for Credit Losses/Loans 1.16% 1.15% 1.17% (1) Loan amounts include deferred fees/costs. (2) AOCI effect on tangible book value per share was ($2.35) for Q3 2026, ($1.70) for Q2 2026 and ($2.09) for Q3 2025. (3) Annualized. (4) Non-GAAP financial measure. See reconciliation in this presentation. (5) Reflects the Company's regulatory capital ratios. 7
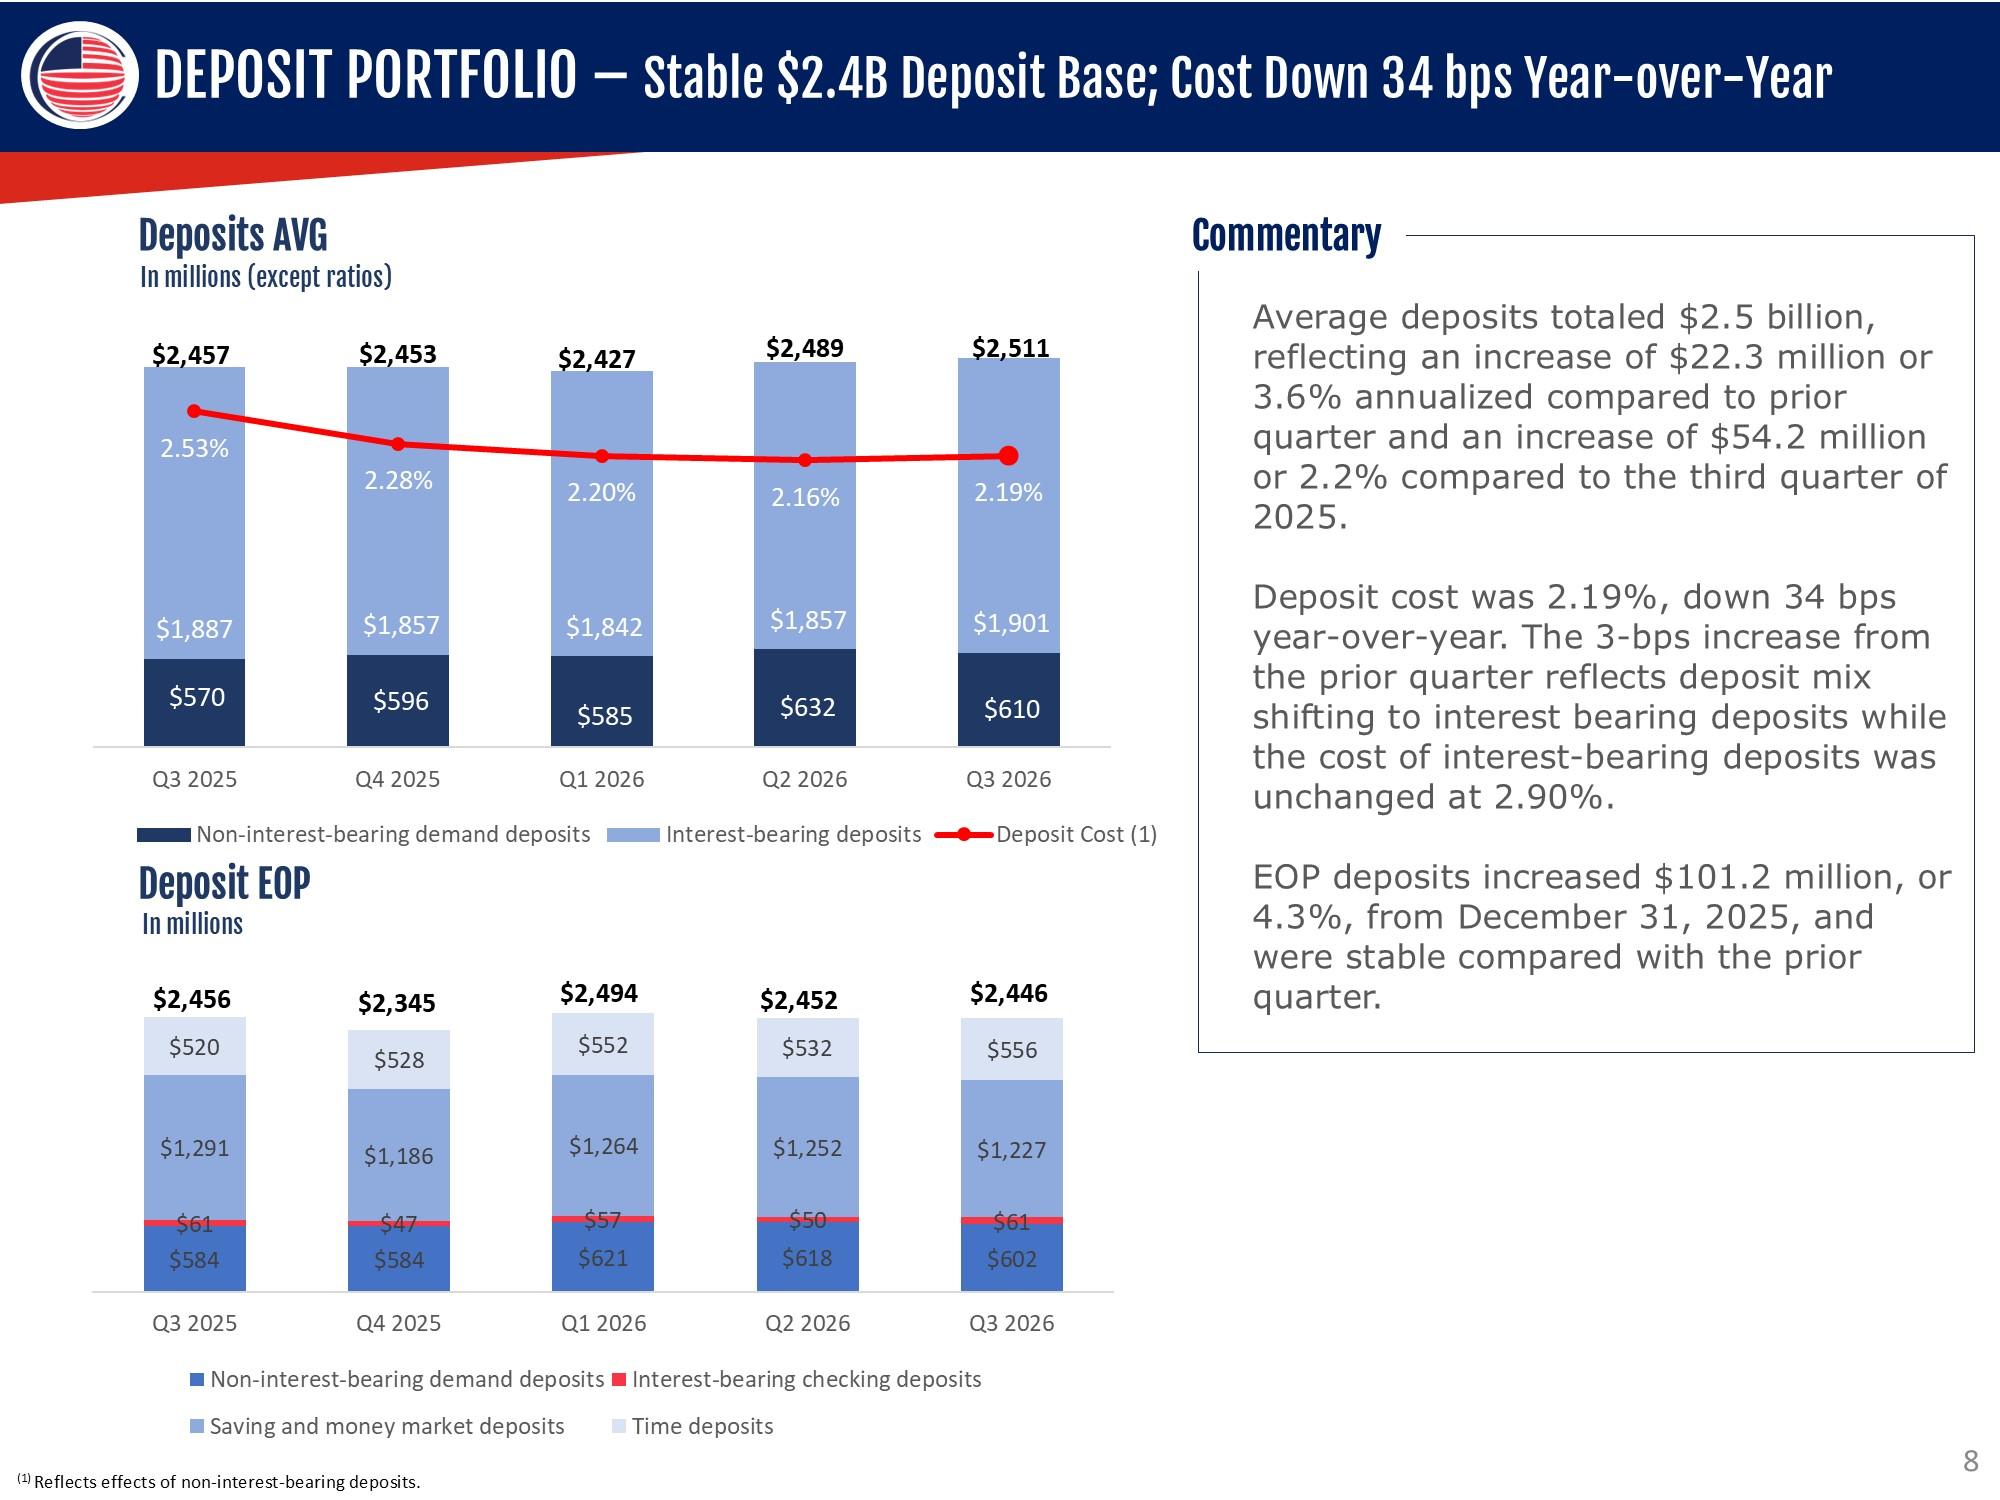
DEPOSIT PORTFOLIO – Stable $2.4B Deposit Base; Cost Down 34 bps Year-over-Year Deposits AVG In millions (except ratios) $2,457 $2,453 $2,427 $2,489 $2,511 2.53% 2.28% 2.20% 2.16% 2.19% $1,887 $1,857 $1,842 $1,857 $1,901 $570 $596 $585 $632 $610 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Non-Interest-bearing demand deposits Interest-bearing deposits Deposit Cost (1) Deposit EOP In millions $2,456 $2,345 $2,494 $2,452 $2,446 $520 $528 $552 $532 $556 $1,291 $1,186 $1,264 $1,252 $1,227 $61 $47 $57 $50 $61 $584 $584 $621 $618 $602 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Non-interest-bearing demand deposits Interest-bearing checking deposits Saving and money market deposits Time deposits Commentary Average deposits totaled $2.5 billion, reflecting an increase of $22.3 million or 3.6% annualized compared to prior quarter and an increase of $54.2 million or 2.2% compared to the third quarter of 2025. Deposit cost was 2.19%, down 34 bps year-over-year. The 3-bps increase from the prior quarter reflects deposit mix shifting to interest bearing deposits while the cost of interest-bearing deposits was unchanged at 2.90%. EOP deposits increased $101.2 million, or 4.3%, from December 31, 2025, and were stable compared with the prior quarter. (1) Reflects effects of non-interest-bearing deposits. 8
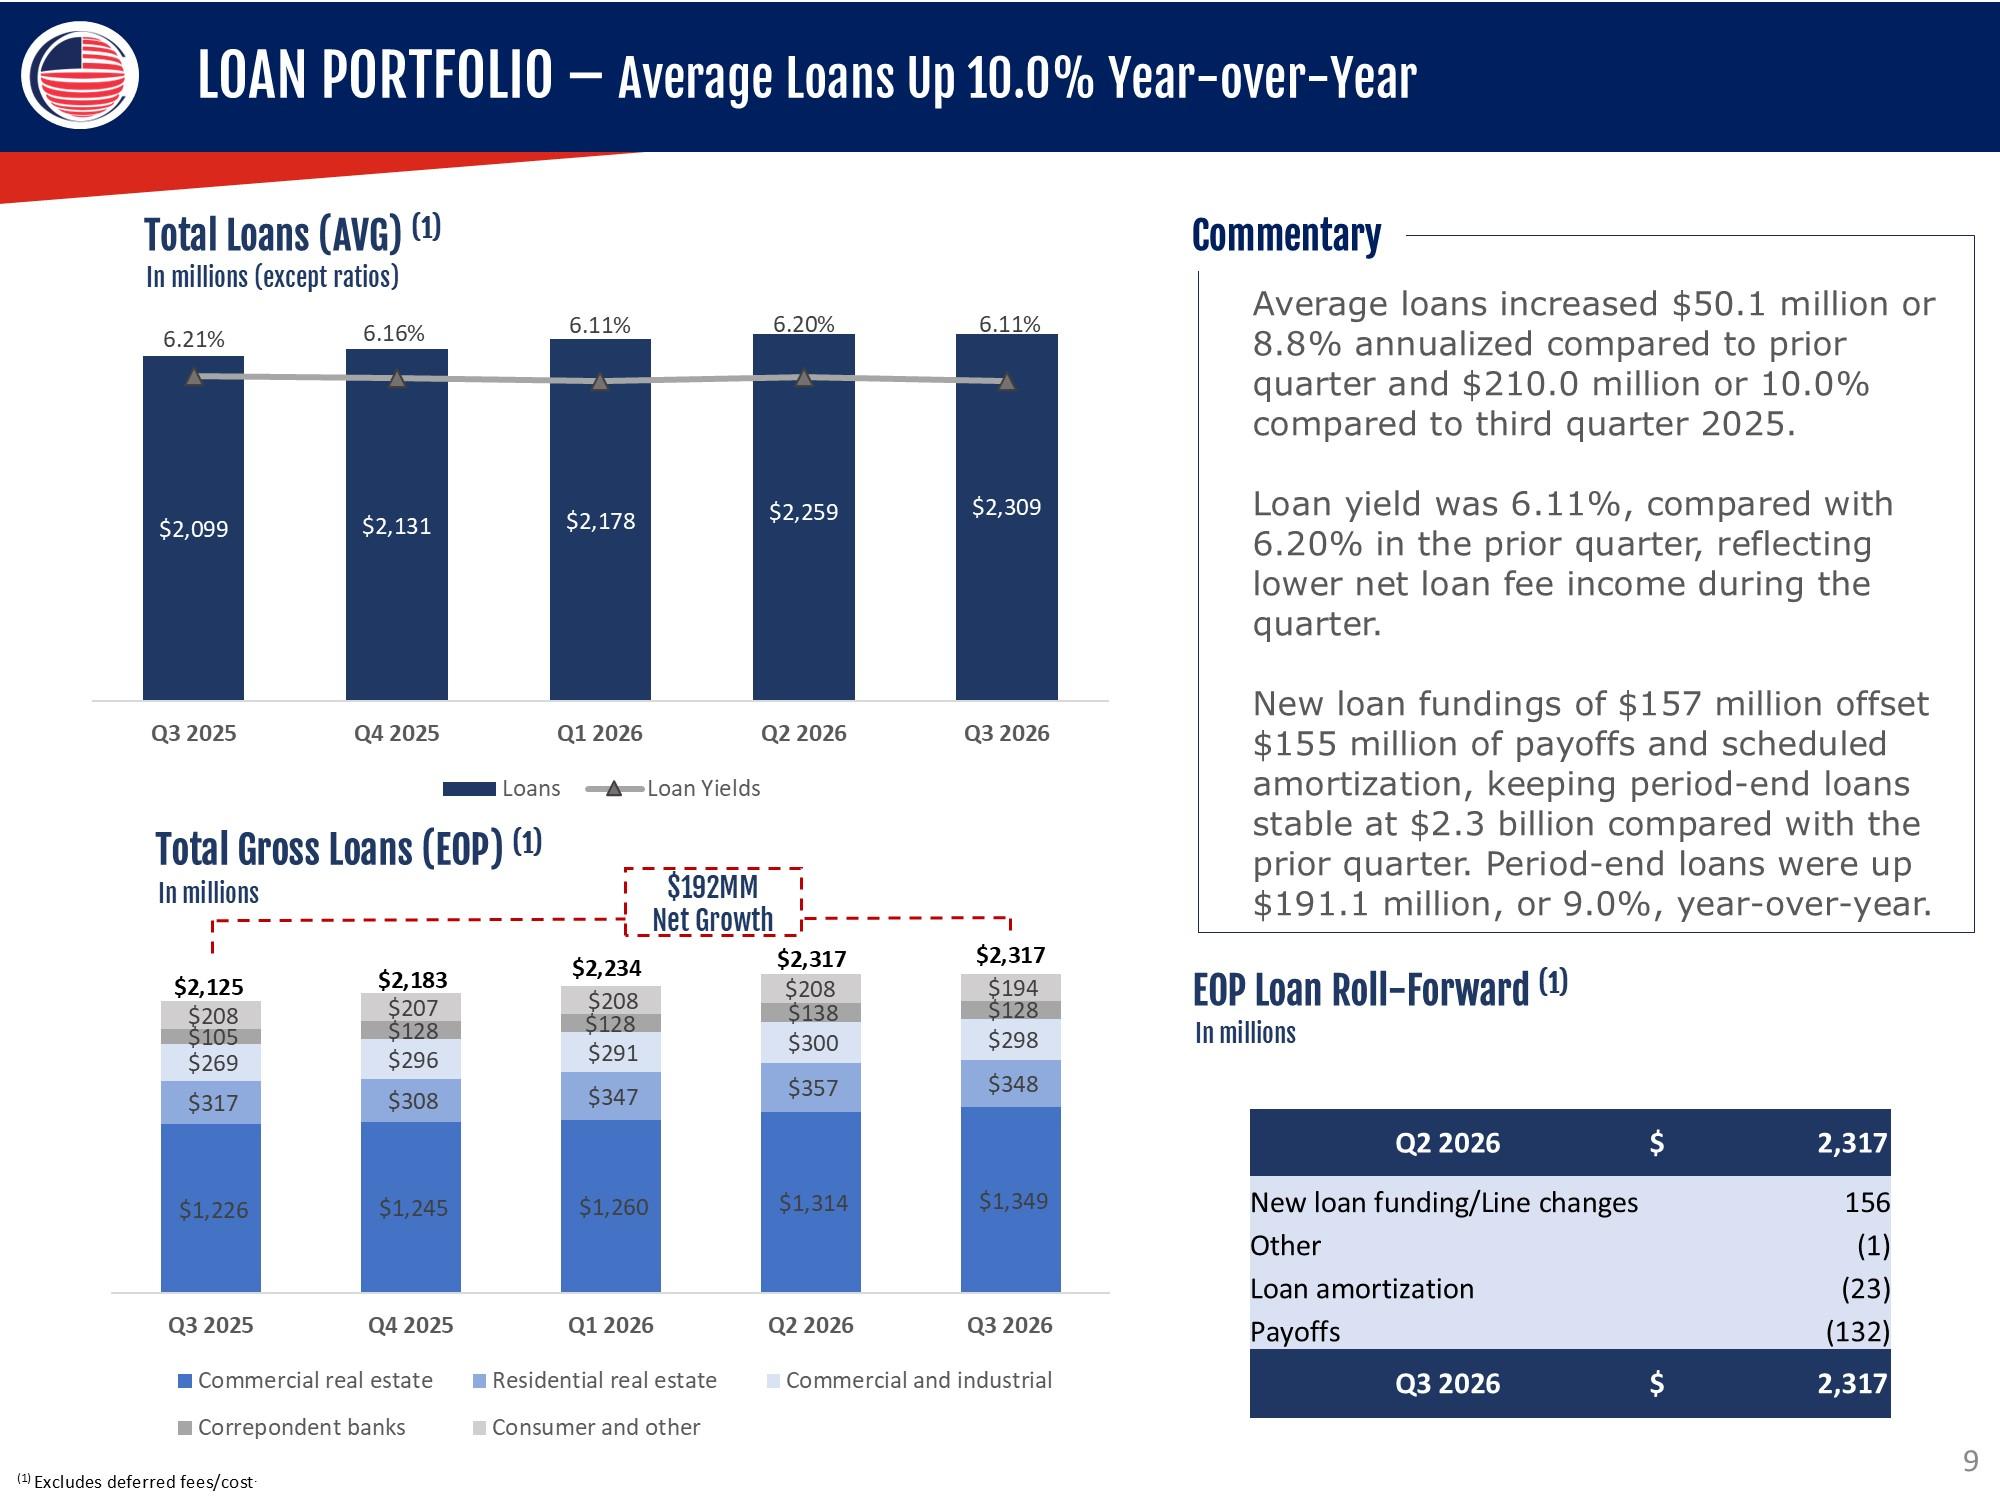
LOAN PORTFOLIO – Average Loans Up 10.0% Year-over-Year Total Loans (AVG) (1) In millions (except ratios) 6.21% 6.16% 6.11% 6.20% 6.11% $2,099 $2,131 $2,178 $2,259 $2,309 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Loans Loan Yields Total Gross Loans (EOP) (1) In millions $2,125 $2,183 $2,234 $2,317 $2,317 $208 $207 $208 $208 $194 $105 $128 $128 $138 $128 $269 $296 $291 $300 $298 $317 $308 $347 $357 $348 $1,226 $1,245 $1,260 $1,314 $1,349 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Commercial real estate Residential real estate Commercial real estate Correspondent banks Consumer and other Commentary Average loans increased $50.1 million or 8.8% annualized compared to prior quarter and $210.0 million or 10.0% compared to third quarter 2025. Loan yield was 6.11%, compared with 6.20% in the prior quarter, reflecting lower net loan fee income during the quarter. New loan fundings of $157 million offset $155 million of payoffs and scheduled amortization, keeping period-end loans stable at $2.3 billion compared with the prior quarter. Period-end loans were up $191.1 million, or 9.0%, year-over-year. EOP Loan Roll-Forward (1) In millions Q2 2026 $ 2,317 New loan funding/Line changes 156 Other (1) Loan amortization (23) Payoffs (132) Q3 2026 $ 2,317 (1) Excludes deferred fees/cost. 9
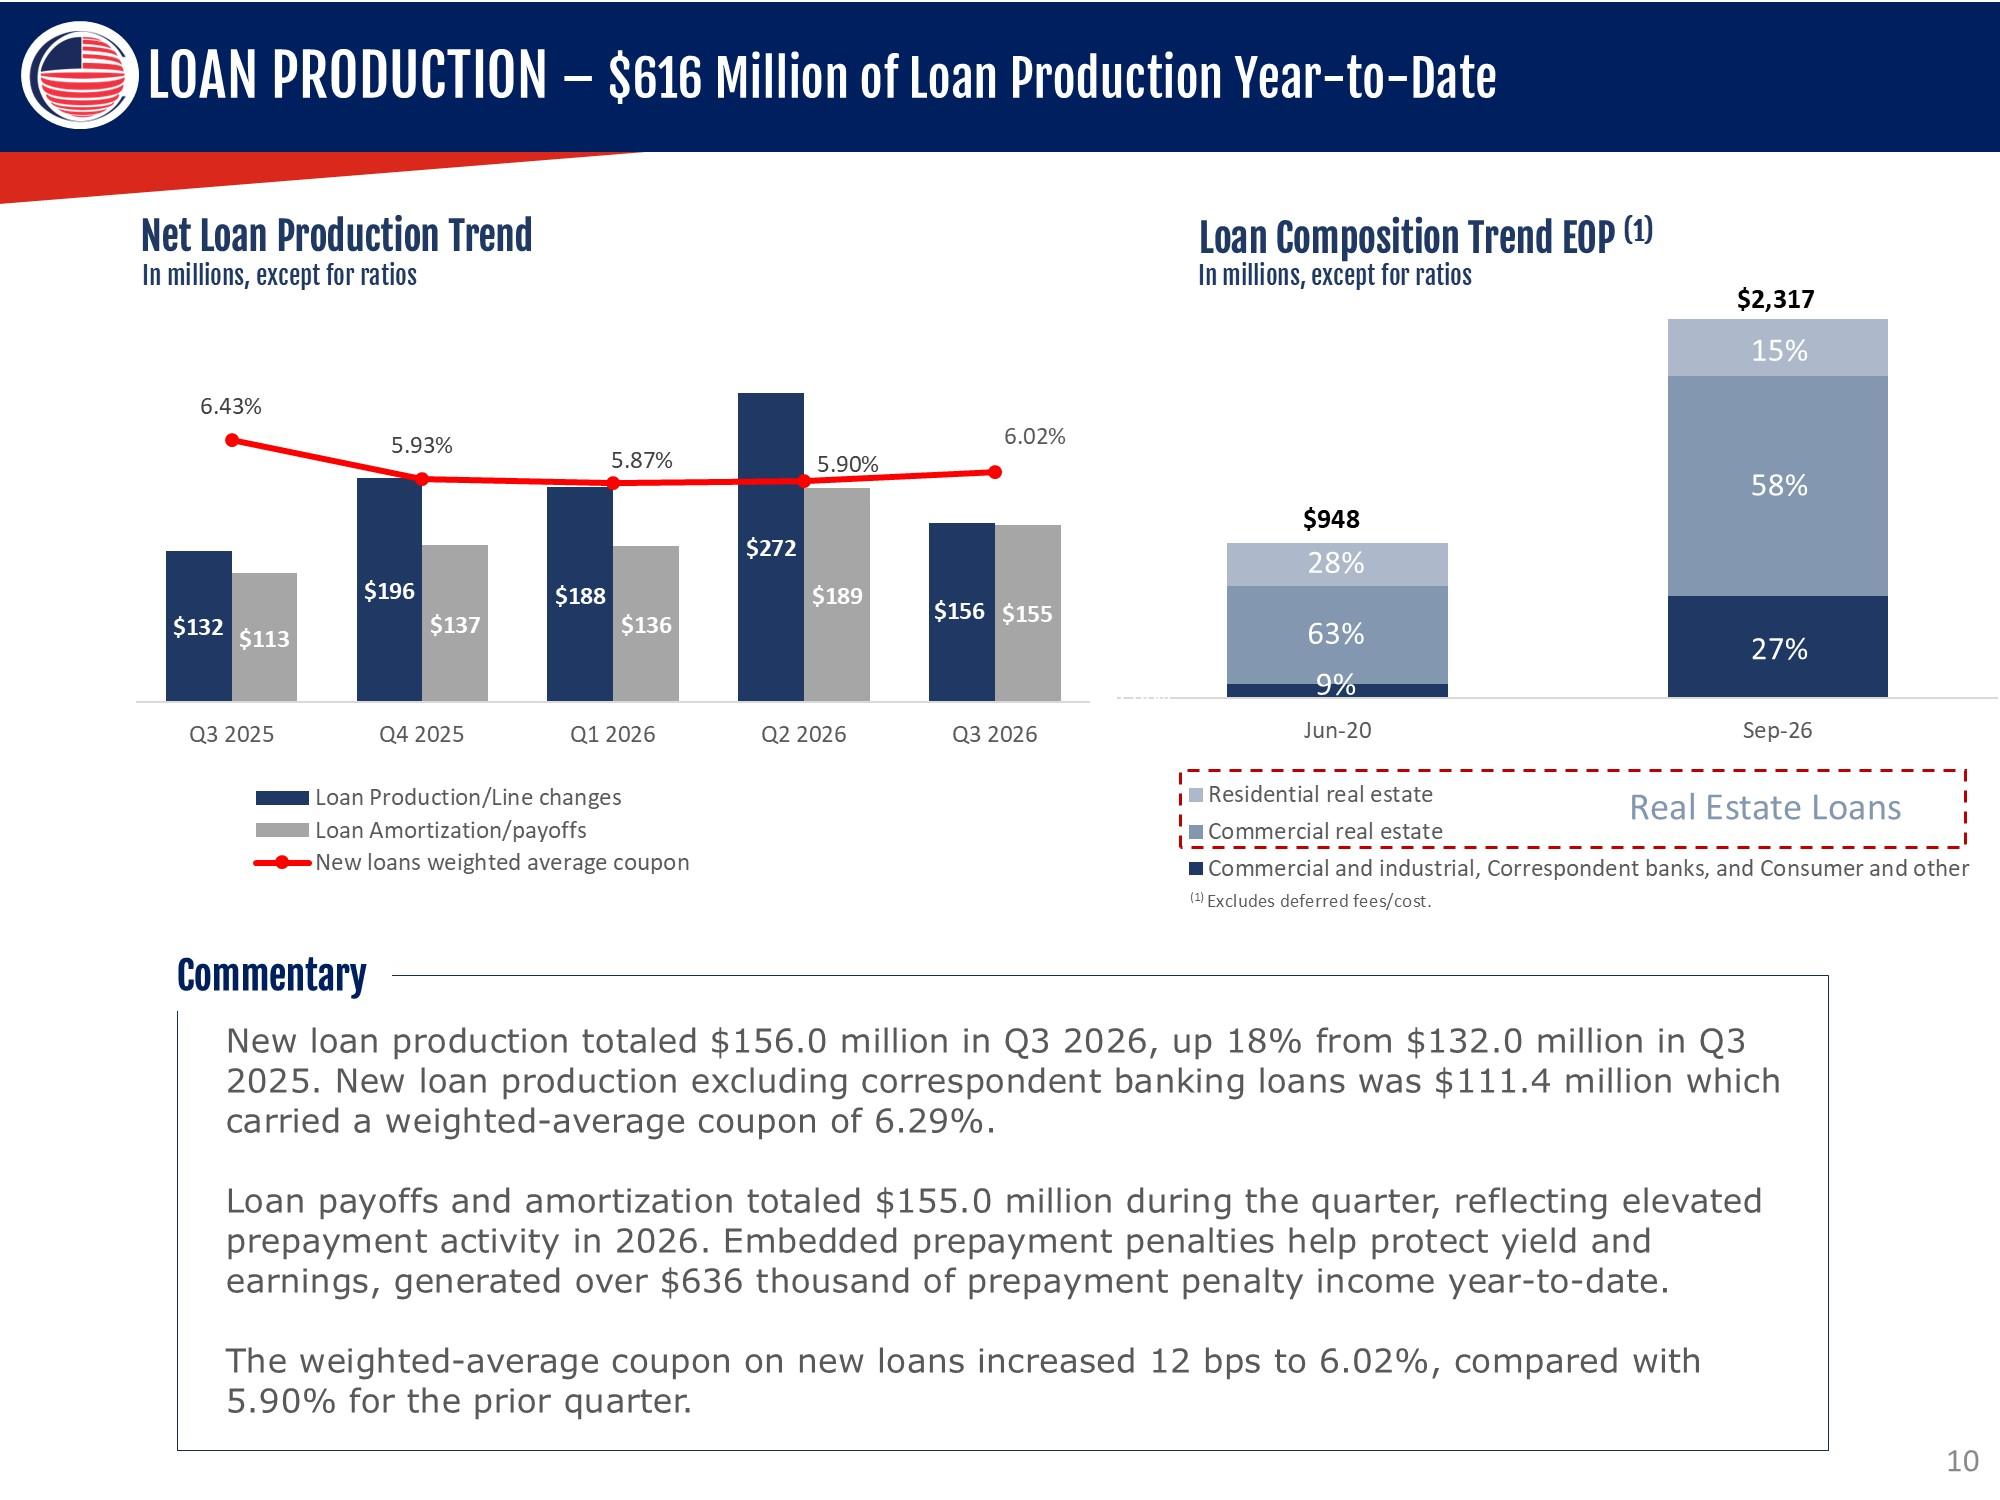
LOAN PRODUCTION – $616 Million of Loan Production Year-to-Date Net Loan Production Trend In millions, except for ratios 6.43% 5.93% 5.87% 5.90% 6.02% $132 $113 $196 $137 $188 $136 $272 $189 $156 $155 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Loan Production/Line changes Loan Amortization/payoffs New loans weighted average coupon Loan Composition Trend EOP (1) In millions, except for ratios $948 $2,317 28% 15% 63% 58% 9% 27% Jun-20 Sep-26 Residential real estate Commercial real estate Real Estate Loans Commercial and industrial, correspondent banks, and Consume rand other Commentary New loan production totaled $156.0 million in Q3 2026, up 18% from $132.0 million in Q3 2025. New loan production excluding correspondent banking loans was $111.4 million which carried a weighted-average coupon of 6.29%. Loan payoffs and amortization totaled $155.0 million during the quarter, reflecting elevated prepayment activity in 2026. Embedded prepayment penalties help protect yield and earnings, generated over $636 thousand of prepayment penalty income year-to-date. The weighted-average coupon on new loans increased 12 bps to 6.02%, compared with 5.90% for the prior quarter. 10
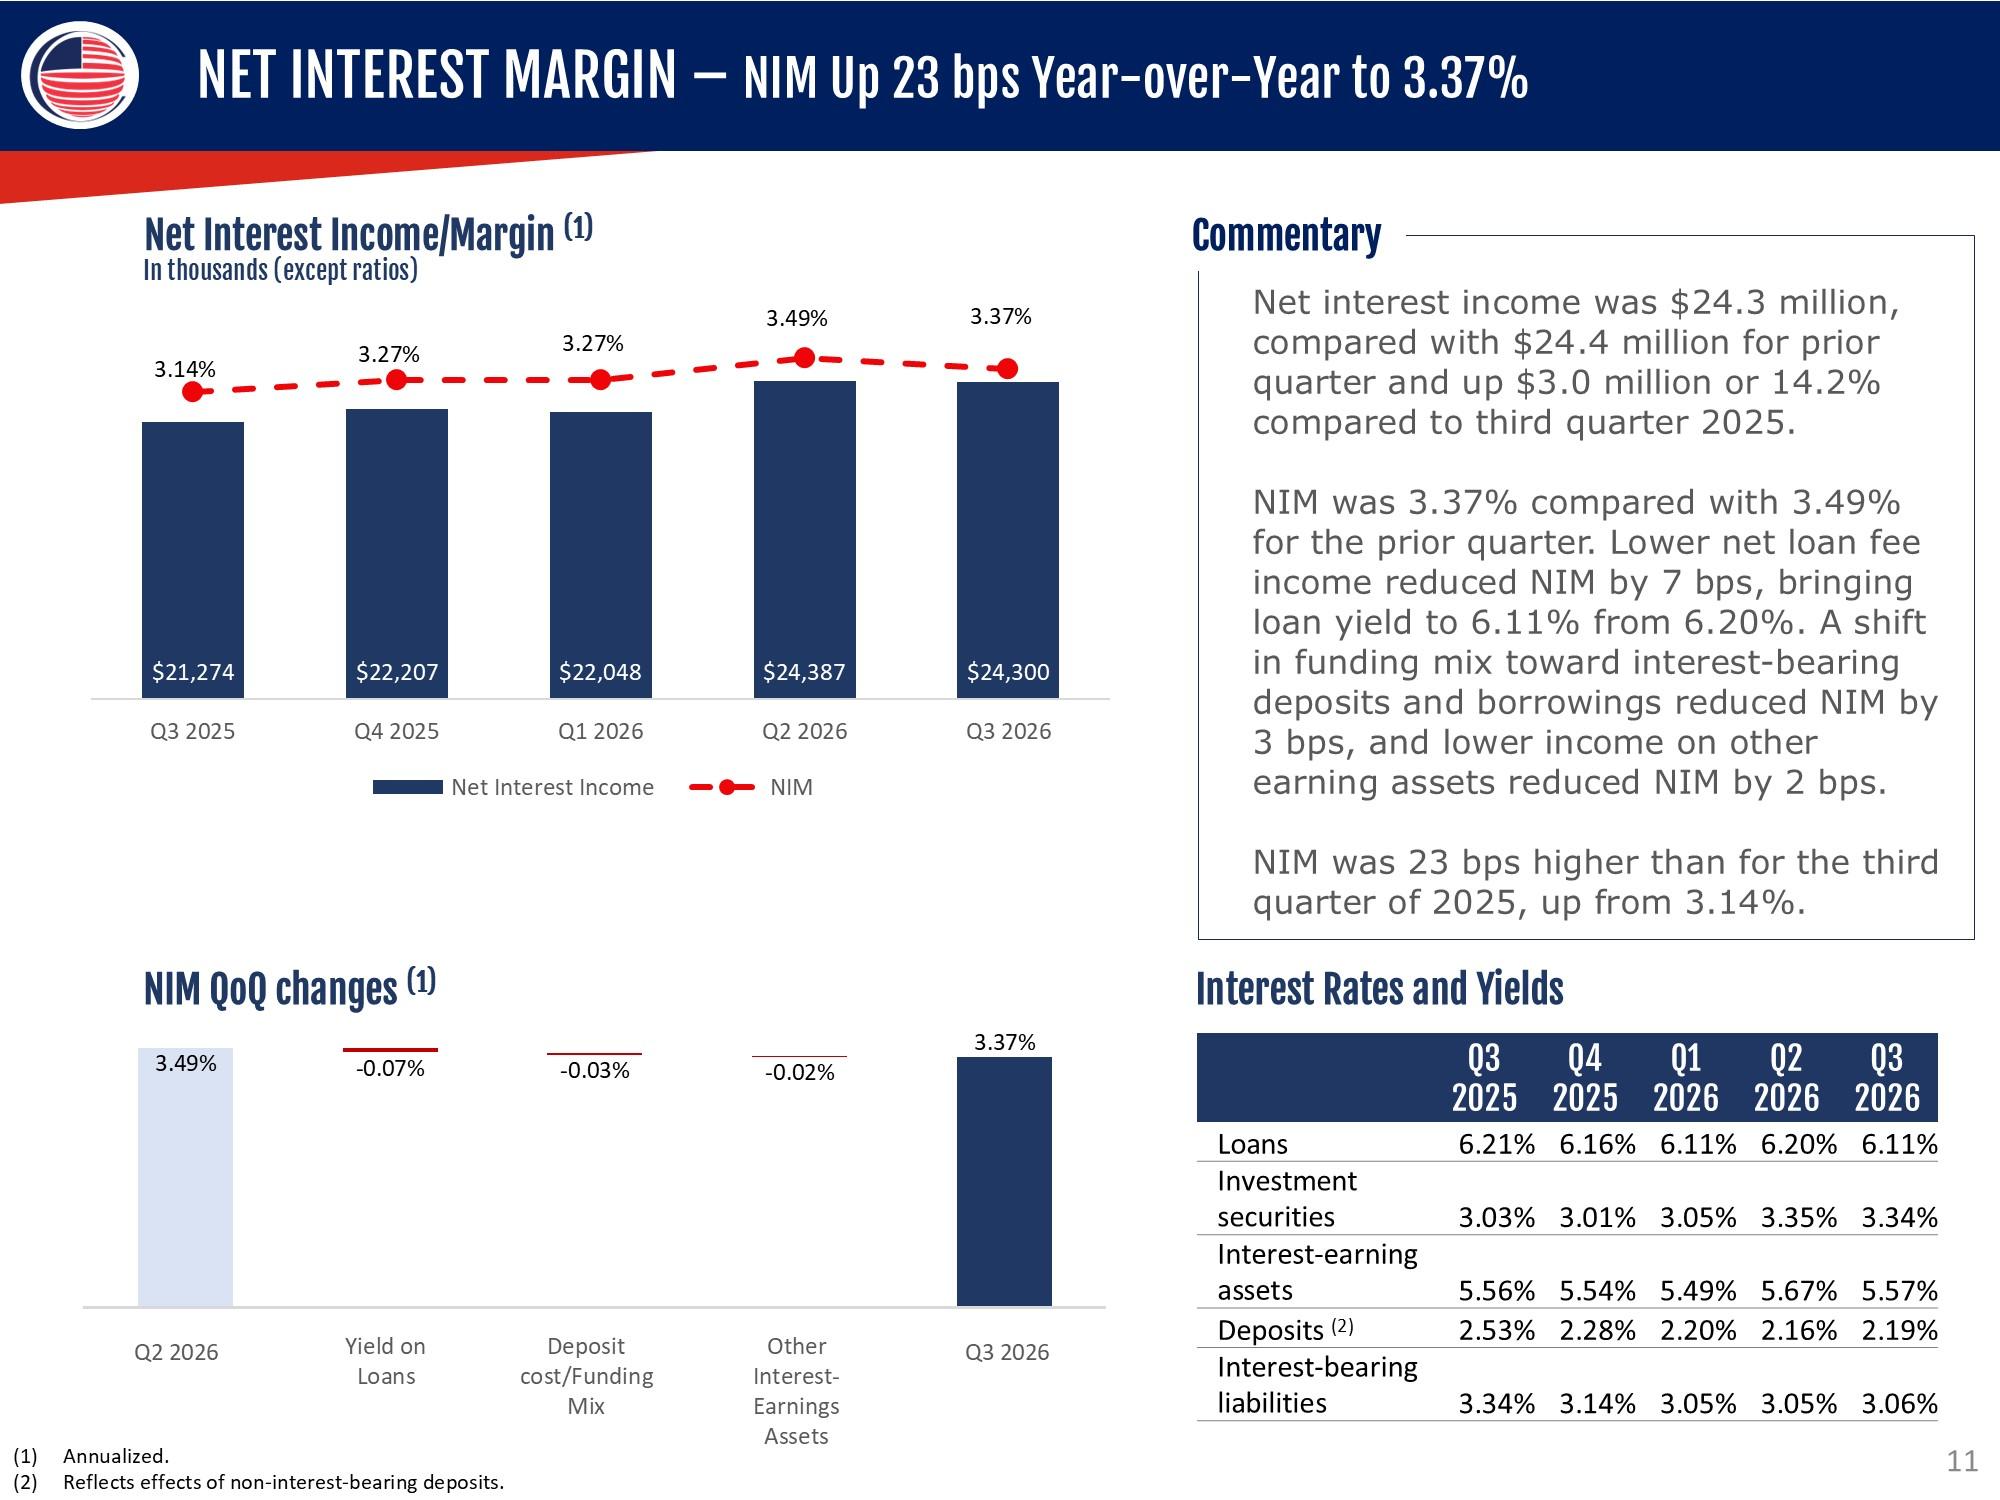
NET INTEREST MARGIN – NIM Up 23 bps Year-over-Year to 3.37% Net Interest Income/Margin (1) In thousands (except ratios) 3.14% 3.27% 3.27% 3.49% 3.37% $21,274 $22,207 $22,048 $24,387 $24,300 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Net interest income NIM NIM QoQ changes (1) 3.49% -0.07% -0.03% -0.02% 3.37% Q2 2026 Yield on Loans Deposit cost/Funding Mix Other Interest-Eearnings Assets Q3 2026 Commentary Net interest income was $24.3 million, compared with $24.4 million for prior quarter and up $3.0 million or 14.2% compared to third quarter 2025. NIM was 3.37% compared with 3.49% for the prior quarter. Lower net loan fee income reduced NIM by 7 bps, bringing loan yield to 6.11% from 6.20%. A shift in funding mix toward interest-bearing deposits and borrowings reduced NIM by 3 bps, and lower income on other earning assets reduced NIM by 2 bps. NIM was 23 bps higher than for the third quarter of 2025, up from 3.14%. Interest Rates and Yields Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Loans 6.21% 6.16% 6.11% 6.20% 6.11% Investment securities 3.03% 3.01% 3.05% 3.35% 3.34% Interest-earning assets 5.56% 5.54% 5.49% 5.67% 5.57% Deposits (2) 2.53% 2.28% 2.20% 2.16% 2.19% Interest-bearing liabilities 3.34% 3.14% 3.05% 3.05% 3.06% Annualized. Reflects effects of non-interest-bearing deposits. 11
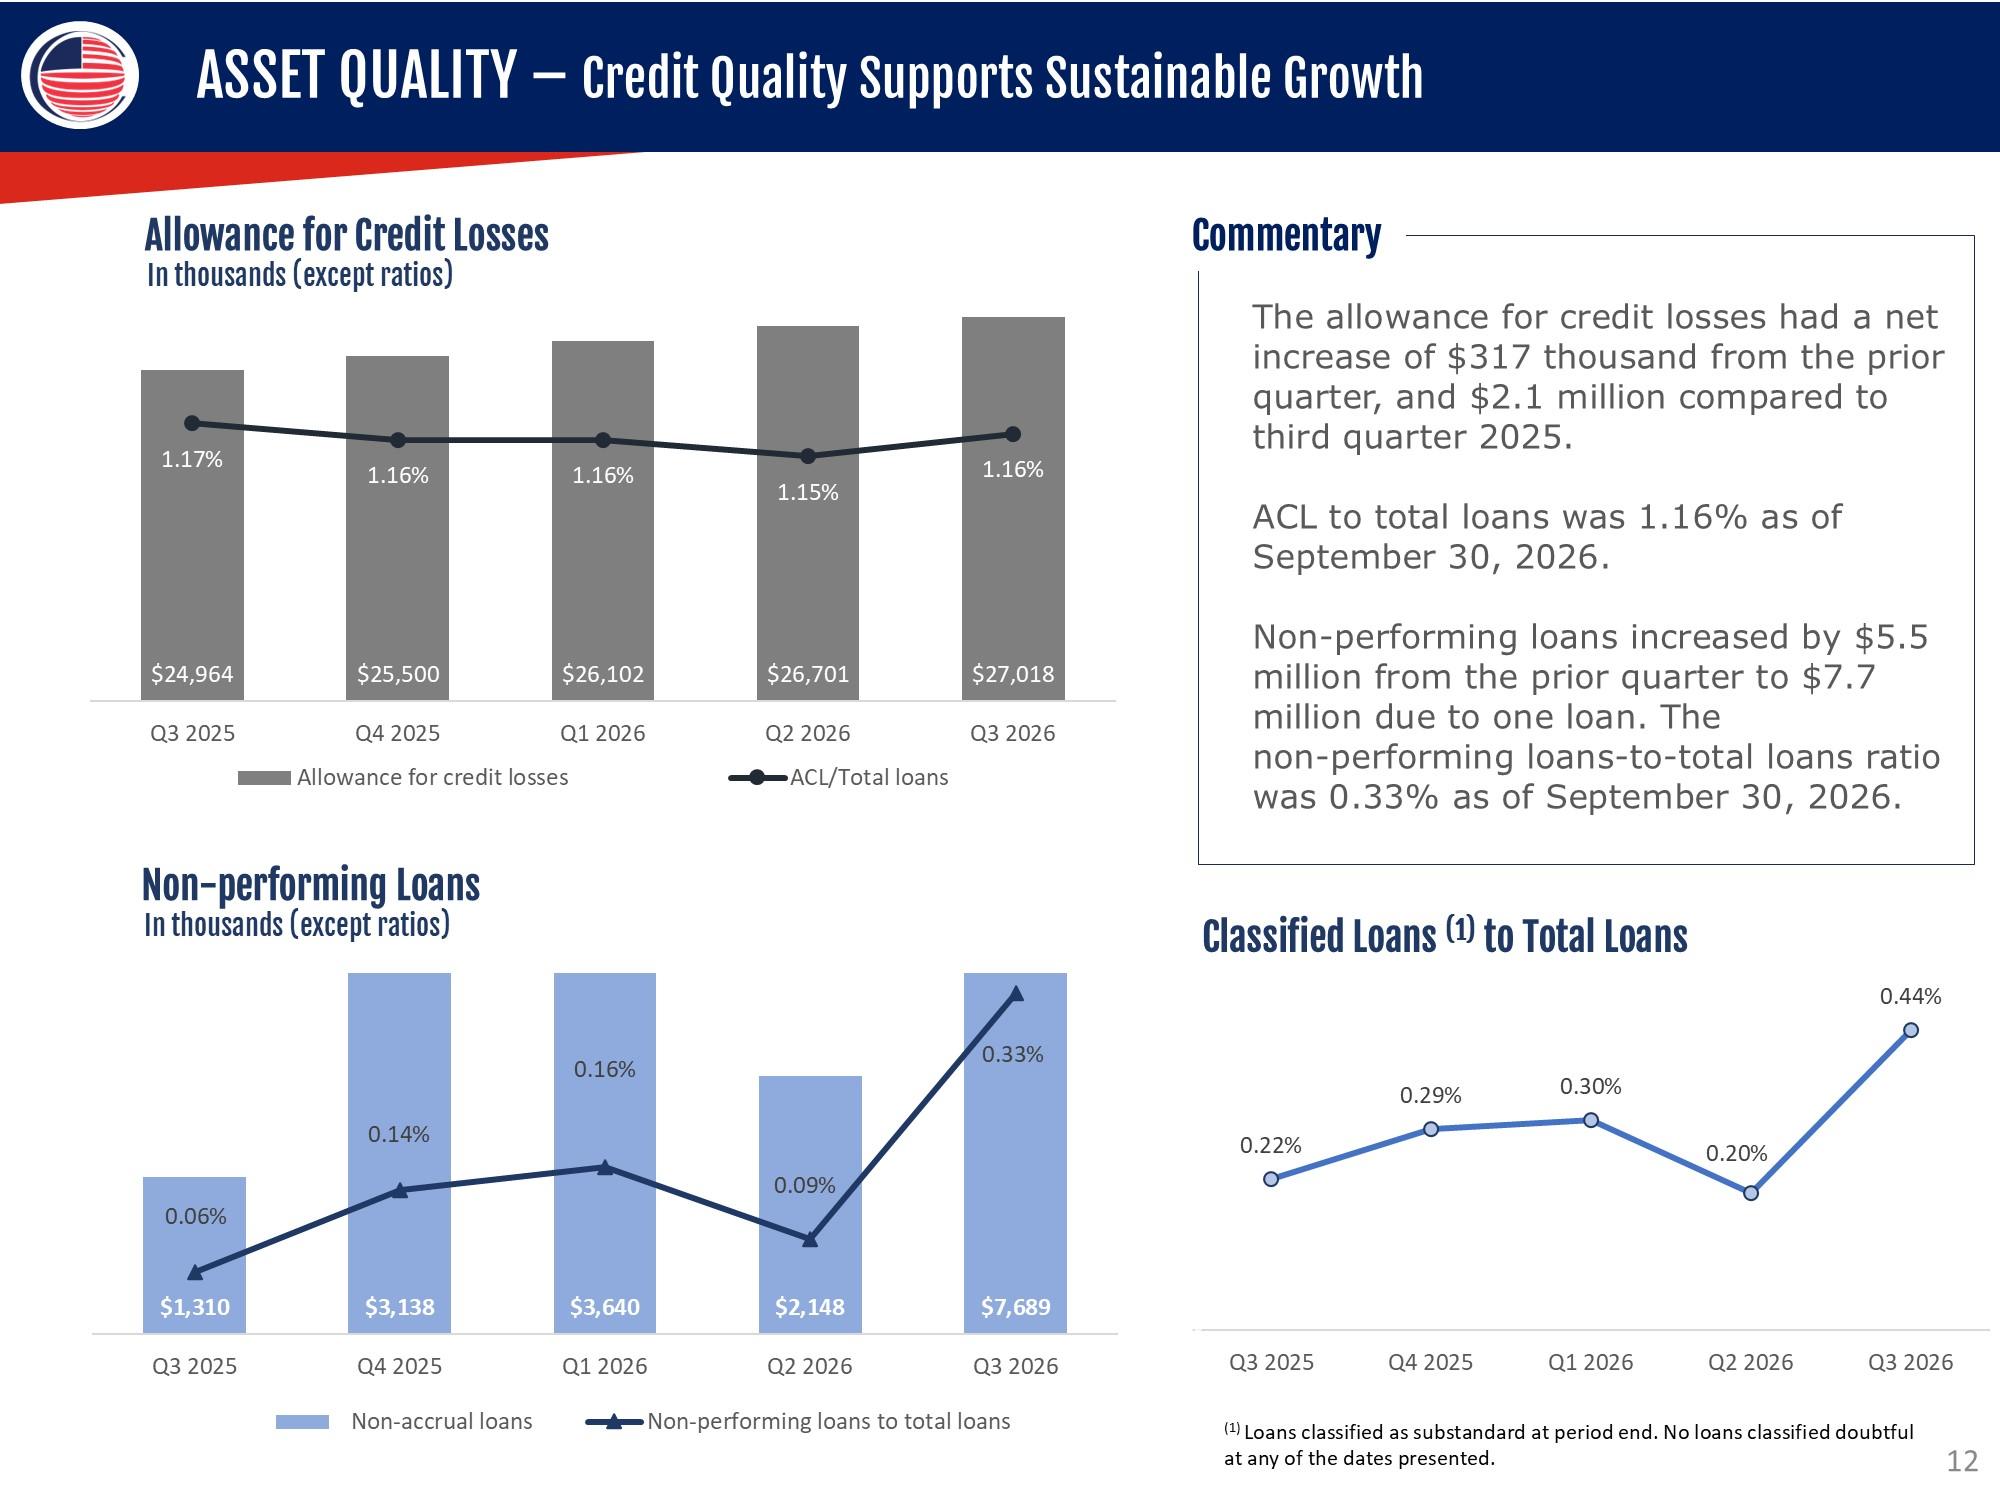
ASSET QUALITY – Credit Quality Supports Sustainable Growth Allowance for Credit Losses In thousands (except ratios) 1.17% 1.16% 1.16% 1.15% 1.16% $24,964 $25,500 $26,102 $26,701 $27,018 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Allowance for credit losses Non-performing Loans In thousands (except ratios) 0.06% 0.14% 0.16% 0.09% 0.33% $1,310 $3,138 $3,640 $2,148 $7,689 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 Non-accrual loans Non-performing loans to total loans Commentary The allowance for credit losses had a net increase of $317 thousand from the prior quarter, and $2.1 million compared to third quarter 2025. ACL to total loans was 1.16% as of September 30, 2026. Non‑performing loans increased by $5.5 million from the prior quarter to $7.7 million due to one loan. The non‑performing loans‑to‑total loans ratio was 0.33% as of September 30, 2026. Classified Loans (1) to Total Loans 0.22% 0.29% 0.30% 0.20% 0.44% Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 (1) Loans classified as substandard at period end. No loans classified doubtful at any of the dates presented. 12
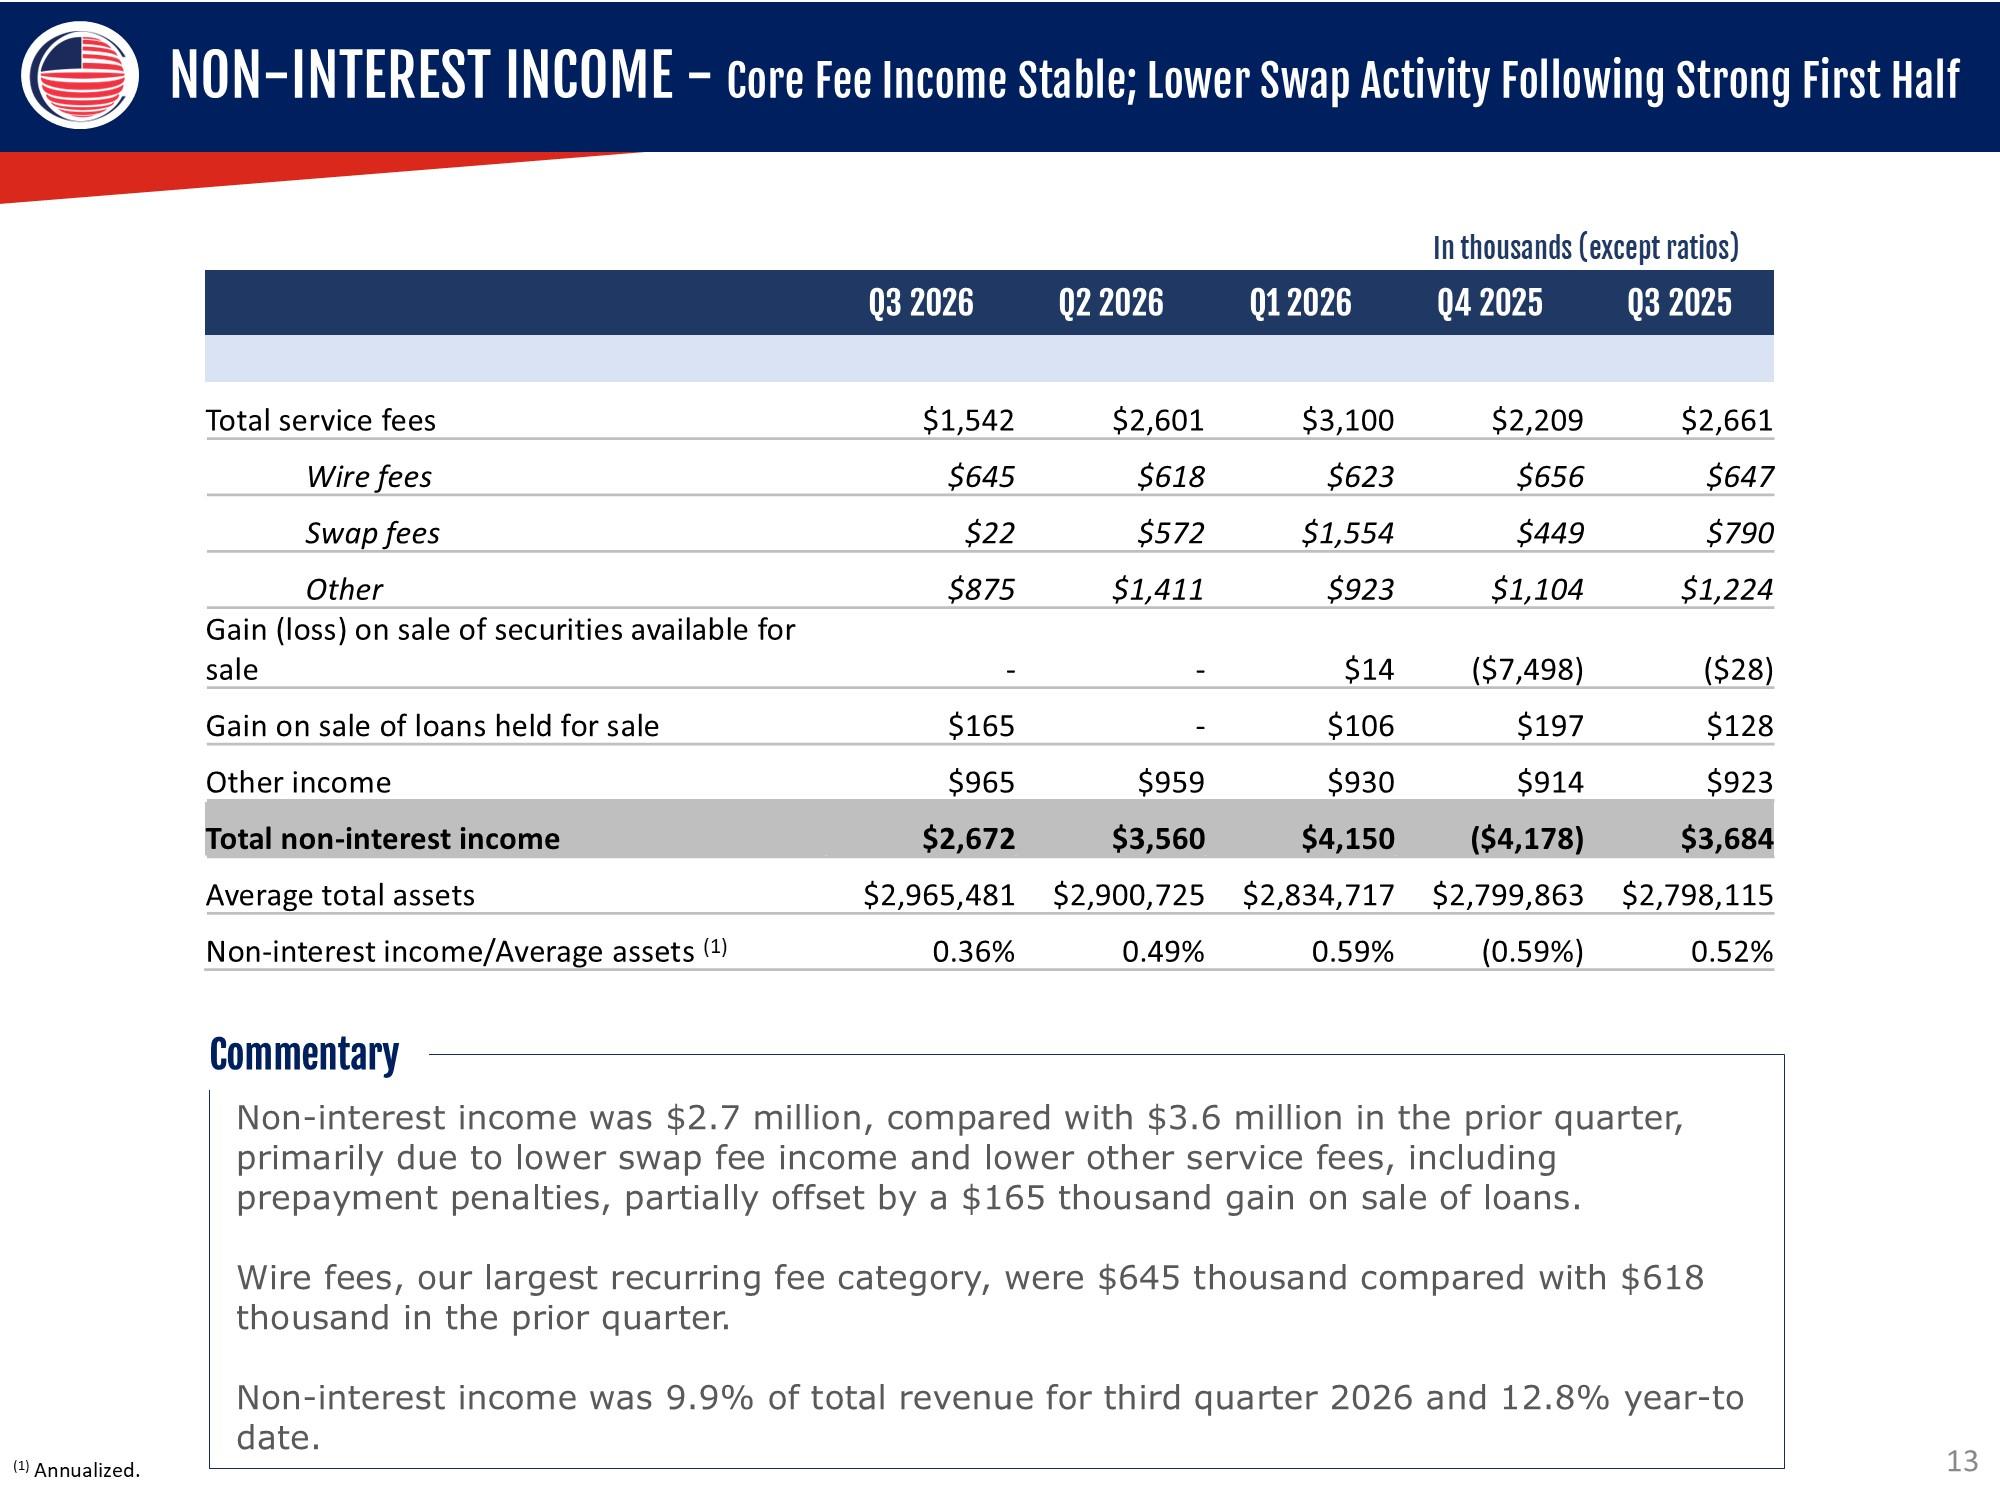
NON-INTEREST INCOME - Core Fee Income Stable; Lower Swap Activity Following Strong First Half In thousands (except ratios) Q3 2026 Q2 2026 Q1 2026 Q4 2025 Q3 2025 Total service fees $1,542 $2,601 $3,100 $2,209 $2,661 Wire fees $645 $618 $623 $656 $647 Swap fees $22 $572 $1,554 $449 $790 Other $875 $1,411 $923 $1,104 $1,224 Gain (loss) on sale of securities available for sale - - $14 ($7,498) ($28) Gain on sale of loans held for sale $165 - $106 $197 $128 Other income $965 $959 $930 $914 $923 Total non-interest income $2,672 $3,560 $4,150 ($4,178) $3,684 Average total assets $2,965,481 $2,900,725 $2,834,717 $2,799,863 $2,798,115 Non-interest income/Average assets (1) 0.36% 0.49% 0.59% (0.59%) 0.52% Commentary Non-interest income was $2.7 million, compared with $3.6 million in the prior quarter, primarily due to lower swap fee income and lower other service fees, including prepayment penalties, partially offset by a $165 thousand gain on sale of loans. Wire fees, our largest recurring fee category, were $645 thousand compared with $618 thousand in the prior quarter. Non-interest income was 9.9% of total revenue for third quarter 2026 and 12.8% year-to date. (1) Annualized. 13
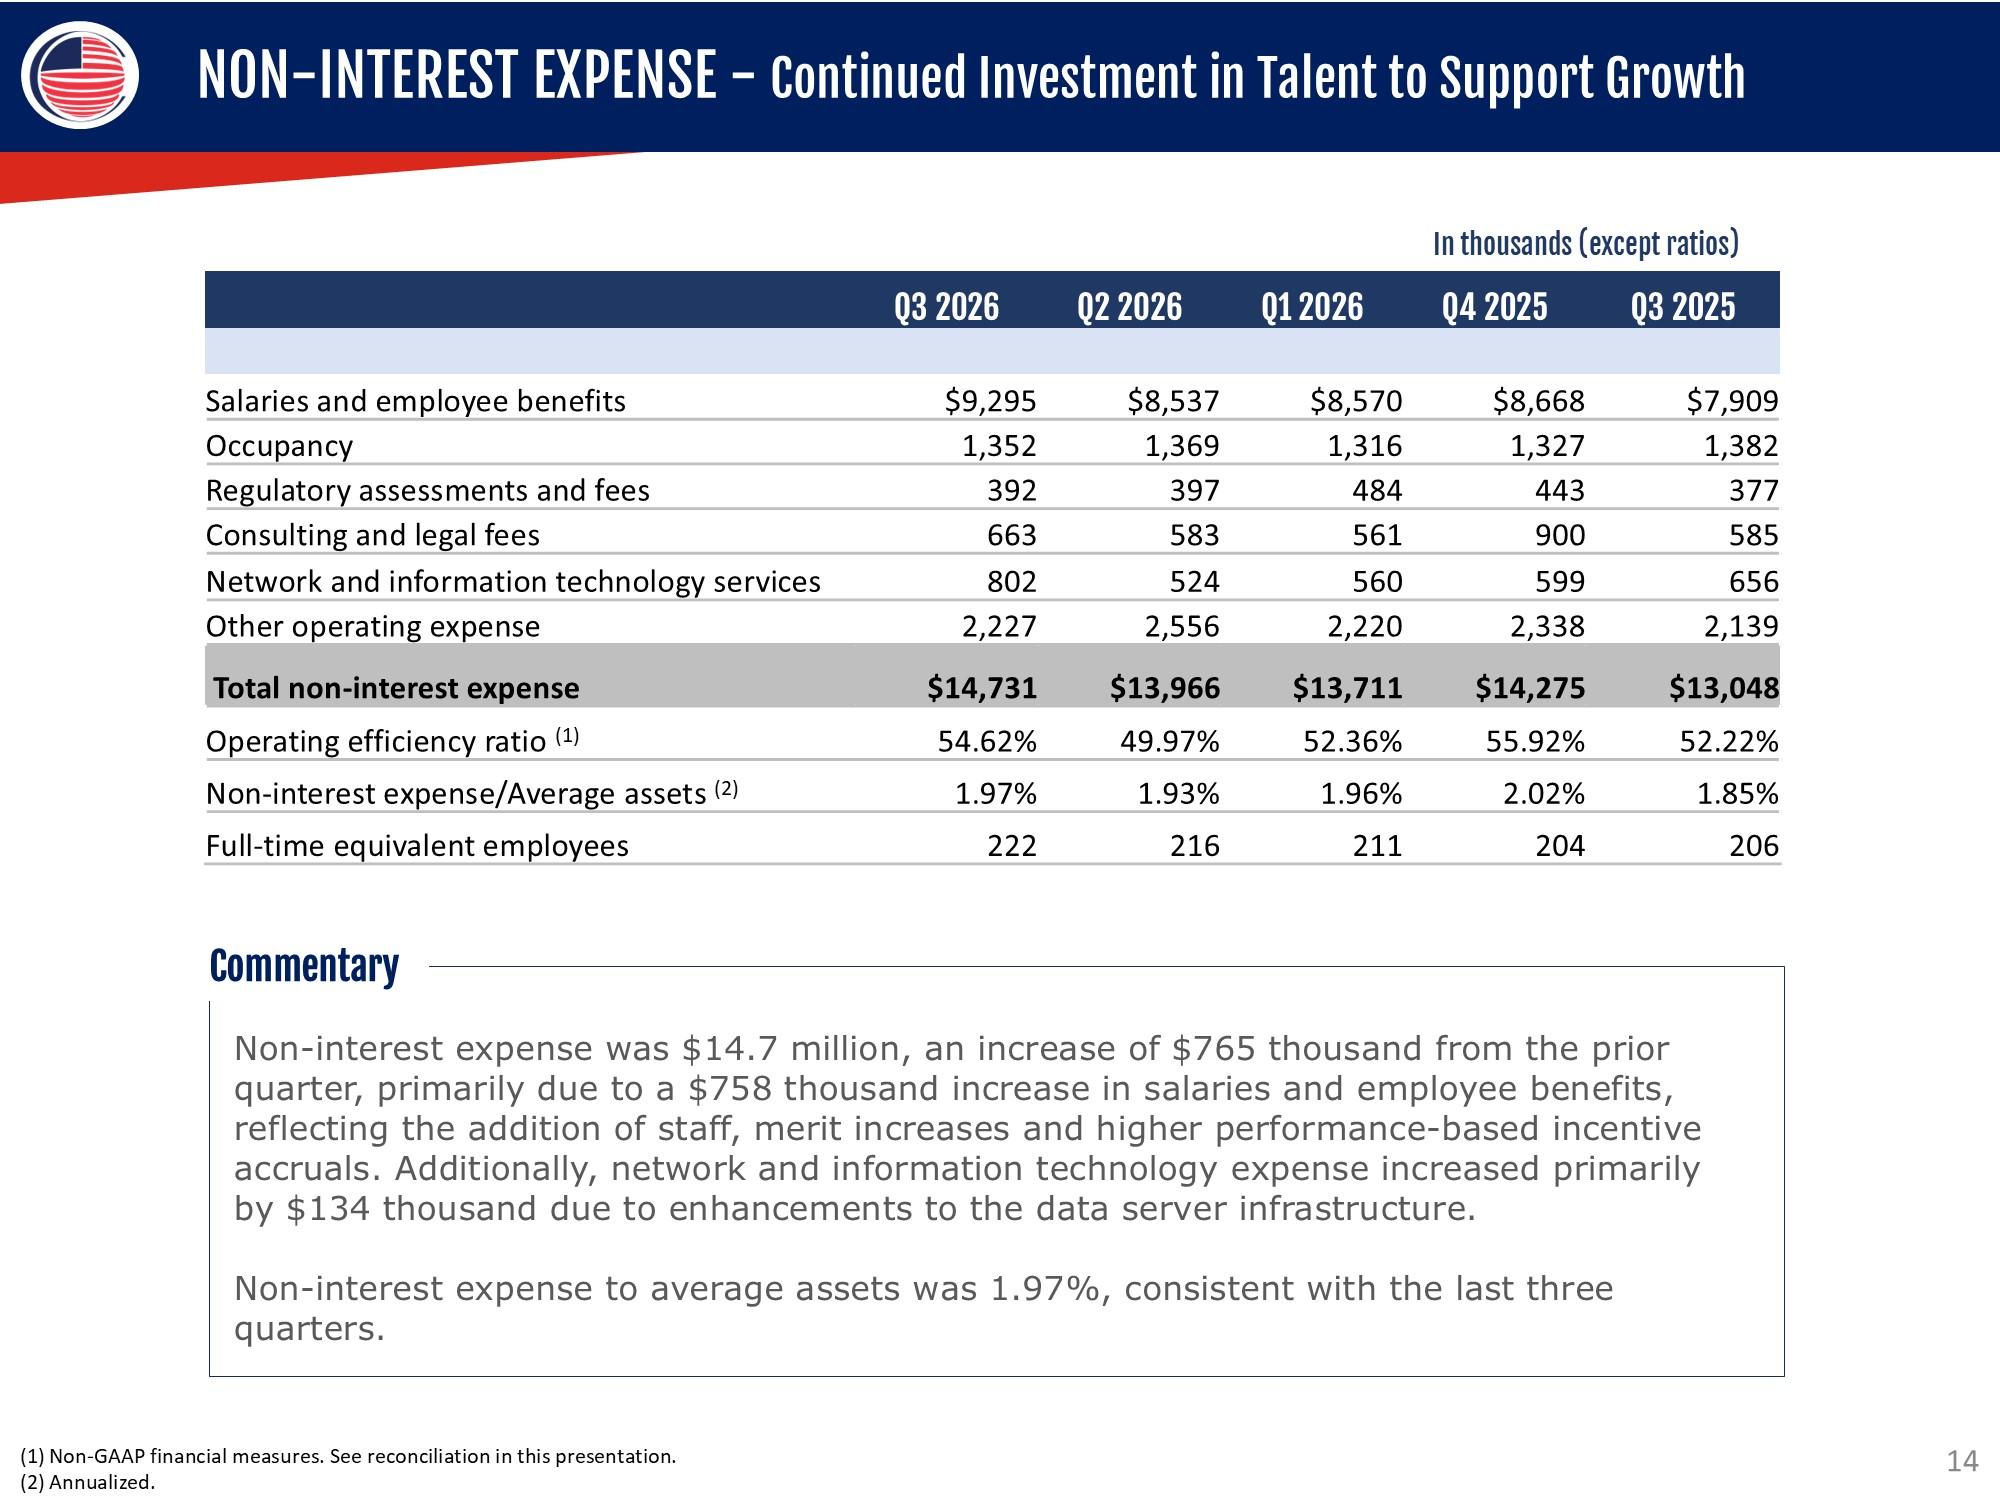
NON-INTEREST EXPENSE - Continued Investment in Talent to Support Growth In thousands (except ratios) Q3 2026 Q2 2026 Q1 2026 Q4 2025 Q3 2025 Salaries and employee benefits $9,295 $8,537 $8,570 $8,668 $7,909 Occupancy 1,352 1,369 1,316 1,327 1,382 Regulatory assessments and fees 392 397 484 443 377 Consulting and legal fees 663 583 561 900 585 Network and information technology services 802 524 560 599 656 Other operating expense 2,227 2,556 2,220 2,338 2,139 Total non-interest expense $14,731 $13,966 $13,711 $14,275 $13,048 Operating efficiency ratio (1) 54.62% 49.97% 52.36% 55.92% 52.22% Non-interest expense/Average assets (2) 1.97% 1.93% 1.96% 2.02% 1.85% Full-time equivalent employees 222 216 211 204 206 Commentary Non-interest expense was $14.7 million, an increase of $765 thousand from the prior quarter, primarily due to a $758 thousand increase in salaries and employee benefits, reflecting the addition of staff, merit increases and higher performance-based incentive accruals. Additionally, network and information technology expense increased primarily by $134 thousand due to enhancements to the data server infrastructure. Non-interest expense to average assets was 1.97%, consistent with the last three quarters. (1) Non-GAAP financial measures. See reconciliation in this presentation. (2) Annualized. 14
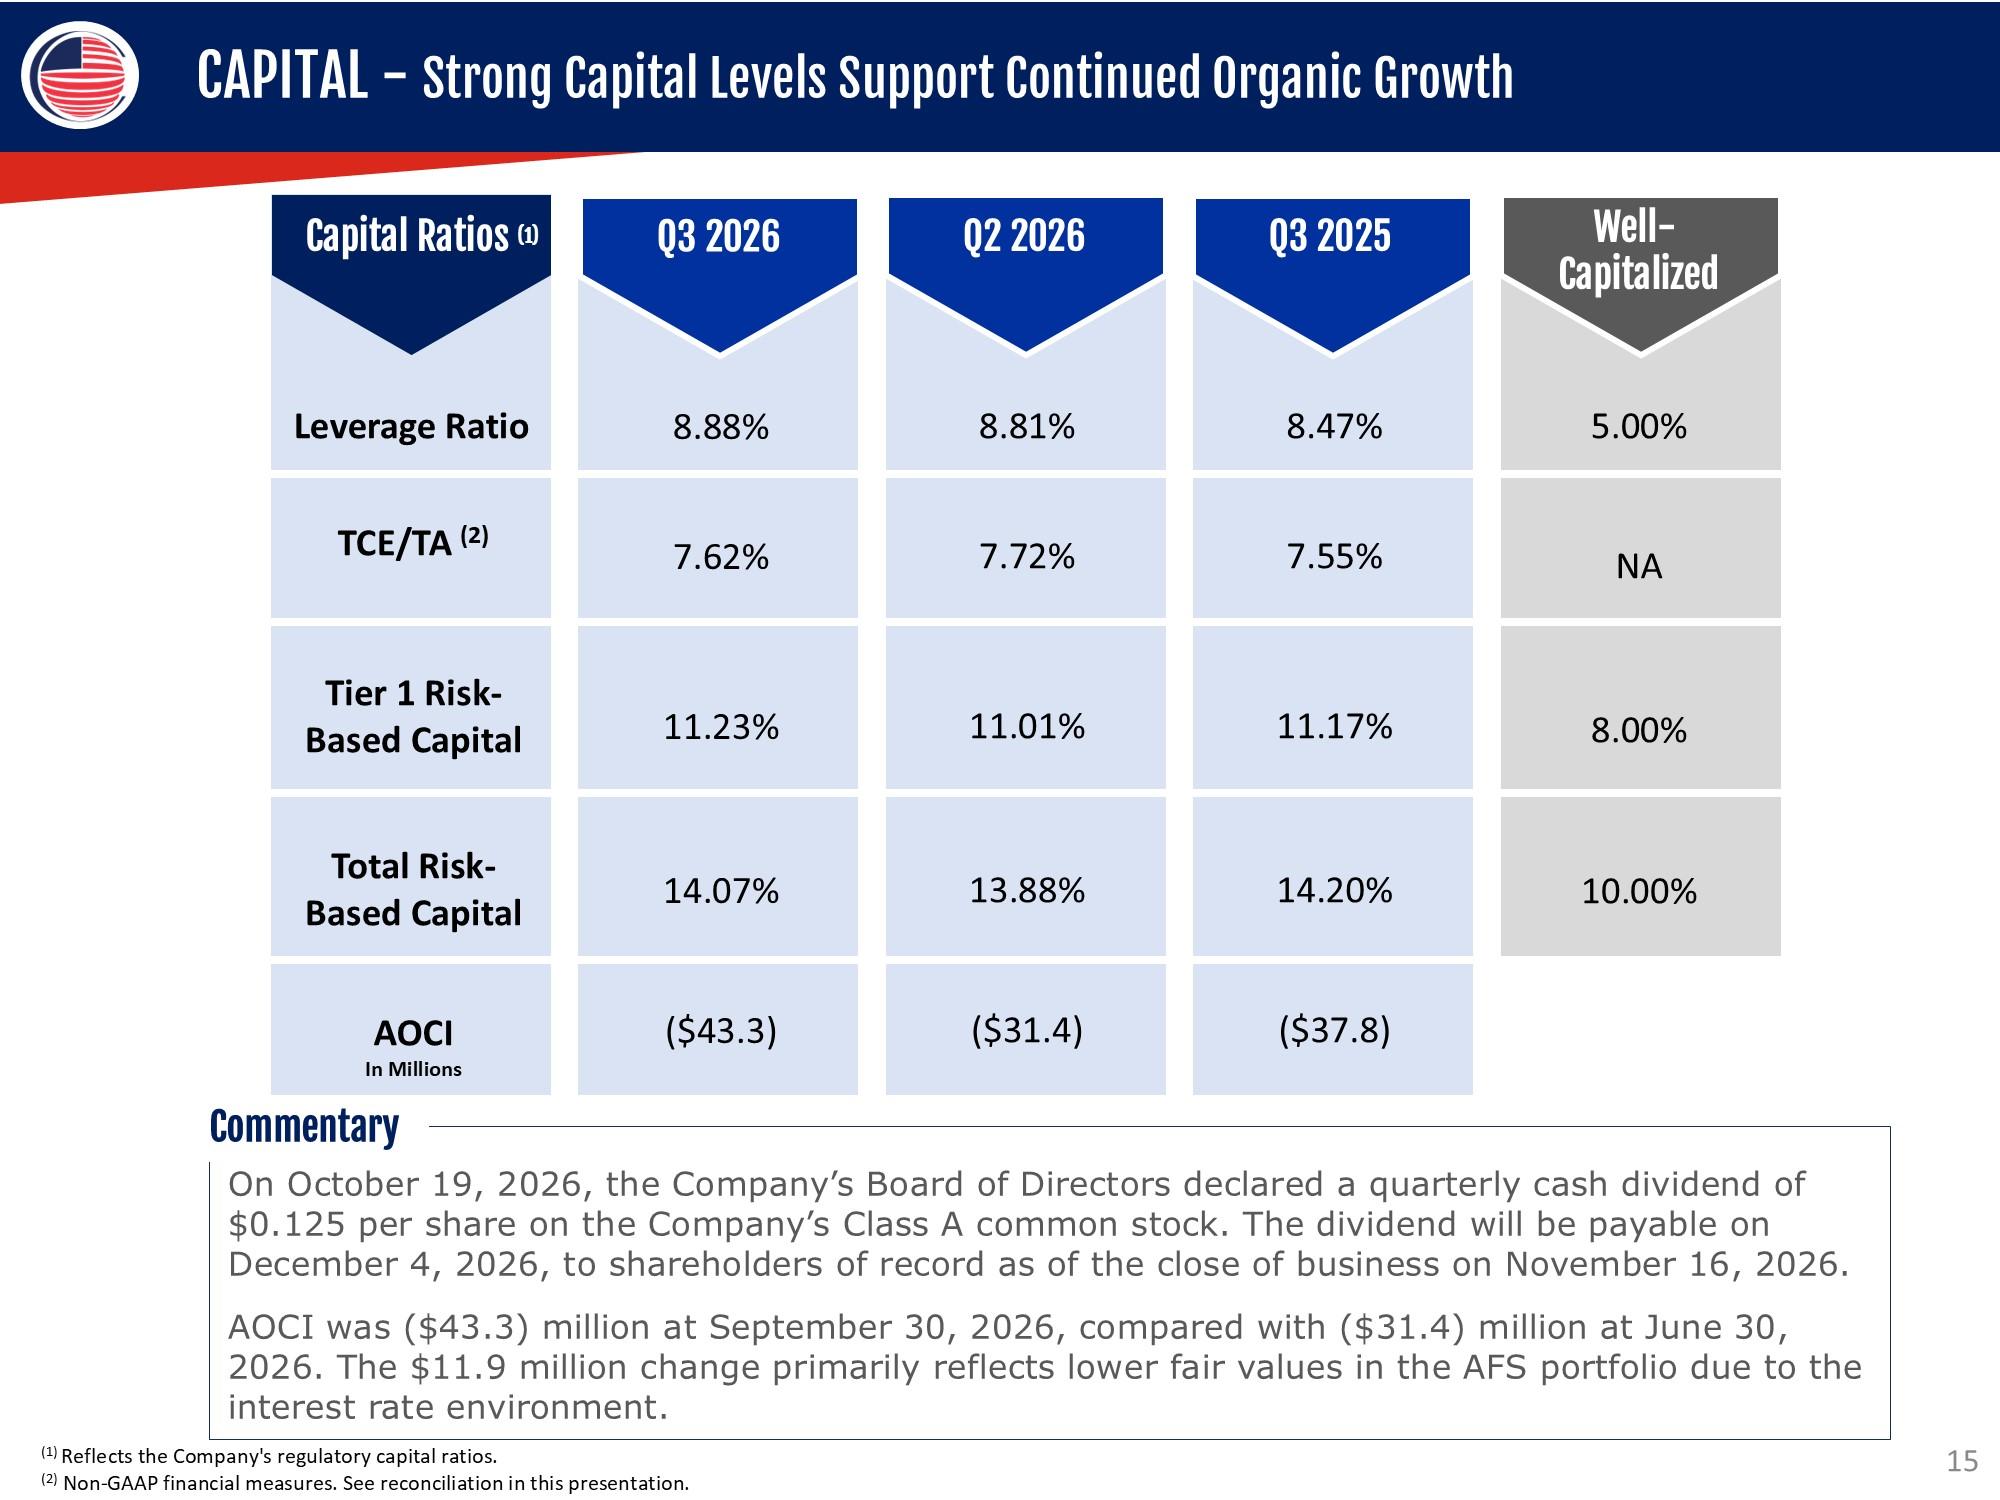
CAPITAL - Strong Capital Levels Support Continued Organic Growth Capital Ratios (1) Leverage Ratio TCE/TA (2) Tier 1 Risk-Based Capital Total Risk-Based Capital AOCI In Millions Q3 2026 8.88% 7.62% 11.23% 14.07% ($43.3) Q2 2026 8.81% 7.72% 11.01% 13.88% ($31.4) Q3 2025 8.47% 7.55% 11.17% 14.20% ($37.8) Well-Capitalized 5.00% NA 8.00% 10.00% Commentary On October 19, 2026, the Company’s Board of Directors declared a quarterly cash dividend of $0.125 per share on the Company’s Class A common stock. The dividend will be payable on December 4, 2026, to shareholders of record as of the close of business on November 16, 2026. AOCI was ($43.3) million at September 30, 2026, compared with ($31.4) million at June 30, 2026. The $11.9 million change primarily reflects lower fair values in the AFS portfolio due to the interest rate environment. (1) Reflects the Company's regulatory capital ratios. (2) Non-GAAP financial measures. See reconciliation in this presentation. 15
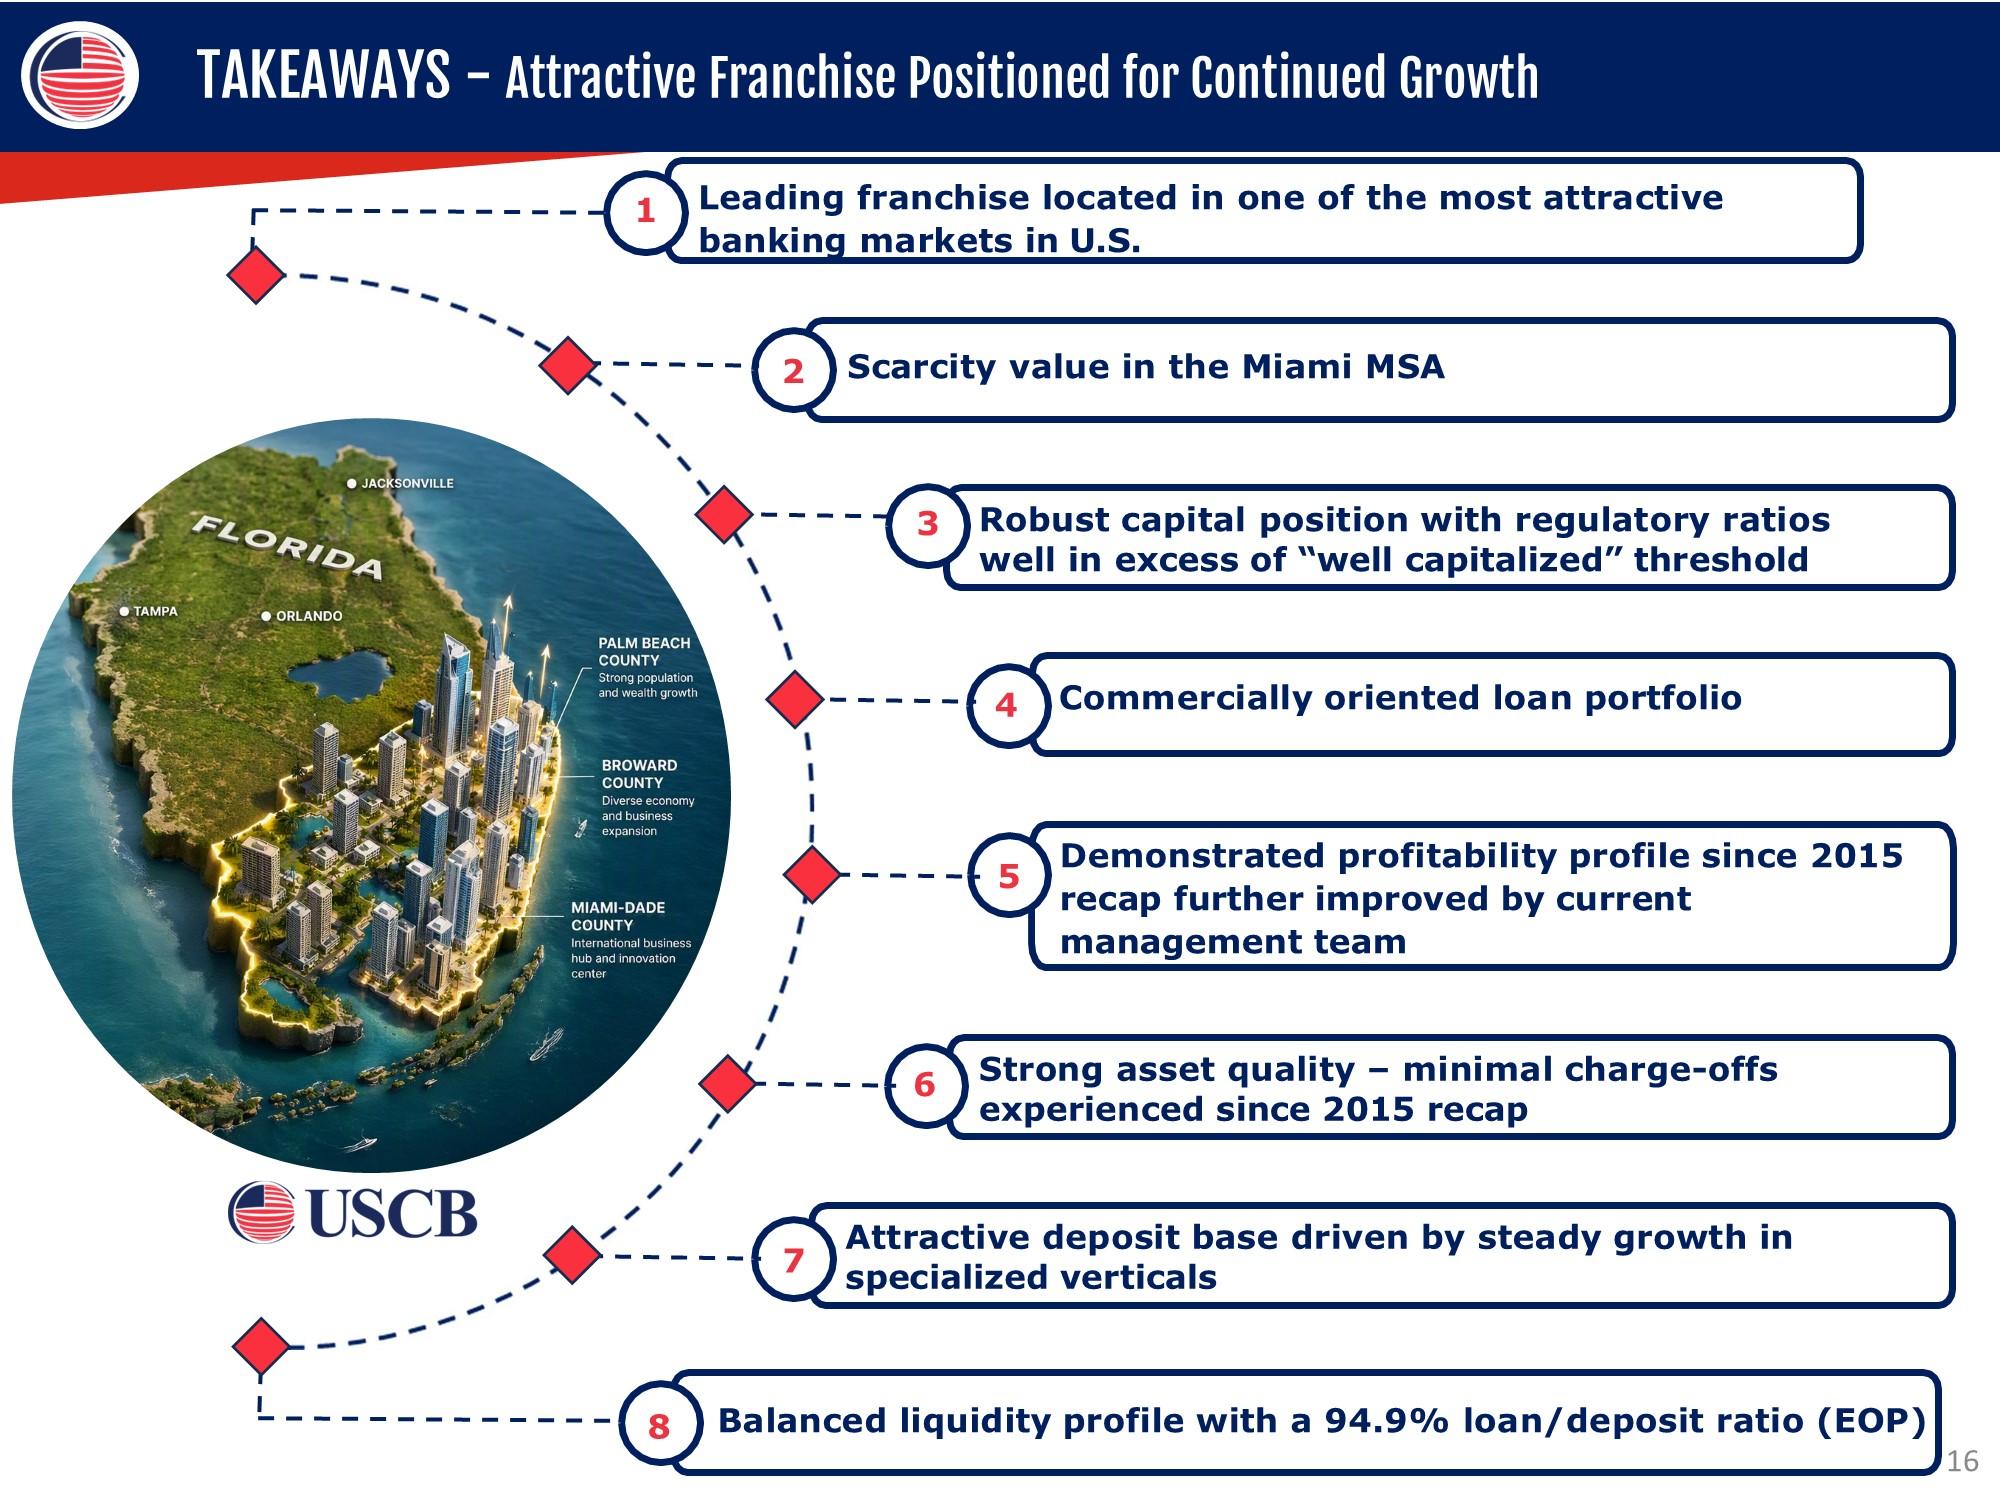
TAKEAWAYS - Attractive Franchise Positioned for Continued Growth Commercially oriented loan portfolio Leading franchise located in one of the most attractive banking markets in U.S. Scarcity value in the Miami MSA Robust capital position with regulatory ratios well in excess of “well capitalized” threshold Commercially oriented loan portfolio Demonstrated profitability profile since 2015 recap further improved by current management team Strong asset quality – minimal charge-offs experienced since 2015 recap Attractive deposit base driven by steady growth in specialized verticals Balanced liquidity profile with a 94.9% loan/deposit ratio (EOP) 16
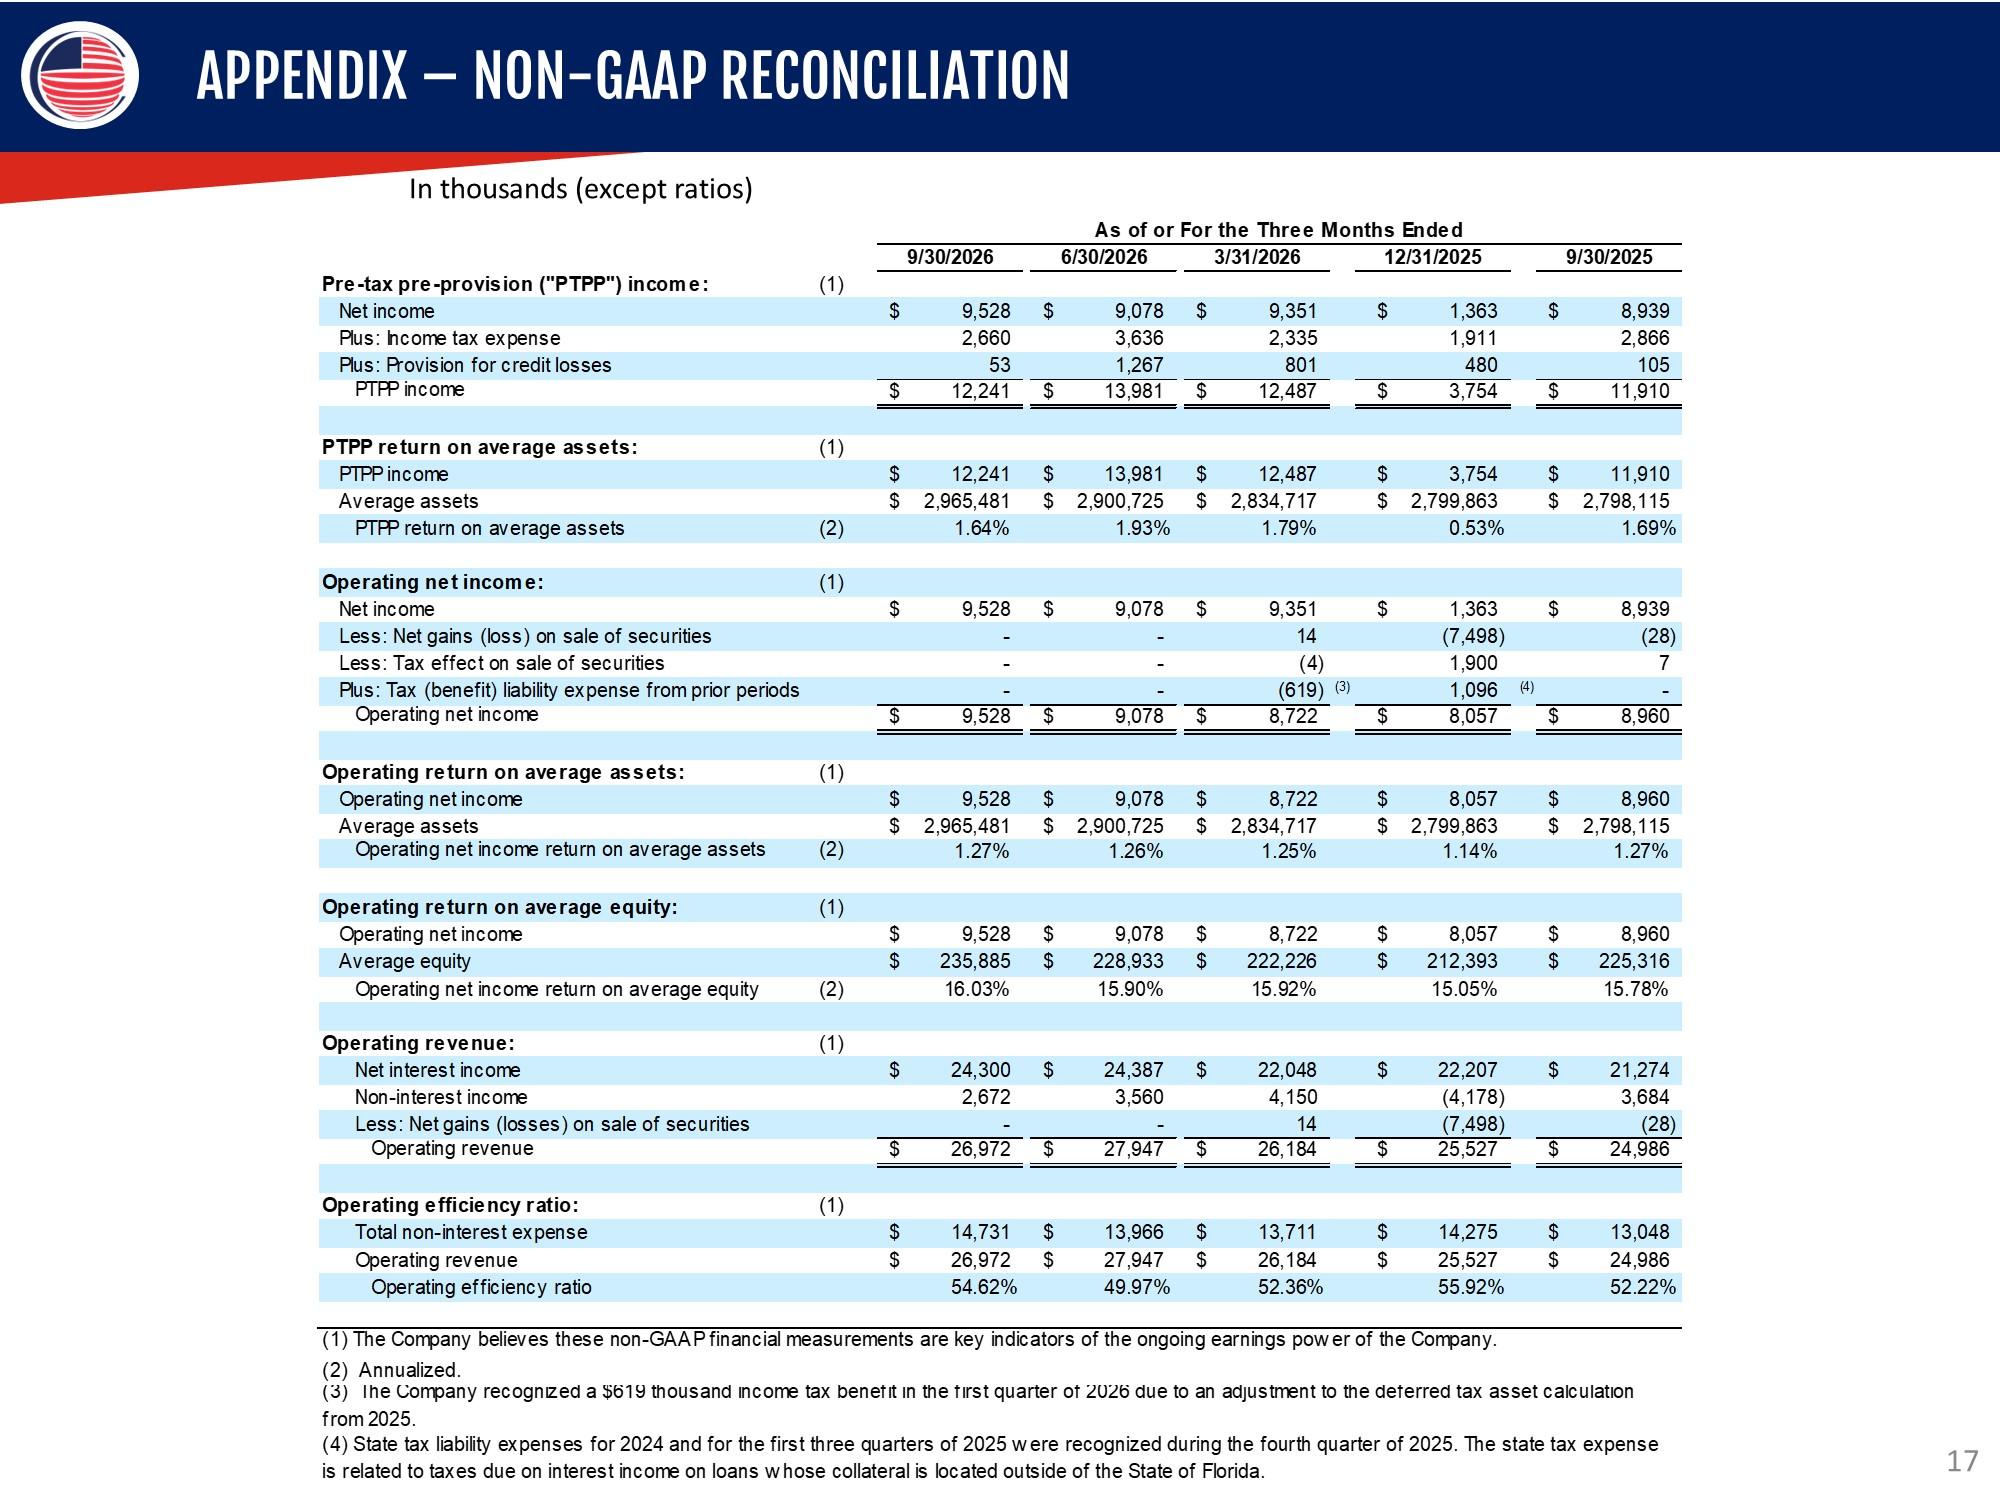
APPENDIX – NON-GAAP RECONCILIATION In thousands (except ratios) As of or For the Three Months Ended Line item 9/30/2026 6/30/2026 3/31/2026 12/31/2025 9/30/2025 Pre-tax pre-provision (“PTPP”) income: (1) Net income $9,528 $9,078 $9,351 $1,363 $8,939 Plus: Income tax expense 2,660 3,636 2,335 1,911 2,866 Plus: Provision for credit losses 53 1,267 801 480 105 PTPP income $12,241 $13,981 $12,487 $3,754 $11,910 PTPP return on average assets: (1) PTPP income $12,241 $13,981 $12,487 $3,754 $11,910 Average assets $2,965,481 $2,900,725 $2,834,717 $2,799,863 $2,798,115 PTPP return on average assets (2) 1.64% 1.93% 1.79% 0.53% 1.69% Operating net income: (1) Net income $9,528 $9,078 $9,351 $1,363 $8,939 Less: Net gains (loss) on sale of securities – – 14 (7,498) (28) Less: Tax effect on sale of securities – – (4) 1,900 7 Plus: Tax (benefit) liability expense from prior periods – – (619) (3) 1,096 (4) – Operating net income $9,528 $9,078 $8,722 $8,057 $8,960 Operating return on average assets: (1) Operating net income $9,528 $9,078 $8,722 $8,057 $8,960 Average assets $2,965,481 $2,900,725 $2,834,717 $2,799,863 $2,798,115 Operating net income return on average assets (2) 1.27% 1.26% 1.25% 1.14% 1.27% Operating return on average equity: (1) Operating net income $9,528 $9,078 $8,722 $8,057 $8,960 Average equity $235,885 $228,933 $222,226 $212,393 $225,316 Operating net income return on average equity (2) 16.03% 15.90% 15.92% 15.05% 15.78% Operating revenue: (1) Net interest income $24,300 $24,387 $22,048 $22,207 $21,274 Non-interest income 2,672 3,560 4,150 (4,178) 3,684 Less: Net gains (losses) on sale of securities – – 14 (7,498) (28) Operating revenue $26,972 $27,947 $26,184 $25,527 $24,986 Operating efficiency ratio: (1) Total non-interest expense $14,731 $13,966 $13,711 $14,275 $13,048 Operating revenue $26,972
$27,947 $26,184 $25,527 $24,986 Operating efficiency ratio 54.62% 49.97% 52.36% 55.92% 52.22% Footnotes: The Company believes these non-GAAP financial measurements are key indicators of the ongoing earnings power of the Company. Annualized. The Company recognized a $619 thousand income tax benefit in the first quarter of 2026 due to an adjustment to the deferred tax asset calculation from 2025. State tax liability expenses for 2024 and for the first three quarters of 2025 were recognized during the fourth quarter of 2025. The state tax expense is related to taxes due on interest income on loans whose collateral is located outside of the State of Florida. 17
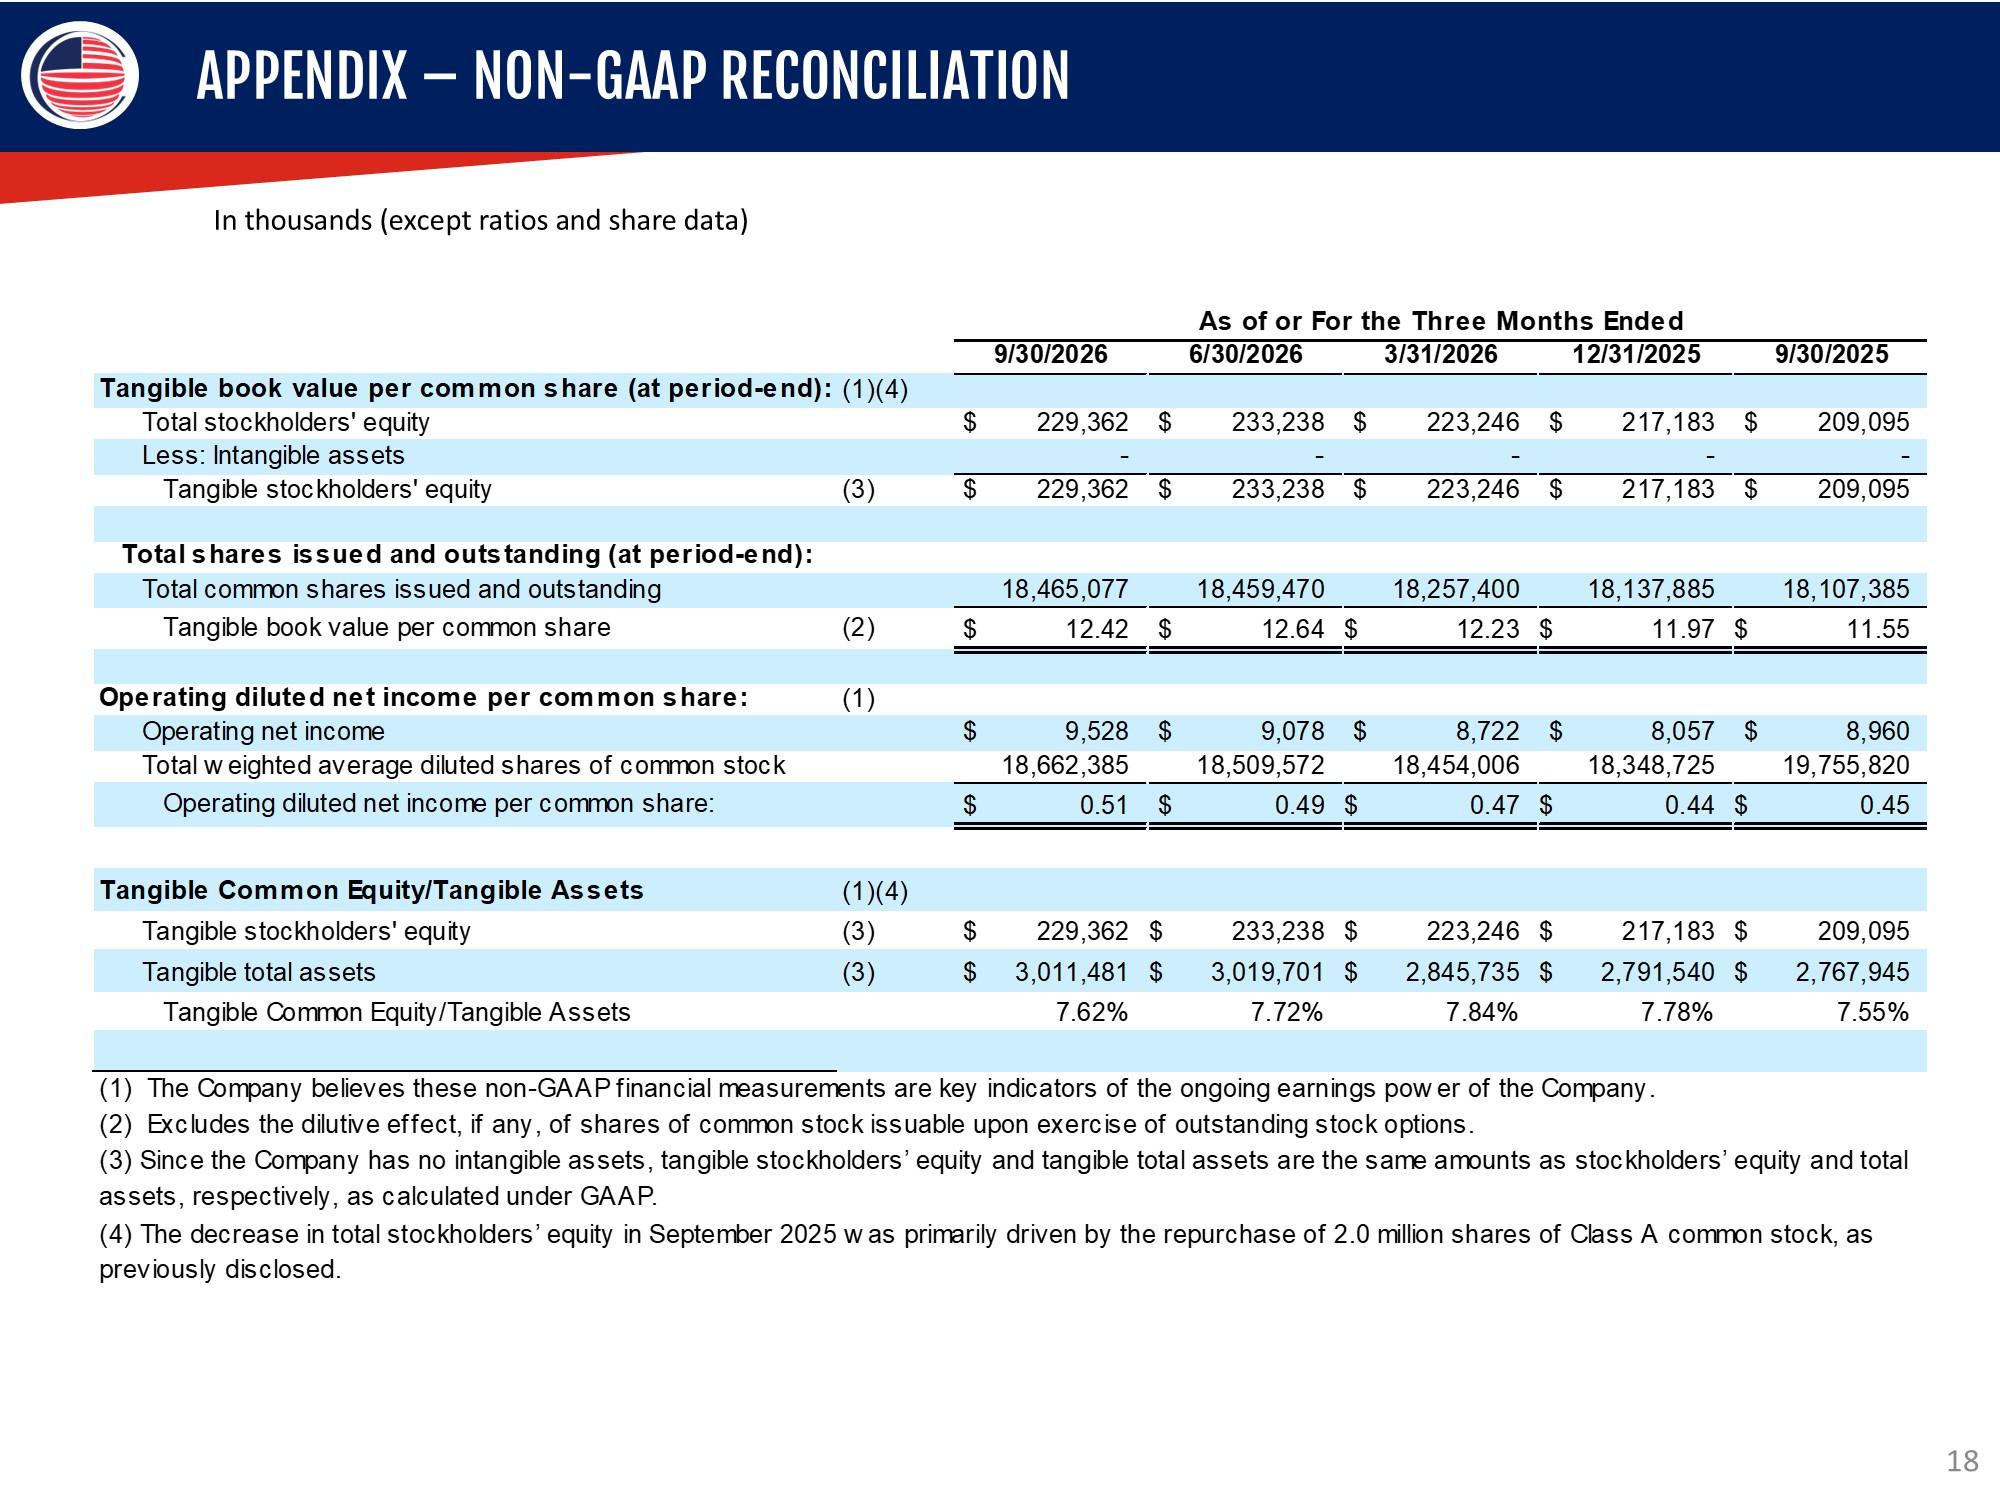
APPENDIX – NON-GAAP RECONCILIATION In thousands (except ratios and share data) As of or For the Three Months Ended Line item 9/30/2026 6/30/2026 3/31/2026 12/31/2025 9/30/2025 Tangible book value per common share (at period-end): (1)(4) Total stockholders’ equity $229,362 $233,238 $223,246 $217,183 $209,095 Less: Intangible assets – – – – – Tangible stockholders’ equity (3) $229,362 $233,238 $223,246 $217,183 $209,095 Total shares issued and outstanding (at period-end): Total common shares issued and outstanding 18,465,077 18,459,470 18,257,400 18,137,885 18,107,385 Tangible book value per common share (2) $12.42 $12.64 $12.23 $11.97 $11.55 Operating diluted net income per common share: (1) Operating net income $9,528 $9,078 $8,722 $8,057 $8,960 Total weighted average diluted shares of common stock 18,662,385 18,509,572 18,454,006 18,348,725 19,755,820 Operating diluted net income per common share $0.51 $0.49 $0.47 $0.44 $0.45 Tangible Common Equity/Tangible Assets (1)(4) Tangible stockholders’ equity (3) $229,362 $233,238 $223,246 $217,183 $209,095 Tangible total assets (3) $3,011,481 $3,019,701 $2,845,735 $2,791,540 $2,767,945 Tangible Common Equity/Tangible Assets 7.62% 7.72% 7.84% 7.78% 7.55% Footnotes: The Company believes these non-GAAP financial measurements are key indicators of the ongoing earnings power of the Company. Excludes the dilutive effect, if any, of shares of common stock issuable upon exercise of outstanding stock options. Since the Company has no intangible assets, tangible stockholders’ equity and tangible total assets are the same amounts as stockholders’ equity and total assets, respectively, as calculated under GAAP. The decrease in total stockholders’ equity in September 2025 was primarily driven by the repurchase of 2.0 million shares of Class A common stock, as previously disclosed.
18
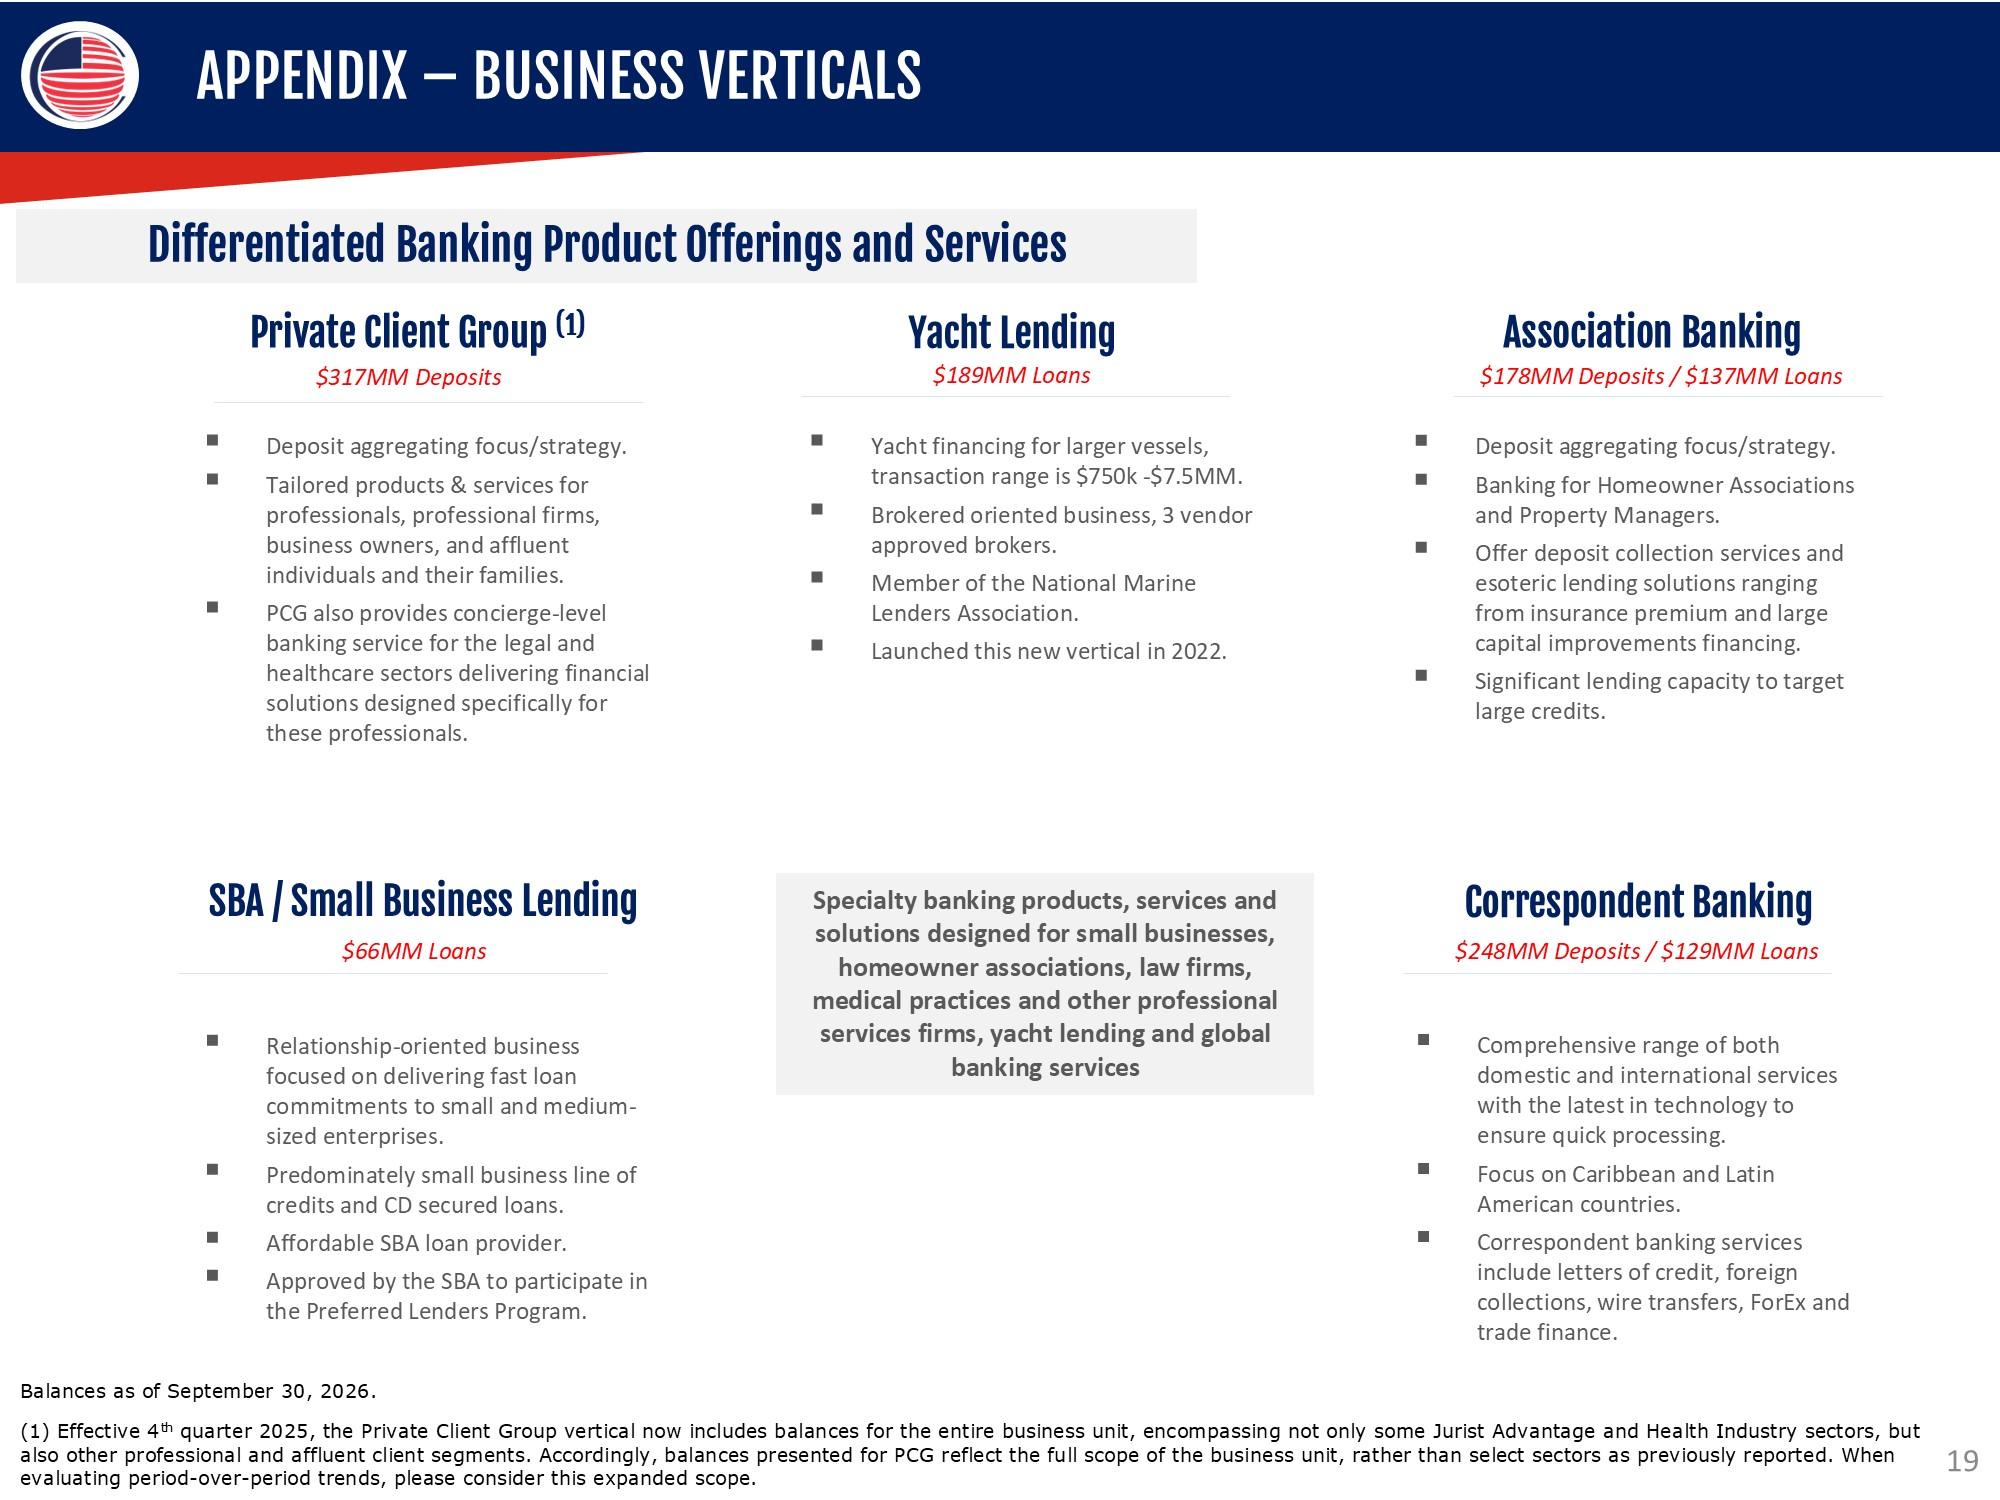
APPENDIX – BUSINESS VERTICALS Private Client Group (1) $317MM Deposits Deposit aggregating focus/strategy. Tailored products & services for professionals, professional firms, business owners, and affluent individuals and their families. PCG also provides concierge-level banking service for the legal and healthcare sectors delivering financial solutions designed specifically for these professionals. Yacht Lending $189MM Loans Yacht financing for larger vessels, transaction range is $750k -$7.5MM. Brokered oriented business, 3 vendor approved brokers. Member of the National Marine Lenders Association. Launched this new vertical in 2022. Association Banking $178MM Deposits / $137MM Loans Deposit aggregating focus/strategy. Banking for Homeowner Associations and Property Managers. Offer deposit collection services and esoteric lending solutions ranging from insurance premium and large capital improvements financing. Significant lending capacity to target large credits. SBA / Small Business Lending $66MM Loans Relationship-oriented business focused on delivering fast loan commitments to small and medium-sized enterprises. Predominately small business line of credits and CD secured loans. Affordable SBA loan provider. Approved by the SBA to participate in the Preferred Lenders Program. Specialty banking products, services and solutions designed for small businesses, homeowner associations, law firms, medical practices and other professional services firms, yacht lending and global banking services Correspondent Banking $248MM Deposits / $129MM Loans Comprehensive range of both domestic and international services with the latest in technology to ensure quick processing. Focus on Caribbean and Latin American countries. Correspondent banking services include letters of credit, foreign collections, wire transfers, ForEx and trade finance. Balances as of
September 30, 2026. (1) Effective 4th quarter 2025, the Private Client Group vertical now includes balances for the entire business unit, encompassing not only some Jurist Advantage and Health Industry sectors, but also other professional and affluent client segments. Accordingly, balances presented for PCG reflect the full scope of the business unit, rather than select sectors as previously reported. When evaluating period-over-period trends, please consider this expanded scope. 19
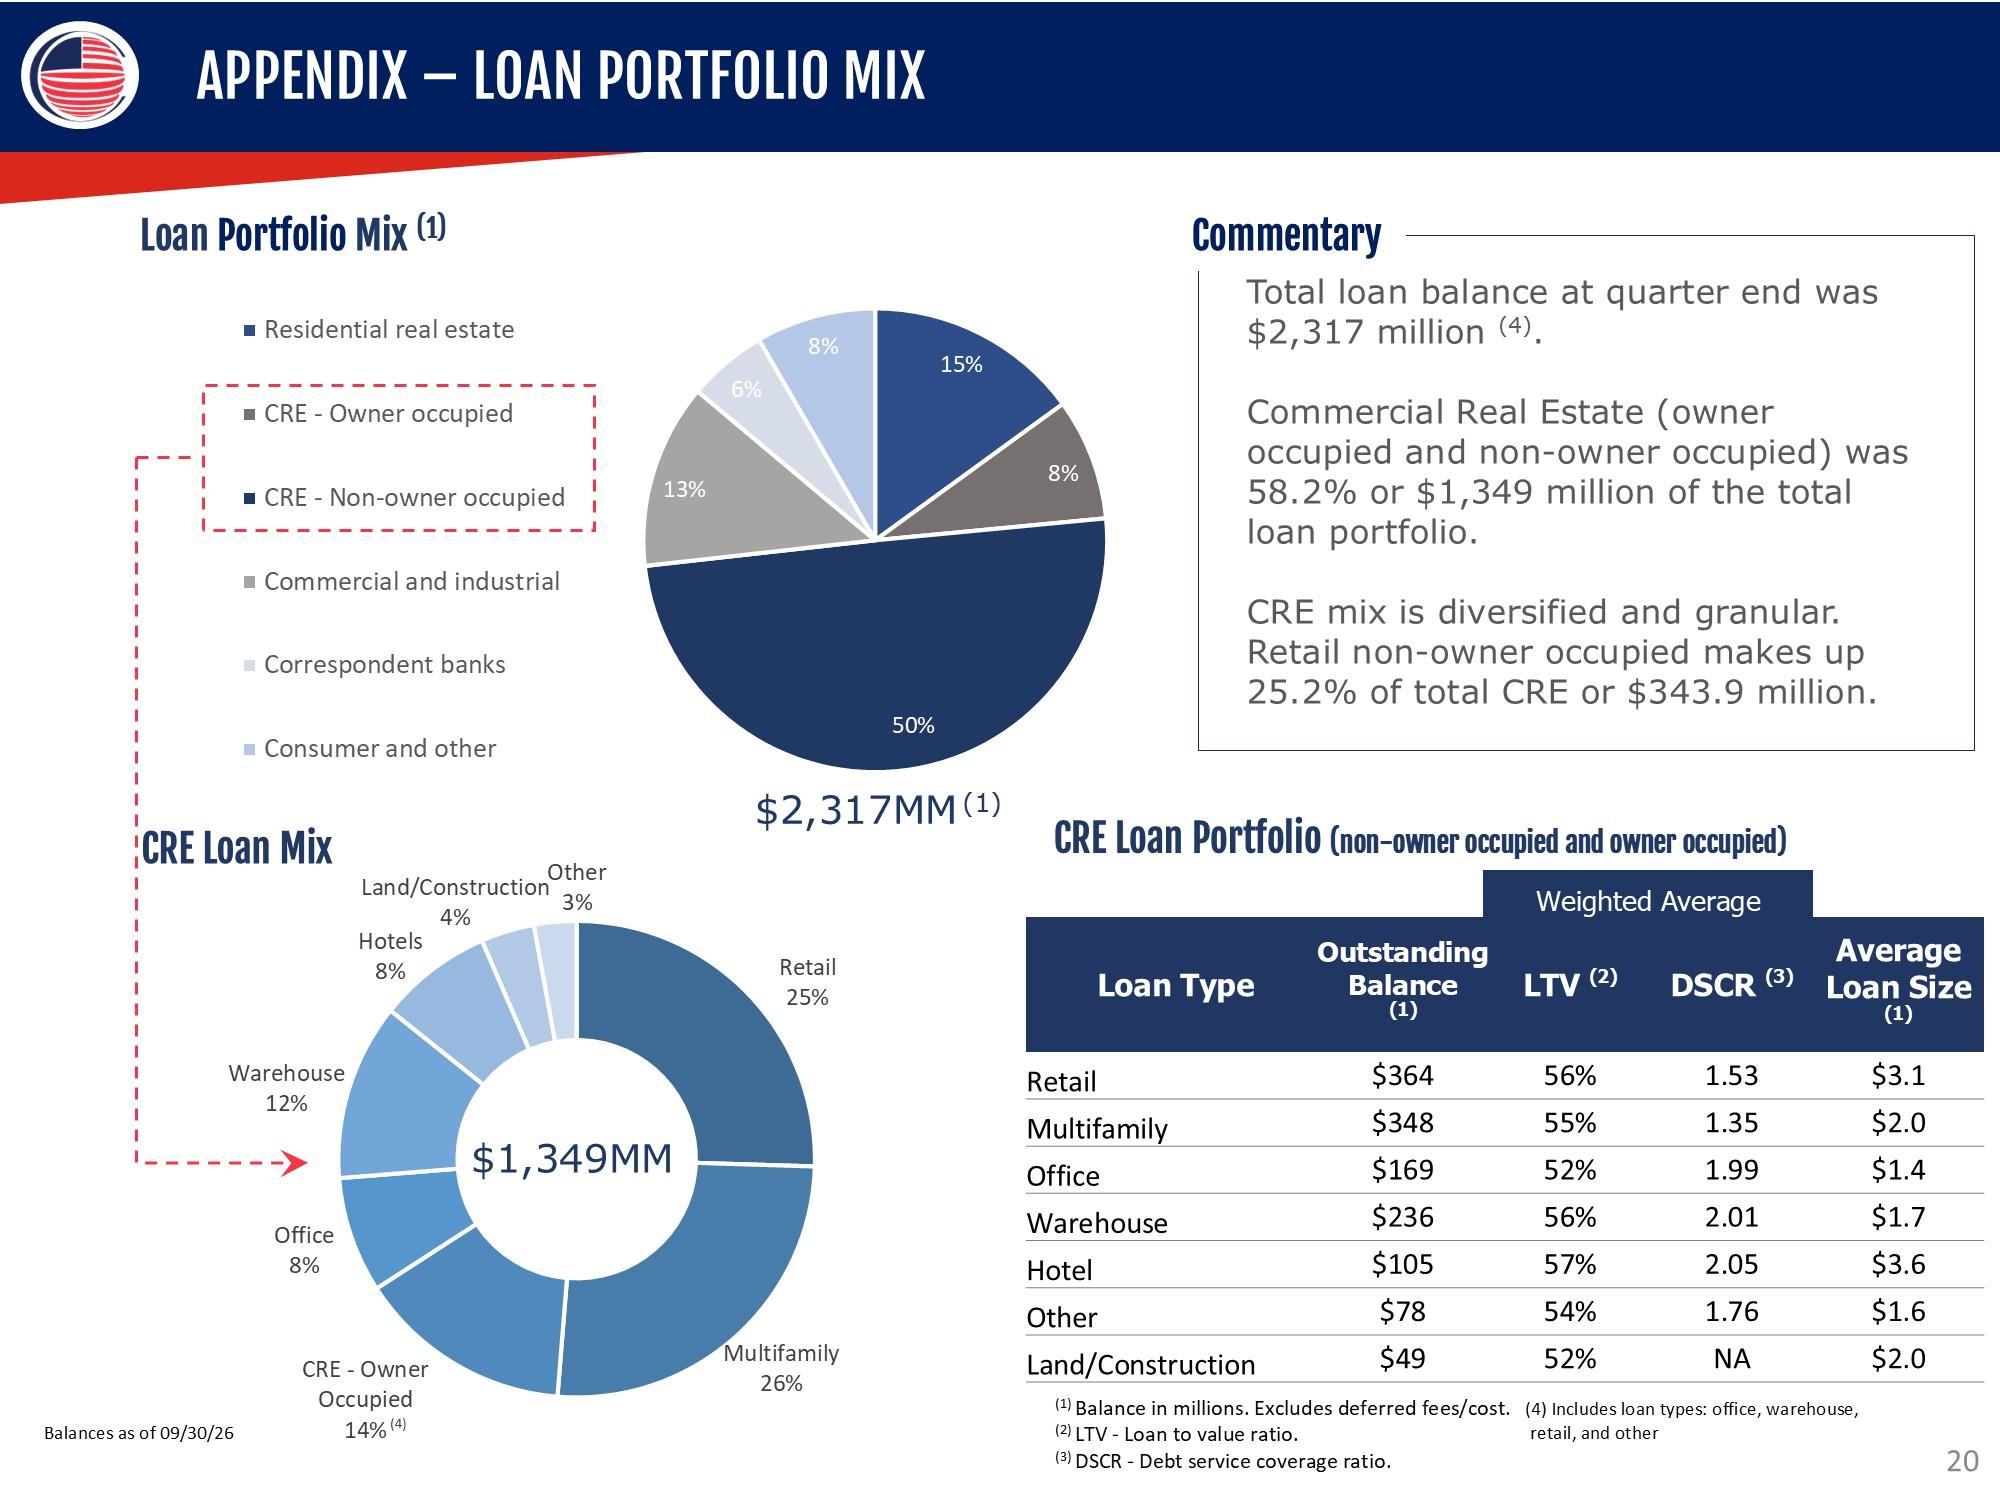
APPENDIX – LOAN PORTFOLIO MIX Loan Portfolio Mix (1) Residential real estate 15% CRE – Owner occupied 8% CRE – Non-owner occupied 50% Commercial and industrial 13% Correspondent banks 6% Consumer and other 8% Commentary Total loan balance at quarter end was $2,317 million (4). Commercial Real Estate (owner occupied and non-owner occupied) was 58.2% or $1,349 million of the total loan portfolio. CRE mix is diversified and granular. Retail non-owner occupied makes up 25.2% of total CRE or $343.9 million. CRE Loan Mix Other 3% Retail 25% Multifamily 26% CRE – Owner Occupied 14% Office 8% Warehouse 12% Hotels 8% Land/Construction 4% $1,349MM CRE Loan Portfolio (non-owner occupied and owner occupied) Weighted Average Loan Type Outstanding Balance (1) LTV (2) DSCR (3) Average Loan Size (1) Retail $364 56% 1.53 $3.1 Multifamily $348 55% 1.35 $2.0 Office $169 52% 1.99 $1.4 Warehouse $236 56% 2.01 $1.7 Hotel $105 57% 2.05 $3.6 Other $78 54% 1.76 $1.6 Land/Construction $49 52% NA $2.0 (1) Balance in millions. Excludes deferred fees/cost. (2) LTV - Loan to value ratio. (3) DSCR - Debt service coverage ratio. (4) Includes loan types: office, warehouse, retail and other 20
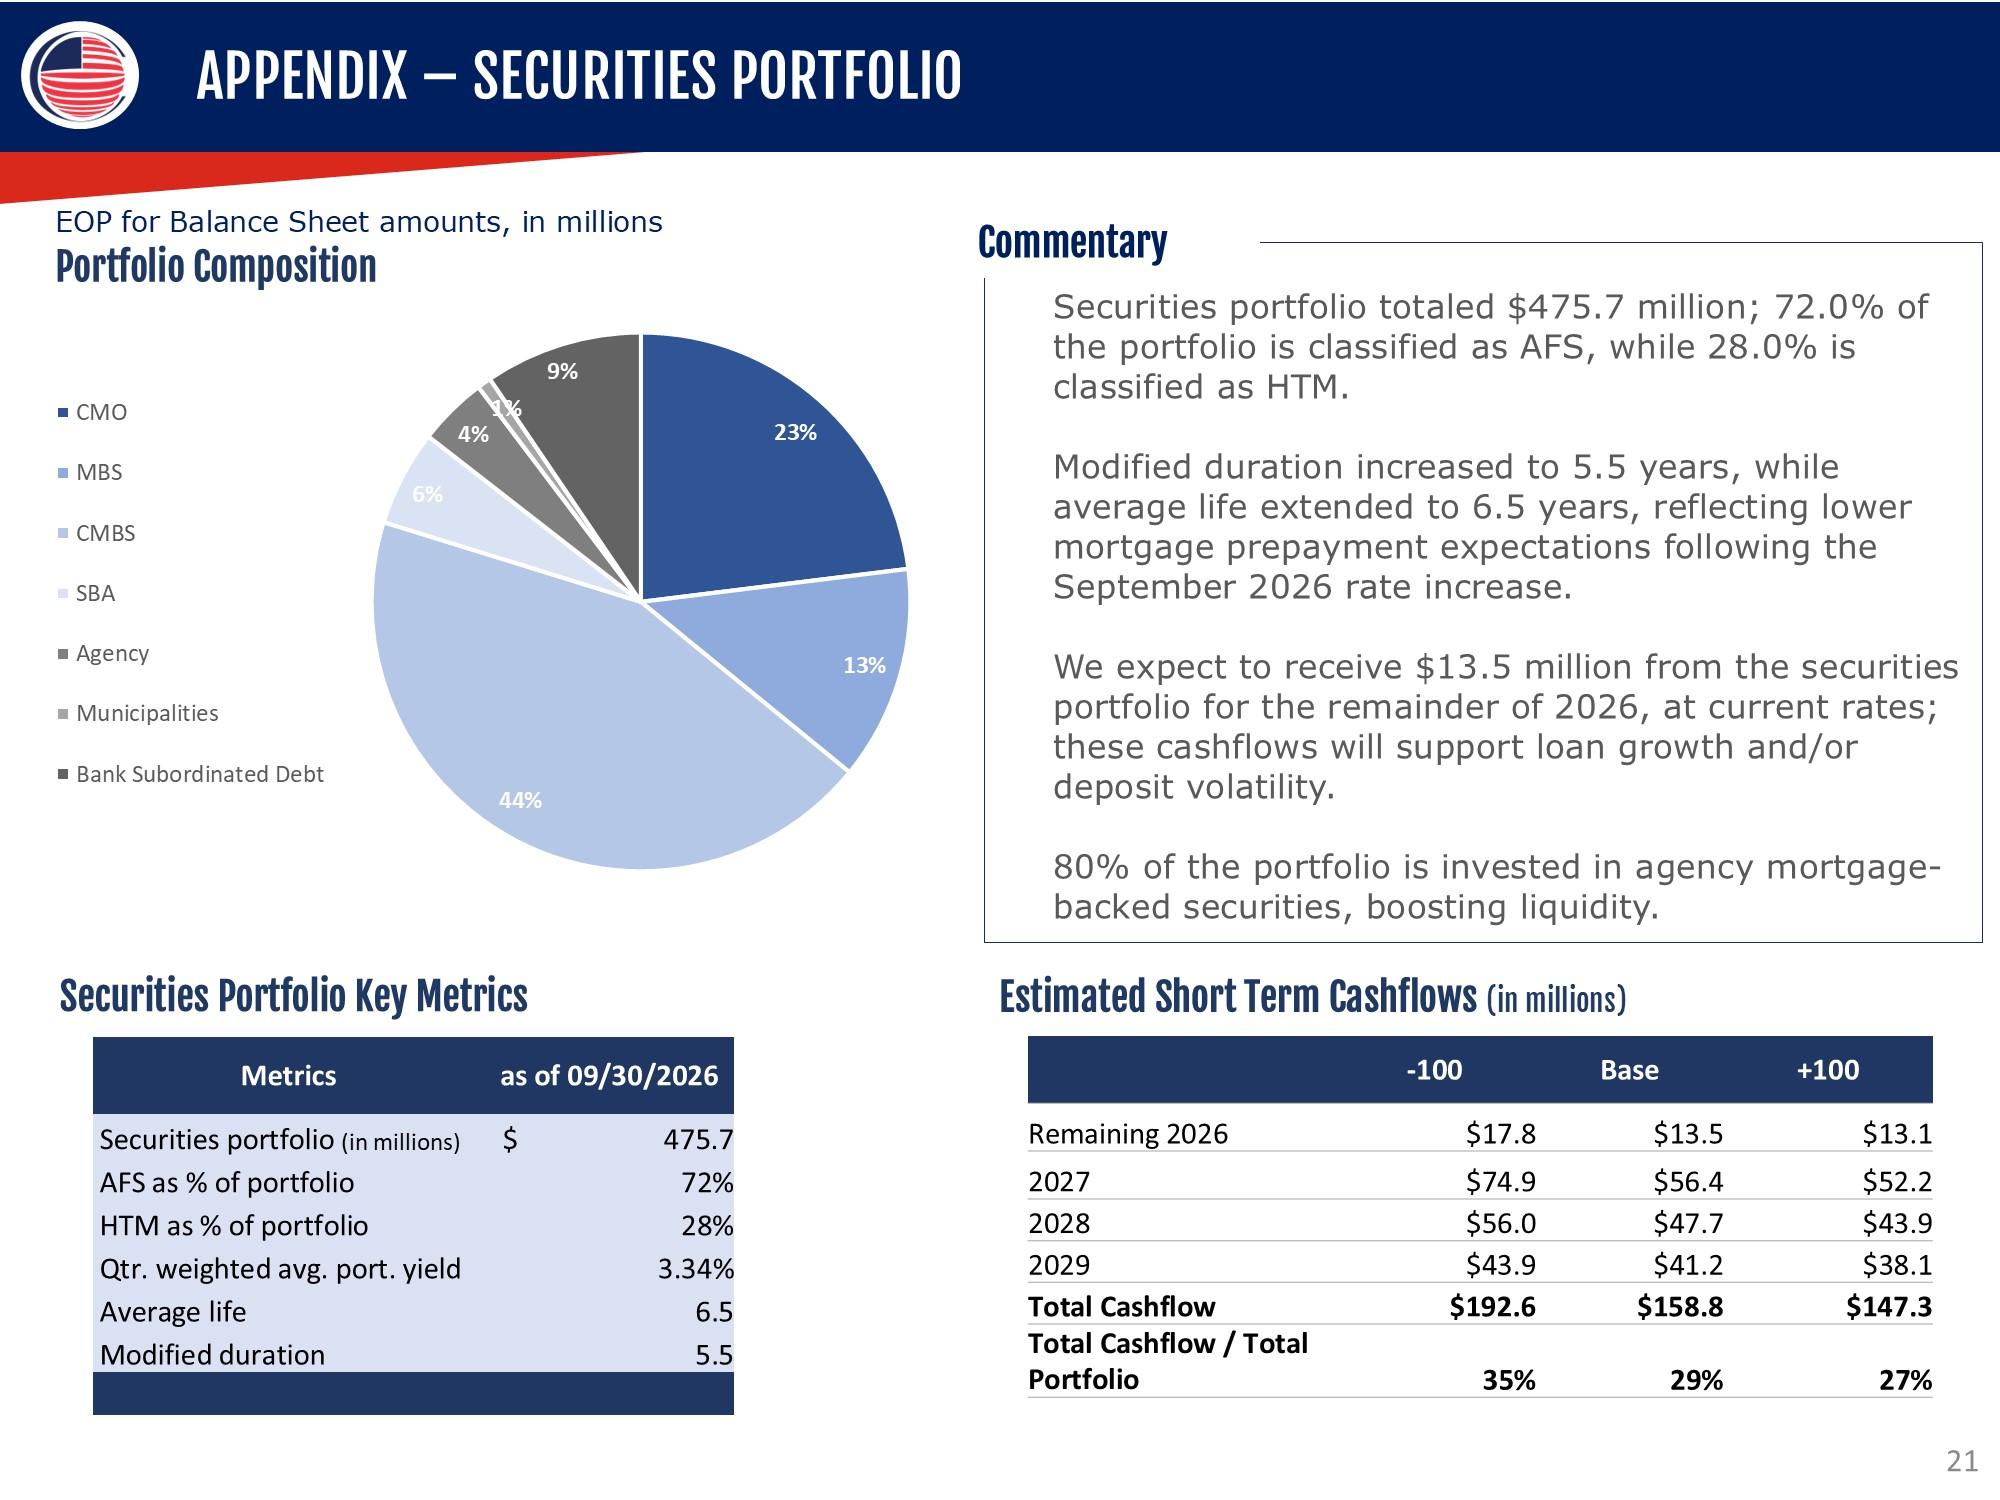
APPENDIX – SECURITIES PORTFOLIO EOP for Balance Sheet amounts, in millions Portfolio Composition CMO 24% MBS 13% CMBS 44% SBA 6% Agency 4% Municipalities 1% Bank Subordinated Debt 9% Commentary Securities portfolio totaled $475.7 million; 72.0% of the portfolio is classified as AFS, while 28.0% is classified as HTM. Modified duration increased to 5.5 years, while average life extended to 6.5 years, reflecting lower mortgage prepayment expectations following the September 2026 rate increase. We expect to receive $13.5 million from the securities portfolio for the remainder of 2026, at current rates; these cashflows will support loan growth and/or deposit volatility. 80% of the portfolio is invested in agency mortgage-backed securities, boosting liquidity. Securities Portfolio Key Metrics Metrics as of 09/30/2026 Securities portfolio (in millions) $ 475.7 AFS as % of portfolio 72% HTM as % of portfolio 28% Qtr. weighted avg. port. yield 3.34% Average life 6.5 Modified duration 5.5 Estimated Short Term Cashflows (in millions) -100 Base +100 Remaining 2026 $17.8 $13.5 $13.1 2027 $74.9 $56.4 $52.2 2028 $56.0 $47.7 $43.9 2029 $43.9 $41.2 $38.1 Total Cashflow $192.6 $158.8 $147.3 Total Cashflow / Total Portfolio 35% 29% 27% 21
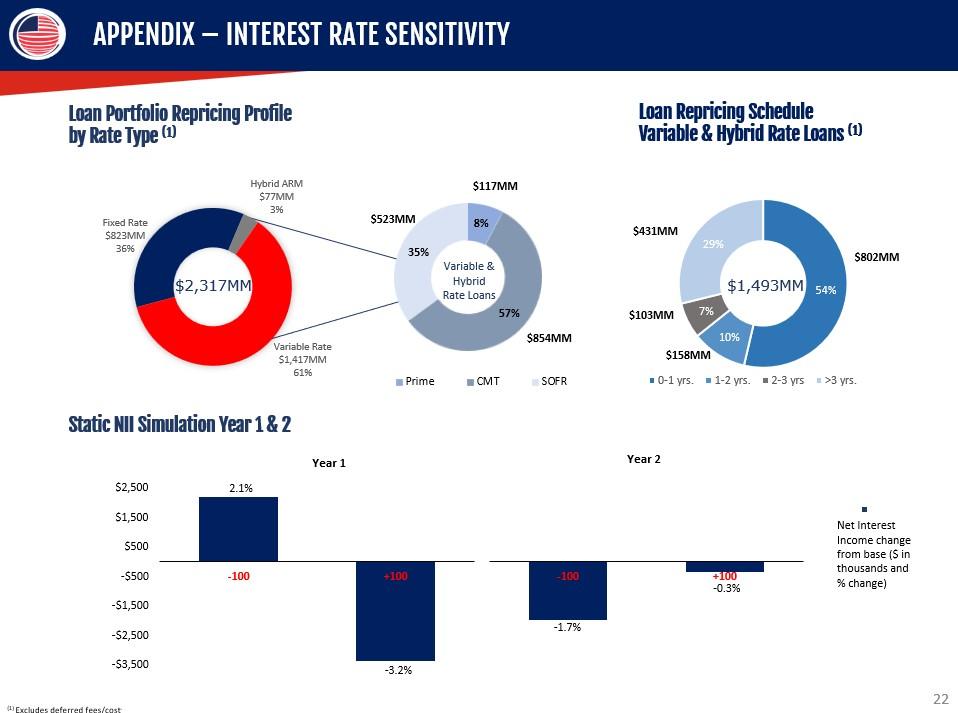
APPENDIX – INTEREST RATE SENSITIVITY Loan Portfolio Repricing Profile by Rate Type (1) Fixed Rate $823MM 36% Hybrid ARM $77M 3% Variable Rate $1,417MM 61 $2,317MM Variable & Hybrid Rate Loans $523MM 35% $177MM 8% $854MM 57% Prime CMT SOFR Loan Repricing Schedule Variable & Hybrid Rate Loans (1) $431MM 29% $802MM 54% $158MM 10% $103MM 7% $1,493MM Yrs 1-2 yrs 2-3 yrs >3 yrs. Static NII Simulation Year 1 & 2 Net Interest Income change from base ($ in thousands and % change) 2.1% -100 +100 -3.2% -100 -1.7% +100 -0.3% Excludes deferred fees/cost. 22 $2,500
CONTACT INFORMATION LOU DE LA AGUILERA Chairman, President & CEO (305) 715-5186 laguilera@uscentury.com ROB ANDERSON EVP, Chief Financial Officer (305) 715-5393 rob.anderson@uscentury.com INVESTOR RELATIONS InvestorRelations@uscentury.com 23