Exhibit 99.2 Enterprise Financial Services Corp 2026 Third Quarter Earnings Webcast
2 Some of the information in this report may contain “forward-looking statements” within the meaning of and intended to be covered by the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. Such forward-looking statements may include projections based on management’s current expectations and beliefs concerning future developments and their potential effects on Enterprise Financial Services Corp (the “Company” or “EFSC”) including, without limitation, plans, strategies and goals, and statements about the Company’s expectations regarding revenue and asset growth, financial performance and profitability, loan and deposit growth, liquidity, yields and returns, loan diversification and credit management, stockholder value creation and the impact of acquisitions. Forward-looking statements are typically identified by words such as “believe,” “expect,” “anticipate,” “intend,” “outlook,” “estimate,” “forecast,” “project,” “pro forma,” “pipeline” and other similar words and expressions. Forward-looking statements are subject to numerous assumptions, risks and uncertainties, which change over time. Forward-looking statements speak only as of the date they are made. Because forward-looking statements are subject to assumptions and uncertainties, actual results or future events could differ, possibly materially, from those anticipated in the forward-looking statements and future results could differ materially from historical performance. They are neither statements of historical fact nor guarantees or assurances of future performance. While there is no assurance that any list of risks and uncertainties or risk factors is complete, important factors that could cause actual results to differ materially from those in the forward-looking statements include the following, without limitation: our ability to efficiently integrate acquisitions into our operations, retain the customers of these businesses and grow the acquired operations; our ability to collect insurance proceeds from claims made related to tax recapture events; credit risk; changes in the appraised valuation of real estate securing impaired loans; outcomes of litigation and other contingencies; exposure to general and local economic and market conditions, high unemployment rates, higher inflation and its impacts (including U.S. federal government measures to address higher inflation), impacts of trade and tariff policies, U.S. fiscal debt, budget, debt ceiling and tax matters, and any slowdown in global economic growth; risks associated with rapid increases or decreases in prevailing interest rates; our ability to attract and retain deposits and access to other sources of liquidity; changes in business prospects that could impact goodwill estimates and assumptions; consolidation within the banking industry; competition from banks and other financial institutions; the ability to attract and retain relationship officers and other key personnel; burdens imposed by federal and state regulation; changes in legislative or regulatory requirements, as well as current, pending or future legislation or regulation that could have a negative effect on our revenue and business, including rules and regulations relating to bank products and financial services; changes in accounting policies and practices or accounting standards; natural disasters (including wildfires and earthquakes); terrorist activities, war and geopolitical instability (including in Israel, Iran and Ukraine and the imposition of additional sanctions and export controls in connection therewith), or pandemics, or other health emergencies and their effects on economic and business environments in which we operate, including the related disruption to the financial market and other economic activity, cybersecurity threats and the cost of defending against them, and those factors and risks referenced from time to time in the Company’s filings with the Securities and Exchange Commission (the “SEC”), including in the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2025, and the Company’s other filings with the SEC. The Company cautions that the preceding list is not exhaustive of all possible risk factors and other factors could also adversely affect the Company’s results. For any forward-looking statements made in this press release or in any documents, EFSC claims the protection of the safe harbor for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. Annualized, pro forma, projected and estimated numbers in this document are used for illustrative purposes only, are not forecasts and may not reflect actual results. Readers are cautioned not to place undue reliance on any forward-looking statements. Except to the extent required by applicable law or regulation, EFSC disclaims any obligation to revise or publicly release any revision or update to any of the forward-looking statements included herein to reflect events or circumstances that occur after the date on which such statements were made. Forward-Looking Statements
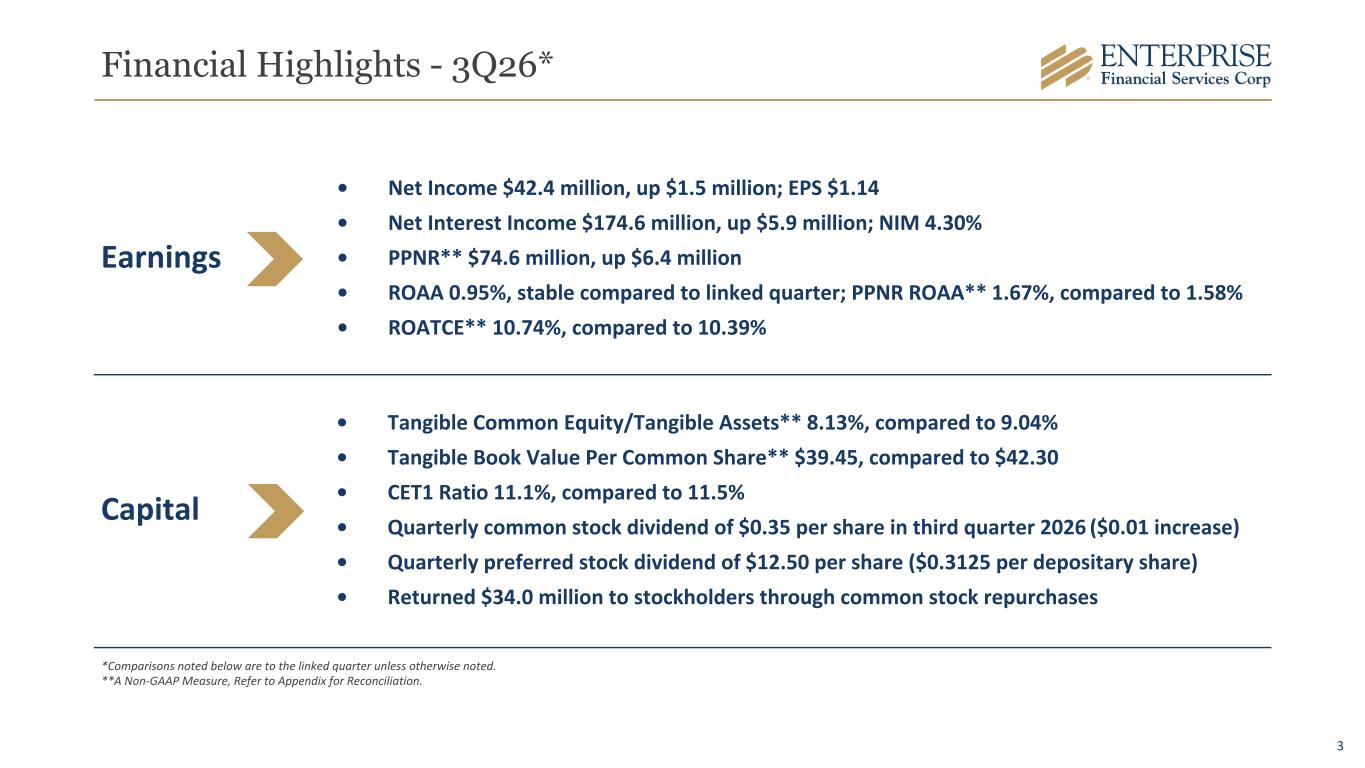
3 Financial Highlights - 3Q26* Capital • Tangible Common Equity/Tangible Assets** 8.13%, compared to 9.04% • Tangible Book Value Per Common Share** $39.45, compared to $42.30 • CET1 Ratio 11.1%, compared to 11.5% • Quarterly common stock dividend of $0.35 per share in third quarter 2026 ($0.01 increase) • Quarterly preferred stock dividend of $12.50 per share ($0.3125 per depositary share) • Returned $34.0 million to stockholders through common stock repurchases • Net Income $42.4 million, up $1.5 million; EPS $1.14 • Net Interest Income $174.6 million, up $5.9 million; NIM 4.30% • PPNR** $74.6 million, up $6.4 million • ROAA 0.95%, stable compared to linked quarter; PPNR ROAA** 1.67%, compared to 1.58% • ROATCE** 10.74%, compared to 10.39% Earnings *Comparisons noted below are to the linked quarter unless otherwise noted. **A Non-GAAP Measure, Refer to Appendix for Reconciliation.
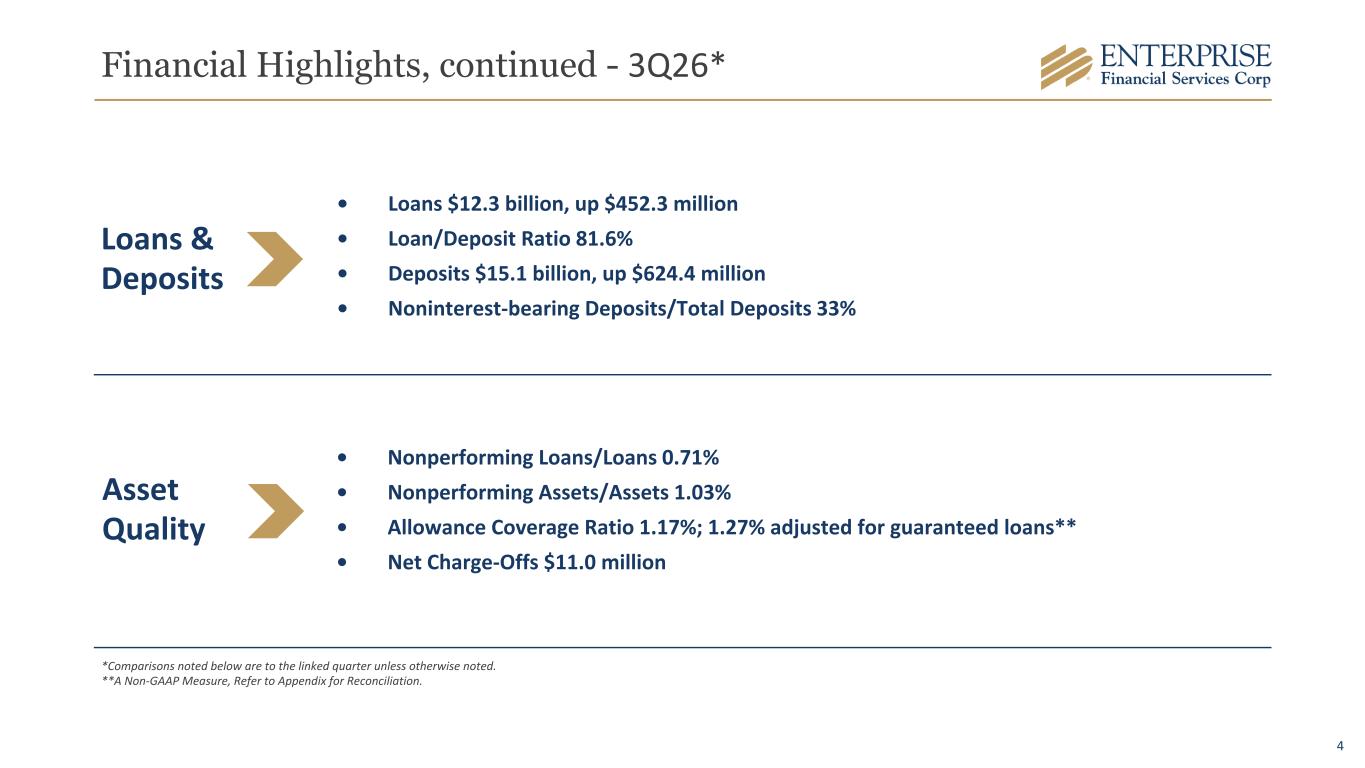
4 Financial Highlights, continued - 3Q26* Loans & Deposits • Loans $12.3 billion, up $452.3 million • Loan/Deposit Ratio 81.6% • Deposits $15.1 billion, up $624.4 million • Noninterest-bearing Deposits/Total Deposits 33% Asset Quality • Nonperforming Loans/Loans 0.71% • Nonperforming Assets/Assets 1.03% • Allowance Coverage Ratio 1.17%; 1.27% adjusted for guaranteed loans** • Net Charge-Offs $11.0 million *Comparisons noted below are to the linked quarter unless otherwise noted. **A Non-GAAP Measure, Refer to Appendix for Reconciliation.
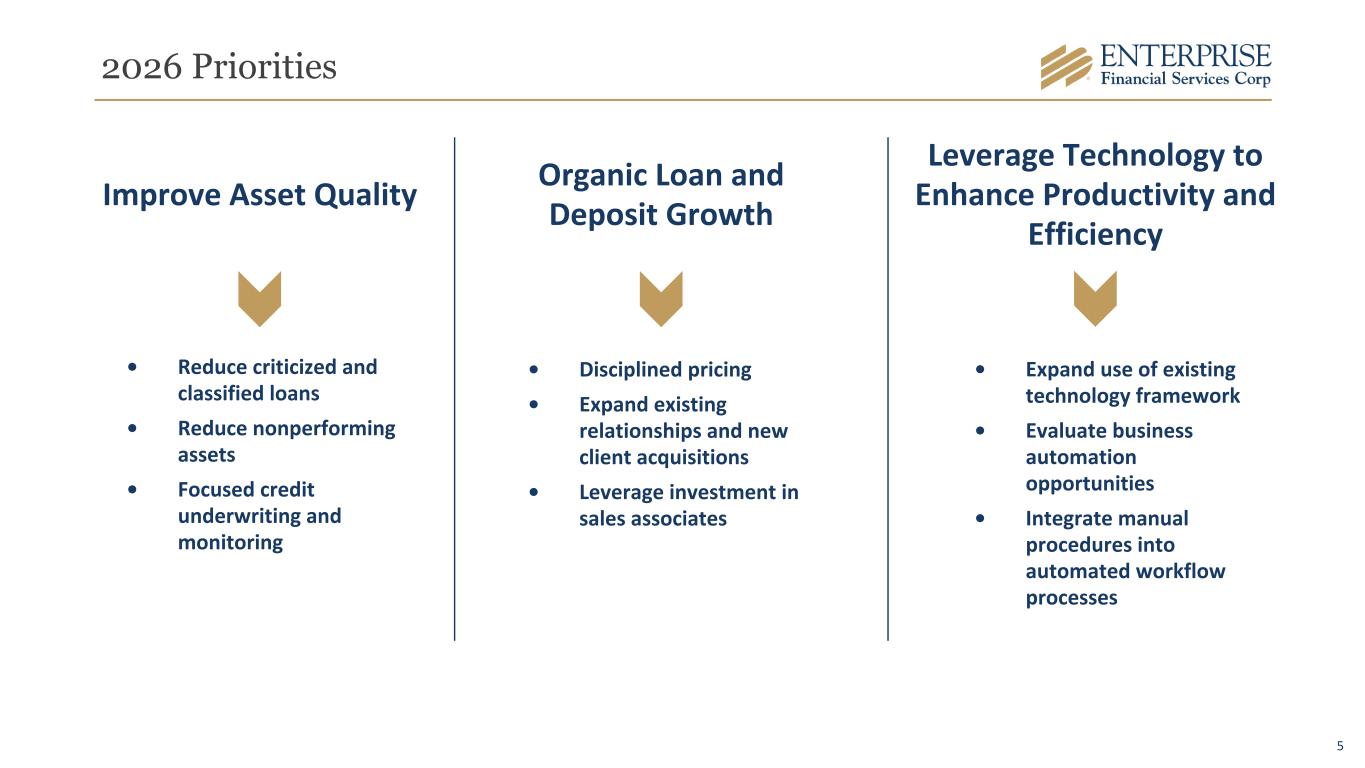
5 2026 Priorities Improve Asset Quality • Reduce criticized and classified loans • Reduce nonperforming assets • Focused credit underwriting and monitoring Leverage Technology to Enhance Productivity and Efficiency • Expand use of existing technology framework • Evaluate business automation opportunities • Integrate manual procedures into automated workflow processes Organic Loan and Deposit Growth • Disciplined pricing • Expand existing relationships and new client acquisitions • Leverage investment in sales associates
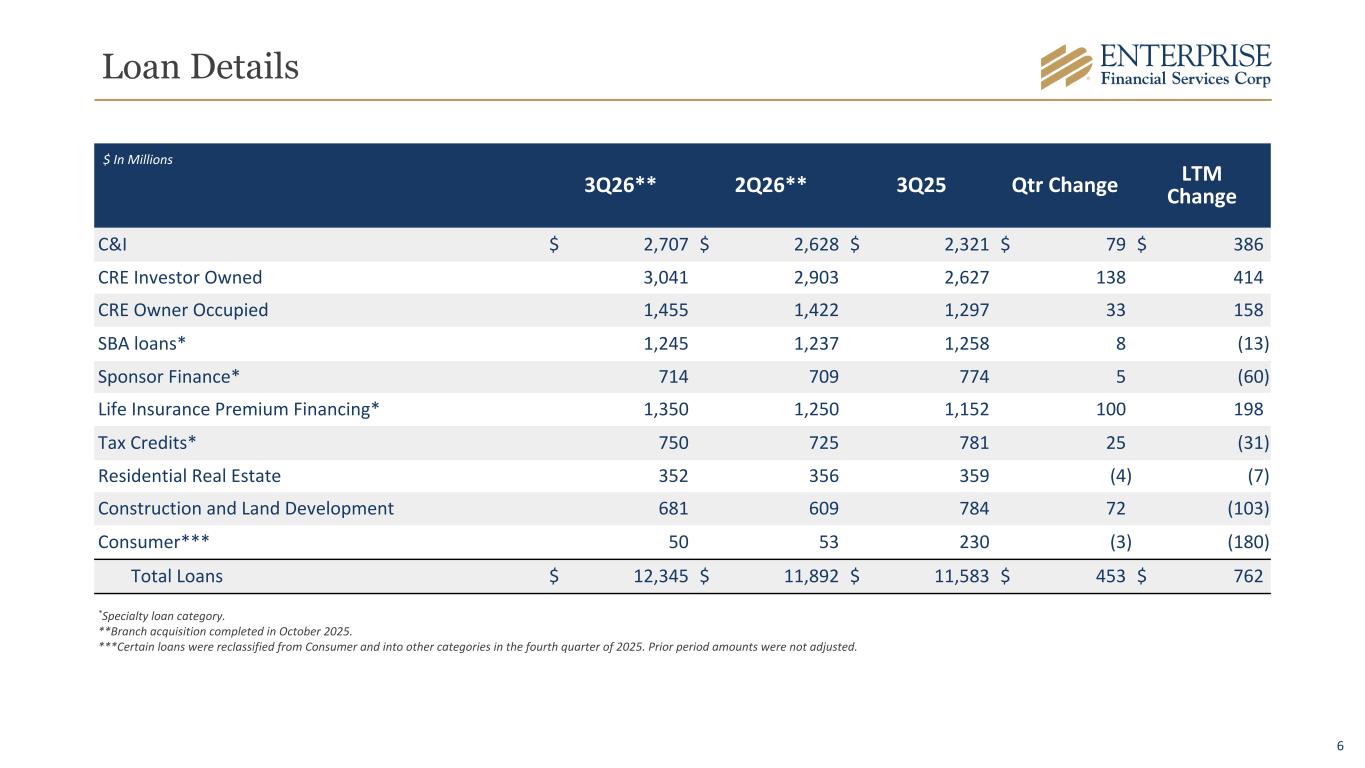
6 Loan Details 3Q26** 2Q26** 3Q25 Qtr Change LTM Change C&I $ 2,707 $ 2,628 $ 2,321 $ 79 $ 386 CRE Investor Owned 3,041 2,903 2,627 138 414 CRE Owner Occupied 1,455 1,422 1,297 33 158 SBA loans* 1,245 1,237 1,258 8 (13) Sponsor Finance* 714 709 774 5 (60) Life Insurance Premium Financing* 1,350 1,250 1,152 100 198 Tax Credits* 750 725 781 25 (31) Residential Real Estate 352 356 359 (4) (7) Construction and Land Development 681 609 784 72 (103) Consumer*** 50 53 230 (3) (180) Total Loans $ 12,345 $ 11,892 $ 11,583 $ 453 $ 762 *Specialty loan category. **Branch acquisition completed in October 2025. ***Certain loans were reclassified from Consumer and into other categories in the fourth quarter of 2025. Prior period amounts were not adjusted. $ In Millions
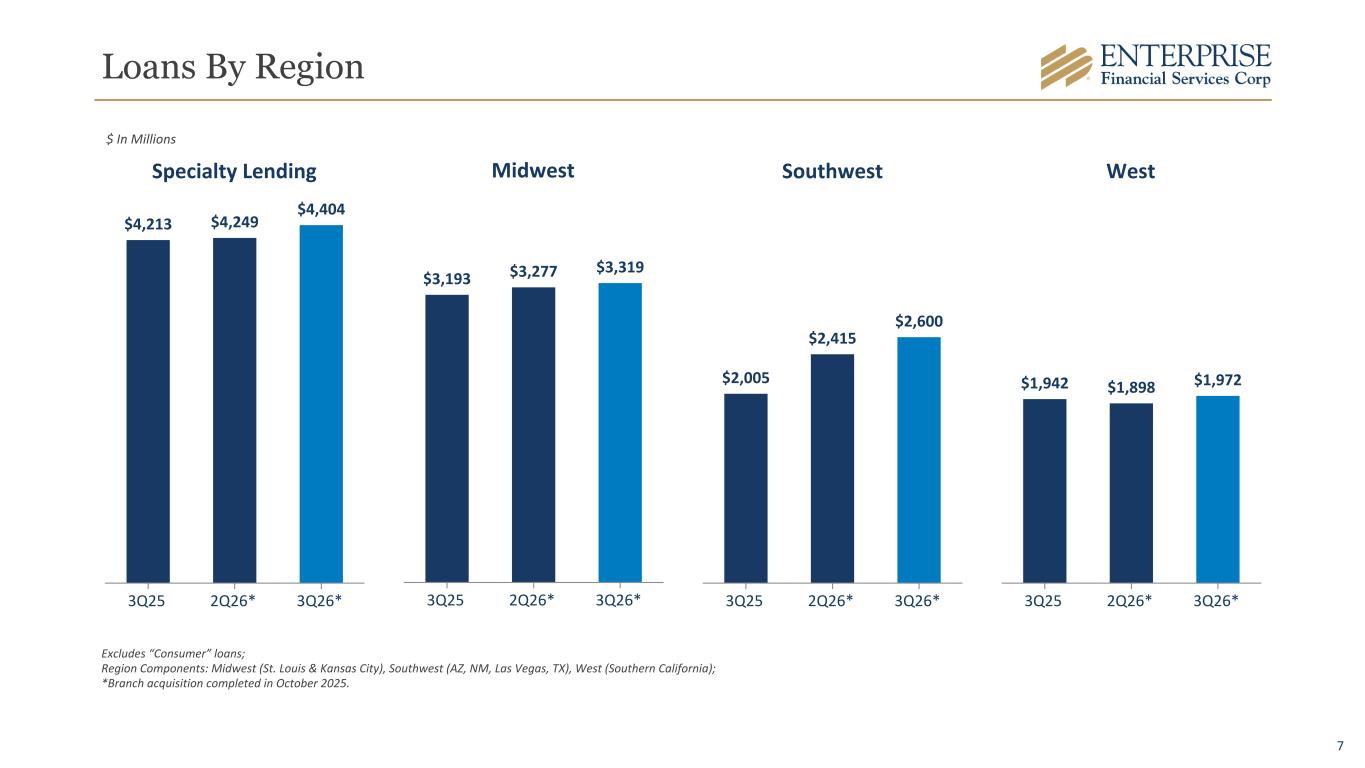
7 Loans By Region Specialty Lending $4,213 $4,249 $4,404 3Q25 2Q26* 3Q26* $ In Millions Midwest $3,193 $3,277 $3,319 3Q25 2Q26* 3Q26* Southwest $2,005 $2,415 $2,600 3Q25 2Q26* 3Q26* Excludes “Consumer” loans; Region Components: Midwest (St. Louis & Kansas City), Southwest (AZ, NM, Las Vegas, TX), West (Southern California); *Branch acquisition completed in October 2025. West $1,942 $1,898 $1,972 3Q25 2Q26* 3Q26*
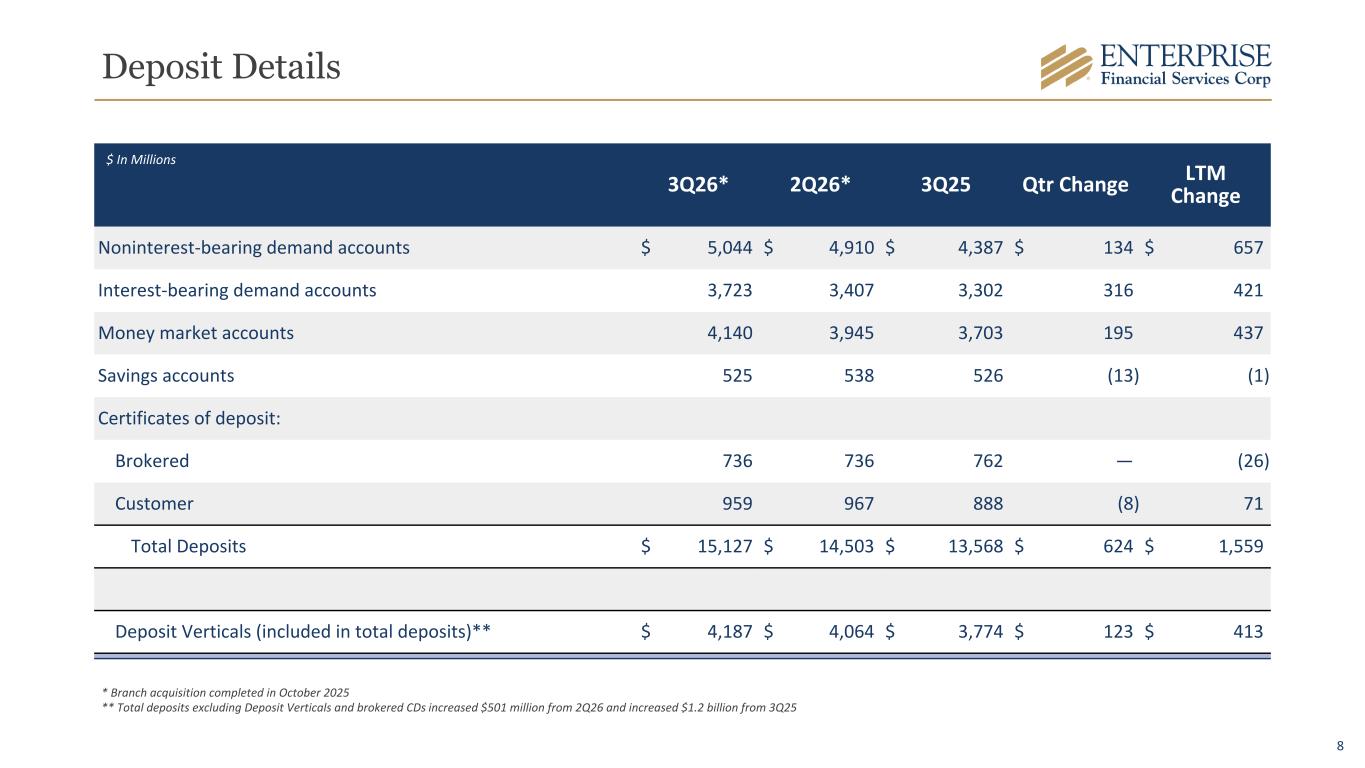
8 Deposit Details 3Q26* 2Q26* 3Q25 Qtr Change LTM Change Noninterest-bearing demand accounts $ 5,044 $ 4,910 $ 4,387 $ 134 $ 657 Interest-bearing demand accounts 3,723 3,407 3,302 316 421 Money market accounts 4,140 3,945 3,703 195 437 Savings accounts 525 538 526 (13) (1) Certificates of deposit: Brokered 736 736 762 — (26) Customer 959 967 888 (8) 71 Total Deposits $ 15,127 $ 14,503 $ 13,568 $ 624 $ 1,559 Deposit Verticals (included in total deposits)** $ 4,187 $ 4,064 $ 3,774 $ 123 $ 413 $ In Millions * Branch acquisition completed in October 2025 ** Total deposits excluding Deposit Verticals and brokered CDs increased $501 million from 2Q26 and increased $1.2 billion from 3Q25
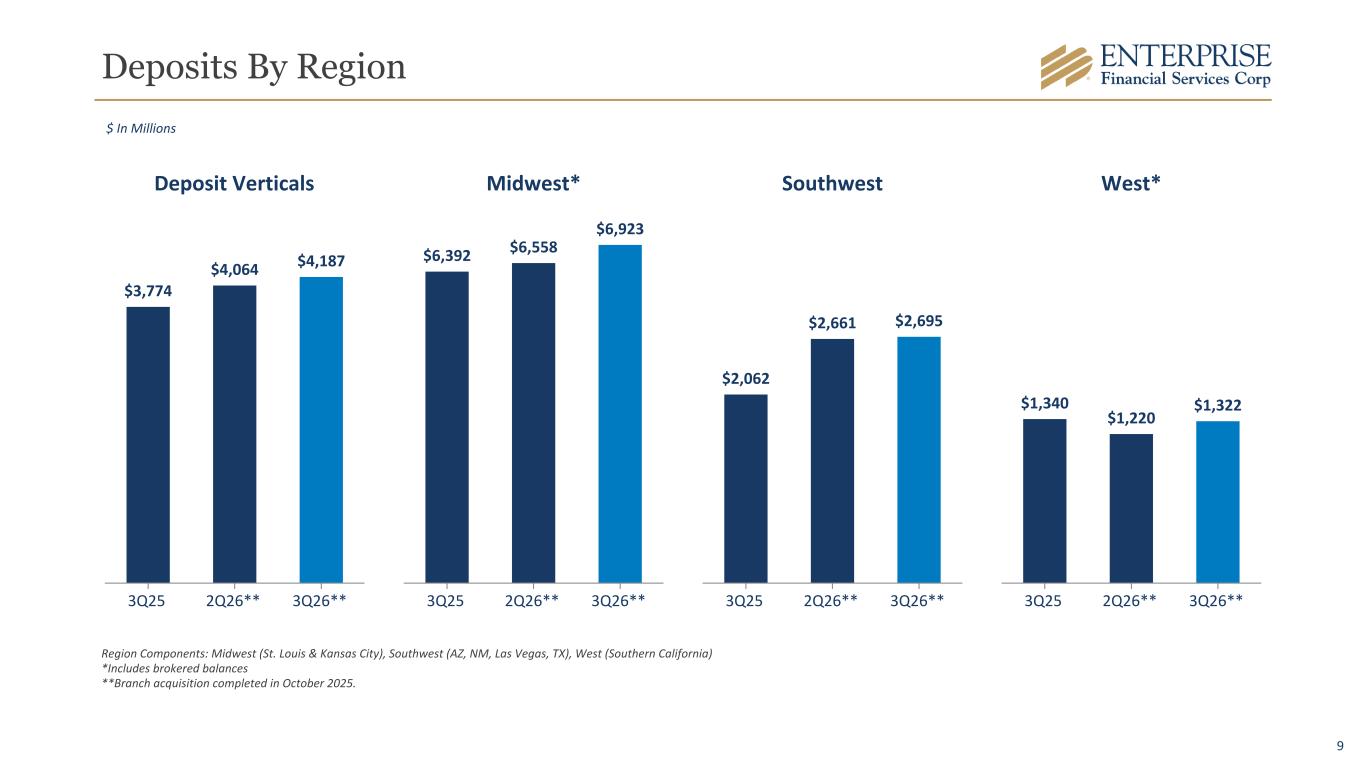
9 Deposits By Region Deposit Verticals $3,774 $4,064 $4,187 3Q25 2Q26** 3Q26** $ In Millions Region Components: Midwest (St. Louis & Kansas City), Southwest (AZ, NM, Las Vegas, TX), West (Southern California) *Includes brokered balances **Branch acquisition completed in October 2025. Midwest* $6,392 $6,558 $6,923 3Q25 2Q26** 3Q26** West* $1,340 $1,220 $1,322 3Q25 2Q26** 3Q26** Southwest $2,062 $2,661 $2,695 3Q25 2Q26** 3Q26**
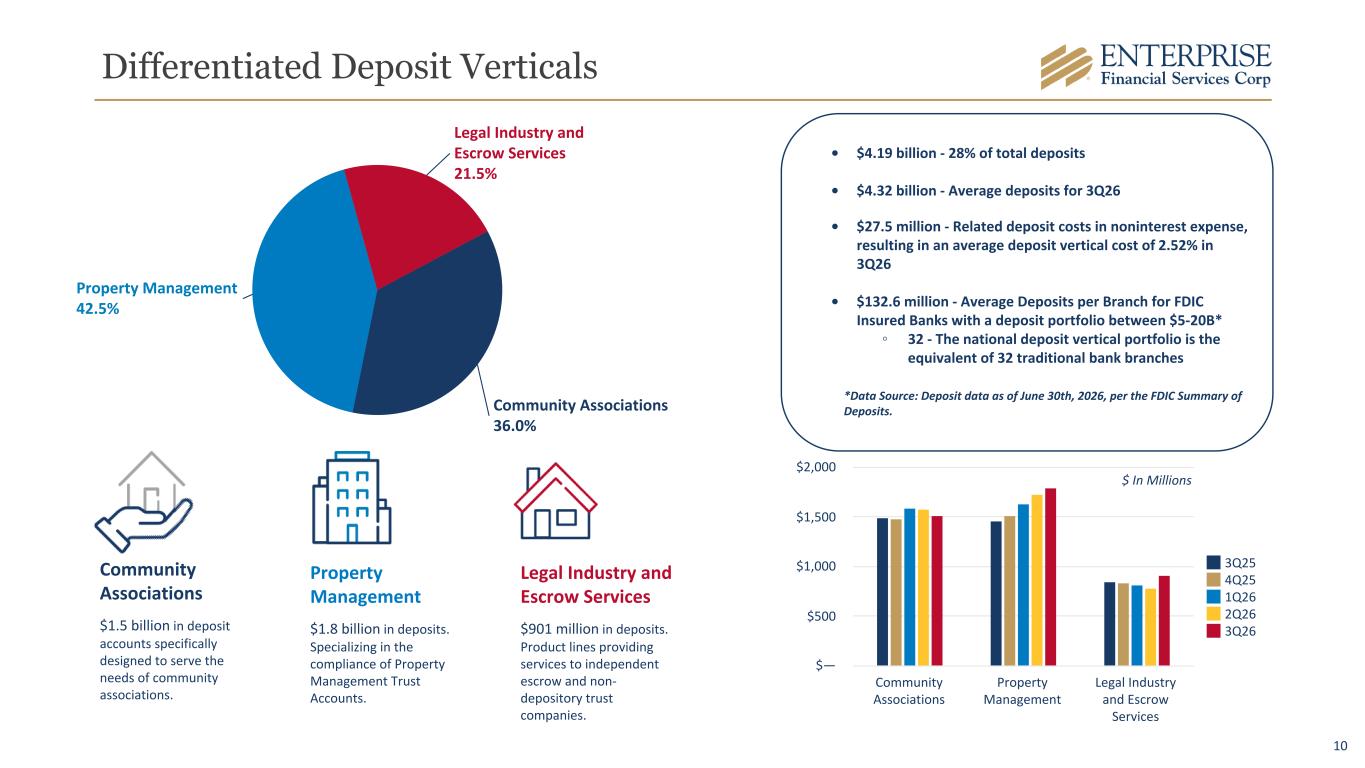
10 Differentiated Deposit Verticals Community Associations 36.0% Property Management 42.5% Legal Industry and Escrow Services 21.5% Community Associations $1.5 billion in deposit accounts specifically designed to serve the needs of community associations. Property Management $1.8 billion in deposits. Specializing in the compliance of Property Management Trust Accounts. Legal Industry and Escrow Services $901 million in deposits. Product lines providing services to independent escrow and non- depository trust companies. • $4.19 billion - 28% of total deposits • $4.32 billion - Average deposits for 3Q26 • $27.5 million - Related deposit costs in noninterest expense, resulting in an average deposit vertical cost of 2.52% in 3Q26 • $132.6 million - Average Deposits per Branch for FDIC Insured Banks with a deposit portfolio between $5-20B* ◦ 32 - The national deposit vertical portfolio is the equivalent of 32 traditional bank branches *Data Source: Deposit data as of June 30th, 2026, per the FDIC Summary of Deposits. 3Q25 4Q25 1Q26 2Q26 3Q26 Community Associations Property Management Legal Industry and Escrow Services $— $500 $1,000 $1,500 $2,000 $ In Millions
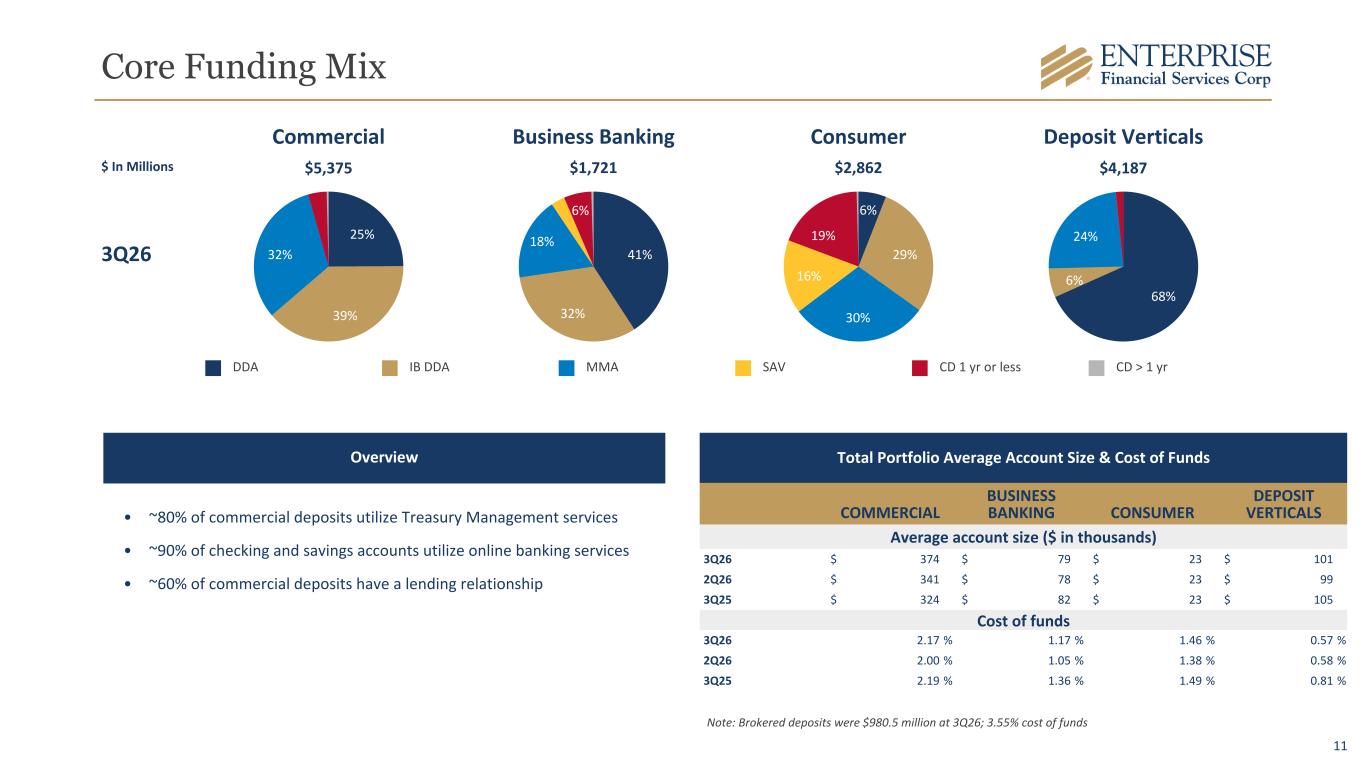
11 Core Funding Mix Commercial Business Banking Consumer $ In Millions Note: Brokered deposits were $980.5 million at 3Q26; 3.55% cost of funds Deposit Verticals 3Q26 Total Portfolio Average Account Size & Cost of Funds COMMERCIAL BUSINESS BANKING CONSUMER DEPOSIT VERTICALS Average account size ($ in thousands) 3Q26 $ 374 $ 79 $ 23 $ 101 2Q26 $ 341 $ 78 $ 23 $ 99 3Q25 $ 324 $ 82 $ 23 $ 105 Cost of funds 3Q26 2.17 % 1.17 % 1.46 % 0.57 % 2Q26 2.00 % 1.05 % 1.38 % 0.58 % 3Q25 2.19 % 1.36 % 1.49 % 0.81 % • ~80% of commercial deposits utilize Treasury Management services • ~90% of checking and savings accounts utilize online banking services • ~60% of commercial deposits have a lending relationship Overview 25% 39% 32% 41% 32% 18% 6% 6% 29% 30% 16% 19% 68% 6% 24% $5,375 $4,187$2,862$1,721 DDA IB DDA MMA SAV CD 1 yr or less CD > 1 yr
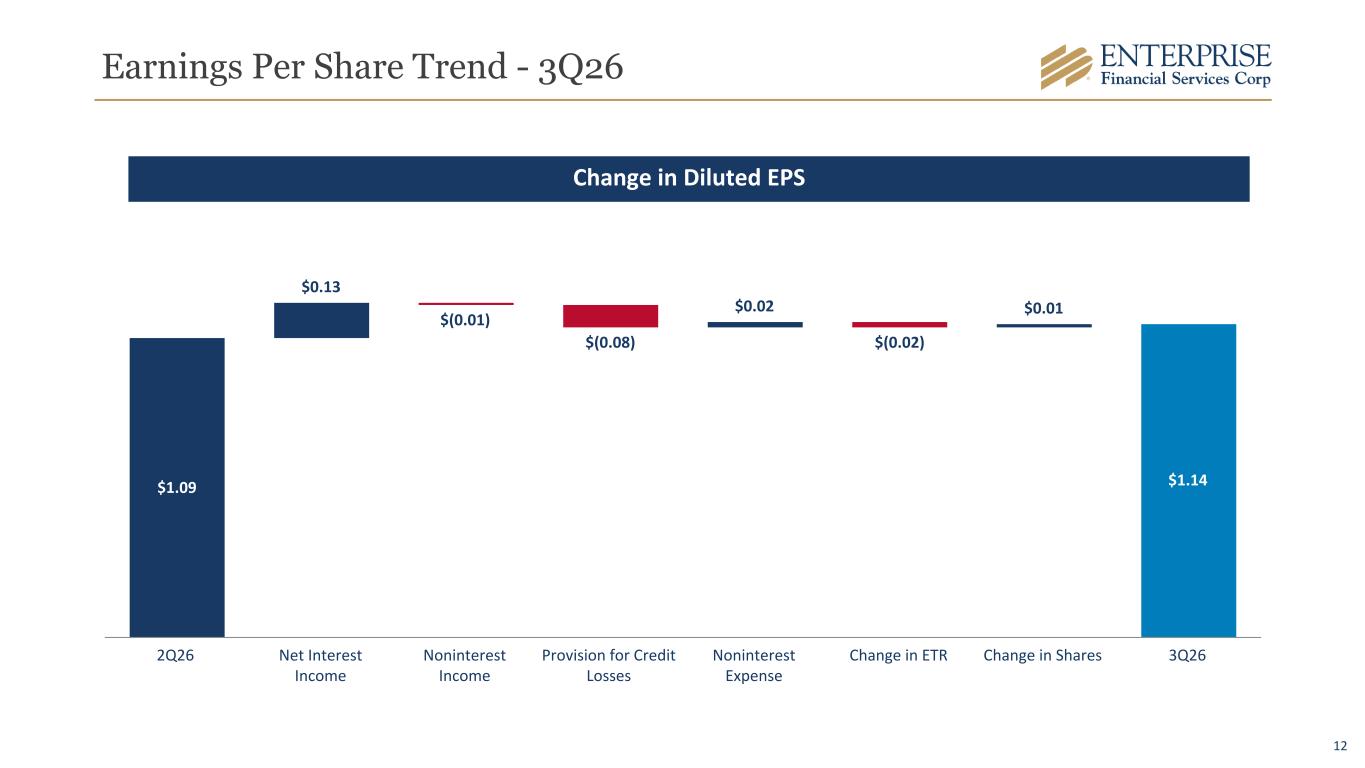
12 Earnings Per Share Trend - 3Q26 $1.09 $0.13 $(0.01) $(0.08) $0.02 $(0.02) $0.01 $1.14 2Q26 Net Interest Income Noninterest Income Provision for Credit Losses Noninterest Expense Change in ETR Change in Shares 3Q26 Change in Diluted EPS
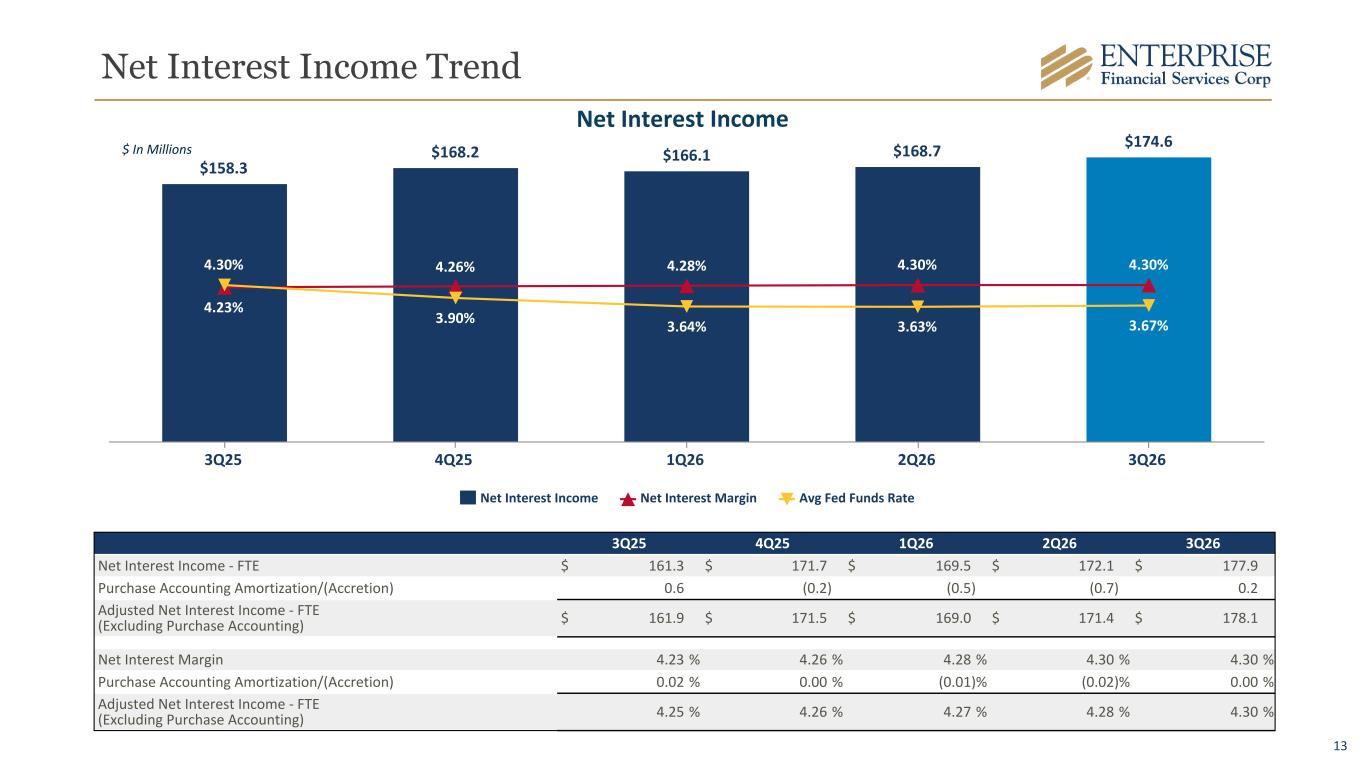
13 $158.3 $168.2 $166.1 $168.7 $174.6 4.23% 4.26% 4.28% 4.30% 4.30%4.30% 3.90% 3.64% 3.63% 3.67% Net Interest Income Net Interest Margin Avg Fed Funds Rate 3Q25 4Q25 1Q26 2Q26 3Q26 Net Interest Income Trend $ In Millions Net Interest Income 3Q25 4Q25 1Q26 2Q26 3Q26 Net Interest Income - FTE $ 161.3 $ 171.7 $ 169.5 $ 172.1 $ 177.9 Purchase Accounting Amortization/(Accretion) 0.6 (0.2) (0.5) (0.7) 0.2 Adjusted Net Interest Income - FTE (Excluding Purchase Accounting) $ 161.9 $ 171.5 $ 169.0 $ 171.4 $ 178.1 Net Interest Margin 4.23 % 4.26 % 4.28 % 4.30 % 4.30 % Purchase Accounting Amortization/(Accretion) 0.02 % 0.00 % (0.01) % (0.02) % 0.00 % Adjusted Net Interest Income - FTE (Excluding Purchase Accounting) 4.25 % 4.26 % 4.27 % 4.28 % 4.30 %
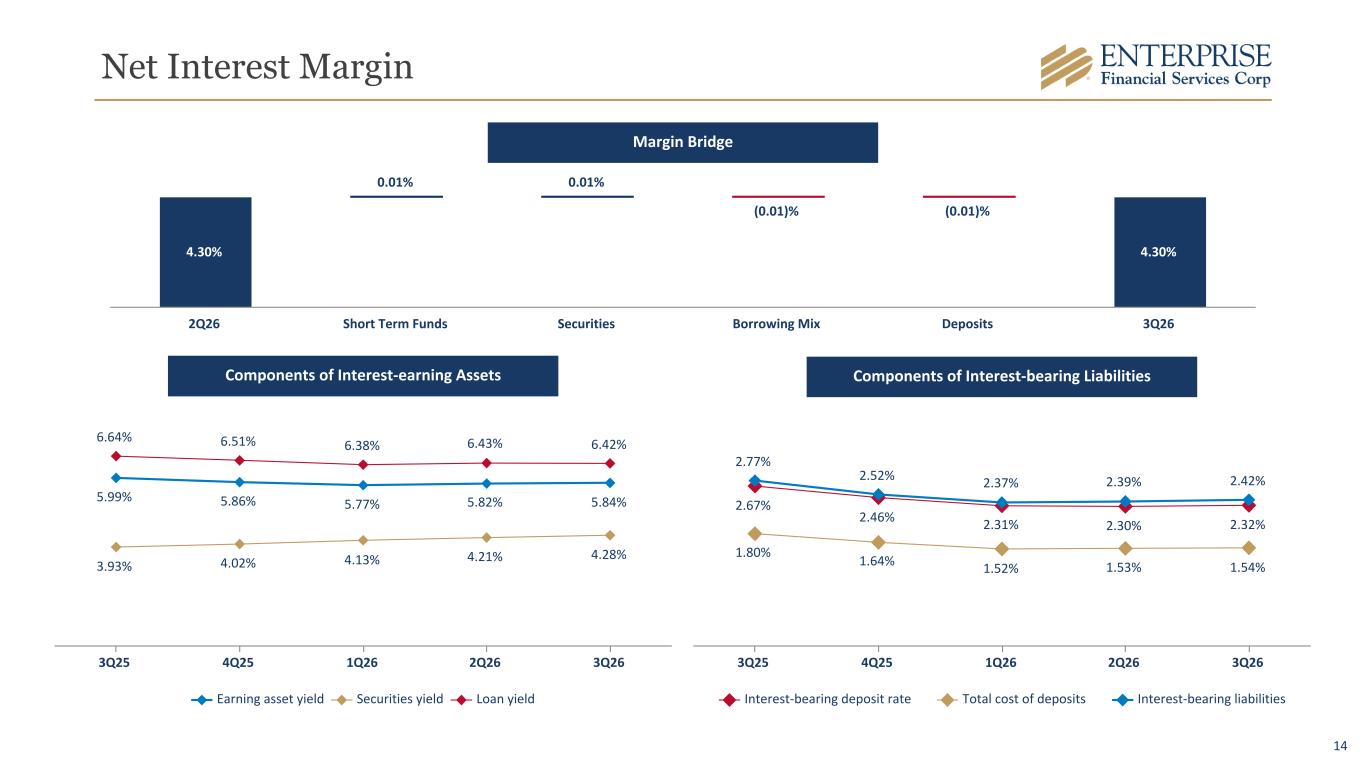
14 Net Interest Margin 6.64% 6.51% 6.38% 6.43% 6.42% 3.93% 4.02% 4.13% 4.21% 4.28% 5.99% 5.86% 5.77% 5.82% 5.84% Earning asset yield Securities yield Loan yield 3Q25 4Q25 1Q26 2Q26 3Q26 2.67% 2.46% 2.31% 2.30% 2.32% 1.80% 1.64% 1.52% 1.53% 1.54% 2.77% 2.52% 2.37% 2.39% 2.42% Interest-bearing deposit rate Total cost of deposits Interest-bearing liabilities 3Q25 4Q25 1Q26 2Q26 3Q26 Components of Interest-bearing LiabilitiesComponents of Interest-earning Assets 4.30% 0.01% 0.01% (0.01)% (0.01)% 4.30% 2Q26 Short Term Funds Securities Borrowing Mix Deposits 3Q26 Margin Bridge
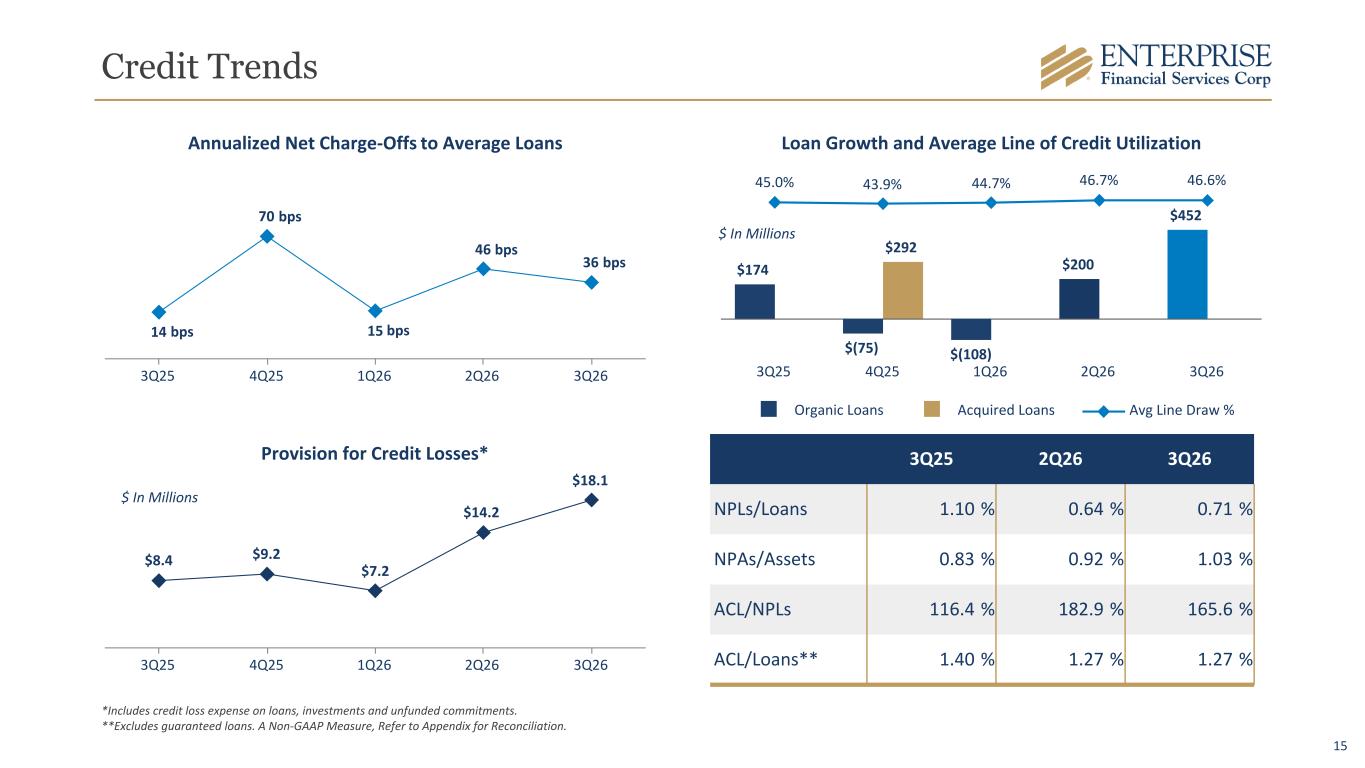
15 14 70 15 46 36 3Q25 4Q25 1Q26 2Q26 3Q26 $174 $(75) $(108) $200 $452 $292 45.0% 43.9% 44.7% 46.7% 46.6% Organic Loans Acquired Loans Avg Line Draw % 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 2Q26 3Q26 NPLs/Loans 1.10 % 0.64 % 0.71 % NPAs/Assets 0.83 % 0.92 % 1.03 % ACL/NPLs 116.4 % 182.9 % 165.6 % ACL/Loans** 1.40 % 1.27 % 1.27 % Annualized Net Charge-Offs to Average Loans Provision for Credit Losses* $8.4 $9.2 $7.2 $14.2 $18.1 3Q25 4Q25 1Q26 2Q26 3Q26 $ In Millions bps bps bps bps bps $ In Millions Loan Growth and Average Line of Credit Utilization *Includes credit loss expense on loans, investments and unfunded commitments. **Excludes guaranteed loans. A Non-GAAP Measure, Refer to Appendix for Reconciliation. Credit Trends
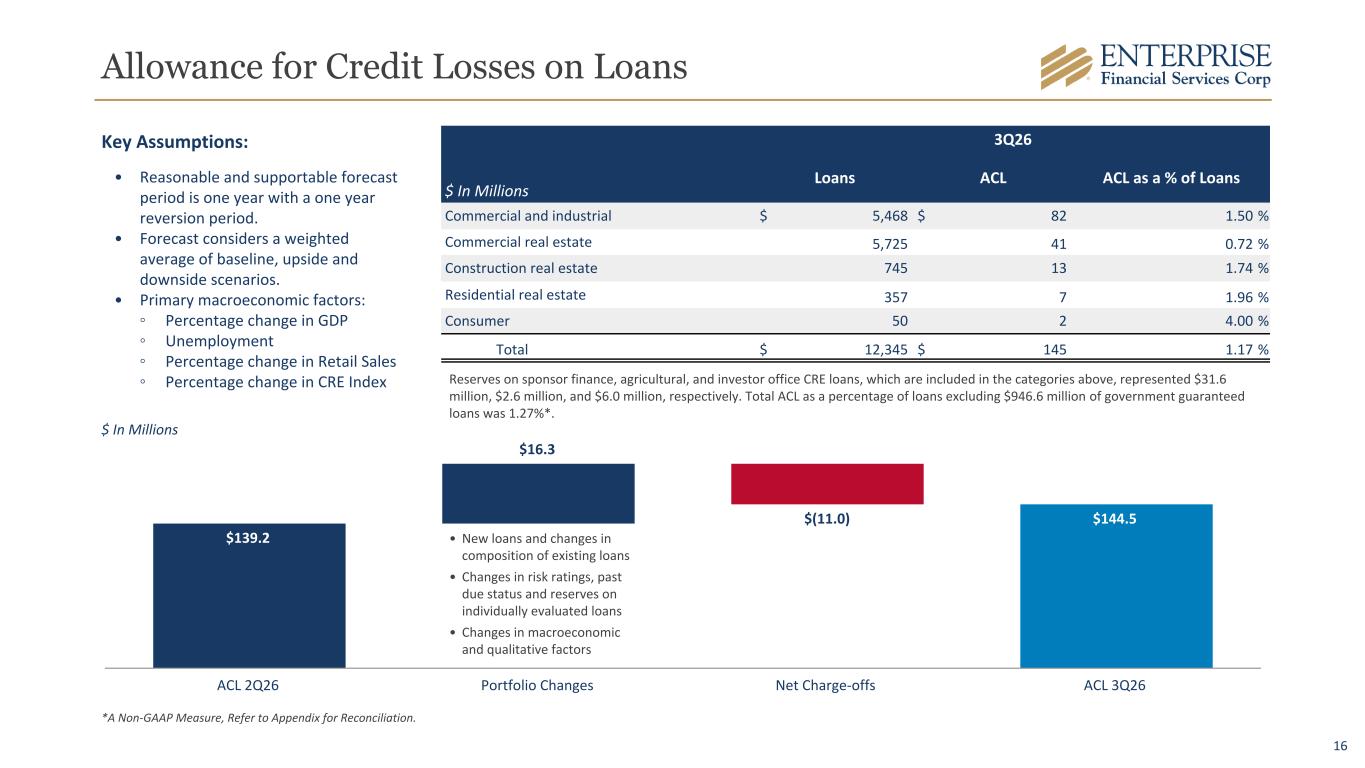
16 $139.2 $16.3 $(11.0) $144.5 ACL 2Q26 Portfolio Changes Net Charge-offs ACL 3Q26 Allowance for Credit Losses on Loans $ In Millions • New loans and changes in composition of existing loans • Changes in risk ratings, past due status and reserves on individually evaluated loans • Changes in macroeconomic and qualitative factors $ In Millions 3Q26 Loans ACL ACL as a % of Loans Commercial and industrial $ 5,468 $ 82 1.50 % Commercial real estate 5,725 41 0.72 % Construction real estate 745 13 1.74 % Residential real estate 357 7 1.96 % Consumer 50 2 4.00 % Total $ 12,345 $ 145 1.17 % Reserves on sponsor finance, agricultural, and investor office CRE loans, which are included in the categories above, represented $31.6 million, $2.6 million, and $6.0 million, respectively. Total ACL as a percentage of loans excluding $946.6 million of government guaranteed loans was 1.27%*. Key Assumptions: • Reasonable and supportable forecast period is one year with a one year reversion period. • Forecast considers a weighted average of baseline, upside and downside scenarios. • Primary macroeconomic factors: ◦ Percentage change in GDP ◦ Unemployment ◦ Percentage change in Retail Sales ◦ Percentage change in CRE Index *A Non-GAAP Measure, Refer to Appendix for Reconciliation.
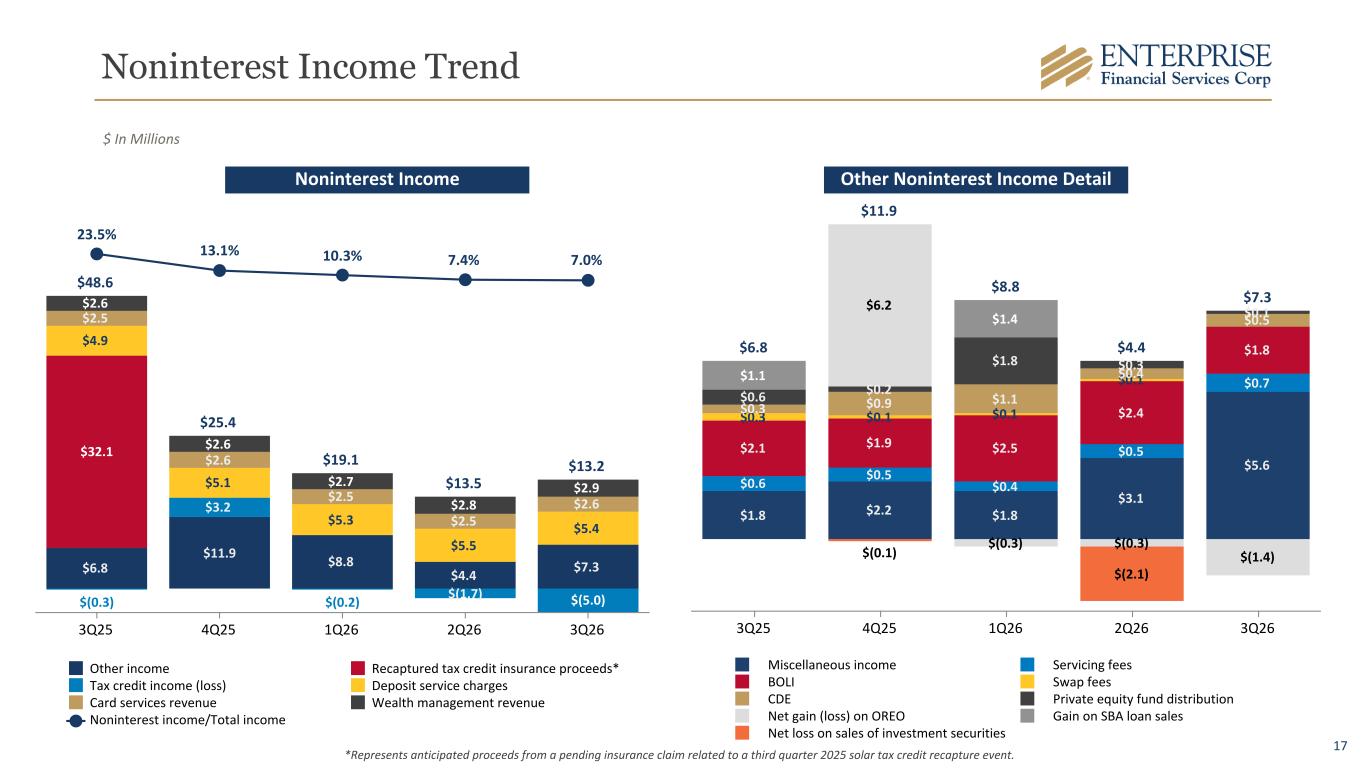
17 Noninterest Income Trend $48.6 $25.4 $19.1 $13.5 $13.2 $6.8 $11.9 $8.8 $4.4 $7.3 $32.1 $(0.3) $3.2 $(0.2) $(1.7) $(5.0) $4.9 $5.1 $5.3 $5.5 $5.4 $2.5 $2.6 $2.5 $2.5 $2.6 $2.6 $2.6 $2.7 $2.8 $2.9 23.5% 13.1% 10.3% 7.4% 7.0% Other income Recaptured tax credit insurance proceeds* Tax credit income (loss) Deposit service charges Card services revenue Wealth management revenue Noninterest income/Total income 3Q25 4Q25 1Q26 2Q26 3Q26 $6.8 $11.9 $8.8 $4.4 $7.3 $1.8 $2.2 $1.8 $3.1 $5.6 $0.6 $0.5 $0.4 $0.5 $0.7 $2.1 $1.9 $2.5 $2.4 $1.8 $0.3 $0.1 $0.1 $0.1 $0.3 $0.9 $1.1 $0.4 $0.5 $0.6 $0.2 $1.8 $0.3 $0.1$6.2 $(0.3) $(0.3) $(1.4) $1.1 $1.4 $(0.1) $(2.1) Miscellaneous income Servicing fees BOLI Swap fees CDE Private equity fund distribution Net gain (loss) on OREO Gain on SBA loan sales Net loss on sales of investment securities 3Q25 4Q25 1Q26 2Q26 3Q26 $ In Millions Noninterest Income Other Noninterest Income Detail *Represents anticipated proceeds from a pending insurance claim related to a third quarter 2025 solar tax credit recapture event.
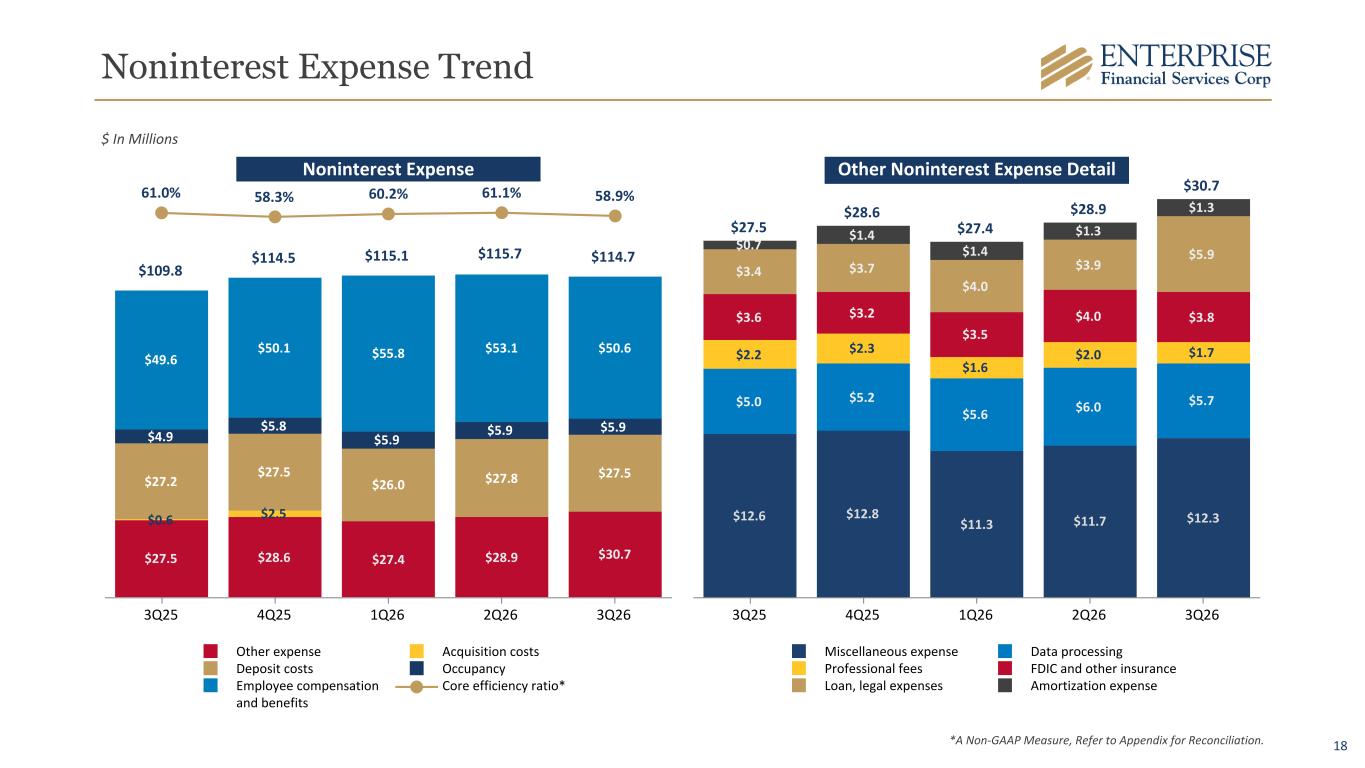
18 Noninterest Expense Trend Noninterest Expense $ In Millions $27.5 $28.6 $27.4 $28.9 $30.7 $0.6 $2.5 $27.2 $27.5 $26.0 $27.8 $27.5 $4.9 $5.8 $5.9 $5.9 $5.9 $49.6 $50.1 $55.8 $53.1 $50.6 61.0% 58.3% 60.2% 61.1% 58.9% $109.8 $114.5 $115.1 $115.7 $114.7 Other expense Acquisition costs Deposit costs Occupancy Employee compensation and benefits Core efficiency ratio* 3Q25 4Q25 1Q26 2Q26 3Q26 $27.5 $28.6 $27.4 $28.9 $30.7 $12.6 $12.8 $11.3 $11.7 $12.3 $5.0 $5.2 $5.6 $6.0 $5.7 $2.2 $2.3 $1.6 $2.0 $1.7 $3.6 $3.2 $3.5 $4.0 $3.8 $3.4 $3.7 $4.0 $3.9 $5.9 $0.7 $1.4 $1.4 $1.3 $1.3 Miscellaneous expense Data processing Professional fees FDIC and other insurance Loan, legal expenses Amortization expense 3Q25 4Q25 1Q26 2Q26 3Q26 *A Non-GAAP Measure, Refer to Appendix for Reconciliation. Other Noninterest Expense Detail
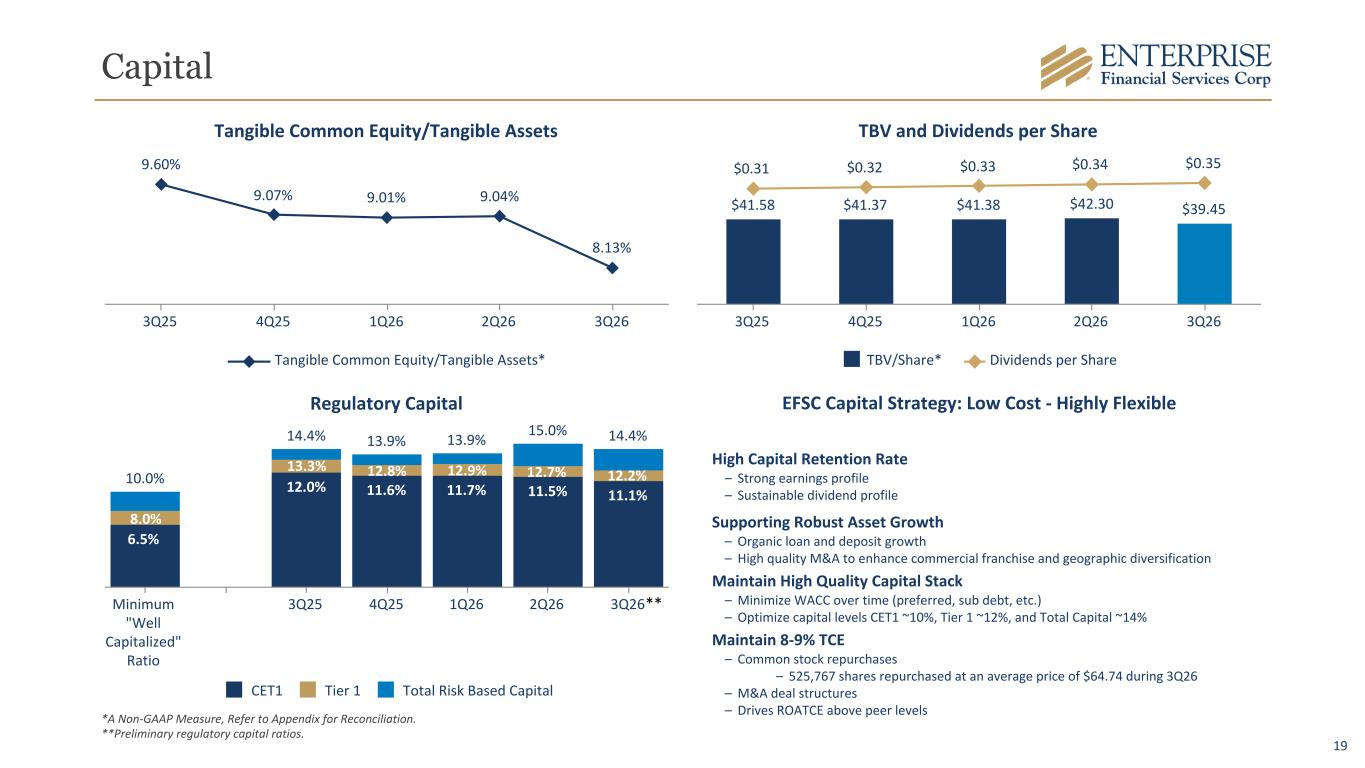
19 Capital Tangible Common Equity/Tangible Assets 9.60% 9.07% 9.01% 9.04% 8.13% Tangible Common Equity/Tangible Assets* 3Q25 4Q25 1Q26 2Q26 3Q26 *A Non-GAAP Measure, Refer to Appendix for Reconciliation. **Preliminary regulatory capital ratios. Regulatory Capital 10.0% 14.4% 13.9% 13.9% 15.0% 14.4% 6.5% 12.0% 11.6% 11.7% 11.5% 11.1% CET1 Tier 1 Total Risk Based Capital Minimum "Well Capitalized" Ratio 3Q25 4Q25 1Q26 2Q26 3Q26 8.0% 13.3% 12.8% 12.9% 12.7% EFSC Capital Strategy: Low Cost - Highly Flexible High Capital Retention Rate – Strong earnings profile – Sustainable dividend profile Supporting Robust Asset Growth – Organic loan and deposit growth – High quality M&A to enhance commercial franchise and geographic diversification Maintain High Quality Capital Stack – Minimize WACC over time (preferred, sub debt, etc.) – Optimize capital levels CET1 ~10%, Tier 1 ~12%, and Total Capital ~14% Maintain 8-9% TCE – Common stock repurchases – 525,767 shares repurchased at an average price of $64.74 during 3Q26 – M&A deal structures – Drives ROATCE above peer levels TBV and Dividends per Share $41.58 $41.37 $41.38 $42.30 $39.45 $0.31 $0.32 $0.33 $0.34 $0.35 TBV/Share* Dividends per Share 3Q25 4Q25 1Q26 2Q26 3Q26 12.2% **
Appendix
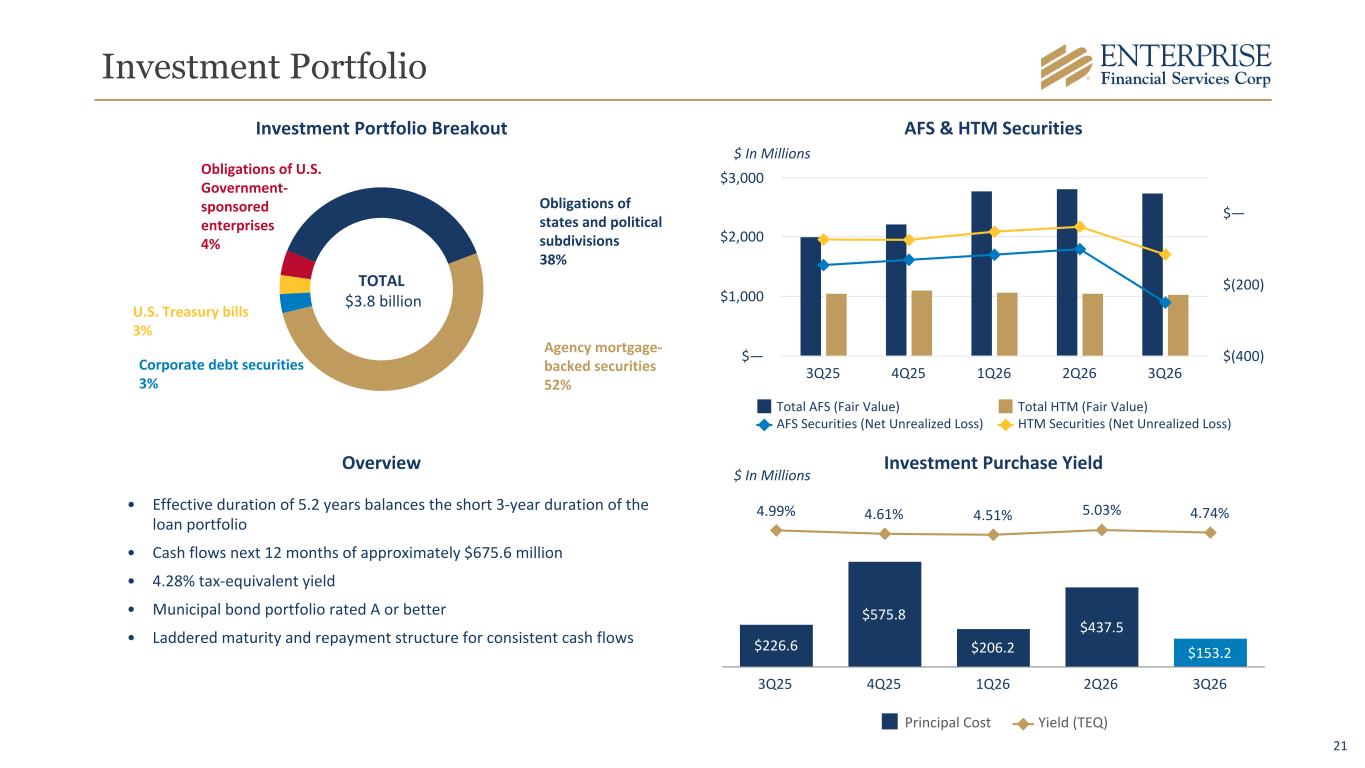
21 Investment Portfolio Breakout AFS & HTM Securities Obligations of U.S. Government- sponsored enterprises 4% Obligations of states and political subdivisions 38% Agency mortgage- backed securities 52% Corporate debt securities 3% U.S. Treasury bills 3% TOTAL $3.8 billion • Effective duration of 5.2 years balances the short 3-year duration of the loan portfolio • Cash flows next 12 months of approximately $675.6 million • 4.28% tax-equivalent yield • Municipal bond portfolio rated A or better • Laddered maturity and repayment structure for consistent cash flows Overview Total AFS (Fair Value) Total HTM (Fair Value) AFS Securities (Net Unrealized Loss) HTM Securities (Net Unrealized Loss) 3Q25 4Q25 1Q26 2Q26 3Q26 $— $1,000 $2,000 $3,000 $(400) $(200) $— $ In Millions $226.6 $575.8 $206.2 $437.5 $153.2 4.99% 4.61% 4.51% 5.03% 4.74% Principal Cost Yield (TEQ) 3Q25 4Q25 1Q26 2Q26 3Q26 Investment Purchase Yield $ In Millions Investment Portfolio
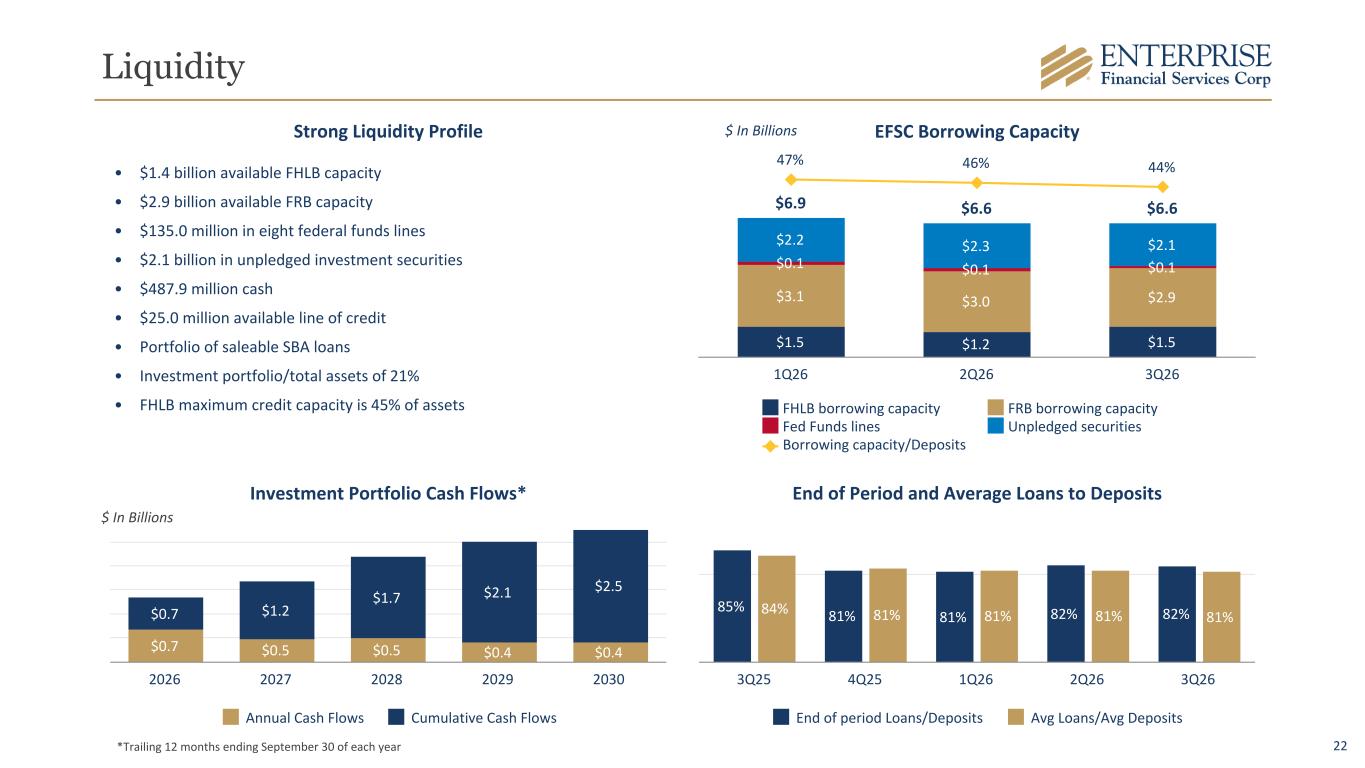
22 EFSC Borrowing Capacity $6.9 $6.6 $6.6 $1.5 $1.2 $1.5 $3.1 $3.0 $2.9 $0.1 $0.1 $0.1 $2.2 $2.3 $2.1 47% 46% 44% FHLB borrowing capacity FRB borrowing capacity Fed Funds lines Unpledged securities Borrowing capacity/Deposits 1Q26 2Q26 3Q26 $ In Billions End of Period and Average Loans to Deposits 85% 81% 81% 82% 82%84% 81% 81% 81% 81% End of period Loans/Deposits Avg Loans/Avg Deposits 3Q25 4Q25 1Q26 2Q26 3Q26 • $1.4 billion available FHLB capacity • $2.9 billion available FRB capacity • $135.0 million in eight federal funds lines • $2.1 billion in unpledged investment securities • $487.9 million cash • $25.0 million available line of credit • Portfolio of saleable SBA loans • Investment portfolio/total assets of 21% • FHLB maximum credit capacity is 45% of assets $0.7 $0.5 $0.5 $0.4 $0.4 $0.7 $1.2 $1.7 $2.1 $2.5 Annual Cash Flows Cumulative Cash Flows 2026 2027 2028 2029 2030 Investment Portfolio Cash Flows* $ In Billions Strong Liquidity Profile *Trailing 12 months ending September 30 of each year Liquidity
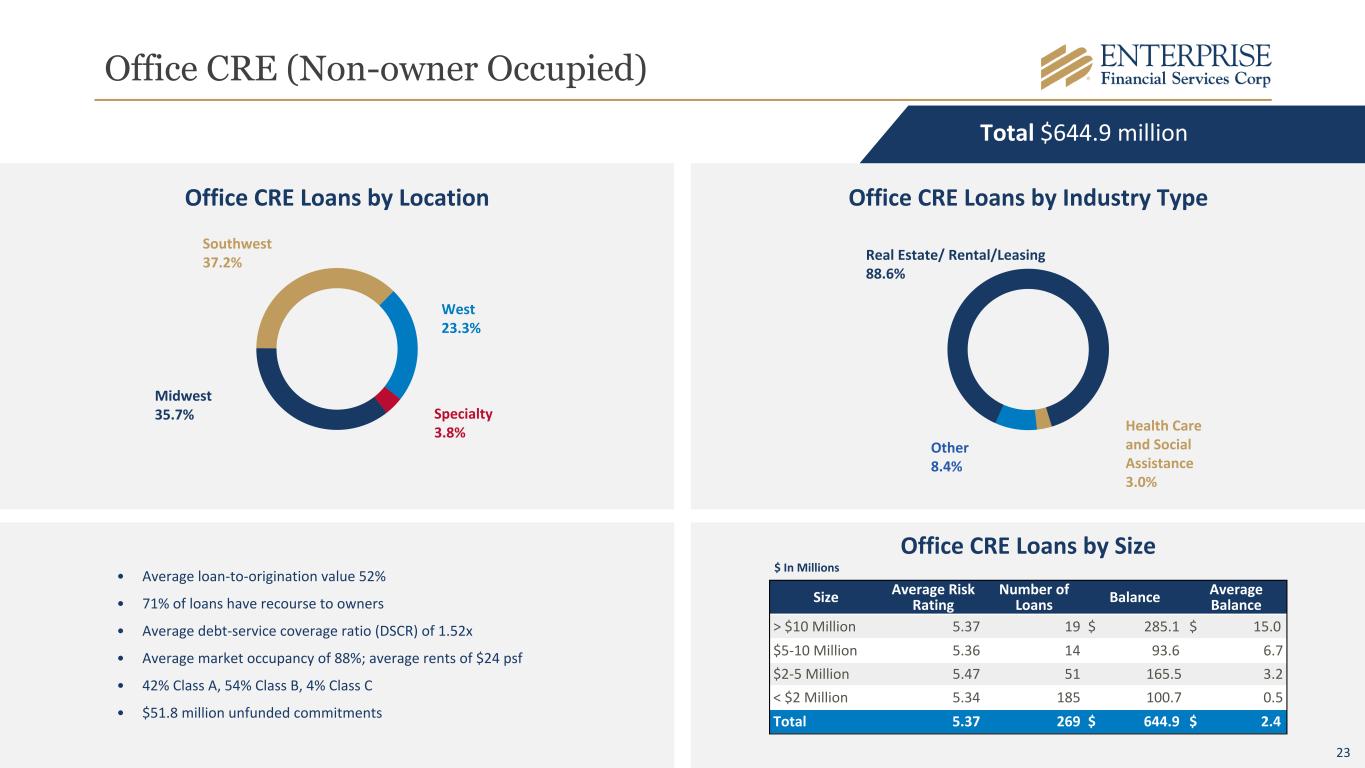
23 Office CRE (Non-owner Occupied) Total $644.9 million Midwest 35.7% Southwest 37.2% West 23.3% Specialty 3.8% Office CRE Loans by Location Real Estate/ Rental/Leasing 88.6% Health Care and Social Assistance 3.0% Other 8.4% Office CRE Loans by Industry Type Size Average Risk Rating Number of Loans Balance Average Balance > $10 Million 5.37 19 $ 285.1 $ 15.0 $5-10 Million 5.36 14 93.6 6.7 $2-5 Million 5.47 51 165.5 3.2 < $2 Million 5.34 185 100.7 0.5 Total 5.37 269 $ 644.9 $ 2.4 Office CRE Loans by Size $ In Millions • Average loan-to-origination value 52% • 71% of loans have recourse to owners • Average debt-service coverage ratio (DSCR) of 1.52x • Average market occupancy of 88%; average rents of $24 psf • 42% Class A, 54% Class B, 4% Class C • $51.8 million unfunded commitments 23
24 Use of Non-GAAP Financial Measures The Company’s accounting and reporting policies conform to generally accepted accounting principles in the United States (“GAAP”) and the prevailing practices in the banking industry. However, the Company provides other financial measures, such as tangible common equity, PPNR, ROATCE, allowance coverage ratio adjusted for guaranteed loans, PPNR return on average assets (“PPNR ROAA”), core efficiency ratio, tangible common equity to tangible assets, and tangible book value per common share, in this release that are considered “non-GAAP financial measures.” Generally, a non-GAAP financial measure is a numerical measure of a company’s financial performance, financial position, or cash flows that exclude (or include) amounts that are included in (or excluded from) the most directly comparable measure calculated and presented in accordance with GAAP. The Company considers its tangible common equity, PPNR, ROATCE, allowance coverage ratio adjusted for guaranteed loans, PPNR return on average assets (“PPNR ROAA”), core efficiency ratio, tangible common equity to tangible assets, and tangible book value per common share, collectively “core performance measures,” presented in this earnings release and the included tables as important measures of financial performance, even though they are non-GAAP measures, as they provide supplemental information by which to evaluate the impact of certain non-comparable items, and the Company’s operating performance on an ongoing basis. Core performance measures exclude certain other income and expense items, such as the FDIC special assessment, acquisition costs, accrued insurance proceeds anticipated to be received as a result of recaptured tax credits, the net gain or loss on sales of fixed assets, the net gain or loss on other real estate owned (“OREO”), and the net gain or loss on sales of investment securities, that the Company believes to be not indicative of or useful to measure the Company’s operating performance on an ongoing basis. The attached tables contain a reconciliation of these core performance measures to the GAAP measures. The Company believes that the tangible common equity ratio provides useful information to investors about the Company’s capital strength even though it is considered to be a non-GAAP financial measure and is not part of the regulatory capital requirements to which the Company is subject. The Company believes these non-GAAP measures and ratios, when taken together with the corresponding GAAP measures and ratios, provide meaningful supplemental information regarding the Company’s performance and capital strength. The Company’s management uses, and believes that investors benefit from referring to, these non-GAAP measures and ratios in assessing the Company’s operating results and related trends and when forecasting future periods. However, these non-GAAP measures and ratios should be considered in addition to, and not as a substitute for or preferable to, ratios prepared in accordance with GAAP. In the attached tables, the Company has provided a reconciliation of, where applicable, the most comparable GAAP financial measures and ratios to the non-GAAP financial measures and ratios, or a reconciliation of the non-GAAP calculation of the financial measures for the periods indicated.
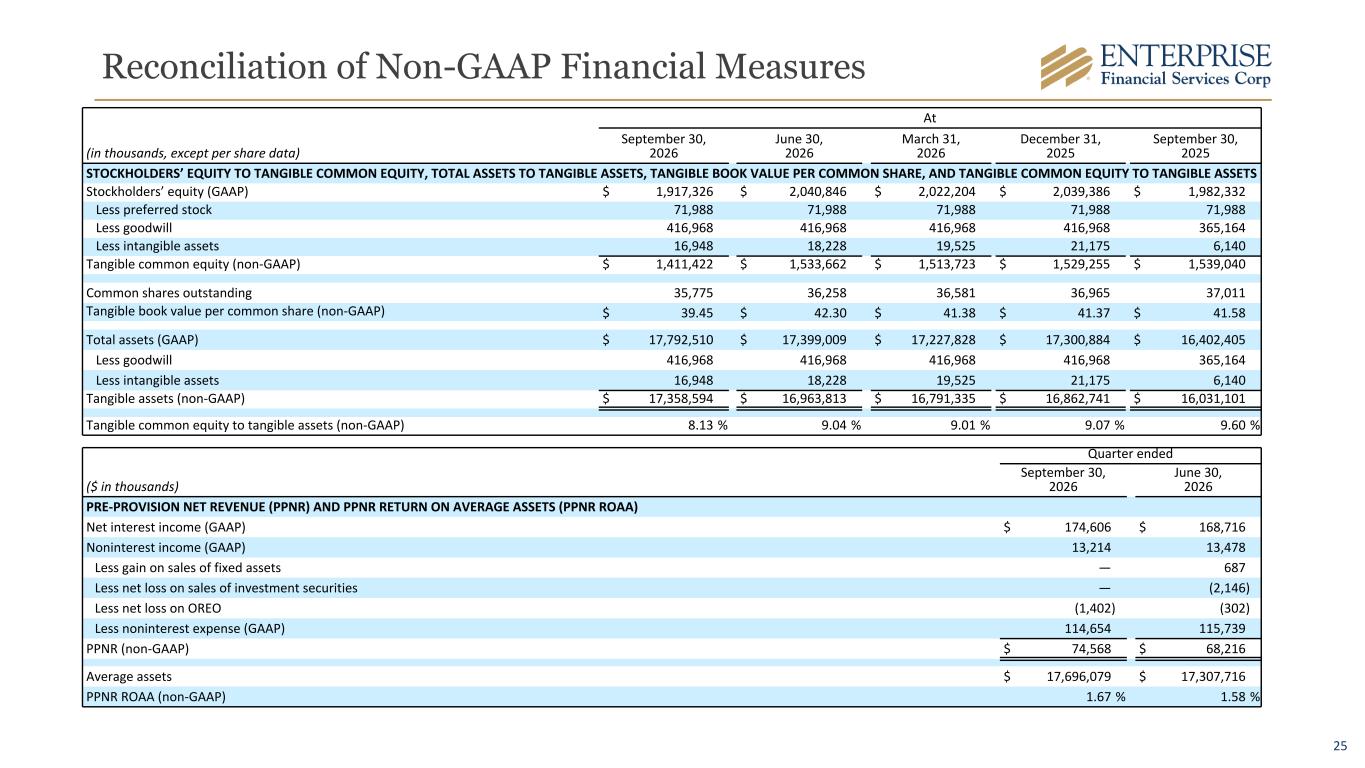
25 Reconciliation of Non-GAAP Financial Measures At (in thousands, except per share data) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 STOCKHOLDERS’ EQUITY TO TANGIBLE COMMON EQUITY, TOTAL ASSETS TO TANGIBLE ASSETS, TANGIBLE BOOK VALUE PER COMMON SHARE, AND TANGIBLE COMMON EQUITY TO TANGIBLE ASSETS Stockholders’ equity (GAAP) $ 1,917,326 $ 2,040,846 $ 2,022,204 $ 2,039,386 $ 1,982,332 Less preferred stock 71,988 71,988 71,988 71,988 71,988 Less goodwill 416,968 416,968 416,968 416,968 365,164 Less intangible assets 16,948 18,228 19,525 21,175 6,140 Tangible common equity (non-GAAP) $ 1,411,422 $ 1,533,662 $ 1,513,723 $ 1,529,255 $ 1,539,040 Common shares outstanding 35,775 36,258 36,581 36,965 37,011 Tangible book value per common share (non-GAAP) $ 39.45 $ 42.30 $ 41.38 $ 41.37 $ 41.58 Total assets (GAAP) $ 17,792,510 $ 17,399,009 $ 17,227,828 $ 17,300,884 $ 16,402,405 Less goodwill 416,968 416,968 416,968 416,968 365,164 Less intangible assets 16,948 18,228 19,525 21,175 6,140 Tangible assets (non-GAAP) $ 17,358,594 $ 16,963,813 $ 16,791,335 $ 16,862,741 $ 16,031,101 Tangible common equity to tangible assets (non-GAAP) 8.13 % 9.04 % 9.01 % 9.07 % 9.60 % Quarter ended ($ in thousands) September 30, 2026 June 30, 2026 PRE-PROVISION NET REVENUE (PPNR) AND PPNR RETURN ON AVERAGE ASSETS (PPNR ROAA) Net interest income (GAAP) $ 174,606 $ 168,716 Noninterest income (GAAP) 13,214 13,478 Less gain on sales of fixed assets — 687 Less net loss on sales of investment securities — (2,146) Less net loss on OREO (1,402) (302) Less noninterest expense (GAAP) 114,654 115,739 PPNR (non-GAAP) $ 74,568 $ 68,216 Average assets $ 17,696,079 $ 17,307,716 PPNR ROAA (non-GAAP) 1.67 % 1.58 %
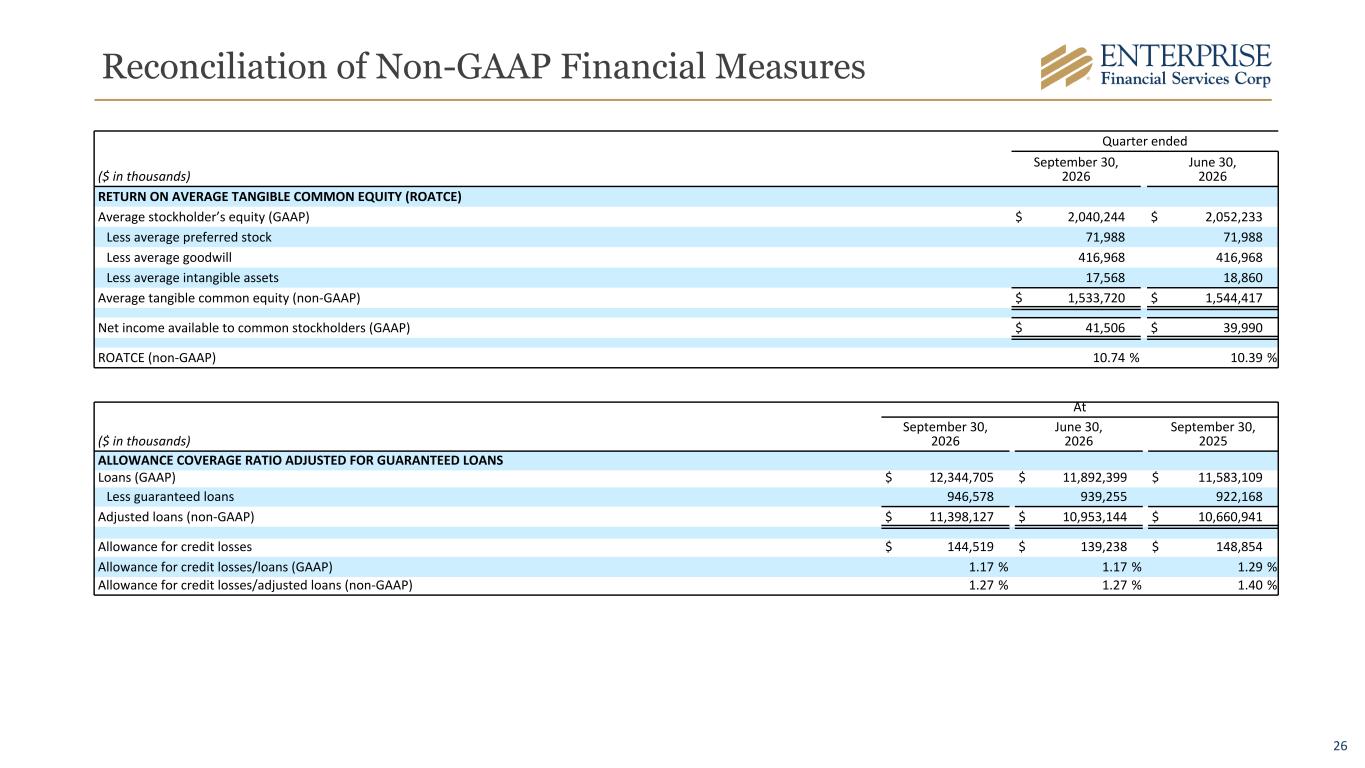
26 Reconciliation of Non-GAAP Financial Measures Quarter ended ($ in thousands) September 30, 2026 June 30, 2026 RETURN ON AVERAGE TANGIBLE COMMON EQUITY (ROATCE) Average stockholder’s equity (GAAP) $ 2,040,244 $ 2,052,233 Less average preferred stock 71,988 71,988 Less average goodwill 416,968 416,968 Less average intangible assets 17,568 18,860 Average tangible common equity (non-GAAP) $ 1,533,720 $ 1,544,417 Net income available to common stockholders (GAAP) $ 41,506 $ 39,990 ROATCE (non-GAAP) 10.74 % 10.39 % At ($ in thousands) September 30, 2026 June 30, 2026 September 30, 2025 ALLOWANCE COVERAGE RATIO ADJUSTED FOR GUARANTEED LOANS Loans (GAAP) $ 12,344,705 $ 11,892,399 $ 11,583,109 Less guaranteed loans 946,578 939,255 922,168 Adjusted loans (non-GAAP) $ 11,398,127 $ 10,953,144 $ 10,660,941 Allowance for credit losses $ 144,519 $ 139,238 $ 148,854 Allowance for credit losses/loans (GAAP) 1.17 % 1.17 % 1.29 % Allowance for credit losses/adjusted loans (non-GAAP) 1.27 % 1.27 % 1.40 %
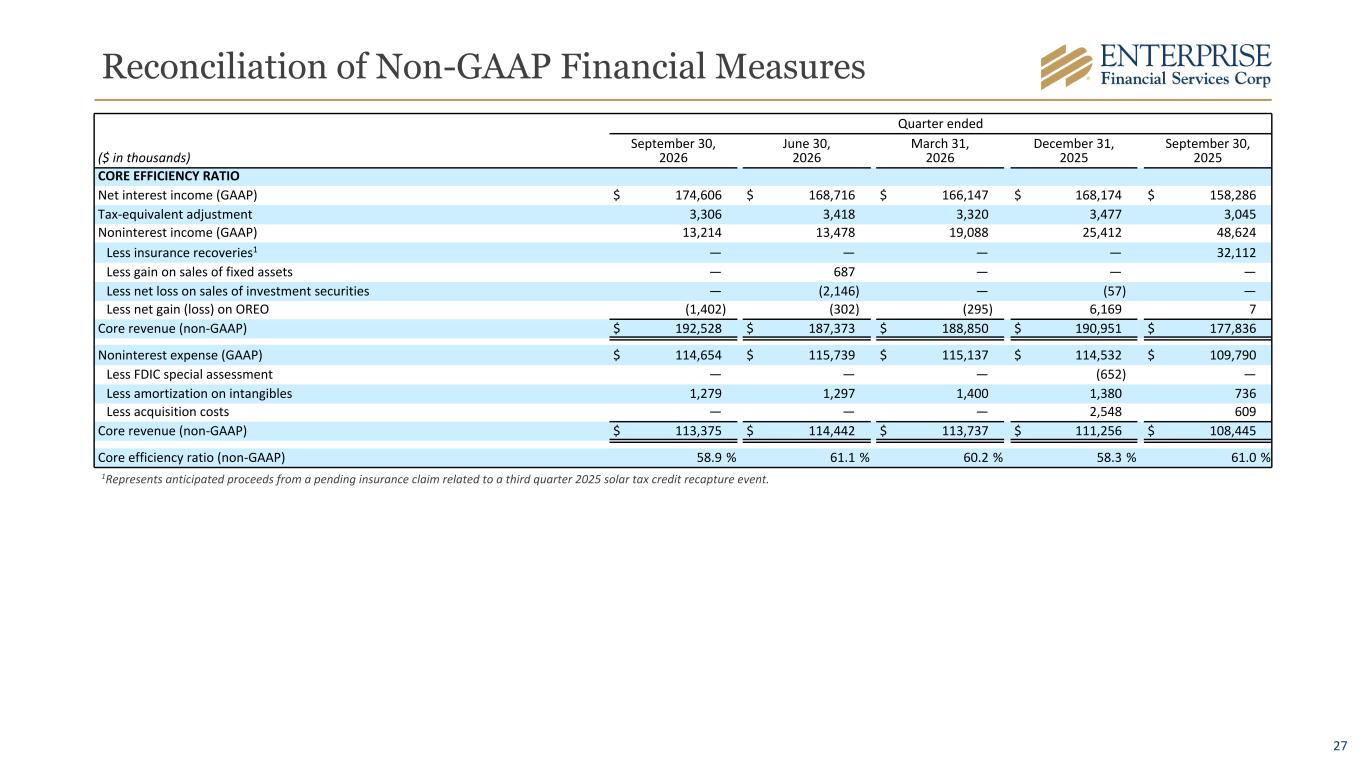
27 Reconciliation of Non-GAAP Financial Measures Quarter ended ($ in thousands) September 30, 2026 June 30, 2026 March 31, 2026 December 31, 2025 September 30, 2025 CORE EFFICIENCY RATIO Net interest income (GAAP) $ 174,606 $ 168,716 $ 166,147 $ 168,174 $ 158,286 Tax-equivalent adjustment 3,306 3,418 3,320 3,477 3,045 Noninterest income (GAAP) 13,214 13,478 19,088 25,412 48,624 Less insurance recoveries1 — — — — 32,112 Less gain on sales of fixed assets — 687 — — — Less net loss on sales of investment securities — (2,146) — (57) — Less net gain (loss) on OREO (1,402) (302) (295) 6,169 7 Core revenue (non-GAAP) $ 192,528 $ 187,373 $ 188,850 $ 190,951 $ 177,836 Noninterest expense (GAAP) $ 114,654 $ 115,739 $ 115,137 $ 114,532 $ 109,790 Less FDIC special assessment — — — (652) — Less amortization on intangibles 1,279 1,297 1,400 1,380 736 Less acquisition costs — — — 2,548 609 Core revenue (non-GAAP) $ 113,375 $ 114,442 $ 113,737 $ 111,256 $ 108,445 Core efficiency ratio (non-GAAP) 58.9 % 61.1 % 60.2 % 58.3 % 61.0 % 1Represents anticipated proceeds from a pending insurance claim related to a third quarter 2025 solar tax credit recapture event.