Exhibit 99.2
3Q 2026 Financial Results 1 October 22, 2026
Forward Looking Statements 2 Certain statements contained in this presentation that are not historical facts may constitute forward - looking statements within the meaning of Section 27 A of the Securities Act of 1933 , as amended, and Section 21 E of the Securities Exchange Act of 1934 , as amended, and are intended to be covered by the safe harbor provisions of the Private Securities Litigation Reform Act of 1995 . The Company may also make forward - looking statements in other documents it files with the Securities and Exchange Commission ("SEC"), in our annual reports to shareholders, in press releases and other written materials, and in oral statements made by our officers, directors or employees . You can identify forward looking statements by the use of the words “believe,” “expect,” “anticipate,” “intend,” “estimate,” “assume,” “outlook,” “will,” “should,” and other expressions that predict or indicate future events and trends and which do not relate to historical matters, including statements regarding the Company’s business, credit quality, financial condition, liquidity and results of operations . Forward - looking statements may differ, possibly materially, from what is included in this press release due to factors and future developments that are uncertain and beyond the scope of the Company’s control . These include, but are not limited to, changes in interest rates ; general economic conditions (including the impact of ongoing armed conflicts, tariffs, inflation, and concerns about liquidity) on a national basis or in the local markets in which the Company operates ; turbulence in the capital and debt markets ; competitive pressures from other financial institutions ; changes in consumer behavior due to changing political, business and economic conditions, or legislative or regulatory initiatives ; changes in the value of securities and other assets in the Company’s investment portfolio ; increases in loan and lease default and charge - off rates ; the adequacy of allowances for loan and lease losses ; decreases in deposit levels that necessitate increases in borrowing to fund loans and investments ; operational risks including, but not limited to, cybersecurity incidents, fraud, natural disasters, and future pandemics ; changes in regulation ; the possibility that future credit losses may be higher than currently expected due to changes in economic assumptions and adverse economic developments ; the risk that goodwill and intangibles recorded in the Company’s financial statements will become impaired ; and changes in assumptions used in making such forward - looking statements . Forward - looking statements involve risks and uncertainties which are difficult to predict . The Company’s actual results could differ materially from those projected in the forward - looking statements as a result of, among others, the risks outlined in the Company’s Annual Report on Form 10 - K, as updated by its Quarterly Reports on Form 10 - Q and other filings submitted to the SEC . The Company does not undertake any obligation to update any forward - looking statement to reflect circumstances or events that occur after the date the forward - looking statements are made . Non - GAAP In addition to financial measures presented in accordance with U . S . generally accepted accounting principles (“GAAP”), this presentation contains certain non - GAAP financial measures, including, without limitation, operating earnings, and the ratios of tangible common equity to tangible assets . The presentation of non - GAAP financial information is not intended to be considered in isolation or as a substitute for any measure prepared in accordance with GAAP . Please see the Earnings Release for certain Non - GAAP reconciliations .
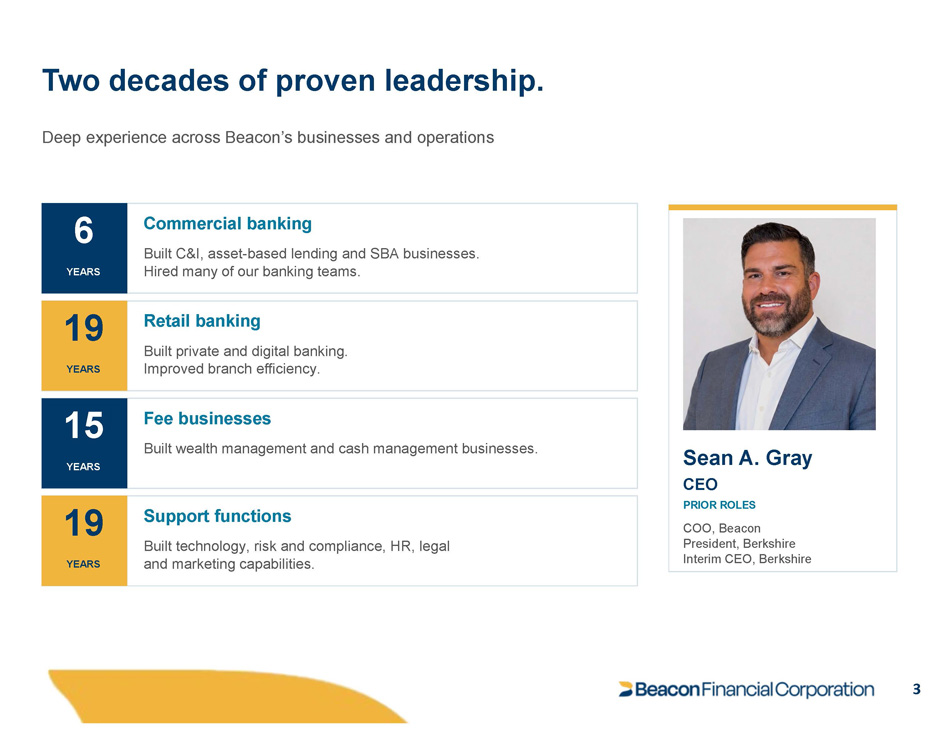
Two decades of proven leadership. Deep experience across Beacon’s businesses and operations Commercial banking Built C&I, asset - based lending and SBA businesses. Hired many of our banking teams. Retail banking Built private and digital banking. Improved branch efficiency. Fee businesses Built wealth management and cash management businesses. Support functions Built technology, risk and compliance, HR, legal and marketing capabilities. Sean A. Gray CEO PRIOR ROLES COO, Beacon President, Berkshire Interim CEO, Berkshire 3 6 YEARS 19 YEARS 15 YEARS 19 YEARS
$0.73 Quarterly GAAP EPS $0.3225 Quarterly Dividend Per Share Highlights Board authorized additional $75 million in stock buybacks bringing total plan to $125 million. Total assets of $21.9 billion. Total loans of $17.7 billion. Total deposits of $18.2 billion. Margin of 3.85%. ROA of 1.11% and ROTE of 12.02%. Core efficiency ratio of 53.54%. Fortress Balance Sheet / Asset Quality Loans to Deposits of 97%. NPAs to total assets of 0.75%. Reserve to Loans coverage of 1.32%. Total Risk Based Capital of 14.6% and Tangible Common Equity (TCE) of 9.4%. ICRE to Total Risk Based Capital of 295%. 4 $0.77 Quarterly Operating EPS
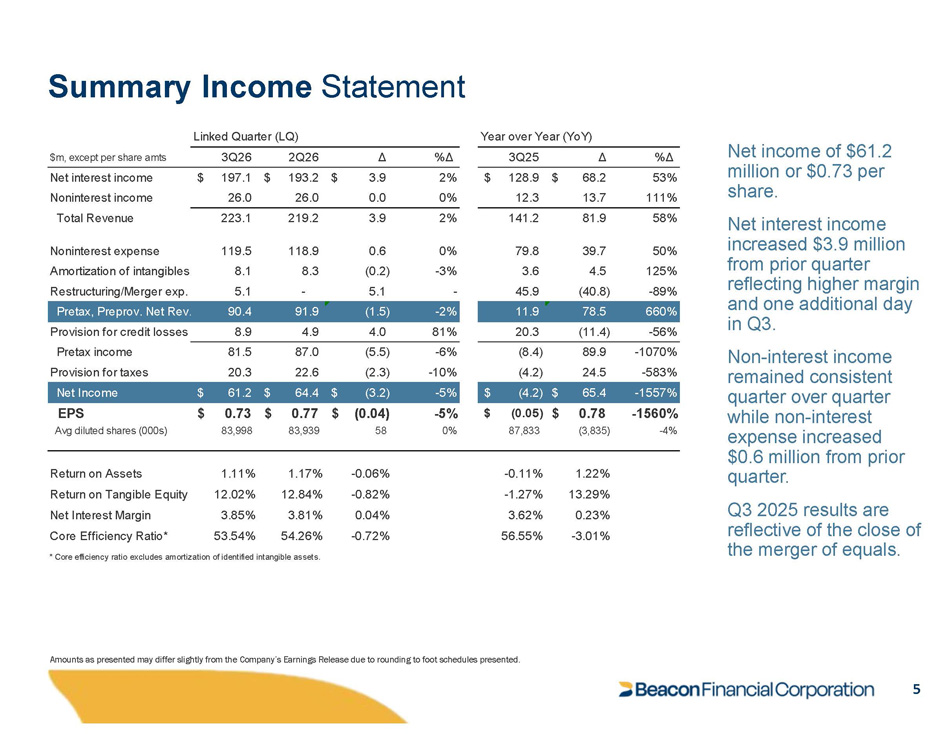
Summary Income Statement Amounts as presented may differ slightly from the Company’s Earnings Release due to rounding to foot schedules presented. 5 Net income of $61.2 million or $0.73 per share. Net interest income increased $3.9 million from prior quarter reflecting higher margin and one additional day in Q3. Non - interest income remained consistent quarter over quarter while non - interest expense increased $0.6 million from prior quarter. Q3 2025 results are reflective of the close of the merger of equals. %Δ Δ 3Q25 %Δ Δ 2Q26 3Q26 $m, except per share amts 53% $ 68.2 $ 128.9 2% $ 3.9 $ 193.2 $ 197.1 Net interest income 111% 13.7 12.3 0% 0.0 26.0 26.0 Noninterest income 58% 81.9 141.2 2% 3.9 219.2 223.1 Total Revenue 50% 39.7 79.8 0% 0.6 118.9 119.5 Noninterest expense 125% 4.5 3.6 - 3% (0.2) 8.3 8.1 Amortization of intangibles - 89% (40.8) 45.9 - 5.1 - 5.1 Restructuring/Merger exp. 660% 78.5 11.9 - 2% (1.5) 91.9 90.4 Pretax, Preprov. Net Rev. - 56% (11.4) 20.3 81% 4.0 4.9 8.9 Provision for credit losses - 1070% 89.9 (8.4) - 6% (5.5) 87.0 81.5 Pretax income - 583% 24.5 (4.2) - 10% (2.3) 22.6 20.3 Provision for taxes - 1557% $ 65.4 $ (4.2) - 5% $ (3.2) $ 64.4 $ 61.2 Net Income - 1560% $ 0.78 $ (0.05) - 5% $ (0.04) $ 0.77 $ 0.73 EPS - 4% (3,835) 87,833 0% 58 83,939 83,998 Avg diluted shares (000s) 1.22% - 0.11% - 0.06% 1.17% 1.11% Return on Assets 13.29% - 1.27% - 0.82% 12.84% 12.02% Return on Tangible Equity 0.23% 3.62% 0.04% 3.81% 3.85% Net Interest Margin - 3.01% 56.55% - 0.72% 54.26% 53.54% Core Efficiency Ratio* * Core efficiency ratio excludes amortization of identified intangible assets. Linked Quarter (LQ) Year over Year (YoY)
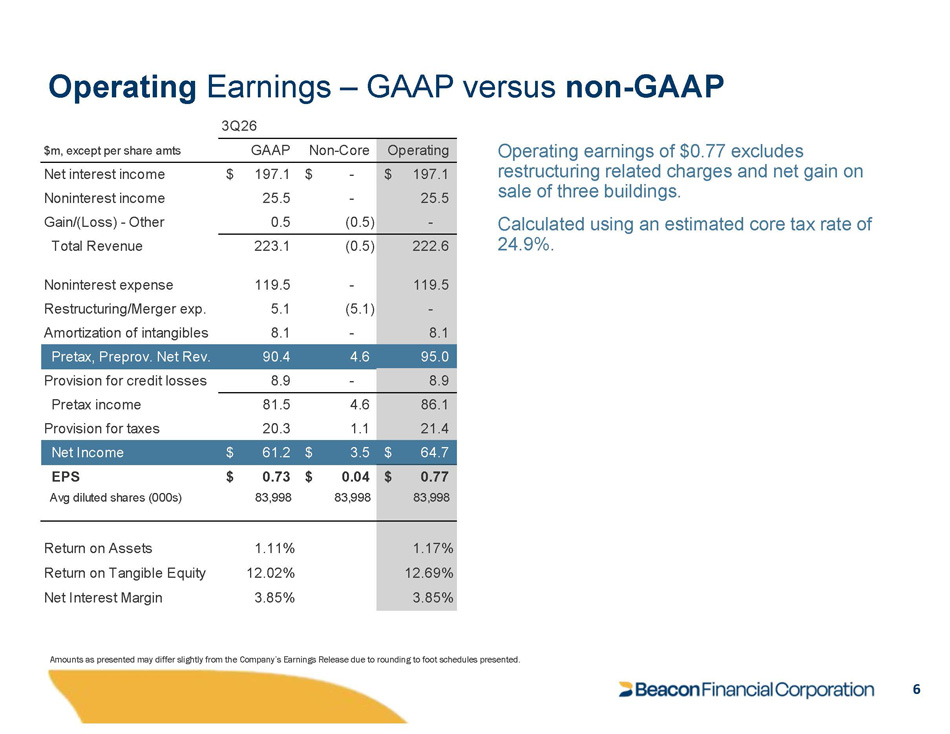
Operating Earnings – GAAP versus non - GAAP Amounts as presented may differ slightly from the Company’s Earnings Release due to rounding to foot schedules presented. 6 Operating earnings of $0.77 excludes restructuring related charges and net gain on sale of three buildings. Calculated using an estimated core tax rate of 24.9%. Operating Non - Core GAAP $m, except per share amts $ 197.1 $ 197.1 $ - Net interest income 25.5 25.5 - Noninterest income - 0.5 (0.5) Gain/(Loss) - Other 222.6 223.1 (0.5) Total Revenue 119.5 119.5 - Noninterest expense - 5.1 (5.1) Restructuring/Merger exp. 8.1 8.1 - Amortization of intangibles 95.0 4.6 90.4 Pretax, Preprov. Net Rev. 8.9 8.9 - Provision for credit losses 86.1 4.6 81.5 Pretax income 21.4 1.1 20.3 Provision for taxes $ 64.7 $ 3.5 $ 61.2 Net Income $ 0.77 EPS $ 0.73 $ 0.04 83,998 Avg diluted shares (000s) 83,998 83,998 1.17% 1.11% Return on Assets 12.69% 12.02% Return on Tangible Equity 3.85% 3.85% Net Interest Margin 3Q26
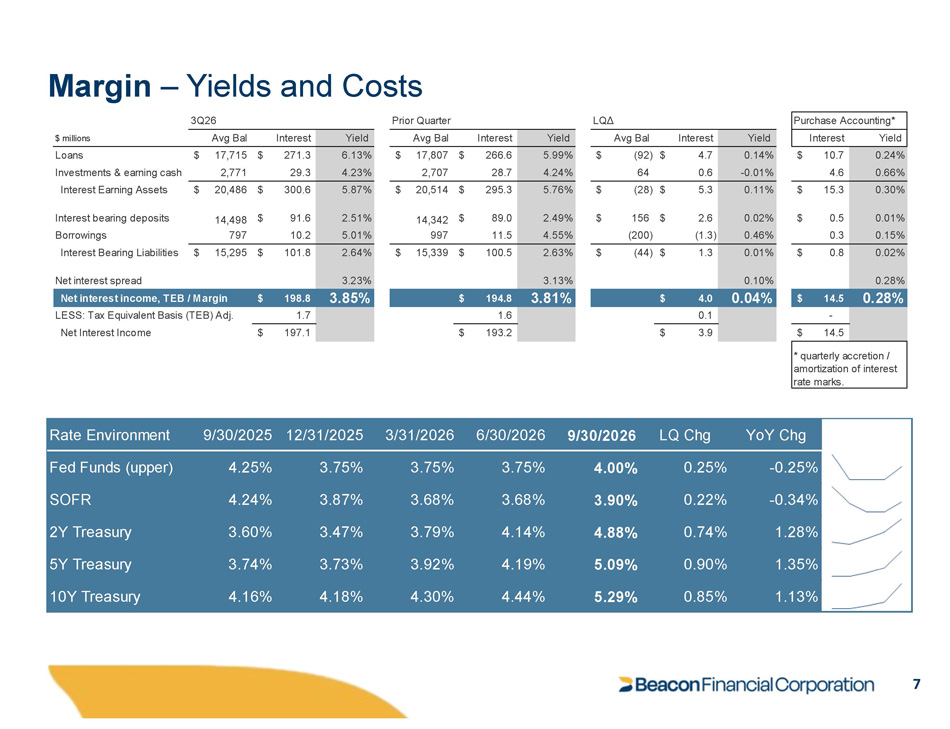
Margin – Yields and Costs Yield Interest Avg Bal $ millions 6.13% $ 271.3 $ 17,715 Loans 4.23% 29.3 2,771 Investments & earning cash 5.87% $ 300.6 $ 20,486 Interest Earning Assets 2.51% $ 91.6 14,498 Interest bearing deposits 5.01% 10.2 797 Borrowings 2.64% $ 101.8 $ 15,295 Interest Bearing Liabilities 3.23% Net interest spread Yield Interest Avg Bal 5.99% $ 266.6 $ 17,807 4.24% 28.7 2,707 5.76% $ 295.3 $ 20,514 2.49% $ 89.0 14,342 4.55% 11.5 997 2.63% 3.13% $ 100.5 $ 15,339 Yield Interest Avg Bal 0.14% $ 4.7 $ (92) - 0.01% 0.6 64 0.11% $ 5.3 $ (28) 0.02% $ 2.6 $ 156 0.46% (1.3) (200) 0.01% 0.10% $ 1.3 $ (44) Purchase Accounting* Yield Interest 0.24% $ 10.7 0.66% 4.6 0.30% $ 15.3 0.01% $ 0.5 0.15% 0.3 0.02% 0.28% $ 0.8 3Q26 Prior Quarter LQΔ Net interest income, TEB / Margin $ 198.8 3.85% $ 194.8 3.81% $ 4.0 0.04% $ 14.5 0.28% - $ 14.5 * quarterly accretion / amortization of interest rate marks. LESS: Tax Equivalent Basis (TEB) Adj. 1.7 Net Interest Income $ 197.1 1.6 0.1 193.2 $ 3.9 $ YoY Chg LQ Chg 9/30/2026 6/30/2026 3/31/2026 12/31/2025 9/30/2025 Rate Environment - 0.25% 0.25% 4.00% 3.75% 3.75% 3.75% 4.25% Fed Funds (upper) - 0.34% 0.22% 3.90% 3.68% 3.68% 3.87% 4.24% SOFR 1.28% 0.74% 4.88% 4.14% 3.79% 3.47% 3.60% 2Y Treasury 1.35% 0.90% 5.09% 4.19% 3.92% 3.73% 3.74% 5Y Treasury 1.13% 0.85% 5.29% 4.44% 4.30% 4.18% 4.16% 10Y Treasury 7
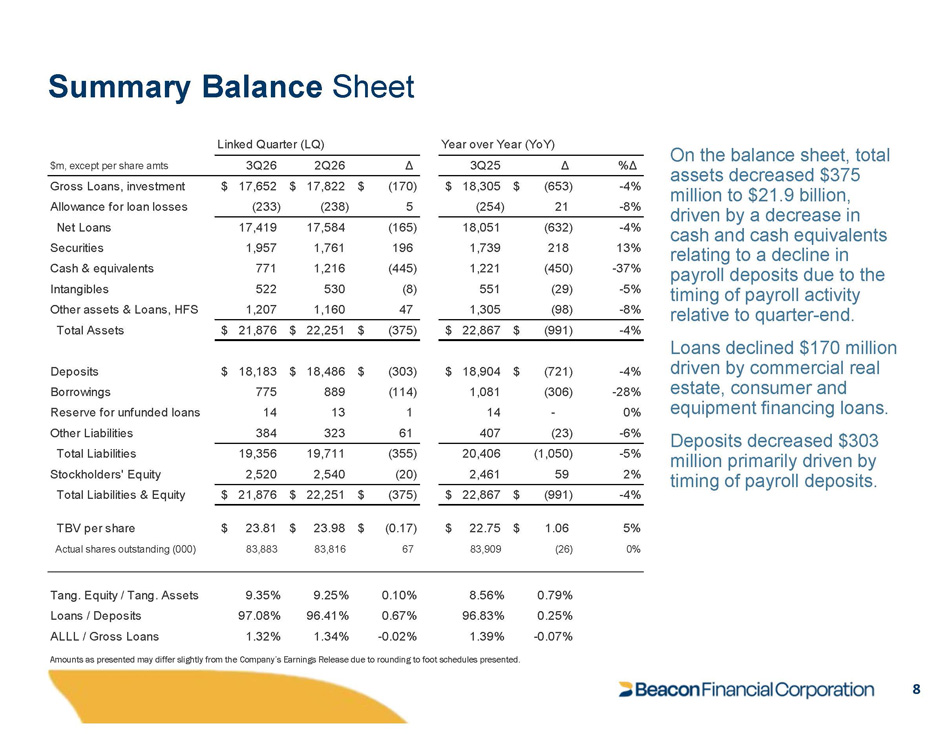
Summary Balance Sheet 8 On the balance sheet, total assets decreased $375 million to $21.9 billion, driven by a decrease in cash and cash equivalents relating to a decline in payroll deposits due to the timing of payroll activity relative to quarter - end. Deposits decreased $ 303 million primarily driven by timing of payroll deposits . %Δ Δ 3Q25 Δ 2Q26 3Q26 $m, except per share amts - 4% $ (653) $ 18,305 $ (170) $ 17,822 $ 17,652 Gross Loans, investment - 8% 21 (254) 5 (238) (233) Allowance for loan losses - 4% (632) 18,051 (165) 17,584 17,419 Net Loans 13% 218 1,739 196 1,761 1,957 Securities - 37% (450) 1,221 (445) 1,216 771 Cash & equivalents - 5% (29) 551 (8) 530 522 Intangibles - 8% (98) 1,305 47 1,160 1,207 Other assets & Loans, HFS - 4% $ (991) $ 22,867 $ (375) $ 22,251 $ 21,876 Loans declined $170 million driven by commercial real - 4% $ (721) $ 18,904 $ (303) $ 18,486 $ 18,183 estate, consumer and equipment financing loans. - 28% 0% (306) - 1,081 14 (114) 1 889 13 775 14 Total Assets Deposits Borrowings Reserve for unfunded loans - 6% (23) 407 61 323 384 Other Liabilities - 5% (1,050) 20,406 (355) 19,711 19,356 Total Liabilities 2% 59 2,461 (20) 2,540 2,520 Stockholders' Equity - 4% $ (991) $ 22,867 $ (375) $ 22,251 $ 21,876 Total Liabilities & Equity 5% $ 1.06 $ 22.75 $ (0.17) $ 23.98 $ 23.81 TBV per share 0% (26) 83,909 67 83,816 83,883 Actual shares outstanding (000) 0.79% 8.56% 0.10% 9.25% 9.35% Tang. Equity / Tang. Assets 0.25% 96.83% 0.67% 96.41% 97.08% Loans / Deposits - 0.07% 1.39% - 0.02% 1.34% 1.32% ALLL / Gross Loans Linked Quarter (LQ) Year over Year (YoY) Amounts as presented may differ slightly from the Company’s Earnings Release due to rounding to foot schedules presented.
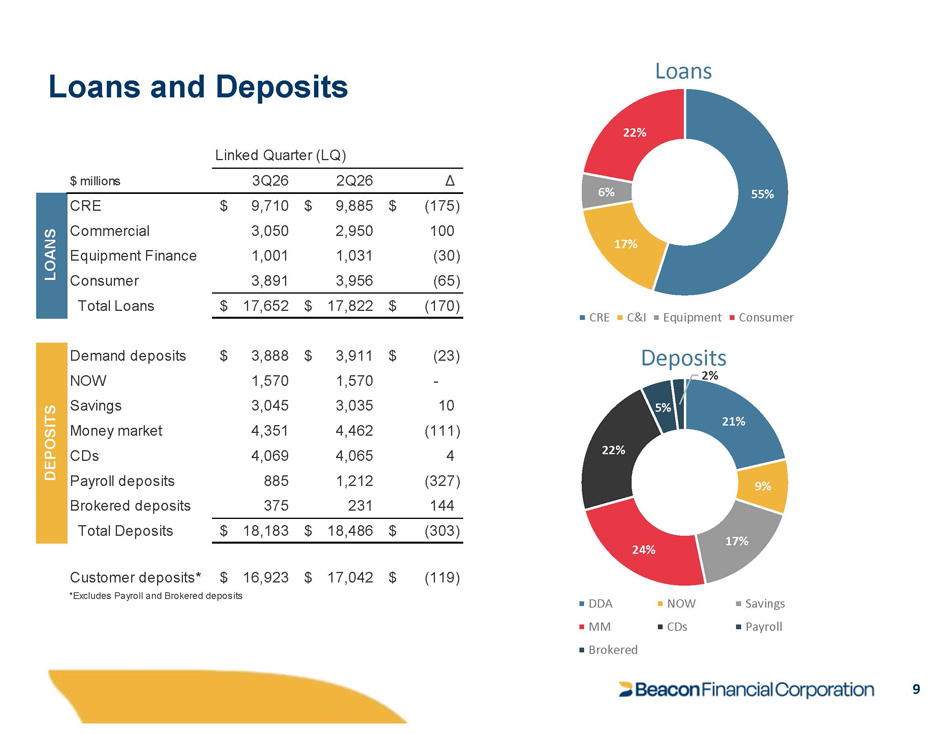
Loans and Deposits 55% 17% 6% 22% Loans Consumer 21% 9% 17% 24% 22% 5% CRE C&I Equipment Deposits 2% NOW CDs Savings Payroll DDA MM Brokered $ millions 3Q26 2Q26 Δ $ 9,710 3,050 1,001 3,891 $ 9,885 2,950 1,031 3,956 $ (175) 100 (30) (65) CRE Commercial Equipment Finance Consumer Total Loans $ 17,652 $ 17,822 $ (170) Demand deposits NOW Savings Money market CDs Payroll deposits Brokered deposits Total Deposits $ 3,888 1,570 3,045 4,351 4,069 885 375 $ 3,911 $ 1,570 3,035 4,462 4,065 1,212 231 (23) - 10 (111) 4 (327) 144 $ 18,183 $ 18,486 $ (303) Customer deposits* $ 16,923 *Excludes Payroll and Brokered deposits $ 17,042 $ (119) Linked Quarter (LQ) LOANS DEPOSITS 9
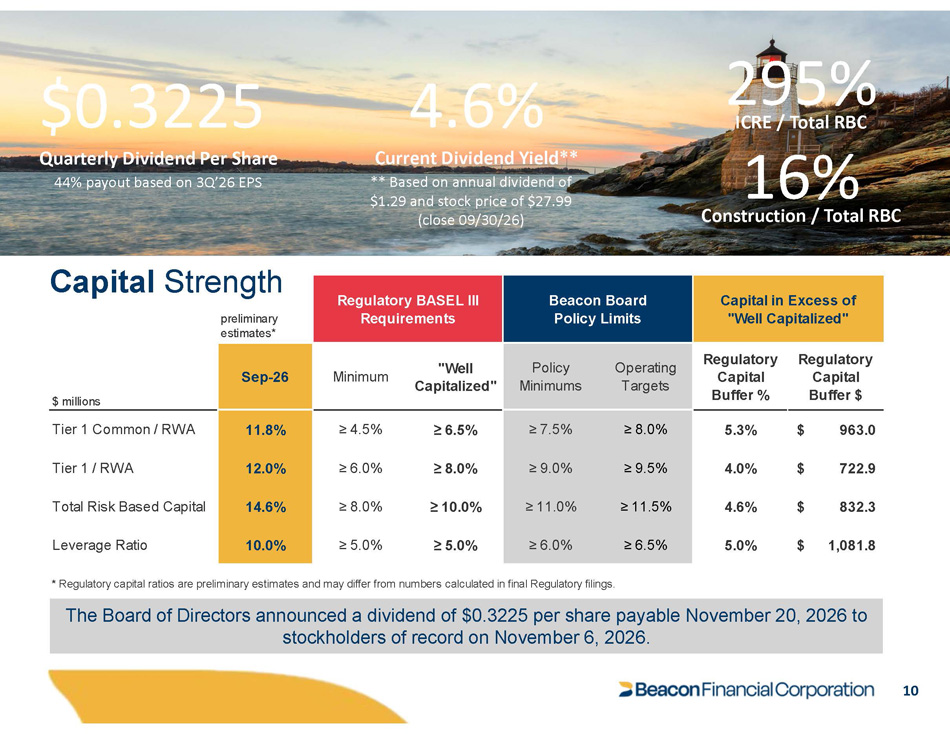
Capital Strength 10 preliminary estimates* Capital in Excess of "Well Capitalized" Beacon Board Policy Limits Regulatory BASEL III Requirements Regulatory Capital Buffer $ Regulatory Capital Buffer % Operating Targets Policy Minimums "Well Capitalized" Minimum Sep - 26 $ millions $ 963.0 5.3% ≥ 8.0% ≥ 7.5% ≥ 6.5% ≥ 4.5% 11.8% Tier 1 Common / RWA $ 722.9 4.0% ≥ 9.5% ≥ 9.0% ≥ 8.0% ≥ 6.0% 12.0% Tier 1 / RWA $ 832.3 4.6% ≥ 11.5% ≥ 11.0% ≥ 10.0% ≥ 8.0% 14.6% Total Risk Based Capital $ 1,081.8 5.0% ≥ 6.5% ≥ 6.0% ≥ 5.0% ≥ 5.0% 10.0% Leverage Ratio * Regulatory capital ratios are preliminary estimates and may differ from numbers calculated in final Regulatory filings. $0.3225 Quarterly Dividend Per Share 44% payout based on 3Q’26 EPS 4.6% Current Dividend Yield** ** Based on annual dividend of $1.29 and stock price of $27.99 (close 09/30/26) 295% ICRE / Total RBC The Board of Directors announced a dividend of $0.3225 per share payable November 20, 2026 to stockholders of record on November 6, 2026. 16% Construction / Total RBC
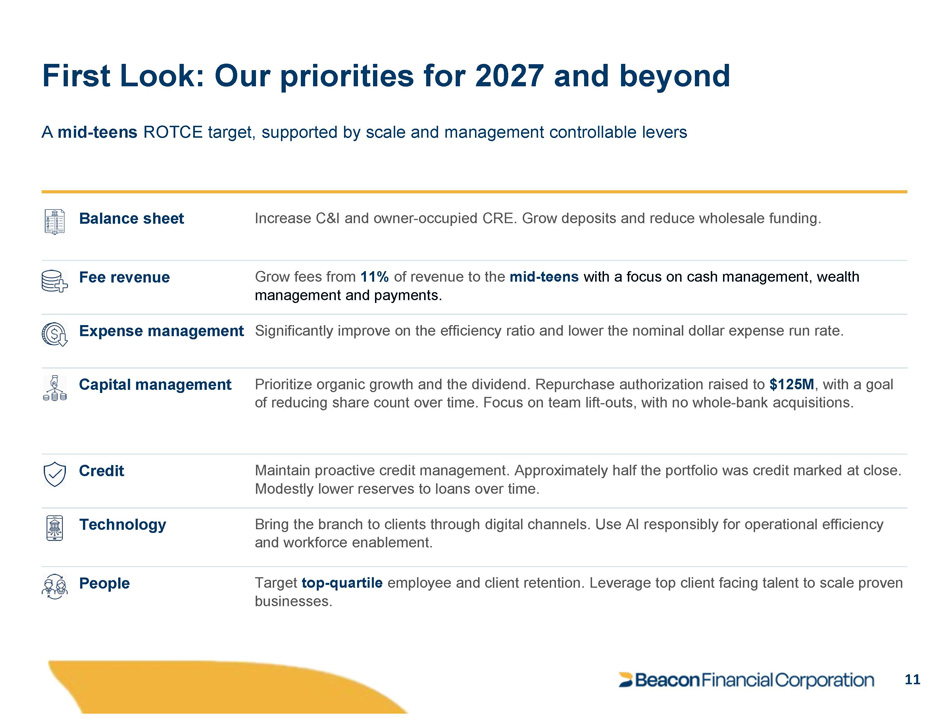
First Look: Our priorities for 2027 and beyond Balance sheet Increase C&I and owner - occupied CRE. Grow deposits and reduce wholesale funding. Fee revenue Grow fees from 11% of revenue to the mid - teens with a focus on cash management, wealth management and payments. Expense management Significantly improve on the efficiency ratio and lower the nominal dollar expense run rate. Capital management Prioritize organic growth and the dividend. Repurchase authorization raised to $125M , with a goal of reducing share count over time. Focus on team lift - outs, with no whole - bank acquisitions. Credit Maintain proactive credit management. Approximately half the portfolio was credit marked at close. Modestly lower reserves to loans over time. Technology Bring the branch to clients through digital channels. Use AI responsibly for operational efficiency and workforce enablement. People Target top - quartile employee and client retention. Leverage top client facing talent to scale proven businesses. A mid - teens ROTCE target, supported by scale and management controllable levers 11
APPENDIX NYSE: BBT 12
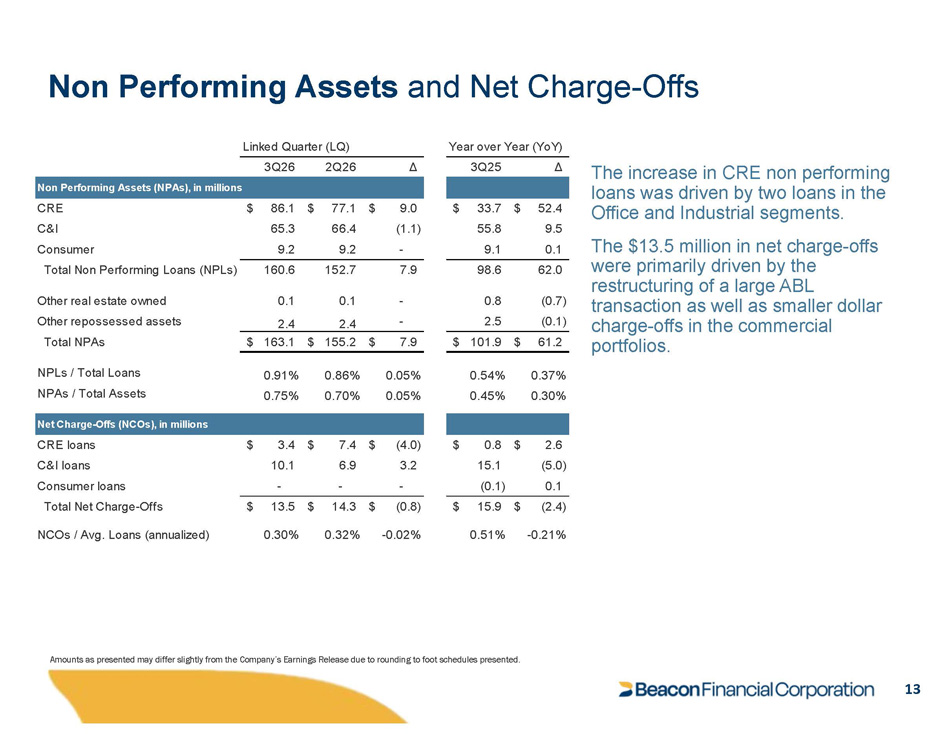
Non Performing Assets and Net Charge - Offs 13 The increase in CRE non performing loans was driven by two loans in the Office and Industrial segments . The $13.5 million in net charge - offs were primarily driven by the restructuring of a large ABL transaction as well as smaller dollar charge - offs in the commercial portfolios. Year (YoY) Year over Linked Quarter (LQ) Δ 3Q25 Δ 3Q26 2Q26 Non Performing Assets (NPAs), in millions $ 52.4 $ 33.7 $ 9.0 $ 86.1 $ 77.1 CRE 9.5 55.8 (1.1) 66.4 65.3 C&I 0.1 9.1 - 9.2 9.2 Consumer 62.0 98.6 7.9 152.7 160.6 Total Non Performing Loans (NPLs) (0.7) 0.8 0.1 0.1 - Other real estate owned (0.1) 2.5 2.4 2.4 - Other repossessed assets $ 61.2 $ 101.9 $ 7.9 $ 155.2 $ 163.1 Total NPAs 0.37% 0.54% 0.05% 0.86% 0.91% NPLs / Total Loans 0.30% 0.45% 0.05% 0.70% 0.75% NPAs / Total Assets Net Charge - Offs (NCOs), in millions $ 2.6 $ 0.8 $ (4.0) $ 7.4 $ 3.4 CRE loans (5.0) 15.1 3.2 6.9 10.1 C&I loans 0.1 (0.1) - - Consumer loans - $ (2.4) $ 15.9 $ (0.8) $ 14.3 Total Net Charge - Offs $ 13.5 - 0.21% 0.51% - 0.02% 0.32% 0.30% NCOs / Avg. Loans (annualized) Amounts as presented may differ slightly from the Company’s Earnings Release due to rounding to foot schedules presented.
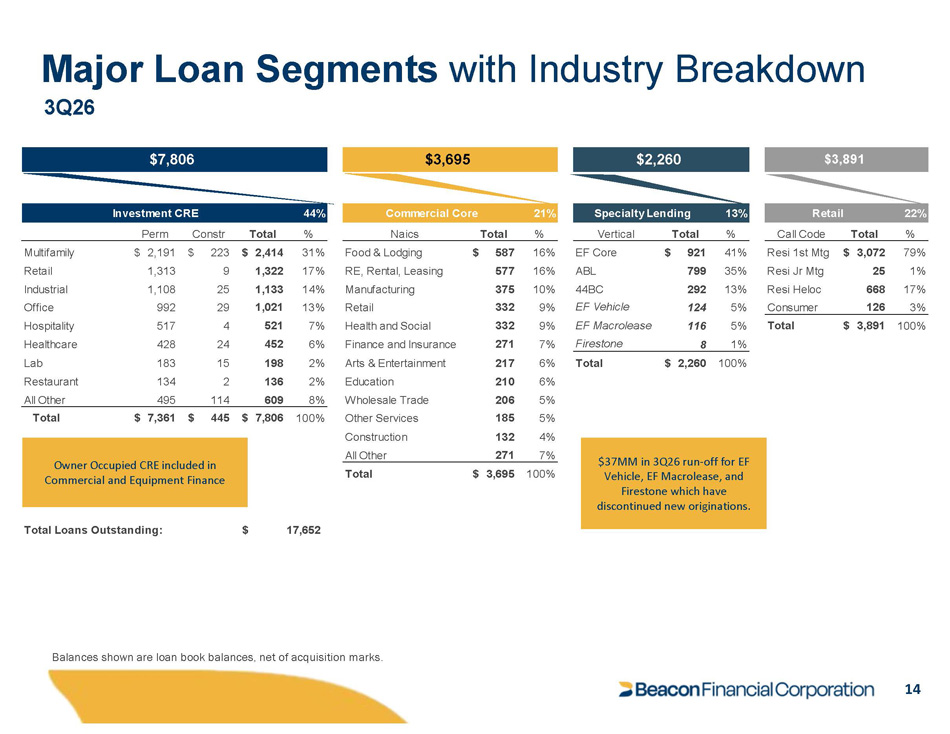
$7,806 $3,695 $2,260 $3,891 Investment CRE 44% Commercial Core 21% Specialty Lending 13% Retail 22% Perm Constr Total % Naics Total % Vertical Total % Call Code Total % 79% $ 3,072 Resi 1st Mtg 41% $ 921 EF Core 16% $ 587 Food & Lodging 31% $ 2,414 $ 223 $ 2,191 Multifamily 1% 25 Resi Jr Mtg 35% 799 ABL 16% 577 RE, Rental, Leasing 17% 1,322 9 1,313 Retail 17% 668 Resi Heloc 13% 292 44BC 10% 375 Manufacturing 14% 1,133 25 1,108 Industrial Consumer 126 3% 5% 124 EF Vehicle 9% 332 Retail 13% 1,021 29 992 Office 100% $ 3,891 Total 5% 116 EF Macrolease 9% 332 Health and Social 7% 521 4 517 Hospitality Firestone 8 1% 7% 271 Finance and Insurance 6% 452 24 428 Healthcare Total $ 2,260 100% 6% 217 Arts & Entertainment 2% 198 15 183 Lab 6% 210 Education 2% 136 2 134 Restaurant 5% 206 Wholesale Trade 8% 609 114 495 All Other 5% 185 Other Services 100% $ 7,806 $ 445 $ 7,361 Total 4% 132 Construction All Other 271 7% Total $ 3,695 100% Total Loans Outstanding: $ 17,652 Owner Occupied CRE included in Commercial and Equipment Finance Balances shown are loan book balances, net of acquisition marks. Major Loan Segments with Industry Breakdown 3Q26 $37MM in 3Q26 run - off for EF Vehicle, EF Macrolease, and Firestone which have discontinued new originations. 14
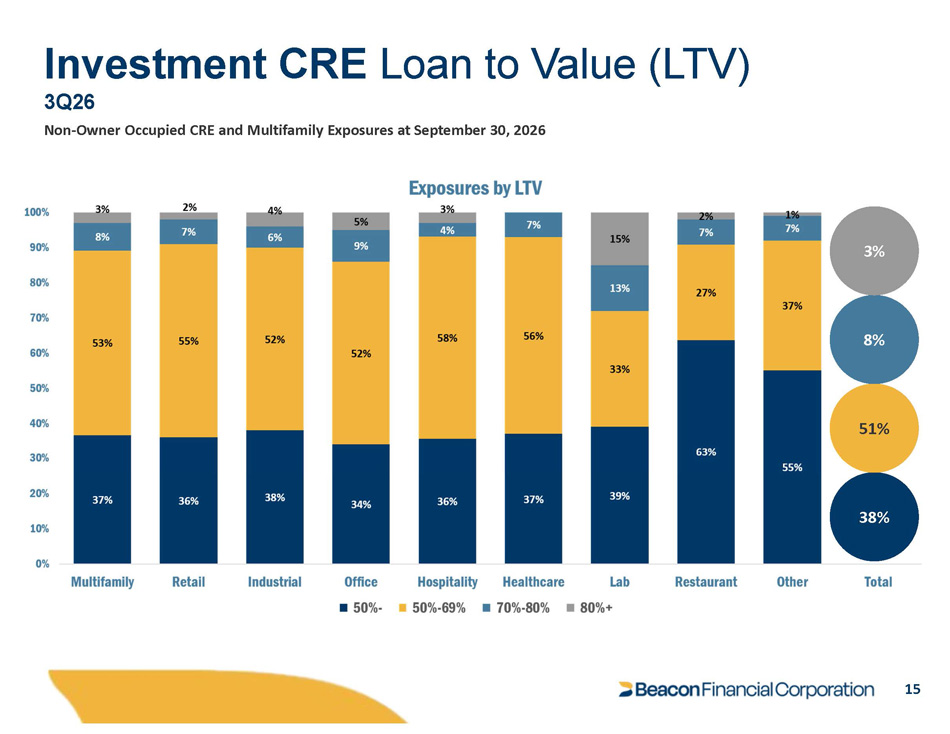
3Q26 Non - Owner Occupied CRE and Multifamily Exposures at September 30, 2026 38% 51% 8% 3% 15 Investment CRE Loan to Value (LTV)
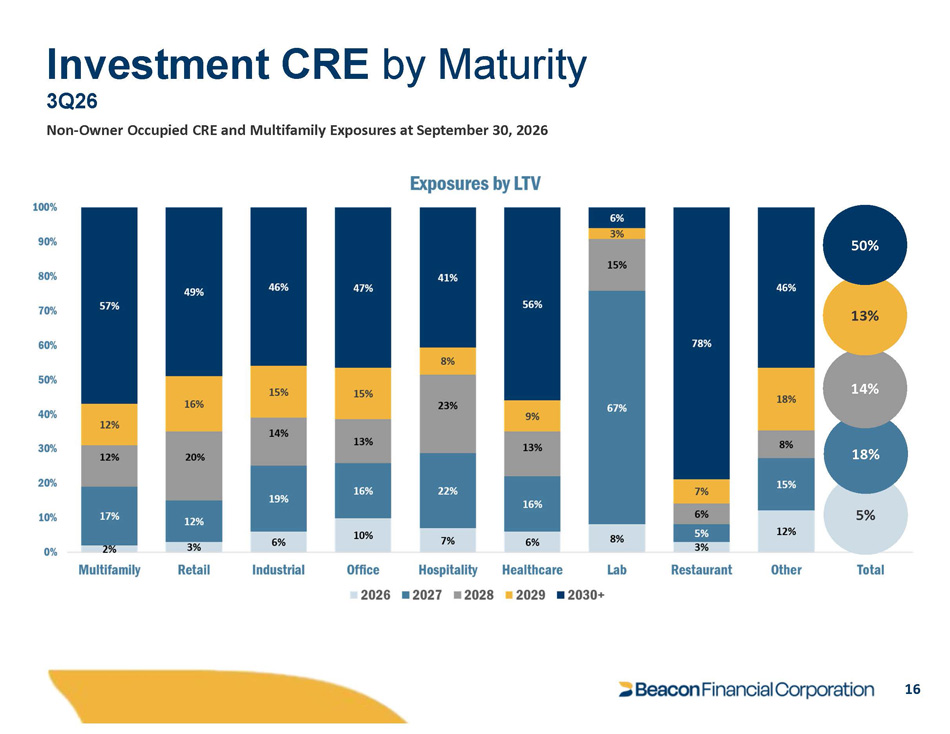
5% 14% 18% Investment CRE by Maturity 3Q26 Non - Owner Occupied CRE and Multifamily Exposures at September 30, 2026 13% 50% 16
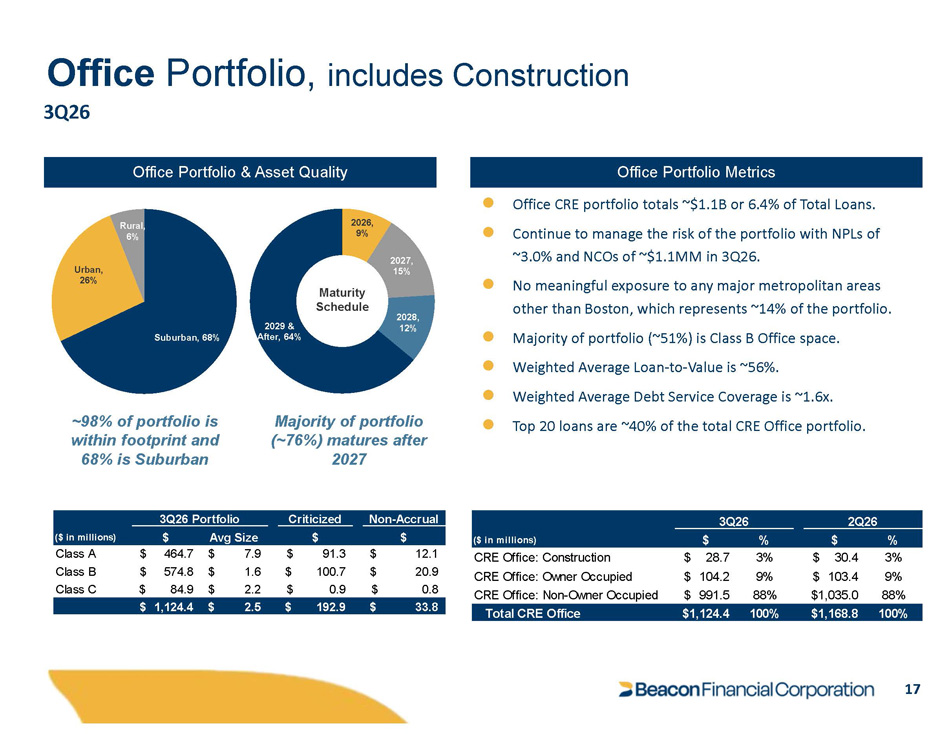
● Office CRE portfolio totals ~$1.1B or 6.4% of Total Loans. ● Continue to manage the risk of the portfolio with NPLs of ~3.0% and NCOs of ~$1.1MM in 3Q26. ● No meaningful exposure to any major metropolitan areas other than Boston, which represents ~14% of the portfolio. ● Majority of portfolio (~51%) is Class B Office space. ● Weighted Average Loan - to - Value is ~56%. ● Weighted Average Debt Service Coverage is ~1.6x. ● Top 20 loans are ~40% of the total CRE Office portfolio. Office Portfolio & Asset Quality Office Portfolio Metrics Suburban, 68% Urban, 26% Rural, 6% 2026, 9% 2027, 15% 2028, 12% 2029 & After, 64% Maturity Schedule ~98% of portfolio is within footprint and 68% is Suburban Majority of portfolio (~76%) matures after 2027 Office Portfolio, includes Construction 3Q26 3Q26 Portfolio Criticized Non - Accrual ($ in millions) $ Avg Size $ $ $ 12.1 $ 91.3 $ 7.9 $ 464.7 Class A $ 20.9 $ 100.7 $ 1.6 $ 574.8 Class B $ 0.8 $ 0.9 $ 2.2 $ 84.9 Class C $ 33.8 $ 192.9 $ 2.5 $ 1,124.4 3Q26 2Q26 ($ in millions) $ % $ % 3% $ 30.4 3% $ 28.7 CRE Office: Construction 9% $ 103.4 9% $ 104.2 CRE Office: Owner Occupied 88% $1,035.0 88% $ 991.5 CRE Office: Non - Owner Occupied 100% $1,168.8 100% $1,124.4 Total CRE Office 17
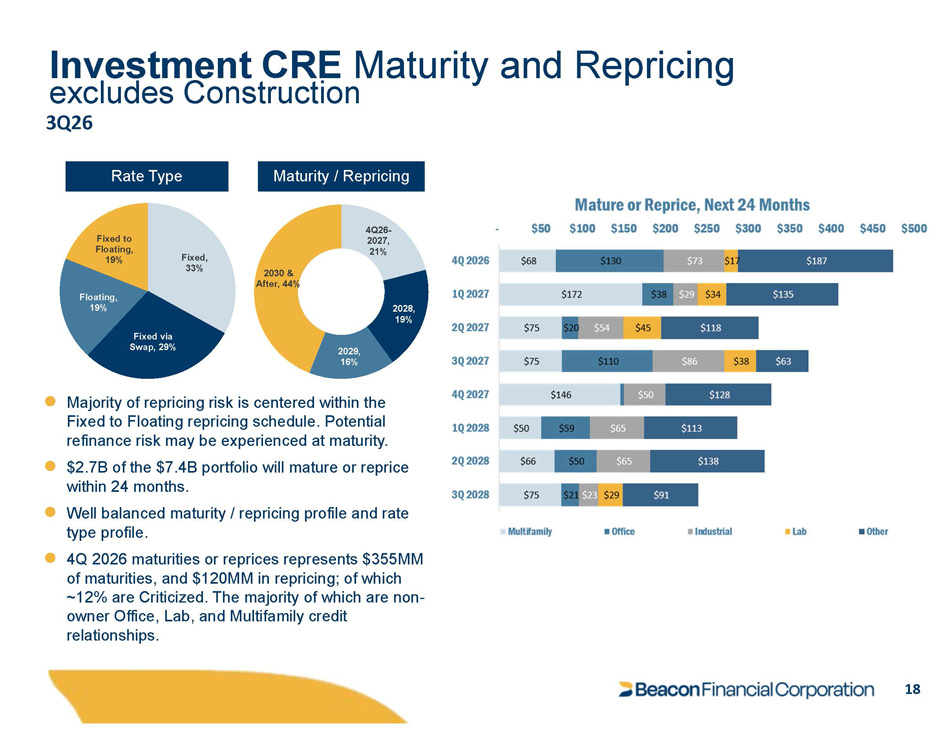
● Majority of repricing risk is centered within the Fixed to Floating repricing schedule . Potential refinance risk may be experienced at maturity . ● $2.7B of the $7.4B portfolio will mature or reprice within 24 months. ● Well balanced maturity / repricing profile and rate type profile. ● 4Q 2026 maturities or reprices represents $355MM of maturities, and $120MM in repricing; of which ~12% are Criticized. The majority of which are non - owner Office, Lab, and Multifamily credit relationships. Rate Type Fixed, 33% Fixed via Swap, 29% Floating, 19% Fixed to Floating, 19% 4Q26 - 2027, 21% 2028, 19% 2029, 16% 2030 & After, 44% Maturity / Repricing Investment CRE Maturity and Repricing excludes Construction 3Q26 18
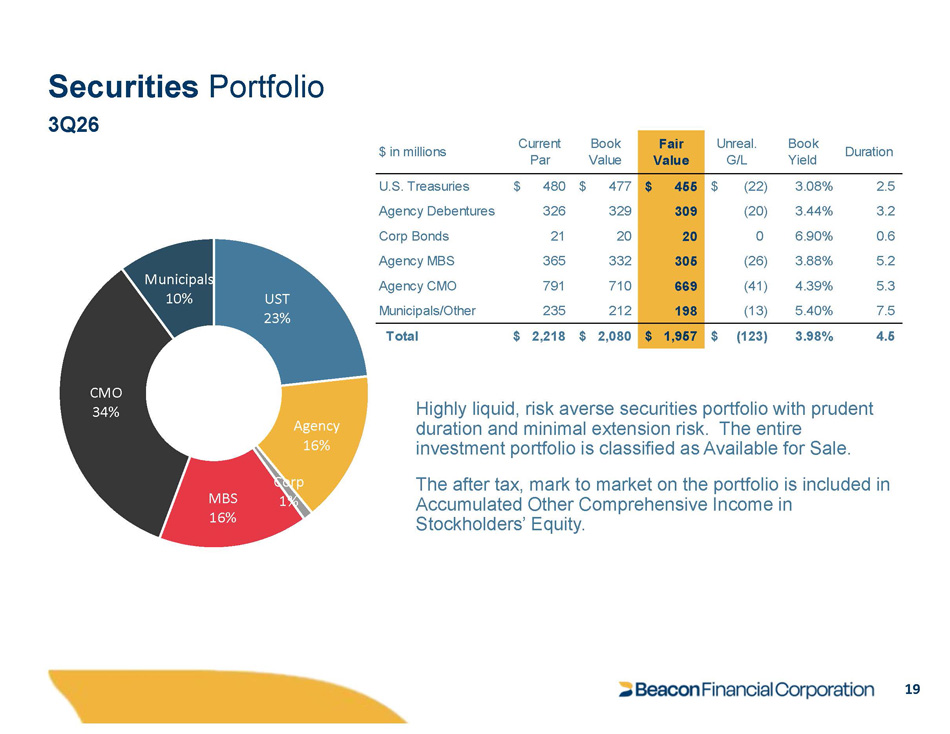
Securities Portfolio 3Q26 UST 23% 19 Agency 16% Corp 1% MBS 16% CMO 34% Municipals 10% Duration Book Yield Unreal. G/L Fair Value Book Value Current Par $ in millions 2.5 3.08% $ (22) $ 455 $ 477 $ 480 U.S. Treasuries 3.2 3.44% (20) 309 329 326 Agency Debentures 0.6 6.90% 0 20 20 21 Corp Bonds 5.2 3.88% (26) 305 332 365 Agency MBS 5.3 4.39% (41) 669 710 791 Agency CMO 7.5 5.40% (13) 198 212 235 Municipals/Other 4.5 3.98% $ (123) $ 1,957 $ 2,080 $ 2,218 Total Highly liquid, risk averse securities portfolio with prudent duration and minimal extension risk. The entire investment portfolio is classified as Available for Sale. The after tax, mark to market on the portfolio is included in Accumulated Other Comprehensive Income in Stockholders’ Equity.
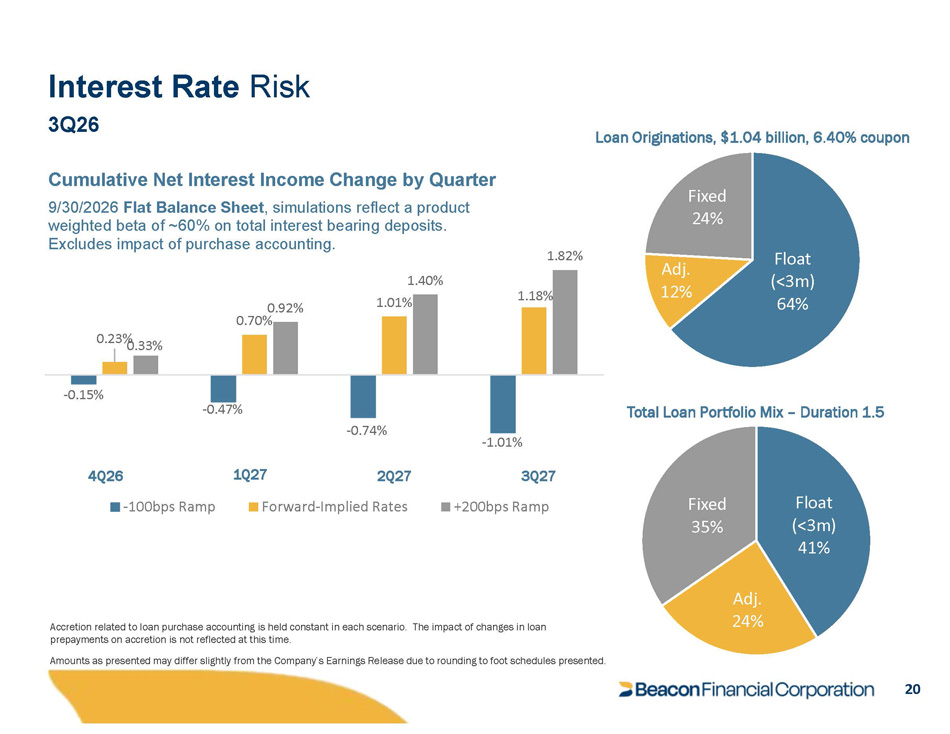
Interest Rate Risk 3Q26 Float (< 3 m) 64 % Adj. 12% Fixed 24% Loan Originations, $1.04 billion, 6.40% coupon Total Loan Portfolio Mix – Duration 1.5 - 0.15% - 0.47% - 0.74% - 1.01% 0.23% 0.70% 1.01% 1.18% 0.33% 0.92% 1.40% 1.82% Cumulative Net Interest Income Change by Quarter 9/30/2026 Flat Balance Sheet , simulations reflect a product weighted beta of ~60% on total interest bearing deposits. Excludes impact of purchase accounting. - 100bps Ramp Forward - Implied Rates +200bps Ramp Float (< 3 m) 41 % 20 Adj. 24% Fixed 35% 1Q27 2Q27 3Q27 4Q26 Accretion related to loan purchase accounting is held constant in each scenario. The impact of changes in loan prepayments on accretion is not reflected at this time. Amounts as presented may differ slightly from the Company’s Earnings Release due to rounding to foot schedules presented.
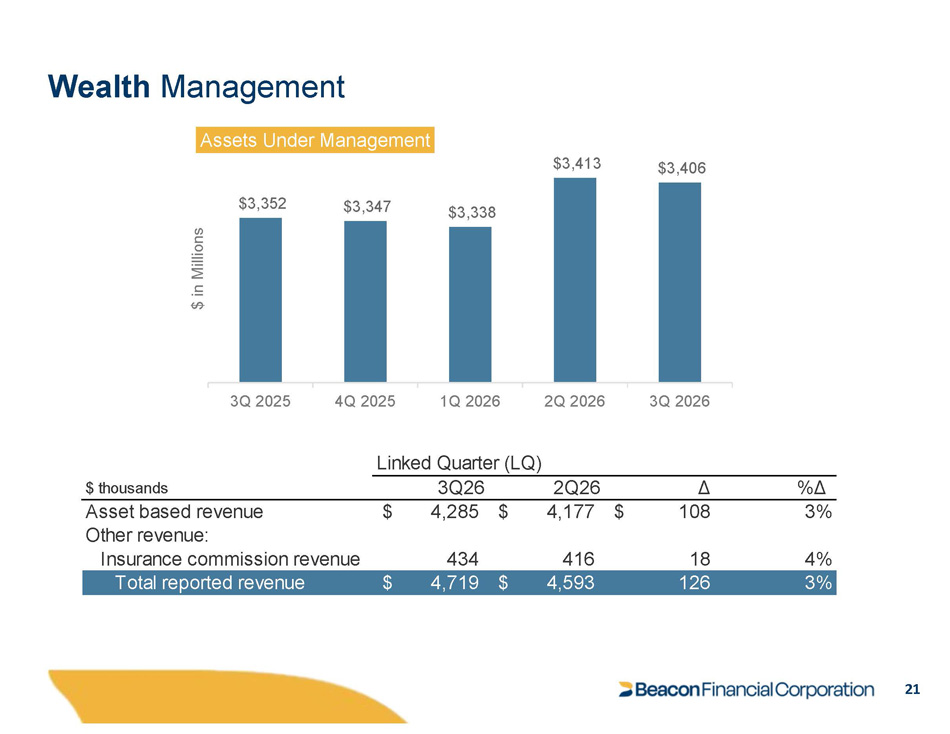
Wealth Management %Δ Δ 2Q26 3Q26 $ thousands 3% $ 108 $ 4,177 $ 4,285 Asset based revenue 4% 18 416 434 Other revenue: Insurance commission revenue 3% 126 $ 4,593 $ 4,719 Total reported revenue Linked Quarter (LQ) $3,352 21 $3,347 $3,338 $3,413 $3,406 3Q 2025 4Q 2025 1Q 2026 2Q 2026 3Q 2026 $ in Millions Assets Under Management
NYSE: BBT 22