Third Quarter 2026 Earnings Call Presentation October 21, 2026
Forward-Looking Statements and Non-GAAP Financial Measures Forward-looking statements in this report relating to WesBanco’s plans, strategies, objectives, expectations, intentions and adequacy of resources, are made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. The information contained in this report should be read in conjunction with WesBanco’s Form 10-K for the year ended December 31, 2025 and documents subsequently filed by WesBanco with the Securities and Exchange Commission (“SEC”) including WesBanco’s Form 10-Q for the quarters ended March 31, 2026 and June 30, 2026, which are available at the SEC’s website, www.sec.gov or at WesBanco’s website, www.WesBanco.com. Investors are cautioned that forward-looking statements, which are not historical fact, involve risks and uncertainties, including those detailed in WesBanco’s most recent Annual Report on Form 10-K under “Risk Factors” in Part I, Item 1A and in our other reports filed with the SEC. Such statements are subject to important factors that could cause actual results to differ materially from those contemplated by such statements, including, without limitation, changes in interest rates, spreads on earning assets and interest-bearing liabilities, and associated interest rate sensitivity; sources of liquidity available to WesBanco and its related subsidiary operations; potential future credit losses and the credit risk of commercial, real estate, and consumer loan customers and their borrowing activities; actions of the Federal Reserve Board, the Federal Deposit Insurance Corporation, the Consumer Financial Protection Bureau, the SEC, the Financial Institution Regulatory Authority, the Municipal Securities Rulemaking Board, the Securities Investors Protection Corporation, and other regulatory bodies; potential legislative and federal and state regulatory actions and reform, including, without limitation, the impact of the implementation of the Dodd-Frank Act; adverse decisions of federal and state courts; fraud, scams and schemes of third parties; cyber-security breaches; competitive conditions in the financial services industry; rapidly changing technology affecting financial services; marketability of debt instruments and corresponding impact on fair value adjustments; and/or other external developments materially impacting WesBanco’s operational and financial performance. WesBanco does not assume any duty to update forward-looking statements. While forward-looking statements reflect our good-faith beliefs, they are not guarantees of future performance. All forward-looking statements are necessarily only estimates of future results. Accordingly, actual results may differ materially from those expressed in or contemplated by the particular forward-looking statement, and, therefore, you are cautioned not to place undue reliance on such statements. Further, any forward-looking statement speaks only as of the date on which it is made, and we undertake no obligation to update any forward-looking statement to reflect events or circumstances after the date on which the statement is made or to reflect the occurrence of unanticipated events or circumstances, except as required by applicable law. In addition to the results of operations presented in accordance with Generally Accepted Accounting Principles (GAAP), WesBanco's management uses, and this presentation contains or references, certain non-GAAP financial measures. WesBanco believes these financial measures provide information useful to investors in understanding our operational performance and business and performance trends which facilitate comparisons with the performance of others in the financial services industry. Although WesBanco believes that these non-GAAP financial measures enhance investors' understanding of WesBanco's business and performance, these non-GAAP financial measures should not be considered an alternative to GAAP. The non-GAAP financial measures contained therein should be read in conjunction with the audited financial statements and analysis as presented in the Annual Report on Form 10-K as well as the unaudited financial statements and analyses as presented in the Quarterly Reports on Forms 10-Q for WesBanco and its subsidiaries, as well as other filings that the company has made with the SEC. Reconciliations of non-GAAP financial measures to the most directly comparable GAAP financial measures are included in the tables at the end of this presentation.
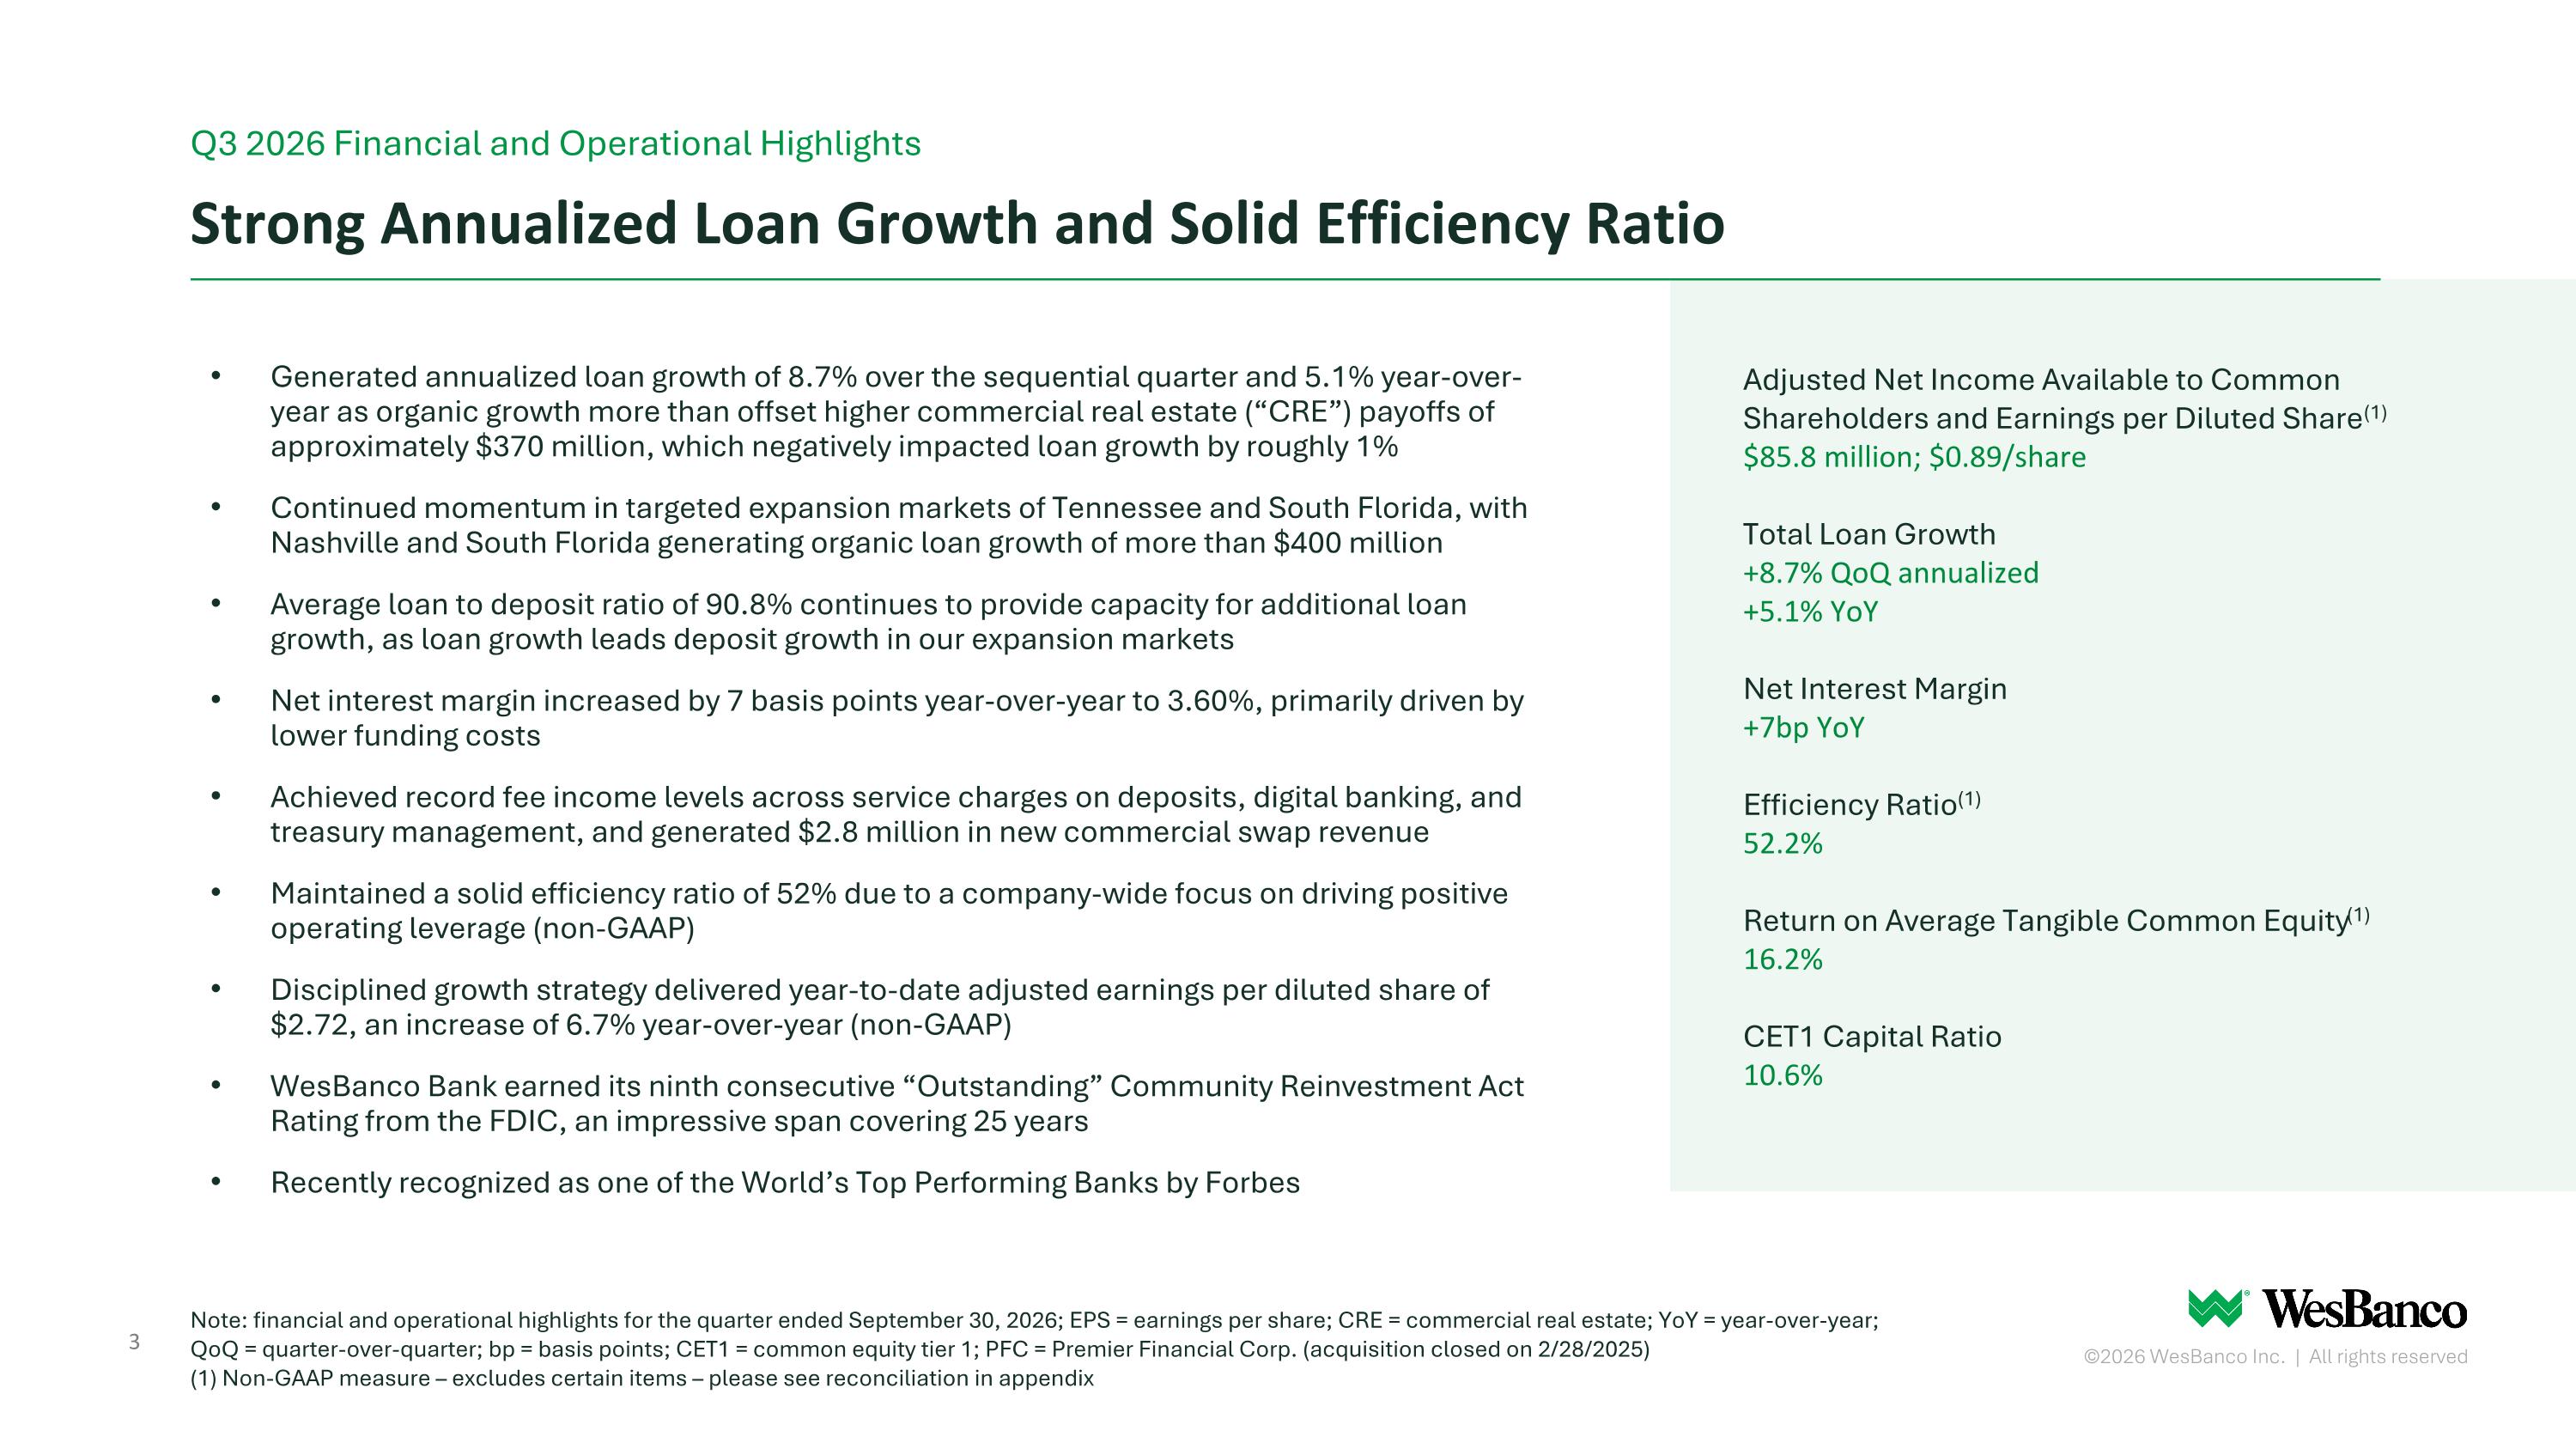
Generated annualized loan growth of 8.7% over the sequential quarter and 5.1% year-over-year as organic growth more than offset higher commercial real estate (“CRE”) payoffs of approximately $370 million, which negatively impacted loan growth by roughly 1% Continued momentum in targeted expansion markets of Tennessee and South Florida, with Nashville and South Florida generating organic loan growth of more than $400 million Average loan to deposit ratio of 90.8% continues to provide capacity for additional loan growth, as loan growth leads deposit growth in our expansion markets Net interest margin increased by 7 basis points year-over-year to 3.60%, primarily driven by lower funding costs Achieved record fee income levels across service charges on deposits, digital banking, and treasury management, and generated $2.8 million in new commercial swap revenue Maintained a solid efficiency ratio of 52% due to a company-wide focus on driving positive operating leverage (non-GAAP) Disciplined growth strategy delivered year-to-date adjusted earnings per diluted share of $2.72, an increase of 6.7% year-over-year (non-GAAP) WesBanco Bank earned its ninth consecutive “Outstanding” Community Reinvestment Act Rating from the FDIC, an impressive span covering 25 years Recently recognized as one of the World’s Top Performing Banks by Forbes Strong Annualized Loan Growth and Solid Efficiency Ratio Adjusted Net Income Available to Common Shareholders and Earnings per Diluted Share(1) $85.8 million; $0.89/share Total Loan Growth +8.7% QoQ annualized +5.1% YoY Net Interest Margin +7bp YoY Efficiency Ratio(1) 52.2% Return on Average Tangible Common Equity(1) 16.2% CET1 Capital Ratio 10.6% Note: financial and operational highlights for the quarter ended September 30, 2026; EPS = earnings per share; CRE = commercial real estate; YoY = year-over-year; QoQ = quarter-over-quarter; bp = basis points; CET1 = common equity tier 1; PFC = Premier Financial Corp. (acquisition closed on 2/28/2025) (1) Non-GAAP measure – excludes certain items – please see reconciliation in appendix Q3 2026 Financial and Operational Highlights
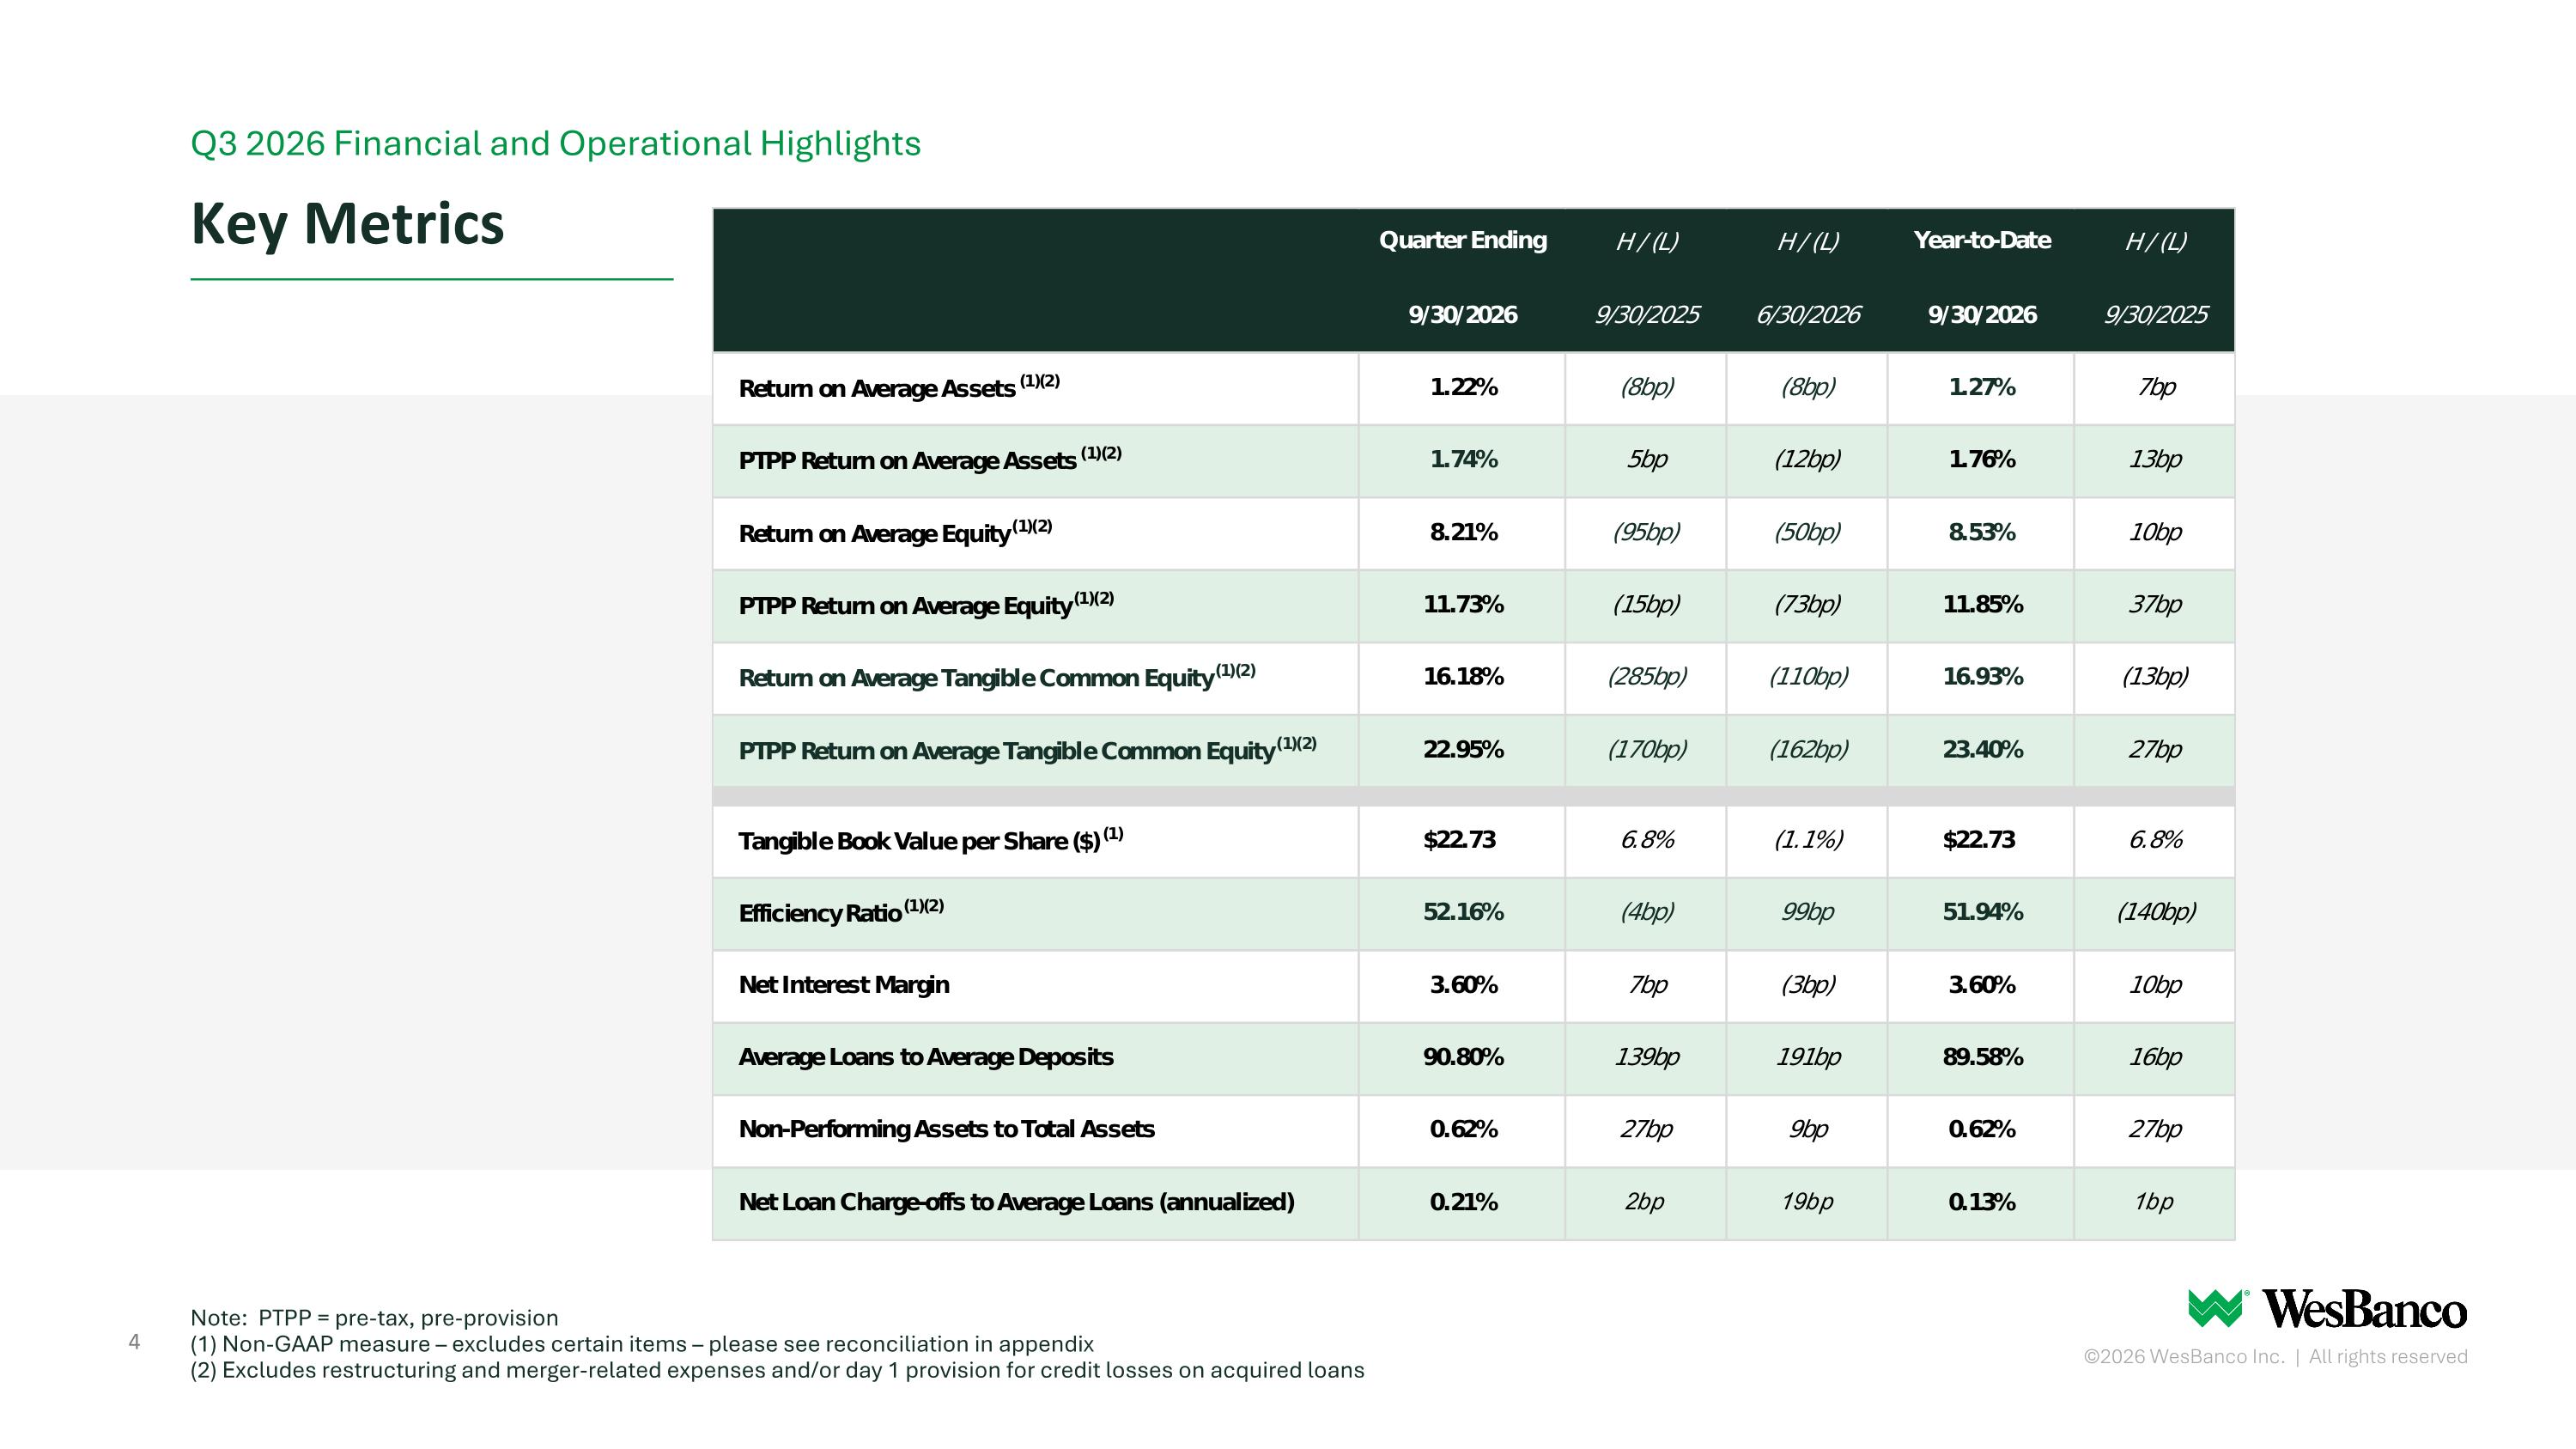
Note: PTPP = pre-tax, pre-provision (1) Non-GAAP measure – excludes certain items – please see reconciliation in appendix (2) Excludes restructuring and merger-related expenses and/or day 1 provision for credit losses on acquired loans Key Metrics Q3 2026 Financial and Operational Highlights
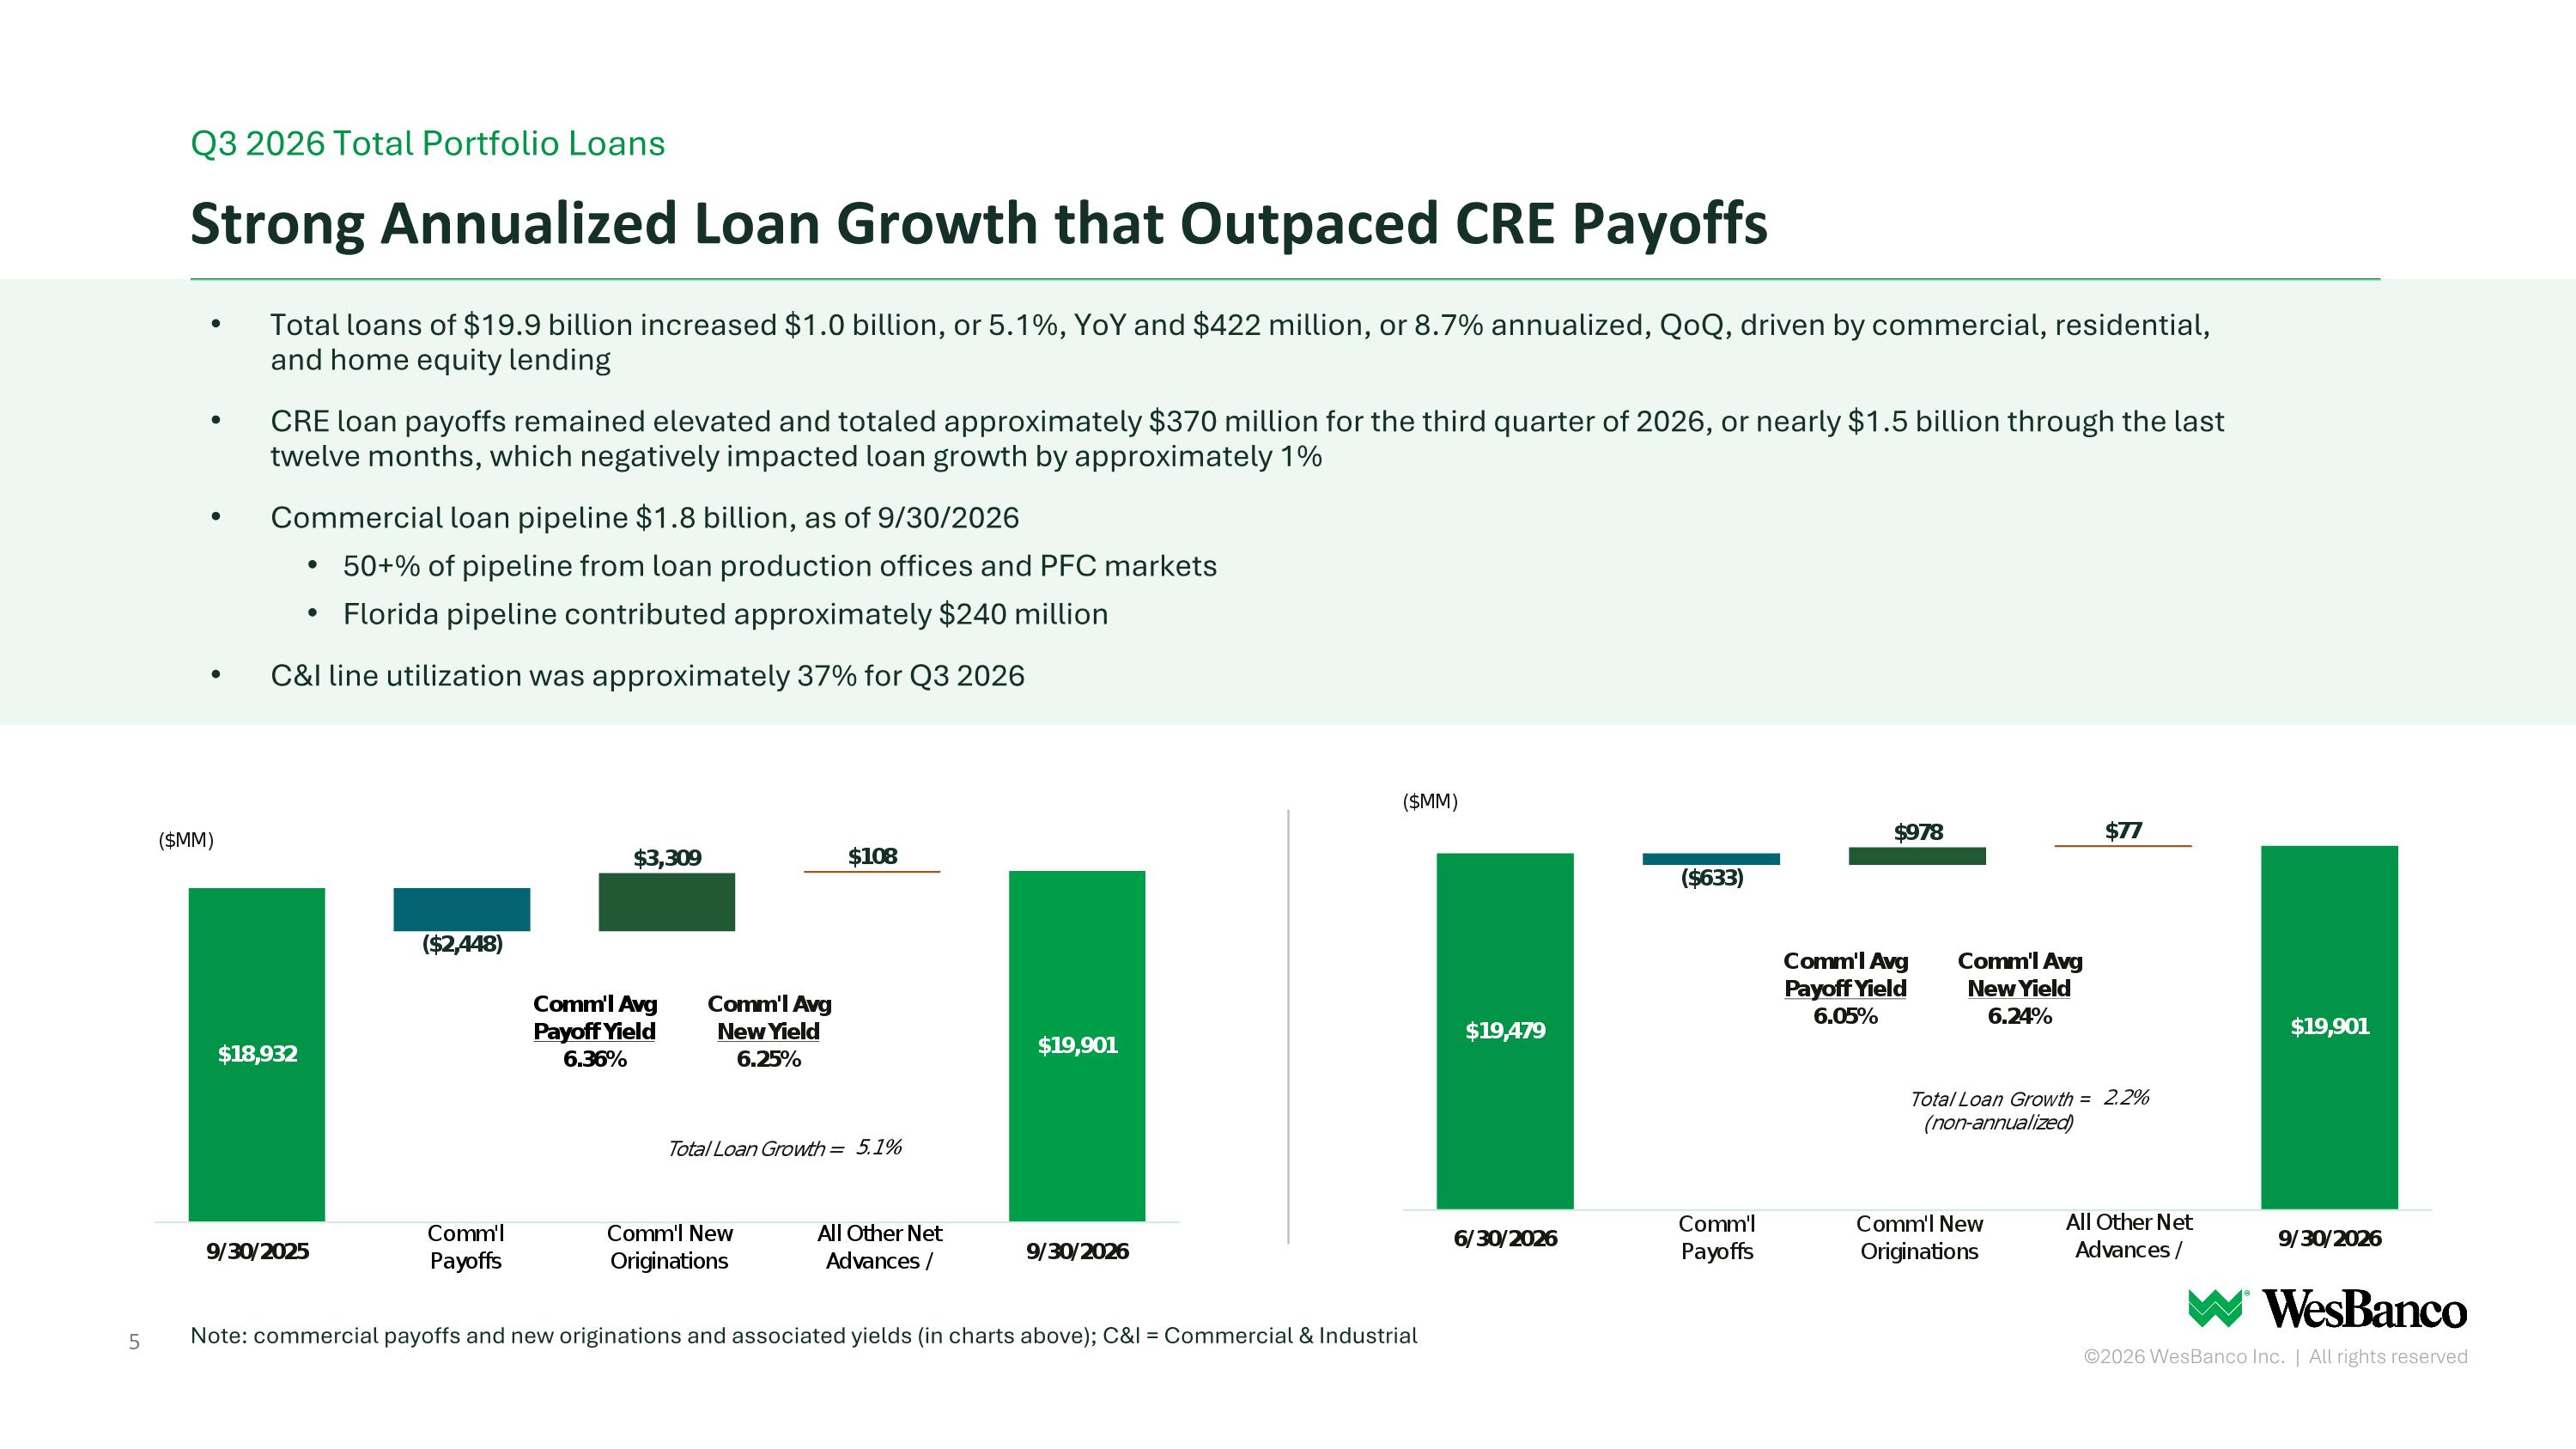
Strong Annualized Loan Growth that Outpaced CRE Payoffs Note: commercial payoffs and new originations and associated yields (in charts above); C&I = Commercial & Industrial Q3 2026 Total Portfolio Loans Total loans of $19.9 billion increased $1.0 billion, or 5.1%, YoY and $422 million, or 8.7% annualized, QoQ, driven by commercial, residential, and home equity lending CRE loan payoffs remained elevated and totaled approximately $370 million for the third quarter of 2026, or nearly $1.5 billion through the last twelve months, which negatively impacted loan growth by approximately 1% Commercial loan pipeline $1.8 billion, as of 9/30/2026 50+% of pipeline from loan production offices and PFC markets Florida pipeline contributed approximately $240 million C&I line utilization was approximately 37% for Q3 2026
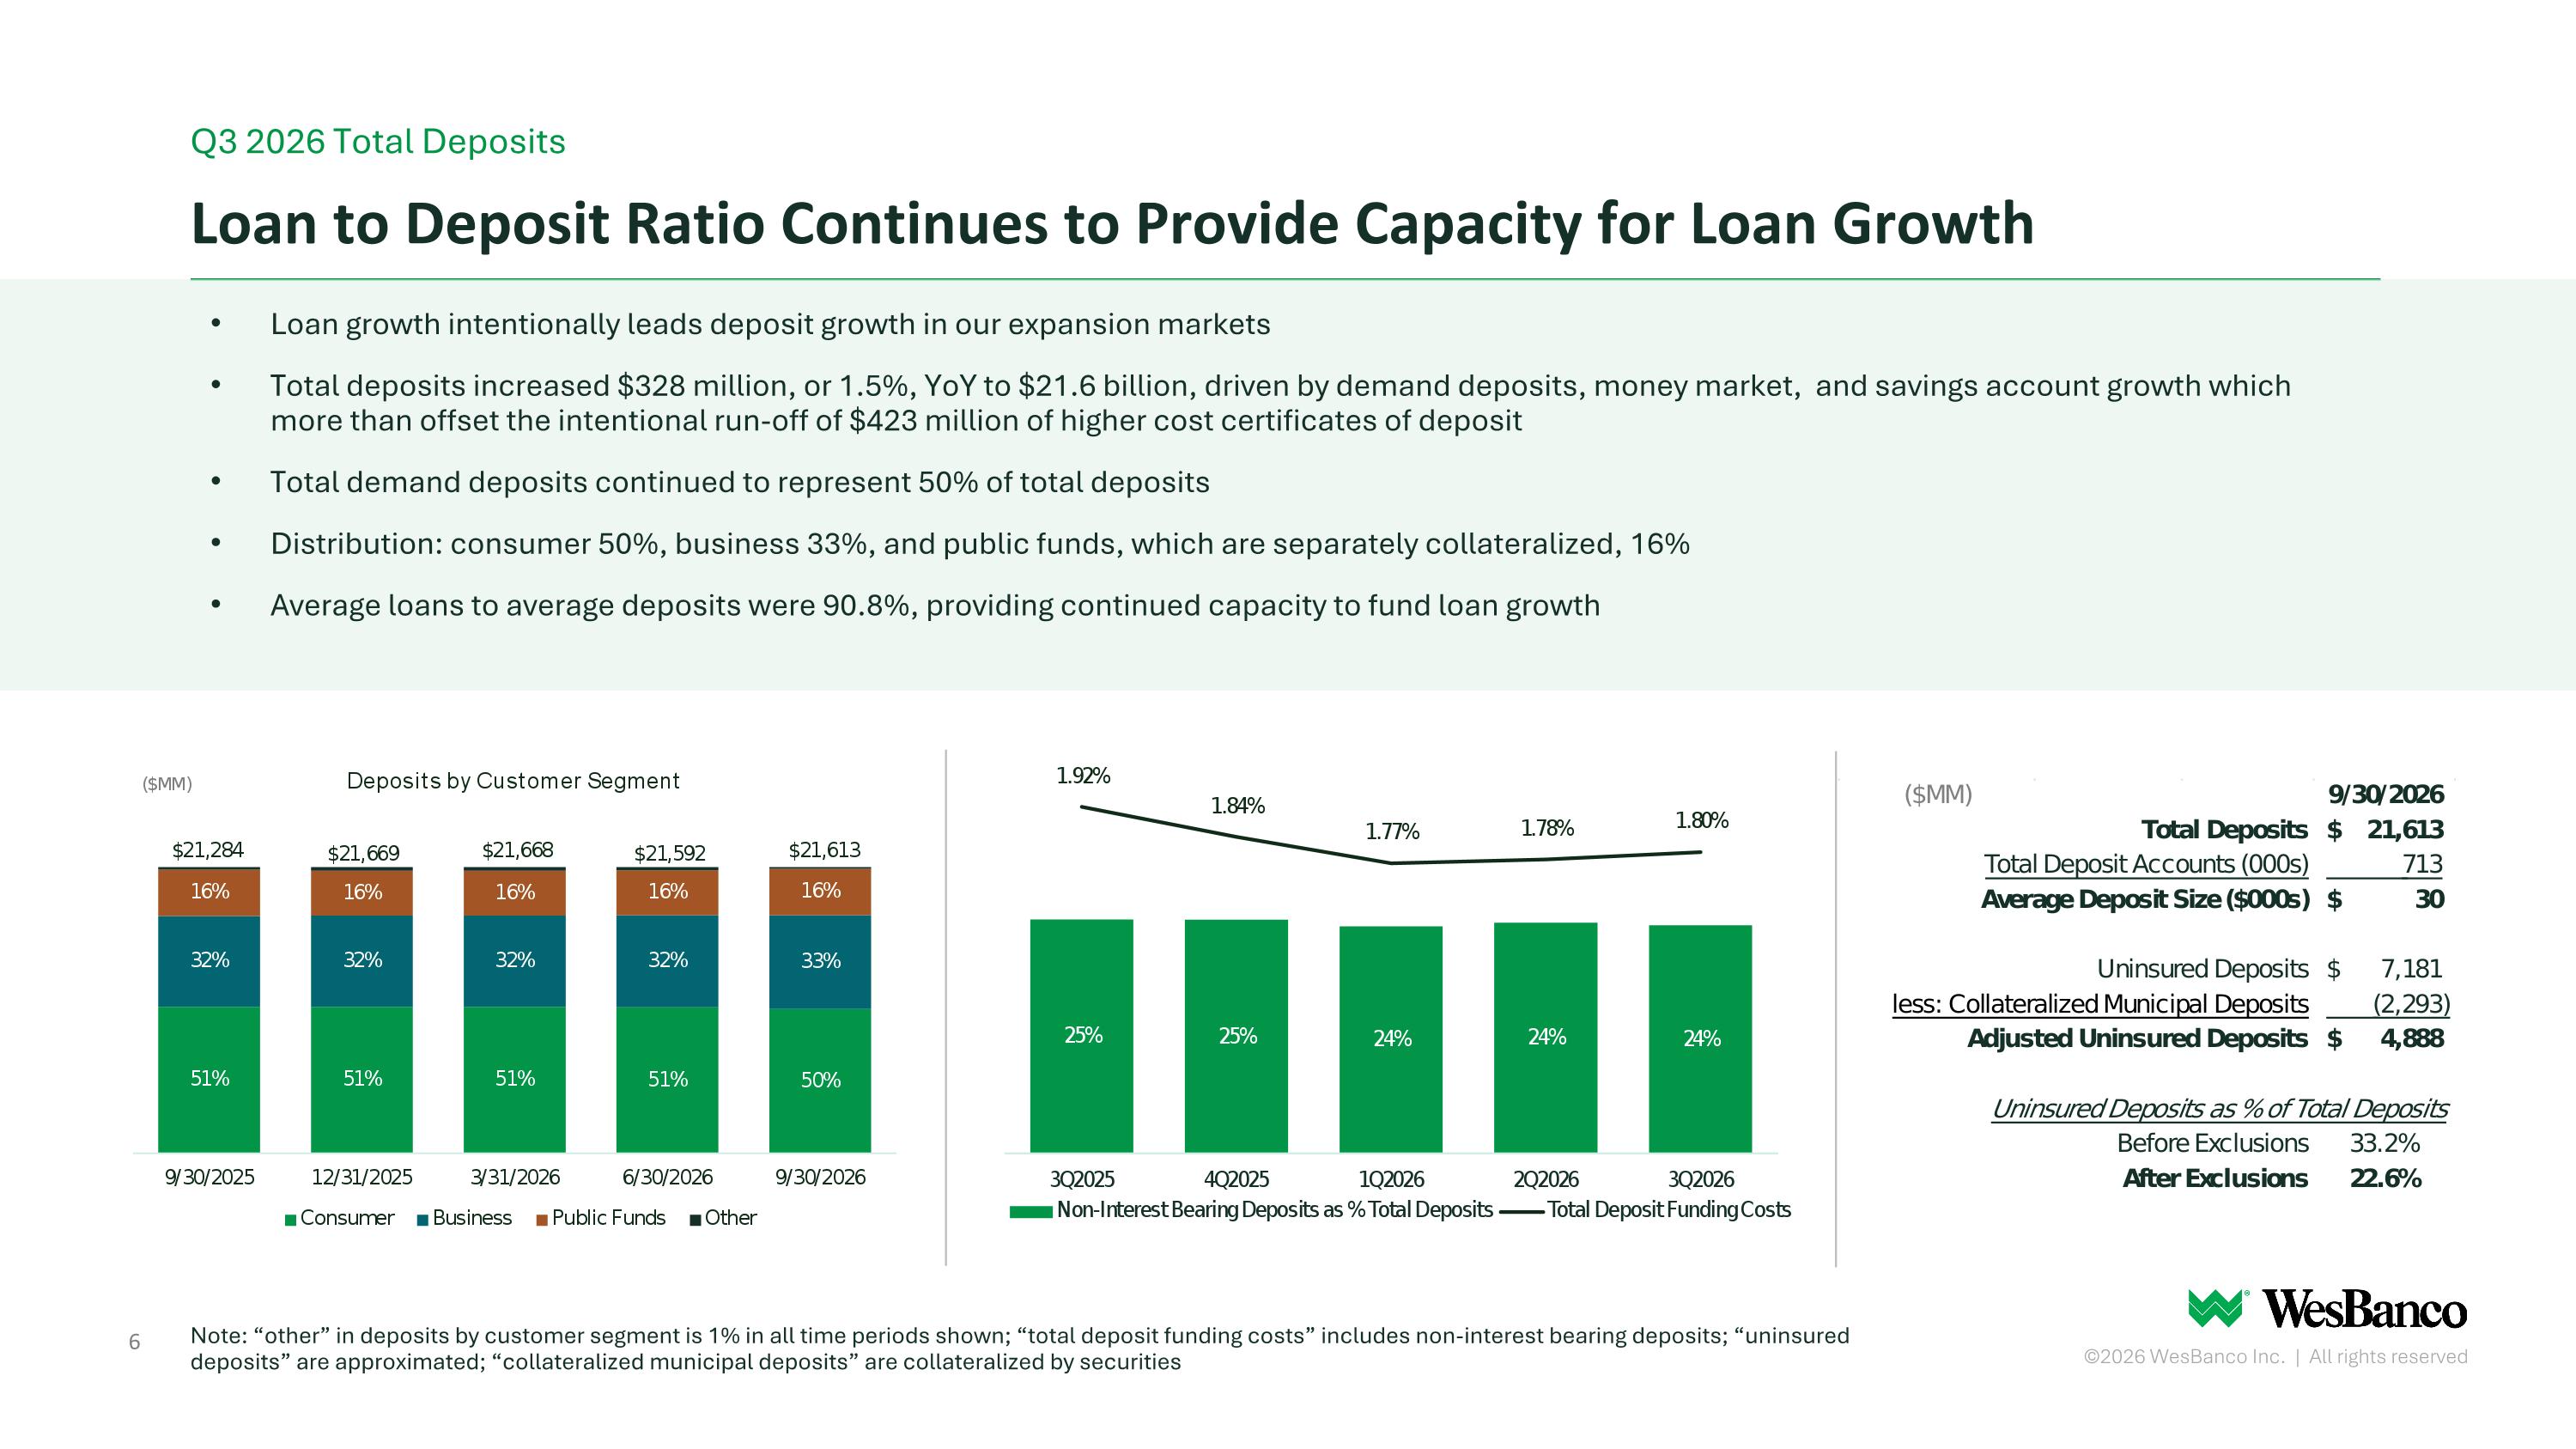
Loan to Deposit Ratio Continues to Provide Capacity for Loan Growth Note: “other” in deposits by customer segment is 1% in all time periods shown; “total deposit funding costs” includes non-interest bearing deposits; “uninsured deposits” are approximated; “collateralized municipal deposits” are collateralized by securities Q3 2026 Total Deposits Loan growth intentionally leads deposit growth in our expansion markets Total deposits increased $328 million, or 1.5%, YoY to $21.6 billion, driven by demand deposits, money market, and savings account growth which more than offset the intentional run-off of $423 million of higher cost certificates of deposit Total demand deposits continued to represent 50% of total deposits Distribution: consumer 50%, business 33%, and public funds, which are separately collateralized, 16% Average loans to average deposits were 90.8%, providing continued capacity to fund loan growth
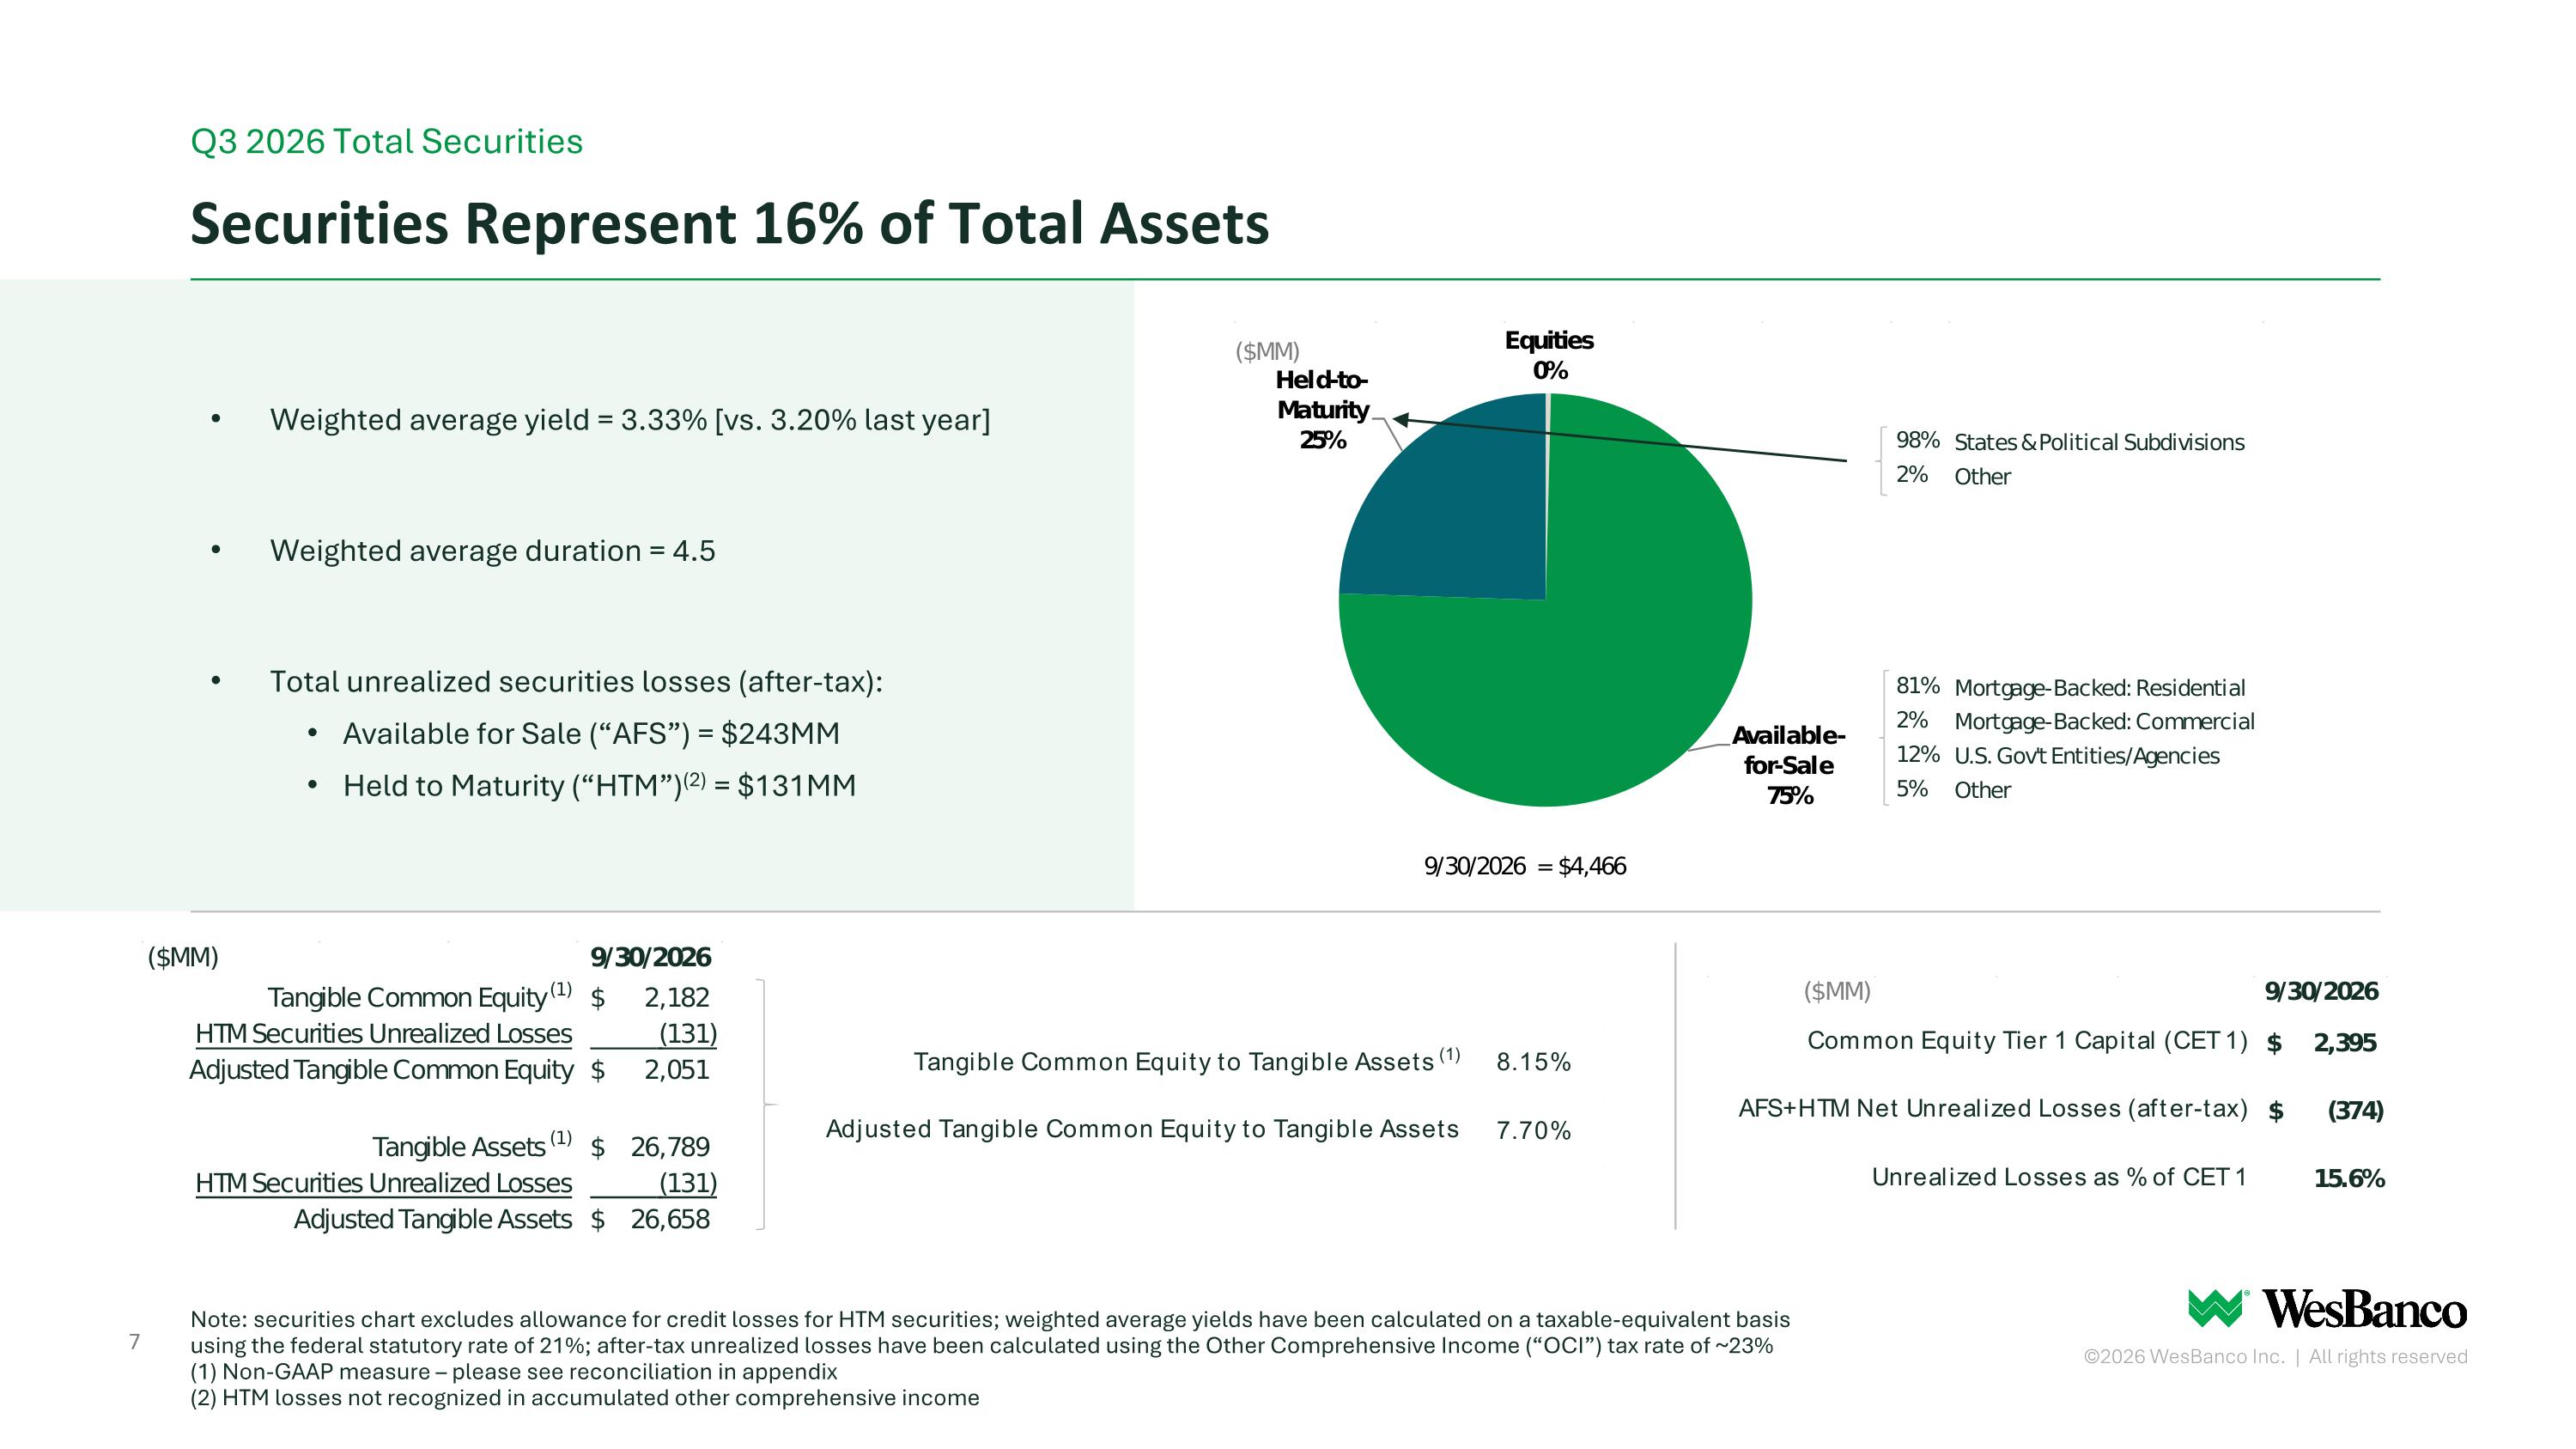
Weighted average yield = 3.33% [vs. 3.20% last year] Weighted average duration = 4.5 Total unrealized securities losses (after-tax): Available for Sale (“AFS”) = $243MM Held to Maturity (“HTM”)(2) = $131MM Securities Represent 16% of Total Assets Note: securities chart excludes allowance for credit losses for HTM securities; weighted average yields have been calculated on a taxable-equivalent basis using the federal statutory rate of 21%; after-tax unrealized losses have been calculated using the Other Comprehensive Income (“OCI”) tax rate of ~23% (1) Non-GAAP measure – please see reconciliation in appendix (2) HTM losses not recognized in accumulated other comprehensive income Q3 2026 Total Securities
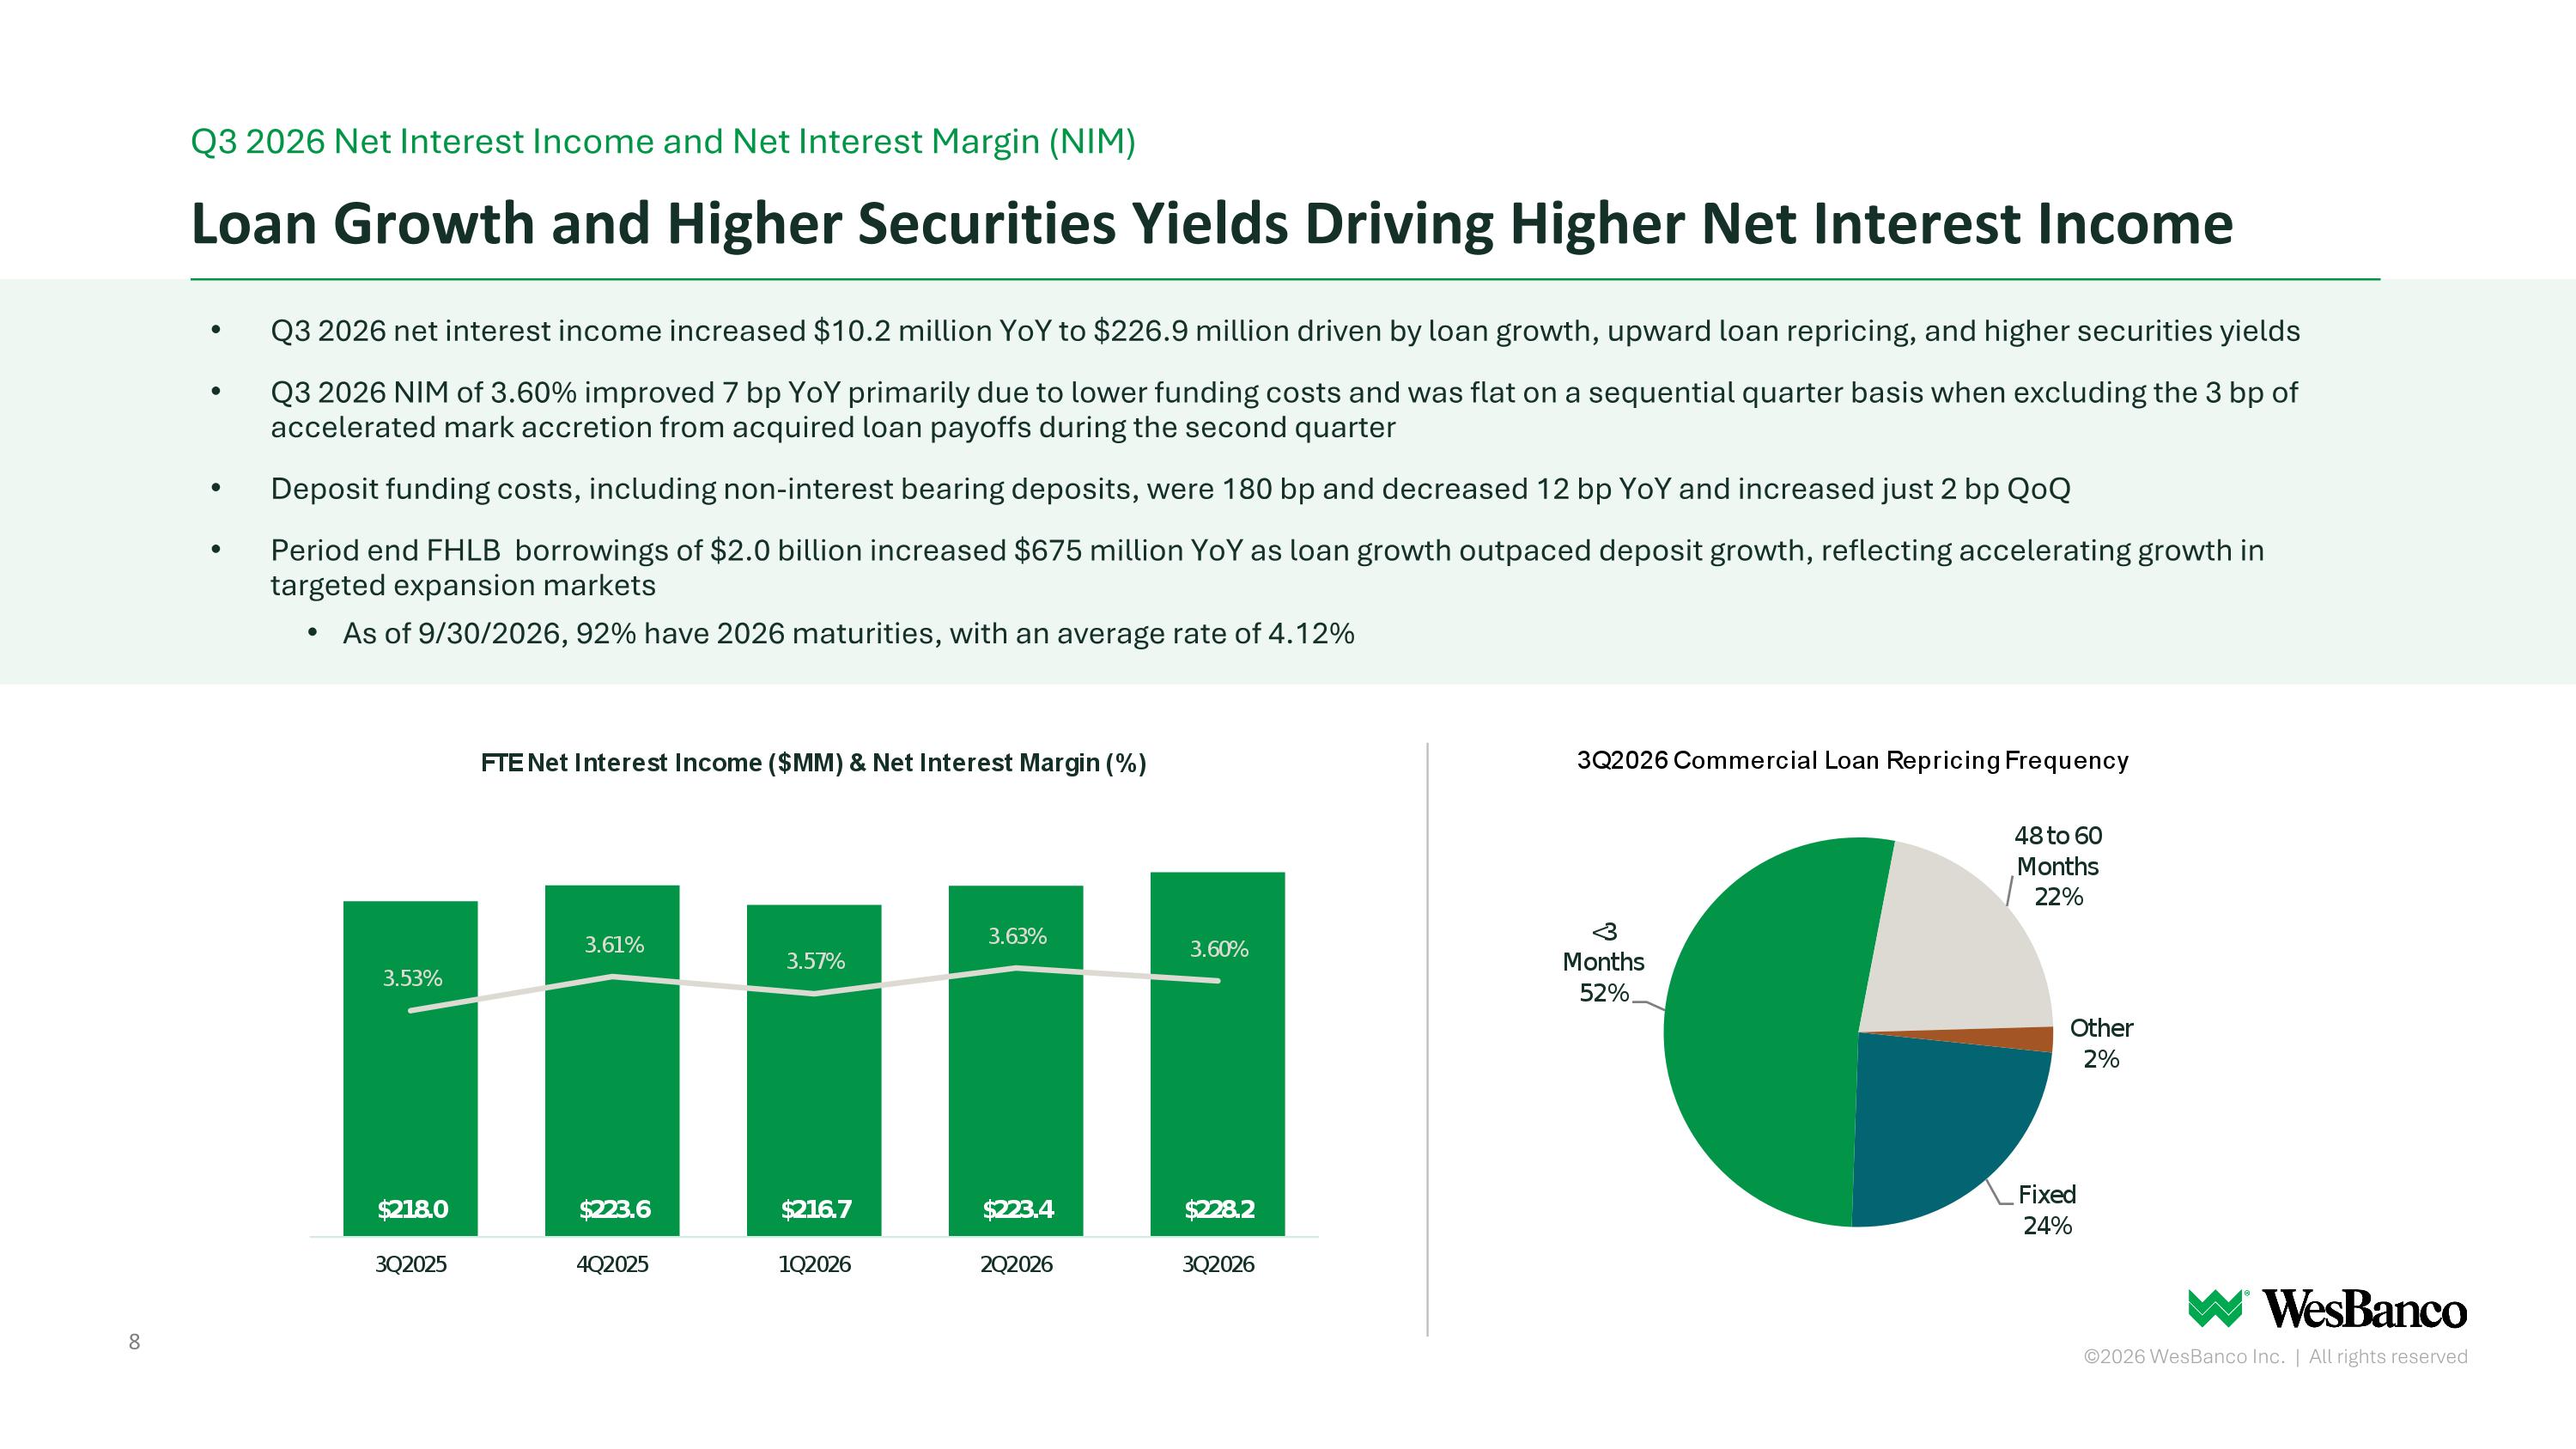
Q3 2026 net interest income increased $10.2 million YoY to $226.9 million driven by loan growth, upward loan repricing, and higher securities yields Q3 2026 NIM of 3.60% improved 7 bp YoY primarily due to lower funding costs and was flat on a sequential quarter basis when excluding the 3 bp of accelerated mark accretion from acquired loan payoffs during the second quarter Deposit funding costs, including non-interest bearing deposits, were 180 bp and decreased 12 bp YoY and increased just 2 bp QoQ Period end FHLB borrowings of $2.0 billion increased $675 million YoY as loan growth outpaced deposit growth, reflecting accelerating growth in targeted expansion markets As of 9/30/2026, 92% have 2026 maturities, with an average rate of 4.12% Loan Growth and Higher Securities Yields Driving Higher Net Interest Income Q3 2026 Net Interest Income and Net Interest Margin (NIM)
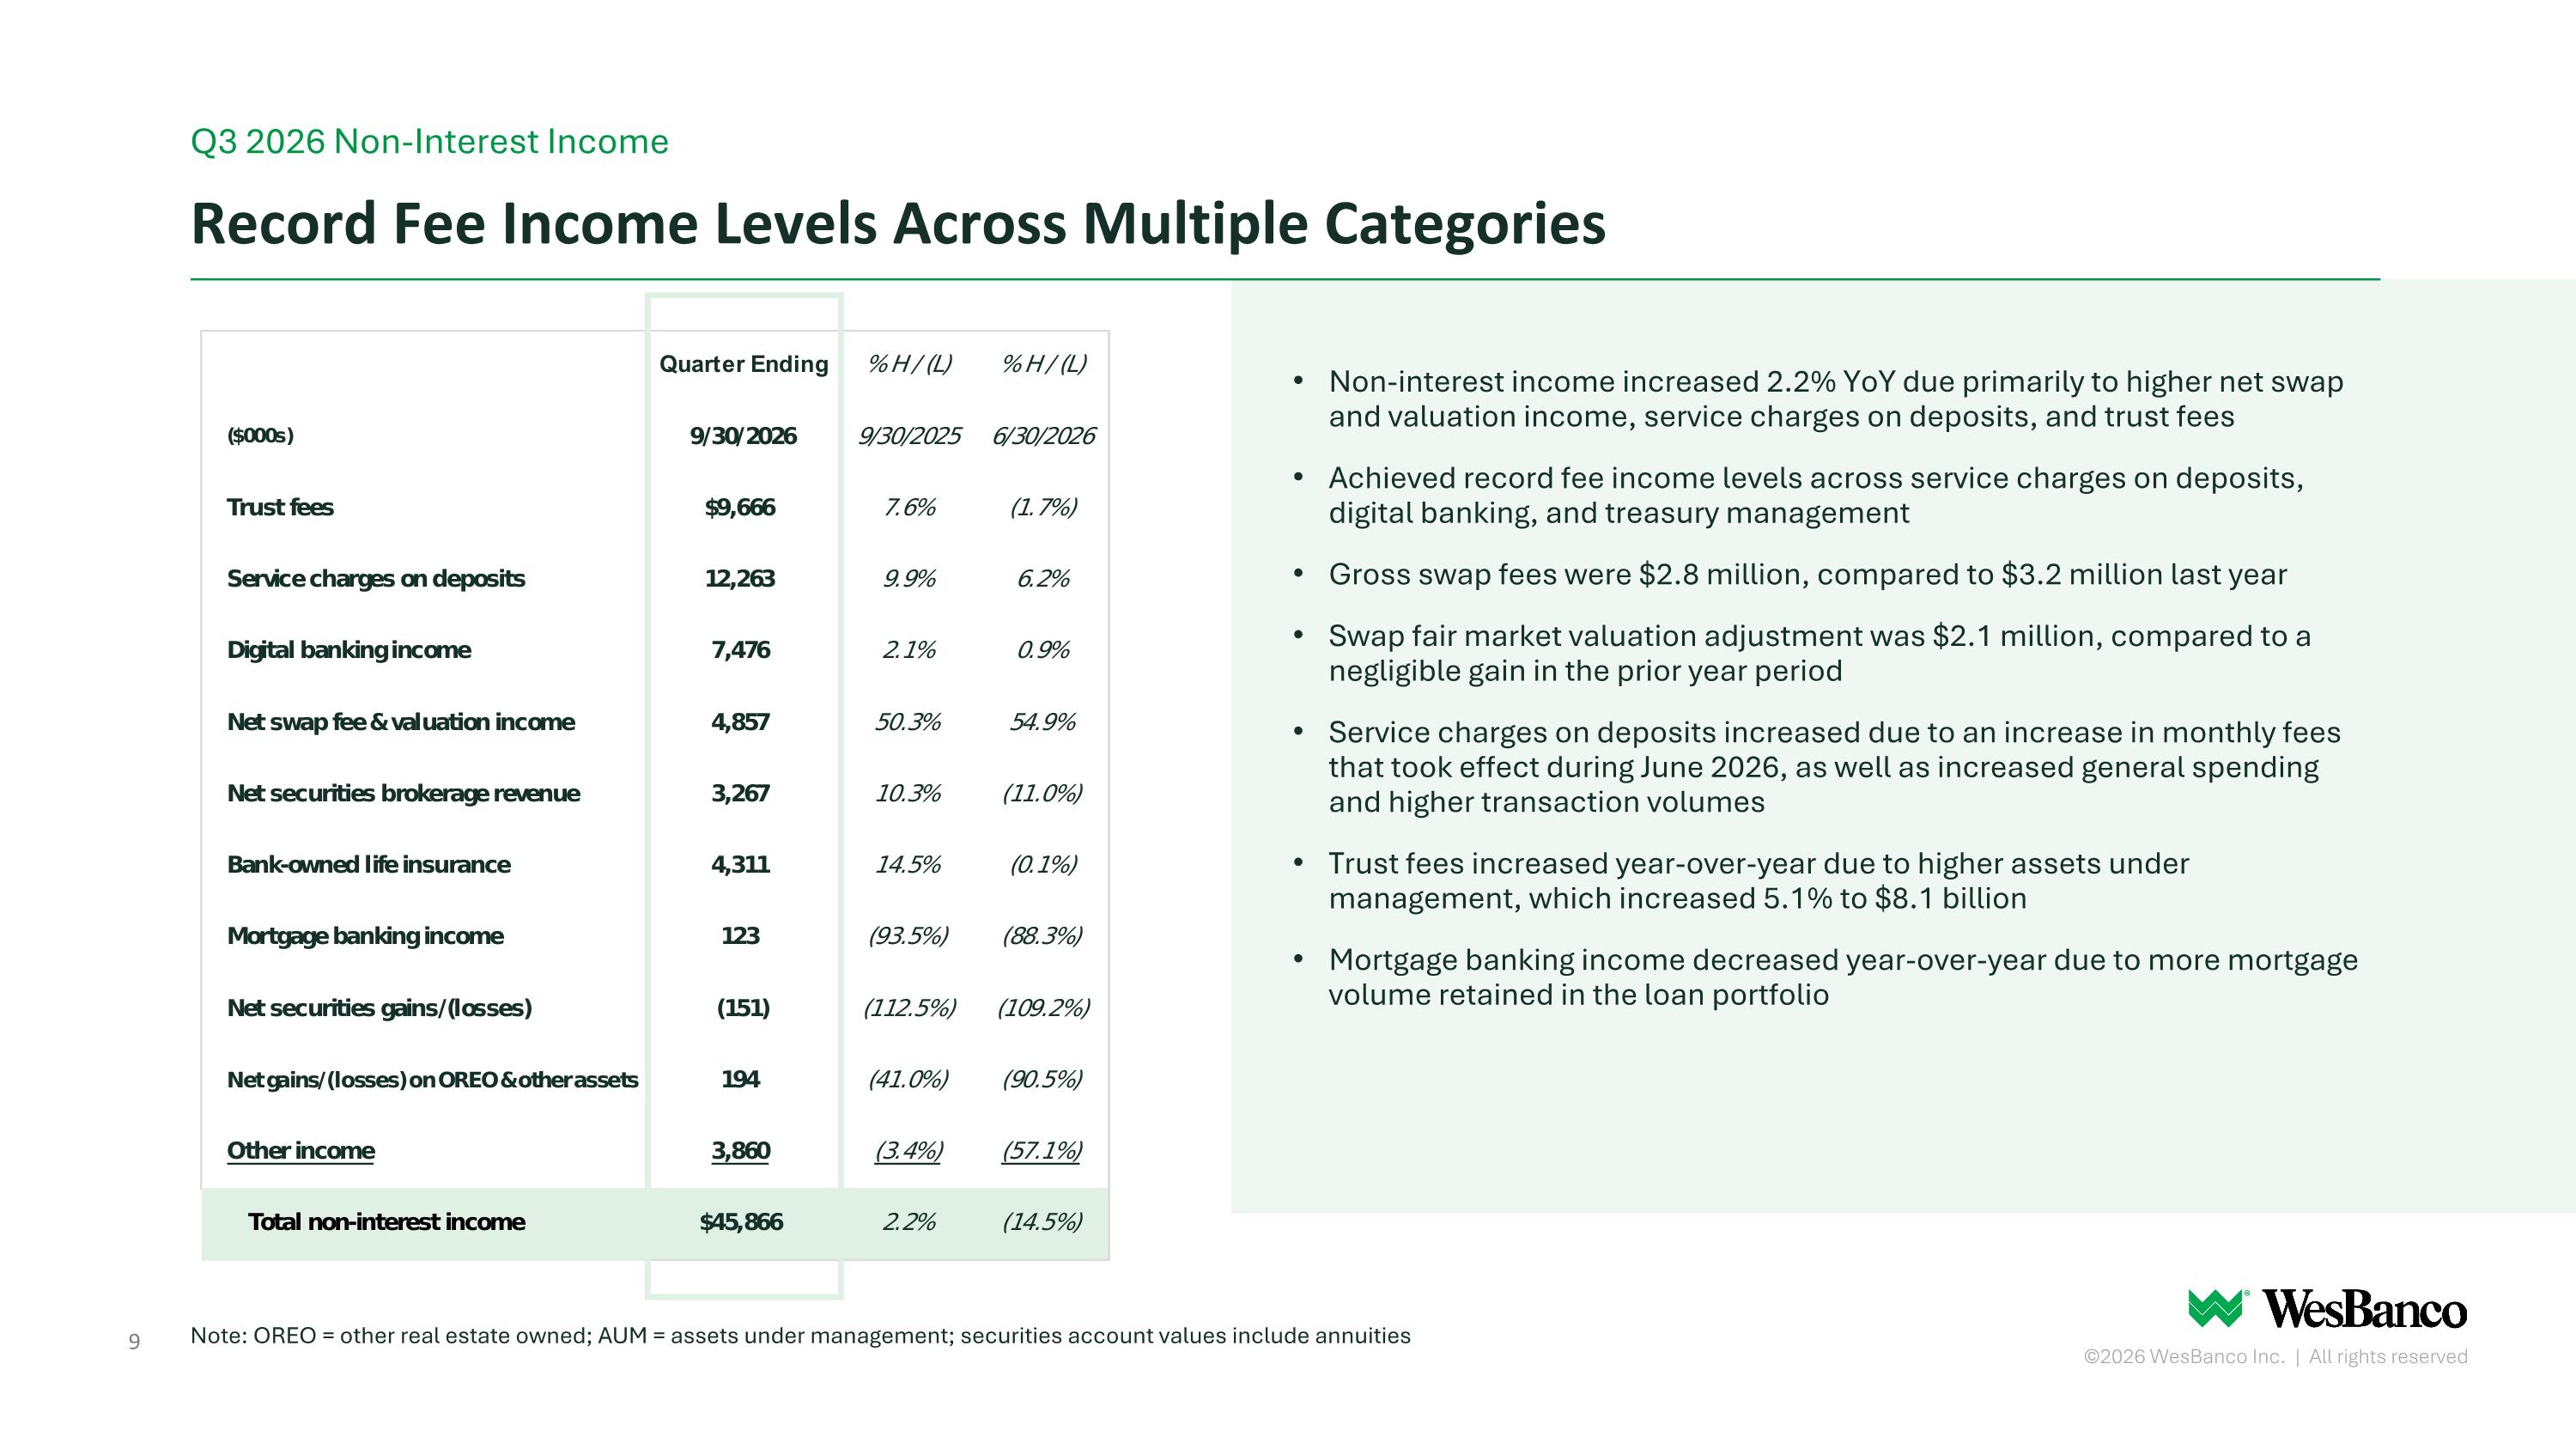
Note: OREO = other real estate owned; AUM = assets under management; securities account values include annuities Record Fee Income Levels Across Multiple Categories Q3 2026 Non-Interest Income Non-interest income increased 2.2% YoY due primarily to higher net swap and valuation income, service charges on deposits, and trust fees Achieved record fee income levels across service charges on deposits, digital banking, and treasury management Gross swap fees were $2.8 million, compared to $3.2 million last year Swap fair market valuation adjustment was $2.1 million, compared to a negligible gain in the prior year period Service charges on deposits increased due to an increase in monthly fees that took effect during June 2026, as well as increased general spending and higher transaction volumes Trust fees increased year-over-year due to higher assets under management, which increased 5.1% to $8.1 billion Mortgage banking income decreased year-over-year due to more mortgage volume retained in the loan portfolio
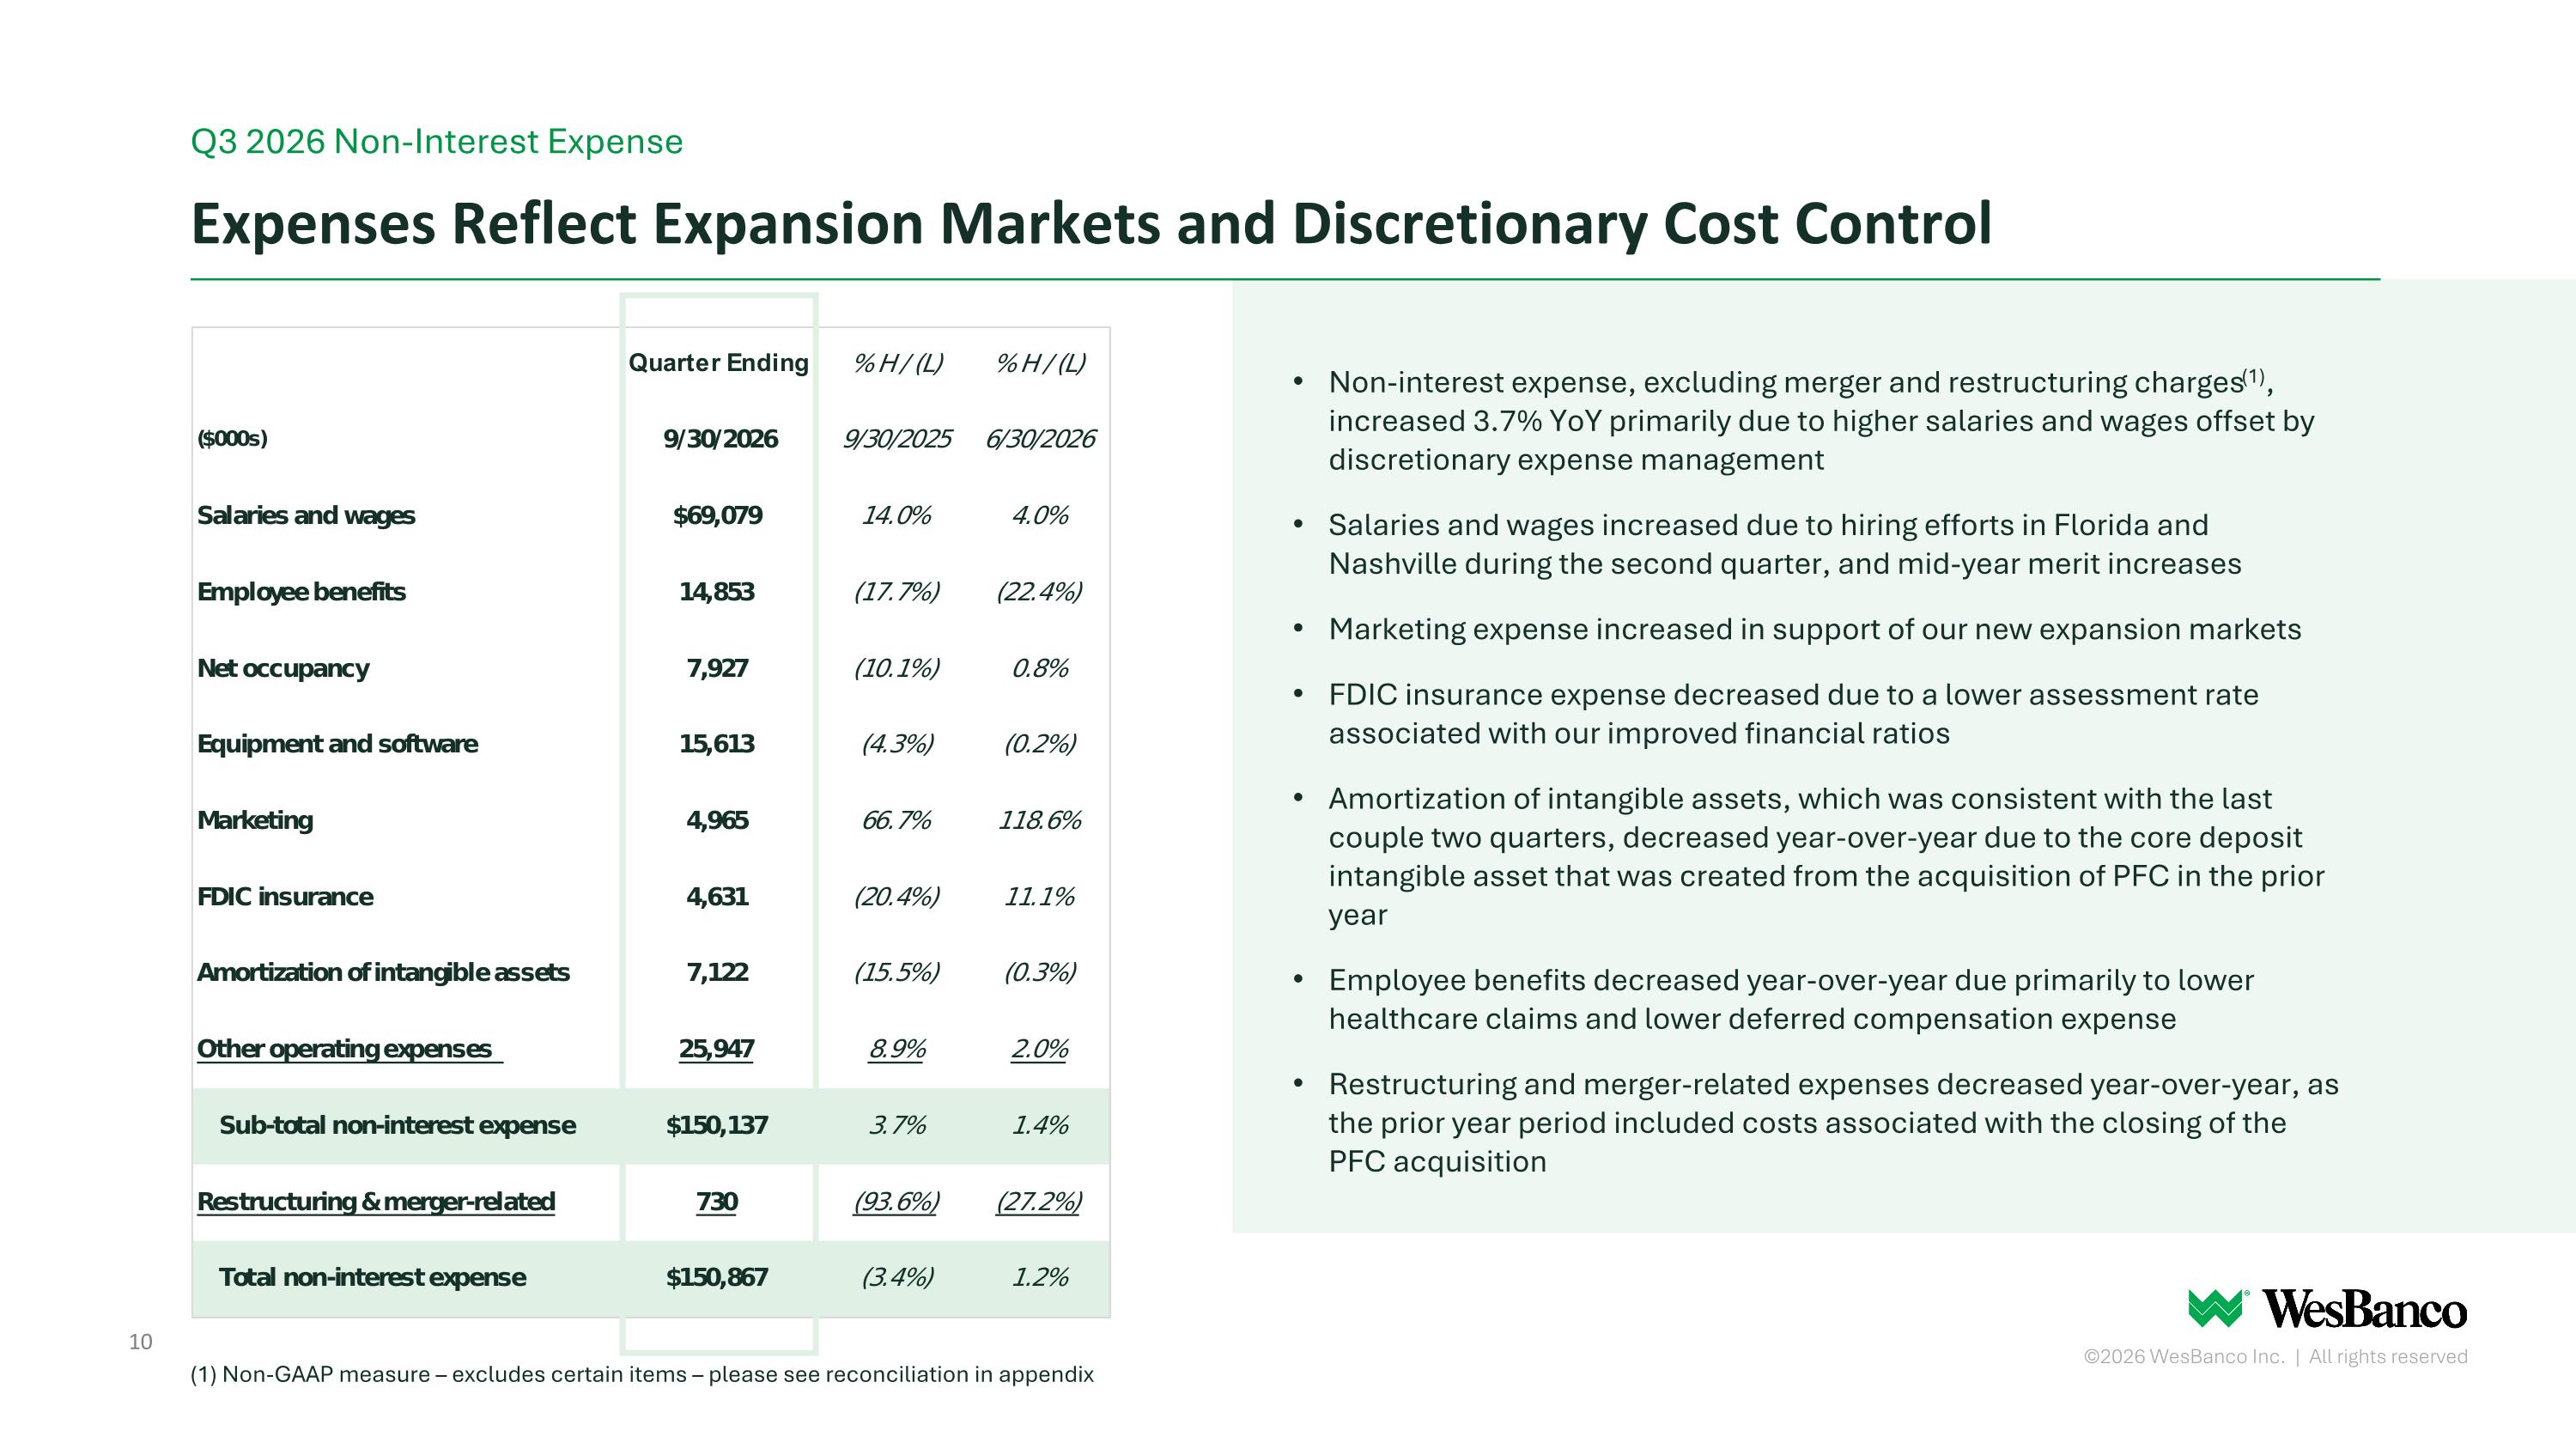
Expenses Reflect Expansion Markets and Discretionary Cost Control Q3 2026 Non-Interest Expense Non-interest expense, excluding merger and restructuring charges(1), increased 3.7% YoY primarily due to higher salaries and wages offset by discretionary expense management Salaries and wages increased due to hiring efforts in Florida and Nashville during the second quarter, and mid-year merit increases Marketing expense increased in support of our new expansion markets FDIC insurance expense decreased due to a lower assessment rate associated with our improved financial ratios Amortization of intangible assets, which was consistent with the last couple two quarters, decreased year-over-year due to the core deposit intangible asset that was created from the acquisition of PFC in the prior year Employee benefits decreased year-over-year due primarily to lower healthcare claims and lower deferred compensation expense Restructuring and merger-related expenses decreased year-over-year, as the prior year period included costs associated with the closing of the PFC acquisition (1) Non-GAAP measure – excludes certain items – please see reconciliation in appendix
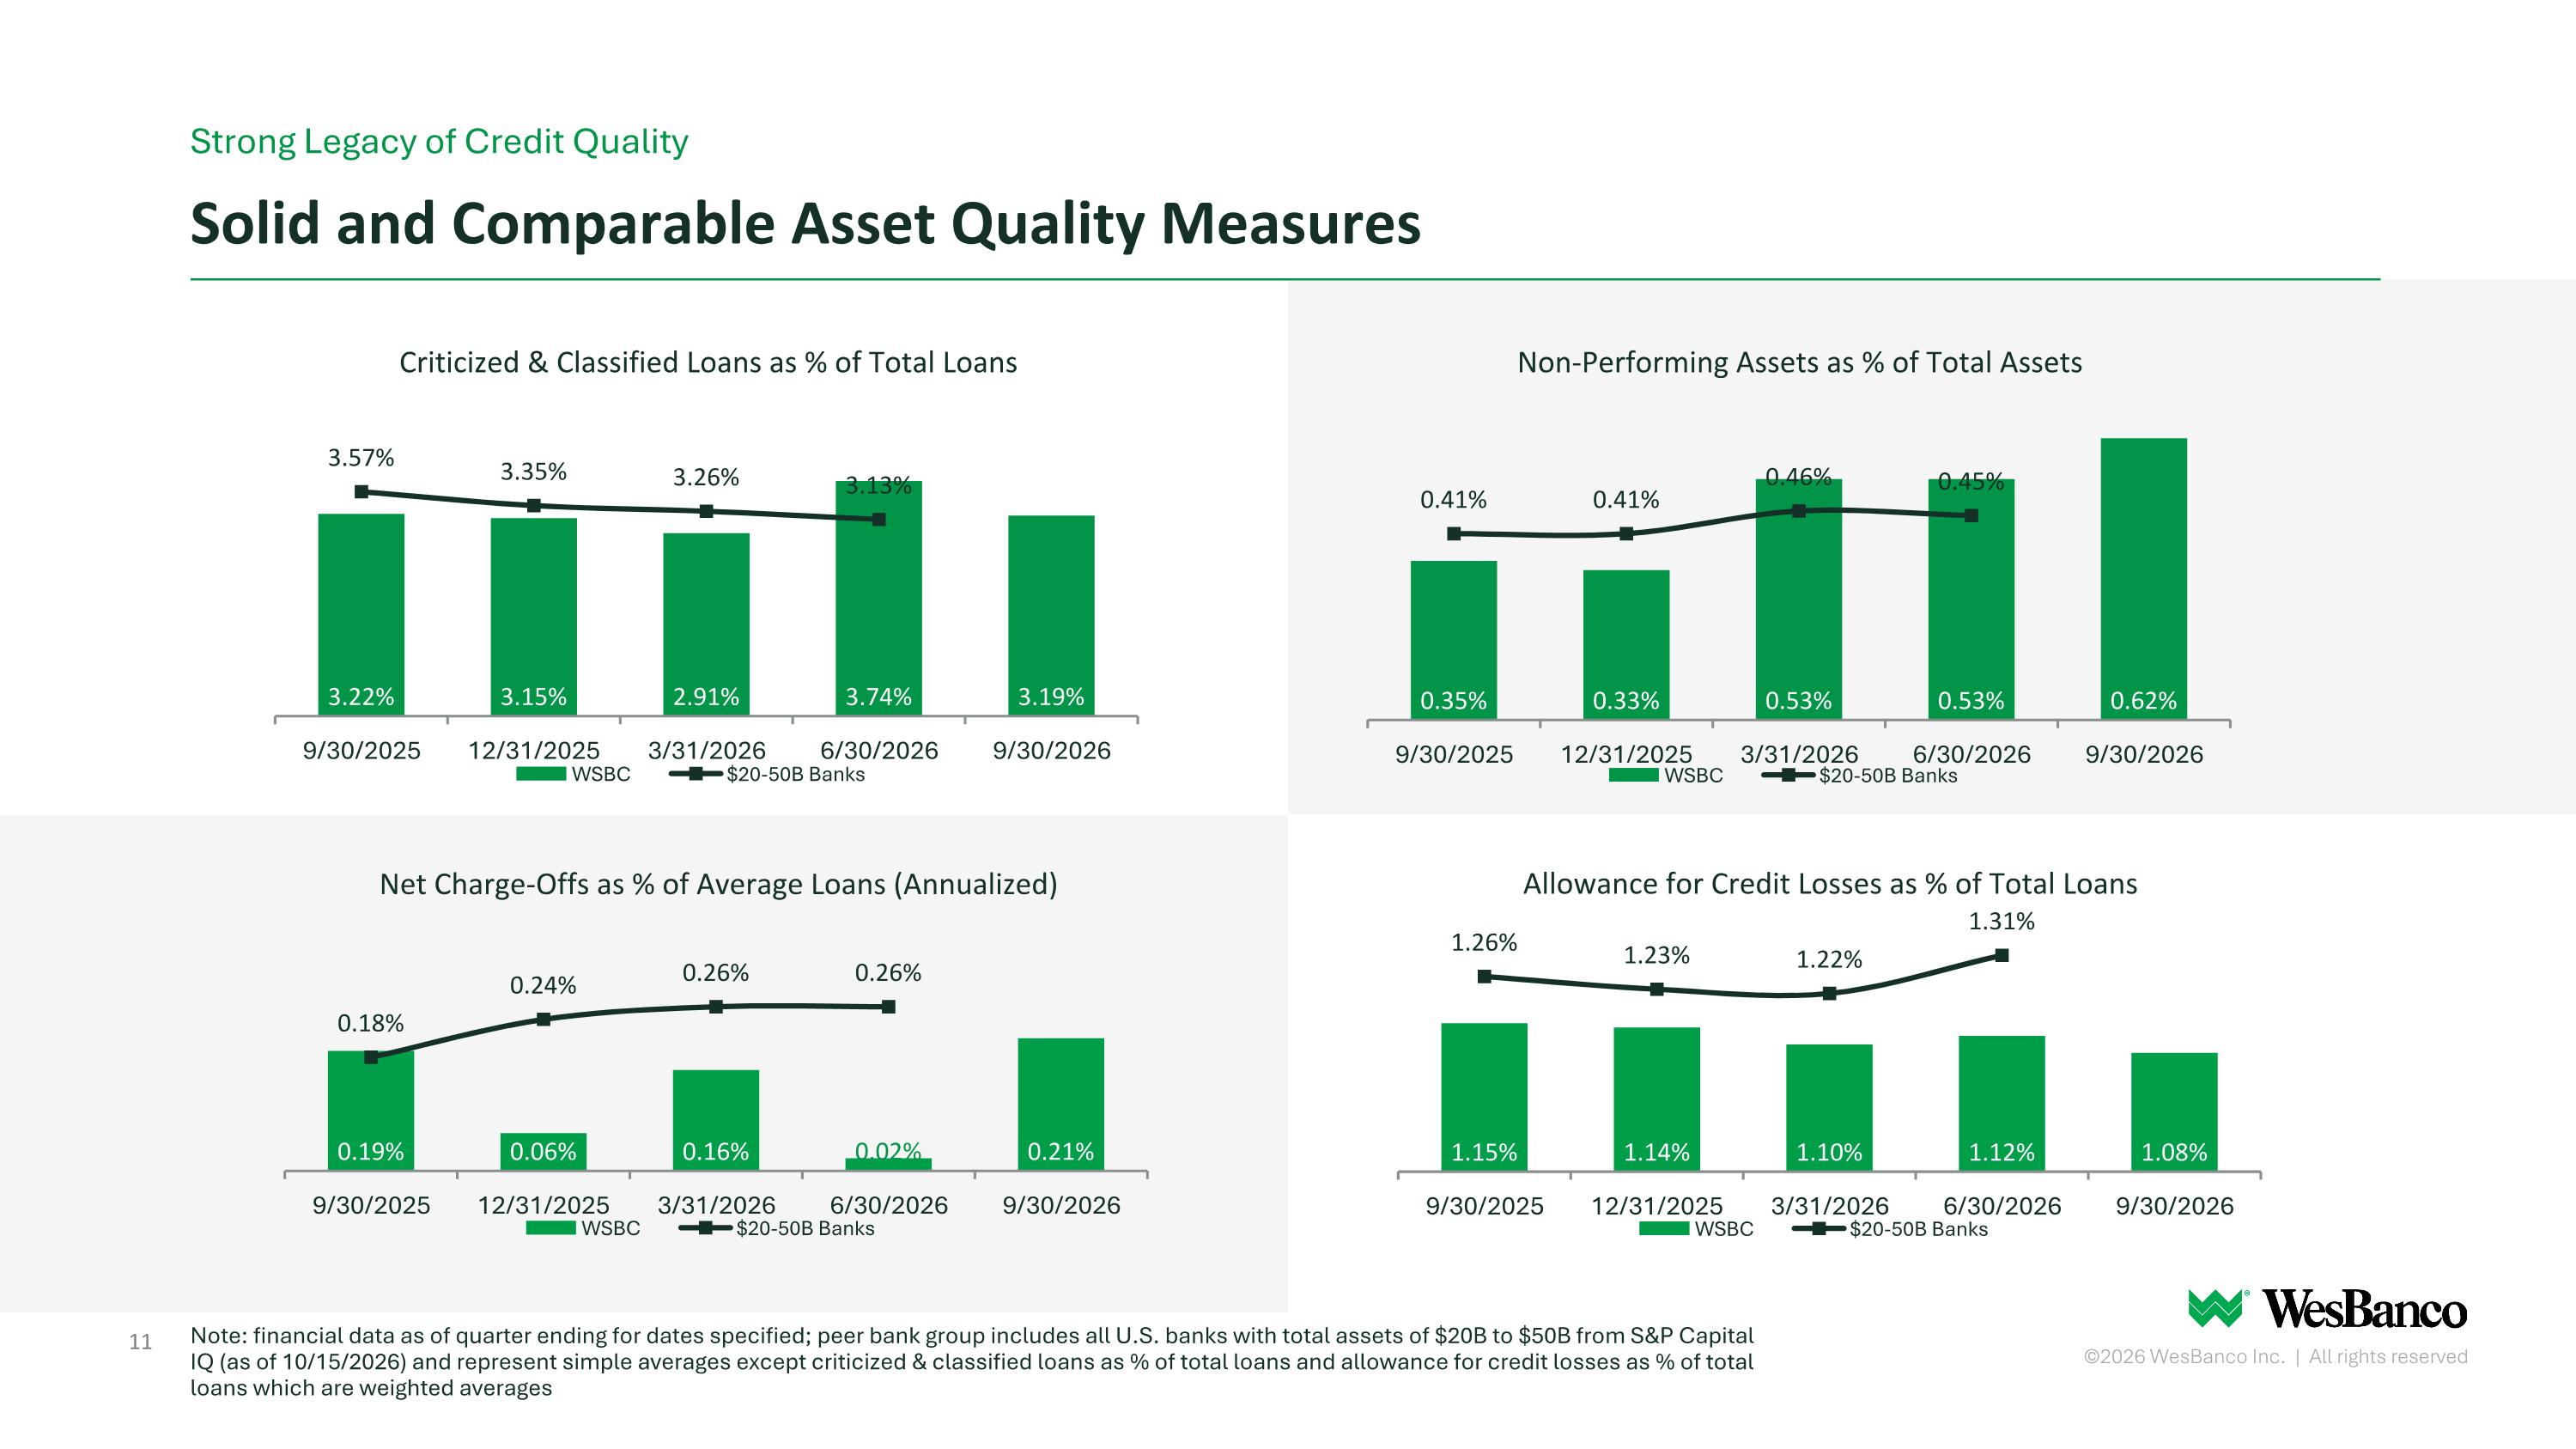
Solid and Comparable Asset Quality Measures Note: financial data as of quarter ending for dates specified; peer bank group includes all U.S. banks with total assets of $20B to $50B from S&P Capital IQ (as of 10/15/2026) and represent simple averages except criticized & classified loans as % of total loans and allowance for credit losses as % of total loans which are weighted averages Strong Legacy of Credit Quality Criticized & Classified Loans as % of Total Loans Non-Performing Assets as % of Total Assets Net Charge-Offs as % of Average Loans (Annualized) Allowance for Credit Losses as % of Total Loans
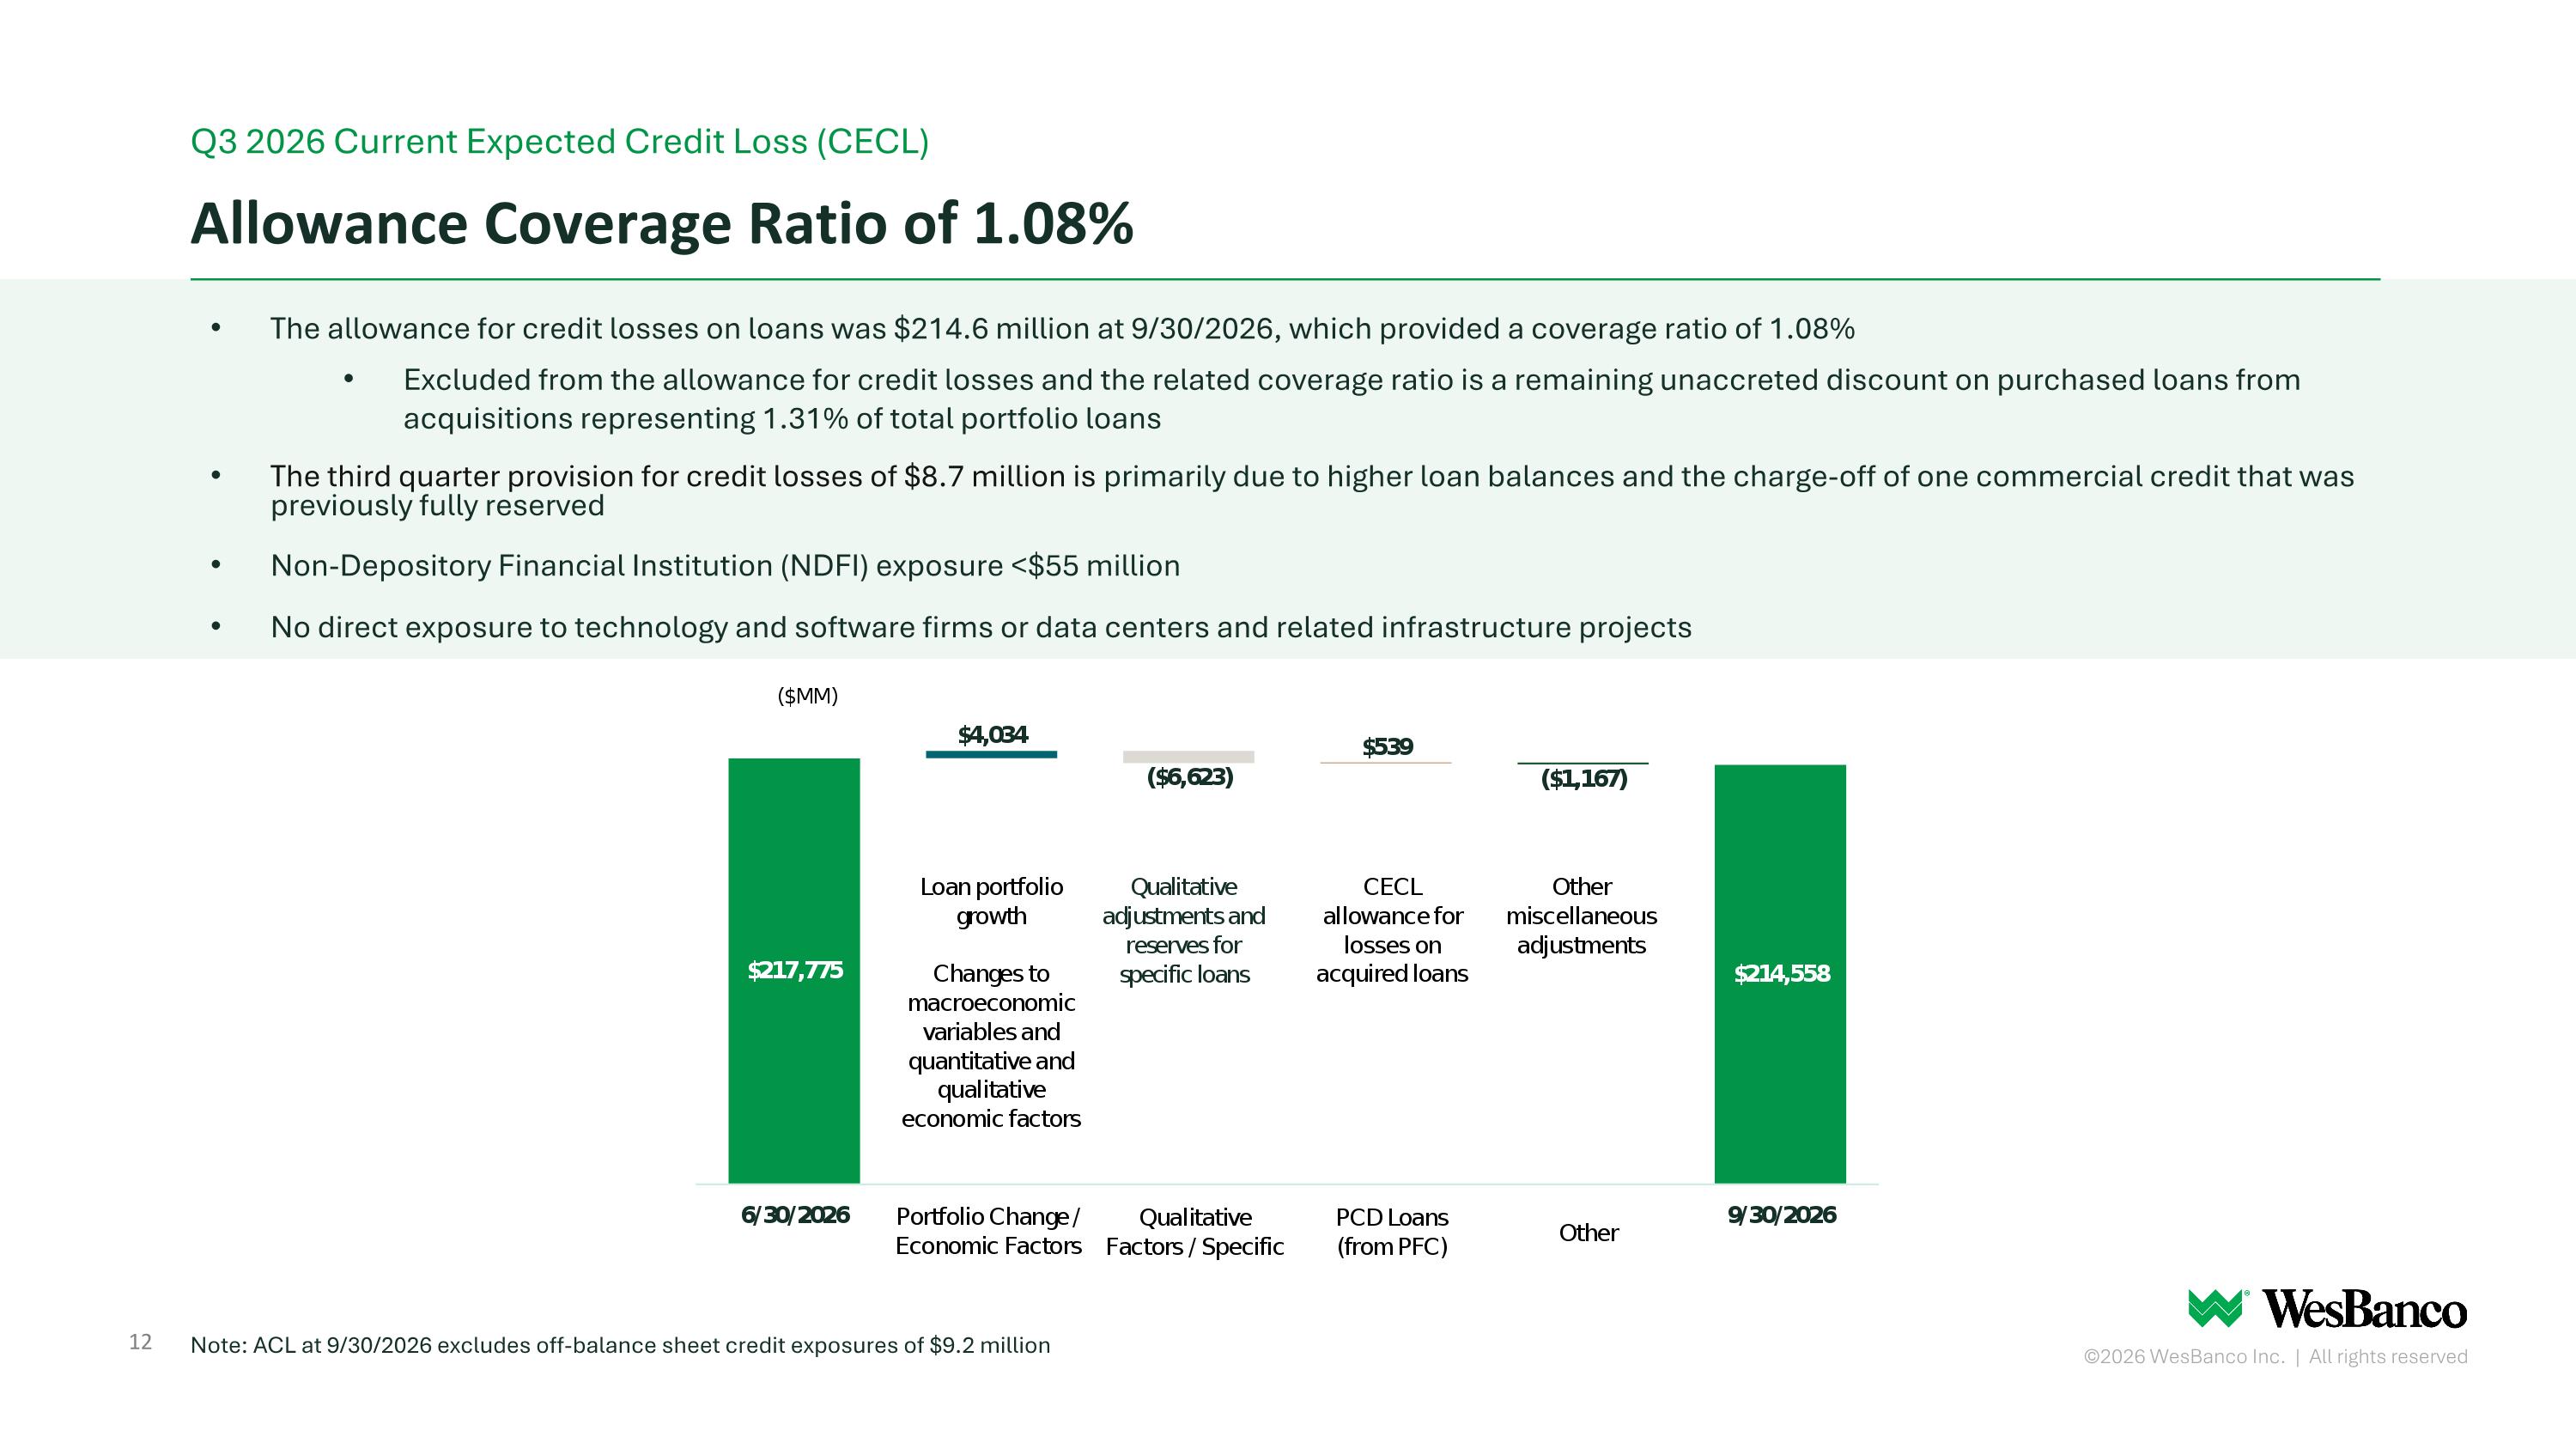
The allowance for credit losses on loans was $214.6 million at 9/30/2026, which provided a coverage ratio of 1.08% Excluded from the allowance for credit losses and the related coverage ratio is a remaining unaccreted discount on purchased loans from acquisitions representing 1.31% of total portfolio loans The third quarter provision for credit losses of $8.7 million is primarily due to higher loan balances and the charge-off of one commercial credit that was previously fully reserved Non-Depository Financial Institution (NDFI) exposure <$55 million No direct exposure to technology and software firms or data centers and related infrastructure projects Allowance Coverage Ratio of 1.08% Q3 2026 Current Expected Credit Loss (CECL) Note: ACL at 9/30/2026 excludes off-balance sheet credit exposures of $9.2 million
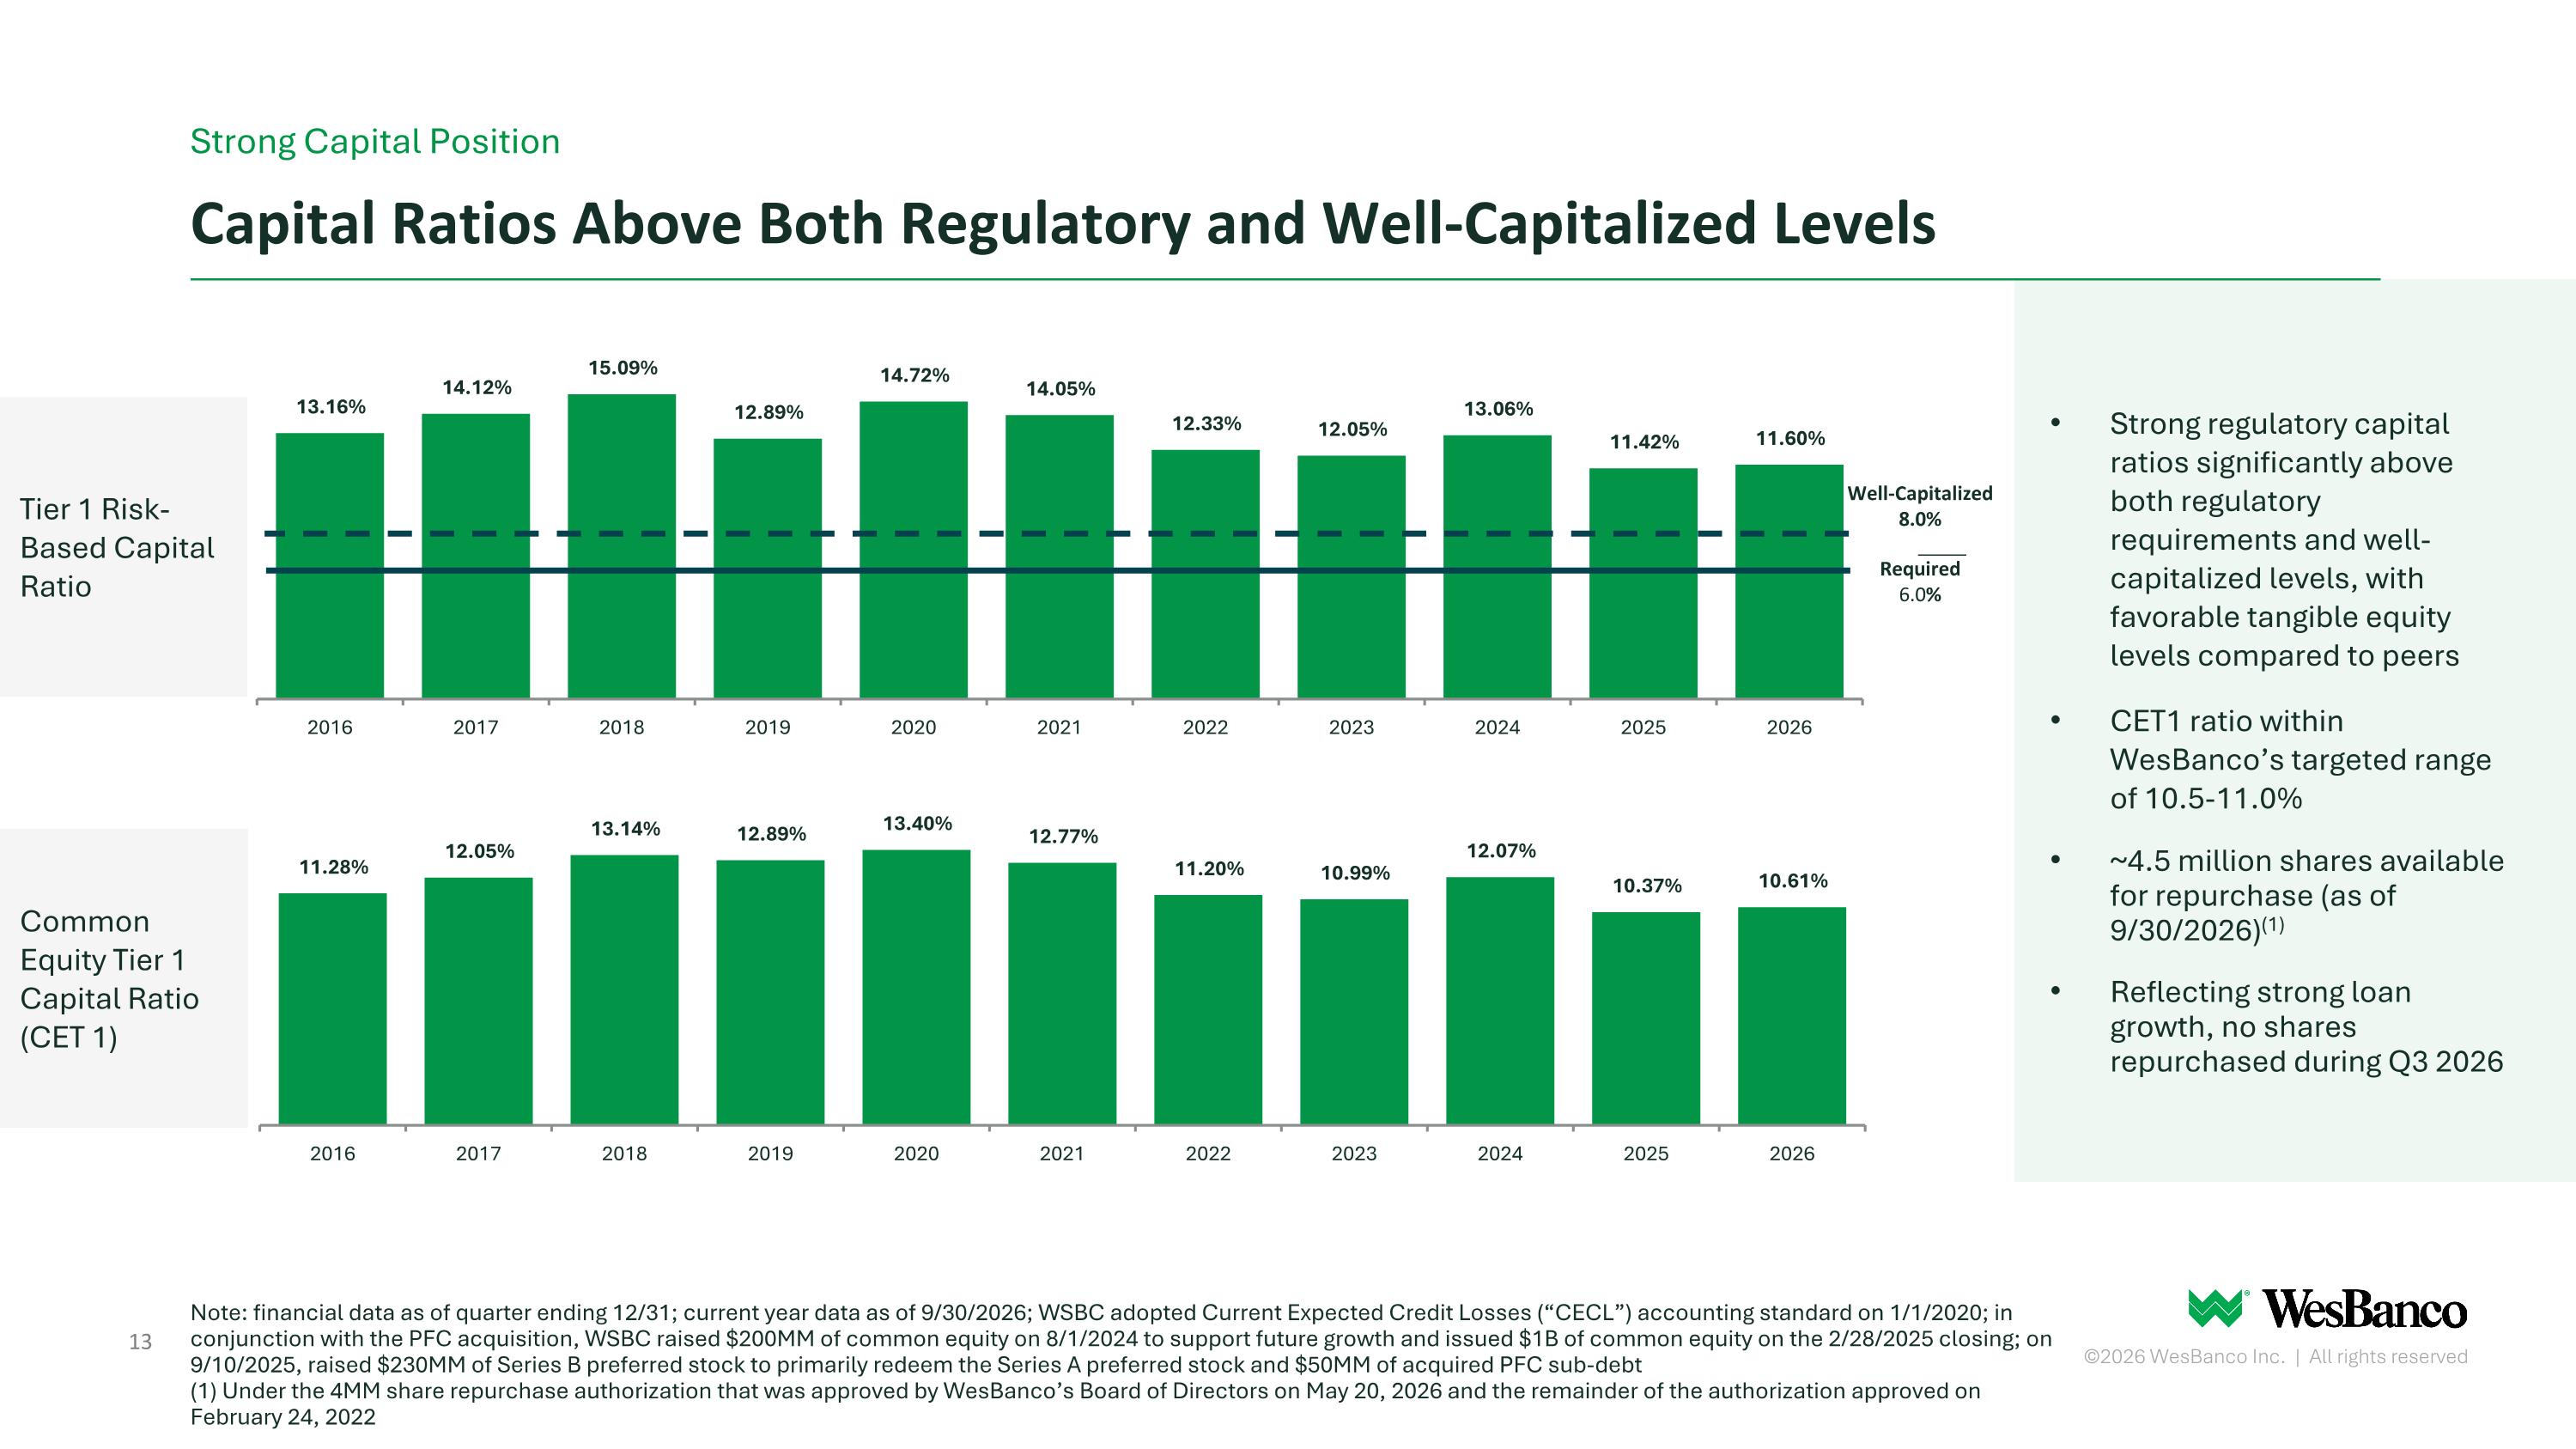
Strong regulatory capital ratios significantly above both regulatory requirements and well-capitalized levels, with favorable tangible equity levels compared to peers CET1 ratio within WesBanco’s targeted range of 10.5-11.0% ~4.5 million shares available for repurchase (as of 9/30/2026)(1) Reflecting strong loan growth, no shares repurchased during Q3 2026 Capital Ratios Above Both Regulatory and Well-Capitalized Levels Strong Capital Position Note: financial data as of quarter ending 12/31; current year data as of 9/30/2026; WSBC adopted Current Expected Credit Losses (“CECL”) accounting standard on 1/1/2020; in conjunction with the PFC acquisition, WSBC raised $200MM of common equity on 8/1/2024 to support future growth and issued $1B of common equity on the 2/28/2025 closing; on 9/10/2025, raised $230MM of Series B preferred stock to primarily redeem the Series A preferred stock and $50MM of acquired PFC sub-debt (1) Under the 4MM share repurchase authorization that was approved by WesBanco’s Board of Directors on May 20, 2026 and the remainder of the authorization approved on February 24, 2022 Common Equity Tier 1 Capital Ratio (CET 1) Tier 1 Risk-Based Capital Ratio Well-Capitalized 8.0% Required 6.0%
Appendix
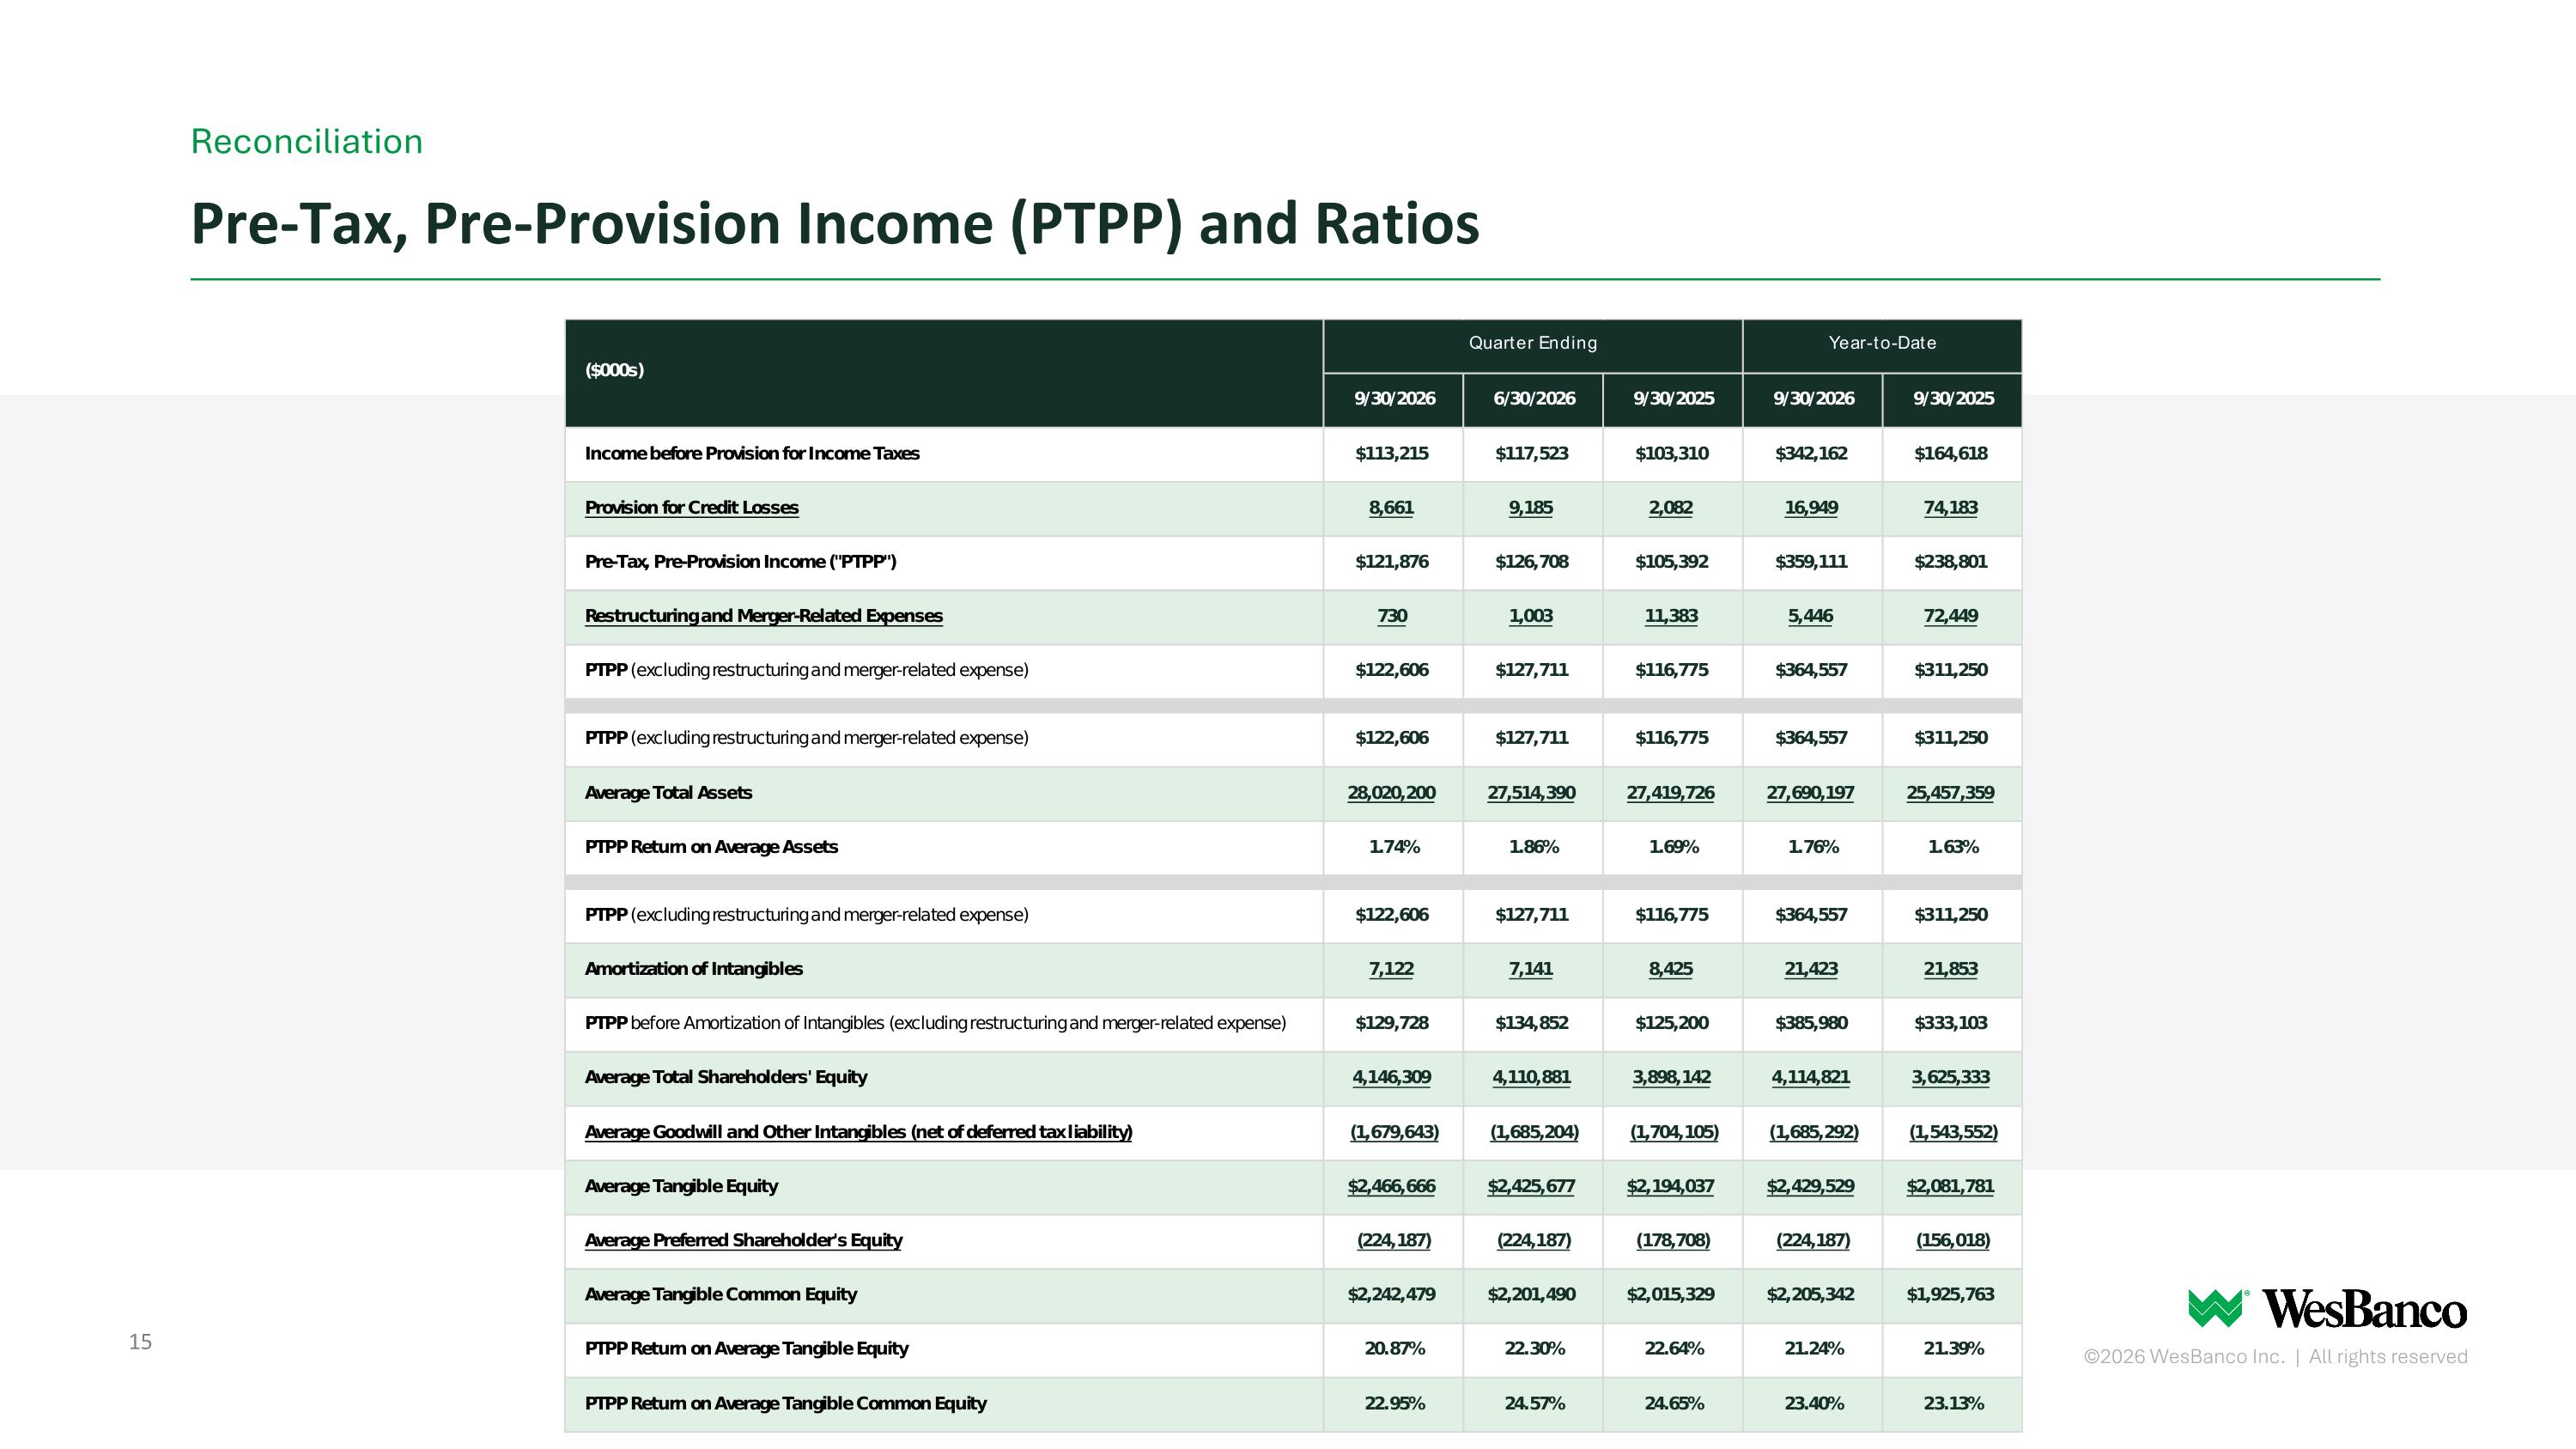
Pre-Tax, Pre-Provision Income (PTPP) and Ratios Reconciliation
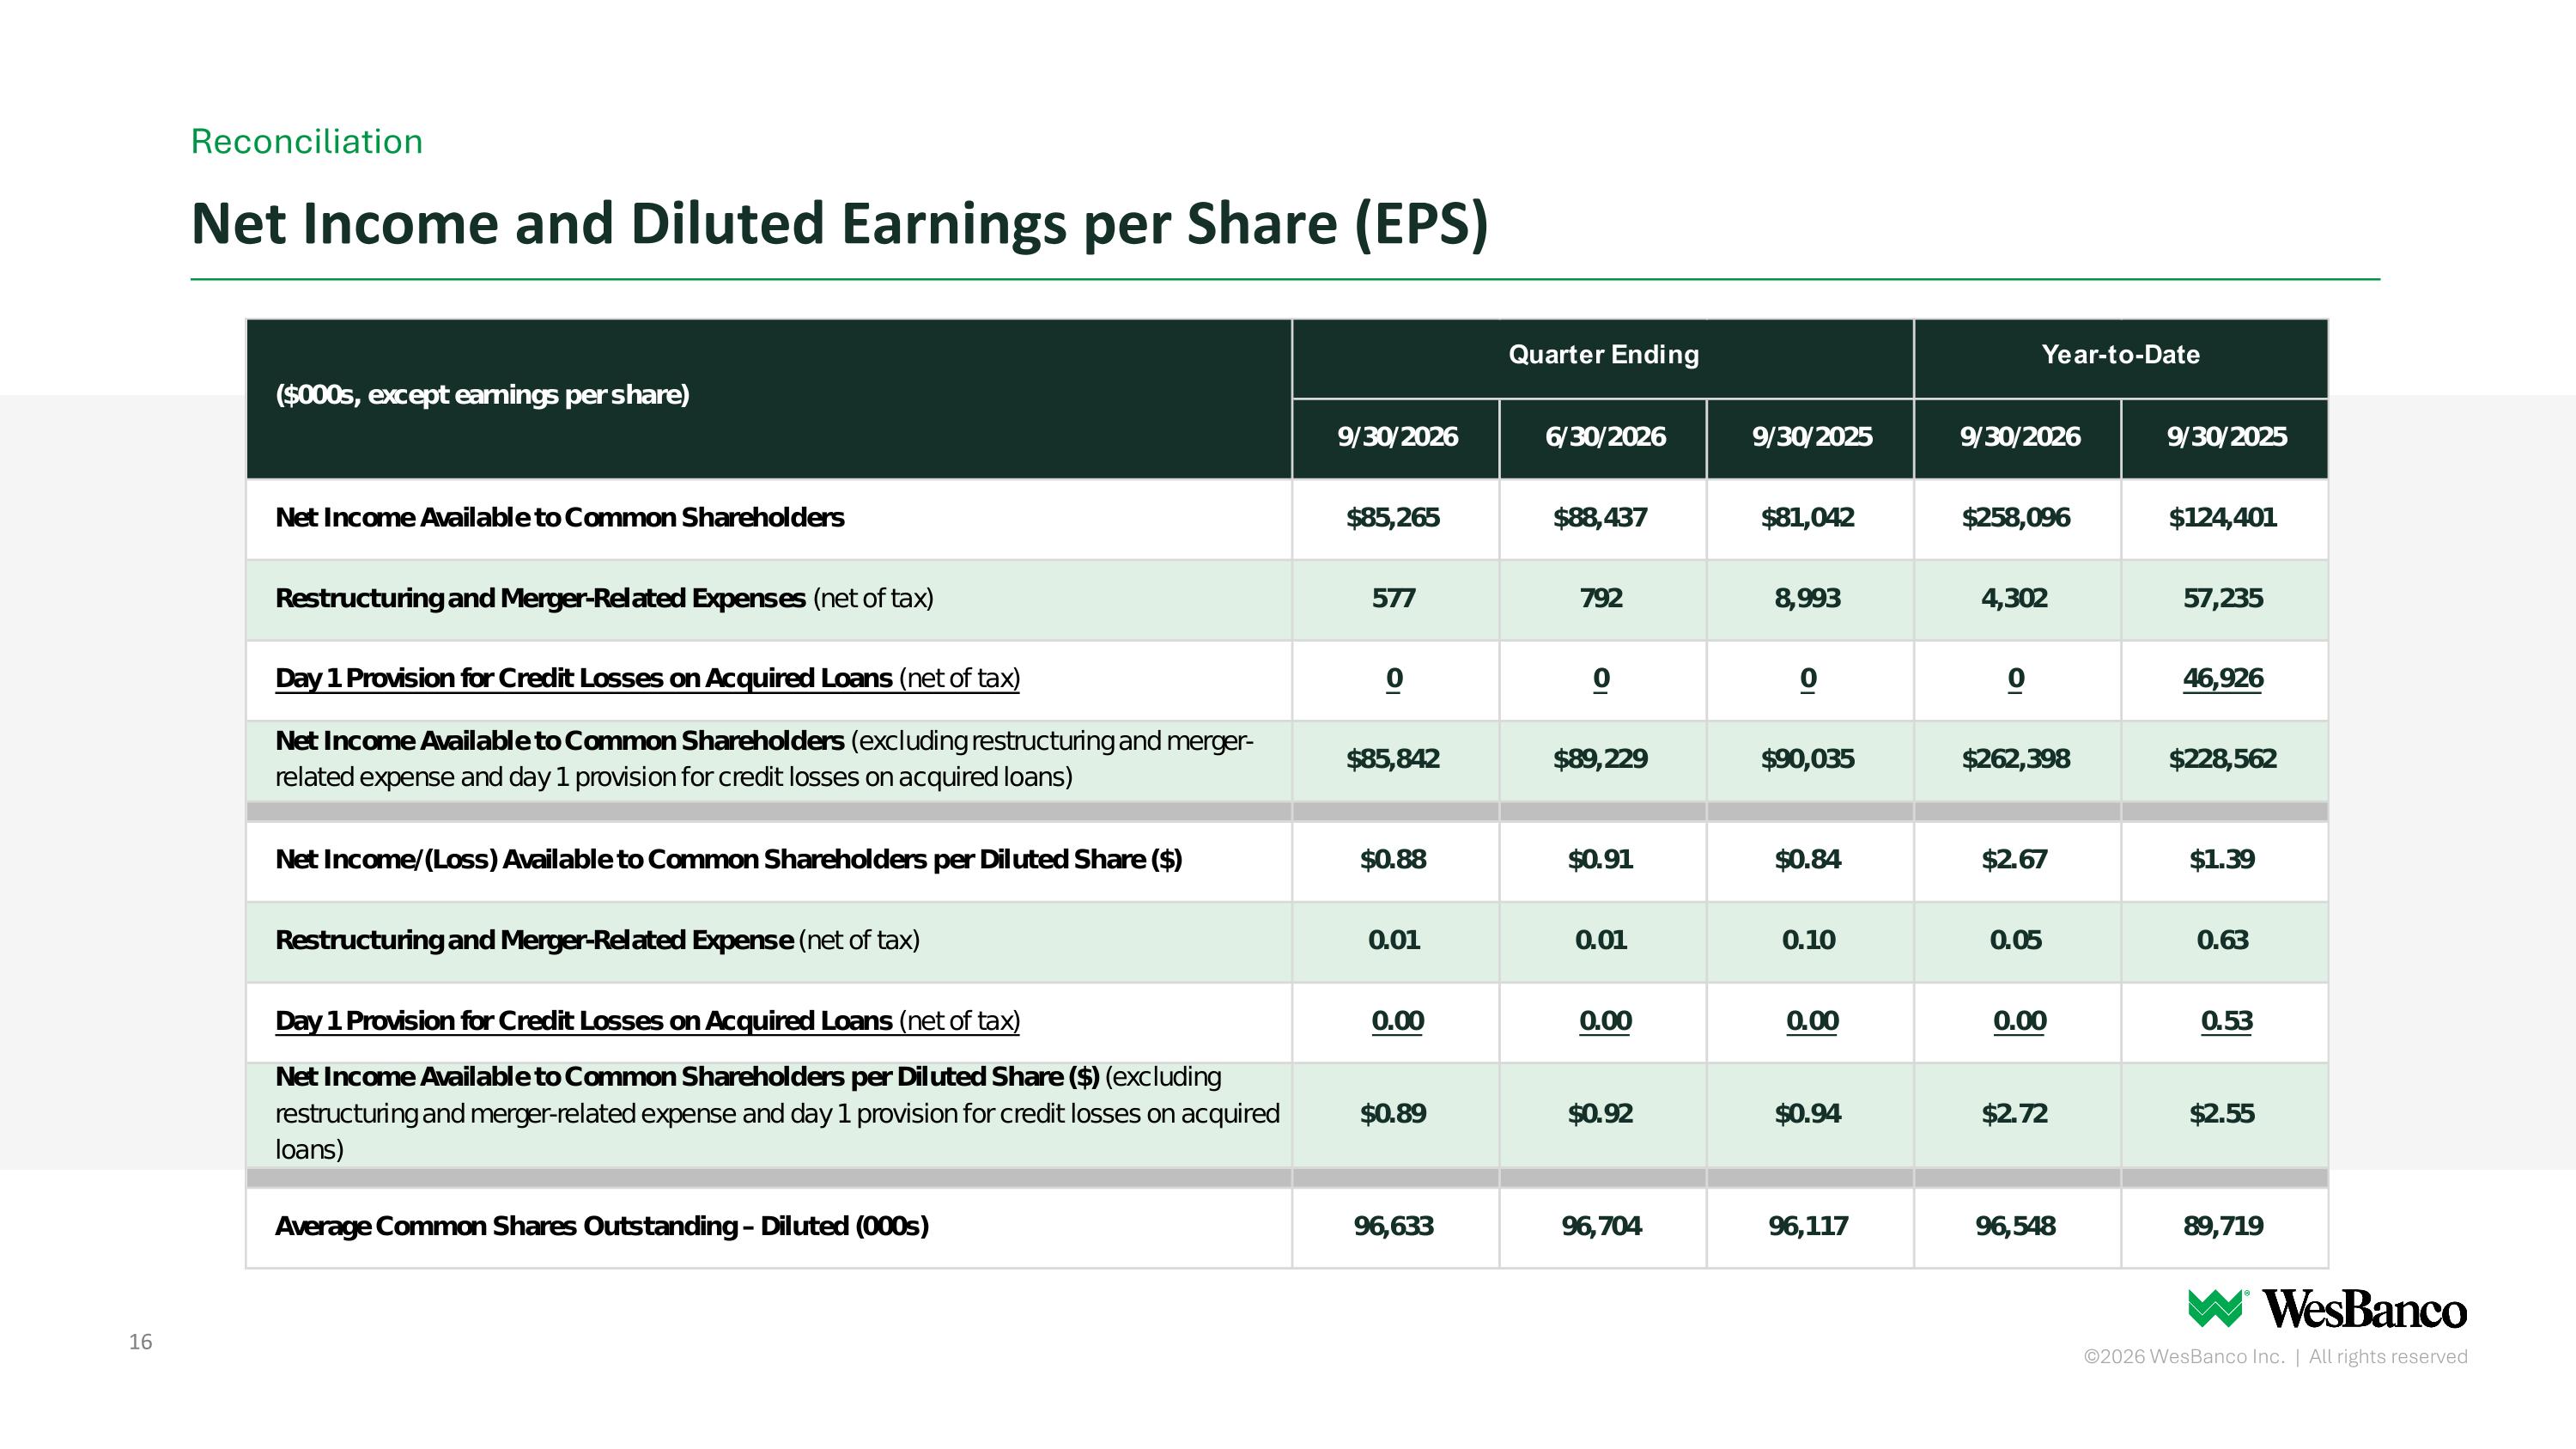
Net Income and Diluted Earnings per Share (EPS) Reconciliation
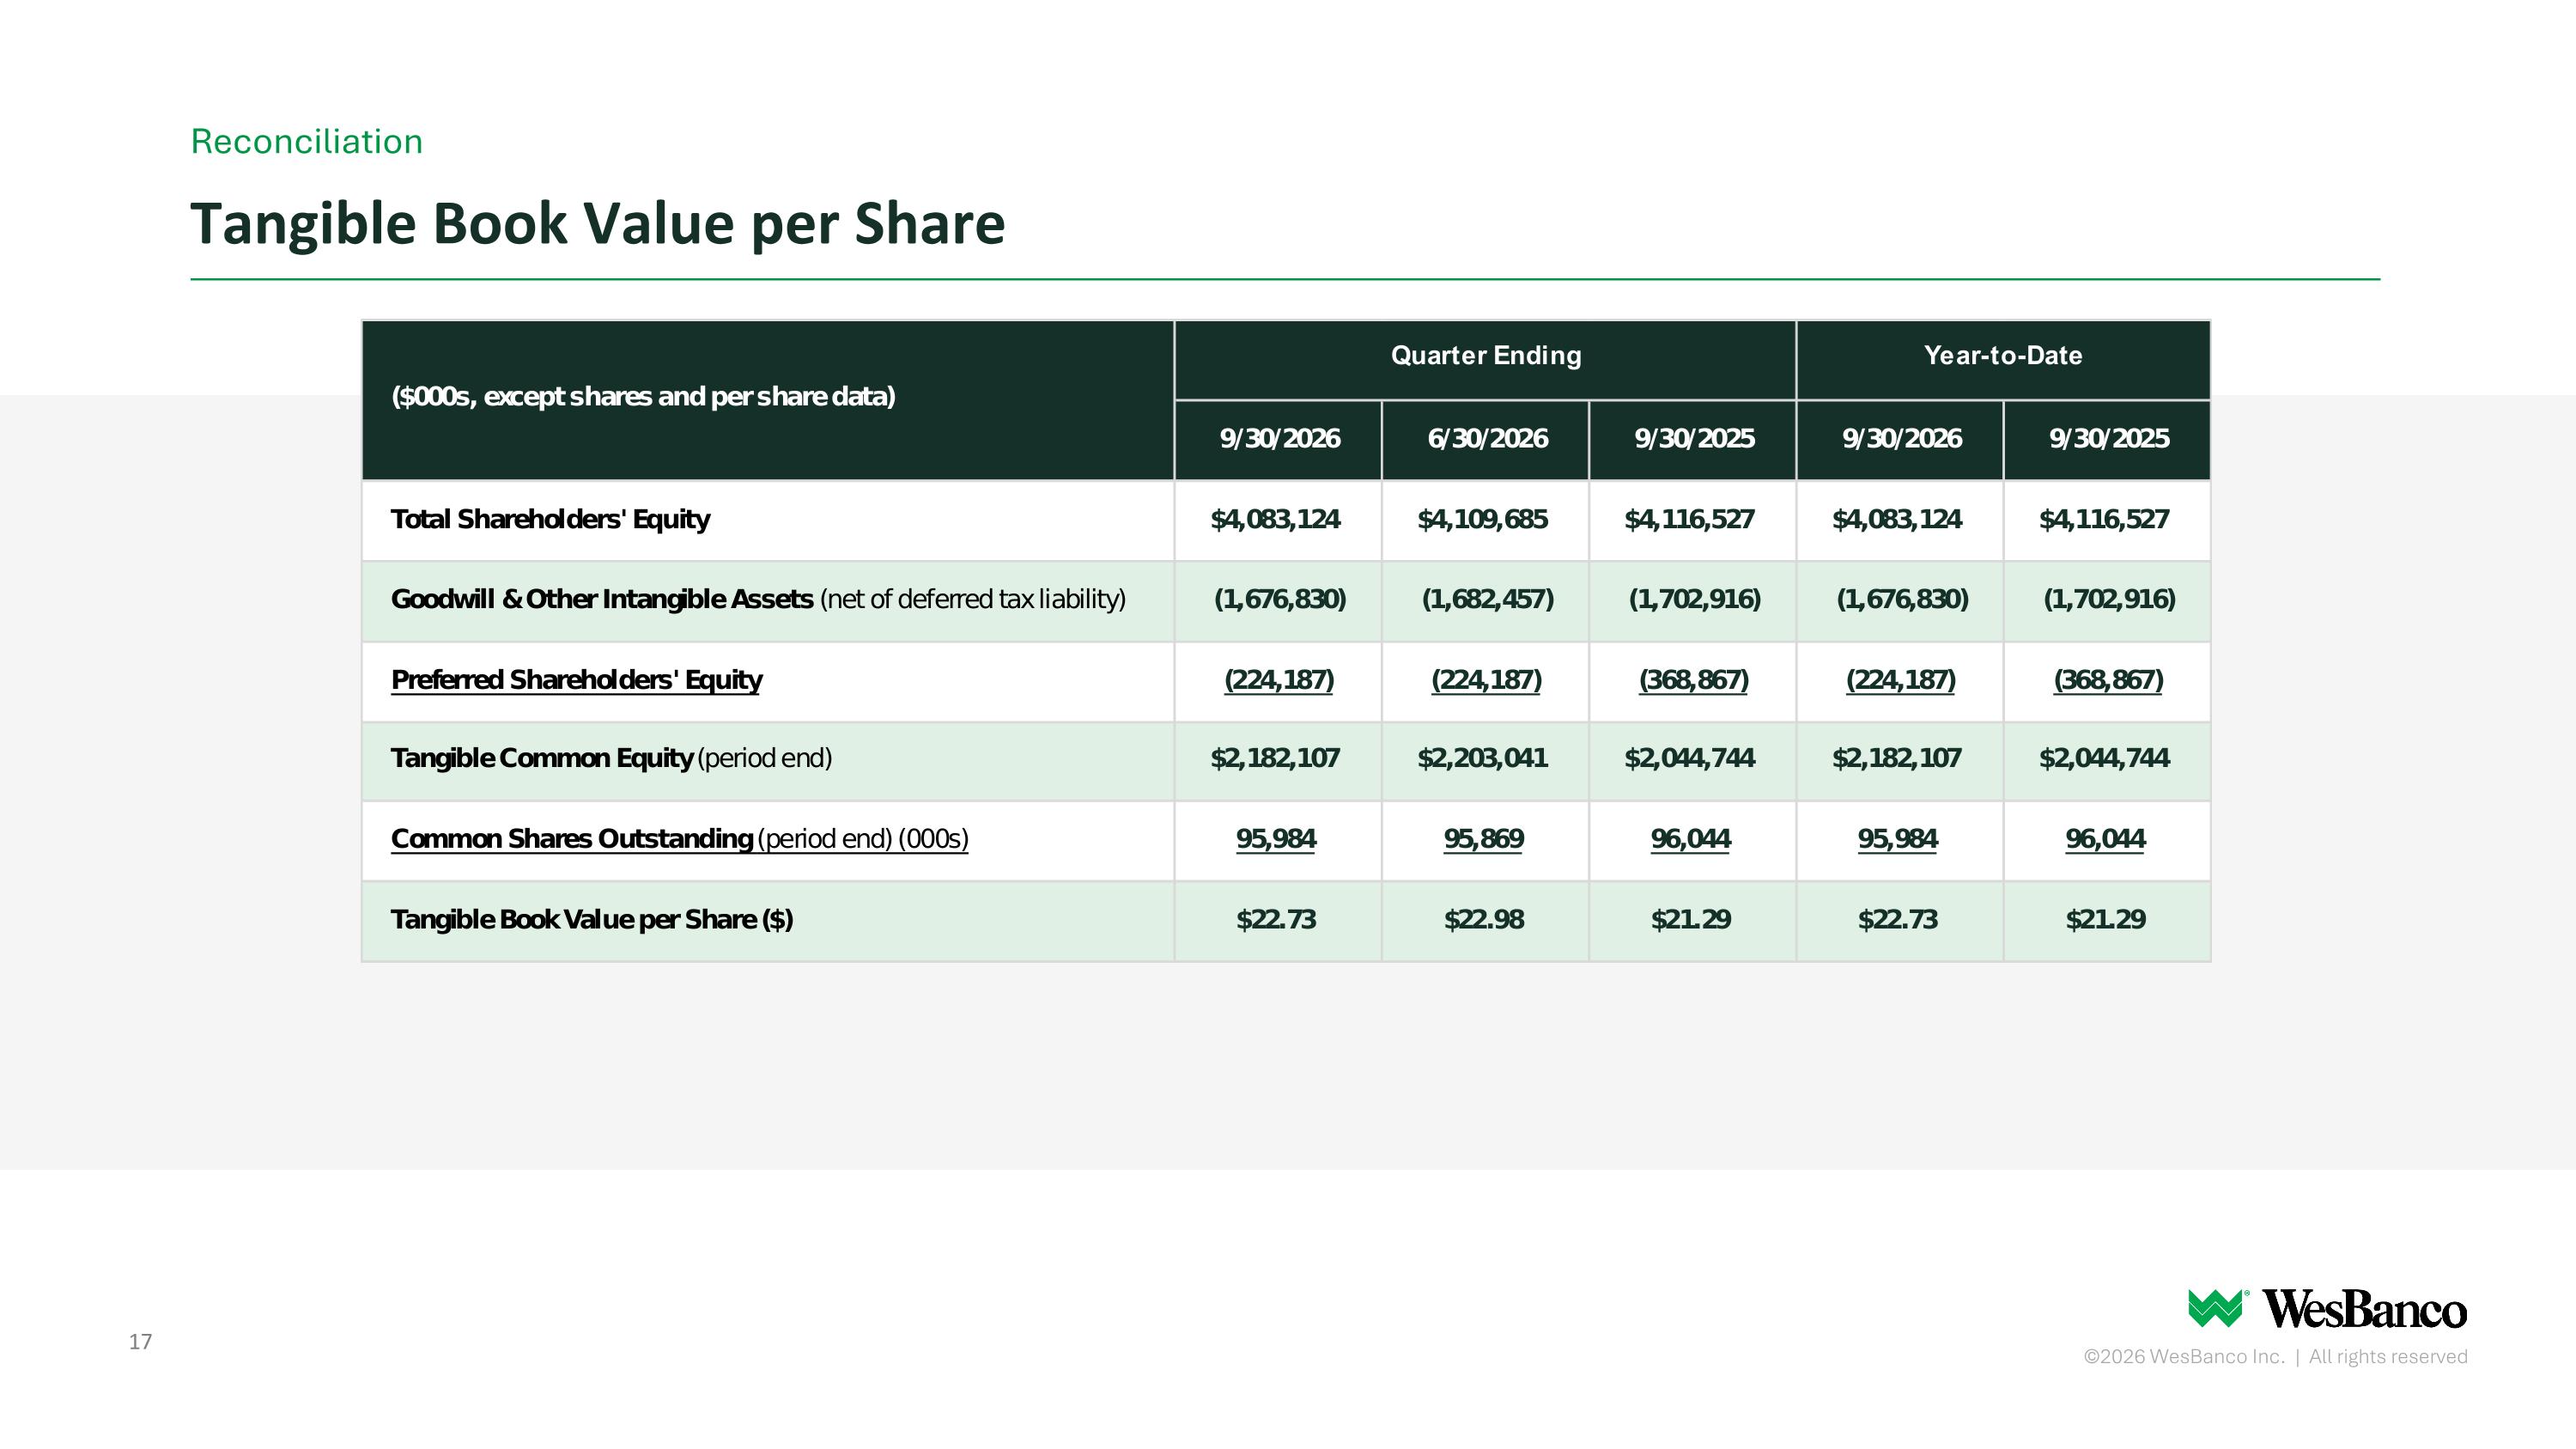
Tangible Book Value per Share Reconciliation
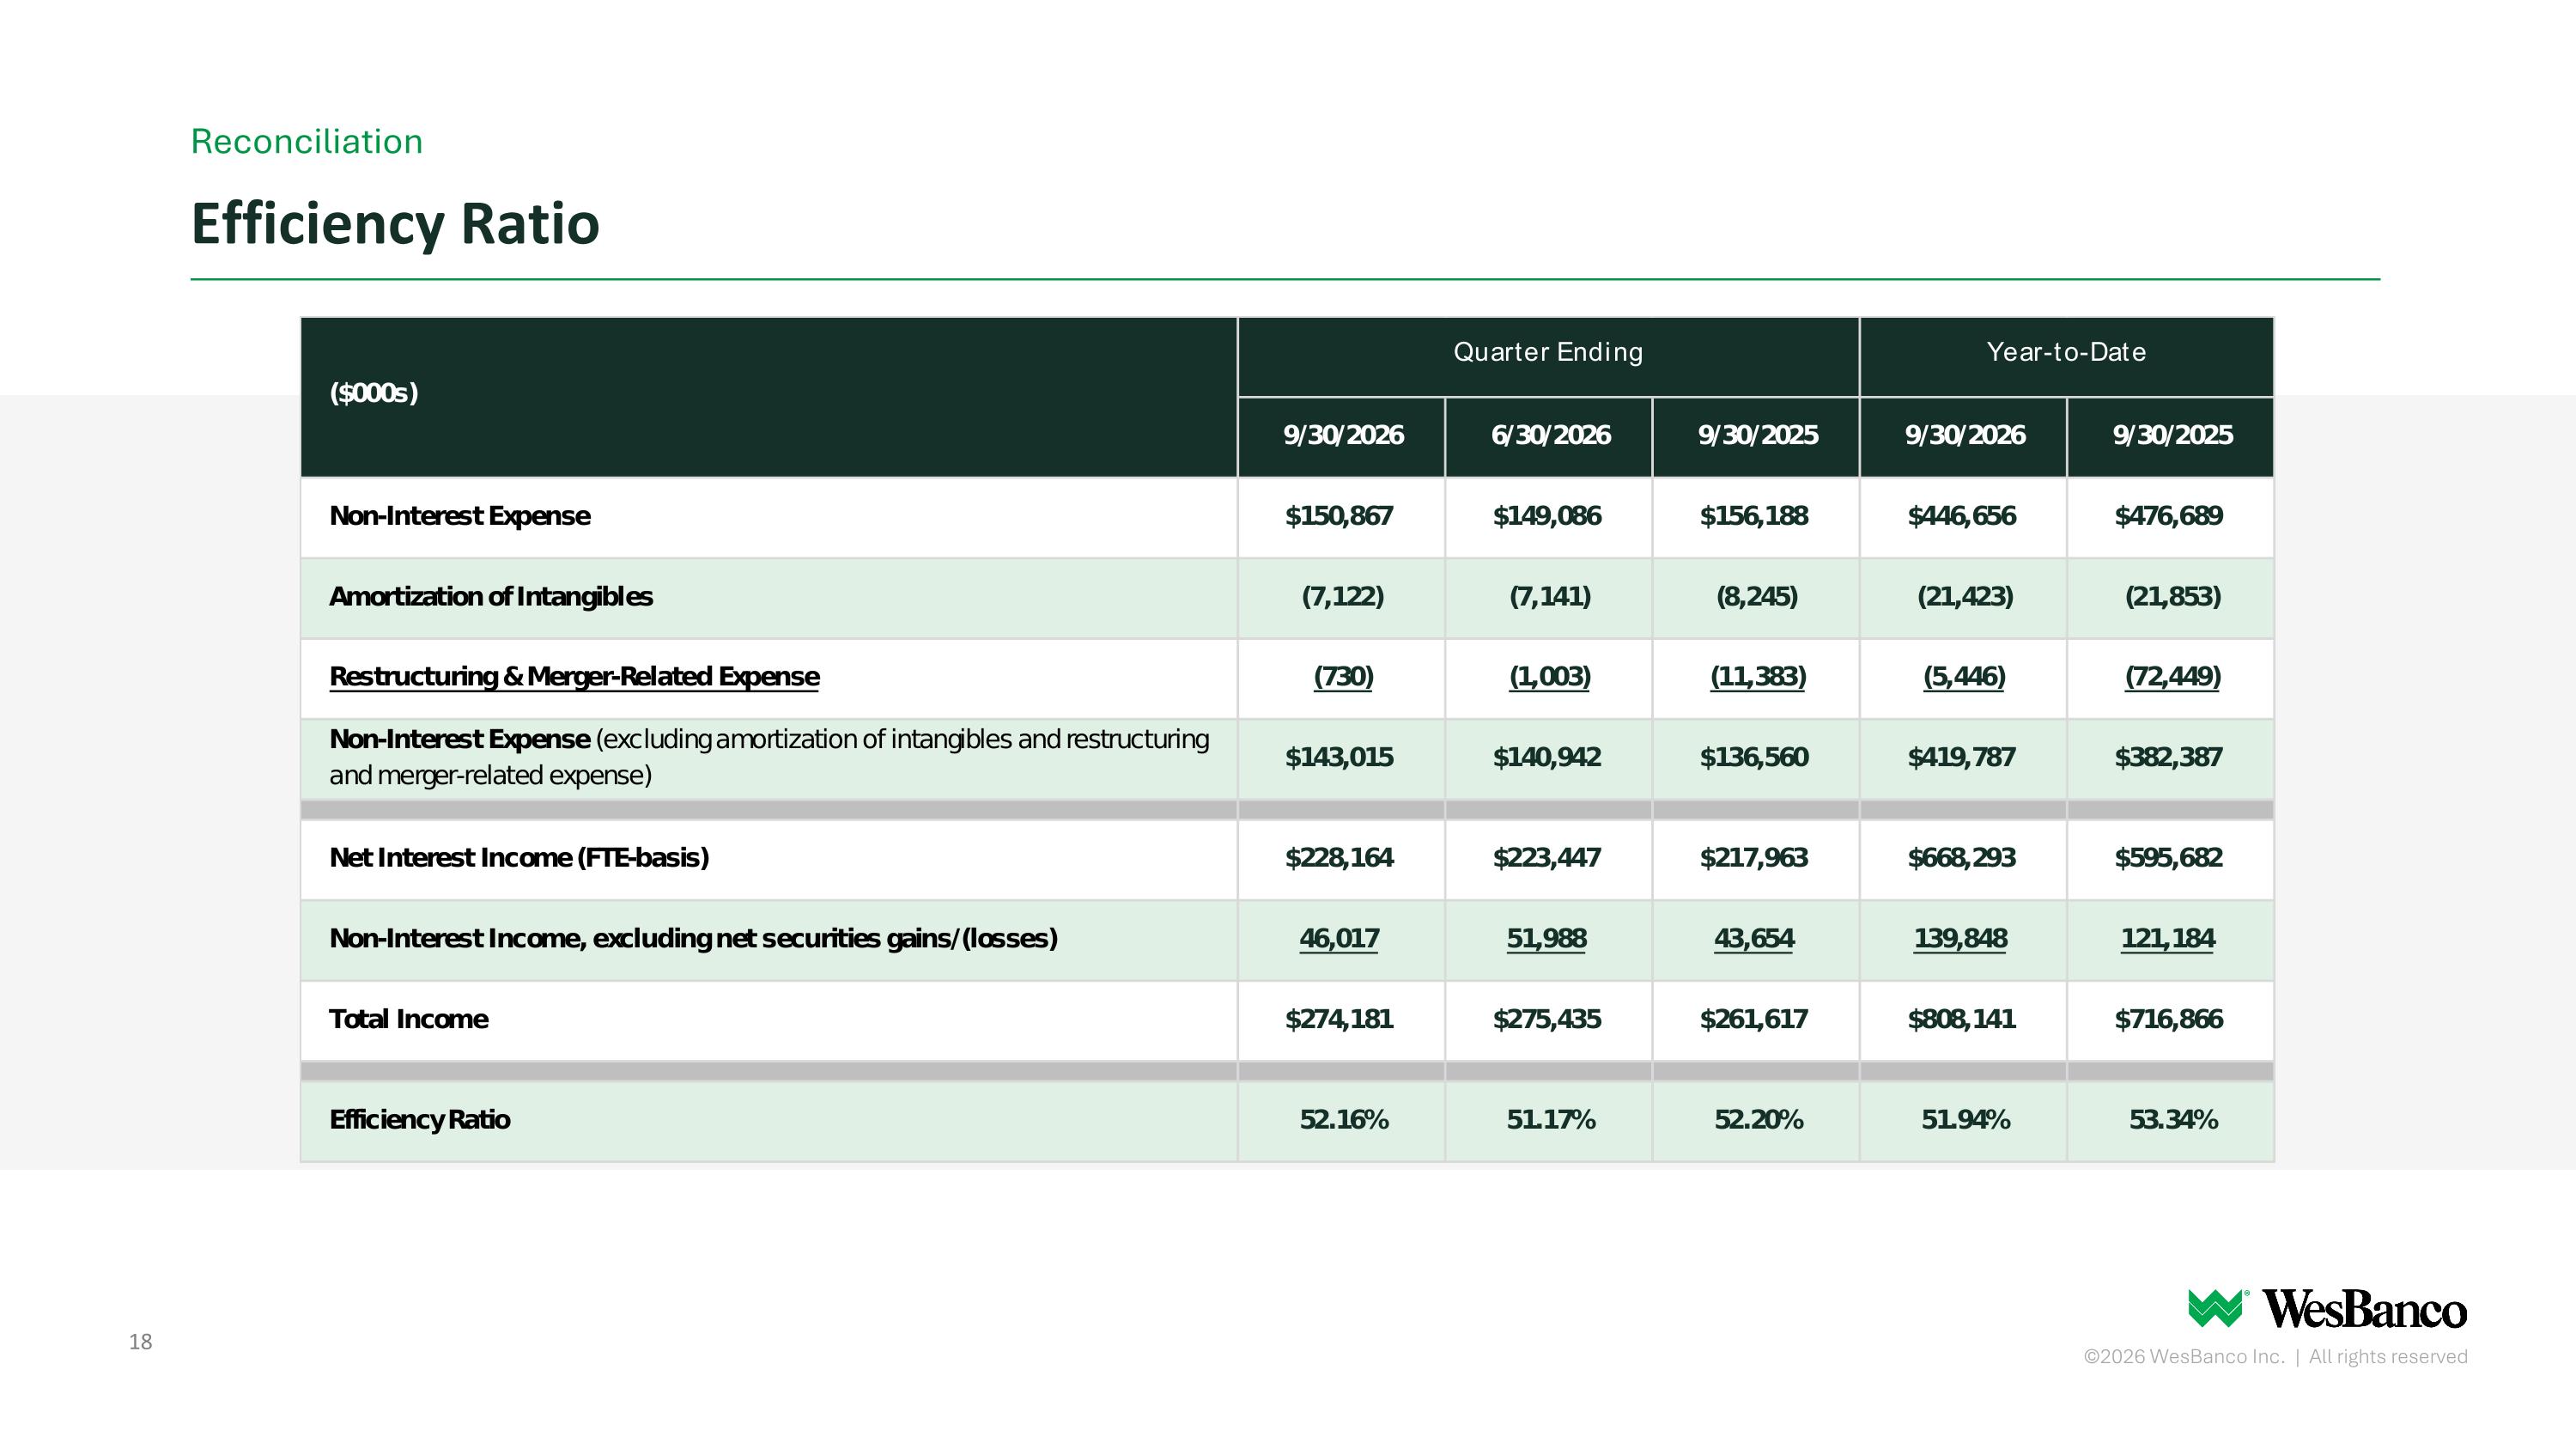
Efficiency Ratio Reconciliation
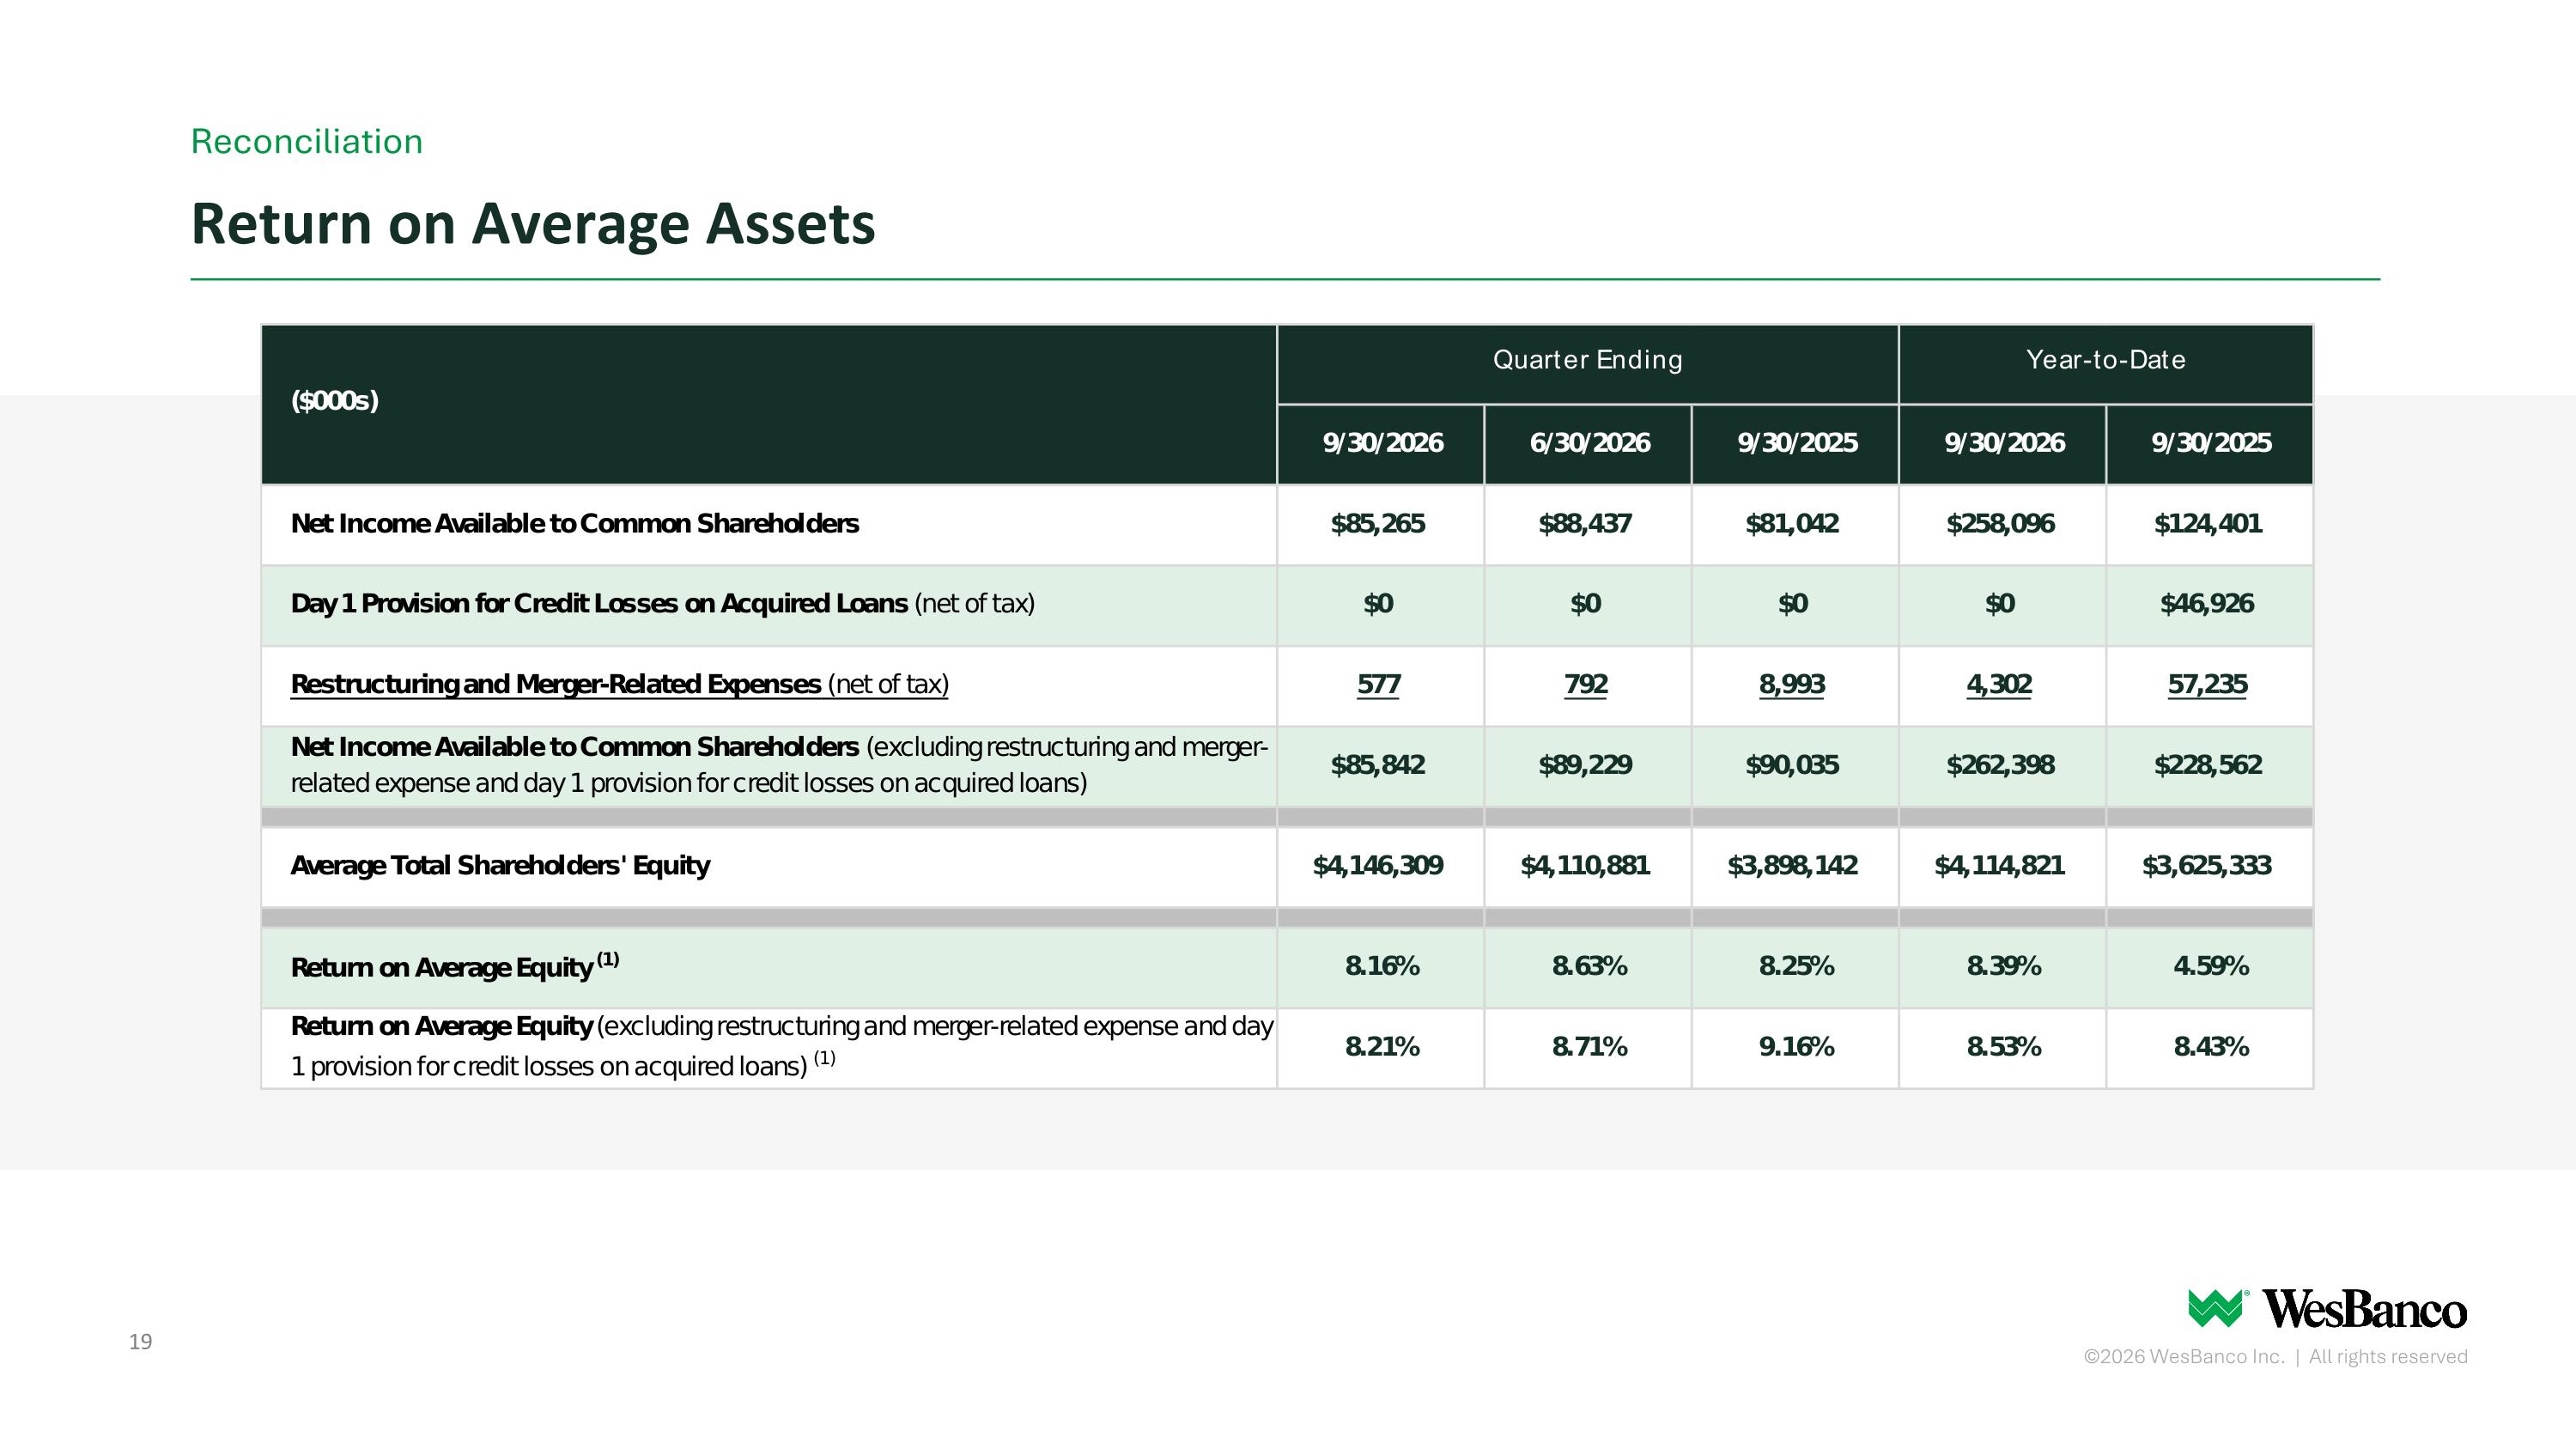
Return on Average Assets Reconciliation
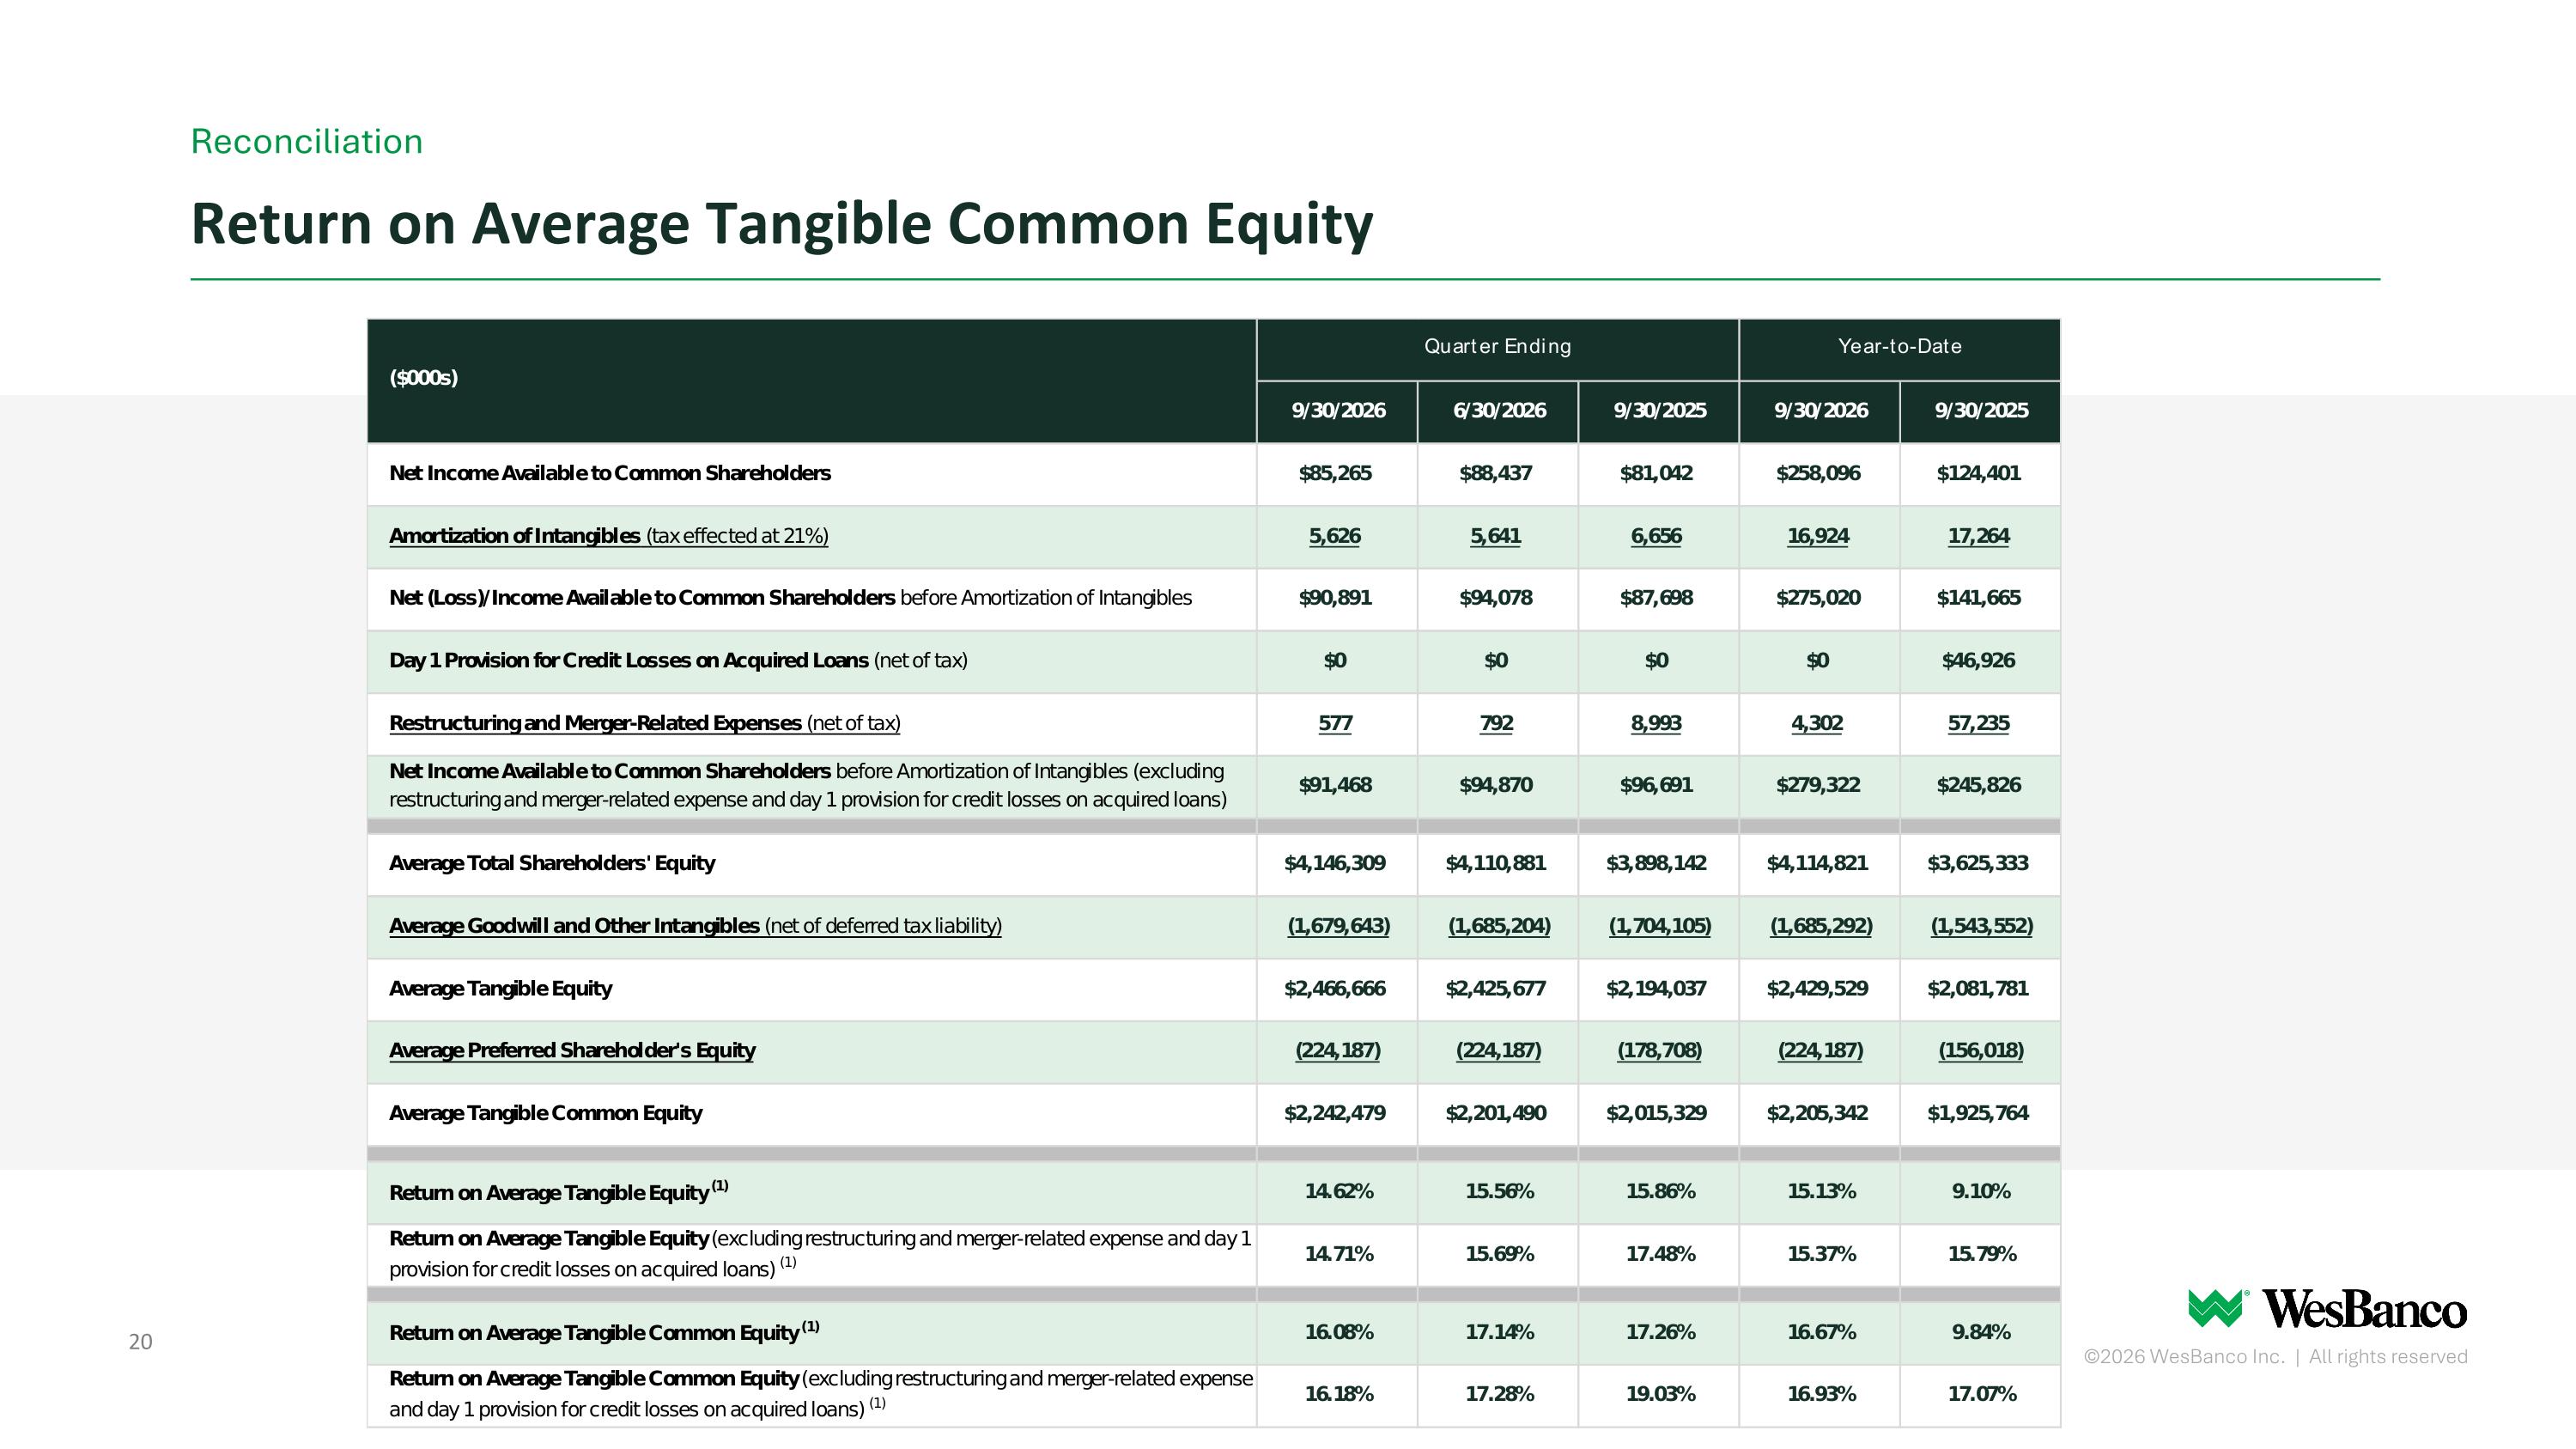
Return on Average Tangible Common Equity Reconciliation
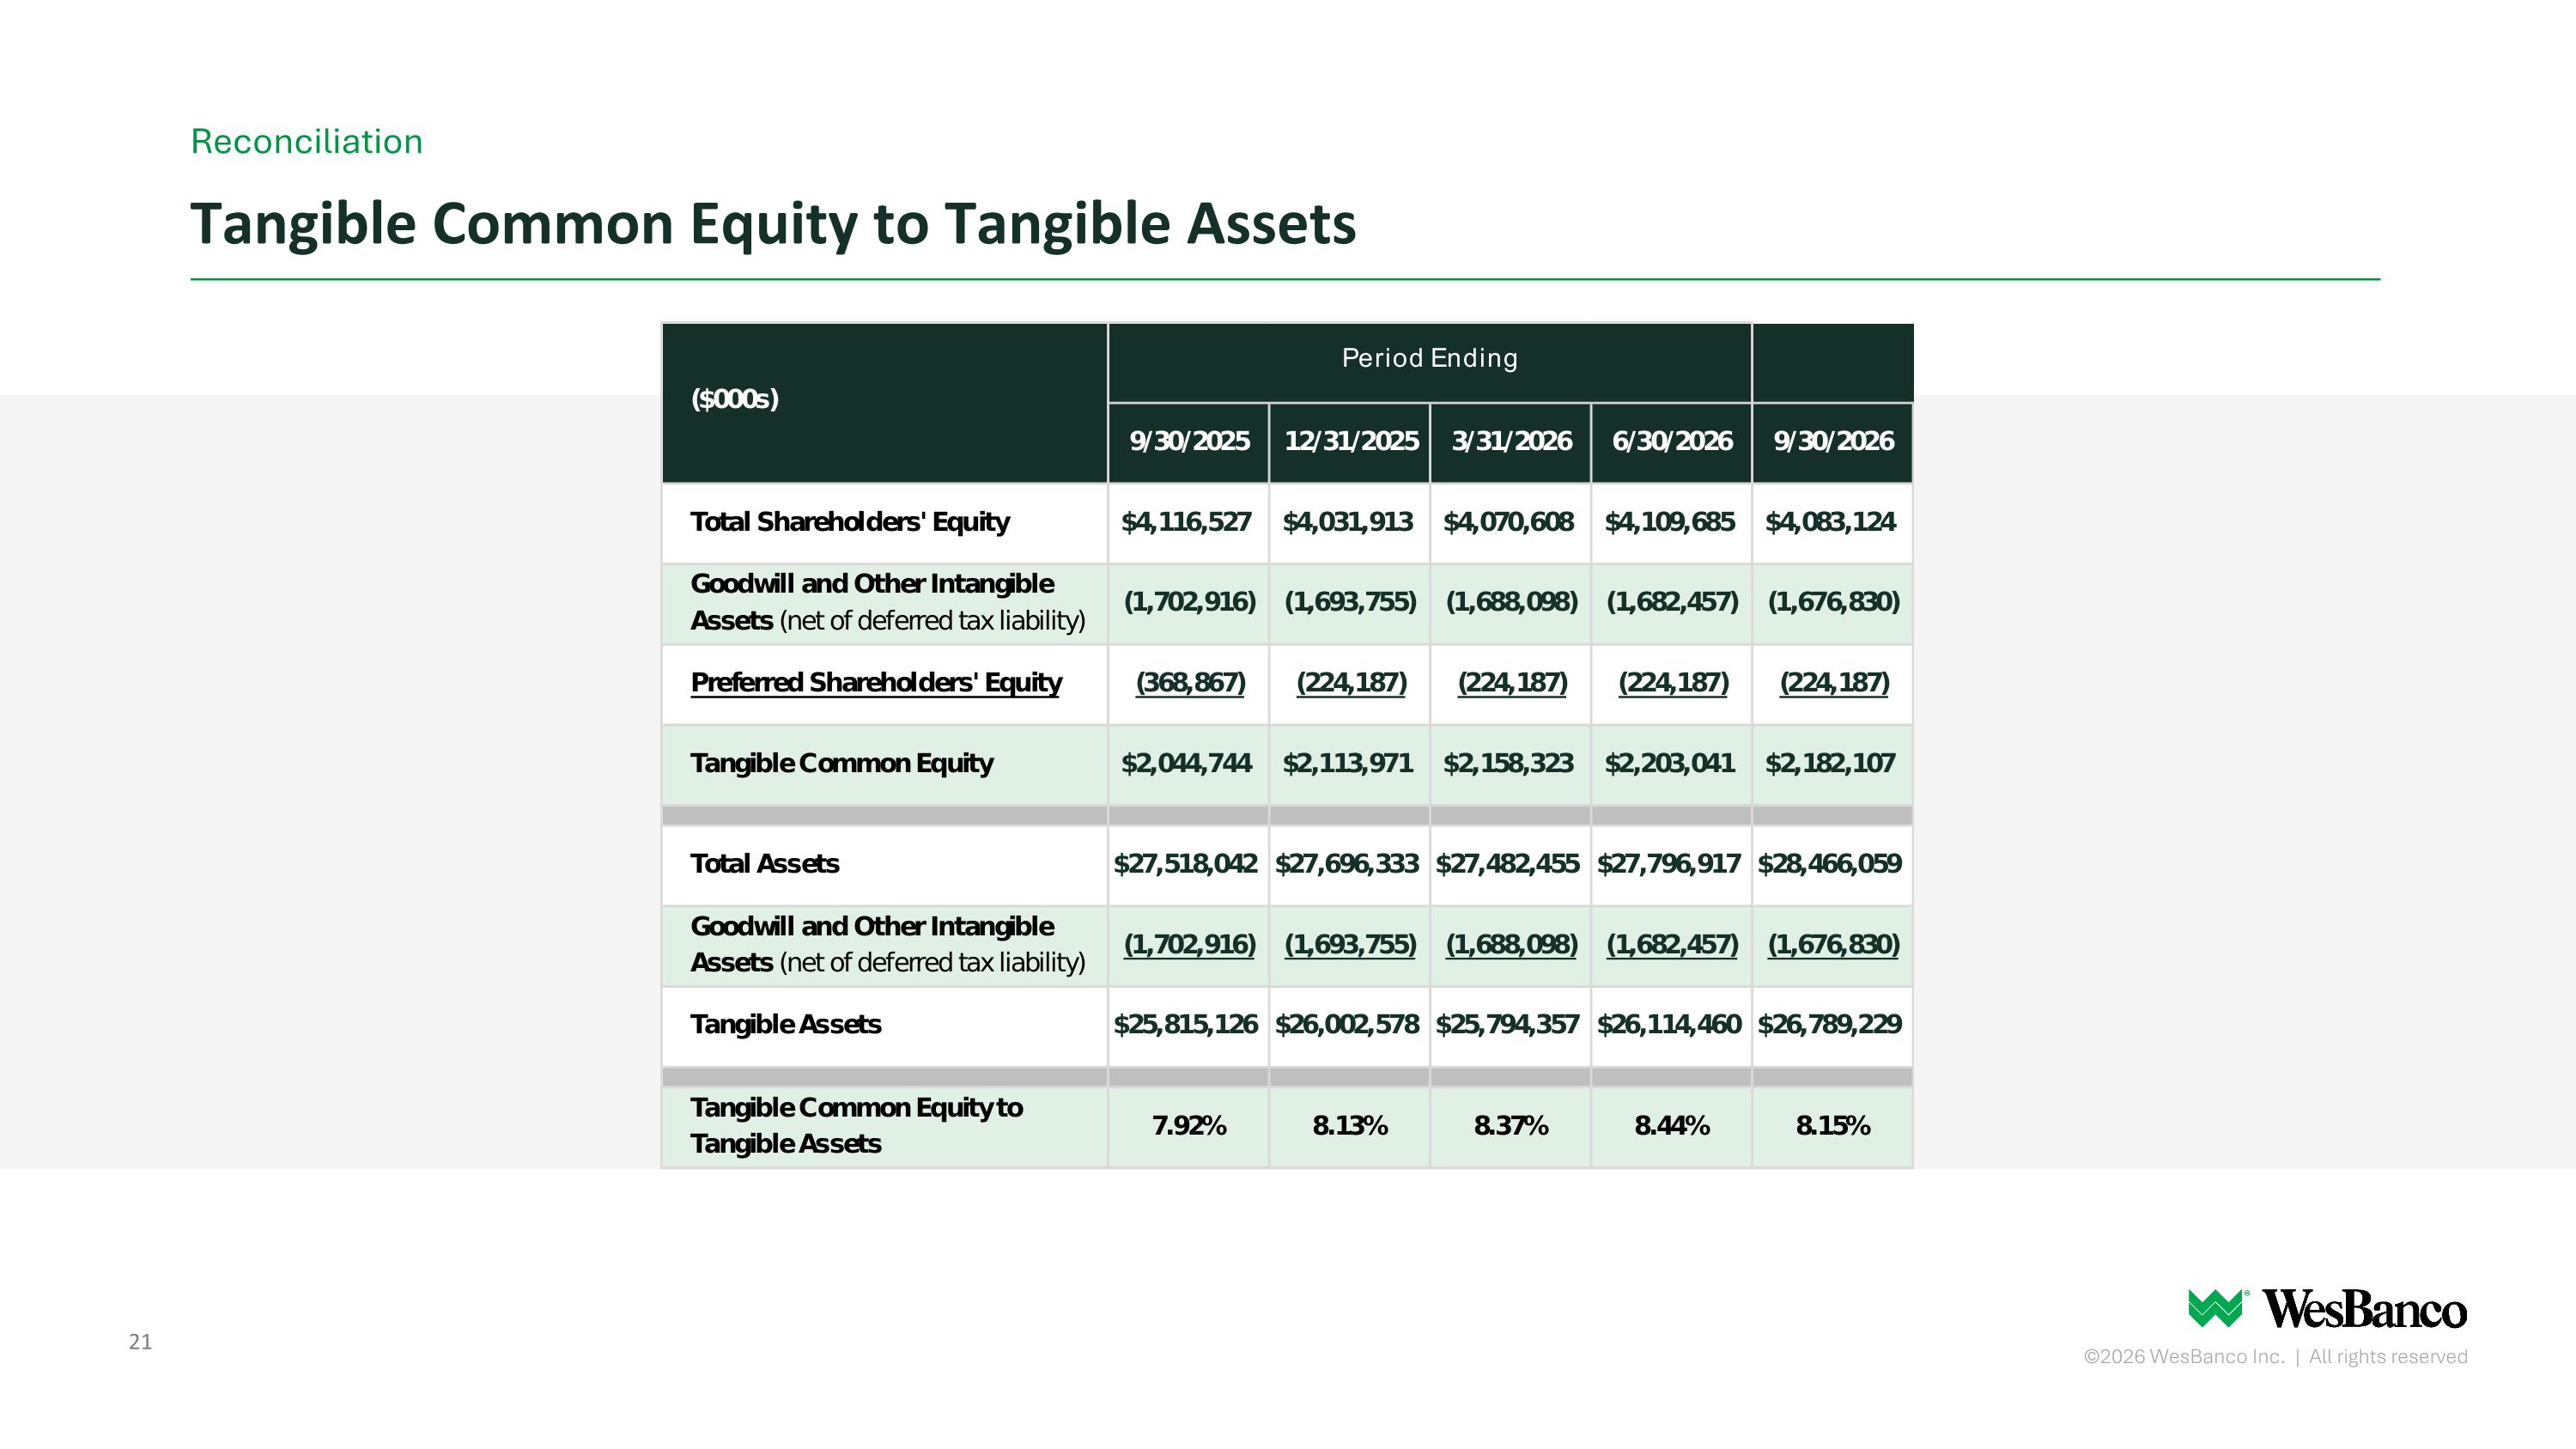
Tangible Common Equity to Tangible Assets Reconciliation